


If Ann and Bob were to gift the investments of $1,000,000 to each of
their children and grandchildren, they would all be subject to the gift
tax. Under the IRS gift tax, a tax is placed “on the transfer of property
by one individual to another while receiving nothing, or less than full
value, in return. The tax applies whether or not the donor intends the
transfer to be a gift” (IRS, n.d.). However, this gift tax would only
apply while Ann and Bob are still living. If they were to set it up so
that this amount was gifted to each child and grandchild after they
pass away, an estate tax would apply. Each of these can range
anywhere from 18% - 40%; although, the recipient is not taxed,
rather, the person who is gifting will incur the tax. Based on the
current rates, Bob and Ann’s total assets would be taxed at 40% - that
comes out to taxes owed of “$345,800 plus 40% of the amount over
$1,000,000” (Reynolds, 2022). There are, however, a few options to
reduce this taxable estate. There are annual exclusion rates if Ann
and Bob were to gift smaller amounts over a long period of time,
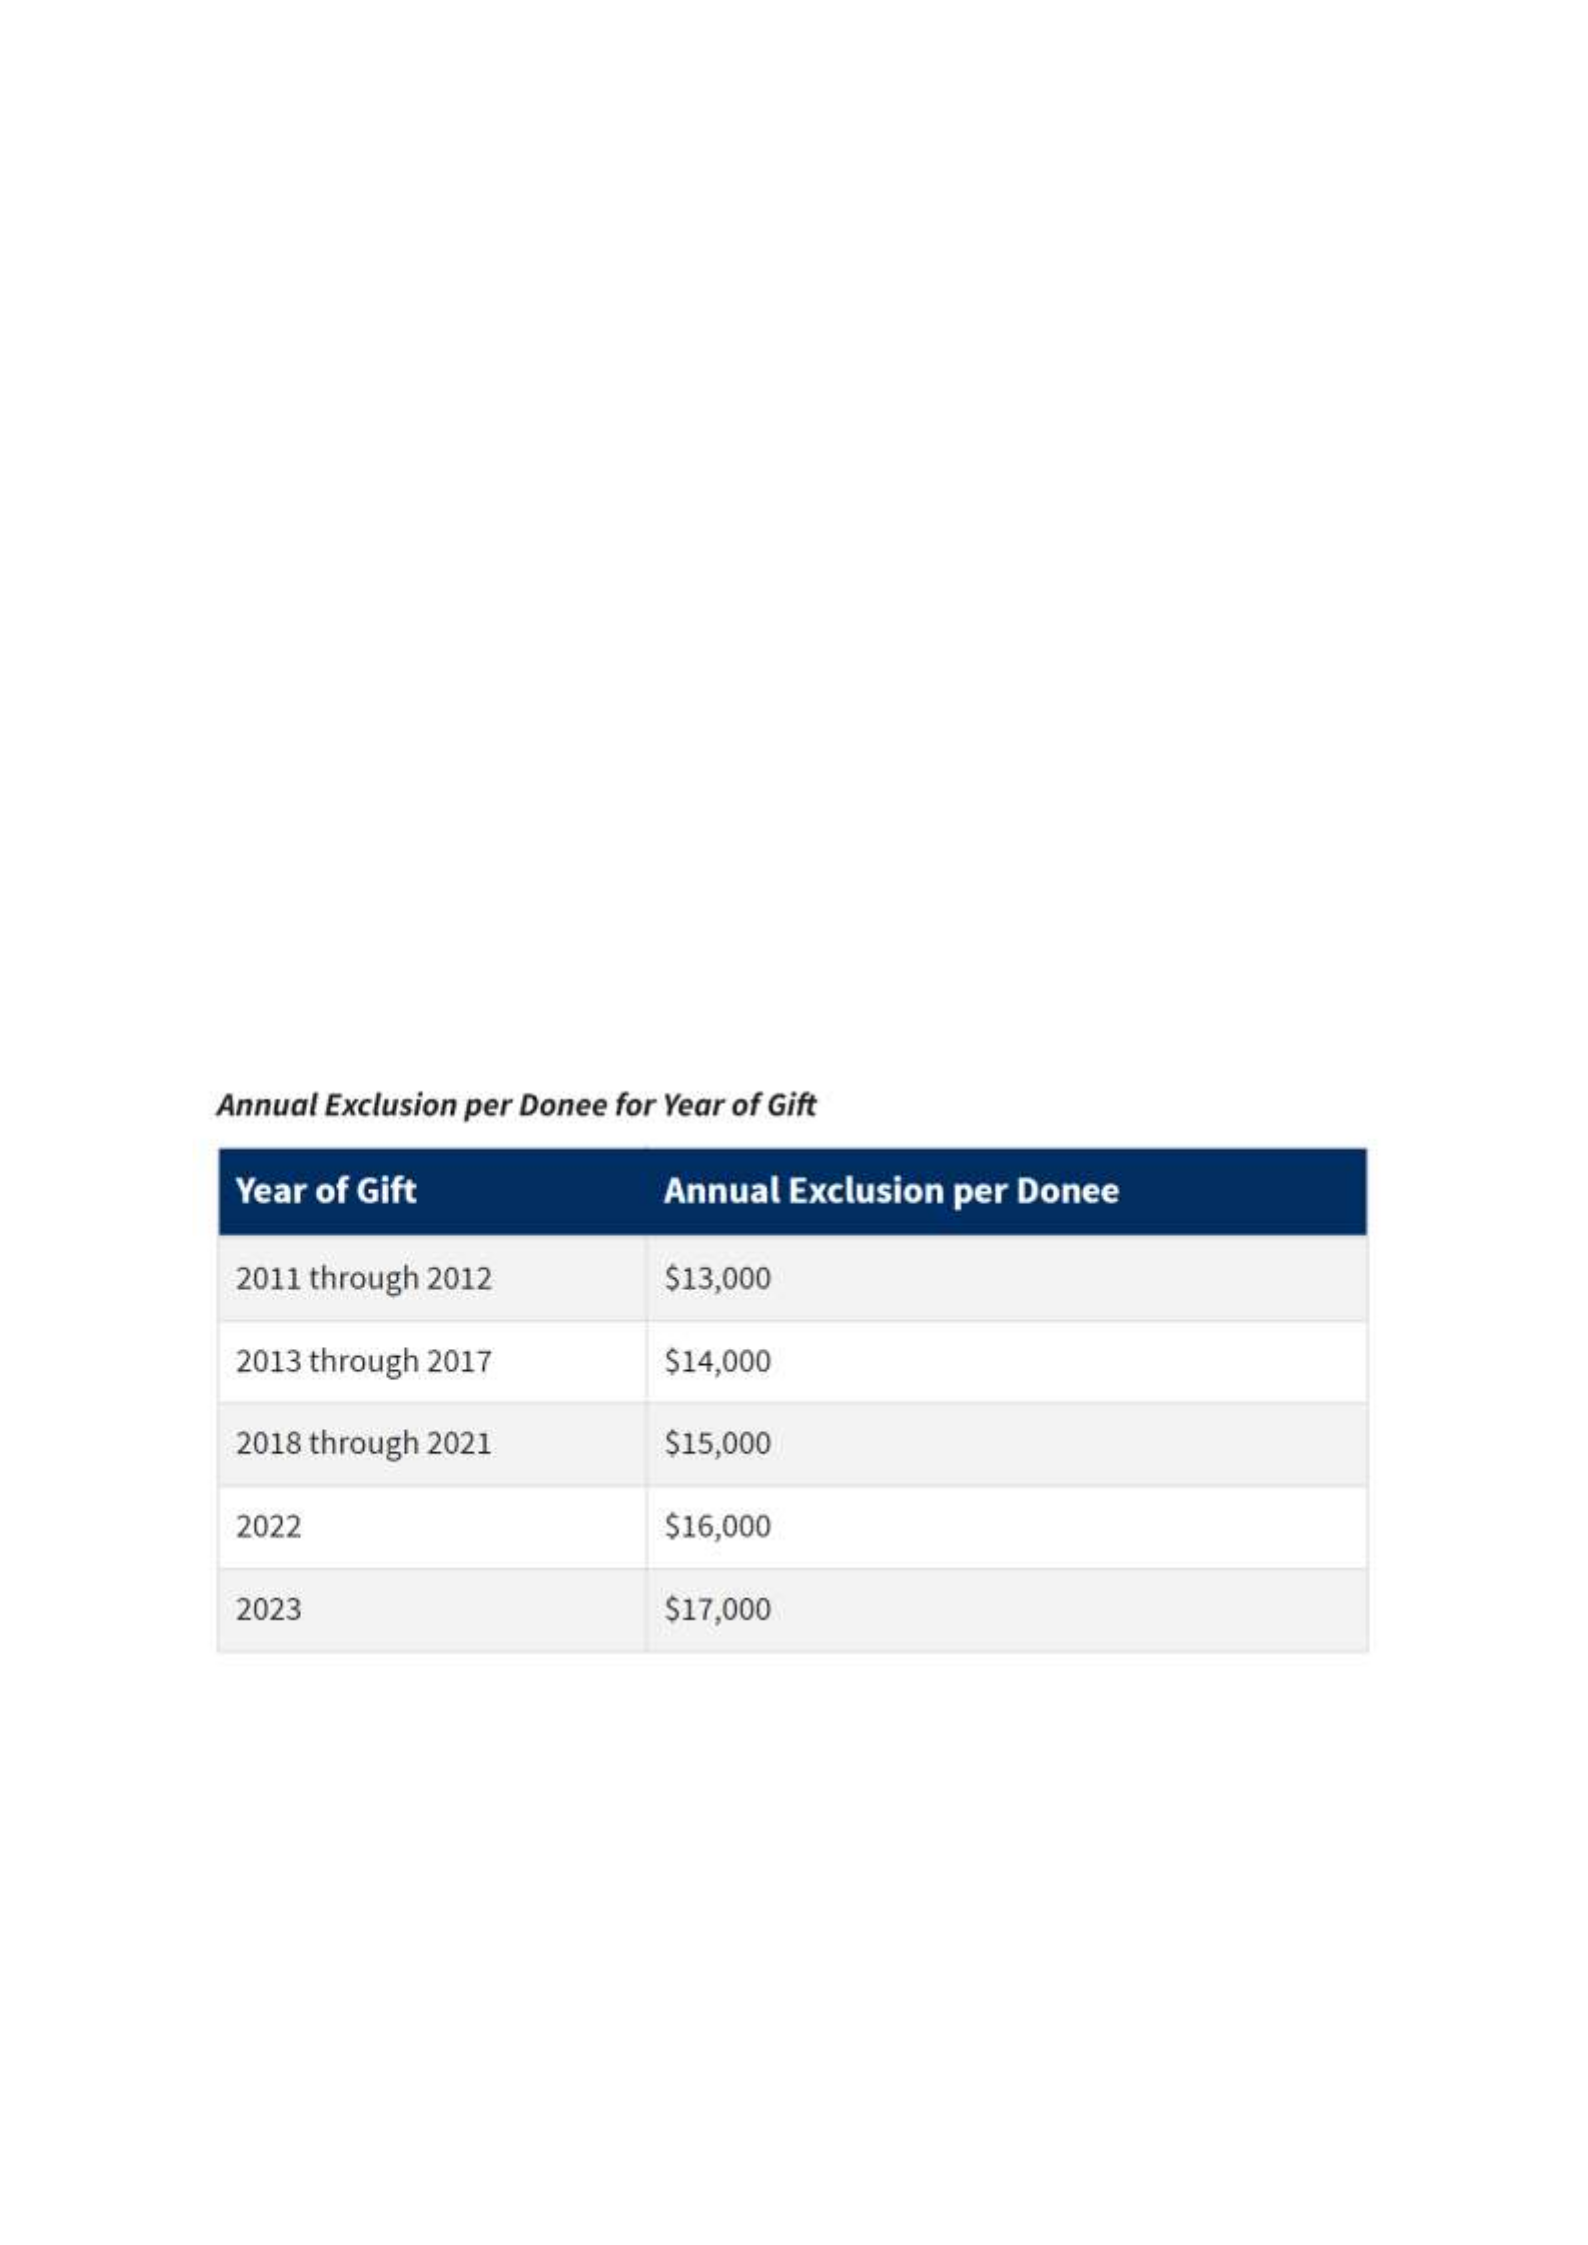
ultimately reaching the $1,000,000 per family member. The annual
exclusion rates are as follows:
This means that, in the current year, they would be allowed to gift
$17,000 per family member, tax-free. Another option, under IRC
Section 2503, a taxable gift is defined as the total amount of gifts
made throughout the calendar year, excluding some deductions. “In
the case of gifts (other than gifts of future interests in property) made
to any person by the donor during the calendar year, the first $10,000
of such gifts to such person shall not, for purposes of subsection (a),

be included in the total amount of gifts made during such year.”
Additionally, “In the case of gifts made in a calendar year after 1998,
the $10,000 amount contained in paragraph (1) shall be increased by
an amount equal to - (A) $10,000, multiplied by (B) the cost-of-living
adjustment determined under section 1 (f)(3) for such calendar year
by substituting “calendar year 1997” for “calendar year 1992” in
subparagraph (B) thereof. If any amount as adjusted under the
preceding sentence is not a multiple of $1,000, such amount shall be
rounded to the next lowest multiple of $1,000” (LandCAN, n.d.).
- Shelby
Gift tax. Internal Revenue Service. (n.d.). Retrieved March 2, 2023,
from https://www.irs.gov/businesses/small-businesses-self-
employed/gift-tax
LandCAN. (n.d.). IRC section 2503 - taxable gifts. Land Conservation
Assistance Network. Retrieved March 2, 2023, from
https://www.landcan.org/article/IRC-Section-2503-Taxable-
Gifts/745
Reynolds, P. (2022, December 28). Estate taxes: Who pays? and how
much? Investopedia. Retrieved March 2, 2023, from
https://www.investopedia.com/articles/personal-
finance/120715/estate-taxes-who-pays-what-and-how-much.asp

