


Town of Cromwell, Connecticut
Comprehensive Annual Financial Report
Comprehensive Annual Financial Report
of the
Town of Cromwell, Connecticut
Town of Cromwell, Connecticut
Comprehensive Annual Financial Report
For the Year Ended June 30, 2020
Table of Contents
Page
Introductory Section
Letter of Transmittal
1-5
Organizational Chart
6
Principal Officials
7
Certificate of Achievement for Excellence in Financial
Reporting for the Year Ended June 30, 2019
8
Financial Section
Independent Auditors’ Report
9-11
Management’s Discussion and Analysis
12-20
Exhibits
Basic Financial Statements
Government-Wide Financial Statements
A
Statement of Net Position
21-22
B
Statement of Activities
23
Fund Financial Statements
C
Balance Sheet - Governmental Funds and Reconciliation
of Fund Balance to Net Position of Governmental Activities
24-25
D
Statement of Revenues, Expenditures and Changes
in Fund Balances - Governmental Funds
26
E
Reconciliation of the Statement of Revenues, Expenditures
and Changes in Fund Balances of Governmental
Funds to Statement of Activities
27
F
Statement of Net Position - Proprietary Funds
28
G
Statement of Revenues, Expenses and Changes in
Net Position - Proprietary Funds
29
H
Statement of Cash Flows - Proprietary Funds
30
I
Statement of Fiduciary Net Position - Fiduciary Funds
31
Town of Cromwell, Connecticut
Comprehensive Annual Financial Report
For the Year Ended June 30, 2020
Table of Contents
Exhibits
Page
J
Statement of Changes in Fiduciary Net Position - Fiduciary Funds
32
K
Notes to Financial Statements
33-85
RSI
Required Supplementary Information
Budgetary Comparison Schedules
1A
Schedule of Revenues and Other Financing Sources -
Budget and Actual – General Fund
86-87
1B
Schedule of Expenditures and Other Financing Uses -
Budget and Actual – General Fund
88-89
1C
Schedule of Revenues, Expenditures and Changes in
Fund Balance - Budget and Actual - Sewer Usage Fund
90
1D
Notes to Required Supplementary Information
91
Employees' Pension Plan
2A
Schedule of Changes in Net Pension Liability and Related Ratios
and Schedule of Investment Returns
92
2B
Schedule of Contributions
93
2C
Notes to Required Supplementary Information
94
Connecticut Municipal Employees' Retirement System
3A
Schedule of Proportionate Share of the Net Pension Liability
and Schedule of Contributions
95
3B
Notes to Required Supplementary Information
96
Connecticut State Teachers' Retirement System
4A
Schedule of Proportionate Share of the Net Pension Liability
and Schedule of Contributions
97
4B
Notes to Required Supplementary Information
98
Town of Cromwell, Connecticut
Comprehensive Annual Financial Report
For the Year Ended June 30, 2020
Table of Contents
Page
RSI
Other Post-Employment Benefit (OPEB) Plan
5A
Schedule of Changes in Net OPEB Liability and Related Ratios
and Schedule of Investment Returns
99
5B
Schedule of Contributions
100
5C
Notes to Required Supplementary Information
101
Connecticut State Teachers' Retirement Board Retiree Health Insurance Plan
6A
Schedule of Proportionate Share of the Net OPEB Liability and
Schedule of Contributions
102
6B
Notes to Required Supplementary Information
103
Schedules
Supplemental Schedules
General Fund
1
Combining Balance Sheet
104
2
Combining Statement of Revenues, Expenditures and
105
Changes in Fund Balances
3
Report of Tax Collector
106
Other Governmental Funds
4
Combining Balance Sheet
107-108
5
Combining Statement of Revenues, Expenditures and
Changes in Fund Balances
109-110
6
Schedule of Revenues, Expenditures and Changes in
Fund Balance - Budget and Actual - Dog License Fund
111
Internal Service Funds
7
Combining Statement of Net Position
112
8
Combining Statement of Revenues, Expenses and Changes in
Net Position
113
9
Combining Statement of Cash Flows
114
Town of Cromwell, Connecticut
Comprehensive Annual Financial Report
For the Year Ended June 30, 2020
Table of Contents
Page
Schedules
Fiduciary Funds
10
Statement of Changes in Assets and Liabilities - Agency Fund
115
Tables
Statistical Section
1
Net Position by Component
116
2
Changes in Net Position
117
3
Fund Balances, Governmental Funds
118
4
Changes in Fund Balances - Governmental Funds
119
5
Assessed and Estimated Actual Value of Taxable Property
120
6
Principal Property Taxpayers
121
7
Property Tax Rates, Levies and Collections
122
8
Direct and Overlapping Property Tax Rates
123
9
Ratios of Outstanding Debt by Type
124
10
Direct and Overlapping Governmental Activities Debt
125
11
Schedule of Debt Limitation
126
12
Legal Debt Margin Information
127
13
Demographic and Economic Statistics
128
14
Principal Employers
129
15
Full-Time Equivalent Employees by Function/Program
130
16
Operating Indicators by Function/Program
131
17
Capital Asset Statistics by Function/Program
132
Introductory
Section
1
December 2, 2020
To the Town Manager, Town Council, Board of Finance and Citizens of the Town of Cromwell:
State law requires that every general-purpose local government publish, within six months of the close of
each fiscal year, a complete set of audited financial statements. This report is published to fulfill that
requirement for the fiscal year ended June 30, 2020.
Management assumes full responsibility for the completeness and reliability of the information contained
in this report, in conformity with generally accepted accounting principles (GAAP) and based upon a
comprehensive framework of internal control that it has established for this purpose. The internal control
structure is designed to provide reasonable, but not absolute, assurance that these objectives are met.
The concept of reasonable assurance recognizes that: (1) the cost of a control should not exceed the
benefits likely to be derived; and (2) the valuation of costs and benefits requires estimates and
judgments by management.
In addition to internal accounting controls, the Town maintains budgetary controls to ensure compliance
with legal provisions embodied in the annual appropriated budget for the General Fund approved at the
annual referendum and as may be amended during the fiscal year. The General Fund level of budgetary
control (that is, the level at which expenditures cannot legally exceed the appropriated amount) is at the
departmental level. The Town maintains annual budgets for other funds, such as the Sewer Usage
Fund, Sewer Assessment Fund, Sidewalk Fund, and the Dog License Fund. The Town also maintains
project length budgets for all capital projects.
PKF O’Connor Davies, a public accounting firm fully licensed and qualified to perform audits of
municipalities within the State of Connecticut, was appointed by the Town Council in April 2020. PKF
O’Connor Davies has issued an unmodified (“clean”) opinion on the Town of Cromwell’s financial
statements for the year ended June 30, 2020. The independent audit involved examining, on a test
basis, evidence supporting the amounts and disclosures in the financial statement; assessing the
accounting principles used; and evaluating the overall financial statement presentation. The
independent auditor’s report is presented as the first component of the financial section of this report.
This report includes all of the funds and accounts of the Town, and includes all activities controlled or
dependent on the Town. The Cromwell Board of Education and the Cromwell Water Pollution Control
Authority are considered departments of the Town and therefore, these activities are included in this
report. The Cromwell Fire/Water District and the Mattabassett District are governmental entities having
operations within the Town, but are separate legal entities. Their operations have therefore not been
included in the Town’s financial statements.

2
The independent audit of the Town’s financial statements was part of broader, state and federally
mandated “Single Audit” designed to meet the special needs of state and federal grantor agencies.
The standards governing the Single Audit engagements require the independent auditor to report not
only on the fair presentation of the financial statements, but also on the audited government’s internal
controls and compliance with legal requirements, with special emphasis on internal controls and legal
requirements involving the administration of Federal awards. These reports are available in the
Town’s separately issued Single Audit Reports.
Generally accepted accounting principles require that management provide a narrative introduction,
overview, and analysis to accompany the basic financial statements in the form of Management’s
discussion and analysis (MD&A). The MD&A is intended to complement this transmittal letter and
should be read in conjunction with it and can be found immediately following the independent
auditor’s report.
Profile of the Town of Cromwell
The Town comprises 13.5 square miles in the approximate geographical center of the State. It is 14
miles south of Hartford and 28 miles northeast of New Haven. The Connecticut River forms the
eastern boundary of the Town. A major north/south highway, Interstate 91, with two Cromwell exits,
runs through the Town. Also, Connecticut Routes 99, 372 and 3 bisect the Town. The Central
Connecticut Expressway (Route 9) enhances the Town’s location as it connects I-95 in Old Saybrook,
I-91 in Cromwell and I-84, the State’s major east/west highway, in New Britain. Given the Town’s
location and accessibility to major roadways, the Town contributes a great deal of its residents to the
area’s labor force. c The estimated 2020 population of Cromwell is 14,684.
The Town of Cromwell municipal government operates under a Town Charter with a Council/Manager
form of government. The legislative power of the Town is vested in a combination of a Mayor and the
six-member Town Council, with a Board of Finance responsible for presenting fiscal operating
budgets for Referendum approval. The Town Manager is the chief executive officer and is
responsible for the administration of all Town matters with the exception of education.
The Town provides a full range of municipal services including public safety (police, animal
control and civil preparedness), public works (roads, building and grounds, solid waste management,
engineering, motor pool and building inspections), health, sanitation, zoning compliance, senior
citizen services, youth services, social services, recreation, library, education and schools and general
government administrative service. As a separate legal entity, the Cromwell Fire District provides fire,
ambulance and water services.
Local Economy and Major Initiatives
The Town’s position as a residential community is illustrated by the fact that approximately 63.0% of
the October 2018 grand list was residential; relatively unchanged from the previous year. On June
30, 2020, 91.1% of the Town’s available labor force was employed. This compares favorably to the
Hartford labor market area rate of 90.1% and the State rate of 89.8%.
The Town has several residential subdivisions that are more than 50% and an additional subdivision,
Arbor Meadows began construction in 2019 with plans for 75 homes. Covenant Village’s Retirement
facility continued construction on a major expansion project. The first phase will include 54 new
residential units, new dining and recreation facilities and a new entrance road from West Street (Rt.
372). Construction also began for Cromwell Village, a new multi-family development containing 162
luxury residential units, located at the former NIKE Site on Country Squire Drive. The
scale and variety of new residential development continues to enhance Cromwell’s reputation as
a great place to live.

3
In Cromwell’s “northern tier”, Scannell Properties leased the 403,000 square foot warehouse to
Amazon. Amazon began the site modifications and interior construction of the building in January
2020. Also in the “northern tier”, NIC Systems Corporation completed their 13,000 square foot office
and warehouse building, and the Planning and Zoning Commission approved two 31,000 square foot
warehouse buildings and one 5,000 square foot office building on Commerce Drive.
Cromwell Growers, one of Cromwell’s top 10 taxpayers, began construction of 119,000 square feet of
new greenhouse space and 42,500 square feet of new warehouse and loading dock space. Marriott
Springhill Suites Hotel continued construction of a 125-room hotel at 76 Berlin Road. Construction
also began on a new Starbucks Coffee Shop on Route 372. Renovation and expansion of existing
commercial facilities continued with several new businesses opening this year on Berlin Road (Rt.
372), Shunpike Road (Rt. 3), and on Main Street (Rt. 99).
Regulatory boards and commissions, to the extent possible, continue to evaluate the impact their
decisions have on the grand list. Diversification of the grand list is considered as part of the Town’s
economic development initiatives.
Major initiatives tend to be measured by large expenditures and/or project size and are
usually thought of in terms of capital projects. However, presented below are the highlights of the
Town’s special programmatic and service initiatives followed by the explanation of capital initiatives.
Programs and Services:
•
The Health Department actively participated in management of the COVID-19 pandemic on
State- and Town-wide levels regarding reporting, tracing, and control of the spread
of the virus.
•
An Open House was held on February 20, 2020 to showcase the completed library expansion
and renovation project. This project was partially funded by a state grant. The library
provided curbside pickup of books, DVDs, and other materials due to the pandemic. Virtual
programs were also held.
•
In 2020, the Recreation Department continued offer programs for pre-school and school age
children, adults, and individuals with special needs. Virtual programs were provided to the
community during the pandemic. Summer camp, movies, and concerts were held following
social distancing guidelines.
•
Support services and referrals to citizens of Cromwell were provided as needed. Cromwell
Human Services partnered with the CT Food Bank to offer perishable food items to the needy
and staff provided curbside pickup for food pantry items.
Capital Projects:
•
Construction continued on the new 38,600 square foot Public Works Facility, with an estimated
completion by the end of calendar year 2020. The Town continued work on three
infrastructure projects, funded primarily through Federal/State grant funds as well as other
improvements to infrastructure.
•
School construction projects were put on hold due to the pandemic and the necessity of
providing a new paradigm for educating students.
Cromwell’s growth in both residential and commercial areas reflect its strong and healthy local
economy. Cromwell has maintained a AAA credit rating from Standard & Poor’s Rating Agency since
2014.

4
Long-Term Financial Planning
The Town of Cromwell established a Long-Range Capital Planning Committee in March 2007 and has
successfully made strategic improvements to the Town’s infrastructure and facilities, using a
combination of cash reserves and debt. This Committee reviews capital improvement requests from
various departments, including Education, with a short- and long-term perspective, prioritizing needs
and using financial forecasting and analysis.
The Town’s Capital Improvement Program, approved annually by the Town Council, includes a 5-year
planning document. The Town has historically used unassigned General Fund fund balance to
support a Capital and Nonrecurring Fund. The Town Council established a Capital Fund in February
2020 to support higher cost requests, such as the future acquisition or construction of facilities, large
equipment, or major infrastructure improvements. The Town Council identified several projects and
pieces of equipment to be funded, or partially funded, with cash reserves through the Capital Fund.
These items, including the Town Hall roof replacement, the Watrous Park tennis court refurbishment,
and road improvements, will be addressed by the Board of Finance later in calendar year 2020.
The Town seeks to maintain a debt ratio (annual service debt to budget) between 8% and 10% with
the intention of creating better stability of mill rates and maintaining constant and adequate funding for
the capital needs of the community. Various school facility projects have been discussed, as well as
the expansion of parks for sports/community use and a senior/community center.
Relevant Financial Policies and Practices
Cromwell’s Town Council has formally adopted key financial policies. The Town's financial policies
have been applied consistently with the prior year and had no notable current year effect on the
financial statements.
The Town Council adopted a revised Fund Balance Policy at their January 8, 2020 meeting. The
policy provides guidelines for budgeting decisions and to insure adequate reserves to fund operations
by providing sufficient working capital and a margin of safety to address local and regional
emergencies without borrowing. The level of unassigned fund balance that the Town strives to
maintain is an amount no less than 15% of the Town’s general fund budget and no greater than 17%,
with the intent of the Town to aim for an amount equal to 60 days of operating expenses from the
current operating budget. The policy also addresses use of fund balance. In accordance with prudent
budgeting practices, the Unassigned Fund Balance will not be used on a routine basis to lower taxes
or to offset normal operating expenditures.
Elected officials and management decided to maintain a higher level of unassigned fund balance due
to a 90-day property tax deferral for July 2020 and other uncertainties related to the pandemic. The
Town of Cromwell’s General Fund fund balance has historically been used to fund large capital
projects and prefund reimbursement-type grant opportunities. The Board of Finance
committed
$325,000 toward the 2021 budget to fund the 2020-21 request for road improvements. This is in
keeping with the Board of Finance’s historical practices and philosophy. An additional $38,300 was
allocated toward 2020-21 General Fund expenses. Additional allocation for capital projects will be
reviewed in fiscal year 2020-21.
The Town’s Debt Management and Capital Planning policy is used in assessing and planning the
Town’s capital needs, the determination of appropriate funding methods, and the management of debt
and capital assets at a portfolio level.
5
Certificate of Achievement and Acknowledgments
The Government Finance Officers Association of the United States and Canada (GFOA) awarded a
Certificate of Achievement for Excellence in Financial Reporting to the Town of Cromwell, Connecticut
for its Comprehensive Annual Financial Report (CAFR) for the fiscal year ended June 30, 2019. This
was the twenty-ninth consecutive year that the government has achieved this prestigious award. In
order to be awarded a Certificate of Achievement, a government must publish an easily readable and
efficiently organized Comprehensive Annual Financial Report. This report must satisfy both generally
accepted accounting principles and applicable legal requirements.
A Certificate of Achievement is valid for a period of one year only. We believe that our current
Comprehensive Annual Financial Report continues to meet the Certificate of Achievement Program’s
requirements and we are submitting it to the GFOA to determine its eligibility for another certificate.
The preparation of this comprehensive annual financial report on a timely basis was made possible by
the efficient and dedicated service of the entire staff of the Finance Department, to whom I extend my
sincere appreciation. I also thank the Town Manager, the Town Council, and the Board of Finance for
the interest and support in planning and conducting the financial operations of the Town in a
responsible and progressive manner.
Respectfully submitted,
Marianne Sylvester
Finance Director
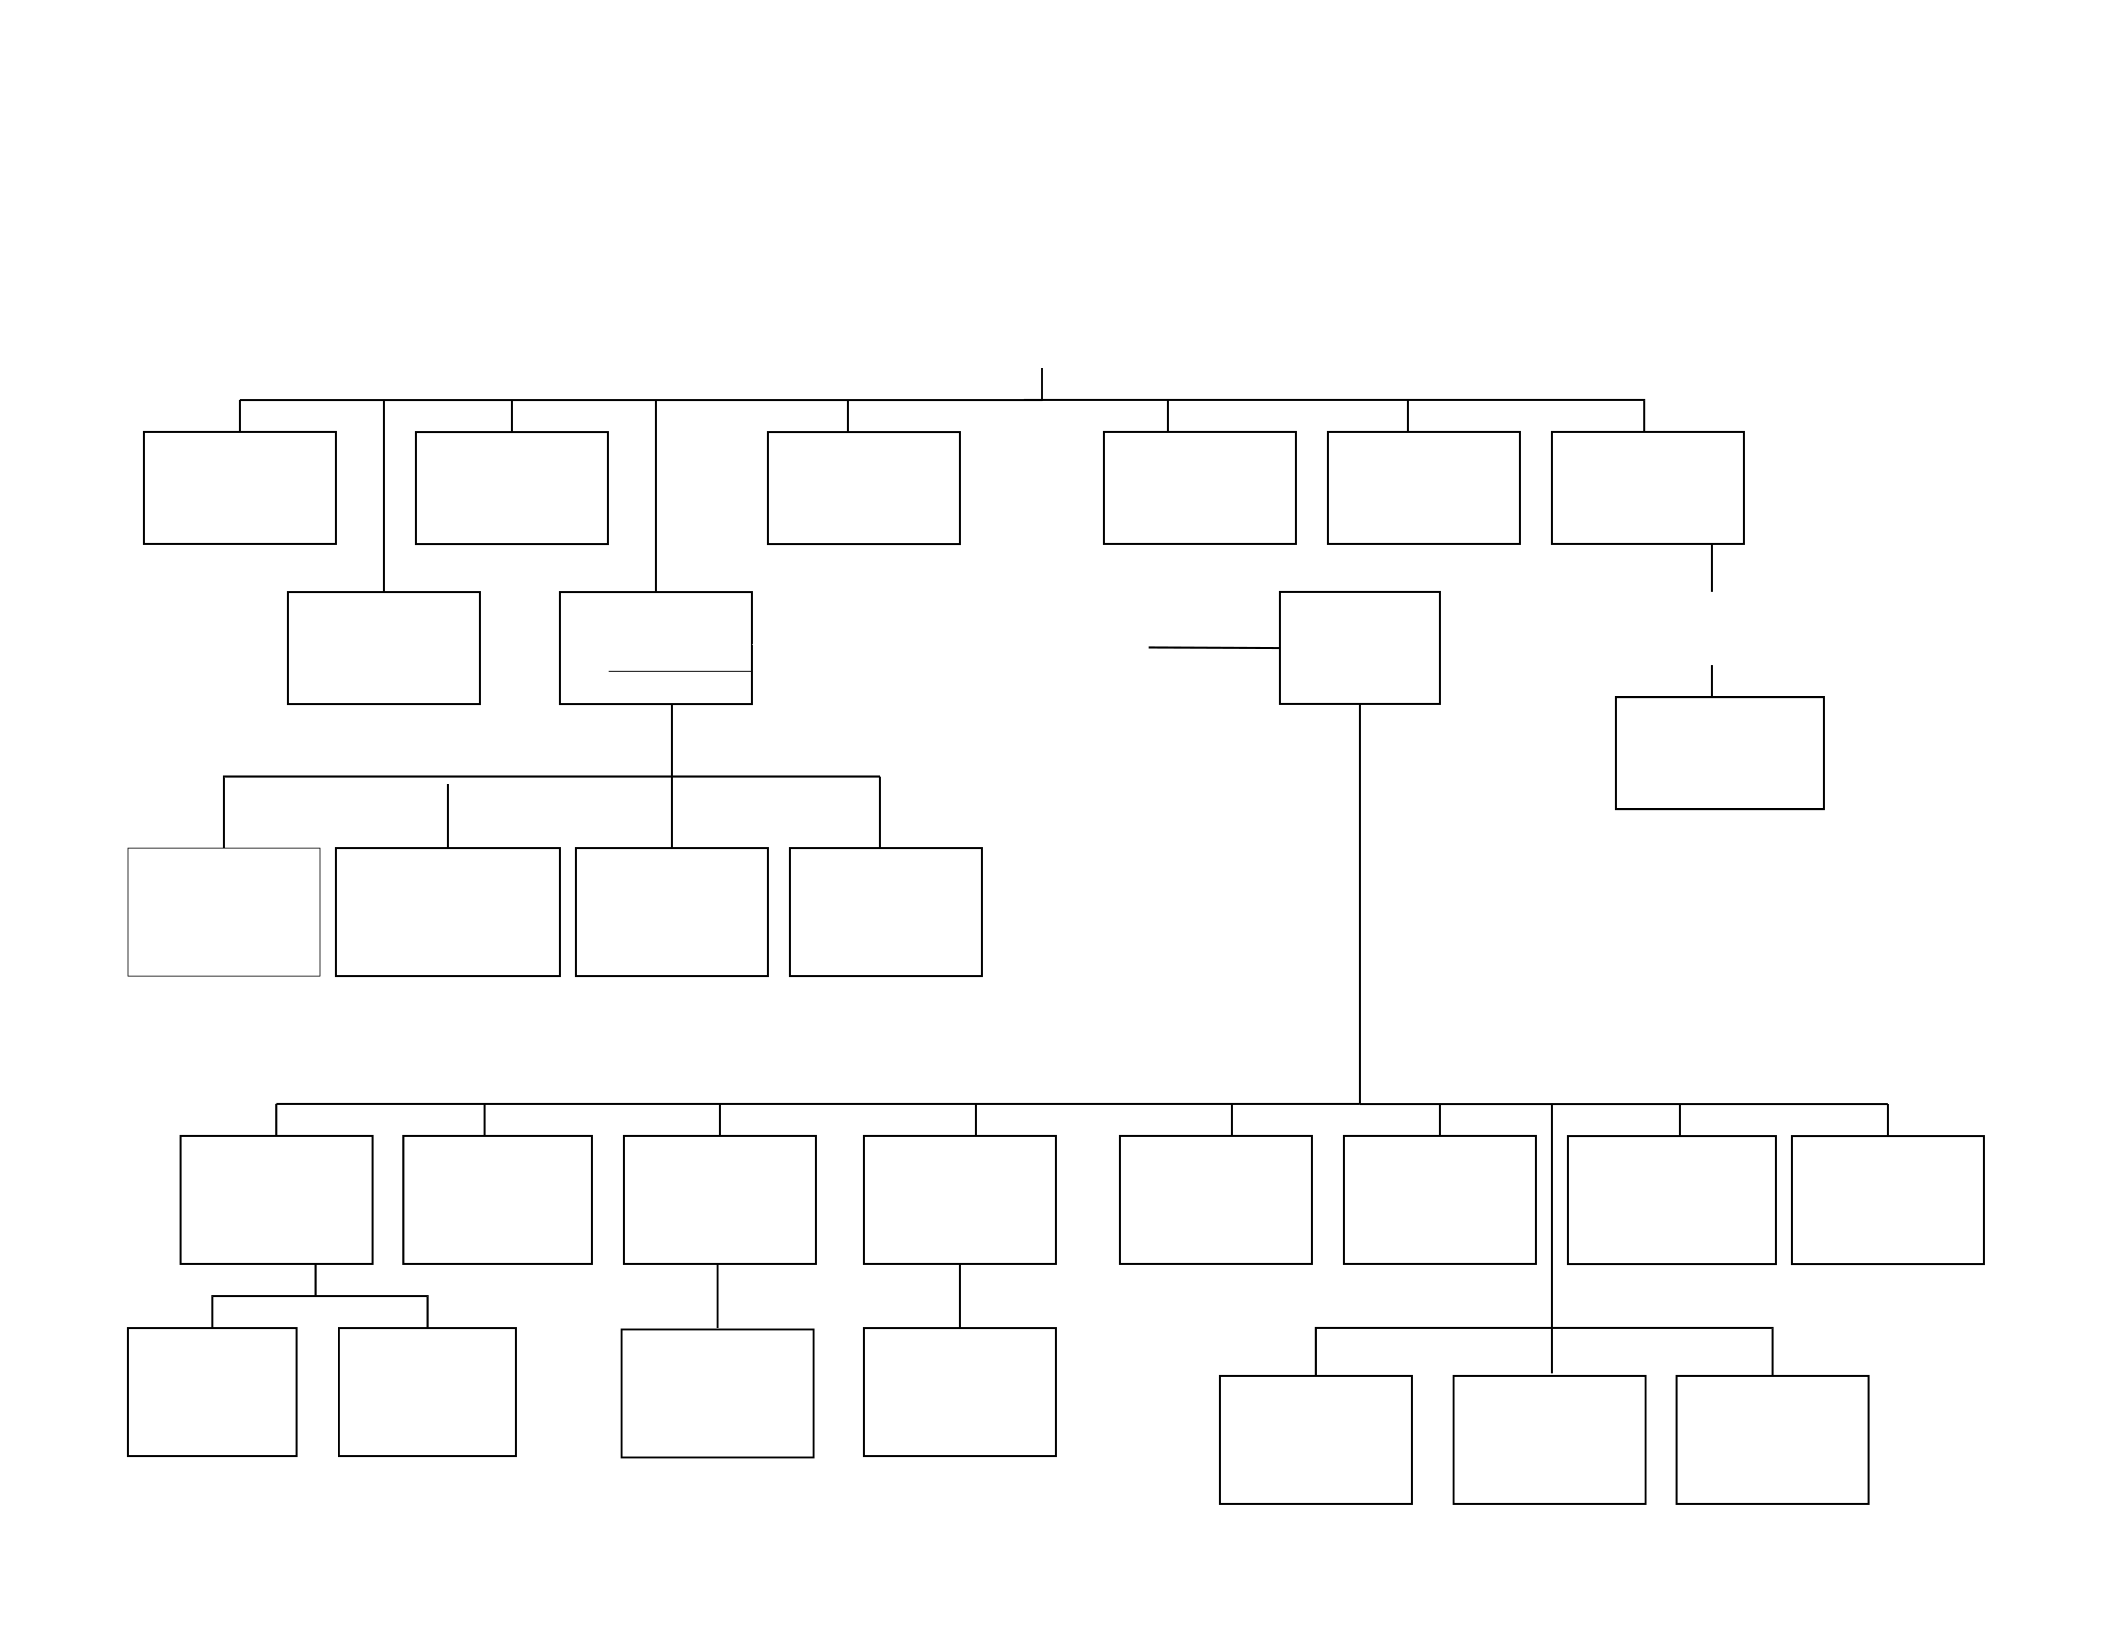
ORGANIZATIONAL CHART
CROMWELL VOTERS ELECT
TOWN
CLERK
TAX
COLLECTOR
REGISTRAR
OF VOTERS
BOARD OF
ASSESSMENT
APPEALS
PLANNING
AND ZONING
BOARD OF
EDUCATION
BOARD
OF
FINANCE
TOWN
COUNCIL
APPOINTS
TOWN
MANAGER
APPOINTS
ECONOMIC
DEVELOPMENT
COMMISSION
CONSERVATION/
INLAND-WETLAND
COMMISSION
WATER
POLUTION
CONTROL
AUTHORITY
TOWN
ATTORNEY
PUBLIC
WORKS
DIRECTOR
FINANCE
DIRECTOR
COMMUNITY
DEVELOPER/
PLANNER
CHIEF OF
POLICE
RECREATION
DIRECTOR
SENIOR/HUMAN
SERVICES
DIRECTOR
LIBRARY
DIRECTOR
CIVIL
PREPAREDNESS
DIRECTOR
TOWN
ENGINEER
SEWER
DEPT
ZONING
COMPLIANCE
OFFICER
ANIMAL
CONTROL
OFFICER
BUILDING
OFFICIAL
DIRECTOR
OF
HEALTH
ASSESSOR
SUPERINTENT
OF SCHOOLS
6
7
Town of Cromwell, Connecticut
Principal Officials
June 30, 2020
Mayor
Town Clerk
Tax Collector
Enzo Faienza
JoAnn Doyle
Douglas Sienna
Town Council
Jennifer Donohue
Pat Ahlquist
Jack Henehan
Al Walters
Steve Fortenbach
James Demetriades
Board of Finance
Julius Neto, Chairman
Allan Spotts, Vice -
Chairman Steve Wygonowski
John Ireland
Daniel Kelly
Edwin Maley, Jr.
Board of Education
Michael J. Camilleri, Chairman
Jennifer Lamberson
Jeffrey Matrullo
Kathryn Russ
John Flanders
Lindsey Merli
Celine Kelleher
Dipti Post
Laurie Cantwell
Superintendent of Schools
Enza Macri
Administration
Town Manager Anthony J. Salvatore
Animal Control Officer Cheryl Gagnon
Assessor Shawna Baron
Building Official David Jolley
Chief of Police Denise LaMontagne
Developer/Planner Stuart Popper
Director of Finance Marianne Sylvester
Director of Human Services/Senior Center/Youth Services Amy Saada
Director of Public Works Louis Spina
Director of Recreation Scott Kieras
Library Director Kara Canney
Town Engineer Jonathan Harriman
Zoning Officer Bruce Driska
q
2
Government
Finance
Officers
Association
Certificate
of
Achievement
for
Excellence
in
Financial
Reporting
Presented
to
Town
of
Cromwell
Connecticut
For
its
Comprehensive
Annual
Financial
Report
For
the
Fiscal
Year
Ended
June
30,
2019
Pustopte.
P-
Movritt
Executive
Director/CEO
8
Financial
Section
9
Independent Auditors’ Report
Town Council
Town of Cromwell, Connecticut
Report on the Financial Statements
We have audited the accompanying financial statements of the governmental activities, each major fund and
the aggregate remaining fund information of the Town of Cromwell, Connecticut (“Town”), as of and for the
year ended June 30, 2020, and the related notes to the financial statements, which collectively comprise the
Town's basic financial statements as listed in the table of contents.
Management's Responsibility for the Financial Statements
Management is responsible for the preparation and fair presentation of these financial statements in
accordance with accounting principles generally accepted in the United States of America; this includes the
design, implementation and maintenance of internal control relevant to the preparation and fair presentation of
financial statements that are free from material misstatement, whether due to fraud or error.
Auditors’ Responsibility
Our responsibility is to express opinions on these financial statements based on our audit. We conducted
our audit in accordance with auditing standards generally accepted in the United States of America and the
standards applicable to financial audits contained in Government Auditing Standards, issued by the
Comptroller General of the United States. Those standards require that we plan and perform the audit to
obtain reasonable assurance about whether the financial statements are free from material misstatement.
An audit involves performing procedures to obtain audit evidence about the amounts and disclosures in
the financial statements. The procedures selected depend on the auditors’ judgment,
including the assessment of the risks of material misstatement of the financial statements, whether due to
fraud or error. In making those risk assessments, the auditor considers internal control relevant to the
entity's preparation and fair presentation of the financial statements in order to design audit procedures
that are appropriate in the circumstances, but not for the purpose of expressing an opinion on the
effectiveness of the entity's internal control. Accordingly, we express no such opinion. An audit also
includes evaluating the appropriateness of accounting policies used and the reasonableness of
significant accounting estimates made by management, as well as evaluating the overall presentation of
the financial statements.
We believe that the audit evidence we have obtained is sufficient and appropriate to provide a basis for our
audit opinions.

Town Council
Town of Cromwell, Connecticut
Page
10
10
Opinions
In our opinion, the financial statements referred to above present fairly, in all material respects, the respective
financial position of the governmental activities, each major fund and the aggregate remaining fund
information of the Town, as of June 30, 2020, and the respective changes in financial position, and, where
applicable, cash flows thereof for the year then ended in accordance with accounting principles generally
accepted in the United States of America.
Other Matters
Required Supplementary Information
Accounting principles generally accepted in the United States of America require that the management's
discussion and analysis, the budgetary comparison information, and the pension and other post-
employment benefit schedules as listed in the table of contents, be presented to supplement the basic
financial statements. Such information, although not a part of the basic financial statements, is required by
the Governmental Accounting Standards Board, who considers it to be an essential part of financial
reporting for placing the basic financial statements in an appropriate operational, economic or historical
context. We have applied certain limited procedures to the required supplementary information in
accordance with auditing standards generally accepted in the United States of America, which consisted
of inquiries of management about the methods of preparing the information and comparing the information
for consistency with management's responses to our inquiries, the basic financial statements and other
knowledge we obtained during our audit of the basic financial statements. We do not express an opinion
or provide any assurance on the information because the limited procedures do not provide us with
sufficient evidence to express an opinion or provide any assurance.
Supplementary and Other Information
Our audit was conducted for the purpose of forming opinions on the financial statements that collectively
comprise the Town’s basic financial statements. The introductory section, supplemental schedules and
statistical sections are presented for purposes of additional analysis and are not a required part of the basic
financial statements.
The supplemental schedules are the responsibility of management and were derived from and relate
directly to the underlying accounting and other records used to prepare the basic financial statements.
Such information has been subjected to the auditing procedures applied in the audit of the basic financial
statements and certain additional procedures, including comparing and reconciling such information
directly to the underlying accounting and other records used to prepare the basic financial statements or
to the basic financial statements themselves, and other additional procedures in accordance with auditing
standards generally accepted in the United States of America. In our opinion, the supplemental schedules
are fairly stated in all material respects in relation to the basic financial statements as a whole.
Town Council
Town of Cromwell, Connecticut
Page
11
11
The introductory and statistical sections have not been subjected to the auditing procedures applied in the
audit of the basic financial statements and, accordingly, we do not express an opinion or provide any
assurance on them.
Other Reporting Required by Government Auditing Standards
In accordance with Government Auditing Standards, we have also issued our report dated December 2,
2020, on our consideration of the Town's internal control over financial reporting and on our tests of its
compliance with certain provisions of laws, regulations, contracts, and grant agreements and other matters.
The purpose of that report is solely to describe the scope of our testing of internal control over financial
reporting and compliance and the results of that testing, and not to provide an opinion on the effectiveness
of the Town’s internal control over financial reporting or on compliance. That report is an integral part of an
audit performed in accordance with Government Auditing Standards in considering the Town’s internal control
over financial reporting and compliance.
Wethersfield, Connecticut
December 2, 2020
12
Management’s Discussion and Analysis
For the Year Ended June 30, 2020
As management of the Town of Cromwell, Connecticut (“Town”), we offer readers of the Town's financial
statements this narrative overview and analysis of the financial activities of the Town for the fiscal year
ended June 30, 2020. Please read it in conjunction with the Town’s financial statements immediately
following this section.
Financial Highlights
•
The assets and deferred outflows of resources of the Town exceeded its liabilities and deferred inflows
of resources at the close of the most recent fiscal year by $108,325,288 (net position). Unrestricted net
position was $7,029,988.
The Town's total net position increased by $1,842,399. The increase is substantially due to the following:
➢ positive operations of the general fund of $ 305,583
➢ positive operations of the sewer usage fund of 296,070
The positive operations were offset by:
➢ the negative operations in the capital projects fund of (3,323,589)
➢ the negative operations in other governmental funds of (413,251)
Conversion to accrual basis on Exhibit E:
➢ capital outlay net of depreciation expense of $ 3,173,274
➢ net principal debt activity of 3,320,800
➢ change in pension liability of (2,981,580)
➢ change in pension and OPEB deferred inflows/outflows 1,826,393
The Town’s governmental funds reported combined fund balance of $24,906,785 a
decrease of
$3,135,187 compared to the prior year. The change is based on the operating results of each major
fund noted above and described in further detail in the Financial Analysis of the Town’s Fund section.
•
At the end of the current fiscal year, unassigned fund balance for the general fund was $13,892,356
or 26.75% of total general fund budgetary expenditures and transfers.
•
The Town’s total bonds and notes payable decreased by $3,320,800 or 13.24% due to scheduled
principal payments.
•
Net capital assets increase by $3,173,274 or 2.73%. The increase is attributable to capital asset
additions for construction in progress, infrastructure improvements and vehicles in excess of
depreciation expense.
13
Management’s Discussion and Analysis (continued)
Overview of the basic financial statements
This discussion and analysis is intended to serve as an introduction to the Town of Cromwell’s basic
financial statements. The Town's basic financial statements comprise three components: 1) government-
wide financial statements, 2) fund financial statements and 3) notes to financial statements. The statement
of fiduciary net position is used to present financial information about activities for which the Town acts
solely as an agent for the benefit of employees and others.
Government-wide financial statements
The government-wide financial statements are designed to provide readers with a broad overview of the
Town's finances, in a manner similar to a private-sector business.
The statement of net position presents information on all of the Town's assets, deferred outflows of
resources, liabilities and deferred inflows of resources with the difference between these accounts reported
as net position. Over time, increases or decreases in net position may serve as a useful indicator of whether
the financial position of the Town is improving or deteriorating.
The statement of activities presents information showing how the Town's net position changed during the
most recent fiscal year. All changes in net position are reported as soon as the underlying event giving rise
to the change occurs, regardless of the timing of related cash flows. Thus, revenues and expenses reported in
this statement are for some items that will only result in cash flows in future fiscal periods (e.g.,
uncollected taxes and earned but unused vacation leave).
The government-wide financial statements present the functions of the Town that are principally supported
by taxes and intergovernmental revenues (governmental activities). The governmental activities of the
Town include general government, public safety, public works, culture and recreation, human services and
education.
Fund financial statements
A fund is a grouping of related accounts that is used to maintain control over resources that have been
segregated for specific activities or objectives. The Town uses fund accounting to ensure and demonstrate
compliance with finance-related legal requirements. All of the funds of the Town can be divided into three
categories: governmental funds, proprietary funds and fiduciary funds.
Governmental funds
Governmental funds are used to account for essentially the same functions reported as governmental
activities in the government-wide financial statements. However, unlike the government-wide financial
statements, governmental fund financial statements focus on near-term inflows and outflows of spendable
resources, as well as on balances of spendable resources available at the end of the fiscal year. Such
information may be useful in evaluating a Town's near-term financing requirements.
Because the focus of governmental funds is narrower than that of the government-wide financial
statements, it is useful to compare the information presented for governmental funds with similar
information presented for governmental activities in the government-wide financial statements. By doing
so, readers may better understand the long-term impact of the Town's near-term financing decisions. Both
the governmental fund balance sheet and the governmental fund statement of revenues, expenditures and
changes in fund balances provide a reconciliation to facilitate this comparison between governmental funds
and governmental activities.
Management’s Discussion and Analysis (continued)
14
Information is presented separately in the governmental fund balance sheet and in the governmental fund
statement of revenues, expenditures and changes in fund balances for the General Fund, Sewer Usage
Fund
and
Capital
Projects
Fund,
which
are
considered
to
be
major
funds.
Data
from
the
other
governmental
funds are combined into a single, aggregated presentation. Individual fund data for each of these other
governmental funds is provided in the combining statements on Schedules 4 and 5.
Proprietary funds
The Town maintains two proprietary funds, both of which are internal service funds. Internal service
funds are an accounting device used to accumulate and allocate costs internally among the Town's
various functions. The Town uses an internal service fund to account for its dental benefits and heart
and hypertension claims. Because these services predominantly benefit governmental rather than
business- type functions, they have been included within governmental activities in the government-wide
financial statements.
Fiduciary funds
Fiduciary funds are used to account for resources held for the benefit of parties outside the Town. Fiduciary
funds are not reflected in the government-wide financial statements because the resources of those funds
are not available to support the Town's own programs. The accounting used for fiduciary funds is much
like that used for proprietary funds.
Notes to financial statements
The notes provide additional information that is essential to a full understanding of the data provided in the
government-wide and fund financial statements.
Required supplementary information
In addition to the basic financial statements and accompanying notes, this report also presents
certain required supplementary information as follows:
•
A budgetary comparison schedule for the General Fund to demonstrate compliance
with this budget.
•
Schedules to demonstrate the Town’s progress in funding its obligation to provide pension benefits.
•
Schedules to demonstrate the Town’s progress in funding its obligation to provide other
post- employment benefits.
Other information
The combining statements referred to earlier in connection with other governmental funds are presented
immediately following the required supplementary information on pensions and other post-employment
benefits.
Management’s Discussion and Analysis (continued)
15
Government-wide financial analysis
As noted earlier, net position may serve over time as a useful indicator of a government's financial position.
In the case of the Town, assets and deferred outflows of resources exceeded liabilities and deferred inflows of
resources by $108,325,288 at the close of the most recent fiscal year.
By far the largest portion of the Town's net position (90.44%) reflects its investment in capital assets (e.g.,
land, construction in progress, buildings and improvements, improvements other than buildings, furniture
and equipment, and infrastructure), less any related debt used to acquire those assets that is still
outstanding. The Town uses these capital assets to provide services to citizens; consequently, these
assets are not available for future spending. Although the Town's investment in its capital assets is reported
net of related debt, it should be noted that the resources needed to repay this debt must be provided
from other sources, since the capital assets themselves cannot be used to liquidate these liabilities.
Government-wide financial analysis
Summary
Statement
of
Net
Position
June 30
2020
2019
(as
restated)
Current
and
other
assets
$ 33,378,592
$ 34,349,381
Capital
assets
(net)
119,261,424
116,088,150
Total
assets
152,640,016
150,437,531
Deferred
outflows
of
resources
5,372,162
4,141,462
Current liabilities outstanding
9,978,685
4,049,267
Long-term liabilities outstanding
34,844,275
38,663,487
Total
liabilities
44,822,960
42,712,754
Deferred
inflows
of
resources
4,863,930
5,383,350
Net
position:
Net
investment
in
capital
assets
97,968,700
94,991,214
Restricted
3,326,600
2,981,762
Unrestricted
7,029,988
8,509,913
Total
net
position
$ 108,325,288
$ 106,482,889
A small portion of the Town's net
position,
3.07%, represents
resources
that are subject to
external
restrictions on how they may be used.
The unrestricted balance is 6.49%, and may be used to meet the Town’s ongoing obligations to citizens
Management’s Discussion and Analysis (continued)
16
and creditors.
Management’s Discussion and Analysis (continued)
17
Government-wide financial analysis (continued)
Statement
of
Changes
in
Net
Position
For
the
Years
Ended
June
30
2020
2019
Revenues:
Program
revenues:
Charges
for
services
$ 4,755,977
$ 4,874,528
Operating
grants
and
contributions
11,779,381
11,328,763
Capital
grants
and
contributions
1,710,793
1,944,708
General
revenues:
Property
taxes
43,949,313
44,067,022
Grants
and
contributions
not
restricted
to
specific
programs
106,486
57,517
Income
from
investments
585,010
646,578
Other
157,036
171,121
Total
revenues
63,043,996
63,090,237
Expenses:
Property taxes comprise 69.71% of revenues, followed by grants and contributions 21.57%, charges for
services 7.54% and investment earnings/other 1.18%.
Significant revenue related changes are as follows:
•
Operating grants and contributions increased by $450,618 primarily due to an increase in education
grants of $269,913 for the following: Excess Cost, Education Cost Sharing, Child Nutrition Cluster
and on-behalf amount for Connecticut State Teachers’ Retirement pension and OPEB.
•
Capital grants and contributions decreased by $233,915 primarily due a $911,006 decrease in the
amount received for the highway planning grant from the prior year, offset against a $808,190
increase in State LOTCIP grant.
General
government
4,056,518
3,927,840
Public
safety
5,956,091
5,649,536
Public
works
9,658,198
9,277,331
Culture
and
recreation
1,353,059
1,323,812
Human
services
819,289
746,421
Education
39,114,940
37,882,197
Interest
243,502
507,863
Total
expenses
61,201,597
59,315,000
Change
in
net
position
1,842,399
3,775,237
Net
position
-
July
1
(as
restated)
106,482,889
103,379,053
Restatements
(Note
VI)
-
(671,401)
Net
position
-
June
30
$ 108,325,288
$
106,482,889
Management Discussion and Analysis
18
Government-wide financial analysis (continued)
With respect to expenses, 63.91% of the Town's expenses relate to education, followed by 15.78% to
public works, 9.73% to public safety, 6.63% to general government, 2.21% to culture and recreation, 1.34%
to human services and 0.40% to interest on long-term debt.
•
Public safety expenses increased by $306,555 primarily due to an increase in MERS
pension expense of $571,071 offset by decreases in wages of $123,849 for police outside
services.
•
Public works expenses increased by $380,867 primarily due to an increase in various road
repairs below the capitalization threshold of $298,442.
•
Education expenses increased by $1,232,743 primarily due to an increase in the operational budget
of $976,548.
Financial analysis of the Town's funds
As noted earlier, the Town uses fund accounting to ensure and demonstrate compliance with
finance- related legal requirements.
Governmental funds
The focus of the Town's governmental funds is to provide information on near-term inflows, outflows and
balances of expendable resources. Such information is useful in assessing the Town's financing
requirements. In particular, unassigned fund balance may serve as a useful measure of a Town's net
resources available for spending at the end of the fiscal year.
The Town reports fund balance in 5 categories. The following are the categories and definitions:
•
Nonspendable fund balance - not in spendable form such as inventories and prepaid expenditures.
•
Restricted fund balance - limitations imposed by external parties, grantors or by legislation.
•
Committed fund balance - can only be spent for specific purposes as established by the
government’s highest level of decision-making authority or contractual obligations.
•
Assigned fund balance - amounts that are intended for a specific purpose but do not
meet the definition of restricted or committed (i.e., designated for subsequent year’s budget).
•
Unassigned fund balance - amounts available for any purpose.
As
of
the
end
of
the
current
fiscal
year,
the
Town's
governmental
funds
reported
a
combined
ending
fund
balance
of
$24,906,785,
a
decrease
of
$3,135,187
in
comparison
with
the
prior
year.
The
components
of
fund
balance
was
as
follows:
Nonspendable
for
endowments
$ 6,237
Restricted
3,320,363
Committed
6,815,702
Assigned
872,127
Unassigned
13,892,356
Total
$
24,906,785
Management’s Discussion and Analysis (continued)
19
Governmental funds (continued)
General fund. The general fund is the operating fund of the Town. At the end of the current fiscal year,
unassigned fund balance of the general fund was $13,892,356, while total fund balance was $14,678,699.
As a measure of the general fund's liquidity, it may be useful to compare both unassigned fund balance
and total fund balance to total fund expenditures. Unassigned fund balance represents 26.75% of total
general fund budgetary expenditures and transfers out, while total fund balance represents 28.26% of that
same amount.
During the current fiscal year, the fund balance of the Town's general fund increased by $305,583. The
increase was primarily due to property tax revenues exceeding the amount budgeted by $547,797 and
charges for services exceeding the amount budgeted by $571,016. In addition, expenditures were
underspent by a total of $1,612,918. The discussion of expenditures that were underspent are discussed
further under budgetary highlights.
These items were offset by the Town budgeting the use of fund balance of $879,001 and additional
appropriations of $2,200,000 which are discussed under budgetary highlights.
Sewer usage fund. The fund accounts for the Town’s sewer usage operations. During the year, revenues
exceeded expenditures by $296,070, a decrease in change in fund balance compared to $533,784 in the
prior year. The decrease is primarily due to there being $199,595 less outlet charges as there was less
new construction compared to the prior year. Fund balance at year end was $2,292,883.
Expenditures were $83,808 high than the prior year. This is substantially due to increases for employee
benefits of $29,287 and payments for sewer treatment of $29,375.
Capital projects fund. This fund accounts for various capital and capital nonrecurring projects. The
Capital Projects Fund’s net change in fund balance was a decrease of $3,323,589 for the fiscal year.
This is a result of the construction costs for the Public Works/WPCA Facility of $4,559,562 and the
Library Construction Renovation Project of $871,797 offset by a transfer in of $2,200,000 from the
general fund. The deficit operations is due to bonds being issued in the prior year for expenditures in the
current year.
Proprietary funds
The dental insurance internal service fund and the heart and hypertension fund are the Town’s only
proprietary funds. Unrestricted net position for the dental insurance fund at year end was $157,822, an
increase of $48,933 from the prior year, due to claims coming in less than anticipated due to the impact of
the coronavirus pandemic. Unrestricted net position for the heart and hypertension fund at year end was
$94,541 an increase of $17,876 from the prior year due to due to claims coming in less than anticipated.
General fund budgetary highlights
The difference between the original budget and the final amended budget was $2,200,000. The significant
additional appropriations were:
•
Appropriation of fund balance of $2,200,000 for the Library Renovation and Reconstruction Project.
Expenditures
•
General government expenditures were underspent by $695,102 due to the under expending
of benefits due to conservative budgeting practices.
•
Public safety expenditures were underspent by $300,299 due to vacancies in the police department.
•
Public works expenditures were underspent $264,036 due to less vehicle
maintenance than anticipated and vacancies.
Management’s Discussion and Analysis (continued)
20
Capital assets and debt administration
Capital assets
The Town's investment in capital assets amounts to $119,261,424 (net of accumulated depreciation). This
investment in capital assets is as follows:
Capital
Assets
(Net
of
Accumulated
Depreciation)
June
30
2020
2019
Land
$ 8,795,275
$ 8,683,782
Construction
in
progress
14,394,865
7,678,495
Buildings
and
improvements
45,011,512
46,828,330
Improvements
other
than
buildings
1,597,155
1,627,377
Furniture
and
equipment
2,463,980
2,766,814
Infrastructure
46,998,637
48,503,352
Total
$ 119,261,424
$ 116,088,150
The capital assets (net of depreciation) increased in the current year by $3,173,274. The increase is due
to capital additions exceeding depreciation expense. In the current year, the Town had capital asset
additions totaling $7,757,901 and deductions totaling $88,150.
Major
capital
asset
events
during
the
current
fiscal
year
included
the
following:
Construction
in
progress
additions
of:
➢
Public
Works/WPCA
Facility
$
4,559,562
➢
Library
Expansion
and
Renovation
871,798
➢
Coles
Road
Reconstruction
808,191
Vehicle
purchases:
➢
2020
Ford
Escape
26,093
➢
2019
Ford
Expedition
47,747
➢
2020
Chevrolet
Silverado
49,881
➢
2019
Spartan
Bus
67,392
Infrastructure
Improvements:
➢
Various
Road
Projects
583,812
Land
additions
of:
➢
Main
Street
Downtown
Parking
Lot
111,493
Additional information on the Town's capital assets can be found in Note III D.
Management’s Discussion and Analysis (concluded)
21
Long-term debt
At the end of the fiscal year, the Town had total bonded debt and notes outstanding of $21,760,661. All
debt is backed by the full faith and credit of the Town.
Long-Term
Debt
June 30
2020 2019
General
obligation
bonds
$
21,425,000
$
24,435,000
Equipment
financing
notes
335,661
646,461
Total
$ 21,760,661
$
25,081,461
During the current fiscal year, the Town's total long-term debt decreased by $3,320,800 due to scheduled
principal payments.
The Town maintains an AAA credit rating from Standard and Poor’s during the fiscal year for
general obligation debt.
State Statutes limit the amount of general obligation debt a governmental entity may issue to 7 times total
prior year tax collections including interest and lien fees. The current debt limitation for the
Town is
$329,906,374, which is significantly in excess of the Town's outstanding general obligation debt.
Additional information on the Town's long-term debt can be found in Note III F.
Economic factors and next year's budgets and rates
•
The unemployment rate for the State is currently 10.1%, which is an increase from a rate of 3.6% a
year ago. The Town’s unemployment rate was 8.9% as compared to 3.0% in the prior year. The
increases are due to the impact of the coronavirus pandemic.
•
Inflationary trends in the region compare favorably to national indices.
•
The potential impact of the pandemic on the local economy, businesses and Town revenues is being
closely monitored. The July 2020 collections were in line with the prior year. Any impact on the
property tax revenues is expected to occur with the January 2021 semi-annual payment, if at all. The
State of Connecticut through the Governor’s executive order, required local governments to offer
taxpayers/rate payers one or both of the following programs: interest rate reduction program
and/or the payment deferral program through October 1, 2020. The Town implemented the
payment deferral program. For the collection period ended July 31, 2020, collections were in line with
the prior year.
All of these factors were considered in preparing the Town’s budget for the 2021 fiscal year.
Requests for information
This financial report is designed to provide a general overview of the Town's finances for all those with an
interest in the government's finances. For questions concerning any of the information provided in this
report or requests for additional financial information contact the Finance Department, Town of Cromwell,
41 West Street, Cromwell, Connecticut 06416 or visit www.cromwellct.com.
Basic
Financial
Statements
Exhibit
A
(21
of
2)
Town of Cromwell,
Connecticut
Statement of Net
Position
Governmental
Activities
June
30,
2020
The notes to the financial statements are an integral part of this statement.
21
Current
assets:
Assets
Cash
$ 4,934,230
Investments
Receivables
(net):
Property taxes
26,286,283
503,157
Intergovernmental
108,648
Assessments and usage
447,230
Other
221,435
Other
assets
18,400
Total
current
assets
32,519,383
Noncurrent assets:
Restricted assets:
Temporarily restricted:
Cash 271,249
Investments 241,257
Permanently restricted:
Investments
6,237
Total restricted assets
518,743
Receivables (net):
Property taxes
239,328
Assessments and usage
101,138
Total
receivables
(net)
340,466
Capital assets (net of accumulated depreciation):
Land
8,795,275
Construction
in
progress
14,394,865
Buildings and improvements
45,011,512
Improvements other than buildings
1,597,155
Furniture
and
equipment
2,463,980
Infrastructure
46,998,637
Total
capital
assets
(net
of
accumulated
depreciation)
119,261,424
Total
noncurrent
assets
120,120,633
Total
assets
152,640,016
Deferred Outflows of Resources
Deferred
charge
on
refunding
238,514
Pension
related
4,687,833
OPEB
related
445,815
Total
deferred
outflows
of
resources
5,372,162
(Continued)
Exhibit
A
(22
of
2)
Town of Cromwell,
Connecticut
Statement of Net
Position
Governmental
Activities
c
June
c
30,
c
2020
The notes to the financial statements are an integral part of this statement.
22
Liabilities
Liabilities:
Current liabilities:
Accounts
payable
$ 1,696,850
Retainage payable
318,392
Accrued
payroll
and
related
liabilities
424,715
Accrued
interest
payable
98,901
Unearned revenue
3,935,721
Bonds
and
notes
payable
3,086,206
Compensated absences
313,130
Claims
payable
104,770
Total
current
liabilities
9,978,685
Noncurrent liabilities:
Performance bonds
407,099
Bonds,
notes
and
related
liabilities
21,240,059
Compensated absences
1,252,518
Net
pension
liability
9,297,732
Net
OPEB
liability
2,605,823
Claims
payable
41,044
Total noncurrent liabilities
34,844,275
Total
liabilities
44,822,960
Deferred
Inflows
of
Resources
Pension
related
2,004,290
OPEB
related
2,859,640
Total
deferred
inflows
of
resources
4,863,930
Net
Position
Net
investment
in
capital
assets
97,968,700
Restricted
for:
Endowments:
Nonexpendable
6,237
Expendable
4,310
Public
safety
23,212
Public
works
2,904,870
Culture
and
recreation
163,256
Human services
52,841
Education
171,874
Unrestricted
7,029,988
Total
net
position
$
108,325,288
(Concluded)
Exhibit B
Town of Cromwell, Connecticut
Statement of Activities
Governmental Activities
For The Year Ended June 30, 2020
Program Revenues
Net (Expenses)
Operating Capital Revenues and
Charges for Grants and Grants and Changes in
Functions/Programs Expenses Services Contributions Contributions Net Position
General government
$ 4,056,518
$ 508,943
$ 12,958
$ -
$ (3,534,617)
Public safety
5,956,091
585,833
15,995
-
(5,354,263)
Public works
9,658,198
3,039,697
-
1,310,793
(5,307,708)
Culture and recreation
1,353,059
209,704
88,733
400,000
(654,622)
Human services
819,289
32,549
24,000
-
(762,740)
Education
39,114,940
379,251
11,637,695
-
(27,097,994)
Interest
243,502
c -c c
c -c c
c -c c
c (243,502)
Total
$ 61,201,597
c c $c 4,755,977c c
c c $c 11,779,381c c
c c $c 1,710,793c c
(42,955,446)
General revenues:
Property taxes
43,949,313
Grants and contributions not restricted to specific programs
106,486
Income from investments
585,010
Other
157,036
Total general revenues
44,797,845
Change in net position
1,842,399
Net position - July 1, 2019 (as restated)
106,482,889
Net position - June 30, 2020
$ 108,325,288
The notes to the financial statements are an integral part of this statement.
23
24
Exhibit
C
(1
of
2)
Town
of
Cromwell,
Connecticut
Balance
Sheet
Governmental
Funds
June
30,
2020
Other
Total
Sewer
Capital
Governmental
Governmental
General
Usage
Projects
Funds
Funds
Assets
Cash
$ 73,177
$
2,940,581
$ -
$
1,600,809
$
4,614,567
Restricted
cash
267,702
-
-
-
267,702
Investments
15,275,264
1,000,000
9,637,265
305,754
26,218,283
Restricted
investments
240,494
-
-
-
240,494
Receivables
(net):
Property
taxes
742,485
-
-
-
742,485
Intergovernmental
34,235
-
566
73,847
108,648
Sewer
assessments
and
use
charges
-
345,495
176,523
-
522,018
Other
218,286
-
809
2,340
221,435
Due
from
other
funds
-
-
-
85,384
85,384
Other
-
-
-
18,400
18,400
Total
assets
$
16,851,643
$
4,286,076
$ 9,815,163
$
2,086,534
$
33,039,416
Liabilities
Accounts
payable
$ 534,520
$ 34,400
$ 1,098,487
$ 29,410
$
1,696,817
Retainage
payable
-
-
318,392
-
318,392
Accrued
payroll
and
related
liabilities
403,456
12,868
-
8,391
424,715
Due
to
other
funds
85,384
-
-
-
85,384
Unearned
revenue
-
1,600,430
1,682,886
652,405
3,935,721
Performance
bonds
407,099
-
-
-
407,099
Total
liabilities
1,430,459
1,647,698
3,099,765
690,206
6,868,128
Deferred
Inflows
of
Resources
Unavailable
revenue:
Property
taxes
742,485
-
-
-
742,485
Sewer
assessments
and
use
charges
-
345,495
176,523
-
522,018
Total
deferred
inflows
of
resources
742,485
345,495
176,523
-
1,264,503
Fund
Balances
Nonspendable
-
-
-
6,237
6,237
Restricted
-
2,292,883
611,987
415,493
3,320,363
Committed
199,866
-
5,926,888
688,948
6,815,702
Assigned
586,477
-
-
285,650
872,127
Unassigned
13,892,356
-
-
-
13,892,356
Total
fund
balances
14,678,699
2,292,883
6,538,875
1,396,328
24,906,785
Total
liabilities,
deferred
inflows
of
resources
and
fund
balances
$
16,851,643
$
4,286,076
$ 9,815,163
$
2,086,534
$
33,039,416
(Continued)

25
The notes to the financial statements are an integral part of this statement.
Exhibit C
26
(2 of 2)
Town of Cromwell, Connecticut
Reconciliation of Fund Balance
to Net Position of Governmental Activities
June 30, 2020
Amounts reported in the statement of net position (Exhibit A) are
different from the governmental fund balance sheet due to:
Total fund balance (Exhibit C, Page 1 of 2)
$ 24,906,785
Capital assets used in governmental activities are not financial resources and, therefore,
are not reported in the funds:
Beginning capital assets
116,088,150
Current year additions (net of construction in progress)
7,669,751
Depreciation expense
(4,496,477)
Other long-term assets and deferred outflows of resources are not available resources and, therefore,
are not reported in the funds:
Allowance for doubtful accounts
(12,000)
Deferred charge on refunding
238,514
Deferred outflows related to pensions
4,687,833
Deferred outflows related to OPEB
445,815
Other long-term assets are not available to pay for current period expenditures and, therefore,
are unavailable in the funds:
Property tax - accrual basis change 742,485
Sewer use and assessments receivable - accrual basis change 522,018
Internal service funds are used by management to charge the cost of
dental insurance and heart and hypertension to individual
departments:
The assets and liabilities of the internal service funds are included in the
statement of net position 252,363
Some liabilities and deferred inflows of resources, including bonds payable, are not due
and payable in the current period and, therefore, are not reported in the funds:
Bonds and notes payable
(21,760,661)
Premium
(2,565,604)
Compensated absences
(1,565,648)
Net pension liability
(9,297,732)
Net OPEB liability
(2,605,823)
Accrued interest payable
(98,901)
Deferred inflows related to pensions
(2,004,290)
Deferred inflows related to OPEB
(2,859,640)
Net position (Exhibit A)
$ 108,325,288
The notes to the financial statements are an integral part of this statement.
(Concluded)
Exhibit
D
The notes to the financial statements are an integral part of this statement.
27
Town of Cromwell, Connecticut
Statement of Revenues, Expenditures and Changes in Fund Balances
Governmental
Funds
For
The
Year
Ended
June
30,
2020
Revenues:
General
Sewer
Usage
Capital
Projects
Other
Governmental
Funds
Total
Governmental
Funds
Property
taxes
$
44,480,132
$ -
$ -
$ -
$
44,480,132
Intergovernmental
9,905,753
-
1,935,057
2,182,813
14,023,623
Charges
for
services
1,841,994
2,118,511
53,940
585,932
4,600,377
Income from investments
391,685
33,568
158,550
1,207
585,010
Contributions
-
-
-
73,037
73,037
Other
157,014
c
22
-
-
157,036
c
Total revenues
56,776,578
c
2,152,101
c
2,147,547
c
2,842,989
c
63,919,215
c
Expenditures:
Current:
General government
6,136,323
-
-
19,262
6,155,585
Public
safety
3,656,951
-
-
31,557
3,688,508
Public
works
3,983,024
1,856,031
-
-
5,839,055
Culture and recreation
800,919
-
-
267,182
1,068,101
Human services
617,696
-
-
45,896
663,592
Education
35,074,925
-
-
2,642,399
37,717,324
Debt
service
3,704,100
-
-
249,944
3,954,044
Capital
outlay
-
c
-
7,968,193
c
-
c
7,968,193
c
Total expenditures
53,973,938
c
1,856,031
c
7,968,193
c
3,256,240
c
67,054,402
c
Excess (deficiency) of
revenues
over
expenditures
2,802,640
c
296,070
c
(5,820,646)
(413,251)
(3,135,187)
Other financing sources
(uses):
Transfers
in
316,943
-
2,814,000
-
3,130,943
Transfers
out
(2,814,000)
-
c
(316,943)
-
(3,130,943)
Net
other
financing
sources
(uses)
(2,497,057)
-
c
2,497,057
c
-
c
-
Net
change
in
fund
balances
305,583
296,070
(3,323,589)
(413,251)
(3,135,187)
Fund
balances
-
July
1,
2019
(as
restated)
14,373,116
c
1,996,813
c
9,862,464
c
1,809,579
c
28,041,972
c
Fund
balances
-
June
30,
2020
$
14,678,699
c
$
2,292,883
c
$
6,538,875
c
$
1,396,328
c
$
24,906,785
c
The notes to the financial statements are an integral part of this statement.
28
Exhibit
E
Town of Cromwell, Connecticut
Reconciliation of the Statement of Revenues, Expenditures and
Changes
in
Fund
Balances
of
Governmental
Funds
to
Statement
of
Activities
For
The
Year
Ended
June
30,
2020
Amounts
reported
in
the
statement
of
activities
(Exhibit
B)
are
different
due
to:
Net
change
in
fund
balances
-
total
governmental
funds
(Exhibit
D)
Governmental
funds
report
capital
outlays
as
expenditures.
However,
in
the
statement
of
activities
the
cost
of
those
assets
is
allocated
over
their
estimated
useful
lives
and
reported
as
depreciation
expense.
$
(3,135,187)
Capital
outlay
7,669,751
Depreciation expense
(4,496,477)
Total
3,173,274
Revenues
in
the
statement
of
activities
that
do
not
provide
current
financial
resources
are
not
reported
as
revenues
in
the
funds:
Change
in
property
tax
-
accrual
basis
change
(530,819)
Change
in
sewer
use/assessments
-
accrual
basis
change
129,250
Change
in
sewer
interest
and
lien
revenue
38,350
Change
in
allowance
for
doubtful
accounts
(12,000)
Library
grant
(500,000)
Total
(875,219)
The
issuance
of
long-term
debt
(e.g.,
bonds,
equipment
financing
notes)
provides
current
financial
resources
to
governmental
funds,
while
the
repayment
of
the
principal
of
long-term
debt
consumes
the
current
financial
resources
of
governmental
funds.
Neither
transaction,
however,
has
any
effect
on
net
position.
Also,
governmental
funds
report
the
effect
of
premiums,
discounts,
and
similar
items
when
debt
is
first
issued,
whereas
these
amounts
are
deferred
and
amortized
in
the
statement
of
activities.
The
details
of
these
differences
in
the
treatment
of
long-term
debt
and
related
items
are
as
follows:
Principal repayments:
General
obligation
bonds
and
notes
3,320,800
Some
expenses
reported
in
the
statement
of
activities
do
not
require
the
use
of
current
financial
resources
and,
therefore,
are
not
reported
as
expenditures
in
governmental
funds:
Amortization of premium
471,432
Change
in:
Compensated absences
(23,380)
Net
pension
liability
(2,981,580)
Net
OPEB
liability
80,747
Accrued interest payable
(5,351)
Amortization of deferred charges
(76,339)
Amortization
of
deferred
outflows
related
to
pension
950,895
Amortization
of
deferred
inflows
related
to
pension
681,090
Amortization
of
deferred
outflows
related
to
OPEB
356,144
Amortization
of
deferred
inflows
related
to
OPEB
(161,736)
Total
(708,078)
Internal
Service
Funds
are
used
by
management
to
charge
costs
of
dental
insurance
and
heart
and
hypertension
to
individual
departments
66,809
Change
in
net
position
(Exhibit
B) $
1,842,399
The notes to the financial statements are an integral part of this statement.
29
Exhibit F
Town of Cromwell, Connecticut
Statement of Net Position
Proprietary Funds
June 30, 2020
Assets
Internal
Service Funds
Cash $ 323,210
Investments 75,000
Total assets 398,210
Liabilities
Current liabilities:
Accounts payable
33
Claims payable
104,770
Total current liabilities
104,803
Noncurrent liability:
Claims payable
41,044
Total liabilities
145,847
Unrestricted
Net Position
$ 252,363
The notes to the financial statements are an integral part of this statement.
30
Exhibit G
Town of Cromwell, Connecticut
Statement of Revenues, Expenses and Changes in Net Position
Proprietary Funds
For The Year Ended June 30, 2020
Internal
Service Funds
Operating revenues:
Charges for services $ 321,603
Operating expenses:
Claims
254,794
Change in net position
66,809
Total net position - July 1, 2019 (as restated)
185,554
Total net position - June 30, 2020
$ 252,363
The notes to the financial statements are an integral part of this statement.
31
Town of Cromwell, Connecticut
Statement of Cash Flows
Proprietary Funds
For The Year Ended June 30,
2020
Exhibit H
Internal
Service Funds
Cash flows from (used in) operating activities:
Cash received for charges for services $ 321,603
Cash paid for benefits and claims (250,978)
Cash paid for administration 33
Net cash from (used in) operating activities 70,658
Cash and cash equivalents - July 1, 2019 (as restated) 327,552
Cash and cash equivalents - June 30, 2020 $ 398,210
Reconciliation to Exhibit F cash:
Cash and cash equivalents per above $ 398,210
Cash and cash equivalents reported as investments (75,000)
Cash - Exhibit F $ 323,210
Reconciliation of operating income (loss) to net cash
from operating activities:
Operating income (loss)
$ 66,809
Adjustments to reconcile operating income (loss) to net cash
from operating activities:
Increase (decrease) in:
Accounts payable 33
Claims payable 3,816
Net cash from operating activities $ 70,658
The notes to the financial statements are an integral part of this statement.
32
Exhibit I
Town of Cromwell, Connecticut
Statement of Fiduciary Net Position
Fiduciary Funds
June 30, 2020
Private-
Pension and Purpose
OPEB Trust Trust Agency
Funds Fund Funds
Assets
Cash
Investments:
$ 354,775
$ 50,469
$ 352,561
Common stock
13,288,393
-
-
Common stock - international
4,702,067
-
-
U.S. government obligations
4,930,999
-
-
Corporate bonds
2,472,562
-
-
Real estate investment trusts
770,360
-
-
Money market mutual fund
593,627
-
-
Pooled fixed income
333,655
-
-
Total investments
27,091,663
-
-
Accrued interest
47,611
-
-
Total assets
27,494,049
50,469
352,561
Liabilities
Payable to student organizations - - 352,561
Net Position
Restricted for:
Pension benefits
25,832,889
-
-
OPEB benefits
1,661,160
-
-
Individuals
-
50,469
-
Total net position
$ 27,494,049
$ 50,469
$ -
The notes to the financial statements are an integral part of this statement.
33
Exhibit J
Town of Cromwell, Connecticut
Statement of Changes in Fiduciary Net Position
Fiduciary Funds
For The Year Ended June 30, 2020
Private-
Pension and Purpose
OPEB Trust Trust
Funds Fund
Additions:
Contributions:
Employer
$ 1,111,300
$ -
Plan members
262,761
-
State Teachers' Retirement subsidy
27,718
-
Private
-
1,578
Total contributions 1,401,779 1,578
Investment income (loss):
Net change in fair value of investments
937,197
-
Interest and dividends
556,970
-
Total investment income (loss)
1,494,167
-
Less investment expenses
216,652
-
Net investment income (loss)
1,277,515
-
Total additions
2,679,294
1,578
Deductions:
Benefits
1,649,021
-
Administration
19,085
-
Scholarships
-
3,341
Total deductions
1,668,106
3,341
Changes in net position
1,011,188
(1,763)
Net position - July 1, 2019 (as restated)
26,482,861
52,232
Net position - June 30, 2020
$ 27,494,049
$ 50,469

Exhibit K
34
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
History and organization
The Town of Cromwell, Connecticut (“Town”) operates under a Mayor-Council form of government
established by a charter. The Town offers a full range of services authorized by the charter, including
general government, public safety, public works, culture and recreation, human services and education
to its residents.
Accounting principles generally accepted in the United States of America require that the reporting entity
include (1) the primary government; (2) organizations for which the primary government is financially
accountable; and (3) other organizations for which the nature and significance of their relationship with
the primary government are such that exclusion would cause the reporting entity’s financial statements to
be misleading or incomplete. The Town does not report any component units.
I.
Summary of significant accounting policies
A.
Government-wide and fund financial statements
The government-wide financial statements (i.e., the statement of net position and the statement of
activities) report information on all of the nonfiduciary activities of the Town. Governmental activities
are normally supported by taxes and intergovernmental revenues.
The statement of activities demonstrates the degree to which the direct expenses of a given function
or segment is offset by program revenues. Direct expenses are those that are clearly identifiable
with a specific function or segment. Program revenues include 1) charges to customers or
applicants who purchase, use or directly benefit from goods, services or privileges provided by a
given function or segment and 2) grants and contributions that are restricted to meeting the
operational or capital requirements of a particular function or segment. Taxes and other items not
properly included among program revenues are reported instead as general revenues.
Separate financial statements are provided for governmental funds, proprietary funds, and fiduciary
funds, even though the latter are excluded from the government-wide financial statements. Major
individual governmental funds are reported as separate columns in the fund financial statements.
B.
Measurement focus, basis of accounting and financial statement presentation
The government-wide financial statements are reported using the economic resources
measurement focus and the accrual basis of accounting, as are the proprietary fund and fiduciary
fund financial statements. Agency funds do not have a measurement focus but are accounted for
using the accrual basis of accounting. Revenues are recorded when earned and expenses are
recorded when a liability is incurred, regardless of the timing of related cash flows. Property taxes
are recognized as revenues in the year for which they are levied. Grants and similar items are
recognized as revenues as soon as all eligibility requirements imposed by the provider have been
met.

Exhibit K
Town of Cromwell, Connecticut
35
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
B. Measurement focus, basis of accounting and financial statement presentation (continued)
Governmental fund financial statements are reported using the current financial resources
measurement focus and the modified accrual basis of accounting. Revenues are recognized as soon
as they are both measurable and available. Revenues are considered to be available when they are
collectible within the current period or soon enough thereafter to pay liabilities of the current period.
For this purpose, the Town considers reimbursement grants to be available if they are collected within
one year of the end of the current fiscal period. Expenditures generally are recorded when a liability
is incurred, as under accrual accounting. However, debt service expenditures, as well as
expenditures related to compensated absences, pension and OPEB benefits, certain other employee
benefits, and claims and judgments, are recorded only when payment is due. General capital asset
acquisitions are reported as expenditures in the governmental funds.
Expenditure reimbursement type grants, certain intergovernmental revenues, charges for services,
transfers and interest associated with the current fiscal period are all considered to be susceptible to
accrual and so have been recognized as revenues of the current fiscal period. Only the portion of
special assessments receivable due within the current fiscal period is considered to be susceptible to
accrual as revenue of the current period. All other revenue items are considered to be
measurable and available only when cash is received by the Town.
The Town reports the following major governmental funds:
The General Fund is the Town's primary operating fund. It accounts for all financial resources of
the general government, except those required to be accounted for in another fund.
The Sewer Usage Fund is used to account for and report resources and expenditures that are
restricted, for the operation and maintenance of the sewer plant.
The Capital Projects Fund is used to account for and report resources and expenditures that are
restricted, committed or assigned for the acquisition and construction of capital facilities, including
those that are financed through special assessments.
Additionally, the Town reports the following fund types:
Special Revenue Funds are used to account for and report the proceeds of specific revenue
resources that are restricted, committed or assigned to expenditures for specified purposes other
than debt.
The Debt Service Fund is used to account for and report resources and expenditures that are
assigned for the repayment of debt.
The Permanent Funds are used to report resources that are legally restricted to the extent that
only earnings, not principal, may be used for purposes that support the Town’s programs.

Exhibit K
Town of Cromwell, Connecticut
36
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
B. Measurement focus, basis of accounting and financial statement presentation (continued)
The Internal Service Fund accounts for risk financing activities for dental insurance benefits and
heart and hypertension as allowed by GASB Statement No. 10.
The Pension Trust Fund accounts for the activities of the Employee Retirement Plan, which
accumulates resources for pension benefit payments to qualified employees.
The OPEB Trust Fund accounts for the activities of the OPEB Plan, which accumulates resources
for OPEB benefits.
The Private-Purpose Trust Fund accounts for the receipt of private donations to be used for
student awards.
Agency Funds account for monies held on behalf of student groups.
As a general rule, the effect of interfund activity has been eliminated from the government-wide
financial statements. Exceptions are charges between certain Town functions because elimination of
these charges would distort the direct costs and program revenues reported for the various functions
concerned.
Amounts reported as program revenues include 1) charges to customers or applicants for goods,
services or privileges provided, 2) operating grants and contributions and 3) capital grants and
contributions, including special assessments. Internally dedicated resources are reported as general
revenues rather than as program revenues. Likewise, general revenues include all taxes.
Proprietary funds distinguish operating revenues and expenses from nonoperating items. The
principal operating revenues of the Town’s internal service fund are charges to other funds for dental
insurance and heart and hypertension claims.
For purposes of measuring the net pension and OPEB liability, deferred outflows of resources and
deferred inflows of resources related to pensions and OPEB, and pension and OPEB expense,
information about the fiduciary net position and additions to/deductions from fiduciary net position of
the Town pension plans and OPEB, the Connecticut State Teachers’ Retirement System (TRS), and
the Connecticut State Retiree Health Insurance Plan (“RHIP”) have been determined on the same
basis as they are reported by the Town’s pension and OPEB plans, TRS, and RHIP. For this
purpose, benefit payments (including refunds of employee contributions) are recognized when
due and payable in accordance with benefit terms.
C. Assets, liabilities, deferred outflows/inflows of resources and equity
1.
Cash and investments
a.
Cash
The Town considers cash as cash on hand and demand deposits.
For cash flow purposes the Town considers cash equivalents money market accounts and
short-term investments with original maturities of three months or less from the date of
acquisition.
Exhibit K
Town of Cromwell, Connecticut
37
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
C. Assets, liabilities, deferred outflows/inflows of resources and equity (continued)
b.
Investments
In general, State of Connecticut Statutes allow the Town to invest in obligations of the United
States of America or United States government sponsored corporations, in shares or other
interests in any custodial arrangement, pool or no-load, open-end management type
investment company or investment trust (as defined), in obligations of any State or political
subdivision rated within the top two rating categories of any nationally recognized rating
service, or in obligations of the State of Connecticut or political subdivision rated within the top
three rating categories of any nationally recognized rating service. For the capital nonrecurring
fund, not more than 31% can be invested in equity securities. Investment income is recorded in
the fund in which it was earned.
State Treasurers Investment Fund is an investment pool managed by the State of
Connecticut Office of the State Treasurer. Investments must be made in instruments
authorized by Connecticut General Statutes 3-27c - 3-27e. Investment guidelines are
adopted by the State Treasurer. The fair value of the position in the pool is the same as the
value of the pool shares.
The Town's pension and OPEB funds have adopted a formal investment policy that defines
allowable investments, prohibited investments, prohibited transactions, asset allocation
guidelines, diversification guidelines and fixed income and cash guidelines.
The investment guidelines are as follows:
Target
Allocation
Asset Class
Town
Plan
OPEB
Plan
Equities
47.00%
57.50%
Fixed income
35.00%
18.00%
International equity
13.00%
20.00%
REITs
5.00%
2.50%
Cash
0.00%
2.00%
Total
c 100.00%
c 100.00%
c.
Method used to value investments
Investments for the Town are reported at fair value. Securities traded on a
national or international exchange are valued at the last reported sales price at current
exchange rates.

Exhibit K
Town of Cromwell, Connecticut
38
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
C. Assets, liabilities, deferred outflows/inflows of resources and equity (continued)
Fair value of investments
The Town measures and records its investments using fair value measurement guidelines
established by accounting principles generally accepted in the United States of America
(GAAP). These guidelines recognize a three-tiered fair value hierarchy, as follows:
Level 1: Quoted prices for identical investments in active markets;
Level 2: Quoted prices for identical investments in markets that are not active; and
Level 3: Unobservable inputs.
d.
Risk policies
Interest rate risk – Interest rate risk is the risk that the government will incur losses in fair value
caused by changing interest rates.
Credit risk – Credit risk is the risk that an issuer or other counterparty will not fulfill its specific
obligation even without the entity’s complete failure.
Concentration of credit risk – Concentration of credit risk is the risk attributed to the magnitude
of an entity’s investments in a single issuer. The Town maintains a diversified portfolio to
minimize the risk of loss resulting from an over-concentration of assets in a specific issuer
Custodial credit risk – Custodial credit risk is the risk that, in the event of the failure of the
counterparty, the Town will not be able to recover the value of its investment or collateral
securities that are in the possession of an outside party. The Town does not have a formal
policy with respect to custodial credit risk.
Foreign currency risk – Foreign currency risk is the risk that the value of the investment may
be affected by changes in the rate of exchange. The Town does not have a formal policy with
respect to foreign currency risk.

Exhibit K
Town of Cromwell, Connecticut
39
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
C. Assets, liabilities, deferred outflows/inflows of resources and equity (continued)
2.
Receivables and payables
a.
Interfunds
Activity between funds that are representative of lending/borrowing arrangements outstanding
at the end of the fiscal year are referred to as either "due to/from other funds" (i.e., the current
portion of interfund loans) or "advances to/from other funds" (i.e., the non-current portion
of interfund loans).
b.
Property taxes and other receivables
In the fund financial and government-wide financial statements, all trade and property tax
receivables are shown net of an allowance for uncollectibles. Allowance percentages range
from 2% to 50% of outstanding receivable balances and are calculated based upon prior
collections.
In the fund financial statements, property tax revenues are recognized when they become
available. Only taxes collected during the fiscal year are recorded as revenue.
Property taxes are assessed on property as of October 1. Taxes are billed in the following
July and are due in two installments, July 1, and January 1. Personal property and motor
vehicle taxes are billed in July and are due in one installment, on July 1, and supplemental
motor vehicle taxes are due in full January 1. Liens are effective on the assessment date
and are continued by filing before the end of the year following the due date.
3.
Restricted assets
The restricted assets for the Town are restricted for performance bonds, employee HRA
accounts and endowments. Performance bonds are restricted until the monies are returned to
the vendor after satisfactory completion of contract or the Town calls the bond for
nonperformance. Amounts in employee HRA accounts are restricted for employees. The trust
agreement restricts the expenditure of the investment income only for the designated purpose.
Exhibit K
Town of Cromwell, Connecticut
40
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
C. Assets, liabilities, deferred outflows/inflows of resources and equity (continued)
4.
Capital assets
Capital assets, which include property, plant, equipment, and infrastructure assets are reported in
the government-wide financial statements. Capital assets are defined by the Town as assets with
an initial, individual cost of more than the capitalization threshold for that asset type and an
estimated useful life in excess of one year. Such assets are recorded at historical cost or
estimated historical cost if purchased or constructed. Donated capital assets are recorded at
acquisition value at the date of donation.
The costs of normal maintenance and repairs that do not add to the value of the asset or materially
extend the asset lives are not capitalized. Major outlays for capital assets and improvements are
capitalized as projects are constructed. Property, plant and equipment of the Town are
depreciated using the straight-line method over the following estimated useful lives:
Capitalization
Assets
c Years
Threshold
Buildings and improvements
10-50
$ 5,000
Improvements other than buildings
3-20
5,000
Infrastructure
10-65
5,000
Furniture and equipment
3-20
5,000
5.
Deferred outflows/inflows of resources
In addition to assets, the statement of net position will sometimes report a separate section for
deferred outflows of resources. This separate financial statement element, deferred outflows of
resources, represents a consumption of net position that applies to a future period(s) and so will
not be recognized as an outflow of resources (expense/expenditure) until then.
In addition to liabilities, the statement of net position will sometimes report a separate section for
deferred inflows of resources. This separate financial statement element, deferred inflows of
resources, represents an acquisition of net position that applies to a future period(s) and so will
not be recognized as an inflow of resources (revenue) until that time.
The Town reports deferred outflows and inflows of resources related to pensions and OPEB in
the government-wide statements for differences between expected and actual experience,
changes in assumptions, net difference between projected and actual earnings on plan
investments, changes in proportional share and contributions subsequent to measurement date.
The deferred outflow or inflow related to differences between expected and actual experience,
changes in assumptions, and changes in proportional share will be amortized over the average
remaining service life of all plan members. The deferred outflow or inflow related to the net
difference between projected and actual earnings on plan investments will be amortized over
a five-year period.
Exhibit K
Town of Cromwell, Connecticut
41
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
C. Assets, liabilities, deferred outflows/inflows of resources and equity (continued)
Deferred outflows of resources also include deferred outflows relating to advance refunding of
debt. These amounts are deferred and are amortized over the life of the debt.
For governmental funds, the Town reports unavailable revenue, which arises only under the
modified accrual basis of accounting. Accordingly, unavailable revenue is reported only in the
governmental funds’ balance sheet. The governmental funds report unavailable revenues from
several sources: property taxes (including advance collections, if any), sewer assessment and
use charges. These amounts are recognized as an inflow of resources in the period that the
amounts become available.
6.
Compensated absences
Town employees accumulate vacation and sick leave hours for subsequent use or for payment
upon termination or retirement. Sick leave and vacation leave expenditures are recognized in
the governmental funds in the current year to the extent they are paid during the year or the
vested amount is expected to be paid with available resources. A liability for these amounts has
been recorded in the government-wide financial statements.
7.
Long-term obligations
In the government-wide financial statements, long-term debt and other long-term obligations are
reported as liabilities in the governmental activities' statement of net position. Bond premiums and
discounts are deferred and amortized over the life of the bonds using the effective interest method.
Bonds payable are reported net of the applicable bond premium or discount. Issuance costs,
whether or not withheld from the actual debt proceeds received, are reported as debt service
expenses.
In the fund financial statements, governmental fund types recognize bond premiums and
discounts, as well as bond issuance costs, during the current period. The face amount of debt
issued is reported as other financing sources. Premiums received on debt issuances are reported
as other financing sources while discounts on debt issuances are reported as other financing
uses. Issuance costs, whether or not withheld from the actual debt proceeds received, are
reported as debt service expenditures.
8.
Net position and fund balances
In the government-wide financial statements, net position is classified into the following categories:
Net Investment in Capital Assets
This category presents the net position that reflects capital assets net of only the debt
applicable to the acquisition or construction of these assets. Debt issued for non-capital
purposes, and unspent bond proceeds, are excluded.
Exhibit K
Town of Cromwell, Connecticut
42
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
C. Assets, liabilities, deferred outflows/inflows of resources and equity (continued)
Restricted Net Position
This category presents the net position restricted by external parties (creditors, grantors,
contributors or laws and regulations).
Unrestricted Net Position
This category presents the net position of the Town which is not restricted.
Sometimes the Town will fund outlays for a particular purpose from both restricted (e.g. restricted
bond or grant proceeds) and unrestricted resources. In order to calculate the amounts to report
as restricted net position and unrestricted net position in the government-wide financial
statements, a flow assumption must be made about the order in which the resources are
considered to be applied. It is the Town’s policy to consider restricted net position to have been
depleted before unrestricted net position is applied.
In the fund financial statements, fund balances are classified into the following categories:
Nonspendable
This category presents amounts that cannot be spent either because they are in
nonspendable form or because they are legally or contractually required to be maintained
intact.
Restricted
This category presents amounts that can be spent only for specific purposes because of
enabling legislation or because of constraints that are externally imposed by creditors,
grantors, contributors or the laws or regulations of other governments.
Committed
This category presents amounts that can be used only for specific purposes determined by
a formal action at the highest level of decision-making authority for the Town. Commitments
may be established, modified or rescinded only through resolutions approved by the Town
Council.
Assigned
This category presents amounts that do not meet the criteria to be classified as restricted or
committed but that are intended to be used for specific purposes. Under the Town’s fund
balance policy, the Town Council has by resolution authorized the Finance Director to assign
fund balance. Intent is also expressed by a properly approved purchase order
(encumbrance).
Unassigned
This
category
presents
amounts
that
do
not
meet
the
criteria
above
and
are
available
for
any
purpose. This category is only reported in the general fund for positive amounts and in any
other fund that has a fund balance deficit.

Exhibit K
Town of Cromwell, Connecticut
43
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
C. Assets, liabilities, deferred outflows/inflows of resources and equity (continued)
When an expenditure is incurred for purposes for which both restricted and unrestricted fund
balance is available, the Town considers restricted funds to have been spent first. When an
expenditure is incurred for which committed, assigned or unassigned fund balances are
available, the Town considers amounts to have been spent first out of committed funds, then
assigned funds and finally unassigned funds, as needed, unless Town Council has provided
otherwise in its commitment or assignment actions.
Minimum fund balance policy
The Town Council has adopted a minimum fund balance policy for the General Fund. The policy
establishes the intent to maintain a level of unassigned fund balance of an amount no less than
15% of the Town’s general fund budget and no greater than 17%, with the goal of an amount
equal to 60 days of operating expenditures from the current operating budget. Any excess funds
may be utilized for other municipal fiscal purposes, such as capital improvement needs or to
take advantage of opportunities that would have a positive impact for the Town, including but
not limited to land acquisition or land development rights.
Exception to this policy may be considered for an unassigned fund balance between 12% and
15% if funds are used to support grant opportunities with the expectation of full reimbursement
of the Town’s appropriation within a specified period of time. In accordance with prudent
budgeting practices, the unassigned fund balance will not be used on a routine basis to lower
taxes or to offset normal operating expenditures.
9.
Use of estimates
The preparation of the financial statements in conformity with accounting principles generally
accepted in the United States of America requires management to make estimates and
assumptions that affect the reported amounts of assets and liabilities, deferred outflows and
inflows of resources including disclosures of contingent assets and liabilities and reported
revenues, expenses and expenditures during the fiscal year. Actual results could differ from
those estimates, particularly given the significant social and economic disruptions and
uncertainties associated with the ongoing COVID-19 pandemic and the mitigation responses.
Any such differences are not expected to be material for the year ended June 30, 2020.
10.
Reclassifications
Certain amounts presented in the prior year data have been reclassified in order to be consistent
with the current year's presentation.
II.
Stewardship, compliance and accountability
A.
Basis of budgeting
The Town has legally adopted annual budgets for the General Fund, Sewer Usage, Dog License,
Sewer Assessment and Sidewalk funds. The legal level of control is the department level for the
General Fund and the fund level for all other funds.
The Town uses the budgetary basis of accounting under which purchase orders for contracts or other
commitments are recorded in order to reserve that portion of the applicable appropriation.
Encumbrances are recognized as a valid and proper charge against a budget appropriation in the
year in which the purchase order, contract or other commitment is issued and, accordingly,
encumbrances outstanding at year end are reported in the budgetary statements included as required
supplementary information.
Exhibit K
Town of Cromwell, Connecticut
44
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
II.
Stewardship, compliance and accountability (continued)
B.
Donor-restricted endowments
The Town has received certain endowments for the cemetery. The amounts are reflected in net
position as restricted for endowments. Investment income is approved for disbursement by the
Trustee. At year end, there was no appreciation available for appropriation.
The Town allocates investment income of donor-restricted endowments in accordance with donor
restrictions and Connecticut law, which has adopted the provisions of the Uniform Prudent
Management of Institutional Funds Act ("UPMIFA"). Under UPMIFA, investment income earned on
donor-restricted endowment funds is considered to be unrestricted in the absence of explicit donor
restrictions. Further, in the absence of explicit donor restrictions regarding investment appreciation,
such appreciation is treated the same as the related investment income. Investment losses that
reduce the value of endowment investments below the original principal amount serve to reduce
restricted net position or unrestricted net position, depending upon the applicable donor’s
stipulations regarding the treatment of investment income and appreciation.
C.
Capital projects authorizations
The following is a summary of certain capital projects:
Project
Authorization
Cumulative
Expenditures
Balance
Coles Road
$ 2,716,078
$ 2,479,933
$ 236,145
Library
Expansion
and
Renovation
3,660,000
3,198,864
461,136
North
Road
Extension
Bridge
1,716,000
445,371
1,270,629
Public Works Facility
9,300,000
7,581,082
1,718,918
River Landing
300,377
40,737
259,640
Willowbrook
Road
3,250,000
2,419,215
830,785
Sewer
Rehabilitation
1,595,000
1,510,500
84,500
Industrial
Park
1,445,000
1,403,039
41,961
Total
$
23,982,455
$ 19,078,741
$ 4,903,714
III.
Detailed notes
A.
Cash and investments
1.
Deposits – custodial credit risk
At year end, the Town’s bank balance was $21,519,494 and was exposed to custodial credit risk
as follows:
Uninsured
and
uncollateralized
$
12,941,380
Uninsured
and
collateral
held
by
the
pledging
bank’s
trust
department,
not
in
the
Town’s
name
5,590,114
Total
amount
subject
to
custodial
credit
risk
$ 18,531,494
Financial instruments that potentially subject the Town to significant concentrations of credit risk
consist primarily of cash. From time to time, the Town's cash account balances exceeded the
Federal Deposit Insurance Corporation limit. The Town reduces its credit risk by maintaining its
cash deposits with major financial institutions and monitoring their credit ratings.
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
A. Cash and investments
(continued)
45
2.
Investments
a.
The Town's investments consisted of the following types and maturities. Specific identification
was used to determine maturities:
Investment
Maturities
(In
Years)
Fair
Less
1-5
5-10
Over
10
Type
of
Investment
Value
N/A
Than
1
Years
Years
Years
Bank
money
market
$
15,888,099
$ -
$
15,888,099
$ -
$ -
$ -
Common
stock
13,288,393
13,288,393
-
-
-
-
Common
stock
-
international
4,702,067
4,702,067
-
-
-
-
Pooled
fixed
income
9,491,333
-
9,491,333
-
-
-
U.S.
government
obligations
4,930,999
-
1,105,548
2,796,496
943,133
85,823
Corporate
bonds
2,472,562
-
99,601
873,803
1,311,917
187,240
Certificates
of
deposit
1,488,000
-
1,488,000
-
-
-
Real
estate
investment
trusts
770,360
770,360
-
-
-
-
Money
market
mutual
funds
593,627
-
593,627
-
-
-
Total
$
53,625,440
$
18,760,820
$
28,666,208
$
3,670,298
$
2,255,050
$
273,063
b.
The Town had the following recurring fair value measurements:
Quoted Market Significant
Prices in Active Observable
Markets Inputs
Amount
Level
1
Level
2
Investments
by
fair
value
level
Common stock
$ 13,288,393
$ 13,288,393
$ -
Common stock - international
4,702,067
4,702,067
-
U.S.
government
obligations
4,930,999
-
4,930,999
Corporate
bonds
2,472,562
-
2,472,562
Real estate investment trusts
770,360
770,360
-
Money
market
mutual
fund
593,627
593,627
-
Total
investments
by
fair
value
level
26,758,008
19,354,447
7,403,561
Other investments
Bank
money
market
15,888,099
Pooled
fixed
income
9,491,333
Certificates of deposit
1,488,000
Total
other
investments
26,867,432
Total
investments
$ 53,625,440
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
A. Cash and investments
(continued)
46
Level 1: Quoted prices for identical investments in active markets;
Level 2: Observable inputs other than quoted prices for identical securities in markets that are not
active. The fair value was determined based on quoted prices in less active, dealer or
broker markets. Fair values are primarily obtained from third party pricing services for
identical or comparable assets.
c.
The Town's investments subject to credit risk had average ratings by Standard & Poor's as
follows:
Ratings
Type
of
Investment
AAA AA A BBB BB B Totals
U.S.
government
obligations
$
4,930,999
$ -
$ -
$ -
$ -
$ -
$
4,930,999
Corporate
bonds
335,013
415,664
661,412
535,640
369,254
155,579
2,472,562
Total
$
5,266,012
$
415,664
$
661,412
$
535,640
$
369,254
$
155,579
$
7,403,561
d.
Certain investments are covered by the Securities Investor Protection Corporation ("SIPC")
up to $500,000, including $250,000 of cash from sale or for purchase of investments, but not
cash held solely for the purpose of earning interest. SIPC protects securities such as notes,
stocks, debentures, certificates of deposit and money funds.
The following Town investments are held by the counterparty's trust department or agent but
not in the Town's name and, therefore, are subject to custodial credit risk.
Amount
Total
Less
Insured
Amounts
Subject to
Custodial
Credit Risk
Common stock
$ 13,288,393
$ 500,000
$ 12,788,393
Common stock - international
4,702,067
-
4,702,067
U.S. government obligations
4,930,999
-
4,930,999
Corporate bonds
2,472,562
-
2,472,562
Total
$ 25,394,021
$ 500,000
$ 24,894,021
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
47
B.
Receivables
Receivable balances have been disaggregated by type and presented separately in the financial
statements. Only receivables with allowances for uncollectible accounts, including the applicable
allowances for uncollectible accounts, are presented below.
Property Taxes
Taxes
Interest and
Lien Fees
Total
Current portion
$ 291,898
$ 211,259
$ 503,157
Long-term portion
$ 595,599
$ 148,729
$ 744,328
Less allowance for uncollectible
(325,000)
(180,000)
(505,000)
Net long-term portion
$ 270,599
$ (31,271)
$ 239,328
Totals
$ 562,497
$ 179,988
$ 742,485
Sewer assessments and use charges
Assessments
and
Use charges
Interest
and
Lien Fees
Total
Current portion
$ 428,055
$ 19,175
$ 447,230
Long-term portion
$ 93,963
$ 19,175
$ 113,138
Less allowance for uncollectible
(11,000)
(1,000)
(12,000)
Net long-term portion
$ 82,963
$ 18,175
$ 101,138
Totals
$ 511,018
$ 37,350
$ 548,368
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
48
C.
Interfund accounts
1.
Interfund payables and receivables
A summary of interfund balances is as follows:
Corresponding
Fund Due
From Due
To
General Fund Educational grants
$ -
Other governmental funds
$ 85,384
Educational grants General Fund
85,384 -
Total
$ 85,384
$ 85,384
All interfund balances resulted from the time lag between the dates payments occurred between
funds for interfund goods, payroll and services provided or in instances where certain funds do
not have a cash account.
2.
Interfund transfers
A summary of interfund transfers for the fiscal year is as follows:
Corresponding Transfers Transfers
Fund In Out
General Fund Capital Projects $ 316,943 $ 2,814,000
Capital Projects General Fund 2,814,000 316,943
Total $ 3,130,943 $ 3,130,943
Transfers are used to move budgeted appropriations from the general fund for funding of capital
projects and various programs and activities in other funds.
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
49
D.
Capital assets
Capital asset activity for the fiscal year was as follows:
Balance
c
July
1,
2019
c Increases
Decreases
Balance
June 30, 2020
Capital assets, not being depreciated:
Land
$ 8,683,782
$ 111,493
$ -
$ 8,795,275
Construction in progress
7,678,495
6,804,520
88,150
14,394,865
Total capital assets, not being depreciated
16,362,277
6,916,013
88,150
23,190,140
Capital assets, being depreciated:
Buildings and improvements
77,643,730
-
-
77,643,730
Improvements other than buildings
2,591,888
-
-
2,591,888
Furniture
and
equipment
10,310,976
258,076
-
10,569,052
Infrastructure
108,379,642
583,812
-
108,963,454
Total capital assets, being depreciated
198,926,236
841,888
-
c c 199,768,124
Total capital assets
215,288,513
7,757,901
88,150
c c 222,958,264
Less accumulated depreciation for:
Buildings and improvements
30,815,400
1,816,818
-
32,632,218
Improvements other than buildings
964,511
30,222
-
994,733
Furniture
and
equipment
7,544,162
560,910
-
8,105,072
Infrastructure
59,876,290
2,088,527
-
61,964,817
Total accumulated depreciation
99,200,363
4,496,477
-
c c 103,696,840
Total capital assets being depreciated, net
99,725,873
(3,654,589)
-
96,071,284
Governmental activities capital assets, net
$ 116,088,150
$ 3,261,424
$ 88,150
$ 119,261,424
Depreciation expense was charged to functions/programs of the Town as follows:
General government
$ 156,985
Public safety
243,374
Public works
2,511,844
Culture and recreation
79,995
Human services
7,353
Education
1,496,926
Total depreciation expense
$ 4,496,477
E. Construction commitments
The Town has the following construction commitments:
Coles
road
reconstruction
$ 1,357,283
WPCA
facility
3,558,270
Total
$ 4,915,553
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
50
F. Changes in long-term obligations
1. Summary of changes
Original
Date
of
Date
of
Interest
Balance
July
1,
Balance
June
30,
Current
Long-term
Description Amount
Issue
Maturity
Rate
2019
Additions
Deductions
2020
Portion
Portion
Bonds:
(as
restated)
General
purpose:
Improvement $
3,787,000
4/18/2013
2023
0.52%-2.15%
$
1,727,187
$ -
$
437,187
$
1,290,000
$ 437,187
$ 852,813
Refunding 6,540,000
12/28/2017
2029
1.26%-2.30%
3,487,000
-
532,000
2,955,000
532,000
2,423,000
Improvement
5,326,800
10/8/2016
2026
3.00%-4.00%
5,326,800
-
242,831
5,083,969
218,250
4,865,719
Total
general
purpose
10,540,987
-
1,212,018
9,328,969
1,187,437
8,141,532
Schools:
Improvement
598,000
4/18/2013
2023
0.52%-2.15%
272,813
-
62,813
210,000
62,813
147,187
Refunding 9,690,000
4/18/2013
2023
0.37%-2.15%
4,000,000
-
1,000,000
3,000,000
1,000,000
2,000,000
Refunding 2,656,250
4/18/2015
2021
1.50%
980,000
-
500,000
480,000
480,000
-
School 193,200
10/8/2016
2036
3.00%-4.00%
193,200
-
7,169
186,031
6,750
179,281
Refunding 6,540,000
12/28/2017
2029
1.26%-2.30%
1,508,000
-
228,000
1,280,000
228,000
1,052,000
Total
schools
6,954,013
-
1,797,982
5,156,031
1,777,563
3,378,468
Sewer:
Refunding 6,940,000
5/30/2019
2039
1.37%-3.02%
6,940,000
-
-
6,940,000
-
6,940,000
Total
bonds
24,435,000
-
3,010,000
21,425,000
2,965,000
18,460,000
Notes:
Equipment
financing
notes
646,461
-
310,800
335,661
121,206
214,455
Total
bonds
and
notes
25,081,461
-
3,320,800
21,760,661
3,086,206
18,674,455
Premium
3,037,036
-
471,432
2,565,604
-
2,565,604
Total
bonds,
notes
and
related
liabilities
28,118,497
-
3,792,232
24,326,265
3,086,206
21,240,059
Compensated
absences
1,542,268
738,235
714,855
1,565,648
313,130
1,252,518
Net
pension
liability
6,316,152
5,594,779
2,613,199
9,297,732
-
9,297,732
Net
OPEB
liability
2,686,570
769,370
850,117
2,605,823
-
2,605,823
Heart
and
hypertension
claims
payable
126,998
9,999
183
136,814
95,770
41,044
Total
long-term
obligations
$
38,790,485
$
7,112,383
$
7,970,586
$
37,932,282
$
3,495,106
$
34,437,176
All long-term liabilities are generally liquidated by the general fund except for claims payable which is
liquidated from the internal service fund.
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
F. Changes in long-term obligations
(continued)
51
2.
The following is a summary of principal and interest amounts of bond and note maturities:
Fiscal Year
c Ended June 30,
Bonds
Principal
Notes
c Principal
Total
Interest
2021
$ 2,965,000
$ 212,346
$ 600,626
2022
2,765,000
123,315
772,627
2023
2,785,000
-
644,499
2024
930,000
-
530,575
2025
960,000
-
488,750
2026
965,000
-
444,300
2027
900,000
-
401,000
2028
1,015,000
-
356,500
2029
970,000
-
309,100
2030
710,000
-
263,950
2031
725,000
-
231,800
2032
740,000
-
199,000
2033
760,000
-
165,300
2034
775,000
-
138,100
2035
795,000
-
107,100
2036
810,000
-
79,950
2037
825,000
-
52,350
2038
505,000
-
30,900
2039
525,000
-
15,750
Total $ 21,425,000 $ 335,661 $ 5,832,177
3.
Assets pledged as collateral
The Town’s outstanding equipment financing notes of $335,661 are secured with collateral of the
equipment purchased.
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
F. Changes in long-term obligations
(continued)
52
4.
Statutory debt limitations
The Town's indebtedness does not exceed the legal debt limitations as required by
Connecticut General Statutes as reflected in the following schedule:
Category
Debit
Limit Net
Indebtedness
Balance
General
purpose
$ 106,041,335
$ 12,902,540
$ 93,138,795
Schools
212,082,669
5,156,031
206,926,638
Sewers
176,735,558
6,940,000
169,795,558
Urban
renewal
153,170,817
-
153,170,817
Pension
deficit
141,388,446
-
141,388,446
The total overall statutory debt limit for the Town is equal to seven times annual receipts
from taxation, $329,906,374.
The indebtedness reflected above includes bonds outstanding in addition to the amount of bonds
authorized and unissued against which bond anticipation notes are issued and outstanding.
5.
Overlapping debt
A summary of overlapping debt is presented below:
Debt
outstanding
Total
Overlapping c
Cromwell
Fire
District
$ 5,887,789
$ 3,573,571
Mattabassett
District
57,112,706
4,917,404
Total
$ 63,000,495
$ 8,490,975
6.
Authorized/unissued bonds
The amount of authorized, unissued bonds are as follows:
Authorized
but Unissued
Willowbrook Road
$ 3,250,000
Public Works Facility
2,360,000
North Road Extension Bridge
1,716,000
Coles Road Reconstruction
225,000
Total
$ 7,551,000
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
F. Changes in long-term obligations
(continued)
53
7.
Prior year defeasance of debt
In prior years, the Town defeased certain bonds by placing the proceeds of new bonds in an
irrevocable trust to provide for all future debt service payments on the old bonds. Accordingly, the
trust account assets and the liability for the defeased bonds are not included in the Town’s financial
statements. At year end $5,720,000 of bonds outstanding are considered defeased.
G. Fund balances and restricted net position
Fund balances are composed of the following:
Other
Fund
Balance
Sewer Capital Governmental
Component
General
Usage
Projects
Funds
Total
Nonspendable:
Cemetery
maintenance
Restricted:
$ -
$ -
$ -
$
6,237
$ 6,237
The amount of restricted net position, which was restricted by enabling legislation, totaled $3,076,744.
Sewer
operations
- 2,292,883 -
-
2,292,883
Sewer
assessment
- - 611,987
-
611,987
Culture
and
recreation
programs
- - -
226,343
226,343
Human
services
programs
- - -
12,966
12,966
Cafeteria
operations
- - -
171,874
171,874
Cemetery
maintenance
- - -
4,310
4,310
Total
restricted
- 2,292,883 611,987
415,493
3,320,363
Committed:
Public
safety
programs
- - -
429,165
429,165
Public
works
- - 2,795,027
13,104
2,808,131
Culture
and
recreation
programs
- - -
245,473
245,473
Human
services
programs
- - -
744
744
Education
programs
199,866 - -
462
200,328
Capital
projects
- - 3,131,861
-
3,131,861
Total
committed
199,866 - 5,926,888
688,948
6,815,702
Assigned:
Subsequent
years
budget
363,300
- - -
363,300
Contingency
223,177
- - -
223,177
Debt
service
-
-
-
285,650
285,650
Total
assigned
586,477
-
-
285,650
872,127
Unassigned
c 13,892,356
-
-
-
c
13,892,356
Total
$
14,678,699
$ 2,292,883
$
6,538,875
$
1,396,328
$
24,906,785

Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
54
IV.
Other information
A.
Risk management
The Town is exposed to various risks of loss including torts, theft of, damage to and destruction of
assets; errors or omissions; injuries to employees and natural disasters. Generally, the Town obtains
commercial insurance for these risks, but has chosen to retain limited risks employee dental claims.
The Town contracts with outside organizations to pay claims and provide administrative services.
Additionally, insurance coverage has been purchased to limit the Town’s liability for worker’s
compensation, general liability and medical claims. Settled claims have not exceeded commercial
coverage in any of the past three years, and there has not been any significant reductions in insurance
coverage from amounts held in prior years.
The Town is a self-insured provider of claims under C.G.S. 7-433c, the Heart and Hypertension Act.
The liability is adjusted annually to reflect cost of living increases. The plan is funded by budget
appropriations.
The Town is a member in Connecticut Interlocal Risk Management Association (“CIRMA”). CIRMA is a
public entity risk pool established under the provisions of the Connecticut General Statutes Section 7-
479a et. seq. The Town is liable only for contributions to the pool. Members do not retain the risk of
loss, as they have transferred the risk by purchasing pool coverage with no deductible retention. A
separate agreement limits the member’s obligation to pay indemnification obligations and expenses
should CIRMA be unable to do so.
The Town is a member of CIRMA's Liability-Automobile-Property Pool a risk sharing pool. The Town
paid CIRMA for provisions of general liability, automobile liability, employee benefit liability, law
enforcement liability, public officials and property coverage. The premium is subject to these
coverages and claims and expense payments falling within the deductible amounts are the
responsibility of the Town. CIRMA's Liability-Automobile-Property Pool retains $1,000,000 per
occurrence for each line of liability coverage.
The Town is also a member of CIRMA's Workers' Compensation Pool, a risk sharing pool. The
Workers' Compensation Pool provides statutory benefits pursuant to the provisions of the Connecticut
Workers' Compensation Act. The coverage is subject to an insured loss retrospective rating plan and
losses incurred in the coverage period will be evaluated at 18, 30 and 42 months after the effective
date of coverage. The premium is subject to a payroll audit at the close of the coverage period.
CIRMA's Workers' Compensation Pool retains $1,000,000 per occurrence and purchases reinsurance
about that amount to the limit of liability of $10,000,000 per occurrence.
The Town utilizes a risk management fund (the Internal Service Fund) to account for and finance its
uninsured risks of loss for dental claims and heart and hypertension. The fund records all claim
expenditures and liabilities when it is probable that a loss has occurred and the amount of that loss
can be reasonably estimated. All Town departments and agencies are charged premiums by the
Internal Service Fund, which are included in department and agency expenditures, to cover the
estimated cost of claims payment based on historical cost estimates of the amounts needed to pay
prior and current year claims. Claims liabilities include an estimate of claims incurred but not reported
and are the Town's best estimate based on available information.
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
55
A.
Risk management (continued)
The Town records all claim expenditures and liabilities when it is probable that a loss has
occurred and the amount of that loss can be reasonably estimated in the government-wide
statements. The claims liability reported is based upon accounting principles which require that a
liability for estimated claims incurred but not reported be accrued. The amount of claim accrual is
based on the ultimate costs of settling the claim, which include past experience data, inflation and
other future economic and social factors and incremental claim adjustment expenses, net of
estimated subrogation recoveries. The claim accrual does not include other allocated or
unallocated claims adjustment expenses.
Current
year
Claims
Payable
July
1
Claims
and
Changes
in
Estimates
Claims
Paid
Claims
Payable
June
30
Current
Portion
Long-Term
Portion
Heart
and
Hypertension*
2019-2020
$ 126,998
$ 9,999
$ 183
$ 136,814
$ 95,770
$ 41,044
Dental
insurance
2018-2019
12,000
331,739
328,739
15,000
15,000
-
2019-2020
15,000
244,795
250,795
9,000
9,000
-
Totals
2018-2019
$ 12,000
$ 331,739
$ 328,739
$ 15,000
$ 15,000
$ -
2019-2020
$ 141,998
$ 254,794
$ 250,978
$ 145,814
$ 104,770
$ 41,044
*Reported as an internal service fund for the first time for this fiscal year.
B.
Commitments and litigation
Amounts received or receivable from Federal and State grantor agencies are subject to audit and
adjustment by grantor agencies. Any disallowed claims, including amounts already collected, may
constitute a liability of the applicable funds. The amount, if any, of expenditures which may be
disallowed by the grantor cannot be determined at this time, although the Town expects such
amounts, if any, to be immaterial.
The Town is a defendant in various lawsuits and the outcome of these lawsuits is not presently
determinable. In the opinion of the Town attorney, the resolution of these matters will not have a
material adverse effect on the financial condition of the Town.

Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
56
C.
Jointly governed
organizations The
Mattabassett District
The Mattabassett District (the “District”) is a quasi-municipal district established in accordance with
State Statutes to provide sewer treatment services for the constituent Towns of Berlin and Cromwell
and the constituent Cities of New Britain and Middletown and contractually to the Metropolitan
District and the Town of Farmington. As a result of the 2010 census data released in February 2011
and the June 2011 amendment to the state statutes creating the District, the Mattabassett Board of
Directors representation is as follows: New Britain – five members, Middletown – four members,
Berlin – three members and Cromwell – three members. The Town pays an annual assessment
to the District. The annual assessment includes funds for the payment of the Town’s portion of the
District’s debt service. The District’s financial statements can be obtained from
www.mattabassettdistrict.org/audits.
D.
Contingencies
Coronavirus
In March 2020, the United States declared the outbreak of Coronavirus a national emergency.
Similarly, the Governor of the State of Connecticut declared a state of emergency and has since
issued over 70 executive orders regarding the pandemic. One of the most significant executive
orders required local governments to offer taxpayers/rate payers one or both of the following
programs: interest rate reduction program and payment deferral program. The interest rate
reduction program reduced the interest rate charged on delinquent taxes/user fees from 18% to 3%
for the period April 1, 2020 through October 1, 2020. The payment deferral program also was
effective April 1, 2020 for local governments with quarterly payments and July 1, 2020 for those with
semi-annual payments. This program allowed taxpayers/rate payers to defer payment of amounts
due without incurring any penalty interest until October 1, 2020. The Town implemented the
payment deferral program. The impact of this program on property tax and user fee revenues and
delinquent interest collections was not significant during this period.
The state of emergency has had a negative impact on the Town’s economically sensitive revenues
such as park and recreation program fees, interest earnings and certain other charges for
services for the last quarter of the fiscal year and the impact continues into the 2021 fiscal year.
On the expenditure side, expenditures for health and safety measures, including additional
personnel costs, technology and supplies are expected to increase and may exceed adopted
budgets. There continues to be uncertainty related to the duration, possible reemergence and
future severity of the pandemic, as well as to what actions may be taken by the Federal
government, the State of Connecticut and health care authorities to contain or mitigate its effects.
This includes the nature and extent of any financial support.
The Town is continuously monitoring its financial condition and will take proactive measures as
necessary to maintain operations and meet its obligations. Given this level of uncertainty,
management cannot reasonably estimate the complete impact on the Town’s future financial
position at this time.
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
57
V.
Pensions and other post-employment benefit plans
A.
Town pension plans
1.
Plan description
a.
Plan administration
The Town of Cromwell is the administrator of a single-employer public employee retirement
system plan established and administered by the Town to provide benefits that covers the
employees of the Town, except full-time policemen (covered by the State of Connecticut
Municipal Employees Retirement Fund) and certified teachers (covered by the State of
Connecticut Teachers’ Retirement System). The plan is considered to be part of the Town
of Cromwell’s financial reporting entity and is included in the Town’s financial reports as a
pension trust fund. The Plan was established by Town Meeting. The plan does not issue a
standalone report. Benefits and refunds of post-employment defined plans are recognized
when due and payable in accordance with the terms of the Plan. The Town’s General Fund
contributes an amount as recommended by their Actuary to fund the net pension obligations.
Under the plan, all full-time employees are eligible except for police officers and teachers.
Employees are 100 percent vested after ten years of service. Normal retirement age is sixty-
two or five years of participation in the plan, whichever is later. If an employee leaves
covered employment or dies before 10 years of service, accumulated employee
contributions and related investment earnings are refunded. Benefits and contributions are
established by the Town, via negotiated contracts, and may be amended only by the
approval of the Town Council, and as agreed upon with the appropriate bargaining unit.
The general administration and management of the Town pension plan and the
responsibility for carrying out the provision of the plan shall be placed in the Town Retirement
Board. This board shall be made up of five members consisting of the following officials of
the Town of Cromwell: Mayor, Town Manager, Town Finance Director/Town Treasurer; the
Business Manager from the Board of Education; and the Executive Director of the Cromwell
Fire District.
b.
Plan membership
As of July 1, 2019 for the Town, the memberships in the Plans are comprised of the following:
Retirees and beneficiaries receiving benefits
91
Inactive with vested benefits
70
Active plan members
180
Total
341
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
A. Town pension plans
(continued)
58
Normal retirement service
requirement
Normal retirement benefits
Early retirement service
requirement
Early retirement benefits
Vesting
62 or 5 years of participation in the plan, whichever is later
1.00-1.50% of average annual compensation during the
highest 3 consecutive years of service multiplied by years of
credited service
Age 55 plus 15 years of credited service
Normal retirement benefit formula, subject to aucuarial
reduction
10 years service
2.
Benefit provisions
3.
Contributions
Each participant is required to contribute 2.50% of their salary to the plan.
4.
Investments
a.
Investment policy
The pension plans' policy in regard to the allocation of invested assets is established and
may be amended by the Retirement Board by a majority vote of its members. It is the policy
of the Town's Retirement Board to pursue an investment strategy that reduces risk through
the prudent diversification of the portfolio across a broad selection of distinct asset classes.
The following is the Board’s adopted asset allocation policy for the plans:
Target
Asset Class
c
Allocation
U.S. large cap core
30.00%
U.S mid cap core
11.00%
U.S small cap core
6.00%
International equity
11.00%
International emerging market equity
2.00%
REITs
5.00%
Fixed income
35.00%
Total
100.00%
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
A. Town pension plans
(continued)
59
b.
Concentrations
There were no investments in any one organization that represented 5% or more of the
pension plan’s net position.
c.
Rate of return
The long-term expected rate of return on pension plan investments was determined using a
building-block method in which best-estimate ranges of expected future real rates of return
(expected returns, net of pension plan investment expense and inflation) are developed for
each major asset class. These ranges are combined to produce the long-term expected
rate of return by weighting the expected future real rates of return by the target asset
allocation percentage and by adding expected inflation. Best estimates of arithmetic real
rates of return for each major asset class included in the pension plan’s target asset
allocation (see the discussion of the pension plan’s investment policy) are as follows:
Asset Class
U.S. large cap core
5.01%
U.S mid cap core
6.62%
U.S small cap core
7.70%
International equity
5.11%
International emerging market equity
9.78%
REITs
4.09%
Fixed income
1.29%
Long-term expected nominal rate of return was 6.57%.
d.
Annual money-weighted rate of return
The annual money-weighted rate of return on pension plan investments, net of pension plan
investment expense, was 5.29%.
The money-weighted rate of return expresses investment performance, net of
investment expense, adjusted for the changing amounts actually invested.
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
A. Town pension plans
(continued)
60
Actuarial valuation date
Actuarial cost method
Amortization method
Asset valuation method
Investment rate of return
Inflation
Salary increases
Mortality rates
July 1, 2019
Entry age normal
Level percentage
5 year smoothing
6.90%
2.60%
3.60%
Pub - 2010 Public
Retirement Plans amount-
weighted mortality tables
(with separate tables for
general employees, public
safety and teachers),
projected to the valuation
date with scale MP-2019
5.
Net pension liability
The components of the net pension liability were as follows:
Total
pension
liability
$ 30,591,016
Plan
fiduciary
net
position
25,832,889
Net
pension
liability
Plan
fiduciary
net
position
as
a
percentage
$ 4,758,127
of
the
total
pension
liability
84.45%
6.
Actuarial methods and significant assumptions
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
A. Town pension plans
(continued)
61
7.
Changes from prior year
a.
Changes in assumptions
•
The inflation assumption was increased from 2.50% to 2.60%, this impacted both
the salary scale and payroll growth assumptions.
•
Projected salary increases were increased from 3.50% to 3.60%.
•
The Mortality assumption was updated from RP-2014 with scale MP-2018 to Pub-
2010 with scale MP-2019. The change in mortality assumptions increased liabilities by
2.8%.
b.
Changes in benefit terms
There were no changes in benefit terms.
8.
Discount rate
The discount rate used to measure the total pension liability was 6.90%.
The projection of cash flows used to determine the discount rate assumed that plan member
contributions will be made at the current contribution rate and that Town contributions will be
made at rates equal to the difference between actuarially determined contribution rates and the
member rate. Based on those assumptions, the pension plan’s projected fiduciary net position
will be sufficient to cover projected benefit payments and administrative expenses indefinitely.
Therefore, the long-term expected rate of return on pension plan investments was used to
discount plan liabilities.
9.
Changes in the net pension liability
The Town’s net pension liability was measured at June 30, 2020, and the total pension liability
used to calculate the net pension liability was determined by an actuarial valuation as of July 1,
2019. The changes in net pension liability were as follows:
Increase
(Decrease)
Total
Pension Plan
Fiduciary
Net Net
Pension
Liability Position Liability
Town (a) (b)
(a)
-
(b)
Balance
at
July
1,
2019
$
27,706,206
$ 24,918,808
$ 2,787,398
Service
cost
844,931
-
844,931
Interest
1,869,027
-
1,869,027
Differences
between
expected
and
actual
experience
729,657
-
729,657
Changes
in
assumptions
787,826
-
787,826
Contributions
-
employer
-
704,628
(704,628)
Contributions
-
member
-
262,761
(262,761)
Net
investment
income
-
1,293,323
(1,293,323)
Benefit
payments,
including
refunds
of
member
contributions
(1,346,631)
(1,346,631)
-
Net
change
2,884,810
914,081
1,970,729
Balance
at
June
30,
2020
$
30,591,016
$ 25,832,889
$
4,758,127
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
A. Town pension plans
(continued)
62
10.
Sensitivity of the net pension liability to changes in the discount rate
The following presents the net pension liability, calculated using the discount rate as well as
what the Town’s net pension liability would be if it were calculated using a discount rate that is
1-percentage point lower or 1-percentage point higher than the current rate:
1% Current 1%
Decrease
Discount
Rate
Increase
Net
pension
liability
$ 8,120,083
$ 4,758,127
$ 1,891,671
11.
Pension expense and deferred outflows and inflows of resources
The Town recognized pension expense of $1,180,318 for the plan.
The Town reported deferred outflows of resources and deferred inflows of resources related to
pensions from the following sources:
Deferred
Deferred
Outflows
of
Inflows
of
Description
of
Outflows/Inflows
Resources
c Resources
Net
Differences
between
expected
and
actual
experience
$ 771,912
$
(1,202,650)
$ (430,738)
Changes
in
assumptions
1,183,535
(237,127)
946,408
Net
difference
between
projected
and
actual
earnings
on
pension
plan
investments
418,107
-
418,107
Total
$ 2,373,554
$
(1,439,777)
$ 933,777
Actual investment earnings below (or above) projected earnings are amortized over 5 years.
Changes of assumptions and experience losses (gains) are amortized over the average
remaining service period of actives and inactive employees, which was 6.4 years.
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
A. Town pension plans
(continued)
63
The amounts reported as deferred outflows and inflows of resources related to pensions will be
recognized in pension expense as follows:
Year Ending
June 30,
2021
$ 69,228
2022
121,639
2023
153,366
2024
281,293
2025
213,410
Thereafter
94,841
Total
$ 933,777
B.
Connecticut municipal employees’ retirement system
1.
Plan description
The Connecticut Municipal Employees’ Retirement System (“MERS”) is the public pension plan
offered by the State of Connecticut for municipal employees in participating municipalities.
MERS is a cost-sharing defined benefit pension plan administered by the Connecticut State
Retirement Commission.
Municipalities may designate which departments (including elected officials if so specified) are to
be covered under the Connecticut Municipal Employees’ Retirement System (“MERS”). This
designation may be the result of collective bargaining. Only employees covered under the State
Teachers’ Retirement System may not be included. There are no minimum age or service
requirements. Membership is mandatory for all regular full time employees of participating
departments except Police and Fire hired after age 60.
The plan has 4 sub plans as follows:
•
General employees with social security
•
General employees without social security
•
Policemen and firemen with social security
•
Policemen and firemen without social security
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
B. Connecticut municipal employees’ retirement system (continued)
64
2.
Benefit provisions
Normal retirement
General employees
Age 55 with 5 years of continuous service, or 15 years of active aggregate
service or 25 years of aggregate service
Police and firemen
Compulsory retirement age is age 65
Benefit calculation
The maximum benefit is 100% of average final compensation and the
minimum benefit is $1,000 annually. Both the minimum and the maximum
include workers’ compensation and social security benefits
With social security
1.50% of the average final compensation not in excess of the year’s
breakpoint plus 2.00% of average final compensation in excess of the
year’s breakpoint, times years of service. If any member covered by social
security retires before age 62, the benefit until age 62 is reached or a
social security disability award is received, is computed as if the member
is not under social security
Without social security
2.00% of average final compensation, times years of service
Final average
compensation
Average of the three highest paid years of service
Early retirement
5 years of continuous service or 15 years of active aggregate service
Early retirement
amount
Calculated on the basis of average final compensation and service to date
of termination. Deferral to normal retirement age, or an actuarially
reduced allowance may begin at the time of separation
Service connected
disability amount
Calculated based on compensation and service to the date of the disability
with a minimum benefit (including workers’ compensation benefits) of 50%
of compensation at the time of disability
Non-service connected
disability service
requirement
10 years of service
Non-service connected
disability service
amount
Calculated based on compensation and service to the date of the disability
Pre-retirement death
benefit amount
Lump-sum return of contributions with interest of if vested and married,
the surviving spouse will receive a lifetime benefit
Cost of living increases
2.50% - 6.00% depending on retirement date and increase in CPI
3.
Contributions
Employer
Participating municipalities make annual contributions consisting of a normal cost contribution, a
contribution for the amortization of the net unfunded accrued liability and a prior service
amortization payment which covers the liabilities of the system not met by member contributions.
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
B. Connecticut municipal employees’ retirement system (continued)
65
Employees
For employees not covered by social security, each person is required to contribute 5.00% of
compensation.
For employees covered by social security, each person is required to contribute 2.25% of
compensation up to the social security taxable wage base plus 5% of compensation, if any, in
excess of such base.
4.
Pension liabilities, pension expense, and deferred outflows of resources and
deferred inflows of resources related to pensions
The Town reported $4,539,605 for its proportionate share of the net pension liability. The net
pension liability was measured as of June 30, 2019, and the total pension liability used to
calculate the net pension liability was determined by an actuarial valuation as of June 30, 2019.
The Town’s proportionate share of the net pension liability was based upon the Town’s 2019
actuarial (expected) payroll relative to the payroll of all the participating employers as of that
date. The Town’s proportional share was 6.230267% for the police and fire with social security
sub plan. There was no change in the percentage for the general employees sub plan or the
police and fire sub plan from the prior year.
Subsequent to the measurement date, there were no changes in benefit terms or any expected
changes that will have an impact on the measurement of net pension liability.
For the fiscal year, the Town recognized pension expense of $1,370,588. The Town reported
deferred outflows of resources and deferred inflows of resources related to pensions from the
following sources:
Deferred
Deferred
Net
Deferred
Description
of
Outflows/Inflows
Outflows
of
Resources
Inflows
of
Resources
Outflows
and
Inflows
Net
difference
between
projected
and
actual
earnings
on
pension
plan
investments
$ 209,444
$ -
$ 209,444
Change
in
assumptions
1,254,189
-
1,254,189
Change
in
proportional
share
280,086
(195,152)
84,934
Difference
between
expected
and
actual
experience
55,715
(369,361)
(313,646)
Contributions
subsequent
to
the
measurement
date
514,845
-
514,845
Total
$
2,314,279
$
(564,513)
1,749,766
Contributions
subsequent
to
the
measurement
date
to
be
recognized
as
a
reduction
of
the
net
pension
liability
in
the
subsequent
year
(514,845)
Net
amortized
amount
of
deferred
inflows
and
outflows
$
1,234,921
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
B. Connecticut municipal employees’ retirement system (continued)
66
Investment rate of return
Inflation
Salary increases
Cost of living adjustments
Mortality rates
7.00%
2.50%
3.50-10.00%, including inflation
Future cost-of-living adjustments for members who
retire on or after January 1, 2002 are 60% of the
annual increase in the CPI up to 6.00%. The minimum
annual COLA is 2.50%, the maximum is 6.00%.
Mortality rates were based on RP-2014 Combined
Mortality Table adjusted to 2006 and projected to 2015
with Scale MP-2017 and projected to 2022 with Scale
BB for General Employees and the RP-2014 Blue
Collar Mortality Table adjusted to 2006 and projected to
2015 with Scale MP-2017 and projected to 2022 with
Scale BB for Police and Fire. For disabled retirees,
the RP-2014 Disabled Mortality Table projected with
Scale BB to 2020 was used.
Other amounts reported as deferred outflows (inflows) of resources related to pensions will be
recognized in pension expense as follows:
Year Ending
June 30,
2022
$ 497,584
2023
276,914
2024
375,919
2025
84,504
Total
$ 1,234,921
5.
Actuarial assumptions
The total pension liability was determined by an actuarial valuation as of June 30, 2019,
using the following actuarial assumptions, applied to all periods included in the measurement:
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
B. Connecticut municipal employees’ retirement system (continued)
67
The actuarial assumptions used in the June 30, 2019 valuation were based on the results of an
actuarial experience study for the 5-year period ended June 30, 2017.
Long-term expected rate of return
The long-term expected rate of return on pension plan investments was determined using a
statistical analysis in which best-estimate ranges of expected future real rates of return
(expected returns, net of pension plan investment expense and inflation) are developed for each
major asset class. These ranges are combined to produce the long-term expected rate of return
by weighting the expected future real rates of return by the target asset allocation percentage
and by adding expected inflation.
The target asset allocation and best estimates of arithmetic real rates of return for each major
class are summarized in the following table:
Asset Class
Allocation
Long-Term Target
Expected Real
Rate of Return
Domestic equity
20.00%
5.30%
Developed market international
11.00%
5.10%
Emerging market international
9.00%
7.40%
Core fixed income
16.00%
1.60%
Inflation linked bond
5.00%
1.30%
Emerging market debt
5.00%
2.90%
High yield bond
6.00%
3.40%
Real estate
10.00%
4.70%
Private equity
10.00%
7.30%
Alternative investments
7.00%
3.20%
Liquidity fund
1.00%
0.90%
Total
c 100.00%
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
B. Connecticut municipal employees’ retirement system (continued)
68
6.
Discount rate
The discount rate used to measure the total pension liability was 7.00%. The projection of cash
flows used to determine the discount rate assumed that plan member contributions will be made
at the current contribution rate and that employer contributions will be made at rates equal to
the difference between actuarially determined contribution rates and the member rate. Based
on those assumptions, the pension plan's fiduciary net position was projected to be available to
make all projected future benefit payments of current plan members. Therefore, the long-term
expected rate of return on pension plan investments was applied to all periods of projected
benefit payments to determine the total pension liability.
7.
Sensitivity of the net pension liability to changes in the discount rate
The following presents the Town’s proportional share of the net pension (asset) liability of
MERS, calculated using the discount rate, as well as what the net pension liability would be if it
were calculated using a discount rate that is 1-percentage-point lower or 1-percentage-point
higher than the current rate:
1%
Decrease
Current
Discount
1%
Increase
(6.00%)
(7.00%)
(8.00%)
Town's proportional share of the
net pension liability
$ 6,808,508
$ 4,539,605
$ 2,643,970
8.
Plan fiduciary net position
Detailed information about the MERS plan’s fiduciary net position is available in the separately
issued State of Connecticut Comprehensive Annual Financial Report as of and for the year
ended June 30, 2019.
C.
Connecticut state teachers’ retirement system
1.
Plan description
Teachers, principals, superintendents or supervisors engaged in service of public schools are
provided with pensions through the Connecticut State Teachers’ Retirement System (“TRS”), a
cost sharing multiple-employer defined benefit pension plan administered by the Teachers’
Retirement Board (“TRB”). Chapter 167a of the State Statutes grants authority to establish and
amend the benefit terms to the TRB. TRS issues a publicly available financial report that can be
obtained at www.ct.gov/trb.
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
C. Connecticut state teachers’ retirement system (continued)
69
Normal retirement
Benefit calculation
Early retirement
Early retirement
amount
Service connected
disability amount
Non-service
connected disability
service requirement
Vesting - Service
Vesting - Amount
Pre-retirement death
benefit amount
Age 60 with 20 years of credited service in Connecticut, or 35 years of
credited service including at least 25 years of service in Connecticut
2.00% of the average annual salary times the years of credited service
(maximum benefit is 75% of average annual salary during the 3 years of
highest salary).
25 years of credited service including 20 years of Connecticut service, or
age 55 with 20 years of credited service including 15 years of Connecticut
service.
Benefit amounts are reduced by 6.00% per year for the first 5 years
preceding normal retirement age and 4.00% per year for the next 5 years
preceding the normal retirement age. Effective July 1, 1999, the reduction
for individuals with 30 or more years of service is 3.00% per year by which
retirement precedes normal retirement date.
2.00% of average annual salary times credited service to date of disability,
but not less than 15% of average annual salary, nor more than 50% of
average annual salary. In addition, disability benefits under this plan
(without regard to cost-of-living adjustments) plus any initial award of
social security benefits and workers’ compensation cannot exceed 75% of
annual average salary.
Five years of credited service
10 years of service
100%
Lump-sum return of contributions with interest or surviving spouse benefit
depending on length of service.
2.
Benefit provisions
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
C. Connecticut state teachers’ retirement system (continued)
70
3.
Contributions
State of Connecticut
Per Connecticut General Statutes Section 10-183z (which reflects Public Act 79-436 as
amended), contribution requirements of active employees and the State of Connecticut are
amended and certified by the State Teachers’ Retirement Board and appropriated by the
General Assembly. The contributions are actuarially determined as an amount that, when
combined
with
employee
contributions
and
investment
earnings,
is
expected
to
finance
the
costs
of the benefits earned by employees during the year, with any additional amount to finance any
unfunded accrued liability.
Employer (school districts)
School district employers are not required to make contributions to the plan.
Employees
Effective January 1, 2018, each teacher is required to contribute 7.00% of their salary for the
pension benefit.
4.
Pension liabilities, pension expense, and deferred outflows of resources and
deferred inflows of resources related to pensions
The Town reports no amounts for its proportionate share of the net pension liability, and related
deferred outflows and inflows due to the statutory requirement that the State pay 100% of the
required contribution. The amounts recognized by the Town as its proportionate share of the
net pension liability, the related state support, and the total portion of the net pension liability
that was associated with the Town were as follows:
Town’s proportionate share of the net pension liability $ -
State’s proportionate share of the net pension liability
associated with the Town 58,819,764
Total $ 58,819,764
The net pension liability was measured as of June 30, 2019, and the total pension liability used
to calculate the net pension liability was determined by an actuarial valuation as of June 30,
2018. The Town has no proportionate share of the net pension liability.
During the year the Town recognized pension expense and revenue of $4,452,343 for on-behalf
amounts for contributions to the plan by the State.
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
C. Connecticut state teachers’ retirement system (continued)
71
Investment
rate
of
return
Inflation
Salary
increases
Mortality
rates
6.90%
2.50%
3.25-6.50%,
including
inflation
Mortality
rates
were
based
on
the
RP-2014
White
Collar
table
with
employee
and
annuitant
rates
blended
from
ages
50
to
80,
projected
to
the
year
2020
using
the
BB
improvement
scale.
5.
Actuarial assumptions
The total pension liability was determined by an actuarial valuation as of June 30, 2018, using
the following actuarial assumptions, applied to all periods included in the measurement:
Future cost-of-living increases - For teachers who retired prior to September 1, 1992, pension
benefit adjustments are made in accordance with increases in the Consumer Price Index, with
a minimum of 3% and a maximum of 5.00% per annum. For teachers who were members of the
Teachers’ Retirement System before July 1, 2007, and retire on or after September 1, 1992,
pension benefit adjustments are made that are consistent with those provided for social security
benefits on January 1 of the year granted, with a maximum of 6.00% per annum. If the return
on assets in the previous year was less than 8.50%, the maximum increase is 1.50%. For
teachers who were members of the Teachers’ Retirement System after July 1, 2007, pension
benefit adjustments are made that are consistent with those provided for social security benefits
on January 1 of the year granted, with a maximum of 5.00% per annum. If the return on
assets in the previous year was less than 11.50%, the maximum increase is 3.00%, and if the
return on the assets in the previous year was less than 8.50%, the maximum increase is
1.00%.
The actuarial assumptions used in the June 30, 2018 valuation were based on the results of an
actuarial experience study for the period July 1, 2010 - June 30, 2015.
Changes in assumptions and inputs
•
The inflation assumption was decreased from 2.75% to 2.50%.
•
The investment rate of return was decreased from 8.00% to 6.90%.
Long-term expected rate of return
The long-term expected rate of return on pension plan investments was determined using a log-
normal distribution analysis in which best-estimate ranges of expected future real rates of return
(expected returns, net of pension plan investment expense and inflation) are developed for each
major asset class. These ranges are combined to produce the long-term expected rate of return
by weighting the expected future real rates of return by the target asset allocation percentage
and by adding expected inflation.
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
C. Connecticut state teachers’ retirement system (continued)
72
The target asset allocation and best estimates of geometric rates of return for each major class
are summarized in the following table:
Long-Term
Target Expected Real
Asset Class Allocation Rate of Return
Public equity - US equity 20.00% 8.10%
Public equity - international developed equity 11.00% 8.50%
Public equity - emerging markets equity 9.00% 10.40%
Fixed income - core fixed income 16.00% 4.60%
Fixed income - inflation linked bonds 5.00% 3.60%
Fixed income - high yield 6.00% 6.50%
Fixed income - emerging market debt 5.00% 5.20%
Private equity 10.00% 9.80%
Real estate 10.00% 7.00%
Alternative investments - real assets 4.00% 8.20%
Alternative investments - hedge funds 3.00% 5.40%
Liquidity fund 1.00% 2.90%
Total 100.00%
6.
Discount rate
The discount rate used to measure the total pension liability was 6.90%. The projection of cash
flows used to determine the discount rate assumed that plan member contributions will be made
at the current contribution rate and that State contributions will be made at rates equal to the
difference between actuarially determined contribution rates and the member rate. Based on
those assumptions, the pension plan's fiduciary net position was projected to be available to
make all projected future benefit payments of current plan members. Therefore, the long-term
expected rate of return on pension plan investments was applied to all periods of projected
benefit payments to determine the total pension liability.
7.
Sensitivity of the net pension liability to changes in the discount rate
The Town’s proportionate share of the net pension liability is $0 and, therefore, the change in
the discount rate would only impact the amount recorded by the State of Connecticut.
8.
Plan fiduciary net position
Detailed information about the Connecticut State Teachers’ Retirement Plan fiduciary net
position is available in the separately issued State of Connecticut Comprehensive Annual
Financial Report as of and for the year ended June 30, 2019.
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
73
D. Total pension plans
Net Pension
Liability
Deferred
Outflows of
c Resources
Deferred
Inflows of
c Resources
Pension
Expense
Town
$ 4,758,127
$ 2,373,554
$ (1,439,777)
$ 1,180,318
MERS
4,539,605
2,314,279
(564,513)
1,370,588
Total
$ 9,297,732
$ 4,687,833
$ (2,004,290)
$ 2,550,906
E.
Other post-employment benefit plan
1.
Plan description
a.
Plan administration
The Town administers one single-employer defined benefit, post-retirement healthcare plan
for the Town and Board of Education through the Town of Cromwell Other Post-Employment
Benefit (“OPEB”) trust fund. The plan provides health and life insurance benefits to eligible
retirees and their spouses. The plan does not issue standalone financial reports.
b.
Plan membership
As of July 1, 2019 the plans' membership consisted of:
Retirees and beneficiaries receiving benefits 47
Active members 380
Total 427
2.
Benefit provisions
In addition to providing pension benefits, various Town employee agreements provide for a
portion of health insurance coverage or subsidized coverage to retired employees. These
benefits are negotiated through union contracts, personnel policies, and/or individual
employment agreements.
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
E. Other post-employment benefit plan
(continued)
74
Town employees
Police employees
Public works employees
Noncertified education
employees
Teachers and administrators
Employer
Employees hired before October 1, 2012, pay any amount over
$6,000 with at least 10 years of service for ages 62 to 65. For
ages 65 and above, the retiree pays 100 % of the cost
Employees pay any amount over $6,000 with at least 25 years of
service up to age 65. For ages 65 and above, the retiree pays
100 % of the cost
100% of the cost of insurance up to age 65
100% of the cost of insurance after 10-15 years of service upon
retiring, for up to 5 years
(1)
Actuarially determined on a bi-annual basis using the entry age
normal method
3.
Contributions
(1) Teachers who no longer work for the Board of Education are allowed by State Statute to
participate in the Town's group medical insurance plan until they formally begin receiving benefits
from the State Teachers' Retirement Plan. These retirees are required to contribute the cost of
the insurance to the Town.
4.
Investments
a.
Investment policy
The OPEB plans' policy in regard to the allocation of invested assets is established and may
be amended by the Retirement Board. It is the policy of the Town's Retirement Board to
pursue an investment strategy that reduces risk through the prudent diversification of the
portfolio across a broad selection of distinct asset classes.
The following was the Board's adopted asset allocation policy the Employees' OPEB Plan:
Asset Class
Target
Allocation
U.S. large cap core
28.00%
U.S. mid cap core
7.00%
U.S. small cap core
4.00%
International
equity
20.00%
Emerging markets equity
5.00%
Alternative equity
13.50%
REITs
2.50%
Fixed income
18.00%
Cash
2.00%
Total
100.00%
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
E. Other post-employment benefit plan
(continued)
75
b.
Concentrations
There were no investments in any one organization that represents 5% or more of the
OPEB plans' net position.
c.
Rate of return
The long-term expected rate of return on OPEB plan investments was determined using a
building-block method in which best-estimate ranges of expected future real rates of return
(expected returns, net of OPEB plan investment expense and inflation) are developed for
each major asset class. These ranges are combined to produce the long-term expected
rate of return by weighting the expected future real rates of return by the target asset
allocation percentage and by adding expected inflation. Best estimates of arithmetic real
rates of return for each major asset class included in the OPEB plan’s target asset allocation
(see the discussion of the OPEB plan’s investment policy) are as follows:
Asset Class
Long-Term
Expected Real
Rate of Return
U.S. large cap core
4.83%
U.S. mid cap core
6.62%
U.S. small cap core
7.70%
International equity
5.33%
Emerging markets equity
9.60%
Alternative equity
4.19%
REITs
4.10%
Fixed income
1.29%
Cash
0.00%
Inflation rate
2.60%
d.
The annual money-weighted rate of return on OPEB plan investments, net of
investment expense was (2.17%).
The money-weighted rate of return expresses investment performance, net of investment
expense, adjusted for the changing amounts actually invested.
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
E. Other post-employment benefit plan
(continued)
76
5.
Net OPEB liability
The components of the net OPEB liability were measured as of June 30, 2020 and
were as follows:
Total OPEB liability
$ 4,266,983
Plan fiduciary net position
1,661,160
Net OPEB liability
$ 2,605,823
Plan fiduciary net position as a percentage of the total OPEB liability
38.93%
6. Actuarial methods and significant assumptions:
Actuarial valuation date
July 1, 2019
Actuarial Cost Method
Entry Age Normal
Investment Rate of Return
6.90%
Salary Increases
2.60%
Inflation
2.60%
Healthcare cost trend rates:
Initial medical trend rate
6.60%
Ultimate medical trend rate
4.60%
Mortality rates
Pub-2010 Public Retirement
Plans Amount-Weighted
Mortality Tables (with separate
tables for General
Employees, Public Safety and
Teachers), projected to the
valuation date with Scale MP-
2019.
The discount rate for the plan was based on the Standard and Poors municipal bond 20-
year high grade index as of the measurement date for the Board of Education plan only.

Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
E. Other post-employment benefit plan
(continued)
77
7.
Changes from prior year
a.
Changes in assumptions
The Town’s plan had the following changes in assumptions:
•
The discount rate decreased from 7.00% to 6.90%.
•
Salary increases and the inflation rate were reduced from 2.75% to 2.60%.
•
The healthcare cost trend rate decreased from 6.80% to 6.60%.
•
The mortality assumption was updated to better reflect anticipated experiences and was
based on the Pub-2010 Public Retirement with Scale MP-2019 from the RP-2014 with
Scale MP-2016.
b.
Changes in benefit terms
There were no changes in benefit terms in the current year.
8.
Discount rate
The discount rate used to measure the total OPEB liability was 6.90%.
The projection of cash flows used to determine the discount rate assumed that plan member
contributions will be made at the current contribution rate and that Town contributions will be
made at rates equal to the difference between actuarially determined contribution rates and the
member rate. Based on those assumptions, the OPEB plan's fiduciary net position was
projected to be available to make all projected future benefit payments of current plan members.
Therefore, the long-term expected rate of return on OPEB plan investments was applied to all
periods of projected benefit payments to determine the total OPEB liability.
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
E. Other post-employment benefit plan
(continued)
78
9.
Changes in the net OPEB liability
The Town’s OPEB liability was measured at June 30, 2020 and the total OPEB liability used to
calculate the net OPEB liability was determined by an actuarial valuation as of July 1, 2019.
Increase
(Decrease)
Total
OPEB Plan
Fiduciary
Net Total
OPEB
Liability Position Liability
(a)
(b)
(a)
-
(b)
Balance
at
July
1,
2019
$ 4,250,623
$
1,564,053
$ 2,686,570
Service
cost
162,635
-
162,635
Interest
298,523
-
298,523
Differences
between
expected
and
actual
experience
(415,727)
-
(415,727)
Changes
in
assumptions
273,319
-
273,319
Contributions
-
employer
-
406,672
(406,672)
Contributions
-
State
Teachers'
Retirement
subsidy
-
27,718
(27,718)
Net
investment
income
-
(15,808)
15,808
Benefit
payments,
including
refunds
of
member
contributions
(302,390)
(302,390)
-
Administrative
expenses
-
(19,085)
19,085
Net
change
16,360
97,107
(80,747)
Balance
at
June
30,
2020
$ 4,266,983
$ 1,661,160
$ 2,605,823
10.
Sensitivity of the OPEB liability to changes in the discount rate
The following presents the OPEB liability, as well as what the OPEB liability would be if it were
calculated using a discount rate that is 1-percentage-point lower or 1-percentage-point higher
than the current discount rate:
Current
OPEB
Liability 1%
Decrease Discount
Rate 1%
Increase
Town
OPEB
Plan
$
3,030,492
$
2,605,823
$
2,234,299
11.
Sensitivity of the OPEB liability to changes in the healthcare cost trend rate
The following presents the OPEB liability, as well as what the OPEB liability would be if it were
calculated using trend rates that are 1-percentage-point lower or 1-percentage-point higher than
the current trend rates:
Current
OPEB
Liability
1%
Decrease Trend
Rate 1%
Increase
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
E. Other post-employment benefit plan
(continued)
79
Town
OPEB
Plan
$
2,207,306
$
2,605,823
$
3,078,492
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
E. Other post-employment benefit plan
(continued)
80
12.
OPEB expense and deferred outflows of resources related to OPEB
For the fiscal year, the Town recognized OPEB expense of $131,517. The Town reported
deferred outflows of resources and deferred inflows of resources related to OPEB from the
following sources:
Description
of
Inflows
Differences between expected and
actual
Deferred
Outflows of
Resources c
Deferred
Inflows of
Resources
Net
experience
$ 31,151
$ (1,969,098)
$ (1,937,947)
Changes
in
assumptions
252,922
(890,542)
(637,620)
Net
difference
between
projected
and
actual
earnings on OPEB plan investments
161,742
-
161,742
Total
$ 445,815
$ (2,859,640)
$ (2,413,825)
Actual investment earnings below (or above) projected earnings are amortized over 5 years
for both plans. Experience losses (gains) are amortized over the average remaining service
period of actives and inactives, which was 13.4 years.
Amounts reported as deferred outflows (inflows) of resources related to OPEB will be
recognized in OPEB expense as follows:
Year Ended June 30,
2021
$ (187,897)
2022
(187,895)
2023
(185,306)
2024
(201,236)
2025
(231,019)
Thereafter
(1,420,472)
Total
$ (2,413,825)
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
F. Connecticut state teachers’ retirement board retiree health insurance
plan
81
Normal
retirement
Early
retirement
Service
connected
disability
service
requirement
Non-service
connected
disability
service
requirement
Vesting
-
Service
Age
60
with
20
years
of
credited
service
in
Connecticut,
or
35
years
of
credited
service
including
at
least
25
years
of
service
in
Connecticut
25
years
of
credited
service
including
20
years
of
Connecticut
service,
or
age
55
with
20
years
of
credited
service
including
15
years
of
Connecticut
service
No
service
requirement
Five
years
of
credited
service
10
years
of
service
1.
Plan description
Teachers, principals, superintendents or supervisors engaged in service of public schools that
are currently receiving a retirement or disability benefit through the Connecticut Teachers’
Retirement System are eligible to participate in the Connecticut State Teachers’ Retirement
System Retiree Health Insurance Plan (“TRS-RHIP”) - a cost sharing multiple-employer defined
benefit other post-employment benefit plan administered by the Teachers’ Retirement Board
(“TRB”). Chapter 167a Section 10-183t of the State Statutes grants authority to establish and
amend the benefit terms to the TRB. TRS-RHIP issues a publicly available financial report that
can be obtained at www.ct.gov/trb.
2.
Benefit provisions
The Plan provides for retiree health insurance benefits. Eligibility is as follows:
Retiree health care coverage
Any member that is currently receiving a retirement or disability benefit is eligible to participate in
the Plan. There are two types of the health care benefits offered through the system. Subsidized
Local School District Coverage provides a subsidy paid to members still receiving coverage
through their former employer and the TRB Sponsored Medicare Supplemental Plans provide
coverage for those participating in Medicare, but not receiving Subsidized Local School
District Coverage.
Any member that is not currently participating in Medicare Parts A & B is eligible to continue health
care coverage with their former employer. A subsidy of up to $110 per month for a retired member
plus an additional $110 per month for a spouse enrolled in a local school district plan is provided to
the school district to first offset the retiree’s share of the cost of coverage, any remaining portion is
used to offset the district’s cost.
The subsidy amount is set by statute, and has not increased since July of 1996. A subsidy amount of
$220 per month may be paid for a retired member, spouse or the surviving spouse of a member who
has attained the normal retirement age to participate in Medicare, is not eligible for Part A of
Medicare without cost, and contributes at least $220 per month towards coverage under a local
school district plan.

Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
F. Connecticut state teachers’ retirement board retiree health insurance plan
(continued)
82
Any member that is currently participating in Medicare Parts A & B is eligible to either continue
health care coverage with their former employer, if offered, or enroll in the plan sponsored by the
System. If they elect to remain in the plan with their former employer, the same subsidies as
above will be paid to offset the cost of coverage.
If a member participating in Medicare Parts A & B so elects, they may enroll in one of the CTRB
Sponsored Medicare Supplemental Plans. Active members, retirees, and the State pay equally
toward the cost of the basic coverage (medical and prescription drug benefits).
Those participants electing vision, hearing, and/or dental are required by the System’s funding
policy to pay the full cost of coverage for these benefits, and no liability is assumed by the Plan
for these benefits.
Survivor health care coverage
Survivors of former employees or retirees remain eligible to participate in the Plan and continue
to be eligible to receive either the $110 monthly subsidy or participate in the TRB-Sponsored
Medicare Supplemental Plans, as long as they do not remarry.
3.
Contributions
State of Connecticut
Per Connecticut General Statutes Section 10-183z, contribution requirements of active
employees and the State of Connecticut are amended and certified by the State Teachers’
Retirement Board and appropriated by the General Assembly. The State contributions are not
currently actuarially funded. The State appropriates from the General Fund one third of the annual
costs of the Plan. Administrative costs of the Plan are financed by the State. Based upon Chapter
167a, Subsection D of Section 10-183t of the Connecticut statutes, it is assumed the State will
pay for any long-term shortfall arising from insufficient active member contributions.
Employer (School Districts)
School district employers are not required to make contributions to the plan.
Employees
Each member is required to contribute 1.25% of their annual salary.
4.
OPEB liabilities, OPEB expense, deferred outflows of resources and deferred inflows
of resources related to OPEB
The Town reports no amounts for its proportionate share of the net OPEB liability, and related
deferred outflows and inflows due to the statutory requirement that the State pay 100% of the
required contribution. The amounts recognized by the Town as its proportionate share of the net
OPEB liability, the related state support, and the total portion of the net OPEB liability that was
associated with the Town were as follows:
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
F. Connecticut state teachers’ retirement board retiree health insurance plan
(continued)
83
Investment
rate
of
return
Inflation
Health
care
cost
trend
rate
Pre-Medicare
Medicare
Salary
increases
Mortality
rates
Year
fund
net
position
will
be
depleted
3.00%
2.50%
5.95%
decreasing
to
4.75%
by
2025
5.00%
decreasing
to
4.75%
by
2028
3.25-6.50%,
including
inflation
Mortality
rates
were
based
on
the
RP-2014
White
Collar
table
with
employee
and
annuitant
rates
blended
from
ages
50
to
80,
projected
to
the
year
2020
using
the
BB
improvement
scale.
2020
Town’s proportionate share of the net OPEB liability $ -
State’s proportionate share of the net OPEB liability
associated with the Town 9,173,275
Total $ 9,173,275
The net OPEB liability was measured as of June 30, 2019, and the total OPEB liability used to
calculate the net OPEB liability was determined by an actuarial valuation as of June 30, 2018.
The Town has no proportionate share of the net OPEB liability.
The Town recognized OPEB expense and revenue of $121,686 for on-behalf amounts for the
benefits provided by the State.
5.
Actuarial methods and significant assumptions
The total OPEB liability was determined by an actuarial valuation as of June 30, 2018, using the
following actuarial assumptions, applied to all periods included in the measurement:
Mortality rates were based on the RP-2014 White Collar table with employee and annuitant rates
blended from ages 50 to 80, projected to the year 2020 using the BB improvement scale.
The actuarial assumptions used in the June 30, 2018 valuation were based on the results of an
actuarial experience study for the period July 1, 2010 - June 30, 2015.
Changes in assumptions and inputs
•
The discount rate was decreased from 3.87% to 3.50% to reflect the change in the
Municipal Bond Index rate.
Additionally, expected annual per capita claims costs were updated to better reflect
anticipated medical and prescription drug claim experience both before and after the plan
change that became effective on January 1, 2019. Further, the expected rate of inflation was
decreased and the Real Wage Growth assumption was increased.

Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
F. Connecticut state teachers’ retirement board retiree health insurance plan
(continued)
84
Long-term expected rate of return
The long-term expected rate of return on OPEB plan investments was determined using a log-
normal distribution analysis in which best-estimate ranges of expected future real rates of return
(expected returns, net of OPEB plan investment expense and inflation) are developed for each
major asset class. These ranges are combined to produce the long-term expected rate of return
by weighing the expected future real rates of return by the target asset allocation percentage and
by adding expected inflation.
All the plan assets are assumed to be invested in cash equivalents due to the need for liquidity.
The expected rate of return is 3.00%.
Affordable Care Act (ACA)
The impact of the Affordable Care Act (ACA) was addressed in this valuation. Review of the
information currently available did not identify any specific provisions of the ACA that are
anticipated to significantly impact results. While the impact of certain provisions such as the excise
tax on high-value health insurance plans beginning in 2020 (if applicable), mandated benefits and
participation changes due to the individual mandate should be recognized in the determination of
liabilities, overall future plan costs and the resulting liabilities are driven by amounts employers
and retirees can afford (i.e., trend). The trend assumption forecasts the anticipated increase to
initial per capita costs, taking into account health care cost inflation, increases in benefit utilization,
plan changes, government-mandated benefits, and technological advances.
Given the uncertainty regarding the ACA’s implementation (e.g., the impact of excise tax on high-
value health insurance plans, changes in participation resulting from the implementation of state-
based health insurance exchanges), continued monitoring of the ACA’s impact on the Plan’s
liability will be required.
6.
Discount rate
The discount rate used to measure the total OPEB liability was 3.50%. The Municipal Bond Index
Rate was used in the determination in the discount rate. The projection of cash flows used to
determine the discount rate assumed that plan member contributions will be made at the current
contribution rate and that no future employer contributions were assumed to be made.
7.
Sensitivity of the OPEB liability to changes in the discount rate and the health care
cost trend rate
The Town’s proportionate share of the net OPEB liability is $0 and, therefore, the change in the
discount rate would only impact the amount recorded by the State of Connecticut.
8.
Plan fiduciary net position
Detailed information about the Connecticut State Teachers’ OPEB Plan fiduciary net position is
available in the separately issued State of Connecticut Comprehensive Annual Financial Report
as of and for the year ended June 30, 2019.
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
85
G. Pension and other post-employment benefit plan statements
Combining Statement of Fiduciary Net Position
June 30, 2020
Assets
Employee OPEB
Pension
Fund Trust
Fund
Total
Cash
Investments:
$ 354,775
$ -
$ 354,775
Common
stock
12,427,635
860,758
13,288,393
Common
stock
-
international
4,270,614
431,453
4,702,067
U.S.
government
obligations
4,930,999
-
4,930,999
Corporate
bonds
2,472,562
-
2,472,562
Real
estate
investment
trusts
770,360
-
770,360
Money
market
mutual
fund
558,333
35,294
593,627
Pooled
fixed
income
-
333,655
333,655
Total
investments
25,430,503
1,661,160
27,091,663
Accrued
interest
47,611
-
47,611
Total
assets
25,832,889
1,661,160
27,494,049
Net
Position
Restricted
for:
Pension
benefits
25,832,889
-
25,832,889
OPEB
benefits
-
1,661,160
1,661,160
Total
net
position
$ 25,832,889
$ 1,661,160
$ 27,494,049
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
86
G. Pension and other post-employment benefit plan statements (continued)
Combining
Statement
of
Changes
in
Fiduciary
Net
Position
For the Year Ended June 30, 2020
Additions:
Contributions:
Employee
Pension
Fund
OPEB
Trust
Fund
Total
Employer
$ 704,628
$ 406,672
$ 1,111,300
Plan
members
262,761
-
262,761
State
Teachers'
Retirement
subsidy
-
27,718
27,718
Total
contributions
967,389
434,390
1,401,779
Investment
income
(loss):
Net
change
in
fair
value
of
investments
988,326
(51,129)
937,197
Interest
and
dividends
521,649
35,321
556,970
Total
investment
income
(loss)
1,509,975
(15,808)
1,494,167
Less
investment
expenses
216,652
-
216,652
Net
investment
income
(loss)
1,293,323
(15,808)
1,277,515
Total
additions
2,260,712
418,582
2,679,294
Deductions:
Benefits
1,346,631
302,390
1,649,021
Administration
-
19,085
19,085
Total
deductions
1,346,631
321,475
1,668,106
Changes
in
net
position
914,081
97,107
1,011,188
Net
position
-
July
1,
2019
24,918,808
1,564,053
26,482,861
Net
position
-
June
30,
2020
$ 25,832,889
$ 1,661,160
$ 27,494,049
Exhibit K
Town of Cromwell, Connecticut
Notes to Financial Statements
As of and for the Year Ended June 30, 2020
87
VI.
Prior period adjustment and fund reclassification
Beginning equity balances were restated as follows:
Other
Internal
Private-
Purpose
Governmental
General
Capital
Governmental
Service
Trust
Activities
Fund
Projects
Fund
Activities
Funds
Funds
Net
position/Fund
balance
as
previously
reported
at
June
30,
2019
$
107,154,290
$14,553,116
$
9,403,827
$
2,524,111
$
108,889
$ -
To
reclassify
funds
to
capital
projects
funds
-
-
458,637
(458,637)
-
-
To
record
allowance
for
tax
interest
receivable
-
(180,000)
-
-
-
-
To
record
equipment
financing
notes
(492,171)
-
-
-
-
-
To
record
liability
for
heart
and
hypertension
claims
(126,998)
-
-
-
(126,998)
-
To
reclassify
funds
to
private
purpose
trust
funds
(52,232)
-
-
(52,232)
-
52,232
To
reclassify
funds
to
internal
service
funds
-
-
-
(203,663)
203,663
-
Net
position/fund
balance
as
restated
at
July
1,
2019
$
106,482,889
$14,373,116
$
9,862,464
$
1,809,579
$
185,554
$
52,232
***
Required
Supplementary
Information
Type
Description
Budgetary
Schedule of Revenues and Other Financing Sources - Budget and Actual
- General Fund
Schedule of Revenues and Other Financing Uses - Budget and Actual -
General Fund
Notes to Required Supplementary Information - Budgets and Budgetary
Accounting
Pension Plans
Employees'
State Teachers' Retirement System
Municipal Employees' Retirement
System
Schedule of Changes in Net Pension Liability and Related Ratios and
Schedule of Investment Returns
Schedule of Contributions
Notes to Required Supplementary Information
Other Post-Employment Benefits Plans
OPEB
State Teacher's Retirement Board Retiree
Health Insurance Plan
Schedule of Changes in Net OPEB Liability and Related Ratios and
Schedule of Investment Returns
Schedule of Contributions
Notes to Required Supplementary Information
86
RSI-1A
(1 of 2)
Town of Cromwell, Connecticut
Required Supplementary Information
General Fund
Schedule of Revenues and Other Financing
Sources
Budget and Actual
For The Year Ended June 30, 2020
Variance
Additional
With
Original
Appropriations
Final
Final
Budget
and Transfers
Budget
Actual
Budget
Property taxes:
Current taxes
$ 43,131,835
$ -
$ 43,131,835
$ 43,170,933
$ 39,098
Prior year's levies
200,000
-
200,000
478,295
278,295
Interest and liens
125,000
-
125,000
268,977
143,977
Motor vehicle supplement - current year
350,000
-
350,000
433,925
83,925
Other
500
-
500
2,635
2,135
Telecommunication - PILOT
25,000
-
25,000
25,367
367
Mattabassett - PILOT
100,000
-
100,000
100,000
-
Total property taxes
43,932,335
-
43,932,335
44,480,132
547,797
Intergovernmental revenues:
Town:
Youth service grant
14,000
14,000
14,000
-
Tax relief - disability
900
-
900
1,107
207
Tax relief - veterans
3,152
-
3,152
2,608
(544)
Town aid road grant
276,136
-
276,136
275,736
(400)
State owned property - PILOT
8,749
-
8,749
8,749
-
College and university - PILOT
37,974
-
37,974
37,974
-
Emergency
management
4,500
-
4,500
-
(4,500)
Judicial department
4,000
-
4,000
6,969
2,969
Senior/disabled grant
17,980
-
17,980
17,980
-
Other - Town
500
-
500
12,958
12,458
Other - education
500
-
500
21,277
20,777
Municipal revenue sharing
31,099
-
31,099
31,099
-
Total Town
399,490
-
399,490
430,457
30,967
Education:
Education cost sharing
15,027
-
15,027
15,364
337
Special education excess cost
4,831,486
-
4,831,486
4,885,903
54,417
Total education
4,846,513
-
4,846,513
4,901,267
54,754
Total intergovernmental revenues
5,246,003
-
5,246,003
5,331,724
85,721
Charges for services:
Copier revenue
13,000
-
13,000
17,056
4,056
Conveyance taxes
185,000
-
185,000
178,492
(6,508)
Recording fees
75,000
-
75,000
87,913
12,913
Vital statistics
18,000
-
18,000
16,961
(1,039)
Town clerk miscellaneous
3,000
-
3,000
3,523
523
Public works miscellaneous
300
-
300
1,261
961
Gun permits
4,000
-
4,000
3,272
(728)
Parking tickets
5,500
-
5,500
4,860
(640)
Game/peddler permits
1,200
-
1,200
1,553
353
Alarm registration and fees
7,000
-
7,000
10,905
3,905
Communication tower income
40,000
-
40,000
40,000
-
Police outside services - cruiser use
19,000
-
19,000
32,905
13,905
Police copying and lab fees
1,500
-
1,500
2,841
1,341
Police department miscellaneous
10,000
-
10,000
3,637
(6,363)
Animal control citations
750
-
750
225
(525)
SRO - Board of Education
64,969
-
64,969
67,636
2,667
Senior services department
1,500
-
1,500
644
(856)
Senior services department miscellaneous
-
-
-
750
750
(Continued)
87
Town of Cromwell,
Connecticut
RSI-1A
(2 of 2)
Required
Supplementary
Information
General Fund
Schedule of Revenues and Other Financing
Sources Budget and Actual
For The Year Ended June 30, 2020
Variance
Additional With
Original Appropriations Final Final
Budget and Transfers
Budget
Actual
Budget
Charges for services: (continued)
Recreation department miscellaneous
$ -
$ -
$ -
$ 20
$ 20
Youth service department
4,000
-
4,000
810
(3,190)
Library department fines/ fees
8,000
-
8,000
2,791
(5,209)
Assessor's office miscellaneous
500
-
500
1,297
797
Planning and zoning
7,500
-
7,500
4,038
(3,462)
Zoning Board of Appeals
1,000
-
1,000
868
(132)
Inland-wetlands
750
-
750
1,333
583
Sewer usage
36,454
-
36,454
36,454
-
Fire district fees
57,617
-
57,617
57,665
48
School rentals
2,000
-
2,000
1,160
(840)
Lease/rentals
Licenses and permits:
4,000
-
4,000
3,645
(355)
Building department
225,000
-
225,000
752,665
527,665
Food licenses
20,000
-
20,000
16,880
(3,120)
Health department plan review
500
-
500
2,705
2,205
Transfer station
45,000
-
45,000
49,706
4,706
Salons, pools & hot tubs
5,000
-
5,000
3,135
(1,865)
Health department
-
-
-
28,450
28,450
Total charges for services
867,040
-
867,040
1,438,056
571,016
Income from investments
300,000
-
300,000
388,913
88,913
Other:
Board of Education miscellaneous
2,000
-
2,000
878
(1,122)
Insurance dividends/returns
20,000
-
20,000
49,582
29,582
Other revenue
30,000
-
30,000
106,554
76,554
Total other
52,000
-
52,000
157,014
105,014
Total revenues
50,397,378
-
50,397,378
51,795,839
1,398,461
Other financing sources:
Appropriation of fund balance
879,001
2,200,000
3,079,001
-
(3,079,001)
Transfers in:
Capital projects fund
-
-
-
316,943
316,943
Outside services fund
75,000
-
75,000
128,490
53,490
Total other financing sources
954,001
c c 2,200,000
3,154,001
445,433
(2,708,568)
Total revenues and other financing sources
$ 51,351,379
$ 2,200,000
$ 53,551,379
$ 52,241,272
$ (1,310,107)
(Concluded)
RSI-1B
(88
of
2)
Town
of
Cromwell,
Connecticut
Required Supplementary
Information
General
Fund
Schedule
of
Expenditures
and
Other
Financing
Uses
Budget
and
Actual
For
The
Year
Ended
June
30,
2020
88
Variance
Additional
With
Original
Appropriations
Final
Final
Budget
c
and
Transfers
Budget
Actual
Budget
General
government:
Town
manager
$ 381,915
$ -
$ 381,915
$ 369,043
$ 12,872
Town
clerk
219,242
-
219,242
210,238
9,004
Elections
department
79,203
-
79,203
54,446
24,757
Economic
development
23,530
-
23,530
18,883
4,647
Town
planner
133,323
-
133,323
132,741
582
Development
compliance
103,201
-
103,201
102,523
678
Building
inspection
203,710
-
203,710
201,801
1,909
Finance
department
421,531
-
421,531
404,582
16,949
Tax
collector
144,353
-
144,353
137,121
7,232
Assessor's
office
241,994
-
241,994
239,021
2,973
Donations
and
dues
50,522
-
50,522
46,317
4,205
Legal
228,764
30,000
258,764
258,114
650
Central
services
186,800
-
186,800
181,410
5,390
Insurance
584,000
-
584,000
554,010
29,990
General
expense
10,002
-
10,002
3,995
6,007
Town
council
39,905
-
39,905
39,203
702
Board
of
finance
1,350
16
1,366
1,365
1
Charter
revision
commission
100
-
100
-
100
Board
of
assessment
appeals
1,200
-
1,200
940
260
Commission
support
disabled
100
-
100
-
100
Planning
and
zoning
commission
3,525
-
3,525
1,127
2,398
Zoning
board
of
appeals
1,250
-
1,250
389
861
Inland
wetlands
2,300
-
2,300
785
1,515
Conservation
commission
1,210
-
1,210
140
1,070
Employee
benefits
3,846,399
(108,020)
3,738,379
3,178,129
560,250
c
Total
general
government
6,909,429
(78,004)
6,831,425
6,136,323
695,102
Public
works:
Public
works
administration
4,211,223
33,118
c
4,244,341
3,980,305
264,036
c
Public
safety:
Emergency management
19,050
-
19,050
18,264
786
Police
department
3,531,214
44,886
3,576,100
3,279,713
296,387
Animal
control
89,371
c
-
89,371
c
86,245
c
3,126
Total
public
safety
3,639,635
c
44,886
c
3,684,521
3,384,222
300,299
Human
services:
Health
department
198,293
-
198,293
194,386
3,907
Human
services
131,951
-
131,951
131,131
820
Senior
services
109,980
-
109,980
70,420
39,560
Transportation
services
189,396
-
189,396
130,425
58,971
Youth
services
95,298
c
-
95,298
c
91,334
c
3,964
Total
human
services
724,918
-
724,918
617,696
107,222
Culture
and
recreation:
Recreation
department
252,731
-
252,731
243,790
8,941
Library
594,581
-
594,581
557,129
37,452
c
Total
culture
and
recreation
847,312
-
847,312
800,919
46,393
c
(Continued)
RSI-1B
(89
of
2)
Town
of
Cromwell,
Connecticut
Required Supplementary
Information
General
Fund
Schedule
of
Expenditures
and
Other
Financing
Uses
Budget
and
Actual
For
The
Year
Ended
June
30,
2020
89
Original
Budget
Additional
Appropriations
c and Transfers
Final
Budget
Actual
Variance
With
Final
Budget
Education
$
30,700,762
$ -
$
30,700,762
$
30,500,896
$ 199,866
Debt
service
3,704,100
-
3,704,100
3,704,100
-
Total
expenditures
50,737,379
-
50,737,379
49,124,461
1,612,918
Other
financing
uses:
Transfers
out:
Capital
projects
funds
614,000
c
2,200,000
2,814,000
2,814,000
-
Total
expenditures
and
other
financing
uses
$
51,351,379
$ 2,200,000
$
53,551,379
$
51,938,461
$
1,612,918
Reconciliation
to
Exhibit
D
Revenues
c
Expenditures
Budgetary
Basis
-
RSI-1
$
51,795,839
$
49,124,461
Other
funds
(Schedule
2)
406,710
275,448
State
Teachers'
pension
on
behalf
amount
4,452,343
4,452,343
State
Teachers'
OPEB
on
behalf
amount
121,686
121,686
GAAP
Basis
-
Exhibit
D
$
56,776,578
$
53,973,938
(Concluded)
90
RSI-1C
Town of Cromwell, Connecticut
Required Supplementary Information
Sewer Usage Fund
Schedule of Revenues, Expenditures and Changes in Fund Balance
Budget and Actual
For the Year Ended June 30, 2020
Additional Variance
Original Appropriations Final With Final
Budget and Transfers
Budget
Actual
Budget
Revenues:
User charges
$ 2,059,750
$ -
$ 2,059,750
$ 1,993,323
$ (66,427)
Prior year collections (all components)
20,000
-
20,000
-
(20,000)
Outlet charge
-
-
-
100,205
100,205
Permits and inspection charges
20,000
-
20,000
16,270
(3,730)
Service charges
15,000
-
15,000
8,713
(6,287)
Income from investments
17,445
-
17,445
33,568
16,123
Other
-
-
-
22
22
Total revenues
2,132,195
-
2,132,195
2,152,101
19,906
Expenditures:
Regular wages
420,746
-
420,746
425,831
(5,085)
Part-time wages
16,071
(4,600)
11,471
9,108
2,363
Overtime wages
56,254
-
56,254
36,877
19,377
Department expenses
29,700
-
29,700
16,198
13,502
Outside services
95,049
-
95,049
74,446
20,603
Vehicle maintenance
8,000
-
8,000
5,581
2,419
Gasoline and fuel
8,610
-
8,610
7,270
1,340
Equipment repair and maintenance
25,000
-
25,000
17,634
7,366
Liability and property insurance
38,000
1,400
39,400
39,301
99
Materials and supplies
26,000
-
26,000
25,840
160
Utilities and oil
35,000
3,200
38,200
30,761
7,439
Payments for sewer treatment
926,471
-
926,471
922,157
4,314
Meter and pump station repairs
24,000
-
24,000
22,608
1,392
Prior year obligations
3,500
-
3,500
-
3,500
Damage claims
100
-
100
-
100
Employee benefits
266,007
-
266,007
222,419
43,588
Interest
100,000
-
100,000
-
100,000
Total expenditures
2,078,508
-
2,078,508
1,856,031
222,477
Net change in fund balance
$ 53,687
$ -
$ 53,687
296,070
$ 242,383
Fund balance - July 1, 2019
1,996,813
Fund balance - June 30, 2020
$ 2,292,883

91
RSI-1D
Town of Cromwell, Connecticut
Notes to Required Supplementary Information
For the Year Ended June 30, 2020
Budgets and Budgetary Accounting
The Town adheres to the following procedures in establishing the budgetary data included in the General Fund
and Sewer Usage Fund financial statements. The operating budget, which is prepared by function and department,
includes proposed expenditures and the means of financing them.
The budgets are adopted on a basis consistent with Generally Accepted Accounting Principles (modified accrual
basis) with the following exception for the general fund:
• The Town does not recognize as revenue or expenditures payments made for the State Teachers'
pension and OPEB by the State of Connecticut on the Town's behalf.
• Certain funds that are required to be reported as part of the general fund under the requirements of GASB 54
The Town Manager compiles the budget requests from the Town departments and agencies, with the exception of
the Board of Education, and presents the budget to the Town Council. The Town Council reviews and deliberates on
the budget and submits it for consideration to the Board of Finance. The Board of Education submits its budget
estimates directly to the Board of Finance. The Board of Finance, after its review process, presents a recommended
budget for approval to referendum. The Town Charter provides the manner and timetable by which the budget
process is initiated for approval by Town Meeting.
The legal level of control is on the department level for the General Fund. The Board of Finance by resolution and
only upon the recommendation of a majority of the entire Town Council may make supplemental appropriations not to
exceed one percent of the total annual appropriation of the fiscal year. Additional appropriations of more than one
percent require Town Meeting approval.
The legal level of control for the sewer fund is the fund level
Additional appropriations for the fiscal year amounted to approximately $2,200,000.
Unencumbered appropriations for the General Fund and the Sewer Usage Fund lapse at the end of the year.
The Board of Education is authorized under state law to make any transfers required within their budget at
their discretion. Any additional appropriations must have Board of Education and Board of Finance approval.
RSI-2A
Town of Cromwell, Connecticut
Required Supplementary Information
Employees' Pension
Plan Last Seven Years
(1)
2020
2019
2018
2017
2016
2015
2014
Schedule of Changes in Net Pension Liability and Related
Ratios
Total pension
liability: Service cost
$ 844,931
$ 837,849
$ 803,687
$ 837,912
$ 869,728
$ 844,396
$ 804,187
Interest
1,869,027
1,878,174
1,758,940
1,781,296
1,671,584
1,642,818
1,522,557
Differences between expected and actual experience
729,657
(400,403)
290,202
(932,074)
(93,482)
(2,263,343)
-
Changes in assumptions
787,826
21,266
-
(588,427)
-
2,184,823
-
Benefit payments, including refunds of member contributions
(1,346,631)
(1,227,055)
(1,141,661)
(912,881)
(830,072)
(760,080)
(766,744)
Net change in total pension liability
2,884,810
1,109,831
1,711,168
185,826
1,617,758
1,648,614
1,560,000
Total pension liability - July 1
27,706,206
26,596,375
24,885,207
24,699,381
23,081,623
21,433,009
19,873,009
Total pension liability - June 30 (a)
$
30,591,016
$
27,706,206
$
26,596,375
$
24,885,207
$
24,699,381
$
23,081,623
$
21,433,009
Plan fiduciary net
position: Contributions -
employer
$ 704,628
$ 686,652
$ 674,271
$ 708,939
$ 688,458
$ 704,153
$ 663,086
Contributions - member
262,761
257,142
235,765
252,453
205,530
235,516
239,118
Net investment income (loss)
1,293,323
1,581,452
1,303,537
1,728,565
(77,346)
389,952
2,629,667
Benefit payments, including refunds of member contributions
(1,346,631)
(1,227,055)
(1,141,661)
(912,881)
(830,072)
(760,080)
(766,744)
Administration expenses
-
-
-
(2,272)
(1,530)
(1,530)
(1,530)
Net change in plan fiduciary net position
914,081
1,298,191
1,071,912
1,774,804
(14,960)
568,011
2,763,597
Plan fiduciary net position - July 1
24,918,808
23,620,617
22,548,705
20,773,901
20,788,861
20,220,850
17,457,253
Plan fiduciary net position - June 30 (b)
$
25,832,889
$
24,918,808
$
23,620,617
$
22,548,705
$
20,773,901
$
20,788,861
$
20,220,850
Net pension liability (asset) - June 30 (a)-(b
$
4,758,127
$ 2,787,398
$ 2,975,758
$ 2,336,502
$ 3,925,480
$ 2,292,762
$ 1,212,159
Plan fiduciary net position as a percentage of the total pension liability
84.45%
89.94%
88.81%
90.61%
84.11%
90.07%
94.34%
Covered payroll
$
9,534,714
$ 8,501,263
$ 9,044,251
$ 9,072,753
$ 9,379,937
$ 9,153,162
$ 8,987,085
Net pension liability as a percentage of covered payroll
49.90%
32.79%
32.90%
25.75%
41.85%
25.05%
13.49%
Schedule of Investment Returns
Annual money weighted rate of return, net of investment expense
5.29%
6.75%
5.87%
8.39%
(0.37%)
1.89%
14.76%
(1) These schedules are intended to present information for 10 years. Additional years will be presented as they become available.
92
RSI-2B
Town
of
Cromwell,
Connecticut
Required
Supplementary
Information
Employees'
Pension
Plan
Schedule
of
Contributions
Last
Ten
Years
2020
2019
2018
2017
2016
2015
2014
2013
2012
2011
Actuarially
determined
contributions
$ c c
704,628
$
c
686,652
$
c
674,271
$
c
708,939
$
c
688,375
$
c
704,153
$
c
663,086
$
c
732,759
$
c
711,591
$
c
684,425
Contributions
in
relation
to
the
actuarially
determined
contribution
704,628
686,652
674,271
708,939
688,458
704,153
663,086
732,759
711,591
684,425
Contribution
excess
(deficiency)
$ -
$ -
$ -
$ -
$ 83
$ -
$ -
$ -
$ -
$ -
Covered
payroll
$
9,534,714
c
$
8,501,263
c
$
9,044,251
c
$
9,072,753
c
$
9,379,937
c
$
9,153,162
c
$
8,974,085
c
$
8,546,748
c
$
8,952,815
c
$
8,558,671
c
Contributions
as
a
percentage
of
covered
payroll
7.39%
8.08%
7.46%
7.81%
7.34%
7.69%
7.39%
8.57%
7.95%
8.00%
93
None
None
None
None
None
None
None
None
None
None
Projected Unit Credit
Projected Unit Credit
Projected Unit Credit
Projected Unit Credit
Projected Unit Credit
Projected Unit Credit
Projected Unit Credit
Projected Unit Credit
Projected Unit Credit
Projected Unit Credit
Level dollar
Level dollar
Level dollar
Level dollar
Level dollar
Level dollar
Level dollar
Level dollar
Level dollar
Level dollar
2.50%
2.50%
2.75%
2.75%
3.00%
3.00%
3.50%
3.50%
3.50%
3.50%
6.90%
6.90%
7.00%
7.00%
7.10%
7.50%
7.50%
7.50%
8.00%
8.00%
Changes of Benefit Terms
Actuarial Cost Method
Amortization Method
Inflation
Investment Rate of Return
RSI-2C
Town of Cromwell, Connecticut
Notes to Required Supplementary Information
Employees' Pension Plan
Schedule of Contributions
Last Ten Years
2020 2019 2018 2017 2016 2015 2014 2013 2012 2011
Actuarial methods and assumptions used to determine contribution rates:
N/A - not available
RP-2014
adjusted
to
RP-2014
adjusted
to
RP-2014 Mortality
RP-2014 Mortality
RP-2014 Mortality
RP-2000 Mortality
RP-2000 Mortality
2006 Total Dataset
2006 Total Dataset
Table with separate
Table with separate
Table with separate
Table with separate
Table with separate
Mortality Table
Mortality Table
male and female
rates,
male and female
rates,
male and female
rates,
male and female
rates,
male and female
rates,
projected to valuation
projected to valuation
with no collar
with no collar
with no
with no
with no collar
date with scale MP-
date with scale MP-
adjustments, combined
adjustments, combined
collar adjustments,
collar adjustments,
adjustment, combined
2018.
2018.
table for non-
annuitants
and
table for non-
annuitants
and
combined table for
non-
annuitants and
combined table for
non-
annuitants and
table for non-
annuitants
and
N/A
N/A
N/A
annuitants, projected
annuitants, projected
annuitants, projected
annuitants, projected
annuitants, projected
to the valuation date
to the valuation date
to the valuation date
to the valuation date
to the valuation date
with Scale AA.
with Scale AA.
with
with
with Scale AA.
Scalec AA.
Scalec AA.
Mortality Rate
3.50%
3.50%
2.75% - 6.50%
dependent on age
2.75% - 6.50%
dependent on age
3.00%-6.50%
dependent on age
5.00% (3.5% cost-of
living, 1.5% steps)
5.00% (3.5% cost-of
living, 1.5% steps)
5.00%
5.00%
5.00%
Salary Increases
5 year smoothing
5 year smoothing
5 year smoothing
5 year smoothing
5 year smoothing
5 year smoothing
5 year smoothing
5 year smoothing
5 year smoothing
5 year smoothing
Asset Valuation Method
July 1, 2018
July 1, 2018
July 1, 2017
July 1, 2016
July 1, 2014
July 1, 2013
July 1, 2013
July 1, 2012
July 1, 2011
July 1, 2010
The actuarially determined
contribution rates
are calculated as of
94
RSI-3A
Town
of
Cromwell,
Connecticut
Required Supplementary
Information
Connecticut Municipal Employees' Retirement
System
Last
Six
Years
(1)
2020
c
2019
2018
2017
2016
2015
Schedule
of
Proportionate
Share
of
the
Net
Pension
Liability
Town's
proportion
of
the
net
pension
(asset)
liability
c c
6.230267%
6.171665%
6.940000%
6.940000%
6.900000%
6.890000%
Town's
proportionate
share
of
the
net
pension
(asset)
liability
$
4,539,605
$
3,528,754
$
2,835,008
c
$
3,314,849
c
$
2,109,958
c
$
1,667,341
c
Town's
covered
payroll
$
2,767,141
c
$
2,942,089
$
2,863,631
$
2,836,483
$
2,762,664
$
2,762,664
Town's
proportionate
share
of
the
net
pension
(asset)
liability
as
a
percentage
of
its
covered
payroll
164.05%
119.94%
99.00%
116.86%
76.37%
60.35%
Total
plan
fiduciary
net
position
as
a
percentage
of
the
total
pension
liability
73.60%
73.60%
91.68%
88.29%
92.72%
90.48%
Schedule of
Contributions
Contractually required contribution
$ 571,638
$ 459,149
$ 470,204
$ 479,910
$ 517,138
$ 423,789
Contributions in relation to the contractually required contribution
571,638
459,149
470,204
479,910
517,138
423,789
Contribution deficiency (excess)
$ -
$ -
$ -
$ -
$ -
$ -
Town's
covered
payroll
$
2,767,141
c
$
3,030,352
$
2,863,631
$
2,836,483
$
2,762,664
$
2,762,664
Contributions
as
a
percentage
of
covered
payroll
20.66%
15.15%
16.42%
16.92%
18.72%
15.34%
The
Town
participates
in
the
police
officers
and
firefighters
with
social
security.
(1)
This
schedule
is
intended
to
present
information
for
10
years.
Additional
years
will
be
presented
as
the
information
becomes
available.
95
June
30,
2018
June
30,
2018
June
30,
2016
June
30,
2016
June
30,
2014
June
30,
2014
Entry
age
Entry
age
Entry
age
Entry
age
Entry
age
Entry
age
Level
dollar,
closed
Level
dollar,
closed
Level
dollar,
closed
Level
dollar,
closed
Level
dollar,
closed
Level
dollar,
closed
21
years
21
years
23
years
23
years
27
years
27
years
5
year
smoothing
5
year
smoothing
5
year
smoothing
5
year
smoothing
5
year
smoothing
5
year
smoothing
2.50%
2.50%
3.25%
3.25%
3.25%
3.25%
3.50%-10.00%,
average,
including
inflation
3.50%-10.00%,
average,
including
inflation
4.25%-11.00%,
average,
including
inflation
4.25%-11.00%,
average,
including
inflation
4.25%-11.00%,
average,
including
inflation
4.25%-11.00%,
average,
including
inflation
After
January
1,
2002,
2.5%
minimum
After
January
1,
2002,
2.5%
minimum
After
January
1,
2002,
2.5%
minimum
After
January
1,
2002,
2.5%
minimum
After
January
1,
2002,
2.5%
minimum
After
January
1,
2002,
2.5%
minimum
Prior
to
January
1,
2002,
2.5%
up
to
age
65.
3.25%
c
afterwards
Prior
to
January
1,
2002,
2.5%
up
to
age
65.
3.25%
c
afterwards
Prior
to
January
1,
2002,
2.5%
c
up
c
to
c
age
c
65.
3.25%
c
afterwards
Prior
to
January
1,
2002,
2.5%
c
up
c
to
c
age
c
65.
3.25%
c
afterwards
Prior
to
January
1,
2002,
2.5%
c
up
c
to
c
age
c
65.
3.25%
c
afterwards
Prior
to
January
1,
2002,
2.5%
c
up
c
to
c
age
c
65.
3.25%
c
afterwards
3.00%
3.00%
3.50%
3.50%
3.50%
3.50%
7.00%
7.00%
8.00%
8.00%
8.00%
8.00%
The
actuarially
determined
contribution
rates
are
calculated
as
of
Actuarial
Cost
Method
Amortization
Method
Remaining
Amortization
Period
Asset
Valuation
Method
Inflation
Salary
Increases
Cost-of-Living
Adjustments
Social
Security
Wage
Base
Investment
Rate
of
Return
RSI-3B
Town
of
Cromwell,
Connecticut
Notes
to
Required
Supplementary
Information
Connecticut
Municipal
Employees'
Retirement
System
Schedule
of
Contributions
Last
Six
Years
(1)
2020 2019 2018 2017 2016 2015
Actuarial
methods
and
assumptions
used
to
determine
contribution
rates:
(1)
This
schedule
is
intended
to
present
information
for
10
years.
Additional
years
will
be
presented
as
the
information
becomes
available.
None
None
None
None
None
None
Changes
of
Benefit
Terms
96
RSI-4A
Town of Cromwell, Connecticut
Required Supplementary Information
Connecticut State Teachers' Retirement System
Last Six Years (3)
2020
2019
2018
2017
2016
2015
Schedule of Proportionate Share of the Net Pension Liability
Town's proportion of the net pension liability
0.00%
0.00%
0.00%
0.00%
0.00%
0.00%
Town's proportionate share of the net pension liability
$
-
$
-
$
-
$
-
$
-
$
-
State of Connecticut's proportionate share of the net pension liability
associated with the Town
58,819,764
45,353,455
45,941,954
48,469,113
36,803,580
34,017,535
Total
$ 58,819,764
$ 45,353,455
$ 45,941,954
$ 48,469,113
$ 36,803,580
$ 34,017,535
Town's covered payroll
(2)
(2)
(2)
(2)
(2)
(2)
Town's proportionate share of the net pension liability as a percentage
of its covered payroll
0.00%
0.00%
0.00%
0.00%
0.00%
0.00%
Plan fiduciary net position as a percentage of the total pension liability
52.00%
57.69%
55.93%
52.26%
59.50%
61.51%
Schedule of Contributions
2020
2019
2018
2017
2016
2015
Contractually required contribution (1)
$
-
$ -
$
-
$
-
$
-
$
-
Contributions in relation to the contractually required contribution
-
-
-
-
-
-
Contribution deficiency (excess)
$ -
$ -
$ -
$ -
$ -
$ -
Town's covered payroll
(2)
(2)
(2)
(2)
(2)
(2)
Contributions as a percentage of covered payroll
0.00%
0.00%
0.00%
0.00%
0.00%
0.00%
(1)
Local employers are not required to contribute to the plan.
(2)
Not applicable since 0% proportional share of the net pension liability
(3)
These schedules are intended to present information for 10 years. Additional years will be presented as they become available.
97
June 30, 2018
June 30, 2018
June 30, 2016
June 30, 2016
June 30, 2014
June 30, 2014
Entry age
Entry age
Entry age
Entry age
Entry age
Entry age
Level percent of salary,
closed
Level percent of salary,
closed
Level percent of salary,
closed
Level percent of salary,
closed
Level percent of salary,
closed
Level percent of salary,
closed
17.6 years
17.6 years
20.4 years
20.4 years
21.4 years
22.4 years
4 year smoothing
4 year smoothing
4 year smoothing
4 year smoothing
4 year smoothing
4 year smoothing
2.50%
2.50%
2.75%
2.75%
3.00%
3.00%
3.25%-6.50%,
average, including
inflation
3.25%-6.50%,
average, including
inflation
3.25%-6.50%,
average, including
inflation
3.25%-6.50%,
average, including
inflation
3.75%-7.00%,
average, including
inflation
3.75%-7.00%,
average, including
inflation
8.00%
8.00%
8.00%
8.00%
8.50%
8.50%
RP-2014 White Collar
table with employee and
annuitant rates blended
from ages 50 to 80,
projected to the year
2020 using the BB
improvement scale and
further adjusted to grade
in increases (5% for
females and 8% for
males) to rates over age
80. For disabled retirees,
the RPH-2014 Disabled
Mortality table projected to
2017 using the BB
improvementc scale.
RP-2000 Combined
Mortality Table projected 19
years using scale AA, with
a two year setback for
males and females for the
period after service
retirement and for
dependent beneficiaries.
RP-2000 Combined
Mortality Table projected 19
years using scale AA, with
a two year setback for
males and females for the
period after service
retirement and for
dependent beneficiaries.
The actuarially determined
contribution rates are calculated as of
Actuarial Cost Method
Amortization Method
Remaining Amortization Period
Asset Valuation Method
Inflation
Salary Increases
Investment Rate of Return
Mortality
RSI-4B
Town of Cromwell, Connecticut
Notes to Required Supplementary Information
Connecticut State Teachers' Retirement
System Schedule of Contributions
Last Six Years (1)
2020 2019 2018 2017 2016 2015
Actuarial methods and assumptions used to determine contribution rates:
(1) This schedule is intended to present information for 10 years. Additional years will be presented as they become available.
None
Beginning January 1,
2018, member
contributions increased
from 6% to 7% of salary
None
None
None
None
Changes of Benefit Terms
98
RSI-5A
Town of Cromwell, Connecticut
Other Post-Employment Benefit (OPEB)
Plan Last Four Years (1)
2020 2019 2018 2017
Schedule of Changes in Net OPEB Liability and Related
Ratios
Total OPEB liability:
Service cost
$ 162,635
$ 155,706
$ 268,162
$ 260,985
Interest
298,523
286,889
353,821
339,240
Differences between expected and actual experience
(415,727)
36,301
(2,012,609)
(153,061)
Changes of benefit terms
-
-
(29,592)
-
Changes of assumptions
273,319
-
(1,131,229)
-
Benefit payments, including refunds of member contributions
(302,390)
(336,267)
(294,060)
(183,909)
Net change in total OPEB liability
16,360
142,629
(2,845,507)
263,255
Total OPEB liability - July 1
4,250,623
4,107,994
6,953,501
6,690,246
Total OPEB liability - June 30 (a)
$ 4,266,983
$ 4,250,623
$ 4,107,994
$ 6,953,501
Plan fiduciary net
position: Contributions -
employer
$ 406,672
$ 589,868
$ 556,379
$ 407,346
Contributions - TRB subsidy
27,718
26,399
27,682
26,563
Net investment income
(15,808)
35,283
71,871
48,235
Benefit payments, including refunds of member contributions
(302,390)
(336,267)
(294,060)
(183,909)
Administration expenses
(19,085)
(16,718)
(6,253)
(3,899)
Net change in plan fiduciary net position
97,107
298,565
355,619
294,336
Plan fiduciary net position - July 1
1,564,053
1,265,488
909,869
615,533
Plan fiduciary net position - June 30 (b)
$ 1,661,160
$ 1,564,053
$ 1,265,488
$ 909,869
Net OPEB liability - June 30 (a)-(b)
$ 2,605,823
$ 2,686,570
$ 2,842,506
$ 6,043,632
Plan fiduciary net position as a percentage of the total OPEB
liability
38.93%
36.80%
30.81%
13.09%
Covered payroll
$25,023,019
$24,256,883
$ 23,607,672
$ 22,740,011
Net pension liability as a percentage of covered payroll
10.41%
11.08%
12.04%
26.58%
Schedule of Investment Returns
Annual money weighted rate of return, net of investment expense (2.17%) 1.37% 7.21% 6.55%
(1) These schedules are intended to present information for 10 years. Additional years will be presented as they become available.

99
RSI-5B
Town of Cromwell, Connecticut
Required Supplementary Information
Other Post-Employment Benefit (OPEB)
Plan Schedule of Contributions
Last Ten Years
determined contribution
406,672 589,868 556,379 407,346 390,700 496,200 417,000 405,200 298,530 252,465 c
Contribution excess (deficiency)
$ (10,328) c c $ 177,268 c $ (99,621) c c $ (240,654) c c $ (217,800) c c $ (101,700) c c $ (391,500) c c $ (389,600) c c $ (587,900) c c $ (617,727)
Covered payroll
$ 25,023,019 c c c $ 24,256,893 c c $ 23,607,672 c c c $ 22,740,011 c c c $ 22,077,700 c c c $ 24,434,000 c c c $ 24,434,000 c c c $ 20,594,000 c c $
20,594,000 c c c $ 20,257,000 c
Contributions as a percentage of covered payroll
1.63% 2.43% 2.36% 1.79% 1.77% 2.03% 1.71% 1.97% 1.45% 1.25%
100
2020
2019
2018
2017
2016
2015
2014
2013
2012
2011
Actuarially determined contributions
Contributions in relation to the actuarially
$ 417,000 $
412,600 $
656,000 $
648,000 $
608,500 $
597,900 $
808,500 $
794,800 $
886,430 $
870,192
None
None
None
None
None
None
None
None
None
None
Entry
Age
Normal
Entry
Age
Normal
Projected
unit
credit
Projected
unit
credit
Projected
unit
credit
Projected
unit
credit
Projected
unit
credit
Projected
unit
credit
Projected
unit
credit
Projected
unit
credit
5
year
smoothing
5
year
smoothing
5
year
smoothing
5
year
smoothing
5
year
smoothing
5
year
smoothing
5
year
smoothing
5
year
smoothing
5
year
smoothing
5
year
smoothing
2.75%
2.75%
5.00%
N/A
N/A
N/A
N/A
N/A
N/A
N/A
7.00%
7.00%
5.00%
5.00%
5.00%
5.00%
4.50%
4.50%
4.50%
4.50%
Changes
of
Benefit
Terms
Actuarial
Cost
Method
Asset
Valuation
Method
Salary
Increases
Investment
Rate
of
Return
RSI-5C
Town
of
Cromwell,
Connecticut
Notes
to
Required
Supplementary
Information
Other
Post-Employment
Benefit
(OPEB)
Plan
Schedule
of
Contributions
Last
Ten
Years
2020 2019 2018 2017 2016 2015 2014 2013 2012 2011
Actuarial
methods
and
assumptions
used
to
determine
contribution
rates:
N/A
-
not
available
Town,
Public
Works,
BOE
Non-Certified:
RP-
2014
Adjusted
to
2006
Total
Dataset
Mortality
Table
projected
to
valuation
date
with
Scale
MP-
2016.
Police:
RP-2014
Adjusted
to
200
Blue
Collar
Mortality
Table
projected
to
valuation
date
with
Scale
c
MP-
2016.
Town,
Public
Works,
BOE
Non-Certified:
RP-
2014
Adjusted
to
2006
Total
Dataset
Mortality
Table
projected
to
valuation
date
with
Scale
MP-
2016.
Police:
RP-2014
Adjusted
to
200
Blue
Collar
Mortality
Table
projected
to
valuation
date
with
Scale
c
MP-
2016.
N/A
N/A
N/A
N/A
N/A
N/A
N/A
N/A
Mortality
Rate
5.00%
5.00%
5.00%
5.00%
5.00%
5.00%
5.00%
5.00%
5.00%
5.00%
Healthcare
and
dental
Inflation
Rate
-
Ultimate
8.00%
8.00%
8.00%
8.00%
9.00%
9.00%
10.00%
10.00%
8.00%
8.00%
Healthcare
Inflation
Rate
-
Initial
2.75%
2.75%
None
None
None
None
None
None
None
None
Inflation
Rate
Level
dollar
Level
dollar
Level
dollar
Level
dollar
Level
dollar
Level
dollar
Level
dollar
Level
dollar
Level
dollar
Level
dollar
Amortization
Method
July
1,
2017
July
1,
2017
July
1,
2015
July
1,
2015
July
1,
2013
July
1,
2013
July
1,
2011
July
1,
2011
July
1,
2009
July
1,
2009
The
actuarially
determined
contribution
rates
are
calculated
as
of
101
RSI-6A
Town of Cromwell, Connecticut
Required Supplementary Information
Connecticut State Teachers' Retirement Board Retiree Health Insurance
Plan Last Three Years (3)
2020 2019 2018
Schedule of Proportionate Share of the Net OPEB Liability
Town's proportionate share of the net OPEB liability
0.00%
0.00%
0.00%
Town's proportionate share of the collective net OPEB liability
$
-
$
-
$
-
State of Connecticut's proportionate share of the net OPEB liability associated with the Town
9,173,275
9,066,455
11,824,927
Total
$ 9,173,275
$ 9,066,455
c $ 11,824,927
Town's covered payroll
(2)
(2)
(2)
Town's proportionate share of the net OPEB liability as a percentage of its covered payroll
0.00%
0.00%
0.00%
Plan fiduciary net position as a percentage of the total OPEB liability
2.08%
1.49%
1.79%
Schedule of Contributions
Contractually required contribution (1)
$
-
$
-
$
-
Contributions in relation to the contractually required contribution
-
-
-
Contribution deficiency (excess)
$ -
$ -
$ -
Town's covered payroll
(2)
(2)
(2)
Contributions as a percentage of covered payroll
0.00%
0.00%
0.00%
(1) Local employers are not required to contribute to the plan
(2) Not applicable since 0% proportional share of the net OPEB liability
(3) These schedules are intended to present information for 10 years. Additional years will be presented as they become available.
102
None
None
None
July
1,
2018
July
1,
2018
July
1,
2016
Entry
age
Entry
age
Entry
age
Level
percent
of
payroll
Level
percent
of
payroll
Level
percentage,
open
30
years
30
years
30
years
Fair
Value
Fair
Value
Fair
Value
Initial
7.25%
decreasing
to
5.00%
(ultimate)
c
by
c
2022
Initial
7.25%
decreasing
to
5.00%
(ultimate)
c
by
c
2022
Initial
7.25%
decreasing
to
5.00%
(ultimate)
c
by
c
2022
3.25%
to
6.50%,
including
inflation
3.25%
to
6.50%,
including
inflation
3.25%
to
6.50%,
including
inflation
3.00%
3.00%
4.25%
RP-2014
White
Collar
table
with
employee
and
annuitant
rates
blended
from
ages
50
to
80,
projected
to
the
year
2020
using
the
BB
improvement
scale
and
further
adjusted
to
grade
in
increases
(5%
for
females
and
8%
for
males)
to
rates
over
age
80.
c
For
disabled
retirees,
the
RPH-2014
Disabled
Mortality
table
projected
to
2017
using
the
BB
improvement
scale.
Changes
of
Benefit
Terms
The
actuarially
determined
contribution
rates
are
calculated
as
of
Actuarial
Cost
Method
Amortization
Method
Amortization
Period
Asset
Valuation
Method
Healthcare
Inflation
Rate
Salary
Increases
Investment
Rate
of
Return
Mortality
Rate
RSI-6B
Town
of
Cromwell,
Connecticut
Connecticut
State
Teachers'
Retirement
Board
Retiree
Health
Insurance
Plan
Notes
to
Required
Supplementary
Information
Schedule
of
Contributions
Last
Three
Years
(1)
2020 2019 2018
Actuarial
methods
and
assumptions
used
to
determine
contribution
rates:
(1) These
schedules
are
intended
to
present
information
for
10
years.
Additional
years
will
be
presented
as
they
become
available.
Inflation
103
2.75%
2.75%
2.75%
Supplemental
Schedules
General
Fund
The general fund is the principal fund of the Town and is used to account for all activities of the Town, except
those required to be accounted for in another fund. The general fund accounts for the normal recurring activities
of the Town (i.e., general government, public safety, public works, culture and recreation, human services,
education, etc.). These activities are funded principally by property taxes, user fees and grants from other
governmental units.
For reporting in accordance with generally accepted accounting principles, the general fund includes certain
funds that are required to be reported as part of the general fund under the requirements of GASB 54.
104
Schedule
1
Town
of
Cromwell,
Connecticut
General
Fund
Combining Balance Sheet
June
30,
2020
Outside
General Contingency Services Elimination
Fund
Fund
Fund
Entries
Total
Assets
Cash
$ -
$ 73,177 $ - $ -
$ 73,177
Restricted
cash
267,702
- - -
267,702
Investments
15,125,264
150,000 - -
15,275,264
Restricted investments
240,494
- - -
240,494
Receivables
(net):
Property
taxes
742,485
- - -
742,485
Intergovernmental
34,235
- - -
34,235
Other
61,448
- 156,838 -
218,286
Due
from
other
funds
75,038
-
-
(75,038)
-
Total
assets
$
16,546,666
$
223,177 $
156,838 $
(75,038)
$
16,851,643
Liabilities
Accounts
payable
$ 534,520
$ - $ -
$ -
$ 534,520
Accrued
payroll
and
related
liabilities
321,656
- 81,800
-
403,456
Due
to
other
funds
85,384
- 75,038
(75,038)
85,384
Performance
bonds
407,099
-
-
-
407,099
Total
liabilities
1,348,659
-
156,838
(75,038)
1,430,459
Deferred
Inflows
of
Resources
Unavailable
revenue:
Property
taxes
742,485
-------------------------------------------------------------------
742,485
Fund
Balances
Committed
199,866
-
- -
199,866
Assigned
363,300
223,177
- -
586,477
Unassigned
13,892,356
-
-
-
13,892,356
Total
fund
balances
14,455,522
223,177
-
-
14,678,699
Total
liabilities,
deferred
inflows
of
resources
and
fund
balances $
16,546,666
$
223,177
$
156,838
$
(75,038)
$
16,851,643
105
Schedule
2
Town of Cromwell, Connecticut
General Fund
Combining Statement of Revenues, Expenditures and Changes in Fund
Balances
For
The
Year
Ended
June
30,
2020
Revenues:
General
Fund
Contingency
Fund
Outside
Services
Fund
Elimination
c
Entries
Total
Property taxes
$ 44,480,132
$ -
$ -
$ -
$
44,480,132
Intergovernmental
9,905,753
-
-
-
9,905,753
Charges for services
1,438,056
-
403,938
-
1,841,994
Income from investments
388,913
2,772
-
-
391,685
Other
157,014
-
-
-
157,014
c
Total revenues
c
56,369,868
c
2,772
c
403,938
-
c
56,776,578
c
Expenditures:
Current:
General government
6,136,323
- -
-
6,136,323
Public
safety
3,384,222
- 272,729
-
3,656,951
Public
works
3,980,305
- 2,719
-
3,983,024
Culture and recreation
800,919
- -
-
800,919
Human services
617,696
- -
-
617,696
Education
35,074,925
- -
-
35,074,925
Debt
service
3,704,100
-
-
-
3,704,100
c
Total expenditures
c
53,698,490
c
-
275,448
-
53,973,938
c
Excess (deficiency) of revenues
over expenditures
2,671,378
2,772
128,490
-
2,802,640
c
Other financing sources (uses):
Transfers
in
445,433
-
-
(128,490)
316,943
Transfers
out
(2,814,000)
-
c
(128,490)
c
128,490
c
(2,814,000)
Net other financing sources (uses)
(2,368,567)
-
(128,490)
-
(2,497,057)
Net
change
in
fund
balances
302,811
2,772
-
-
305,583
Fund
balances
-
July
1,
2019
(as
restated)
14,152,711
220,405
-
-
14,373,116
Fund
balances
-
June
30,
2020
$ 14,455,522 c
$
223,177
$ -
c
$ -
$
14,678,699
Schedule 3
Town of Cromwell, Connecticut
Report of Tax Collector
For The Year Ended June 30, 2020
Lawful Corrections Collections
Grand
Uncollected
Taxes
Current
Year
Adjusted
Taxes
Net Taxes
Interest
Uncollected
Taxes
List Year
July 1, 2019*
Levy
c Additions
c Deductions
Collectible
Collected
c c and Liens
Total
June 30, 2020
2010
$ 2,544
$ -
$ -
$ -
$ 2,544
$ 78
$ -
$ 78
$ 2,466
2011
17,751
-
-
-
17,751
5,864
328
6,192
11,887
2012
29,941
-
-
-
29,941
2,887
366
3,253
27,054
2013
77,478
-
-
-
77,478
17,462
3,989
21,451
60,016
2014
102,571
-
4
-
102,575
30,015
10,993
41,008
72,560
2015
143,215
-
168
-
143,383
51,323
19,065
70,388
92,060
2016
198,273
-
1,166
81,623
117,816
29,620
38,781
68,401
88,196
2017
656,710
-
4,197
277,279
383,628
219,736
73,206
292,942
163,892
Total Prior
Years
1,228,483
-
5,535
358,902
875,116
356,985
146,728
503,713
518,131
2018
-
44,453,357
110,283
319,249
44,244,391
43,875,025
345,037
44,220,062
369,366
Total
$ 1,228,483
$ 44,453,357
$
115,818
$ 678,151
$ 45,119,507
$ 44,232,010
$ 491,765
$ 44,723,775
887,497
Tax interest receivable 359,988
Tax allowance for doubtful accounts (325,000)
* Amount restated for overpayments Interest allowance for doubtful accounts (180,000)
Net taxes receivable - General Fund $ 742,485
106
Other
Governmental
Funds
Special Revenue Funds
Special revenue funds are used to account for specific revenues that are restricted, committed, or assigned to
expenditures for particular purposes.
Fund
Funding Source
Function
Human Services
State grant
Human services programs and
emergency assistance
Public Safety
Grants and receipt of fees
Public safety programs
Culture and Recreation
State grant and receipt of fees
Culture and recreation programs
Town Improvement Program
State grant
Project improvements as
determined by the Town Council
Public Donations Grant
Donations
Various Town programs
Dog License
Licenses and fees
Animal control program
School Cafeteria
Sale of food and grants
School lunch and breakfast program
Educational Grants
State and Federal grants
Education programs
Solar Incentive
Grant
Public works programs
Debt Service Fund
The debt service fund is used to account for and report resources for the payment of future debt service
payments
Permanent Funds
Permanent funds are used to report resources that are legally restricted to the extent that only earnings, not
principal, may be used for purposes as categorized by the fund title. The Town's permanent fund is the Cemetery
Trust Fund. The Cemetery Trust Fund accounts for the principal amounts bequeathed to the Town with the
stipulation that only the interest thereon may be expended on the care and maintenance of the cemetery.
Schedule
4
(1
of
2)
Town
of
Cromwell,
Connecticut
Combining
Balance
Sheet
Other
Governmental
Funds
June
30,
2020
Special
Revenue
Funds
Assets
Public
Health
Public
c
Safety
Culture
c
and
c
Recreation
c c
Town
c
Improvement
c c c c
Program
Public
c
Donations
c
Grant
Dog
c c c c c
License
Cash
$ 12,966
$
c c
410,993
$
c
274,424
$ -
$
c
216,690
$ 26,226
Investments
Receivables:
-
-
-
13,104
-
-
Intergovernmental
- - - - -
-
Other
- - - - 183
2,157
Due
from
other
funds
- - - - -
-
Other
-
c
c
-
c c
c
-
c c
c
-
c c
c
-
c c
c
-
c c
Total
assets
$ 12,966
c
c
$
c c
410,993
c c
c c
$
c
274,424
c c
c
$ 13,104
c c
c
$
c
216,873
c c
c c
$ 28,383
c c
Liabilities
Accounts
payable
$ - $ 1,850
$ 4,147
$ - $ 6,943
$ 8,361
Accrued
payroll
and
related
liabilities
- -
8,391
- -
-
Unearned
revenue
-
c
-
c
-
c
-
c
-
c
-
c
Total
liabilities
-
c
1,850
c
12,538
c
-
c
6,943
c
8,361
c
Fund
Balances
Nonspendable
-
-
-
-
-
-
Restricted
12,966
-
16,413
-
209,930
-
Committed
-
409,143
245,473
13,104
-
20,022
Assigned
-
c
-
c
-
-
c
-
c
-
c
Total
fund
balances
12,966
c
409,143
c
261,886
13,104
c
209,930
c
20,022
c
Total
liabilities
and
fund
balances
$ 12,966
c
$
410,993
$
274,424
c
$ 13,104
c
$
216,873
$ 28,383
c
(Continued)
107
Schedule
4
(2
of
2)
Town
of
Cromwell,
Connecticut
Combining
Balance
Sheet
Other
Governmental
Funds
June
30,
2020
Special
Revenue
Funds
Permanent
c
Funds
Assets
Total Total
Special Other
School Educational Solar Revenue Debt Cemetery Governmental
c Cafeteria
Grants Incentive
Funds
Service
Trust
Funds
Cash
$
116,200
$
539,019
$
744
$ 1,597,262
$ -
$
3,547
$
1,600,809
Investments
-
-
-
13,104
285,650
7,000
305,754
Receivables:
Intergovernmental
73,847
-
-
73,847
-
-
73,847
Other
-
-
-
2,340
-
-
2,340
Due
from
other
funds
-
85,384
-
85,384
-
-
85,384
Other
18,400
c
-
-
18,400
c
-
-
c
18,400
c
Total
assets
$
208,447
c
$
624,403
c
$
744
c
$ 1,790,337 c
$
285,650
c
$
10,547
c
$
2,086,534
c
Liabilities
Accounts
payable
$ 8,109
$ - $ - $ 29,410
$ - $ - $ 29,410
Accrued
payroll
and
related
liabilities
-
- - 8,391
- - 8,391
Unearned
revenue
28,464
c
623,941
c
-
652,405
c
-
-
c
652,405
c
Total
liabilities
36,573
c
623,941
c
-
690,206
c
-
-
c
690,206
c
Fund
Balances
Nonspendable
-
-
-
-
-
6,237
6,237
Restricted
171,874
-
-
411,183
-
4,310
415,493
Committed
-
462
744
688,948
-
-
688,948
Assigned
-
-
c
-
c
-
c
285,650
c
-
285,650
c
Total
fund
balances
171,874
c
462
c
744
c
c
1,100,131
c
285,650
c
10,547
c
1,396,328
Total
liabilities
and
fund
balances
$
208,447
c
$
624,403
c
$
744
c
$ 1,790,337 c
$
285,650
c
$
10,547
c
$
2,086,534
c
(Concluded)
108
Town of Cromwell, Connecticut
Schedule 5
(1 of 2)
Combining Statement of Revenues, Expenditures and Changes in Fund Balances
Other Governmental Funds
For The Year Ended June 30, 2020
Special Revenue Funds
Revenues:
Public
Health
Public
Safety
Culture and
Recreation
Town
Improvement
c Program
Public
Donations
Grant
Dog
c License
Intergovernmental
$ 10,000
$ 15,995
$ 5,500
$ -
$ 10,196
$ -
Charges for services
-
65,585
202,205
-
-
7,687
Income from investments
-
466
127
163
-
320
Contributions
-
-
-
-
73,037
-
Total revenues
10,000
82,046
207,832
163
83,233
8,007
Expenditures:
Current:
General government
-
-
-
-
19,262
-
Public safety
-
20,652
-
-
5,143
5,762
Culture and recreation
-
-
257,498
-
9,684
-
Human services
5,706
-
-
-
40,190
-
Education
-
-
-
-
-
-
Total expenditures
5,706
20,652
257,498
-
74,279
5,762
Net change in fund balances
4,294
61,394
(49,666)
163
8,954
2,245
Fund balances - July 1, 2019 (as restated)
8,672
347,749
311,552
12,941
200,976
17,777
Fund balances - June 30, 2020
$ 12,966
$ 409,143
$ 261,886
$ 13,104
$ 209,930
$ 20,022
(Continued)
109
Town of Cromwell, Connecticut
Schedule 5
(2 of 2)
Combining Statement of Revenues, Expenditures and Changes in Fund
Balances
Other
Governmental
Funds
For
The
Year
Ended
June
30,
2020
Special Revenue Funds
Permanent
Funds
Total Total
Special Other
110
School
c Cafeteria
Educational
Grants
Solar
Incentive
Revenue
Funds
Debt
Service
Cemetery
Trust
Governmental
Funds
Revenues:
Intergovernmental
$
405,165
$
1,735,957
$ -
$ 2,182,813
$ -
$ -
$
2,182,813
Charges
for
services
310,455
-
-
585,932
-
-
585,932
Income
from
investments
-
-
-
1,076
-
131
1,207
Contributions
-
-
-
73,037
-
-
73,037
Total
revenues
715,620
1,735,957
-
2,842,858
-
131
2,842,989
Expenditures:
Current:
General government
-
-
-
19,262
-
-
19,262
Public
safety
-
-
-
31,557
-
-
31,557
Culture
and
recreation
-
-
-
267,182
-
-
267,182
Human
services
-
-
-
45,896
-
-
45,896
Education
781,862
1,860,537
-
2,642,399
-
-
2,642,399
Debt
service
-
-
-
-
249,944
-
249,944
Total expenditures
781,862
1,860,537
-
3,006,296
249,944
-
3,256,240
Net
change
in
fund
balances
(66,242)
(124,580)
-
(163,438)
(249,944)
131
(413,251)
Fund
balances
-
July
1,
2019
(as
restated)
238,116
125,042
744
1,263,569
535,594
10,416
1,809,579
Fund
balances
-
June
30,
2020
$
171,874
$ 462
$ 744
$ 1,100,131
$ 285,650
$ 10,547
$
1,396,328
(Concluded)
111
Schedule
6
Town of Cromwell, Connecticut
Dog License Fund
Schedule of Revenues, Expenditures and Changes in Fund
Balance
Budget
and
Actual
For
the
Year
Ended
June
30,
2020
Additional Variance
Original Appropriations Final With
Final
Budget
and Transfers
Budget
Actual Budget
Revenues:
Charges for services
$ 6,500
$ -
$ 6,500
$ 7,687
$ 1,187
Income from investments
-
-
-
320
c
320
Total revenues
6,500
-
6,500
8,007
c
1,507
Expenditures:
Veterinary fees
4,000
-
4,000
1,612
2,388
Contracted services
10,924
-
10,924
8,463
2,461
Vehicle maintenance
1,500
-
1,500
246
1,254
Equipment repair/replacement
1,000
-
1,000
608
392
Departmental expense
1,200
-
1,200
1,176
24
Training/workshops
1,200
-
1,200
1,014
186
Uniforms
1,200
-
1,200
674
526
Gasoline/other fluids
3,000
-
3,000
1,993
c
1,007
Total expenditures
24,024
-
24,024
15,786
c
8,238
Excess (deficiency) of revenues over
expenditures
(17,524)
-
(17,524)
(7,779)
9,745
Other financing sources
(uses) Appropriation of fund
balance
7,500
-
7,500
-
(7,500)
Transfers
in
10,024
-
10,024
10,024
c
-
Net
change
in
fund
balance
$ -
$ -
$ -
2,245
$ 2,245
Fund
balance
-
July
1,
2019
17,777
c
Fund
balance
-
June
30,
2020
$
20,022
c
Reconciliation to Schedule 5
Expenditures
Budgetary Basis
$ 15,786
Amount
paid
from
General
Fund
(10,024)
GAAP
Basis
-
Schedule
5,
Page
1
$ 5,762
Internal
Service
Funds
Internal Service funds are used to account for the providing of goods or services provided by one department
to other departments of the Town on a cost reimbursement basis or accounting for risk retention.
Fund
Function
Dental Insurance
To account for dental and other benefits for Town and Board of
Education employees.
Heart and Hypertension
To account for Heart and Hypertension claims of Police and Fire
employees.
112
Schedule 7
Town of Cromwell, Connecticut
Internal Service Funds
Combining Statement of Net
Position June 30, 2020
Heart
Dental and
c Insurance Hypertension Total
Assets
Cash $ 166,822 $
156,388 $ 323,210
Investments - 75,000 75,000
Total assets 166,822 231,388 398,210
Liabilities
Current liabilities:
Accounts payable
-
33
33
Claims payable
9,000
95,770
104,770
Total current liabilities
9,000
95,803
104,803
Noncurrent liability:
Claims payable
-
41,044
41,044
Total liabilities
9,000
136,847
145,847
Net Position
Unrestricted
$ 157,822
$ 94,541
$ 252,363
Schedule
113
Town of Cromwell, Connecticut
Internal Service Funds
113
Combining Statement of Revenues, Expenses and Changes in Net
Position For The Year Ended June 30, 2020
Heart
Dental
and
c Insurance
Hypertension
Total
Operating revenues:
Charges for services $
293,728
$ 27,875 $ 321,603
Operating expenses:
Claims
244,795
9,999
254,794
Change in net position
48,933
17,876
66,809
Total net position - July 1, 2019 (as restated)
108,889
76,665
185,554
Total net position - June 30, 2020
$ 157,822
$ 94,541
$ 252,363
Schedule
114
Town of Cromwell, Connecticut
Internal Service Funds
114
Combining Statement of Cash Flows
For The Year Ended June 30, 2020
Dental
Heart
and
c Insurance
Hypertension
Total
Cash flows from (used in) operating activities:
Cash received for charges for services $ 293,728
$ 27,875
$ 321,603
Cash paid for benefits and claims (250,795)
(183)
(250,978)
Cash paid for administration -
33
33
Net cash from (used in) operating activities 42,933
27,725
70,658
Cash and cash equivalents - July 1, 2019 (as restated) 123,889
203,663
327,552
Cash and cash equivalents - June 30, 2020 $ 166,822
$ 231,388
$ 398,210
Reconciliation to schedule 7:
Cash and cash equivalents per above $ 166,822
$ 231,388
$ 398,210
Cash and cash equivalents reported as investments -
(75,000)
(75,000)
Cash - schedule 7 $ 166,822
$ 156,388
$ 323,210
Reconciliation of operating income (loss) to net cash
from operating activities:
Operating income (loss)
$
48,933
$
17,876
$
66,809
Adjustments to reconcile operating income (loss) to
net cash from operating activities:
Increase (decrease) in:
Accounts and other payables
-
33
33
Claims payable
(6,000)
9,816
3,816
Net cash from operating activities
$ 42,933
$ 27,725
$ 70,658
Fiduciary
Funds
Fiduciary Funds
Fiduciary funds are used to account for assets held by the Town in a trustee capacity for individuals, private
organizations, other governments, and/or other funds. These include pension trust, private-purpose trust, and
agency funds.
Pension Trust Fund
Fund
Function
Employees Pension Fund
To account for the activities of the Employees’ Retirement
System, which accumulates resources for pension benefit
payments to qualified employees.
OPEB Trust Fund
Fund
Function
OPEB Trust Fund
To account for the activities of the Town OPEB Plan which
accumulates resources for OPEB benefits.
Private - Purpose Trust
Fund
Function
The Pitruzzello Scholarship Fund
To account for the principle amounts bequeathed to the Town with
the stipulation that only the interest thereon may be expended
annually for two scholarships to the Cromwell High School
graduating class.
Agency Funds
Fund
Function
Student Activities Fund
To account for various activities as defined by State Statutes
undertaken by students of the public school system.
Schedule 10
Town of Cromwell, Connecticut
Agency Funds
Statement of Changes in Assets and
Liabilities For the Year Ended June 30, 2020
Balance Balance
July 1, 2019 Additions Deductions June 30, 2020
Assets
Student activities:
Cash
$ 367,786
$ 966,145
$ 981,370
$ 352,561
Due from other funds
1,000
-
1,000
-
Total assets
$ 368,786
$ 966,145
$ 982,370
$ 352,561
Liabilities
Student activities:
Payable to student organizations
$ 368,786
$ 966,145
$ 982,370
$ 352,561
115
Statistical
Section
This part of the Town's comprehensive annual financial report presents detailed information as a context for
understanding what the information in the financial statements, note disclosures, and required supplementary
information says about the Town's overall financial health.
Table
Description
Financial Trend (Tables 1-4)
These schedules contain trend information to help the reader
understand how the Town's financial performance and well-being
have changed over time.
Revenue Capacity (Tables 5-8)
These schedules contain information to help the reader assess the
Town's most significant local revenue source, the property tax.
Debt Capacity (Tables 9-12)
These schedules present information to help the reader assess
the affordability of the Town's current levels of outstanding debt
and the Town's ability to issue additional debt in the future.
Demographic and
Economic Information
(Tables 13-14)
These schedules offer demographic and economic indicators to
help the reader understand the environment within which the
Town's financial activities take place.
Operating Information (Tables 15-17)
These schedules contain service and infrastructure data to help
the reader understand how the information in the Town's financial
report relates to the services the Town provides and the activities
it performs.
Sources: Unless otherwise noted, the information in these schedules is derived from the comprehensive
annual financial reports for the fiscal year.
Table 1
Town of Cromwell,
Connecticut
Net Position by Component
Last Ten Years
(Unaudited)
June 30,
2019
2020
(as
restated)
2018 2017 2016 2015 2014 2013 2012 2011
Net investment in capital assets
Restricted for:
Endowments:
$
97,968,700
$
94,991,214
$
92,647,243
$
90,614,975
$
90,372,051
$ 90,158,279
$
90,349,694
$
91,271,301
$
92,786,514
$ 90,389,434
Nonexpendable
6,237
6,237
56,237
56,237
56,237
56,237
56,237
56,269
56,269
6,269
Expendable
4,310
4,179
5,801
5,287
4,813
4,267
3,825
3,061
3,010
3,749
Public safety
23,212
27,225
24,248
23,879
8,886
8,886
10,068
10,156
11,067
9,439
Public works
2,904,870
2,572,726
1,980,141
1,708,358
1,913,160
1,764,852
1,704,788
1,607,149
1,527,723
1,634,286
Culture and recreation
163,256
108,538
86,998
104,555
105,992
105,677
110,568
108,518
115,767
64,941
Human service
52,841
34,444
32,305
25,535
21,494
21,399
15,359
5,966
7,505
7,059
Education
171,874
228,413
293,160
299,840
207,981
149,950
90,207
-
84,767
80,844
Unrestricted
7,029,988 c
8,509,913 c
8,252,920 c
7,805,843 c
6,425,203 c
6,221,114 c
8,400,738 c
7,519,118 c
5,874,087 c
7,354,902 c
Total net position $ 108,325,288 c c c $ 106,482,889 c c c $ c 103,379,053 c c $ 100,644,509 c c c $ 99,115,817 c c $ 98,490,661 c c c $ 100,741,484 c c c $ 100,581,538 c c c $
100,466,709 c c c $ 99,550,923 c
116
Table 2
Town of Cromwell,
Connecticut
Changes in Net
Position Last Ten
Years (Unaudited)
For the Year Ended June 30,
2020
2019
2018
2017
2016
2015
2014
2013
2012
2011
Expenses:
General government
$ 4,056,518
$ 3,927,840
$ 5,467,135
$ 6,018,788
$ 5,688,367
$ 5,472,277
$ 5,557,370
$ 5,578,265
$ 5,018,686
$ 4,745,753
Public safety
5,956,091
5,649,536
3,869,319
3,578,942
4,233,769
3,584,653
3,484,220
3,451,918
3,346,263
3,266,290
Public works
9,658,198
9,277,331
8,439,623
8,312,654
7,819,385
8,199,804
7,687,149
7,507,231
7,781,074
7,084,009
Culture and recreation
1,353,059
1,323,812
1,103,036
1,086,816
1,060,721
1,015,493
1,001,837
1,018,166
1,015,892
980,589
Human services
819,289
746,421
606,146
683,617
623,442
606,338
595,427
610,927
609,527
586,961
Education
39,114,940
37,882,197
38,257,417
37,792,620
35,274,601
34,400,356
33,609,091
32,074,662
31,961,198
31,258,609
Interest 243,502
507,863
667,621
680,936
715,187
881,704
948,731
1,164,077
1,275,276
1,377,511
Total expenses 61,201,597 c
c c c 59,315,000
c c 58,410,297
c c 58,154,373
c c c 55,415,472
c c 54,160,625
c c c 52,883,825
c c 51,405,246
c c c 51,007,916
c c c 49,299,722
Program revenues:
Charges for
services:
117
General government
508,943
627,956
716,693
737,467
572,676
700,864
695,823
697,430
518,033
449,200
Public safety
585,833
461,081
465,612
537,403
721,983
527,056
409,662
64,938
318,768
370,556
Public works
3,039,697
2,890,947
2,633,822
2,296,825
2,139,166
2,049,278
1,800,683
2,327,371
1,837,469
1,750,064
Culture and recreation
209,704
354,096
49,834
54,822
52,573
149,472
150,762
54,089
118,897
122,853
Human services
32,549
13,821
17,188
14,474
9,856
7,633
10,859
5,186
7,679
5,779
Education
379,251
526,627
519,432
572,506
591,605
615,086
457,598
516,707
595,128
563,268
Operating grants and contributions
11,779,381
11,328,763
12,033,737
12,263,848
9,486,370
9,871,178
9,695,887
9,055,543
9,265,156
8,646,431
Capital grants and contributions 1,710,793 c
1,944,708 c
338,128
147,340
880,759
343,140
529,426
206,751
87,739
2,705,585
Total program revenues 18,246,151 c
c c c 18,147,999
c c 16,774,446
c c 16,624,685
c c c 14,454,988
c c 14,263,707
c c c 13,750,700
c c 12,928,015
c c c 12,748,869
c c c 14,613,736
Net expenses (42,955,446)
c
(41,167,001)
c (41,635,851)
c (41,529,688)
c (40,960,484)
c (39,896,918)
c
(39,133,125)
c (38,477,231)
c
(38,259,047)
c
(34,685,986)
General
revenues:
Property taxes
43,949,313
44,067,022
43,490,210
42,288,843
41,105,060
40,220,941
38,905,611
38,233,934
37,080,402
36,897,559
Grants and contributions not
restricted to specific programs
106,486
57,517
77,996
144,436
152,474
242,913
244,792
230,094
384,656
246,964
Income from investments
585,010
646,578
371,990
150,791
74,416
45,660
46,556
38,321
34,986
71,930
Other
157,036
171,121
392,924
474,310
253,690
193,413
96,112
89,711
359,789
2,922,546
Total general revenues
c c c 44,797,845
c c c 44,942,238
c c 44,333,120
c c 43,058,380
c c c 41,585,640
c c 40,702,927
c c c 39,293,071
c c 38,592,060
c c c 37,859,833
c c c 40,138,999
Capital contributions
-
-
1,856,522 c
-
-
-
-
-
1,315,000
-
Changec inc netc position
c c $c 1,842,399c
c
c c $c 3,775,237c c
c c $c 4,553,791c c
c c $c 1,528,692c c
c c $ 625,156c c
c c $ 806,009c c
c c $ 159,946c c
c c $ 114,829c c
c c $ 915,786c c
c c $c 5,453,013c c
Table 3
Town of Cromwell, Connecticut
Fund Balances, Governmental Funds
Last Ten Years
(Modified Accrual Basis of
Accounting)
(Unaudited)
June 30
2019
2020
(as restated)
2018
2017
2016
2015
2014
2013
2012
2011
General fund:
Nonspendable
$ -
$ -
$ -
$ -
$ -
$ -
$ -
$ -
$ 5,758
$ -
Committed
199,866
879,001
629,000
690,000
872,400
1,005,793
161,500
51,000
70,000
37,600
Assigned
586,477
249,088
21,595
1,621
24,536
50,402
51,186
15,434
8,146
9,830
Unassigned
13,892,356
13,245,027
11,641,051
9,416,756
7,764,001
7,730,698
7,634,146
6,539,226
4,834,817
4,242,189
Total general fund
14,678,699
14,373,116
12,291,646
10,108,377
8,660,937
8,786,893
7,846,832
6,605,660
4,918,721
4,289,619
All other governmental funds:
Nonspendable
6,237
6,237
72,390
72,295
72,651
85,239
92,458
95,162
92,587
45,464
Restricted
3,320,363
3,222,518
3,103,638
5,244,756
3,317,127
2,841,738
4,072,626
6,056,630
3,859,611
4,295,655
Committed
6,615,836
9,684,102
5,019,276
5,266,008
3,074,316
2,891,600
2,912,762
2,718,022
2,700,839
3,306,672
Assigned
285,650
755,999
691,919
435,441
1,778,374
1,478,962
1,516,291
1,659,841
1,616,171
1,595,934
Unassigned
-
-
-
(24,100)
-
-
-
(153,504)
(213,923)
-
Total all other governmental funds
10,228,086
13,668,856
8,887,223
10,994,400
8,242,468
7,297,539
8,594,137
10,376,151
8,055,285
9,243,725
118
Grand total
$
24,906,785
$ 28,041,972
$ 21,178,869
$ 21,102,777 c
$ 16,903,405
$ 16,084,432 c
$ 16,440,969
$ 16,981,811
$ 12,974,006
$ 13,533,344
Table 4
Town of Cromwell, Connecticut
Changes in Fund Balances - Governmental
Funds Last Ten Years
(Modified Accrual Basis of Accounting)
(Unaudited)
For the Year Ended June 30
2020
2019
2018
2017
2016
2015
2014
2013
2012
2011
Revenues:
Property taxes
$ 44,480,132
$ 43,939,302
$ 43,419,649
$ 42,184,309
$ 40,874,985
$ 39,967,103
$ 38,862,600
$ 38,277,712
$ 37,357,669
$ 36,823,715
Intergovernmental
14,023,623
10,530,630
12,575,512
12,688,152
10,649,238
10,628,891
10,509,748
9,523,609
9,945,197
10,959,068
Charges for services
4,600,377
4,224,160
3,989,624
3,798,882
3,745,960
3,562,034
3,088,594
3,261,535
3,096,675
3,143,438
Income from investments
585,010
646,578
371,990
150,791
74,416
45,660
46,556
38,335
34,986
71,930
Contributions
73,037
59,834
78,659
79,041
43,347
52,472
-
-
145,516
85,306
Other
157,036
694,796
634,892
691,946
436,387
430,639
508,603
490,742
826,604
731,873
Total revenues 63,919,215
60,095,300
61,070,326
59,593,121
55,824,333
54,686,799
53,016,101
51,591,933
51,406,647
51,815,330
Expenditures:
Current:
General government
6,155,585
5,899,074
5,447,494
5,533,320
5,401,356
5,277,296
5,225,911
5,187,874
5,063,775
4,911,295
Public safety
3,688,508
3,815,962
3,609,148
3,574,082
3,637,247
3,548,071
3,321,403
3,319,469
3,153,617
3,052,028
Public works
5,839,055
5,774,110
6,039,651
5,855,601
5,554,003
5,874,665
5,402,073
5,303,360
5,640,953
5,111,350
Culture and recreation
1,068,101
1,054,597
1,050,555
1,005,917
984,242
939,627
932,059
941,065
938,222
897,512
Human services
663,592
633,652
605,908
633,474
571,553
556,978
546,442
565,727
549,850
546,407
Education
37,717,324
34,087,170
36,804,161
35,971,609
33,215,350
32,722,230
31,672,231
30,328,029
30,460,100
29,616,635
Debt service:
Principal
3,320,800
2,780,000
2,925,343
2,907,414
2,881,922
2,700,000
2,165,000
2,570,000
2,590,000
2,703,589
Interest
633,244
839,111
867,893
797,683
878,716
1,024,114
1,101,877
2,053,521
1,318,438
1,485,189
Capital outlay
7,968,193
6,012,633
3,735,424
5,253,390
1,922,893
2,408,200
3,189,947
2,431,475
2,251,030
8,488,214
Total expenditures 67,054,402
60,896,309
61,085,577
61,532,490
55,047,282
55,051,181
53,556,943
52,700,520
51,965,985
56,812,219
Excess (deficiency) of revenues over
expenditures (3,135,187) (801,009) (15,251) (1,939,369) 777,051 (364,382) (540,842) (1,108,587) (559,338) (4,996,889)
Other financing sources (uses):
Issuance of refunding debt
-
6,940,000
6,540,000
-
-
-
-
14,075,000
-
-
Payment to refunded bond escrow agent
-
-
(7,235,849)
-
-
-
-
(10,891,758)
-
-
Issuance of debt
-
-
-
5,520,000
-
-
-
14,075,000
-
-
Premium
-
950,014
787,192
618,741
-
-
-
1,933,149
-
-
Transfers in
3,130,943
1,874,344
1,415,747
2,731,682
3,398,598
850,726
1,455,919
564,388
1,026,429
1,522,014
Transfers out
(3,130,943)
(1,874,344)
(1,415,747)
(2,731,682)
(3,398,598)
(850,726)
(1,455,919)
(564,388)
(1,026,429)
(1,522,014)
Net other financing sources (uses)
-
7,890,014
91,343
6,138,741
-
-
-
5,116,391
-
-
Net change in fund balances
$ (3,135,187)
$ 7,089,005
$ 76,092
$ c c c
4,199,372
$ 777,051
$ (364,382)
$ (540,842)
$ 4,007,804
$ (559,338)
$ (4,996,889)
Debt service as a percentage of
noncapital expenditures
6.66%
6.59%
6.61%
6.58%
7.08%
7.07%
6.49%
9.20%
7.86%
8.67%
119
Town
of
Cromwell,
Connecticut
Assessed
and
Estimated
Actual
Value
of
Taxable
Property
Last
Ten
Years
(Unaudited)
Table
5
Real
Property
Personal
Property
Totals
(1) (1) (2) (1) (1) (1) (1) (2) (2) (3)
Total
Total Motor Percentage
Industrial
and Motor Vehicle
and of
Total
(1) Assessed
actual
values
taken
from
the
Board
of
Assessment
Appeals
corrected
abstracts
for
the
respective
year.
(2) Personal
property
value
based
on
a
70%
assessment
ratio.
(3) From
Table
7.
120
c c
Residential Commercial
Motor
Personal
Vehicle
and
Personal
Personal
Property
Total
Assessed
Value
to
Total
Year
Net
Real
Property
Vehicle
Property
Property
Less
Estimated
Total
Estimated
Total
Direct
Ended
Assessed
Assessed
Estimated
Actual
Assessed
Assessed
Assessed
Exempt
Actual
Assessed
Actual
Estimated
Tax
June
30
Value
Value
Value
Value
Value
Value
Property
Value
Value
Value
Actual
Value
c c
Rate
2020
$
913,393,280
$
403,215,194
$
1,880,869,249
$
117,983,740
$
170,625,700
$
288,609,440
$154,761,795
$
412,299,200
$
1,450,456,119
$
2,072,080,170
70.00%
30.33
2019
907,313,244
404,893,598
1,874,581,203
116,742,813
164,241,820
280,984,633
148,445,958
401,406,619
1,444,745,517
2,063,922,167
70.00%
30.33
2018
879,765,080
313,842,920
1,705,154,286
115,518,845
149,529,320
265,048,165
105,902,880
378,640,236
1,352,753,285
1,932,504,693
70.00%
31.68
2017
875,706,010
313,087,250
1,698,276,086
113,093,380
125,194,040
238,287,420
103,740,845
340,410,600
1,323,339,835
1,890,485,479
70.00%
31.38
2016
869,068,040
310,767,740
1,685,479,686
110,848,030
100,078,570
210,926,600
100,443,445
301,323,714
1,290,318,935
1,843,312,764
70.00%
31.38
2015
859,849,100
310,009,490
1,671,226,557
108,712,650
91,992,430
200,705,080
98,711,015
286,721,543
1,271,852,655
1,816,932,364
70.00%
31.18
2014
855,174,540
307,626,058
1,661,143,711
106,322,210
85,231,700
191,553,910
97,046,655
273,648,443
1,257,307,853
1,796,154,076
70.00%
30.75
2013
988,568,681
346,750,399
1,907,598,686
105,985,220
80,652,960
186,638,180
110,139,555
266,625,971
1,411,817,705
2,016,882,436
70.00%
27.06
2012
979,848,650
344,645,530
1,892,134,543
99,133,353
77,960,740
177,094,093
109,326,488
252,991,561
1,392,261,785
1,988,945,407
70.00%
26.80
2011
968,599,140
347,044,110
1,879,490,357
95,397,097
74,082,420
169,479,517
107,479,838
242,113,596
1,377,642,929
1,968,061,327
70.00%
26.84
Town of Cromwell,
Connecticut
Principal Property Taxpayers
Current Year and Nine Years
Ago (Unaudited)
Table 6
2020
2011
Assessed
Percentage
Net Taxable
Assessed
Percentage
Net Taxable
Name
Value
Rank
Grand List
Value
c Rank
Grand List
Algonquin Gas Trans Co.
$ 89,471,670
1
6.17%
$ c 9,961,440
3
0.72%
Covenant Home Inc.
22,989,700
2
1.58%
24,961,440
1
1.81%
Scannell LLC
16,504,320
3
1.14%
-
N/A
0.00%
HBN-CSC LLC
16,482,210
4
1.14%
-
N/A
0.00%
Connecticut Light and Power
12,089,410
5
0.83%
7,525,020
6
0.55%
TNO Cromwell LLC
10,994,340
6
0.76%
-
N/A
0.00%
Cromwell Realty LLC
10,114,338
7
0.70%
-
N/A
0.00%
Tournament Playes Club
9,251,200
8
0.64%
-
N/A
0.00%
Infinitely Cromwell Property Limited
8,958,740
9
0.62%
8,761,700
4
0.64%
Main Street Equity LLC
8,518,300
10
0.59%
8,733,930
5
0.63%
Shaner SPE Associates Limited
N/A
N/A
N/A
10,395,000
2
0.75%
IRNM Fee Cromwell LLC
N/A
N/A
N/A
7,175,000
7
0.52%
CSE Cromwell LLC
N/A
N/A
N/A
6,835,040
8
0.50%
R A Cromwell LLC
N/A
N/A
N/A
6,789,200
9
0.49%
Leigh Cromwell LLC
N/A
N/A
N/A
6,720,000
10
0.49%
Totals
$ 205,374,228
14.17%
$ 97,857,770
7.10%
Based on October 1, 2018 and 2009 net taxable grand list
of:
N/A - Not applicable.
Source: Town Assessor Department.
$ 1,450,456,119 $ 1,377,642,929
121
Table 7
Town of Cromwell, Connecticut
Property Tax Rates, Levies and
Collections Last Ten Years
(Unaudited)
Total Collections to Date
Year
Ended
c June 30
(1)
Tax Rate
c c c in Mills
Grand
List of
c c c October 1,
Total
Adjusted
Tax Levy
Net
Current Tax
c c Collections
Percent of
Current Levy
c c Collected
Collections in
Subsequent
Years
Total
c c Collections
Percentage of
c Levy Collected
Current
Delinquent
Balance
2020
30.33
2018
$ 44,244,391
$ 43,875,025
99.17%
$ -
$ 43,875,025
99.2%
$ 369,366
2019
30.33
2017
43,606,214
43,272,536
99.23%
219,736
43,492,272
99.7%
163,892
2018
31.68
2016
42,885,783
42,431,842
98.94%
365,745
42,797,587
99.8%
88,196
2017
31.38
2015
42,023,539
41,732,354
99.31%
199,125
41,931,479
99.8%
92,060
2016
31.38
2014
40,523,481
40,371,928
99.63%
78,993
40,450,921
99.8%
72,560
2015
31.18
2013
39,984,367
39,681,046
99.24%
243,305
39,924,351
99.8%
60,016
2014
30.75
2012
38,809,552
38,491,271
99.18%
291,227
38,782,498
99.9%
27,054
2013
27.06
2011
38,242,374
37,862,390
99.01%
368,097
38,230,487
100.0%
11,887
2012
26.80
2010
37,316,375
36,967,505
99.07%
346,404
37,313,909
100.0%
2,466
2011
26.84
2009
36,870,036
36,484,059
98.95%
385,977
36,870,036
100.0%
-
Source: Town Tax Collector
(1) Tax levy is per $1,000 of the assessed value of taxable property.
122
123
Table 8
Town of Cromwell, Connecticu
Direct and Overlapping Property Tax
Rates Last Ten Years
(Unaudited)
Fiscal
c c Year
(1)
Town
Operating
c Millage
(1)
Debt
Service
c Millage
(1)
School
Operating
c Millage
Total
Town
c Millage
Cromwell
Fire District
Total Direct
and
Overlapping
Rate
2020
10.00
2.13
18.20
30.33
2.50
32.83
2019
10.00
2.13
18.20
30.33
2.50
32.83
2018
10.46
2.22
19.00
31.68
2.25
33.93
2017
10.35
2.20
18.83
31.38
2.25
33.63
2016
9.41
2.51
19.46
31.38
2.25
33.63
2015
9.98
2.54
18.66
31.18
2.10
33.28
2014
10.10
2.23
18.42
30.75
2.10
32.85
2013
8.70
2.31
16.05
27.06
1.89
28.95
2012
8.52
2.40
15.88
26.80
1.89
28.69
2011
8.46
2.62
15.76
26.84
1.80
28.64
(1) The Town has no individual direct rates
Source: Cromwell Fire District, and Town of Cromwell
Table
9
Town
of
Cromwell,
Connecticut
Ratios
of
Outstanding
Debt
by
Type
Last
Ten
Years
(Unaudited)
Year
Ended
c
June
30
General
Obligation
Bonds
Equipment
Financing
Notes
c c
Premium
Total
Percentage
of
Actual
Taxable
Value
of
Property
Percentage
of
Personnel
Income
Debt
Per
c
Capita
2020
$
21,425,000
$ 335,661
$
2,565,604
$
24,326,265
1.18%
3.43%
$
1,657
2019
24,435,000
646,461
3,037,036
28,118,497
1.36%
4.26%
2,005
2018
22,750,605
-
2,475,605
25,226,210
1.31%
4.06%
1,796
2017
25,565,187
-
2,020,187
27,585,374
1.46%
4.44%
1,958
2016
22,516,126
-
1,661,126
24,177,252
1.31%
4.08%
1,718
2015
25,502,134
-
1,882,134
27,384,268
1.51%
4.62%
1,945
2014
26,320,000
-
2,103,142
28,423,142
1.58%
4.86%
2,022
2013
28,485,000
-
2,324,150
30,809,150
1.53%
4.65%
2,183
2012
27,625,000
889,864
450,914
28,965,778
1.46%
4.56%
2,078
2011
30,215,000
946,243
478,608
31,639,851
1.61%
5.01%
2,265
Note:
Details
regarding
the
Town's
outstanding
debt
can
be
found
in
the
notes
to
the
financial
statements.
124
125
Table 10
Town of Cromwell, Connecticut
Direct and Overlapping Governmental Activities
Debt June 30, 2020
(Dollars in Thousands)
(Unaudited)
Debt
Percentage
Applicable
Amount
Applicable
Government Unit
c Outstanding
c c c to Town (1)
to Town
Overlapping debt:
Cromwell Fire District
Governmental funds
$ 3,573,571
100.00%
$ 3,573,571
(Water) Enterprise fund
2,314,218
0.00%
-
Mattabassett District
57,112,706
8.61%
4,917,404
Subtotal, overlapping debt
8,490,975
Town of Cromwell, direct debt
24,326,265
Total direct and overlapping debt
$ 32,817,240
(1) 100% of the residents of the Fire Districts are also residents of the Town of Cromwell; accordingly all tax
supported debt for the Fire District is included with the Town of Cromwell as overlapping debt. Debt supported
by revenue sourced by the enterprise fund are not included.
The Town is responsible for a pro-rata share of the Mattabassett District's debt based on population
Source: Cromwell Fire District, Mattabassett District and Town of Cromwell.
126
Table
11
Town of Cromwell, Connecticut
Schedule
of
Debt
Limitation
Connecticut General Statutes, Section 7-374 (b)
For
The
Year
Ended
June
30,
2020
(Unaudited)
Tax
Base:
Total
tax
collections
(including
interest
and
lien
fees)
for
prior
year
Town $
43,510,899
Cromwell
Fire
District
3,618,583
Total
Base
(1) $
47,129,482
General Urban Pension
Debt
limitation:
Purpose
Schools
Sewers
Renewal
Deficit
2
1/4
times
base
$ 106,041,335
$ - $
- $ - $ -
4
1/2
times
base - 212,082,669 - - -
3
3/4
times
base - - 176,735,558 - -
3
1/4
times
base
3
times base
- - -
-
-
-
153,170,817
-
-
c
141,388,446
Total
debt
limitation
c c
106,041,335
c c
212,082,669
176,735,558
c c
153,170,817
c c
141,388,446
Indebtedness:
Bonds
payable
9,328,969
5,156,031
6,940,000
-
-
Cromwell
Fire
District
3,573,571
-
-
-
-
Total indebtedness
12,902,540
5,156,031
6,940,000
-
-
Debt
limitation
in
excess
of
outstanding
debt
$
93,138,795
$ 206,926,638
$
169,795,558
$153,170,817
$141,388,446
The
total
net
indebtedness
above
amounts
to:
$
24,998,571
In
no
event
shall
total
indebtedness
exceed
seven
times
the
base
for
debt
limitation
computation: $329,906,374
(1)
Mattabassett
District
debt
is
not
included
as
part
of
the
Town's
debt
limitation
as
the
debt
is
not
repaid
from
property
taxes,
but
with
other
revenue
sources.
127
Table 12
Town of Cromwell, Connecticut
Legal Debt Margin
Information Last Ten Years
(Unaudited)
Year
Ended
June 30
Debt
Limit
Net Debt
Applicable
To Limit
Legal
Debt
Margin
Total
Net Debt
c Applicable
2020
$ 329,906,374
$ 24,998,571
$ 304,907,803
7.58%
2019
332,493,497
33,342,428
299,151,069
10.03%
2018
323,300,411
26,495,286
296,805,125
8.20%
2017
314,497,673
29,993,143
284,504,530
9.54%
2016
306,281,304
37,046,449
269,234,855
12.10%
2015
300,113,527
39,855,090
260,258,437
13.28%
2014
291,022,753
40,104,676
250,918,077
13.78%
2013
286,559,168
40,486,360
246,072,808
14.13%
2012
281,084,951
32,602,147
248,482,804
11.60%
2011
275,077,180
37,208,816
237,868,364
13.53%
Table 13
Town of Cromwell,
Connecticut
Demographic and Economic
Statistics
Last
Ten
Years
(Unaudited)
(1)
(2)
(2)
(2)
(3)
(4)
(5)
Year
Ended
Per
Capita
Personal
Median
Median
Household
Education
Level
in
Years
of
School
Unemployment
c
June
30
c
Population
c c
Income
Income
Age
Income
Schooling
c
Enrollment
Percentage
2020
14,684
$ 48,862
$
717,489,608
43
$ 85,856
46%
at
least
4
yrs
of
college
1,998
8.9%
2019
14,021
45,954
644,321,034
43
85,856
46%
at
least
4
yrs
of
college
1,946
3.0%
2018
14,049
39,906
560,639,394
45
83,739
42%
at
least
4
yrs
of
college
1,973
4.0%
2017
14,086
40,905
576,187,830
44
82,081
42%
at
least
4
yrs
of
college
2,013
4.7%
2016
14,077
39,178
551,508,706
44
80,028
40%
at
least
4
yrs
of
college
1,993
4.9%
2015
14,076
38,463
541,405,188
44
80,134
N/A
1,982
4.5%
2014
14,059
43,611
613,127,049
44
80,134
N/A
1,969
5.6%
2013
14,116
42,900
605,576,400
43
81,718
N/A
1,971
6.7%
2012
13,940
43,249
602,891,060
45
83,670
N/A
1,992
6.8%
2011
13,968
44,206
617,469,408
44
73,665
N/A
2,018
7.3%
(1)
Source:
State
of
Connecticut
Health
Department,
except
2013
and
2015
which
is
a
CERC
estimate.
(2)
Source:
State
of
Connecticut
Fiscal
Indicators
-
CERC
(estimate
used
for
2006)
(3)
Source:
Connecticut
Economic
Resource
Center
Town
Profile
(4)
Source:
Superintendent
of
Schools
(5) Source: Connecticut Labor
Department
N/A
-
Not
available
128
Table 14
Town of Cromwell,
Connecticut
Principal Employers
Current Year and Nine Years
Ago (Unaudited)
2020
2011
Employer
Nature of Business
Number
of
Employees
c Rank
Percentage
of Total
Employment
Number
of
Employees
c Rank
Percentage
of Total
Employment
Adelbrook Behavioral & Developmental Services
(formerly The Children's Home)
Residential School
354
1
4.84%
N/A
1
N/A
Wal-Mart
Department Store
312
2
4.27%
200
2
3.01%
Stop & Shop
Supermarket
298
3
4.07%
180
4
2.71%
GKN Aerospace
Aircraft Parts
270
4
3.69%
N/A
N/A
N/A
Covenant Village
Retirement Village
234
5
3.20%
185
3
2.79%
Cromwell Growers
Landscaping/Florist
200
6
2.73%
N/A
N/A
N/A
Shop Rite
Supermarket
148
7
2.02%
N/A
N/A
N/A
Autumn Lake Health Care (formerly Haven Health Center)
Convalescent Home
130
8
1.78%
145
5
2.19%
Lowe's
Home Supply Store
125
9
1.71%
115
8
1.73%
Tournament Players Club
Country Club
120
10
1.64%
N/A
N/A
N/A
Liturgical Publication
Publisher
N/A
N/A
N/A
127
6
1.91%
Conference Center
Hotel/Conference Center
N/A
N/A
N/A
122
7
1.84%
Safe Home Security
Home Security
N/A
N/A
N/A
115
9
1.73%
K-Mart
Department Store
N/A
N/A
N/A
112
10
1.69%
Totals
2,191 c
29.95%
1,301 c
19.60%
N/A - Not applicable.
Source: Connecticut Department of Labor
129
Table 15
Town of Cromwell, Connecticut
Full-Time Equivalent Employees by
Function/Program Last Ten Years
(Unaudited)
Full-Time Equivalent Employees as of June 30
Function/Program
c c 2020
c c 2019
c c 2018
c c 2017
c c 2016
c c 2015
c c 2014
c c 2013
c c 2012
c c 2011
General government
37
35
36
36
36
37
36
36
35
35
Police
36
38
37
37
37
38
36
36
36
36
Fire
14
10
10
10
10
10
11
9
9
9
Refuse collection
1
1
1
1
1
1
2
2
2
2
Other public works
29
30
30
30
30
30
31
31
32
32
Parks and recreation
3
3
3
2
2
2
2
2
2
2
Library
6
5
5
5
5
5
17
17
17
17
Education
324
304
296
301
304
304
306
311
313
310
Total
Source: Town's payroll department.
450
426
418
422
425
427
441
444
446
443
130
Table
16
Town
of
Cromwell,
Connecticut
Operating
Indicators
by
Function/Program
Last
Ten
Years
(Unaudited)
Fiscal
Year
Ended
June
30
Function
/
Program
c c
2020
c c
2019
c c
2018
c c
2017
c c
2016
c c
2015
c c
2014
c c
2013
c c
2012
c c
2011
General
government:
(1)
Building
permits
issued
712
688
667
603
638
855
853
916
930
785
Police:
(2)
Physical
arrests
345
350
261
326
347
428
492
399
428
443
Parking
violations
107
96
114
126
132
141
113
61
104
144
Traffic
violations
1,447
469
646
611
683
782
901
570
558
601
Other
public
works:
(3)
Street
resurfacing
(miles)
2.00
2.80
5.30
2.00
N/A
1.93
2.73
2.00
1.73
6.00
Parks
and
recreation:
Athletic
field
permits
issued
195
225
223
216
N/A
N/A
N/A
N/A
N/A
N/A
Library:
(4)
Volumes
in
collection
65,078
62,096
68,924
70,525
77,728
83,765
83,647
83,423
82,536
81,990
Total
volumes
borrowed
94,450
95,092
74,931
71,227
81,501
99,986
101,772
99,038
105,223
105,252
Source:
(1) Town
of
Cromwell
Building
Inspector
(2) Town
of
Cromwell
Police
Department
Records
(per
calendar
year)
(3) Town
of
Cromwell
Public
Works
Department
(per
calendar
year)
(4) Town
of
Cromwell
Librarian
N/A
-
Not
applicable.
131
Table
17
Town of Cromwell, Connecticut
Capital Asset Statistics by
Function/Program
Last
Ten
Years
(Unaudited)
June
30
Function
/
Program
c c
2020
c c
2019
c c
2018
c c
2017
c c
2016
c c
2015
c c
2014
c c
2013
c c
2012
c c
2011
Police:
(1)
Stations
1
1
1
1
1
1
1
1
1
1
Patrol
units
16
16
16
16
16
16
15
15
14
14
Other
Public
Works:
(2)
Streets
(miles)
57.78
57.78
56.70
56.70
56.70
56.70
56.70
56.35
56.34
56
Streetlights*
1,228
1,227
1,218
1,218
1,208
1,208
1,166
1,164
1,163
1,153
Traffic
signals*
21
21
21
21
21
21
15
15
15
15
Park
and
Recreation:
(3)
Acreage**
215
200
200
200
200
200
200
157
157
157
Playgrounds
2
2
2
2
2
2
2
3
3
3
Baseball/softball diamonds
15
15
15
15
15
15
15
15
15
15
Soccer/football fields
18
18
18
18
14
14
14
10
10
10
Community centers
1
1
1
1
1
1
1
1
1
1
Sources:
(1) Town of Cromwell Police Department Records
(2)
Town
of
Cromwell
Public
Works
Department
(3) Town of Cromwell Recreation Department
Notes:
* Street lights and traffic signals are not owned by the Town
** Acreage does not include any fields that are maintained by the Board of
Education
N/A
-
Not
applicable.
132

