


Harper 5
Introduction
Since the “White Claw Summer” of 2019, the shelves of American grocery stories and
the commercials during Sunday Night Football have been filled with hard seltzer brands. Hard
seltzers have taken the American alcohol market by storm and provided direct competition for
the beer category – and there is no indication that this disruptive category is going to disappear
any time soon. 2019 saw a 226% increase in category growth followed by 165% in 2020 (Weitz).
In 2020, category leader White Claw alone saw 275% growth (Schwarz). While these levels of
growth are not sustainable in the long-run, a report from Grand View Research in 2019 still
predicted a “compound annual growth rate (CAGR) of 16.2% from 2020 to 2027” of the market
size for the hard seltzer category worldwide (“Hard Seltzer Market Size, Share & Trends
Analysis Report By ABV Content (1.0% To 4.9%, 5.0% To 6.9%), By Distribution Channel
(On-Trade, Off-Trade), By Region, And Segment Forecasts, 2020 - 2027”).
Still, while hard seltzers have taken a hold of the alcohol market in America, globally this
has been an isolated incident. Since approximately 2021, however, there has been an emergence
of the category beyond American borders. Some of these brands have been extensions of already
successful American hard seltzer brands, while others have been new global or localized brands.
For many American industries, Europe is seen as the natural next step for global expansion. As a
result, this thesis will analyze the potential for hard seltzers in the European market. Moreover, it
will analyze the potential for seven key brands in particular: White Claw, Truly, Bud Light
Seltzer, Vizzy, Topo Chico, Mike’s Hard Seltzer, and Pure Piraña. The first part of this thesis will
establish context through secondary research by looking at the conditions of entering the
European alcohol market and an overview of the hard seltzer category. The second part of this
thesis will look at primary research consisting of data from two surveys, one for Americans and

Harper 6
one for Europeans. This data will demonstrate similarities and differences between the two
groups in drinking preferences and behavior as well as awareness and enjoyment of hard seltzers.
In addition, the secondary research will consist of a case study looking at the efforts of White
Claw in Vienna, Austria. This thesis will conclude with an analysis of the above sections to
determine for the hard seltzer category and each of the key brands whether there exists a
sparkling opportunity.

Harper 7
Entering the European Alcohol Market
The following section will establish the conditions in which hard seltzers are entering the
European alcohol market. It will do this by first addressing the challenges of entering any market
abroad, next looking at the challenges of entering the European market in particular, and finally
looking at the history and current conditions of the European alcohol market.
Challenges of Entering Markets Abroad
For many companies, introducing a successful product or service in a foreign market
seems like a natural next step to ensure its continued and growing success. However, as many
companies have come to recognize, success at home does not necessarily guarantee success
abroad. Moreover, in order to be successful abroad, a company is likely to have to adjust the
strategy it used at home to achieve the same goals. Yet, it is hard to understand what adjustments
need to be made and even more difficult to implement them. As a result, business history is
littered with case studies of companies failing to successfully adjust their strategy to create value
for their foreign customers, such as in the case of Wal-Mart’s expansion into Germany or
Target’s expansion into Canada (Ghemawat).
In order to avoid becoming another case study of how to not succeed in a foreign market,
companies wishing to expand abroad must evaluate the challenges they will face during the
process. One of the most widely accepted methodologies for evaluating these challenges is the
CAGE Distance Framework developed by Pankaj Ghemawat. This methodology measures the
“distance” between two countries across four dimensions: cultural, administrative, geographic,
and economic. Each dimension of distance encompasses a different set of factors that influence
business practices which can help a company understand the differences, difficulties, and
opportunities of doing business in a particular country as opposed to their own (Kennedy).

Harper 8
The first dimension of distance in the CAGE Distance Framework is cultural distance.
Cultural distance is often what people think of first when considering the difficulties of doing
business in another country. It encompasses the invisible norms that shape the behavior, beliefs,
and practices of individuals and groups. This includes language, religion, values, and social
norms. The more similar two countries are in regards to these dimensions of society, the closer
they are on the spectrum of cultural distance–and the more likely the foreign market is to be
receptive to a similar approach of introducing a product to what was used in the home market
(Ghemawat). Two countries that have a shared history of colonialism are also very likely to be
closer on the spectrum of cultural distance. However, just because two countries have a greater
degree of cultural distance does not necessarily mean that a company should no longer enter that
market. In some cases, the market is still viable with a potential to create value in it–but it is
essential to recognize what those cultural differences are and adjust your strategy accordingly.
The second dimension of the CAGE Distance Framework encompasses administrative
distance. Administrative distance represents all differences in the legal and political structures of
two countries. Differences in the laws and regulations of two countries in regards to trade, labor,
and transportation can severely affect a business’s ability to be successful in that
country–particularly if their competitive advantage is related to one of those factors (Kennedy).
Moreover, failure to recognize these differences can lead to legal issues and conflict. In addition,
the overall political structure of a country can create distance. How closely tied business and
government are, the level of corruption in a country, and how sound its institutions are,
particularly the judicial system, impact how a successful business operates in that country. A
company looking to enter a foreign market must research this dimension of distance extensively

Harper 9
to understand whether they believe they can and are willing to successfully operate within the
specific legal and political structure of that country.
The third dimension of the CAGE Distance Framework is geographic distance.
Geographic distance involves the physical distance between two countries as well as any other
barriers that arise from that separation. Typically, a company is more likely to be successful in a
market that is closer to its headquarters than one that is further away (Ghemawat). This is
because the greater distance between two countries increases the cost and time required for
transportation of products as well as potential complications in communication that arise from
operating in different time zones (Kennedy). Furthermore, geographic barriers such as bodies of
water and mountain ranges can increase the difficulty in transportation and require further
planning (Ghemawat). These factors must be taken into consideration when deciding whether it
is worth it and truly profitable to enter a foreign market.
The fourth and final dimension of the CAGE Distance Framework is economic distance.
Economic distance encompasses all other factors related to the economy of each country that
impact the ability of a company to succeed. For example, entering a country that uses the same
currency and economic systems will result in greater ease of transactions. Moreover, entering a
country with a similar GDP per capita increases the likelihood of being able to market the
product in the same way. Any differences in economic conditions or systems indicate that
extensive planning and adjustment will be necessary to be successful in that country (Kennedy).
Distance does not necessarily indicate disaster; however, it is essential that companies
recognize the difficulties they may face when entering certain countries. From there, they must
select countries in which they believe they can truly be successful despite distance through
extensive planning and careful consideration.

Harper 10
Challenges of Entering the European Market
Europe is many companies’ first choices for a location to expand their successful U.S.
product into a global brand. This makes sense; on a spectrum of distance, Europe is closer
geographically than other markets and has similar standards of living, democratic forms of
governance, and large populations of English speakers. Also, the collection of most of the
wealthiest countries in Europe into one economic unit, the European Union, makes the market
seem even more enticing (McIntyre). However, focusing on the similarities of the United States
and Europe and the appeal of the E.U. often leads businesses into a trap of false comfort.
While English may be the common language spoken around the world in business, that
does not mean that it is enough to be successful. Europe features a large variety of native
languages, and even within those languages there are often many different dialects spoken
depending on the specific location and culture. It is important to be sensitive to the specific
language and dialect of a culture, as words and phrases can have very different meanings
depending on the language and dialect–even if the language largely spoken in that culture is
English. Moreover, countries in Europe vary from the United States and each other in their
beliefs and customs, so a successful marketing strategy in one country may be offensive or
irrelevant in another.
If a company wants to successfully market to an audience in a specific country or culture,
they need to be sure to be using the right language, ideas, words, and phrases to make a lasting
connection, and that is only possible if they pay specific attention to the local culture and involve
or hire local individuals in their decision-making. This means that it may not be wise to expand
to a large number of markets in Europe at once; a one-size-fits-all strategy is not possible across
this expansive continent, even in the English-speaking countries, and extensive research is

Harper 11
needed for each individual market. On the topic of marketing, it is also important to note that
Europeans are not used to the types of invasive marketing strategies deployed in the American
market. European sports do not feature frequent commercial breaks, and Europeans do not
appreciate the “bold and busy packaging you see on many American products” (“4 Differences
between American & European Business Culture”). They also are less impressed by displays of
wealth and success; they prefer products to speak for themselves with much simpler branding.
Moreover, not only does the language and culture vary between countries, they also vary
in economic processes. Despite many countries being members of the European Union and
having synchronized economic policy, they differ in their preference for cash versus virtual
transactions as well as their ability to support virtual transactions depending on their level of
internet connectivity. Also, while many companies use the United Kingdom as their starting
point for Europe due to its use of English, geographic accessibility, and cultural proximity
because of its shared colonial history with the United States, it is important to note that it is no
longer a member state of the European Union and has different currency, economic policies, and
regulations than the other prominent European markets. This means that just because a company
has found success navigating the market in the United Kingdom does not mean that it will find
success in the European Union (“4 Differences between American & European Business
Culture”).
A mistake managers often make is thinking that Europe is a project they can focus on for
a few months and then leave to others. Instead, expanding into Europe, while a potentially
extremely profitable strategy, is a significant undertaking that requires careful consideration.
Another pitfall that many successful American companies fall into is forgetting how hard they
had to work to win over their audience in the United States; often, it has been many years since

Harper 12
their original entrance into the American market, and they have forgotten how important
marketing and sales are to generate a loyal consumer base. This phenomenon is often referred to
as “success amnesia”. It is absolutely essential to hire people who understand the specific
European market you are entering and can focus on selling the unique competitive advantage of
the company to a new audience with different values and expectations (McIntyre). Once again,
this is why it is so important to focus on a few core markets in Europe at the beginning of
expansion; you must learn how to sell to your audience in the format that is acceptable for that
country and culture in order to be successful, and this takes time and dedication.
Alcohol in Europe
Alcohol has always been a staple of European culture. For most of Western history, water
was not reliably safe to drink. As a result, for most of the last 10,000 years, people turned to
alternative beverages such as coffee and water for their daily sources of fluids and calories. This
gave alcohol the well-deserved title of “aqua vitae” in the Middle Ages, or “the water of life.”
Resultantly, while intoxication was not the goal of alcohol consumption, “the ‘side effects’ of
this constant, low-level intake must have been almost universal” and “throughout Western
history the normal state of mind may have been one of inebriation” (Vallee). In many cultures,
alcohol also served as a distraction from the dullness and exhaustion of daily life and pains
which could not be remedied during this time.
While alcohol was unintentionally consumed beforehand, the advent of alcohol coincides
with the arrival of agriculture. The abundance of barley and wheat produced on the river deltas
of Egypt and Mesopotamia naturally led to the development of beer by 3,000 B.C. Similarly,
agriculture allowed for the domestication of specific grapes which led to development of
cultivated wine by about 6,000 B.C in Armenia. In the past, beer was considered the drink of

Harper 13
commoners, while wine was solely consumed by the affluent. However, in about 30 B.C., wine
became available to the greater population in Rome as a result of the widespread expansion of
vineyards driving prices down.
For the first 9,000 years of its consumption, the alcohol content in beverages such as
mead, beer, and wine was relatively low. In about 700 A.D., however, Arab alchemists changed
the game by introducing highly concentrated alcohol through the process of distillation. This
method spread to Europe in about 1100 A.D. through the medical school in Salerno, Italy and
gradually spread to northern Europe. This was the first significant change in alcohol
consumption since the dawn of Western civilization.
Not only did wine and beer become stronger as a result of this change, but Europe also
began to consume a new form of distilled alcohol: spirits. The dispersion of spirit consumption
was closely tied with widespread plagues in Europe in the 14th century. While spirits were not a
cure for disease, they did help alleviate pain and enhance the moods of victims. Following the
end of the plague in Europe was a time of urbanization and self-indulgence that resulted in a
virtual continentwide bender (Vallee). It is estimated that in Central Europe during the 16th
century per-capita alcohol consumption was about 1 to 1.5 liters per day (Kümin). This constant
inebriation was only partially curtailed in the 17th century by the popularization of beverages
made from boiled water such as coffee, tea, and cocoa. At the end of the 19th century, the
invention of filtered and treated water coincided with the spread of religious anti-alcohol
sentiment resulting in a significant part of the population turning away from alcohol
consumption (Vallee). By this time, per-capita alcohol consumption decreased to 1 liter per day,
though with huge social and geographic variations (Kümin). Moreover, the 19th century also
introduced “the recognition of alcohol dependence as an illness” (Vallee). The acknowledgement

Harper 14
of alcohol abuse leading to liver disease and mental dysfunction combined with social
condemnation of drunkenness further enabled the spreading of the temperance movement in
Europe (Vallee).
These movements led to some European countries actually enforcing prohibition laws
like that of the United States in the 1910s and 1920s including Iceland, Norway, Hungary, and
Finland (Chepkemoi). In other countries, governments instead focused on encouraging people to
turn away from beverages with high alcohol content to those with low alcohol content. For
example, Belgium, Denmark, and the UK chose to increase taxation of beverages with higher
alcohol content in order to shift consumption patterns. As a result of the affluence and
celebration in the wake of the end of World War II, the 1950s saw a reimergence of high alcohol
consumption in the West–that has not been tempered since (D. Smith).
This thesis talks about trends in alcohol consumption in Europe as a whole; however,
traditionally, since the departure from drinking alcohol solely as “the water of life”, alcohol
consumption culture in Europe was split between the North/East and South. In the past, Northern
and Eastern drinkers would consume more grain-based drinks such as beer and spirits often with
the purpose of getting drunk. Southerners, on the other hand, would be more inclined to drink
wine as part of a daily diet with meals. While this split does still maintain its legacy in modern
drinking culture, it is much less profound. Since the 1960s, the globalization of the alcohol
industry and convergence of cultures has made it so Northerners and Easterners will often drink
wine and during meals and Southerners will consume grain-based drinks and outside of meal
time (Engs). In fact, the late 1970s and early 1980s saw young people embracing these “new”
beverages as part of youth pop culture–“beer in the south and wine in the north” (D. Smith).

Harper 15
Still, the splits in divisions in drinking behavior are deeply rooted in European culture
and are subdivided by transnational regions today. These divisions mean that it is impossible to
describe a single drinking culture in Europe, but the aforementioned internationalization dilutes
these differences and enables us to identify overall trends in modern drinking behavior in
Europe. The legacy of alcohol as “the water of life” has not escaped Europe; still down from 1 to
1.5 liters of alcohol per day, according to the World Health Organization, “each year in Europe,
every person aged 15 and over consumes, on average, 9.5 litres of pure alcohol, which is
equivalent to around 190 litres of beer, 80 litres of wine or 24 litres of spirits”, representing the
highest alcohol consumption per capita in the world (Bello). In fact, as of 2019, nine out of ten of
the countries with the highest consumption were European Union member states. This is even
after a decrease of yearly alcohol consumption across the continent between 2000 and 2019 of
2.5 liters. Moreover, while there is great variation across the continent (in part due to the
prevalence of Eastern countries with “Muslim-majority populations, for whom the consumption
of alcohol is prohibited and condemned”), within the European Union there are only five
countries with annual per capita consumption below 10 liters (Italy, Malta, Croatia, Sweden, and
the Netherlands), none of which are below 8 (Bello).
Across the continent, there are also some key trends in preference taking place at the
moment. There is an increased demand for specialty, or craft, beer, with 6,000 breweries entering
the market from 2020 to 2021. Companies such as Anheuser-Busch InBev are already taking
note of this and “bringing craft beers as an essential part of their growth plans” (“Europe
Alcoholic Beverage Market Analysis - Industry Report - Trends, Size & Share”). In addition,
consumers are now demanding both unique and high-quality alcoholic beverages. This is causing
companies to have to be innovative with new beverages and adding twists to old concepts

Harper 16
including introducing exotic ingredients to their alcoholic beverages. For example, “in March
2022, Whitley Neill, a premium gin brand in the United Kingdom, launched a new gin variant,
Oriental Spiced Gin” which “consists of different botanicals and spices like coriander, ginger,
chili, cumin, saffron, star anise, and grains of paradise” (“Europe Alcoholic Beverage Market
Analysis - Industry Report - Trends, Size & Share”). Moreover, there is also a trend of concern
for health in the European audience which has caused companies to have to create more
functional drinks that have fewer negative health impacts. This has caused a growth in demand
for natural wines and using natural ingredients for gin production such as in the case of Oriental
Spiced Gin (“Europe Alcoholic Beverage Market Analysis - Industry Report - Trends, Size &
Share”).

Harper 17
Hard Seltzers
Hard seltzers are the 21st century disruptors of the alcohol market. These beverages
consist of “carbonated water combined with alcohol and fruit flavoring” and are direct
challengers to other alcoholic beverages including beer, in particular (Hagan). In 2019, the
category saw an increase of 226% followed by an increase of 165% in 2020 (Weitz). Category
leader White Claw alone saw a staggering increase of sales of 275% in 2020 (Schwarz). Even
after accounting for the gradual steadying of market growth, a report from Grand View Research
in 2019 predicted a “compound annual growth rate (CAGR) of 16.2% from 2020 to 2027” of the
market size of hard seltzer worldwide, taking it from the already impressive $4.4 billion to $14.5
billion (“Hard Seltzer Market Size, Share & Trends Analysis Report By ABV Content
(1.0% To 4.9%, 5.0% To 6.9%), By Distribution Channel (On-Trade, Off-Trade), By Region,
And Segment Forecasts, 2020 - 2027”). This aligns with the decrease of growth to 30% by July
2021 (Weitz). Regardless of the end of the initial hard seltzer boom, the hard seltzer category has
situated itself firmly within the alcohol market, and it is here to stay. This section seeks to give
an overview of the hard seltzer market.
Origin of Hard Seltzers
While canned alternatives to beer and wine such as Mike’s Hard Lemonade and
Budweiser’s Lime-a-rita have existed for years, they have often been limited in their scope of
marketing to women and lacked the appeal to truly challenge other persistent categories in the
industry. In 1993, the first seltzer-like drink, Zima by Coors Brewing Company, entered the
alcohol market and experienced moderate success, but a lack of strategic marketing and taste
appeal led it to eventually be taken off the market.

Harper 18
The first true hard seltzer was developed by a man named Nick Shields, an owner of a
small beer brand, in 2012 after witnessing a group of women all ordering vodka sodas. He was
inspired to develop something better that would “bridge the gap between beer, wine, and
cocktails with a new kind of alcoholic beverage” (Gray). He then went on to develop a
fermentation process similar to brewing beer using sugar, water, and yeast followed by the
addition of fruit flavoring that would be the advent of the hard seltzer.
Shields used this process to create the first hard seltzer brand, SpikedSeltzer, in 2013. The
success of this brand led it to be noticed by Anheuser-Busch InBev which acquired his company,
Boathouse Beverage LLC, in 2015. By 2016, others had recognized the potential for the hard
seltzer category, and more brands, including two of its current leaders, White Claw and Truly,
had entered the market (Gray).
Target Audience
One of the reasons for the growing success of the hard seltzer category is that the leaders
such as White Claw and Truly have designed brands that appeal to a large variety of consumers.
Nielsen reports that the beverage “is most popular among Caucasians between the ages of 21 and
44 from affluent neighborhoods, and it appeals to both genders” (Dimitrakis). Hard seltzers have
been able to broaden their customer base so well and experience exponential growth because
they, after the initial failure of Bon & Viv discussed in the Bud Light Seltzer brand evaluation,
have focused on gender-neutral marketing. While hard seltzers do provide an opportunity for
women (and men) who do not enjoy drinking beer but want a similarly convenient alternative to
have one, the hard seltzer market has done this while avoiding the limiting and, frankly, sexist,
feminization of their products that was employed by other beer alternatives (such as Smirnoff Ice
and wine coolers). As a result, while there is still a bias towards women as customers, this is

Harper 19
limited, with leader White Claw having a customer base that “is nearly split down the middle:
53% women and 47% men” (MAKE Digital Team).
Moreover, the audience for hard seltzers is broad because it appeals to many of the
market demands of the target age range of consumers indicated by Nielsen previously, 21 to 44,
meaning mainly those from the Millennial and Gen Z generations. First, hard seltzers are
perceived as being healthier than other alcoholic alternatives (whether or not this is actually true
is addressed in the following section, “The ‘Healthy’ Alternative”). Millennials and Gen Zers
have a focus on creating a sense of holistic wellness in their lives, with the Natural Marketing
Institute finding that 77% of Millennials “view a healthy, balanced lifestyle as ‘very’ or
‘extremely’ important”. Next, hard seltzer brands listen to their audience and try to provide a
wide variety of desired flavors to consumers that they previously had not been able to find in an
alcoholic beverage. Consumers also have the ability to purchase hard seltzers in variety packs
which appeals to their desire for diversity and the ability to share the beverage with others in
social settings. This option is clearly desirable as 63% of sales for hard seltzers come from
variety packs. In addition, increased income inequality matched with rising costs and lower
wages have caused those in the Millenial and Gen Z generations to begin prioritizing experiences
and shared moments with friends as opposed to materialistic goods. In response, hard seltzer
brands have marketed themselves as “lifestyle brands”, pairing themselves through marketing
with social events and exciting activities such as boating and hiking. Finally, Millennials and
Gen Zers spend a lot of time consuming digital media, and hard seltzer brands have responded to
this. “Hard seltzer brands spent $41.8 million on digital advertising between January and
October 2021” (Dimitrakis). The brands have also benefited from word-of-mouth advertising by
appealing to the social media generation, where popularized phrases like “there are no laws when

Harper 20
you drink Claws” and social media accounts such as “whiteclawmeme” and
“whiteclawchronicals” generate free publicity and solidify the brands’ position as true lifestyle
brands (Dimitrakis).
While the market trends referenced in the previous paragraph appeal directly towards
Millennials and Gen Zers, they are widely applicable to many individuals living in the 21st
century and can also apply to those of older and upcoming alcohol consuming generations. This
universality is the key to the category’s growing and predicted future success in the alcohol
market.
The “Healthy” Alternative
Consumers are supposedly attracted to hard seltzers because they have been marketed as
a healthier and more flavorful alternative to other alcoholic beverages. However, there are some
beers that do have fewer calories than hard seltzers, so how can this be true?
Hard seltzers consistently market themselves as having 100 calories, while beers range
from approximately 64 to 175 calories. In general, there is much less consistency and emphasis
on minimizing calories in the beer market. Hard seltzers also avoid using grains in production
which allow brands to advertise having two or fewer carbs per drink, where again beer brands
feature a much wider range of carb counts. Finally, while both seltzers and beers average at
approximately 5% alcohol by volume, hard seltzers like White Claw and Truly stay consistent at
this mark while beers range from 2.3% to 8%. This consistency in production has allowed hard
seltzer brands to successfully market their products as a healthy alternative to beer despite this
not always being the case (Sukesh).
This reputation as the healthy alternative to beers and other alcoholic beverages is key to
appealing to the current target audience of casual alcoholic beverages, Millennials and Gen Zers.

Harper 21
Health conscious Gen Z is purchasing less alcohol than their Millennial counterparts, with only
84% purchasing alcohol consistently. This is down from 90% of Millennials who also are less
likely to purchase alcohol than the Gen X and Boomer generations. When these groups do
purchase alcohol, they, particularly Gen Zers, are more likely to choose options that have less
alcohol content, fewer calories and carbs, and more variety in flavor. This had led younger
members of these groups to turn to hard seltzers (Carswell).
Another benefit of hard seltzers that appeals to its consumers is its placement in the
Ready-to-Drink category. As opposed to cocktails which also provide consumers with more
flavorful options than wine and beer, hard seltzers are convenient to purchase from a grocery
store and to drink in a variety of locations. This is a strong contributing factor married with the
perception of being a healthy option as to why the younger generations are turning to these
beverages (Lin).
Moreover, 49% of Gen Z and 38% of Millennials consider the ability to have a good time
as a priority in selecting alcoholic beverages, leading them to focus more on seltzers which
provide a lighter and more flavorful alternative in social settings (Carswell). With 42.28% of the
United States population consisting of the Millennial and Gen Z generations as of 2020 and
much of the Gen Z generation approaching the legal age of alcohol consumption, it is essential
that companies recognize the significance of this trend and focus on strategies such as the
emphasis on their hard seltzer brands in order to appeal to these generations (Duffin).
COVID-19
Furthermore, the COVID-19 pandemic has accelerated the consumer shift towards the
already growing trend of seltzers. When the pandemic began, consumers turned away from craft
breweries and restaurants towards popular brands they could quickly grab from the grocery store.

Harper 22
The younger generation, previously enthralled with the craft brewery trend, began turning even
more towards hard seltzer brands like White Claw and Truly that met their consumer preferences
(Swartz). Even as some regulations and customs changed during the pandemic, customers
continued returning to the convenience of drinking hard seltzers at home.
Joining the Competition
Instead of seeing hard seltzers as a threat to their survival, breweries commonly known
for producing beer have recognized the significance of the hard seltzer movement and have
begun embracing their own brands to challenge the core leaders today such as White Claw. As
stated by Ann Legan, the VP of Brand Marketing at Corona, “seltzer is a huge trend that has
impacted the beer industry in the past year, and we don’t see that stopping anytime soon”
(Swartz). Leading players such as Anheuser-Busch InBev, Boston Beer Company, Molson Coors
Beverage Company, New Belgium Brewing Company, and Heineken have already introduced
their own hard seltzer brands into the market, some having released multiple.
Fizzling Out?
Some worry that the industry is becoming saturated from all of these market entries. This
argument is not without basis; while there were only 10 hard seltzer brands in the beginning
2018, as of 2020 there were over 65 and this number continues to grow as many alcoholic and
non-alcoholic beverage companies attempt to join in on the craze. Consumers walking down the
aisles in the grocery store now have an overwhelming number of seltzers from which to choose
(Lin). All of those entranced by the hard seltzer craze were jolted with a rude awakening in
October 2021 when the popular brand Truly’s parent company, Boston Beer Company, threw out
millions of cases of the beverage. This was, unfortunately, inevitable; still caught up in the hype
of the last few years of continued success, many hard seltzer brands, including Boston Beer,

Harper 23
overestimated their predicted growth and success. Now, left with an excess of product with a
shelf life, it had no choice but to throw out its product.
Other companies such as Constellation Brands also claim to be facing similar cases of
excessive and costly inventory due to overly optimistic predictions. In a more extreme case,
other companies are having to completely reconsider the viability of their brands in the market.
In July of 2021, Molson Coors had to discontinue its Coors Seltzer in order to focus on its two
more successful brands in the crowded market, Vizzy and Topo Chico. While the over-saturation
of the market is part of the reason for the slow down, other factors also likely had an impact. For
example, during summer 2021, many people began to return to bars and restaurants after staying
home during the pandemic, and they began opting for the more exciting cocktails once again in
the place of standard hard seltzers. In addition, for those that remained drinking at home, the
invention of the canned RTD Cocktail category may have taken some of their attention away
from hard seltzers.
However, while the initial craze is over, hard seltzers have earned their place in the
alcohol industry and are here to stay. It was inevitable that the remarkable three digit growth of
the industry would have to slow down (Hartmans). From 2022 to 2023, “the global hard seltzer
market grew from $12.45 billion in 2022 to $14.65 billion in 2023 at a compound annual growth
rate (CAGR) of 17.7%” (“Hard Seltzer Global Market Report 2023: Rising Consumer Preference
for Carbonated Beverages with Lower Alcohol Content Drives Growth”). Now, like in other
steady markets in the alcohol industry, it will be essential for brands to truly differentiate
themselves and focus on creating a strong distribution network in order to remain relevant and
earn their place amongst the limited shelf space of grocery stores–and, while many startups will

Harper 24
begin to fizzle out, the strongest players have been and will continue to build upon their previous
success as the category continues to grow.
Beyond the United States
While hard seltzers have taken hold of the alcohol market in America, globally this has
been an isolated incident thus far. Producers of seltzers have not yet tapped the market potential
of other regions such as Europe, though they have begun considering the option and some have
already begun experimenting in the market. As of 2023, the global hard seltzer market has
revenue worth $21.65 billion; the United States market generates $17.24 billion, or
approximately 80%, of that revenue (“Hard Seltzer - Worldwide: Statista Market dForecast).
While this number indicates a clear continued bias toward the home market of the United States,
the other 20% being generated worldwide should still give hope to companies currently
expanding or looking to expand their products abroad. The current primary markets to which
hard seltzers have expanded are Canada, Australia, and the United Kingdom. The first brand to
make its way to the United Kingdom was Mike’s Hard Seltzer in late 2019 followed by the much
anticipated arrival of White Claw in June 2020. Other seltzer brands have since followed their
lead and begun to spread out across the continent (Cawood). Hard seltzers have changed the
alcohol industry in America, and the next few years will be key to understanding their potential
in the global market.

Harper 25
Brand Profiles
The seven brands that will be the focus of this thesis are White Claw, Truly, Bud Light
Seltzer, Vizzy, Topo Chico, Mike’s Hard Seltzer, and Pure Piraña due to their profiles as major
players in the market. White Claw and Truly are included because they have consistently been
the category leaders since hard seltzers first began gaining prominence in 2016. Bud Light
Seltzer was selected in turn because it has also performed increasingly well in recent years and is
now considered the third-largest brand in the category in the United States. Alternatively, Vizzy
has been referenced as a “brand to watch” by NielsenIQ and has been growing quickly in
prominence due to its unique positioning as the “healthy” choice. Mike’s Hard Seltzer and Topo
Chico Hard Seltzer are both significant players due to their association with beverages that are
already household names, Mike’s Hard Lemonade and Topo Chico. In addition, they are both
being promoted by companies that each offer tremendous benefits in their own way, Mark
Anthony Brands and Coca-Cola, respectively. Finally, Pure Piraña was selected because of its
unique global strategy and absence in the United States market.
White Claw
The phrase “White Claw'' is, at this point, almost synonymous with the phrase “hard
seltzer”. Founded in 2016, the brand White Claw is part of Canada native Anthony von Mandl’s
expansive alcohol company, Mark Anthony Brands, Inc. Before venturing into hard seltzers, von
Mandl had already experimented with flavored malt beverages with the 1996 brand Mike’s Hard
Lemonade which features alcoholic lemonade (Fisk).
While seltzers had existed since 2013, White Claw’s entrance revolutionized the
category. Unlike other hard seltzer and canned alcoholic beverages that targeted a very
traditionally feminine audience with pink colors and sweet flavors, White Claw’s brand featured

Harper 26
a variety of simple flavors including Black Cherry, Natural Lime, and Mango and gender-neutral
minimalist silver cans with a black-and-white classic wave logo. This changed the perception of
hard seltzers; no longer were they just drinks for women, instead they were a beverage that could
be shared amongst all in fun social gatherings.
As this image evolved, White Claw began to not just represent a beverage for its
consumers, but, instead, a feeling. White Claws became synonymous with having a good time.
People wanted to be seen in groups–and on Instagram–with their visually appealing cans. They
were convenient, portable, and seemingly healthy–a badge of honor for many (Gray).
This reputation eventually evolved into two iconic phrases being associated with the
brand in 2019, the year White Claw truly took off. First, YouTube personality Trevor Wallace
popularized the phrase “ain’t no laws when you’re drinking claws” that positively isolated White
Claw from other alcoholic beverages. Not long after, celebrities began calling 2019 a “White
Claw Summer '', and the brand came to symbolize the summer itself; White Claw began to
appear in home decor and halloween costumes. While the White Claw Summer ended and some
of the hype died down, White Claw continues to be a beverage of choice for many and the
feeling associated with it has not disappeared (Fisk).
As their brand grew in popularity, so did their sales numbers, increasing at triple digit
rates for years. By 2019, White Claw was by far the largest seller of hard seltzers and had
captured over 50% of all hard seltzer sales. White Claw has continued this legacy since, still
capturing the top seller position in the category and, in conjunction with Truly, the second most
popular brand, continues to hold the majority of the market share of the category (Gray).
In 2020, the brand expanded into Canada, the United Kingdom, the Netherlands, and
Ireland and immediately became the #1 hard seltzer in these locations capturing 25% of the

Harper 27
market. Stating that they have “been blown away by the success of White Claw in every market
[they’ve] entered to date”, White Claw then decided to further expand across Europe to Austria,
Belgium, Finland, Germany, Switzerland, and Sweden in June 2021 (“White Claw Enters Five
New European Markets”). In June 2022, White Claw reportedly continued to lead the hard
seltzer category in the United Kingdom capturing 42.4% of the market with sales of 7.2 million
pounds and growth of 69% (Leonard-Bedwell). It appears, at least for now, that White Claw’s
leadership in the hard seltzer category will not be constrained to the United States market.
Truly
Also arriving in the market in 2016 was Truly, White Claw’s continued closest
competitor in the United States. The Truly brand is a part of Boston Beer Company, an extremely
successful alcohol company that has featured brands like Sam Adams, Dogfish Head, and Angry
Orchard. Like Mark Anthony Brands, before the creation of the Truly brand, Boston Beer
Company had already begun exploring beyond beer with the introduction of its Twisted Tea
brand in 2001.
While it did not have the immediate explosion of popularity that White Claw did, Truly
was able to benefit from White Claw popularizing hard seltzers by using the excitement around
the category to generate an audience for their own unique brand. Unlike White Claw, which
relies on its core flavors to continuously attract return customers, Truly proudly advertises their
slogan claiming that “no one is just one flavor”. Their competitive advantage lies in the variety
they offer, ranging from different lines of flavor categories to lines with higher alcohol content to
lines with fewer calories and only one gram of sugar (Pomranz).
As of today, the ever-changing portfolio of Truly includes the Berry Mix Back, the Citrus
Mix Pack, the Tropical Mix Pack, the Lemonade Mix Pack (including a separate Lemonade

Harper 28
Freeze Pop option), the Iced Tea Mix Pack, the Punch Mix Pack, the Holiday Party Pack, and the
newest addition, the Margarita Style Mix Pack–leading to over 30 unique flavors (“Truly Hard
Seltzer: No One Is Just One Flavor”). By comparison, White Claw, despite its position as the
leader of the category, has only 12 core flavors it has been consistently marketing. It is important
to note that recently, in the second half of 2022 and early 2023, White Claw has begun to
introduce some new flavor packs and even a vodka brand into its mix (“Our Products”). This is
likely an attempt to lessen Truly’s competitive advantage and will be an important trend for the
industry to watch moving forward.
However, while Truly has more flavors than White Claw and other brands, it is not only
this characteristic that gives it its competitive advantage. Their flavors are truly innovative and
unique from each other, giving their consumers variety they may be missing in other beverages.
They continue to evolve their portfolio as consumers ask for new options based on their own
specific preference (Pomranz). This has allowed them to gain customers that White Claw has not
been able to capture, to maintain sales growth over the years, and to capture the second highest
market share in the category. This has led White Claw and Truly combined to hold almost 75%
of the market (Gray). Truly has yet to announce a global market expansion for their brand.
Bud Light Seltzer
Bud Light Seltzer, a member of the Anheuser-Busch family, is the latest and most
successful brand in the company’s involvement in the hard seltzer category. Seeing the decline in
demand for beer and knowing it needed to expand its portfolio in order to maintain sustained
growth, Anheuser-Busch made the significant decision to acquire Nick Shields’s company,
Boathouse Beverage LLC, in order to gain control of the revolutionary first true hard seltzer
brand, SpikedSeltzer.

Harper 29
This brand had small yet steady and growing success; however, in 2019 Anheuser-Busch
attempted to gain further success amongst competitors like Truly and White Claw by rebranding
SpikedSeltzer to be Bon & Viv, a brand that targeted women with mermaids as a major
marketing tool. This failed to gain any significant prominence or sales, along with its next
attempt in the hard seltzer market, the Natural Light Seltzer. This led former head of
Anheuser-Busch InBev’s North American business, Michel Doukeris, to create a new business
unit called Beyond Beer to specifically focus on the opportunities in the seltzer, canned wine,
and cocktail categories.
In 2020, with this new foundation intact, Anheuser-Busch InBev gave the hard seltzer
category another shot with the introduction of the Bud Light Seltzer, hoping to benefit from the
extreme success of the Bud Light brand. Much like Truly, the focus of the strategy of Bud Light
Seltzer has been creating variety in the number and types of flavors and variety packs. As a result
of its success in creating diverse and appealing flavors, despite the large number of other seltzers
in the market fighting for prominence in the shadow of White Claw and Truly, Bud Light Seltzer
has managed to obtain 10% of the hard seltzer market and is currently the third most successful
brand in the category in the United States (Gray). This success led Anheuser-Busch InBev to
introduce Bud Light Seltzer into the United Kingdom market in April 2021 (Hook). In June
2022, Bud Light Seltzer had also captured the third place position in the United Kingdom behind
White Claw and Topo Chico having increased sales by 189% to 920 thousand pounds within a
year (Leonard-Bedwell). The brand has not yet indicated any intention of expanding across the
continent.

Harper 30
Vizzy
Vizzy, although not yet reporting revenues resembling any of the top three brands, is also
an extremely important player in the hard seltzer market right now and has been recognized as a
brand to watch. Vizzy represents Molson Coors’s latest attempt in early 2020 at making a mark
in the hard seltzer category.
Vizzy’s key competitive advantage is that it has “all of the things the other hard seltzers
have but with a meaningful addition that drinkers actually care about, antioxidant vitamin C”
(Struble). This plays directly into the target consumer for hard seltzers; someone who wants to
enjoy an alcoholic beverage while also promoting their health. This key strength combined with
appealing core flavors has allowed Vizzy to grow its sales significantly in the last few years,
growing by 51% in the third quarter of 2021 when most brands were in a slump, and is beginning
to be considered the number four brand.
This success is in part due to Molson Coors taking a bet on the hard seltzer market by
expanding the capacity of its seltzer and innovation capacity by 400% as of December 2020.
Moreover, when Molson Coors decided to discontinue its Coors Seltzer, it then put even more
direct attention on Vizzy and its other remaining hard seltzer, Topo Chico. Molson Coors
recognizes the significance of the hard seltzer market and, unlike other brands, has invested
significantly in a product that stands out in the crowd with its unique health benefits–even from
White Claw and Truly (Struble).
However, this success could be at risk; the Center for Science in the Public Interest and
Consumer Federation of America have made a public request to the Food and Drug
Administration asking them to pursue legal action against Vizzy for illegally marketing the
health benefits of their product. The letter references a 2015 document in which the FDA

Harper 31
claimed that beverages that mixed alcohol with vitamins and minerals were not appropriate, and
that it is wrong for the company to advertise Vizzy as a “"healthful source of nutrients, obscuring
the fact that alcoholic beverages provide empty calories, are associated with serious health
conditions and can impair the body's metabolism of nutrients" (Doering). While the FDA has not
taken action, this case does further the question of how “healthy” hard seltzers are and how much
longer they will be able to use this as a competitive advantage against other alcohol categories.
Regardless, for now, Vizzy is here to stay with its unique marketing, and it is likely that other
brands will follow their lead (Doering). Vizzy has not yet expanded nor announced intention to
expand into the European market.
Topo Chico
Topo Chico is a truly unique case in the hard seltzer category; the story of Topo Chico
began in 1895 when the company began bottling mineral water from a spring in Monterrey,
Mexico in which an Aztec princess was said to have been restored back to health after falling ill
in the 1400s. The name of the beverage refers to a mountain near this spring called the Cerro del
Topo Chico. The sparkling water company grew in success in Mexico and eventually began to
slowly enter the United States market with a modest distribution system throughout Texas,
Georgia, Florida, and Chicago in 1987. At this point, the drink was hard to find in the United
States and primarily purchased by expat Mexicans. Slowly, Topo Chico expanded into more
stores, and by 2015 a cult following had developed–particularly in Texas. Topo Chico also
benefited from the trend of consumers looking toward sparking water for a healthier alternative
to sugary drinks, and, by “2016, Los Angeles Magazine ranked Topo Chico as the top sparkling
water on the market, ahead of other popular brands, including Perrier, San Pellegrino and
LaCroix” (Gerlsbeck).

Harper 32
This proven success led Coca-Cola to acquire the brand in 2017 (as part of its strategy to
become a total beverage company) and immediately widen its distribution. This led to a boom in
sales with the brand growing by 39% from 2018 to 2019. A key challenge for the company was
not getting the market to buy the drink but instead getting enough of the drink to the market to
meet demand. This is because Topo Chico continues to only be sourced from the same spring
even after the acquisition of the company by Coca-Cola (Kambhampaty). Riding on the success
of this distribution, in September 2020 the company released Topo Chico Hard Seltzer in Latin
America followed by European markets of Austria, the United Kingdom, Greece, Ireland, and
Ukraine in early 2021 (“Coca-Cola to Launch New Topo Chico Hard Seltzer in Europe in
2021”). As of June 2022, Topo Chico reportedly has captured the second most market share,
after White Claw, in the United Kingdom with 11.4%. This represents a 160% increase to 1.9
million pounds within a year (Leonard-Bedwell).
Unlike other hard seltzer brands that proved their success in the United States and then
decided to take their brands abroad, it was after these successes that Topo Chico Hard Seltzer
was finally introduced in limited American markets in March 2021–just in time for another hard
seltzer summer. Within a month, Topo Chico Hard Seltzer had acquired almost 20% of the
market in Texas, its unofficial home base, and 3.2% of the market nationwide (Noel). Building
on this success, in January 2022 the variety pack was released nationwide while, simultaneously,
the company also released a new line of seltzers called Topo Chico Ranch Water Hard Seltzer
inspired by the cocktail most popular in Texas, Ranch Water (Molson Coors).
Topo Chico’s approach of testing the hard seltzer brand in select and global markets
before reaching the competitive arena of the United States hard seltzer market makes it unique
from leading brands like White Claw and Truly–and this, combined with Coca-Cola’s existing

Harper 33
global network, may make it a key competitor to these brands during the expansion of hard
seltzers into the global market despite its lagging start.
Mike’s Hard Seltzer
Long before Anthony von Mandl brought upon the world the White Claw Summer, he
and his company Mark Anthony Brewing had already begun to revolutionize the alcohol market
through another beer alternative: Mike’s Hard Lemonade. Von Mandl noticed that “up to 25% of
guys didn’t particularly want to drink beer, but couldn’t be seen holding anything else in their
hand” (“Mike's Hard Lemonade: Company Profile”). Due to its unique and tasty flavor
compared to the other canned beverage available at the time, Mike’s Hard Lemonade sold 10
million cases without a premeditated marketing campaign. Since then, the company has
continued to release innovative flavors in addition to its original lemonade pack and has
maintained a strong following (“Mike's Hard Lemonade: Company Profile”).
Almost inevitably, in the wake of the sustained success of its White Claw brand and the
entrance of many strong competitors to the category, in February 2021 Mark Anthony Brewing
released Mike’s Hard Seltzer to the world. This new spin on their beloved beverage has “been
incredibly incremental to the portfolio, attracting new 21- to 34-year-old consumers to the brand”
and, in 2022 after a year of being on the market, Mike’s Hard Seltzer was “the number-eight hard
seltzer brand out of over 300 with just one SKU” (Bria). Although not the only brand with
lemonade flavors (other brands such as Truly, Bud Light, and Topo Chico all released lemonade
seltzers around the same time), Mike’s Hard Seltzer is able to take advantage of its existing
customer base nostalgic for Mike’s Hard Lemonade and the expertise that Mark Anthony
Brewing has curated through developing and sustaining the success of White Claw (Nelson). By
April of 2021, Mike’s Hard Seltzer was already released into the European market in Belgium,

Harper 34
France, the Netherlands, and Germany after already being tested in the United Kingdom (Arthur
April 2021).
Pure Piraña
Heineken, a popular beer company based in the Netherlands, decided to also join the hard
seltzer category in fall 2020 with the Pure Piraña brand. Instead of entering the fierce
competition of the United States hard seltzer market, Heineken opted to introduce Pure Piraña
first to two of their largest markets: Mexico and New Zealand. The brand decided to focus on
providing refreshing all-natural low-calorie beverages (Whymark 2020). Though this marketing
strategy is not unique to the category, Pure Piraña does provide beverages at 92 calories, 8
calories fewer than the aforementioned category standard.
Following promising sales in Mexico and New Zealand, the company decided in March
2021 to release their flavors into the European market starting with Austria, Ireland, the
Netherlands, Portugal, Spain, and later the United Kingdom (Whymark 2021). Heineken made
this move deciding not to become just another hard seltzer in the United States but instead to
attempt to be at the forefront of hard seltzer market’s introduction to Europe and “be the biggest
player in it” (Carroll). In October of 2021, it even announced that the brand would be expanding
further into the duty-free cruise and ferry market (A. Smith).
However, despite this optimism, Heinekin has been honest about its European
performance. In the United Kingdom in particular, the company admitted in August 2022 that
“while the UK seltzer market continues to show value and penetration growth in its third full
year, the segment is not yet moving the dial from a scale point of view and has a long way to go
to match the success of seltzers in the US” due to the fact that “the US already had a very
developed soft seltzer market, with some great brands and great flavour varieties. So that was a

Harper 35
bridge where you could just add alcohol” (Carroll). Accordingly, Heinekin plans to continue
investing in the Pure Piraña brand, but is also looking at other categories such as ciders and light
beers to meet the demands of young, health-conscious consumers in Europe (Carroll). While
other hard seltzer brands have not been so forthcoming with the European performance so far, it
is likely that others are feeling similar pushback in the market. As a result, Pure Piraña should
still be considered a strong contender for the global hard seltzer market due to its unique strategy
of focusing on conquering the global market rather than focusing first on the United States
market.

Harper 36
Primary Research
The primary research for this thesis comprises of two surveys aimed at addressing two
different topics: the drinking cultures of the United States vs. Europe and general awareness and
enjoyment of hard seltzers. The results of these surveys will be analyzed in the following section
in conjunction with the secondary research from the previous sections of this thesis in order to
draw conclusions about the viability of the hard seltzer category in Europe.
In addition to the surveys, this research also includes a case study focusing on White
Claw’s current activity in Vienna attempting to reach and appeal to university students. It will
include interviews with three different Austrian entities (unimag, OeAD, and the Erasmus Buddy
Network) which will address their ties and involvement with White Claw.
Methodology
The first survey, titled “Hard Seltzers in the United States Survey”, aimed to create a
baseline for the drinking culture and the awareness and appeal of hard seltzers in the United
States. Since hard seltzers have successfully fit into the drinking culture in the United States, the
similarities and differences between the drinking cultures in this baseline and Europe may help
determine the potential for the hard seltzer category in the latter. 77 United States natives who
drink alcohol participated in this survey, with 44 identifying as women, 32 identifying as men,
and 1 identifying as non-binary. Regarding age, 48 participants were 18 to 21 years old, 14 were
22 to 25 years old, 1 was 26 t0 29 years old, and 11 were 30 years old or older. A more in-depth
breakdown of these demographics is available in Figure A.
The second survey, titled “Hard Seltzers in Europe Survey”, is meant to bring clarity into
both the drinking culture of Europe and the current awareness and appeal of the hard seltzer
category. This survey consisted of 36 European participants, with 20 identifying as women and

Harper 37
16 identifying as men. By age, this survey includes 17 people who were 18 to 21 years old, 17
who were 22 to 25 years old, 1 individual who was 26 to 29 years old, and 1 who was 30+. In
this survey, I also asked the Europeans to disclose from which country they originate. Overall, 16
countries of origin were included, with the most popular countries of origin being Austria,
France, and Germany, each with 5-6 participants. The other countries represented include the
Czech Republic, England, Finland, Italy, the Netherlands, Norway, Poland, Portugal, Scotland,
Spain, Sweden, and Switzerland. More in-depth breakdowns of these demographics are available
in Figures B and C.
Both surveys are composed of two different parts: a quantitative section and an optional
qualitative section. In the quantitative section, participants were asked a series of questions to
gauge their alcohol habits and preferences, particularly in relation to hard seltzers. In the
following section, I will indicate a “U” if the question was just asked in “Hard Seltzers in the
United States Survey” and an “E” if the question was just asked in “Hard Seltzers in Europe
Survey”. Answer options will be in the parentheses. The questions were as following:
●Did you know what a hard seltzer was before taking this survey? (Yes or No)
●Have you drunk a hard seltzer before? (Yes or No)
●U: Have you drunk a hard seltzer in the United States? (Yes or No) E: Have you drunk a
hard seltzer in Europe? (Yes or No)
●U: Which of these brands have you seen being sold at bars, restaurants, and/or stores in
the United States? E: Which of these brands have you seen being sold at bars, restaurants,
and/or stores in Europe? (Select all that apply: White Claw, Truly, Topo Chico, Bud Light
Seltzer, Vizzy, Pure Pirana, Mike’s Hard Seltzer)

Harper 38
●U: Where have you seen hard seltzers in the United States? E: Where have you seen hard
seltzers in Europe? (Select all that apply: I have never seen a hard seltzer in Europe/do
not know what that is, Bar, Restaurant, Store, Party, University, Give-away, Advertising,
Other)
●On a scale from 1 to 10, how much do you enjoy drinking hard seltzers? (1=least favorite
drink, 10=favorite drink, 0=never have tried one)
●Which of the following hard seltzer brands do you enjoy drinking? (Select all that apply:
White Claw, Truly, Topo Chico, Bud Light Seltzer, Vizzy, Pure Pirana, Mike’s Hard
Seltzer, None of the above, I have haver drank a hard seltzer)
●Why do you drink alcoholic beverages? (Select all that apply: To have fun, To get drunk,
To have a sense of belonging in social settings, To celebrate, To enhance a
feeling/situation, For the taste, To cope with problems/stressors)
●What are your highest priorities when selecting alcoholic beverages? (Select all that
apply: Flavor, High alcohol content (%), Low alcohol content (%), What other people are
drinking, Accessibility, Convenience for holding in social settings, Health, Price)
After collecting data from participants, I then analyzed it in Excel to see what was
relevant to my thesis and what was not. I then took the relevant data and manipulated it in Excel
and PowerBI to produce statistics, charts, and tables to aid in my analysis.
The optional qualitative section of my research was composed of one area with five
different questions that participants had the option of answering if they elected. I chose to make
this part optional for two reasons: one, not everyone has thought about this topic enough or done
enough research to have an educated opinion which is not necessary for the remainder of the
survey, and two, in order to be able to generate the maximum participation rate I wanted to keep

Harper 39
the mandatory survey as brief as possible with a one to two minute completion time. The
qualitative section was as follows:
●If you have time and are willing, please answer any or all of the following questions to
help with the qualitative analysis for my thesis. How would you describe the drinking
culture of the United States (U) / Europe (E)? How do you believe the drinking culture of
the United States is different from the drinking culture of Europe? Do you believe hard
seltzers have a future in Europe? What brand(s) do you think has the most potential in
Europe? Do you have any other thoughts?
I received 11 responses to this section in “Hard Seltzers in the United States Survey” and
five responses to this section in “Hard Seltzers in Europe Survey”. I then looked through these
responses to identify trends and determine general opinion about the drinking cultures in the
United States and Europe, how they compare, and how hard seltzers fit into them. I also used
some direct quotes from this section to support my qualitative analysis.
Limitations
First, one limitation of these survey results is that both surveys are based on voluntary
samples. While a random sample would have provided better statistical representation, I did not
have the resources within this thesis to obtain it. Instead, I had to find participants from my
greater personal network that were willing to take the survey. As a result, the demographics of
the participants are slightly skewed toward my personal demographic, 21-year-old woman,
which is another limitation of this thesis. One reason for this in the European data is because I
was denied my request to distribute the survey to all students and faculty at the Vienna
University of Economics and Business (WU) where I was studying abroad since my research
was being conducted through the University of South Carolina, not WU. I had to instead mainly

Harper 40
rely on the relatively younger network I created studying and traveling through Europe as well as
international students at the University of South Carolina. While I tried my best to create
diversity in my participants by finding people who would voluntarily participate from different
age groups and gender identities, there is a slight bias towards women and 18 to 21 year old
participants. Moreover, in both surveys, the vast majority of the data encompasses participants
from the ages of 18 to 25. However, since hard seltzers are typically primarily marketed toward
Gen Zers/Millennials with a slight bias toward women over men, this slight imbalance does not
invalidate the results or the subsequent analysis. Finally, while 16 European countries are
represented in the demographics of participants, this does not indicate a perfect representation of
Europe. The data is also slightly skewed towards Austria, Germany, and France as can be seen in
Figure C.
As a result of these limitations, my analysis of the drinking culture of Americans and
Europeans will not claim to be based on fully representative data of these populations. Instead, it
will be focused on the target demographics of hard seltzers, Millennials and Gen Zers, and
include a generalization of the European market. This bias in age is validated by White Claw’s
decision to specifically target university students in Austria indicating a personal bias towards
the younger age groups (as discussed in the section entitled “Case Study: White Claw in
Vienna”). Lastly, this generalization of the European market is validated by the discussion of the
internationalization of the European alcohol market discussed in the previous section titled
“Alcohol in Europe”.
Quantitative Results
The quantitative results of these surveys can be grouped into two parts: awareness of
hand seltzers and priorities and reasons for drinking alcohol. In some of the following results, the

Harper 41
terms “high”, “medium”, and “low” will be used to refer to concepts like awareness, enjoyment,
and priorities. These terms refer to the proportion of study participants who agreed with that
statement. For all of these questions, “high” refers to 70% of participants or higher, “medium”
refers to 30-69%, “low” refers to 10-29%, and “minimal or none” refers to 0-9%. To clarify, the
individuals themselves did not measure the degree to which they enjoy or prioritize something;
instead, they simply indicated whether or not they enjoyed or prioritized something, and the
results represent an aggregate of each survey group. For example, a high proportion of
enjoyment of White Claw in Europe indicates that a large proportion of Europeans enjoy
drinking White Claw. Lastly, for these types of questions, participants were not limited in the
number of options they could select. This means that a participant selecting that they enjoy
White Claw did not prevent them from selecting that they also enjoy Truly. A breakdown of
these questions can be reviewed in the “Methodology” section above.
In terms of awareness, Americans clearly (and unsurprisingly) are much more familiar
with hard seltzers than Europeans. Before taking this survey, as can be seen in Figures D and E,
only 69% of Europeans knew what a hard seltzer was compared to 100% of Americans and 75%
of Europeans had tried one compared to 97% of Americans (it is assumed that some Europeans
initially did not know that what they were drinking was a hard seltzer to account for these
conflicting numbers).
In the following section, I will use the word “awareness” to refer to whether the subject
can remember seeing a particular brand of hard seltzer on their continent of origin or any brand
in a particular type of location. This is not intended to accurately measure precise frequency but
instead be an estimation of the scope of the current presence of hard seltzers in each market.
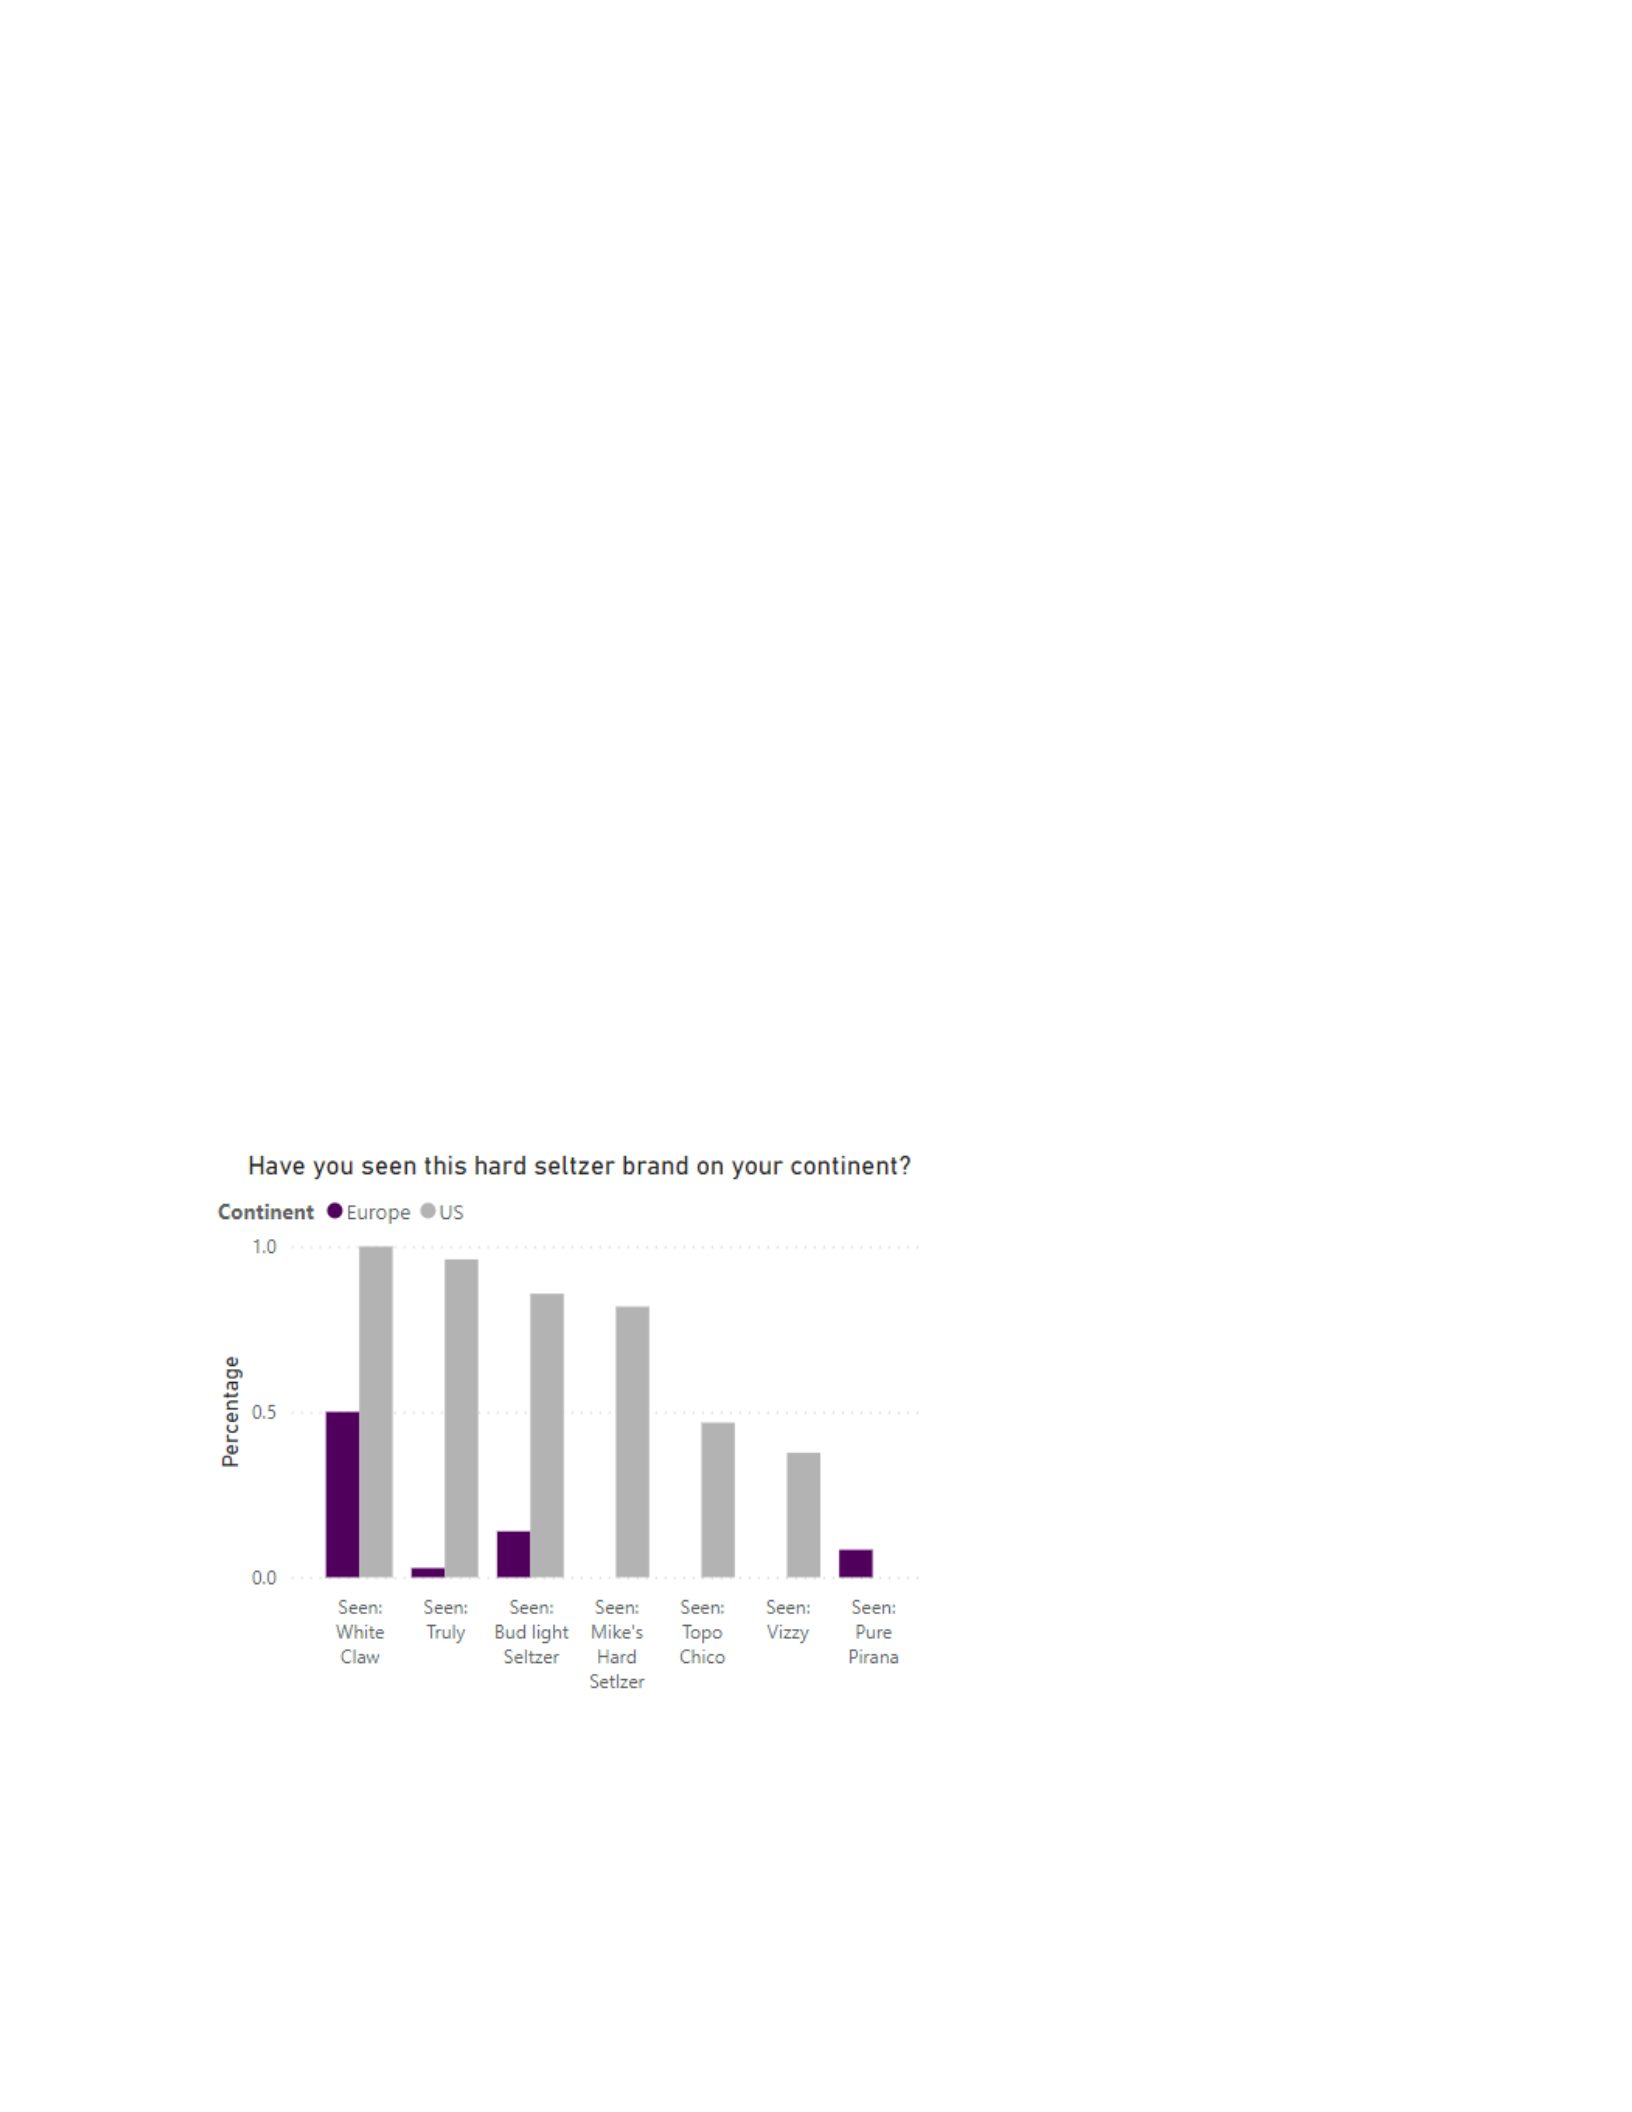
Looking at the hard seltzer brands highlighted in this thesis, a high percentage of Americans
Harper 42
have awareness of White Claw, Truly, Bud Light Seltzer, and Mike’s Hard Seltzer on their
continent, a medium percentage of Americans have awareness of Topo Chico and Vizzy, and no
Americans are aware of Pure Piraña. On the other hand, a medium proportion of Europeans have
awareness of White Claw on their continent, a low proportion of Europeans have awareness of
Bud Light Seltzer, and a minimal proportion of or no Europeans are aware of Truly, Mike’s Hard
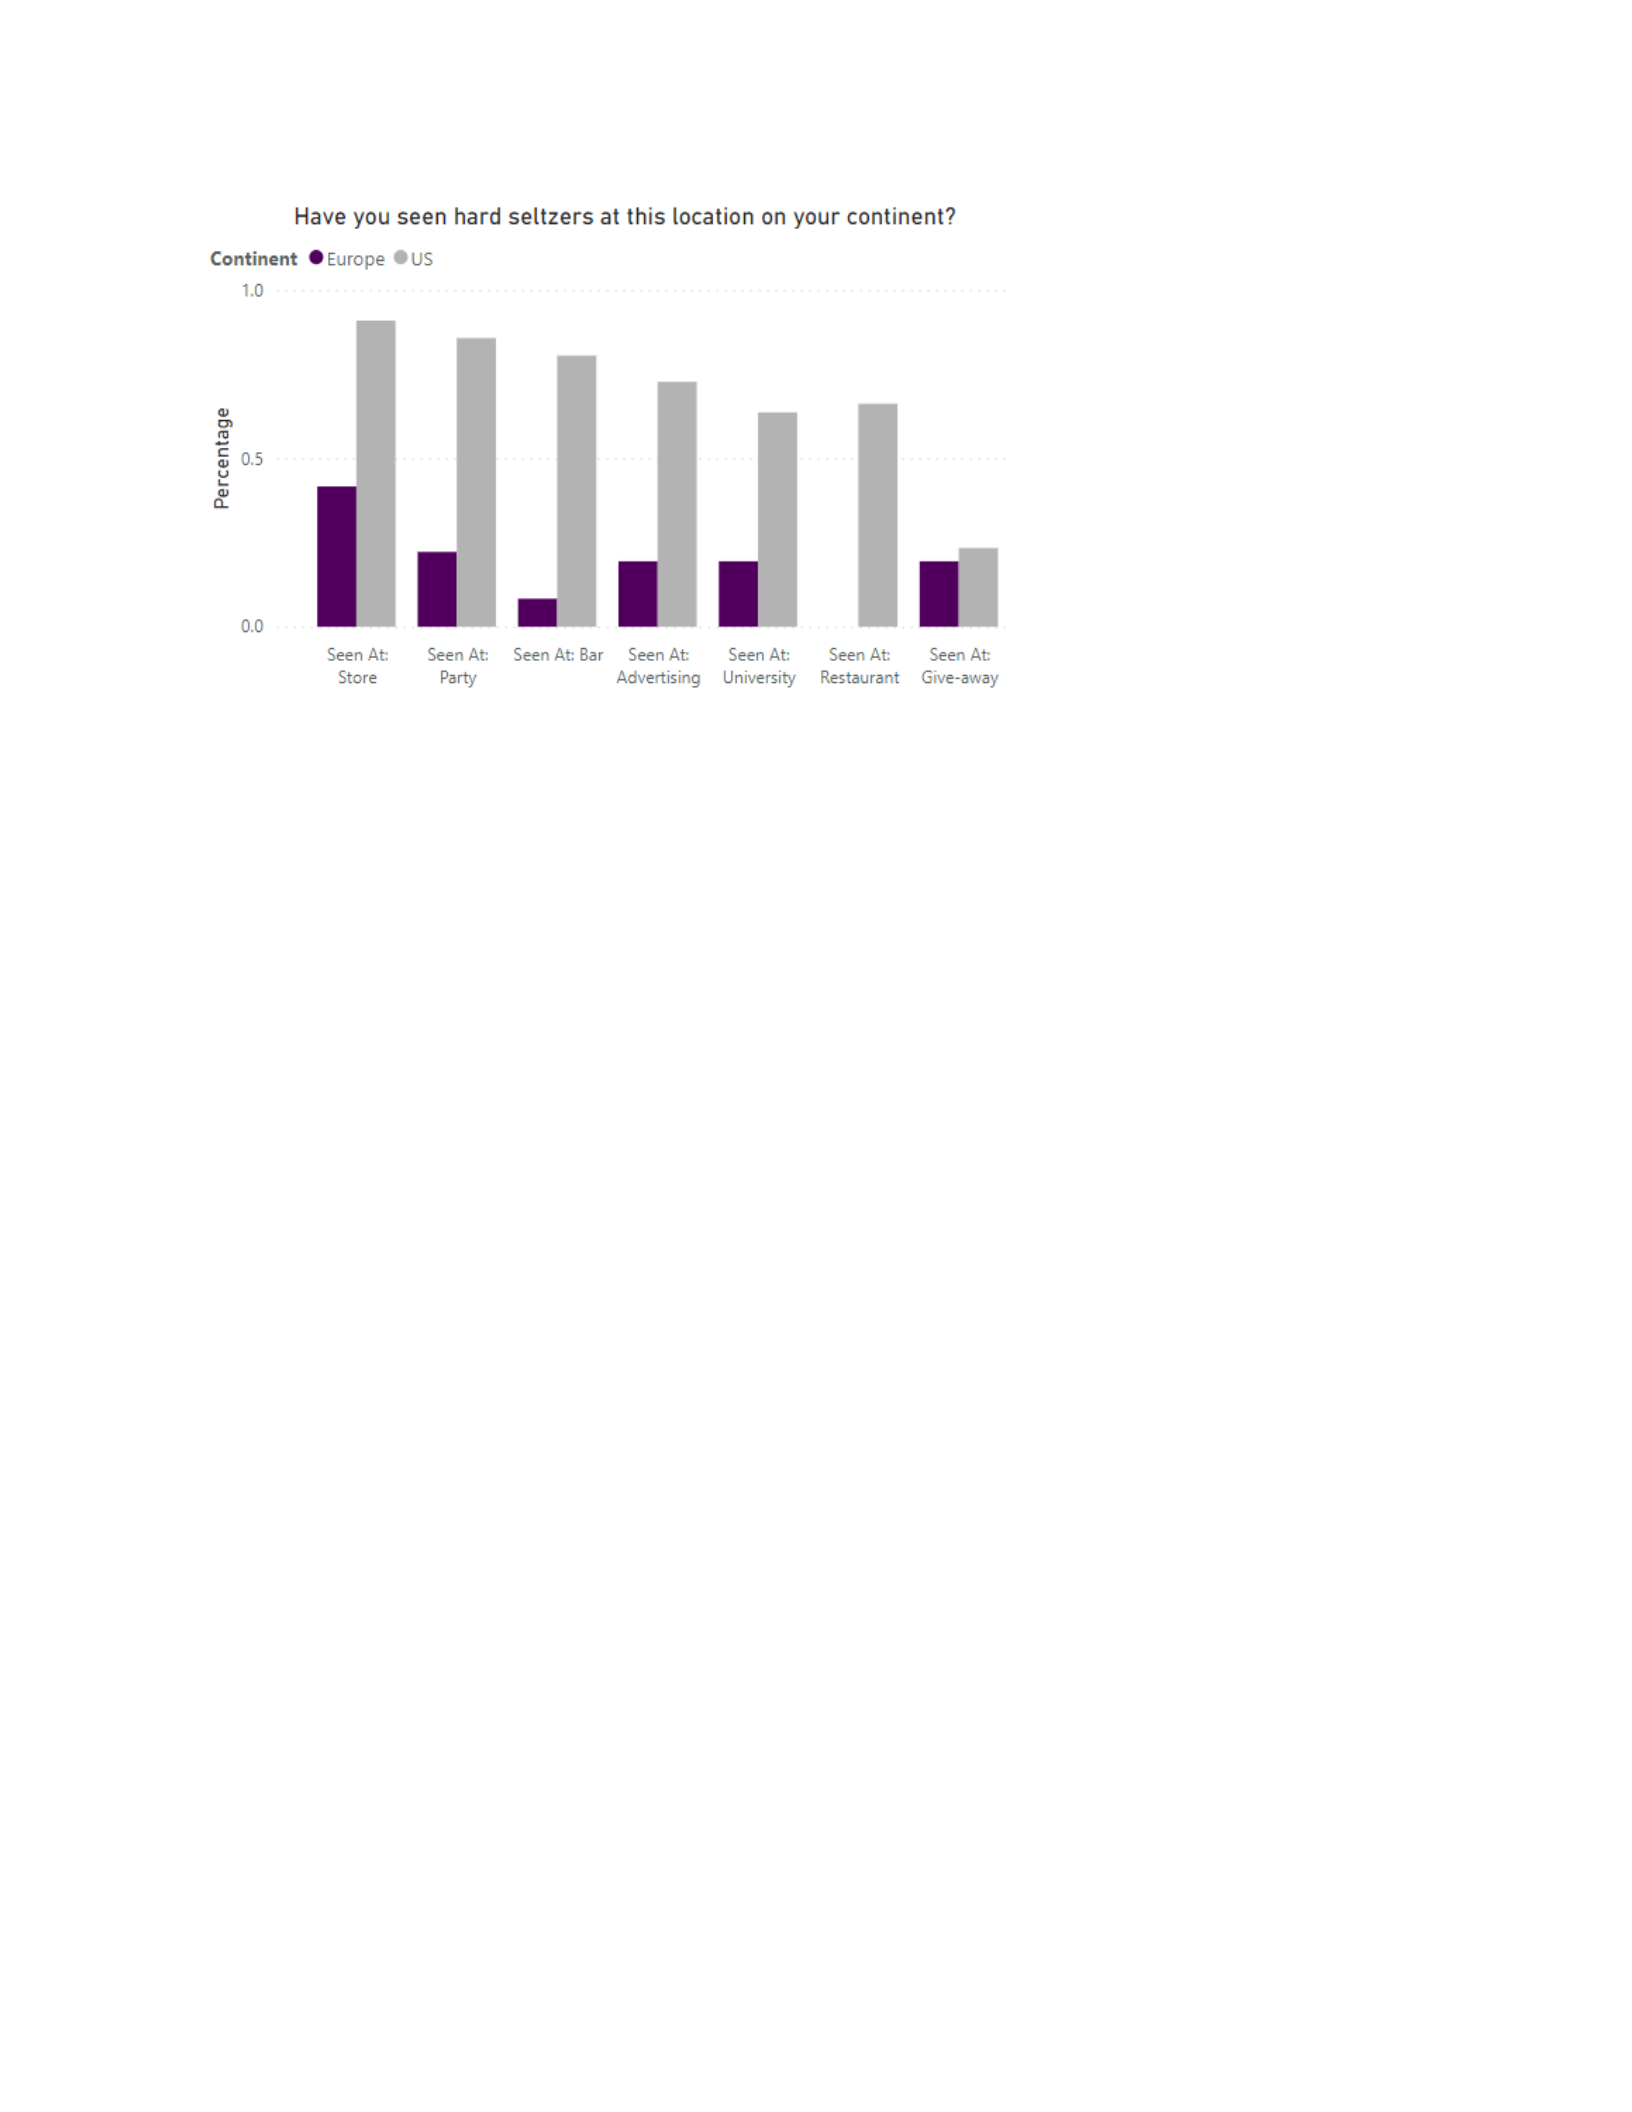
Seltzer, Topo Chico, Vizzy, and Pure Piraña (See Figure F). When asked where on their continent
individuals have seen hard seltzers, a high proportion of Americans had awareness of hard
seltzers at stores, parties, bars, and in advertising, a medium proportion had awareness at
university and restaurants, and a low proportion had awareness at give-aways. Europeans had a
medium percentage of awareness of hard seltzers at stores, a low percentage of awareness at
parties, advertising, university, and give-aways, and a minimal or non-existent percentage of
awareness at bars and restaurants (See Figure G).
Figure F
N (Europe) = 36, N (US) = 77
Harper 43
Figure G
N (Europe) = 36, N (US) = 77
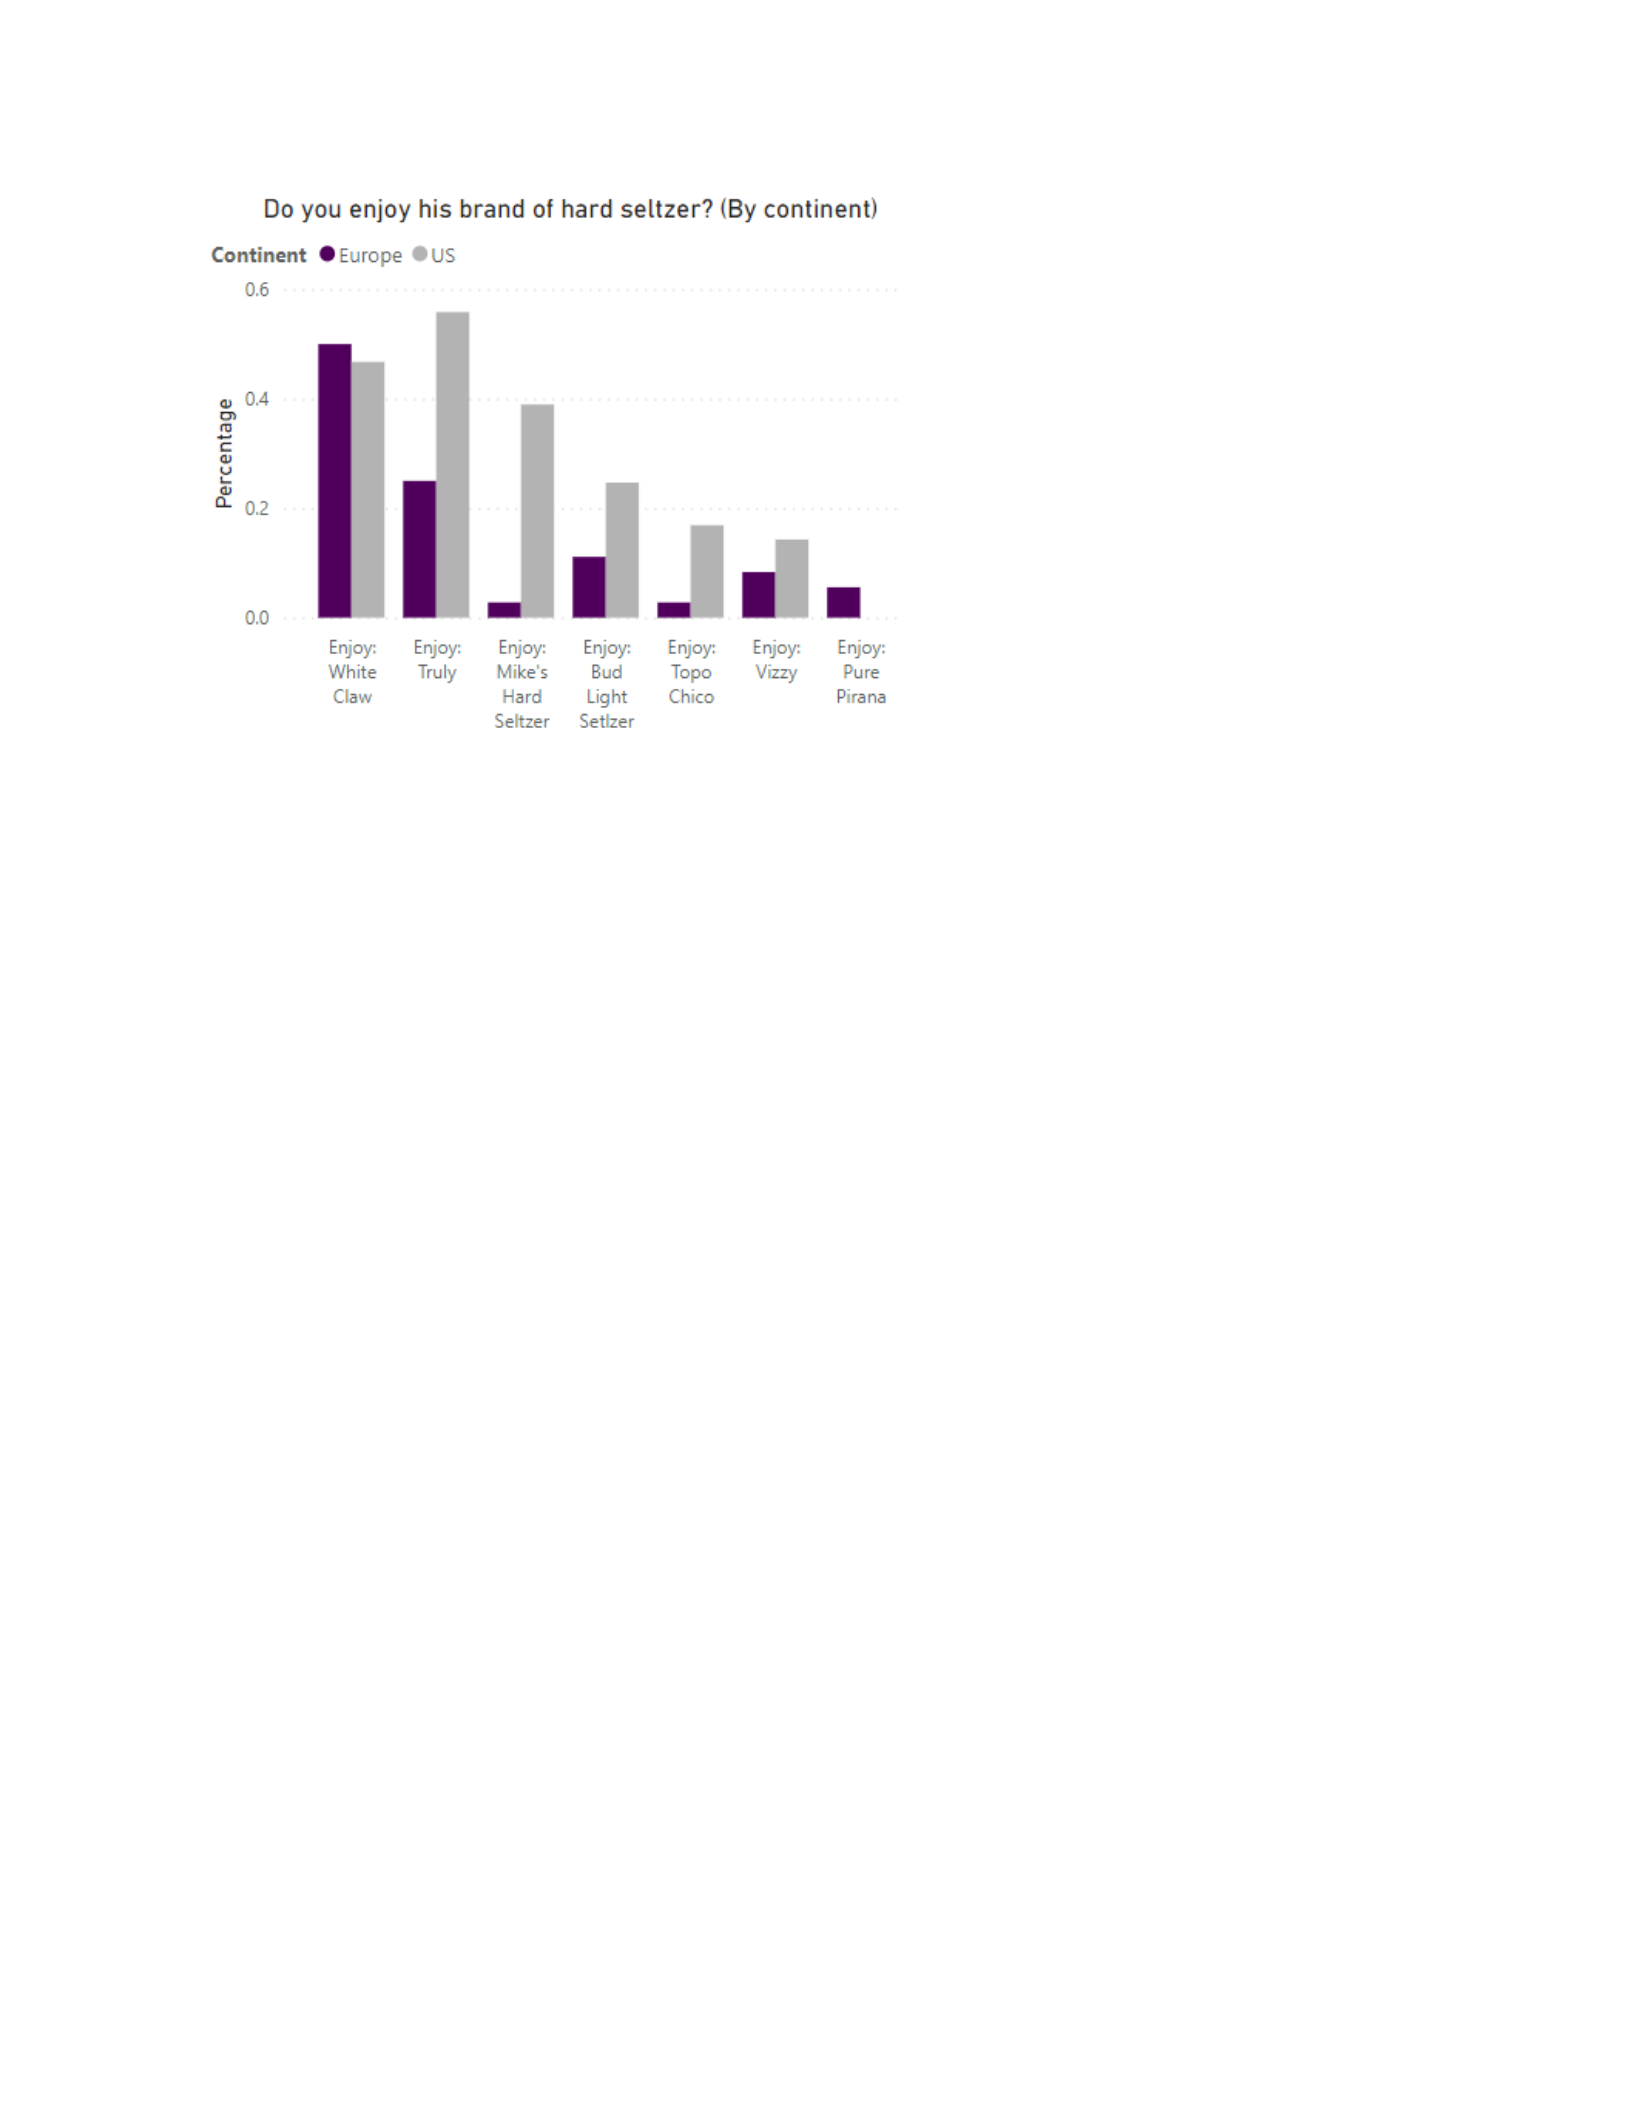
Regarding enjoyment of specific brands, which does not have to be limited to continent
as was awareness, a medium proportion of Americans enjoy White Claw, Truly, and Mike’s Hard
Seltzer, a low proportion enjoy Bud Light Seltzer, Topo Chico, and Vizzy, and none enjoy Pure
Piraña. Europeans have a medium percentage of enjoyment of White Claw, a low percentage of
enjoyment of Truly and Bud Light Seltzer, and minimal or no percentage of enjoyment of Mike’s
Hard Seltzer, Topo Chico, Vizzy, and Pure Piraña (See Figure H). It is important to note that
some of the lack of enjoyment of each brand can be derived from lack of awareness of that brand
or hard seltzers in general. This aligns well with the parallels in the differences between brands
in Figures F and H.
Harper 44
Figure H
N (Europe) = 36, N (US) = 77
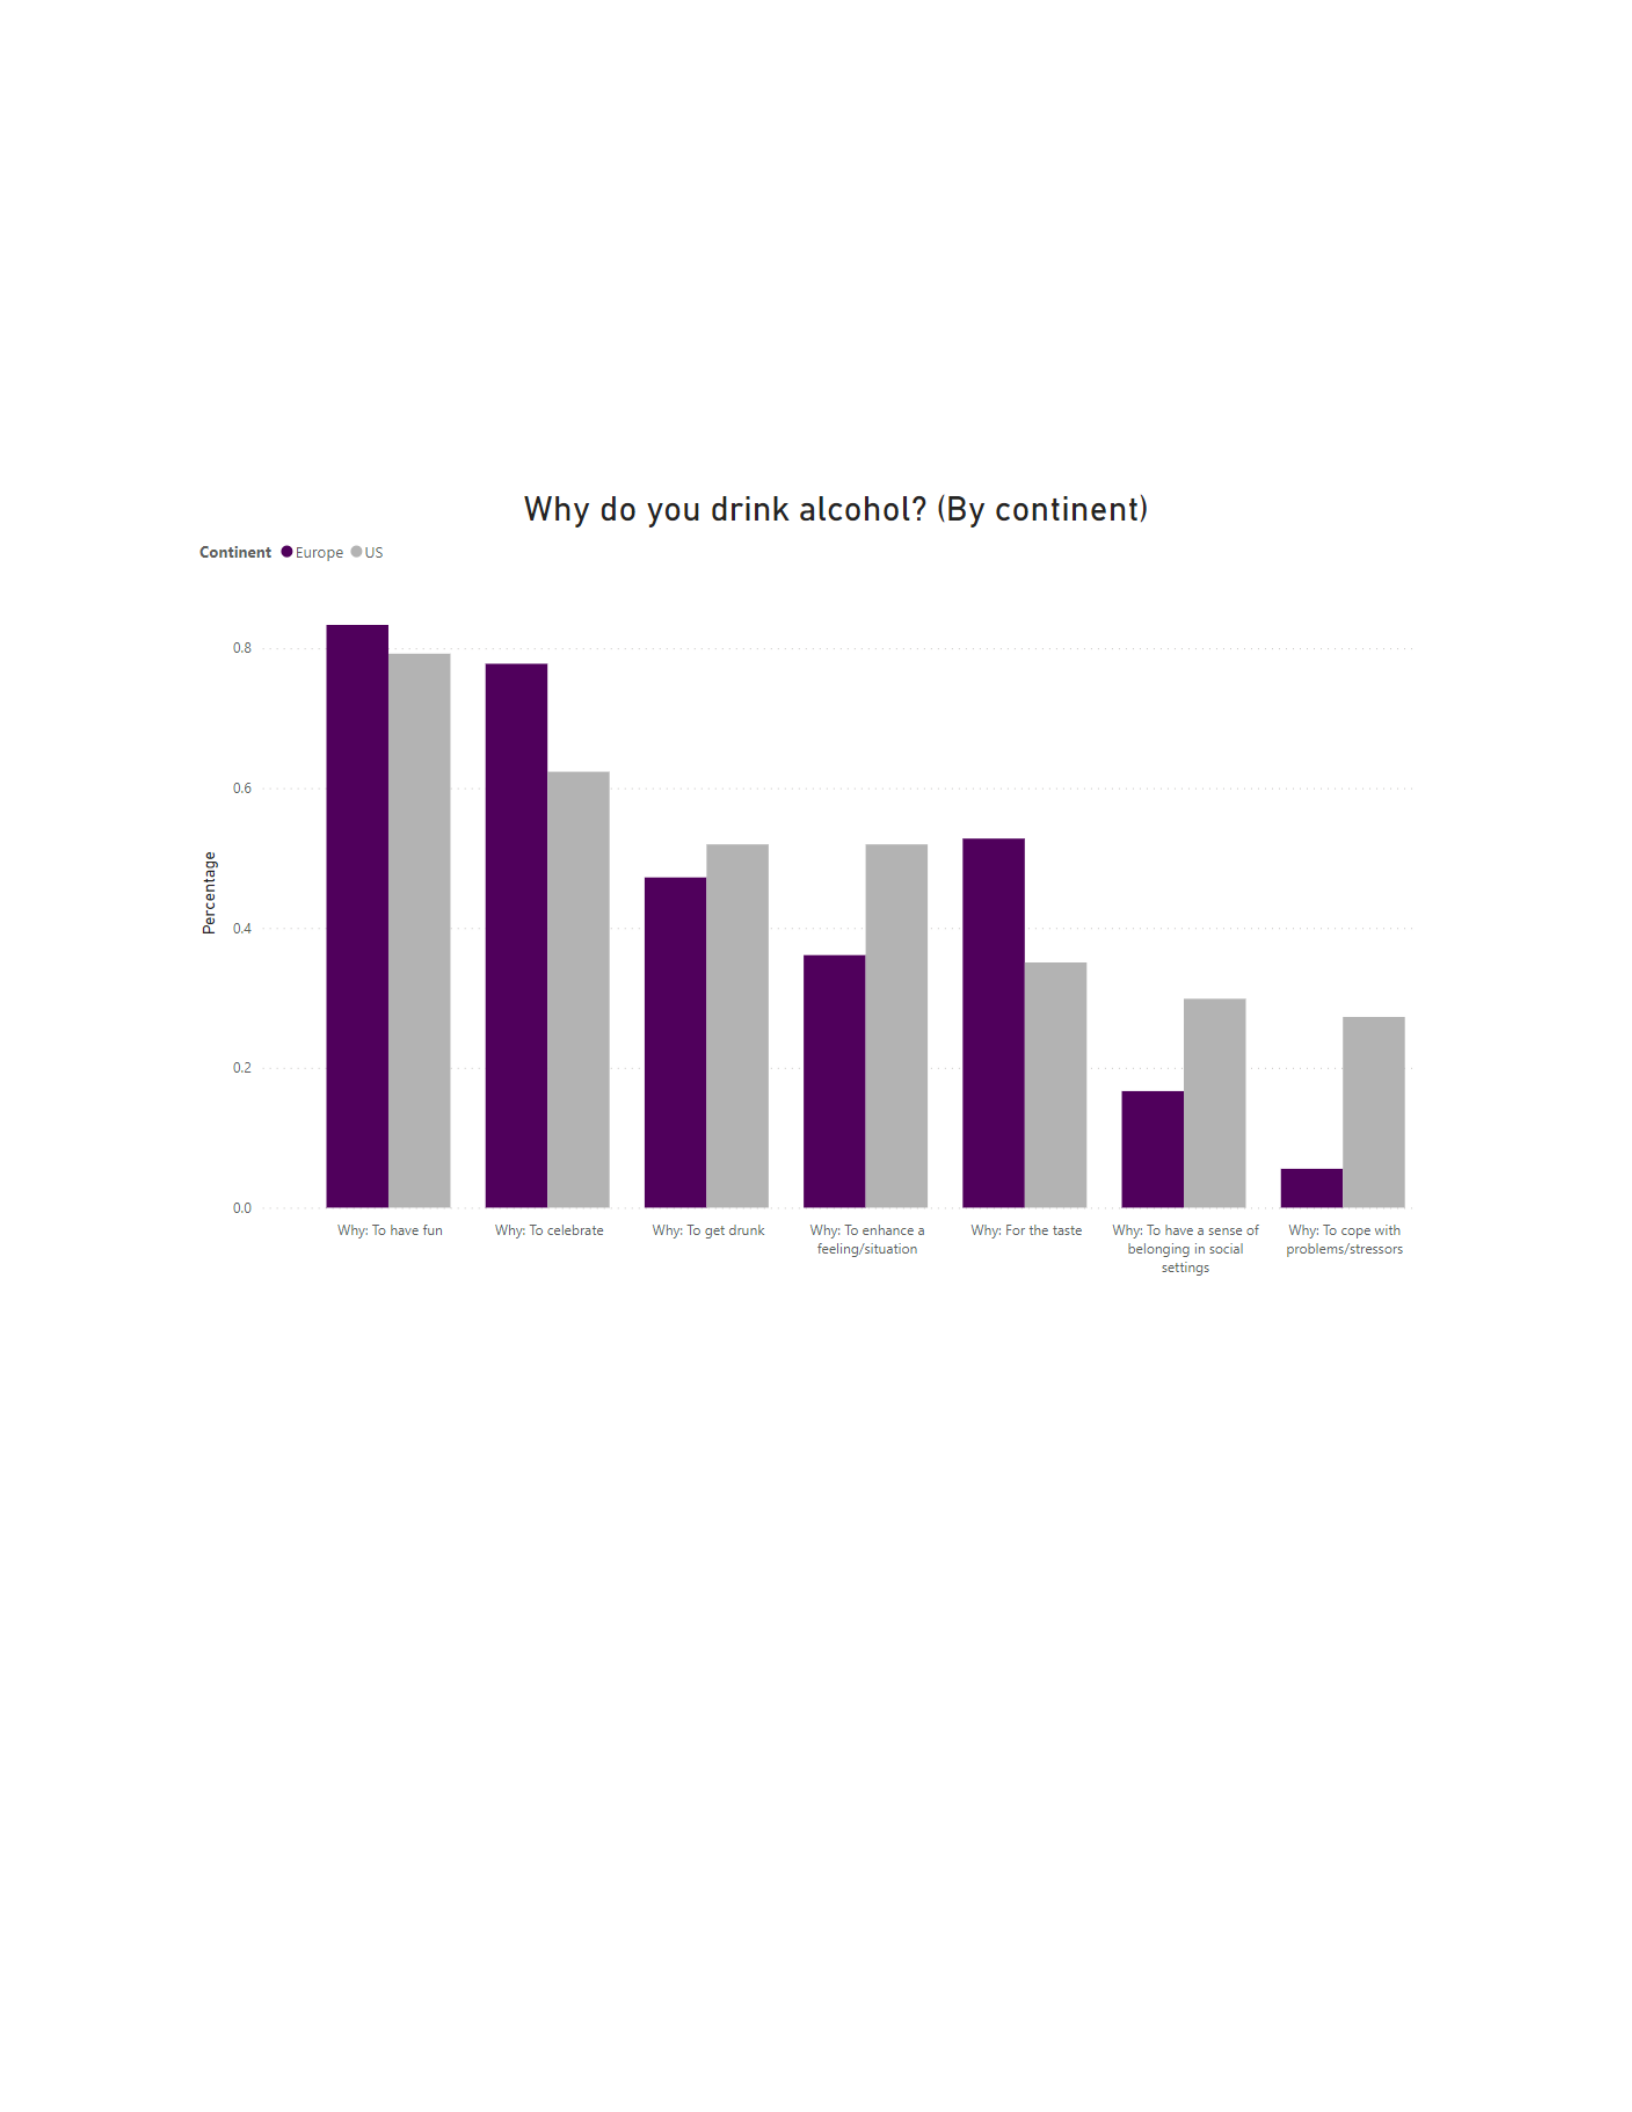
The final two questions of the quantitative section asked subjects their reasons for
drinking alcohol and priorities when selecting alcoholic beverages. Focusing on why individuals
drink alcohol, for Americans having fun is of importance to a high percentage of participants,
celebrating, getting drunk, enhancing a feeling or situation, and the taste are important to a
medium percentage, and having a sense of belonging in social settings and coping with problems
or stressors are important to a low percentage (Figure I). For Europeans, having fun and
celebrating is important to a high percentage of participants, getting drunk, enhancing a feeling
or situation, and the taste are of importance to a medium percentage, having a sense of belonging
in social settings is important to a low percentage, and coping with problems or stressors is
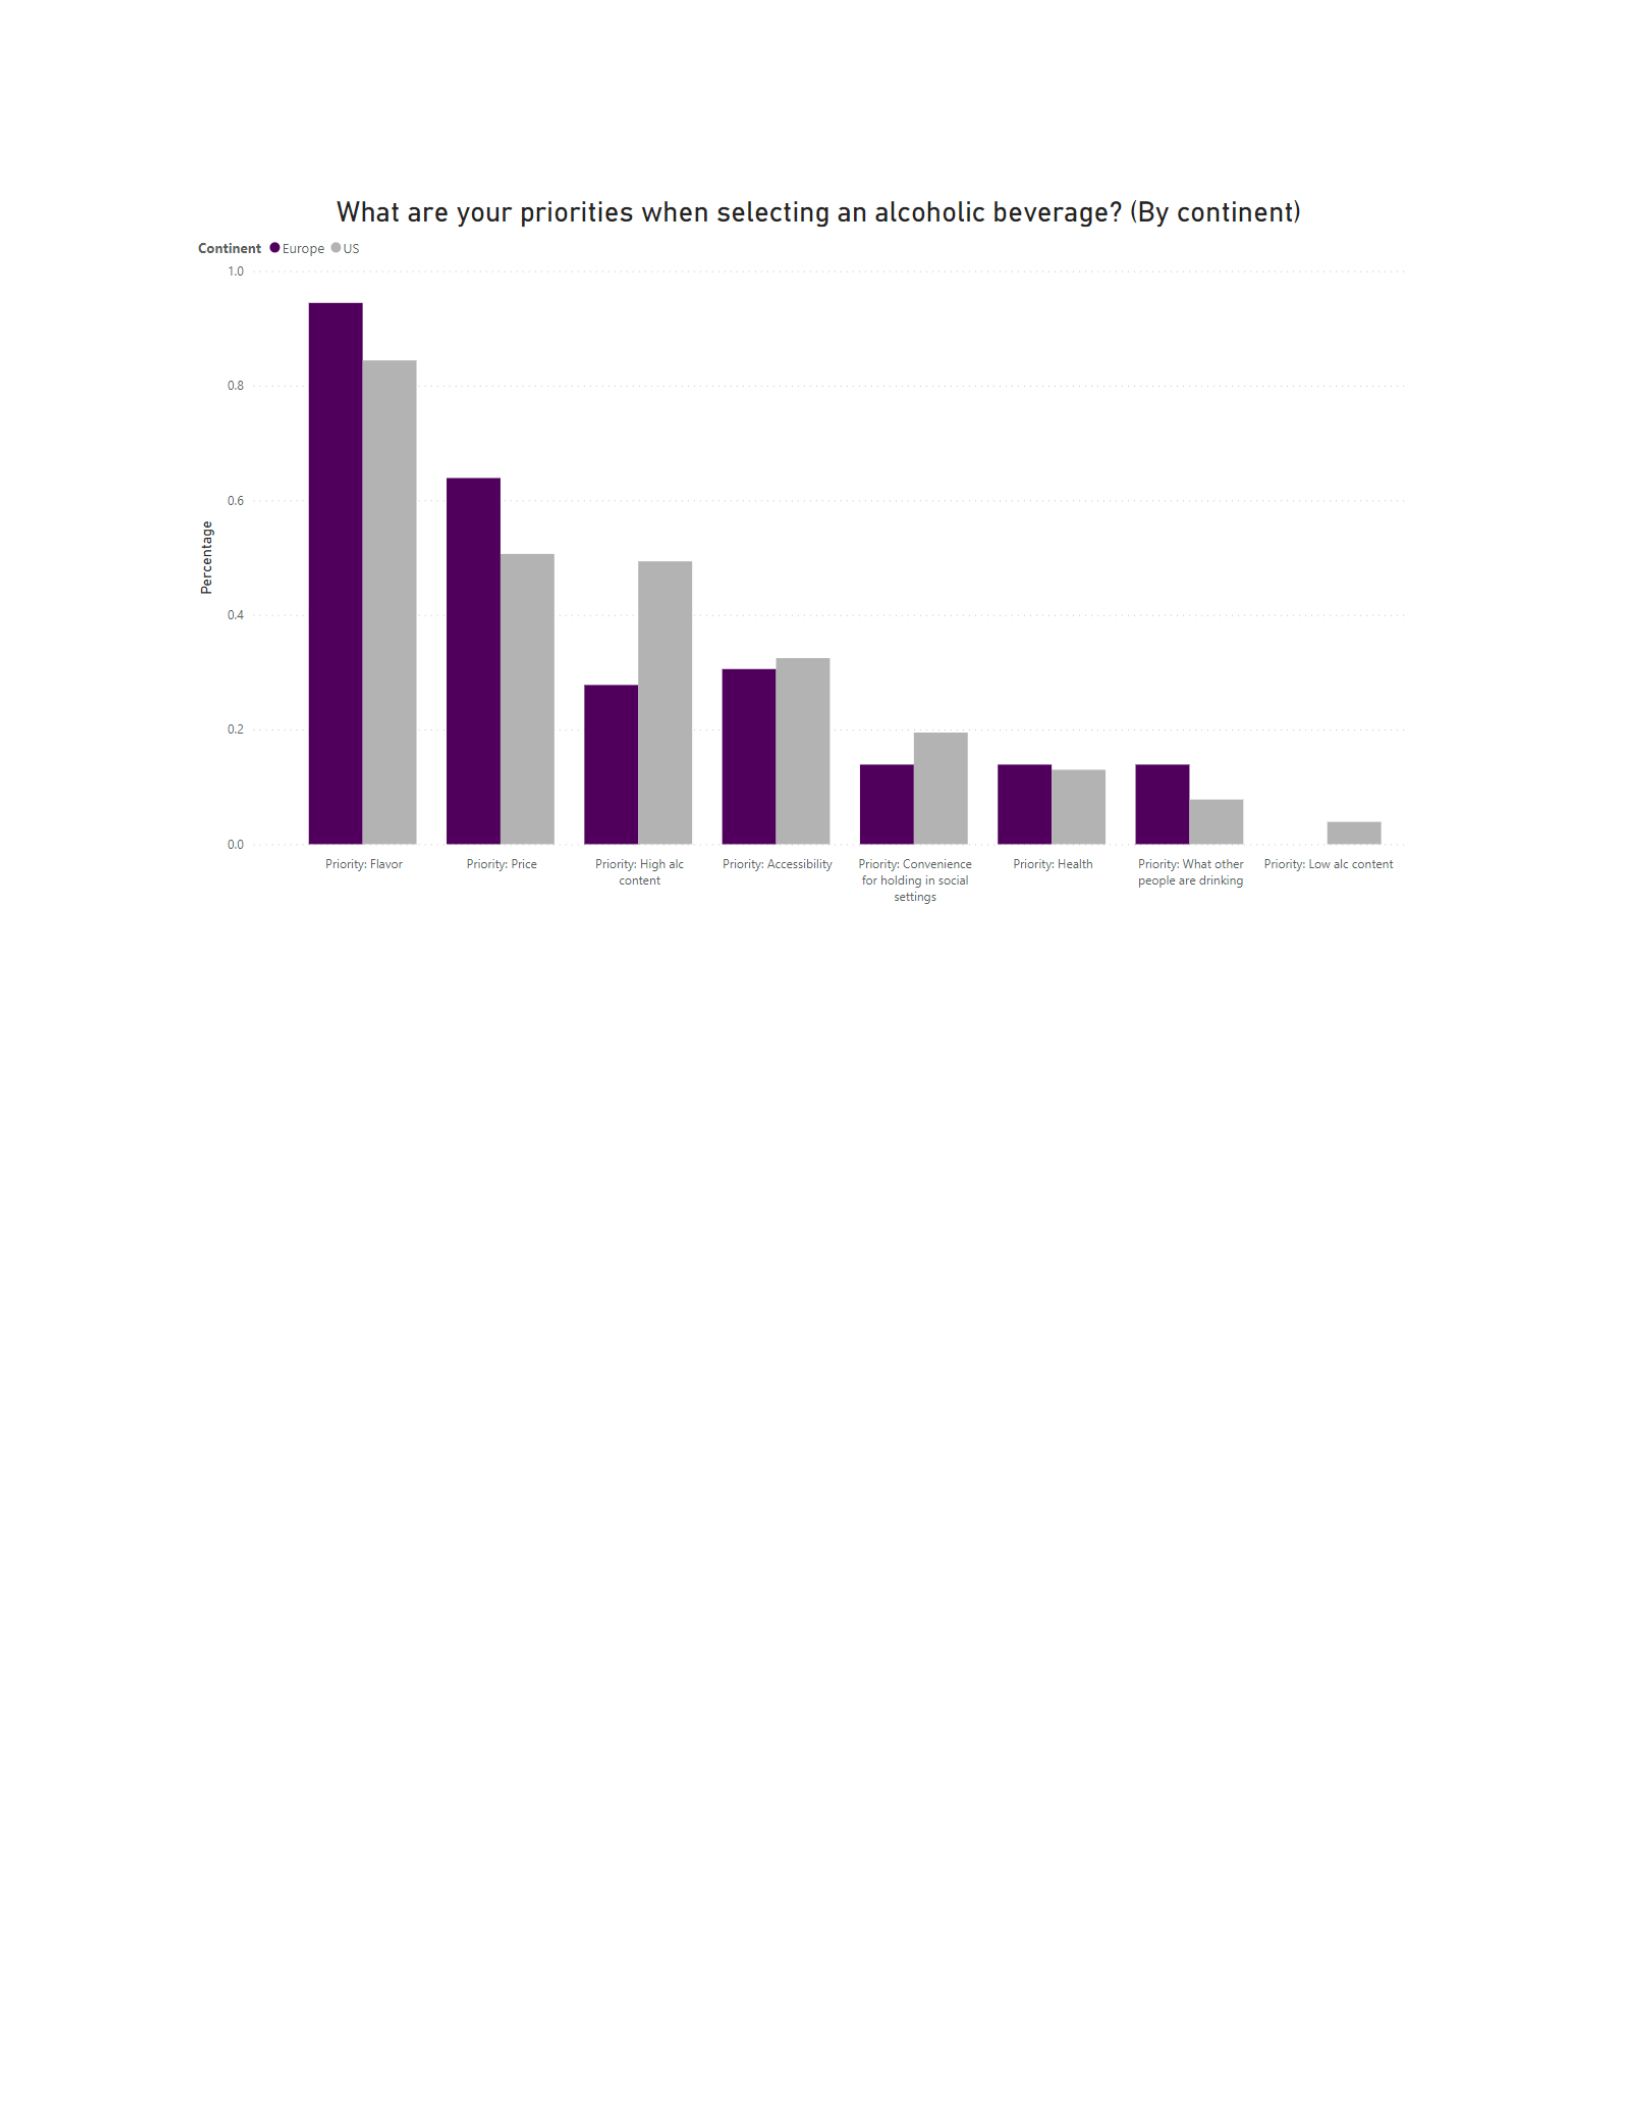
important to a minimal percentage. Looking at priorities for the American group, flavor is a
priority for a high proportion of subjects, price and high alcohol content are priorities for a
medium proportion, convenience for holding in social settings and health are important for a low
proportion, and what other people are drinking and low alcohol content are priorities for a
minimal proportion. For Europeans, flavor is prioritized by a high percentage of participants,
Harper 45
price is prioritized by a medium percentage, high alcohol content, accessibility, convenience for
holding in social settings, health, and what other people are drinking are prioritized by a low
percentage, and low alcohol content is not a priority for any participants when selecting an
alcoholic beverage (See Figure J).
Figure I
N (Europe) = 36, N (US) = 77
Harper 46
Figure J
N (Europe) = 36, N (US) = 77
Qualitative Results
Throughout the qualitative results of these surveys, a clear divide in drinking culture
between the United States and Europe became apparent. In general, both Americans and
Europeans seem to believe that “in Europe, they take time to enjoy alcohol through the course of
a meal or night and work up a light buzz” while in America “people aim to get drunk as quickly
as possible”. Some say this is because “Europeans have taste. They enjoy drinking rather than to
just get drunk”. Others point out that the drinking culture is more centered around partying in the
United States and can come with a lot of peer pressure while in Europe they “drink responsibly
and have less peer pressure when it comes to drinking”. Both Europeans and Americans seem to
believe that they are the ones who drink more excessively–but for different reasons. Europeans
point out that “most people (above the age of 15) drink on a frequent basis” and that “people can
handle alcohol better because they are more used to it. It is part of Austrian culture to drink a

Harper 47
beer at lunch.” As one American pointed out, “from what I’ve experienced studying abroad in
Europe, people drink intermittently over a longer period of time from afternoon to night.” On the
other hand, Americans believe that their drinking culture focused on partying causes people “to
get drunk as quickly as possible and end up binge drinking within two hours time.” The previous
section entitled “Alcohol in Europe” describes how Europeans do, in fact, drink more than
Americans, on average. The significant insight from this section, however, is not how much
Europeans and Americans drink, but how and with what aim; though the quantitative section of
this analysis indicates that getting drunk is of medium importance to both Americans and
Europeans, response bias might be in play. It is possible that some Americans tried to present
themselves in a better light when taking this survey. Still, even with this bias, Americans still
edge out Europeans with 52% of Americans and 47% of Europeans citing this as a reason they
drink alcohol. Therefore, the conclusion from this section is that Europeans drink more
frequently but without the intention of getting drunk while Americans drink more intermittently
but with more focus on getting drunk and partying. On a more somber note, one American also
pointed out that “it is too easy to fall into the trap of using it as a coping mechanism”.
Regarding the potential for hard seltzers in Europe, one man from Switzerland had a very
strong opinion claiming that “hard seltzer and all that kind of tasteless stuff has no belonging in
that culture rich continent”. It is important to note that this participant had never tried a hard
seltzer himself. Another European, a woman from Austria, also noted the lack of flavor in hard
seltzer, but instead said “hard seltzers might be interesting for those who would like to drink
something alcoholic without any strong taste. Just like Spritzer (white wine with sparkling water)
is very popular in Austria - especially on warm summer days.” Americans, who, on average,

Harper 48
have more familiarity with hard seltzers, seem to believe that “seltzer will make its way to
Europe”.
Both Europeans and Americans disagree on which brands have the potential to be
successful in Europe. Many believe that “White Claw would have a future in Europe since its
already extremely popular in the states”. Moreover, the woman from Austria believes that there
is potential because “it is advertised a lot and even distributed in public places to make
consumers aware.” One American pointed out that this is the case also because it is a “less sweet
tasting brand”. While one American believes that Bud Light Seltzers do not have a potential
“because Bud Light as a brand is very “American” based on the stereotypes of the people who
drink their beer”, another American provided a more logistical argument that “those sponsored
by the big brand beer co ( Budweiser, Corona, etc) as they can give up shelf space to introduce”
will be more successful.
Others think that the brands highlighted in this thesis are not necessarily the path forward
for the hard seltzer market. One man from Finland specifically highlighted Laitila, a brand that
“has managed to beat White Claw by a lot in popularity in Finland because of the taste
difference”. He believes that “local brands will do well in Europe as they know the consumers'
taste preferences” as “the drinking culture in Europe varies from country to country.” An
American, on the other hand, believes that these differences do not mean that the big companies
will fail; their success just “relies heavily on how they market” to different countries and
cultures. Finally, another American believes that perhaps already popular “seltzer water brands
like Pellegrino and Perrier” would be successful “if they released a spiked line”. Clearly, there is
no clear consensus on the future of hard seltzers in Europe; if there was, there would be no need
for this thesis. Yet, this section does seem to indicate that while hard seltzers can have a future in

Harper 49
Europe, their success will depend on how well they adapt and market their products to the
European market. Moreover, it may depend even more on how they adapt to the markets of
specific countries, and they may be met by local challengers such as Laitila when doing so.
Case Study: White Claw in Vienna
During my time studying abroad in Vienna, Austria from February through May 2022, I
observed an interesting phenomenon; while I did not often see hard seltzers available on the
menus of many bars or restaurants, I was encountering them in settings associated with my
university, the Vienna University of Economics and Business (WU). I eventually narrowed down
these instances to three different sources: unimag, an Austrian university magazine, OeAD, an
organization that provides housing to students across Austria, and the Erasmus Buddy Network,
an organization that supports exchange students during their semester abroad at WU. Each of
these entities was giving away White Claws for free alongside their services during my semester
abroad, and I reached out to representatives from each of these entities to uncover the reason
why.
Unimag is a free growing student lifestyle magazine distributed throughout the country of
Austria at universities. It provides students with insights and tips on entering their careers, advice
on what, where, and how to study in Austria, profiles on different residencies in different parts of
Austria, and articles about student life, festivals, music, sports, technology, fashion, and books.
This magazine is distributed physically at universities and also for free on their website,
unimag.at. Alongside their newspapers, they also sometimes give away White Claws for free to
students (see Figure K). According to Philpp Ossberger, a manager of unimag with whom I
corresponded, the magazine had a paid cooperation with White Claw’s Austrian distribution

Harper 50
company. They distributed the beverages to ten different universities in the cities of Vienna,
Graz, Linz, and Salzburg on behalf of the organization.
OeAD “is a non-profit student residence provider for international and national students,
and offers accommodations for around 12,000 students annually throughout Austria” (“About
us”). In Vienna alone, students have 25 different apartment buildings from which to choose.
When entering their office in Vienna during my semester abroad, there were often White Claws
available on a desk in the waiting area. Marianne from the team at the OeAd office in Vienna
explained that the White Claws were provided by a company called Freudebringer.
Freudebringer is a company that distributes samples of products from other companies “to
specific target groups via network partners such as thermal baths, fitness centers, doctors,
crèches and many other partnerships.” They take care of all logistics and organization and plan
their distribution based on market research (“Freudebringer”). For unspecified reasons, Marianne
said that this partnership did not continue into spring 2023.
The Erasmus Buddy Network (EBN) is an organization that connects exchange students
at WU with each other and students of the university through fun trips and activities run by
members of the student union at WU. Programs include a buddy program to help exchange
students with their initial arrival in Vienna, trips to cities in Austria and surrounding countries
such as Salzburg, Hallstatt, Prague, Budapest, and Cracow, and activities such as a welcome
dinner, night sledding, wine hikes, dance classes, brewery tours, bowling, ice skating, and a
weekly meet-up at a bar. At some of these events, the leaders would provide students with White
Claws. For example, at 10 a.m. on the bus ride to Salzburg, the leaders distributed cases of White
Claws to the students (see Figure L). According to Elias Germann, the head of EBN during my
semester abroad, White Claw is a sponsor of the student union and provides the beverages to

Harper 51
EBN for free who then decides to distribute them at their events for free most of the time. This
partnership was in effect from the summer of 2021 until the summer of 2022. While White Claw
did not express a reason for ending it, Germann predicts that it was because White Claw was
using this relationship as a tool to enter the market and no longer needs it now that it has
established itself.
Clearly, White Claw has seen the potential for the young adult market in Vienna and
Austria as a whole and has attempted to capitalize on it through accessing university students.
The question is, are these young adults receptive? Germann was able to give some insights into
this topic during our conversation. He says that while students initially did not know what hard
seltzers were, now most are happy to receive them for free. Moreover, students who do not like
beer, particularly women, are excited that they are now available in addition or instead of beer,
the beverage traditionally provided at EBN events. This is supported by the data from the
quantitative research of this thesis, which shows that White Claw is by far the most brand
recognition in Europe and is the current hard seltzer of choice for Europeans (see Figures F and
H).
Moreover, during our conversation, Germann predicted based on what he has seen at
EBN events that the hard seltzer category will become a popular new category for alcoholic
beverages in Europe but will not push other beverages out of the market.

Harper 52
Analysis
While all four dimensions of the CAGE framework are important when deciding to enter
a foreign market, culture is the most important dimension in the hard seltzer case. The brands of
hard seltzers this thesis focuses on are part of established alcohol companies; in general,
established alcohol companies have already expanded brands in other categories abroad, so they
would already have the framework to address much of the concerns regarding administrative,
geographic, and economic distance. As a result, this analysis will comprise of two parts: “Hard
Seltzer Viability” and “Brand Viability”. The first section will analyze the differences in drinking
culture between the United States and Europe based on the research outlined in the previous
section. It will then address how hard seltzers fit into each culture and the overall viability of the
category in Europe. The second section will then take a closer look at each of the seven key
brands of this thesis, White Claw, Truly, Bud Light Seltzer, Vizzy, Topo Chico, Mike’s Hard
Seltzer, and Pure Piraña, and their individual potential in the European market. This section will
address how each brand fits into the cultural analysis as well as any relevant elements of
administrative, geographic, and economic distance as applicable.
Hard Seltzer Viability
Hard seltzers were not just a beverage that entered the United States but, rather, a
phenomenon - but will the White Claw Summer reach Europe? In short, no. Nevertheless, this
does not mean that hard seltzers will not find success across the pond. This section will
distinguish the key differences between the drinking cultures of the United States and Europe
and how hard seltzers fit into them.
Based on my data, the reasons that are important to the greatest percentage of both
Americans and Europeans when drinking alcohol are to have fun and to celebrate. However,

Harper 53
celebrating is much more important to Europeans (78%) than Americans (62%). Moreover, while
getting drunk appears to be important to only marginally more Americans than Europeans (52%
vs. 47%), the qualitative section of this thesis seems to indicate that this may be a result of
response bias, and getting drunk may be important to more Americans than they revealed in this
survey. Furthermore, enhancing a feeling or situation, having a sense of belonging in social
settings, and coping with problems and stressors appear to be important to significantly more
Americans than Europeans. On the other hand, a greater percentage of Europeans drink to enjoy
the taste of their beverage (53% vs. 35%).
This data, along with the insights from the qualitative section, indicates that Americans
put more emphasis on drinking alcohol for a situation than do Europeans. Specifically,
Americans drink to party and to enjoy situations. Europeans also drink for situations such as
celebrations, but they are much more focused on taste. This aligns with the insight that
Europeans tend to drink more excessively than Americans, but that this drinking occurs over
large stretches of time in more casual settings. It matters more to them what they are drinking as
the focus for them is not to get drunk in order to enjoy a setting but instead to enjoy a beverage
over time. Moreover, when looking at priorities when selecting alcoholic beverages, flavor is
highly important and the most significant priority for both Americans and Europeans. Yet, it is a
priority for nearly all Europeans (94%) compared to 84% of Americans. Not only is there a gap
here, but the qualitative section makes it clear that consumers have different preferences for
flavor. It appears that many Europeans are not as interested in sweet flavors but do still enjoy
seltzer water; in addition, in some markets such as Austria and Italy, spritzers, which have
similar sweet and bubbly flavor profiles, are already popular. Furthermore, high alcohol content
is a priority for significantly more Americans (49%) than Europeans (28%). This supports the

Harper 54
argument that perhaps getting drunk is far more important to Americans than Europeans, and
they value efficiency to reach the point of getting drunk much more than Europeans.
Overall, this analysis thus far of drinking cultures lends itself to the conclusion that hard
seltzers fit into European drinking culture just not in the same way as in American drinking
culture. Hard seltzers are an efficient and convenient way to drink in social settings; while this is
of some importance to Europeans, particularly in celebrations, it is much less important. This
still means that some Europeans will choose to pick up convenient hard seltzers at parties and
celebrations while having fun, but this will not cause the same cultural wave that hard seltzers
caused in the United States.
Additionally, part of the appeal of hard seltzers to Americans is the aesthetic as a
“lifestyle brand”; they are likely to bring them to parties but also activities such as boating and
hiking in order to achieve a certain aesthetic marketed to them. As discussed in the “Alcohol in
Europe” section, Europeans do not respond as much to invasive marketing and are less likely to
align themselves to an alcohol brand for the sake of achieving a certain “lifestyle”. To
Europeans, it is much more important to enjoy the flavor of a beverage and to want to enjoy it
over a longer period of time. For those who enjoy sparkling water and sweet flavors, then, hard
seltzers would be a great addition to their alcohol preference portfolio. The “Alcohol in Europe”
section also indicates that Europeans currently are demanding more variety in flavor of
high-quality alcoholic beverages, so these individuals would gladly accept this change. For those
who do not particularly enjoy these flavors, however, they are not likely to choose hard seltzers
just because they see others drinking them. This is further confirmed by the fact that only 17% of
Europeans admitted that having a sense of belonging in social settings is a reason for them to
drink and what other people are drinking only mattered to 8% of Europeans.

Harper 55
Through the “White Claw in Vienna” case study, there appears to be evidence of this
dynamic playing out in practice. When presented with hard seltzers, many Europeans were not
opposed to them. As seen in the quantitative section, the only ones who strongly oppose them are
those who do not enjoy these specific flavors. Moreover, for those who do not enjoy beer, hard
seltzers are a welcome surprise at events that used to only feature beer. Still, despite having been
in Austria since June 2021, hard seltzers have not become a phenomenon in Vienna, the capital
city. This confirms that Europeans are open to them and some will begin to drink them once
familiar with them, but there is nothing about them that stands out. This may also be explained
by the deeply-rooted nature of alcohol in Europe discussed in “Alcohol in Europe”. Unlike in the
United States, a relatively young culture, alcohol is ingrained in many parts of European cultures
and celebrations. Though Europeans claim to want to expand their palates and have been doing
so slowly over the last century, there is still a tendency to return back to traditional preferences in
each region. It will take time for hard seltzers to root themselves within drinking culture despite
their acceptance into it.
Next, in order to be successful, hard seltzer brands will have to be aware of the
differences between drinking cultures in different countries and regions. One strategy for alcohol
companies would be to individualize the brand and flavors offered to each region. To cover all of
Europe in this way, however, would require extensive resources and may not be worth this
investment since hard seltzers are not likely to be the phenomenon they are in the United States.
Moreover, local brands like Laitila in Finland are likely to be able to accomplish this goal of
appealing to local consumers with greater ease anyway. A less intensive and safer bet would be
to focus on the Northern and Eastern countries such as Germany, Austria, and Switzerland that
currently already have a preference for beer and other grain-based beverages (for which hard

Harper 56
seltzers are an alternative). While companies should still work with locals on the ground who can
help them adapt to the market, it is not likely that they will need as many or as varied alterations
to their current flavor profiles. In addition, it is less likely they will need to market as hard to get
consumers to try their beverage as they would for a country that prefers wine. If a company sees
great success in regions that enjoy beer, then it may be time to consider expanding into a greater
variety of countries. One potential expansion past this region that may be viable would be Italy
where spritzers are a popular beverage of choice.
Finally, from an administrative standpoint, given the stricter marketing laws in Europe, it
is unlikely that hard seltzer companies will be able to market themselves as a “healthy”
alternative to other alcoholic beverages - especially when this stance is already being challenged
in the United States. However, while in “The ‘Healthy’ Alternative” it seemed as if this was
important to Millennial and Gen Z consumers, the quantitative data seems to indicate that health
is not as important to consumers as is often assumed. Millennials and Gen Z may care about their
health more and may be drinking less than previous generations, but only 14% of Europeans and
13% of Americans listed it as a priority when selecting an alcoholic beverage. This indicates that
having to shift marketing techniques should not be a devastating blow to hard seltzers’ potential
in the European market. Moreover, the calorie and carb counts themselves will indicate to those
consumers in Europe who do care about the health in their beverage whether hard seltzers are a
healthier option for them compared to their alternatives.
Brand Viability
While hard seltzers may have a place in the European alcohol market, not all brands have
the same potential for success; this section will evaluate the viability of the seven key brands:
White Claw, Truly, Bud Light Seltzer, Vizzy, Topo Chico, Mike’s Hard Seltzer, and Pure Piraña.

Harper 57
It is important to note, that, beyond these brands, there is a lot of potential for specialty
regionalized hard seltzers in Europe. However, regionalized brands are less likely to take over
the continent without the resources and agility of large alcohol companies. As a result, while it is
important to keep them in mind and research whether they are emerging when deciding whether
to enter a potential market in Europe, they will not be considered heavily in this analysis.
After careful consideration, the two hard seltzers with the most potential for success in
Europe are White Claw and Topo Chico. After these brands, Bud Light Seltzer, Pure Piraña, and
Mike’s Hard Seltzer can expect moderate success. If Truly decided to enter the global market, it
may also be able to acquire moderate success. Finally, Vizzy should not expect to be able to find
success in Europe.
White Claw has already seen more success in the European market than any hard seltzer
brand, and this success should very well continue. White Claw is positioned well in the European
market for a few key reasons: first, while Europeans may not align themselves to “lifestyle
brands” of alcohol in the same way that Americans do, they still listen. As mentioned in its brand
profile, White Claw is synonymous with hard seltzer in popular culture in the United States, and
in a globalized economy this inevitably reached the European continent. This is confirmed by the
fact that despite many of the key brands in this thesis having made their way to Europe in the last
few years, 50% of Europeans had heard of White Claw and 50% said they enjoyed it as well. On
the other hand, the next greatest percentage of awareness on the continent was Bud Light Seltzer
at 14% and enjoyment was Truly at 25% (enjoyment was not limited to the continent; it is likely
that some Europeans had had the beverage in the United States). In the end, all hard seltzers are
still just flavored sparkling water; branding and early-mover advantage are a key reason for this
wide distinction from other brands. Furthermore, as discussed in the “Hard Seltzer Viability”

Harper 58
section, Europeans prefer both simple branding and simple flavors; part of what gave the White
Claw brand its wave of success was its simple flavors and “gender-neutral minimalist silver cans
with a black-and-white classic wave logo” as mentioned in its profile. The cultural phenomenon
of White Claw was not pushed on Americans but instead manifested in social media as a result
of its appeal; while it is unlikely that Europeans will be shouting “ain’t no laws when you’re
drinking claws” on the beach anytime soon, they have already taken a liking to the beverage and
it seems to fit into the European alcohol market nicely. Evidence of this can be seen in the
“White Claw in Vienna” case and the fact that, as mentioned in its profile, it has captured 42.4%
of the hard seltzer category in the United Kingdom. Furthermore, White Claw has been
incredibly strategic in selecting areas of expansion, focusing on countries that have a preference
for beer such as the United Kingdom, Belgium, Austria, and Germany (which, as mentioned in
the previous section, are more likely to adopt the category).
Topo Chico should also expect to see great success in Europe. Topo Chico has a unique
origin story that distinguishes it from other brands; Europeans are likely to find a connection to
this brand given their deeply-rooted alcohol culture. Moreover, rather than being an American
brand trying to catch up to the success of White Claw, Topo Chico has always been a global
brand – it did not even enter the American market until it had found success globally. This
includes having launched in Europe in early 2021 before most American brands, including White
Claw, had made their way to the market. Furthermore, its flavor profile is already adapted to the
European palate rather than that of the United States. The distinction of the brand along with its
early-mover advantage makes it a prime candidate to lead the category in Europe. In addition,
from an administrative and geographic perspective, Coca-Cola’s extensive global logistical
network will allow it to reach audiences more rapidly and with more intensity than other brands.

Harper 59
This claim that Topo Chico will be White Claw’s main competitor in the European
market is supported by the fact from its brand profile that it currently owns the second most
market share after White Claw in Great Britain. Interestingly, however, my data does not support
this claim. Topo Chico had 0% awareness on the continent and 3% enjoyment by Europeans.
Personally, however, I did see Topo Chico a lot during my time in Austria. (See Figure N for an
advertisement I saw about once a week). Though Austrians are one of the most featured groups
in this study, there are still only 5 of them; as discussed in the limitations section, this data cannot
be perceived as being fully representative of the European population. Furthermore, as hard
seltzers are still emerging in Europe, many participants are likely not looking for them (unlike
me who was looking for indications of the category’s presence). This, combined with the fact
that alcohol companies cannot and do not conduct as invasive marketing in Europe as in the
United States, may be causing individuals to miss brands that are not the notorious White Claw.
As a result, without my own research supporting the statement, I can only cautiously proclaim
Topo Chico to have some of the most potential in the European market. More extensive research
is necessary to confirm this.
Next, Bud Light Seltzer, Mike’s Hard Seltzer, and Pure Piraña can all expect moderate
success in the category. While these brands are not incongruent with the European market, there
is also nothing that makes them stand out to European consumers. Bud Light Seltzer has
experienced moderate success in the United States, being cited as the number three brand after
White Claw and Truly, and has also captured third place in Great Britain thus far. However, there
is no indication that it will amount to anything special in the European market. As one
respondent noted in the qualitative section of my research, Bud Light is an American brand
associated with American stereotypes of beer consumption which stand in contrast to European

Harper 60
beer consumption and tradition; as a result, much like how Bud Light has not won over the
European consumer, Bud Light Seltzer, whose only distinguishing factor is its tie to the Bud
Light brand, is unlikely to do so. This level of moderate success is supported by my data which
shows a 14% level of awareness of the brand on the continent and 11% level of enjoyment by
Europeans.
Much like Bud Light Seltzer, Mike’s Hard Seltzer earns its competitive advantage
through its nostalgic association with another very American brand, Mike’s Hard Lemonade.
While this does not preclude the brand from success in Europe, it does not indicate that Mike’s
Hard Seltzer will reach the levels of success of White Claw and Topo Chico. The main driving
force for its success will be its association with Mark Anthony Brewing, the company behind the
phenomenally successful White Claw brand. By sharing White Claw shelf space and market
information with the Mike’s Hard Seltzer brand, the latter is likely to find moderate success.
Pure Piraña is a brand that had the potential for success in Europe but may have already
entered the market too late. Pure Piraña took a global strategy for entering the hard seltzer
category, much like Topo Chico, and is backed by a global alcohol company, Heineken. This
seems to indicate that it should be a major player in the category. However, it entered the global
market long after White Claw and both the global and European markets after Topo Chico. In
fact, by the time it entered the European market, the global and the European markets were
already saturated with many hard seltzer brands. Without a solid background of success and
without early-mover advantage, the brand would have to rely on another distinguishing factor to
become a key player. Their main distinguishing claim is to be a refreshing low-calorie beverage
with 92 calories instead of the category average of 100. Since health has been established as
being important to a low proportion of American and European consumers when choosing

Harper 61
alcoholic beverages, this distinction (along with the brand’s association with Heineken) is
enough to provide Pure Piraña with moderate but not leading success in Europe. This is backed
by the fact that the brand reports having found growth and success in the United Kingdom
market but that these results have been disappointing in the face of their goal to lead the
category.
Truly has not yet decided to enter the European market; if it were to do so, however, it
should also expect moderate success. Truly would be able to benefit from the carry-over name
recognition and success from being a leader in the American market that White Claw
experienced. Moreover, even though Truly is not easily available in Europe, 25% of Europeans
still reported to enjoy the beverage. Yet, this success would not mirror the success that White
Claw found in Europe. This is because Truly’s key distinguishing characteristic is its variety.
Europeans are far less keen on having a large variety of flavors than Americans and more
focused on having a few simple high-quality flavors. In addition, without the invasive marketing
of America, Truly cannot promote this variety and continuous innovation quite as easily. As a
result, this high performer in the United States should only expect to have moderate success in
Europe.
Vizzy is the only player that definitely lacks a future in Europe. It gains its competitive
advantage from marketing itself as a healthy hard seltzer with its addition of antioxidant vitamin
C. While this claim obviously appealed to some and allowed it to experience notable growth, it
has not yet allowed it to become a challenger for a top spot in the hard seltzer category. This can
partially be explained by the fact that, as discussed in the “Hard Seltzer Viability” section, both
Americans and Europeans do not actually value health as much as expected when selecting an
alcoholic beverage. This is partially intuitive, as it is impossible for alcohol itself to ever be

Harper 62
considered healthy. Furthermore, Vizzy is already under public scrutiny for its health claims and
the FDA is being called upon to investigate it. It is unlikely then, in a culture that values health
even more than in the United States and has much more stringent marketing laws, that Vizzy
would be able to use being the “healthiest” hard seltzer as a competitive advantage in the
European market. Without any other key distinguishing factors from other brands or marketable
success in the United States, it is extremely unlikely that Vizzy would find success in Europe.

Harper 63
Canned Cocktails: The European Alternative?
When observing the shelves of popular grocery stores Spar and Billa in Vienna, I noticed
that while hard seltzers had not yet consistently found their place next to beer in the alcohol
section, another emerging beyond beer beverage had: canned cocktails (see Figure M).
Canned cocktails, also known as read-to-drink (RTD) cocktails, mimic a wide variety of
popular cocktails such as daiquiris, mojitos, manhattans, negronis, and martinis using sodas or
fruit juices as bases. These beverages attempt, with mixed success, to offer customers the taste of
popular cocktails in a convenient, portable, and affordable can. Emerging in 2019, right after the
peak of White Claw’s popularity, canned cocktails still maintain a relatively small market share,
but Grandview Research predicts that they should expect “a compound annual growth rate of
13.4 percent between 2022 and 2030” (Lashbrook). In Vienna, consumers now have options for
RTD beverages such as a Bacardi rum and cola, Beefeater gin and tonic, and Stiegel grapefruit
radler (deriving from a popular Austrian cocktail that combines beer and lemonade).
While a deeper analysis of this emerging competitor is beyond the scope of this thesis, as
companies attempt to promote their hard seltzer brands in Europe, further analysis of canned
cocktails is recommended to understand their threat to hard seltzers. Furthermore, for companies
with the resources to do so, it is recommended to analyze the viability of their own
diversification into the canned cocktail category in Europe.

Harper 64
Conclusion
The White Claw wave is crashing on the shores of the European continent, but it will not
be the tidal wave that it was in the United States. Hard seltzers have become a key alcohol
category in the United States by becoming a convenient and tasty alternative to beer; and,
although its explosive growth has slowed down, it is not expected to stop. Instead, hard seltzer
brands are expanding across the globe including to the continent of Europe. The question is, how
much opportunity is there for the category in Europe? Both Europeans and Americans drink to
have fun and to celebrate; however, American drinking culture puts far more emphasis on getting
drunk to party and enjoy a situation. Americans will try to choose a drink that they can enjoy in a
social setting with a relatively high alcohol content. Moreover, they are also susceptible to
invasive marketing, including that which tells them that drinking hard seltzers like White Claw
will allow them to enjoy a “lifestyle” or that a brand like Vizzy will provide them with “health
benefits”. Hard seltzers fit perfectly into this culture; Americans finally have a convenient,
efficient, and tasty alternative to beer to enjoy during parties and celebrations and to use to get
drunk. They also get to experience being a part of the hard seltzer lifestyle.
On the other hand, Europeans drink more excessively but over much longer periods of
time. Resultantly, their focus is on selecting flavors that they can enjoy during these drinking
periods. There is also not as much pressure to drink particular beverages or to drink at all.
Additionally, alcohol is more deeply rooted in European culture than that of the United States,
and this culture varies throughout different regions on the continent. For example, the more
Northern and Eastern regions have a greater preference for beer; still, Europeans are demanding
more variety in high-quality alcohol options. Finally, Europeans are not as responsive to invasive
marketing techniques, and there is much more regulation on them. As a result of these

Harper 65
similarities and differences, much like in the “White Claw in Europe” case, Europeans who
enjoy the flavor of hard seltzers will pick them up when available as a convenient alternative to
beers and during celebrations. On the other hand, hard seltzers will not become the phenomenon
that they were in the United States, and it will take time for them to take root in the alcohol
market due to the highly traditional nature of alcohol culture in Europe. Moreover, hard seltzer
brands will not be able to market themselves as “healthy” in Europe under stricter marketing
laws, but this should not be an obstacle as health is not as important to alcohol consumers when
selecting an alcoholic beverage as is generally believed.
Out of the key brands, White Claw and Topo Chico should expect to be the leaders in the
European market due to their unique characteristics and early-mover advantage. From there, Bud
Light Seltzer, Mike’s Hard Seltzer, Pure Piraña, and, if it should choose to enter the European
market, Truly, should expect moderate success in the European market. Without a compatible
competitive advantage, Vizzy should expect no potential for success in Europe. In addition,
localized brands that can appeal to the specific tastes of European regions and countries should
be considered as a threat within individual regions and properly researched. On the other hand,
these localized brands are not likely to have the success across the continent that these larger
brands (as members of large companies with extensive networks) can expect. Lastly, the
emerging category of ready-to-drink canned cocktails should also be seen as a threat to hard
seltzers in Europe and should be further researched. On the other hand, they could also be a key
alternative opportunity for alcohol brands looking to expand in Europe.
Overall, this thesis was limited by two key components: survey limitations and the
constantly evolving nature of the ready-to-drink market at the moment. First, my surveys were
voluntary and limited to my personal network and to my ability to distribute. As a result, I was

Harper 66
not able to have as representative and large of a participant pool as I would have wanted nor
could my line of questioning be as intensive as I would have liked. Instead, I had to try my best
to capture as much data as I could within my resources. Given the opportunity, I would want to
further my research with a more comprehensive participant pool and a longer and more precise
line of questioning. Second, the global ready-to-drink market has evolved very quickly while I
have been writing my thesis. When I released my survey to Europeans in Spring of 2022, I did
not know all of the questions I would want to ask now in Spring 2023. Furthermore, when I
selected my thesis topic in Spring of 2021, many hard seltzers had not hit the global market and
ready-to-drink canned cocktails had not reached a point of significant popularity. Still, this thesis
captures the current hard seltzer market and its future prospects as well as it can given these
limitations. As the European alcohol market continues to evolve, further research should be done
looking at the progress of the hard seltzer category, the key brands of this thesis (particularly
White Claw and Topo Chico), and the emerging competition from ready-to-drink canned
cocktails. Likely, researchers will continue to see steady progress of the category in spite of
competition from canned cocktails, but, while this progress will be led by Topo Chico and White
Claw, they will not witness a “White Claw Summer” in Europe.

