


Running Head: ACC 675 a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a 1
ACC675 : 9-1 Final Project Submission: Case Study Analysis
SNHU

ACC 675 a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a 2
Overview of the organization
Trinity Industries came into existence in 1958 when Trinity Steel and Dallas Tank merged
together. The first CEO of the company was W Ray Wallace. Initially, the business was a
struggling propane tank producer, but it gradually transformed into a successful business that
diversified its services and products into other sectors like construction, energy, industrial and
transportation. The business was mainly involved in manufacturing freight as well as tank rail
cars, transportation of tank barges, pressurized or liquified commodities, tank barges and dry
cargo. The profile of Trinity Industries’ line of business was vast. However, the revenue from
Trinity’s Rail Group significantly contributed to its revenue.
Size of the organization
The size of Trinity Industries expanded with the passage of time. Under the leadership of
the first CEO, the company went on to become a strong $ 2.4 billion provider that offered its
commodities and services in diverse industries. In the year 2007, under the leadership of Timothy
Wallace, the company grew into a massive $ 3.8 billion enterprise.
Sector or industry
The business operations of Trinity Industries expanded to a broad range of industries such
as construction, transportation and energy. In the transportation sector, the business played a key
role as the Rail Group of the business generated high revenue and employed more than half of the
organizational staff. Some of the competitors that intensified the level of competition for Trinity
Rail Group were American Railcar Industries, Union Pacific Railroad, and Canadian Pacific
Railway. a

ACC 675 a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a 3
Structure or line of business
The line of business operations of Trinity Industries was broad as the business had
diversified into numerous sectors. One of the main lines of business was Trinity’s Rail Group,
which strengthened the financial position of the business. The other lines of business of Trinity
Industries included Rail Leasing and Management Services Group, Construction Products Group,
Energy Equipment Group and Inland Barge Group. In each of the areas, the business was able to
generate revenue and showcase strong financial performance. a a
Organizational structure
The company had a broad organizational structure, as the members that made up the
structure were responsible for managing the five line of business operations. The structure helped
the business to have numerous controls in place, including ‘A’ controls, ‘B’ controls, ‘C’ controls
and other unranked controls. The CEO played a central role in the organization, offering
leadership direction to the entire organization so that it could focus on each of its core business
areas to achieve its business objectives and maximize its profitability (UP: Annual reports - union
pacific corporation, 2021). a
Yearly revenue performance
Trinity Industries showcased strong financial performance while operating in the market
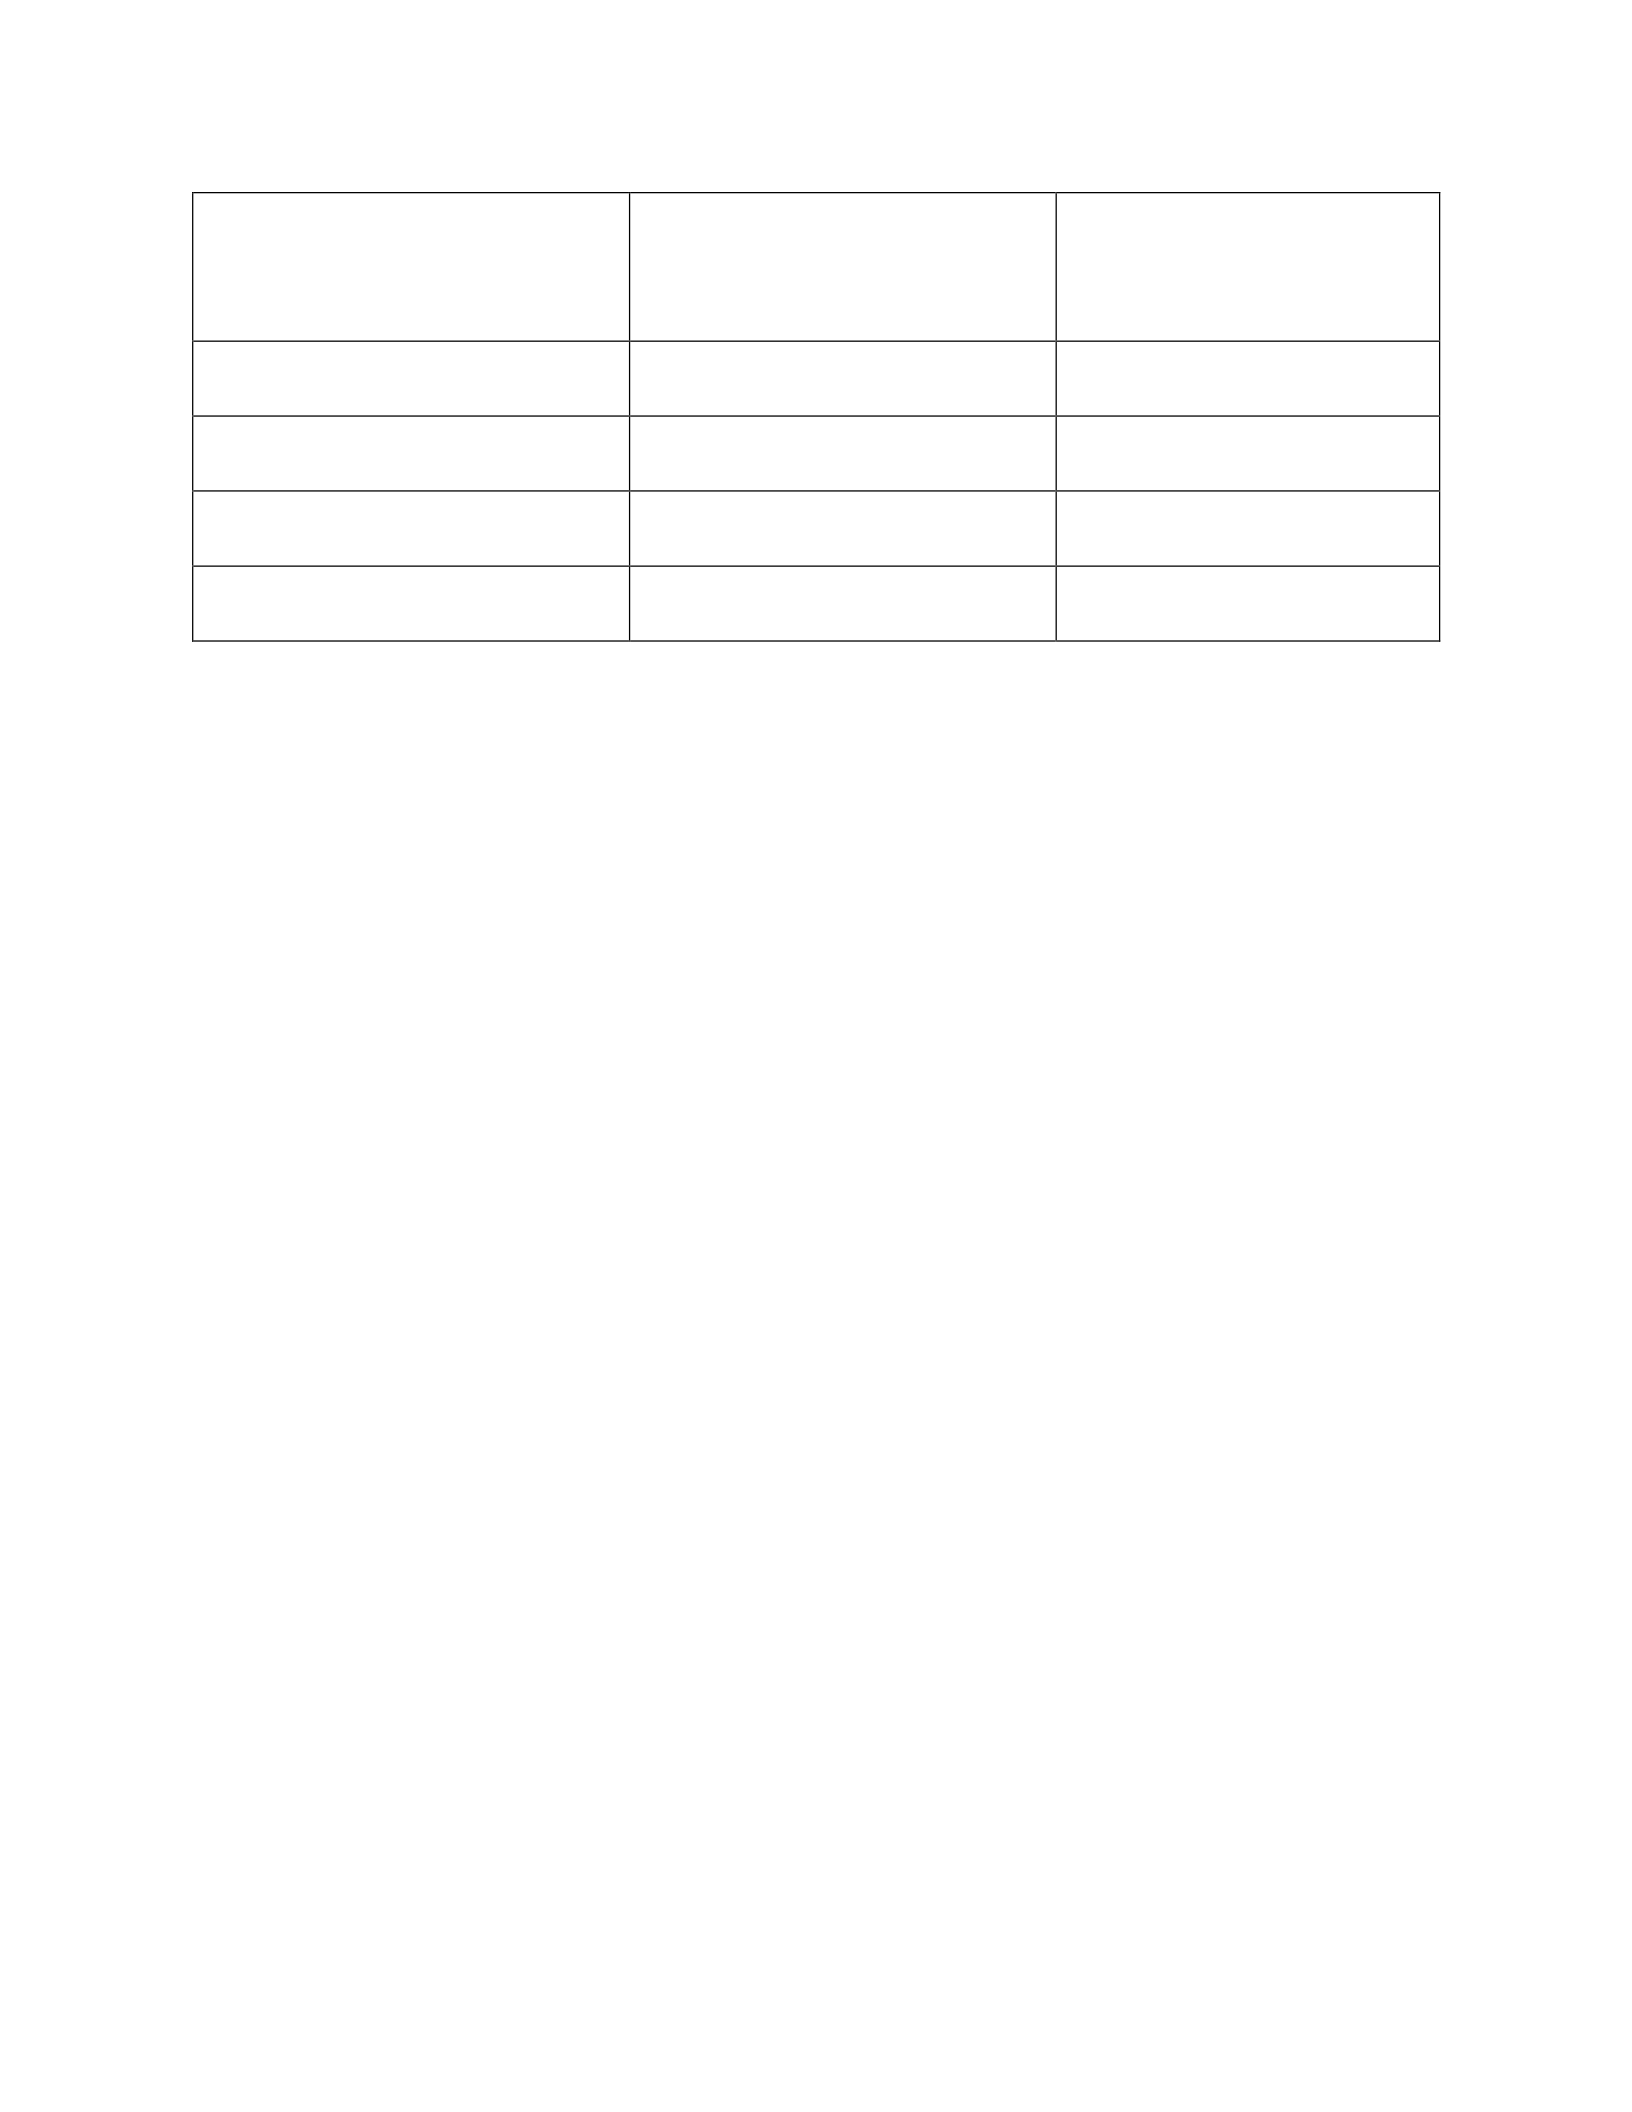
setting, which helped it to establish itself as a strong layer. The table presented below gives an
insight into the annual revenue of the company. The revenues of its competitors have also been
taken into account to identify how the businesses fared against each other.
ACC 675 a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a 4
Company name
Annual revenue – 2007 (in
USD million)
Annual revenue – 2006
(in USD million)
Trinity Industries
3832.8
3218.9
American Railcar Industries
698.12
646.05
Union Pacific Railroad
16,283
15,578
Canadian Pacific Railway
4707.6
4583.2
Source: (SEC report, 2021)
Management and Culture
The staff of Trinity Industries played a crucial role in helping the company reach new
heights while diversifying its business operations. The first CEO, Wallace, led the company for
four decades and played a key role in transforming it into a major player in the industry (UP:
Annual reports - union pacific corporation, 2021). Later his son took over as the CEO and used his
knowledge to help the company further grow in the evolving business landscape. A culture of
accountability and responsibility was established, which helped to carry out the business
operations in a streamlined manner.
Critical elements to Trinity’s decisive success
In the context of Trinity Industries’, a diverse range of elements may arise and play a
critical role in the organization’s decisive success in its first year of Sarbanes–Oxley compliance.
One of the main elements is the existence of a standardized reporting system that is followed
within the organization. Another chief element is the documentation of the control environment
within the organization. Considerable effort is involved in documenting and testing the automated
and manual controls. The other critical elements in the business context are the evaluation of the

ACC 675 a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a 5
gap relating to SOX compliance and the recommendations that have been made to address the
current gaps so that proper compliance can be ensured by the business entity.
Internal Controls
According to the Public Company Accounting Oversight Board (PCAOB), a number of
internal controls need to be introduced for the purpose of preparing accurate and reliable financial
reports. One of the main internal controls is company policies, procedures, and practices that have
been designed to ensure reasonable assurance about the reliability of the financial reporting of a
firm. Policies also influence the processes that are adopted by firms for preparing and accurately
presenting financial statements as per the generally accepted accounting principles (GAAP) (No,
2004,p . 4). The other internal controls are governance framework, risk assessment, entry-level
controls, and the testing strategy. In the context of Trinity Industries’, the specific internal
controls that are in place to prepare accurate and reliable financial reports include validation
testing, roll-out organizational self-assessment, and documentation of the control environment. a
Material weakness
A material weakness in terms of SOX compliance refers to a deficiency or combination of
deficiencies relating to internal control over the financial reporting activity. Due to the existence
of such a weakness, there is a possibility of a material misstatement to arise that may distort a
company’s interim or annual financial statements (No, 2004). Some of the signs of material
weakness include identification of fraudulent activities in part of the senior management, poor
and ineffective oversight of a firm’s external financial reporting and internal control over
financial reporting by its audit team (No, 2004)..
Material weaknesses specific to Trinity Industries’

ACC 675 a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a 6
In the specific case involving Trinity Industries’ there exist a number of material
weaknesses that have the potential to compromise the accuracy and validity of the financial
statements of the organization. One of the chief weaknesses is the identification of 14 deficiencies
according to the external audit testing that was conducted by E&Y. Another vital sign of material
weakness within the organization is the adoption of a practice-based bottom-up analysis of the
work practices within the organization. For identifying the internal controls, input was taken from
the organizational members, and then suitable flowcharts and control matrices were designed for
internal control purposes. Based on such an approach, there was no proper framework in place
that could be followed by the organizational personnel to address gaps and deficiencies that
existed in the organizational processes.
Standards in PCAOB regarding material weakness
PCAOB has introduced a number of standards in order to effectively address the issue
relating to material weaknesses that may arise and distort the financial reporting processes of
organizations. The Auditing Standard 5 of PCAOB focuses on performing an audit of internal
controls over financial reporting that is integrated with the audit of the financial statements. It
mainly focuses on the steps that an auditor needs to take in order to effectively perform an audit to
ensure the effectiveness of internal control over the financial reporting function and ascertain
there exist no material weaknesses. According to Sarbanes–Oxley (SOX) Section 404, it is
essential for companies to include an assessment of the overall effectiveness of internal controls
(Sarbanes-Oxley Section 404 A Guide for Small Business. SEC Emblem, 2017).
Factors contributing to Trinity Industries’ success
ACC 675 a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a 7
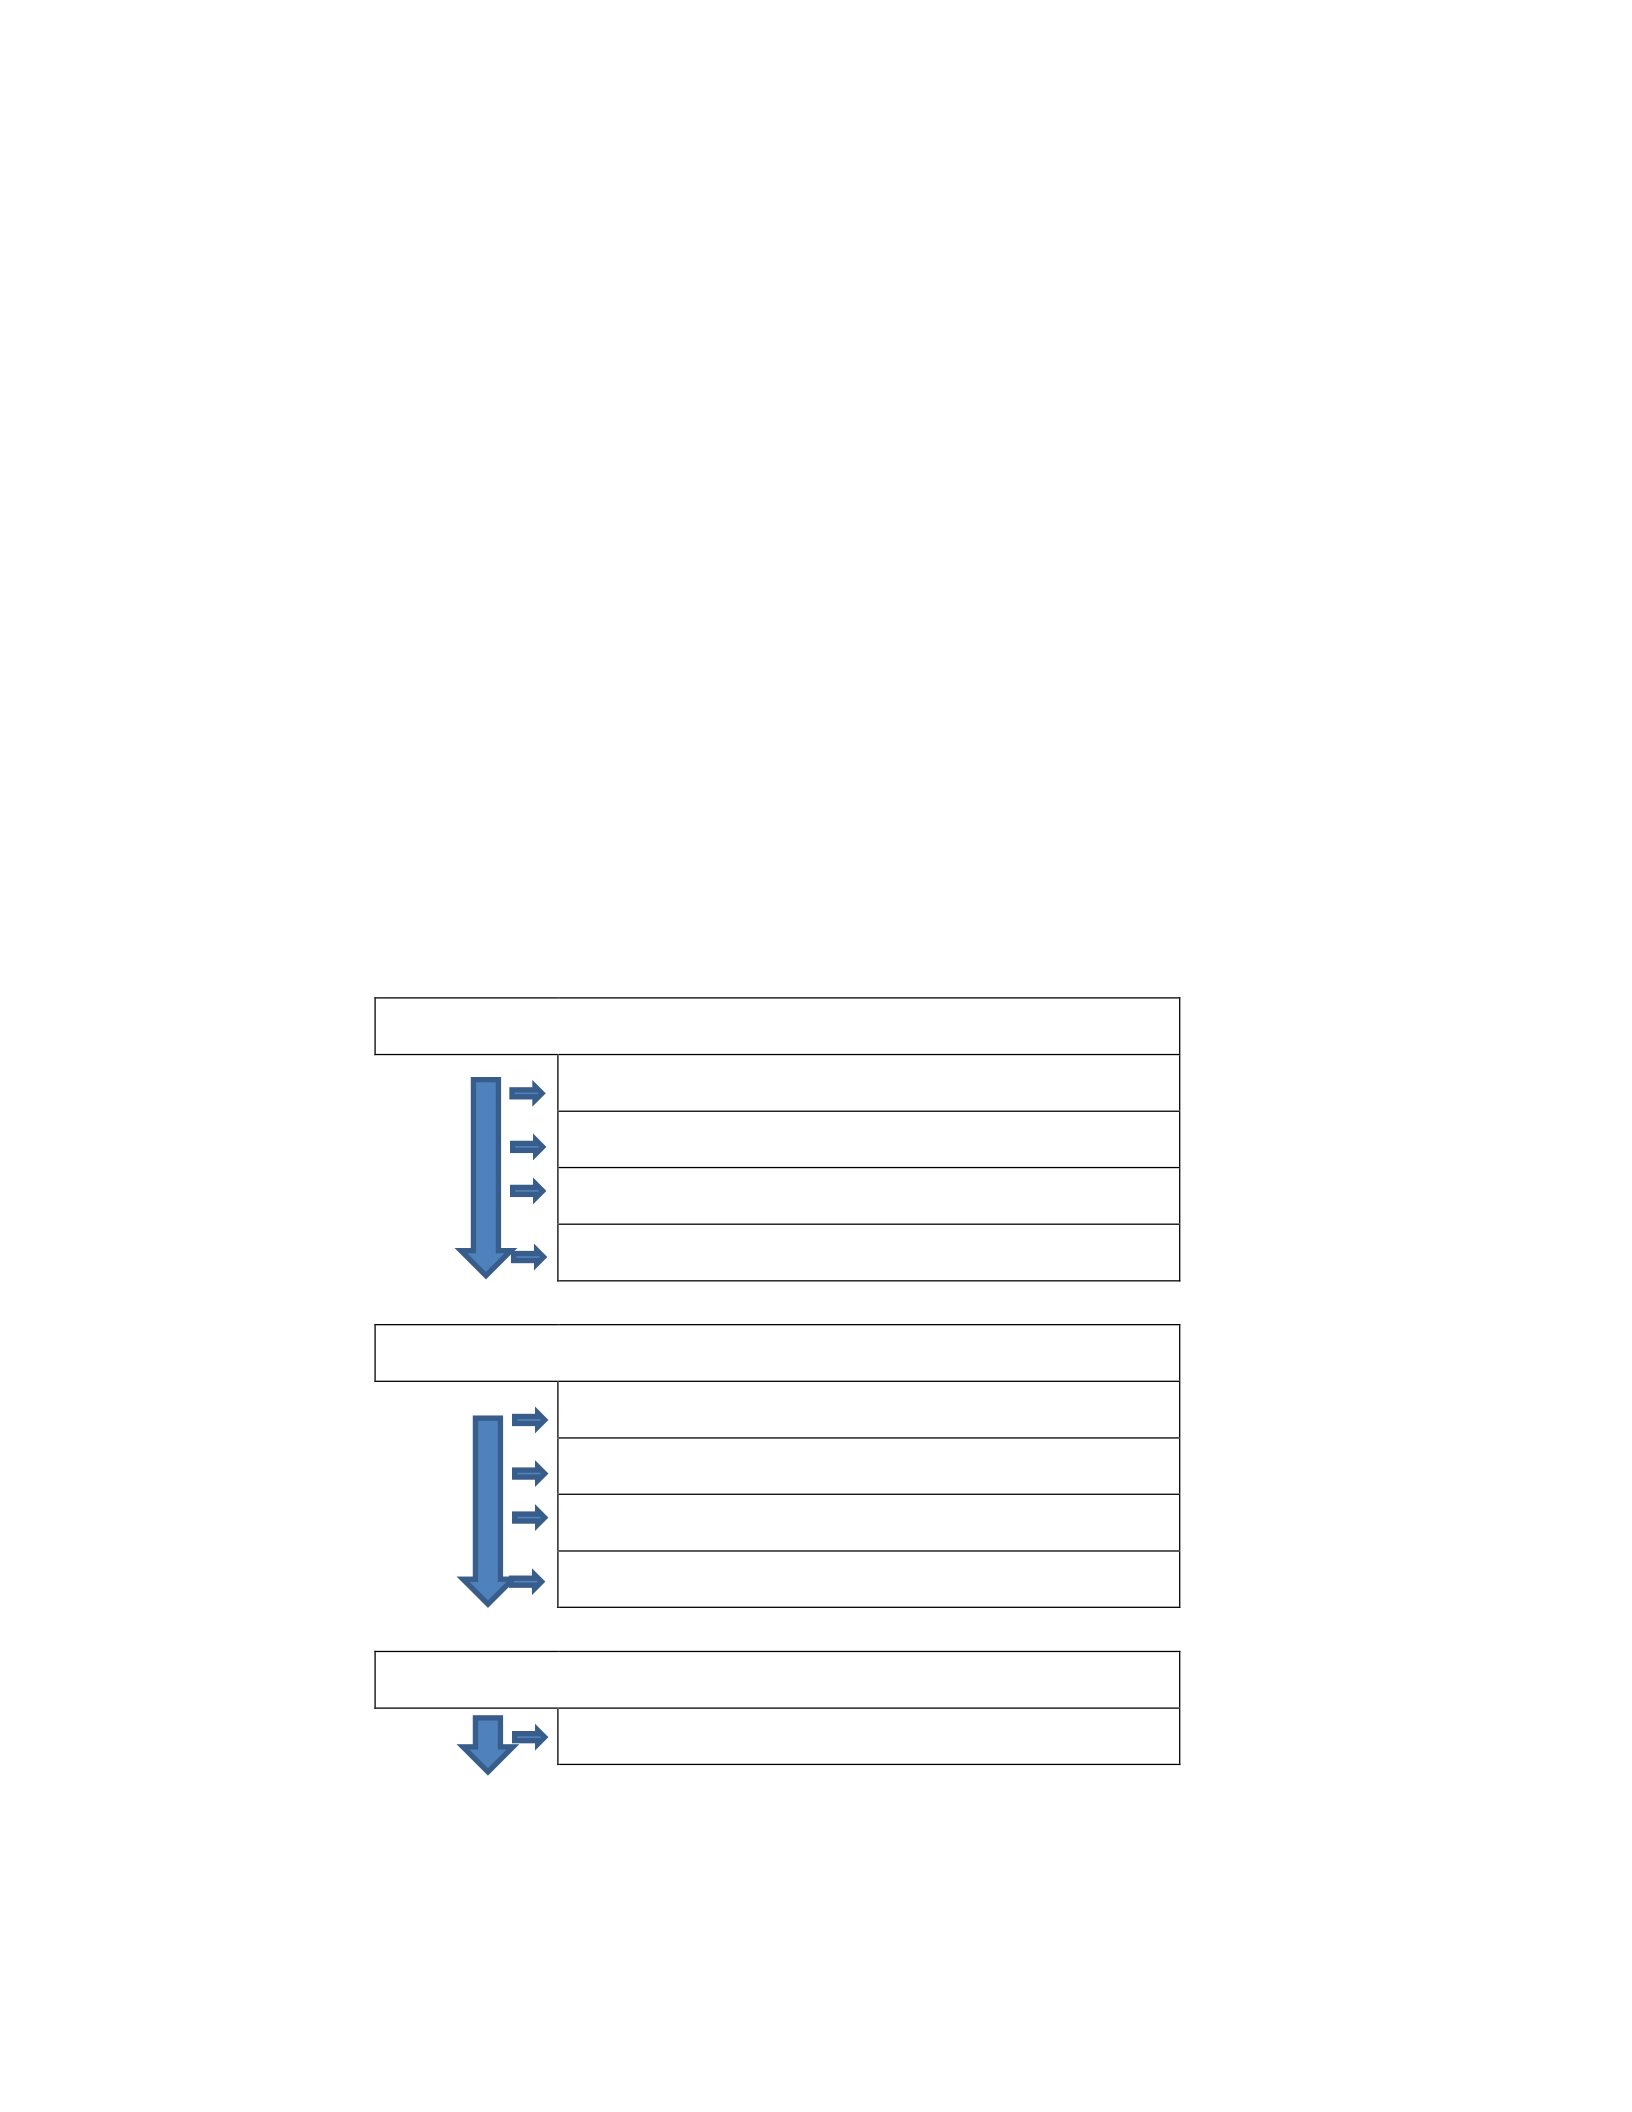
Some of the key factors that influenced the success of Trinity Industries’, as a business
include the existence of a diverse range of controls, namely ‘A’ controls, ‘B’ controls, ‘C’
controls and unranked controls. These controls played a key role in identifying gaps in the
business processes and operations. Another vital success factor involves a high emphasis on
training. Four levels of training were introduced, including high-level guidance on SOX (for
senior executives), COSO training for the controllers in Trinity, SOX documentation training for
diverse documentation teams, and control owner training. This strategy empowered the staff
members to gain a better insight into SOX and the need to comply with it. A self-assessment
process was also introduced to increase the accountability of the management team. The
flowchart captures the factors in a visual format.
Introduction of controls
‘A’ controls
‘B’ controls
‘C’ controls
Unranked controls
Training
High-level guidance on SOX
COSO training for the controllers
SOX documentation training
Control owner training
Self-assessment process
For better accountability

ACC 675 a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a 8
IV. Bottom-Up Approach
Strengths and Weaknesses
The main strength of the bottom-up approach that was adopted by Trinity in the first year
was that the insight of organizational members as taken regarding the controls and processes. It
gave the management a ground-level insight into the measures that were in place. However, the
main weakness of the bottom-up approach for internal control was the over-cost relating to SOC
compliance. In the context of Trinity, none of the identified control gaps (265 gaps) had been
identified as high priority, based on the bottom-up approach. The approach was effective since
there existed no weakness of material in the initial year relating to SOX compliance.
Recommendations
In Year 1, the main thing that the company could have done differently was to use the top-
down approach. It would have helped Trinity Industries to have better control over the existing
control mechanisms. It is an ideal alternative since it would have enabled the company to
minimize the workload while reducing the expenses relating to SOX compliance. It would have
helped to understand the overall risk pertaining to internal control over financial reporting
(Viewpoint : PWC. Viewpoint, 2022).
Comparison with top-down risk approach
The top-down approach is a risk-based approach that focuses on allocating resources on
the specific areas where there is a probability of higher risk. A thorough understanding of a firm’s
financial reporting risks is of high importance (Deloitte Us: Audit, Consulting, advisory, and Tax
Services. Deloitte United States, 2021). This simple method relies on historical data. A major

ACC 675 a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a 9
weakness is that it creates differences between the team members and decision-makers. The
bottom-up approach considers every risk to be of equal importance, so it is not possible to
prioritize risks. In order to give a comprehensive insight into a risk, the process takes a
considerable amount of time and resources.
Compliance project
In the first year, the adoption of the bottom-up approach was more appropriate for
completing the compliance project successfully. As the SOX compliance requirement was a fairly
new concept for the business, such a detailed process worked well for the company and helped it
to get familiar with the new set of regulations, i.e., the Sarbanes-Oxley Act (SOX) (Bottom-up
approach for compliance: The master position. emmanuel . W3, 2009).
Impact on the internal control structure
When the top-down approach is adopted to manage internal controls, the senior
management has the responsibility to develop suitable internal controls. These controls do not lie
within the normal or general perception relating to normal controls. Their involvement is critical
to impact the effectiveness of the internal control structure (Save Money on Sarbanes-Oxley
Section 404(a) Compliance. Marmann & Associates, P.C. - Certified Public Accountants &
Consultants, 2021). When the bottom-up approach is adopted, the role of leaders is restricted
since they are not directly involved in formulating the internal control structure. The teams and
organizational members are the ones that deploy control measures and are responsible for framing
the internal control structure that is adopted in organizations.
Chief insights

ACC 675 a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a 10
The pilot project that was conducted at Trinity Industries was highly insightful. It shed
light on the gaps that existed relating to the internal controls. By conducting the pilot study, the
business was able to ascertain that there existed several control gaps at diverse levels within the
organization. It also revealed that there existed gaps between the AS-IS practices and the SOX-
compliant manner of operating. It served as a foundation for conducting an in-depth gap analysis.
Testing processes
The specific testing processes that were carried out by Trinity to ensure compliance
included analytical tests, inquiry and observations, tests of transactions, and tests of balances. The
role of each of these substantive tests was of paramount importance since they helped to locate
loopholes that existed in the existing processes and protocols. While performing the tests, Trinity
started with the initial transactions and then moved upwards toward the financial statements of the
company. Based on the bottom-up approach, it was able to identify a total of 265 gaps that needed
to be filled to improve the internal controls. The company failed to take appropriate approach
measures in designing the controls since, in June 2004, 1573 of its control activities broke down.
The most useful testing process
The most useful testing process that was carried out by the company, which helped in
assessing its accounting system was gap analysis. By performing a detailed gap analysis, the
company was able to identify 1249 control activities along with 265 gaps. It further shed light on
the fact that out of the 265 gaps, 172 were related with documentation, and none of the gas had
been categorized as high priority risks.

ACC 675 a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a 11
Recommendations
To: Trinity Industries management
From: Auditing team
Date: December 13, 2022
Subject: Results of the first year of testing and recommendations
The results of the first year of testing at Trinity Industries shows that there exists
considerable gas relating to internal controls. It can affect its ability to comply with the SOX
regulations and requirements in the future. Although the bottom-up approach was suitable in the
first year, in the subsequent years, it might not help the company to have an effective control over
its internal controls.
Based on the in-depth analysis, the recommendation that has been made for Trinity is that
it must adopt a top-down risk approach in subsequent years. This approach will help the company,
especially its leaders, to develop robust internal controls that can help in identifying gaps that may
diminish the effectiveness of the internal controls.
Thank You
V. SOX-related expenses
Recommendations for further reducing SOX-related expenses
For reducing the SOX-related expenses in the year 2008, Trinity must replace its four
general ledger packages with Oracle Financials. It has been estimated that the Oracle solution will
enable the business to save $ 0.5 million on SOX compliance expenses. Centralization of

ACC 675 a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a 12
accounting transactions can help to have better control over the financial aspects. The manual
SOX controls must be replaced with an automated solution. Although it can increase the cost
burden for Trinity, in the long run, it would generate favourable results. The business must try to
reduce its costs relating to its current IT system and BPCS so that the activities can be carried out
in a centralized and standardized manner.
Major sources of cost
One of the major sources of the cost that Trinity will have to incur relating to its
compliance maintenance and testing relates to the Oracle initiative, which is worth $ 28 million.
Similarly, the business has to maintain and test diverse control environments, including business
specific applications and IT support in Europe and Mexico. This would also act as a major source
of cost for the company. As BPCS operates in seven diverse locations, the development,
maintenance and testing of the controls in each of the locations would lead to the magnification of
the business costs to a significant extent.
Ranking of main sources of cost
The main sources of cost in the context of Trinity Industries’ in terms of value include:
• Oracle initiative
• Accounting Service Center (ASC) project
• Maintenance and testing
Comparison of the software system
ACC 675 a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a 13
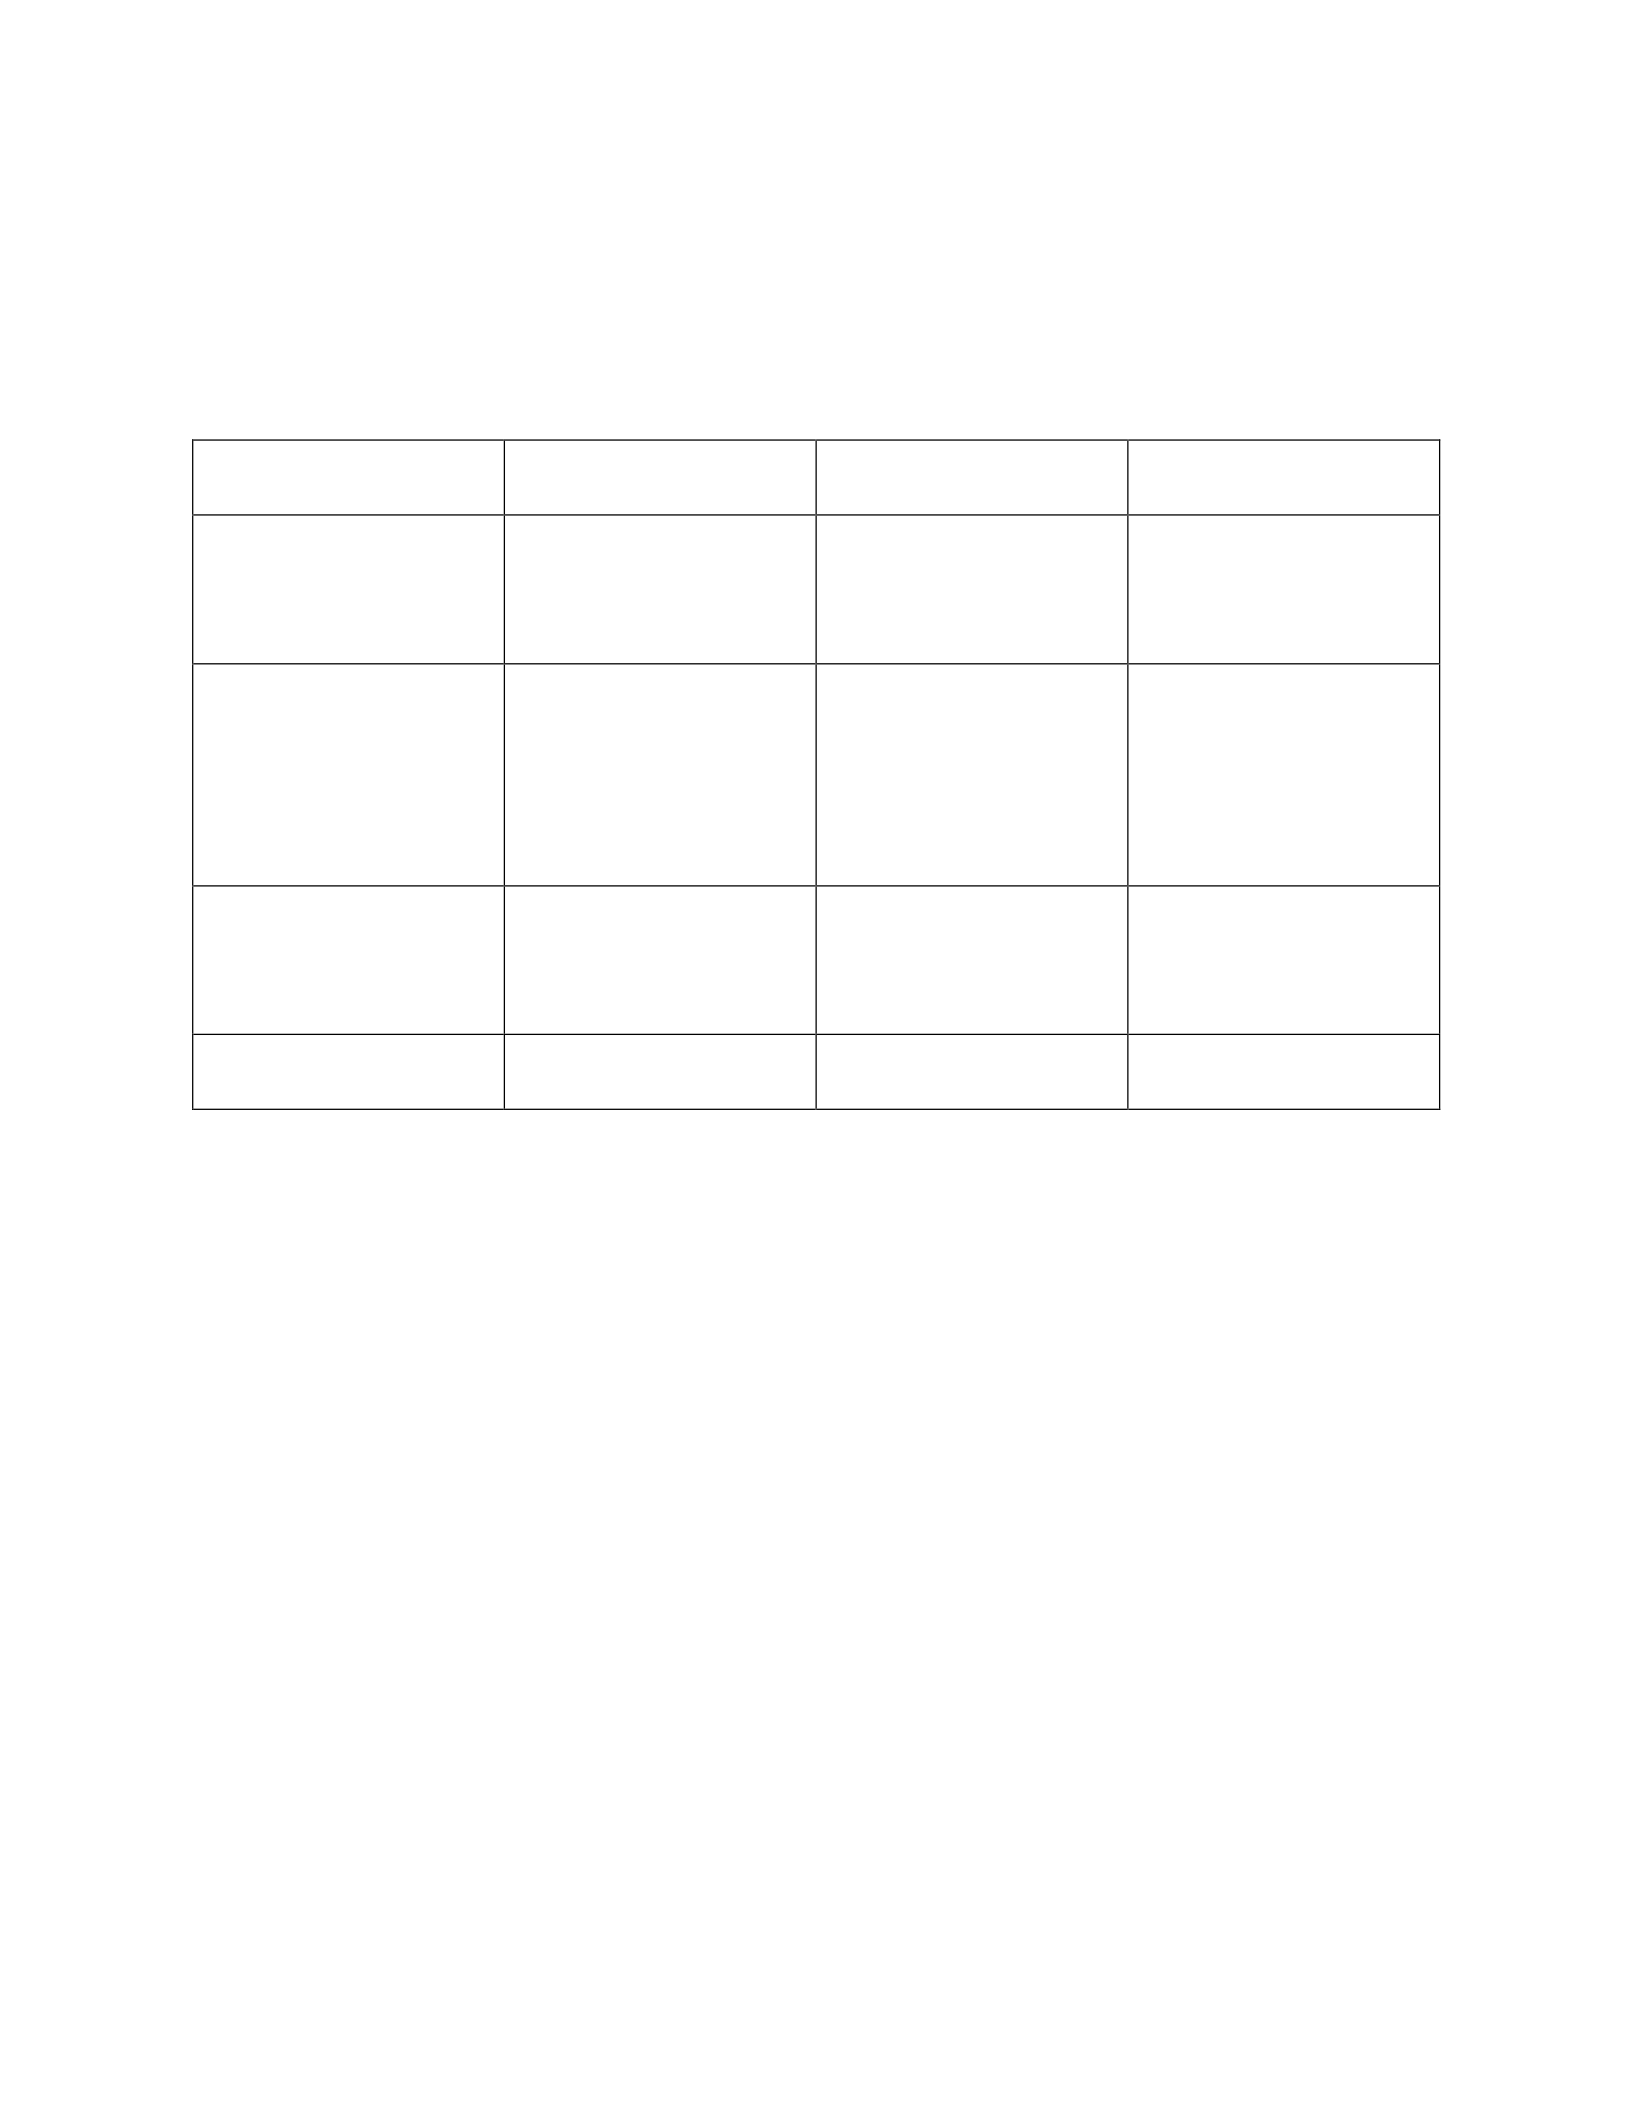
Oracle has been selected as the ultimate software system that can be introduced in Trinity
Industries.’ However, its advantages and disadvantage have been compared with that of two other
systems including SAP and Microsoft solutions.
Oracle
SAP
Microsoft
Reporting
Improved reporting
effectiveness
Good reporting
control
Robust reporting
mechanisms
Time efficiency
Timely closure of
books
The book closure
process can be
manually changed
Time-efficient
procedures
Information
Better availability of
financial information
High information
availability
High information
availability
Cost
Affordable cost
High cost
High cost
Selection of Oracle
Based on the comparison between diverse software systems that can be introduced in the
business context, Oracle has been identified as the ideal software system for Trinity Industries.’ It
can play a vital role in managing the accounting transactions of the business as well as the
accuracy of the financial details that are reported in a cost-efficient manner. One of the main
reasons for identifying Oracle is ta t eh innovative system is aligned with the exact needs of the
business. Another vital reason for choosing Oracle is that it is a much more affordable option as
compared to the alternative options that are available in the market and the current system that the

ACC 675 a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a 14
company has in place to control its accounting transactions as well as processes. It is a suitable
system that can meet the business needs effectively.
V a IFRS
Trinity’s compliance with International Financial Reporting Standards (IFRS) has been
examined. The changes that the company would have to make to comply with IFRS has been
identified.
a. Implications of change in accounting standards
Change in accounting standards can have a direct and significant impact on the processes and
approaches that are adopted within the Trinity organization. One of the basic areas of difference is
the adoption of a holistic approach to lease classification. The accountants in the company would
have to rely on their own judgment for the purpose of classifying the leases of the business. The
move to IFRS standards would also have a significant impact on the control activities of the
company. Currently, the controls in the company are designed to ensure compliance with rules
(assumption). The alteration in the underlying logic will force the company to make adjustments
in the control processes. It can also have a major impact on the information system that is adopted
throughout the company. There will be a need for new data, and changes in calculations and
reporting methods will also have to be made (Schultze, 2011,p . 20).
b. Changes to improve internal control compliance
Trinity Industries will have to take a number of steps to strengthen its internal control
compliance. IFRS stresses diverse aspects such as risk management as well as business processes
so that robust internal control can exist in place. The internal audit team needs to possess profound

ACC 675 a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a 15
knowledge relating to the IFRS standard so that the financial statements can represent accurate
details by emphasizing clarity, relevance, comparability as well as reliability (Morley, 2016). A
fundamental change that Trinity will have to make is in its information system so that necessary
and appropriate data can be captured, which can strengthen the reporting. The inventory
transactions must be captured at a comprehensive level so that they can present complete, timely
and accurate information, and the value of inventory must be correctly captured. The controls
must be thoroughly checked and maintained so that the possibility of gaps can be reduced or
eliminated.
c. Impact of standards on Trinity due to IFRS
Some of the main standards of the International Financial Reporting Standards that will have a
significant impact on Trinity Industries include IFRS 16, which relates to leases and IFRS 10,
which relates to financial statements (Schultze, 2011). It is assumed the company followed US
GAAP, which already has a number of rules pertaining to lease classification. However, while
following IFRS, the accountants would have to expand their knowledge of lease treatment and the
company’s lease agreements so that accurate classification can be made. Similarly, while
preparing the consolidated financial statements, consistent principles need to be followed as IFRS
is a principles-based method (Morley, 2016). a
d. Role of infrastructure in supporting IFRS compliance project
The infrastructure that is in place at Trinity Industries will play an instrumental role in
enabling the company to support the IFRS compliance project. a
• Trinity governance infrastructure – The governance infrastructure that exists within the
company will play a key role in complying with IFRS. Currently, the Information Systems

ACC 675 a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a 16
Audit and Control Association (ISACA) focuses on developing suitable standards while
providing guidance and education relating to information systems governance and audit.
• Trinity IT infrastructure – The existing IT controls that are adopted within the
organization need to be strengthened so that the general controls can become more
detailed and focused and help to create a more effective internal control environment
within the firm.
• Trinity process infrastructure – The processes that are adopted within the company
need to be made more systematic and methodical so that gaps that may affect controls can
be identified and tackled effectively. The processes need to be made more robust and
consistent. a

ACC 675 a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a 17
References
Bottom-up approach for compliance: The master position. emmanuel . W3. (2009). Retrieved
December 13, 2022, from https://www.w3.org/2009/policy-ws/papers/Pigout.pdf
Deloitte Us: Audit, Consulting, advisory, and Tax Services. Deloitte United States. (2021).
Retrieved December 13, 2022, from https://www2.deloitte.com/
Morley, M. (2016, December 1). Clarity: The first principle of IFRS (part 1 of 4). TheGAAP.net.
Retrieved December 21, 2022, from https://thegaap.net/clarity-the-first-principle-of-
international-financial-reporting-standards-part-1-of-4/
No, A. S. (2004). An Audit of Internal Control Over Financial Reporting Performed in
Conjunction with An Audit of Financial Statements. AUDITING.
Sarbanes-Oxley Section 404 A Guide for Small Business. SEC Emblem. (2017, July 14).
Retrieved December 2, 2022, from
https://www.sec.gov/info/smallbus/404guide/evaluation3#:~:text=Simply%20put%2C%20
a%20material%20weakness,annual%20or%20interim%20financial%20statements.
Save Money on Sarbanes-Oxley Section 404(a) Compliance. Marmann & Associates, P.C. -
Certified Public Accountants & Consultants. (2021). Retrieved December 13, 2022, from
http://www.marmanngroup.com/news/print_mm_analysis.html
Schultze, U. (2011). The SOX compliance journey at Trinity Industries. Journal of Information
Technology Teaching Cases, 1(2), 91-113.

ACC 675 a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a 18
SEC report. (2021). Retrieved November 17, 2022, from https://sec.report/
UP: Annual reports - union pacific corporation. (2021). Retrieved November 17, 2022, from
https://www.up.com/up/investors/annuals/
Viewpoint : PWC. Viewpoint. (2022, December 8). Retrieved December 13, 2022, from
https://viewpoint.pwc.com/us/en.html

