


Using fixed income ETFs to mitigate risk
Investing in a broad range of businesses is less risky than investing in just one—because
investing in just one would mean taking on the specific risk and performance of only that
business. The same principle applies to investing in a range of asset classes rather than just
equities. It spreads the risk. A fixed income exchange-traded fund (ETF) is one easy way to
access a broad range of bonds that may help investors diversify, reduce downside risk, and
dampen volatility.
A fixed income ETF is a pooled portfolio of bonds that trades daily on an exchange. This means
that fixed income ETFs offer intraday trading and continuous transparent pricing while
commonly seeking to replicate the return of a chosen index.
A single fixed income ETF can hold hundreds or thousands of bonds, providing potential
diversification benefits as well as access at a lower cost than would be possible to obtain by
buying each issue separately.
Correlation: Foundation of diversity
To start, it’s helpful to understand correlation, one of the foundational measures of portfolio
diversification. Correlation is a measure of the extent to which two investments move in relation
to one other. A correlation of +1 indicates a perfect positive correlation. In other words, when
one asset moves up or down, the other asset does too. Conversely, a correlation of –1 is a perfect
negative correlation. When one asset moves up or down, the other does the opposite.
Adding investments with a lower correlation can help diversify a portfolio and potentially
mitigate risk. U.S. Treasuries, municipal bonds, and U.S. corporate bonds have historically
shown low to negative correlations to equities as represented by the S&P 500® Index (see chart).
. Managing downside risk
While diversification is one benefit of adding fixed income to a portfolio, it’s not the only one.
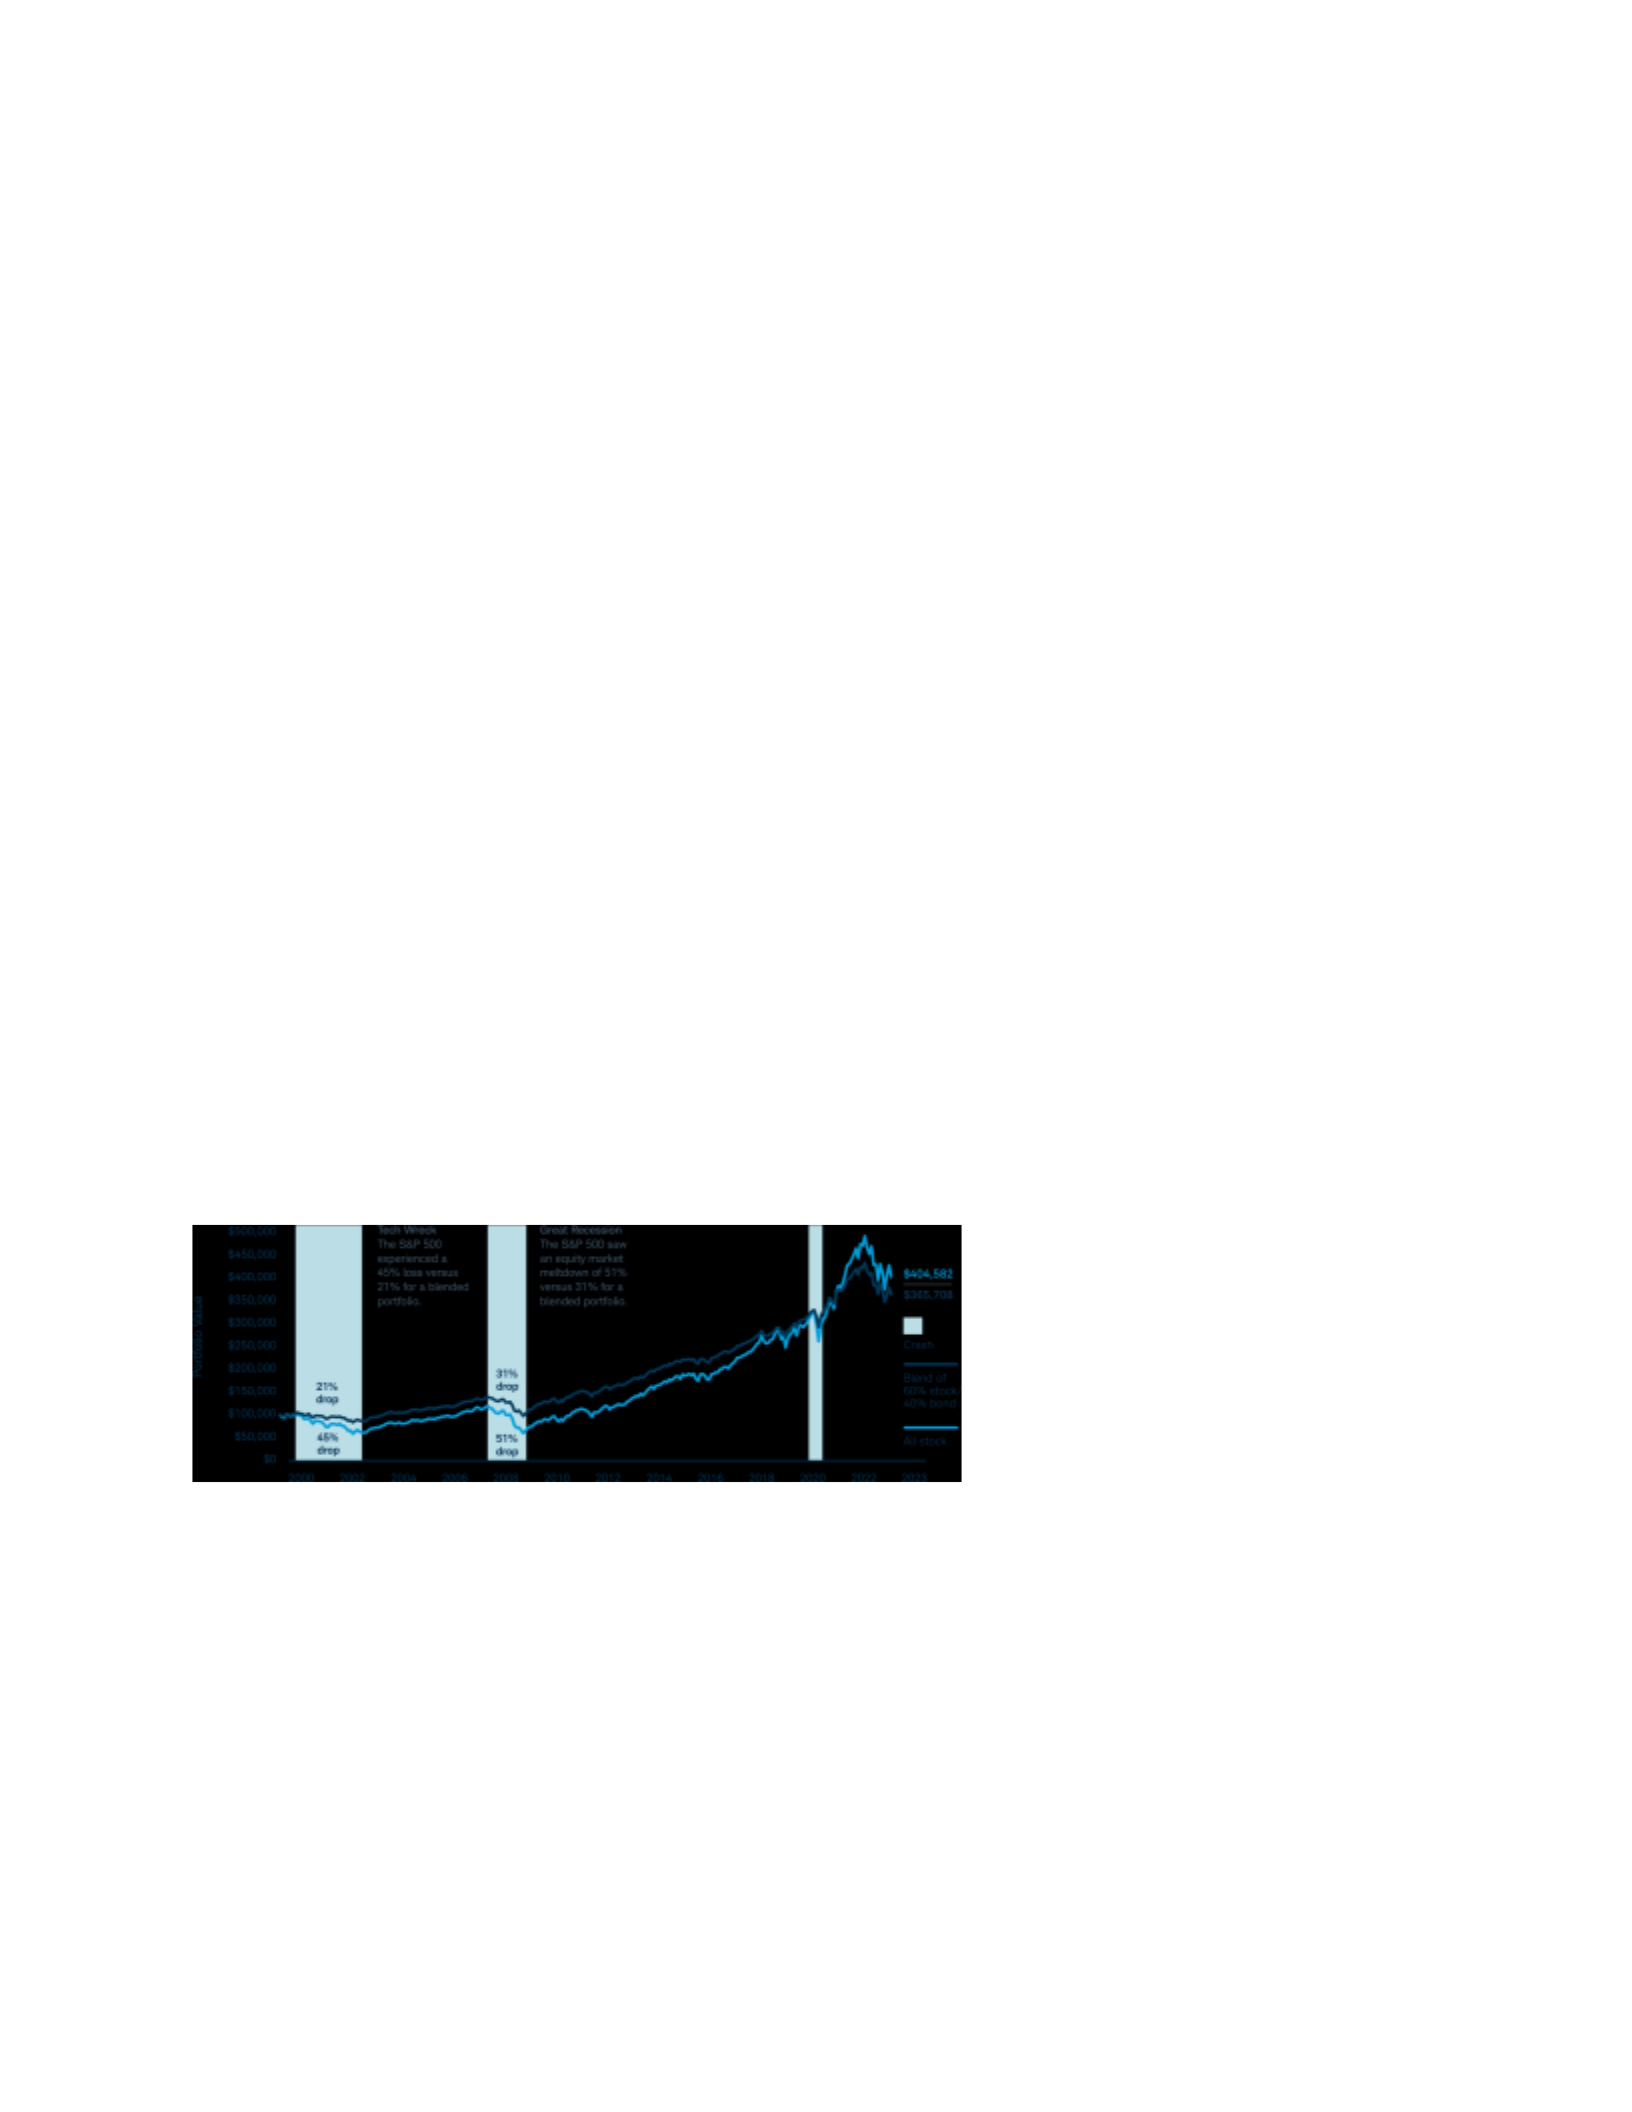
Helping to manage downside risk and volatility are also key advantages. The example below
shows a historical performance comparison between an all-stock portfolio and a 60% stock/40%
bond portfolio. Through two dramatic downturns, the stock/bond portfolio didn’t decline as
much as the all-stock portfolio. In other words, allocating a portion of a portfolio to bonds
mitigated downside risk and improved performance.
A balanced portfolio has helped reduce volatility over time
(December 1999 - December 2022)
Source: Schwab Center for Financial Research, with data provided by Morningstar, Inc. Stocks
are represented by total annual returns of the S&P 500® Index, and bonds are represented by total
annual returns of the Bloomberg US Aggregate Bond Index. The 60/40 portfolio is a
hypothetical portfolio consisting of 60% S&P 500® Index stocks and 40% Bloomberg US
Aggregate Bond Index bonds. The portfolio is rebalanced annually. Returns include reinvestment
of dividends, interest, and capital gains. Indices are unmanaged, do not incur fees or expenses,
and cannot be invested in directly. For additional information, please see
Schwab.com/IndexDefinitions. Diversification does not eliminate the risk of investment losses.
Past performance is no guarantee of future results.
Dampening volatility
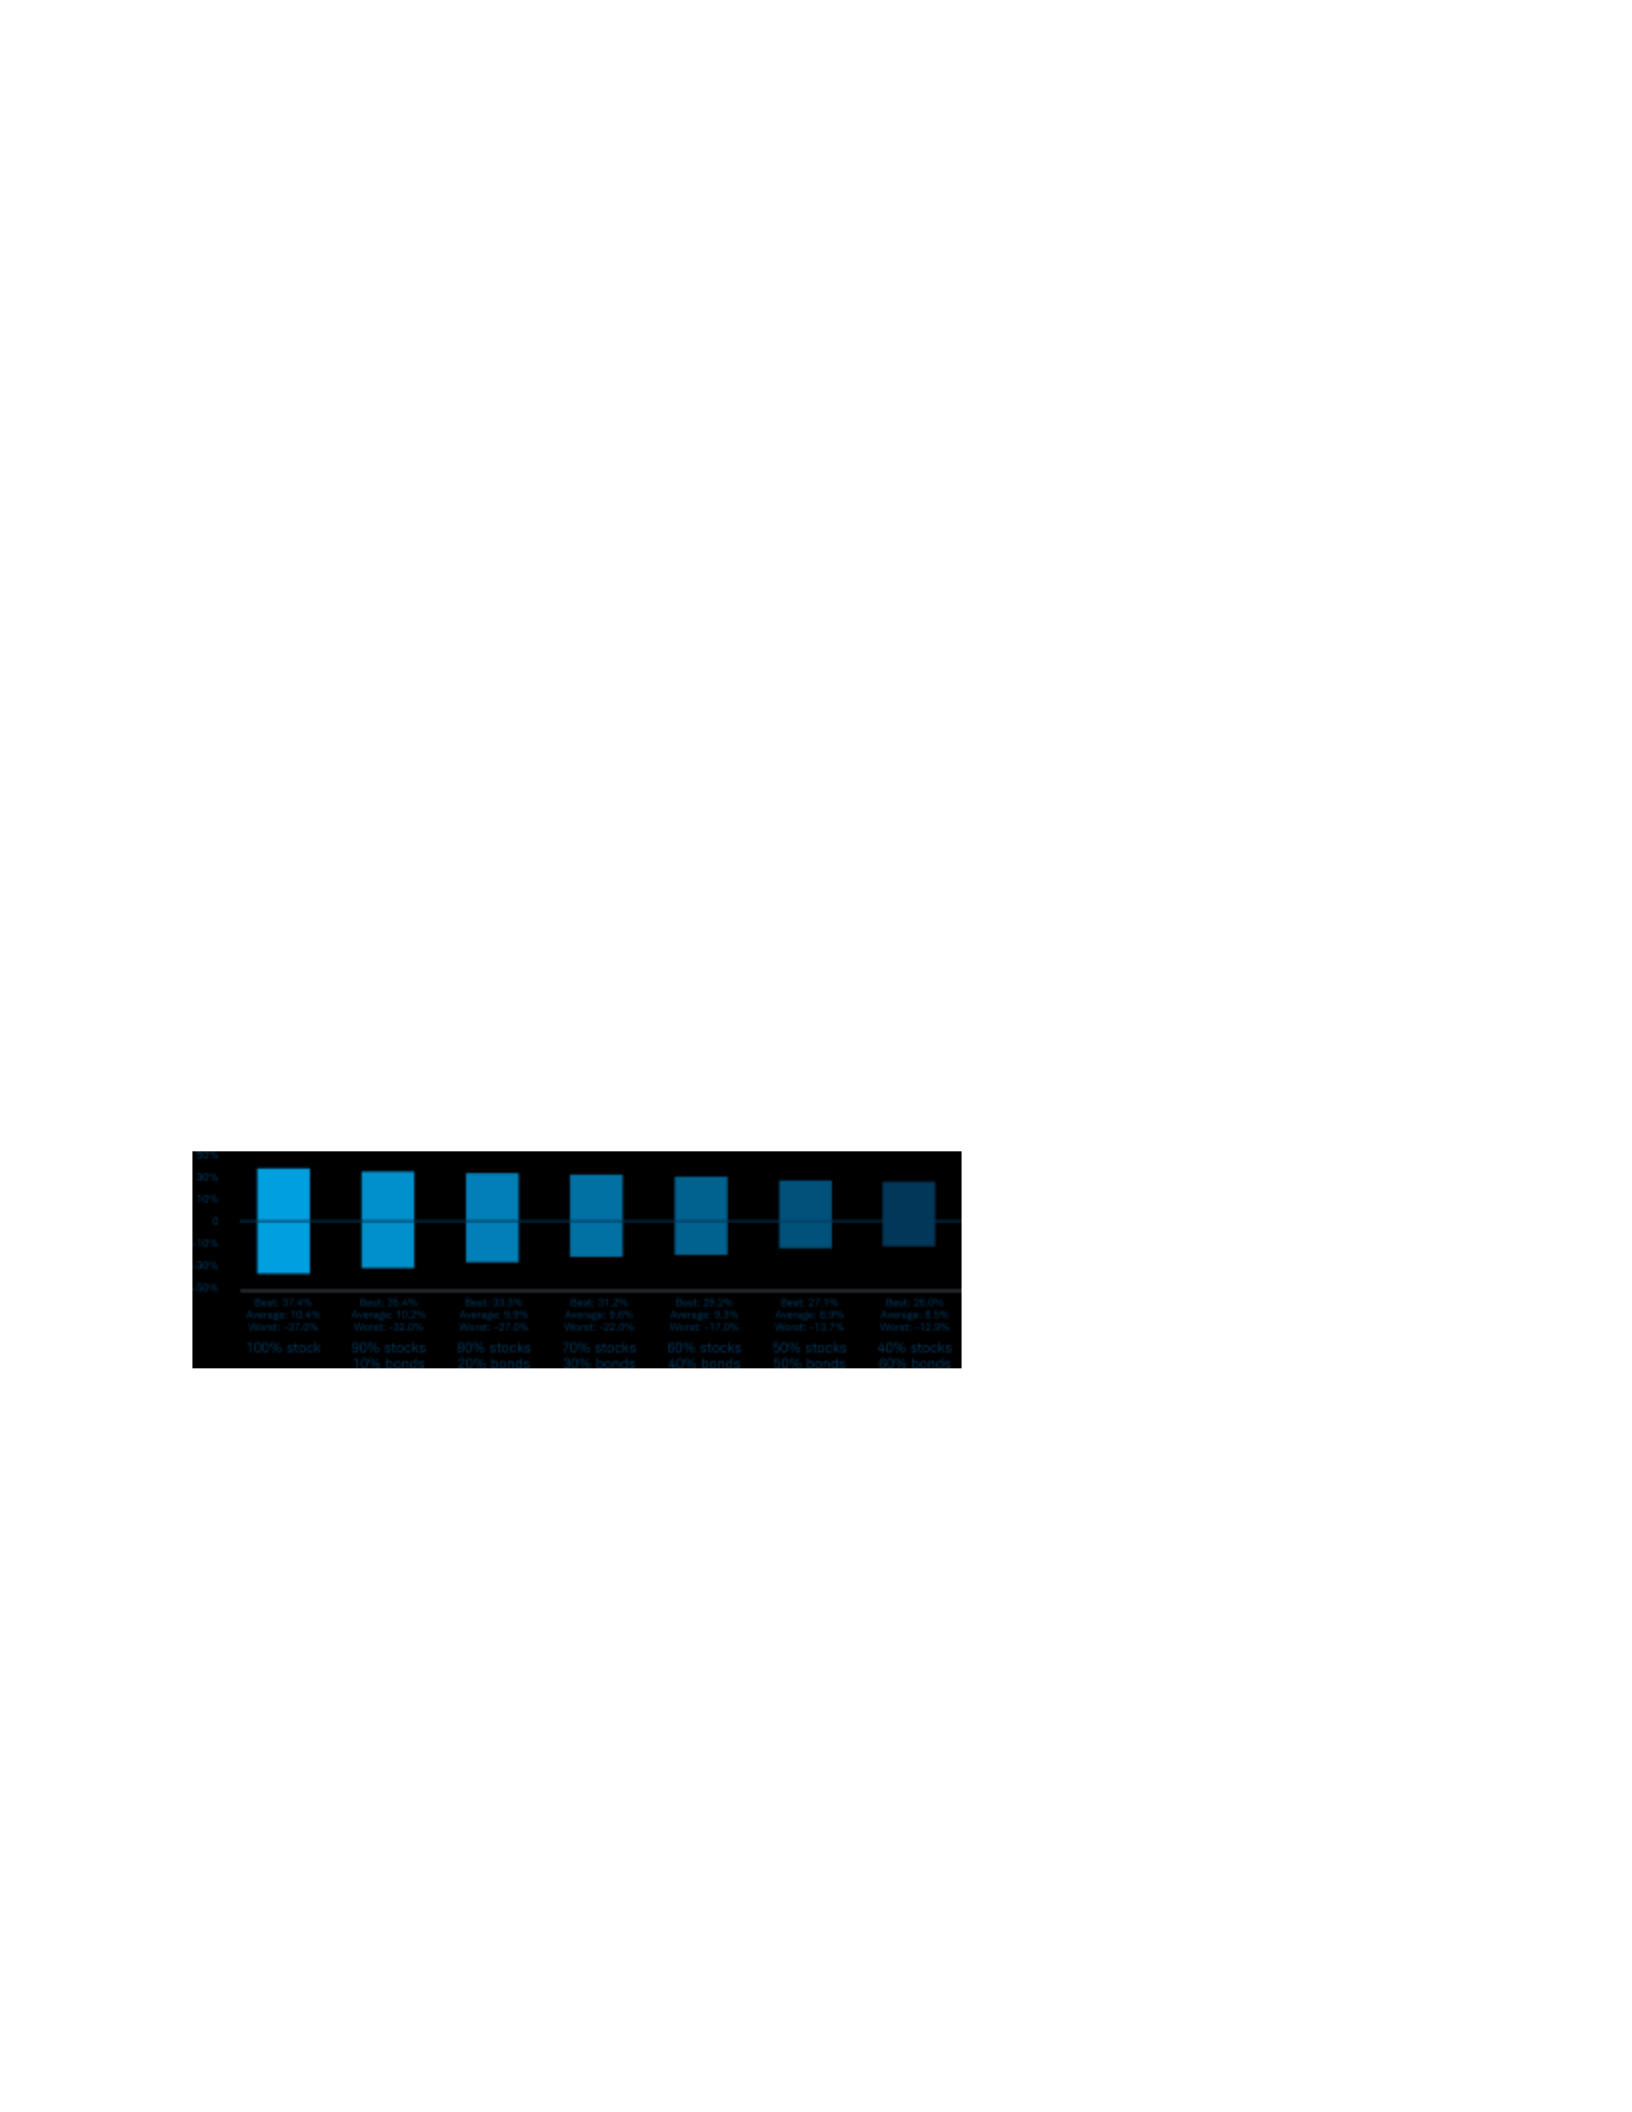
Evidence shows that the more bonds are included in the portfolio, the less volatility the portfolio
typically experiences. The chart below illustrates the volatility-dampening effect of increasing
levels of bonds versus equities in a portfolio. Across the board, adding fixed income securities to
a portfolio reduced volatility and the dispersion of returns.
Fixed income investments can lower portfolio volatility
Range of annual returns (1970-2022)
Building a diversified portfolio is a sound investment strategy. Fixed income ETFs can help
investors diversify while also seeking to protect downside risk, reduce volatility over time,
preserve capital, and provide periodic income. Plus, fixed income ETFs typically offer liquidity,
price visibility, and low costs.

But fixed income ETFs aren’t risk-free, and diversification doesn’t guarantee against investment
loss. Investors should evaluate an investment based on its investment objectives and associated
risks.
What is a fixed rate bond?
A fixed rate bond (or fixed term deposit) is a savings account that you can put money into for a
set period of time. It's usually 1, 2 or 3 years, but can also be as long as 5 years.
In exchange for agreeing to not withdraw your money during this term, you get a fixed rate of
interest that is generally higher than what you would get from a savings account that allows
regular withdrawals.
A fixed rate bond may be suitable for those looking to invest a lump sum, or those looking for a
mid to long term savings account.
As you agree to lock your money away for a fixed term, it's not suitable for those wanting access
to their money, especially on a regular basis.
Keep in mind that it's usually recommended to have at least 3 months’ worth of monthly income
in an instant or limited access savings account before you opt to lock your money away.
How do fixed rate bonds work?
Fixed rate bonds are available with different terms. In general, the longer the term, the higher the
interest rate. Most fixed rate bonds require a minimum deposit to open the account. Unlike many

other savings accounts, you are usually only allowed to pay in once, which is when you open the
account.

