


3.1 The Balance Sheet
Public companies are obliged to file their financial statements with the SEC each quarter. These quarterly
reports (or 10Qs) provide the investor with information about the company’s earnings during the quarter
and its assets and liabilities at the end of the quarter. In addition, companies need to file annual financial
statements (or 10Ks) that provide rather more detailed information about the outcome for the entire
year.
The financial statements show the firm’s balance sheet, the income statement, and a statement of cash
flows. We will review each in turn.1
Firms need to raise cash to pay for the many assets used in their businesses. In the process of raising that
cash, they also acquire obligations or “liabilities” to those who provide the funding. The balance
sheet presents a snapshot of the firm’s assets and liabilities at one particular moment. The assets—
representing the uses of the funds raised—are listed on the left-hand side of the balance sheet. The
liabilities—representing the sources of that funding—are listed on the right.
Some assets can be turned more easily into cash than others; these are known as liquid assets. The
accountant puts the most liquid assets at the top of the list and works down to the least liquid. Look, for
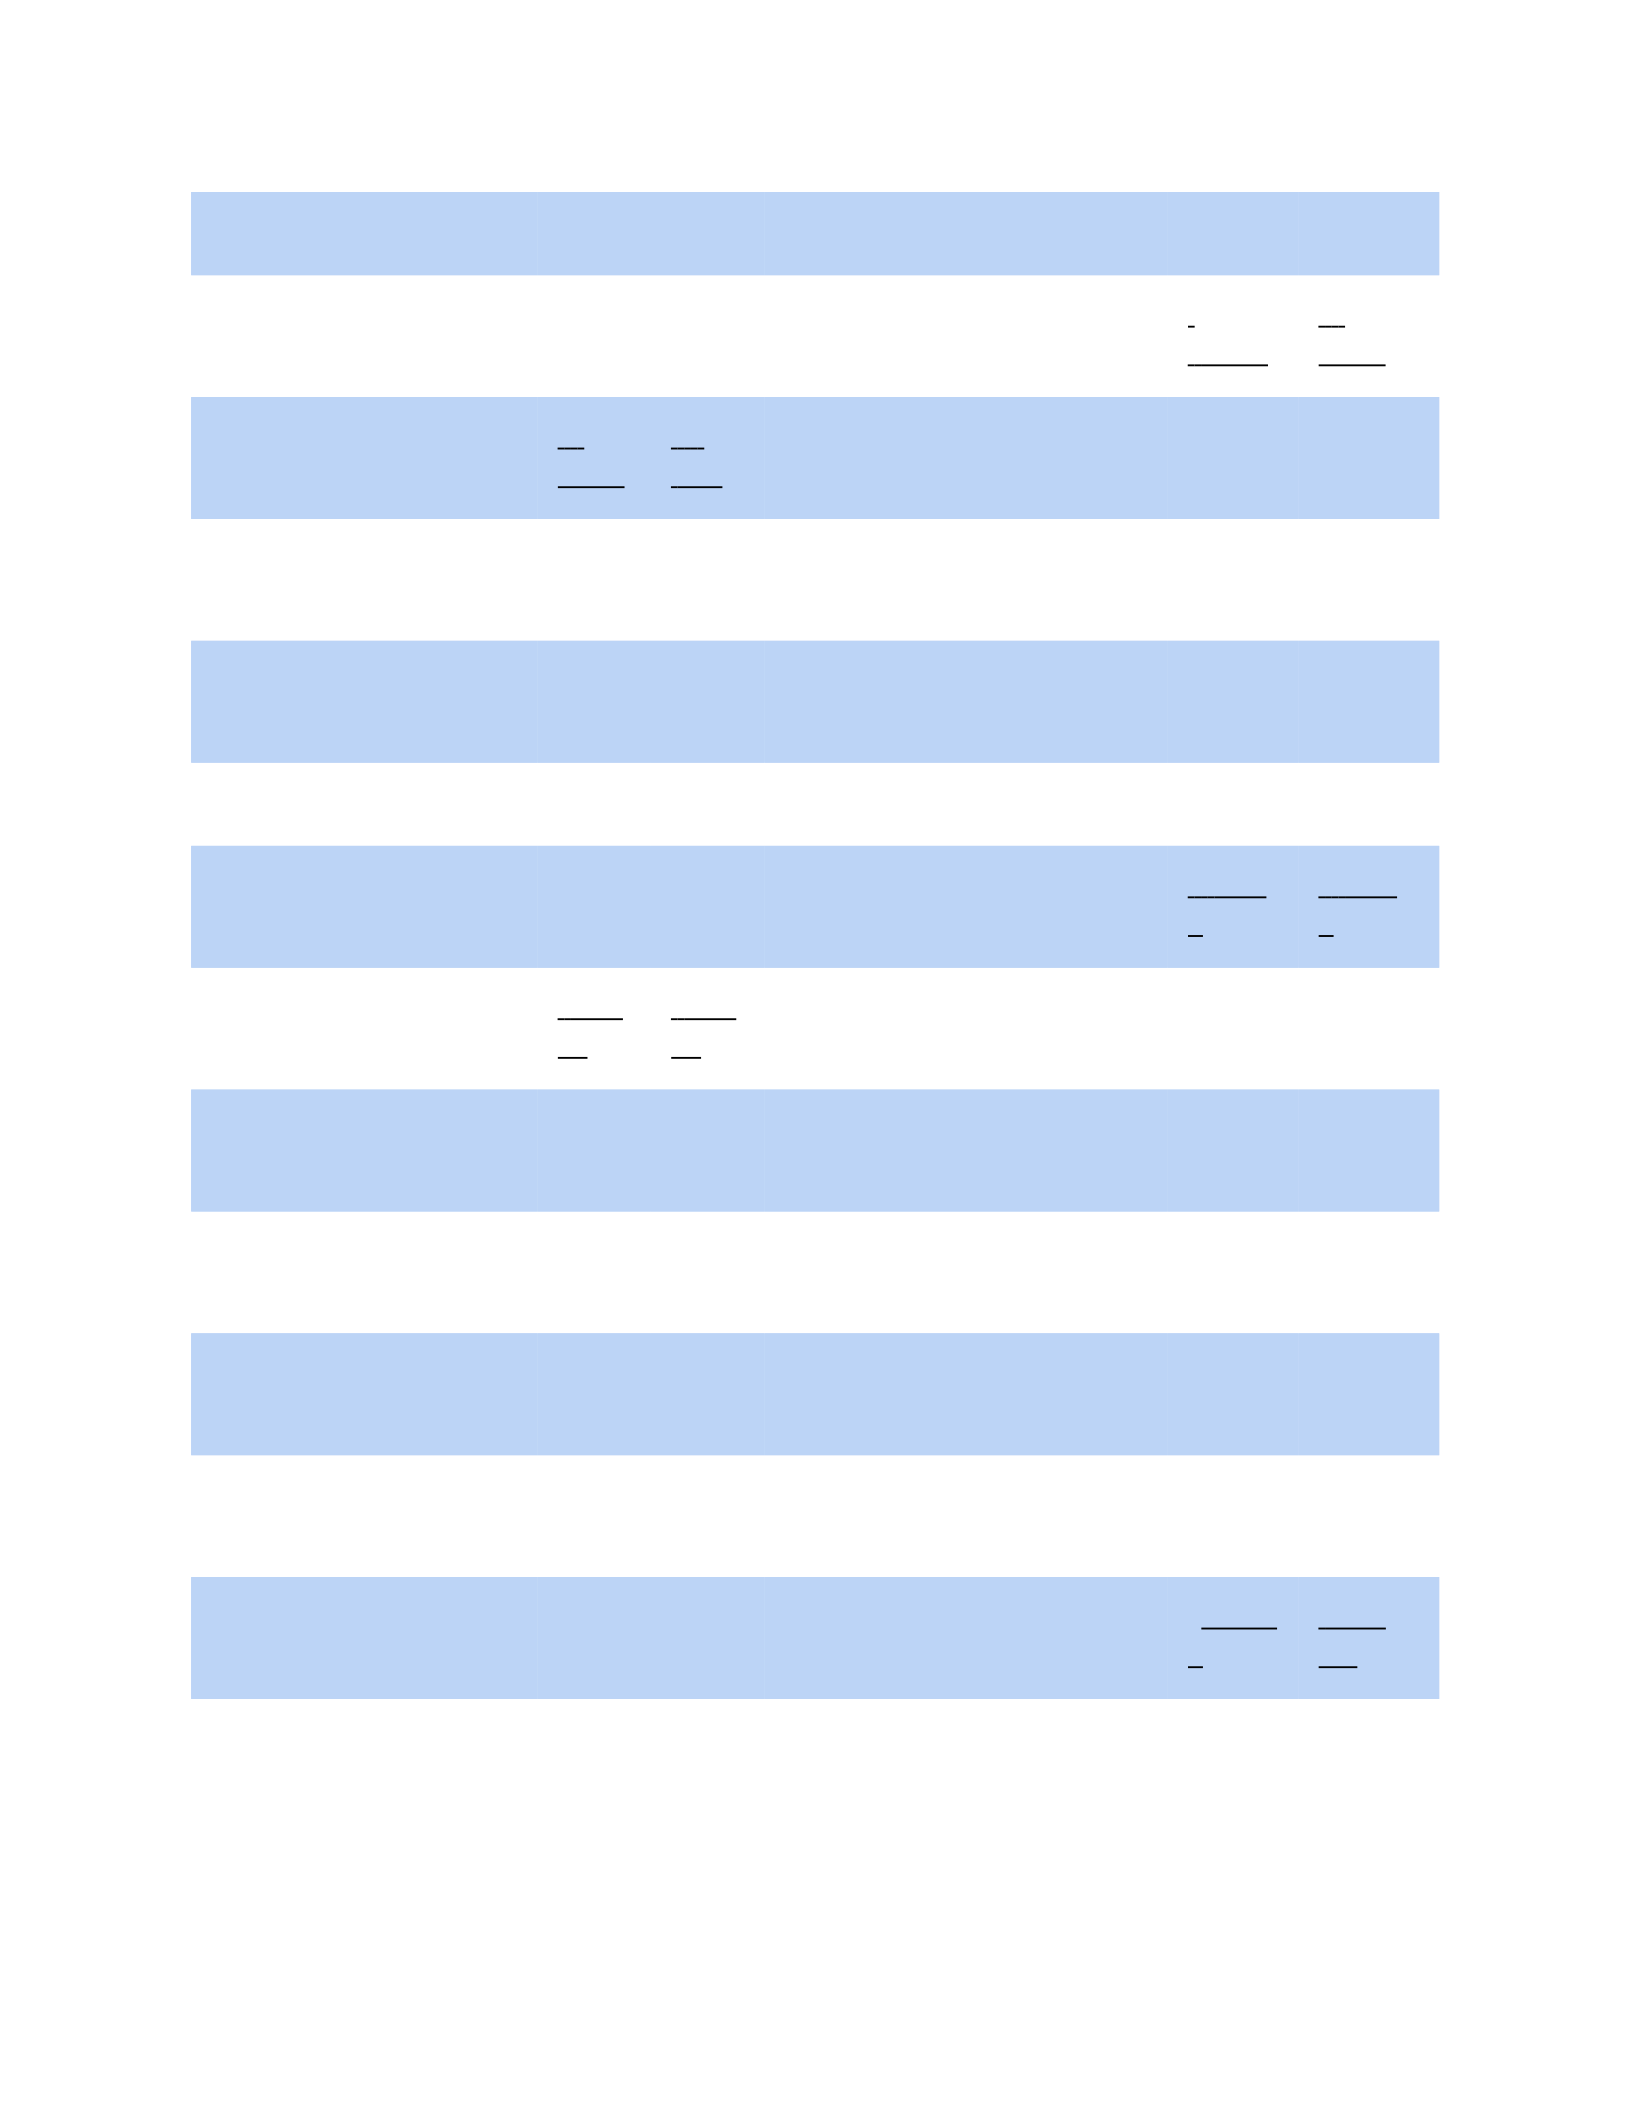
example, at Table 3.1, which shows the consolidated balance sheet for Home Depot (HD), at the end of
its 2014 fiscal year.2 (“Consolidated” simply means that the balance sheet shows the position of Home
Depot and any companies it owns.) You can see that Home Depot had $1,723 million of cash and
marketable securities. In addition, it had sold goods worth $1,484 million but had not yet received
payment. These payments are due soon, and therefore the balance sheet shows the unpaid bills
oraccounts receivable (or simply receivables) as a current asset. The next asset consists of inventories.
These may be (1) raw materials and ingredients that the firm bought from suppliers, (2) work in progress,
and (3) finished products waiting to be shipped from the warehouse. For Home Depot, inventories
consist largely of goods in the warehouse or on the store shelves; for manufacturing companies,
inventories would be more skewed toward raw materials and work in progress. Of course, there are
always some items that don’t fit into neat categories. So there is a fourth entry, other current assets.
Page 59
Table 3.1 Home Depot’s balance sheet (figures in $ millions)
End of Fiscal End of Fiscal
Assets 2014 2013
Liabilities and Shareholders’
Equity 2014 2013
Current assets Current liabilities
Cash and marketable
securities
$1,72
3
$1,92
9 Debt due for repayment $328 $33
Receivables 1,484 1,398 Accounts payable 9,473 9,379
Inventories
11,07
9
11,05
7 Other current liabilities
1,468
1,337
Other current assets
1,016
895 Total current liabilities
$11,26
9
$10,7
49
Total current assets
$15,3
02
$15,2
79
Fixed assets Long-term debt
$16,86
9
$14,6
91
Tangible fixed assets Deferred income taxes 642 514
Property, plant, and
equipment
$40,3
53
$39,0
64 Other long-term liabilities
1,84
4
2,04
2
Less accumulated
depreciation
17,6
33
15,7
16
Net tangible fixed
assets
$22,7
20
$23,3
48 Total liabilities
$30,62
4
$27,9
96
Intangible assets
(goodwill) 1,353 1,289 Shareholders’ equity
Other assets 571 602
Common stock and other
paid-in capital $8,521
$8,53
6
Retained earnings 26,995
23,18
0
Total assets
$39,9
46
$40,5
18 Treasury stock
(26,19
4)
(19,1
94)
Total shareholders’ equity $9,322
$12,5
22
Total liabilities and $39,94 $40,5
shareholders’ equity 6 18
Note: Column sums subject to rounding error.
Source: Derived from Home Depot annual reports.
Up to this point, all the assets in Home Depot’s balance sheet are likely to be used or turned into cash in
the near future. They are therefore described as current assets. The next assets listed in the balance
sheet are longer-lived or fixed assets and include items such as buildings, equipment, and vehicles.
The balance sheet shows that the gross value of Home Depot’s property, plant, and equipment is
$40,353 million. This is what the assets originally cost. But they are unlikely to be worth that now. For
example, suppose the company bought a delivery van 2 years ago; that van may be worth far less now
than Home Depot paid for it. It might, in principle, be possible for the accountant to estimate separately
the value today of the van, but this would be costly and somewhat subjective. Accountants rely instead
on rules of thumb to estimate the depreciation in the value of assets, and with rare exceptions they stick
to these rules. For example, in the case of that delivery van, the accountant may deduct a third of the
original cost each year to reflect its declining value. So if Home Depot bought the van 2 years ago for
$15,000, the balance sheet would show that accumulated depreciation is 2 × $5,000 = $10,000. Net of
depreciation the value is only $5,000. Table 3.1 shows that Home Depot’s total accumulated
depreciation on fixed assets is $17,633 million. So while the assets cost $40,353 million, their net value
in the accounts is only $40,353 − $17,633 = $22,720 million.
In addition to its tangible assets, Home Depot also has valuable intangible assets, such as its brand
name, skilled management, and a well-trained labor force. Accountants are generally reluctant to record
these intangible assets in the balance sheet unless they can be readily identified and valued.
There is, however, one important exception. When Home Depot has acquired other businesses in the
past, it has paid more for their assets than the value shown in the firms’ accounts. This difference is
shown in Home Depot’s balance sheet as “goodwill.” Most of the intangible assets on Home Depot’s
balance sheet consist of goodwill.
Now look at the right-hand portion of Home Depot’s balance sheet, which shows where the money to
buy its assets came from. The accountant starts by looking at the company’s liabilities—that is, the
money owed by the company. First come those liabilities that are likely to be paid off most rapidly. For
example, Home Depot has borrowed $328 million, due to be repaid shortly. It also owes its suppliers
$9,473 million for goods that have been delivered but not yet paid for. These unpaid bills are shown
as accounts payable (orpayables). Both the borrowings and the payables are debts that Home Depot
must repay within the year. They are therefore classified as current liabilities.
Home Depot’s current assets total $15,302 million; its current liabilities amount to $11,269 million.
Therefore, the difference between the value of Home Depot’s current assets and its current liabilities is
$15,302 − $11,269 = $4,033 million. This figure is known as Home Depot’s net current assets or net
working capital. It roughly measures the company’s potential reservoir of cash.
Below the current liabilities Home Depot’s accountants have listed the firm’s long-term liabilities, such as
debts that come due after the end of a year. You can see that banks and other investors have made long-
term loans to Home Depot of $16,869 million.
Home Depot’s liabilities are financial obligations to various parties. For example, when Home Depot buys
goods from its suppliers, it has a liability to pay for them; when it borrows from the bank, it has a liability
to repay the loan. Thus the suppliers and the bank have first claim on the firm’s assets. What is left over
after the liabilities have been paid off belongs to the shareholders. This figure is known as the
shareholders’ equity. For Home Depot the total value of shareholders’ equity amounts to $9,322
million. Table 3.1shows that Home Depot’s equity is made up of three parts. One portion, $8,521 million,
has resulted from the occasional sale of new shares to investors. A much larger amount, $26,995 million,
has come from earnings that Home Depot has retained and reinvested in the business on the
shareholders’ behalf.3 Finally, treasury stock is a large negative number, −$26,194 million. This
represents the amount that Home Depot has spent on buying back its shares. The money to repurchase
them has gone out of the firm and reduced shareholders’ equity.
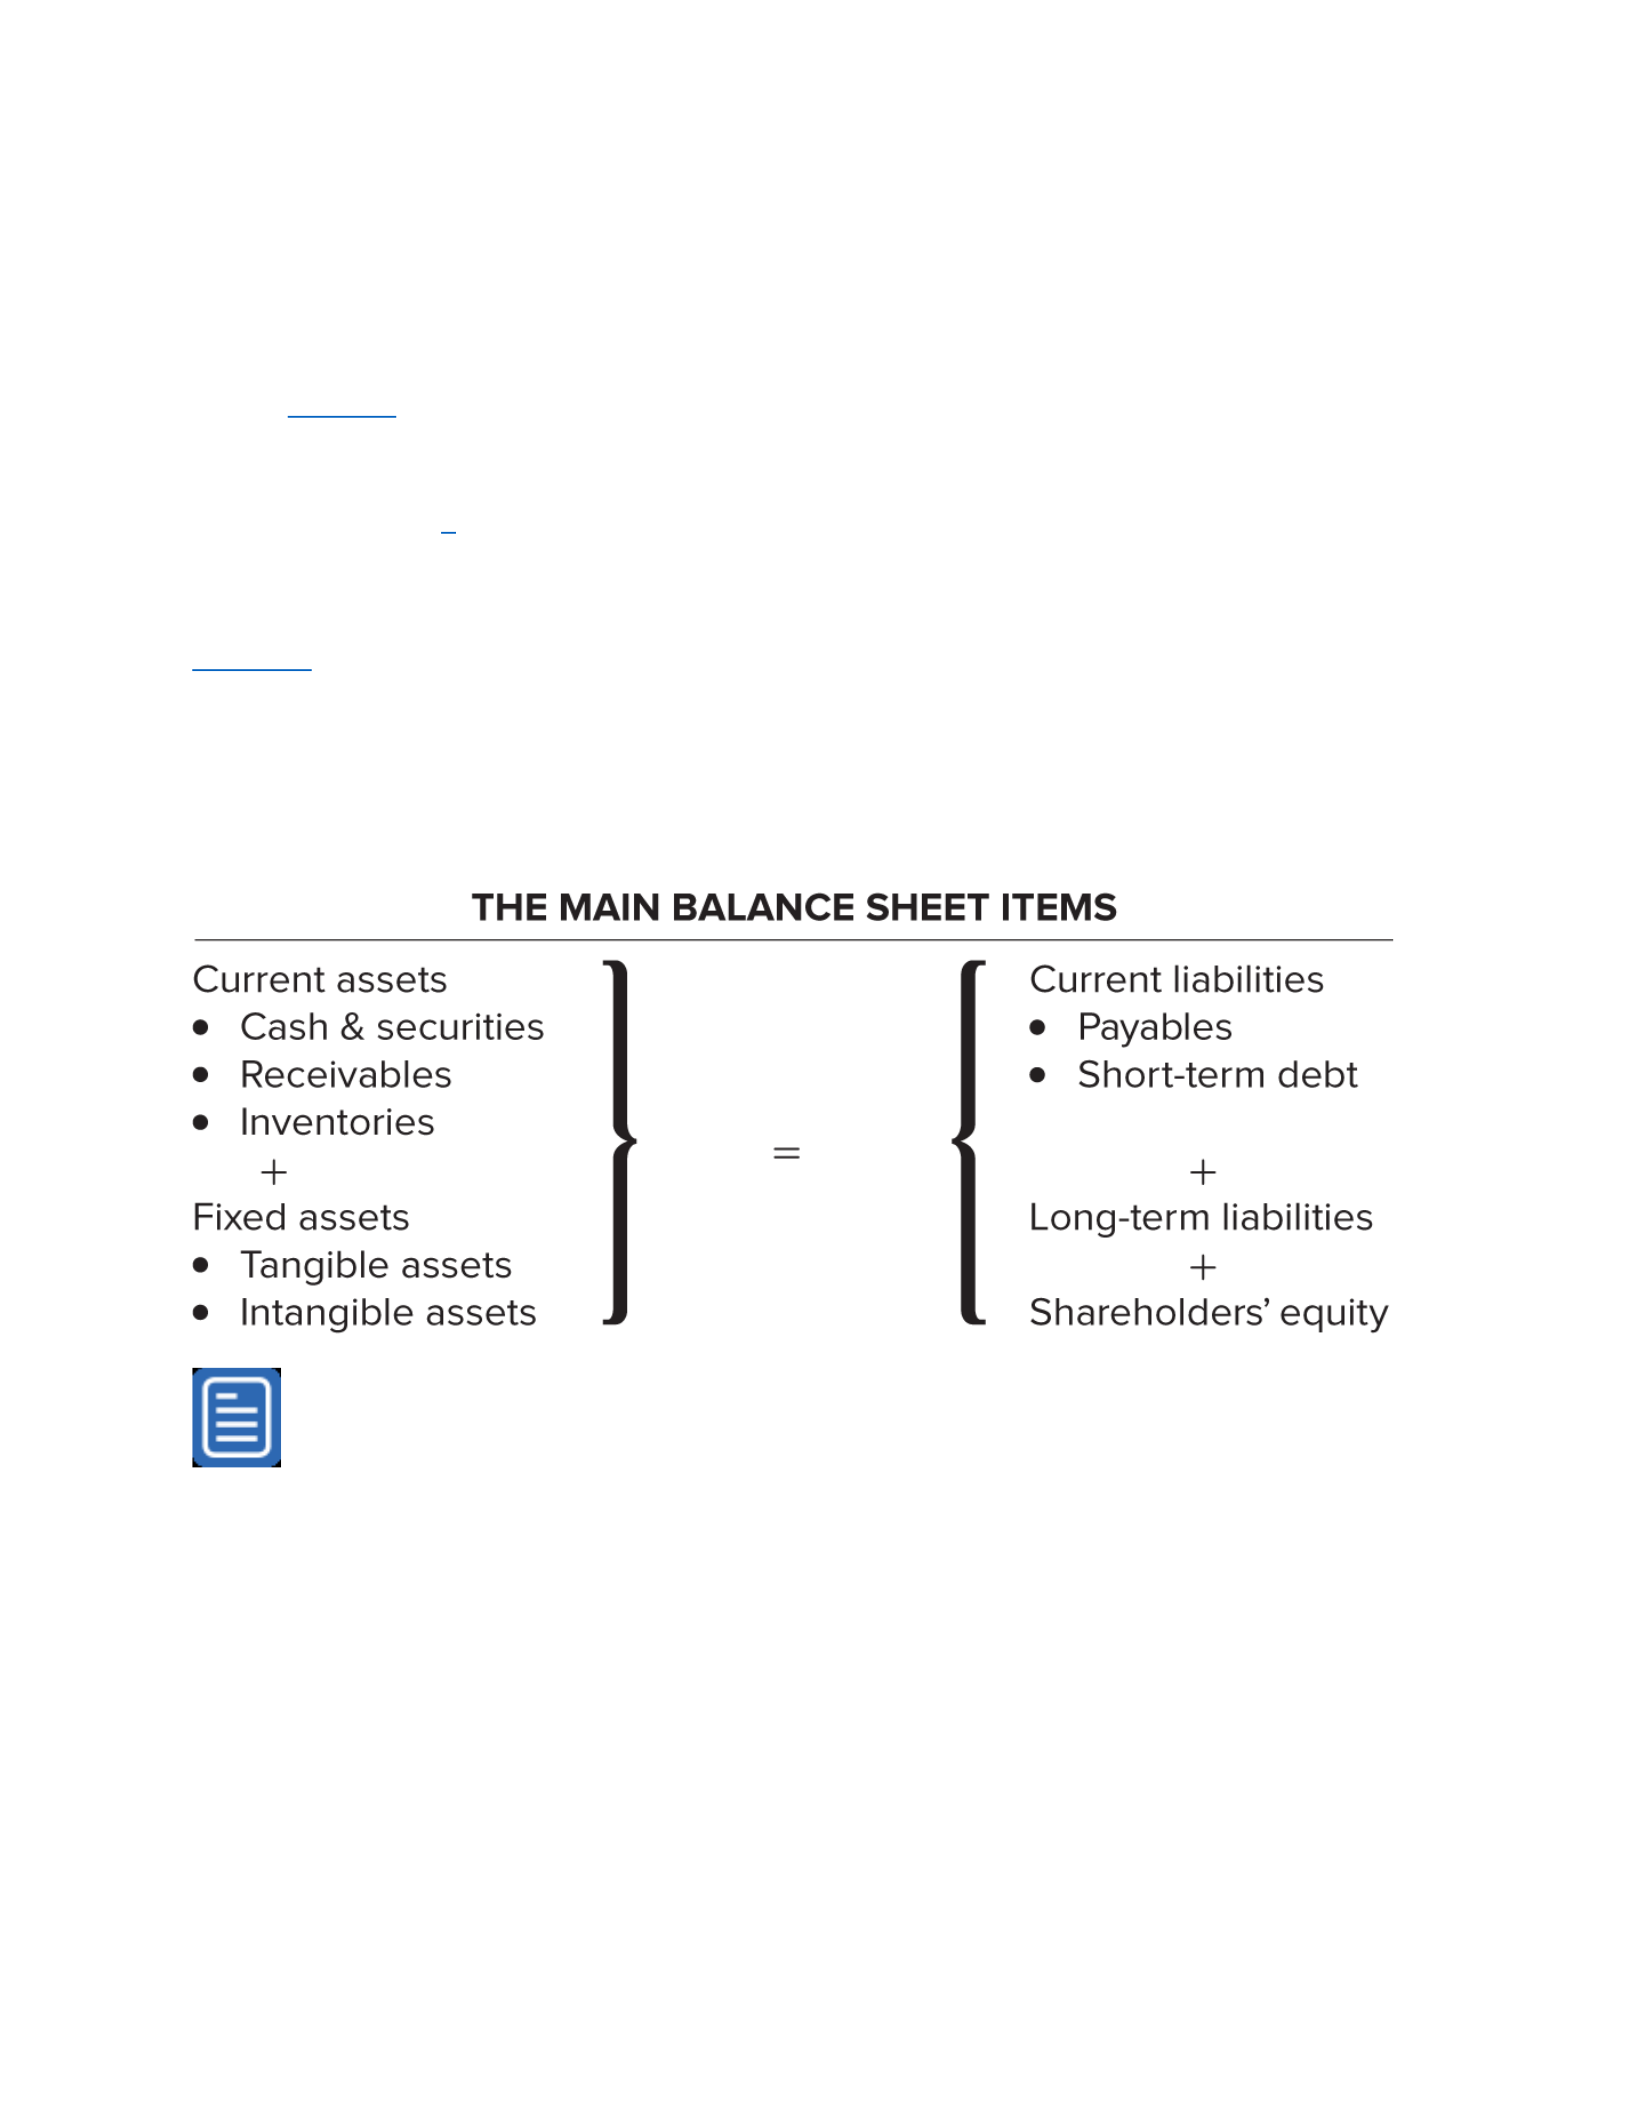
Figure 3.1 shows how the separate items in the balance sheet link together. There are two classes of
assets—current assets, which will soon be used or turned into cash, and long-term or “fixed” assets,
which may be either tangible or intangible. There are also two classes of liability—current liabilities,
which are due for payment shortly, and long-term liabilities.
Page 60Figure 3.1 Assets and liabilities on the balance sheet
The difference between the assets and the liabilities represents the amount of the shareholders’ equity.
This is the basic balance sheet identity. Shareholders are sometimes called “residual claimants” on the
firm. We mean by this that shareholders’ equity is what is left over when the liabilities of the firm are
subtracted from its assets:
Shareholders’ equity = net assets = total assets – total liabilitiesShareholders’ equity
= net assets = total assets – total liabilities (3.1)
3.1 SELF-TEST
Suppose that Home Depot borrows $500 million by issuing new long-term bonds. It places $100 million
of the proceeds in the bank and uses $400 million to buy new machinery. What items of the balance
sheet would change? Would shareholders’ equity change?
When comparing financial statements, analysts often calculate a common-size balance sheet , which re-
expresses all items as a percentage of total assets. Table 3.2 is Home Depot’s common-size balance
sheet. The financial manager might look at this common-size balance sheet and notice right away that in
2014 receivables accounted for a higher proportion of the firm’s assets than they did in the previous
year. There may be good reasons for this, but the manager might wish to check that the company has
not become lazy in collecting its customers’ unpaid bills.
Page 61
Table 3.2 Common-size balance sheet of Home Depot (all items expressed as a percentage of total
assets)
End of Fiscal End of Fiscal
Assets 2014 2013
Liabilities and Shareholders’
Equity 2014 2013
Current assets Current liabilities
Cash and
marketable
securities 4.3% 4.8% Debt due for repayment 0.8% 0.1%
Receivables 3.7 3.5 Accounts payable 23.7 23.1
Inventories 27.7 27.3 Other current liabilities 3.7 3.3
Other current
assets 2.5 2.2 Total current liabilities 28.2% 26.5%
Total current
assets 38.3% 37.7%
Fixed assets Long-term debt 42.2% 36.3%
Tangible fixed
assets Deferred income taxes 1.6 1.3
Property,
plant, and
101.0% 96.4% Other long-term liabilities 4.6 5.0
equipment
Less
accumulated
depreciation 44.1 38.8
Net
tangible fixed
assets 56.9% 57.6% Total liabilities 76.7% 69.1%
Intangible
assets (goodwill) 3.4% 3.2% Shareholders’ equity:
Other assets 1.4% 1.5%
Common stock and other
paid-in capital 21.3% 21.1%
Retained earnings 67.6 57.2
Total assets 100.0% 100.0% Treasury stock (65.6) (47.4)
Total shareholders’
equity 23.3% 30.9%
Total liabilities and
shareholders’ equity 100.0% 100.0%
Note: Column sums subject to rounding error.
By the way, it is easy to obtain the financial statements of almost any publicly traded firm. Most firms
make their annual reports available on the web. You also can find key financial statements of most firms
at Yahoo! Finance (finance.yahoo.com) or Google Finance (finance.google.com).
Book Values and Market Values
Throughout this book, we will frequently make a distinction between the book values of the assets
shown in the balance sheet and their market values.
Items in the balance sheet are valued according to generally accepted accounting principles, commonly
called GAAP. These state that assets must be shown in the balance sheet at their historical cost adjusted
for depreciation. Book values are therefore “backward-looking” measures of value. They are based on
the past cost of the asset, not its current market price or value to the firm. For example, suppose that 2
years ago Home Depot built an office building for $30 million and that in today’s market the building
would sell for $40 million. The book value of the building would be less than its market value, and the
balance sheet would understate the value of Home Depot’s asset.
Or consider a specialized plant that Intel develops for producing special-purpose computer chips at a
cost of $800 million. The book value of the plant is $800 million less accumulated depreciation. But
suppose that shortly after the plant is constructed, a new chip makes the existing one obsolete. The
market value of Intel’s new plant could fall by 50% or more. In this case, market value would be less than
book value.
The difference between book value and market value is greater for some assets than for others. It is zero
in the case of cash but potentially very large for fixed assets where the accountant starts with initial cost
and then depreciates that figure according to a prespecified schedule. The purpose of depreciation is to
allocate the original cost of the asset over its life, and the rules governing the depreciation of asset
values do not reflect actual loss of market value. Usually the market value of fixed assets is much higher
than the book value, but sometimes it is less.
Page 62
The same goes for the right-hand side of the balance sheet. In the case of liabilities, the accountant
simply records the amount of money that you have promised to pay. For short-term liabilities, this figure
is generally close to the market value of that promise. For example, if you owe the bank $1 million
tomorrow, the accounts show a book liability of $1 million. As long as you are not bankrupt, that $1
million is also roughly the value to the bank of your promise. But now suppose that $1 million is not due
to be repaid for several years. The accounts still show a liability of $1 million, but how much your debt is
worth depends on what happens to interest rates. If interest rates rise after you have issued the debt,
lenders may not be prepared to pay as much as $1 million for your debt; if interest rates fall, they may be
prepared to pay more than $1 million.4 Thus the market value of a long-term liability may be higher or
lower than the book value. Market values of assets and liabilities do not generally equal their book
values. Book values are based on historical or original values. Market values measure current values of
assets and liabilities.
The difference between book value and market value is likely to be greatest for shareholders’ equity. The
book value of equity measures the cash that shareholders have contributed in the past plus the cash that
the company has retained and reinvested in the business on their behalf. But this often bears little
resemblance to the total market value that investors place on the shares.
If the market price of the firm’s shares falls through the floor, don’t try telling the shareholders that the
book value is satisfactory—they won’t want to hear. Shareholders are concerned with the market value
of their shares; market value, not book value, is the price at which they can sell their shares. Managers
who wish to keep their shareholders happy will focus on market values.
We will often find it useful to think about the firm in terms of a market-value balance sheet. Like a
conventional balance sheet, a market-value balance sheet lists the firm’s assets, but it records each asset
at its current market value rather than at historical cost less depreciation. Similarly, each liability is
shown at its market value. The difference between the market values of assets and liabilities is the
market value of the shareholders’ equity claim. The stock price is simply the market value of
shareholders’ equity divided by the number of outstanding shares.
EXAMPLE 3.1 MARKET- VERSUS BOOK-VALUE BALANCE SHEETS
Jupiter has developed a revolutionary auto production process that enables it to produce cars 20% more
efficiently than any rival. It has invested $10 billion in building its new plant. To finance the investment,
Jupiter borrowed $4 billion and raised the remaining funds by selling new shares of stock in the firm.
There are currently 100 million shares of stock outstanding. Investors are very excited about Jupiter’s
prospects. They believe that the flow of profits from the new plant justifies a stock price of $75.
If these are Jupiter’s only assets, the book-value balance sheet immediately after it has made the
investment is as follows:
BOOK-VALUE BALANCE SHEET FOR JUPITER MOTORS
(Figures in $ billions)
Assets
Liabilities and
Shareholders’ Equity
Auto plant 10 Debt 4
Shareholders’ equity 6
Page 63
Investors are placing a market value on Jupiter’s equity of $7.5 billion ($75 per share times 100 million
shares). We assume that the debt outstanding is worth $4 billion.5 Therefore, if you owned all Jupiter’s
shares and all its debt, the value of your holdings would be $7.5 + $4 = $11.5 billion. In this case, you
would own the company lock, stock, and barrel and would be entitled to all its cash flows. Because you
can buy the entire company for $11.5 billion, the total value of Jupiter’s assets must also be $11.5 billion.
In other words, the market value of the assets must be equal to the market value of the liabilities plus
the market value of the shareholders’ equity.
We can now draw up the market-value balance sheet as follows:
MARKET-VALUE BALANCE SHEET FOR JUPITER MOTORS
(Figures in $ billions)
Assets
Liabilities and
Shareholders’ Equity
Auto plant 11.5 Debt 4
Shareholders’ equity 7.5
Notice that the market value of Jupiter’s plant is $1.5 billion more than the plant cost to build. The
difference is due to the superior profits that investors expect the plant to earn. Thus, in contrast to the
balance sheet shown in the company’s books, the market-value balance sheet is forward-looking. It
depends on the profits that investors expect the assets to provide.
Is it surprising that market value generally exceeds book value? It shouldn’t be. Firms find it attractive to
raise money to invest in various projects because they believe the projects will be worth more than they
cost. Otherwise, why bother? You will usually find that shares of stock sell for more than the value
shown in the company’s books.
3.2 SELF-TEST
a. What would be Jupiter’s price per share if the auto plant had a market value of $14 billion?
b. How would you reassess the value of the auto plant if the value of outstanding stock was $8
billion?
3.2 The Income Statement
If Home Depot’s balance sheet resembles a snapshot of the firm at a particular time, its income
statement is like a video. It shows how profitable the firm has been during the past year.
Look at the summary income statement in Table 3.3. You can see that during fiscal 2014, Home Depot
sold goods worth $83,176 million and that the total cost of acquiring and selling those goods was
$54,222 + $16,699 = $70,921 million. The largest expense item, amounting to $54,222 million, consisted
of the cost of goods sold. This included the acquisition cost of Home Depot's goods, the wages of its
employees, and the other expenses incurred to obtain and sell its wares. Almost all the remaining
expenses were administrative expenses such as head office costs, advertising, and distribution.
Page 64
Table 3.3 Home Depot’s income statement, fiscal 2014
$ Million % of Sales
Net sales $ 83,176 100.0%
Other income 337 0.4
Cost of goods sold 54,222 65.2
Selling, general, and administrative expenses 16,699 20.1
Depreciation _ 1,786 _2.1
Earnings before interest and income taxes (EBIT) $ 10,806 13.0%
Interest expense __ 830 _1.0
Taxable income $ 9,976 12.0%
Taxes _ 3,631 _4.4
Net income $ 6,345 7.6%
Allocation of net income
Dividends $2,530 3.0%
Addition to retained earnings $3,815 4.6%
Source: Derived from Home Depot annual reports.
In addition to these out-of-pocket expenses, Home Depot also made a deduction for the value of the
plant and equipment used up in producing the goods. In 2014, this charge for depreciation was $1,786
million. Thus Home Depot’s earnings before interest and taxes (EBIT) were
EBIT=total
revenues+other income−costs−depreciation=83,176+337−(54,222+16,699)−1,786=$10,806 millionEBIT=t
otal revenues+other income-costs−depreciation=83,176+337−(54,222+16,699)−1,786=$10,806 million
The remainder of the income statement shows where these earnings went. As we saw earlier, Home
Depot has partly financed its investment in plant and equipment by borrowing. In 2014, it paid $830
million of interest on this borrowing. A further slice of the profit went to the government in the form of
taxes. This amounted to $3,631 million. The $6,345 million that was left over after paying interest and
taxes belonged to the shareholders. Of this sum, Home Depot paid out $2,530 million in dividends and
reinvested the remaining $3,815 million in the business. Presumably, these reinvested funds made the
company more valuable.
The $3,815 of earnings that Home Depot retained and reinvested in the firm show up on its balance
sheet as an increase in retained earnings. Notice that retained earnings inTable 3.1 increased by $3,815
million in 2014, from $23,180 million to $26,995 million. However, shareholders’ equity fell during the
year because Home Depot also repurchased some of its stock.
Just as it is sometimes useful to prepare a common-size balance sheet, we can also prepare a common-
size income statement. In this case, all items are expressed as a percentage of revenues. The last column
of Table 3.3 is Home Depot’s common-size income statement. You can see, for example, that the cost of
goods sold consumed 65.2% of revenues and that selling, general, and administrative expenses absorbed
a further 20.1%.
Income versus Cash Flow
It is important to distinguish between Home Depot’s income and the cash that the company generated.
Here are two reasons that income and cash are not the same:
1. Depreciation. When Home Depot’s accountants prepare the income statement, they do not
simply count the cash coming in and the cash going out. Instead, the accountant starts with the
cash payments but then divides these payments into two groups—current Page 65expenditures
(such as wages) and capital expenditures (such as the purchase of new machinery). Current
expenditures are deducted from current profits. However, rather than deducting the cost of
long-lived machinery in the year it is purchased, the accountant spreads its acquisition cost over
its forecasted life by making an annual charge for depreciation.
Thus, when calculating profits, the accountant does not deduct the expenditure on new equipment that
year, even though cash is paid out. However, the accountant doesdeduct depreciation on assets
previously purchased, even though no cash is currently paid out. For example, suppose a $100,000
investment is depreciated by $10,000 a year for 10 years.6 This depreciation is treated as an annual
expense, although the cash actually went out of the door when the asset was first purchased. For this
reason, the deduction for depreciation is classified as a noncash expense.
To calculate the cash produced by the business, it is necessary to add the depreciation charge (which is
not a cash payment) back to accounting profits and tosubtract the expenditure on new capital
equipment (which is a cash payment).
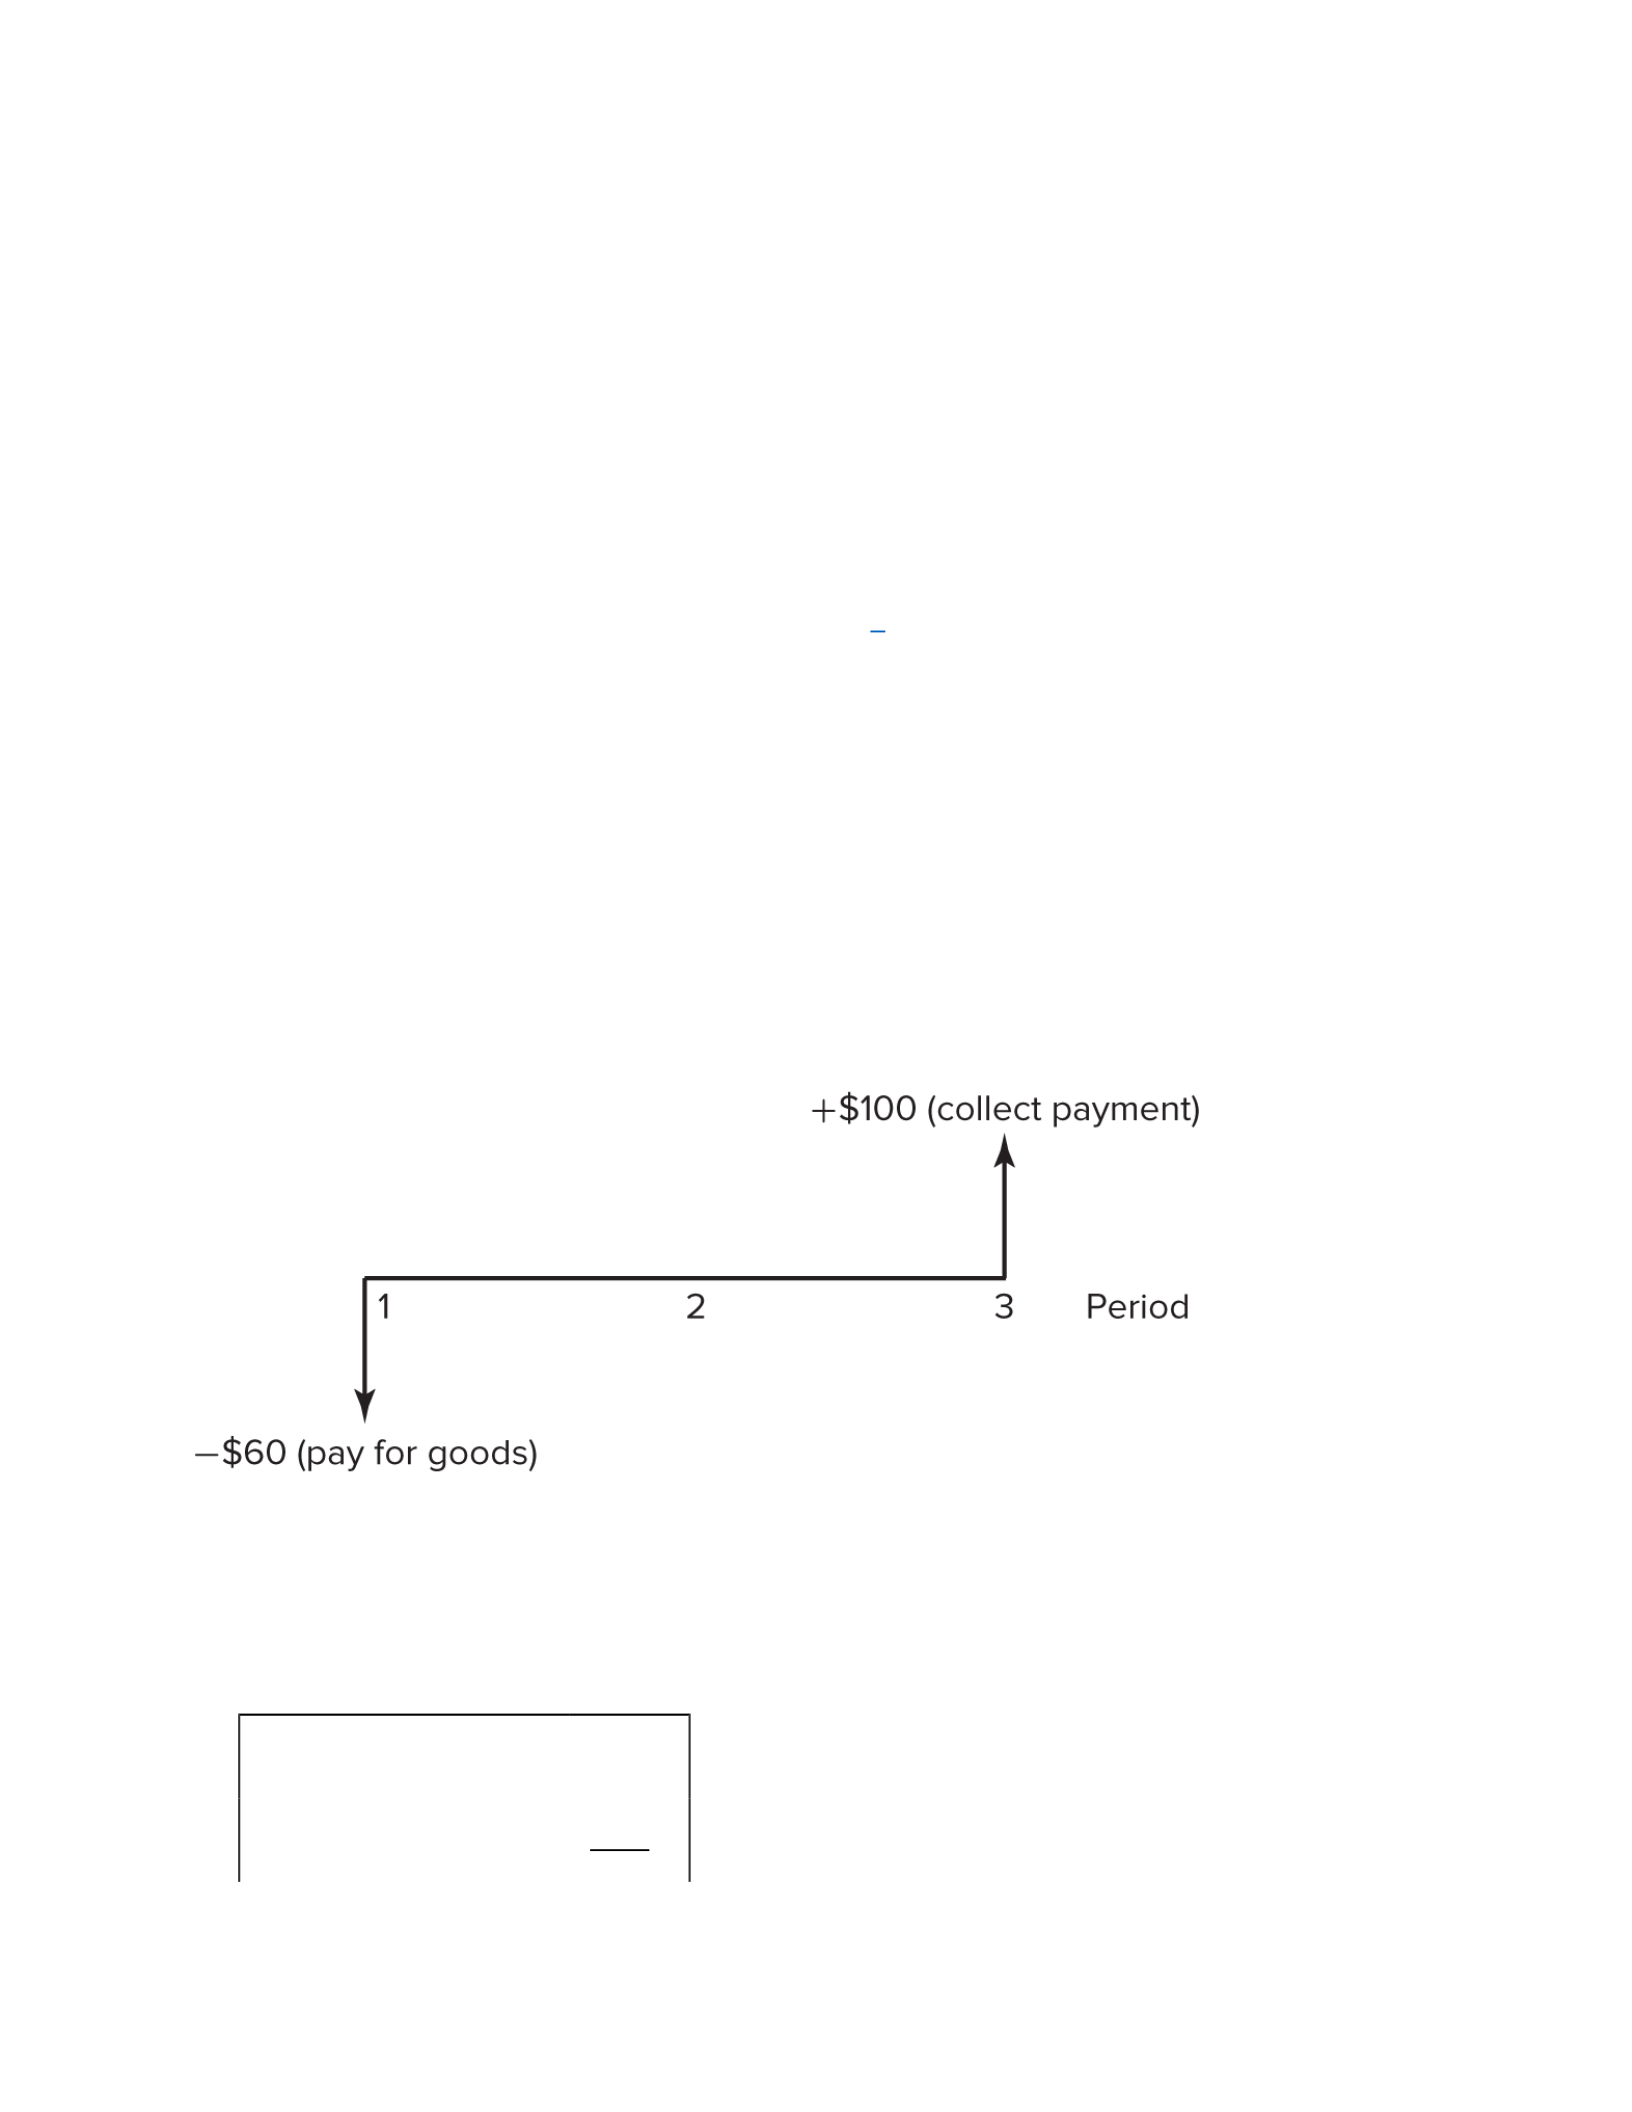
2. Cash versus accrual accounting. Consider a manufacturer that spends $60 to produce goods in
period 1. In period 2 it sells these goods for $100, but its customers pay their bills with a delay,
so payment is not received until period 3. The following diagram shows the firm’s cash flows. In
period 1 there is a cash outflow of $60. Then, when customers pay their bills in period 3, there is
an inflow of $100.
It would be misleading to say that the firm was running at a loss in period 1 (when cash flow was
negative) or that it was extremely profitable in period 3 (when cash flow was positive). Therefore, to
construct the income statement, the accountant looks at when the sale was made (period 2 in our
example) and gathers together all the revenues and expenses associated with that sale. For our
company, the income statement would show:
Revenue $100
Less cost of goods sold 60
Profit $ 40
This practice of matching revenues and expenses is known as accrual accounting. Of course, the
accountant does not ignore the actual timing of the cash expenditures and payments. So the cash outlay
in the first period will be treated not as an expense but as an investment in inventories. Subsequently, in
period 2, when the goods are taken out of inventory and sold, the accountant shows a reduction in
inventories.
To go from the cost of goods sold in the income statement to the cash outflows, we need to subtract the
investment in inventories that is shown in the balance sheet:
Period: 1 2
Cost of goods sold (income statement) 0 60
+ Investment in inventories (balance sheet) 60 –60
= Cash paid out 60 0
Page 66
The accountant also does not ignore the fact that the firm has to wait until period 3 to collect its bills.
When the sale is made in period 2, the figure for accounts receivable in the balance sheet is increased to
show that the company’s customers owe an extra $100 in unpaid bills. Later, when the customers pay
those bills in period 3, accounts receivable are reduced by $100. Therefore, to go from the sales shown
in the income statement to the cash inflows, we need to subtract the investment in receivables:
Period: 2 3
Sales (income statement) 100 0
−Investment in receivables (balance sheet) 100 –100
= Cash received 0 +100
We will return to these issues in more detail in Chapter 9, but for now we summarize the key points as
follows: Cash outflow is equal to the cost of goods sold, which is shown in the income
statement, plus the change in inventories. Cash inflow is equal to the sales shown in the income
statement less the change in uncollected bills.
EXAMPLE 3.2 PROFITS VERSUS CASH FLOWS
Suppose our manufacturer spends a further $80 to produce goods in period 2. It sells these goods in
period 3 for $120, but customers do not pay their bills until period 4.
The cash flows from these transactions are now as follows:
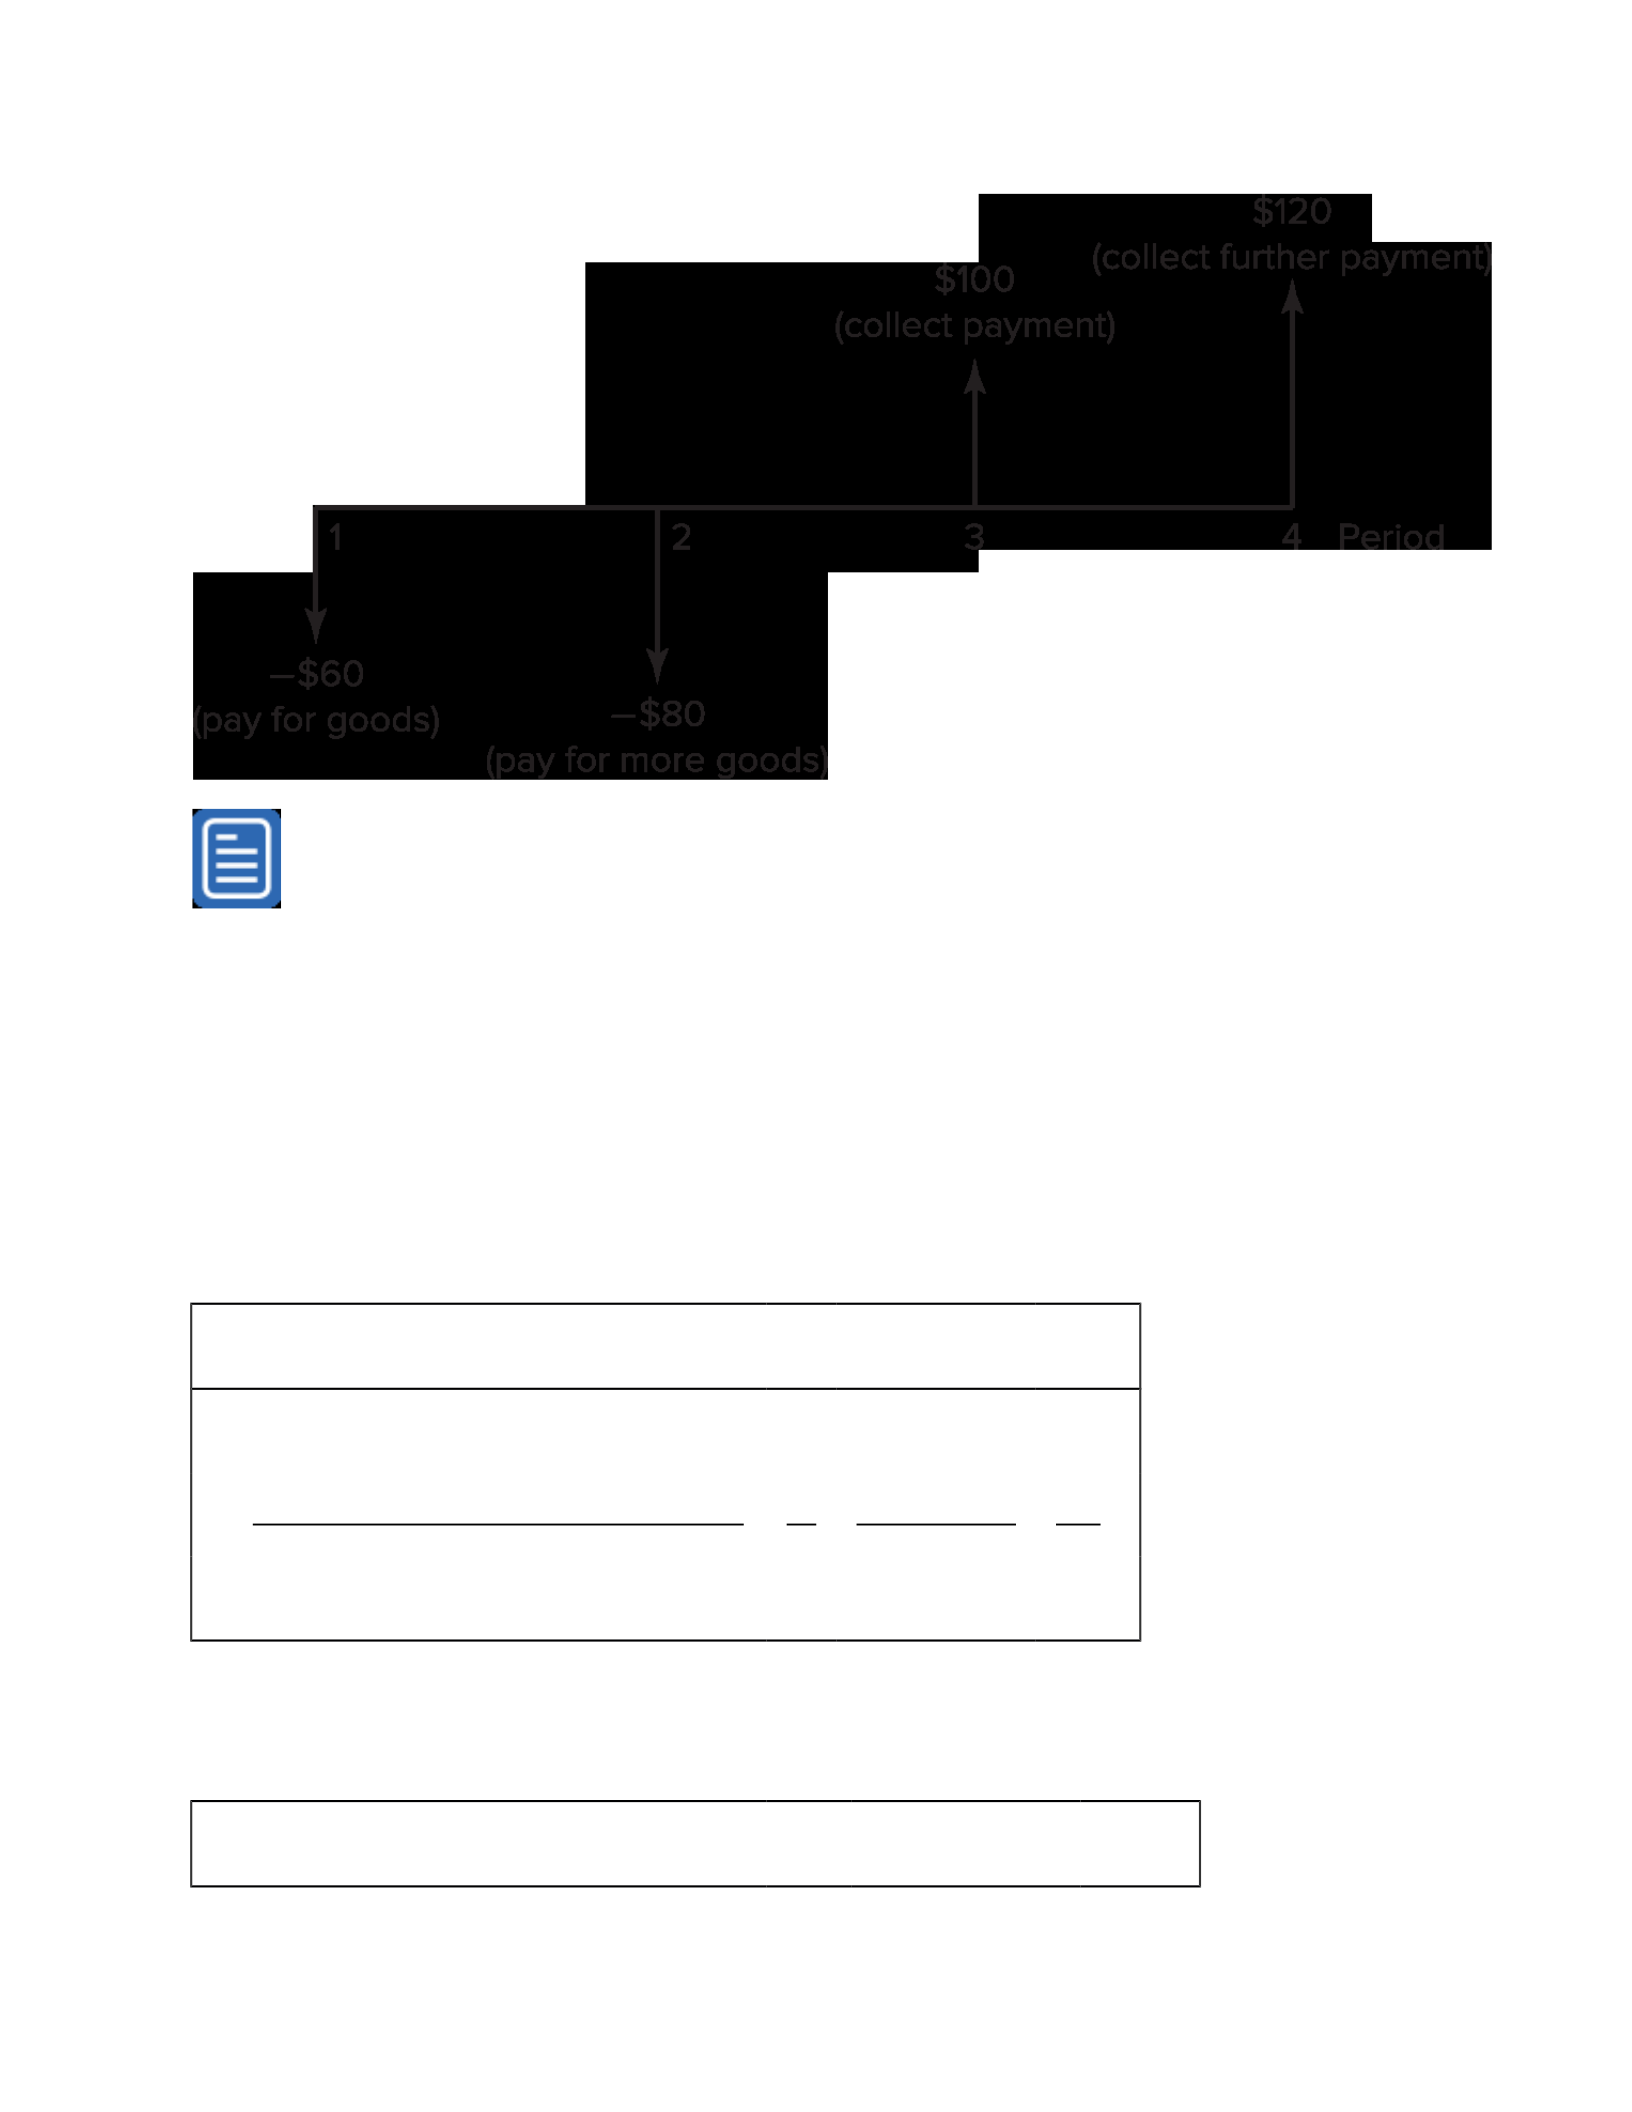
How do the new transactions affect the income statement and the balance sheet? The income statement
will match costs with revenues and record the cost of goods sold when the sales are made in periods 1
and 2. The difference between the costs shown in the income statement and the cash flows is recorded
as an investment (and later, disinvestment) in inventories. Thus, in period 1 the accountant shows an
investment in inventories of $60 just as before. In period 2, these goods are taken out of inventory and
sold, but the firm also produces a further $80 of goods. Thus, there is a net increase in inventories of
$20. As these goods in turn are sold in period 3, inventories are reduced by $80. The following table
confirms that the cash outflow in each period is equal to the cost of goods sold that is shown in the
income statement plus the change in inventories.
Period: 1 2 3
Cost of goods sold (income statement) 0 60 80
+ Investment in inventories (balance sheet) 60 −60 + 80 = 20 −80
= Cash paid out 60 80 0
Page 67
The following table provides a similar reconciliation of the difference between the revenues shown in
the income statement and the cash inflow:
Period: 2 3 4
Sales (income statement) 100 120 0
− Investment in receivables (balance sheet) 100 −100 + 120 = 20 −120
= Cash received 0 +100 +120
In the income statement the accountant records sales of $100 in period 1 and $120 in period 2. The fact
that the firm has to wait for payment is recognized in the balance sheet as an investment in receivables.
The cash that the company receives is equal to the sales shown in the income statement less the
investment in receivables.
3.3 SELF-TEST
Consider a firm that spends $200 to produce goods in period 1. In period 2, it sells half of those goods
for $150, but it doesn't collect payment until one period later. In period 3, it sells the other half of the
goods for $150, and it collects payment on these sales in period 4. Calculate the profits and the cash
flows for this firm in periods 1 to 4.
3.3 The Statement of Cash Flows
The firm requires cash when it buys new plant and machinery or when it pays interest to the bank and
dividends to the shareholders. Therefore, the financial manager needs to keep track of the cash that is
coming in and going out.
We have seen that the firm’s cash flow can be quite different from its net income. These differences can
arise for at least two reasons:
1. The income statement does not recognize capital expenditures as expenses in the year that the
capital goods are paid for. Instead, it spreads those expenses over time in the form of an annual
deduction for depreciation.
2. The income statement uses the accrual method of accounting, which means that revenues and
expenses are recognized when sales are made, rather than when the cash is received or paid
out.
The statement of cash flows shows the firm’s cash inflows and outflows from operations as well as from
its investments and financing activities. Table 3.4 is the cash-flow statement for Home Depot. It contains
three sections. The first shows the cash flow from operations. This is the cash generated from Home
Depot’s normal business activities. Next comes the cash that Home Depot has invested in plant and
equipment or in the acquisition of new businesses. The final section reports cash flows from financing
activities such as the sale of new debt or stock. We will look at each of these sections in turn.
Page 68
Table 3.4 Home Depot’s statement of cash flows (figures in $ millions)
Cash Provided by Operations
Net income $6,345
Depreciation 1,786
Changes in working capital items
Decrease (increase) in accounts receivable −86
Decrease (increase) in inventories −22
Decrease (increase) in other current assets −121
Increase (decrease) in accounts payable 94
Increase (decrease) in other current liabilities 131
Total decrease (increase) in working capital −$ 4
Cash provided by operations $8,127
Cash Flows from Investments
Cash provided by (used for) disposal of (additions to) property, plant, and equipment −$1,289
Sales (acquisitions) of other long-term assets __ 31
Cash provided by (used for) investments −$1,258
Cash Provided by (Used for) Financing Activities
Increase (decrease) in short-term debt $ 295
Increase (decrease) in long-term debt 2,178
Dividends −2,530
Repurchases of stock −7,000
Other _ −18
Cash provided by (used for) financing activities −$7,075
Net increase (decrease) in cash and cash equivalents −$ 206
Source: Calculated from data in Tables 3.1 and 3.3.
The first section, cash flow from operations, starts with net income but adjusts that figure for those parts
of the income statement that do not involve cash coming in or going out. Therefore, it adds back the
allowance for depreciation because depreciation is not a cash outflow, even though it is treated as an
expense in the income statement.
Any additions to current assets (other than cash itself) need to be subtracted from net income because
these absorb cash but do not show up in the income statement. Conversely, any additions to current
liabilities need to be added to net income because these release cash. For example, you can see that the
increase of $86 million in accounts receivable is deducted from income. In addition, Home Depot
increased inventories by $22 million. This increase in inventory levels also absorbed cash and must be
deducted from net income when calculating cash flows. On the other hand, Home Depot does not pay all
its bills immediately. These delayed payments show up as payables. In 2014, Home Depot had larger bills
outstanding than a year earlier: Accounts payable increased by $94 million. Delaying these payments
freed up extra cash.
We have pointed out that depreciation is not a cash payment; it is simply the accountant’s allocation to
the current year of the original cost of the capital equipment. However, cash does flow out the door
when the firm actually buys and pays for new capital equipment. Therefore, these capital expenditures
are set out in the second section of the cash-flow statement. You can see that Home Depot spent $1,289
million on new capital equipment. Notice that (gross) property, plant, and equipment on Home Depot’s
balance sheet increased by precisely this amount. On the other hand, Home Depot freed up $31 million
by selling off other investments. Total cash used by investments was $1,258 million.
Finally, the third section of the cash-flow statement shows the cash from financing activities. For
example, Home Depot raised $2,178 million by issuing long-term debt. But it paid out $2,530 million to
stockholders in the form of dividends and used another $7,000 million to repurchase stock.7
To summarize, the cash-flow statement tells us that Home Depot generated $8,127 million from
operations, spent $1,258 million on new investments, and used $7,075 million in financing activities.
Home Depot earned and raised less cash than it spent. Page 69Therefore, its cash balance decreased by
$206 million. To calculate this change in cash balance, we subtract the uses of cash from the sources:
In Millions
Cash flow from operations $8,127
− Cash flow for new investment −1,258
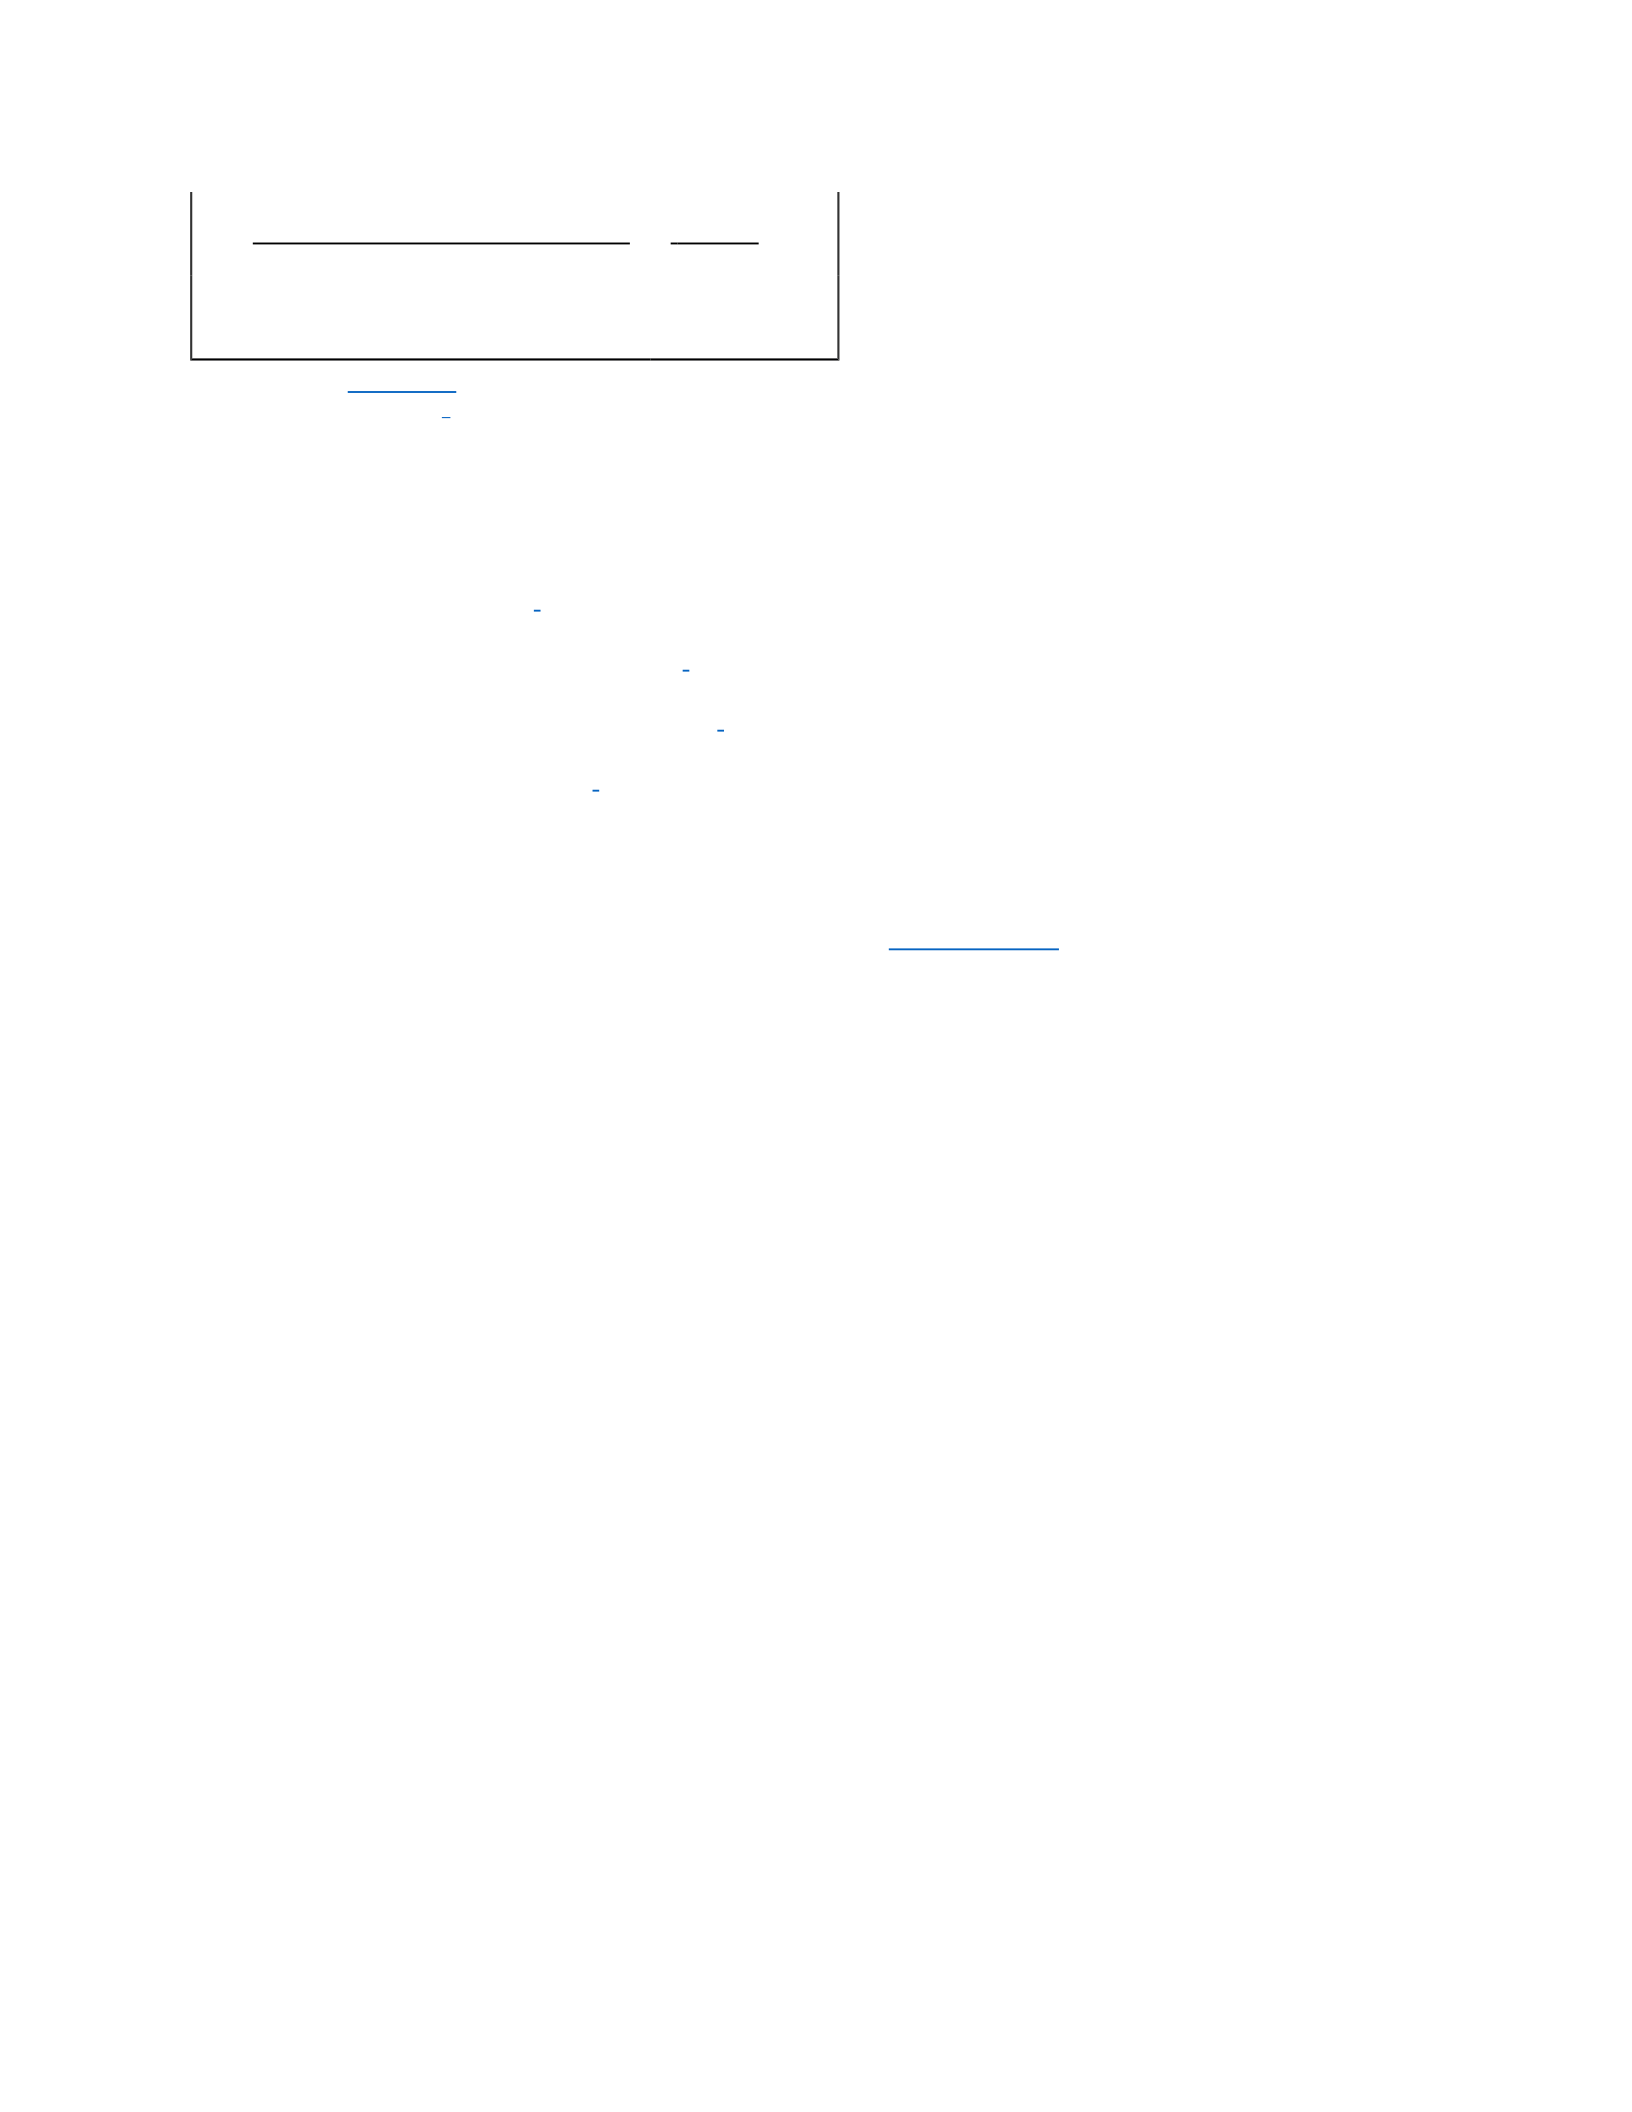
+ Cash provided by new financing −7,075
= Change in cash balance −$206
Look back at Table 3.1 and you will see that cash accounts on the balance sheet did indeed decrease by
$206 million in 2014.8
3.4 SELF-TEST
1. Would the following activities increase or decrease the firm’s cash balance?
a. Inventories are increased.
b. The firm reduces its accounts payable.
c. The firm issues additional common stock.
d. The firm buys new equipment.
Free Cash Flow
The value of a company depends on how much cash it can generate for investors after it has paid for any
new capital investments. This cash is called the company’s free cash flow. Free cash flow is available to
be paid out to investors as interest or dividends or to repay debt or buy back stock.
EXAMPLE 3.3 FREE CASH FLOW FOR HOME DEPOT
Let’s use Home Depot’s income and cash-flow statements to calculate its free cash flow in 2014. We start
with the earnings produced by the firm’s ongoing operations. This is equal to
Net income + debt interest = $6,345 + $830 = $7,175 millionNet income + debt interest = $6,345 + $830
= $7,175 million
We need to make two adjustments to this figure for those parts of the income statement that do not
involve cash coming in or going out. First, we must add back depreciation because depreciation is not a
cash outflow, even though it is treated as an expense in the income statement. Second, accounting
income is not cash in the bank. For example, the firm may need to lay out money to buy materials ahead
of time, or its customers may not pay for their purchases immediately. Therefore, to measure the cash
from ongoing operations, we need to subtract those additions to net working capital shown in the top
panel of the statement of cash flows. This gives us cash flow from operations:
Cash flow from operations =(net income + interest) + depreciation – additions to net working capital= $7,
175 + $1,786 – $4 = $8,957 millionCash flow from operations =(net income + interest) + depreciation – a
dditions to net working capital= $7,175 + $1,786 – $4 = $8,957 million
Page 70
This cash is not all available to be paid out to investors, for the company needs some of the cash for new
capital expenditures. So the capital that is free for distribution is
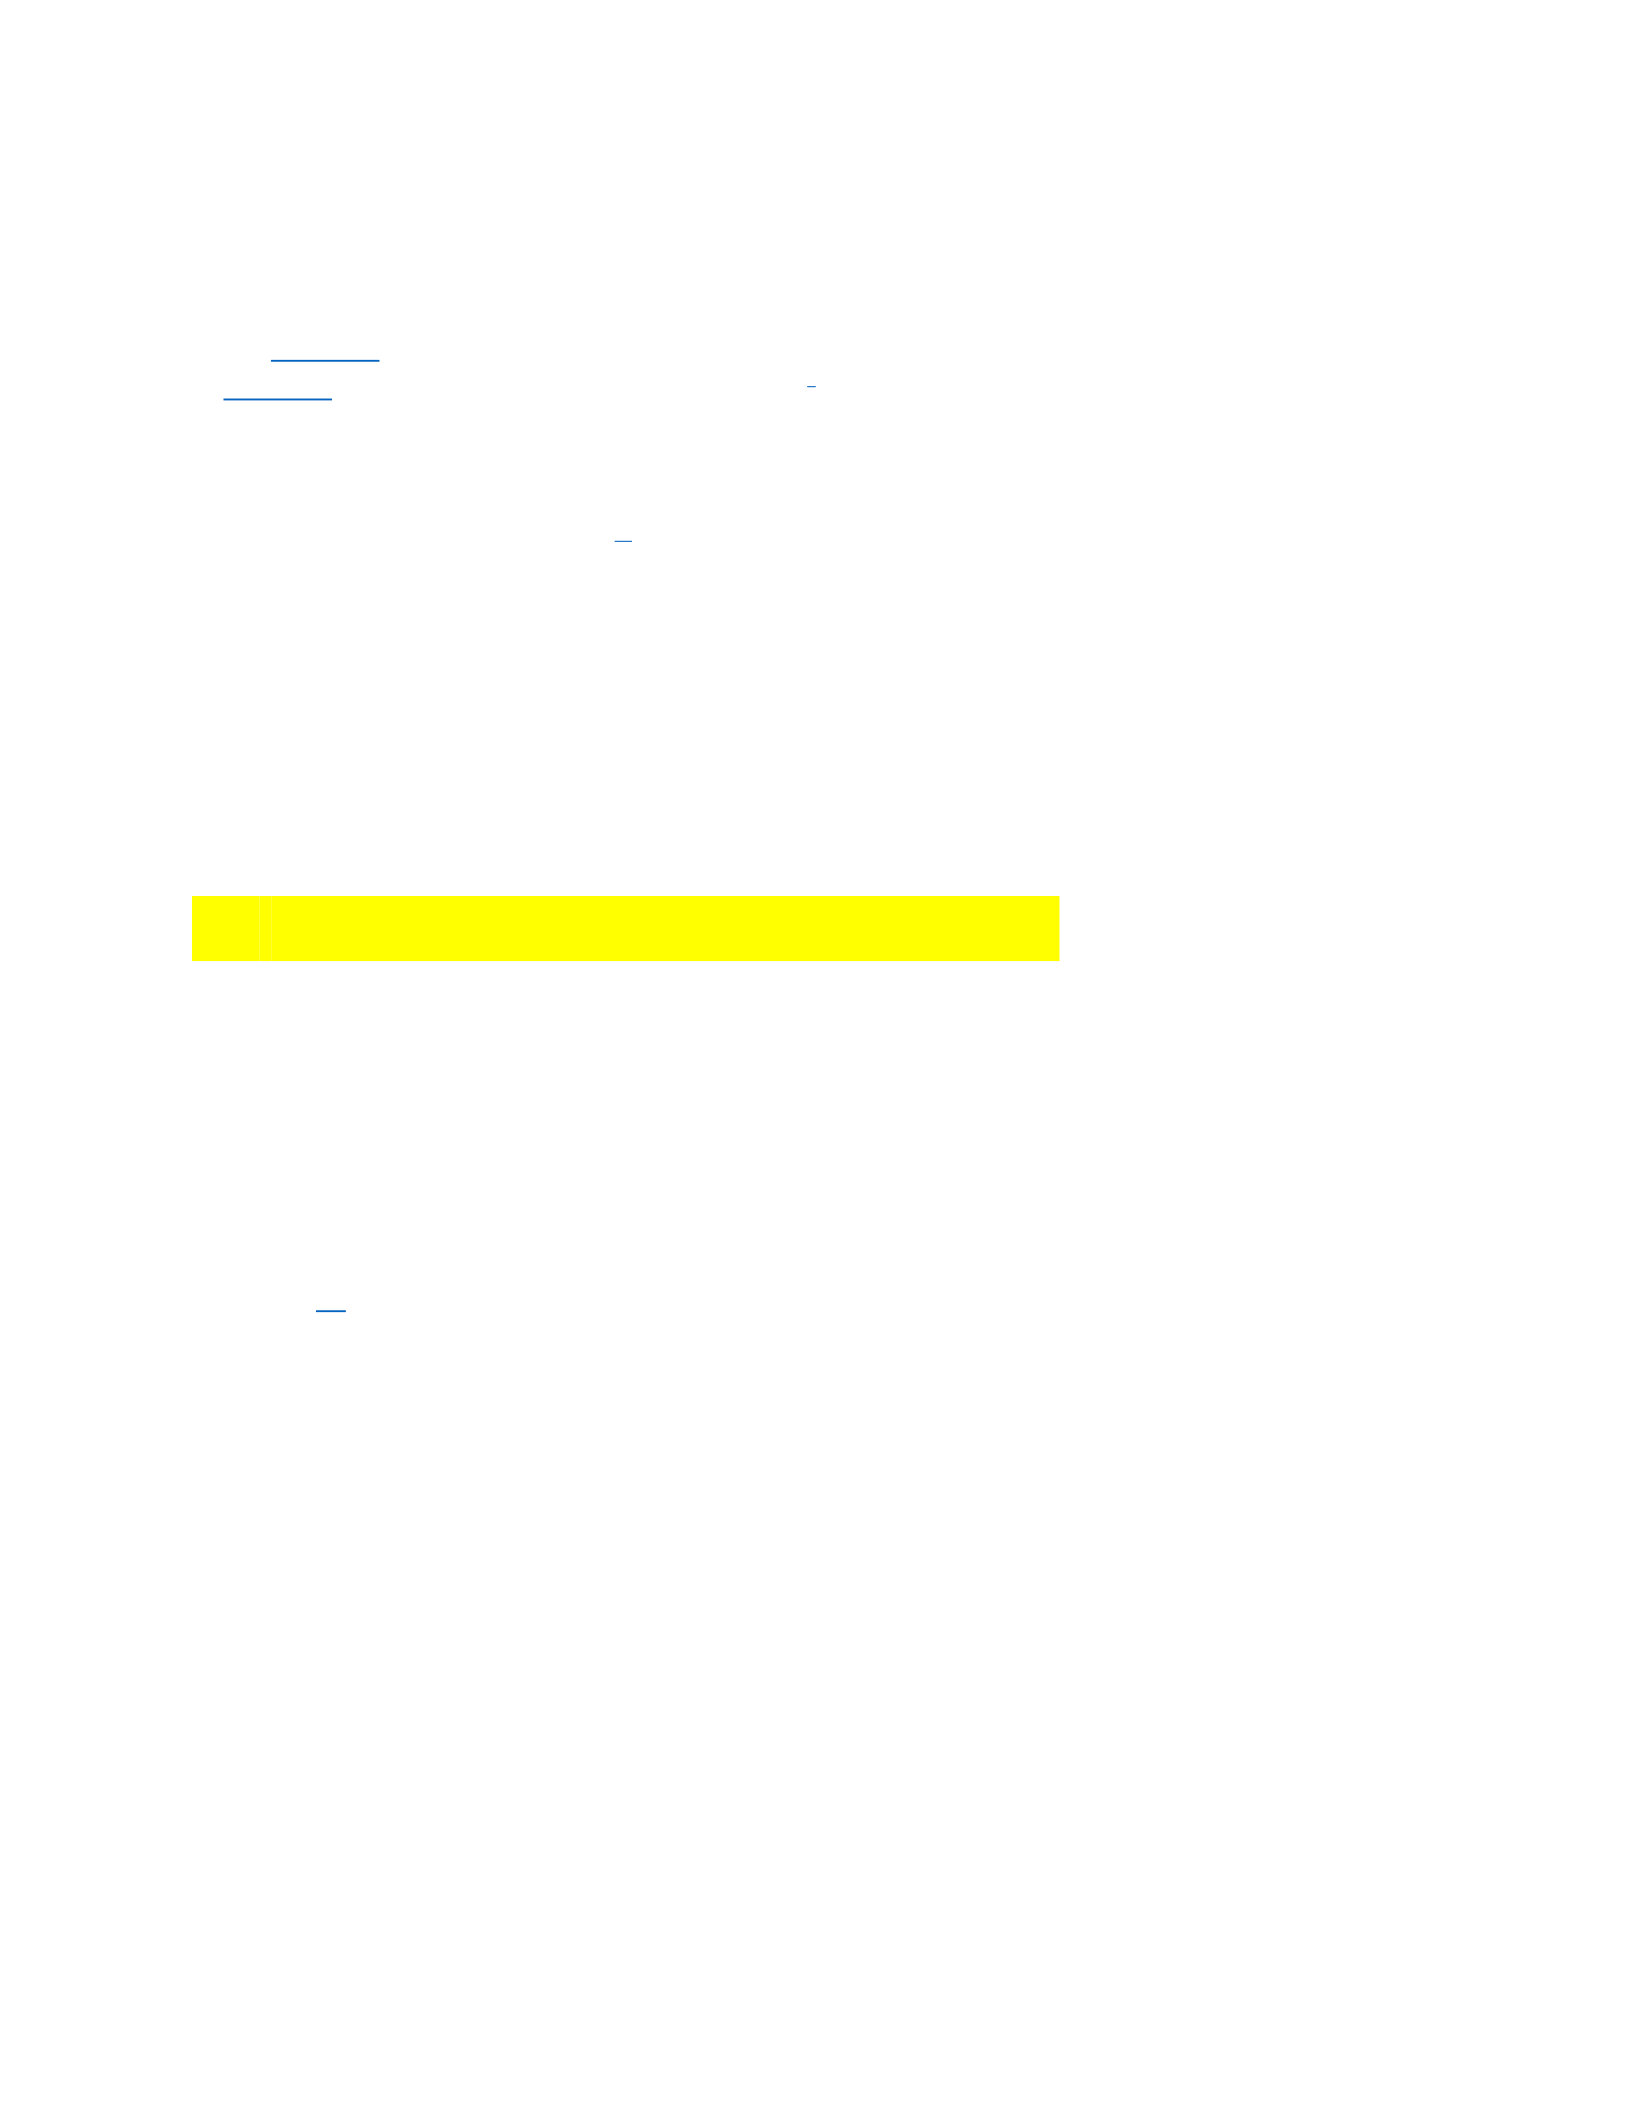
Free cash flow =cash flow from operations – capital expenditures= $8,957 – $1,258 = $7,699 millionFree
cash flow =cash flow from operations – capital expenditures= $8,957 – $1,258 = $7,699 million
Notice that free cash flow differs from the addition-to-cash balances found in the statement of cash
flows (Table 3.4). First, when we calculate free cash flow, we ignore altogether items in the last panel
of Table 3.4, “Cash provided by financing activities.”9 This is because free cash flow measures how much
cash the company’s operations generate for possible distribution to investors. The available amount
should not be confused with the amount that the company actually raised by financing activities.
Second, we add back interest payments when computing free cash flow, as those payments are part of
the distributions made to investors.10
It is often useful to ask what Home Depot’s free cash flow would have been if the company had been
financed entirely by equity. In that case, all the free cash flow would belong to the shareholders.
However, if Home Depot no longer paid out $830 million as interest, pretax income would be increased
by that amount, and the company would pay an additional .35 × 830 = $290.50 million in tax. Thus, if the
company was financed solely by equity, free cash flow would have been $7,699 − $290.50 = $7,408.50
million.
3.4 Accounting Practice and Malpractice
Managers of public companies face constant scrutiny. Much of that scrutiny focuses on earnings.
Security analysts forecast earnings per share, and investors then wait to see whether the company can
meet or beat the forecasts. A shortfall, even if it is only a cent or two, can be a big disappointment.
Investors might judge that if you could not find that extra cent or two of earnings, the firm must be in a
really bad way.
Managers complain about this pressure, but do they do anything about it? Unfortunately, the answer
appears to be yes, according to Graham, Harvey, and Rajgopal, who surveyed about 400 senior
managers.11 Most of the managers said that accounting earnings were the single most important
number reported to investors. Most admitted to adjusting their firms’ operations and investments to
produce the earnings that investors were looking for. For example, 80% were prepared to decrease
discretionary spending on R&D, advertising, or plant maintenance to meet earnings targets.
Of course, managers may not need to adjust the firm’s operations if they can instead adjust their
accounting methods. U.S. accounting rules are spelled out by the Financial Accounting Standards Board
(FASB) and its generally accepted accounting principles (GAAP). Yet, inevitably, rules and principles leave
room for discretion, and managers under pressure to perform are tempted to take advantage of this
leeway to satisfy Page 71investors. Investors worry about the fact that some companies seem
particularly prone to inflate their earnings by playing fast and loose with accounting practice. They refer
to such companies as having “low-quality” earnings, and they place a correspondingly lower value on the
firms’ stock.
Here are some examples of ambiguities in accounting rules that have been used by companies to conceal
unflattering information:
Revenue recognition. As we saw earlier, firms record a sale when it is made, not when the
customer actually pays. But the date of sale is not always obvious. Suppose it is November and
you are concerned that if your firm does not meet its sales target, you can forget about your
annual bonus. You contact your main customers, and they agree to increase their December
orders as long as they have the right to return any unsold goods. Your firm then books these
shipments as “sales,” even though there is a high likelihood that many of the goods will be
returned. That is almost certainly illegal and will get you into serious trouble. But suppose
instead that you tell your customers that the price of your product may rise in the new year and
suggest that they place an extra order in December. This practice, known as “channel stuffing,”
increases this year’s sales at the expense of next year’s sales.
Many companies have been thought to use channel stuffing to overstate their earnings, but very blatant
instances are liable to attract the SEC’s attention. For example, in 2002 the pharmaceutical giant, Bristol
Myers Squibb, disclosed that wholesalers were holding hundreds of millions of dollars in excessive
inventories of its products and the company’s earnings for 2002 might be just half of its 2001 earnings as
wholesalers worked down these inventories. Following an investigation by the SEC, the company agreed
to pay $150 million to settle accusations that this channel stuffing had improperly inflated its sales and
earnings. In Chapter 1, we mentioned Hewlett-Packard’s disastrous acquisition of the British company
Autonomy. Hewlett-Packard paid $11.1 billion for Autonomy. Just over a year later, it wrote down the
value of the company by $8.8 billion, alleging that Autonomy had used channel stuffing to greatly inflate
its revenues.
Cookie-jar reserves. The giant mortgage-pass-through firm Freddie Mac earned the Wall Street
nickname “Steady Freddie” for its unusually smooth and predictable pattern of earnings growth,
at least until 2008 when it suddenly collapsed in the wake of the meltdown in subprime
mortgages. Unfortunately, it emerged in 2003 that Freddie achieved this predictability in part by
misusing its reserve accounts. Normally, such accounts are intended to allow for the likely
impact of events that might reduce earnings, such as the failure of customers to pay their bills.
But Freddie seemed to “overreserve” against such contingencies so that it could “release” those
reserves and bolster income in a bad year. Its steady growth was largely a matter of earnings
management.
Off–balance sheet assets and liabilities. Before its bankruptcy in 2001 (at that time, the second
largest in U.S. history), Enron had accumulated large debts and had also guaranteed the debts of
other companies in which it had an ownership stake. To present a fair view of the firm, Enron
should have recognized these potential liabilities on its balance sheet. But the firm created and
placed paper firms—so-called special-purpose entities (SPEs)—in the middle of its transactions
and excluded these liabilities from its financial statements.
The collapse of Enron illustrates how dishonest managers with creamy compensation packages may be
tempted to conceal the truth from investors. If the company had been more transparent to outsiders—
that is, if they could have assessed its true profitability and prospects—its problems would have shown
up right away in a falling stock price. This in turn would have generated extra scrutiny from security
analysts, bond rating agencies, lenders, and investors.
Page 72

With transparency, corporate troubles generally lead to corrective action. But the top management of a
troubled and opaque company may be able to maintain its stock price and postpone the discipline of the
market. Market discipline caught up with Enron only a month or two before bankruptcy.
Enron was not the only company to be mired in accounting scandals in the early years of the century.
Firms such as Global Crossing, Qwest Communications, and WorldCom misstated profits by billions of
dollars. Overseas, the Italian dairy company Parmalat falsified the existence of a bank account to the
tune of $5.5 billion, and the French media and entertainment company Vivendi came close to
bankruptcy after it was accused of accounting fraud. In response to these scandals, Congress passed the
Sarbanes-Oxley Act, widely known as SOX. A major goal of SOX is to increase transparency and ensure
that companies and their accountants provide directors, lenders, and shareholders with the information
they need to monitor progress.
SOX created the Public Accounting Oversight Board to oversee the auditing of public companies; it
banned accounting firms from offering other services to companies whose accounts they audit; it
prohibited any individual from heading a firm’s audit for more than 5 years; and it required that the
board’s audit committee consist of directors who are independent of the company’s management.
Sarbanes-Oxley also required that management certify that the financial statements present a fair view
of the firm’s financial position and demonstrate that the firm has adequate controls and procedures for
financial reporting. All this has come at a price. Managers and investors worry that the costs of SOX and
the burden of meeting detailed, inflexible regulations are pushing some corporations to return from
public to private ownership. Some blame SOX and onerous regulation in the United States for the fact
that an increasing number of foreign companies have chosen to list their shares in London rather than
New York.
There is also a vigorous debate over “rules-based” versus “principles-based” approaches to accounting
standards. The United States follows a rules-based approach, Page 73with detailed rules governing
virtually every circumstance that possibly can be anticipated. In contrast, the European Union takes a
principles-based approach to accounting. Its International Financial Reporting Standards set out general
approaches that financial statements should take to valuing assets. Europe and the United States have
been engaged for years in attempts to coordinate their systems, and many in the United States have
lobbied for the greater simplicity that principles-based accounting standards might offer. The nearby box
reports on these efforts.
FINANCE IN PRACTICE THE RISE AND STALL OF CONVERGENCE IN ACCOUNTING STANDARDS
The International Financial Reporting Standards (IFRS), which are set by the London-based International
Accounting Standards Board (IASB), aim to harmonize financial reporting around the world. They are the
basis for reporting throughout the European Union. In addition, some 100 other countries, such as
Australia, Canada, Brazil, India, and China, have adopted them or plan to do so.
For some years, the SEC has worked to bring U.S. accounting standards more in line with international
rules. For example, until 2007 foreign companies that traded on U.S. stock exchanges were required to
show how their accounts differed from U.S. GAAP. This was a very expensive exercise that cost some
companies millions of dollars annually and caused many to delist their stocks. These companies can now
simply report results using international accounting standards. Subsequently, in August 2008, the SEC
released its plans to allow some large U.S. multinationals, representing approximately $2.5 trillion in
market capitalization, to eventually use IFRS for financial statements.
BEYOND THE PAGE
Accounting acronyms
mhhe.com/brealey9e
This shift from GAAP to IFRS would involve a major change in the way that accountants in the United
States approach their task. IFRS tend to be “principles-based,” which means that there are no hard-and-
fast codes to follow. Instead, companies must be ready to defend their accounting practices in light of
the general principles laid out in the IFRS. By contrast, in the United States, GAAP are accompanied by
thousands of pages of prescriptive regulatory guidance and interpretations from auditors and accounting
groups. For example, more than 160 pieces of authoritative literature relate to how and when companies
record revenue. This leaves less room for judgment, but detailed rules rapidly become out of date, and
unscrupulous companies have been able to structure transactions so that they keep to the letter but not
the spirit of the rules.
By 2014, it had become clear that the SEC’s plan to move to IFRS was effectively dead and that, while the
SEC and IASB would continue to collaborate on accounting rules, there was little prospect of any
agreement over a single global standard that included the United States.
3.5 Taxes
Taxes often have a major effect on financial decisions. Therefore, we should explain how corporations
and investors are taxed.
Corporate Tax
Companies pay tax on their income. Table 3.5 shows that there are special low rates of corporate tax for
small companies, but for large companies (those with income over $18.33 million) the corporate tax rate
is 35%.12 Thus for every $100 that the firm earns it pays $35 in corporate tax.
Table 3.5 Corporate tax rates, 2016
Taxable Income ($) Tax Rate (%)
0–50,000 15
50,001–75,000 25
75,001–100,000 34
100,001–18,333,333 Varies between 39 and 34
Over 18,333,333 35
When firms calculate taxable income, they are allowed to deduct expenses. These expenses include an
allowance for depreciation. However, the Internal Revenue Service (IRS) specifies the rates of
depreciation that the company can use for different types of equipment. The rates of depreciation used
to calculate taxes are not the same as the rates used when the firm reports its profits to shareholders.13
The company is also allowed to deduct interest paid to debtholders when calculating its taxable income,
but dividends paid to shareholders are not deductible. These dividends are therefore paid out of after-
tax income. Table 3.6 provides an example of how interest payments reduce corporate taxes. Although
EBIT for both firms A and B Page 74is $100 million, firm A, which has $40 million of interest expense, has
lower pretax income and therefore pays less taxes.
Table 3.6 Firms A and B both have earnings before interest and taxes (EBIT) of $100 million, but A pays
out part of its profits as debt interest. This reduces the corporate tax paid by A.
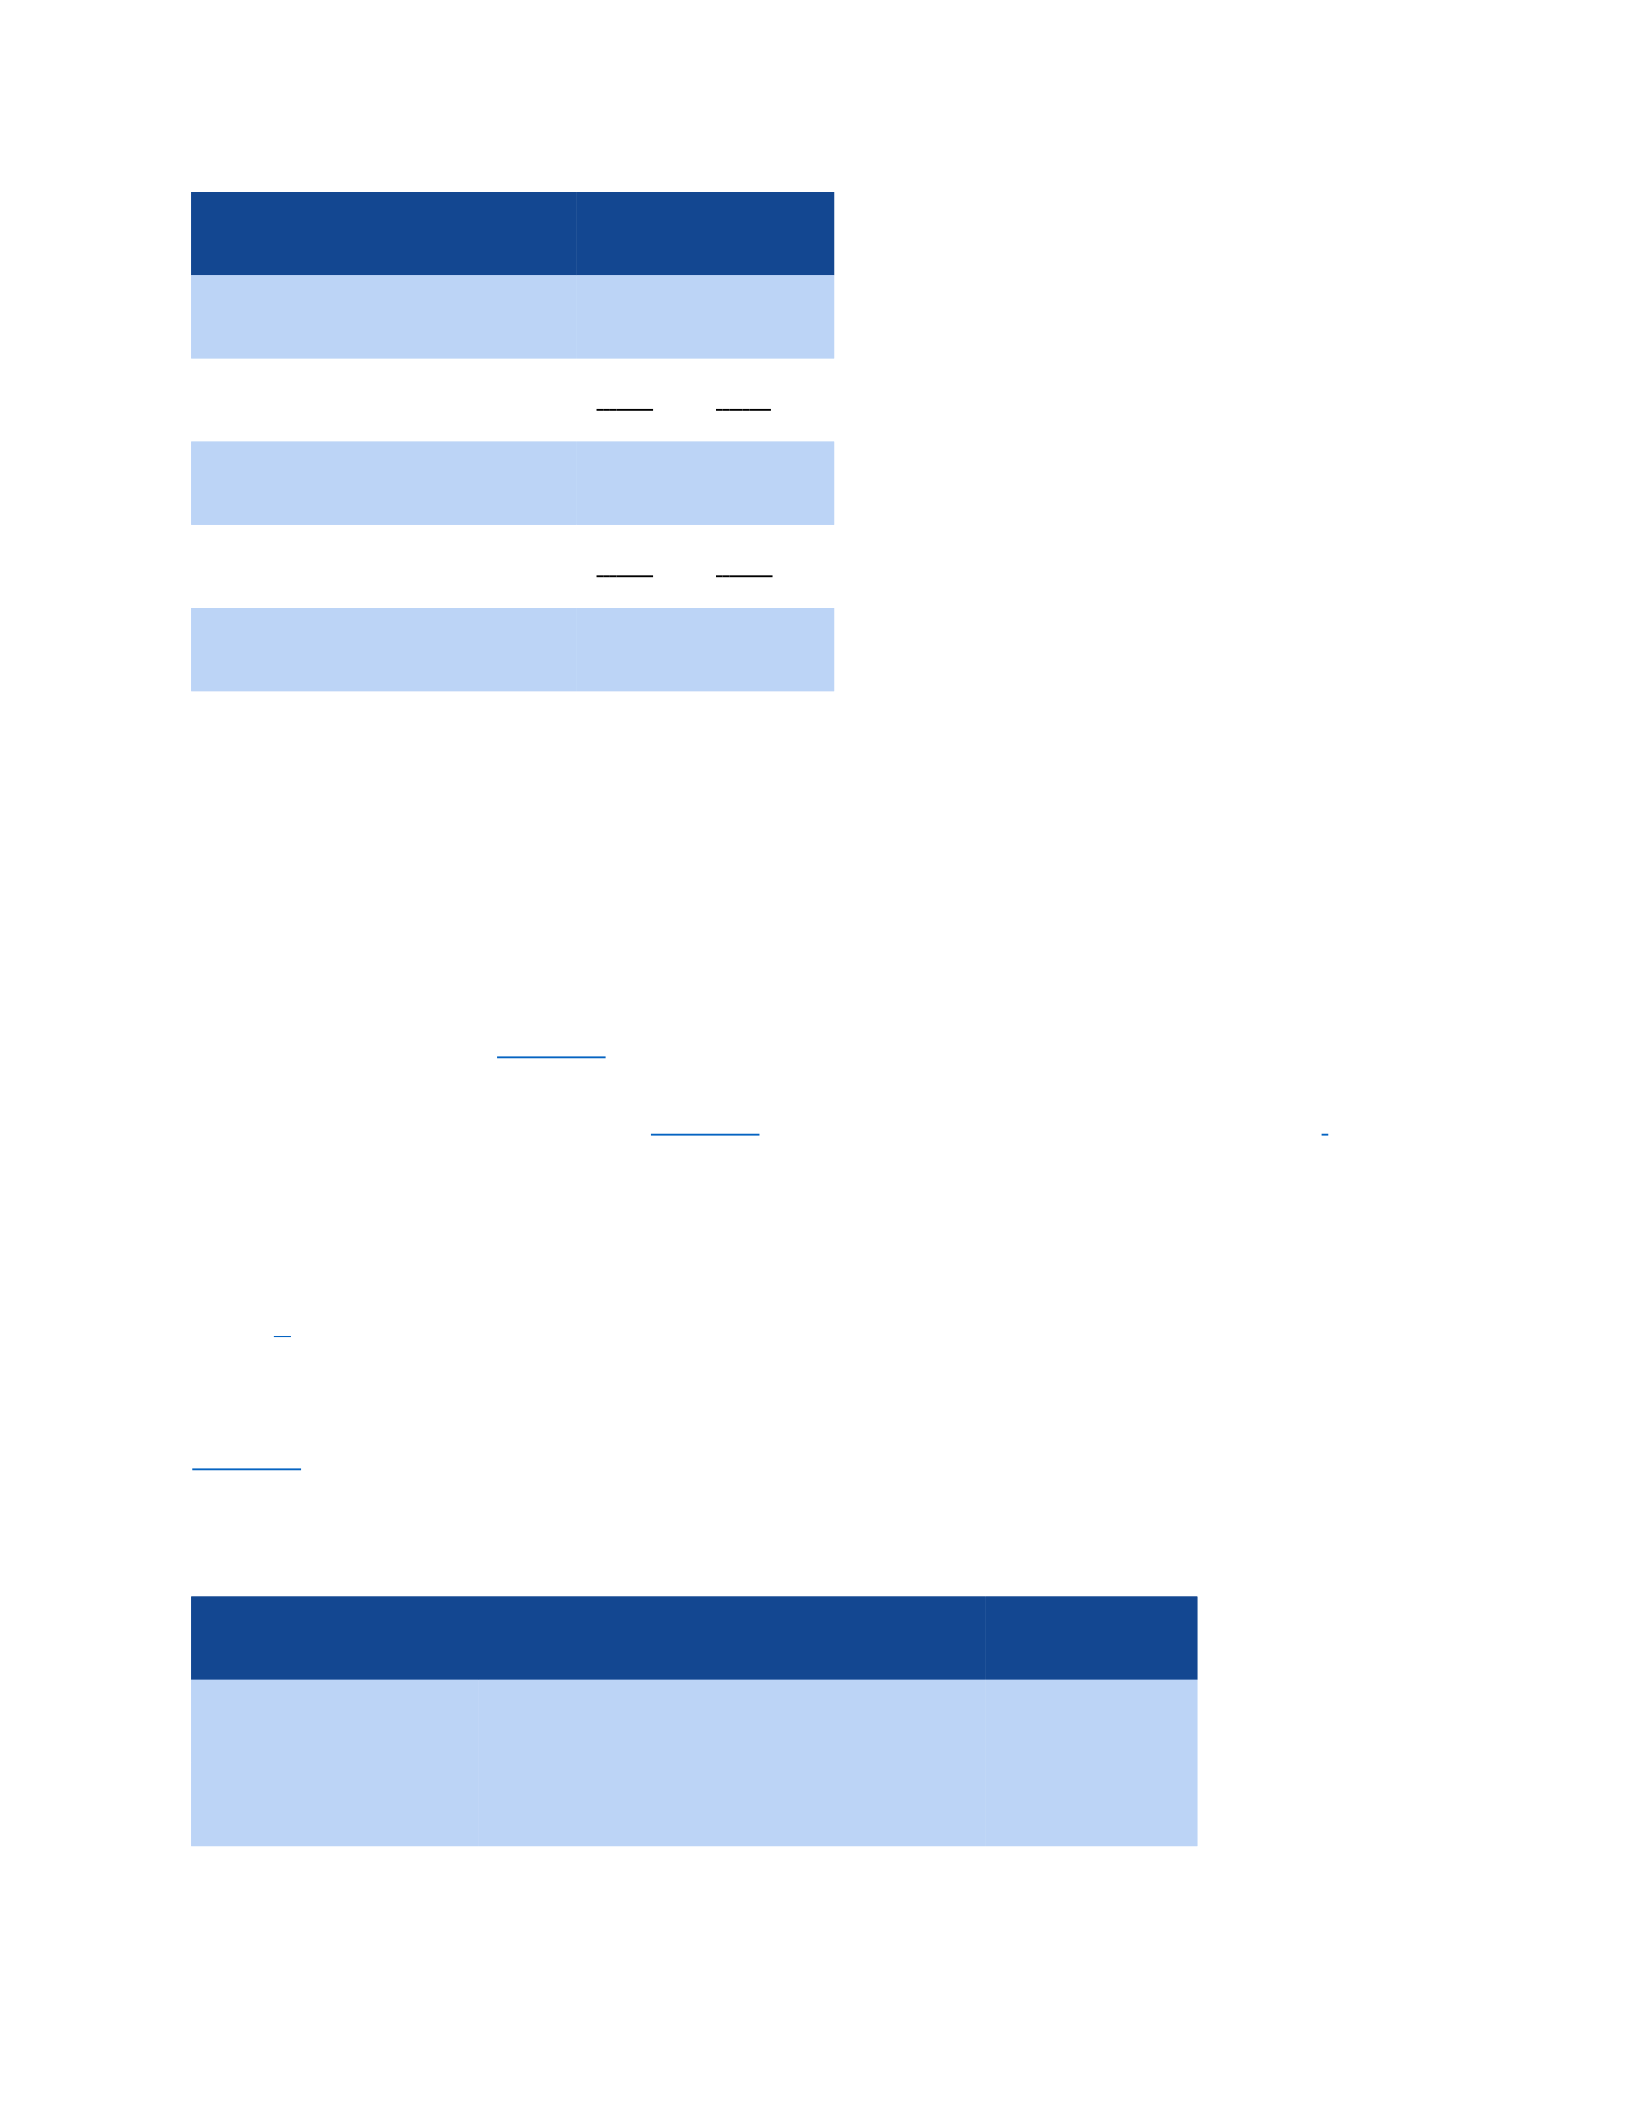
Firm A Firm B
EBIT $100 $100
Interest 40 0
Pretax income $ 60 $100
Tax (35% of pretax income) 21 35
Net income $ 39 $ 65
Note: Figures in millions of dollars.
The bad news about taxes is that each extra dollar of revenue increases taxable income by $1 and results
in 35 cents of extra taxes. The good news is that each extra dollar of expense reduces taxable income by
$1 and therefore reduces taxes by 35 cents. For example, if the firm borrows money, every dollar of
interest it pays on the loan reduces taxes by 35 cents. Therefore, a dollar of interest reduces after-tax
income by only 65 cents.
3.5 SELF-TEST
Recalculate the figures in Table 3.6, assuming that firm A now has to make interest payments of $60
million. What happens to taxes paid? Does net income fall by the additional $20 million interest payment
compared with the case considered in Table 3.6, where interest expense was only $40 million?
When firms make profits, they pay 35% of the profits to the Internal Revenue Service. But the process
doesn’t work in reverse; if the firm suffers a loss, the IRS does not send it a check for 35% of the loss.
However, the firm can carry the losses back, deduct them from taxable income in earlier years, and claim
a refund of past taxes. Losses can also be carried forward and deducted from taxable income in the
future.14
Personal Tax
Table 3.7 shows the U.S. rates of personal tax. Notice that as income increases, the tax rate also
increases. Notice also that the top personal tax rate is higher than the top corporate rate.
Table 3.7 Personal tax rates, 2016
Taxable Income ($)
Single Taxpayers Married Taxpayers Filing Joint Returns Tax Rate (%)
0–9,275 0–18,550 10.0
9,276–37,650 18,551–75,300 15.0
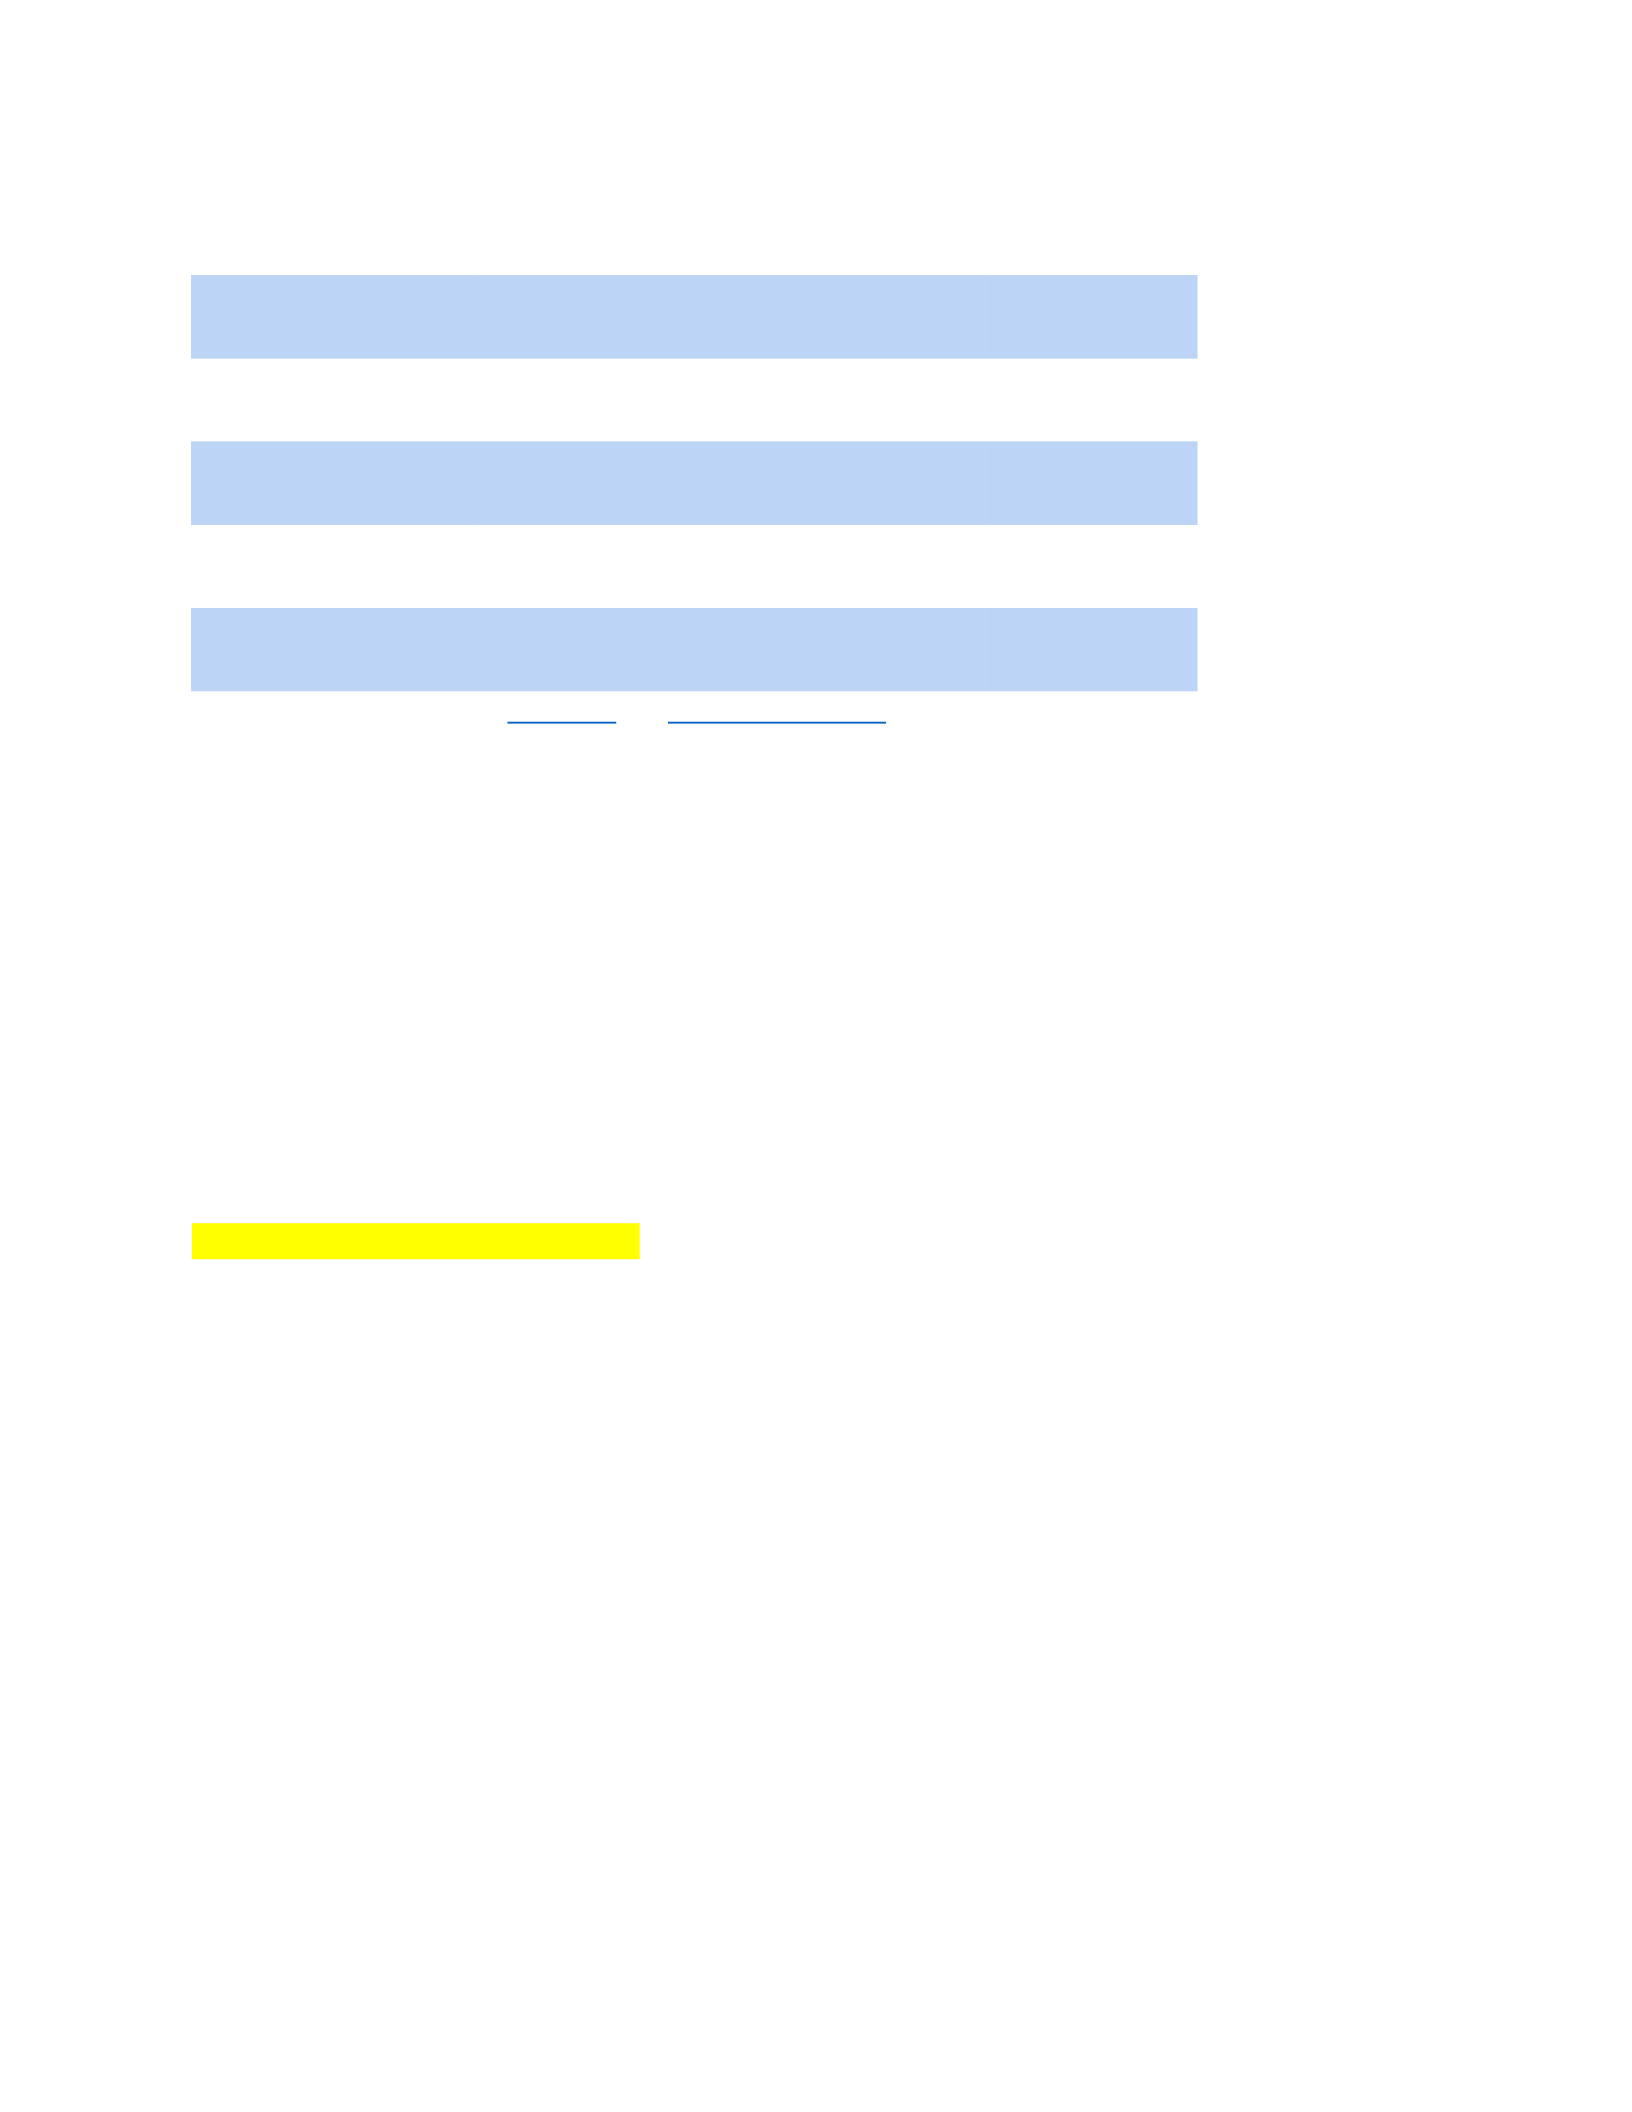
37,651–91,150 75,301–151,900 25.0
91,151–190,150 151,901–231,450 28.0
190,151–413,350 231,451–413,350 33.0
413,351–415,050 413,351–466,950 35.0
415,051 and above 466,951 and above 39.6
The tax rates presented in Table 3.7 are marginal tax rates. The marginal tax rate is the tax that the
individual pays on each extra dollar of income. For example, as a single taxpayer, you would pay 10 cents
of tax on each extra dollar you earn when your income is below $9,275, but once income exceeds
$9,275, you would pay 15 cents of tax on each extra dollar of income up to an income of $37,650. If your
total income is $50,000, your tax bill is 10% of the first $9,275 of income, 15% of the next $28,375 (i.e.,
37,650 − 9,275), and 25% of the remaining $12,350:
Tax = (.10 × $9,275) + (.15 × $28,375) + (.25 × $12,350) = $8,271.25Tax = (.10 × $9,275) + (.15 × $28,375)
+ (.25 × $12,350) = $8,271.25
BEYOND THE PAGE
Average and marginal tax rates
SOLUTIONS TO SELF-TEST QUESTIONS
1. 3.1
Cash and equivalents would increase by $100 million. Property, plant, and equipment would increase by
$400 million. Long-term debt would increase by $500 million. Shareholders’ equity would not increase:
Assets and liabilities have increased equally, leaving shareholders’ equity unchanged.
1. 3.2
a. If the auto plant were worth $14 billion, the equity in the firm would be worth $14 − $4
= $10 billion. With 100 million shares outstanding, each share would be worth $100.
b. If the outstanding stock were worth $8 billion, we would infer that the market values the
auto plant at $8 + $4 = $12 billion.
1. 3.3
The profits for the firm are recognized in periods 2 and 3 when the sales take place. In both of those
periods, profits are $150 − $100 = $50. Cash flows are derived as follows.
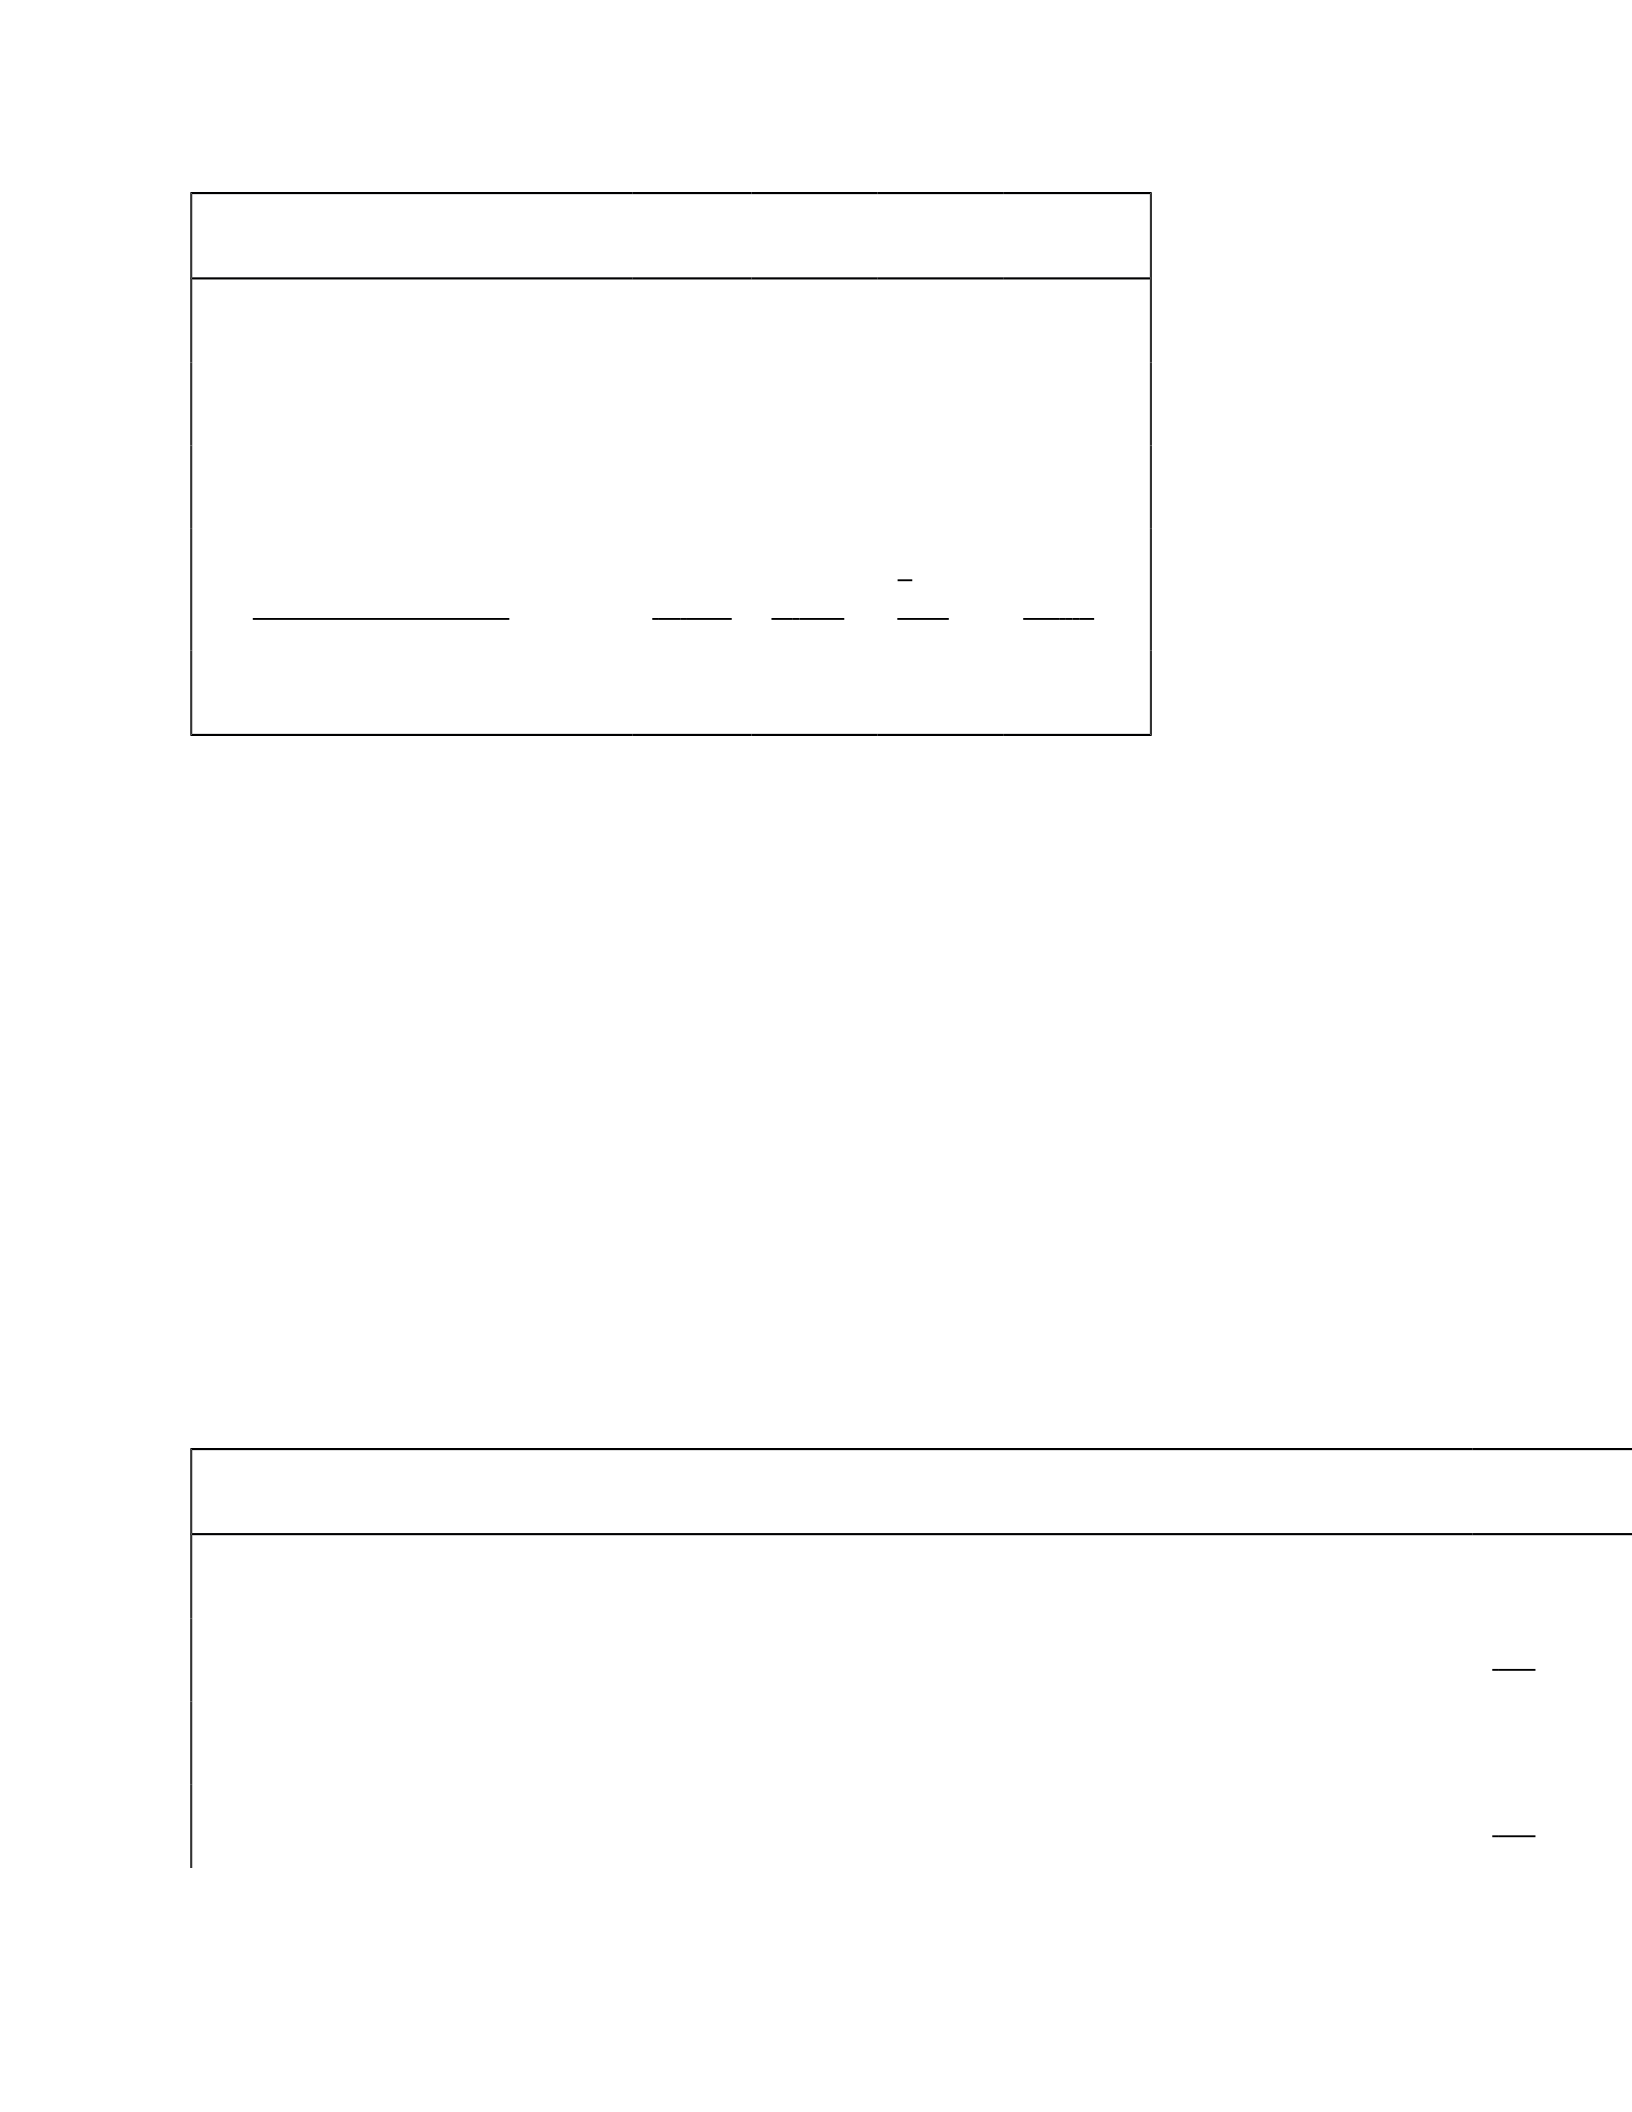
Period: 1 2 3 4
Sales $ 0 $150 $150 $ 0
− Change in accounts receivable 0 150 0 – 150
− Cost of goods sold 0 100 100 0
− Change in inventories – 200 – 100
–
100 0
= Net cash flow −$200 $ 0 +$150 +$150
In period 2, half the units are sold for $150 but no cash is collected, so the entire $150 is treated as an
increase in accounts receivable. Half the $200 cost of production is recognized, and a like amount is
taken out of inventory. In period 3, the firm sells another $150 of product but collects $150 from its
previous sales, so there is no change in outstanding accounts receivable. Net cash flow is the $150
collected in this period on the sale that occurred in period 2. In period 4, cash flow is again $150, as the
accounts receivable from the sale in period 3 are collected.
1. 3.4
a. An increase in inventories uses cash, reducing the firm’s net cash balance.
b. A reduction in accounts payable uses cash, reducing the firm’s net cash balance.
c. An issue of common stock is a source of cash.
d. The purchase of new equipment is a use of cash, and it reduces the firm’s net cash
balance.
1. 3.5
Firm A
EBIT 100
Interest 60
Pretax income 40
Tax (35% of pretax income) 14
Net income 26
Note: Figures in millions of dollars.
Page 84
Taxes owed by firm A fall from $21 million to $14 million. The reduction in taxes is 35% of the extra $20
million of interest income. Net income does not fall by the full $20 million of extra interest expense. It
instead falls by interest expense less the reduction in taxes, or $20 million − $7 million = $13 million.
1. 3.6
For a single taxpayer with taxable income of $80,000, total taxes paid are
(.10×9,275)+[.15×(37,650−9,275)]+[.25×(80,000 −37,650)]=$15,771.25(.10×9,275)+[.15×(37,650−9,275)]
+[.25×(80,000 -37,650)]=$15,771.25
The marginal tax rate is 25%, but the average tax rate is only 15,771.25/80,000 = .197, or 19.7%. For the
married taxpayers filing jointly with taxable income of $80,000, total taxes paid are
(.10×18,550)+[.15×(75,300−18,550)]+[.25×(80,000−75,800)]=$11,542.50(.10×18,550)+
[.15×(75,300−18,550)]+[.25×(80,000−75,800)]=$11,542.50
The marginal tax rate is 25%, and the average tax rate is 11,542.50/80,000 = .144, or 14.4%.
mhhe.com/brealey9e
Page 75
The average tax rate is simply the total tax bill divided by total income. In this example it is
$8,271.25/$50,000 = .165, or 16.5%. Notice that the average rate is lower than the marginal rate. This is
because of the lower rates on the first $37,650.
3.6 SELF-TEST
What are the average and marginal tax rates for a single taxpayer with a taxable income of $80,000?
What are the average and marginal tax rates for married taxpayers filing joint returns if their joint taxable
income is also $80,000?
The tax rates in Table 3.7 apply to “ordinary income,” primarily income earned as salary or wages.
Interest earnings also are treated as ordinary income.
The U.S. government also taxes investment earnings, for example dividends or capital gains. The
treatment of dividend income in the United States leads to what is commonly dubbed the “double
taxation” of corporate earnings. Each dollar the company earns is taxed at the corporate rate. Then, if
the company pays a dividend out of this after-tax income, the shareholder pays personal income taxes
on the distribution. The original earnings are taxed first as corporate income and again as dividend
income. Suppose instead that the company earns a dollar which is paid out as interest. The dollar
escapes corporate tax because the interest payment is considered a business expense that reduces the
firm’s taxable income.
Capital gains are also taxed, but only when the gains are realized. Suppose that you bought Bio-technics
stock when it was selling for 10 cents a share. Its market price today is $1 a share. As long as you hold on
to your stock, there is no tax to pay on your gain. But if you sell, the 90 cents of capital gain is taxed.
Table 3.8 shows tax rates on investment income. For most investors, the effective tax rate is either 15%
or 18.8% (15% plus a potential 3.8% surcharge), but the highest income investors pay an effective rate of
23.8%.
Table 3.8 Tax rates on investment income* corresponding to 2016 tax brackets**
Taxable Income ($)
Single Taxpayers Married Taxpayers Filing Joint Returns Tax Rate (%)
0–9,275 0–18,550 0
9,276–37,650 18,551–75,300 0
37,651–91,150 75,301–151,900 15
91,151–190,150 151,901–231,450 15
190,151–413,350 231,451–413,350 15
413,351–415,050 413,351–466,950 15
415,051 and above 466,951 and above 20
Financial managers need to worry about the tax treatment of investment income because tax policy will
affect the prices individuals are willing to pay for the company’s stock or bonds. We will return to these
issues in Part 5 of the text.
The tax rates in Table 3.7 and Table 3.8 apply to individuals. But financial institutions are major investors
in corporate securities. These institutions often have special tax provisions. For example, pension funds
are not taxed on interest or dividend income or on capital gains.

