Article Critique: AIS and Associates Topic: Business Process and Controls
2
Article Critique: How To Deal With Payroll Fraud And Security
This paper will summarize and critique the article “How To Deal With Payroll Fraud
And Security” by Pavel Shynkarenko. The payroll process is an interacting system of people,
equipment, activities, and controls that generate information flows to support the repetitive work
routine of the payroll department. The payroll process maintains records containing data for
payroll taxes and fringe benefits, attendance reporting, timekeeping, and paying employees for
work performed. Business today is all about leveraging technology for efficiency, effectiveness,
security, and convenience. Payroll, just like cash disbursements, is an area that is vulnerable to
fraudulent activities. Companies make thousands of payments to employees for payroll and
expense account reimbursements every payroll period. Payroll fraud presents a serious risk for
businesses; it can jeopardize an entire organization if not addressed. It occurs in various forms
and at different levels within a company. According to an ACFE report, more than half of
occupational fraud incidents took place in four key departments: operations (14%), accounting
(12%), executive and upper management (9%), and sales (12%). This article examines ways to
identify payroll fraud and protect businesses, focusing on challenges like fake employees and
contractors, poor compliance, prepayments, ghost workers, and worker misclassification.
Strategic partners have the technological infrastructure necessary to manage payments, receipts,
contracts, and assignments on a unified platform, which upholds the legal validity of agreements
and reduces the risk of contract breaches or any form of payroll fraud.
Summary
Shynkarenko opens the article with a definition of payroll fraud, a significant challenge
that can threaten organizations of all sizes. The author shares two recent examples. The first
Article Critique: AIS and Associates Topic: Business Process and Controls
3
involves a former payroll director at a hospital in Atlanta, Georgia, who altered information on
vacation and severance payments, embezzling more than $500,000 (Shynkarenko, 2023). In the
second case, an ex-business owner in New York City misappropriated over $1.7 million meant
for payroll taxes to fund his lifestyle (Shynkarenko, 2023). Payroll fraud comes in different
shapes and forms and is also perpetrated at various levels within the organization. According to
the ACFE report, fraud happens in operations, accounting, and executive/upper management.
While owners and executives were only responsible for 20% of the fraud committed, they were
guilty, by far, of the most significant financial losses (Shynkarenko, 2023).
According to Shynkarenko, the most common type of payroll fraud is fake workers and
contractors. A ghost employee or contractor is someone recorded on the payroll system who does
not work for the business. In a case in Florida, a ghost worker cheated and defrauded an airport
operator for over $900,000. Some people take fraud commitment seriously by creating detailed
contractor accounts, descriptions, emails, and fake references. One recommended step to
mitigate the risks of having fake workers and contractors is to work with contract service
providers that can give an itemized report, which must include the services rendered, the dates on
which the service was performed, and how much each service was.
Other methods described in the article are prepayment and ghosting. This can affect
contractors who prepay a freelancer for their services, get ghosted, over-trust their clients, and
choose to work for them even if they have not been paid yet. A recommended solution to prevent
prepayment and ghosting is to work with platforms that offer escrow services. Escrow provides
the role of a neutral place for funds to be held, and the funds get released once a milestone is
reached or the project is completed. This way, the risk for both sides is low on not getting paid or
receiving the products or services paid for in advance.
Article Critique: AIS and Associates Topic: Business Process and Controls
4
Worker misclassification is another common way payroll fraud is committed, as
mentioned by Shynkarenko (2023). Employers misclassify workers as independent contractors
when they should be treated as employees. Misclassification is often an effort to reduce labor
costs and evade workplace laws, virtually all of which only cover employees. In addition, many
employers, particularly in industries like construction, pay workers cash wages “off the books.
(Erlich & Gerstein, 2019)” This, too, is a method of avoiding employers’ legal obligations,
including minimum wage, overtime, prevailing wage, workers’ compensation premiums,
unemployment insurance contributions, and employer FICA taxes.
Addressing payroll fraud effectively requires several key strategies. Shynkarenko notes
that implementing internal controls, providing a hotline, offering employee fraud awareness
training, and establishing support programs can decrease payroll fraud losses by 51%. When
hiring international contractors, freelancers must adhere to the applicable laws and regulations of
the country where they operate. Additionally, having strategic partners that can provide a
comprehensive technological infrastructure ensures that payments, receipts, contracts, and
assignments are managed within a single platform. This approach protects the legal validity of
agreements and reduces the risk of contract breaches or payroll fraud by any party involved.
Critique
Shynkarenko wrote the article from an interesting perspective on dealing with payroll
fraud and security. The title was specific and gave a clear idea of what the article would cover.
The author, Pavel Shynkarenko, has over 20 years of experience in financial, HR, and legal
technologies. The article references ACFE 2019 Occupational Fraud: Report to the Nations and
other credible research and surveys. The sources are not clearly defined. However, hyperlinks
within the article take you to the source. The article focused more on the ghost international
Article Critique: AIS and Associates Topic: Business Process and Controls
5
contractors. However, it can be related to any contractors and the recommendation to protect the
business from payroll fraud. It can be used in the US hiring contractors. The hypophysis is not
clear in the article. The article is informational and straightforward in answering the title
question. In the article, there is no specific conclusion. However, the author's conclusion about
preventing payroll fraud can be deducted from the last paragraph. It
The article seemed objective, as facts and data were reported. The information in the
article can be applied to most small or large businesses. The article is easy to read, follow, and
understand, making it enjoyable. This article is just for information purposes; if needed for a
research paper, this article is not a proper resource. The data presented in this article can be
gathered from ACFE reports. A very similar article written by Tamas Kadar, “How HR Can
Dodge Payroll Fraud (2023)” could have been used as a reference for Shynkarenko's article.
Conclusion
Over the years, payroll fraud has become more and more challenging for businesses.
Payroll fraud is a common problem that HR professionals can counter with risk-based
management of employee data and processes. A sophisticated security system is also vital, as it
makes it easier to safeguard data and tackle fraud. Strong internal control is a must if a company
is looking to prevent payroll fraud. Understanding which scheme types are more common in
specific industries can help management and anti-fraud professionals assess their relevant fraud
risks and effectively guide prevention and detection efforts. Building effective reporting and
analytics can provide a powerful tool to improve the efficiency and effectiveness of operations.
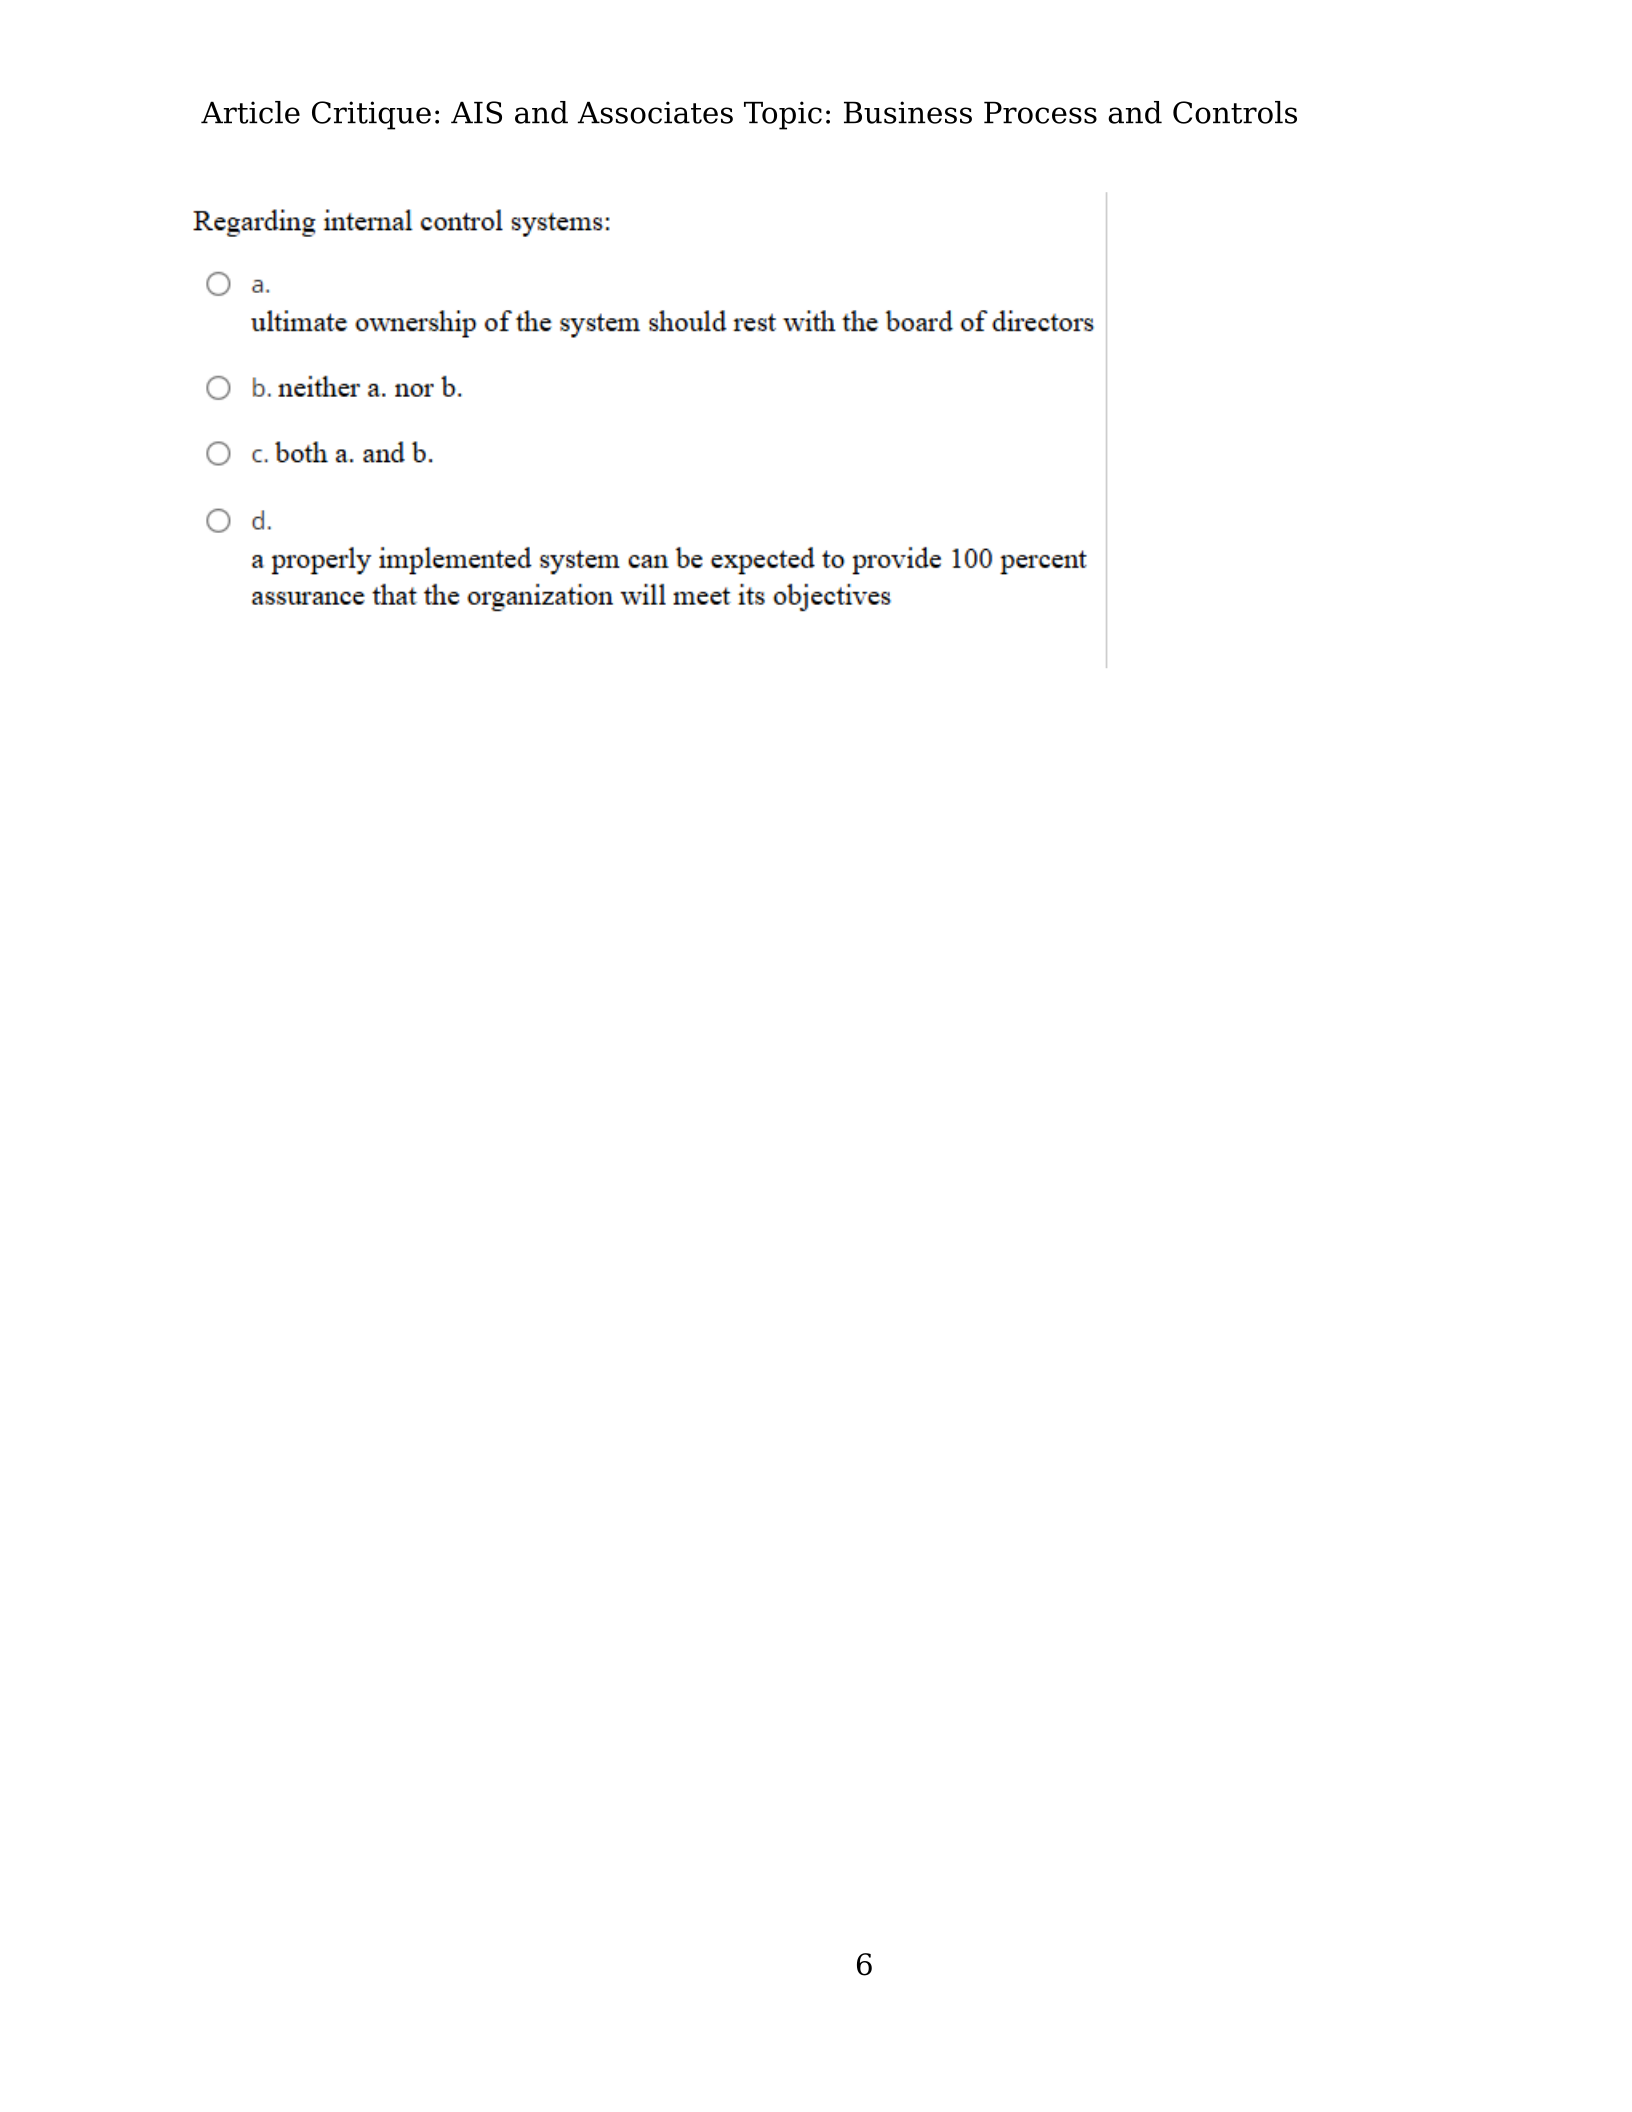
Regarding
intemal
control
systems:
Oa
ultimate
ownership
of
the
system
should
rest
with
the
board
of
directors
©
b.neither
a.
nor
b.
O
cbotha.
and
b.
Od
a
properly
implemented
system can
be
expected
to
provide
100
percent
assurance
that
the
organization
will
meet
its
objectives
Article Critique: AIS and Associates Topic: Business Process and Controls
6
Article Critique: AIS and Associates Topic: Business Process and Controls
7
References
ACFE. (2024). Occupational Fraud 2024: A Report to the Nations. Retrieved from Association
of Certified Fraud Examiners:
https://www.acfe.com/-/media/files/acfe/pdfs/rttn/2024/2024-report-to-the-nations.pdf
Atake, A., Omoaka, G., & Orlu, C. C. (2018). The Relevance of Payroll Control To Fraud
Prevention In A Payroll System. Retrieved from Templars Thought Leadership:
https://www.templars-law.com/app/uploads/2018/12/TEMPLARS_THE-RELEVANCE-
OF-PAYROLL-CONTROL-TO-FRAUD-PREVENTION-IN-A-PAYROLL-
SYSTEM.pdf
Bible. (n.d.). English Standard Version 2016.
Gelinas, U. J., Dull, R. B., Wheeler, P. R., & Hill, M. C. (2018). Accounting Information Systems
(11th Edition ed.).
Kadar, T. (2023, Jul). How HR Can Dodge Payroll Fraud. Core HR, HRIS, and Payroll
Excellence Essentials. Retrieved from https://go.openathens.net/redirector/liberty.edu?
url=https://www.proquest.com/magazines/how-hr-can-dodge-payroll-fraud/docview/
3033030396/se-2?accountid=12085
Shynkarenko, P. (2023, Jul). How To Deal With Payroll Fraud And Security. Core HR, HRIS,
and Payroll Excellence Essentials. Retrieved from
https://go.openathens.net/redirector/liberty.edu?url=https://www.proquest.com/
magazines/how-deal-with-payroll-fraud-security/docview/3033030405/se-2?
accountid=12085