


CHAPTER 6 HW ( Advance Accounting)
1)
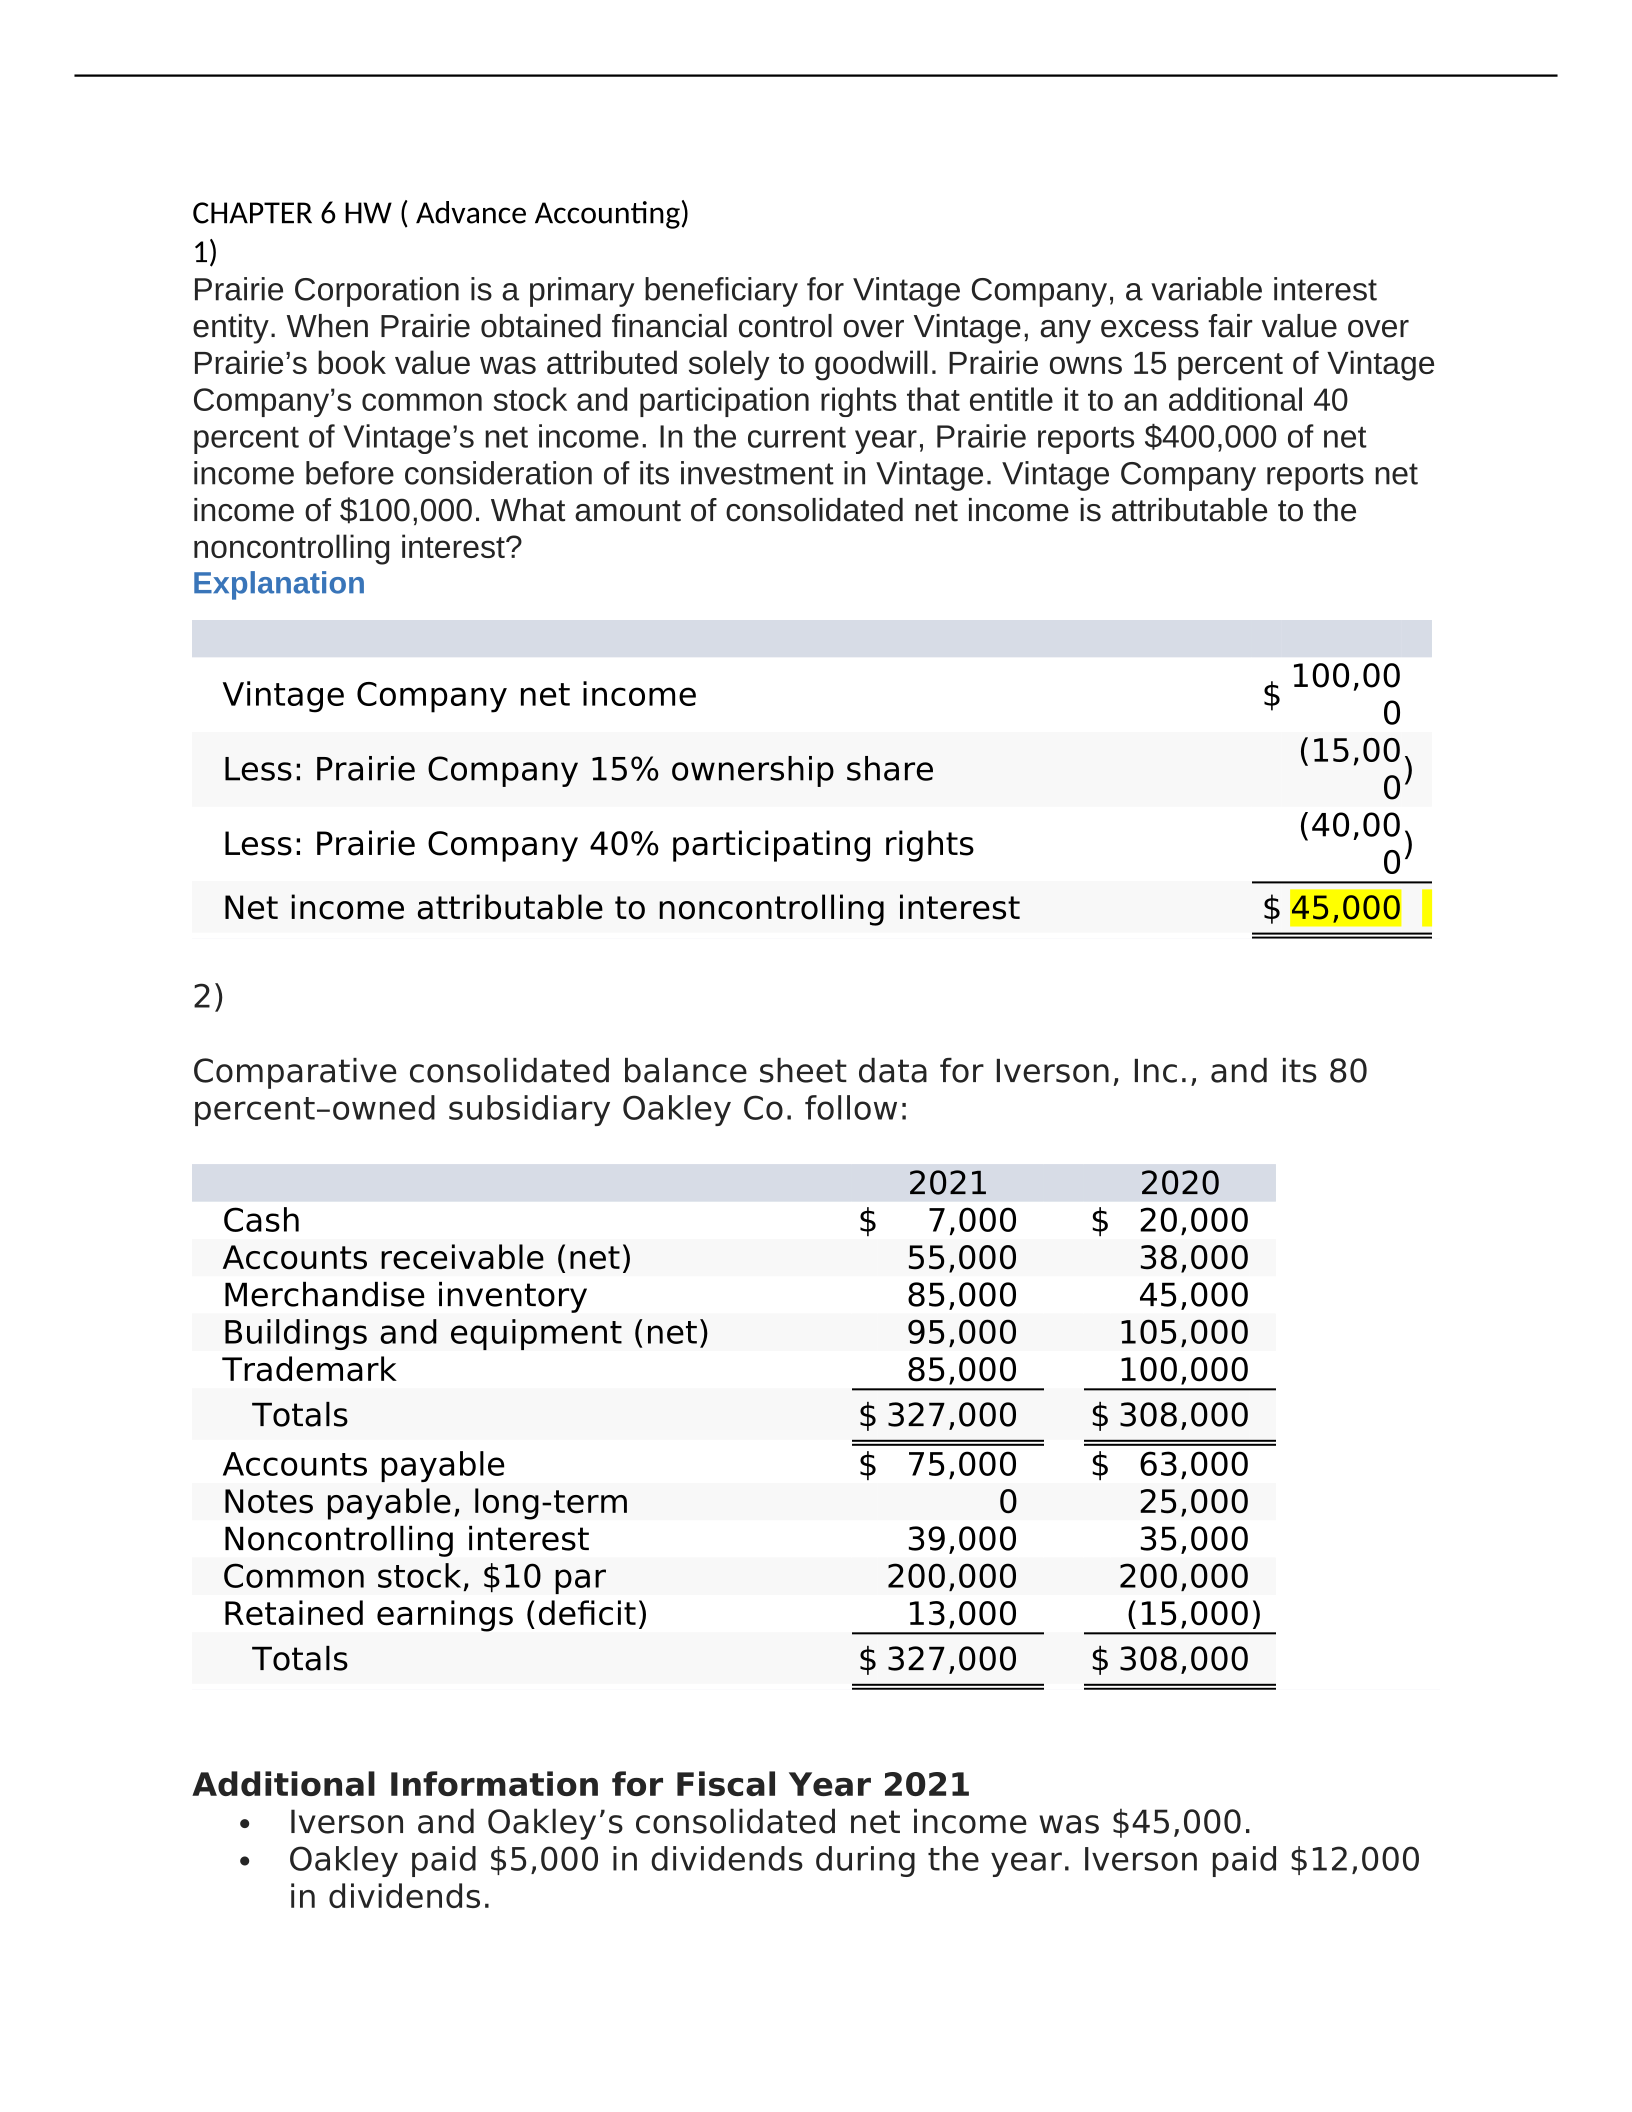
Prairie Corporation is a primary beneficiary for Vintage Company, a variable interest
entity. When Prairie obtained financial control over Vintage, any excess fair value over
Prairie’s book value was attributed solely to goodwill. Prairie owns 15 percent of Vintage
Company’s common stock and participation rights that entitle it to an additional 40
percent of Vintage’s net income. In the current year, Prairie reports $400,000 of net
income before consideration of its investment in Vintage. Vintage Company reports net
income of $100,000. What amount of consolidated net income is attributable to the
noncontrolling interest?
Explanation
Vintage Company net income $ 100,00
0
Less: Prairie Company 15% ownership share (15,00
0)
Less: Prairie Company 40% participating rights (40,00
0)
Net income attributable to noncontrolling interest $ 45,000
2)
Comparative consolidated balance sheet data for Iverson, Inc., and its 80
percent–owned subsidiary Oakley Co. follow:
2021 2020
Cash $ 7,000 $ 20,000
Accounts receivable (net) 55,000 38,000
Merchandise inventory 85,000 45,000
Buildings and equipment (net) 95,000 105,000
Trademark 85,000 100,000
Totals $ 327,000 $ 308,000
Accounts payable $ 75,000 $ 63,000
Notes payable, long-term 0 25,000
Noncontrolling interest 39,000 35,000
Common stock, $10 par 200,000 200,000
Retained earnings (deficit) 13,000 (15,000)
Totals $ 327,000 $ 308,000
Additional Information for Fiscal Year 2021
Iverson and Oakley’s consolidated net income was $45,000.
Oakley paid $5,000 in dividends during the year. Iverson paid $12,000
in dividends.
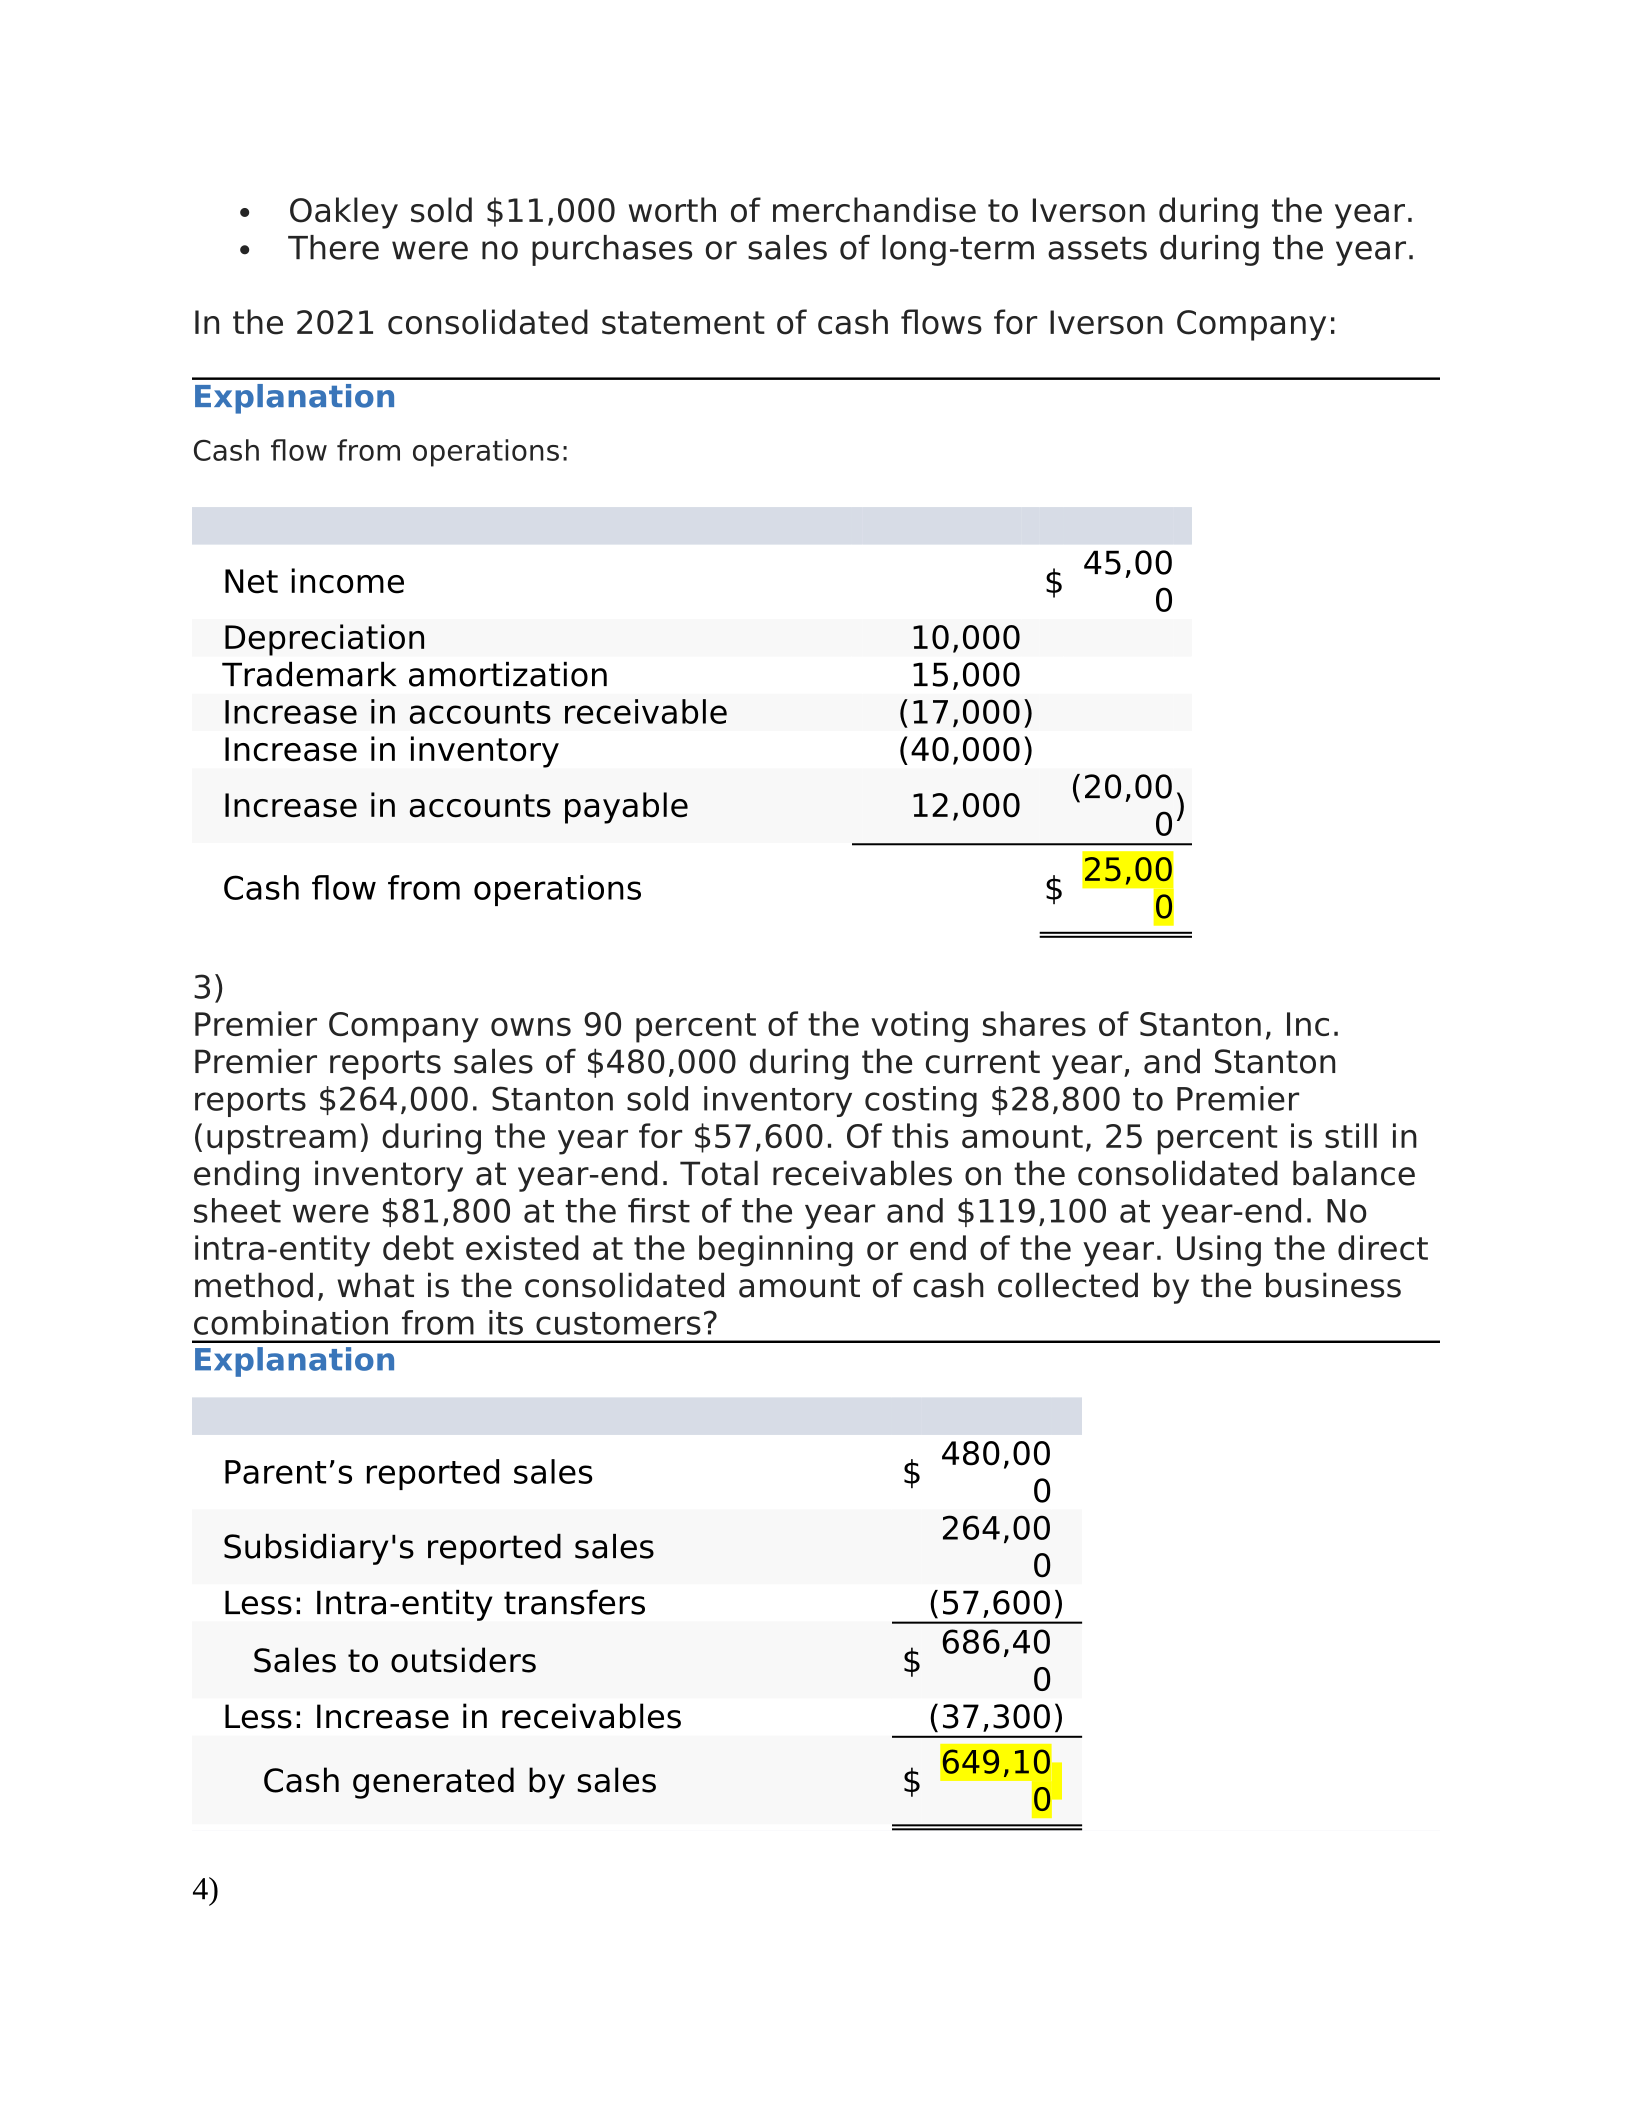
Oakley sold $11,000 worth of merchandise to Iverson during the year.
There were no purchases or sales of long-term assets during the year.
In the 2021 consolidated statement of cash flows for Iverson Company:
Explanation
Cash flow from operations:
Net income $ 45,00
0
Depreciation 10,000
Trademark amortization 15,000
Increase in accounts receivable (17,000)
Increase in inventory (40,000)
Increase in accounts payable 12,000 (20,00
0)
Cash flow from operations $ 25,00
0
3)
Premier Company owns 90 percent of the voting shares of Stanton, Inc.
Premier reports sales of $480,000 during the current year, and Stanton
reports $264,000. Stanton sold inventory costing $28,800 to Premier
(upstream) during the year for $57,600. Of this amount, 25 percent is still in
ending inventory at year-end. Total receivables on the consolidated balance
sheet were $81,800 at the first of the year and $119,100 at year-end. No
intra-entity debt existed at the beginning or end of the year. Using the direct
method, what is the consolidated amount of cash collected by the business
combination from its customers?
Explanation
Parent’s reported sales $ 480,00
0
Subsidiary's reported sales 264,00
0
Less: Intra-entity transfers (57,600)
Sales to outsiders $ 686,40
0
Less: Increase in receivables (37,300)
Cash generated by sales $ 649,10
0
4)
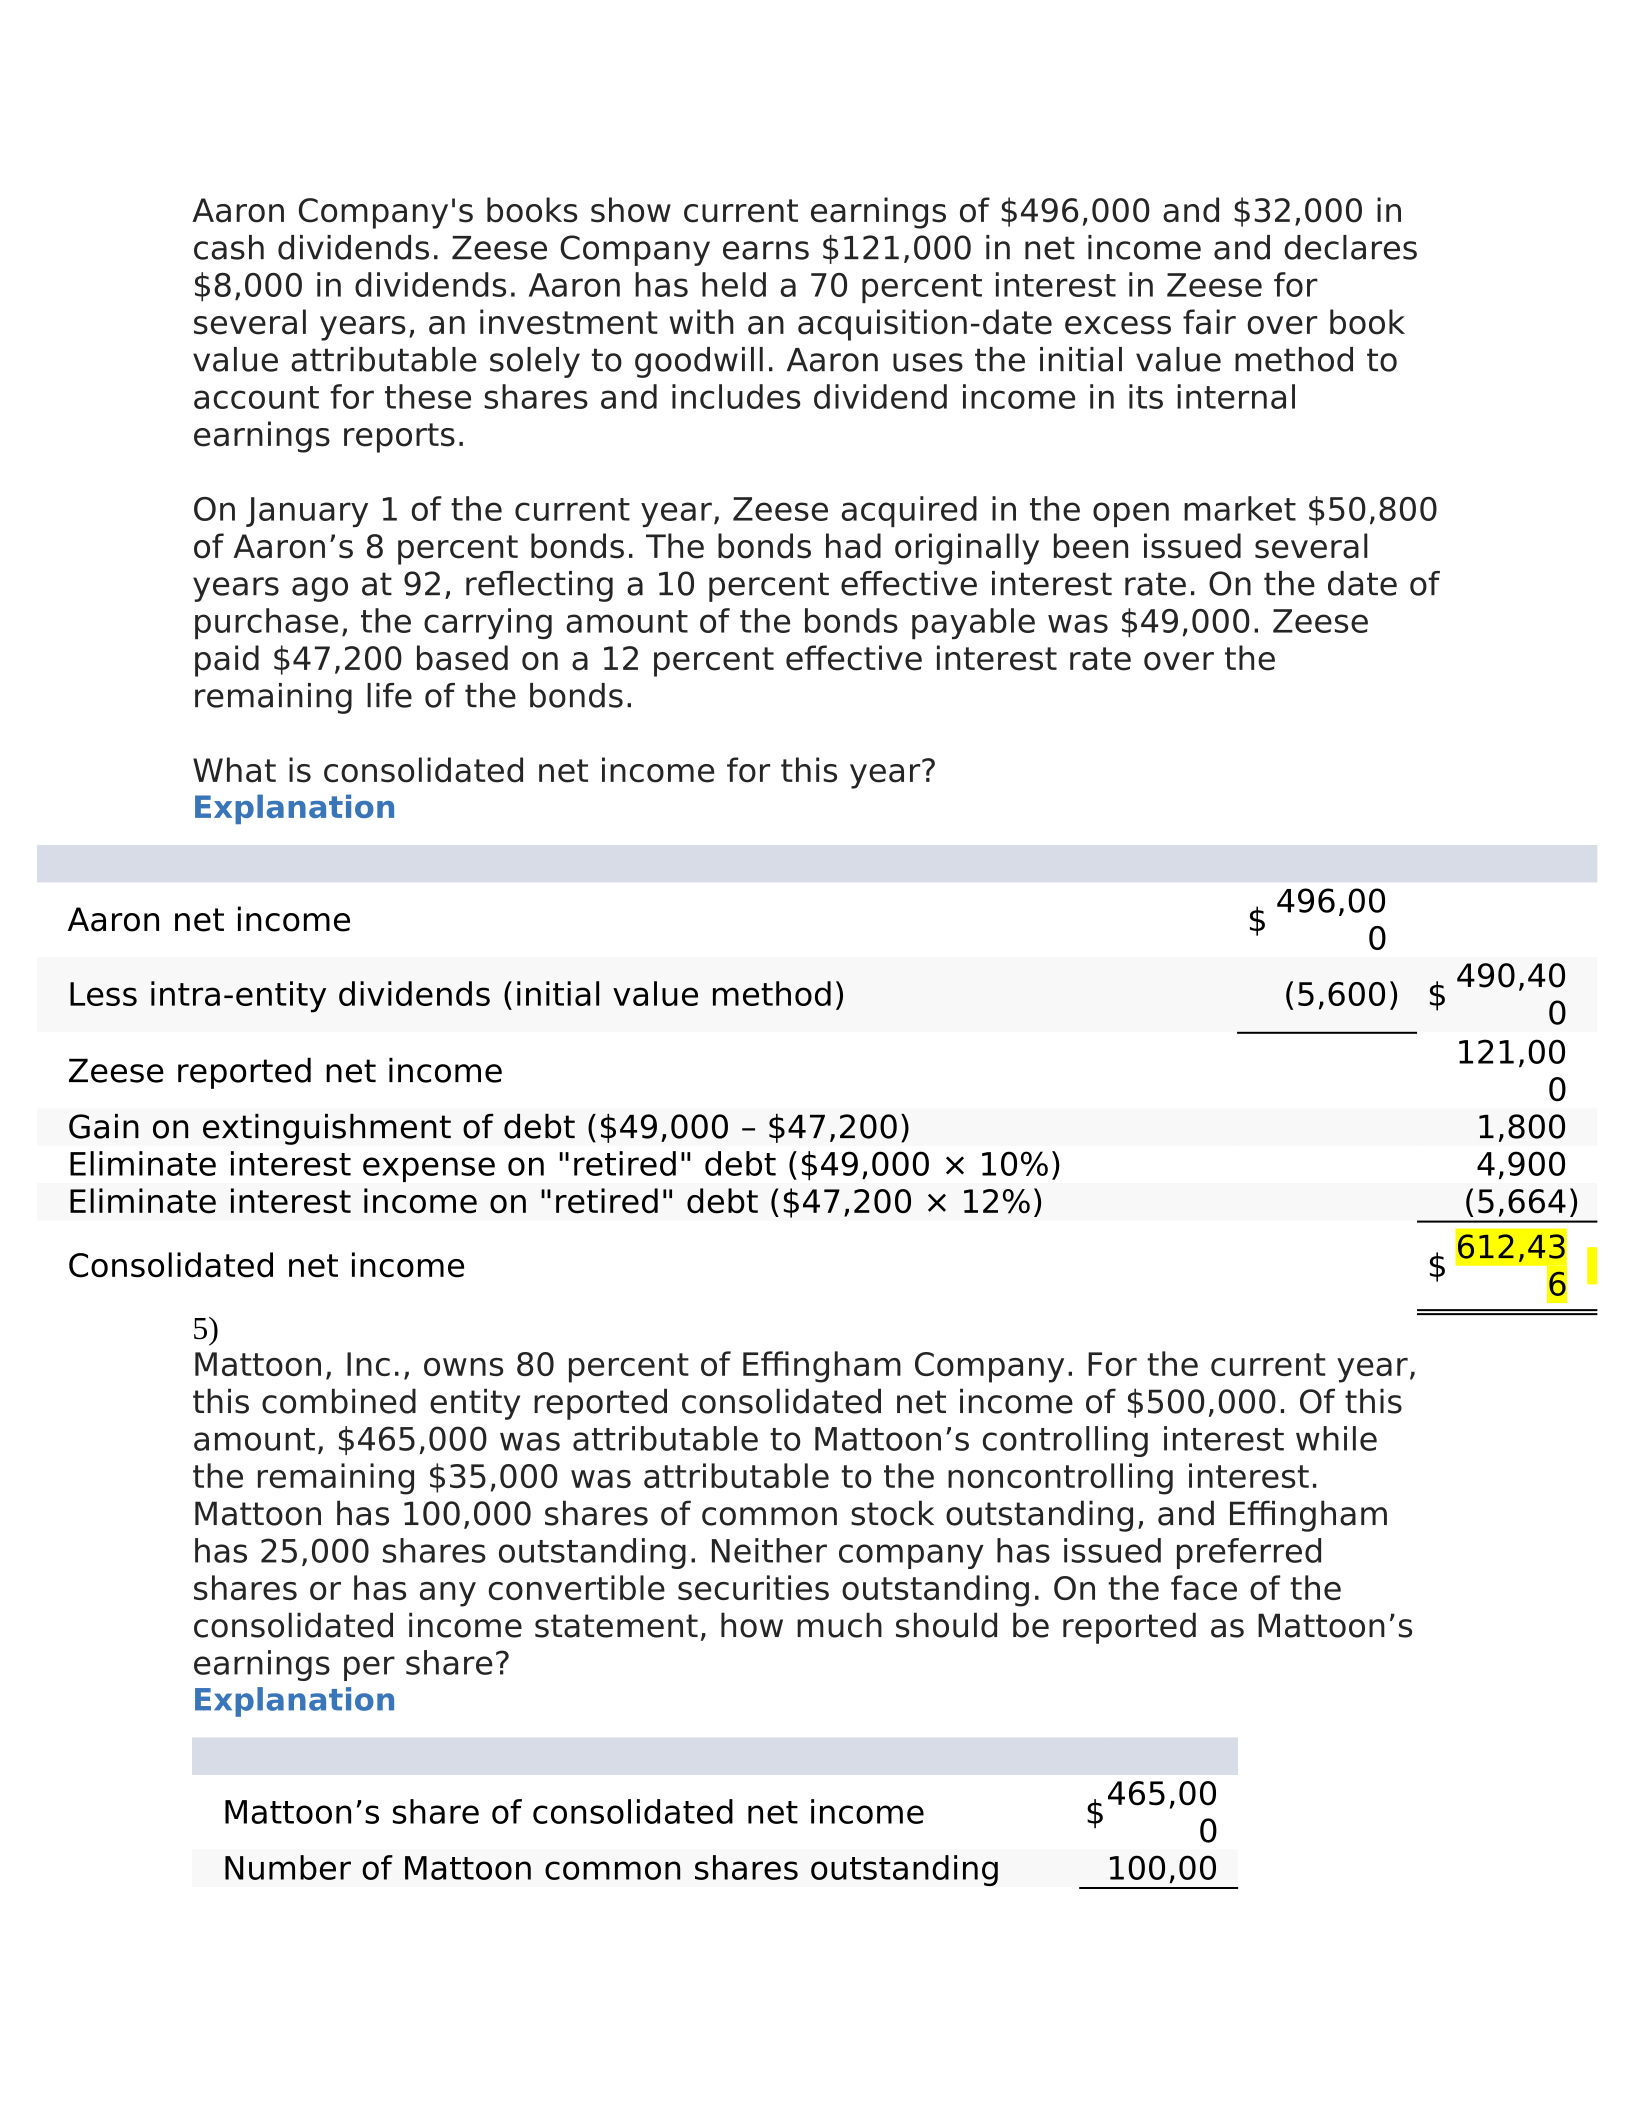
Aaron Company's books show current earnings of $496,000 and $32,000 in
cash dividends. Zeese Company earns $121,000 in net income and declares
$8,000 in dividends. Aaron has held a 70 percent interest in Zeese for
several years, an investment with an acquisition-date excess fair over book
value attributable solely to goodwill. Aaron uses the initial value method to
account for these shares and includes dividend income in its internal
earnings reports.
On January 1 of the current year, Zeese acquired in the open market $50,800
of Aaron’s 8 percent bonds. The bonds had originally been issued several
years ago at 92, reflecting a 10 percent effective interest rate. On the date of
purchase, the carrying amount of the bonds payable was $49,000. Zeese
paid $47,200 based on a 12 percent effective interest rate over the
remaining life of the bonds.
What is consolidated net income for this year?
Explanation
Aaron net income $ 496,00
0
Less intra-entity dividends (initial value method) (5,600) $ 490,40
0
Zeese reported net income 121,00
0
Gain on extinguishment of debt ($49,000 – $47,200) 1,800
Eliminate interest expense on "retired" debt ($49,000 × 10%) 4,900
Eliminate interest income on "retired" debt ($47,200 × 12%) (5,664)
Consolidated net income $ 612,43
6
5)
Mattoon, Inc., owns 80 percent of Effingham Company. For the current year,
this combined entity reported consolidated net income of $500,000. Of this
amount, $465,000 was attributable to Mattoon’s controlling interest while
the remaining $35,000 was attributable to the noncontrolling interest.
Mattoon has 100,000 shares of common stock outstanding, and Effingham
has 25,000 shares outstanding. Neither company has issued preferred
shares or has any convertible securities outstanding. On the face of the
consolidated income statement, how much should be reported as Mattoon’s
earnings per share?
Explanation
Mattoon’s share of consolidated net income $465,00
0
Number of Mattoon common shares outstanding 100,00
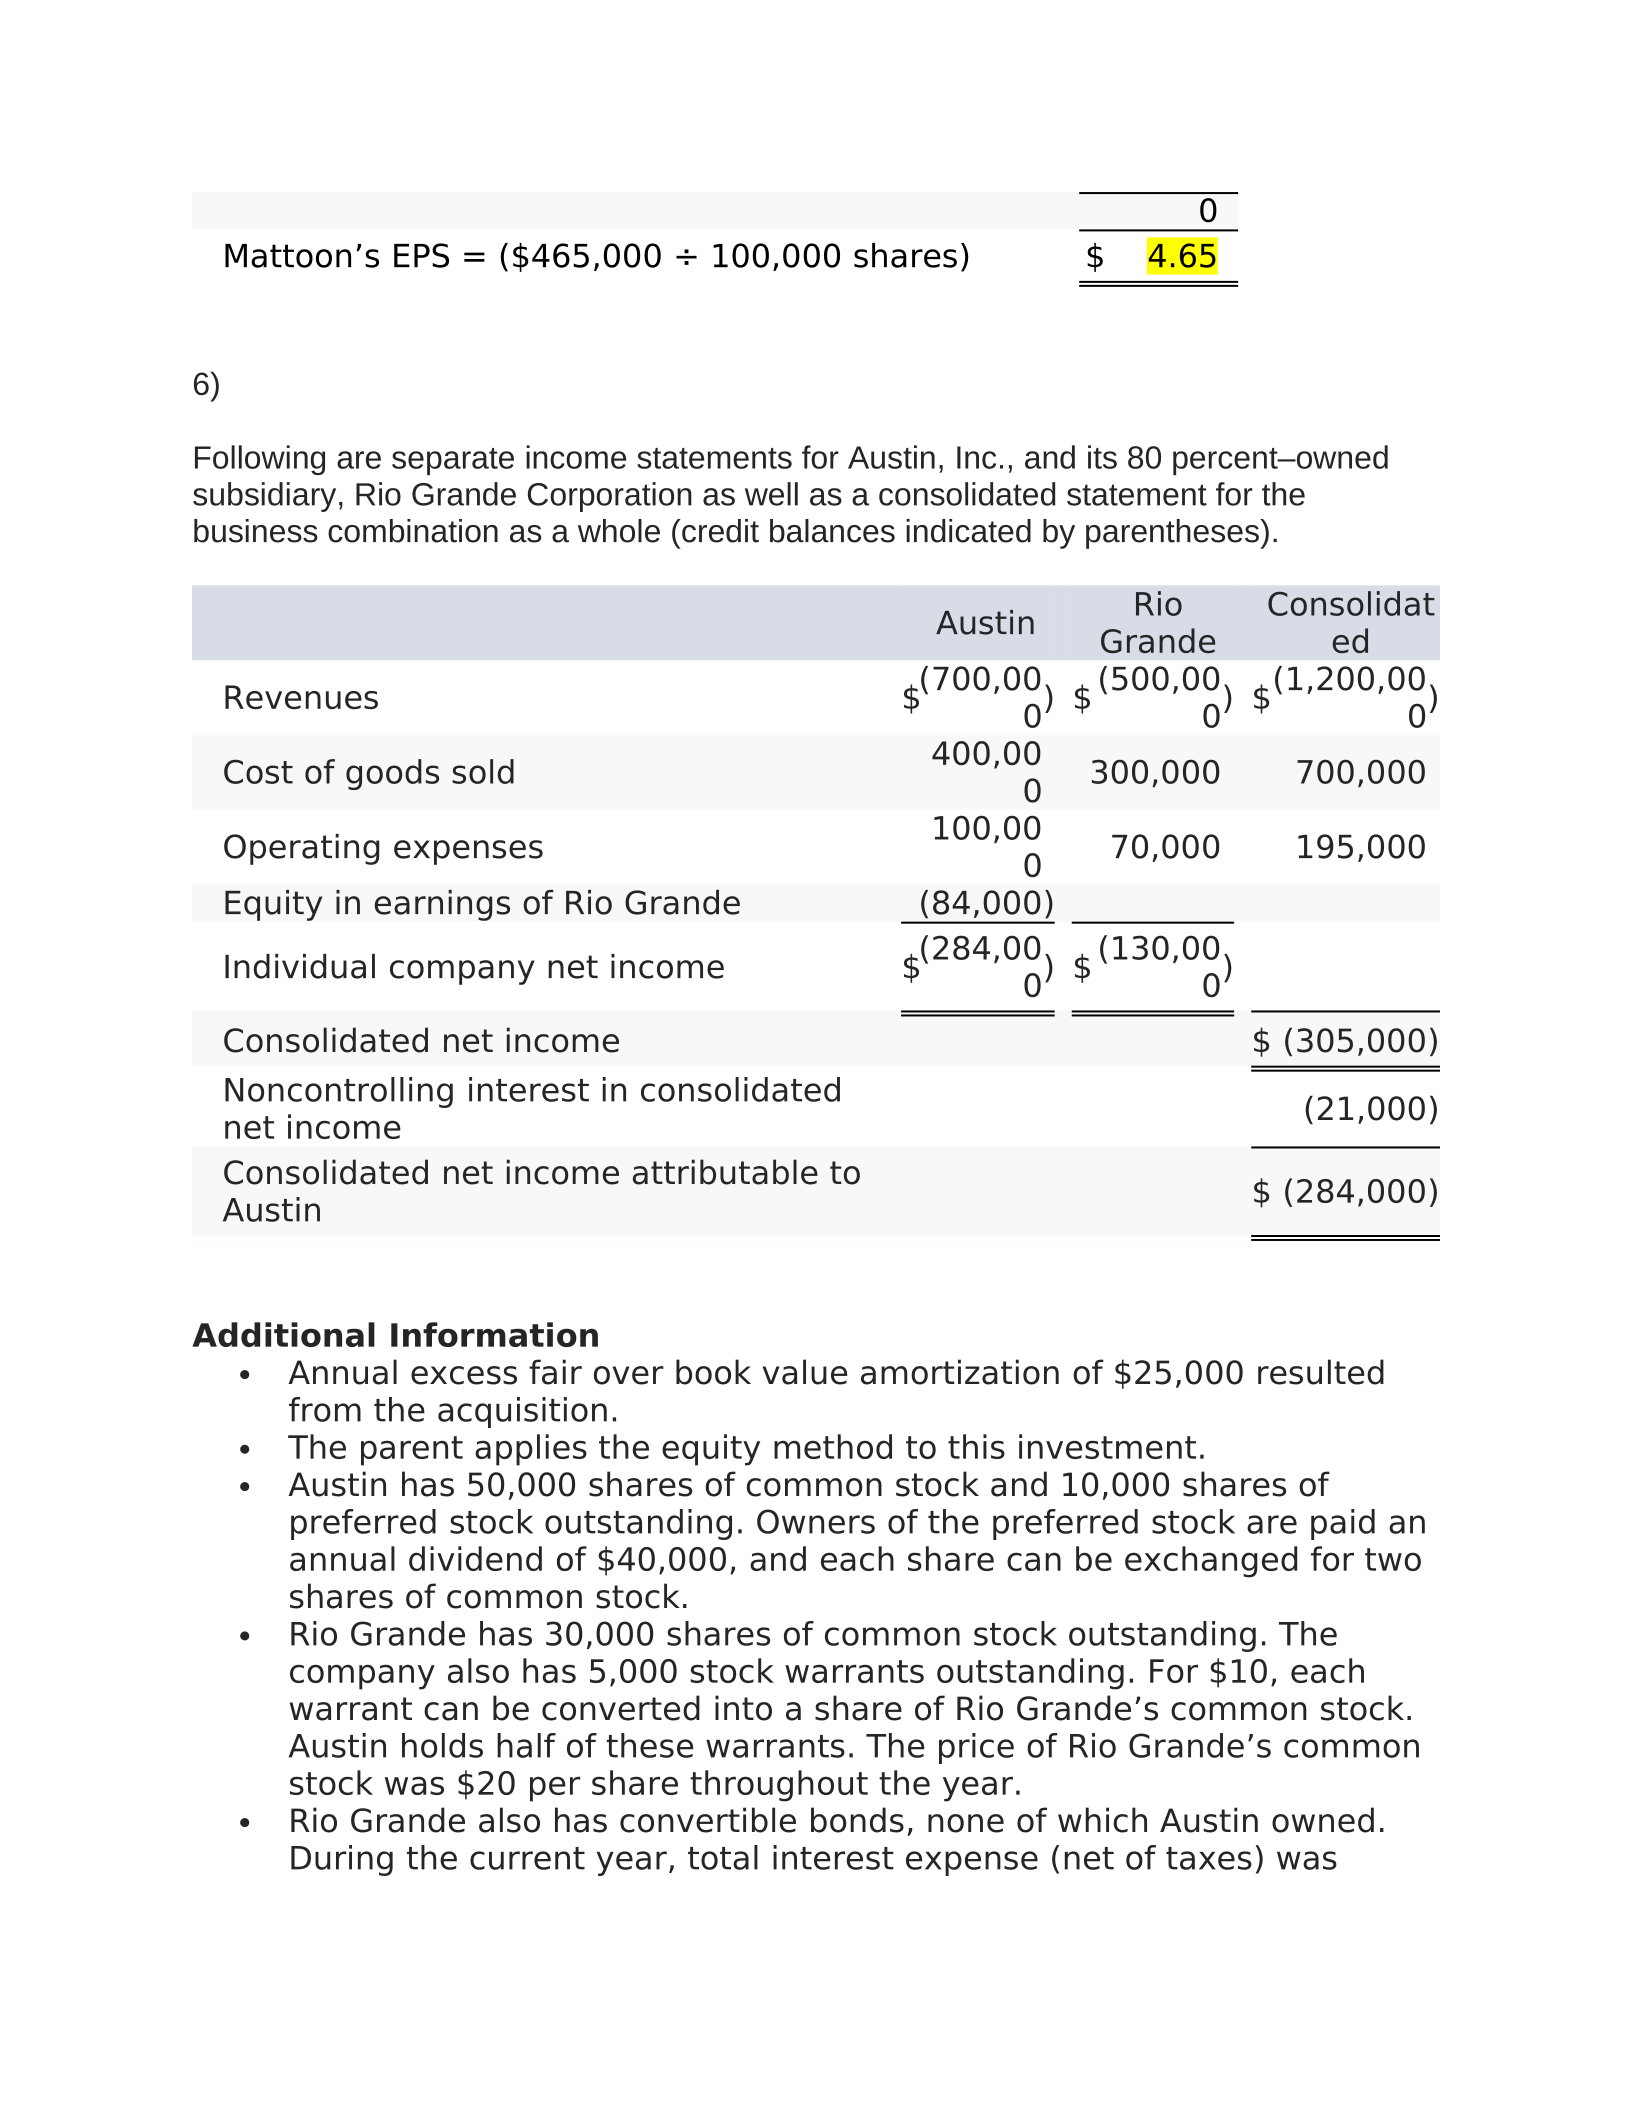
0
Mattoon’s EPS = ($465,000 ÷ 100,000 shares) $ 4.65
6)
Following are separate income statements for Austin, Inc., and its 80 percent–owned
subsidiary, Rio Grande Corporation as well as a consolidated statement for the
business combination as a whole (credit balances indicated by parentheses).
Austin Rio
Grande
Consolidat
ed
Revenues $(700,00
0) $ (500,00
0) $(1,200,00
0)
Cost of goods sold 400,00
0 300,000 700,000
Operating expenses 100,00
0 70,000 195,000
Equity in earnings of Rio Grande (84,000)
Individual company net income $(284,00
0) $ (130,00
0)
Consolidated net income $ (305,000)
Noncontrolling interest in consolidated
net income (21,000)
Consolidated net income attributable to
Austin $ (284,000)
Additional Information
Annual excess fair over book value amortization of $25,000 resulted
from the acquisition.
The parent applies the equity method to this investment.
Austin has 50,000 shares of common stock and 10,000 shares of
preferred stock outstanding. Owners of the preferred stock are paid an
annual dividend of $40,000, and each share can be exchanged for two
shares of common stock.
Rio Grande has 30,000 shares of common stock outstanding. The
company also has 5,000 stock warrants outstanding. For $10, each
warrant can be converted into a share of Rio Grande’s common stock.
Austin holds half of these warrants. The price of Rio Grande’s common
stock was $20 per share throughout the year.
Rio Grande also has convertible bonds, none of which Austin owned.
During the current year, total interest expense (net of taxes) was
$22,000. These bonds can be exchanged for 10,000 shares of the
subsidiary’s common stock.
Explanation
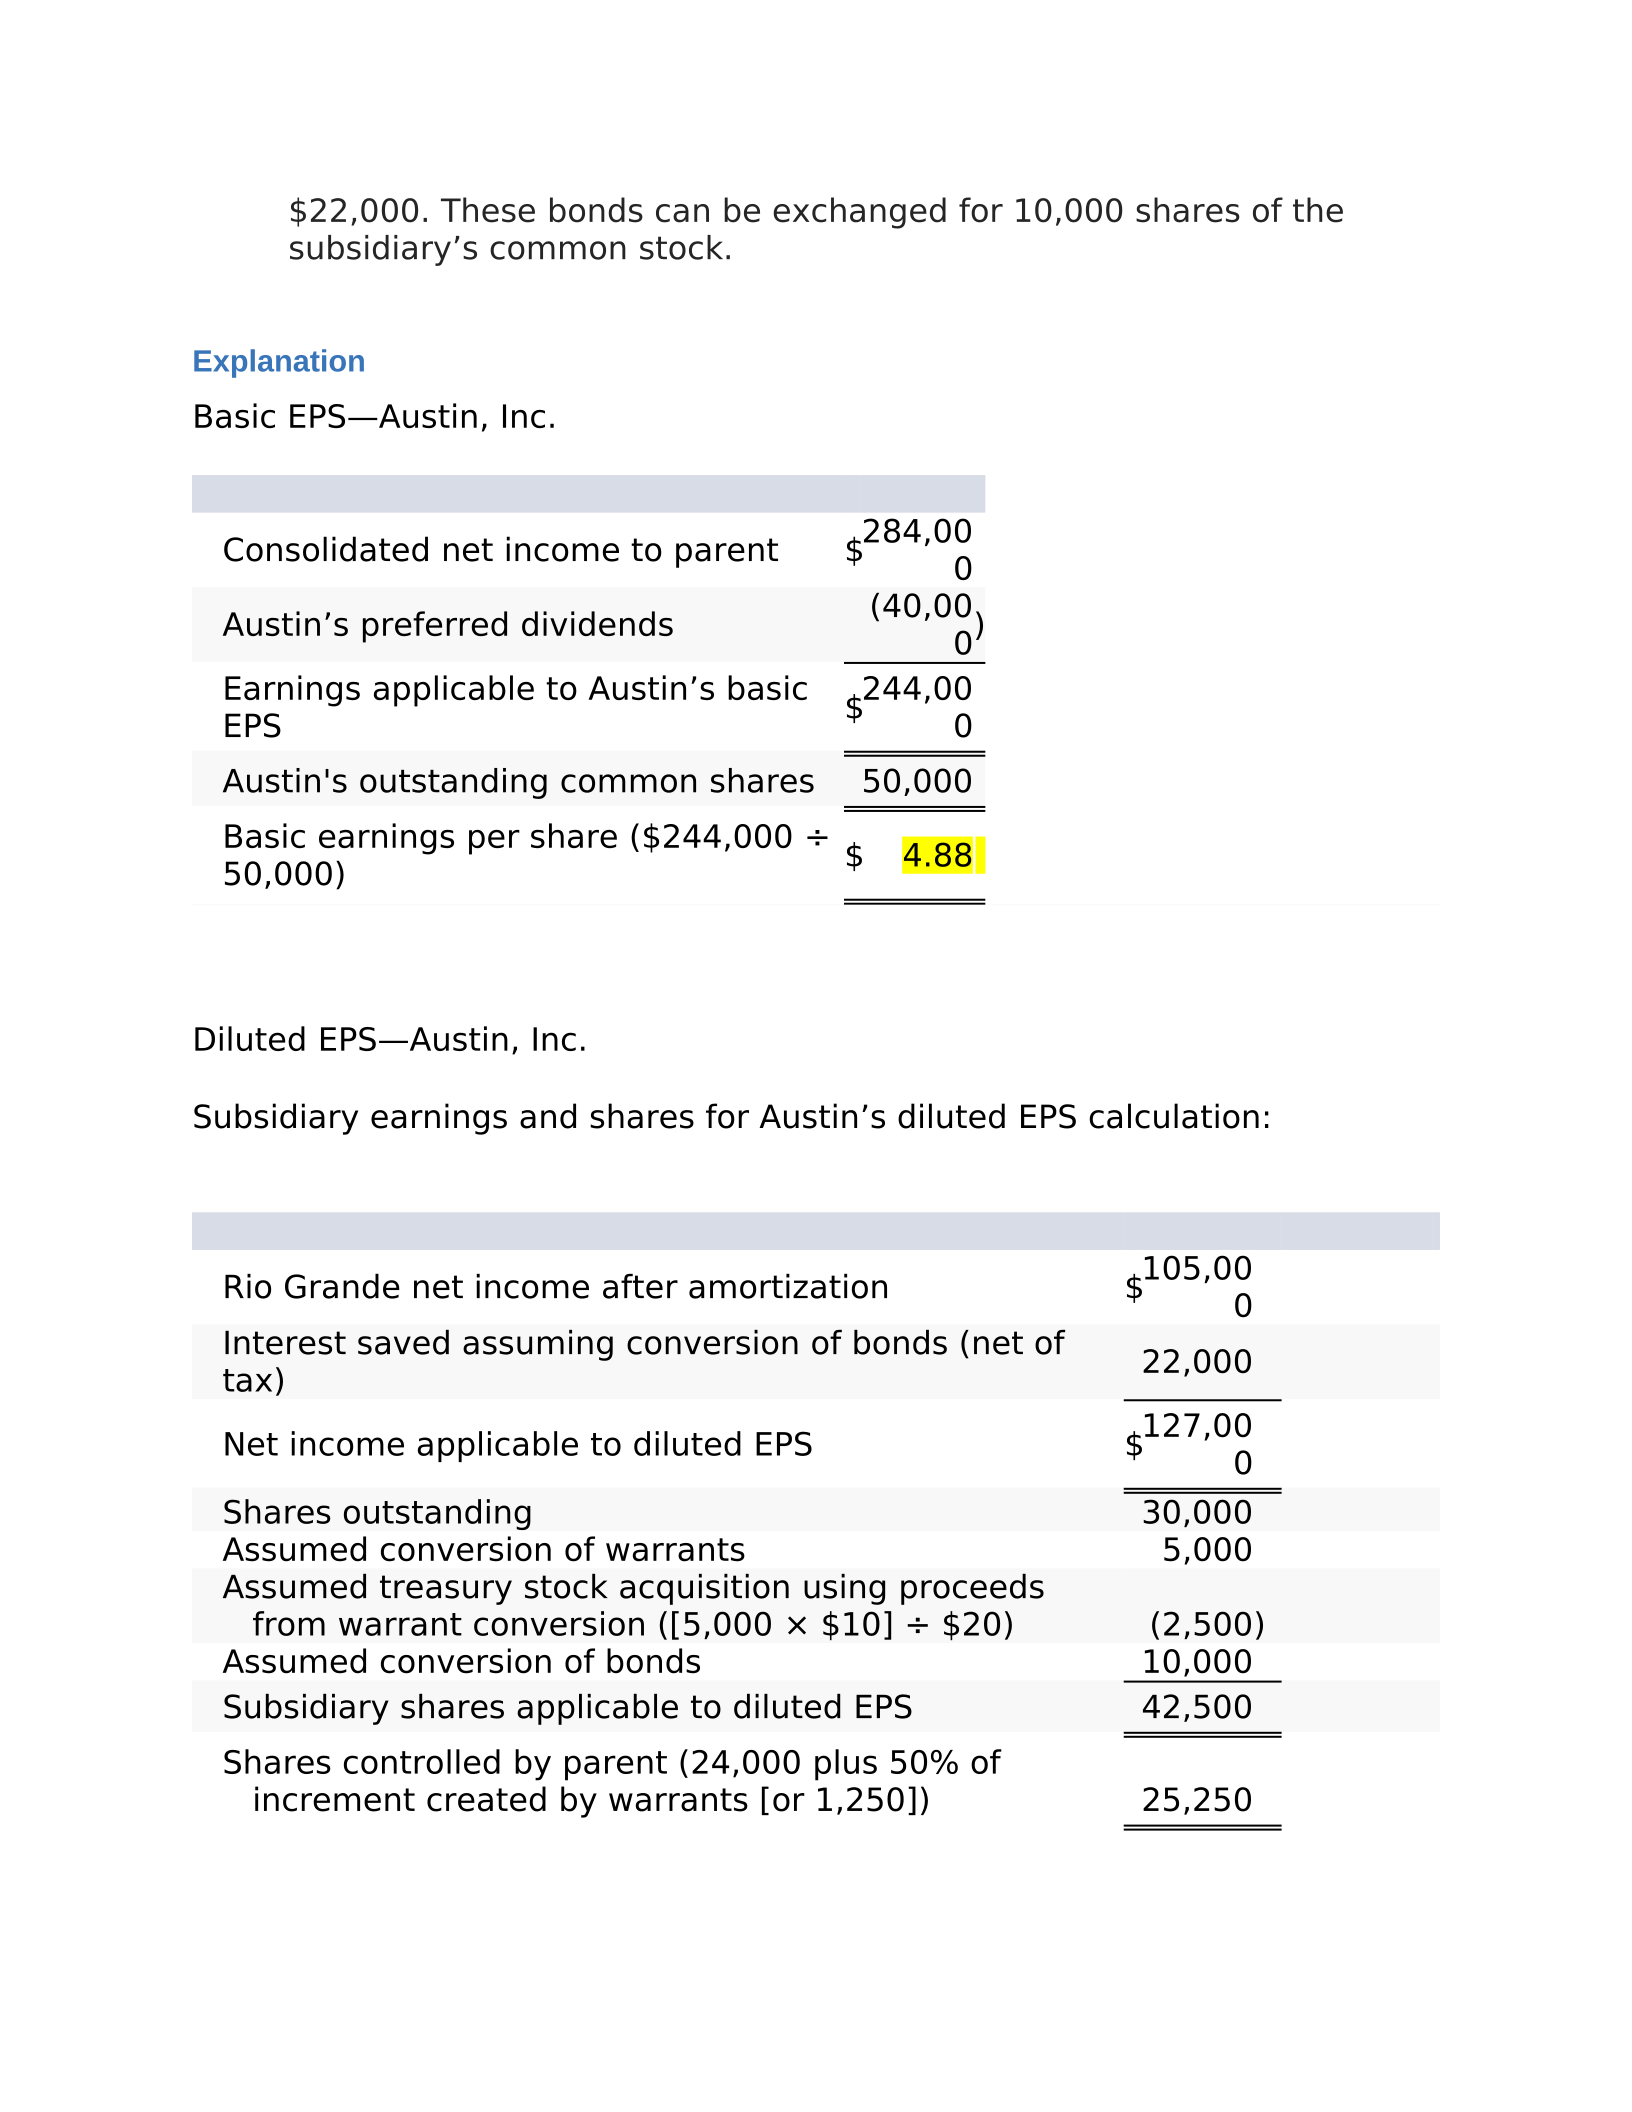
Basic EPS—Austin, Inc.
Consolidated net income to parent $284,00
0
Austin’s preferred dividends (40,00
0)
Earnings applicable to Austin’s basic
EPS $244,00
0
Austin's outstanding common shares 50,000
Basic earnings per share ($244,000 ÷
50,000) $ 4.88
Diluted EPS—Austin, Inc.
Subsidiary earnings and shares for Austin’s diluted EPS calculation:
Rio Grande net income after amortization $105,00
0
Interest saved assuming conversion of bonds (net of
tax) 22,000
Net income applicable to diluted EPS $127,00
0
Shares outstanding 30,000
Assumed conversion of warrants 5,000
Assumed treasury stock acquisition using proceeds
from warrant conversion ([5,000 × $10] ÷ $20) (2,500)
Assumed conversion of bonds 10,000
Subsidiary shares applicable to diluted EPS 42,500
Shares controlled by parent (24,000 plus 50% of
increment created by warrants [or 1,250]) 25,250
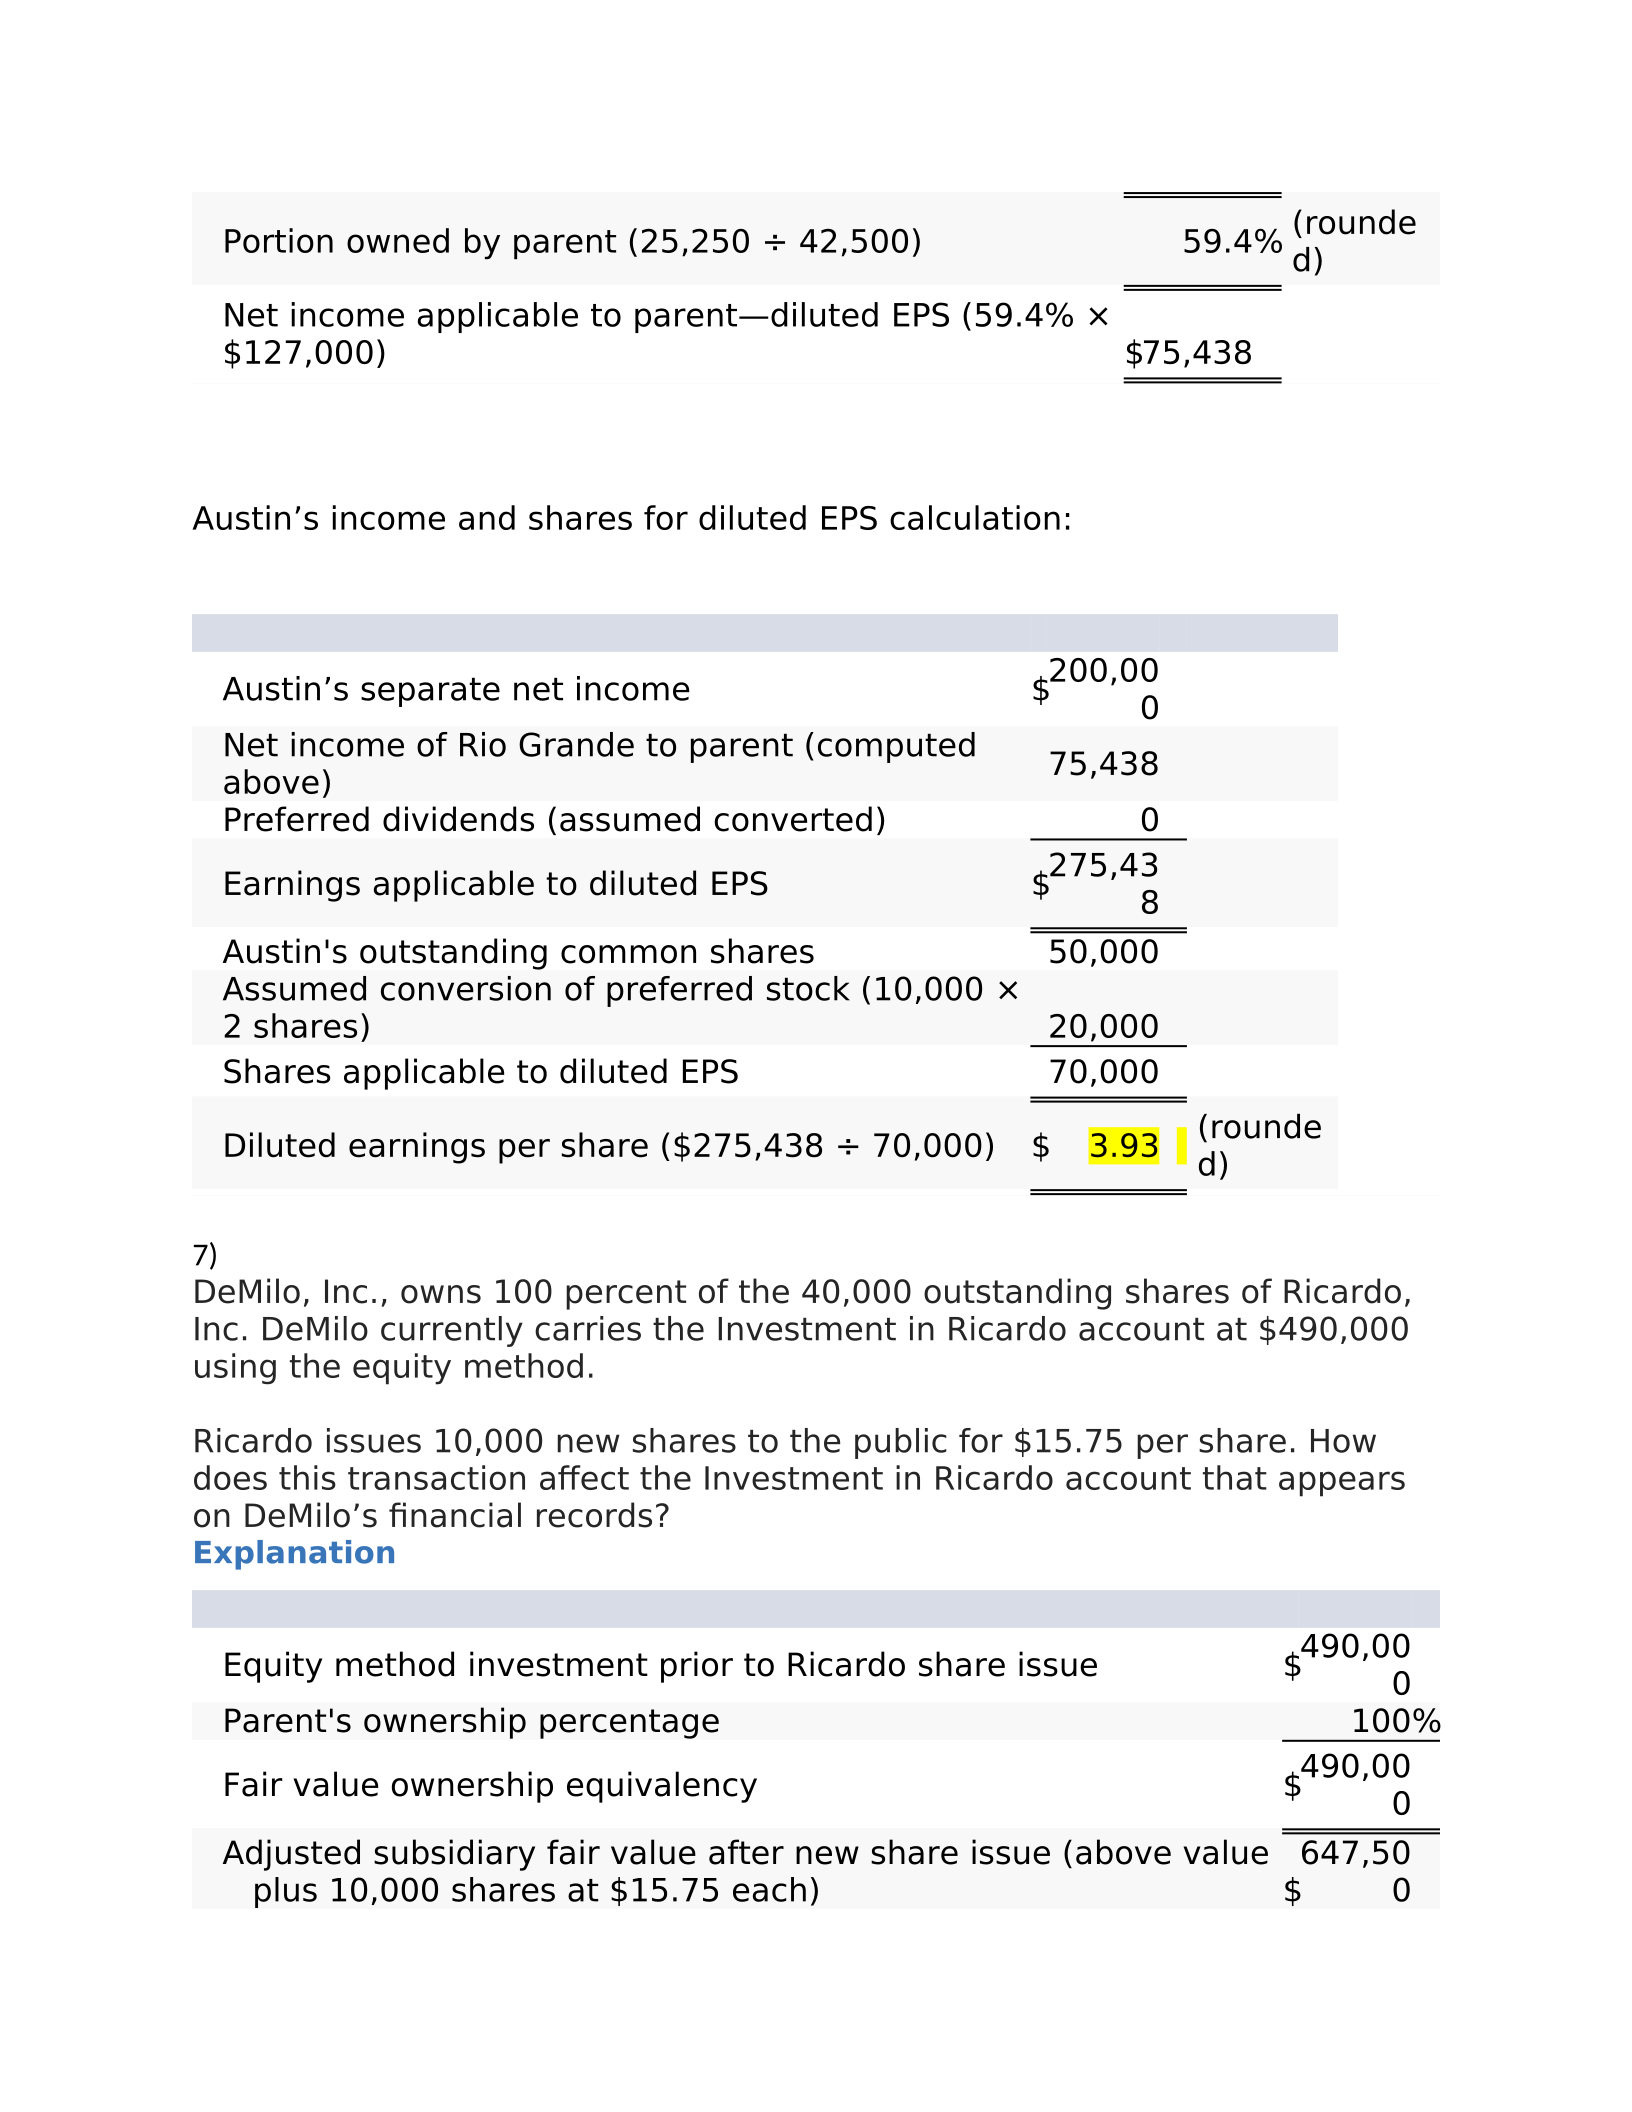
Portion owned by parent (25,250 ÷ 42,500) 59.4% (rounde
d)
Net income applicable to parent—diluted EPS (59.4% ×
$127,000) $75,438
Austin’s income and shares for diluted EPS calculation:
Austin’s separate net income $200,00
0
Net income of Rio Grande to parent (computed
above) 75,438
Preferred dividends (assumed converted) 0
Earnings applicable to diluted EPS $275,43
8
Austin's outstanding common shares 50,000
Assumed conversion of preferred stock (10,000 ×
2 shares) 20,000
Shares applicable to diluted EPS 70,000
Diluted earnings per share ($275,438 ÷ 70,000) $ 3.93 (rounde
d)
7)
DeMilo, Inc., owns 100 percent of the 40,000 outstanding shares of Ricardo,
Inc. DeMilo currently carries the Investment in Ricardo account at $490,000
using the equity method.
Ricardo issues 10,000 new shares to the public for $15.75 per share. How
does this transaction affect the Investment in Ricardo account that appears
on DeMilo’s financial records?
Explanation
Equity method investment prior to Ricardo share issue $490,00
0
Parent's ownership percentage 100%
Fair value ownership equivalency $490,00
0
Adjusted subsidiary fair value after new share issue (above value
plus 10,000 shares at $15.75 each) $
647,50
0
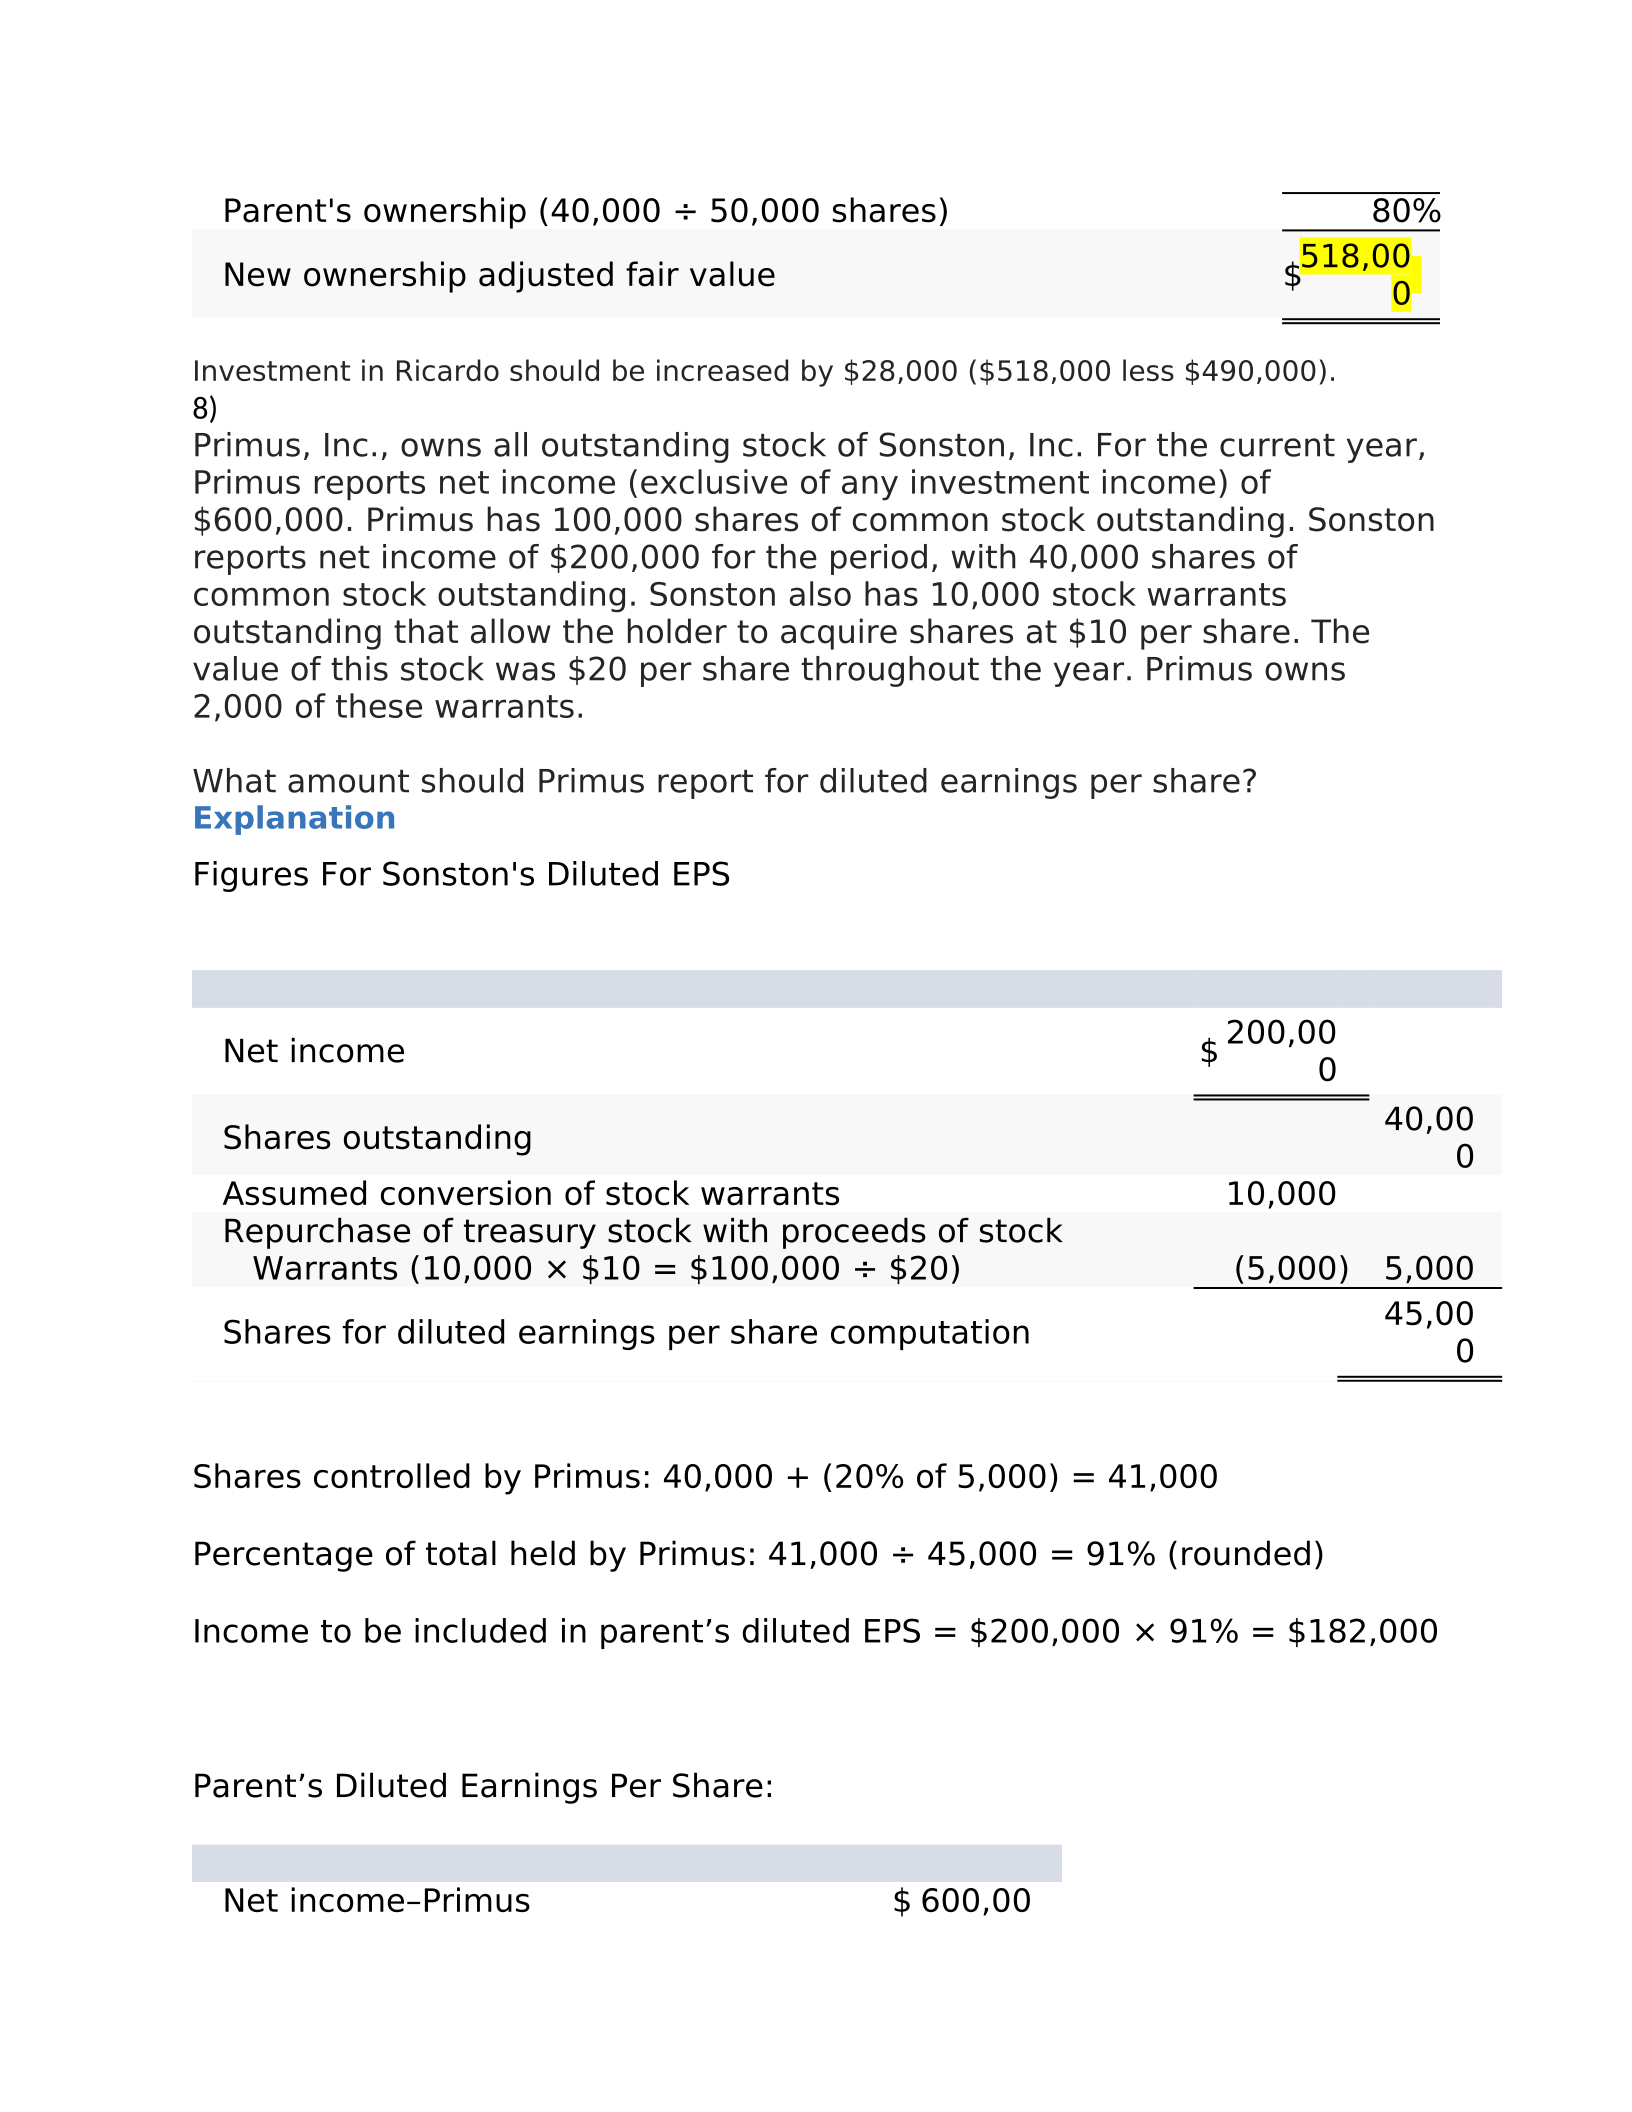
Parent's ownership (40,000 ÷ 50,000 shares) 80%
New ownership adjusted fair value $518,00
0
Investment in Ricardo should be increased by $28,000 ($518,000 less $490,000).
8)
Primus, Inc., owns all outstanding stock of Sonston, Inc. For the current year,
Primus reports net income (exclusive of any investment income) of
$600,000. Primus has 100,000 shares of common stock outstanding. Sonston
reports net income of $200,000 for the period, with 40,000 shares of
common stock outstanding. Sonston also has 10,000 stock warrants
outstanding that allow the holder to acquire shares at $10 per share. The
value of this stock was $20 per share throughout the year. Primus owns
2,000 of these warrants.
What amount should Primus report for diluted earnings per share?
Explanation
Figures For Sonston's Diluted EPS
Net income $ 200,00
0
Shares outstanding 40,00
0
Assumed conversion of stock warrants 10,000
Repurchase of treasury stock with proceeds of stock
Warrants (10,000 × $10 = $100,000 ÷ $20) (5,000) 5,000
Shares for diluted earnings per share computation 45,00
0
Shares controlled by Primus: 40,000 + (20% of 5,000) = 41,000
Percentage of total held by Primus: 41,000 ÷ 45,000 = 91% (rounded)
Income to be included in parent’s diluted EPS = $200,000 × 91% = $182,000
Parent’s Diluted Earnings Per Share:
Net income–Primus $ 600,00
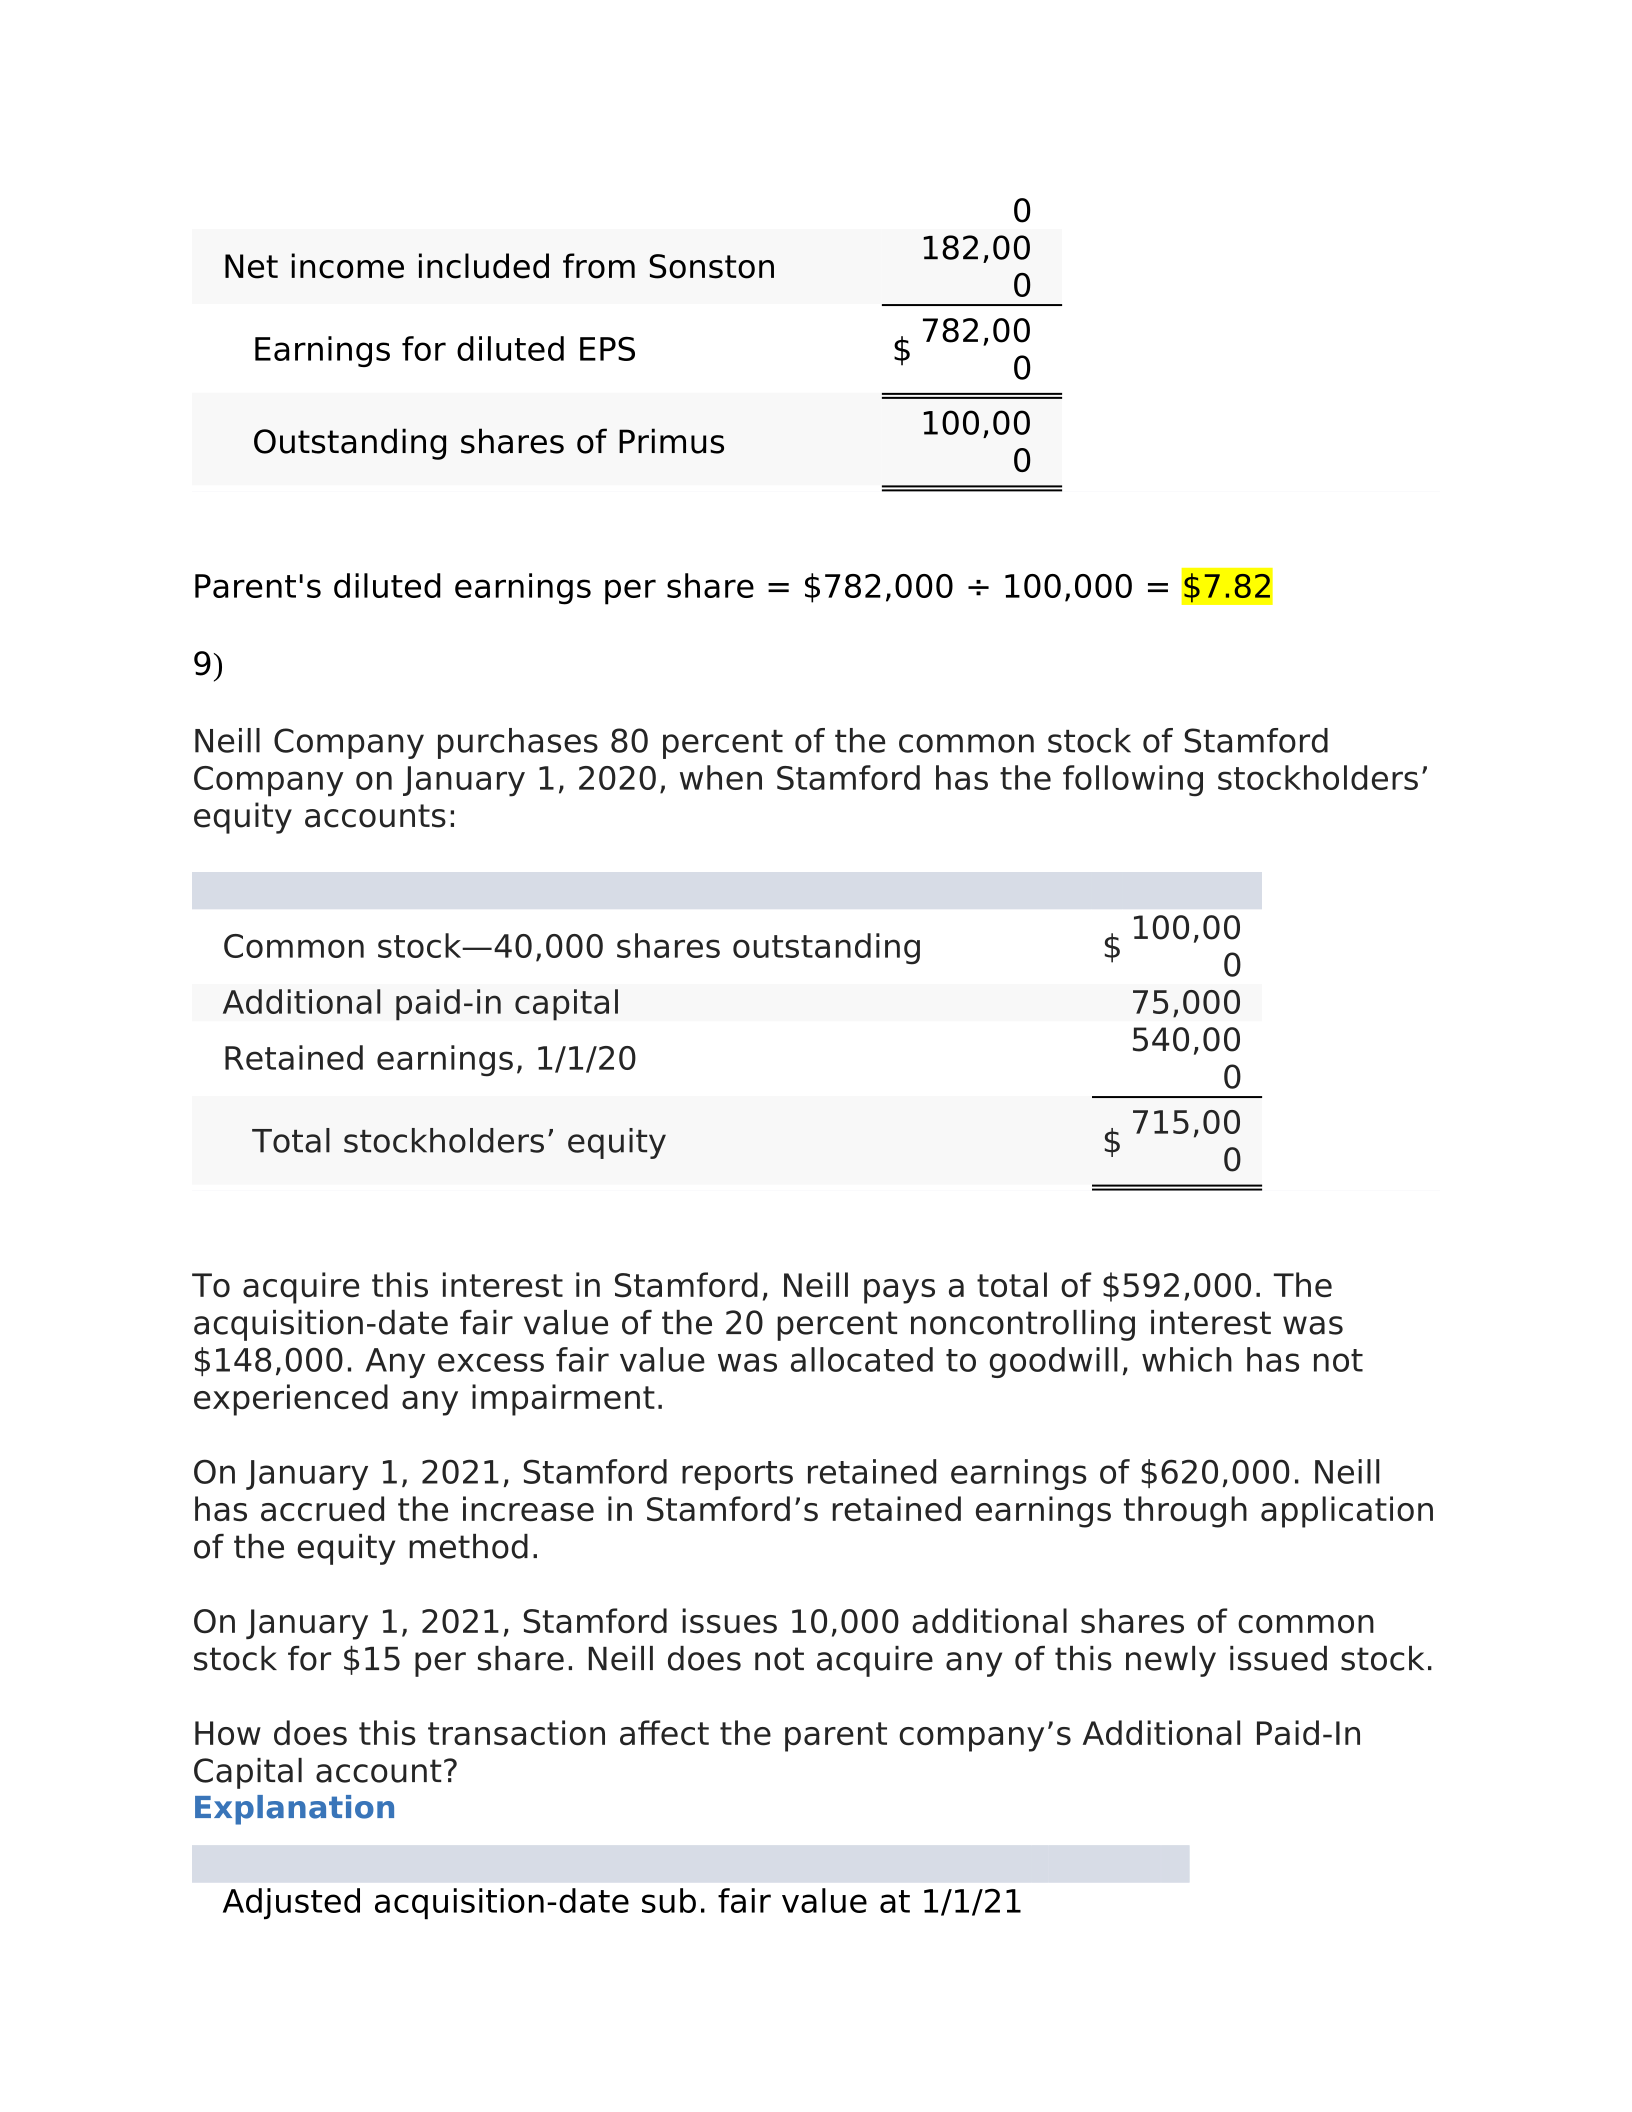
0
Net income included from Sonston 182,00
0
Earnings for diluted EPS $ 782,00
0
Outstanding shares of Primus 100,00
0
Parent's diluted earnings per share = $782,000 ÷ 100,000 = $7.82
9)
Neill Company purchases 80 percent of the common stock of Stamford
Company on January 1, 2020, when Stamford has the following stockholders’
equity accounts:
Common stock—40,000 shares outstanding $ 100,00
0
Additional paid-in capital 75,000
Retained earnings, 1/1/20 540,00
0
Total stockholders’ equity $ 715,00
0
To acquire this interest in Stamford, Neill pays a total of $592,000. The
acquisition-date fair value of the 20 percent noncontrolling interest was
$148,000. Any excess fair value was allocated to goodwill, which has not
experienced any impairment.
On January 1, 2021, Stamford reports retained earnings of $620,000. Neill
has accrued the increase in Stamford’s retained earnings through application
of the equity method.
On January 1, 2021, Stamford issues 10,000 additional shares of common
stock for $15 per share. Neill does not acquire any of this newly issued stock.
How does this transaction affect the parent company’s Additional Paid-In
Capital account?
Explanation
Adjusted acquisition-date sub. fair value at 1/1/21
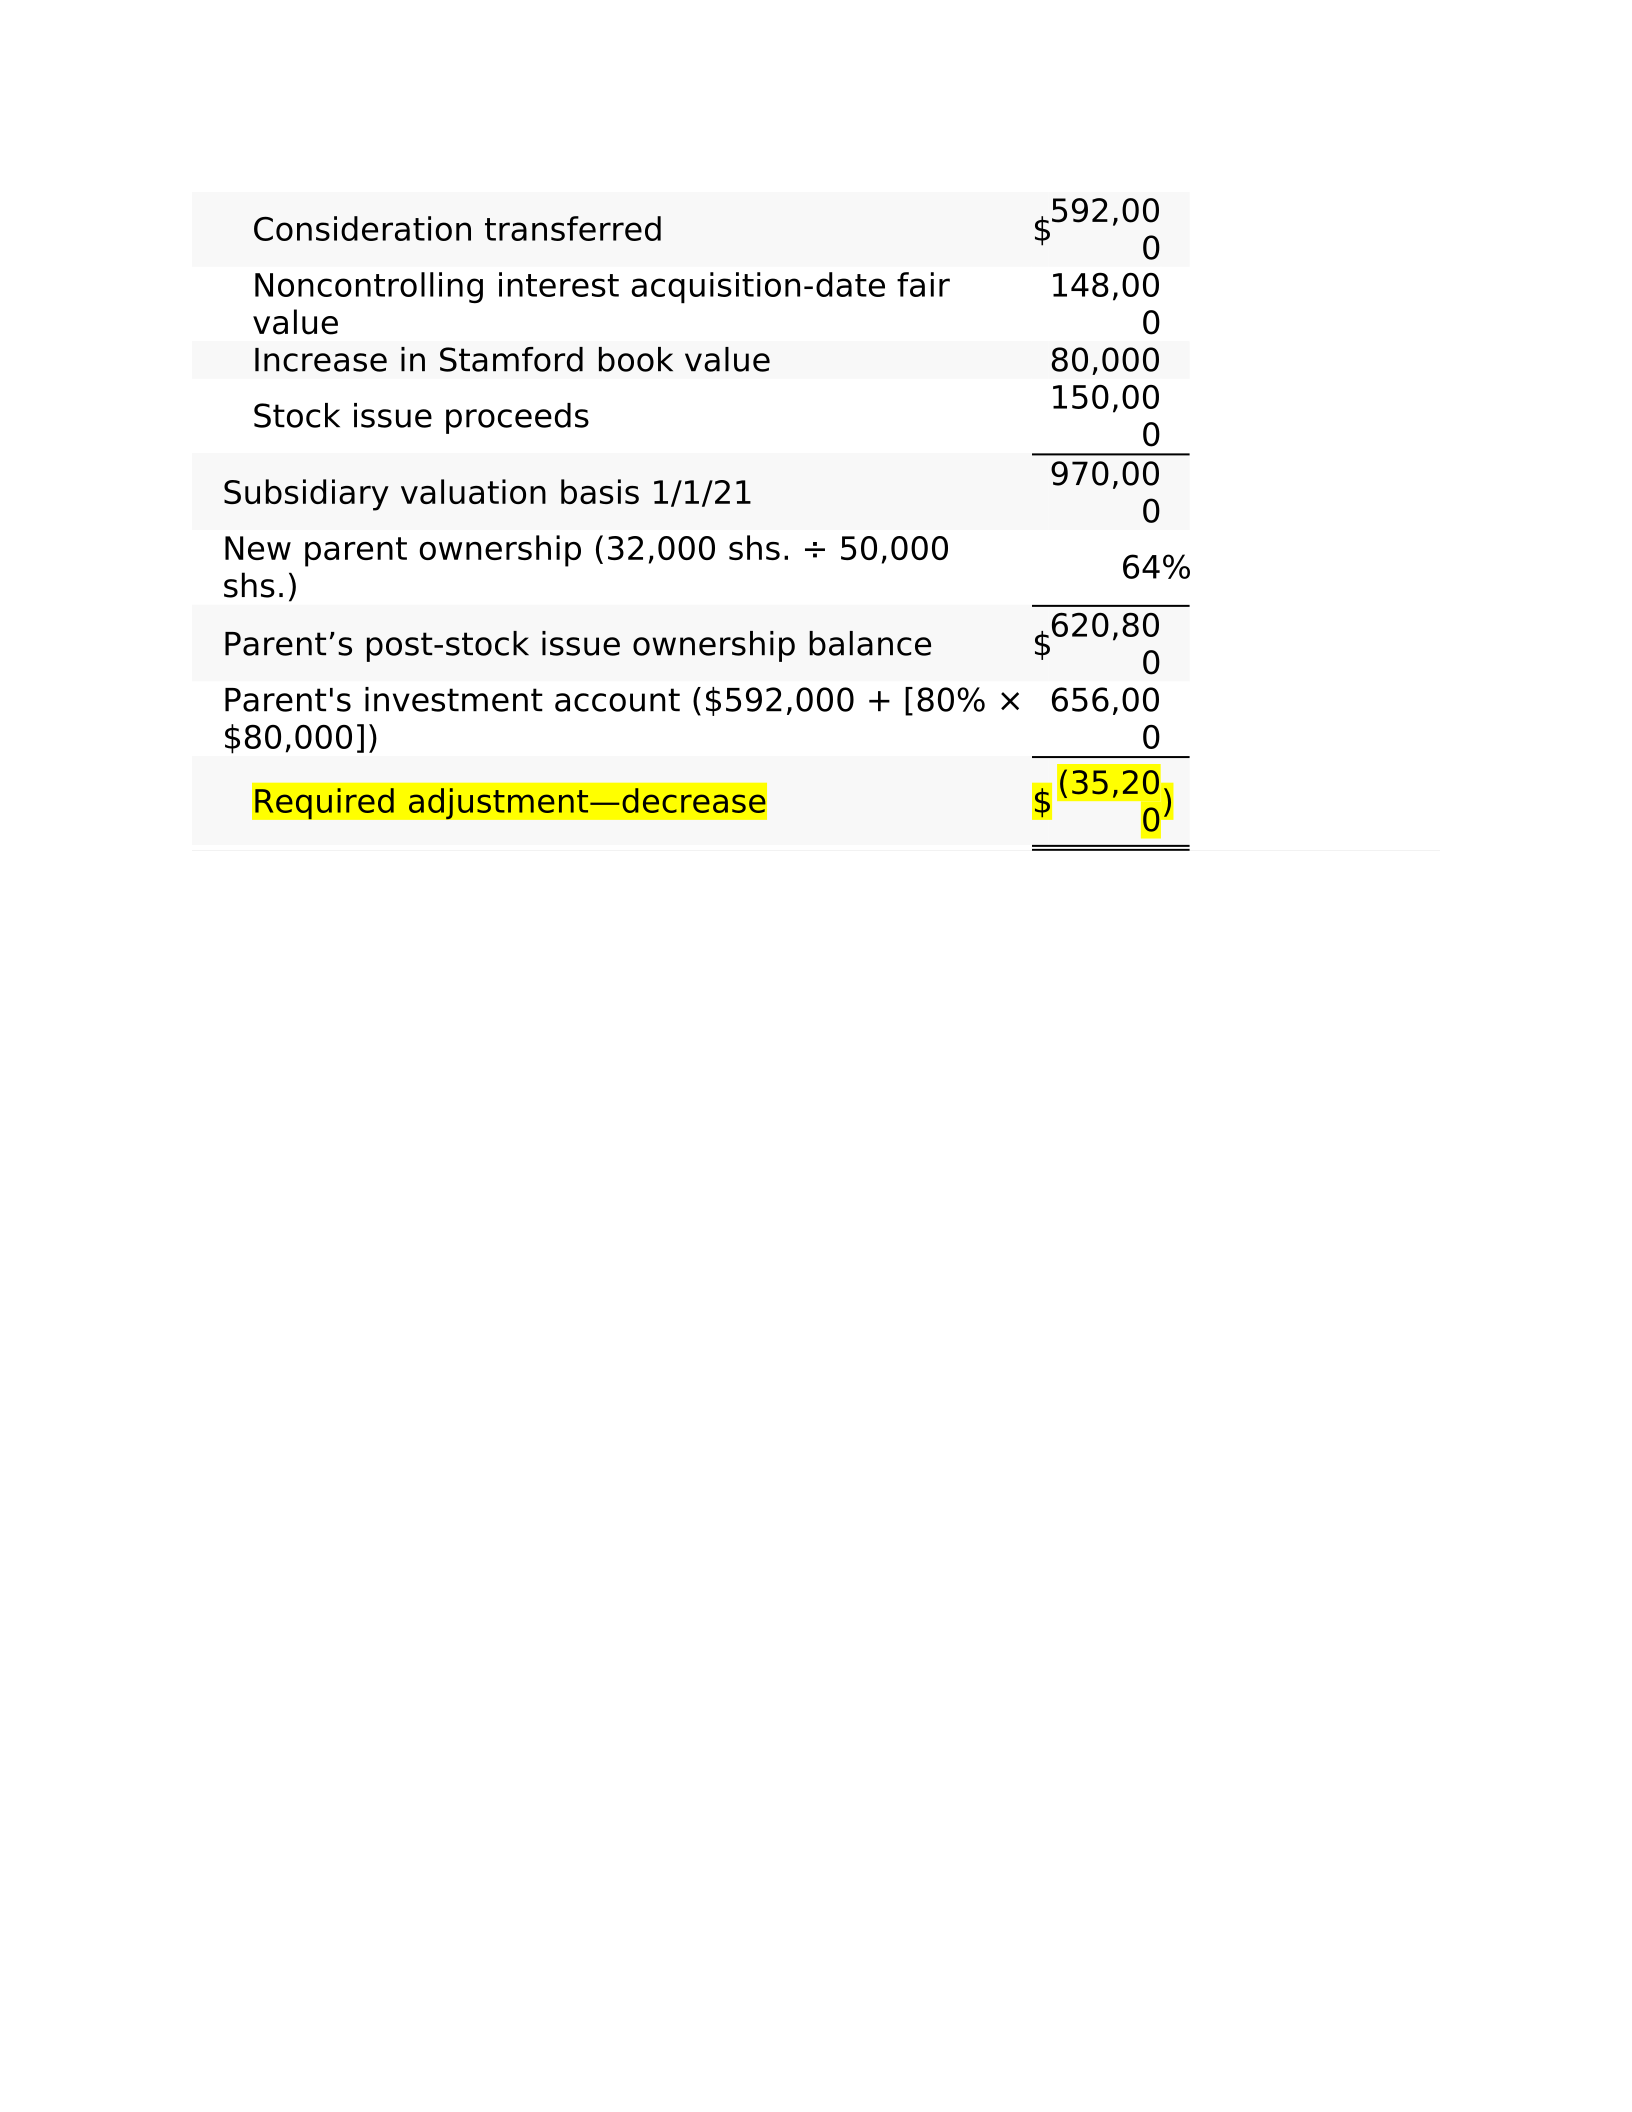
Consideration transferred $592,00
0
Noncontrolling interest acquisition-date fair
value 148,00
0
Increase in Stamford book value 80,000
Stock issue proceeds 150,00
0
Subsidiary valuation basis 1/1/21 970,00
0
New parent ownership (32,000 shs. ÷ 50,000
shs.) 64%
Parent’s post-stock issue ownership balance $620,80
0
Parent's investment account ($592,000 + [80% ×
$80,000]) 656,00
0
Required adjustment—decrease $ (35,20
0)
Powered by TCPDF (www.tcpdf.org)

