


ACCT 302 - INTERMEDIATE
ACCOUNTING II - Ratio analysis and
interpretation
Question Bank - Set 5
Liberty University
Question 1
Question
A company has the following financial information for the current year:
Total assets:
$
500,000
Total liabilities:
$
200,000
Net income:
$
50,000
Shareholders’ equity:
$
300,000
Calculate the following ratios and interpret the results:
1. Debt-to-equity ratio
2. Return on assets (ROA)
Solution
Step 1: Calculate Debt-to-equity Ratio The debt-to-equity ratio is calcu-
lated as total liabilities divided by shareholders’ equity.
Debt-to-equity ratio = Total liabilities
Shareholders’ equity
Substitute the given values into the formula:
Debt-to-equity ratio = $200,000
$300,000 =2
3= 0.67
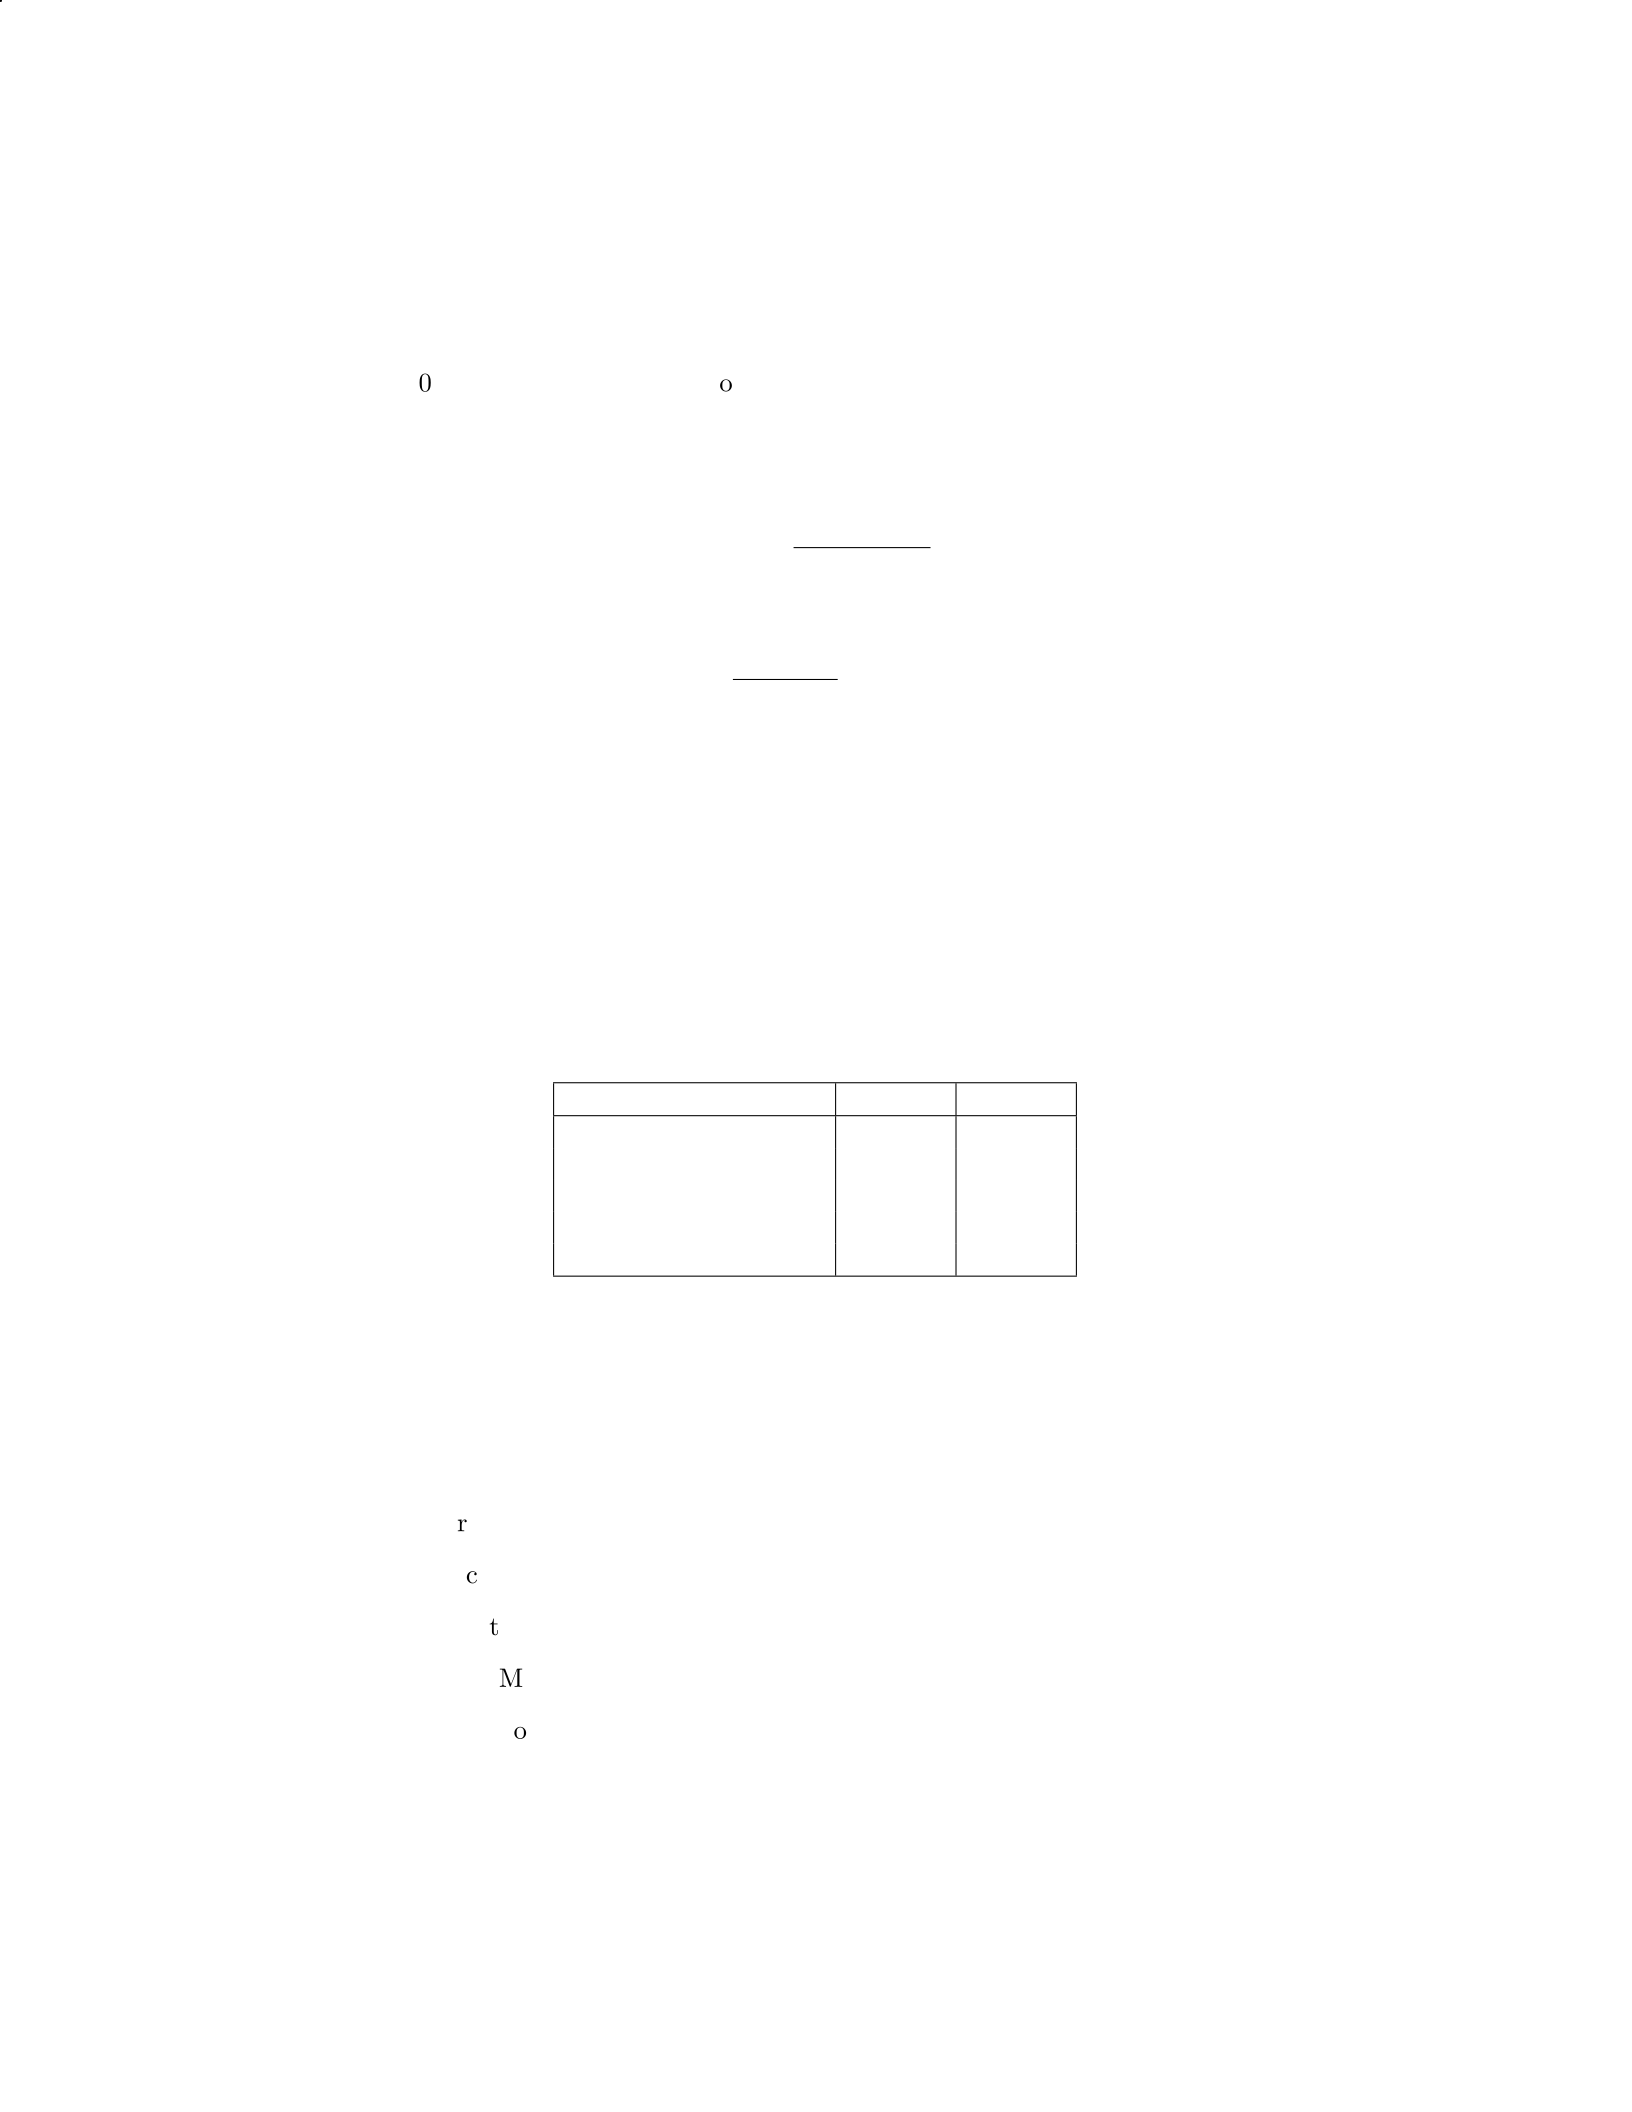
Interpretation: A debt-to-equity ratio of 0.67 means that the company
has
$
0.67 in debt for every
$
1 of shareholders’ equity. This indicates that the
company is relying more on equity financing compared to debt financing.
Step 2: Calculate Return on Assets (ROA) Return on Assets (ROA)
is calculated as net income divided by total assets.
ROA = Net income
Total assets
Substitute the given values into the formula:
ROA = $50,000
$500,000 = 0.1 = 10%
Interpretation: An ROA of 10% means that the company generates a
profit of 10 cents for every dollar of assets it owns. This shows how efficiently
the company is using its assets to generate profit.
Question 2
Question
A company reported the following financial information for two consecutive
years:
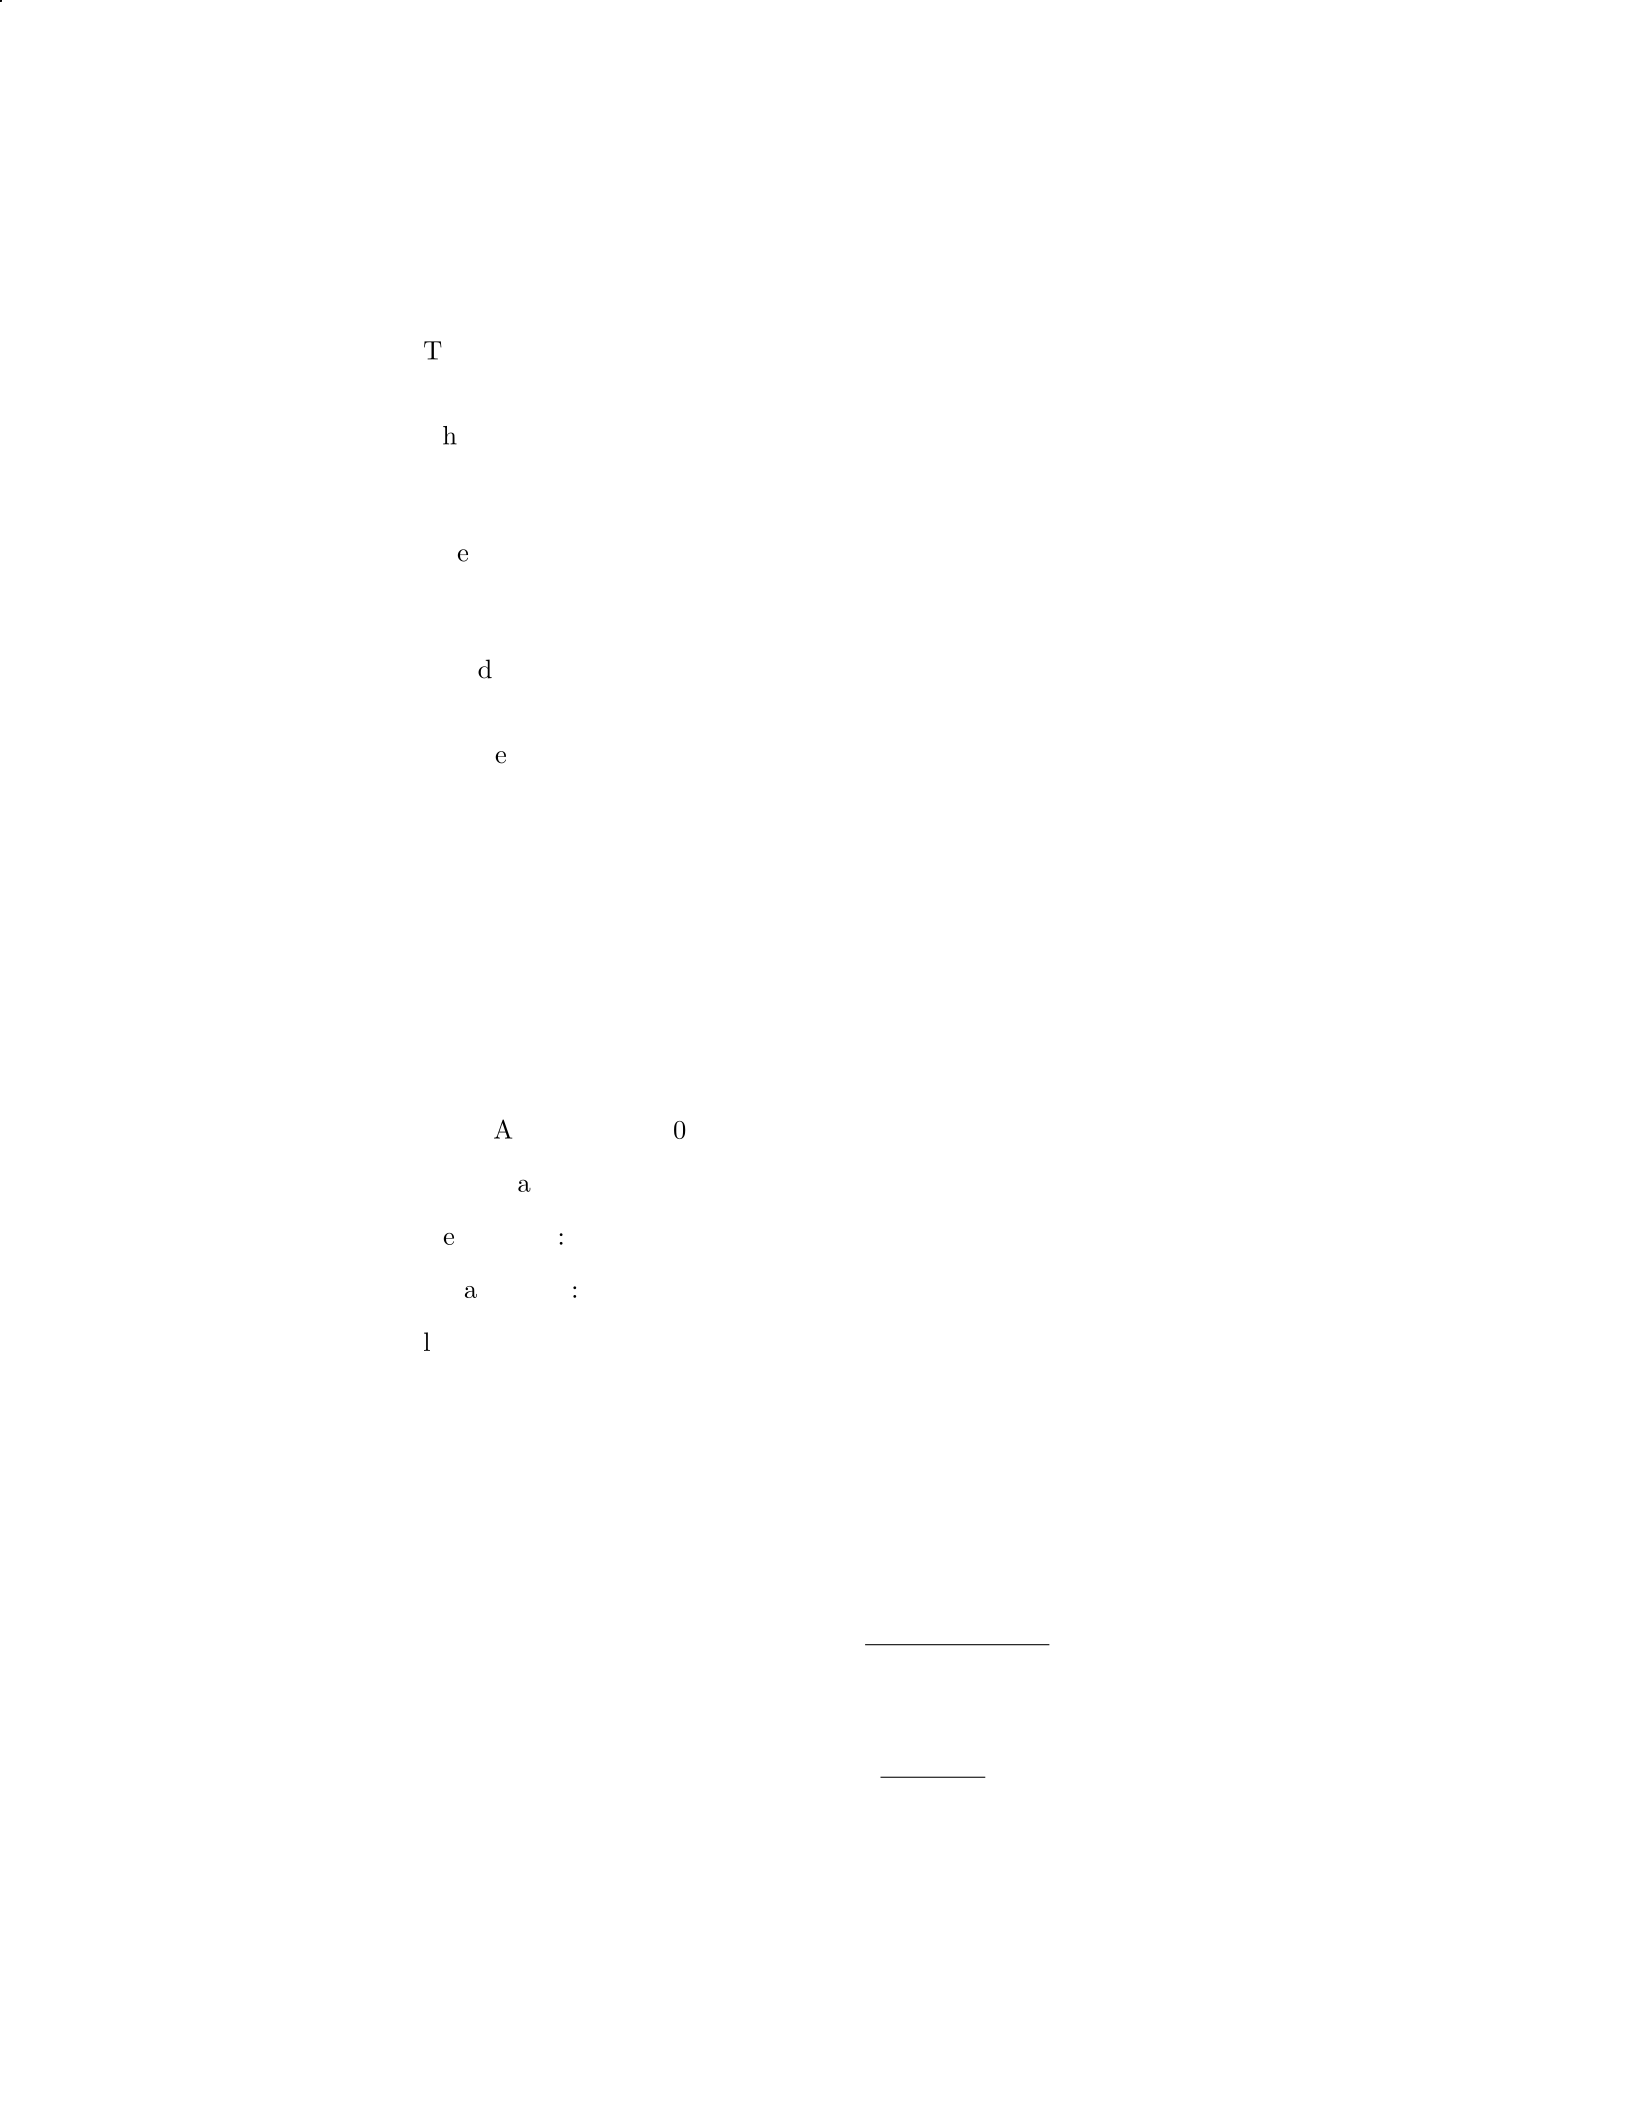
Ratio Year 1 Year 2
Current Ratio 1.5 2.0
Quick Ratio 1.0 1.2
Debt to Equity Ratio 0.7 1.0
Profit Margin 15% 12%
Return on Equity 20% 18%
Based on the information provided, analyze the company’s financial perfor-
mance over the two years and provide an interpretation of the ratios.
Solution
Step 1: Calculate the changes in the ratios over the two years.
Current Ratio Change: 2.0−1.5=0.5
Quick Ratio Change: 1.2−1.0=0.2
Debt to Equity Ratio Change: 1.0−0.7=0.3
Profit Margin Change: 12% −15% = −3%
Return on Equity Change: 18% −20% = −2%
Step 2: Analyze the changes in the ratios.
2
The increase in the Current Ratio from 1.5 to 2.0 indicates that the com-
pany’s liquidity position improved over the two years.
The increase in the Quick Ratio from 1.0 to 1.2 also reflects an improve-
ment in the company’s ability to meet its short-term obligations using its
most liquid assets.
The Debt to Equity Ratio increased from 0.7 to 1.0, indicating that the
company took on more debt relative to its equity. This may increase
financial risk.
The decrease in Profit Margin from 15% to 12% suggests a decline in the
company’s profitability, which could be a concern.
The decrease in Return on Equity from 20% to 18% indicates that the
company generated less profit with each dollar of equity investment.
Overall, the company’s liquidity improved, but there are concerns regarding
increasing debt levels and declining profitability.
Question 3
Question
A company’s financial statements show the following figures:
Total Assets:
$
800,000
Total Liabilities:
$
400,000
Net Income:
$
100,000
Total Equity:
$
400,000
Calculate the following ratios and interpret the results:
1. Debt-to-Equity Ratio
2. Return on Assets (ROA)
Solution
Step 1: Calculate the Debt-to-Equity Ratio The Debt-to-Equity Ratio is
calculated as:
Debt-to-Equity Ratio = Total Liabilities
Total Equity
Substitute the given values into the formula:
Debt-to-Equity Ratio = $400,000
$400,000 = 1
3
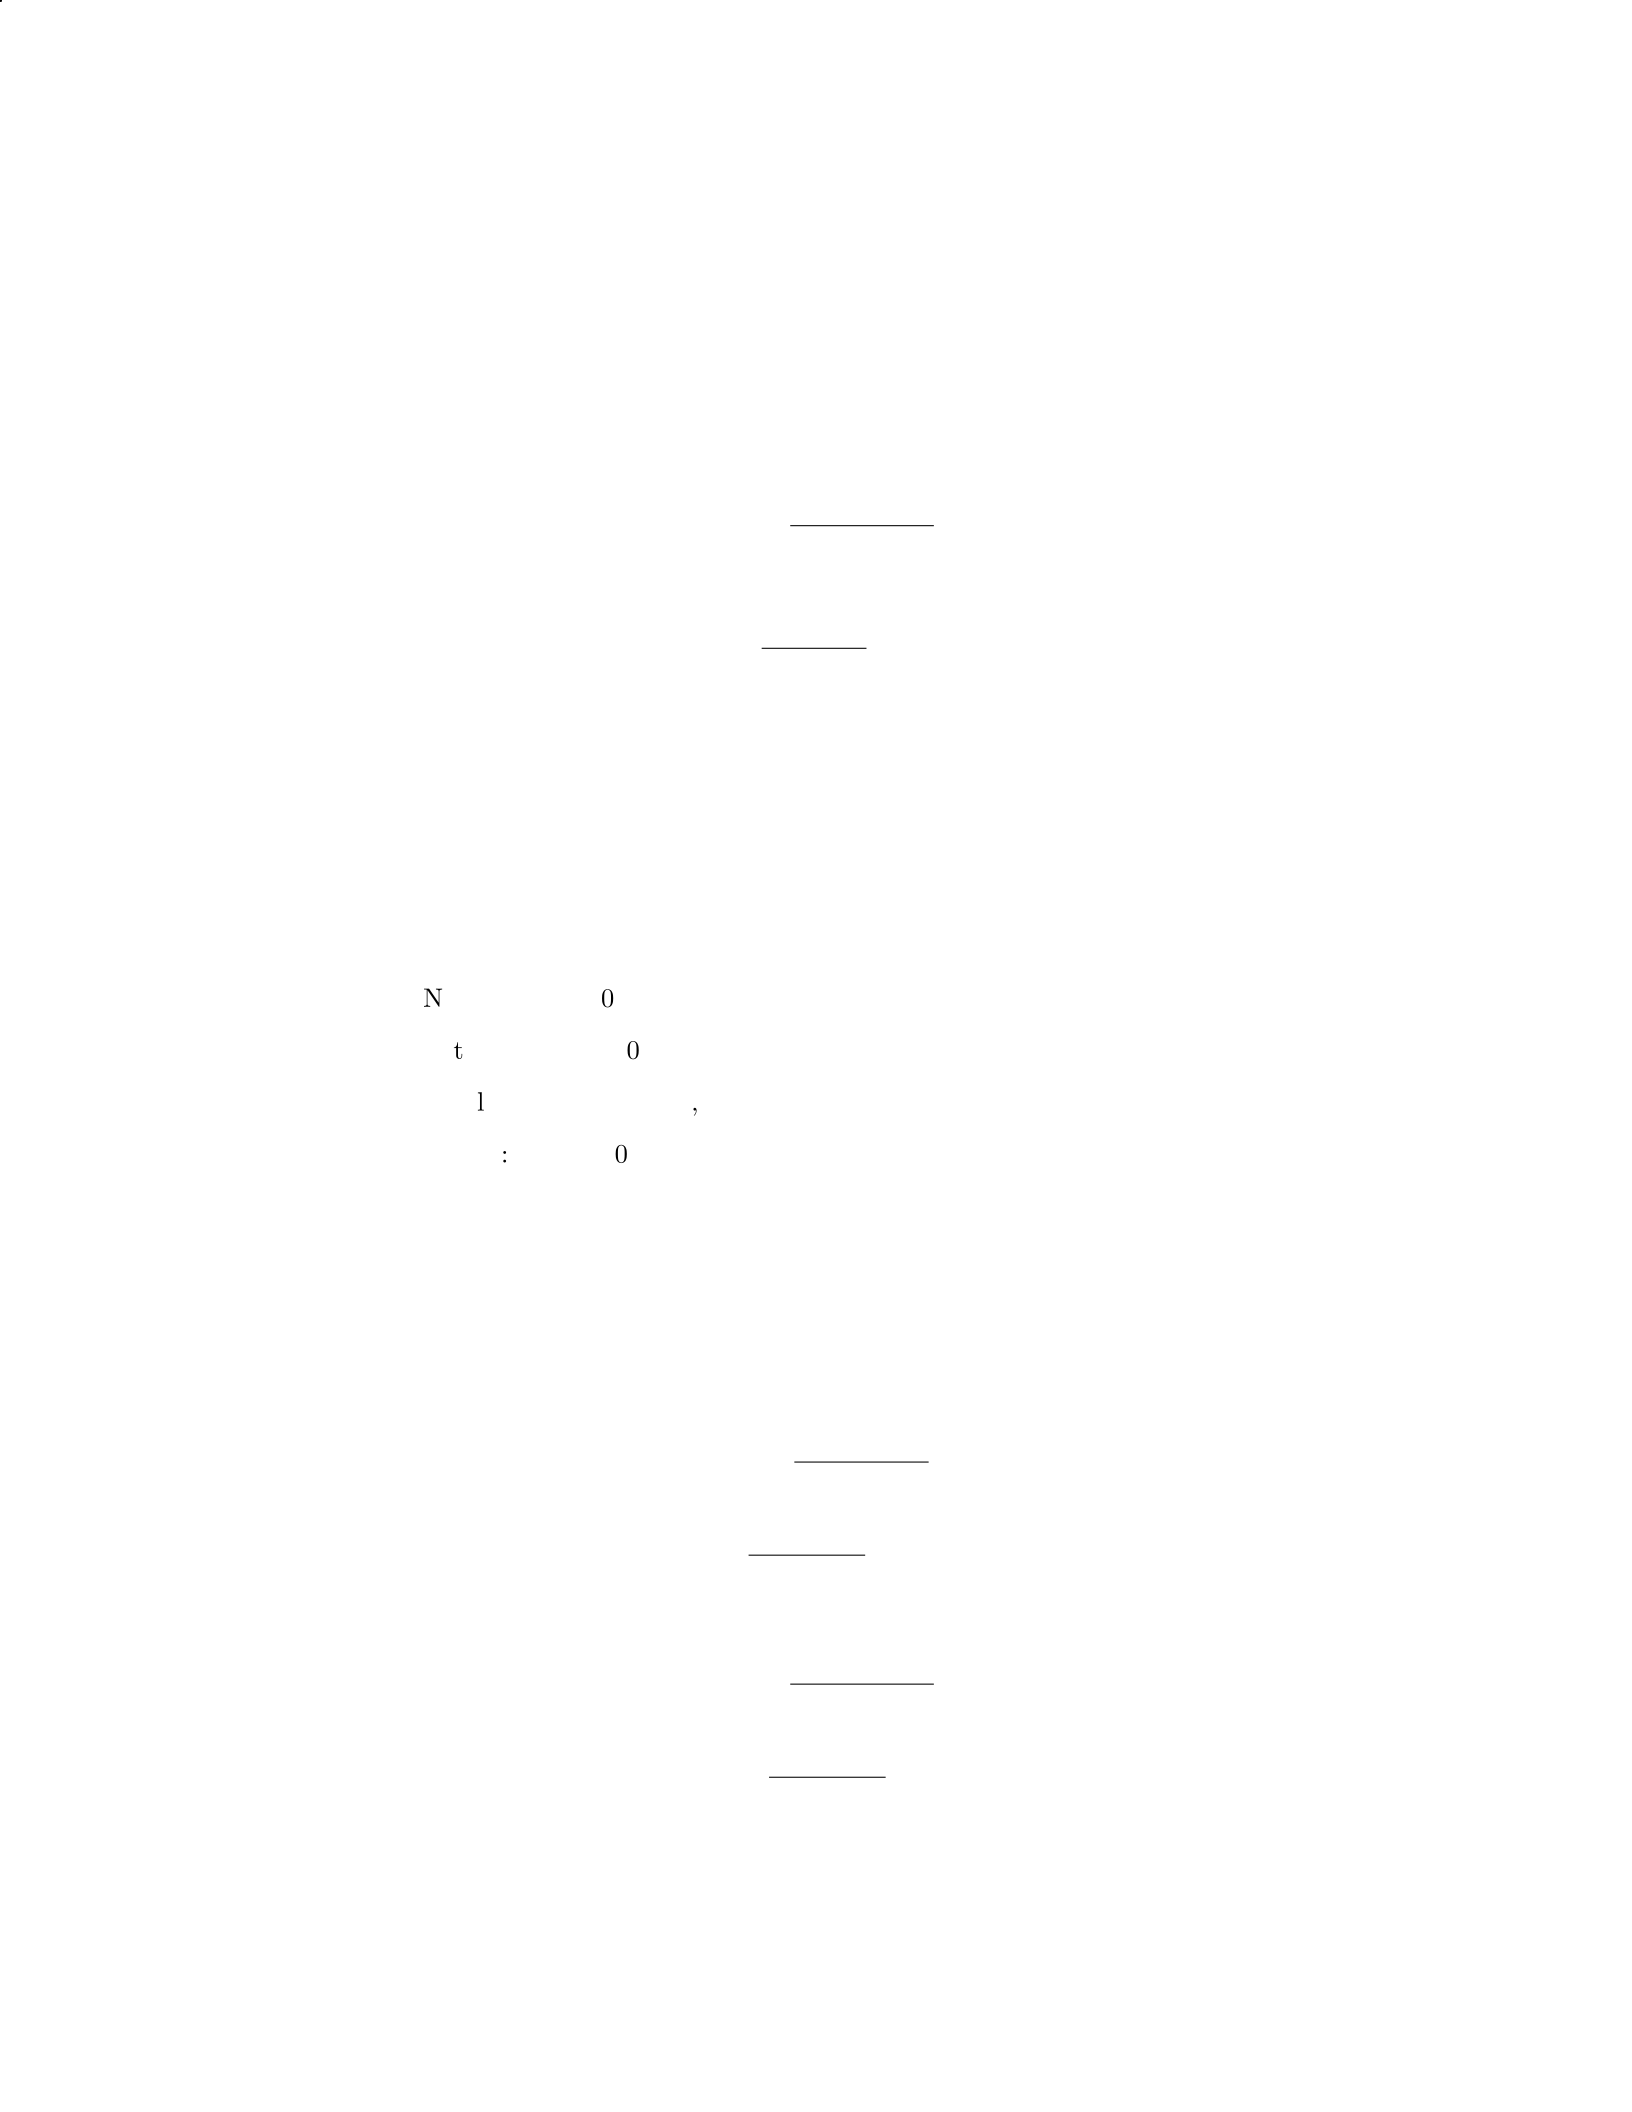
Step 2: Interpret the Debt-to-Equity Ratio A debt-to-equity ratio
of 1 means that the company has an equal amount of debt and equity. This
indicates that the company is equally financed by creditors and shareholders.
Step 3: Calculate the Return on Assets (ROA) The Return on Assets
(ROA) is calculated as:
ROA = Net Income
Total Assets
Substitute the given values into the formula:
ROA = $100,000
$800,000 = 0.125
Step 4: Interpret the Return on Assets (ROA) An ROA of 0.125 (or
12.5
Question 4
Question
A company’s financial statements show the following figures for the current year:
Net income:
$
500,000
Total assets:
$
2,500,000
Total liabilities:
$
1,000,000
Equity:
$
1,500,000
Calculate the company’s return on equity (ROE), return on assets (ROA), and
debt-to-equity ratio. Interpret the results in the context of the company’s fi-
nancial performance.
Solution
Step 1: Calculate the return on equity (ROE).
ROE = Net Income
Equity
ROE = 500,000
1,500,000 = 0.3333
Step 2: Calculate the return on assets (ROA).
ROA = Net Income
Total Assets
ROA = 500,000
2,500,000 = 0.2
4
Step 3: Calculate the debt-to-equity ratio.
Debt-to-Equity ratio = Total Liabilities
Equity
Debt-to-Equity ratio = 1,000,000
1,500,000 = 0.6667
Step 4: Interpretation of the results. - The return on equity (ROE) of 0.3333
means that for every dollar of equity invested in the company, the company
generated
$
0.3333 in net income. - The return on assets (ROA) of 0.2 indicates
that the company generated
$
0.2 in net income for every dollar of assets it
owns. - The debt-to-equity ratio of 0.6667 suggests that the company has higher
reliance on debt financing compared to equity financing, indicating a higher level
of financial leverage.
Question 5
Question
A company reported the following financial information for the current year: -
Total revenue:
$
2,500,000 - Cost of goods sold:
$
1,200,000 - Operating expenses:
$
600,000 - Net income:
$
400,000 Calculate the following ratios and interpret the
results: 1. Gross profit margin 2. Operating profit margin 3. Net profit margin
Solution
1. Gross profit margin
Gross profit = Total revenue −Cost of goods sold
= $2,500,000 −$1,200,000
= $1,300,000
Gross profit margin = Gross profit
Total revenue ×100%
=$1,300,000
$2,500,000 ×100%
= 52%
The gross profit margin of the company is 52
2. Operating profit margin
Operating profit = Total revenue −Cost of goods sold −Operating expenses
= $2,500,000 −$1,200,000 −$600,000
= $700,000
5
Operating profit margin = Operating profit
Total revenue ×100%
=$700,000
$2,500,000 ×100%
= 28%
The operating profit margin of the company is 28
3. Net profit margin
Net profit margin = Net income
Total revenue ×100%
=$400,000
$2,500,000 ×100%
= 16%
The net profit margin of the company is 16
Question 6
Question
A company reported the following financial information for the year:
Gross profit margin: 40%
Return on assets: 15%
Current ratio: 2.5
Based on this information, analyze the company’s performance and financial
health.
Solution
To analyze the company’s performance and financial health, we will interpret
each of the provided ratios:
Gross profit margin: This ratio indicates the efficiency of a company in
generating profits from its revenue after deducting the cost of goods sold.
A higher gross profit margin is generally preferred as it indicates that the
company is effectively managing its production costs.
Return on assets (ROA): This ratio measures how effectively a com-
pany is using its assets to generate profit. A higher ROA indicates that the
company is generating more profit with less investment in assets, which is
a positive sign.
6

Current ratio: This ratio assesses a company’s liquidity and its ability
to pay off its short-term liabilities with its short-term assets. A current
ratio of 2.5 means that the company has 2.50incurrentassetsforevery1
in current liabilities. A ratio above 2 is generally considered healthy as it
indicates the company can easily cover its short-term obligations.
Interpretation:
The company’s gross profit margin of 40% indicates that it is effectively
managing its production costs and generating a good profit from its rev-
enue.
A return on assets of 15% shows that the company is generating a de-
cent profit relative to its total assets. This indicates that the company is
utilizing its assets efficiently to generate profit.
The current ratio of 2.5 suggests that the company has strong liquidity
and is capable of covering its short-term obligations. This indicates a
healthy financial position.
Based on the analysis of the provided ratios, we can conclude that the com-
pany is performing well in terms of profitability, asset utilization, and liquidity.
Question 7
Question
A company reported the following financial information for the year: Current
ratio of 2.5, Quick ratio of 1.8, Debt-to-equity ratio of 0.6, and Return on equity
of 12
Solution
To analyze the company’s financial performance, we will interpret each ratio
individually and then provide an overall assessment.
Step 1: Current Ratio The current ratio is calculated as:
Current Ratio = Current Assets
Current Liabilities
Given that the current ratio is 2.5, it means that for every dollar of current li-
abilities, the company has 2.5ofcurrentassetstocoverthoseobligations.Acurrentratioof 2.5isgenerallyconsideredhealthyasitindicatesthecompanyhasenoughcurrentassetstomeetitsshort−
termliabilities.
Step 2: Quick Ratio The quick ratio is calculated as:
Quick Ratio = Current Assets −Inventory
Current Liabilities
With a quick ratio of 1.8, it implies that the company has 1.8ofquickassets(currentassetsexcludinginventory)availabletocovereachdollarof currentliabilities.Aquickratioabove1istypicallyseenasagoodsign, indicatingthecompanyhasenoughliquidassetstosettleitsshort−
termobligations.
7
Step 3: Debt-to-Equity Ratio The debt-to-equity ratio is calculated as:
Debt-to-Equity Ratio = Total Debt
Total Equity
Given a debt-to-equity ratio of 0.6, it means that the company has 60 cents
in debt for every dollar of equity. A lower debt-to-equity ratio indicates lower
financial risk and a stronger financial position.
Step 4: Return on Equity (ROE) The return on equity is calculated as:
ROE = Net Income
Shareholders’ Equity ×100%
With a return on equity of 12
Step 5: Overall Assessment Based on the analysis of the ratios, the
company appears to be in a strong financial position. The high current ratio and
quick ratio indicate good liquidity and ability to meet short-term obligations.
Additionally, the low debt-to-equity ratio suggests lower financial risk. Finally,
the return on equity of 12
Question 8
Question
Company XYZ has the following financial information for the year 2020:
Total Assets:
$
500,000
Total Liabilities:
$
200,000
Total Revenue:
$
800,000
Net Income:
$
100,000
Calculate the following ratios for Company XYZ and interpret what each
ratio reveals about the company’s financial performance:
1. Debt to Equity Ratio
2. Return on Assets
3. Profit Margin
Solution
Step 1: Calculate Debt to Equity Ratio
Debt to Equity Ratio = Total Liabilities
Total Equity
Given:
8
Total Assets:
$
500,000
Total Liabilities:
$
200,000
Total Equity = Total Assets - Total Liabilities Total Equity =
$
500,000 -
$
200,000 Total Equity =
$
300,000
Debt to Equity Ratio = $200,000
$300,000 = 0.67
The Debt to Equity Ratio of 0.67 suggests that Company XYZ has
$
0.67 in
debt for every
$
1 of equity.
Step 2: Calculate Return on Assets (ROA)
ROA =N etIncome
T otalAssets
Given:
Net Income:
$
100,000
Total Assets:
$
500,000
ROA =$100,000
$500,000 = 0.20
The Return on Assets (ROA) of 0.20 indicates that for every
$
1 of assets,
Company XYZ is generating
$
0.20 in profit.
Step 3: Calculate Profit Margin
P rofitMargin =N etIncome
T otalRevenue
Given:
Net Income:
$
100,000
Total Revenue:
$
800,000
P rofitMargin =$100,000
$800,000 = 0.125 = 12.5%
The Profit Margin of 12.5% indicates that Company XYZ is able to keep
12.5 cents of profit for every dollar of revenue generated.
Question 9
Question
A company’s current ratio is 2.5, while its quick ratio is 1.8. Interpret these
ratios and explain what they indicate about the company’s liquidity.
9
Solution
To interpret the current and quick ratios, we need to understand what they
represent and what values are considered healthy.
Step 1: Understand the ratios
Current Ratio: This ratio measures the company’s ability to pay off its
short-term liabilities with its short-term assets. It is calculated as:
Current Ratio = Current Assets
Current Liabilities
Quick Ratio: Also known as the acid-test ratio, this ratio provides a more
stringent test of liquidity as it excludes inventory from current assets. It
is calculated as:
Quick Ratio = Current Assets - Inventory
Current Liabilities
Step 2: Interpret the given ratios
Current Ratio of 2.5: This means that for every dollar of current liabili-
ties, the company has 2.50ofcurrentassets.Acurrentratioabove1indicatesthatthecompanyhasenoughcurrentassetstocoveritscurrentliabilities.Aratioof 2.5isconsideredhealthyandshowsthatthecompanyisabletomeetitsshort−
termobligationscomfortably.
Quick Ratio of 1.8: This ratio indicates that the company has 1.80ofquickassets(currentassetsexcludinginventory)f oreverydollarof currentliabilities.Aquickratioof 1.8isalsoconsideredgood, asitshowsthatthecompanyhasenoughliquidassetstocoveritsshort−
termliabilitieswithoutrelyingonsellinginventory.
Step 3: Conclusion The company’s current ratio of 2.5 and quick ratio
of 1.8 both suggest that the company is in a strong liquidity position. It has
more than enough current assets to cover its current liabilities and can meet its
short-term obligations comfortably without having to rely heavily on inventory.
Question 10
Question
A company has the following financial information for the year:
Item Amount
Sales
$
500,000
Cost of Goods Sold
$
300,000
Gross Profit
$
200,000
Operating Expenses
$
120,000
Net Income
$
80,000
Total Assets
$
600,000
Total Liabilities
$
200,000
Calculate the following ratios for the company and provide an interpretation
for each ratio:
10
1. Gross Profit Margin
2. Operating Profit Margin
3. Return on Assets
4. Return on Equity
Solution
Step 1: Calculate Gross Profit Margin The Gross Profit Margin is calcu-
lated using the formula:
Gross Profit Margin = Gross Profit
Sales ×100%
Substitute the given values:
Gross Profit Margin = 200,000
500,000 ×100% = 40%
Interpretation: The Gross Profit Margin of 40% indicates that for every
$
1 of sales made, the company retains
$
0.40 as gross profit after accounting for
the cost of goods sold.
Step 2: Calculate Operating Profit Margin The Operating Profit Mar-
gin is calculated using the formula:
Operating Profit Margin = Operating Income
Sales ×100%
Operating Income can be calculated as:
Operating Income = Gross Profit−Operating Expenses = 200,000−120,000 = 80,000
Now, substitute the values into the formula:
Operating Profit Margin = 80,000
500,000 ×100% = 16%
Interpretation: The Operating Profit Margin of 16% indicates that for
every
$
1 of sales made, the company retains
$
0.16 as operating profit after
accounting for both the cost of goods sold and operating expenses.
Step 3: Calculate Return on Assets (ROA) The Return on Assets is
calculated using the formula:
ROA = Net Income
Total Assets ×100%
Substitute the given values:
ROA = 80,000
600,000 ×100% ≈13.33%
11
Interpretation: The ROA of approximately 13.33% indicates that the com-
pany generates about 13.33 cents of net income for every dollar of total assets.
Step 4: Calculate Return on Equity (ROE) The Return on Equity is
calculated using the formula:
ROE = Net Income
Total Equity ×100%
Total Equity can be calculated as:
Total Equity = Total Assets −Total Liabilities = 600,000 −200,000 = 400,000
Now substitute the values into the formula:
ROE = 80,000
400,000 ×100% = 20%
Interpretation: The ROE of 20% indicates that for every dollar of total
equity invested in the company, shareholders earned a return of 20 cents in net
income.
Question 11
Question
A company reported the following financial information for the year: - Current
assets:
$
500,000 - Non-current assets:
$
1,000,000 - Current liabilities:
$
300,000
- Non-current liabilities:
$
600,000 - Sales revenue:
$
2,000,000 - Cost of goods
sold:
$
1,200,000 - Operating expenses:
$
300,000
Calculate the following ratios and interpret their meaning: 1. Current ratio
2. Acid-test (quick) ratio 3. Debt to equity ratio 4. Gross profit margin 5.
Operating profit margin
Solution
1. Current ratio:
Current ratio = Current assets
Current liabilities
Current ratio = 500,000
300,000 = 1.67
Interpretation: A current ratio of 1.67 indicates that the company has
$
1.67
in assets for every
$
1 of liabilities, which suggests good short-term liquidity.
2. Acid-test (quick) ratio:
Acid-test ratio = Current assets - Inventory
Current liabilities
12
Given that inventory is not provided, let’s assume it’s
$
100,000.
Acid-test ratio = 500,000 −100,000
300,000 = 1.33
Interpretation: An acid-test ratio of 1.33 suggests that the company may
have some difficulty meeting its short-term obligations without relying on the
sale of inventory.
3. Debt to equity ratio:
Debt to equity ratio = Total liabilities
Shareholders’ equity
Debt to equity ratio = 300,000 + 600,000
500,000 + 1,000,000 =900,000
1,500,000 = 0.6
Interpretation: A debt to equity ratio of 0.6 indicates that the company is
using more equity than debt to finance its assets, which is generally considered
favorable.
4. Gross profit margin:
Gross profit margin = Sales revenue - Cost of goods sold
Sales revenue ×100%
Gross profit margin = 2,000,000 −1,200,000
2,000,000 ×100% = 40%
Interpretation: A gross profit margin of 40
5. Operating profit margin:
Operating profit margin = Operating income
Sales revenue ×100%
Operating profit margin = 2,000,000 −1,200,000 −300,000
2,000,000 ×100% = 25%
Interpretation: An operating profit margin of 25
Question 12
Question
A company has the following financial information for the year 2020:
Total assets:
$
800,000
Total liabilities:
$
400,000
Revenue:
$
600,000
Net income:
$
100,000
Calculate the following ratios and interpret them:
1. Debt-to-Asset ratio
2. Profit margin
13
Solution
Step 1: Calculate the Debt-to-Asset ratio
The Debt-to-Asset ratio is calculated as:
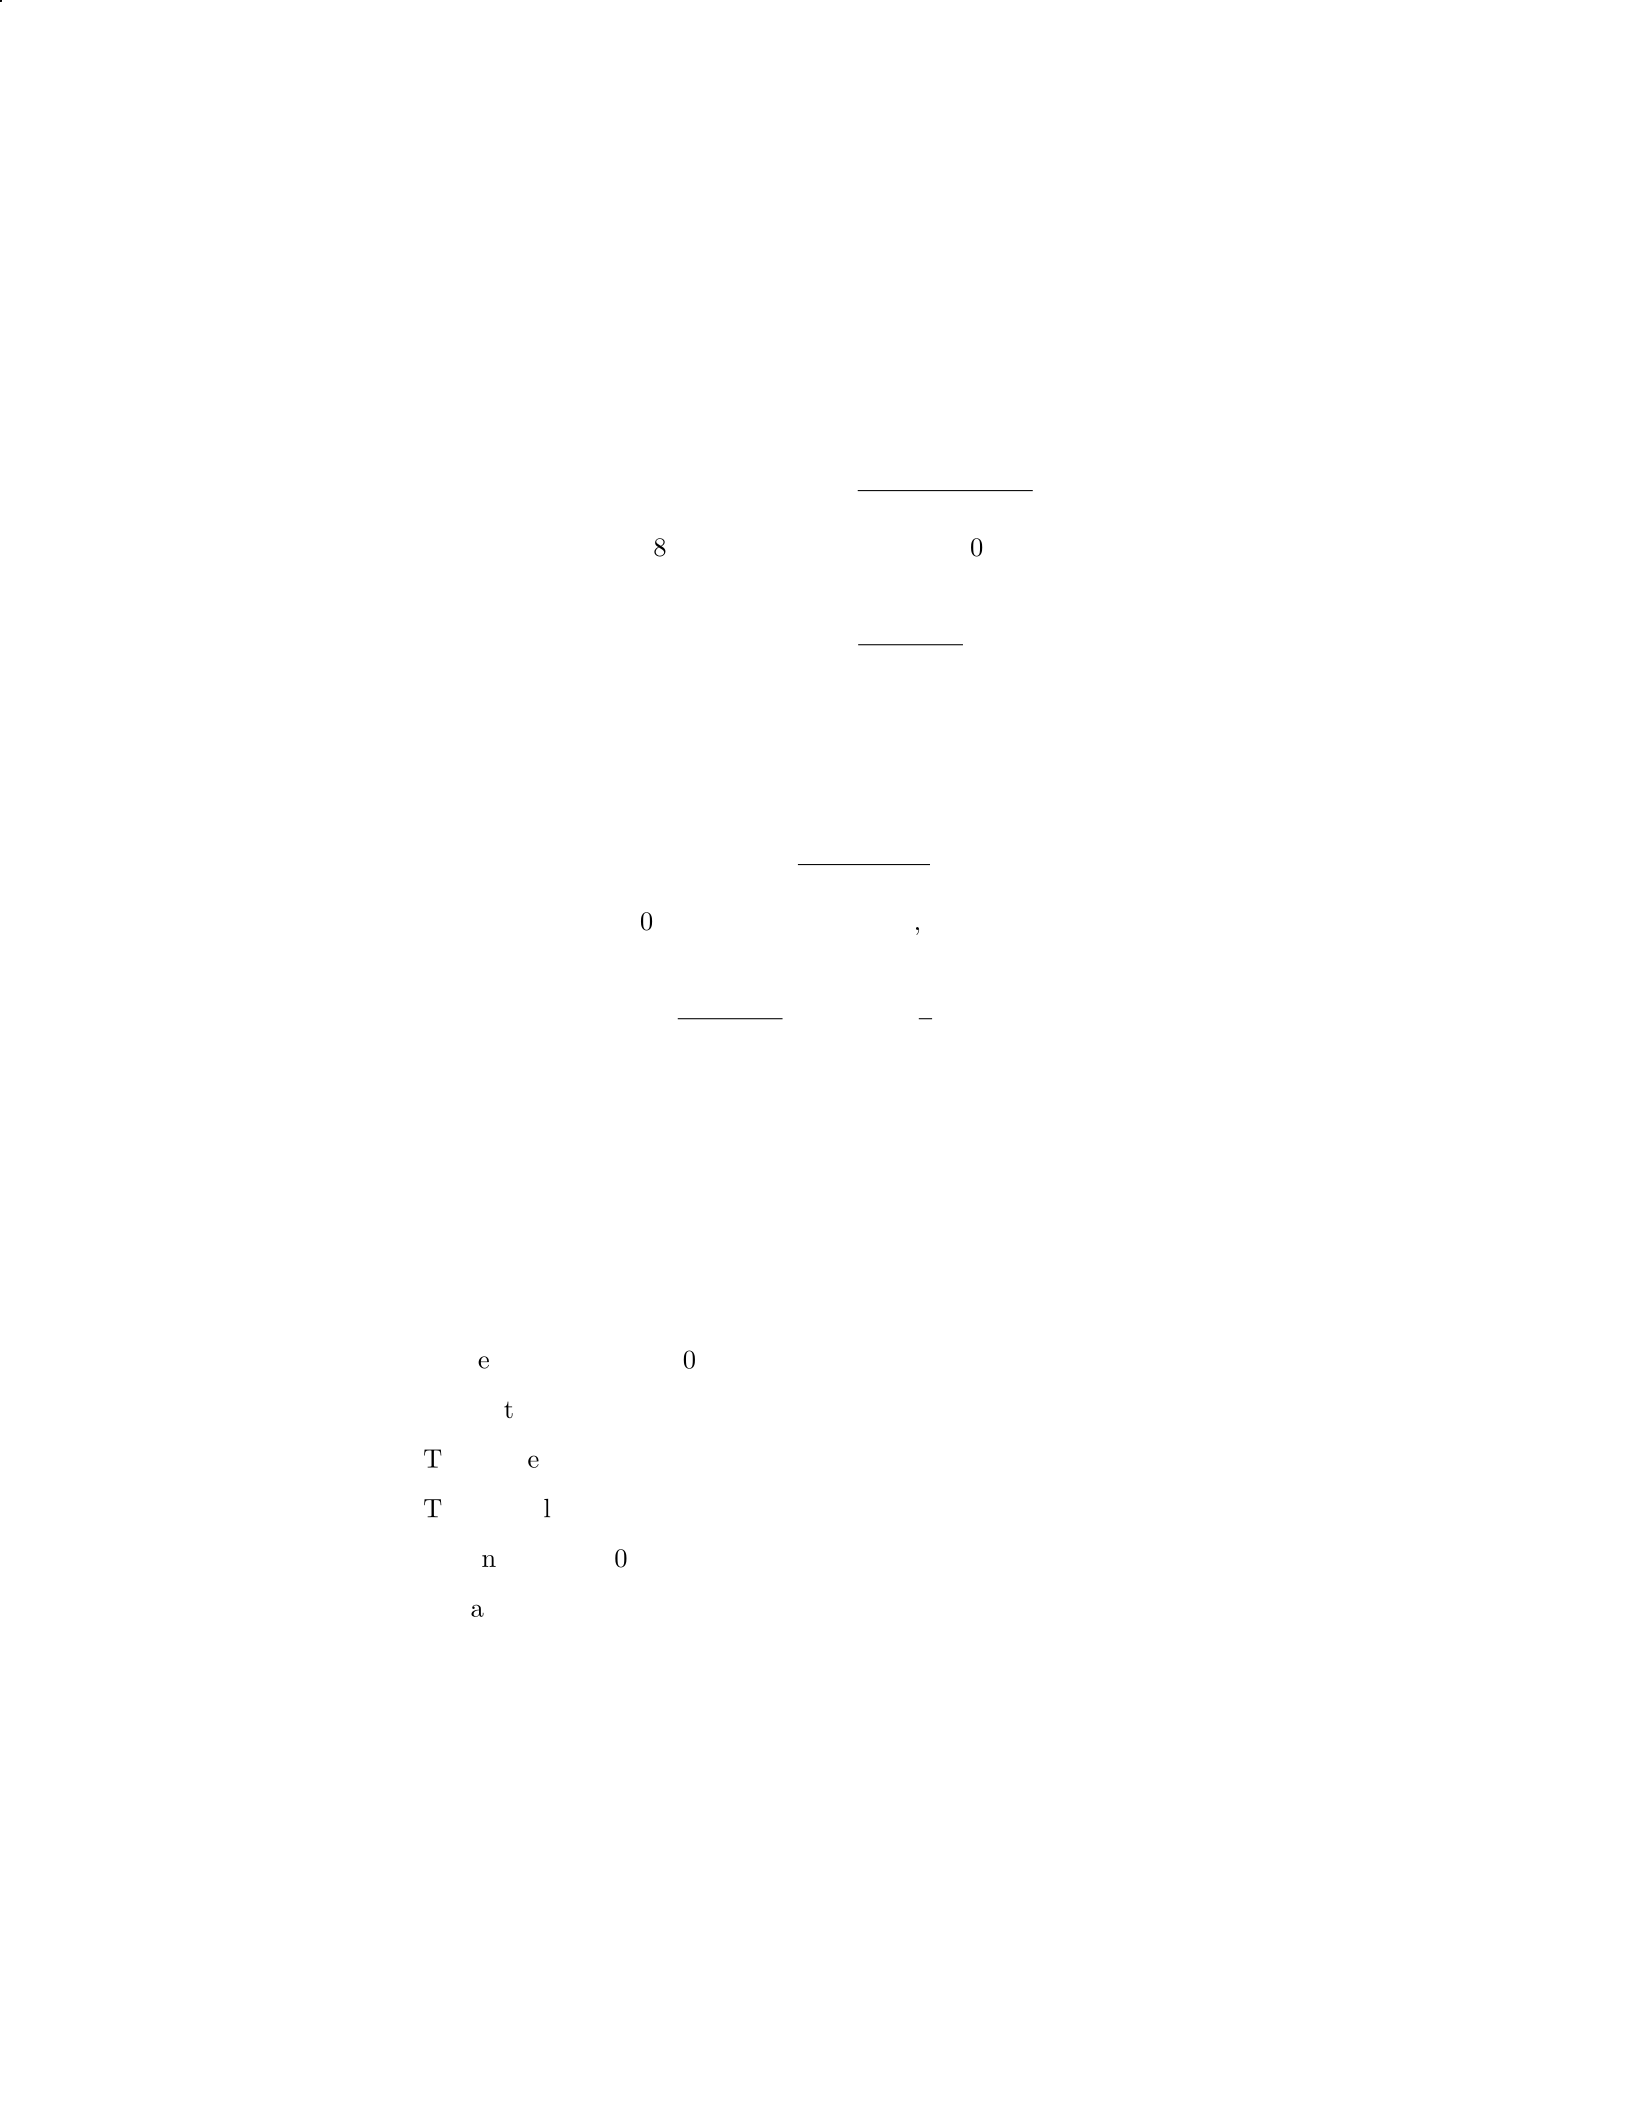
Debt-to-Asset ratio = Total liabilities
Total assets
Given: Total assets:
$
800,000 Total liabilities:
$
400,000
Plugging in the values:
Debt-to-Asset ratio = $400,000
$800,000 = 0.5
Step 2: Interpret the Debt-to-Asset ratio
A Debt-to-Asset ratio of 0.5 means that 50
Step 3: Calculate the Profit margin
The Profit margin is calculated as:
Profit margin = Net income
Revenue ×100%
Given: Revenue:
$
600,000 Net income:
$
100,000
Plugging in the values:
Profit margin = $100,000
$600,000 ×100% = 1
6×100% = 16.67%
Step 4: Interpret the Profit margin
A Profit margin of 16.67
Question 13
Question
A company has the following financial information for the year:
Current assets:
$
500,000
Current liabilities:
$
200,000
Total assets:
$
1,000,000
Total liabilities:
$
400,000
Net income:
$
100,000
Calculate the following ratios and interpret them in terms of the company’s
financial performance:
1. Current ratio
2. Debt-to-asset ratio
3. Return on assets (ROA)
14
Solution
Step 1: Calculate the current ratio. The current ratio is given by:
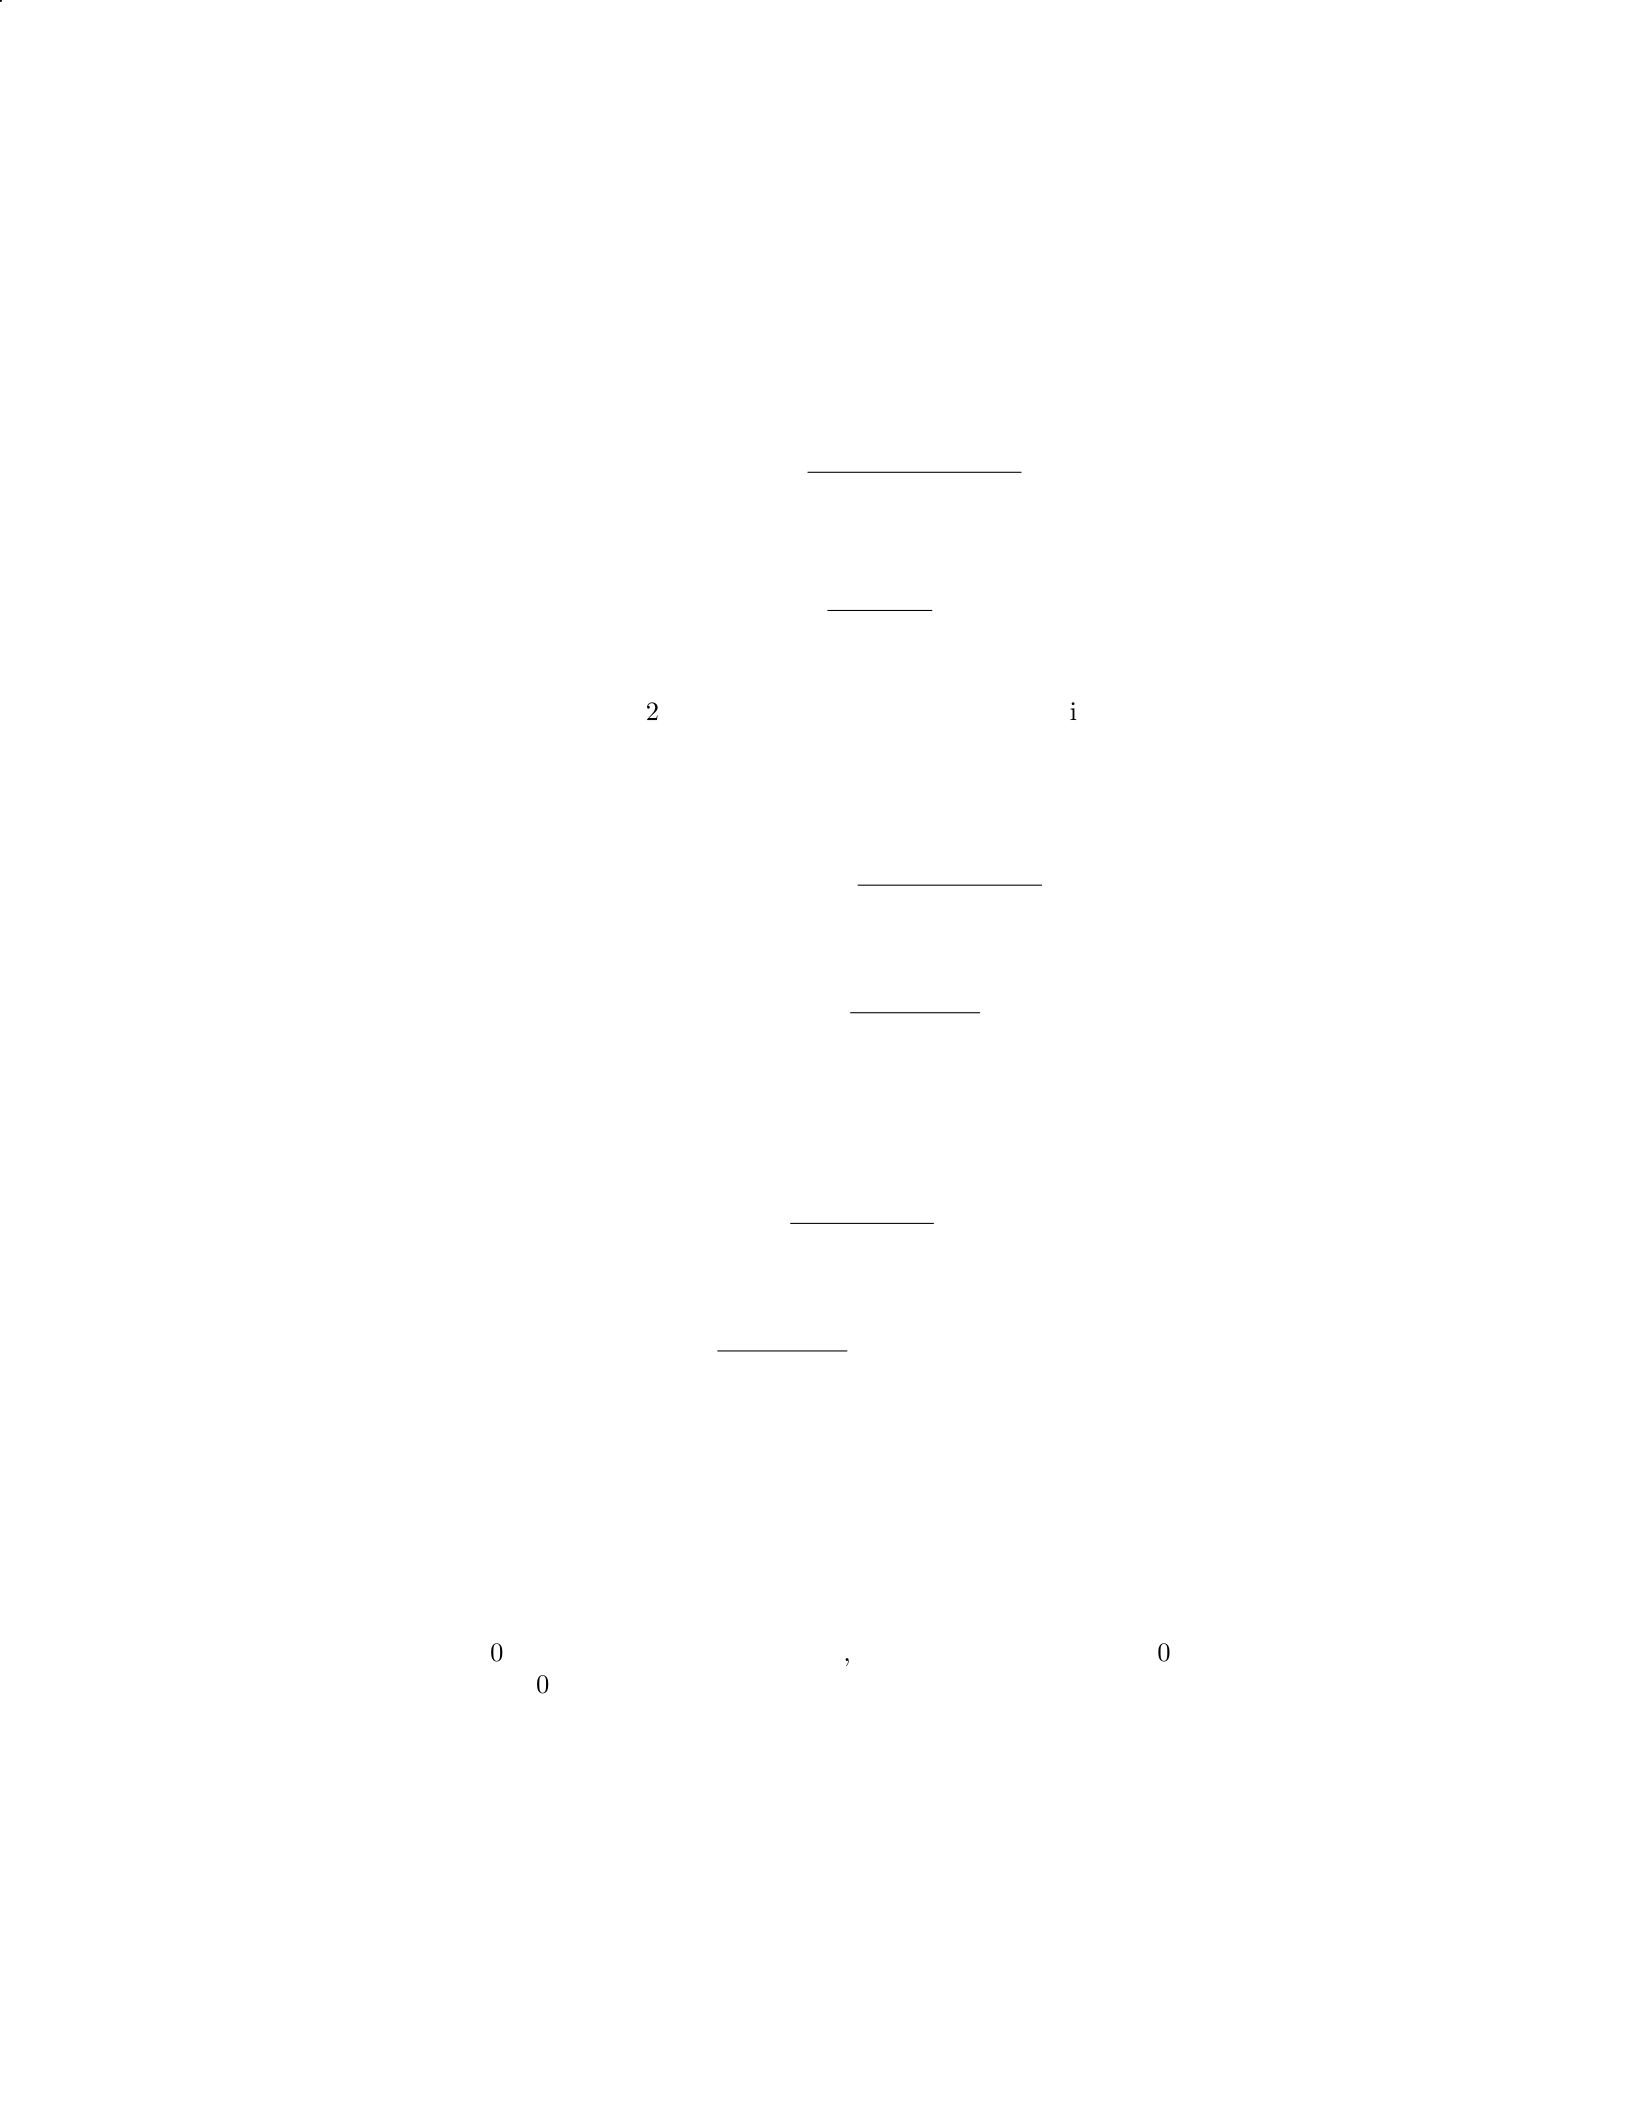
Current Ratio = Current Assets
Current Liabilities
Substitute the given values:
Current Ratio = $500,000
$200,000 = 2.5
Step 2: Interpretation of the current ratio: A current ratio of 2.5 means
that the company has
$
2.50 in current assets for every
$
1 in current liabili-
ties. This indicates that the company is able to meet its short-term obligations
comfortably.
Step 3: Calculate the debt-to-asset ratio. The debt-to-asset ratio is given
by:
Debt-to-Asset Ratio = Total Liabilities
Total Assets
Substitute the given values:
Debt-to-Asset Ratio = $400,000
$1,000,000 = 0.4
Step 4: Interpretation of the debt-to-asset ratio: A debt-to-asset ratio of
0.4 means that 40
Step 5: Calculate the return on assets (ROA). The return on assets is given
by:
ROA = Net Income
Total Assets
Substitute the given values:
ROA = $100,000
$1,000,000 = 0.1 or 10%
Step 6: Interpretation of the return on assets: An ROA of 10
Question 14
Question
A company reported the following financial information for the year: - Total
assets:
$
800,000 - Total liabilities:
$
300,000 - Total equity:
$
500,000 - Net
income:
$
100,000 Calculate the following ratios and interpret the results: a)
Debt-to-Assets Ratio b) Return on Equity c) Return on Assets
15
Solution
a) Debt-to-Assets Ratio:
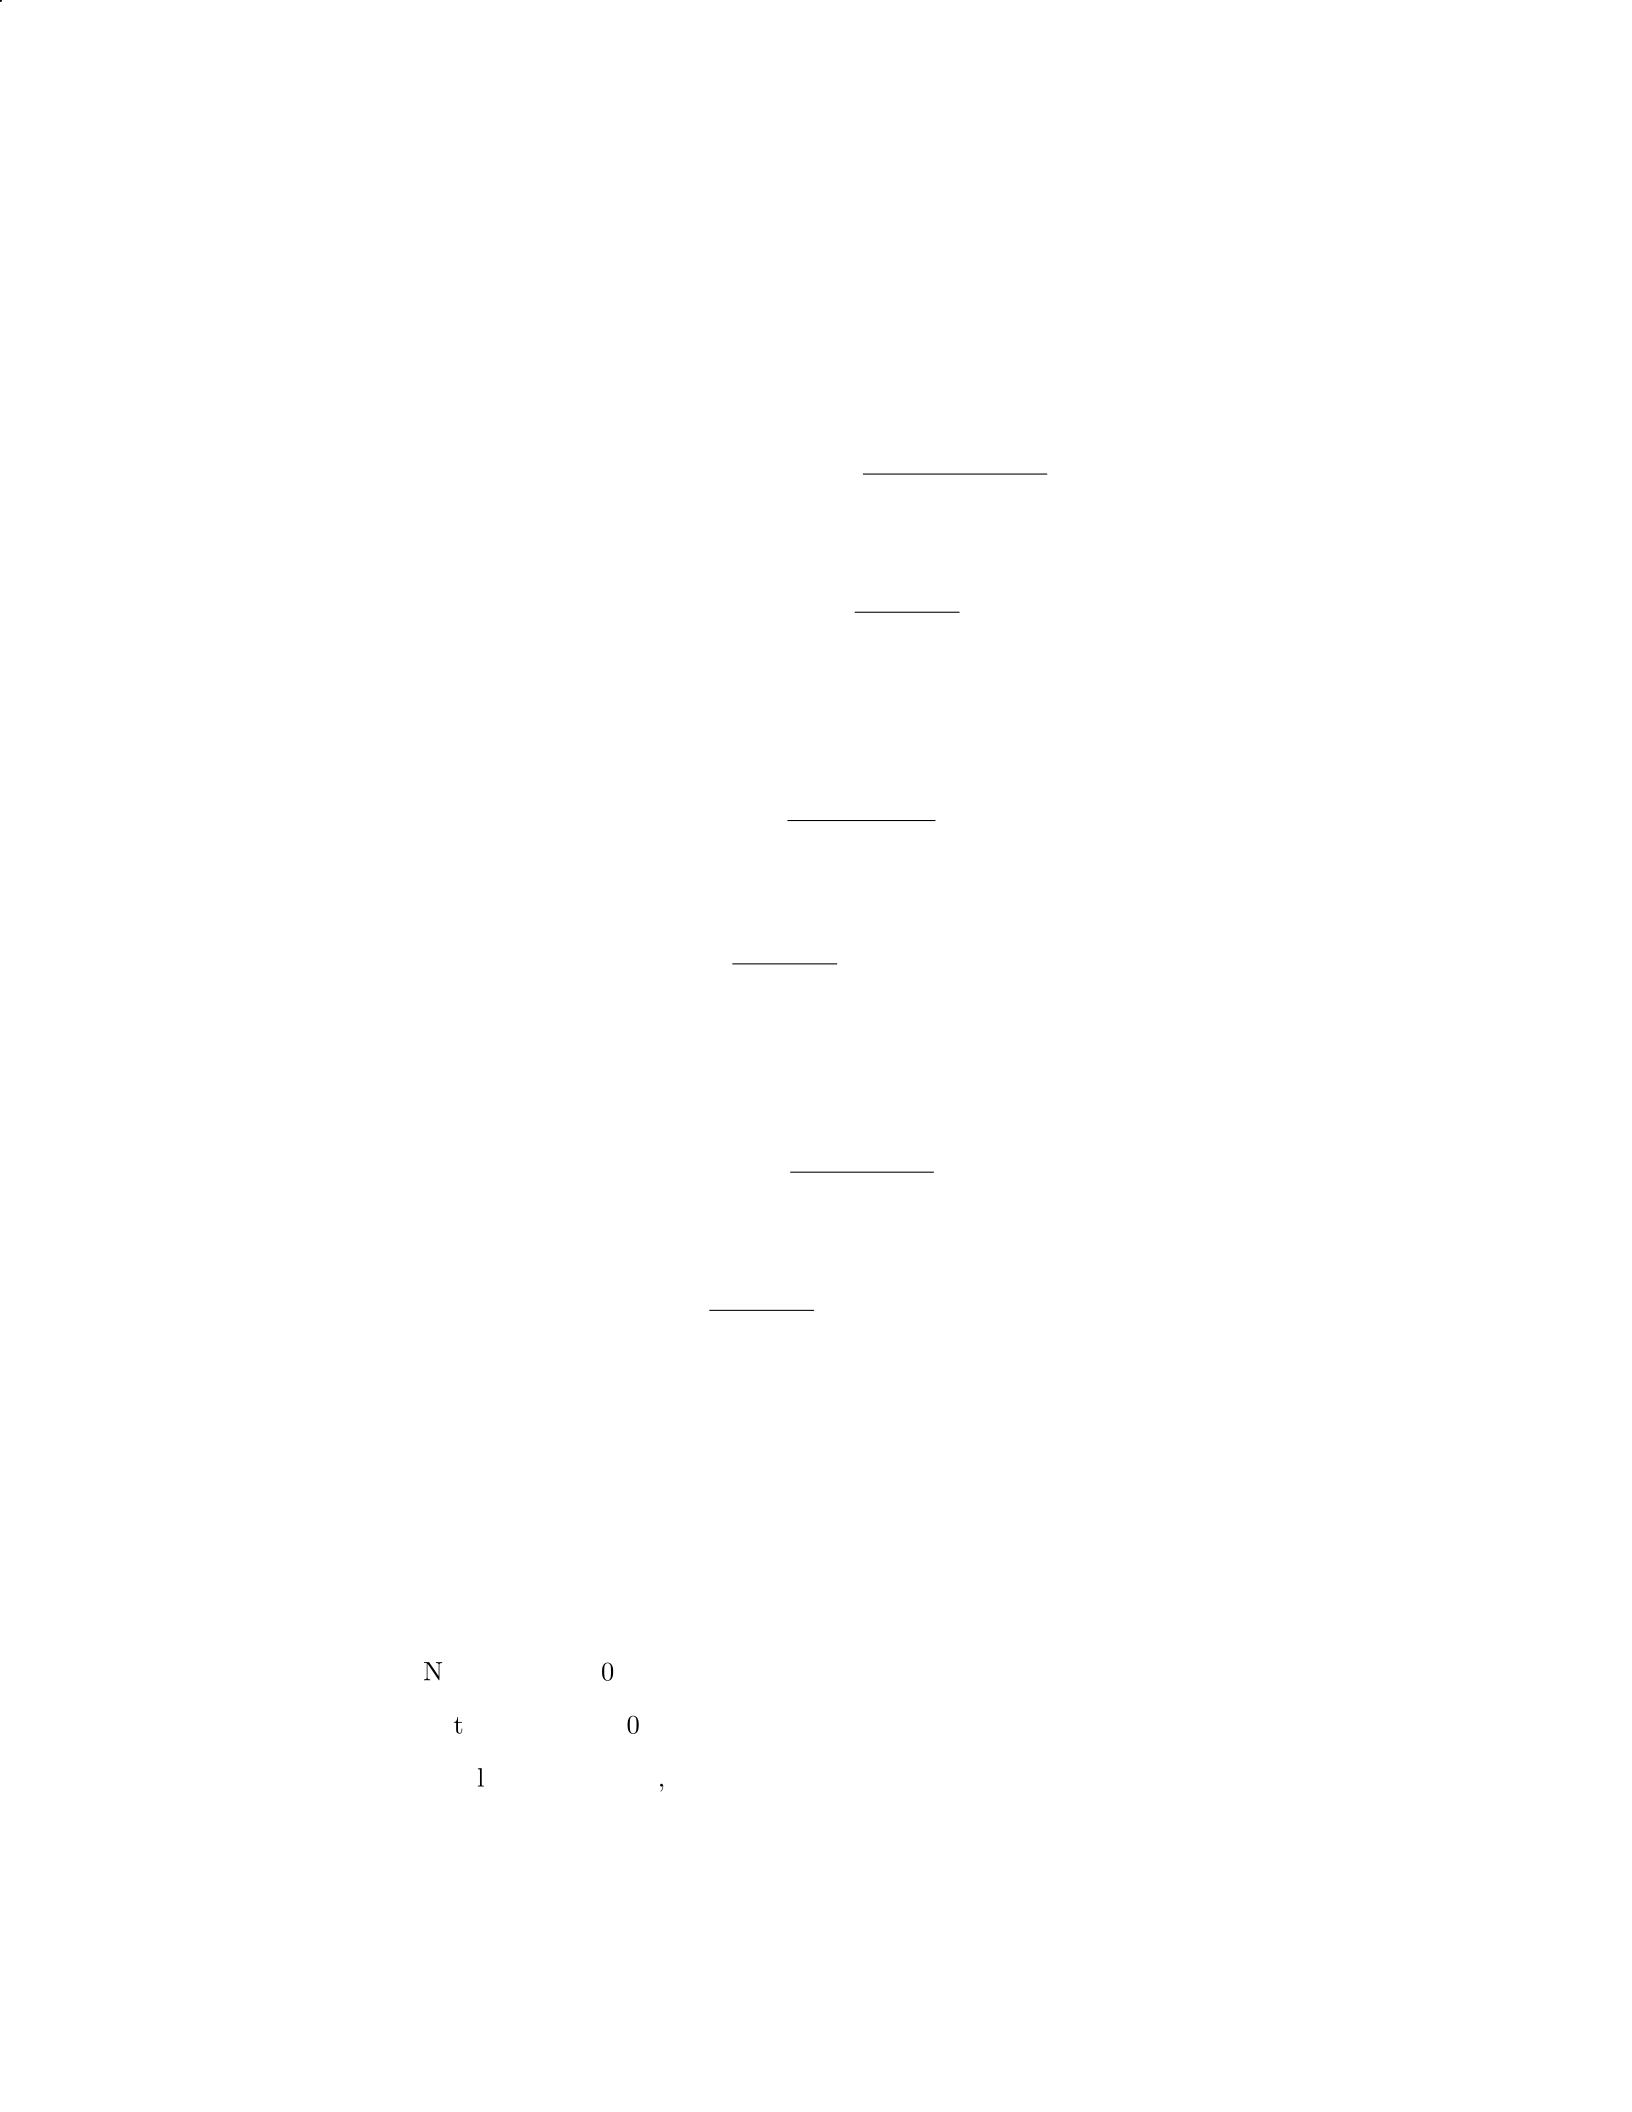
Debt-to-Assets Ratio = Total Liabilities
Total Assets
Step 1: Calculate the Debt-to-Assets Ratio:
Debt-to-Assets Ratio = $300,000
$800,000 = 0.375
Step 2: Interpretation: The Debt-to-Assets Ratio of 0.375 indicates that 37.5%
of the company’s assets are financed by debt.
b) Return on Equity (ROE):
ROE = Net Income
Total Equity
Step 1: Calculate the Return on Equity:
ROE = $100,000
$500,000 = 0.2 = 20%
Step 2: Interpretation: The Return on Equity of 20% indicates that for every
dollar of equity, the company generated 20 cents of profit.
c) Return on Assets (ROA):
ROA = Net Income
Total Assets
Step 1: Calculate the Return on Assets:
ROA = $100,000
$800,000 = 0.125 = 12.5%
Step 2: Interpretation: The Return on Assets of 12.5% indicates that for every
dollar of assets, the company generated 12.5 cents of profit.
Question 15
Question
A company has the following financial information for the year 2020:
Net income:
$
500,000
Total assets:
$
2,000,000
Total equity:
$
1,000,000
16
Sales:
$
1,500,000
Calculate the following ratios and interpret them:
1. Return on equity (ROE)
2. Return on assets (ROA)
3. Profit margin
Solution
Let’s begin by calculating the three ratios one by one.
Step 1: Calculate Return on Equity (ROE)
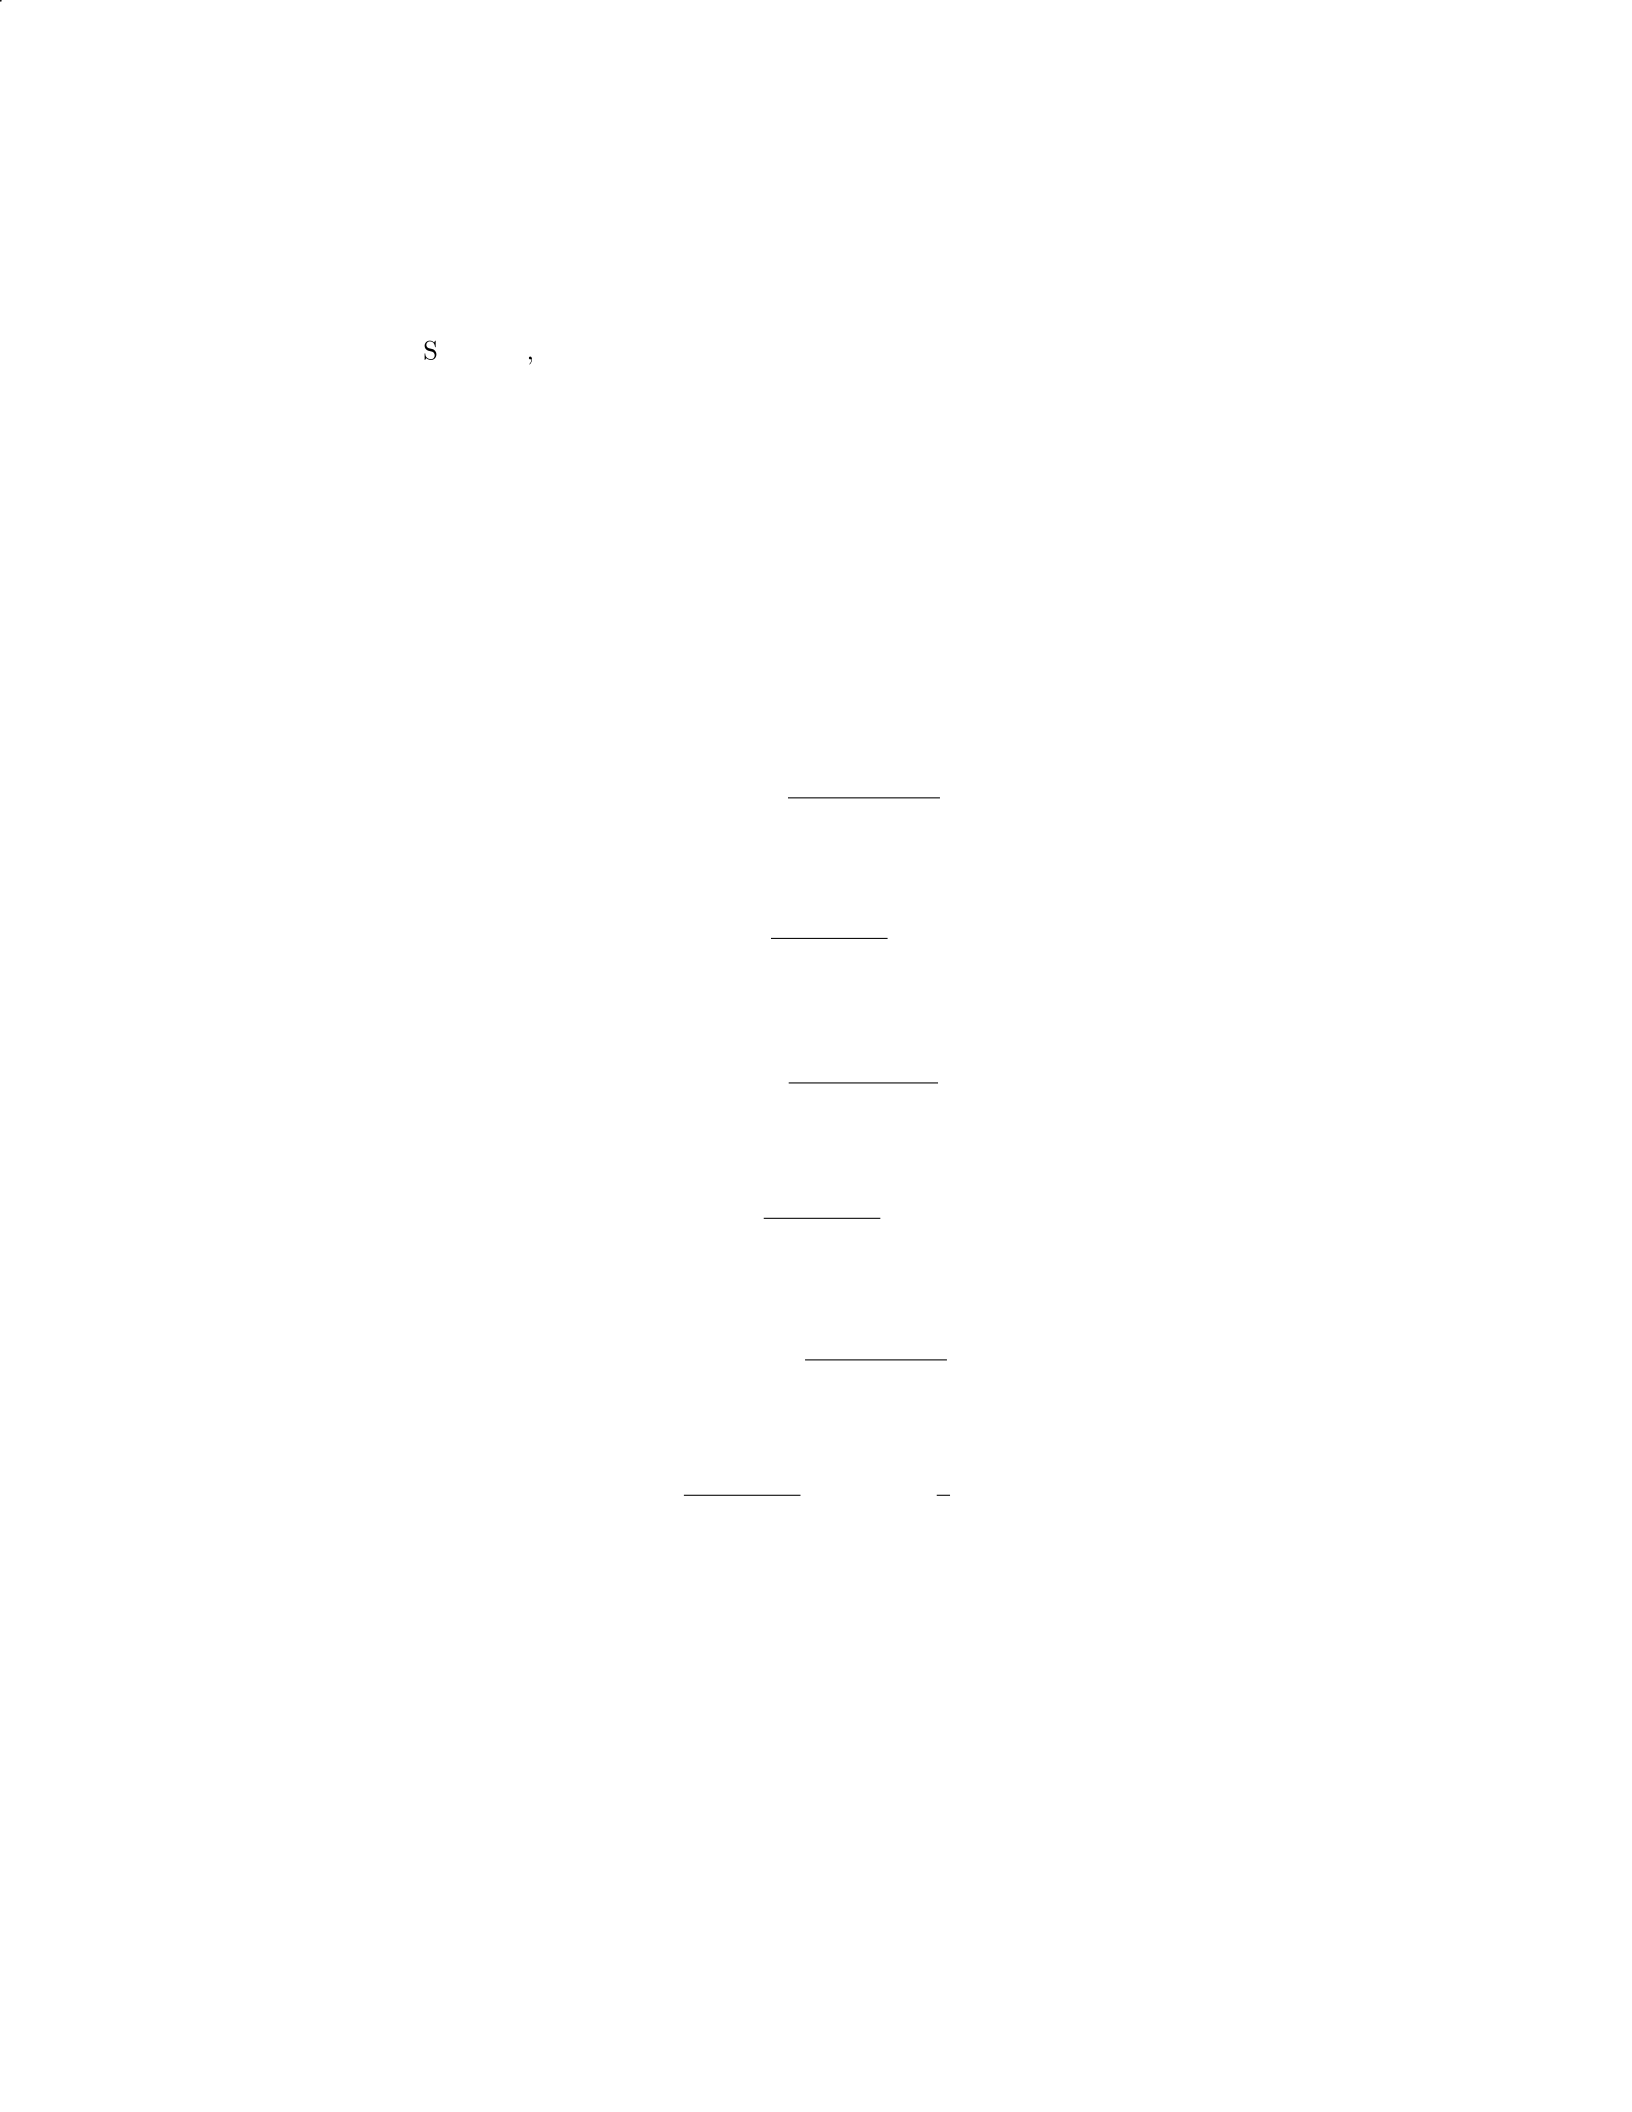
ROE =N et Income
T otal Equity
Substitute the given values:
ROE =500,000
1,000,000 = 0.5
Step 2: Calculate Return on Assets (ROA)
ROA =N et Income
T otal Assets
Substitute the given values:
ROA =500,000
2,000,000 = 0.25
Step 3: Calculate Profit Margin
P rofit Margin =N et Income
Sales ×100%
Substitute the given values:
P rofit Margin =500,000
1,500,000 ×100% = 1
3×100% = 33.33%
Interpretation:
1. The Return on Equity (ROE) of 0.5 indicates that for every dollar of
equity, the company generates 50 cents in net income.
2. The Return on Assets (ROA) of 0.25 suggests that the company generates
25 cents in net income for every dollar of total assets.
3. The Profit Margin of 33.33% shows that the company retains 33.33 cents
as profit from every dollar of sales after deducting all expenses.
17
Question 16
Question
A company’s current ratio is 2.5, while its acid-test ratio is 1.2. Determine
the amount of inventory the company has if its current liabilities amount to
600,000.
Solution
Step 1: Calculate the company’s current assets using the current ratio formula:
Current Ratio = Current Assets
Current Liabilities
2.5 = Current Assets
600,000
Current Assets = 2.5×600,000
Current Assets = 1,500,000
Step 2: Calculate the company’s quick assets using the acid-test ratio for-
mula:
Acid-Test Ratio = Quick Assets
Current Liabilities
Given that the acid-test ratio is:
1.2 = Quick Assets
600,000
Quick Assets = 1.2×600,000
Quick Assets = 720,000
Step 3: Calculate the company’s inventory by subtracting quick assets from
current assets:
Inventory = Current Assets −Quick Assets
Inventory = 1,500,000 −720,000
Inventory = 780,000
Therefore, the company has 780,000worthofinventory.
Question 17
Question
A company reported the following financial information for the current year: -
Current assets:
$
300,000 - Total assets:
$
600,000 - Current liabilities:
$
150,000
- Total liabilities:
$
400,000 Calculate the company’s current ratio and interpret
the result in terms of the company’s ability to meet its short-term obligations.
18
Solution
Step 1: Calculate the current ratio. The current ratio is calculated as the ratio
of current assets to current liabilities.
Current ratio = Current assets
Current liabilities
Step 2: Plug in the given values. The current assets are
$
300,000 and the
current liabilities are
$
150,000.
Current ratio = 300,000
150,000
Step 3: Simplify the ratio.
Current ratio = 2
Step 4: Interpret the result. A current ratio of 2 means that the company
has
$
2 in current assets for every
$
1 in current liabilities. This indicates that
the company has a strong ability to meet its short-term obligations, as it has
more than enough current assets to cover its current liabilities. A current ratio
of 2 is considered healthy and is generally preferred by investors and creditors
as it represents a lower risk of default.
Question 18
Question
A company’s current ratio is 2.5 and its quick ratio is 1.8. Explain the signifi-
cance of these ratios in terms of the company’s liquidity position.
Solution
Step 1: Understanding the Ratios The current ratio and quick ratio are both
measures of a company’s liquidity, which refers to its ability to meet short-term
obligations with its current assets. - The current ratio is calculated by dividing
current assets by current liabilities. - The quick ratio (also known as the acid-test
ratio) is calculated by dividing quick assets (current assets excluding inventory)
by current liabilities.
Step 2: Interpreting the Ratios A current ratio of 2.5 means that for every
dollar of current liabilities, the company has 2.50ofcurrentassets.T hisindicatesthatthecompanyhasastrongliquiditypositionandshouldbeabletocoveritsshort−
termobligationscomfortably.
A quick ratio of 1.8 means that for every dollar of current liabilities, the com-
pany has 1.80ofquickassets.T hisratioprovidesamoreconservativemeasureof liquiditycomparedtothecurrentratiosinceitexcludesinventory, whichmaynotbeeasilyconvertedintocash.
Step 3: Significance of the Ratios - A current ratio above 1 indicates that
the company has more current assets than current liabilities, which is generally
considered a good sign. - A current ratio of 2.5 indicates that the company
19
has a strong liquidity position and is in a good position to meet its short-term
obligations. - A quick ratio of 1.8 shows that the company has a sufficient level
of quick assets to cover its current liabilities, indicating a good ability to meet
short-term obligations without relying heavily on inventory.
In conclusion, the company appears to be in a healthy liquidity position
based on its current and quick ratios, suggesting that it should not have trouble
meeting its short-term financial obligations.
Question 19
Question
Company XYZ has the following financial information for the year ended De-
cember 31, 20X1:
Total assets:
$
800,000
Total liabilities:
$
300,000
Net income:
$
100,000
Total equity:
$
500,000
Total revenue:
$
600,000
Cost of goods sold:
$
200,000
Operating expenses:
$
150,000
Interest expense:
$
20,000
Calculate the following ratios and provide an interpretation for each:
1. Return on assets (ROA)
2. Return on equity (ROE)
3. Asset turnover
4. Debt to equity ratio
Solution
Step 1: Calculate Return on Assets (ROA)
ROA =N et Income
T otal Assets
ROA =$100,000
$800,000 = 0.125or12.5%
20
Interpretation: The return on assets for Company XYZ is 12.5%. This
means that for every
$
1 of assets, the company generates
$
0.125 of net income.
Step 2: Calculate Return on Equity (ROE)
ROE =N et Income
T otal Equity
ROE =$100,000
$500,000 = 0.2or20%
Interpretation: The return on equity for Company XYZ is 20%. This
indicates that for every
$
1 of equity, the company generates
$
0.20 of net income.
Step 3: Calculate Asset Turnover
Asset T urnover =T otal Revenue
Average T otal Assets
Average T otal Assets =Beginning T otal Assets +Ending T otal Assets
2=$800,000 + $800,000
2= $800,000
Asset T urnover =$600,000
$800,000 = 0.75
Interpretation: The asset turnover for Company XYZ is 0.75. This means
that the company generates
$
0.75 of revenue for every
$
1 of assets.
Step 4: Calculate Debt to Equity Ratio
Debt to Equity Ratio =T otal Liabilities
T otal Equity
Debt to Equity Ratio =$300,000
$500,000 = 0.6or 0.6:1
Interpretation: The debt to equity ratio for Company XYZ is 0.6 or 0.6:1.
This means that the company has
$
0.60 of debt for every
$
1 of equity.
Question 20
Question
A company has the following financial information for the year: - Total Revenue:
900,000−Costof GoodsSold :400,000 - Gross Profit: 500,000−OperatingExpenses :300,000
- Net Income: 200,000
Calculate and interpret the following ratios: a) Gross Profit Margin b) Op-
erating Profit Margin c) Net Profit Margin
21
Solution
a) To calculate the Gross Profit Margin, we use the formula:
Gross Profit Margin = Gross Profit
Total Revenue ×100%
Step 1: Calculate the Gross Profit:
Gross Profit = Total Revenue −Cost of Goods Sold =
900,000 - 400,000 =500,000
Step 2: Calculate the Gross Profit Margin:
Gross Profit Margin = $500,000
$900,000 ×100% = 5
9×100% ≈55.56%
The Gross Profit Margin for the company is approximately 55.56%.
b) To calculate the Operating Profit Margin, we use the formula:
Operating Profit Margin = Operating Income
Total Revenue ×100%
Step 1: Calculate the Operating Income:
Operating Income = Total Revenue−Cost of Goods Sold−Operating Expenses =
900,000 - 400,000−300,000 = 200,000
Step 2: Calculate the Operating Profit Margin:
Operating Profit Margin = $200,000
$900,000 ×100% = 2
9×100% ≈22.22%
The Operating Profit Margin for the company is approximately 22.22%.
c) To calculate the Net Profit Margin, we use the formula:
Net Profit Margin = Net Income
Total Revenue ×100%
Step 1: Calculate the Net Profit Margin:
Net Profit Margin = $200,000
$900,000 ×100% = 2
9×100% ≈22.22%
The Net Profit Margin for the company is approximately 22.22%.
22
Question 21
Question
A company has the following financial information for the year:
Sales:
$
500,000
Gross Profit:
$
250,000
Net Income:
$
100,000
Total Assets:
$
800,000
Total Liabilities:
$
400,000
Calculate the following ratios and interpret the company’s financial perfor-
mance:
1. Gross Profit Margin
2. Net Profit Margin
3. Return on Assets (ROA)
4. Debt to Equity Ratio
Solution
1. Step 1: Calculate Gross Profit Margin
The formula for Gross Profit Margin is:
Gross Profit Margin = Gross Profit
Sales ×100%
Substituting the given values:
Gross Profit Margin = 250,000
500,000 ×100% = 50%
2. Step 2: Calculate Net Profit Margin
The formula for Net Profit Margin is:
Net Profit Margin = Net Income
Sales ×100%
Substituting the given values:
Net Profit Margin = 100,000
500,000 ×100% = 20%
23
3. Step 3: Calculate Return on Assets (ROA)
The formula for Return on Assets is:
ROA = Net Income
Total Assets ×100%
Substituting the given values:
ROA = 100,000
800,000 ×100% = 12.5%
4. Step 4: Calculate Debt to Equity Ratio
The formula for Debt to Equity Ratio is:
Debt to Equity Ratio = Total Liabilities
Total Equity
First, we need to calculate Total Equity:
Total Equity = Total Assets−Total Liabilities = 800,000−400,000 = 400,000
Now, substitute the values to find the Debt to Equity Ratio:
Debt to Equity Ratio = 400,000
400,000 = 1
Interpretation:
The Gross Profit Margin of 50% indicates that the company is able to
generate a high percentage of sales revenue as gross profit.
The Net Profit Margin of 20% shows that 20% of the company’s sales
translate to net income.
The ROA of 12.5% indicates that the company is generating 12.5 cents of
profit for every dollar of assets it owns.
The Debt to Equity Ratio of 1 suggests that the company has the same
amount of debt as equity, which may indicate a balanced financial struc-
ture.
Question 22
Question
Company XYZ has provided the following financial information for the current
year:
24
Net Income:
$
500,000
Total Assets:
$
2,000,000
Current Liabilities:
$
400,000
Common Stock:
$
600,000
Retained Earnings:
$
300,000
Calculate the following ratios for Company XYZ and interpret each ratio:
1. Return on Assets (ROA)
2. Current Ratio
3. Debt-to-Equity Ratio
Solution
Step 1: Calculate Return on Assets (ROA)
ROA =N et Income
T otal Assets
Substitute the given values:
ROA =500,000
2,000,000 = 0.25 or 25%
Interpretation: ROA indicates that for every dollar of assets, Company
XYZ generated 25 cents of profit.
Step 2: Calculate Current Ratio
Current Ratio =Current Assets
Current Liabilities
Given that Current Assets =T otal Assets−Common Stock−Retained Earnings:
Current Assets = 2,000,000 −600,000 −300,000 = 1,100,000
Substitute the values to calculate the Current Ratio:
Current Ratio =1,100,000
400,000 = 2.75
Interpretation: The current ratio of 2.75 indicates that the company has
2.75 dollars in current assets for every dollar of current liabilities, suggesting
good liquidity.
Step 3: Calculate Debt-to-Equity Ratio
Debt −to −Equity Ratio =T otal Liabilities
Equity
25
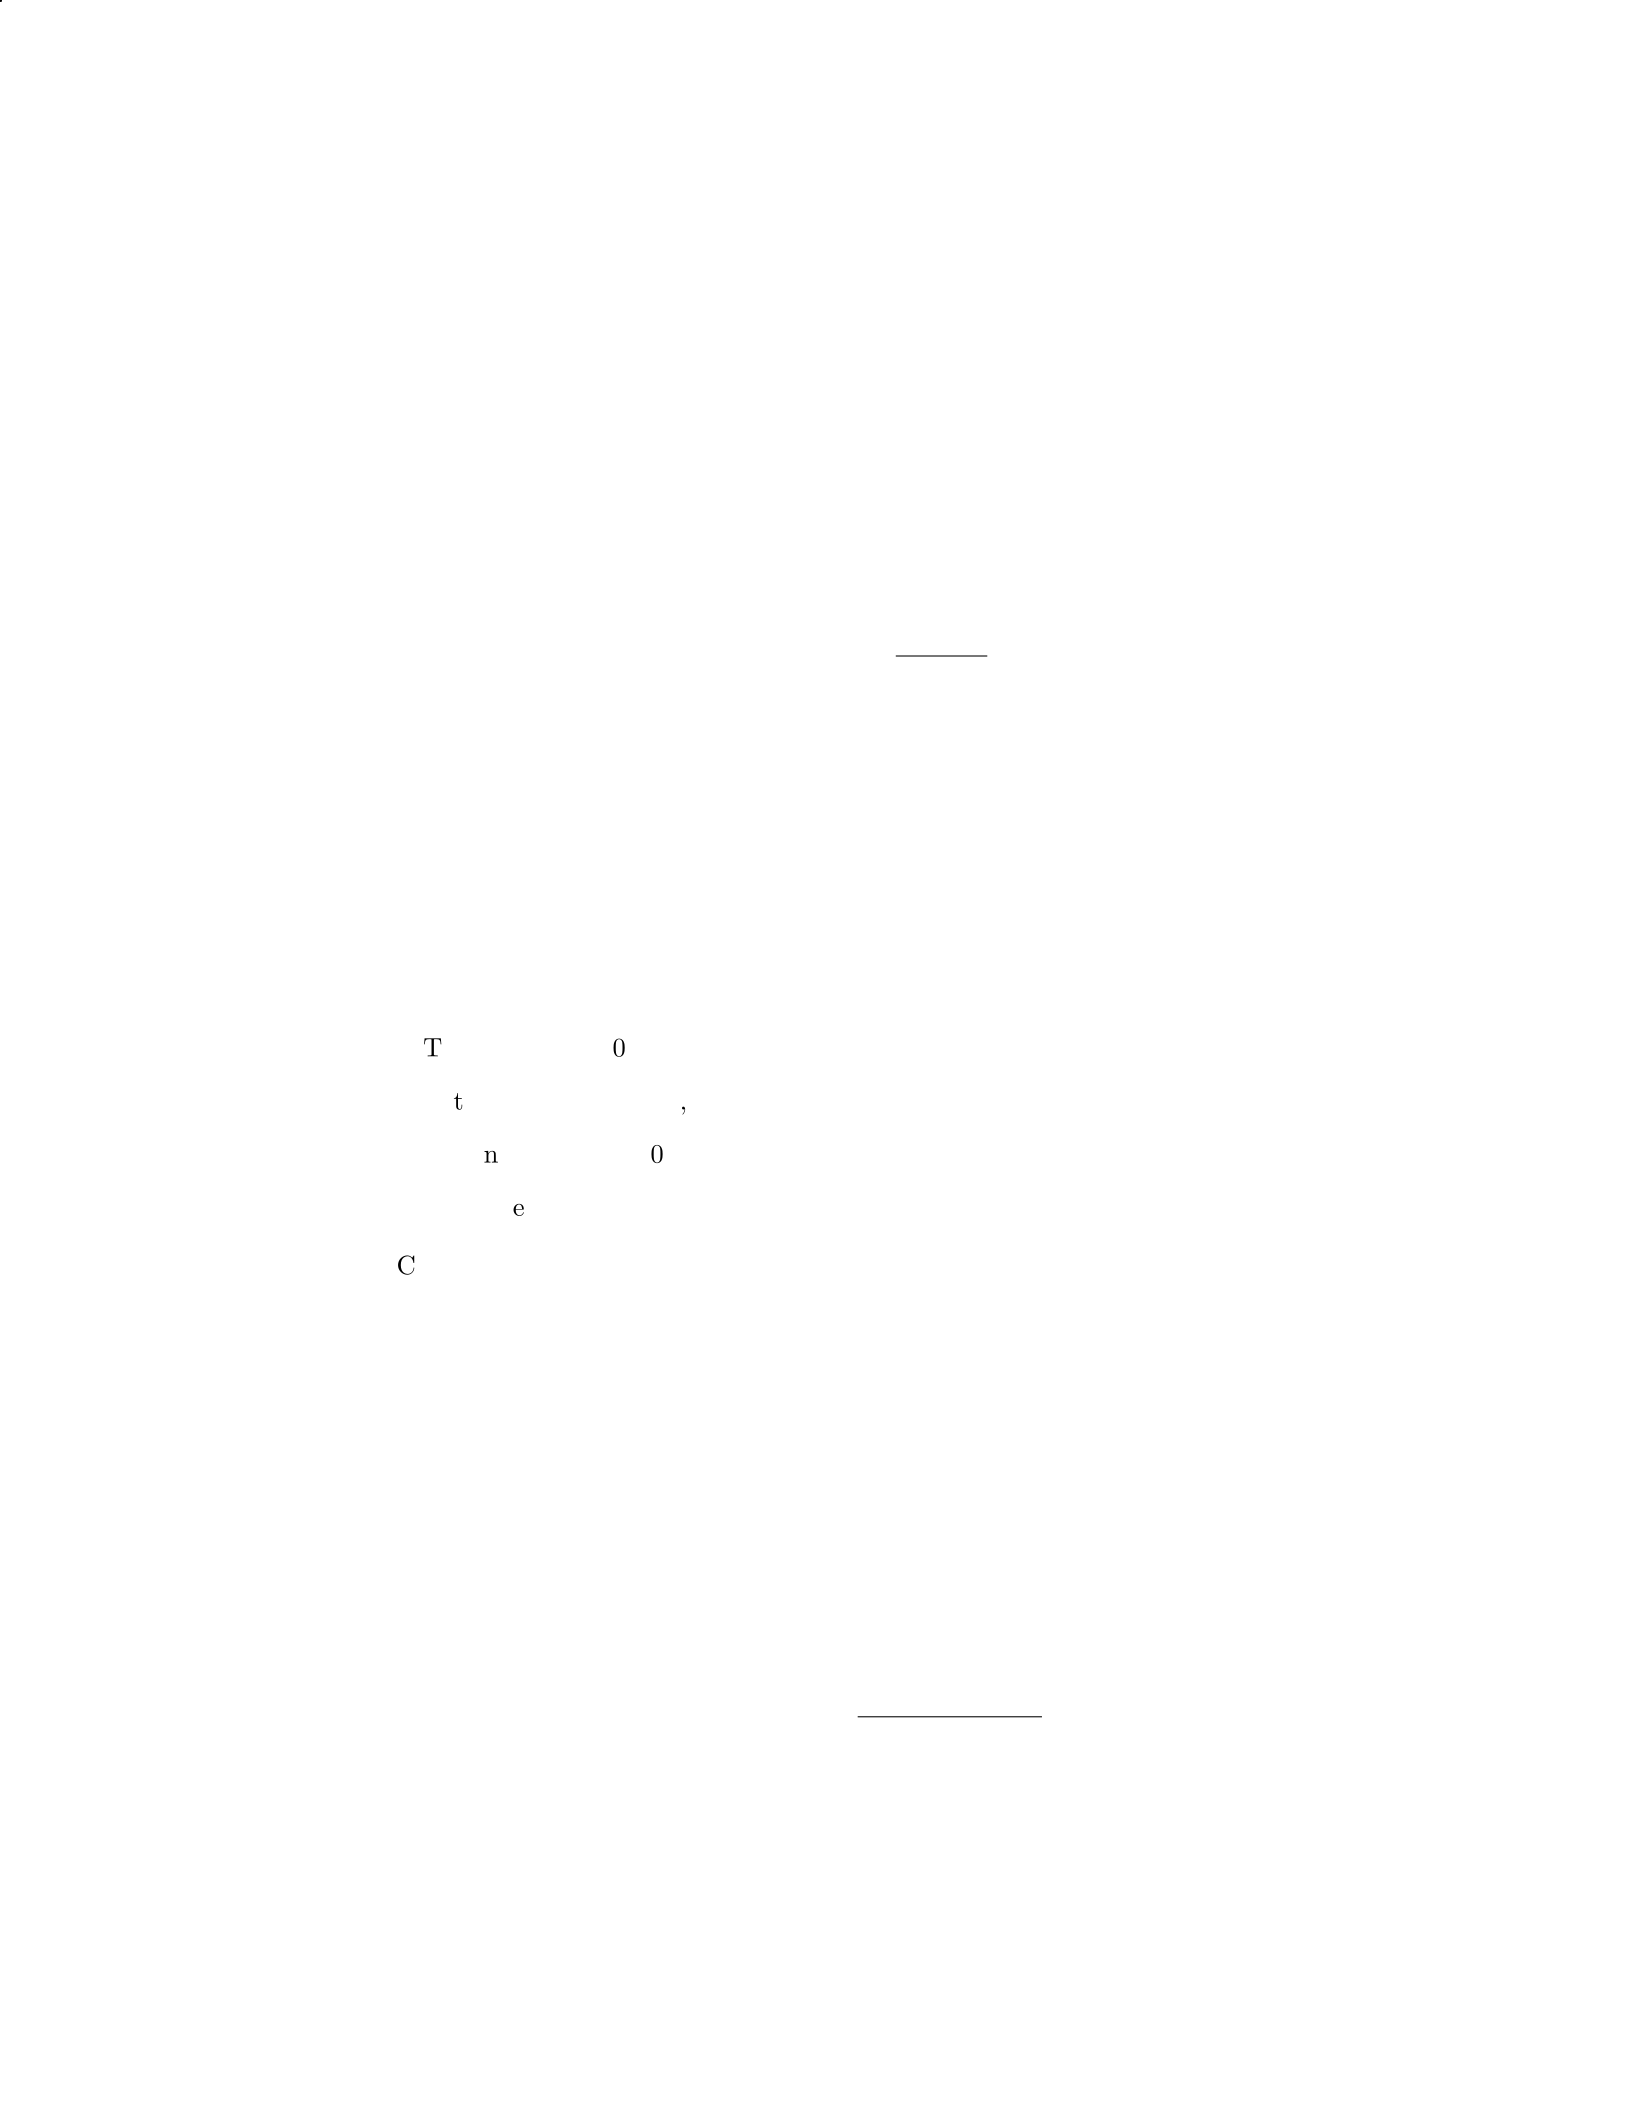
Given that T otal Liabilities =Current Liabilities:
T otal Liabilities = 400,000
And that Equity =Common Stock +Retained Earnings:
Equity = 600,000 + 300,000 = 900,000
Substitute the values to calculate the Debt-to-Equity Ratio:
Debt −to −Equity Ratio =400,000
900,000 = 0.44
Interpretation: The Debt-to-Equity Ratio of 0.44 indicates that the com-
pany has more equity financing than debt financing, which is generally consid-
ered a less risky financial structure.
Question 23
Question
A company has the following financial information for the year 2021:
Total Assets:
$
500,000
Total Liabilities:
$
200,000
Net Income:
$
50,000
Total Revenue:
$
300,000
Calculate and interpret the following ratios:
1. Debt-to-Asset Ratio
2. Return on Assets (ROA)
3. Profit Margin
Solution
To calculate the ratios, we will use the given financial information for the com-
pany.
Step 1: Calculate the Debt-to-Asset Ratio The Debt-to-Asset Ratio
is calculated by dividing Total Liabilities by Total Assets.
Debt-to-Asset Ratio = Total Liabilities
Total Assets
26
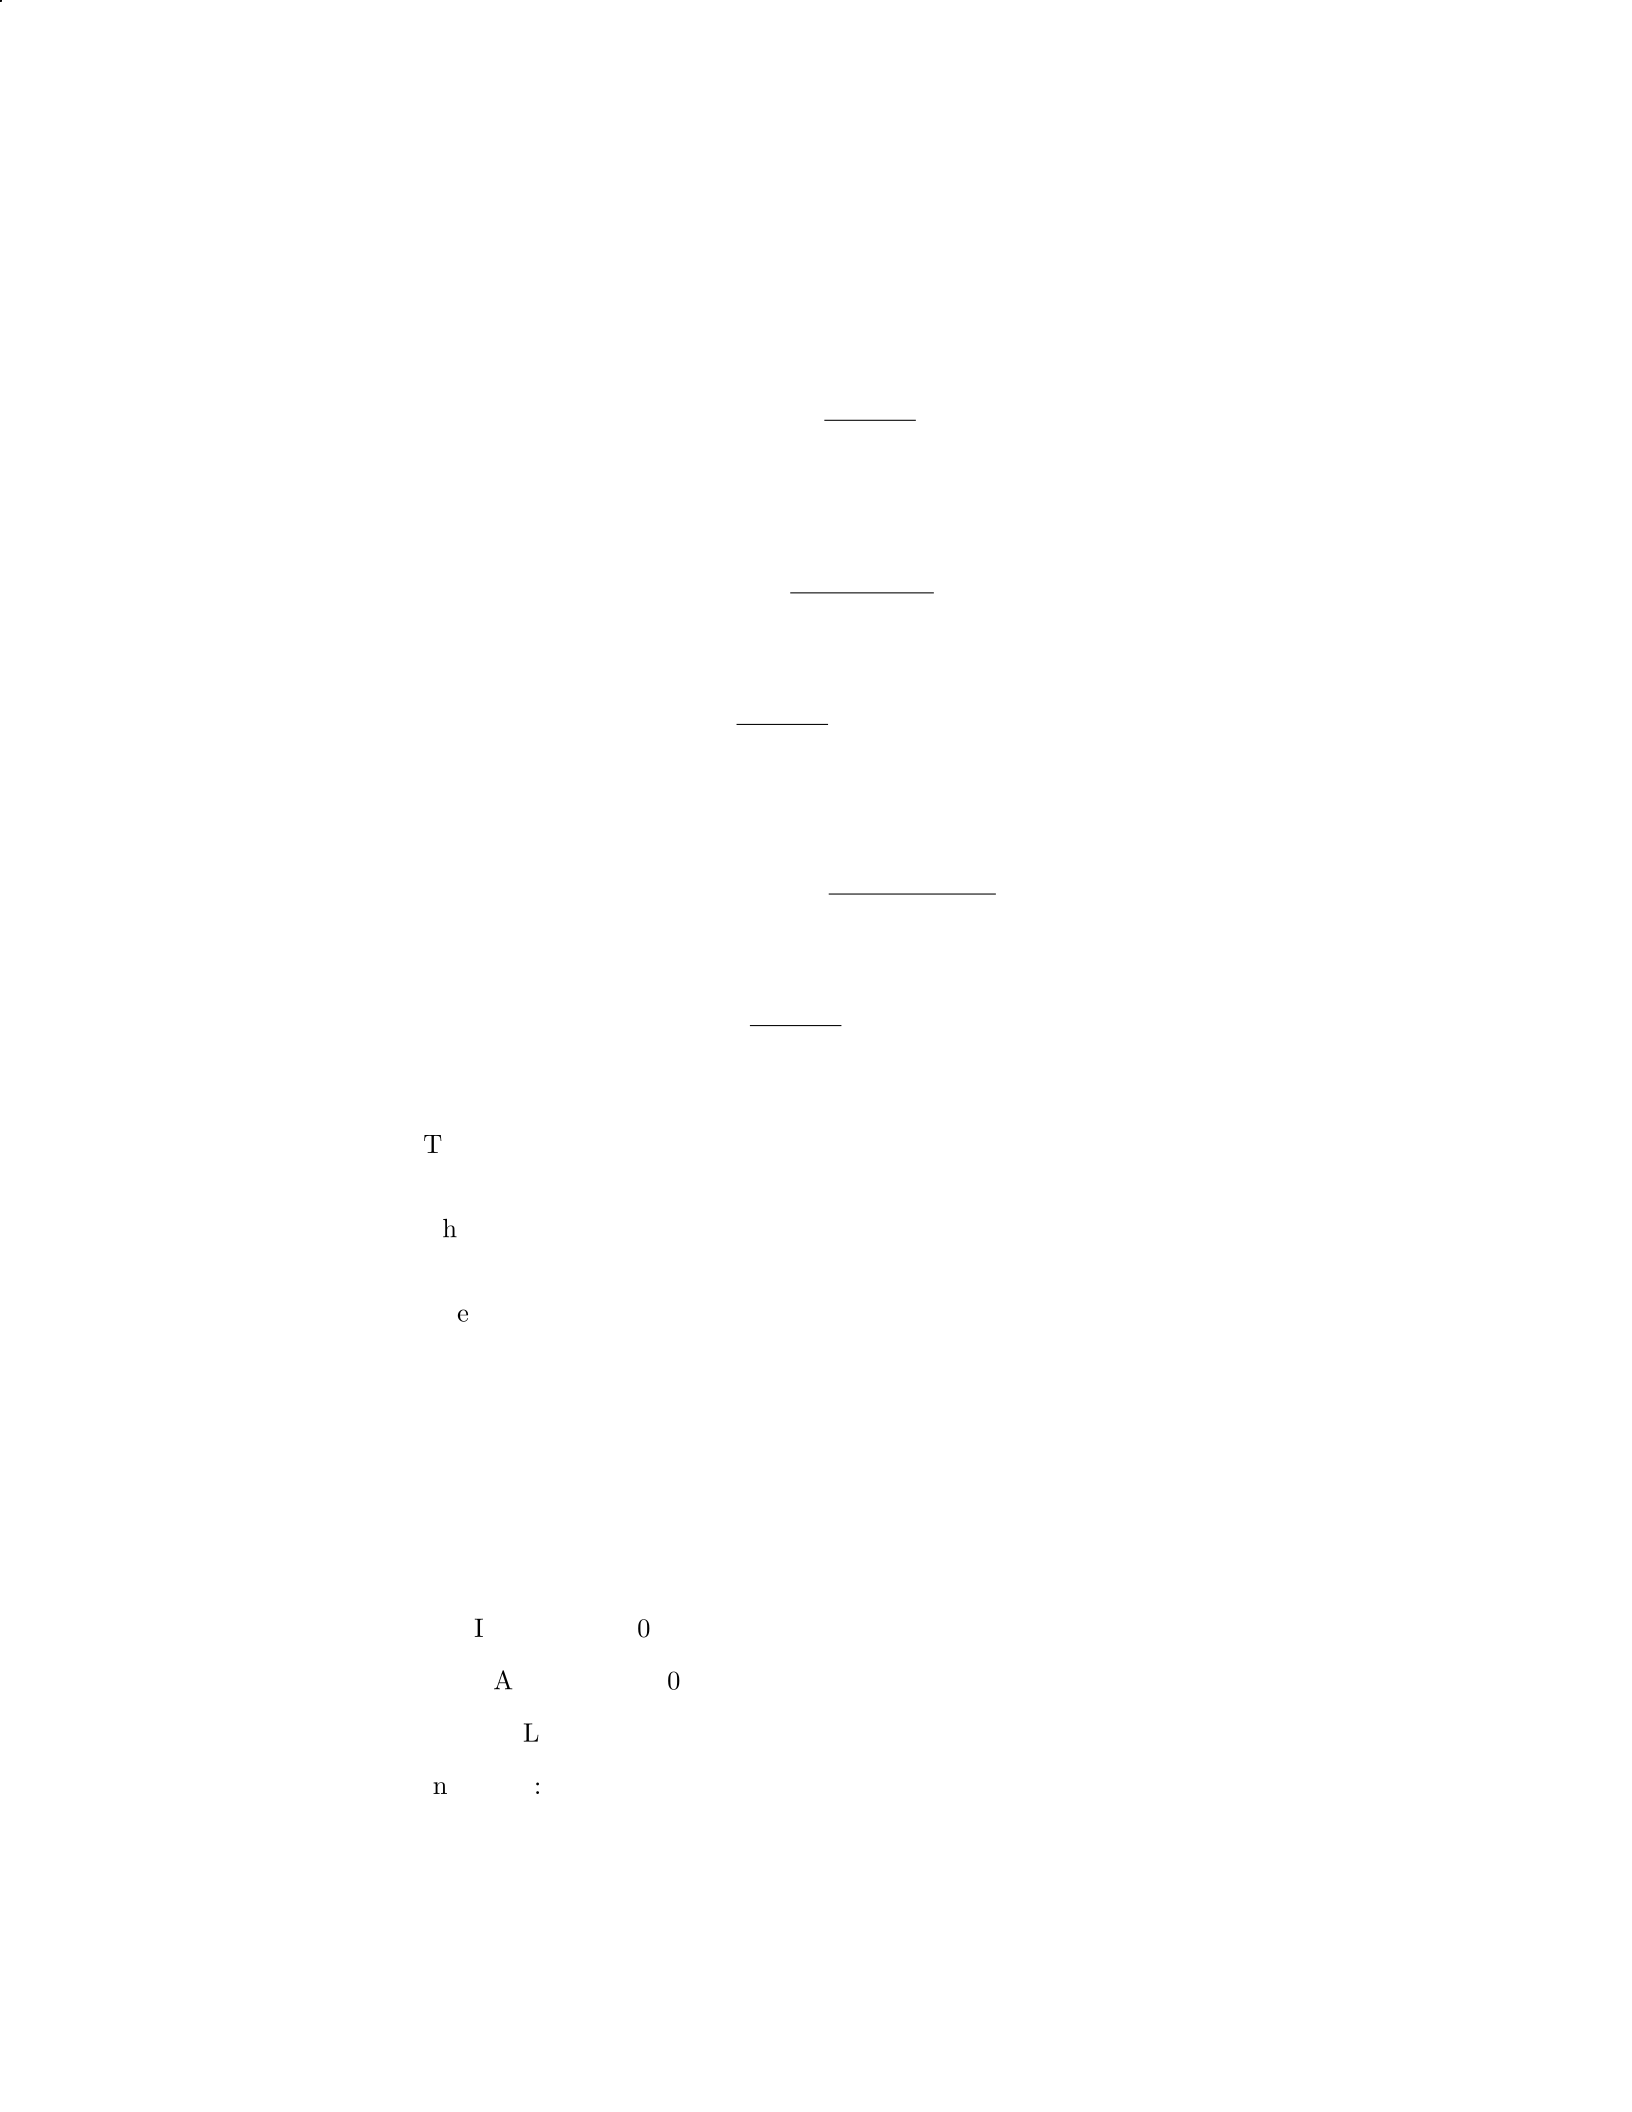
Substitute the given values:
Debt-to-Asset Ratio = 200,000
500,000 = 0.4 or 40%
Step 2: Calculate the Return on Assets (ROA) The Return on Assets
(ROA) is calculated by dividing Net Income by Total Assets.
ROA = Net Income
Total Assets
Substitute the given values:
ROA = 50,000
500,000 = 0.1 or 10%
Step 3: Calculate the Profit Margin The Profit Margin is calculated
by dividing Net Income by Total Revenue.
Profit Margin = Net Income
Total Revenue
Substitute the given values:
Profit Margin = 50,000
300,000 = 0.1667 or 16.67%
Interpretation:
The Debt-to-Asset Ratio of 40% indicates that 40% of the company’s
assets are financed by debt.
The ROA of 10% shows that the company generated a 10% return on its
total assets.
The Profit Margin of 16.67% means that the company earned 16.67 cents
of profit for every dollar of revenue generated.
Question 24
Question
Company ABC has provided the following financial information for the year
2020:
Net Income:
$
500,000
Total Assets:
$
2,000,000
Current Liabilities:
$
300,000
Inventory:
$
100,000
27
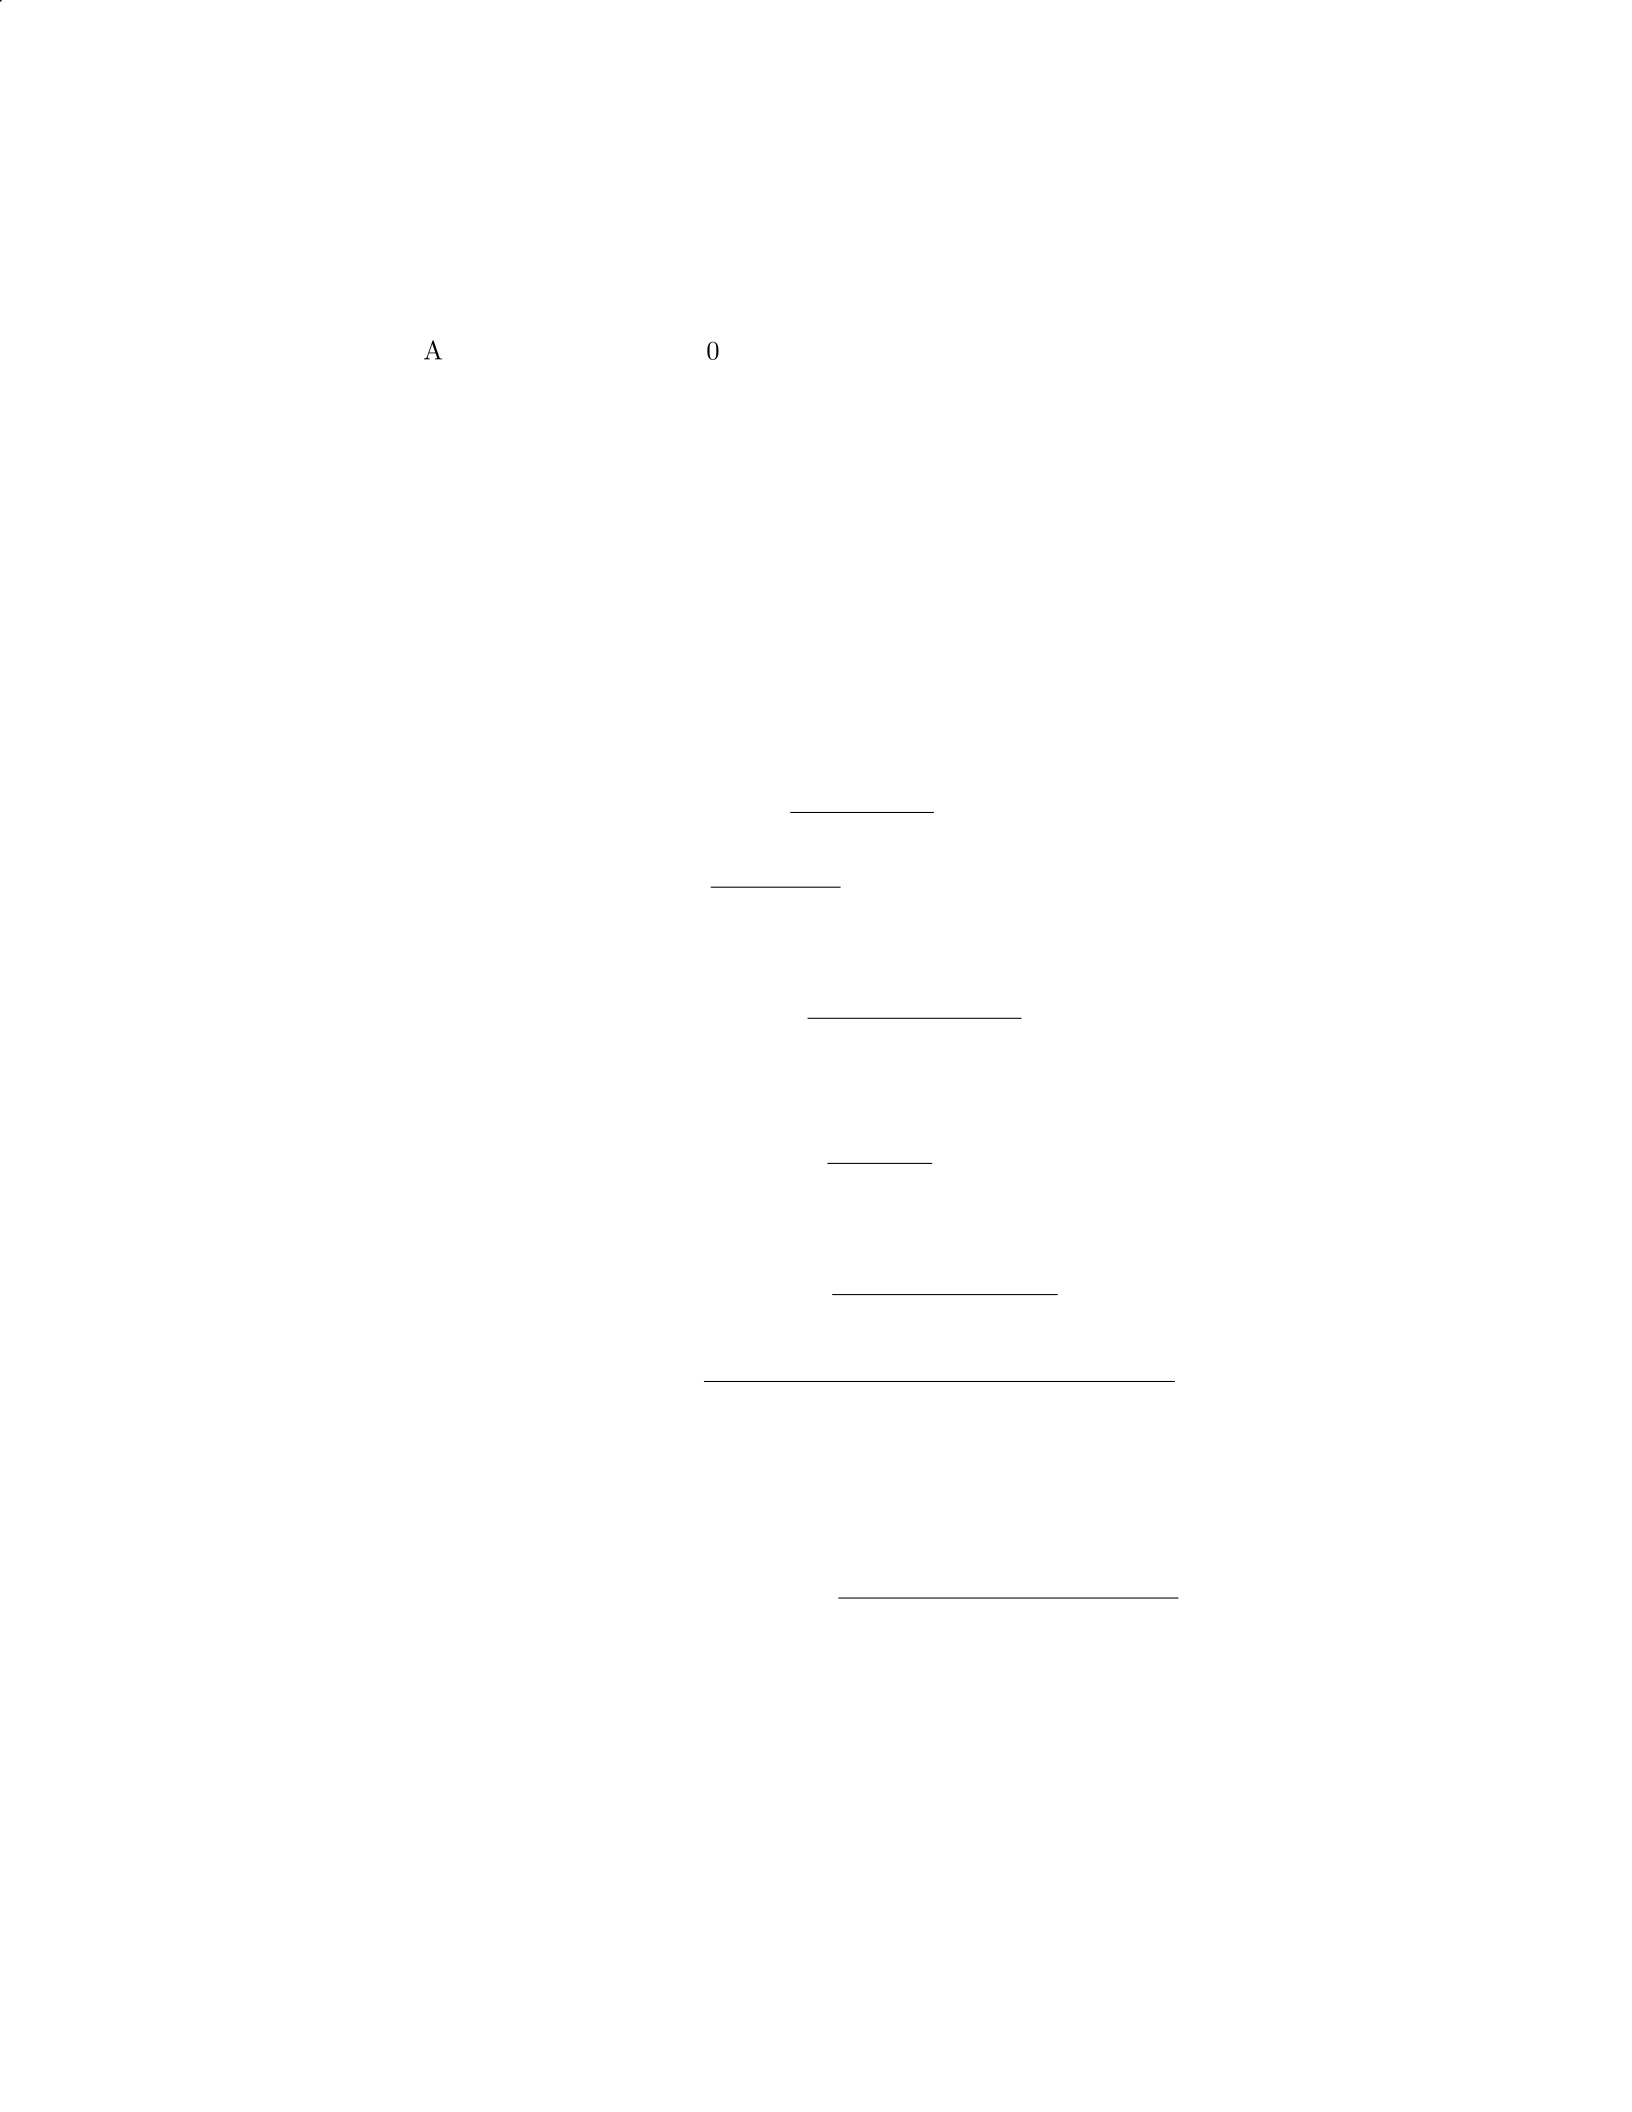
Accounts Receivable:
$
50,000
Calculate the following ratios for Company ABC:
1. Return on Assets (ROA)
2. Current Ratio
3. Inventory Turnover
4. Accounts Receivable Turnover
Solution
1. Return on Assets (ROA)
ROA = Net Income
Total Assets
ROA = $500,000
$2,000,000 = 0.25 or 25%
2. Current Ratio
Current Ratio = Current Assets
Current Liabilities
Current Assets = Inventory+Accounts Receivable = $100,000+$50,000 = $150,000
Current Ratio = $150,000
$300,000 = 0.5
3. Inventory Turnover
Inventory Turnover = Cost of Goods Sold
Average Inventory
Average Inventory = Beginning Inventory + Ending Inventory
2
Assuming Cost of Goods Sold is not given, we cannot directly calculate
Inventory Turnover.
4. Accounts Receivable Turnover
Accounts Receivable Turnover = Net Credit Sales
Average Accounts Receivable
Net Credit Sales = Total Sales −Cash Sales
Since Total Sales and Cash Sales are not provided, we cannot directly cal-
culate Accounts Receivable Turnover.
28
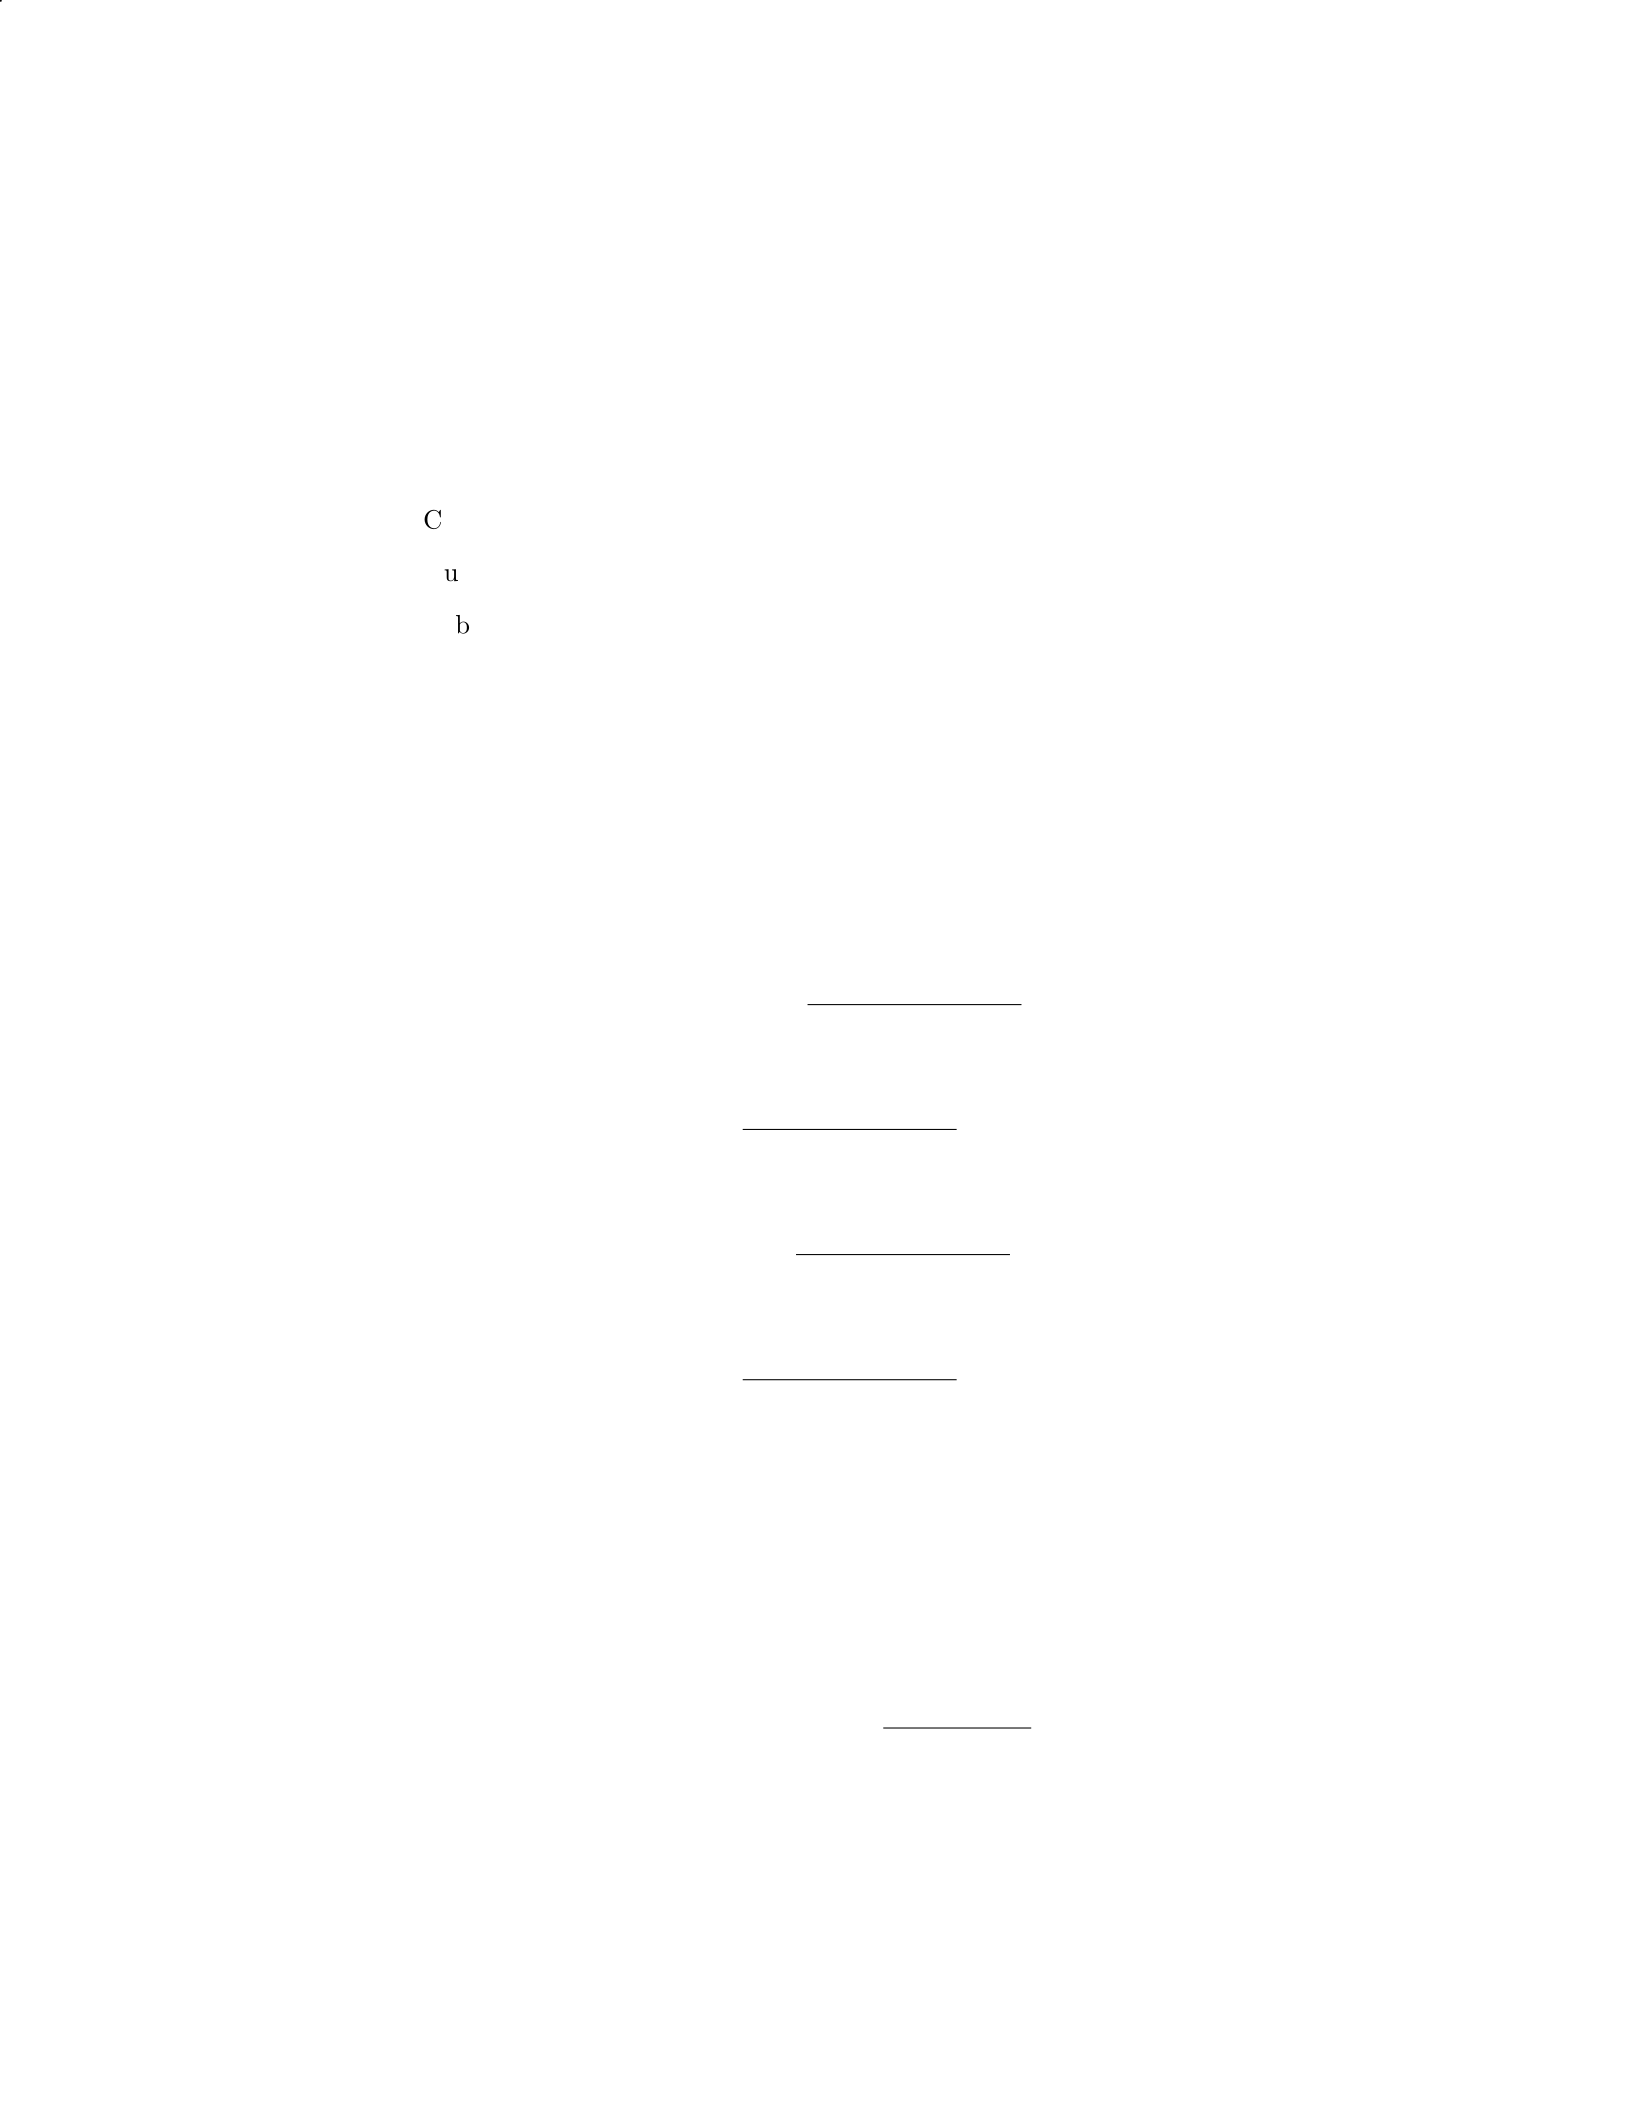
Question 25
Question
Company XYZ has the following financial ratios for the year 2020:
Current ratio = 2.5
Quick ratio = 1.5
Debt-to-equity ratio = 0.8
Based on the information provided, analyze the financial health of Company
XYZ and provide your interpretation.
Solution
To analyze the financial health of Company XYZ, we will evaluate each ratio
individually and then provide an overall interpretation.
Step 1: Calculate the Current Assets and Current Liabilities The
current ratio is given by:
Current Ratio = Current Assets
Current Liabilities
Given that the current ratio is 2.5, we can set up the following equation:
2.5 = Current Assets
Current Liabilities
Step 2: Find the Quick Assets The quick ratio is given by:
Quick Ratio = Quick Assets
Current Liabilities
Given that the quick ratio is 1.5, we have:
1.5 = Quick Assets
Current Liabilities
Step 3: Interpretation of the Current Ratio and Quick Ratio A cur-
rent ratio of 2.5 indicates that Company XYZ has 2.50ofcurrentassetsforevery1
of current liabilities, which suggests that the company is in a good position to
meet its short-term obligations. The quick ratio of 1.5 shows that the com-
pany has 1.50ofquickassets(assetsthatcanbeeasilyliquidated)f orevery1 of cur-
rent liabilities.
Step 4: Analyze the Debt-to-Equity Ratio The debt-to-equity ratio is
given by:
Debt-to-Equity Ratio = Total Debt
Total Equity
Given that the debt-to-equity ratio is 0.8, we have:
29
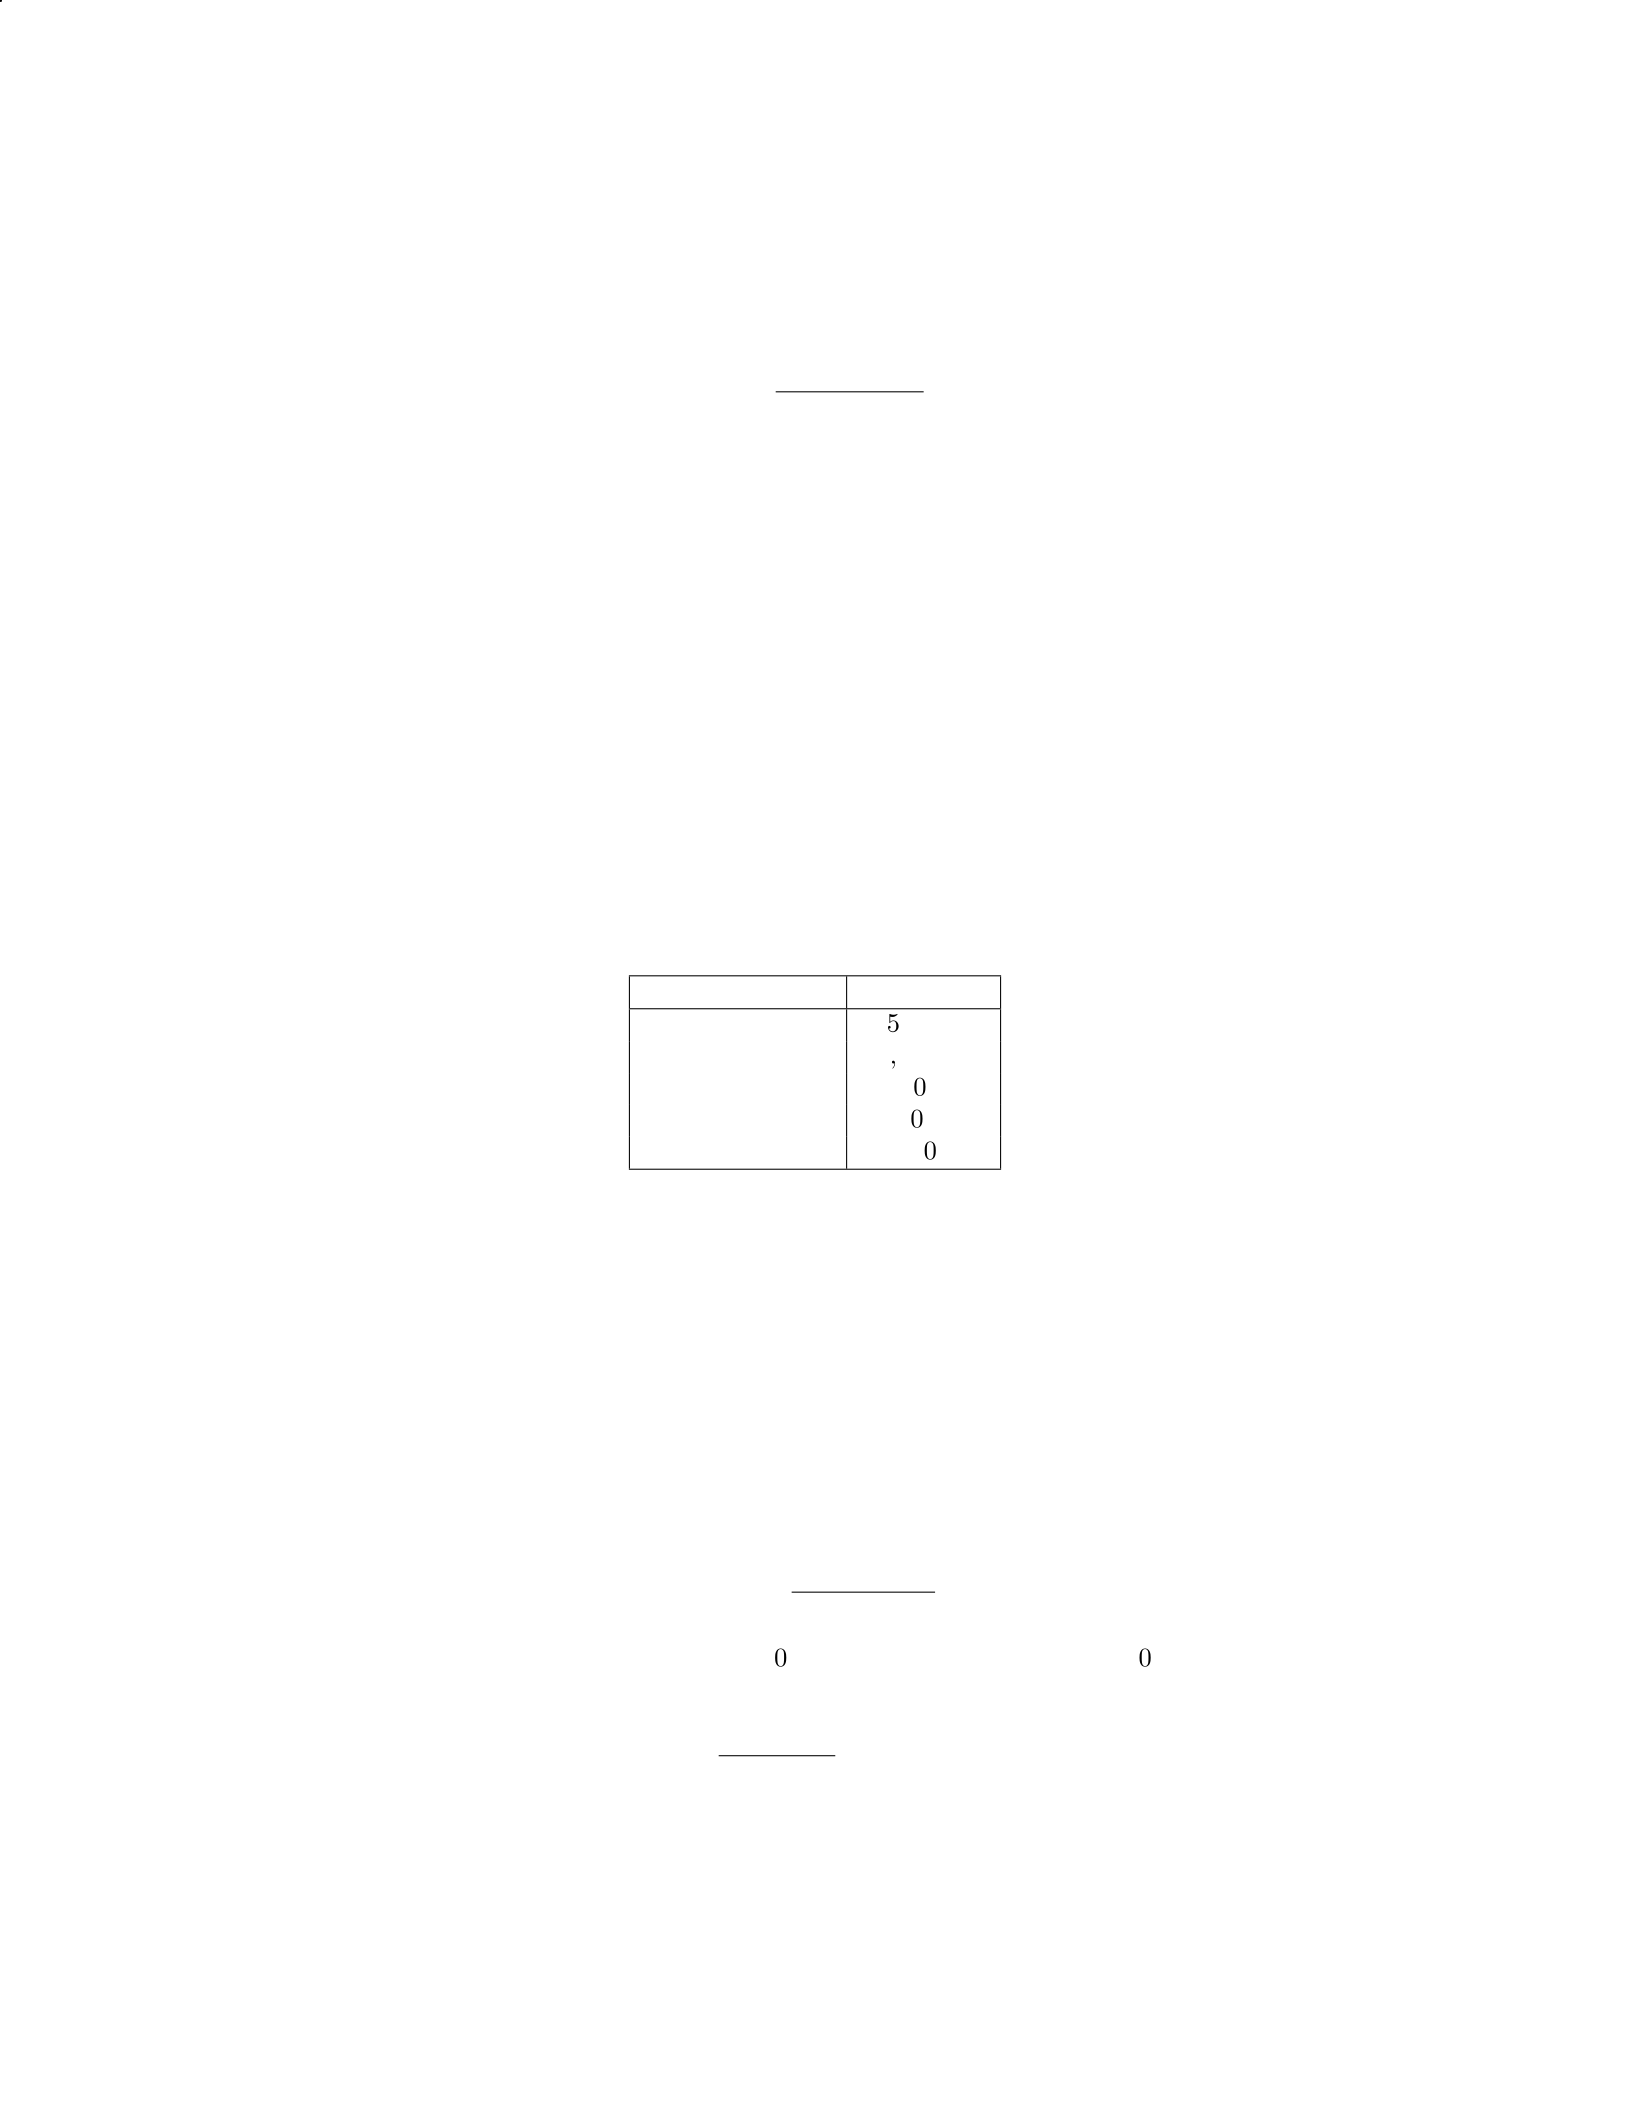
0.8 = Total Debt
Total Equity
Step 5: Interpretation of the Debt-to-Equity Ratio A debt-to-equity
ratio of 0.8 suggests that for every 1ofequity, thecompanyhas0.80 of debt. This
indicates that Company XYZ has a conservative capital structure with a higher
proportion of equity compared to debt.
Step 6: Overall Interpretation Based on the ratios calculated, Company
XYZ appears to be in a healthy financial position. The current and quick ratios
indicate strong liquidity and ability to meet short-term obligations. Addition-
ally, the conservative debt-to-equity ratio suggests a lower financial risk due to
a higher proportion of equity in the capital structure. Overall, Company XYZ
seems to have a favorable financial health in the year 2020.
Question 26
Question
A company had the following financial information for the year:
Metric Value
Net Income
$
500,000
Total Assets
$
2,000,000
Total Liabilities
$
800,000
Total Equity
$
1,200,000
Revenue
$
1,000,000
Calculate the following ratios and interpret them in the context of the com-
pany’s performance:
1. Return on Assets (ROA)
2. Debt to Equity Ratio
3. Profit Margin
Solution
Step 1: Calculate Return on Assets (ROA)
ROA =N etIncome
T otalAssets
Given that Net Income is
$
500,000 and Total Assets are
$
2,000,000, we can
calculate ROA as:
ROA =500,000
2,000,000 = 0.25 or 25%
30
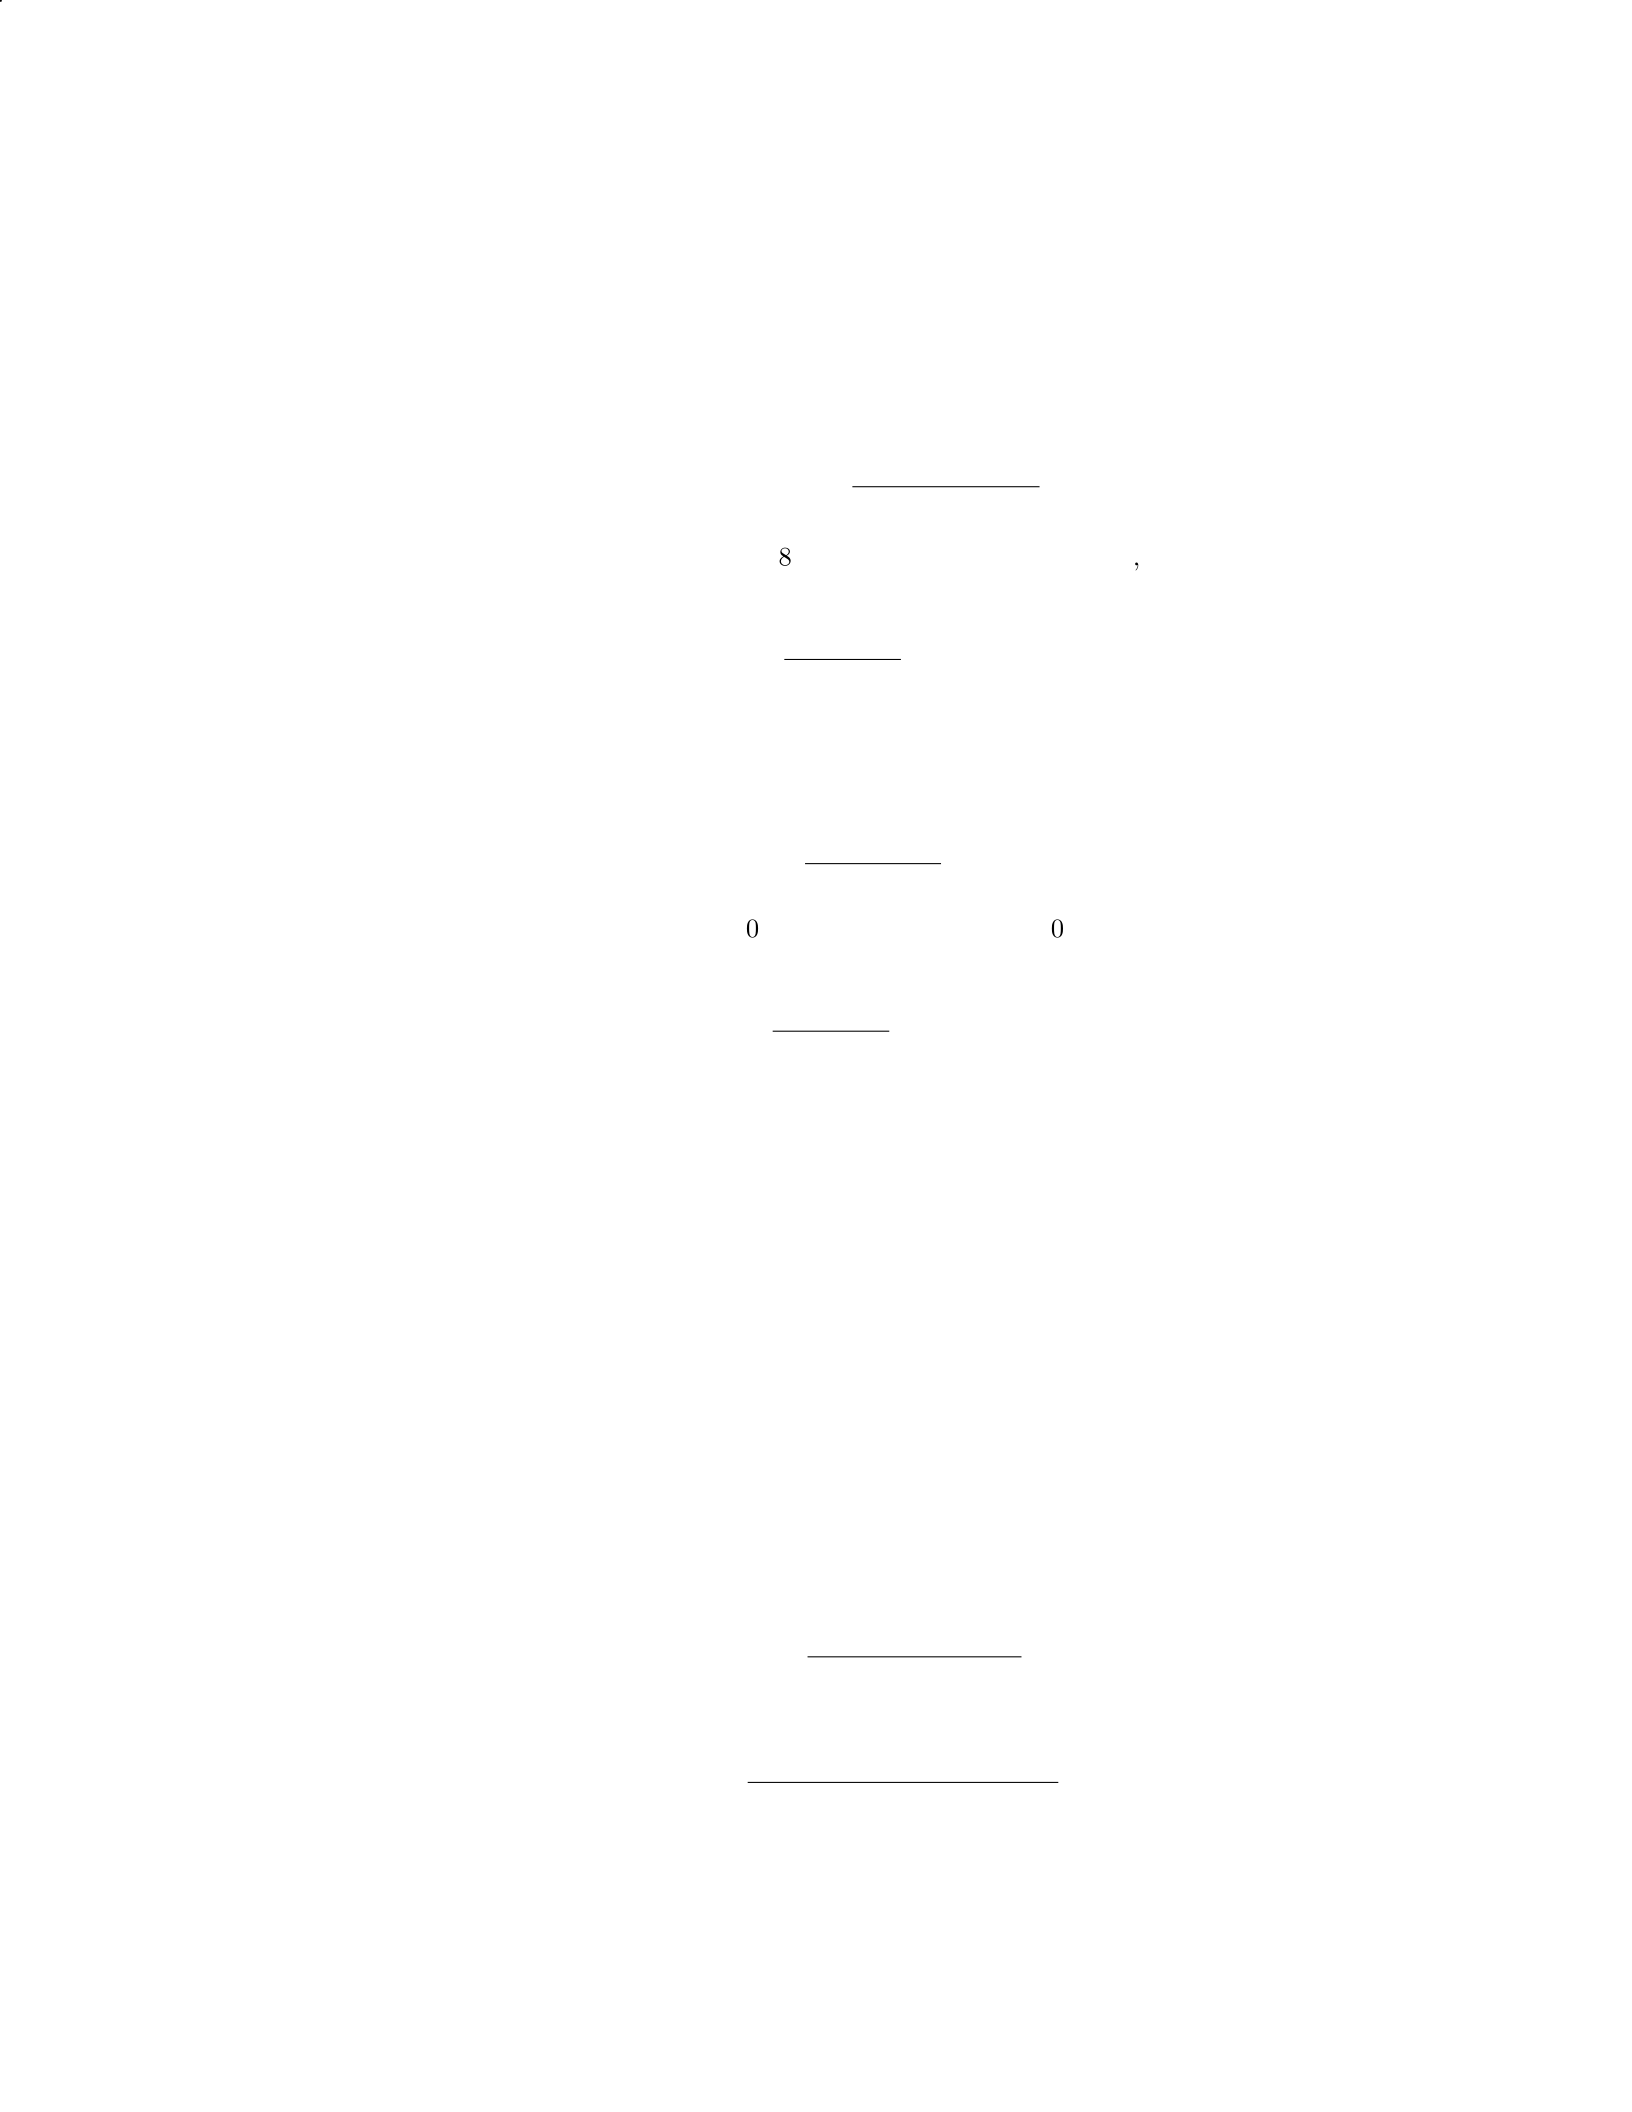
The company generated a return of 25% on its total assets. This indicates
that the company is efficient in generating income from its assets.
Step 2: Calculate Debt to Equity Ratio
DebttoEquityRatio =T otalLiabilities
T otalEquity
Given that Total Liabilities are
$
800,000 and Total Equity is
$
1,200,000, we
can calculate the Debt to Equity Ratio as:
DebttoEquityRatio =800,000
1,200,000 = 0.67 or 0.67 : 1
The company’s Debt to Equity Ratio is 0.67, indicating that it has more
equity than debt. This shows a lower financial risk for the company.
Step 3: Calculate Profit Margin
P rofitM argin =N etIncome
Revenue ×100%
Given that Net Income is
$
500,000 and Revenue is
$
1,000,000, we can cal-
culate the Profit Margin as:
P rofitM argin =500,000
1,000,000 ×100% = 50%
The company’s Profit Margin is 50%, meaning that for every dollar of rev-
enue, the company keeps 50 cents as profit. This implies that the company is
operating efficiently in terms of generating profit.
Question 27
Question
A company reported a current ratio of 2.5 and a quick ratio of 1.8. Interpret
these ratios and discuss what they indicate about the company’s liquidity posi-
tion.
Solution
Step 1: Interpretation of Current Ratio and Quick Ratio
The current ratio is calculated as:
Current Ratio = Current Assets
Current Liabilities
The quick ratio is calculated as:
Quick Ratio = Current Assets - Inventory
Current Liabilities
31
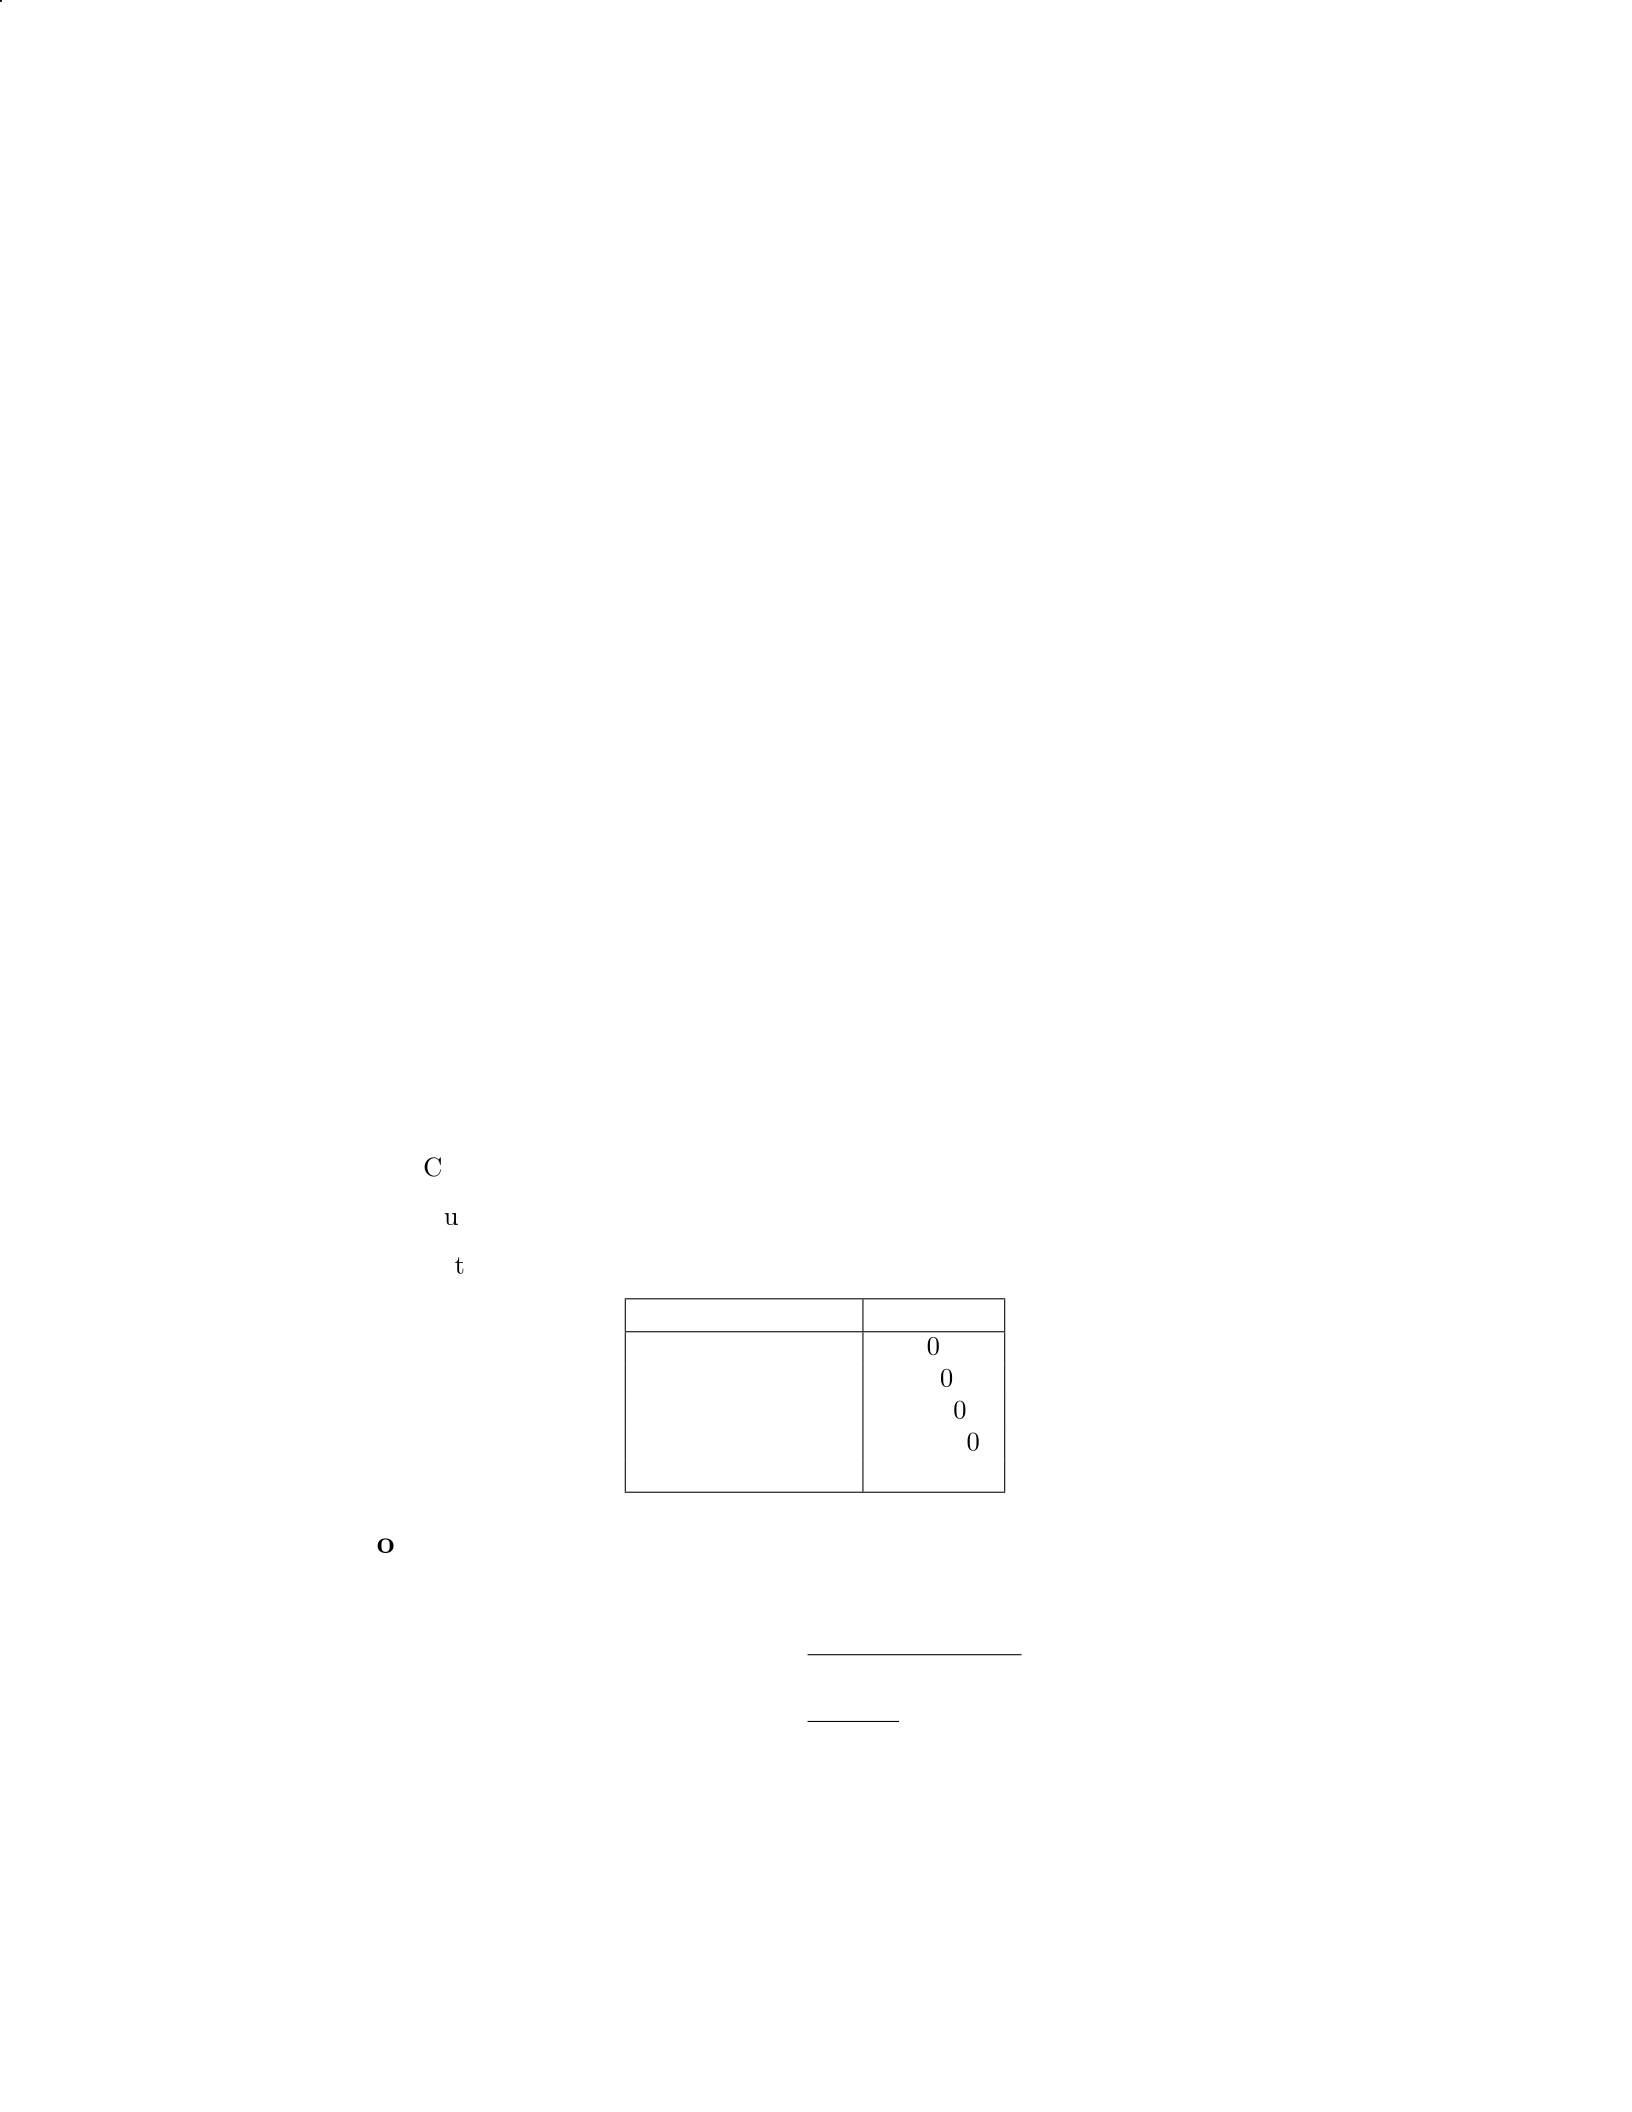
Step 2: Interpretation of Current Ratio
A current ratio of 2.5 means that the company has 2.5 times more current
assets than current liabilities. This indicates that the company is able to cover
its short-term obligations comfortably.
Step 3: Interpretation of Quick Ratio
A quick ratio of 1.8 means that the company has 1.8 times more liquid assets
(current assets excluding inventory) than current liabilities. This ratio provides
a more stringent measure of liquidity compared to the current ratio.
Step 4: Discussion on Liquidity Position
The current ratio of 2.5 and quick ratio of 1.8 suggest that the company has
a healthy liquidity position. The high current ratio indicates that the company
has a strong ability to pay off its short-term liabilities using its current assets.
The quick ratio further confirms this liquidity position by excluding inventory
from the calculation, focusing only on the most liquid current assets.
Overall, based on these ratios, the company appears to be in a comfortable
position to meet its short-term obligations. However, it is important to consider
other factors such as cash flow and solvency ratios for a more comprehensive
analysis of the company’s financial health.
Question 28
Question
Given the following financial data for Company XYZ, calculate the following
ratios and interpret the results:
Current ratio
Quick ratio
Return on assets (ROA)
Item Amount
Current assets
$
80,000
Current liabilities
$
30,000
Inventory
$
20,000
Total assets
$
200,000
Net income
$
40,000
Solution
Step 1: Calculate the Current Ratio
Current Ratio = Current Assets
Current Liabilities
=$80,000
$30,000
= 2.67
32
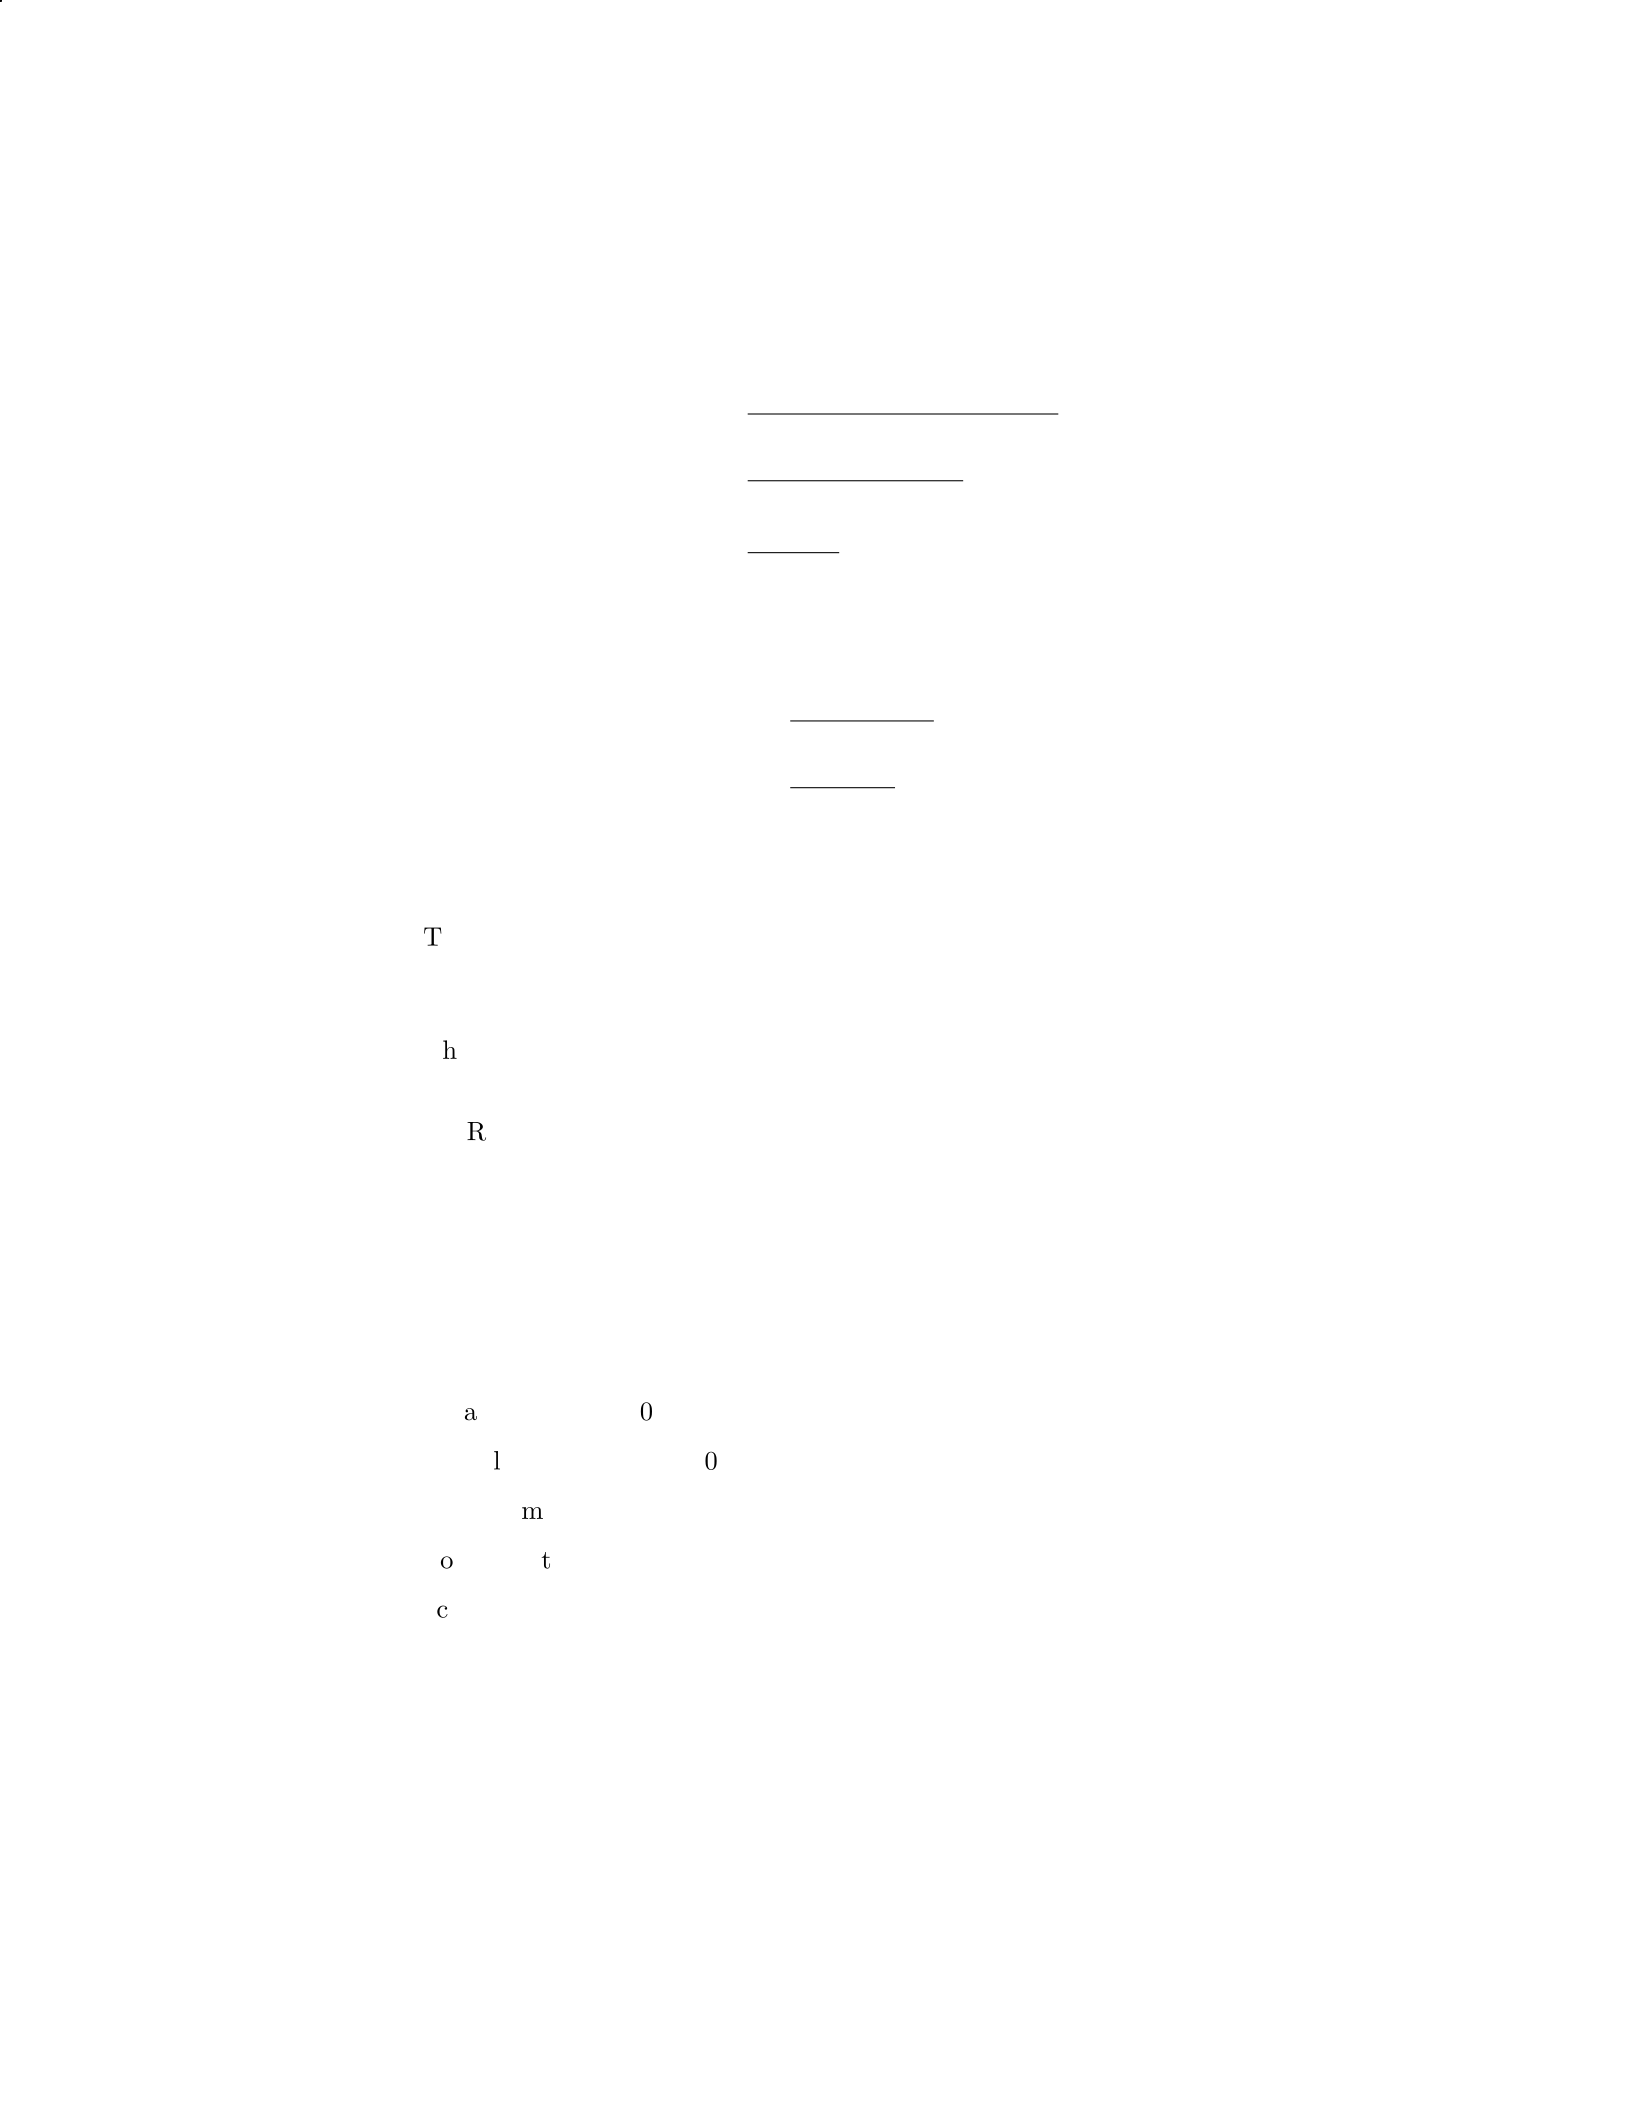
Step 2: Calculate the Quick Ratio
Quick Ratio = Current Assets - Inventory
Current Liabilities
=$80,000 −$20,000
$30,000
=$60,000
$30,000
= 2
Step 3: Calculate the Return on Assets (ROA)
ROA = Net Income
Total Assets
=$40,000
$200,000
= 0.20 or 20%
Step 4: Interpretation
The current ratio of 2.67 indicates that Company XYZ has more than
enough current assets to cover its current liabilities, which is considered
favorable.
The quick ratio of 2 shows that Company XYZ can cover its current
liabilities with a margin of safety without relying on selling inventory.
An ROA of 20
Question 29
Question
A company’s financial statements report the following information for the cur-
rent year:
Total assets:
$
800,000
Total liabilities:
$
400,000
Net income:
$
120,000
Total equity:
$
400,000
Calculate the following ratios and interpret what each ratio reveals about
the company:
1. Debt-to-total-assets ratio
2. Return on equity (ROE) ratio
3. Equity multiplier
33
Solution
Let’s first calculate the ratios and then interpret what each ratio reveals about
the company.
Step 1: Calculate the debt-to-total-assets ratio
Debt-to-total-assets ratio = Total liabilities
Total assets
=$400,000
$800,000
= 0.5
Step 2: Calculate the return on equity (ROE) ratio
ROE = Net income
Total equity
=$120,000
$400,000
= 0.3
Step 3: Calculate the equity multiplier
Equity multiplier = Total assets
Total equity
=$800,000
$400,000
= 2
Interpretation:
Debt-to-total-assets ratio (0.5): This ratio indicates that 50
Return on equity (ROE) ratio (0.3): This ratio shows that for every
dollar of equity invested, the company generates
$
0.30 in net income. A
higher ROE typically indicates a more efficient use of equity capital and
better profitability.
Equity multiplier (2): The equity multiplier of 2 signifies that the
company has
$
2 of assets for every
$
1 of equity. This indicates the extent
to which the company is leveraging its equity to finance its assets.
Question 30
Question
A company has the following financial information for the year 2020:
Net Sales:
$
500,000
34
Cost of Goods Sold:
$
300,000
Total Assets:
$
800,000
Total Liabilities:
$
400,000
Calculate the following ratios for the company:
1. Gross Profit Margin
2. Return on Assets
Interpret each ratio in the context of the company’s performance.
Solution
To calculate the ratios, we will use the following formulas:
Gross Profit Margin = Net Sales−Cost of Goods Sold
Net Sales
Return on Assets = Net Income
Total Assets
Step 1: Calculate Gross Profit Margin
Gross Profit Margin = 500,000 −300,000
500,000
=200,000
500,000
= 0.4 or 40%
Step 2: Calculate Return on Assets We need to find Net Income first.
Since it is not provided, we will use the formula: Net Income = Net Sales - Cost
of Goods Sold.
Net Income = 500,000 −300,000
= 200,000
Now we can calculate the Return on Assets:
Return on Assets = 200,000
800,000
= 0.25 or 25%
Interpretation:
35
Question 31
Question
A company has the following financial information for the year: - Net
Income:
$
200,000 - Total Revenue:
$
1,000,000 - Cost of Goods Sold:
$
600,000 - Total Assets:
$
2,000,000 Calculate and interpret the company’s:
a) Profit Margin b) Return on Assets c) Gross Profit Margin
Solution
a) To calculate the Profit Margin, we use the formula:
Profit Margin = Net Income
Total Revenue ×100%
Step 1: Calculate the Profit Margin.
Profit Margin = 200,000
1,000,000 ×100% = 1
5×100% = 20%
b) To calculate the Return on Assets, we use the formula:
Return on Assets = Net Income
Total Assets ×100%
Step 2:Gross Profit Margin (40
Question 31
Question
A company has the following financial information for the year:
- Net Income:
$
200,000 - Total Revenue:
$
1,000,000 - Cost of
Goods Sold:
$
600,000 - Total Assets:
$
2,000,000 Calculate and
interpret the company’s: a) Profit Margin b) Return on Assets
c) Gross Profit Margin
Solution
a) To calculate the Profit Margin, we use the formula:
Profit Margin =Net Income
Total Revenue ×100%
Step 1:Return on Assets (25
36
Question 31
Question
A company has the following financial information for the year: - Net Income:
$
200,000 - Total Revenue:
$
1,000,000 - Cost of Goods Sold:
$
600,000 - Total
Assets:
$
2,000,000 Calculate and interpret the company’s: a) Profit Margin b)
Return on Assets c) Gross Profit Margin
Solution
a) To calculate the Profit Margin, we use the formula:
Profit Margin = Net Income
Total Revenue ×100%
Step 1: Calculate the Profit Margin.
Profit Margin = 200,000
1,000,000 ×100% = 1
5×100% = 20%
b) To calculate the Return on Assets, we use the formula:
Return on Assets = Net Income
Total Assets ×100%
Step 2: Calculate the Return on Assets.
Return on Assets = 200,000
2,000,000 ×100% = 1
10 ×100% = 10%
c) To calculate the Gross Profit Margin, we use the formula:
Gross Profit Margin = Revenue −Cost of Goods Sold
Revenue ×100%
Step 3: Calculate the Gross Profit Margin.
Gross Profit Margin = 1,000,000 −600,000
1,000,000 ×100% = 400,000
1,000,000×100% = 40%
Interpretation: a) The company has a Profit Margin of 20b) The company
has a Return on Assets of 10c) The Gross Profit Margin of 40
Question 32
Question
A company reported the following financial information for the year:
Net income:
$
500,000
37
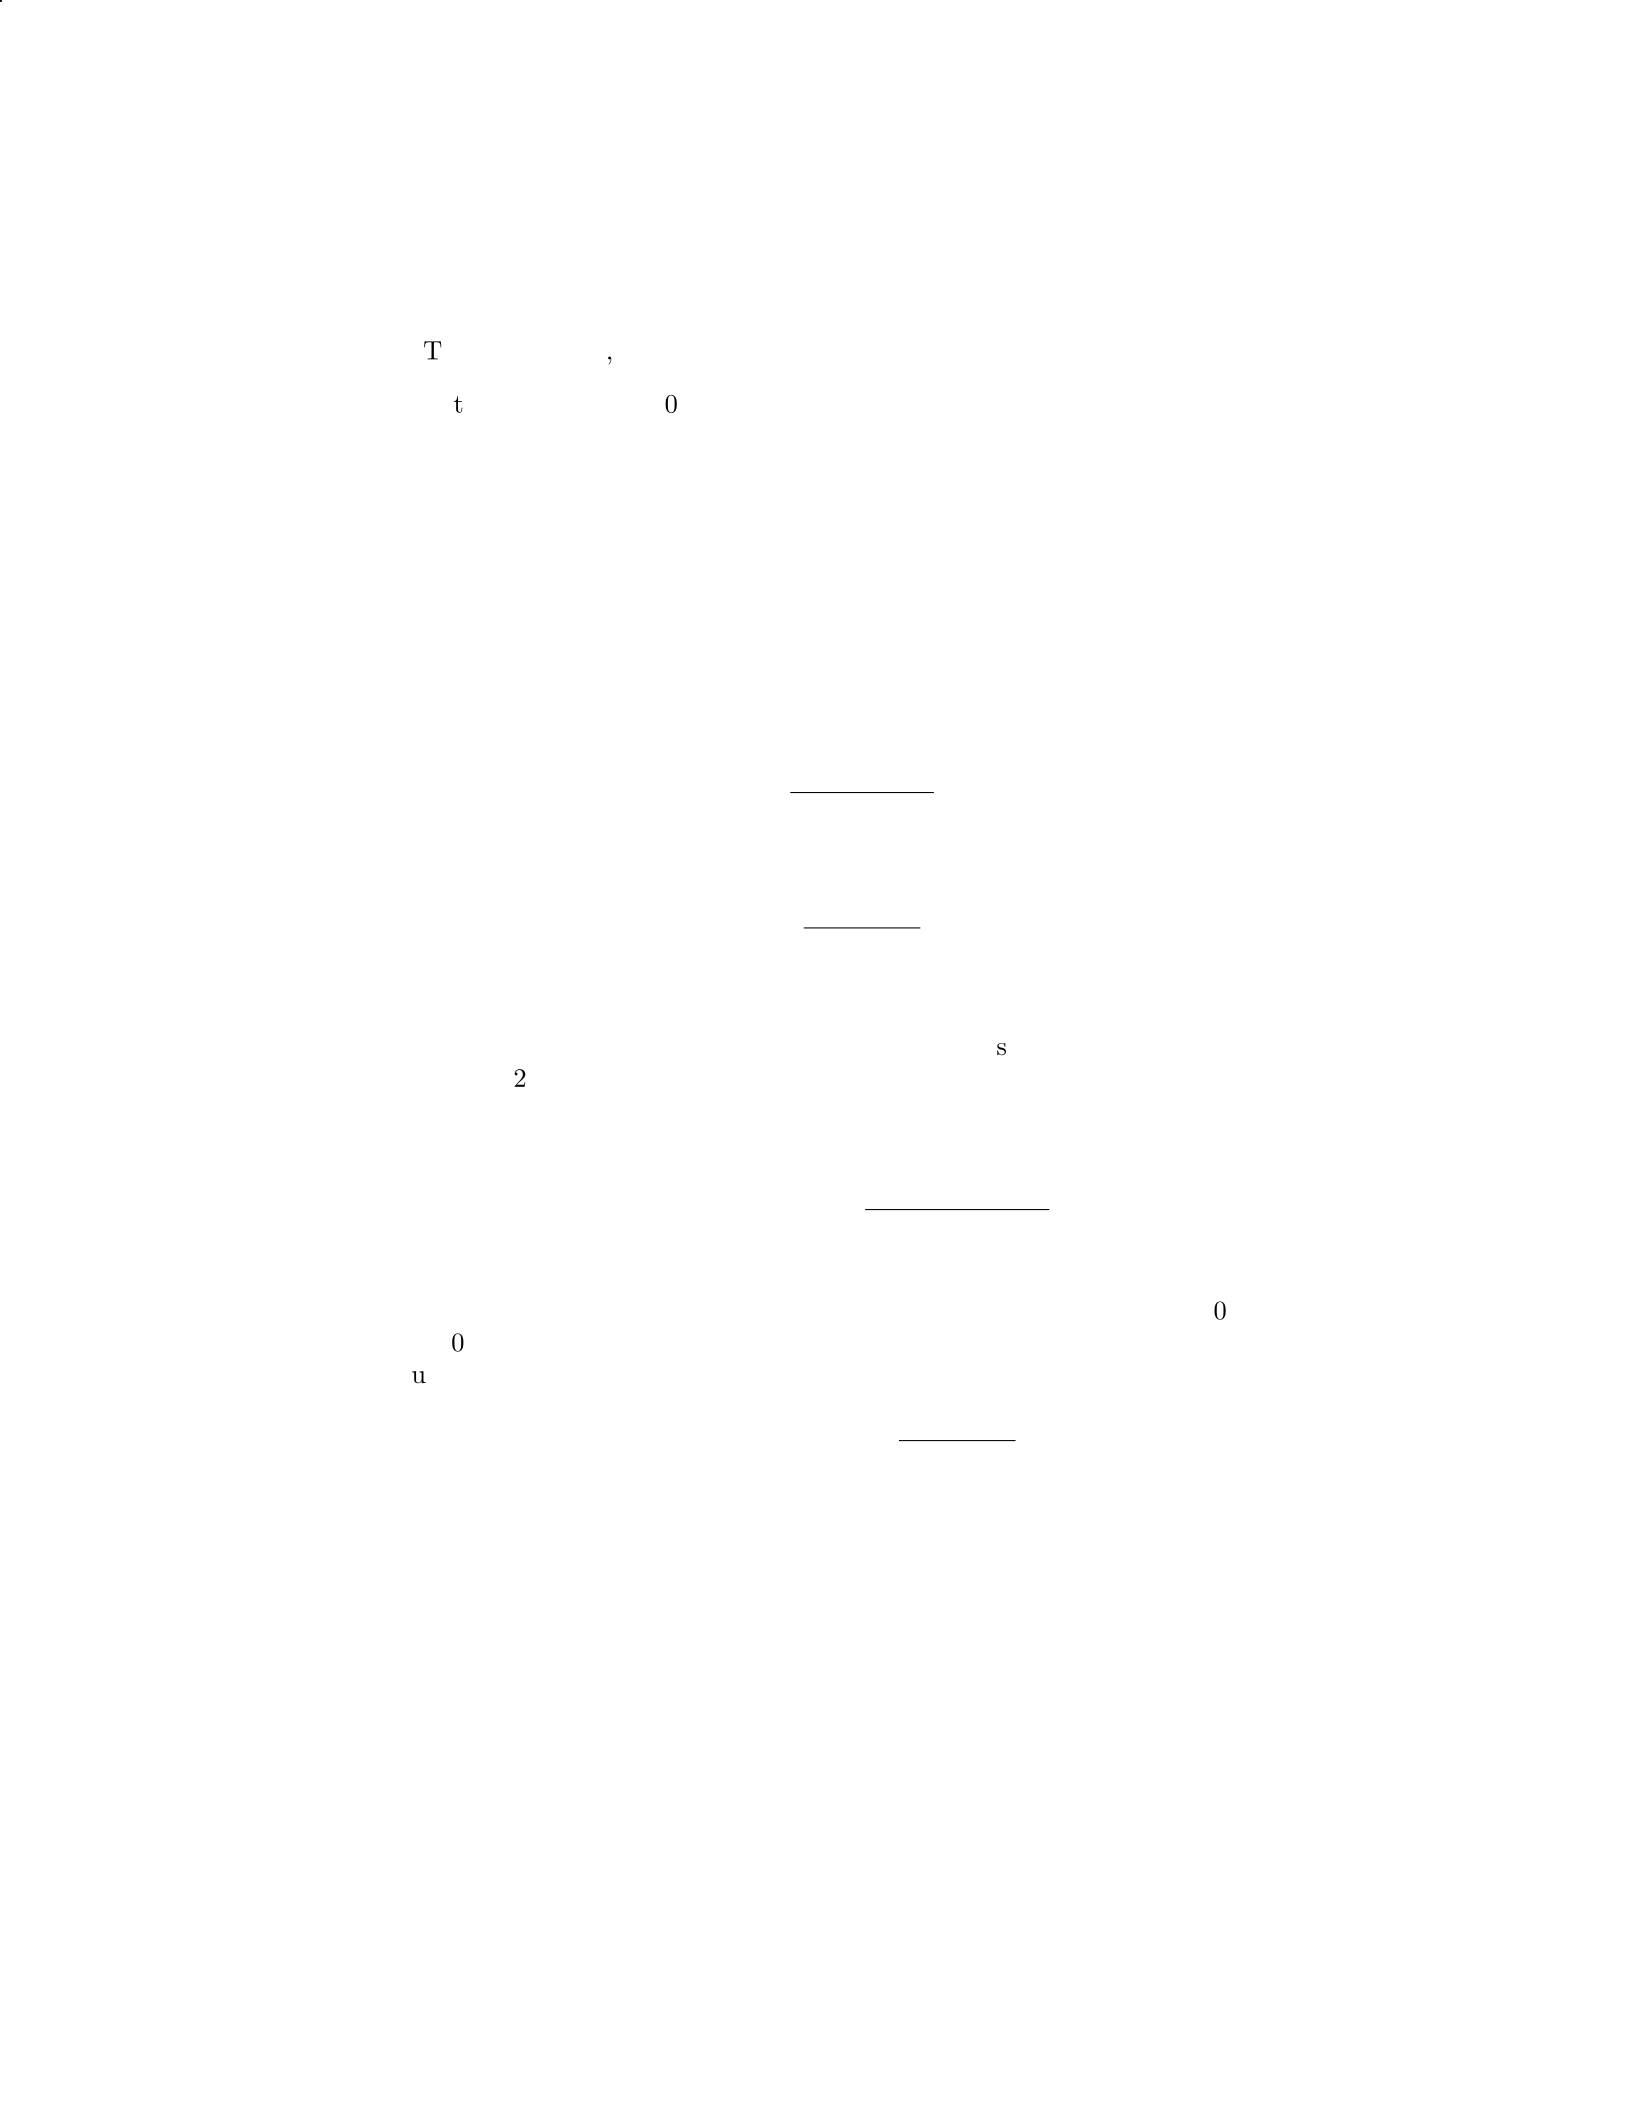
Total assets:
$
2,000,000
Total liabilities:
$
1,200,000
Calculate the following ratios and interpret the results:
1. Return on Assets (ROA)
2. Debt to Equity Ratio
Solution
Step 1: Calculate the Return on Assets (ROA) The Return on Assets
(ROA) ratio is calculated as:
ROA = Net Income
Total Assets
Substitute the given values into the formula:
ROA = 500,000
2,000,000
ROA = 0.25 = 25%
Interpretation: This means that for every
$
1 of assets, the company gen-
erates
$
0.25 (25 cents) in net income.
Step 2: Calculate the Debt to Equity Ratio The Debt to Equity Ratio
is calculated as:
Debt to Equity Ratio = Total Liabilities
Total Equity
Given that Total Equity is calculated as Total Assets minus Total Liabili-
ties, we have: Total Equity = Total Assets - Total Liabilities =
$
2,000,000 -
$
1,200,000 =
$
800,000
Substitute the values into the formula:
Debt to Equity Ratio = 1,200,000
800,000
Debt to Equity Ratio = 1.5
Interpretation: This ratio indicates that the company’s total liabilities
are 1.5 times its total equity, suggesting that the company relies more on debt
financing than equity financing.
38
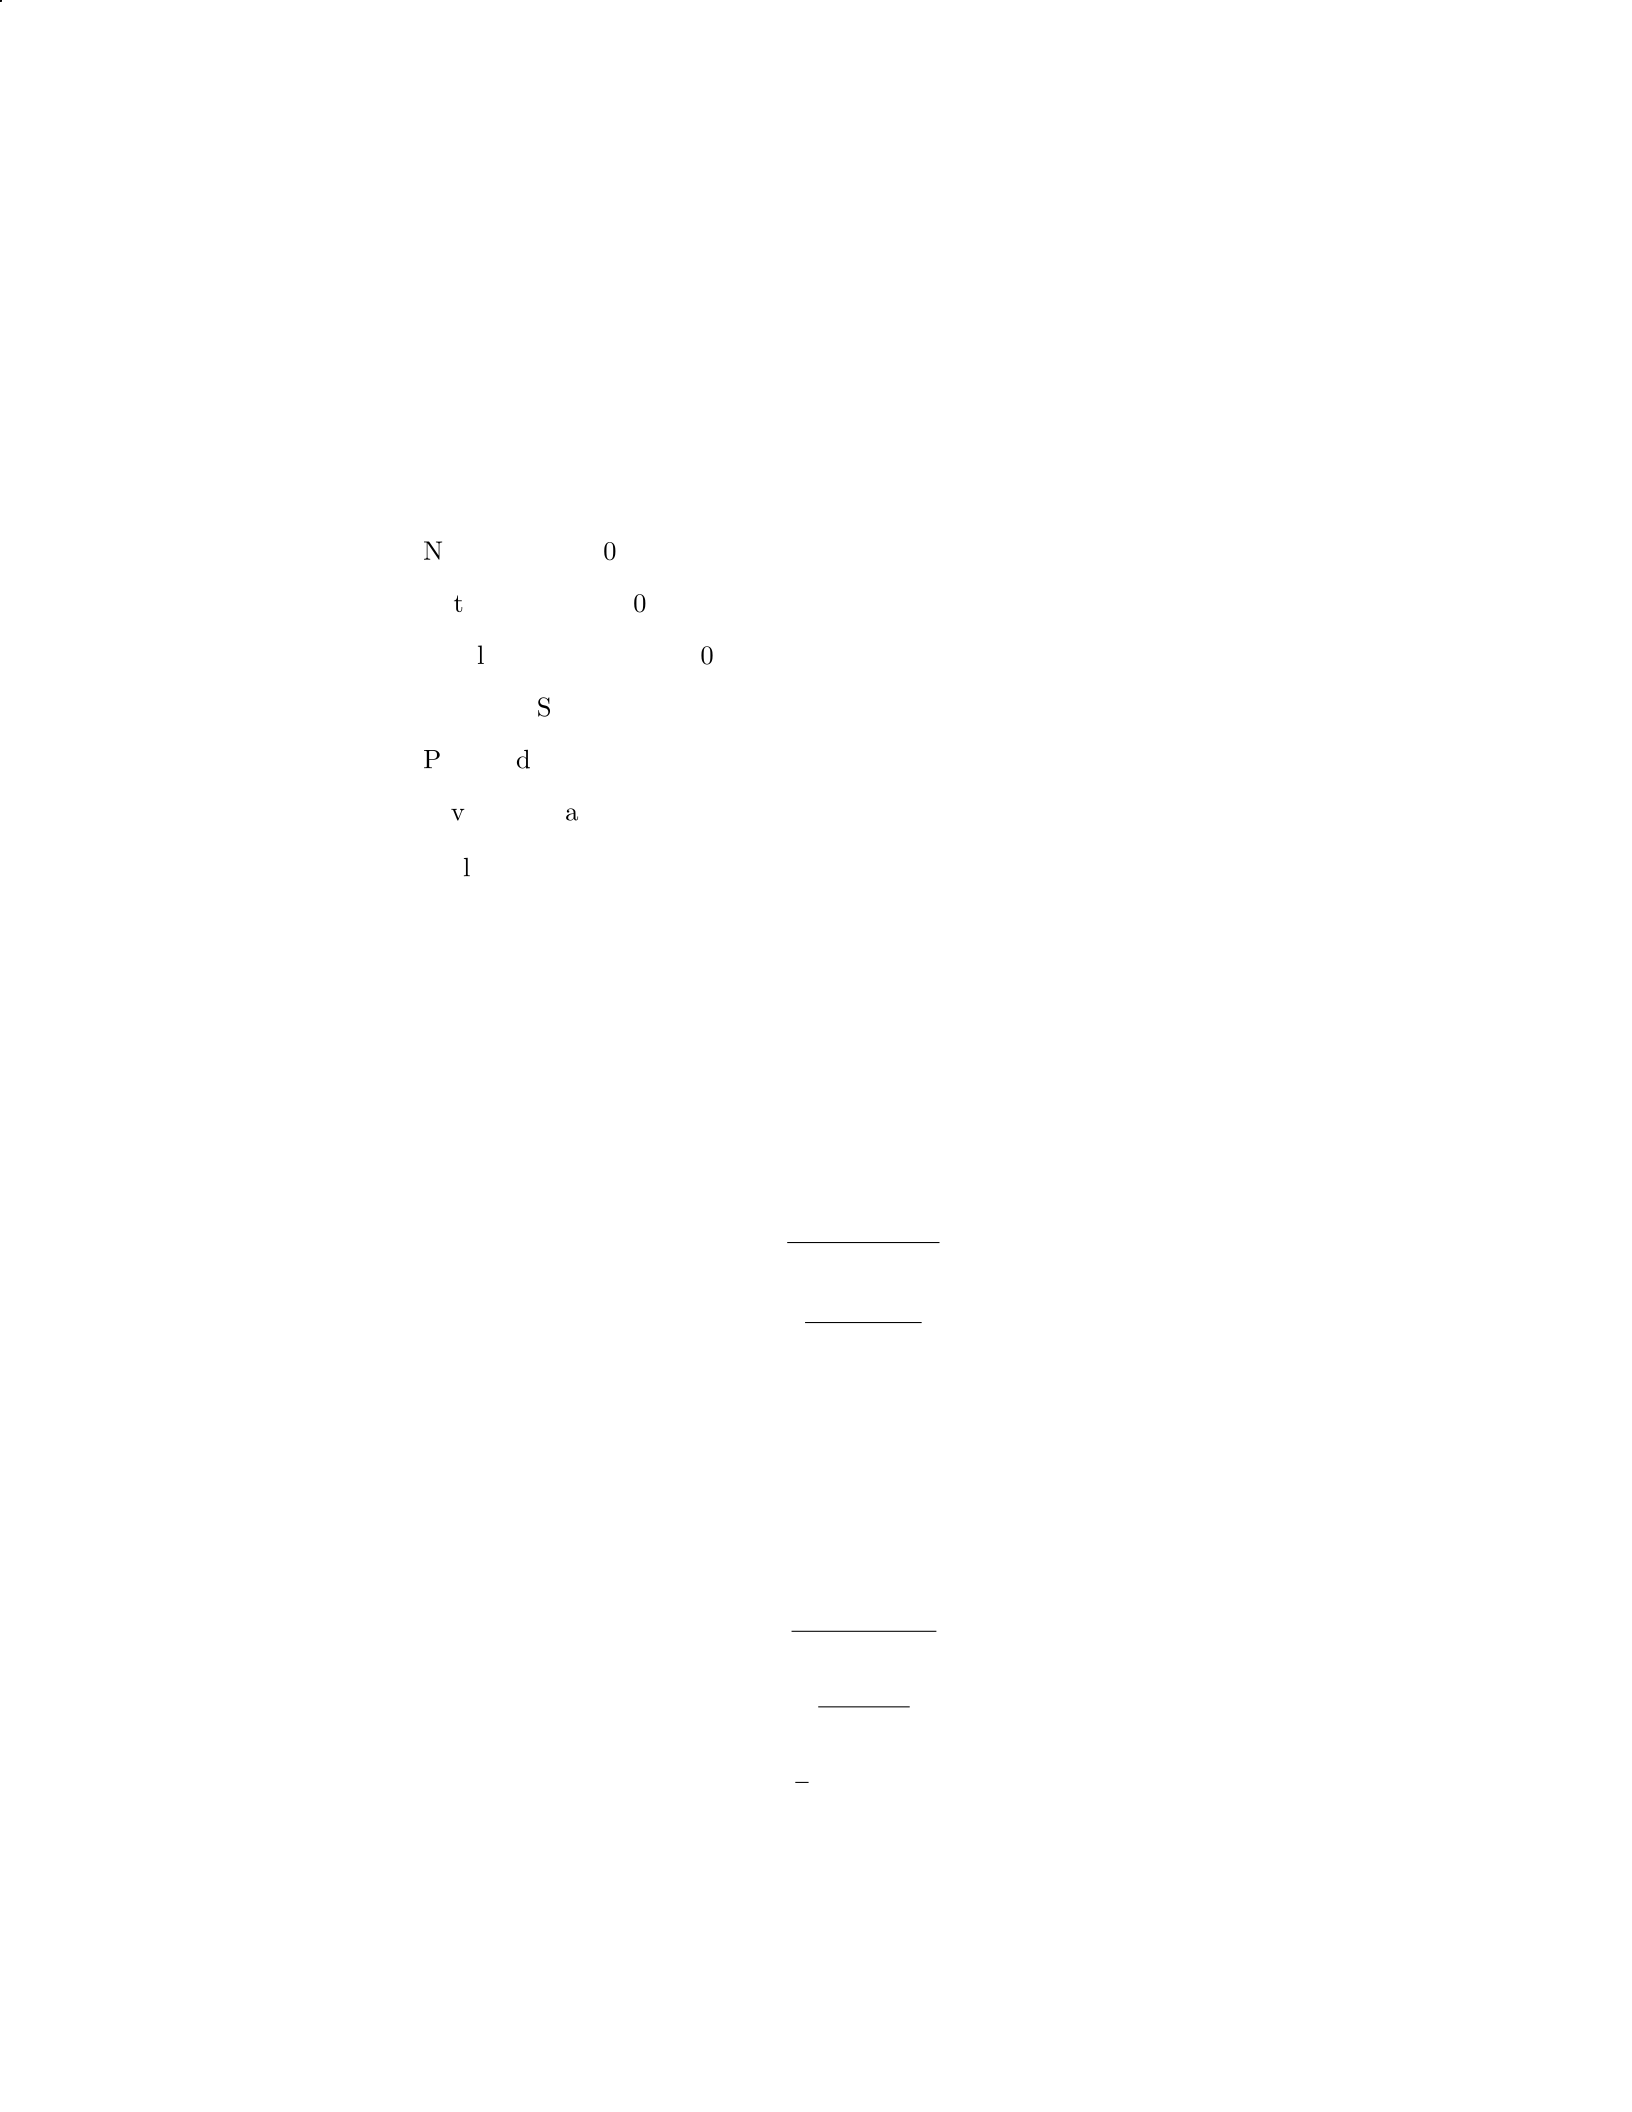
Question 33
Question
A company’s financial statements show the following information for the year
ending December 31, 2020:
Net Income:
$
500,000
Total Assets:
$
2,000,000
Total Liabilities:
$
800,000
Common Stock:
$
500,000
Preferred Stock:
$
100,000
Dividends Paid:
$
50,000
Calculate the following ratios for the company:
1. Return on Assets (ROA)
2. Return on Equity (ROE)
3. Earnings per Share (EPS)
Solution
Step 1: Calculate Return on Assets (ROA) ROA is calculated as the ratio
of Net Income to Total Assets.
ROA =N et Income
T otal Assets
ROA =500,000
2,000,000
ROA = 0.25 or 25%
Step 2: Calculate Return on Equity (ROE) ROE is calculated as the
ratio of Net Income to Equity (Common Stock + Preferred Stock).
Equity =Common Stock +P ref erred Stock
Equity = 500,000 + 100,000 = 600,000
ROE =N et Income
Equity
ROE =500,000
600,000
ROE =5
6or 83.33%
39
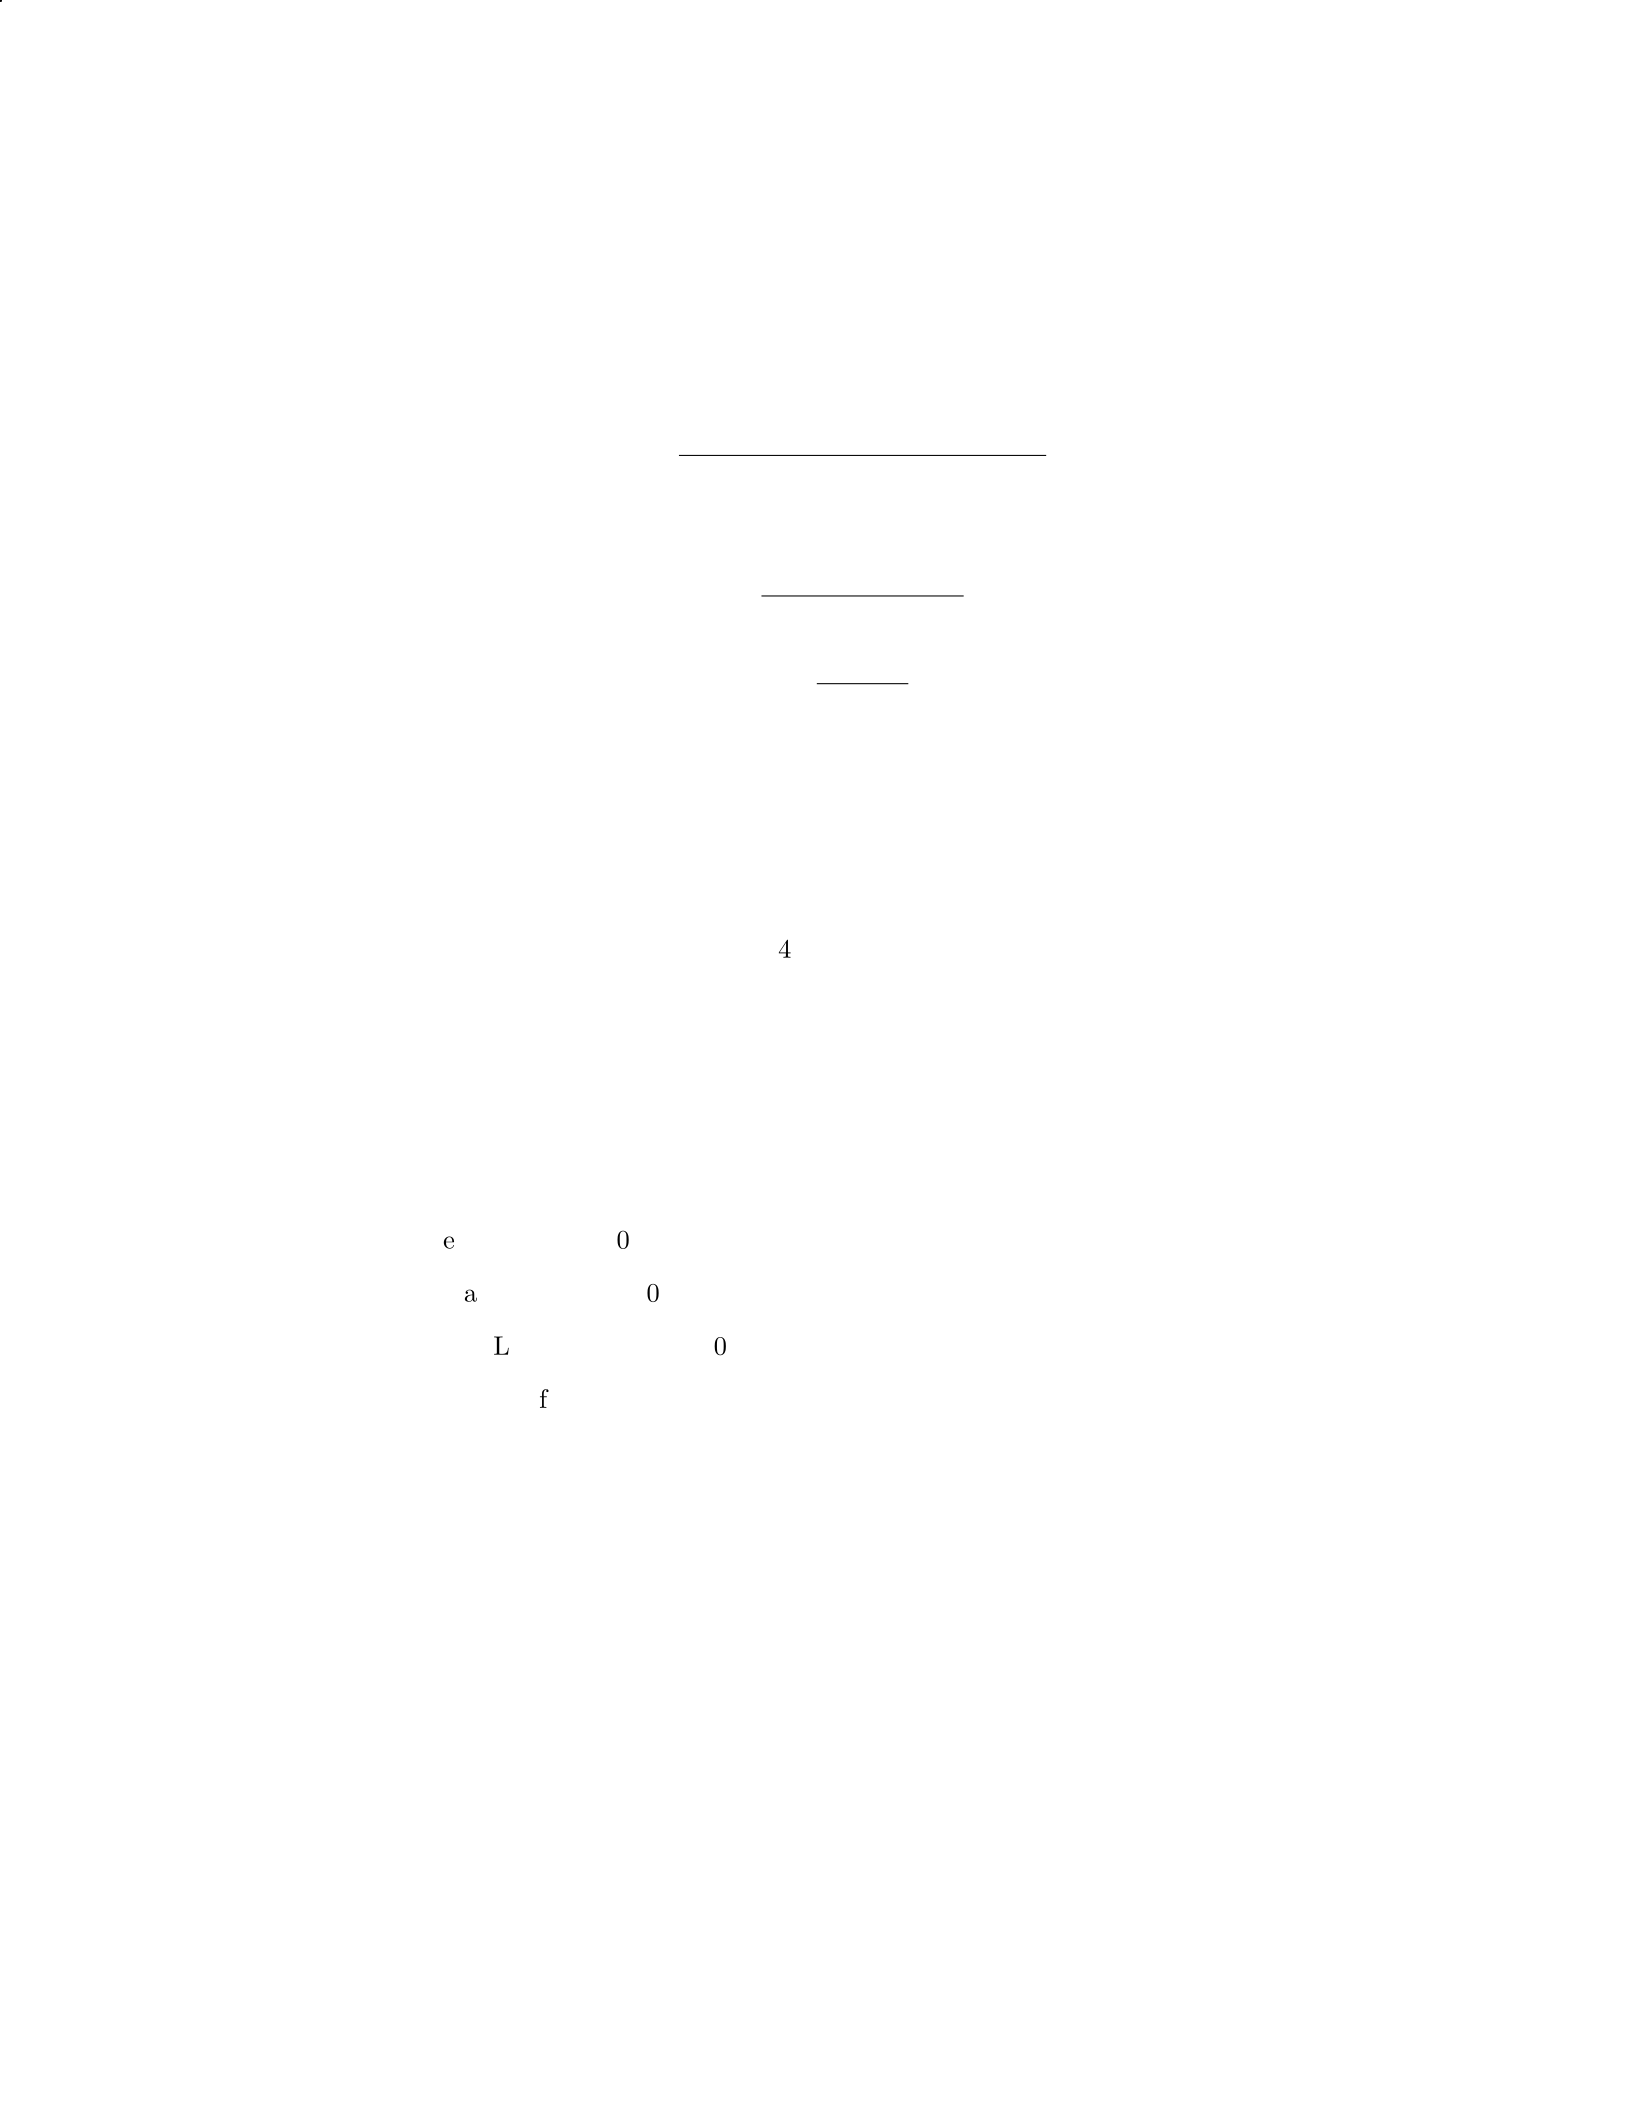
Step 3: Calculate Earnings per Share (EPS) EPS is calculated as the
ratio of Net Income minus Dividends Paid to the Average Number of Shares.
EP S =N et Income −Dividends P aid
Average Number of Shares
Assuming the Average Number of Shares is 100,000.
EP S =500,000 −50,000
100,000
EP S =450,000
100,000
EP S = 4.5
Therefore, the calculated ratios are:
1. Return on Assets (ROA) = 25%
2. Return on Equity (ROE) = 83.33%
3. Earnings per Share (EPS) =
$
4.5
Question 34
Question
Company XYZ has the following financial information for the year ending De-
cember 31, 2021:
Net Income:
$
500,000
Total Assets:
$
2,000,000
Total Liabilities:
$
800,000
Number of Shares Outstanding: 100,000
Calculate the following ratios and interpret the results:
1. Return on Assets (ROA)
2. Return on Equity (ROE)
3. Earnings per Share (EPS)
40
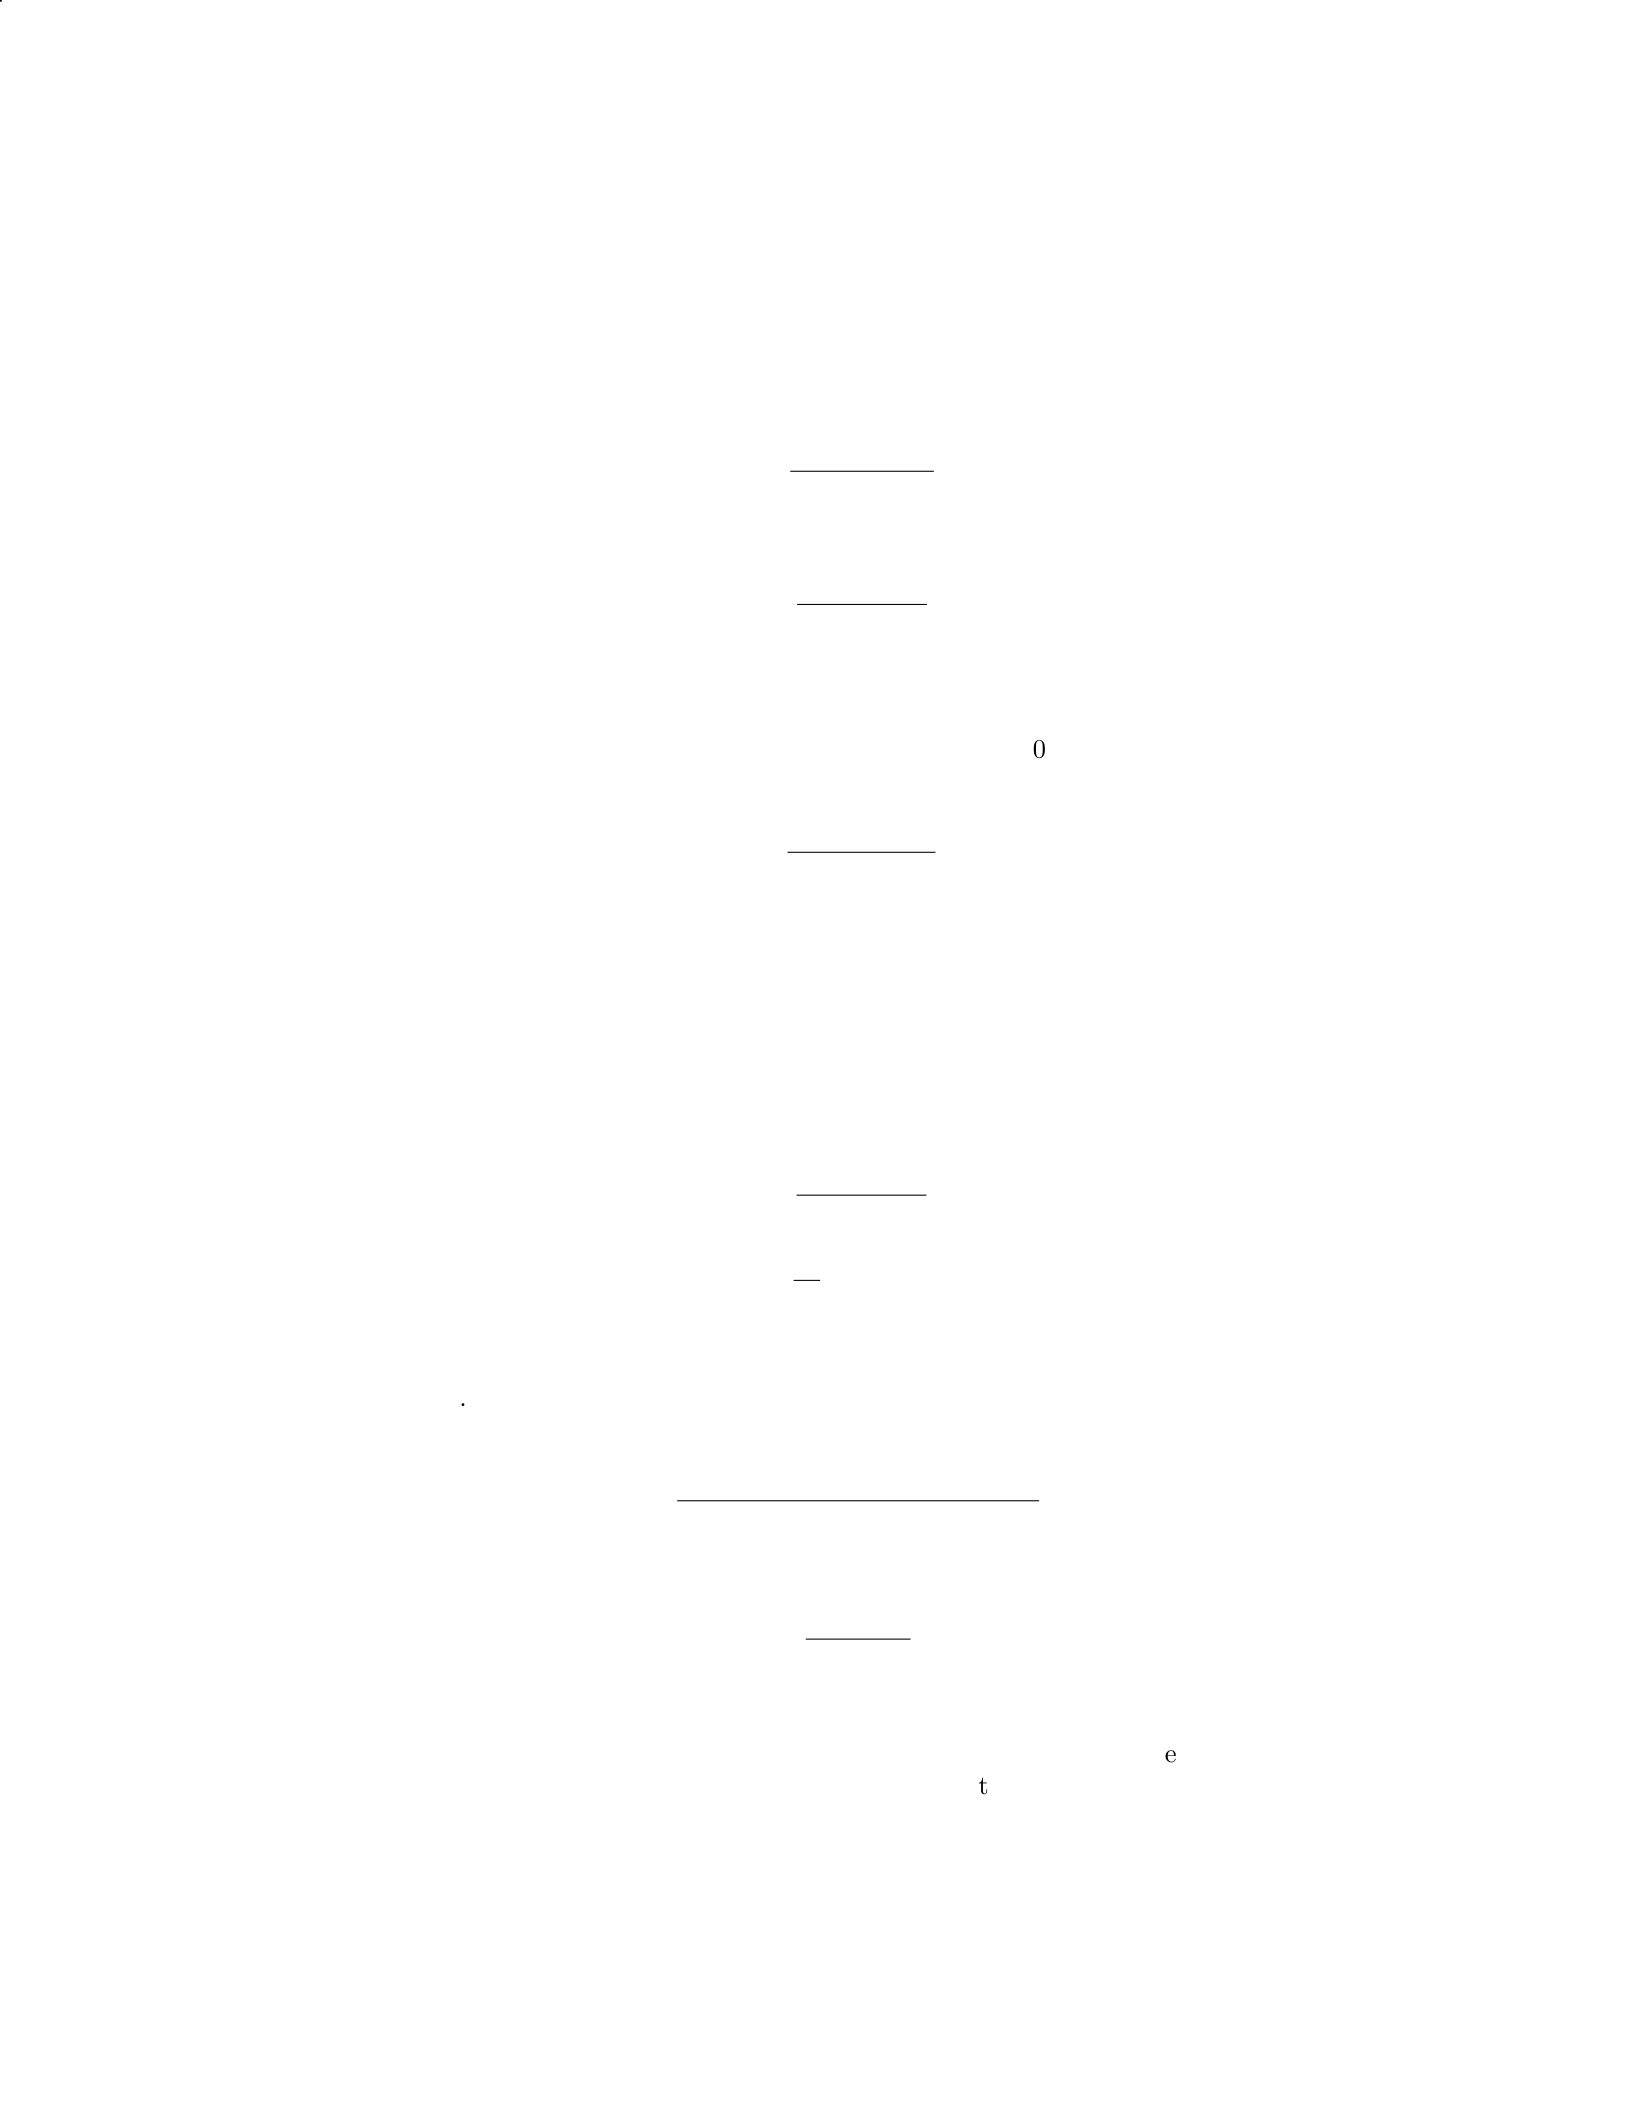
Solution
Step 1: Calculate Return on Assets (ROA)
ROA = Net Income
Total Assets
Substitute the given values into the formula:
ROA = $500,000
$2,000,000
ROA = 0.25
Step 2: Interpret ROA The Return on Assets (ROA) ratio of 0.25 means
that for every dollar of assets, Company XYZ generated
$
0.25 in net income.
Step 3: Calculate Return on Equity (ROE)
ROE = Net Income
Total Equity
Calculate Total Equity:
Total Equity = Total Assets −Total Liabilities
Total Equity = $2,000,000 −$800,000
Total Equity = $1,200,000
Substitute the given values into the formula:
ROE = $500,000
$1,200,000
ROE = 5
12 ≈0.4167
Step 4: Interpret ROE The Return on Equity (ROE) ratio of approxi-
mately 0.4167 means that for every dollar of equity, Company XYZ generated
about
$
0.42 in net income.
Step 5: Calculate Earnings per Share (EPS)
EPS = Net Income
Number of Shares Outstanding
Substitute the given values into the formula:
EPS = $500,000
100,000
EPS = $5
Step 6: Interpret EPS The Earnings per Share (EPS) of
$
5 means that
each share of Company XYZ’s stock represents
$
5 of the company’s earnings.
41
Question 35
Question
A company reported the following financial information for the current year:
Net Income:
$
250,000
Total Assets:
$
1,500,000
Total Liabilities:
$
600,000
Shareholders’ Equity:
$
900,000
Calculate the following ratios and interpret the results:
1. Return on Assets (ROA)
2. Return on Equity (ROE)
Solution
Step 1: Calculate Return on Assets (ROA)
ROA measures how efficiently the company is using its assets to generate
income. It is calculated as:
ROA = Net Income
Total Assets
Given Net Income =
$
250,000 and Total Assets =
$
1,500,000:
ROA = 250,000
1,500,000 = 0.1667 = 16.67%
Step 2: Interpretation of ROA
The company’s ROA of 16.67% indicates that for every dollar of assets, the
company generates
$
0.1667 of net income.
Step 3: Calculate Return on Equity (ROE)
ROE measures how efficiently the company is using shareholders’ equity to
generate income. It is calculated as:
ROE = Net Income
Shareholders’ Equity
Given Net Income =
$
250,000 and Shareholders’ Equity =
$
900,000:
ROE = 250,000
900,000 ≈0.2778 = 27.78%
Step 4: Interpretation of ROE
The company’s ROE of 27.78% indicates that for every dollar of shareholders’
equity, the company generates
$
0.2778 of net income. This suggests that the
company is effectively using shareholders’ equity to generate profits.
42
Question 16
Question
A company’s current ratio is 2.5, while its acid-test ratio is 1.2. Determine
the amount of inventory the company has if its current liabilities amount to
600,000.
Solution
Step 1: Calculate the company’s current assets using the current ratio formula:
Current Ratio = Current Assets
Current Liabilities
2.5 = Current Assets
600,000
Current Assets = 2.5×600,000
Current Assets = 1,500,000
Step 2: Calculate the company’s quick assets using the acid-test ratio for-
mula:
Acid-Test Ratio = Quick Assets
Current Liabilities
Given that the acid-test ratio is:
1.2 = Quick Assets
600,000
Quick Assets = 1.2×600,000
Quick Assets = 720,000
Step 3: Calculate the company’s inventory by subtracting quick assets from
current assets:
Inventory = Current Assets −Quick Assets
Inventory = 1,500,000 −720,000
Inventory = 780,000
Therefore, the company has 780,000worthofinventory.
Question 17
Question
A company reported the following financial information for the current year: -
Current assets:
$
300,000 - Total assets:
$
600,000 - Current liabilities:
$
150,000
- Total liabilities:
$
400,000 Calculate the company’s current ratio and interpret
the result in terms of the company’s ability to meet its short-term obligations.
18
Solution
Step 1: Calculate the current ratio. The current ratio is calculated as the ratio
of current assets to current liabilities.
Current ratio = Current assets
Current liabilities
Step 2: Plug in the given values. The current assets are
$
300,000 and the
current liabilities are
$
150,000.
Current ratio = 300,000
150,000
Step 3: Simplify the ratio.
Current ratio = 2
Step 4: Interpret the result. A current ratio of 2 means that the company
has
$
2 in current assets for every
$
1 in current liabilities. This indicates that
the company has a strong ability to meet its short-term obligations, as it has
more than enough current assets to cover its current liabilities. A current ratio
of 2 is considered healthy and is generally preferred by investors and creditors
as it represents a lower risk of default.
Question 18
Question
A company’s current ratio is 2.5 and its quick ratio is 1.8. Explain the signifi-
cance of these ratios in terms of the company’s liquidity position.
Solution
Step 1: Understanding the Ratios The current ratio and quick ratio are both
measures of a company’s liquidity, which refers to its ability to meet short-term
obligations with its current assets. - The current ratio is calculated by dividing
current assets by current liabilities. - The quick ratio (also known as the acid-test
ratio) is calculated by dividing quick assets (current assets excluding inventory)
by current liabilities.
Step 2: Interpreting the Ratios A current ratio of 2.5 means that for every
dollar of current liabilities, the company has 2.50ofcurrentassets.T hisindicatesthatthecompanyhasastrongliquiditypositionandshouldbeabletocoveritsshort−
termobligationscomfortably.
A quick ratio of 1.8 means that for every dollar of current liabilities, the com-
pany has 1.80ofquickassets.T hisratioprovidesamoreconservativemeasureof liquiditycomparedtothecurrentratiosinceitexcludesinventory, whichmaynotbeeasilyconvertedintocash.
Step 3: Significance of the Ratios - A current ratio above 1 indicates that
the company has more current assets than current liabilities, which is generally
considered a good sign. - A current ratio of 2.5 indicates that the company
19
has a strong liquidity position and is in a good position to meet its short-term
obligations. - A quick ratio of 1.8 shows that the company has a sufficient level
of quick assets to cover its current liabilities, indicating a good ability to meet
short-term obligations without relying heavily on inventory.
In conclusion, the company appears to be in a healthy liquidity position
based on its current and quick ratios, suggesting that it should not have trouble
meeting its short-term financial obligations.
Question 19
Question
Company XYZ has the following financial information for the year ended De-
cember 31, 20X1:
Total assets:
$
800,000
Total liabilities:
$
300,000
Net income:
$
100,000
Total equity:
$
500,000
Total revenue:
$
600,000
Cost of goods sold:
$
200,000
Operating expenses:
$
150,000
Interest expense:
$
20,000
Calculate the following ratios and provide an interpretation for each:
1. Return on assets (ROA)
2. Return on equity (ROE)
3. Asset turnover
4. Debt to equity ratio
Solution
Step 1: Calculate Return on Assets (ROA)
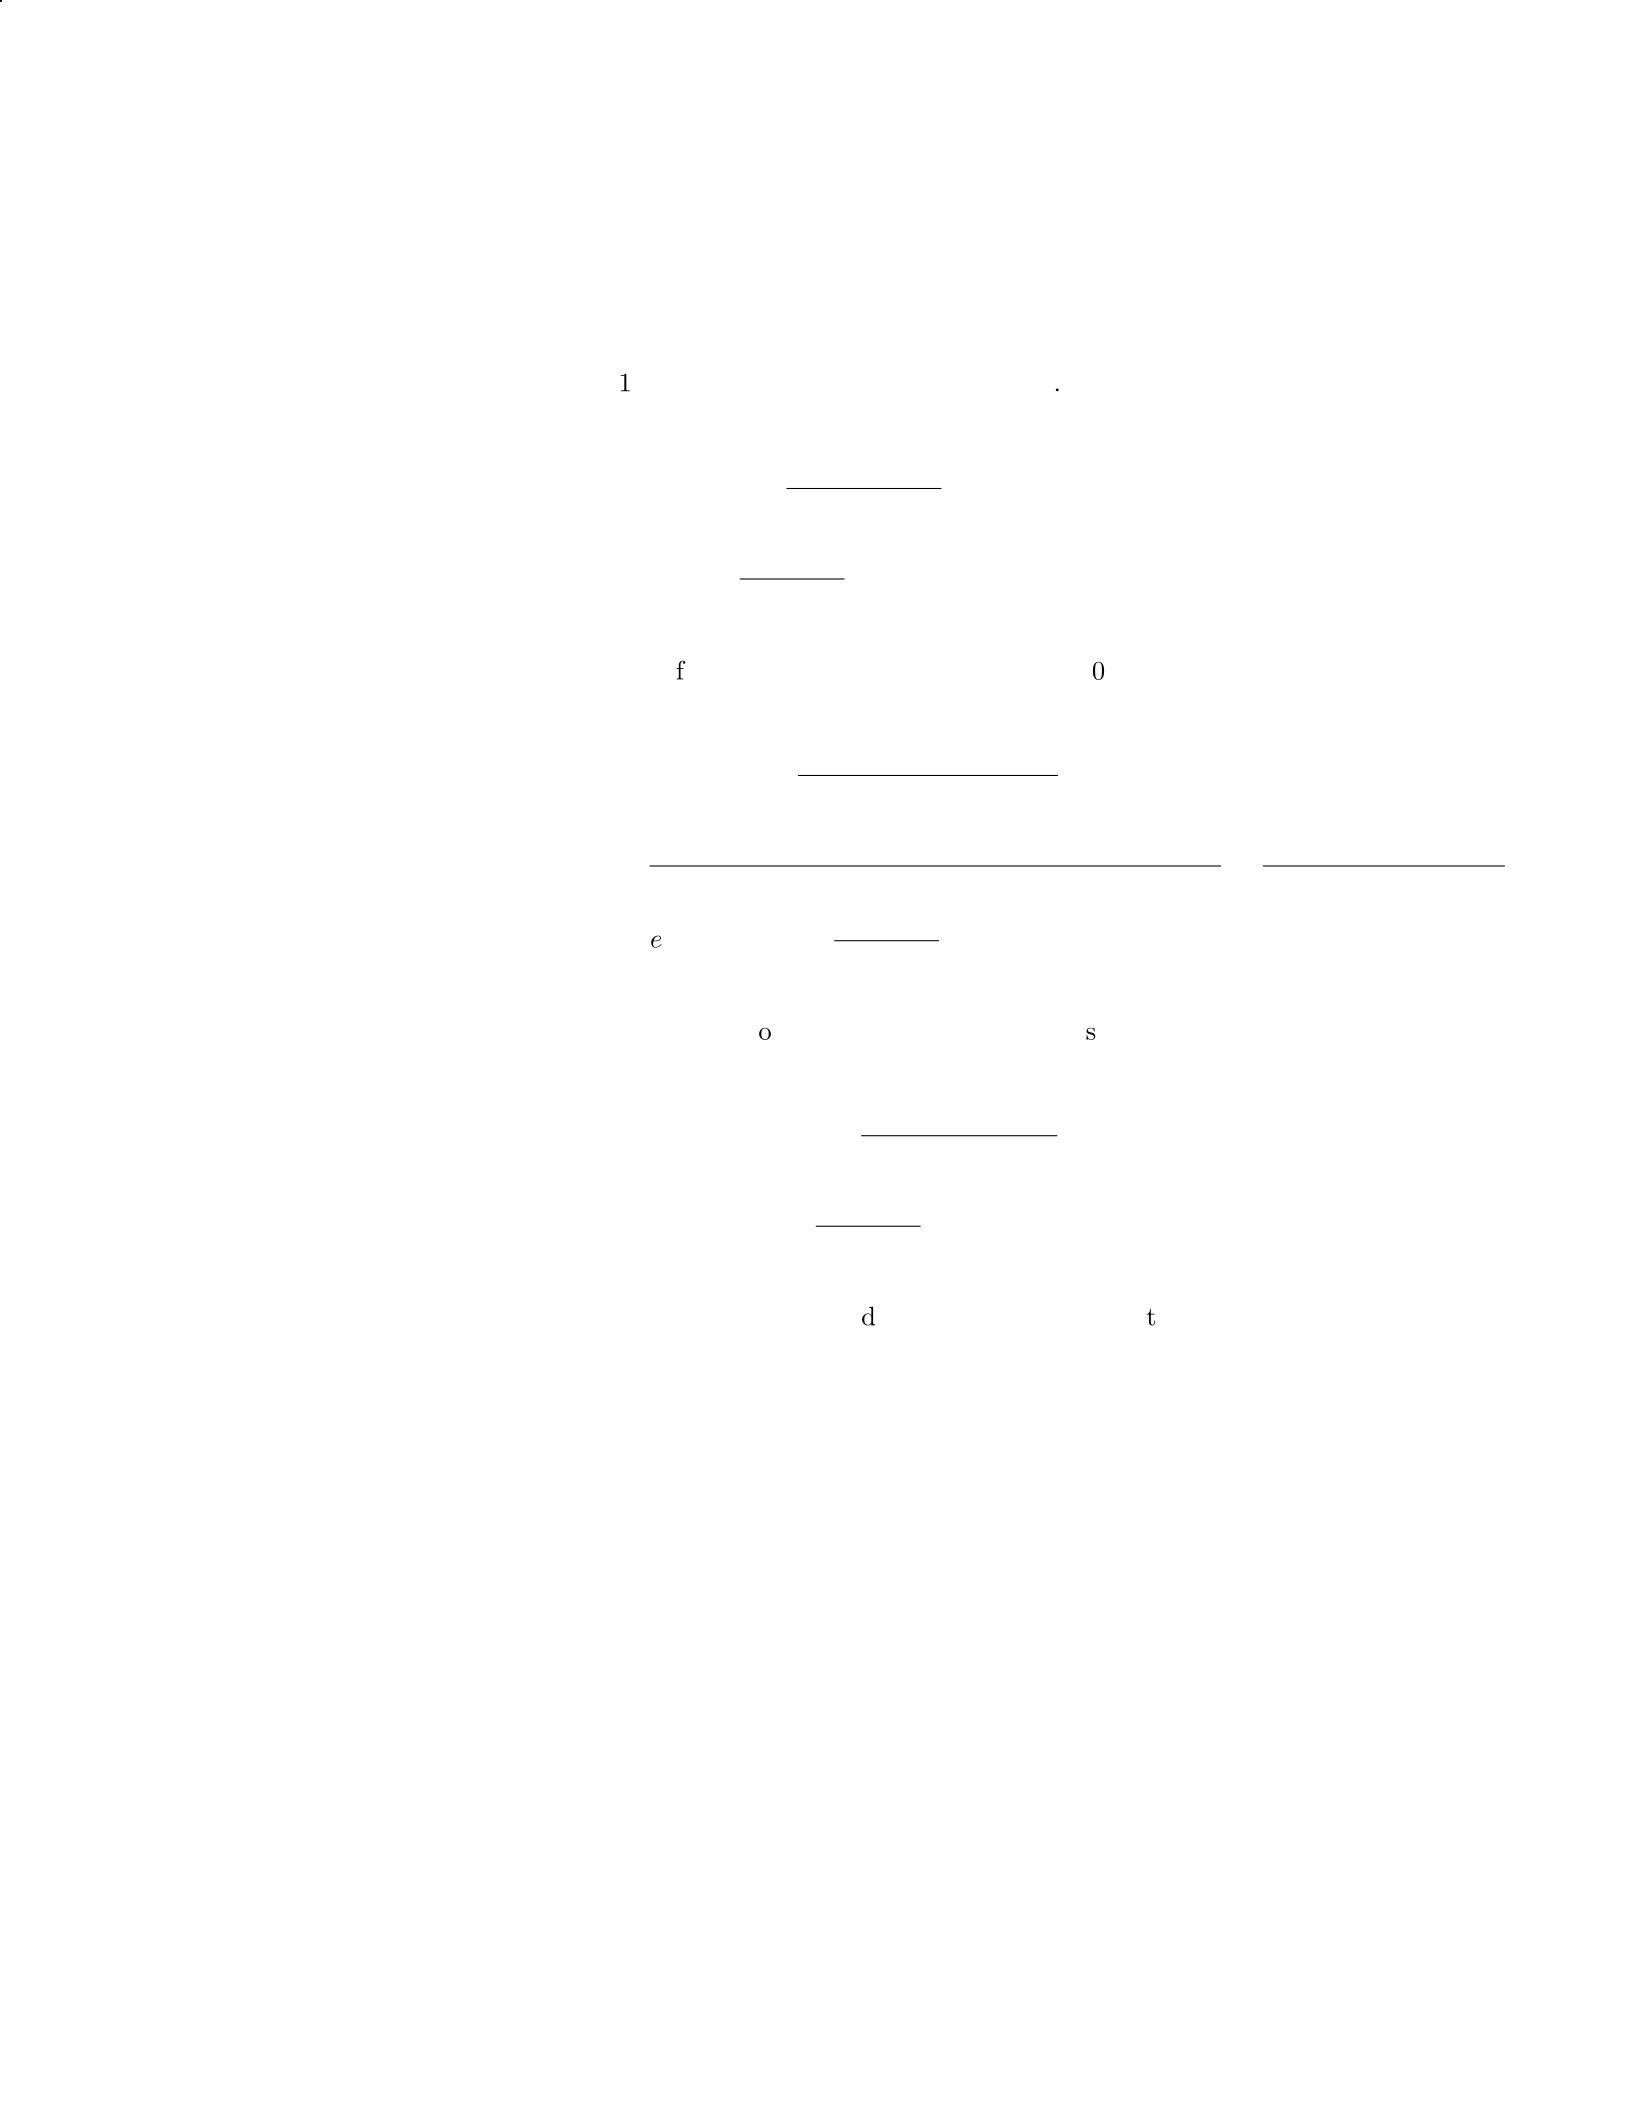
ROA =N et Income
T otal Assets
ROA =$100,000
$800,000 = 0.125or12.5%
20
Interpretation: The return on assets for Company XYZ is 12.5%. This
means that for every
$
1 of assets, the company generates
$
0.125 of net income.
Step 2: Calculate Return on Equity (ROE)
ROE =N et Income
T otal Equity
ROE =$100,000
$500,000 = 0.2or20%
Interpretation: The return on equity for Company XYZ is 20%. This
indicates that for every
$
1 of equity, the company generates
$
0.20 of net income.
Step 3: Calculate Asset Turnover
Asset T urnover =T otal Revenue
Average T otal Assets
Average T otal Assets =Beginning T otal Assets +Ending T otal Assets
2=$800,000 + $800,000
2= $800,000
Asset T urnover =$600,000
$800,000 = 0.75
Interpretation: The asset turnover for Company XYZ is 0.75. This means
that the company generates
$
0.75 of revenue for every
$
1 of assets.
Step 4: Calculate Debt to Equity Ratio
Debt to Equity Ratio =T otal Liabilities
T otal Equity
Debt to Equity Ratio =$300,000
$500,000 = 0.6or 0.6:1
Interpretation: The debt to equity ratio for Company XYZ is 0.6 or 0.6:1.
This means that the company has
$
0.60 of debt for every
$
1 of equity.
Question 20
Question
A company has the following financial information for the year: - Total Revenue:
900,000−Costof GoodsSold :400,000 - Gross Profit: 500,000−OperatingExpenses :300,000
- Net Income: 200,000
Calculate and interpret the following ratios: a) Gross Profit Margin b) Op-
erating Profit Margin c) Net Profit Margin
21
Solution
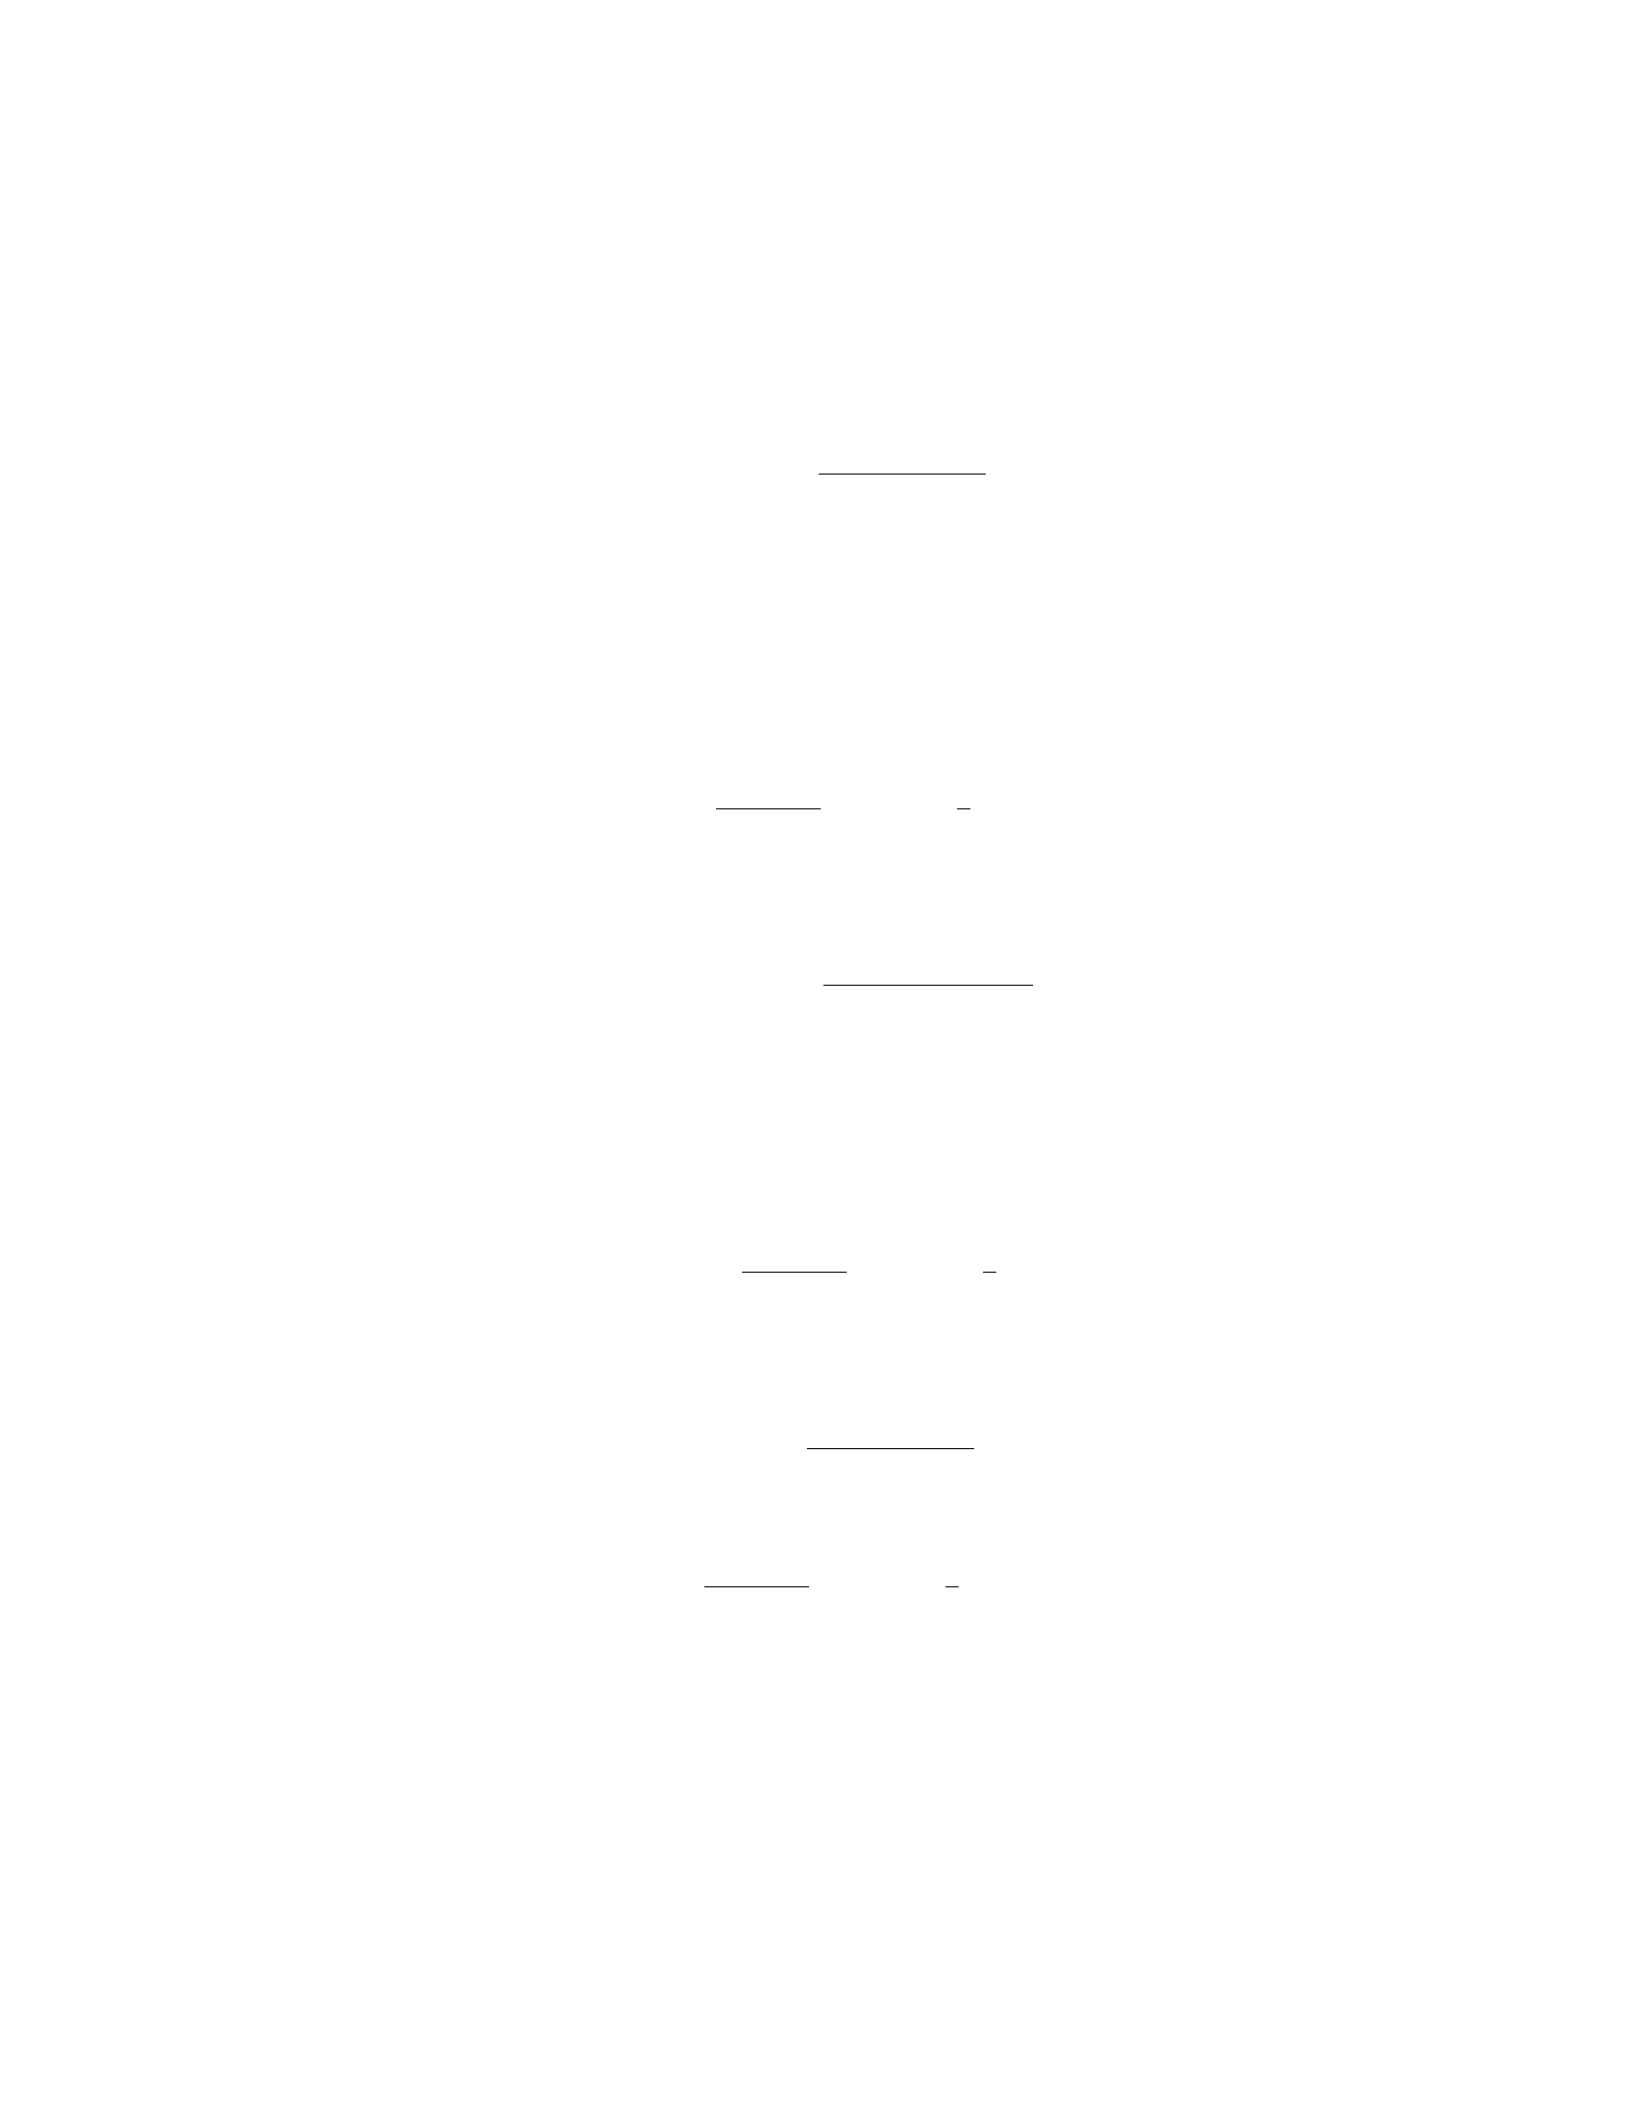
a) To calculate the Gross Profit Margin, we use the formula:
Gross Profit Margin = Gross Profit
Total Revenue ×100%
Step 1: Calculate the Gross Profit:
Gross Profit = Total Revenue −Cost of Goods Sold =
900,000 - 400,000 =500,000
Step 2: Calculate the Gross Profit Margin:
Gross Profit Margin = $500,000
$900,000 ×100% = 5
9×100% ≈55.56%
The Gross Profit Margin for the company is approximately 55.56%.
b) To calculate the Operating Profit Margin, we use the formula:
Operating Profit Margin = Operating Income
Total Revenue ×100%
Step 1: Calculate the Operating Income:
Operating Income = Total Revenue−Cost of Goods Sold−Operating Expenses =
900,000 - 400,000−300,000 = 200,000
Step 2: Calculate the Operating Profit Margin:
Operating Profit Margin = $200,000
$900,000 ×100% = 2
9×100% ≈22.22%
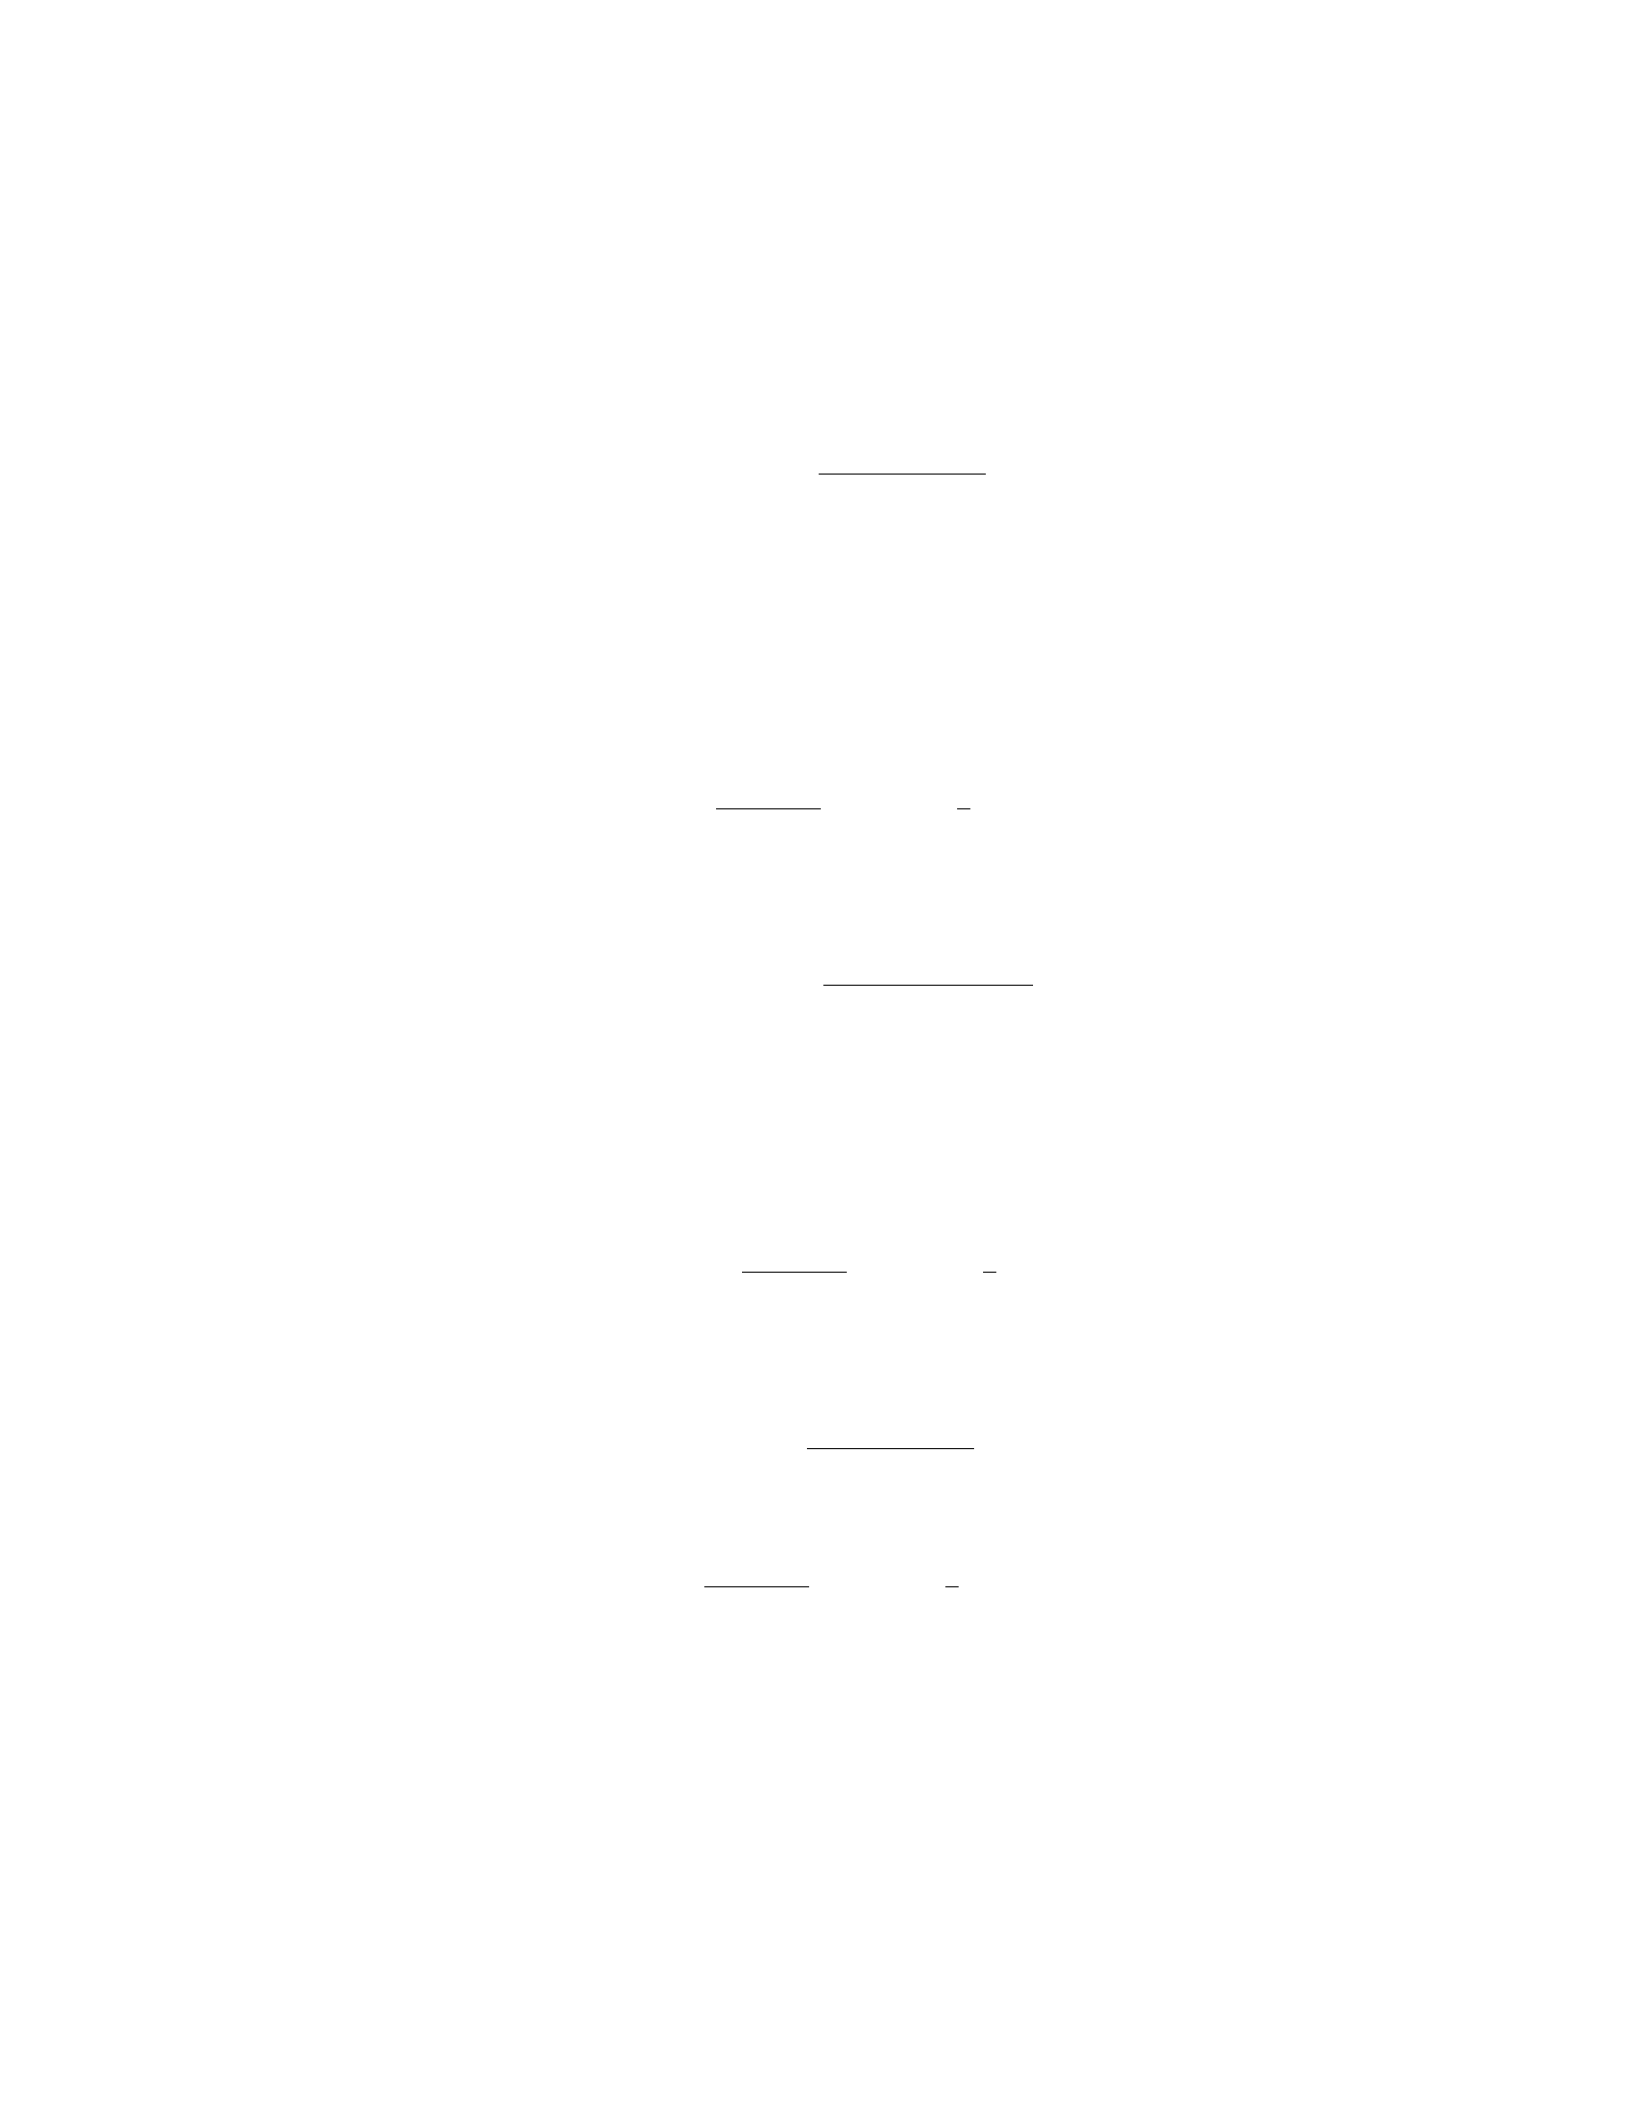
The Operating Profit Margin for the company is approximately 22.22%.
c) To calculate the Net Profit Margin, we use the formula:
Net Profit Margin = Net Income
Total Revenue ×100%
Step 1: Calculate the Net Profit Margin:
Net Profit Margin = $200,000
$900,000 ×100% = 2
9×100% ≈22.22%
The Net Profit Margin for the company is approximately 22.22%.
22
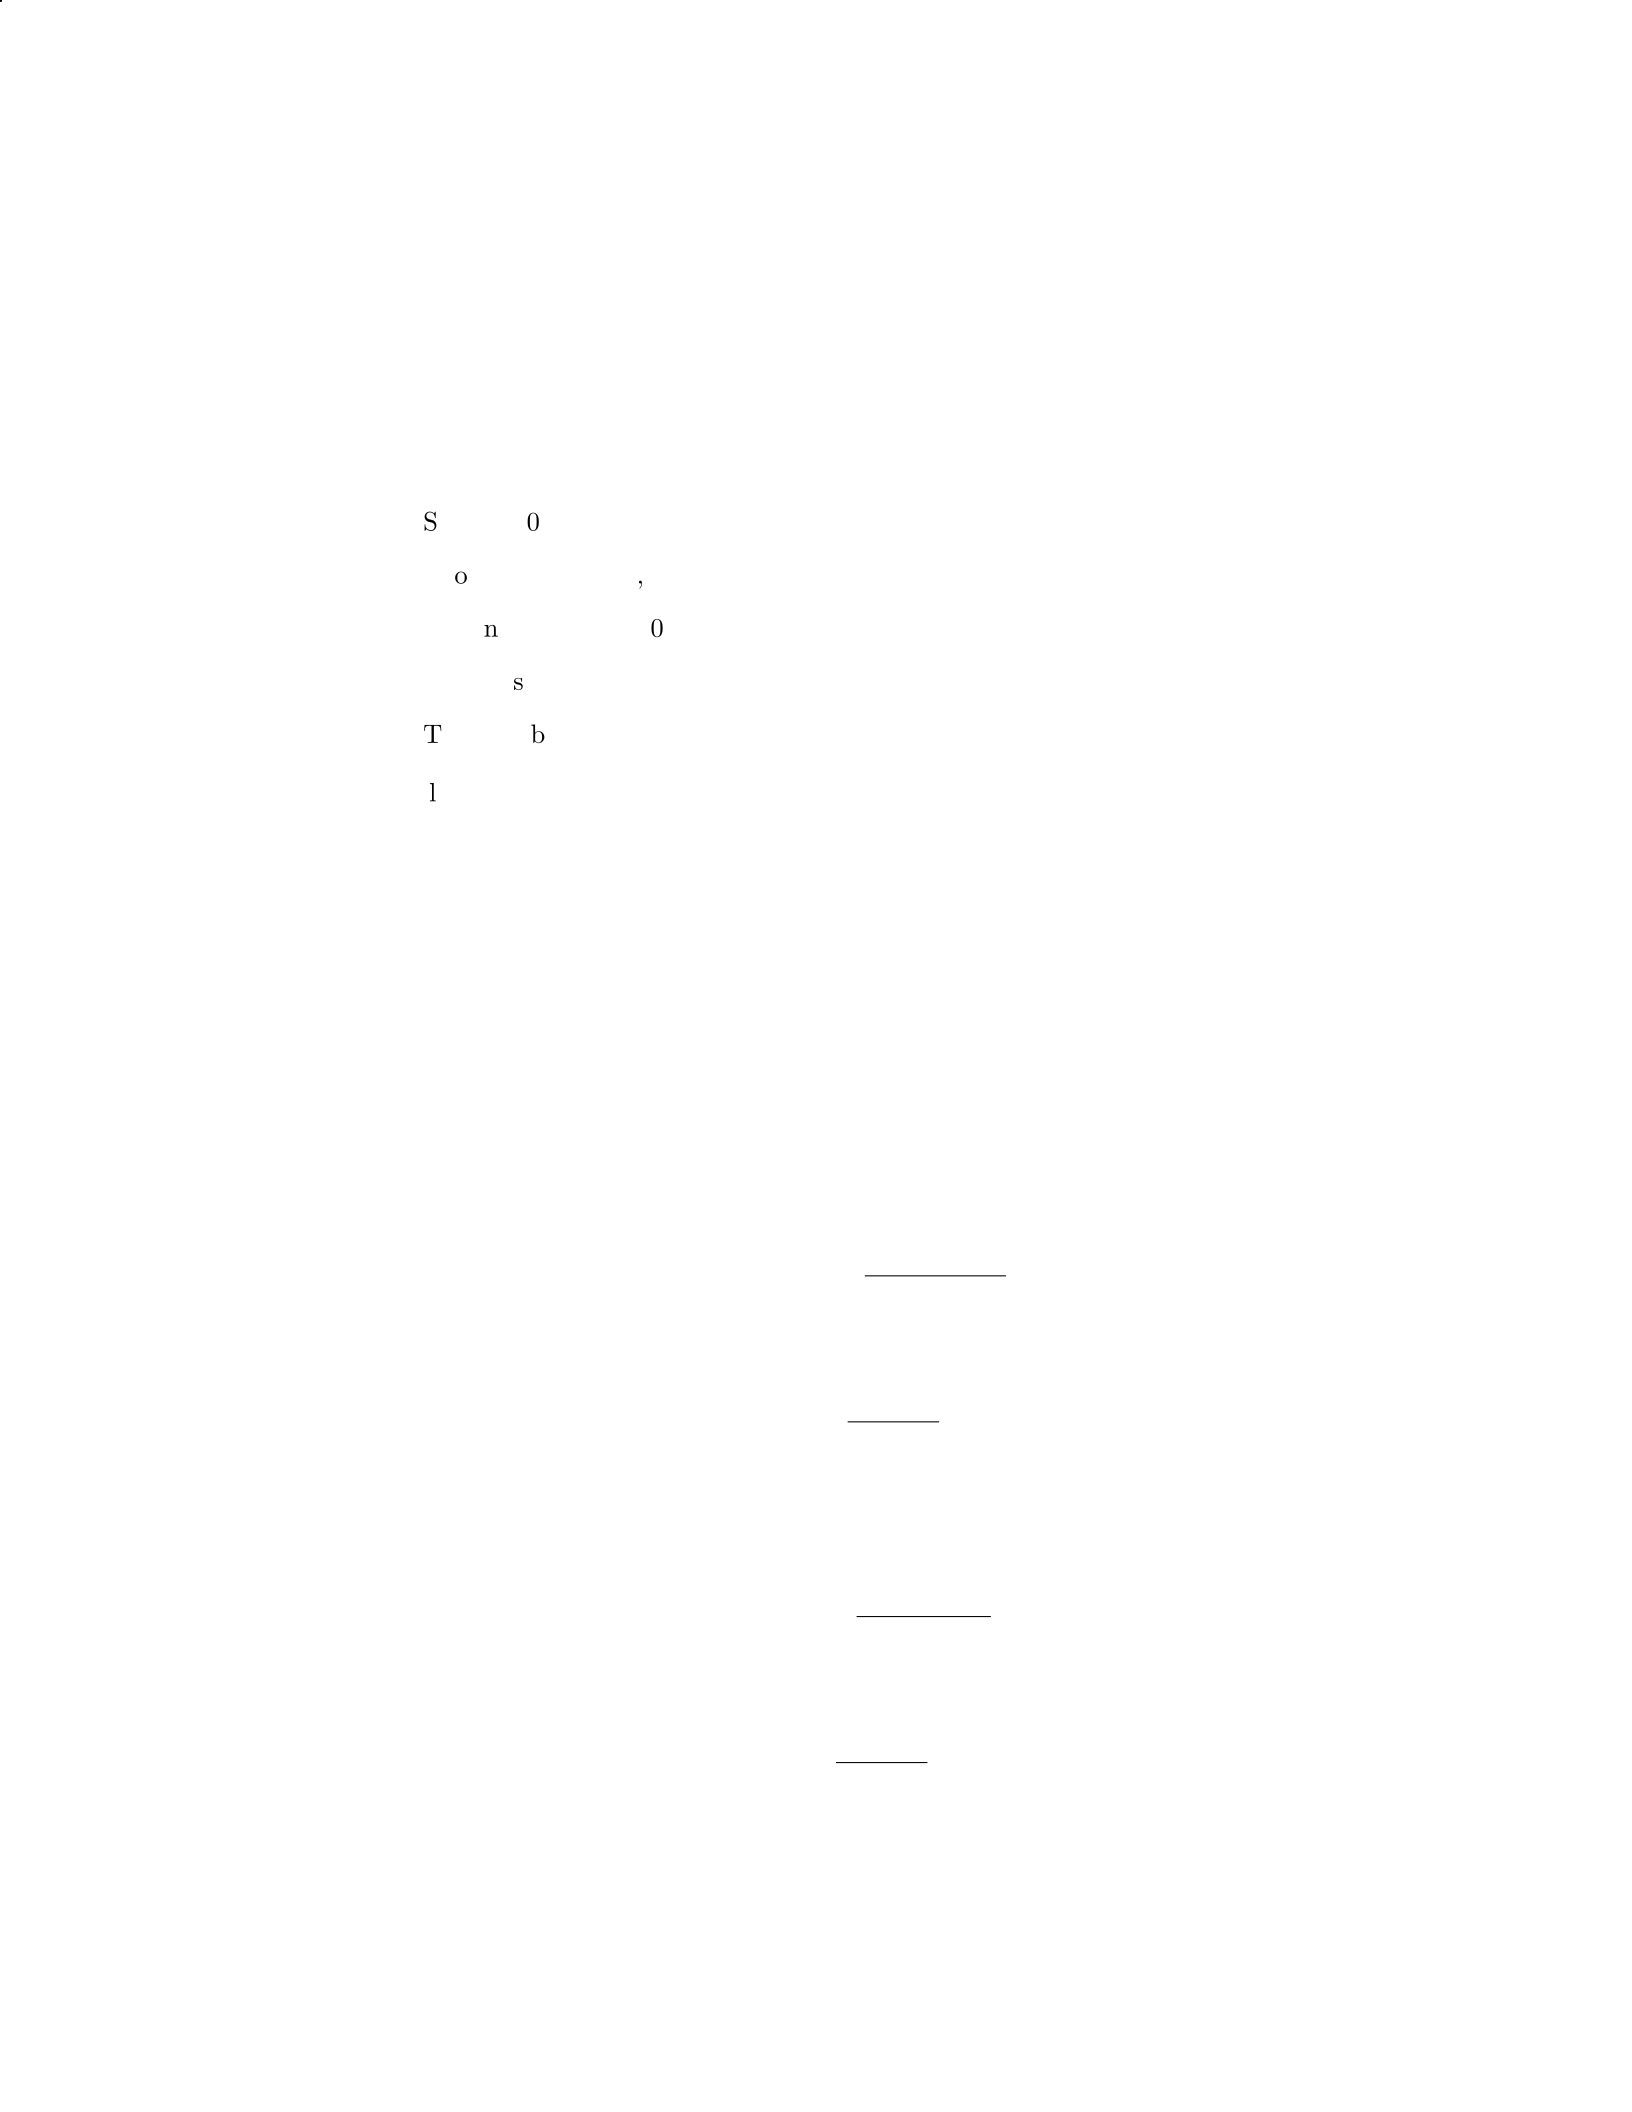
Question 21
Question
A company has the following financial information for the year:
Sales:
$
500,000
Gross Profit:
$
250,000
Net Income:
$
100,000
Total Assets:
$
800,000
Total Liabilities:
$
400,000
Calculate the following ratios and interpret the company’s financial perfor-
mance:
1. Gross Profit Margin
2. Net Profit Margin
3. Return on Assets (ROA)
4. Debt to Equity Ratio
Solution
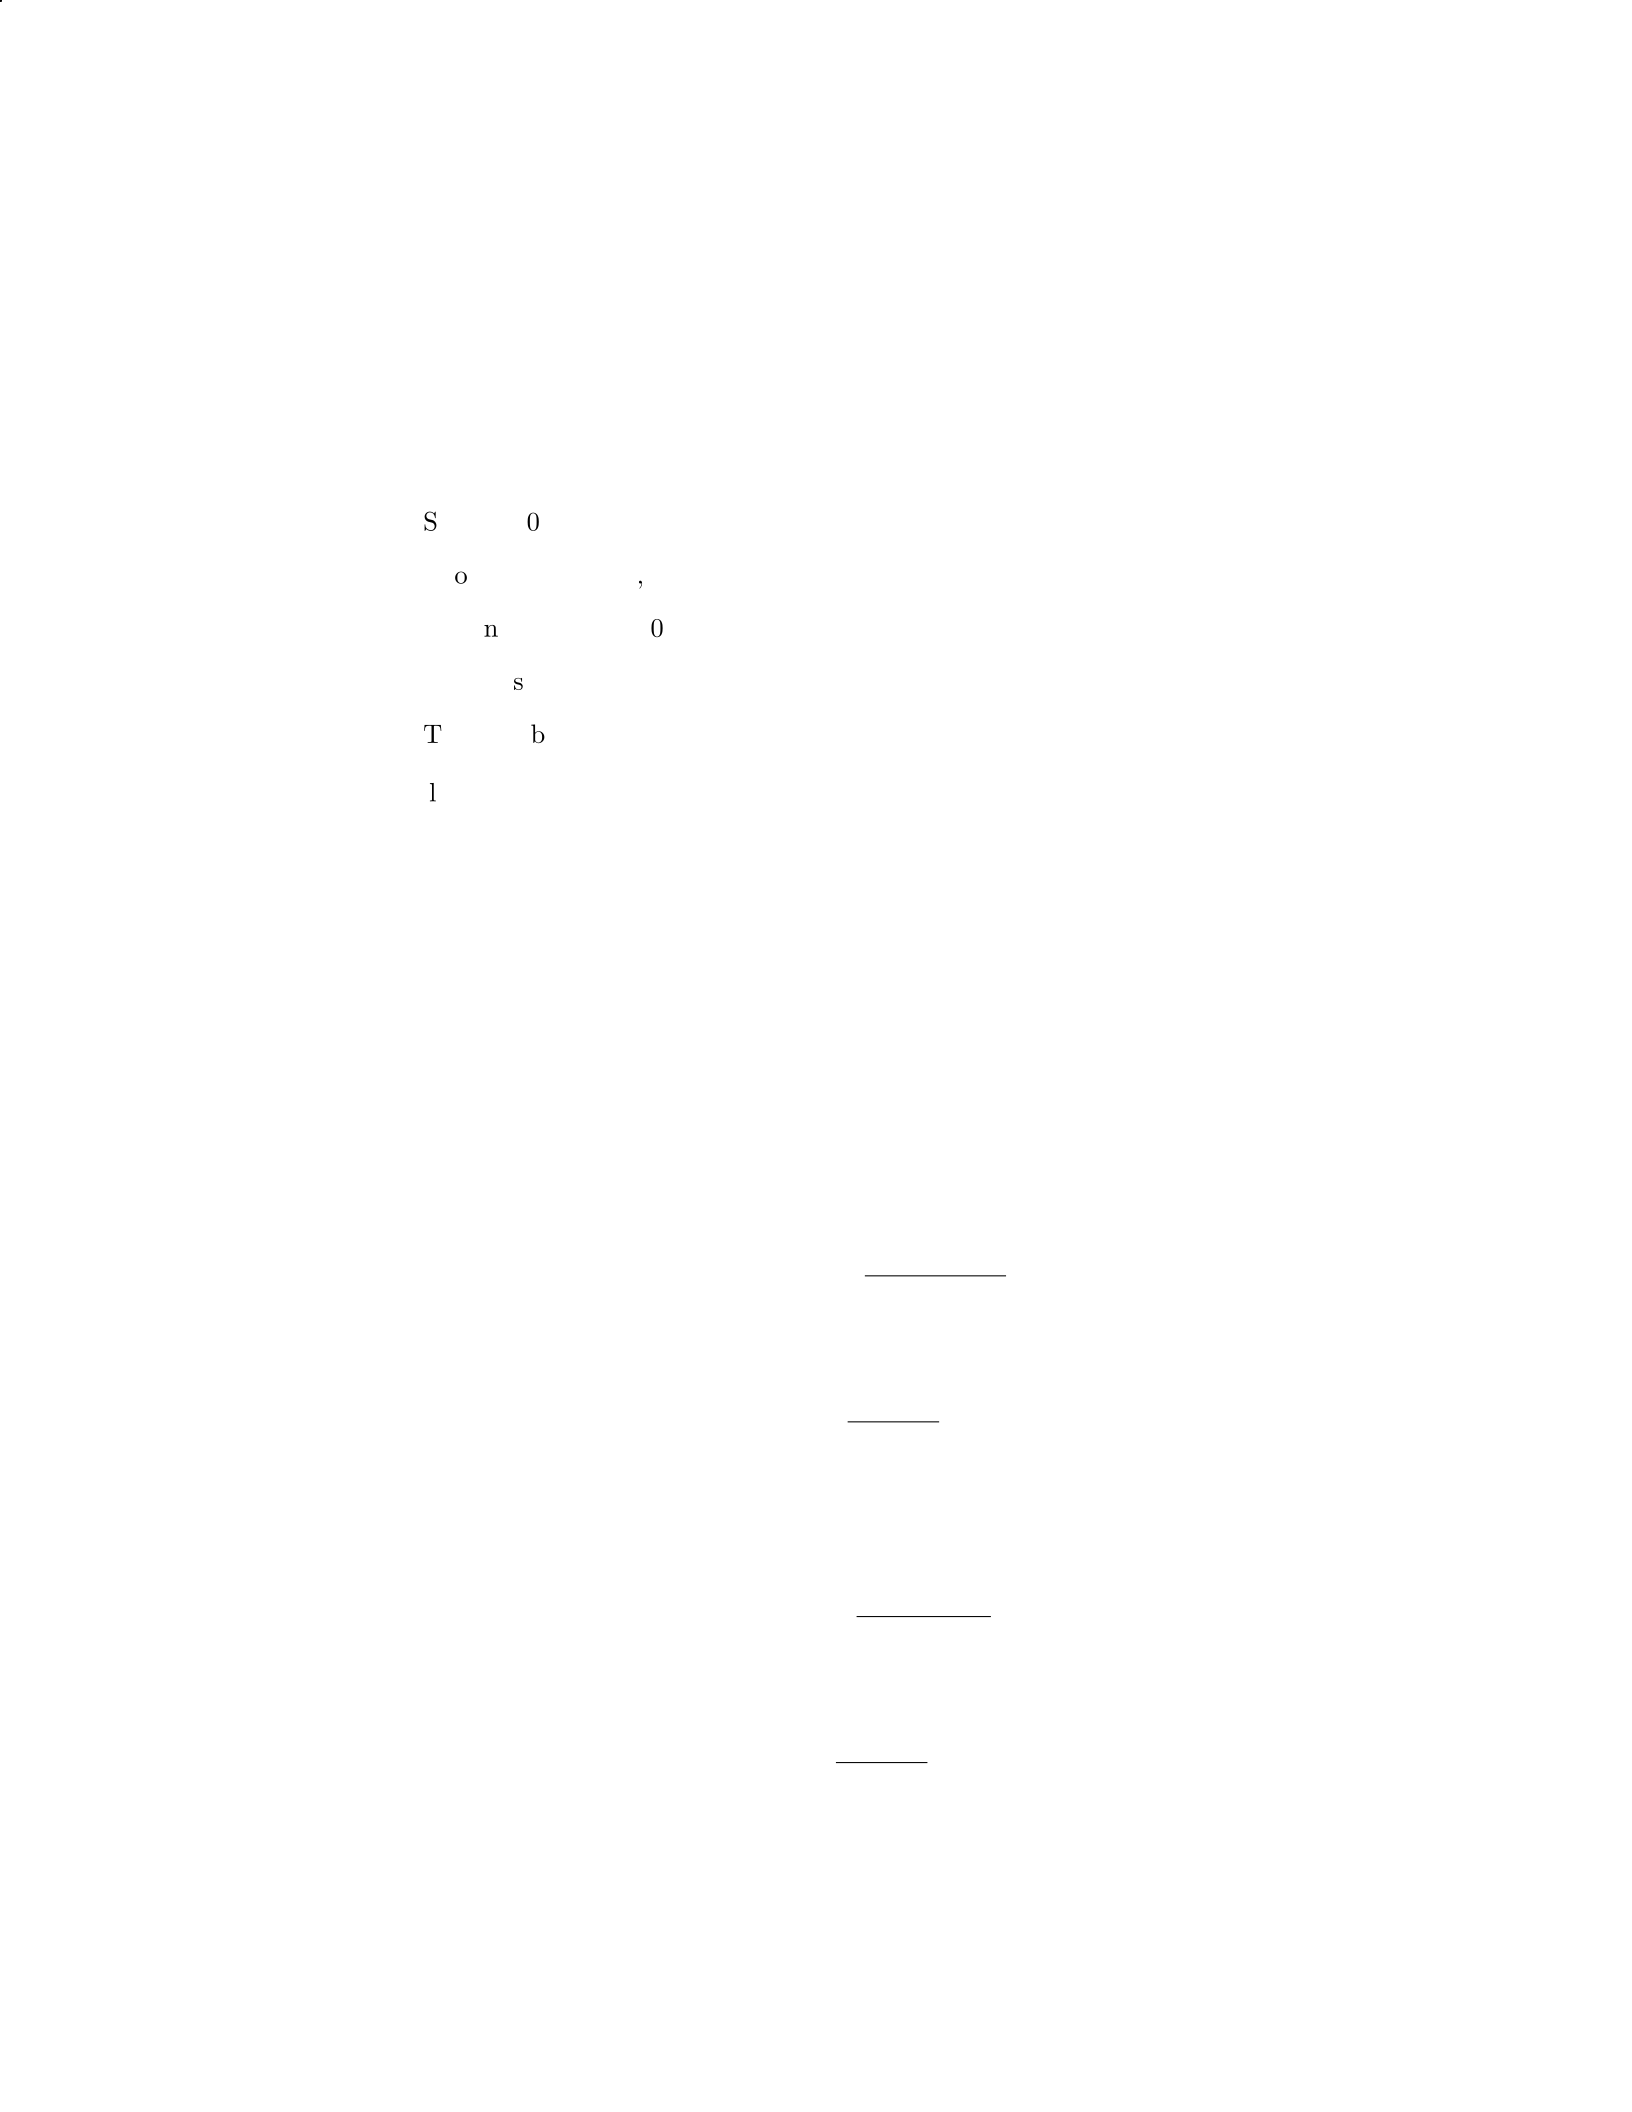
1. Step 1: Calculate Gross Profit Margin
The formula for Gross Profit Margin is:
Gross Profit Margin = Gross Profit
Sales ×100%
Substituting the given values:
Gross Profit Margin = 250,000
500,000 ×100% = 50%
2. Step 2: Calculate Net Profit Margin
The formula for Net Profit Margin is:
Net Profit Margin = Net Income
Sales ×100%
Substituting the given values:
Net Profit Margin = 100,000
500,000 ×100% = 20%
23
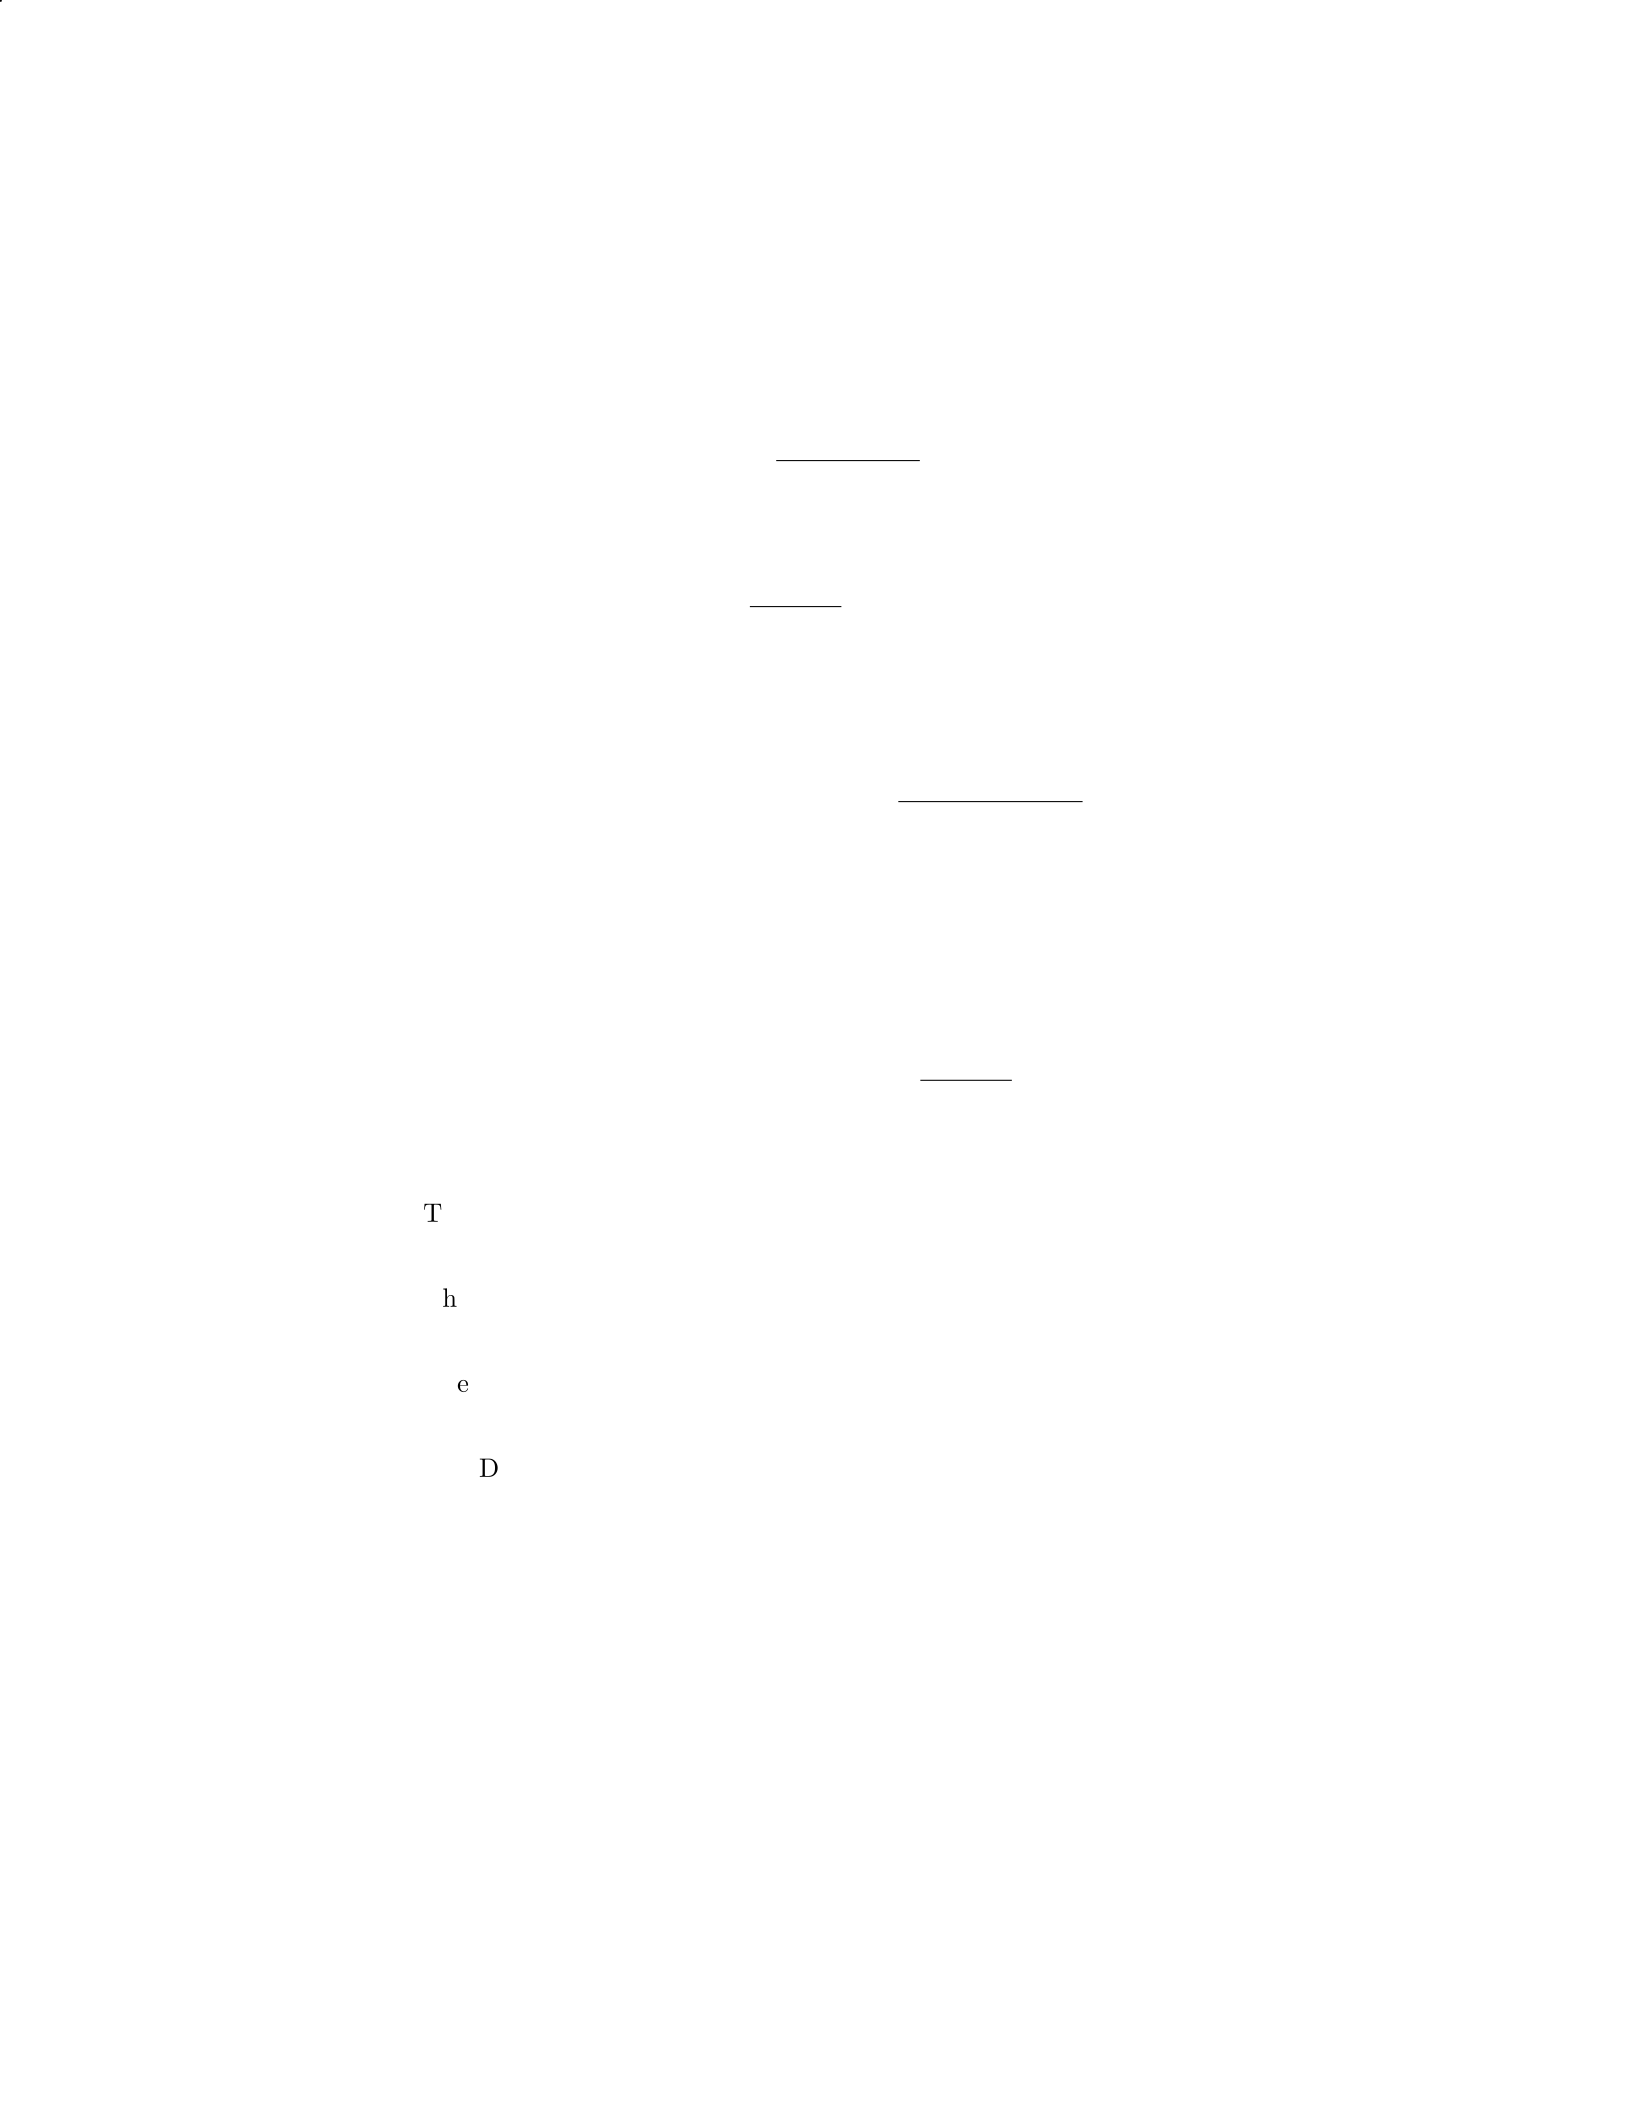
3. Step 3: Calculate Return on Assets (ROA)
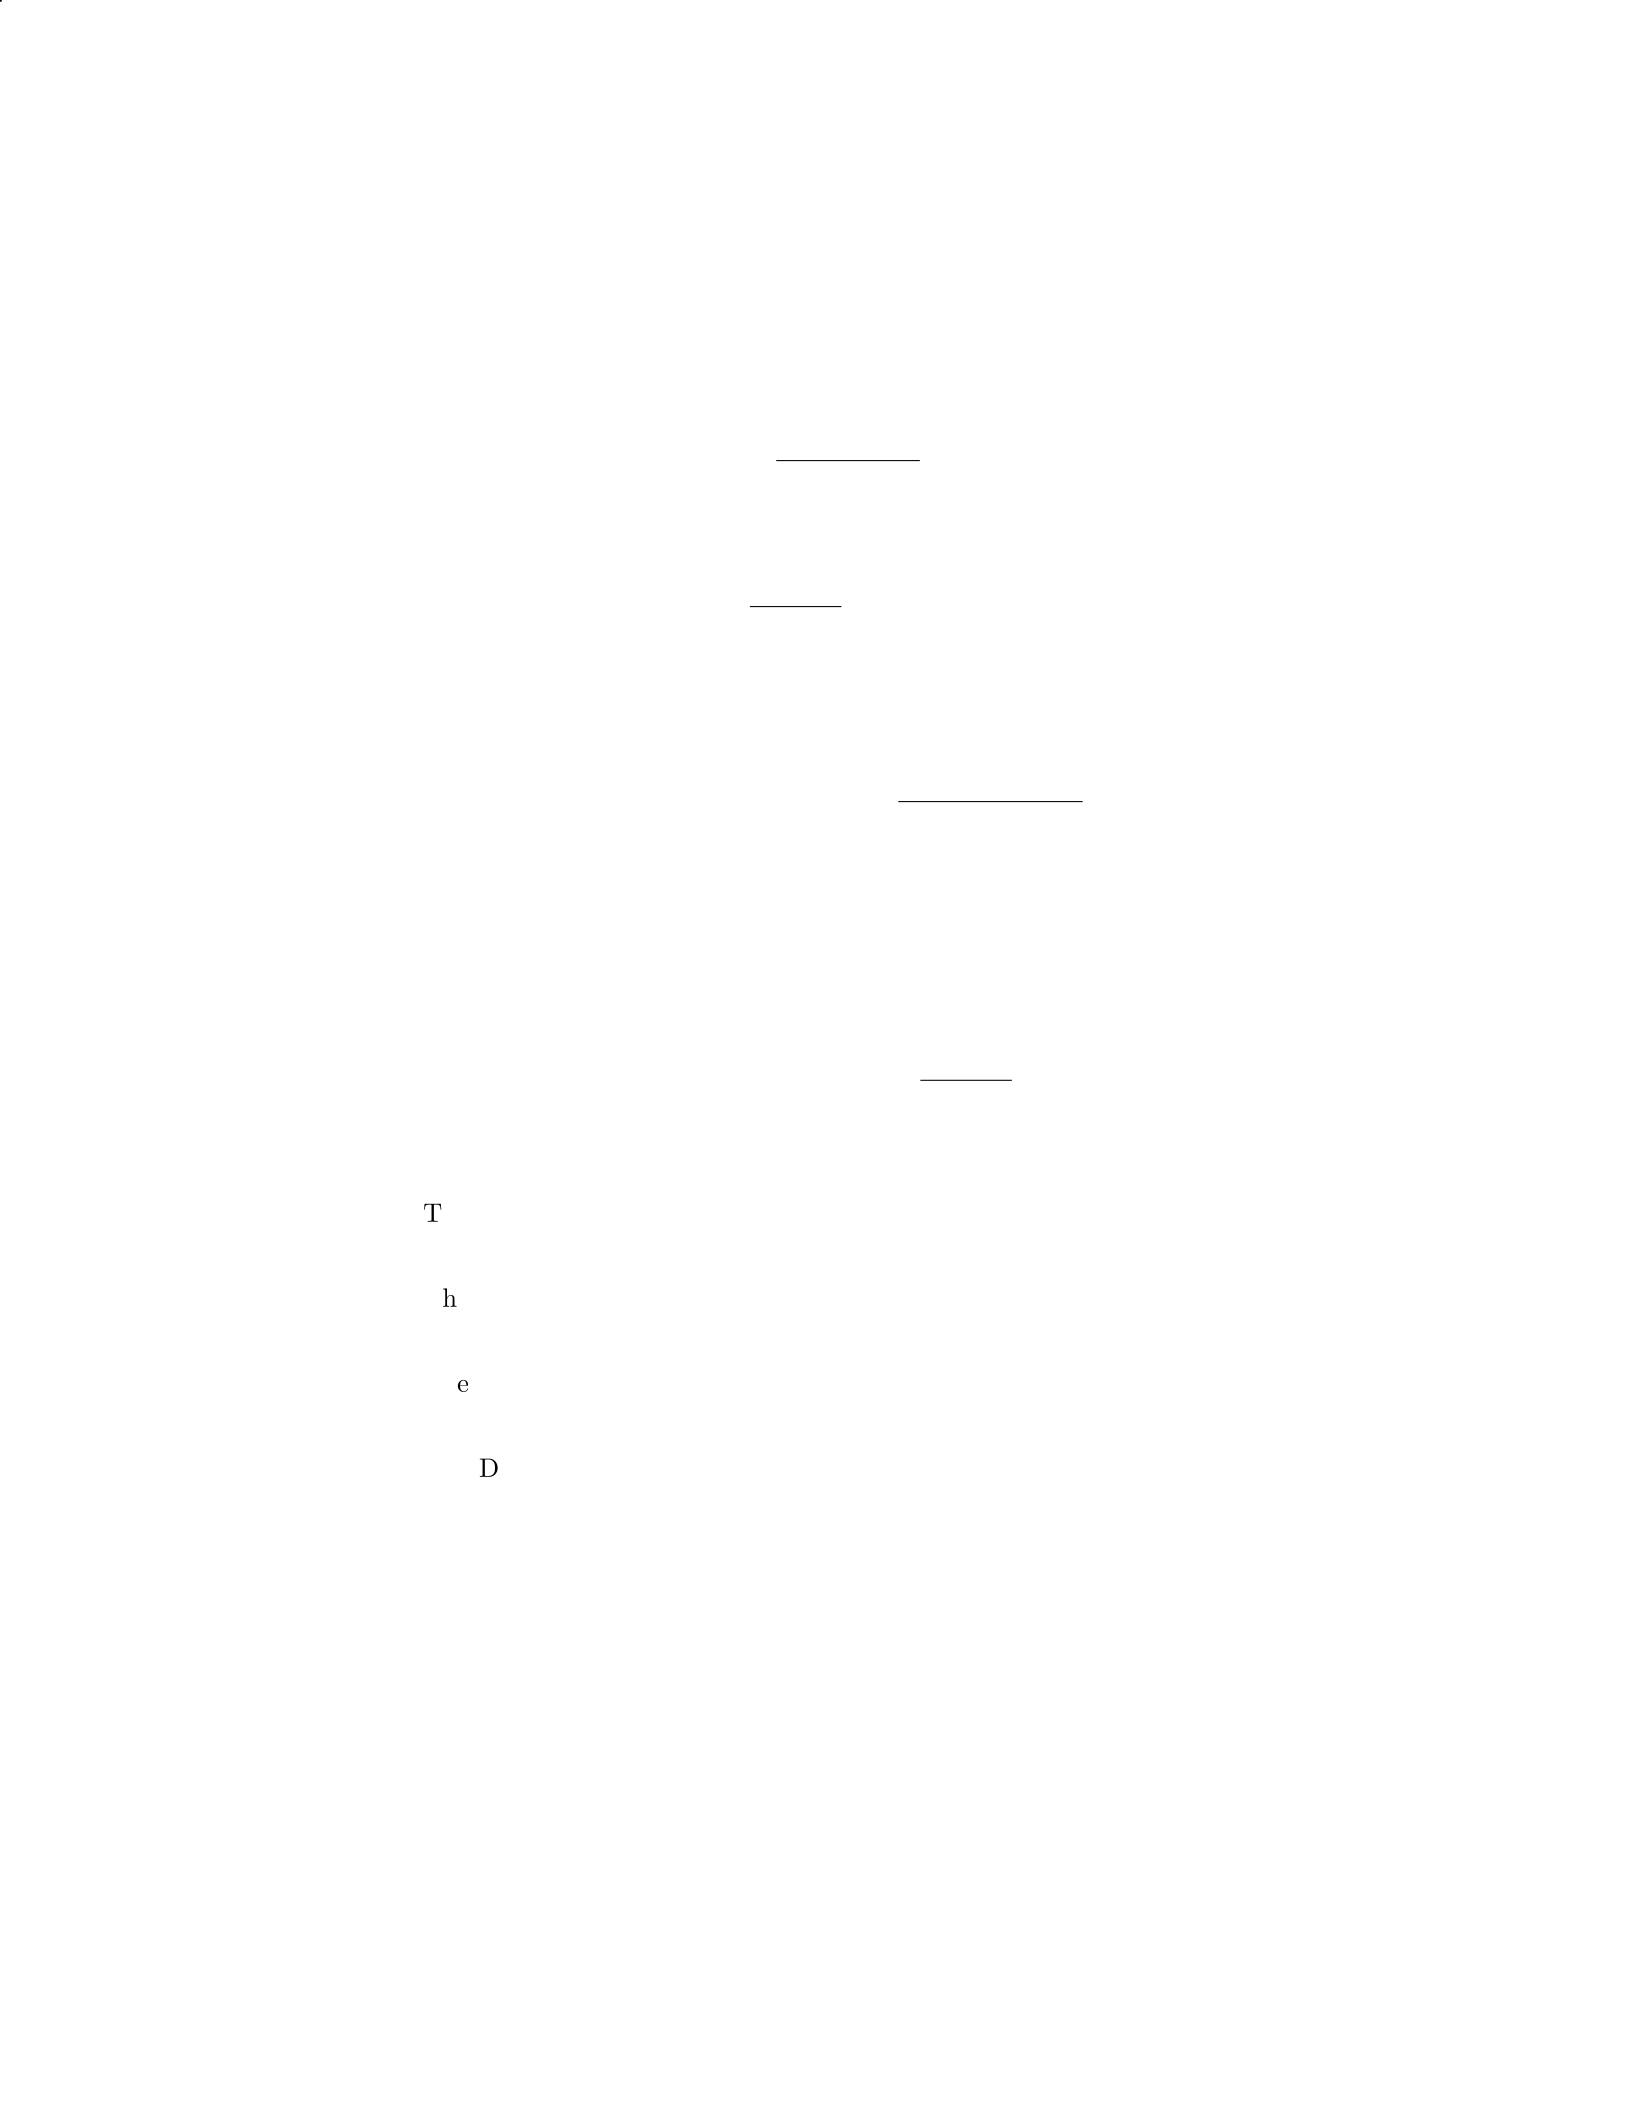
The formula for Return on Assets is:
ROA = Net Income
Total Assets ×100%
Substituting the given values:
ROA = 100,000
800,000 ×100% = 12.5%
4. Step 4: Calculate Debt to Equity Ratio
The formula for Debt to Equity Ratio is:
Debt to Equity Ratio = Total Liabilities
Total Equity
First, we need to calculate Total Equity:
Total Equity = Total Assets−Total Liabilities = 800,000−400,000 = 400,000
Now, substitute the values to find the Debt to Equity Ratio:
Debt to Equity Ratio = 400,000
400,000 = 1
Interpretation:
The Gross Profit Margin of 50% indicates that the company is able to
generate a high percentage of sales revenue as gross profit.
The Net Profit Margin of 20% shows that 20% of the company’s sales
translate to net income.
The ROA of 12.5% indicates that the company is generating 12.5 cents of
profit for every dollar of assets it owns.
The Debt to Equity Ratio of 1 suggests that the company has the same
amount of debt as equity, which may indicate a balanced financial struc-
ture.
Question 22
Question
Company XYZ has provided the following financial information for the current
year:
24

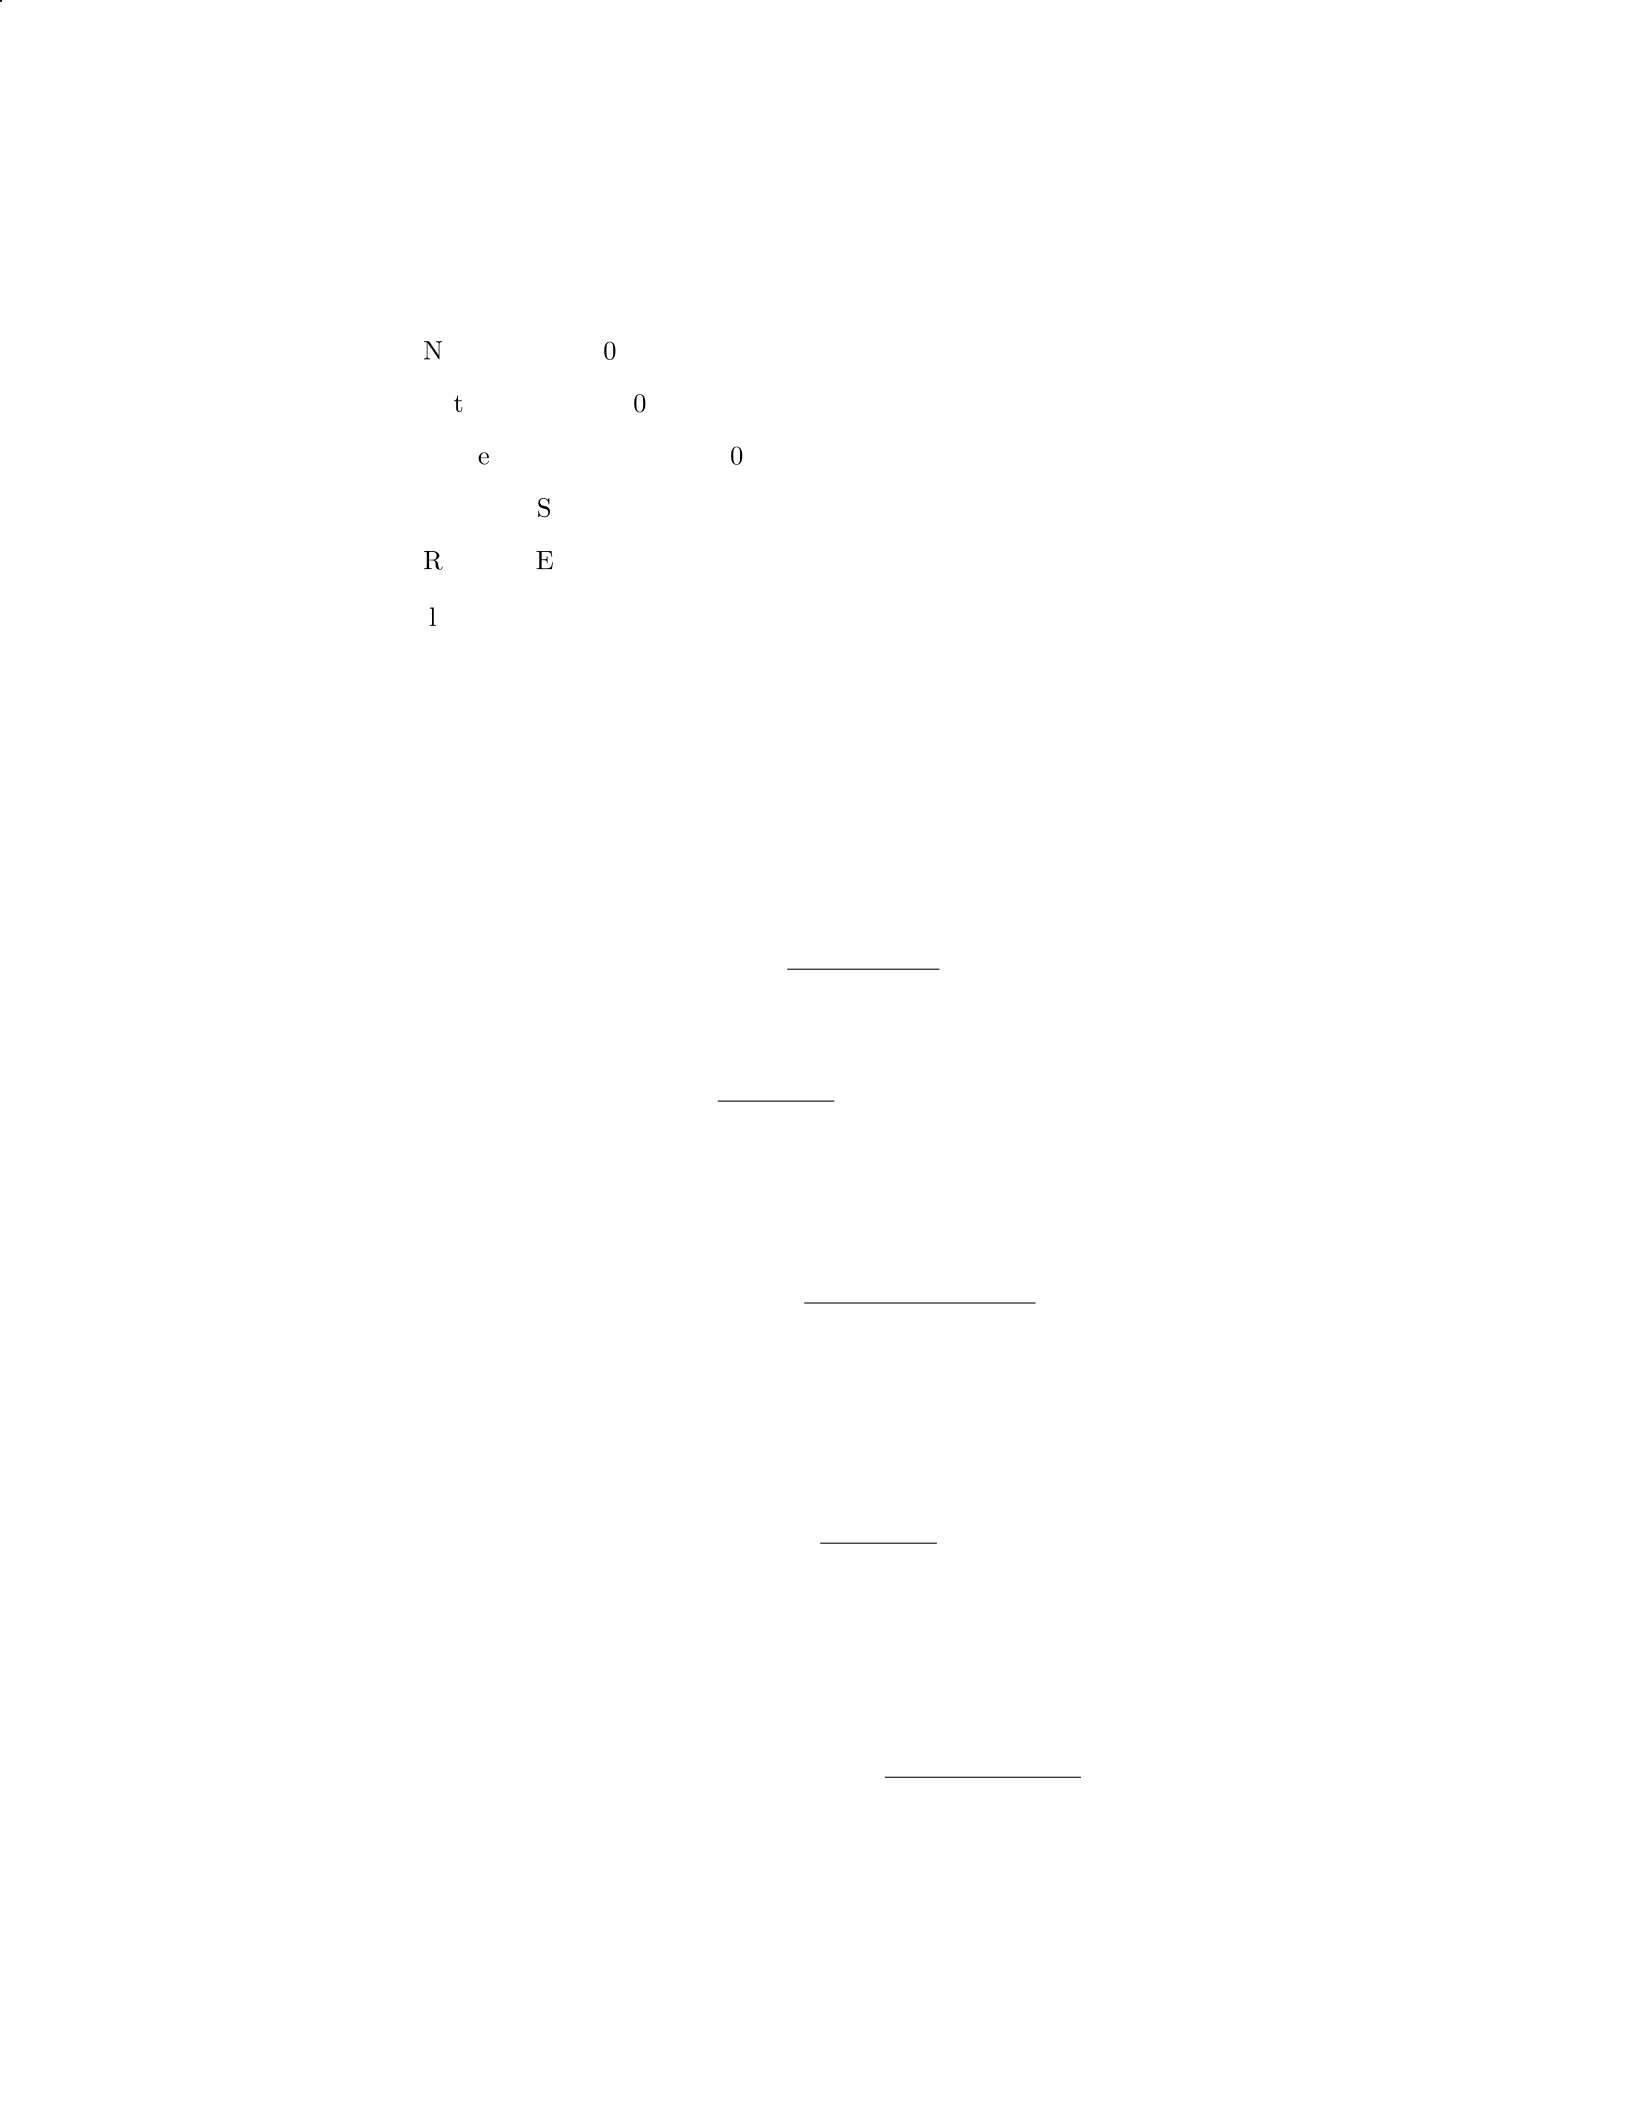
Net Income:
$
500,000
Total Assets:
$
2,000,000
Current Liabilities:
$
400,000
Common Stock:
$
600,000
Retained Earnings:
$
300,000
Calculate the following ratios for Company XYZ and interpret each ratio:
1. Return on Assets (ROA)
2. Current Ratio
3. Debt-to-Equity Ratio
Solution
Step 1: Calculate Return on Assets (ROA)
ROA =N et Income
T otal Assets
Substitute the given values:
ROA =500,000
2,000,000 = 0.25 or 25%
Interpretation: ROA indicates that for every dollar of assets, Company
XYZ generated 25 cents of profit.
Step 2: Calculate Current Ratio
Current Ratio =Current Assets
Current Liabilities
Given that Current Assets =T otal Assets−Common Stock−Retained Earnings:
Current Assets = 2,000,000 −600,000 −300,000 = 1,100,000
Substitute the values to calculate the Current Ratio:
Current Ratio =1,100,000
400,000 = 2.75
Interpretation: The current ratio of 2.75 indicates that the company has
2.75 dollars in current assets for every dollar of current liabilities, suggesting
good liquidity.
Step 3: Calculate Debt-to-Equity Ratio
Debt −to −Equity Ratio =T otal Liabilities
Equity
25
Given that T otal Liabilities =Current Liabilities:
T otal Liabilities = 400,000
And that Equity =Common Stock +Retained Earnings:
Equity = 600,000 + 300,000 = 900,000
Substitute the values to calculate the Debt-to-Equity Ratio:
Debt −to −Equity Ratio =400,000
900,000 = 0.44
Interpretation: The Debt-to-Equity Ratio of 0.44 indicates that the com-
pany has more equity financing than debt financing, which is generally consid-
ered a less risky financial structure.
Question 23
Question
A company has the following financial information for the year 2021:
Total Assets:
$
500,000
Total Liabilities:
$
200,000
Net Income:
$
50,000
Total Revenue:
$
300,000
Calculate and interpret the following ratios:
1. Debt-to-Asset Ratio
2. Return on Assets (ROA)
3. Profit Margin
Solution
To calculate the ratios, we will use the given financial information for the com-
pany.
Step 1: Calculate the Debt-to-Asset Ratio The Debt-to-Asset Ratio
is calculated by dividing Total Liabilities by Total Assets.
Debt-to-Asset Ratio = Total Liabilities
Total Assets
26
Substitute the given values:
Debt-to-Asset Ratio = 200,000
500,000 = 0.4 or 40%
Step 2: Calculate the Return on Assets (ROA) The Return on Assets
(ROA) is calculated by dividing Net Income by Total Assets.
ROA = Net Income
Total Assets
Substitute the given values:
ROA = 50,000
500,000 = 0.1 or 10%
Step 3: Calculate the Profit Margin The Profit Margin is calculated
by dividing Net Income by Total Revenue.
Profit Margin = Net Income
Total Revenue
Substitute the given values:
Profit Margin = 50,000
300,000 = 0.1667 or 16.67%
Interpretation:
The Debt-to-Asset Ratio of 40% indicates that 40% of the company’s
assets are financed by debt.
The ROA of 10% shows that the company generated a 10% return on its
total assets.
The Profit Margin of 16.67% means that the company earned 16.67 cents
of profit for every dollar of revenue generated.
Question 24
Question
Company ABC has provided the following financial information for the year
2020:
Net Income:
$
500,000
Total Assets:
$
2,000,000
Current Liabilities:
$
300,000
Inventory:
$
100,000
27
Accounts Receivable:
$
50,000
Calculate the following ratios for Company ABC:
1. Return on Assets (ROA)
2. Current Ratio
3. Inventory Turnover
4. Accounts Receivable Turnover
Solution
1. Return on Assets (ROA)
ROA = Net Income
Total Assets
ROA = $500,000
$2,000,000 = 0.25 or 25%
2. Current Ratio
Current Ratio = Current Assets
Current Liabilities
Current Assets = Inventory+Accounts Receivable = $100,000+$50,000 = $150,000
Current Ratio = $150,000
$300,000 = 0.5
3. Inventory Turnover
Inventory Turnover = Cost of Goods Sold
Average Inventory
Average Inventory = Beginning Inventory + Ending Inventory
2
Assuming Cost of Goods Sold is not given, we cannot directly calculate
Inventory Turnover.
4. Accounts Receivable Turnover
Accounts Receivable Turnover = Net Credit Sales
Average Accounts Receivable
Net Credit Sales = Total Sales −Cash Sales
Since Total Sales and Cash Sales are not provided, we cannot directly cal-
culate Accounts Receivable Turnover.
28
Question 25
Question
Company XYZ has the following financial ratios for the year 2020:
Current ratio = 2.5
Quick ratio = 1.5
Debt-to-equity ratio = 0.8
Based on the information provided, analyze the financial health of Company
XYZ and provide your interpretation.
Solution
To analyze the financial health of Company XYZ, we will evaluate each ratio
individually and then provide an overall interpretation.
Step 1: Calculate the Current Assets and Current Liabilities The
current ratio is given by:
Current Ratio = Current Assets
Current Liabilities
Given that the current ratio is 2.5, we can set up the following equation:
2.5 = Current Assets
Current Liabilities
Step 2: Find the Quick Assets The quick ratio is given by:
Quick Ratio = Quick Assets
Current Liabilities
Given that the quick ratio is 1.5, we have:
1.5 = Quick Assets
Current Liabilities
Step 3: Interpretation of the Current Ratio and Quick Ratio A cur-
rent ratio of 2.5 indicates that Company XYZ has 2.50ofcurrentassetsforevery1
of current liabilities, which suggests that the company is in a good position to
meet its short-term obligations. The quick ratio of 1.5 shows that the com-
pany has 1.50ofquickassets(assetsthatcanbeeasilyliquidated)f orevery1 of cur-
rent liabilities.
Step 4: Analyze the Debt-to-Equity Ratio The debt-to-equity ratio is
given by:
Debt-to-Equity Ratio = Total Debt
Total Equity
Given that the debt-to-equity ratio is 0.8, we have:
29
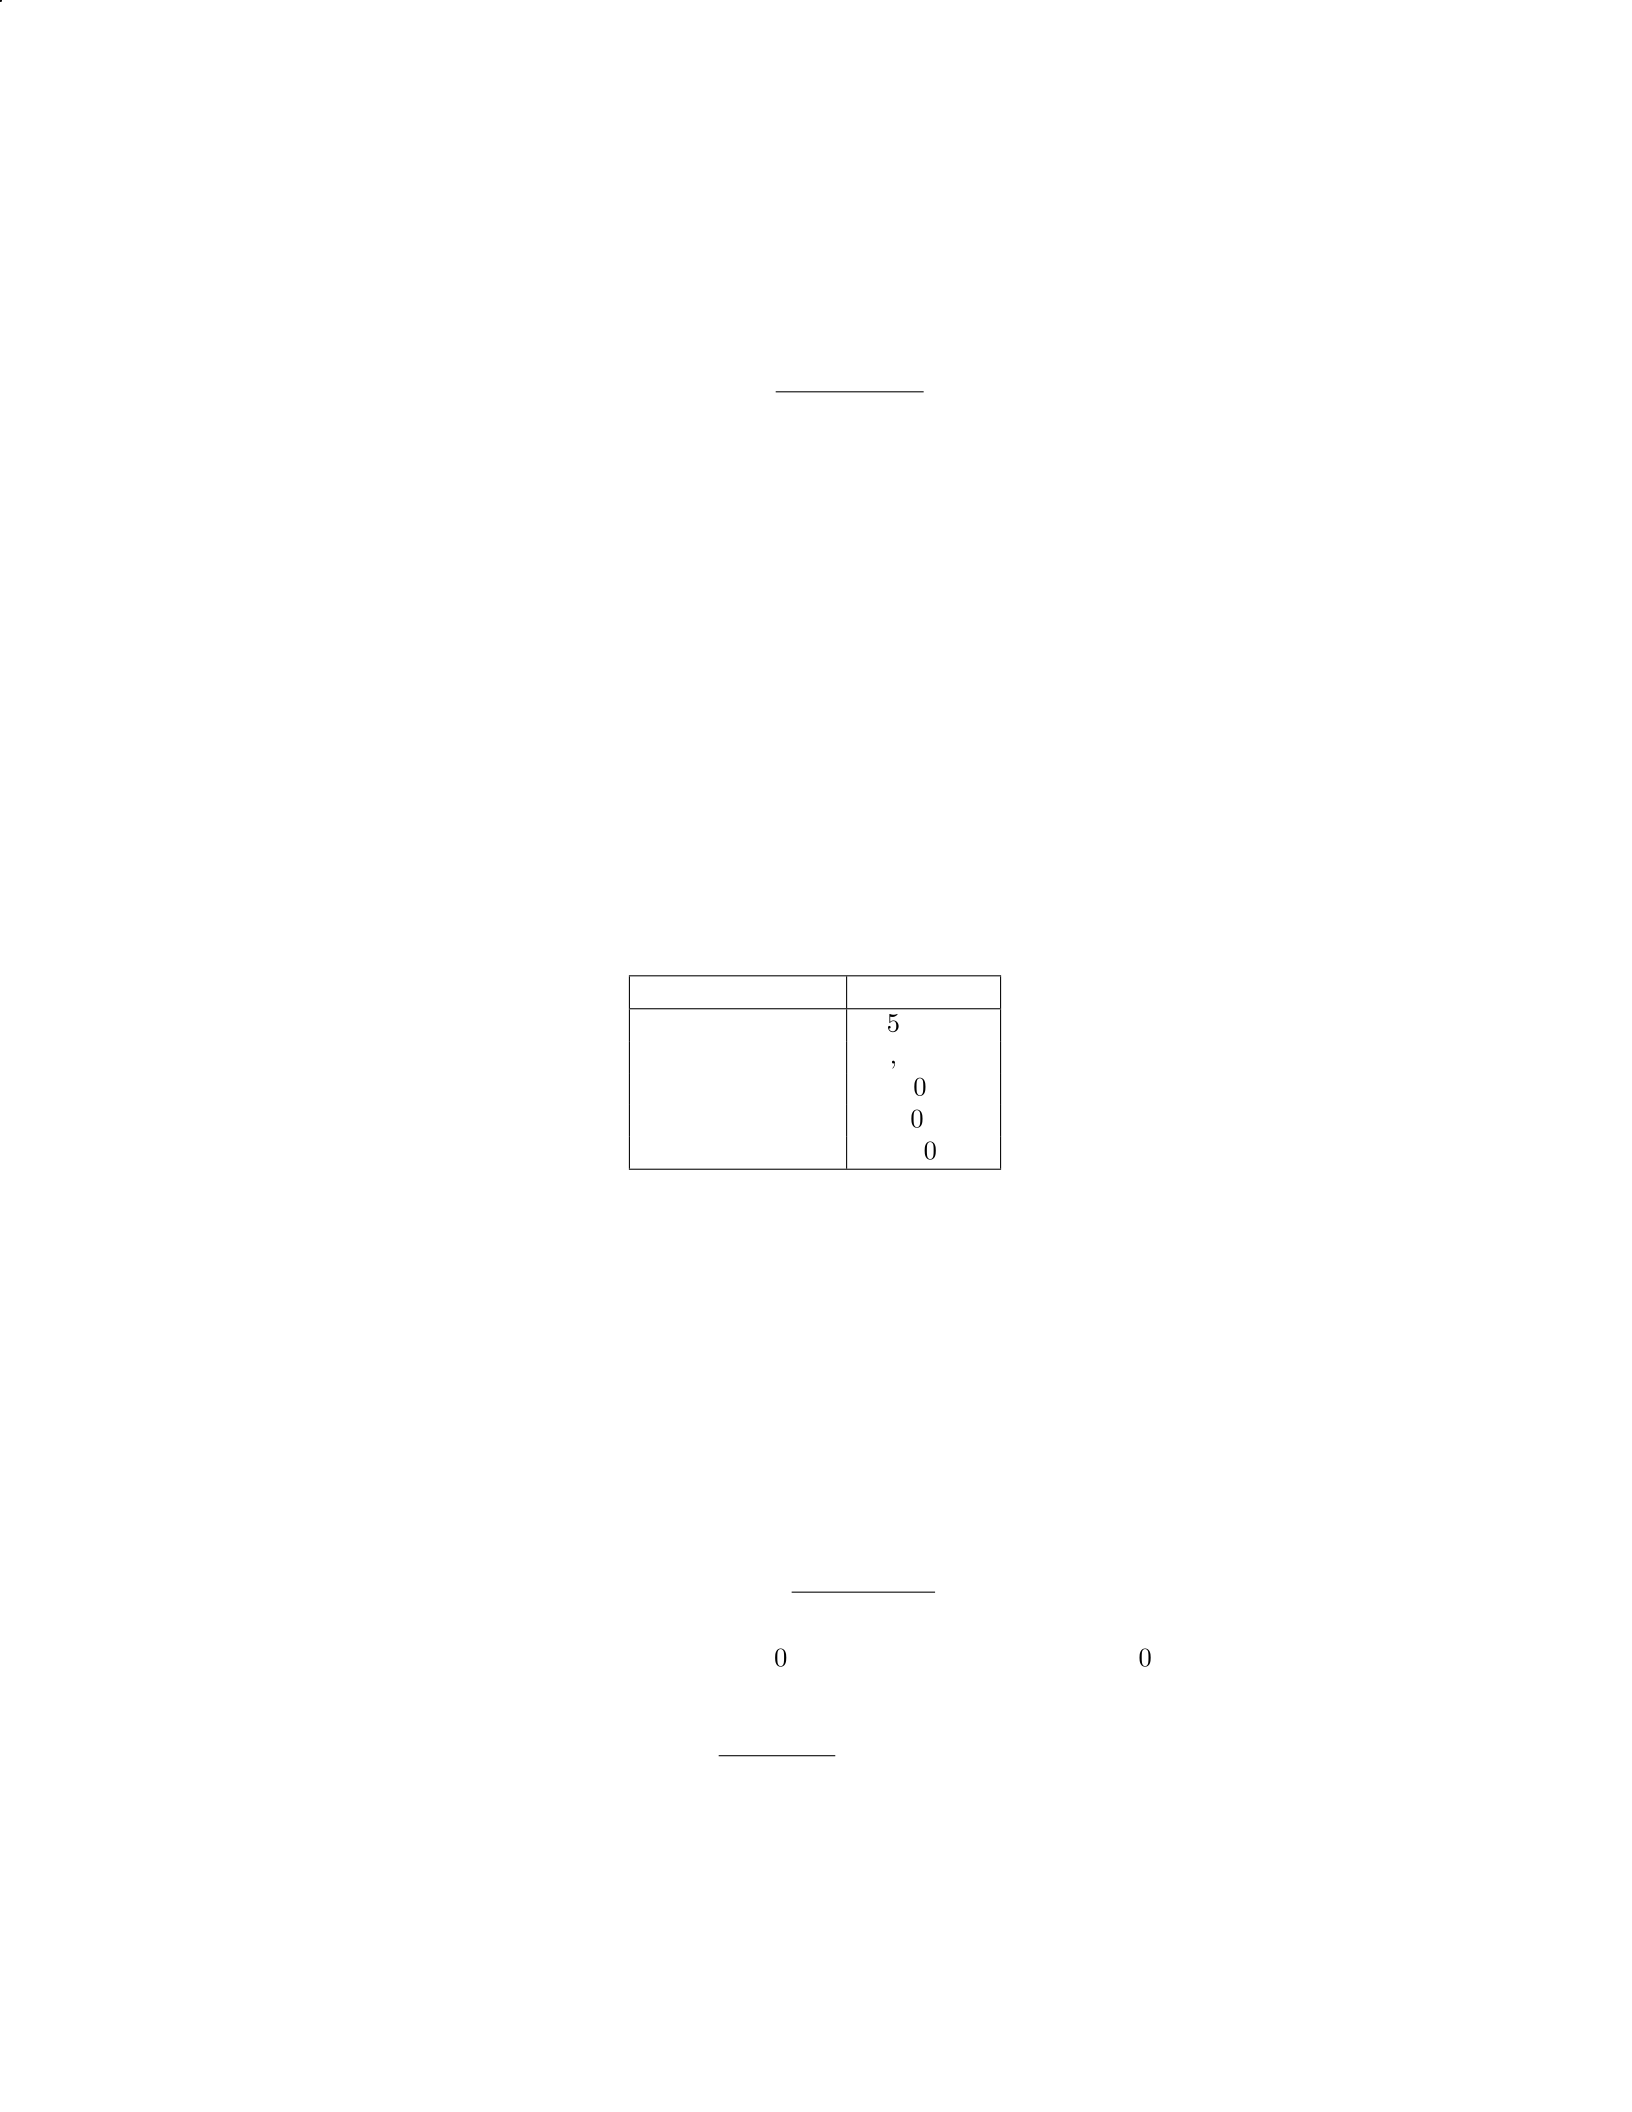
0.8 = Total Debt
Total Equity
Step 5: Interpretation of the Debt-to-Equity Ratio A debt-to-equity
ratio of 0.8 suggests that for every 1ofequity, thecompanyhas0.80 of debt. This
indicates that Company XYZ has a conservative capital structure with a higher
proportion of equity compared to debt.
Step 6: Overall Interpretation Based on the ratios calculated, Company
XYZ appears to be in a healthy financial position. The current and quick ratios
indicate strong liquidity and ability to meet short-term obligations. Addition-
ally, the conservative debt-to-equity ratio suggests a lower financial risk due to
a higher proportion of equity in the capital structure. Overall, Company XYZ
seems to have a favorable financial health in the year 2020.
Question 26
Question
A company had the following financial information for the year:
Metric Value
Net Income
$
500,000
Total Assets
$
2,000,000
Total Liabilities
$
800,000
Total Equity
$
1,200,000
Revenue
$
1,000,000
Calculate the following ratios and interpret them in the context of the com-
pany’s performance:
1. Return on Assets (ROA)
2. Debt to Equity Ratio
3. Profit Margin
Solution
Step 1: Calculate Return on Assets (ROA)
ROA =N etIncome
T otalAssets
Given that Net Income is
$
500,000 and Total Assets are
$
2,000,000, we can
calculate ROA as:
ROA =500,000
2,000,000 = 0.25 or 25%
30
The company generated a return of 25% on its total assets. This indicates
that the company is efficient in generating income from its assets.
Step 2: Calculate Debt to Equity Ratio
DebttoEquityRatio =T otalLiabilities
T otalEquity
Given that Total Liabilities are
$
800,000 and Total Equity is
$
1,200,000, we
can calculate the Debt to Equity Ratio as:
DebttoEquityRatio =800,000
1,200,000 = 0.67 or 0.67 : 1
The company’s Debt to Equity Ratio is 0.67, indicating that it has more
equity than debt. This shows a lower financial risk for the company.
Step 3: Calculate Profit Margin
P rofitM argin =N etIncome
Revenue ×100%
Given that Net Income is
$
500,000 and Revenue is
$
1,000,000, we can cal-
culate the Profit Margin as:
P rofitM argin =500,000
1,000,000 ×100% = 50%
The company’s Profit Margin is 50%, meaning that for every dollar of rev-
enue, the company keeps 50 cents as profit. This implies that the company is
operating efficiently in terms of generating profit.
Question 27
Question
A company reported a current ratio of 2.5 and a quick ratio of 1.8. Interpret
these ratios and discuss what they indicate about the company’s liquidity posi-
tion.
Solution
Step 1: Interpretation of Current Ratio and Quick Ratio
The current ratio is calculated as:
Current Ratio = Current Assets
Current Liabilities
The quick ratio is calculated as:
Quick Ratio = Current Assets - Inventory
Current Liabilities
31
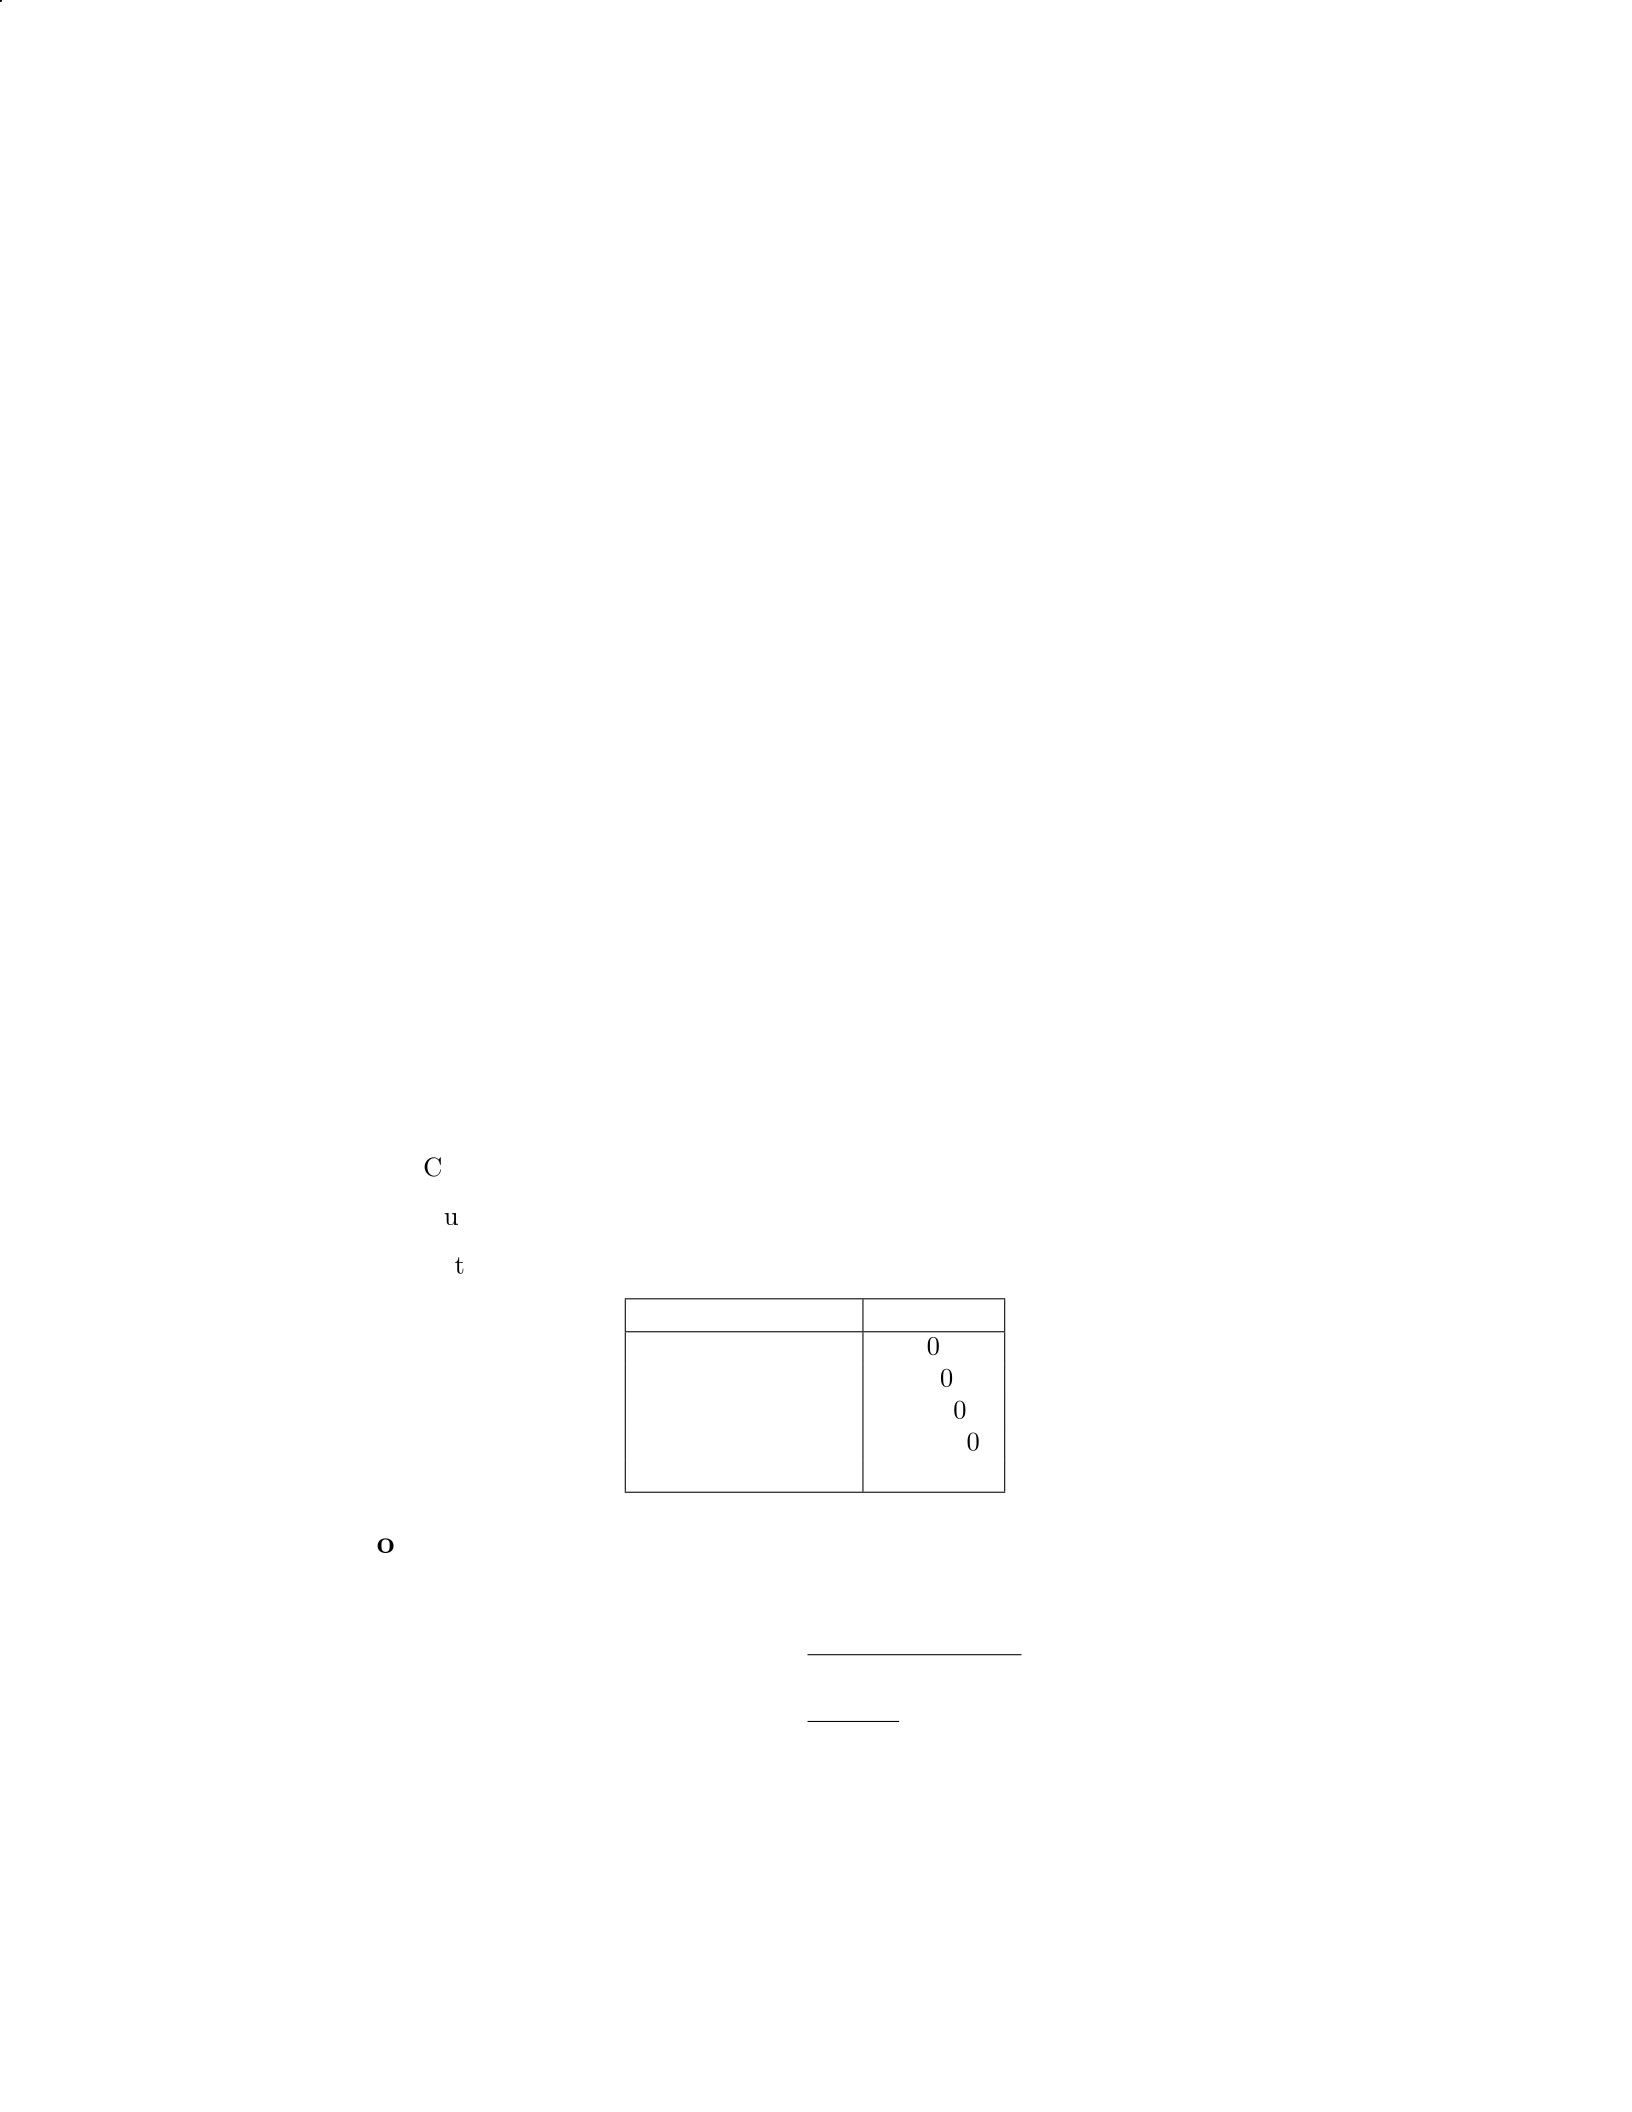
Step 2: Interpretation of Current Ratio
A current ratio of 2.5 means that the company has 2.5 times more current
assets than current liabilities. This indicates that the company is able to cover
its short-term obligations comfortably.
Step 3: Interpretation of Quick Ratio
A quick ratio of 1.8 means that the company has 1.8 times more liquid assets
(current assets excluding inventory) than current liabilities. This ratio provides
a more stringent measure of liquidity compared to the current ratio.
Step 4: Discussion on Liquidity Position
The current ratio of 2.5 and quick ratio of 1.8 suggest that the company has
a healthy liquidity position. The high current ratio indicates that the company
has a strong ability to pay off its short-term liabilities using its current assets.
The quick ratio further confirms this liquidity position by excluding inventory
from the calculation, focusing only on the most liquid current assets.
Overall, based on these ratios, the company appears to be in a comfortable
position to meet its short-term obligations. However, it is important to consider
other factors such as cash flow and solvency ratios for a more comprehensive
analysis of the company’s financial health.
Question 28
Question
Given the following financial data for Company XYZ, calculate the following
ratios and interpret the results:
Current ratio
Quick ratio
Return on assets (ROA)
Item Amount
Current assets
$
80,000
Current liabilities
$
30,000
Inventory
$
20,000
Total assets
$
200,000
Net income
$
40,000
Solution
Step 1: Calculate the Current Ratio
Current Ratio = Current Assets
Current Liabilities
=$80,000
$30,000
= 2.67
32
Step 2: Calculate the Quick Ratio
Quick Ratio = Current Assets - Inventory
Current Liabilities
=$80,000 −$20,000
$30,000
=$60,000
$30,000
= 2
Step 3: Calculate the Return on Assets (ROA)
ROA = Net Income
Total Assets
=$40,000
$200,000
= 0.20 or 20%
Step 4: Interpretation
The current ratio of 2.67 indicates that Company XYZ has more than
enough current assets to cover its current liabilities, which is considered
favorable.
The quick ratio of 2 shows that Company XYZ can cover its current
liabilities with a margin of safety without relying on selling inventory.
An ROA of 20
Question 29
Question
A company’s financial statements report the following information for the cur-
rent year:
Total assets:
$
800,000
Total liabilities:
$
400,000
Net income:
$
120,000
Total equity:
$
400,000
Calculate the following ratios and interpret what each ratio reveals about
the company:
1. Debt-to-total-assets ratio
2. Return on equity (ROE) ratio
3. Equity multiplier
33
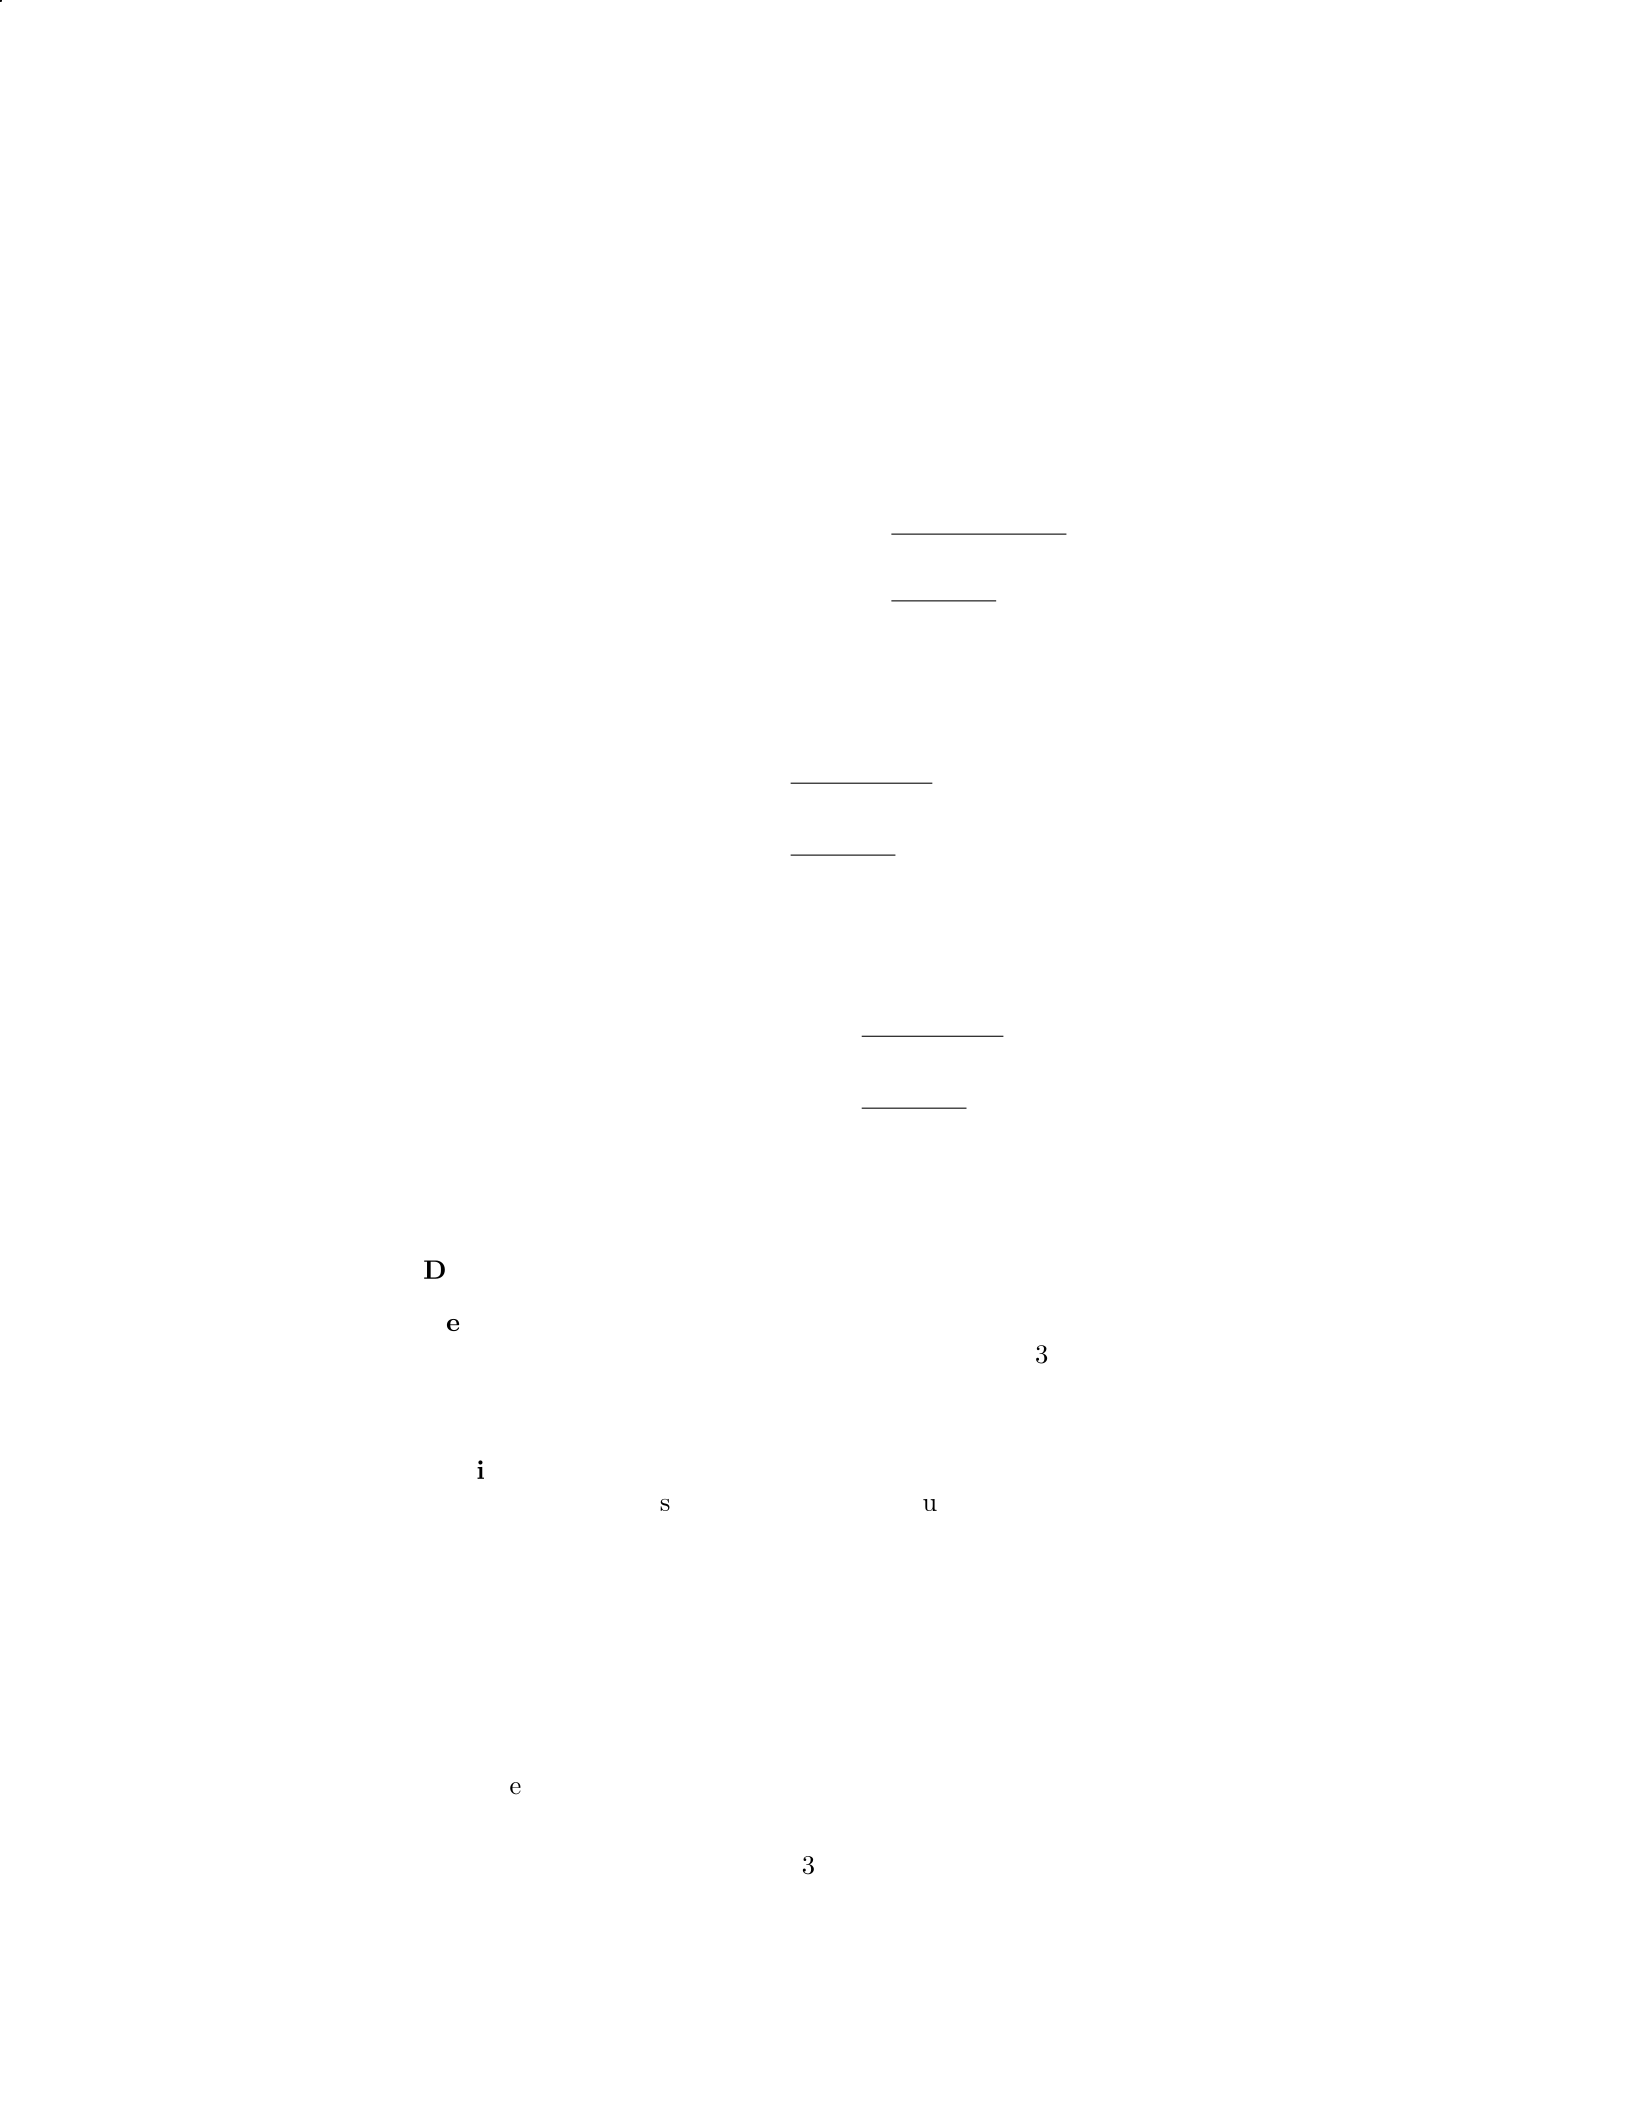
Solution
Let’s first calculate the ratios and then interpret what each ratio reveals about
the company.
Step 1: Calculate the debt-to-total-assets ratio
Debt-to-total-assets ratio = Total liabilities
Total assets
=$400,000
$800,000
= 0.5
Step 2: Calculate the return on equity (ROE) ratio
ROE = Net income
Total equity
=$120,000
$400,000
= 0.3
Step 3: Calculate the equity multiplier
Equity multiplier = Total assets
Total equity
=$800,000
$400,000
= 2
Interpretation:
Debt-to-total-assets ratio (0.5): This ratio indicates that 50
Return on equity (ROE) ratio (0.3): This ratio shows that for every
dollar of equity invested, the company generates
$
0.30 in net income. A
higher ROE typically indicates a more efficient use of equity capital and
better profitability.
Equity multiplier (2): The equity multiplier of 2 signifies that the
company has
$
2 of assets for every
$
1 of equity. This indicates the extent
to which the company is leveraging its equity to finance its assets.
Question 30
Question
A company has the following financial information for the year 2020:
Net Sales:
$
500,000
34
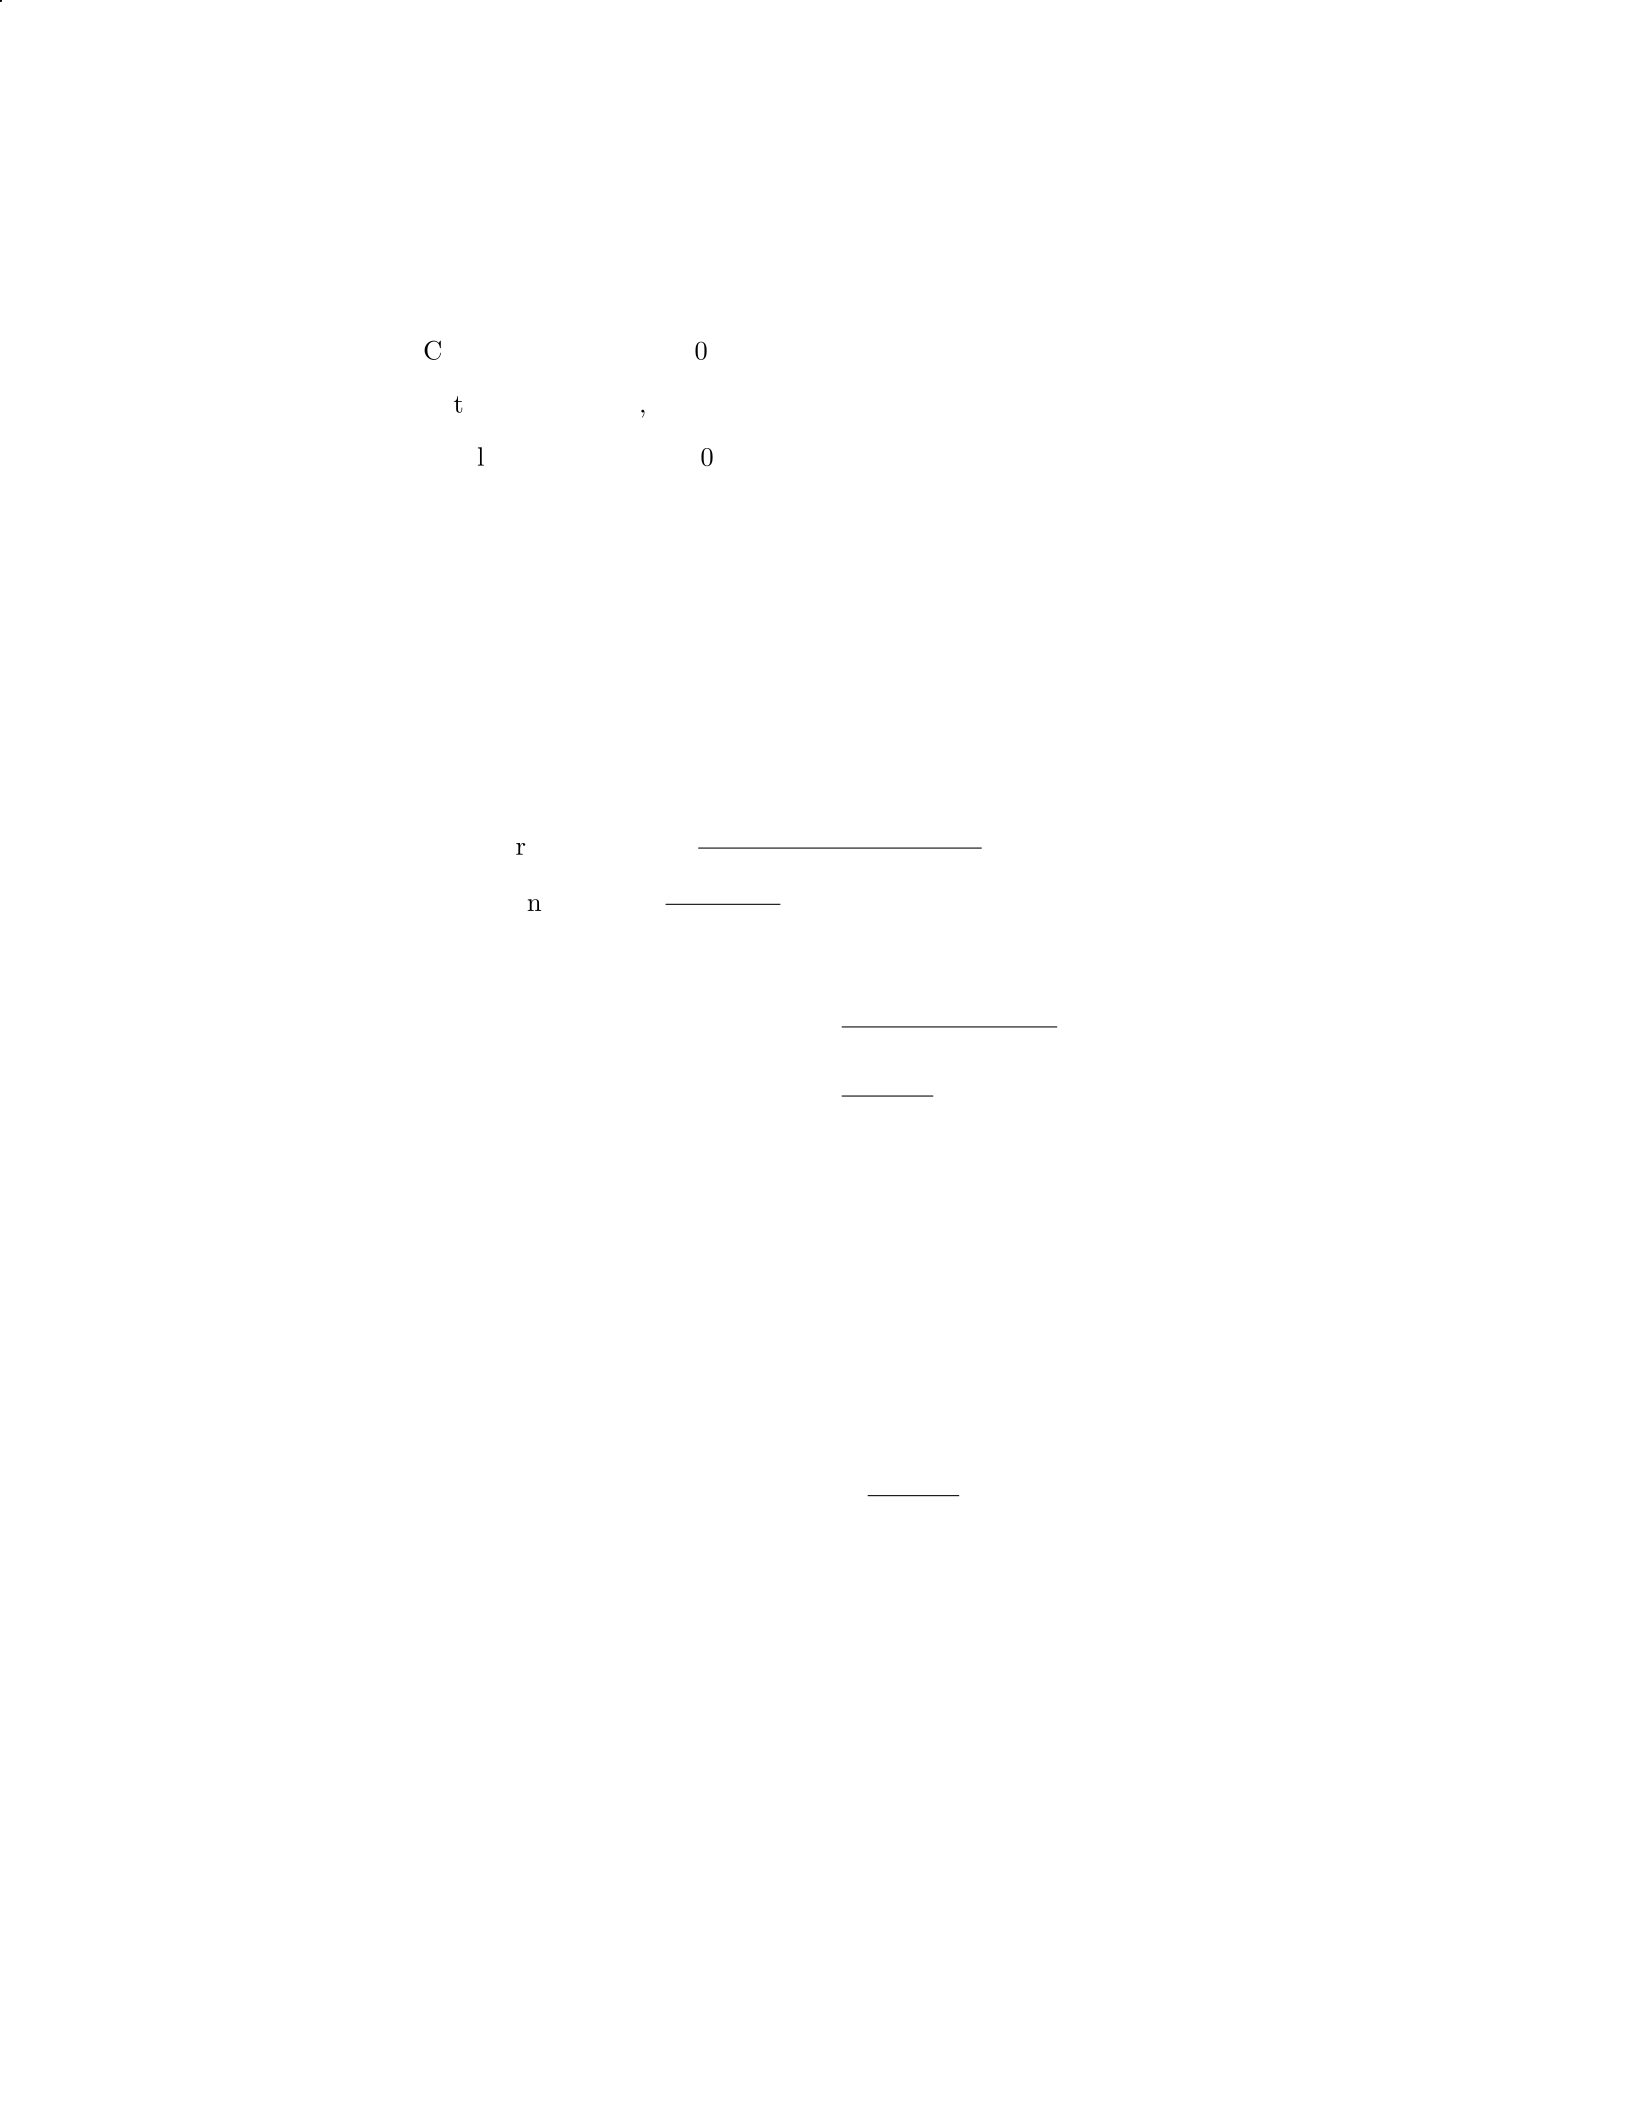
Cost of Goods Sold:
$
300,000
Total Assets:
$
800,000
Total Liabilities:
$
400,000
Calculate the following ratios for the company:
1. Gross Profit Margin
2. Return on Assets
Interpret each ratio in the context of the company’s performance.
Solution
To calculate the ratios, we will use the following formulas:
Gross Profit Margin = Net Sales−Cost of Goods Sold
Net Sales
Return on Assets = Net Income
Total Assets
Step 1: Calculate Gross Profit Margin
Gross Profit Margin = 500,000 −300,000
500,000
=200,000
500,000
= 0.4 or 40%
Step 2: Calculate Return on Assets We need to find Net Income first.
Since it is not provided, we will use the formula: Net Income = Net Sales - Cost
of Goods Sold.
Net Income = 500,000 −300,000
= 200,000
Now we can calculate the Return on Assets:
Return on Assets = 200,000
800,000
= 0.25 or 25%
Interpretation:
35
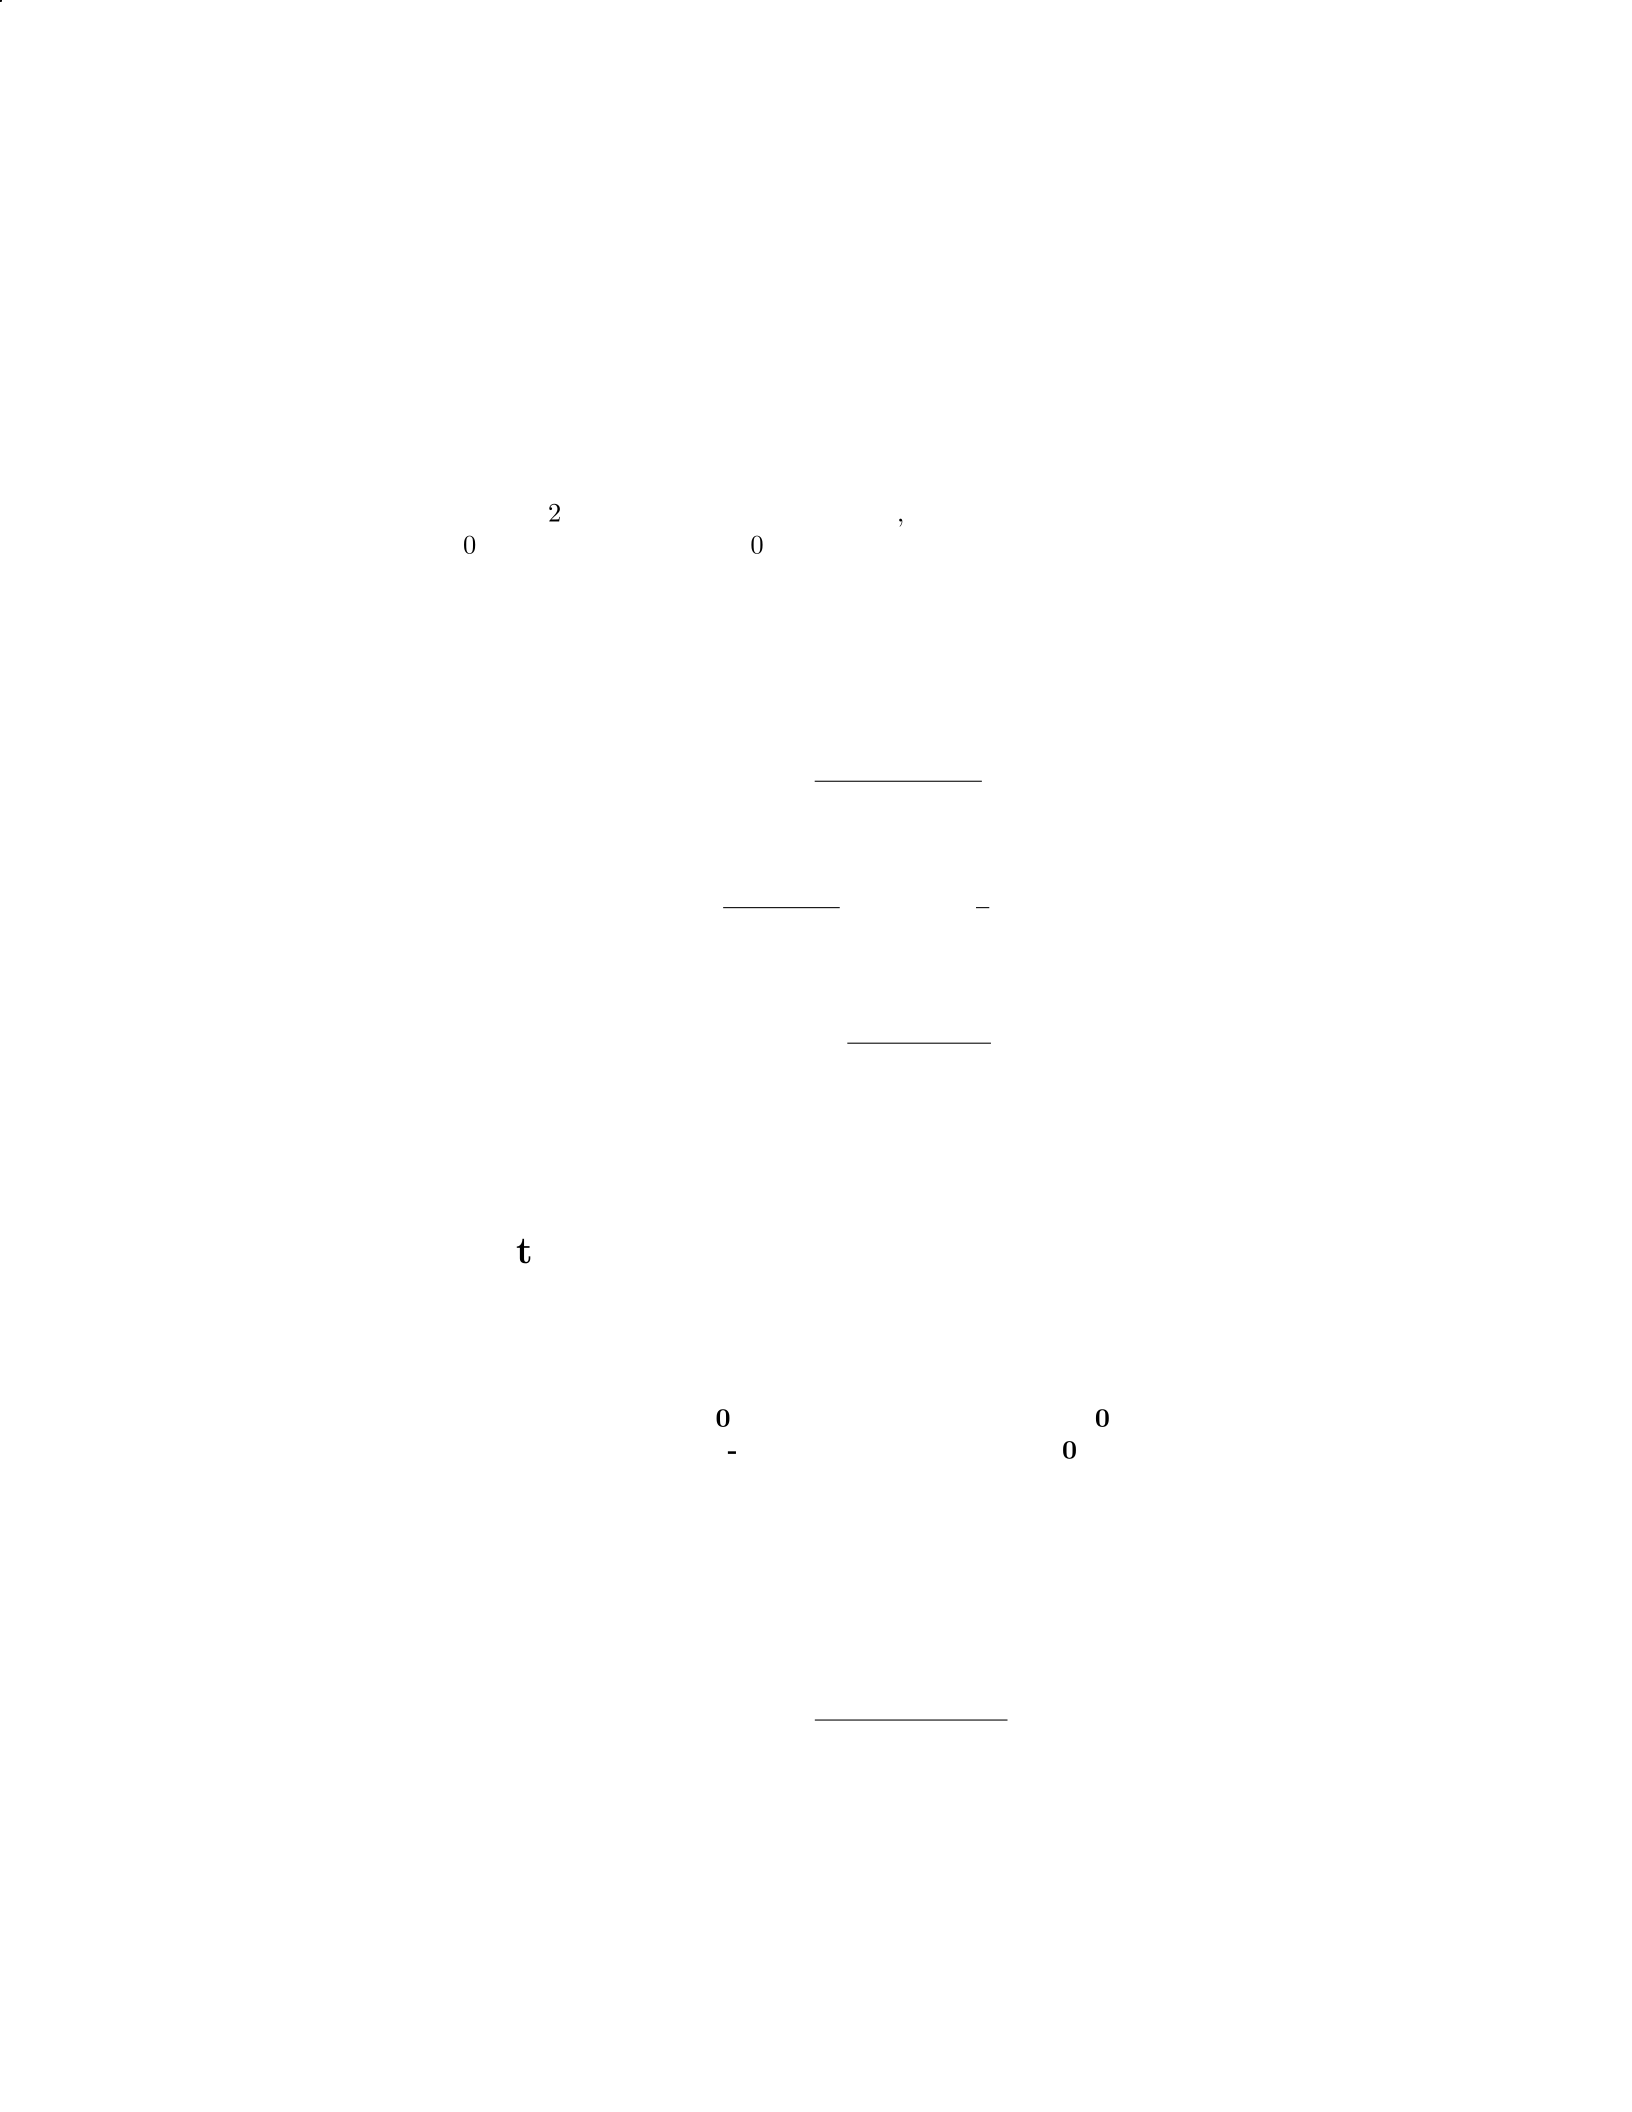
Question 31
Question
A company has the following financial information for the year: - Net
Income:
$
200,000 - Total Revenue:
$
1,000,000 - Cost of Goods Sold:
$
600,000 - Total Assets:
$
2,000,000 Calculate and interpret the company’s:
a) Profit Margin b) Return on Assets c) Gross Profit Margin
Solution
a) To calculate the Profit Margin, we use the formula:
Profit Margin = Net Income
Total Revenue ×100%
Step 1: Calculate the Profit Margin.
Profit Margin = 200,000
1,000,000 ×100% = 1
5×100% = 20%
b) To calculate the Return on Assets, we use the formula:
Return on Assets = Net Income
Total Assets ×100%
Step 2:Gross Profit Margin (40
Question 31
Question
A company has the following financial information for the year:
- Net Income:
$
200,000 - Total Revenue:
$
1,000,000 - Cost of
Goods Sold:
$
600,000 - Total Assets:
$
2,000,000 Calculate and
interpret the company’s: a) Profit Margin b) Return on Assets
c) Gross Profit Margin
Solution
a) To calculate the Profit Margin, we use the formula:
Profit Margin =Net Income
Total Revenue ×100%
Step 1:Return on Assets (25
36
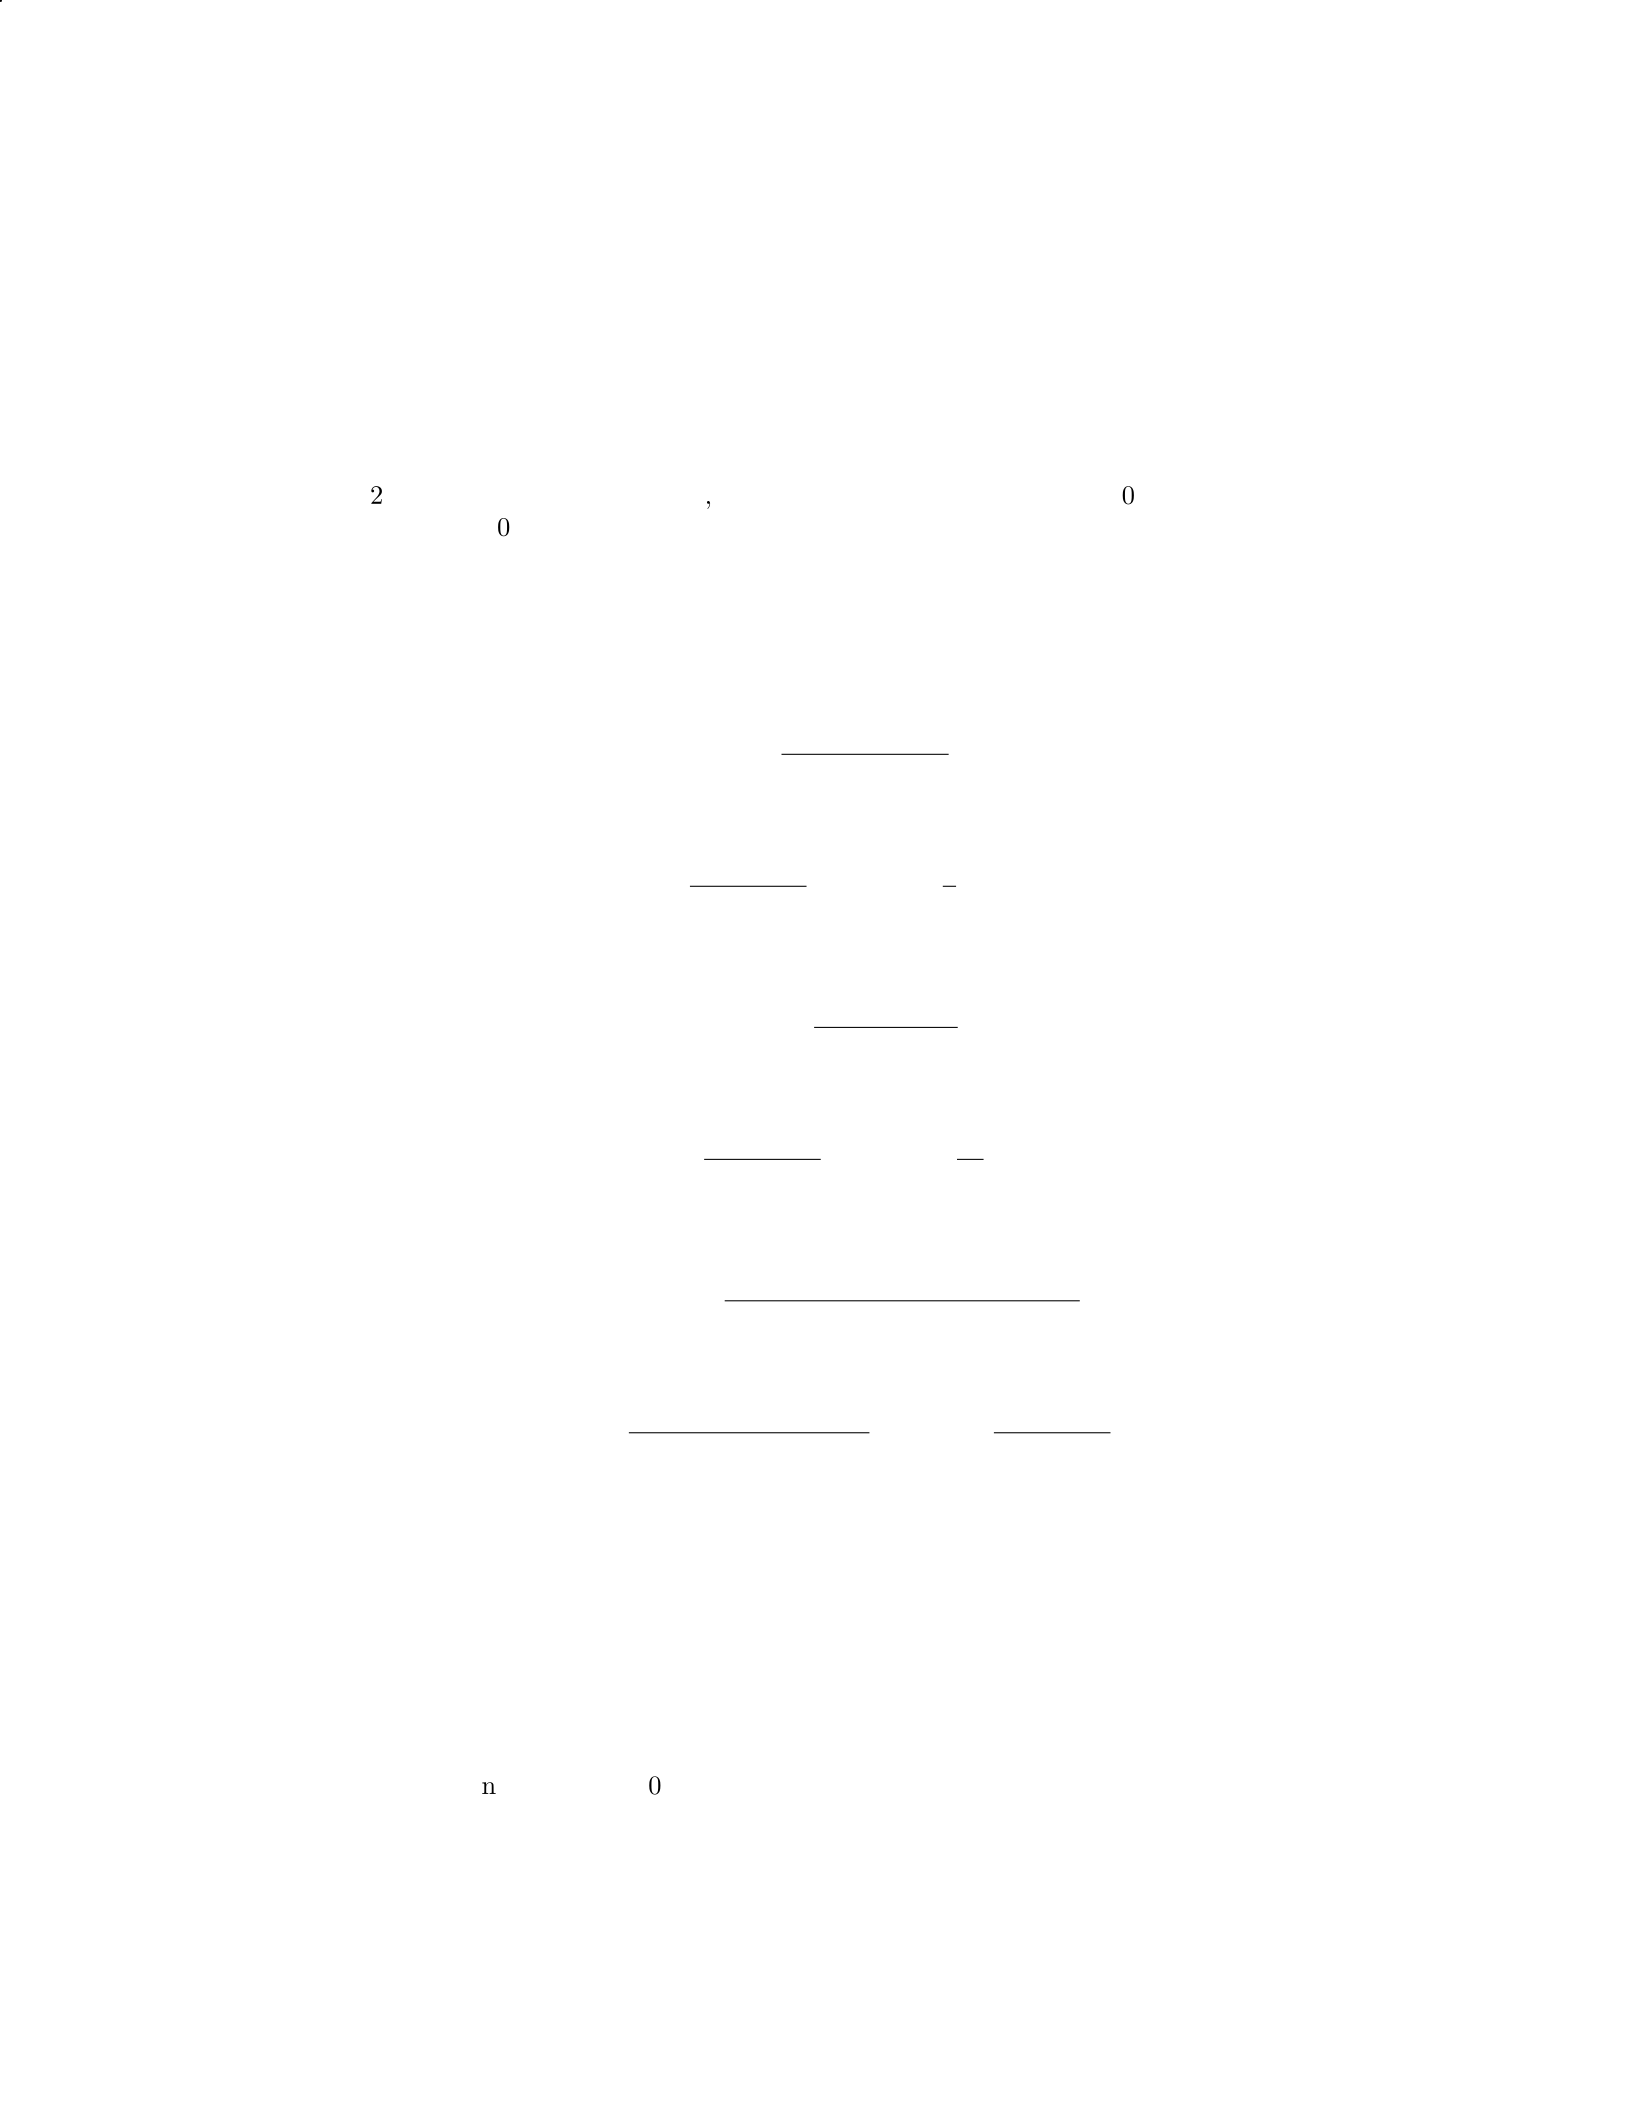
Question 31
Question
A company has the following financial information for the year: - Net Income:
$
200,000 - Total Revenue:
$
1,000,000 - Cost of Goods Sold:
$
600,000 - Total
Assets:
$
2,000,000 Calculate and interpret the company’s: a) Profit Margin b)
Return on Assets c) Gross Profit Margin
Solution
a) To calculate the Profit Margin, we use the formula:
Profit Margin = Net Income
Total Revenue ×100%
Step 1: Calculate the Profit Margin.
Profit Margin = 200,000
1,000,000 ×100% = 1
5×100% = 20%
b) To calculate the Return on Assets, we use the formula:
Return on Assets = Net Income
Total Assets ×100%
Step 2: Calculate the Return on Assets.
Return on Assets = 200,000
2,000,000 ×100% = 1
10 ×100% = 10%
c) To calculate the Gross Profit Margin, we use the formula:
Gross Profit Margin = Revenue −Cost of Goods Sold
Revenue ×100%
Step 3: Calculate the Gross Profit Margin.
Gross Profit Margin = 1,000,000 −600,000
1,000,000 ×100% = 400,000
1,000,000×100% = 40%
Interpretation: a) The company has a Profit Margin of 20b) The company
has a Return on Assets of 10c) The Gross Profit Margin of 40
Question 32
Question
A company reported the following financial information for the year:
Net income:
$
500,000
37
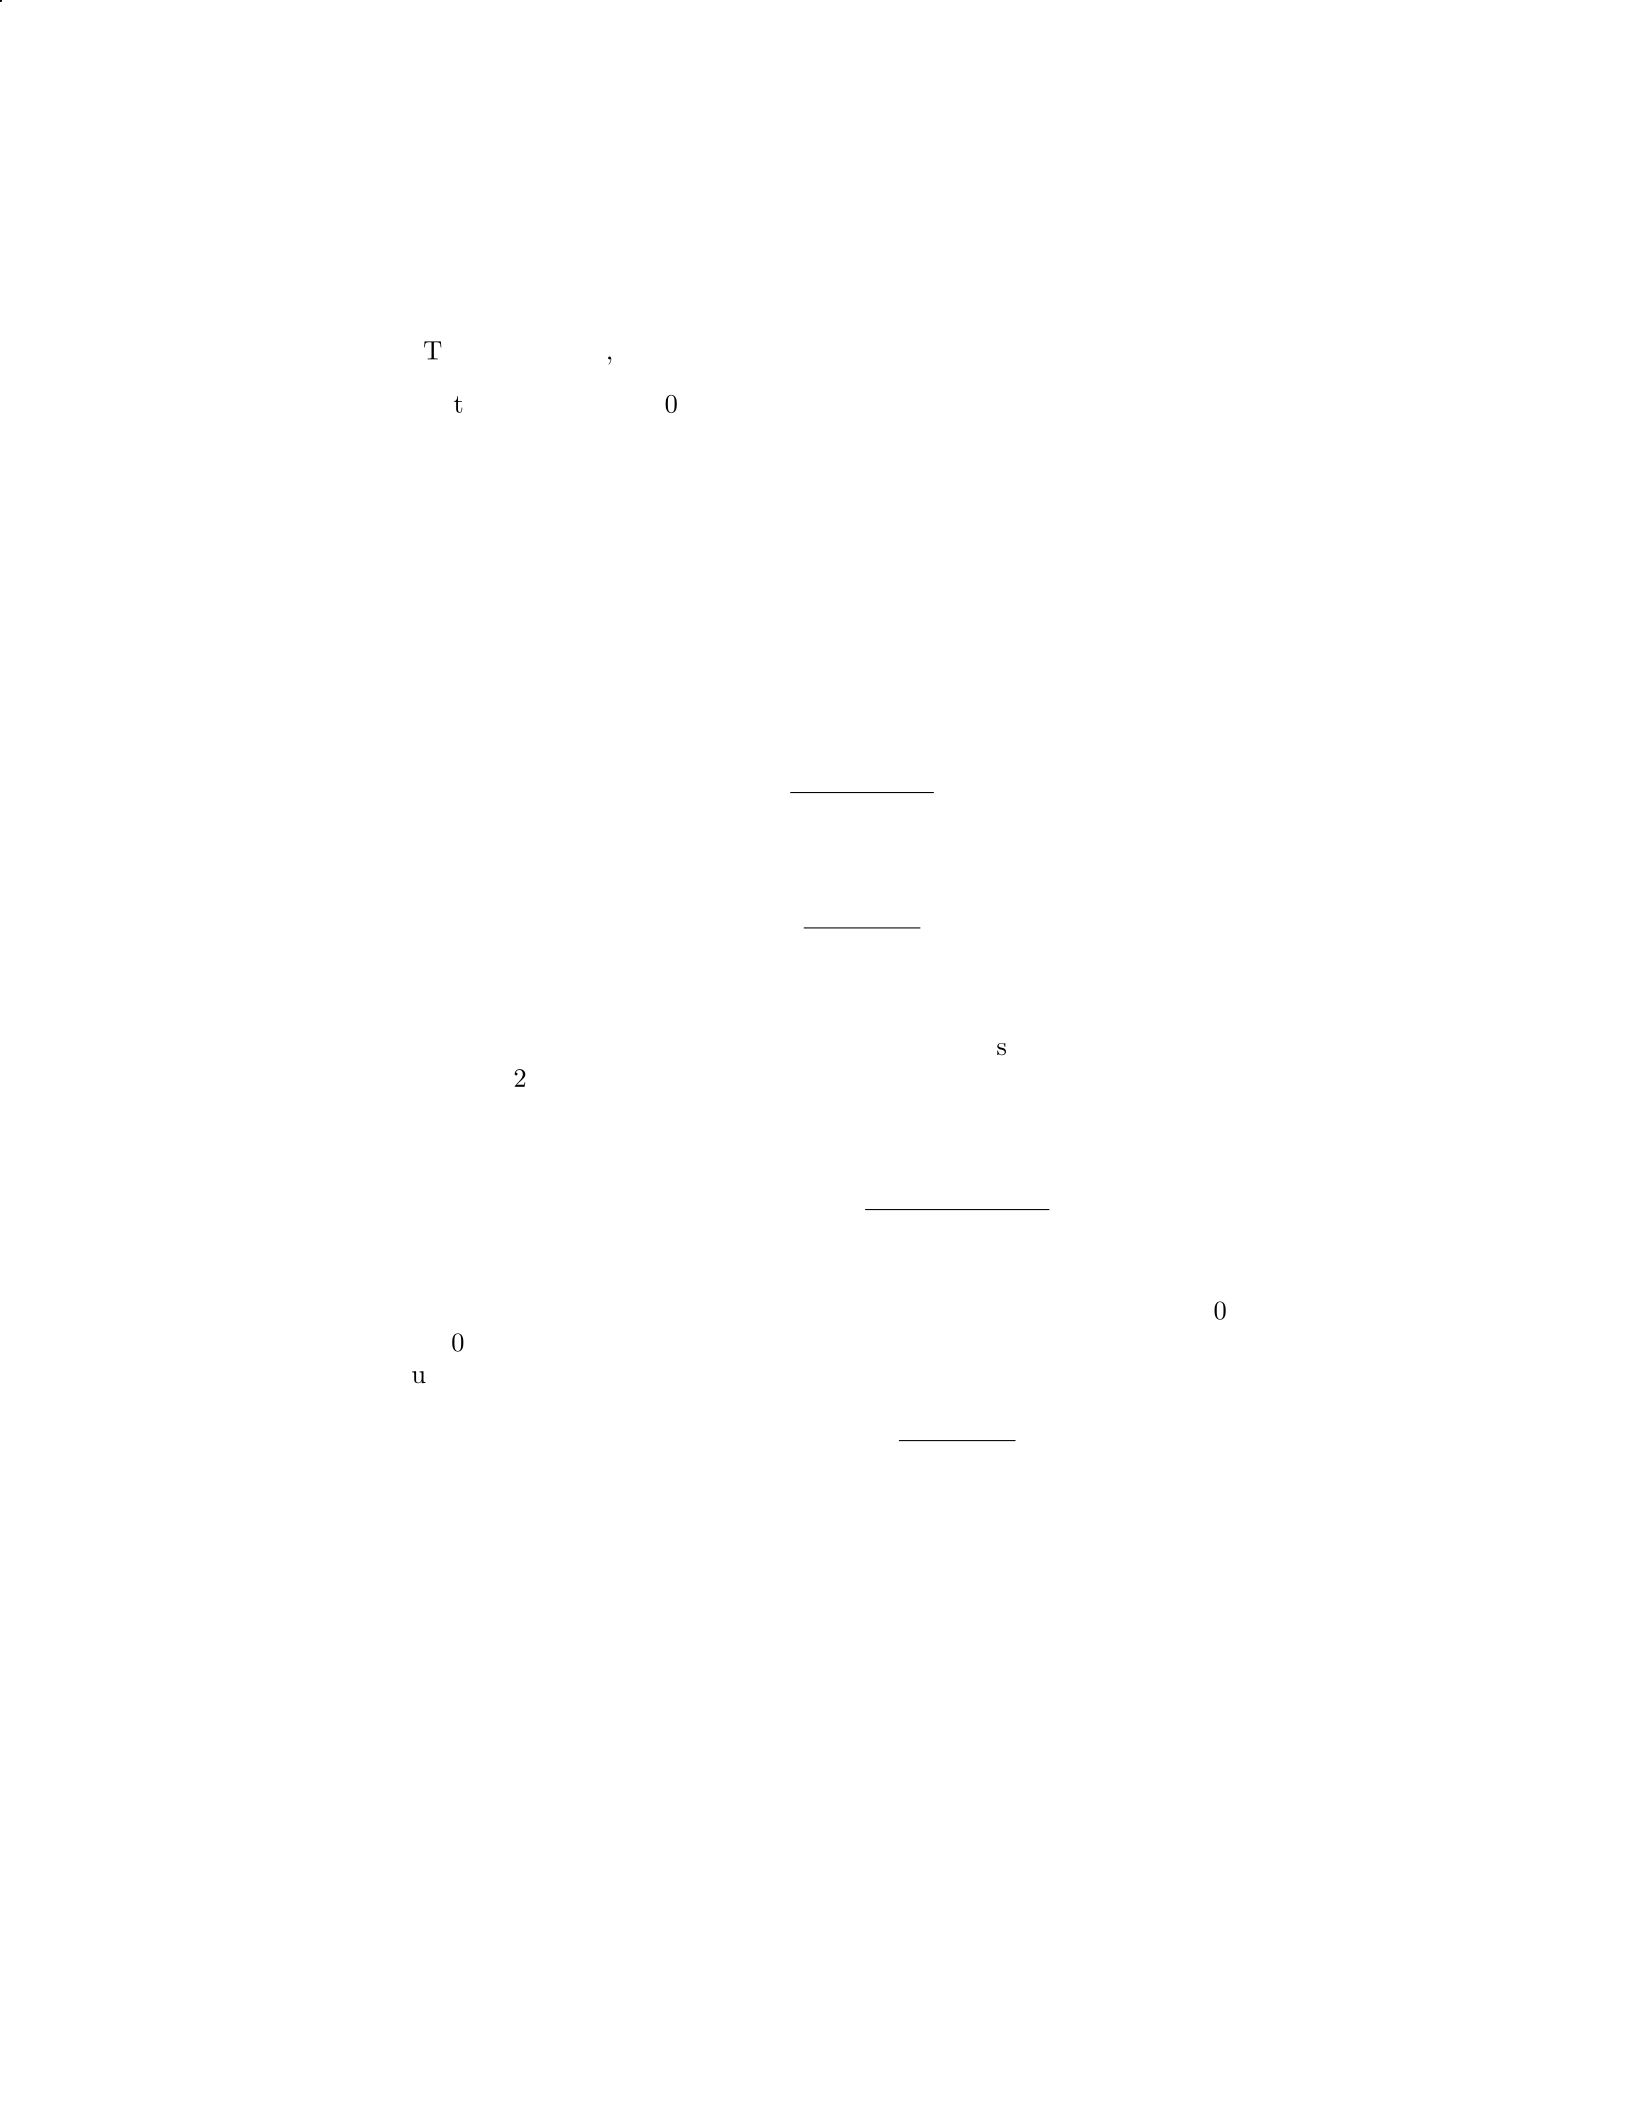
Total assets:
$
2,000,000
Total liabilities:
$
1,200,000
Calculate the following ratios and interpret the results:
1. Return on Assets (ROA)
2. Debt to Equity Ratio
Solution
Step 1: Calculate the Return on Assets (ROA) The Return on Assets
(ROA) ratio is calculated as:
ROA = Net Income
Total Assets
Substitute the given values into the formula:
ROA = 500,000
2,000,000
ROA = 0.25 = 25%
Interpretation: This means that for every
$
1 of assets, the company gen-
erates
$
0.25 (25 cents) in net income.
Step 2: Calculate the Debt to Equity Ratio The Debt to Equity Ratio
is calculated as:
Debt to Equity Ratio = Total Liabilities
Total Equity
Given that Total Equity is calculated as Total Assets minus Total Liabili-
ties, we have: Total Equity = Total Assets - Total Liabilities =
$
2,000,000 -
$
1,200,000 =
$
800,000
Substitute the values into the formula:
Debt to Equity Ratio = 1,200,000
800,000
Debt to Equity Ratio = 1.5
Interpretation: This ratio indicates that the company’s total liabilities
are 1.5 times its total equity, suggesting that the company relies more on debt
financing than equity financing.
38
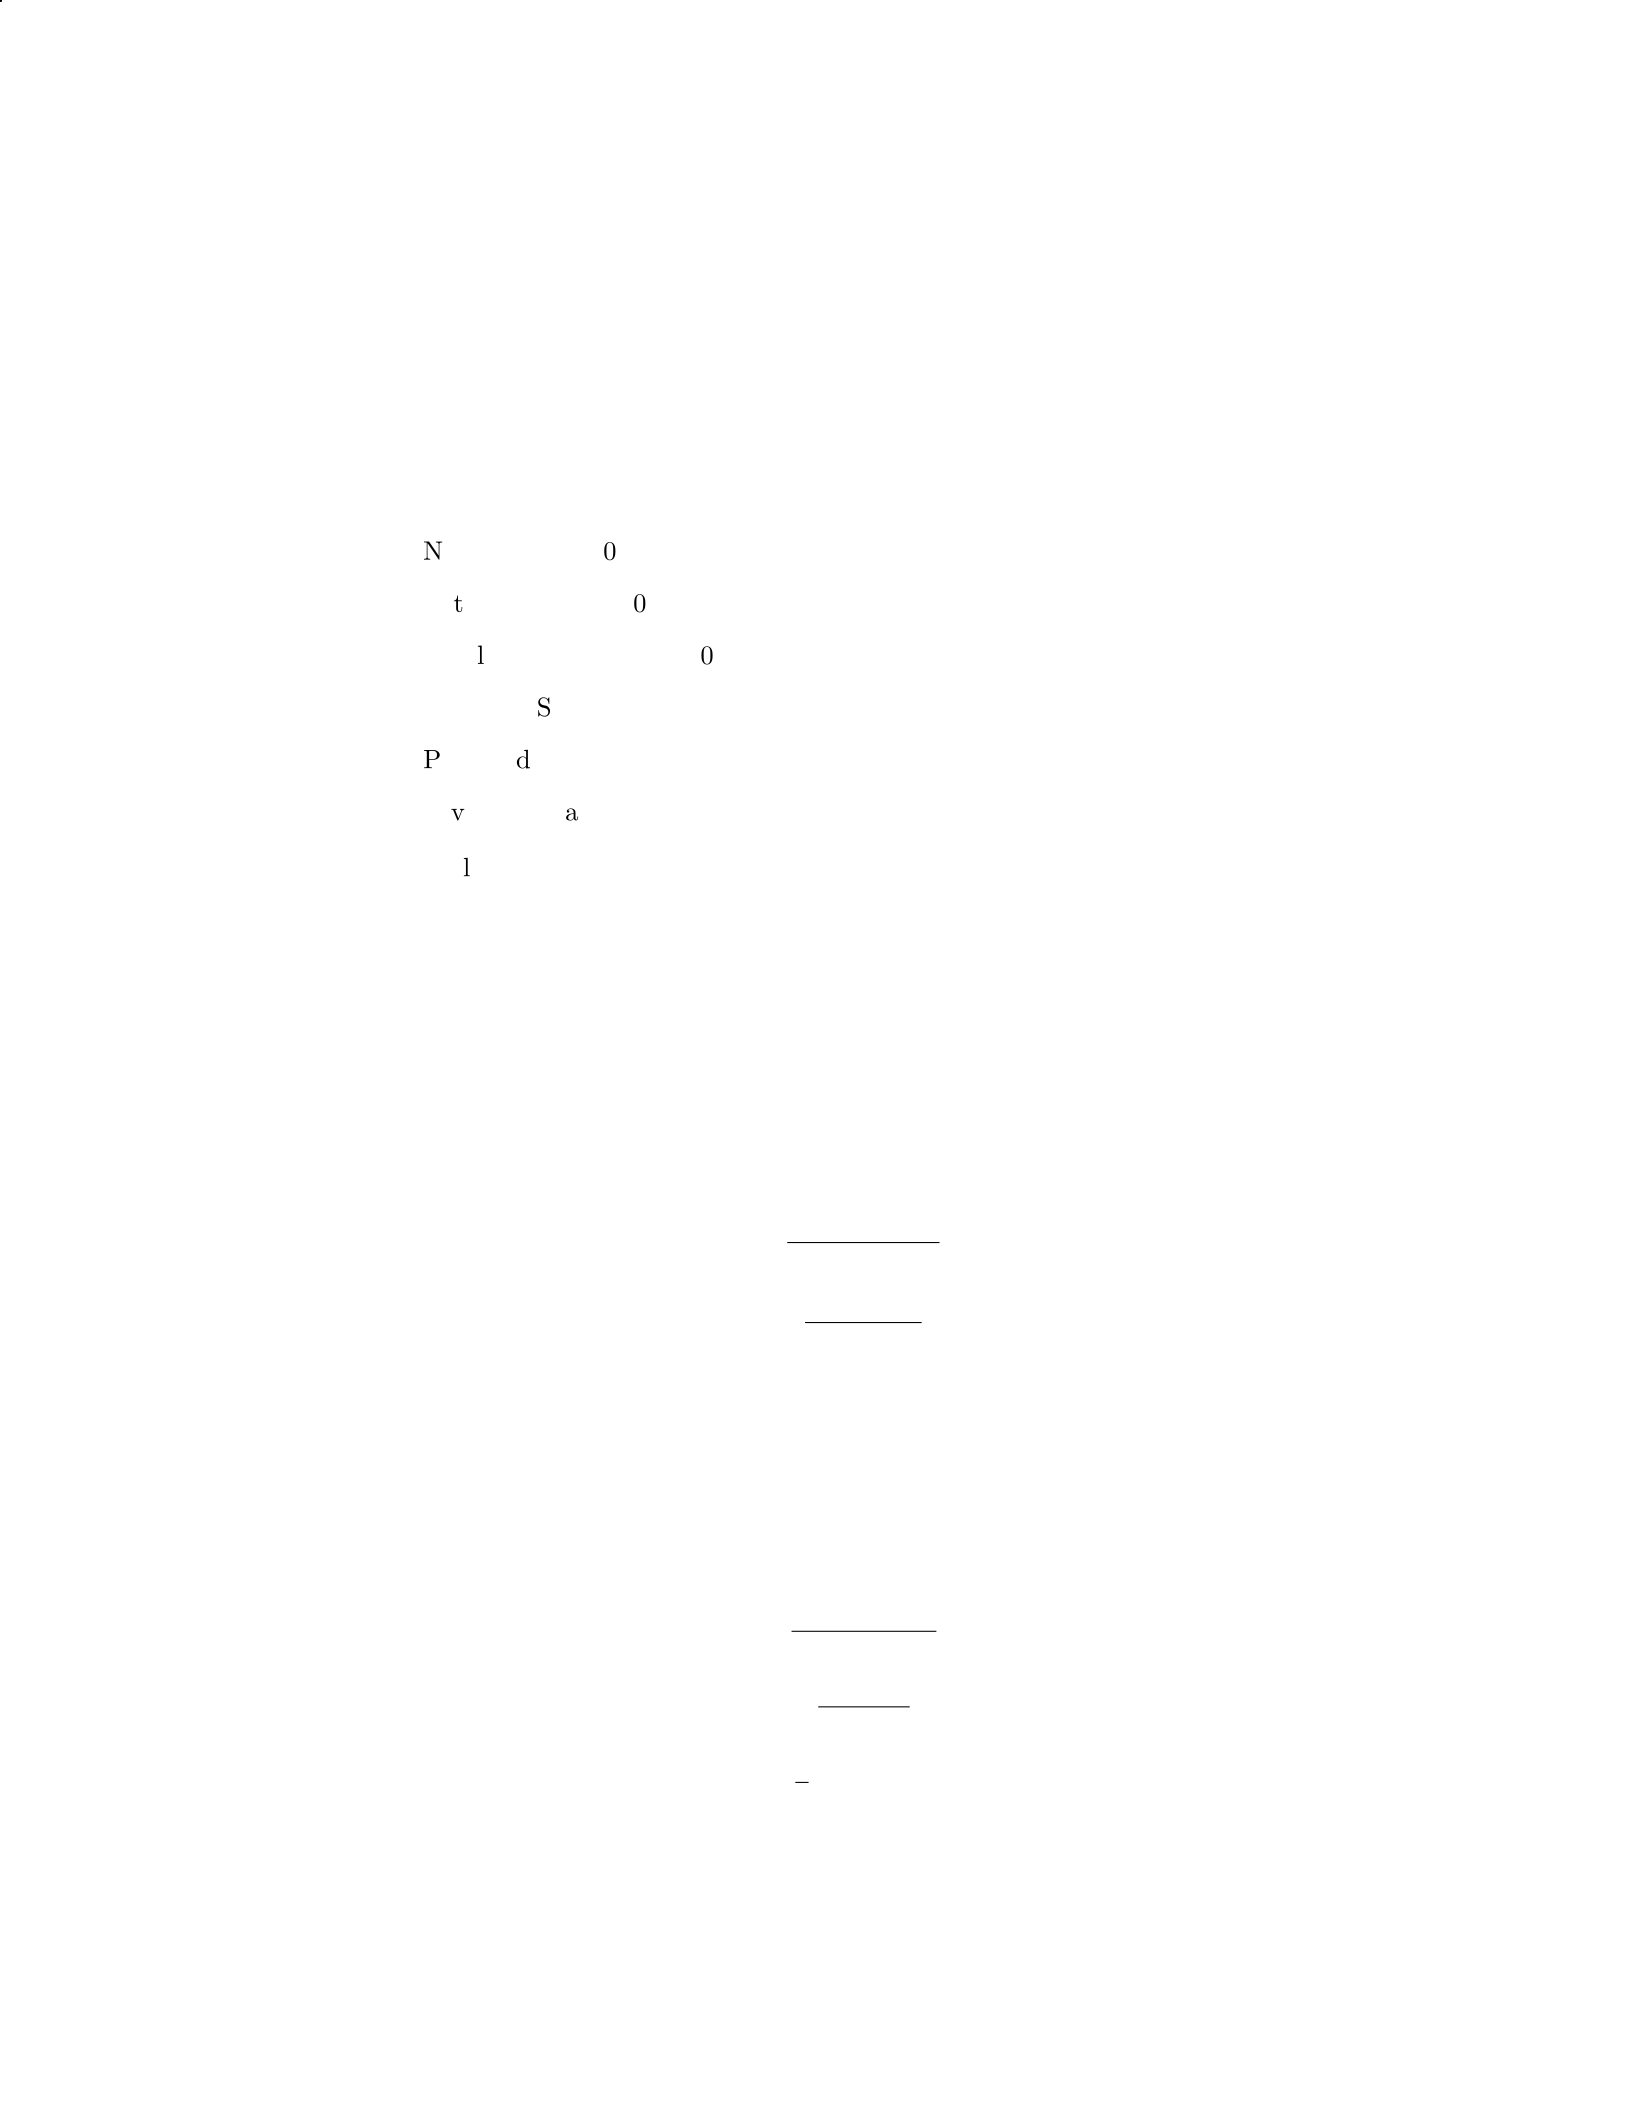
Question 33
Question
A company’s financial statements show the following information for the year
ending December 31, 2020:
Net Income:
$
500,000
Total Assets:
$
2,000,000
Total Liabilities:
$
800,000
Common Stock:
$
500,000
Preferred Stock:
$
100,000
Dividends Paid:
$
50,000
Calculate the following ratios for the company:
1. Return on Assets (ROA)
2. Return on Equity (ROE)
3. Earnings per Share (EPS)
Solution
Step 1: Calculate Return on Assets (ROA) ROA is calculated as the ratio
of Net Income to Total Assets.
ROA =N et Income
T otal Assets
ROA =500,000
2,000,000
ROA = 0.25 or 25%
Step 2: Calculate Return on Equity (ROE) ROE is calculated as the
ratio of Net Income to Equity (Common Stock + Preferred Stock).
Equity =Common Stock +P ref erred Stock
Equity = 500,000 + 100,000 = 600,000
ROE =N et Income
Equity
ROE =500,000
600,000
ROE =5
6or 83.33%
39
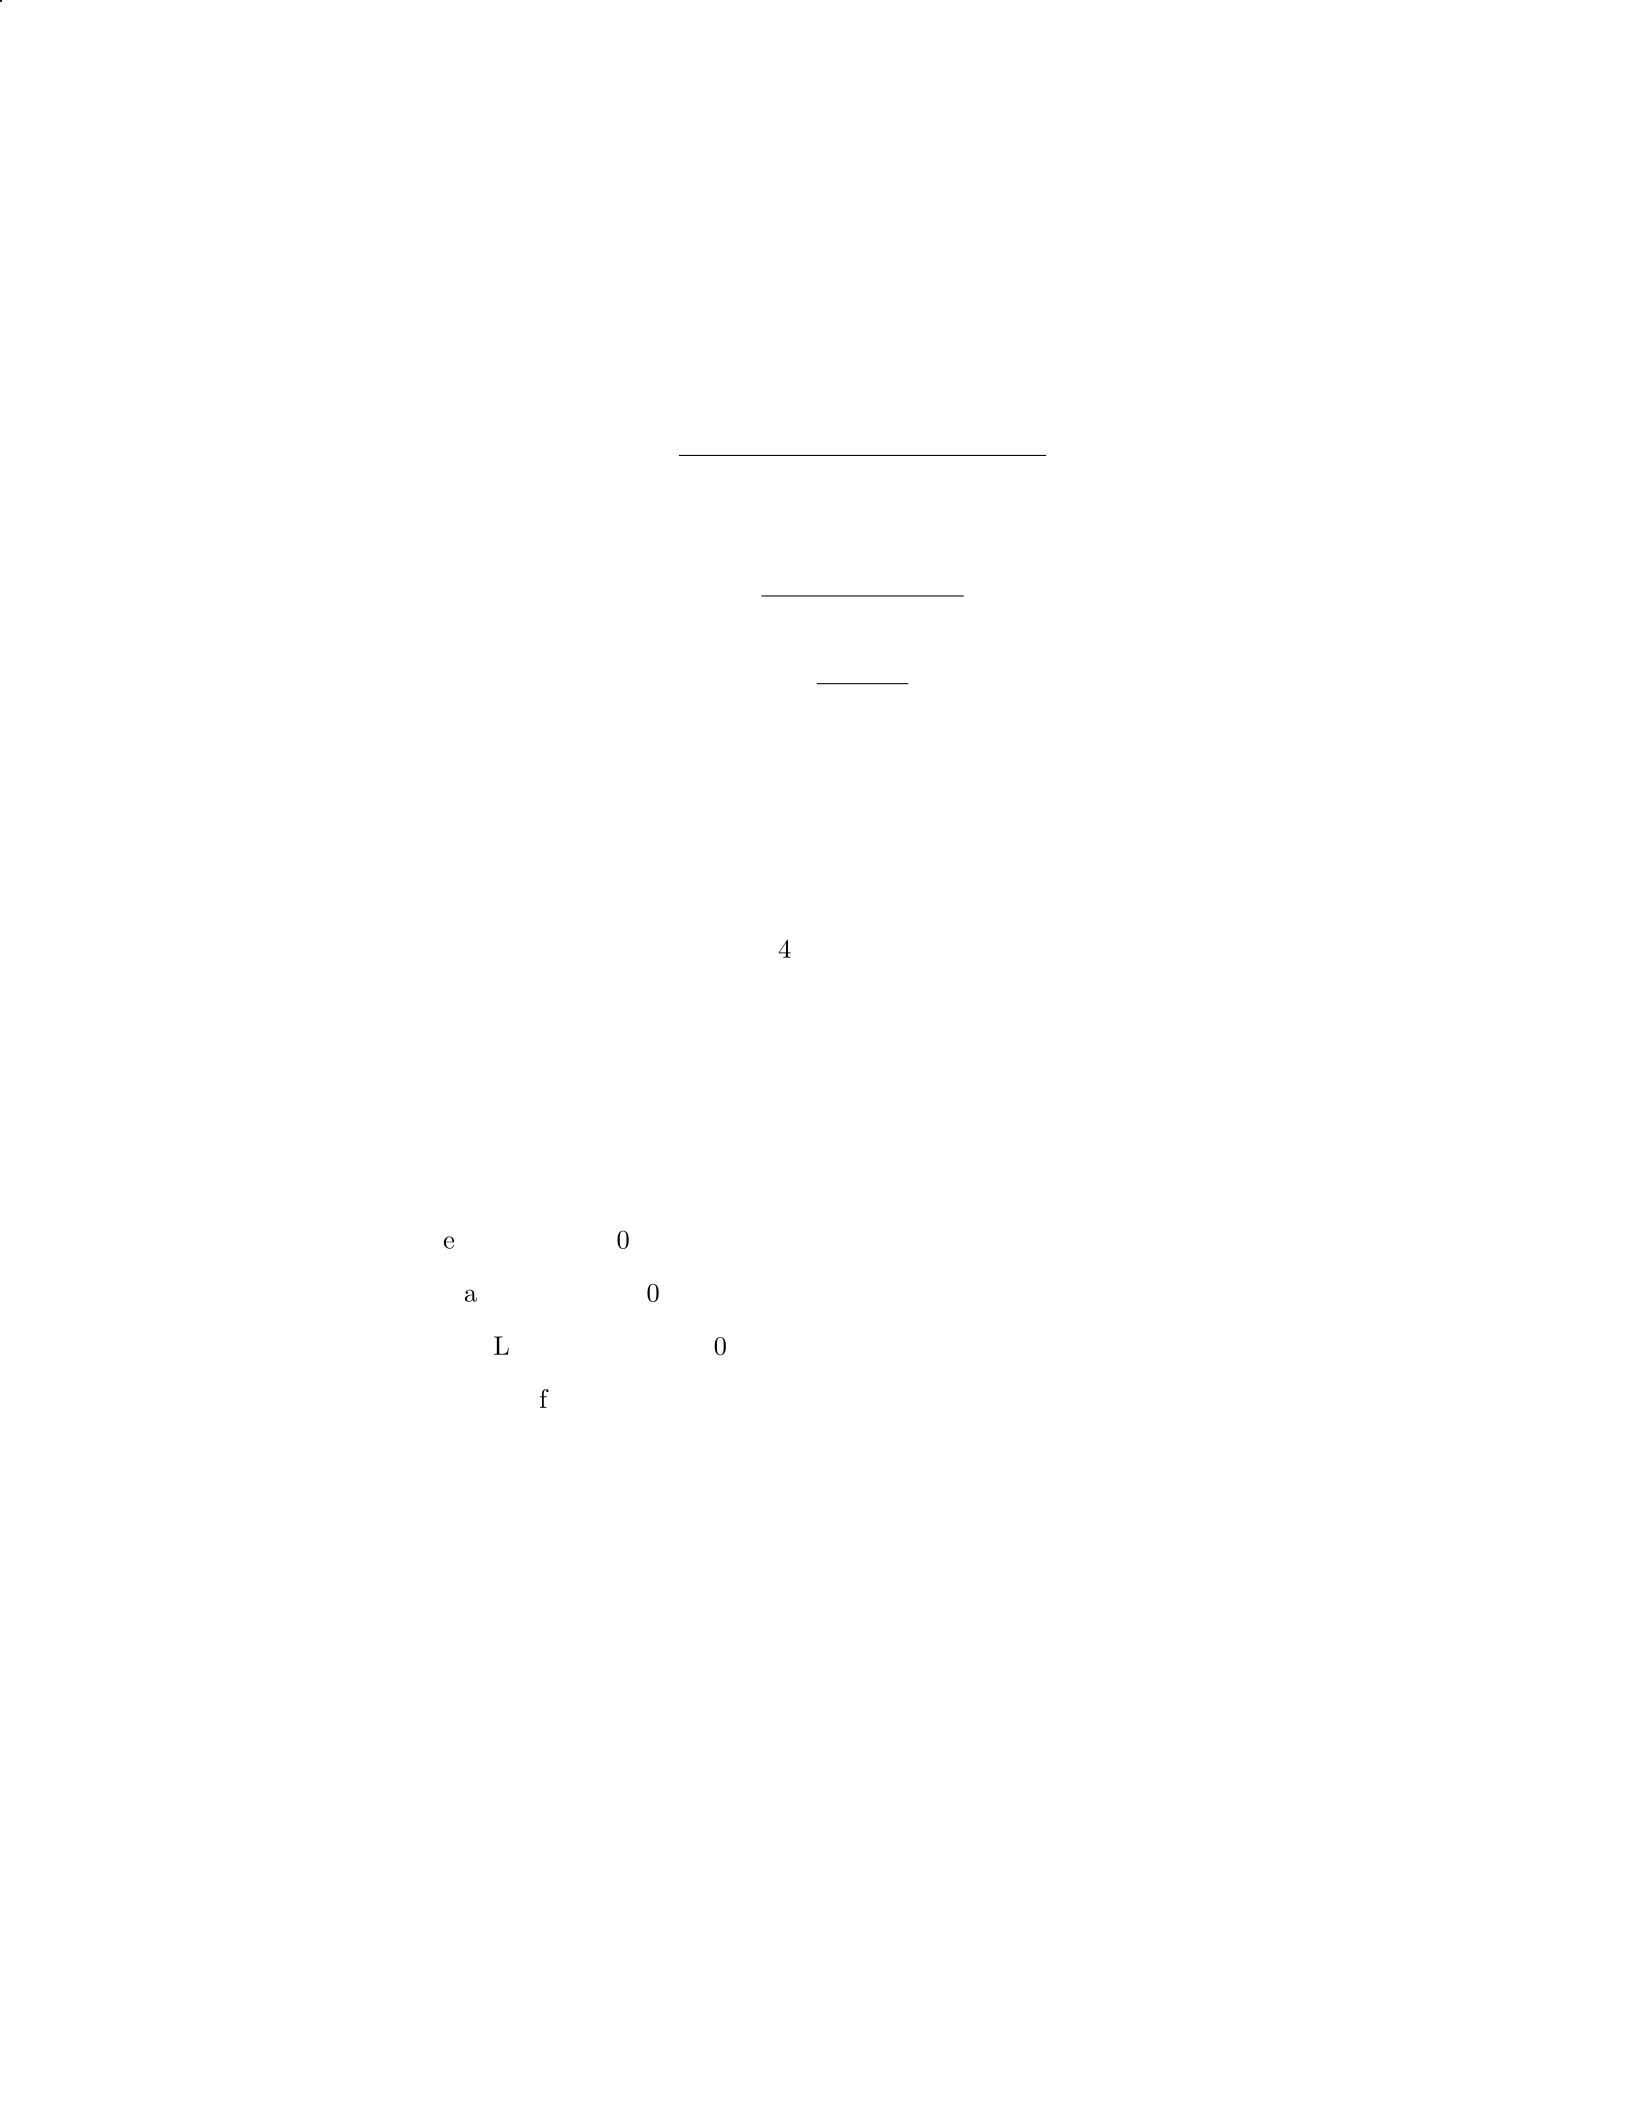
Step 3: Calculate Earnings per Share (EPS) EPS is calculated as the
ratio of Net Income minus Dividends Paid to the Average Number of Shares.
EP S =N et Income −Dividends P aid
Average Number of Shares
Assuming the Average Number of Shares is 100,000.
EP S =500,000 −50,000
100,000
EP S =450,000
100,000
EP S = 4.5
Therefore, the calculated ratios are:
1. Return on Assets (ROA) = 25%
2. Return on Equity (ROE) = 83.33%
3. Earnings per Share (EPS) =
$
4.5
Question 34
Question
Company XYZ has the following financial information for the year ending De-
cember 31, 2021:
Net Income:
$
500,000
Total Assets:
$
2,000,000
Total Liabilities:
$
800,000
Number of Shares Outstanding: 100,000
Calculate the following ratios and interpret the results:
1. Return on Assets (ROA)
2. Return on Equity (ROE)
3. Earnings per Share (EPS)
40
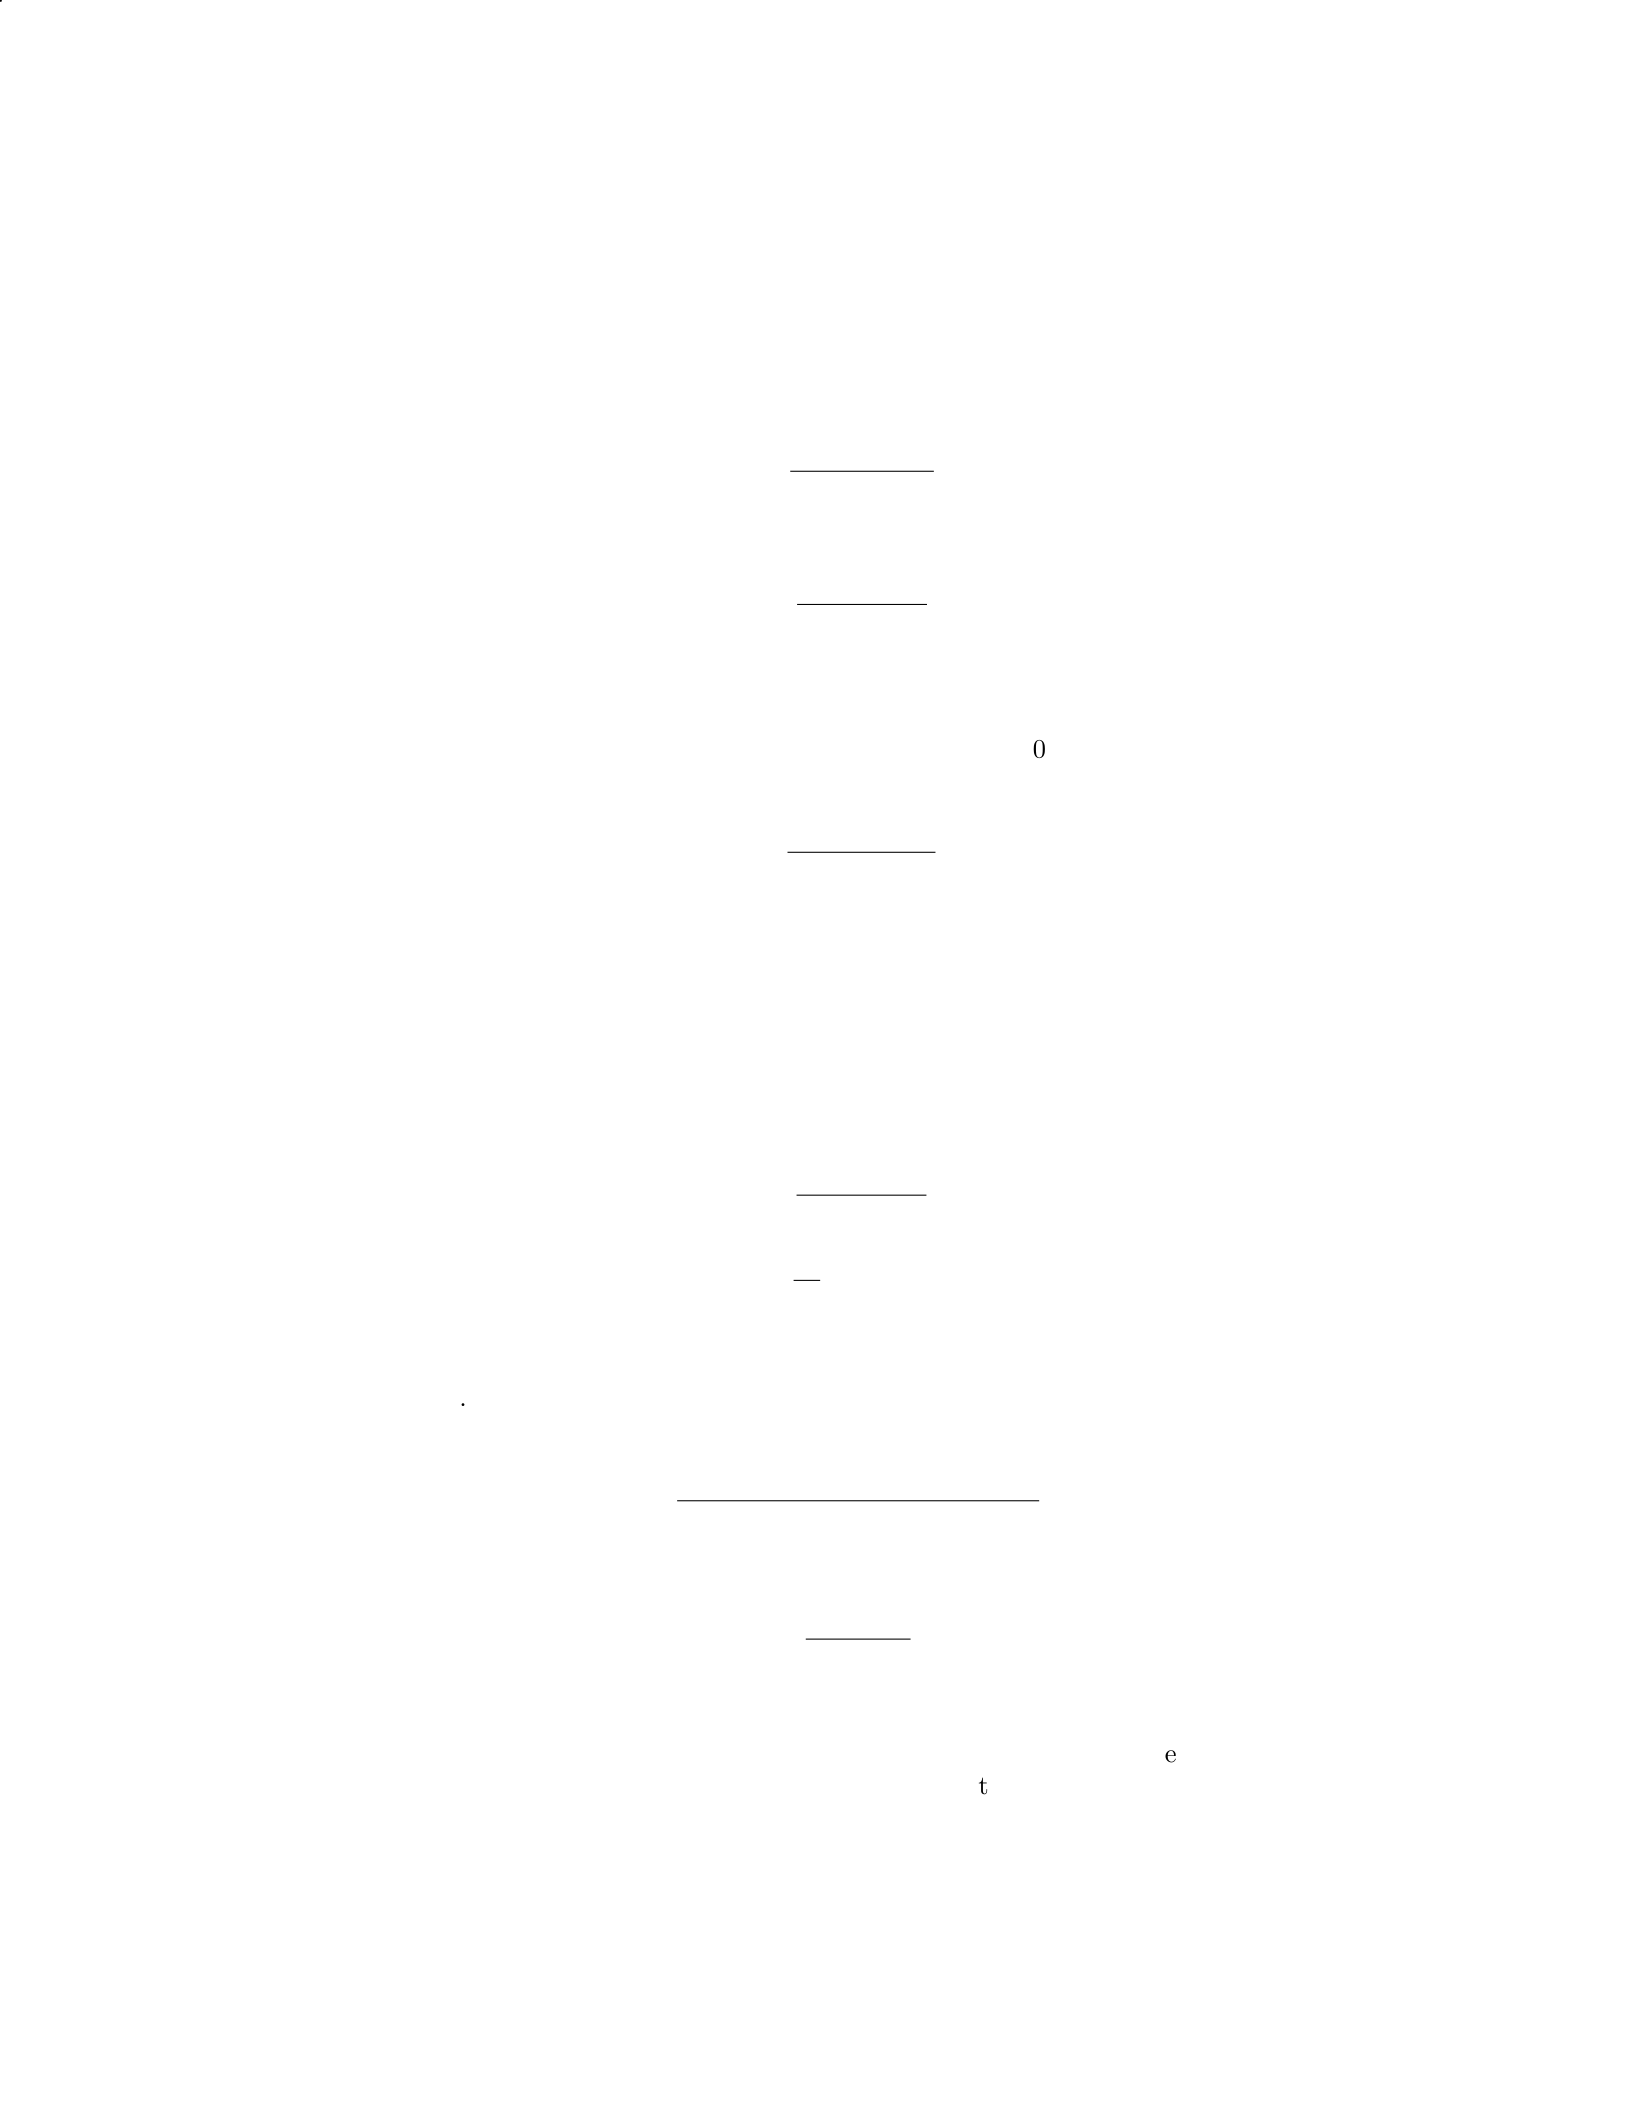
Solution
Step 1: Calculate Return on Assets (ROA)
ROA = Net Income
Total Assets
Substitute the given values into the formula:
ROA = $500,000
$2,000,000
ROA = 0.25
Step 2: Interpret ROA The Return on Assets (ROA) ratio of 0.25 means
that for every dollar of assets, Company XYZ generated
$
0.25 in net income.
Step 3: Calculate Return on Equity (ROE)
ROE = Net Income
Total Equity
Calculate Total Equity:
Total Equity = Total Assets −Total Liabilities
Total Equity = $2,000,000 −$800,000
Total Equity = $1,200,000
Substitute the given values into the formula:
ROE = $500,000
$1,200,000
ROE = 5
12 ≈0.4167
Step 4: Interpret ROE The Return on Equity (ROE) ratio of approxi-
mately 0.4167 means that for every dollar of equity, Company XYZ generated
about
$
0.42 in net income.
Step 5: Calculate Earnings per Share (EPS)
EPS = Net Income
Number of Shares Outstanding
Substitute the given values into the formula:
EPS = $500,000
100,000
EPS = $5
Step 6: Interpret EPS The Earnings per Share (EPS) of
$
5 means that
each share of Company XYZ’s stock represents
$
5 of the company’s earnings.
41
Question 35
Question
A company reported the following financial information for the current year:
Net Income:
$
250,000
Total Assets:
$
1,500,000
Total Liabilities:
$
600,000
Shareholders’ Equity:
$
900,000
Calculate the following ratios and interpret the results:
1. Return on Assets (ROA)
2. Return on Equity (ROE)
Solution
Step 1: Calculate Return on Assets (ROA)
ROA measures how efficiently the company is using its assets to generate
income. It is calculated as:
ROA = Net Income
Total Assets
Given Net Income =
$
250,000 and Total Assets =
$
1,500,000:
ROA = 250,000
1,500,000 = 0.1667 = 16.67%
Step 2: Interpretation of ROA
The company’s ROA of 16.67% indicates that for every dollar of assets, the
company generates
$
0.1667 of net income.
Step 3: Calculate Return on Equity (ROE)
ROE measures how efficiently the company is using shareholders’ equity to
generate income. It is calculated as:
ROE = Net Income
Shareholders’ Equity
Given Net Income =
$
250,000 and Shareholders’ Equity =
$
900,000:
ROE = 250,000
900,000 ≈0.2778 = 27.78%
Step 4: Interpretation of ROE
The company’s ROE of 27.78% indicates that for every dollar of shareholders’
equity, the company generates
$
0.2778 of net income. This suggests that the
company is effectively using shareholders’ equity to generate profits.
42

