


ACCT 302 - INTERMEDIATE
ACCOUNTING II - Ratio analysis and
interpretation
Question Bank - Set 1
Liberty University
Question 1
Question
A company’s financial statements show the following information for the year:
Net Income:
$
200,000
Total Assets:
$
1,000,000
Total Liabilities:
$
400,000
Stockholders’ Equity:
$
600,000
Calculate the following ratios for the company and interpret the results:
1. Return on Assets (ROA)
2. Return on Equity (ROE)
Solution
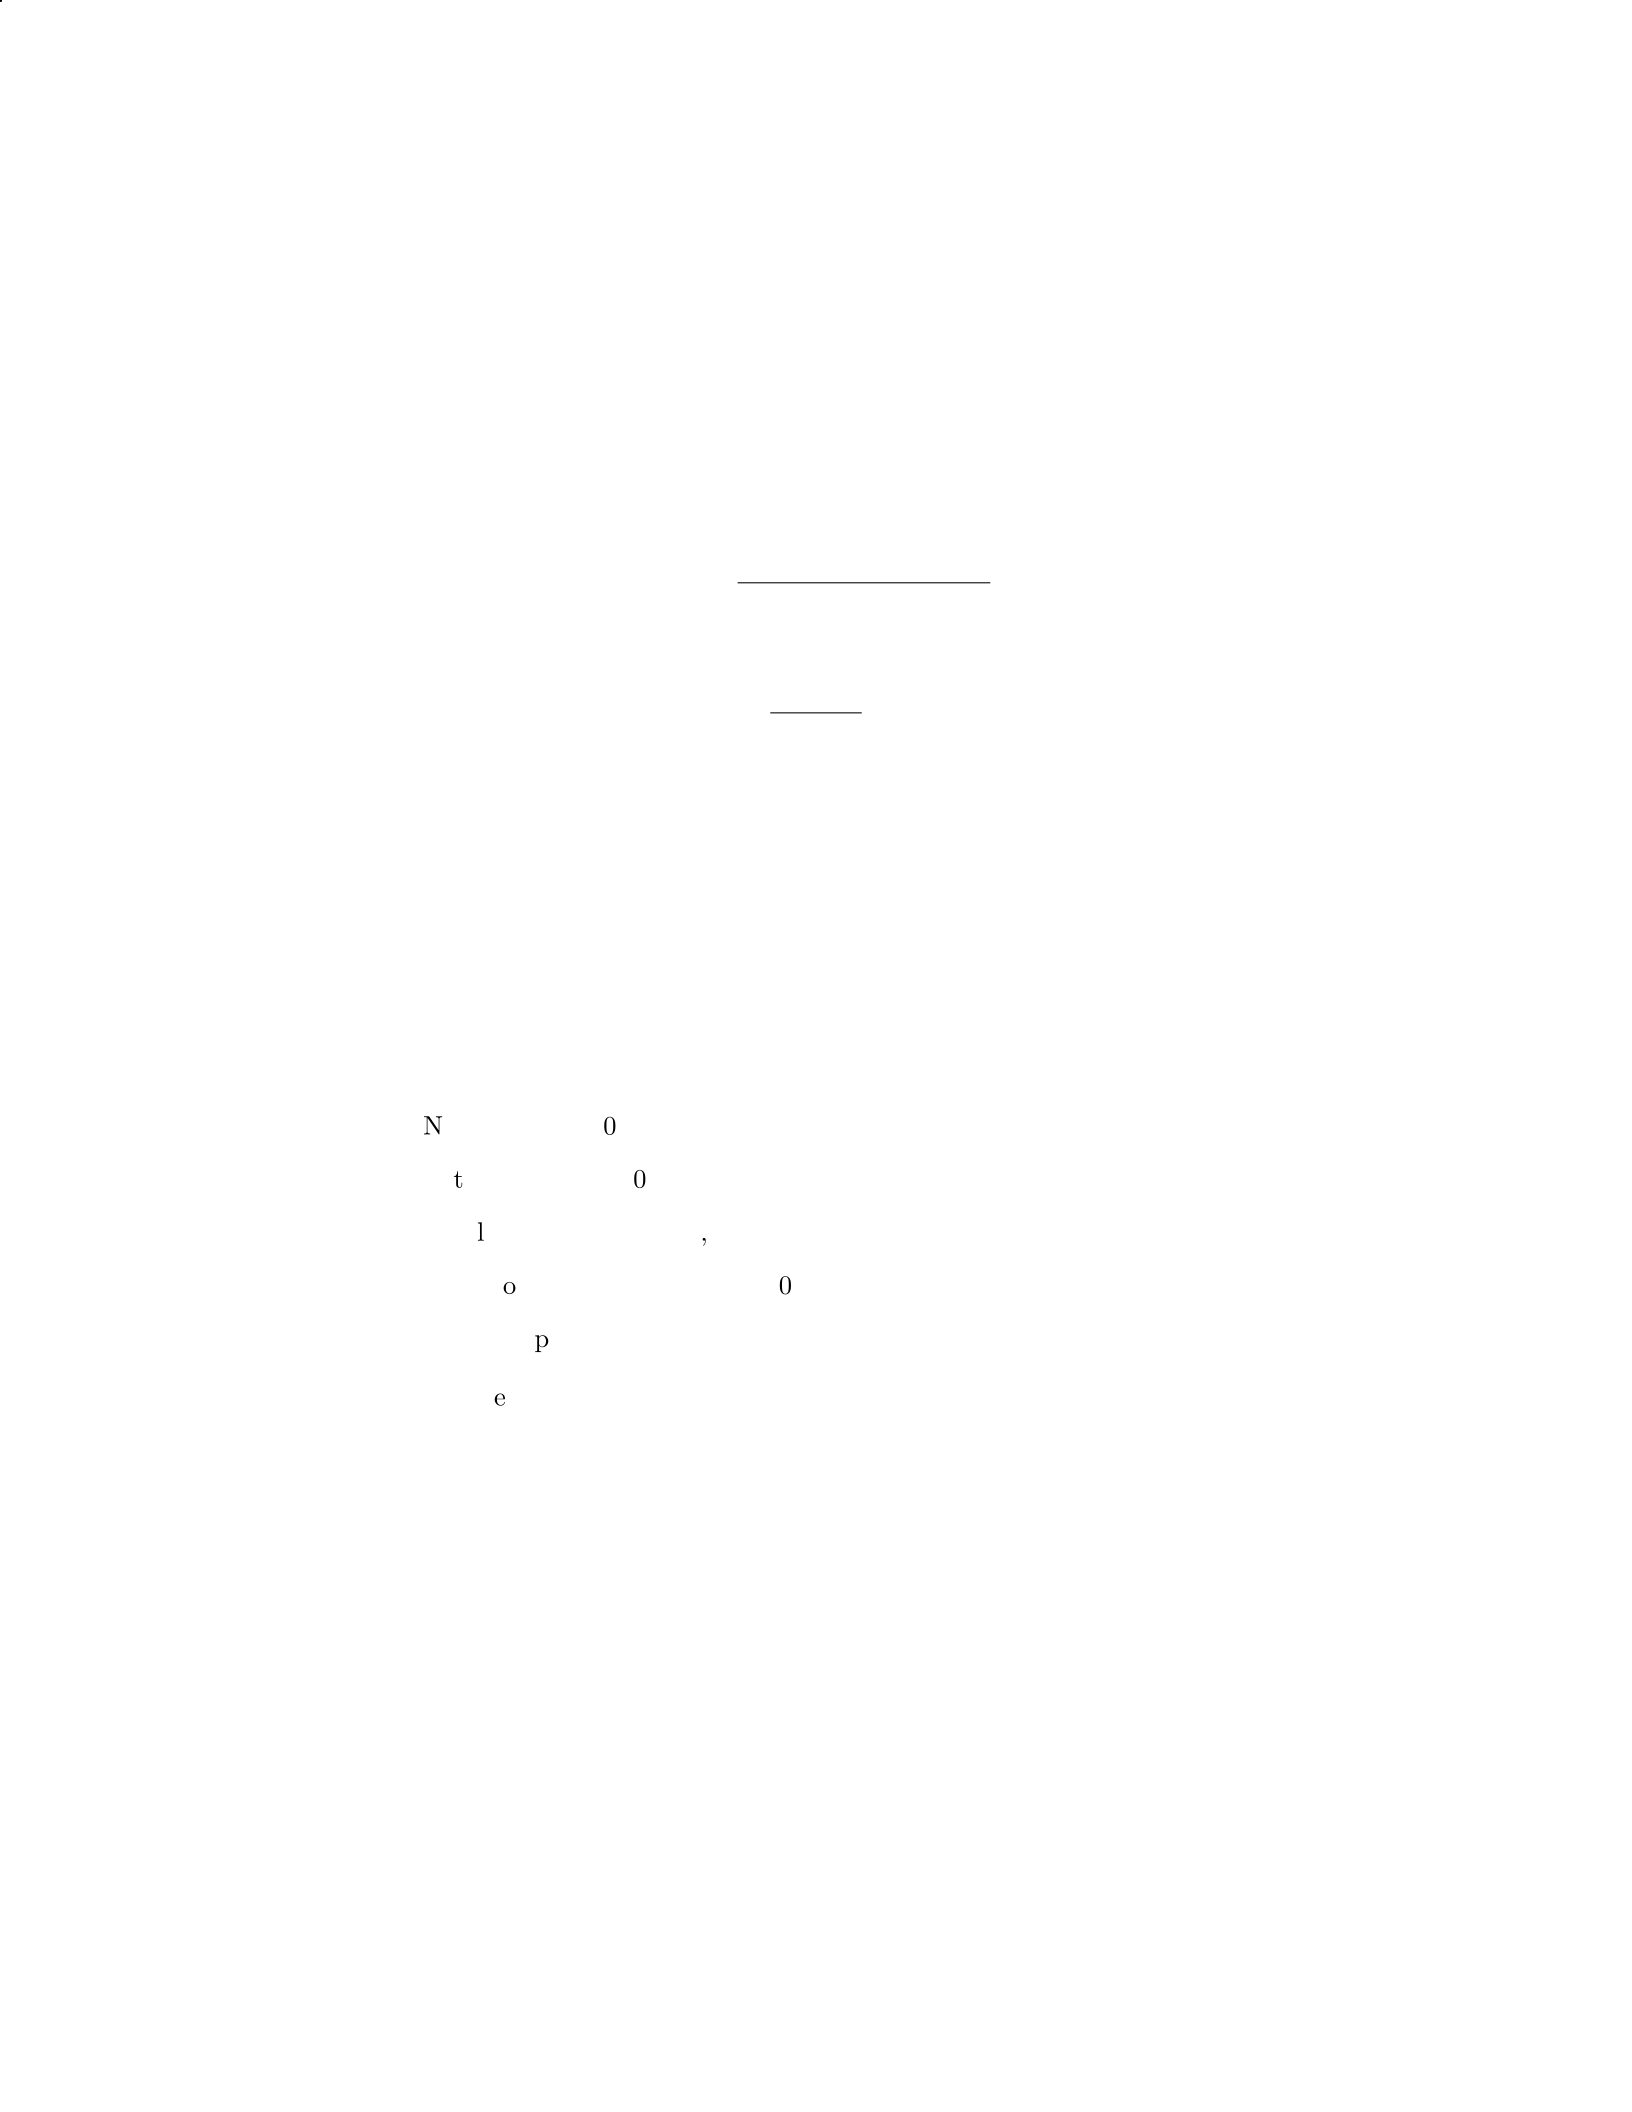
Step 1: Calculate Return on Assets (ROA)
ROA is calculated by dividing the net income by the total assets:
ROA =Net Income
T otal Assets
Substitute the given values:
ROA =200,000
1,000,000 = 0.2
Step 2: Interpretation of ROA
ROA of 0.2 means that for every dollar of assets the company has, it gen-
erates 20 cents in net income. This indicates that the company is generating a
solid return on its assets.
Step 3: Calculate Return on Equity (ROE)
ROE is calculated by dividing the net income by the stockholders’ equity:
ROE =Net Income
Stockholders′Equity
Substitute the given values:
ROE =200,000
600,000 ≈0.333
Step 4: Interpretation of ROE
ROE of approximately 0.333 means that for every dollar of stockholders’
equity, the company generates 33.3 cents in net income. This indicates that the
company is effectively generating profit for its shareholders.
Question 2
Question
A company has reported the following financial information for the year 2020:
Net Income:
$
500,000
Total Assets:
$
5,000,000
Total Liabilities:
$
3,000,000
Shareholders’ Equity:
$
2,000,000
Earnings per Share:
$
5
Calculate the following ratios for the company for the year 2020, and inter-
pret the results:
1. Return on Assets (ROA)
2. Return on Equity (ROE)
3. Debt-to-Equity Ratio
2
Solution
We will calculate each ratio step by step:
Step 1: Calculate Return on Assets (ROA)
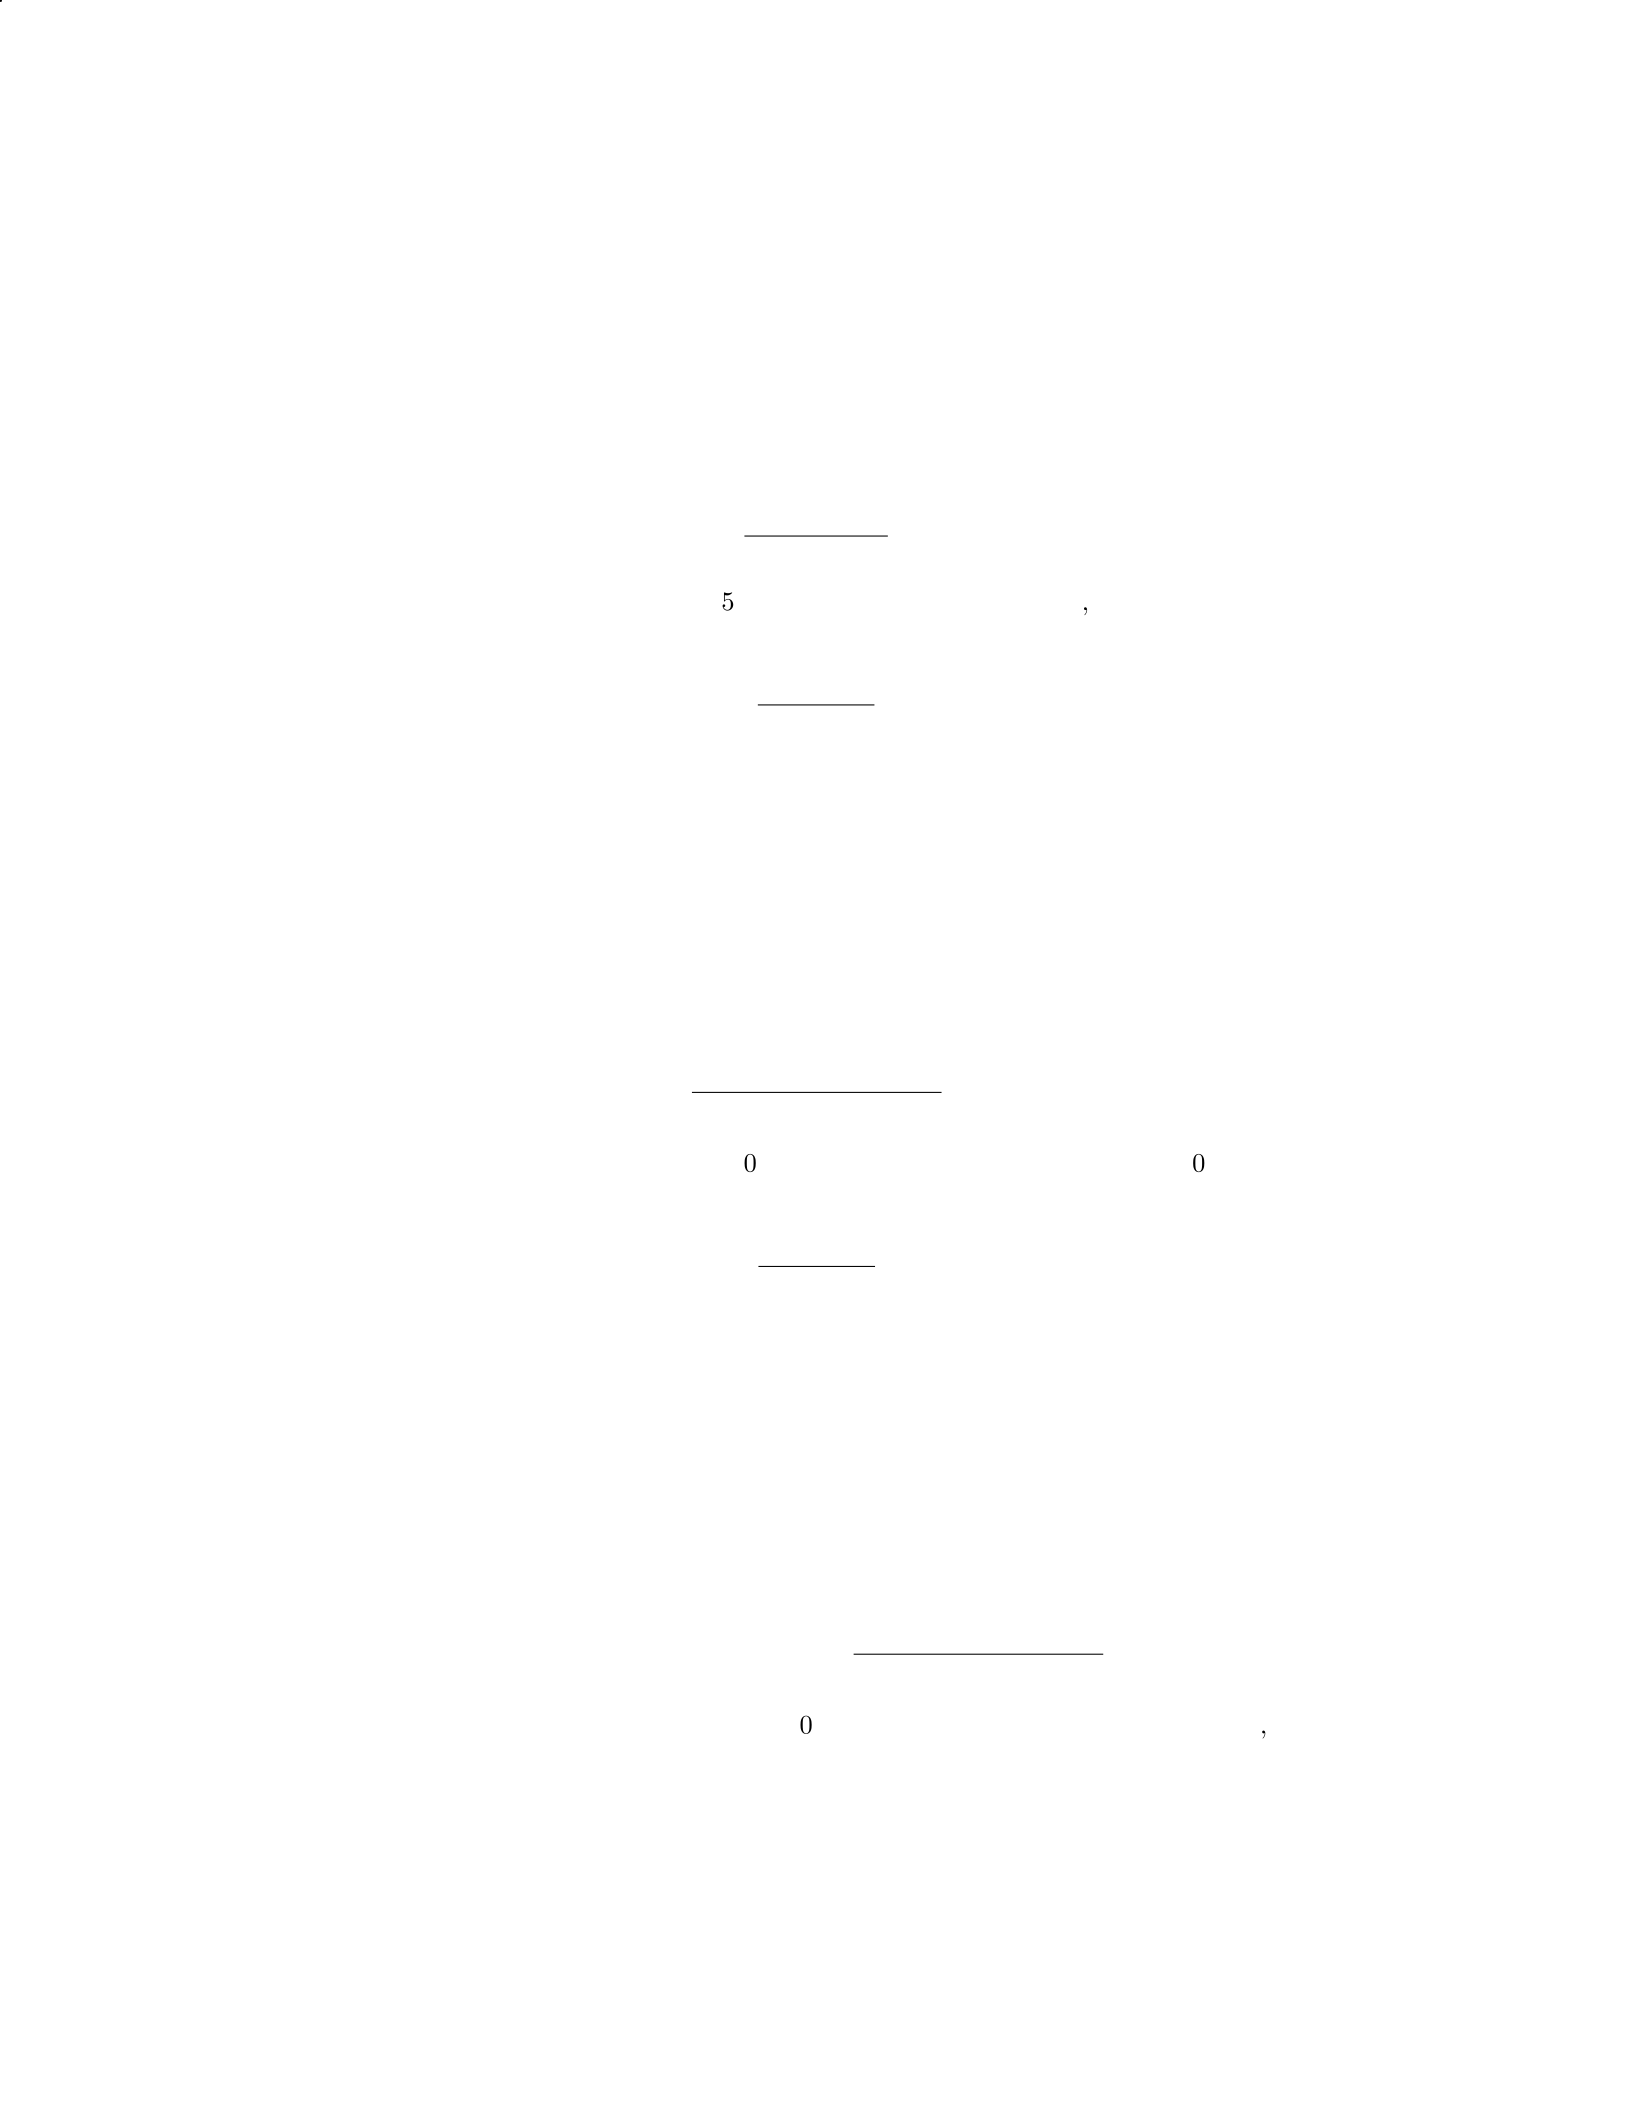
ROA is calculated using the formula:
ROA =NetIncome
T otalAssets ×100%
Given that Net Income =
$
500,000 and Total Assets =
$
5,000,000, we can
plug these values into the formula to find ROA.
ROA =500,000
5,000,000 ×100%
ROA = 0.10 ×100%
ROA = 10%
Step 2: Interpretation of ROA
ROA of 10% means that for every dollar of assets, the company generated a
profit of 10 cents. This indicates that the company is efficiently using its assets
to generate profits.
Step 3: Calculate Return on Equity (ROE)
ROE is calculated using the formula:
ROE =NetIncome
Shareholders′Equity ×100%
Given that Net Income =
$
500,000 and Shareholders’ Equity =
$
2,000,000,
we can plug these values into the formula to find ROE.
ROE =500,000
2,000,000 ×100%
ROE = 0.25 ×100%
ROE = 25%
Step 4: Interpretation of ROE
ROE of 25% means that for every dollar of equity, the company generated
a profit of 25 cents. This indicates that the company is generating a healthy
return for its shareholders.
Step 5: Calculate Debt-to-Equity Ratio
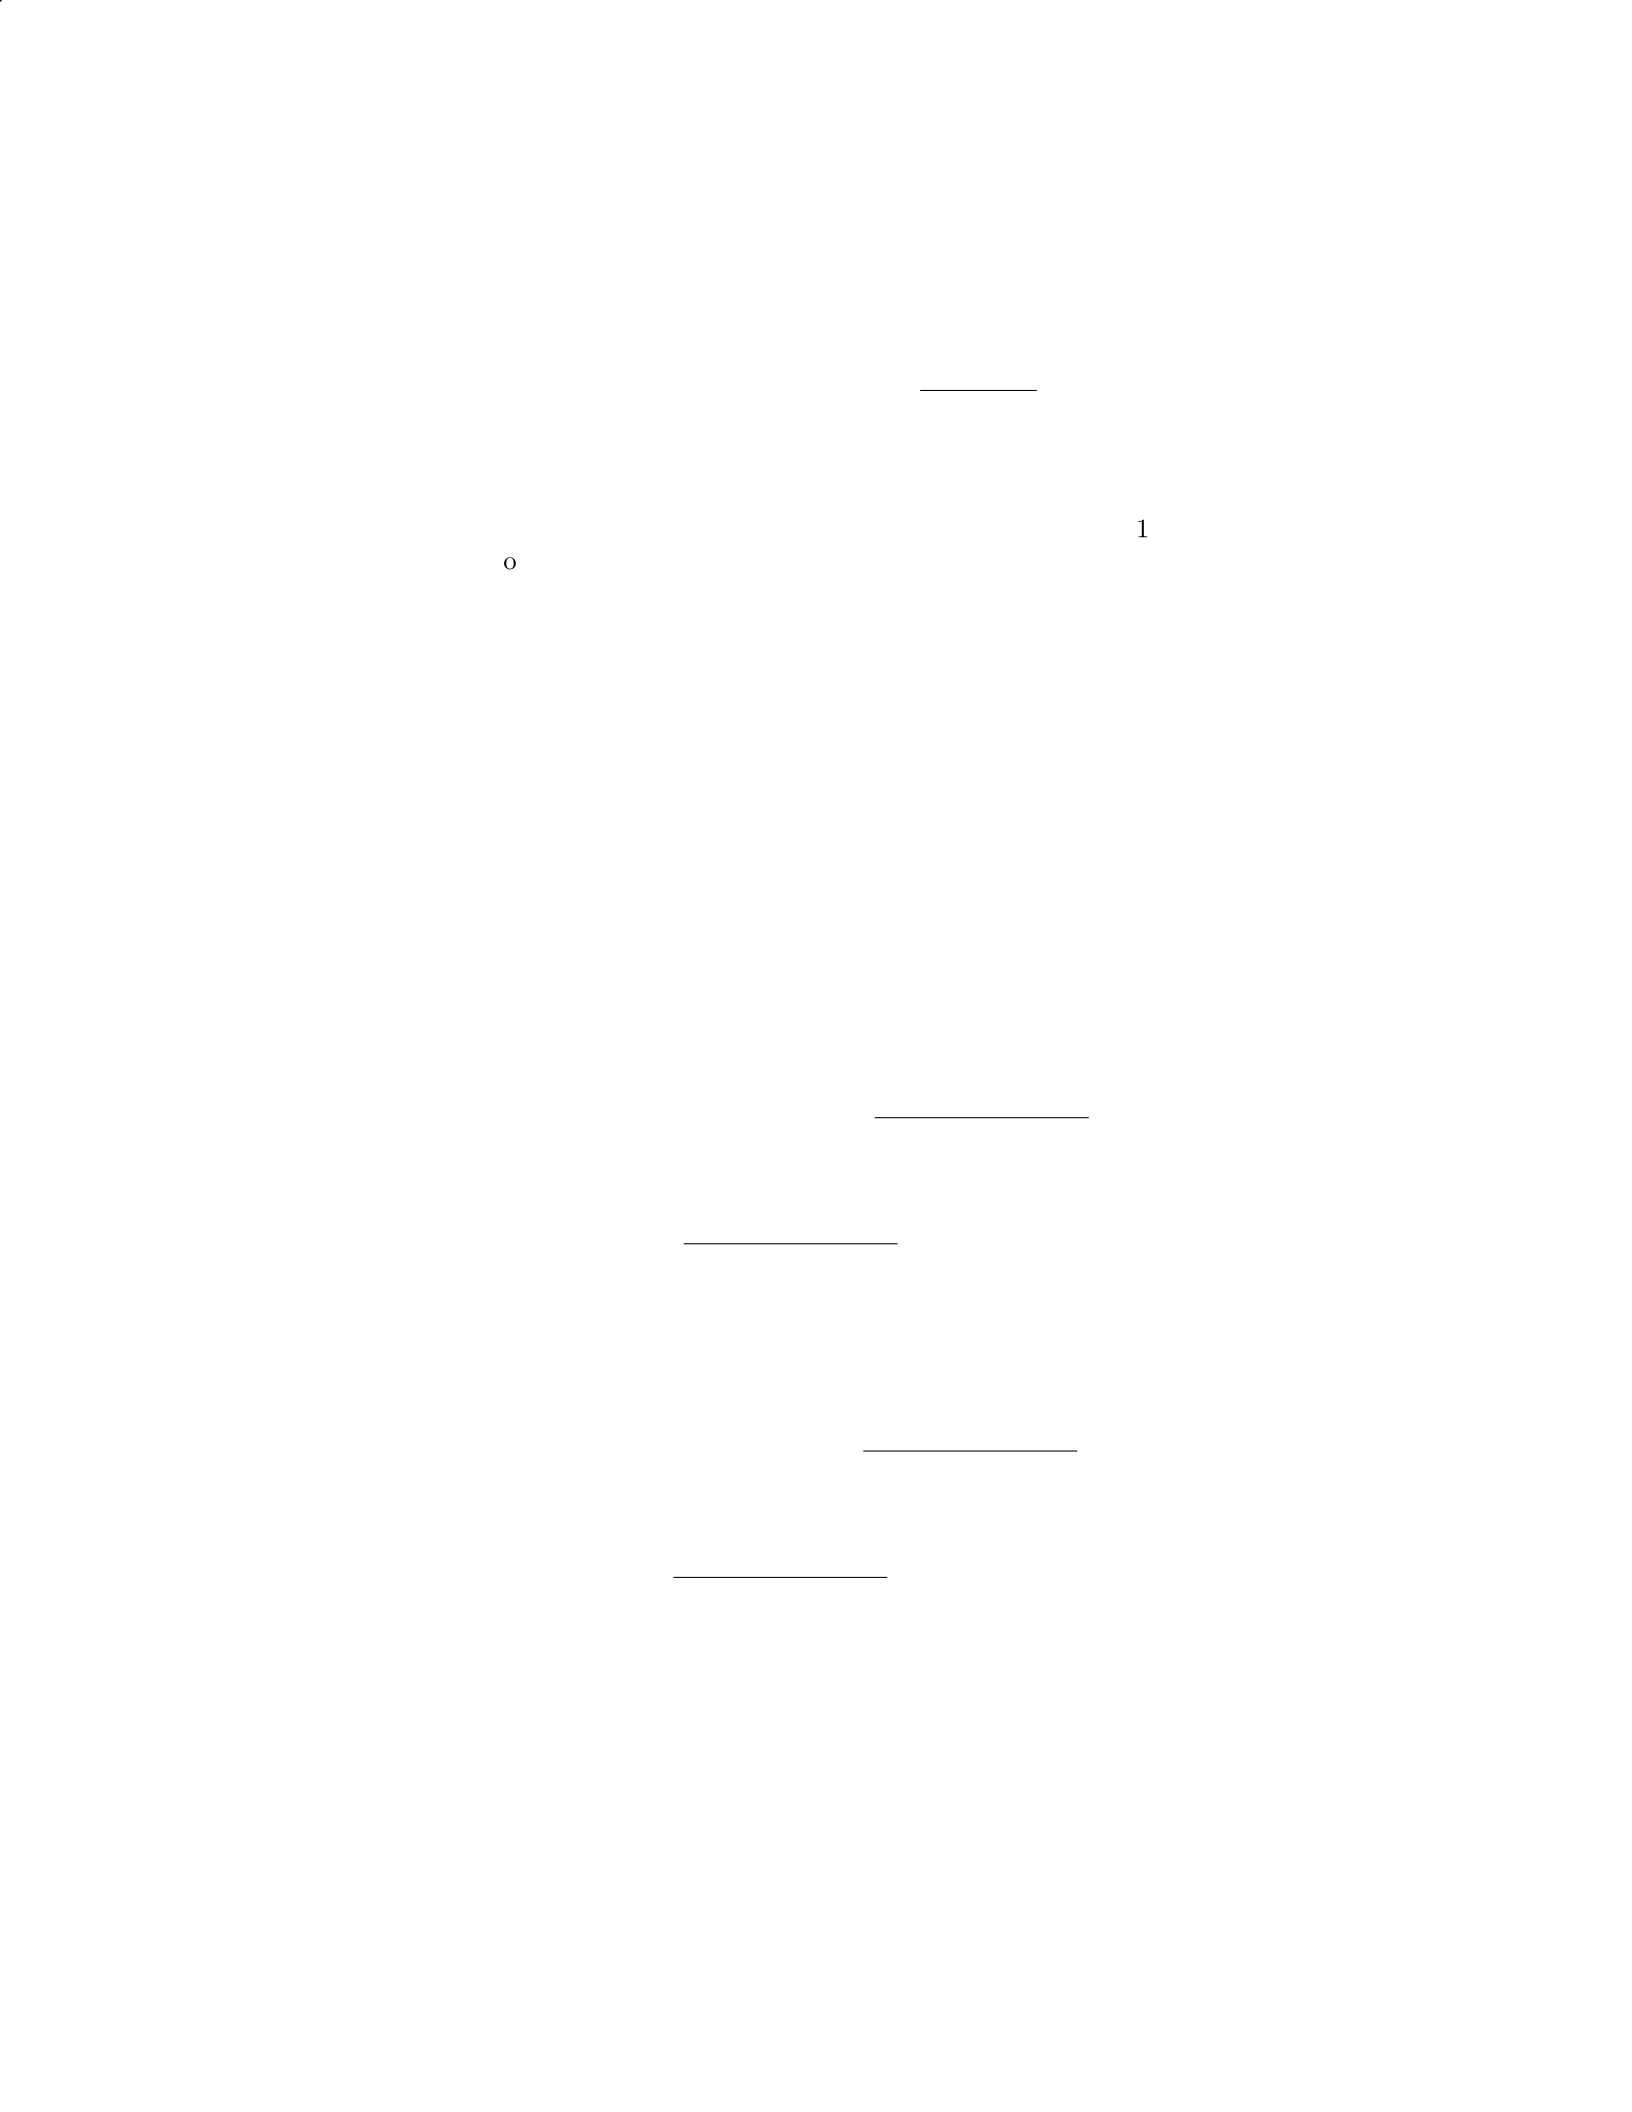
Debt-to-Equity Ratio is calculated using the formula:
Debt −to −EquityRatio =T otalLiabilities
Shareholders′Equity
Given that Total Liabilities =
$
3,000,000 and Shareholders’ Equity =
$
2,000,000,
we can plug these values into the formula to find the Debt-to-Equity Ratio.
3
Debt −to −EquityRatio =3,000,000
2,000,000
Debt −to −EquityRatio = 1.5
Step 6: Interpretation of Debt-to-Equity Ratio
A Debt-to-Equity Ratio of 1.5 indicates that the company has
$
1.50 in debt
for every
$
1 of equity. This suggests that the company is relying more on debt
financing compared to equity financing. Investors and creditors may view this
ratio as indicating higher financial risk compared to a lower ratio.
Question 3
Question
A company’s current ratio is 2, quick ratio is 1.5, and debt to equity ratio is
0.5. Analyze the company’s financial health and provide an interpretation of
the ratios.
Solution
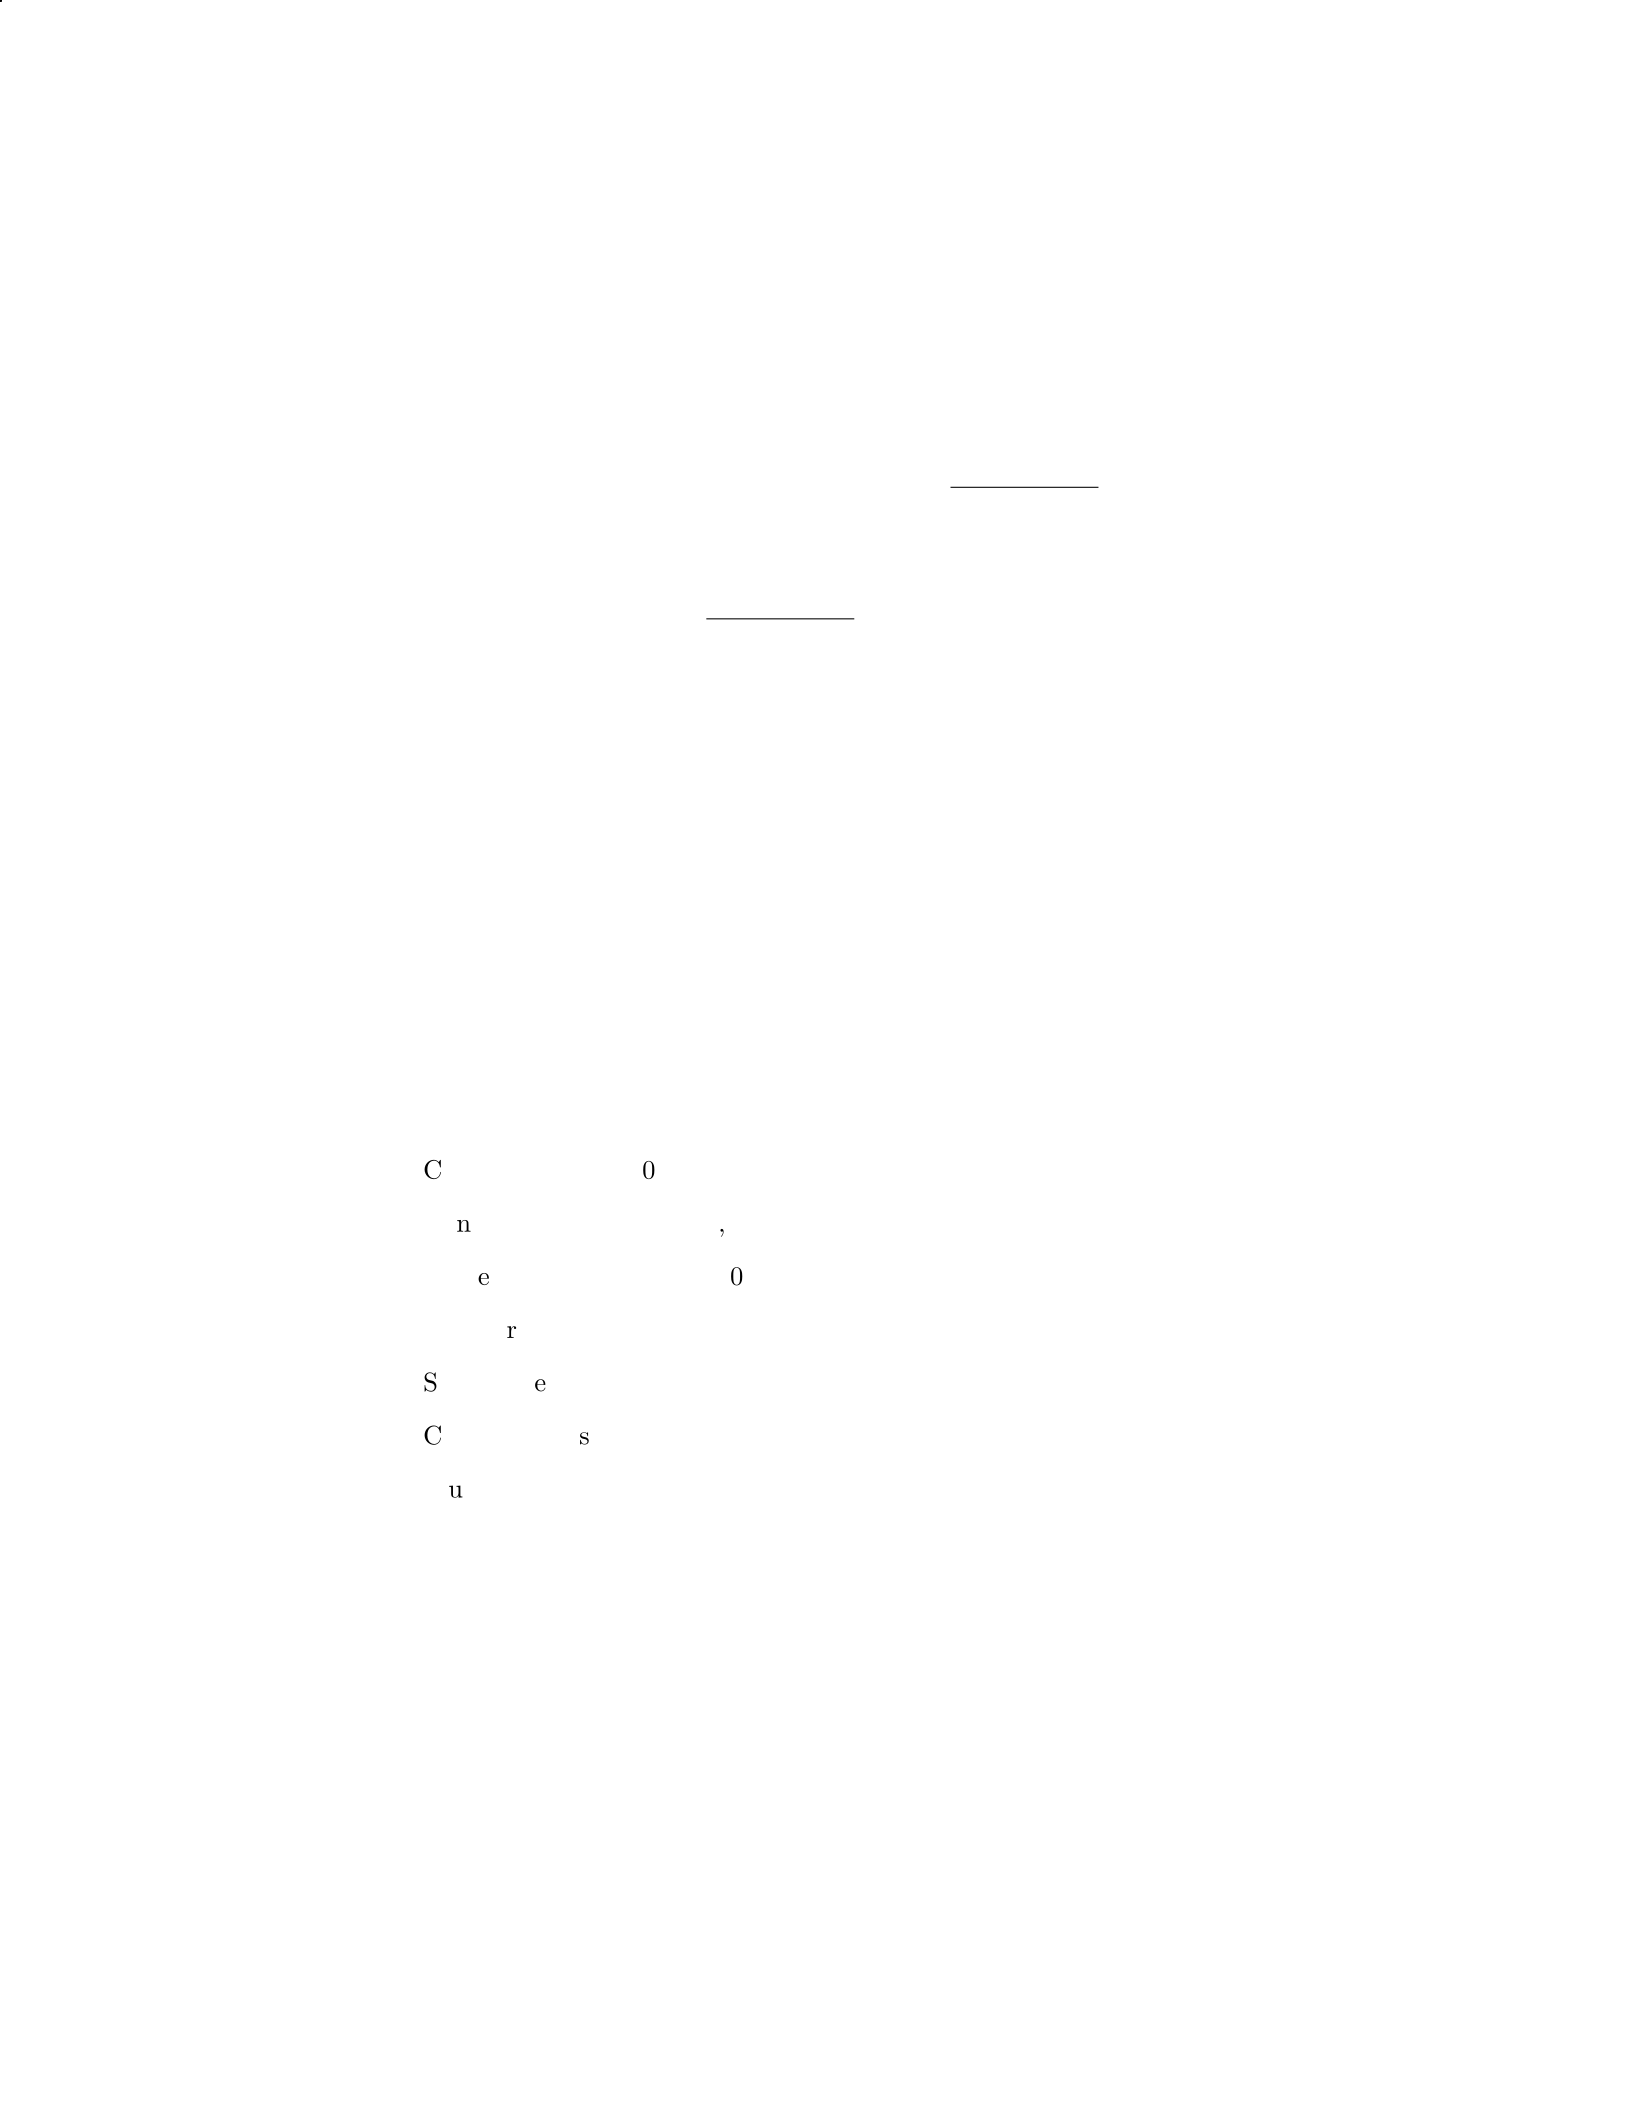
Step 1: Calculate the Current Assets to Current Liabilities Ratio (Cur-
rent Ratio)
Current Ratio = Current Assets
Current Liabilities
Given that Current Ratio = 2
Current Assets
Current Liabilities = 2
Current Assets = 2 ×Current Liabilities
Step 2: Calculate the Quick Assets to Current Liabilities Ratio
(Quick Ratio)
Quick Ratio = Quick Assets
Current Liabilities
Given that Quick Ratio = 1.5
Quick Assets
Current Liabilities = 1.5
Quick Assets = 1.5×Current Liabilities
Step 3: Interpret the Current and Quick Ratios - The current ratio
of 2 indicates that the company has twice as many current assets as current
liabilities, which signifies good liquidity. - The quick ratio of 1.5 shows that the
company’s quick assets (assets that can be quickly converted to cash) can cover
4
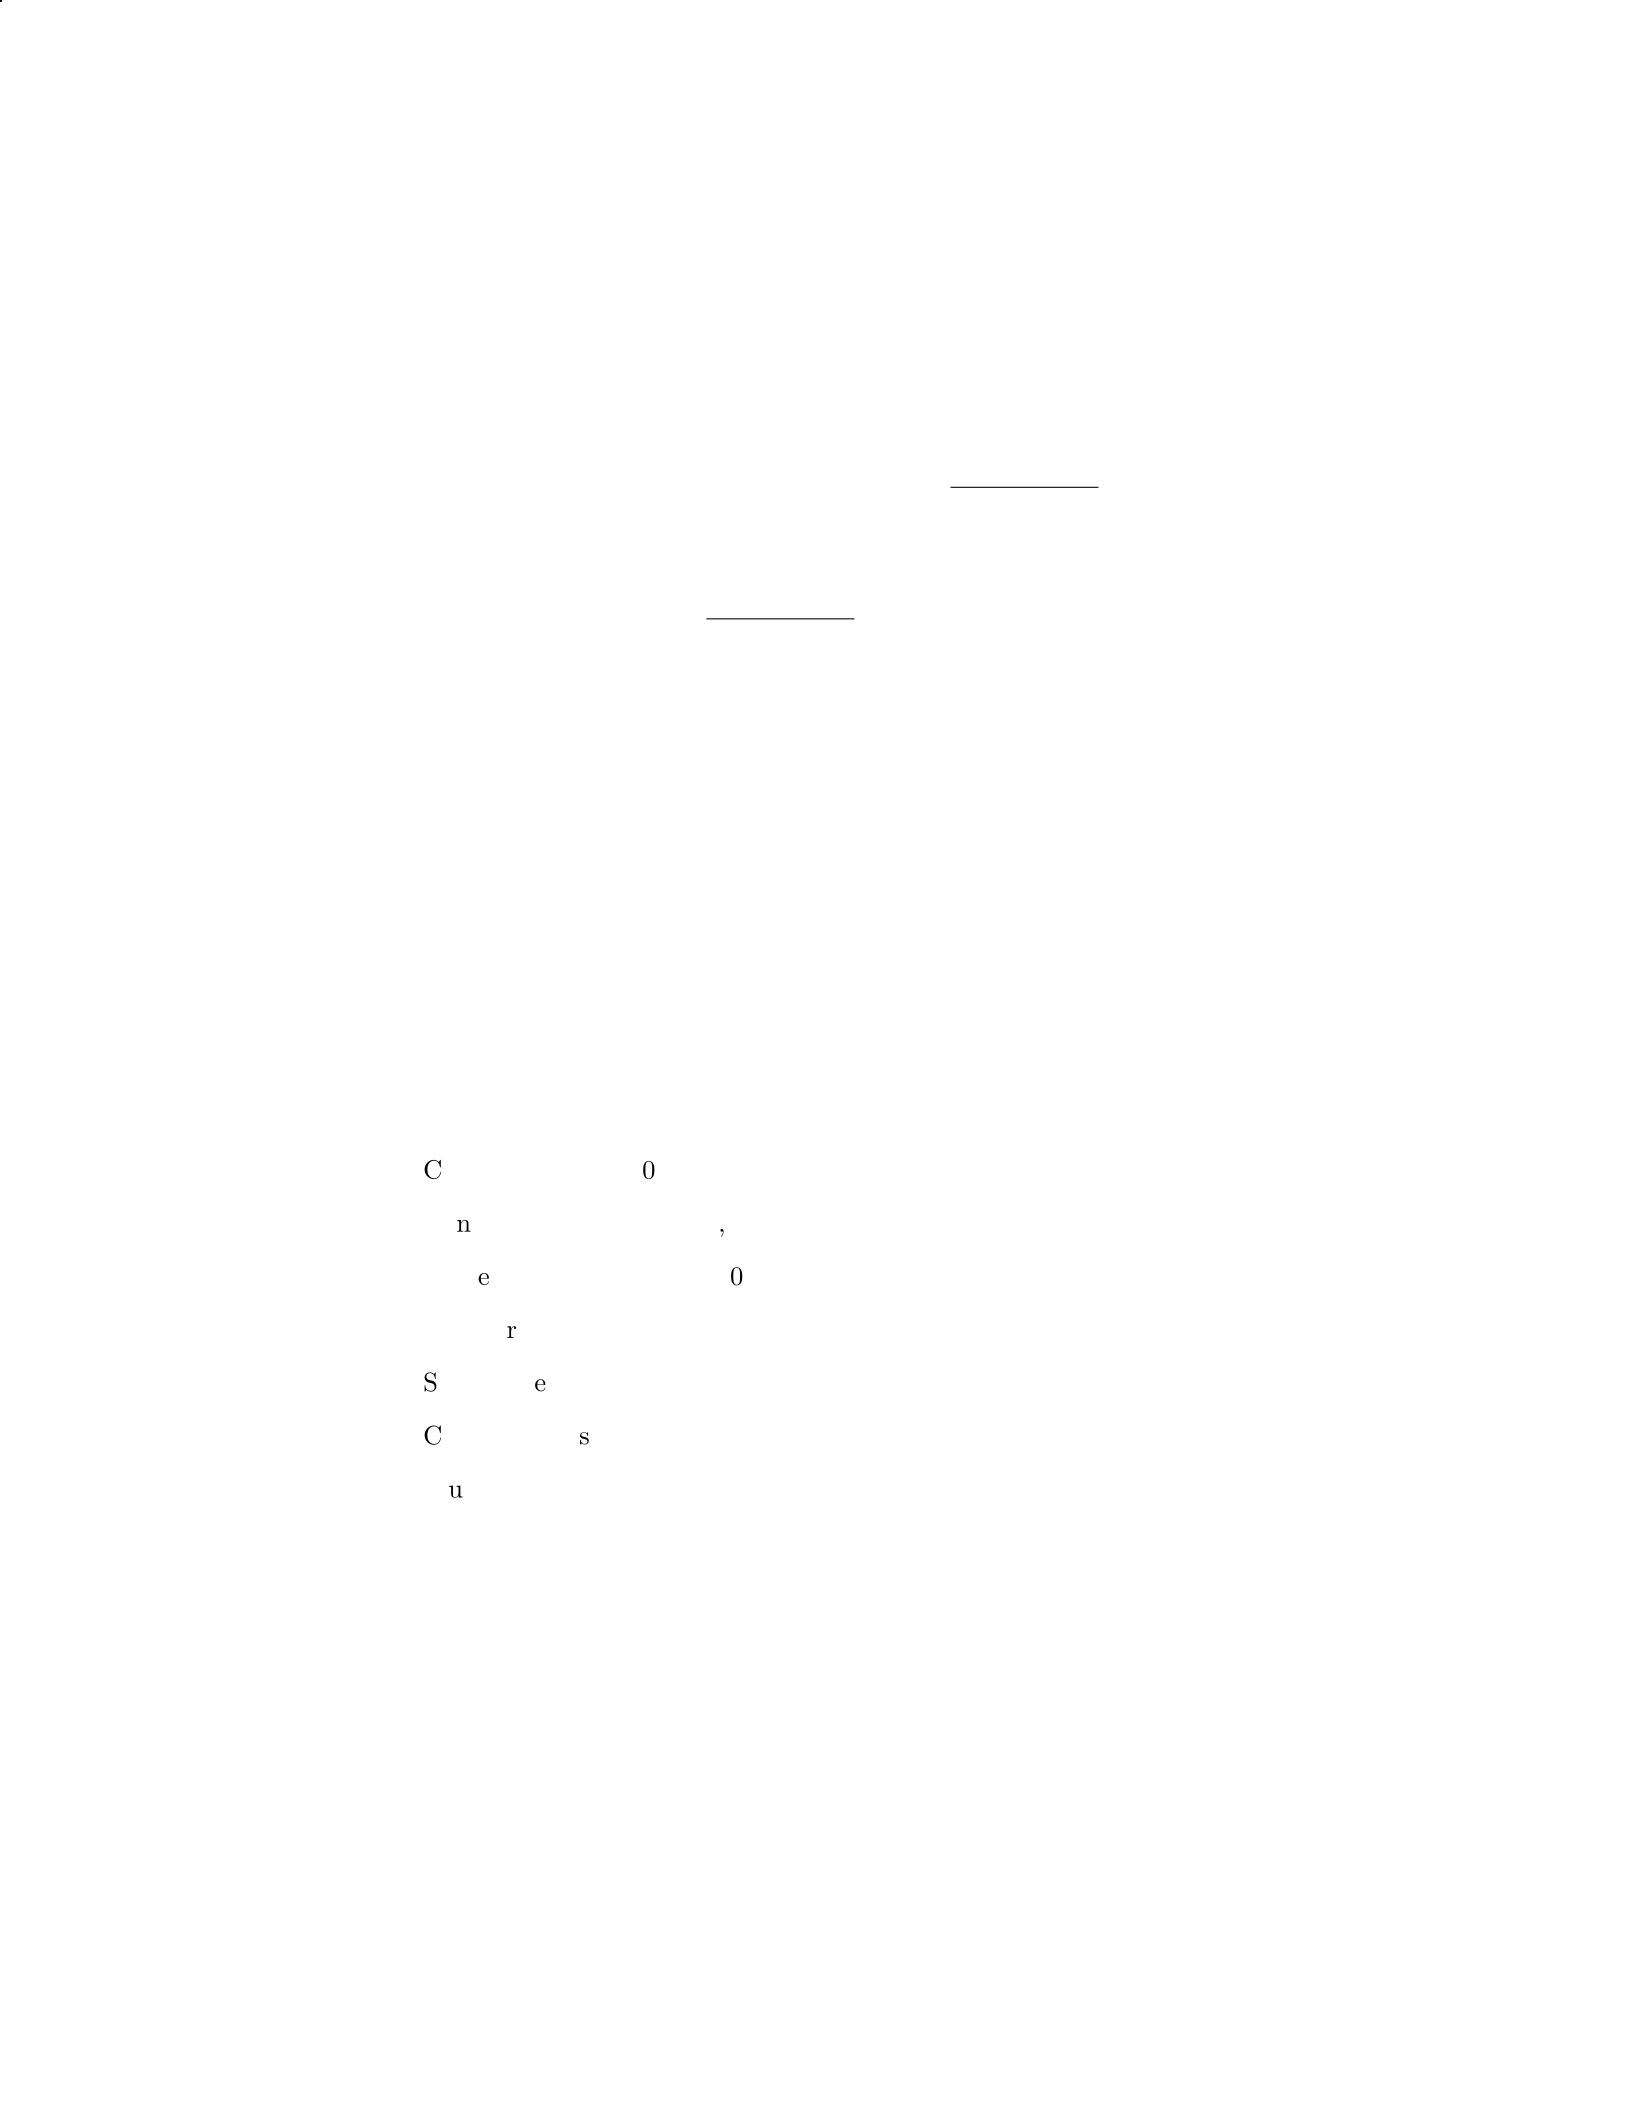
1.5 times its current liabilities. This also indicates good liquidity, with a more
conservative approach than the current ratio.
Step 4: Calculate the Debt to Equity Ratio
Debt to Equity Ratio = Total Debt
Total Equity
Given that Debt to Equity Ratio = 0.5
Total Debt
Total Equity = 0.5
Total Debt = 0.5×Total Equity
Step 5: Interpret the Debt to Equity Ratio - A debt to equity ratio of
0.5 indicates that the company has half as much debt as equity. This suggests
that the company relies more on equity financing than debt, which is considered
healthy.
In summary, the company appears to have good liquidity based on the cur-
rent and quick ratios. Additionally, the debt to equity ratio suggests a healthy
balance between debt and equity financing.
Question 4
Question
A company’s financial statements show the following information for the year:
Current Assets:
$
400,000
Non-current Assets:
$
600,000
Current Liabilities:
$
200,000
Non-current Liabilities:
$
300,000
Sales Revenue:
$
1,000,000
Cost of Goods Sold:
$
500,000
Calculate the following ratios for the company:
1. Current Ratio
2. Quick Ratio
3. Gross Profit Margin
5
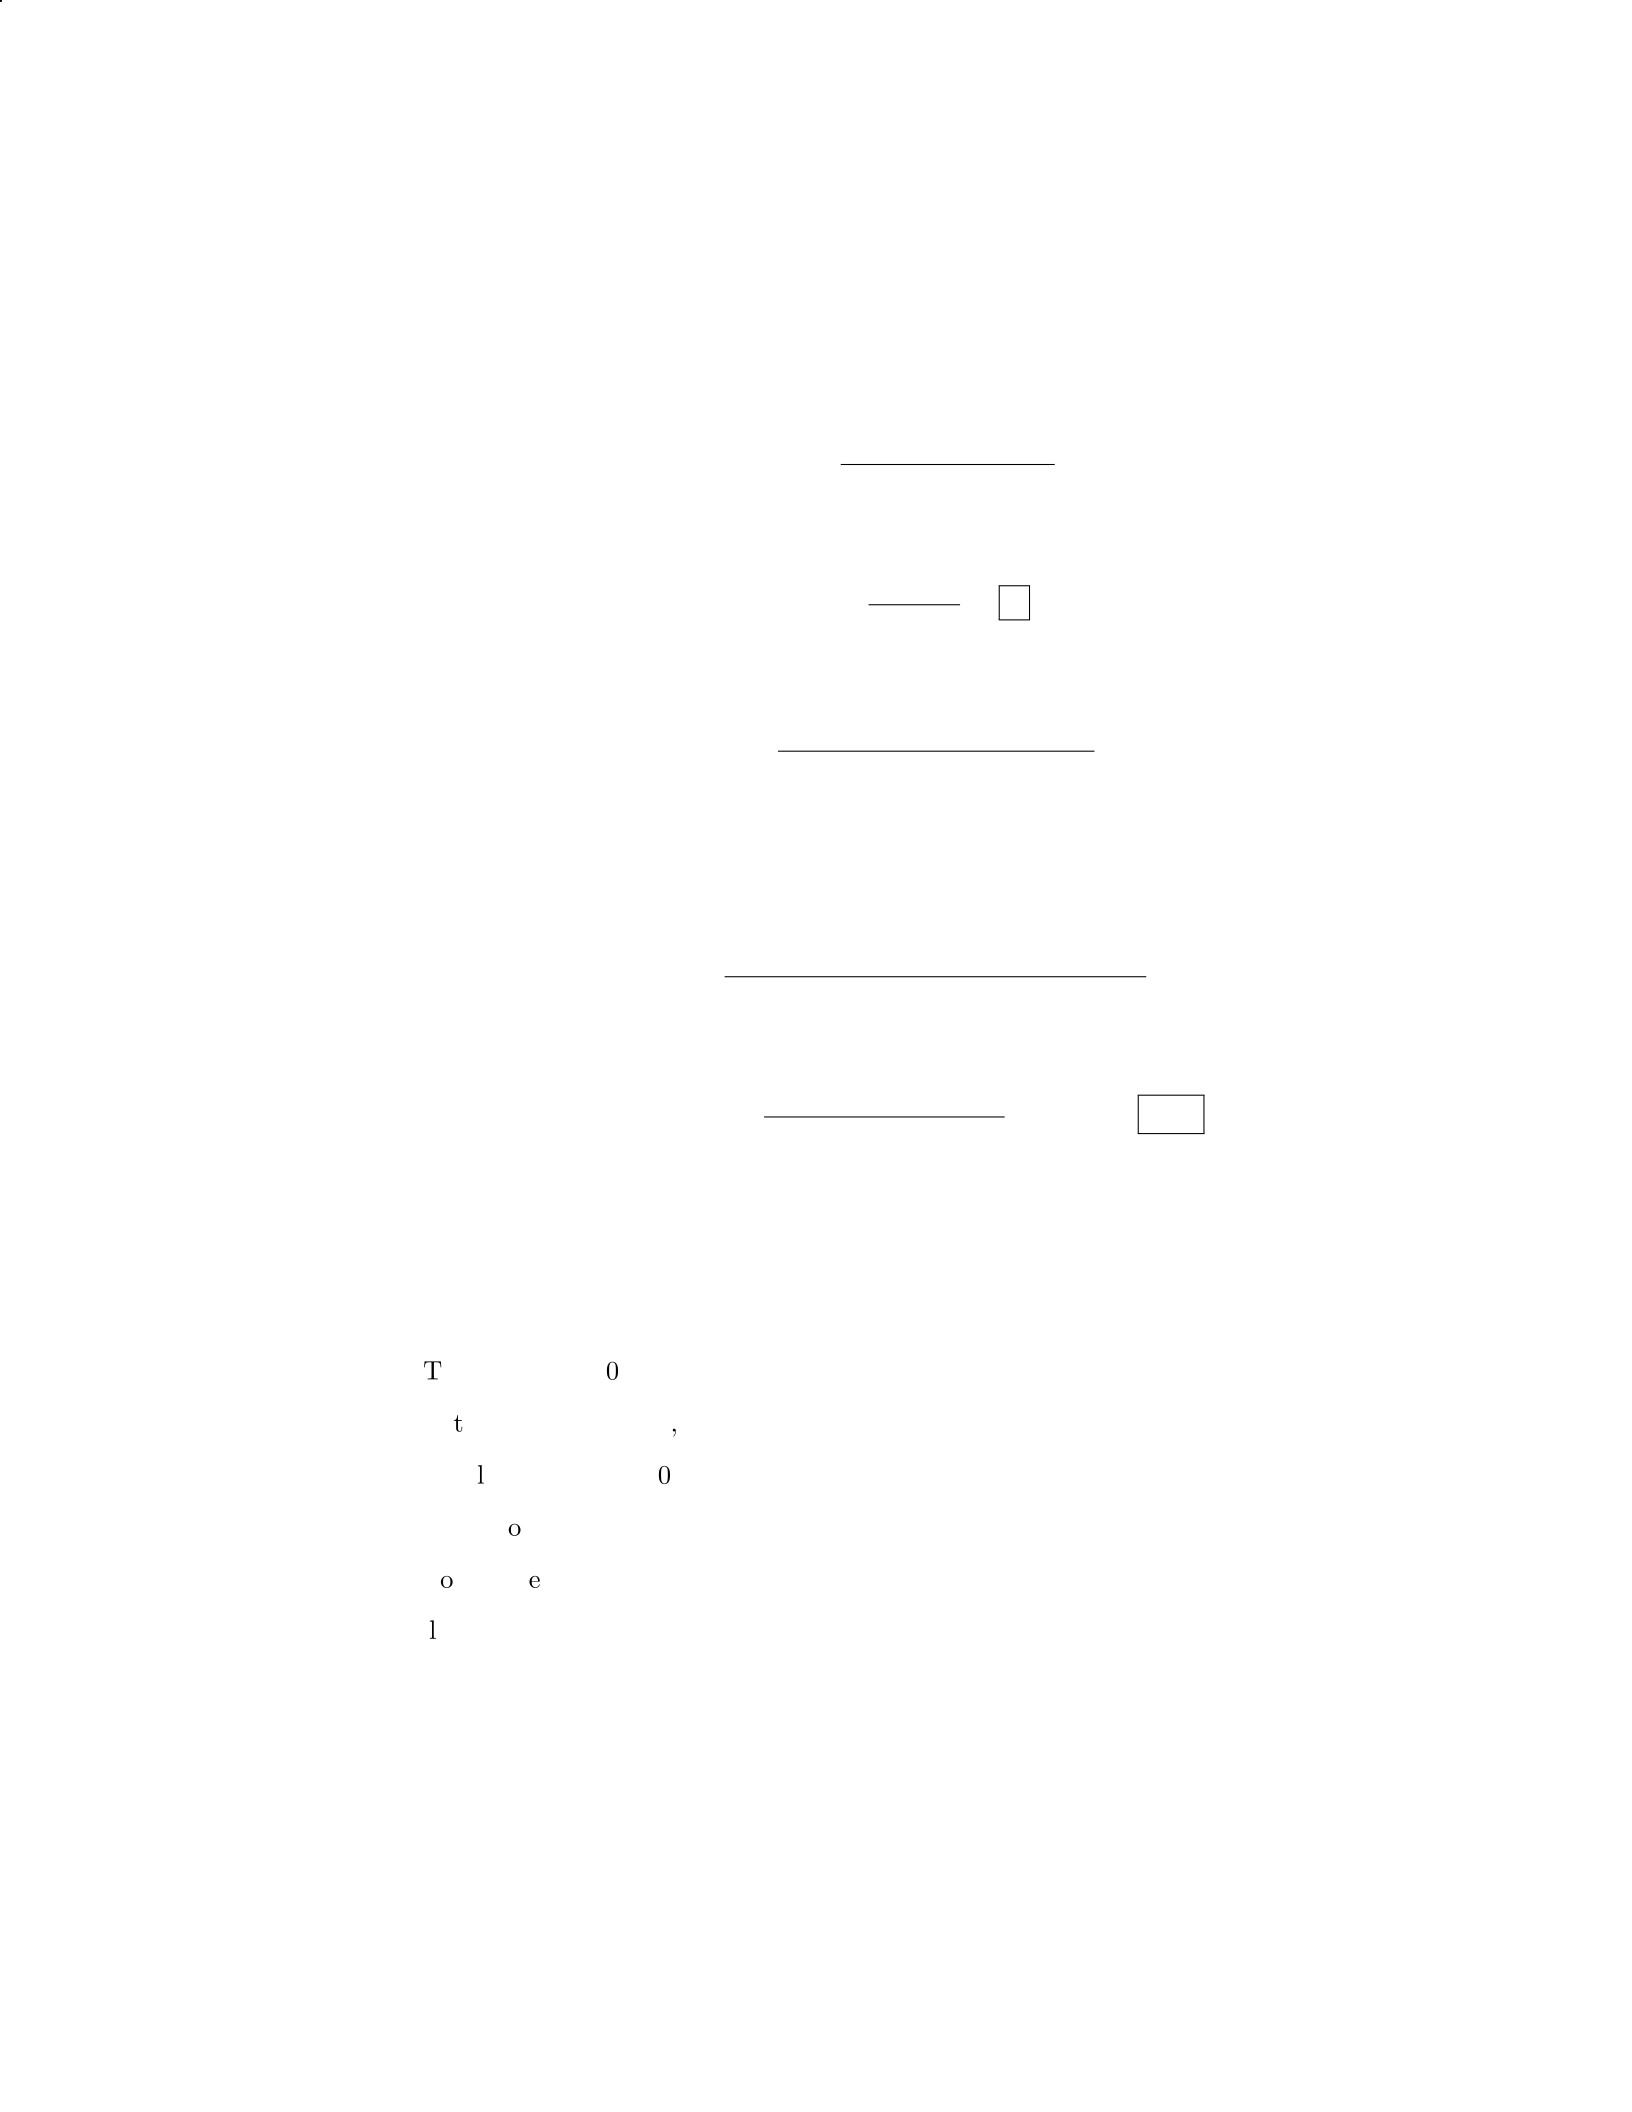
Solution
1. Current Ratio The current ratio is calculated as:
Current Ratio = Current Assets
Current Liabilities
Step 1: Calculate the Current Ratio
Current Ratio = 400,000
200,000 = 2
2. Quick Ratio The quick ratio is calculated as:
Quick Ratio = Current Assets −Inventory
Current Liabilities
Given that the Inventory is not provided, we cannot calculate the Quick
Ratio.
3. Gross Profit Margin The gross profit margin is calculated as:
Gross Profit Margin = Sales Revenue −Cost of Goods Sold
Sales Revenue ×100%
Step 1: Calculate Gross Profit Margin
Gross Profit Margin = 1,000,000 −500,000
1,000,000 ×100% = 50%
Question 5
Question
A company has the following financial information for the year:
Total assets:
$
500,000
Total liabilities:
$
200,000
Total equity:
$
300,000
Net income:
$
50,000
Total revenue:
$
400,000
Calculate the following ratios and provide an interpretation for each:
1. Debt to Equity Ratio
2. Return on Assets
3. Profit Margin
6
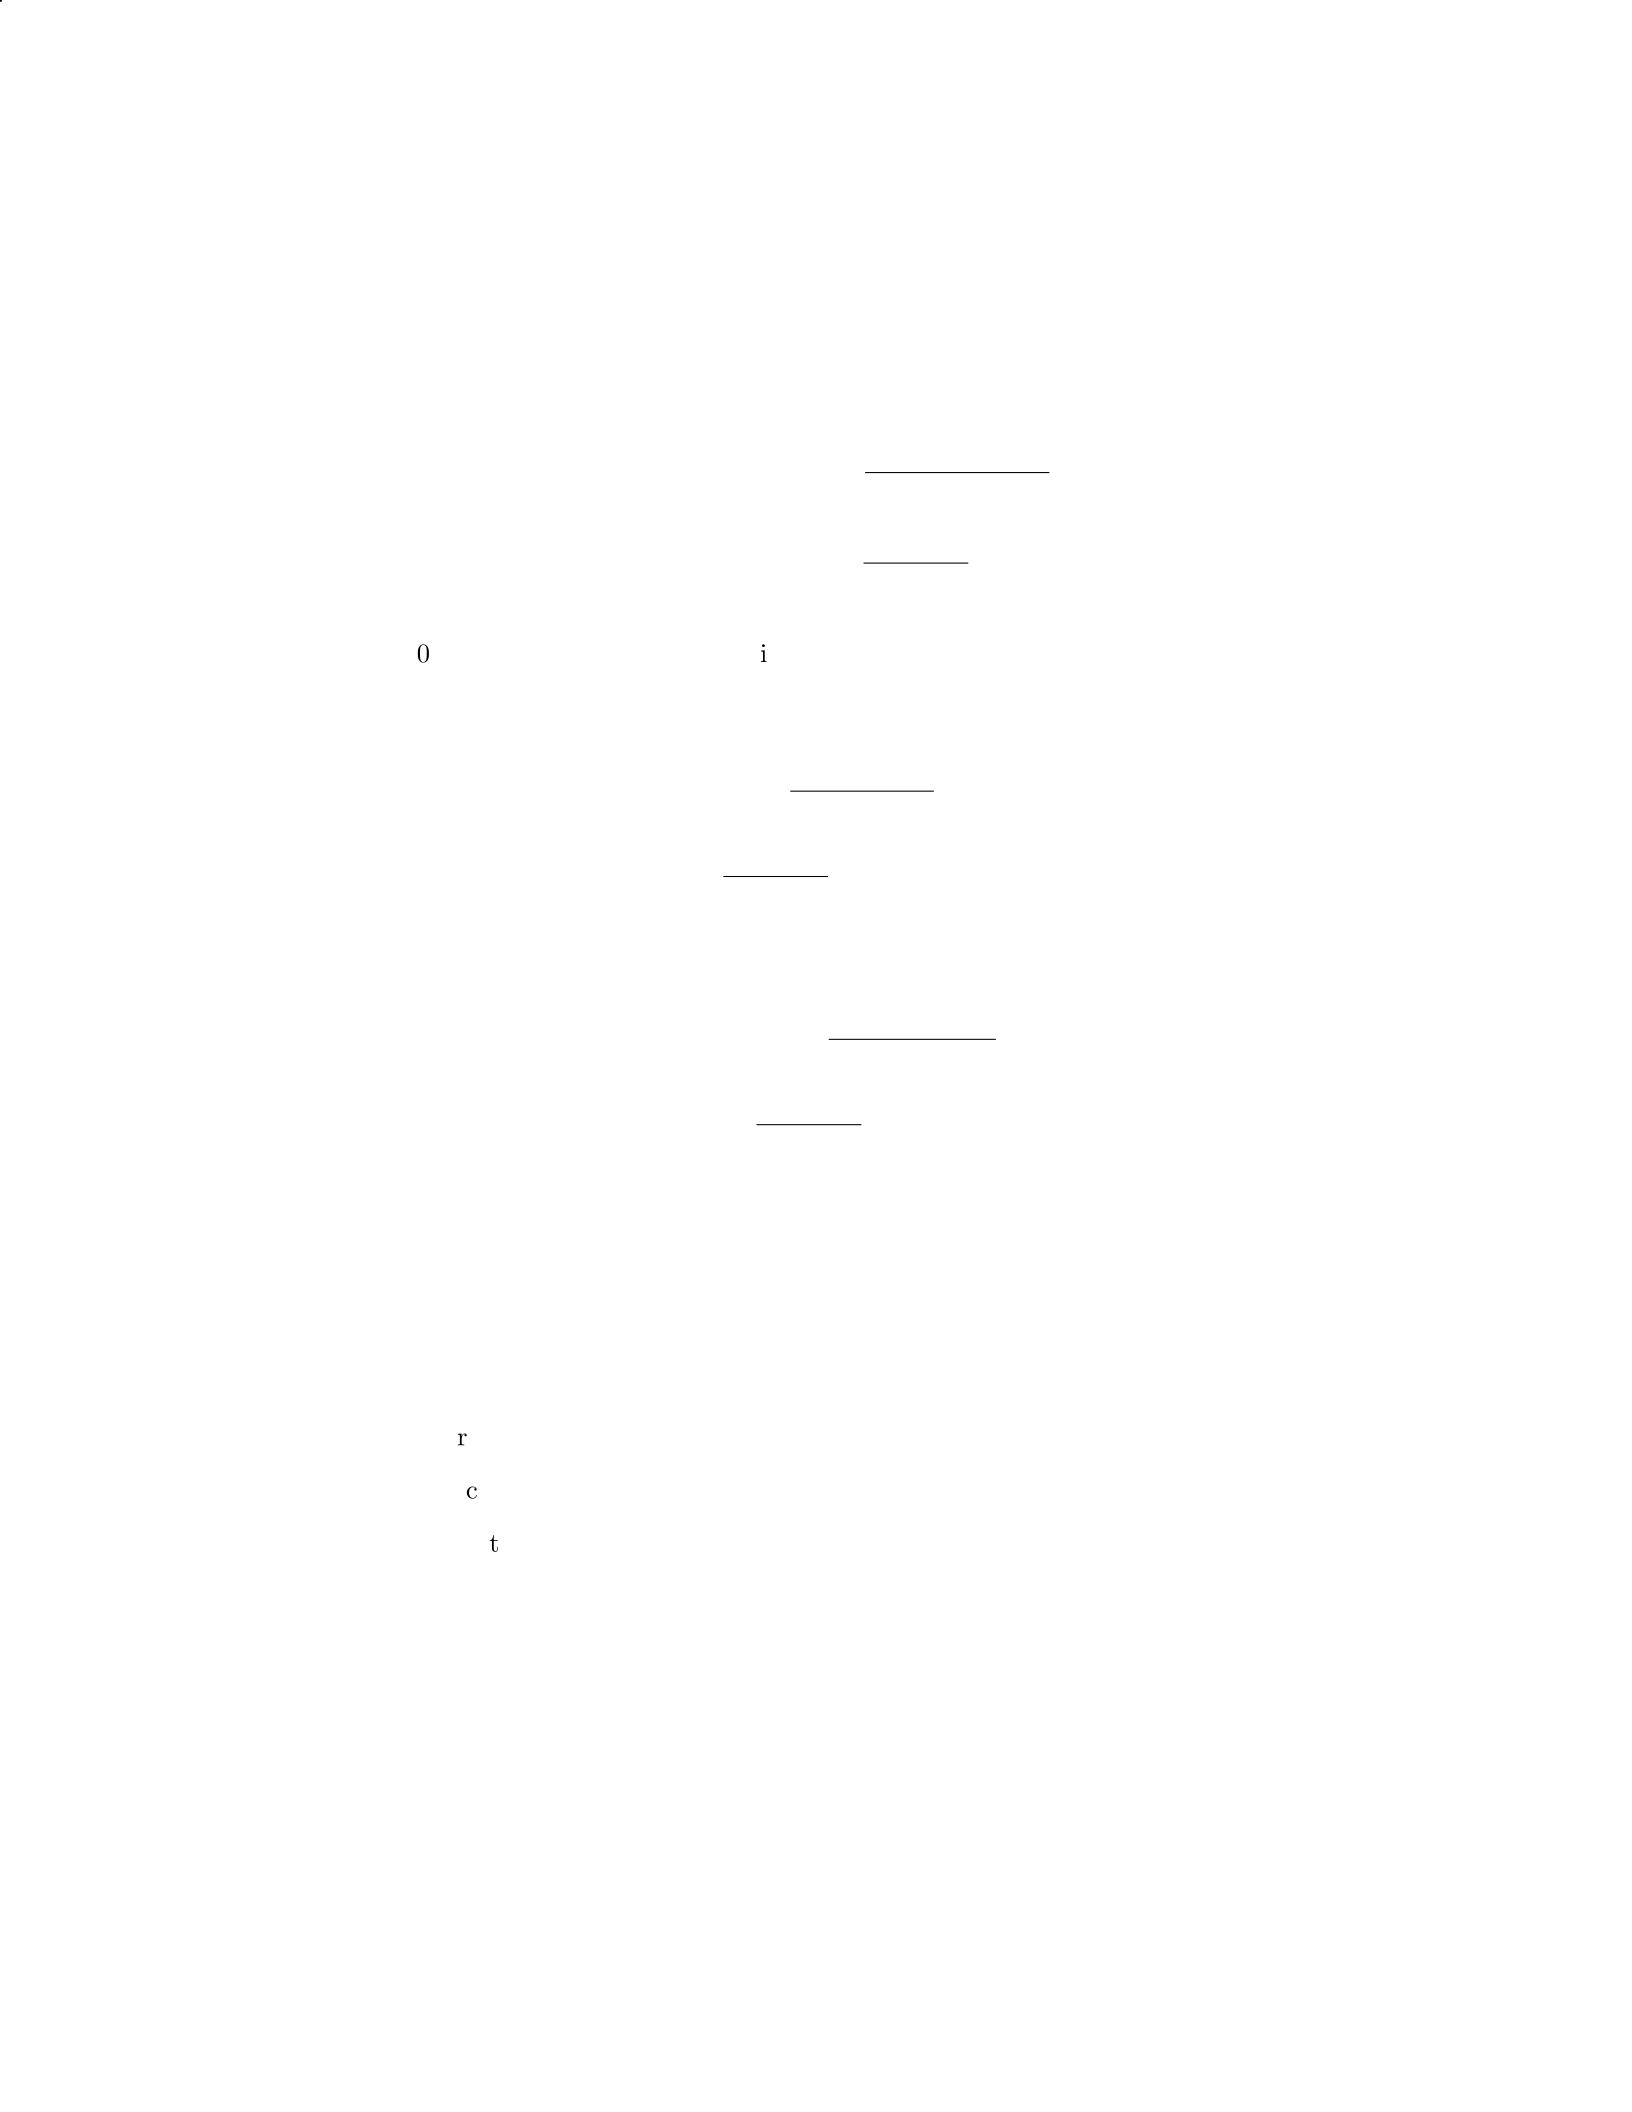
Solution
Step 1: Calculate the Debt to Equity Ratio
Debt to Equity Ratio = Total Liabilities
Total Equity
Debt to Equity Ratio = $200,000
$300,000 = 0.67
Interpretation: A debt to equity ratio of 0.67 indicates that the company
has
$
0.67 in liabilities for every
$
1 in equity. This suggests that the company is
relying more on equity financing compared to debt financing.
Step 2: Calculate the Return on Assets (ROA)
ROA = Net Income
Total Assets
ROA = $50,000
$500,000 = 0.10 or 10%
Interpretation: A return on assets of 10
Step 3: Calculate the Profit Margin
Profit Margin = Net Income
Total Revenue
Profit Margin = $50,000
$400,000 = 0.125 or 12.5%
Interpretation: A profit margin of 12.5
Question 6
Question
A company reports the following financial information for the current year:
Current ratio = 2
Quick ratio = 1.5
Debt to equity ratio = 0.6
Based on this information, analyze the company’s financial health and perfor-
mance.
7
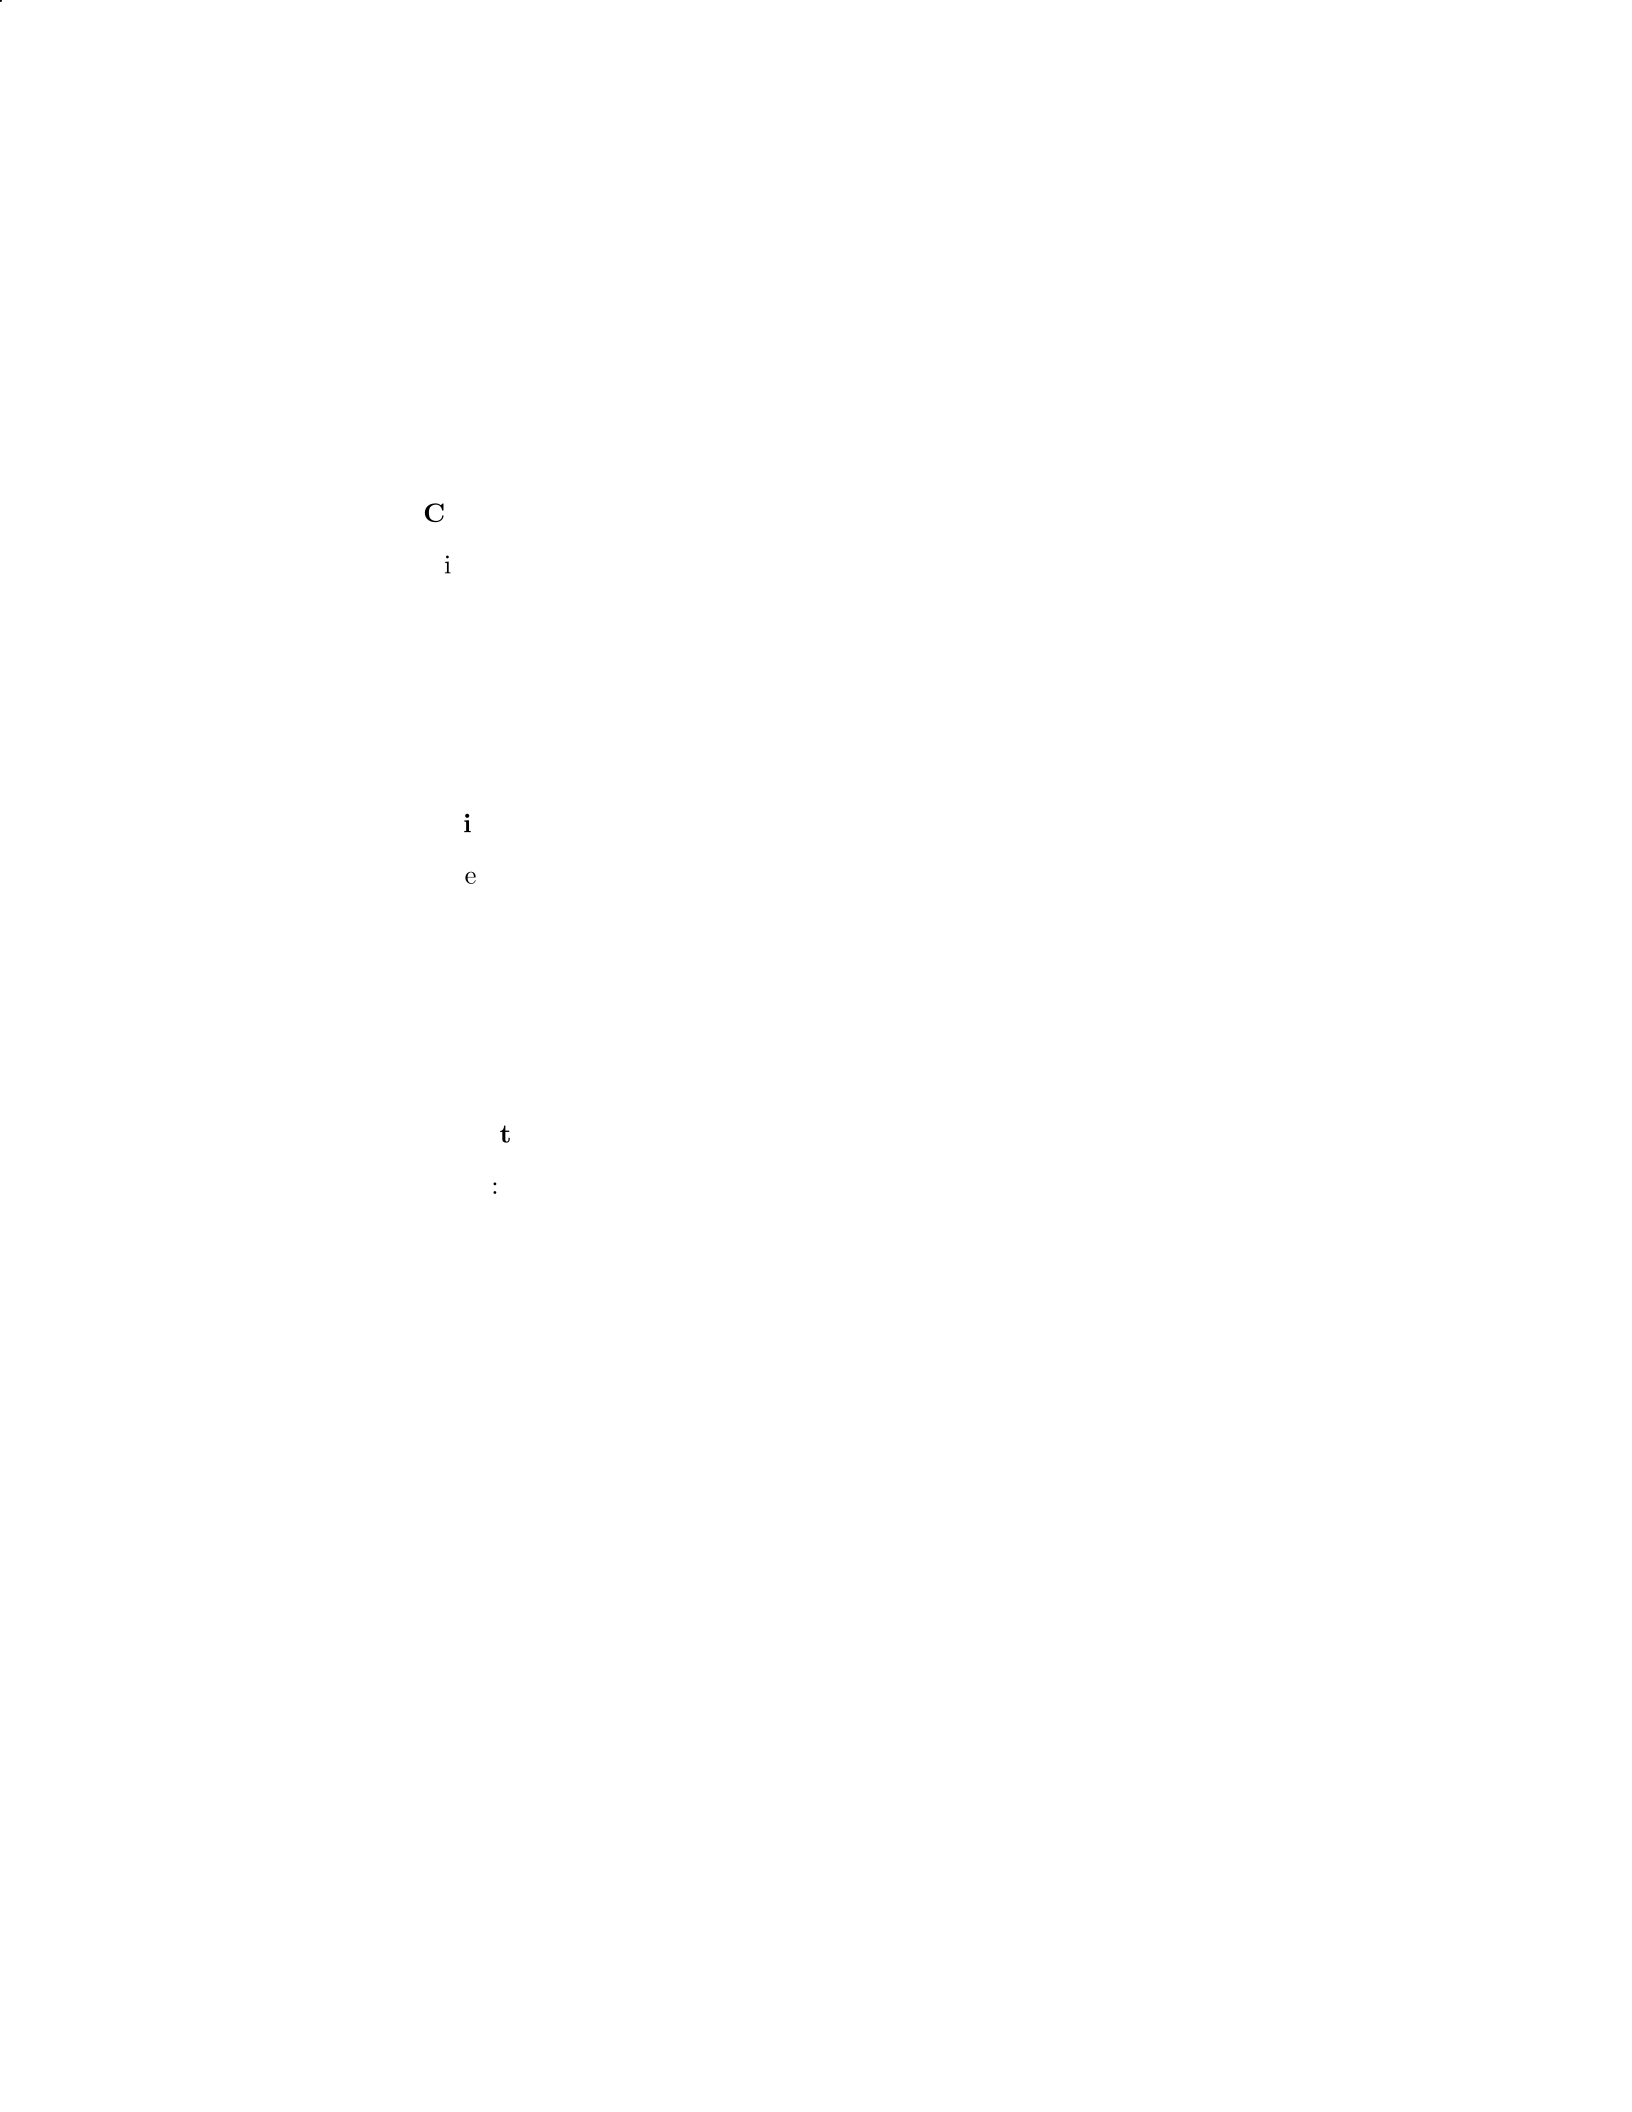
Solution
To analyze the company’s financial health and performance, we will interpret
each ratio in relation to industry benchmarks and ideal values.
Step 1: Calculate and Interpret the Current Ratio
Current Ratio = Current Assets / Current Liabilities
Given: Current Ratio = 2
A current ratio of 2 indicates that the company has 2worthofcurrentassetsf orevery1
of current liabilities. Generally, a current ratio above 1 is considered healthy,
but the ideal value varies by industry. A current ratio of 2 signifies that the
company may have excess current assets, which could be invested for further
growth opportunities.
Step 2: Calculate and Interpret the Quick Ratio
Quick Ratio = (Current Assets - Inventory) / Current Liabilities
Given: Quick Ratio = 1.5
A quick ratio of 1.5 implies that the company has 1.50ofliquidassetsavailabletocovereach1
of current liabilities. This ratio is slightly lower than the current ratio, indicat-
ing that the company’s inventory may not be as easily converted to cash in the
short term. It is important to compare this ratio with industry standards to
assess the company’s ability to meet short-term obligations.
Step 3: Calculate and Interpret the Debt to Equity Ratio
Debt to Equity Ratio = Total Debt / Shareholders’ Equity
Given: Debt to Equity Ratio = 0.6
A debt to equity ratio of 0.6 signifies that the company relies more on equity
financing than debt financing. This ratio indicates a healthy balance between
debt and equity, but the ideal ratio can vary based on industry and company-
specific factors. It is crucial to benchmark this ratio against industry peers to
evaluate the company’s leverage and financial risk.
Based on the interpretation of the current, quick, and debt to equity ratios,
the company appears to have a stable financial position with a strong liquidity
position, moderate leverage, and a healthy balance between debt and equity
financing. Further analysis and comparison with industry averages will pro-
vide a more comprehensive assessment of the company’s financial health and
performance.
Question 7
Question
A company reported the following financial information for the year: - Current
ratio: 2.5 - Quick ratio: 1.8 - Debt to equity ratio: 0.7
8
Based on this information, analyze the company’s liquidity, efficiency, and
financial leverage. Provide an interpretation of these ratios in relation to the
company’s financial health.
Solution
To analyze the company’s liquidity, efficiency, and financial leverage, we will
interpret the given ratios - current ratio, quick ratio, and debt to equity ratio.
Step 1: Interpret the Current Ratio The current ratio is calculated as
Current Assets divided by Current Liabilities. It measures the company’s ability
to pay its short-term obligations with its short-term assets. The company’s
current ratio of 2.5 indicates that it has 2.50ofcurrentassetsf orevery1.00 of
current liabilities. A current ratio above 1.0 generally indicates good liquidity.
In this case, the company’s current ratio of 2.5 suggests that the company is in
a good position to meet its short-term obligations.
Step 2: Interpret the Quick Ratio The quick ratio (acid-test ratio) is
calculated as (Current Assets - Inventory) divided by Current Liabilities. It
provides a more stringent measure of liquidity as it excludes inventory, which
may not be easily convertible to cash. The company’s quick ratio of 1.8 indicates
that it has 1.80ofquickassets(currentassetsexcludinginventory)f orevery1.00
of current liabilities. A quick ratio above 1.0 is generally considered healthy.
Therefore, the company’s quick ratio of 1.8 also suggests good liquidity.
Step 3: Interpret the Debt to Equity Ratio The debt to equity ratio
is calculated as Total Debt divided by Total Equity. It measures the company’s
financial leverage or the proportion of debt and equity used to finance its assets.
A debt to equity ratio of 0.7 means the company has 0.70ofdebtforevery1.00 of
equity. A lower debt to equity ratio indicates lower financial risk. In this case,
the company’s debt to equity ratio of 0.7 suggests that the company is using
more equity to finance its operations, which is generally positive.
Overall, based on the ratios provided, the company appears to have good
liquidity, efficient management of its short-term obligations, and a conservative
capital structure with low financial leverage. This indicates a healthy financial
position and suggests that the company is managing its resources effectively.
Question 8
Question
A company has the following financial information for the year: - Current As-
sets:
$
500,000 - Current Liabilities:
$
200,000 - Total Assets:
$
1,500,000 - Total
Liabilities:
$
600,000 - Shareholders’ Equity:
$
900,000
Calculate the following ratios and interpret the results: a) Current ratio b)
Debt-to-equity ratio
9
Solution
Step 1: Calculate the current ratio. The current ratio is calculated as:
Current Ratio = Current Assets
Current Liabilities
Substitute the given values:
Current Ratio = 500,000
200,000 = 2.5
Step 2: Interpret the current ratio. A current ratio of 2.5 indicates that
the company has
$
2.50 in current assets for every
$
1 in current liabilities. This
signifies that the company has an excess of current assets to cover its current
liabilities.
Step 3: Calculate the debt-to-equity ratio. The debt-to-equity ratio is cal-
culated as:
Debt-to-equity Ratio = Total Liabilities
Shareholders’ Equity
Substitute the given values:
Debt-to-equity Ratio = 600,000
900,000 = 0.67
Step 4: Interpret the debt-to-equity ratio. A debt-to-equity ratio of 0.67
implies that for every
$
1 of shareholders’ equity, the company has
$
0.67 in
total liabilities. This ratio indicates that the company is financing a significant
portion of its assets through equity rather than debt.
Question 9
Question
The current ratio of Company ABC is 2.5, while its quick ratio is 1.5. Analyze
and interpret these ratios in the context of the company’s liquidity.
Solution
Step 1: Calculate the current assets and current liabilities of Company
ABC.
The current ratio is given by:
Current Ratio = Current Assets
Current Liabilities
Given that the current ratio is 2.5, we can write:
2.5 = Current Assets
Current Liabilities
10
Step 2: Interpret the current ratio.
A current ratio of 2.5 indicates that the company has 2.50worthofcurrentassetsf orevery1.00
of current liabilities. This implies that the company’s current assets are more
than double its current liabilities, suggesting that Company ABC is likely able
to meet its short-term obligations.
Step 3: Calculate the quick assets of Company ABC.
The quick ratio is given by:
Quick Ratio = Quick Assets
Current Liabilities
Given that the quick ratio is 1.5 and the current ratio is 2.5, we can infer that
quick assets are less than current assets. Therefore, to calculate quick assets,
we can use the formula:
Quick Assets = Current Assets −Inventory
Step 4: Interpret the quick ratio.
A quick ratio of 1.5 indicates that the company has 1.50ofquickassetsforevery1.00
of current liabilities. This ratio is slightly lower than the current ratio, which
suggests that the company’s inventory may not be as easily converted to cash
compared to its other current assets, such as accounts receivable.
Step 5: Draw conclusions about Company ABC’s liquidity position.
Overall, with a current ratio of 2.5 and a quick ratio of 1.5, Company ABC
appears to have a healthy liquidity position. The company has more than
enough current assets to cover its current liabilities, and even after excluding
inventory, it still has enough quick assets to meet its short-term obligations.
However, the slightly lower quick ratio compared to the current ratio indicates
that the company may have a significant portion of its current assets tied up in
inventory that may not be as easily converted to cash.
Question 10
Question
Company XYZ reported a current ratio of 2.5 and a quick ratio of 1.8. Evaluate
the liquidity position of Company XYZ based on these ratios.
Solution
Step 1: Calculate the Current Assets and Current Liabilities
Using the formula for the current ratio:
Current Ratio = Current Assets
Current Liabilities
we can derive the current assets of Company XYZ as:
Current Assets = Current Ratio ×Current Liabilities
11
Given that the current ratio is 2.5, we have:
Current Assets = 2.5×Current Liabilities
Step 2: Calculate the Quick Assets
Using the formula for the quick ratio:
Quick Ratio = Quick Assets
Current Liabilities
we can derive the quick assets of Company XYZ as:
Quick Assets = Quick Ratio ×Current Liabilities
Given that the quick ratio is 1.8, we have:
Quick Assets = 1.8×Current Liabilities
Step 3: Interpretation of the Ratios
The current ratio measures a company’s ability to pay its short-term obliga-
tions with its short-term assets, while the quick ratio provides a more stringent
measure by excluding inventory from current assets.
Comparing the two ratios, we can see that the current ratio is higher than
the quick ratio, indicating that a significant portion of the current assets consists
of inventory. In this case, the liquidity position may be slightly overstated by
the current ratio, as inventory may not be as quickly converted to cash in case
of an emergency.
Overall, with a current ratio of 2.5 and a quick ratio of 1.8, Company XYZ
appears to have a healthy liquidity position. However, it is important to take
into consideration the composition of current assets to accurately assess the
company’s ability to meet its short-term obligations.
Question 11
Question
A company has reported the following financial ratios for the current year:
Ratio Value
Current Ratio 2.5
Quick Ratio 1.8
Debt-to-Equity Ratio 0.6
Return on Assets 0.12
Return on Equity 0.2
Based on these ratios, analyze and interpret the company’s financial perfor-
mance.
12
Solution
Step 1: Current Ratio and Quick Ratio
The current ratio is 2.5, indicating that the company has 2.5ofcurrentassetsf oreverydollarof currentliabilities.T hissuggeststhatthecompanyisabletomeetitsshort−
termobligationscomfortably.T hequickratiois1.8, whichisslightlylowerthanthecurrentratio.T hissuggeststhatthecompany′sabilitytomeetshort−
termliabilitieswithitsmostliquidassets(excludinginventory)isstillstrongbutslightlylessthanitsoverallabilitytopayoffallcurrentliabilities.
Step 2: Debt-to-Equity Ratio
The debt-to-equity ratio of 0.6 indicates that the company has more equity
than debt financing, which is generally considered favorable. A lower
debt-to-equity ratio implies lower financial risk and less reliance on debt
to finance operations.
Step 3: Return on Assets (ROA) and Return on Equity (ROE)
The return on assets of 0.12 means that the company generated 12 cents of
profit for every dollar of assets it owns. This ratio measures the company’s
efficiency in using its assets to generate profits.
The return on equity of 0.2 indicates that the company generated 20 cents
of profit for every dollar of equity. This ratio measures the company’s
ability to generate profits from shareholders’ investments.
Overall, based on the provided ratios:
The company appears to have strong liquidity with both current and quick
ratios above 1.
The company has a healthy mix of debt and equity financing with a low
debt-to-equity ratio.
The company is profitable, as evidenced by positive returns on assets and
equity.
This analysis suggests that the company is in a stable financial position with
efficient use of assets and strong profitability.
Question 12
Question
A company has the following financial information for two consecutive years:
Year 1: Net Income =
$
500,000; Total Assets =
$
2,000,000
Year 2: Net Income =
$
700,000; Total Assets =
$
2,500,000
Calculate the return on assets (ROA) for each year and interpret the results
in terms of the company’s performance.
13
Solution
Step 1: Calculate the Return on Assets (ROA) for Year 1.
ROA =NetIncome
T otalAssets
ROAY ear1=500,000
2,000,000 = 0.25
Step 2: Calculate the Return on Assets (ROA) for Year 2.
ROAY ear2=700,000
2,500,000 = 0.28
Step 3: Interpretation:
In Year 1, the company had a Return on Assets (ROA) of 0.25 or 25%.
This means that for every
$
1 of assets, the company generated 25 cents of
net income.
In Year 2, the company’s ROA improved to 0.28 or 28%. This indicates
that in Year 2, the company was more efficient in generating income from
its assets compared to Year 1.
Overall, the increasing trend in ROA from Year 1 to Year 2 suggests an
improvement in the company’s performance in utilizing its assets to generate
profit.
Question 13
Question
A company has the following financial information for the year:
Total assets:
$
500,000
Total liabilities:
$
200,000
Net income:
$
50,000
Total revenue:
$
300,000
Calculate the following ratios and interpret the results:
1. Debt-to-Assets Ratio
2. Return on Assets Ratio
14
Solution
Step 1: Calculate the Debt-to-Assets Ratio The Debt-to-Assets Ratio is
calculated as:
Debt-to-Assets Ratio = Total Liabilities
Total Assets
Substitute the given values:
Debt-to-Assets Ratio = $200,000
$500,000 = 0.4
Step 2: Interpretation of the Debt-to-Assets Ratio The Debt-to-
Assets Ratio of 0.4 indicates that 40% of the company’s assets are financed by
debt. This suggests that the company relies relatively more on equity financing
and is less risky in terms of leverage.
Step 3: Calculate the Return on Assets Ratio The Return on Assets
Ratio is calculated as:
Return on Assets Ratio = Net Income
Total Assets
Substitute the given values:
Return on Assets Ratio = $50,000
$500,000 = 0.1 = 10%
Step 4: Interpretation of the Return on Assets Ratio The Return
on Assets Ratio of 10% indicates that for every dollar of assets, the company
generates
$
0.10 of net income. This ratio is a measure of how efficiently the
company is using its assets to generate profit. A higher ratio suggests better
asset utilization and profitability.
Question 14
Question
A company’s financial statements show the following information for the current
year:
Net Income:
$
500,000
Total Assets:
$
2,000,000
Total Liabilities:
$
1,000,000
Shareholders’ Equity:
$
1,000,000
Calculate the following ratios and interpret the results:
1. Return on Assets (ROA)
2. Debt-to-Equity Ratio
15
Solution
Step 1: Calculate Return on Assets (ROA)
The Return on Assets (ROA) ratio is calculated by dividing Net Income by
Total Assets.
ROA = Net Income
Total Assets
Plugging in the values:
ROA = $500,000
$2,000,000
ROA = 0.25 or 25%
Interpretation: This means that for every dollar of assets, the company
generated 0.25or25%ofnetincome.
Step 2: Calculate Debt-to-Equity Ratio
The Debt-to-Equity ratio is calculated by dividing Total Liabilities by Share-
holders’ Equity.
Debt-to-Equity Ratio = Total Liabilities
Shareholders’ Equity
Plugging in the values:
Debt-to-Equity Ratio = $1,000,000
$1,000,000
Debt-to-Equity Ratio = 1
Interpretation: A Debt-to-Equity ratio of 1 means that the company has
the same amount of debt as it has equity. This indicates that the company’s
financing is balanced between debt and equity.
Question 15
Question
A company reported the following financial ratios for the year: current ratio of
2.5, quick ratio of 1.5, and debt-to-equity ratio of 0.75. Explain the interpreta-
tion of each ratio and discuss what these ratios indicate about the company’s
financial health.
Solution
Step 1: Interpretation of Ratios
16
Current Ratio: The current ratio is a measure of a company’s ability to
cover its short-term liabilities with its short-term assets. A current ratio of
2.5 means that the company has 2.50worthofcurrentassetsf orevery1.00
of current liabilities.
Quick Ratio: The quick ratio (also known as the acid-test ratio) is a
more stringent measure than the current ratio. It excludes inventory from
current assets to focus on the most liquid assets. A quick ratio of 1.5 means
that the company has 1.50ofhighlyliquidassetsthatcanbequicklyconvertedintocashtocover1.00
of current liabilities.
Debt-to-Equity Ratio: The debt-to-equity ratio shows the proportion
of debt financing relative to equity financing. A debt-to-equity ratio of
0.75 means that the company has 0.75ofdebtforevery1.00 of equity.
Step 2: Financial Health Interpretation
A current ratio above 1 indicates that the company can meet its short-
term obligations. A current ratio of 2.5 is considered healthy as it shows
a strong ability to cover short-term liabilities.
A quick ratio of 1.5 is also above 1, which indicates that the company can
meet its short-term obligations without relying on selling inventory. This
shows good liquidity.
A debt-to-equity ratio of 0.75 indicates that the company is using more
equity financing relative to debt financing. This could be seen as a positive
sign as it indicates lower financial risk.
Overall, based on the ratios provided, the company appears to have good
short-term liquidity and a conservative approach to capital structure.
However, it is important to consider other factors such as industry norms,
historical trends, and future outlook before making a definitive assessment
of the company’s financial health.
Question 16
Question
A company’s financial statements show the following figures for two consecutive
years:
Year 1: Net Income =
$
500,000; Total Assets =
$
2,000,000
Year 2: Net Income =
$
600,000; Total Assets =
$
2,500,000
Calculate the return on assets (ROA) for both years and interpret the results
in terms of the company’s performance.
17
Solution
Step 1: Calculate the Return on Assets (ROA) for Year 1 and Year 2 using the
formula:
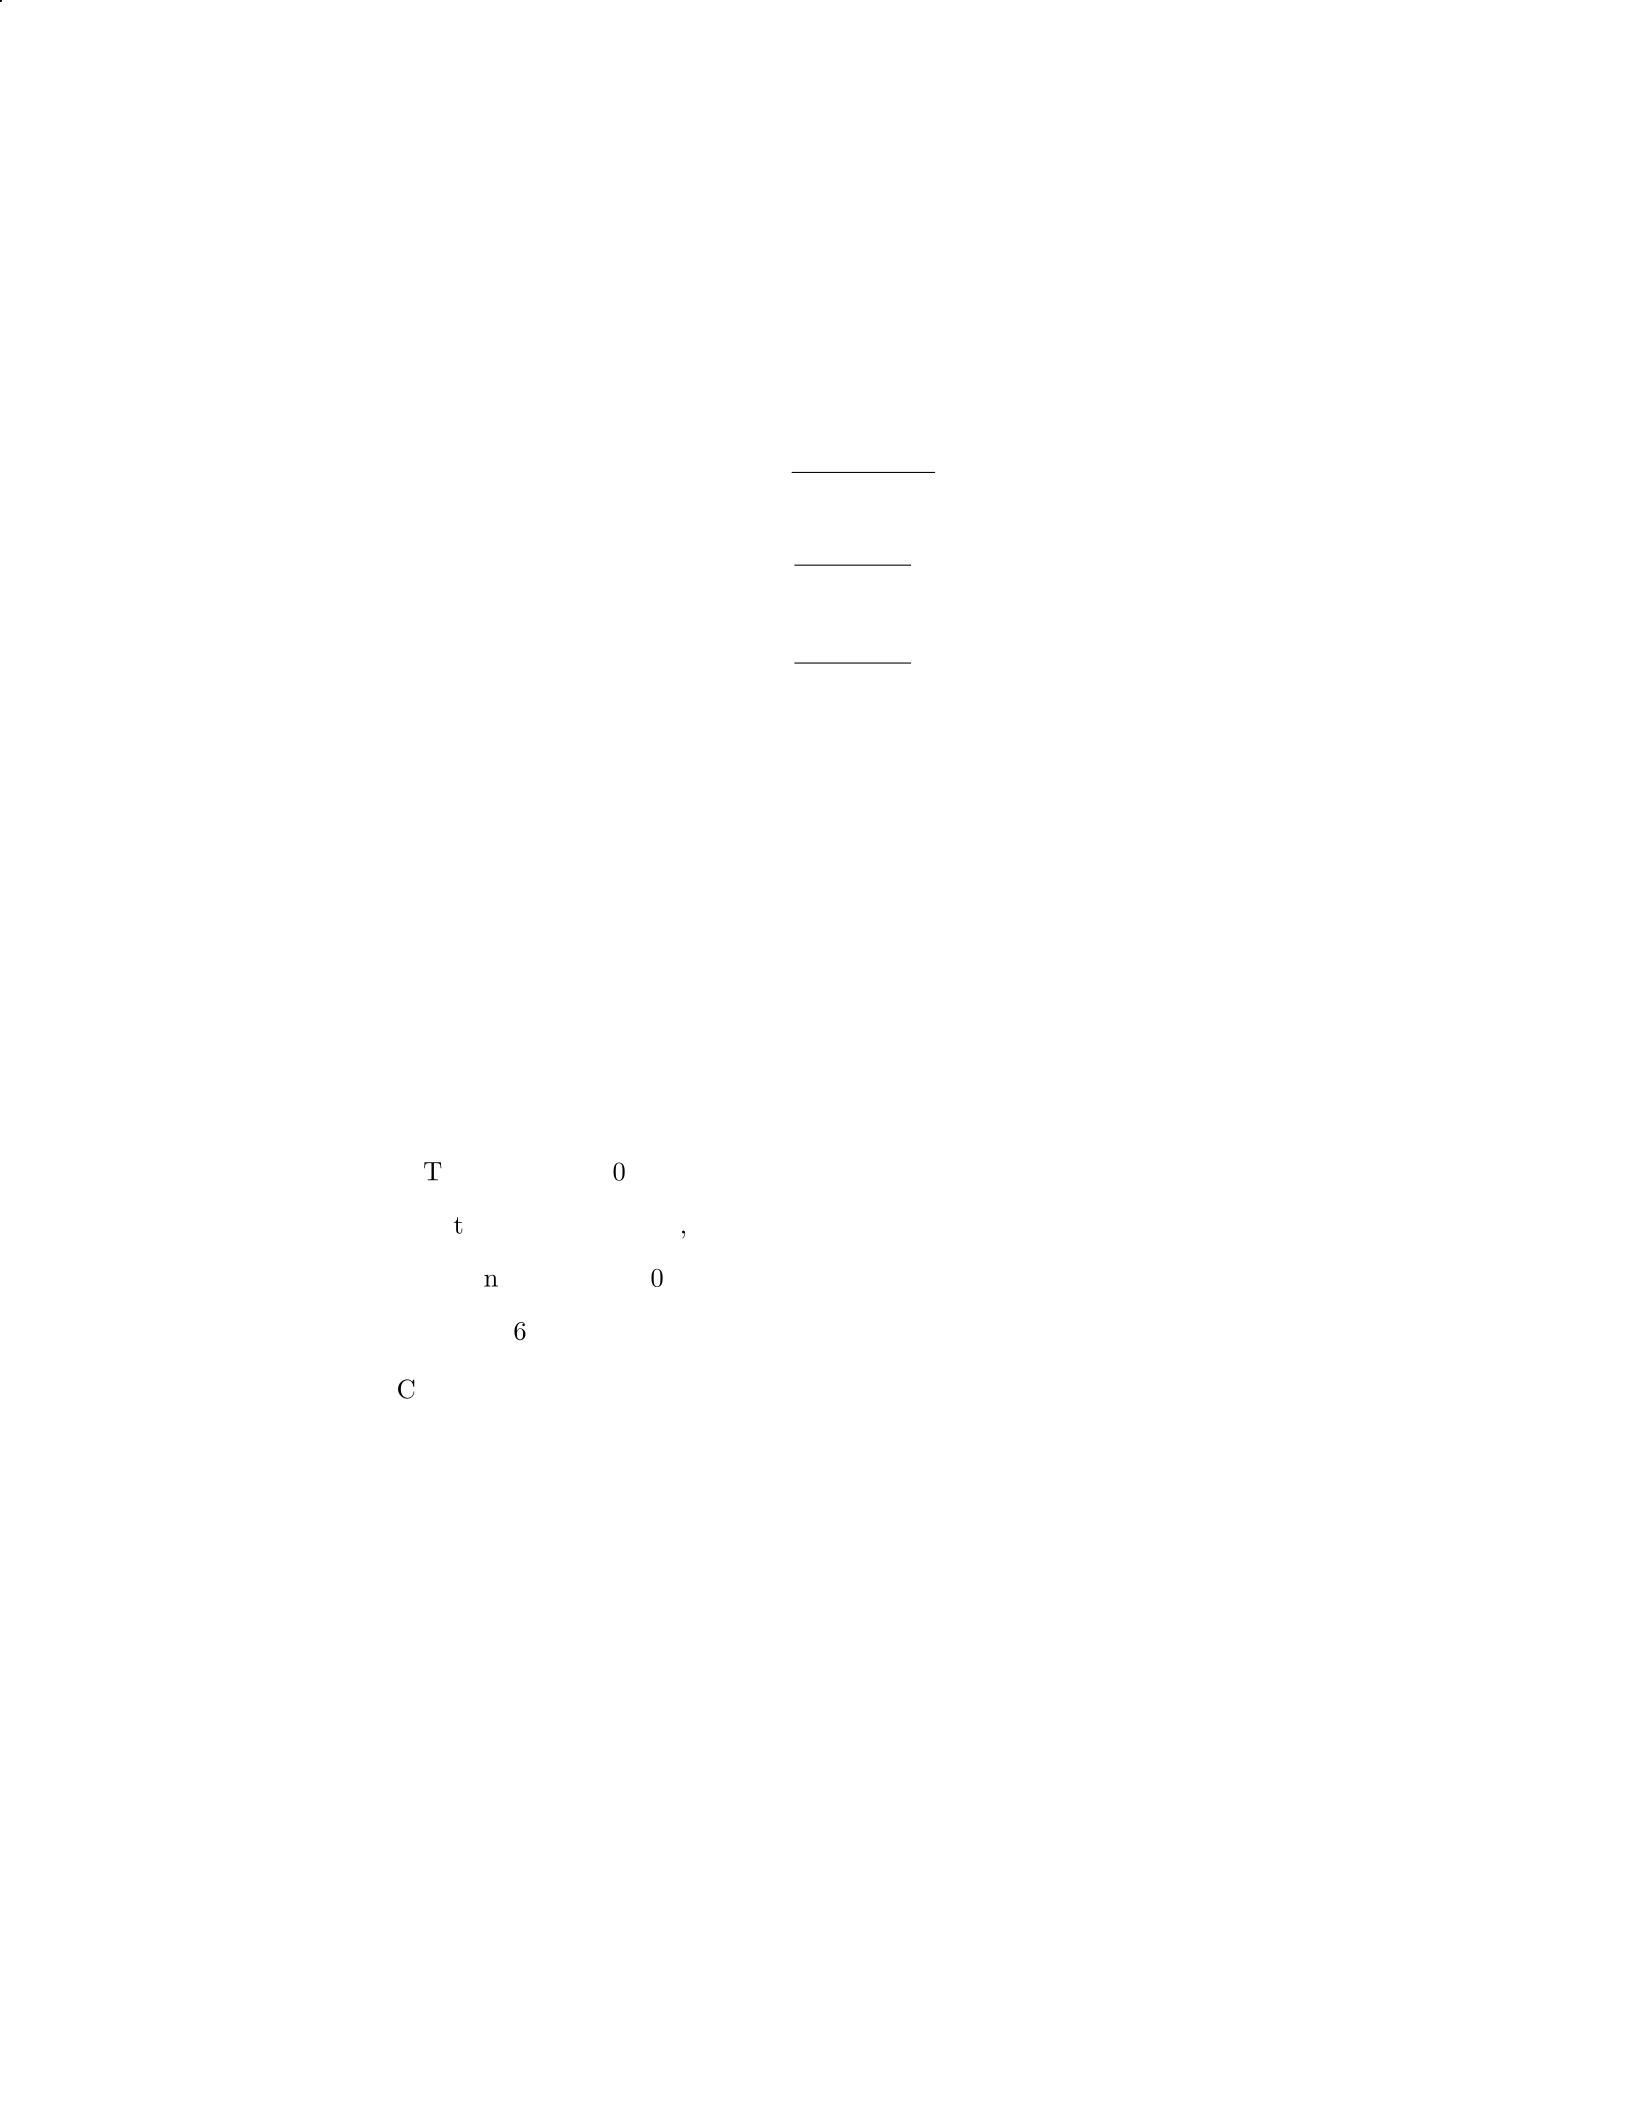
ROA =NetIncome
T otalAssets
For Year 1:
ROAYear 1 =500,000
2,000,000 = 0.25
For Year 2:
ROAYear 2 =600,000
2,500,000 = 0.24
Step 2: Interpret the ROA values for both years: - In Year 1, the company
had a ROA of 0.25, meaning that for every dollar of assets, the company gener-
ated 0.25innetincome.−InY ear2, thecompany′sROAdecreasedto0.24, indicatingaslightdecreaseinef ficiencyingeneratingincomefromitsassets.
Overall, the company’s performance in terms of generating income from its
assets slightly declined from Year 1 to Year 2. It is important for the company to
analyze the reasons behind this decrease and take corrective actions to improve
its efficiency in utilizing assets to generate income.
Question 17
Question
A company’s financial statements show the following data for the current year:
Total Assets:
$
800,000
Total Liabilities:
$
400,000
Net Income:
$
120,000
Sales:
$
600,000
Calculate the following financial ratios and provide an interpretation of each:
1. Debt-to-Asset Ratio
2. Return on Assets
3. Profit Margin
18
Solution
Let’s calculate each ratio step by step:
Step 1: Calculate the Debt-to-Asset Ratio
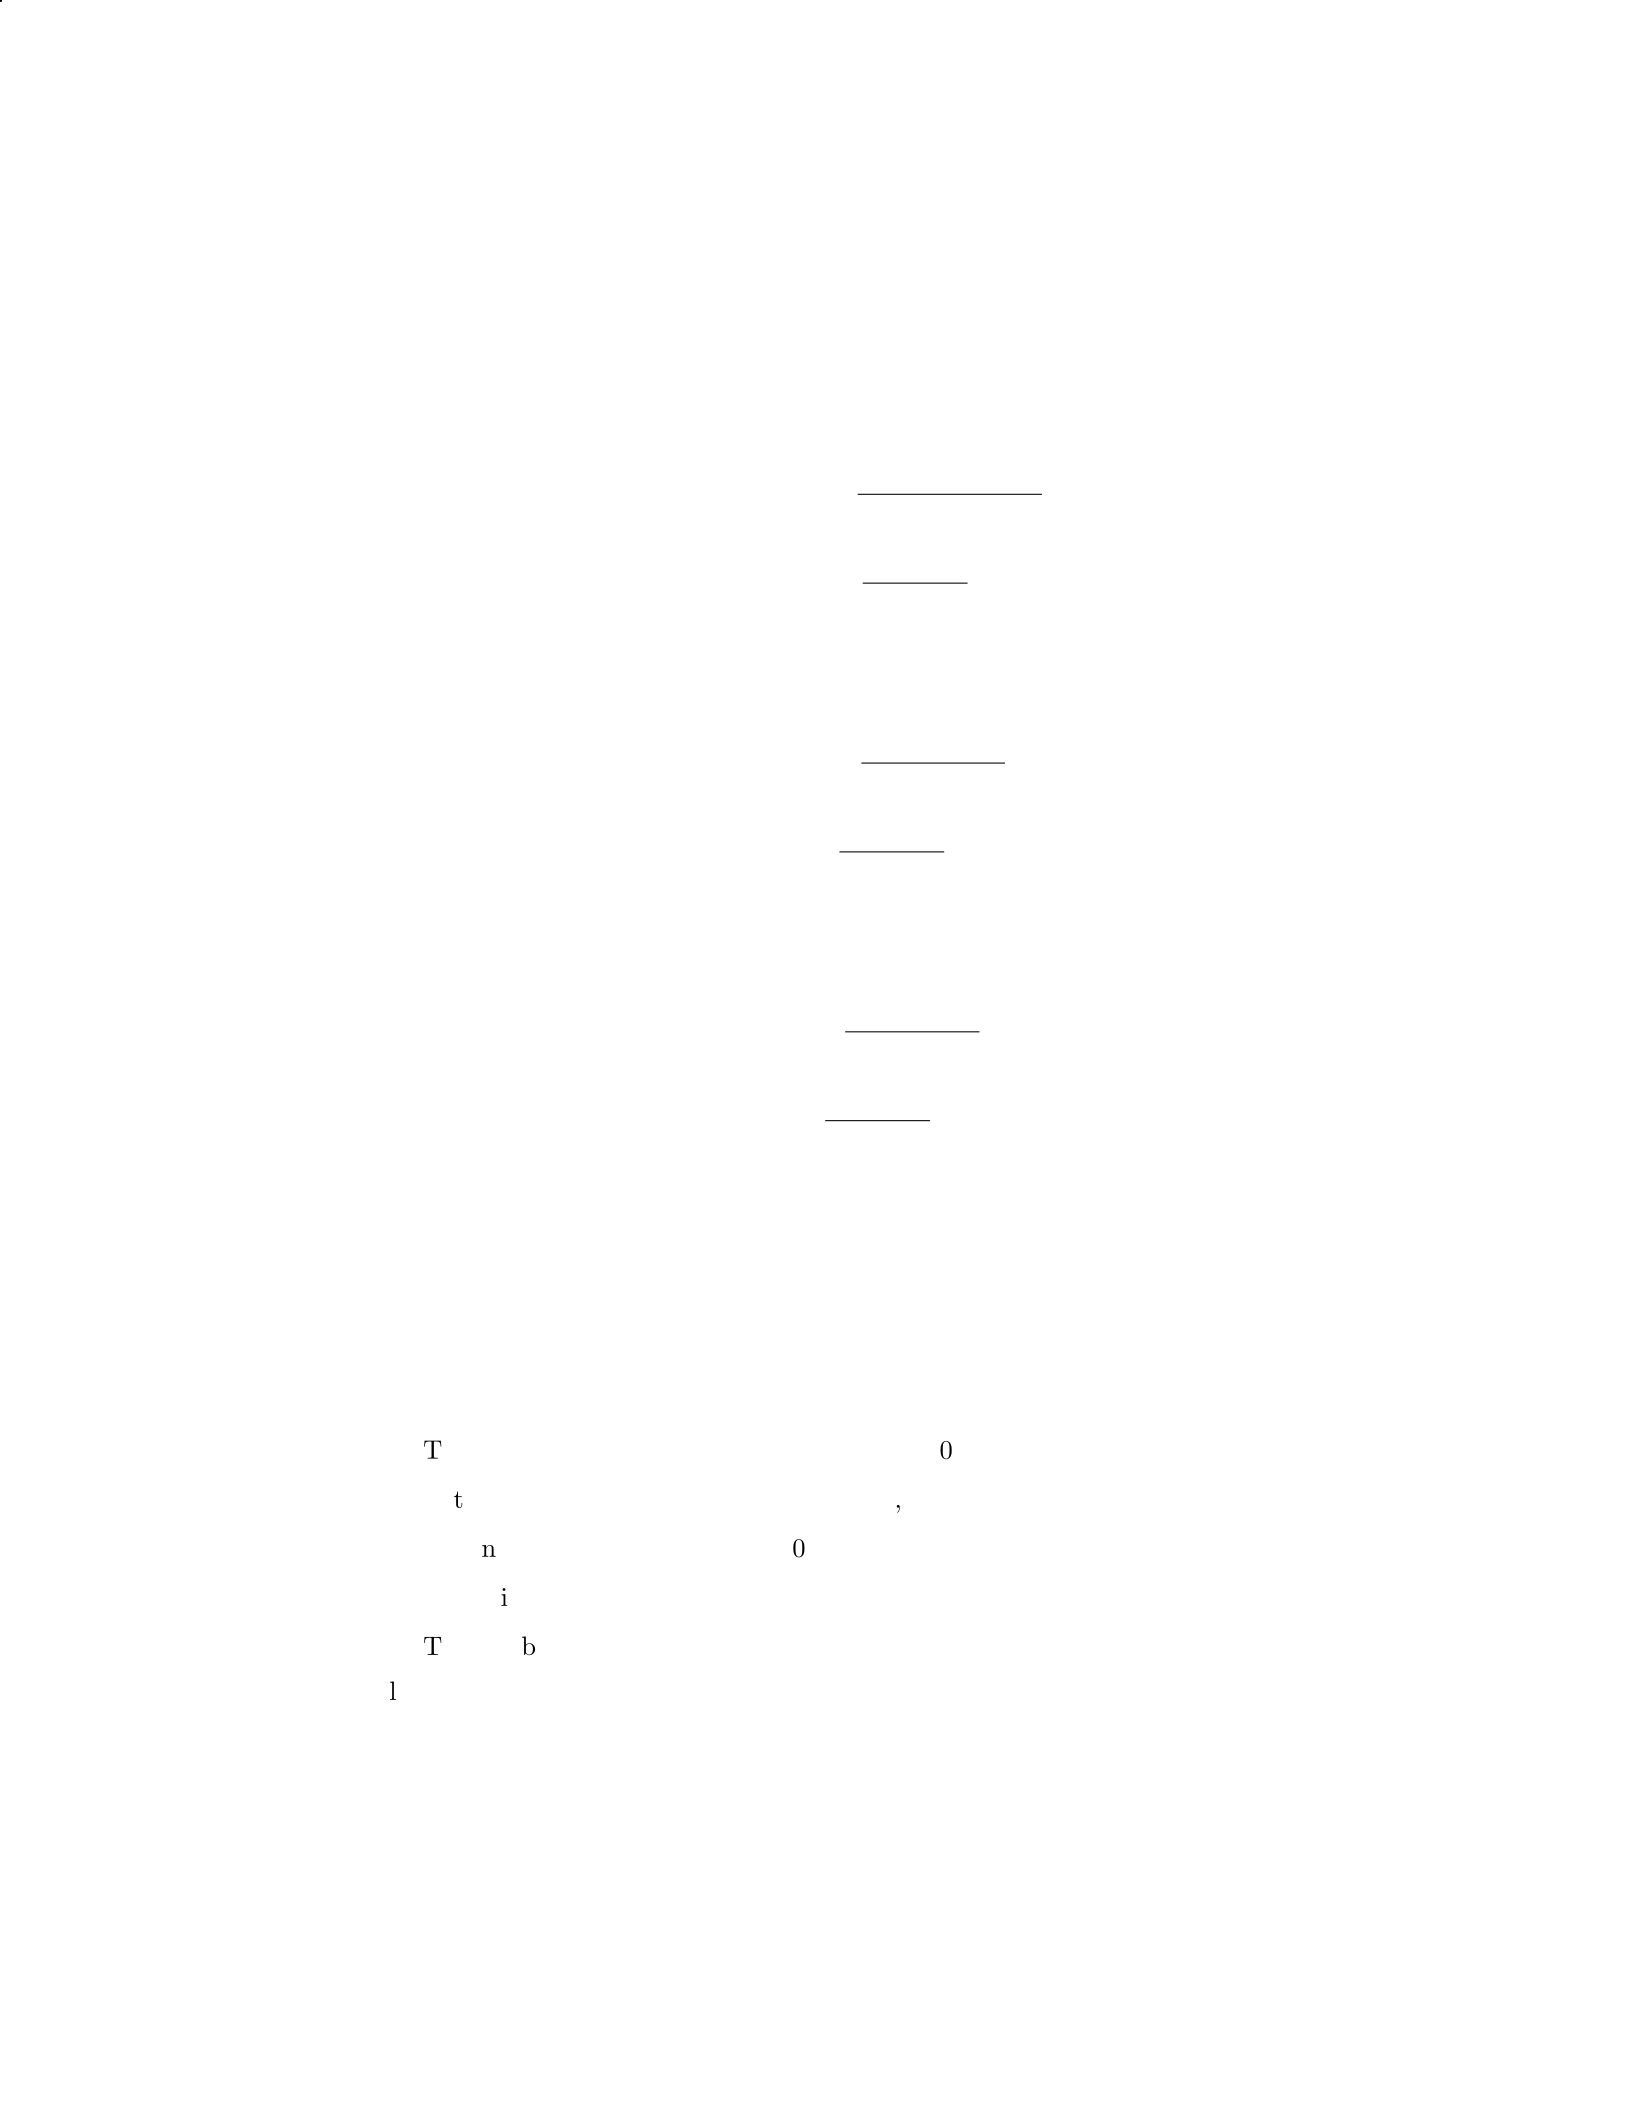
Debt-to-Asset Ratio = Total Liabilities
Total Assets
Debt-to-Asset Ratio = $400,000
$800,000 = 0.5
The Debt-to-Asset ratio is 0.5, which means that 50% of the company’s
assets are financed by debt.
Step 2: Calculate the Return on Assets
Return on Assets = Net Income
Total Assets
Return on Assets = $120,000
$800,000 = 0.15
The Return on Assets is 0.15, or 15%. This means that the company gener-
ated a profit of 15% for every dollar of assets it possesses.
Step 3: Calculate the Profit Margin
Profit Margin = Net Income
Sales
Profit Margin = $120,000
$600,000 = 0.2
The Profit Margin is 0.2, or 20%. This indicates that the company’s net
income is 20% of its total sales.
Question 18
Question
A company has the following financial information for the year:
Total assets at the beginning of the year:
$
500,000
Total assets at the end of the year:
$
700,000
Net income for the year:
$
100,000
Total liabilities at the beginning of the year:
$
300,000
Total liabilities at the end of the year:
$
400,000
Calculate the following ratios and interpret them:
1. Return on Assets (ROA)
2. Debt to Asset Ratio
19
Solution
1. Return on Assets (ROA)
Step 1: Calculate the average total assets:
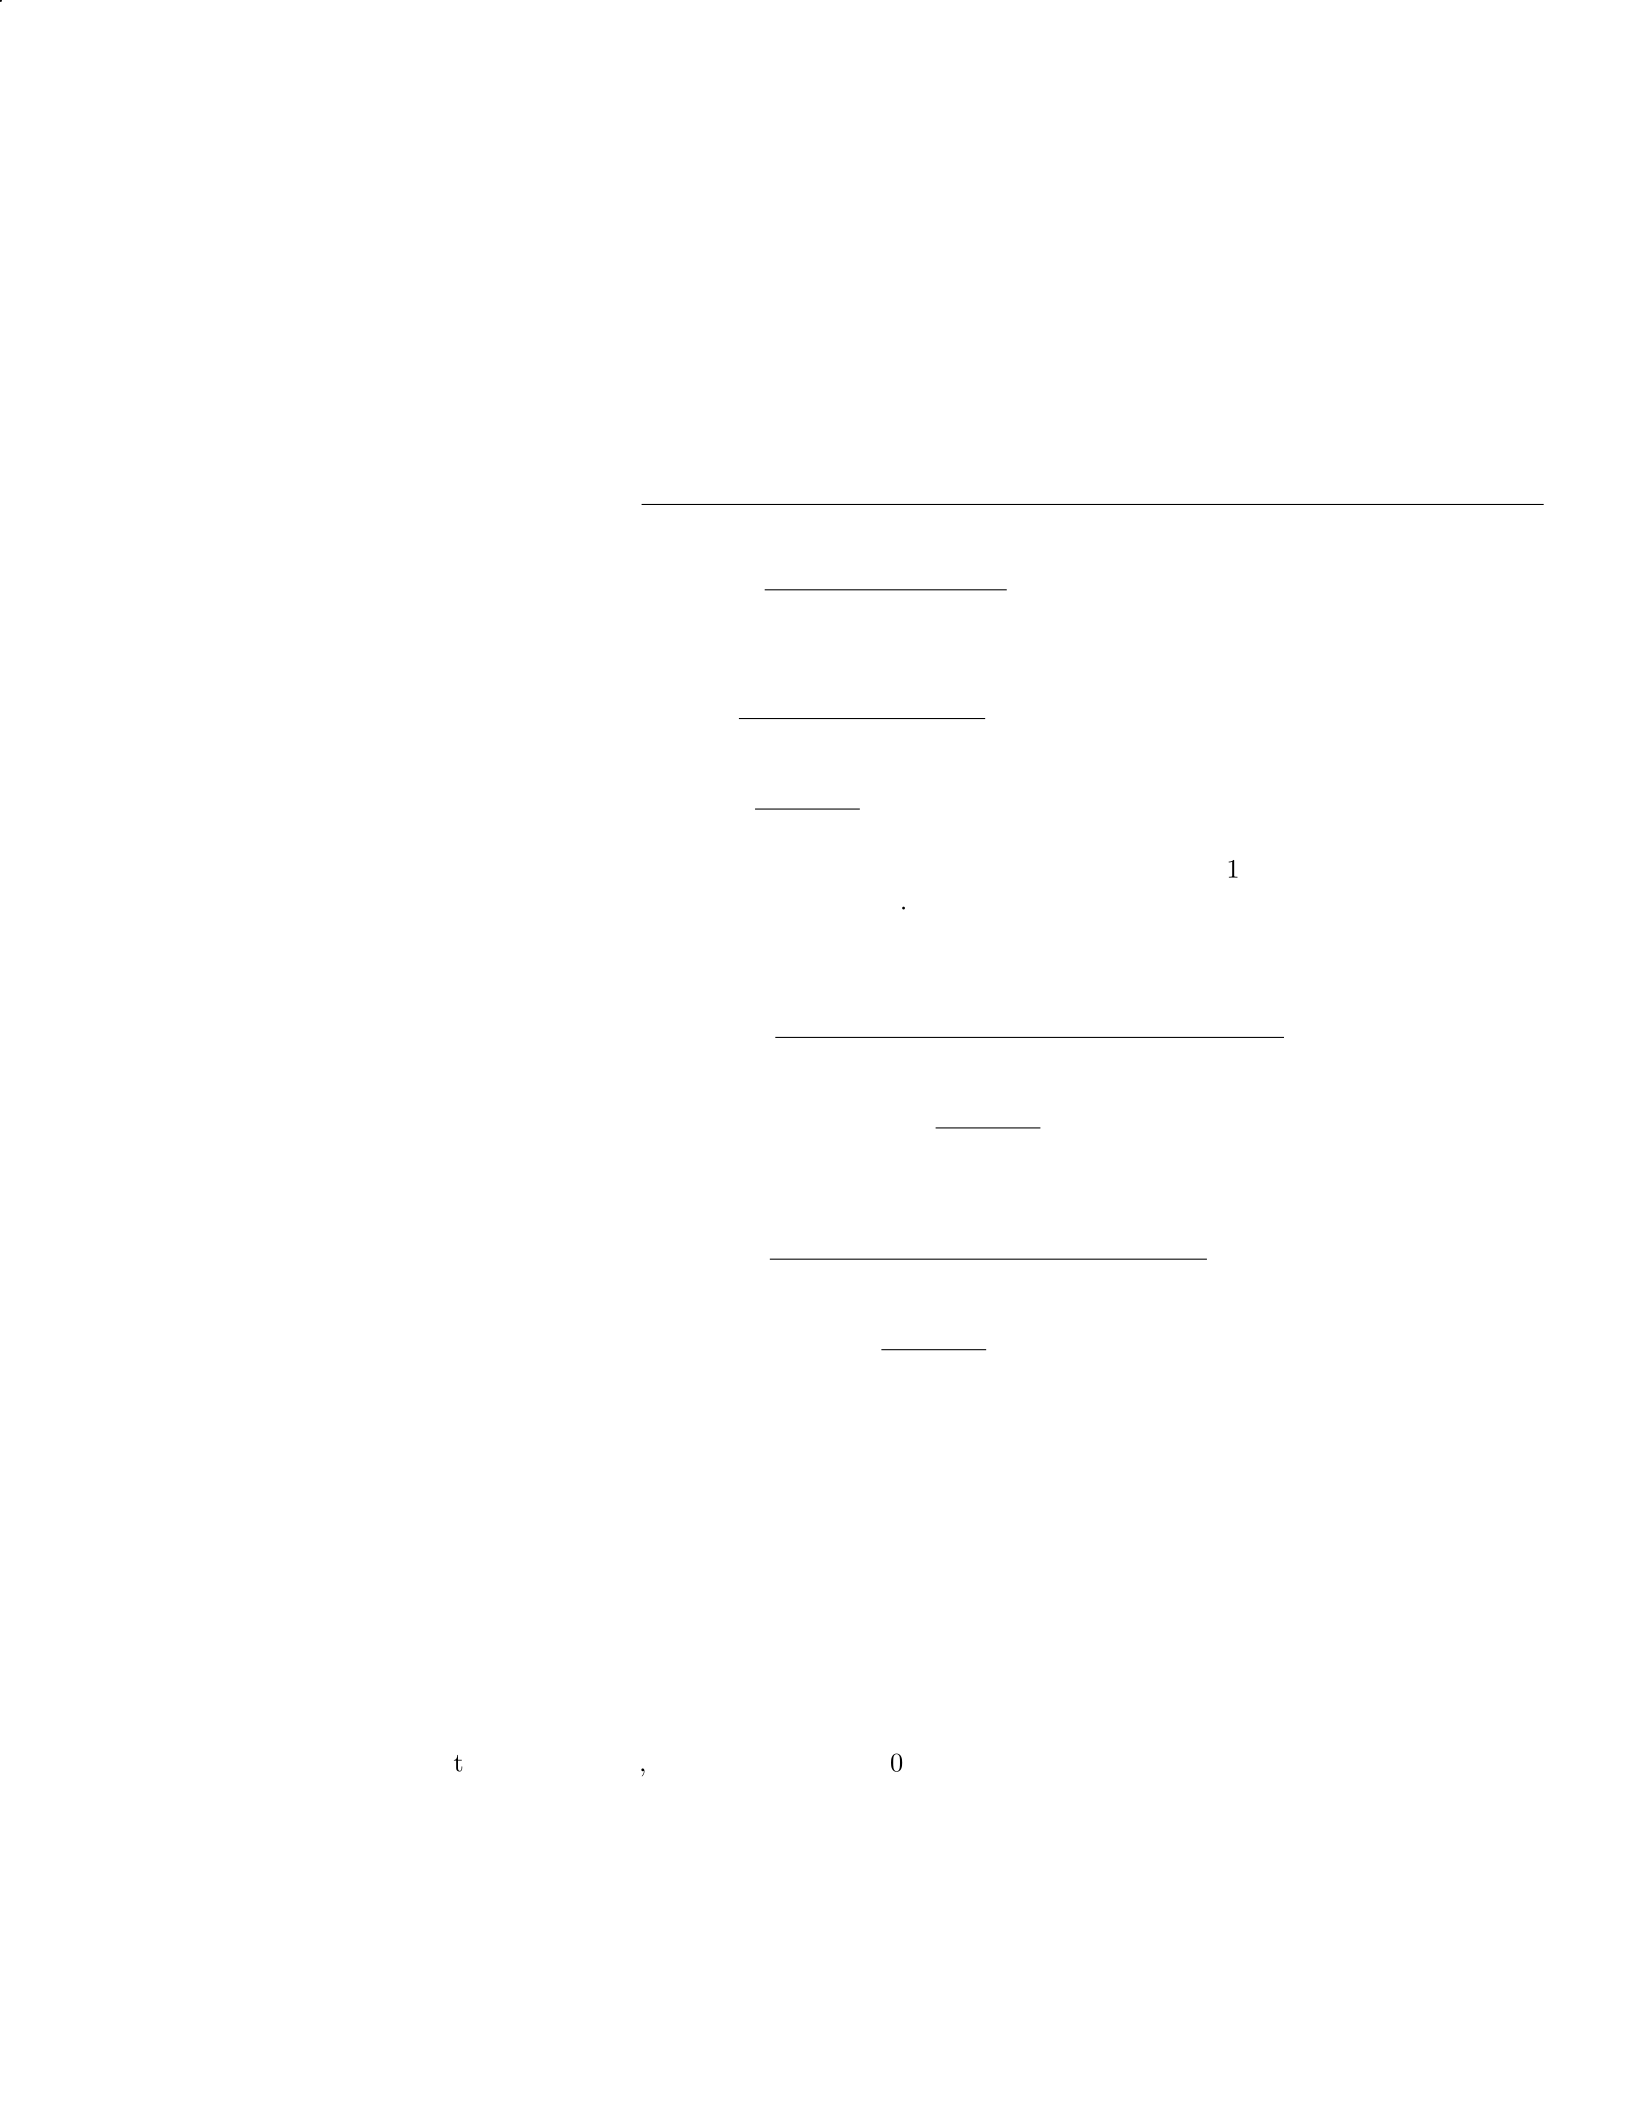
Average Total Assets = Total assets at the beginning of the year + Total assets at the end of the year
2
Average Total Assets = $500,000 + $700,000
2= $600,000
Step 2: Calculate the Return on Assets (ROA):
ROA = Net Income
Average Total Assets
ROA = $100,000
$600,000 = 0.1667
Step 3: Interpretation: The ROA of 0.1667 means that for every
$
1 of
average total assets, the company generates
$
0.1667 of net income.
2. Debt to Asset Ratio
Step 1: Calculate the Debt to Asset Ratio at the beginning of the year:
Debt to Asset Ratio (Beginning) = Total liabilities at the beginning of the year
Total assets at the beginning of the year
Debt to Asset Ratio (Beginning) = $300,000
$500,000 = 0.6
Step 2: Calculate the Debt to Asset Ratio at the end of the year:
Debt to Asset Ratio (End) = Total liabilities at the end of the year
Total assets at the end of the year
Debt to Asset Ratio (End) = $400,000
$700,000 ≈0.5714
Step 3: Interpretation: The Debt to Asset Ratio decreased from 0.6 to
approximately 0.5714, indicating that the company relied less on debt financing
compared to the previous year.
Question 19
Question
A company reported the following financial information for the years 2020 and
2021:
Total Assets:
$
500,000 (2020) and
$
600,000 (2021)
20
Total Liabilities:
$
200,000 (2020) and
$
250,000 (2021)
Net Income:
$
50,000 (2020) and
$
75,000 (2021)
Calculate and interpret the following ratios for the year 2021:
1. Debt-to-Assets Ratio
2. Return on Assets
Solution
Step 1: Calculate the Debt-to-Assets Ratio The Debt-to-Assets Ratio is calcu-
lated as:
Debt-to-Assets Ratio = Total Liabilities
Total Assets
Substitute the given values for 2021:
Debt-to-Assets Ratio = $250,000
$600,000
Calculating the ratio:
Debt-to-Assets Ratio = 0.4167 or 41.67%
Interpretation: The Debt-to-Assets Ratio of 41.67% means that 41.67% of
the company’s assets are financed by debt.
Step 2: Calculate Return on Assets The Return on Assets (ROA) is calcu-
lated as:
ROA = Net Income
Total Assets
Substitute the given values for 2021:
ROA = $75,000
$600,000
Calculating the ROA:
ROA = 0.125 or 12.5%
Interpretation: The ROA of 12.5% indicates that the company generated a
return of 12.5 cents for every dollar of assets in 2021.
Question 20
Question
A company’s financial statements report the following information for the year
ended December 31, 20X5:
21
Net income: $250,000
Total assets: $2,500,000
Total liabilities: $1,000,000
Total equity: $1,500,000
Number of shares outstanding: 100,000
Calculate the following ratios and provide an interpretation for each:
1. Return on assets (ROA)
2. Return on equity (ROE)
3. Earnings per share (EPS)
Solution
Step 1: Calculate Return on Assets (ROA)
ROA =Net Income
T otal Assets
Substitute the given values:
ROA =250,000
2,500,000 = 0.10
Step 2: Interpretation of ROA The ROA of 0.10 means that for every
dollar of assets, the company generated 0.10 in net income. It indicates that
the company is generating a 10
Step 3: Calculate Return on Equity (ROE)
ROE =Net Income
T otal Equity
Substitute the given values:
ROE =250,000
1,500,000 ≈0.17
Step 4: Interpretation of ROE The ROE of approximately 0.17 indicates
that the company generated 0.17 in net income for every dollar of equity. This
ratio reflects the company’s profitability from the shareholders’ perspective.
Step 5: Calculate Earnings per Share (EPS)
EP S =Net Income
Number of Shares Outstanding
22
Substitute the given values:
EP S =250,000
100,000 = $2.50
Step 6: Interpretation of EPS The EPS of
$
2.50 means that each share
of the company earned
$
2.50 during the year. It is an important measure for
investors as it indicates the company’s profitability on a per-share basis.
Question 21
Question
A company reported the following financial information for the year ending
December 31, 2020:
Total Assets:
$
900,000
Total Liabilities:
$
400,000
Total Equity:
$
500,000
Net Income:
$
120,000
Sales Revenue:
$
800,000
Calculate the following financial ratios for the company based on the given
information:
1. Debt to Equity Ratio
2. Return on Assets (ROA)
3. Profit Margin
Solution
Let’s calculate each of the financial ratios step by step:
Step 1: Calculate Debt to Equity Ratio The Debt to Equity Ratio is
calculated as:
Debt to Equity Ratio = Total Liabilities
Total Equity
Substitute the given values:
Debt to Equity Ratio = 400,000
500,000 = 0.8
Step 2: Calculate Return on Assets (ROA) The Return on Assets
(ROA) is calculated as:
ROA = Net Income
Total Assets
23
Substitute the given values:
ROA = 120,000
900,000 = 0.1333
Step 3: Calculate Profit Margin The Profit Margin is calculated as:
Profit Margin = Net Income
Sales Revenue
Substitute the given values:
Profit Margin = 120,000
800,000 = 0.15
Therefore, the calculated financial ratios are:
1. Debt to Equity Ratio: 0.8
2. ROA: 0.1333 or 13.33%
3. Profit Margin: 0.15 or 15%
Question 22
Question
A company has the following financial information for the year:
Total assets:
$
500,000
Total liabilities:
$
200,000
Net income:
$
50,000
Total revenue:
$
300,000
Total expenses:
$
250,000
Calculate the following ratios and provide an interpretation for each:
1. Debt-to-Asset Ratio
2. Return on Assets (ROA)
3. Profit Margin
24
Solution
Step 1: Calculate the Debt-to-Asset Ratio: The Debt-to-Asset Ratio is calcu-
lated as:
Debt-to-Asset Ratio = Total Liabilities
Total Assets
Given that Total liabilities is
$
200,000 and Total assets is
$
500,000, we can
substitute these values into the formula:
Debt-to-Asset Ratio = 200,000
500,000 = 0.4
Interpretation: The Debt-to-Asset Ratio of 0.4 indicates that 40
Step 2: Calculate the Return on Assets (ROA): The Return on Assets
(ROA) is calculated as:
ROA = Net Income
Total Assets ×100%
Given that Net income is
$
50,000 and Total assets is
$
500,000, we can sub-
stitute these values into the formula:
ROA = 50,000
500,000 ×100% = 10%
Interpretation: The ROA of 10
Step 3: Calculate the Profit Margin: The Profit Margin is calculated as:
Profit Margin = Net Income
Total Revenue ×100%
Given that Net income is
$
50,000 and Total revenue is
$
300,000, we can
substitute these values into the formula:
Profit Margin = 50,000
300,000 ×100% = 16.67%
Interpretation: The Profit Margin of 16.67
Question 23
Question
A company has the following financial information for the year:
Current assets:
$
500,000
Total assets:
$
1,000,000
Current liabilities:
$
200,000
25
Total liabilities:
$
400,000
Sales revenue:
$
800,000
Cost of goods sold:
$
400,000
Cash:
$
100,000
Calculate the following financial ratios for the company:
1. Current ratio
2. Quick ratio
3. Debt ratio
4. Operating profit margin
Interpret the results and provide recommendations for the company based
on the ratios calculated.
Solution
Step 1: Calculate the Current Ratio
Current Ratio = Current Assets
Current Liabilities
=$500,000
$200,000
= 2.5
Step 2: Calculate the Quick Ratio
Quick Ratio = Current Assets −Inventory
Current Liabilities
=$500,000 −$400,000
$200,000
=$100,000
$200,000
= 0.5
Step 3: Calculate the Debt Ratio
Debt Ratio = Total Liabilities
Total Assets
=$400,000
$1,000,000
= 0.4
26
Step 4: Calculate the Operating Profit Margin
Operating Profit Margin = Sales Revenue −Cost of Goods Sold
Sales Revenue ×100%
=$800,000 −$400,000
$800,000 ×100%
=$400,000
$800,000 ×100%
= 50%
Interpretation and Recommendations:
Current Ratio of 2.5 indicates that the company has more than enough
current assets to cover its current liabilities, which is a positive sign.
Quick Ratio of 0.5 suggests that the company may have difficulty meeting
its short-term obligations without relying on inventory sales.
Debt Ratio of 0.4 signifies that 40
Operating Profit Margin of 50
Based on the ratios calculated, the company should focus on improving
its liquidity by reducing reliance on inventory for short-term obligations and
consider reducing debt levels to lower financial risk. They should also continue
to maintain or improve their profit margins to ensure long-term sustainability.
Question 24
Question
A company has the following financial information for the year:
Net income:
$
500,000
Total assets:
$
2,500,000
Total liabilities:
$
1,000,000
Total equity:
$
1,500,000
Calculate the following ratios and interpret the results:
1. Return on Assets (ROA)
2. Return on Equity (ROE)
3. Debt-to-Equity ratio
27
Solution
Let’s calculate each ratio and interpret the results:
1. Return on Assets (ROA):
ROA =Net Income
T otal Assets
ROA =$500,000
$2,500,000
ROA = 0.20 or 20%
The company’s ROA is 20%, which means that for every dollar of assets,
the company generates 0.20ofprof it.
2. Return on Equity (ROE):
ROE =Net Income
T otal Equity
ROE =$500,000
$1,500,000
ROE = 0.3333 or 33.33%
The company’s ROE is 33.33%, indicating that for every dollar of equity, the
company generates 0.33ofprof it.
3. Debt-to-Equity ratio:
Debt −to −Equity ratio =T otal Liabilities
T otal Equity
Debt −to −Equity ratio =$1,000,000
$1,500,000
Debt −to −Equity ratio = 0.6667 or 0.67
The company’s Debt-to-Equity ratio is 0.67, which means that the company has
more debt than equity. This could indicate higher financial risk.
Question 25
Question
A company reported the following financial information:
Total assets:
$
500,000
Current ratio: 2.5
28
Quick ratio: 1.5
Calculate the company’s current liabilities and quick assets. Provide your an-
swers to the nearest dollar.
Solution
Step 1: Calculate the company’s current liabilities using the current ratio for-
mula:
Current Ratio = Current Assets
Current Liabilities
Given that the current ratio is 2.5 and total assets are
$
500,000, we can find the
current assets by multiplying the current ratio by the current liabilities:
2.5 = Current Assets
Current Liabilities
Current Assets = 2.5×Current Liabilities
We know that current assets + current liabilities = total assets. Substituting
in the given values:
Total Assets = $500,000
Current Assets + Current Liabilities = $500,000
2.5×Current Liabilities + Current Liabilities = $500,000
3.5×Current Liabilities = $500,000
Current Liabilities = $500,000
3.5
Current Liabilities = $142,857
Step 2: Calculate the company’s quick assets using the quick ratio formula:
Quick Ratio = Quick Assets
Current Liabilities
Given that the quick ratio is 1.5 and the current liabilities are
$
142,857, we can
find the quick assets by multiplying the quick ratio by the current liabilities:
1.5 = Quick Assets
Current Liabilities
Quick Assets = 1.5×Current Liabilities
Quick Assets = 1.5×$142,857
Quick Assets = $214,285.50
Therefore, the company’s current liabilities are
$
142,857 and its quick assets
are
$
214,285.50.
29
Question 26
Question
A company’s financial statements show the following information:
Total assets:
$
500,000
Total liabilities:
$
200,000
Total equity:
$
300,000
Net income:
$
50,000
Calculate the return on equity (ROE) for the company based on the given
information.
Solution
To calculate the return on equity (ROE), we use the formula:
ROE = Net Income
Total Equity ×100%
Step 1: Calculate the ROE using the provided information.
ROE = 50,000
300,000 ×100%
Step 2: Simplify the expression.
ROE = 1
6×100%
Step 3: Calculate the ROE.
ROE = 16.67%
Therefore, the return on equity (ROE) for the company is 16.67%.
Question 27
Question
A company has the following financial data for the year ending December 31,
20XX:
Net sales:
$
500,000
Cost of goods sold:
$
300,000
Total assets:
$
800,000
30
Total liabilities:
$
400,000
Calculate the following ratios and interpret the results:
1. Gross profit margin
2. Return on assets
Solution
To calculate the required ratios, we first need to find the values of gross profit
and net income.
Step 1: Calculate Gross Profit
Gross Profit = Net Sales −Cost of Goods Sold
= $500,000 −$300,000
= $200,000
Step 2: Calculate Net Income
Net Income = Net Sales −Cost of Goods Sold −Operating Expenses
= $500,000 −$300,000 −Operating Expenses
Given that we do not have the operating expenses, we cannot determine the
exact net income. Therefore, we will only be able to calculate the Gross Profit
Margin using the information we have.
Step 3: Calculate Gross Profit Margin
Gross Profit Margin = Gross Profit
Net Sales ×100%
=$200,000
$500,000 ×100%
= 40%
Step 4: Calculate Return on Assets (ROA)
ROA = Net Income
Total Assets ×100%
=Net Sales −Cost of Goods Sold −Operating Expenses
Total Assets ×100%
Since we do not have the operating expenses to determine net income, we
cannot calculate the Return on Assets (ROA) ratio.
Therefore, the Gross Profit Margin for the company is 40%, but we cannot
calculate the Return on Assets without the operating expenses.
31
Question 28
Question
Company XYZ has provided the following financial information for the year
ending December 31, 20X1:
Total Assets:
$
500,000
Total Liabilities:
$
200,000
Total Equity:
$
300,000
Net Income:
$
50,000
Revenue:
$
400,000
Using this information, calculate and interpret the following ratios:
1. Debt-to-Equity Ratio
2. Return on Assets
3. Profit Margin
Solution
Step 1: Calculate Debt-to-Equity Ratio The Debt-to-Equity Ratio is cal-
culated as:
Debt-to-Equity Ratio = Total Liabilities
Total Equity
Given that Total Liabilities =
$
200,000 and Total Equity =
$
300,000, we
can calculate the Debt-to-Equity Ratio:
Debt-to-Equity Ratio = 200,000
300,000 = 0.67
Step 2: Interpret Debt-to-Equity Ratio A Debt-to-Equity Ratio of 0.67
indicates that for every dollar of equity, the company has 0.67of debt.T hissuggeststhatthecompanyisf inancedmorebyequitythandebt.
Step 3: Calculate Return on Assets (ROA) The Return on Assets is
calculated as:
Return on Assets = Net Income
Total Assets
Given that Net Income =
$
50,000 and Total Assets =
$
500,000, we can
calculate the Return on Assets:
Return on Assets = 50,000
500,000 = 0.1 = 10%
32
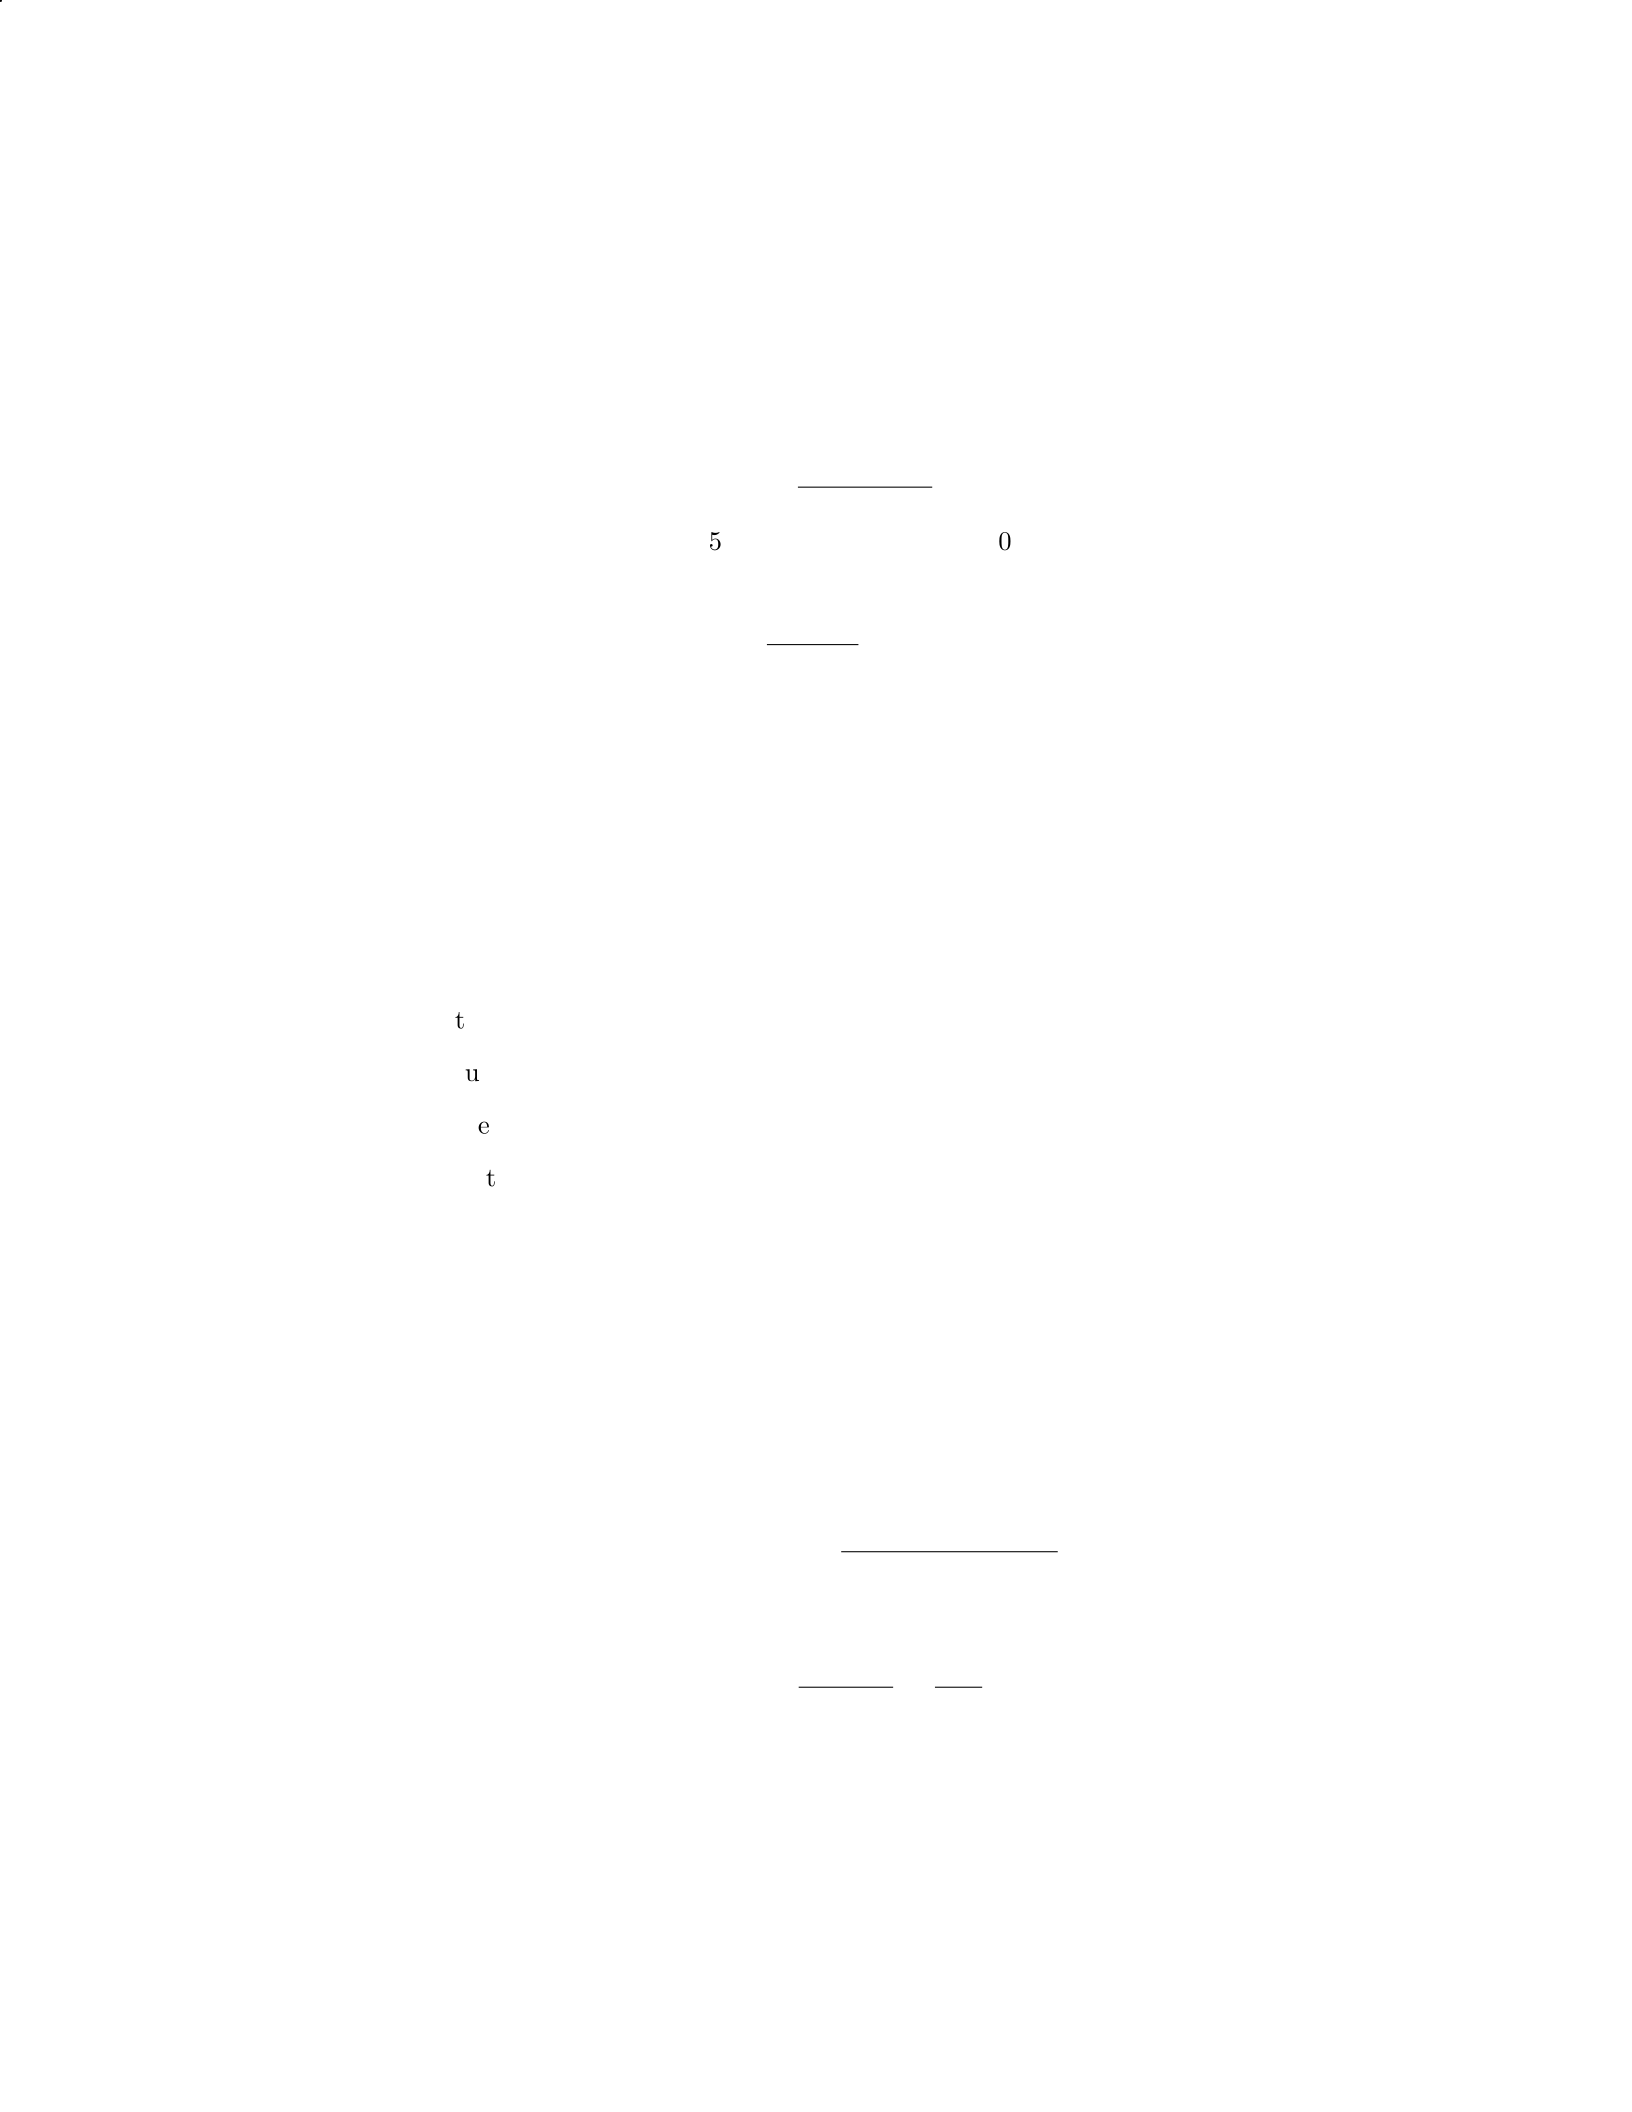
Step 4: Interpret Return on Assets A Return on Assets of 10% indicates
that the company generated a profit of 10 cents for every dollar of assets.
Step 5: Calculate Profit Margin The Profit Margin is calculated as:
Profit Margin = Net Income
Revenue ×100%
Given that Net Income =
$
50,000 and Revenue =
$
400,000, we can calculate
the Profit Margin:
Profit Margin = 50,000
400,000 ×100% = 12.5%
Step 6: Interpret Profit Margin A Profit Margin of 12.5% indicates that
the company keeps 12.5 cents from every dollar of sales as profit after covering
all expenses.
Question 29
Question
A company has the following financial information for the past year:
Net profit margin: 12
Return on assets: 10
Current ratio: 1.5
Acid-test ratio: 1.0
Determine whether the company is in a strong financial position based on
these ratios.
Solution
To determine whether the company is in a strong financial position, we will
analyze each of the given ratios.
Step 1: Calculate the Gross Profit Margin The gross profit margin
can be calculated using the formula:
Gross Profit Margin = Net Sales −COGS
Net Sales
Given that the Net Profit Margin is 12
Gross Profit Margin = 12% + 1
1−12% =13
0.88 ≈14.77%
Step 2: Analyze the Return on Assets (ROA) The Return on Assets
is 10
33
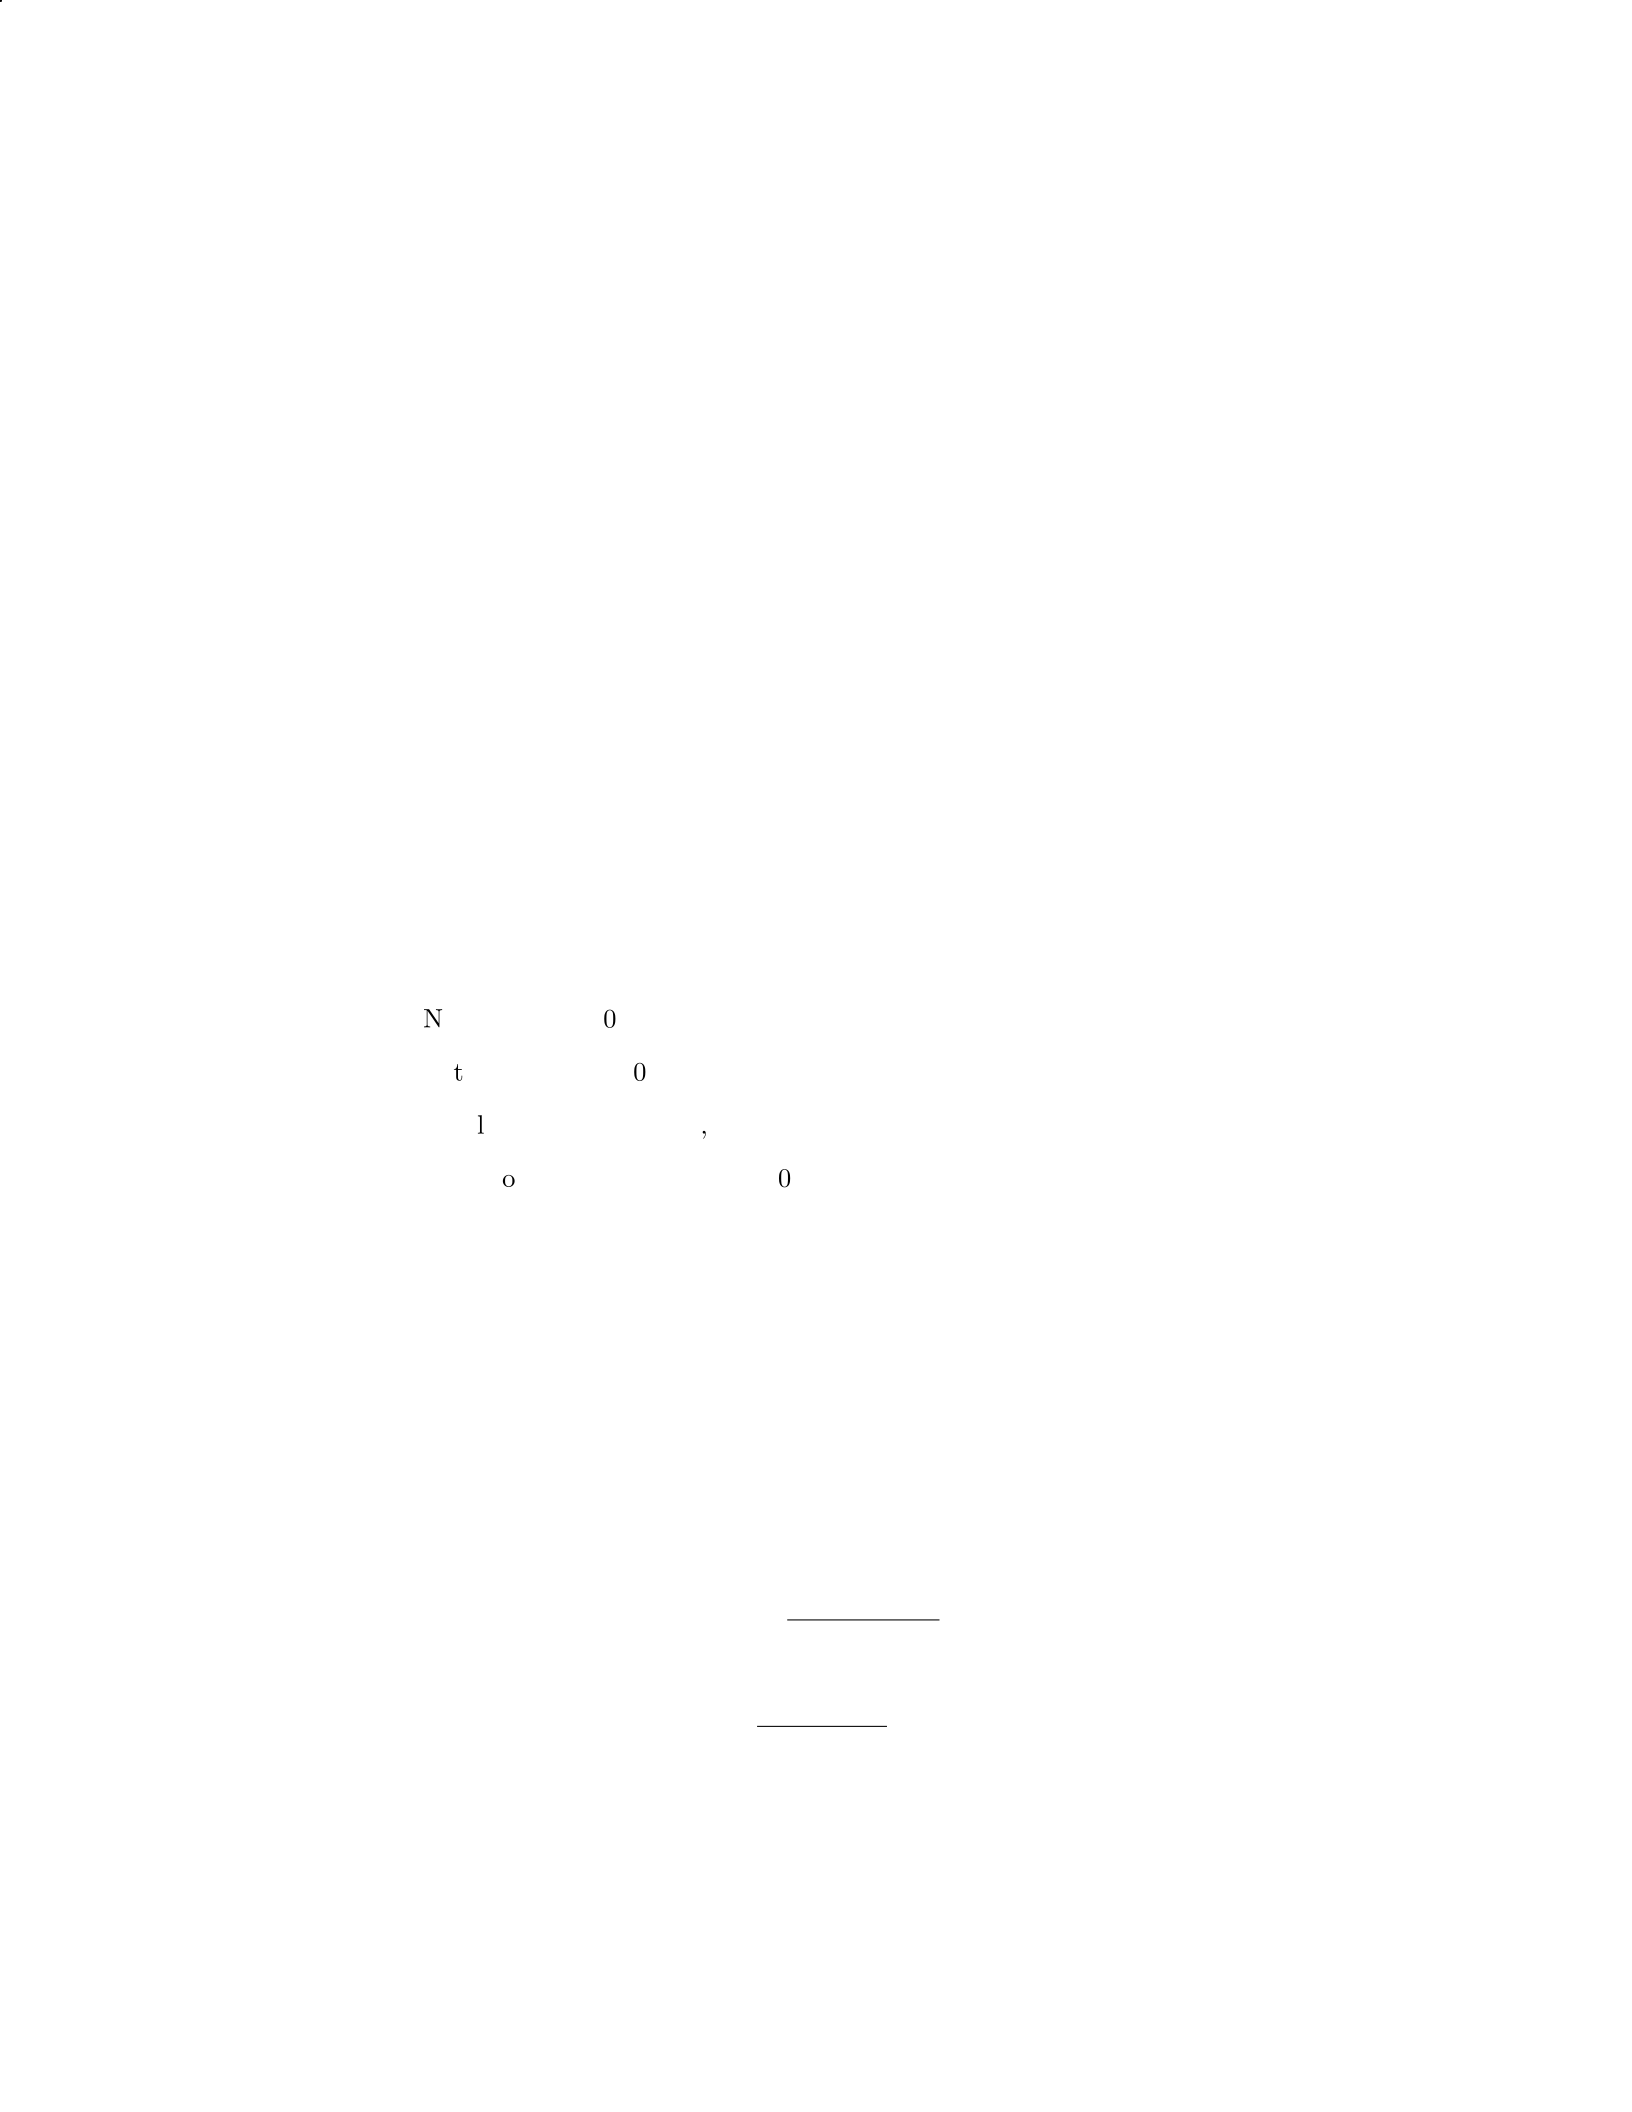
Step 3: Analyze the Current Ratio The Current Ratio is 1.5, which
means that the company has 1.50ofcurrentassetsf orevery1 of current liabili-
ties. A current ratio above 1 generally indicates good liquidity.
Step 4: Analyze the Acid-test Ratio The Acid-test Ratio is 1.0, which
means that the company has just enough liquid assets to cover its current lia-
bilities. This ratio is lower than what is generally considered ideal.
Step 5: Interpretation Based on the analysis of the ratios: - The com-
pany’s Net Profit Margin and Gross Profit Margin are in a good range. - The
Return on Assets is acceptable at 10- The Current Ratio is above 1, indicating
good liquidity. - The Acid-test Ratio of 1.0 may be a concern as it indicates a
lower level of liquidity.
Overall, the company appears to be in a moderately strong financial position,
but it may need to improve its liquidity position by increasing its liquid assets
relative to current liabilities.
Question 30
Question
A company reported the following financial information for the year:
Net Income:
$
500,000
Total Assets:
$
2,000,000
Total Liabilities:
$
1,000,000
Stockholders’ Equity:
$
1,000,000
Calculate the following ratios for the company and interpret the results:
1. Return on Assets (ROA)
2. Return on Equity (ROE)
3. Debt-to-Equity Ratio
Solution
Step 1: Calculate Return on Assets (ROA)
The Return on Assets (ROA) is calculated as:
ROA =Net Income
T otal Assets
In this case:
ROA =$500,000
$2,000,000 = 0.25
Step 2: Interpret ROA
34
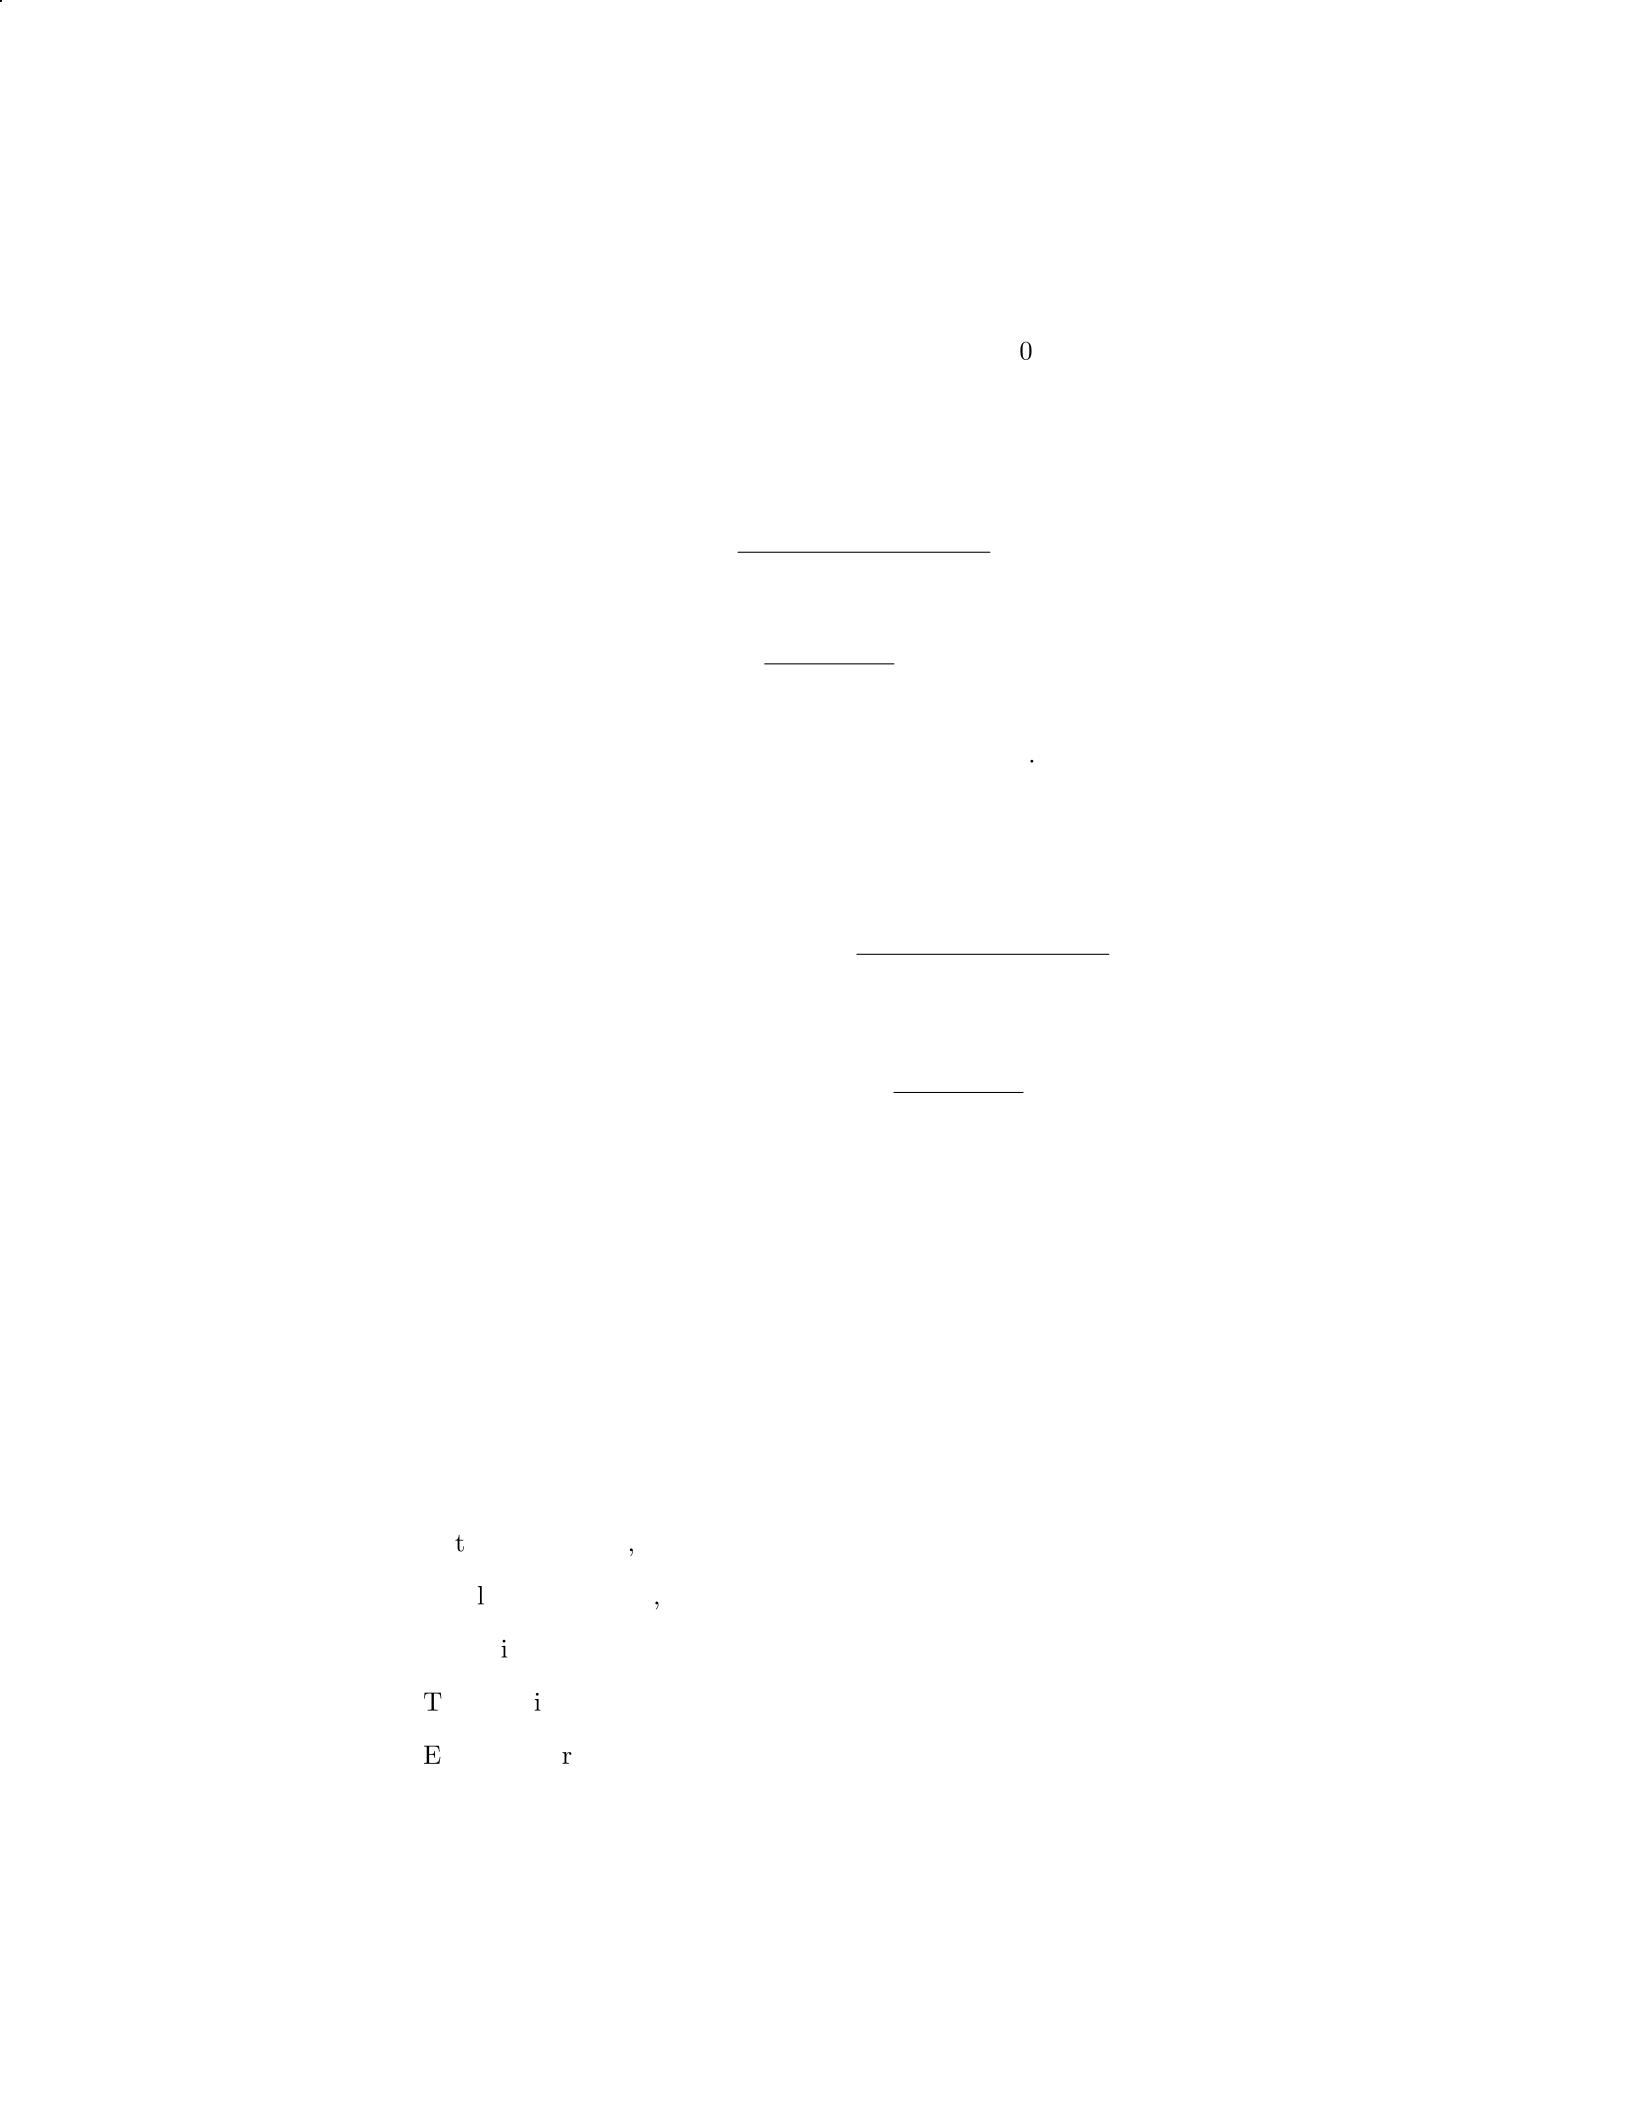
The ROA of 0.25 means that the company generated
$
0.25 in profit for every
dollar of assets it has. This indicates that the company is effectively utilizing
its assets to generate profits.
Step 3: Calculate Return on Equity (ROE)
The Return on Equity (ROE) is calculated as:
ROE =Net Income
Stockholders′Equity
In this case:
ROE =$500,000
$1,000,000 = 0.5
Step 4: Interpret ROE
The ROE of 0.5 means that the company generated
$
0.50 in profit for every
dollar of stockholders’ equity. This indicates that the company is generating a
good return for its shareholders.
Step 5: Calculate Debt-to-Equity Ratio
The Debt-to-Equity Ratio is calculated as:
Debt −to −Equity Ratio =T otal Liabilities
Stockholders′Equity
In this case:
Debt −to −Equity Ratio =$1,000,000
$1,000,000 = 1
Step 6: Interpret Debt-to-Equity Ratio
A debt-to-equity ratio of 1 means that the company has an equal amount of
debt and equity. This indicates that the company is equally financed by debt
and equity.
Question 31
Question
Company XYZ has provided the following financial information for the year
2020:
Net income:
$
500,000
Total assets:
$
2,000,000
Total liabilities:
$
800,000
Total equity:
$
1,200,000
Earnings per share:
$
2.50
35
Using the above information, calculate the following ratios for Company
XYZ and interpret what each ratio indicates about the company’s financial
performance:
1. Return on Assets (ROA)
2. Debt to Equity Ratio
3. Price-Earnings (P/E) Ratio
Solution
Step 1: Calculate Return on Assets (ROA)
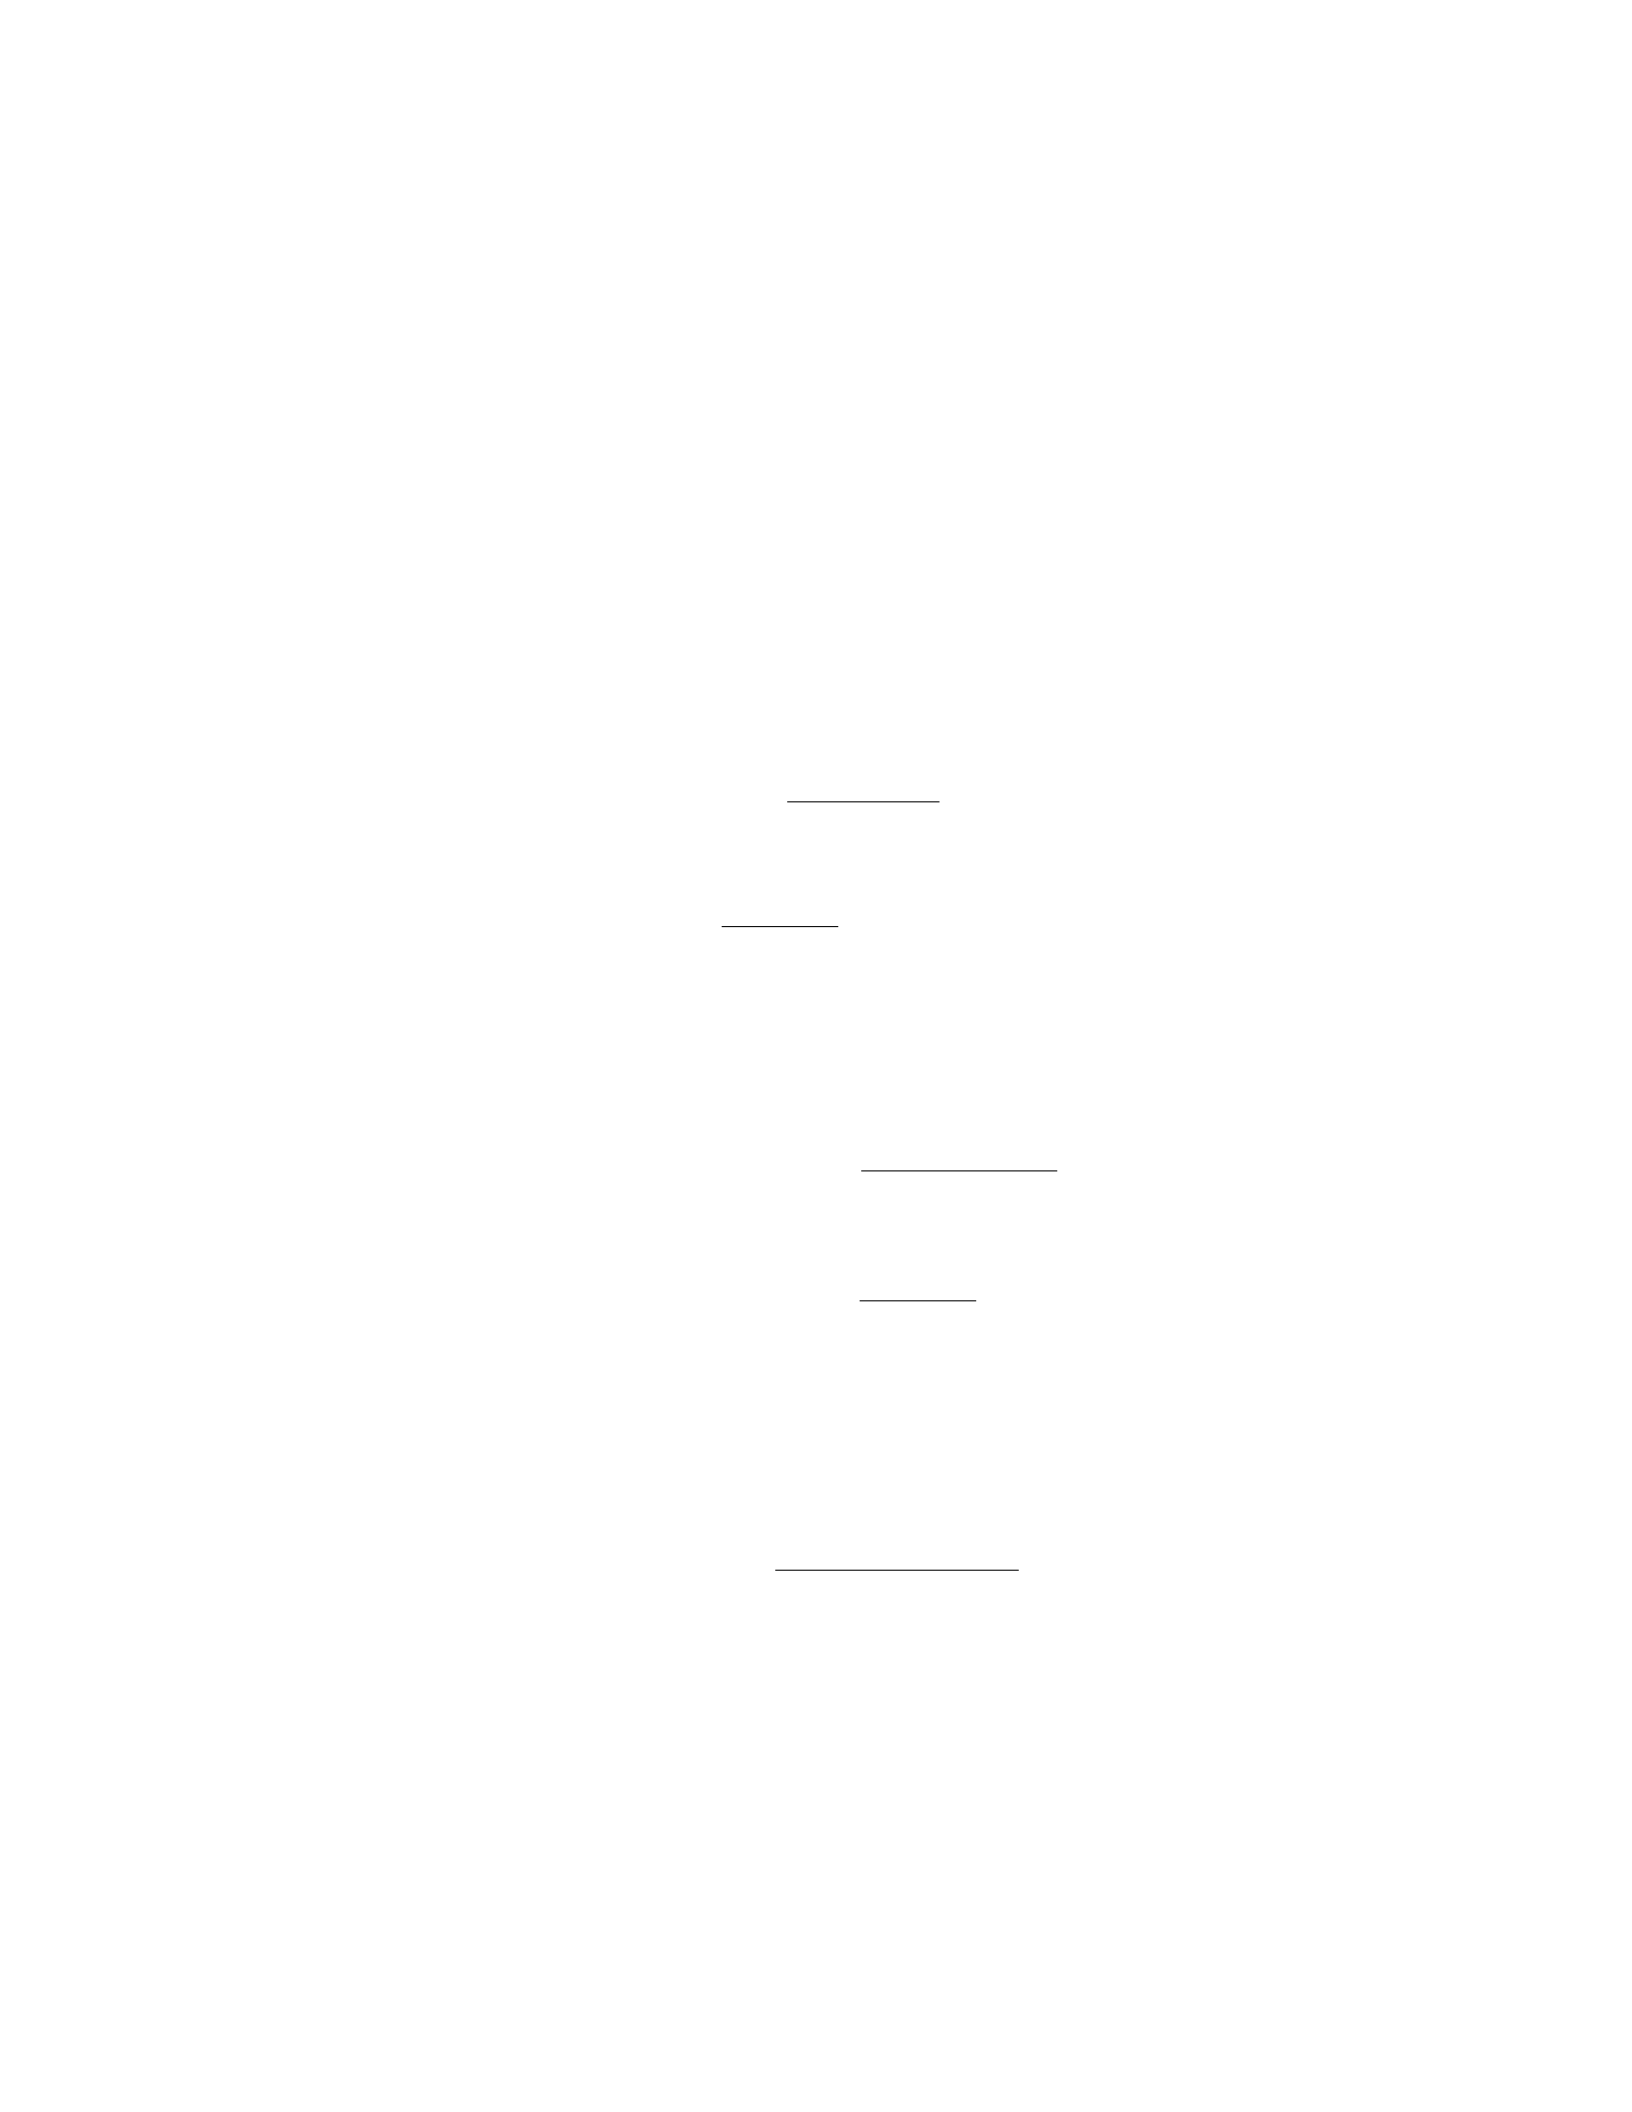
Return on Assets (ROA) is calculated as the ratio of Net Income to Total
Assets:
ROA =Net Income
T otal Assets
Substitute the given values into the formula:
ROA =500,000
2,000,000 = 0.25 = 25%
ROA of 25% indicates that Company XYZ generated 25 cents of profit for
every dollar of assets it owns.
Step 2: Calculate Debt to Equity Ratio
Debt to Equity Ratio is calculated as the ratio of Total Liabilities to Total
Equity:
Debt to Equity Ratio =T otal Liabilities
T otal Equity
Substitute the given values into the formula:
Debt to Equity Ratio =800,000
1,200,000 = 0.67
A Debt to Equity Ratio of 0.67 indicates that for every dollar of equity, the
company has 67 cents in debt.
Step 3: Calculate Price-Earnings (P/E) Ratio
Price-Earnings (P/E) Ratio is calculated as the ratio of Price per Share to
Earnings per Share:
P/E Ratio =P rice per Share
Earnings per Share
However, the Price per Share is not provided, so we cannot calculate the
P/E Ratio with the given information.
In conclusion, Company XYZ has an ROA of 25%, a Debt to Equity Ratio
of 0.67, but the P/E Ratio cannot be calculated without the Price per Share
information.
36
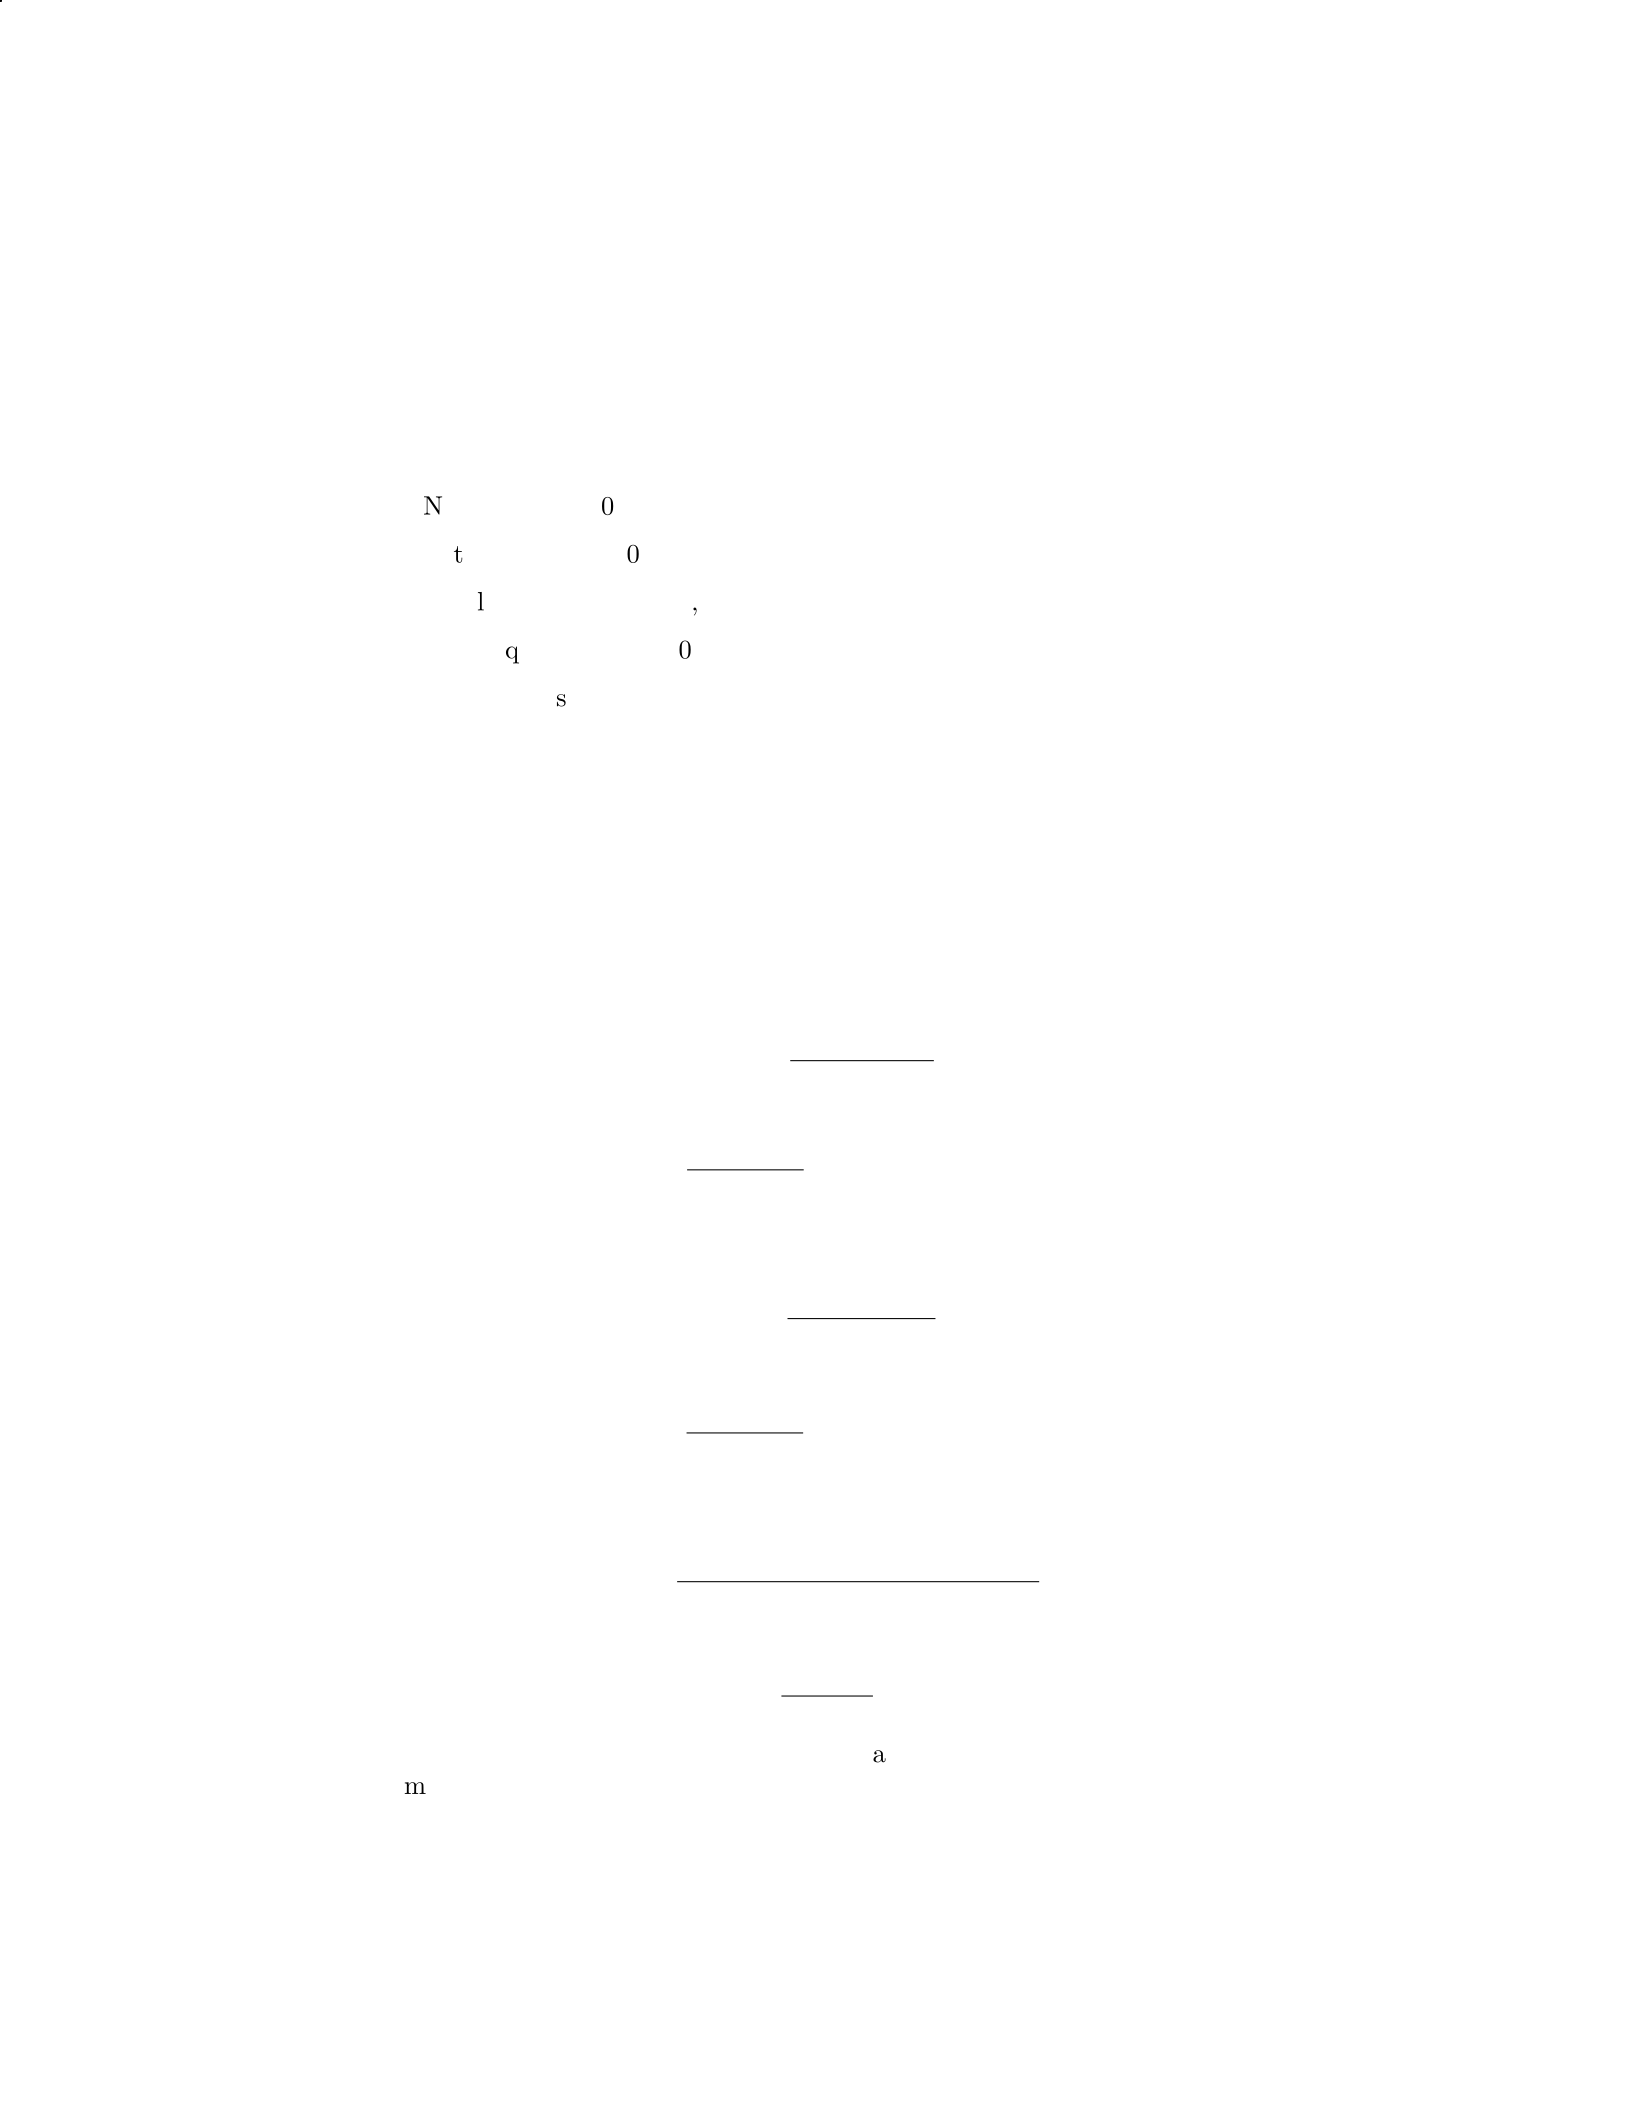
Question 32
Question
A company has the following financial information for the year:
Net income:
$
500,000
Total assets:
$
3,000,000
Total liabilities:
$
1,200,000
Total equity:
$
1,800,000
Number of shares outstanding: 100,000
Calculate the following ratios and interpret them:
1. Return on assets (ROA)
2. Return on equity (ROE)
3. Earnings per share (EPS)
Solution
Step 1: Calculate Return on Assets (ROA) ROA is calculated as:
ROA = Net Income
Total Assets
Substitute the given values:
ROA = 500,000
3,000,000 = 0.1667 or 16.67%
The ROA of the company is 16.67
Step 2: Calculate Return on Equity (ROE) ROE is calculated as:
ROE = Net Income
Total Equity
Substitute the given values:
ROE = 500,000
1,800,000 = 0.2778 or 27.78%
The ROE of the company is 27.78
Step 3: Calculate Earnings per Share (EPS) EPS is calculated as:
EPS = Net Income
Number of Shares Outstanding
Substitute the given values:
EPS = 500,000
100,000 = $5
The EPS of the company is
$
5, which means that each share earns
$
5 of net
income.
37
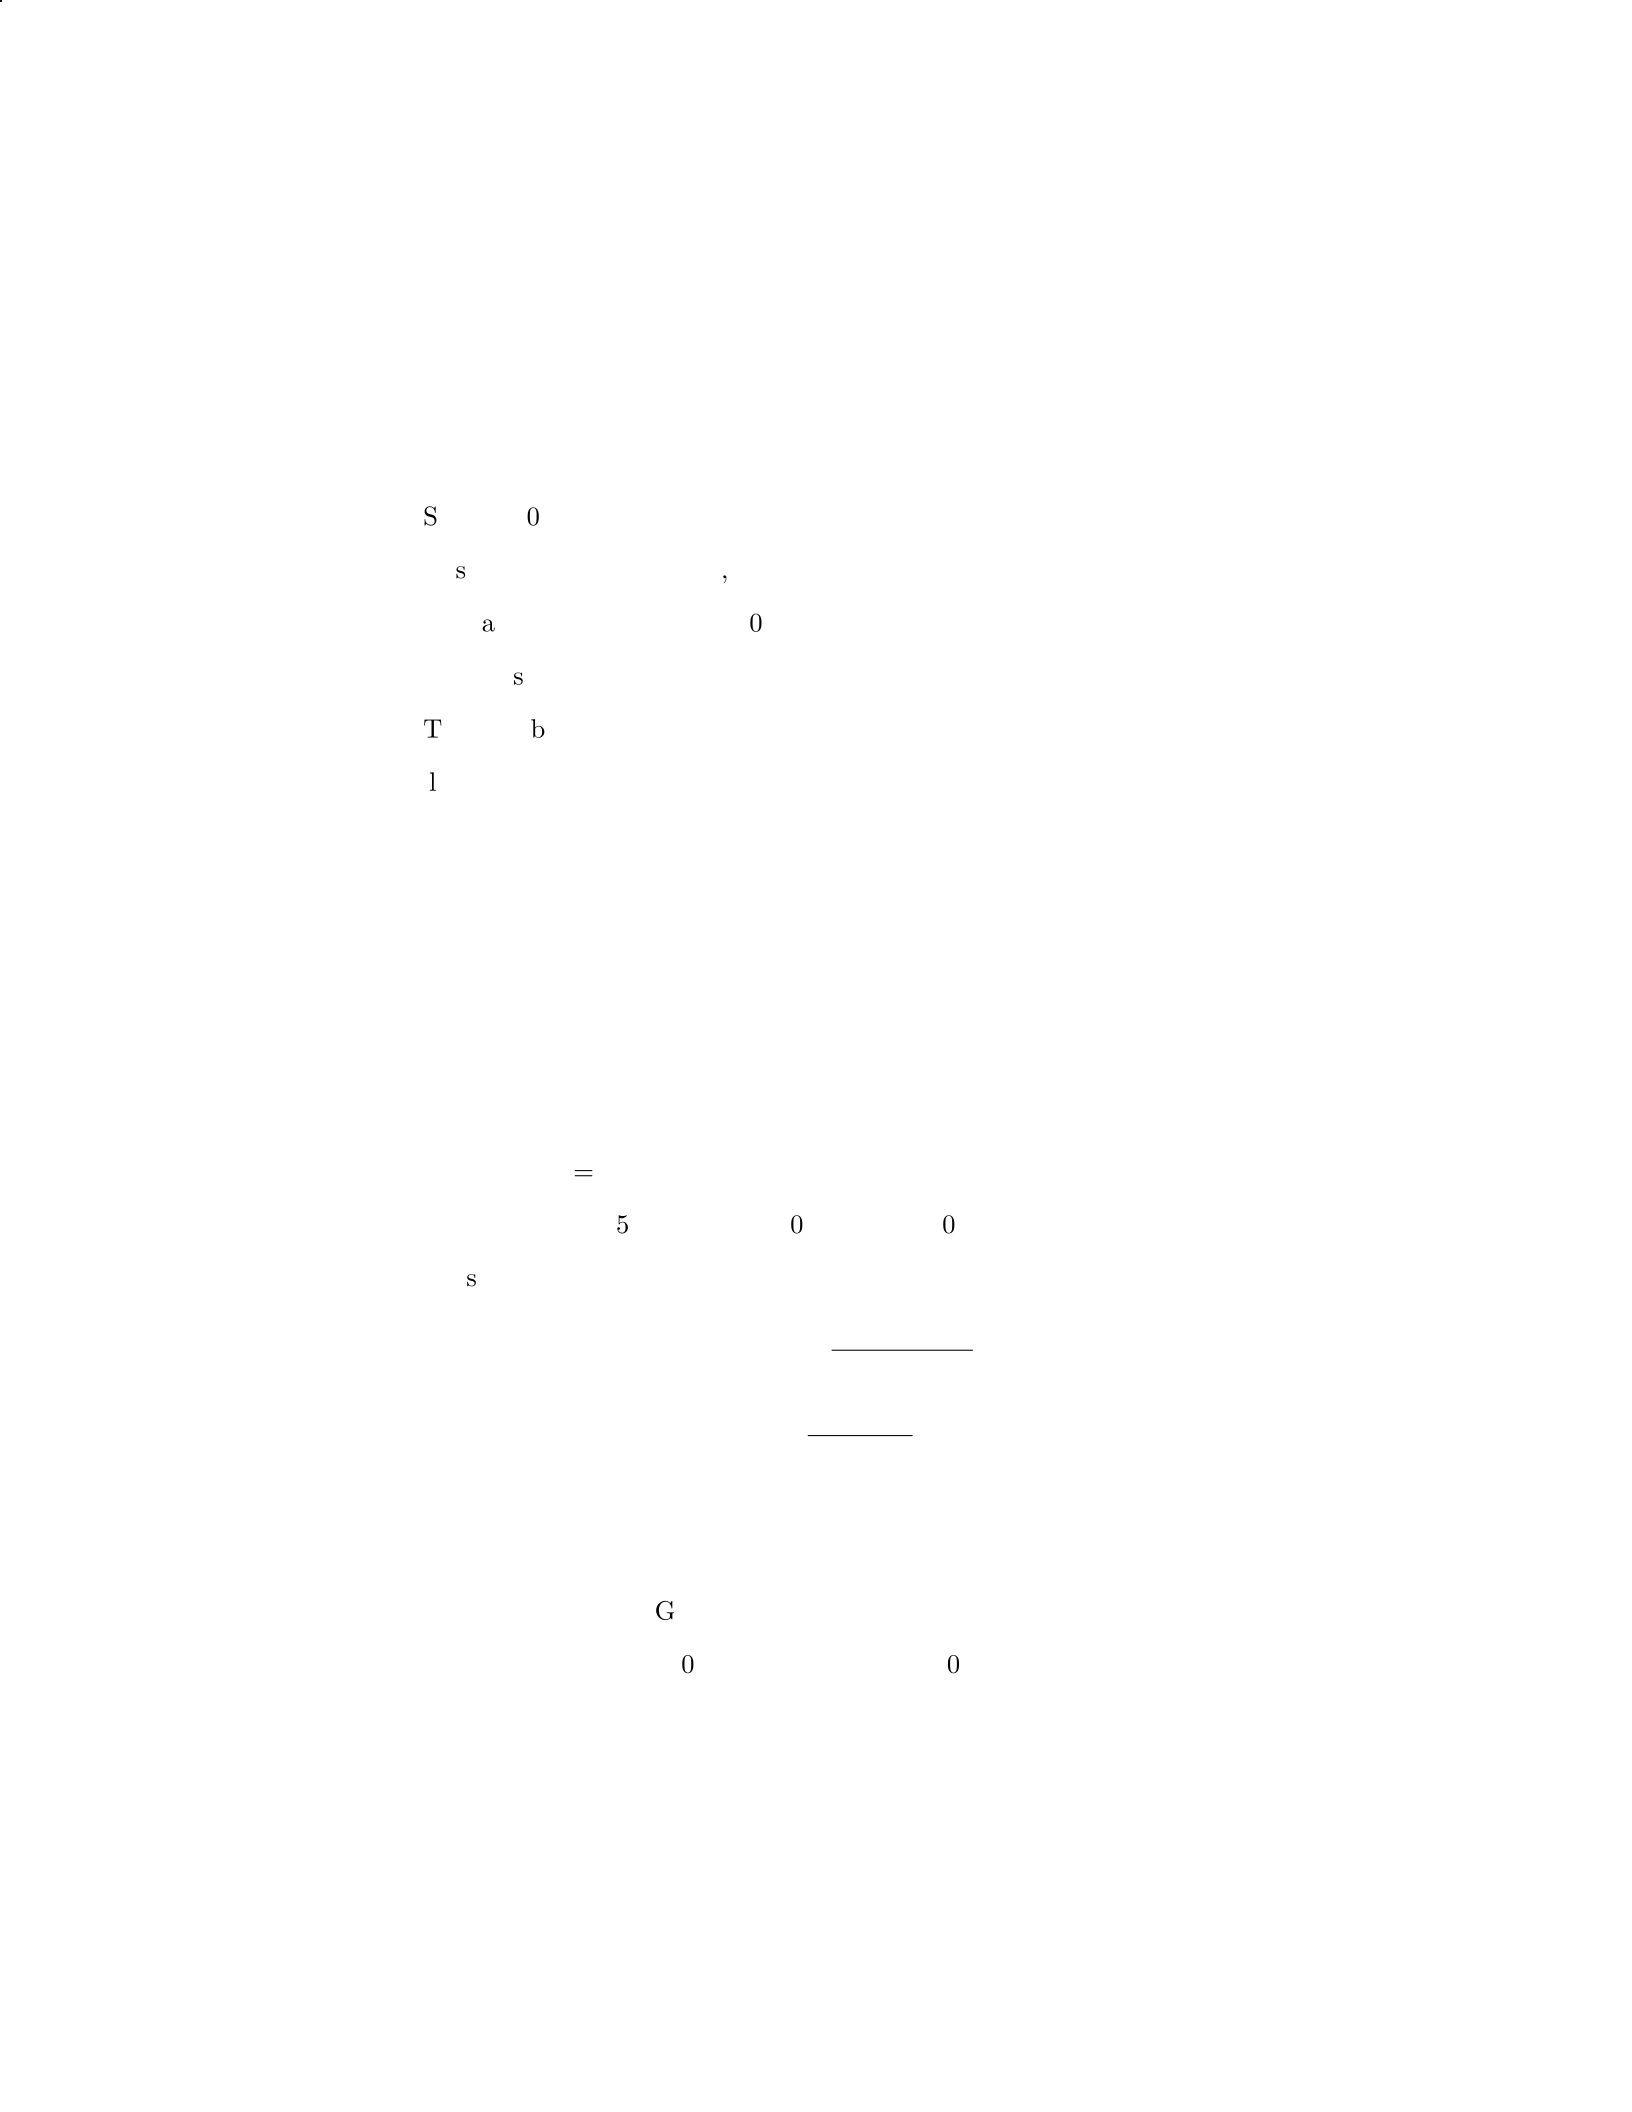
Question 33
Question
A company reported the following financial information for the current year:
Sales:
$
500,000
Cost of Goods Sold:
$
300,000
Operating Expenses:
$
80,000
Total Assets:
$
600,000
Total Liabilities:
$
200,000
Calculate the following ratios and interpret them:
1. Gross Profit Margin
2. Operating Profit Margin
3. Return on Assets
4. Debt-to-Asset Ratio
Solution
Step 1: Calculate Gross Profit Margin
Gross Profit = Sales - Cost of Goods Sold
Gross Profit =
$
500,000 -
$
300,000 =
$
200,000
The Gross Profit Margin is calculated as:
Gross Profit Margin = Gross Profit
Sales ×100%
Gross Profit Margin = $200,000
$500,000 ×100% = 40%
Interpretation: This means that for every dollar of sales, the company keeps
40 cents as gross profit.
Step 2: Calculate Operating Profit Margin
Operating Profit = Gross Profit - Operating Expenses
Operating Profit =
$
200,000 -
$
80,000 =
$
120,000
38
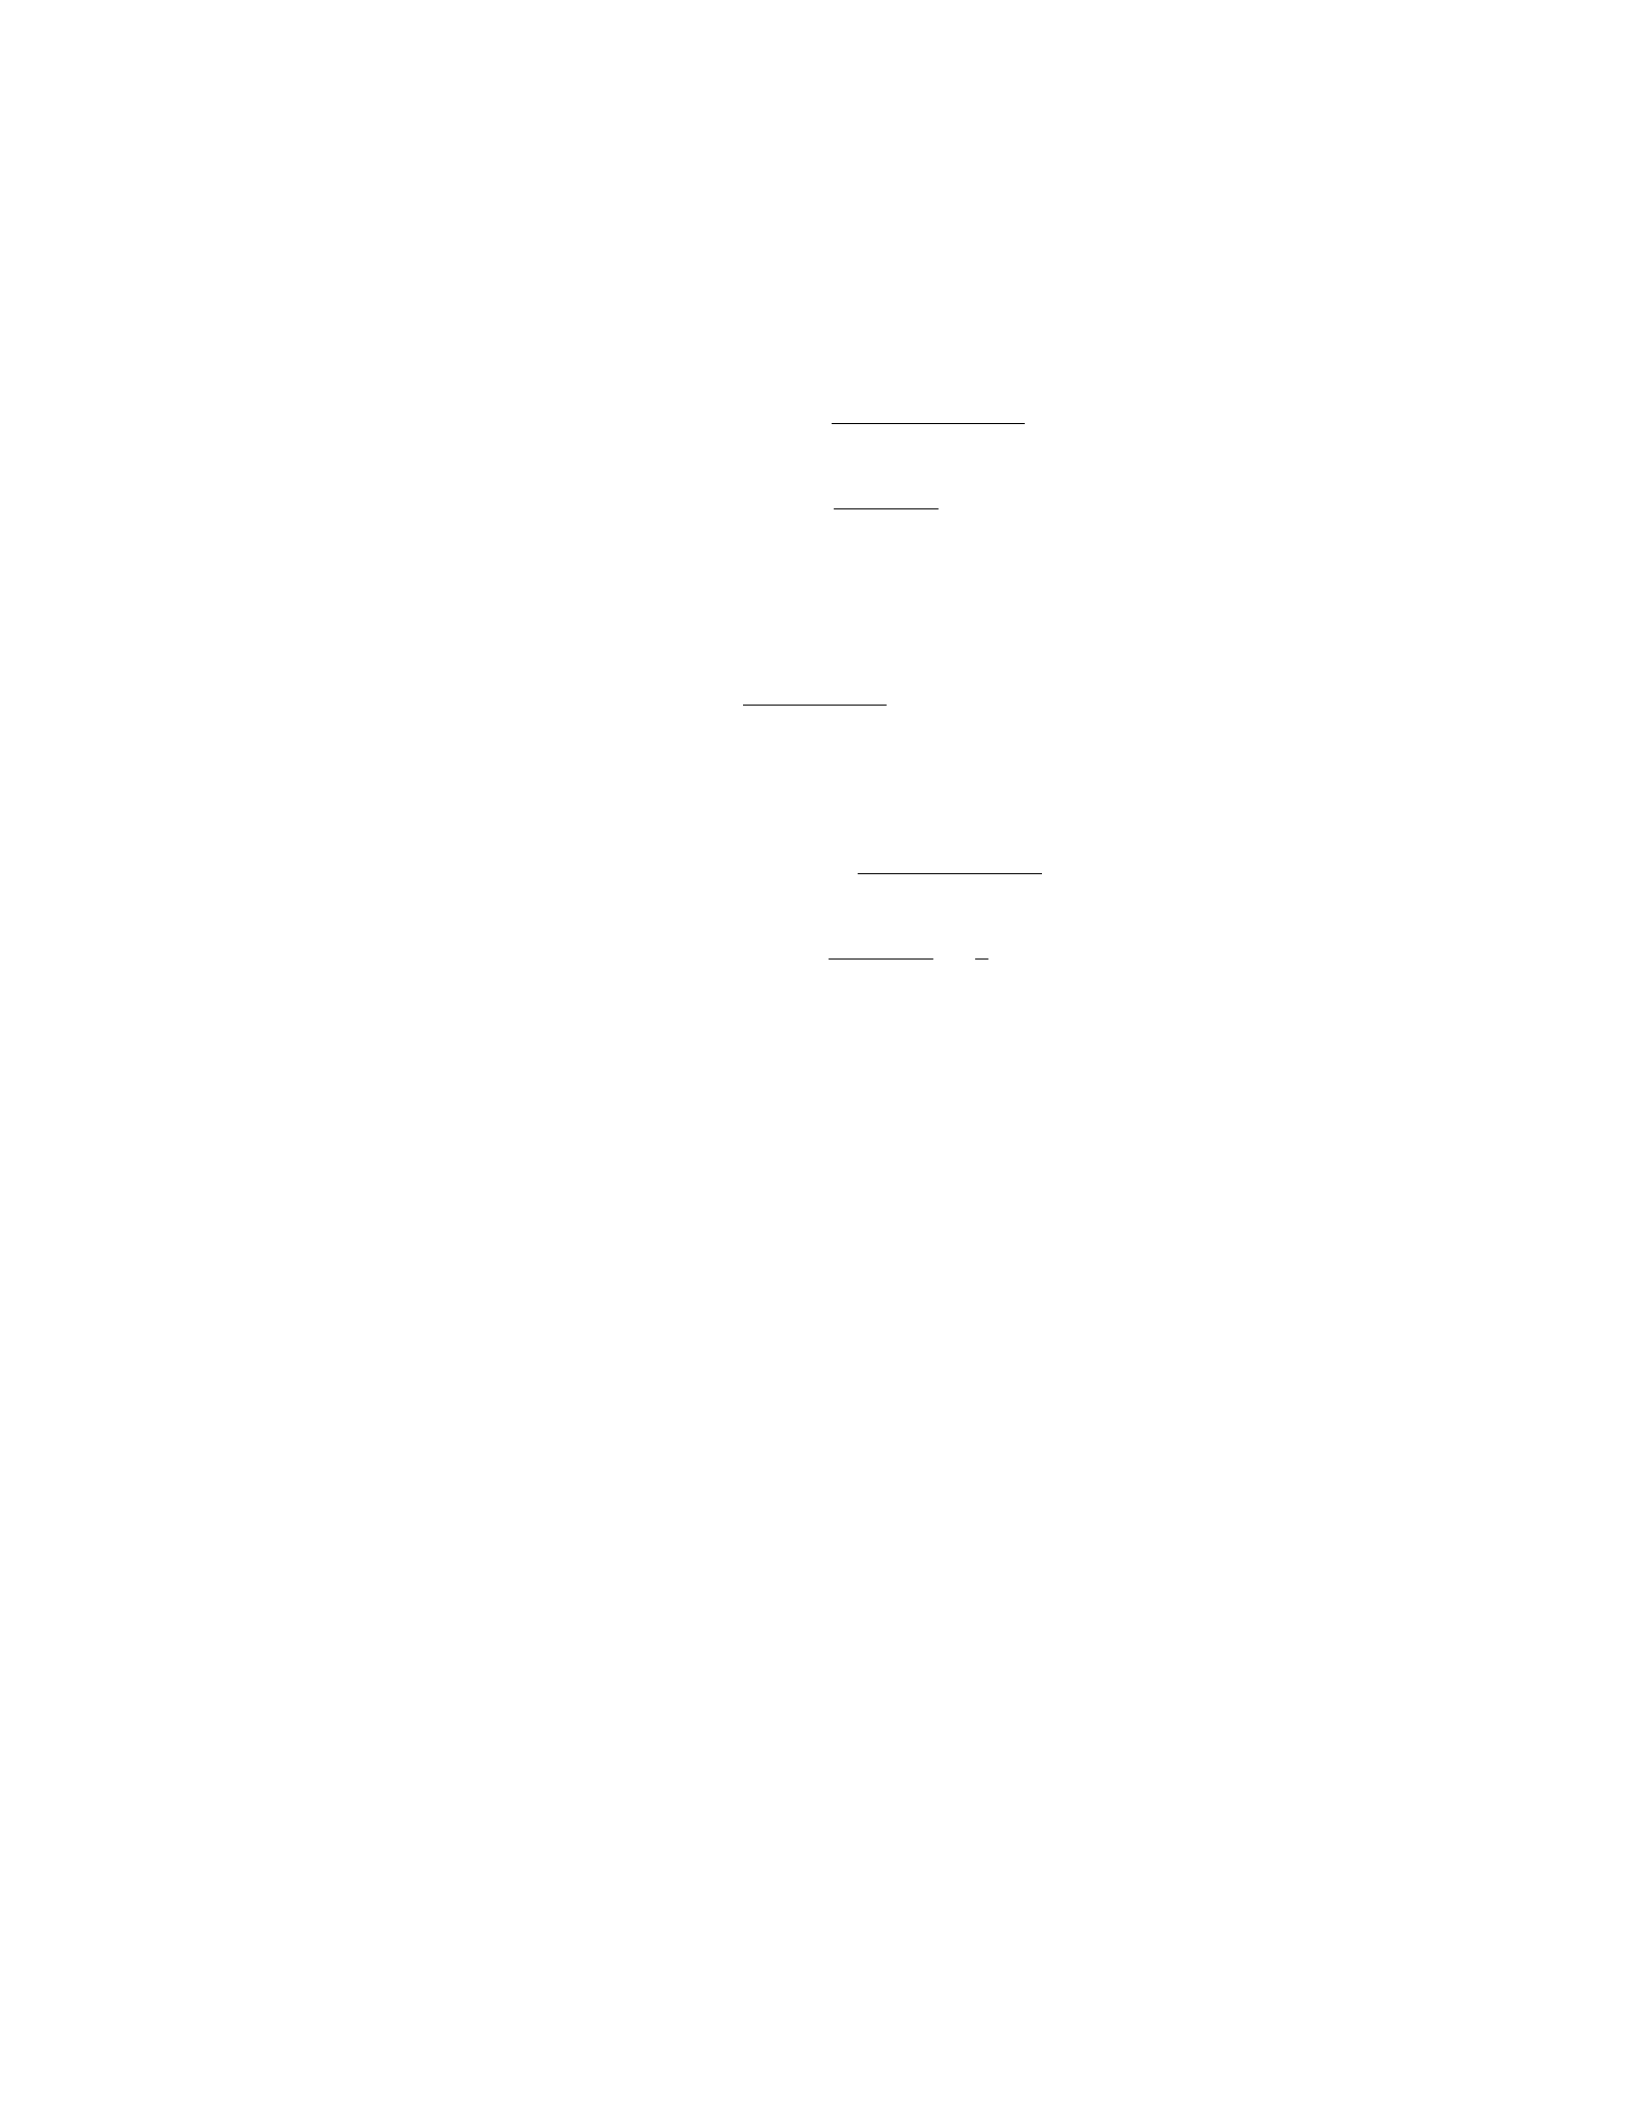
The Operating Profit Margin is calculated as:
Operating Profit Margin = Operating Profit
Sales ×100%
Operating Profit Margin = $120,000
$500,000 ×100% = 24%
Interpretation: This means that for every dollar of sales, the company gen-
erates 24 cents in operating profit.
Step 3: Calculate Return on Assets (ROA)
ROA = Net Income
Total Assets ×100%
As Net Income is not provided, we cannot calculate ROA.
Step 4: Calculate Debt-to-Asset Ratio
Debt-to-Asset Ratio = Total Liabilities
Total Assets
Debt-to-Asset Ratio = $200,000
$600,000 =1
3= 0.33
Interpretation: This means that 33
Question 34
Question
A company has a current ratio of 2.5 and a quick ratio of 1.5. Interpret these
ratios in the context of the company’s liquidity position.
Solution
Step 1: Understand the meaning of the ratios. The current ratio is calculated
as current assets divided by current liabilities, while the quick ratio (also known
as the acid-test ratio) is calculated as (current assets - inventory) divided by
current liabilities. These ratios are used to assess a company’s ability to meet
its short-term obligations.
Step 2: Interpret the current ratio. A current ratio of 2.5 means that
the company has 2.5 times more current assets than current liabilities. This
indicates that the company has a strong liquidity position and is able to meet
its short-term obligations comfortably.
Step 3: Interpret the quick ratio. A quick ratio of 1.5 means that the
company has 1.5 times more quick assets (current assets excluding inventory)
than current liabilities. This ratio also suggests that the company has a good
liquidity position, although it is slightly lower than the current ratio.
39
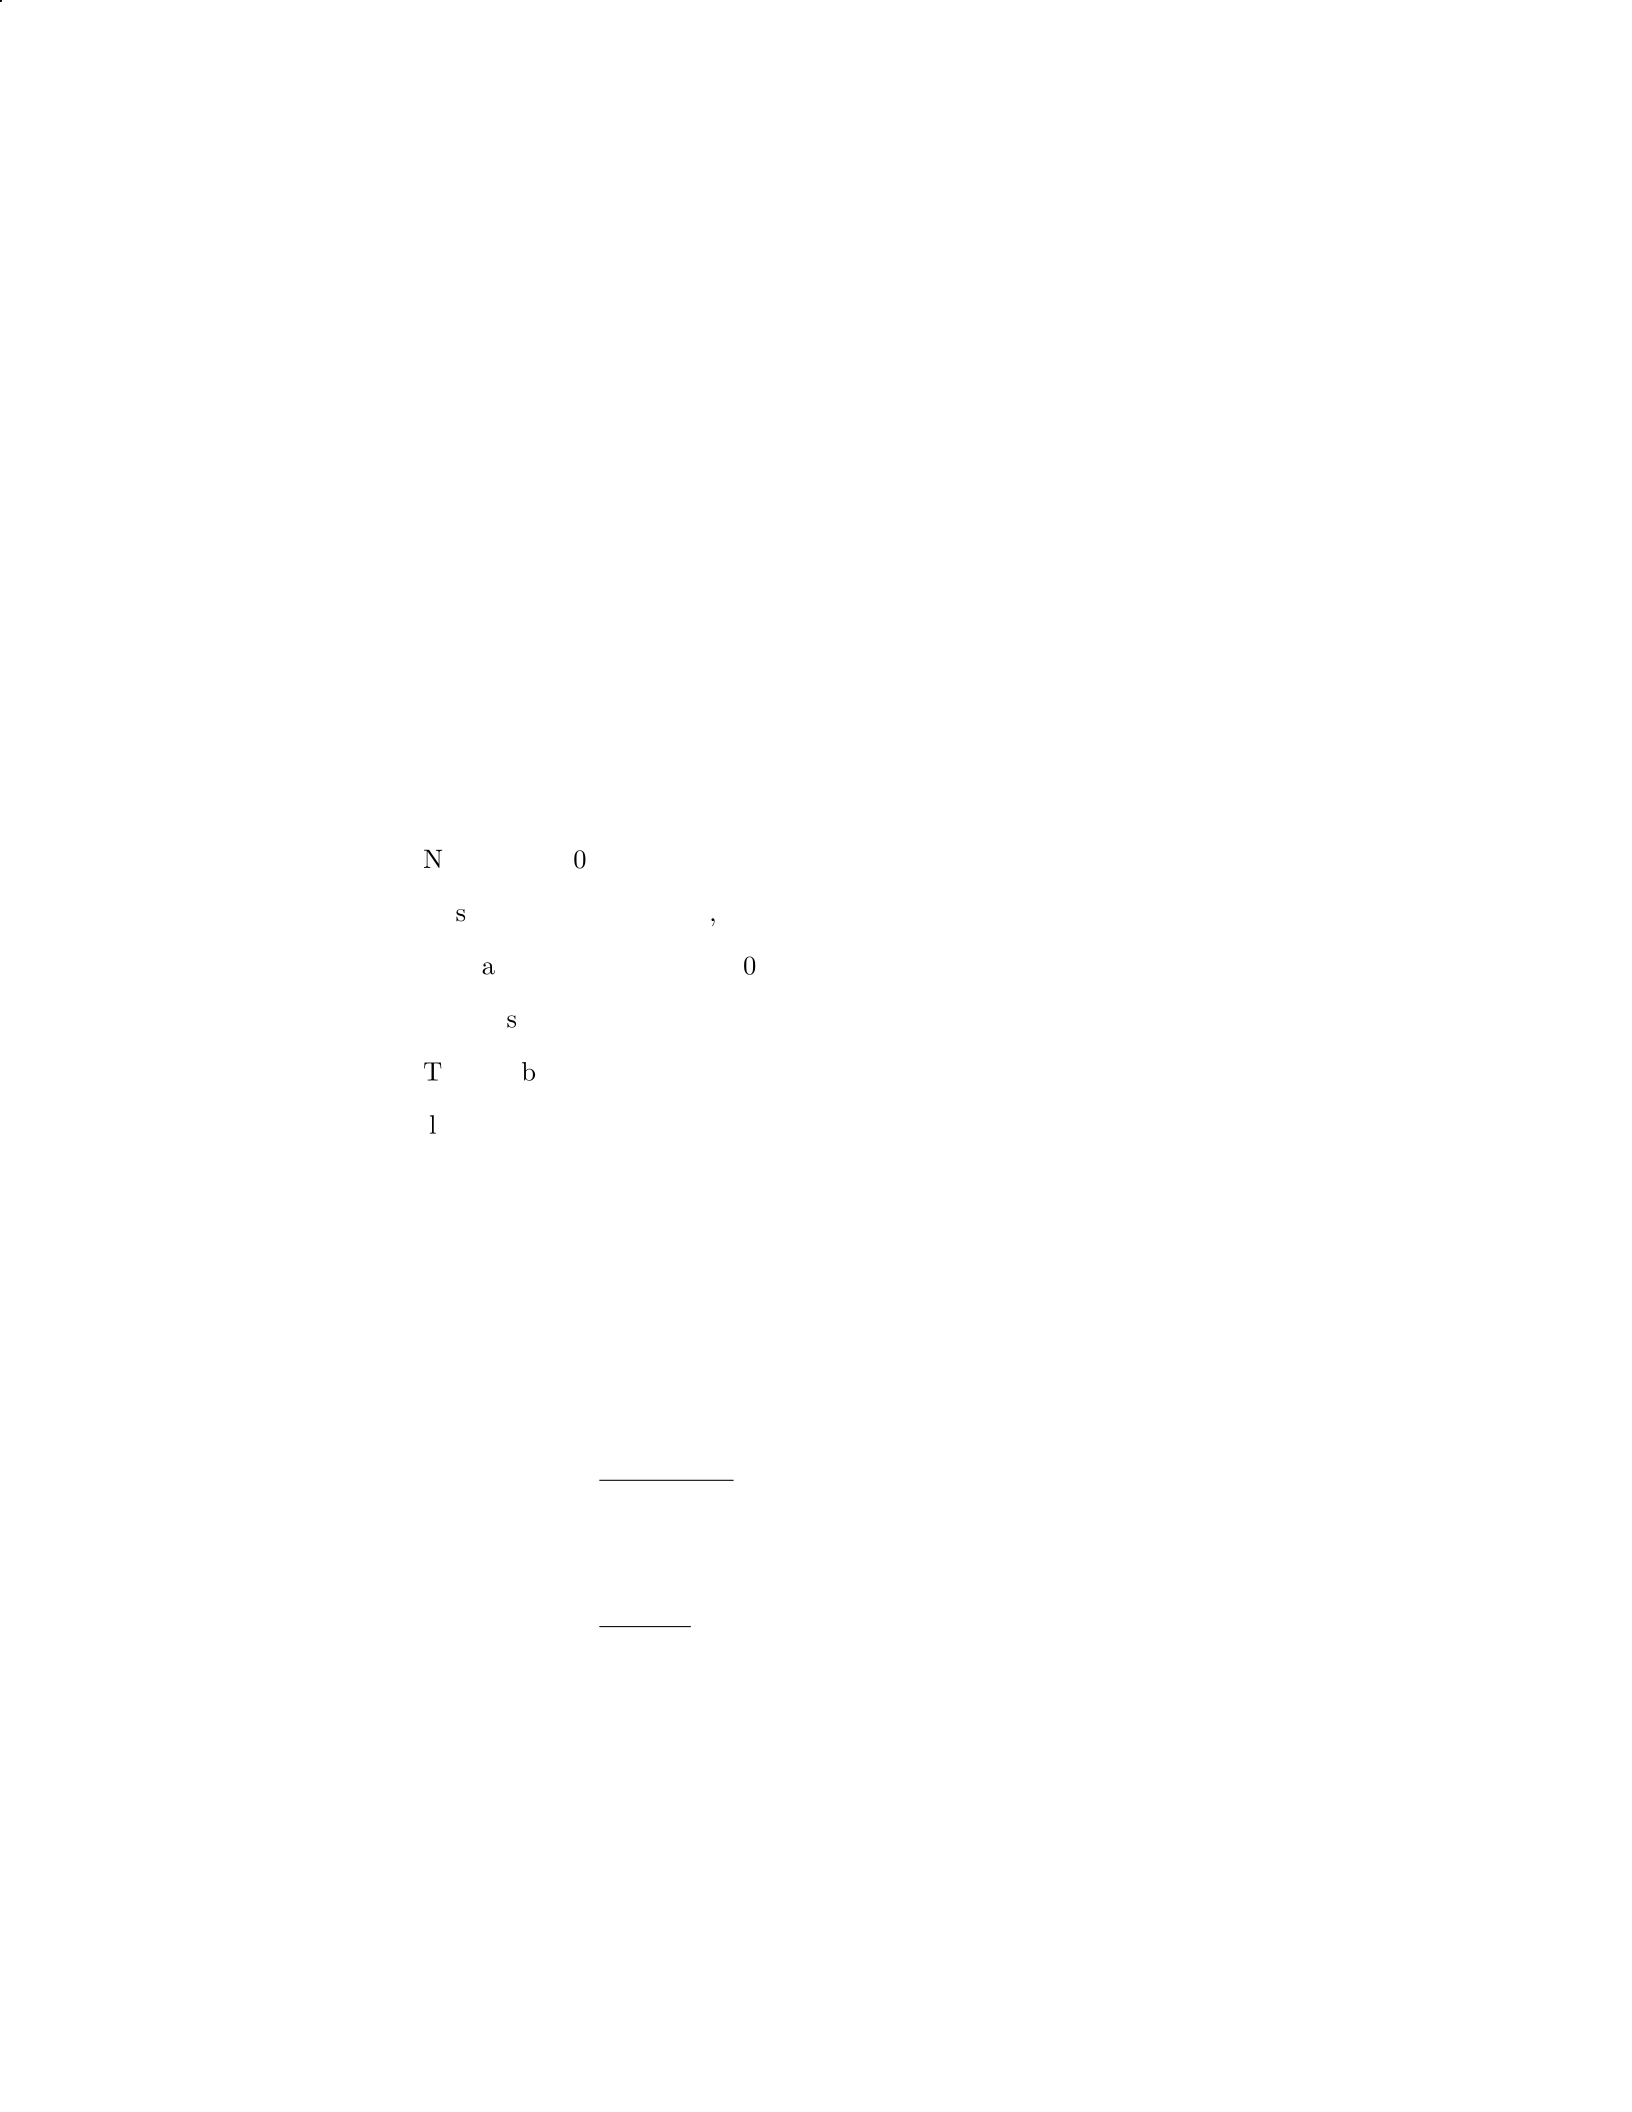
Step 4: Comparison and implications. The fact that the current ratio is
higher than the quick ratio indicates that a significant portion of the company’s
current assets is tied up in inventory. While this may not be a cause for concern,
it is important to monitor inventory levels to ensure they are not excessive and
affect the company’s liquidity.
In conclusion, the company has a strong liquidity position as indicated by
both the current ratio of 2.5 and the quick ratio of 1.5. However, the composition
of current assets, particularly inventory, should be monitored to ensure optimal
liquidity management.
Question 35
Question
Company ABC has the following financial information for the year 2020:
Net sales:
$
500,000
Cost of goods sold:
$
300,000
Operating expenses:
$
80,000
Total assets:
$
600,000
Total liabilities:
$
200,000
Calculate the following ratios for Company ABC and interpret the results:
1. Profit margin
2. Return on assets
3. Debt-to-equity ratio
Solution
Step 1: Calculate the Profit Margin
Profit Margin = Net Income
Net Sales
Net Income = Net Sales −Cost of Goods Sold −Operating Expenses
Net Income = $500,000 −$300,000 −$80,000 = $120,000
Profit Margin = 120,000
500,000 = 0.24 = 24%
Interpretation: Company ABC has a profit margin of 24%, indicating that
for every dollar of sales, the company generates a profit of 24 cents.
40
Step 2: Interpretation of ROA
ROA of 0.2 means that for every dollar of assets the company has, it gen-
erates 20 cents in net income. This indicates that the company is generating a
solid return on its assets.
Step 3: Calculate Return on Equity (ROE)
ROE is calculated by dividing the net income by the stockholders’ equity:
ROE =Net Income
Stockholders′Equity
Substitute the given values:
ROE =200,000
600,000 ≈0.333
Step 4: Interpretation of ROE
ROE of approximately 0.333 means that for every dollar of stockholders’
equity, the company generates 33.3 cents in net income. This indicates that the
company is effectively generating profit for its shareholders.
Question 2
Question
A company has reported the following financial information for the year 2020:
Net Income:
$
500,000
Total Assets:
$
5,000,000
Total Liabilities:
$
3,000,000
Shareholders’ Equity:
$
2,000,000
Earnings per Share:
$
5
Calculate the following ratios for the company for the year 2020, and inter-
pret the results:
1. Return on Assets (ROA)
2. Return on Equity (ROE)
3. Debt-to-Equity Ratio
2
Solution
We will calculate each ratio step by step:
Step 1: Calculate Return on Assets (ROA)
ROA is calculated using the formula:
ROA =NetIncome
T otalAssets ×100%
Given that Net Income =
$
500,000 and Total Assets =
$
5,000,000, we can
plug these values into the formula to find ROA.
ROA =500,000
5,000,000 ×100%
ROA = 0.10 ×100%
ROA = 10%
Step 2: Interpretation of ROA
ROA of 10% means that for every dollar of assets, the company generated a
profit of 10 cents. This indicates that the company is efficiently using its assets
to generate profits.
Step 3: Calculate Return on Equity (ROE)
ROE is calculated using the formula:
ROE =NetIncome
Shareholders′Equity ×100%
Given that Net Income =
$
500,000 and Shareholders’ Equity =
$
2,000,000,
we can plug these values into the formula to find ROE.
ROE =500,000
2,000,000 ×100%
ROE = 0.25 ×100%
ROE = 25%
Step 4: Interpretation of ROE
ROE of 25% means that for every dollar of equity, the company generated
a profit of 25 cents. This indicates that the company is generating a healthy
return for its shareholders.
Step 5: Calculate Debt-to-Equity Ratio
Debt-to-Equity Ratio is calculated using the formula:
Debt −to −EquityRatio =T otalLiabilities
Shareholders′Equity
Given that Total Liabilities =
$
3,000,000 and Shareholders’ Equity =
$
2,000,000,
we can plug these values into the formula to find the Debt-to-Equity Ratio.
3
Debt −to −EquityRatio =3,000,000
2,000,000
Debt −to −EquityRatio = 1.5
Step 6: Interpretation of Debt-to-Equity Ratio
A Debt-to-Equity Ratio of 1.5 indicates that the company has
$
1.50 in debt
for every
$
1 of equity. This suggests that the company is relying more on debt
financing compared to equity financing. Investors and creditors may view this
ratio as indicating higher financial risk compared to a lower ratio.
Question 3
Question
A company’s current ratio is 2, quick ratio is 1.5, and debt to equity ratio is
0.5. Analyze the company’s financial health and provide an interpretation of
the ratios.
Solution
Step 1: Calculate the Current Assets to Current Liabilities Ratio (Cur-
rent Ratio)
Current Ratio = Current Assets
Current Liabilities
Given that Current Ratio = 2
Current Assets
Current Liabilities = 2
Current Assets = 2 ×Current Liabilities
Step 2: Calculate the Quick Assets to Current Liabilities Ratio
(Quick Ratio)
Quick Ratio = Quick Assets
Current Liabilities
Given that Quick Ratio = 1.5
Quick Assets
Current Liabilities = 1.5
Quick Assets = 1.5×Current Liabilities
Step 3: Interpret the Current and Quick Ratios - The current ratio
of 2 indicates that the company has twice as many current assets as current
liabilities, which signifies good liquidity. - The quick ratio of 1.5 shows that the
company’s quick assets (assets that can be quickly converted to cash) can cover
4
1.5 times its current liabilities. This also indicates good liquidity, with a more
conservative approach than the current ratio.
Step 4: Calculate the Debt to Equity Ratio
Debt to Equity Ratio = Total Debt
Total Equity
Given that Debt to Equity Ratio = 0.5
Total Debt
Total Equity = 0.5
Total Debt = 0.5×Total Equity
Step 5: Interpret the Debt to Equity Ratio - A debt to equity ratio of
0.5 indicates that the company has half as much debt as equity. This suggests
that the company relies more on equity financing than debt, which is considered
healthy.
In summary, the company appears to have good liquidity based on the cur-
rent and quick ratios. Additionally, the debt to equity ratio suggests a healthy
balance between debt and equity financing.
Question 4
Question
A company’s financial statements show the following information for the year:
Current Assets:
$
400,000
Non-current Assets:
$
600,000
Current Liabilities:
$
200,000
Non-current Liabilities:
$
300,000
Sales Revenue:
$
1,000,000
Cost of Goods Sold:
$
500,000
Calculate the following ratios for the company:
1. Current Ratio
2. Quick Ratio
3. Gross Profit Margin
5
Solution
1. Current Ratio The current ratio is calculated as:
Current Ratio = Current Assets
Current Liabilities
Step 1: Calculate the Current Ratio
Current Ratio = 400,000
200,000 = 2
2. Quick Ratio The quick ratio is calculated as:
Quick Ratio = Current Assets −Inventory
Current Liabilities
Given that the Inventory is not provided, we cannot calculate the Quick
Ratio.
3. Gross Profit Margin The gross profit margin is calculated as:
Gross Profit Margin = Sales Revenue −Cost of Goods Sold
Sales Revenue ×100%
Step 1: Calculate Gross Profit Margin
Gross Profit Margin = 1,000,000 −500,000
1,000,000 ×100% = 50%
Question 5
Question
A company has the following financial information for the year:
Total assets:
$
500,000
Total liabilities:
$
200,000
Total equity:
$
300,000
Net income:
$
50,000
Total revenue:
$
400,000
Calculate the following ratios and provide an interpretation for each:
1. Debt to Equity Ratio
2. Return on Assets
3. Profit Margin
6
Solution
Step 1: Calculate the Debt to Equity Ratio
Debt to Equity Ratio = Total Liabilities
Total Equity
Debt to Equity Ratio = $200,000
$300,000 = 0.67
Interpretation: A debt to equity ratio of 0.67 indicates that the company
has
$
0.67 in liabilities for every
$
1 in equity. This suggests that the company is
relying more on equity financing compared to debt financing.
Step 2: Calculate the Return on Assets (ROA)
ROA = Net Income
Total Assets
ROA = $50,000
$500,000 = 0.10 or 10%
Interpretation: A return on assets of 10
Step 3: Calculate the Profit Margin
Profit Margin = Net Income
Total Revenue
Profit Margin = $50,000
$400,000 = 0.125 or 12.5%
Interpretation: A profit margin of 12.5
Question 6
Question
A company reports the following financial information for the current year:
Current ratio = 2
Quick ratio = 1.5
Debt to equity ratio = 0.6
Based on this information, analyze the company’s financial health and perfor-
mance.
7
Solution
To analyze the company’s financial health and performance, we will interpret
each ratio in relation to industry benchmarks and ideal values.
Step 1: Calculate and Interpret the Current Ratio
Current Ratio = Current Assets / Current Liabilities
Given: Current Ratio = 2
A current ratio of 2 indicates that the company has 2worthofcurrentassetsf orevery1
of current liabilities. Generally, a current ratio above 1 is considered healthy,
but the ideal value varies by industry. A current ratio of 2 signifies that the
company may have excess current assets, which could be invested for further
growth opportunities.
Step 2: Calculate and Interpret the Quick Ratio
Quick Ratio = (Current Assets - Inventory) / Current Liabilities
Given: Quick Ratio = 1.5
A quick ratio of 1.5 implies that the company has 1.50ofliquidassetsavailabletocovereach1
of current liabilities. This ratio is slightly lower than the current ratio, indicat-
ing that the company’s inventory may not be as easily converted to cash in the
short term. It is important to compare this ratio with industry standards to
assess the company’s ability to meet short-term obligations.
Step 3: Calculate and Interpret the Debt to Equity Ratio
Debt to Equity Ratio = Total Debt / Shareholders’ Equity
Given: Debt to Equity Ratio = 0.6
A debt to equity ratio of 0.6 signifies that the company relies more on equity
financing than debt financing. This ratio indicates a healthy balance between
debt and equity, but the ideal ratio can vary based on industry and company-
specific factors. It is crucial to benchmark this ratio against industry peers to
evaluate the company’s leverage and financial risk.
Based on the interpretation of the current, quick, and debt to equity ratios,
the company appears to have a stable financial position with a strong liquidity
position, moderate leverage, and a healthy balance between debt and equity
financing. Further analysis and comparison with industry averages will pro-
vide a more comprehensive assessment of the company’s financial health and
performance.
Question 7
Question
A company reported the following financial information for the year: - Current
ratio: 2.5 - Quick ratio: 1.8 - Debt to equity ratio: 0.7
8
Based on this information, analyze the company’s liquidity, efficiency, and
financial leverage. Provide an interpretation of these ratios in relation to the
company’s financial health.
Solution
To analyze the company’s liquidity, efficiency, and financial leverage, we will
interpret the given ratios - current ratio, quick ratio, and debt to equity ratio.
Step 1: Interpret the Current Ratio The current ratio is calculated as
Current Assets divided by Current Liabilities. It measures the company’s ability
to pay its short-term obligations with its short-term assets. The company’s
current ratio of 2.5 indicates that it has 2.50ofcurrentassetsf orevery1.00 of
current liabilities. A current ratio above 1.0 generally indicates good liquidity.
In this case, the company’s current ratio of 2.5 suggests that the company is in
a good position to meet its short-term obligations.
Step 2: Interpret the Quick Ratio The quick ratio (acid-test ratio) is
calculated as (Current Assets - Inventory) divided by Current Liabilities. It
provides a more stringent measure of liquidity as it excludes inventory, which
may not be easily convertible to cash. The company’s quick ratio of 1.8 indicates
that it has 1.80ofquickassets(currentassetsexcludinginventory)f orevery1.00
of current liabilities. A quick ratio above 1.0 is generally considered healthy.
Therefore, the company’s quick ratio of 1.8 also suggests good liquidity.
Step 3: Interpret the Debt to Equity Ratio The debt to equity ratio
is calculated as Total Debt divided by Total Equity. It measures the company’s
financial leverage or the proportion of debt and equity used to finance its assets.
A debt to equity ratio of 0.7 means the company has 0.70ofdebtforevery1.00 of
equity. A lower debt to equity ratio indicates lower financial risk. In this case,
the company’s debt to equity ratio of 0.7 suggests that the company is using
more equity to finance its operations, which is generally positive.
Overall, based on the ratios provided, the company appears to have good
liquidity, efficient management of its short-term obligations, and a conservative
capital structure with low financial leverage. This indicates a healthy financial
position and suggests that the company is managing its resources effectively.
Question 8
Question
A company has the following financial information for the year: - Current As-
sets:
$
500,000 - Current Liabilities:
$
200,000 - Total Assets:
$
1,500,000 - Total
Liabilities:
$
600,000 - Shareholders’ Equity:
$
900,000
Calculate the following ratios and interpret the results: a) Current ratio b)
Debt-to-equity ratio
9
Solution
Step 1: Calculate the current ratio. The current ratio is calculated as:
Current Ratio = Current Assets
Current Liabilities
Substitute the given values:
Current Ratio = 500,000
200,000 = 2.5
Step 2: Interpret the current ratio. A current ratio of 2.5 indicates that
the company has
$
2.50 in current assets for every
$
1 in current liabilities. This
signifies that the company has an excess of current assets to cover its current
liabilities.
Step 3: Calculate the debt-to-equity ratio. The debt-to-equity ratio is cal-
culated as:
Debt-to-equity Ratio = Total Liabilities
Shareholders’ Equity
Substitute the given values:
Debt-to-equity Ratio = 600,000
900,000 = 0.67
Step 4: Interpret the debt-to-equity ratio. A debt-to-equity ratio of 0.67
implies that for every
$
1 of shareholders’ equity, the company has
$
0.67 in
total liabilities. This ratio indicates that the company is financing a significant
portion of its assets through equity rather than debt.
Question 9
Question
The current ratio of Company ABC is 2.5, while its quick ratio is 1.5. Analyze
and interpret these ratios in the context of the company’s liquidity.
Solution
Step 1: Calculate the current assets and current liabilities of Company
ABC.
The current ratio is given by:
Current Ratio = Current Assets
Current Liabilities
Given that the current ratio is 2.5, we can write:
2.5 = Current Assets
Current Liabilities
10
Step 2: Interpret the current ratio.
A current ratio of 2.5 indicates that the company has 2.50worthofcurrentassetsf orevery1.00
of current liabilities. This implies that the company’s current assets are more
than double its current liabilities, suggesting that Company ABC is likely able
to meet its short-term obligations.
Step 3: Calculate the quick assets of Company ABC.
The quick ratio is given by:
Quick Ratio = Quick Assets
Current Liabilities
Given that the quick ratio is 1.5 and the current ratio is 2.5, we can infer that
quick assets are less than current assets. Therefore, to calculate quick assets,
we can use the formula:
Quick Assets = Current Assets −Inventory
Step 4: Interpret the quick ratio.
A quick ratio of 1.5 indicates that the company has 1.50ofquickassetsforevery1.00
of current liabilities. This ratio is slightly lower than the current ratio, which
suggests that the company’s inventory may not be as easily converted to cash
compared to its other current assets, such as accounts receivable.
Step 5: Draw conclusions about Company ABC’s liquidity position.
Overall, with a current ratio of 2.5 and a quick ratio of 1.5, Company ABC
appears to have a healthy liquidity position. The company has more than
enough current assets to cover its current liabilities, and even after excluding
inventory, it still has enough quick assets to meet its short-term obligations.
However, the slightly lower quick ratio compared to the current ratio indicates
that the company may have a significant portion of its current assets tied up in
inventory that may not be as easily converted to cash.
Question 10
Question
Company XYZ reported a current ratio of 2.5 and a quick ratio of 1.8. Evaluate
the liquidity position of Company XYZ based on these ratios.
Solution
Step 1: Calculate the Current Assets and Current Liabilities
Using the formula for the current ratio:
Current Ratio = Current Assets
Current Liabilities
we can derive the current assets of Company XYZ as:
Current Assets = Current Ratio ×Current Liabilities
11
Given that the current ratio is 2.5, we have:
Current Assets = 2.5×Current Liabilities
Step 2: Calculate the Quick Assets
Using the formula for the quick ratio:
Quick Ratio = Quick Assets
Current Liabilities
we can derive the quick assets of Company XYZ as:
Quick Assets = Quick Ratio ×Current Liabilities
Given that the quick ratio is 1.8, we have:
Quick Assets = 1.8×Current Liabilities
Step 3: Interpretation of the Ratios
The current ratio measures a company’s ability to pay its short-term obliga-
tions with its short-term assets, while the quick ratio provides a more stringent
measure by excluding inventory from current assets.
Comparing the two ratios, we can see that the current ratio is higher than
the quick ratio, indicating that a significant portion of the current assets consists
of inventory. In this case, the liquidity position may be slightly overstated by
the current ratio, as inventory may not be as quickly converted to cash in case
of an emergency.
Overall, with a current ratio of 2.5 and a quick ratio of 1.8, Company XYZ
appears to have a healthy liquidity position. However, it is important to take
into consideration the composition of current assets to accurately assess the
company’s ability to meet its short-term obligations.
Question 11
Question
A company has reported the following financial ratios for the current year:
Ratio Value
Current Ratio 2.5
Quick Ratio 1.8
Debt-to-Equity Ratio 0.6
Return on Assets 0.12
Return on Equity 0.2
Based on these ratios, analyze and interpret the company’s financial perfor-
mance.
12
Solution
Step 1: Current Ratio and Quick Ratio
The current ratio is 2.5, indicating that the company has 2.5ofcurrentassetsf oreverydollarof currentliabilities.T hissuggeststhatthecompanyisabletomeetitsshort−
termobligationscomfortably.T hequickratiois1.8, whichisslightlylowerthanthecurrentratio.T hissuggeststhatthecompany′sabilitytomeetshort−
termliabilitieswithitsmostliquidassets(excludinginventory)isstillstrongbutslightlylessthanitsoverallabilitytopayoffallcurrentliabilities.
Step 2: Debt-to-Equity Ratio
The debt-to-equity ratio of 0.6 indicates that the company has more equity
than debt financing, which is generally considered favorable. A lower
debt-to-equity ratio implies lower financial risk and less reliance on debt
to finance operations.
Step 3: Return on Assets (ROA) and Return on Equity (ROE)
The return on assets of 0.12 means that the company generated 12 cents of
profit for every dollar of assets it owns. This ratio measures the company’s
efficiency in using its assets to generate profits.
The return on equity of 0.2 indicates that the company generated 20 cents
of profit for every dollar of equity. This ratio measures the company’s
ability to generate profits from shareholders’ investments.
Overall, based on the provided ratios:
The company appears to have strong liquidity with both current and quick
ratios above 1.
The company has a healthy mix of debt and equity financing with a low
debt-to-equity ratio.
The company is profitable, as evidenced by positive returns on assets and
equity.
This analysis suggests that the company is in a stable financial position with
efficient use of assets and strong profitability.
Question 12
Question
A company has the following financial information for two consecutive years:
Year 1: Net Income =
$
500,000; Total Assets =
$
2,000,000
Year 2: Net Income =
$
700,000; Total Assets =
$
2,500,000
Calculate the return on assets (ROA) for each year and interpret the results
in terms of the company’s performance.
13
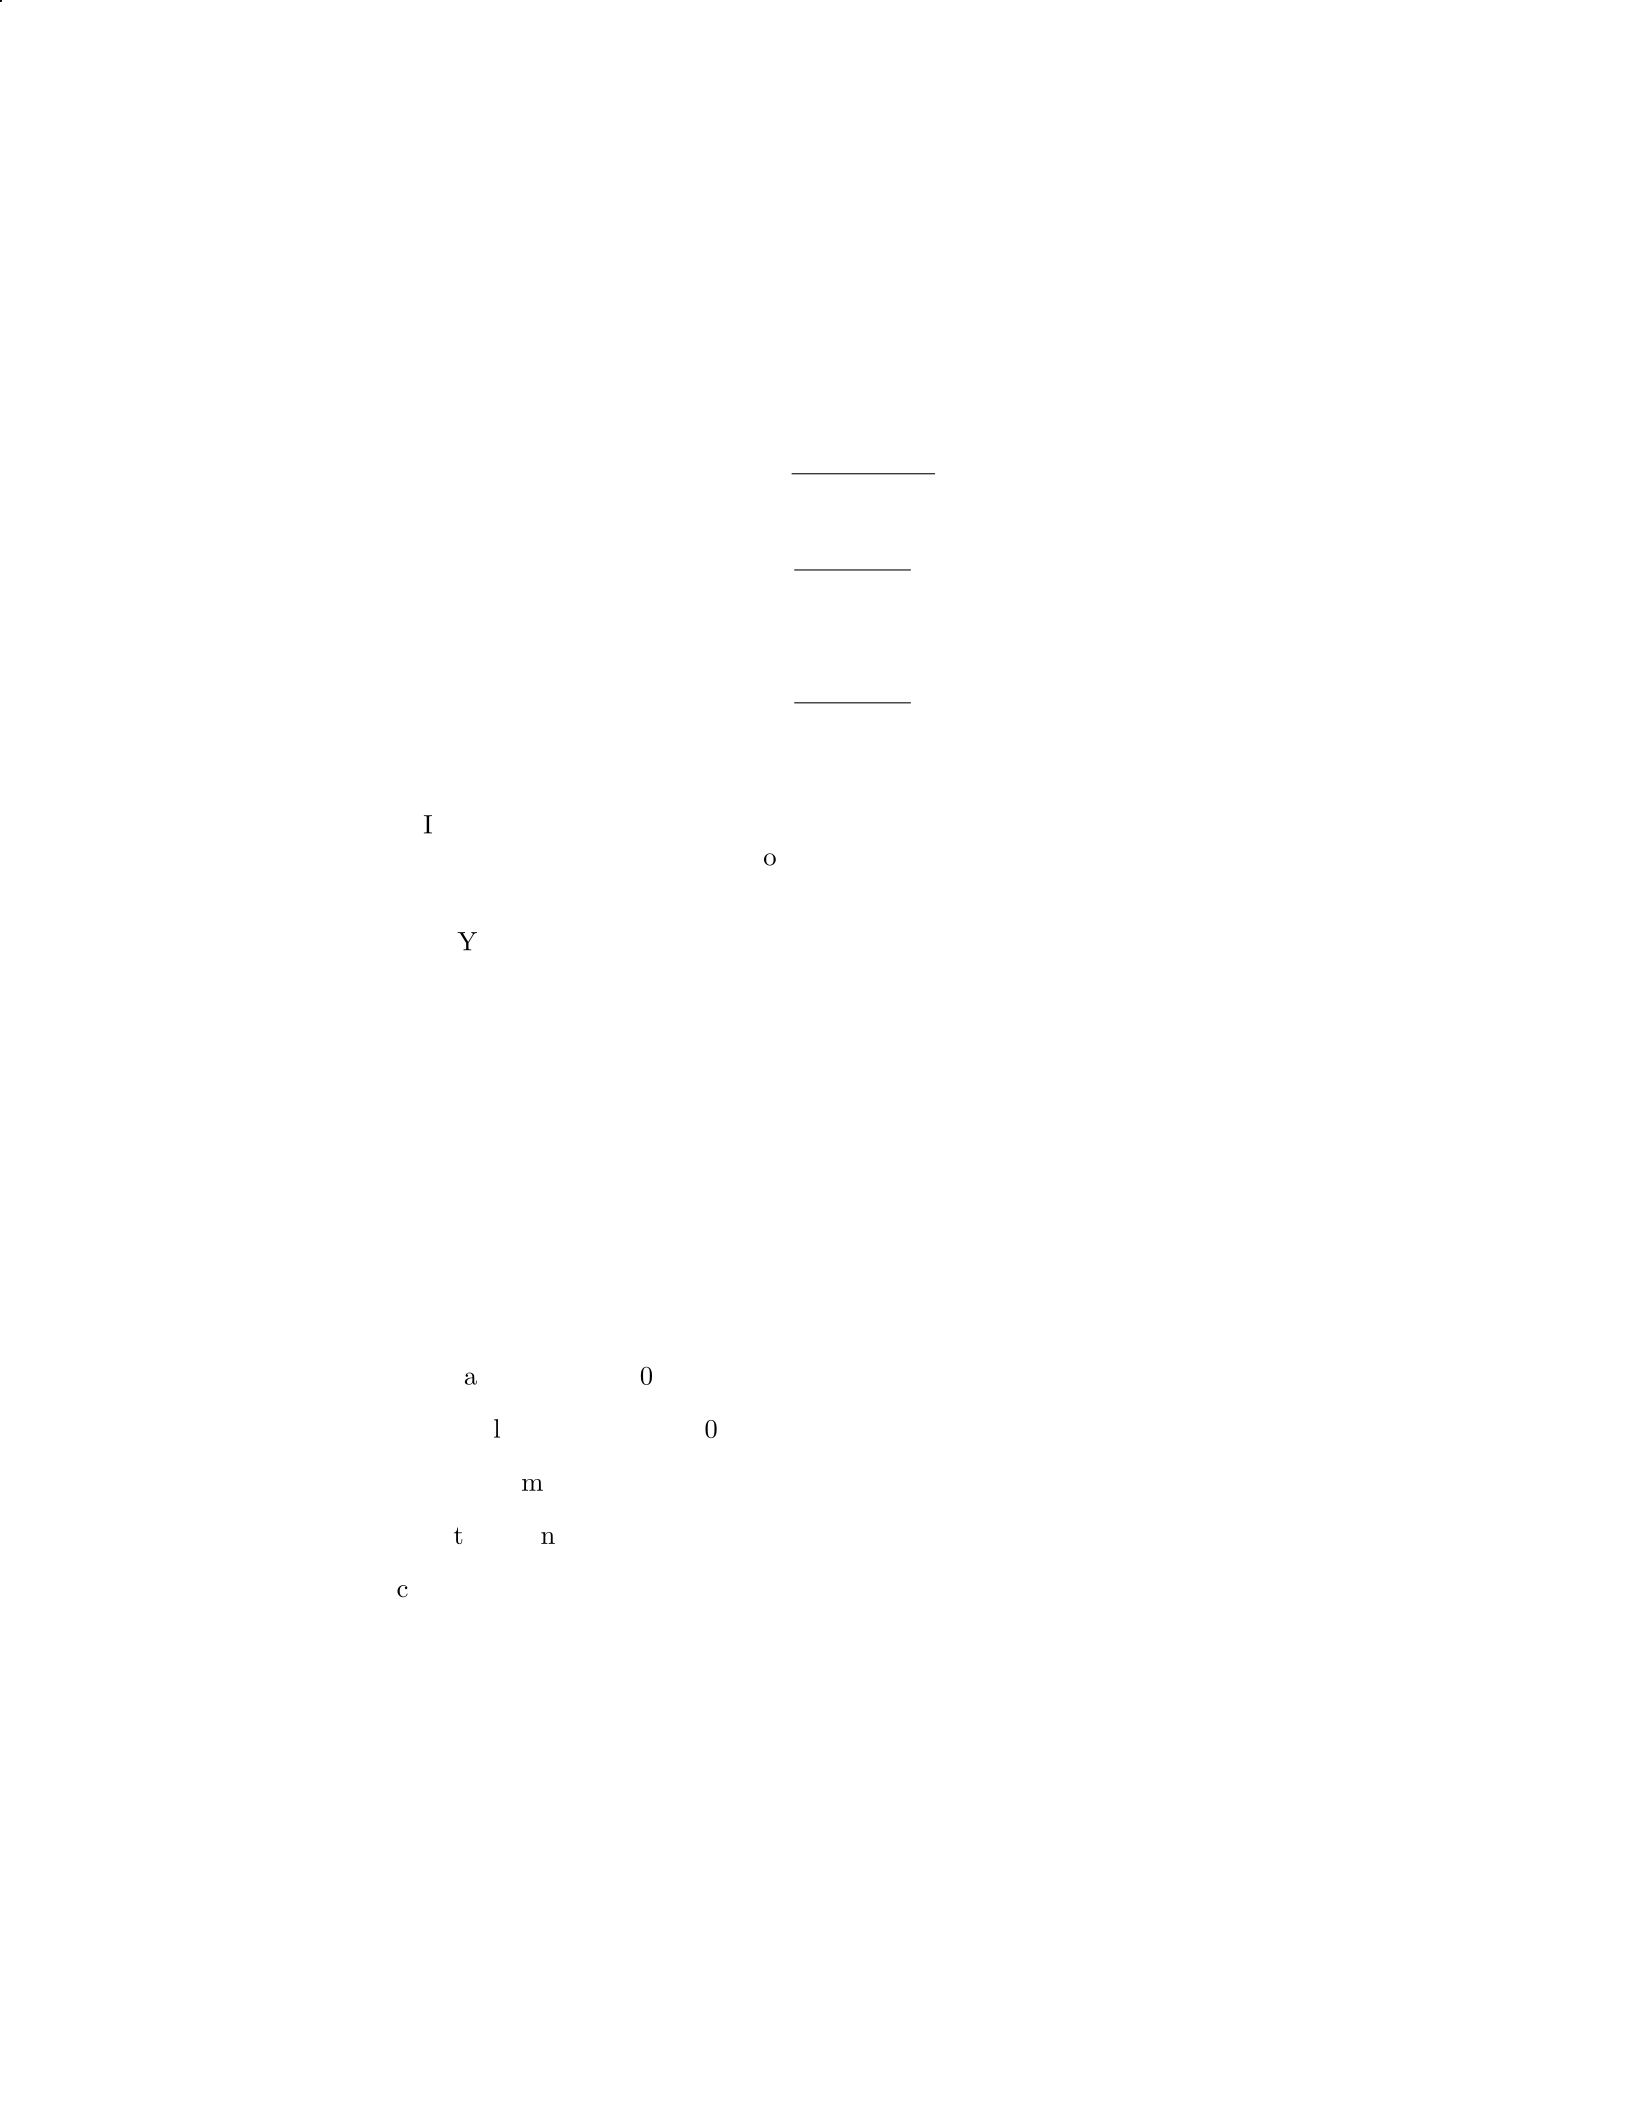
Solution
Step 1: Calculate the Return on Assets (ROA) for Year 1.
ROA =NetIncome
T otalAssets
ROAY ear1=500,000
2,000,000 = 0.25
Step 2: Calculate the Return on Assets (ROA) for Year 2.
ROAY ear2=700,000
2,500,000 = 0.28
Step 3: Interpretation:
In Year 1, the company had a Return on Assets (ROA) of 0.25 or 25%.
This means that for every
$
1 of assets, the company generated 25 cents of
net income.
In Year 2, the company’s ROA improved to 0.28 or 28%. This indicates
that in Year 2, the company was more efficient in generating income from
its assets compared to Year 1.
Overall, the increasing trend in ROA from Year 1 to Year 2 suggests an
improvement in the company’s performance in utilizing its assets to generate
profit.
Question 13
Question
A company has the following financial information for the year:
Total assets:
$
500,000
Total liabilities:
$
200,000
Net income:
$
50,000
Total revenue:
$
300,000
Calculate the following ratios and interpret the results:
1. Debt-to-Assets Ratio
2. Return on Assets Ratio
14
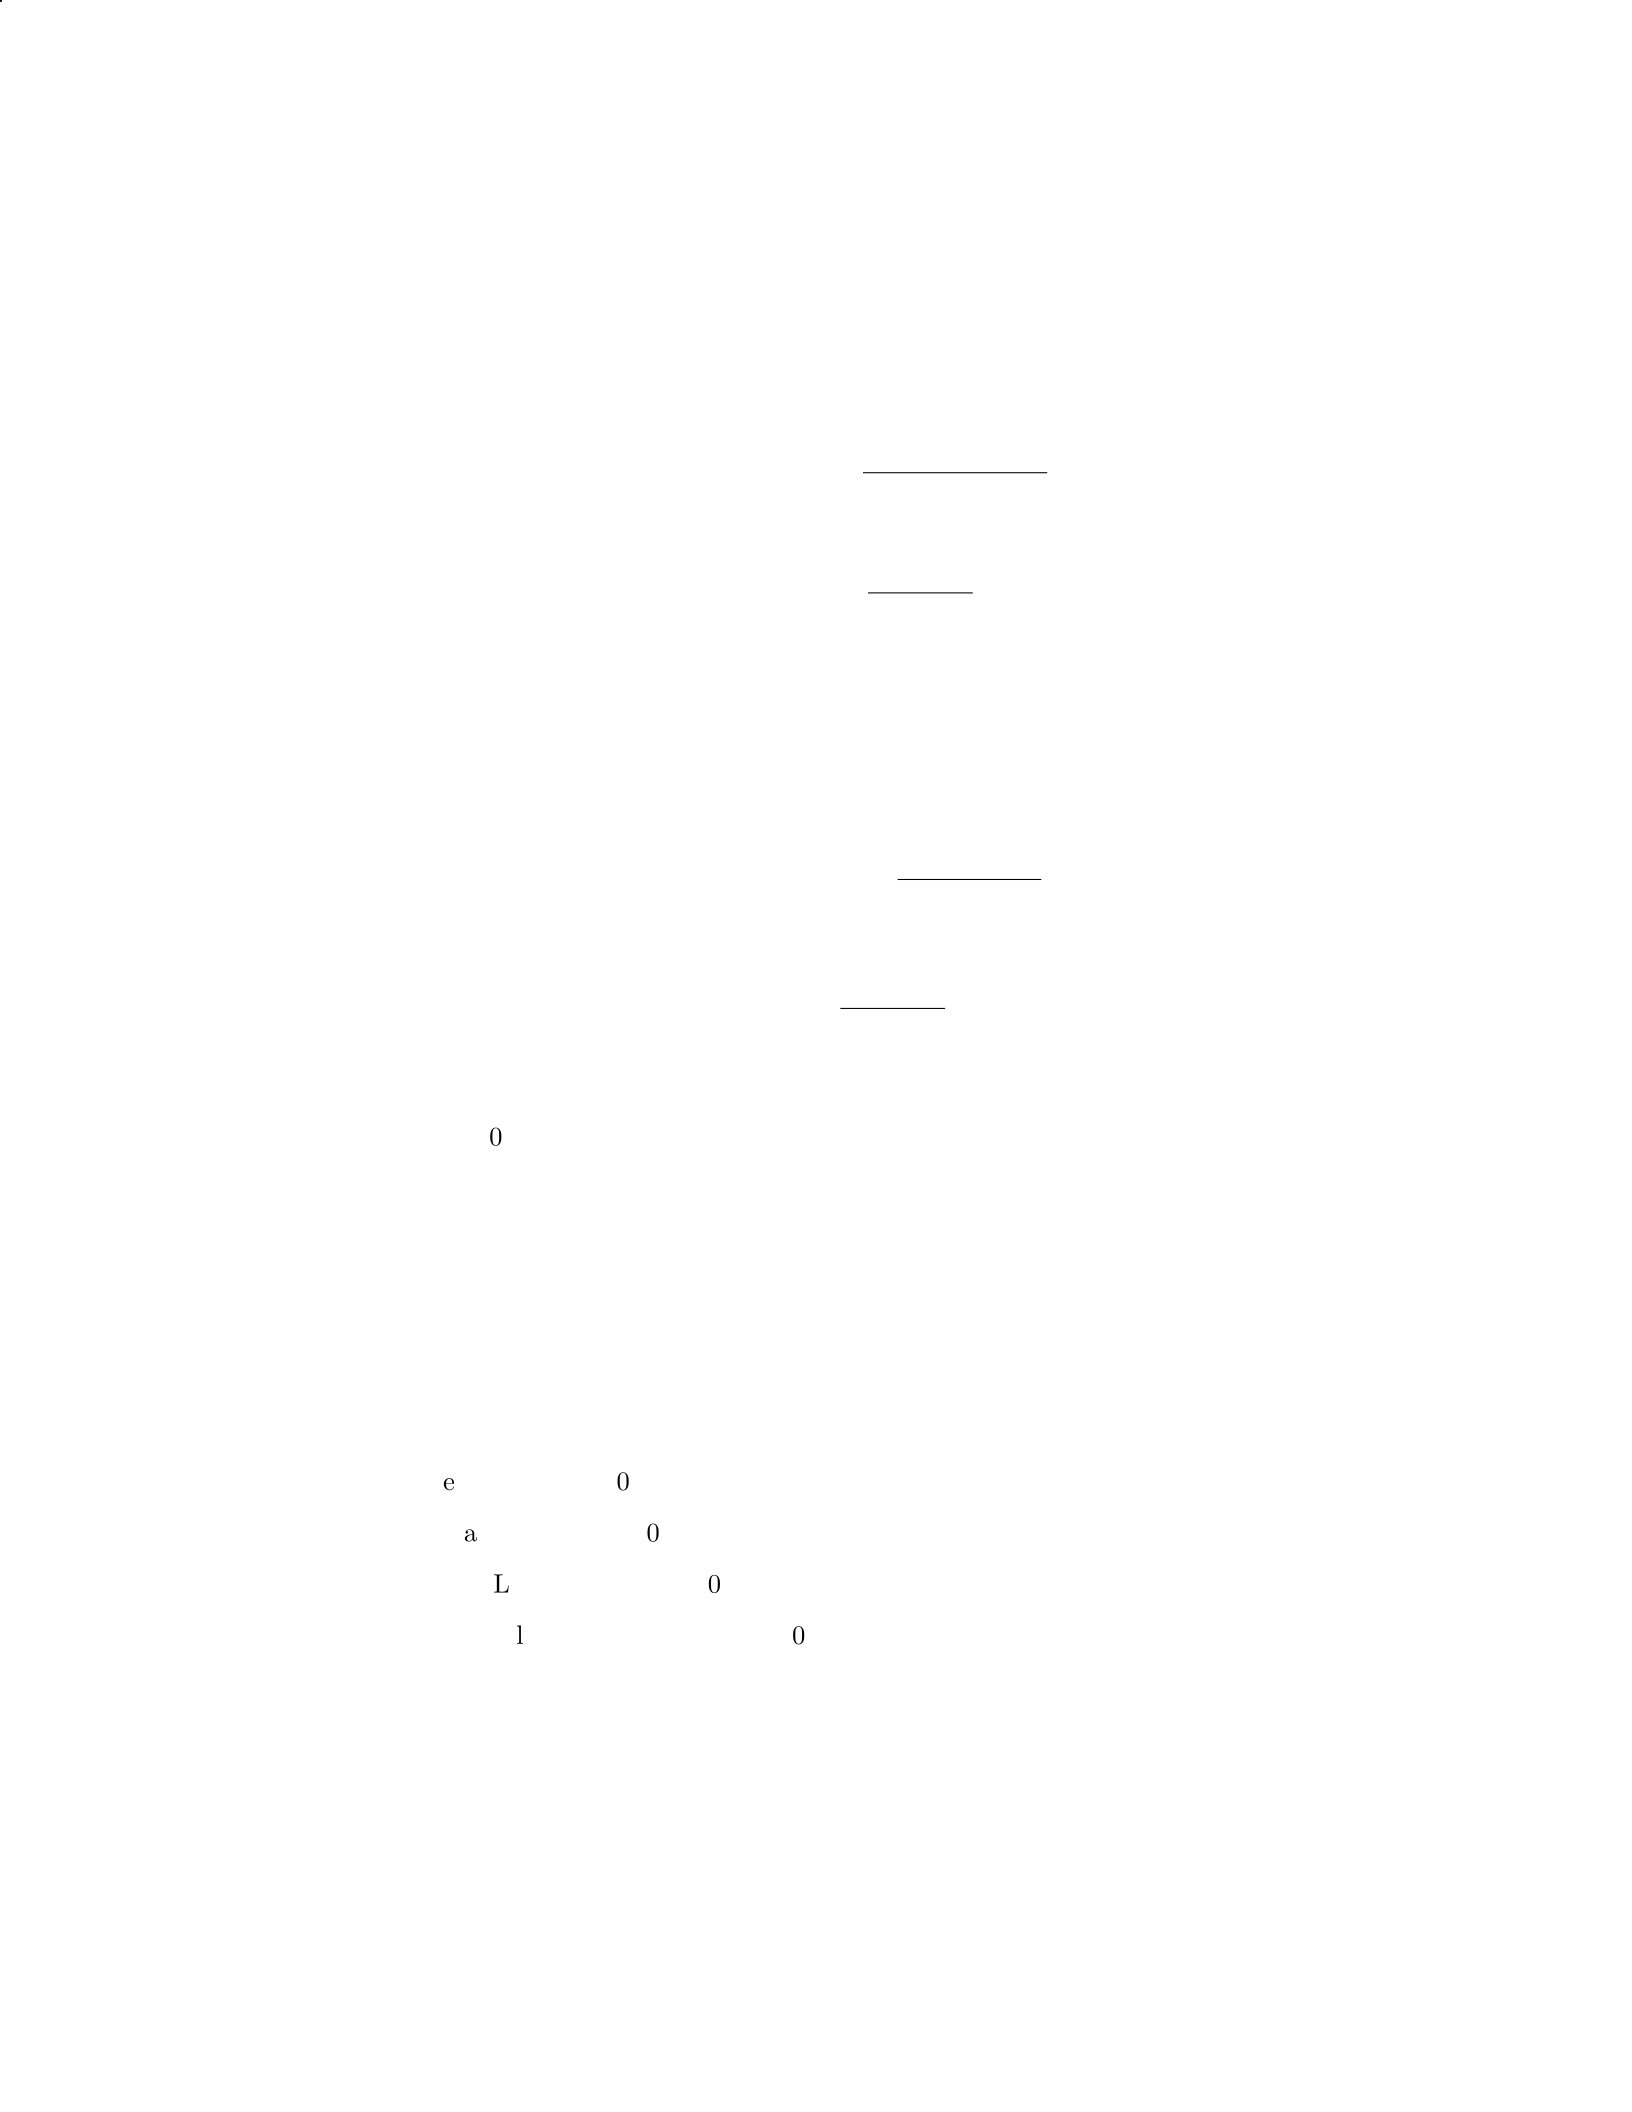
Solution
Step 1: Calculate the Debt-to-Assets Ratio The Debt-to-Assets Ratio is
calculated as:
Debt-to-Assets Ratio = Total Liabilities
Total Assets
Substitute the given values:
Debt-to-Assets Ratio = $200,000
$500,000 = 0.4
Step 2: Interpretation of the Debt-to-Assets Ratio The Debt-to-
Assets Ratio of 0.4 indicates that 40% of the company’s assets are financed by
debt. This suggests that the company relies relatively more on equity financing
and is less risky in terms of leverage.
Step 3: Calculate the Return on Assets Ratio The Return on Assets
Ratio is calculated as:
Return on Assets Ratio = Net Income
Total Assets
Substitute the given values:
Return on Assets Ratio = $50,000
$500,000 = 0.1 = 10%
Step 4: Interpretation of the Return on Assets Ratio The Return
on Assets Ratio of 10% indicates that for every dollar of assets, the company
generates
$
0.10 of net income. This ratio is a measure of how efficiently the
company is using its assets to generate profit. A higher ratio suggests better
asset utilization and profitability.
Question 14
Question
A company’s financial statements show the following information for the current
year:
Net Income:
$
500,000
Total Assets:
$
2,000,000
Total Liabilities:
$
1,000,000
Shareholders’ Equity:
$
1,000,000
Calculate the following ratios and interpret the results:
1. Return on Assets (ROA)
2. Debt-to-Equity Ratio
15
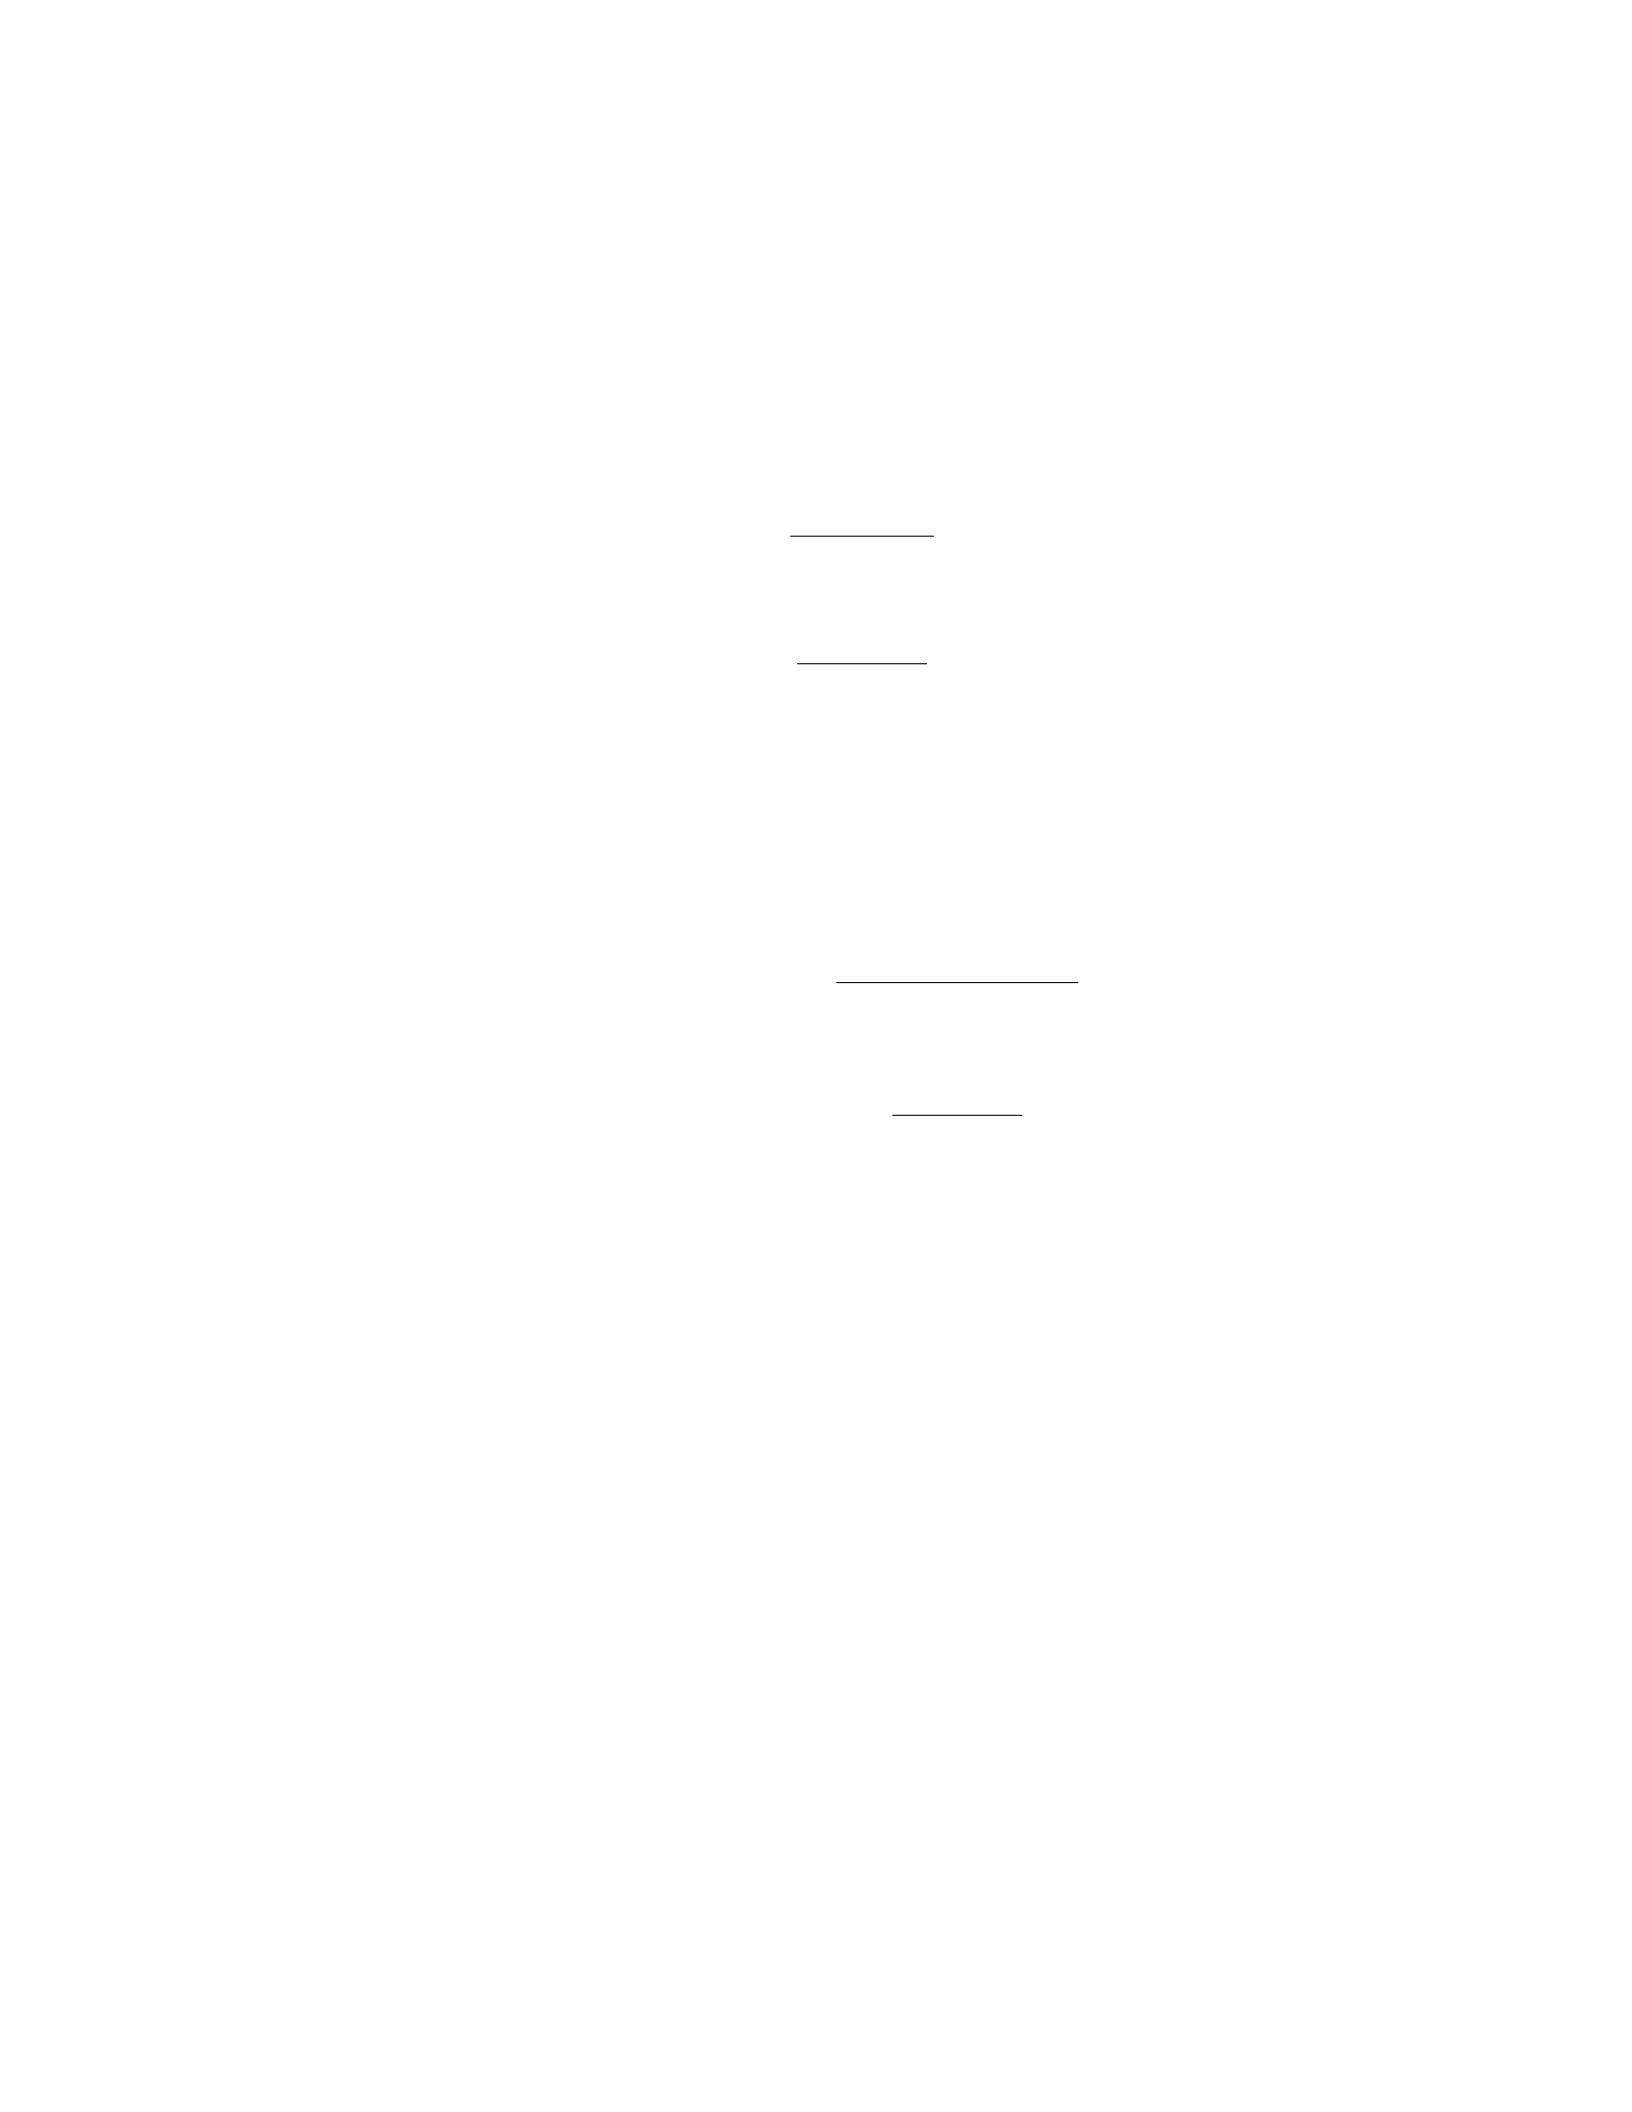
Solution
Step 1: Calculate Return on Assets (ROA)
The Return on Assets (ROA) ratio is calculated by dividing Net Income by
Total Assets.
ROA = Net Income
Total Assets
Plugging in the values:
ROA = $500,000
$2,000,000
ROA = 0.25 or 25%
Interpretation: This means that for every dollar of assets, the company
generated 0.25or25%ofnetincome.
Step 2: Calculate Debt-to-Equity Ratio
The Debt-to-Equity ratio is calculated by dividing Total Liabilities by Share-
holders’ Equity.
Debt-to-Equity Ratio = Total Liabilities
Shareholders’ Equity
Plugging in the values:
Debt-to-Equity Ratio = $1,000,000
$1,000,000
Debt-to-Equity Ratio = 1
Interpretation: A Debt-to-Equity ratio of 1 means that the company has
the same amount of debt as it has equity. This indicates that the company’s
financing is balanced between debt and equity.
Question 15
Question
A company reported the following financial ratios for the year: current ratio of
2.5, quick ratio of 1.5, and debt-to-equity ratio of 0.75. Explain the interpreta-
tion of each ratio and discuss what these ratios indicate about the company’s
financial health.
Solution
Step 1: Interpretation of Ratios
16
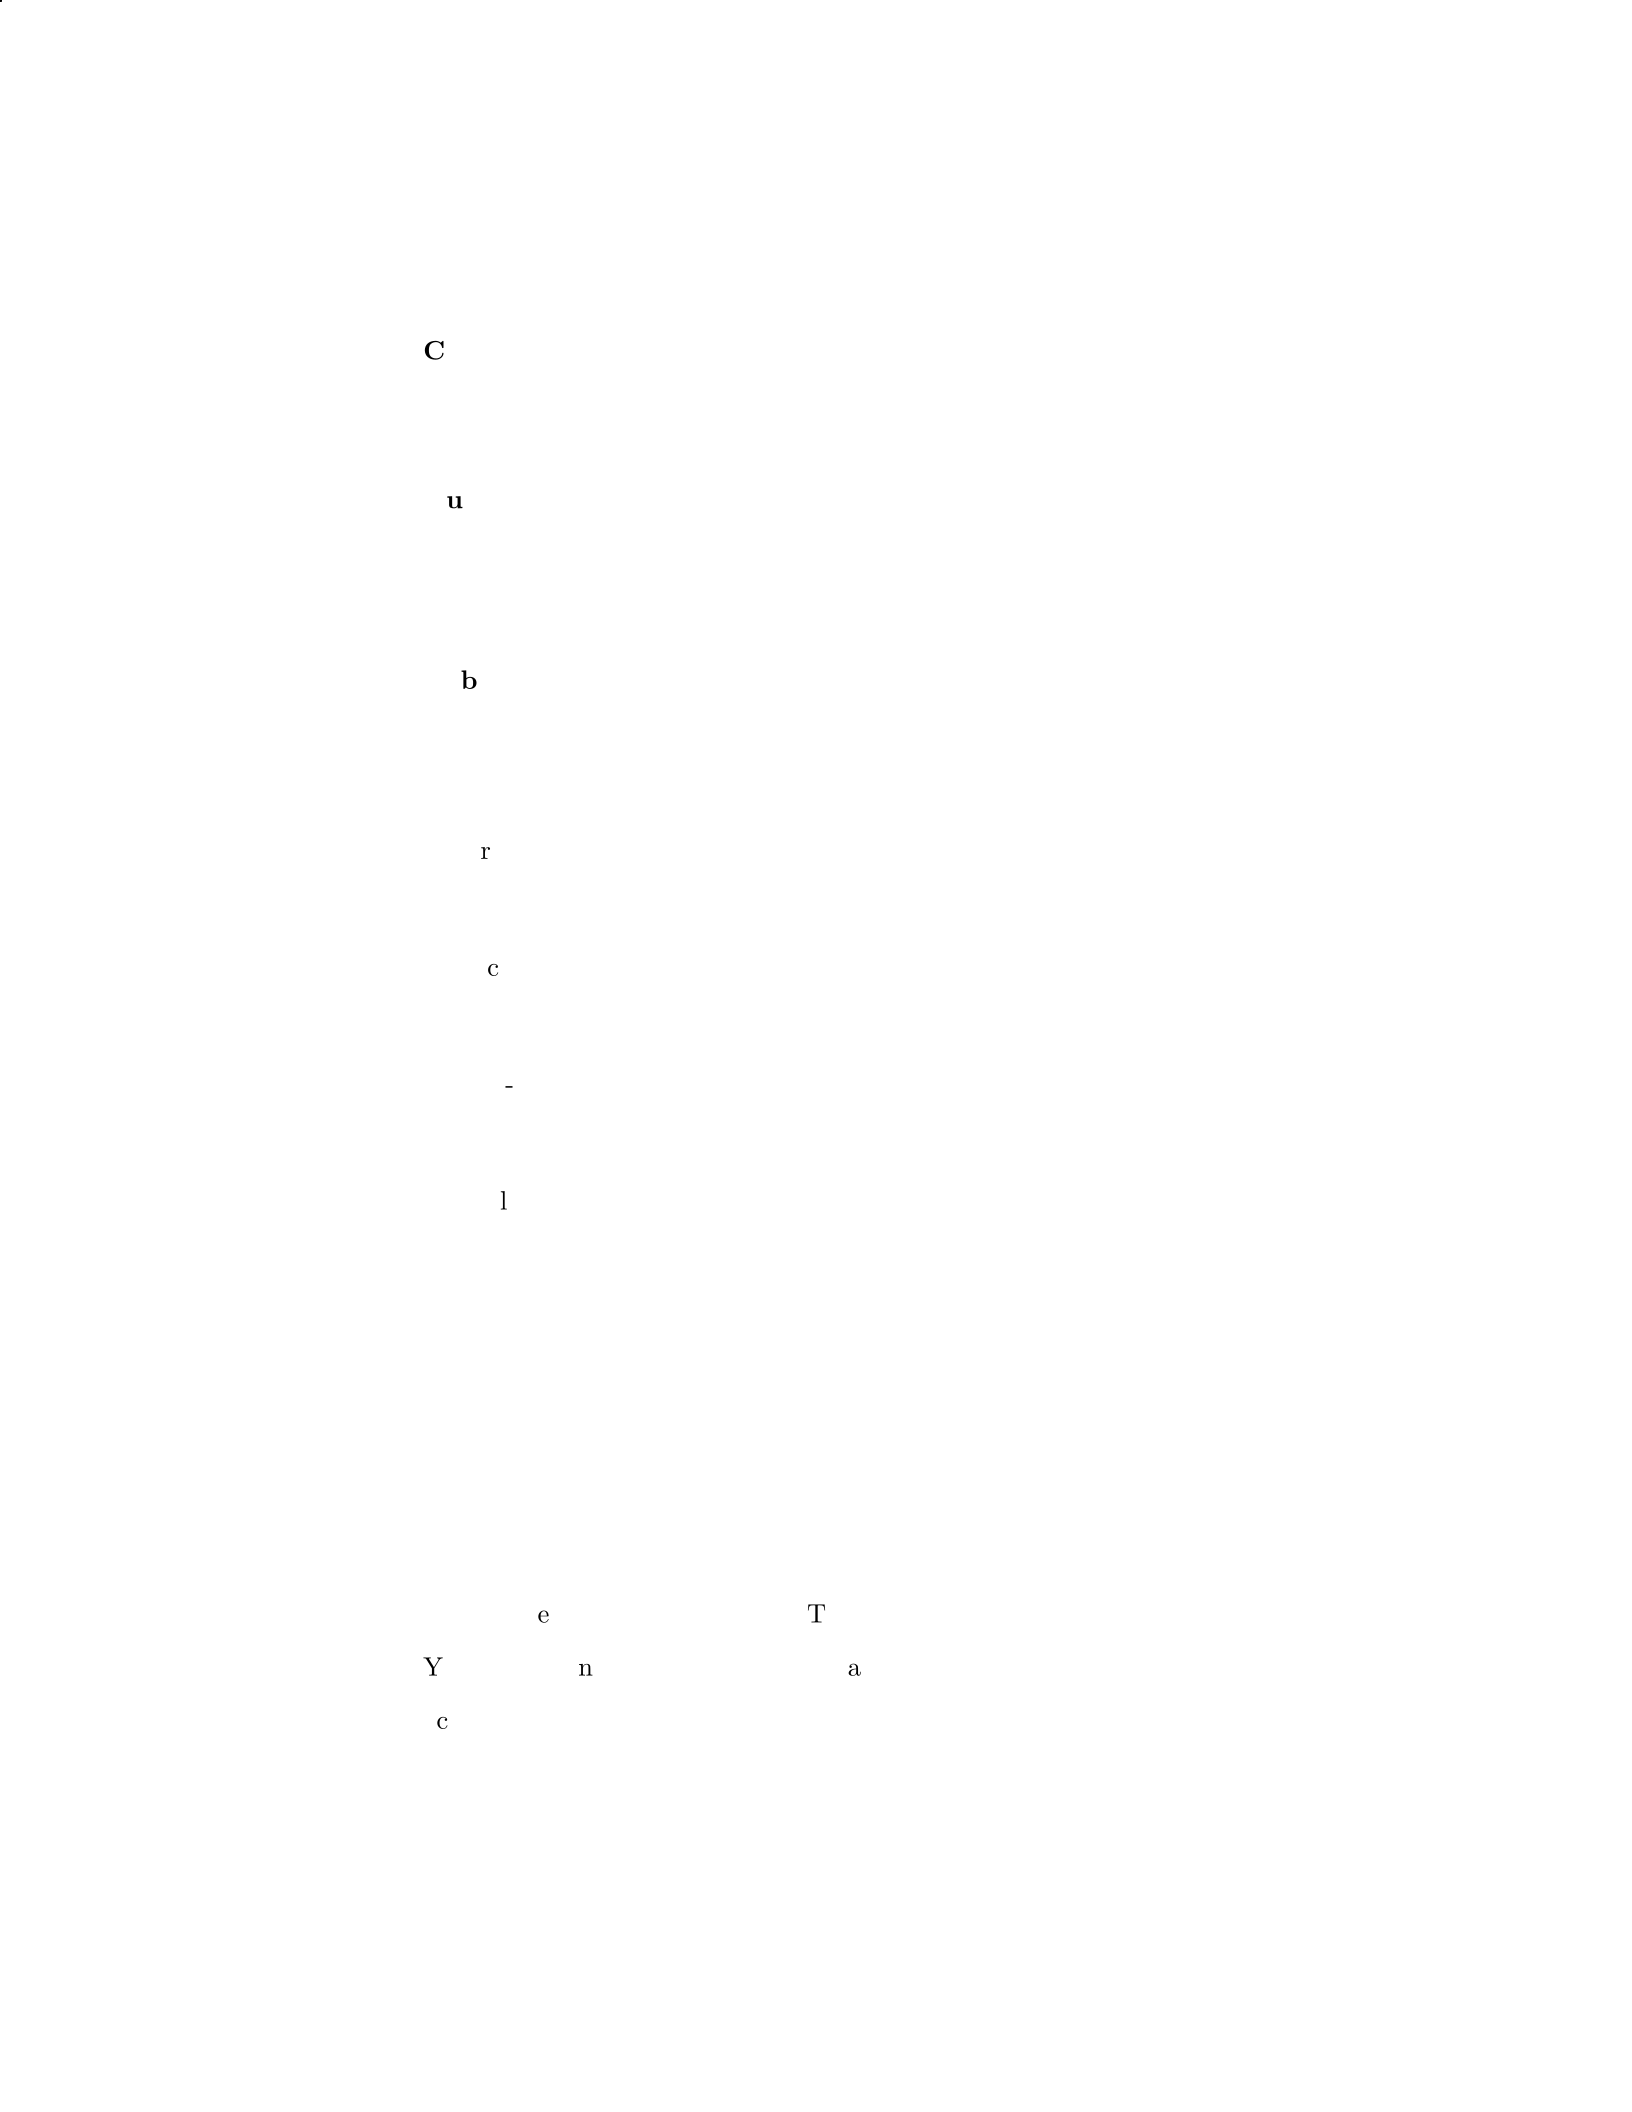
Current Ratio: The current ratio is a measure of a company’s ability to
cover its short-term liabilities with its short-term assets. A current ratio of
2.5 means that the company has 2.50worthofcurrentassetsf orevery1.00
of current liabilities.
Quick Ratio: The quick ratio (also known as the acid-test ratio) is a
more stringent measure than the current ratio. It excludes inventory from
current assets to focus on the most liquid assets. A quick ratio of 1.5 means
that the company has 1.50ofhighlyliquidassetsthatcanbequicklyconvertedintocashtocover1.00
of current liabilities.
Debt-to-Equity Ratio: The debt-to-equity ratio shows the proportion
of debt financing relative to equity financing. A debt-to-equity ratio of
0.75 means that the company has 0.75ofdebtforevery1.00 of equity.
Step 2: Financial Health Interpretation
A current ratio above 1 indicates that the company can meet its short-
term obligations. A current ratio of 2.5 is considered healthy as it shows
a strong ability to cover short-term liabilities.
A quick ratio of 1.5 is also above 1, which indicates that the company can
meet its short-term obligations without relying on selling inventory. This
shows good liquidity.
A debt-to-equity ratio of 0.75 indicates that the company is using more
equity financing relative to debt financing. This could be seen as a positive
sign as it indicates lower financial risk.
Overall, based on the ratios provided, the company appears to have good
short-term liquidity and a conservative approach to capital structure.
However, it is important to consider other factors such as industry norms,
historical trends, and future outlook before making a definitive assessment
of the company’s financial health.
Question 16
Question
A company’s financial statements show the following figures for two consecutive
years:
Year 1: Net Income =
$
500,000; Total Assets =
$
2,000,000
Year 2: Net Income =
$
600,000; Total Assets =
$
2,500,000
Calculate the return on assets (ROA) for both years and interpret the results
in terms of the company’s performance.
17
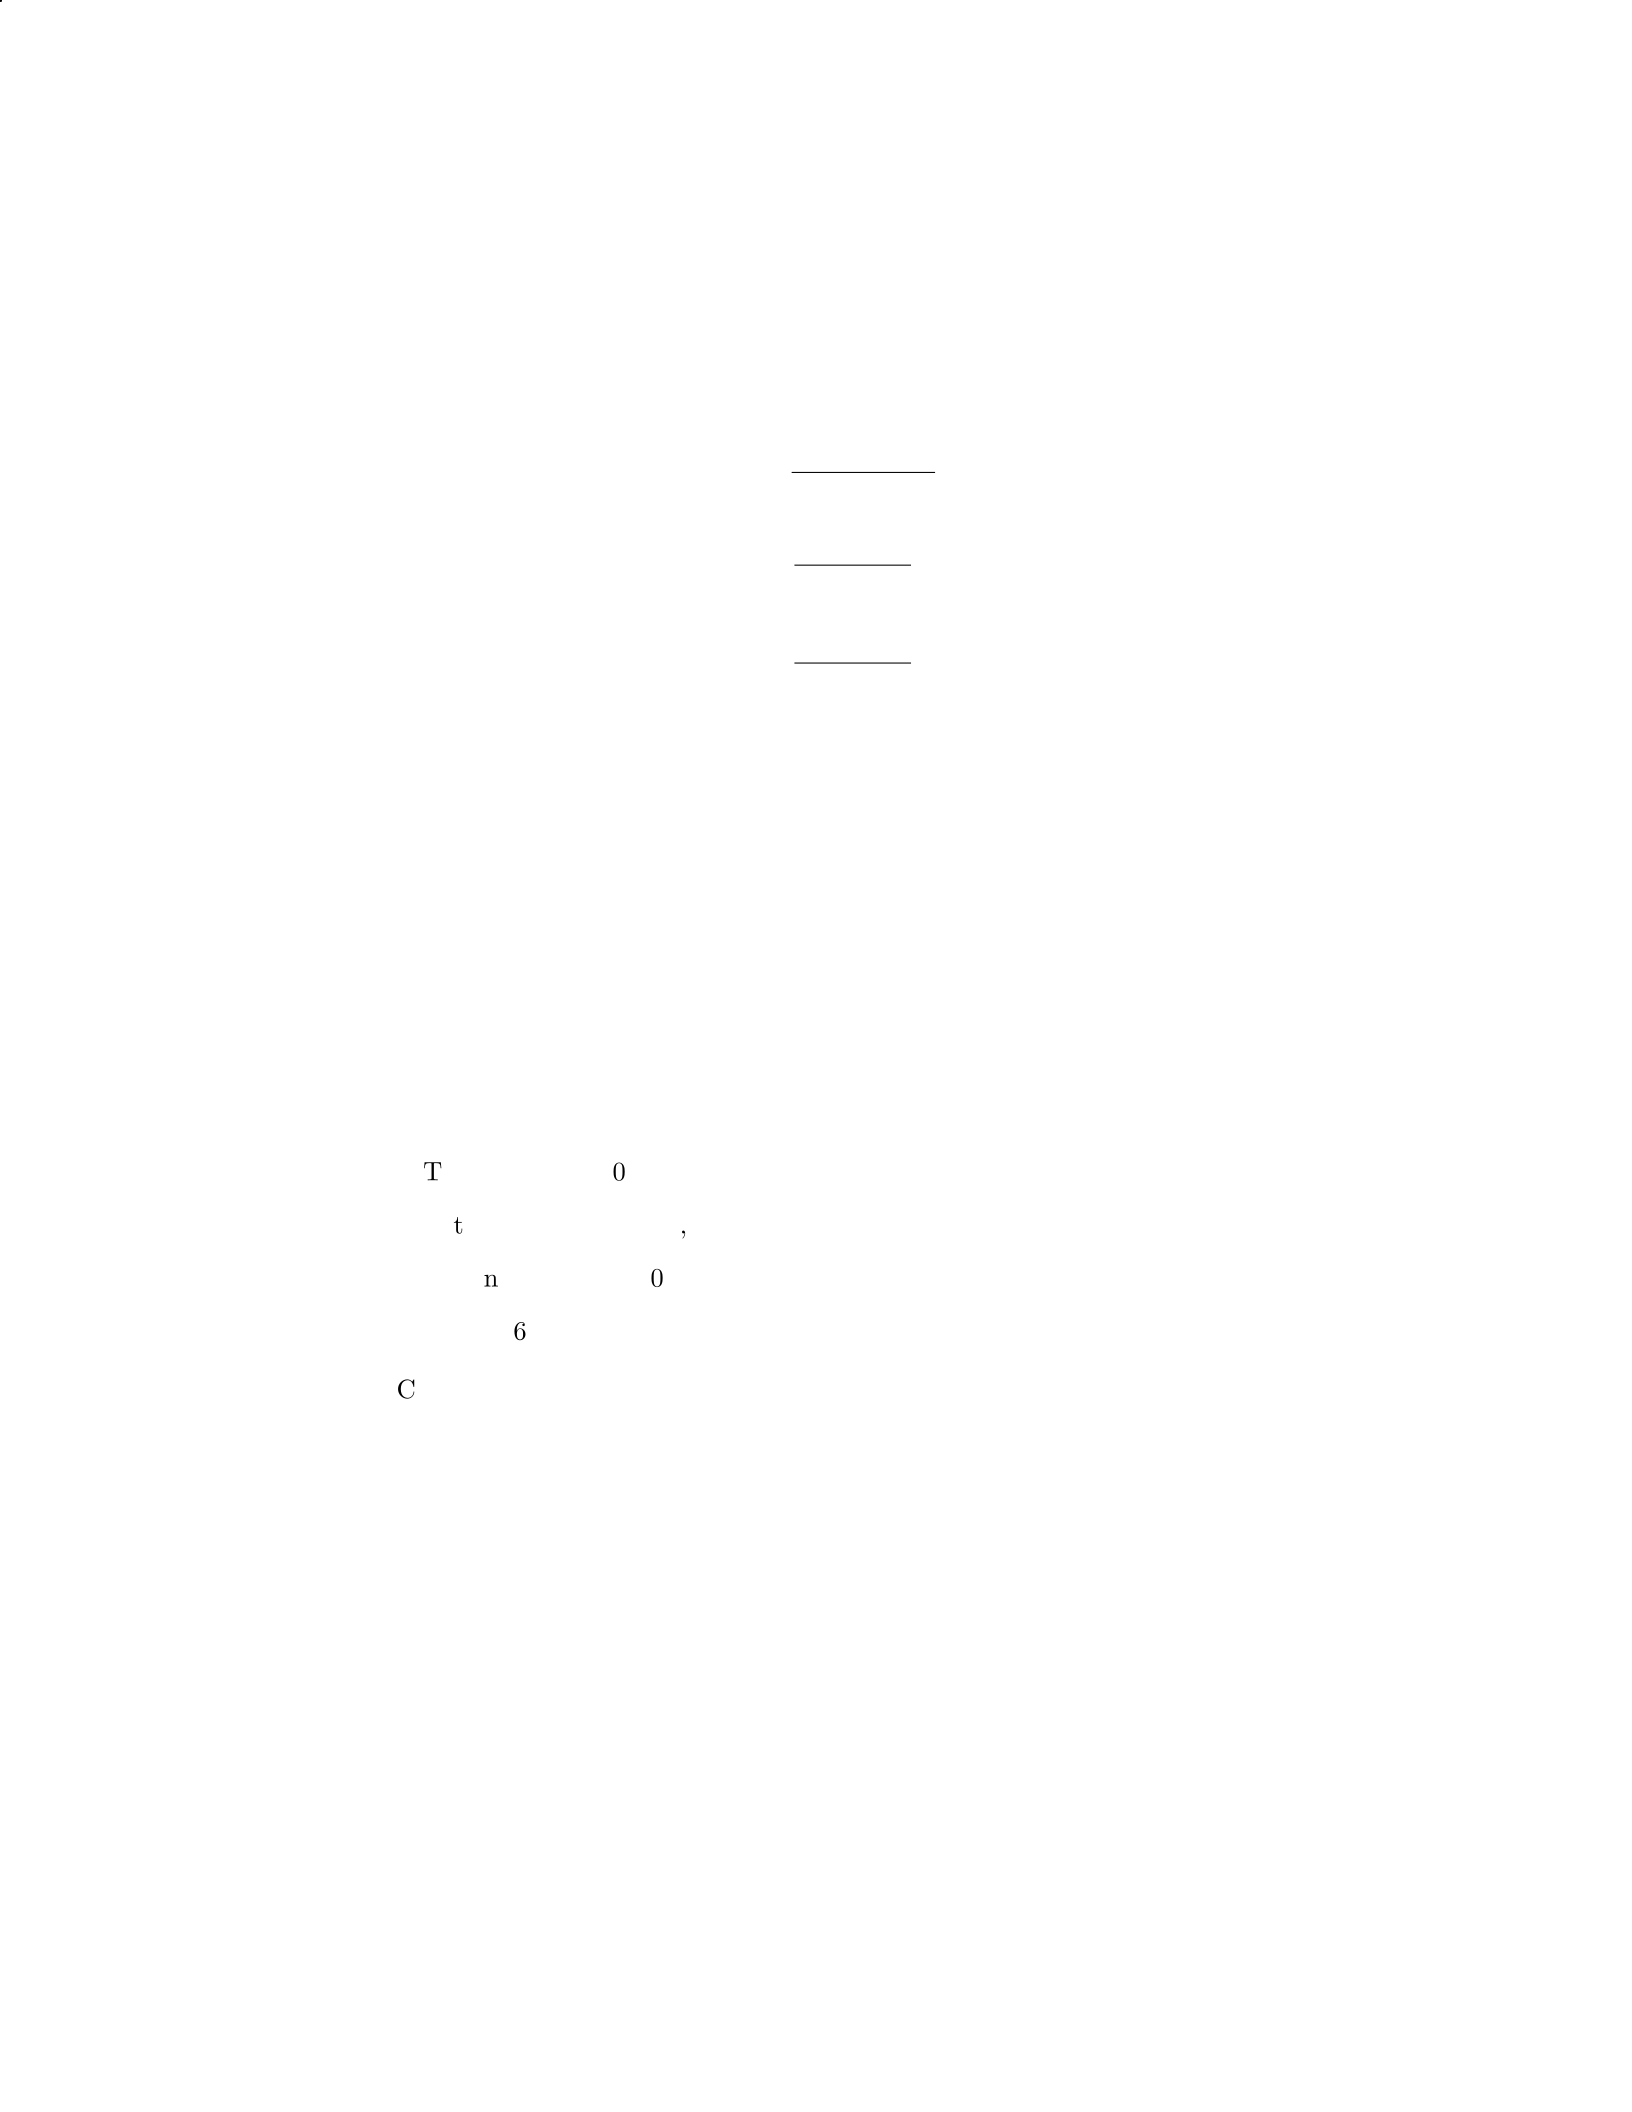
Solution
Step 1: Calculate the Return on Assets (ROA) for Year 1 and Year 2 using the
formula:
ROA =NetIncome
T otalAssets
For Year 1:
ROAYear 1 =500,000
2,000,000 = 0.25
For Year 2:
ROAYear 2 =600,000
2,500,000 = 0.24
Step 2: Interpret the ROA values for both years: - In Year 1, the company
had a ROA of 0.25, meaning that for every dollar of assets, the company gener-
ated 0.25innetincome.−InY ear2, thecompany′sROAdecreasedto0.24, indicatingaslightdecreaseinef ficiencyingeneratingincomefromitsassets.
Overall, the company’s performance in terms of generating income from its
assets slightly declined from Year 1 to Year 2. It is important for the company to
analyze the reasons behind this decrease and take corrective actions to improve
its efficiency in utilizing assets to generate income.
Question 17
Question
A company’s financial statements show the following data for the current year:
Total Assets:
$
800,000
Total Liabilities:
$
400,000
Net Income:
$
120,000
Sales:
$
600,000
Calculate the following financial ratios and provide an interpretation of each:
1. Debt-to-Asset Ratio
2. Return on Assets
3. Profit Margin
18
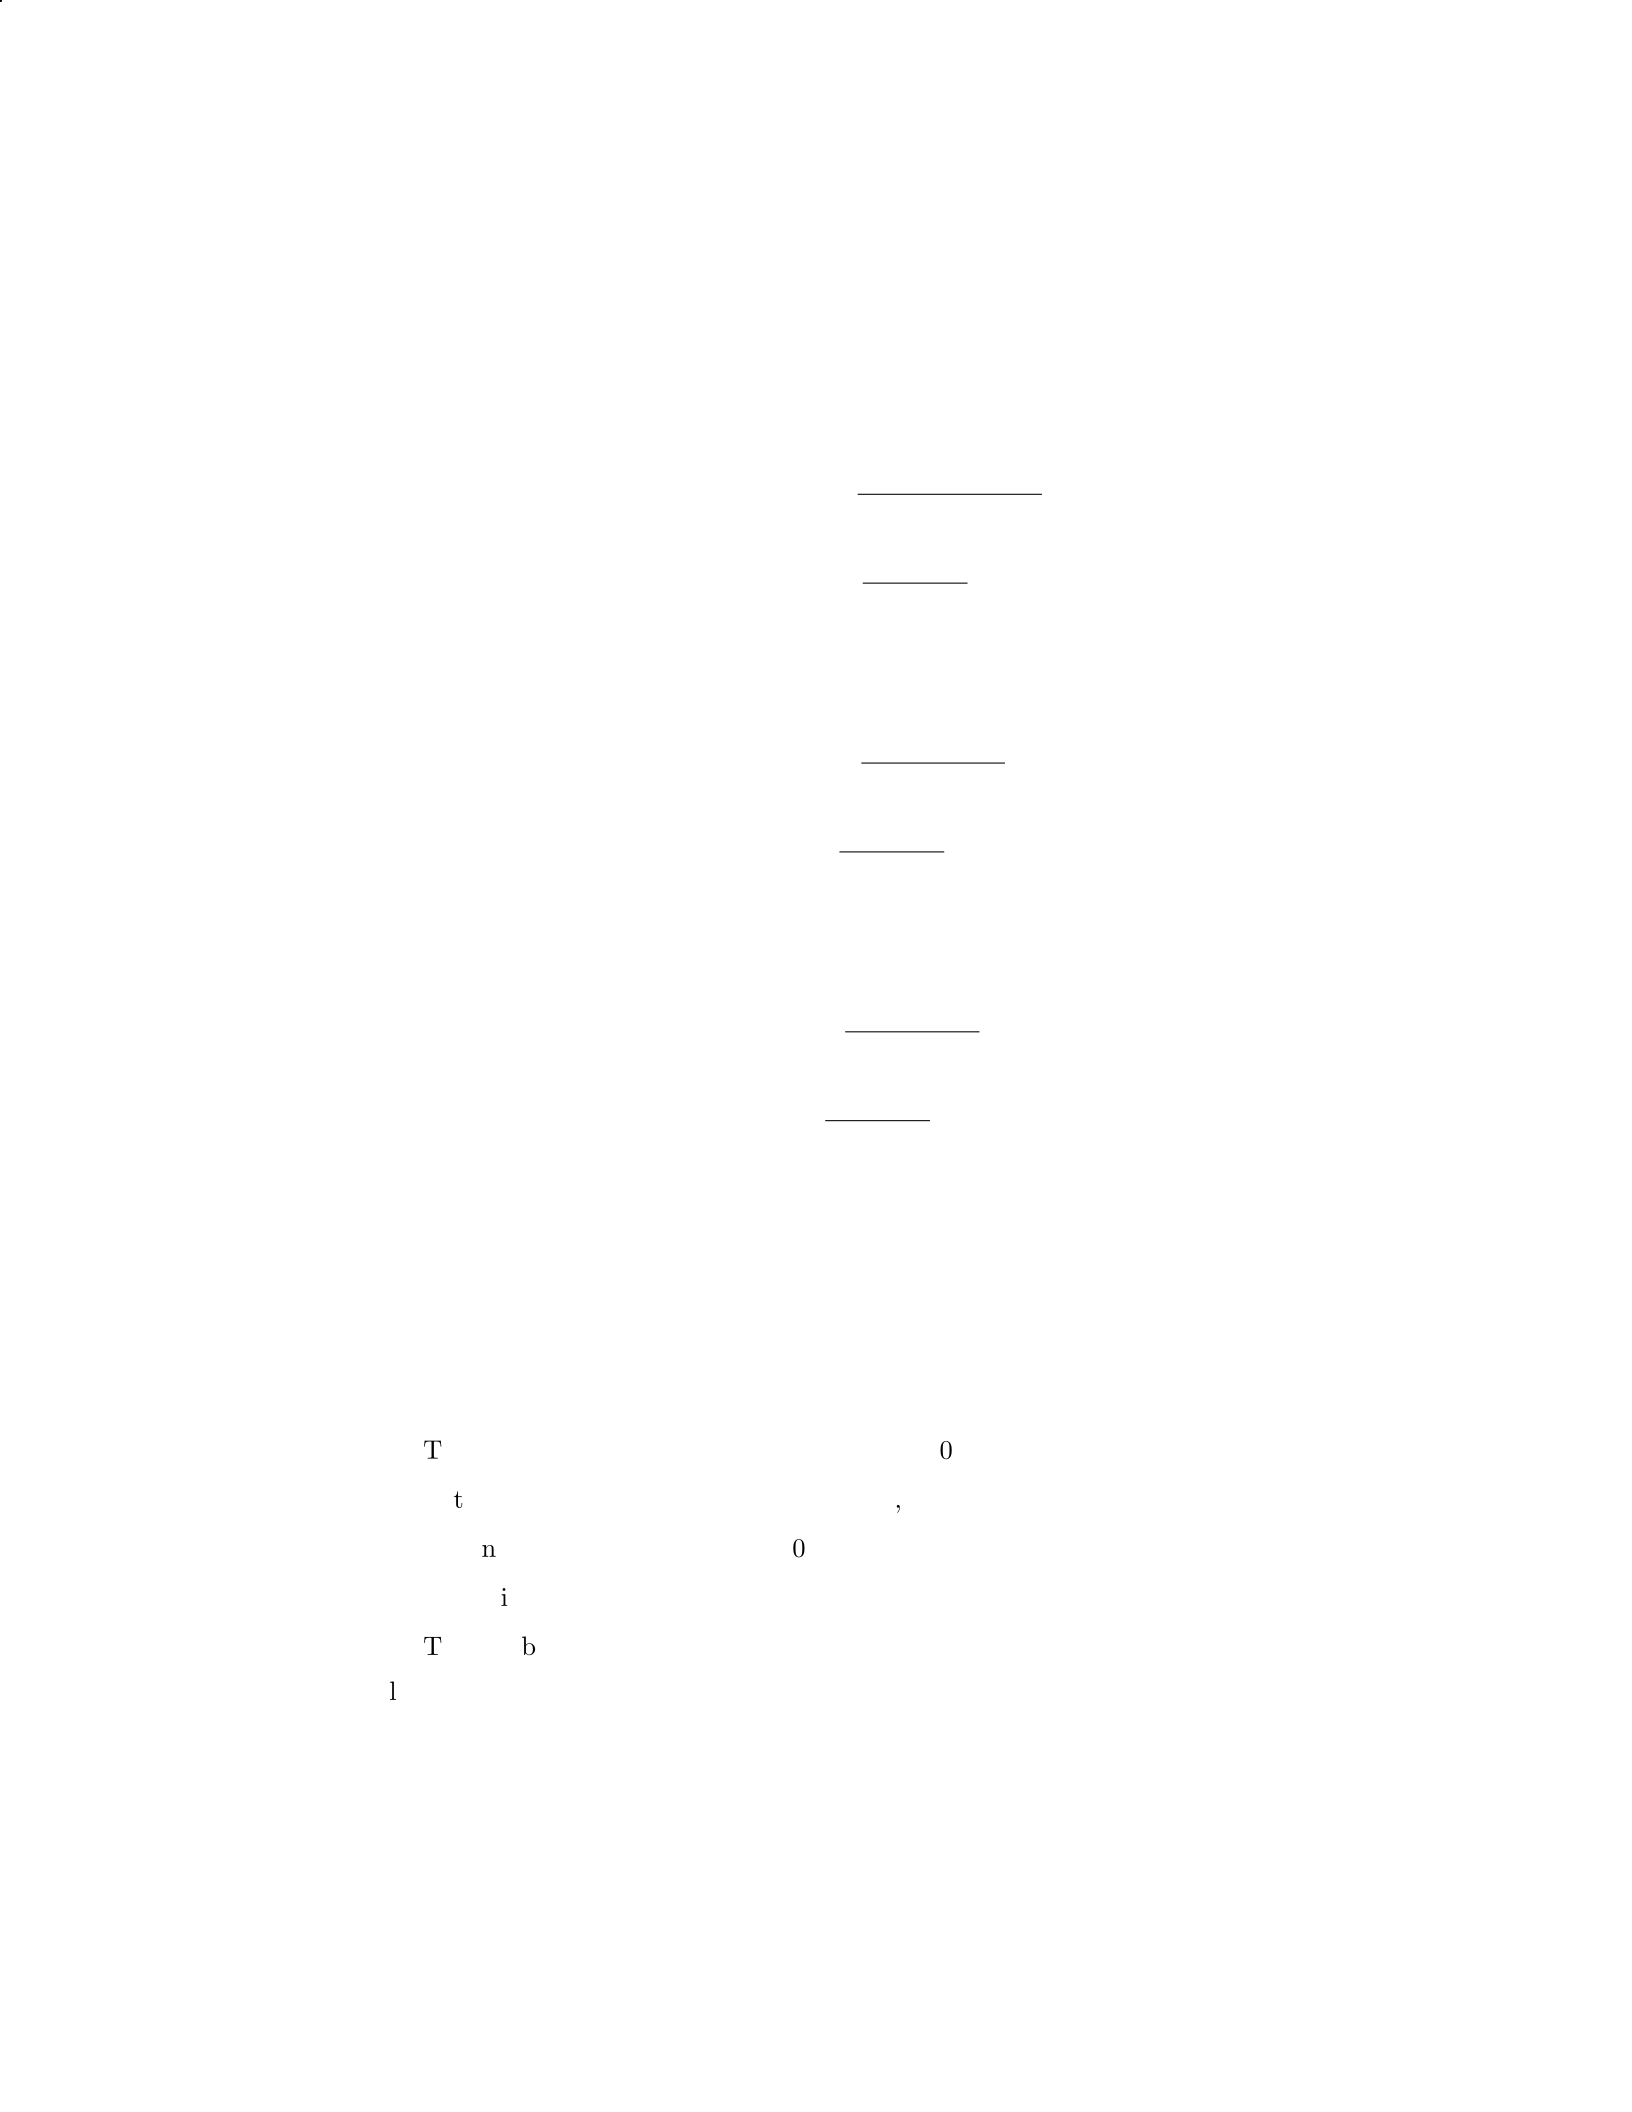
Solution
Let’s calculate each ratio step by step:
Step 1: Calculate the Debt-to-Asset Ratio
Debt-to-Asset Ratio = Total Liabilities
Total Assets
Debt-to-Asset Ratio = $400,000
$800,000 = 0.5
The Debt-to-Asset ratio is 0.5, which means that 50% of the company’s
assets are financed by debt.
Step 2: Calculate the Return on Assets
Return on Assets = Net Income
Total Assets
Return on Assets = $120,000
$800,000 = 0.15
The Return on Assets is 0.15, or 15%. This means that the company gener-
ated a profit of 15% for every dollar of assets it possesses.
Step 3: Calculate the Profit Margin
Profit Margin = Net Income
Sales
Profit Margin = $120,000
$600,000 = 0.2
The Profit Margin is 0.2, or 20%. This indicates that the company’s net
income is 20% of its total sales.
Question 18
Question
A company has the following financial information for the year:
Total assets at the beginning of the year:
$
500,000
Total assets at the end of the year:
$
700,000
Net income for the year:
$
100,000
Total liabilities at the beginning of the year:
$
300,000
Total liabilities at the end of the year:
$
400,000
Calculate the following ratios and interpret them:
1. Return on Assets (ROA)
2. Debt to Asset Ratio
19
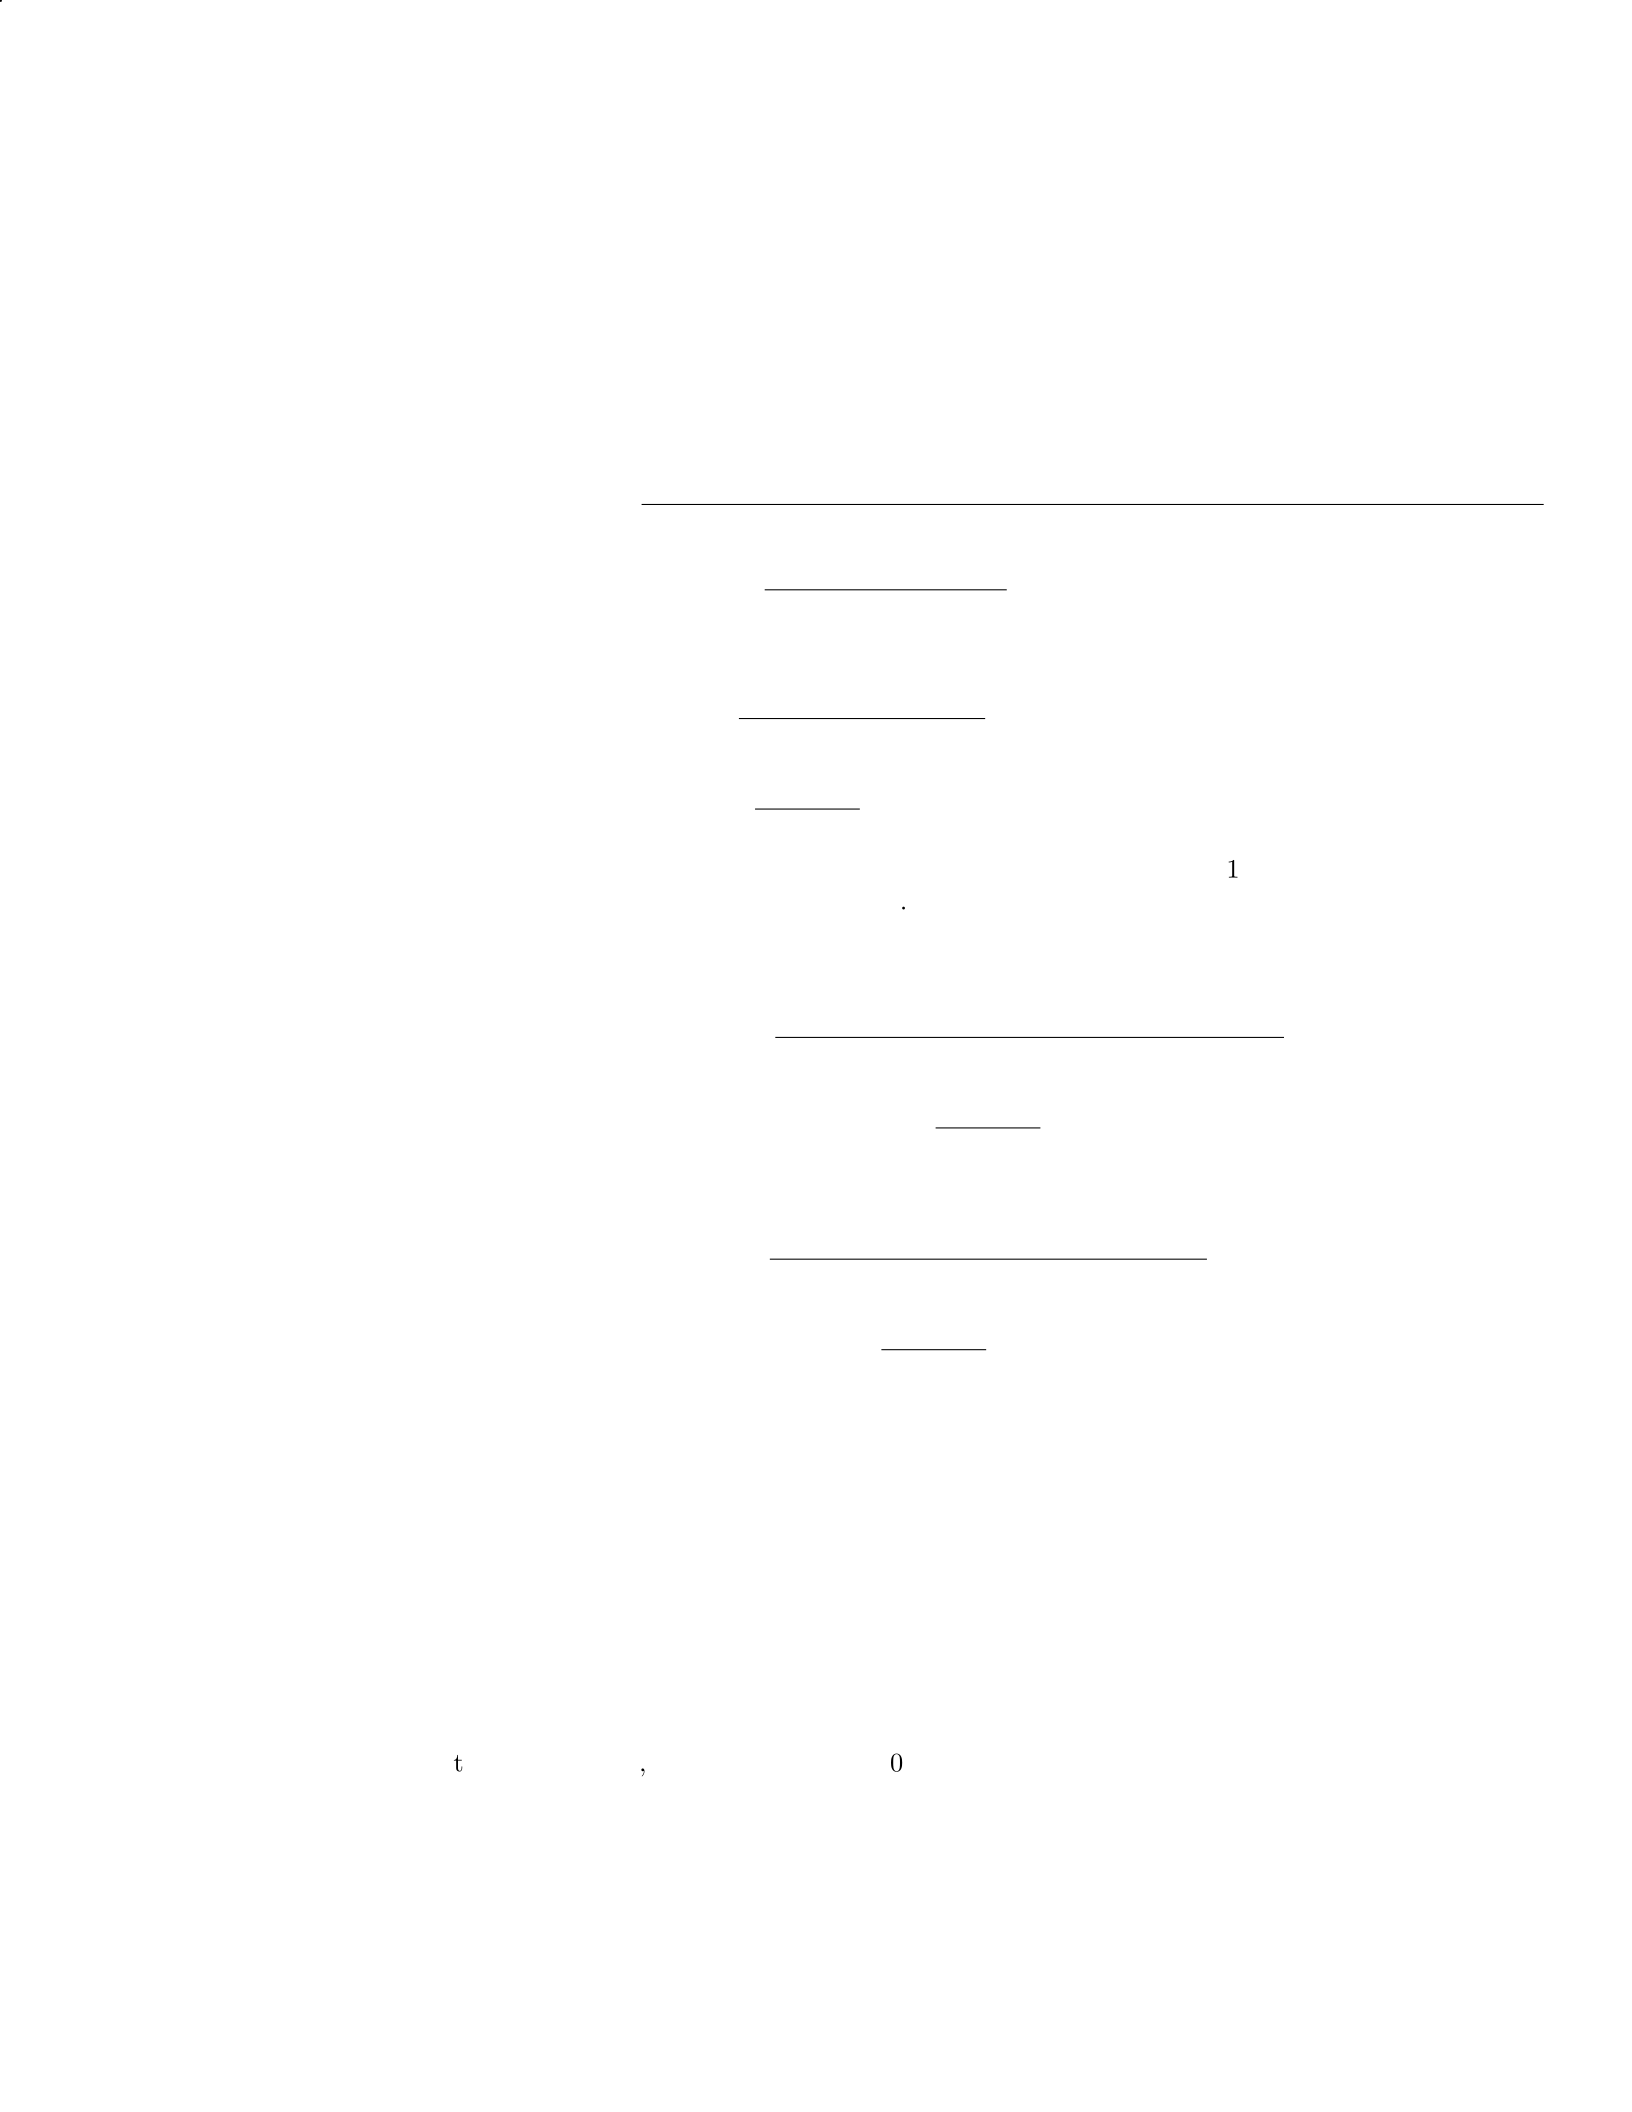
Solution
1. Return on Assets (ROA)
Step 1: Calculate the average total assets:
Average Total Assets = Total assets at the beginning of the year + Total assets at the end of the year
2
Average Total Assets = $500,000 + $700,000
2= $600,000
Step 2: Calculate the Return on Assets (ROA):
ROA = Net Income
Average Total Assets
ROA = $100,000
$600,000 = 0.1667
Step 3: Interpretation: The ROA of 0.1667 means that for every
$
1 of
average total assets, the company generates
$
0.1667 of net income.
2. Debt to Asset Ratio
Step 1: Calculate the Debt to Asset Ratio at the beginning of the year:
Debt to Asset Ratio (Beginning) = Total liabilities at the beginning of the year
Total assets at the beginning of the year
Debt to Asset Ratio (Beginning) = $300,000
$500,000 = 0.6
Step 2: Calculate the Debt to Asset Ratio at the end of the year:
Debt to Asset Ratio (End) = Total liabilities at the end of the year
Total assets at the end of the year
Debt to Asset Ratio (End) = $400,000
$700,000 ≈0.5714
Step 3: Interpretation: The Debt to Asset Ratio decreased from 0.6 to
approximately 0.5714, indicating that the company relied less on debt financing
compared to the previous year.
Question 19
Question
A company reported the following financial information for the years 2020 and
2021:
Total Assets:
$
500,000 (2020) and
$
600,000 (2021)
20
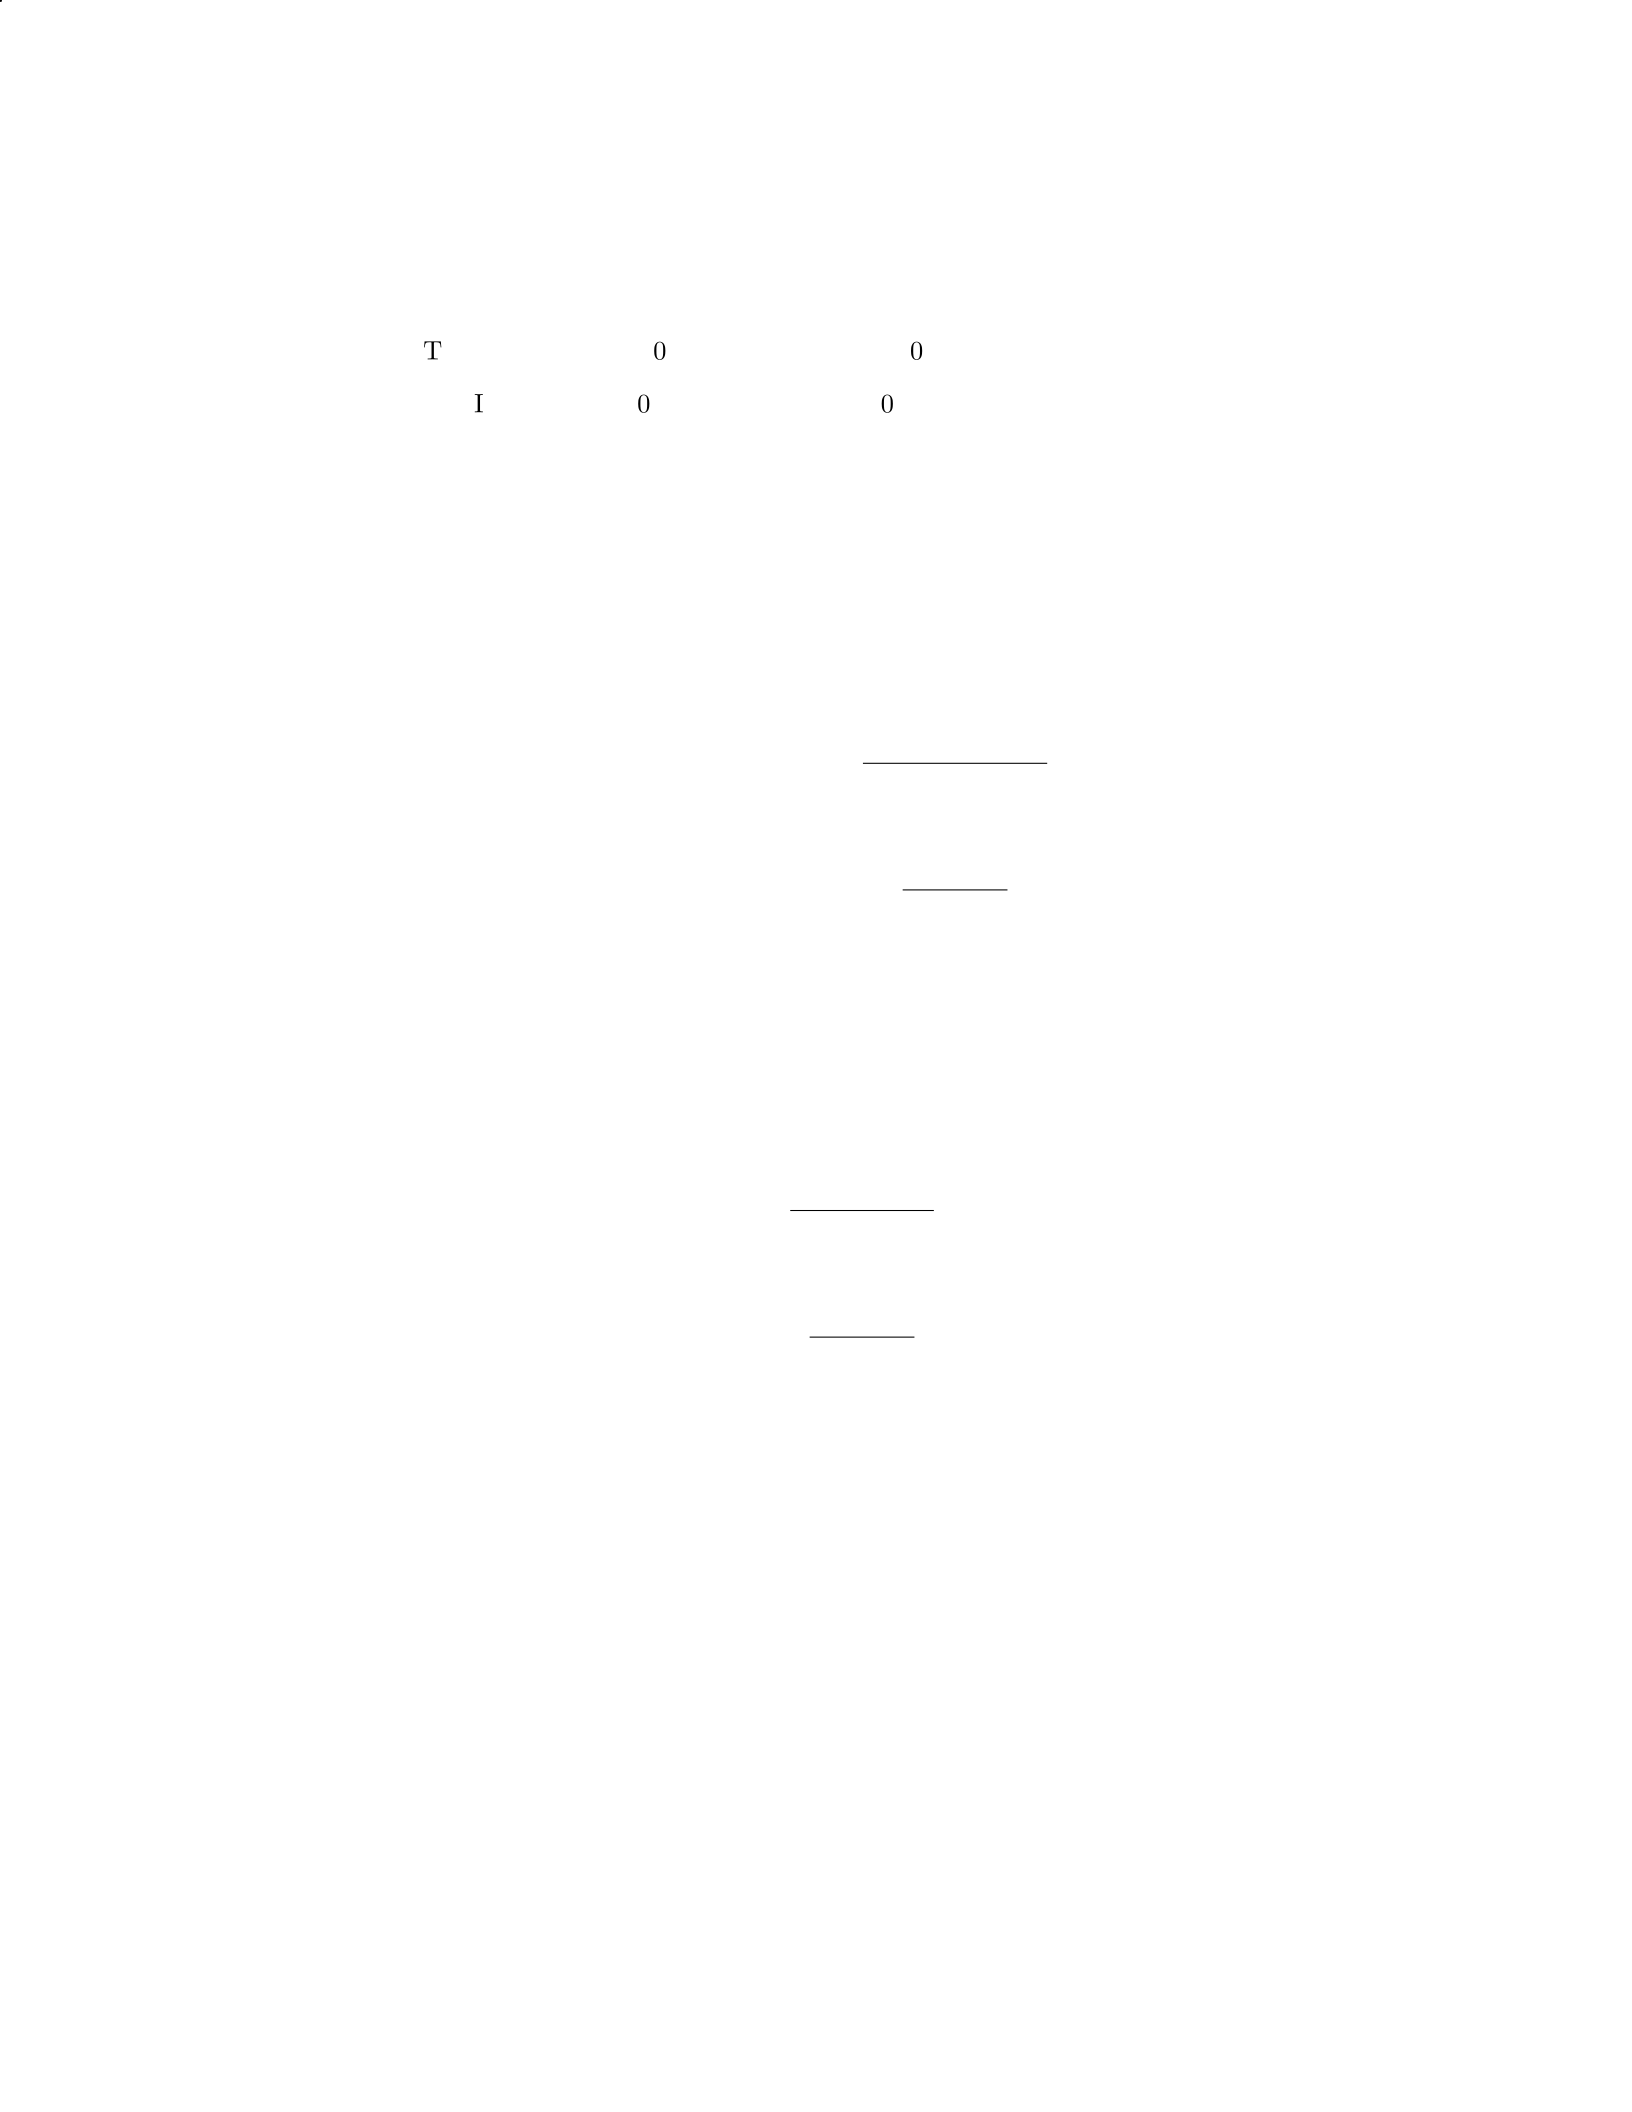
Total Liabilities:
$
200,000 (2020) and
$
250,000 (2021)
Net Income:
$
50,000 (2020) and
$
75,000 (2021)
Calculate and interpret the following ratios for the year 2021:
1. Debt-to-Assets Ratio
2. Return on Assets
Solution
Step 1: Calculate the Debt-to-Assets Ratio The Debt-to-Assets Ratio is calcu-
lated as:
Debt-to-Assets Ratio = Total Liabilities
Total Assets
Substitute the given values for 2021:
Debt-to-Assets Ratio = $250,000
$600,000
Calculating the ratio:
Debt-to-Assets Ratio = 0.4167 or 41.67%
Interpretation: The Debt-to-Assets Ratio of 41.67% means that 41.67% of
the company’s assets are financed by debt.
Step 2: Calculate Return on Assets The Return on Assets (ROA) is calcu-
lated as:
ROA = Net Income
Total Assets
Substitute the given values for 2021:
ROA = $75,000
$600,000
Calculating the ROA:
ROA = 0.125 or 12.5%
Interpretation: The ROA of 12.5% indicates that the company generated a
return of 12.5 cents for every dollar of assets in 2021.
Question 20
Question
A company’s financial statements report the following information for the year
ended December 31, 20X5:
21
Net income: $250,000
Total assets: $2,500,000
Total liabilities: $1,000,000
Total equity: $1,500,000
Number of shares outstanding: 100,000
Calculate the following ratios and provide an interpretation for each:
1. Return on assets (ROA)
2. Return on equity (ROE)
3. Earnings per share (EPS)
Solution
Step 1: Calculate Return on Assets (ROA)
ROA =Net Income
T otal Assets
Substitute the given values:
ROA =250,000
2,500,000 = 0.10
Step 2: Interpretation of ROA The ROA of 0.10 means that for every
dollar of assets, the company generated 0.10 in net income. It indicates that
the company is generating a 10
Step 3: Calculate Return on Equity (ROE)
ROE =Net Income
T otal Equity
Substitute the given values:
ROE =250,000
1,500,000 ≈0.17
Step 4: Interpretation of ROE The ROE of approximately 0.17 indicates
that the company generated 0.17 in net income for every dollar of equity. This
ratio reflects the company’s profitability from the shareholders’ perspective.
Step 5: Calculate Earnings per Share (EPS)
EP S =Net Income
Number of Shares Outstanding
22
Substitute the given values:
EP S =250,000
100,000 = $2.50
Step 6: Interpretation of EPS The EPS of
$
2.50 means that each share
of the company earned
$
2.50 during the year. It is an important measure for
investors as it indicates the company’s profitability on a per-share basis.
Question 21
Question
A company reported the following financial information for the year ending
December 31, 2020:
Total Assets:
$
900,000
Total Liabilities:
$
400,000
Total Equity:
$
500,000
Net Income:
$
120,000
Sales Revenue:
$
800,000
Calculate the following financial ratios for the company based on the given
information:
1. Debt to Equity Ratio
2. Return on Assets (ROA)
3. Profit Margin
Solution
Let’s calculate each of the financial ratios step by step:
Step 1: Calculate Debt to Equity Ratio The Debt to Equity Ratio is
calculated as:
Debt to Equity Ratio = Total Liabilities
Total Equity
Substitute the given values:
Debt to Equity Ratio = 400,000
500,000 = 0.8
Step 2: Calculate Return on Assets (ROA) The Return on Assets
(ROA) is calculated as:
ROA = Net Income
Total Assets
23
Substitute the given values:
ROA = 120,000
900,000 = 0.1333
Step 3: Calculate Profit Margin The Profit Margin is calculated as:
Profit Margin = Net Income
Sales Revenue
Substitute the given values:
Profit Margin = 120,000
800,000 = 0.15
Therefore, the calculated financial ratios are:
1. Debt to Equity Ratio: 0.8
2. ROA: 0.1333 or 13.33%
3. Profit Margin: 0.15 or 15%
Question 22
Question
A company has the following financial information for the year:
Total assets:
$
500,000
Total liabilities:
$
200,000
Net income:
$
50,000
Total revenue:
$
300,000
Total expenses:
$
250,000
Calculate the following ratios and provide an interpretation for each:
1. Debt-to-Asset Ratio
2. Return on Assets (ROA)
3. Profit Margin
24
Solution
Step 1: Calculate the Debt-to-Asset Ratio: The Debt-to-Asset Ratio is calcu-
lated as:
Debt-to-Asset Ratio = Total Liabilities
Total Assets
Given that Total liabilities is
$
200,000 and Total assets is
$
500,000, we can
substitute these values into the formula:
Debt-to-Asset Ratio = 200,000
500,000 = 0.4
Interpretation: The Debt-to-Asset Ratio of 0.4 indicates that 40
Step 2: Calculate the Return on Assets (ROA): The Return on Assets
(ROA) is calculated as:
ROA = Net Income
Total Assets ×100%
Given that Net income is
$
50,000 and Total assets is
$
500,000, we can sub-
stitute these values into the formula:
ROA = 50,000
500,000 ×100% = 10%
Interpretation: The ROA of 10
Step 3: Calculate the Profit Margin: The Profit Margin is calculated as:
Profit Margin = Net Income
Total Revenue ×100%
Given that Net income is
$
50,000 and Total revenue is
$
300,000, we can
substitute these values into the formula:
Profit Margin = 50,000
300,000 ×100% = 16.67%
Interpretation: The Profit Margin of 16.67
Question 23
Question
A company has the following financial information for the year:
Current assets:
$
500,000
Total assets:
$
1,000,000
Current liabilities:
$
200,000
25
Total liabilities:
$
400,000
Sales revenue:
$
800,000
Cost of goods sold:
$
400,000
Cash:
$
100,000
Calculate the following financial ratios for the company:
1. Current ratio
2. Quick ratio
3. Debt ratio
4. Operating profit margin
Interpret the results and provide recommendations for the company based
on the ratios calculated.
Solution
Step 1: Calculate the Current Ratio
Current Ratio = Current Assets
Current Liabilities
=$500,000
$200,000
= 2.5
Step 2: Calculate the Quick Ratio
Quick Ratio = Current Assets −Inventory
Current Liabilities
=$500,000 −$400,000
$200,000
=$100,000
$200,000
= 0.5
Step 3: Calculate the Debt Ratio
Debt Ratio = Total Liabilities
Total Assets
=$400,000
$1,000,000
= 0.4
26
Step 4: Calculate the Operating Profit Margin
Operating Profit Margin = Sales Revenue −Cost of Goods Sold
Sales Revenue ×100%
=$800,000 −$400,000
$800,000 ×100%
=$400,000
$800,000 ×100%
= 50%
Interpretation and Recommendations:
Current Ratio of 2.5 indicates that the company has more than enough
current assets to cover its current liabilities, which is a positive sign.
Quick Ratio of 0.5 suggests that the company may have difficulty meeting
its short-term obligations without relying on inventory sales.
Debt Ratio of 0.4 signifies that 40
Operating Profit Margin of 50
Based on the ratios calculated, the company should focus on improving
its liquidity by reducing reliance on inventory for short-term obligations and
consider reducing debt levels to lower financial risk. They should also continue
to maintain or improve their profit margins to ensure long-term sustainability.
Question 24
Question
A company has the following financial information for the year:
Net income:
$
500,000
Total assets:
$
2,500,000
Total liabilities:
$
1,000,000
Total equity:
$
1,500,000
Calculate the following ratios and interpret the results:
1. Return on Assets (ROA)
2. Return on Equity (ROE)
3. Debt-to-Equity ratio
27
Solution
Let’s calculate each ratio and interpret the results:
1. Return on Assets (ROA):
ROA =Net Income
T otal Assets
ROA =$500,000
$2,500,000
ROA = 0.20 or 20%
The company’s ROA is 20%, which means that for every dollar of assets,
the company generates 0.20ofprof it.
2. Return on Equity (ROE):
ROE =Net Income
T otal Equity
ROE =$500,000
$1,500,000
ROE = 0.3333 or 33.33%
The company’s ROE is 33.33%, indicating that for every dollar of equity, the
company generates 0.33ofprof it.
3. Debt-to-Equity ratio:
Debt −to −Equity ratio =T otal Liabilities
T otal Equity
Debt −to −Equity ratio =$1,000,000
$1,500,000
Debt −to −Equity ratio = 0.6667 or 0.67
The company’s Debt-to-Equity ratio is 0.67, which means that the company has
more debt than equity. This could indicate higher financial risk.
Question 25
Question
A company reported the following financial information:
Total assets:
$
500,000
Current ratio: 2.5
28
Quick ratio: 1.5
Calculate the company’s current liabilities and quick assets. Provide your an-
swers to the nearest dollar.
Solution
Step 1: Calculate the company’s current liabilities using the current ratio for-
mula:
Current Ratio = Current Assets
Current Liabilities
Given that the current ratio is 2.5 and total assets are
$
500,000, we can find the
current assets by multiplying the current ratio by the current liabilities:
2.5 = Current Assets
Current Liabilities
Current Assets = 2.5×Current Liabilities
We know that current assets + current liabilities = total assets. Substituting
in the given values:
Total Assets = $500,000
Current Assets + Current Liabilities = $500,000
2.5×Current Liabilities + Current Liabilities = $500,000
3.5×Current Liabilities = $500,000
Current Liabilities = $500,000
3.5
Current Liabilities = $142,857
Step 2: Calculate the company’s quick assets using the quick ratio formula:
Quick Ratio = Quick Assets
Current Liabilities
Given that the quick ratio is 1.5 and the current liabilities are
$
142,857, we can
find the quick assets by multiplying the quick ratio by the current liabilities:
1.5 = Quick Assets
Current Liabilities
Quick Assets = 1.5×Current Liabilities
Quick Assets = 1.5×$142,857
Quick Assets = $214,285.50
Therefore, the company’s current liabilities are
$
142,857 and its quick assets
are
$
214,285.50.
29
Question 26
Question
A company’s financial statements show the following information:
Total assets:
$
500,000
Total liabilities:
$
200,000
Total equity:
$
300,000
Net income:
$
50,000
Calculate the return on equity (ROE) for the company based on the given
information.
Solution
To calculate the return on equity (ROE), we use the formula:
ROE = Net Income
Total Equity ×100%
Step 1: Calculate the ROE using the provided information.
ROE = 50,000
300,000 ×100%
Step 2: Simplify the expression.
ROE = 1
6×100%
Step 3: Calculate the ROE.
ROE = 16.67%
Therefore, the return on equity (ROE) for the company is 16.67%.
Question 27
Question
A company has the following financial data for the year ending December 31,
20XX:
Net sales:
$
500,000
Cost of goods sold:
$
300,000
Total assets:
$
800,000
30
Total liabilities:
$
400,000
Calculate the following ratios and interpret the results:
1. Gross profit margin
2. Return on assets
Solution
To calculate the required ratios, we first need to find the values of gross profit
and net income.
Step 1: Calculate Gross Profit
Gross Profit = Net Sales −Cost of Goods Sold
= $500,000 −$300,000
= $200,000
Step 2: Calculate Net Income
Net Income = Net Sales −Cost of Goods Sold −Operating Expenses
= $500,000 −$300,000 −Operating Expenses
Given that we do not have the operating expenses, we cannot determine the
exact net income. Therefore, we will only be able to calculate the Gross Profit
Margin using the information we have.
Step 3: Calculate Gross Profit Margin
Gross Profit Margin = Gross Profit
Net Sales ×100%
=$200,000
$500,000 ×100%
= 40%
Step 4: Calculate Return on Assets (ROA)
ROA = Net Income
Total Assets ×100%
=Net Sales −Cost of Goods Sold −Operating Expenses
Total Assets ×100%
Since we do not have the operating expenses to determine net income, we
cannot calculate the Return on Assets (ROA) ratio.
Therefore, the Gross Profit Margin for the company is 40%, but we cannot
calculate the Return on Assets without the operating expenses.
31
Question 28
Question
Company XYZ has provided the following financial information for the year
ending December 31, 20X1:
Total Assets:
$
500,000
Total Liabilities:
$
200,000
Total Equity:
$
300,000
Net Income:
$
50,000
Revenue:
$
400,000
Using this information, calculate and interpret the following ratios:
1. Debt-to-Equity Ratio
2. Return on Assets
3. Profit Margin
Solution
Step 1: Calculate Debt-to-Equity Ratio The Debt-to-Equity Ratio is cal-
culated as:
Debt-to-Equity Ratio = Total Liabilities
Total Equity
Given that Total Liabilities =
$
200,000 and Total Equity =
$
300,000, we
can calculate the Debt-to-Equity Ratio:
Debt-to-Equity Ratio = 200,000
300,000 = 0.67
Step 2: Interpret Debt-to-Equity Ratio A Debt-to-Equity Ratio of 0.67
indicates that for every dollar of equity, the company has 0.67of debt.T hissuggeststhatthecompanyisf inancedmorebyequitythandebt.
Step 3: Calculate Return on Assets (ROA) The Return on Assets is
calculated as:
Return on Assets = Net Income
Total Assets
Given that Net Income =
$
50,000 and Total Assets =
$
500,000, we can
calculate the Return on Assets:
Return on Assets = 50,000
500,000 = 0.1 = 10%
32
Step 4: Interpret Return on Assets A Return on Assets of 10% indicates
that the company generated a profit of 10 cents for every dollar of assets.
Step 5: Calculate Profit Margin The Profit Margin is calculated as:
Profit Margin = Net Income
Revenue ×100%
Given that Net Income =
$
50,000 and Revenue =
$
400,000, we can calculate
the Profit Margin:
Profit Margin = 50,000
400,000 ×100% = 12.5%
Step 6: Interpret Profit Margin A Profit Margin of 12.5% indicates that
the company keeps 12.5 cents from every dollar of sales as profit after covering
all expenses.
Question 29
Question
A company has the following financial information for the past year:
Net profit margin: 12
Return on assets: 10
Current ratio: 1.5
Acid-test ratio: 1.0
Determine whether the company is in a strong financial position based on
these ratios.
Solution
To determine whether the company is in a strong financial position, we will
analyze each of the given ratios.
Step 1: Calculate the Gross Profit Margin The gross profit margin
can be calculated using the formula:
Gross Profit Margin = Net Sales −COGS
Net Sales
Given that the Net Profit Margin is 12
Gross Profit Margin = 12% + 1
1−12% =13
0.88 ≈14.77%
Step 2: Analyze the Return on Assets (ROA) The Return on Assets
is 10
33
Step 3: Analyze the Current Ratio The Current Ratio is 1.5, which
means that the company has 1.50ofcurrentassetsf orevery1 of current liabili-
ties. A current ratio above 1 generally indicates good liquidity.
Step 4: Analyze the Acid-test Ratio The Acid-test Ratio is 1.0, which
means that the company has just enough liquid assets to cover its current lia-
bilities. This ratio is lower than what is generally considered ideal.
Step 5: Interpretation Based on the analysis of the ratios: - The com-
pany’s Net Profit Margin and Gross Profit Margin are in a good range. - The
Return on Assets is acceptable at 10- The Current Ratio is above 1, indicating
good liquidity. - The Acid-test Ratio of 1.0 may be a concern as it indicates a
lower level of liquidity.
Overall, the company appears to be in a moderately strong financial position,
but it may need to improve its liquidity position by increasing its liquid assets
relative to current liabilities.
Question 30
Question
A company reported the following financial information for the year:
Net Income:
$
500,000
Total Assets:
$
2,000,000
Total Liabilities:
$
1,000,000
Stockholders’ Equity:
$
1,000,000
Calculate the following ratios for the company and interpret the results:
1. Return on Assets (ROA)
2. Return on Equity (ROE)
3. Debt-to-Equity Ratio
Solution
Step 1: Calculate Return on Assets (ROA)
The Return on Assets (ROA) is calculated as:
ROA =Net Income
T otal Assets
In this case:
ROA =$500,000
$2,000,000 = 0.25
Step 2: Interpret ROA
34
The ROA of 0.25 means that the company generated
$
0.25 in profit for every
dollar of assets it has. This indicates that the company is effectively utilizing
its assets to generate profits.
Step 3: Calculate Return on Equity (ROE)
The Return on Equity (ROE) is calculated as:
ROE =Net Income
Stockholders′Equity
In this case:
ROE =$500,000
$1,000,000 = 0.5
Step 4: Interpret ROE
The ROE of 0.5 means that the company generated
$
0.50 in profit for every
dollar of stockholders’ equity. This indicates that the company is generating a
good return for its shareholders.
Step 5: Calculate Debt-to-Equity Ratio
The Debt-to-Equity Ratio is calculated as:
Debt −to −Equity Ratio =T otal Liabilities
Stockholders′Equity
In this case:
Debt −to −Equity Ratio =$1,000,000
$1,000,000 = 1
Step 6: Interpret Debt-to-Equity Ratio
A debt-to-equity ratio of 1 means that the company has an equal amount of
debt and equity. This indicates that the company is equally financed by debt
and equity.
Question 31
Question
Company XYZ has provided the following financial information for the year
2020:
Net income:
$
500,000
Total assets:
$
2,000,000
Total liabilities:
$
800,000
Total equity:
$
1,200,000
Earnings per share:
$
2.50
35
Using the above information, calculate the following ratios for Company
XYZ and interpret what each ratio indicates about the company’s financial
performance:
1. Return on Assets (ROA)
2. Debt to Equity Ratio
3. Price-Earnings (P/E) Ratio
Solution
Step 1: Calculate Return on Assets (ROA)
Return on Assets (ROA) is calculated as the ratio of Net Income to Total
Assets:
ROA =Net Income
T otal Assets
Substitute the given values into the formula:
ROA =500,000
2,000,000 = 0.25 = 25%
ROA of 25% indicates that Company XYZ generated 25 cents of profit for
every dollar of assets it owns.
Step 2: Calculate Debt to Equity Ratio
Debt to Equity Ratio is calculated as the ratio of Total Liabilities to Total
Equity:
Debt to Equity Ratio =T otal Liabilities
T otal Equity
Substitute the given values into the formula:
Debt to Equity Ratio =800,000
1,200,000 = 0.67
A Debt to Equity Ratio of 0.67 indicates that for every dollar of equity, the
company has 67 cents in debt.
Step 3: Calculate Price-Earnings (P/E) Ratio
Price-Earnings (P/E) Ratio is calculated as the ratio of Price per Share to
Earnings per Share:
P/E Ratio =P rice per Share
Earnings per Share
However, the Price per Share is not provided, so we cannot calculate the
P/E Ratio with the given information.
In conclusion, Company XYZ has an ROA of 25%, a Debt to Equity Ratio
of 0.67, but the P/E Ratio cannot be calculated without the Price per Share
information.
36
Question 32
Question
A company has the following financial information for the year:
Net income:
$
500,000
Total assets:
$
3,000,000
Total liabilities:
$
1,200,000
Total equity:
$
1,800,000
Number of shares outstanding: 100,000
Calculate the following ratios and interpret them:
1. Return on assets (ROA)
2. Return on equity (ROE)
3. Earnings per share (EPS)
Solution
Step 1: Calculate Return on Assets (ROA) ROA is calculated as:
ROA = Net Income
Total Assets
Substitute the given values:
ROA = 500,000
3,000,000 = 0.1667 or 16.67%
The ROA of the company is 16.67
Step 2: Calculate Return on Equity (ROE) ROE is calculated as:
ROE = Net Income
Total Equity
Substitute the given values:
ROE = 500,000
1,800,000 = 0.2778 or 27.78%
The ROE of the company is 27.78
Step 3: Calculate Earnings per Share (EPS) EPS is calculated as:
EPS = Net Income
Number of Shares Outstanding
Substitute the given values:
EPS = 500,000
100,000 = $5
The EPS of the company is
$
5, which means that each share earns
$
5 of net
income.
37
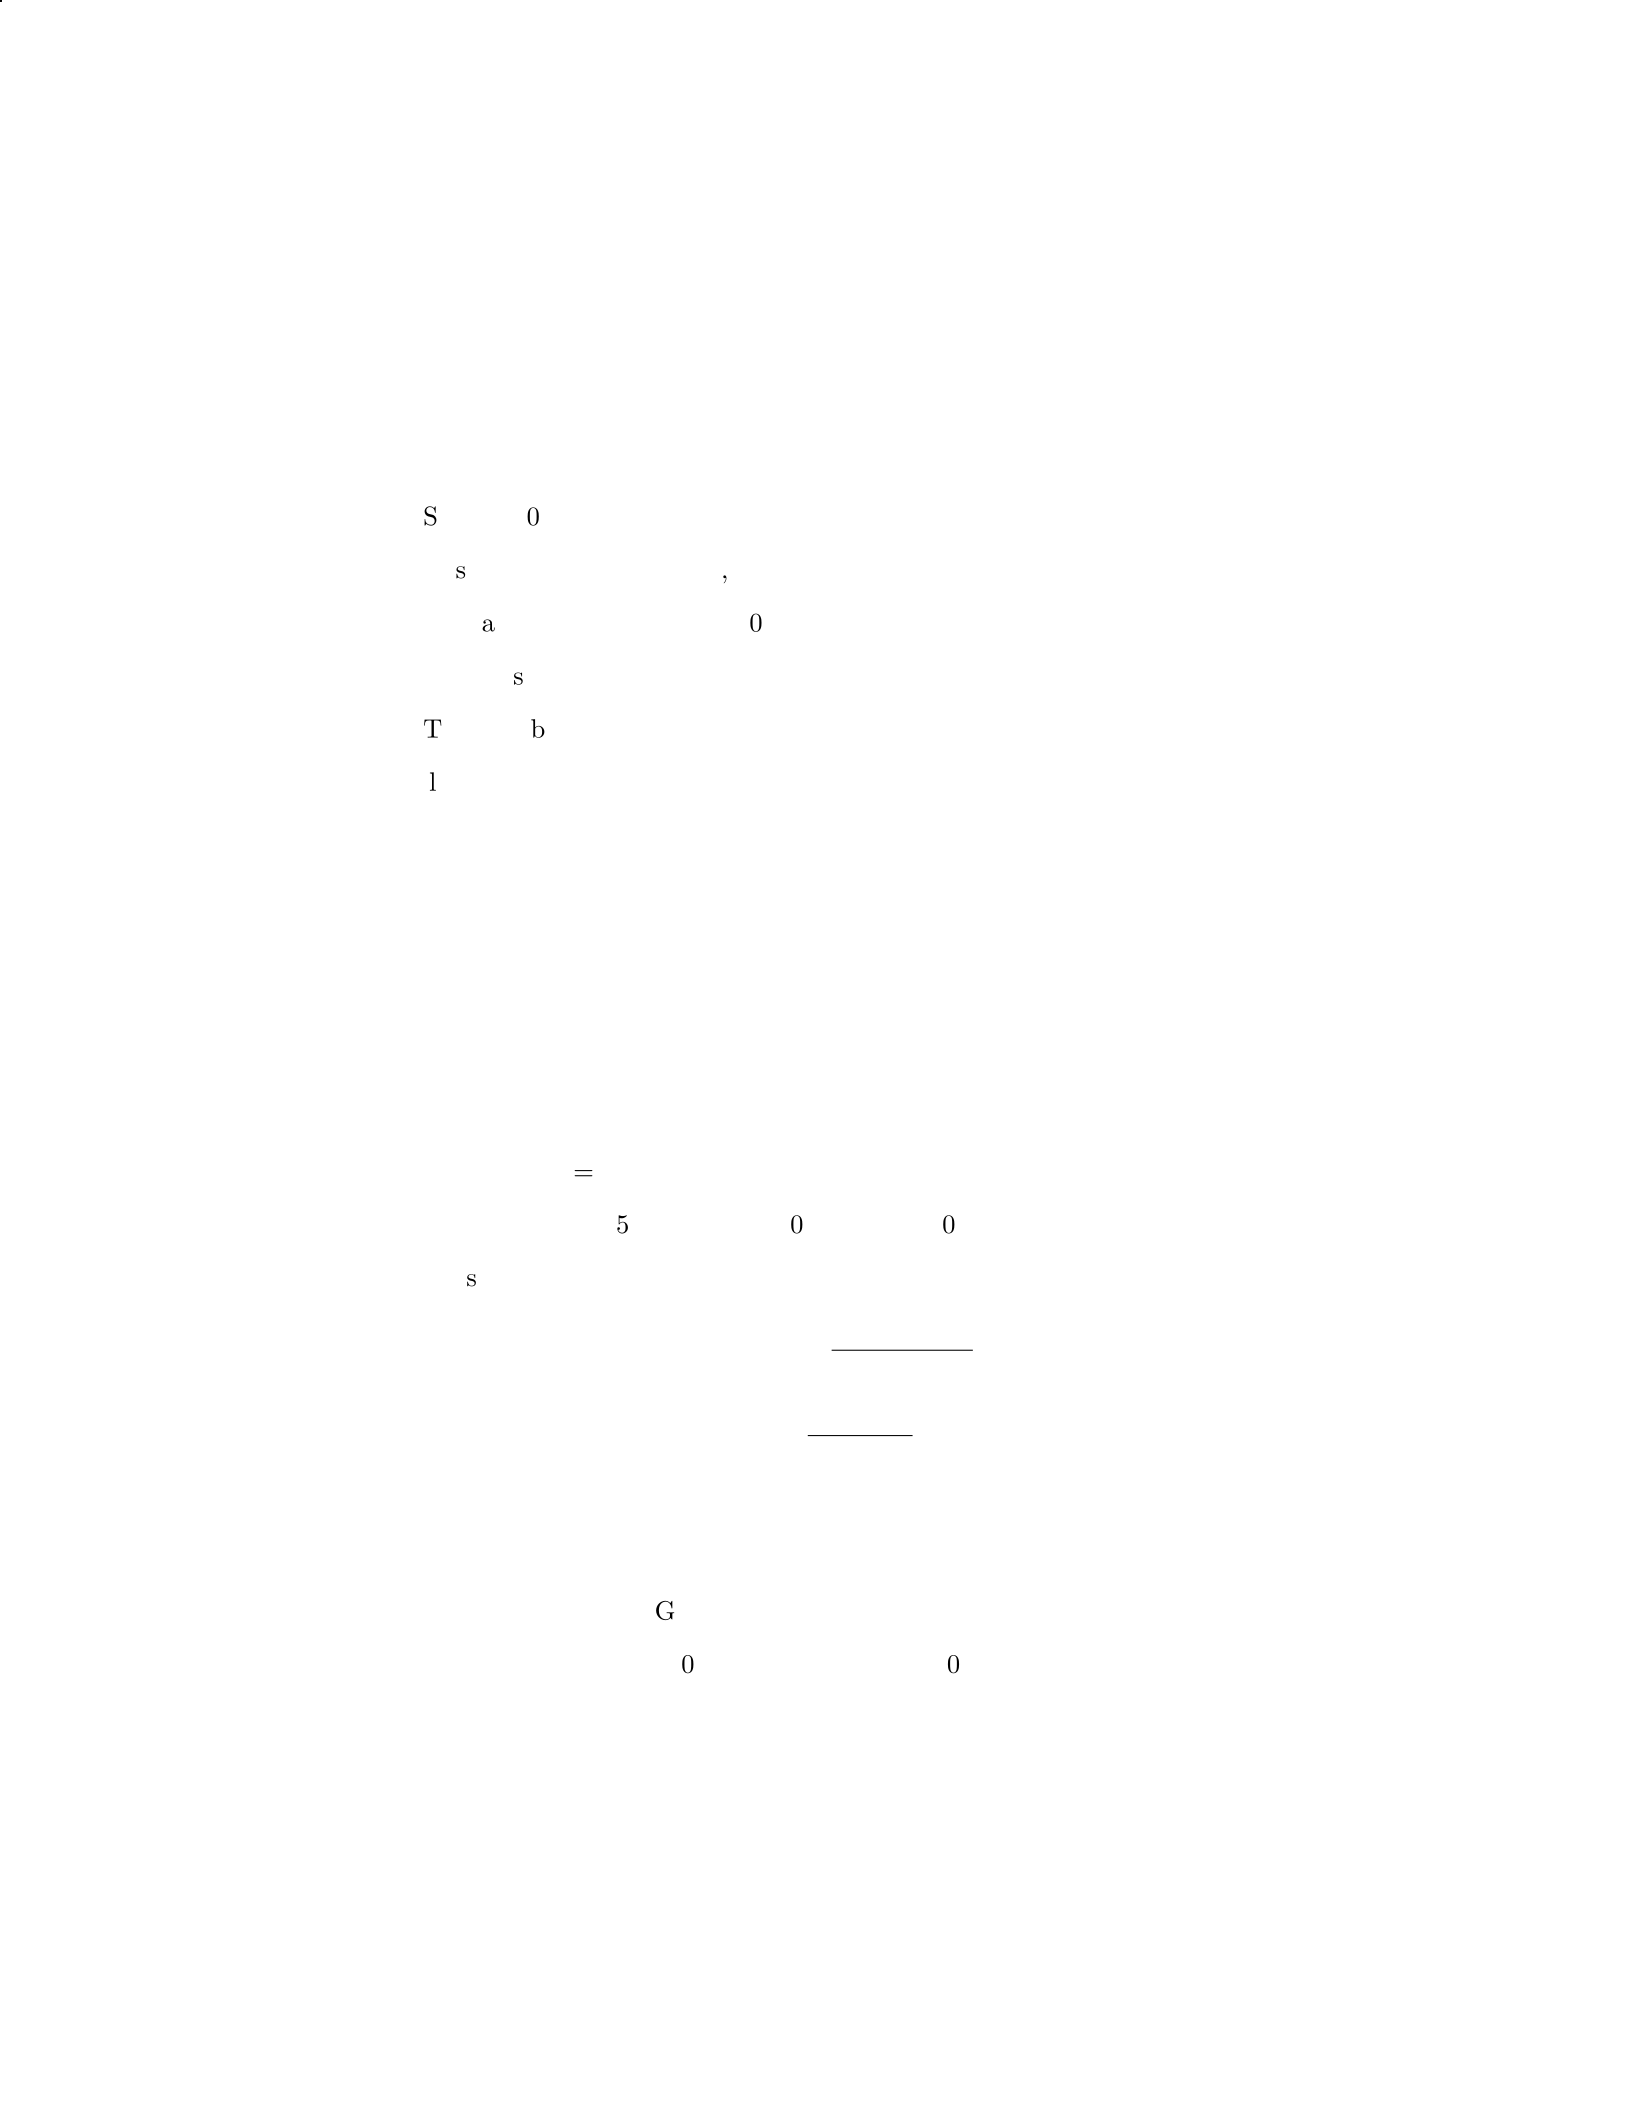
Question 33
Question
A company reported the following financial information for the current year:
Sales:
$
500,000
Cost of Goods Sold:
$
300,000
Operating Expenses:
$
80,000
Total Assets:
$
600,000
Total Liabilities:
$
200,000
Calculate the following ratios and interpret them:
1. Gross Profit Margin
2. Operating Profit Margin
3. Return on Assets
4. Debt-to-Asset Ratio
Solution
Step 1: Calculate Gross Profit Margin
Gross Profit = Sales - Cost of Goods Sold
Gross Profit =
$
500,000 -
$
300,000 =
$
200,000
The Gross Profit Margin is calculated as:
Gross Profit Margin = Gross Profit
Sales ×100%
Gross Profit Margin = $200,000
$500,000 ×100% = 40%
Interpretation: This means that for every dollar of sales, the company keeps
40 cents as gross profit.
Step 2: Calculate Operating Profit Margin
Operating Profit = Gross Profit - Operating Expenses
Operating Profit =
$
200,000 -
$
80,000 =
$
120,000
38
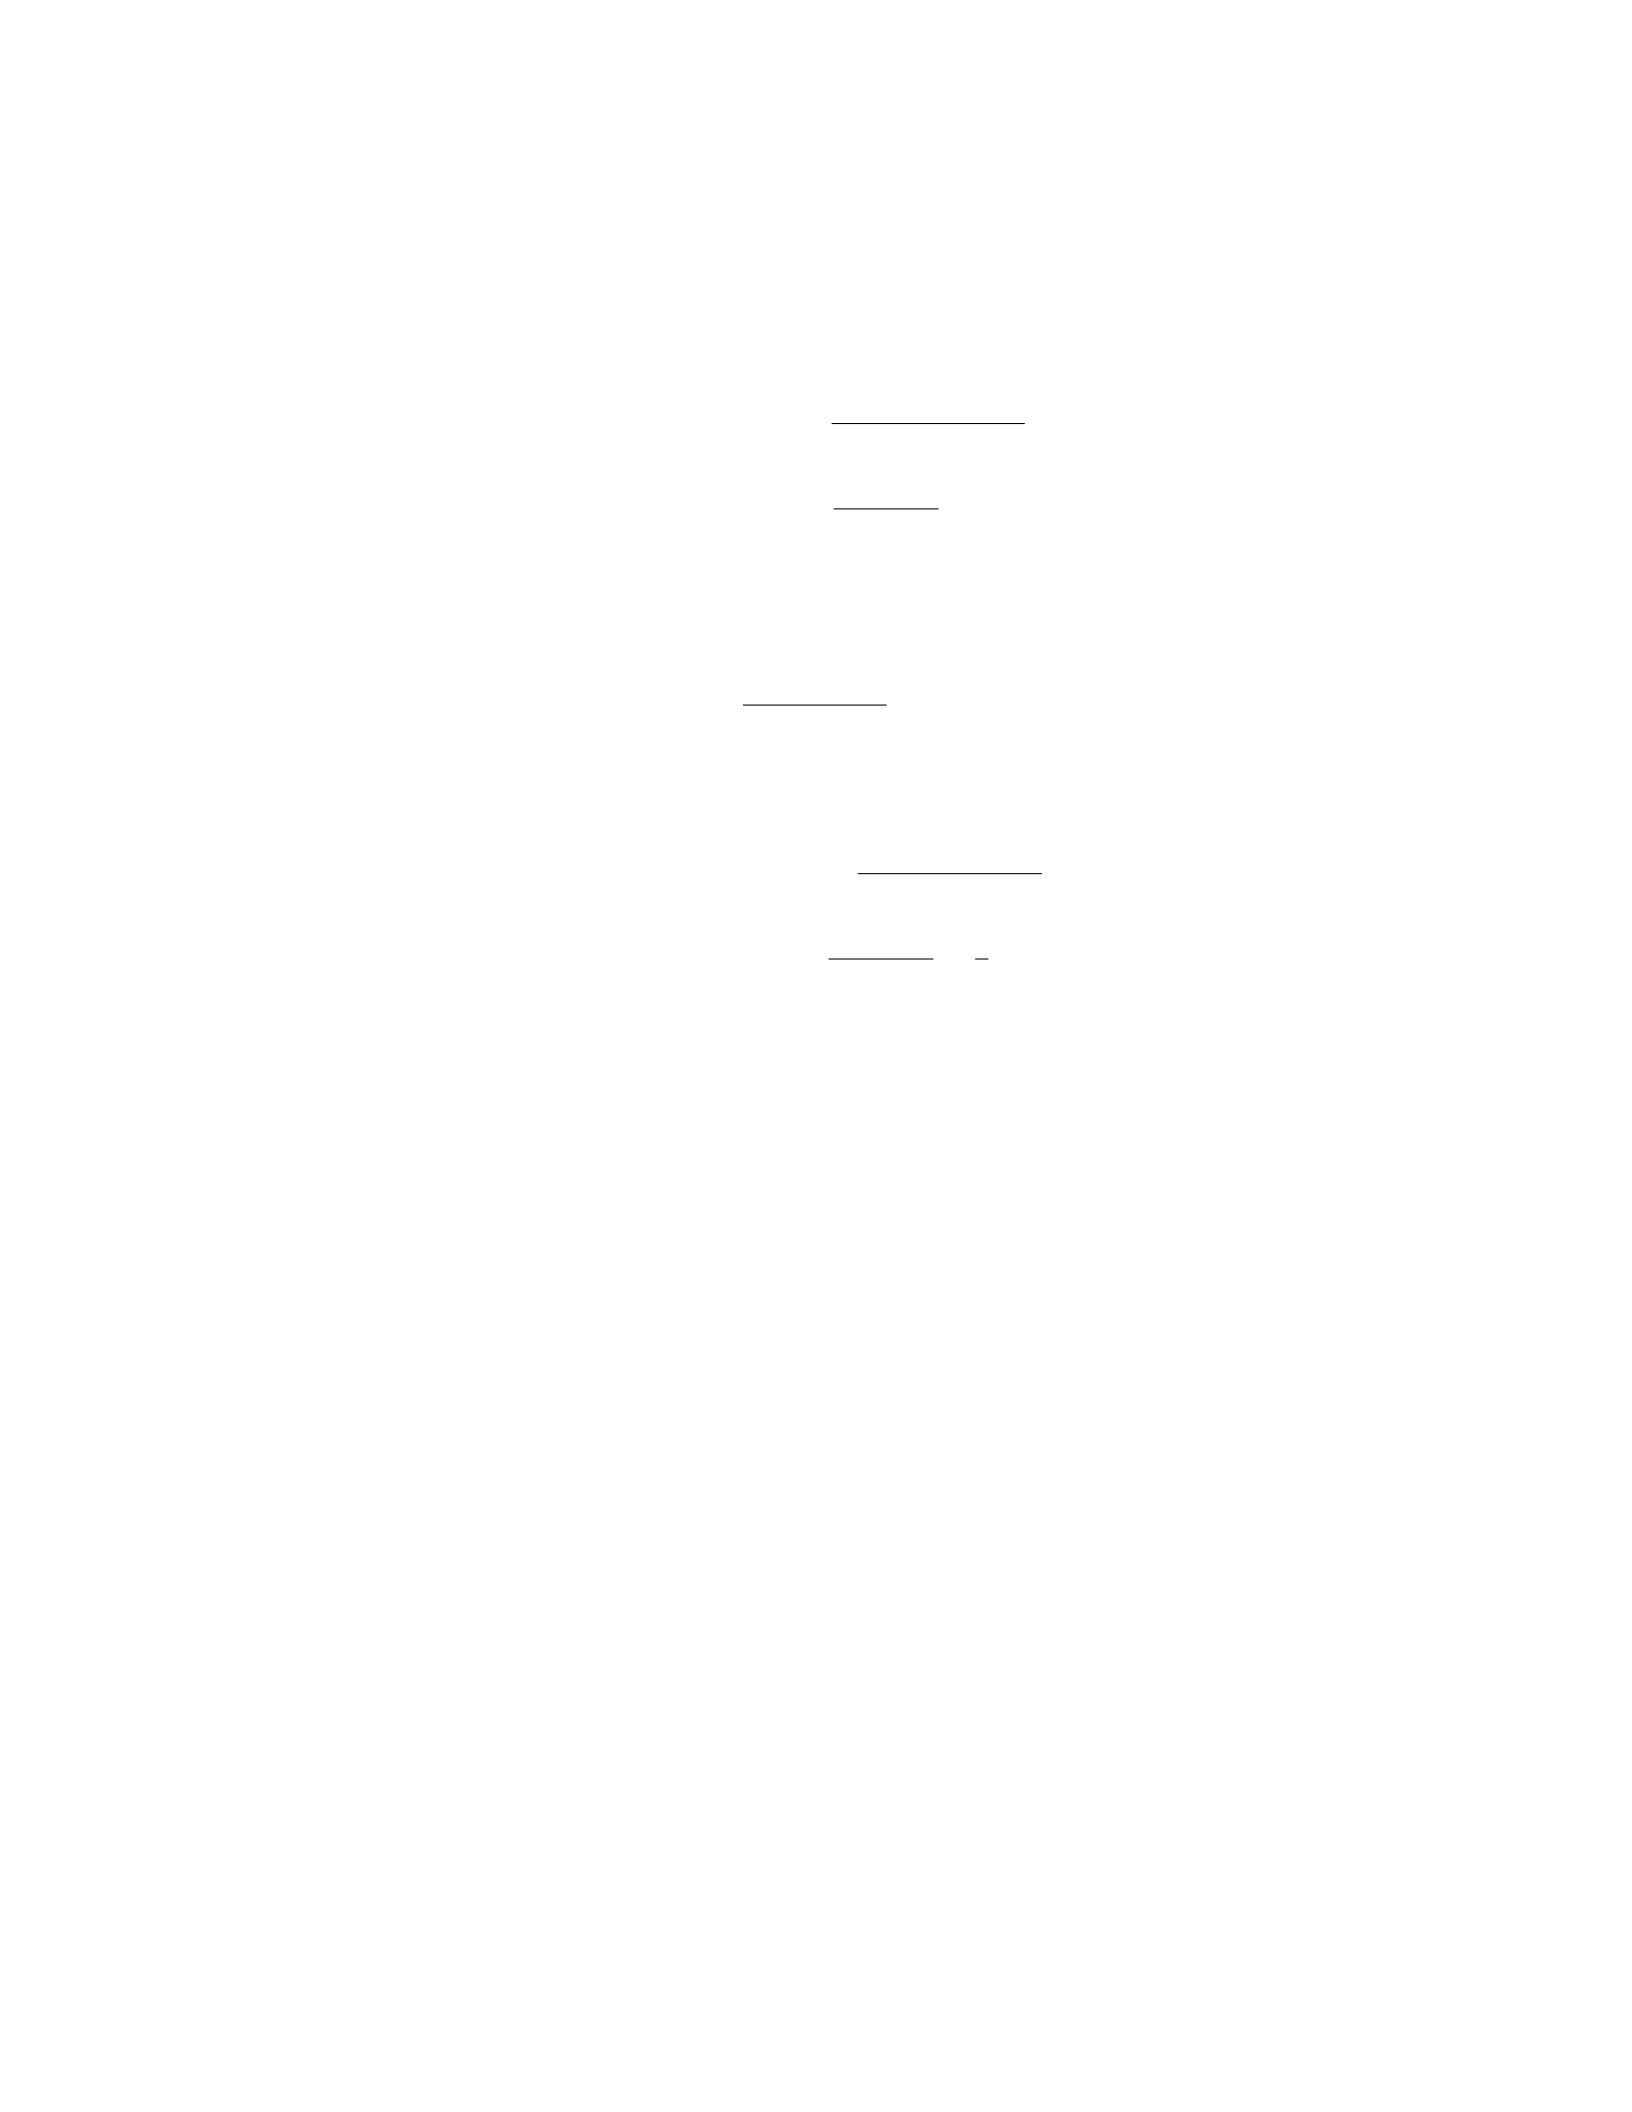
The Operating Profit Margin is calculated as:
Operating Profit Margin = Operating Profit
Sales ×100%
Operating Profit Margin = $120,000
$500,000 ×100% = 24%
Interpretation: This means that for every dollar of sales, the company gen-
erates 24 cents in operating profit.
Step 3: Calculate Return on Assets (ROA)
ROA = Net Income
Total Assets ×100%
As Net Income is not provided, we cannot calculate ROA.
Step 4: Calculate Debt-to-Asset Ratio
Debt-to-Asset Ratio = Total Liabilities
Total Assets
Debt-to-Asset Ratio = $200,000
$600,000 =1
3= 0.33
Interpretation: This means that 33
Question 34
Question
A company has a current ratio of 2.5 and a quick ratio of 1.5. Interpret these
ratios in the context of the company’s liquidity position.
Solution
Step 1: Understand the meaning of the ratios. The current ratio is calculated
as current assets divided by current liabilities, while the quick ratio (also known
as the acid-test ratio) is calculated as (current assets - inventory) divided by
current liabilities. These ratios are used to assess a company’s ability to meet
its short-term obligations.
Step 2: Interpret the current ratio. A current ratio of 2.5 means that
the company has 2.5 times more current assets than current liabilities. This
indicates that the company has a strong liquidity position and is able to meet
its short-term obligations comfortably.
Step 3: Interpret the quick ratio. A quick ratio of 1.5 means that the
company has 1.5 times more quick assets (current assets excluding inventory)
than current liabilities. This ratio also suggests that the company has a good
liquidity position, although it is slightly lower than the current ratio.
39
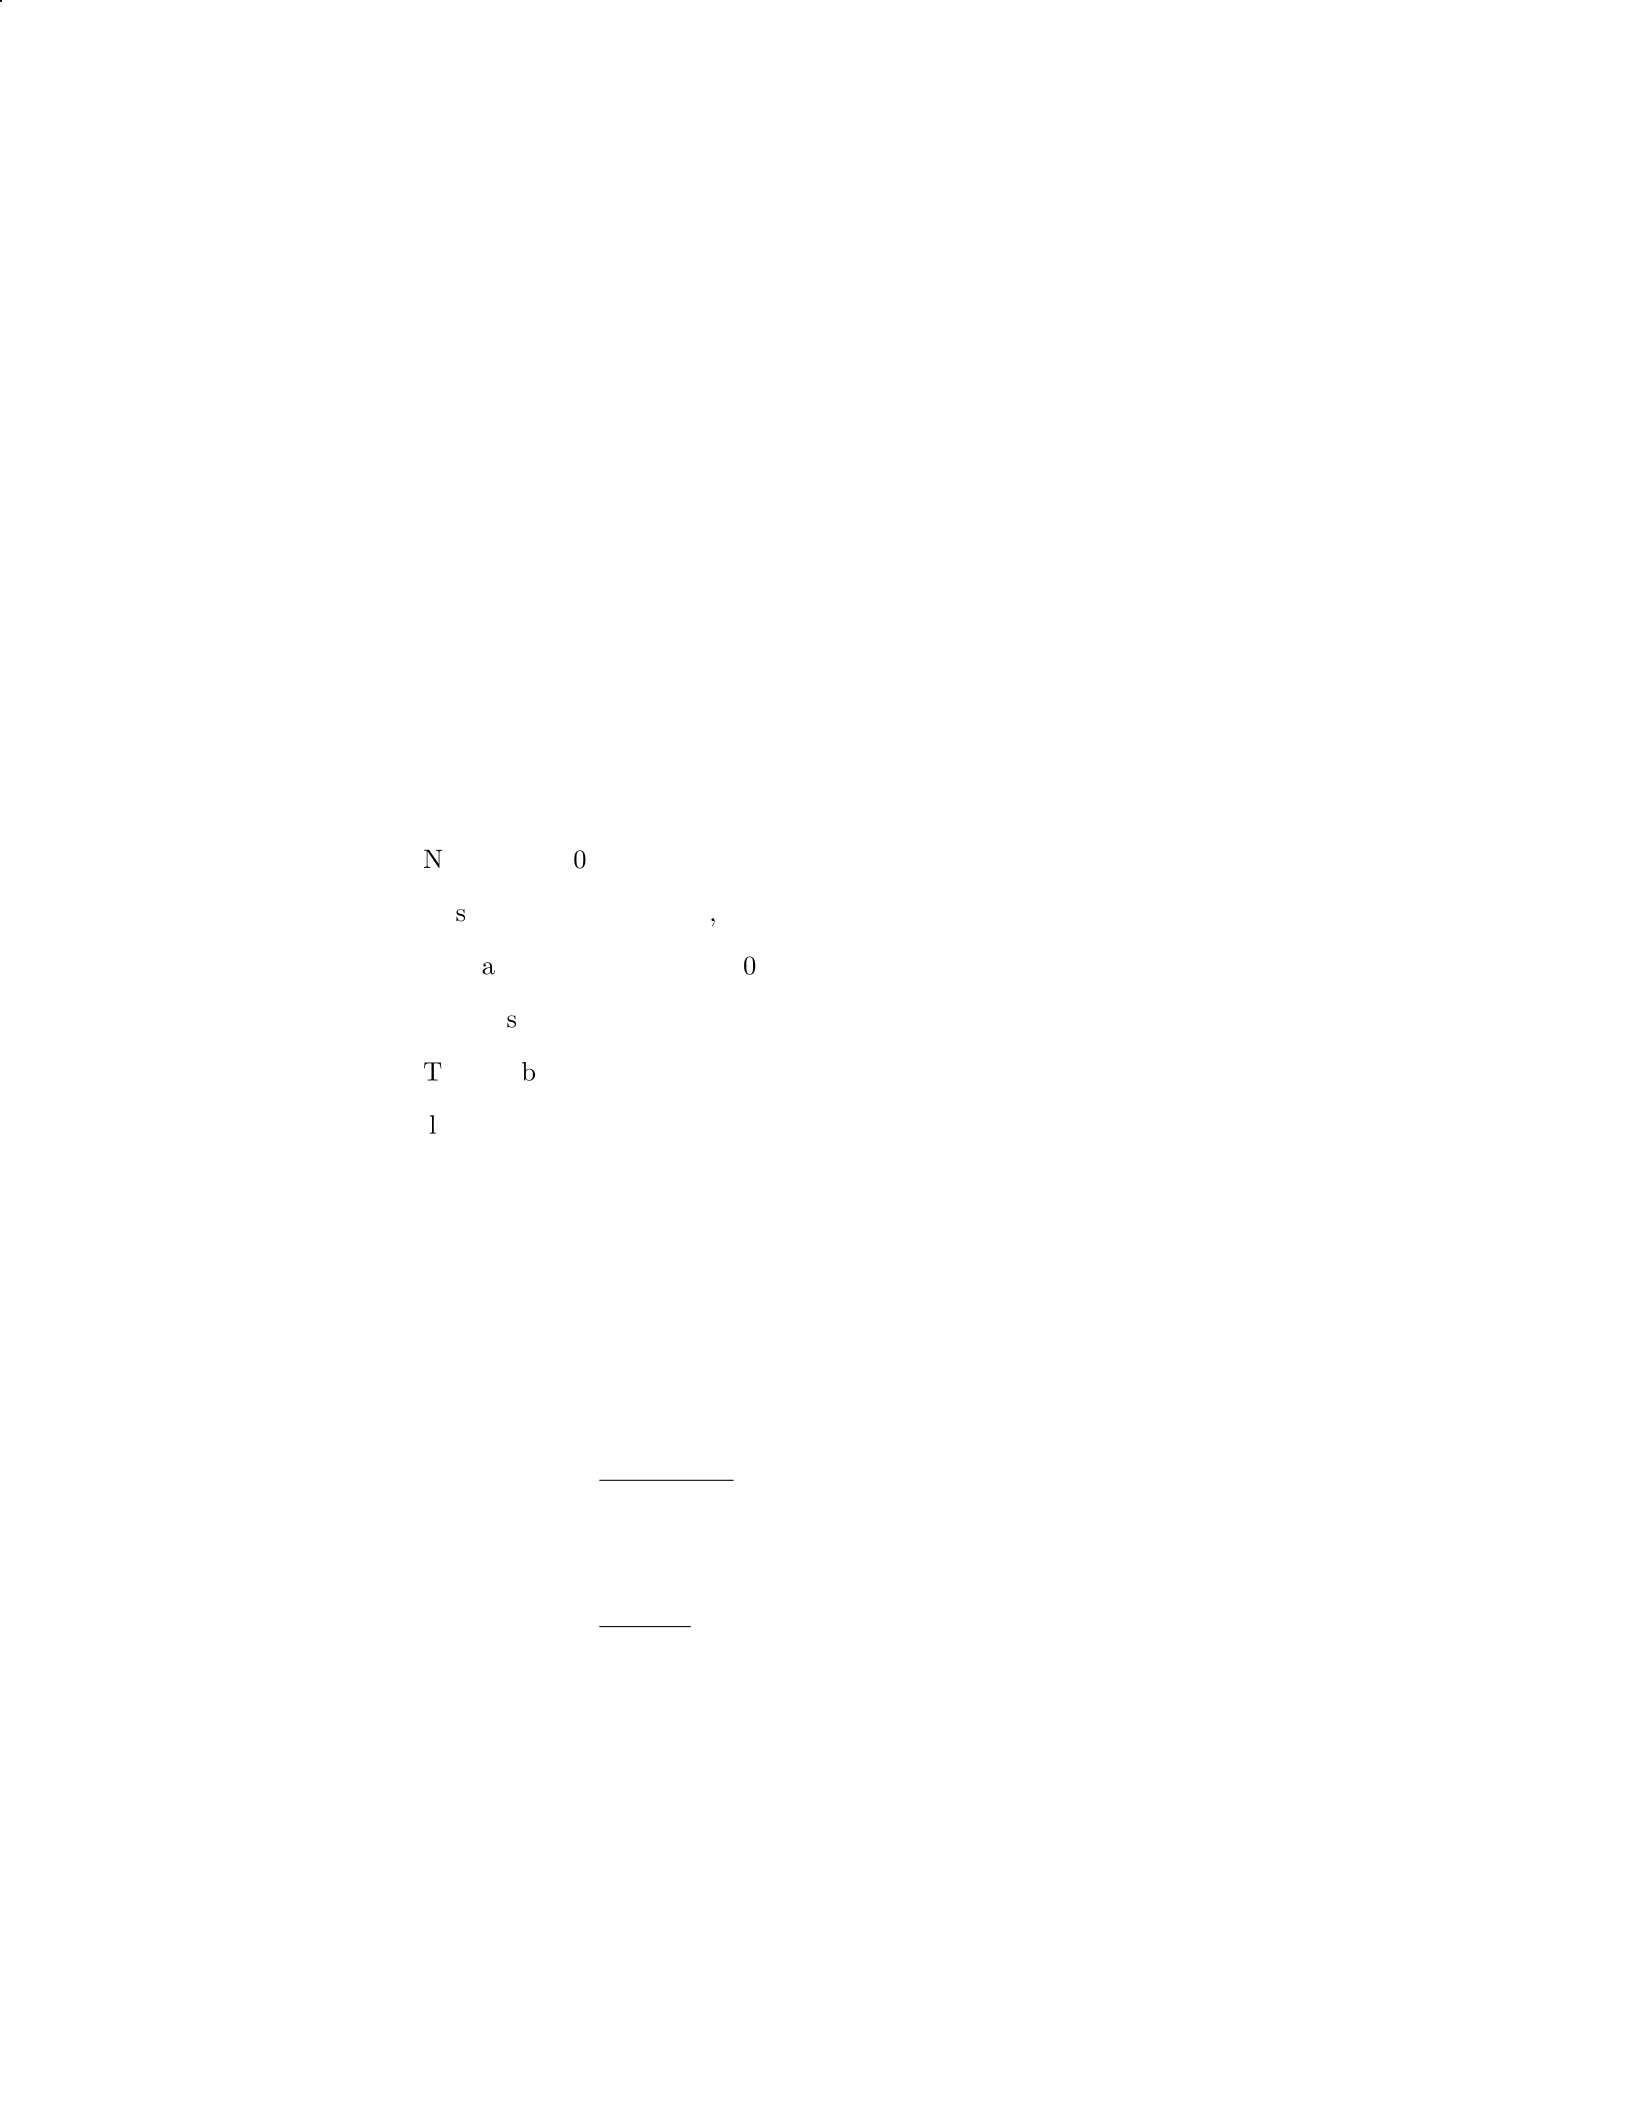
Step 4: Comparison and implications. The fact that the current ratio is
higher than the quick ratio indicates that a significant portion of the company’s
current assets is tied up in inventory. While this may not be a cause for concern,
it is important to monitor inventory levels to ensure they are not excessive and
affect the company’s liquidity.
In conclusion, the company has a strong liquidity position as indicated by
both the current ratio of 2.5 and the quick ratio of 1.5. However, the composition
of current assets, particularly inventory, should be monitored to ensure optimal
liquidity management.
Question 35
Question
Company ABC has the following financial information for the year 2020:
Net sales:
$
500,000
Cost of goods sold:
$
300,000
Operating expenses:
$
80,000
Total assets:
$
600,000
Total liabilities:
$
200,000
Calculate the following ratios for Company ABC and interpret the results:
1. Profit margin
2. Return on assets
3. Debt-to-equity ratio
Solution
Step 1: Calculate the Profit Margin
Profit Margin = Net Income
Net Sales
Net Income = Net Sales −Cost of Goods Sold −Operating Expenses
Net Income = $500,000 −$300,000 −$80,000 = $120,000
Profit Margin = 120,000
500,000 = 0.24 = 24%
Interpretation: Company ABC has a profit margin of 24%, indicating that
for every dollar of sales, the company generates a profit of 24 cents.
40
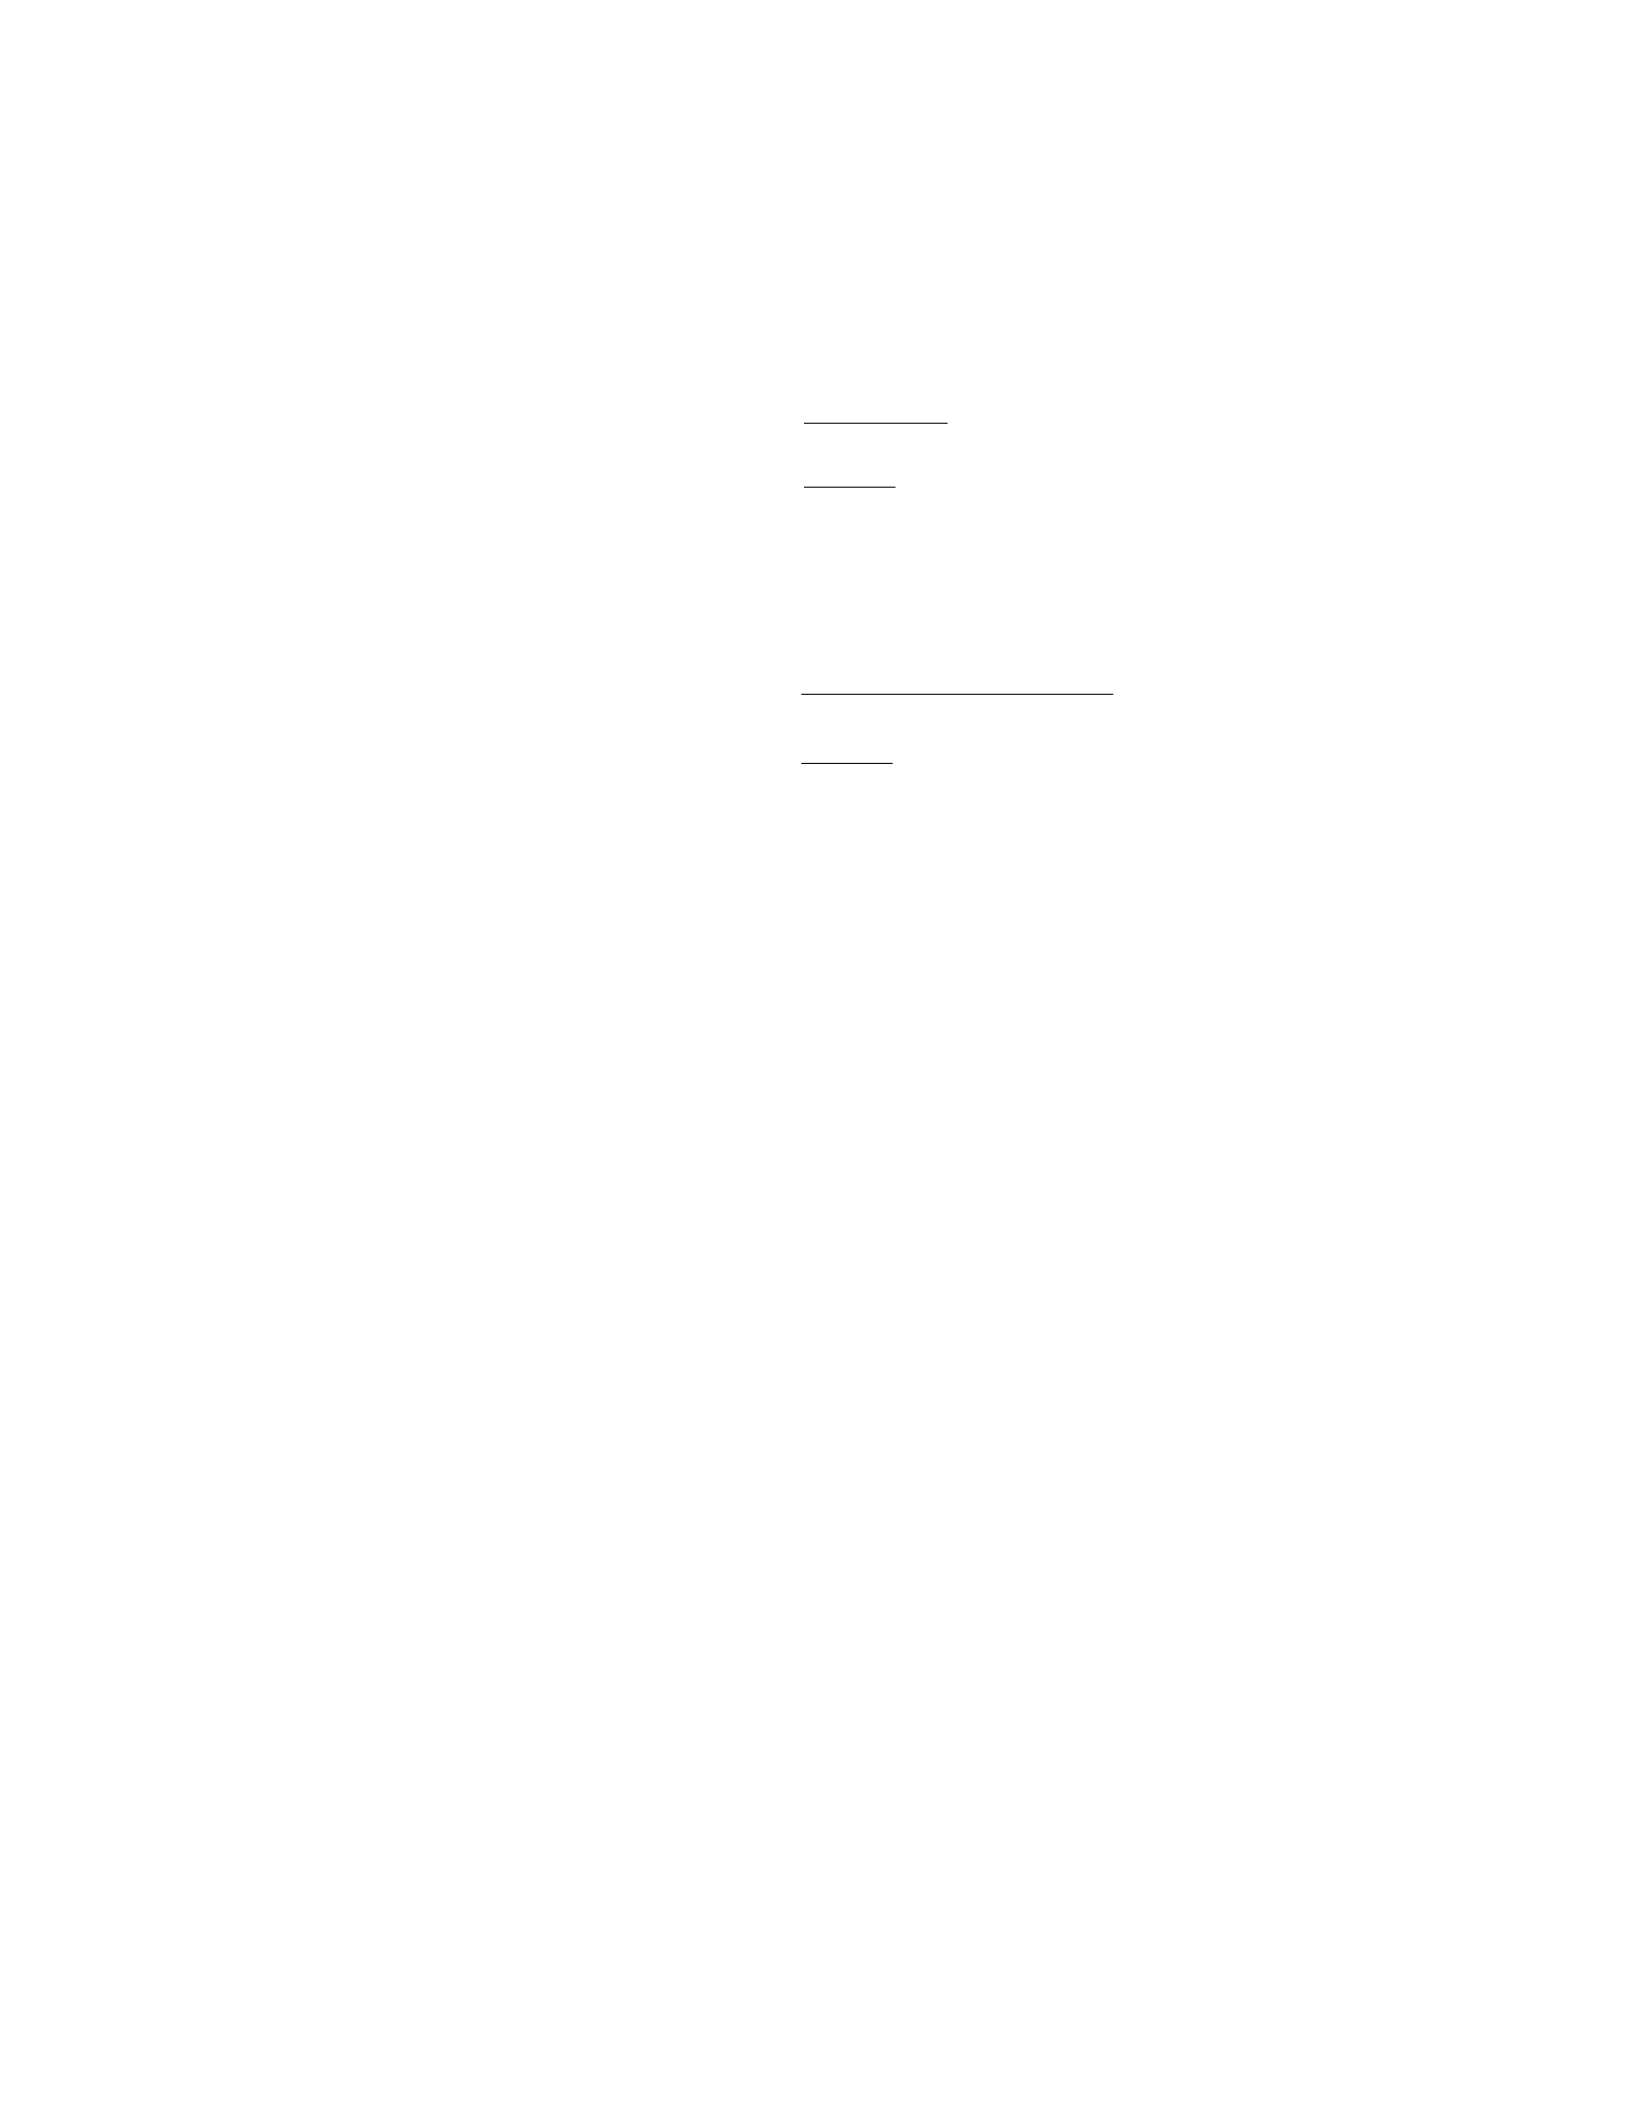
Step 2: Calculate the Return on Assets
Return on Assets = Net Income
Total Assets
Return on Assets = 120,000
600,000 = 0.20 = 20%
Interpretation: The return on assets for Company ABC is 20%. This means
that for every dollar of assets, the company generates a return of 20 cents.
Step 3: Calculate the Debt-to-Equity Ratio
Debt-to-Equity Ratio = Total Liabilities
Total Shareholders’ Equity
Debt-to-Equity Ratio = 200,000
400,000 = 0.50 = 50%
Interpretation: Company ABC has a debt-to-equity ratio of 50%, meaning
that the company’s debt level is half its equity. This indicates that the company
is relying more on equity financing rather than debt financing.
41

