Seth Heglar
L27821185
ACCT 301
Aug 8th, 2024
Ethics Case 10 – 8 Research & Development
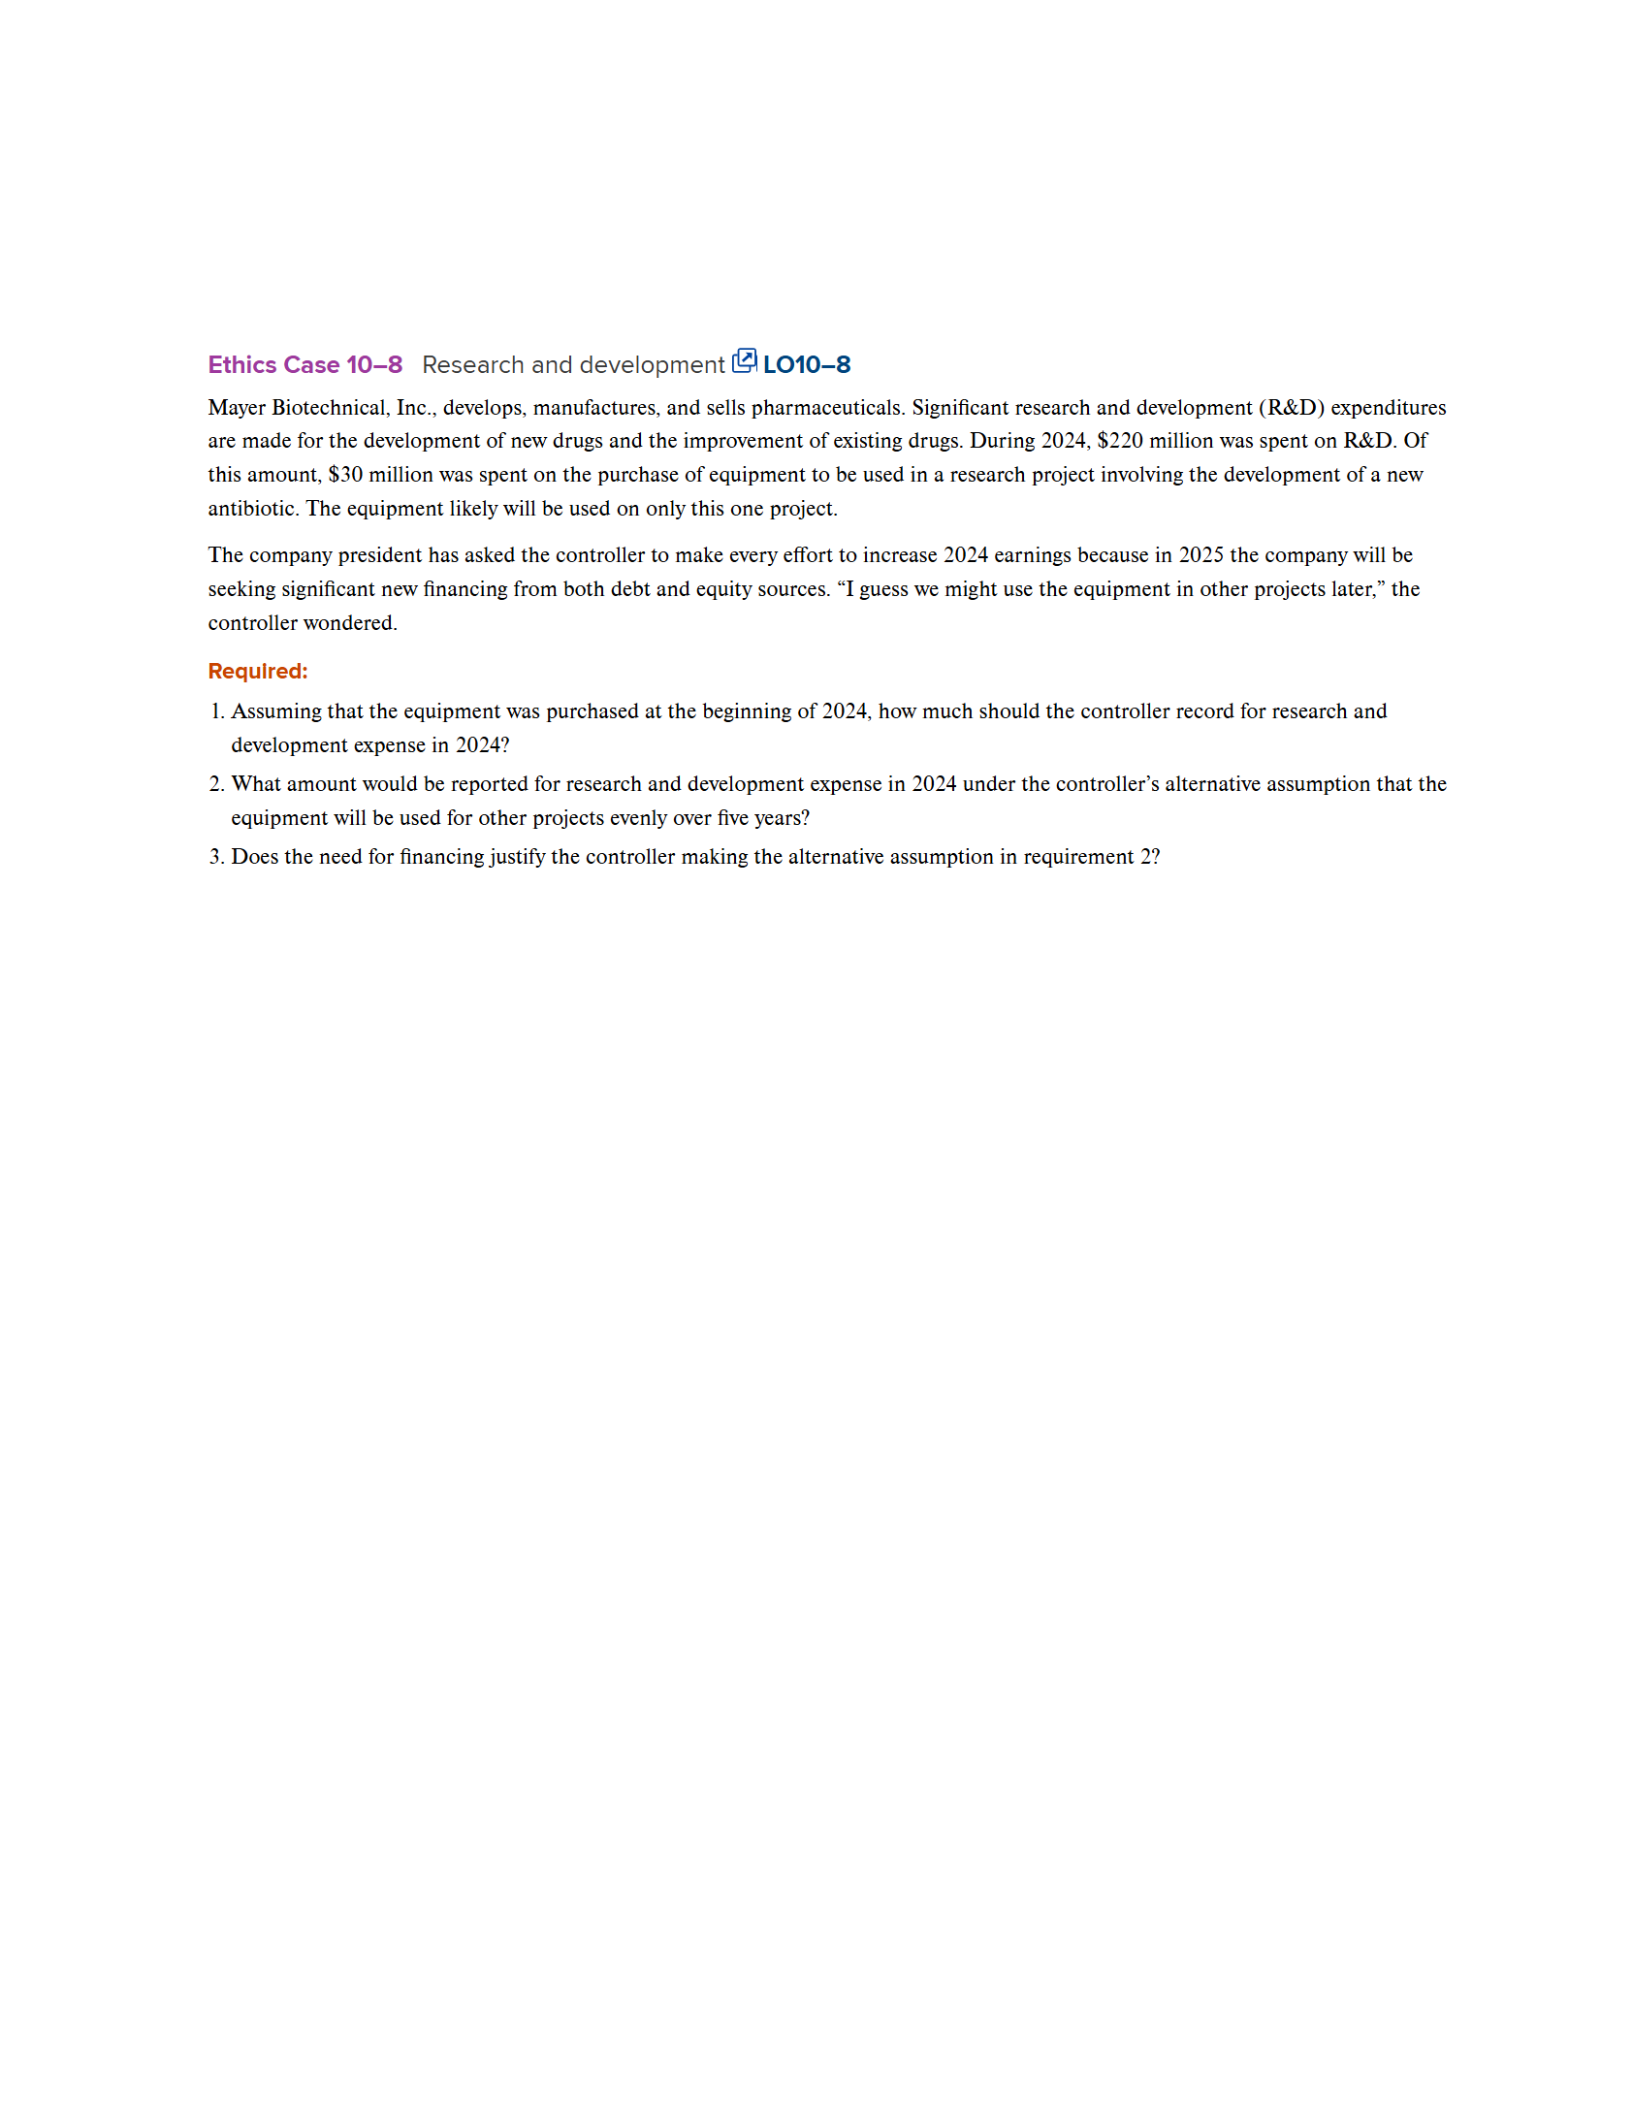
1) Mayer Biotechnical Inc purchased equipment in the amount of $30
million for purposes of research and development in the year 2024. If
we are to assume that the company is only using this equipment for
one time for this research, and the was bought at the beginning of
2024, they would expense the total amount of $30 million. Research
and development costs are treated as expenses because one does not
know the future profitability of said research. “Research and
development (R&D) expenses are direct expenditures relating to a
company’s efforts to develop, design, and enhance its products,
services, technologies, or processes… The IRS offers tax breaks for
R&D expenses, and these may also be capitalized as business
expense.” (Kindness, 2022). Being able to utilize this expensing
method would lower the companies before tax income by $30 million.
2) Alternatively, if the controller is to assume that the company is going
to use the equipment for more than one year and this specific research
and development process. The controller will be able to capitalize the
expense over a period of time, and for equipment this would be over a
five-year period. The controller states “I guess we might use the
equipment in other projects later.”, so they are giving the assumption
in order to capitalize the expense. Expensing this equipment cost of
$30 million over five years would be to divide the cost by 5, thus being
able to expense $6 million in the year of 2024. Doing this relative to

Seth Heglar
L27821185
ACCT 301
Aug 8th, 2024
the first option is bringing the expense down from $30 million to $6
million, thus lowering the before tax income by $6 million, which would
be increasing the earnings by $24 million relative to the expenses
being capitalized. This is an option of Mayer Biotechnical is planning to
use the equipment for more than just this single research and
development project, which in the ethics case it does state “will likely
be used only the one project”, so there is opportunity for the company
to utilize said equipment more than just this one time.
3) As a controller they must adhere to GAAP and the ethical principles of
accounting, but also has to look after the company, and explore what
options might be available in order to increase the chances of receiving
funding either by debt or equity. This is a very tricky situation that the
controller has found themselves in, because in theory the company
could use this equipment in the future, but they don’t have plans (to
my knowledge) of doing so past this one research and development
project. I do not think, ethically speaking, it would be right for the
controller to choose option two and capitalize the expense over time.
Biblically speaking, Jesus tells us in Luke 6:1 “Do to others as you
would have them do to you.” (The Holy Bible, 2020). Jesus is telling us
we should perform actions that resemble integrity and speak truth. As
a believer, we should do things the way we would want them done to
us. I wouldn’t want someone “falsifying” their financial statements in
order to receive my funding, and I don’t think Jesus would want us to
exploit a bank in the same way.