


MONEY WITHOUT MASTERS: AN EXPLORATION OF VOLATILITY IN
CRYPTO MARKETS
CHAPTER I
I. INTRODUCTION
“Stay away from it. It’s a mirage, basically. In terms of cryptocurrencies, generally, I can
say almost with certainty that they will come to a bad ending.” – Warren Buffett
“I do think Bitcoin is the first [encrypted money] that has the potential to do something
like change the world.” – Peter Thiel, co-founder of PayPal
1.1 Background
Are cryptocurrencies really currencies? Defined as “a form of digital currency that can
serve as a medium of exchange and a store of value … but lacking (sic) the backing of
any central authority or government (Cetina & Hoffman, 2022), cryptocurrencies are
disrupting the financial services industry (Cheung et al., 2015). Once used only by
technology enthusiasts and dark web actors, cryptocurrencies have garnered widespread
adoption with the potential to reduce, or even eliminate, the use of local fiat currencies
(Taskinsoy, 2019). In 2021, cryptocurrencies surpassed a global market capitalization of
$2 trillion representing approximately 4% of global gross domestic product (GDP)
(Chinchalkar, 2021). Yet, there is little consensus that digital currency is to be treated like
1

traditional currency. Markets, governments, even cryptocurrency users have struggled to
assign an existing label to them (Vigna & Casey, 2016). Some see cryptocurrencies as
securities, to be traded like corporate stocks (Hacker & Thomale, 2018). Others view
cryptocurrencies as a form of digital asset, a digital representation of their ownership of
“cyber space” (Bentov et al., 2019). Despite the lack of a discernable definition, millions
of people, organizations, and now countries have progressed toward cryptocurrency
adoption.
In 2008, when the Bitcoin whitepaper was published, cryptocurrencies exploded
as a market force with the potential for applications ranging from expedited check
processing to national currencies (for example, in El Salvador). The Libra Association,
with members including Facebook and Mastercard, considered the development of its
own cryptocurrency that would replace the need for fiat currencies – a project that never
actually launched (Kharif, 2022; The Libra Association, 2019). However, other consortia
have since emerged to develop cryptocurrencies which are still underway (Phillips,
2022). Still, great debate remains as to whether cryptocurrencies are money, securities,
commodities, or their own thing entirely. Furthermore, cryptocurrency price volatility
may be preventing cryptocurrencies from becoming a mainstream mechanism for
payments.
In 2017, it was estimated that there were between 2.9 and 5.8 million unique,
active Bitcoin users while there were only a handful of corporations accepting Bitcoin
payments (Hileman & Rauchs, 2017). By 2022, that number ballooned to more than 180
million users (Howarth, 2022). Cryptocurrencies represent a new era in transaction
dynamics. This study seeks to understand how various characteristics of
cryptocurrencies
2

– and the blockchain technology that supports them – impacts their volatility.
Cryptocurrency prices and price volatility are the subject of much speculation
amongst investors. Some liken cryptocurrencies to the “tulip fever” during the Dutch
Golden age when people paid exorbitant prices for tulip bulbs that had no value. Others
see cryptocurrencies as the next iteration of finance – one where centralized banks and
other entities no longer control the economy. Several studies have attempted to explain
the fluctuations in cryptocurrency prices with the results largely explaining what does not
impact prices. For example, Baur, Dimpfl, and Kuck (2018) conducted a study to
understand whether gold spot prices had any predictive relationship to Bitcoin price
volatility but found no such relationship. To date, relatively little is known about the
behavior of digital assets as their volatility does not appear in alignment with the
behavior of currencies, securities, or commodities. Stablecoins, a form of digital asset
that are designed to mimic the price performance to the specific fiat currencies to which
they are “pegged” have received virtually no attention in academic literature. Further, few
studies have looked at internal factors, such as blockchain performance variables, to see
if predictive relationships might exist between them and cryptocurrency prices. A few
studies have examined individual blockchain performance variables, such as hash rate,
for their predictive relationships to cryptocurrency prices, but none have looked at a
comprehensive set of these variables.
This study was conducted in three parts. Study 1a predicts the volatility of six
cryptocurrencies using existing asset classes (i.e., securities, commodities, and fiat
currencies). These asset classes, particularly securities and commodities, remain part
of the ongoing debate on cryptocurrency classification today. Using a data science
3

approach, this study predicts the volatility of cryptocurrency prices using fiat
currencies (US dollar, Euro, Yen, etc.), securities (S&P 500, etc.), and commodities
(gold, etc.) over the past ten years and identifies patterns of behavior that might
suggest an asset class. Study 1a includes other economic indicators, such the
Consumer Price Index (CPI) and the U.S. Unemployment Rate, to further improve the
predictability of the models.
Unlike prior studies which were looking for predictive relationships between
certain market forces and cryptocurrency prices, Study 1a expands upon previous
research in three ways: First, this study evaluates the performance of six different
cryptocurrencies; second, this study analyzes ten years of data using advanced machine
learning models, including neural networks, to predict volatility in cryptocurrency
prices; and, third, this study utilizes a comprehensive set of economic variables to
predict this volatility.
Study 1b expands upon the methodology used in Study 1a to assess volatility in
stablecoin prices. Stablecoin volatility is assessed by predicting each coin’s “depegging”,
or what causes the coins to fall below its stated $1 valuation. Like Study 1a, Study 1b
relies on a comprehensive suite of economic variables to predict the depegging of three
stablecoins: Tether (USDT), U.S. Dollar Coin (USDC), and Binance Coin (BUSD).
Study 2 focuses on a different perspective on cryptocurrency performance – an
examination of internal factors rather than market forces. Using traditional artificial
neural networks and related statistical modeling techniques, this study evaluates 12
blockchain performance variables, or technical attributes that measure the efficiency of a
blockchain (hash rate, average block size, etc.), to ascertain if any of them (or groups of
4

them) have predictive relationships with a cryptocurrency’s price volatility. Study 2
focuses specifically on Bitcoin because 1) it has the most historical data, and 2) its
blockchain performance variables are the most accessible. Few studies to date have
attempted to evaluate these variables as a comprehensive set for predictive properties. As
the technology that underpins cryptocurrency performance is continuing to evolve, this
examination of predictor variables that are unrelated to market forces may be
illuminating.
1.2 Purpose of the Study
The purpose of this study is to examine the economic and technical factors that
may influence cryptocurrency price volatility. Prior studies have assessed economic
indicators in relation to cryptocurrency markets; others have investigated the effects of
technical architecture on blockchain performance. Neither area of study has been able to
identify the ways in which cryptocurrency markets are influenced by economic factors or
technology. This study is the first of its kind to assess cryptocurrency markets through the
lens of both economic and blockchain performance.
Studies 1a and 1b seek to broaden the understanding of cryptocurrency behavior
by evaluating the nine largest traditional cryptocurrencies in terms of market
capitalization in comparison to the behaviors of other asset classes (such as securities,
commodities, and fiat currencies) and other economic indicators (such as CPI and the
U.S. Unemployment Rate) over a ten-year period. These asset classes, particularly
securities and commodities, remain part of the ongoing debate on cryptocurrency
classification. By comparing cryptocurrency behavior to these asset classes, this study
informs conversations about appropriate classification of crypto assets. This study also
5

examines the economic behavior of stablecoins, a subcategory of cryptocurrencies that are
backed by another asset. Stablecoins have, to date, received little to no attention in
academic literature.
Study 2 suggests that the relationship between economic performance and
cryptocurrency prices depends on the technical architecture of the cryptocurrency’s
blockchain. Unlike other technical architectures, blockchain design is characterized by
the ways in which it achieves consensus. In other words, blockchain architecture is the
mechanism by which cryptocurrency investors commit and verify transactions on a
blockchain. Since achieving consensus relies on the behavior of individuals, it is
reasonable to expect that the intersecting relationships between numerous variables that
represent a blockchain’s architecture might collectively influence cryptocurrency price
volatility. Specifically, Study 2 looks at the predictive properties of blockchain
performance variables on Bitcoin price volatility.
1.3 Research Questions
Study 1a seeks to broaden the understanding of cryptocurrency volatility by
evaluating the six largest traditional cryptocurrencies in terms of market capitalization –
Bitcoin (BTC), Ethereum (ETH), Binance Coin (BNB), Ripple (XRP), Cardano (ADA),
and Dogecoin (DOGE). Study 1b expands upon Study 1a by exploring prince volatility
of the three largest stablecoins by market capitalization – Tether (USDT), USD Coin
(USDC), and Binance USD (BUSD). Together, these cryptocurrencies were evaluated in
comparison to the behaviors of the three major asset classes (securities, commodities, and
fiat currencies), to other economic indicators over a ten-year period, and to other
cryptocurrencies.
6

Study 1a addresses the following research questions:
Question 1a: How effective are advanced machine learning models in
predicting cryptocurrency price volatility?
Question 1b: Which variables are most significant in cryptocurrency
price volatility?
Study 1b addresses the following research question:
Question 2a: How effective are advanced machine learning models in
predicting the depegging of a stablecoin?
Question 2b: Which variables are most significant in predicting
stablecoin depegging?
Study 2 looks at the predictive properties of blockchain performance variables on
Bitcoin price volatility.
Question 3a: How effective are advanced machine learning models in
predicting price volatility of Bitcoin?
Question 3b: Which blockchain variables are most significant in
predicting Bitcoin price volatility?
1.4 Overview of Study Design
Data science harnesses the power of big data, characterized by its volume, variety,
and velocity, to advance the analytics about cryptocurrency behavior (Delen, 2021). This
approach helps to answer descriptive questions such as “what happened”, “why is it
happening”, and “how often does it happen” and predictive questions such as “what else
is most likely to happen” and “how else will it happen” (Delen, 2021).
The three studies followed the Cross-Industry Standard Process for Data Mining
7

(CRISP-DM) process to examine over 500,000 data points (Delen, 2021; Shearer, 2000).
Various models were developed that best suit the data and the research questions posed in
this study. Broadly speaking, predictive models were developed to address the research
questions. Studies 1a and 1b seek to understand whether cryptocurrencies price volatility
can be predicted by assessing economic variables. These questions are not attempting to
use these factors to predict cryptocurrency prices. Study 2 looks to see if Bitcoin price
volatility can be predicted by certain blockchain performance variables. Several
predictive models were used in both studies.
1.5 Significance of the Study
Studies to date have identified some potential correlations between the
performance of cryptocurrencies and other asset classes or economic indicators.
However, their results are limited to the study of one or two cryptocurrencies and few
other predictor variables. As such, their results are conflicting and suggest few reliable
conclusions. This study examines over 500,000 publicly available data points spanning a
10-year period to:
1. Evaluate a suite of cryptocurrencies, including stablecoins which have little
representation in the academic literature;
2. Simultaneously examine the cryptocurrency price volatility using
numerous economic indicators;
3. Simultaneously evaluate a suite of internal characteristics (blockchain
performance variables) of cryptocurrencies for any predictive properties;
and
8

4. Utilize a data science approach which enables broad and comprehensive
analysis of cryptocurrency behavior.
The academic literature on the behavior of cryptocurrencies, and particularly
how their behavior relates to other economic or technical indicators, is sparse. Given that
cryptocurrencies emerged for the first time in 2008, this represents a new field of study
and therefore, a greenfield opportunity to contribute to the literature on the behavioral
characteristics of cryptocurrencies.
1.6 Assumptions
While the two studies in this paper examine several predictor variables (asset
classes, economic indicators, and blockchain performance variables), the number of
potential predictor variables (even within the broad categories of variables selected for
this paper) are limitless. As such, the specific predictor variables selected for these
studies represent a natural inherent assumption. A discussion of some of the potential
variables that may be related to cryptocurrency price can be found in Chapter II, Other
Potential Influences on Cryptocurrencies.
The timing and potential impact of new or expanded regulatory oversite that
relates specifically to cryptocurrency activity is not captured in these studies. The
Securities and Exchanges Commission (SEC) and Commodity Futures Trading
Commission (CFTC) are still developing their positions on the asset classification of
cryptocurrencies. Further, the Office of the Comptroller of the Current (OCC) issued its
first interpretative letter for banks in 2020, while the Federal Deposit Insurance
9

Corporation (FDIC) and the Federal Reserve issued their letters in 2022. Another
assumption in this paper is that the impact of new or expanded regulatory oversite has not
yet been realized.
As discussed in this paper, the two largest cryptocurrencies, Bitcoin and
Ethereum, utilize proof-of-work consensus protocols to validate blockchain transactions.
However, in September 2022, Ethereum moved to a proof-of-stake consensus which is
different in many material respects from proof-of-work (Ethereum, 2022). Another major
assumption of this paper is that the studied variables pre-date this change in Ethereum’s
validation approach.
At the time of this paper’s publication, the volatility of cryptocurrency markets is
a well-observed phenomenon. A “crypto winter” is broadly defined as a period in which
most cryptocurrencies experience lower values (Chohan, 2022). While a several crypto
winters have been observed in the past, the record prices of cryptocurrencies in 2020
made the crypto winter experienced in 2022 particularly obvious (and painful, for some)
(Chohan, 2022). As the 10-year scope of this paper includes data only to June1, 2022, it
is unclear how the market downturn of the 2022 crypto winter may impact the efficacy of
the paper’s predictive models.
Finally, certain global events have been observed to influence cryptocurrency
prices. For example, when facing economic sanctions, countries sometimes turn to crypto
markets to allow for cross-border payments. With the ongoing political events between
Ukraine and Russia, there is discussion that economic sanctions on Russia will encourage
more Russian activity in crypto markets, thus inflating the price of cryptocurrencies.
Another example was the sharp increase in cryptocurrency activity observed during the
10

Covid-19 pandemic, a time when U.S. interest rates were low and stock market
performance was volatile (Katsiampa, Yarovaya, & Zięba, 2022). The analysis described
in Chapter III did not attempt to tease out the impact of these (or other) global events.
1.7 Definition of Terms
Asset Class – A group of investments that exhibit similar economic behaviors. For this
study, three asset classes are considered: 1) securities (such as the S&P 500 and
Dow Jones Industrial Average), 2) commodities (such as gold spot price and
crude oil spot price), and 3) fiat currencies (such as the U.S. dollar, Euro, and
Japanese Yen).
Artificial Neural Networks (ANN) – Conceptually, neural networks are analogous to
networks in the human brain that can learn from past experiences. Artificial
neural networks are developed via neural computing which employs pattern
recognition for machine learning and predictive modeling.
Block – A block represents a set of transactions that is stored and encrypted on a blockchain.
Blocks are linked together cryptographically using hash values.
Blockchain – The most well-known type of Distributed ledger technology (DLT),
blockchain, originated as the architecture supporting the Bitcoin
cryptocurrency (Nakamoto, 2008a). Several technical variables that are unique
to a blockchain influence its overall performance or efficiency. These include
hash rate, block size, and mempool size. A description of the blockchain
performance variables considered in this study can be found in Chapter II,
Blockchain.
11

Cryptocurrency – A type of digital asset. They can be broadly grouped into two categories:
1) Traditional cryptocurrencies such as Bitcoin and Ethereum, and 2)
Stablecoins such as Tether and US Dollar Coin. Bitcoin is often recognized as the
world’s first cryptocurrency. Created in 2008, Bitcoin was the first electronic cash to use
distributed leger technology (Nakamoto, 2008a; Popper, 2015). The use of a blockchain,
one type of distributed ledger technology, distinguishes cryptocurrencies from traditional
currencies and the other digital payments mechanisms that preceded it.
Cryptography – Mathematical algorithms used for encrypting data. There are three
major classifications of cryptography: 1) symmetric key encryption, 2)
asymmetric key encryption, and 3) hash functions).
Digital Asset – Anything (such as art, manuscripts, money, etc.) that can be stored digitally
and is considered to have intrinsic value.
Distributed Ledger – A distributed ledger can be thought of as a database that is shared
and synchronized real-time across multiple nodes (Nofer, Gomber, Hinz, &
Schiereck, 2017). Unlike a cloud-based database where multiple users can view
and edit one master database stored in a centralized location, a distributed ledger
must have the support from most nodes before a modification to the ledger can be
made (Sankar, Sindhu, & Sethumadhavan, 2017). Blockchain is one type of
distributed ledger.
Cross Industry Standard Process for Data Mining (CRISP-DM) – A framework that
guides data science research. Steps in this data preparation framework
include data consolidation, data cleaning, data transformation, and data
reduction
12

(Shearer, 2000).
Consensus Protocols – Algorithms that ensure all nodes on a blockchain agree on which
transactions are legitimate and are valid to add to the blockchain. The two most
used consensus protocols are: 1) Proof-of-Work (PoW), 2) Proof-of-Stake (PoS).
Crypto Winter – A period in which most cryptocurrencies experience lower values.
Data Science – A methodological approach to analytics that utilizes machine learning
algorithms to reveal the prediction accuracy of certain variables. Models include
Artificial Neurol Network (ANN), Decision Tree (DT), Recurrent Neural
Network (RNN), Long Short-Term Memory (LSTM), Bayseian Neural Network
(BNN), and Random Forest (RF).
Financial Services – The broad classification of businesses in the financial industry
that include and support banks, credit unions, insurance companies, wealth
management firms, credit card companies, etc.
Fork – Phenomenon that occurs when blocks at a blockchains are mined at conflicting
times or when a consensus cannot be reached. In this event, the blockchain
splits in a process known as “forking” (da Silva et al., 2019), which causes
inconsistencies on the blockchain network.
Hash Rate – The speed at which blocks are added to a blockchain used a proof-of-work
consensus protocol. Higher the hash rates mean that there are more miners
validating transactions, so it is also a representation of the total computational
power used by the blockchain.
Hash Value – A cryptographic term which represents the mathematical calculation of the
data in a block. If the data in the block changes, the hash will also change. In a
blockchain, the hash for one block is used to create the hash for the next block.
13

This means that if the data in one block changes, it will change the hash of that block as
well as the hashes of every other block in the ledger (Di Pierro, 2017).
KNIME Analytics Platform – Open-source, advanced analytics software that is used in data
science research.
Mining – One method of recording and verifying transactions on a proof-of-work
blockchain. To verify transactions, miners must solve a complex hashing
problem. The first miner to find a solution is rewarded by receiving newly
minted crypto coins from that specific blockchain.
Proof-of-Stake (PoS) – A consensus protocol which chooses the creator of a new block
based on the wealth, or stake, of the verification node. PoS blockchains do not
provide a block reward. Instead, the nodes performing validation, called forgers,
charge fees for each transaction on the blockchain. These fees, also called “gas
prices”, fluctuate with demand. Unlike PoW, complex mathematics is not used to
validate transactions, so the protocol requires virtual no consumption of energy.
Ethereum 2.0 converted from PoS to PoW in September 2022.
Proof-of-Work (PoW) – Requires that a subset of nodes, called miners, calculate a
mathematical problem, called the “proof-of-work”, to determine who can validate
transactions on the blockchain and receive a block reward (Gervais et al., 2016).
In recent years, proof-of-work consensus has come under scrutiny due to its heavy
consumption of energy and other limited resources (Xue et al., 2018). PoW is the
consensus protocol used by Bitcoin.
Stablecoin – A type of cryptocurrency that attempts to peg its value to another financial
instrument. For example, the values of Tether and Binance USD are supposed to
14

be pegged to the value of the U.S. dollar. In theory, stablecoins were designed to
offer price stability and less volatility. In practice, however, many stablecoins
have struggled to achieve this objective.
Volatility or Daily Volatility – The statistical measure of the dispersion of return, for Bitcoin.
Daily volatility was calculated using the Garman-Klass (GK) volatility measure
(Garman & Klass, 1980).
15

CHAPTER II
II. CONCEPTUAL BACKGROUND AND REVIEW OF LITERATURE
2.1 Introduction
Money, whether it is represented by a stone, forged coin, paper note, or line of
computer code, does not implicitly have intrinsic value. The value of money is dependent
on the perception of its importance by the people who use it as a medium of exchange, a
store of value, or a unit of account. While there have been countless developments in
monetary technology over the course of human history, cryptocurrencies represent a
novel monetary development, both technically and economically. Technically,
cryptocurrencies are decentralized, meaning that no single entity controls the information
or infrastructure. Economically, cryptocurrencies exist digitally and, as a result, appear to
have different interactions with the money of the physical world. Together, these two
attributes make comparisons between cryptocurrencies and traditional financial assets
worthy of exploration.
The academic literature on cryptocurrencies has primarily focused on the pricing
and valuation of cryptocurrencies (Alessandretti, ElBahrawy, Aiello, & Baronchelli,
2018; Sovbetov, 2018). Research on the behavior of cryptocurrencies, and particularly
how their behavior relates to other financial asset classes, is sparse. Given the steady
16

increase in cryptocurrency activity over the past decade, and the sharp increase during the
Covid-19 pandemic, this represents a new field of study and a greenfield opportunity to
contribute to the literature on the behavioral characteristics of cryptocurrencies.
2.2 Longitudinal Review of Cryptocurrency Development
2.2.1 History of Cryptocurrencies
While it is commonly believed that cryptocurrencies emerged in 2008, the earliest
attempt at distributed transactions can be traced back to a company called DigiCash
founded by David Chaum in 1989 (Nakamoto, 2008a; O'mahony, Peirce, & Tewari,
1997). Chaum created the concept of blind signatures which allowed for anonymity in
digital transactions (Chaum, 1983). The prefix “crypto” is derived from the Greek word
κρυπτός meaning concealed, secret, or hidden. The ability to create anonymity in
transactions was essential to early cryptocurrency research. Blind signatures are a
derivation of digital signatures which rely on public-key cryptographic hashes to validate
the integrity and authenticity of a digital transaction, message, or document (Diffie &
Hellman, 1976; Merkle, 1987). DigiCash used blind signatures to disguise transactions
before posting to the network thus allowing for anonymous transactions on a public
ledger (Chaum, Fiat, & Naor, 1988). Blockchain technology would come to rely on blind
signatures to facilitate anonymous transactions (Zheng, Xie, Dai, Chen, & Wang, 2018).
In 1993, computer scientists from Bell Research Laboratory and IBM worked alongside
the Financial Services Technology Consortium (FSTC), a consortium of banks,
technology companies, and government entities, to develop a hash-based system for
protecting blocks of data within a newly design electronic check processing format
(O'mahony et al., 1997) (see Appendix I for FSTC members in 1998). To facilitate the
17

development of uniform structural components of an electronic check., the FSTC
developed the Financial Service Market Language (FSML) which included the creation
of blocks to represent components of physical checks (O'mahony et al., 1997). According
to Donal O’mahony, the block structure was set up such that “[a] signature block
contains the names of the other blocks that is signs, along with a hash of each of those
blocks. Therefore, the e-check signature is actually a signed hash of the concatenated
hashes of several blocks.” (O'mahony et al., 1997, p. 142).
Daniel Schutzer, former Vice President and Director of External Organizations,
Standards, and Advanced Technology at Citibank as well as former President of the
FSTC discussed the need for “electronic money” in Banking and Finance on the
Internet, published in 1998, describing it as a departure from paper currency (Schutzer,
1998). He goes on to elaborate on benefits of electronic cash stating: “[t]here are strong
incentives for moving to electronic money, including increased convenience, timeliness,
flexibility, and control of payments both on and off the ‘Net...[it] requires some changes
in how consumers think about money, and a total shift will not occur overnight.”
(Schutzer, 1998, p. 183). The work of the FSTC represents an important, and often
overlooked, element in the development of modern cryptocurrencies. For example,
Schutzer directly references earlier iterations of digital cash, including DigiCash
(Schutzer, 1998, p. 189).
He also describes a future state initiative to develop “electronic wallets” to host digital
cash (Schutzer, 1998, p. 202). Many scholars acknowledge cryptocurrency research and
development by entrepreneurs and computer scientists, but few recognize the work done
by financial services organizations. Despite widespread recognition, the FSTC appears to
18

be directly involved in the development of decentralized ledgers and digital currencies.
In 2002, Adam Back released a white paper which described an email filtration process
based on a proof-of-work system (Back, 2002). The email filtration process relied on a
cost-function, originally developed by Cynthia Dwork and Moni Naor, which required the
sender to calculate a computationally expensive problem to send a message (Back, 2002;
Dwork & Naor, 1992). The proposed proof-of-work model required clients to compute
tokens (𝒯) using cost-function MINT (𝑠,𝑤), where w is the amount of work required
to mint a token, to participate in a protocol with a server in processes termed minting. The
server verifies the value of the token using the function VALUE (). This process reduces
the likelihood a server would experience resource depletion as is commonly the case with
Denial of Service (or DOS) attacks (Back, 2002; Moore, Shannon, Brown, Voelker, &
Savage, 2006). Nakamoto used the idea of a proof-of-work to develop the consensus
protocol that powers the Bitcoin blockchain (Back et al., 2014; Nakamoto, 2008a).
Other efforts focused on the development of decentralized digital currency. In
1998, computer engineer Wei Dai published the white paper “b-money, an anonymous,
distributed electronic cash system” where Dai defines the b-money protocol, a protocol
that eventually served as a blueprint for Bitcoin (Dai’s paper is directly cited in the
Bitcoin white paper) (Dai, 1998; Nakamoto, 2008a). The b-money protocol is a set of
two protocols. The first protocol relies on a broadcast channel in which every participant
keeps and maintains a copy of the database tracking the amount of money owned by
given individuals. This protocol also describes a money creation system in which users
solve computational problems that “have no value, either practical or intellectual” in
order to receive newly minted coins (Dai, 1998). The money creation process described
19

by Dai is the first introduction to the cryptocurrency creation process that will become
known as “mining” (Bhaskar & Chuen, 2015). At the time of publication in 1997, Dai
described the first protocol as “impractical” because of its heavy reliance on a
decentralized anonymous ledger system. The second b-money protocol reduces the
reliance on a completely decentralized ledger system by assigning transaction
verification responsibilities to a subset of participants (Dai, 1998). In this protocol, Dai
explains that the verification participants must hold a certain deposit of the virtual
currency to use in case of fines or rewards. The second protocol’s reliance on a subset of
participants for transaction verification would eventually be incorporated into the Bitcoin
mining process (Bhaskar & Chuen, 2015).
Development on electronic currencies, or underlying distributed ledgers, appears to slow
rapidly in the early to mid-2000s. Then, in the midst of the Great Recession on
October 31, 2008, Satoshi Nakamoto sends a whitepaper titled Bitcoin: A Peer-to-Peer
Electronic Cash System to an online cryptography mailing group called Metzdowd
(Nakamoto, 2008b). The paper is short, only eight pages in length, and includes
eight references, some of which specifically reference b-money and Hashcash
(Nakamoto, 2008a). The paper lays the foundation for what will eventually become
Bitcoin, the world’s first cryptocurrency (Popper, 2015). Its author, Satoshi
Nakamoto, was determined to be a pseudonym whose true identity has never been
revealed (Popper,
2015).
Following publication of the Bitcoin whitepaper, cryptocurrencies exploded as a
market force with the potential for applications ranging from payments to central bank
digital currencies (CBDCs). In 2014, Vitalik Buterin published Ethereum White Paper: A
20

Next Generation Smart Contract & Decentralized Application Platform to Metzdowd, the
same cryptography mailing list where Satoshi Nakamoto published the Bitcoin
whitepaper (Buterin, 2014). Then in 2019, Facebook announced their development of a
stablecoin, Libra, via their consortium, the Libra Association. Libra never launched and
in 2021 the remaining intellectual property was sold to a private bank (Arauz, 2021;
Kharif, 2022; The Libra Association, 2019). Since then, other consortia have since
emerged to develop cryptocurrencies which are still underway (Phillips, 2022). Despite
these advancements in cryptocurrency development, debate remains as to whether
cryptocurrencies are money, securities, commodities, or their own thing entirely.
2.2.2 Types of Cryptocurrencies
Traditional cryptocurrencies. Popular cryptocurrencies, such as Bitcoin or
Ethereum, are considered “traditional” cryptocurrencies as they rely on the basic
underlying structure and assumptions put forward by Satoshi Nakamoto. These
cryptocurrencies are exchanged on public blockchains where transaction information
is openly available and do not have any backing assets, meaning their value is derived
entirely by market forces (Ante, Fiedler, & Strehle, 2021). While traditional
cryptocurrencies remain popular, their high price volatility is believed to prevent them
from being used as a mainstream means of payment (Manaa et al., 2019).
Stablecoins. Unlike traditional cryptocurrencies, stablecoins are designed to maintain
a stable value relative to other assets, typically national fiat currencies (President's
Working Group on Financial Markets, Federal Deposit Insurance Corporation, &
Office of the Comptroller of the Currency, 2021). Stablecoins have expanded use cases
compared to traditional cryptocurrencies – stablecoins are used to facilitate trading and
21

payments as well as lending and borrowing other cryptocurrencies (President's
Working Group on Financial Markets et al., 2021). Popular stablecoins include Tether,
U.S. Dollar Coin (USDC), and Binance USD.
Other cryptocurrencies. Many other types of cryptocurrencies exist with new
variations constantly entering the marketplace. One specific type of cryptocurrency
worthy of note is central bank digital currencies (CBDCs). Several nation states, and their
corresponding central banks, are interested in creating a national cryptocurrency. They
often utilize many of the properties of stablecoins to create these national
cryptocurrencies, referred to as CBDCs. Countries currently researching, testing, or
offering a CBDC include: the Bahamas (Central Bank of The Bahamas, 2019), the
European Union (European Central Bank, 2020), China (People's Bank of China, 2021),
England (Bank of England, 2021), and the United States (Federal Reserve Bank of
Boston & Massachusetts Institute of Technology Digital Currency Initiative, 2022).
2.2.3 Overview of Cryptocurrency Prices
By design, cryptocurrencies are decentralized assets. They do not require
intermediation from banks and therefore can largely evade control by governments and
central banks. Without connection to central banks, cryptocurrencies have no inherent
connection to the ‘real’ economy. For this reason, it is reasonable to expect that
cryptocurrencies could be used to hedge against uncertainty in traditional markets such as
the stock market or traditional fiat currencies. Baek and Elbeck (2015) demonstrated this
point by showing that fluctuations in cryptocurrency prices are driven by market
participants. Even more interesting, Klein, Thu, and Walther (2018) showed that Bitcoin
22

is positively correlated with downward markets suggesting that cryptocurrencies serve as
a store of value during declines in the market (Conlon & McGee, 2020).
2.3 Predicting Cryptocurrency Price Volatility via Existing Asset Class and Economic Indicator
Data
Studies 1a and 1b seek to understand whether the volatility of cryptocurrency
prices can be predicted by other asset classes or economic indicators. The studies
evaluate cryptocurrencies, including “traditional” cryptocurrencies and stablecoins,
commodities, securities, fiat currencies, and other economic indicators.
2.3.1 Cryptocurrencies as Currencies
Given their name, cryptocurrencies are often mentioned in colloquial
conversation as if they are currencies, like the yen or euro. However, governments,
economists, and computer scientists disagree on the appropriate classification for
cryptocurrencies. In the United States, the Internal Revenue Service (IRS) issued notice
2014-21 stating that cryptocurrencies are to be treated as property, not currencies
(Internal Revenue Service, 2014; Lerer, 2019). Economists, on the other hand, are not
consistent in their view of cryptocurrencies. Kirkby (2018) found similarities in the
performance of Bitcoin and the Venezuelan bolívar but concludes that cryptocurrencies
would “be a bad idea” (p. 528).
(White, 2015) describes cryptocurrencies as “competing private irredeemable
monies” but Smith and Kumar (2018) clarify that cryptocurrencies have a lack of
institutional liability and, therefore, cannot be deemed irredeemable monies such as
bank deposits.
Economists identify three characteristics of money: it serves as a store of value, a
unit of account, and a medium of exchange (Hennerich, 2021). Many researchers agree
23

that various assets, including cryptocurrencies, can be used as units of account; likewise
there is consensus that in order to become a medium of exchange, an asset must meet
the other two qualities (Ammous, 2018). This leaves store of value as the property to
scrutinize in the context of cryptocurrencies. Unlike fiat currencies, cryptocurrencies
have no central banks, and, therefore, no mechanism to set interest rates and control
money supply growth. Instead, cryptocurrency supply growth is set by predetermined
algorithms that not only serve as economic policy, but also finance the infrastructure
required to support transactions. Ammous (2018) found that Bitcoin has had an annual
growth rate over 100% since 2013, with growth rates expected to increase to 200% by
2024. By comparison, broad money growth for 167 countries between 1960 and 2015
averaged 32.16% with the money supply growth for Organization for Economic
Cooperation and Development (OECD) countries dropping to an average rate of 7.17%
from 1990 to 2015 (Ammous, 2018). This suggests that the growth rate of Bitcoin is too
high to allow for it to become a store of value.
2.3.2 Cryptocurrencies as Securities
For those who view cryptocurrencies as assets, the next question becomes: what type
of asset? Gary Gensler, current chairman of the U.S. Securities and Exchange
Commission (SEC), stated that he believes “the vast majority of [cryptocurrencies] are
securities” (Gensler, 2022). Gensler’s rationale for this belief is that cryptocurrency
investors are expecting to earn a profit making cryptocurrencies investment contracts
under the U.S. Supreme Court’s 1946 Howey Test (Gensler, 2022; Henning, 2018).
24

Gensler’s predecessor, former SEC Chairman Jay Clayton, told journalists from CNBC
that “cryptocurrencies are replacements for sovereign currencies, replace the dollar, the
euro, the yen with bitcoin. That type of currency is not a security” (Rooney, 2019).
Researchers, like SEC chairmen, are unclear if cryptocurrencies function as securities.
Bitcoin, for instance, appears to not act safe-haven for the S&P 500 (Conlon & McGee,
2020). However, cryptocurrencies issued via initial coin offerings (ICO), the act of raising
money by issuing cryptocurrency tokens, appear to behave similarly to public equity
offered by initial public offerings (IPOs) (Lyandres, Palazzo, & Rabetti, 2019). This
implies that that ICO tokens do behave like securities. Further analysis is needed to
understand the behavior pattern of cryptocurrencies relative to securities.
2.3.3 Cryptocurrencies as Commodities
If not securities or currencies, then perhaps cryptocurrencies can be seen as
commodities. The U.S. Commodity Futures Trading Commission (CFTC) states that
cryptocurrencies, like Bitcoin, meet the definition of a commodity under the Commodity
Exchange Act (U.S. Commodity Futures Trading Commission, 2020). However, like
securities and currencies, research is not clear on the performance of cryptocurrencies as
commodities. Klein et al. (2018) found that Bitcoin does not serve as a safe-haven
investment, the prominent feature of gold, and therefore does not consider Bitcoin to be a
commodity (often referred to as the “new gold”). Other studies show that
cryptocurrencies like Bitcoin and Ethereum serve as a functional hedge and safe-haven
for individual commodities (Naeem, Farid, Balli, & Hussain Shahzad, 2021; Okorie &
Lin, 2020). Significant discrepancies exist in the literature as to whether cryptocurrencies
behave, and should be considered, commodities.
25

2.3.4 Other Economic Influences on Cryptocurrency Prices
Some studies suggest that the only statistically significant indicator of cryptocurrency
performance is the spread between daily high and low prices (Baek & Elbeck, 2015). In
other words, cryptocurrency prices cannot be reliably predicted using economic
modelling for traditional assets. This suggests that cryptocurrencies may be an entirely
new asset class.
2.4 Predicting Bitcoin Price Volatility Using Blockchain Performance Variables
Study 2 looks at the predictive properties of certain internal blockchain
performance variables on Bitcoin price volatility given that the technology that underpins
cryptocurrency performance continues to evolve.
2.4.1 Overview of Blockchain
Blockchain technology originated as the ledger system supporting the
cryptocurrency Bitcoin (Nakamoto, 2008a). A distributed ledger can be thought of as a
database that is shared and synchronized real-time across multiple nodes (Nofer et al.,
2017). Unlike a cloud-based database where multiple users can view and edit one master
database stored in a centralized location, a distributed ledger must have the support from
most nodes before a modification to the ledger can be made (Sankar et al., 2017).
Each block of transactions on a distributed ledger has a unique identifier, known as a
hash. Hash values are mathematical calculations based on the data in the block itself, so if
the data in the block changes, the hash will also change (Di Pierro, 2017). In a
blockchain, the hash for one block is used to create the hash for the next block. This
means that if the data in one block changes, it will change the hash of that block as well
26
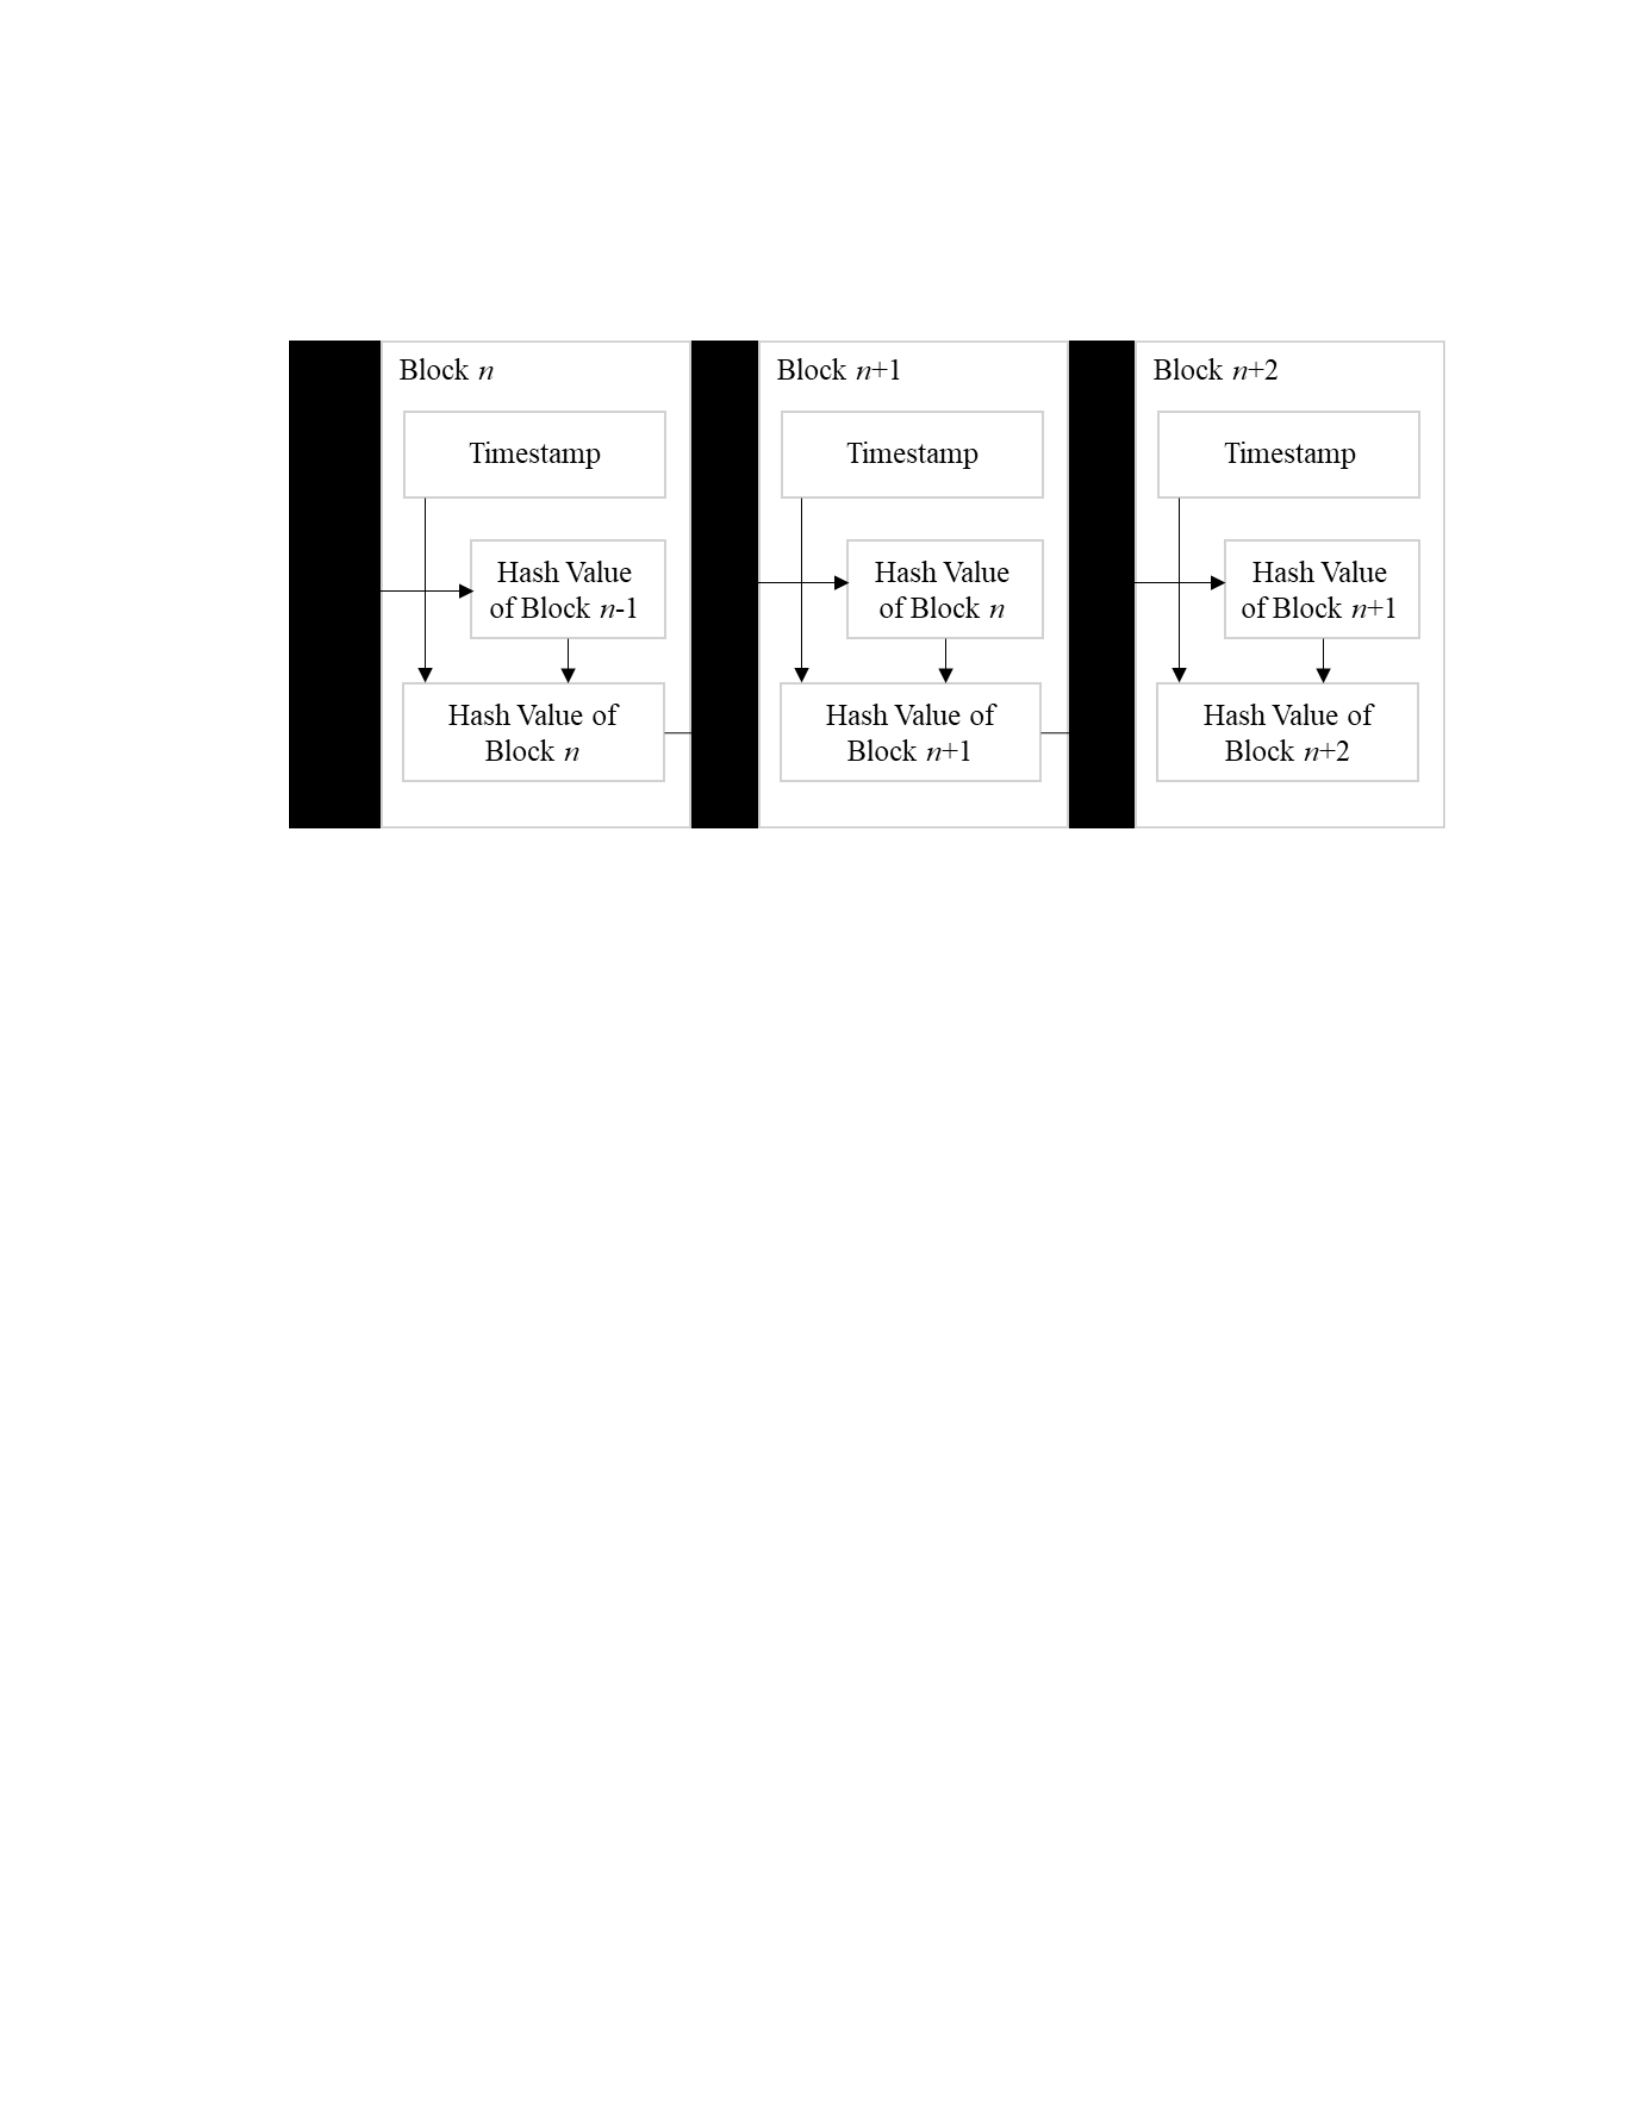
as the hashes of every other block in the ledger (Di Pierro, 2017). The collection of
interconnected blocks is why this technology is called “blockchain” (Figure 1).
Figure 1. Graphical Depiction of Blockchain Technology
Since a copy of the distributed ledger, or blockchain, is maintained on each node
in the network, the need for a central authority is eliminated (Pelt, Jansen, Baars, &
Overbeek, 2021). The decentralized nature of a blockchain also makes it more resilient,
though not immune, to traditional cyber-attacks since each copy of the ledger would need
to be attacked simultaneously for the attack on the blockchain to be successful (Sayeed &
Marco-Gisbert, 2019). Because there is no single holder of the information stored on a
blockchain, as is the case with traditional databases, blockchains are tamper-resistant
while also serving as a distributed source of truth for all transactions (Li, Jiang, Chen,
Luo, & Wen, 2020).
2.4.2 Consensus Protocols
Consensus protocols ensure all nodes on a blockchain agree on which transactions are
legitimate and valid to add to the blockchain. Consensus algorithms establish the
protocol rules and ensure compliance with the rules to ensure that all transactions occur
27

in a trustless manner. Consensus protocols facilitate agreement, collaboration,
cooperation, equal rights for each node, and mandatory participation of each node in the
consensus process.
The technical origin of consensus protocols is the theory of “Byzantine fault
tolerance” which describes a situation in which a computer system, particularly
distributed computer systems, fail without clear information that the system has failed
(Castro & Liskov, 2002). In blockchain, the establishment of a Byzantine fault tolerance
allows trustless networks to function even when malicious nodes are present (Gramoli,
2020). Consensus protocols establish the Byzantine fault tolerance for blockchain-based
systems.
There are many different types of consensus protocols. The most popular protocol, and
the protocol used by many cryptocurrency blockchains including Bitcoin, is proof-of-
work (PoW). PoW consensus requires that a subset of nodes, called miners, calculate a
mathematical problem, called the “proof-of-work”, to determine who can validate
transactions on the blockchain and receive the block reward (Gervais et al., 2016). In
recent years, proof-of-work consensus has come under scrutiny due to the heavy
consumption of computing power, energy, and other limited resources (Xue et al.,
2018).
Proof-of-stake (PoS) is another way to validate transactions and achieve
distributed consensus. Unlike the PoW, PoS chooses the creator of a new block based on
the wealth, or stake, of the verification node. PoS blockchains do not provide a block
reward. Instead, the nodes performing validation, called forgers, charge fees for each
transaction on the blockchain. These fees, also called “gas prices”, fluctuate with demand.
28

In delegated proof-of-stake (DPoS), nodes on the blockchain vote for witnesses to secure
the network. The vote strength of a particular node is determined by the size of their
stake. Nodes with a larger stake will influence the network more than nodes with a lesser
stake. Version 2.0 of the Ethereum blockchain, deployed in September 2022, uses a
PoS consensus protocol (Ethereum, 2022).
Other consensus protocols include proof-of-elapsed time (PoET) (Castro &
Liskov, 1999), proof-of-benefit (Liu, Liu, Jiang, Zhao, & Wang, 2018), proof-of-learning
(Bravo-Marquez, Reeves, & Ugarte, 2019), and proof-of-accuracy (Kudin, Kovalenko, &
Shvidchenko, 2019). While these consensus protocols are being researched for their
applicability to cryptocurrencies, they are not widely used at this time (Oyinloye, Teh,
Jamil, & Alawida, 2021).
2.4.3 Mining
Blockchain maintenance, commonly referred to as mining on proof-of-work
blockchains, involves the recording and verifying transactions. To verify transactions,
miners must solve a complex hashing problem. The first miner to find a solution is
rewarded by receiving newly minted crypto coins from that specific blockchain (Lo &
Medda, 2019). There are two types of mining: solo mining and pool mining. In solo
mining, each miner uses their personal hardware and registers themselves as a miner.
The first miner to find the solution informs the other miners that the solution has been
found. In solo mining, the rewards are not shared (Qin, Yuan, & Wang, 2018). By
contrast, in pool mining, individuals do not have enough computing power to mine
resources on their own. Instead, the miners combine resources to mine the blockchain
faster. Pool mining allows for economies of scale since the cost of mining is lower for all
29
miners. Although the mining rewards are shared in pool mining, there is greater
opportunity for higher mining income (Salimitari, Chatterjee, Yuksel, & Pasiliao, 2017).
2.4.4 Bitcoin Price Volatility and the Impact of Blockchain Performance
While some scholars, such as (Buchholz, Delaney, Warren, & Parker, 2012), find
that changes in Bitcoin price (as price of any currency) is directly impacted by supply
and demand, there is a growing body of research that suggests the price volatility of
Bitcoin cannot be explained using traditional economic and financial theories, such as
future purchasing power parity, uncovered interest rate parity, or cash-flow models,
because supply and demand fundamentals do not apply to Bitcoin markets. (Ciaian,
Rajcaniova, & Kancs, 2016; Gordon, 1962; Kristoufek, 2013; Krugman & Obstfeld,
2009; Levi, 2005).
The literature (Table 1) shows conflicting results on the effect of blockchain variables
on Bitcoin price.
Table 1. Review of the Literature on Blockchain Variables and Bitcoin Price
30
Authors Models Variables Considered Results
Chen
(2023)
Random forest,
LSTM
47 variables including
Bitcoin price, total fees, hash
rate, 10-year Treasury Yield
Bitcoin price
after October
2018 has become
less predictable;
U.S. stock
market index, the
price of oil, ETH
price, and the
difficulty of
finding blocks of
Bitcoin impact
price.
Ji, Kim,
and Im
(2019)
DNNs, LTSM,
CNNs,
ResNets, and
ensemble
models
Bitstamp Bitcoin market
(USD) time series data, 29
variables on bitcoin
blockchain including hash
rate, average block size,
and
Predictability of
all deep learning
models studied in
this work was
comparable.

number of transactions per
block
Aalborg,
Molnár,
and de
Vries
(2019)
Predictive
regression
Return, volatility, trading
volume, transaction volume,
change in the number of
unique Bitcoin addresses, the
VIX index and Google
searches for “Bitcoin”
Considered
variables cannot
predict Bitcoin
returns.
Guizani
and Nafti
(2019)
Auto
Regressive
Distributed
Lag ARDL
model,
cointegration
test (Pesaran,
Shin, & Smith,
2001),
Granger
causation test
as defined by
Toda and
Yamamoto
(1995)
Number of addresses,
attractiveness indicator,
mining difficulty, transaction
volume, stock prices,
EUR/USD exchange rate,
macroeconomic
development
Number of
addresses,
attractiveness
indicator, and
mining difficulty
have
significant
impact on BTC
price.
McNally,
Roche,
and Caton
(2018)
RNN, LSTM,
ARIMA
Bitcoin price index (BPI),
the closing price, the
opening price, daily high
and daily low are also
included as well as
blockchain data such as the
mining difficulty and hash
rate
RNN and LSTM
are effective for
Bitcoin
prediction.
Estrada
(2017)
Granger
causation test
as defined by
Toda and
Yamamoto
(1995)
Bitcoin price and the S&P
500, Bitcoin price and the
VIX, Bitcoin
realized volatility and the
S&P 500, and Bitcoin
realized volatility and the
VIX
No statistically
significant
Granger
causality when
analyzing the
time series of
BTC and the
S&P 500 and
BTC and the
VIX.
31

Ciaian et al.
(2016)
Augmented
Dickey-Fuller
test, the Phillips-
Perron test,
Granger
causation test,
vector error
correction
model
Bitcoin price, total number
of Bitcoins in circulation,
total unique Bitcoin
transactions per day, number
of unique Bitcoin addresses
used per day, Bitcoin days
destroyed for any
transaction, exchange rate
between U.S. dollar and
Euro, oil price, and Dow
Jones stock market index
Supply demand
fundamentals
have a strong
impact on
Bitcoin price.
The Dow Jones
Index, exchange
rate and oil
price
do not
significantly
affect Bitcoin
price.
Kristoufek
(2015)
Wavelet
analysis,
specifically
wavelet
coherence
Bitcoin price index (BPI),
total Bitcoin in circulation,
number of transactions,
estimated output volume,
trade volume vs. transaction
volume ratio, hash rate,
difficulty, exchanges, search
engine trends, Financial
Stress Index (FSI), gold
price,
Usage in trade,
money supply
and price level
play a role in
Bitcoin price
over the long
term.
Van Wijk
(2013)
Ordinary Least
Squares
regression,
vector error
correction
model
Closing value of the
exchange rate of Bitcoin,
closing value of the Dow
Jones Index, closing value of
the FTSE 100 Index, closing
value of the Nikkei 225
Index, exchange rates
between the U.S. dollar and
the Euro and the Yen, Brent
oil price, West Texas
Intermediate (WTI) oil price,
UBS Bloomberg
Constant Maturity
Commodity Index (CMCI)
of Oil
The Dow Jones
index, the
eurodollar
exchange rate,
and oil price
significantly
impact Bitcoin
prices.
Buchholz
et al.
(2012)
Augmented
Dickey Fuller
Tests, Breusch-
Godfrey test,
Supply of Bitcoin in
existence, total number of
Bitcoin transactions per day,
total value of Bitcoin
Volatility
significantly
effects price,
significantly
32
Engle-Granger transactions, price of Bitcoin less volatility
from
2.4.5 Blockchain Performance Variables – Not Previously Studied
Study 2 includes some additional blockchain performance variables related to
Bitcoin that have not received attention in the academic literature.
Average Block Size – The size of a block on a blockchain represents the amount of
data that the block can store. A year after Satoshi Nakamoto mined the first
Bitcoin genesis block, he modified the protocol to limit the size of these blocks to
1 MB (which can store 200-500 transactions). This decision was controversial
because, within certain limits, larger blocks enable higher transaction-per-second
rates. By 2017, a variety of protocol changes enabled much larger blocks on
Bitcoin’s blockchain.
Hash Rate – Hash rates reflect the amount of computing power on a network and
are computed by the number of transactions that can be performed on a network
per second. Relative to cryptocurrency mining, higher hash rates typically mean
that there are more miners on that network. They are also a measure of both the
health and security of a cryptocurrency network.
Consensus Difficulty – As previously described, Bitcoin uses a Proof-of-Work
(PoW) consensus protocol (decentralized and fault-tolerant) to validate
transactions on its network. PoW has shown to be relatively resilient and secure,
however it requires significant computing power and can be slow when networks
are busy. Consensus difficulty is a relative measure of how difficult it is to mine
33
test, vector
error
correction
model, ARCH
and GARCH
models
in U.S. dollars, average
transaction value, Google
searches, daily mentions
of
“bitcoin” on Twitter, daily
mentions of “Bitcoin” on
RSS-News feed.
negative shocks
compared to
positive shocks,
volatility
significantly
effects demand

a new block based on how much hashing power has been deployed on the
network.
(Mingxiao, Xiaofeng, Zhe, Xiangwei, & Qijun, 2017).
Transactions Per Block – A new Bitcoin block is generated every 10 minutes or
so. These blocks contain a record of every transaction and all those that occurred
before them (often between 200-500 transactions in each block). This variable
measures the average number of transactions per block in the last 24 hours.
Mempool Size – The number of transactions waiting to be confirmed by miners.
It is also a reflection of congestion on a network: the higher the mempool size, the
longer the transactions time might be.
Total Transaction Fees (USD) – This measure represents the total USD value of all
transaction fees paid to miners in a 24-hour period.
Miners’ Revenue (USD) – The dollar amount includes the transaction fees paid to
miners and the value of the Bitcoin blocks received as a reward for processing the
transaction confirmations.
Cost Per Transaction – This is calculated by the miners’ revenue divided by the number
of transactions.
Median Confirmation Time – This is the median time for a transaction with miner
fees to be included in a mined block and added to the public ledger.
2.5 Other Potential Influences on Cryptocurrencies
While the studies in this paper examine several predictor variables (asset classes,
economic indicators, and blockchain performance variables), the number of potential
predictor variables (even within the broad categories of variables selected for this
34

paper) are limitless. Forking is one of the variables not specifically considered in this
paper but is worthy of discussion and represents an opportunity for future research.
When blocks on a blockchain are mined at conflicting times, or when a consensus
cannot be reached, the blockchain splits in a process known as “forking” (da Silva et
al., 2019). Forking causes inconsistencies on the blockchain network. When a fork
happens and transactions are mined on both ‘sides’ of the forked blockchain, those
transactions on the side that is ultimately not accepted must be mined again. Studies
show that forking can impact of the performance of a blockchain (da Silva et al., 2019).
If we assume that blockchain performance is a critical component to cryptocurrency
prices, then it is reasonable to expect that activities that reduce blockchain performance
may reduce the value of cryptocurrencies as well.
35

CHAPTER III
III. METHODOLOGY
3.1 Introduction
Data science harnesses the power of big data, characterized by its volume, variety,
and velocity, to advance the analytics about cryptocurrency behavior (Delen, 2021). This
approach helps to answer descriptive questions such as “what happened”, “why is it
happening”, and “how often does it happen” and predictive questions such as “what else
is most likely to happen” and “how else will it happen” (Delen, 2021).
3.2 Approach
The studies in this paper follow the Cross-Industry Standard Process for Data Mining
(CRISP-DM) process to examine over 500,000 data points (Delen, 2021; Shearer,
2000). CRISP-DM provides a 6-step approach to data mining:
1) Business Understanding – In this step, an understanding of the business
circumstances and related problem(s) is developed. Chapter II outlines both
the historical and current state of cryptocurrency markets and suggests several
questions for which data mining might be applicable.
36

2) Data Understanding – The available data (all of which is public for this study)
is matched to the business problem. This chapter outlines the study’s data
sources and their applicability to the research questions. Research studies in
this space tend to employ one of two different strategies depending on the
types of data they evaluate. Structured data, or that which is numerical or
categorical, is best analyzed through derivations of regressions and neural
networks. Unstructured data such as text, images, and video is better served by
approaches that use natural language processing methodologies like sentiment
analysis (Delen, 2021), and there are some interesting recent studies of
cryptocurrency behavior that have used this approach (Karalevicius,
Degrande, & De Weerdt, 2018; McMillan, Myers, Nguyen, Robinson, &
Kennard, 2022; Polasik, Piotrowska, Wisniewski, Kotkowski, & Lightfoot,
2015). Given that all the variables to be evaluated in this study are numerical,
only structured data analytics techniques were used.
3) Data Preparation – Prior to mining, raw data was prepared (preprocessed) to
improve its quality and avoid the potential for errors due to inconsistencies,
erroneous values, or other GIGO (garbage-in/garbage-out) problems. See
Figure 2 below.
4) Model Building – In this step, various models were developed that best suit
the data and the research questions posed in this study. Studies 1a and 1b
(questions 1a, 1b, 2a, and 2b) seek to understand whether the price volatility
of cryptocurrencies aligns with that of certain asset classes or economic
indicators. Study 2 (questions 3a and 3b) looks to see if Bitcoin’s price
37

volatility can be predicted by certain blockchain performance variables. For
all these questions, the predictive models described in the Testing and
Evaluation section below were used.
5) Testing and Evaluation – Once the models were built, this step evaluated the
findings for accuracy and assesses the findings’ applicability to the business
problem.
6) Deployment – In this final step, the findings are presented in such a way they
are accessible to a variety of end-users.
The open-source advanced analytics tool, KNIME Analytics Platform 4.7.2, was
used for data preparation, model development, testing, and evaluation. KNIME Analytics
Platform was selected because of its open and expandable architecture which combines
the functionality of several tools (including Excel, Power BI, and Python) into a single
workflow (Delen, 2021).
3.3 Data Set and Procedures
Publicly available data from a variety of sources (see Tables 2-6) over the ten
years spanning January 1, 2012, through June 1, 2022, was mined through a variety of
methodological approaches. Prior to mining, raw data was prepared (preprocessed) to
improve its quality and avoid the potential for errors due to inconsistencies, erroneous
values, or other GIGO (garbage-in/garbage-out) problems. Data preparation occurred in
38
multiple phases (
Figure 2): data consolidation, data cleaning, data transformation, and data reduction
(Delen, 2021).
39
Figure 2. Process for Data Preparation
3.4 Measures
Six types of variables were examined to inform the research questions posed in
the two studies: Cryptocurrency prices, security prices, commodity prices, fiat currency
prices, economic indicator values or prices, and blockchain performance variables. These
variables were chosen specifically because they are broad, global, well-understood, and
represent the most likely factors to predict cryptocurrency volatility. Further, these
variables, particularly securities and commodities, continue to be part of the ongoing
debate on cryptocurrency classification. The variables are quantitative, and specifically,
they are either date stamps, prices, or numerical values. They are available through
reliable public sources dating back to 2012 and with a granularity (frequency) that lends
itself to data science methodologies. In fact, this study examines over 500,000 data points
40
to explore its research questions. The Data Dictionary in Appendix II details all of the
variables and descriptions; however, they are summarized as follows:
3.4.1 Dependent Variables
Cryptocurrency Price. All the research questions posed in this study are focused
on the volatility of cryptocurrencies as measured by price. Studies 1a and 1b considered
six cryptocurrencies and three stablecoins, respectively (Table 2Table 2). Stablecoins are
a type of cryptocurrency that are designed to peg their values to other financial
instruments. For example, the values of Tether and Binance USD are supposed to be
pegged to the value of the U.S. dollar. Study 2 also looked at price volatility but only for
Bitcoin.
Prices for the cryptocurrency in these studies are all publicly available and were
downloaded from nasdaq.com. All of these cryptocurrencies and stablecoins were also
included as predictor variables. Additionally, Solona (SOL) which was excluded as a
dependent variable because of its limited history, was included as a predictor variable in
studies 1a and 1b.
Table 2. Cryptocurrencies Considered in the Studies
Bitcoin (BTC) $557b Traditional The world’s first cryptocurrency
and the largest cryptocurrency by
market capitalization. Capped total
coin issuance at 21 million coins.
Ethereum (ETH) $219b Traditional The second largest
cryptocurrency by market
capitalization and the platform
that allows for smart contracts.
Tether (USDT) $72b Stablecoin Tether is the largest stablecoin with
its value pegged to the U.S. dollar.
U.S. Dollar Coin $53b Stablecoin Second largest stablecoin, pegged to
41
Name Market Cap.
(as of 5/27/22)
Type Description
(USDC) the U.S. dollar. Reserve assets held
in regulated U.S. banks.
Binance Coin
(BNB)
$50b Traditional Cryptocurrency issued by crypto
trading platform Binance.
Originally created as a token to pay
for discounted trades.
Ripple (XRP) $19b Traditional Commonly used for cross-
border transactions and
exchanges into various types of
fiat currencies.
Binance USD
(BUSD)
$18b Stablecoin Like BNB, BUSD is the stablecoin
version of Binance’s
cryptocurrency offering. Regulated
by the NYDFS.
Cardano (ADA) $16b Traditional Created by the founder of Ethereum,
Cardano uses smart contracts to
enable identity management.
Dogecoin (DOGE) $10b Traditional Created from a fork in the Bitcoin
blockchain, Dogecoin has
unlimited issuance. Can be used for
payments facilitation.
3.4.2 Nominal Dependent Variable
Volatility is the nominal dependent variable, and it was created by calculating the daily
volatility, or the statistical measure of the dispersion of return, for Bitcoin. Daily
volatility was calculated using the Garman-Klass (GK) volatility measure (Garman &
Klass, 1980) as shown in Equation 1.
𝑍 1 𝐻 2𝐶
�
�
Equation 1. Garman-Klass (GK) Volatility Measure
While several studies of cryptocurrency rely on Generalized AutoRegressive Conditional
42
= √ 𝑛 ∑ 2 [(𝑙𝑜𝑔 𝑖
�
�
𝑖
)−(2 log
(2)− 1) (log 𝑖
𝑂
𝑖
)]

Heteroskedasticity (GARCH) to measure volatility, recent studies suggest that GK is
more efficient in measuring cryptocurrency volatility (Brauneis & Mestel, 2018; Tan,
Chan, & Ng, 2020). To create a nominal variable for volatility, the top 20% were
classified as “high volatility” while the remaining 80% were classified as “low
volatility”.
Using KNIME Analytics Platform, the two data sources were combined via the
Joiner node. The join was configured as an inner join with both the top and bottom input
being the identifier derived from dates. No columns were excluded at the join stage. Next,
the raw and imputed spread values were excluded from the dataset as the newly imputed
dependent variable was derived from the spread values and including them in the models
would be redundant. The spread values, BTC_Spread_OpenClose and
BTC_Spread_OpenClose_flat, were removed using the Column Filter node configured
for manual selection and enforced exclusion. In addition, the daily high, low, and adjusted
close were excluded to focus the model on the spread values.
3.4.3 Predictor Variables (Studies 1a and 1b)
The following predictor variables pertain to Study 1a and Study 1b:
Commodities. This study evaluates cryptocurrency volatility compared to ten commodity
variables (Table 3). Most of the mainstream cryptocurrencies, including
Bitcoin and Ethereum, are considered to be commodities by the Commodity Futures
Trading Commission (CFTC) (Miller, 2022). However, studies show that since the
shortrun price of commodities like gold and oil are uncertain, cryptocurrencies like
Bitcoin do not have a supply-side uncertainty (Gronwald, 2019). For this reason, there is
academic debate as to whether cryptocurrencies are truly commodities.
43
Name Definition Freq. of
Data
Data Source
Daily
The first two variables, gold spot price and gold mining production, were
selected for their popular comparison to cryptocurrencies. While studies have examined
the relationship between gold prices and cryptocurrency prices and found little predictive
or behavioral relationships, gold is still viewed by many as the most common
comparative physical asset for cryptocurrencies. Gold is also an effective hedge against
the consumer price index (CPI), and thus seen as an effective hedge against inflation
(Bampinas & Panagiotidis, 2015).
The next eight variables, which include variables relating to crude oil prices and
production as well as natural gas prices and production, were selected due to their
relevance in the energy markets. Cryptocurrency mining, the process by which new coins
are minted and transactions are approved to the blockchain, is essential to the functioning
of a cryptocurrency. However, mining is energy intensive. Some estimate that Bitcoin
mining, for example, consumes as much energy as the city of Houston (Tabuchi, 2022).
Given the importance of crude oil and natural gas to energy prices, it was important to
include those commodity variables in the study.
Table 3. Commodities Considered in Studies 1a and 1b
Gold spot Spot price of gold in U.S. dollars. World Gold Council –
price Gold spot price
Crude oil spot Crude Oil in Dollars per Barrel, Daily U.S. Energy Information price Products in
Dollars per Gallon. Administration
(Cushing, OK)
Crude oil spot Crude oil in U.S. dollars per barrel, Daily U.S. Energy Information price (Europe
products in U.S. dollars per gallon. Administration
Brent)
Crude oil
production
Crude oil production in barrels, by
country.
Monthly U.S. Energy Information
Administration
Natural gas U.S. price in dollars of natural gas Monthly U.S. Energy Information
44
spot price
(residential)
delivered to residential consumers;
U.S. dollars per thousand cubic
feet.
Administration
Natural gas
spot price
(industrial)
U.S. price in dollars of natural gas
delivered to industrial consumers;
U.S. dollars per thousand cubic
feet.
Monthly U.S. Energy Information
Administration
Natural gas
spot price
(commercial
)
U.S. price in dollars of natural gas
delivered to commercial
consumers; U.S. dollars
per thousand cubic feet.
Monthly U.S. Energy Information
Administration
Natural gas
imports
U.S. natural gas imports in millions of
cubic feet.
Monthly U.S. Energy Information
Administration
Natural gas
exports
U.S. natural gas exports in millions
of cubic feet.
Monthly U.S. Energy Information
Administration
Securities. This study evaluates cryptocurrency prices compared to three
measures of securities (Table 4). These three indices of the U.S. and Americas stock
market were selected for their size and relevance in capturing fluctuations in the
securities market. Like commodities, these variables continue to be part of the ongoing
debate on cryptocurrency classification. The Securities and Exchange Commission
(SEC), for example, recently launched an investigation into cryptocurrency trading
platform Coinbase over questions that some cryptocurrencies listed in their platform
were unregistered securities (Beyoud & Versprille, 2022)
Table 4. Securities Considered in Studies 1a and 1b
Name Definition Freq. of
Data
Data Source
S&P 500 daily
closing price
Open, high, low, and close price of
the S&P 500 in U.S. dollars.
Daily WSJ Markets
45
Name Definition Freq. of
Data
Data Source
Daily
NASDAQ
Composite
Index daily
close price
Open, high, low, and close price of
the NASDAQ in U.S. dollars.
Daily WSJ Markets –
NASDAQ Composite
Index
Dow Jones
Industrial
Average daily
close price
Open, high, low, and close price of
the Dow Jones Industrial Average in
U.S. dollars.
Daily WSJ M arkets – Dow
Jones Industrial Average
Fiat currencies. This study evaluates cryptocurrency prices compared to fiat
currency variables (Table 5). These five fiat currencies were selected as they are ranked
as the five largest fiat currencies by market capitalization by CoinMarketCap.com. For
each fiat currency, there are two variables. The first is the daily open, high, low, and
close price for each currency. The second is the currencies M1, a variable that is
calculated differently for each currency but is intended to capture the total amount of the
currency in circulation. Note that for some currencies, the full 10-year data set is not
available.
Table 5. Fiat Currencies Considered in Studies 1a and 1b
U.S. Dollar Open, high, low, and close price of WSJ Markets – Dollar
(USD) the U.S. dollar index in U.S. Index
dollars.
Chinese Yuan Open, high, low, and close price of Daily WSJ Markets – Chinese
(CNY) the Chinese Yuan index in U.S. Yuan
dollars.
Yen (JPY) Open, high, low, and close price of
the Japanese Yen in U.S. dollars.
Daily WSJ Markets – Japanese
Yen
Euro (EUR) Open, high, low, and close price of
the Euro in U.S. dollars.
Daily WSJ Markets – Euro
46
British Pound
(GBP)
Open, high, low, and close price of
the British Pound in U.S. dollars.
Daily WSJ Market – British
Pound
M1 for U.S.
Dollar
(circulating
supply)
M1 consists of (1) currency outside
the U.S. Treasury, Federal Reserve
Banks, and the vaults of depository
institutions; (2) demand deposits at
commercial banks less cash items
in the process of collection and
Federal Reserve float; and (3) other
checkable deposits (OCDs).
Monthly Federal Reserve Bank of
St. Louis
M1 for
Chinese Yuan
(circulating
supply)
M1 comprises currency in
circulation plus demand deposits in
national currency of resident
nonbank non-government sectors
with the PBC and banking
institutions.
Monthly Federal Reserve Bank of
St. Louis - China
M1 for
Japanese Yen
(circulating
supply)
M1 comprises notes and coins in
circulation outside banking
corporations and demand and
savings deposits of households,
nonfinancial corporations, local
governments, securities
companies, Tanshi companies, and
some other financial corporations
such as securities finance
companies with banking
corporations in national currency.
Monthly Federal Reserve Bank of
St. Louis - Japan
M1 for Euro
(circulating
supply)
M1 comprises currency in
circulation and overnight deposits.
Monthly Federal Reserve Bank of
St. Louis – Euro Area
M1 for British
Pound
(circulating
M1 comprises currency in
circulation and overnight deposits.
Monthly Federal Reserve Bank of
St. Louis – United
Kington
supply)
Other economic indicators. This study evaluates cryptocurrency prices
compared to three other economic variables (Table 6). These variables are important
47
indicators of economic performance although they are not assets specifically. These
variables, Treasury bill rate, Consumer Price Index, and U.S. unemployment rate, are
included in the study to capture economic volatility that may not be reflected in the other
asset classes.
Table 6. Other Economic Indicators Considered in Studies 1a and 1b
Name Definition Freq. of
Data
Data Source
Treasury Note 4-week, 13-week, 26- week and
52-week coupon and bank discount
rate in U.S. dollars.
Daily U.S. Department of the
Treasury
Consumer
Price Index
(urban
consumers)
All items less food and energy in
U.S. city average (often used as a
proxy for inflation).
Monthly U.S. Bureau of Labor
Statistics
U.S.
unemployment
rate
Rate of unemployment
(percentage) for adults over 16
years of age.
Monthly U.S. Bureau of Labor
Statistics
3.4.4 Predictor Variables (Study 2)
The following set of predictor variables pertain to Study 2:
Blockchain Performance Variables. Study 2 looks intrinsically at the
performance of the underlying blockchains for Bitcoin. The 15 variables included for
analysis in this study pertain to the performance and efficiency of the Bitcoin blockchain
(Table 7). Studies show that consensus algorithms play an important role in the efficiency
of blockchain transactions (Mingxiao et al., 2017). Other studies suggest that financial
transactions, and thus, value is increased when blockchains perform more efficiently
(Cocco, Pinna, & Marchesi, 2017). This study assesses the effect of these variables on
Bitcoin price volatility to better understand the role of blockchain mechanics on
48
Bitcoin price volatility. These data are all publicly available and were downloaded
from blockchain.com.
Table 7. Blockchain Performance Variables Considered in Study 2
Name Definition Freq. of
Data
Average block size The average block size in MB. Daily
Hash rate The estimated number of tera hashes per second
(trillions of hashes per second).
Daily
Consensus difficulty A relative measure of how difficult it is to find a new
block. The difficulty is adjusted periodically as a
function of how much hashing power has been
deployed on the network.
Daily
Confirmed transactions
per day
The number of transactions processed each day. Daily
Transactions per block The number of transactions included in each block. Daily
Trade volume The total USD value of trading volume on major
bitcoin exchanges.
Daily
Mempool size The number of transactions waiting to be confirmed. Daily
Estimated transaction
volume
The total estimated value in USD of transactions on the
blockchain.
Daily
Total transaction fees
(USD)
The total USD value of all transaction fees paid to
miners.
Daily
Fees per transaction
(USD)
Average transaction fees in USD per transaction. Daily
Miners’ revenue (USD) Total value in USD of Coinbase block rewards and
transaction fees paid to miners.
Daily
Cost per transaction Miners’ revenue divided by the number of transactions. Daily
Median confirmation
time The median time for a transaction with miner fees to be
included in a mined block and added to the public ledger.
Daily
Market capitalization The total U.S. dollar market capitalization of a Daily
49
particular asset
Market price The average USD market price across major bitcoin Daily
exchanges.
3.4.5 Data Set Preparation
In accordance with the procedures outlined above in Section 3.3, data sets were
prepared for model development. For all three studies, a unique identifier derived from
record date is utilized as the primary key. For this study’s dependent variables (i.e.,
cryptocurrency price), the publicly available data includes prices for every single day of
the 10-years under evaluation. For some of the predictor variables, however, daily price
(or unit) data is not always available. For example, for the variables reflecting market data
(e.g., gold spot price) prices are available for every weekday, but not for Saturdays and
Sundays. In these cases, KNIME Analytics Platform estimated the values for the weekend
days using linear interpolation. For some of the predictors (e.g., natural gas imports),
relevant units are only available monthly. In those cases, the monthly value is used as a
proxy for every day within that month. In aggregate, Study 1a includes 3,805 records
(representing days) with 67 variables in each record for a total of 254,935 data points,
although some cryptocurrencies do not have the full 3,805 days of data due to their more
recent launch. Study 1b includes 3,805 records (representing days) with 64 variables in
each record for a total of 243,520 data points. Study 2 includes the same 3,805 records
(representing days) with 13 unique variables for a total of 49,465 data points.
As with Studies 1a and 1b, the numeric value for date is also utilized as the
primary key in Study 2. The input data is derived from two CSV files. The first is an
50

aggregation of the bitcoin blockchain performance data which includes average block
size, cost per transaction, estimated transaction volume, fees per transaction, hash rate,
median confirmation time, mempool size, miner revenue, network difficulty, number of
transactions, number of transactions per block, and trade volume. The second is an
aggregated set of data that includes daily open, high, low, close, adjusted close, volume,
and spread for each of the ten cryptocurrencies.
3.5 Testing and Evaluation
Various models were developed and tested that best suit the data and the research questions
posed in this study.
3.5.1 Prediction Models
Studies 1a and 1b look to see if cryptocurrency price volatility can be predicted
by blockchain performance variables. For this question, the following prediction models
were developed:
Decision Trees – This model evaluates the training data by recursively dividing
the data into several, cascading subsets based on a binary classification. Each classified
subset is assessed for its prediction accuracy. This division continues until the model is
dominated by one classification. The Gini Index is the most common method of assessing
the goodness of the split (Delen, 2021).
Ensembles Models – With this modeling approach, multiple analytics models are
combined into a single outcome to produce better predictions. According to Delen (2021,
p. 190), “rather than build models and then select the single best model, the ensemble
approach build many models (Figure 3) and uses them all for the task they are intended to
perform.”
51
Figure 3. Simple Taxonomy for Ensemble Models
•Random Forest – This model expands the prediction accuracy of
decision tree models by aggregating the results of several decision tree
models and creating a bootstrapping ensemble, also known as ‘bagging’.
The resulting bootstrapping ensemble is created by taking a random
subset of the input variables. As a result, random forest models do not use
all the available training data (on average, only 37% of training data is
used in bagging) (Abbott, 2014; Delen, 2021, p. 233). The results of
random forest models tend to outperform the results of standard decision
tree models since the prediction outcomes are determined from averages,
thus smoothing variations in the input data.
•Gradient Boosted Trees – This approach iteratively improves prediction
models by “boosting” records that were incorrectly classified in prior
iterations. In other words, the feedback from incorrectly predicted records
determines which records to boost in subsequent iterations to improve
52

prediction accuracy. Conceptually, Gradient Boosted Trees are a type of
neural network which is analogous to networks in the human brain that
can learn from past experiences. Neural networks learn from data without
rigid assumptions, and therefore, can be used to generalize (Delen, 2021).
•Multi-Layer Perceptron (MLP) – A multi-layer perceptron neural
network is known as “deep feedforward networks”. MLP networks can
process very large data sets in which multiple layers can be examined to
identify sophisticated patterns that might otherwise not be seen. In these
deep networks, no feedback connections are allowed.
•Naïve Bayes – This model employs a simple method of probability-based
classification. The model assumes that the input variables are not
independent, meaning that the presence or absence of the variables have
no impact on the presence or absence of the other variables (Delen, 2021).
Study 2 looked to see if Bitcoin price volatility can be predicted by blockchain
performance variables. For this question, the Naïve Bayes model was replaced with the
model below:
Logistic Regression – This is a data analysis technique that employes correlation
analysis used to identify relationships between two or more variables.
3.5.3 Prediction Accuracy
The performance of each model was assessed by the following metrics:
Accuracy – This reflects the ratio of True Positive (TP) and True Negatives (TN)
instances over the total number of instances which is represented by TP + TN + False
Positives (FP) + False Negatives (FN).
53
𝑇𝑃 + 𝑇𝑁
𝐴𝑐𝑐𝑢𝑟𝑎𝑐𝑦 =
𝑇𝑃 + 𝑇𝑁 + 𝐹𝑃 + 𝐹𝑁
Equation 2. Accuracy
Sensitivity (or True Positive Rate, TPR) – This is the ratio of TP over the total positives (which
includes TP and FN).
𝑇𝑃
𝑆𝑒𝑛𝑠𝑖𝑡𝑖𝑣𝑖𝑡𝑦 =
𝑇𝑃 + 𝐹𝑁
Equation 3. Sensitivity
Specificity (or True Negative Rate, TNR) – This is the ratio of TN over the total
negatives (which includes TN and FP). The False Positive Rate (FPR) is calculated as 1 –
Specificity.
𝑇𝑁
𝑆𝑝𝑒𝑐𝑖𝑓𝑖𝑐𝑖𝑡𝑦 =
𝑇𝑁 + 𝐹𝑃
Equation 4. Specificity
𝑇𝑁
𝐹𝑎𝑙𝑠𝑒 𝑃𝑜𝑠𝑖𝑡𝑖𝑣𝑒 𝑅𝑎𝑡𝑒 = 1 −
𝑇𝑁 + 𝐹𝑃
Equation 5. False Positive Rate
For all the models developed in this study, various methods were used to assess the
accuracy of the prediction findings (Delen, 2021):
54

Simple Split – This method randomly divides the data into at least two groups
including a training set and a validation set. The training data set is used to build the
algorithm that is later used to test the model’s prediction accuracy on the validation set.
k-Fold Cross-Validation – Given that the two (or more) data sets used in a Simple Spit
are rarely identical, k-Fold Cross-Validation attempts to minimize bias associated with
these differences. To do this, k-Fold Cross-Validation uses rotation estimation
methodology in which 1) the entire data set is divided into k subsets (or number of folds)
that are equal in size and mutually exclusive, 2) the model runs its training algorithm k
times, and 3) the prediction accuracy of the model is calculated by averaging the
individual prediction accuracies of the k models. k (or the number of folds) can be set to
any number, but the most used number is 10.
Area Under the Receiver Operating Characters (ROC) Curve (AUC) – This is
a graphical representation of prediction accuracy in which the TPR is plotted on the yaxis
and the FPR is plotted on the x-axis. This metric does reflect the prediction accuracy of an
individual model. Instead, it ranks how well each model performs. Models with higher
AUC values are likely to have higher accuracy values.
CHAPTER IV
55

IV. RESULTS
4.1 Introduction
To answer the research questions posed in the three studies, 50 models which
included the nominal dependent variable (i.e., volatility), the dependent variables (i.e.,
prices for nine cryptocurrencies), and the predictor variables were developed. In every
model, one or more of the predictor variables predicted volatility accuracy at a 90%
or greater accuracy rate by at least one type of machine learning model. Given that
90% accuracy represents a well-known standard for efficacious model prediction
(Delen, 2021), the results of these analyses are relevant and will inform our
understanding of cryptocurrency behavior.
The detailed models are presented in Appendix III; however, the sections below
present the ten summary models that illustrate the studies’ results and suggest findings
that will be explored in Chapter 5.
4.2 Study 1a – Predicting Cryptocurrency Price Volatility from Economic Variables
Study 1a asked the following questions:
Question 1a: How effective are advanced machine learning models in
predicting cryptocurrency price volatility?
Question 1b: Which variables are most significant in cryptocurrency
56

price volatility?
To answer these questions, the first models seek to understand whether the
economic predictor variables could accurately predict the volatility of cryptocurrency
prices. Figure 4 depicts the volatility of the six traditional cryptocurrencies since 2018.
(For reference, ADA = Cardano, BNB = Binance, BTC = Bitcoin, DOGE = Dogecoin,
ETH = Ethereum or Ether, and XRP = Ripple.) Given that Dogecoin (DOGE) clearly
represents outsized volatility in comparison to the other five cryptocurrencies, Figure 5
presents the same volatility trends but with DOGE removed to better visualize overall
volatility.
Greater volatility corresponds to specific time periods that appear consistent with
what is generally known about cryptocurrencies. For example, in the years prior to 2022,
the volatility of certain cryptocurrencies corresponds to the timeframe in which they were
launched. In 2022, the “crypto winter” impacted all cryptocurrencies, although Ripple
(XRP) and Binance (BNB) experienced the largest volatility.
57
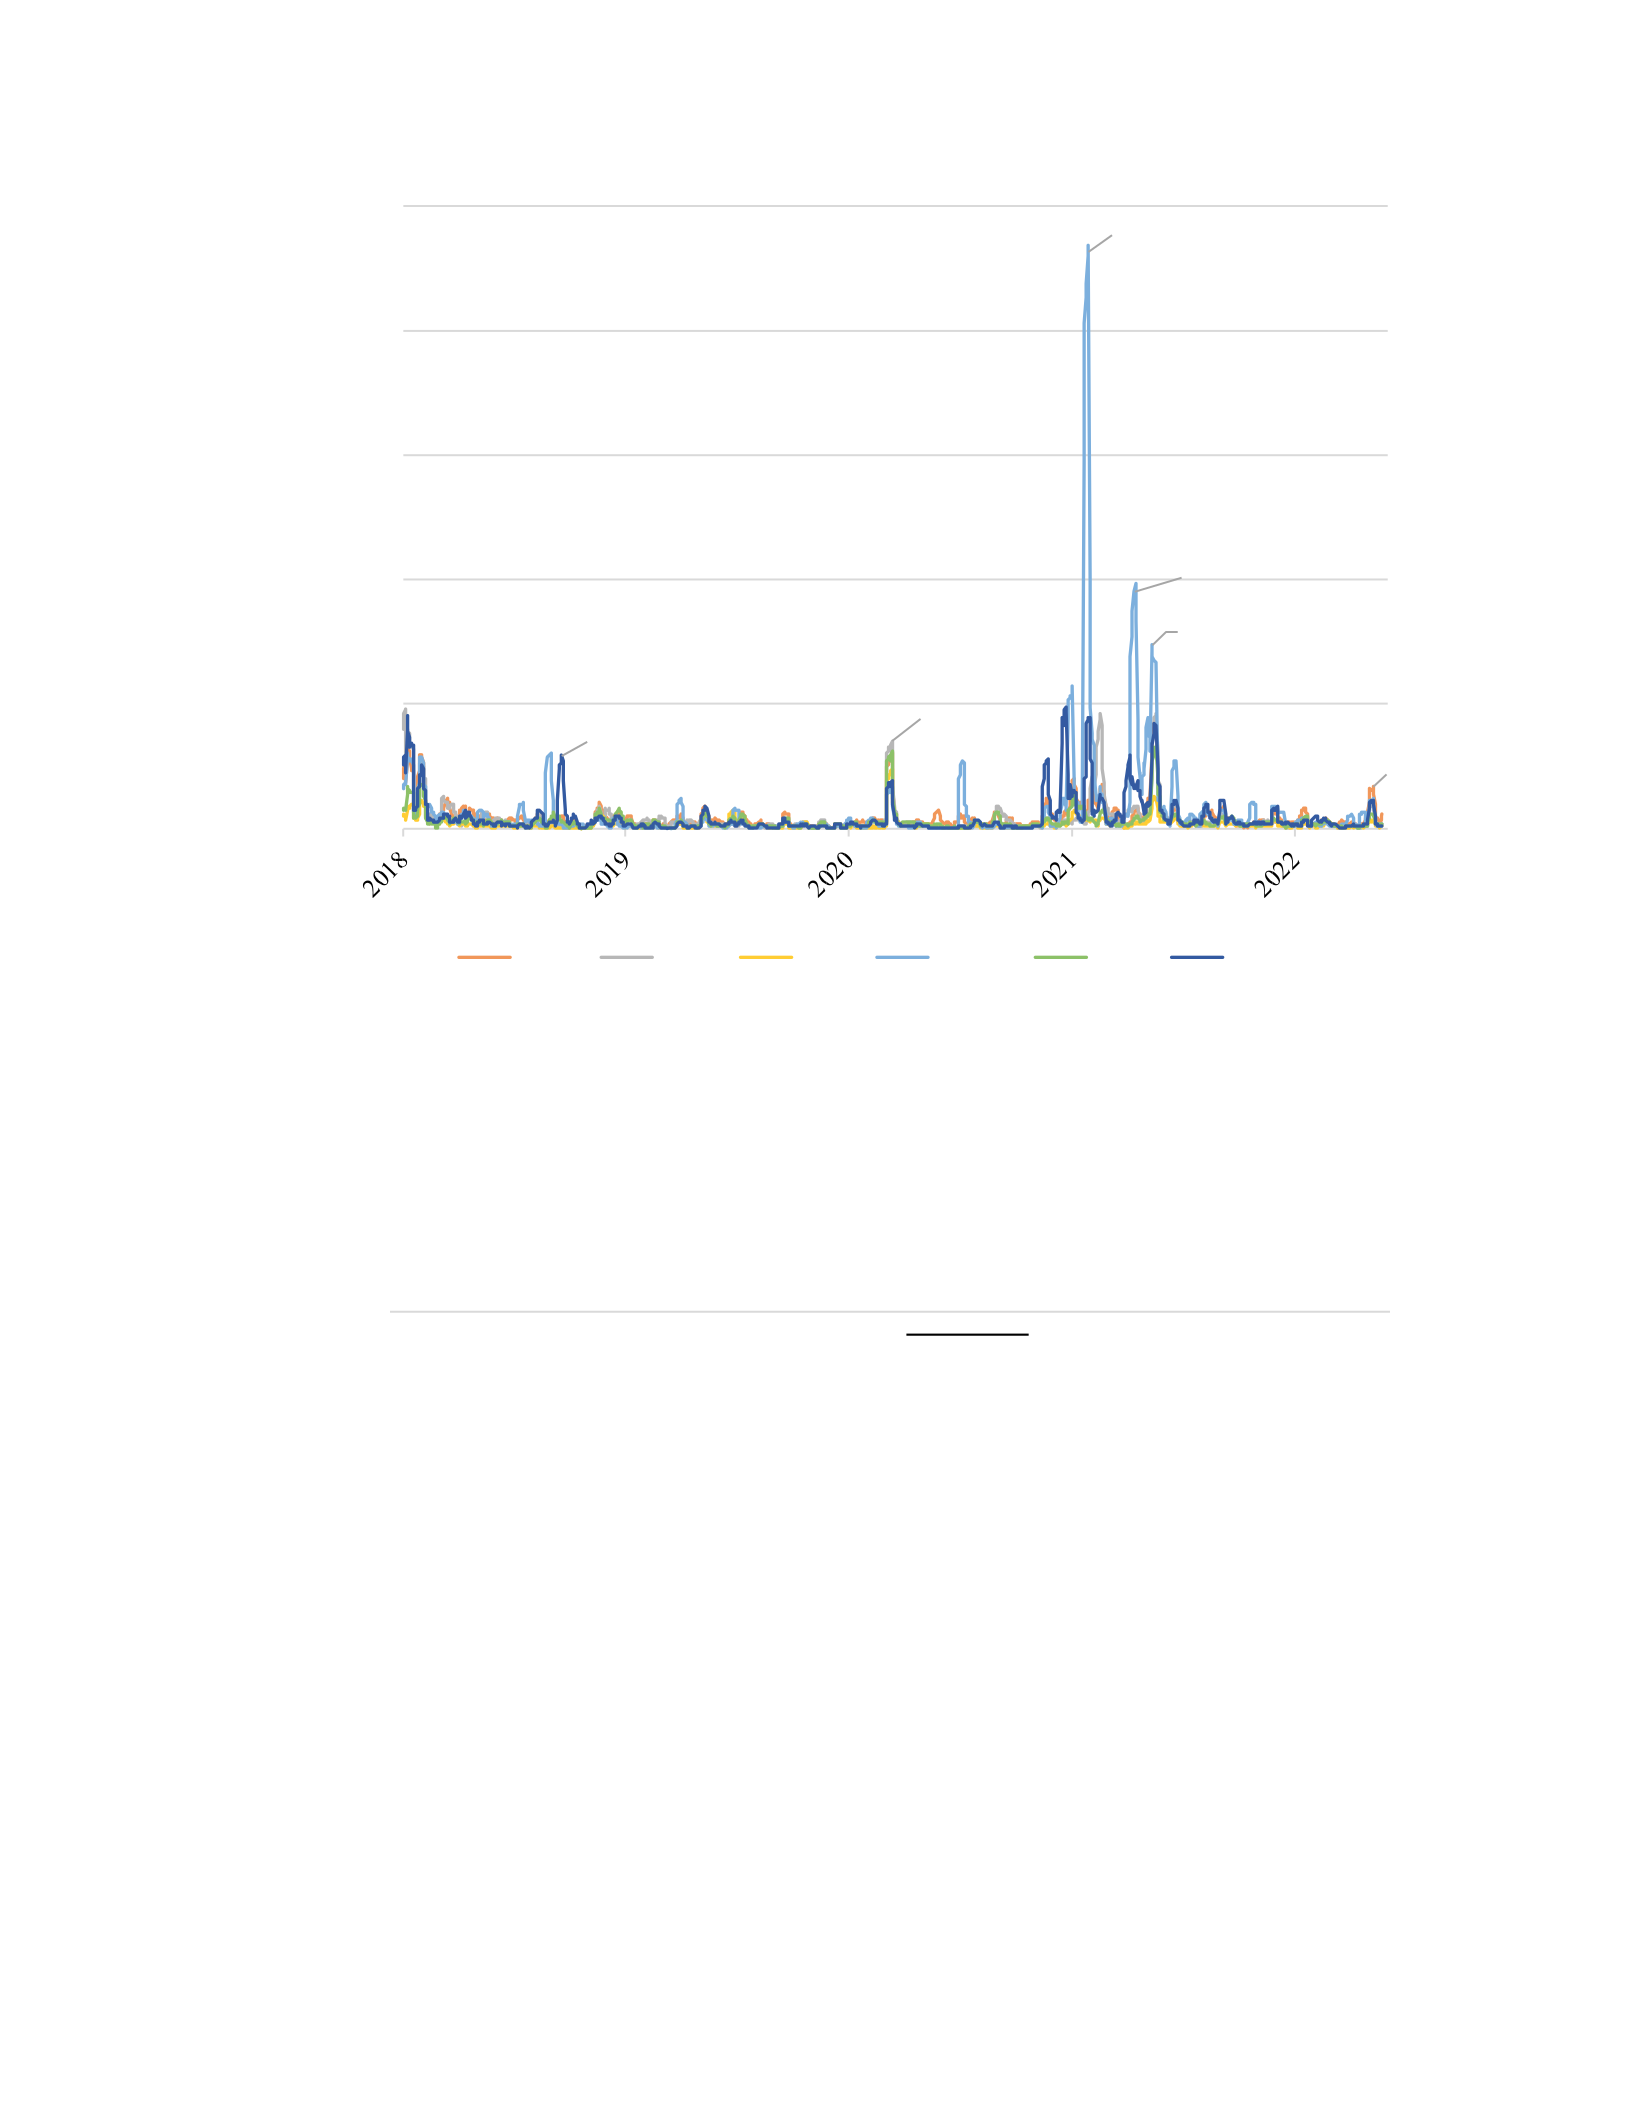
Figure 4. GK Volatility of Cryptocurrencies (all)
600%
58
169.50%
%353.87
2315.98%
%952.15
%737.63
292.31%
0%
500%
%1000
1500%
%2000
%2500
ADA BNB BTC DOGE ETH XRP
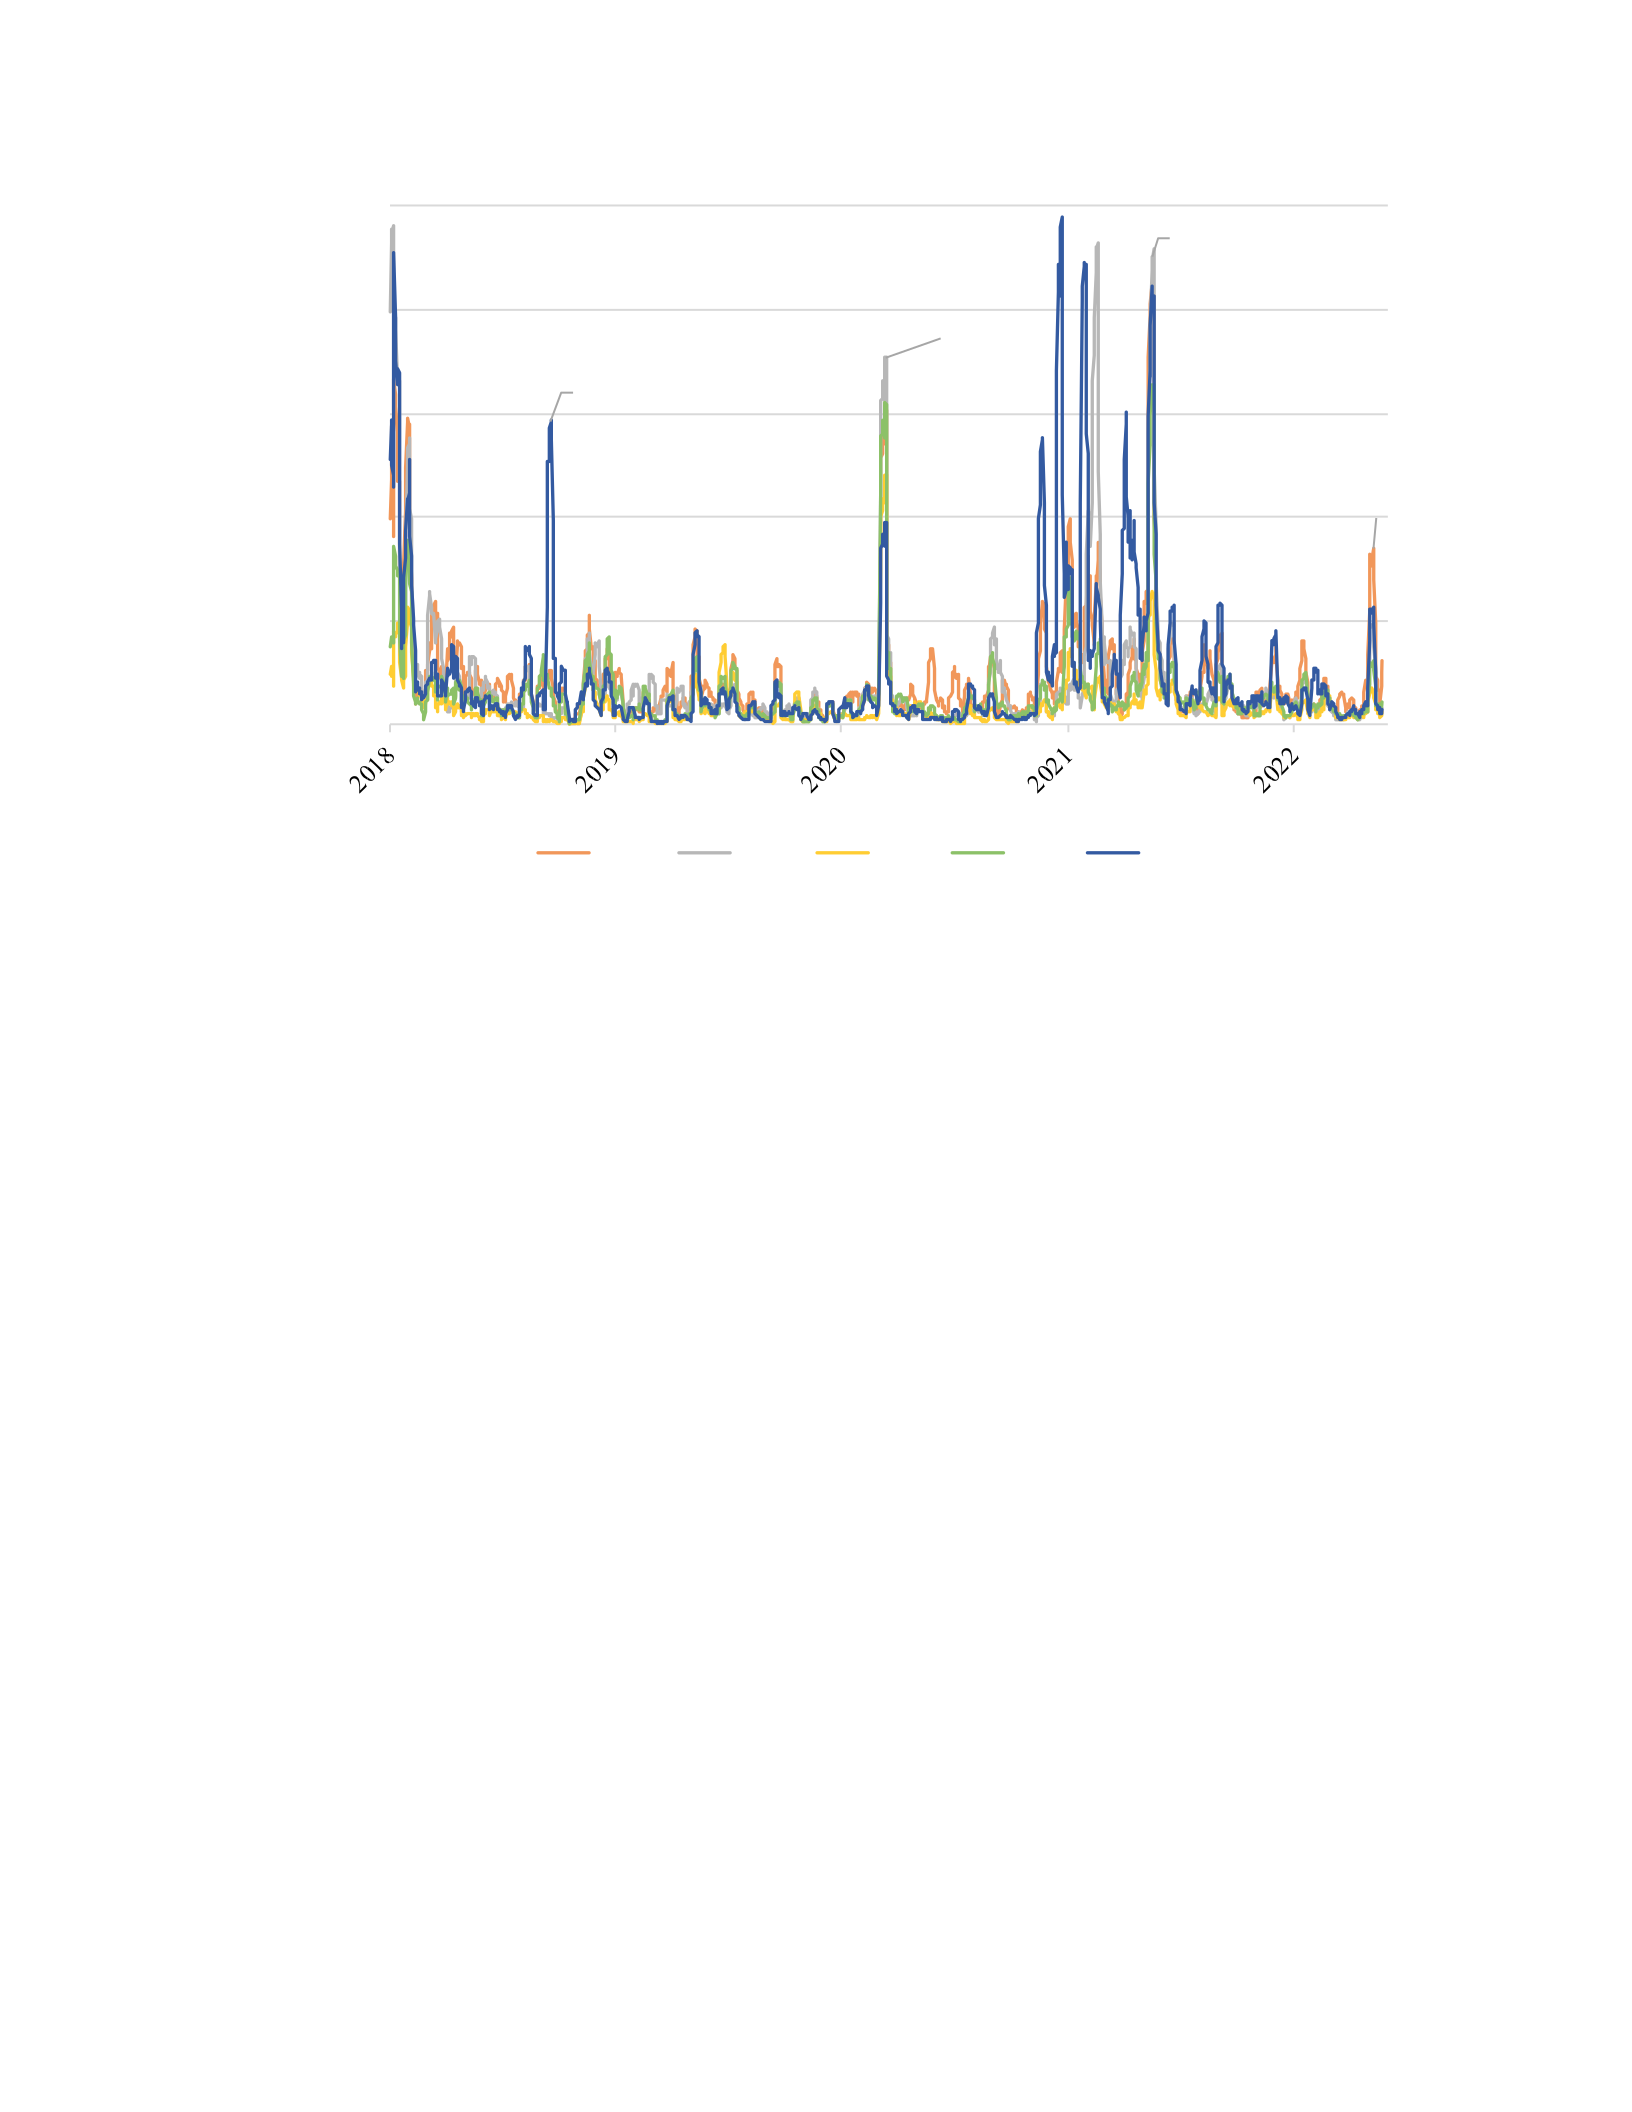
Figure 5. GK Volatility of Cryptocurrencies (without DOGE)
The next six models include all the economic predictor variables and the volatility
measure for each of the six traditional cryptocurrencies. Figure 6 below looks at all the
economic variables and their abilities to predict Cardano (ADA) volatility. As shown in
Table 8, the Random Forest model predicted Cardano (ADA) volatility with the highest
prediction accuracy (92.8%). Figure 7 ranks the importance of the predictor variables as
explained by the Random Forest model (the only model that ranks variable importance).
Interestingly, Crude Oil Production (a commodity) is the most important predictor of
Cardano’s (ADA) price volatility. The other ranked variables are some fiat currencies and
other cryptocurrency/stablecoin volumes and prices. The NASDAQ Daily Spread (a
security measure) appears to have some predictive ability, but it is low.
59
169.50%
353.87%
451.18%
292.31%
%0
%100
200%
300%
400%
%500
ADA BNB BTC ETH XRP
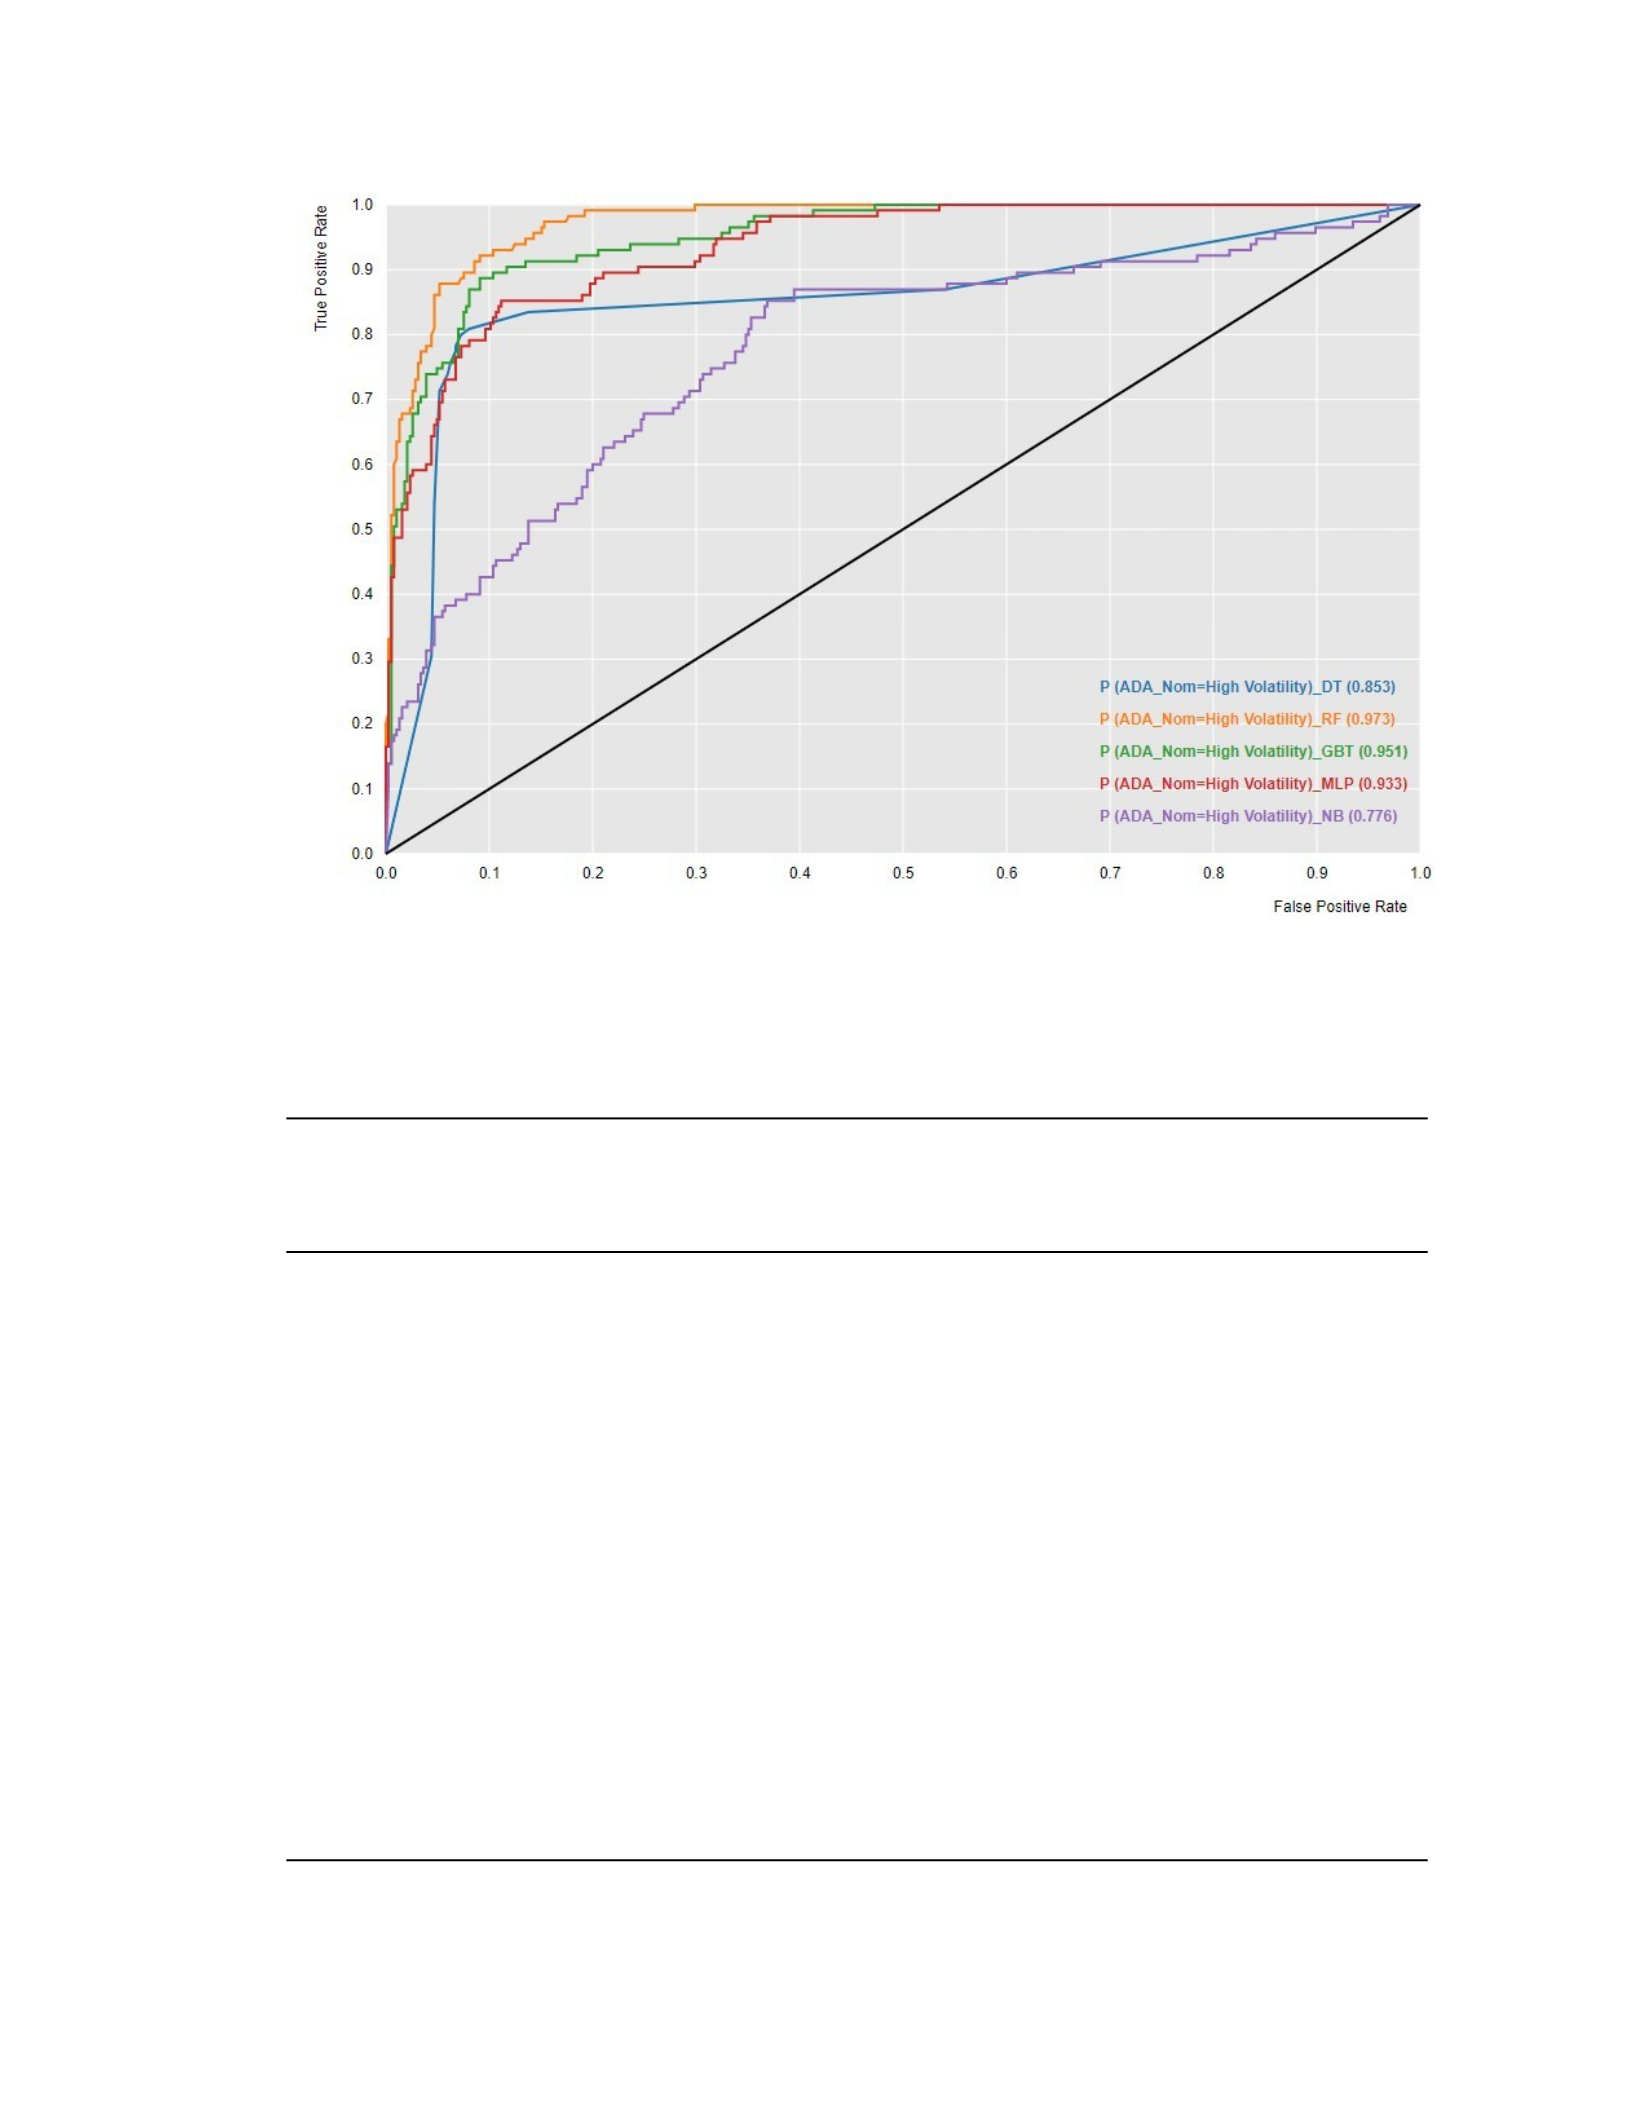
Figure 6. ROC Curve for Cryptocurrency Volatility Prediction Models (ADA)
Table 8. Study 1a - ADA Volatility Model Prediction Results
Model TP TN FP FN Accuracy Sensitivity Specificity
False
Positive
Rate
Decision Trees 90 359 26 25 0.898 0.783 0.932 0.068
Random Forest 97 367 18 18 0.928 0.843 0.953 0.047
Gradient
Boosted Trees 88 360 25 27 0.896 0.765 0.935 0.065
Multi-Layer
Perceptron
Neural Network
98 338 47 17 0.872 0.852 0.878 0.122
Naïve Bayes 90 252 133 25 0.684 0.783 0.655 0.345
60
Crude_Oil_Production _U.S.0.772
XRP_Adj_Close0.752
BTC_Volume
USDT_Volume
Euro_Prices_Close
ETH_Volume
XRP_Spread_OpenClose
SOL_Adj_Close
US_Dollar_Circulation
NASDAQ_Daily_Spread
Figure 7. Random Forest Variable Importance (ADA)
Figure 8 below looks at all the economic variables and their abilities to predict
Binance (BNB) volatility. As shown in Table 9, three models predicted Binance (BNB)
volatility with over 90% accuracy; however, the Random Forest model had the highest
prediction accuracy (96.5%). Table 9 ranks the importance of the predictor variables for
the Random Forest model. Again, a commodity, Natural Gas Production –Residential, is
the most important predictor. Other predictors of Binance’s (BNB) volatility include
some fiat currencies and other cryptocurrency/stablecoin volumes and prices. However,
another commodity, Natural Gas Imports, also shows predictive ability. As with Cardano
(XRP), a security measure, the Dow Jones Daily Spread, has some predictive ability, but
it is low (Figure 9).
61
0.564
0.526
0.41
0.385
0.371
0.31
0.299
0.287
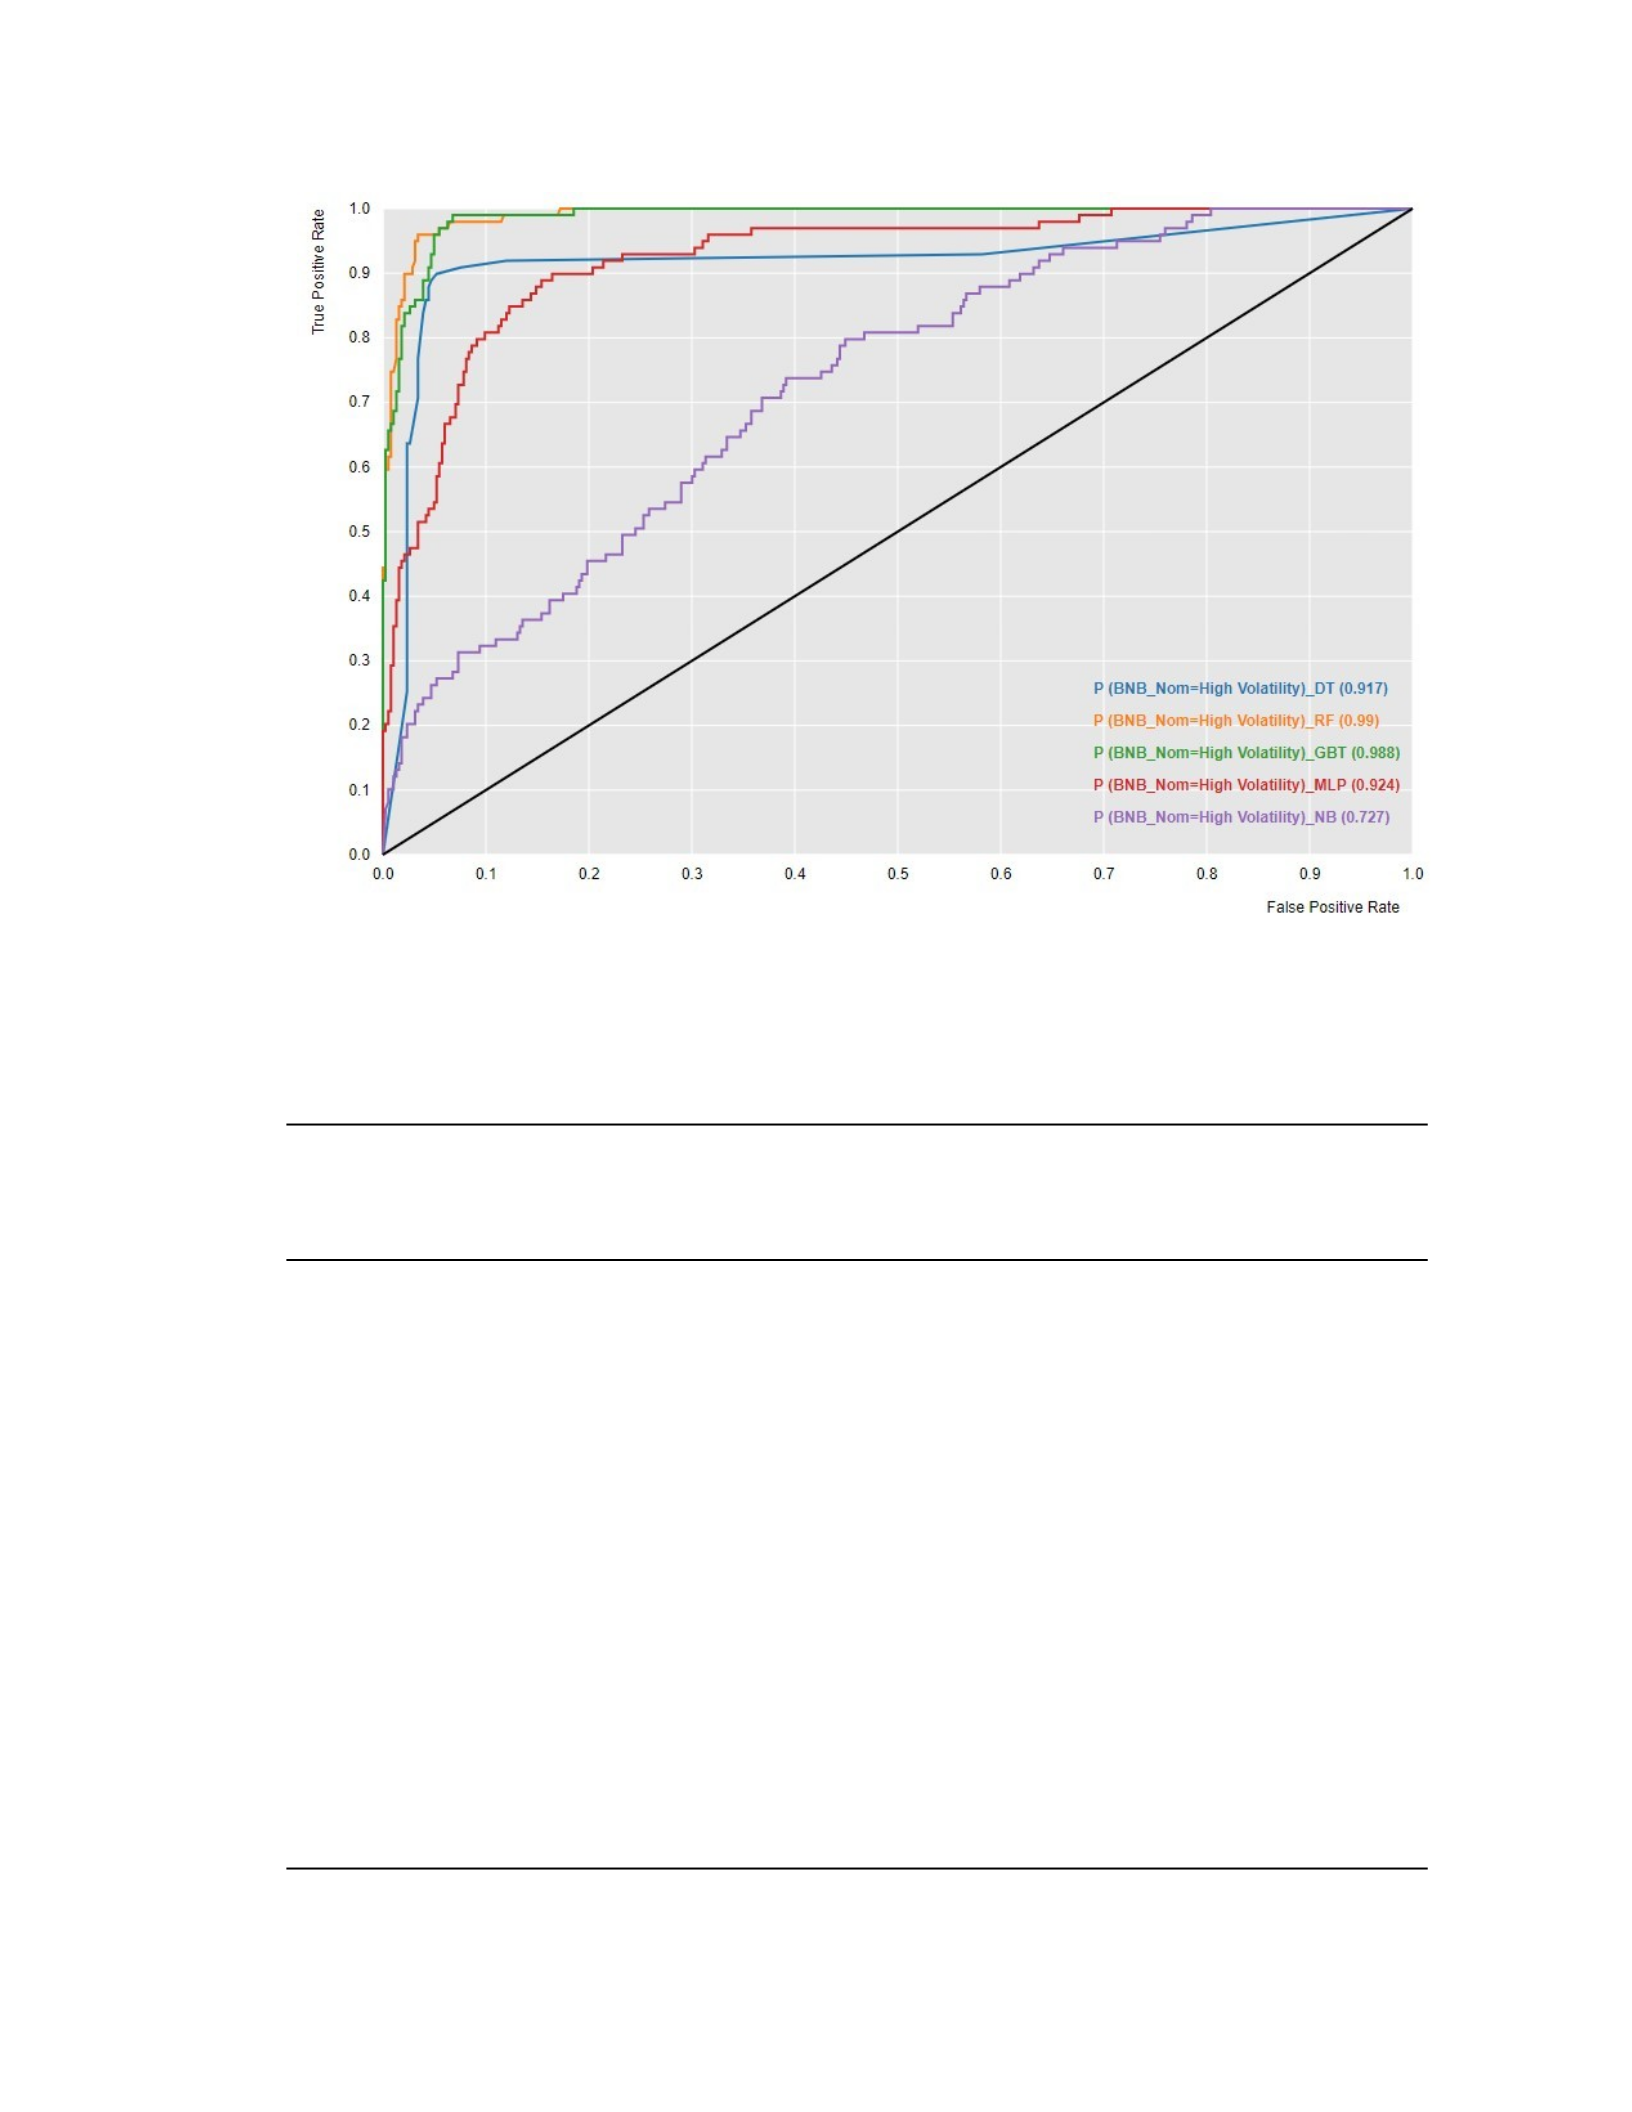
Figure 8. ROC Curve for Cryptocurrency Volatility Prediction Models (BNB)
Table 9. Study 1a - BNB Volatility Model Prediction Results
Model TP TN FP FN Accuracy Sensitivity Specificity
False
Positive
Rate
Decision Trees 87 366 17 12 0.940 0.879 0.956 0.044
Random Forest 94 371 12 5 0.965 0.949 0.969 0.031
Gradient
Boosted Trees 88 368 15 11 0.946 0.889 0.961 0.039
Multi-Layer
Perceptron
Neural Network
86 329 54 13 0.861 0.869 0.859 0.141
Naïve Bayes 53 283 100 46 0.697 0.535 0.739 0.261
Natural_Gas_Price_Residential0.85
62
US_Dollar_Circulation 0.798
XRP_Adj_Close
USDT_Volume
Natural_Gas_Imports
British_Pound_Value_Change
Euro_Prices_Close
Dow_Jones_Daily_Spread
DOGE_Spread_OpenClose
US_Dollar_Close
Figure 9. Random Forest Variable Importance (BNB)
Figure 10 below looks at all the economic variables and their abilities to predict
Bitcoin (BTC) volatility. As previously discussed, Bitcoin has the longest history
(launched in 2008) and is, by far, the largest cryptocurrency in terms of market
capitalization. As shown in Table 10, three models predicted Bitcoin’s (BTC) volatility
with over 90% accuracy; however, the Random Forest model had the highest prediction
accuracy (94.8%). Figure 11 ranks the importance of the predictor variables for the
Random Forest model. The top four predictors were all measures of fiat currency – with
the U.S. Dollar Circulation and U.S. Dollar Close as the top predictors. This finding raises
interesting questions about its potential classification relative to the other studied
cryptocurrencies which will be explored further in Chapter 5. A commodity, Natural Gas
Price –Residential, is also predictor of Bitcoin (BTC) volatility. The Dow Jones Daily
Spread, a security measure, has some predictive ability, but it is low.
63
0.66
0.517
0.505
0.49
0.413
0.378
0.356
0.306
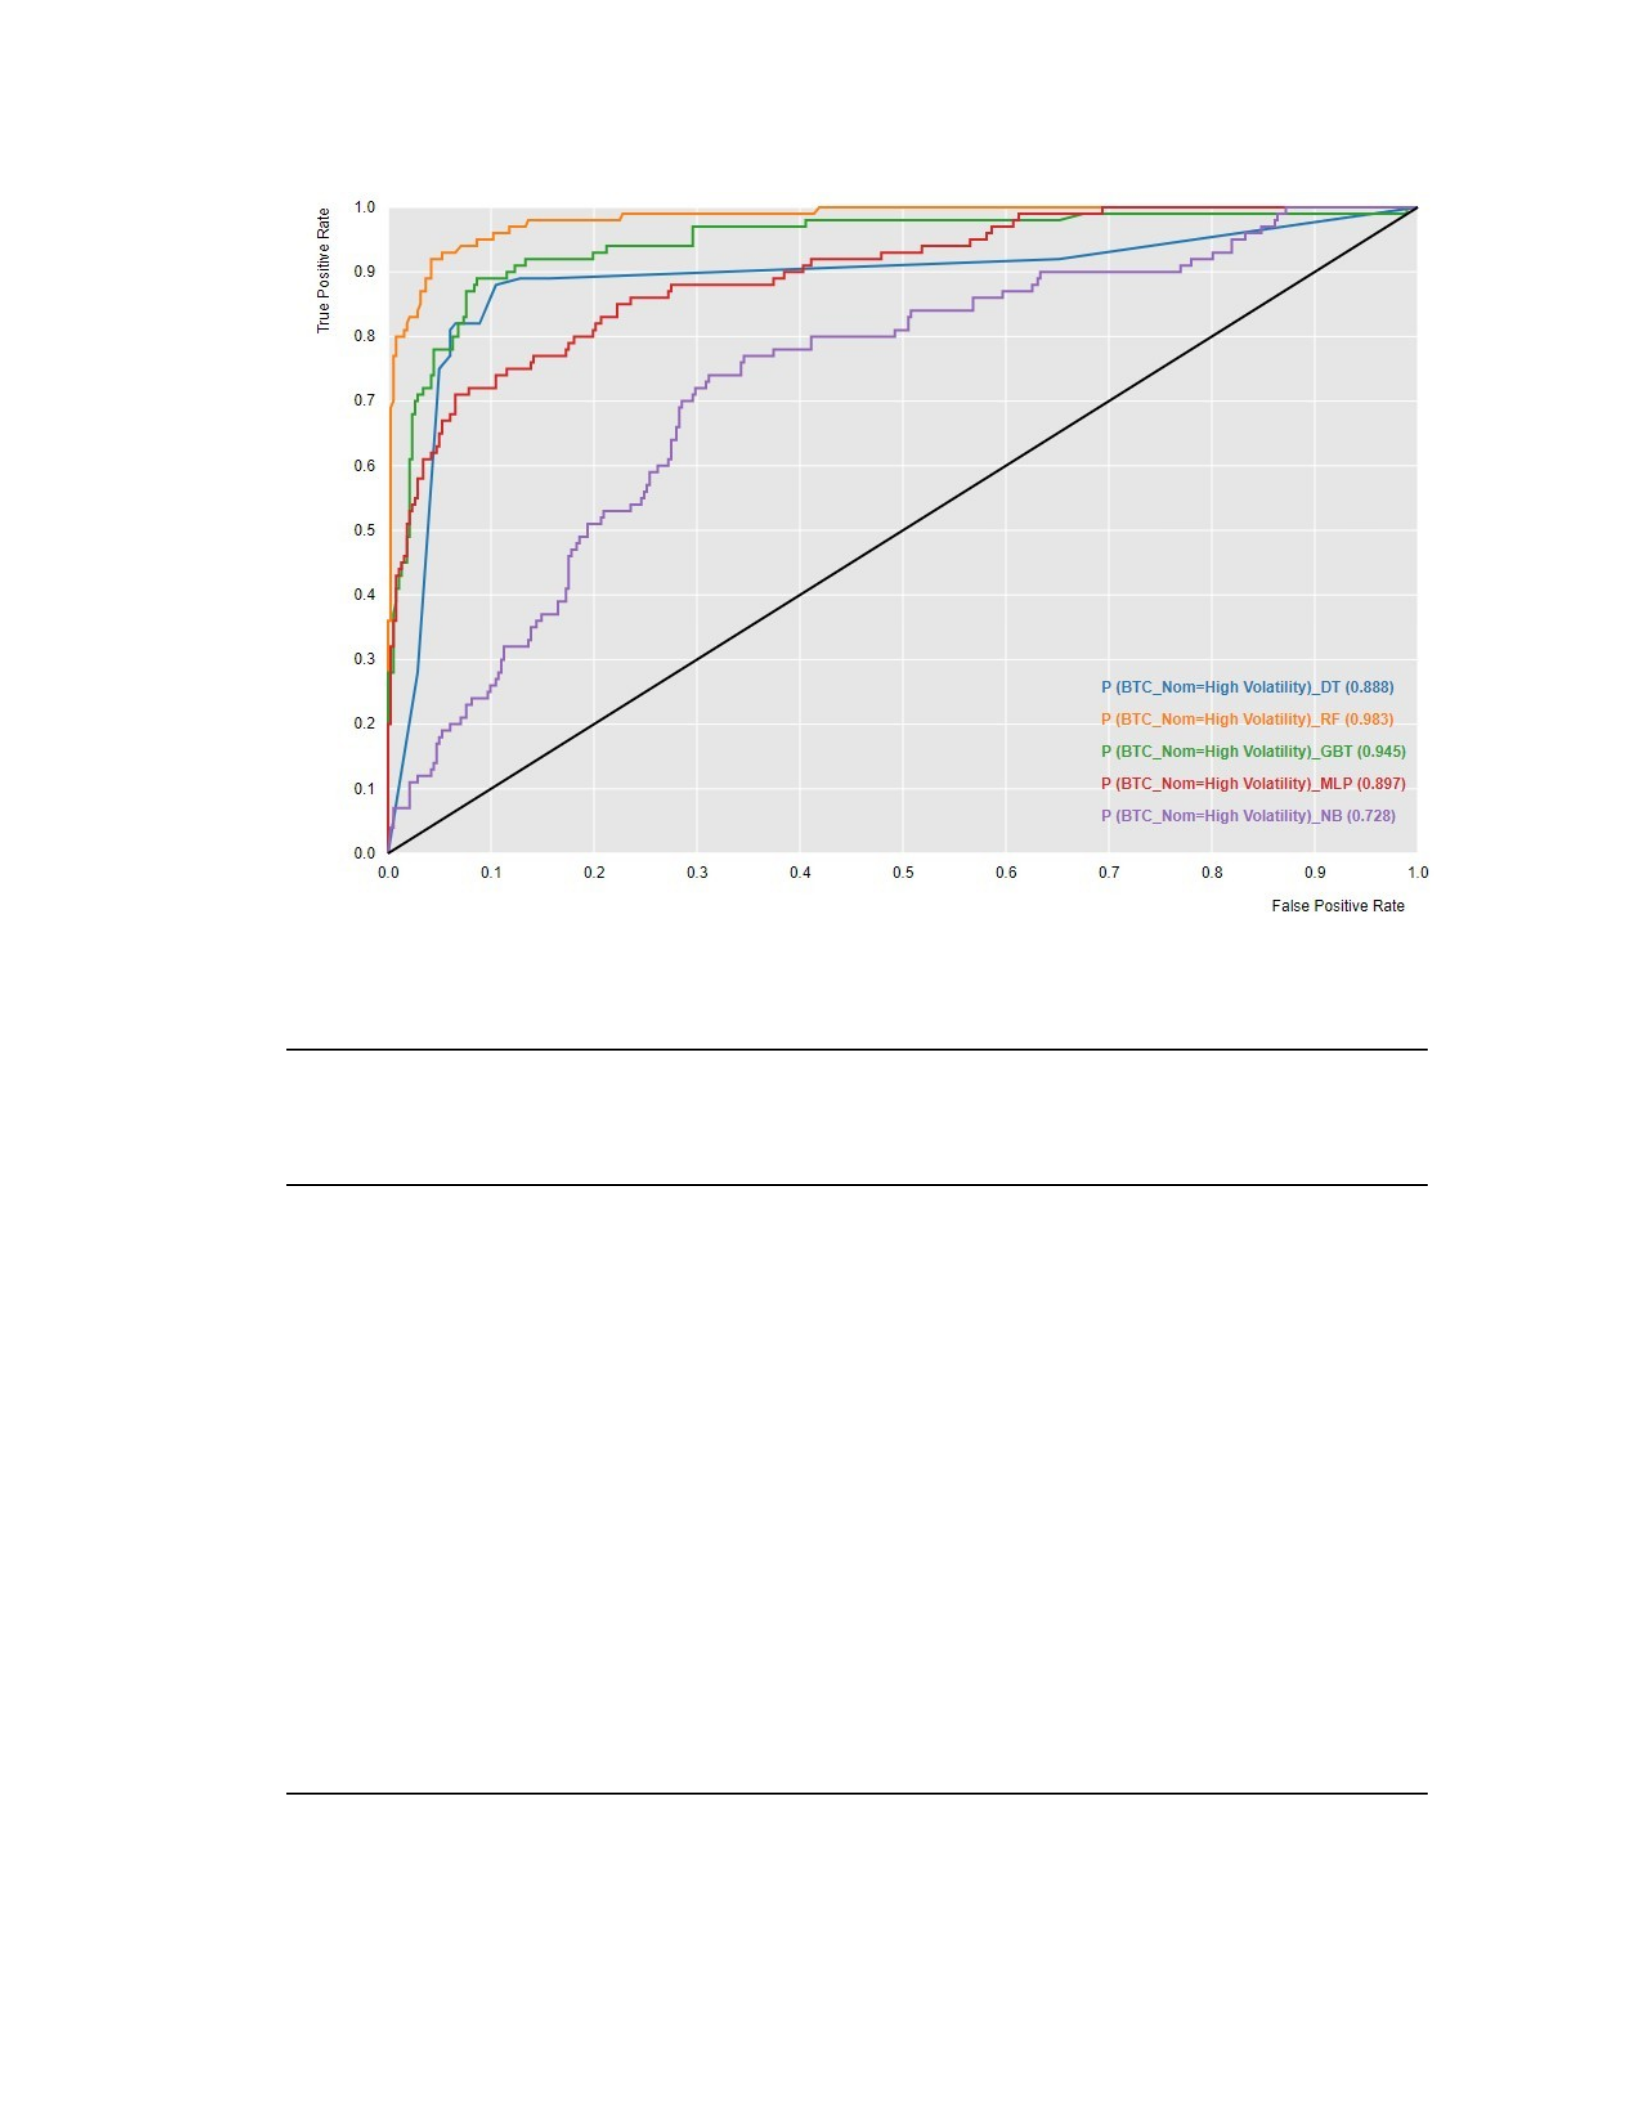
Figure 10. ROC Curve for Cryptocurrency Volatility Prediction Models (BTC)
Table 10. Study 1a - BTC Volatility Model Prediction Results
Model TP TN FP FN Accuracy Sensitivity Specificity
False
Positive
Rate
Decision Trees 81 359 23 19 0.913 0.810 0.940 0.060
Random Forest 91 366 16 9 0.948 0.910 0.958 0.042
Gradient
Boosted Trees 74 366 16 26 0.913 0.740 0.958 0.042
Multi-Layer
Perceptron
Neural Network
73 350 32 27 0.878 0.730 0.916 0.084
Naïve Bayes 53 293 89 47 0.718 0.530 0.767 0.233
64
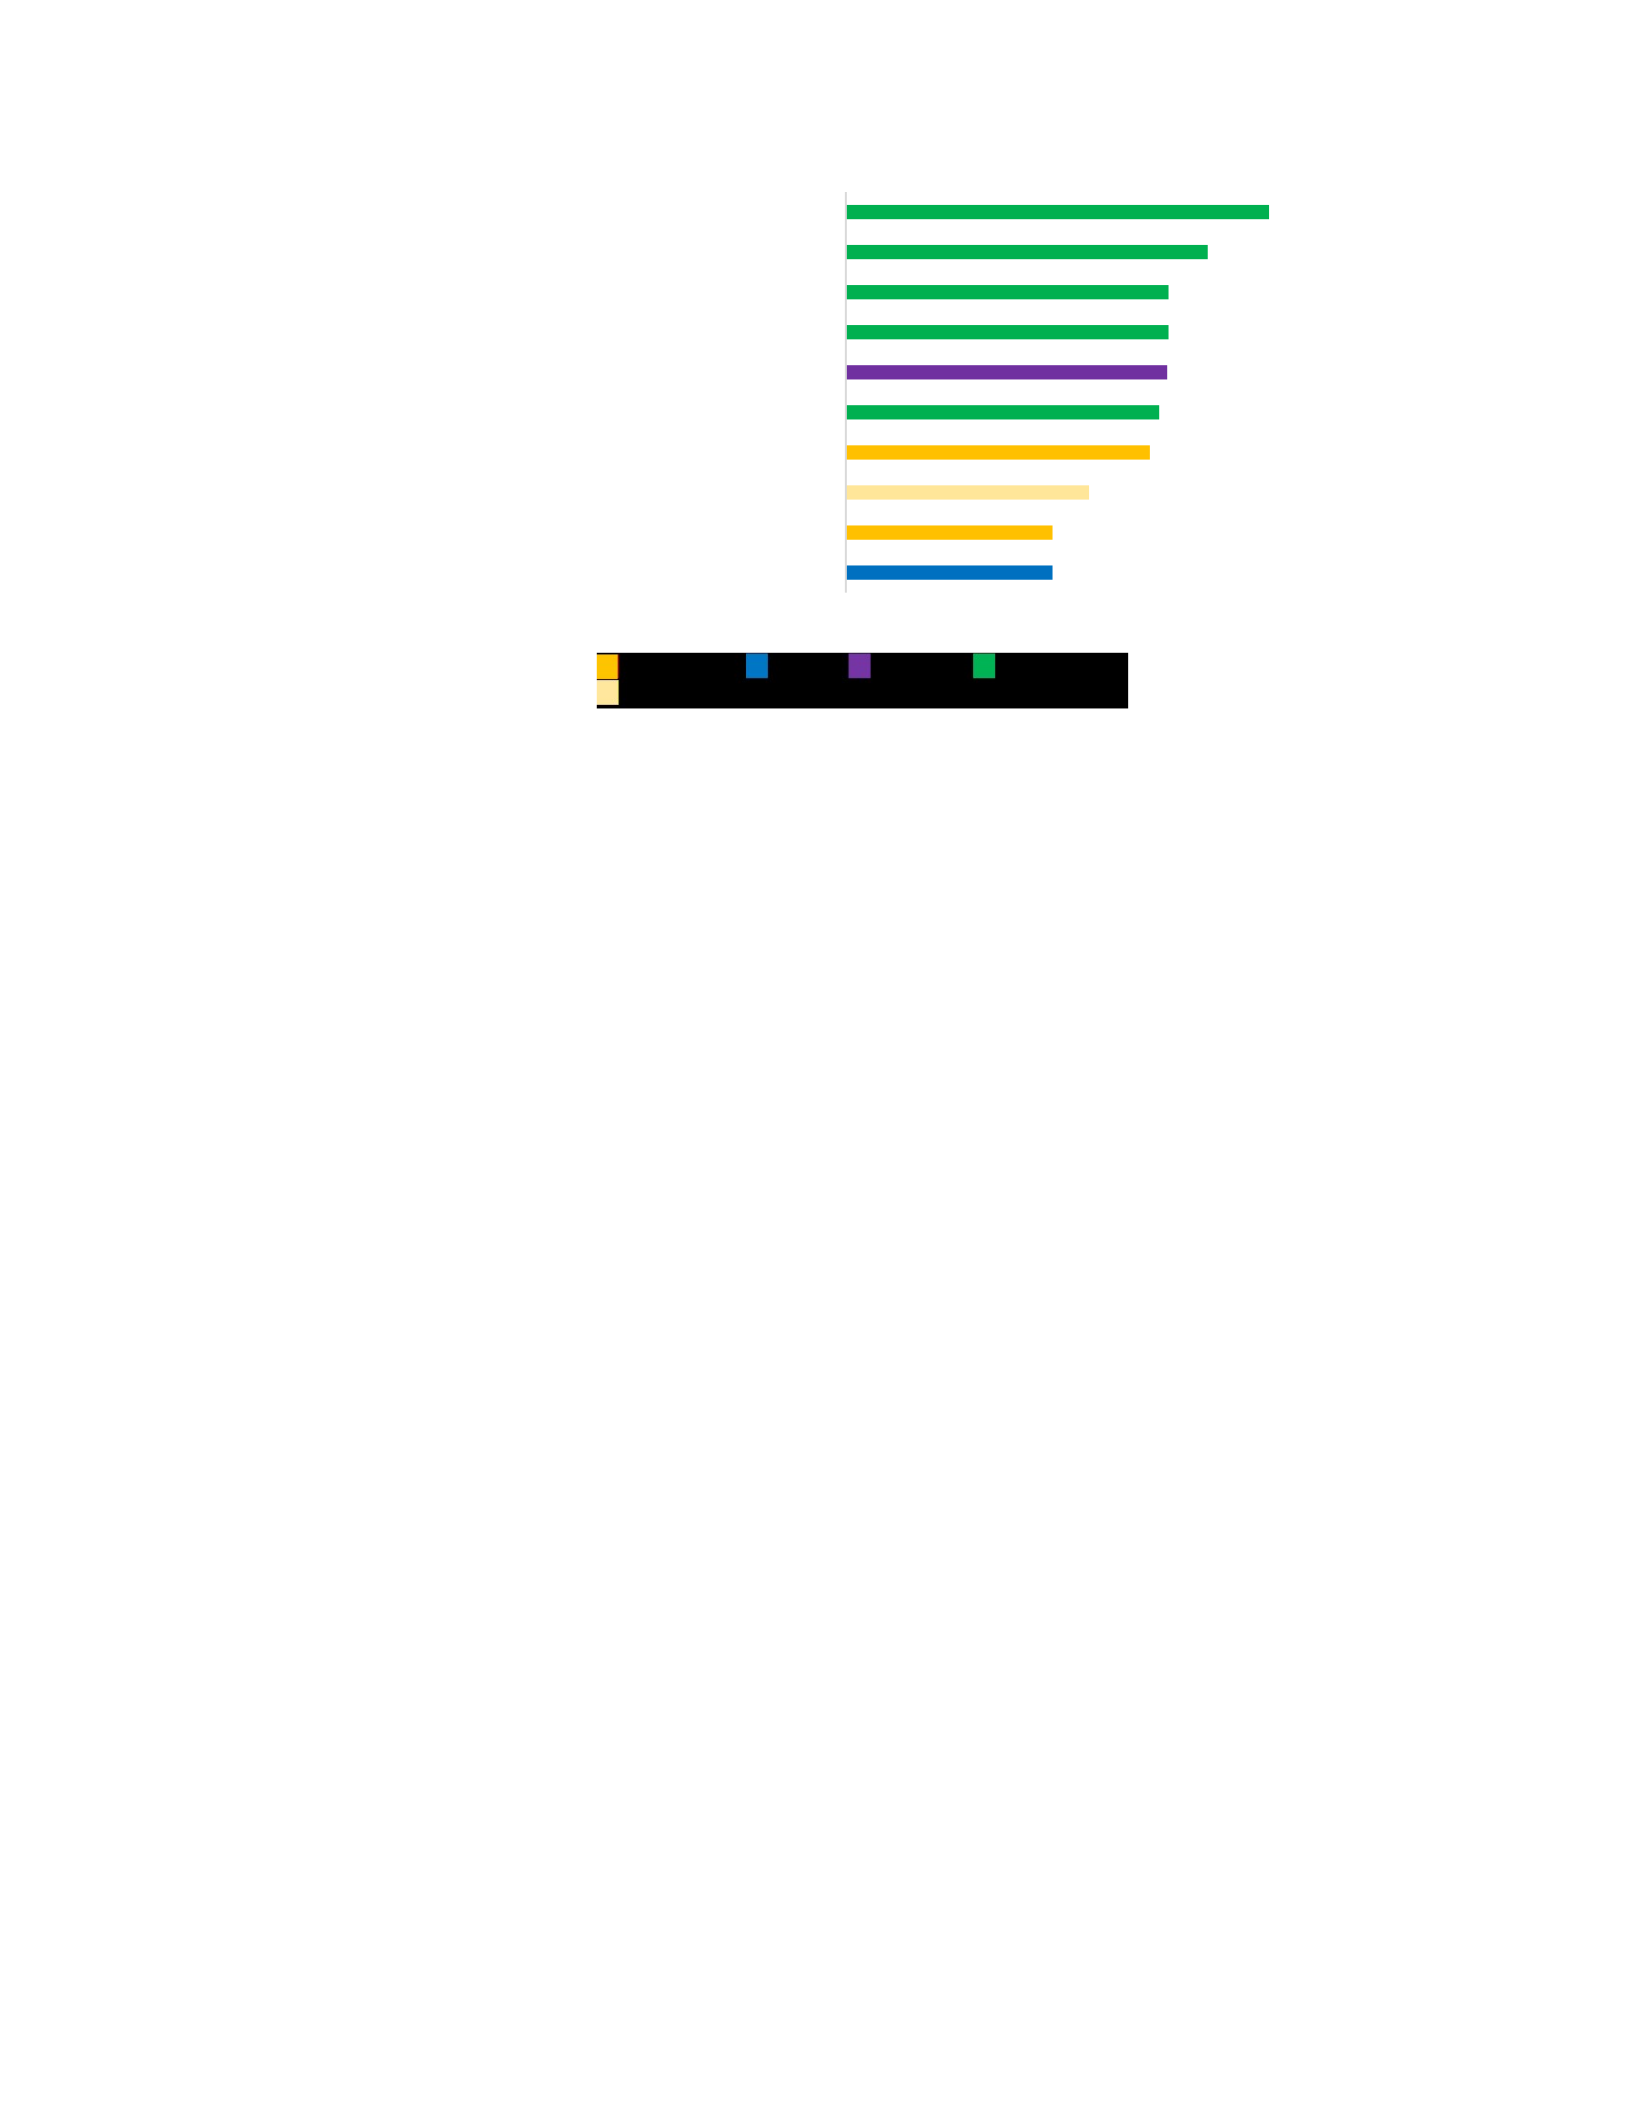
Figure 11. Random Forest Variable Importance (BTC)
Figure 12 below looks at all the economic variables and their abilities to predict
Dogecoin (DOGE) volatility. As previously discussed, Dogecoin exhibited some of the
highest levels of volatility of any of the studied cryptocurrencies. As shown in Table 11,
the Random Forest model had the highest prediction accuracy (94.4%). Figure 13 ranks
the importance of the predictor variables for the Random Forest model. The top two
predictors were measures of other cryptocurrencies – Cardona (XRP) and Tether
(USDT). Two commodities, Natural Gas Price –Residential and Natural Gas Imports,
were also predictors of Dogecoin (DOGE) volatility. The remaining predictors were other
cryptocurrency and fiat currency measures.
65
0.31
0.31
0.365
0.456
0.47
0.48
0.484
0.484
0.543
0.635
Dow_Jones_Daily_Spread
DOGE_Adj_Close
USDC_Spread_OpenClose
BNB_Spread_OpenClose
Treasury_Rates_52_Weeks_Bank_Discount
Natural_Gas_Price_Residential
Euro_Prices_Close
Treasury_Rates_52_Weeks_Coupon
US_Dollar_Close
US_Dollar_Circulation
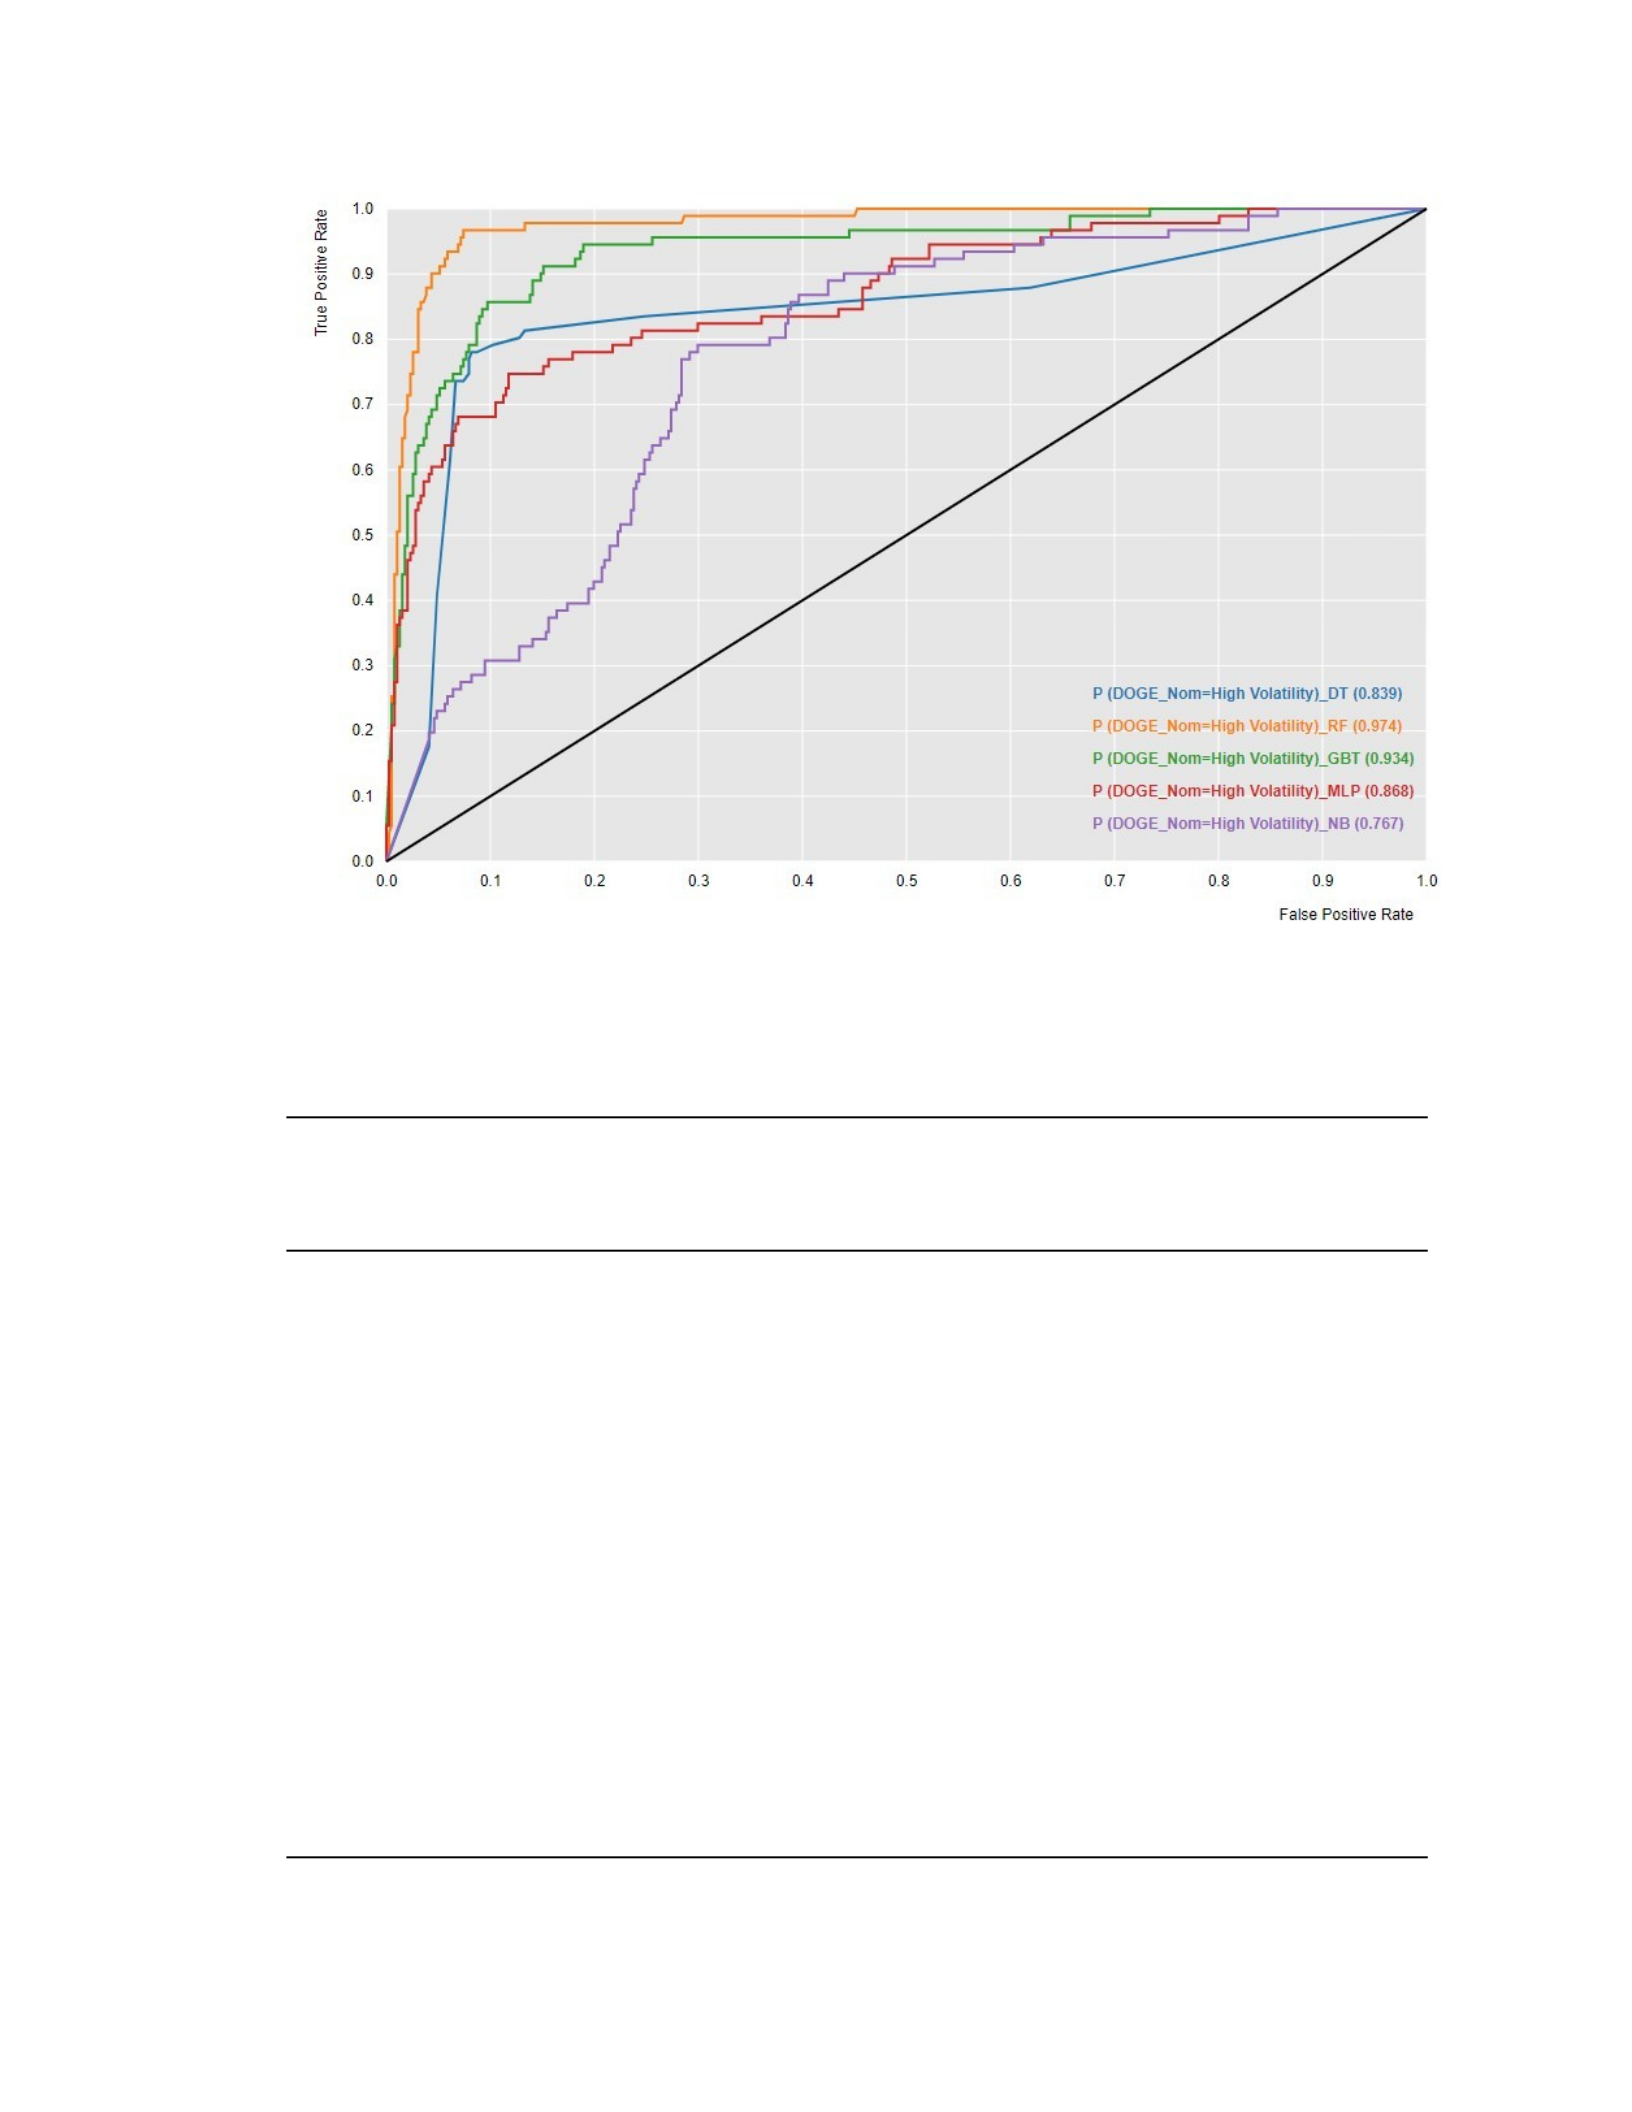
Figure 12. ROC Curve for Cryptocurrency Volatility Prediction Models (DOGE)
Table 11. Study 1a - DOGE Volatility Model Prediction Results
Model TP TN FP FN Accuracy Sensitivity Specificity
False
Positive
Rate
Decision Trees 69 360 31 22 0.890 0.758 0.921 0.079
Random Forest 76 379 12 15 0.944 0.835 0.969 0.031
Gradient
Boosted Trees 68 364 27 23 0.896 0.747 0.931 0.069
Multi-Layer
Perceptron
Neural Network
65 343 48 26 0.846 0.714 0.877 0.123
Naïve Bayes 72 247 144 19 0.662 0.791 0.632 0.368
66
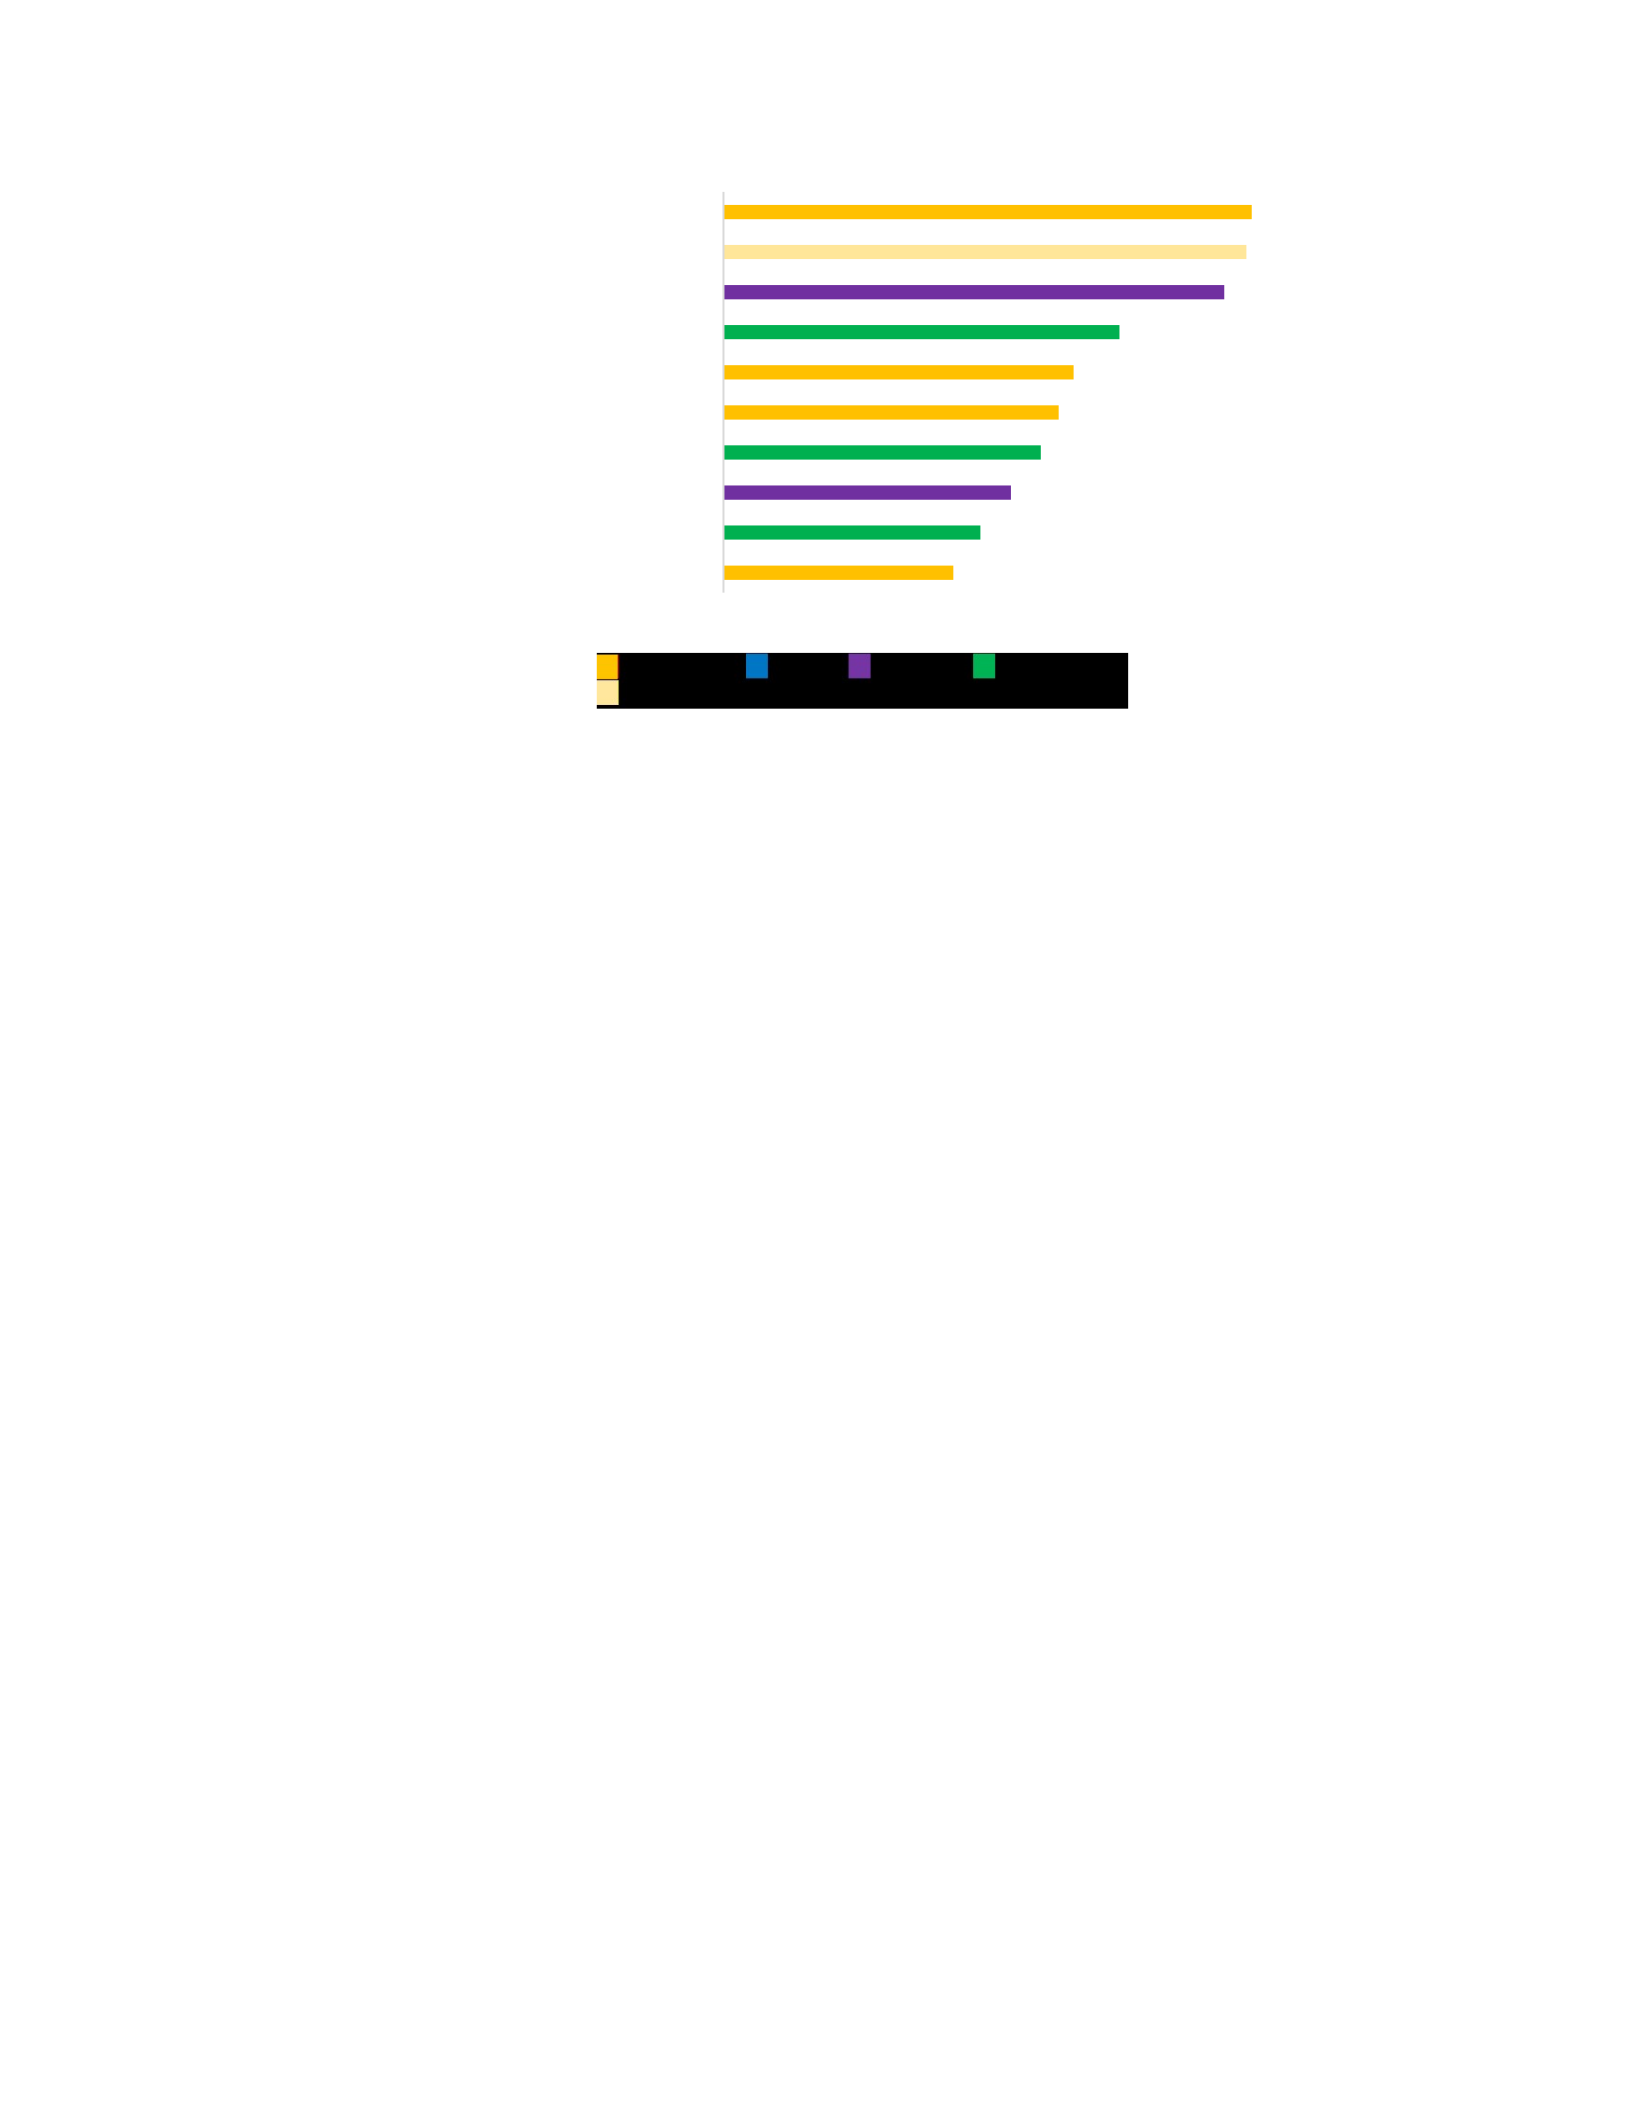
Japanese_Yen_Clos
e
Figure 13. Random Forest Variable Importance (DOGE)
Figure 14 below looks at all the economic variables and their abilities to
predict Ethereum (ETH) volatility. Launched in 2015, Ethereum is the second largest
cryptocurrency in terms of market capitalization. As shown in Table 12, two models
predicted Ethereum’s (ETH) volatility with over 90% accuracy; however, the Random
Forest model had the highest prediction accuracy (94.6%). Figure 15 ranks the
importance of the predictor variables for the Random Forest model. The top predictor
was a measure of fiat currency – U.S. Dollar Circulation. However, a commodity
measure, Natural Gas Price – Residential, exhibited nearly identical predictive
abilities. The remaining predictors of Ethereum (ETH) price volatility were measures
of commodities, securities, fiat currencies, and other cryptocurrencies.
67
0.351
0.393
0.439
0.485
0.51
0.535
0.605
0.765
0.799
0.807
BTC_Volume
US_Dollar_Close
Natural_Gas_Imports
Euro_Prices_Close
XRP_Volume
XRP_Spread_OpenClose
Natural_Gas_Price_Residential
USDT_Volume
XRP_Adj_Close
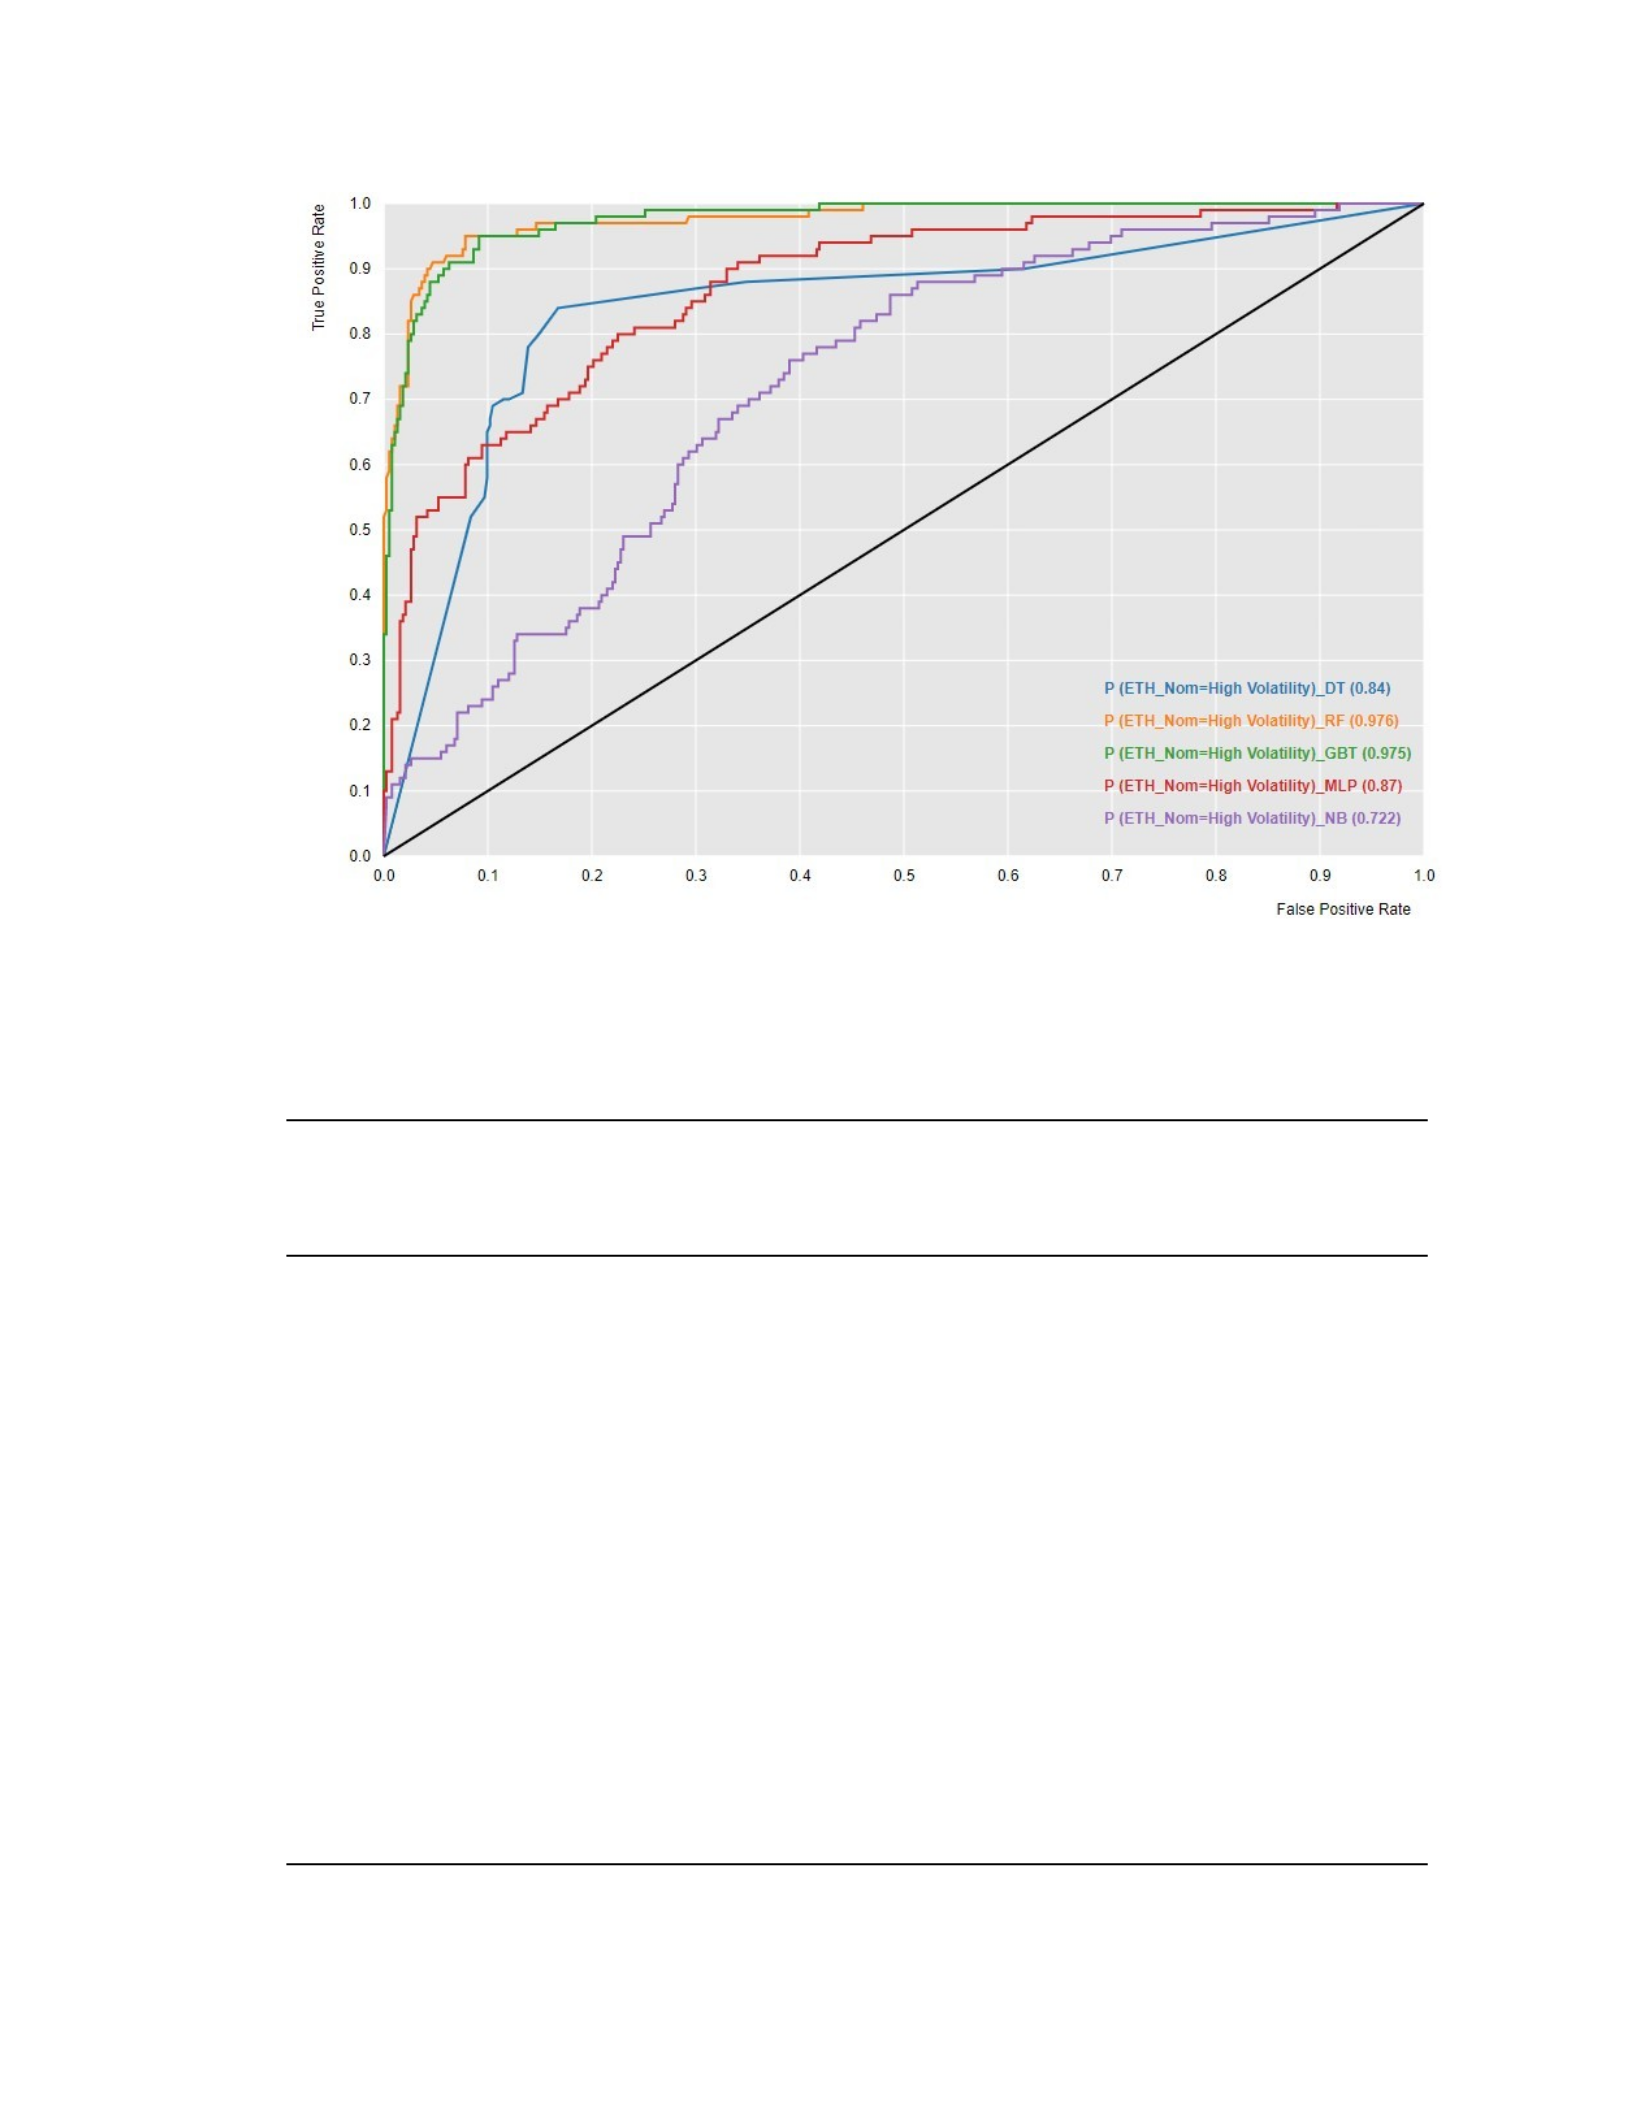
Figure 14. ROC Curve for Cryptocurrency Volatility Prediction Models (ETH)
Table 12. Study 1a - ETH Volatility Model Prediction Results
Model TP TN FP FN Accuracy Sensitivity Specificity
False
Positive
Rate
Decision Trees 70 336 46 30 0.842 0.700 0.880 0.120
Random Forest 88 368 14 12 0.946 0.880 0.963 0.037
Gradient
Boosted Trees 83 369 13 17 0.938 0.830 0.966 0.034
Multi-Layer
Perceptron
Neural Network
78 302 80 22 0.788 0.780 0.791 0.209
Naïve Bayes 46 295 87 54 0.707 0.460 0.772 0.228
68
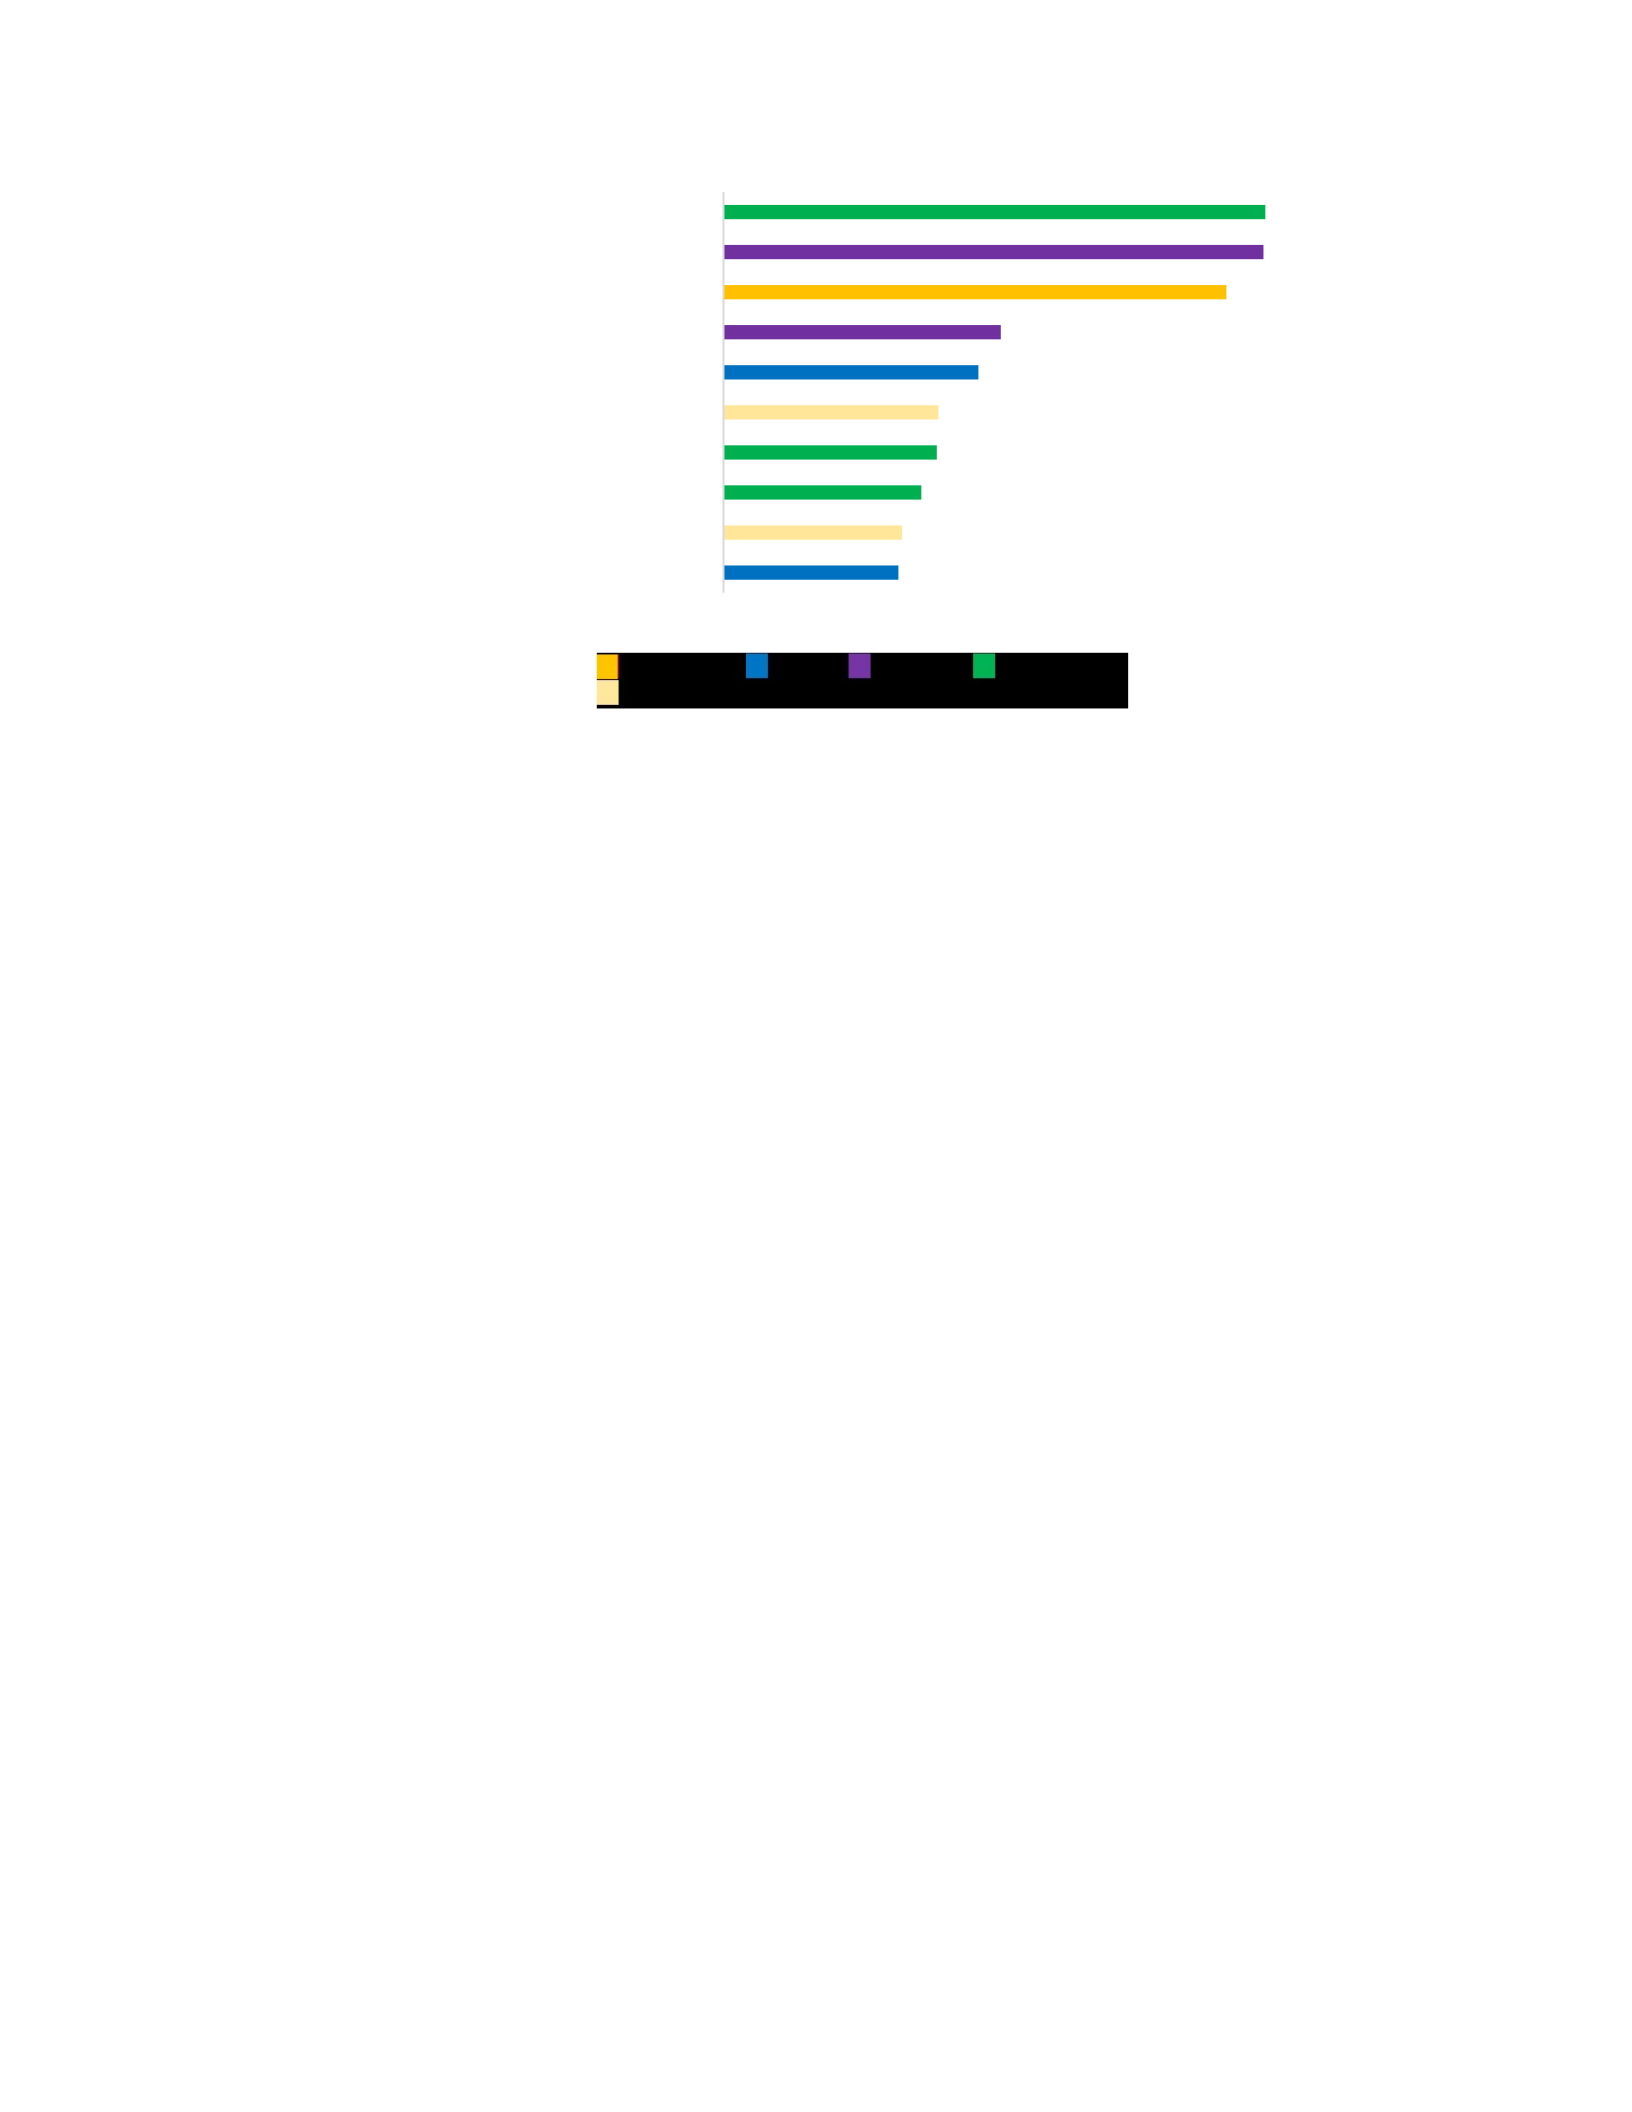
Figure 15. Random Forest Variable Importance (ETH)
Figure 16 below looks at all the economic predictor variables and their abilities to
predict Ripple (XRP) volatility. As shown in Table 13, the Random Forest model
predicted Ripple (XRP) volatility with the highest prediction accuracy (92.9%). Figure 17
ranks the importance of the predictor variables for the Random Forest model. Again,
Natural Gas Price – Residential, a commodity, is the most important predictor of Ripple’s
(XRP) price volatility. Interestingly, the other ranked variables are most often measures
of fiat currencies, although the stablecoin, Tether (USDT), also shows predictive
abilities.
69
0.297
0.303
0.336
0.362
0.365
0.43
0.471
0.854
0.917
0.92
SP500_Daily_Spread
USDT_Volume
Japanese_Yen_Daily_Spread
Euro_Prices_Close
USDC_Spread_OpenClose
Dow_Jones_Daily_Spread
Natural_Gas_Imports
XRP_Adj_Close
Natural_Gas_Price_Residential
US_Dollar_Circulation
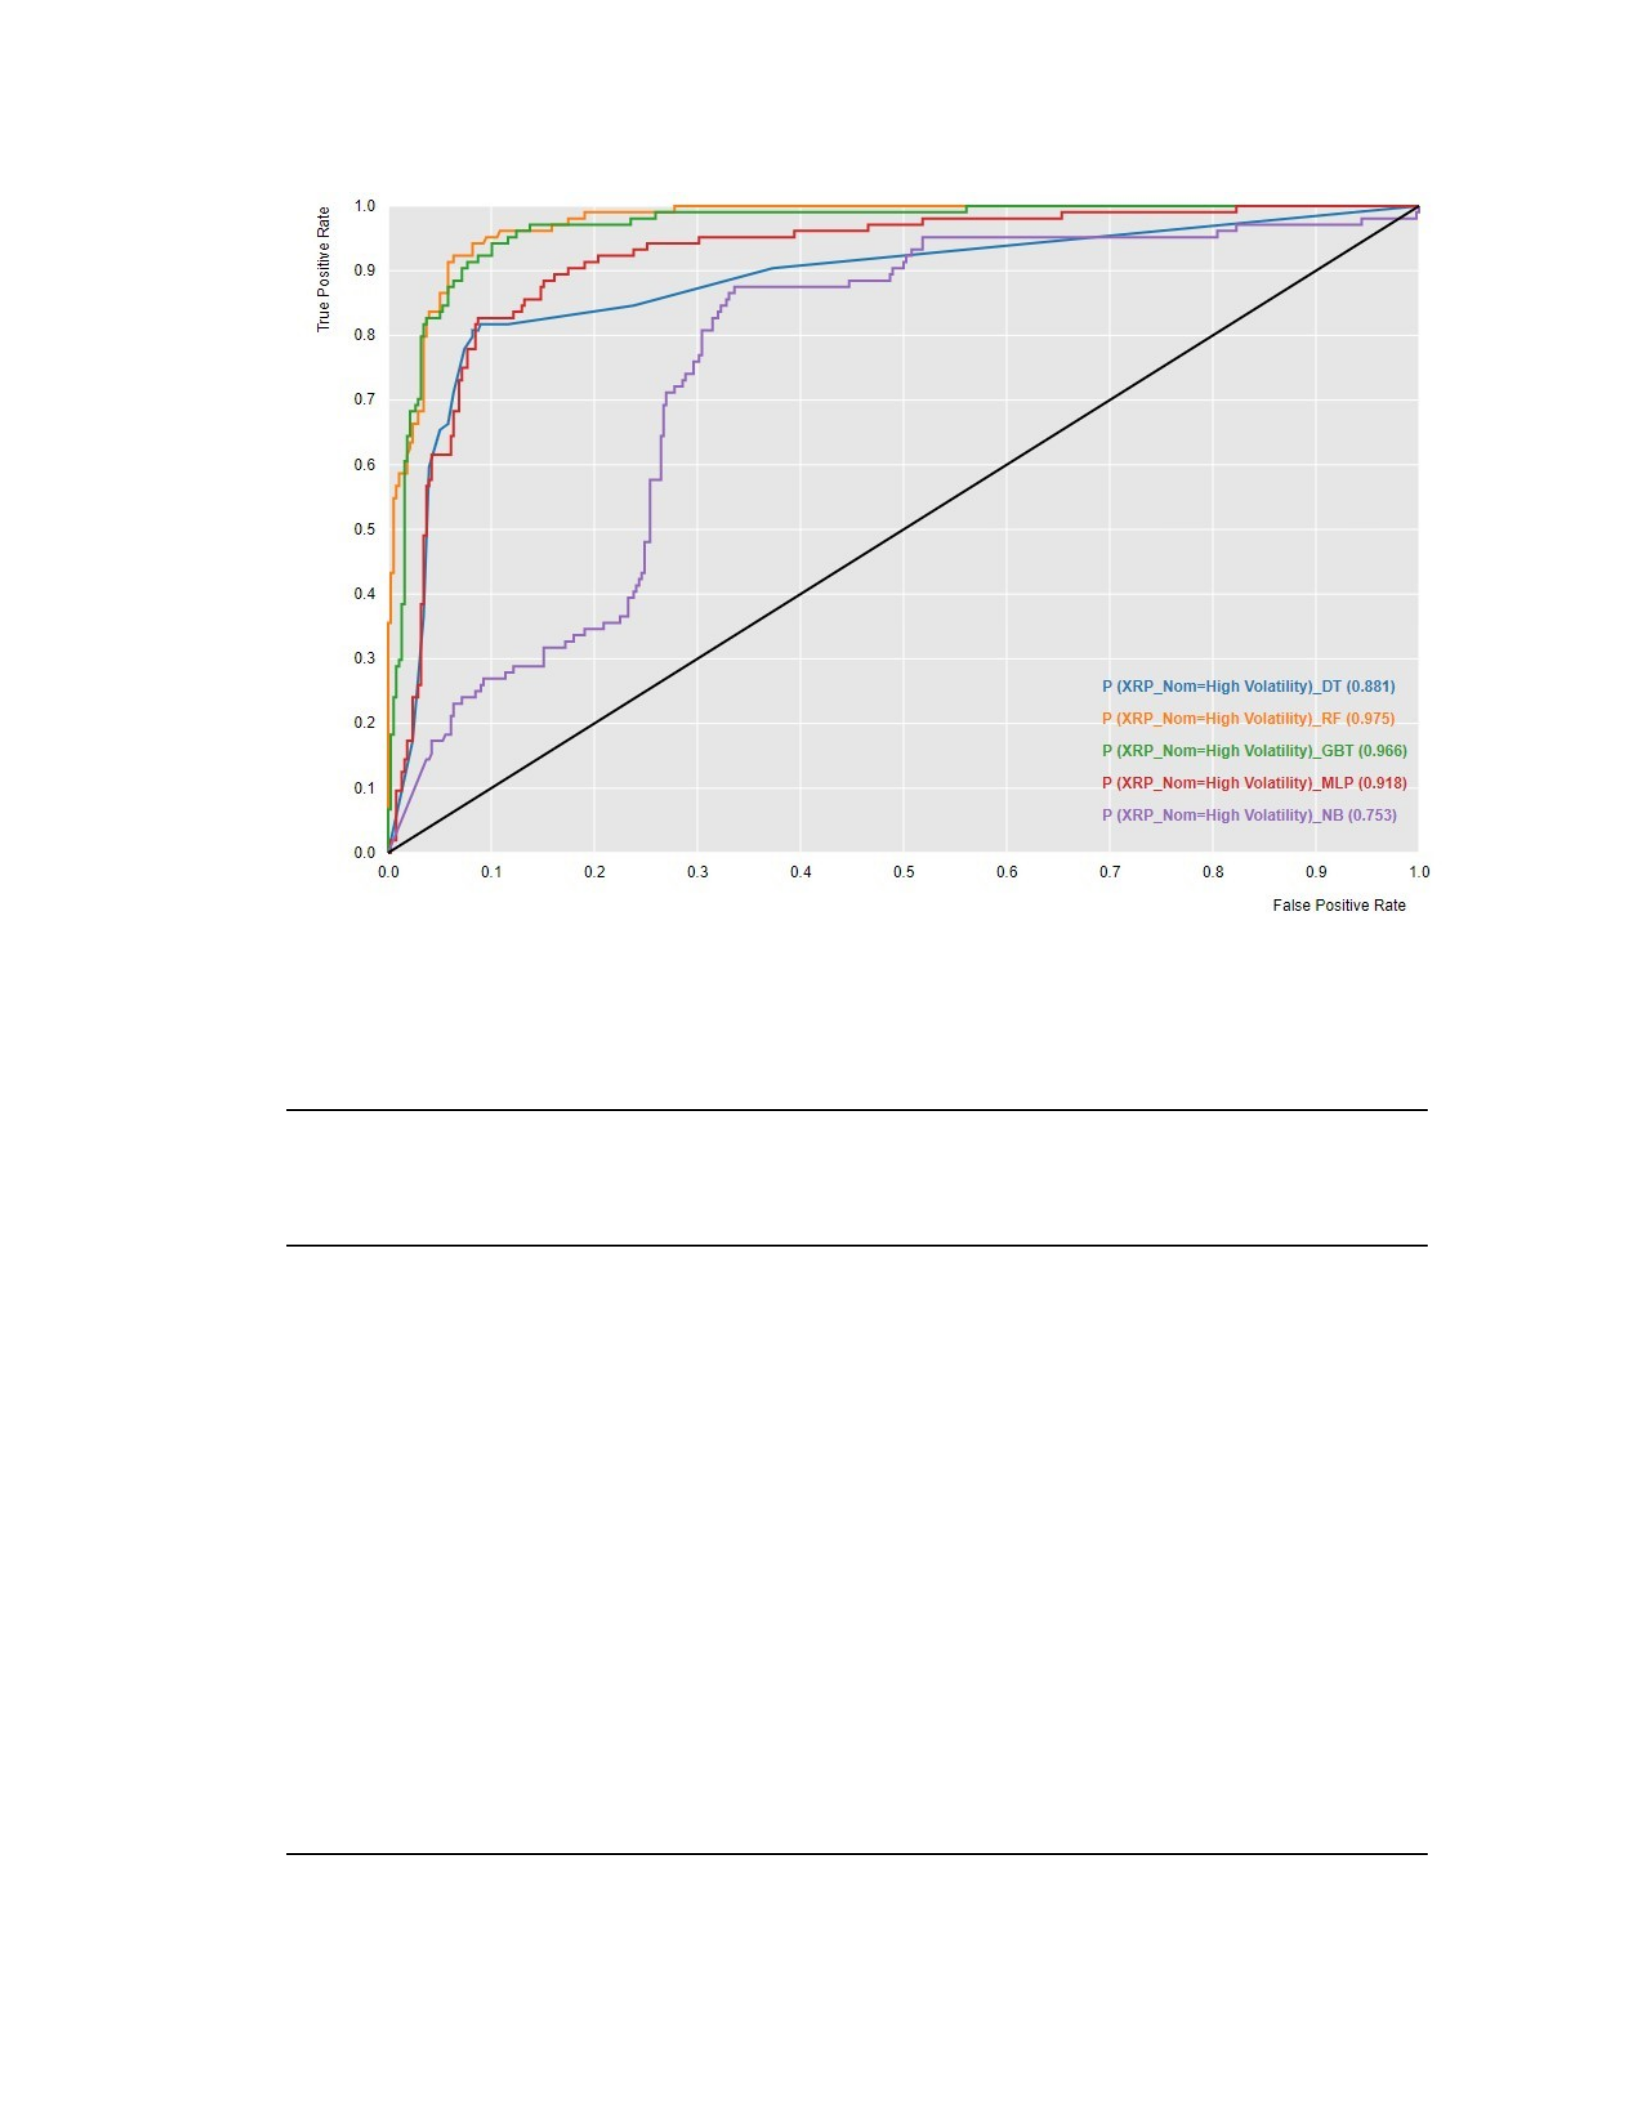
Figure 16. ROC Curve for Cryptocurrency Volatility Prediction Models (XRP)
Table 13. Study 1a - XRP Volatility Model Prediction Results
Model TP TN FP FN Accuracy Sensitivity Specificity
False
Positive
Rate
Decision Trees 83 347 31 21 0.892 0.798 0.918 0.082
Random Forest 90 358 20 14 0.929 0.865 0.947 0.053
Gradient
Boosted Trees 89 356 22 15 .923 0.856 0.942 0.058
Multi-Layer
Perceptron
Neural Network
87 340 38 17 0.886 0.837 0.899 0.101
Naïve Bayes 71 277 101 33 0.722 0.683 0.733 0.267
70
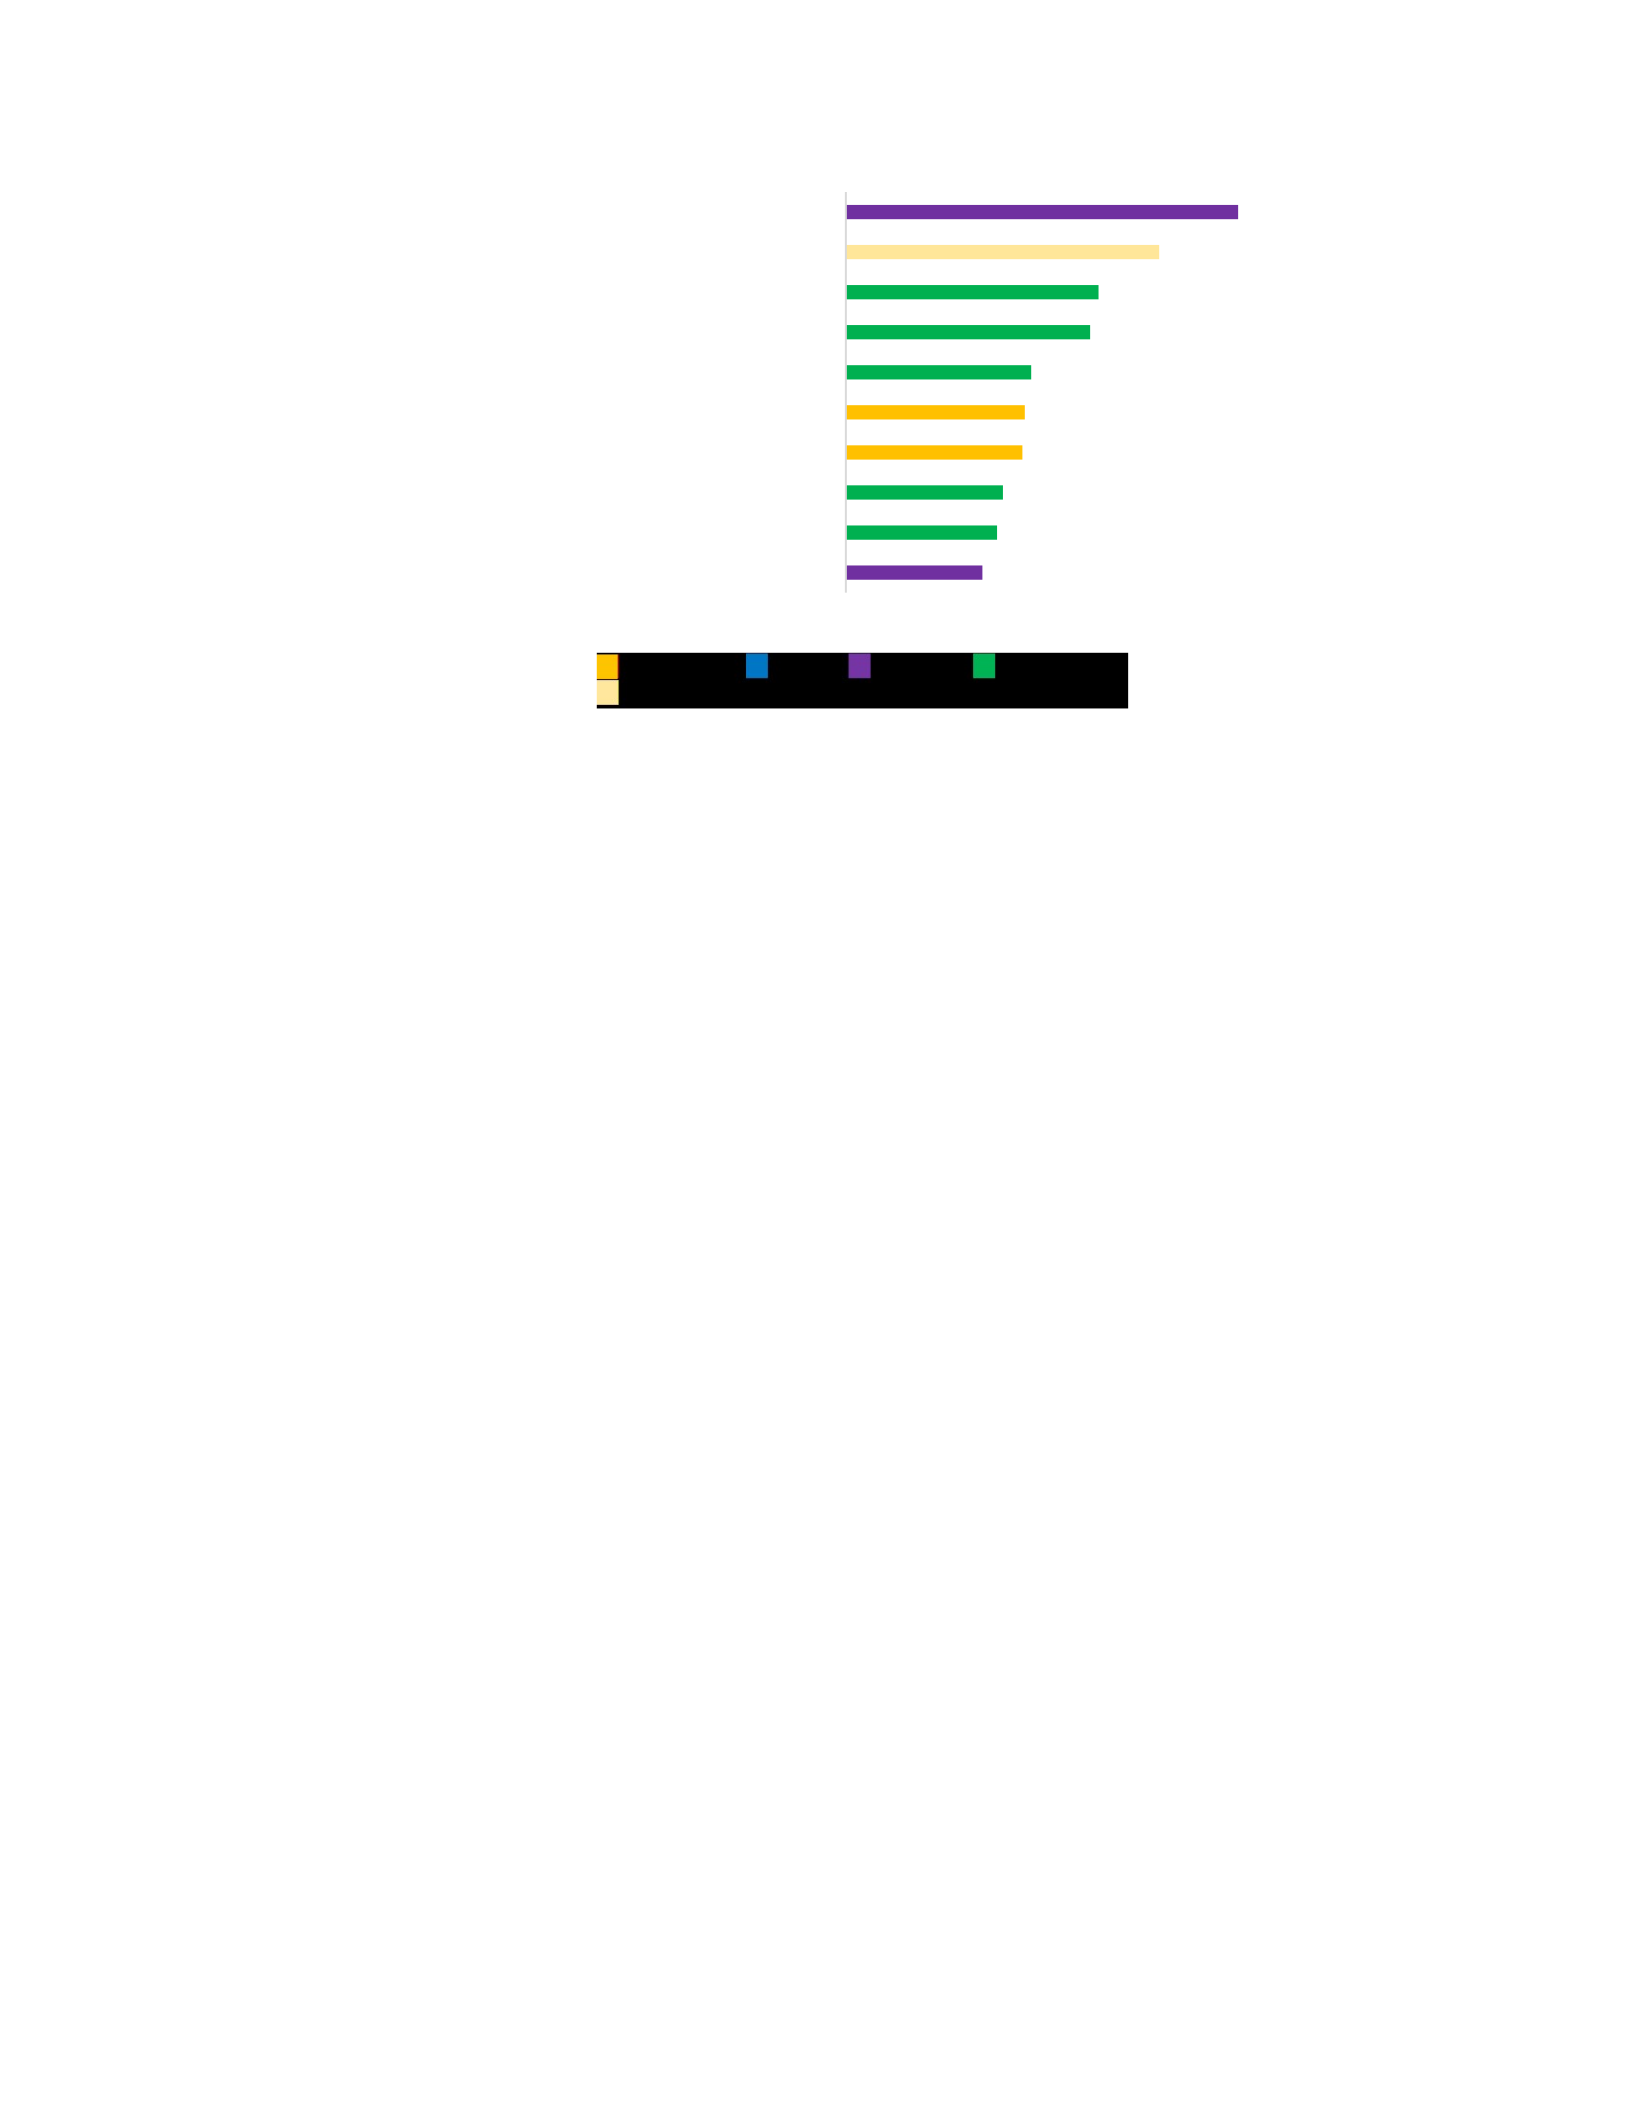
Figure 17. Random Forest Variable Importance (XRP)
4.2 Study 1b – Predicting Stablecoin Depegging from Economic Variables
Study 1b asked the following questions:
Question 2a: How effective are advanced machine learning models in
predicting the depegging of a stablecoin?
Question 2b: Which variables are most significant in predicting
stablecoin depegging?
Stablecoins are, by their very names, designed to mimic the performance of
specific fiat currencies (i.e., they are designed to be pegged to certain fiat currencies).
Study 1b seeks to understand which, if any, economic variables can predict depegging
behavior by considering the three largest stablecoins in terms of market capitalization.
(For reference, USDT = Tether, USDC = U.S. Dollar Coin, and BUSD = Binance USD.)
These three stablecoins were intended to be pegged to the U.S. dollar. For the purposes
of this study, depegging is defined as instances in which the price of the stablecoins fell
below $1.00 U.S.
71
0.351
0.389
0.404
0.454
0.46
0.477
0.628
0.65
0.806
1.009
Natural_Gas_Imports
Treasury_Rates_52_Weeks_Bank_Discount
Treasury_Rates_52_Weeks_Coupon
BTC_Volume
DOGE_Volume
Japanese_Yen_Close
Euro_Prices_Close
US_Dollar_Close
USDT_Volume
Natural_Gas_Price_Residential
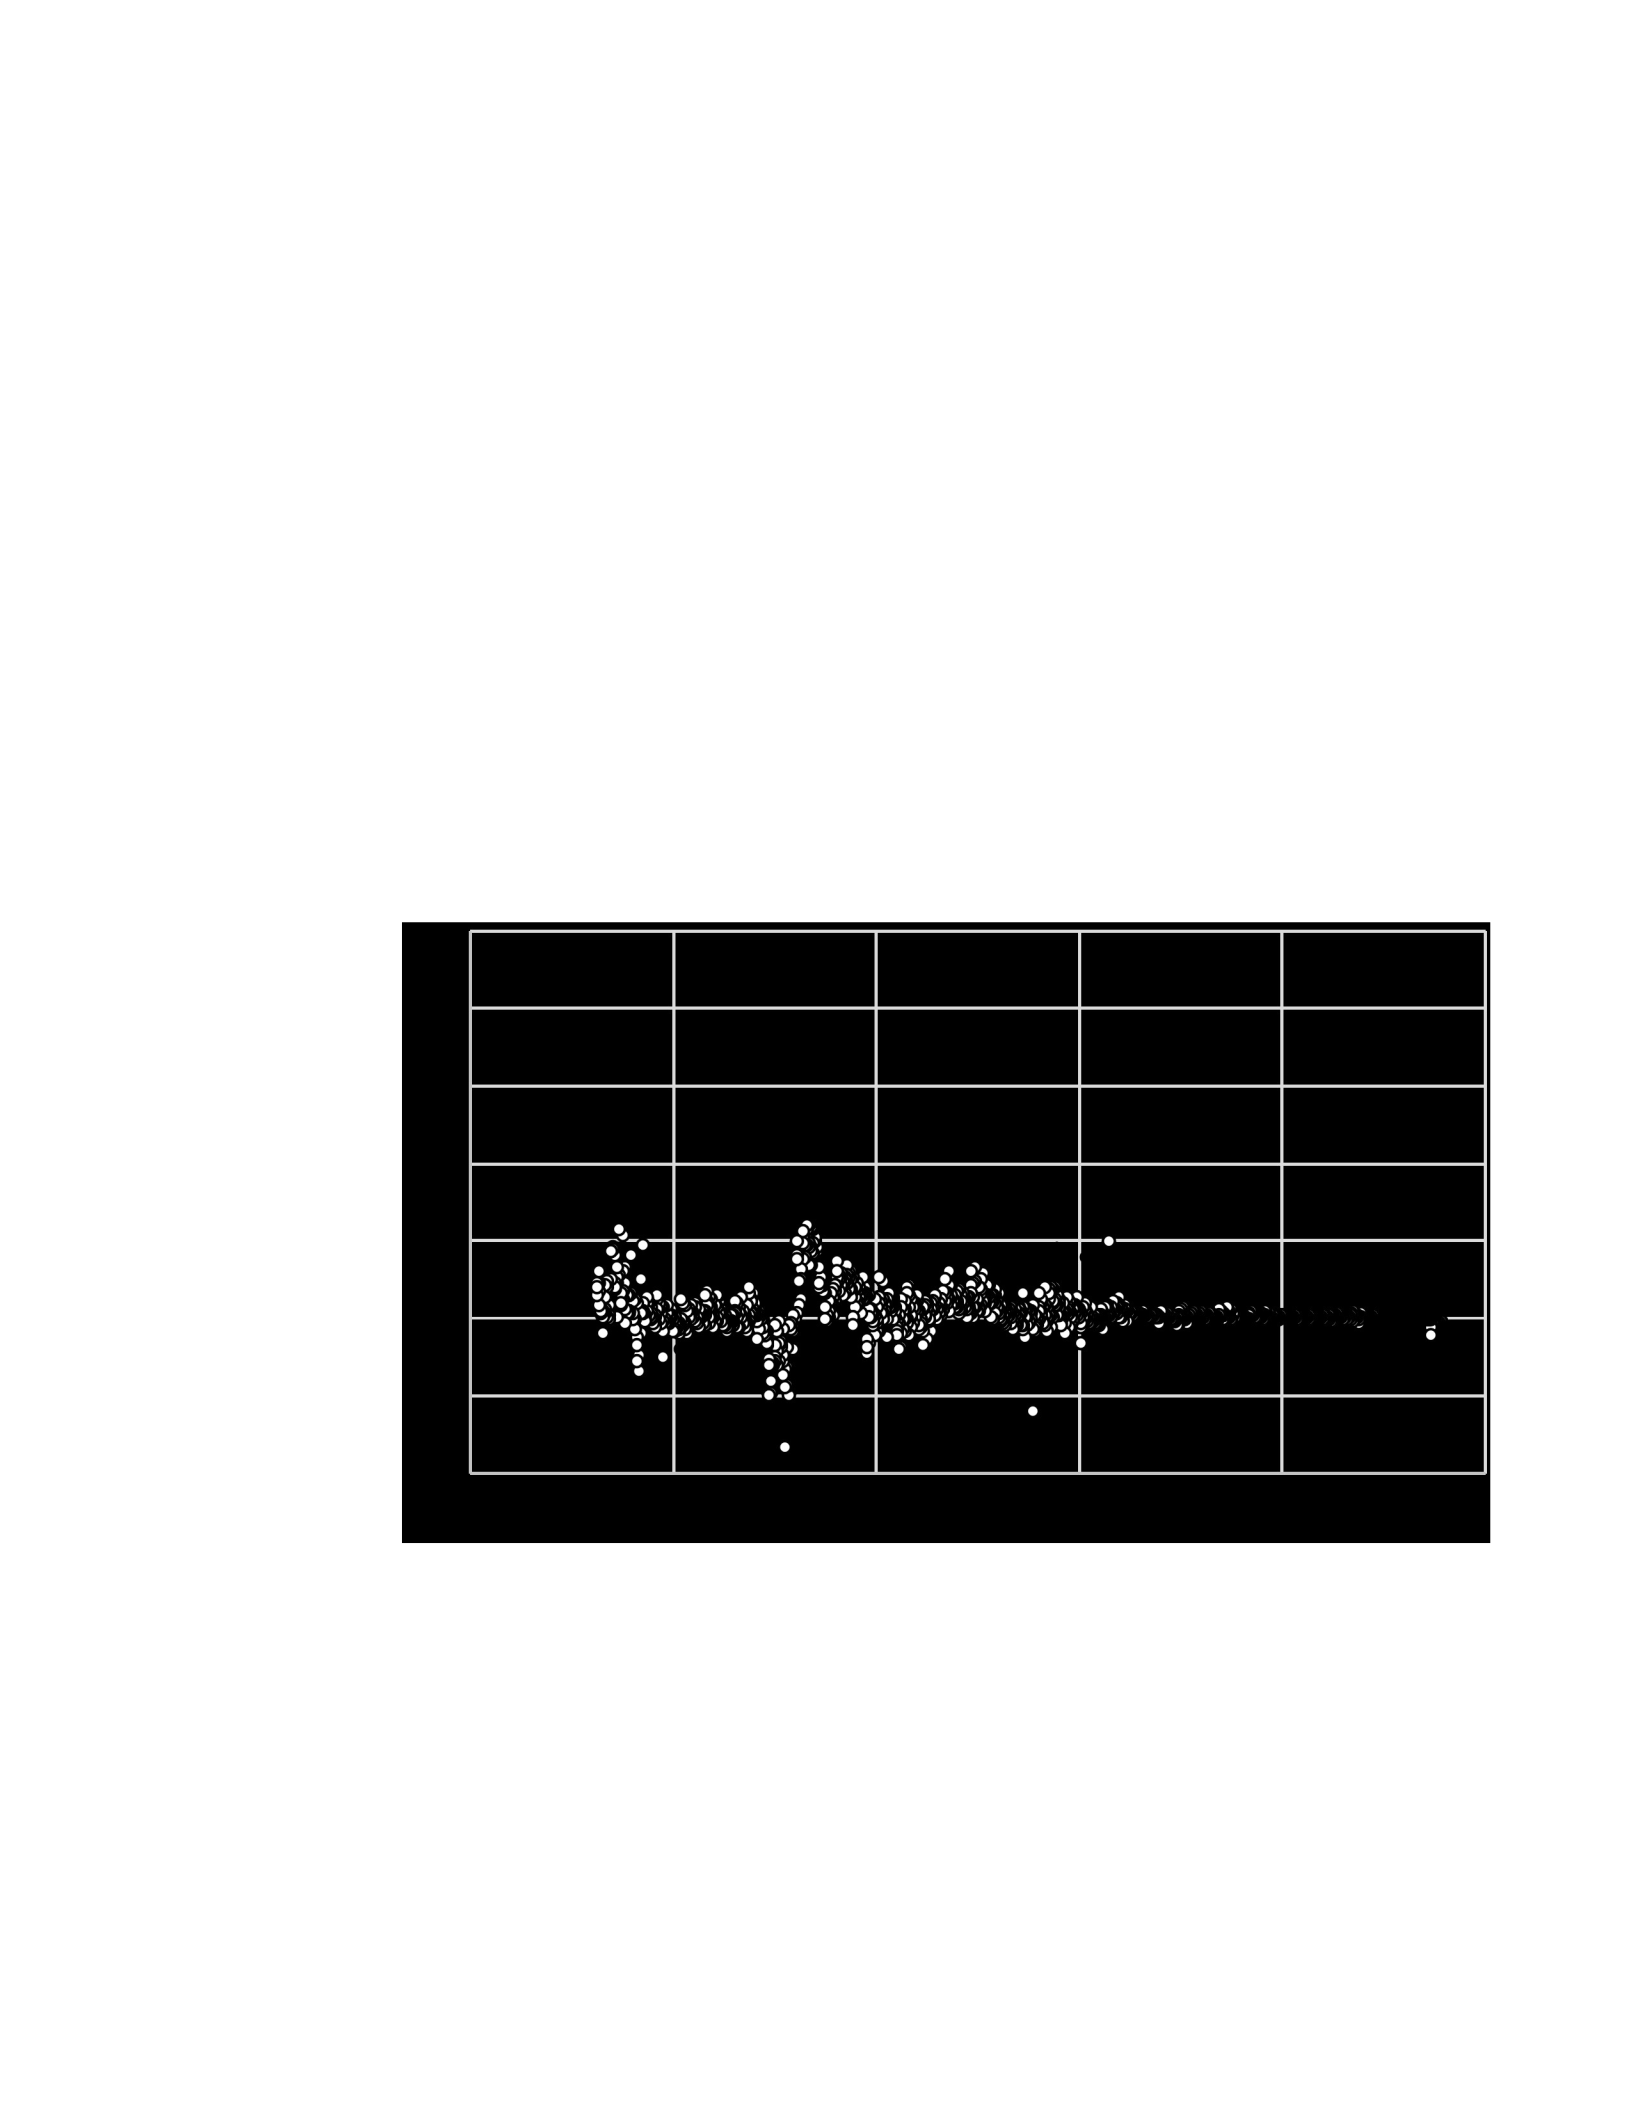
Figure 18 below shows the depegging instances for Tether (USDT). As shown, the
price of Tether fell below the U.S. dollar numerous times, and particularly during the
2017 – 2021 period. As shown in Table 14, two models predicted Tether’s (USDT)
depegging with over 90% accuracy with the Random Forest model at a prediction
accuracy of 91.8% and the Gradient Boosted Trees at 91.9%. Figure 20 ranks the
importance of the predictor variables for the Random Forest model (the only model that
ranks variable importance). The top two predictors were cryptocurrencies – Solana
(SOL) and Ethereum (ETH). The NASDAQ close, a security measure, also showed
strong predictive abilities. The remaining predictors of Tether (USDT) depegging were
measures of fiat currencies and other cryptocurrencies.
Figure 18. Peg Value Scatterplot (USDT)
72
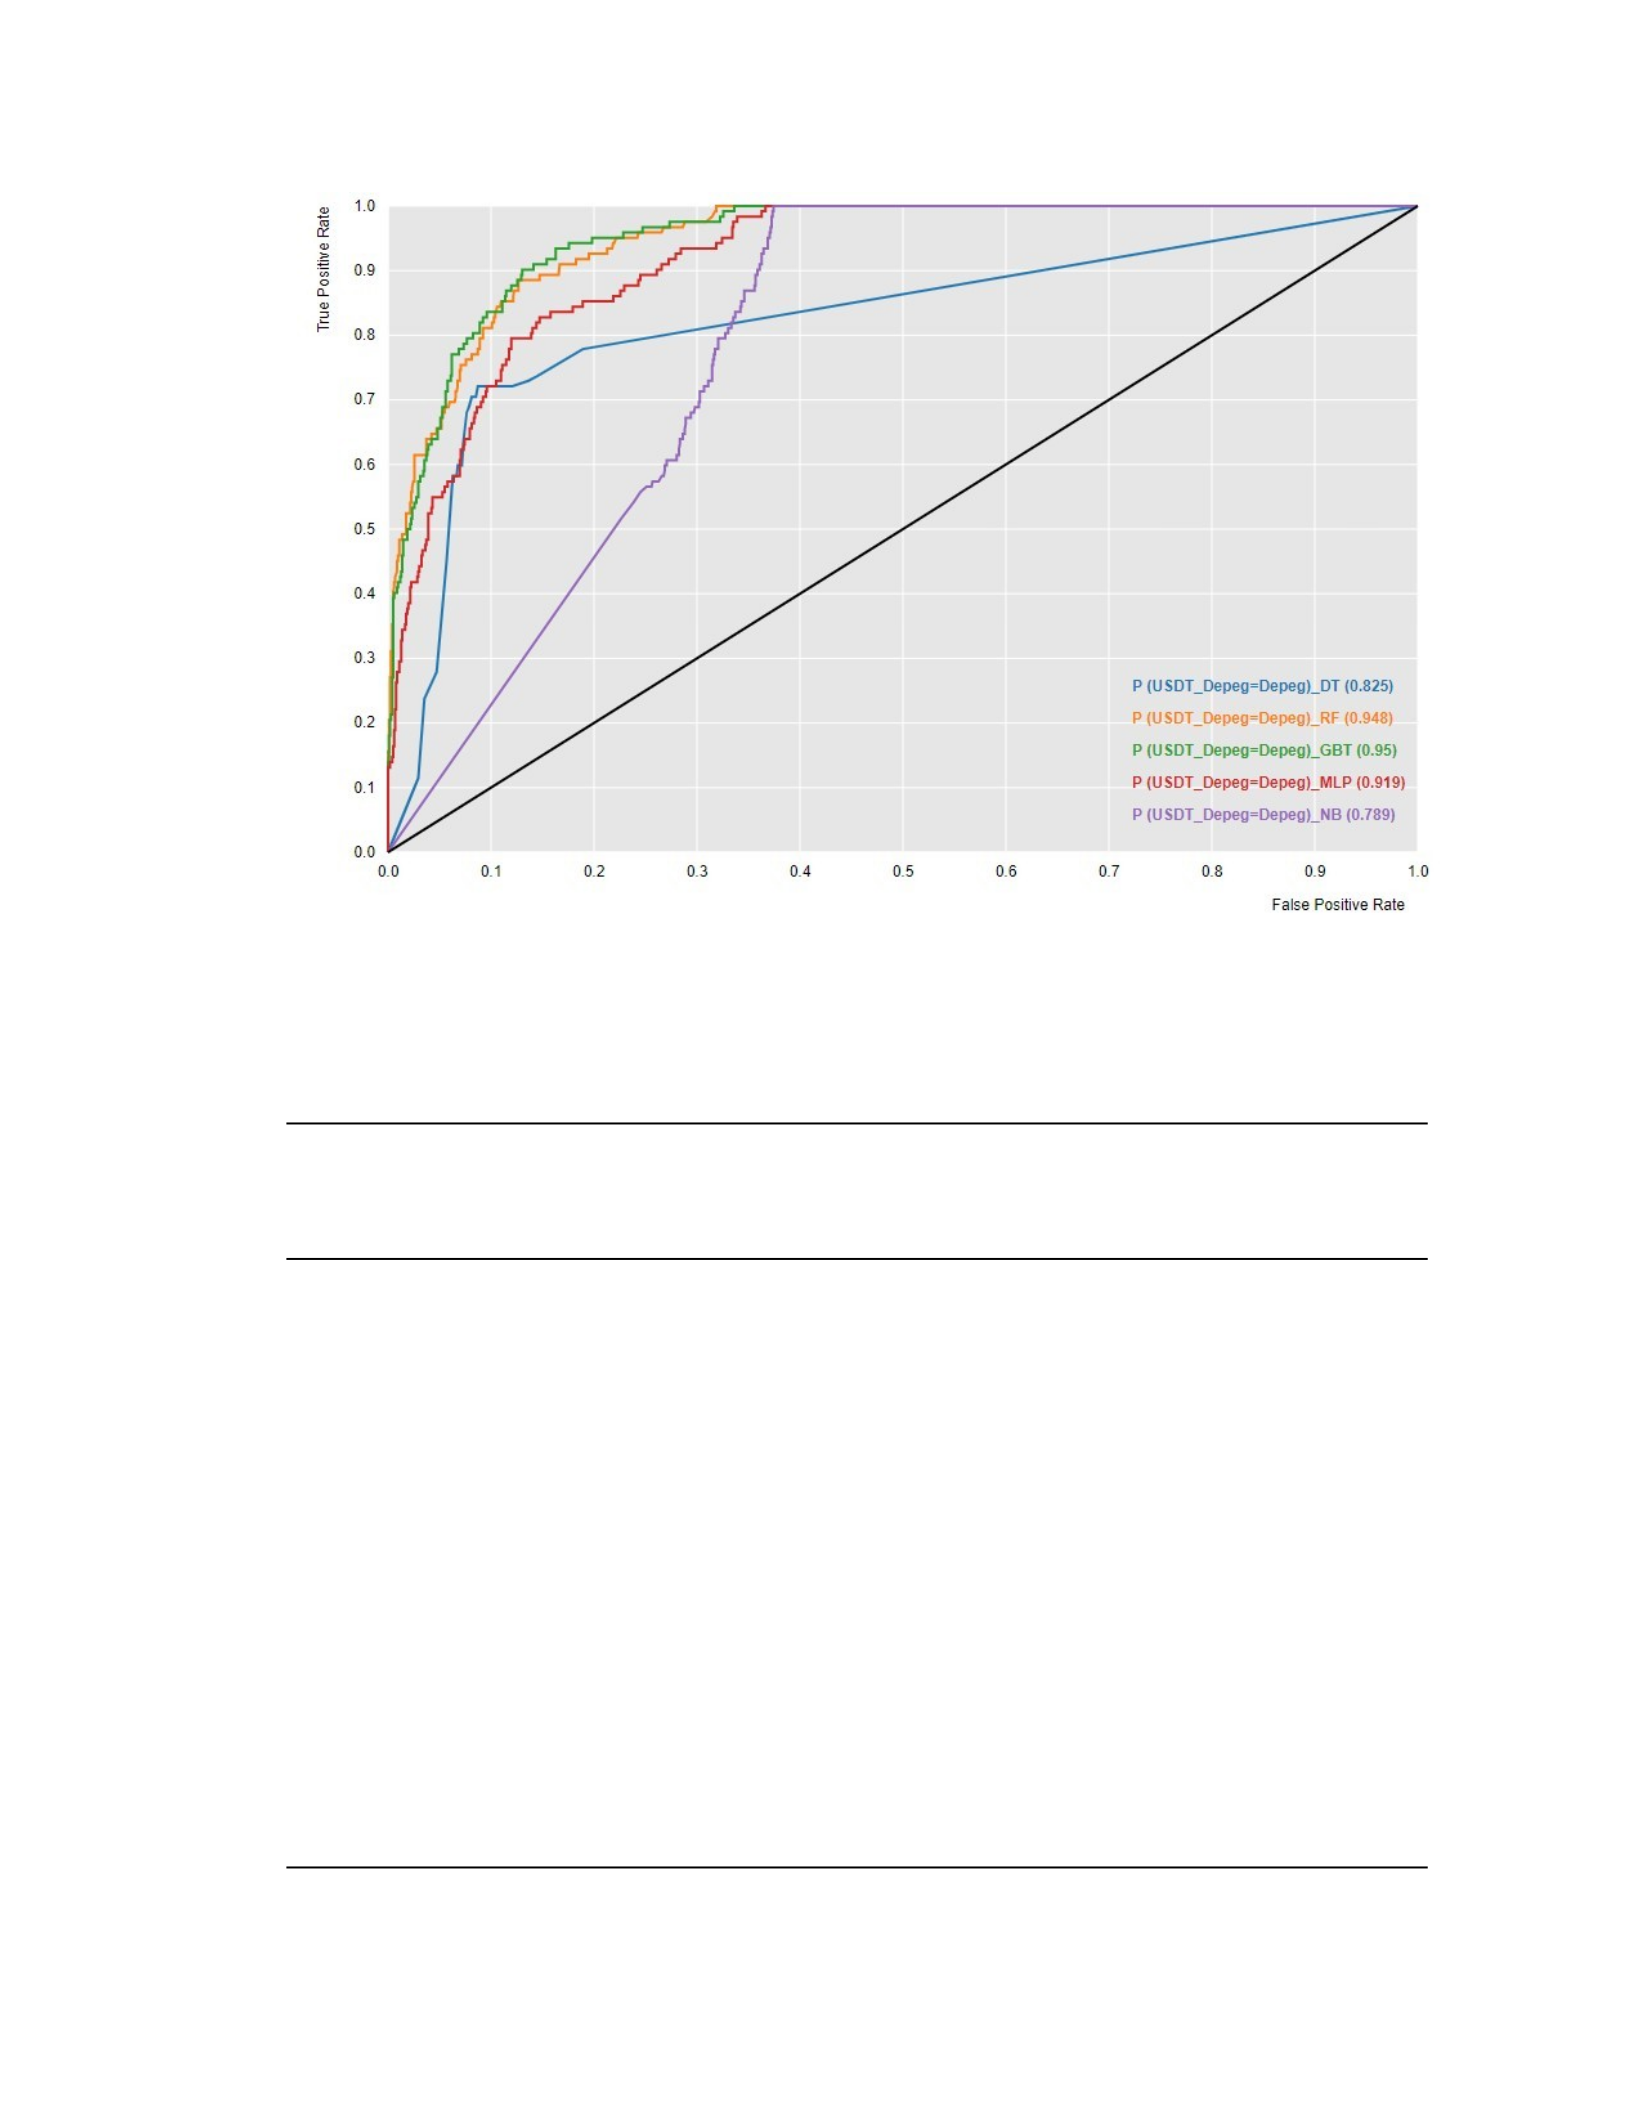
Figure 19. ROC Curve for Cryptocurrency Volatility Prediction Models (USDT)
Table 14. Study 1b - USDT Depegging Model Prediction Results
Model TP TN FP FN Accuracy Sensitivity Specificity
False
Positive
Rate
Decision Trees 86 933 87 36 0.892 0.705 0.915 0.085
Random Forest 81 967 53 41 0.918 0.664 0.948 0.052
Gradient
Boosted Trees 82 968 52 40 0.919 0.672 0.949 0.051
Multi-Layer
Perceptron
Neural Network
102 844 176 20 0.828 0.836 0.827 0.173
Naïve Bayes 122 581 439 0 0.616 1 0.570 0.430
73
Figure 20. Random Forest Variable Importance (USDT)
Figure 21 below shows the depegging instances for U.S. Dollar Coin (USDC). As
shown, the price of Ethereum fell below the U.S. dollar numerous times, and particularly
during the initial years after its launch. As shown in Table 15, two models predicted
Ether’s (USDC) depegging with over 90% accuracy with the Random Forest model at a
prediction accuracy of 90.3% and the Gradient Boosted Trees model at 91.6%. Figure 23
ranks the importance of the predictor variables for the Random Forest model (the only
model that ranks variable importance). The top two predictors of U.S. Dollar Coin’s
(USDC) depegging were stablecoins – Binance USD (BUSD) and Tether (USDT). The
next two were measures related to the U.S. Dollar. Interestingly, three commodities
measures also showed predictive abilities.
74
0.403
0.433
0.475
0.49
0.494
0.563
0.614
0.735
0.987
1.003
XRP_Volume
Treasury_Rate_52_Weeks_Coupon
Crude_Oil_Production_U.S.
DOGE_Adj_Close
BTC_Volume
US_Dollar_M1
US_Dollar_Circulation
NASDAQ_Close
ETH_Adj_Close
SOL_Adj_Close
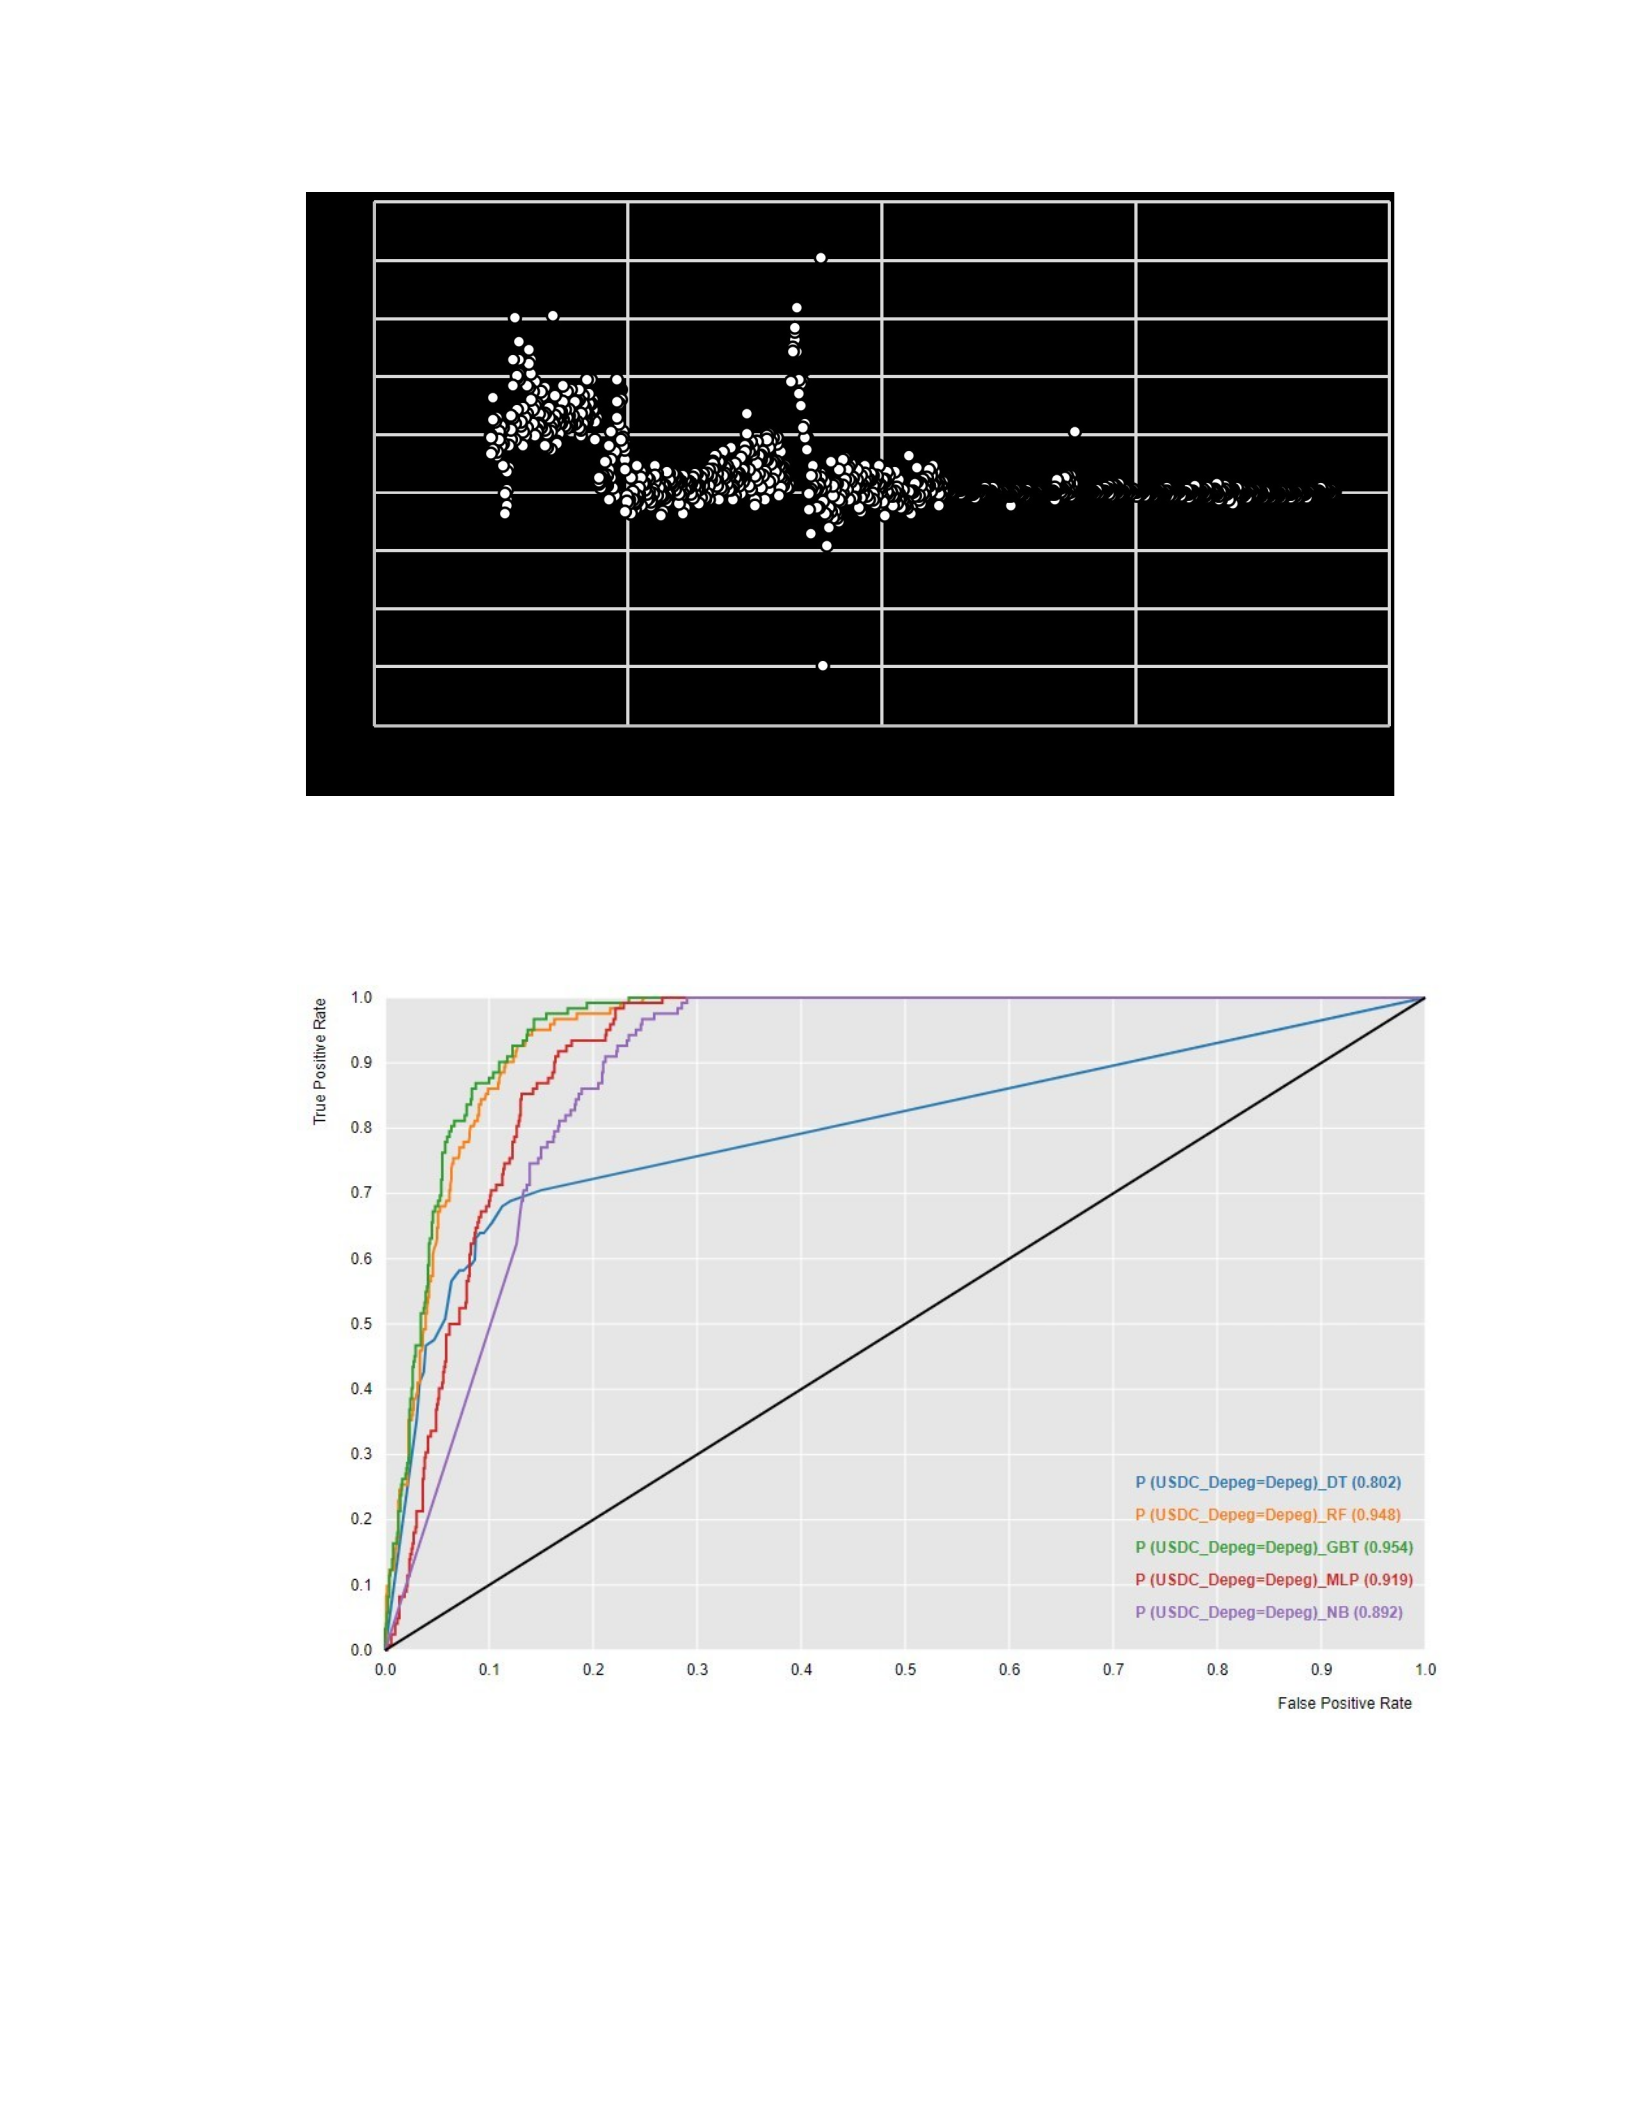
Figure 21. Peg Value Scatterplot (USDC)
Figure 22. ROC Curve for Cryptocurrency Volatility Prediction Models (USDC)
Table 15. Study 1b - USDC Depegging Model Prediction Results
75
Model TP TN FP FN Accuracy Sensitivity Specificity
False
Positive
Rate
Decision Trees 73 932 88 49 0.880 0.598 0.914 0.086
Random Forest 98 933 87 24 0.903 0.803 0.915 0.085
Gradient
Boosted Trees 99 947 73 23 0.916 0.811 0.928 0.072
Multi-Layer
Perceptron
Neural Network
107 857 163 15 0.844 0.877 0.840 0.160
Naïve Bayes 115 775 245 7 0.779 0.943 0.760 0.240
Figure 23. Random Forest Variable Importance (USDC)
Figure 24 below shows the depegging instances for Binance USD (BUSD). As shown,
the price of Binance USD seemed to hover closer to the U.S. dollar than either
Tether or U.S. Dollar Coin. As shown in Table 16, three models predicted Binance USD
(BUSD) depegging with over 90% accuracy. The Decision Trees model had a prediction accuracy
of 91.8%, the Random Forest model had an accuracy of 92.6%, and the Gradient Boosted Trees
76
0.329
0.452
0.454
0.467
0.495
0.621
0.682
0.703
0.935
0.965
Treasury_Rates_8_Weeks_Coupon
BNB_Close
Treasury_Rates_8_Weeks_Bank_Discount
SOL_Volume
Natural_Gas_Exports
BTC_Volume
US_Dollar_Circulation
US_Dollar_M1
USDT_Volume
BUSD_Adj_Close
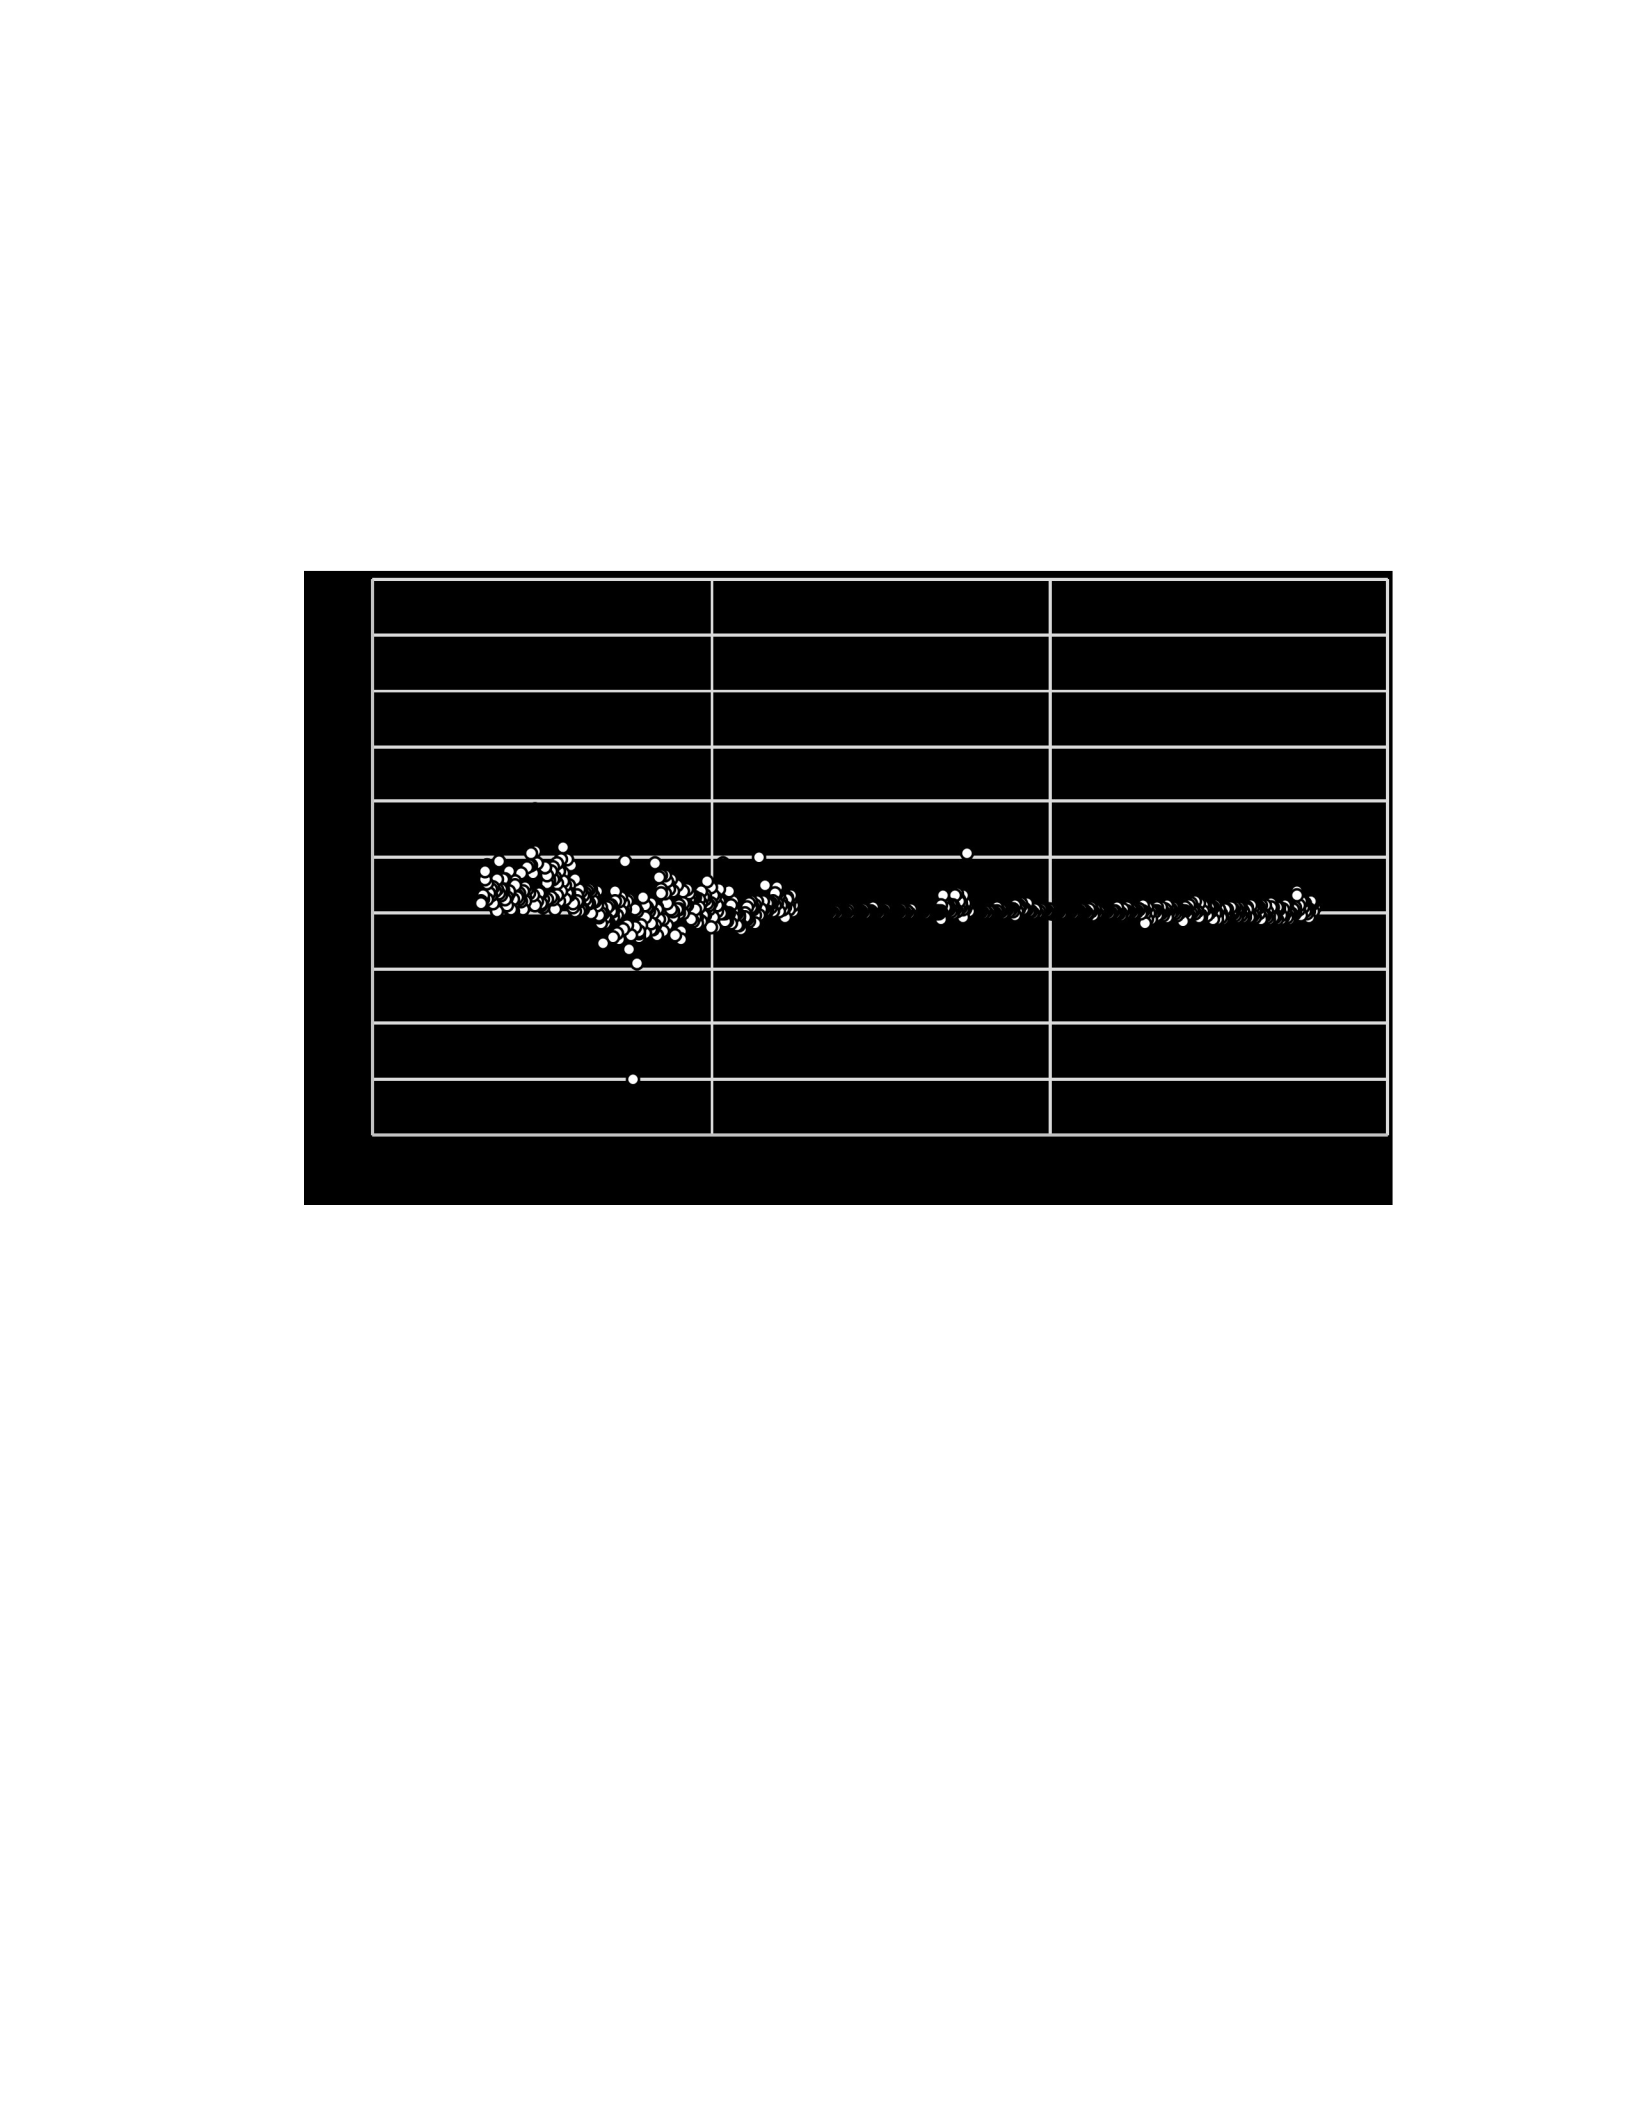
model was 93.2%. Figure 26 ranks the importance of the predictor variables for the Random
Forest model (the only model that ranks variable importance). The top four predictors of Binance
USD’s (BUSD) depegging were all measures related to the U.S. dollar. The remaining predictors
were securities (NASDAQ Close and SP500 Close), fiat currencies (Chinese Yuan), and other
cryptocurrencies. No commodities predicted Binance USD’s depegging.
1
Figure 24. Peg Value Scatterplot (BUSD)
77
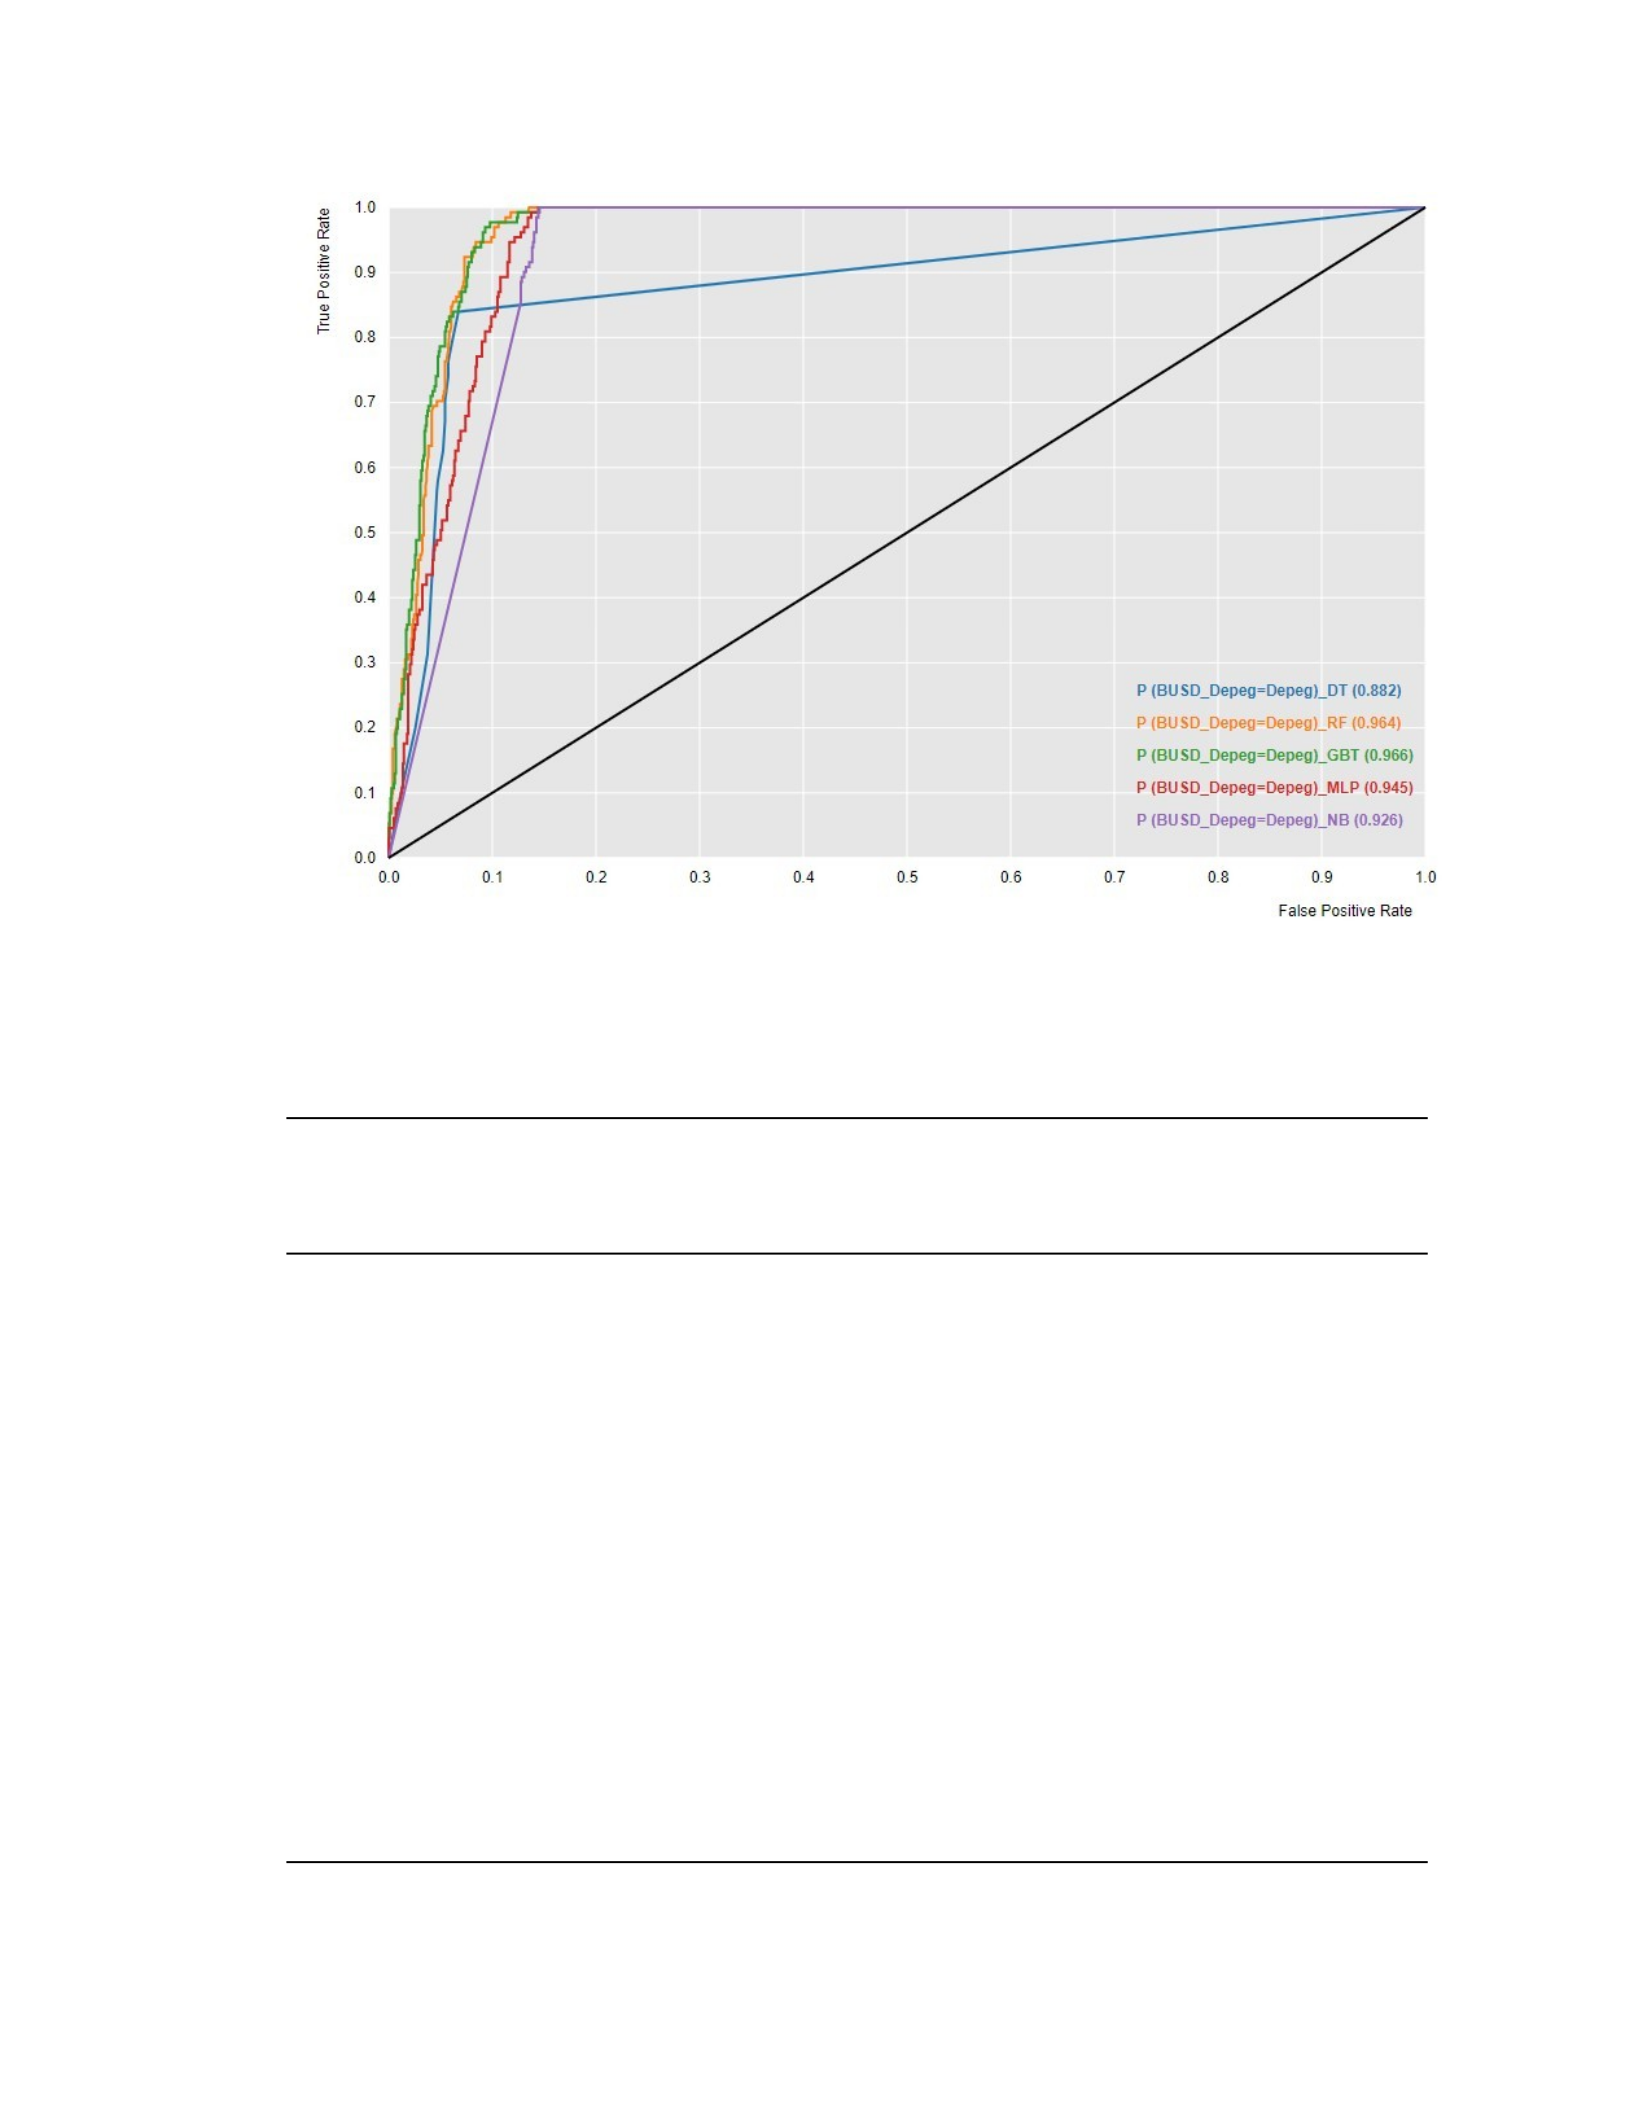
Figure 25. ROC Curve for Cryptocurrency Volatility Prediction Models (BUSD)
Table 16. Study 1b - BUSD Depegging Model Prediction Results
Model TP TN FP FN Accuracy Sensitivity Specificity
False
Positive
Rate
Decision Trees 92 956 55 39 0.918 0.702 0.946 0.054
Random Forest 106 951 60 25 0.926 0.809 0.941 0.059
Gradient
Boosted Trees 101 963 48 30 0.932 0.771 0.953 0.047
Multi-Layer
Perceptron
Neural Network
125 889 122 6 0.888 0.954 0.879 0.121
Naïve Bayes 131 856 155 0 0.864 1 0.847 0.153
78
US_Dollar_Circulation1.002 USDC_Adj_Close0.974
US_Dollar_M1
USDC_Volume
NASDAQ_Close
USDT_Volume
Chinese_Yuan_M1
SP500_Close
BTC_Volume
DOGE_Volume
Figure 26. Random Forest Variable Importance (BUSD)
4.3 Study 2 – Predicting Bitcoin Price Volatility from Blockchain Variables
Study 2 asked the following questions:
Question 3a: How effective are advanced machine learning models in
predicting price volatility of Bitcoin?
Question 3b: Which blockchain variables are most significant in
predicting Bitcoin price volatility?
Study 2 looked at price volatility in relation to the variables that underpin the
cryptocurrency’s blockchain as opposed to the economic variables evaluated in Studies
1a and 1b. Given that Bitcoin has the most longevity and thus, historical data, Study 2
analysis focused on Bitcoin price volatility. Figure 27 graphically depicts the price
volatility of Bitcoin. As shown in Table 17, two models predicted Bitcoin volatility with
over 90% accuracy. The Decision Trees model had a prediction accuracy of 90.6% and
79
0.883
0.754
0.64
0.529
0.523
0.484
0.386
0.351
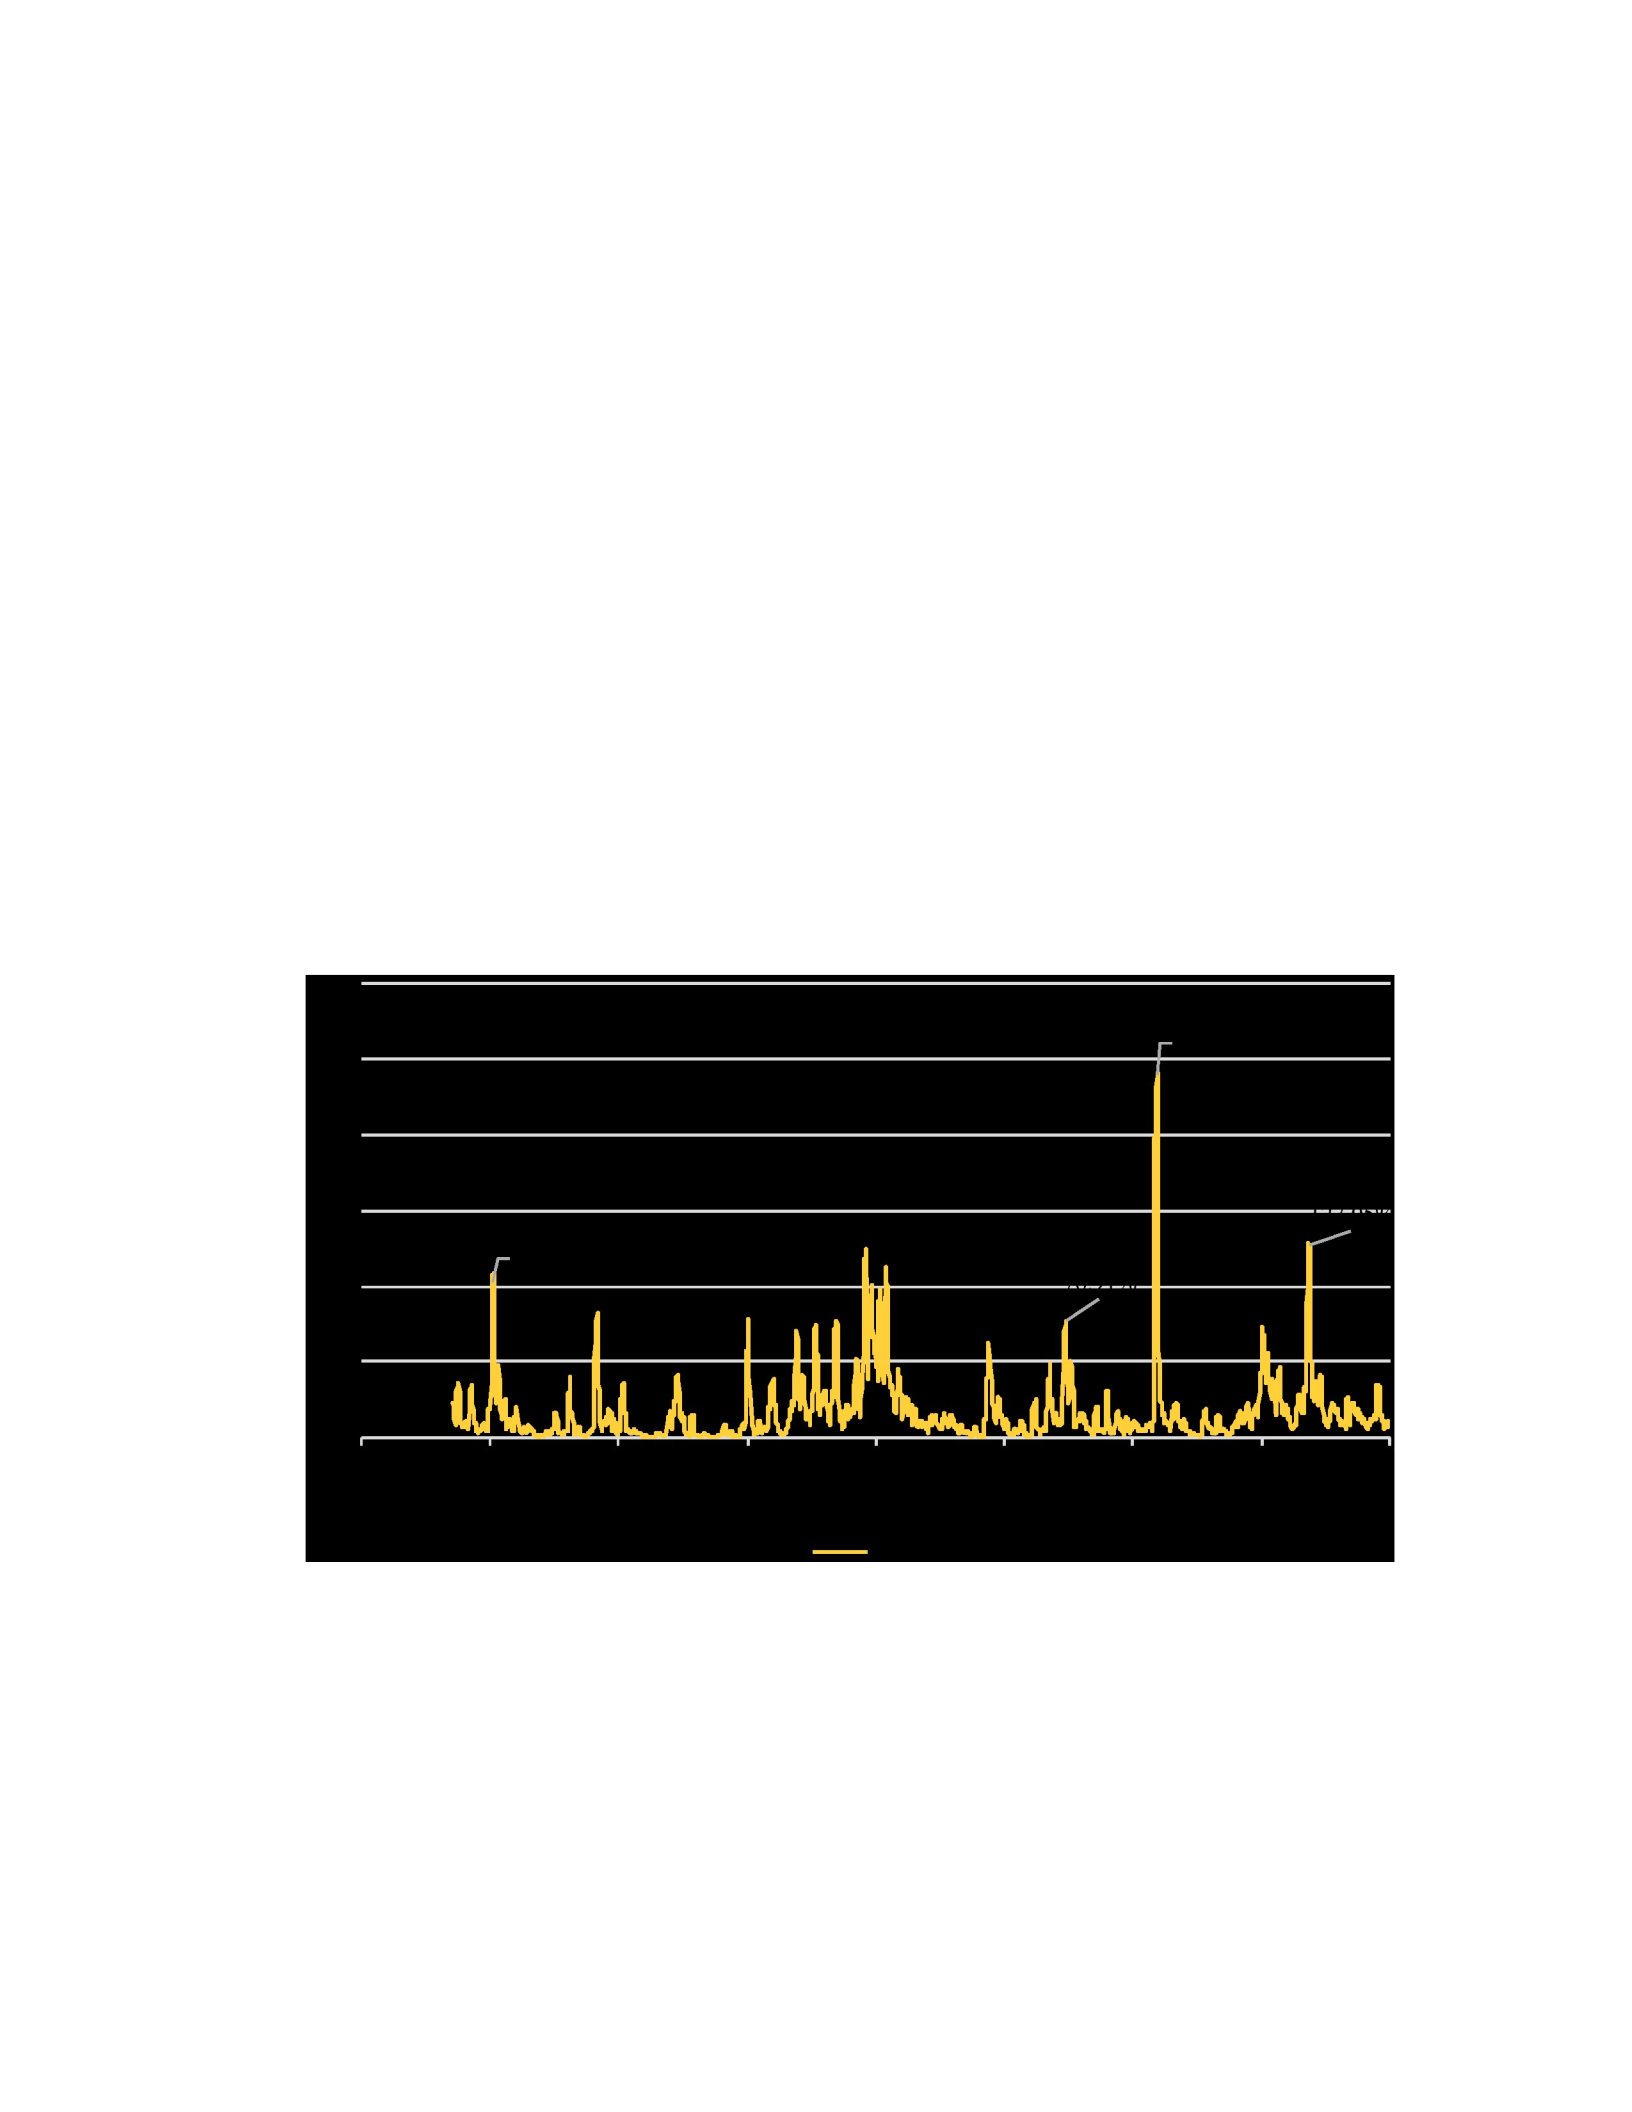
the Gradient Boosted Trees model had an accuracy of 90.3%. Figure 29 ranks the
importance of the predictor variables for the Random Forest model (the only model that
ranks variable importance). The blockchain variable that exhibited the overwhelmingly
highest prediction accuracy was mempool size. Mempool size reflects the number of
transactions waiting to be confirmed to the blockchain. As such, it is a proxy for
resource availability (e.g., computing power and/or number of miners for whom
validation is profitable). This suggests that resource availability on the Bitcoin
blockchain is the largest single predictor of Bitcoin price volatility – an idea that will be
further explored in
Chapter 5.
Figure 27. GK Volatility of Bitcoin (2014 - 2022)
80
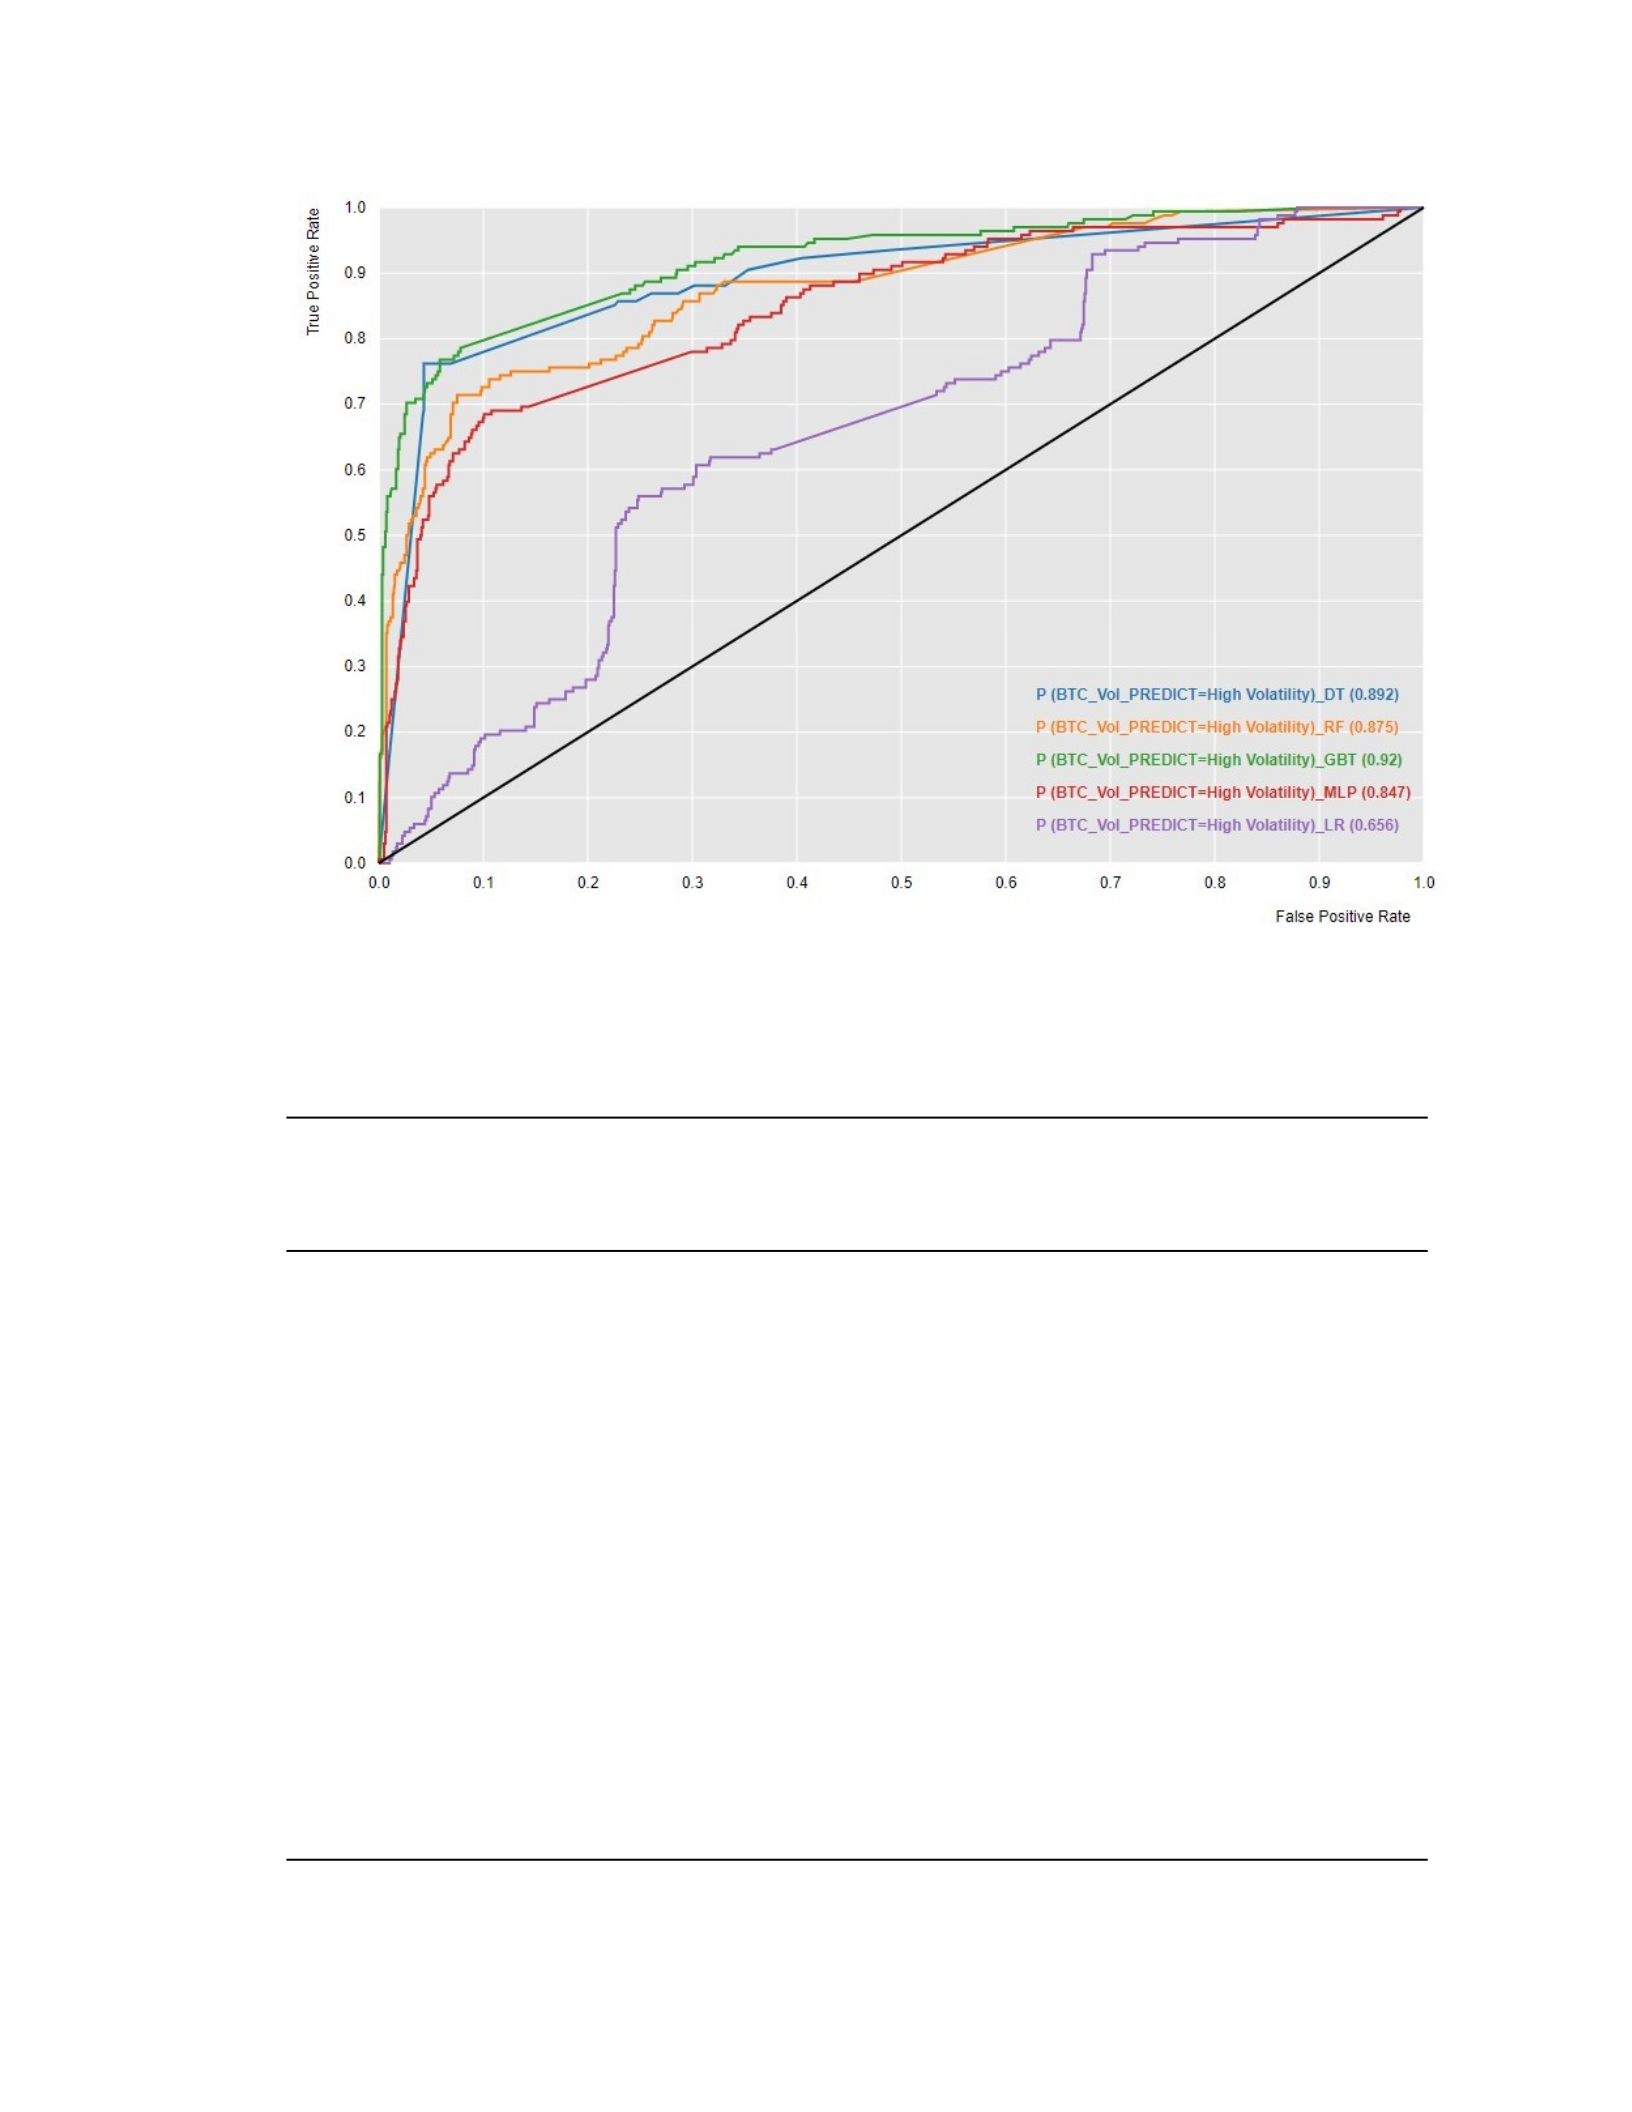
Figure 28. ROC Curve for Bitcoin Price Volatility Prediction Results
Table 17. Study 2 - Bitcoin Blockchain Model Prediction Results
Model TP TN FP FN Accuracy Sensitivity Specificity
False
Positive
Rate
Decision Trees 128 907 67 40 0.906 0.762 0.931 0.069
Random Forest 120 891 83 48 0.885 0.714 0.915 0.085
Gradient
Boosted Trees 130 901 73 38 0.903 0.774 0.925 0.075
Multi-Layer
Perceptron
Neural Network
115 876 98 53 0.868 0.685 0.899 0.101
Logistic
Regression 94 715 259 74 0.708 0.560 0.734 0.266
81
Figure 29. Random Forest Variable Importance for Bitcoin Volatility
82
0.003
0.134
0.159
0.255
0.321
0.344
0.35
0.388
0.416
0.444
0.447
1.058
Median_Confirmation_Time
Cost_Per_Transaction
n_Transactions
Estimated_Transaction_Volume
Miners_Revenue
Fees_Per_Transaction
n_Transactions_Per_Block
Network_Difficulty
Avg_Block_Size
Hash_Rate
Trade_Volume
Mempool_Size

CHAPTER V
V. DISCUSSION AND CONCLUSION
5.1 Introduction
The three studies presented in this paper resulted in models with high levels of
prediction accuracy. Study 1a looked at the predictive abilities of certain economic
variables on the price volatility of six traditional cryptocurrencies. Study 1b looked at the
predictive abilities of those same economic variables on the depegging of three
stablecoins (i.e., when the prices of those stablecoins fell below the U.S. dollar). Finally,
Study 2 looked at the predictive abilities of various blockchain variables on the price
volatility of Bitcoin.
All three studies were designed to better understand the volatility of
cryptocurrencies. Table 18 below summarizes the prediction results from each
cryptocurrency’s best volatility model. As shown, the Random Forest (RF) model had the
best accuracy results for all the traditional cryptocurrencies considered in Study 1a.
Gradient Boosted Trees (GBT) models had the best accuracy results for the stablecoins
considered in Study 1b and for the variables considered in Study 2.
Table 18. Top Volatility Model Prediction Results
83
Crypto-
currency
Model
Type
TP TN FP FN Accuracy Sensitivity Specificity
False
Positive
Rate
Cardano
(ADA) RF 97 367 18 18 .928 .843 .953 .047
Binance
(BNB) RF 94 371 12 5 .965 .949 .969 .031
Bitcoin (BTC) RF 91 366 16 9 .948 .910 .958 .042
Dogecoin
(DOGE) RF 76 379 12 15 .944 .835 .969 .031
Ethereum
(ETH) RF 88 368 14 12 .946 .880 .963 .037
Ripple (XRP) RF 90 358 20 14 .929 .865 .947 .053
Tether
(USDT) GBT 82 968 52 40 .919 .672 .949 .051
U.S. Dollar
Coin (USDC) GBT 99 947 73 23 .916 .811 .928 .072
Binance USD
(BUSD) GBT 101 963 48 30 .932 .771 .953 .047
Bitcoin
Blockchain GBT 130 901 73 38 .903 .774 .925 .075
Research questions 1a, 2a, and 3a specifically asked if advanced machine
learning models with the studied variables could accurately predict cryptocurrency price
volatility. Given that all three studies produced prediction models with high levels of
accuracy
84

(accuracy > 90%), these results positively answer those three research questions. More
importantly, they will inform both the academic and industry literature on this new field
of study.
5.2 Discussion
To best frame the findings in the three studies, it is helpful to begin with a discussion of the
results of Study 2.
5.2.1 Study 2 Discussion
The random forest prediction model results from Study 2 show that resource availability
or the cost of transactions is the most important variable for determining Bitcoin price
volatility. Figure 29 indicated that mempool size exhibits the best prediction ability on
Bitcoin price volatility. Given the mempool size is a proxy for resource availability (i.e.,
computing powers and/or number of miners for whom validation is profitable), the
results suggest that volatility in Bitcoin prices follows standard economic behaviors
associated with supply and demand.
Mempool size is a value reflecting the number of transactions waiting to be confirmed
and added to the blockchain. In proof-of-work blockchains, such as the Bitcoin
blockchain, transaction confirmation is executed by validator nodes (often called
“miners”). The results of Study 2 suggest that the most significant predictor of Bitcoin
volatility is the number of transactions that have been executed but not confirmed. This
implies that volatility increases when the margin on validation services is insufficient. On
the Bitcoin blockchain, the validation reward is fixed (the current reward is 6.25
Bitcoins), so it is reasonable to expect that the primary driver of mempool size is the cost
of validation. Since proof-of-work blockchains require validator nodes to calculate a
85

mathematical proof-of-work, validation is an energy intensive process. Therefore, the
cost of validation is likely correlated to the cost of energy.
5.2.2 Study 1a Discussion
As shown in Table 19 below, commodity variables were the top predictive
variable for most cryptocurrencies (4 of the 6). Interestingly, both Bitcoin and Ethereum
had fiat currencies as the top predictor variable (although the difference between the top
two predictor variables – one fiat currency and one commodity – in the Ethereum model
were negligible). Ethereum and Bitcoin are the two largest cryptocurrencies by market
capitalization, so the predictive power of fiat currencies in determining volatility is
worthy of further review. Except for DOGE, no other cryptocurrencies in the study had
another cryptocurrency (including Bitcoin) as the top predictive variable. Cryptocurrency
critics often cite the interconnectedness of cryptocurrencies as a driver of volatility. The
results from Study 1a do not support that conclusion.
While commodity variables appear to be the most important predictive variable
across the cryptocurrencies included in Study 1a, it is one specific type of commodity that
appears to drive importance – energy. Three of the four cryptocurrencies (BNB, XRP, and
ETH) where commodities were the top predictive variable had residential natural gas as
the top predictor variable. The fourth, ADA, had crude oil production as the top predictor
variable. As described in section 5.2.1 above, the results are in alignment with the results
from Study 2.
While not the direct focus of this study, it is worth noting that the natural gas
variable with the most predictive importance was residential consumption, not
commercial. These findings suggest that the miners themselves, or the entities
86
responsible for validating transactions on the blockchain, may be more diverse than
previously believed. It also suggests that there may be a significant volume of
mining activity occurring in residential locations.
Table 19. Top Predictive Variable (by class) for Traditional Cryptocurrencies
Traditional Other
currenciesCrypto- Stablecoins Securities Commodities CurrenciesFiat
EconomicIndicators
Cardano X
(ADA)
Binance
(BNB) X
Bitcoin
(BTC) X
Dogecoin X X
(DOGE)
Ethereum
(ETH) X X
Ripple (XRP) X
5.2.3 Study 1b Discussion
As shown in Table 20 below, depegging behavior of both Tether (USDT) and
U.S. Dollar Coin (USDC) was best predicted by other cryptocurrencies. The results from
Study 1b indicate a clear relationship between U.S. Dollar Coin and Binance USD as
87
both stablecoins appear high on the variable importance list for one another. Tether
depegging, a stablecoin with a long history of speculation that it is under-reserved, was
most predicted by Solana which may suggest a relationship between the two coins. U.S.
Dollar Coin, the newest and least volatile stablecoin, was the only stablecoin with a fiat
currency as the top predictor variable.
Table 20. Top Predictive Variable (by class) for Stablecoins
Other
TraditionalcurrenciesCrypto- Stablecoins Securities Commodities CurrenciesFiat
EconomicIndicators
Tether
(USDT) X
US Dollar
Coin X
(USDC)
Binance
USD X
(BUSD)
5.3 Conclusions
Since their inception, cryptocurrencies have been the source of substantial speculation.
Extreme price fluctuations, public collapses, and nefarious use cases all drive conjecture.
The three studies in this paper sought to illuminate the drivers of cryptocurrency behavior
by using machine learning techniques to evaluate the predictive properties of a wide
range of economic and blockchain performance variables. The results suggest that
volatility in cryptocurrency markets is subject to the traditional economic drivers of
88

supply and demand, however the supply and demand mechanisms themselves may be
unexpected and require further research.
Machine learning models do not lend themselves to discrete conclusions. Rather, the
models deployed in this study serve to predict volatility amongst the cryptocurrencies
and stablecoins assessed in the studies. The model results serve as observations that
imply relationships and directionality that should be assessed in further studies. It is also
important to remember that machine learning models rely on the collection of the
variables included within the model. Any conclusions regarding specific variables and
their importance within the models are for discussion purposes only as the full model
accuracy reflects the full ranges of variables. This section describes observations from
the models as well as inferences as to the root cause of certain model outcomes. Study
1a explored the economic drivers of volatility amongst the six largest traditional
cryptocurrencies. In general, it appears that commodities, not fiat currencies, securities,
or other cryptocurrencies, are the primary predictors of volatility for traditional
cryptocurrencies. These results are surprising given recent claims by the U. S. Securities
and Exchange Commission (SEC) that many cryptocurrencies, including Cardano
(ADA), Binance Coin (BNB), and Ripple (XRP) included in this study, are, in fact,
securities (U.S. Securities and Exchange Commission, 2023a, 2023b). However, given
the well-studied relationship between energy prices and cryptocurrency prices, it is
reasonable to expect that commodities, particularly oil and natural gas, would have
predictive properties for cryptocurrency volatility.
When assessed alongside the results of Study 2, the combined observation is that
commodities, and specifically oil and residential natural gas consumption, are the
primary predictors of mempool size and, thus, cryptocurrency volatility. While this
89

observation is not inherently new, it does provide enhanced clarity into the relationship
between energy, blockchain performance, and cryptocurrency volatility. These results
suggest that the triangulation between those three factors may be more significant than
previously believed. Considering these results, disruptions, or changes to energy
markets, such as the recent Russian invasion of Ukraine, may have an outsized impact on
blockchain performance and thus cryptocurrency prices. Similarly, significant changes to
blockchain consensus mechanisms, as in the case of Ethereum’s recent change to
proofof-stake consensus, may impact cryptocurrency volatility.
Perhaps the most interesting results come from Study 1b. Often marketed as a stable
alternative to highly volatile cryptocurrencies, stablecoins have positioned themselves
as the next generation of cryptocurrencies. Even sovereign states, including the United
States, are actively researching CBDCs, a form of state-backed stablecoin. Given this
attention, the observation that stablecoin depegging may not be predicted by the fiat
currencies that back them is novel. Oddly enough, it seems as though stablecoins are
more dependent on cryptocurrency markets than cryptocurrencies themselves. If or how
this may impact future CBDCs remains to be seen.
5.4 Limitations
While the three studies in this paper examined several predictor variables
(asset classes, economic indicators, and blockchain performance variables), the
number of potential predictor variables (even within the broad categories of variables
selected for this paper) are limitless. As such, the specific predictor variables selected
for these studies represent a natural inherent limitation. A discussion of some of the
90

potential variables that may be related to cryptocurrency price can be found in Chapter
II, Other Potential Influences on Cryptocurrencies.
The timing and potential impact of new or expanded regulatory oversite that
relates specifically to cryptocurrency activity is not captured in these studies. The
Securities and Exchanges Commission (SEC) and Commodity Futures Trading
Commission (CFTC) are still developing their positions on the asset classification of
cryptocurrencies. Further, the Office of the Comptroller of the Current (OCC) issued its
first interpretative letter for banks in 2020, while the Federal Deposit Insurance
Corporation (FDIC) and the Federal Reserve issued their letters in 2022. The downstream
impact of regulatory oversite on cryptocurrency behavior is a major opportunity for
future research, however another limitation in this paper is that the impact of new or
expanded regulatory oversite has not yet been realized.
As discussed in this paper, the two largest cryptocurrencies, Bitcoin and
Ethereum, utilize proof-of-work consensus protocols to validate blockchain transactions.
In September 2022, Ethereum moved to a proof-of-stake consensus protocol which is
different in many material respects from proof-of-work (Ethereum, 2022). The
downstream impact of Ethereum’s new blockchain validation approach is another
opportunity for future research as the predictive properties of the studied variables may
change with respect to Ethereum once the change from proof-of-work to proof-of-stake is
fully realized. Regardless, another limitation of this paper is that the studied variables
pre-date this change in Ethereum’s validation approach.
At the time of this paper’s publication, the volatility of cryptocurrency markets is
a well-observed phenomenon. A “crypto winter” is broadly defined as a period in which
91

most cryptocurrencies experience lower values (Chohan, 2022). While several crypto
winters have been observed in the past, the record prices of cryptocurrencies in 2020
made the crypto winter experienced in 2022 particularly obvious (and painful, for some)
(Chohan, 2022). As the scope of this paper includes data only to June 1, 2022, it is unclear
how the market downturn of the 2022 crypto winter may impact the efficacy of the
paper’s predictive models. Additionally, Study 2 relies on a calculation of daily volatility
for prediction. Predictive results may be biased based on the measure of volatility used in
the study.
Finally, certain global events have been observed to influence cryptocurrency
prices. For example, when facing economic sanctions, countries sometimes turn to crypto
markets to allow for cross-border payments. With the ongoing political events between
Ukraine and Russia, there is discussion that economic sanctions on Russia will encourage
more Russian activity in crypto markets, thus inflating the price of cryptocurrencies.
Another example was the sharp increase in cryptocurrency activity observed during the
Covid-19 pandemic, a time when U.S. interest rates were low and stock market
performance was volatile (Katsiampa et al., 2022). The analysis described in Chapter III
did not attempt to tease out the impact of these (or other) global events.
5.5 Recommendations for Future Research
These studies utilized data science techniques to explore
volatility in cryptocurrency markets. Future studies could expand upon these findings to
further evaluate the significance of the relationships overserved in these studies.
Additionally, future studies should explore the effectiveness of these models in predicting
the volatility from the 2022-2023 crypto winter as those data were not included in these
92

studies. From a methodological perspective, future models could expand upon the
models in these studies by incorporating additional variables that may further improve
the predictability and effectiveness of the models. For example, these studies did not
incorporate any natural language processing (NLP) techniques that may further explain
volatility in cryptocurrency markets. Future studies that combine the variables explored
in these studies along with NLP and other techniques may provide additional insights into
the behavior of cryptocurrency markets. Future studies that seek to study volatility may
also benefit from comparing several measures of volatility. Certain measures, like
GARCH, may provide additional perspective on cryptocurrency volatility.
From a variable inclusion and data standpoint, further studies could continue to explore
the details of additional cryptocurrency and commodity variables. Future studies should
research the significance of commodities in driving cryptocurrency prices. Such studies
may assist legislators and regulators in determining the appropriate classification for
cryptocurrencies and other similar assets.
93


