


For questions 1-10 , please keep your answers brief. You may use only the space provided (I will
not grade answers attached elsewhere)
1) (2 points) What does D.C.F. typically stand for in finance?
Discounted Cash Flow, as in a DCF analysis.
2) (2 points) Which is a better capital budgeting tool: NPV or IRR? Why?
NPV is better is because it incorporates IRR and a host of other factors. NPV tells us the actual
dollar value of a project with the IRR included, as opposed to the IRR only giving us a percentage
without any tangible information on a return.
3) (2 points) For an all equity firm, what is the difference between the cost of equity and the discount
rate?
The cost of equity is the cost of capital. It refers to the actual cost of financing the firm though equity,
and be considered as the firm’s required return rate.
The discount rate estimates how much the firm’s future cash flows are worth now, and is determined
byy the rate of return of some other investment (usually something safe with US government debt).
4) (2 points) True or False: The interest tax shield provides an incentive for firms to finance projects
with equity. Explain your answer.
False. The interest tax shield provides an incentive to finance with debt, because the interest counts
as a tax deduction. No such protection exists for equity financing.
5) (3 points) True or False: Firms have an optimal capital structure. Explain your answer.
False. An optimal capital structure is 99.9% debt. This is because since the interest payments are tax
shields, the money is essentially “free” and has an opportunity cost of $0 and 0%.
6) (3 points) What kind of capital budgeting mistakes will optimistic managers make?
Three main mistakes:
a) The cash flow projections are overly optimistic and don’t adequately take negative factors into
account.
b) They rely on those cash flow projections without making adjustments of accommodations for
issues
c) They set the expected rate of return too high, or the discount rate too low.
d) They don’t account for changes in the cost of capital, especially since COC increases with increases
in financing.
7) (3 points) Should firms with exposure to oil prices (inputs or outputs) command higher expected
returns? Explain your reasoning.
Yes. Oil prices generally have a higher market volatility. The risk is higher, and thus the return is
also higher.
8) (3 points) You hear a credible rumor about a pending acquisition of a major oil company. Can you
expect to make a profit off this rumor? Why or why not?
No, you cannot expect to make a profit off of this rumor. It is not a material, factual event and
there is no tangible way to provide a return. M&A requires government intervention and
regulation, which at times can stop the transaction from even occurring. If you attempted to make
a bet or generate a profit, it would be for nothing if the government doesn’t approve it or the deal
doesn’t otherwise go through.
9) (5 points) The risk free rate is 4%, the market risk premium is 6% and the CAPM holds. Your firm
uses a constant hurdle rate for all decision of 18%, but has projects of varying risk. Indicate on the
graph below the regions where (a) you correctly accept projects, (b) you correctly reject projects, (c)
you incorrectly accept projects, and (d) you incorrectly reject projects.
rf=4%
18%
E[R]
10) (5 points) A put and a call on the same underlying security have the same maturity and exercise
price. If they also sell for the same price, prove which one is in the money. (Hint: Put-Call Parity
holds)
The call option is in the money. In the call option, this is true if the strike price is less than the
current market price. Demonstrated here:
In call option = if strike price < current market price
Then call option is “in the money”.
Example :
Strike price = 80
Current market price = 100
Here 80<100
Hence ” in the money” is 100 - 80 = 20
In put option = if strike price > current market price
Then put option is “in the money”.
Example :
Strike price = 100
Current market price = 80
Here 100>80
Hence ” in the money” is 100 - 80 = 20
β
11) (10 points) You own a portfolio of Treasury bonds that has a market value of $88,096.90 today. This
portfolio contains 63 zero coupon bonds, each with a face value of $1000, that mature in exactly one
year. The portfolio also contains 28 zero coupon bonds ($1000 face value each) that mature in
exactly two years. The yield to maturity on the one year bonds is 3%. What is the price per bond of
the two year bonds?
Price of One Year Zero coupon Bond = 1000/1.03 = 970.8738
Value of one year zero coupon bond = 63*970.8738 = 61,165.05
Value of two year zero coupon bond = 88096.90- 61,165.05 = $ 26,931.85
price per bond of the two year bonds = 26931.85/28
price per bond of the two year bonds = 961.85
12) (15 points) The Crane Car Company has an equity beta, , of 0.7 and 20% debt in its capital
structure. The company has risk-free debt that costs 4% before taxes, and the expected rate
of return on the market is 16%. Crane is considering the acquisition of a new project in the
large truck manufacturing business that is expected to yield 20% on after-tax operating cash
flows. Boyle Big Rigs, which is in the same product line (and risk class) as the project being
considered, has an equity beta, , of 1.8 and has 40% debt in its capital structure. Crane will
finance the new project with 20% long-term debt and marginal tax rates are 35% on
everything. Find the WACC for the new project and decide what Crane Co should do.
Cost of equity Ke = Rf + (Rm –Rf)x beta
= 0.04 + (0.16 -0.04) x 1.80
= 25.60%
Cost of debt = 35%
WACC = Kd x Wd x (1-t) + Ke x We
= (0.04 x 0.40 x (1-0.35)) + (0.2560 x 0.60)
= 0.0104 + 0.1536
= 16.40%
Since expected yield is greater than WACC, the project should be accepted.
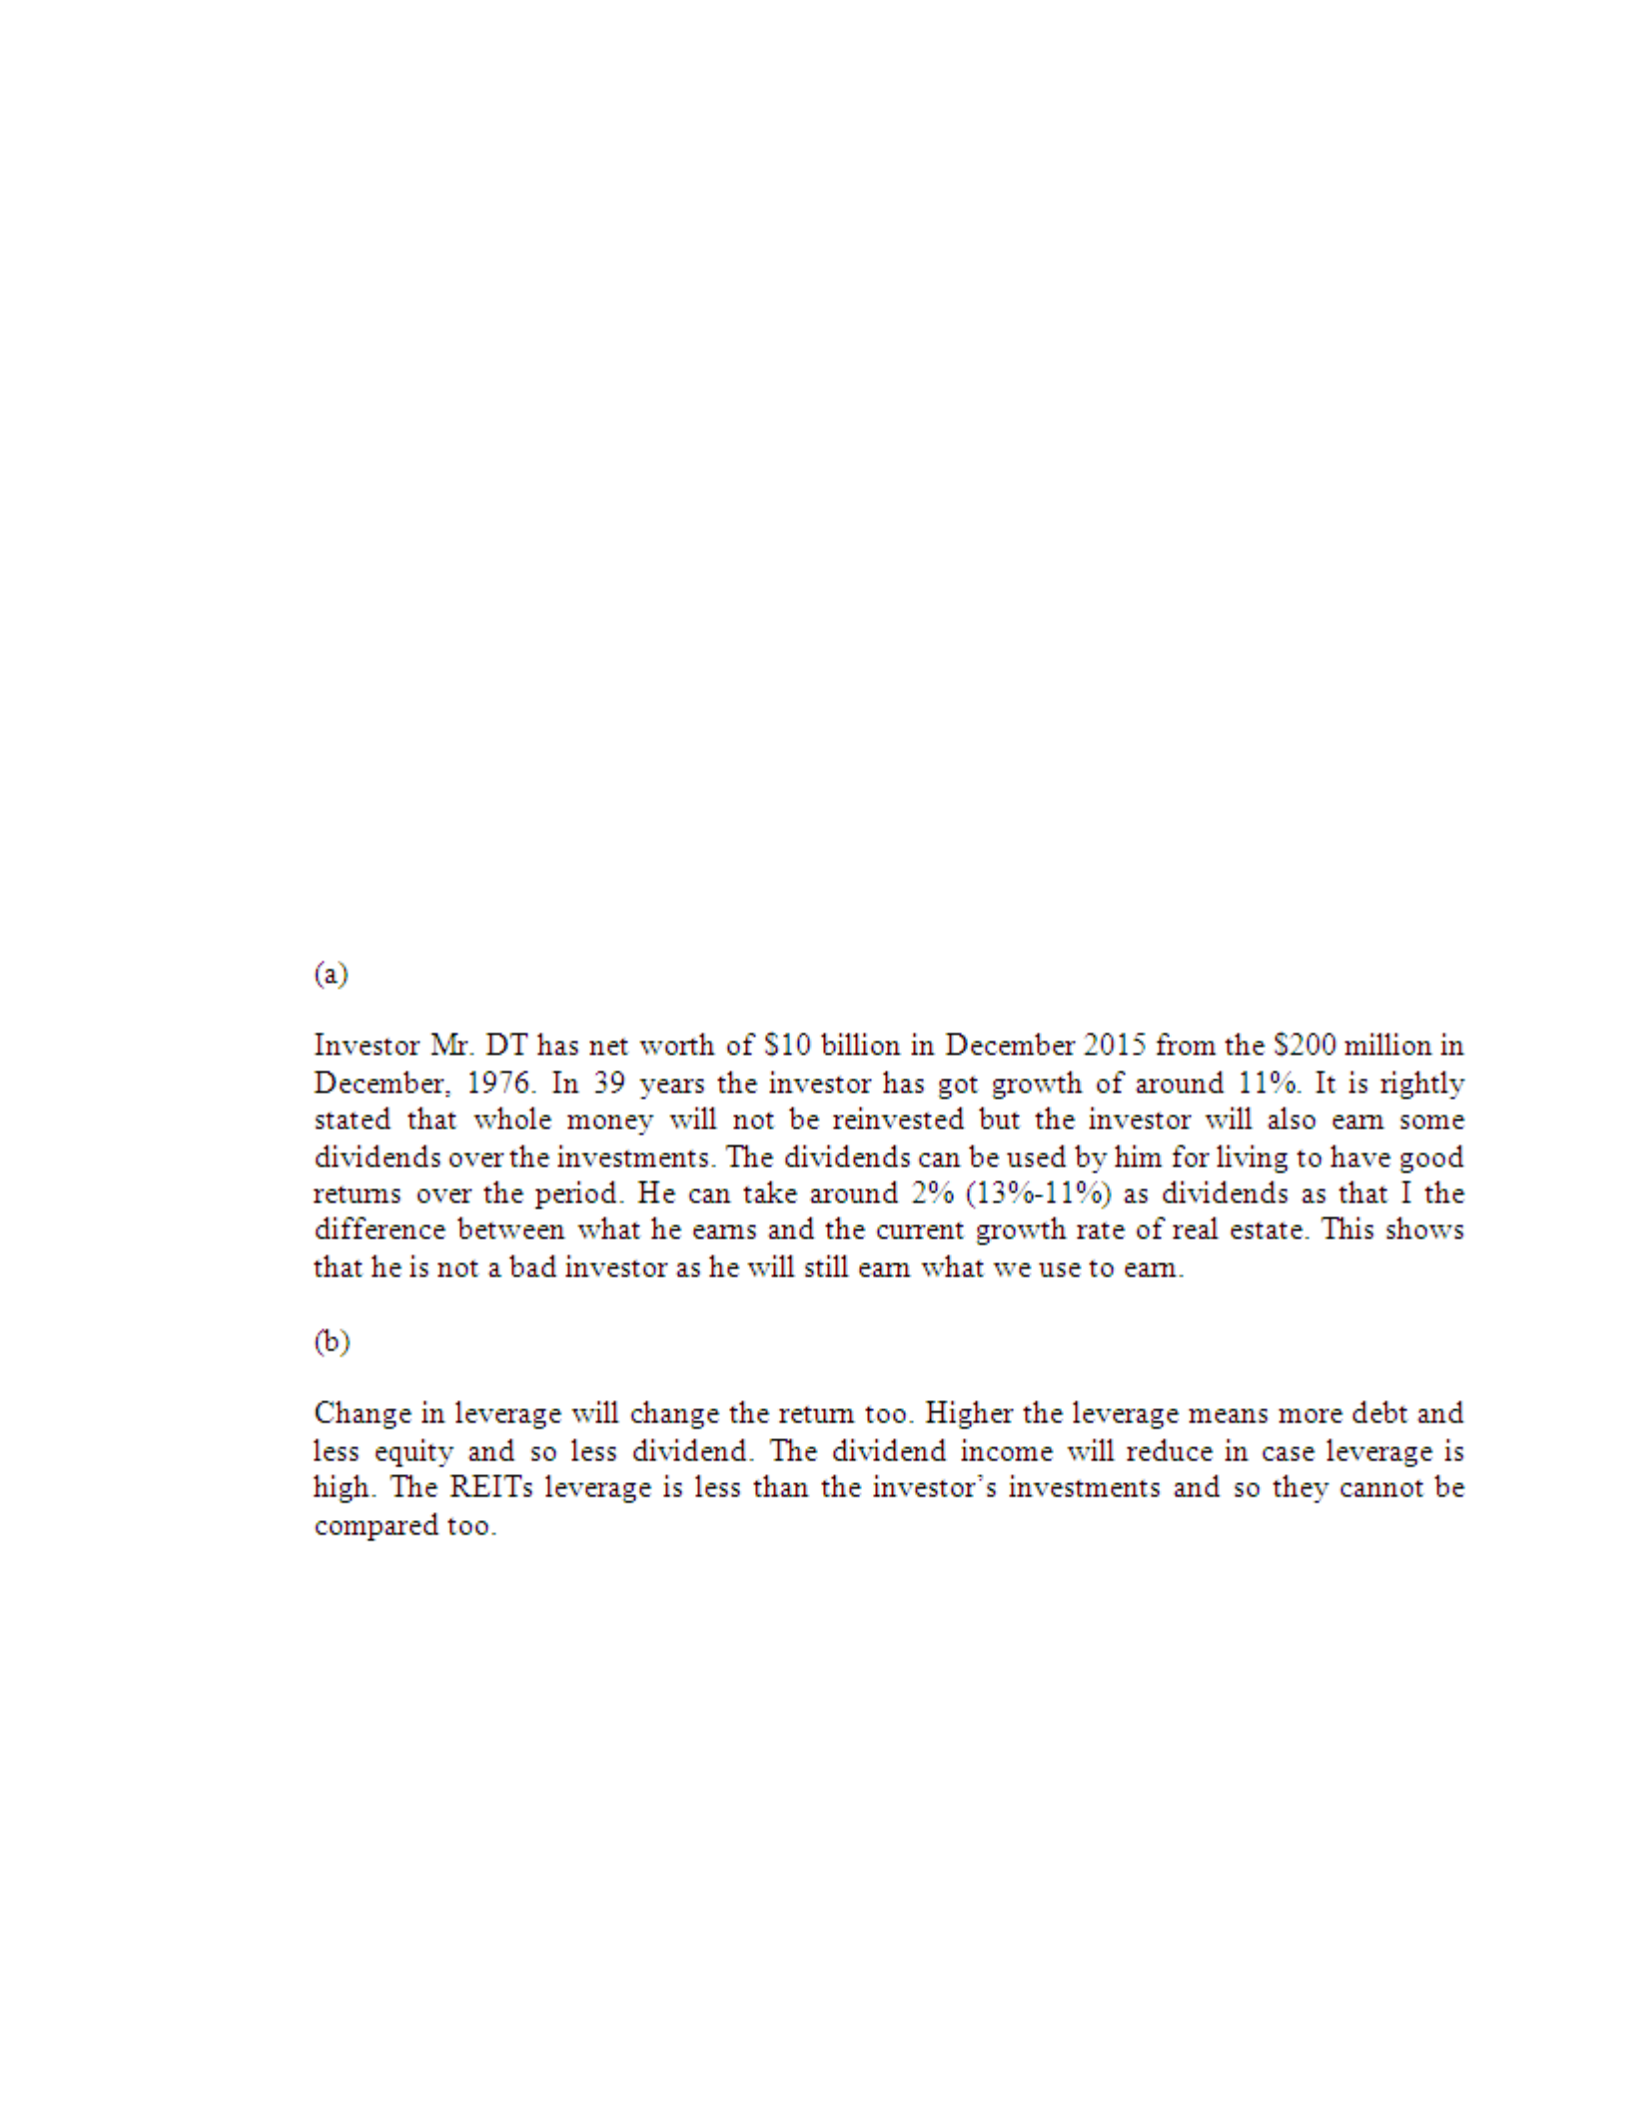
13) (15 points) Donald Trump’s net worth as of December 2015 was reported to be $10 Billion dollars.
In December of 1976, the New York Times reported his net worth at $200 Million. According to Mr.
Trump, this increase in wealth was generated by investments in commercial real estate. Over this
same time period, the “FTSE NAREIT All Equity REITs Index”, an index that tracks the performance of
commercial real estate, averaged 13.0% total geometric return per year. Assume that the estimates
of net worth are measured as of December 31st and that Mr. Trump’s investments have the same risk
and leverage as REITs.
a) In order to tell whether Mr. Trump is a good investor, we must assume something about his
spending. Clearly, he cannot reinvest all his wealth each period (the man’s got to eat). How
much in dividends would he have to take out of his portfolio (as a percent of his wealth) each
year over this period for you to conclude he is not a bad investor?
b) In words, how would your answer change if you learned that Mr. Trump’s investments were
levered at 69% while REITs were levered at 36% (No calculations please!)
14) (20 points) Consider a firm that is financed THREE ways: common equity, preferred equity, and long
term debt. The firm is considering replacing all of the machinery in its Cleveland plant. They have
more than enough cash on hand to pay for the project without raising external capital. Some
relevant information about the firm is given below. Based on all three sources of funding, what cost
of capital should the firm use to evaluate the project? (Assume that the Cleveland plant is
representative of all the firms’ projects).
Stock Price (common shares) $12
Number of common shares outstanding 6M
Stock Price (preferred shares) $6
Number of preferred shares outstanding 10M
Market value of Total Debt outstanding 40M
Equity beta (for common stock) 2
Risk-free rate
4.5%
Historical return on the S&P 500 12.0
%
Dividends per share on common stock
$0.00
Dividends per share on preferred stock
$1.00
Yield to maturity on the firm’s long term debt
6.5%
Coupon rate on the firms long term debt
3.0%
Corporate tax rate 35%
Answer:
Calculating the weights
Value
Weigh
t
Market value of Common stock 72
41.86
%
Market value of preferred stock 60
34.88
%
Market value of debt 40
23.26
%
172 1
Calculating cost of equity using
CAPM modeil
Beta 2
Risk free rate 4.50%
Return 12%
Cost of equity = 19.50%
Calculating cost of preferred shares
Cost of preferred shares 16.67%
Calculating cost of debt
Cost of debt = 4.23%
WACC =
Weights of equity * cos of equity + weight of debt * cost
of debt + weight of preferred * cost of preferred
WACC = 14.96%
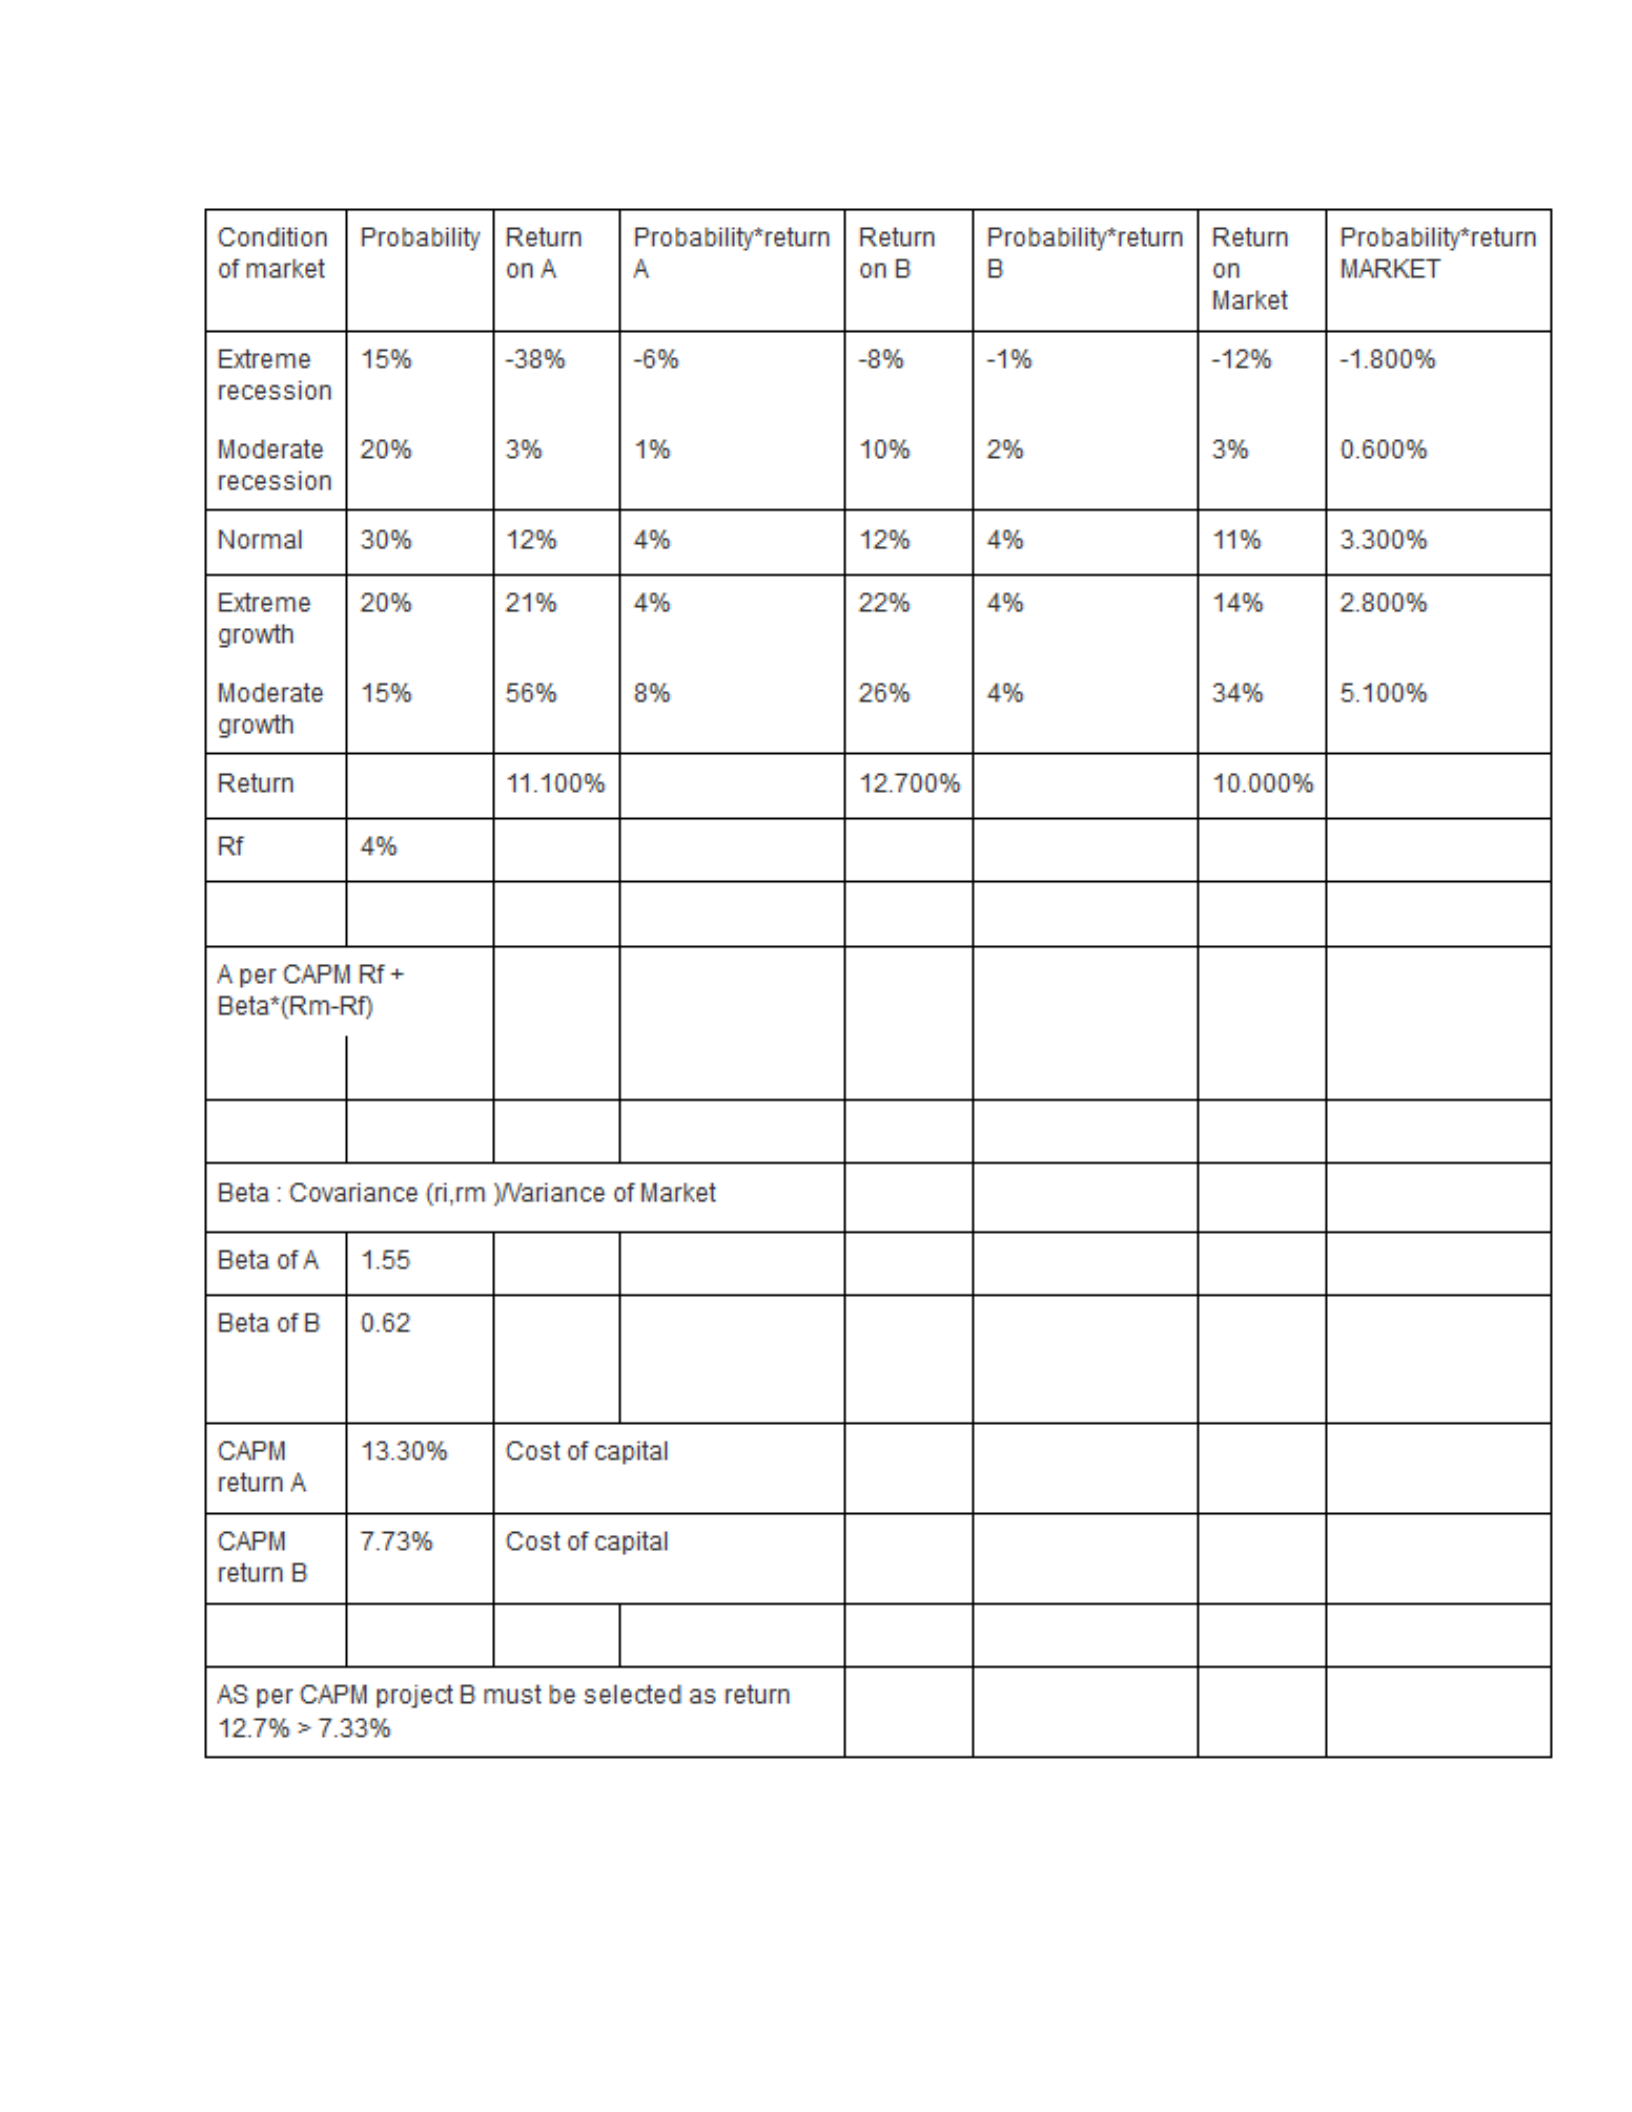
15) (10 points) A firm is considering two mutually exclusive projects, A and B. The projects are different
in that they have different returns depending on general economic conditions. The firm forecasts
that return on the market, and the returns on each project, along with their associated probabilities
will be given by the following table. You can assume a 4% risk free rate. Assume the CAPM holds
and compare the returns to the cost of capital and decide which project the firm should choose.
Extreme
Recession
Moderate
Recession Normal Moderate
Growth
Extreme
Growth
Pr[economic condition] 15% 20% 30% 20% 15%
Return on the market -12% 3% 11% 14% 34%
Return on project A -38% 3% 12% 21% 56%
Return on project B -8% 10% 12% 22% 26%
Condition
Probability
Return
Probabilty*retun
Return
Probabiliy*return
Return
Probability'return
of
market,
ona
A
onB
|B
on
MARKET
Market
Exieme
159%
38%
-0% -3%
[196
-12%
-1.800%
recession
Moderate
20%
3%
1%
10%
2%
3%
0.600%
recession
Normal
30%
12%
4%
12%
4%
11%
3.300%
Extreme
20% 21%
4%
22%
4%
14%
2.800%
growth
Moderate
15%
56%
8%
26%
4%
34%
5.100%
growth
Return
1.100%
12.700%
10.00%
Ri
4%
Aper
CAPM
RE+
Beta*(Rm-RN)
Beta
Covariance
(rim
Wariance
of
Market
Beta
ofA
1.85
Beta
ofB
0.62
capm
—|
13.30%
|
Cost
of capital
return
A
capm
[7.73%
—|
Cost
of capital
return
B
AS
per
CAPIM
project
B
must
be selected as
return
127%>7.33%


