


1
MODERATING EFFECT OF INVESTMENT OPPORTUNITY SET AND
MACROECONOMIC INDICATORS ON THE DETERMINANTS OF
FIRM VALUE
I INTRODUCTION
The Indonesian Capital Market is one of the investment instruments that can be used as
an alternative for investors to invest their funds. The
capital
market
itself consists of the
money market, debt market and capital market. The number of investors
in Indonesia continues
to increase from year to year. According to data from the Indonesian Central Securities
Depository (KSEI) at the end of 2022, with reference to the Single Investor Identification
(SID), the number of Indonesian investors reached 10.3 million investors. The number of
investors as of 2022 has increased by 37.54% when compared to 2021. A comparison of the
growth of public companies listed on the Indonesia Stock Exchange (IDX) and the growth of
investors in Indonesia can be seen in Figure 1.
The increasing number of investors shows the positive value that the
Indonesian capital
market
has great potential in the future. In the period 2018-2021, there were 217 companies
listed on the Indonesia Stock Exchange. This number is the highest achievement when
compared to other ASEAN capital markets (Haffiyan and Mahardika 2022). The number of
public companies listed on the Indonesia Stock Exchange as of December 2022 has reached
825 companies. This number has increased by 7.70% when compared to the beginning of
2022 (BEI 2022).
The capital market, especially the stock market, offers two types of benefits for
investors in the form of capital gains and dividends. Capital gain is the profit that
a person gets
from buying and selling assets, be it stocks, bonds or real estate, while dividends are part of
the company's profit or income, the amount of which is determined by the board of directors
and authorized by the shareholders' meeting
to be distributed to shareholders (BPPB 2021).
Table 1 shows the
number of publicly listed companies on the Indonesia Stock Exchange that
pay dividends in the last 5 years, namely from 2017-2021.
Table 1 Companies listed on the Indonesia Stock Exchange
Description
Number of companies
Listed company
825
Companies that pay dividends for the period 2017-2021
359
2
Companies that regularly distribute dividends for the period 2017-
2021
116
Companies included in the IDX High Dividend index
20
Of the 825 publicly listed companies on the Indonesia Stock Exchange, during the
period 2017-2021 there were 359 companies that had distributed cash dividends to their
shareholders. Of all the companies that pay dividends, there are 116 companies that regularly
pay dividends over the past 5 years. The Indonesia Stock Exchange classifies companies that
pay dividends through the IDX High Dividend 20 index. IDX High Dividend 20
(IDXHIDIV20)
is an index that lists 20 companies that regularly pay
cash
dividends
to
shareholders in the last 3 years with a high dividend yield (IDX 2022).
Dividend yield (DY) can be said to be high if it has a yield of more than the BI 7-Day
Reverse Repo Rate (BI7DRR) or free rate markets such as Government Securities (SBN).
This index can be an alternative for
long-term
investors
with the aim of obtaining higher
returns on investment in the
capital
market
. A comparison of the average dividend yield of
companies listed on IDXHIDIV20 with the average BI7DRR from 2019-2021 can be seen in
Figure 2.
In the last 3 years, 20 companies listed in
IDXHIDIV20 mostly have a dividend yield
greater than BI7DRR. The largest dividend yield was owned by MPMX in 2019, where the
dividend yield
reached 33.10%. Some companies in the index have dividend yields below
BI7DRR, but some of these companies are recorded to
distribute cash dividends 2 times a year
which are divided into
interim dividends and final dividends. These companies include
ADRO, ASII, BBCA, ITMG, TOWR, UNTR, and UNVR. Lowest dividend yield in the
index
IDXHIDIV20 belongs to the issuer ANTM with a percentage of 0.46% in 2020.
The IDX High Dividend 20 index has stock movements that fluctuate following the
direction of the price movement of the composite stock price index on the Indonesia Stock
Exchange. Figure 3 shows the stock movements of JCI and IDXHIDIV20 which tend to have
similar patterns. In March 2020, JCI decreased by 16.76% when compared to 2019. The
IDXHIDIV20 stock index price also decreased by 18.08% as of March 2020 when compared
to the end of 2019. As of December 2021, the JCI closed higher with an increase of 45%
since March 2020. Similarly, the IDXHIDIV20 index also showed a gain of 38.27% as of
December 2021 when compared to March 2020. The decline in IDXHIDIV20 share price
was greater than the JCI, while the increase in JCI was greater than IDXHIDIV20.
The share price performance of JCI and IDXHIDIV20 can be seen from the
share price

3
growth
which varies from year to year. Figure 4 shows a comparison of JCI and
IDXHIDIV20 share price growth for the last 3 years from January 2019 to December 2021.
Based on Figure 4, it can be seen that the performance of JCI and IDXHIDIV20 stock prices
fluctuate where JCI with an average month to month growth from January 2019 to December
2021 amounted to 0.29%, while IDXHIDIV20 0.11%. This shows that the JCI share price is
higher than the IDXHIDIV20. A company's share price often reflects the value of the
company. The higher the share price of a company, the greater the value of the company.
Firm value is influenced by internal and external factors. These factors include dividend
policy, capital structure, ownership, free cash flow, company size, type of company
management
, interest rates, exchange rates, economic growth and inflation (Alfianti and Santosa
2022, Wijaya et al. 2021, Sintyana and Artini 2019, Hendayana and Riyanti
2019, Gunawan et
al. 2018, Lubis et al. 2017, Manurung et al. 2016, Suffah and Riduwan 2016).
1.1 Problem Formulation
Dividend policy is one of the important issues in finance (Kurniasih et al. 2011). The
dividend policy set by the company fluctuates. Dividend policy is set in the form of cash
dividends and stock dividends. Dividend policy is directly related to corporate funding
because it is
related to the company's capital structure where dividends are distributed from the
company's profits
. Corporate profits issued as dividends will reduce the company's
capital to
fund its operational activities, pay its debts,
or invest its cash flow for expansion (Oded 2019,
Sualehkhattak and
Hussain 2017). Table 2 shows the historical earnings of companies listed in
IDX High Dividend for the last 5 years.
Profit condition of IDXHIDIV20 companies is always in a positive position in the last
5 years
even though it is recorded to fluctuate up and down in that period. This is in accordance
with corporate action in Indonesia where only companies with positive profits are allowed to
distribute dividends (Kurniasih et al. 2011). UNVR experienced a 36.59% decrease in profit
from 2018 to 2021, while HMSP experienced a 47.99% decrease in profit from 2019 to
2021. KLBF has profits that have consistently increased from 2017 to 2021, namely by
31.74%. Other issuers on average experienced a decrease in profit from 2018 to 2020 and
then returned to score an increase in profit in 2021. Good company profitability increases
company value because it shows the company's prospects in the future (Febriyani et al.
2020).
Dividend policy positively affects firm value (Giriati
2016). Firm value will be
maximized by a
high
dividend payout ratio
. This causes the share price of companies that pay
high
dividends to
also increase, which has an impact on increasing firm value
(Suartawan and
4
Yasa 2016). Dividend payments can reduce equity which can result in an increase in the debt
to equity ratio (DER) which can have an impact on firm value. Company management uses
short debt to increase firm value. Increasing total assets must be done to increase firm value
and firm size, which means management must reduce equity (Ayuba et al. 2019).
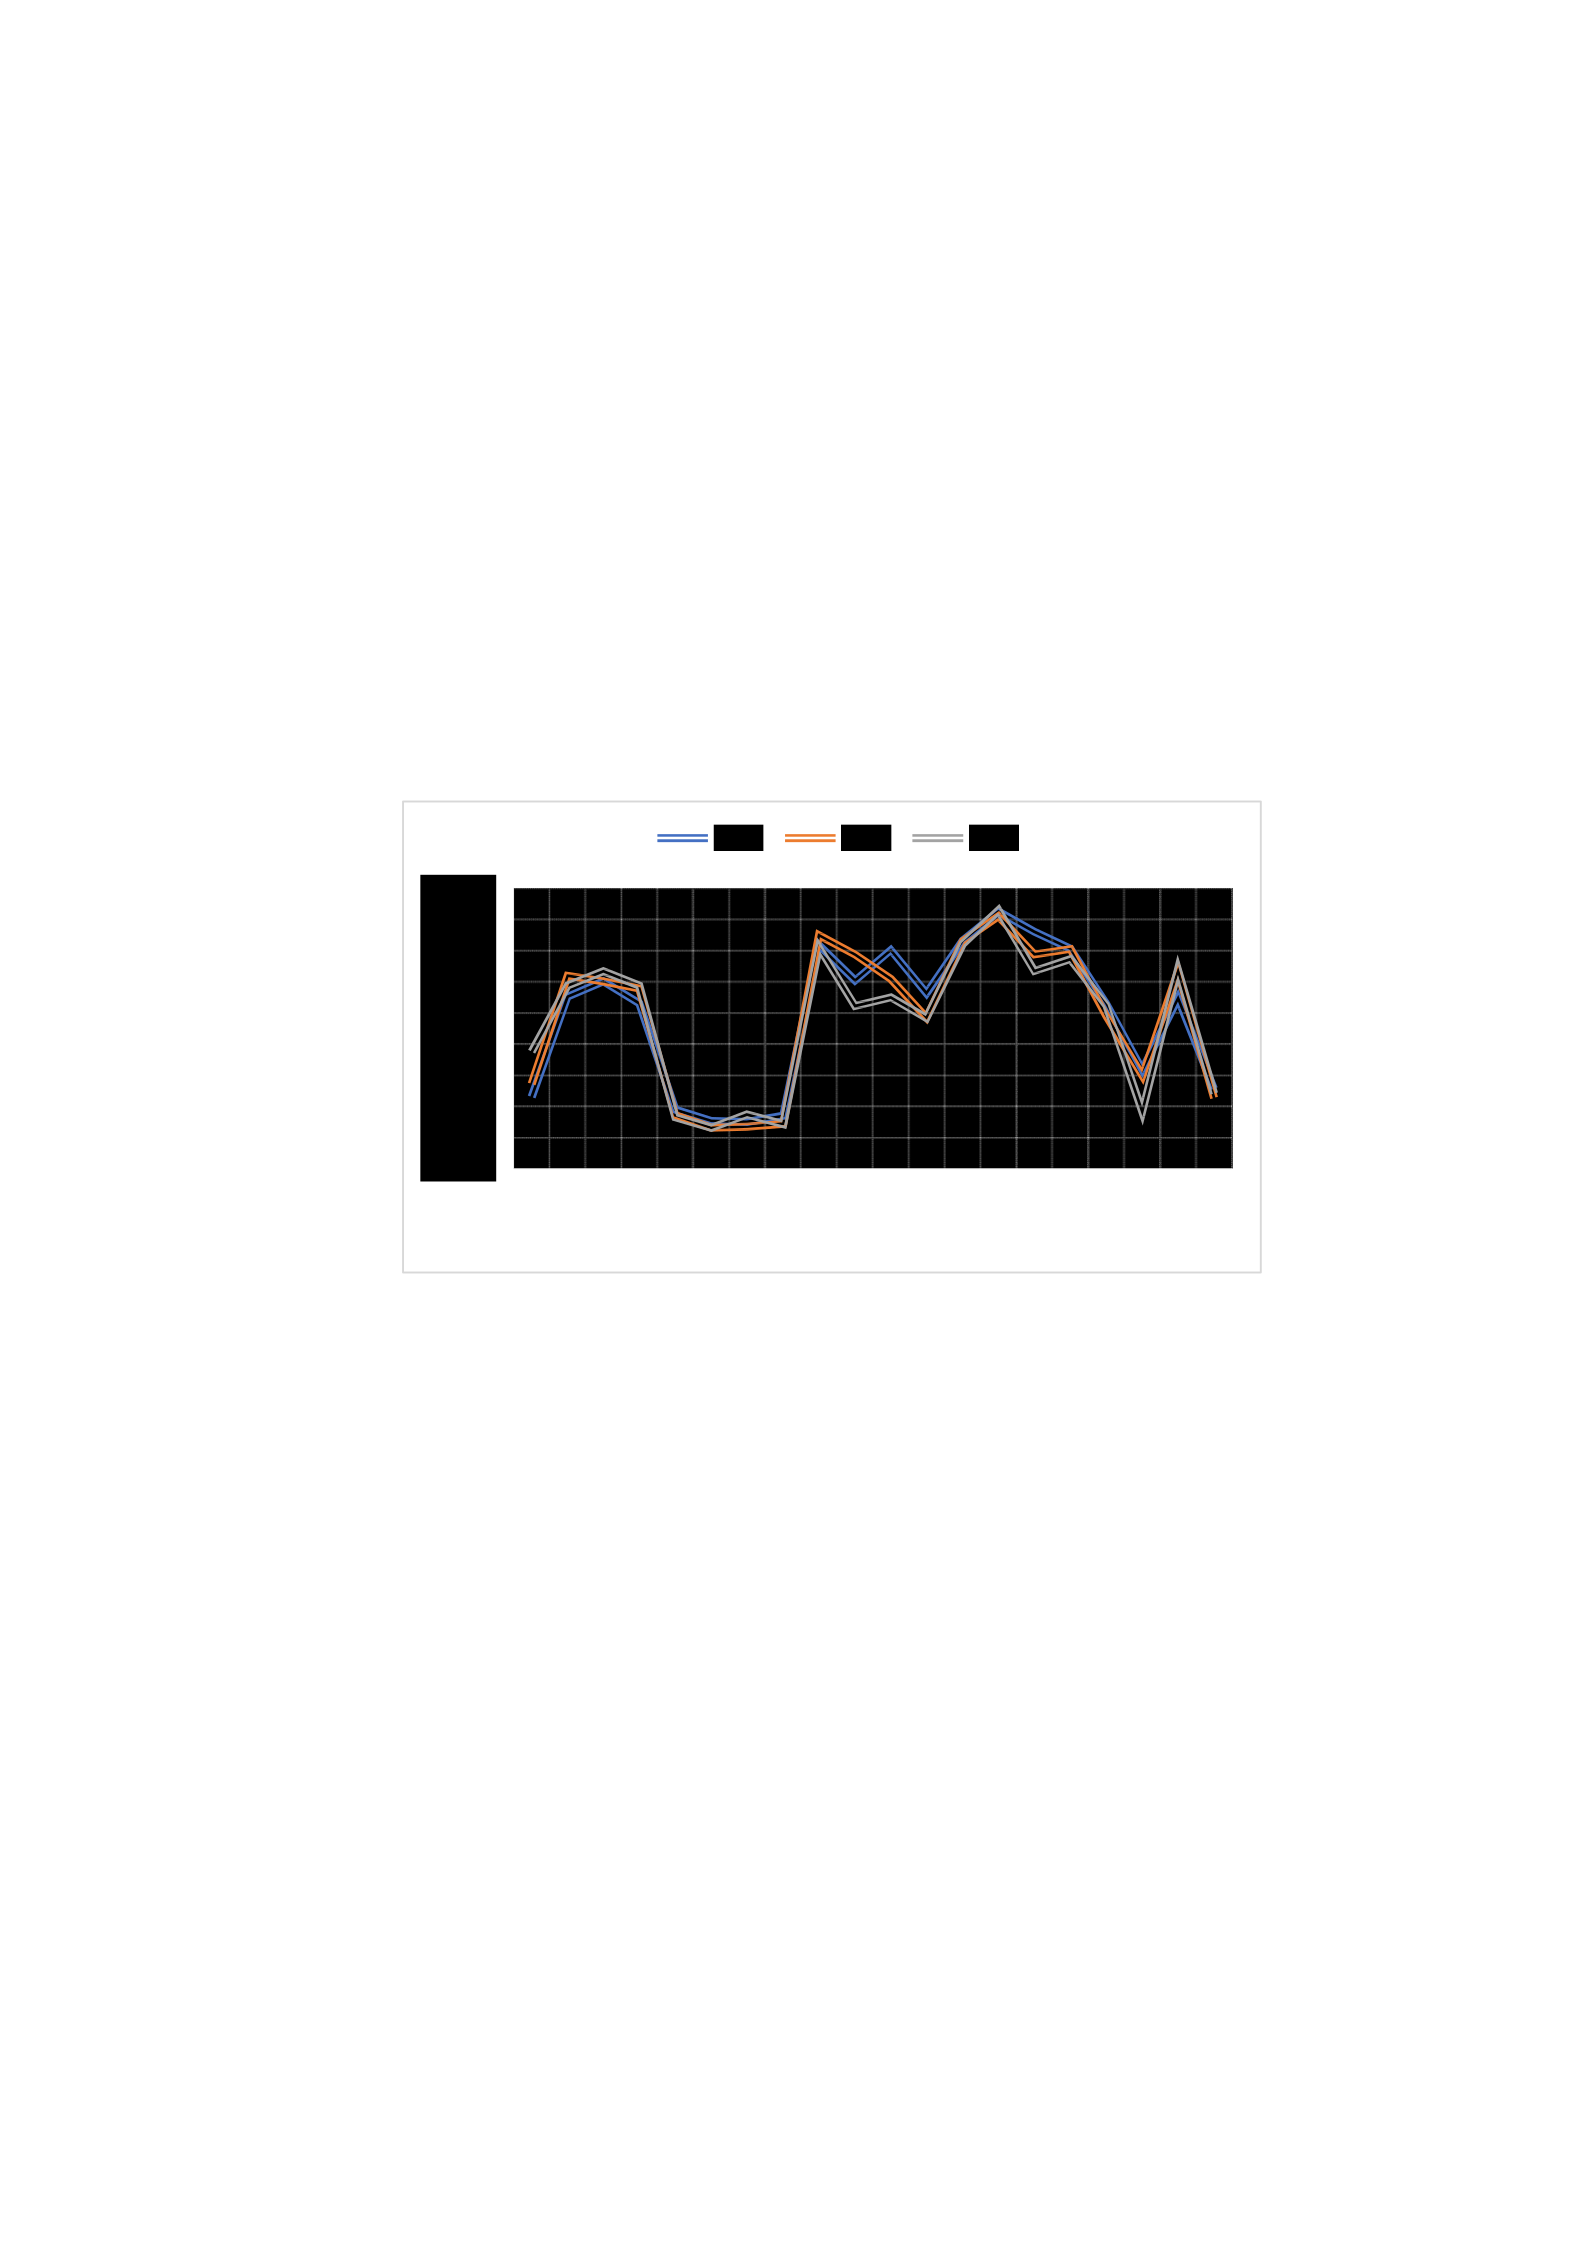
Figure 5 shows the changes in equity of IDXHIDIV20 companies for the
2019-2021
period
. During this period, it can be seen that the changes in equity in each company listed on
IDXHDIV20 did not experience significant changes from 2019 to 2021. Companies in
IDXHIDIV20 have diverse equity. Equity shows the capital owned by the company. A high
equity portion indicates a low level of debt, while a low equity portion indicates a high level
of debt. Capital structure has an opposite effect on business profitability where the higher the
debt of a business, the lower the rate of return (Dang et al. 2019).
2019
2020
2021
90.00%
80.00%
70.00%
60.00%
50.00%
40.00%
30.00%
20.00%
10.00%
0.00%

5
Companies with large cash flows should have higher dividend payments and high
leverage (Sualehkhattak and Hussain 2017). IDXHIDIV20 indexed companies pay higher
dividends than other issuers on the Exchange, but their leverage varies and some are even
classified as low with a value below 50%. When associated with firm value, debt has a
negative effect and signal effect on firm value (Sadiq et al. 2020).
The company's investment decisions determined by management can affect the
perspective of investors and company owners so that it can affect the company's value
(Suartawan and Yasa 2016). This shows that the ownership structure plays a role in
increasing or decreasing the value of the company. Good Corporate Governance (GCG) as
corporate governance is proven to have a significant effect on company performance
(Hastori et al. 2015). Meanwhile, Febriyanti et al. (2020) state that GCG has no effect on firm
value. The implementation of GCG in the company is important in supporting company
performance which has an impact on company value.
Idxhidiv20 indexed companies pay dividends, if it is assumed that the company spends
money on shareholders so that the company may lose the opportunity to utilize profits to
invest (Investment Opportunity Set). Investment Opportunity Set (IOS) is the opportunity to
invest in positive NPV projects that may or may not be undertaken by the company. IOS is
an important component of market value which is an important characteristic of the
company
and has a major influence on the way the company is viewed by managers,
owners, investors
and creditors (Kallapur 2001).
Several studies related to IOS conducted previously show mixed results when
associated with each factor that affects firm value. Dividend policy and IOS have a weak
relationship. Companies with a high level of firm value from IOS tend to have less debt. Free
cash flow and IOS are negatively correlated (Kallapur 2001). Signaling theory predicts a
positive relationship between IOS and leverage (Watts & Smith, 1992). This suggests the
potential for IOS to increase or decrease firm value through other factors.
External factors such as macroeconomics can also affect firm value through the
financial policies that companies implement. When
interest
rates are
high, companies tend to
distribute high dividends (Guney et al. 2014). Interest rates are also related to capital structure
where in
trade-off
theory
companies tend to increase debt because loan interest is lower than
taxes to be paid (Staking and Babbel 1995). In addition, lending rates have also been shown
to moderate the relationship between
working capital
management
and firm profitability
(Erdian et al. 2022).
High
interest rates
will reduce the present value of future cash flows
thereby reducing the attractiveness of investment opportunities (Ningsih and Waspada 2017).
This
shows that there is a role for interest rates in influencing firm value through
dividends and

6
capital structure.
Companies in IDXHIDIV20 are recorded to have cash reserves and debt in foreign
currency. In addition, some companies are also listed
conduct international transactions
using foreign currencies such as issuers
ADRO and ANTM. Changes in exchange rates are
crucial. If the
exchange
rate of
the country of origin weakens over the exchange rate of the
destination country, then when the company conducts transactions in foreign currency, the
company will get a greater profit (Kurniadi et al. 2014). Conversely, if there is a
strengthening of the exchange rate of the country of origin against the destination country,
the company will experience a loss. Losses and profits are determined by the value of
currencies in international cooperation (Ekawarna and Muslim 2008). This shows the role of
foreign exchange rates in influencing firm value through profitability and free cash flow.
The condition of companies in the IDXHIDIV20 and the results of previous studies
show varying results on firm value, especially when associated with agency theory, pecking
order, signaling, trade-off and others. Some inconsistent research results also indicate a gap
that needs to be completed with further research. Therefore, it is important for companies
listed on the IDXHIDIV20 index to understand the effect of dividend policy, capital
structure, ownership, free cash flow, profitability and
Good Corporate Governance on firm
value. Moderation of IOS and
macroeconomic
variables
also needs to be done to support the
analysis of firm value on IDXHIDIV20. IOS and macroeconomic indicators as moderation
can distinguish this study from previous studies where previous studies have shown that IOS,
interest rates and exchange rates also affect the determinants of firm value used in this study.
Based on the results of the description above, the problem formulation for this study is as
follows:
1.
What is the dividend policy, capital structure, ownership, free cash flow, profitability,
board size, audit committee, firm value, and IOS in IDXHIDIV20 indexed
companies?
2.
What is the effect of dividend policy, capital structure, ownership, free cash flow,
board size profitability, and audit committee on the value of IDXHIDIV20 indexed
companies?
3.
What is the moderating effect of IOS and macroeconomic indicators on the
determinants of firm value indexed by IDXHIDIV20?
Dividend Policy Theory
1.1.1
Irrelevant dividend theory
In dividend irrelevance theory, Miller and Modligiani put forward the theory that

7
dividend policy has no effect on firm value. This approach reveals that the market price of
shares depends on the company's earnings on investments made and not on the dividends
paid by the company. According to residual theory, dividend policy
is part of financial
decisions because available profits can be retained
in the business to be reinvested. The
decision to pay dividends or retain company profits is considered a residual decision (Singh
and Kaur 2020). The value of a company depends only on the profit generated by its assets,
not on how that profit is split between dividends and retained earnings (Suffah and Riduwan
2016).
1.1.2
Dividend theory is relevant
In dividend relevance theory, Walter and Gordon state that dividend policy is relevant
to firm value. Walter and Gordon's model reveals that the value of the firm depends on the
firm's earnings level, dividend payments, constant reinvestment rate and the expected rate of
return of shareholders. A firm's dividend policy depends on the availability of good
investment opportunities. This is based on the
opinion that investors generally choose to obtain
current income in the
form of dividends. This condition indicates a direct relationship
between dividend policy and firm value (Singh and Kaur 2020). The theories that are in line
with this opinion are clientele effect theory and bird in the hand theory (Suffah and Riduwan
2016).
1.2 Capital Structure Theory
1.2.1 Trade-off Theory
The trade-off theory approach model states that the optimal capital structure can be
determined by balancing the tax shield benefit of leverage with the cost of financial distress
and agency problems. This approach states that firms base funding decisions on an optimum
capital structure to increase firm value. The trade-off theory reveals that companies balance
the benefits of debt funding (favorable corporate taxation) with interest rates (Syaifuddin
2008).
The optimal level of debt
is
reached when tax shields
reach the maximum amount against
the cost of
financial distress. The theory implies that there is a trade-off between
tax
savings
and
the cost of financial distress in determining the capital structure. Companies with high
profitability will try to reduce their taxes by increasing their debt ratio which has an impact
on tax reduction (Kurniasari and Wibowo 2017).
1.2.2
Pecking order
theory
Myers' opinion on pecking order theory states that "companies
with high profitability
have low debt levels, because companies with high profitability have abundant internal

8
sources of funds. This theory is more directed at explaining the order of funding sources.
Pecking order theory explains why companies with high profitability have low debt levels
(Kurniasari and Wibowo 2017).
The sequencing scenario for selecting funding sources includes: 1) The company
prefers to use internal resources (retained earnings) rather than external funding. 2) If
external funding is needed, then the company
chooses from low-risk debt, to more risky debt,
then
to convertible bonds, preferred stock and finally common stock. 3) There is a constant
dividend policy, where the company issues a policy of determining a constant dividend
payment regardless of the company's profit and loss.
4) Inventory shortages are anticipated by taking the
available
investment portfolio
(Kurniasari
and Wibowo 2017).
1.2.3
Signaling Theory
This theory reveals that parties related to the company do not have the same
information about the company's prospects and risks (Kurniasari and Wibowo 2017).
Signaling theory states that dividends are used to signal management's expectations
regarding changes in future corporate profits (Kurniasih et al. 2011). Signaling theory states
that capital structure is a signal delivered by managers to the market. Managers are able to
use more debt as a more credible signal. This is because companies that increase debt are
seen as companies that have confidence in the company's future prospects. Investors are
expected to capture this signal as a sign that the company has good prospects. Signaling
theory shows that companies with high growth options
have more important asymmetric
information which leads to
high
leverage
(Danila et al. 2020).
1.2.4
Agency Theory
The agency theory approach explains that the capital structure is structured to reduce
conflicts between various interest groups. The conflict that may occur between shareholders
and managers is the concept of free cash flow. There is a tendency for managers to hold
resources so that they have full control over their resources. Debt is considered as one way to
reduce free cash flow agency conflicts. The use of debt by the
company will force managers to
release cash from the company for
interest payments (Kurniasari and Wibowo 2017). Agency
theory suggests
that a board consisting of more directors is more likely to act
as a better monitor
of the company's executive management so that the board becomes more vigilant. This
affects the quality of strategic decision making which in turn can have a positive impact on
company performance (Singh et al. 2017).
1.3
Company Value
Firm value is the goal of corporate finance. The preference of enterprise value

9
indicators over accounting-based financial performance measures is to use market prices of
financial assets such as stocks that reflect an assessment of the level of business risk.
Measures of firm value can include the company's intangible assets. Measures of firm value
accommodate assumptions to maximize shareholder wealth (Ayuba et al. 2019). Corporate
decisions affect firm value (Brigham and Houston 2009).
Chung and Pruitt (1994) state that Tobin's Q
as a proxy for market valuation plays an
important role in various financial interactions such as investment and diversification
decisions, the relationship between ownership and firm value, the relationship between
management performance and bidding, investment
opportunity set, finance, dividend and
compensation policies. The use of Tobin's
Q as a measure in reflecting firm value is considered
an assessment of future performance by maximizing present value (Shatnawi
et al. 2021,
Gregory 2021). Klapper and Love (2002) state that
good corporate
governance
will have a high
Tobin'sQ value.
Corporate financial
management
regarding important decisions taken by the
company, including investment decisions, funding and dividend policy (Giriati 2016).
1.4 Investment Opportunity Set (IOS)
Investment Opportunity Set (IOS) describes the breadth of opportunities or investment
opportunities of a company but is highly dependent on the company's spending choices for
future interests (Suartawan and Yasa 2016). Smith and Wrath (1992) state that the
component of firm value is a result of investment choices to be used in the future and is a
proxy for IOS itself. Proxies that can be used to express IOS are divided into
price-based IOS,
investment-based IOS and variance-based IOS (Kallapur 2001).
IOS is considered to influence
the way managers, owners, investors and
creditors
view
the company so that it becomes one of
the important components in
market value (Hidayah 2015).
1.5
Macroeconomics
Macroeconomics is one of the external factors that can affect
company conditions. In
macroeconomics, there are endogenous variables used including national output, price level
or changes (inflation), interest rate, employment opportunities, unemployment, etc.
(Nazamuddin 2020). According to Bodie et al. (2008) several macroeconomic variables that
can be used to assess macroeconomic conditions include gross domestic growth (GDP),
unemployment, inflation, interest rates, exchange rates, current accounts and budget deficits.
Interest rates are the price of using money as rent for the use of money for a certain
period of time (Andrianto et al. 2019). Interest rates become banking intermediaries that
influence the economic decisions of both households and companies. A decrease in interest

10
rates can reduce lending rates which can increase demand for credit. Decrease in interest rates
It can also reduce the cost of capital for companies to make investments so that the economy
can increase (OJK 2019).
Exchange rates are divided into nominal exchange rates and real exchange rates. The
nominal exchange rate is the price of a country's currency against another country's currency,
while the real exchange rate measures the rate at which a country's goods and services
can be
exchanged for another country's goods and services (Hubbard and O'Brien 2012).
Economically, gains or losses as a result of international cooperation are detected through
currency exchange rates (Ekawarna and Muslim 2008).
1.6 Review of Previous Research
A company's main objective is to maximize the value of its shares, and value is based
on its future cash flows. The stock price reflects the value of the company. Firm value can be
maximized through corporate financial decisions (Brigham and Houston 2009). Firm value
can be influenced by various factors including dividend policy, capital structure, free cash
flow, liquidity, profitability, leverage, firm size and
growth
opportunities
(Alfianti and Santosa
2022, Sintyana and Artini 2019, Gunawan et al.
2018, Lubis et al. 2017, Manurung et al. 2016,
Suffah and Riduwan 2016). In addition
, macroeconomic conditions such as changes in interest
rates, exchange rates, economic growth and inflation can also affect firm value (Wijaya et al.
2021,
Hendayana and Riyanti 2019).
Dividend policy expressed in the dividend payout ratio has been widely used as a
variable to determine the percentage of dividend payments from company profits. Dividend
payout ratio affects firm value (Giriati 2016). Al Saeed (2018) states that dividends affect
company performance. Tobins Q does not increase or decrease dividend payments (Saadu et
al. 2020). Low dividend policy is used so that cash flow can increase investment opportunities
(Danila et al. 2020).
The optimal capital structure can maximize firm value which is proxied through the
debt to equity ratio showing its effect on firm value. Previous research reveals that capital
structure affects firm value (Ayuba et al. 2019). Capital structure has a negative effect on
firm value (Dang et al, 2019). Other studies show different results where capital structure has
a positive effect on firm value with MV proxy, while capital structure has no significant
effect on firm value with TobinsQ proxy (Al-Nsour and Al- Muhtadi 2019).
Ownership in the form of ownership percentage and ownership concentration is
studied by Singh et al. (2017) which shows that ownership dominated by the board of
directors positively affects firm performance. Board composition and ownership

11
concentration have an impact on firm value. Managerial ownership is significantly related to
firm performance or firm value (Shatnawi et al. 2021). This contrasts with the findings of
Almari et al. (2021) and Oyedokun et al. (2020) which state that management ownership has
a negative effect on firm value where this type of management management reduces firm
value. Institutional and family ownership have a positive impact on firm value.
Free cash flow (FCF) as a determinant of firm value is part of the research of Alias et
al. (2013). The results showed that duality weakens the insignificant positive effect of free
cash flow
on dividends while independent directors strengthen the
insignificant
positive effect
of free cash flow on dividend payments. The type of
company management that is separated
based on its management, namely sharia
and conventional, is a variable examined in the
research of Ben-Nasr and Ghouma (2021).
Profitability in the form of the Return on Equity (ROE) proxy is studied for its effect
on firm value which shows that profitability has a positive effect on firm value (Alfianti and
Santosa 2022, Lubis et al. 2017, Suffah and Riduwan 2016). This shows that the higher the
return on investment, the higher the company value. Profitability can trigger an increase in
stock prices so that the market ratio will also increase.
Investment Opportunity Set (IOS) studied by Myint (2017) shows that leverage can
affect the company's ability to capture investment opportunities. The relationship between
IOS and other variables that affect firm value has been studied previously. Hutchinshon and
Gul (2004) state that managerial ownership positively affects the relationship between IOS
and financial performance. Free cash flow and IOS are negatively related: A larger IOS
means that the firm has more net current projects available. Free cash flow indicates poor
IOS. This is related to agency costs where managers utilize fund expenditure for non-optimal
investments (Kallapur 2001). Profitability is positively related to IOS, where the greater the
profitability of a company, the greater its IOS (Riahi- Belkaoui 2002). Islamic companies
pay more dividends if they do not find IOS compared to conventional companies (Ben-Nasr
and Ghouma 2021).
Interest rates have a positive and insignificant effect on firm value (Hendayana and
Riyanti 2019). However, the opposite result is stated by Wijaya
et al. (2021) where interest
rates have a negative and insignificant effect on firm value
. The level of debt and interest rate
risk on economic value
simultaneously affects firm value (Staking and Babbel 1995).
Corporate
profitability
is not affected by interest rates (Sasongko and Hamzah 2022) while lending rates
moderate the relationship between working capital management and corporate profitability
(Erdian et al. 2022).
The rupiah exchange rate affects company profitability (Hendramiko et al. 2020). The

12
rupiah exchange rate is also the most influential factor on firm value where companies need
to pay attention and anticipate this factor (Pasaribu et al. 2019). This is supported by Ihsan et
al. (2018) which states that exchange rate variations have a significant effect on firm value.
The exchange rate has a positive and insignificant effect on firm value (Sartika et al. 2019).
Agustina and Ardiansari's research (2015) shows that an increase in exchange rates has no
effect on firm value.
Tobin's Q is widely used to assess company performance or value.
company (Butt et al. 2021, Ayuba et al. 2019).
Tobin's Q encourages managers
in
maximizing the value of the company from the invested capital so that it leads to an increase
in stock prices (Ishaq et al. 2021). Research by Shatnawi et al. (2021) and Singh et al. (2017)
shows that this variable can reflect the value of the company as depicted through the stock
price (market-based performance).
The effect of firm size on firm value is utilized as an
independent variable and control
variable in previous studies. The results show that company size is positively correlated with
firm value (Dang et al. 2019, Al-Nsour and Al-Muhtadi 2019). Meanwhile, Luu (2021)
states that company size has a negative impact on firm value. The existence of the covid-19
pandemic also shows a decrease in firm value in countries domiciled in the covid-19 affected
area. However, the negative impact of covid-19 does not affect firm value in companies
with
sustainable and environmentally oriented performance (Bose et al. 2021). In addition
, the type of
management of Islamic and conventional companies has
different
criteria
. Companies that are
sharia companies have limitations
in terms of
both
funding and income which can have an
impact on the capital structure and company performance (Mai 2019).
Research Approach:
The research methods used in this study were descriptive statistics and panel data
regression. Descriptive statistics is an analysis technique that provides an overview of the
data that has been collected descriptively so that conclusions are obtained. Panel data
regression is an analytical method that utilizes a combination of cross series and time series
data where the same cross section unit is measured at different times. Panel data regression is
compiled to determine the research model.
Data Type and Source:
The type of data used in this study is secondary data in the form of quarterly and
annual financial reports from
IDXHIDIV20
indexed companies
on the Indonesia Stock
Exchange. The financial statement data taken is for a
period of 5 years from 2017-2021. All

13
sources of financial statement data are obtained from the official website of the Indonesia
Stock Exchange and the official websites of related companies. Data on the rupiah exchange
rate and BI7DRR are obtained from the official website of Bank Indonesia. Other supporting
data is obtained through literature studies from publications both textbooks, scientific papers,
online and print media, as well as reports published by related institutions related to dividend
policy, capital structure, free cash flow, type of management, Investment Opportunity Set
(IOS) and firm value.
Sampling Technique:
The sampling method is done by purposive sampling which is a sampling technique
with certain considerations. This method is suitable for quantitative research. The sample of
this study used IDXHIDIV20 indexed companies listed on the Indonesia Stock Exchange.
The specific criteria for companies that will be used as research objects are as follows:
•
IDXHIDIV20 indexed companies listed on the Indonesia Stock Exchange.
•
The company paid cash dividends every year in the period 2017-2021.
•
The company publishes quarterly and annual reports that can be accessed on the Indonesia
Stock Exchange website and the company's official website.
Table 4 shows the list of IDXHIDIV20 indexed companies. Of the 20 companies listed
in IDXHIDIV20, there are 2 companies that do not meet the requirements in the study,
namely not distributing dividends for a period of 5 consecutive years. These companies are
ANTM and MPMX, where ANTM did not pay dividends in 2017 while MPMX did not pay
dividends in 2018. Therefore, both companies were excluded from the study.
Definition of Operational Variables
Dependent Variable
The dependent variable is an independent variable that is structurally a variable caused
by changes in other variables that are the object of research (Hardani et al. 2020). Firm value
is the dependent variable in this study. Firm value is
proxied through Tobin's Q
as the
measurement variable where Tobin's Q is the ratio of the market value of the
company's assets
to the company's replacement cost (Shatnawi et al., 2021). 2021, Butt et al. 2021, Ismawati
2018, Sualehkhattak and Hussain 2017, Rehman 2016).
Independent Variable
Independent variables are variables that cause or have theoretical possibilities that have
an impact on other variables (Hardani et al. 2020). In this study, there are 5 independent
variables consisting of dividend policy, capital structure, ownership, free cash flow, and
14
profitability.
1. Dividend policy
Dividend policy is a ratio used to describe the amount of dividends issued by the
company. Dividend policy can be expressed in the Dividend Payout Ratio as a proxy in
measurement in accordance with the research of Danila et al. (2020), El-Halaby et al. (2018),
Sualehkhattak and Hussain (2017), Khan et al. (2016), and Rehman (2016).
DPR =
Dividend per share
Earning per share
2.
Capital structure
Capital structure is a ratio that shows the ratio of debt to the company's capital. Capital
structure can also be expressed in leverage. Capital structure can be measured using the Debt
to Equity Ratio (DER) proxy according to research by Andy et al. (2021), Setiadharma and
Machali (2017), and Manurung et al. (2016).
Debt to Equity Ratio (DER) = Total Debt (liabilities)
Total Capital (equity)
3.
Ownership
Company ownership is the portion of the company's share ownership either owned by
individuals or by foreign institutions. Ownership can determine the status of shareholders
including the majority or minority. The calculation of ownership can use the following
formula:
Ownership =
Total share ownership
x 100%
Total number of shares
To measure ownership structure, ownership concentration is used as a proxy (Singh et
al. 2017). Ownership concentration is calculated based on the percentage of the top 5
shareholders divided by the number of outstanding shares (Al
Sa'eed 2018, Sualehkhattak
and Hussain 2017).
4.
Free cash flow
Free cash flow is the amount of cash that can be withdrawn without harming a
company's ability to operate and generate future cash flows (Brigham and Houston 2009).
Free cash flow or free cash flow describes the amount of cash available after financing the

15
company's operations, which the company can use to invest. Free cash flow (FCF) is
measured by the following formula according to Brealey et al. (2015) modified by Vipond
(2018).
Control Variabes :
Control variables are variables that control the effect of
independent variables on non-
independent variables (Hardani et al. 2020). This study uses
control variables in the form of
company size, type of management and covid pandemic to improve the ability to predict the
research model, improve research results and avoid endogeneity problems and bias caused
by omitted correlated variables (Erdian 2022).
1.
Company size
Company size indicates how large the company is based on the assets owned.
Company performance is inversely proportional to company size
where large companies tend
to have large agency conflicts
(Fama and Babiak 1968). Another opinion states that company
size has a significant effect on company performance where large companies have greater
opportunities to access funds (Short and Keasey
2008). In this study, company size is
calculated using the
company's
total
assets (Ayubi et al. 2019, Setiadharma and Machali 2017,
Khamess et al.
2015). The formula for calculating company size is as follows:
Firm Size =LkTA which is the natural logarithm of Total Assets
2.
Type of company management
The type of company management is categorized into 2 types, namely
sharia
companies
(SC) and non-sharia companies (NSC). This variable is a dummy variable symbolized by 1
for Islamic companies and 0 for non-sharia companies (Ben-Nasr and Ghouma 2021).
3. Covid-19 Pandemic
The Covid-19 pandemic is used as a control variable to see whether the Covid
pandemic controls the effect of the independent variables on firm value. The Covid-19
pandemic is expressed in dummy where 1 is for covid pandemic conditions and 0 for
conditions outside the Covid-19 pandemic.
1.1.1 Moderating Variable
Moderating variables are defined as variables that strengthen or weaken the
relationship between independent variables and independent variables (Hardani et al. 2020).
16
This study uses Investment Opportunity Set (IOS) and macroeconomics as variables that
moderate the effect of dividend policy, capital structure, ownership, free cash flow and
profitability on firm value.
1. Investment Opportunity Set (IOS)
IOS describes the opportunity to invest in projects that have a positive net present
value (Kallapur 2001). IOS can be proxied by using Market to Book Asset (MBA), Market to
Book Equity (MBE) and Earning Price ratio (Danila et al. 2020). IOS for this study is
expressed by MBVE where this value is calculated based on prices that see company growth
from the company's ability to obtain and manage company capital (Sudiani and Wiksuana
2018).
Market to Book Value of Equity (IOSMBE) = Shares outstanding xshare
price
Book value of equity
2.
Interest Rate
Interest rates in this study use the Bank Indonesia 7 Days Repo Rate (BI7DRR) set by
Bank Indonesia as the basis for calculating interest rates. The BI7DRR proxy follows
research from Mubarok et al. (2014), Ningsih and Waspada (2017) and Sasongko and
Hamzah (2022). BI7DRR is a benchmark interest rate used to influence the money market,
banking and real sector (OJK 2019).
3.
Exchange Rate
The exchange rate describes the position of the home country's exchange rate against other
countries
(Kurniadi et al. 2014). This study uses the exchange rate of the Rupiah against the
United States Dollar obtained from Bank Indonesia following the research of Hendramiko et
al. (2020) and Pasaribu et al. (2019).
Data Processing and Data Analysis Techniques
1.1.2
Descriptive Analysis
Descriptive statistics by analyzing the financial statements of related companies. In this
study, a descriptive approach was taken to provide an overview of the condition of
IDXHIDIV20 indexed companies on the
Indonesia
Stock Exchange
based on the company's
financial statements. Descriptive statistics
include
at least
4 tests, namely the minimum,
maximum, mean, and standard deviation values. This descriptive analysis can help in the
process of determining the company's managerial strategy.

17
1.1.3
Panel Data Regression Analysis
This study uses a panel data regression model. Panel data combines time series
observations with cross section so as to provide
more informative data, more variability, less
collinearity,
more degrees of freedom and more efficiency (Gurajati 2004). Stages in panel
data regression include determining the estimation model, testing the suitability of the model,
testing assumptions and testing hypotheses (Erdian et al. 2022).
The panel data regression analysis method consists of 3 models, namely: Ordinary
Least
Square (Common effect) / Pooled Least Square, Fixed effect model and
Random effect
model. The formation of the panel data regression analysis model is a modification of
previous research, namely Erdian et al. (2022), Danila et al. (2020), El-Halaby (2018), and
Sualehkhattak and Hussain (2017). The panel data regression model design of the study in
general can be described in the following model:
a. Without moderation
TQit = α + β1 DPRit + β2 DERit + β3 COit + β4 FCFit + β5 ROEit + β6
BDit + β7 KAit + β8 LnTAit + β9 Ftypeit + β10 Covidit + εit
b.
With IOS moderation
TQit
=
α + β1
DPRit
+ β2
DERit +
β3
COit
+ β4
FCFit
+ β5
ROEit
+ β6
BDit +
β7 KAit
+
β8 IOSMBEit
+
β9 LnTAit + β10 Ftypeit
+
β11 Covidit
+
εit
TQit
=
α + β1 DPRit + β2 DERit + β3 COit + β4 FCFit + β5 ROEit + β6
BDit + β7 KAit + β8 DPRit*IOSit + β9 DERit*IOSit + β10 COit*IOSit + β11 FCFit*IOSit + β12 ROEit*IOSit + β13
BDit*IOSt + β14 KAit*IOSt + β15 LnTAit + β16 Ftypeit + β17 Covidit + εit
c.
With interest rate moderation
TQit
=
α + β1 DPRit + β2 DERit + β3 COit + β4 FCFit + β5 ROEit + β6
BDit + β7 KAit + β8 SBIit + β9 LnTAit + β10 Ftypeit + β11 Covidit
+
εit
TQit
=
α + β1 DPRit + β2 DERit + β3 COit + β4 FCFit + β5 ROEit + β6
BDit + β7 KAit + β8 DPRit*SBIit + β9 DERit*SBIit + β10

18
•
Model fit testing
Testing to determine the best panel data regression estimation model in
modeling the
effect of dividend policy, capital structure, ownership, free cash flow and profitability on
firm value. In this study, testing of research results was carried out using 3 tests to determine
the best technique for panel data regression (Singagerda 2018):
1.
Chow Test or F Statistical Test
The F statistical test is used to determine the best between the common effect model
and the fixed effect model. If the calculated F value is greater than the F table then the
selected model is the fixed effect model. Vice versa, if the calculated F value is
smaller than
the F table then the best
common effect
model.
2. Langrange Multiplier (LM)
The langrange multiplier test is used to select the best model between the
common effect
model and the random effect model. If the chi count value is greater than the
chi table, then the
common effect model is considered the best model. Meanwhile, if the chi count is smaller
than the chi table, then the random effect model is better.
3.
Hausman
test
The Hausman test aims to choose the best model between the fixed effect model and the
random effect model. If the Hausman value is greater than the chi table,
then the random effect
model is considered the best model. Meanwhile, if the
Hausman
value is
smaller than the chi
table, the fixed effect model is considered better.
•
Classical Assumption Test
The classic assumption test is carried out using the Normality test, Muktikolinearity
test, Heteroscedasticity test and Autocorrelation test.
1.
Normality Test
The normality test is carried out to determine the residual distribution of the model in
the hope that the residual model can be normally distributed. The residual value is said to be
normally distributed if the standardized residual value is mostly close to the average value. If
the significance value> 0.05 then the residual value is normally distributed. Conversely, if
the significance value <0.05, the residual value is not normally distributed (Sihabudin et al.
2021). The normality test is carried out on the residuals but not on the research variables.
Testing the residual distribution is done using the Jarque-Barbera test.
2.
Multicollinearity Test
Multicollinearity is a condition where one or more pairs of independent variables have
a strong correlation. The Multicollinearity
test aims to test whether there is a correlation

19
between the independent variables in the multicollinearity test
regression model. The
multicollinearity test can be done using the
correlation
test
or using the VIF value. The VIF
value ranges from 1 to +∞,
a high
value
indicates a strong dependency relationship between
one independent variable and a group of other independent variables. VIF value
≥10 indicates the potential danger of multicollinearity in the analysis model
regression (Kusumawardhani et al. 2021).
3.
Heteroscedasticity Test
The heteroscedasticity test is used to determine the presence of deviations from the
classic assumption of heteroscedasticity where there is an inequality of
variance from the
residuals for all observations in the regression model (Sihabuddin et al. 2021). The
heteroscedasticity test
is
carried out to see whether the residuals have a
patterned relationship
with the independent variables (Firdaus et al, 2020).
4.
Autocorrelation Test
Autocorrelation or serial correlation is the correlation between data series organized by
time series. The autocorrelation test can be done with Durbin Watson, Lagrange Multiplier,
Breusch-Godfrey, or Run test (Sihabuddin et al. 2021).
•
Hypothesis testing
Testing the research hypothesis was carried out by conducting a different test to
determine the effect between variables in the study. Hypothesis testing can be measured from
the goodness of fit of the multiple linear regression function formed. The significance test is
carried out using the coefficient of determination R
2
, F statistical test (simultaneous), and t
statistical test (partial) (Nainggolan 2022).
1. Coefficient of determination R2
The coefficient of determination R
2
is used to assess the ability of the model to explain how
much the dependent variable can be explained by the independent variable. The coefficient of
determination (R
2
) ranges from 0 < R2 ≤ 1, where
the smaller R
2
the smaller the ability of
the variable to explain the dependent variable (Kuncoro 2004).
2. F statistical test
The F statistical test shows whether all independent variables have a joint influence on the
dependent variable (Kuncoro 2004). This test is used to determine which independent
variables simultaneously affect the dependent variable. If the significance value <0.05, the
independent variable has a significant effect on the dependent variable (Rijaluddin 2022).
3. Statistical test t
The t statistical test is used to determine the significance of the independent variable
partially. Independent variables are tested partially to determine their effect on the dependent

20
variable by assuming that other variables are constant. If the p-value <0.05%, each
independent variable has a positive effect on the dependent variable (Rijaluddin 2022).
4.1 IDXHIDIV20 Company Overview
The Indonesia Stock Exchange (IDX) classifies listed companies into several stock
indices. A stock index is a statistical measure that reflects the overall price movement of a
set of stocks selected based on certain criteria and methodology and evaluated regularly.
Currently, the
IDX has 42 stock indices, one of which is the
IDX
High Dividend
20
(IDXHIDIV20) which is an index that measures the price performance of 20 stocks that have
paid cash dividends for the last 3 years and have a high dividend yield (BEI 2021).
IDXHIDIV20 is calculated based on the performance of stock price movements by
considering dividends as a supporting factor for investment decisions. There are main criteria
to be included in IDXHIDIV20, namely regularly distributing cash dividends in the last 3
years. The second requirement, IDX also uses daily trading value in the period of one month,
three months and 12 months with a minimum daily transaction value of 1 billion rupiah. In
addition, market capitalization is also one of the criteria for companies included in the
IDXHIDIV10 with a limit of no more than 15% in the index. The existence of this index can
help investors in compiling their investment portfolio.
The index was launched on May 17, 2018 with a base date of January 30, 2009.
IDXHIDIV20 indexed companies are evaluated four times a year, divided into major and
minor evaluations. Major evaluations are conducted in January and minor evaluations are
conducted in April, July
and September. IDXHIDIV20 consists of 20 companies from several
sectors with the dominance of the financial sector at 44.8% then infrastructure 19.4%;
industrial 10.7%; consumer non cyclical 10.3%; energy 8.9%; basic
materials 3.4%; healthcare 1.8% and consumer cyclical 0.7% (IDX 2021).
IDXHIDIV20 is classified based on dividends. Dividends are
company
profits
that are
distributed to shareholders. Dividends are one of the considerations used by investors in
investing in a company with regard to potential returns. Dividends are one of the corporate
actions that can drive stock prices and company value (Suwendiyanti and Gantino 2022). In
addition, dividends can also be used as a clue that the company has positive profitability and
signals the company's good prospects in the future (Febriyani et al. 2020).
Figure 7 shows the historical dividend payout ratio (DPR) of IDXHIDIV20 companies
from 2017 to 2021. The dividend payout ratio paid by IDXHIDIV20 companies varies
between companies. Issuers ADMF and HEXA tend to have constant DPR from 2017-2021,

21
while other issuers have fluctuating dividend payout ratios. ADRO paid out the largest
dividend in 2020 despite a drop in revenue due to the Covid-19 pandemic. Companies such
as HEXA, HMSP, ITMG, PTBA, TLKM and UNVR tend to have a high dividend payout
ratio with a dividend payout ratio above 70%.
The issuer BBNI is recorded to have the lowest DPR among the 18 companies listed on
IDXHIDIV20. Since 2018 BBNI has routinely distributed 25% of the company's profit as
dividends. Issuer HMSP has the highest DPR among
all issuers in IDXHIDIV20. HMSP was
recorded to distribute dividends
of
more
than 100% in 2018, 2019 and 2021 with a ratio of
100.69%, 101.56% and 103.16% of net profit for the year. Dividend payout ratio at a level
close to 100% means that the company distributes all profits as dividends while dividend
payments above 100% indicate that the company distributes dividends in excess of its net
income.
Some investors consider that a healthy dividend payout ratio ranges from 30%-55%.
The higher the dividend payout, the higher the
chance of unsustainability. A 55%-70% DPR
ratio indicates that the company is
not very growth-focused. A payout ratio close to 100%
indicates that the company is investor-focused and does not indicate any significant changes
in the company. If the DPR exceeds 100%, it
means that the company distributes dividends in
excess of the net profit generated in
that year by using available money to cover the shortfall in
dividends (What 2021).
The high dividend policy implemented by IDXHIDIV20 companies is one of the
crucial financial decisions. Payment of dividends to shareholders means distributing profits
generated by the company. The greater the amount of dividends paid to shareholders, the less
company funds that can be saved or utilized by the
company. If it is related to the condition of
the company's profits, it can be seen that
in the 2017-2021 period, IDXHIDIV20 companies
always recorded positive profits so that they were able to pay dividends to their shareholders.
Figure 8 shows the profits of IDXHIDIV20 companies from quarter 1 2017 to quarter 4
2021.
The net profit of IDXHIDIV20 companies was recorded to fluctuate from the first
quarter of 2017 to the fourth quarter of 2021. Several companies recorded a
decrease in net
profit in 2020 due to the Covid-19 pandemic
which had an impact on reducing income. Of the
18 IDXHIDIV20 companies, only 5 companies recorded an increase in net profit in 2020,
namely CPIN, INDF, KLBF, TLKM, TOWR. The five issuers that recorded an increase in
profit in 2020 are companies
related to consumer goods, health and telecommunications. This is
in accordance
with the conditions that occurred in 2020, where there was a Covid-19

22
pandemic. The Covid-19 pandemic has caused restrictions on the movement of people which
has an impact on the increasing need for telecommunications. The increased need for food
and medicine during the Covid-19 pandemic also contributed to the increase in the net profit
of related companies.
The use of company profits as dividends can affect the
condition of the company's
capital structure where retained earnings are included in the
company's equity
category
. If the
profit is retained and not issued as dividends, the company's equity will be greater. High
equity can minimize the debt ratio. Debt to equity ratio describes how the company's
financial decisions are made by looking at the ratio between debt and capital structure. The
higher the DER, the higher the company's debt.
Figure 9 shows the DER pattern of IDXHIDIV20 companies for the period Q1 2017-
Q4 2021. The DER condition of IDXHIDIV20 companies is quite large where a financially
healthy company is indicated by a DER ratio
below 1 or below 100% (Andirerei 2019). Issuers
BBNI, BBRI, BMRI,
BBCA, ADMF, TOWR and UNVR have DER above 100%. Issuers
BBNI, BBRI, BMRI, BBCA and ADMF have high DER because they are included in the
banking or financial sector. The banking or financial sector tends to have a high DER because
the debt ratio also consists of saving and borrowing funds by third parties. High DER can also
indicate the level of distribution.
High DER conditions can be associated with trade off theory where companies tend to
balance debt with the benefits received. In banking companies, the benefit received with a
high level of DER is the receipt of interest paid by third parties. The construction sector
utilizes debt to finance operational activities. This is due to the construction business line
which requires large initial investment costs.
While UNVR has a high DER level for the
consumer sector
, the ROE offered by the company is also quite high (Figure 10). This
condition can be attributed to the signaling theory where a high capital structure indicates
good prospects in the future. Other issuers are recorded to have fluctuating DER. KLBF has
the lowest DER value among all companies in IDXHIDIV20 with a value of <30%. This
condition can be attributed to the pecking order theory where companies with high
profitability tend to utilize their own capital to run their business.
From the figure it can be seen that UNVR provides the highest ROE
among all issuers
in IDXHIDIV20. UNVR has ROE above 100% in a
period of 5 consecutive years. This
condition shows that UNVR has very good profitability. When viewed as a whole, ROE in
IDXHIDIV20 companies has a good value so that it can be said that
the companies listed in

23
IDXHIDIV20 have excellent profitability
also good. The existence of good profitability can
lead to agency conflicts. Therefore, according to agency theory, the capital structure should
be structured in order to reduce agency conflicts.
High dividend payments as a consequence of positive earnings are decisions related to
share ownership. The greater the concentration of share ownership of a company, the conflict
of interest can be minimized because the parties with interests become more centralized.
Ownership if associated with agency theory shows that the concentration of ownership of
companies in IDXHIDIV20 is dominated by ownership concentration above 50% so that it
can reduce agency conflicts in IDXHIDIV20 (Figure 11).
Figure 11 shows the ownership concentration pattern of IDXHIDIV20 indexed
companies, which tends to be stable over time. Changes in ownership concentration can be
seen in the TOWR issuer, which has increased from 32.72% in Q1 2017 to 54.36% in Q4
2021. This increase was due to an increase in institutional share ownership by PT Sapta
Adhikari Investama and managerial ownership. Another issuer that experienced ownership
changes was BBCA, where the increase in ownership was due to the addition of ownership
by PT Dwimuria Investama Andalan. Issuer BBNI experienced a decrease in ownership
concentration due to a decrease in the amount of ownership by foreign business entities.
Issuer BBRI experienced a slight decrease in ownership concentration in Q4 2021 due to a
decrease in share ownership by commissioners and directors. Issuer BMRI experienced a
decrease in share ownership due to the transfer of shares from NKRI to the Indonesia
Investment Authority. KLBF experienced changes in ownership due to changes in ownership
by PT Gira Sole Prima, PT Santa Seha Sanadi, PT
Diptanala Bahana, PT Lucasta Murni
Cemerlang, PT Ladang Ira Panen and PT Bina
Arta Charisma. Meanwhile, the issuer PTBA
experienced a change in concentration ownership due to changes in the number of shares
owned by PT Indonesia Asahan Aluminum.
Based on Figure 12, it can be seen that several issuers in IDXHIDIV20 have negative
free cash flow. Negative free cash flow indicates that the company's cash flow is smaller than
the operating expenses that must be paid by the company. Negative free cash flow does not
mean that the company has poor performance. Negative free cash flow can be a good
indicator for the company as long as interest expenses < interest income. In addition,
negative free cash flow can also be caused by the placement of funds at Bank Indonesia and
other banks, as well as loans provided by banks to other parties (Kurniawan 2021).
Corporate governance (CG) is a priority for economic growth around the world. CG
allows management to identify company objectives, fulfill legal obligations, protect
shareholder rights, and to maintain transparency with the public regarding progress and

24
general business status (Shatnawi et al. 2021). The implementation of good corporate
governance can be seen from various aspects, one of which is the size or number of boards,
both the board of
commissioners and the board of directors and the existence of an audit
committee. Figure 13 shows the board size of IDXHIDIV20 companies at the end of 2021
reduced to 10 people from Q2 2020 to Q4 2021. This change is a result of changes in the
number of members of the board of directors and the board of commissioners.
Issuers that recorded an increase in board size were BBNI, which increased from 18
people in 2017 to 22 people at the end of
2021. BMRI also experienced an increase in board
size from 18 people
to 22 people. BBNI and BMRI both experienced an increase in
board size
with each addition of 2 people on the board of directors and
2 people on the board of
commissioners. Other issuers in IDXHIDIV20 also experienced
changes in the number of
board sizes, but the changes that occurred were not too large.
Changes in both the addition and
reduction of board size are between 1
-
2 people.
The audit committee on IDXHIDIV20 shows the ratio of the number of audit committees to
non-independent commissioners. In the IDXHIDIV20, the ratio range is between 50% and
250%. Issuer CPIN has an audit committee ratio of 250% in Q1 2017 and Q4 2017 to Q3
2018. This shows that the percentage of audit committee members is 250% of non-
independent commissioners. In such conditions, the number of audit committee members is
greater than the number of non-independent commissioners. BBRI also had an audit
committee ratio of 250% in Q1 2021. ASII has the lowest audit committee ratio of 50%,
which indicates that the audit committee members are 50% of the non-independent
commissioners.
The ratio of audit committees in several companies is constant from period to
period.
These issuers are ADMF, KLBF and UNTR with a ratio of 75%, ADRO with a ratio of
100%, BBCA and HEXA with a ratio of 150%, and INDF with a ratio of 60%. Other issuers
in IDXHIDIV20 experienced fluctuations in changes in the ratio of the audit committee in
accordance with changes in the number of audit committee members and the number of non-
independent commissioners. The role of the audit committee in the company is crucial,
especially because of the function of the audit committee in maintaining the quality and
transparency of the company's financial statements and audit process (Hastori et al. 2015).
IOS indicates good growth opportunities for the company in the present and future.
UNVR has the highest IOS when compared to other issuers in IDXHIDIV20. The IOS gap
between UNVR and other issuers in IDXHIDIV20 appears quite far when viewed from
Figure 15. The high IOS value of UNVR can be caused by the high market price of UNVR

25
when compared to the company's capital. HMSP also has a fairly high IOS value when
compared to other issuers, but in 2020 the IOS value of HMSP began to be at the same level
as other issuers in IDXHIDIV20. Apart from these two issuers, issuers in IDXHIDIV20 have
an almost similar IOS distribution. This can be seen in Figure 15, where the IOS lines
converge in the same area, namely between 0-10.
IOS is one of the indicators used by various parties in seeing a company. This
condition is related to company value where companies with high IOS have good company
value because they are considered capable of having good prospects in the future (Giriati
2016). Figure 16 shows how the company value of IDXHIDIV20. From the figure it can be
seen that in the period Q1 2017
-
Q4 2021, the value of IDXHIDIV20 companies varies.
Issuers HMSP and UNVR were recorded as having
high enterprise values with values above 6.
This condition shows that the
company
value of
the two issuers is very high when compared to
the issuers in the IDXHIDIV20.
other companies in IDXHIDIV20. Figure 16 also shows that
companies in the IDXHIDIV20 have a high enterprise value which means that companies in
the IDXHIDIV20 have a higher market value than their book value.
Unexpected conditions such as a pandemic can affect company performance. The
Covid-19 pandemic that occurred in early 2020 affected world economic conditions, which
indirectly affected the performance of capital markets around the world but actually
increased the number of capital market investors (Suwendiyanti and Gantino 2022).
Macroeconomic conditions can also affect the world economy which has an impact on
company performance. Macroeconomic conditions that can be considered include the
benchmark interest rate policy and the rupiah exchange rate.
Bank Indonesia issued BI7DRR as the new benchmark interest rate or policy rate in
order to strengthen the monetary operating framework since August 19, 2016. This was done
as an effort to strengthen policy effectiveness in order to achieve the set inflation target (BI
2020). The benchmark interest rate issued by Bank Indonesia is one of the determining
factors in the process of determining lending and investment interest. An increase or
decrease in the benchmark interest rate has an impact on the rise and fall of lending rates and
investment
returns
. The exchange rate is also one of the macroeconomic factors that can
determine the amount of profit or loss of the company. This is due to
changes in foreign
exchange rates that can change the value of the rupiah currency.
Figure 17 shows the historical
BI7DRR and the rupiah exchange rate against the dollar from Q1 2017- Q4 2021.
Figure 17 shows the fluctuation of BI7DRR from the period of TW I 2017- TW IV
2021. BI7DRR increased in 2018 driven by efforts to reduce the current account deficit to a
26
safe limit. The increase in policy rates was also to strengthen the attractiveness of
domestic
financial assets
by anticipating an increase in global interest rates in a few months into the future
(BI 2018). In 2019, BI7DRR has decreased until 2021. The
decline in the benchmark interest
rate was partly due to the Covid19 pandemic so that the government tried to carry out
monetary policy by lowering interest rates. The decline in interest rates was taken by Bank
Indonesia as an effort to keep inflation low, maintain external stability, and efforts to
encourage economic recovery during the Covid-19 pandemic (Ekarina and Fedrichson
2020).
IDXHIDIV20 consists of various companies from various industrial sectors where
some of them are companies that carry out international trade activities so that the rupiah
exchange rate greatly affects the company's profit and loss. Figure 17 shows the historical
rupiah exchange rate which tends to be stable. The rupiah was recorded to have increased in
Q1 2020 which reached Rp 16,367.00 per rupiah dollar when the Covid-19 pandemic began
to enter Indonesia. Bank Indonesia seeks to continue the Rupiah exchange rate stabilization
policy amidst global financial market uncertainty by stabilizing and strengthening the Rupiah
(Ekarina and Fedrichson 2020).
4.2
Descriptive Analysis
Descriptive analysis was carried out as a whole on the variables
used in this study. This
analysis aims to provide an
overview
of the
condition of operational variables. The
Tobin's Q
variable reflects the value of the
company, while the dividend payout ratio (DPR), debt to
equity ratio (DER), concentration ownership (CO), free cash flow (FCF), board size (BD),
audit committee (KA) as determinants of company value. In addition, total assets (LnTA),
type of company management (Ftype) and Covid-19 pandemic conditions (Covid) as control
variables as well as investment opportunity cost (IOS) and macroeconomic indicators (SBI
and exchange rates) as moderating variables. The companies that became the research
sample were 18 companies with a total of 18 observations 360 observations from quarter I
2017 to quarter IV 2021. Table 5 shows the results of descriptive analysis of the research
variables.
Table 5 Descriptive Analysis
Variables
Mean
Median
Maximum
Minimum
Std. Dev.
TOBIN'S Q
2,24
1,39
15,35
0,70
2,29
DPR (%)
59,39
50,03
103,77
25,00
22,67
27
DER (%)
207,24
91,63
684,01
18,64
205,67
CO (%)
64,42
58,75
98,15
32,72
16,09
FCF
0,06
0,04
0,48
-0,17
0,01
ROE (%)
15,51
10,72
145,09
1,67
19,23
BD (Person)
14,68
14,00
23,00
9,00
3,92
KA
111,00
100,00
250,00
50,00
44,23
Total Assets (Billion IDR)
301.353,60
70.060,60
1.725.611,00
3.190,39
445.106,50
FTYPE
0,50
0,50
1,00
0,00
0,50
Covid
0,40
0,00
1,00
0,00
0,49
IOS
3,89
2,06
56,79
0,49
6,41
SBI (%)
4,60
4,38
6,00
3,50
0,86
Exchange rate (IDR)
14.255,75
14.261,00
16.367,00
13.319,00
666,68
4.2.1
Company value
Firm value reflects how the company is seen in the perspective of current and potential
future value. The higher the company value, the better the company is both from the
company's performance and from the investor's point of view. The value of IDXHIDIV20
companies reflected through
Tobin's Q
value
shows an
average of 2.24 with a median value of
1.39. The
average
value of
Tobin's Q in IDXHIDIV20 is more than 1, which indicates that the
value of IDXHIDIV20 companies is higher than their book value. This Tobin's Q value
shows
that the average IDXHIDIV20 company value is above 1, which means that the company is
able to maximize its market value.
The maximum Tobin's Q with a value of 15.35 belongs to the issuer UNVR in the
fourth quarter of 2020, while the minimum Tobin's Q of 0.70 belongs to the issuer ADRO
in the
first quarter of 2020. This shows that UNVR has the
best company
value
, while ADRO has
the worst company value in
IDXHIDIV20. UNVR has the highest Tobin's Q value in quarter
IV 2020
due to UNVR experiencing an increase in share prices on the stock exchange
which causes an increase in company value. ADRO has the lowest company value in the
third quarter of 2017 due to the low share price in that period.
Companies in IDXHIDIV20 have a firm value that exceeds the value of their assets,
indicating that investors have high expectations of companies in IDXHIDIV20. In
managerial economics, firm value is defined as the expected value of future investment
returns equal to shareholder wealth (Sunaryo 2012). If the company is able to provide
sustainable profit expectations to shareholders, the market value becomes greater than the
funds invested by
shareholders, which is reflected through the stock price. This shows that What
happens to companies in IDXHIDIV20 is able to illustrate
these
conditions
where the company's

28
ability to provide investors with expectations of large profits in the future makes the value of
IDXHIDIV20 companies greater than the value of their assets.
4.2.2 Dividend Payout Ratio (DPR)
Dividend payout ratio shows the ratio of the company's net income distributed as
dividends. The DPR value is usually not more than 1 or 100% because
this means that the
company distributes all of the company's net profit as
dividends. The DPR of IDXHIDIV20
indexed companies has an average DPR value of 59.39% with a median value of 50.03%.
The DPR indicates that on average, IDXHIDIV20 companies distribute 59.39% of their
company profits as dividends to shareholders. The maximum DPR of 103.77% belongs to
the issuer HMSP in 2021, while the minimum DPR value of 25.00% belongs to the issuer
BBNI in 2018-2019.
The DPR value on the issuer HMSP shows a value of more than 100% where this
occurred in 2021. In 2021, HMSP distributed dividends of 117 rupiah per share, which is
more than the company's net profit generated that year. According to the results of a search
in an article published by Kontan with the author Qolbi (2019), it was found that HMSP's
DPR was more than 100% because part of the dividends distributed in 2021 was taken from
the retained earnings balance. Dividends that are too large can lead to unsustainability and
become a warning for both companies and investors (What is 2021).
Companies in IDXHIDIV20 are classified based on their performance of paying out
cash dividends with a relatively high dividend yield over the past 3 years. However, when
viewed from the distribution of dividend payout rates between companies, it varies from
25% to more than 100%. This shows that a high dividend payout rate does not always
provide a high dividend yield where this dividend yield is highly dependent on the stock
price. Baker et al. (2019) revealed that companies with high dividend yields are considered
superior and can attract investors.
HMSP distributes DPR more than 100% so that the calculation of dividend yield is
high when compared to the share price. This can attract investors and increase investor
confidence that the company is still performing well. However, for the company, a dividend
payout ratio above 100% can threaten the sustainability of the company and eliminate the
company's opportunity to grow. On the other hand, BBNI has a DPR ratio of 25% but its
dividend yield is also relatively high. This shows that the company BBNI has a price that is
not too high in the market when compared to the dividends received by investors.
4.2.3
Debt to Equity Ratio
(DER)
The capital structure of the company is expressed in the DER ratio which shows the
ratio between debt and capital owned by the company. The greater the DER value, the greater

29
the company's debt compared to its capital. The average DER of IDXHIDIV20 companies is
207.24% with a median value of 91.63%. The highest DER is owned by BBNI issuers in the
third quarter of 2020 with a value of 684.01%, while the lowest DER is owned by KLBF
issuers with a value of 18.64% in the fourth quarter of 2018.
The issuer BBNI has a DER value of 684.01% which indicates that BBNI's debt is
684.01% greater than its capital. This is due to the type of BBNI company which is a
banking company where the value of customer and third party debt or credit is considered as
company debt, causing the company to have a high DER value. BBNI's total liabilities in Q3
2020 reached 772.4 trillion rupiah which was dominated by customer deposits which reached
673.86 trillion rupiah.
The issuer KLBF has 18.64% debt when compared to its capital. This shows that
KLBF tends to utilize its own capital to
run its company. Based on information from the
financial statements,
this
condition
is in accordance with KLBF's group policy of maintaining
a healthy capital structure to secure access to funding at a reasonable cost.
High capital structure such as the case of BBNI where the company belongs to the
banking category gives a different meaning from the capital structure in general where the
capital structure is composed of debt and capital. In the banking world, the capital structure
consists of capital reserves (deposits) which are not
found in other companies from the non-
financial sector (Gropp and Heider 2009).
BBNI's debt is dominated by customer deposits
which are included in other financial liabilities measured at amortized cost
using the effective
interest rate method. In terms of capital management, BBNI
has met the minimum standard of
capital adequacy ratio of 22.88% where the minimum standard of Bank Indonesia is 9.8%.

