


FINANCIAL MANAGEMENT AGRIBUSINESS
ARIZONA STATE UNIVERSITY
AGB 410 - AGRIBUSINESS MANAGEMENT
WEEK 5
Introduction:
Every agribusiness company always needs funds in order to meet the needs of daily
operations and to develop the company. The need for funds is in the form of working capital
and for the purchase of fixed assets. To meet these needs, the company must find a source of
funds with a composition that results in the lowest cost burden. For this reason, efforts must
be made to manage finances.
Financial management can be defined as all company activities related to efforts to
obtain funds at low cost and efforts to use and allocate these funds efficiently (Sutrisno, 2001:
3). Meanwhile, according to Suratiyah (2001: 3) financial management discusses investment,
spending, and management of assets with several predetermined objectives. In connection
with agribusiness, agribusiness financial management is devoted to companies that produce
agribusiness products and farms in the field by allocating funds effectively and efficiently.
Agribusiness financial management cannot be separated from other corporate functions,
such as agribusiness marketing, production (farming and agro-industry) and agribusiness
human resources. Therefore, financial managers must cooperate with managers of these
functions. For example, new product development, promotion plans, price distribution, and
product pricing.
In relation to corporate goals, the goal of agribusiness companies is to increase the
prosperity of shareholders or owners. The prosperity of shareholders This is shown in the
form of higher share prices which are a reflection of investment, funding and dividend policy
decisions. Therefore, the prosperity of shareholders can be used as analysis and rational
action in the decision-making process.
To discuss agribusiness financial management cannot be separated from financial
statements. Therefore, a brief discussion of financial statements is necessary. The
agribusiness financial report is the final result of the agribusiness accounting process which
includes two main reports, namely the balance sheet and profit and loss statement. Financial
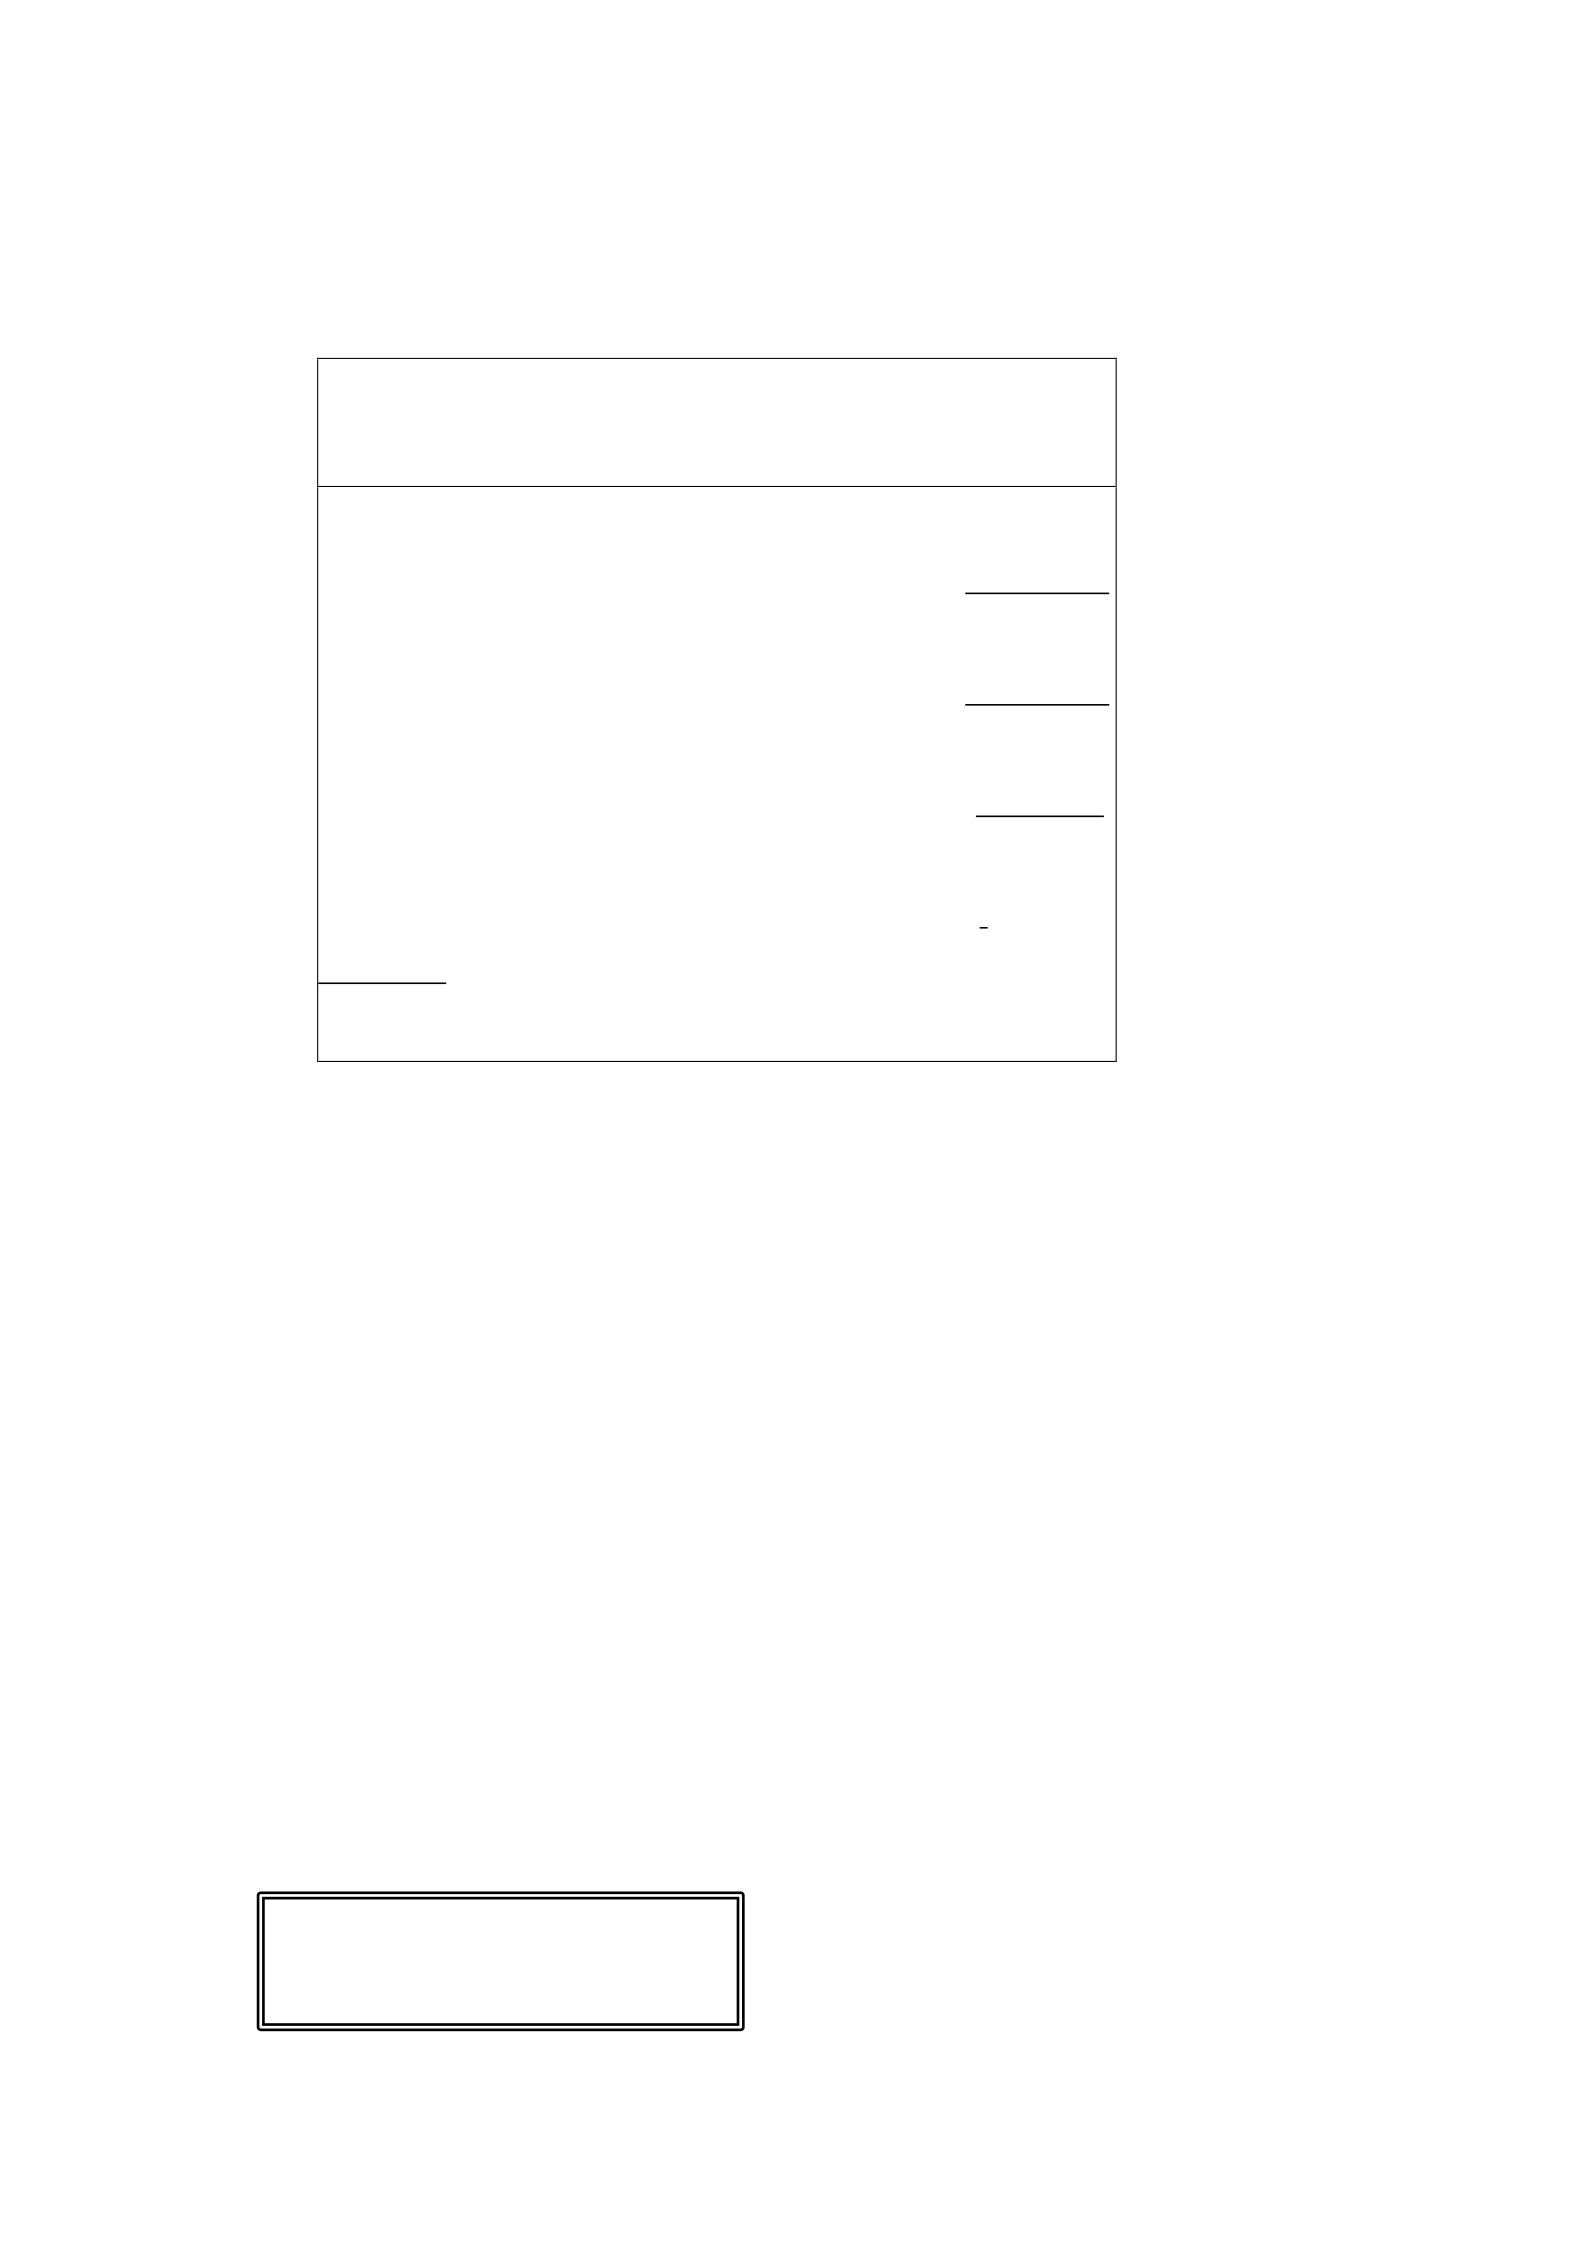
statements are prepared with the intention of providing financial information of a company to
interested parties as a consideration in making decisions.
"PT AGRIFOOD"
Profit and Loss Statement 2004
Income Rp 12,400,000
Cost of Goods Sold 57.000.000
Gross Profit 67.000.000
Operating Expenses 26.500.000
Earning Before Interest & Tax (EBIT) 40.500.000
Flowers 7.500.000
Earning Before Tax (EBT) 33.000.000
30% tax
9.900.000
Earning After Tax (EAT) 23.100.000
Figure 5.5 Income Statement of PT Agrifood
For managers of agribusiness companies, of course, they want to know whether the
company is running well. To find out whether the company is running well, the manager
must know the performance of the company he manages. Company performance is simply
known from three aspects, namely: liquidity, solvency, and profitability.
Liquidity is the ability of agribusiness companies to fulfill their obligations that must be
met immediately. Liquidity is related to the issue of short-term creditors' trust in the
company, meaning that the higher the liquidity, the more trust short-term creditors will have.
The liquidity of agribusiness companies is indicated by the size of current assets or assets that
are easily turned into cash, such as cash, securities, accounts receivable, and inventory. If the
company's liquidity is found to be 2.5, it means that every one rupiah of current debt will be
guaranteed by current assets of Rp 2.50. The greater the liquidity, the greater the company's
ability to pay short-term debt.
Current Assets
Liquidity = --------------------
Current Payables
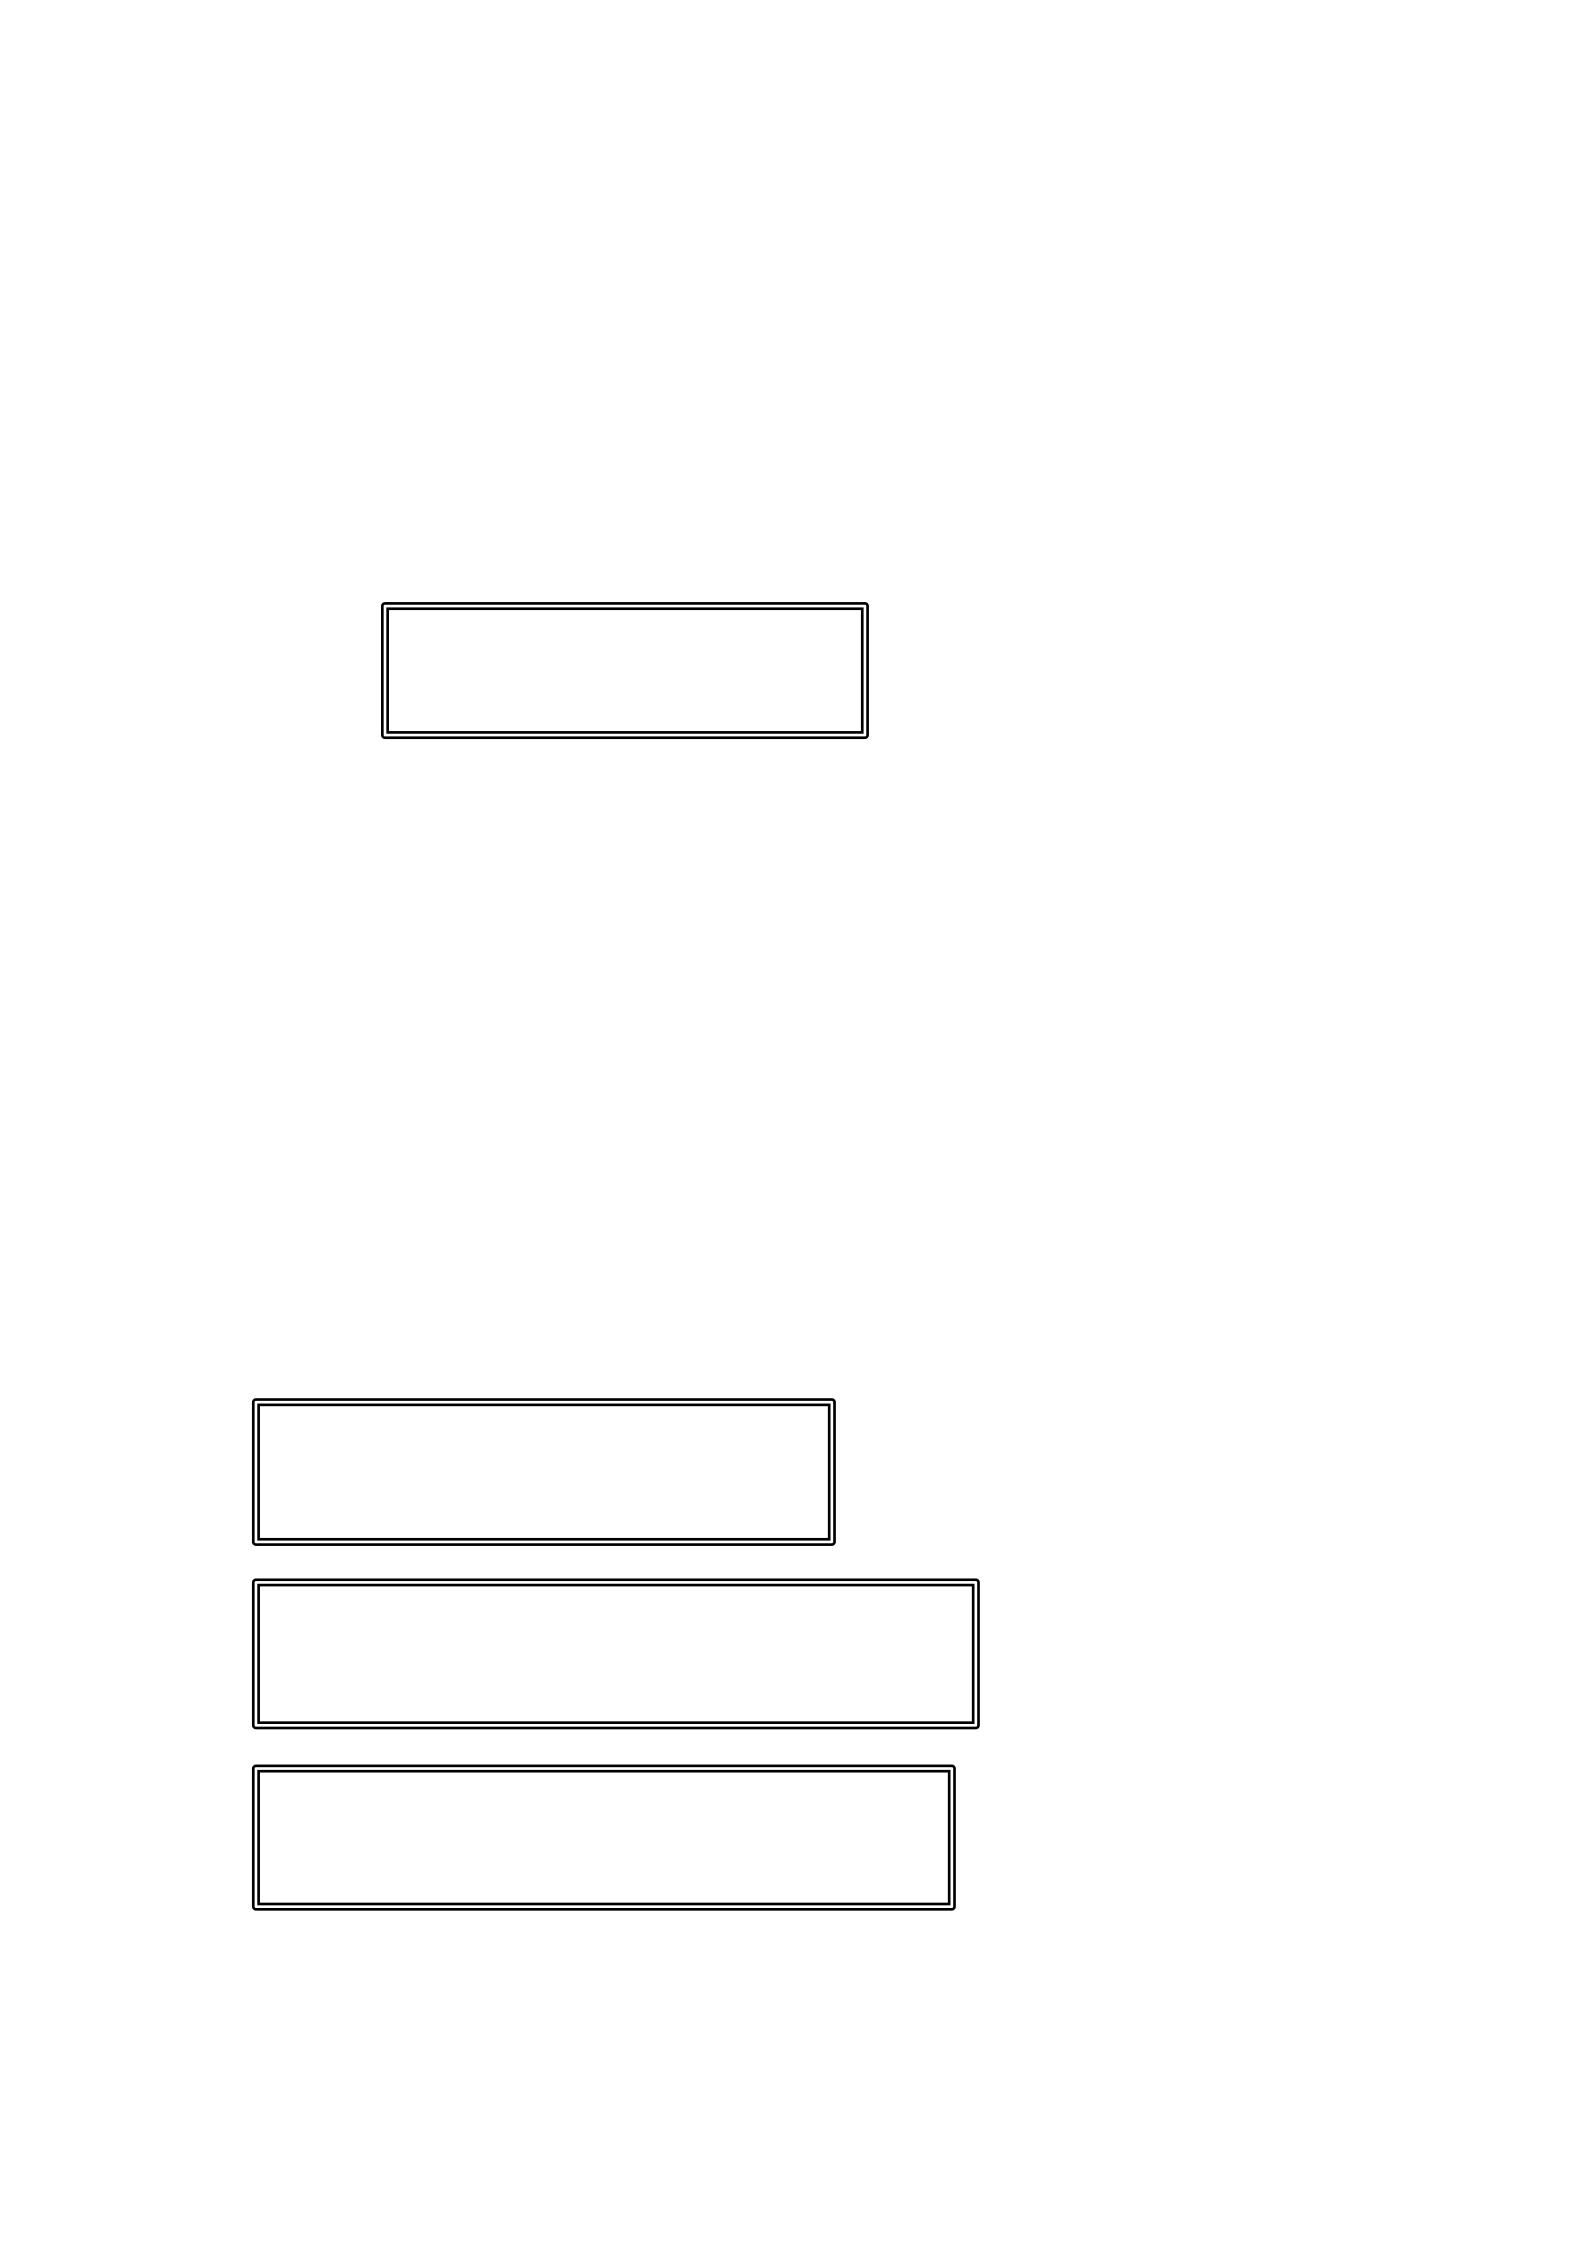
Total Assets
Solvency = -------------------
Total Debt
Profitability =x
100%
Total Capital
EBIT
Economic Rentability ---------------------- =x 100%
MS + MA
EAT
Own Capital Rentability ----------------- =x 100%
MS
Solvency is the ability of agribusiness companies to fulfill all their obligations if the
company is liquidated. Usually the problem that arises when an agribusiness company is
liquidated (closed) concerns whether the assets owned by the company are able to cover all
debts. To cover all debts, the company guarantees with all its wealth (assets). Thus, the
company's solvency can be calculated by dividing total assets by total debt. If solvency
produces a number 3, it means that every Rp 1,- of company debt is guaranteed by Rp 3,- of
assets owned by the company.
Rentability is the ability of agribusiness companies to generate profits with all the
capital that works in it. All capital working in the company is own capital and foreign capital.
Rentability is divided into two types of profitability, namely economic profitability and own
capital profitability. Economic profitability (RE) is the company's ability to generate profits
with all capital, while own capital profitability (RMS) is the company's ability to generate
profits with its own capital. The difference according to Sutrisno (2001:18) is in RE because
what works is all capital (own capital and equity).
foreign capital) then the profit shared is operating profit or EBIT (Earning Before
Interest and Tax), while in RMS, because only equity capital works, the profit shared is profit
for shareholders, namely EAT (Earning After Tax).

where
MS : equity capital
MA : foreign capital
1. Financial Management Functions Agribusiness
The agribusiness financial management function consists of three decisions that must be
made by a company, namely investment decisions, funding decisions, and dividend decisions.
Each decision must be oriented towards achieving the goals of the agribusiness company.
a. Agribusiness Investment Decision
Investment decisions are a matter of how agribusiness financial managers should
allocate funds into forms of investment that will bring future profits. The form, type and
composition of these investments will affect and support the level of future profits. The
expected future profits from these investments cannot be estimated with certainty. Therefore,
investment will contain risk or uncertainty. The risks and expected returns from the
investment will greatly affect the achievement of the company's goals, policies, and values.
b. Agribusiness Funding Decisions
Funding decisions are often referred to as capital structure policies. In this decision,
managers are required to consider and analyze the combination of sources of funds that are
economical for the company to finance its investment needs and business activities.
c. Agribusiness dividend decision
Dividends are part of the profits paid by the company to shareholders. Therefore,
dividends are part of the income expected by shareholders. According to Sutrisno (2001: 6),
dividend decisions are financial management decisions to determine the percentage of profits
distributed to shareholders in cash,
The stability of dividends paid out, stock dividends, stock splits, and the recall of
outstanding shares are all aimed at determining the prosperity of shareholders.
2. Financial Analysis Agribusiness
a. Break Even Point (BEP)

Break even point (BEP) is a condition where in that period the company does not make a
profit and also does not suffer losses. This means that at that time the income received is
equal to the costs incurred.
In the BEP analysis, basic assumptions are used, namely (1) Costs must be separated
into two types of costs, variable costs and fixed costs. If there are semi-variable costs must be
allocated to the two types of costs, (2) The selling price per unit does not change during the
analysis period, and (3) Agribusiness companies produce one type of product if they produce
more than one product, the balance of income for each price is fixed.
There are two ways to determine BEP, namely the graphical approach and the
mathematical approach. Graphical approach, one of the determination of the BEP point is to
describe the elements of cost and income into a graphical image. The graph shows the lines
of variable costs, fixed costs, total costs, and total income line (Figure 5.6).
b. Leverage
Leverage problems arise because companies use assets that cause them to pay fixed
costs and use debt that causes agribusiness companies to bear fixed costs. Thus leverage is
the use of assets or sources of funds where for this use the company must bear fixed costs or
fixed expenses.
Leverage is divided into two types, namely operating leverage and financial leverage.
Companies use operating and financial leverage with the aim that the profits earned by
agribusiness companies are greater than their assets and sources of funds. Thus, it will
increase profits for shareholders.
1) Operating leverage
Operating leverage is the use of assets that cause agribusiness companies to bear fixed
costs in the form of depreciation. The use of operating leverage by agribusiness companies is
expected so that the income earned from the use of these assets is sufficient to cover fixed
and variable costs.
Operating leverage measures changes in revenue or sales against operating profit. By
knowing the level of operating leverage, management can estimate changes in operating
profit as a result of changes in sales. The measure of operating leverage is the degree of
operating leverage (DOL), meaning that if DOL is found to be 2, then if sales increase or
decrease by 10 percent, ordinary profits are predicted to increase or decrease by 2 times the
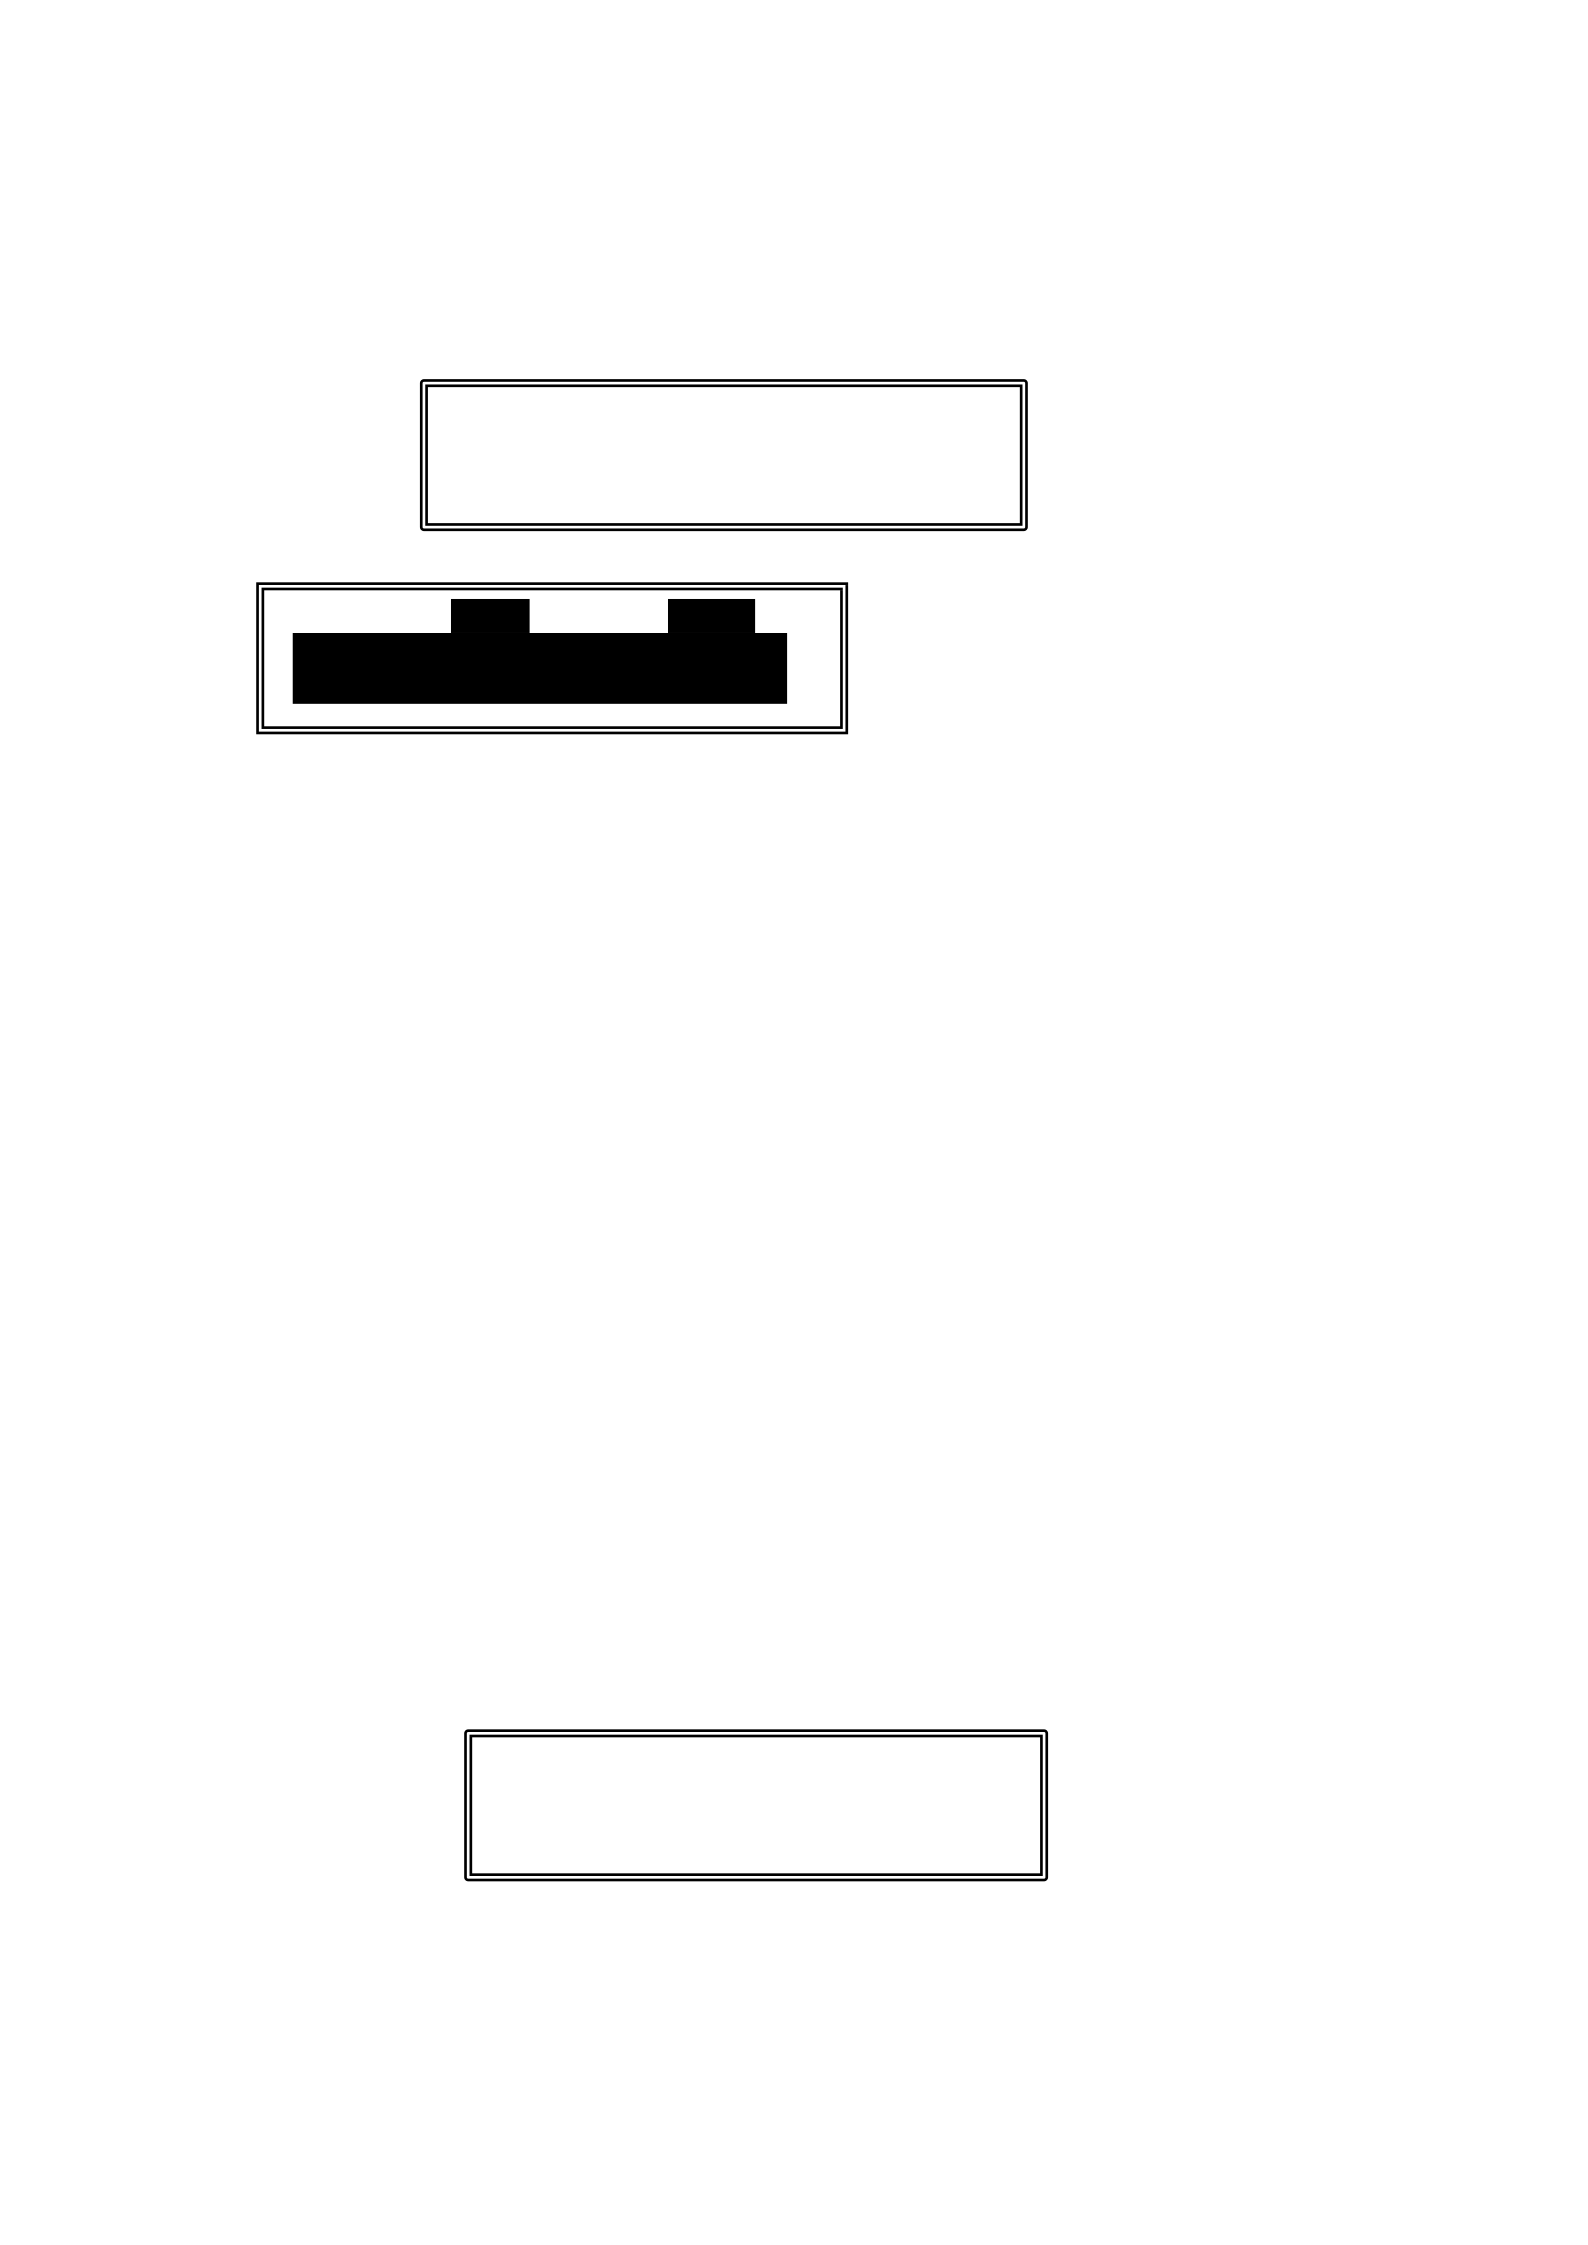
% change in EBIT DOL=
---------------------------------------
% change in sales
EBIT
Q(P-V) BT
DFL = ------------
= ------------------
EBIT - i Q(P-V) - BT- i
increase or decrease in sales, meaning 2 x 10% = 20%. The higher the DOL the more risky
the company is, because it has to bear increasingly large fixed costs. To calculate the amount
of DOL, the formula is used:
or
Description:
Q = quantity
P = price per unit
V = variable cost per unit
BT = total fixed cost
S = sales
BV = total variable cost
2) Finance leverage
Financial leverage is the use of funds that causes the company to bear a fixed burden in
the form of interest. The use of funds that cause this fixed burden is expected to generate
more income than the expenses incurred.
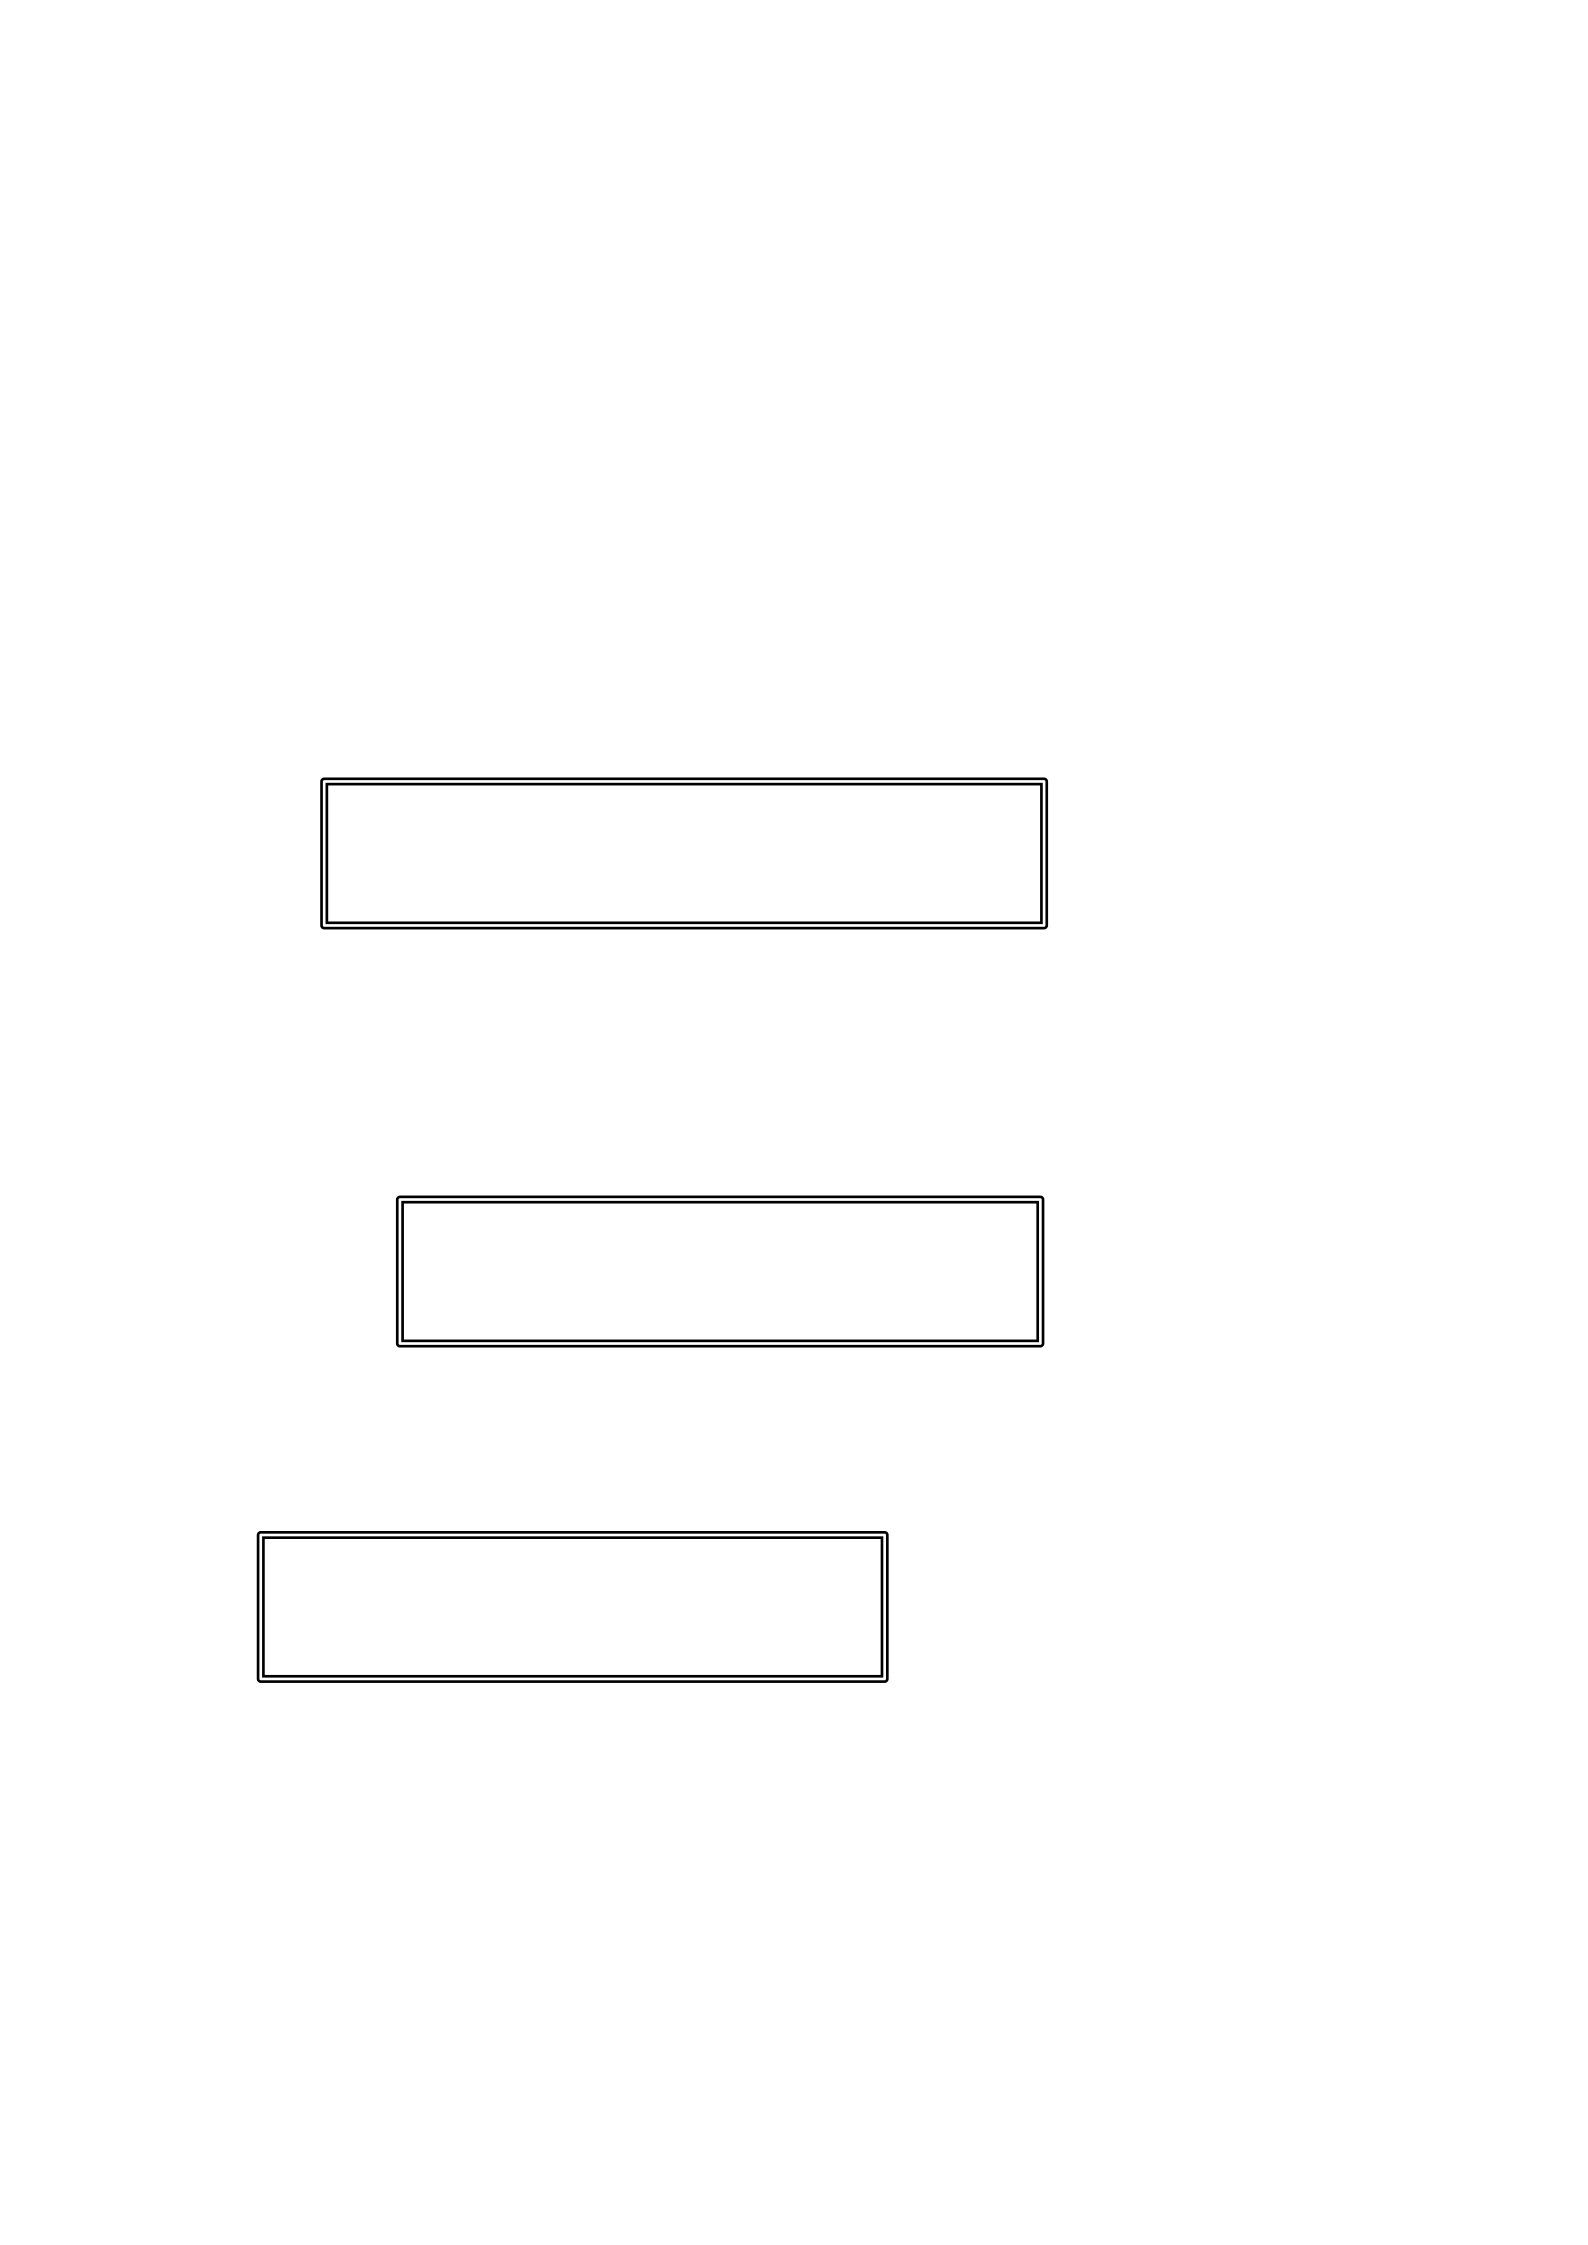
Financial leverage measures the effect of changes in operating profit (EBIT) on changes
in income for shareholders (EAT). What affects the owner's income is the amount of EBIT
received and the capital structure owned. The measure of the level of financial leverage is the
degree of financial leverage (DFL), and to measure the amount of DFL the following formula
is used:
where :
i = interest in rupiah
)
DOL =-------------- = ----------------
BV - BT (P-V) - BT
7
Cost of goods sold
Inventory turnover = -----------------------------
Average inventory
Credit sales
Accounts receivable turnover = ------------------
------
Average receivables
c. Agribusiness Financial Ratios
1) Activity Ratio
The activity ratio measures the effectiveness of an agribusiness company in utilizing its
resources. The ratio is expressed as a comparison of sales with various elements of assets.
Activity ratios include inventory turnover, receivable turnover, fixed assets turnover, and
asset turnover.
Inventory turnover is the main component of goods sold. Therefore, the higher the
inventory turnover the more effective the agribusiness company is in managing inventory,
which is calculated by the formula:
Receivable turnover is a measure of the effectiveness of receivable management. The
faster the receivable turnover, the more effective the company is in managing its receivables,
which is calculated by the formula:
Fixed assets turnover is the ratio between sales and total assets owned by agribusiness
companies, which is calculated by the formula:
Asset turnover is a measure of the effectiveness of asset utilization in generating sales.
The greater the asset turnover, the more effectively the agribusiness company manages its
assets, which is calculated by the formula :
Sales Fixed
asset turnover = -----------------
Fixed
assets
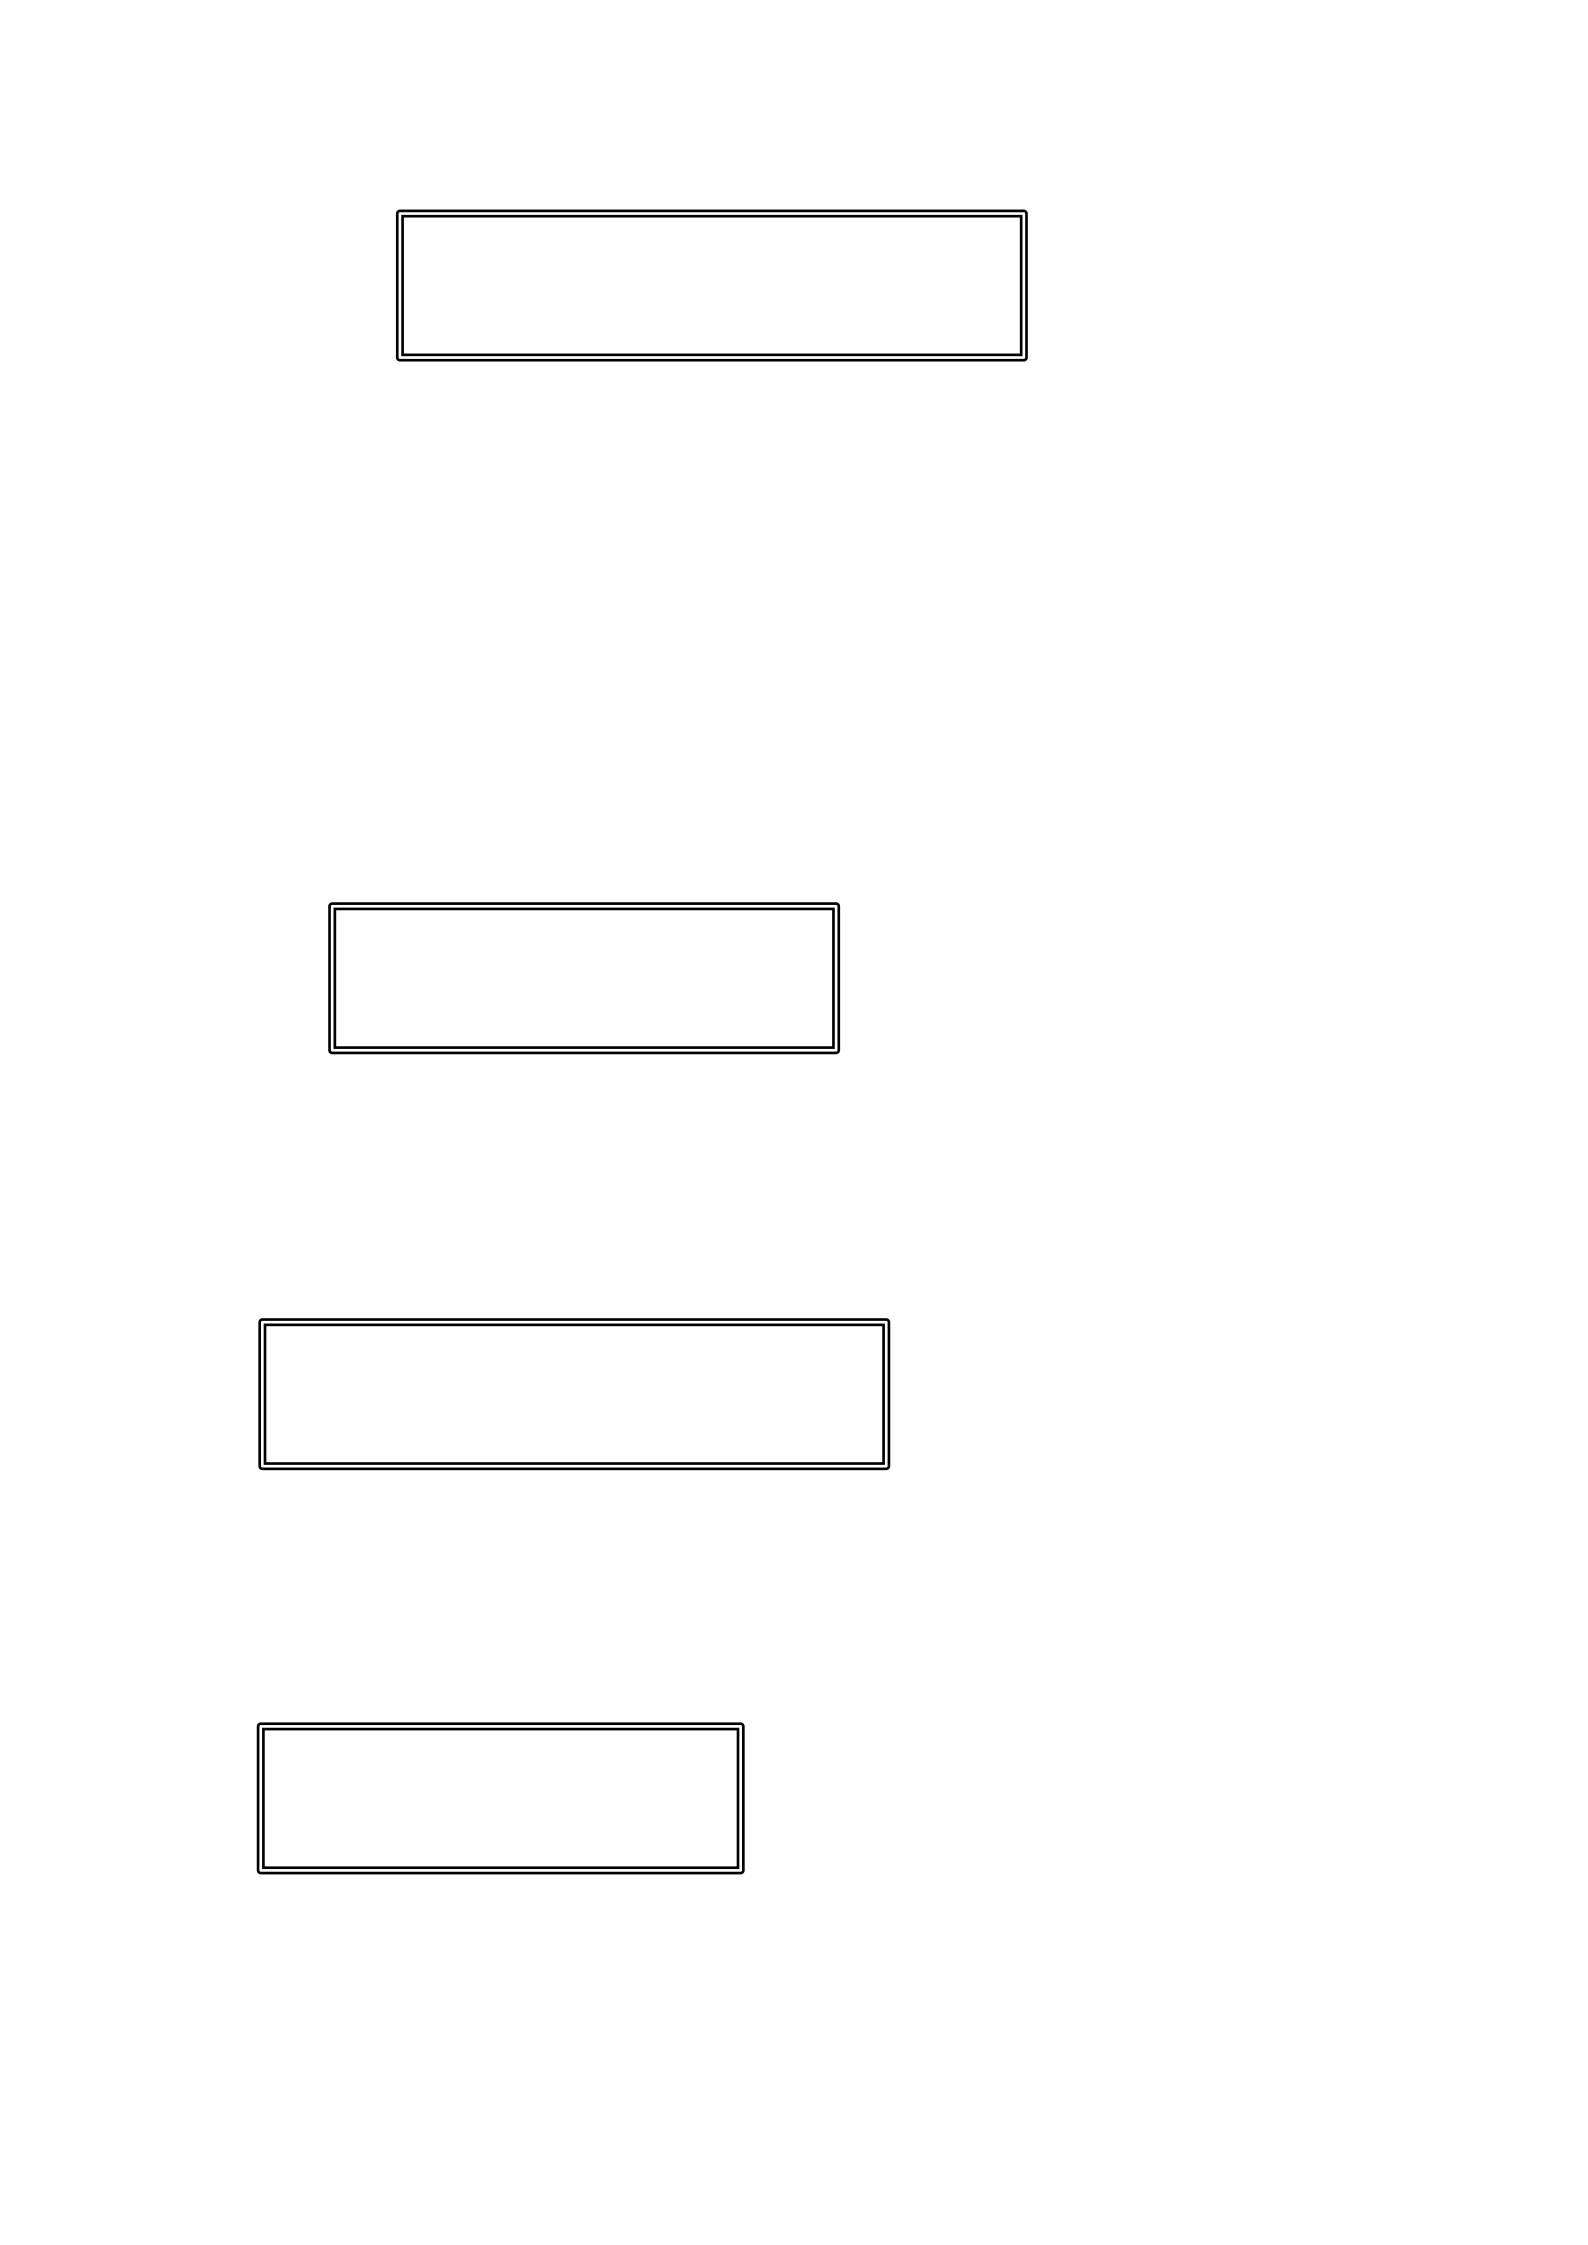
Sales
Fixed
asset turnover = -----------------
Total
Assets
Current assets
Current ratio = ------------------
Current payables
Current assets - inventory
Quick ratio = ---------------------------------
Current payables
2) Liquidity Ratio
Liquidity ratio is the ability of agribusiness companies to pay their obligations that must
be met immediately, namely short-term debt. Liquidity ratios include current ratio, quick
ratio / acid test ratio, and cash ratio.
Current ratio is the ratio between current assets owned by agribusiness companies and
short-term debt. Current assets include cash, accounts receivable, securities, inventory, and
other current assets. While short-term debt includes accounts payable, notes payable, bank
loans, salary payable, and other debts that must be paid immediately. The formula used is :
Quick ratio / acid test ratio is the ratio between current assets after deducting current
debt. This ratio shows the amount of liquid tools that are most quickly used to pay off current
debt. The formula used is :
Cash ratio is a ratio that compares cash and current assets that can immediately become
cash with current debt. Current assets that can immediately become cash are securities or
securities. The formula used is :
3) Profit Ratio
Profit is the result of the policies taken by management. The profit ratio aims to measure
Cash +
Securities
Cash ratio = -------------------
Current payables
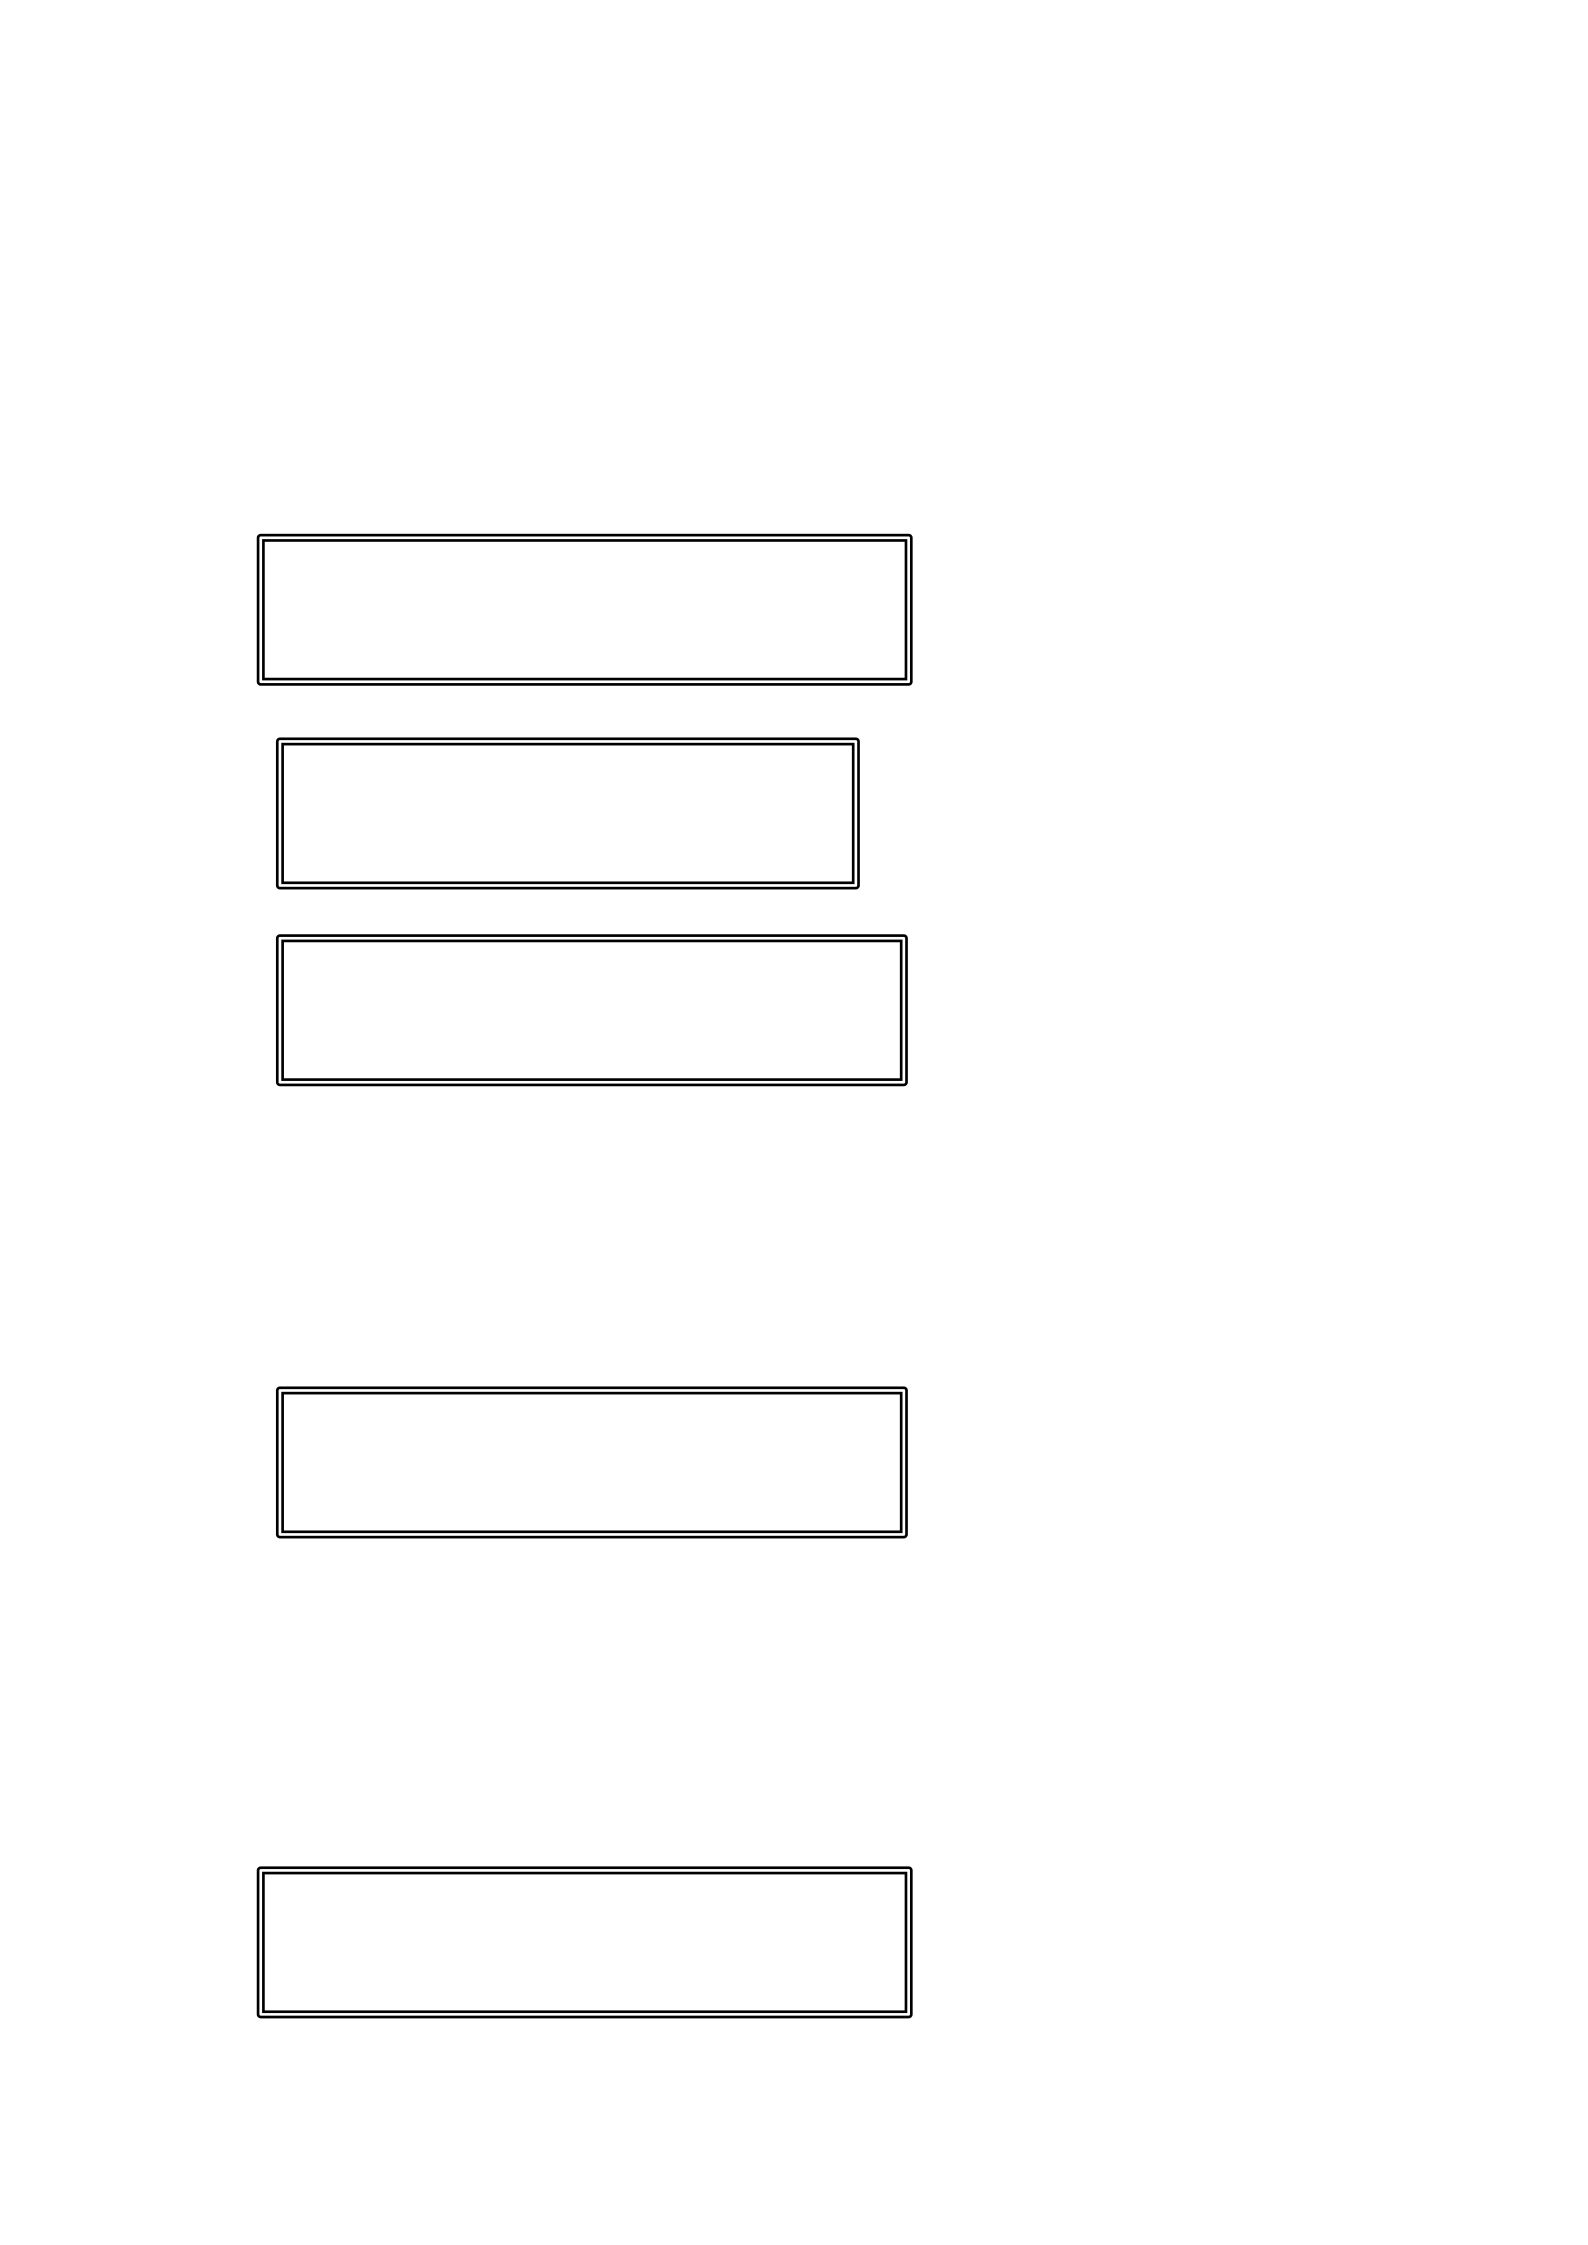
EAT
Profit margin ---------------------- =x 100%
sales
EBIT
Net profit margin =
--------------------
x 100%
sales
EBIT
Return on assets ----------------------- =x 100%
Total
assets
how much profit can be obtained by agribusiness companies. The greater the level of profit
shows the better management in managing agribusiness companies. The profit ratio can be
measured by profit margin, return on assets (ROA), return on equity (ROE), return on
investment (ROI), and earning per share (EPS).
Profit margin is the ability of agribusiness companies to generate profits compared to
sales achieved. The formula used is as follows:
Return on assets (ROA) is also called economic profitability which is a measure of the
ability of agribusiness companies to generate profits with all the assets owned by agribusiness
companies. In this case the profit generated is earnings before interest and tax or EBIT. The
formula used is :
Return on equity (ROE) is also called the rate of return on net worth, namely the ability
of agribusiness companies to generate profits with their own capital, so that this ROE is
called own capital profitability. The profit calculated is net profit after tax or EAT. The
formula used is :
Gross profit
Gross profit margin ---------------------- =x 100%
sales
EAT
Return on equity -------------------------- =x 100%
Own capital
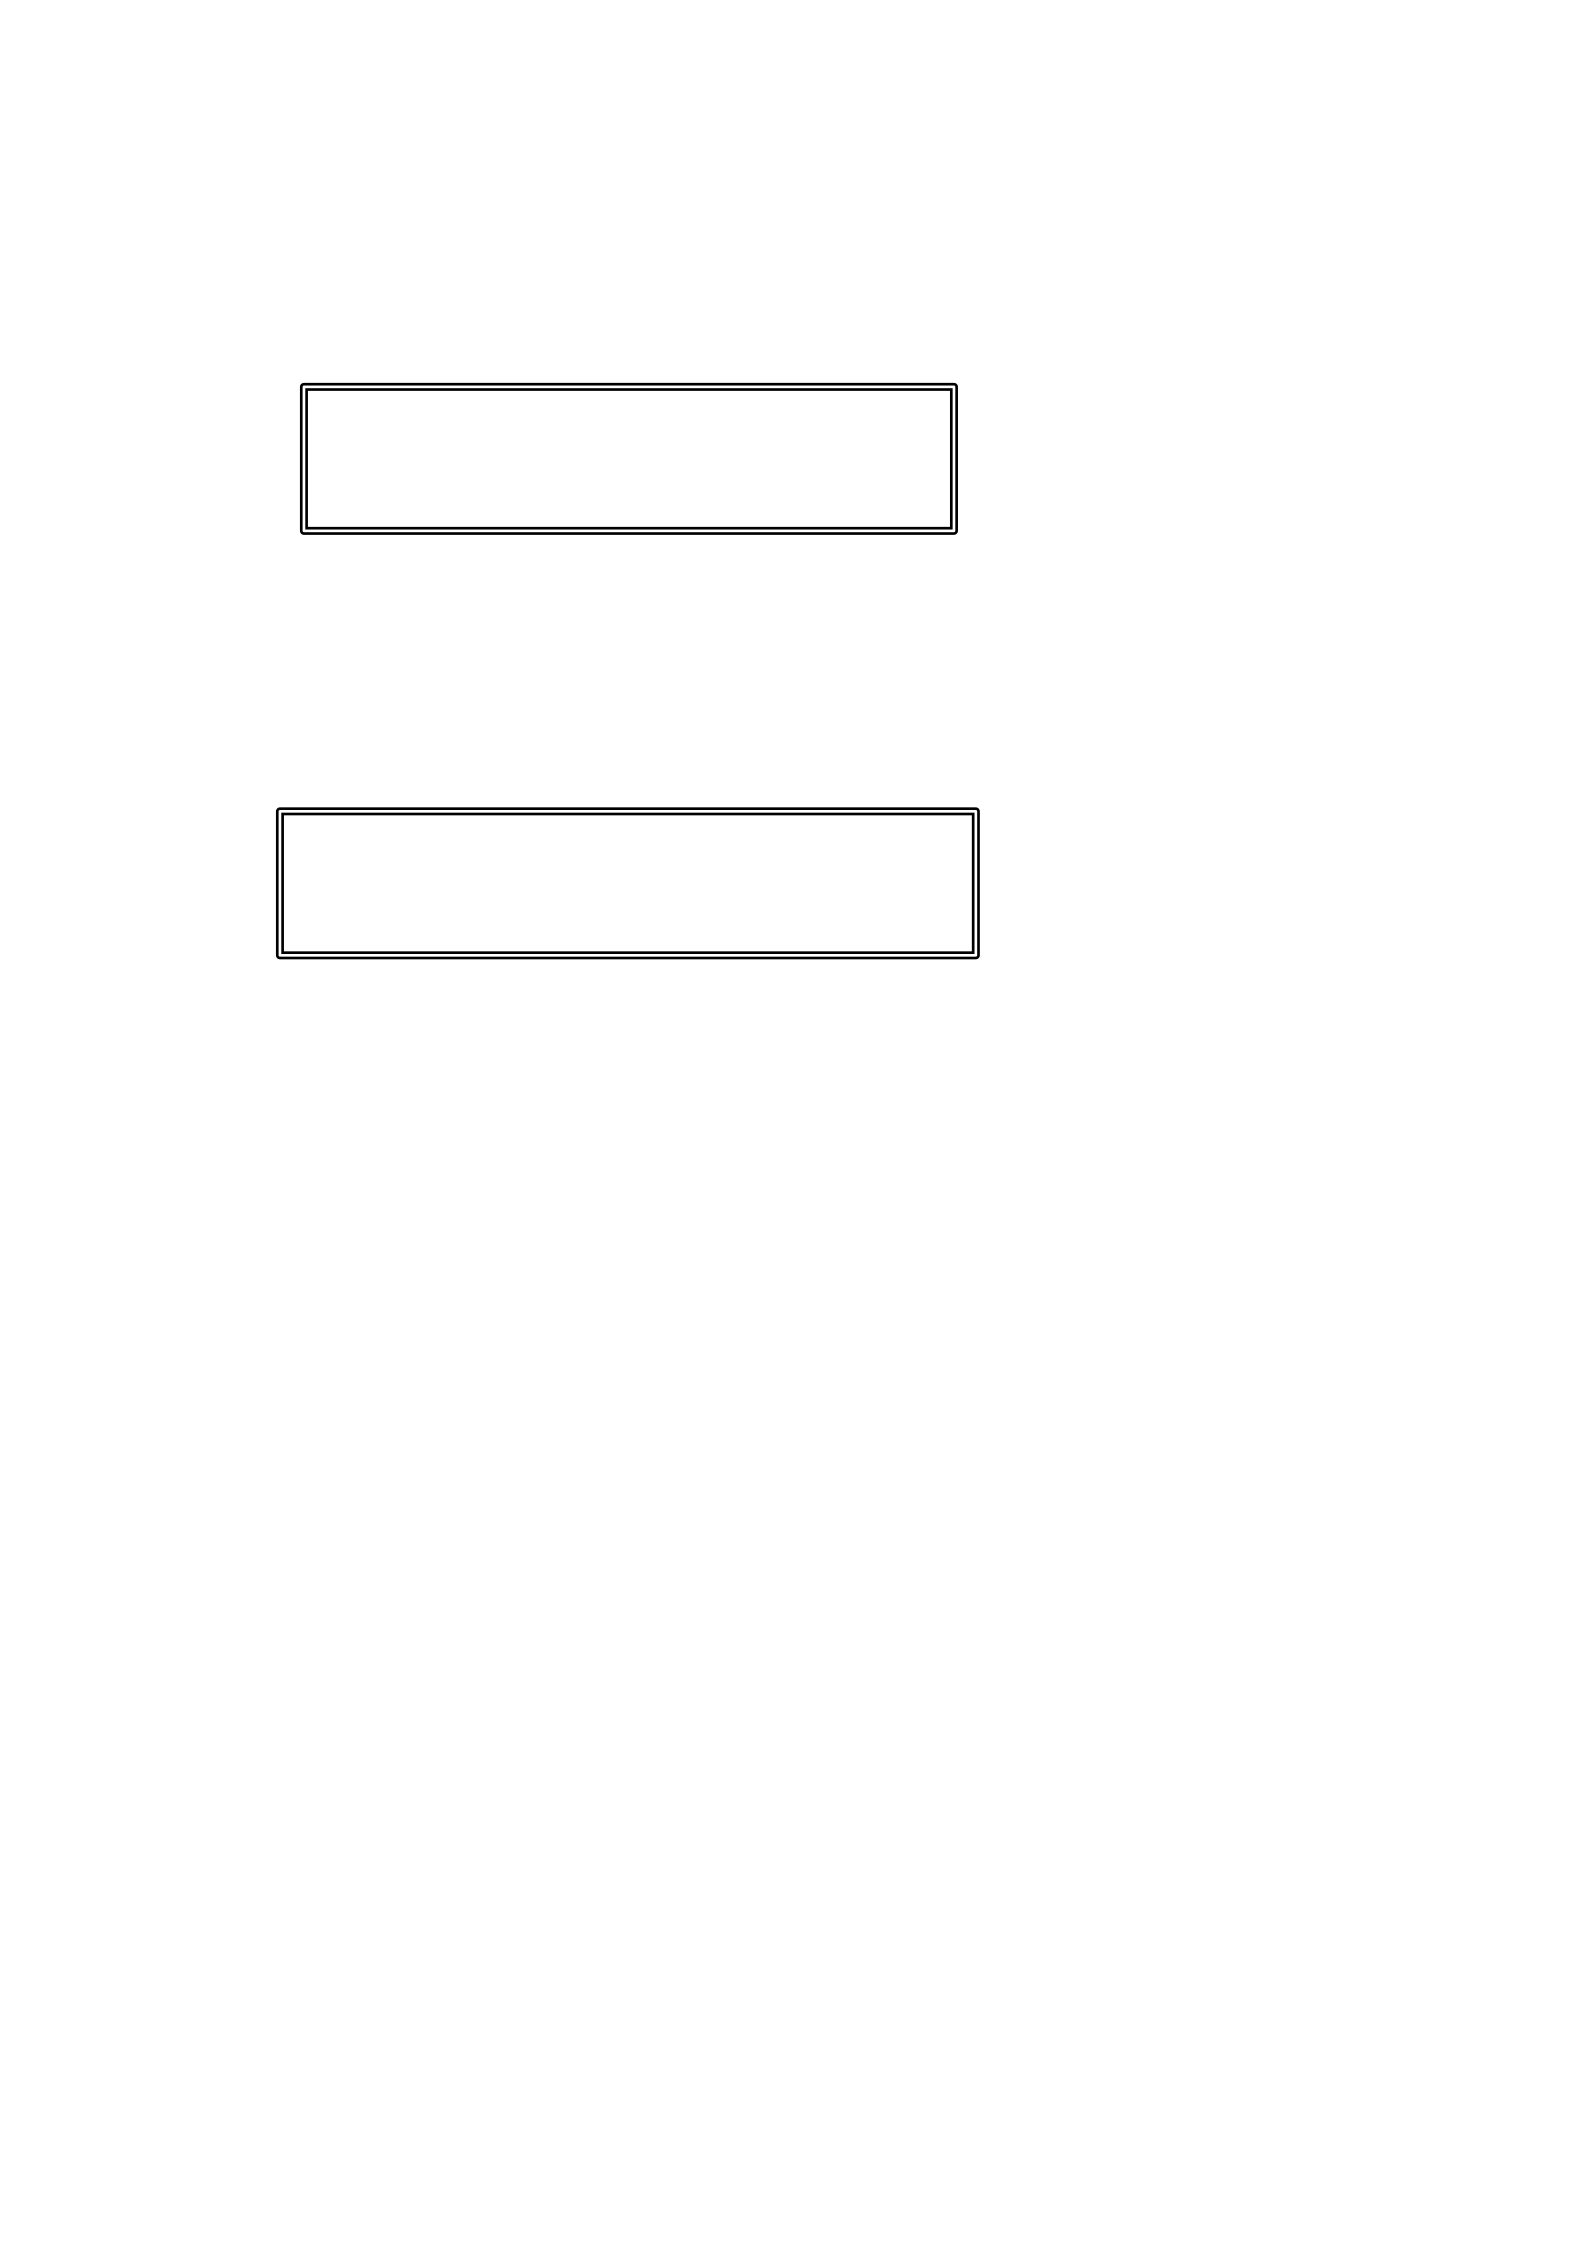
EAT
Return on investment -------------------- =x 100%
Investment
EAT
Earning per share = ----------------------------
Number of shares
Return on investment (ROI) is the ability of agribusiness companies to generate profits
that will be used to cover the investment spent. The profit used to measure this ratio is net
profit after tax or EAT. The formula used is :
Earning per share (EPS) is a measure of an agribusiness company's ability to generate
profit per share owner. The profit used as a measure is profit for the owner or EAT. The
formula used is :
4) Leverage Ratio
The leverage ratio shows how much agribusiness company funds are spent with debt. If
the agribusiness company has no leverage factor = 0, it means that the agribusiness company
in operation fully uses its own capital or without using debt.
The lower the leverage factor, the less risk agribusiness companies have if economic
conditions decline. There are 5 (five) leverage ratios that can be utilized by agribusiness
companies, namely: total debt to total asset ratio, debt to equity ratio, time interest earned
ratio, fixed charge coverge ratio, and debt service ratio.
Total debt to total asset ratio, the ratio of total debt to total assets, commonly called the
debt ratio, which measures the percentage of funds originating from debt. Debt is all debt
owned by agribusiness companies, both short and long term. Creditors prefer a low debt ratio
because the level of security of their funds is getting better. The formula used to calculate the
debt ratio is :
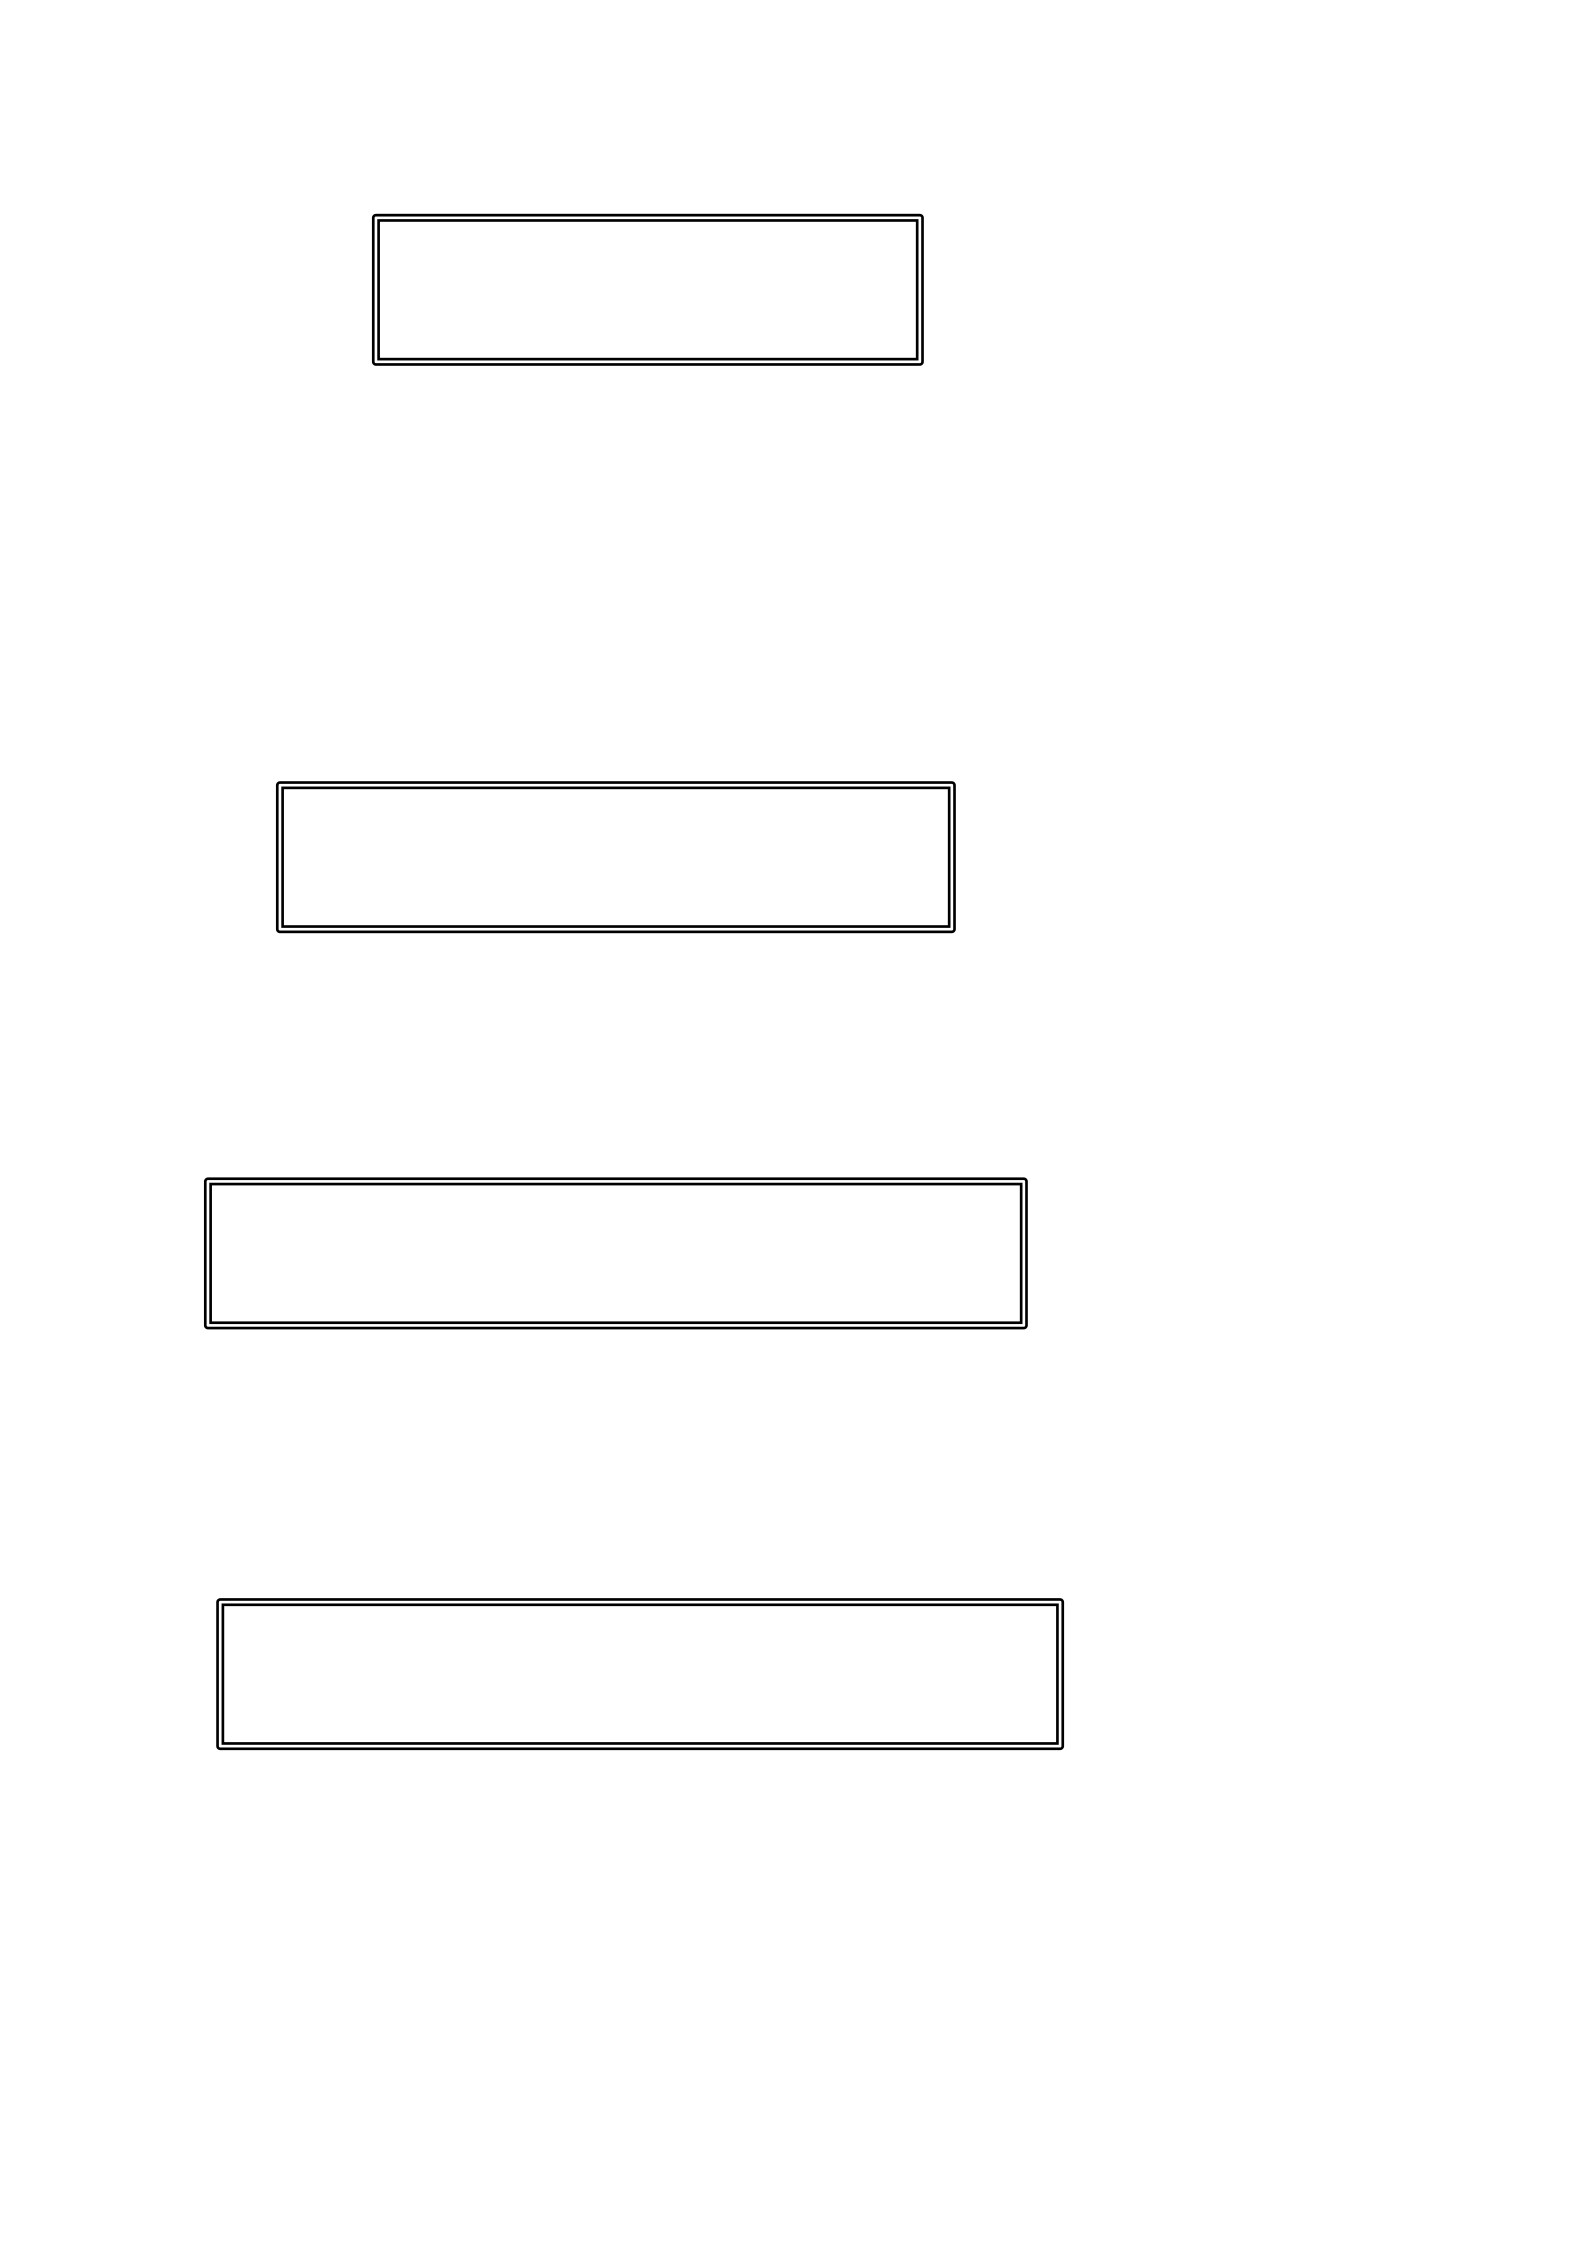
Total
debt
Debt ratio ------------------------ =x 100%
Total
assets
Total
debt
Debt to equity ratio =
------------------------
x 100%
Capital
Earnings before interest and tax
Time interest earned ratio = ---------------------------------------
Interest expense
EBIT + Interest + Rent installment
Fixed charge coverge ratio = -------------------------------------------
Interest + Rent installment
Debt to equity ratio is the balance between debt owned by agribusiness companies and
their own capital. The higher the ratio means that there is less equity capital compared to the
debt. For agribusiness companies, the amount of debt should not exceed their own capital so
that the fixed costs are not too high. For a conservative approach, the maximum amount of
debt is equal to equity, meaning that the maximum debt to equity is 100 percent. To calculate
debt to equity, the formula is used:
Time interest earned ratio or coverge ratio is the ratio between earnings before interest
and tax and interest expense. This ratio measures the ability of agribusiness companies to
meet their fixed costs in the form of interest with the profits they earn. The formula used is :
Fixed charge coverge ratio, this ratio measures the ability of agribusiness companies to
cover their fixed expenses including preferred stock dividend payments, interest, loan
installments, and rent. The formula used is :
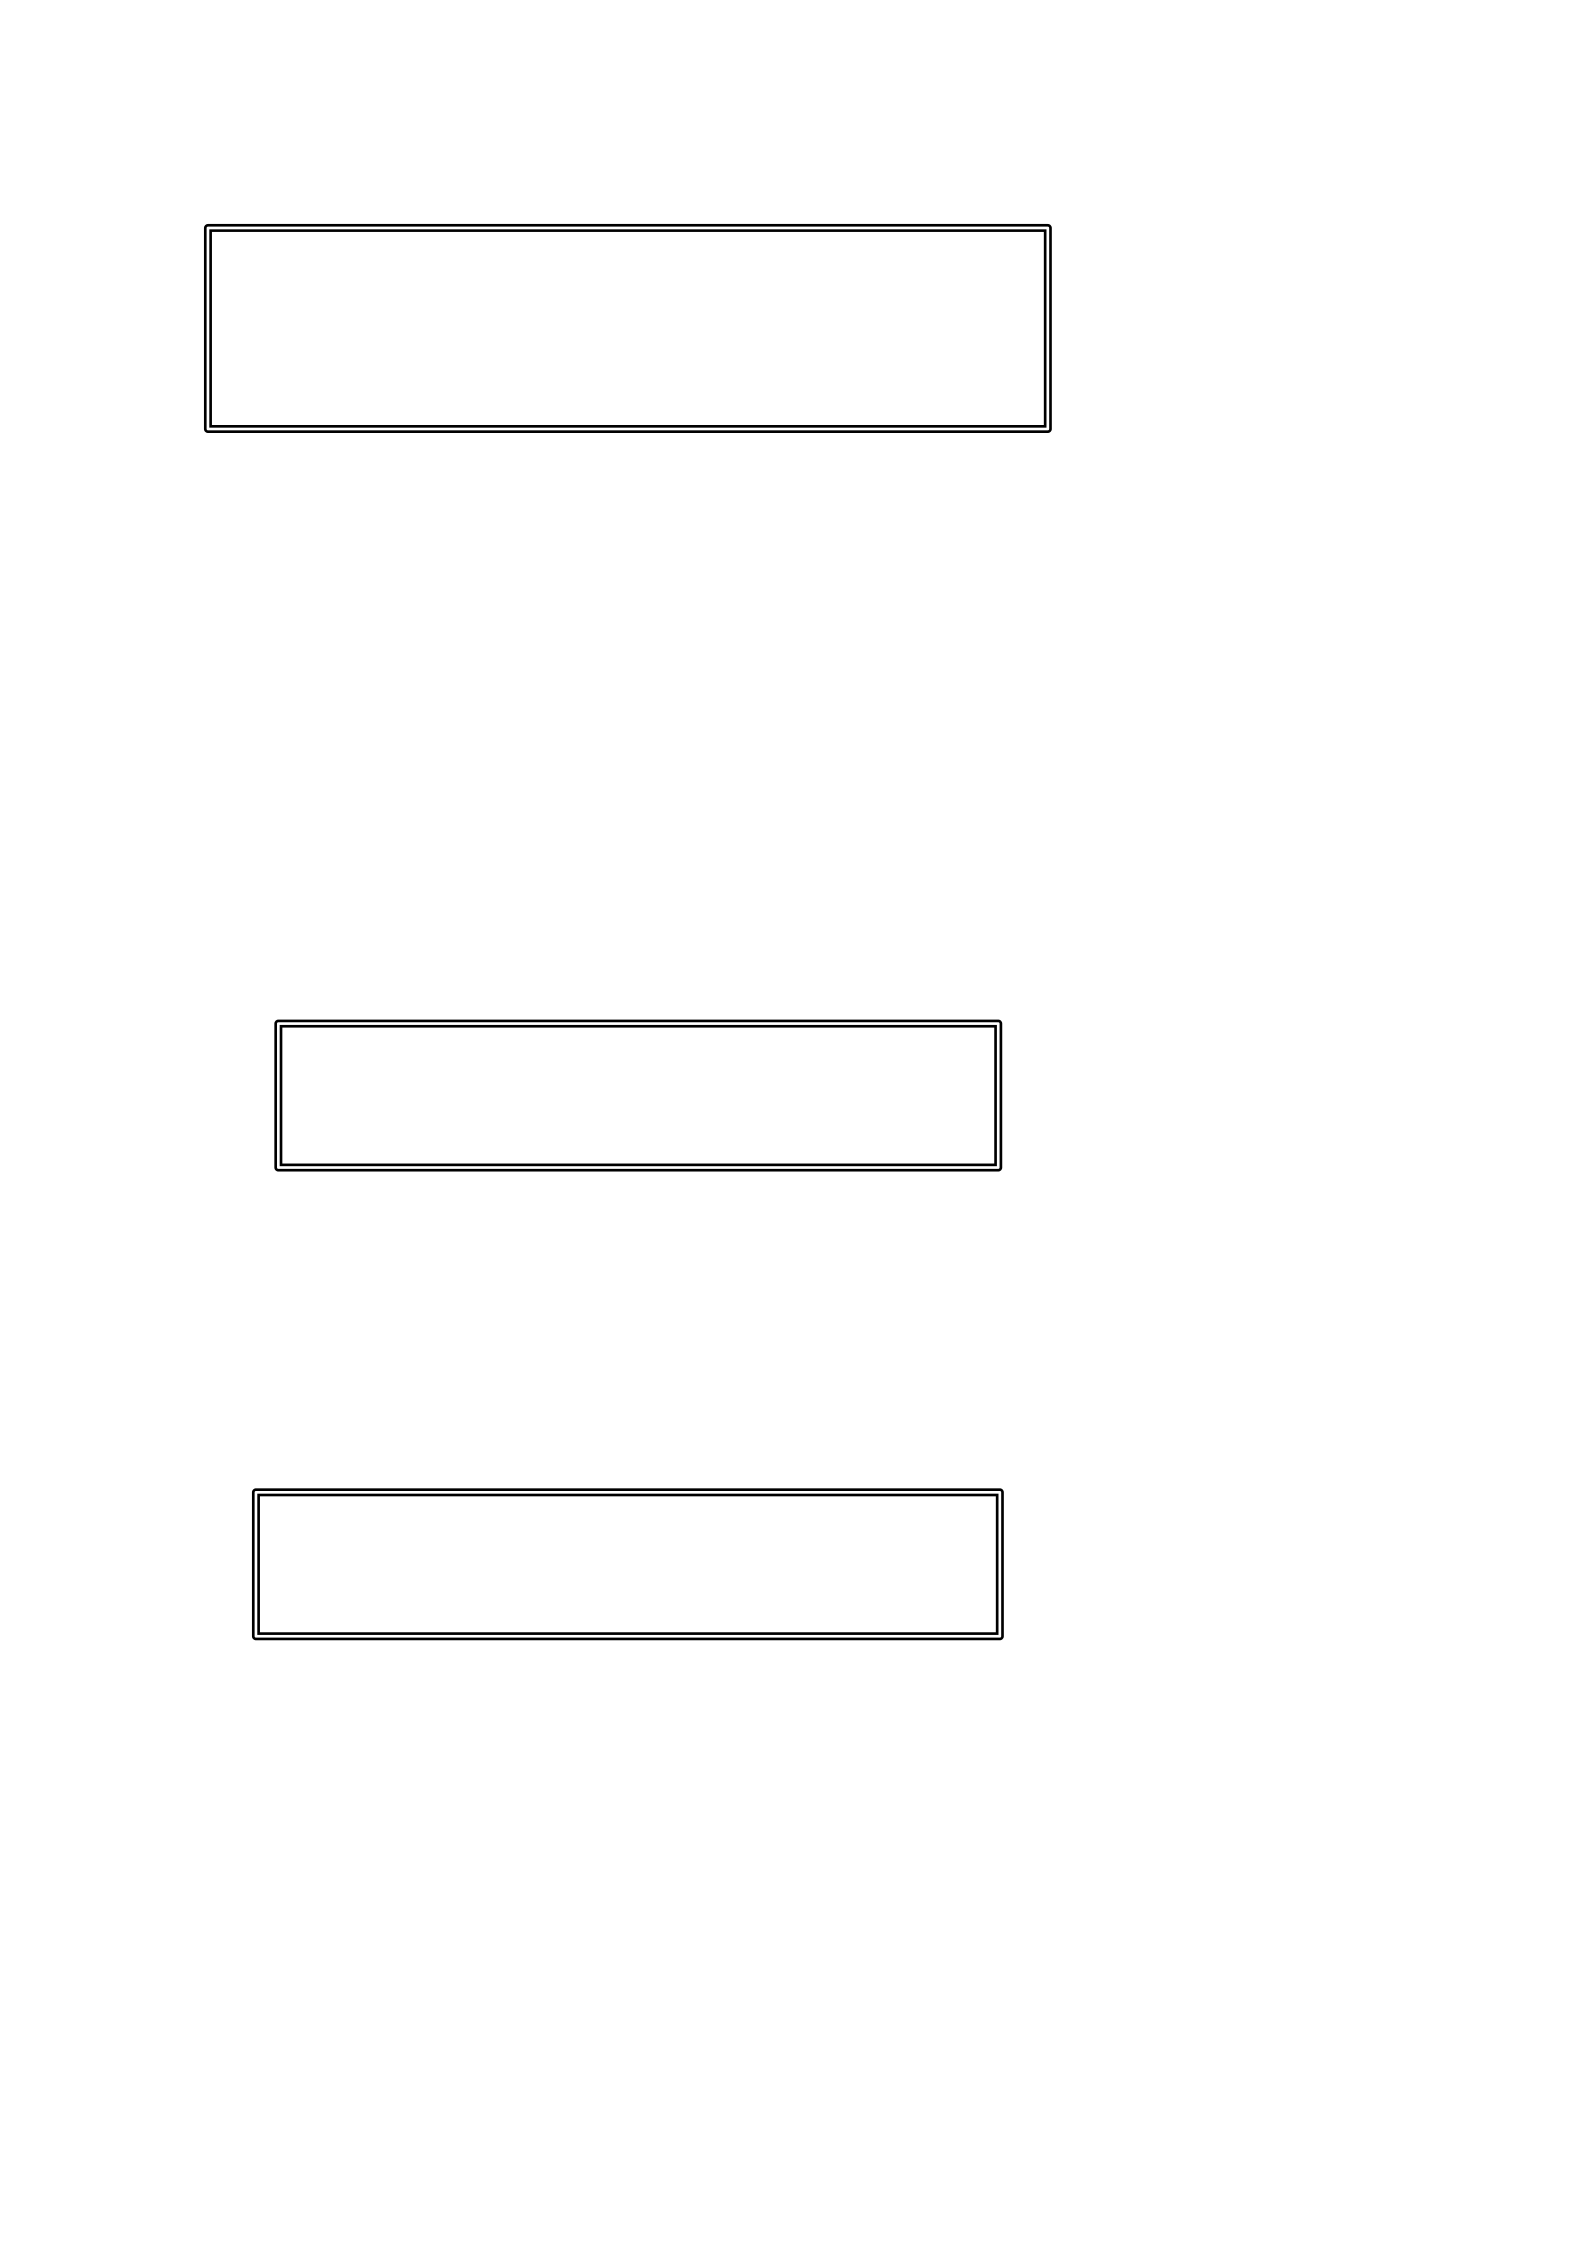
Debt service ratio is the ability of agribusiness companies to meet their fixed expenses
including the basic budget. The formula used is :
Earnings before interest and tax
Debt service ratio = ----------------------------------------------------------
Loan principal installment
Interest + Rent + ----------------------------------
(1- tax rate)
Stock market price
Price earning ratio = -------------------------------
Earnings per share
Stock market price
Market to book value ratio = --------------------------
Book value of shares
5) Assessment Ratio
The valuation ratio is a ratio to measure the ability of agribusiness companies to create
value to the public (investors) or to shareholders. This ratio provides information on how
much people value agribusiness companies, so they are willing to buy shares of agribusiness
companies at a higher price than the book value of the shares. This ratio consists of price
earning ratio (PER) and market to book value ratio (MBV).
This price earning ratio (PER) measures how much the comparison between the share
price of agribusiness companies and the profits earned by shareholders. The formula used is :
Market to book value ratio (MBV) is to find out how much the share price is in the
market compared to the book value of the shares. The higher this ratio shows that
agribusiness companies are more trusted, meaning that the value of agribusiness companies is
higher. The formula used is :
B. Investment Management Agribusiness
(Agribusiness Investment Management )
Investment is a commitment of funds or other resources made today with the aim of
obtaining a number of benefits in the future Investment decisions made in agribusiness, such
as farming or manufacturing businesses or agribusiness companies will be covered by future

revenues. These receipts come from the projected profits earned on the investment in
question.
According to Tandelilin (2001:3) investment can be related to a variety of activities,
namely investing a number of funds in real assets (land, gold, machinery, and buildings), as
well as financial assets (deposits, stocks, or bonds) which are common investment activities.
The purpose of investment is basically to make some money or to improve the investor's
welfare. The source of funds for investment can come from current assets, loans from other
parties, or savings. Investors who reduce their current consumption will have the possibility
of excess funds to save. If the funds from the savings are invested, they will provide hope for
an increase in the investor's consumption ability in the future, which is obtained from the
increase in the investor's welfare.
The process in the investment system includes understanding the basics of investment
decisions and how to organize activities in the investment decision process. To understand
the process, an investor must first know some basic investment concepts that will be the basis
for the investment decision-making stage to be made.
The fundamental thing in the investment decision process is understanding the
relationship between the expected return and risk of an investment. According to Tandelilin
(2001:6), the return expected by investors from the investment made is compensation for the
opportunity cost of a decrease in purchasing power due to the influence of inflation, while
risk is how much risk must be borne from the investment. Generally, the greater the risk, the
greater the expected rate of return.
1. Agribusiness Return and Risk
a. In the context of agribusiness investment management, it is necessary to
distinguish between expected return and realized return. Expected return is the level of
return that investors anticipate in the future. Meanwhile, the realized return or actual return
is the level of return that has been obtained by investors in the past. When an investor invests
his funds, he will require a certain level of return and if the investment period has passed, the
investor will be faced with the actual level of return he receives. Between the expected level
of return and the actual level of return obtained by investors from investments made may be
different. The difference between the expected return and the actual return is a risk that must
always be considered in the agribusiness investment process.
b. Risk, risk can be defined as the possibility of actual returns that differ from
expected returns. In economics in general and investment science in particular, there is an
assumption that investors are rational beings. Rational investors will certainly not like
uncertainty or risk. Investors who have an aversion to risk are called risk-averse investors.
Investors like this do not want to take the risk of an investment if the investment does not
provide a reasonable expectation of return as compensation for the risk that the investor must
bear. Meanwhile, investors who like or enjoy facing risks are called risk-lover invertors. It is
natural for agribusiness investors to expect the highest possible return from their investment,
but the important thing must always be considered, namely how much risk must be borne
from the investment. Generally, the greater the risk, the greater the expected return.
2. Investment Valuation Methods Agribusiness
Various agribusiness investment appraisal methods can be applied to the business sector,
but here we focus on agricultural (farming, fisheries, livestock, plantation, horticulture, food,
and forestry) and manufacturing (agro-industry) businesses. Investment methods that can be
applied to agricultural/on-farm businesses are R/C, B/C, NPV, and IRR (Soekartawi, 2002:
85), while for manufacturing (agro-industry)/of-farm are ARR, PP, NPV, IRR, and PI.
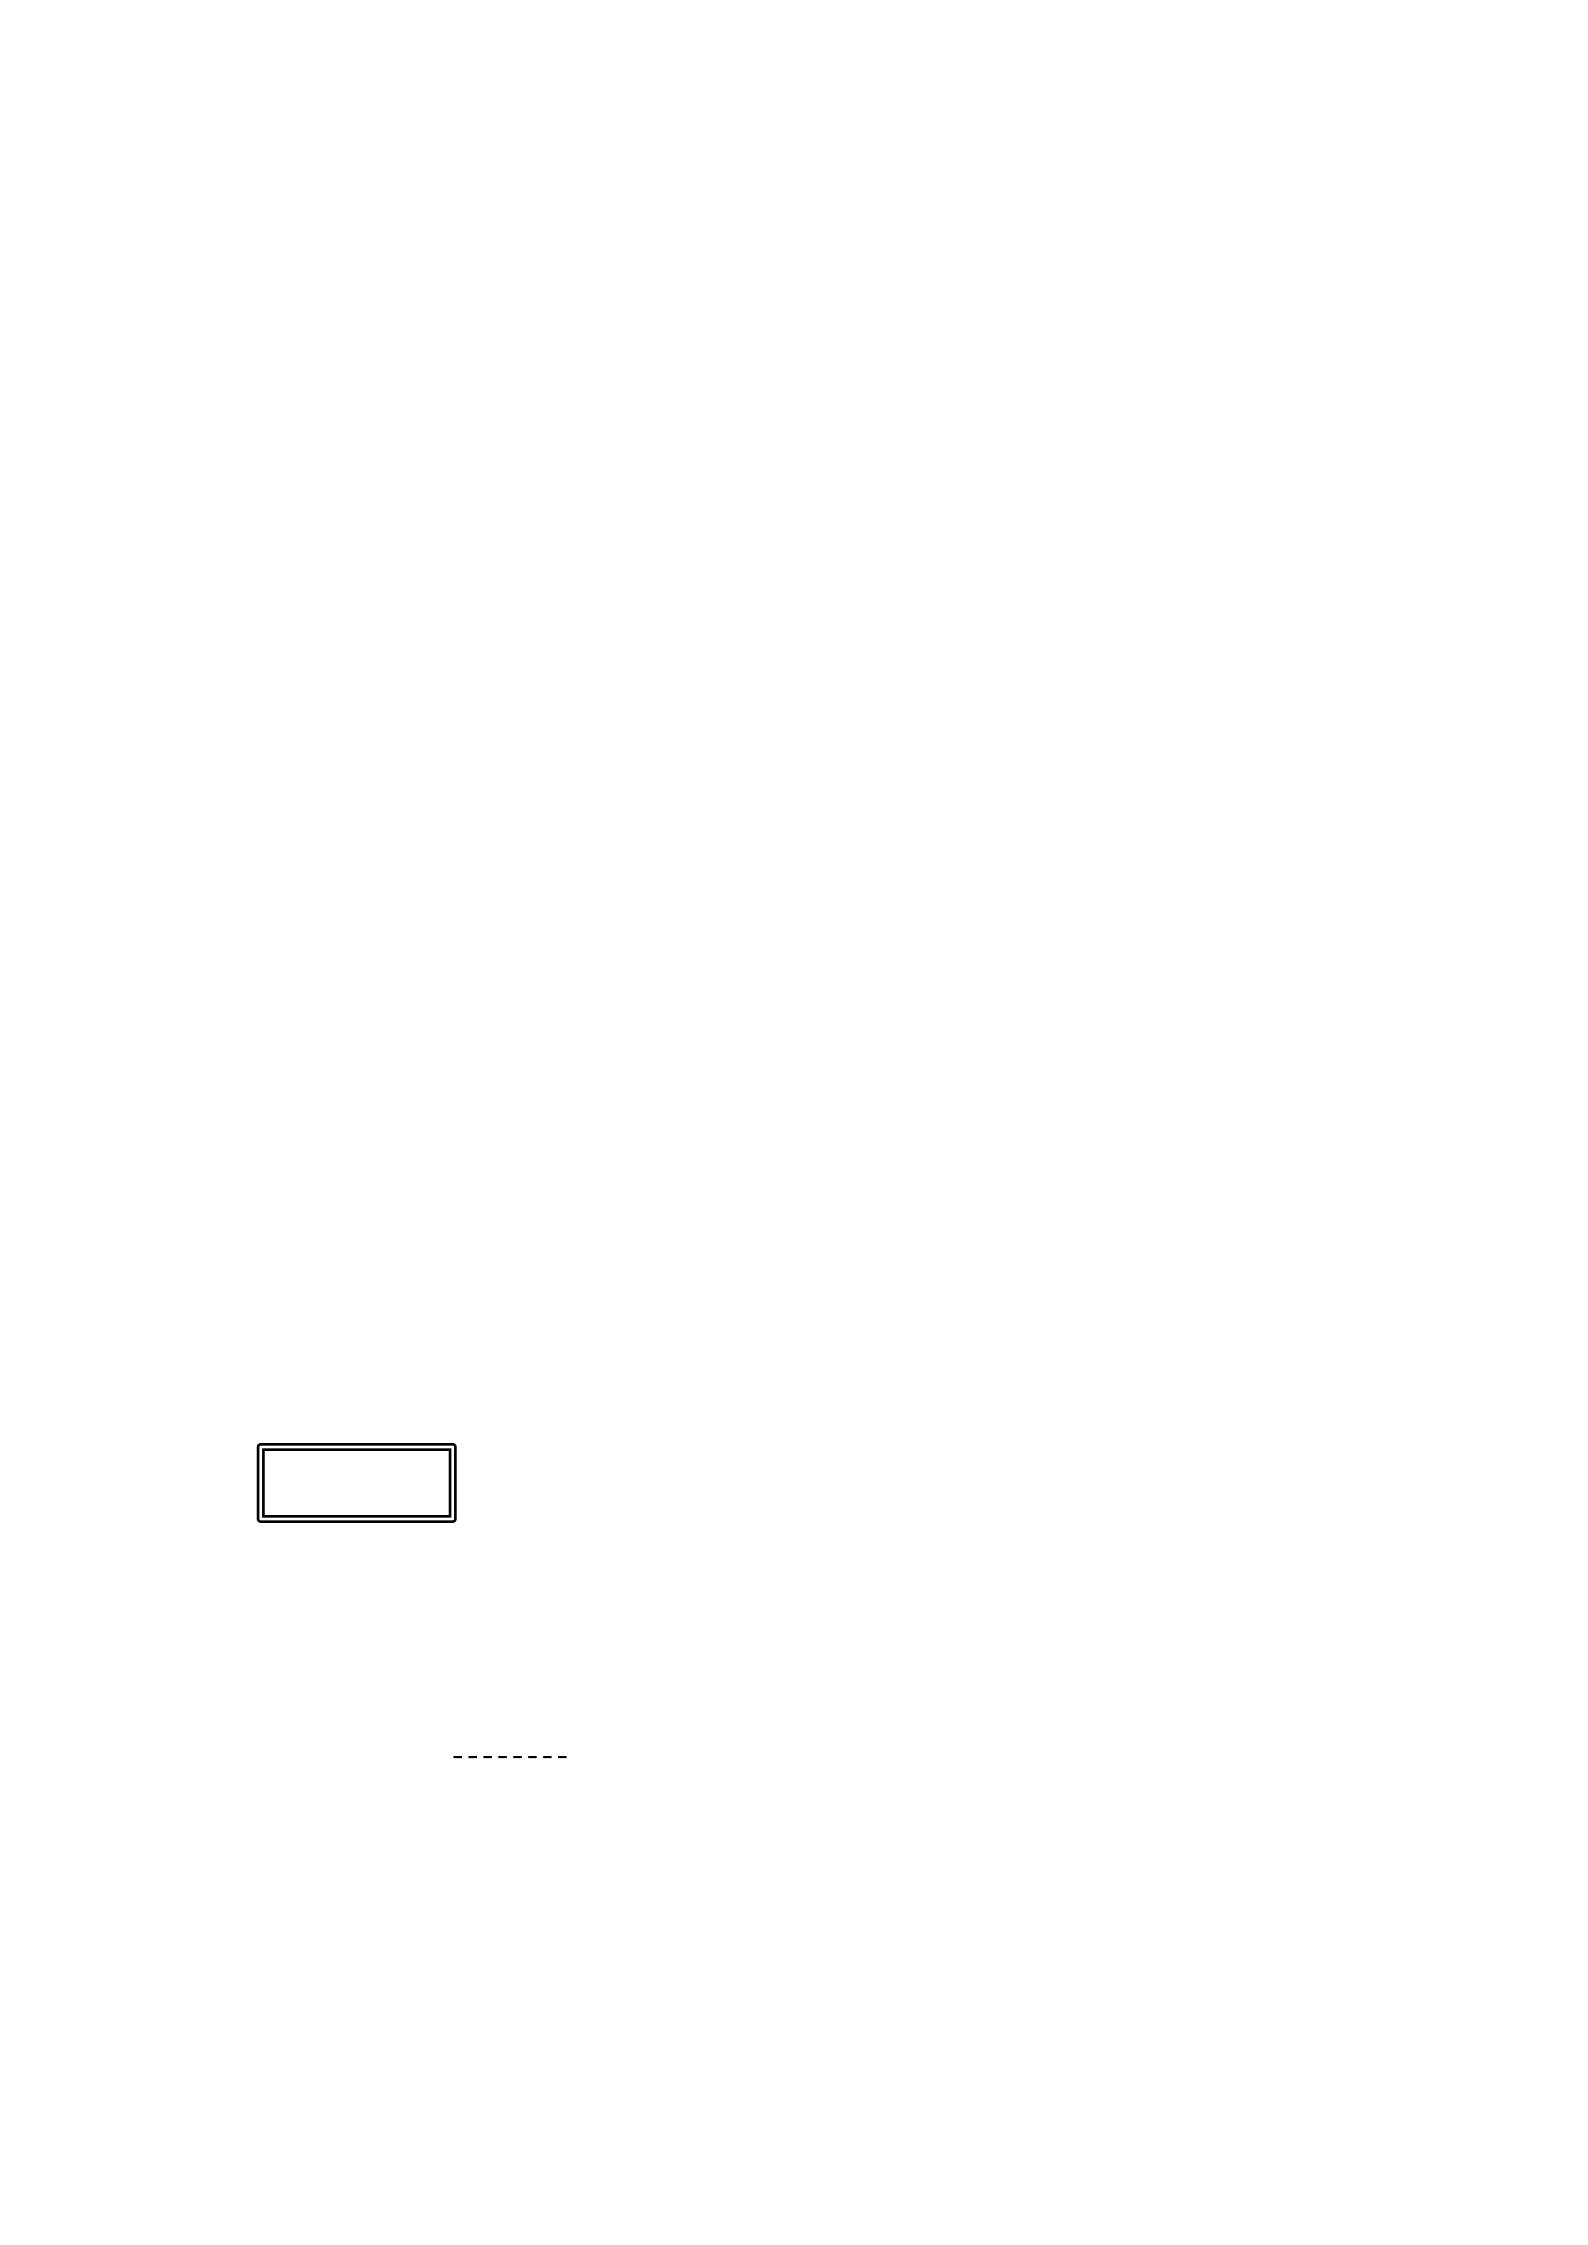
a. R/C (Return Cost Ratio) or known as the ratio between revenue and costs. In this
method, fixed costs are used as costs incurred in farming that do not depend on the amount of
output obtained, such as taxes, land rent, and agricultural equipment, while variable costs are
defined as costs incurred for farming that are influenced by the amount of output obtained,
such as inputs and labor.
R = Py . Y
C = FC + VC
(Py.Y)
a =
(FC + VC)
where :
R : revenue/income
C : cost
a = R/C
Present Value B
B/C = ---------------------
Present Value C
Average EAT
ARR
------------------------------ =x 100%
Average Investment
Py : output price
Y : output
FC : fixed cost
VC : variable cost
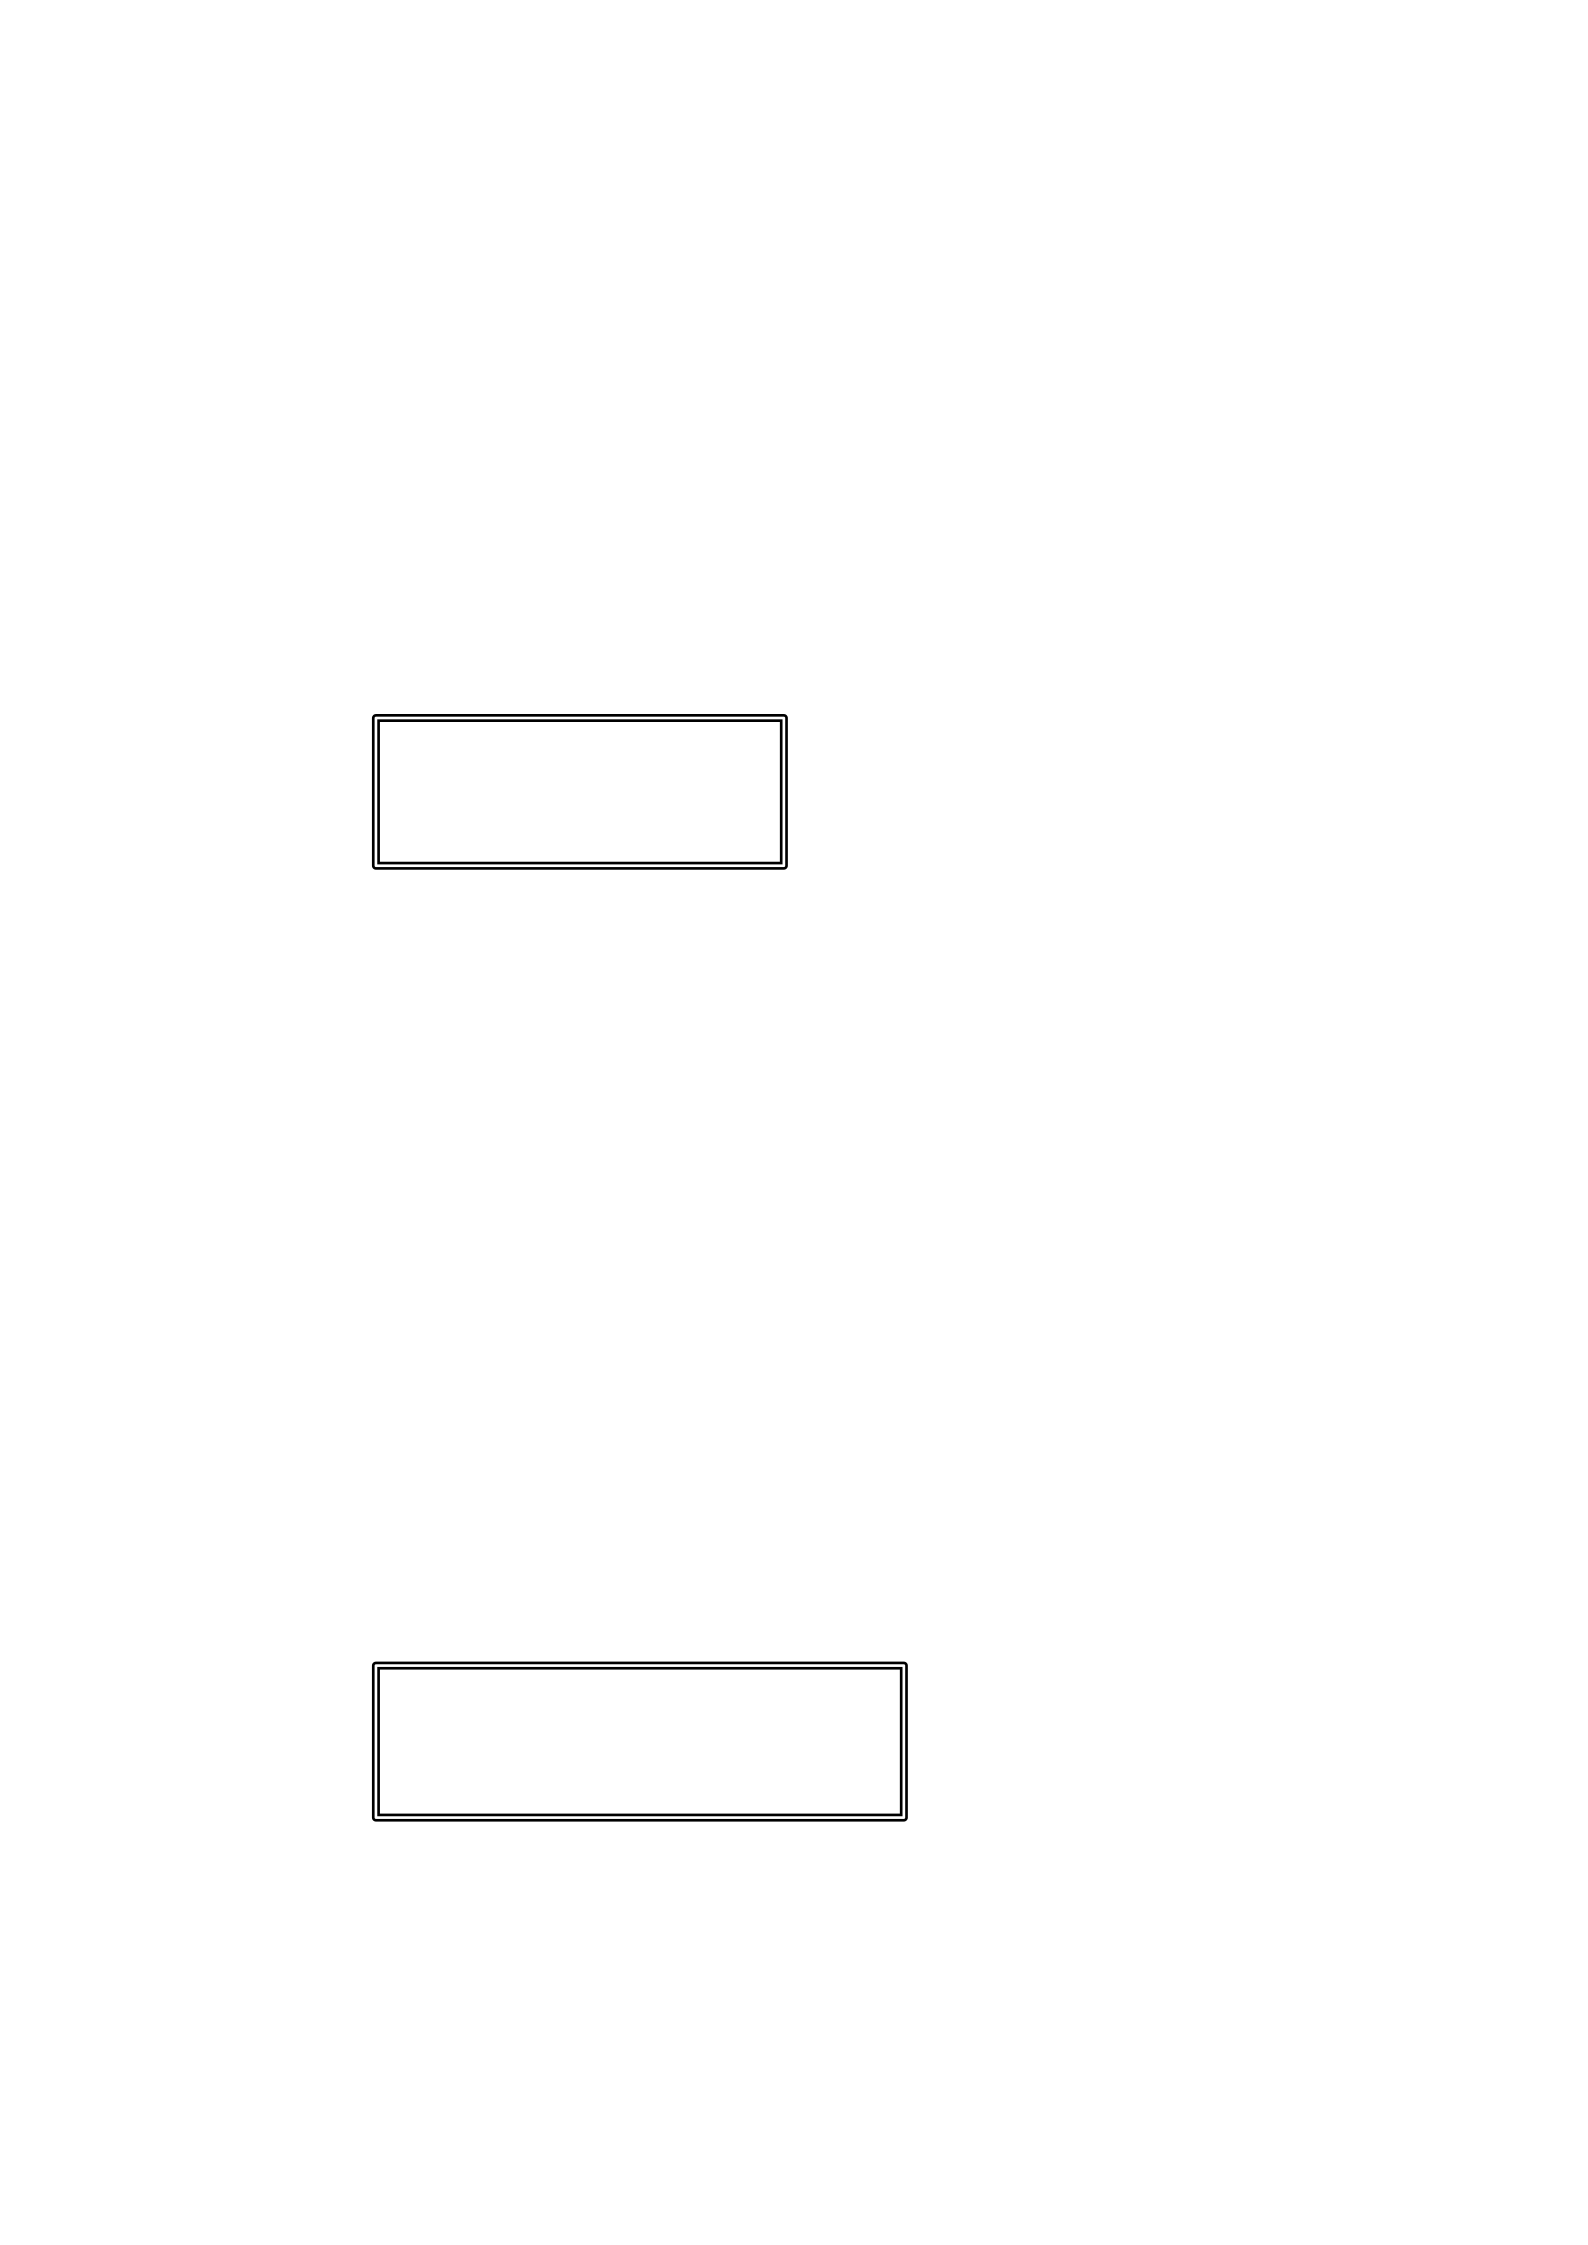
b. B/C (Benefit Cost Ratio) is in principle the same as R/C analysis, except that the
B/C ratio analysis of the data concerned is the magnitude of the benefits and the analysis is
used to compare the same two agribusiness businesses. The criteria used in a farming project
are said to provide benefits if B/C> 1.
where :
B : advantage
C : cost
i : prevailing interest rate
t : farming period
c. ARR (Accounting Rate of Return) is an investment appraisal method that
measures how much profit from an investment. This method uses the basis of accounting
profit so that the figure used is profit after tax (EAT) compared to the average investment. To
calculate the EAT by summing up the EAT over the life of the investment divided by the life
of the investment, while to calculate the average investment is the investment plus the
residual value divided by 2. If the ARR is greater than the required profit, then the investment
project is feasible or profitable, and vice versa.
d. PP (Payback Period) is comparing the payback period with the target length of
return on investment. If the payback period is smaller than the target return on investment,
then the investment project is feasible, and vice versa.
NPV = Present Value B - Present Value C
NPV rr
IRR = rr ----------------------------+x (rt-rr)
TPV rr - TPV rt
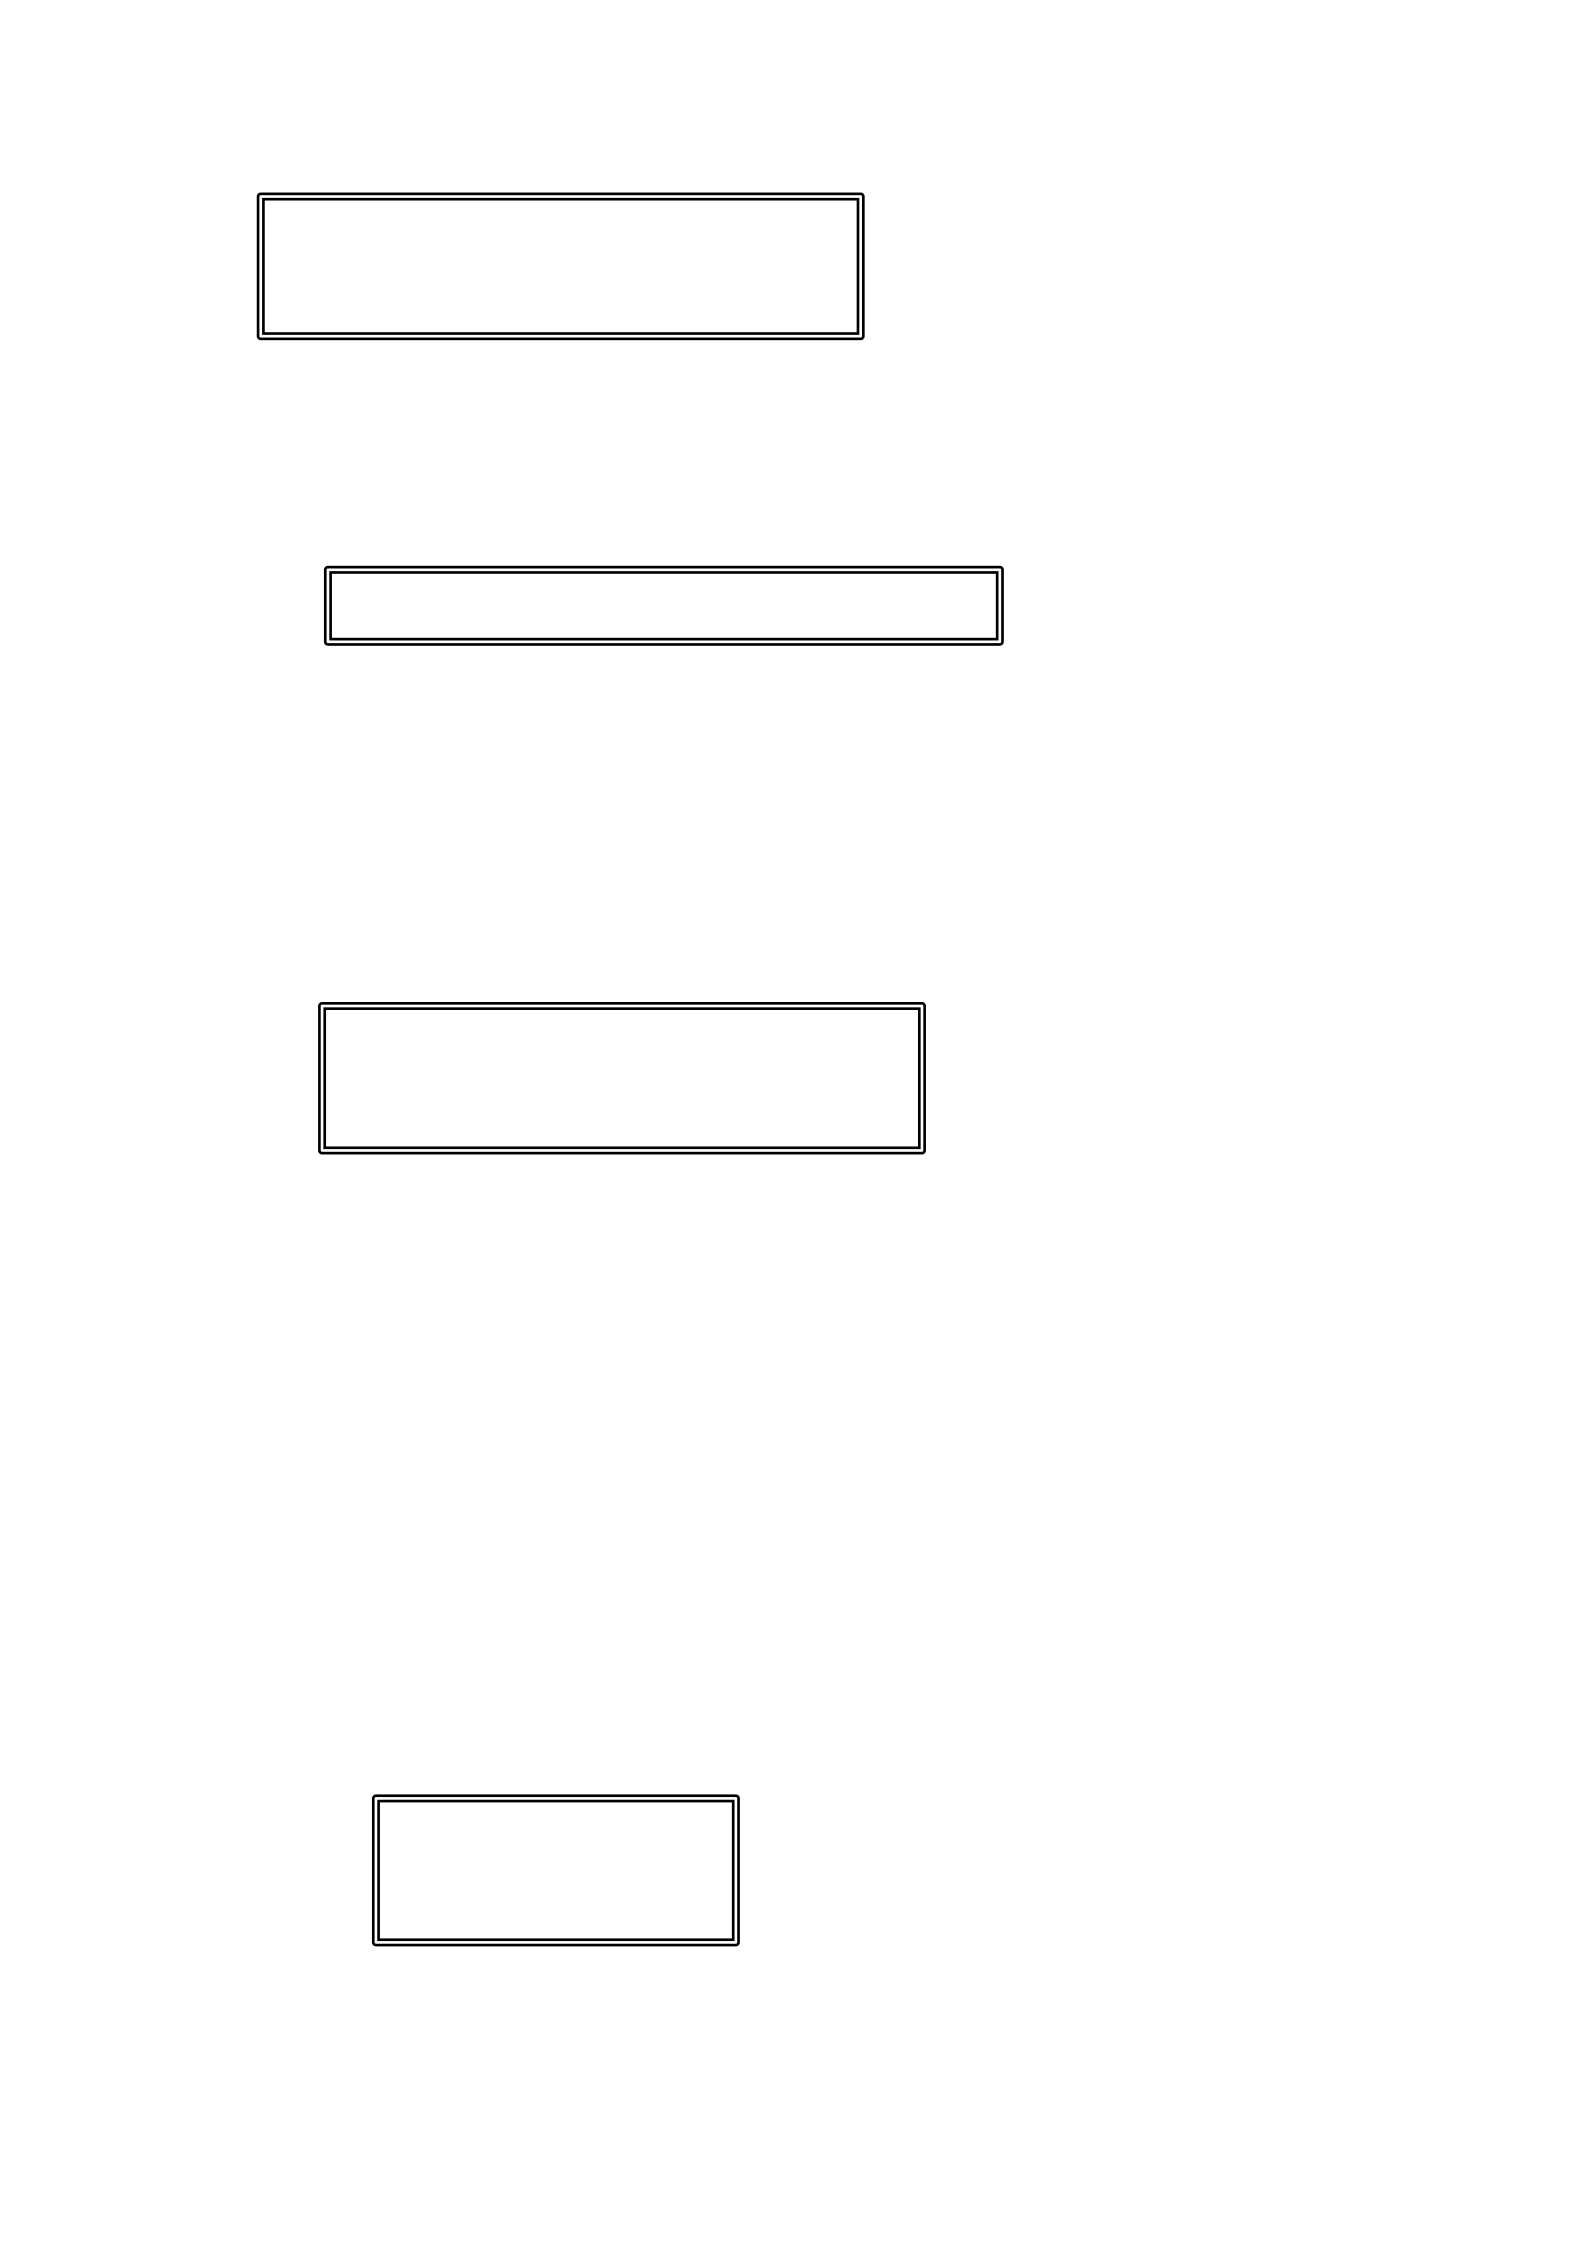
e. NPV (Net Present Value) is the difference between the present value of benefits
and the present value of costs. If the value is positive, it means that the investment project is
feasible.
f. IRR (Internal Rate of Return) is a discount rate that can equalize the PV of
cashflow with the PV of investment. To find the amount of IRR, NPV data is needed, which
has two poles, namely positive and negative. If the IRR value is greater than the required
profit, then the investment project is feasible.
where :
rr : lower discount rate (r) rt : higher discount rate (r) TPV : Total Present Value
NPV : Net Present Value
g. PI (Profitability Index) is to calculate the ratio between the present value of
revenue and the present value of investment. This method is often used to rank several
projects to be selected from several alternative projects. To select a project from several
alternative projects that are prioritized which have the greatest profitability index. If the
profitability index is greater than 1, then the investment project is feasible to run.
C. Strategic Management Agribusiness
Investment
Payback Period ------------------- =x 1 year
Cashflow
PV of
Casflow
PI = -------
-----------
Investment
Multi
Agribusiness
Strategic
Agribusine
ss Unit
Agribusiness
Research and
Development
Agribusin
ess
Agribusine
ss
Marketing
Agribusin
ess
Finance
(Agribusiness Strategic Management )
Strategy is a long-term goal of a company, as well as the utilization and allocation of all
resources that are important to achieve these goals (Rangkuti, 2001: 4). Meanwhile,
according to Stoner et al. cit Tjiptono (2001: 3), the concept of strategy can be defined based
on two perspectives, namely from the perspective of what the organization intends to do and
from the perspective of what the organization eventually does.
Based on the first perspective, strategy can be defined as a program to determine and
achieve organizational goals and implement its mission. The meaning of this strategy is that
managers play an active, conscious, and rational role in formulating organizational strategy.
In a turbulent and ever-changing environment this view is more widely applied. While the
second perspective as a pattern of response or response of the organization to its environment
over time. In this definition, every organization must have a strategy, even though the
strategy is never formulated explicitly. This view is applied to managers who are reactive,
which only respond and adjust to the environment passively when needed.
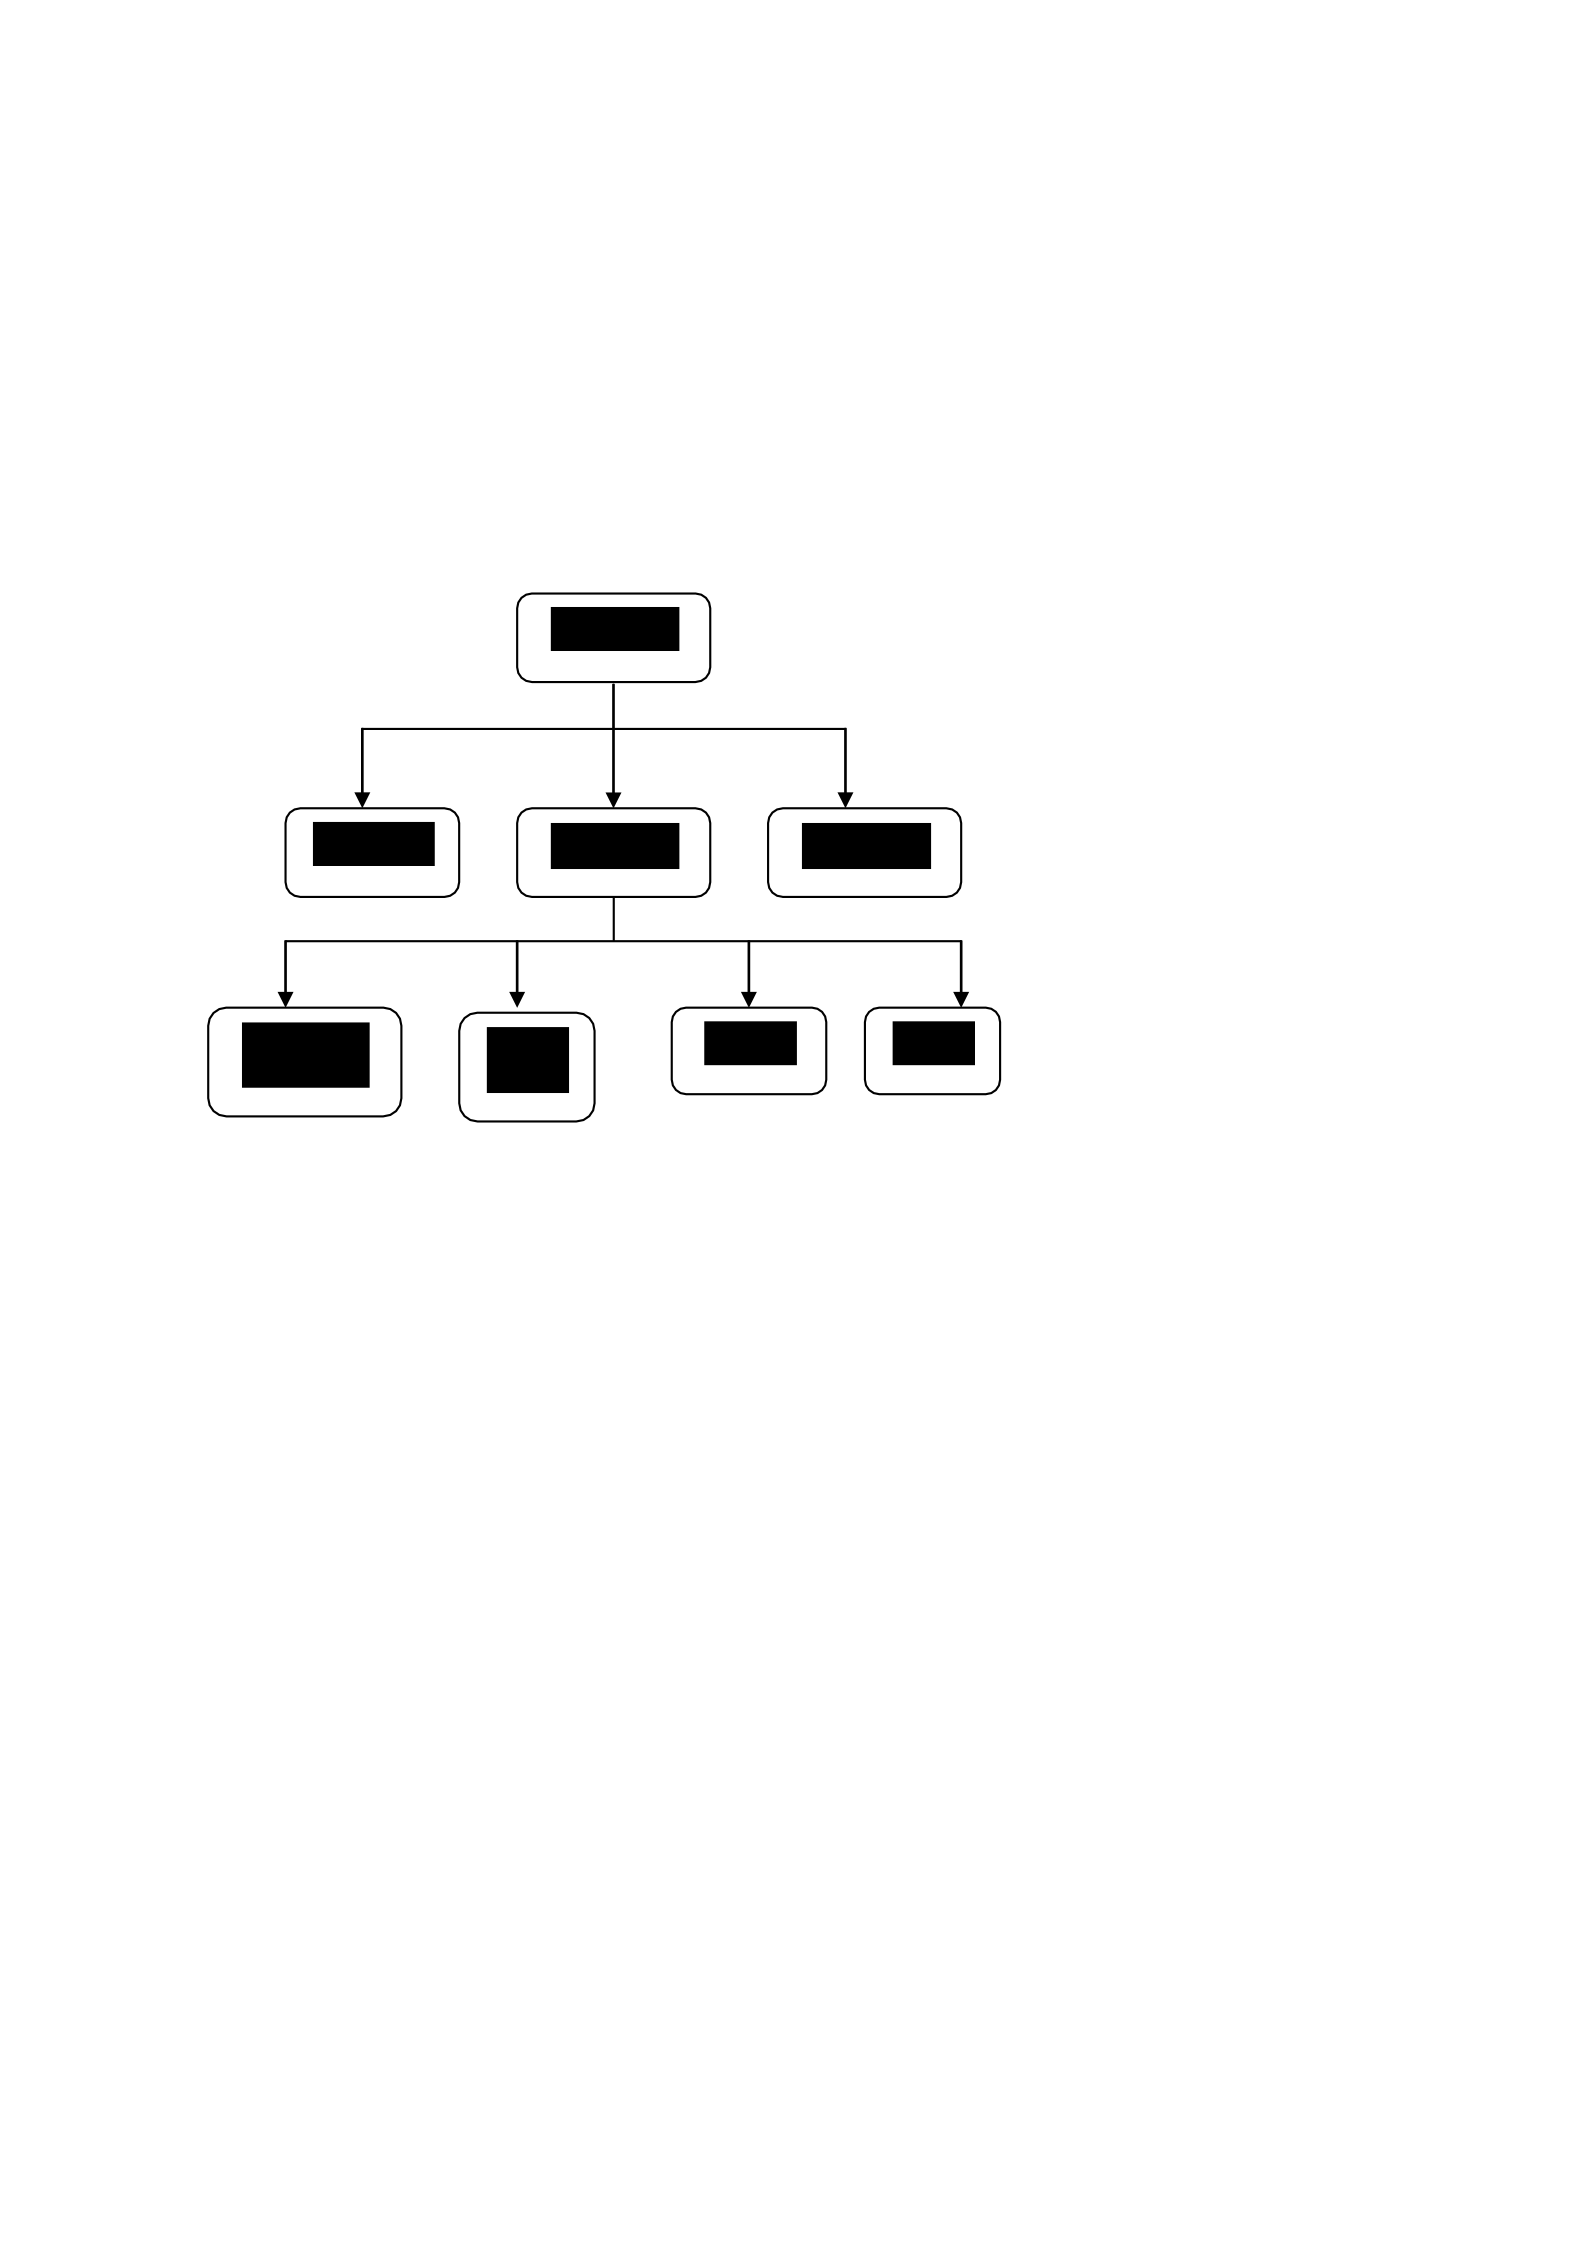
In an agribusiness company, there are three levels of strategy, namely the agribusiness
corporate level, the agribusiness unit/line level, and the agribusiness functional level (Figure
5.7.).
The strategy carried out by agribusiness companies consists of: agribusiness corporate
level strategy formulated by top management that regulates the activities and operations of
organizations that have more than one line or business unit. In developing these level
objectives, each company needs to understand one of several alternatives, such as market

position, innovation, productivity, physical and financial resources, profitability, managerial
achievement and development, employee achievement and attitude, and social responsibility;
agribusiness unit level strategy is more directed at managing the activities and operations of
a business. Basically, business unit level strategy seeks to determine the approach that a
business should take towards its market and how to implement that approach by utilizing
existing resources and under certain market conditions.
The strategy according to Porter (1980) cit Rangkuti (2001:6) can use generic startegy
in the form of differentiation by creating perceptions of certain values to consumers
(perceptions of superior product performance, product innovation, better service, and a
superior brand image), focus to gain competitive advantage in accordance with the expected
market segmentation and target, and cost leadership; and agribusiness functional level
strategy within the framework of agribusiness management functions (traditionally
consisting of agribusiness research and development, finance, production, marketing,
personnel / human resources) that can support business unit level strategy. The objectives of
functional strategy development are to communicate short-term objectives, to define the
actions needed to achieve short-term objectives, and to create an environment conducive to
achieving those objectives.
Strategic management is an art and science of making (formulation), implementing
(implementation), and evaluating (evaluating) strategic decisions between functions that
enable an organization to achieve future goals (Wahyudi, 1996: 14). Meanwhile, according to
Pearce and Richard (1997: 20), strategic management is defined as a set of actions that result
in the formulation and implementation of plans designed to achieve company goals. Then
according to Bosemen and Arvind (1996: 20), Strategic management is a process concerned
with determining the future direction of an organization and implementing decisions aimed at
achieving an organization's long and short-term objectives.
Furthermore, Mulyadi and Johny (2001: 397) also say that strategic management is a
process used by management and employees to formulate and implement strategies in
providing the best customer value to realize the organization's vision.
Viewed from the concept of strategy and strategic management, agribusiness strategic
management is the formulation, implementation, and evaluation of strategies designed to
achieve the goals of agribusiness companies in the long and short term. From this definition it
can be concluded: (1) agribusiness strategic management consists of 3 (three) processes as
follows: a). Strategic creation process, the process of developing a vision, mission, and long-

term goals by identifying opportunities and threats as external factors and strengths and
weaknesses as internal factors, as well as developing alternative strategies and determining
strategies; b). The process of strategic implementation, determining annual operational goals,
corporate policies, motivating employees, and allocating resources so that the established
agribusiness strategy can be implemented; and c). the process of agribusiness evaluation and
control includes efforts to monitor all results of strategy development and implementation,
including monitoring individual and corporate performance and taking corrective measures if
necessary; and (2) agribusiness strategic management focuses on combining marketing,
research and development, finance, and production/operational aspects of an agribusiness.
To make it easier to understand the process of agribusiness strategic management, an
agribusiness strategic management model with steps can be developed (Figure 5.8).
Before conducting agribusiness strategy, macro environmental analysis is carried out
in the form of looking at the state of population growth of a country and government policies
regarding agribusiness, such as agricultural politics and economic and business law,
agricultural technology, and socio-economic agriculture. Analysis of the agribusiness
industry environment in the form of competitive forces among others: the threat of new
entrants, the number of new entrants interested in entering the agribusiness industry will
depend on the size of the barriers to entry (barriers of entry) of the industry. These barriers
to entry according to Wahyudi (1996: 57) are economies of scale, product differentiation,
capital requirements, switching costs, access to distribution channels, government policy,
cost advantages independent of scale, and competitor response. Threats Substitute products
in the form of prices that tend to become cheaper than products produced by companies and
produced by large-scale and highly profitable agribusiness industries; bargaining power of
suppliers, suppliers will have high bargaining power if they are more concentrated than the
industry they supply, there are no substitute suppliers, the agribusiness industry is not the
most important buyer for suppliers, their products are the most important input for the
agribusiness industry, they have the power to carry out forward integration strategies;
bargaining power of buyers, buyers will have a high bargaining power if they are the largest
part of the company's sales, they are concentrated (gathered) in location, the product has no
difference (undifferentiated) with competitors' products, they have complete information, the
cost to sell the product is high competition from similar companies, the high level of
competition among competitors in an agribusiness industry depends on the number of
competitors, the size and strength of the competitors, the growth rate of the agribusiness
industry, between products have little difference, high barriers to exit the agribusiness
industry, and fixed costs are relatively very high. Determining the type of agribusiness
depends on what agribusiness sector (food, horticulture, plantation, livestock, fishery, and
forestry) the agribusiness company/organization is engaged in. After this determination, an
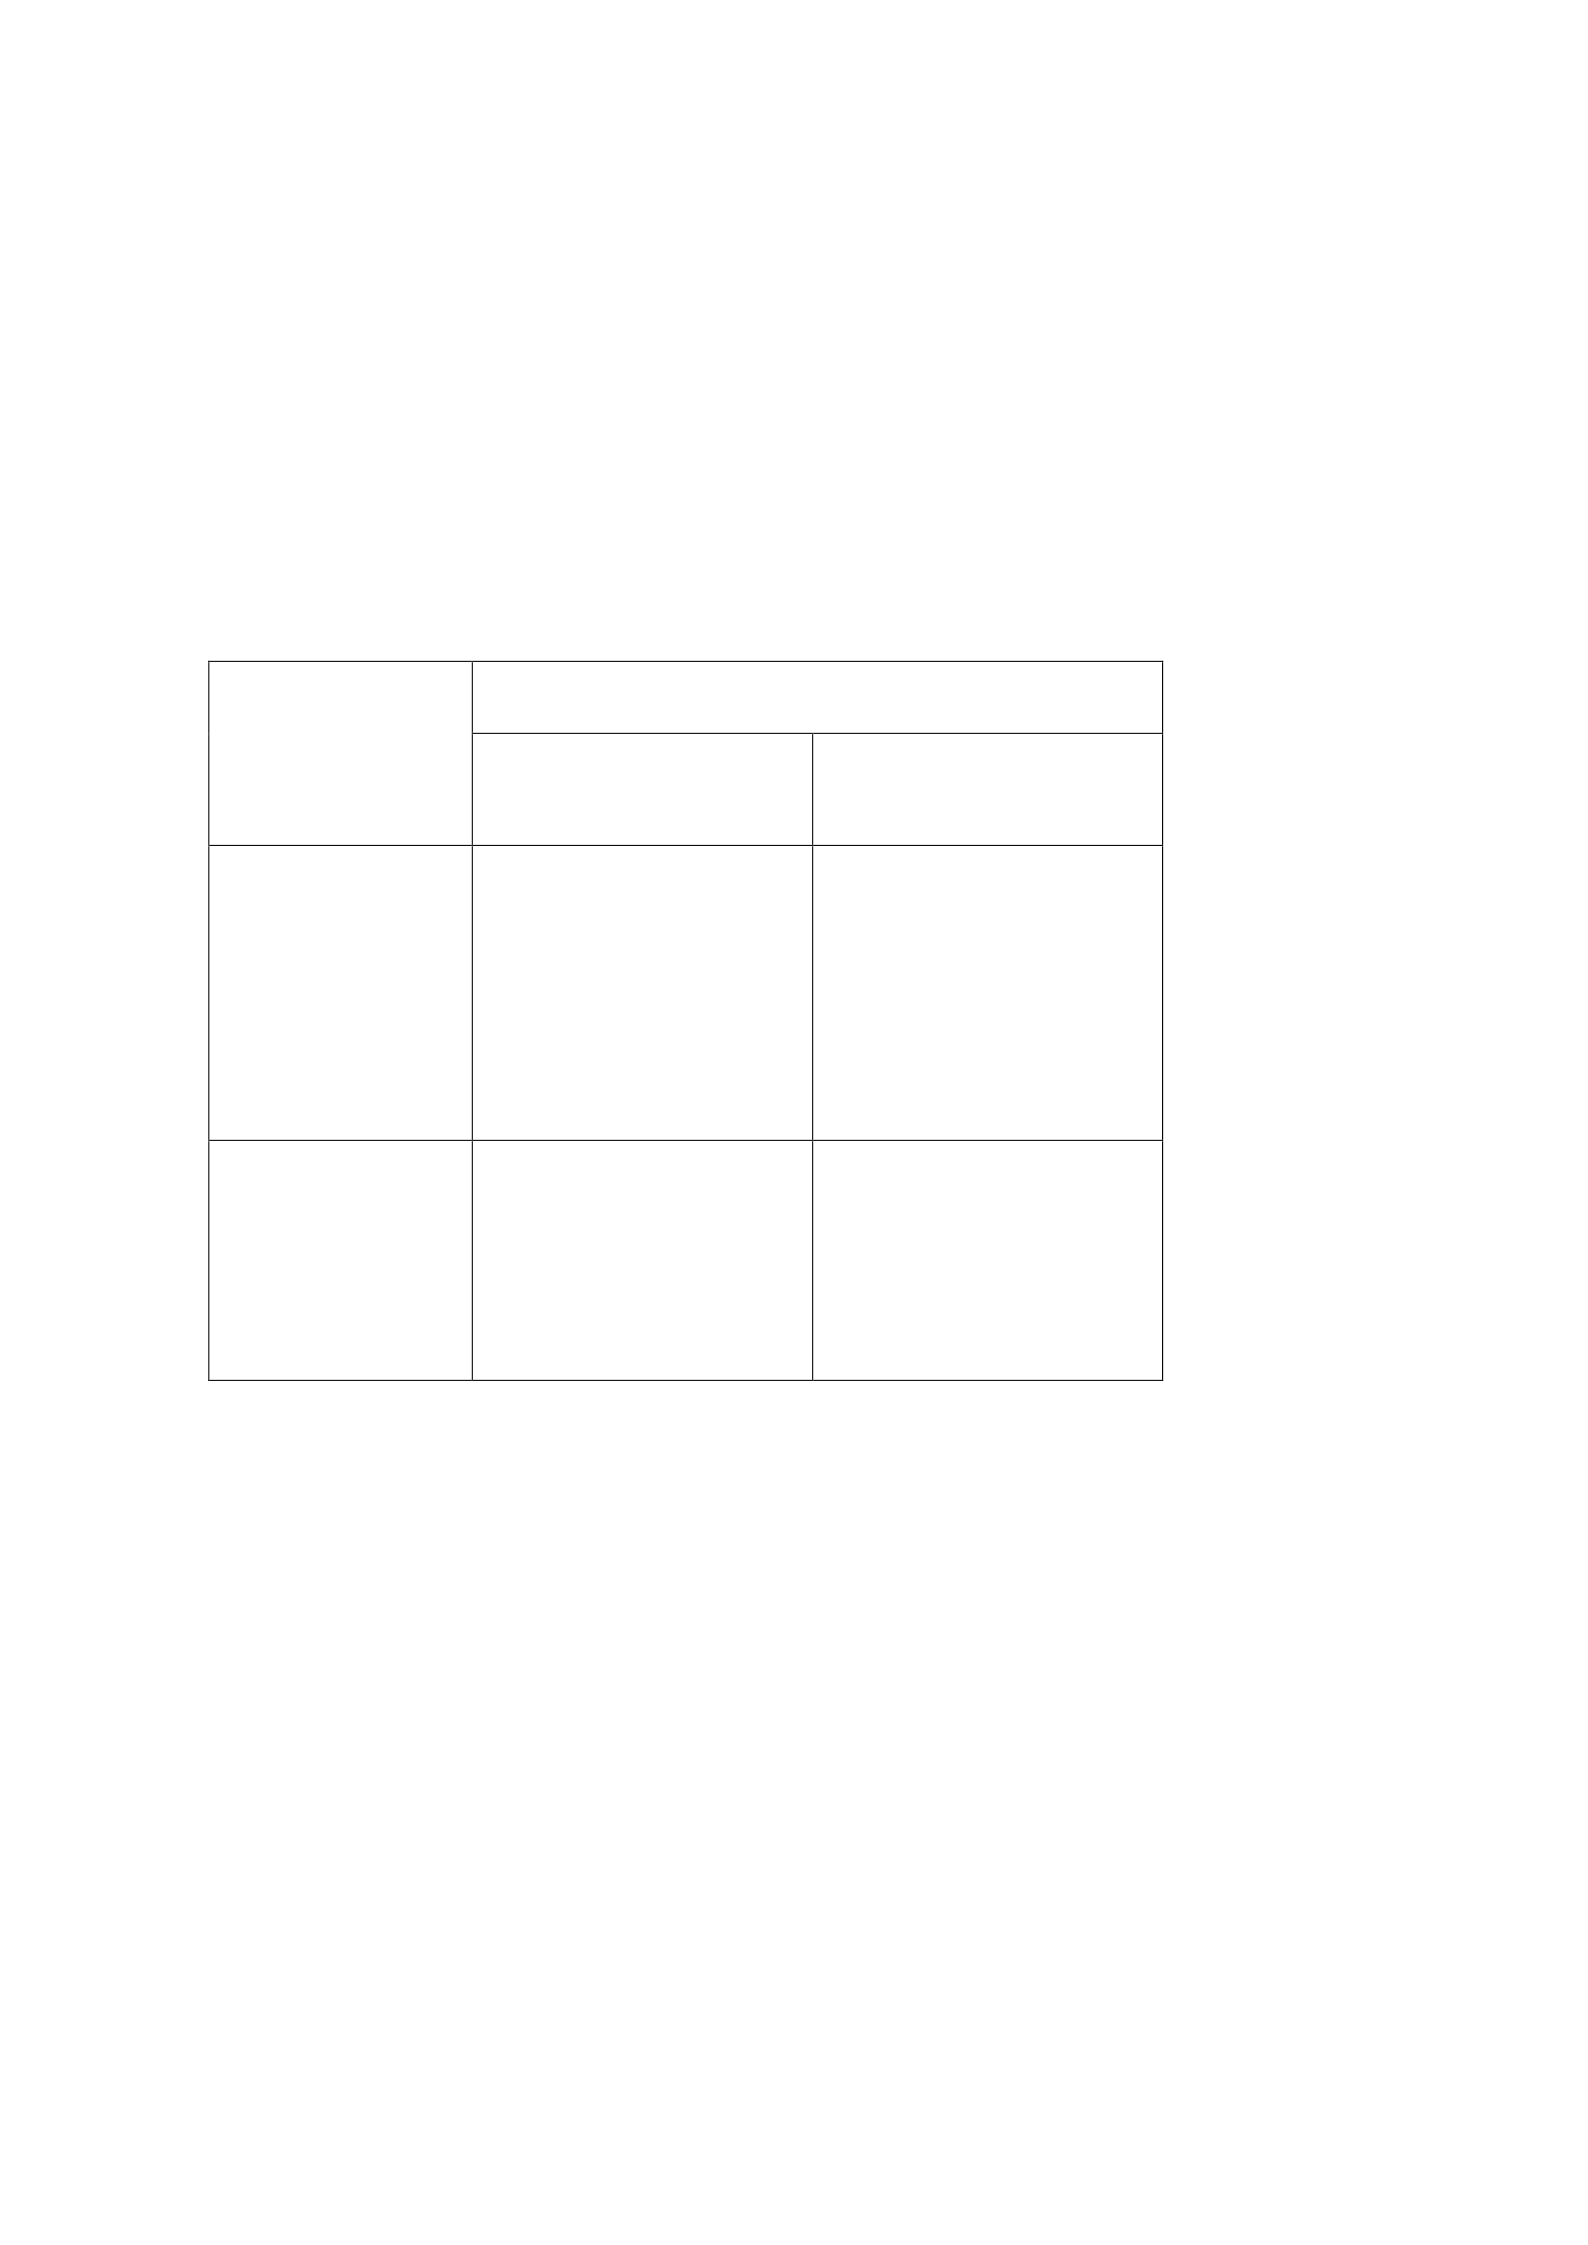
external and internal analysis known as Strenght, Weakness, Opportunity, and Threats) or
SWOT (Table 5.1.) is used.
Table 5.1 Agribusiness SWOT Matrix
External
Factor
Internal Factor
Strenght (S)
Weaknesses (W)
Opportunies
(O)
(SO)
-Strategy of using
strengths to capitalize
opportunity
(WO)
-Strategy of
minimizing weaknesses to
take advantage of them
opportunity
Treaths (T)
(ST)
-Strategy of using
strengths to overcome
threats‖
(WT)
-Strategy of
minimizing weaknesses to
avoid threats‖
Planning agribusiness activities can be done through the stages of strategy formulation,
strategic planning, programming, budgeting, implementation, and monitoring.
1. Strategy Formulation
Strategy formulation can be through the vision, mission, goals, basic beliefs, and values
of the agribusiness organization. Vision is the future condition to be realized, mission is the
path of choice to get to the future, goals are what is to be achieved, basic values are the
values that agribusiness organizations uphold in realizing the vision, and basic beliefs are
beliefs about the truth of the vision and the truth of the path chosen to realize the vision.
2. Strategic Planning
Strategic planning can be in the form of strategic objectives, targets, and strategic
initiatives. Strategic goals are conditions that will be realized in the future which are the
elaboration of organizational goals, targets to measure the success of achieving these goals,
strategic initiatives are qualitative statements about the strategic steps chosen to realize
strategic goals, the system that can be used to carry out strategic planning is a strategic
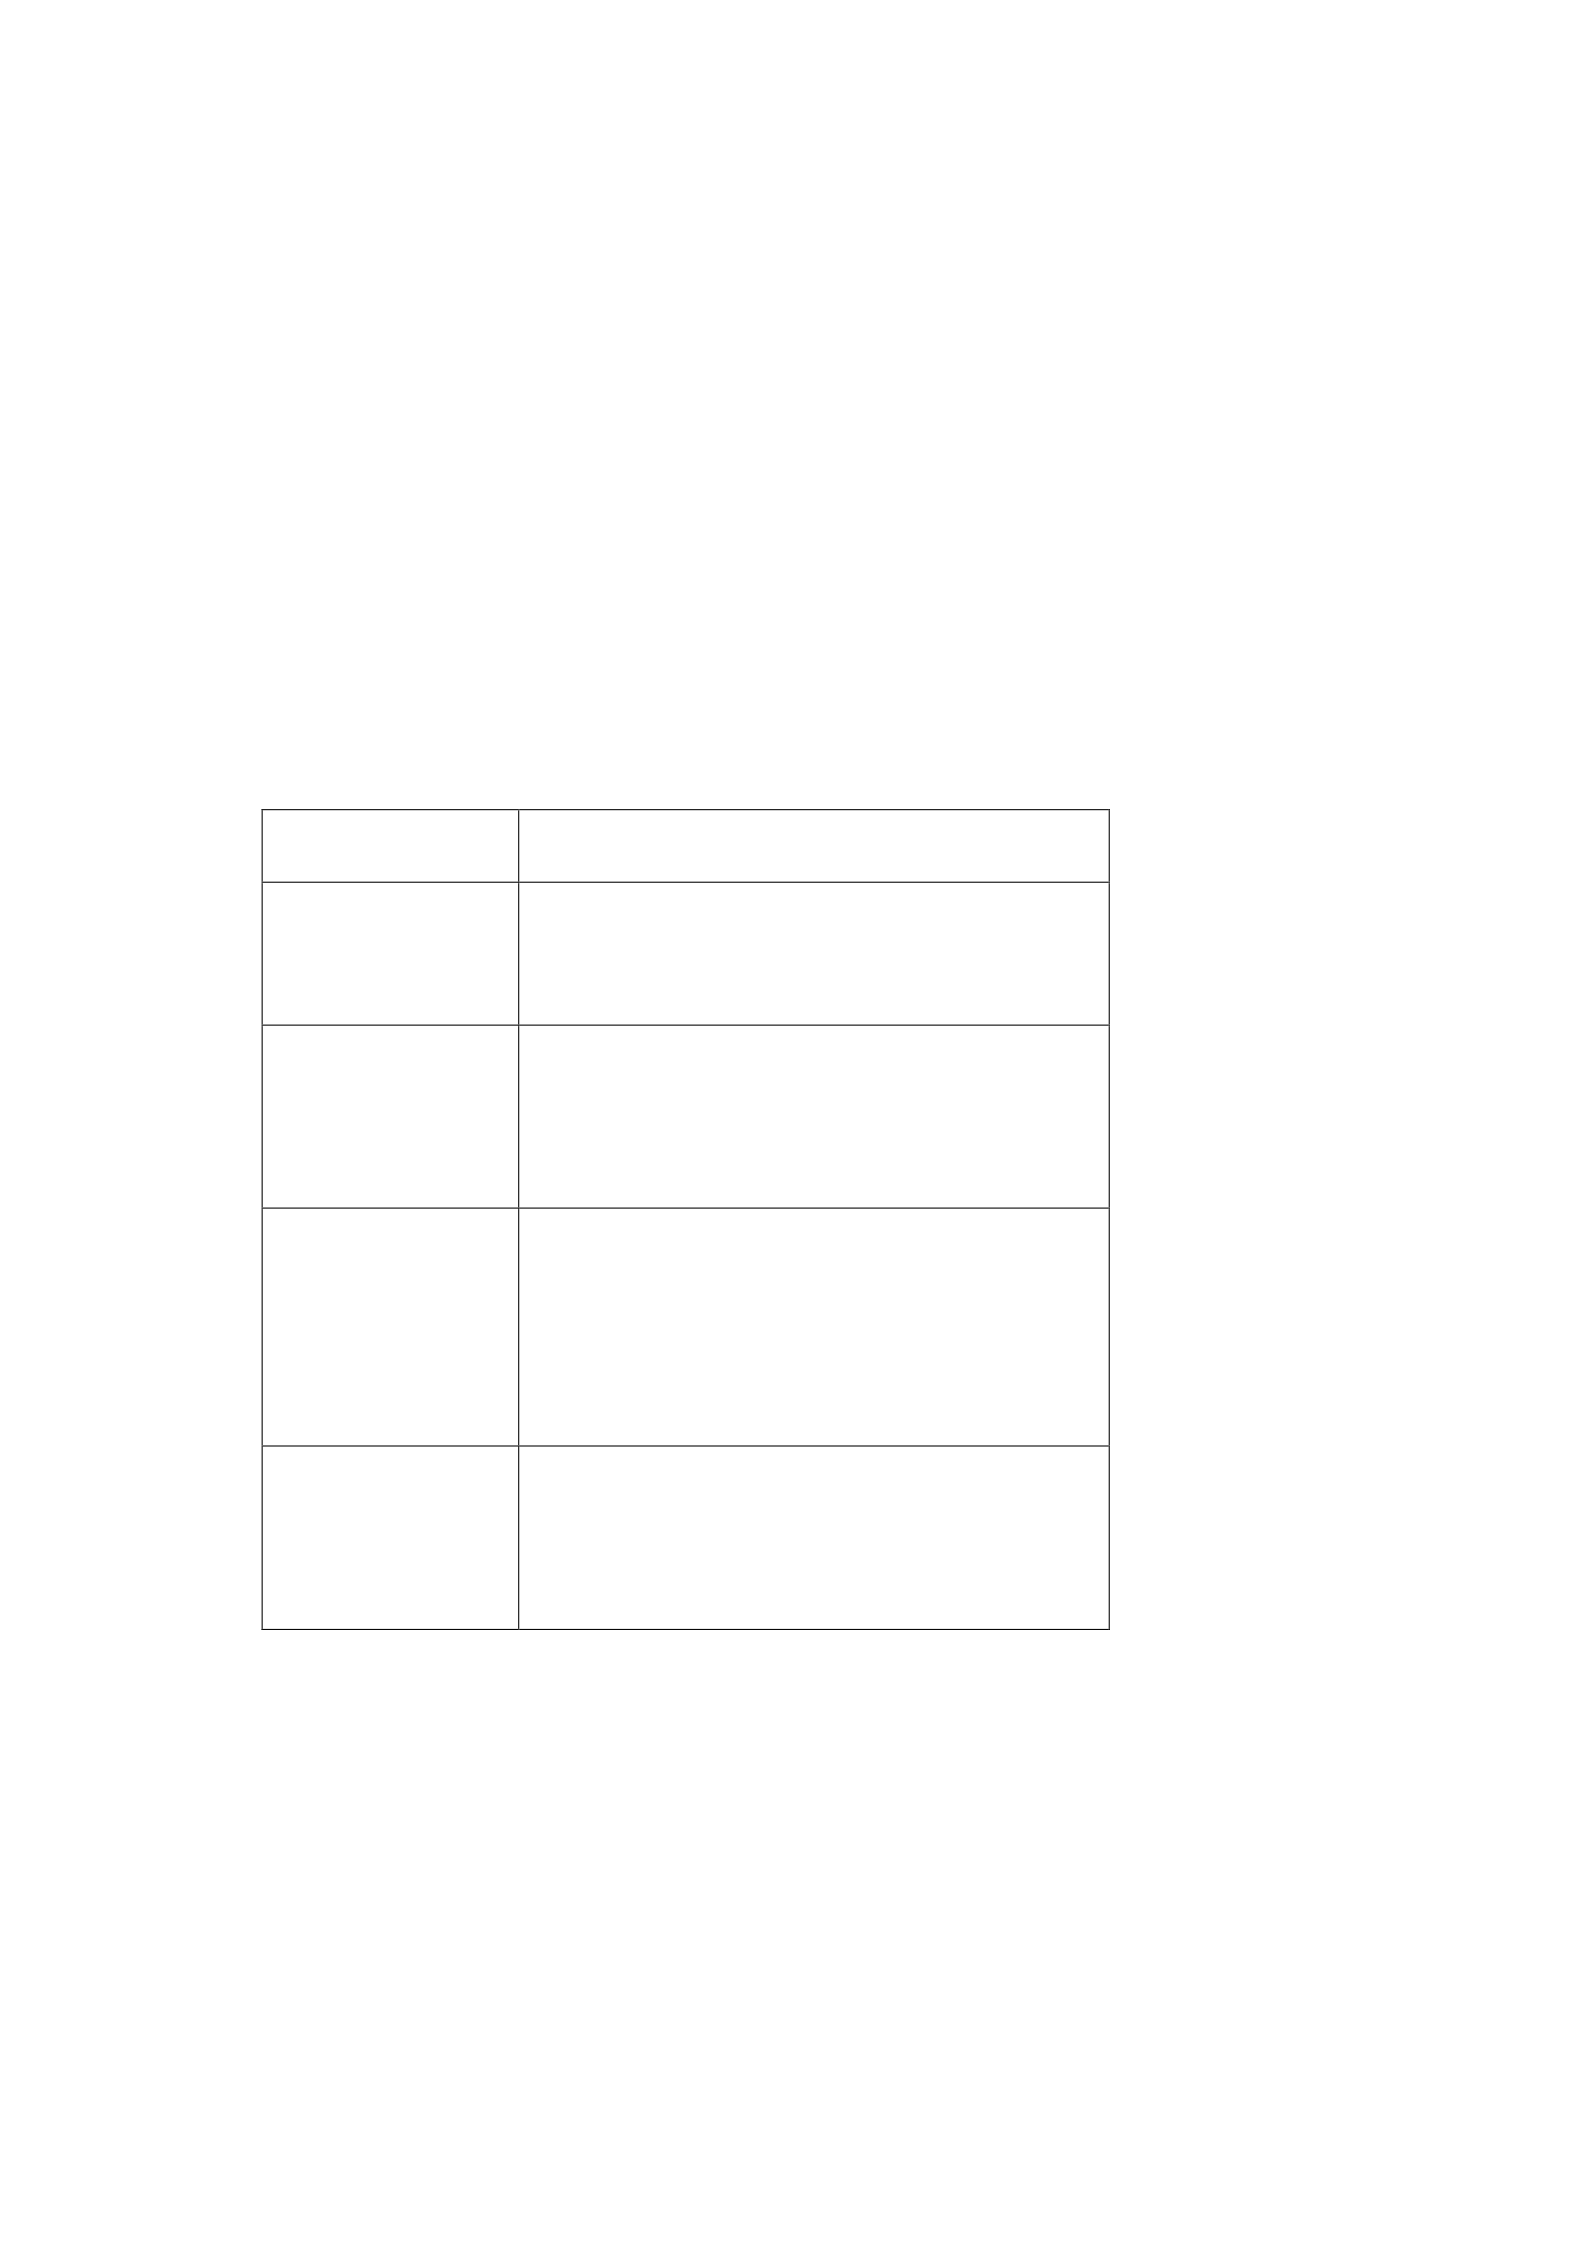
planning system with a balanced scorecard framework. Balanced scorecard is a set of
performance measures covering four perspectives (financial, customer, business processes /
internal, and learning and growth (Mulyadi and Johny, 2001: 344). The balanced scorecard
framework can be realized in agribusiness companies in each perspective as in Table 5.2.
Table 5.2 Balanced Scorcard framework in 4 (four) generic strategic objectives that are
realized
in each perspective
Perspective
Strategic Objectives
Finance
shareholder value (increased ROI,
revenue growth, reduced costs)
Customer
increased customer trust, speed of
service, and quality relationships and
customers
Business/inter
nal processes
organizational capital (improving the
quality of customer service processes, state-
of- the-art-technology, integrated customer
service processes)
Learning and
growth
Human capital (increased personal
capability and increased personnel
commitment).
Source: Mulyadi and Johny (2001:498)
3. Programming
Programming is the process of preparing a long-term plan to describe the strategic
initiatives chosen to realize strategic goals. The programming system can be divided into 2
(two) types, namely new programs and ongoing programs. (1) New programs can be created
by anyone and anywhere in the agribusiness organization. The program can come from the

top leadership with the head office team or various units.
(2) The current program can be an existing product classified according to its life cycle,
such as development, introduction, growth, maturity, and decline. To classify products
according to their life cycle, data is needed on the main competitors (size, strengths, and
weaknesses), the market (size and composition) and the expected changes in the market.
4. Budgeting
Agribusiness budgeting can be used in the form of activity based budgeting (ABB). ABB
or activity-based budgeting is the process of planning the deployment and direction of all
company activities to create value as shown in Figure 5.9 (Mulyadi and Johny, 2001: 574).
There are two things contained in this definition, namely ABB which focuses on value
creation and ABB is a process of planning deployment and all activities of agribusiness
companies. The focus on value creation can be in the form of long-term planning to generate
adequate profits within the budget period and short-term planning in the form of revenues,
costs, and assets. Then the focus on deployment planning and direction can be in the form of
(1) revenue-generating activities for the company such as sales and credit activities;
(2) product supply activities such as production (manufacturing);
(3) service activities in the form of agribusiness finance and accounting functions, as
well as activities in planning value-promoting measures such as cost reduction and asset
productivity improvement; (4) service activities in the form of environmental cleaning
services.
The focus of budgeting lies in planning activities that are used to generate value and
customers, both internal and external. Because costs arise as a result of activities, if you are
going to reduce costs, the effective way is to manage the causes of these costs (activities).
Budget is a strategic step to implement cost reduction through planning activities that
consume costs.
5. Implementation
Implementation or application of agribusiness strategy management can be done by
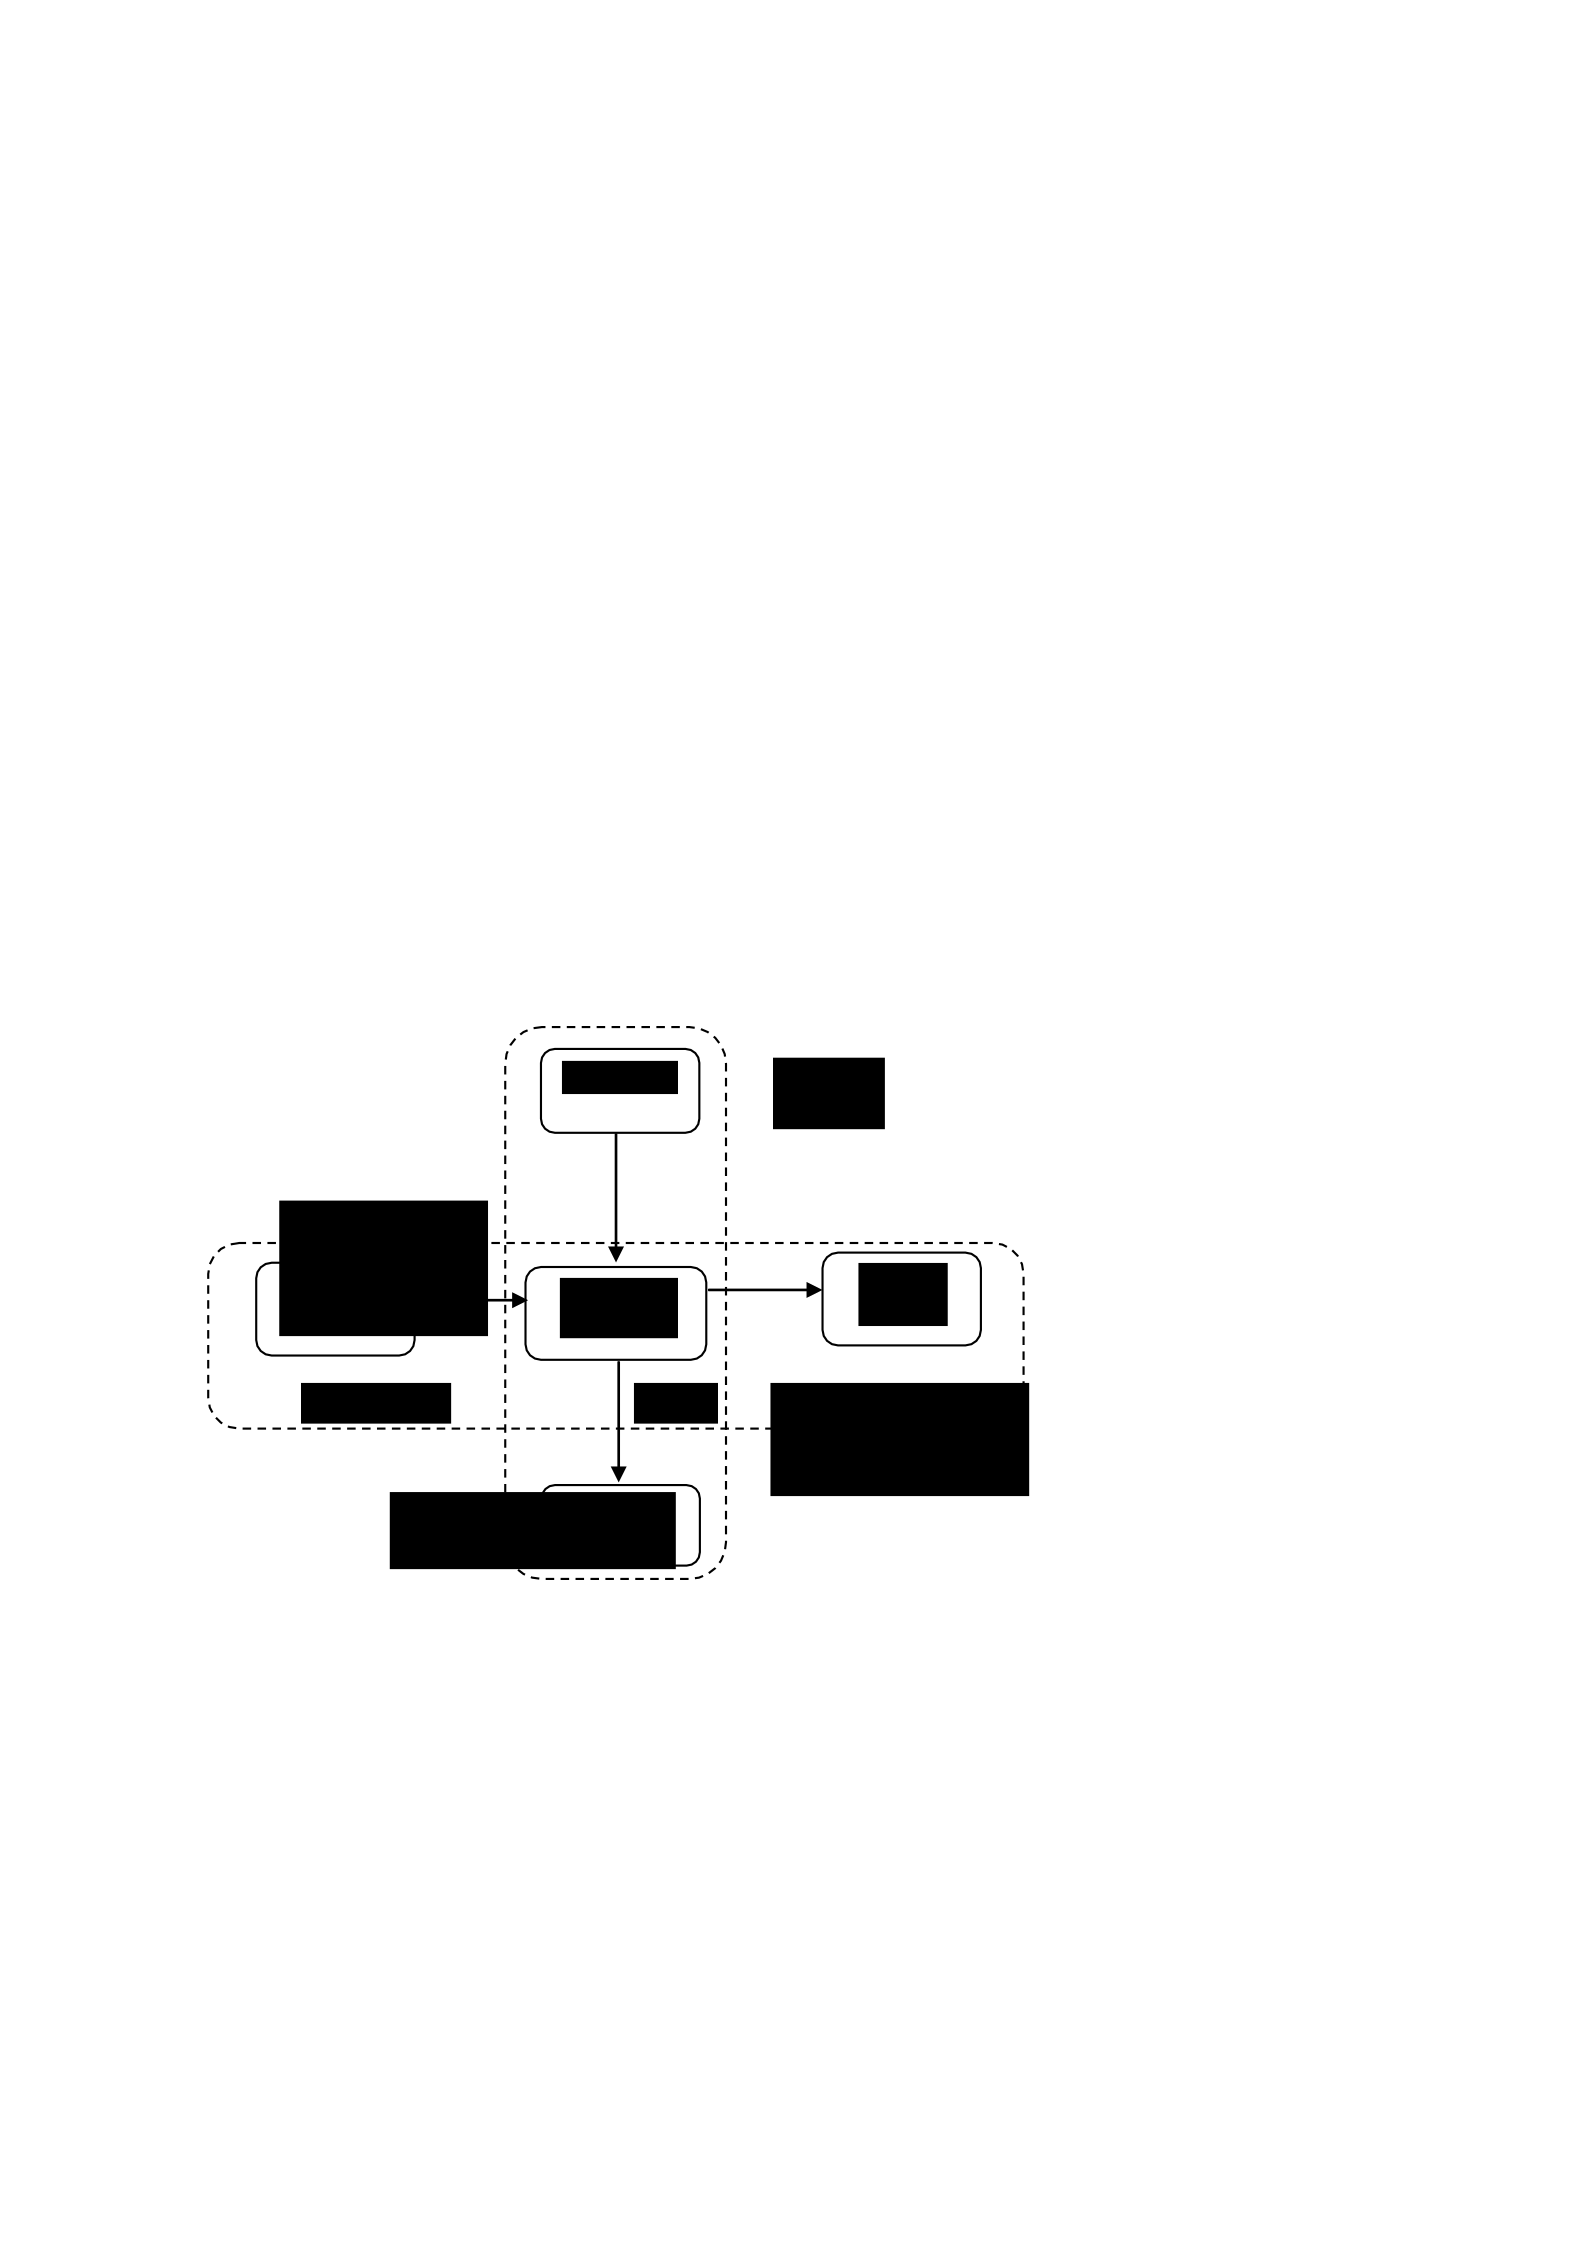
using Activity Based Management (ABM) (Figure 5.10). ABM or activity-based management
according to Mulyadi and Johny, (2001: 614) is an integrated and systematic management
approach to activities with the aim of increasing customer value and profit achieved from the
provision of value. From this definition, it contains two important meanings, namely focusing
Resources
Drivers
Agribusin
ess
Perfor
mance
Measur
on integrated and systematic management of activities and aiming to increase customer value
and profit.
(1) Focusing on integrated and systemized management activities can be shown in the
form of activities to implement product manufacturing in a quality and efficient manner, and
(2)
The aim is to increase customer and profit in the form of activity-based management
with continuous improvement of customer value and elimination of waste. With the
elimination of waste, costs can be reduced and profits increased as a result.
A driver is the cause of a particular consumption. There are two kinds of cost drivers,
namely resource drivers and activity drivers. Resource drivers are factors that cause the
consumption of resources by activities, while activity drivers are factors that cause the
consumption of activities by cost objects. For example, the quantity of agribusiness products
ordered by customers is a driver of product processing activities so that quantity is an activity
driver.
Activity is the process of identifying, describing, and evaluating the activities carried out
by the organization. Activity analysis can be carried out through steps, namely what is done,
how many people are involved in the activity, the time and resources needed to carry out the
activity, and the assessment of the value of the activity for the organization, including
recommendations for selecting and maintaining activities that add value. Financial
performance measures of activity efficiency can be classified into financial performance and
non-financial performance. (1) Financial performance includes cost trend reports,

benchmarking, activity-based budgeting, and life-cycle budgeting (Mulyadi and Johny,
2001:629), while (2) non-financial performance includes productivity measures, quality
measures, and time measures.
6. Monitoring
In the monitoring system, two systems can be used to realize the control stage in the
agribusiness strategic management process, namely the Effective Management Control
(EMC) System and the Activity Bases Costing (ABC) System.
(1) EMC (Effective Management Control) system is a management control to achieve
certain goals through expected behavior. To make the management control function effective,
management needs to choose the type of control that can overcome the causes of why
individuals in agribusiness organizations/companies are unwilling and/or unable to achieve
predetermined organizational goals. Types of control can be grouped into two groups, namely
main control (of personnel) and additional control (control of outputs and actions) and the
organization's avoidance of undesirable individual behavior). The main control over
personnel usually arises because of the mismatch between vision, mission, and goals
(organization and individuals/employees). For this reason, top management is responsible for
formulating it by communicating the vision, mission and goals to every member of the
organization so that what is desired is realized. Then additional control of outputs where
personnel are required to be accountable for outputs according to predetermined goals, such
as expected outputs based on efficiency, quality, and accuracy when delivering products;
additional control of certain actions and encourage employees to perform expected actions
and prevent employees from performing unexpected actions; and avoidance of control
problems can be done by centralizing the concentration of decision making in the
organization into the hands of top management to avoid companies from the low quality of
decision making by lower managers.
(2) The ABC (Activity Bases Costing) system arises from management's need for
agribusiness accounting information that is able to reflect resource consumption in various
activities to produce agribusiness products. ABC according to Anderson and Harold
(1992:97) cit Tunggal (2000:21) is an accounting system that focuses on the activities carried
out to produce, while ABC according to Mulyadi and Johny (2001:679) is an activity-based
cost accounting to control costs through the provision of information about the activities that
cause costs (Figure 5.11). If managers want to reduce these costs, they can only be

significantly reduced through activity-based management (ABM). The ABC system is a cost
information system that provides complete information about activities to enable company
employees to manage activities. The result obtained from activities is an improvement in the
activities used by agribusiness companies to produce products for customers so that as a
result the benefits of products for customers are increasing and the costs of producing these
products are decreasing.

