


Chap 4
Costs of Quality (COQ)
As part of TQM, many companies prepare costs of quality reports. Costs of
quality reports categorize and list the costs incurred by the company
related to quality. Once managers know the extent of their costs of quality,
they can start to identify ways for the company to improve quality while at
the same time controlling costs.
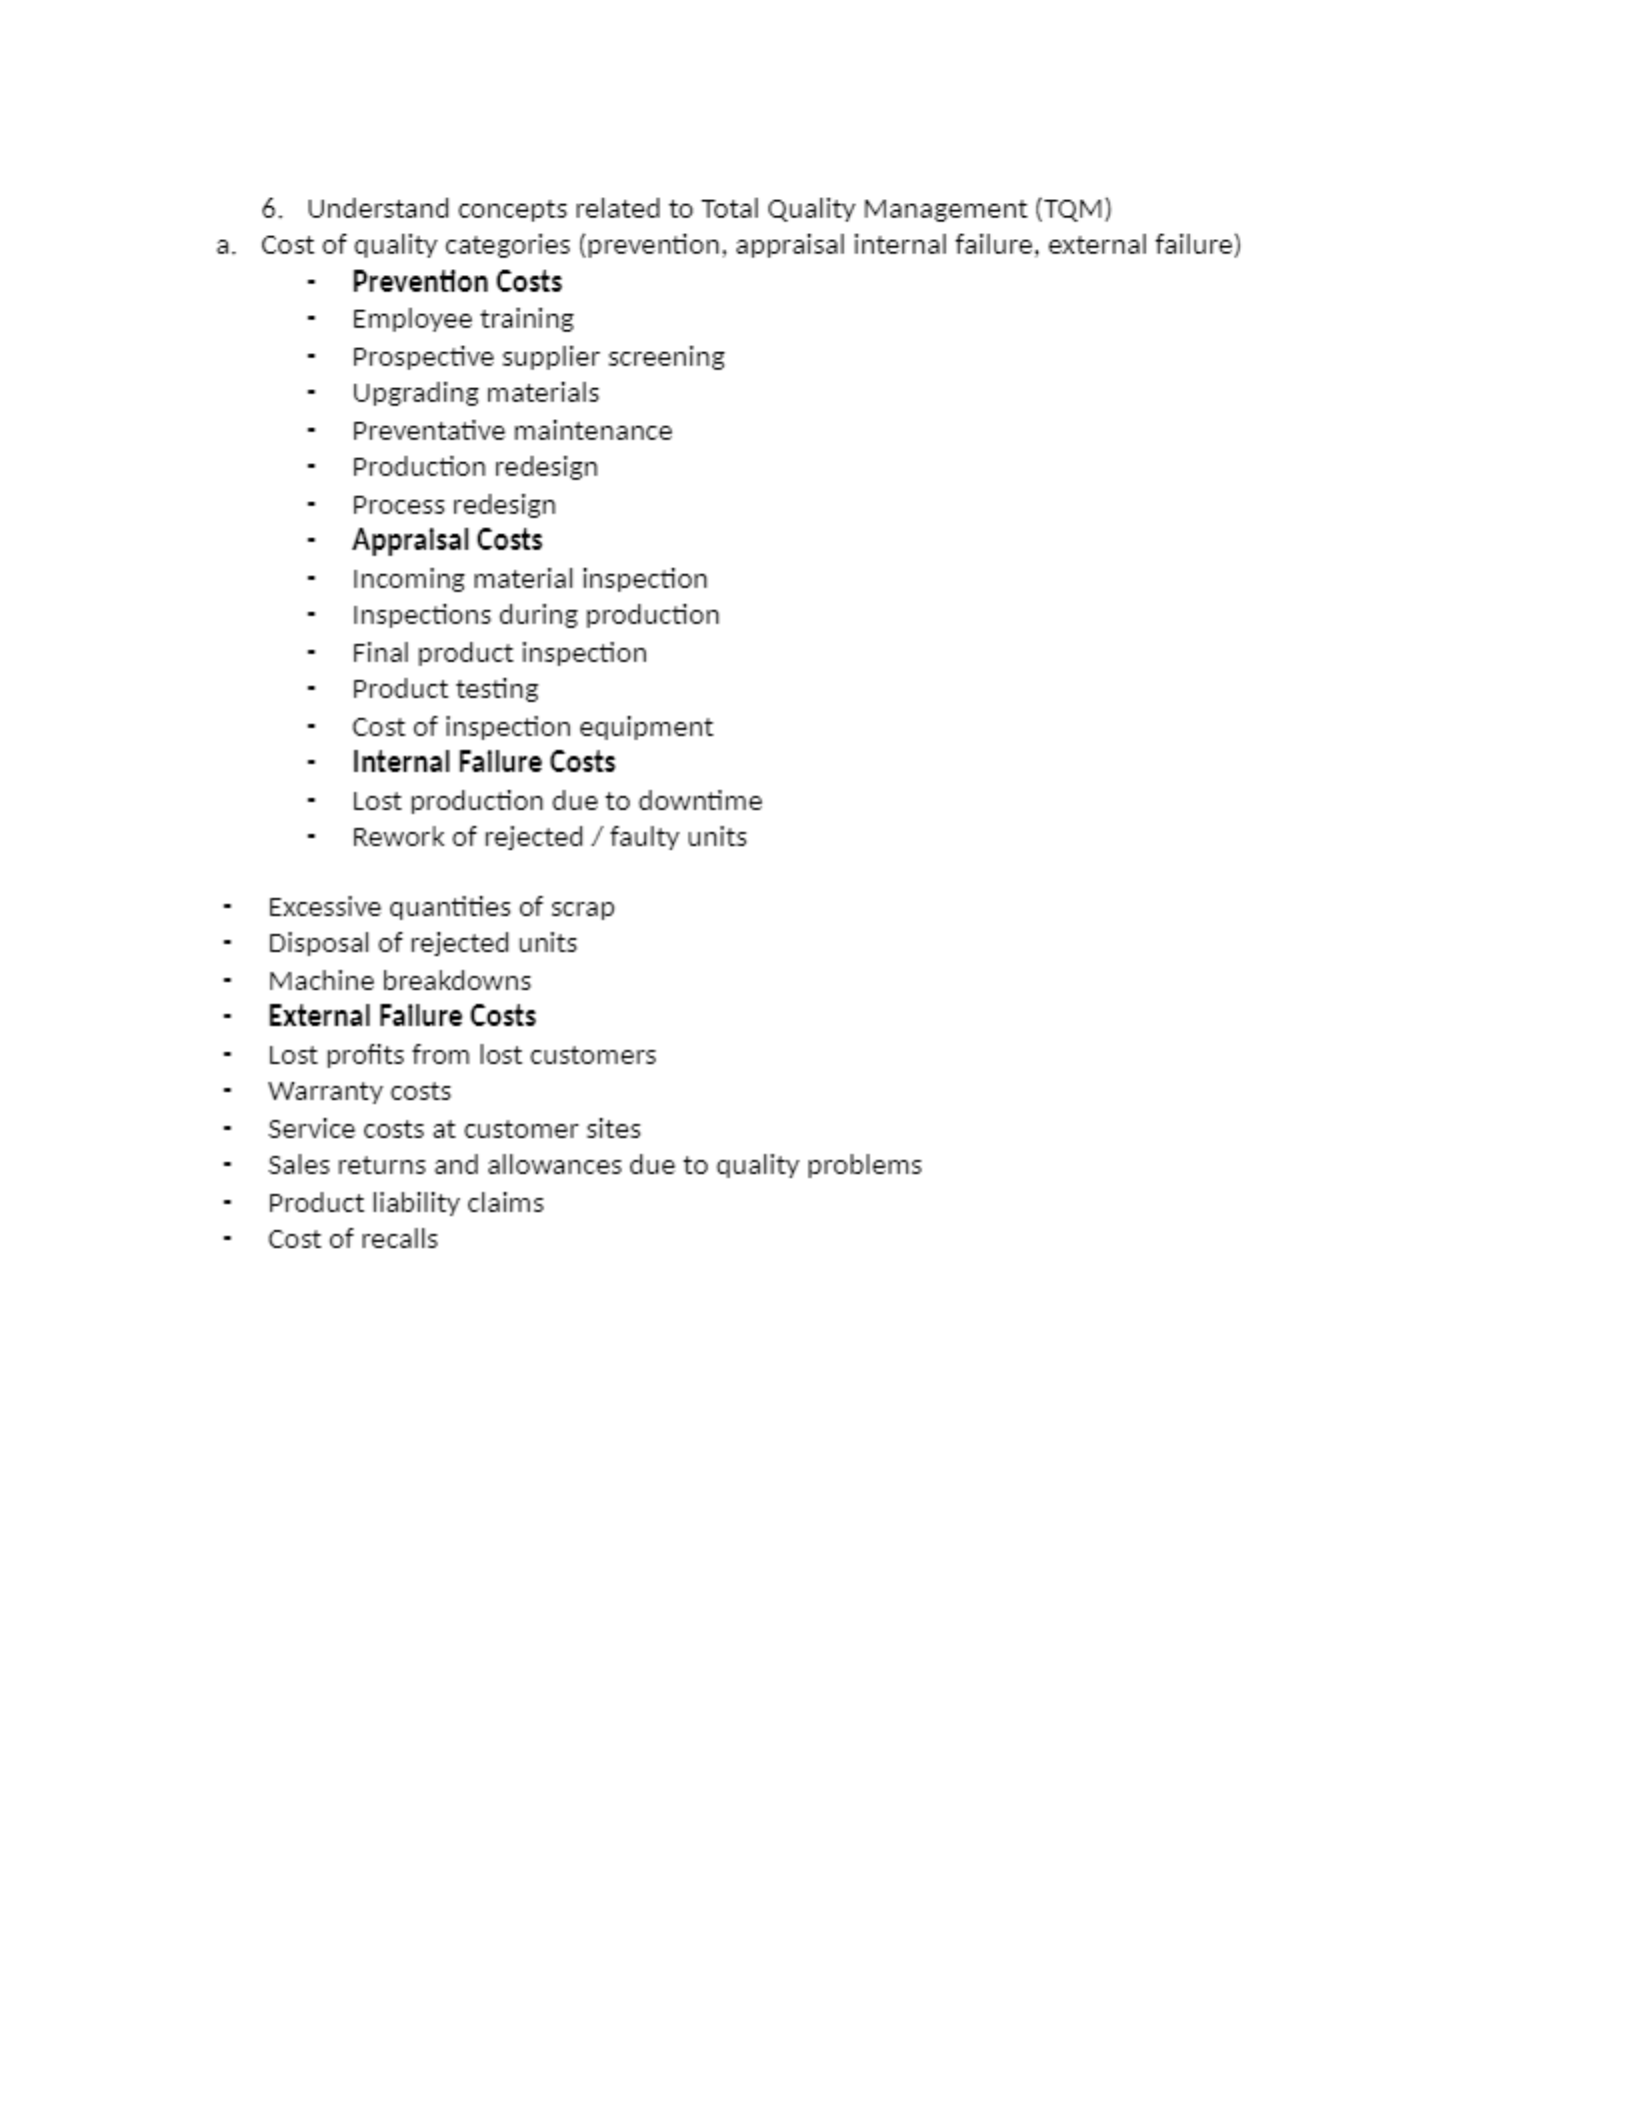
Quality-related costs generally fall into four different categories: prevention
costs, appraisal costs, internal failure costs, and external failure costs. These
categories form the framework for a costs of quality report. We’ll briefly
describe each next.
Prevention Costs
Prevention costs are costs incurred to avoid producing poor-quality goods
or services. Often, poor quality is caused by the variability of the production
process or the complexity of the product design. To reduce the variability of
the production process, companies often automate as much of the process
as possible. Employee training can help decrease variability in nonautomated
processes. In addition, reducing the complexity of the product design or
manufacturing process can prevent the potential for error: The fewer parts or
processes, the fewer things that can go wrong. Frequently, companies need
to literally “go back to the drawing board” (the R&D and design stages of the
value chain) to make a significant difference in preventing production
problems.
Appraisal Costs
Appraisal costs are costs incurred to detect poor-quality goods or services.
Intel incurs appraisal costs when it tests its products. One procedure, called
burn-in, heats circuits to a high temperature. A circuit that fails the burn-in
test is also likely to fail in customer use. Nissan tests 100% of the vehicles
that roll off the assembly lines at its plant in Canton, Mississippi. Each vehicle
is put through the paces on Nissan’s all-terrain test track. Any problems are
identified before the vehicle leaves the plant.
Internal Failure Costs
Internal failure costs are costs incurred on defective units before delivery
to customers.
For example, if Nissan does identify a problem, the vehicle is reworked to
eliminate the defect before it is allowed to leave the plant. In the worst-case
scenario, a product may be so defective that it cannot be reworked and must
be completely scrapped. In this case, the entire cost of manufacturing the
defective unit, plus any disposal cost, would be an internal failure cost.
External Failure Costs
ACC241 Exam 1 Concepts Review

External failure costs are costs incurred because the defective goods or
services are not detected until after delivery is made to customers. For
example, Maytag had to recall 250,000 washing machines because water
was leaking on the electrical connections, which had the potential to cause
an electrical short and ignite the circuit boards.9 Along with incurring
substantial cost for repairing or replacing these recalled washers, the
publicity of a defect such as this could cause significant damage to the
company’s reputation. Damage to a company’s reputation from selling
defective units to end customers can considerably harm the company’s
future sales. Unsatisfied customers will avoid buying from the company in
the future. Even worse, unsatisfied customers tend to tell their neighbors,
family, and friends about any poor experiences with products or services. As
a result, a company’s reputation for poor quality can increase at an
exponential rate. To capture the extent of this problem, external failure costs
should include an estimate of how much profit the company is losing due to
having a bad reputation for poor quality.
The Cost Hierarchy: A Useful Guide for Setting up Activity Cost Pools
Some companies use a classification system, called the cost hierarchy, to
establish activity cost pools. Companies often have hundreds of different
activities. However, to keep the ABC system manageable, companies need to
keep the system as simple as possible, yet refined enough to accurately
determine product costs.5 The cost hierarchy, pictured in Exhibit 4-20, helps
managers understand the nature of each activity cost pool, and what drives
it.
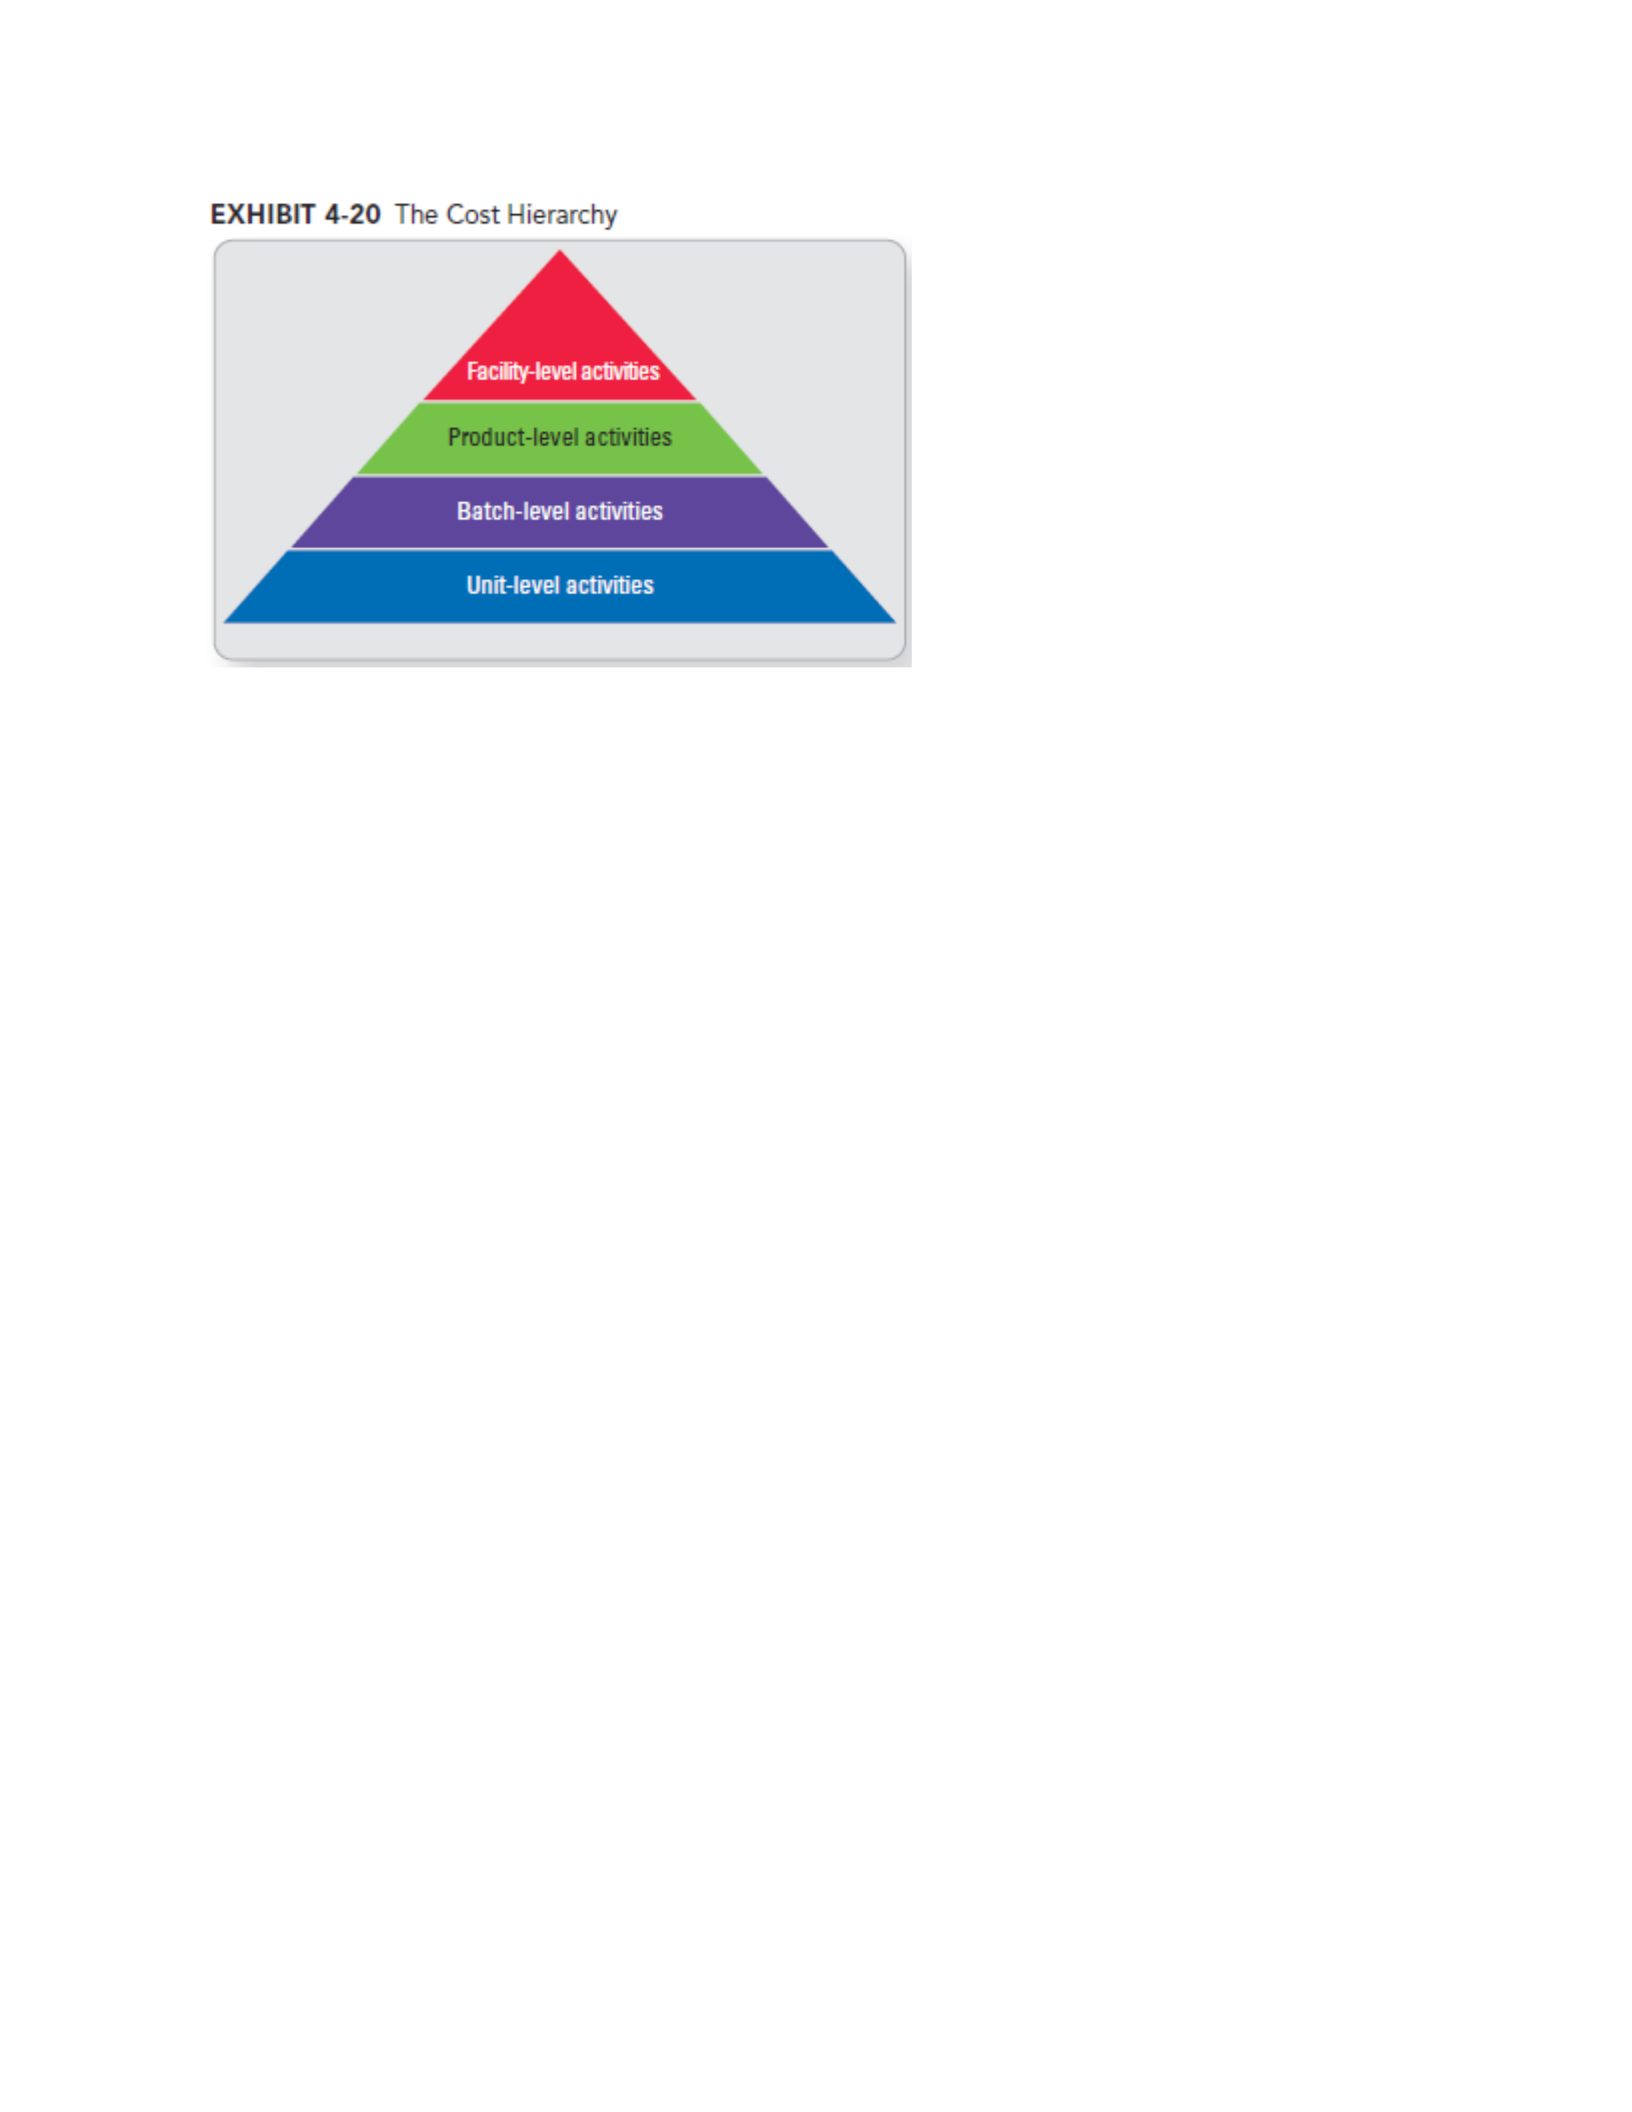
There are four categories of activity costs in this hierarchy, each determined
by the underlying factor that drives its costs:
1. Unit-level activities—activities and costs incurred for every unit.
Examples include inspecting and packaging each unit the company
produces.
2. Batch-level activities—activities and costs incurred for every batch,
regardless of the number of units in the batch. One example would be
machine setup. Once the machines are set up for the specifications of the
production run, the company could produce a batch of 1, 10, or 100 units,
yet the company only incurs the machine setup cost once for the entire
batch.
3. Product-level activities—activities and costs incurred for a particular
product, regardless of the number of units or batches of the product
produced. Examples include the cost to research, develop, design, and
market new models.
4. Facility-level activities—activities and costs incurred no matter how
many units, batches, or products are produced in the plant. An example is
facility upkeep: the cost of depreciation, insurance, property tax, and
maintenance on the entire production plant.
Chapter 2
Service companies
-Provide a service only
-No inventory
-Ex: Advertising agencies, banks, law firms, insurance companies
Merchandisers
- Resell products purchased from suppliers
- one inventory account
Ex: Walmart, Best Buy, Amazon

Manufacturers
- Use labor and other inputs to convert raw materials into finished products
ex: Procter and Gamble, Dell computer, General mills- Three inventory accounts
Three inventory accounts
Raw Materials, Work in process, finished goods
Value Chain
Activities that add value to products and services and cost money
Value chain activities
- Research and development
- design
- production or purchases
- marketing
- distribution
- customer service
Cost object
Anything for which managers want a separate measurement of cost
- Direct cost
- Indirect cost
Total costs
used internally only
inventoriable product costs
used for external reporting
Direct Costs
Direct materials
direct labor
Manufacturing overhead
indirect costs are related to manufacturing that are not direct materials or direct labor
Prime costs
Direct materials + direct labor
conversion costs
manufacturing overhead + direct labor
direct and indirect labor costs
- salaries and wages
- fringe benefits
- payroll taxes

Merchandiser income statement
+ Sales
- Cost of goods sold
---------------------
= Gross profit
- Operating expenses
----------------------
= Operating income
Service income statement
Service revenues
- Operating expenses
------------------
Operating income
Cost of Goods sold calculation for merchandiser
+ beginning inventory
+ purchases
+ import duties or tariffs
+ freight-in
---------------------
= Cost of goods available for sale
- ending inventory
-------------------
= cost of goods sold
Cost of Goods Manufactured calculation for manufacturers
+ Beginning work in process inventory
+ Direct materials used
+ Direct labor
+ Manufacturing overhead
----------------------------
= Total manufacturing costs to account for
- Ending work in process inventory
----------------------------
= Cost of goods manufactured
Cost of goods sold calculation for manufacturers
+ Beginning finished goods inventory
+ Cost of goods manufactured
----------------------
= Cost of goods available for sale
- Ending finished goods inventory
----------------------
= Cost of goods sold

Manufacturer income statement
+ Sales
- Cost of goods sold
-------------------
= Gross profit
- Operating expenses
--------------------
= Operating income
Controllable costs
Management can influence or change cost
Uncontrollable costs
Management cannot change or influence cost in the short run
Relevant costs
Differential costs, which are costs that differ between alternatives
Irrelevant costs
Costs that do not differ between alternatives or sunk costs - costs incurred in the past that cannot
be changed
Variable costs
Change in total cost in direct proportion to changes in volume
Fixed costs
Stay constant in total cost over a wide range of activity levels
Marginal cost
Cost of making one more unit
True
Direct costs can be traced to specific units
d
An example of direct labor would be which of the following?
a: slaray of the vice - president of operations
b: wages of factory security
c: salary of production manager
d: wages of assembly line personnel
c
how do variable costs per unit behave?
a: they decrease as production increases
b: they decrease as production decreases

c: they remain the same througout production levels within the relevant range
d: they increase as production decreases
b
which of the following is not an example of an indirect cost incurred in manufacturing
automobiles?
a: plant supervisor salary
b: cost of the automobile engines
c: machinery depreciation in the factory
d: plant utilities
c
which element of the value chain would depreciation on a factory be classified as?
a: distribution
b: design
c: production
d: research and development
true
retailers sell their products to consumers
true
manufacturing companies usually have three types of inventory
true
if a company wants to determine a products cost, it must assign both direct and indirect costs
c
which of the following is an example of a fixed cost for a manufacturer?
a: delivery fuel expense
b: income taxes
c: fire insurance on buildings
d: machine repair expense
b
which of the follwoing are classified as a manufacturing overhead?
a: direct materials and direct labor
b: indirect labor and indirect materials
c: factory rent and direct labor
d: all materials
true
indirect costs cannot be traced to the cost objects, so they are allocated
false
cost of goods sold is a major expense of service companies

variable
A(n) _______ cost is one whose total amount changes in direct proportion to a change in volume
d
which of the following items could be an example of a cost object?
a: an international plant
b: the accounting department
c: a manufacturing plant
d: all of the above are examples of potential cost objects
true
a marginal cost is the cost of making one more unit of a product
true
costs can be either direct or indirect, depending upon the cost object
false
fixed costs vary in total over a wide range of activity levels
b
which statement describes direct materials in a manufacturing setting?
a: direct materials do not become part of the finished product
b: direct materials are used to determine total inventoriable product costs
c: direct materials cannot be separately and conveniently traced
d: direct materials are used to determine total manufacturing overhead
true
only manufacturing companies have finished goods inventory
c
which type of company typically produces its own inventory?
A: wholesaler
b: service company
c: manufacturer
d: retailer
b
which of the following activities is not included in the value chain?
a: customer service
b: reporting
c: design
d: production
ACC241
Exam#1
Study
Guide
(1)
©
Rate
3
more
documents
to
eam
a
free
unlock.
yr
Helpful
4
Unhelpful
+
[Bice
4.
Understand
the
general
role of
management
accounting
a.
The
four
primary
responsibilities
of
a
manager
-
Planning
-
Directing
=
Controlling
-
Decision
Making
b._
Differences
between
management
accounting
and
financial
accounting
~
Financial
~
Managerial
~
External
Users
+
Internal
Users
-
Aids
in
making
credit/investment
decisions.
Planning,
directing,
controlling
-
General
Purpose
Financial
Statements
_-
Internal
reports
are
desired
~
Compliance
with
GAAP
Not
bound
by
authoritaitive
rules
c.
How
management
accountants
fit
into
an
organization's
structure
-
They
go
beyond
working
in
the
controllers
office
+
They
work
in
marketing
-
They
work
in
manufacturing
~
They
workin
finance
d._
Skills
required
of
management
accountants
-
Teamwork
=
Analytical
Communication
-
Business
Knowledge
-
Accounting
Knowledge
©.
The
role
of the
IMA
(Institute
Management
of
Accountants)
Develops
and
advances
the
careers
of
management
accountants
through:
Certification,
practice
and
development,
networking,
advocacy
of
ethical
nd
professional
conduct
Educates
the
public
about
the
role
of
management
accountants
Publishes
a
monthly
professional
journal
Issues
the
certificate
of
Management
Accountant
(CMA)
decision-making
framework
Maintain
professional
competence
by
continually
developing
their
knowledge
and
skills
Preserve
confidentiality
of
information
Uphold
their
integrity
Perform
duties
with
credibility
by
communicating
fairly
and
objectively,
nd
disclosing
all
information
that
is
relevant
to
decision
makers
g.
The
purpose
and
major
provisions
of
the
Sarbanes-Oxley
Act
Purpose
was
to
enhance
internal
control,
financial
reporting,
audit
practices
and
oversight
of the
accounting
profession.
Provisions:
CEO
and
CFO
assume
responsibility
Audit
committee
must
be
independent
New
requirements
for
CPA
firms
Stiffer
Punishments
2.
Understand
the
general
role
of
management
accounting
a,
The
differences
between
service
companies,
merchandising
and
manufacturing
‘companies
and
the
type
of
inventory
they
have
b.
The
value
chi
Sell
intangible
services
Make
up
largest
part
of
economy
Have
little
to
no
inventory
Merchandising
Companies:
Resell
tangible
products
purchased
from
suppliers
Carry
significant
inventories
Manufacturing
Compat
Raw
material
to
finished
products
Carries
three
types
of
inventory:
raw
material,
work
goods
process
and
finished
and
its
elements
Interdependent
activities
that
add
value to
a
company's
products
and
services
Research
and
development
Design
Production or
Purchases
Marketing
bution
Costumer
Service
c.
Terms
used
to
describe
cost;
Cost
Objects,
Direct
Costs,
and
Indirect
Costs
Cost
object
is
anything
that
a
manager
desires
to
have
a
separate
cost
measurement
for.
EX:
Unit
of
product,
Class
of
customer
ct
cost
is
a
cost that
can
be
traced
to
a
cost
object
EX:
Steak
Indirect
cost
is
a
cost
that
relates
to
a
cost
object
but
cannot
be
traced
EX:
Property
taxes
Direct
costs
assigned
to
costs
by
tracing
‘Terms
used
to
describe
cost;
Cost
Objects,
Direct
Costs,
and
Indirect
Costs,
=
Cost
object
is
anything
that
a
manager
desires
to
have
a
separate
cost
measurement
for.
EX:
Unit
of
product,
Class
of
customer
=
Direct
cost
is
a
cost that
can
be
traced
to
a
cost
object
EX:
Steak
=
Indirect
cost
is
a
cost
that
relates
to
a
cost
object
but
cannot
be
traced
EX:
Property
taxes
~
Direct
costs
assigned
to
costs
by
tracing
=
Indirect
costs
are
allocated
to cost
objects
Inventoriable
Costs
(Direct
Material,
Direct Labor,
and
manufacturing
overhead)
Versus
period
cost.
~
_Inventoriable
costs
are
only
the
costs
incurred
during
the
production
of
purchase
phase
of
the
value chain
-
Allother
costs
beside
direct
material,
labor,
and
manufacturing
overhead
is
considered
a
period
cost.
Prime
Costs
versus
Conversion
Costs
~
Prime
Costs
are
the
costs
that
are
directly
traced
to
finished
products
and
consist
of
direct
materials
and
direct
labor
=
Conversion
Costs
are
the
cost
incurred
to
convert
raw
materials
to
finished
goods
and
consists
of
direct
labor
and
manufacturing
overhead
Controllable
Cost
versus
Uncontrollable
Cost
~
Controllable
costs
are
costs
that
management
can
readily
change
in
the
near
term.
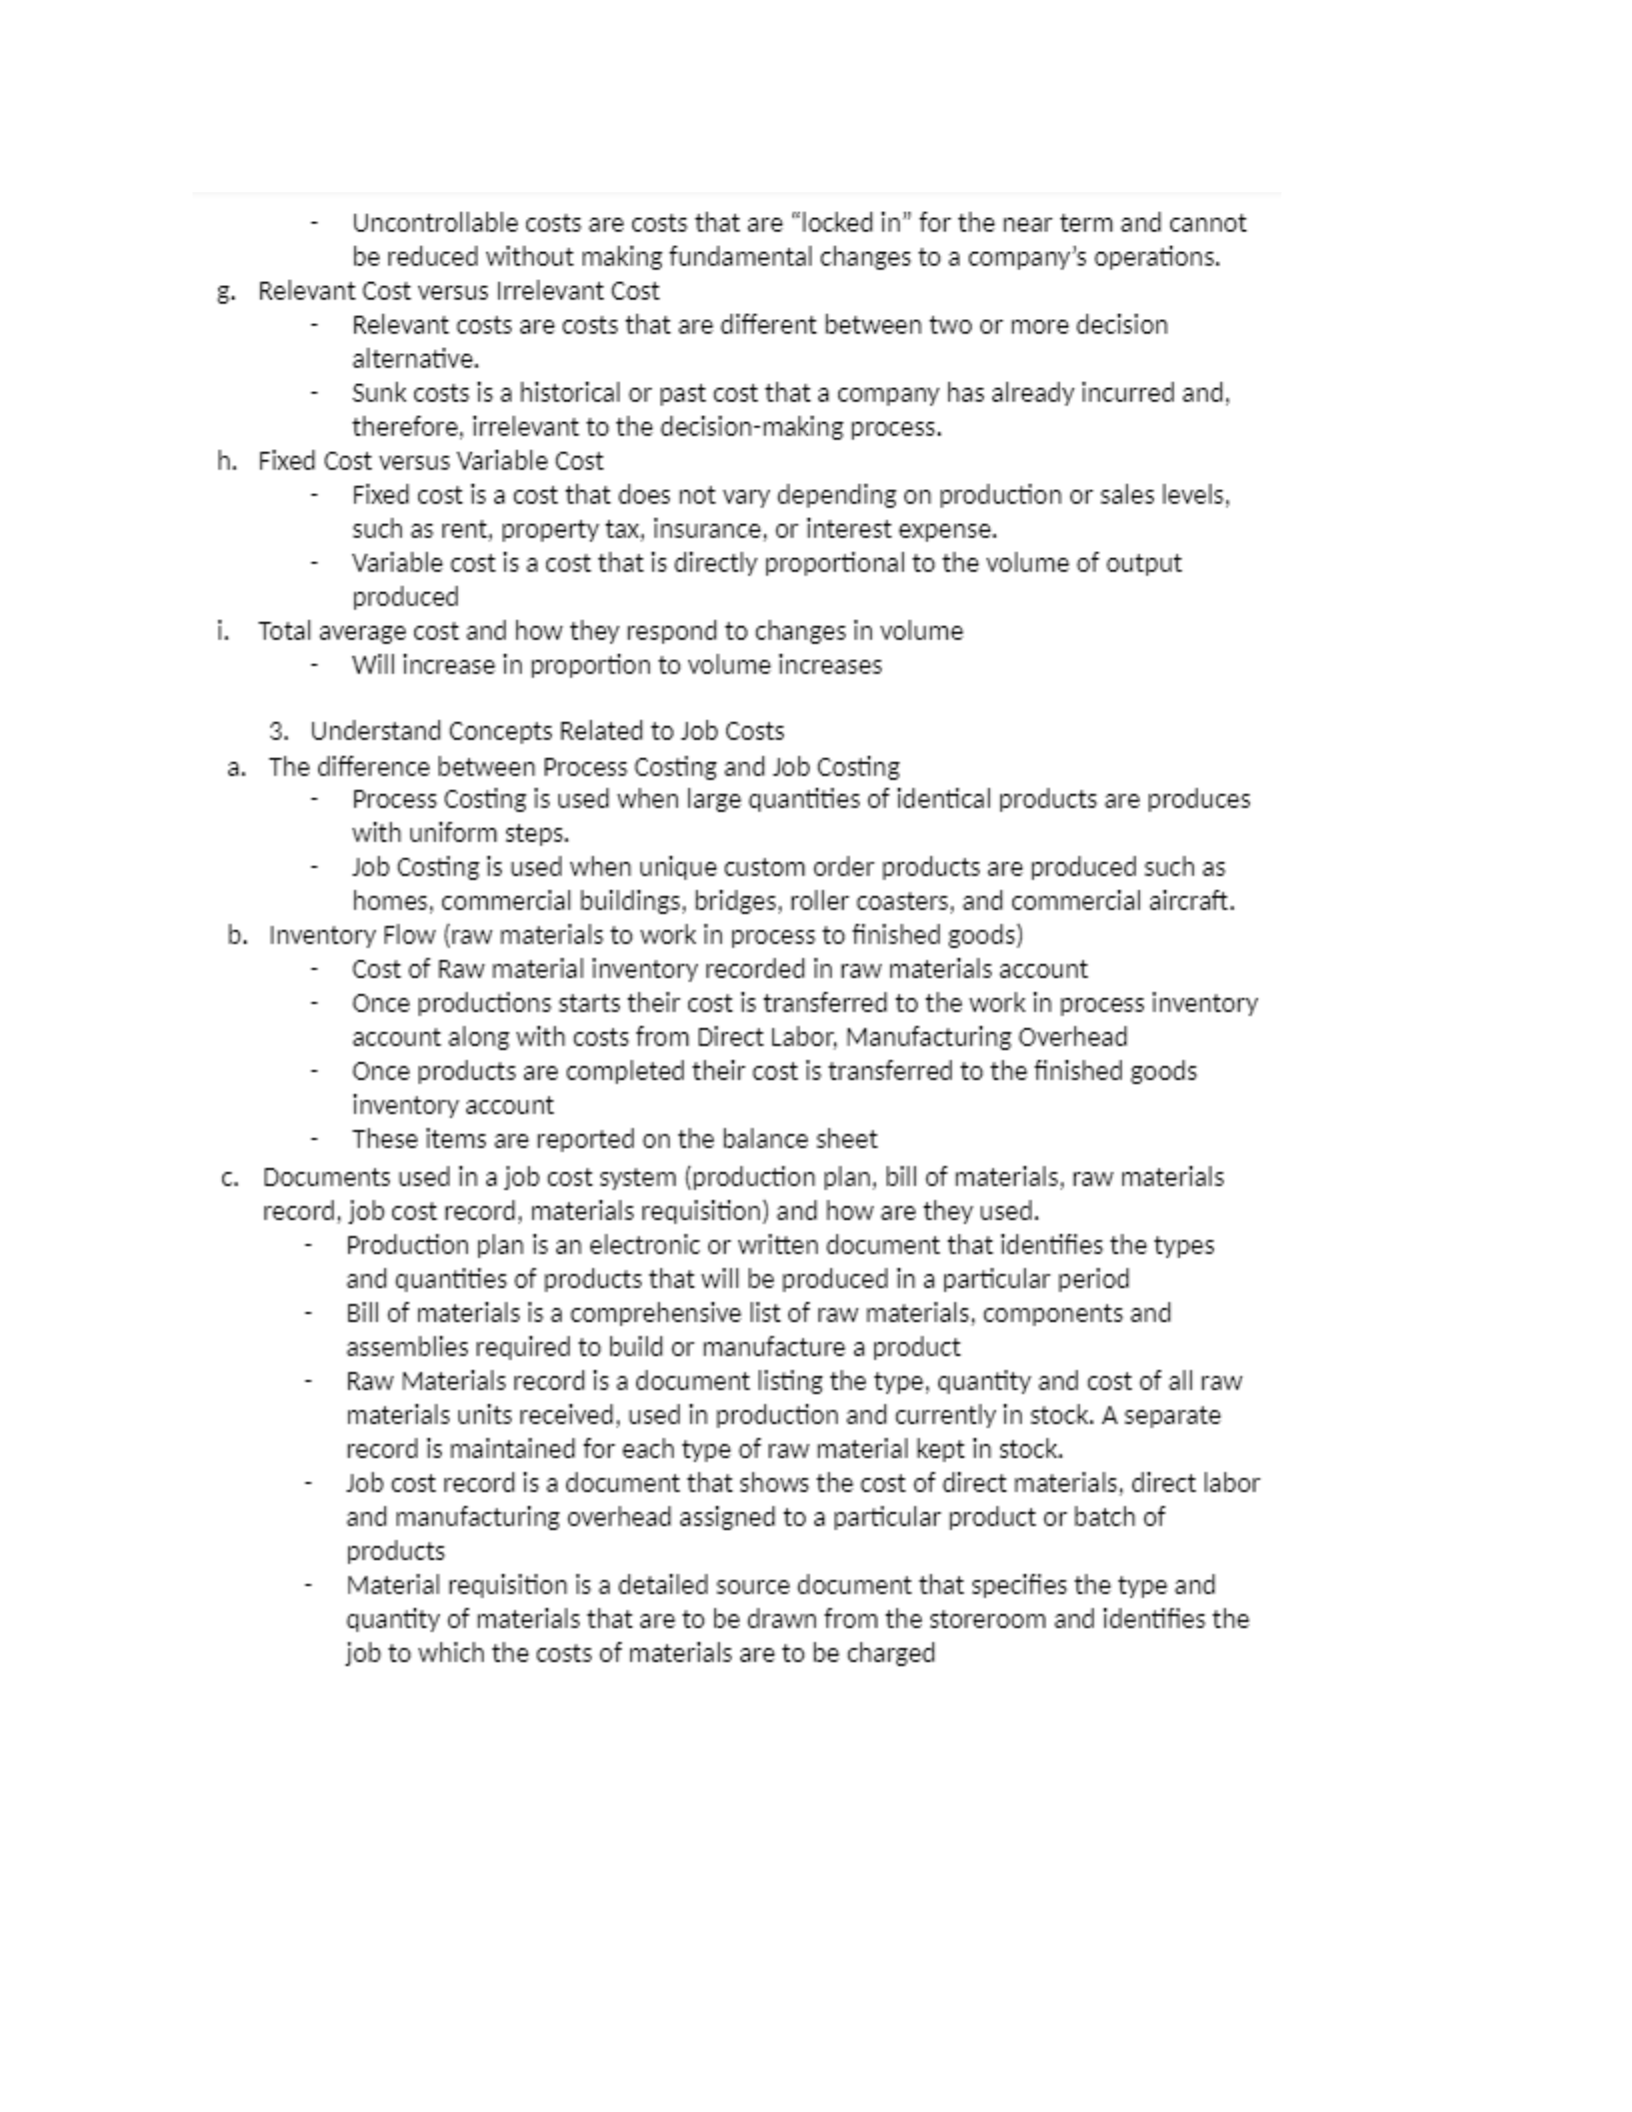
=
Uncontrollable
costs
are
costs
that
are
“locked
in”
for
the
near
term
and
cannot,
be
reduced
without
making
fundamental
changes
to
a
company’s
operations.
g.
Relevant
Cost
versus
Irrelevant
Cost
=
Relevant
costs
are
costs
that
are
different
between
two
or
more
decision
alternative.
~
Sunk
costsis
2
historical
or
past
cost
that
a
company
has
already
incurred
and,
therefore,
irrelevant
to
the
decision-making
process.
h.
Fixed
Cost
versus
Variable
Cost
~
Fixed
cost
is
a
cost that
does
not vary
depending
on
production
or
sales
levels,
such as
rent,
property
tax,
insurance,
or
interest
expense.
~
Variable
cost
is
a
cost that
is
directly
proportional
to
the
volume
of
output
produced
Total
average
cost
and
how
they
respond
to
changes
volume
~
Will
increase
in
proportion
to
volume
increases
3.
Understand
Concepts
Related
to
Job
Costs
a.
The
difference
between
Process
Costing
and
Job
Costing
=
Process
Costing
is
used
when
large
quantities
of
identical
products
are
produces
with
uniform
steps.
~
Job
Costing
is
used
when
unique
custom
order
products
are
produced
such
as
homes,
commercial
buildings,
bridges,
roller
coasters,
and
commercial
aircraft.
b.
Inventory
Flow
(raw
materials
to work
in
process
to
finished
goods)
+
Cost
of
Raw
material
inventory
recorded
in
raw
materials
account
=
Once
productions
starts
their
cost
is
transferred
to
the
work
in
process
inventory
‘account
along
with
costs
from
Direct
Labor,
Manufacturing
Overhead
-
Once
products
are
completed
their
cost
is
transferred
to
the
finished
goods
inventory
account
~
These
items
are
reported
on
the
balance
sheet
Documents
used
in
a
job
cost
system
(production
plan,
of
materials,
raw
materials
record,
job
cost
record,
materials
requisition)
and
how
are
they
used.
=
Production
plan
is
an
electronic
or
written
document
that
identifies
the
types
‘and
quantities
of
products
that
will
be
produced
in
a
particular
period
~
Bill
of
materials
a
comprehensive
list
of
raw
materials,
components
and
assemblies
required
to
build
or
manufacture
a
product
~
Raw
Materials
record
is
a
document
listing
the
type,
quantity
and
cost
of
all
raw
materials
units
received,
used
in
production
and
currently
in
stock.
A
separate
record
is
maintained
for
each
type
of
raw
material
kept
in
stock.
=
Job
cost
record
is
a
document
that
shows
the
cost
of
direct
materials,
direct
labor
‘and
manufacturing
overhead
assigned
to
a
particular
product
or
batch
of
products
-
Material
requisition
is
a
detailed
source
document
that
specifies
the
type
and
quantity
of
materials
that
are
to
be
drawn
from
the
storeroom
and
identifies
the
job
to
which
the
costs
of
materials are
to
be
charged
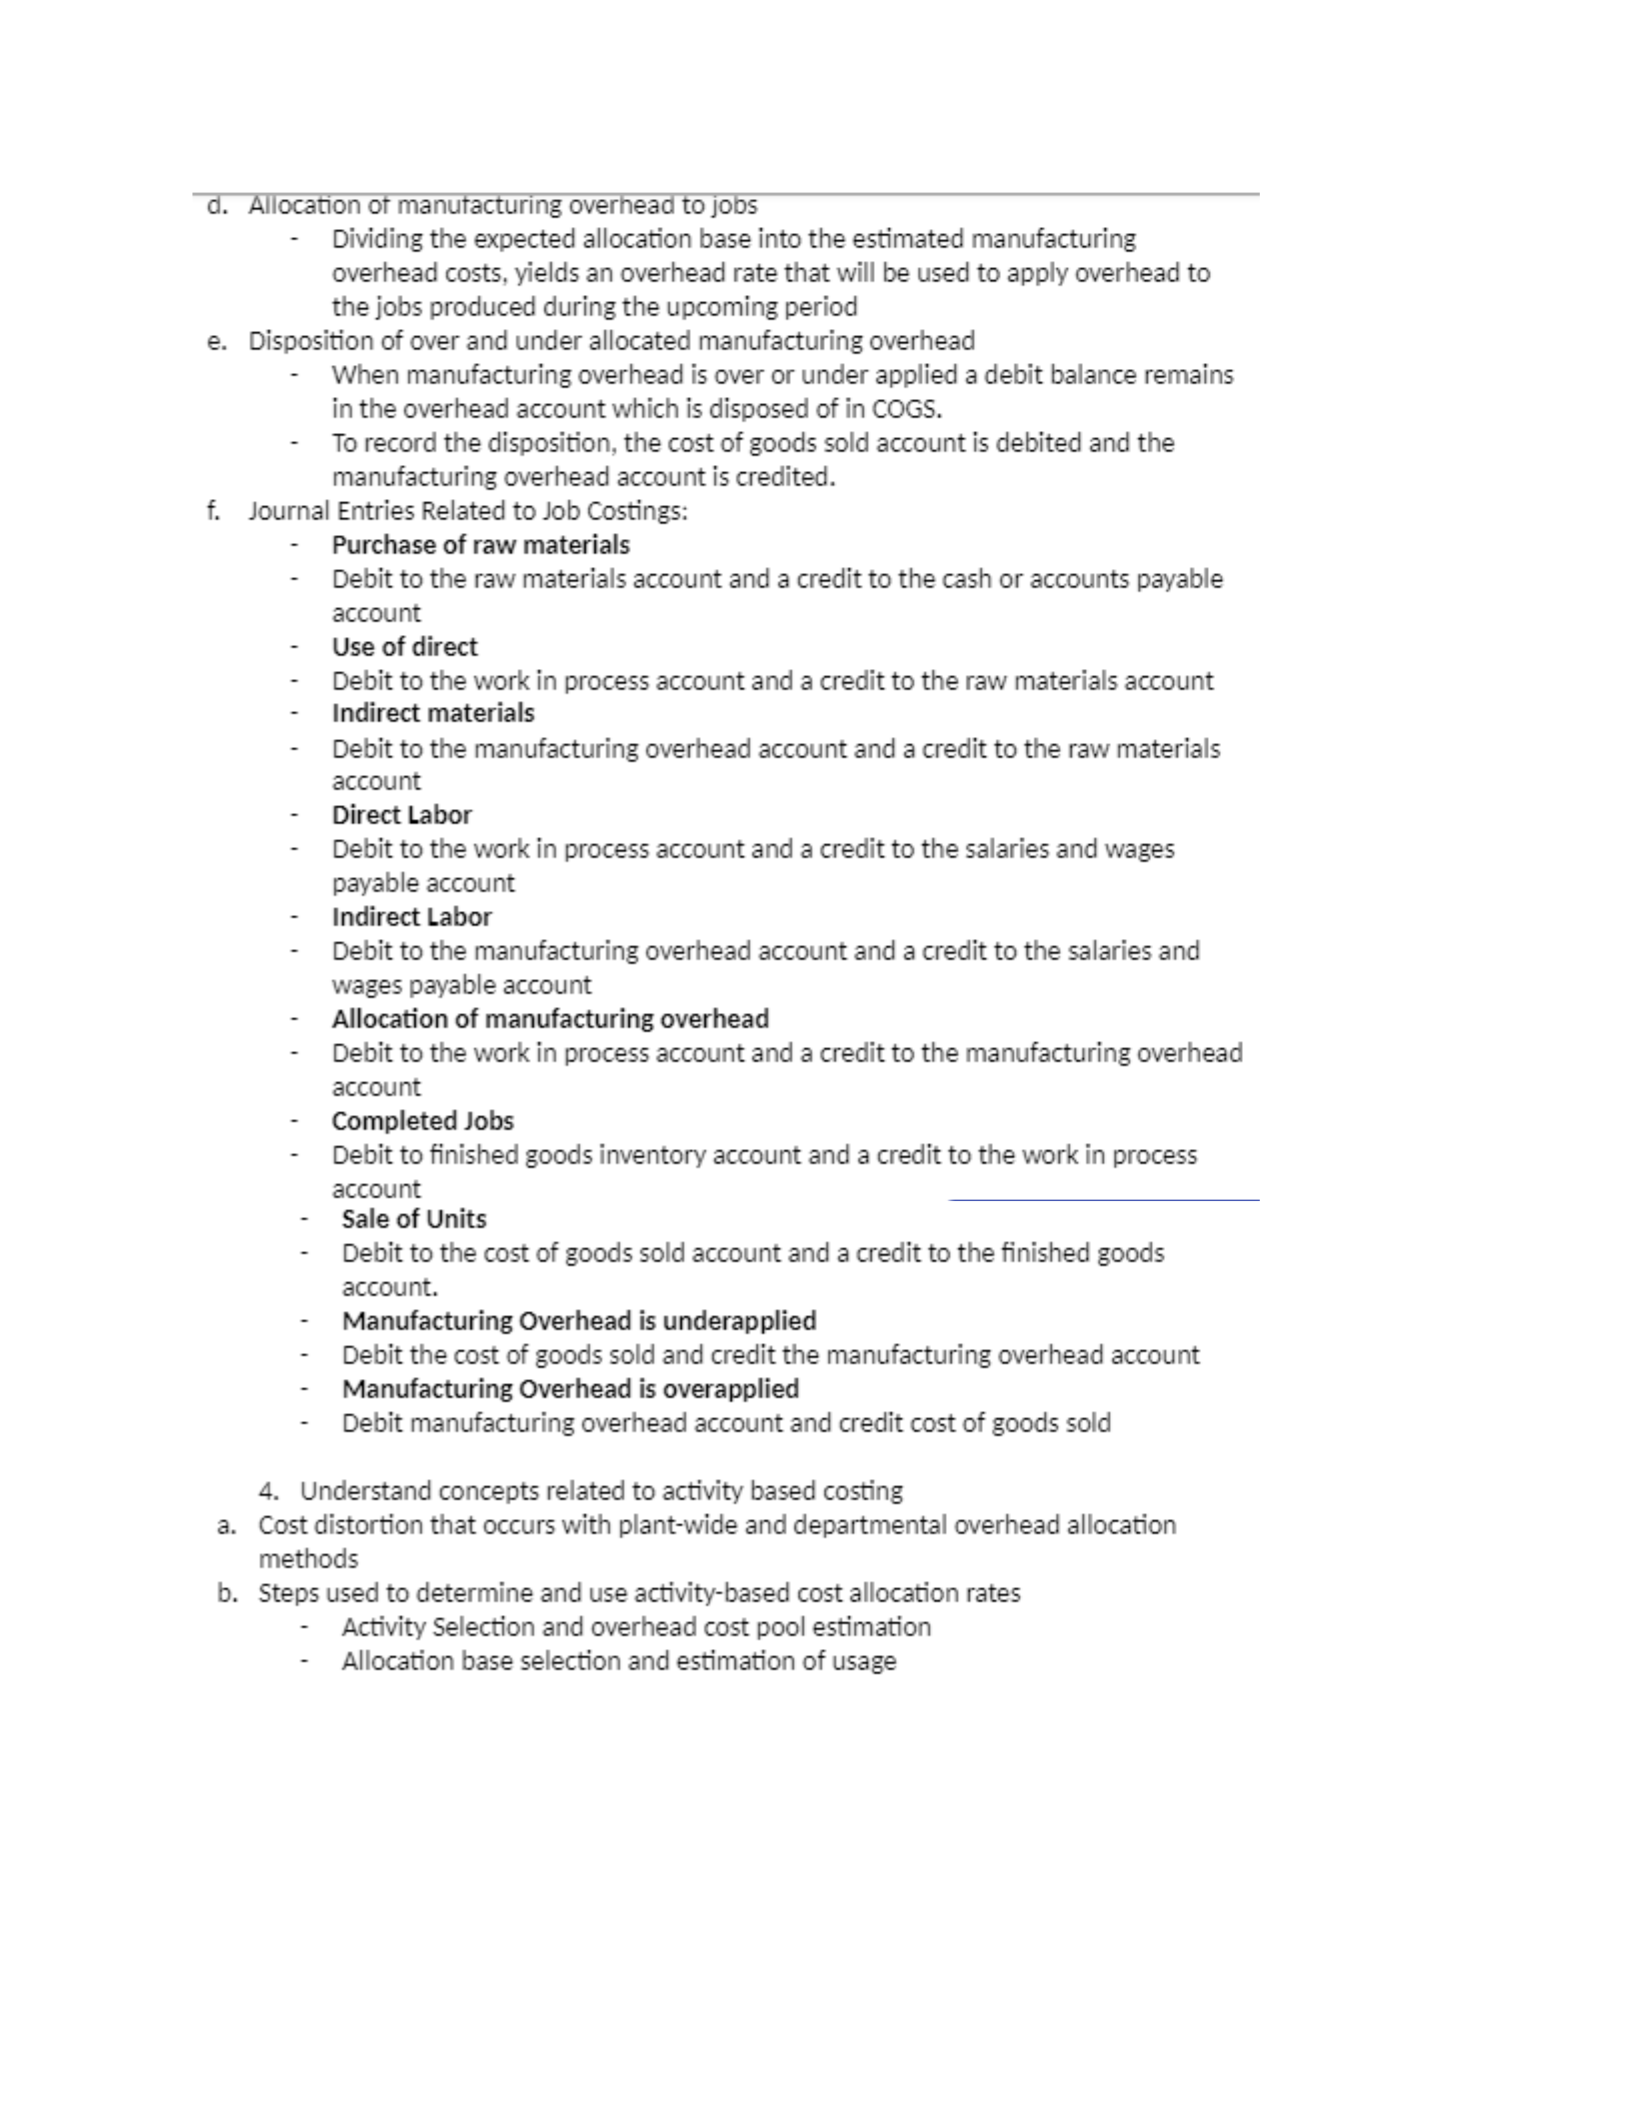
G._Allocation
of
manufacturing
overhead
to
Jobs
ing
the
expected
allocation
base
into
the
estimated
manufacturing
overhead
costs,
yields
an
overhead
rate
that
will
be
used
to
apply
overhead
to
the
jobs
produced
during
the
upcoming
period
.
Disposition
of
over
and
under
allocated
manufacturing
overhead
=
When
manufacturing
overhead
is
over
or
under
applied
a
debit
balance
remains
in
the
overhead
account
which
is
disposed
of
in
COGS.
~
To
record
the
disposition,
the
cost
of
goods
sold
account
is
debited
and
the
manufacturing
overhead
account
is
credited.
Journal
Entries
Related
to
Job
Costings:
=
Purchase
of
raw
materials
=
Debit
to
the
raw
materials
account
and
a
credit
to
the
cash or
accounts
payable
account
~
Use
of
direct
~
Debit
to
the
work
in
process
account
and
a
credit
to
the
raw
materials
account
=
Indirect
materials
~
Debit
to
the
manufacturing
overhead
account
and
a
credit
to
the
raw
materials
account
~
Direct
Labor
~
Debit
to
the
work
in
process
account
and
a
credit
to
the
salaries
and
wages
payable
account
=
Indirect
Labor
~
Debit
to
the
manufacturing
overhead
account
and
a
credit
to
the
salaries
and
wages
payable
account
=
Allocation
of
manufacturing
overhead
~
Debit
to
the
work
in
process
account
and
a
credit
to
the
manufacturing
overhead
‘account
-
Completed
Jobs
=
Debit
to
finished
goods
inventory
account
and
a
credit
to
the
work
in
process
account
=
Sale of
Unit
~
Debit
to
the
cost
of
goods
sold
account
and
a
credit to
the
finished
goods
‘account.
~
Manufacturing
Overhead
is
underapplied
=
Debit
the
cost
of
goods
sold
and
credit
the
manufacturing
overhead
account
-
Manufacturing
Overhead
is
overapplied
~
Debit
manufacturing
overhead
account
and
credit
cost
of
goods
sold
4.
Understand
concepts
related
to
activity
based
costing
3.
Cost
distortion
that
occurs
with
plant-wide
and
departmental
overhead
allocation
methods
b,
Steps
used
to
determine
and
use
activity-based cost
allocation
rates
=
Activity
Selection
and
overhead
cost
pool
estimation
=
Allocation
base
selection
and
estimation
of
usage
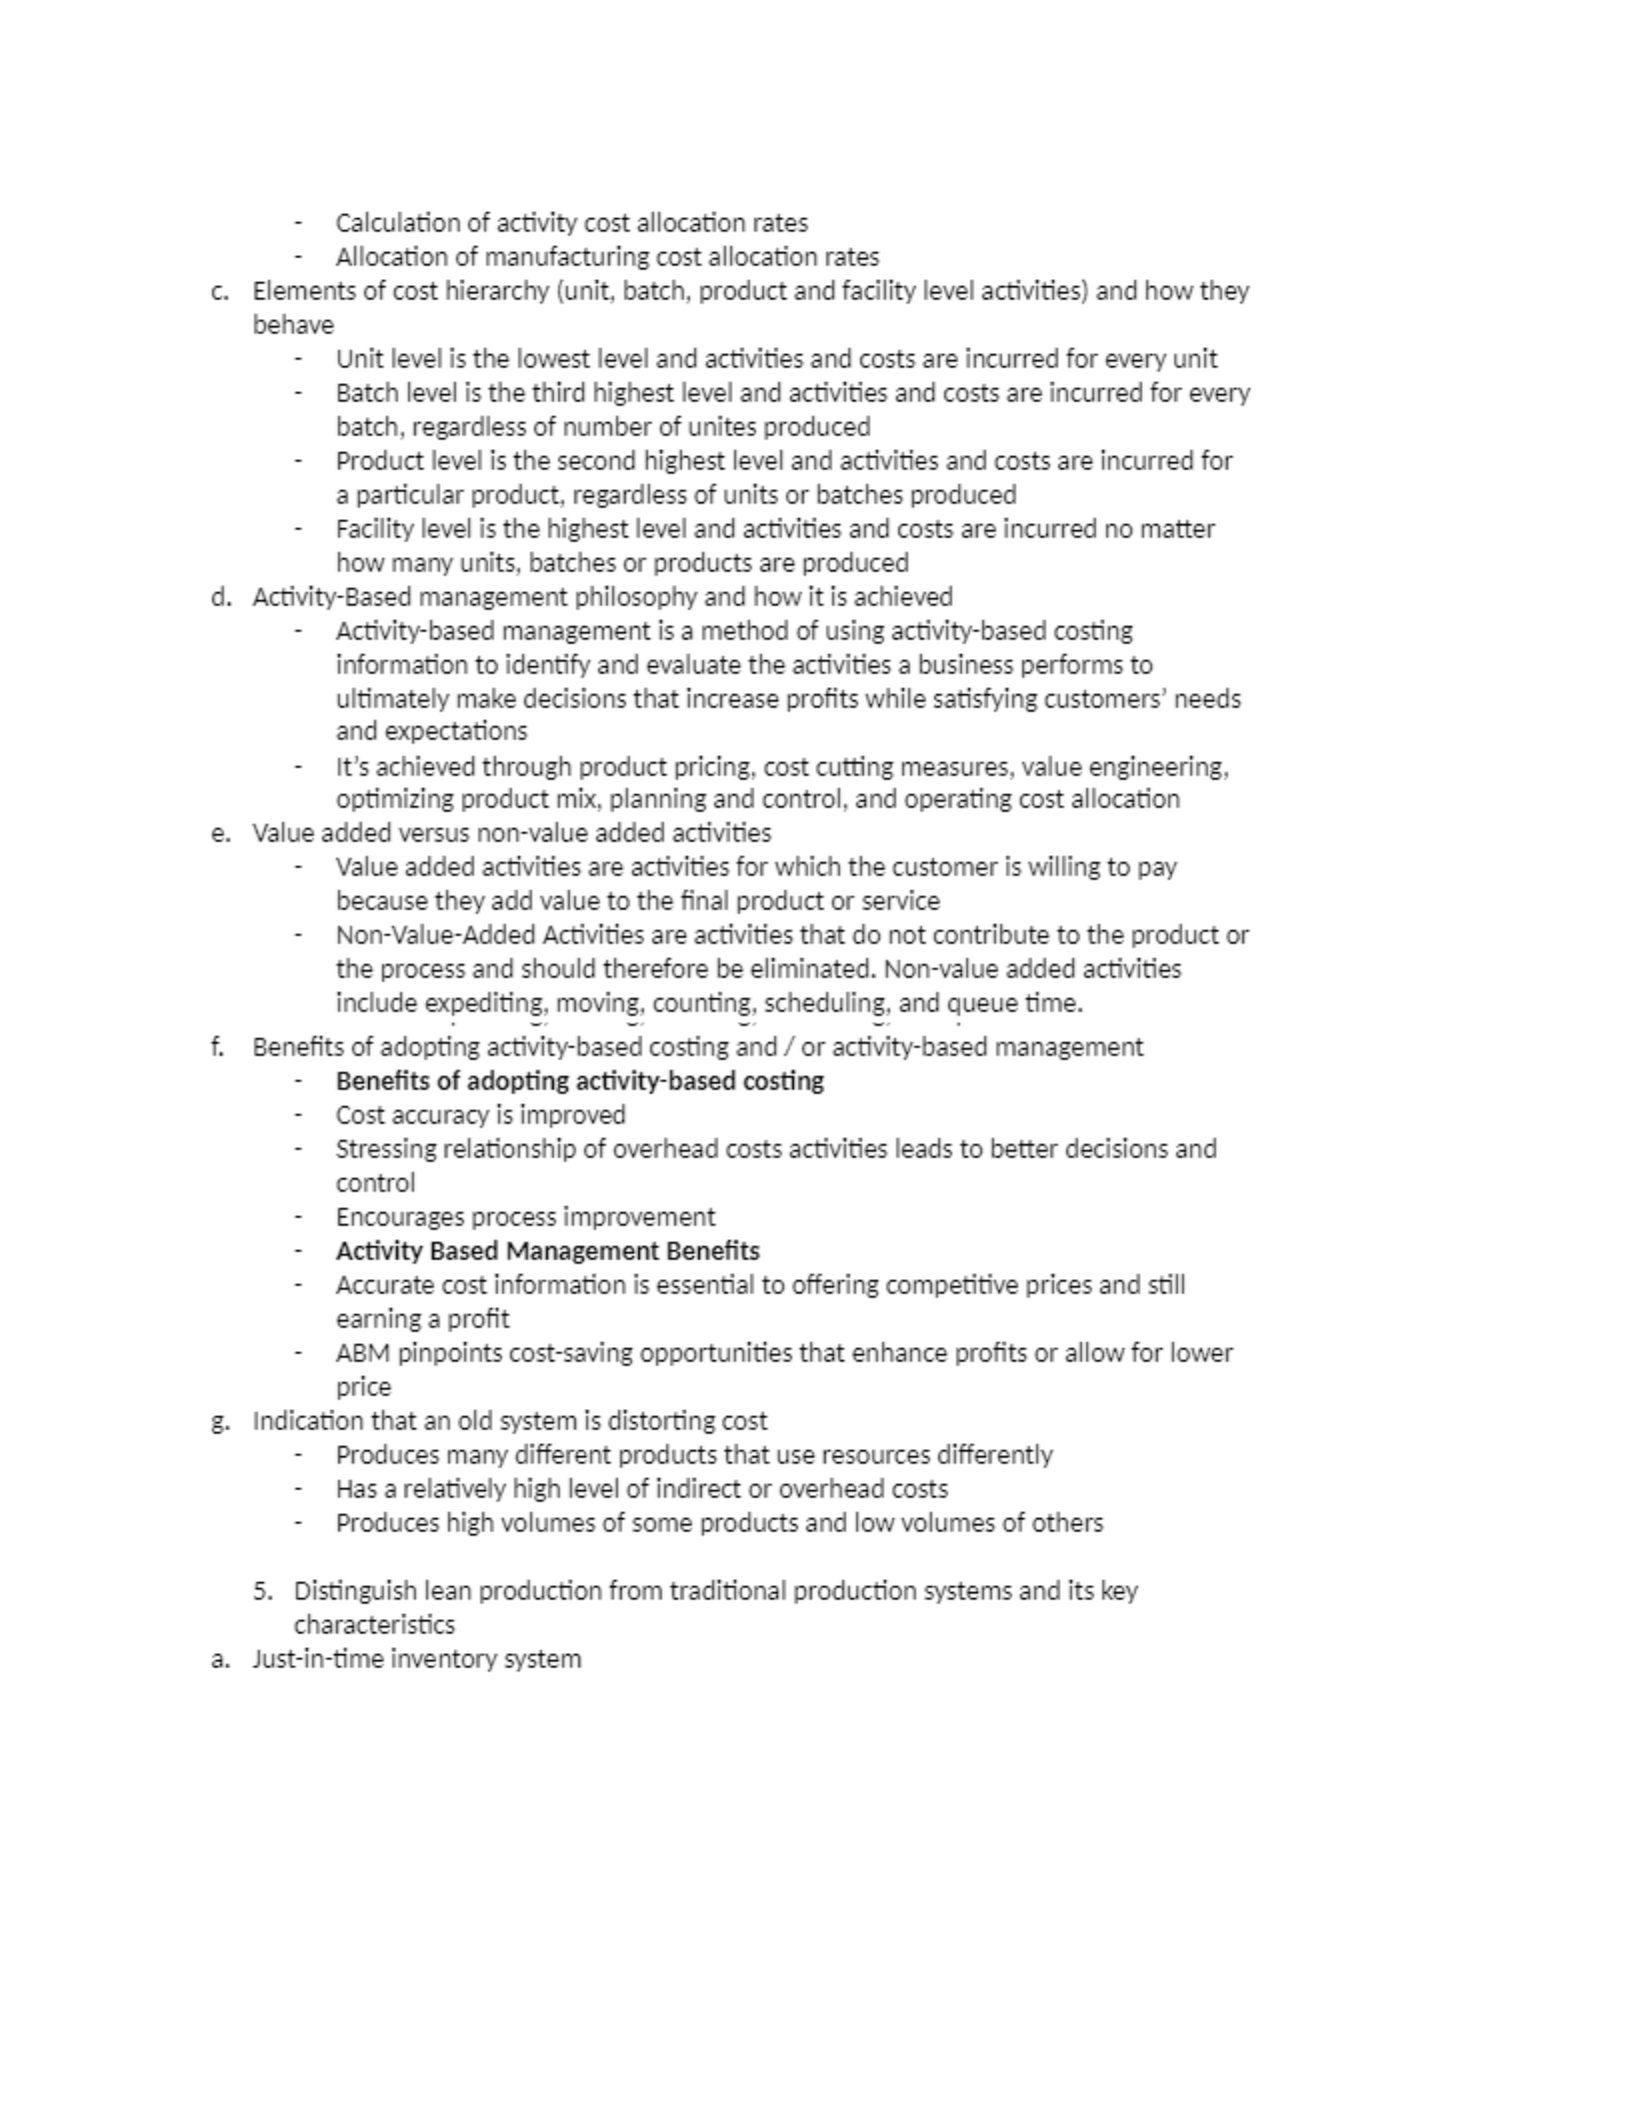
~
Calculation
of
activity
cost
allocation
rates
=
Allocation
of
manufacturing
cost
allocation rates
Elements
of cost
hierarchy
(unit,
batch,
product
and
facility
level
activities)
and
how
they
behave
=
Unit
level
is
the
lowest
level
and
activities
and
costs
are
incurred
for
every
unit
~
Batch
level
the
third
highest
level
and
activities
and
costs
are
incurred
for
every
batch,
regardless
of
number
of
unites
produced
~
Product
level
is
the
second
highest
level
and
activities
and
costs
are
incurred
for
4
particular
product,
regardless
of
units
or
batches
produced
~
Facility
level
is
the
highest
level
and
activities
and
costs
are
incurred
no
matter,
how
many
units,
batches
or
products
are
produced
d._Activity-Based
management
philosophy
and
how
it is
achieved
-
Activity-based
management
is
a
method
of
using
activity-based
costing
information
to
identify
and
evaluate
the
activities
a
business
performs
to
ultimately
make
decisions
that
increase
profits
while
satisfying
customers’
needs
and
expectations
~
It's
achieved
through
product
pricing,
cost
cutting
measures,
value
engineering,
optimizing
product
mix,
planning
and
control,
and
operating
cost
allocation
e.
Value
added
versus
non-value
added
activities
=
Value
added
activities
are
activities
for
which
the
customer
is
willing
to
pay
because
they
add
value
to
the
final
product
or
service
-
_Non-Value-Added
Activities
are
activities
that
do
not
contribute
to
the
product
or
the
process
and
should
therefore
be
eliminated.
Non-value
added
activities
include
expediting,
moving,
counting,
scheduling,
and
queue
time.
f.
Benefits
of
adopting
activity-based
costing
and
/
or
activity-based
management
+
Benefits
of
adopting
activity-based
costing
~
Cost
accuracy
is
improved
~
Stressing
relationship
of
overhead
costs
activities
leads
to
better
decisions
and
control
~
Encourages
process
improvement
-
Activity
Based
Management
Benefits
=
Accurate
cost
information
is
essential
to
offering
competitive
prices
and
still
earning
a
profit
-
ABM
pinpoints
cost-saving
opportunities
that
enhance
profits
or
allow
for
lower
price
Indication
that
an
old
system
is
distorting
cost
~
Produces
many
different
products
that
use
resources
differently
~
Has
a
relatively
high
level
of
indirect
or
overhead
costs
~
Produces
high
volumes
of
some
products
and
law
volumes
of others
5.
Distinguish
lean
production
from
traditional
production
systems
and
its
key
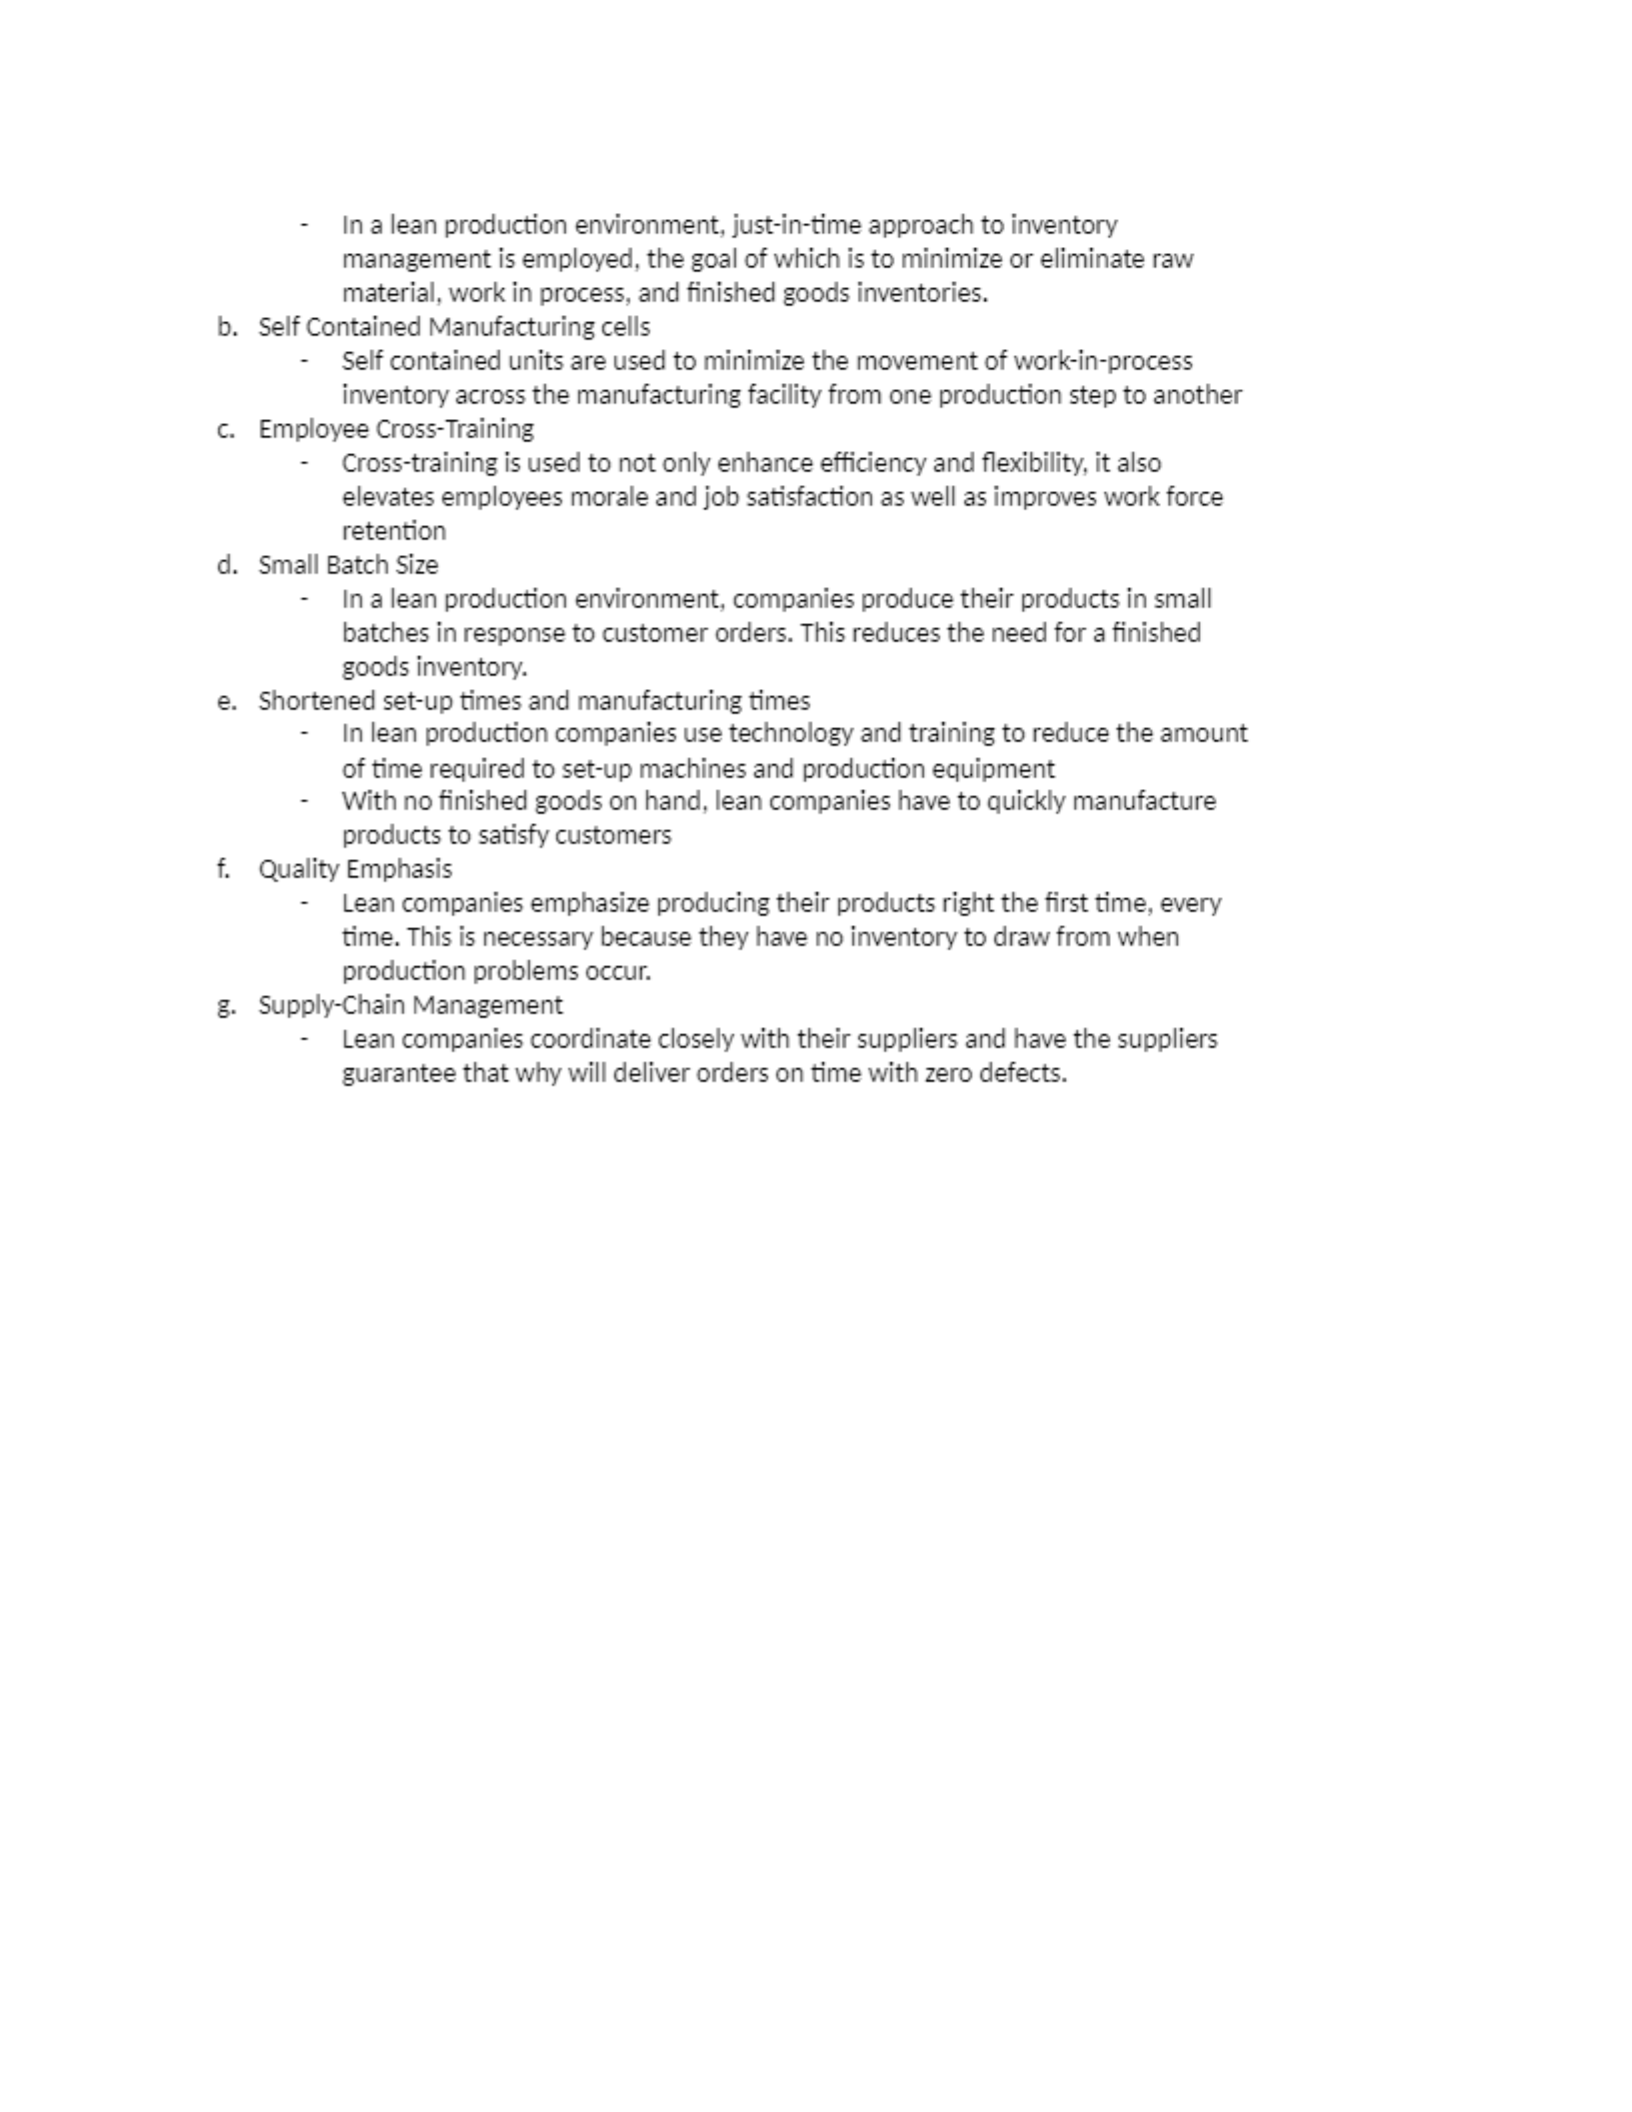
-
Ina
lean
production
environment,
just-in-time
approach
to
inventory
management
is
employed,
the
goal
of
which
is
to
minimize
or
eliminate
raw
material,
work
in
process,
and
finished
goods
inventories.
b. Self
Contained
Manufacturing
cells
=
Self
contained
units
are
used
to
minimize
the
movement
of
work-in-process
inventory
across
the
manufacturing
facility
from
one
production
step
to
another
Employee
Cross-Training
~
Cross-training
is
used
to
not
only
enhance
efficiency
and
flexibility,
it
also
elevates
employees
morale
and
job
satisfaction
as
well as
improves
work
force
retention
.
Small
Batch
Size
~
Ina
lean
production
environment,
companies
produce
their
products
in
small
batches
in
response
to
customer
orders.
This
reduces
the
need
for
a
finished
goods
inventory.
.
Shortened
set-up
times
and
manufacturing
times
=
In
lean
production
companies
use
technology
and
training
to
reduce
the
amount
of
time
required
to
set-up
machines
and
production
equipment
-
With
no
finished
goods
on
hand,
lean
companies
have
to
quickly
manufacture
products
to
satisfy
customers
Quality
Empha:
=
Lean
companies
emphasize
producing
their
products
right
the
first
time,
every
time.
This
necessary
because
they
have no
inventory
to
draw
from
when
production
problems
occur.
Supply-Chain
Management
=
Lean
companies
coordinate
closely
with
their
suppliers
and
have
the
suppliers
guarantee
that
why
will
deliver
orders
on time
with
zero
defects.
a
6.
Understand
concepts
related
to
Total
Quality
Management
(TQM)
Cost
of
quality
categories
(prevention,
appraisal
internal
failure,
external
failure)
+
Prevention
Costs
+
Employee
training
+
Prospective
supplier
screening
+
Upgrading
materials
+
Preventative
maintenance
+
Production
redesign
+
Process
redesign
+
Appraisal
Costs
+
Incoming
material
inspection
+
Inspections
during
production
+
Final
product
inspection
+
Product
testing
+
Cost
of
inspection
equipment.
+
Internal
Failure
Costs
+
Lost
production
due
to
downtime
+
Rework
of
rejected
/
faulty
units
Excessive
quantities
of
scrap
Disposal
of
rejected
units
Machine
breakdowns
External
Fallure
Costs
Lost
profits
from
lost
customers
Warranty
costs
Service
costs
at
customer
sites
Sales
returns
and
allowances
due
to
quality
problems
Product
liability
claims
Cost
of
recalls

