


Class Lecture Notes Module 3 Fundamentals of Economics
Professor Shari Lyman, Ph.D.
This week introduces you to the fundamental issues of economics. c You already know your own
personal concerns and experiences associated with the microeconomic level of being a member
of a household and a member of the labor force, and with the macroeconomic level issues such
as unemployment, interest rates, and inflation. The fundamental objective of this course is to
help you to apply economic concepts, theories, and models in your management decision making
processes.
No study of Economics is complete without acknowledging the Classical Economists. The
Classical Economists were not just economists; they were social philosophers who espoused
social responsibility such as:
1. c Adam Smith and David Ricardo - efficient exchanges.
2. c Reverend Thomas Robert Malthus - efficient resource use and population growth control.
3. c Karl Marx and Fredrick Engels - control and power to the worker.
4. c Sir Alfred Marshall - eliminating poverty.
5. c Robert Thompson - economic, political, and social rights for women.
And, many others.
An understanding an economy of a nation requires you to learn:
1. c Economic reasoning.
2. c Economic terminology.
3. c Economic insights from an economic point of view.
4. c Information about economic institutions.
5. c Information about economic policy options facing society today.
The reasons for studying Economics are many. Before you finish this course, you will have many
of the economic tools necessary to assist you in decision making in your organization. You were
aware of these tools, but perhaps did not know how to apply these tools or to elucidate the
principles to your colleagues or management.
In general, economics is the study of economies. c Economics is the study of the choices people
make to attain their goals, given their scarce resources. Fundamentally, economics is the study
of choice under conditions of scarcity.
Scarcity versus Shortage
Scarcity is the naturally occurring phenomenon that makes resources limited and human wants
unlimited. Due to the existence of scarcity, humans are forced to make choices concerning the
coordination (use and distribution) of available resources.
Do not confuse scarcity with shortage!
Scarcity = naturally occurring phenomenon causing resources to be limited due to the
reproduction cycle of renewable resources and the lack of reproduction of nonrenewable
resources.
Shortage = a market condition in which the quantity demanded is greater than the quantity
supplied, as shown on the Demand and Supply graph.
Categories of Resources
These resources include land, labor, capital (both physical capital and human capital), and
entrepreneurship.

Land = all natural resources, both renewable (examples: water, fish, lumber, sunlight, etc.) and
nonrenewable (examples: coal, copper, oil, etc.)
Labor = the human capital input into the production process. Human capital is the knowledge,
skills, education, talents, and abilities possessed by the individual.
Capital = the physical capital produced in order to produce other products (examples, factories,
plants, tools, machinery, transportation systems, etc.)
Entrepreneurship = the willingness to take risk in the production process and/or market system.
ECONOMIC WAY OF THINKING
Microeconomics is the study of individual units in an economy, i.e., the household and the firm.
With microeconomic analysis, one studies individual decision making concerning consumption,
utility, resource allocation, pricing, and profit. Microeconomics is the study of how households
and firms make choices, how they interact in markets, and how the government attempts to
influence their choices.
Macroeconomics is the study of aggregates in an economy, i.e., price level, employment level,
interest rate, aggregate supply, aggregate demand, monetary system, fiscal policy process, and
international trade. Macroeconomics is the study of the economy as a whole, including topics
such as inflation, unemployment, and economic growth.
In the study of economics, coordination refers to solving the three central problems facing any
economy, i.e., 1) what product and how much of that product to produce; 2) how to produce the
product; and 3) for whom to produce the product.
What, and how much to produce?
How to produce it?
For whom to produce it?
Throughout human history, all nations of the world have attempted to resolve these three
problems for their own population using various economic systems. Examples of some of the
economic systems are: feudalism, mercantilism, capitalism (pure-market system), socialism, and
pure command system.
In a centrally planned economy, the government decides how economic resources and products
will be allocated to answer the questions what to produce, how to produce, and for whom to
produce.
In a market economy, the decisions of households and firms interacting in markets determine how
to allocate economic resources and products in order to answer the questions what to produce,
how to produce, and for whom to produce.
In a mixed economy, most economic decisions result from the interaction of buyers and sellers
in markets, but the government plays a significant role in the allocation of resources.
Economic analysis involves two key components: (1) economic methodology - school of thought
(world view); and, (2) economic methods - models, assumptions, theory.
Methodology is a world view, a school of thought, the fundamental way of looking at the world
in which one exists. Many methodologies exist in the discipline of economics. Some are:
Neoclassical, Keynesian, Post-Keynesian, Marxian, Evolutionary, Behavioralist, Feminist-Marxian,
Austrian, etc.
Models are abstract representations of reality, just like a map of Nevada is not really Nevada,
but an abstract representation of the real geographic area known as Nevada.
Assumptions are ideas that are believed to exist or occur under specific given constraints or
conditions. c The given constraints are the exogenous variables.
Ceteris Paribus is the Latin term used by economists to state that the assumptions are given -
All else equal. This is the requirement that when analyzing the relationship between two
variables - such as price and quantity demanded - other variables must be held constant.
Exogenous variables exist outside the given economic system, but influence the given economic
system, such as the weather, environmental regulation, military policies, etc.
Endogenous variables exist inside the given economic system, and can influence other
endogenous variables, and are influenced by other endogenous variables.
Theories are predictions of human and economic behavior that have been developed by
observing changes in variables in an economic system, based on specific assumptions of human
and economic behavior.
In general, economic analysis consists of four steps:
1. c Characterize the market system.
2. c Identify goals and constraints in that system.
3. c Find the equilibrium of the system.
4. c Determine what happens when a variable or variables change.
Opportunity Cost
Take a moment and think what would you be doing if you were not taking this class?
Your opportunity cost is the value of your next best option sacrificed when taking action during
the decision making process. Opportunity cost is the highest valued alternative that must be
given up to engage in an activity. Therefore, what you would be doing if you were not in this
class, is considered your opportunity cost of taking this course.
*Remember, opportunity cost is the next best option you have that you must sacrifice in order to
have your best (optimum) option.
Circular Flow Model
The simplified version of the circular flow model demonstrates the relationship between the two
markets (product market and resource market), the two flows (money flow and real flow of goods
& services and resources), and the two agents (households and firms).
In the simplified circular flow model, the assumption is that households own all resources and
supply them to the firms through the resource market. The firms produce all the products (goods
and services) and supply them to the households in the product market. As a result, the firms
demand resources and the households demand products.
The real flow is the flow of goods & services and resources. The money flow is the rent, wages,
interest, and profit that flow from the firm to the household through the resource market. Also,
the money flow includes the revenues earned by firms as households spend their income as they
budget for consumption of goods and services.
Circular Flow Model
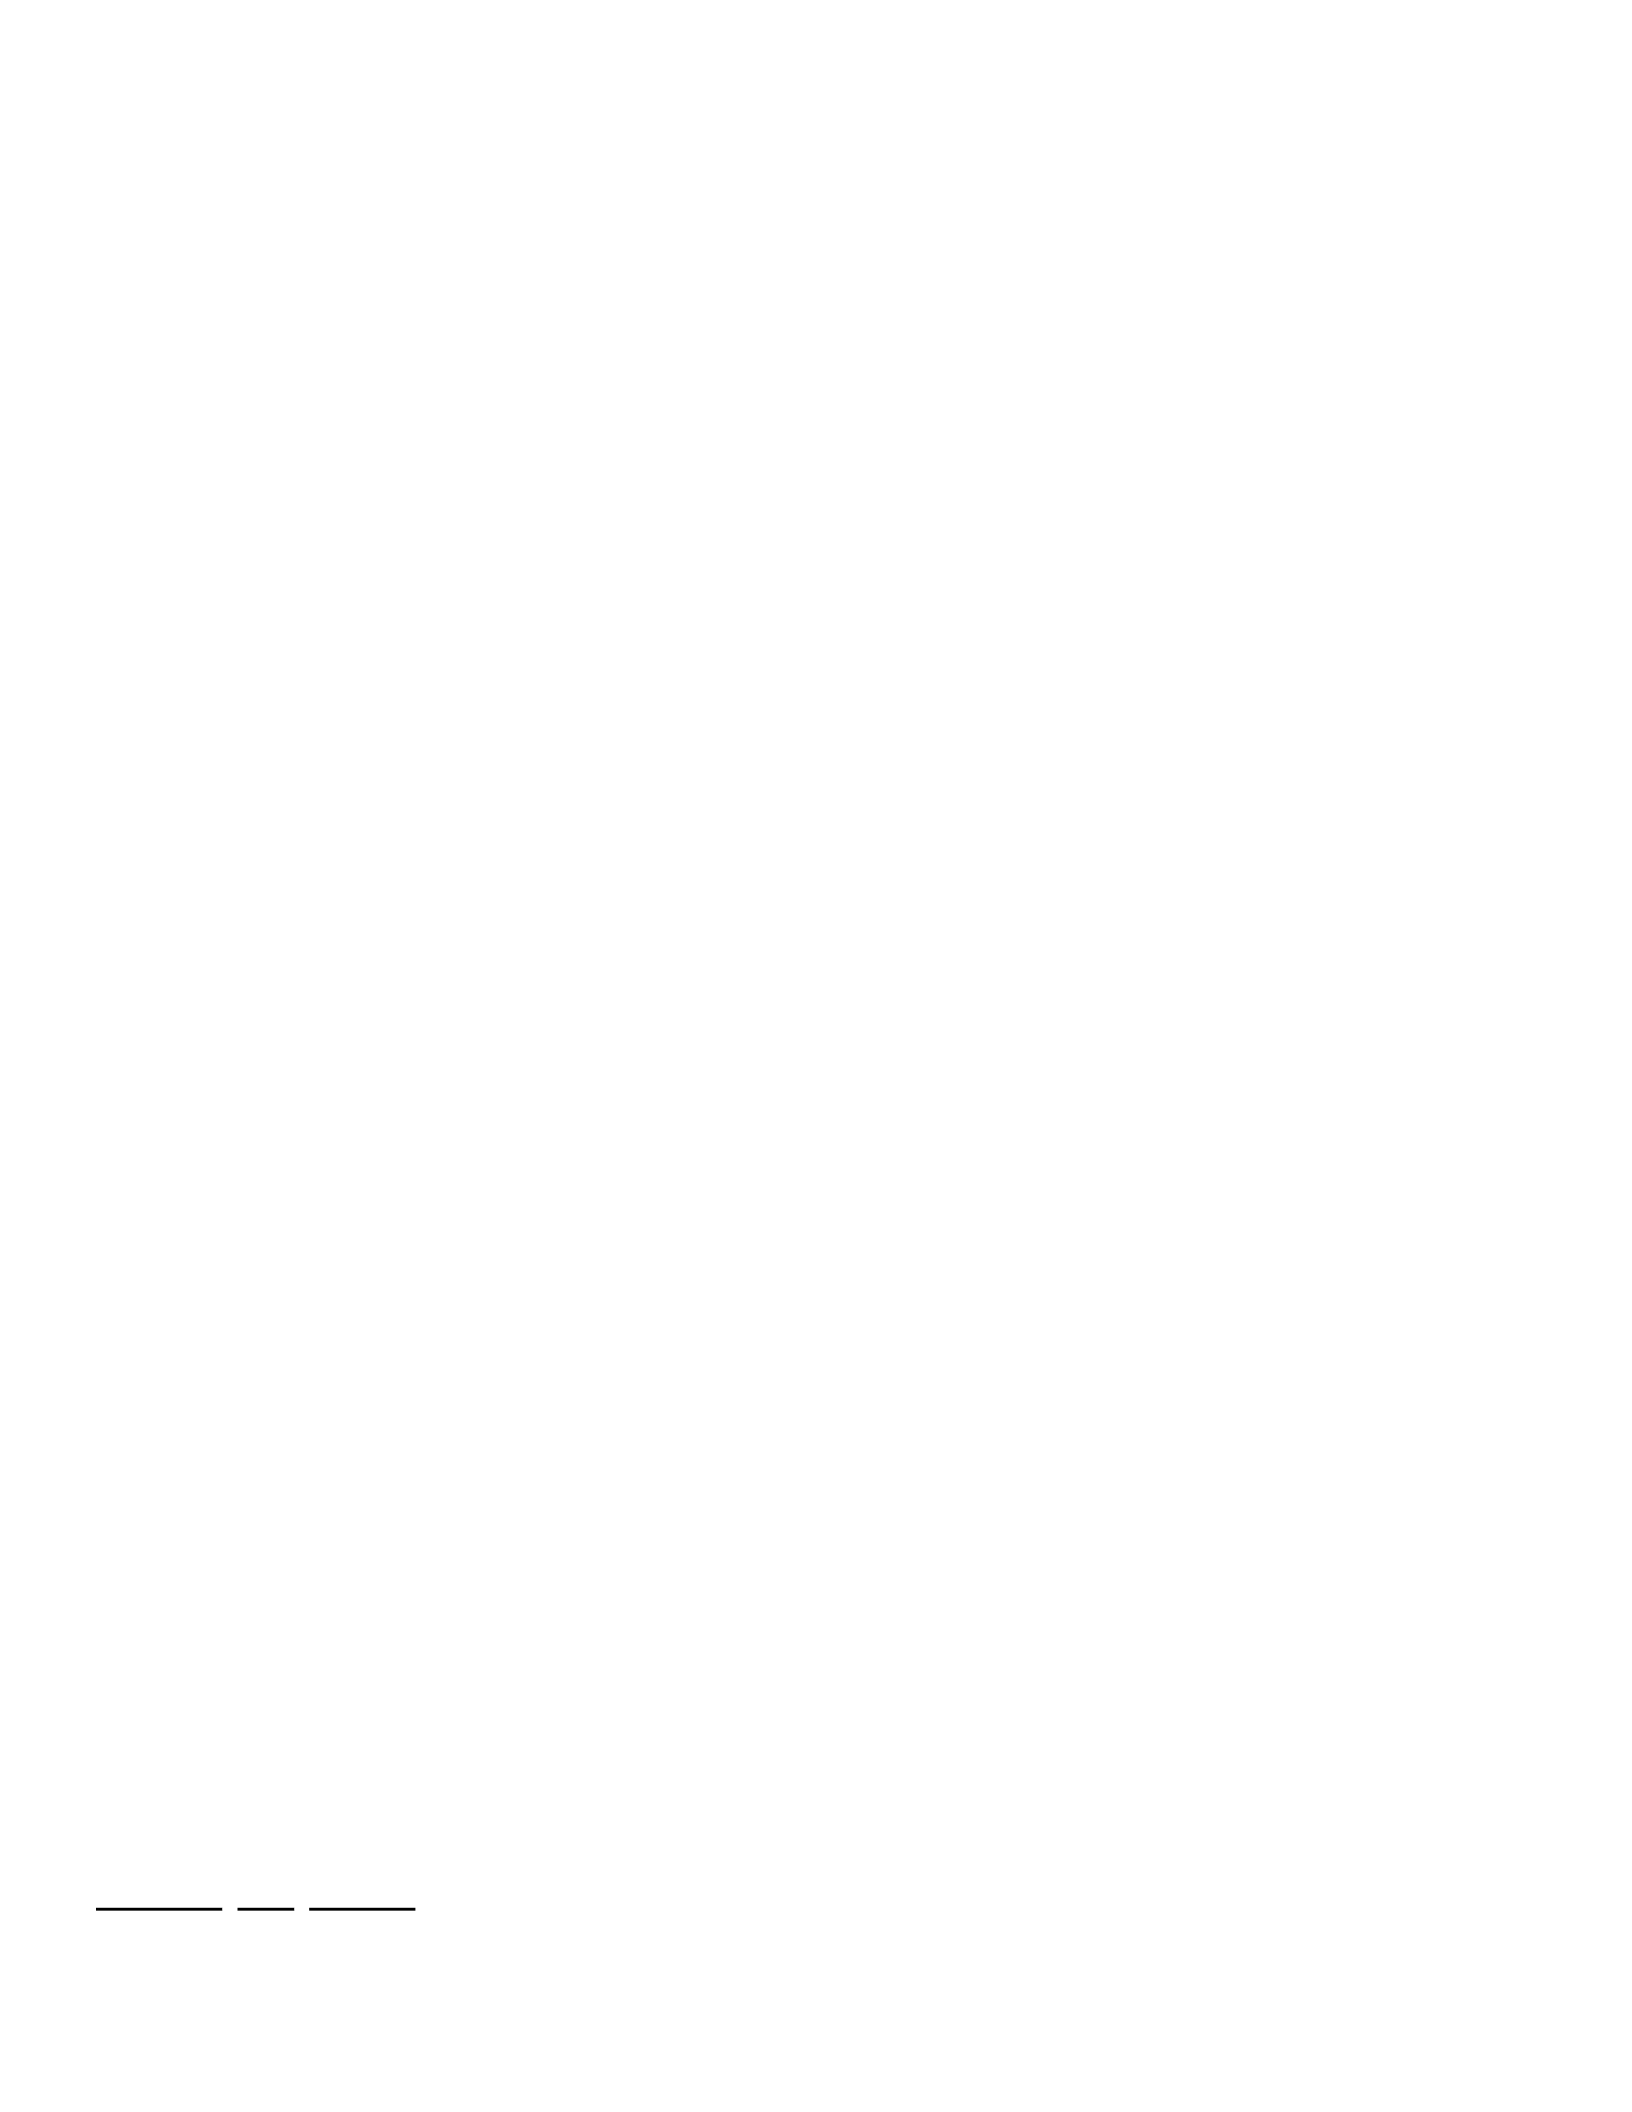
The Circular Flow model above presents a simple economy with 2 agents: households and
firms; 2 markets: Goods and Services market and Factor market; and, 2 flows: the real flow of
resources and produces and the money flow of household income and expenditures, as well as
firm revenue and cost. c
Production Possibilities Frontier Model (PPF)
Firms make choices concerning every aspect of operation, and with every choice, the firm has
an opportunity cost. c Depending on the resource, time, and technology constraints, a firm may
face a constant opportunity cost or an increasing opportunity cost. c Using a production
possibilities frontier (PPF), one can demonstrate the difference between a constant opportunity
cost and an increasing opportunity cost. c Economists use the PPF as a numerical measure for
opportunity cost.
On the PPF graph, if the curve is a straight, downward (negative) sloping line with a constant
slope, then there is a constant trade-off between the two choices. This indicates that the
resources and technology can easily switch production from one product to the other product
without a great deal of retraining, retooling, or restructuring in the production process.
However, many production processes involve an increasing opportunity cost due to the changes
that must take place in the production process to change from producing one product to
producing another product. c In this case, the PPF shows a curve that is bowed out. The bowed
out curve indicates that for every additional unit of one good that is produced additional units of
the other good are sacrificed, and the same for the production of the other good.
Fortunately, in the United States, most of us still have the opportunity to make choices in our
economic decisions. However, every choice has a cost and a benefit. The economic decision
rule is simple: If the relevant benefits of doing something exceed the relevant costs, then the
economic agent will do it. c If the relevant costs of doing something exceed the relevant benefits,
then the economic agent will not do it (Colander, 1998). This is considered a marginal analysis
in which an individual household or firm compares the marginal benefit (marginal revenue) to the
marginal cost. Marginal meaning the additional benefit or cost incurred by consuming or
producing the one additional unit.
The rule is simple, but applying it may not be. For example, what are the expected marginal
(incremental or additional) costs or benefits incurred with your decision? Economists describe the
additional cost to you over and above the costs you have already incurred a marginal cost, and
the additional benefit above what you have derived, a marginal benefit.
So you ask, how does this apply to me? You have to make choices - One or the Other. To
assist you in making this choice, economists have devised a concept called opportunity cost.
The opportunity cost of undertaking an activity is the benefit forgone by undertaking that activity.
When you make the choice, you give up the next best alternative. And remember, opportunity
cost is subjective in that only the economic agent can select the most attractive alternative for
themselves. Thus, when you made the choice of taking this course, you were utilizing opportunity
cost. Would you have chosen to take the funds and go on a trip with your spouse or a friend
instead of this class - that would be your next best alternative.
Demand and Supply Model and Government Intervention
Demand and Supply
Whether an individual or a nation is making a choice to purchase a product or do something,
we make these choices based upon a want or need. c How badly we want or need something

determine what choices we make. c This decision is part of what economists call supply and
demand.
Demand
The definition of demand involves two distinct, but related expressions: demand and quantity
demanded.
a. Demand (market demand) is the amount of goods and services consumers are willing and
able to purchase at all price levels during a specific time period.
b. Quantity demanded is the amount of goods and services consumers are willing and able to
purchase at a specific price during a specific time period.
c. The law of demand incorporates the notion of demand and quantity demanded in describing
human behavior. c The law of demand states that: as the price of a good increases, ceteris
paribus, the quantity demanded decreases; and as the price of a good decreases, ceteris
paribus, the quantity demanded increases. c Therefore, changes in quantity demanded are due
to changes in price, and are reflected as movements along the demand curve.
d. A change in demand is due to a change in a variable other than price, ceteris paribus, and
is reflected as a shift in the demand curve. c Variables that may cause a change in demand are:
income changes; wealth changes; population changes; expectation changes; taste and
preference changes, etc.
e. The relationship between demand and income is obvious when discussing the different types
of goods.
Normal Good
A good is defined as a normal good in the case where income increases causes an increase in
the demand for that good, ceteris paribus; and in the case where income decreases causes a
decrease in the demand for that good, ceteris paribus.
Inferior Good
A good is defined as an inferior good in the case where income increases causes a decrease
in the demand for that good, ceteris paribus; and in the case where income decreases causes
an increase in the demand for that good, ceteris paribus.
Giffen Good
A Giffen Good is a good that does not obey the Law of Demand. c A Giffen good’s demand
increases as price increases due to the fact that the Giffen good is ultra-necessary for basic
survival. c Without the good, the consumer dies.
Professor Giffen discovered that, in Ireland, from 1845 to 1850 during the potato famine, the
price of potatoes increased as the supply of potatoes decreased. c During this same time period,
the demand for potatoes increased.
Professor Giffen found that potatoes were used for every meal. c However, for one meal a week
– usually for the Sunday midday dinner, the families would include a piece of lamb, fish, or
other protein to supplement the meal. c However, when the price of potatoes increased, the
meat had to be foregone and more potatoes were used to make a full meal.
Later studies using Professor Giffen’s work, found that similar situations occurred during rice
famines in China and sorghum famines in African nations. c When a good is an ultra-necessary
good, then it will have an upward sloping demand curve.
Supply
Supply is a more complicated function that demand is. c Supply consists of the production of the
product and how that product might be part of a finished product that becomes a usable good
has to be considered. c However, like the definition of demand, the definition of supply involves
two distinct, but related expressions: supply and quantity supplied.
a. Supply is the amount of goods and services firms are willing and able to provide to the
market at all price levels during a specific time period.
b. Quantity supplied is the amount of goods and services firms are willing and able to provide
to the market at a specific price during a specific time period.
c. Like the law of demand, the law of supply incorporates the notion of supply and quantity
supplied in describing human behavior. c The law of supply states that: as the price of a good
increases, ceteris paribus, the quantity supplied increases; and as the price of a good
decreases, ceteris paribus, the quantity supplied decreases. c Therefore, changes in quantity
supplied are due to changes in price, and are reflected as movements along the supply curve.
d. A change in supply is due to a change in a variable other than price, ceteris paribus, and is
reflected as a shift in the supply curve. c Variables that may cause a change in supply are: price
and/or quantity available of input changes; firm’s expectations changes; price and/or availability
of substitute and/or complementary goods changes; technology changes; production capacity
changes; etc.
By examining supply and demand together, it is possible to calculate with mathematical
equations and demonstrate with graphs the price and quantity at which the market is in
equilibrium, excess demand, or excess supply. c Also, one is able to examine the effects of
shifts (changes) in demand and/or supply, changes in quantity demanded and/or quantity
supplied, changes in equilibrium, and the points of disequilibrium.
Change in Quantity Demanded verses Change in Demand
Change in Quantity Demanded = Movement along the demand curve.
Caused by a change in the market price of the product.
Change in Demand = A shift in the demand curve, either to the left or right.
Change in Quantity Supplied verses Change in Supply
Change in Quantity Supplied = Movement along the supply curve.
Caused by a change in the market price of the product.
Change in Supply = A shift in the supply curve, either to the left or right.
Government Intervention
Price Controls - artificial price settings set by the government to control the market demand
and supply. Price controls include, but are not limited to price ceilings, price floors, etc. c Price
controls tend to result in the formation of underground, illegal markets to accommodate the
demand and supply not accommodated in the market.
Price Ceiling - a legal maximum price for which a seller can sell their good or service.
If the price ceiling is below the equilibrium price, then a shortage will most likely occur. Then,
an underground, illegal market will form to accommodate buyers willing to take the risk and pay
a higher price.
Price Floor - a legal minimum price for which a seller can sell their good or service.
If the price floor is above the equilibrium price, then a surplus will most likely occur. c Then, an
underground, illegal market will form to accommodate buyers willing to take the risk and pay a
lower price.

