


Strategic Financial Management: The Link Between Valuation and Financial Decisions
FIN 7014 - Financial Management
University of Cincinnati

Introduction
Valuation is an important concept in finance. Studies on this subject have contributed to the
existing knowledge on financial decisions in different firms. Valuation approaches are deeply
rooted in literature where many researches and theories have been formulated to address the
same topic. The relationship between the capital structure of an organisation and its value has
also been a subject of many studies over the past years. As the paper will confirm, several
researchers have suggested the possibility of little, if any, the impact of capital structure on a
firm’s value in a perfect market.
However, most researchers confirm that financial position and decision-making processes in a
firm affect its valuation. Taxes, asymmetric information, and agency costs are some of the
imperfections that exist in contemporary business environments. These imperfections maintain
a constant relationship between valuation and capital structure in a firm. The association
between this assessment and financial decisions in organisations dictates some of the business
interventions in the present-day business environment. This paper examines the link between
valuation and financial decisions in businesses. The aim is to evaluate whether there is any
relationship between the two aspects.
Valuation
The valuation of any organisation allows future decision-making to ensure that it is operating
as per the expectations. Different methods are used in valuation, including those that are
supported by theories and contemporary methods. The present models that are deployed in the
evaluation process are a product of extensive research, with many researchers describing them
before their application in management and finance. What are the motives of company
valuation? Different schools of thought exist as to why company valuation is important.
One of the motives for the evaluations of a company is to make decisions in the organisation.
Depending on the decision that is reached after valuation, the involved individuals may decide
on the future of the organisation and the interventions for the areas that are found faulty.
Motives in company valuation may be characterised in different ways, including decision-
dependent and decision-independent motives (Ishakian, Knebusch & Rowen 2013). The other
category of motives is the transaction based vs the non-transaction-based motives (Ishakian,
Knebusch & Rowen 2013). The other class of motives, as described throughout the literature

on valuation, is the dominated vs the non-dominated decision (Ishakian, Knebusch & Rowen
2013).
Valuation serves different functions depending on the concerned firm or organisation. These
functions can be categorised further into minor and major functions. The main functions of
valuation in organisations include decision-making and consultation. According to Ishakian,
Knebusch, and Rowen (2013), managers and other stakeholders use valuation information in
an organisation to make decisions on the future of the organisation with the aim of improving
the organisational performance. Different firms operate on different grounds. They use
different methods of valuation to make financial and other forms of decisions in the
organisation.
The other function of valuation, according to Koziol (2014), is mediation where the firm uses
information from valuation to mediate between concepts, decisions, and individuals.
Hundsdoerfer, Kruschwitz, and Loren (2008) assert that mediation in an organisation provides
crucial information on the financial position of the organisation. Valuation also serves as a
means of argumentation. Using information from valuation, managers and other organisational
stakeholders can argue on the position of the organisation. The information is used to provide
details on the organisational performance, which is important in making a case for any
argument.
Apart from the main functions of valuation, valuation serves other auxiliary functions. One of
these auxiliary functions is information where the parties within an organisation gather
information on this organisation, including its performance and future expectations. Valuation
may also be used as a means of tax measurement where authorities determine the tax that an
organisation should forward over a given period. Many organisations where valuation has been
conducted were found to have some tax measurements, not in line with the expected values
(Mian & Velez-Pareja 2007). Valuation also serves the function of contract configuration where
employees and other parties in the organisation can have their contracts configured with the
expectations of the organisation.
Valuation Methods
Different valuation methods are in use in many organisations. Each of these methods provides
different results. The decision to use one of them is dependent on the firm that is being
evaluated, the financial methods in place, and the preferred approach. The most popular
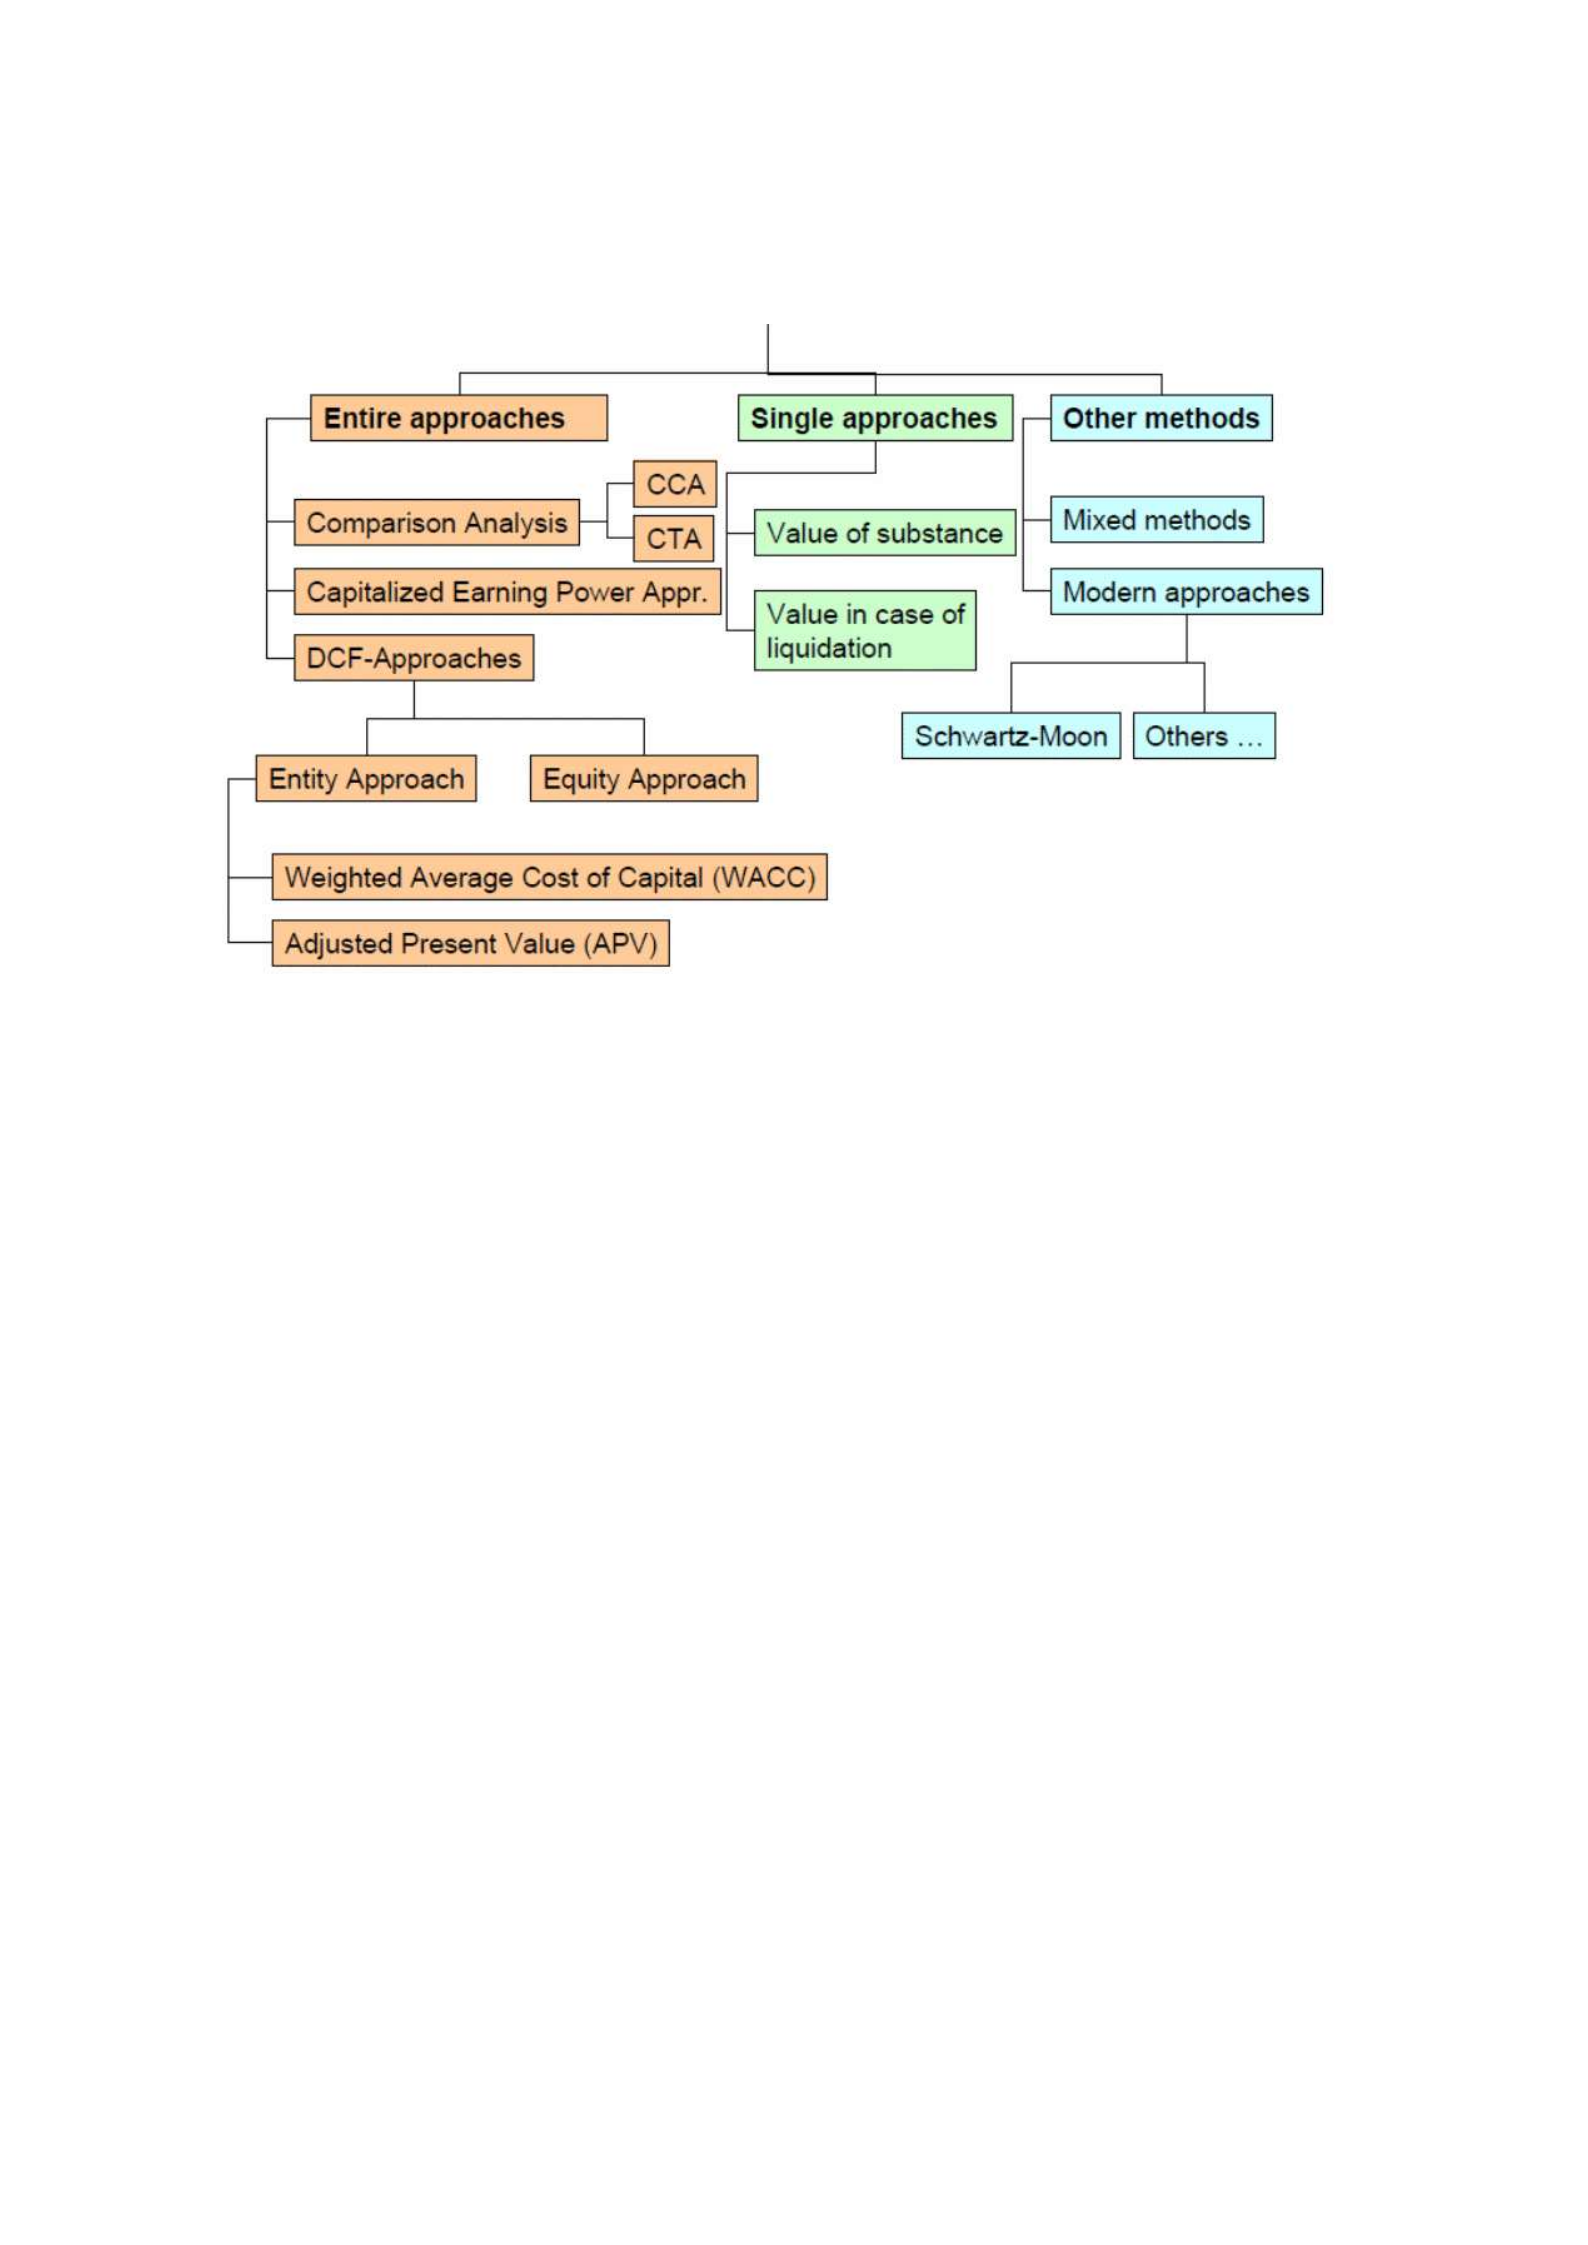
approach depends on the organisation and the region where these organisations exist. Different
methods that are used in valuation are shown below.
Figure 1: An Overview of Valuation Methods (Source Mian & Velez-Pareja 2007)
Different models that are applied during a valuation in organisations lead to a common result
where the organisations are able to plan for future decisions and changes. The valuation that is
obtained in organisations, irrespective of the method used, provides crucial information on the
financial status of the organisation. However, valuation within organisations also allows the
inception of changes whenever they are needed.
Financial Decisions
Organisations face challenges in financing, with one of the most common of them being the
outcomes of financial decisions. Competitiveness in organisations is influenced by the financial
decisions that managers and other stakeholders make. In any industry, financial decisions affect
the outcomes of the interactions between different factors. The financial decisions in an
organisation are also under the influence of other factors such as the valuation in these
organisations. A business in any industry or market must use capital as one of the main factors
in its operations, with this strategy bringing about the cost of capital.
Currently, there are no perfect markets in contemporary organisations. Hence, capital is not
always put to the intended use. A perfect business environment is the only place where capital
can be put to its planned use. However, conditions that are necessary for a perfect market are

hard to achieve. Nevertheless, if it were possible, the perfect world would have an excess
supply of capital. A perfect capital market might mean that the available unlimited capital is
only dependent on the risk of the project being undertaken (Spiegel, & Tookes 2013).
Aside from the perfect capital market, uncertainties, variables, and friction characterise the
existing real-world capital markets. The availability of tax as one of the variables in an
imperfect world ensures that organisations adopt strategies such as debts. An example of such
strategies is when an organisation operates in a capital structure with about 100% of debt
because of the positive corporate tax rate (Spiegel, & Tookes, 2013). Other factors that exist in
an imperfect world to introduce a relationship between valuations and financing include agency
costs, financial distress costs, and information asymmetries (Spiegel, & Tookes, 2013).
The financial position of an organisation ensures that the organisation can persist in an
environment where competition is an evident factor. Valuation effects that financial position of
an organisation. The reverse is also true. The decisions made in an organisation relating to the
financial positions of the organisation may be based on the valuation that is provided for this
organisation.
Weighted Average Cost of Capital
The calculation of the cost of capital is an intricate process that requires the participation of all
stakeholders. The cost of capital is calculated through the estimation of the proportion of debt
that a project consumes against the equity that is absorbed in the respective project (Massari,
Roncaglio & Zanetti 2008). The weighted average cost of capital (WACC) is calculated through
a formula that incorporates the market value of equity and debt (Massari, Roncaglio & Zanetti
2008). These values are adjusted using the costs of debt and equity. For a single firm, the
WACC is calculated as a single unit where the firm is the reference. The organisation, in this
case, is considered a single unit, with the results being for a single project.
The Weighted Average Cost of Capital is an indicator of the financial performance of an
organisation because it indicates the financial position of the organisation under discussion.
Any organisation with sound financial decisions has a favourable WACC, which is considered
a strength in these organisations. The calculation and use of WACC in financial discussions
and problem-solving is challenging for some financial analysts and other financial decision-
makers in organisations. Therefore, it is important to have a discussion on the correct use of
WACC and its implications on the financial decisions in organisations.

The other difficulty in the calculation and use of WACC is tax calculation. Different finance
officers use different methods of calculating the variables (Sabalı 2009). Financing and
investment decisions interact through taxes. WACC is an important concept in evaluating this
interaction. The formula that is used in the calculation of WACC refers to the organisation of
company as a whole upon incorporating the different aspects in financial decisions in the firm.
Therefore, this formula is effective for the “average project” where the right discount rate is
produced (Massari, Roncaglio & Zanetti 2008). Hence, the formula is incorrect when used in
the calculation of WACC for the safer and riskier projects (Magni 2012). The inaccuracy while
using this formula mainly stems from the different sections that individuals calculate in an
organisation, especially where the organisation has different departments.
Capital Structure and Valuations
Capital structure in a firm is a factor that affects valuations in these organisations. The effects
depend on the existing capital structure. According to Sabalı (2009), financing decisions
typically affect value within organisations. Some of the ways that boost value in a firm with
respect to its financing decisions is through the adjustment of the discount rate and the present
value (Massari, Roncaglio & Zanetti 2008).
The discount rate in most organisations is typically adjusted downwards, with the aim being to
account for the existing tax shields (Massari, Roncaglio & Zanetti 2008). Financing decisions
also affect value in organisations through adjusting the present value in these organisations
(Massari, Roncaglio & Zanetti 2008). According to Spiegel and Tookes (2013), the base case
is first calculated with the assumption that it is all equity financed.
Capital structure in organisations affects the value of the organisation from its first year of
operation. The capital structure in organisations is variable depending on several factors such
as the capital debt and the type of industry within which a firm is located. The tax on a firm is
a major factor with reference to its capital value, especially because the tax determines the debt
status of an organisation (Sabalı 2009).
The initial cash that is invested into a firm in the first year affects the value of an organisation
during this year. Most of the organisations that invest significant amounts of capital into their
operations end up being successful in the first year. Over the years that follow, the WACC
formula is highly applicable, as the organisational debts and equities change.

Capital structure in most organisations is affected by the financial decisions made by the
executive. Hence, the value of organisations is dependent on the type of managers that an
organisation keeps. The value of organisation changes with any financial decision made, since
the debt and equities change with these decisions (Massari, Roncaglio & Zanetti 2008).
The value of a firm may be calculated through the estimation of the WACC, which is later used
to discount the FCFF from the debt holders and equity capital contributors (Massari, Roncaglio
& Zanetti 2008). The use of WACC in the estimation of a firm’s value is very effective by far
compared to other methods of value estimation. This finding indicates a relationship between
the value of organisations and the WACC. The WACC is in turn related to the financial
decisions in an organisation. Hence, valuation is related to the financial decisions in the
organisation.
Impact of Tax Shields on WACC
According to Massari, Roncaglio, and Zanetti (2008), tax is a variable in an organisation that
affects the value of these organisations. Interest in organisations is one of the expenses that are
usually considered as tax-deductible expense (Massari, Roncaglio & Zanetti 2008). The
calculation of WACC incorporates tax as a major form of expense. This strategy determines
the value of organisations. However, tax shields in organisations may affect the calculation of
WACC. The effects of tax shields on WACC depend on the business and individuals who are
responsible for financial management in the respective institutions.
The tax shields cause changes on WACC in a number of ways. However, while these effects
are dependent on the type of organisation, the main effect is that the WACC increases with a
reduction in tax shields. Most organisations seek tax shields to lower their WACC and in effect
influence the value and competitiveness of their respective industries. A common result of tax
shields is a downward adjustment of the discount rate to account for any changes in this area
(Massari, Roncaglio & Zanetti 2008). The downward adjustment of discount rates in
organisations allows decisions to be made on the WACC and its overall effect on the firm’s
value.
Tax shields help organisations save their available financial resources, including the provision
of future resources. In areas where tax shields are effectively applied, firms report better results,
performance, and competitiveness compared to areas where these policies are scantily applied.
Adjusting the discount rate downwards is one of the ways that tax shields are accounted for.
The result of this case is a change on the value of firms (Massari, Roncaglio & Zanetti 2008).

The relationship between value of an organisation and tax shields may be demonstrated by the
inherent differences between organisations that operate in different regions with different tax
shield regimens. According to Massari, Roncaglio, and Zanetti (2008), adjustment of WACC
should affect the value of a firm through the effect of this move on the value of the organisation.
Therefore, managers should make sound decisions when it comes to applying for tax shields in
their area.
How Tax Shields affect Firm Value
Tax shields in an organisation affect the firm’s value in a number of ways as indicated above.
A common understanding is that tax is one of the factors that affect WACC, and in effect the
value of an organisation. The worth of any business is affected by the financing decisions in
the organisations, including the availability of tax shields. The discount rate constitutes one of
the factors that may be adjusted to accommodate changes in the value of organisations. Mintz
and Currim (2013) observe that downward adjustment of discount rate accounts for tax shields.
This downward adjustment results in the increase in value of organisations.
Organisations that use the discount rate to effect changes in their firm value often report success
in the use of the method. When an organisation is awarded tax shields, the value changes to
correspond to the changes introduced through the adjustment of the discount rates. Most
organisations can be described as having debts because of the tax shields that they intend to
acquire.
Therefore, contemporary organisations are prone to debts in their quest to attain tax shields
from the respective authorities. The differences in the contemporary organisations arise from
the different capabilities in the use of their debts. Most organisations whose debt status is high
attain significant tax exemptions. They are valued at higher rank compared to organisations
that have a lower debt position. The tax shields in an organisation, therefore, affect the firm
value in organisations.
Mistakes in Using WACC
Several mistakes are established in literature in the use of WACC. The first mistake is in the
calculation of this variable. In fact, some individuals use variables that are not commonly
applied in the formula. The computation of WACC is tedious due to the many variables that
are necessary for the calculation process. This situation makes the calculation difficult to the
extent that some individuals opt for shortcuts that may not be accurate. The other mistake is

that some individuals assume that the formula may be used in the calculation of WACC for a
particular section of the organisation. They forget that this formula considers the firm a single
unit (Mian & Velez-Pareja 2007).
WACC is useful in providing discount for businesses only where they are applied to
organisations or projects with a similar undertaking to the firm under consideration. For
organisations that differ from the firm under consideration, the formula may not be applicable
or provide useful results. WACC may be useful in most of the calculations where the firm under
consideration has the same size as that of other firms that were initially considered. For projects
that are safer or riskier compared to the original organisation, the calculated WACC may be
inaccurate and in some cases incorrect.
The other mistake that individuals make in the use of WACC is the assumption that it can be
applied as a single variable in the determination of a firm’s value. According to Mian and Velez-
Pareja (2007), organisations require the use of many variables to calculate their value. A single
variable may be deceptive depending on the industry within which the firm is located.
Therefore, there is a need to consider a number of variables in the calculation of a firm’s value
as using WACC alone may be inaccurate. Some of the other mistakes that individuals make in
the use of WACC include miscalculation of the debt and equities that are eventually used in the
calculation of this variable.
Adjusting the WACC
The adjustment of WACC may be done through a number of ways depending on the debt ratios
and the business risks (Mintz & Currim 2013). Adjusting the WACC when the risk of the firm’s
debt ratio and the business risk differ from those of the new project is important in the
calculation of a business’ WACC.
The adjustment of WACC is important when the debt ratios and business risks differ in
organisations. The differences between these two variables result from the changes that are
inherent in the organisations. The three main steps that should be followed when adjusting the
WACC include calculation of the opportunity cost, estimation of the cost of the organisations
debt, and recalculation of the WACC using the obtained new values (Mian & Velez-Pareja
2007).
The adjustment of this value allows the correct calculations where the estimated WACC is
obtained against the real WACC. In cases where the WACC is adjusted, the value of the firm’s

debts and opportunity costs are considered the main reasons for the adjustments. There are
many reasons for the adjustments, with the main one being to increase the accuracy of the final
WACC that is obtained for any given firm. WACC is an indicator of the financing side effect
in an organisation. It is a good indicator of value in organisations (Mintz & Currim 2013).
These financing side effects include the value of interest tax shields on debts (Massari,
Roncaglio & Zanetti 2008). Adjustment of the WACC is also important where the actual value
of a firm is to be estimated.
Valuation in Organisations
Valuation affects the financial decisions that are made in organisations. Most of the decisions
that are important in organisations are made only through the consideration of the value of the
organisation since most managers tend to focus on increasing this value. The many valuation
approaches that are currently in use stem from the extensive research done in this area. These
approaches affect the financing decisions in organisations. The methods of valuation affect the
final variable.
Hence, most of these methods have sub approaches within them. Discounted cash flow is
among the most popular methods that are used in the valuation. This strategy focuses on the
financing decisions in the organisation (Massari, Roncaglio & Zanetti 2008). According to
Dong, Hirshleifer, and Teoh (2012), the main ways of estimating the discounted cash flow
include discounting the cash flow at a risk-adjusted discount (Sabalı 2009). This formula is one
of the four main methods that are used in the discounting cash flows. Using these methods
produces significant results.
Although different methods are in use in the valuation of companies, the same results may be
achieved if the assumptions are withheld for each of the methods. The similarity of these
methods ensures that the result is compatible with the businesses for which it was attempted
first. The different proponents for the different approaches in the valuation methods assume
that their methods are the most accurate. The results indicate that these methods are closely
similar. In relative valuation, which is considered one of the most important valuation methods,
the researchers who proposed the method adopted the assumption of individual assets.
However, these methods have similar results when the different assumptions are withheld.
Conclusion

In conclusion, based on the detailed expositions that have been made in the paper, it is clear
that valuation and financing are closely related when consideration for the financial state of an
organisation is made. Valuation may be estimated in organisations using several methods. Some
of these methods have been stated in this essay. The existence of valuation in financial decisions
allows the organisations to make decisions that coincide with their immediate needs.
The paper has proposed that a relationship between valuation and financial decisions in
organisations. This relationship is affected by other factors such as taxation. The WACC is an
important factor to consider when deducing the relationship between valuation and financial
decisions. The available research proves that this concept is applicable in an organisation’s
financial decisions. The essay has looked at the relationship between WACC and valuation in
organisations and the relationship that exists between these two variables and financial
decisions in an organisation. The paper has proved a positive relationship between these
concepts.
Valuation
The valuation of any organisation allows future decision-making to ensure that it is operating
as per the expectations. Different methods are used in valuation, including those that are
supported by theories and contemporary methods. The present models that are deployed in the
evaluation process are a product of extensive research, with many researchers describing them
before their application in management and finance. What are the motives of company
valuation? Different schools of thought exist as to why company valuation is important.
One of the motives for the evaluations of a company is to make decisions in the organisation.
Depending on the decision that is reached after valuation, the involved individuals may decide
on the future of the organisation and the interventions for the areas that are found faulty.
Motives in company valuation may be characterised in different ways, including decision-
dependent and decision-independent motives (Ishakian, Knebusch & Rowen 2013). The other
category of motives is the transaction based vs the non-transaction-based motives (Ishakian,
Knebusch & Rowen 2013). The other class of motives, as described throughout the literature
on valuation, is the dominated vs the non-dominated decision (Ishakian, Knebusch & Rowen
2013).
Valuation serves different functions depending on the concerned firm or organisation. These
functions can be categorised further into minor and major functions. The main functions of

valuation in organisations include decision-making and consultation. According to Ishakian,
Knebusch, and Rowen (2013), managers and other stakeholders use valuation information in
an organisation to make decisions on the future of the organisation with the aim of improving
the organisational performance. Different firms operate on different grounds. They use
different methods of valuation to make financial and other forms of decisions in the
organisation.
The other function of valuation, according to Koziol (2014), is mediation where the firm uses
information from valuation to mediate between concepts, decisions, and individuals.
Hundsdoerfer, Kruschwitz, and Loren (2008) assert that mediation in an organisation provides
crucial information on the financial position of the organisation. Valuation also serves as a
means of argumentation. Using information from valuation, managers and other organisational
stakeholders can argue on the position of the organisation. The information is used to provide
details on the organisational performance, which is important in making a case for any
argument.
Apart from the main functions of valuation, valuation serves other auxiliary functions. One of
these auxiliary functions is information where the parties within an organisation gather
information on this organisation, including its performance and future expectations. Valuation
may also be used as a means of tax measurement where authorities determine the tax that an
organisation should forward over a given period. Many organisations where valuation has been
conducted were found to have some tax measurements, not in line with the expected values
(Mian & Velez-Pareja 2007). Valuation also serves the function of contract configuration where
employees and other parties in the organisation can have their contracts configured with the
expectations of the organisation.
Valuation Methods
Different valuation methods are in use in many organisations. Each of these methods provides
different results. The decision to use one of them is dependent on the firm that is being
evaluated, the financial methods in place, and the preferred approach. The most popular
approach depends on the organisation and the region where these organisations exist. Different
methods that are used in valuation are shown below.
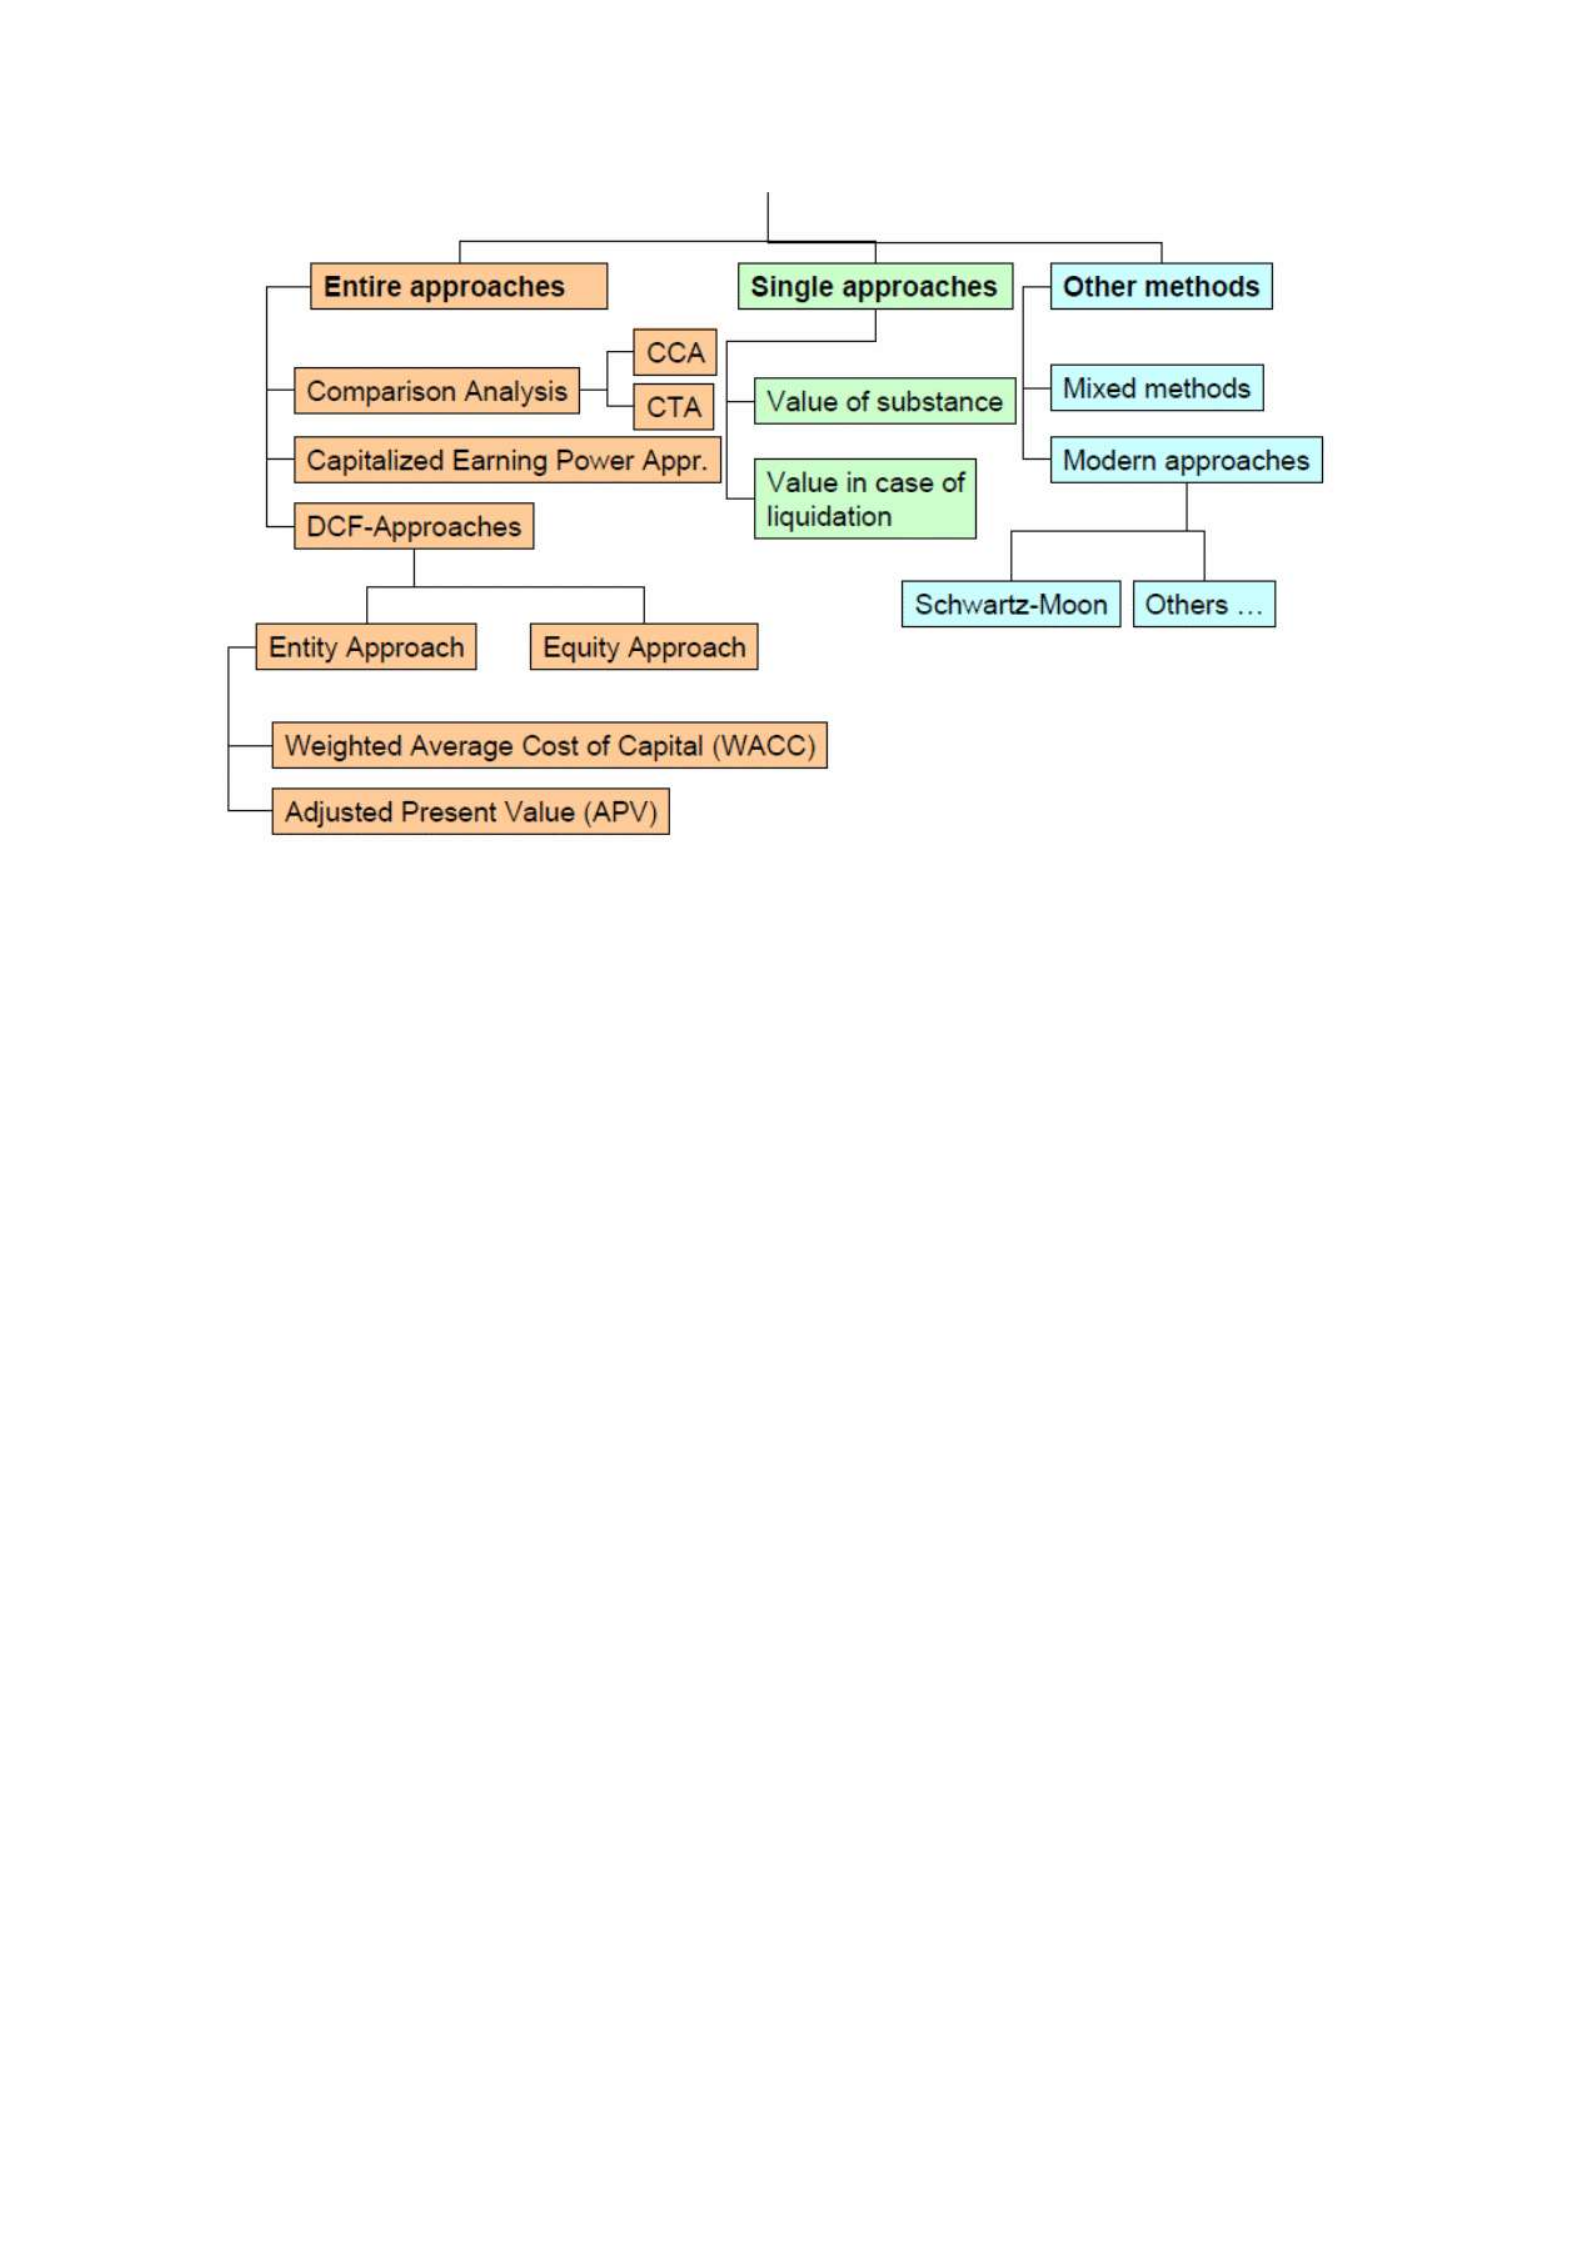
Figure 1: An Overview of Valuation Methods (Source Mian & Velez-Pareja 2007)
Different models that are applied during a valuation in organisations lead to a common result
where the organisations are able to plan for future decisions and changes. The valuation that is
obtained in organisations, irrespective of the method used, provides crucial information on the
financial status of the organisation. However, valuation within organisations also allows the
inception of changes whenever they are needed.
Financial Decisions
Organisations face challenges in financing, with one of the most common of them being the
outcomes of financial decisions. Competitiveness in organisations is influenced by the financial
decisions that managers and other stakeholders make. In any industry, financial decisions affect
the outcomes of the interactions between different factors. The financial decisions in an
organisation are also under the influence of other factors such as the valuation in these
organisations. A business in any industry or market must use capital as one of the main factors
in its operations, with this strategy bringing about the cost of capital.
Currently, there are no perfect markets in contemporary organisations. Hence, capital is not
always put to the intended use. A perfect business environment is the only place where capital
can be put to its planned use. However, conditions that are necessary for a perfect market are
hard to achieve. Nevertheless, if it were possible, the perfect world would have an excess
supply of capital. A perfect capital market might mean that the available unlimited capital is
only dependent on the risk of the project being undertaken (Spiegel, & Tookes 2013).

Aside from the perfect capital market, uncertainties, variables, and friction characterise the
existing real-world capital markets. The availability of tax as one of the variables in an
imperfect world ensures that organisations adopt strategies such as debts. An example of such
strategies is when an organisation operates in a capital structure with about 100% of debt
because of the positive corporate tax rate (Spiegel, & Tookes, 2013). Other factors that exist in
an imperfect world to introduce a relationship between valuations and financing include agency
costs, financial distress costs, and information asymmetries (Spiegel, & Tookes, 2013).
The financial position of an organisation ensures that the organisation can persist in an
environment where competition is an evident factor. Valuation effects that financial position of
an organisation. The reverse is also true. The decisions made in an organisation relating to the
financial positions of the organisation may be based on the valuation that is provided for this
organisation.
Weighted Average Cost of Capital
The calculation of the cost of capital is an intricate process that requires the participation of all
stakeholders. The cost of capital is calculated through the estimation of the proportion of debt
that a project consumes against the equity that is absorbed in the respective project (Massari,
Roncaglio & Zanetti 2008). The weighted average cost of capital (WACC) is calculated through
a formula that incorporates the market value of equity and debt (Massari, Roncaglio & Zanetti
2008). These values are adjusted using the costs of debt and equity. For a single firm, the
WACC is calculated as a single unit where the firm is the reference. The organisation, in this
case, is considered a single unit, with the results being for a single project.
The Weighted Average Cost of Capital is an indicator of the financial performance of an
organisation because it indicates the financial position of the organisation under discussion.
Any organisation with sound financial decisions has a favourable WACC, which is considered
a strength in these organisations. The calculation and use of WACC in financial discussions
and problem-solving is challenging for some financial analysts and other financial decision-
makers in organisations. Therefore, it is important to have a discussion on the correct use of
WACC and its implications on the financial decisions in organisations.
The other difficulty in the calculation and use of WACC is tax calculation. Different finance
officers use different methods of calculating the variables (Sabalı 2009). Financing and
investment decisions interact through taxes. WACC is an important concept in evaluating this

interaction. The formula that is used in the calculation of WACC refers to the organisation of
company as a whole upon incorporating the different aspects in financial decisions in the firm.
Therefore, this formula is effective for the “average project” where the right discount rate is
produced (Massari, Roncaglio & Zanetti 2008). Hence, the formula is incorrect when used in
the calculation of WACC for the safer and riskier projects (Magni 2012). The inaccuracy while
using this formula mainly stems from the different sections that individuals calculate in an
organisation, especially where the organisation has different departments.
Capital Structure and Valuations
Capital structure in a firm is a factor that affects valuations in these organisations. The effects
depend on the existing capital structure. According to Sabalı (2009), financing decisions
typically affect value within organisations. Some of the ways that boost value in a firm with
respect to its financing decisions is through the adjustment of the discount rate and the present
value (Massari, Roncaglio & Zanetti 2008).
The discount rate in most organisations is typically adjusted downwards, with the aim being to
account for the existing tax shields (Massari, Roncaglio & Zanetti 2008). Financing decisions
also affect value in organisations through adjusting the present value in these organisations
(Massari, Roncaglio & Zanetti 2008). According to Spiegel and Tookes (2013), the base case
is first calculated with the assumption that it is all equity financed.
Capital structure in organisations affects the value of the organisation from its first year of
operation. The capital structure in organisations is variable depending on several factors such
as the capital debt and the type of industry within which a firm is located. The tax on a firm is
a major factor with reference to its capital value, especially because the tax determines the debt
status of an organisation (Sabalı 2009).
The initial cash that is invested into a firm in the first year affects the value of an organisation
during this year. Most of the organisations that invest significant amounts of capital into their
operations end up being successful in the first year. Over the years that follow, the WACC
formula is highly applicable, as the organisational debts and equities change.
Capital structure in most organisations is affected by the financial decisions made by the
executive. Hence, the value of organisations is dependent on the type of managers that an
organisation keeps. The value of organisation changes with any financial decision made, since
the debt and equities change with these decisions (Massari, Roncaglio & Zanetti 2008).

The value of a firm may be calculated through the estimation of the WACC, which is later used
to discount the FCFF from the debt holders and equity capital contributors (Massari, Roncaglio
& Zanetti 2008). The use of WACC in the estimation of a firm’s value is very effective by far
compared to other methods of value estimation. This finding indicates a relationship between
the value of organisations and the WACC. The WACC is in turn related to the financial
decisions in an organisation. Hence, valuation is related to the financial decisions in the
organisation.
Impact of Tax Shields on WACC
According to Massari, Roncaglio, and Zanetti (2008), tax is a variable in an organisation that
affects the value of these organisations. Interest in organisations is one of the expenses that are
usually considered as tax-deductible expense (Massari, Roncaglio & Zanetti 2008). The
calculation of WACC incorporates tax as a major form of expense. This strategy determines
the value of organisations. However, tax shields in organisations may affect the calculation of
WACC. The effects of tax shields on WACC depend on the business and individuals who are
responsible for financial management in the respective institutions.
The tax shields cause changes on WACC in a number of ways. However, while these effects
are dependent on the type of organisation, the main effect is that the WACC increases with a
reduction in tax shields. Most organisations seek tax shields to lower their WACC and in effect
influence the value and competitiveness of their respective industries. A common result of tax
shields is a downward adjustment of the discount rate to account for any changes in this area
(Massari, Roncaglio & Zanetti 2008). The downward adjustment of discount rates in
organisations allows decisions to be made on the WACC and its overall effect on the firm’s
value.
Tax shields help organisations save their available financial resources, including the provision
of future resources. In areas where tax shields are effectively applied, firms report better results,
performance, and competitiveness compared to areas where these policies are scantily applied.
Adjusting the discount rate downwards is one of the ways that tax shields are accounted for.
The result of this case is a change on the value of firms (Massari, Roncaglio & Zanetti 2008).
The relationship between value of an organisation and tax shields may be demonstrated by the
inherent differences between organisations that operate in different regions with different tax
shield regimens. According to Massari, Roncaglio, and Zanetti (2008), adjustment of WACC
should affect the value of a firm through the effect of this move on the value of the organisation.

Therefore, managers should make sound decisions when it comes to applying for tax shields in
their area.
How Tax Shields affect Firm Value
Tax shields in an organisation affect the firm’s value in a number of ways as indicated above.
A common understanding is that tax is one of the factors that affect WACC, and in effect the
value of an organisation. The worth of any business is affected by the financing decisions in
the organisations, including the availability of tax shields. The discount rate constitutes one of
the factors that may be adjusted to accommodate changes in the value of organisations. Mintz
and Currim (2013) observe that downward adjustment of discount rate accounts for tax shields.
This downward adjustment results in the increase in value of organisations.
Organisations that use the discount rate to effect changes in their firm value often report success
in the use of the method. When an organisation is awarded tax shields, the value changes to
correspond to the changes introduced through the adjustment of the discount rates. Most
organisations can be described as having debts because of the tax shields that they intend to
acquire.
Therefore, contemporary organisations are prone to debts in their quest to attain tax shields
from the respective authorities. The differences in the contemporary organisations arise from
the different capabilities in the use of their debts. Most organisations whose debt status is high
attain significant tax exemptions. They are valued at higher rank compared to organisations
that have a lower debt position. The tax shields in an organisation, therefore, affect the firm
value in organisations.
Mistakes in Using WACC
Several mistakes are established in literature in the use of WACC. The first mistake is in the
calculation of this variable. In fact, some individuals use variables that are not commonly
applied in the formula. The computation of WACC is tedious due to the many variables that
are necessary for the calculation process. This situation makes the calculation difficult to the
extent that some individuals opt for shortcuts that may not be accurate. The other mistake is
that some individuals assume that the formula may be used in the calculation of WACC for a
particular section of the organisation. They forget that this formula considers the firm a single
unit (Mian & Velez-Pareja 2007).

WACC is useful in providing discount for businesses only where they are applied to
organisations or projects with a similar undertaking to the firm under consideration. For
organisations that differ from the firm under consideration, the formula may not be applicable
or provide useful results. WACC may be useful in most of the calculations where the firm under
consideration has the same size as that of other firms that were initially considered. For projects
that are safer or riskier compared to the original organisation, the calculated WACC may be
inaccurate and in some cases incorrect.
The other mistake that individuals make in the use of WACC is the assumption that it can be
applied as a single variable in the determination of a firm’s value. According to Mian and Velez-
Pareja (2007), organisations require the use of many variables to calculate their value. A single
variable may be deceptive depending on the industry within which the firm is located.
Therefore, there is a need to consider a number of variables in the calculation of a firm’s value
as using WACC alone may be inaccurate. Some of the other mistakes that individuals make in
the use of WACC include miscalculation of the debt and equities that are eventually used in the
calculation of this variable.
Adjusting the WACC
The adjustment of WACC may be done through a number of ways depending on the debt ratios
and the business risks (Mintz & Currim 2013). Adjusting the WACC when the risk of the firm’s
debt ratio and the business risk differ from those of the new project is important in the
calculation of a business’ WACC.
The adjustment of WACC is important when the debt ratios and business risks differ in
organisations. The differences between these two variables result from the changes that are
inherent in the organisations. The three main steps that should be followed when adjusting the
WACC include calculation of the opportunity cost, estimation of the cost of the organisations
debt, and recalculation of the WACC using the obtained new values (Mian & Velez-Pareja
2007).
The adjustment of this value allows the correct calculations where the estimated WACC is
obtained against the real WACC. In cases where the WACC is adjusted, the value of the firm’s
debts and opportunity costs are considered the main reasons for the adjustments. There are
many reasons for the adjustments, with the main one being to increase the accuracy of the final
WACC that is obtained for any given firm. WACC is an indicator of the financing side effect
in an organisation. It is a good indicator of value in organisations (Mintz & Currim 2013).

These financing side effects include the value of interest tax shields on debts (Massari,
Roncaglio & Zanetti 2008). Adjustment of the WACC is also important where the actual value
of a firm is to be estimated.
Valuation in Organisations
Valuation affects the financial decisions that are made in organisations. Most of the decisions
that are important in organisations are made only through the consideration of the value of the
organisation since most managers tend to focus on increasing this value. The many valuation
approaches that are currently in use stem from the extensive research done in this area. These
approaches affect the financing decisions in organisations. The methods of valuation affect the
final variable.
Hence, most of these methods have sub approaches within them. Discounted cash flow is
among the most popular methods that are used in the valuation. This strategy focuses on the
financing decisions in the organisation (Massari, Roncaglio & Zanetti 2008). According to
Dong, Hirshleifer, and Teoh (2012), the main ways of estimating the discounted cash flow
include discounting the cash flow at a risk-adjusted discount (Sabalı 2009). This formula is one
of the four main methods that are used in the discounting cash flows. Using these methods
produces significant results.
Although different methods are in use in the valuation of companies, the same results may be
achieved if the assumptions are withheld for each of the methods. The similarity of these
methods ensures that the result is compatible with the businesses for which it was attempted
first. The different proponents for the different approaches in the valuation methods assume
that their methods are the most accurate. The results indicate that these methods are closely
similar. In relative valuation, which is considered one of the most important valuation methods,
the researchers who proposed the method adopted the assumption of individual assets.
However, these methods have similar results when the different assumptions are withheld.
Conclusion
In conclusion, based on the detailed expositions that have been made in the paper, it is clear
that valuation and financing are closely related when consideration for the financial state of an
organisation is made. Valuation may be estimated in organisations using several methods. Some
of these methods have been stated in this essay. The existence of valuation in financial decisions
allows the organisations to make decisions that coincide with their immediate needs.

The paper has proposed that a relationship between valuation and financial decisions in
organisations. This relationship is affected by other factors such as taxation. The WACC is an
important factor to consider when deducing the relationship between valuation and financial
decisions. The available research proves that this concept is applicable in an organisation’s
financial decisions. The essay has looked at the relationship between WACC and valuation in
organisations and the relationship that exists between these two variables and financial
decisions in an organisation. The paper has proved a positive relationship between these
concepts.
Valuation
The valuation of any organisation allows future decision-making to ensure that it is operating
as per the expectations. Different methods are used in valuation, including those that are
supported by theories and contemporary methods. The present models that are deployed in the
evaluation process are a product of extensive research, with many researchers describing them
before their application in management and finance. What are the motives of company
valuation? Different schools of thought exist as to why company valuation is important.
One of the motives for the evaluations of a company is to make decisions in the organisation.
Depending on the decision that is reached after valuation, the involved individuals may decide
on the future of the organisation and the interventions for the areas that are found faulty.
Motives in company valuation may be characterised in different ways, including decision-
dependent and decision-independent motives (Ishakian, Knebusch & Rowen 2013). The other
category of motives is the transaction based vs the non-transaction-based motives (Ishakian,
Knebusch & Rowen 2013). The other class of motives, as described throughout the literature
on valuation, is the dominated vs the non-dominated decision (Ishakian, Knebusch & Rowen
2013).
Valuation serves different functions depending on the concerned firm or organisation. These
functions can be categorised further into minor and major functions. The main functions of
valuation in organisations include decision-making and consultation. According to Ishakian,
Knebusch, and Rowen (2013), managers and other stakeholders use valuation information in
an organisation to make decisions on the future of the organisation with the aim of improving
the organisational performance. Different firms operate on different grounds. They use
different methods of valuation to make financial and other forms of decisions in the
organisation.

The other function of valuation, according to Koziol (2014), is mediation where the firm uses
information from valuation to mediate between concepts, decisions, and individuals.
Hundsdoerfer, Kruschwitz, and Loren (2008) assert that mediation in an organisation provides
crucial information on the financial position of the organisation. Valuation also serves as a
means of argumentation. Using information from valuation, managers and other organisational
stakeholders can argue on the position of the organisation. The information is used to provide
details on the organisational performance, which is important in making a case for any
argument.
Apart from the main functions of valuation, valuation serves other auxiliary functions. One of
these auxiliary functions is information where the parties within an organisation gather
information on this organisation, including its performance and future expectations. Valuation
may also be used as a means of tax measurement where authorities determine the tax that an
organisation should forward over a given period. Many organisations where valuation has been
conducted were found to have some tax measurements, not in line with the expected values
(Mian & Velez-Pareja 2007). Valuation also serves the function of contract configuration where
employees and other parties in the organisation can have their contracts configured with the
expectations of the organisation.
Valuation Methods
Different valuation methods are in use in many organisations. Each of these methods provides
different results. The decision to use one of them is dependent on the firm that is being
evaluated, the financial methods in place, and the preferred approach. The most popular
approach depends on the organisation and the region where these organisations exist. Different
methods that are used in valuation are shown below.
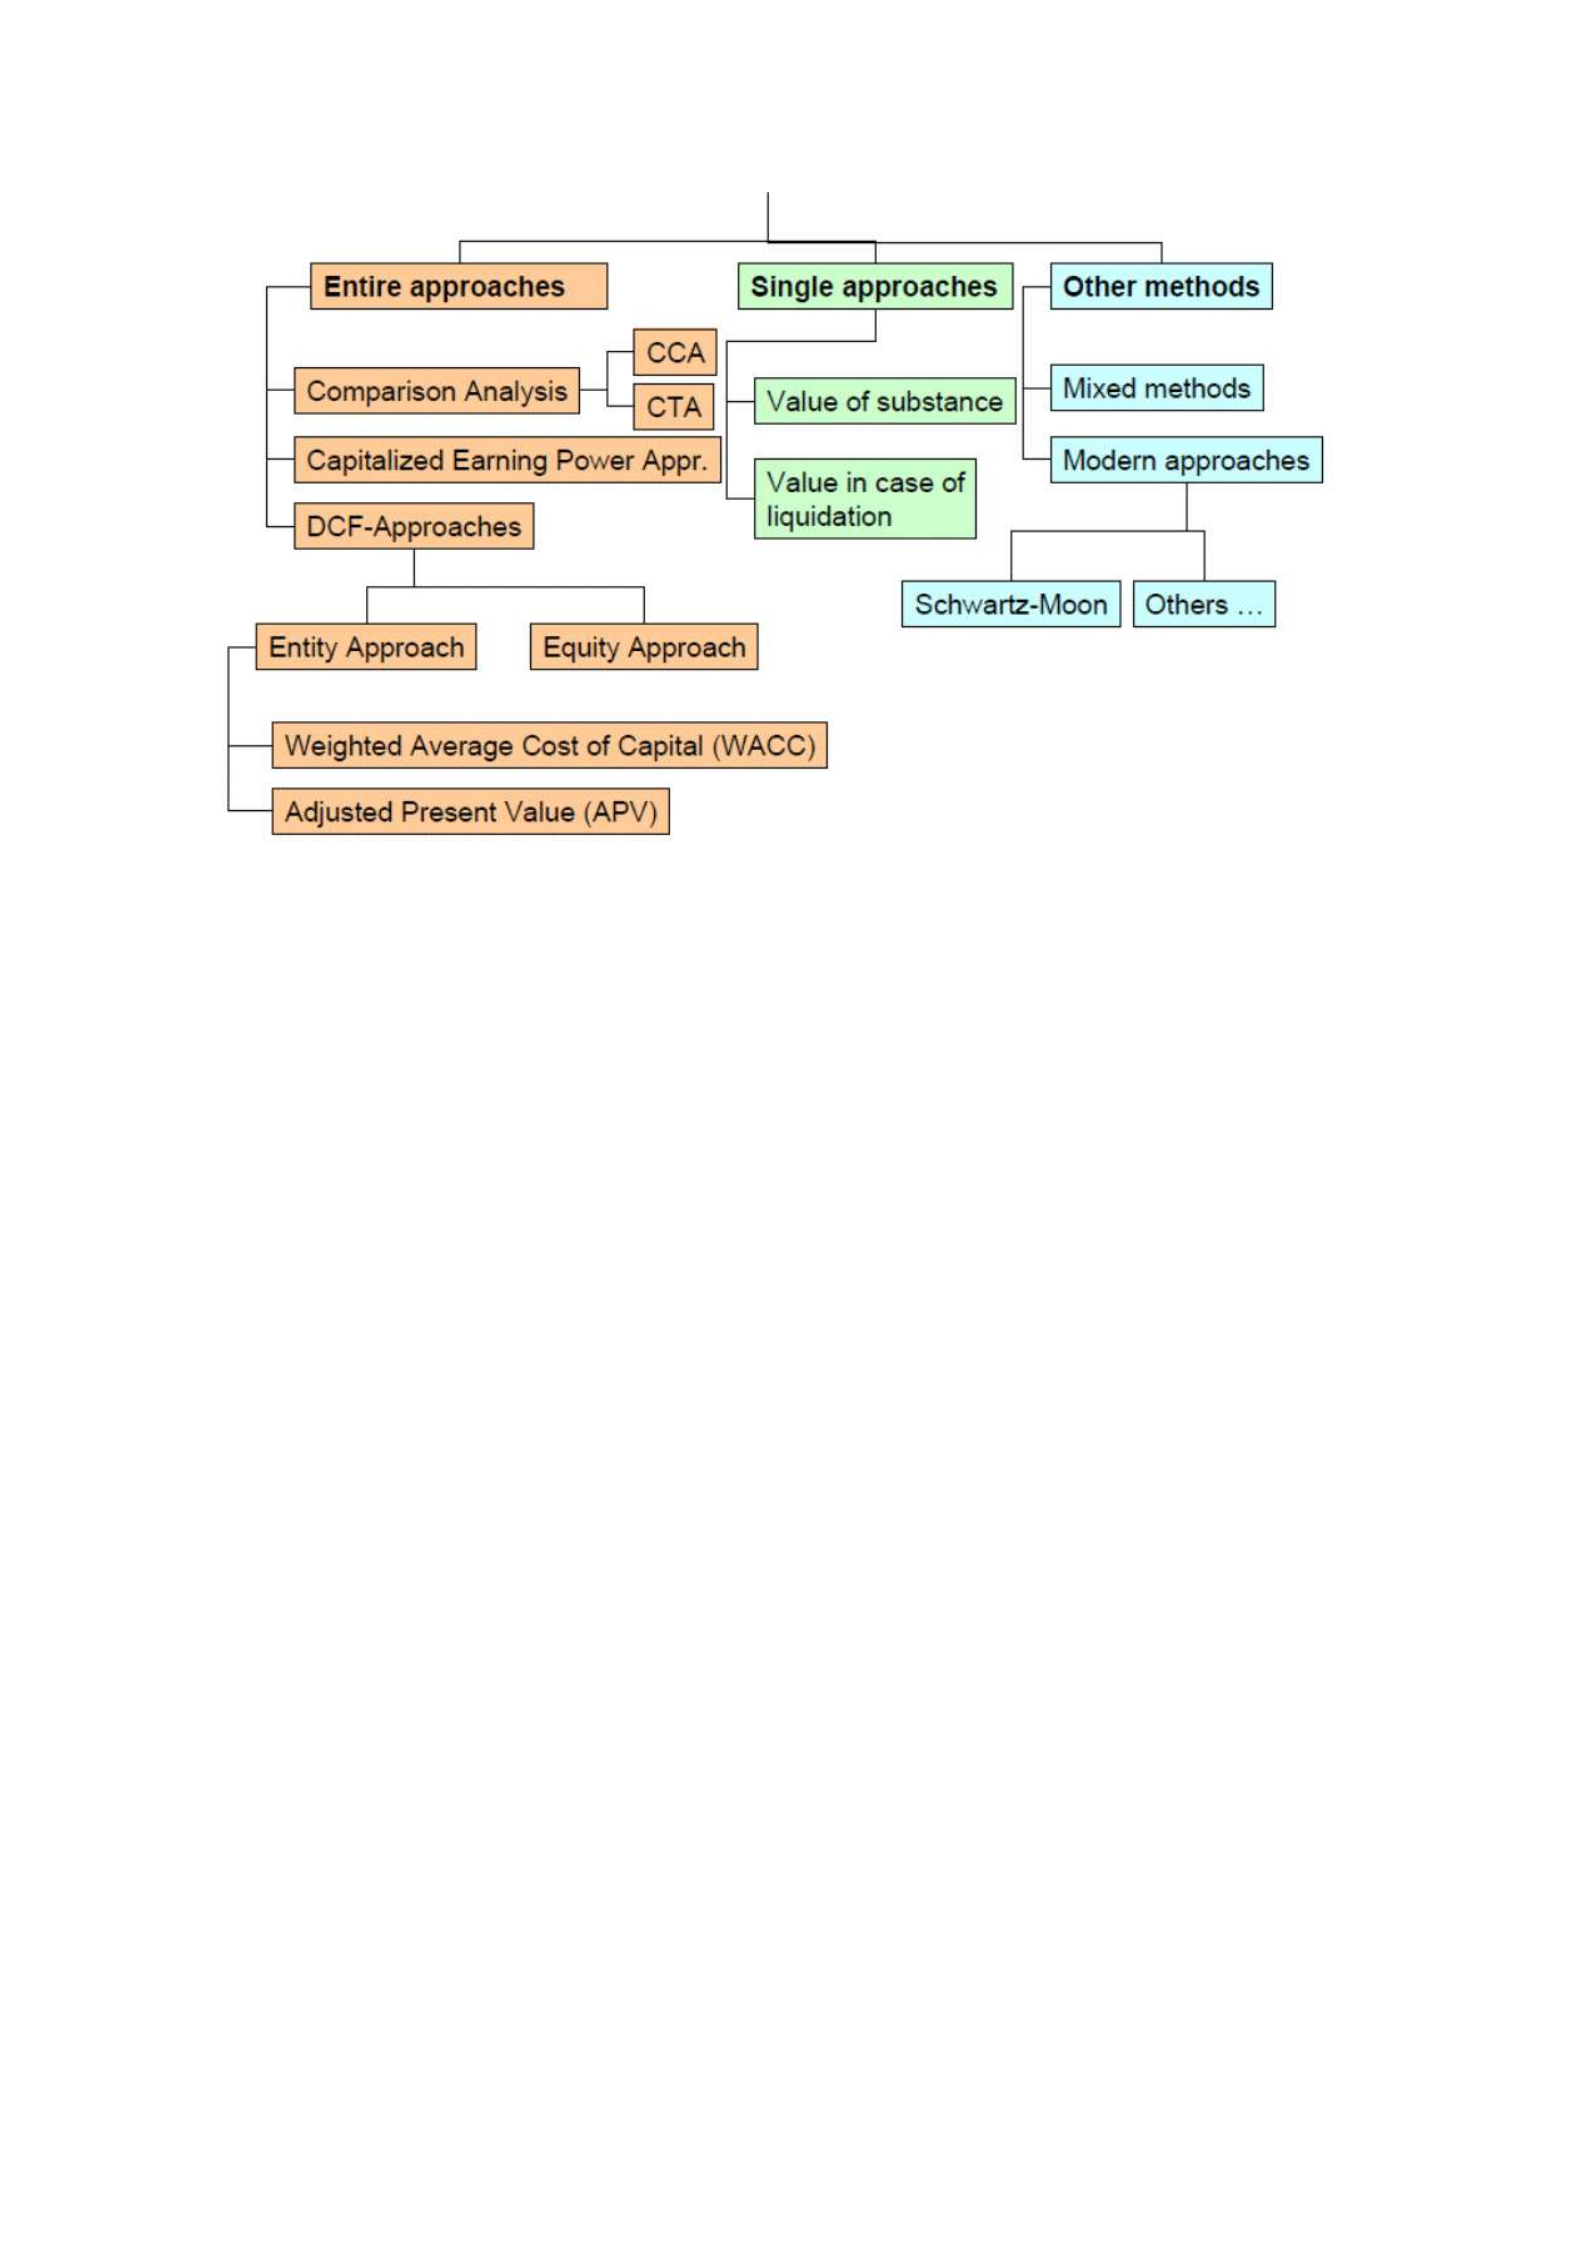
Figure 1: An Overview of Valuation Methods (Source Mian & Velez-Pareja 2007)
Different models that are applied during a valuation in organisations lead to a common result
where the organisations are able to plan for future decisions and changes. The valuation that is
obtained in organisations, irrespective of the method used, provides crucial information on the
financial status of the organisation. However, valuation within organisations also allows the
inception of changes whenever they are needed.
Financial Decisions
Organisations face challenges in financing, with one of the most common of them being the
outcomes of financial decisions. Competitiveness in organisations is influenced by the financial
decisions that managers and other stakeholders make. In any industry, financial decisions affect
the outcomes of the interactions between different factors. The financial decisions in an
organisation are also under the influence of other factors such as the valuation in these
organisations. A business in any industry or market must use capital as one of the main factors
in its operations, with this strategy bringing about the cost of capital.
Currently, there are no perfect markets in contemporary organisations. Hence, capital is not
always put to the intended use. A perfect business environment is the only place where capital
can be put to its planned use. However, conditions that are necessary for a perfect market are
hard to achieve. Nevertheless, if it were possible, the perfect world would have an excess
supply of capital. A perfect capital market might mean that the available unlimited capital is
only dependent on the risk of the project being undertaken (Spiegel, & Tookes 2013).

Aside from the perfect capital market, uncertainties, variables, and friction characterise the
existing real-world capital markets. The availability of tax as one of the variables in an
imperfect world ensures that organisations adopt strategies such as debts. An example of such
strategies is when an organisation operates in a capital structure with about 100% of debt
because of the positive corporate tax rate (Spiegel, & Tookes, 2013). Other factors that exist in
an imperfect world to introduce a relationship between valuations and financing include agency
costs, financial distress costs, and information asymmetries (Spiegel, & Tookes, 2013).
The financial position of an organisation ensures that the organisation can persist in an
environment where competition is an evident factor. Valuation effects that financial position of
an organisation. The reverse is also true. The decisions made in an organisation relating to the
financial positions of the organisation may be based on the valuation that is provided for this
organisation.
Weighted Average Cost of Capital
The calculation of the cost of capital is an intricate process that requires the participation of all
stakeholders. The cost of capital is calculated through the estimation of the proportion of debt
that a project consumes against the equity that is absorbed in the respective project (Massari,
Roncaglio & Zanetti 2008). The weighted average cost of capital (WACC) is calculated through
a formula that incorporates the market value of equity and debt (Massari, Roncaglio & Zanetti
2008). These values are adjusted using the costs of debt and equity. For a single firm, the
WACC is calculated as a single unit where the firm is the reference. The organisation, in this
case, is considered a single unit, with the results being for a single project.
The Weighted Average Cost of Capital is an indicator of the financial performance of an
organisation because it indicates the financial position of the organisation under discussion.
Any organisation with sound financial decisions has a favourable WACC, which is considered
a strength in these organisations. The calculation and use of WACC in financial discussions
and problem-solving is challenging for some financial analysts and other financial decision-
makers in organisations. Therefore, it is important to have a discussion on the correct use of
WACC and its implications on the financial decisions in organisations.
The other difficulty in the calculation and use of WACC is tax calculation. Different finance
officers use different methods of calculating the variables (Sabalı 2009). Financing and
investment decisions interact through taxes. WACC is an important concept in evaluating this

interaction. The formula that is used in the calculation of WACC refers to the organisation of
company as a whole upon incorporating the different aspects in financial decisions in the firm.
Therefore, this formula is effective for the “average project” where the right discount rate is
produced (Massari, Roncaglio & Zanetti 2008). Hence, the formula is incorrect when used in
the calculation of WACC for the safer and riskier projects (Magni 2012). The inaccuracy while
using this formula mainly stems from the different sections that individuals calculate in an
organisation, especially where the organisation has different departments.
Capital Structure and Valuations
Capital structure in a firm is a factor that affects valuations in these organisations. The effects
depend on the existing capital structure. According to Sabalı (2009), financing decisions
typically affect value within organisations. Some of the ways that boost value in a firm with
respect to its financing decisions is through the adjustment of the discount rate and the present
value (Massari, Roncaglio & Zanetti 2008).
The discount rate in most organisations is typically adjusted downwards, with the aim being to
account for the existing tax shields (Massari, Roncaglio & Zanetti 2008). Financing decisions
also affect value in organisations through adjusting the present value in these organisations
(Massari, Roncaglio & Zanetti 2008). According to Spiegel and Tookes (2013), the base case
is first calculated with the assumption that it is all equity financed.
Capital structure in organisations affects the value of the organisation from its first year of
operation. The capital structure in organisations is variable depending on several factors such
as the capital debt and the type of industry within which a firm is located. The tax on a firm is
a major factor with reference to its capital value, especially because the tax determines the debt
status of an organisation (Sabalı 2009).
The initial cash that is invested into a firm in the first year affects the value of an organisation
during this year. Most of the organisations that invest significant amounts of capital into their
operations end up being successful in the first year. Over the years that follow, the WACC
formula is highly applicable, as the organisational debts and equities change.
Capital structure in most organisations is affected by the financial decisions made by the
executive. Hence, the value of organisations is dependent on the type of managers that an
organisation keeps. The value of organisation changes with any financial decision made, since
the debt and equities change with these decisions (Massari, Roncaglio & Zanetti 2008).

The value of a firm may be calculated through the estimation of the WACC, which is later used
to discount the FCFF from the debt holders and equity capital contributors (Massari, Roncaglio
& Zanetti 2008). The use of WACC in the estimation of a firm’s value is very effective by far
compared to other methods of value estimation. This finding indicates a relationship between
the value of organisations and the WACC. The WACC is in turn related to the financial
decisions in an organisation. Hence, valuation is related to the financial decisions in the
organisation.
Impact of Tax Shields on WACC
According to Massari, Roncaglio, and Zanetti (2008), tax is a variable in an organisation that
affects the value of these organisations. Interest in organisations is one of the expenses that are
usually considered as tax-deductible expense (Massari, Roncaglio & Zanetti 2008). The
calculation of WACC incorporates tax as a major form of expense. This strategy determines
the value of organisations. However, tax shields in organisations may affect the calculation of
WACC. The effects of tax shields on WACC depend on the business and individuals who are
responsible for financial management in the respective institutions.
The tax shields cause changes on WACC in a number of ways. However, while these effects
are dependent on the type of organisation, the main effect is that the WACC increases with a
reduction in tax shields. Most organisations seek tax shields to lower their WACC and in effect
influence the value and competitiveness of their respective industries. A common result of tax
shields is a downward adjustment of the discount rate to account for any changes in this area
(Massari, Roncaglio & Zanetti 2008). The downward adjustment of discount rates in
organisations allows decisions to be made on the WACC and its overall effect on the firm’s
value.
Tax shields help organisations save their available financial resources, including the provision
of future resources. In areas where tax shields are effectively applied, firms report better results,
performance, and competitiveness compared to areas where these policies are scantily applied.
Adjusting the discount rate downwards is one of the ways that tax shields are accounted for.
The result of this case is a change on the value of firms (Massari, Roncaglio & Zanetti 2008).
The relationship between value of an organisation and tax shields may be demonstrated by the
inherent differences between organisations that operate in different regions with different tax
shield regimens. According to Massari, Roncaglio, and Zanetti (2008), adjustment of WACC
should affect the value of a firm through the effect of this move on the value of the organisation.

Therefore, managers should make sound decisions when it comes to applying for tax shields in
their area.
How Tax Shields affect Firm Value
Tax shields in an organisation affect the firm’s value in a number of ways as indicated above.
A common understanding is that tax is one of the factors that affect WACC, and in effect the
value of an organisation. The worth of any business is affected by the financing decisions in
the organisations, including the availability of tax shields. The discount rate constitutes one of
the factors that may be adjusted to accommodate changes in the value of organisations. Mintz
and Currim (2013) observe that downward adjustment of discount rate accounts for tax shields.
This downward adjustment results in the increase in value of organisations.
Organisations that use the discount rate to effect changes in their firm value often report success
in the use of the method. When an organisation is awarded tax shields, the value changes to
correspond to the changes introduced through the adjustment of the discount rates. Most
organisations can be described as having debts because of the tax shields that they intend to
acquire.
Therefore, contemporary organisations are prone to debts in their quest to attain tax shields
from the respective authorities. The differences in the contemporary organisations arise from
the different capabilities in the use of their debts. Most organisations whose debt status is high
attain significant tax exemptions. They are valued at higher rank compared to organisations
that have a lower debt position. The tax shields in an organisation, therefore, affect the firm
value in organisations.
Mistakes in Using WACC
Several mistakes are established in literature in the use of WACC. The first mistake is in the
calculation of this variable. In fact, some individuals use variables that are not commonly
applied in the formula. The computation of WACC is tedious due to the many variables that
are necessary for the calculation process. This situation makes the calculation difficult to the
extent that some individuals opt for shortcuts that may not be accurate. The other mistake is
that some individuals assume that the formula may be used in the calculation of WACC for a
particular section of the organisation. They forget that this formula considers the firm a single
unit (Mian & Velez-Pareja 2007).

WACC is useful in providing discount for businesses only where they are applied to
organisations or projects with a similar undertaking to the firm under consideration. For
organisations that differ from the firm under consideration, the formula may not be applicable
or provide useful results. WACC may be useful in most of the calculations where the firm under
consideration has the same size as that of other firms that were initially considered. For projects
that are safer or riskier compared to the original organisation, the calculated WACC may be
inaccurate and in some cases incorrect.
The other mistake that individuals make in the use of WACC is the assumption that it can be
applied as a single variable in the determination of a firm’s value. According to Mian and Velez-
Pareja (2007), organisations require the use of many variables to calculate their value. A single
variable may be deceptive depending on the industry within which the firm is located.
Therefore, there is a need to consider a number of variables in the calculation of a firm’s value
as using WACC alone may be inaccurate. Some of the other mistakes that individuals make in
the use of WACC include miscalculation of the debt and equities that are eventually used in the
calculation of this variable.
Adjusting the WACC
The adjustment of WACC may be done through a number of ways depending on the debt ratios
and the business risks (Mintz & Currim 2013). Adjusting the WACC when the risk of the firm’s
debt ratio and the business risk differ from those of the new project is important in the
calculation of a business’ WACC.
The adjustment of WACC is important when the debt ratios and business risks differ in
organisations. The differences between these two variables result from the changes that are
inherent in the organisations. The three main steps that should be followed when adjusting the
WACC include calculation of the opportunity cost, estimation of the cost of the organisations
debt, and recalculation of the WACC using the obtained new values (Mian & Velez-Pareja
2007).
The adjustment of this value allows the correct calculations where the estimated WACC is
obtained against the real WACC. In cases where the WACC is adjusted, the value of the firm’s
debts and opportunity costs are considered the main reasons for the adjustments. There are
many reasons for the adjustments, with the main one being to increase the accuracy of the final
WACC that is obtained for any given firm. WACC is an indicator of the financing side effect
in an organisation. It is a good indicator of value in organisations (Mintz & Currim 2013).

These financing side effects include the value of interest tax shields on debts (Massari,
Roncaglio & Zanetti 2008). Adjustment of the WACC is also important where the actual value
of a firm is to be estimated.
Valuation in Organisations
Valuation affects the financial decisions that are made in organisations. Most of the decisions
that are important in organisations are made only through the consideration of the value of the
organisation since most managers tend to focus on increasing this value. The many valuation
approaches that are currently in use stem from the extensive research done in this area. These
approaches affect the financing decisions in organisations. The methods of valuation affect the
final variable.
Hence, most of these methods have sub approaches within them. Discounted cash flow is
among the most popular methods that are used in the valuation. This strategy focuses on the
financing decisions in the organisation (Massari, Roncaglio & Zanetti 2008). According to
Dong, Hirshleifer, and Teoh (2012), the main ways of estimating the discounted cash flow
include discounting the cash flow at a risk-adjusted discount (Sabalı 2009). This formula is one
of the four main methods that are used in the discounting cash flows. Using these methods
produces significant results.
Although different methods are in use in the valuation of companies, the same results may be
achieved if the assumptions are withheld for each of the methods. The similarity of these
methods ensures that the result is compatible with the businesses for which it was attempted
first. The different proponents for the different approaches in the valuation methods assume
that their methods are the most accurate. The results indicate that these methods are closely
similar. In relative valuation, which is considered one of the most important valuation methods,
the researchers who proposed the method adopted the assumption of individual assets.
However, these methods have similar results when the different assumptions are withheld.
Conclusion
In conclusion, based on the detailed expositions that have been made in the paper, it is clear
that valuation and financing are closely related when consideration for the financial state of an
organisation is made. Valuation may be estimated in organisations using several methods. Some
of these methods have been stated in this essay. The existence of valuation in financial decisions
allows the organisations to make decisions that coincide with their immediate needs.

The paper has proposed that a relationship between valuation and financial decisions in
organisations. This relationship is affected by other factors such as taxation. The WACC is an
important factor to consider when deducing the relationship between valuation and financial
decisions. The available research proves that this concept is applicable in an organisation’s
financial decisions. The essay has looked at the relationship between WACC and valuation in
organisations and the relationship that exists between these two variables and financial
decisions in an organisation. The paper has proved a positive relationship between these
concepts.
Valuation
The valuation of any organisation allows future decision-making to ensure that it is operating
as per the expectations. Different methods are used in valuation, including those that are
supported by theories and contemporary methods. The present models that are deployed in the
evaluation process are a product of extensive research, with many researchers describing them
before their application in management and finance. What are the motives of company
valuation? Different schools of thought exist as to why company valuation is important.
One of the motives for the evaluations of a company is to make decisions in the organisation.
Depending on the decision that is reached after valuation, the involved individuals may decide
on the future of the organisation and the interventions for the areas that are found faulty.
Motives in company valuation may be characterised in different ways, including decision-
dependent and decision-independent motives (Ishakian, Knebusch & Rowen 2013). The other
category of motives is the transaction based vs the non-transaction-based motives (Ishakian,
Knebusch & Rowen 2013). The other class of motives, as described throughout the literature
on valuation, is the dominated vs the non-dominated decision (Ishakian, Knebusch & Rowen
2013).
Valuation serves different functions depending on the concerned firm or organisation. These
functions can be categorised further into minor and major functions. The main functions of
valuation in organisations include decision-making and consultation. According to Ishakian,
Knebusch, and Rowen (2013), managers and other stakeholders use valuation information in
an organisation to make decisions on the future of the organisation with the aim of improving
the organisational performance. Different firms operate on different grounds. They use
different methods of valuation to make financial and other forms of decisions in the
organisation.

The other function of valuation, according to Koziol (2014), is mediation where the firm uses
information from valuation to mediate between concepts, decisions, and individuals.
Hundsdoerfer, Kruschwitz, and Loren (2008) assert that mediation in an organisation provides
crucial information on the financial position of the organisation. Valuation also serves as a
means of argumentation. Using information from valuation, managers and other organisational
stakeholders can argue on the position of the organisation. The information is used to provide
details on the organisational performance, which is important in making a case for any
argument.
Apart from the main functions of valuation, valuation serves other auxiliary functions. One of
these auxiliary functions is information where the parties within an organisation gather
information on this organisation, including its performance and future expectations. Valuation
may also be used as a means of tax measurement where authorities determine the tax that an
organisation should forward over a given period. Many organisations where valuation has been
conducted were found to have some tax measurements, not in line with the expected values
(Mian & Velez-Pareja 2007). Valuation also serves the function of contract configuration where
employees and other parties in the organisation can have their contracts configured with the
expectations of the organisation.
Valuation Methods
Different valuation methods are in use in many organisations. Each of these methods provides
different results. The decision to use one of them is dependent on the firm that is being
evaluated, the financial methods in place, and the preferred approach. The most popular
approach depends on the organisation and the region where these organisations exist. Different
methods that are used in valuation are shown below.
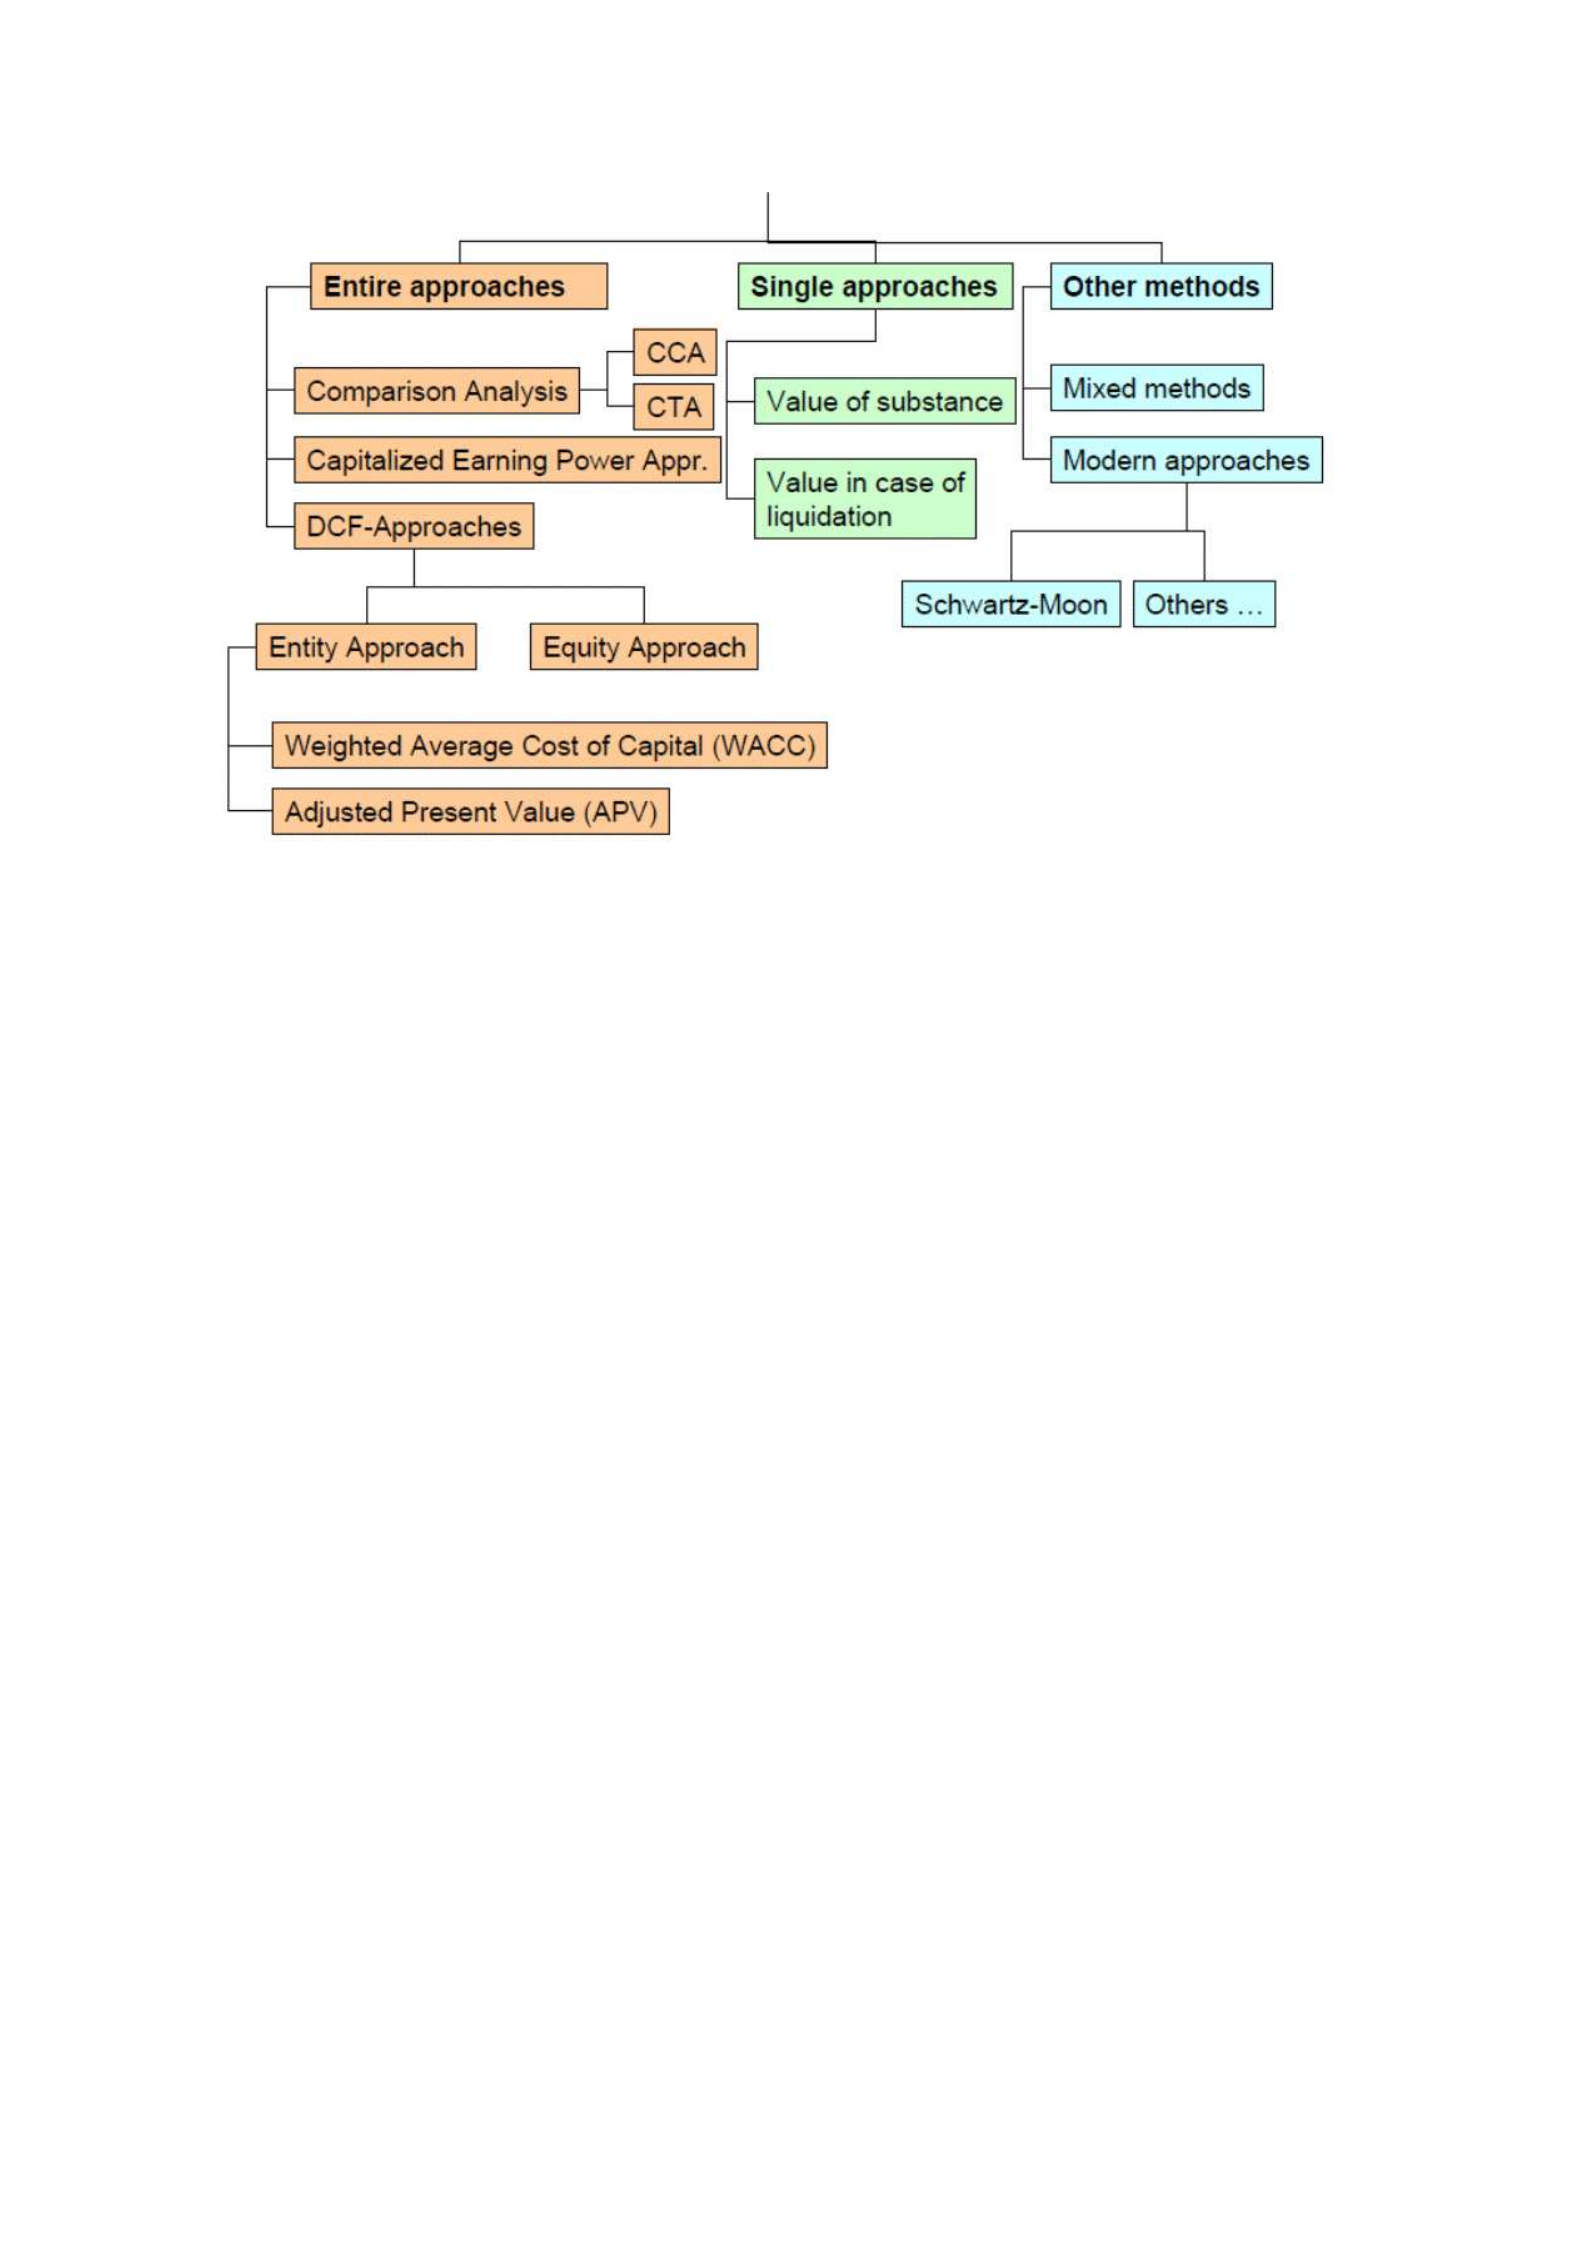
Figure 1: An Overview of Valuation Methods (Source Mian & Velez-Pareja 2007)
Different models that are applied during a valuation in organisations lead to a common result
where the organisations are able to plan for future decisions and changes. The valuation that is
obtained in organisations, irrespective of the method used, provides crucial information on the
financial status of the organisation. However, valuation within organisations also allows the
inception of changes whenever they are needed.
Financial Decisions
Organisations face challenges in financing, with one of the most common of them being the
outcomes of financial decisions. Competitiveness in organisations is influenced by the financial
decisions that managers and other stakeholders make. In any industry, financial decisions affect
the outcomes of the interactions between different factors. The financial decisions in an
organisation are also under the influence of other factors such as the valuation in these
organisations. A business in any industry or market must use capital as one of the main factors
in its operations, with this strategy bringing about the cost of capital.
Currently, there are no perfect markets in contemporary organisations. Hence, capital is not
always put to the intended use. A perfect business environment is the only place where capital
can be put to its planned use. However, conditions that are necessary for a perfect market are
hard to achieve. Nevertheless, if it were possible, the perfect world would have an excess
supply of capital. A perfect capital market might mean that the available unlimited capital is
only dependent on the risk of the project being undertaken (Spiegel, & Tookes 2013).

Aside from the perfect capital market, uncertainties, variables, and friction characterise the
existing real-world capital markets. The availability of tax as one of the variables in an
imperfect world ensures that organisations adopt strategies such as debts. An example of such
strategies is when an organisation operates in a capital structure with about 100% of debt
because of the positive corporate tax rate (Spiegel, & Tookes, 2013). Other factors that exist in
an imperfect world to introduce a relationship between valuations and financing include agency
costs, financial distress costs, and information asymmetries (Spiegel, & Tookes, 2013).
The financial position of an organisation ensures that the organisation can persist in an
environment where competition is an evident factor. Valuation effects that financial position of
an organisation. The reverse is also true. The decisions made in an organisation relating to the
financial positions of the organisation may be based on the valuation that is provided for this
organisation.
Weighted Average Cost of Capital
The calculation of the cost of capital is an intricate process that requires the participation of all
stakeholders. The cost of capital is calculated through the estimation of the proportion of debt
that a project consumes against the equity that is absorbed in the respective project (Massari,
Roncaglio & Zanetti 2008). The weighted average cost of capital (WACC) is calculated through
a formula that incorporates the market value of equity and debt (Massari, Roncaglio & Zanetti
2008). These values are adjusted using the costs of debt and equity. For a single firm, the
WACC is calculated as a single unit where the firm is the reference. The organisation, in this
case, is considered a single unit, with the results being for a single project.
The Weighted Average Cost of Capital is an indicator of the financial performance of an
organisation because it indicates the financial position of the organisation under discussion.
Any organisation with sound financial decisions has a favourable WACC, which is considered
a strength in these organisations. The calculation and use of WACC in financial discussions
and problem-solving is challenging for some financial analysts and other financial decision-
makers in organisations. Therefore, it is important to have a discussion on the correct use of
WACC and its implications on the financial decisions in organisations.
The other difficulty in the calculation and use of WACC is tax calculation. Different finance
officers use different methods of calculating the variables (Sabalı 2009). Financing and
investment decisions interact through taxes. WACC is an important concept in evaluating this

interaction. The formula that is used in the calculation of WACC refers to the organisation of
company as a whole upon incorporating the different aspects in financial decisions in the firm.
Therefore, this formula is effective for the “average project” where the right discount rate is
produced (Massari, Roncaglio & Zanetti 2008). Hence, the formula is incorrect when used in
the calculation of WACC for the safer and riskier projects (Magni 2012). The inaccuracy while
using this formula mainly stems from the different sections that individuals calculate in an
organisation, especially where the organisation has different departments.
Capital Structure and Valuations
Capital structure in a firm is a factor that affects valuations in these organisations. The effects
depend on the existing capital structure. According to Sabalı (2009), financing decisions
typically affect value within organisations. Some of the ways that boost value in a firm with
respect to its financing decisions is through the adjustment of the discount rate and the present
value (Massari, Roncaglio & Zanetti 2008).
The discount rate in most organisations is typically adjusted downwards, with the aim being to
account for the existing tax shields (Massari, Roncaglio & Zanetti 2008). Financing decisions
also affect value in organisations through adjusting the present value in these organisations
(Massari, Roncaglio & Zanetti 2008). According to Spiegel and Tookes (2013), the base case
is first calculated with the assumption that it is all equity financed.
Capital structure in organisations affects the value of the organisation from its first year of
operation. The capital structure in organisations is variable depending on several factors such
as the capital debt and the type of industry within which a firm is located. The tax on a firm is
a major factor with reference to its capital value, especially because the tax determines the debt
status of an organisation (Sabalı 2009).
The initial cash that is invested into a firm in the first year affects the value of an organisation
during this year. Most of the organisations that invest significant amounts of capital into their
operations end up being successful in the first year. Over the years that follow, the WACC
formula is highly applicable, as the organisational debts and equities change.
Capital structure in most organisations is affected by the financial decisions made by the
executive. Hence, the value of organisations is dependent on the type of managers that an
organisation keeps. The value of organisation changes with any financial decision made, since
the debt and equities change with these decisions (Massari, Roncaglio & Zanetti 2008).

The value of a firm may be calculated through the estimation of the WACC, which is later used
to discount the FCFF from the debt holders and equity capital contributors (Massari, Roncaglio
& Zanetti 2008). The use of WACC in the estimation of a firm’s value is very effective by far
compared to other methods of value estimation. This finding indicates a relationship between
the value of organisations and the WACC. The WACC is in turn related to the financial
decisions in an organisation. Hence, valuation is related to the financial decisions in the
organisation.
Impact of Tax Shields on WACC
According to Massari, Roncaglio, and Zanetti (2008), tax is a variable in an organisation that
affects the value of these organisations. Interest in organisations is one of the expenses that are
usually considered as tax-deductible expense (Massari, Roncaglio & Zanetti 2008). The
calculation of WACC incorporates tax as a major form of expense. This strategy determines
the value of organisations. However, tax shields in organisations may affect the calculation of
WACC. The effects of tax shields on WACC depend on the business and individuals who are
responsible for financial management in the respective institutions.
The tax shields cause changes on WACC in a number of ways. However, while these effects
are dependent on the type of organisation, the main effect is that the WACC increases with a
reduction in tax shields. Most organisations seek tax shields to lower their WACC and in effect
influence the value and competitiveness of their respective industries. A common result of tax
shields is a downward adjustment of the discount rate to account for any changes in this area
(Massari, Roncaglio & Zanetti 2008). The downward adjustment of discount rates in
organisations allows decisions to be made on the WACC and its overall effect on the firm’s
value.
Tax shields help organisations save their available financial resources, including the provision
of future resources. In areas where tax shields are effectively applied, firms report better results,
performance, and competitiveness compared to areas where these policies are scantily applied.
Adjusting the discount rate downwards is one of the ways that tax shields are accounted for.
The result of this case is a change on the value of firms (Massari, Roncaglio & Zanetti 2008).
The relationship between value of an organisation and tax shields may be demonstrated by the
inherent differences between organisations that operate in different regions with different tax
shield regimens. According to Massari, Roncaglio, and Zanetti (2008), adjustment of WACC
should affect the value of a firm through the effect of this move on the value of the organisation.

Therefore, managers should make sound decisions when it comes to applying for tax shields in
their area.
How Tax Shields affect Firm Value
Tax shields in an organisation affect the firm’s value in a number of ways as indicated above.
A common understanding is that tax is one of the factors that affect WACC, and in effect the
value of an organisation. The worth of any business is affected by the financing decisions in
the organisations, including the availability of tax shields. The discount rate constitutes one of
the factors that may be adjusted to accommodate changes in the value of organisations. Mintz
and Currim (2013) observe that downward adjustment of discount rate accounts for tax shields.
This downward adjustment results in the increase in value of organisations.
Organisations that use the discount rate to effect changes in their firm value often report success
in the use of the method. When an organisation is awarded tax shields, the value changes to
correspond to the changes introduced through the adjustment of the discount rates. Most
organisations can be described as having debts because of the tax shields that they intend to
acquire.
Therefore, contemporary organisations are prone to debts in their quest to attain tax shields
from the respective authorities. The differences in the contemporary organisations arise from
the different capabilities in the use of their debts. Most organisations whose debt status is high
attain significant tax exemptions. They are valued at higher rank compared to organisations
that have a lower debt position. The tax shields in an organisation, therefore, affect the firm
value in organisations.
Mistakes in Using WACC
Several mistakes are established in literature in the use of WACC. The first mistake is in the
calculation of this variable. In fact, some individuals use variables that are not commonly
applied in the formula. The computation of WACC is tedious due to the many variables that
are necessary for the calculation process. This situation makes the calculation difficult to the
extent that some individuals opt for shortcuts that may not be accurate. The other mistake is
that some individuals assume that the formula may be used in the calculation of WACC for a
particular section of the organisation. They forget that this formula considers the firm a single
unit (Mian & Velez-Pareja 2007).

WACC is useful in providing discount for businesses only where they are applied to
organisations or projects with a similar undertaking to the firm under consideration. For
organisations that differ from the firm under consideration, the formula may not be applicable
or provide useful results. WACC may be useful in most of the calculations where the firm under
consideration has the same size as that of other firms that were initially considered. For projects
that are safer or riskier compared to the original organisation, the calculated WACC may be
inaccurate and in some cases incorrect.
The other mistake that individuals make in the use of WACC is the assumption that it can be
applied as a single variable in the determination of a firm’s value. According to Mian and Velez-
Pareja (2007), organisations require the use of many variables to calculate their value. A single
variable may be deceptive depending on the industry within which the firm is located.
Therefore, there is a need to consider a number of variables in the calculation of a firm’s value
as using WACC alone may be inaccurate. Some of the other mistakes that individuals make in
the use of WACC include miscalculation of the debt and equities that are eventually used in the
calculation of this variable.
Adjusting the WACC
The adjustment of WACC may be done through a number of ways depending on the debt ratios
and the business risks (Mintz & Currim 2013). Adjusting the WACC when the risk of the firm’s
debt ratio and the business risk differ from those of the new project is important in the
calculation of a business’ WACC.
The adjustment of WACC is important when the debt ratios and business risks differ in
organisations. The differences between these two variables result from the changes that are
inherent in the organisations. The three main steps that should be followed when adjusting the
WACC include calculation of the opportunity cost, estimation of the cost of the organisations
debt, and recalculation of the WACC using the obtained new values (Mian & Velez-Pareja
2007).
The adjustment of this value allows the correct calculations where the estimated WACC is
obtained against the real WACC. In cases where the WACC is adjusted, the value of the firm’s
debts and opportunity costs are considered the main reasons for the adjustments. There are
many reasons for the adjustments, with the main one being to increase the accuracy of the final
WACC that is obtained for any given firm. WACC is an indicator of the financing side effect
in an organisation. It is a good indicator of value in organisations (Mintz & Currim 2013).

These financing side effects include the value of interest tax shields on debts (Massari,
Roncaglio & Zanetti 2008). Adjustment of the WACC is also important where the actual value
of a firm is to be estimated.
Valuation in Organisations
Valuation affects the financial decisions that are made in organisations. Most of the decisions
that are important in organisations are made only through the consideration of the value of the
organisation since most managers tend to focus on increasing this value. The many valuation
approaches that are currently in use stem from the extensive research done in this area. These
approaches affect the financing decisions in organisations. The methods of valuation affect the
final variable.
Hence, most of these methods have sub approaches within them. Discounted cash flow is
among the most popular methods that are used in the valuation. This strategy focuses on the
financing decisions in the organisation (Massari, Roncaglio & Zanetti 2008). According to
Dong, Hirshleifer, and Teoh (2012), the main ways of estimating the discounted cash flow
include discounting the cash flow at a risk-adjusted discount (Sabalı 2009). This formula is one
of the four main methods that are used in the discounting cash flows. Using these methods
produces significant results.
Although different methods are in use in the valuation of companies, the same results may be
achieved if the assumptions are withheld for each of the methods. The similarity of these
methods ensures that the result is compatible with the businesses for which it was attempted
first. The different proponents for the different approaches in the valuation methods assume
that their methods are the most accurate. The results indicate that these methods are closely
similar. In relative valuation, which is considered one of the most important valuation methods,
the researchers who proposed the method adopted the assumption of individual assets.
However, these methods have similar results when the different assumptions are withheld.
Conclusion
In conclusion, based on the detailed expositions that have been made in the paper, it is clear
that valuation and financing are closely related when consideration for the financial state of an
organisation is made. Valuation may be estimated in organisations using several methods. Some
of these methods have been stated in this essay. The existence of valuation in financial decisions
allows the organisations to make decisions that coincide with their immediate needs.

The paper has proposed that a relationship between valuation and financial decisions in
organisations. This relationship is affected by other factors such as taxation. The WACC is an
important factor to consider when deducing the relationship between valuation and financial
decisions. The available research proves that this concept is applicable in an organisation’s
financial decisions. The essay has looked at the relationship between WACC and valuation in
organisations and the relationship that exists between these two variables and financial
decisions in an organisation. The paper has proved a positive relationship between these
concepts.
Valuation
The valuation of any organisation allows future decision-making to ensure that it is operating
as per the expectations. Different methods are used in valuation, including those that are
supported by theories and contemporary methods. The present models that are deployed in the
evaluation process are a product of extensive research, with many researchers describing them
before their application in management and finance. What are the motives of company
valuation? Different schools of thought exist as to why company valuation is important.
One of the motives for the evaluations of a company is to make decisions in the organisation.
Depending on the decision that is reached after valuation, the involved individuals may decide
on the future of the organisation and the interventions for the areas that are found faulty.
Motives in company valuation may be characterised in different ways, including decision-
dependent and decision-independent motives (Ishakian, Knebusch & Rowen 2013). The other
category of motives is the transaction based vs the non-transaction-based motives (Ishakian,
Knebusch & Rowen 2013). The other class of motives, as described throughout the literature
on valuation, is the dominated vs the non-dominated decision (Ishakian, Knebusch & Rowen
2013).
Valuation serves different functions depending on the concerned firm or organisation. These
functions can be categorised further into minor and major functions. The main functions of
valuation in organisations include decision-making and consultation. According to Ishakian,
Knebusch, and Rowen (2013), managers and other stakeholders use valuation information in
an organisation to make decisions on the future of the organisation with the aim of improving
the organisational performance. Different firms operate on different grounds. They use
different methods of valuation to make financial and other forms of decisions in the
organisation.

The other function of valuation, according to Koziol (2014), is mediation where the firm uses
information from valuation to mediate between concepts, decisions, and individuals.
Hundsdoerfer, Kruschwitz, and Loren (2008) assert that mediation in an organisation provides
crucial information on the financial position of the organisation. Valuation also serves as a
means of argumentation. Using information from valuation, managers and other organisational
stakeholders can argue on the position of the organisation. The information is used to provide
details on the organisational performance, which is important in making a case for any
argument.
Apart from the main functions of valuation, valuation serves other auxiliary functions. One of
these auxiliary functions is information where the parties within an organisation gather
information on this organisation, including its performance and future expectations. Valuation
may also be used as a means of tax measurement where authorities determine the tax that an
organisation should forward over a given period. Many organisations where valuation has been
conducted were found to have some tax measurements, not in line with the expected values
(Mian & Velez-Pareja 2007). Valuation also serves the function of contract configuration where
employees and other parties in the organisation can have their contracts configured with the
expectations of the organisation.
Valuation Methods
Different valuation methods are in use in many organisations. Each of these methods provides
different results. The decision to use one of them is dependent on the firm that is being
evaluated, the financial methods in place, and the preferred approach. The most popular
approach depends on the organisation and the region where these organisations exist. Different
methods that are used in valuation are shown below.
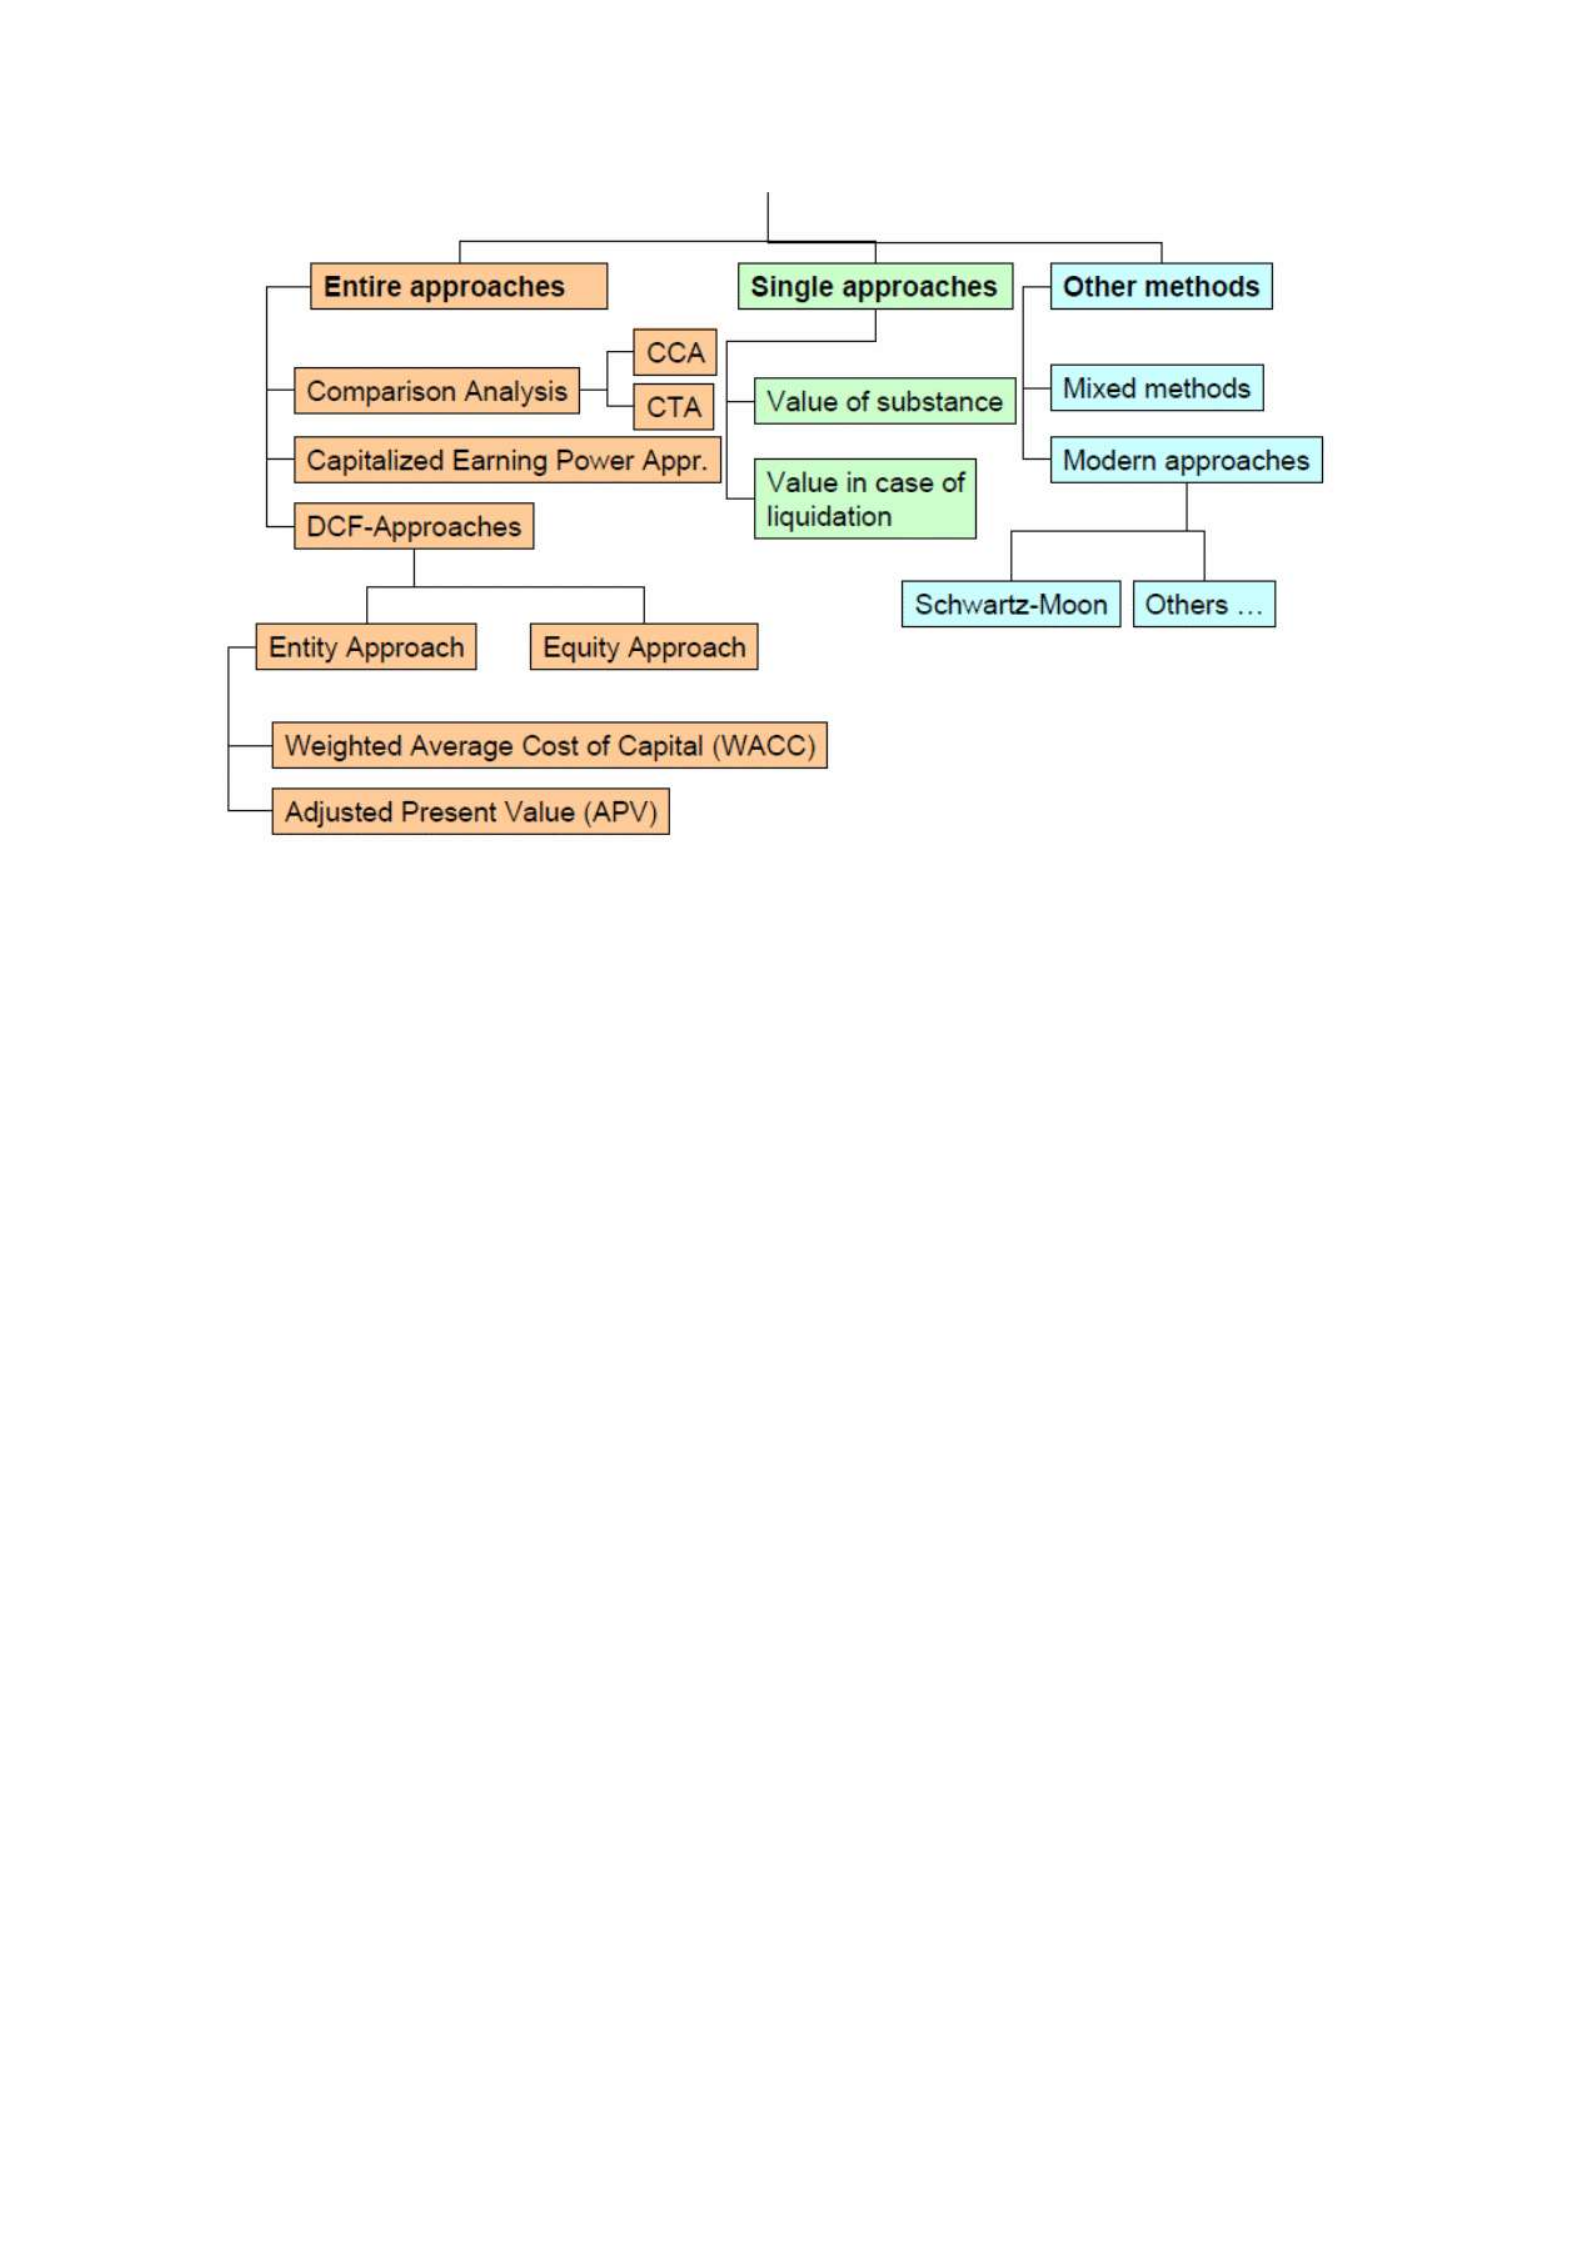
Figure 1: An Overview of Valuation Methods (Source Mian & Velez-Pareja 2007)
Different models that are applied during a valuation in organisations lead to a common result
where the organisations are able to plan for future decisions and changes. The valuation that is
obtained in organisations, irrespective of the method used, provides crucial information on the
financial status of the organisation. However, valuation within organisations also allows the
inception of changes whenever they are needed.
Financial Decisions
Organisations face challenges in financing, with one of the most common of them being the
outcomes of financial decisions. Competitiveness in organisations is influenced by the financial
decisions that managers and other stakeholders make. In any industry, financial decisions affect
the outcomes of the interactions between different factors. The financial decisions in an
organisation are also under the influence of other factors such as the valuation in these
organisations. A business in any industry or market must use capital as one of the main factors
in its operations, with this strategy bringing about the cost of capital.
Currently, there are no perfect markets in contemporary organisations. Hence, capital is not
always put to the intended use. A perfect business environment is the only place where capital
can be put to its planned use. However, conditions that are necessary for a perfect market are
hard to achieve. Nevertheless, if it were possible, the perfect world would have an excess
supply of capital. A perfect capital market might mean that the available unlimited capital is
only dependent on the risk of the project being undertaken (Spiegel, & Tookes 2013).

Aside from the perfect capital market, uncertainties, variables, and friction characterise the
existing real-world capital markets. The availability of tax as one of the variables in an
imperfect world ensures that organisations adopt strategies such as debts. An example of such
strategies is when an organisation operates in a capital structure with about 100% of debt
because of the positive corporate tax rate (Spiegel, & Tookes, 2013). Other factors that exist in
an imperfect world to introduce a relationship between valuations and financing include agency
costs, financial distress costs, and information asymmetries (Spiegel, & Tookes, 2013).
The financial position of an organisation ensures that the organisation can persist in an
environment where competition is an evident factor. Valuation effects that financial position of
an organisation. The reverse is also true. The decisions made in an organisation relating to the
financial positions of the organisation may be based on the valuation that is provided for this
organisation.
Weighted Average Cost of Capital
The calculation of the cost of capital is an intricate process that requires the participation of all
stakeholders. The cost of capital is calculated through the estimation of the proportion of debt
that a project consumes against the equity that is absorbed in the respective project (Massari,
Roncaglio & Zanetti 2008). The weighted average cost of capital (WACC) is calculated through
a formula that incorporates the market value of equity and debt (Massari, Roncaglio & Zanetti
2008). These values are adjusted using the costs of debt and equity. For a single firm, the
WACC is calculated as a single unit where the firm is the reference. The organisation, in this
case, is considered a single unit, with the results being for a single project.
The Weighted Average Cost of Capital is an indicator of the financial performance of an
organisation because it indicates the financial position of the organisation under discussion.
Any organisation with sound financial decisions has a favourable WACC, which is considered
a strength in these organisations. The calculation and use of WACC in financial discussions
and problem-solving is challenging for some financial analysts and other financial decision-
makers in organisations. Therefore, it is important to have a discussion on the correct use of
WACC and its implications on the financial decisions in organisations.
The other difficulty in the calculation and use of WACC is tax calculation. Different finance
officers use different methods of calculating the variables (Sabalı 2009). Financing and
investment decisions interact through taxes. WACC is an important concept in evaluating this

interaction. The formula that is used in the calculation of WACC refers to the organisation of
company as a whole upon incorporating the different aspects in financial decisions in the firm.
Therefore, this formula is effective for the “average project” where the right discount rate is
produced (Massari, Roncaglio & Zanetti 2008). Hence, the formula is incorrect when used in
the calculation of WACC for the safer and riskier projects (Magni 2012). The inaccuracy while
using this formula mainly stems from the different sections that individuals calculate in an
organisation, especially where the organisation has different departments.
Capital Structure and Valuations
Capital structure in a firm is a factor that affects valuations in these organisations. The effects
depend on the existing capital structure. According to Sabalı (2009), financing decisions
typically affect value within organisations. Some of the ways that boost value in a firm with
respect to its financing decisions is through the adjustment of the discount rate and the present
value (Massari, Roncaglio & Zanetti 2008).
The discount rate in most organisations is typically adjusted downwards, with the aim being to
account for the existing tax shields (Massari, Roncaglio & Zanetti 2008). Financing decisions
also affect value in organisations through adjusting the present value in these organisations
(Massari, Roncaglio & Zanetti 2008). According to Spiegel and Tookes (2013), the base case
is first calculated with the assumption that it is all equity financed.
Capital structure in organisations affects the value of the organisation from its first year of
operation. The capital structure in organisations is variable depending on several factors such
as the capital debt and the type of industry within which a firm is located. The tax on a firm is
a major factor with reference to its capital value, especially because the tax determines the debt
status of an organisation (Sabalı 2009).
The initial cash that is invested into a firm in the first year affects the value of an organisation
during this year. Most of the organisations that invest significant amounts of capital into their
operations end up being successful in the first year. Over the years that follow, the WACC
formula is highly applicable, as the organisational debts and equities change.
Capital structure in most organisations is affected by the financial decisions made by the
executive. Hence, the value of organisations is dependent on the type of managers that an
organisation keeps. The value of organisation changes with any financial decision made, since
the debt and equities change with these decisions (Massari, Roncaglio & Zanetti 2008).

The value of a firm may be calculated through the estimation of the WACC, which is later used
to discount the FCFF from the debt holders and equity capital contributors (Massari, Roncaglio
& Zanetti 2008). The use of WACC in the estimation of a firm’s value is very effective by far
compared to other methods of value estimation. This finding indicates a relationship between
the value of organisations and the WACC. The WACC is in turn related to the financial
decisions in an organisation. Hence, valuation is related to the financial decisions in the
organisation.
Impact of Tax Shields on WACC
According to Massari, Roncaglio, and Zanetti (2008), tax is a variable in an organisation that
affects the value of these organisations. Interest in organisations is one of the expenses that are
usually considered as tax-deductible expense (Massari, Roncaglio & Zanetti 2008). The
calculation of WACC incorporates tax as a major form of expense. This strategy determines
the value of organisations. However, tax shields in organisations may affect the calculation of
WACC. The effects of tax shields on WACC depend on the business and individuals who are
responsible for financial management in the respective institutions.
The tax shields cause changes on WACC in a number of ways. However, while these effects
are dependent on the type of organisation, the main effect is that the WACC increases with a
reduction in tax shields. Most organisations seek tax shields to lower their WACC and in effect
influence the value and competitiveness of their respective industries. A common result of tax
shields is a downward adjustment of the discount rate to account for any changes in this area
(Massari, Roncaglio & Zanetti 2008). The downward adjustment of discount rates in
organisations allows decisions to be made on the WACC and its overall effect on the firm’s
value.
Tax shields help organisations save their available financial resources, including the provision
of future resources. In areas where tax shields are effectively applied, firms report better results,
performance, and competitiveness compared to areas where these policies are scantily applied.
Adjusting the discount rate downwards is one of the ways that tax shields are accounted for.
The result of this case is a change on the value of firms (Massari, Roncaglio & Zanetti 2008).
The relationship between value of an organisation and tax shields may be demonstrated by the
inherent differences between organisations that operate in different regions with different tax
shield regimens. According to Massari, Roncaglio, and Zanetti (2008), adjustment of WACC
should affect the value of a firm through the effect of this move on the value of the organisation.

Therefore, managers should make sound decisions when it comes to applying for tax shields in
their area.
How Tax Shields affect Firm Value
Tax shields in an organisation affect the firm’s value in a number of ways as indicated above.
A common understanding is that tax is one of the factors that affect WACC, and in effect the
value of an organisation. The worth of any business is affected by the financing decisions in
the organisations, including the availability of tax shields. The discount rate constitutes one of
the factors that may be adjusted to accommodate changes in the value of organisations. Mintz
and Currim (2013) observe that downward adjustment of discount rate accounts for tax shields.
This downward adjustment results in the increase in value of organisations.
Organisations that use the discount rate to effect changes in their firm value often report success
in the use of the method. When an organisation is awarded tax shields, the value changes to
correspond to the changes introduced through the adjustment of the discount rates. Most
organisations can be described as having debts because of the tax shields that they intend to
acquire.
Therefore, contemporary organisations are prone to debts in their quest to attain tax shields
from the respective authorities. The differences in the contemporary organisations arise from
the different capabilities in the use of their debts. Most organisations whose debt status is high
attain significant tax exemptions. They are valued at higher rank compared to organisations
that have a lower debt position. The tax shields in an organisation, therefore, affect the firm
value in organisations.
Mistakes in Using WACC
Several mistakes are established in literature in the use of WACC. The first mistake is in the
calculation of this variable. In fact, some individuals use variables that are not commonly
applied in the formula. The computation of WACC is tedious due to the many variables that
are necessary for the calculation process. This situation makes the calculation difficult to the
extent that some individuals opt for shortcuts that may not be accurate. The other mistake is
that some individuals assume that the formula may be used in the calculation of WACC for a
particular section of the organisation. They forget that this formula considers the firm a single
unit (Mian & Velez-Pareja 2007).

WACC is useful in providing discount for businesses only where they are applied to
organisations or projects with a similar undertaking to the firm under consideration. For
organisations that differ from the firm under consideration, the formula may not be applicable
or provide useful results. WACC may be useful in most of the calculations where the firm under
consideration has the same size as that of other firms that were initially considered. For projects
that are safer or riskier compared to the original organisation, the calculated WACC may be
inaccurate and in some cases incorrect.
The other mistake that individuals make in the use of WACC is the assumption that it can be
applied as a single variable in the determination of a firm’s value. According to Mian and Velez-
Pareja (2007), organisations require the use of many variables to calculate their value. A single
variable may be deceptive depending on the industry within which the firm is located.
Therefore, there is a need to consider a number of variables in the calculation of a firm’s value
as using WACC alone may be inaccurate. Some of the other mistakes that individuals make in
the use of WACC include miscalculation of the debt and equities that are eventually used in the
calculation of this variable.
Adjusting the WACC
The adjustment of WACC may be done through a number of ways depending on the debt ratios
and the business risks (Mintz & Currim 2013). Adjusting the WACC when the risk of the firm’s
debt ratio and the business risk differ from those of the new project is important in the
calculation of a business’ WACC.
The adjustment of WACC is important when the debt ratios and business risks differ in
organisations. The differences between these two variables result from the changes that are
inherent in the organisations. The three main steps that should be followed when adjusting the
WACC include calculation of the opportunity cost, estimation of the cost of the organisations
debt, and recalculation of the WACC using the obtained new values (Mian & Velez-Pareja
2007).
The adjustment of this value allows the correct calculations where the estimated WACC is
obtained against the real WACC. In cases where the WACC is adjusted, the value of the firm’s
debts and opportunity costs are considered the main reasons for the adjustments. There are
many reasons for the adjustments, with the main one being to increase the accuracy of the final
WACC that is obtained for any given firm. WACC is an indicator of the financing side effect
in an organisation. It is a good indicator of value in organisations (Mintz & Currim 2013).

These financing side effects include the value of interest tax shields on debts (Massari,
Roncaglio & Zanetti 2008). Adjustment of the WACC is also important where the actual value
of a firm is to be estimated.
Valuation in Organisations
Valuation affects the financial decisions that are made in organisations. Most of the decisions
that are important in organisations are made only through the consideration of the value of the
organisation since most managers tend to focus on increasing this value. The many valuation
approaches that are currently in use stem from the extensive research done in this area. These
approaches affect the financing decisions in organisations. The methods of valuation affect the
final variable.
Hence, most of these methods have sub approaches within them. Discounted cash flow is
among the most popular methods that are used in the valuation. This strategy focuses on the
financing decisions in the organisation (Massari, Roncaglio & Zanetti 2008). According to
Dong, Hirshleifer, and Teoh (2012), the main ways of estimating the discounted cash flow
include discounting the cash flow at a risk-adjusted discount (Sabalı 2009). This formula is one
of the four main methods that are used in the discounting cash flows. Using these methods
produces significant results.
Although different methods are in use in the valuation of companies, the same results may be
achieved if the assumptions are withheld for each of the methods. The similarity of these
methods ensures that the result is compatible with the businesses for which it was attempted
first. The different proponents for the different approaches in the valuation methods assume
that their methods are the most accurate. The results indicate that these methods are closely
similar. In relative valuation, which is considered one of the most important valuation methods,
the researchers who proposed the method adopted the assumption of individual assets.
However, these methods have similar results when the different assumptions are withheld.
Conclusion
In conclusion, based on the detailed expositions that have been made in the paper, it is clear
that valuation and financing are closely related when consideration for the financial state of an
organisation is made. Valuation may be estimated in organisations using several methods. Some
of these methods have been stated in this essay. The existence of valuation in financial decisions
allows the organisations to make decisions that coincide with their immediate needs.

The paper has proposed that a relationship between valuation and financial decisions in
organisations. This relationship is affected by other factors such as taxation. The WACC is an
important factor to consider when deducing the relationship between valuation and financial
decisions. The available research proves that this concept is applicable in an organisation’s
financial decisions. The essay has looked at the relationship between WACC and valuation in
organisations and the relationship that exists between these two variables and financial
decisions in an organisation. The paper has proved a positive relationship between these
concepts.
Valuation
The valuation of any organisation allows future decision-making to ensure that it is operating
as per the expectations. Different methods are used in valuation, including those that are
supported by theories and contemporary methods. The present models that are deployed in the
evaluation process are a product of extensive research, with many researchers describing them
before their application in management and finance. What are the motives of company
valuation? Different schools of thought exist as to why company valuation is important.
One of the motives for the evaluations of a company is to make decisions in the organisation.
Depending on the decision that is reached after valuation, the involved individuals may decide
on the future of the organisation and the interventions for the areas that are found faulty.
Motives in company valuation may be characterised in different ways, including decision-
dependent and decision-independent motives (Ishakian, Knebusch & Rowen 2013). The other
category of motives is the transaction based vs the non-transaction-based motives (Ishakian,
Knebusch & Rowen 2013). The other class of motives, as described throughout the literature
on valuation, is the dominated vs the non-dominated decision (Ishakian, Knebusch & Rowen
2013).
Valuation serves different functions depending on the concerned firm or organisation. These
functions can be categorised further into minor and major functions. The main functions of
valuation in organisations include decision-making and consultation. According to Ishakian,
Knebusch, and Rowen (2013), managers and other stakeholders use valuation information in
an organisation to make decisions on the future of the organisation with the aim of improving
the organisational performance. Different firms operate on different grounds. They use
different methods of valuation to make financial and other forms of decisions in the
organisation.

The other function of valuation, according to Koziol (2014), is mediation where the firm uses
information from valuation to mediate between concepts, decisions, and individuals.
Hundsdoerfer, Kruschwitz, and Loren (2008) assert that mediation in an organisation provides
crucial information on the financial position of the organisation. Valuation also serves as a
means of argumentation. Using information from valuation, managers and other organisational
stakeholders can argue on the position of the organisation. The information is used to provide
details on the organisational performance, which is important in making a case for any
argument.
Apart from the main functions of valuation, valuation serves other auxiliary functions. One of
these auxiliary functions is information where the parties within an organisation gather
information on this organisation, including its performance and future expectations. Valuation
may also be used as a means of tax measurement where authorities determine the tax that an
organisation should forward over a given period. Many organisations where valuation has been
conducted were found to have some tax measurements, not in line with the expected values
(Mian & Velez-Pareja 2007). Valuation also serves the function of contract configuration where
employees and other parties in the organisation can have their contracts configured with the
expectations of the organisation.
Valuation Methods
Different valuation methods are in use in many organisations. Each of these methods provides
different results. The decision to use one of them is dependent on the firm that is being
evaluated, the financial methods in place, and the preferred approach. The most popular
approach depends on the organisation and the region where these organisations exist. Different
methods that are used in valuation are shown below.
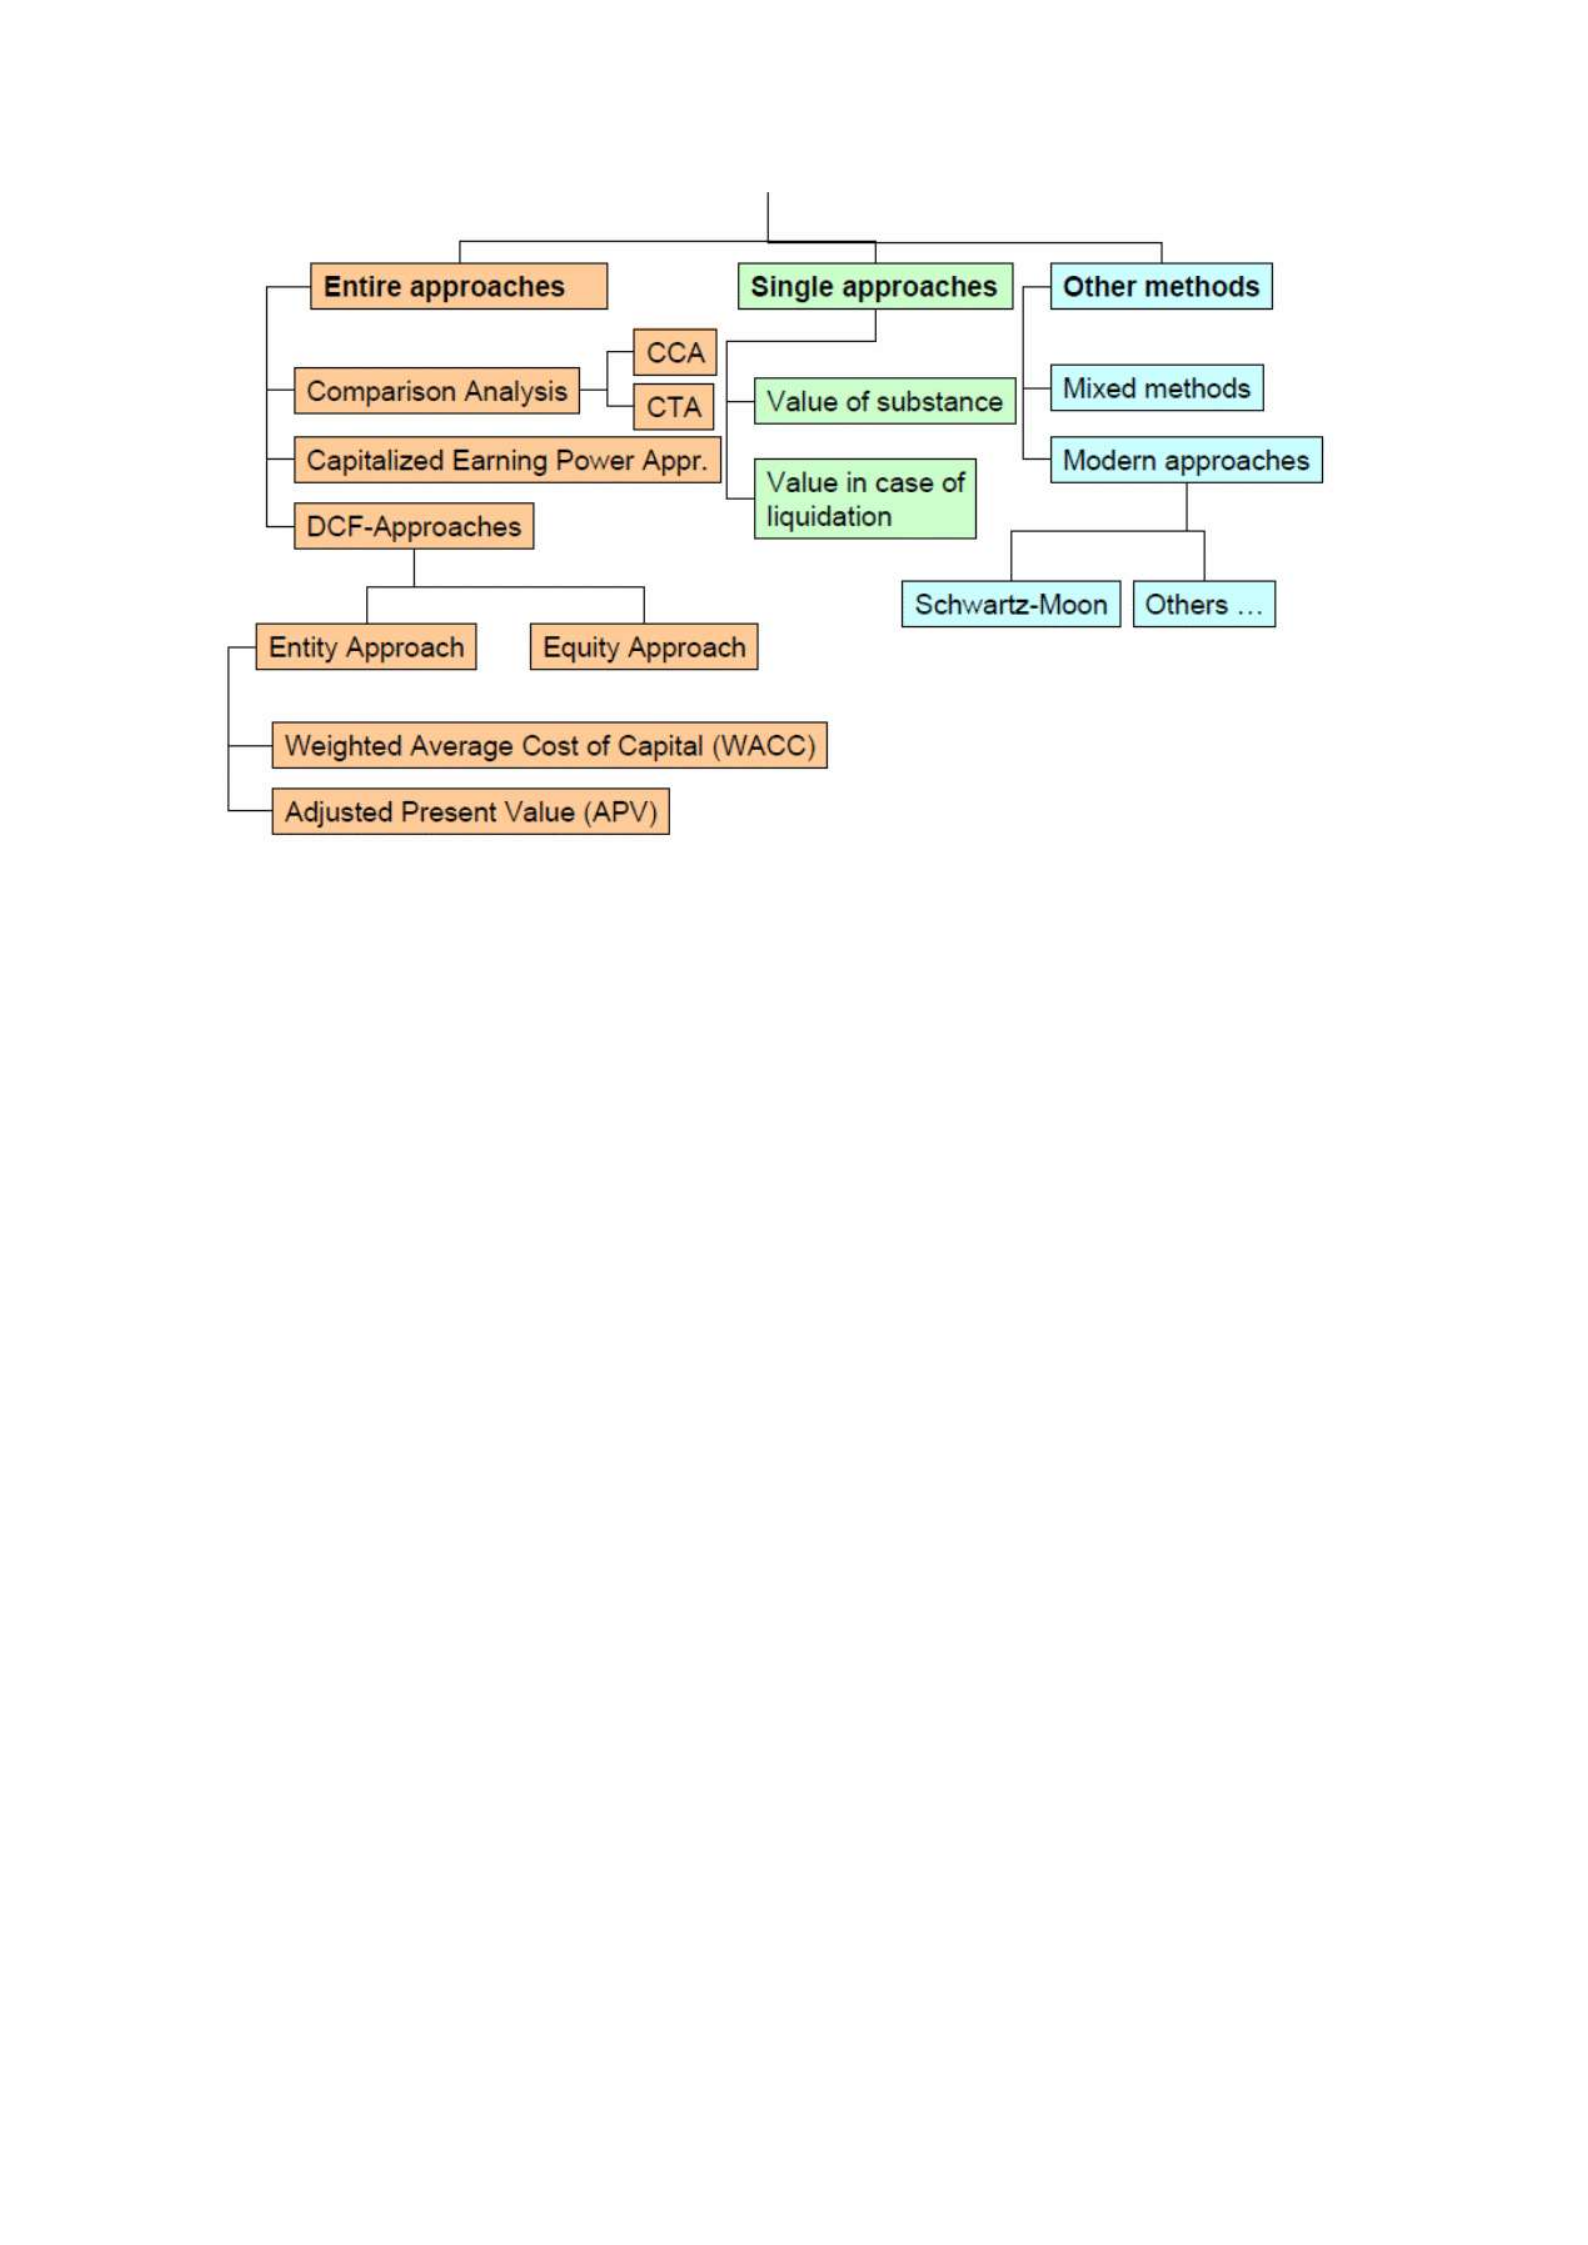
Figure 1: An Overview of Valuation Methods (Source Mian & Velez-Pareja 2007)
Different models that are applied during a valuation in organisations lead to a common result
where the organisations are able to plan for future decisions and changes. The valuation that is
obtained in organisations, irrespective of the method used, provides crucial information on the
financial status of the organisation. However, valuation within organisations also allows the
inception of changes whenever they are needed.
Financial Decisions
Organisations face challenges in financing, with one of the most common of them being the
outcomes of financial decisions. Competitiveness in organisations is influenced by the financial
decisions that managers and other stakeholders make. In any industry, financial decisions affect
the outcomes of the interactions between different factors. The financial decisions in an
organisation are also under the influence of other factors such as the valuation in these
organisations. A business in any industry or market must use capital as one of the main factors
in its operations, with this strategy bringing about the cost of capital.
Currently, there are no perfect markets in contemporary organisations. Hence, capital is not
always put to the intended use. A perfect business environment is the only place where capital
can be put to its planned use. However, conditions that are necessary for a perfect market are
hard to achieve. Nevertheless, if it were possible, the perfect world would have an excess
supply of capital. A perfect capital market might mean that the available unlimited capital is
only dependent on the risk of the project being undertaken (Spiegel, & Tookes 2013).

Aside from the perfect capital market, uncertainties, variables, and friction characterise the
existing real-world capital markets. The availability of tax as one of the variables in an
imperfect world ensures that organisations adopt strategies such as debts. An example of such
strategies is when an organisation operates in a capital structure with about 100% of debt
because of the positive corporate tax rate (Spiegel, & Tookes, 2013). Other factors that exist in
an imperfect world to introduce a relationship between valuations and financing include agency
costs, financial distress costs, and information asymmetries (Spiegel, & Tookes, 2013).
The financial position of an organisation ensures that the organisation can persist in an
environment where competition is an evident factor. Valuation effects that financial position of
an organisation. The reverse is also true. The decisions made in an organisation relating to the
financial positions of the organisation may be based on the valuation that is provided for this
organisation.
Weighted Average Cost of Capital
The calculation of the cost of capital is an intricate process that requires the participation of all
stakeholders. The cost of capital is calculated through the estimation of the proportion of debt
that a project consumes against the equity that is absorbed in the respective project (Massari,
Roncaglio & Zanetti 2008). The weighted average cost of capital (WACC) is calculated through
a formula that incorporates the market value of equity and debt (Massari, Roncaglio & Zanetti
2008). These values are adjusted using the costs of debt and equity. For a single firm, the
WACC is calculated as a single unit where the firm is the reference. The organisation, in this
case, is considered a single unit, with the results being for a single project.
The Weighted Average Cost of Capital is an indicator of the financial performance of an
organisation because it indicates the financial position of the organisation under discussion.
Any organisation with sound financial decisions has a favourable WACC, which is considered
a strength in these organisations. The calculation and use of WACC in financial discussions
and problem-solving is challenging for some financial analysts and other financial decision-
makers in organisations. Therefore, it is important to have a discussion on the correct use of
WACC and its implications on the financial decisions in organisations.
The other difficulty in the calculation and use of WACC is tax calculation. Different finance
officers use different methods of calculating the variables (Sabalı 2009). Financing and
investment decisions interact through taxes. WACC is an important concept in evaluating this

interaction. The formula that is used in the calculation of WACC refers to the organisation of
company as a whole upon incorporating the different aspects in financial decisions in the firm.
Therefore, this formula is effective for the “average project” where the right discount rate is
produced (Massari, Roncaglio & Zanetti 2008). Hence, the formula is incorrect when used in
the calculation of WACC for the safer and riskier projects (Magni 2012). The inaccuracy while
using this formula mainly stems from the different sections that individuals calculate in an
organisation, especially where the organisation has different departments.
Capital Structure and Valuations
Capital structure in a firm is a factor that affects valuations in these organisations. The effects
depend on the existing capital structure. According to Sabalı (2009), financing decisions
typically affect value within organisations. Some of the ways that boost value in a firm with
respect to its financing decisions is through the adjustment of the discount rate and the present
value (Massari, Roncaglio & Zanetti 2008).
The discount rate in most organisations is typically adjusted downwards, with the aim being to
account for the existing tax shields (Massari, Roncaglio & Zanetti 2008). Financing decisions
also affect value in organisations through adjusting the present value in these organisations
(Massari, Roncaglio & Zanetti 2008). According to Spiegel and Tookes (2013), the base case
is first calculated with the assumption that it is all equity financed.
Capital structure in organisations affects the value of the organisation from its first year of
operation. The capital structure in organisations is variable depending on several factors such
as the capital debt and the type of industry within which a firm is located. The tax on a firm is
a major factor with reference to its capital value, especially because the tax determines the debt
status of an organisation (Sabalı 2009).
The initial cash that is invested into a firm in the first year affects the value of an organisation
during this year. Most of the organisations that invest significant amounts of capital into their
operations end up being successful in the first year. Over the years that follow, the WACC
formula is highly applicable, as the organisational debts and equities change.
Capital structure in most organisations is affected by the financial decisions made by the
executive. Hence, the value of organisations is dependent on the type of managers that an
organisation keeps. The value of organisation changes with any financial decision made, since
the debt and equities change with these decisions (Massari, Roncaglio & Zanetti 2008).

The value of a firm may be calculated through the estimation of the WACC, which is later used
to discount the FCFF from the debt holders and equity capital contributors (Massari, Roncaglio
& Zanetti 2008). The use of WACC in the estimation of a firm’s value is very effective by far
compared to other methods of value estimation. This finding indicates a relationship between
the value of organisations and the WACC. The WACC is in turn related to the financial
decisions in an organisation. Hence, valuation is related to the financial decisions in the
organisation.
Impact of Tax Shields on WACC
According to Massari, Roncaglio, and Zanetti (2008), tax is a variable in an organisation that
affects the value of these organisations. Interest in organisations is one of the expenses that are
usually considered as tax-deductible expense (Massari, Roncaglio & Zanetti 2008). The
calculation of WACC incorporates tax as a major form of expense. This strategy determines
the value of organisations. However, tax shields in organisations may affect the calculation of
WACC. The effects of tax shields on WACC depend on the business and individuals who are
responsible for financial management in the respective institutions.
The tax shields cause changes on WACC in a number of ways. However, while these effects
are dependent on the type of organisation, the main effect is that the WACC increases with a
reduction in tax shields. Most organisations seek tax shields to lower their WACC and in effect
influence the value and competitiveness of their respective industries. A common result of tax
shields is a downward adjustment of the discount rate to account for any changes in this area
(Massari, Roncaglio & Zanetti 2008). The downward adjustment of discount rates in
organisations allows decisions to be made on the WACC and its overall effect on the firm’s
value.
Tax shields help organisations save their available financial resources, including the provision
of future resources. In areas where tax shields are effectively applied, firms report better results,
performance, and competitiveness compared to areas where these policies are scantily applied.
Adjusting the discount rate downwards is one of the ways that tax shields are accounted for.
The result of this case is a change on the value of firms (Massari, Roncaglio & Zanetti 2008).
The relationship between value of an organisation and tax shields may be demonstrated by the
inherent differences between organisations that operate in different regions with different tax
shield regimens. According to Massari, Roncaglio, and Zanetti (2008), adjustment of WACC
should affect the value of a firm through the effect of this move on the value of the organisation.

Therefore, managers should make sound decisions when it comes to applying for tax shields in
their area.
How Tax Shields affect Firm Value
Tax shields in an organisation affect the firm’s value in a number of ways as indicated above.
A common understanding is that tax is one of the factors that affect WACC, and in effect the
value of an organisation. The worth of any business is affected by the financing decisions in
the organisations, including the availability of tax shields. The discount rate constitutes one of
the factors that may be adjusted to accommodate changes in the value of organisations. Mintz
and Currim (2013) observe that downward adjustment of discount rate accounts for tax shields.
This downward adjustment results in the increase in value of organisations.
Organisations that use the discount rate to effect changes in their firm value often report success
in the use of the method. When an organisation is awarded tax shields, the value changes to
correspond to the changes introduced through the adjustment of the discount rates. Most
organisations can be described as having debts because of the tax shields that they intend to
acquire.
Therefore, contemporary organisations are prone to debts in their quest to attain tax shields
from the respective authorities. The differences in the contemporary organisations arise from
the different capabilities in the use of their debts. Most organisations whose debt status is high
attain significant tax exemptions. They are valued at higher rank compared to organisations
that have a lower debt position. The tax shields in an organisation, therefore, affect the firm
value in organisations.
Mistakes in Using WACC
Several mistakes are established in literature in the use of WACC. The first mistake is in the
calculation of this variable. In fact, some individuals use variables that are not commonly
applied in the formula. The computation of WACC is tedious due to the many variables that
are necessary for the calculation process. This situation makes the calculation difficult to the
extent that some individuals opt for shortcuts that may not be accurate. The other mistake is
that some individuals assume that the formula may be used in the calculation of WACC for a
particular section of the organisation. They forget that this formula considers the firm a single
unit (Mian & Velez-Pareja 2007).

WACC is useful in providing discount for businesses only where they are applied to
organisations or projects with a similar undertaking to the firm under consideration. For
organisations that differ from the firm under consideration, the formula may not be applicable
or provide useful results. WACC may be useful in most of the calculations where the firm under
consideration has the same size as that of other firms that were initially considered. For projects
that are safer or riskier compared to the original organisation, the calculated WACC may be
inaccurate and in some cases incorrect.
The other mistake that individuals make in the use of WACC is the assumption that it can be
applied as a single variable in the determination of a firm’s value. According to Mian and Velez-
Pareja (2007), organisations require the use of many variables to calculate their value. A single
variable may be deceptive depending on the industry within which the firm is located.
Therefore, there is a need to consider a number of variables in the calculation of a firm’s value
as using WACC alone may be inaccurate. Some of the other mistakes that individuals make in
the use of WACC include miscalculation of the debt and equities that are eventually used in the
calculation of this variable.
Adjusting the WACC
The adjustment of WACC may be done through a number of ways depending on the debt ratios
and the business risks (Mintz & Currim 2013). Adjusting the WACC when the risk of the firm’s
debt ratio and the business risk differ from those of the new project is important in the
calculation of a business’ WACC.
The adjustment of WACC is important when the debt ratios and business risks differ in
organisations. The differences between these two variables result from the changes that are
inherent in the organisations. The three main steps that should be followed when adjusting the
WACC include calculation of the opportunity cost, estimation of the cost of the organisations
debt, and recalculation of the WACC using the obtained new values (Mian & Velez-Pareja
2007).
The adjustment of this value allows the correct calculations where the estimated WACC is
obtained against the real WACC. In cases where the WACC is adjusted, the value of the firm’s
debts and opportunity costs are considered the main reasons for the adjustments. There are
many reasons for the adjustments, with the main one being to increase the accuracy of the final
WACC that is obtained for any given firm. WACC is an indicator of the financing side effect
in an organisation. It is a good indicator of value in organisations (Mintz & Currim 2013).

These financing side effects include the value of interest tax shields on debts (Massari,
Roncaglio & Zanetti 2008). Adjustment of the WACC is also important where the actual value
of a firm is to be estimated.
Valuation in Organisations
Valuation affects the financial decisions that are made in organisations. Most of the decisions
that are important in organisations are made only through the consideration of the value of the
organisation since most managers tend to focus on increasing this value. The many valuation
approaches that are currently in use stem from the extensive research done in this area. These
approaches affect the financing decisions in organisations. The methods of valuation affect the
final variable.
Hence, most of these methods have sub approaches within them. Discounted cash flow is
among the most popular methods that are used in the valuation. This strategy focuses on the
financing decisions in the organisation (Massari, Roncaglio & Zanetti 2008). According to
Dong, Hirshleifer, and Teoh (2012), the main ways of estimating the discounted cash flow
include discounting the cash flow at a risk-adjusted discount (Sabalı 2009). This formula is one
of the four main methods that are used in the discounting cash flows. Using these methods
produces significant results.
Although different methods are in use in the valuation of companies, the same results may be
achieved if the assumptions are withheld for each of the methods. The similarity of these
methods ensures that the result is compatible with the businesses for which it was attempted
first. The different proponents for the different approaches in the valuation methods assume
that their methods are the most accurate. The results indicate that these methods are closely
similar. In relative valuation, which is considered one of the most important valuation methods,
the researchers who proposed the method adopted the assumption of individual assets.
However, these methods have similar results when the different assumptions are withheld.
Conclusion
In conclusion, based on the detailed expositions that have been made in the paper, it is clear
that valuation and financing are closely related when consideration for the financial state of an
organisation is made. Valuation may be estimated in organisations using several methods. Some
of these methods have been stated in this essay. The existence of valuation in financial decisions
allows the organisations to make decisions that coincide with their immediate needs.

The paper has proposed that a relationship between valuation and financial decisions in
organisations. This relationship is affected by other factors such as taxation. The WACC is an
important factor to consider when deducing the relationship between valuation and financial
decisions. The available research proves that this concept is applicable in an organisation’s
financial decisions. The essay has looked at the relationship between WACC and valuation in
organisations and the relationship that exists between these two variables and financial
decisions in an organisation. The paper has proved a positive relationship between these
concepts.
Valuation
The valuation of any organisation allows future decision-making to ensure that it is operating
as per the expectations. Different methods are used in valuation, including those that are
supported by theories and contemporary methods. The present models that are deployed in the
evaluation process are a product of extensive research, with many researchers describing them
before their application in management and finance. What are the motives of company
valuation? Different schools of thought exist as to why company valuation is important.
One of the motives for the evaluations of a company is to make decisions in the organisation.
Depending on the decision that is reached after valuation, the involved individuals may decide
on the future of the organisation and the interventions for the areas that are found faulty.
Motives in company valuation may be characterised in different ways, including decision-
dependent and decision-independent motives (Ishakian, Knebusch & Rowen 2013). The other
category of motives is the transaction based vs the non-transaction-based motives (Ishakian,
Knebusch & Rowen 2013). The other class of motives, as described throughout the literature
on valuation, is the dominated vs the non-dominated decision (Ishakian, Knebusch & Rowen
2013).
Valuation serves different functions depending on the concerned firm or organisation. These
functions can be categorised further into minor and major functions. The main functions of
valuation in organisations include decision-making and consultation. According to Ishakian,
Knebusch, and Rowen (2013), managers and other stakeholders use valuation information in
an organisation to make decisions on the future of the organisation with the aim of improving
the organisational performance. Different firms operate on different grounds. They use
different methods of valuation to make financial and other forms of decisions in the
organisation.

The other function of valuation, according to Koziol (2014), is mediation where the firm uses
information from valuation to mediate between concepts, decisions, and individuals.
Hundsdoerfer, Kruschwitz, and Loren (2008) assert that mediation in an organisation provides
crucial information on the financial position of the organisation. Valuation also serves as a
means of argumentation. Using information from valuation, managers and other organisational
stakeholders can argue on the position of the organisation. The information is used to provide
details on the organisational performance, which is important in making a case for any
argument.
Apart from the main functions of valuation, valuation serves other auxiliary functions. One of
these auxiliary functions is information where the parties within an organisation gather
information on this organisation, including its performance and future expectations. Valuation
may also be used as a means of tax measurement where authorities determine the tax that an
organisation should forward over a given period. Many organisations where valuation has been
conducted were found to have some tax measurements, not in line with the expected values
(Mian & Velez-Pareja 2007). Valuation also serves the function of contract configuration where
employees and other parties in the organisation can have their contracts configured with the
expectations of the organisation.
Valuation Methods
Different valuation methods are in use in many organisations. Each of these methods provides
different results. The decision to use one of them is dependent on the firm that is being
evaluated, the financial methods in place, and the preferred approach. The most popular
approach depends on the organisation and the region where these organisations exist. Different
methods that are used in valuation are shown below.
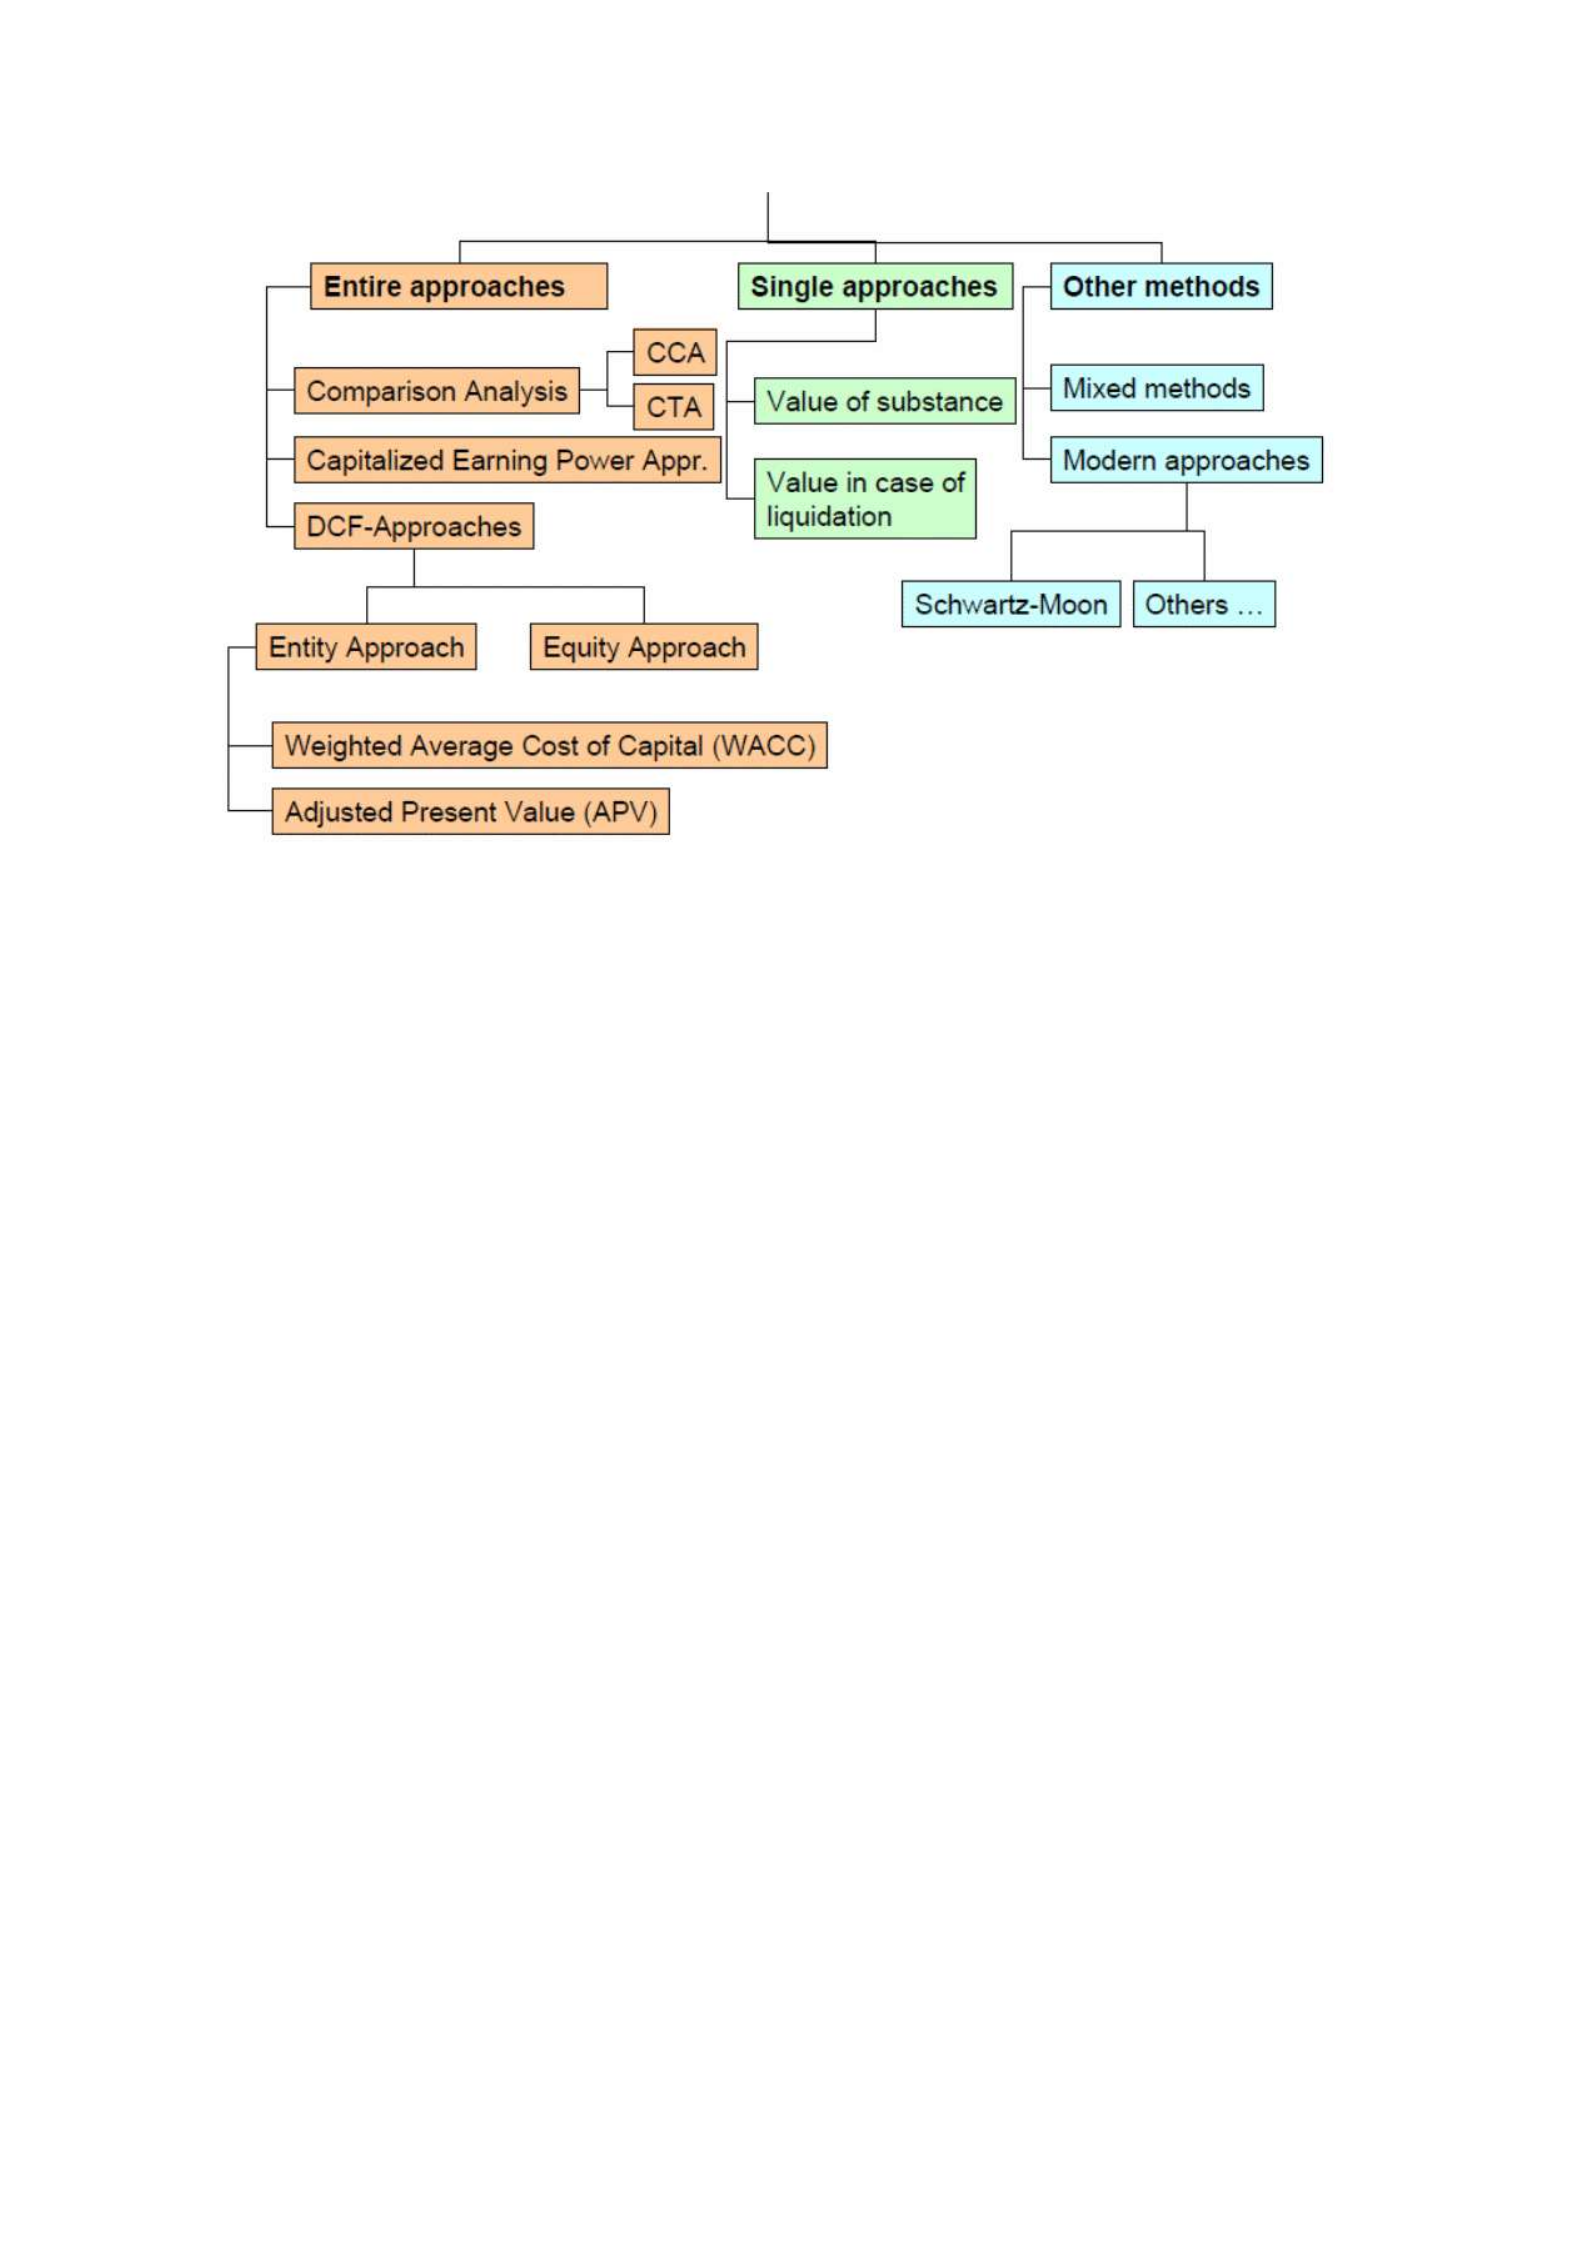
Figure 1: An Overview of Valuation Methods (Source Mian & Velez-Pareja 2007)
Different models that are applied during a valuation in organisations lead to a common result
where the organisations are able to plan for future decisions and changes. The valuation that is
obtained in organisations, irrespective of the method used, provides crucial information on the
financial status of the organisation. However, valuation within organisations also allows the
inception of changes whenever they are needed.
Financial Decisions
Organisations face challenges in financing, with one of the most common of them being the
outcomes of financial decisions. Competitiveness in organisations is influenced by the financial
decisions that managers and other stakeholders make. In any industry, financial decisions affect
the outcomes of the interactions between different factors. The financial decisions in an
organisation are also under the influence of other factors such as the valuation in these
organisations. A business in any industry or market must use capital as one of the main factors
in its operations, with this strategy bringing about the cost of capital.
Currently, there are no perfect markets in contemporary organisations. Hence, capital is not
always put to the intended use. A perfect business environment is the only place where capital
can be put to its planned use. However, conditions that are necessary for a perfect market are
hard to achieve. Nevertheless, if it were possible, the perfect world would have an excess
supply of capital. A perfect capital market might mean that the available unlimited capital is
only dependent on the risk of the project being undertaken (Spiegel, & Tookes 2013).

Aside from the perfect capital market, uncertainties, variables, and friction characterise the
existing real-world capital markets. The availability of tax as one of the variables in an
imperfect world ensures that organisations adopt strategies such as debts. An example of such
strategies is when an organisation operates in a capital structure with about 100% of debt
because of the positive corporate tax rate (Spiegel, & Tookes, 2013). Other factors that exist in
an imperfect world to introduce a relationship between valuations and financing include agency
costs, financial distress costs, and information asymmetries (Spiegel, & Tookes, 2013).
The financial position of an organisation ensures that the organisation can persist in an
environment where competition is an evident factor. Valuation effects that financial position of
an organisation. The reverse is also true. The decisions made in an organisation relating to the
financial positions of the organisation may be based on the valuation that is provided for this
organisation.
Weighted Average Cost of Capital
The calculation of the cost of capital is an intricate process that requires the participation of all
stakeholders. The cost of capital is calculated through the estimation of the proportion of debt
that a project consumes against the equity that is absorbed in the respective project (Massari,
Roncaglio & Zanetti 2008). The weighted average cost of capital (WACC) is calculated through
a formula that incorporates the market value of equity and debt (Massari, Roncaglio & Zanetti
2008). These values are adjusted using the costs of debt and equity. For a single firm, the
WACC is calculated as a single unit where the firm is the reference. The organisation, in this
case, is considered a single unit, with the results being for a single project.
The Weighted Average Cost of Capital is an indicator of the financial performance of an
organisation because it indicates the financial position of the organisation under discussion.
Any organisation with sound financial decisions has a favourable WACC, which is considered
a strength in these organisations. The calculation and use of WACC in financial discussions
and problem-solving is challenging for some financial analysts and other financial decision-
makers in organisations. Therefore, it is important to have a discussion on the correct use of
WACC and its implications on the financial decisions in organisations.
The other difficulty in the calculation and use of WACC is tax calculation. Different finance
officers use different methods of calculating the variables (Sabalı 2009). Financing and
investment decisions interact through taxes. WACC is an important concept in evaluating this

interaction. The formula that is used in the calculation of WACC refers to the organisation of
company as a whole upon incorporating the different aspects in financial decisions in the firm.
Therefore, this formula is effective for the “average project” where the right discount rate is
produced (Massari, Roncaglio & Zanetti 2008). Hence, the formula is incorrect when used in
the calculation of WACC for the safer and riskier projects (Magni 2012). The inaccuracy while
using this formula mainly stems from the different sections that individuals calculate in an
organisation, especially where the organisation has different departments.
Capital Structure and Valuations
Capital structure in a firm is a factor that affects valuations in these organisations. The effects
depend on the existing capital structure. According to Sabalı (2009), financing decisions
typically affect value within organisations. Some of the ways that boost value in a firm with
respect to its financing decisions is through the adjustment of the discount rate and the present
value (Massari, Roncaglio & Zanetti 2008).
The discount rate in most organisations is typically adjusted downwards, with the aim being to
account for the existing tax shields (Massari, Roncaglio & Zanetti 2008). Financing decisions
also affect value in organisations through adjusting the present value in these organisations
(Massari, Roncaglio & Zanetti 2008). According to Spiegel and Tookes (2013), the base case
is first calculated with the assumption that it is all equity financed.
Capital structure in organisations affects the value of the organisation from its first year of
operation. The capital structure in organisations is variable depending on several factors such
as the capital debt and the type of industry within which a firm is located. The tax on a firm is
a major factor with reference to its capital value, especially because the tax determines the debt
status of an organisation (Sabalı 2009).
The initial cash that is invested into a firm in the first year affects the value of an organisation
during this year. Most of the organisations that invest significant amounts of capital into their
operations end up being successful in the first year. Over the years that follow, the WACC
formula is highly applicable, as the organisational debts and equities change.
Capital structure in most organisations is affected by the financial decisions made by the
executive. Hence, the value of organisations is dependent on the type of managers that an
organisation keeps. The value of organisation changes with any financial decision made, since
the debt and equities change with these decisions (Massari, Roncaglio & Zanetti 2008).

The value of a firm may be calculated through the estimation of the WACC, which is later used
to discount the FCFF from the debt holders and equity capital contributors (Massari, Roncaglio
& Zanetti 2008). The use of WACC in the estimation of a firm’s value is very effective by far
compared to other methods of value estimation. This finding indicates a relationship between
the value of organisations and the WACC. The WACC is in turn related to the financial
decisions in an organisation. Hence, valuation is related to the financial decisions in the
organisation.
Impact of Tax Shields on WACC
According to Massari, Roncaglio, and Zanetti (2008), tax is a variable in an organisation that
affects the value of these organisations. Interest in organisations is one of the expenses that are
usually considered as tax-deductible expense (Massari, Roncaglio & Zanetti 2008). The
calculation of WACC incorporates tax as a major form of expense. This strategy determines
the value of organisations. However, tax shields in organisations may affect the calculation of
WACC. The effects of tax shields on WACC depend on the business and individuals who are
responsible for financial management in the respective institutions.
The tax shields cause changes on WACC in a number of ways. However, while these effects
are dependent on the type of organisation, the main effect is that the WACC increases with a
reduction in tax shields. Most organisations seek tax shields to lower their WACC and in effect
influence the value and competitiveness of their respective industries. A common result of tax
shields is a downward adjustment of the discount rate to account for any changes in this area
(Massari, Roncaglio & Zanetti 2008). The downward adjustment of discount rates in
organisations allows decisions to be made on the WACC and its overall effect on the firm’s
value.
Tax shields help organisations save their available financial resources, including the provision
of future resources. In areas where tax shields are effectively applied, firms report better results,
performance, and competitiveness compared to areas where these policies are scantily applied.
Adjusting the discount rate downwards is one of the ways that tax shields are accounted for.
The result of this case is a change on the value of firms (Massari, Roncaglio & Zanetti 2008).
The relationship between value of an organisation and tax shields may be demonstrated by the
inherent differences between organisations that operate in different regions with different tax
shield regimens. According to Massari, Roncaglio, and Zanetti (2008), adjustment of WACC
should affect the value of a firm through the effect of this move on the value of the organisation.

Therefore, managers should make sound decisions when it comes to applying for tax shields in
their area.
How Tax Shields affect Firm Value
Tax shields in an organisation affect the firm’s value in a number of ways as indicated above.
A common understanding is that tax is one of the factors that affect WACC, and in effect the
value of an organisation. The worth of any business is affected by the financing decisions in
the organisations, including the availability of tax shields. The discount rate constitutes one of
the factors that may be adjusted to accommodate changes in the value of organisations. Mintz
and Currim (2013) observe that downward adjustment of discount rate accounts for tax shields.
This downward adjustment results in the increase in value of organisations.
Organisations that use the discount rate to effect changes in their firm value often report success
in the use of the method. When an organisation is awarded tax shields, the value changes to
correspond to the changes introduced through the adjustment of the discount rates. Most
organisations can be described as having debts because of the tax shields that they intend to
acquire.
Therefore, contemporary organisations are prone to debts in their quest to attain tax shields
from the respective authorities. The differences in the contemporary organisations arise from
the different capabilities in the use of their debts. Most organisations whose debt status is high
attain significant tax exemptions. They are valued at higher rank compared to organisations
that have a lower debt position. The tax shields in an organisation, therefore, affect the firm
value in organisations.
Mistakes in Using WACC
Several mistakes are established in literature in the use of WACC. The first mistake is in the
calculation of this variable. In fact, some individuals use variables that are not commonly
applied in the formula. The computation of WACC is tedious due to the many variables that
are necessary for the calculation process. This situation makes the calculation difficult to the
extent that some individuals opt for shortcuts that may not be accurate. The other mistake is
that some individuals assume that the formula may be used in the calculation of WACC for a
particular section of the organisation. They forget that this formula considers the firm a single
unit (Mian & Velez-Pareja 2007).

WACC is useful in providing discount for businesses only where they are applied to
organisations or projects with a similar undertaking to the firm under consideration. For
organisations that differ from the firm under consideration, the formula may not be applicable
or provide useful results. WACC may be useful in most of the calculations where the firm under
consideration has the same size as that of other firms that were initially considered. For projects
that are safer or riskier compared to the original organisation, the calculated WACC may be
inaccurate and in some cases incorrect.
The other mistake that individuals make in the use of WACC is the assumption that it can be
applied as a single variable in the determination of a firm’s value. According to Mian and Velez-
Pareja (2007), organisations require the use of many variables to calculate their value. A single
variable may be deceptive depending on the industry within which the firm is located.
Therefore, there is a need to consider a number of variables in the calculation of a firm’s value
as using WACC alone may be inaccurate. Some of the other mistakes that individuals make in
the use of WACC include miscalculation of the debt and equities that are eventually used in the
calculation of this variable.
Adjusting the WACC
The adjustment of WACC may be done through a number of ways depending on the debt ratios
and the business risks (Mintz & Currim 2013). Adjusting the WACC when the risk of the firm’s
debt ratio and the business risk differ from those of the new project is important in the
calculation of a business’ WACC.
The adjustment of WACC is important when the debt ratios and business risks differ in
organisations. The differences between these two variables result from the changes that are
inherent in the organisations. The three main steps that should be followed when adjusting the
WACC include calculation of the opportunity cost, estimation of the cost of the organisations
debt, and recalculation of the WACC using the obtained new values (Mian & Velez-Pareja
2007).
The adjustment of this value allows the correct calculations where the estimated WACC is
obtained against the real WACC. In cases where the WACC is adjusted, the value of the firm’s
debts and opportunity costs are considered the main reasons for the adjustments. There are
many reasons for the adjustments, with the main one being to increase the accuracy of the final
WACC that is obtained for any given firm. WACC is an indicator of the financing side effect
in an organisation. It is a good indicator of value in organisations (Mintz & Currim 2013).

These financing side effects include the value of interest tax shields on debts (Massari,
Roncaglio & Zanetti 2008). Adjustment of the WACC is also important where the actual value
of a firm is to be estimated.
Valuation in Organisations
Valuation affects the financial decisions that are made in organisations. Most of the decisions
that are important in organisations are made only through the consideration of the value of the
organisation since most managers tend to focus on increasing this value. The many valuation
approaches that are currently in use stem from the extensive research done in this area. These
approaches affect the financing decisions in organisations. The methods of valuation affect the
final variable.
Hence, most of these methods have sub approaches within them. Discounted cash flow is
among the most popular methods that are used in the valuation. This strategy focuses on the
financing decisions in the organisation (Massari, Roncaglio & Zanetti 2008). According to
Dong, Hirshleifer, and Teoh (2012), the main ways of estimating the discounted cash flow
include discounting the cash flow at a risk-adjusted discount (Sabalı 2009). This formula is one
of the four main methods that are used in the discounting cash flows. Using these methods
produces significant results.
Although different methods are in use in the valuation of companies, the same results may be
achieved if the assumptions are withheld for each of the methods. The similarity of these
methods ensures that the result is compatible with the businesses for which it was attempted
first. The different proponents for the different approaches in the valuation methods assume
that their methods are the most accurate. The results indicate that these methods are closely
similar. In relative valuation, which is considered one of the most important valuation methods,
the researchers who proposed the method adopted the assumption of individual assets.
However, these methods have similar results when the different assumptions are withheld.
Conclusion
In conclusion, based on the detailed expositions that have been made in the paper, it is clear
that valuation and financing are closely related when consideration for the financial state of an
organisation is made. Valuation may be estimated in organisations using several methods. Some
of these methods have been stated in this essay. The existence of valuation in financial decisions
allows the organisations to make decisions that coincide with their immediate needs.

The paper has proposed that a relationship between valuation and financial decisions in
organisations. This relationship is affected by other factors such as taxation. The WACC is an
important factor to consider when deducing the relationship between valuation and financial
decisions. The available research proves that this concept is applicable in an organisation’s
financial decisions. The essay has looked at the relationship between WACC and valuation in
organisations and the relationship that exists between these two variables and financial
decisions in an organisation. The paper has proved a positive relationship between these
concepts.
Valuation
The valuation of any organisation allows future decision-making to ensure that it is operating
as per the expectations. Different methods are used in valuation, including those that are
supported by theories and contemporary methods. The present models that are deployed in the
evaluation process are a product of extensive research, with many researchers describing them
before their application in management and finance. What are the motives of company
valuation? Different schools of thought exist as to why company valuation is important.
One of the motives for the evaluations of a company is to make decisions in the organisation.
Depending on the decision that is reached after valuation, the involved individuals may decide
on the future of the organisation and the interventions for the areas that are found faulty.
Motives in company valuation may be characterised in different ways, including decision-
dependent and decision-independent motives (Ishakian, Knebusch & Rowen 2013). The other
category of motives is the transaction based vs the non-transaction-based motives (Ishakian,
Knebusch & Rowen 2013). The other class of motives, as described throughout the literature
on valuation, is the dominated vs the non-dominated decision (Ishakian, Knebusch & Rowen
2013).
Valuation serves different functions depending on the concerned firm or organisation. These
functions can be categorised further into minor and major functions. The main functions of
valuation in organisations include decision-making and consultation. According to Ishakian,
Knebusch, and Rowen (2013), managers and other stakeholders use valuation information in
an organisation to make decisions on the future of the organisation with the aim of improving
the organisational performance. Different firms operate on different grounds. They use
different methods of valuation to make financial and other forms of decisions in the
organisation.

The other function of valuation, according to Koziol (2014), is mediation where the firm uses
information from valuation to mediate between concepts, decisions, and individuals.
Hundsdoerfer, Kruschwitz, and Loren (2008) assert that mediation in an organisation provides
crucial information on the financial position of the organisation. Valuation also serves as a
means of argumentation. Using information from valuation, managers and other organisational
stakeholders can argue on the position of the organisation. The information is used to provide
details on the organisational performance, which is important in making a case for any
argument.
Apart from the main functions of valuation, valuation serves other auxiliary functions. One of
these auxiliary functions is information where the parties within an organisation gather
information on this organisation, including its performance and future expectations. Valuation
may also be used as a means of tax measurement where authorities determine the tax that an
organisation should forward over a given period. Many organisations where valuation has been
conducted were found to have some tax measurements, not in line with the expected values
(Mian & Velez-Pareja 2007). Valuation also serves the function of contract configuration where
employees and other parties in the organisation can have their contracts configured with the
expectations of the organisation.
Valuation Methods
Different valuation methods are in use in many organisations. Each of these methods provides
different results. The decision to use one of them is dependent on the firm that is being
evaluated, the financial methods in place, and the preferred approach. The most popular
approach depends on the organisation and the region where these organisations exist. Different
methods that are used in valuation are shown below.
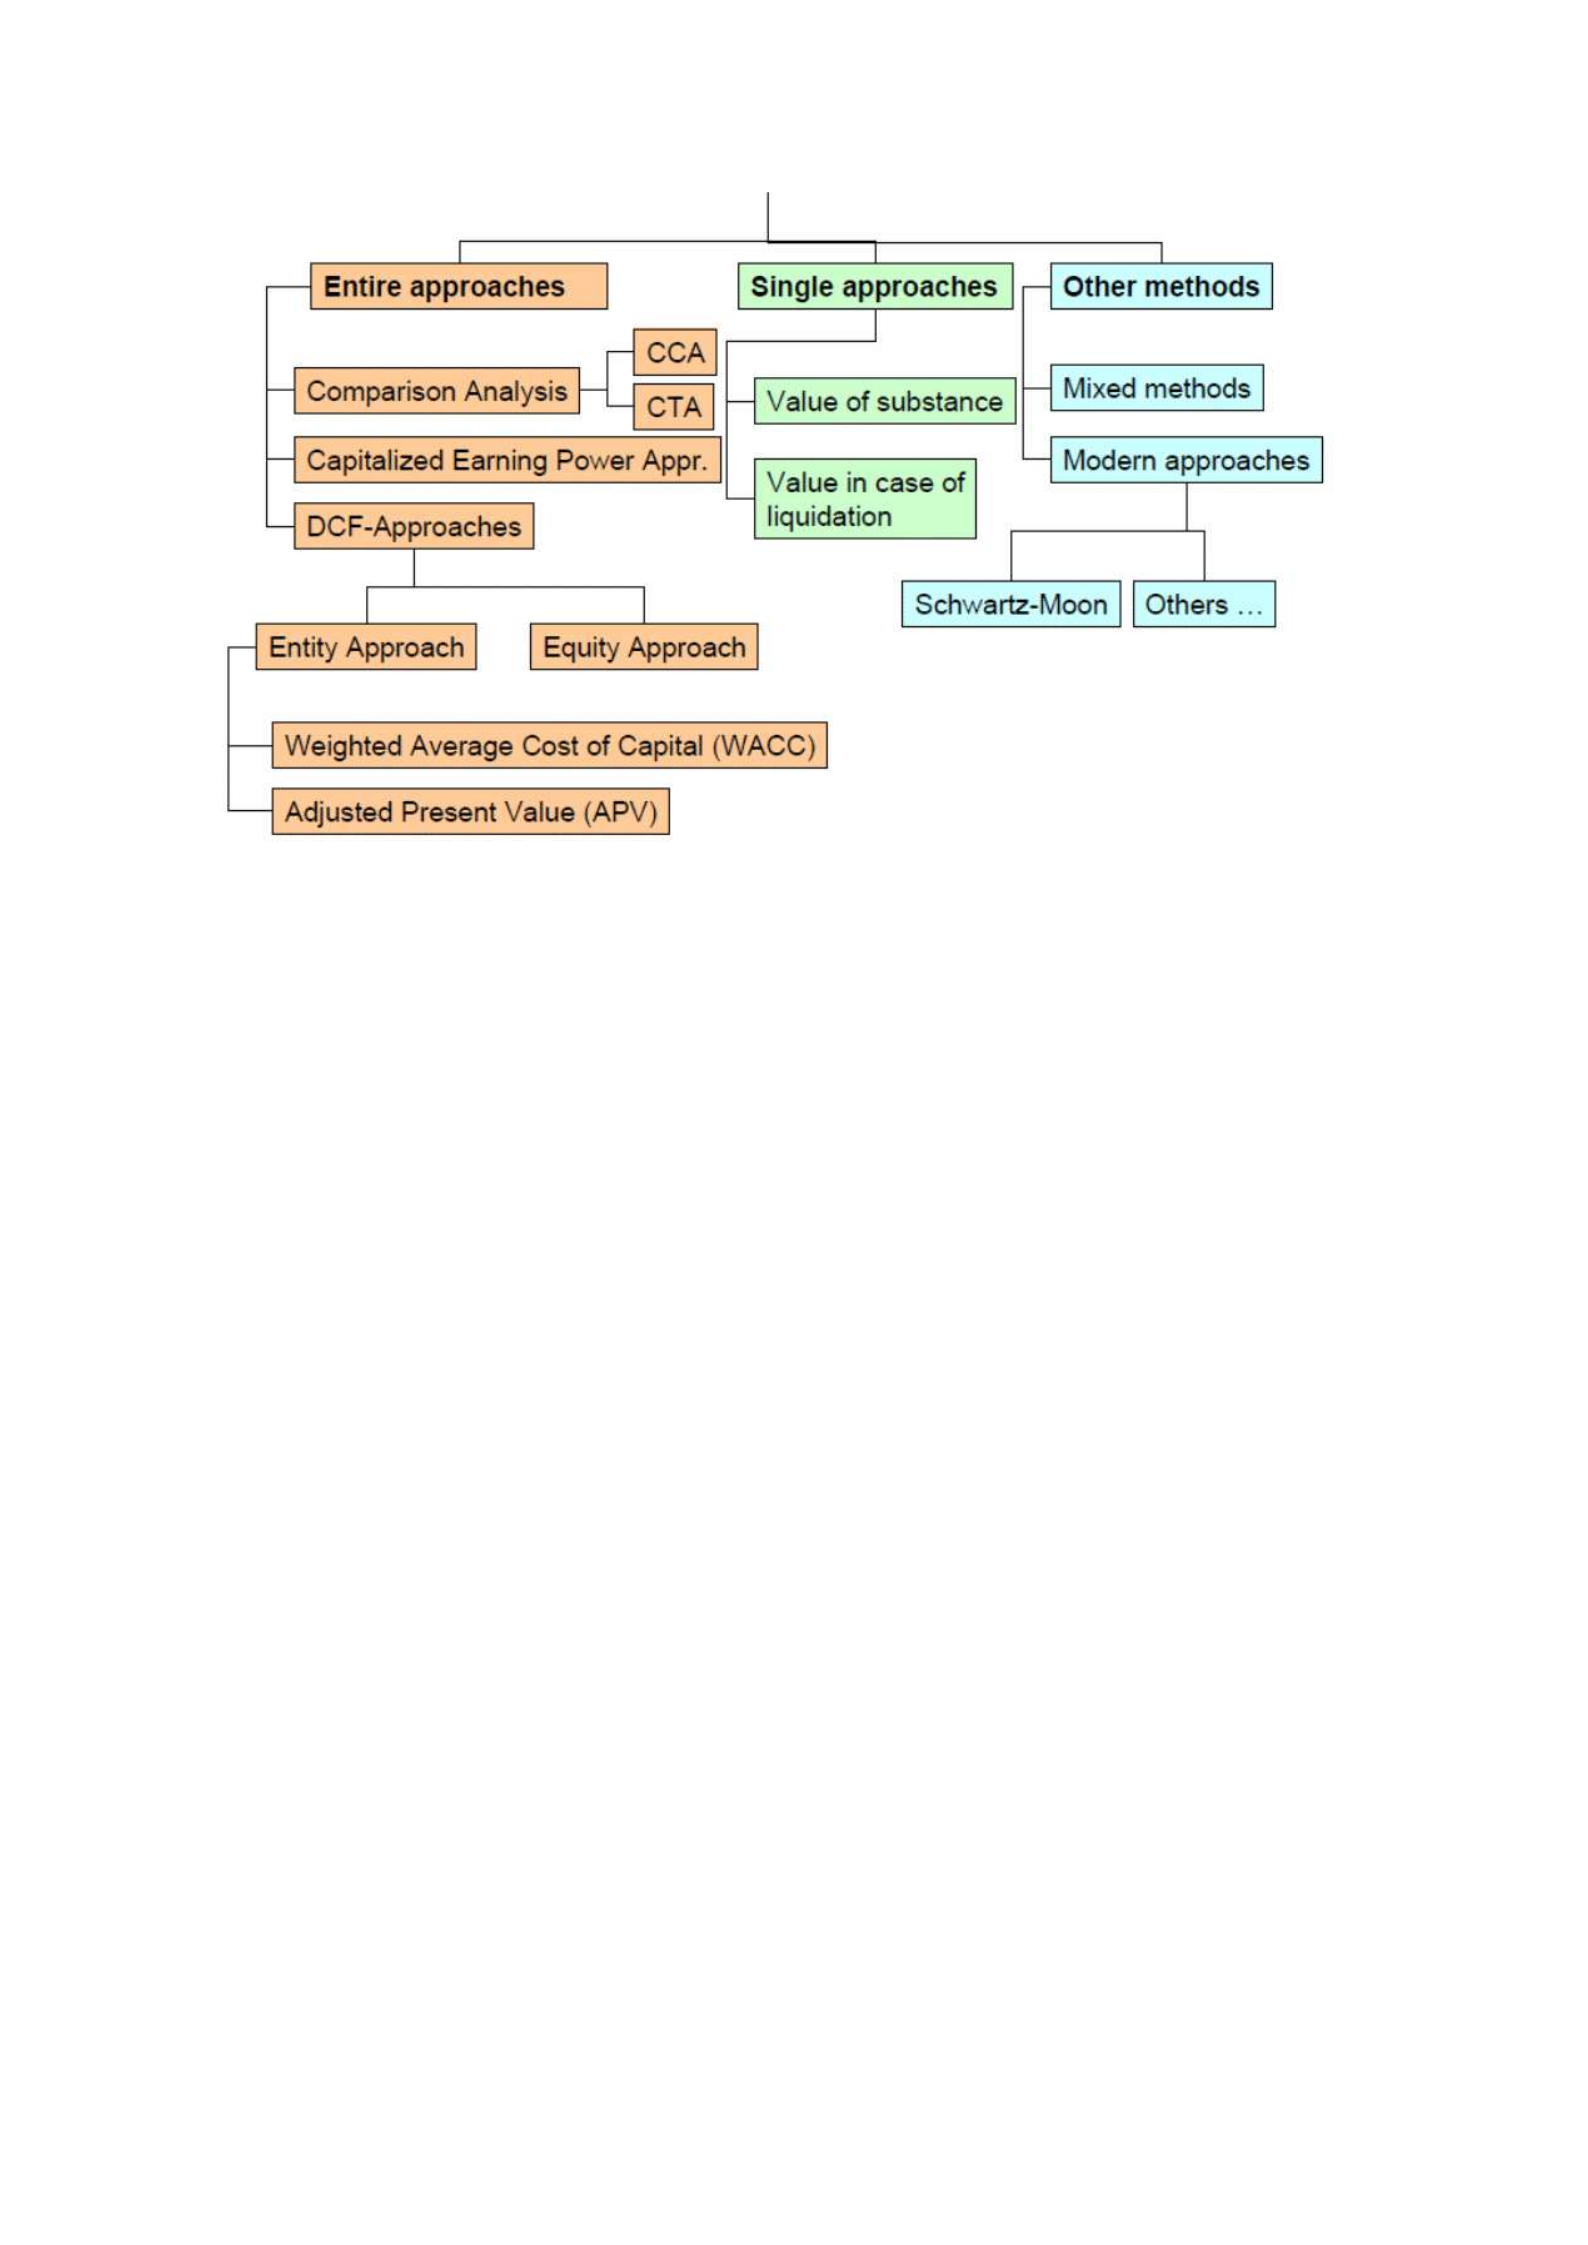
Figure 1: An Overview of Valuation Methods (Source Mian & Velez-Pareja 2007)
Different models that are applied during a valuation in organisations lead to a common result
where the organisations are able to plan for future decisions and changes. The valuation that is
obtained in organisations, irrespective of the method used, provides crucial information on the
financial status of the organisation. However, valuation within organisations also allows the
inception of changes whenever they are needed.
Financial Decisions
Organisations face challenges in financing, with one of the most common of them being the
outcomes of financial decisions. Competitiveness in organisations is influenced by the financial
decisions that managers and other stakeholders make. In any industry, financial decisions affect
the outcomes of the interactions between different factors. The financial decisions in an
organisation are also under the influence of other factors such as the valuation in these
organisations. A business in any industry or market must use capital as one of the main factors
in its operations, with this strategy bringing about the cost of capital.
Currently, there are no perfect markets in contemporary organisations. Hence, capital is not
always put to the intended use. A perfect business environment is the only place where capital
can be put to its planned use. However, conditions that are necessary for a perfect market are
hard to achieve. Nevertheless, if it were possible, the perfect world would have an excess
supply of capital. A perfect capital market might mean that the available unlimited capital is
only dependent on the risk of the project being undertaken (Spiegel, & Tookes 2013).

Aside from the perfect capital market, uncertainties, variables, and friction characterise the
existing real-world capital markets. The availability of tax as one of the variables in an
imperfect world ensures that organisations adopt strategies such as debts. An example of such
strategies is when an organisation operates in a capital structure with about 100% of debt
because of the positive corporate tax rate (Spiegel, & Tookes, 2013). Other factors that exist in
an imperfect world to introduce a relationship between valuations and financing include agency
costs, financial distress costs, and information asymmetries (Spiegel, & Tookes, 2013).
The financial position of an organisation ensures that the organisation can persist in an
environment where competition is an evident factor. Valuation effects that financial position of
an organisation. The reverse is also true. The decisions made in an organisation relating to the
financial positions of the organisation may be based on the valuation that is provided for this
organisation.
Weighted Average Cost of Capital
The calculation of the cost of capital is an intricate process that requires the participation of all
stakeholders. The cost of capital is calculated through the estimation of the proportion of debt
that a project consumes against the equity that is absorbed in the respective project (Massari,
Roncaglio & Zanetti 2008). The weighted average cost of capital (WACC) is calculated through
a formula that incorporates the market value of equity and debt (Massari, Roncaglio & Zanetti
2008). These values are adjusted using the costs of debt and equity. For a single firm, the
WACC is calculated as a single unit where the firm is the reference. The organisation, in this
case, is considered a single unit, with the results being for a single project.
The Weighted Average Cost of Capital is an indicator of the financial performance of an
organisation because it indicates the financial position of the organisation under discussion.
Any organisation with sound financial decisions has a favourable WACC, which is considered
a strength in these organisations. The calculation and use of WACC in financial discussions
and problem-solving is challenging for some financial analysts and other financial decision-
makers in organisations. Therefore, it is important to have a discussion on the correct use of
WACC and its implications on the financial decisions in organisations.
The other difficulty in the calculation and use of WACC is tax calculation. Different finance
officers use different methods of calculating the variables (Sabalı 2009). Financing and
investment decisions interact through taxes. WACC is an important concept in evaluating this

interaction. The formula that is used in the calculation of WACC refers to the organisation of
company as a whole upon incorporating the different aspects in financial decisions in the firm.
Therefore, this formula is effective for the “average project” where the right discount rate is
produced (Massari, Roncaglio & Zanetti 2008). Hence, the formula is incorrect when used in
the calculation of WACC for the safer and riskier projects (Magni 2012). The inaccuracy while
using this formula mainly stems from the different sections that individuals calculate in an
organisation, especially where the organisation has different departments.
Capital Structure and Valuations
Capital structure in a firm is a factor that affects valuations in these organisations. The effects
depend on the existing capital structure. According to Sabalı (2009), financing decisions
typically affect value within organisations. Some of the ways that boost value in a firm with
respect to its financing decisions is through the adjustment of the discount rate and the present
value (Massari, Roncaglio & Zanetti 2008).
The discount rate in most organisations is typically adjusted downwards, with the aim being to
account for the existing tax shields (Massari, Roncaglio & Zanetti 2008). Financing decisions
also affect value in organisations through adjusting the present value in these organisations
(Massari, Roncaglio & Zanetti 2008). According to Spiegel and Tookes (2013), the base case
is first calculated with the assumption that it is all equity financed.
Capital structure in organisations affects the value of the organisation from its first year of
operation. The capital structure in organisations is variable depending on several factors such
as the capital debt and the type of industry within which a firm is located. The tax on a firm is
a major factor with reference to its capital value, especially because the tax determines the debt
status of an organisation (Sabalı 2009).
The initial cash that is invested into a firm in the first year affects the value of an organisation
during this year. Most of the organisations that invest significant amounts of capital into their
operations end up being successful in the first year. Over the years that follow, the WACC
formula is highly applicable, as the organisational debts and equities change.
Capital structure in most organisations is affected by the financial decisions made by the
executive. Hence, the value of organisations is dependent on the type of managers that an
organisation keeps. The value of organisation changes with any financial decision made, since
the debt and equities change with these decisions (Massari, Roncaglio & Zanetti 2008).

The value of a firm may be calculated through the estimation of the WACC, which is later used
to discount the FCFF from the debt holders and equity capital contributors (Massari, Roncaglio
& Zanetti 2008). The use of WACC in the estimation of a firm’s value is very effective by far
compared to other methods of value estimation. This finding indicates a relationship between
the value of organisations and the WACC. The WACC is in turn related to the financial
decisions in an organisation. Hence, valuation is related to the financial decisions in the
organisation.
Impact of Tax Shields on WACC
According to Massari, Roncaglio, and Zanetti (2008), tax is a variable in an organisation that
affects the value of these organisations. Interest in organisations is one of the expenses that are
usually considered as tax-deductible expense (Massari, Roncaglio & Zanetti 2008). The
calculation of WACC incorporates tax as a major form of expense. This strategy determines
the value of organisations. However, tax shields in organisations may affect the calculation of
WACC. The effects of tax shields on WACC depend on the business and individuals who are
responsible for financial management in the respective institutions.
The tax shields cause changes on WACC in a number of ways. However, while these effects
are dependent on the type of organisation, the main effect is that the WACC increases with a
reduction in tax shields. Most organisations seek tax shields to lower their WACC and in effect
influence the value and competitiveness of their respective industries. A common result of tax
shields is a downward adjustment of the discount rate to account for any changes in this area
(Massari, Roncaglio & Zanetti 2008). The downward adjustment of discount rates in
organisations allows decisions to be made on the WACC and its overall effect on the firm’s
value.
Tax shields help organisations save their available financial resources, including the provision
of future resources. In areas where tax shields are effectively applied, firms report better results,
performance, and competitiveness compared to areas where these policies are scantily applied.
Adjusting the discount rate downwards is one of the ways that tax shields are accounted for.
The result of this case is a change on the value of firms (Massari, Roncaglio & Zanetti 2008).
The relationship between value of an organisation and tax shields may be demonstrated by the
inherent differences between organisations that operate in different regions with different tax
shield regimens. According to Massari, Roncaglio, and Zanetti (2008), adjustment of WACC
should affect the value of a firm through the effect of this move on the value of the organisation.

Therefore, managers should make sound decisions when it comes to applying for tax shields in
their area.
How Tax Shields affect Firm Value
Tax shields in an organisation affect the firm’s value in a number of ways as indicated above.
A common understanding is that tax is one of the factors that affect WACC, and in effect the
value of an organisation. The worth of any business is affected by the financing decisions in
the organisations, including the availability of tax shields. The discount rate constitutes one of
the factors that may be adjusted to accommodate changes in the value of organisations. Mintz
and Currim (2013) observe that downward adjustment of discount rate accounts for tax shields.
This downward adjustment results in the increase in value of organisations.
Organisations that use the discount rate to effect changes in their firm value often report success
in the use of the method. When an organisation is awarded tax shields, the value changes to
correspond to the changes introduced through the adjustment of the discount rates. Most
organisations can be described as having debts because of the tax shields that they intend to
acquire.
Therefore, contemporary organisations are prone to debts in their quest to attain tax shields
from the respective authorities. The differences in the contemporary organisations arise from
the different capabilities in the use of their debts. Most organisations whose debt status is high
attain significant tax exemptions. They are valued at higher rank compared to organisations
that have a lower debt position. The tax shields in an organisation, therefore, affect the firm
value in organisations.
Mistakes in Using WACC
Several mistakes are established in literature in the use of WACC. The first mistake is in the
calculation of this variable. In fact, some individuals use variables that are not commonly
applied in the formula. The computation of WACC is tedious due to the many variables that
are necessary for the calculation process. This situation makes the calculation difficult to the
extent that some individuals opt for shortcuts that may not be accurate. The other mistake is
that some individuals assume that the formula may be used in the calculation of WACC for a
particular section of the organisation. They forget that this formula considers the firm a single
unit (Mian & Velez-Pareja 2007).

WACC is useful in providing discount for businesses only where they are applied to
organisations or projects with a similar undertaking to the firm under consideration. For
organisations that differ from the firm under consideration, the formula may not be applicable
or provide useful results. WACC may be useful in most of the calculations where the firm under
consideration has the same size as that of other firms that were initially considered. For projects
that are safer or riskier compared to the original organisation, the calculated WACC may be
inaccurate and in some cases incorrect.
The other mistake that individuals make in the use of WACC is the assumption that it can be
applied as a single variable in the determination of a firm’s value. According to Mian and Velez-
Pareja (2007), organisations require the use of many variables to calculate their value. A single
variable may be deceptive depending on the industry within which the firm is located.
Therefore, there is a need to consider a number of variables in the calculation of a firm’s value
as using WACC alone may be inaccurate. Some of the other mistakes that individuals make in
the use of WACC include miscalculation of the debt and equities that are eventually used in the
calculation of this variable.
Adjusting the WACC
The adjustment of WACC may be done through a number of ways depending on the debt ratios
and the business risks (Mintz & Currim 2013). Adjusting the WACC when the risk of the firm’s
debt ratio and the business risk differ from those of the new project is important in the
calculation of a business’ WACC.
The adjustment of WACC is important when the debt ratios and business risks differ in
organisations. The differences between these two variables result from the changes that are
inherent in the organisations. The three main steps that should be followed when adjusting the
WACC include calculation of the opportunity cost, estimation of the cost of the organisations
debt, and recalculation of the WACC using the obtained new values (Mian & Velez-Pareja
2007).
The adjustment of this value allows the correct calculations where the estimated WACC is
obtained against the real WACC. In cases where the WACC is adjusted, the value of the firm’s
debts and opportunity costs are considered the main reasons for the adjustments. There are
many reasons for the adjustments, with the main one being to increase the accuracy of the final
WACC that is obtained for any given firm. WACC is an indicator of the financing side effect
in an organisation. It is a good indicator of value in organisations (Mintz & Currim 2013).

These financing side effects include the value of interest tax shields on debts (Massari,
Roncaglio & Zanetti 2008). Adjustment of the WACC is also important where the actual value
of a firm is to be estimated.
Valuation in Organisations
Valuation affects the financial decisions that are made in organisations. Most of the decisions
that are important in organisations are made only through the consideration of the value of the
organisation since most managers tend to focus on increasing this value. The many valuation
approaches that are currently in use stem from the extensive research done in this area. These
approaches affect the financing decisions in organisations. The methods of valuation affect the
final variable.
Hence, most of these methods have sub approaches within them. Discounted cash flow is
among the most popular methods that are used in the valuation. This strategy focuses on the
financing decisions in the organisation (Massari, Roncaglio & Zanetti 2008). According to
Dong, Hirshleifer, and Teoh (2012), the main ways of estimating the discounted cash flow
include discounting the cash flow at a risk-adjusted discount (Sabalı 2009). This formula is one
of the four main methods that are used in the discounting cash flows. Using these methods
produces significant results.
Although different methods are in use in the valuation of companies, the same results may be
achieved if the assumptions are withheld for each of the methods. The similarity of these
methods ensures that the result is compatible with the businesses for which it was attempted
first. The different proponents for the different approaches in the valuation methods assume
that their methods are the most accurate. The results indicate that these methods are closely
similar. In relative valuation, which is considered one of the most important valuation methods,
the researchers who proposed the method adopted the assumption of individual assets.
However, these methods have similar results when the different assumptions are withheld.
Conclusion
In conclusion, based on the detailed expositions that have been made in the paper, it is clear
that valuation and financing are closely related when consideration for the financial state of an
organisation is made. Valuation may be estimated in organisations using several methods. Some
of these methods have been stated in this essay. The existence of valuation in financial decisions
allows the organisations to make decisions that coincide with their immediate needs.

The paper has proposed that a relationship between valuation and financial decisions in
organisations. This relationship is affected by other factors such as taxation. The WACC is an
important factor to consider when deducing the relationship between valuation and financial
decisions. The available research proves that this concept is applicable in an organisation’s
financial decisions. The essay has looked at the relationship between WACC and valuation in
organisations and the relationship that exists between these two variables and financial
decisions in an organisation. The paper has proved a positive relationship between these
concepts.
Valuation
The valuation of any organisation allows future decision-making to ensure that it is operating
as per the expectations. Different methods are used in valuation, including those that are
supported by theories and contemporary methods. The present models that are deployed in the
evaluation process are a product of extensive research, with many researchers describing them
before their application in management and finance. What are the motives of company
valuation? Different schools of thought exist as to why company valuation is important.
One of the motives for the evaluations of a company is to make decisions in the organisation.
Depending on the decision that is reached after valuation, the involved individuals may decide
on the future of the organisation and the interventions for the areas that are found faulty.
Motives in company valuation may be characterised in different ways, including decision-
dependent and decision-independent motives (Ishakian, Knebusch & Rowen 2013). The other
category of motives is the transaction based vs the non-transaction-based motives (Ishakian,
Knebusch & Rowen 2013). The other class of motives, as described throughout the literature
on valuation, is the dominated vs the non-dominated decision (Ishakian, Knebusch & Rowen
2013).
Valuation serves different functions depending on the concerned firm or organisation. These
functions can be categorised further into minor and major functions. The main functions of
valuation in organisations include decision-making and consultation. According to Ishakian,
Knebusch, and Rowen (2013), managers and other stakeholders use valuation information in
an organisation to make decisions on the future of the organisation with the aim of improving
the organisational performance. Different firms operate on different grounds. They use
different methods of valuation to make financial and other forms of decisions in the
organisation.

The other function of valuation, according to Koziol (2014), is mediation where the firm uses
information from valuation to mediate between concepts, decisions, and individuals.
Hundsdoerfer, Kruschwitz, and Loren (2008) assert that mediation in an organisation provides
crucial information on the financial position of the organisation. Valuation also serves as a
means of argumentation. Using information from valuation, managers and other organisational
stakeholders can argue on the position of the organisation. The information is used to provide
details on the organisational performance, which is important in making a case for any
argument.
Apart from the main functions of valuation, valuation serves other auxiliary functions. One of
these auxiliary functions is information where the parties within an organisation gather
information on this organisation, including its performance and future expectations. Valuation
may also be used as a means of tax measurement where authorities determine the tax that an
organisation should forward over a given period. Many organisations where valuation has been
conducted were found to have some tax measurements, not in line with the expected values
(Mian & Velez-Pareja 2007). Valuation also serves the function of contract configuration where
employees and other parties in the organisation can have their contracts configured with the
expectations of the organisation.
Valuation Methods
Different valuation methods are in use in many organisations. Each of these methods provides
different results. The decision to use one of them is dependent on the firm that is being
evaluated, the financial methods in place, and the preferred approach. The most popular
approach depends on the organisation and the region where these organisations exist. Different
methods that are used in valuation are shown below.
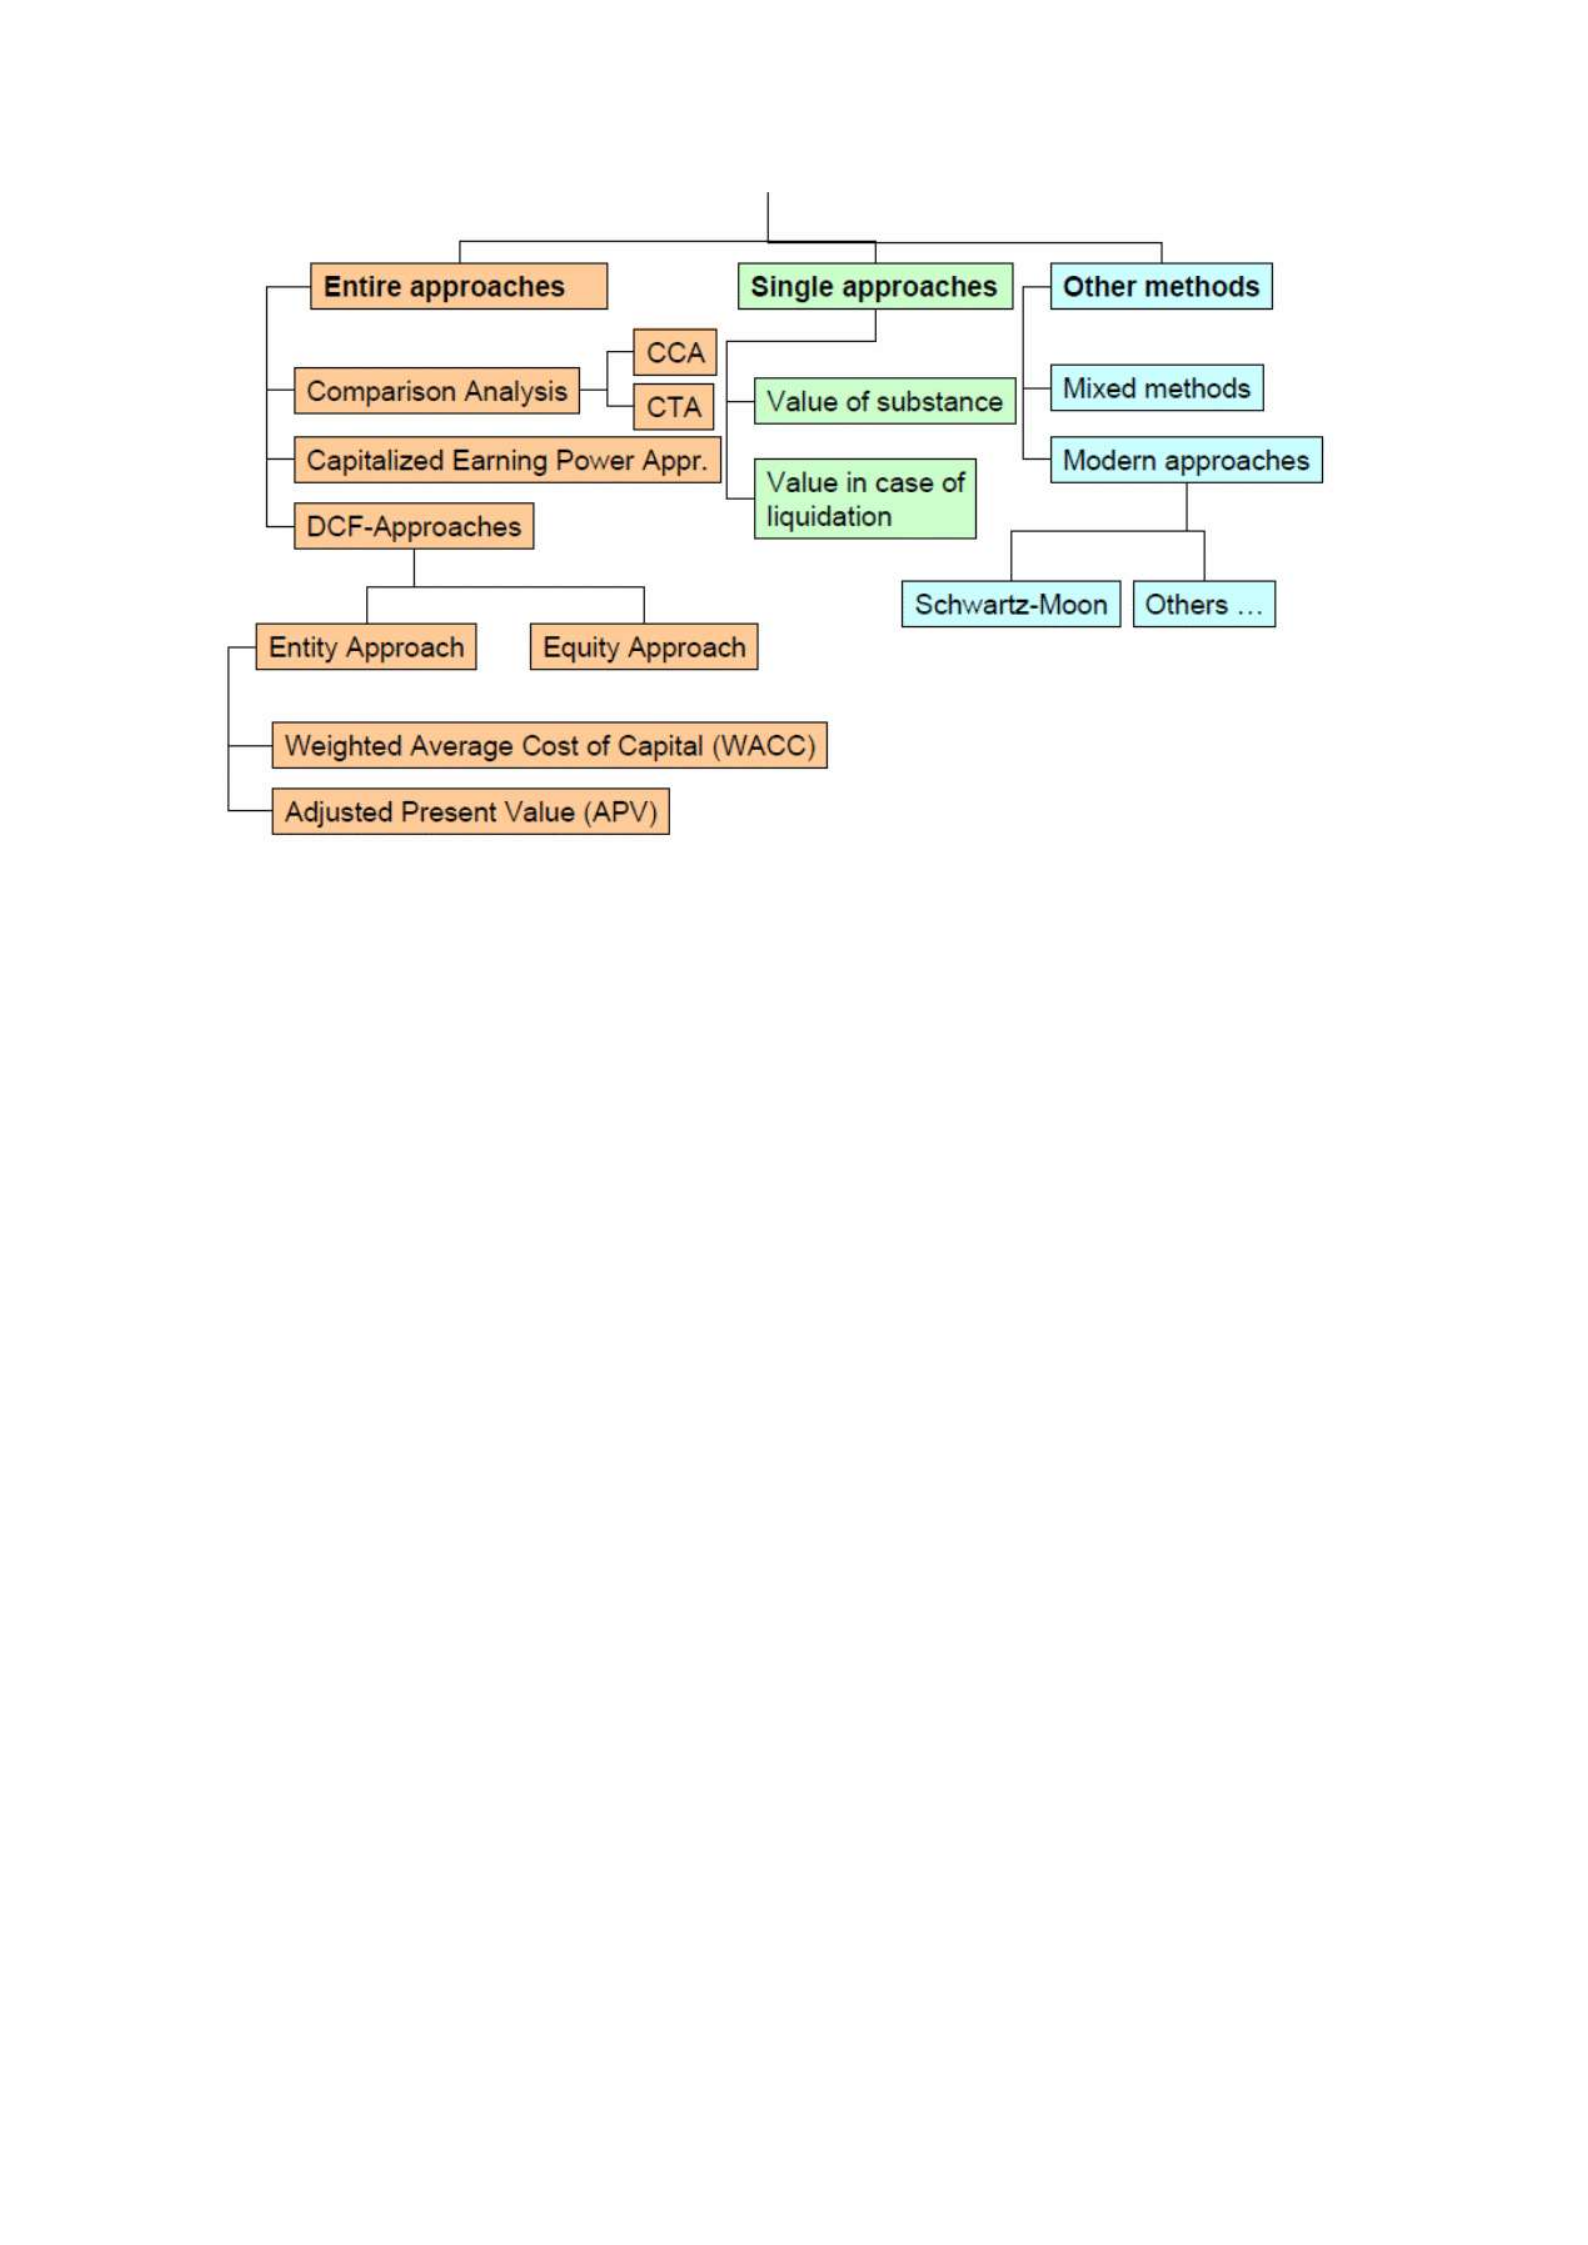
Figure 1: An Overview of Valuation Methods (Source Mian & Velez-Pareja 2007)
Different models that are applied during a valuation in organisations lead to a common result
where the organisations are able to plan for future decisions and changes. The valuation that is
obtained in organisations, irrespective of the method used, provides crucial information on the
financial status of the organisation. However, valuation within organisations also allows the
inception of changes whenever they are needed.
Financial Decisions
Organisations face challenges in financing, with one of the most common of them being the
outcomes of financial decisions. Competitiveness in organisations is influenced by the financial
decisions that managers and other stakeholders make. In any industry, financial decisions affect
the outcomes of the interactions between different factors. The financial decisions in an
organisation are also under the influence of other factors such as the valuation in these
organisations. A business in any industry or market must use capital as one of the main factors
in its operations, with this strategy bringing about the cost of capital.
Currently, there are no perfect markets in contemporary organisations. Hence, capital is not
always put to the intended use. A perfect business environment is the only place where capital
can be put to its planned use. However, conditions that are necessary for a perfect market are
hard to achieve. Nevertheless, if it were possible, the perfect world would have an excess
supply of capital. A perfect capital market might mean that the available unlimited capital is
only dependent on the risk of the project being undertaken (Spiegel, & Tookes 2013).

Aside from the perfect capital market, uncertainties, variables, and friction characterise the
existing real-world capital markets. The availability of tax as one of the variables in an
imperfect world ensures that organisations adopt strategies such as debts. An example of such
strategies is when an organisation operates in a capital structure with about 100% of debt
because of the positive corporate tax rate (Spiegel, & Tookes, 2013). Other factors that exist in
an imperfect world to introduce a relationship between valuations and financing include agency
costs, financial distress costs, and information asymmetries (Spiegel, & Tookes, 2013).
The financial position of an organisation ensures that the organisation can persist in an
environment where competition is an evident factor. Valuation effects that financial position of
an organisation. The reverse is also true. The decisions made in an organisation relating to the
financial positions of the organisation may be based on the valuation that is provided for this
organisation.
Weighted Average Cost of Capital
The calculation of the cost of capital is an intricate process that requires the participation of all
stakeholders. The cost of capital is calculated through the estimation of the proportion of debt
that a project consumes against the equity that is absorbed in the respective project (Massari,
Roncaglio & Zanetti 2008). The weighted average cost of capital (WACC) is calculated through
a formula that incorporates the market value of equity and debt (Massari, Roncaglio & Zanetti
2008). These values are adjusted using the costs of debt and equity. For a single firm, the
WACC is calculated as a single unit where the firm is the reference. The organisation, in this
case, is considered a single unit, with the results being for a single project.
The Weighted Average Cost of Capital is an indicator of the financial performance of an
organisation because it indicates the financial position of the organisation under discussion.
Any organisation with sound financial decisions has a favourable WACC, which is considered
a strength in these organisations. The calculation and use of WACC in financial discussions
and problem-solving is challenging for some financial analysts and other financial decision-
makers in organisations. Therefore, it is important to have a discussion on the correct use of
WACC and its implications on the financial decisions in organisations.
The other difficulty in the calculation and use of WACC is tax calculation. Different finance
officers use different methods of calculating the variables (Sabalı 2009). Financing and
investment decisions interact through taxes. WACC is an important concept in evaluating this

interaction. The formula that is used in the calculation of WACC refers to the organisation of
company as a whole upon incorporating the different aspects in financial decisions in the firm.
Therefore, this formula is effective for the “average project” where the right discount rate is
produced (Massari, Roncaglio & Zanetti 2008). Hence, the formula is incorrect when used in
the calculation of WACC for the safer and riskier projects (Magni 2012). The inaccuracy while
using this formula mainly stems from the different sections that individuals calculate in an
organisation, especially where the organisation has different departments.
Capital Structure and Valuations
Capital structure in a firm is a factor that affects valuations in these organisations. The effects
depend on the existing capital structure. According to Sabalı (2009), financing decisions
typically affect value within organisations. Some of the ways that boost value in a firm with
respect to its financing decisions is through the adjustment of the discount rate and the present
value (Massari, Roncaglio & Zanetti 2008).
The discount rate in most organisations is typically adjusted downwards, with the aim being to
account for the existing tax shields (Massari, Roncaglio & Zanetti 2008). Financing decisions
also affect value in organisations through adjusting the present value in these organisations
(Massari, Roncaglio & Zanetti 2008). According to Spiegel and Tookes (2013), the base case
is first calculated with the assumption that it is all equity financed.
Capital structure in organisations affects the value of the organisation from its first year of
operation. The capital structure in organisations is variable depending on several factors such
as the capital debt and the type of industry within which a firm is located. The tax on a firm is
a major factor with reference to its capital value, especially because the tax determines the debt
status of an organisation (Sabalı 2009).
The initial cash that is invested into a firm in the first year affects the value of an organisation
during this year. Most of the organisations that invest significant amounts of capital into their
operations end up being successful in the first year. Over the years that follow, the WACC
formula is highly applicable, as the organisational debts and equities change.
Capital structure in most organisations is affected by the financial decisions made by the
executive. Hence, the value of organisations is dependent on the type of managers that an
organisation keeps. The value of organisation changes with any financial decision made, since
the debt and equities change with these decisions (Massari, Roncaglio & Zanetti 2008).

The value of a firm may be calculated through the estimation of the WACC, which is later used
to discount the FCFF from the debt holders and equity capital contributors (Massari, Roncaglio
& Zanetti 2008). The use of WACC in the estimation of a firm’s value is very effective by far
compared to other methods of value estimation. This finding indicates a relationship between
the value of organisations and the WACC. The WACC is in turn related to the financial
decisions in an organisation. Hence, valuation is related to the financial decisions in the
organisation.
Impact of Tax Shields on WACC
According to Massari, Roncaglio, and Zanetti (2008), tax is a variable in an organisation that
affects the value of these organisations. Interest in organisations is one of the expenses that are
usually considered as tax-deductible expense (Massari, Roncaglio & Zanetti 2008). The
calculation of WACC incorporates tax as a major form of expense. This strategy determines
the value of organisations. However, tax shields in organisations may affect the calculation of
WACC. The effects of tax shields on WACC depend on the business and individuals who are
responsible for financial management in the respective institutions.
The tax shields cause changes on WACC in a number of ways. However, while these effects
are dependent on the type of organisation, the main effect is that the WACC increases with a
reduction in tax shields. Most organisations seek tax shields to lower their WACC and in effect
influence the value and competitiveness of their respective industries. A common result of tax
shields is a downward adjustment of the discount rate to account for any changes in this area
(Massari, Roncaglio & Zanetti 2008). The downward adjustment of discount rates in
organisations allows decisions to be made on the WACC and its overall effect on the firm’s
value.
Tax shields help organisations save their available financial resources, including the provision
of future resources. In areas where tax shields are effectively applied, firms report better results,
performance, and competitiveness compared to areas where these policies are scantily applied.
Adjusting the discount rate downwards is one of the ways that tax shields are accounted for.
The result of this case is a change on the value of firms (Massari, Roncaglio & Zanetti 2008).
The relationship between value of an organisation and tax shields may be demonstrated by the
inherent differences between organisations that operate in different regions with different tax
shield regimens. According to Massari, Roncaglio, and Zanetti (2008), adjustment of WACC
should affect the value of a firm through the effect of this move on the value of the organisation.

Therefore, managers should make sound decisions when it comes to applying for tax shields in
their area.
How Tax Shields affect Firm Value
Tax shields in an organisation affect the firm’s value in a number of ways as indicated above.
A common understanding is that tax is one of the factors that affect WACC, and in effect the
value of an organisation. The worth of any business is affected by the financing decisions in
the organisations, including the availability of tax shields. The discount rate constitutes one of
the factors that may be adjusted to accommodate changes in the value of organisations. Mintz
and Currim (2013) observe that downward adjustment of discount rate accounts for tax shields.
This downward adjustment results in the increase in value of organisations.
Organisations that use the discount rate to effect changes in their firm value often report success
in the use of the method. When an organisation is awarded tax shields, the value changes to
correspond to the changes introduced through the adjustment of the discount rates. Most
organisations can be described as having debts because of the tax shields that they intend to
acquire.
Therefore, contemporary organisations are prone to debts in their quest to attain tax shields
from the respective authorities. The differences in the contemporary organisations arise from
the different capabilities in the use of their debts. Most organisations whose debt status is high
attain significant tax exemptions. They are valued at higher rank compared to organisations
that have a lower debt position. The tax shields in an organisation, therefore, affect the firm
value in organisations.
Mistakes in Using WACC
Several mistakes are established in literature in the use of WACC. The first mistake is in the
calculation of this variable. In fact, some individuals use variables that are not commonly
applied in the formula. The computation of WACC is tedious due to the many variables that
are necessary for the calculation process. This situation makes the calculation difficult to the
extent that some individuals opt for shortcuts that may not be accurate. The other mistake is
that some individuals assume that the formula may be used in the calculation of WACC for a
particular section of the organisation. They forget that this formula considers the firm a single
unit (Mian & Velez-Pareja 2007).

WACC is useful in providing discount for businesses only where they are applied to
organisations or projects with a similar undertaking to the firm under consideration. For
organisations that differ from the firm under consideration, the formula may not be applicable
or provide useful results. WACC may be useful in most of the calculations where the firm under
consideration has the same size as that of other firms that were initially considered. For projects
that are safer or riskier compared to the original organisation, the calculated WACC may be
inaccurate and in some cases incorrect.
The other mistake that individuals make in the use of WACC is the assumption that it can be
applied as a single variable in the determination of a firm’s value. According to Mian and Velez-
Pareja (2007), organisations require the use of many variables to calculate their value. A single
variable may be deceptive depending on the industry within which the firm is located.
Therefore, there is a need to consider a number of variables in the calculation of a firm’s value
as using WACC alone may be inaccurate. Some of the other mistakes that individuals make in
the use of WACC include miscalculation of the debt and equities that are eventually used in the
calculation of this variable.
Adjusting the WACC
The adjustment of WACC may be done through a number of ways depending on the debt ratios
and the business risks (Mintz & Currim 2013). Adjusting the WACC when the risk of the firm’s
debt ratio and the business risk differ from those of the new project is important in the
calculation of a business’ WACC.
The adjustment of WACC is important when the debt ratios and business risks differ in
organisations. The differences between these two variables result from the changes that are
inherent in the organisations. The three main steps that should be followed when adjusting the
WACC include calculation of the opportunity cost, estimation of the cost of the organisations
debt, and recalculation of the WACC using the obtained new values (Mian & Velez-Pareja
2007).
The adjustment of this value allows the correct calculations where the estimated WACC is
obtained against the real WACC. In cases where the WACC is adjusted, the value of the firm’s
debts and opportunity costs are considered the main reasons for the adjustments. There are
many reasons for the adjustments, with the main one being to increase the accuracy of the final
WACC that is obtained for any given firm. WACC is an indicator of the financing side effect
in an organisation. It is a good indicator of value in organisations (Mintz & Currim 2013).

These financing side effects include the value of interest tax shields on debts (Massari,
Roncaglio & Zanetti 2008). Adjustment of the WACC is also important where the actual value
of a firm is to be estimated.
Valuation in Organisations
Valuation affects the financial decisions that are made in organisations. Most of the decisions
that are important in organisations are made only through the consideration of the value of the
organisation since most managers tend to focus on increasing this value. The many valuation
approaches that are currently in use stem from the extensive research done in this area. These
approaches affect the financing decisions in organisations. The methods of valuation affect the
final variable.
Hence, most of these methods have sub approaches within them. Discounted cash flow is
among the most popular methods that are used in the valuation. This strategy focuses on the
financing decisions in the organisation (Massari, Roncaglio & Zanetti 2008). According to
Dong, Hirshleifer, and Teoh (2012), the main ways of estimating the discounted cash flow
include discounting the cash flow at a risk-adjusted discount (Sabalı 2009). This formula is one
of the four main methods that are used in the discounting cash flows. Using these methods
produces significant results.
Although different methods are in use in the valuation of companies, the same results may be
achieved if the assumptions are withheld for each of the methods. The similarity of these
methods ensures that the result is compatible with the businesses for which it was attempted
first. The different proponents for the different approaches in the valuation methods assume
that their methods are the most accurate. The results indicate that these methods are closely
similar. In relative valuation, which is considered one of the most important valuation methods,
the researchers who proposed the method adopted the assumption of individual assets.
However, these methods have similar results when the different assumptions are withheld.
Conclusion
In conclusion, based on the detailed expositions that have been made in the paper, it is clear
that valuation and financing are closely related when consideration for the financial state of an
organisation is made. Valuation may be estimated in organisations using several methods. Some
of these methods have been stated in this essay. The existence of valuation in financial decisions
allows the organisations to make decisions that coincide with their immediate needs.

The paper has proposed that a relationship between valuation and financial decisions in
organisations. This relationship is affected by other factors such as taxation. The WACC is an
important factor to consider when deducing the relationship between valuation and financial
decisions. The available research proves that this concept is applicable in an organisation’s
financial decisions. The essay has looked at the relationship between WACC and valuation in
organisations and the relationship that exists between these two variables and financial
decisions in an organisation. The paper has proved a positive relationship between these
concepts.
Valuation
The valuation of any organisation allows future decision-making to ensure that it is operating
as per the expectations. Different methods are used in valuation, including those that are
supported by theories and contemporary methods. The present models that are deployed in the
evaluation process are a product of extensive research, with many researchers describing them
before their application in management and finance. What are the motives of company
valuation? Different schools of thought exist as to why company valuation is important.
One of the motives for the evaluations of a company is to make decisions in the organisation.
Depending on the decision that is reached after valuation, the involved individuals may decide
on the future of the organisation and the interventions for the areas that are found faulty.
Motives in company valuation may be characterised in different ways, including decision-
dependent and decision-independent motives (Ishakian, Knebusch & Rowen 2013). The other
category of motives is the transaction based vs the non-transaction-based motives (Ishakian,
Knebusch & Rowen 2013). The other class of motives, as described throughout the literature
on valuation, is the dominated vs the non-dominated decision (Ishakian, Knebusch & Rowen
2013).
Valuation serves different functions depending on the concerned firm or organisation. These
functions can be categorised further into minor and major functions. The main functions of
valuation in organisations include decision-making and consultation. According to Ishakian,
Knebusch, and Rowen (2013), managers and other stakeholders use valuation information in
an organisation to make decisions on the future of the organisation with the aim of improving
the organisational performance. Different firms operate on different grounds. They use
different methods of valuation to make financial and other forms of decisions in the
organisation.

The other function of valuation, according to Koziol (2014), is mediation where the firm uses
information from valuation to mediate between concepts, decisions, and individuals.
Hundsdoerfer, Kruschwitz, and Loren (2008) assert that mediation in an organisation provides
crucial information on the financial position of the organisation. Valuation also serves as a
means of argumentation. Using information from valuation, managers and other organisational
stakeholders can argue on the position of the organisation. The information is used to provide
details on the organisational performance, which is important in making a case for any
argument.
Apart from the main functions of valuation, valuation serves other auxiliary functions. One of
these auxiliary functions is information where the parties within an organisation gather
information on this organisation, including its performance and future expectations. Valuation
may also be used as a means of tax measurement where authorities determine the tax that an
organisation should forward over a given period. Many organisations where valuation has been
conducted were found to have some tax measurements, not in line with the expected values
(Mian & Velez-Pareja 2007). Valuation also serves the function of contract configuration where
employees and other parties in the organisation can have their contracts configured with the
expectations of the organisation.
Valuation Methods
Different valuation methods are in use in many organisations. Each of these methods provides
different results. The decision to use one of them is dependent on the firm that is being
evaluated, the financial methods in place, and the preferred approach. The most popular
approach depends on the organisation and the region where these organisations exist. Different
methods that are used in valuation are shown below.
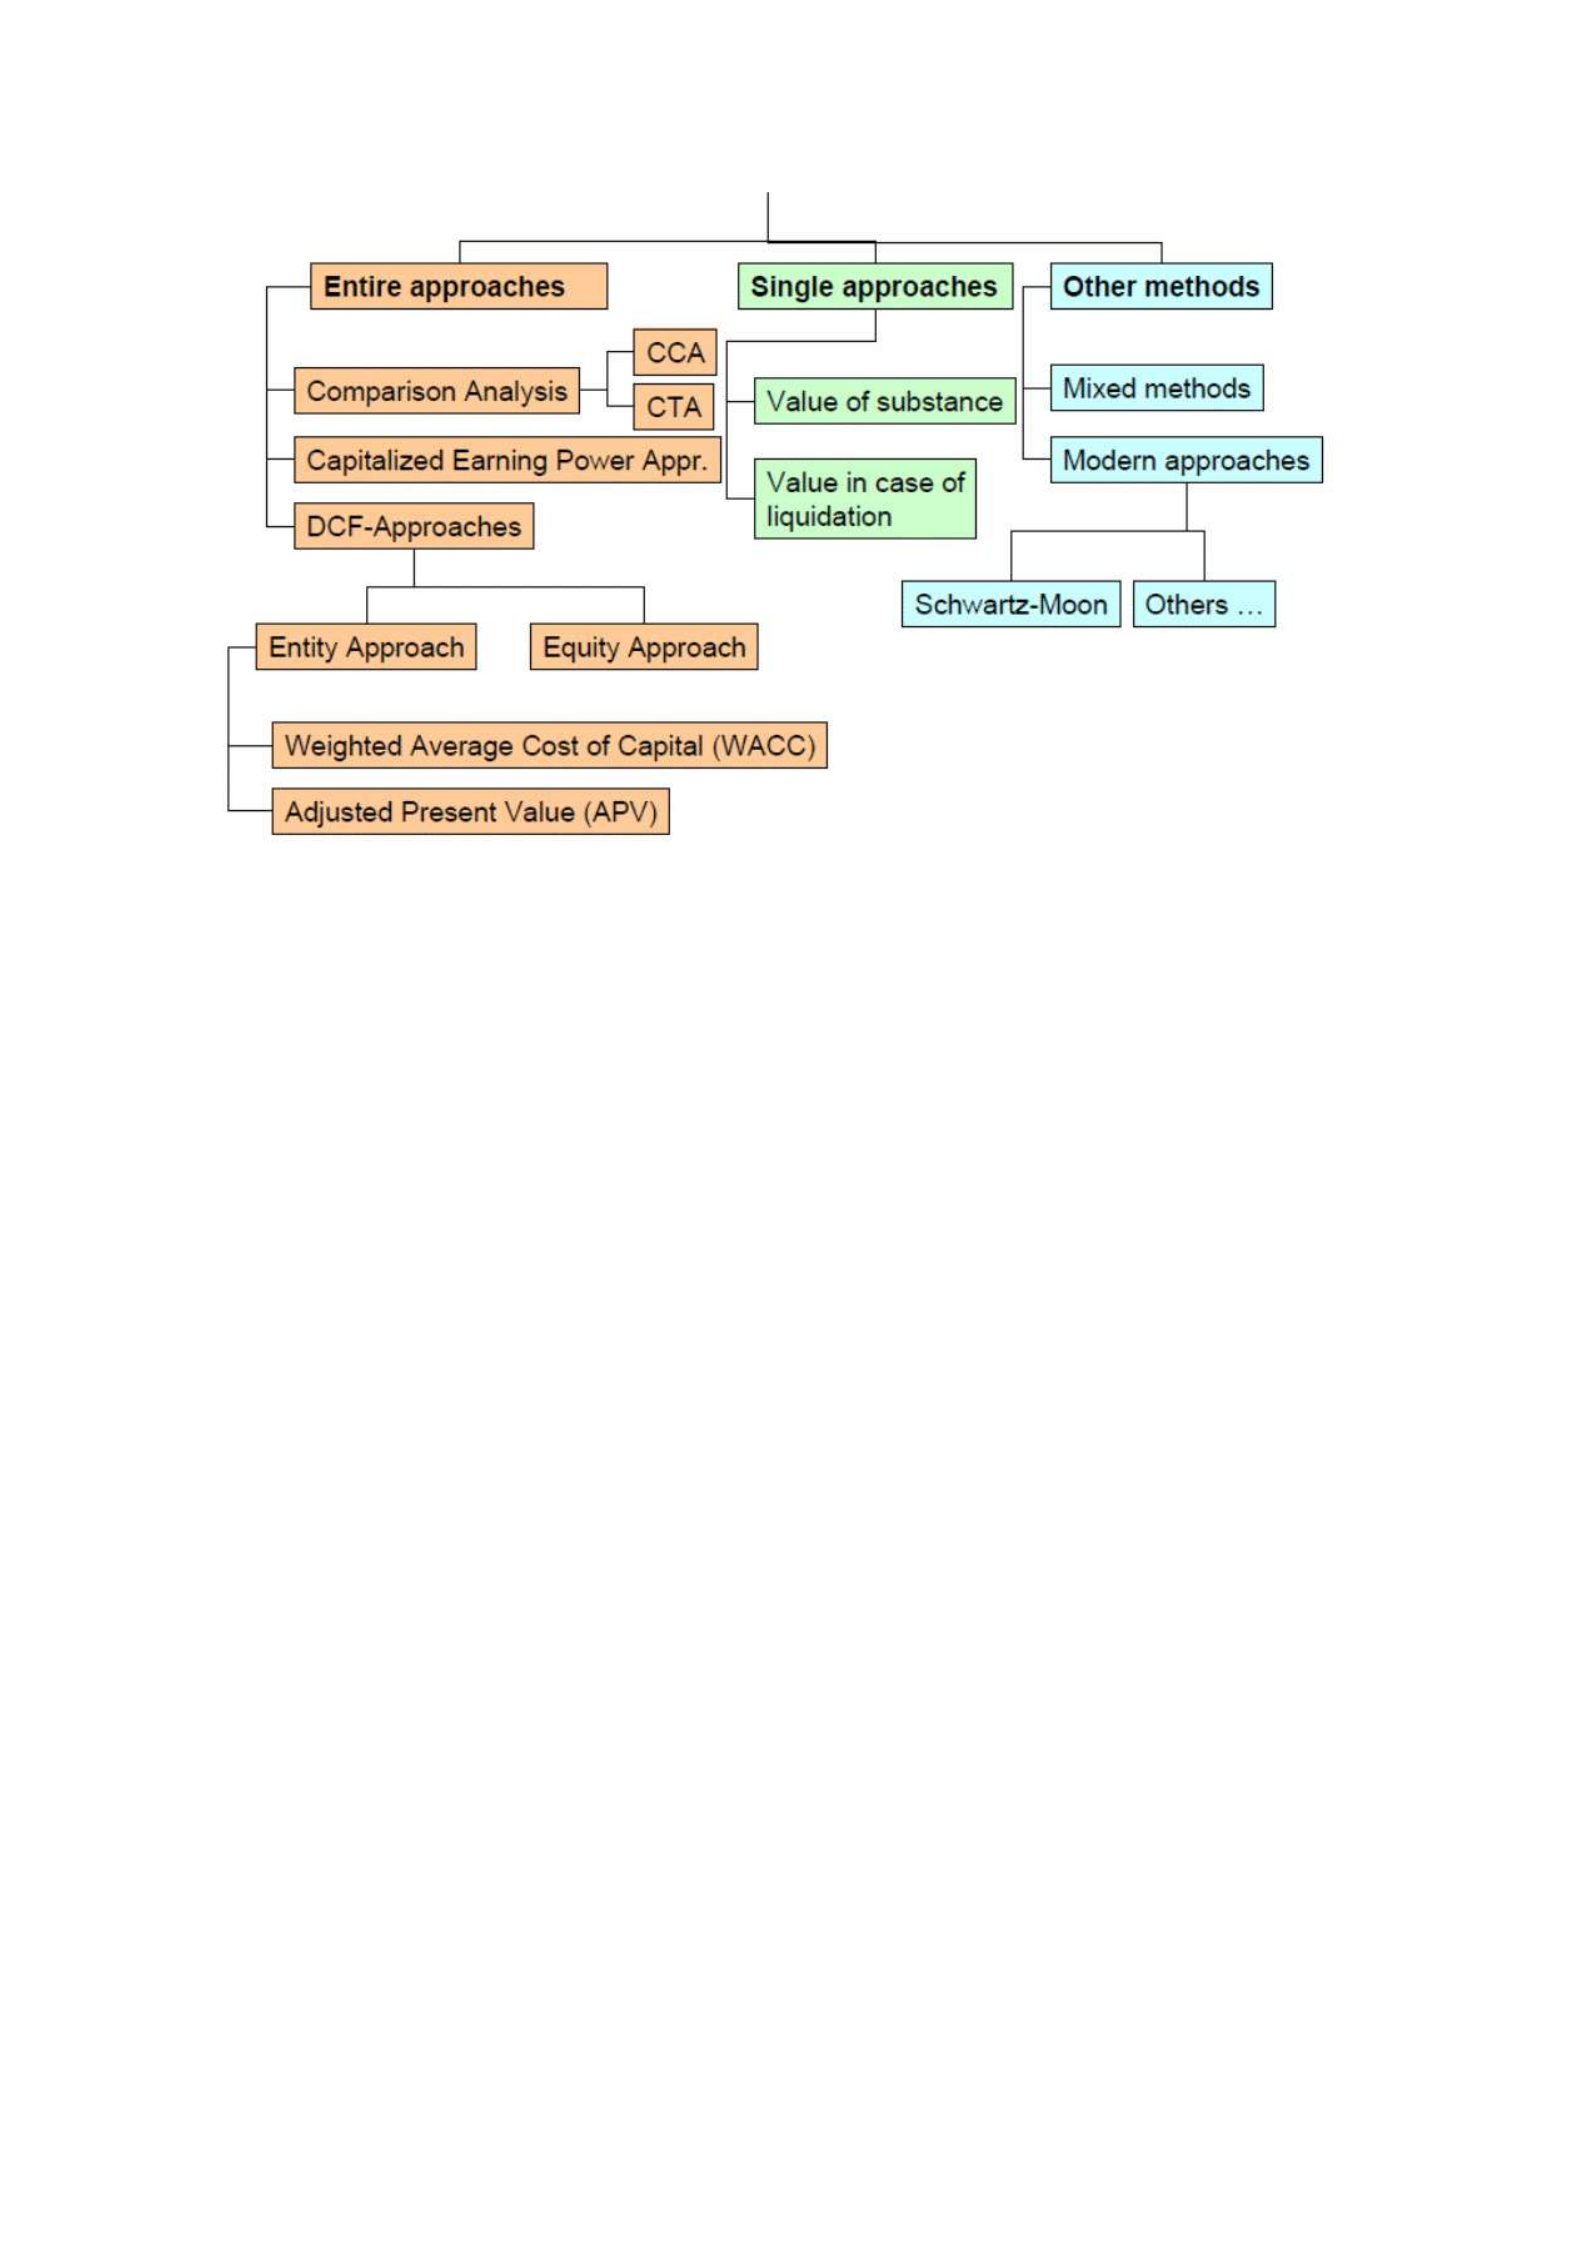
Figure 1: An Overview of Valuation Methods (Source Mian & Velez-Pareja 2007)
Different models that are applied during a valuation in organisations lead to a common result
where the organisations are able to plan for future decisions and changes. The valuation that is
obtained in organisations, irrespective of the method used, provides crucial information on the
financial status of the organisation. However, valuation within organisations also allows the
inception of changes whenever they are needed.
Financial Decisions
Organisations face challenges in financing, with one of the most common of them being the
outcomes of financial decisions. Competitiveness in organisations is influenced by the financial
decisions that managers and other stakeholders make. In any industry, financial decisions affect
the outcomes of the interactions between different factors. The financial decisions in an
organisation are also under the influence of other factors such as the valuation in these
organisations. A business in any industry or market must use capital as one of the main factors
in its operations, with this strategy bringing about the cost of capital.
Currently, there are no perfect markets in contemporary organisations. Hence, capital is not
always put to the intended use. A perfect business environment is the only place where capital
can be put to its planned use. However, conditions that are necessary for a perfect market are
hard to achieve. Nevertheless, if it were possible, the perfect world would have an excess
supply of capital. A perfect capital market might mean that the available unlimited capital is
only dependent on the risk of the project being undertaken (Spiegel, & Tookes 2013).

Aside from the perfect capital market, uncertainties, variables, and friction characterise the
existing real-world capital markets. The availability of tax as one of the variables in an
imperfect world ensures that organisations adopt strategies such as debts. An example of such
strategies is when an organisation operates in a capital structure with about 100% of debt
because of the positive corporate tax rate (Spiegel, & Tookes, 2013). Other factors that exist in
an imperfect world to introduce a relationship between valuations and financing include agency
costs, financial distress costs, and information asymmetries (Spiegel, & Tookes, 2013).
The financial position of an organisation ensures that the organisation can persist in an
environment where competition is an evident factor. Valuation effects that financial position of
an organisation. The reverse is also true. The decisions made in an organisation relating to the
financial positions of the organisation may be based on the valuation that is provided for this
organisation.
Weighted Average Cost of Capital
The calculation of the cost of capital is an intricate process that requires the participation of all
stakeholders. The cost of capital is calculated through the estimation of the proportion of debt
that a project consumes against the equity that is absorbed in the respective project (Massari,
Roncaglio & Zanetti 2008). The weighted average cost of capital (WACC) is calculated through
a formula that incorporates the market value of equity and debt (Massari, Roncaglio & Zanetti
2008). These values are adjusted using the costs of debt and equity. For a single firm, the
WACC is calculated as a single unit where the firm is the reference. The organisation, in this
case, is considered a single unit, with the results being for a single project.
The Weighted Average Cost of Capital is an indicator of the financial performance of an
organisation because it indicates the financial position of the organisation under discussion.
Any organisation with sound financial decisions has a favourable WACC, which is considered
a strength in these organisations. The calculation and use of WACC in financial discussions
and problem-solving is challenging for some financial analysts and other financial decision-
makers in organisations. Therefore, it is important to have a discussion on the correct use of
WACC and its implications on the financial decisions in organisations.
The other difficulty in the calculation and use of WACC is tax calculation. Different finance
officers use different methods of calculating the variables (Sabalı 2009). Financing and
investment decisions interact through taxes. WACC is an important concept in evaluating this

interaction. The formula that is used in the calculation of WACC refers to the organisation of
company as a whole upon incorporating the different aspects in financial decisions in the firm.
Therefore, this formula is effective for the “average project” where the right discount rate is
produced (Massari, Roncaglio & Zanetti 2008). Hence, the formula is incorrect when used in
the calculation of WACC for the safer and riskier projects (Magni 2012). The inaccuracy while
using this formula mainly stems from the different sections that individuals calculate in an
organisation, especially where the organisation has different departments.
Capital Structure and Valuations
Capital structure in a firm is a factor that affects valuations in these organisations. The effects
depend on the existing capital structure. According to Sabalı (2009), financing decisions
typically affect value within organisations. Some of the ways that boost value in a firm with
respect to its financing decisions is through the adjustment of the discount rate and the present
value (Massari, Roncaglio & Zanetti 2008).
The discount rate in most organisations is typically adjusted downwards, with the aim being to
account for the existing tax shields (Massari, Roncaglio & Zanetti 2008). Financing decisions
also affect value in organisations through adjusting the present value in these organisations
(Massari, Roncaglio & Zanetti 2008). According to Spiegel and Tookes (2013), the base case
is first calculated with the assumption that it is all equity financed.
Capital structure in organisations affects the value of the organisation from its first year of
operation. The capital structure in organisations is variable depending on several factors such
as the capital debt and the type of industry within which a firm is located. The tax on a firm is
a major factor with reference to its capital value, especially because the tax determines the debt
status of an organisation (Sabalı 2009).
The initial cash that is invested into a firm in the first year affects the value of an organisation
during this year. Most of the organisations that invest significant amounts of capital into their
operations end up being successful in the first year. Over the years that follow, the WACC
formula is highly applicable, as the organisational debts and equities change.
Capital structure in most organisations is affected by the financial decisions made by the
executive. Hence, the value of organisations is dependent on the type of managers that an
organisation keeps. The value of organisation changes with any financial decision made, since
the debt and equities change with these decisions (Massari, Roncaglio & Zanetti 2008).

The value of a firm may be calculated through the estimation of the WACC, which is later used
to discount the FCFF from the debt holders and equity capital contributors (Massari, Roncaglio
& Zanetti 2008). The use of WACC in the estimation of a firm’s value is very effective by far
compared to other methods of value estimation. This finding indicates a relationship between
the value of organisations and the WACC. The WACC is in turn related to the financial
decisions in an organisation. Hence, valuation is related to the financial decisions in the
organisation.
Impact of Tax Shields on WACC
According to Massari, Roncaglio, and Zanetti (2008), tax is a variable in an organisation that
affects the value of these organisations. Interest in organisations is one of the expenses that are
usually considered as tax-deductible expense (Massari, Roncaglio & Zanetti 2008). The
calculation of WACC incorporates tax as a major form of expense. This strategy determines
the value of organisations. However, tax shields in organisations may affect the calculation of
WACC. The effects of tax shields on WACC depend on the business and individuals who are
responsible for financial management in the respective institutions.
The tax shields cause changes on WACC in a number of ways. However, while these effects
are dependent on the type of organisation, the main effect is that the WACC increases with a
reduction in tax shields. Most organisations seek tax shields to lower their WACC and in effect
influence the value and competitiveness of their respective industries. A common result of tax
shields is a downward adjustment of the discount rate to account for any changes in this area
(Massari, Roncaglio & Zanetti 2008). The downward adjustment of discount rates in
organisations allows decisions to be made on the WACC and its overall effect on the firm’s
value.
Tax shields help organisations save their available financial resources, including the provision
of future resources. In areas where tax shields are effectively applied, firms report better results,
performance, and competitiveness compared to areas where these policies are scantily applied.
Adjusting the discount rate downwards is one of the ways that tax shields are accounted for.
The result of this case is a change on the value of firms (Massari, Roncaglio & Zanetti 2008).
The relationship between value of an organisation and tax shields may be demonstrated by the
inherent differences between organisations that operate in different regions with different tax
shield regimens. According to Massari, Roncaglio, and Zanetti (2008), adjustment of WACC
should affect the value of a firm through the effect of this move on the value of the organisation.

Therefore, managers should make sound decisions when it comes to applying for tax shields in
their area.
How Tax Shields affect Firm Value
Tax shields in an organisation affect the firm’s value in a number of ways as indicated above.
A common understanding is that tax is one of the factors that affect WACC, and in effect the
value of an organisation. The worth of any business is affected by the financing decisions in
the organisations, including the availability of tax shields. The discount rate constitutes one of
the factors that may be adjusted to accommodate changes in the value of organisations. Mintz
and Currim (2013) observe that downward adjustment of discount rate accounts for tax shields.
This downward adjustment results in the increase in value of organisations.
Organisations that use the discount rate to effect changes in their firm value often report success
in the use of the method. When an organisation is awarded tax shields, the value changes to
correspond to the changes introduced through the adjustment of the discount rates. Most
organisations can be described as having debts because of the tax shields that they intend to
acquire.
Therefore, contemporary organisations are prone to debts in their quest to attain tax shields
from the respective authorities. The differences in the contemporary organisations arise from
the different capabilities in the use of their debts. Most organisations whose debt status is high
attain significant tax exemptions. They are valued at higher rank compared to organisations
that have a lower debt position. The tax shields in an organisation, therefore, affect the firm
value in organisations.
Mistakes in Using WACC
Several mistakes are established in literature in the use of WACC. The first mistake is in the
calculation of this variable. In fact, some individuals use variables that are not commonly
applied in the formula. The computation of WACC is tedious due to the many variables that
are necessary for the calculation process. This situation makes the calculation difficult to the
extent that some individuals opt for shortcuts that may not be accurate. The other mistake is
that some individuals assume that the formula may be used in the calculation of WACC for a
particular section of the organisation. They forget that this formula considers the firm a single
unit (Mian & Velez-Pareja 2007).

WACC is useful in providing discount for businesses only where they are applied to
organisations or projects with a similar undertaking to the firm under consideration. For
organisations that differ from the firm under consideration, the formula may not be applicable
or provide useful results. WACC may be useful in most of the calculations where the firm under
consideration has the same size as that of other firms that were initially considered. For projects
that are safer or riskier compared to the original organisation, the calculated WACC may be
inaccurate and in some cases incorrect.
The other mistake that individuals make in the use of WACC is the assumption that it can be
applied as a single variable in the determination of a firm’s value. According to Mian and Velez-
Pareja (2007), organisations require the use of many variables to calculate their value. A single
variable may be deceptive depending on the industry within which the firm is located.
Therefore, there is a need to consider a number of variables in the calculation of a firm’s value
as using WACC alone may be inaccurate. Some of the other mistakes that individuals make in
the use of WACC include miscalculation of the debt and equities that are eventually used in the
calculation of this variable.
Adjusting the WACC
The adjustment of WACC may be done through a number of ways depending on the debt ratios
and the business risks (Mintz & Currim 2013). Adjusting the WACC when the risk of the firm’s
debt ratio and the business risk differ from those of the new project is important in the
calculation of a business’ WACC.
The adjustment of WACC is important when the debt ratios and business risks differ in
organisations. The differences between these two variables result from the changes that are
inherent in the organisations. The three main steps that should be followed when adjusting the
WACC include calculation of the opportunity cost, estimation of the cost of the organisations
debt, and recalculation of the WACC using the obtained new values (Mian & Velez-Pareja
2007).
The adjustment of this value allows the correct calculations where the estimated WACC is
obtained against the real WACC. In cases where the WACC is adjusted, the value of the firm’s
debts and opportunity costs are considered the main reasons for the adjustments. There are
many reasons for the adjustments, with the main one being to increase the accuracy of the final
WACC that is obtained for any given firm. WACC is an indicator of the financing side effect
in an organisation. It is a good indicator of value in organisations (Mintz & Currim 2013).

These financing side effects include the value of interest tax shields on debts (Massari,
Roncaglio & Zanetti 2008). Adjustment of the WACC is also important where the actual value
of a firm is to be estimated.
Valuation in Organisations
Valuation affects the financial decisions that are made in organisations. Most of the decisions
that are important in organisations are made only through the consideration of the value of the
organisation since most managers tend to focus on increasing this value. The many valuation
approaches that are currently in use stem from the extensive research done in this area. These
approaches affect the financing decisions in organisations. The methods of valuation affect the
final variable.
Hence, most of these methods have sub approaches within them. Discounted cash flow is
among the most popular methods that are used in the valuation. This strategy focuses on the
financing decisions in the organisation (Massari, Roncaglio & Zanetti 2008). According to
Dong, Hirshleifer, and Teoh (2012), the main ways of estimating the discounted cash flow
include discounting the cash flow at a risk-adjusted discount (Sabalı 2009). This formula is one
of the four main methods that are used in the discounting cash flows. Using these methods
produces significant results.
Although different methods are in use in the valuation of companies, the same results may be
achieved if the assumptions are withheld for each of the methods. The similarity of these
methods ensures that the result is compatible with the businesses for which it was attempted
first. The different proponents for the different approaches in the valuation methods assume
that their methods are the most accurate. The results indicate that these methods are closely
similar. In relative valuation, which is considered one of the most important valuation methods,
the researchers who proposed the method adopted the assumption of individual assets.
However, these methods have similar results when the different assumptions are withheld.
Conclusion
In conclusion, based on the detailed expositions that have been made in the paper, it is clear
that valuation and financing are closely related when consideration for the financial state of an
organisation is made. Valuation may be estimated in organisations using several methods. Some
of these methods have been stated in this essay. The existence of valuation in financial decisions
allows the organisations to make decisions that coincide with their immediate needs.

The paper has proposed that a relationship between valuation and financial decisions in
organisations. This relationship is affected by other factors such as taxation. The WACC is an
important factor to consider when deducing the relationship between valuation and financial
decisions. The available research proves that this concept is applicable in an organisation’s
financial decisions. The essay has looked at the relationship between WACC and valuation in
organisations and the relationship that exists between these two variables and financial
decisions in an organisation. The paper has proved a positive relationship between these
concepts.
Valuation
The valuation of any organisation allows future decision-making to ensure that it is operating
as per the expectations. Different methods are used in valuation, including those that are
supported by theories and contemporary methods. The present models that are deployed in the
evaluation process are a product of extensive research, with many researchers describing them
before their application in management and finance. What are the motives of company
valuation? Different schools of thought exist as to why company valuation is important.
One of the motives for the evaluations of a company is to make decisions in the organisation.
Depending on the decision that is reached after valuation, the involved individuals may decide
on the future of the organisation and the interventions for the areas that are found faulty.
Motives in company valuation may be characterised in different ways, including decision-
dependent and decision-independent motives (Ishakian, Knebusch & Rowen 2013). The other
category of motives is the transaction based vs the non-transaction-based motives (Ishakian,
Knebusch & Rowen 2013). The other class of motives, as described throughout the literature
on valuation, is the dominated vs the non-dominated decision (Ishakian, Knebusch & Rowen
2013).
Valuation serves different functions depending on the concerned firm or organisation. These
functions can be categorised further into minor and major functions. The main functions of
valuation in organisations include decision-making and consultation. According to Ishakian,
Knebusch, and Rowen (2013), managers and other stakeholders use valuation information in
an organisation to make decisions on the future of the organisation with the aim of improving
the organisational performance. Different firms operate on different grounds. They use
different methods of valuation to make financial and other forms of decisions in the
organisation.

The other function of valuation, according to Koziol (2014), is mediation where the firm uses
information from valuation to mediate between concepts, decisions, and individuals.
Hundsdoerfer, Kruschwitz, and Loren (2008) assert that mediation in an organisation provides
crucial information on the financial position of the organisation. Valuation also serves as a
means of argumentation. Using information from valuation, managers and other organisational
stakeholders can argue on the position of the organisation. The information is used to provide
details on the organisational performance, which is important in making a case for any
argument.
Apart from the main functions of valuation, valuation serves other auxiliary functions. One of
these auxiliary functions is information where the parties within an organisation gather
information on this organisation, including its performance and future expectations. Valuation
may also be used as a means of tax measurement where authorities determine the tax that an
organisation should forward over a given period. Many organisations where valuation has been
conducted were found to have some tax measurements, not in line with the expected values
(Mian & Velez-Pareja 2007). Valuation also serves the function of contract configuration where
employees and other parties in the organisation can have their contracts configured with the
expectations of the organisation.
Valuation Methods
Different valuation methods are in use in many organisations. Each of these methods provides
different results. The decision to use one of them is dependent on the firm that is being
evaluated, the financial methods in place, and the preferred approach. The most popular
approach depends on the organisation and the region where these organisations exist. Different
methods that are used in valuation are shown below.
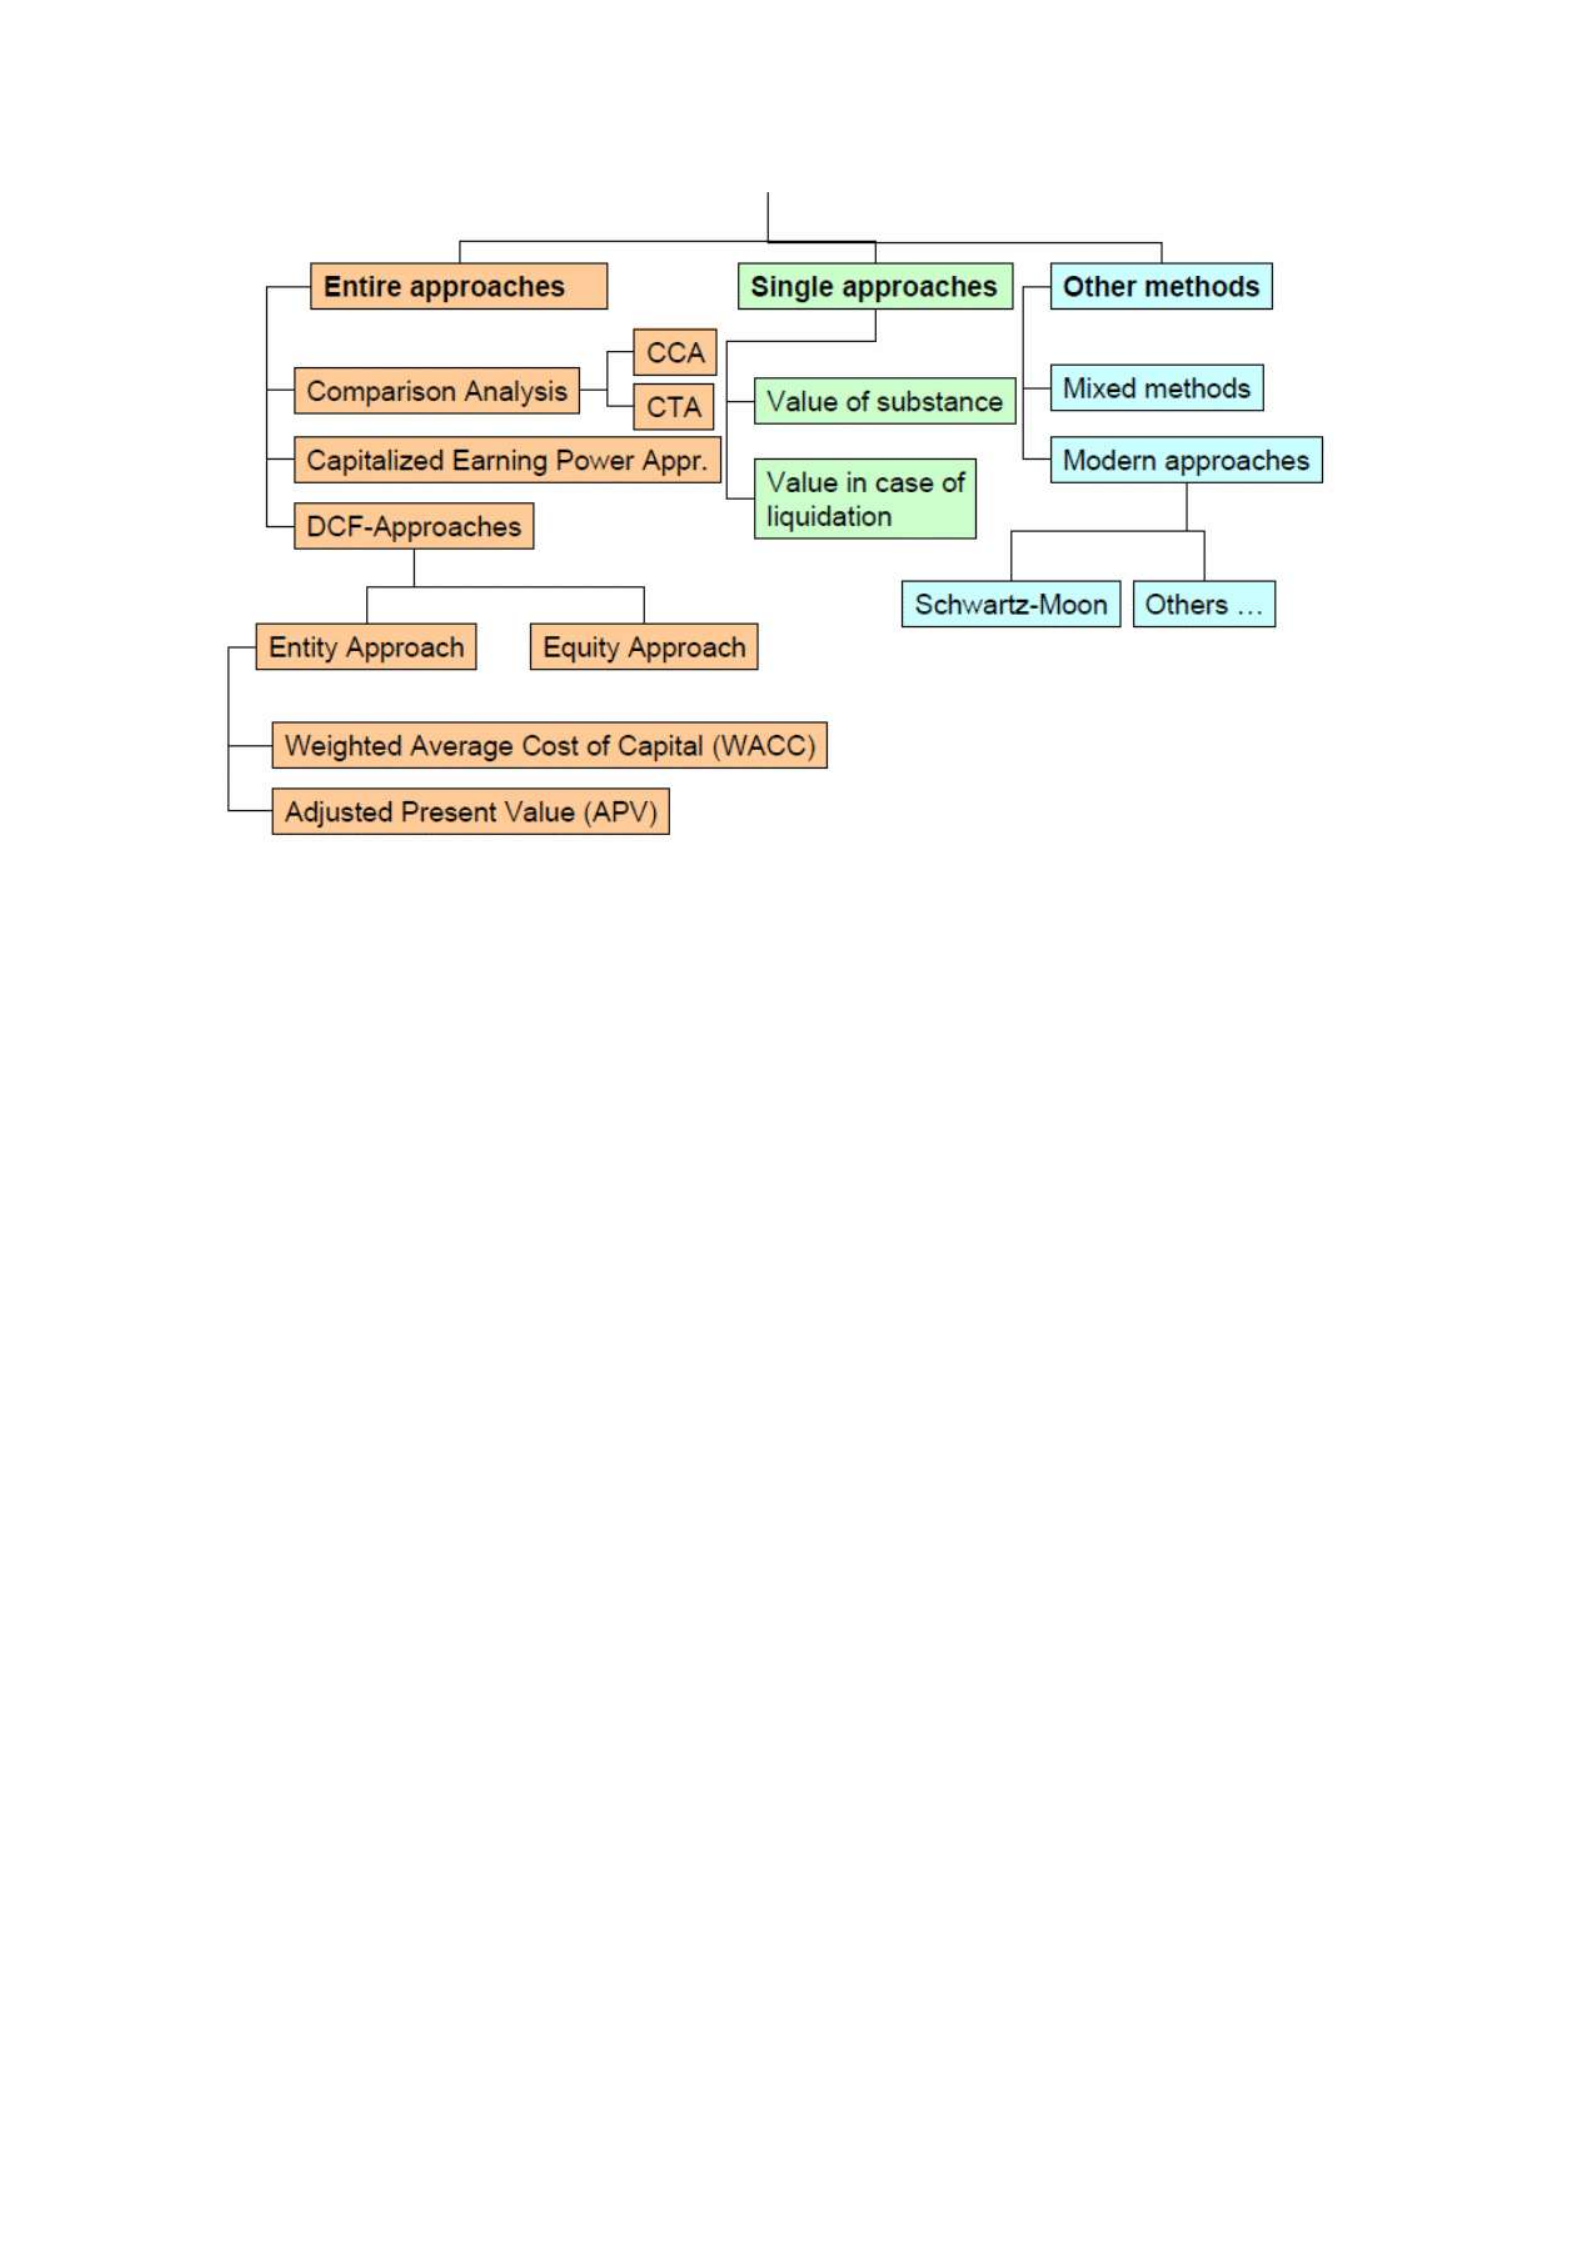
Figure 1: An Overview of Valuation Methods (Source Mian & Velez-Pareja 2007)
Different models that are applied during a valuation in organisations lead to a common result
where the organisations are able to plan for future decisions and changes. The valuation that is
obtained in organisations, irrespective of the method used, provides crucial information on the
financial status of the organisation. However, valuation within organisations also allows the
inception of changes whenever they are needed.
Financial Decisions
Organisations face challenges in financing, with one of the most common of them being the
outcomes of financial decisions. Competitiveness in organisations is influenced by the financial
decisions that managers and other stakeholders make. In any industry, financial decisions affect
the outcomes of the interactions between different factors. The financial decisions in an
organisation are also under the influence of other factors such as the valuation in these
organisations. A business in any industry or market must use capital as one of the main factors
in its operations, with this strategy bringing about the cost of capital.
Currently, there are no perfect markets in contemporary organisations. Hence, capital is not
always put to the intended use. A perfect business environment is the only place where capital
can be put to its planned use. However, conditions that are necessary for a perfect market are
hard to achieve. Nevertheless, if it were possible, the perfect world would have an excess
supply of capital. A perfect capital market might mean that the available unlimited capital is
only dependent on the risk of the project being undertaken (Spiegel, & Tookes 2013).

Aside from the perfect capital market, uncertainties, variables, and friction characterise the
existing real-world capital markets. The availability of tax as one of the variables in an
imperfect world ensures that organisations adopt strategies such as debts. An example of such
strategies is when an organisation operates in a capital structure with about 100% of debt
because of the positive corporate tax rate (Spiegel, & Tookes, 2013). Other factors that exist in
an imperfect world to introduce a relationship between valuations and financing include agency
costs, financial distress costs, and information asymmetries (Spiegel, & Tookes, 2013).
The financial position of an organisation ensures that the organisation can persist in an
environment where competition is an evident factor. Valuation effects that financial position of
an organisation. The reverse is also true. The decisions made in an organisation relating to the
financial positions of the organisation may be based on the valuation that is provided for this
organisation.
Weighted Average Cost of Capital
The calculation of the cost of capital is an intricate process that requires the participation of all
stakeholders. The cost of capital is calculated through the estimation of the proportion of debt
that a project consumes against the equity that is absorbed in the respective project (Massari,
Roncaglio & Zanetti 2008). The weighted average cost of capital (WACC) is calculated through
a formula that incorporates the market value of equity and debt (Massari, Roncaglio & Zanetti
2008). These values are adjusted using the costs of debt and equity. For a single firm, the
WACC is calculated as a single unit where the firm is the reference. The organisation, in this
case, is considered a single unit, with the results being for a single project.
The Weighted Average Cost of Capital is an indicator of the financial performance of an
organisation because it indicates the financial position of the organisation under discussion.
Any organisation with sound financial decisions has a favourable WACC, which is considered
a strength in these organisations. The calculation and use of WACC in financial discussions
and problem-solving is challenging for some financial analysts and other financial decision-
makers in organisations. Therefore, it is important to have a discussion on the correct use of
WACC and its implications on the financial decisions in organisations.
The other difficulty in the calculation and use of WACC is tax calculation. Different finance
officers use different methods of calculating the variables (Sabalı 2009). Financing and
investment decisions interact through taxes. WACC is an important concept in evaluating this

interaction. The formula that is used in the calculation of WACC refers to the organisation of
company as a whole upon incorporating the different aspects in financial decisions in the firm.
Therefore, this formula is effective for the “average project” where the right discount rate is
produced (Massari, Roncaglio & Zanetti 2008). Hence, the formula is incorrect when used in
the calculation of WACC for the safer and riskier projects (Magni 2012). The inaccuracy while
using this formula mainly stems from the different sections that individuals calculate in an
organisation, especially where the organisation has different departments.
Capital Structure and Valuations
Capital structure in a firm is a factor that affects valuations in these organisations. The effects
depend on the existing capital structure. According to Sabalı (2009), financing decisions
typically affect value within organisations. Some of the ways that boost value in a firm with
respect to its financing decisions is through the adjustment of the discount rate and the present
value (Massari, Roncaglio & Zanetti 2008).
The discount rate in most organisations is typically adjusted downwards, with the aim being to
account for the existing tax shields (Massari, Roncaglio & Zanetti 2008). Financing decisions
also affect value in organisations through adjusting the present value in these organisations
(Massari, Roncaglio & Zanetti 2008). According to Spiegel and Tookes (2013), the base case
is first calculated with the assumption that it is all equity financed.
Capital structure in organisations affects the value of the organisation from its first year of
operation. The capital structure in organisations is variable depending on several factors such
as the capital debt and the type of industry within which a firm is located. The tax on a firm is
a major factor with reference to its capital value, especially because the tax determines the debt
status of an organisation (Sabalı 2009).
The initial cash that is invested into a firm in the first year affects the value of an organisation
during this year. Most of the organisations that invest significant amounts of capital into their
operations end up being successful in the first year. Over the years that follow, the WACC
formula is highly applicable, as the organisational debts and equities change.
Capital structure in most organisations is affected by the financial decisions made by the
executive. Hence, the value of organisations is dependent on the type of managers that an
organisation keeps. The value of organisation changes with any financial decision made, since
the debt and equities change with these decisions (Massari, Roncaglio & Zanetti 2008).

The value of a firm may be calculated through the estimation of the WACC, which is later used
to discount the FCFF from the debt holders and equity capital contributors (Massari, Roncaglio
& Zanetti 2008). The use of WACC in the estimation of a firm’s value is very effective by far
compared to other methods of value estimation. This finding indicates a relationship between
the value of organisations and the WACC. The WACC is in turn related to the financial
decisions in an organisation. Hence, valuation is related to the financial decisions in the
organisation.
Impact of Tax Shields on WACC
According to Massari, Roncaglio, and Zanetti (2008), tax is a variable in an organisation that
affects the value of these organisations. Interest in organisations is one of the expenses that are
usually considered as tax-deductible expense (Massari, Roncaglio & Zanetti 2008). The
calculation of WACC incorporates tax as a major form of expense. This strategy determines
the value of organisations. However, tax shields in organisations may affect the calculation of
WACC. The effects of tax shields on WACC depend on the business and individuals who are
responsible for financial management in the respective institutions.
The tax shields cause changes on WACC in a number of ways. However, while these effects
are dependent on the type of organisation, the main effect is that the WACC increases with a
reduction in tax shields. Most organisations seek tax shields to lower their WACC and in effect
influence the value and competitiveness of their respective industries. A common result of tax
shields is a downward adjustment of the discount rate to account for any changes in this area
(Massari, Roncaglio & Zanetti 2008). The downward adjustment of discount rates in
organisations allows decisions to be made on the WACC and its overall effect on the firm’s
value.
Tax shields help organisations save their available financial resources, including the provision
of future resources. In areas where tax shields are effectively applied, firms report better results,
performance, and competitiveness compared to areas where these policies are scantily applied.
Adjusting the discount rate downwards is one of the ways that tax shields are accounted for.
The result of this case is a change on the value of firms (Massari, Roncaglio & Zanetti 2008).
The relationship between value of an organisation and tax shields may be demonstrated by the
inherent differences between organisations that operate in different regions with different tax
shield regimens. According to Massari, Roncaglio, and Zanetti (2008), adjustment of WACC
should affect the value of a firm through the effect of this move on the value of the organisation.

Therefore, managers should make sound decisions when it comes to applying for tax shields in
their area.
How Tax Shields affect Firm Value
Tax shields in an organisation affect the firm’s value in a number of ways as indicated above.
A common understanding is that tax is one of the factors that affect WACC, and in effect the
value of an organisation. The worth of any business is affected by the financing decisions in
the organisations, including the availability of tax shields. The discount rate constitutes one of
the factors that may be adjusted to accommodate changes in the value of organisations. Mintz
and Currim (2013) observe that downward adjustment of discount rate accounts for tax shields.
This downward adjustment results in the increase in value of organisations.
Organisations that use the discount rate to effect changes in their firm value often report success
in the use of the method. When an organisation is awarded tax shields, the value changes to
correspond to the changes introduced through the adjustment of the discount rates. Most
organisations can be described as having debts because of the tax shields that they intend to
acquire.
Therefore, contemporary organisations are prone to debts in their quest to attain tax shields
from the respective authorities. The differences in the contemporary organisations arise from
the different capabilities in the use of their debts. Most organisations whose debt status is high
attain significant tax exemptions. They are valued at higher rank compared to organisations
that have a lower debt position. The tax shields in an organisation, therefore, affect the firm
value in organisations.
Mistakes in Using WACC
Several mistakes are established in literature in the use of WACC. The first mistake is in the
calculation of this variable. In fact, some individuals use variables that are not commonly
applied in the formula. The computation of WACC is tedious due to the many variables that
are necessary for the calculation process. This situation makes the calculation difficult to the
extent that some individuals opt for shortcuts that may not be accurate. The other mistake is
that some individuals assume that the formula may be used in the calculation of WACC for a
particular section of the organisation. They forget that this formula considers the firm a single
unit (Mian & Velez-Pareja 2007).

WACC is useful in providing discount for businesses only where they are applied to
organisations or projects with a similar undertaking to the firm under consideration. For
organisations that differ from the firm under consideration, the formula may not be applicable
or provide useful results. WACC may be useful in most of the calculations where the firm under
consideration has the same size as that of other firms that were initially considered. For projects
that are safer or riskier compared to the original organisation, the calculated WACC may be
inaccurate and in some cases incorrect.
The other mistake that individuals make in the use of WACC is the assumption that it can be
applied as a single variable in the determination of a firm’s value. According to Mian and Velez-
Pareja (2007), organisations require the use of many variables to calculate their value. A single
variable may be deceptive depending on the industry within which the firm is located.
Therefore, there is a need to consider a number of variables in the calculation of a firm’s value
as using WACC alone may be inaccurate. Some of the other mistakes that individuals make in
the use of WACC include miscalculation of the debt and equities that are eventually used in the
calculation of this variable.
Adjusting the WACC
The adjustment of WACC may be done through a number of ways depending on the debt ratios
and the business risks (Mintz & Currim 2013). Adjusting the WACC when the risk of the firm’s
debt ratio and the business risk differ from those of the new project is important in the
calculation of a business’ WACC.
The adjustment of WACC is important when the debt ratios and business risks differ in
organisations. The differences between these two variables result from the changes that are
inherent in the organisations. The three main steps that should be followed when adjusting the
WACC include calculation of the opportunity cost, estimation of the cost of the organisations
debt, and recalculation of the WACC using the obtained new values (Mian & Velez-Pareja
2007).
The adjustment of this value allows the correct calculations where the estimated WACC is
obtained against the real WACC. In cases where the WACC is adjusted, the value of the firm’s
debts and opportunity costs are considered the main reasons for the adjustments. There are
many reasons for the adjustments, with the main one being to increase the accuracy of the final
WACC that is obtained for any given firm. WACC is an indicator of the financing side effect
in an organisation. It is a good indicator of value in organisations (Mintz & Currim 2013).

These financing side effects include the value of interest tax shields on debts (Massari,
Roncaglio & Zanetti 2008). Adjustment of the WACC is also important where the actual value
of a firm is to be estimated.
Valuation in Organisations
Valuation affects the financial decisions that are made in organisations. Most of the decisions
that are important in organisations are made only through the consideration of the value of the
organisation since most managers tend to focus on increasing this value. The many valuation
approaches that are currently in use stem from the extensive research done in this area. These
approaches affect the financing decisions in organisations. The methods of valuation affect the
final variable.
Hence, most of these methods have sub approaches within them. Discounted cash flow is
among the most popular methods that are used in the valuation. This strategy focuses on the
financing decisions in the organisation (Massari, Roncaglio & Zanetti 2008). According to
Dong, Hirshleifer, and Teoh (2012), the main ways of estimating the discounted cash flow
include discounting the cash flow at a risk-adjusted discount (Sabalı 2009). This formula is one
of the four main methods that are used in the discounting cash flows. Using these methods
produces significant results.
Although different methods are in use in the valuation of companies, the same results may be
achieved if the assumptions are withheld for each of the methods. The similarity of these
methods ensures that the result is compatible with the businesses for which it was attempted
first. The different proponents for the different approaches in the valuation methods assume
that their methods are the most accurate. The results indicate that these methods are closely
similar. In relative valuation, which is considered one of the most important valuation methods,
the researchers who proposed the method adopted the assumption of individual assets.
However, these methods have similar results when the different assumptions are withheld.
Conclusion
In conclusion, based on the detailed expositions that have been made in the paper, it is clear
that valuation and financing are closely related when consideration for the financial state of an
organisation is made. Valuation may be estimated in organisations using several methods. Some
of these methods have been stated in this essay. The existence of valuation in financial decisions
allows the organisations to make decisions that coincide with their immediate needs.

The paper has proposed that a relationship between valuation and financial decisions in
organisations. This relationship is affected by other factors such as taxation. The WACC is an
important factor to consider when deducing the relationship between valuation and financial
decisions. The available research proves that this concept is applicable in an organisation’s
financial decisions. The essay has looked at the relationship between WACC and valuation in
organisations and the relationship that exists between these two variables and financial
decisions in an organisation. The paper has proved a positive relationship between these
concepts.
Valuation
The valuation of any organisation allows future decision-making to ensure that it is operating
as per the expectations. Different methods are used in valuation, including those that are
supported by theories and contemporary methods. The present models that are deployed in the
evaluation process are a product of extensive research, with many researchers describing them
before their application in management and finance. What are the motives of company
valuation? Different schools of thought exist as to why company valuation is important.
One of the motives for the evaluations of a company is to make decisions in the organisation.
Depending on the decision that is reached after valuation, the involved individuals may decide
on the future of the organisation and the interventions for the areas that are found faulty.
Motives in company valuation may be characterised in different ways, including decision-
dependent and decision-independent motives (Ishakian, Knebusch & Rowen 2013). The other
category of motives is the transaction based vs the non-transaction-based motives (Ishakian,
Knebusch & Rowen 2013). The other class of motives, as described throughout the literature
on valuation, is the dominated vs the non-dominated decision (Ishakian, Knebusch & Rowen
2013).
Valuation serves different functions depending on the concerned firm or organisation. These
functions can be categorised further into minor and major functions. The main functions of
valuation in organisations include decision-making and consultation. According to Ishakian,
Knebusch, and Rowen (2013), managers and other stakeholders use valuation information in
an organisation to make decisions on the future of the organisation with the aim of improving
the organisational performance. Different firms operate on different grounds. They use
different methods of valuation to make financial and other forms of decisions in the
organisation.

The other function of valuation, according to Koziol (2014), is mediation where the firm uses
information from valuation to mediate between concepts, decisions, and individuals.
Hundsdoerfer, Kruschwitz, and Loren (2008) assert that mediation in an organisation provides
crucial information on the financial position of the organisation. Valuation also serves as a
means of argumentation. Using information from valuation, managers and other organisational
stakeholders can argue on the position of the organisation. The information is used to provide
details on the organisational performance, which is important in making a case for any
argument.
Apart from the main functions of valuation, valuation serves other auxiliary functions. One of
these auxiliary functions is information where the parties within an organisation gather
information on this organisation, including its performance and future expectations. Valuation
may also be used as a means of tax measurement where authorities determine the tax that an
organisation should forward over a given period. Many organisations where valuation has been
conducted were found to have some tax measurements, not in line with the expected values
(Mian & Velez-Pareja 2007). Valuation also serves the function of contract configuration where
employees and other parties in the organisation can have their contracts configured with the
expectations of the organisation.
Valuation Methods
Different valuation methods are in use in many organisations. Each of these methods provides
different results. The decision to use one of them is dependent on the firm that is being
evaluated, the financial methods in place, and the preferred approach. The most popular
approach depends on the organisation and the region where these organisations exist. Different
methods that are used in valuation are shown below.
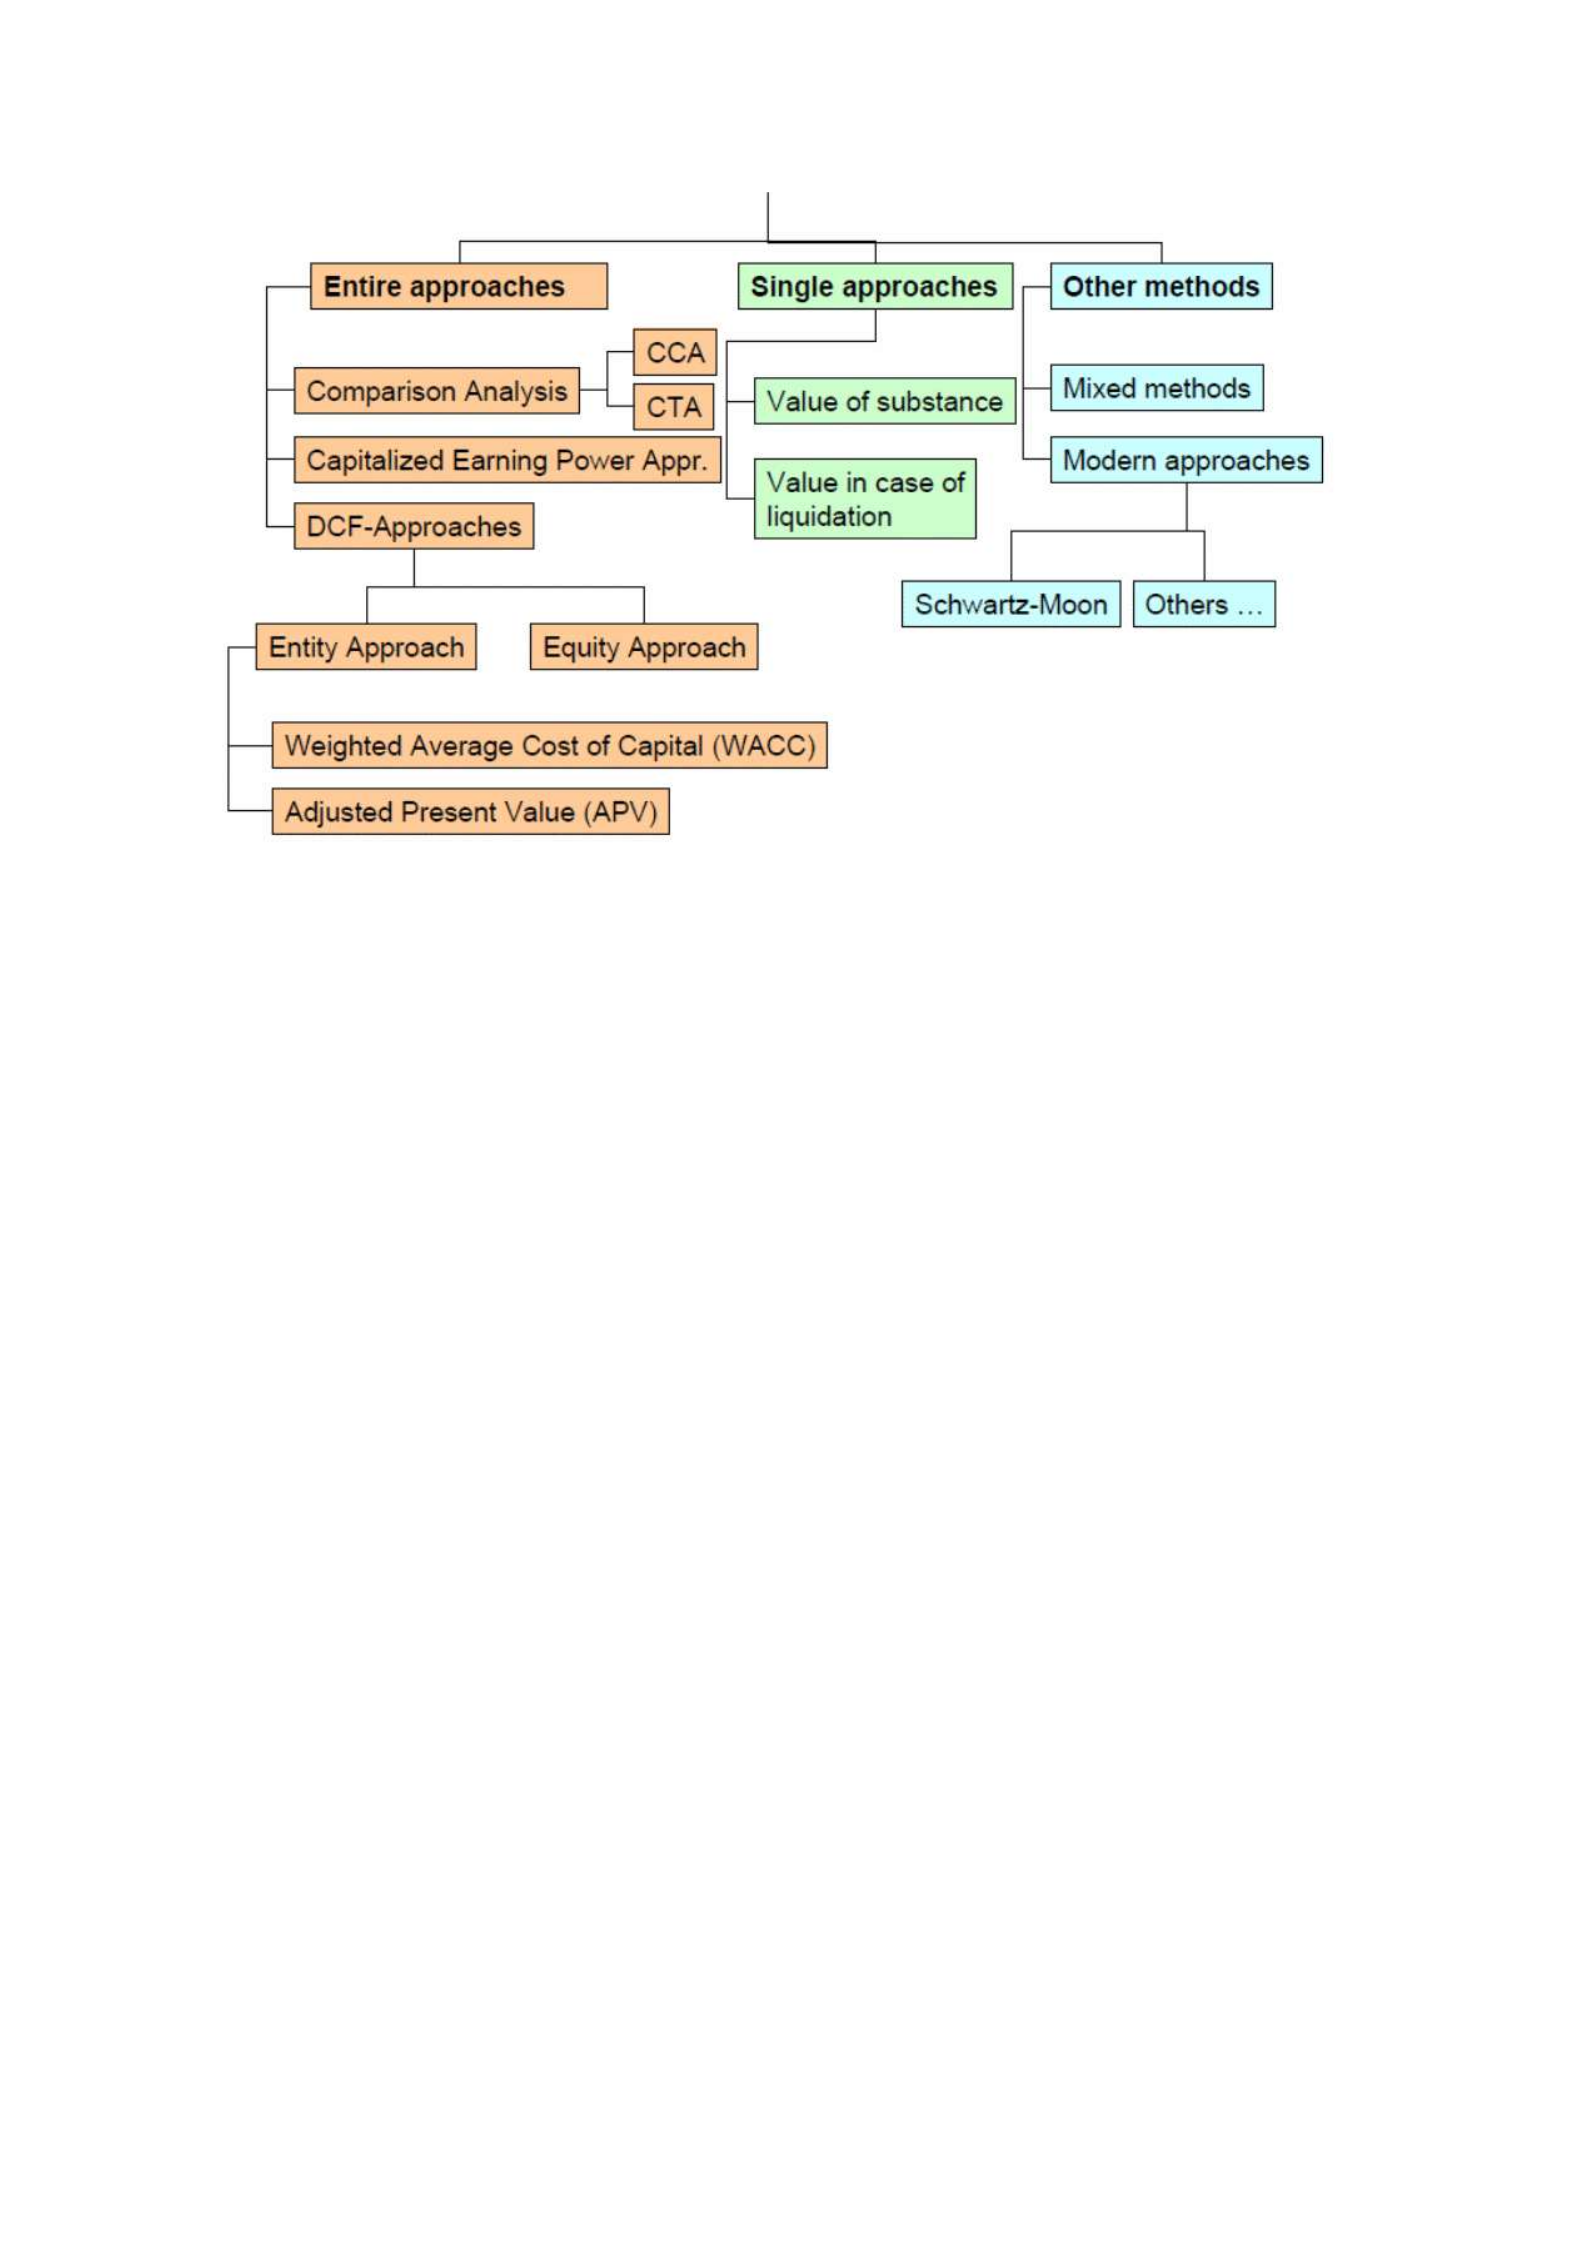
Figure 1: An Overview of Valuation Methods (Source Mian & Velez-Pareja 2007)
Different models that are applied during a valuation in organisations lead to a common result
where the organisations are able to plan for future decisions and changes. The valuation that is
obtained in organisations, irrespective of the method used, provides crucial information on the
financial status of the organisation. However, valuation within organisations also allows the
inception of changes whenever they are needed.
Financial Decisions
Organisations face challenges in financing, with one of the most common of them being the
outcomes of financial decisions. Competitiveness in organisations is influenced by the financial
decisions that managers and other stakeholders make. In any industry, financial decisions affect
the outcomes of the interactions between different factors. The financial decisions in an
organisation are also under the influence of other factors such as the valuation in these
organisations. A business in any industry or market must use capital as one of the main factors
in its operations, with this strategy bringing about the cost of capital.
Currently, there are no perfect markets in contemporary organisations. Hence, capital is not
always put to the intended use. A perfect business environment is the only place where capital
can be put to its planned use. However, conditions that are necessary for a perfect market are
hard to achieve. Nevertheless, if it were possible, the perfect world would have an excess
supply of capital. A perfect capital market might mean that the available unlimited capital is
only dependent on the risk of the project being undertaken (Spiegel, & Tookes 2013).

Aside from the perfect capital market, uncertainties, variables, and friction characterise the
existing real-world capital markets. The availability of tax as one of the variables in an
imperfect world ensures that organisations adopt strategies such as debts. An example of such
strategies is when an organisation operates in a capital structure with about 100% of debt
because of the positive corporate tax rate (Spiegel, & Tookes, 2013). Other factors that exist in
an imperfect world to introduce a relationship between valuations and financing include agency
costs, financial distress costs, and information asymmetries (Spiegel, & Tookes, 2013).
The financial position of an organisation ensures that the organisation can persist in an
environment where competition is an evident factor. Valuation effects that financial position of
an organisation. The reverse is also true. The decisions made in an organisation relating to the
financial positions of the organisation may be based on the valuation that is provided for this
organisation.
Weighted Average Cost of Capital
The calculation of the cost of capital is an intricate process that requires the participation of all
stakeholders. The cost of capital is calculated through the estimation of the proportion of debt
that a project consumes against the equity that is absorbed in the respective project (Massari,
Roncaglio & Zanetti 2008). The weighted average cost of capital (WACC) is calculated through
a formula that incorporates the market value of equity and debt (Massari, Roncaglio & Zanetti
2008). These values are adjusted using the costs of debt and equity. For a single firm, the
WACC is calculated as a single unit where the firm is the reference. The organisation, in this
case, is considered a single unit, with the results being for a single project.
The Weighted Average Cost of Capital is an indicator of the financial performance of an
organisation because it indicates the financial position of the organisation under discussion.
Any organisation with sound financial decisions has a favourable WACC, which is considered
a strength in these organisations. The calculation and use of WACC in financial discussions
and problem-solving is challenging for some financial analysts and other financial decision-
makers in organisations. Therefore, it is important to have a discussion on the correct use of
WACC and its implications on the financial decisions in organisations.
The other difficulty in the calculation and use of WACC is tax calculation. Different finance
officers use different methods of calculating the variables (Sabalı 2009). Financing and
investment decisions interact through taxes. WACC is an important concept in evaluating this

interaction. The formula that is used in the calculation of WACC refers to the organisation of
company as a whole upon incorporating the different aspects in financial decisions in the firm.
Therefore, this formula is effective for the “average project” where the right discount rate is
produced (Massari, Roncaglio & Zanetti 2008). Hence, the formula is incorrect when used in
the calculation of WACC for the safer and riskier projects (Magni 2012). The inaccuracy while
using this formula mainly stems from the different sections that individuals calculate in an
organisation, especially where the organisation has different departments.
Capital Structure and Valuations
Capital structure in a firm is a factor that affects valuations in these organisations. The effects
depend on the existing capital structure. According to Sabalı (2009), financing decisions
typically affect value within organisations. Some of the ways that boost value in a firm with
respect to its financing decisions is through the adjustment of the discount rate and the present
value (Massari, Roncaglio & Zanetti 2008).
The discount rate in most organisations is typically adjusted downwards, with the aim being to
account for the existing tax shields (Massari, Roncaglio & Zanetti 2008). Financing decisions
also affect value in organisations through adjusting the present value in these organisations
(Massari, Roncaglio & Zanetti 2008). According to Spiegel and Tookes (2013), the base case
is first calculated with the assumption that it is all equity financed.
Capital structure in organisations affects the value of the organisation from its first year of
operation. The capital structure in organisations is variable depending on several factors such
as the capital debt and the type of industry within which a firm is located. The tax on a firm is
a major factor with reference to its capital value, especially because the tax determines the debt
status of an organisation (Sabalı 2009).
The initial cash that is invested into a firm in the first year affects the value of an organisation
during this year. Most of the organisations that invest significant amounts of capital into their
operations end up being successful in the first year. Over the years that follow, the WACC
formula is highly applicable, as the organisational debts and equities change.
Capital structure in most organisations is affected by the financial decisions made by the
executive. Hence, the value of organisations is dependent on the type of managers that an
organisation keeps. The value of organisation changes with any financial decision made, since
the debt and equities change with these decisions (Massari, Roncaglio & Zanetti 2008).

The value of a firm may be calculated through the estimation of the WACC, which is later used
to discount the FCFF from the debt holders and equity capital contributors (Massari, Roncaglio
& Zanetti 2008). The use of WACC in the estimation of a firm’s value is very effective by far
compared to other methods of value estimation. This finding indicates a relationship between
the value of organisations and the WACC. The WACC is in turn related to the financial
decisions in an organisation. Hence, valuation is related to the financial decisions in the
organisation.
Impact of Tax Shields on WACC
According to Massari, Roncaglio, and Zanetti (2008), tax is a variable in an organisation that
affects the value of these organisations. Interest in organisations is one of the expenses that are
usually considered as tax-deductible expense (Massari, Roncaglio & Zanetti 2008). The
calculation of WACC incorporates tax as a major form of expense. This strategy determines
the value of organisations. However, tax shields in organisations may affect the calculation of
WACC. The effects of tax shields on WACC depend on the business and individuals who are
responsible for financial management in the respective institutions.
The tax shields cause changes on WACC in a number of ways. However, while these effects
are dependent on the type of organisation, the main effect is that the WACC increases with a
reduction in tax shields. Most organisations seek tax shields to lower their WACC and in effect
influence the value and competitiveness of their respective industries. A common result of tax
shields is a downward adjustment of the discount rate to account for any changes in this area
(Massari, Roncaglio & Zanetti 2008). The downward adjustment of discount rates in
organisations allows decisions to be made on the WACC and its overall effect on the firm’s
value.
Tax shields help organisations save their available financial resources, including the provision
of future resources. In areas where tax shields are effectively applied, firms report better results,
performance, and competitiveness compared to areas where these policies are scantily applied.
Adjusting the discount rate downwards is one of the ways that tax shields are accounted for.
The result of this case is a change on the value of firms (Massari, Roncaglio & Zanetti 2008).
The relationship between value of an organisation and tax shields may be demonstrated by the
inherent differences between organisations that operate in different regions with different tax
shield regimens. According to Massari, Roncaglio, and Zanetti (2008), adjustment of WACC
should affect the value of a firm through the effect of this move on the value of the organisation.

Therefore, managers should make sound decisions when it comes to applying for tax shields in
their area.
How Tax Shields affect Firm Value
Tax shields in an organisation affect the firm’s value in a number of ways as indicated above.
A common understanding is that tax is one of the factors that affect WACC, and in effect the
value of an organisation. The worth of any business is affected by the financing decisions in
the organisations, including the availability of tax shields. The discount rate constitutes one of
the factors that may be adjusted to accommodate changes in the value of organisations. Mintz
and Currim (2013) observe that downward adjustment of discount rate accounts for tax shields.
This downward adjustment results in the increase in value of organisations.
Organisations that use the discount rate to effect changes in their firm value often report success
in the use of the method. When an organisation is awarded tax shields, the value changes to
correspond to the changes introduced through the adjustment of the discount rates. Most
organisations can be described as having debts because of the tax shields that they intend to
acquire.
Therefore, contemporary organisations are prone to debts in their quest to attain tax shields
from the respective authorities. The differences in the contemporary organisations arise from
the different capabilities in the use of their debts. Most organisations whose debt status is high
attain significant tax exemptions. They are valued at higher rank compared to organisations
that have a lower debt position. The tax shields in an organisation, therefore, affect the firm
value in organisations.
Mistakes in Using WACC
Several mistakes are established in literature in the use of WACC. The first mistake is in the
calculation of this variable. In fact, some individuals use variables that are not commonly
applied in the formula. The computation of WACC is tedious due to the many variables that
are necessary for the calculation process. This situation makes the calculation difficult to the
extent that some individuals opt for shortcuts that may not be accurate. The other mistake is
that some individuals assume that the formula may be used in the calculation of WACC for a
particular section of the organisation. They forget that this formula considers the firm a single
unit (Mian & Velez-Pareja 2007).

WACC is useful in providing discount for businesses only where they are applied to
organisations or projects with a similar undertaking to the firm under consideration. For
organisations that differ from the firm under consideration, the formula may not be applicable
or provide useful results. WACC may be useful in most of the calculations where the firm under
consideration has the same size as that of other firms that were initially considered. For projects
that are safer or riskier compared to the original organisation, the calculated WACC may be
inaccurate and in some cases incorrect.
The other mistake that individuals make in the use of WACC is the assumption that it can be
applied as a single variable in the determination of a firm’s value. According to Mian and Velez-
Pareja (2007), organisations require the use of many variables to calculate their value. A single
variable may be deceptive depending on the industry within which the firm is located.
Therefore, there is a need to consider a number of variables in the calculation of a firm’s value
as using WACC alone may be inaccurate. Some of the other mistakes that individuals make in
the use of WACC include miscalculation of the debt and equities that are eventually used in the
calculation of this variable.
Adjusting the WACC
The adjustment of WACC may be done through a number of ways depending on the debt ratios
and the business risks (Mintz & Currim 2013). Adjusting the WACC when the risk of the firm’s
debt ratio and the business risk differ from those of the new project is important in the
calculation of a business’ WACC.
The adjustment of WACC is important when the debt ratios and business risks differ in
organisations. The differences between these two variables result from the changes that are
inherent in the organisations. The three main steps that should be followed when adjusting the
WACC include calculation of the opportunity cost, estimation of the cost of the organisations
debt, and recalculation of the WACC using the obtained new values (Mian & Velez-Pareja
2007).
The adjustment of this value allows the correct calculations where the estimated WACC is
obtained against the real WACC. In cases where the WACC is adjusted, the value of the firm’s
debts and opportunity costs are considered the main reasons for the adjustments. There are
many reasons for the adjustments, with the main one being to increase the accuracy of the final
WACC that is obtained for any given firm. WACC is an indicator of the financing side effect
in an organisation. It is a good indicator of value in organisations (Mintz & Currim 2013).

These financing side effects include the value of interest tax shields on debts (Massari,
Roncaglio & Zanetti 2008). Adjustment of the WACC is also important where the actual value
of a firm is to be estimated.
Valuation in Organisations
Valuation affects the financial decisions that are made in organisations. Most of the decisions
that are important in organisations are made only through the consideration of the value of the
organisation since most managers tend to focus on increasing this value. The many valuation
approaches that are currently in use stem from the extensive research done in this area. These
approaches affect the financing decisions in organisations. The methods of valuation affect the
final variable.
Hence, most of these methods have sub approaches within them. Discounted cash flow is
among the most popular methods that are used in the valuation. This strategy focuses on the
financing decisions in the organisation (Massari, Roncaglio & Zanetti 2008). According to
Dong, Hirshleifer, and Teoh (2012), the main ways of estimating the discounted cash flow
include discounting the cash flow at a risk-adjusted discount (Sabalı 2009). This formula is one
of the four main methods that are used in the discounting cash flows. Using these methods
produces significant results.
Although different methods are in use in the valuation of companies, the same results may be
achieved if the assumptions are withheld for each of the methods. The similarity of these
methods ensures that the result is compatible with the businesses for which it was attempted
first. The different proponents for the different approaches in the valuation methods assume
that their methods are the most accurate. The results indicate that these methods are closely
similar. In relative valuation, which is considered one of the most important valuation methods,
the researchers who proposed the method adopted the assumption of individual assets.
However, these methods have similar results when the different assumptions are withheld.
Conclusion
In conclusion, based on the detailed expositions that have been made in the paper, it is clear
that valuation and financing are closely related when consideration for the financial state of an
organisation is made. Valuation may be estimated in organisations using several methods. Some
of these methods have been stated in this essay. The existence of valuation in financial decisions
allows the organisations to make decisions that coincide with their immediate needs.

The paper has proposed that a relationship between valuation and financial decisions in
organisations. This relationship is affected by other factors such as taxation. The WACC is an
important factor to consider when deducing the relationship between valuation and financial
decisions. The available research proves that this concept is applicable in an organisation’s
financial decisions. The essay has looked at the relationship between WACC and valuation in
organisations and the relationship that exists between these two variables and financial
decisions in an organisation. The paper has proved a positive relationship between these
concepts.
Valuation
The valuation of any organisation allows future decision-making to ensure that it is operating
as per the expectations. Different methods are used in valuation, including those that are
supported by theories and contemporary methods. The present models that are deployed in the
evaluation process are a product of extensive research, with many researchers describing them
before their application in management and finance. What are the motives of company
valuation? Different schools of thought exist as to why company valuation is important.
One of the motives for the evaluations of a company is to make decisions in the organisation.
Depending on the decision that is reached after valuation, the involved individuals may decide
on the future of the organisation and the interventions for the areas that are found faulty.
Motives in company valuation may be characterised in different ways, including decision-
dependent and decision-independent motives (Ishakian, Knebusch & Rowen 2013). The other
category of motives is the transaction based vs the non-transaction-based motives (Ishakian,
Knebusch & Rowen 2013). The other class of motives, as described throughout the literature
on valuation, is the dominated vs the non-dominated decision (Ishakian, Knebusch & Rowen
2013).
Valuation serves different functions depending on the concerned firm or organisation. These
functions can be categorised further into minor and major functions. The main functions of
valuation in organisations include decision-making and consultation. According to Ishakian,
Knebusch, and Rowen (2013), managers and other stakeholders use valuation information in
an organisation to make decisions on the future of the organisation with the aim of improving
the organisational performance. Different firms operate on different grounds. They use
different methods of valuation to make financial and other forms of decisions in the
organisation.

The other function of valuation, according to Koziol (2014), is mediation where the firm uses
information from valuation to mediate between concepts, decisions, and individuals.
Hundsdoerfer, Kruschwitz, and Loren (2008) assert that mediation in an organisation provides
crucial information on the financial position of the organisation. Valuation also serves as a
means of argumentation. Using information from valuation, managers and other organisational
stakeholders can argue on the position of the organisation. The information is used to provide
details on the organisational performance, which is important in making a case for any
argument.
Apart from the main functions of valuation, valuation serves other auxiliary functions. One of
these auxiliary functions is information where the parties within an organisation gather
information on this organisation, including its performance and future expectations. Valuation
may also be used as a means of tax measurement where authorities determine the tax that an
organisation should forward over a given period. Many organisations where valuation has been
conducted were found to have some tax measurements, not in line with the expected values
(Mian & Velez-Pareja 2007). Valuation also serves the function of contract configuration where
employees and other parties in the organisation can have their contracts configured with the
expectations of the organisation.
Valuation Methods
Different valuation methods are in use in many organisations. Each of these methods provides
different results. The decision to use one of them is dependent on the firm that is being
evaluated, the financial methods in place, and the preferred approach. The most popular
approach depends on the organisation and the region where these organisations exist. Different
methods that are used in valuation are shown below.
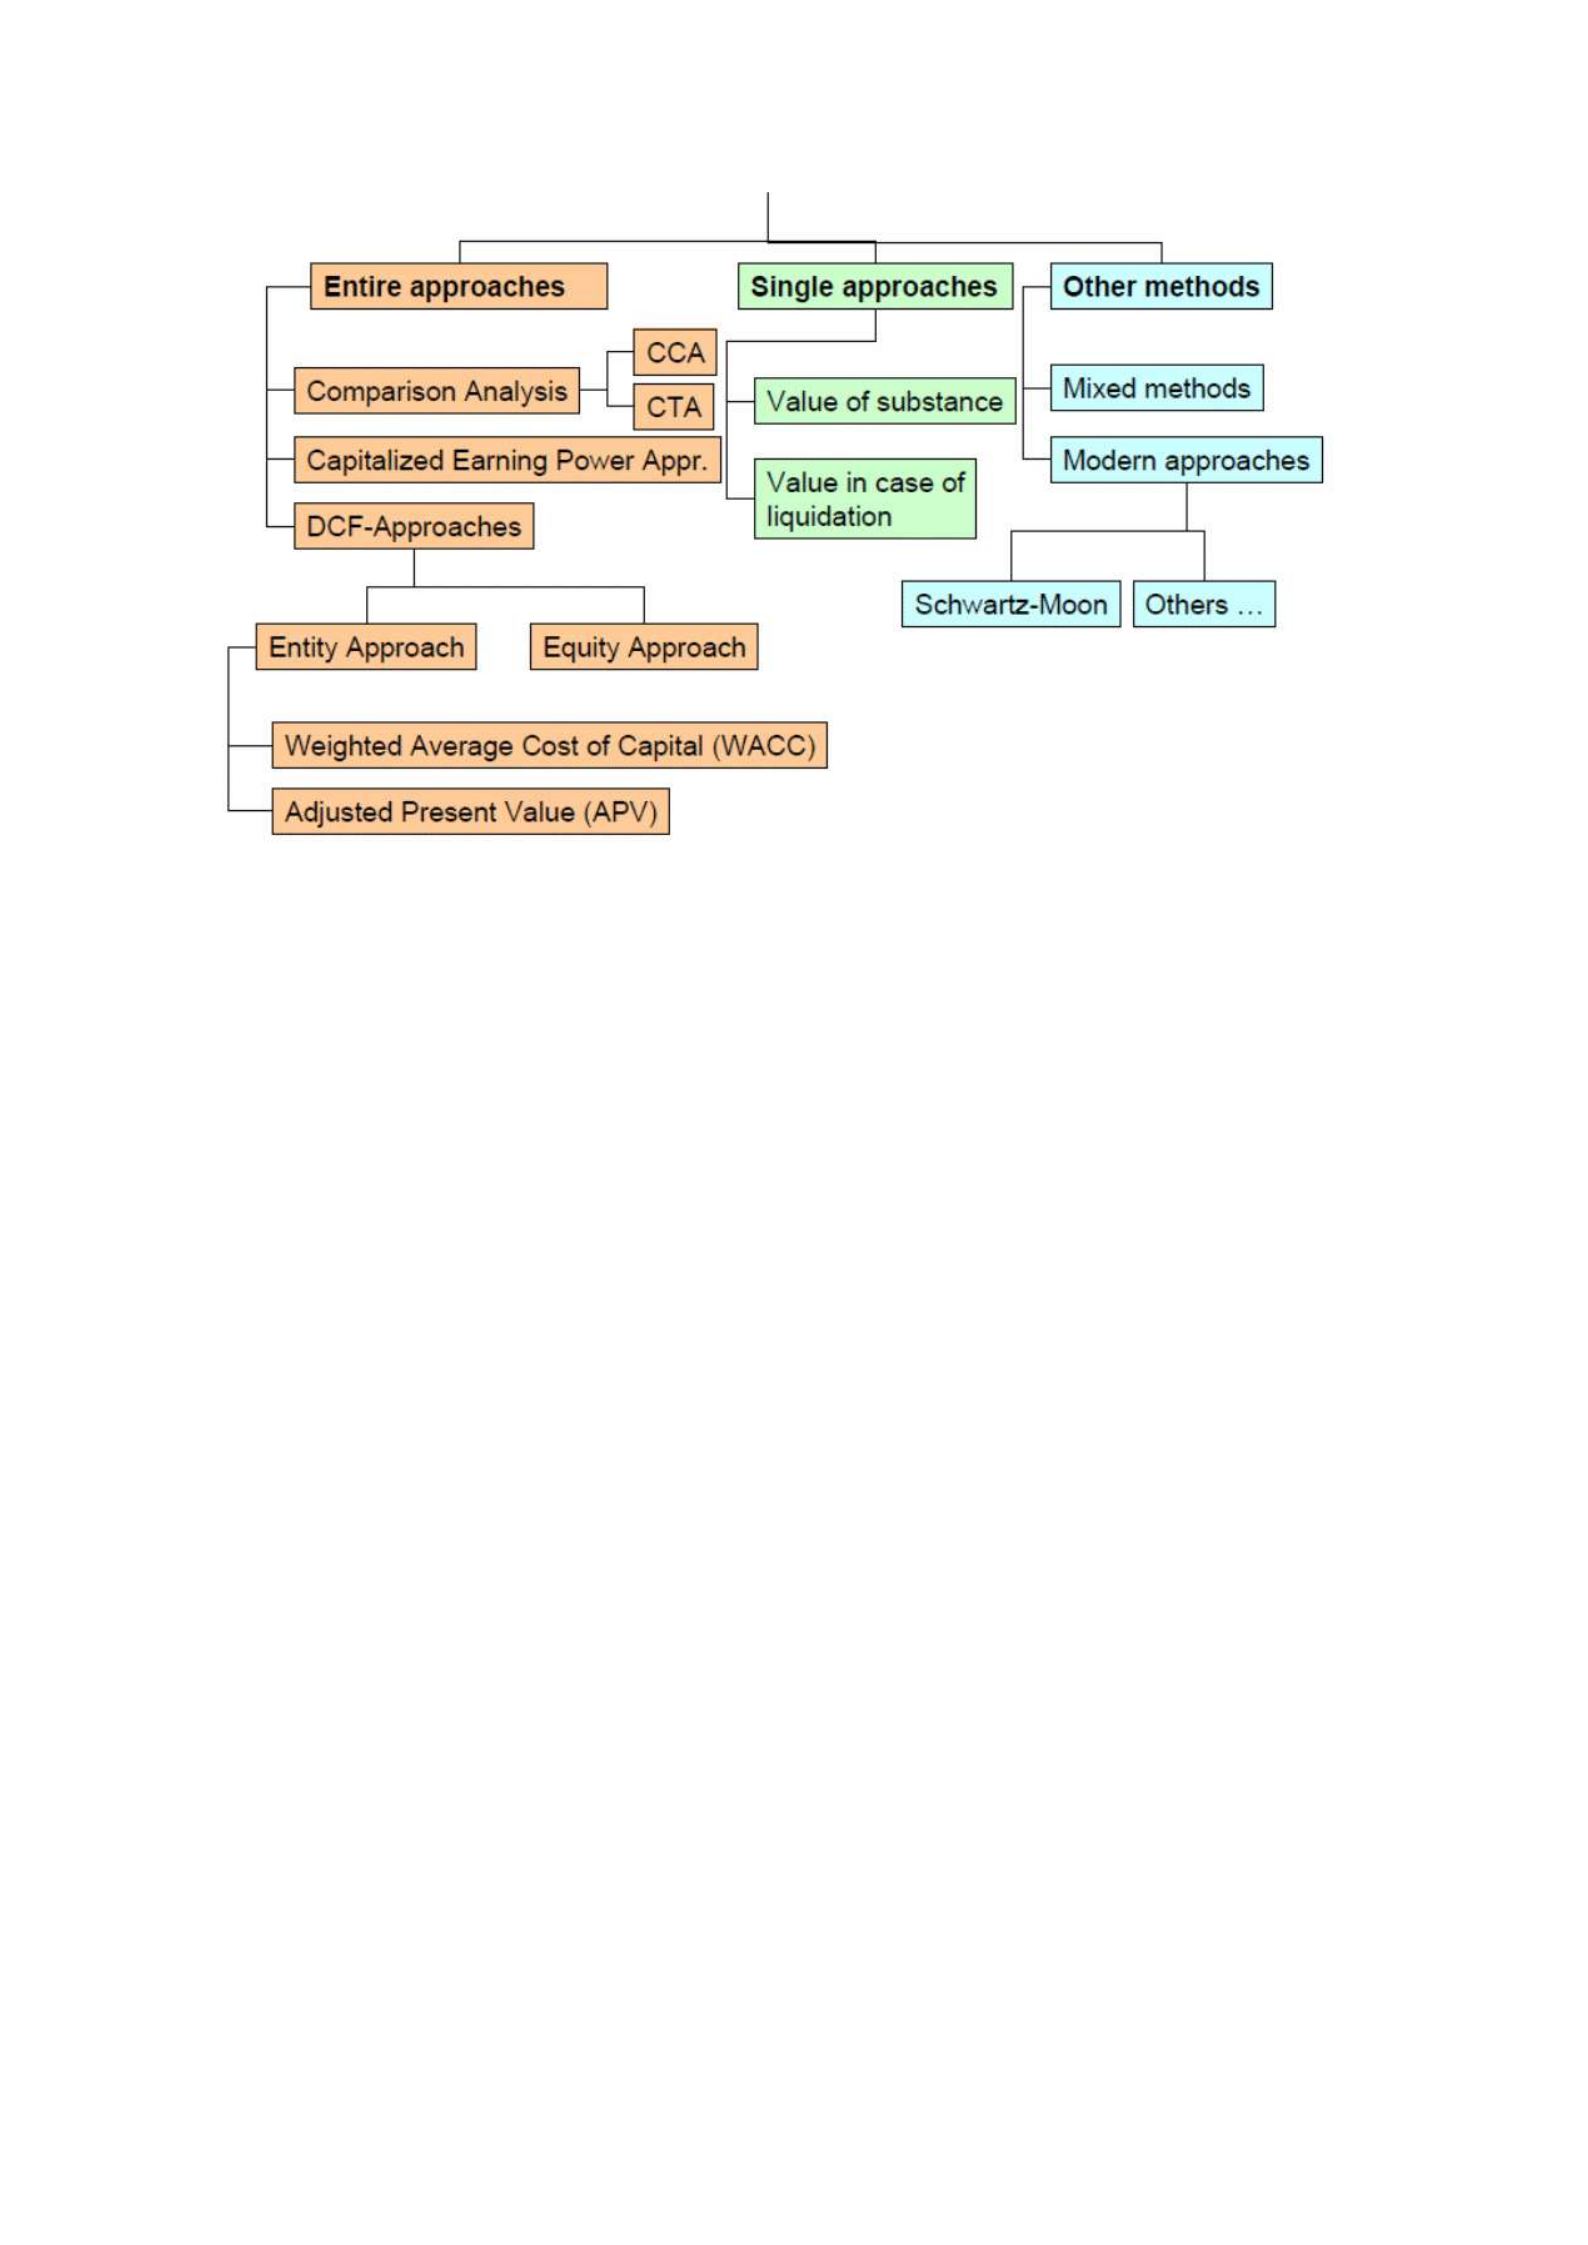
Figure 1: An Overview of Valuation Methods (Source Mian & Velez-Pareja 2007)
Different models that are applied during a valuation in organisations lead to a common result
where the organisations are able to plan for future decisions and changes. The valuation that is
obtained in organisations, irrespective of the method used, provides crucial information on the
financial status of the organisation. However, valuation within organisations also allows the
inception of changes whenever they are needed.
Financial Decisions
Organisations face challenges in financing, with one of the most common of them being the
outcomes of financial decisions. Competitiveness in organisations is influenced by the financial
decisions that managers and other stakeholders make. In any industry, financial decisions affect
the outcomes of the interactions between different factors. The financial decisions in an
organisation are also under the influence of other factors such as the valuation in these
organisations. A business in any industry or market must use capital as one of the main factors
in its operations, with this strategy bringing about the cost of capital.
Currently, there are no perfect markets in contemporary organisations. Hence, capital is not
always put to the intended use. A perfect business environment is the only place where capital
can be put to its planned use. However, conditions that are necessary for a perfect market are
hard to achieve. Nevertheless, if it were possible, the perfect world would have an excess
supply of capital. A perfect capital market might mean that the available unlimited capital is
only dependent on the risk of the project being undertaken (Spiegel, & Tookes 2013).

Aside from the perfect capital market, uncertainties, variables, and friction characterise the
existing real-world capital markets. The availability of tax as one of the variables in an
imperfect world ensures that organisations adopt strategies such as debts. An example of such
strategies is when an organisation operates in a capital structure with about 100% of debt
because of the positive corporate tax rate (Spiegel, & Tookes, 2013). Other factors that exist in
an imperfect world to introduce a relationship between valuations and financing include agency
costs, financial distress costs, and information asymmetries (Spiegel, & Tookes, 2013).
The financial position of an organisation ensures that the organisation can persist in an
environment where competition is an evident factor. Valuation effects that financial position of
an organisation. The reverse is also true. The decisions made in an organisation relating to the
financial positions of the organisation may be based on the valuation that is provided for this
organisation.
Weighted Average Cost of Capital
The calculation of the cost of capital is an intricate process that requires the participation of all
stakeholders. The cost of capital is calculated through the estimation of the proportion of debt
that a project consumes against the equity that is absorbed in the respective project (Massari,
Roncaglio & Zanetti 2008). The weighted average cost of capital (WACC) is calculated through
a formula that incorporates the market value of equity and debt (Massari, Roncaglio & Zanetti
2008). These values are adjusted using the costs of debt and equity. For a single firm, the
WACC is calculated as a single unit where the firm is the reference. The organisation, in this
case, is considered a single unit, with the results being for a single project.
The Weighted Average Cost of Capital is an indicator of the financial performance of an
organisation because it indicates the financial position of the organisation under discussion.
Any organisation with sound financial decisions has a favourable WACC, which is considered
a strength in these organisations. The calculation and use of WACC in financial discussions
and problem-solving is challenging for some financial analysts and other financial decision-
makers in organisations. Therefore, it is important to have a discussion on the correct use of
WACC and its implications on the financial decisions in organisations.
The other difficulty in the calculation and use of WACC is tax calculation. Different finance
officers use different methods of calculating the variables (Sabalı 2009). Financing and
investment decisions interact through taxes. WACC is an important concept in evaluating this

interaction. The formula that is used in the calculation of WACC refers to the organisation of
company as a whole upon incorporating the different aspects in financial decisions in the firm.
Therefore, this formula is effective for the “average project” where the right discount rate is
produced (Massari, Roncaglio & Zanetti 2008). Hence, the formula is incorrect when used in
the calculation of WACC for the safer and riskier projects (Magni 2012). The inaccuracy while
using this formula mainly stems from the different sections that individuals calculate in an
organisation, especially where the organisation has different departments.
Capital Structure and Valuations
Capital structure in a firm is a factor that affects valuations in these organisations. The effects
depend on the existing capital structure. According to Sabalı (2009), financing decisions
typically affect value within organisations. Some of the ways that boost value in a firm with
respect to its financing decisions is through the adjustment of the discount rate and the present
value (Massari, Roncaglio & Zanetti 2008).
The discount rate in most organisations is typically adjusted downwards, with the aim being to
account for the existing tax shields (Massari, Roncaglio & Zanetti 2008). Financing decisions
also affect value in organisations through adjusting the present value in these organisations
(Massari, Roncaglio & Zanetti 2008). According to Spiegel and Tookes (2013), the base case
is first calculated with the assumption that it is all equity financed.
Capital structure in organisations affects the value of the organisation from its first year of
operation. The capital structure in organisations is variable depending on several factors such
as the capital debt and the type of industry within which a firm is located. The tax on a firm is
a major factor with reference to its capital value, especially because the tax determines the debt
status of an organisation (Sabalı 2009).
The initial cash that is invested into a firm in the first year affects the value of an organisation
during this year. Most of the organisations that invest significant amounts of capital into their
operations end up being successful in the first year. Over the years that follow, the WACC
formula is highly applicable, as the organisational debts and equities change.
Capital structure in most organisations is affected by the financial decisions made by the
executive. Hence, the value of organisations is dependent on the type of managers that an
organisation keeps. The value of organisation changes with any financial decision made, since
the debt and equities change with these decisions (Massari, Roncaglio & Zanetti 2008).

The value of a firm may be calculated through the estimation of the WACC, which is later used
to discount the FCFF from the debt holders and equity capital contributors (Massari, Roncaglio
& Zanetti 2008). The use of WACC in the estimation of a firm’s value is very effective by far
compared to other methods of value estimation. This finding indicates a relationship between
the value of organisations and the WACC. The WACC is in turn related to the financial
decisions in an organisation. Hence, valuation is related to the financial decisions in the
organisation.
Impact of Tax Shields on WACC
According to Massari, Roncaglio, and Zanetti (2008), tax is a variable in an organisation that
affects the value of these organisations. Interest in organisations is one of the expenses that are
usually considered as tax-deductible expense (Massari, Roncaglio & Zanetti 2008). The
calculation of WACC incorporates tax as a major form of expense. This strategy determines
the value of organisations. However, tax shields in organisations may affect the calculation of
WACC. The effects of tax shields on WACC depend on the business and individuals who are
responsible for financial management in the respective institutions.
The tax shields cause changes on WACC in a number of ways. However, while these effects
are dependent on the type of organisation, the main effect is that the WACC increases with a
reduction in tax shields. Most organisations seek tax shields to lower their WACC and in effect
influence the value and competitiveness of their respective industries. A common result of tax
shields is a downward adjustment of the discount rate to account for any changes in this area
(Massari, Roncaglio & Zanetti 2008). The downward adjustment of discount rates in
organisations allows decisions to be made on the WACC and its overall effect on the firm’s
value.
Tax shields help organisations save their available financial resources, including the provision
of future resources. In areas where tax shields are effectively applied, firms report better results,
performance, and competitiveness compared to areas where these policies are scantily applied.
Adjusting the discount rate downwards is one of the ways that tax shields are accounted for.
The result of this case is a change on the value of firms (Massari, Roncaglio & Zanetti 2008).
The relationship between value of an organisation and tax shields may be demonstrated by the
inherent differences between organisations that operate in different regions with different tax
shield regimens. According to Massari, Roncaglio, and Zanetti (2008), adjustment of WACC
should affect the value of a firm through the effect of this move on the value of the organisation.

Therefore, managers should make sound decisions when it comes to applying for tax shields in
their area.
How Tax Shields affect Firm Value
Tax shields in an organisation affect the firm’s value in a number of ways as indicated above.
A common understanding is that tax is one of the factors that affect WACC, and in effect the
value of an organisation. The worth of any business is affected by the financing decisions in
the organisations, including the availability of tax shields. The discount rate constitutes one of
the factors that may be adjusted to accommodate changes in the value of organisations. Mintz
and Currim (2013) observe that downward adjustment of discount rate accounts for tax shields.
This downward adjustment results in the increase in value of organisations.
Organisations that use the discount rate to effect changes in their firm value often report success
in the use of the method. When an organisation is awarded tax shields, the value changes to
correspond to the changes introduced through the adjustment of the discount rates. Most
organisations can be described as having debts because of the tax shields that they intend to
acquire.
Therefore, contemporary organisations are prone to debts in their quest to attain tax shields
from the respective authorities. The differences in the contemporary organisations arise from
the different capabilities in the use of their debts. Most organisations whose debt status is high
attain significant tax exemptions. They are valued at higher rank compared to organisations
that have a lower debt position. The tax shields in an organisation, therefore, affect the firm
value in organisations.
Mistakes in Using WACC
Several mistakes are established in literature in the use of WACC. The first mistake is in the
calculation of this variable. In fact, some individuals use variables that are not commonly
applied in the formula. The computation of WACC is tedious due to the many variables that
are necessary for the calculation process. This situation makes the calculation difficult to the
extent that some individuals opt for shortcuts that may not be accurate. The other mistake is
that some individuals assume that the formula may be used in the calculation of WACC for a
particular section of the organisation. They forget that this formula considers the firm a single
unit (Mian & Velez-Pareja 2007).

WACC is useful in providing discount for businesses only where they are applied to
organisations or projects with a similar undertaking to the firm under consideration. For
organisations that differ from the firm under consideration, the formula may not be applicable
or provide useful results. WACC may be useful in most of the calculations where the firm under
consideration has the same size as that of other firms that were initially considered. For projects
that are safer or riskier compared to the original organisation, the calculated WACC may be
inaccurate and in some cases incorrect.
The other mistake that individuals make in the use of WACC is the assumption that it can be
applied as a single variable in the determination of a firm’s value. According to Mian and Velez-
Pareja (2007), organisations require the use of many variables to calculate their value. A single
variable may be deceptive depending on the industry within which the firm is located.
Therefore, there is a need to consider a number of variables in the calculation of a firm’s value
as using WACC alone may be inaccurate. Some of the other mistakes that individuals make in
the use of WACC include miscalculation of the debt and equities that are eventually used in the
calculation of this variable.
Adjusting the WACC
The adjustment of WACC may be done through a number of ways depending on the debt ratios
and the business risks (Mintz & Currim 2013). Adjusting the WACC when the risk of the firm’s
debt ratio and the business risk differ from those of the new project is important in the
calculation of a business’ WACC.
The adjustment of WACC is important when the debt ratios and business risks differ in
organisations. The differences between these two variables result from the changes that are
inherent in the organisations. The three main steps that should be followed when adjusting the
WACC include calculation of the opportunity cost, estimation of the cost of the organisations
debt, and recalculation of the WACC using the obtained new values (Mian & Velez-Pareja
2007).
The adjustment of this value allows the correct calculations where the estimated WACC is
obtained against the real WACC. In cases where the WACC is adjusted, the value of the firm’s
debts and opportunity costs are considered the main reasons for the adjustments. There are
many reasons for the adjustments, with the main one being to increase the accuracy of the final
WACC that is obtained for any given firm. WACC is an indicator of the financing side effect
in an organisation. It is a good indicator of value in organisations (Mintz & Currim 2013).

These financing side effects include the value of interest tax shields on debts (Massari,
Roncaglio & Zanetti 2008). Adjustment of the WACC is also important where the actual value
of a firm is to be estimated.
Valuation in Organisations
Valuation affects the financial decisions that are made in organisations. Most of the decisions
that are important in organisations are made only through the consideration of the value of the
organisation since most managers tend to focus on increasing this value. The many valuation
approaches that are currently in use stem from the extensive research done in this area. These
approaches affect the financing decisions in organisations. The methods of valuation affect the
final variable.
Hence, most of these methods have sub approaches within them. Discounted cash flow is
among the most popular methods that are used in the valuation. This strategy focuses on the
financing decisions in the organisation (Massari, Roncaglio & Zanetti 2008). According to
Dong, Hirshleifer, and Teoh (2012), the main ways of estimating the discounted cash flow
include discounting the cash flow at a risk-adjusted discount (Sabalı 2009). This formula is one
of the four main methods that are used in the discounting cash flows. Using these methods
produces significant results.
Although different methods are in use in the valuation of companies, the same results may be
achieved if the assumptions are withheld for each of the methods. The similarity of these
methods ensures that the result is compatible with the businesses for which it was attempted
first. The different proponents for the different approaches in the valuation methods assume
that their methods are the most accurate. The results indicate that these methods are closely
similar. In relative valuation, which is considered one of the most important valuation methods,
the researchers who proposed the method adopted the assumption of individual assets.
However, these methods have similar results when the different assumptions are withheld.
Conclusion
In conclusion, based on the detailed expositions that have been made in the paper, it is clear
that valuation and financing are closely related when consideration for the financial state of an
organisation is made. Valuation may be estimated in organisations using several methods. Some
of these methods have been stated in this essay. The existence of valuation in financial decisions
allows the organisations to make decisions that coincide with their immediate needs.

The paper has proposed that a relationship between valuation and financial decisions in
organisations. This relationship is affected by other factors such as taxation. The WACC is an
important factor to consider when deducing the relationship between valuation and financial
decisions. The available research proves that this concept is applicable in an organisation’s
financial decisions. The essay has looked at the relationship between WACC and valuation in
organisations and the relationship that exists between these two variables and financial
decisions in an organisation. The paper has proved a positive relationship between these
concepts.
Valuation
The valuation of any organisation allows future decision-making to ensure that it is operating
as per the expectations. Different methods are used in valuation, including those that are
supported by theories and contemporary methods. The present models that are deployed in the
evaluation process are a product of extensive research, with many researchers describing them
before their application in management and finance. What are the motives of company
valuation? Different schools of thought exist as to why company valuation is important.
One of the motives for the evaluations of a company is to make decisions in the organisation.
Depending on the decision that is reached after valuation, the involved individuals may decide
on the future of the organisation and the interventions for the areas that are found faulty.
Motives in company valuation may be characterised in different ways, including decision-
dependent and decision-independent motives (Ishakian, Knebusch & Rowen 2013). The other
category of motives is the transaction based vs the non-transaction-based motives (Ishakian,
Knebusch & Rowen 2013). The other class of motives, as described throughout the literature
on valuation, is the dominated vs the non-dominated decision (Ishakian, Knebusch & Rowen
2013).
Valuation serves different functions depending on the concerned firm or organisation. These
functions can be categorised further into minor and major functions. The main functions of
valuation in organisations include decision-making and consultation. According to Ishakian,
Knebusch, and Rowen (2013), managers and other stakeholders use valuation information in
an organisation to make decisions on the future of the organisation with the aim of improving
the organisational performance. Different firms operate on different grounds. They use
different methods of valuation to make financial and other forms of decisions in the
organisation.

The other function of valuation, according to Koziol (2014), is mediation where the firm uses
information from valuation to mediate between concepts, decisions, and individuals.
Hundsdoerfer, Kruschwitz, and Loren (2008) assert that mediation in an organisation provides
crucial information on the financial position of the organisation. Valuation also serves as a
means of argumentation. Using information from valuation, managers and other organisational
stakeholders can argue on the position of the organisation. The information is used to provide
details on the organisational performance, which is important in making a case for any
argument.
Apart from the main functions of valuation, valuation serves other auxiliary functions. One of
these auxiliary functions is information where the parties within an organisation gather
information on this organisation, including its performance and future expectations. Valuation
may also be used as a means of tax measurement where authorities determine the tax that an
organisation should forward over a given period. Many organisations where valuation has been
conducted were found to have some tax measurements, not in line with the expected values
(Mian & Velez-Pareja 2007). Valuation also serves the function of contract configuration where
employees and other parties in the organisation can have their contracts configured with the
expectations of the organisation.
Valuation Methods
Different valuation methods are in use in many organisations. Each of these methods provides
different results. The decision to use one of them is dependent on the firm that is being
evaluated, the financial methods in place, and the preferred approach. The most popular
approach depends on the organisation and the region where these organisations exist. Different
methods that are used in valuation are shown below.
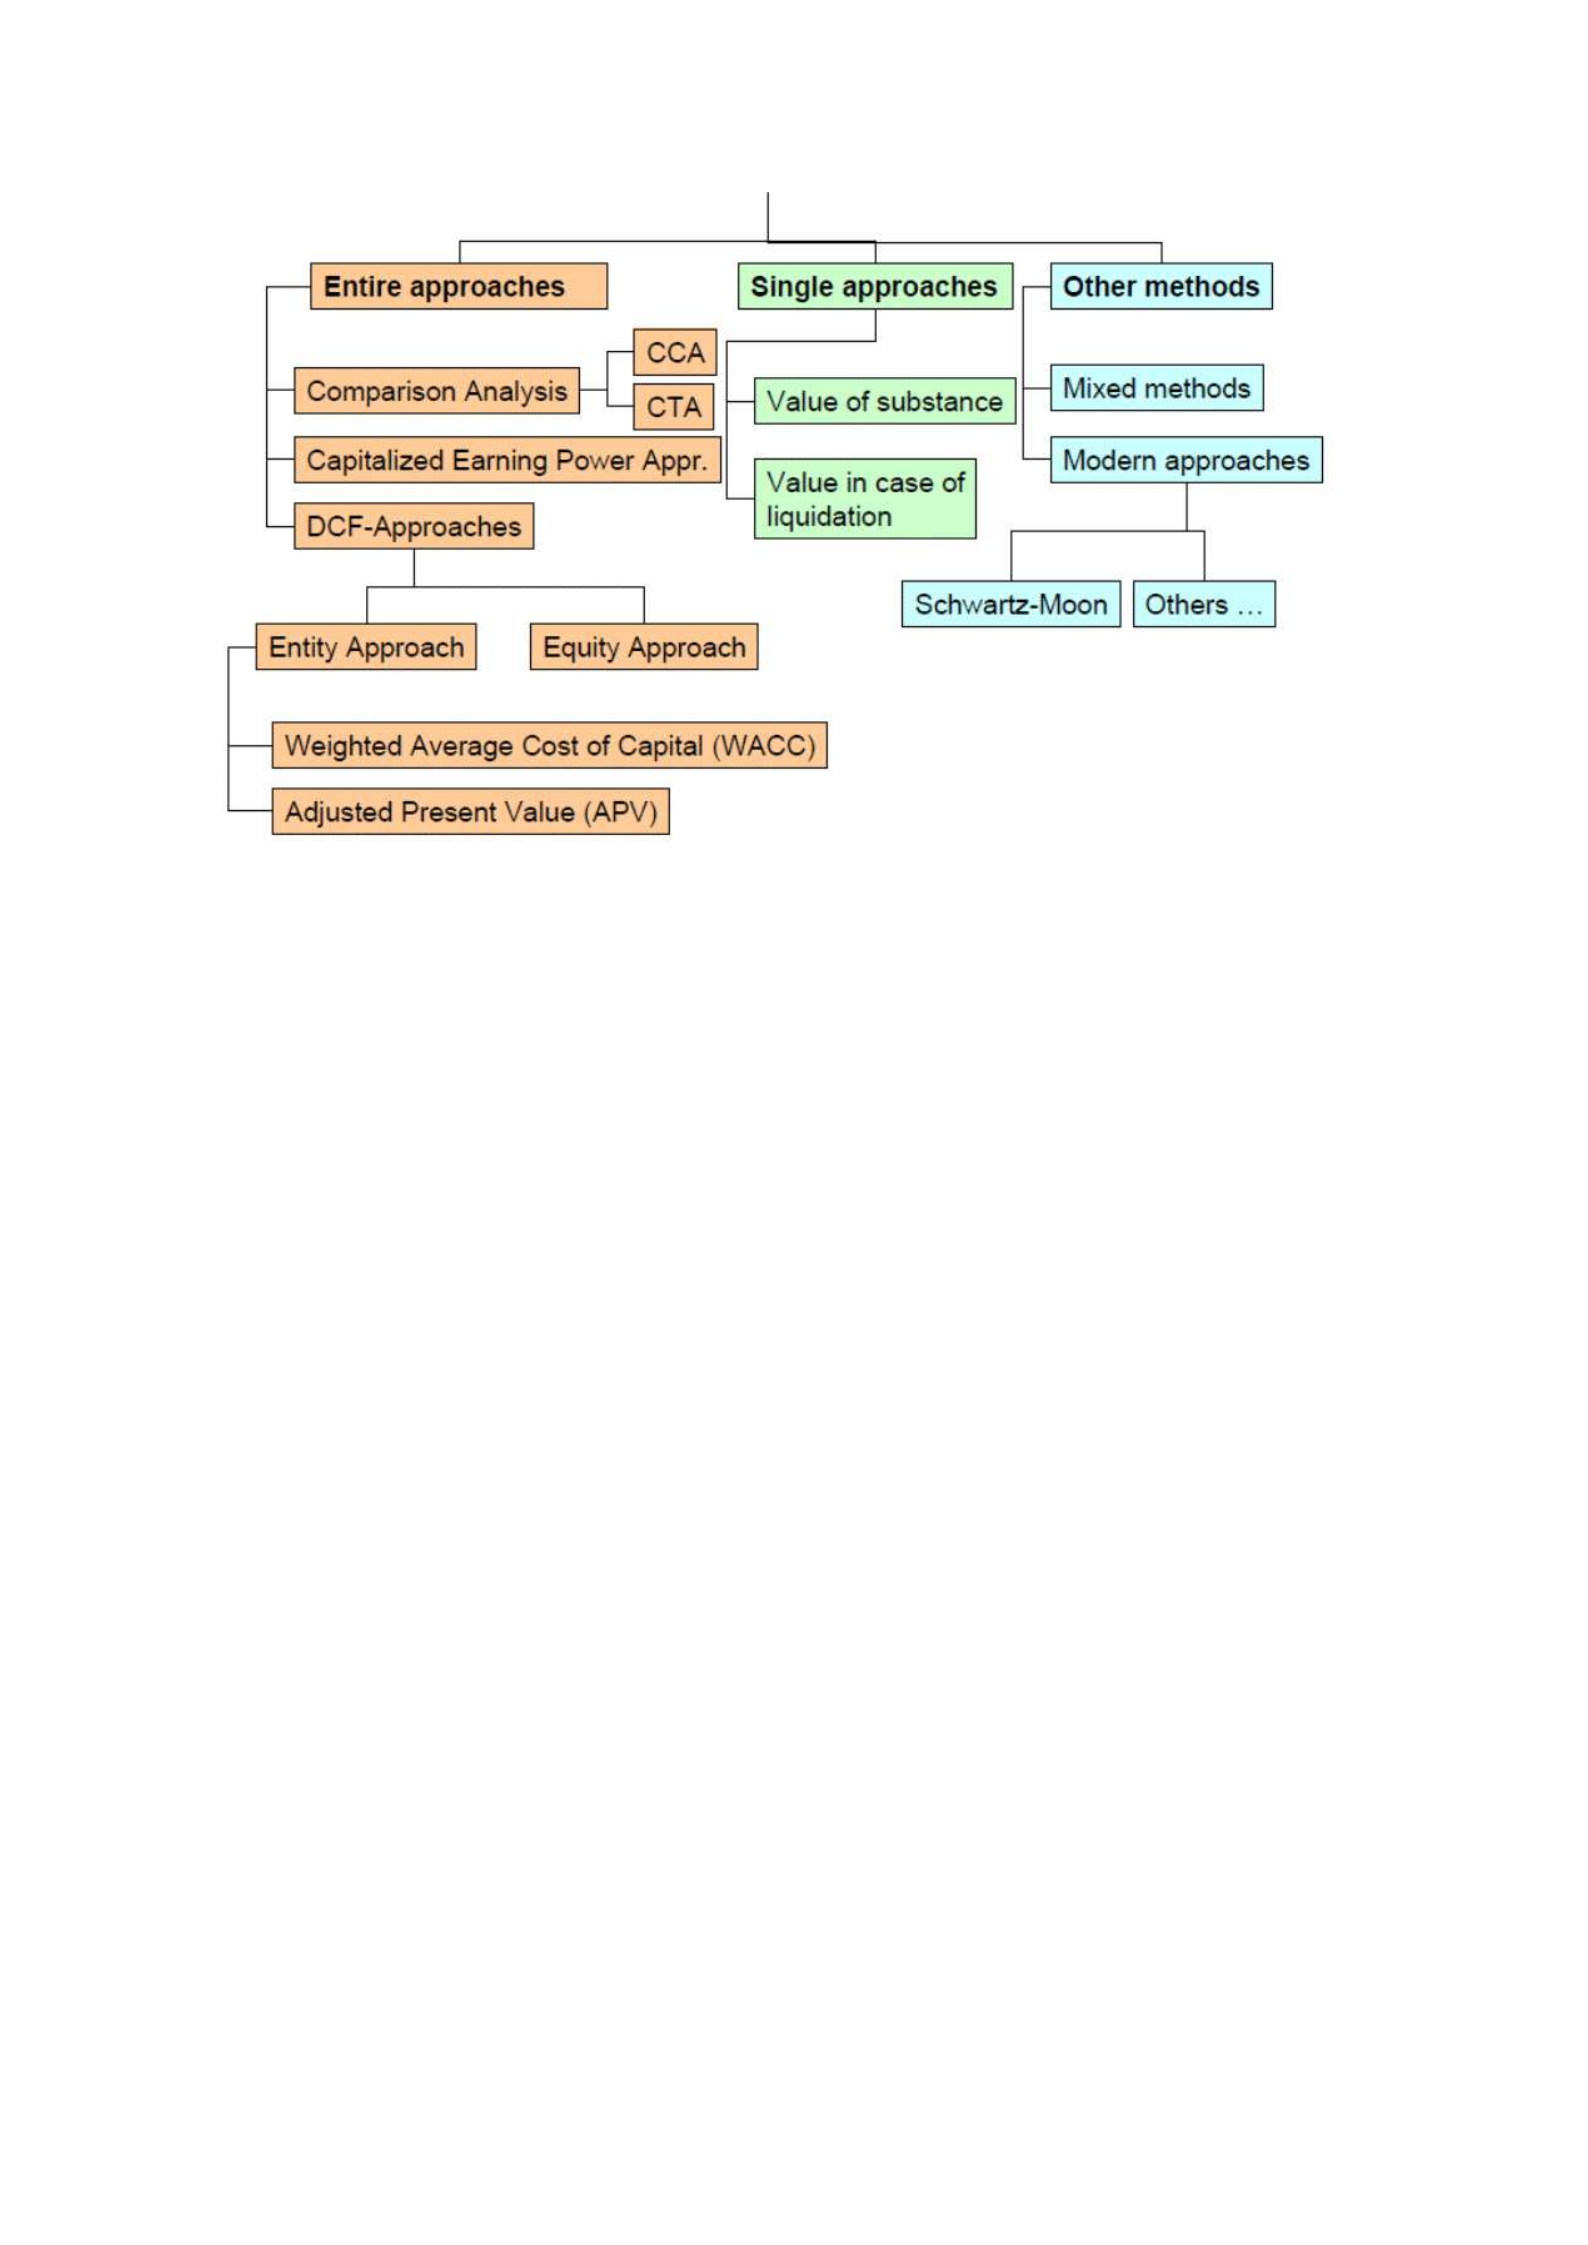
Figure 1: An Overview of Valuation Methods (Source Mian & Velez-Pareja 2007)
Different models that are applied during a valuation in organisations lead to a common result
where the organisations are able to plan for future decisions and changes. The valuation that is
obtained in organisations, irrespective of the method used, provides crucial information on the
financial status of the organisation. However, valuation within organisations also allows the
inception of changes whenever they are needed.
Financial Decisions
Organisations face challenges in financing, with one of the most common of them being the
outcomes of financial decisions. Competitiveness in organisations is influenced by the financial
decisions that managers and other stakeholders make. In any industry, financial decisions affect
the outcomes of the interactions between different factors. The financial decisions in an
organisation are also under the influence of other factors such as the valuation in these
organisations. A business in any industry or market must use capital as one of the main factors
in its operations, with this strategy bringing about the cost of capital.
Currently, there are no perfect markets in contemporary organisations. Hence, capital is not
always put to the intended use. A perfect business environment is the only place where capital
can be put to its planned use. However, conditions that are necessary for a perfect market are
hard to achieve. Nevertheless, if it were possible, the perfect world would have an excess
supply of capital. A perfect capital market might mean that the available unlimited capital is
only dependent on the risk of the project being undertaken (Spiegel, & Tookes 2013).

Aside from the perfect capital market, uncertainties, variables, and friction characterise the
existing real-world capital markets. The availability of tax as one of the variables in an
imperfect world ensures that organisations adopt strategies such as debts. An example of such
strategies is when an organisation operates in a capital structure with about 100% of debt
because of the positive corporate tax rate (Spiegel, & Tookes, 2013). Other factors that exist in
an imperfect world to introduce a relationship between valuations and financing include agency
costs, financial distress costs, and information asymmetries (Spiegel, & Tookes, 2013).
The financial position of an organisation ensures that the organisation can persist in an
environment where competition is an evident factor. Valuation effects that financial position of
an organisation. The reverse is also true. The decisions made in an organisation relating to the
financial positions of the organisation may be based on the valuation that is provided for this
organisation.
Weighted Average Cost of Capital
The calculation of the cost of capital is an intricate process that requires the participation of all
stakeholders. The cost of capital is calculated through the estimation of the proportion of debt
that a project consumes against the equity that is absorbed in the respective project (Massari,
Roncaglio & Zanetti 2008). The weighted average cost of capital (WACC) is calculated through
a formula that incorporates the market value of equity and debt (Massari, Roncaglio & Zanetti
2008). These values are adjusted using the costs of debt and equity. For a single firm, the
WACC is calculated as a single unit where the firm is the reference. The organisation, in this
case, is considered a single unit, with the results being for a single project.
The Weighted Average Cost of Capital is an indicator of the financial performance of an
organisation because it indicates the financial position of the organisation under discussion.
Any organisation with sound financial decisions has a favourable WACC, which is considered
a strength in these organisations. The calculation and use of WACC in financial discussions
and problem-solving is challenging for some financial analysts and other financial decision-
makers in organisations. Therefore, it is important to have a discussion on the correct use of
WACC and its implications on the financial decisions in organisations.
The other difficulty in the calculation and use of WACC is tax calculation. Different finance
officers use different methods of calculating the variables (Sabalı 2009). Financing and
investment decisions interact through taxes. WACC is an important concept in evaluating this

interaction. The formula that is used in the calculation of WACC refers to the organisation of
company as a whole upon incorporating the different aspects in financial decisions in the firm.
Therefore, this formula is effective for the “average project” where the right discount rate is
produced (Massari, Roncaglio & Zanetti 2008). Hence, the formula is incorrect when used in
the calculation of WACC for the safer and riskier projects (Magni 2012). The inaccuracy while
using this formula mainly stems from the different sections that individuals calculate in an
organisation, especially where the organisation has different departments.
Capital Structure and Valuations
Capital structure in a firm is a factor that affects valuations in these organisations. The effects
depend on the existing capital structure. According to Sabalı (2009), financing decisions
typically affect value within organisations. Some of the ways that boost value in a firm with
respect to its financing decisions is through the adjustment of the discount rate and the present
value (Massari, Roncaglio & Zanetti 2008).
The discount rate in most organisations is typically adjusted downwards, with the aim being to
account for the existing tax shields (Massari, Roncaglio & Zanetti 2008). Financing decisions
also affect value in organisations through adjusting the present value in these organisations
(Massari, Roncaglio & Zanetti 2008). According to Spiegel and Tookes (2013), the base case
is first calculated with the assumption that it is all equity financed.
Capital structure in organisations affects the value of the organisation from its first year of
operation. The capital structure in organisations is variable depending on several factors such
as the capital debt and the type of industry within which a firm is located. The tax on a firm is
a major factor with reference to its capital value, especially because the tax determines the debt
status of an organisation (Sabalı 2009).
The initial cash that is invested into a firm in the first year affects the value of an organisation
during this year. Most of the organisations that invest significant amounts of capital into their
operations end up being successful in the first year. Over the years that follow, the WACC
formula is highly applicable, as the organisational debts and equities change.
Capital structure in most organisations is affected by the financial decisions made by the
executive. Hence, the value of organisations is dependent on the type of managers that an
organisation keeps. The value of organisation changes with any financial decision made, since
the debt and equities change with these decisions (Massari, Roncaglio & Zanetti 2008).

The value of a firm may be calculated through the estimation of the WACC, which is later used
to discount the FCFF from the debt holders and equity capital contributors (Massari, Roncaglio
& Zanetti 2008). The use of WACC in the estimation of a firm’s value is very effective by far
compared to other methods of value estimation. This finding indicates a relationship between
the value of organisations and the WACC. The WACC is in turn related to the financial
decisions in an organisation. Hence, valuation is related to the financial decisions in the
organisation.
Impact of Tax Shields on WACC
According to Massari, Roncaglio, and Zanetti (2008), tax is a variable in an organisation that
affects the value of these organisations. Interest in organisations is one of the expenses that are
usually considered as tax-deductible expense (Massari, Roncaglio & Zanetti 2008). The
calculation of WACC incorporates tax as a major form of expense. This strategy determines
the value of organisations. However, tax shields in organisations may affect the calculation of
WACC. The effects of tax shields on WACC depend on the business and individuals who are
responsible for financial management in the respective institutions.
The tax shields cause changes on WACC in a number of ways. However, while these effects
are dependent on the type of organisation, the main effect is that the WACC increases with a
reduction in tax shields. Most organisations seek tax shields to lower their WACC and in effect
influence the value and competitiveness of their respective industries. A common result of tax
shields is a downward adjustment of the discount rate to account for any changes in this area
(Massari, Roncaglio & Zanetti 2008). The downward adjustment of discount rates in
organisations allows decisions to be made on the WACC and its overall effect on the firm’s
value.
Tax shields help organisations save their available financial resources, including the provision
of future resources. In areas where tax shields are effectively applied, firms report better results,
performance, and competitiveness compared to areas where these policies are scantily applied.
Adjusting the discount rate downwards is one of the ways that tax shields are accounted for.
The result of this case is a change on the value of firms (Massari, Roncaglio & Zanetti 2008).
The relationship between value of an organisation and tax shields may be demonstrated by the
inherent differences between organisations that operate in different regions with different tax
shield regimens. According to Massari, Roncaglio, and Zanetti (2008), adjustment of WACC
should affect the value of a firm through the effect of this move on the value of the organisation.

Therefore, managers should make sound decisions when it comes to applying for tax shields in
their area.
How Tax Shields affect Firm Value
Tax shields in an organisation affect the firm’s value in a number of ways as indicated above.
A common understanding is that tax is one of the factors that affect WACC, and in effect the
value of an organisation. The worth of any business is affected by the financing decisions in
the organisations, including the availability of tax shields. The discount rate constitutes one of
the factors that may be adjusted to accommodate changes in the value of organisations. Mintz
and Currim (2013) observe that downward adjustment of discount rate accounts for tax shields.
This downward adjustment results in the increase in value of organisations.
Organisations that use the discount rate to effect changes in their firm value often report success
in the use of the method. When an organisation is awarded tax shields, the value changes to
correspond to the changes introduced through the adjustment of the discount rates. Most
organisations can be described as having debts because of the tax shields that they intend to
acquire.
Therefore, contemporary organisations are prone to debts in their quest to attain tax shields
from the respective authorities. The differences in the contemporary organisations arise from
the different capabilities in the use of their debts. Most organisations whose debt status is high
attain significant tax exemptions. They are valued at higher rank compared to organisations
that have a lower debt position. The tax shields in an organisation, therefore, affect the firm
value in organisations.
Mistakes in Using WACC
Several mistakes are established in literature in the use of WACC. The first mistake is in the
calculation of this variable. In fact, some individuals use variables that are not commonly
applied in the formula. The computation of WACC is tedious due to the many variables that
are necessary for the calculation process. This situation makes the calculation difficult to the
extent that some individuals opt for shortcuts that may not be accurate. The other mistake is
that some individuals assume that the formula may be used in the calculation of WACC for a
particular section of the organisation. They forget that this formula considers the firm a single
unit (Mian & Velez-Pareja 2007).

WACC is useful in providing discount for businesses only where they are applied to
organisations or projects with a similar undertaking to the firm under consideration. For
organisations that differ from the firm under consideration, the formula may not be applicable
or provide useful results. WACC may be useful in most of the calculations where the firm under
consideration has the same size as that of other firms that were initially considered. For projects
that are safer or riskier compared to the original organisation, the calculated WACC may be
inaccurate and in some cases incorrect.
The other mistake that individuals make in the use of WACC is the assumption that it can be
applied as a single variable in the determination of a firm’s value. According to Mian and Velez-
Pareja (2007), organisations require the use of many variables to calculate their value. A single
variable may be deceptive depending on the industry within which the firm is located.
Therefore, there is a need to consider a number of variables in the calculation of a firm’s value
as using WACC alone may be inaccurate. Some of the other mistakes that individuals make in
the use of WACC include miscalculation of the debt and equities that are eventually used in the
calculation of this variable.
Adjusting the WACC
The adjustment of WACC may be done through a number of ways depending on the debt ratios
and the business risks (Mintz & Currim 2013). Adjusting the WACC when the risk of the firm’s
debt ratio and the business risk differ from those of the new project is important in the
calculation of a business’ WACC.
The adjustment of WACC is important when the debt ratios and business risks differ in
organisations. The differences between these two variables result from the changes that are
inherent in the organisations. The three main steps that should be followed when adjusting the
WACC include calculation of the opportunity cost, estimation of the cost of the organisations
debt, and recalculation of the WACC using the obtained new values (Mian & Velez-Pareja
2007).
The adjustment of this value allows the correct calculations where the estimated WACC is
obtained against the real WACC. In cases where the WACC is adjusted, the value of the firm’s
debts and opportunity costs are considered the main reasons for the adjustments. There are
many reasons for the adjustments, with the main one being to increase the accuracy of the final
WACC that is obtained for any given firm. WACC is an indicator of the financing side effect
in an organisation. It is a good indicator of value in organisations (Mintz & Currim 2013).

These financing side effects include the value of interest tax shields on debts (Massari,
Roncaglio & Zanetti 2008). Adjustment of the WACC is also important where the actual value
of a firm is to be estimated.
Valuation in Organisations
Valuation affects the financial decisions that are made in organisations. Most of the decisions
that are important in organisations are made only through the consideration of the value of the
organisation since most managers tend to focus on increasing this value. The many valuation
approaches that are currently in use stem from the extensive research done in this area. These
approaches affect the financing decisions in organisations. The methods of valuation affect the
final variable.
Hence, most of these methods have sub approaches within them. Discounted cash flow is
among the most popular methods that are used in the valuation. This strategy focuses on the
financing decisions in the organisation (Massari, Roncaglio & Zanetti 2008). According to
Dong, Hirshleifer, and Teoh (2012), the main ways of estimating the discounted cash flow
include discounting the cash flow at a risk-adjusted discount (Sabalı 2009). This formula is one
of the four main methods that are used in the discounting cash flows. Using these methods
produces significant results.
Although different methods are in use in the valuation of companies, the same results may be
achieved if the assumptions are withheld for each of the methods. The similarity of these
methods ensures that the result is compatible with the businesses for which it was attempted
first. The different proponents for the different approaches in the valuation methods assume
that their methods are the most accurate. The results indicate that these methods are closely
similar. In relative valuation, which is considered one of the most important valuation methods,
the researchers who proposed the method adopted the assumption of individual assets.
However, these methods have similar results when the different assumptions are withheld.
Conclusion
In conclusion, based on the detailed expositions that have been made in the paper, it is clear
that valuation and financing are closely related when consideration for the financial state of an
organisation is made. Valuation may be estimated in organisations using several methods. Some
of these methods have been stated in this essay. The existence of valuation in financial decisions
allows the organisations to make decisions that coincide with their immediate needs.

The paper has proposed that a relationship between valuation and financial decisions in
organisations. This relationship is affected by other factors such as taxation. The WACC is an
important factor to consider when deducing the relationship between valuation and financial
decisions. The available research proves that this concept is applicable in an organisation’s
financial decisions. The essay has looked at the relationship between WACC and valuation in
organisations and the relationship that exists between these two variables and financial
decisions in an organisation. The paper has proved a positive relationship between these
concepts.
Valuation
The valuation of any organisation allows future decision-making to ensure that it is operating
as per the expectations. Different methods are used in valuation, including those that are
supported by theories and contemporary methods. The present models that are deployed in the
evaluation process are a product of extensive research, with many researchers describing them
before their application in management and finance. What are the motives of company
valuation? Different schools of thought exist as to why company valuation is important.
One of the motives for the evaluations of a company is to make decisions in the organisation.
Depending on the decision that is reached after valuation, the involved individuals may decide
on the future of the organisation and the interventions for the areas that are found faulty.
Motives in company valuation may be characterised in different ways, including decision-
dependent and decision-independent motives (Ishakian, Knebusch & Rowen 2013). The other
category of motives is the transaction based vs the non-transaction-based motives (Ishakian,
Knebusch & Rowen 2013). The other class of motives, as described throughout the literature
on valuation, is the dominated vs the non-dominated decision (Ishakian, Knebusch & Rowen
2013).
Valuation serves different functions depending on the concerned firm or organisation. These
functions can be categorised further into minor and major functions. The main functions of
valuation in organisations include decision-making and consultation. According to Ishakian,
Knebusch, and Rowen (2013), managers and other stakeholders use valuation information in
an organisation to make decisions on the future of the organisation with the aim of improving
the organisational performance. Different firms operate on different grounds. They use
different methods of valuation to make financial and other forms of decisions in the
organisation.

The other function of valuation, according to Koziol (2014), is mediation where the firm uses
information from valuation to mediate between concepts, decisions, and individuals.
Hundsdoerfer, Kruschwitz, and Loren (2008) assert that mediation in an organisation provides
crucial information on the financial position of the organisation. Valuation also serves as a
means of argumentation. Using information from valuation, managers and other organisational
stakeholders can argue on the position of the organisation. The information is used to provide
details on the organisational performance, which is important in making a case for any
argument.
Apart from the main functions of valuation, valuation serves other auxiliary functions. One of
these auxiliary functions is information where the parties within an organisation gather
information on this organisation, including its performance and future expectations. Valuation
may also be used as a means of tax measurement where authorities determine the tax that an
organisation should forward over a given period. Many organisations where valuation has been
conducted were found to have some tax measurements, not in line with the expected values
(Mian & Velez-Pareja 2007). Valuation also serves the function of contract configuration where
employees and other parties in the organisation can have their contracts configured with the
expectations of the organisation.
Valuation Methods
Different valuation methods are in use in many organisations. Each of these methods provides
different results. The decision to use one of them is dependent on the firm that is being
evaluated, the financial methods in place, and the preferred approach. The most popular
approach depends on the organisation and the region where these organisations exist. Different
methods that are used in valuation are shown below.
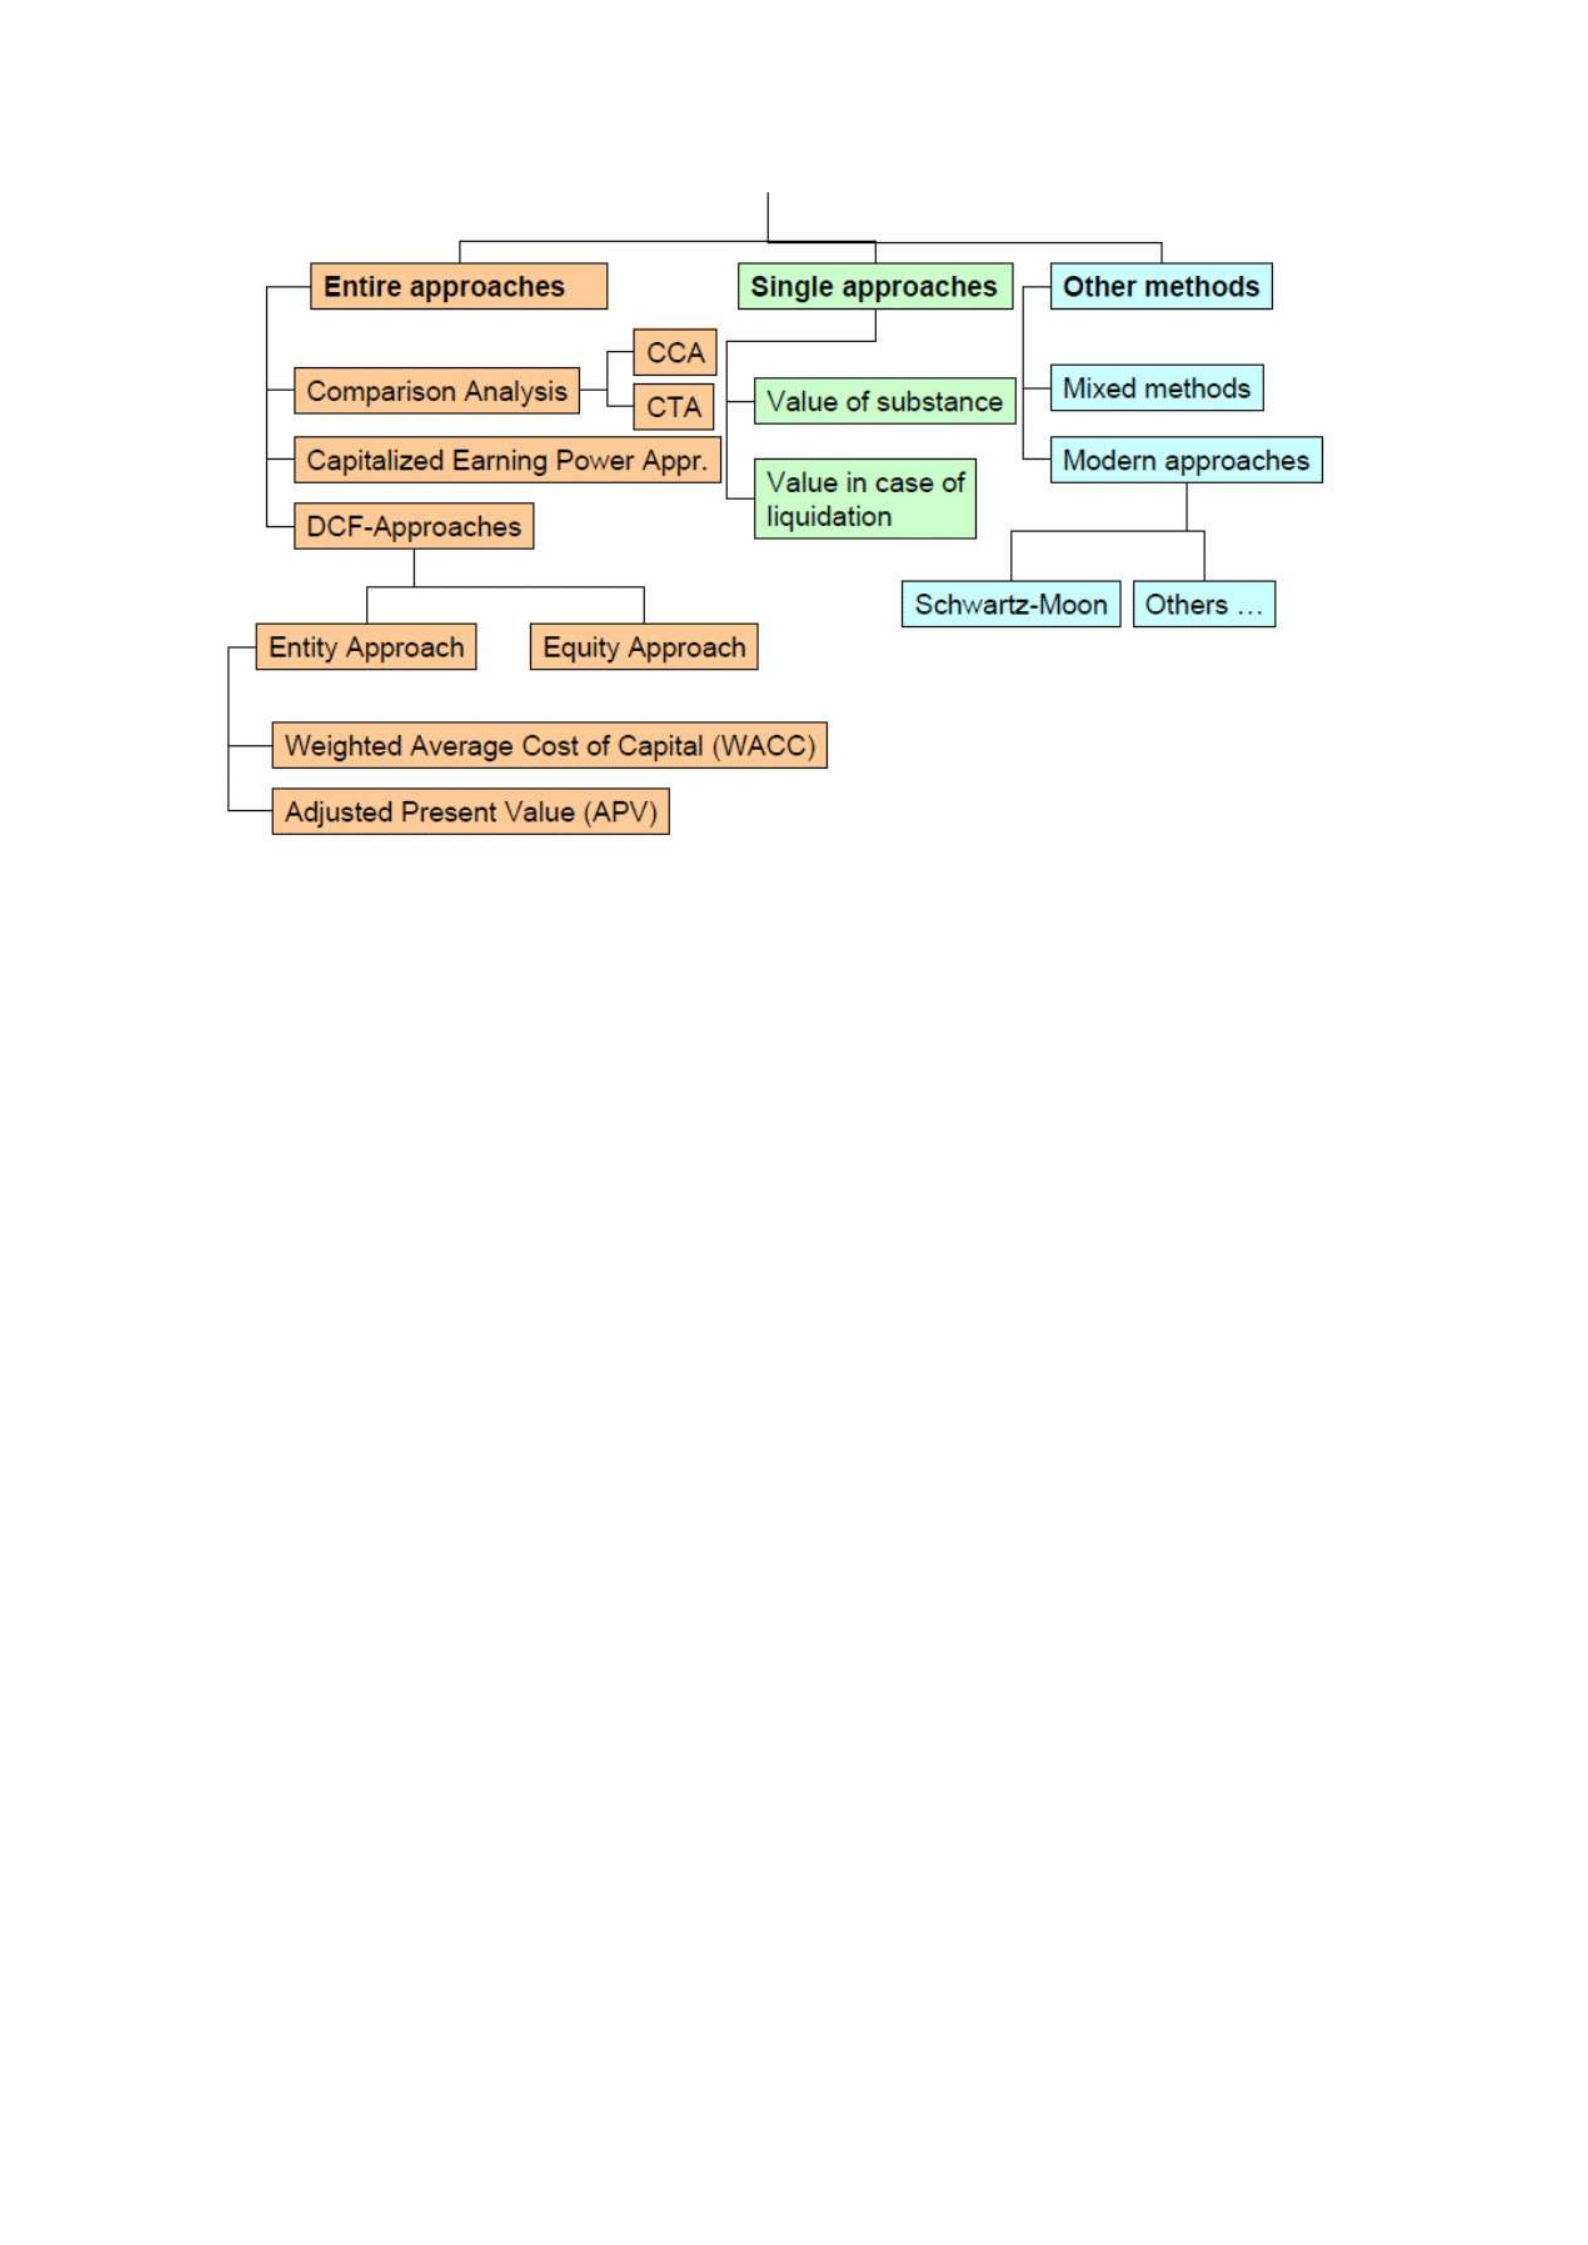
Figure 1: An Overview of Valuation Methods (Source Mian & Velez-Pareja 2007)
Different models that are applied during a valuation in organisations lead to a common result
where the organisations are able to plan for future decisions and changes. The valuation that is
obtained in organisations, irrespective of the method used, provides crucial information on the
financial status of the organisation. However, valuation within organisations also allows the
inception of changes whenever they are needed.
Financial Decisions
Organisations face challenges in financing, with one of the most common of them being the
outcomes of financial decisions. Competitiveness in organisations is influenced by the financial
decisions that managers and other stakeholders make. In any industry, financial decisions affect
the outcomes of the interactions between different factors. The financial decisions in an
organisation are also under the influence of other factors such as the valuation in these
organisations. A business in any industry or market must use capital as one of the main factors
in its operations, with this strategy bringing about the cost of capital.
Currently, there are no perfect markets in contemporary organisations. Hence, capital is not
always put to the intended use. A perfect business environment is the only place where capital
can be put to its planned use. However, conditions that are necessary for a perfect market are
hard to achieve. Nevertheless, if it were possible, the perfect world would have an excess
supply of capital. A perfect capital market might mean that the available unlimited capital is
only dependent on the risk of the project being undertaken (Spiegel, & Tookes 2013).

Aside from the perfect capital market, uncertainties, variables, and friction characterise the
existing real-world capital markets. The availability of tax as one of the variables in an
imperfect world ensures that organisations adopt strategies such as debts. An example of such
strategies is when an organisation operates in a capital structure with about 100% of debt
because of the positive corporate tax rate (Spiegel, & Tookes, 2013). Other factors that exist in
an imperfect world to introduce a relationship between valuations and financing include agency
costs, financial distress costs, and information asymmetries (Spiegel, & Tookes, 2013).
The financial position of an organisation ensures that the organisation can persist in an
environment where competition is an evident factor. Valuation effects that financial position of
an organisation. The reverse is also true. The decisions made in an organisation relating to the
financial positions of the organisation may be based on the valuation that is provided for this
organisation.
Weighted Average Cost of Capital
The calculation of the cost of capital is an intricate process that requires the participation of all
stakeholders. The cost of capital is calculated through the estimation of the proportion of debt
that a project consumes against the equity that is absorbed in the respective project (Massari,
Roncaglio & Zanetti 2008). The weighted average cost of capital (WACC) is calculated through
a formula that incorporates the market value of equity and debt (Massari, Roncaglio & Zanetti
2008). These values are adjusted using the costs of debt and equity. For a single firm, the
WACC is calculated as a single unit where the firm is the reference. The organisation, in this
case, is considered a single unit, with the results being for a single project.
The Weighted Average Cost of Capital is an indicator of the financial performance of an
organisation because it indicates the financial position of the organisation under discussion.
Any organisation with sound financial decisions has a favourable WACC, which is considered
a strength in these organisations. The calculation and use of WACC in financial discussions
and problem-solving is challenging for some financial analysts and other financial decision-
makers in organisations. Therefore, it is important to have a discussion on the correct use of
WACC and its implications on the financial decisions in organisations.
The other difficulty in the calculation and use of WACC is tax calculation. Different finance
officers use different methods of calculating the variables (Sabalı 2009). Financing and
investment decisions interact through taxes. WACC is an important concept in evaluating this

interaction. The formula that is used in the calculation of WACC refers to the organisation of
company as a whole upon incorporating the different aspects in financial decisions in the firm.
Therefore, this formula is effective for the “average project” where the right discount rate is
produced (Massari, Roncaglio & Zanetti 2008). Hence, the formula is incorrect when used in
the calculation of WACC for the safer and riskier projects (Magni 2012). The inaccuracy while
using this formula mainly stems from the different sections that individuals calculate in an
organisation, especially where the organisation has different departments.
Capital Structure and Valuations
Capital structure in a firm is a factor that affects valuations in these organisations. The effects
depend on the existing capital structure. According to Sabalı (2009), financing decisions
typically affect value within organisations. Some of the ways that boost value in a firm with
respect to its financing decisions is through the adjustment of the discount rate and the present
value (Massari, Roncaglio & Zanetti 2008).
The discount rate in most organisations is typically adjusted downwards, with the aim being to
account for the existing tax shields (Massari, Roncaglio & Zanetti 2008). Financing decisions
also affect value in organisations through adjusting the present value in these organisations
(Massari, Roncaglio & Zanetti 2008). According to Spiegel and Tookes (2013), the base case
is first calculated with the assumption that it is all equity financed.
Capital structure in organisations affects the value of the organisation from its first year of
operation. The capital structure in organisations is variable depending on several factors such
as the capital debt and the type of industry within which a firm is located. The tax on a firm is
a major factor with reference to its capital value, especially because the tax determines the debt
status of an organisation (Sabalı 2009).
The initial cash that is invested into a firm in the first year affects the value of an organisation
during this year. Most of the organisations that invest significant amounts of capital into their
operations end up being successful in the first year. Over the years that follow, the WACC
formula is highly applicable, as the organisational debts and equities change.
Capital structure in most organisations is affected by the financial decisions made by the
executive. Hence, the value of organisations is dependent on the type of managers that an
organisation keeps. The value of organisation changes with any financial decision made, since
the debt and equities change with these decisions (Massari, Roncaglio & Zanetti 2008).

The value of a firm may be calculated through the estimation of the WACC, which is later used
to discount the FCFF from the debt holders and equity capital contributors (Massari, Roncaglio
& Zanetti 2008). The use of WACC in the estimation of a firm’s value is very effective by far
compared to other methods of value estimation. This finding indicates a relationship between
the value of organisations and the WACC. The WACC is in turn related to the financial
decisions in an organisation. Hence, valuation is related to the financial decisions in the
organisation.
Impact of Tax Shields on WACC
According to Massari, Roncaglio, and Zanetti (2008), tax is a variable in an organisation that
affects the value of these organisations. Interest in organisations is one of the expenses that are
usually considered as tax-deductible expense (Massari, Roncaglio & Zanetti 2008). The
calculation of WACC incorporates tax as a major form of expense. This strategy determines
the value of organisations. However, tax shields in organisations may affect the calculation of
WACC. The effects of tax shields on WACC depend on the business and individuals who are
responsible for financial management in the respective institutions.
The tax shields cause changes on WACC in a number of ways. However, while these effects
are dependent on the type of organisation, the main effect is that the WACC increases with a
reduction in tax shields. Most organisations seek tax shields to lower their WACC and in effect
influence the value and competitiveness of their respective industries. A common result of tax
shields is a downward adjustment of the discount rate to account for any changes in this area
(Massari, Roncaglio & Zanetti 2008). The downward adjustment of discount rates in
organisations allows decisions to be made on the WACC and its overall effect on the firm’s
value.
Tax shields help organisations save their available financial resources, including the provision
of future resources. In areas where tax shields are effectively applied, firms report better results,
performance, and competitiveness compared to areas where these policies are scantily applied.
Adjusting the discount rate downwards is one of the ways that tax shields are accounted for.
The result of this case is a change on the value of firms (Massari, Roncaglio & Zanetti 2008).
The relationship between value of an organisation and tax shields may be demonstrated by the
inherent differences between organisations that operate in different regions with different tax
shield regimens. According to Massari, Roncaglio, and Zanetti (2008), adjustment of WACC
should affect the value of a firm through the effect of this move on the value of the organisation.

Therefore, managers should make sound decisions when it comes to applying for tax shields in
their area.
How Tax Shields affect Firm Value
Tax shields in an organisation affect the firm’s value in a number of ways as indicated above.
A common understanding is that tax is one of the factors that affect WACC, and in effect the
value of an organisation. The worth of any business is affected by the financing decisions in
the organisations, including the availability of tax shields. The discount rate constitutes one of
the factors that may be adjusted to accommodate changes in the value of organisations. Mintz
and Currim (2013) observe that downward adjustment of discount rate accounts for tax shields.
This downward adjustment results in the increase in value of organisations.
Organisations that use the discount rate to effect changes in their firm value often report success
in the use of the method. When an organisation is awarded tax shields, the value changes to
correspond to the changes introduced through the adjustment of the discount rates. Most
organisations can be described as having debts because of the tax shields that they intend to
acquire.
Therefore, contemporary organisations are prone to debts in their quest to attain tax shields
from the respective authorities. The differences in the contemporary organisations arise from
the different capabilities in the use of their debts. Most organisations whose debt status is high
attain significant tax exemptions. They are valued at higher rank compared to organisations
that have a lower debt position. The tax shields in an organisation, therefore, affect the firm
value in organisations.
Mistakes in Using WACC
Several mistakes are established in literature in the use of WACC. The first mistake is in the
calculation of this variable. In fact, some individuals use variables that are not commonly
applied in the formula. The computation of WACC is tedious due to the many variables that
are necessary for the calculation process. This situation makes the calculation difficult to the
extent that some individuals opt for shortcuts that may not be accurate. The other mistake is
that some individuals assume that the formula may be used in the calculation of WACC for a
particular section of the organisation. They forget that this formula considers the firm a single
unit (Mian & Velez-Pareja 2007).

WACC is useful in providing discount for businesses only where they are applied to
organisations or projects with a similar undertaking to the firm under consideration. For
organisations that differ from the firm under consideration, the formula may not be applicable
or provide useful results. WACC may be useful in most of the calculations where the firm under
consideration has the same size as that of other firms that were initially considered. For projects
that are safer or riskier compared to the original organisation, the calculated WACC may be
inaccurate and in some cases incorrect.
The other mistake that individuals make in the use of WACC is the assumption that it can be
applied as a single variable in the determination of a firm’s value. According to Mian and Velez-
Pareja (2007), organisations require the use of many variables to calculate their value. A single
variable may be deceptive depending on the industry within which the firm is located.
Therefore, there is a need to consider a number of variables in the calculation of a firm’s value
as using WACC alone may be inaccurate. Some of the other mistakes that individuals make in
the use of WACC include miscalculation of the debt and equities that are eventually used in the
calculation of this variable.
Adjusting the WACC
The adjustment of WACC may be done through a number of ways depending on the debt ratios
and the business risks (Mintz & Currim 2013). Adjusting the WACC when the risk of the firm’s
debt ratio and the business risk differ from those of the new project is important in the
calculation of a business’ WACC.
The adjustment of WACC is important when the debt ratios and business risks differ in
organisations. The differences between these two variables result from the changes that are
inherent in the organisations. The three main steps that should be followed when adjusting the
WACC include calculation of the opportunity cost, estimation of the cost of the organisations
debt, and recalculation of the WACC using the obtained new values (Mian & Velez-Pareja
2007).
The adjustment of this value allows the correct calculations where the estimated WACC is
obtained against the real WACC. In cases where the WACC is adjusted, the value of the firm’s
debts and opportunity costs are considered the main reasons for the adjustments. There are
many reasons for the adjustments, with the main one being to increase the accuracy of the final
WACC that is obtained for any given firm. WACC is an indicator of the financing side effect
in an organisation. It is a good indicator of value in organisations (Mintz & Currim 2013).

These financing side effects include the value of interest tax shields on debts (Massari,
Roncaglio & Zanetti 2008). Adjustment of the WACC is also important where the actual value
of a firm is to be estimated.
Valuation in Organisations
Valuation affects the financial decisions that are made in organisations. Most of the decisions
that are important in organisations are made only through the consideration of the value of the
organisation since most managers tend to focus on increasing this value. The many valuation
approaches that are currently in use stem from the extensive research done in this area. These
approaches affect the financing decisions in organisations. The methods of valuation affect the
final variable.
Hence, most of these methods have sub approaches within them. Discounted cash flow is
among the most popular methods that are used in the valuation. This strategy focuses on the
financing decisions in the organisation (Massari, Roncaglio & Zanetti 2008). According to
Dong, Hirshleifer, and Teoh (2012), the main ways of estimating the discounted cash flow
include discounting the cash flow at a risk-adjusted discount (Sabalı 2009). This formula is one
of the four main methods that are used in the discounting cash flows. Using these methods
produces significant results.
Although different methods are in use in the valuation of companies, the same results may be
achieved if the assumptions are withheld for each of the methods. The similarity of these
methods ensures that the result is compatible with the businesses for which it was attempted
first. The different proponents for the different approaches in the valuation methods assume
that their methods are the most accurate. The results indicate that these methods are closely
similar. In relative valuation, which is considered one of the most important valuation methods,
the researchers who proposed the method adopted the assumption of individual assets.
However, these methods have similar results when the different assumptions are withheld.
Conclusion
In conclusion, based on the detailed expositions that have been made in the paper, it is clear
that valuation and financing are closely related when consideration for the financial state of an
organisation is made. Valuation may be estimated in organisations using several methods. Some
of these methods have been stated in this essay. The existence of valuation in financial decisions
allows the organisations to make decisions that coincide with their immediate needs.

The paper has proposed that a relationship between valuation and financial decisions in
organisations. This relationship is affected by other factors such as taxation. The WACC is an
important factor to consider when deducing the relationship between valuation and financial
decisions. The available research proves that this concept is applicable in an organisation’s
financial decisions. The essay has looked at the relationship between WACC and valuation in
organisations and the relationship that exists between these two variables and financial
decisions in an organisation. The paper has proved a positive relationship between these
concepts.
Valuation
The valuation of any organisation allows future decision-making to ensure that it is operating
as per the expectations. Different methods are used in valuation, including those that are
supported by theories and contemporary methods. The present models that are deployed in the
evaluation process are a product of extensive research, with many researchers describing them
before their application in management and finance. What are the motives of company
valuation? Different schools of thought exist as to why company valuation is important.
One of the motives for the evaluations of a company is to make decisions in the organisation.
Depending on the decision that is reached after valuation, the involved individuals may decide
on the future of the organisation and the interventions for the areas that are found faulty.
Motives in company valuation may be characterised in different ways, including decision-
dependent and decision-independent motives (Ishakian, Knebusch & Rowen 2013). The other
category of motives is the transaction based vs the non-transaction-based motives (Ishakian,
Knebusch & Rowen 2013). The other class of motives, as described throughout the literature
on valuation, is the dominated vs the non-dominated decision (Ishakian, Knebusch & Rowen
2013).
Valuation serves different functions depending on the concerned firm or organisation. These
functions can be categorised further into minor and major functions. The main functions of
valuation in organisations include decision-making and consultation. According to Ishakian,
Knebusch, and Rowen (2013), managers and other stakeholders use valuation information in
an organisation to make decisions on the future of the organisation with the aim of improving
the organisational performance. Different firms operate on different grounds. They use
different methods of valuation to make financial and other forms of decisions in the
organisation.

The other function of valuation, according to Koziol (2014), is mediation where the firm uses
information from valuation to mediate between concepts, decisions, and individuals.
Hundsdoerfer, Kruschwitz, and Loren (2008) assert that mediation in an organisation provides
crucial information on the financial position of the organisation. Valuation also serves as a
means of argumentation. Using information from valuation, managers and other organisational
stakeholders can argue on the position of the organisation. The information is used to provide
details on the organisational performance, which is important in making a case for any
argument.
Apart from the main functions of valuation, valuation serves other auxiliary functions. One of
these auxiliary functions is information where the parties within an organisation gather
information on this organisation, including its performance and future expectations. Valuation
may also be used as a means of tax measurement where authorities determine the tax that an
organisation should forward over a given period. Many organisations where valuation has been
conducted were found to have some tax measurements, not in line with the expected values
(Mian & Velez-Pareja 2007). Valuation also serves the function of contract configuration where
employees and other parties in the organisation can have their contracts configured with the
expectations of the organisation.
Valuation Methods
Different valuation methods are in use in many organisations. Each of these methods provides
different results. The decision to use one of them is dependent on the firm that is being
evaluated, the financial methods in place, and the preferred approach. The most popular
approach depends on the organisation and the region where these organisations exist. Different
methods that are used in valuation are shown below.
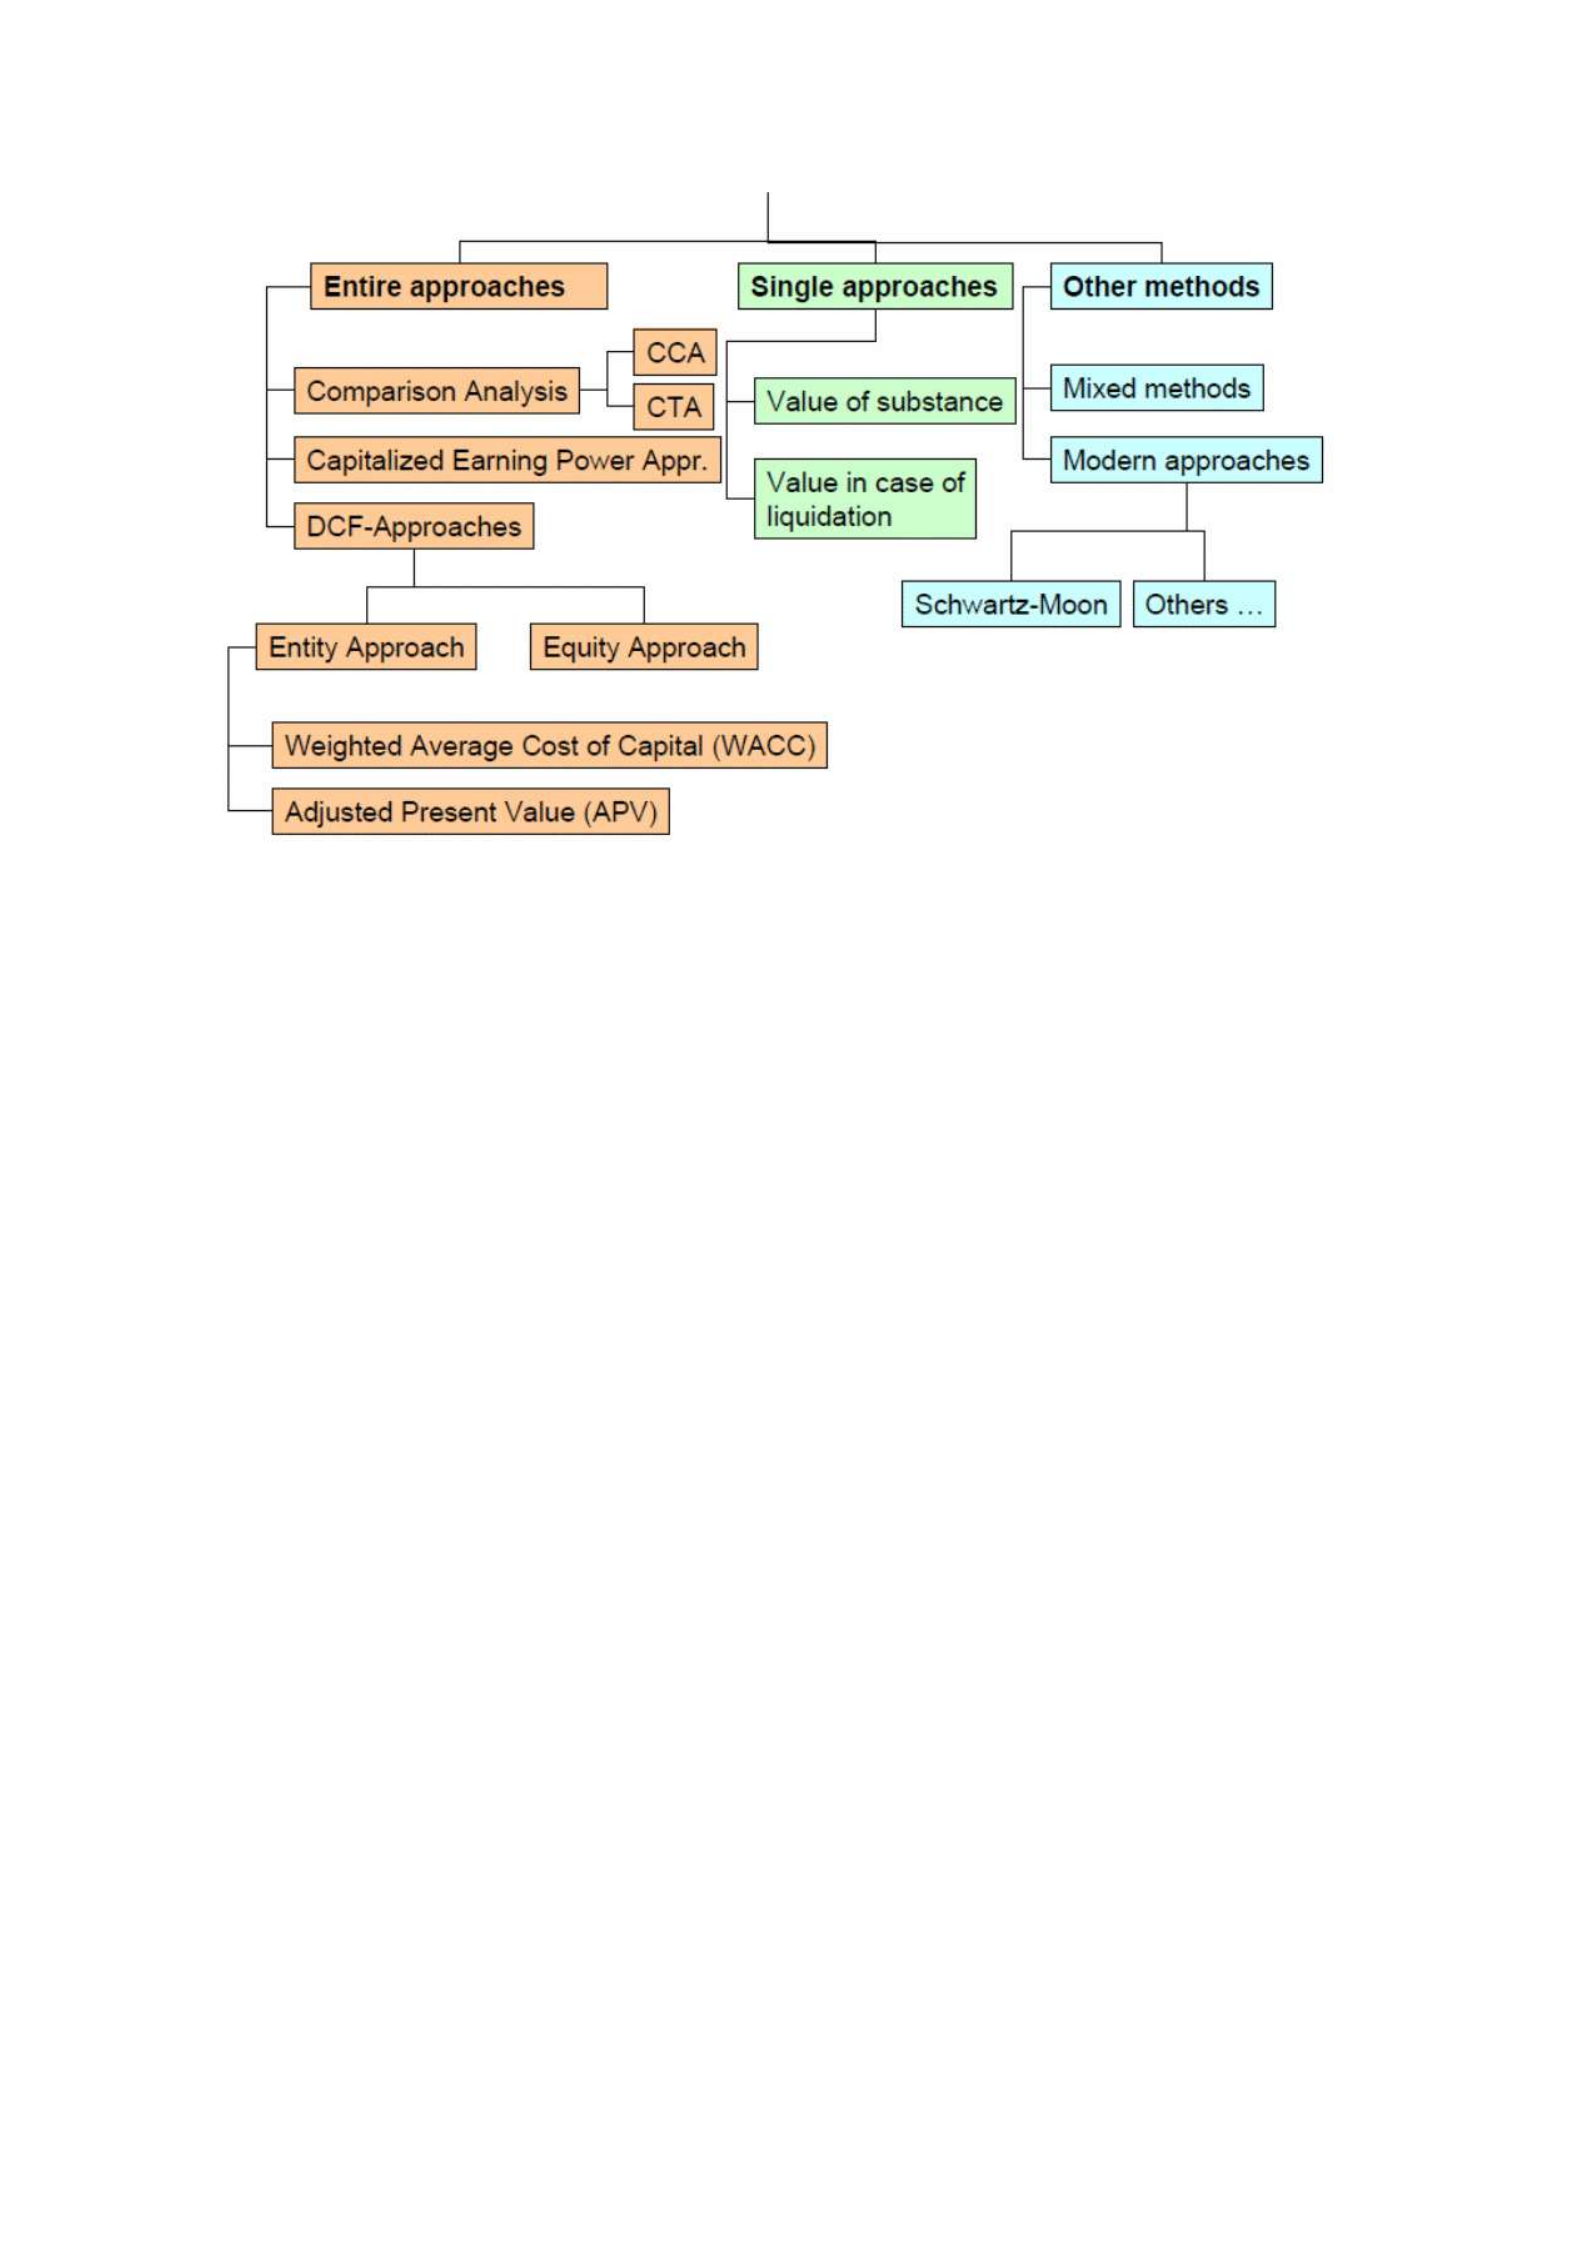
Figure 1: An Overview of Valuation Methods (Source Mian & Velez-Pareja 2007)
Different models that are applied during a valuation in organisations lead to a common result
where the organisations are able to plan for future decisions and changes. The valuation that is
obtained in organisations, irrespective of the method used, provides crucial information on the
financial status of the organisation. However, valuation within organisations also allows the
inception of changes whenever they are needed.
Financial Decisions
Organisations face challenges in financing, with one of the most common of them being the
outcomes of financial decisions. Competitiveness in organisations is influenced by the financial
decisions that managers and other stakeholders make. In any industry, financial decisions affect
the outcomes of the interactions between different factors. The financial decisions in an
organisation are also under the influence of other factors such as the valuation in these
organisations. A business in any industry or market must use capital as one of the main factors
in its operations, with this strategy bringing about the cost of capital.
Currently, there are no perfect markets in contemporary organisations. Hence, capital is not
always put to the intended use. A perfect business environment is the only place where capital
can be put to its planned use. However, conditions that are necessary for a perfect market are
hard to achieve. Nevertheless, if it were possible, the perfect world would have an excess
supply of capital. A perfect capital market might mean that the available unlimited capital is
only dependent on the risk of the project being undertaken (Spiegel, & Tookes 2013).

Aside from the perfect capital market, uncertainties, variables, and friction characterise the
existing real-world capital markets. The availability of tax as one of the variables in an
imperfect world ensures that organisations adopt strategies such as debts. An example of such
strategies is when an organisation operates in a capital structure with about 100% of debt
because of the positive corporate tax rate (Spiegel, & Tookes, 2013). Other factors that exist in
an imperfect world to introduce a relationship between valuations and financing include agency
costs, financial distress costs, and information asymmetries (Spiegel, & Tookes, 2013).
The financial position of an organisation ensures that the organisation can persist in an
environment where competition is an evident factor. Valuation effects that financial position of
an organisation. The reverse is also true. The decisions made in an organisation relating to the
financial positions of the organisation may be based on the valuation that is provided for this
organisation.
Weighted Average Cost of Capital
The calculation of the cost of capital is an intricate process that requires the participation of all
stakeholders. The cost of capital is calculated through the estimation of the proportion of debt
that a project consumes against the equity that is absorbed in the respective project (Massari,
Roncaglio & Zanetti 2008). The weighted average cost of capital (WACC) is calculated through
a formula that incorporates the market value of equity and debt (Massari, Roncaglio & Zanetti
2008). These values are adjusted using the costs of debt and equity. For a single firm, the
WACC is calculated as a single unit where the firm is the reference. The organisation, in this
case, is considered a single unit, with the results being for a single project.
The Weighted Average Cost of Capital is an indicator of the financial performance of an
organisation because it indicates the financial position of the organisation under discussion.
Any organisation with sound financial decisions has a favourable WACC, which is considered
a strength in these organisations. The calculation and use of WACC in financial discussions
and problem-solving is challenging for some financial analysts and other financial decision-
makers in organisations. Therefore, it is important to have a discussion on the correct use of
WACC and its implications on the financial decisions in organisations.
The other difficulty in the calculation and use of WACC is tax calculation. Different finance
officers use different methods of calculating the variables (Sabalı 2009). Financing and
investment decisions interact through taxes. WACC is an important concept in evaluating this

interaction. The formula that is used in the calculation of WACC refers to the organisation of
company as a whole upon incorporating the different aspects in financial decisions in the firm.
Therefore, this formula is effective for the “average project” where the right discount rate is
produced (Massari, Roncaglio & Zanetti 2008). Hence, the formula is incorrect when used in
the calculation of WACC for the safer and riskier projects (Magni 2012). The inaccuracy while
using this formula mainly stems from the different sections that individuals calculate in an
organisation, especially where the organisation has different departments.
Capital Structure and Valuations
Capital structure in a firm is a factor that affects valuations in these organisations. The effects
depend on the existing capital structure. According to Sabalı (2009), financing decisions
typically affect value within organisations. Some of the ways that boost value in a firm with
respect to its financing decisions is through the adjustment of the discount rate and the present
value (Massari, Roncaglio & Zanetti 2008).
The discount rate in most organisations is typically adjusted downwards, with the aim being to
account for the existing tax shields (Massari, Roncaglio & Zanetti 2008). Financing decisions
also affect value in organisations through adjusting the present value in these organisations
(Massari, Roncaglio & Zanetti 2008). According to Spiegel and Tookes (2013), the base case
is first calculated with the assumption that it is all equity financed.
Capital structure in organisations affects the value of the organisation from its first year of
operation. The capital structure in organisations is variable depending on several factors such
as the capital debt and the type of industry within which a firm is located. The tax on a firm is
a major factor with reference to its capital value, especially because the tax determines the debt
status of an organisation (Sabalı 2009).
The initial cash that is invested into a firm in the first year affects the value of an organisation
during this year. Most of the organisations that invest significant amounts of capital into their
operations end up being successful in the first year. Over the years that follow, the WACC
formula is highly applicable, as the organisational debts and equities change.
Capital structure in most organisations is affected by the financial decisions made by the
executive. Hence, the value of organisations is dependent on the type of managers that an
organisation keeps. The value of organisation changes with any financial decision made, since
the debt and equities change with these decisions (Massari, Roncaglio & Zanetti 2008).

The value of a firm may be calculated through the estimation of the WACC, which is later used
to discount the FCFF from the debt holders and equity capital contributors (Massari, Roncaglio
& Zanetti 2008). The use of WACC in the estimation of a firm’s value is very effective by far
compared to other methods of value estimation. This finding indicates a relationship between
the value of organisations and the WACC. The WACC is in turn related to the financial
decisions in an organisation. Hence, valuation is related to the financial decisions in the
organisation.
Impact of Tax Shields on WACC
According to Massari, Roncaglio, and Zanetti (2008), tax is a variable in an organisation that
affects the value of these organisations. Interest in organisations is one of the expenses that are
usually considered as tax-deductible expense (Massari, Roncaglio & Zanetti 2008). The
calculation of WACC incorporates tax as a major form of expense. This strategy determines
the value of organisations. However, tax shields in organisations may affect the calculation of
WACC. The effects of tax shields on WACC depend on the business and individuals who are
responsible for financial management in the respective institutions.
The tax shields cause changes on WACC in a number of ways. However, while these effects
are dependent on the type of organisation, the main effect is that the WACC increases with a
reduction in tax shields. Most organisations seek tax shields to lower their WACC and in effect
influence the value and competitiveness of their respective industries. A common result of tax
shields is a downward adjustment of the discount rate to account for any changes in this area
(Massari, Roncaglio & Zanetti 2008). The downward adjustment of discount rates in
organisations allows decisions to be made on the WACC and its overall effect on the firm’s
value.
Tax shields help organisations save their available financial resources, including the provision
of future resources. In areas where tax shields are effectively applied, firms report better results,
performance, and competitiveness compared to areas where these policies are scantily applied.
Adjusting the discount rate downwards is one of the ways that tax shields are accounted for.
The result of this case is a change on the value of firms (Massari, Roncaglio & Zanetti 2008).
The relationship between value of an organisation and tax shields may be demonstrated by the
inherent differences between organisations that operate in different regions with different tax
shield regimens. According to Massari, Roncaglio, and Zanetti (2008), adjustment of WACC
should affect the value of a firm through the effect of this move on the value of the organisation.

Therefore, managers should make sound decisions when it comes to applying for tax shields in
their area.
How Tax Shields affect Firm Value
Tax shields in an organisation affect the firm’s value in a number of ways as indicated above.
A common understanding is that tax is one of the factors that affect WACC, and in effect the
value of an organisation. The worth of any business is affected by the financing decisions in
the organisations, including the availability of tax shields. The discount rate constitutes one of
the factors that may be adjusted to accommodate changes in the value of organisations. Mintz
and Currim (2013) observe that downward adjustment of discount rate accounts for tax shields.
This downward adjustment results in the increase in value of organisations.
Organisations that use the discount rate to effect changes in their firm value often report success
in the use of the method. When an organisation is awarded tax shields, the value changes to
correspond to the changes introduced through the adjustment of the discount rates. Most
organisations can be described as having debts because of the tax shields that they intend to
acquire.
Therefore, contemporary organisations are prone to debts in their quest to attain tax shields
from the respective authorities. The differences in the contemporary organisations arise from
the different capabilities in the use of their debts. Most organisations whose debt status is high
attain significant tax exemptions. They are valued at higher rank compared to organisations
that have a lower debt position. The tax shields in an organisation, therefore, affect the firm
value in organisations.
Mistakes in Using WACC
Several mistakes are established in literature in the use of WACC. The first mistake is in the
calculation of this variable. In fact, some individuals use variables that are not commonly
applied in the formula. The computation of WACC is tedious due to the many variables that
are necessary for the calculation process. This situation makes the calculation difficult to the
extent that some individuals opt for shortcuts that may not be accurate. The other mistake is
that some individuals assume that the formula may be used in the calculation of WACC for a
particular section of the organisation. They forget that this formula considers the firm a single
unit (Mian & Velez-Pareja 2007).

WACC is useful in providing discount for businesses only where they are applied to
organisations or projects with a similar undertaking to the firm under consideration. For
organisations that differ from the firm under consideration, the formula may not be applicable
or provide useful results. WACC may be useful in most of the calculations where the firm under
consideration has the same size as that of other firms that were initially considered. For projects
that are safer or riskier compared to the original organisation, the calculated WACC may be
inaccurate and in some cases incorrect.
The other mistake that individuals make in the use of WACC is the assumption that it can be
applied as a single variable in the determination of a firm’s value. According to Mian and Velez-
Pareja (2007), organisations require the use of many variables to calculate their value. A single
variable may be deceptive depending on the industry within which the firm is located.
Therefore, there is a need to consider a number of variables in the calculation of a firm’s value
as using WACC alone may be inaccurate. Some of the other mistakes that individuals make in
the use of WACC include miscalculation of the debt and equities that are eventually used in the
calculation of this variable.
Adjusting the WACC
The adjustment of WACC may be done through a number of ways depending on the debt ratios
and the business risks (Mintz & Currim 2013). Adjusting the WACC when the risk of the firm’s
debt ratio and the business risk differ from those of the new project is important in the
calculation of a business’ WACC.
The adjustment of WACC is important when the debt ratios and business risks differ in
organisations. The differences between these two variables result from the changes that are
inherent in the organisations. The three main steps that should be followed when adjusting the
WACC include calculation of the opportunity cost, estimation of the cost of the organisations
debt, and recalculation of the WACC using the obtained new values (Mian & Velez-Pareja
2007).
The adjustment of this value allows the correct calculations where the estimated WACC is
obtained against the real WACC. In cases where the WACC is adjusted, the value of the firm’s
debts and opportunity costs are considered the main reasons for the adjustments. There are
many reasons for the adjustments, with the main one being to increase the accuracy of the final
WACC that is obtained for any given firm. WACC is an indicator of the financing side effect
in an organisation. It is a good indicator of value in organisations (Mintz & Currim 2013).

These financing side effects include the value of interest tax shields on debts (Massari,
Roncaglio & Zanetti 2008). Adjustment of the WACC is also important where the actual value
of a firm is to be estimated.
Valuation in Organisations
Valuation affects the financial decisions that are made in organisations. Most of the decisions
that are important in organisations are made only through the consideration of the value of the
organisation since most managers tend to focus on increasing this value. The many valuation
approaches that are currently in use stem from the extensive research done in this area. These
approaches affect the financing decisions in organisations. The methods of valuation affect the
final variable.
Hence, most of these methods have sub approaches within them. Discounted cash flow is
among the most popular methods that are used in the valuation. This strategy focuses on the
financing decisions in the organisation (Massari, Roncaglio & Zanetti 2008). According to
Dong, Hirshleifer, and Teoh (2012), the main ways of estimating the discounted cash flow
include discounting the cash flow at a risk-adjusted discount (Sabalı 2009). This formula is one
of the four main methods that are used in the discounting cash flows. Using these methods
produces significant results.
Although different methods are in use in the valuation of companies, the same results may be
achieved if the assumptions are withheld for each of the methods. The similarity of these
methods ensures that the result is compatible with the businesses for which it was attempted
first. The different proponents for the different approaches in the valuation methods assume
that their methods are the most accurate. The results indicate that these methods are closely
similar. In relative valuation, which is considered one of the most important valuation methods,
the researchers who proposed the method adopted the assumption of individual assets.
However, these methods have similar results when the different assumptions are withheld.
Conclusion
In conclusion, based on the detailed expositions that have been made in the paper, it is clear
that valuation and financing are closely related when consideration for the financial state of an
organisation is made. Valuation may be estimated in organisations using several methods. Some
of these methods have been stated in this essay. The existence of valuation in financial decisions
allows the organisations to make decisions that coincide with their immediate needs.

The paper has proposed that a relationship between valuation and financial decisions in
organisations. This relationship is affected by other factors such as taxation. The WACC is an
important factor to consider when deducing the relationship between valuation and financial
decisions. The available research proves that this concept is applicable in an organisation’s
financial decisions. The essay has looked at the relationship between WACC and valuation in
organisations and the relationship that exists between these two variables and financial
decisions in an organisation. The paper has proved a positive relationship between these
concepts.
Valuation
The valuation of any organisation allows future decision-making to ensure that it is operating
as per the expectations. Different methods are used in valuation, including those that are
supported by theories and contemporary methods. The present models that are deployed in the
evaluation process are a product of extensive research, with many researchers describing them
before their application in management and finance. What are the motives of company
valuation? Different schools of thought exist as to why company valuation is important.
One of the motives for the evaluations of a company is to make decisions in the organisation.
Depending on the decision that is reached after valuation, the involved individuals may decide
on the future of the organisation and the interventions for the areas that are found faulty.
Motives in company valuation may be characterised in different ways, including decision-
dependent and decision-independent motives (Ishakian, Knebusch & Rowen 2013). The other
category of motives is the transaction based vs the non-transaction-based motives (Ishakian,
Knebusch & Rowen 2013). The other class of motives, as described throughout the literature
on valuation, is the dominated vs the non-dominated decision (Ishakian, Knebusch & Rowen
2013).
Valuation serves different functions depending on the concerned firm or organisation. These
functions can be categorised further into minor and major functions. The main functions of
valuation in organisations include decision-making and consultation. According to Ishakian,
Knebusch, and Rowen (2013), managers and other stakeholders use valuation information in
an organisation to make decisions on the future of the organisation with the aim of improving
the organisational performance. Different firms operate on different grounds. They use
different methods of valuation to make financial and other forms of decisions in the
organisation.

The other function of valuation, according to Koziol (2014), is mediation where the firm uses
information from valuation to mediate between concepts, decisions, and individuals.
Hundsdoerfer, Kruschwitz, and Loren (2008) assert that mediation in an organisation provides
crucial information on the financial position of the organisation. Valuation also serves as a
means of argumentation. Using information from valuation, managers and other organisational
stakeholders can argue on the position of the organisation. The information is used to provide
details on the organisational performance, which is important in making a case for any
argument.
Apart from the main functions of valuation, valuation serves other auxiliary functions. One of
these auxiliary functions is information where the parties within an organisation gather
information on this organisation, including its performance and future expectations. Valuation
may also be used as a means of tax measurement where authorities determine the tax that an
organisation should forward over a given period. Many organisations where valuation has been
conducted were found to have some tax measurements, not in line with the expected values
(Mian & Velez-Pareja 2007). Valuation also serves the function of contract configuration where
employees and other parties in the organisation can have their contracts configured with the
expectations of the organisation.
Valuation Methods
Different valuation methods are in use in many organisations. Each of these methods provides
different results. The decision to use one of them is dependent on the firm that is being
evaluated, the financial methods in place, and the preferred approach. The most popular
approach depends on the organisation and the region where these organisations exist. Different
methods that are used in valuation are shown below.
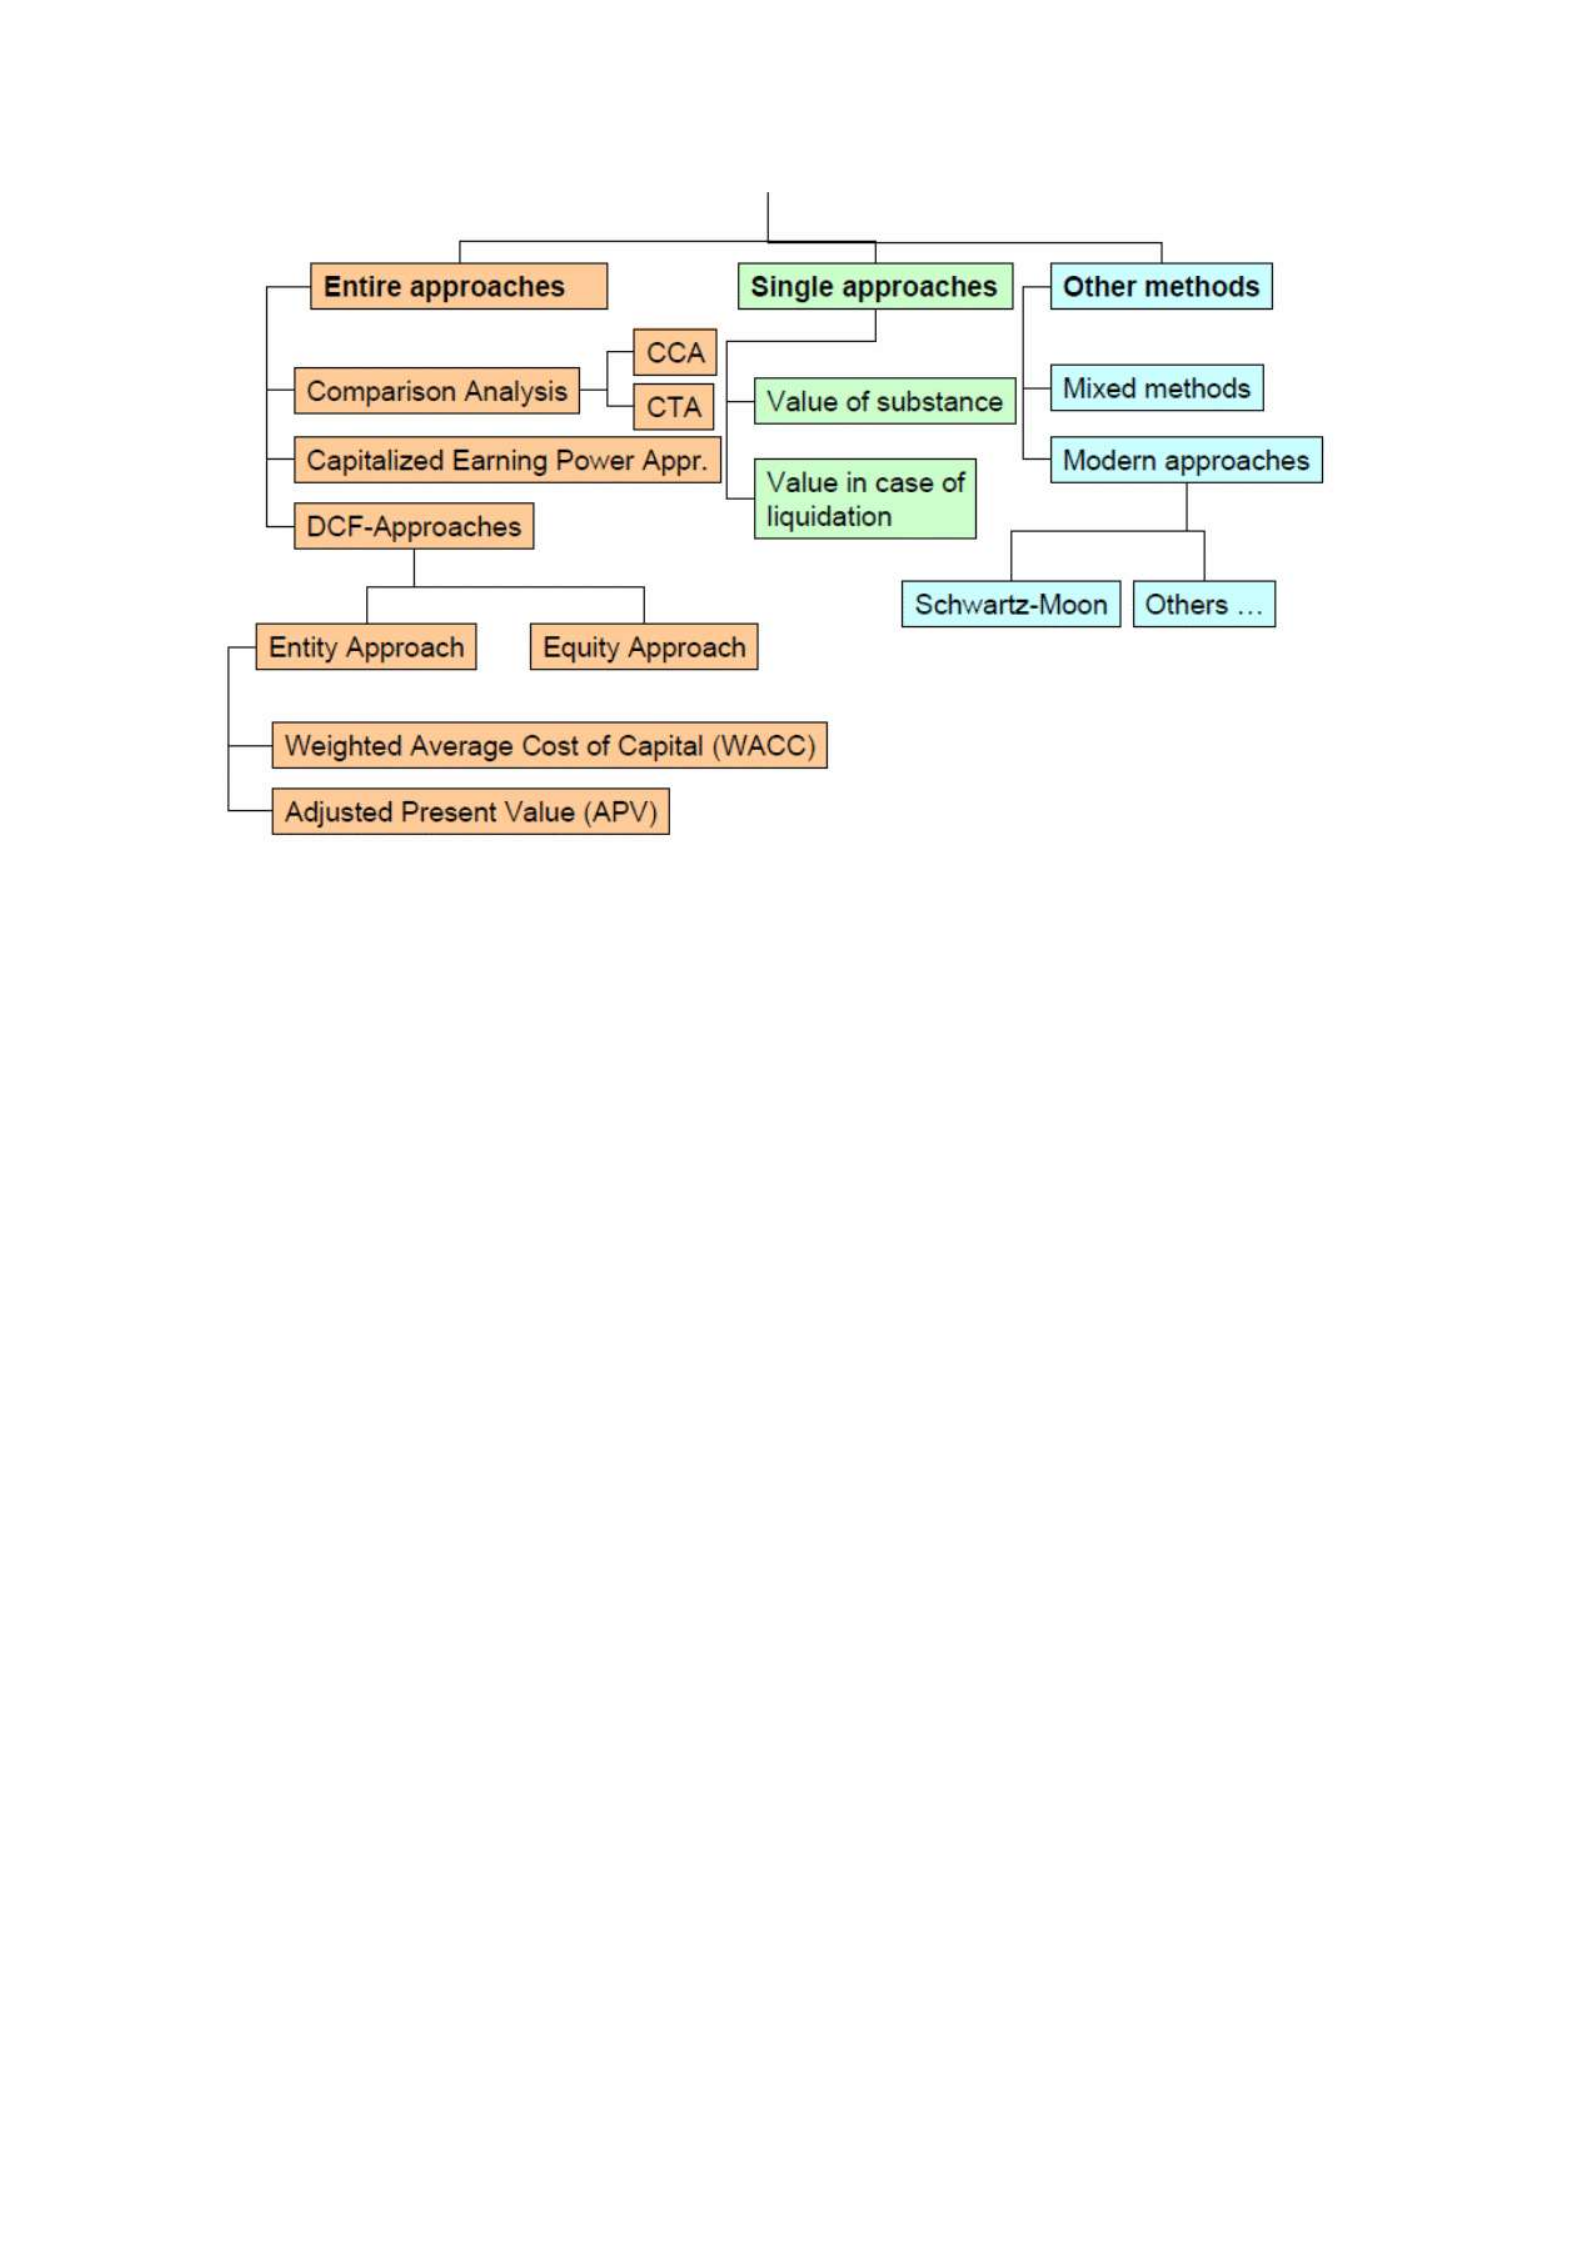
Figure 1: An Overview of Valuation Methods (Source Mian & Velez-Pareja 2007)
Different models that are applied during a valuation in organisations lead to a common result
where the organisations are able to plan for future decisions and changes. The valuation that is
obtained in organisations, irrespective of the method used, provides crucial information on the
financial status of the organisation. However, valuation within organisations also allows the
inception of changes whenever they are needed.
Financial Decisions
Organisations face challenges in financing, with one of the most common of them being the
outcomes of financial decisions. Competitiveness in organisations is influenced by the financial
decisions that managers and other stakeholders make. In any industry, financial decisions affect
the outcomes of the interactions between different factors. The financial decisions in an
organisation are also under the influence of other factors such as the valuation in these
organisations. A business in any industry or market must use capital as one of the main factors
in its operations, with this strategy bringing about the cost of capital.
Currently, there are no perfect markets in contemporary organisations. Hence, capital is not
always put to the intended use. A perfect business environment is the only place where capital
can be put to its planned use. However, conditions that are necessary for a perfect market are
hard to achieve. Nevertheless, if it were possible, the perfect world would have an excess
supply of capital. A perfect capital market might mean that the available unlimited capital is
only dependent on the risk of the project being undertaken (Spiegel, & Tookes 2013).

Aside from the perfect capital market, uncertainties, variables, and friction characterise the
existing real-world capital markets. The availability of tax as one of the variables in an
imperfect world ensures that organisations adopt strategies such as debts. An example of such
strategies is when an organisation operates in a capital structure with about 100% of debt
because of the positive corporate tax rate (Spiegel, & Tookes, 2013). Other factors that exist in
an imperfect world to introduce a relationship between valuations and financing include agency
costs, financial distress costs, and information asymmetries (Spiegel, & Tookes, 2013).
The financial position of an organisation ensures that the organisation can persist in an
environment where competition is an evident factor. Valuation effects that financial position of
an organisation. The reverse is also true. The decisions made in an organisation relating to the
financial positions of the organisation may be based on the valuation that is provided for this
organisation.
Weighted Average Cost of Capital
The calculation of the cost of capital is an intricate process that requires the participation of all
stakeholders. The cost of capital is calculated through the estimation of the proportion of debt
that a project consumes against the equity that is absorbed in the respective project (Massari,
Roncaglio & Zanetti 2008). The weighted average cost of capital (WACC) is calculated through
a formula that incorporates the market value of equity and debt (Massari, Roncaglio & Zanetti
2008). These values are adjusted using the costs of debt and equity. For a single firm, the
WACC is calculated as a single unit where the firm is the reference. The organisation, in this
case, is considered a single unit, with the results being for a single project.
The Weighted Average Cost of Capital is an indicator of the financial performance of an
organisation because it indicates the financial position of the organisation under discussion.
Any organisation with sound financial decisions has a favourable WACC, which is considered
a strength in these organisations. The calculation and use of WACC in financial discussions
and problem-solving is challenging for some financial analysts and other financial decision-
makers in organisations. Therefore, it is important to have a discussion on the correct use of
WACC and its implications on the financial decisions in organisations.
The other difficulty in the calculation and use of WACC is tax calculation. Different finance
officers use different methods of calculating the variables (Sabalı 2009). Financing and
investment decisions interact through taxes. WACC is an important concept in evaluating this

interaction. The formula that is used in the calculation of WACC refers to the organisation of
company as a whole upon incorporating the different aspects in financial decisions in the firm.
Therefore, this formula is effective for the “average project” where the right discount rate is
produced (Massari, Roncaglio & Zanetti 2008). Hence, the formula is incorrect when used in
the calculation of WACC for the safer and riskier projects (Magni 2012). The inaccuracy while
using this formula mainly stems from the different sections that individuals calculate in an
organisation, especially where the organisation has different departments.
Capital Structure and Valuations
Capital structure in a firm is a factor that affects valuations in these organisations. The effects
depend on the existing capital structure. According to Sabalı (2009), financing decisions
typically affect value within organisations. Some of the ways that boost value in a firm with
respect to its financing decisions is through the adjustment of the discount rate and the present
value (Massari, Roncaglio & Zanetti 2008).
The discount rate in most organisations is typically adjusted downwards, with the aim being to
account for the existing tax shields (Massari, Roncaglio & Zanetti 2008). Financing decisions
also affect value in organisations through adjusting the present value in these organisations
(Massari, Roncaglio & Zanetti 2008). According to Spiegel and Tookes (2013), the base case
is first calculated with the assumption that it is all equity financed.
Capital structure in organisations affects the value of the organisation from its first year of
operation. The capital structure in organisations is variable depending on several factors such
as the capital debt and the type of industry within which a firm is located. The tax on a firm is
a major factor with reference to its capital value, especially because the tax determines the debt
status of an organisation (Sabalı 2009).
The initial cash that is invested into a firm in the first year affects the value of an organisation
during this year. Most of the organisations that invest significant amounts of capital into their
operations end up being successful in the first year. Over the years that follow, the WACC
formula is highly applicable, as the organisational debts and equities change.
Capital structure in most organisations is affected by the financial decisions made by the
executive. Hence, the value of organisations is dependent on the type of managers that an
organisation keeps. The value of organisation changes with any financial decision made, since
the debt and equities change with these decisions (Massari, Roncaglio & Zanetti 2008).

The value of a firm may be calculated through the estimation of the WACC, which is later used
to discount the FCFF from the debt holders and equity capital contributors (Massari, Roncaglio
& Zanetti 2008). The use of WACC in the estimation of a firm’s value is very effective by far
compared to other methods of value estimation. This finding indicates a relationship between
the value of organisations and the WACC. The WACC is in turn related to the financial
decisions in an organisation. Hence, valuation is related to the financial decisions in the
organisation.
Impact of Tax Shields on WACC
According to Massari, Roncaglio, and Zanetti (2008), tax is a variable in an organisation that
affects the value of these organisations. Interest in organisations is one of the expenses that are
usually considered as tax-deductible expense (Massari, Roncaglio & Zanetti 2008). The
calculation of WACC incorporates tax as a major form of expense. This strategy determines
the value of organisations. However, tax shields in organisations may affect the calculation of
WACC. The effects of tax shields on WACC depend on the business and individuals who are
responsible for financial management in the respective institutions.
The tax shields cause changes on WACC in a number of ways. However, while these effects
are dependent on the type of organisation, the main effect is that the WACC increases with a
reduction in tax shields. Most organisations seek tax shields to lower their WACC and in effect
influence the value and competitiveness of their respective industries. A common result of tax
shields is a downward adjustment of the discount rate to account for any changes in this area
(Massari, Roncaglio & Zanetti 2008). The downward adjustment of discount rates in
organisations allows decisions to be made on the WACC and its overall effect on the firm’s
value.
Tax shields help organisations save their available financial resources, including the provision
of future resources. In areas where tax shields are effectively applied, firms report better results,
performance, and competitiveness compared to areas where these policies are scantily applied.
Adjusting the discount rate downwards is one of the ways that tax shields are accounted for.
The result of this case is a change on the value of firms (Massari, Roncaglio & Zanetti 2008).
The relationship between value of an organisation and tax shields may be demonstrated by the
inherent differences between organisations that operate in different regions with different tax
shield regimens. According to Massari, Roncaglio, and Zanetti (2008), adjustment of WACC
should affect the value of a firm through the effect of this move on the value of the organisation.

Therefore, managers should make sound decisions when it comes to applying for tax shields in
their area.
How Tax Shields affect Firm Value
Tax shields in an organisation affect the firm’s value in a number of ways as indicated above.
A common understanding is that tax is one of the factors that affect WACC, and in effect the
value of an organisation. The worth of any business is affected by the financing decisions in
the organisations, including the availability of tax shields. The discount rate constitutes one of
the factors that may be adjusted to accommodate changes in the value of organisations. Mintz
and Currim (2013) observe that downward adjustment of discount rate accounts for tax shields.
This downward adjustment results in the increase in value of organisations.
Organisations that use the discount rate to effect changes in their firm value often report success
in the use of the method. When an organisation is awarded tax shields, the value changes to
correspond to the changes introduced through the adjustment of the discount rates. Most
organisations can be described as having debts because of the tax shields that they intend to
acquire.
Therefore, contemporary organisations are prone to debts in their quest to attain tax shields
from the respective authorities. The differences in the contemporary organisations arise from
the different capabilities in the use of their debts. Most organisations whose debt status is high
attain significant tax exemptions. They are valued at higher rank compared to organisations
that have a lower debt position. The tax shields in an organisation, therefore, affect the firm
value in organisations.
Mistakes in Using WACC
Several mistakes are established in literature in the use of WACC. The first mistake is in the
calculation of this variable. In fact, some individuals use variables that are not commonly
applied in the formula. The computation of WACC is tedious due to the many variables that
are necessary for the calculation process. This situation makes the calculation difficult to the
extent that some individuals opt for shortcuts that may not be accurate. The other mistake is
that some individuals assume that the formula may be used in the calculation of WACC for a
particular section of the organisation. They forget that this formula considers the firm a single
unit (Mian & Velez-Pareja 2007).

WACC is useful in providing discount for businesses only where they are applied to
organisations or projects with a similar undertaking to the firm under consideration. For
organisations that differ from the firm under consideration, the formula may not be applicable
or provide useful results. WACC may be useful in most of the calculations where the firm under
consideration has the same size as that of other firms that were initially considered. For projects
that are safer or riskier compared to the original organisation, the calculated WACC may be
inaccurate and in some cases incorrect.
The other mistake that individuals make in the use of WACC is the assumption that it can be
applied as a single variable in the determination of a firm’s value. According to Mian and Velez-
Pareja (2007), organisations require the use of many variables to calculate their value. A single
variable may be deceptive depending on the industry within which the firm is located.
Therefore, there is a need to consider a number of variables in the calculation of a firm’s value
as using WACC alone may be inaccurate. Some of the other mistakes that individuals make in
the use of WACC include miscalculation of the debt and equities that are eventually used in the
calculation of this variable.
Adjusting the WACC
The adjustment of WACC may be done through a number of ways depending on the debt ratios
and the business risks (Mintz & Currim 2013). Adjusting the WACC when the risk of the firm’s
debt ratio and the business risk differ from those of the new project is important in the
calculation of a business’ WACC.
The adjustment of WACC is important when the debt ratios and business risks differ in
organisations. The differences between these two variables result from the changes that are
inherent in the organisations. The three main steps that should be followed when adjusting the
WACC include calculation of the opportunity cost, estimation of the cost of the organisations
debt, and recalculation of the WACC using the obtained new values (Mian & Velez-Pareja
2007).
The adjustment of this value allows the correct calculations where the estimated WACC is
obtained against the real WACC. In cases where the WACC is adjusted, the value of the firm’s
debts and opportunity costs are considered the main reasons for the adjustments. There are
many reasons for the adjustments, with the main one being to increase the accuracy of the final
WACC that is obtained for any given firm. WACC is an indicator of the financing side effect
in an organisation. It is a good indicator of value in organisations (Mintz & Currim 2013).

These financing side effects include the value of interest tax shields on debts (Massari,
Roncaglio & Zanetti 2008). Adjustment of the WACC is also important where the actual value
of a firm is to be estimated.
Valuation in Organisations
Valuation affects the financial decisions that are made in organisations. Most of the decisions
that are important in organisations are made only through the consideration of the value of the
organisation since most managers tend to focus on increasing this value. The many valuation
approaches that are currently in use stem from the extensive research done in this area. These
approaches affect the financing decisions in organisations. The methods of valuation affect the
final variable.
Hence, most of these methods have sub approaches within them. Discounted cash flow is
among the most popular methods that are used in the valuation. This strategy focuses on the
financing decisions in the organisation (Massari, Roncaglio & Zanetti 2008). According to
Dong, Hirshleifer, and Teoh (2012), the main ways of estimating the discounted cash flow
include discounting the cash flow at a risk-adjusted discount (Sabalı 2009). This formula is one
of the four main methods that are used in the discounting cash flows. Using these methods
produces significant results.
Although different methods are in use in the valuation of companies, the same results may be
achieved if the assumptions are withheld for each of the methods. The similarity of these
methods ensures that the result is compatible with the businesses for which it was attempted
first. The different proponents for the different approaches in the valuation methods assume
that their methods are the most accurate. The results indicate that these methods are closely
similar. In relative valuation, which is considered one of the most important valuation methods,
the researchers who proposed the method adopted the assumption of individual assets.
However, these methods have similar results when the different assumptions are withheld.
Conclusion
In conclusion, based on the detailed expositions that have been made in the paper, it is clear
that valuation and financing are closely related when consideration for the financial state of an
organisation is made. Valuation may be estimated in organisations using several methods. Some
of these methods have been stated in this essay. The existence of valuation in financial decisions
allows the organisations to make decisions that coincide with their immediate needs.

The paper has proposed that a relationship between valuation and financial decisions in
organisations. This relationship is affected by other factors such as taxation. The WACC is an
important factor to consider when deducing the relationship between valuation and financial
decisions. The available research proves that this concept is applicable in an organisation’s
financial decisions. The essay has looked at the relationship between WACC and valuation in
organisations and the relationship that exists between these two variables and financial
decisions in an organisation. The paper has proved a positive relationship between these
concepts.
Valuation
The valuation of any organisation allows future decision-making to ensure that it is operating
as per the expectations. Different methods are used in valuation, including those that are
supported by theories and contemporary methods. The present models that are deployed in the
evaluation process are a product of extensive research, with many researchers describing them
before their application in management and finance. What are the motives of company
valuation? Different schools of thought exist as to why company valuation is important.
One of the motives for the evaluations of a company is to make decisions in the organisation.
Depending on the decision that is reached after valuation, the involved individuals may decide
on the future of the organisation and the interventions for the areas that are found faulty.
Motives in company valuation may be characterised in different ways, including decision-
dependent and decision-independent motives (Ishakian, Knebusch & Rowen 2013). The other
category of motives is the transaction based vs the non-transaction-based motives (Ishakian,
Knebusch & Rowen 2013). The other class of motives, as described throughout the literature
on valuation, is the dominated vs the non-dominated decision (Ishakian, Knebusch & Rowen
2013).
Valuation serves different functions depending on the concerned firm or organisation. These
functions can be categorised further into minor and major functions. The main functions of
valuation in organisations include decision-making and consultation. According to Ishakian,
Knebusch, and Rowen (2013), managers and other stakeholders use valuation information in
an organisation to make decisions on the future of the organisation with the aim of improving
the organisational performance. Different firms operate on different grounds. They use
different methods of valuation to make financial and other forms of decisions in the
organisation.

The other function of valuation, according to Koziol (2014), is mediation where the firm uses
information from valuation to mediate between concepts, decisions, and individuals.
Hundsdoerfer, Kruschwitz, and Loren (2008) assert that mediation in an organisation provides
crucial information on the financial position of the organisation. Valuation also serves as a
means of argumentation. Using information from valuation, managers and other organisational
stakeholders can argue on the position of the organisation. The information is used to provide
details on the organisational performance, which is important in making a case for any
argument.
Apart from the main functions of valuation, valuation serves other auxiliary functions. One of
these auxiliary functions is information where the parties within an organisation gather
information on this organisation, including its performance and future expectations. Valuation
may also be used as a means of tax measurement where authorities determine the tax that an
organisation should forward over a given period. Many organisations where valuation has been
conducted were found to have some tax measurements, not in line with the expected values
(Mian & Velez-Pareja 2007). Valuation also serves the function of contract configuration where
employees and other parties in the organisation can have their contracts configured with the
expectations of the organisation.
Valuation Methods
Different valuation methods are in use in many organisations. Each of these methods provides
different results. The decision to use one of them is dependent on the firm that is being
evaluated, the financial methods in place, and the preferred approach. The most popular
approach depends on the organisation and the region where these organisations exist. Different
methods that are used in valuation are shown below.
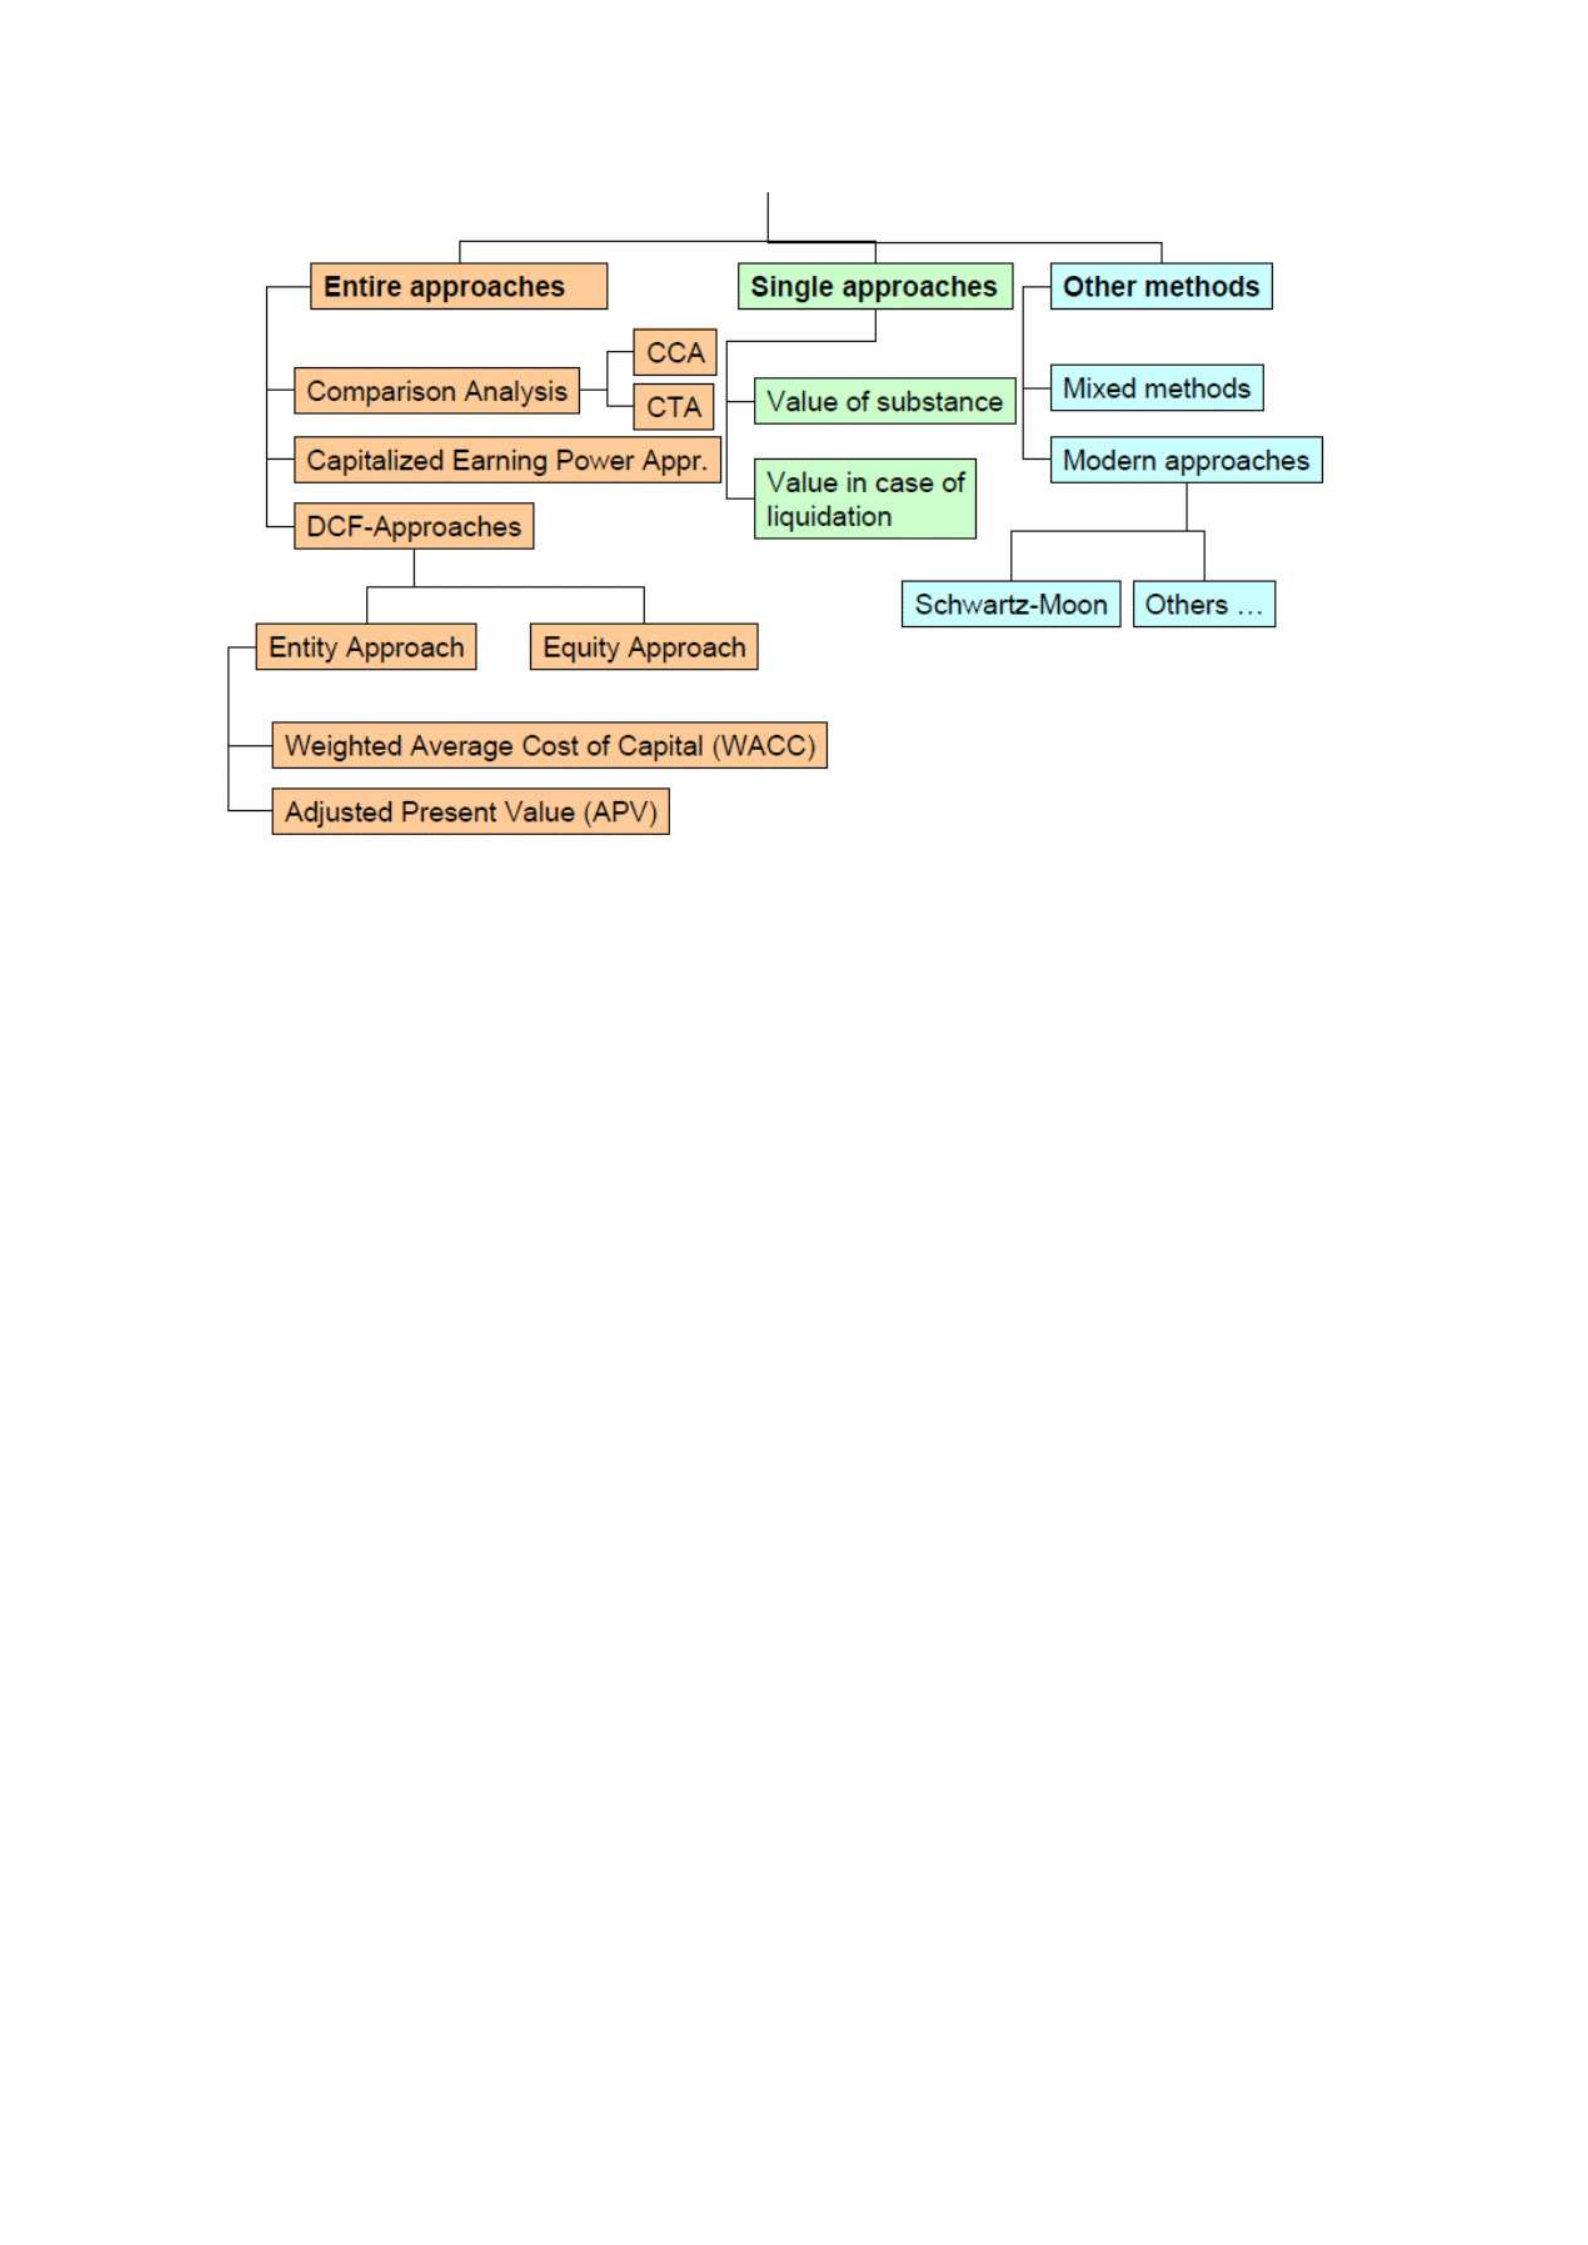
Figure 1: An Overview of Valuation Methods (Source Mian & Velez-Pareja 2007)
Different models that are applied during a valuation in organisations lead to a common result
where the organisations are able to plan for future decisions and changes. The valuation that is
obtained in organisations, irrespective of the method used, provides crucial information on the
financial status of the organisation. However, valuation within organisations also allows the
inception of changes whenever they are needed.
Financial Decisions
Organisations face challenges in financing, with one of the most common of them being the
outcomes of financial decisions. Competitiveness in organisations is influenced by the financial
decisions that managers and other stakeholders make. In any industry, financial decisions affect
the outcomes of the interactions between different factors. The financial decisions in an
organisation are also under the influence of other factors such as the valuation in these
organisations. A business in any industry or market must use capital as one of the main factors
in its operations, with this strategy bringing about the cost of capital.
Currently, there are no perfect markets in contemporary organisations. Hence, capital is not
always put to the intended use. A perfect business environment is the only place where capital
can be put to its planned use. However, conditions that are necessary for a perfect market are
hard to achieve. Nevertheless, if it were possible, the perfect world would have an excess
supply of capital. A perfect capital market might mean that the available unlimited capital is
only dependent on the risk of the project being undertaken (Spiegel, & Tookes 2013).

Aside from the perfect capital market, uncertainties, variables, and friction characterise the
existing real-world capital markets. The availability of tax as one of the variables in an
imperfect world ensures that organisations adopt strategies such as debts. An example of such
strategies is when an organisation operates in a capital structure with about 100% of debt
because of the positive corporate tax rate (Spiegel, & Tookes, 2013). Other factors that exist in
an imperfect world to introduce a relationship between valuations and financing include agency
costs, financial distress costs, and information asymmetries (Spiegel, & Tookes, 2013).
The financial position of an organisation ensures that the organisation can persist in an
environment where competition is an evident factor. Valuation effects that financial position of
an organisation. The reverse is also true. The decisions made in an organisation relating to the
financial positions of the organisation may be based on the valuation that is provided for this
organisation.
Weighted Average Cost of Capital
The calculation of the cost of capital is an intricate process that requires the participation of all
stakeholders. The cost of capital is calculated through the estimation of the proportion of debt
that a project consumes against the equity that is absorbed in the respective project (Massari,
Roncaglio & Zanetti 2008). The weighted average cost of capital (WACC) is calculated through
a formula that incorporates the market value of equity and debt (Massari, Roncaglio & Zanetti
2008). These values are adjusted using the costs of debt and equity. For a single firm, the
WACC is calculated as a single unit where the firm is the reference. The organisation, in this
case, is considered a single unit, with the results being for a single project.
The Weighted Average Cost of Capital is an indicator of the financial performance of an
organisation because it indicates the financial position of the organisation under discussion.
Any organisation with sound financial decisions has a favourable WACC, which is considered
a strength in these organisations. The calculation and use of WACC in financial discussions
and problem-solving is challenging for some financial analysts and other financial decision-
makers in organisations. Therefore, it is important to have a discussion on the correct use of
WACC and its implications on the financial decisions in organisations.
The other difficulty in the calculation and use of WACC is tax calculation. Different finance
officers use different methods of calculating the variables (Sabalı 2009). Financing and
investment decisions interact through taxes. WACC is an important concept in evaluating this

interaction. The formula that is used in the calculation of WACC refers to the organisation of
company as a whole upon incorporating the different aspects in financial decisions in the firm.
Therefore, this formula is effective for the “average project” where the right discount rate is
produced (Massari, Roncaglio & Zanetti 2008). Hence, the formula is incorrect when used in
the calculation of WACC for the safer and riskier projects (Magni 2012). The inaccuracy while
using this formula mainly stems from the different sections that individuals calculate in an
organisation, especially where the organisation has different departments.
Capital Structure and Valuations
Capital structure in a firm is a factor that affects valuations in these organisations. The effects
depend on the existing capital structure. According to Sabalı (2009), financing decisions
typically affect value within organisations. Some of the ways that boost value in a firm with
respect to its financing decisions is through the adjustment of the discount rate and the present
value (Massari, Roncaglio & Zanetti 2008).
The discount rate in most organisations is typically adjusted downwards, with the aim being to
account for the existing tax shields (Massari, Roncaglio & Zanetti 2008). Financing decisions
also affect value in organisations through adjusting the present value in these organisations
(Massari, Roncaglio & Zanetti 2008). According to Spiegel and Tookes (2013), the base case
is first calculated with the assumption that it is all equity financed.
Capital structure in organisations affects the value of the organisation from its first year of
operation. The capital structure in organisations is variable depending on several factors such
as the capital debt and the type of industry within which a firm is located. The tax on a firm is
a major factor with reference to its capital value, especially because the tax determines the debt
status of an organisation (Sabalı 2009).
The initial cash that is invested into a firm in the first year affects the value of an organisation
during this year. Most of the organisations that invest significant amounts of capital into their
operations end up being successful in the first year. Over the years that follow, the WACC
formula is highly applicable, as the organisational debts and equities change.
Capital structure in most organisations is affected by the financial decisions made by the
executive. Hence, the value of organisations is dependent on the type of managers that an
organisation keeps. The value of organisation changes with any financial decision made, since
the debt and equities change with these decisions (Massari, Roncaglio & Zanetti 2008).

The value of a firm may be calculated through the estimation of the WACC, which is later used
to discount the FCFF from the debt holders and equity capital contributors (Massari, Roncaglio
& Zanetti 2008). The use of WACC in the estimation of a firm’s value is very effective by far
compared to other methods of value estimation. This finding indicates a relationship between
the value of organisations and the WACC. The WACC is in turn related to the financial
decisions in an organisation. Hence, valuation is related to the financial decisions in the
organisation.
Impact of Tax Shields on WACC
According to Massari, Roncaglio, and Zanetti (2008), tax is a variable in an organisation that
affects the value of these organisations. Interest in organisations is one of the expenses that are
usually considered as tax-deductible expense (Massari, Roncaglio & Zanetti 2008). The
calculation of WACC incorporates tax as a major form of expense. This strategy determines
the value of organisations. However, tax shields in organisations may affect the calculation of
WACC. The effects of tax shields on WACC depend on the business and individuals who are
responsible for financial management in the respective institutions.
The tax shields cause changes on WACC in a number of ways. However, while these effects
are dependent on the type of organisation, the main effect is that the WACC increases with a
reduction in tax shields. Most organisations seek tax shields to lower their WACC and in effect
influence the value and competitiveness of their respective industries. A common result of tax
shields is a downward adjustment of the discount rate to account for any changes in this area
(Massari, Roncaglio & Zanetti 2008). The downward adjustment of discount rates in
organisations allows decisions to be made on the WACC and its overall effect on the firm’s
value.
Tax shields help organisations save their available financial resources, including the provision
of future resources. In areas where tax shields are effectively applied, firms report better results,
performance, and competitiveness compared to areas where these policies are scantily applied.
Adjusting the discount rate downwards is one of the ways that tax shields are accounted for.
The result of this case is a change on the value of firms (Massari, Roncaglio & Zanetti 2008).
The relationship between value of an organisation and tax shields may be demonstrated by the
inherent differences between organisations that operate in different regions with different tax
shield regimens. According to Massari, Roncaglio, and Zanetti (2008), adjustment of WACC
should affect the value of a firm through the effect of this move on the value of the organisation.

Therefore, managers should make sound decisions when it comes to applying for tax shields in
their area.
How Tax Shields affect Firm Value
Tax shields in an organisation affect the firm’s value in a number of ways as indicated above.
A common understanding is that tax is one of the factors that affect WACC, and in effect the
value of an organisation. The worth of any business is affected by the financing decisions in
the organisations, including the availability of tax shields. The discount rate constitutes one of
the factors that may be adjusted to accommodate changes in the value of organisations. Mintz
and Currim (2013) observe that downward adjustment of discount rate accounts for tax shields.
This downward adjustment results in the increase in value of organisations.
Organisations that use the discount rate to effect changes in their firm value often report success
in the use of the method. When an organisation is awarded tax shields, the value changes to
correspond to the changes introduced through the adjustment of the discount rates. Most
organisations can be described as having debts because of the tax shields that they intend to
acquire.
Therefore, contemporary organisations are prone to debts in their quest to attain tax shields
from the respective authorities. The differences in the contemporary organisations arise from
the different capabilities in the use of their debts. Most organisations whose debt status is high
attain significant tax exemptions. They are valued at higher rank compared to organisations
that have a lower debt position. The tax shields in an organisation, therefore, affect the firm
value in organisations.
Mistakes in Using WACC
Several mistakes are established in literature in the use of WACC. The first mistake is in the
calculation of this variable. In fact, some individuals use variables that are not commonly
applied in the formula. The computation of WACC is tedious due to the many variables that
are necessary for the calculation process. This situation makes the calculation difficult to the
extent that some individuals opt for shortcuts that may not be accurate. The other mistake is
that some individuals assume that the formula may be used in the calculation of WACC for a
particular section of the organisation. They forget that this formula considers the firm a single
unit (Mian & Velez-Pareja 2007).

WACC is useful in providing discount for businesses only where they are applied to
organisations or projects with a similar undertaking to the firm under consideration. For
organisations that differ from the firm under consideration, the formula may not be applicable
or provide useful results. WACC may be useful in most of the calculations where the firm under
consideration has the same size as that of other firms that were initially considered. For projects
that are safer or riskier compared to the original organisation, the calculated WACC may be
inaccurate and in some cases incorrect.
The other mistake that individuals make in the use of WACC is the assumption that it can be
applied as a single variable in the determination of a firm’s value. According to Mian and Velez-
Pareja (2007), organisations require the use of many variables to calculate their value. A single
variable may be deceptive depending on the industry within which the firm is located.
Therefore, there is a need to consider a number of variables in the calculation of a firm’s value
as using WACC alone may be inaccurate. Some of the other mistakes that individuals make in
the use of WACC include miscalculation of the debt and equities that are eventually used in the
calculation of this variable.
Adjusting the WACC
The adjustment of WACC may be done through a number of ways depending on the debt ratios
and the business risks (Mintz & Currim 2013). Adjusting the WACC when the risk of the firm’s
debt ratio and the business risk differ from those of the new project is important in the
calculation of a business’ WACC.
The adjustment of WACC is important when the debt ratios and business risks differ in
organisations. The differences between these two variables result from the changes that are
inherent in the organisations. The three main steps that should be followed when adjusting the
WACC include calculation of the opportunity cost, estimation of the cost of the organisations
debt, and recalculation of the WACC using the obtained new values (Mian & Velez-Pareja
2007).
The adjustment of this value allows the correct calculations where the estimated WACC is
obtained against the real WACC. In cases where the WACC is adjusted, the value of the firm’s
debts and opportunity costs are considered the main reasons for the adjustments. There are
many reasons for the adjustments, with the main one being to increase the accuracy of the final
WACC that is obtained for any given firm. WACC is an indicator of the financing side effect
in an organisation. It is a good indicator of value in organisations (Mintz & Currim 2013).

These financing side effects include the value of interest tax shields on debts (Massari,
Roncaglio & Zanetti 2008). Adjustment of the WACC is also important where the actual value
of a firm is to be estimated.
Valuation in Organisations
Valuation affects the financial decisions that are made in organisations. Most of the decisions
that are important in organisations are made only through the consideration of the value of the
organisation since most managers tend to focus on increasing this value. The many valuation
approaches that are currently in use stem from the extensive research done in this area. These
approaches affect the financing decisions in organisations. The methods of valuation affect the
final variable.
Hence, most of these methods have sub approaches within them. Discounted cash flow is
among the most popular methods that are used in the valuation. This strategy focuses on the
financing decisions in the organisation (Massari, Roncaglio & Zanetti 2008). According to
Dong, Hirshleifer, and Teoh (2012), the main ways of estimating the discounted cash flow
include discounting the cash flow at a risk-adjusted discount (Sabalı 2009). This formula is one
of the four main methods that are used in the discounting cash flows. Using these methods
produces significant results.
Although different methods are in use in the valuation of companies, the same results may be
achieved if the assumptions are withheld for each of the methods. The similarity of these
methods ensures that the result is compatible with the businesses for which it was attempted
first. The different proponents for the different approaches in the valuation methods assume
that their methods are the most accurate. The results indicate that these methods are closely
similar. In relative valuation, which is considered one of the most important valuation methods,
the researchers who proposed the method adopted the assumption of individual assets.
However, these methods have similar results when the different assumptions are withheld.
Conclusion
In conclusion, based on the detailed expositions that have been made in the paper, it is clear
that valuation and financing are closely related when consideration for the financial state of an
organisation is made. Valuation may be estimated in organisations using several methods. Some
of these methods have been stated in this essay. The existence of valuation in financial decisions
allows the organisations to make decisions that coincide with their immediate needs.

The paper has proposed that a relationship between valuation and financial decisions in
organisations. This relationship is affected by other factors such as taxation. The WACC is an
important factor to consider when deducing the relationship between valuation and financial
decisions. The available research proves that this concept is applicable in an organisation’s
financial decisions. The essay has looked at the relationship between WACC and valuation in
organisations and the relationship that exists between these two variables and financial
decisions in an organisation. The paper has proved a positive relationship between these
concepts.
Valuation
The valuation of any organisation allows future decision-making to ensure that it is operating
as per the expectations. Different methods are used in valuation, including those that are
supported by theories and contemporary methods. The present models that are deployed in the
evaluation process are a product of extensive research, with many researchers describing them
before their application in management and finance. What are the motives of company
valuation? Different schools of thought exist as to why company valuation is important.
One of the motives for the evaluations of a company is to make decisions in the organisation.
Depending on the decision that is reached after valuation, the involved individuals may decide
on the future of the organisation and the interventions for the areas that are found faulty.
Motives in company valuation may be characterised in different ways, including decision-
dependent and decision-independent motives (Ishakian, Knebusch & Rowen 2013). The other
category of motives is the transaction based vs the non-transaction-based motives (Ishakian,
Knebusch & Rowen 2013). The other class of motives, as described throughout the literature
on valuation, is the dominated vs the non-dominated decision (Ishakian, Knebusch & Rowen
2013).
Valuation serves different functions depending on the concerned firm or organisation. These
functions can be categorised further into minor and major functions. The main functions of
valuation in organisations include decision-making and consultation. According to Ishakian,
Knebusch, and Rowen (2013), managers and other stakeholders use valuation information in
an organisation to make decisions on the future of the organisation with the aim of improving
the organisational performance. Different firms operate on different grounds. They use
different methods of valuation to make financial and other forms of decisions in the
organisation.

The other function of valuation, according to Koziol (2014), is mediation where the firm uses
information from valuation to mediate between concepts, decisions, and individuals.
Hundsdoerfer, Kruschwitz, and Loren (2008) assert that mediation in an organisation provides
crucial information on the financial position of the organisation. Valuation also serves as a
means of argumentation. Using information from valuation, managers and other organisational
stakeholders can argue on the position of the organisation. The information is used to provide
details on the organisational performance, which is important in making a case for any
argument.
Apart from the main functions of valuation, valuation serves other auxiliary functions. One of
these auxiliary functions is information where the parties within an organisation gather
information on this organisation, including its performance and future expectations. Valuation
may also be used as a means of tax measurement where authorities determine the tax that an
organisation should forward over a given period. Many organisations where valuation has been
conducted were found to have some tax measurements, not in line with the expected values
(Mian & Velez-Pareja 2007). Valuation also serves the function of contract configuration where
employees and other parties in the organisation can have their contracts configured with the
expectations of the organisation.
Valuation Methods
Different valuation methods are in use in many organisations. Each of these methods provides
different results. The decision to use one of them is dependent on the firm that is being
evaluated, the financial methods in place, and the preferred approach. The most popular
approach depends on the organisation and the region where these organisations exist. Different
methods that are used in valuation are shown below.
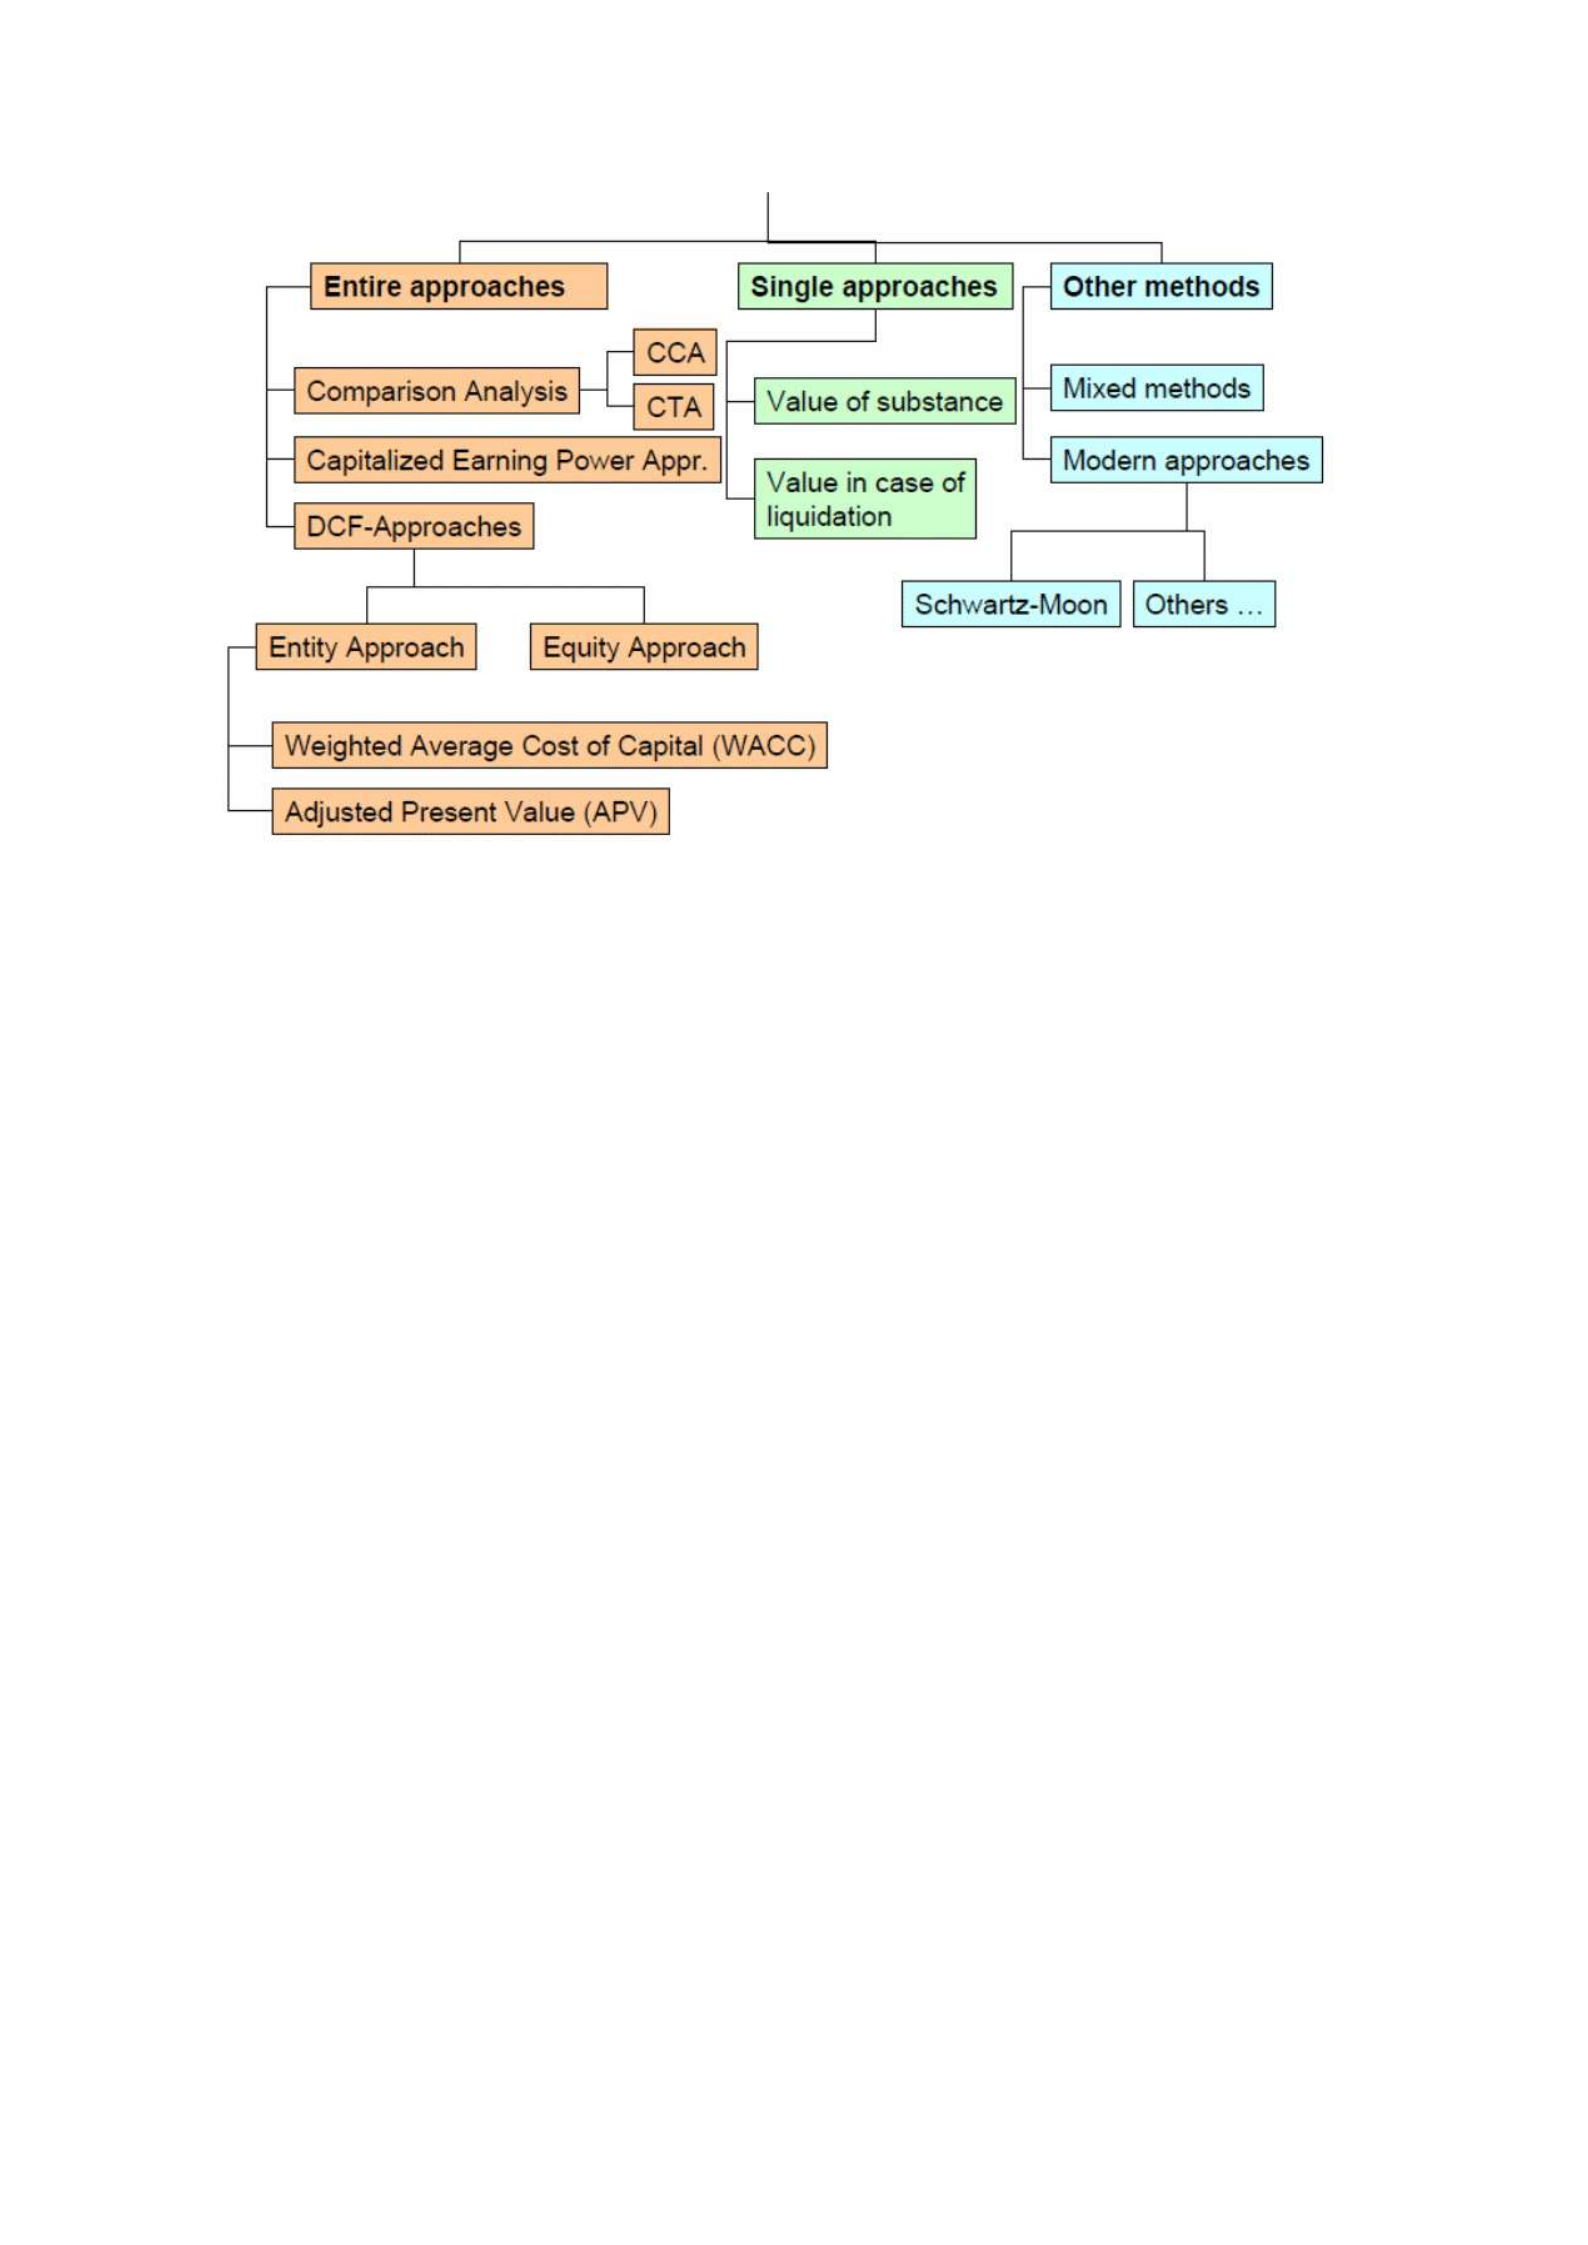
Figure 1: An Overview of Valuation Methods (Source Mian & Velez-Pareja 2007)
Different models that are applied during a valuation in organisations lead to a common result
where the organisations are able to plan for future decisions and changes. The valuation that is
obtained in organisations, irrespective of the method used, provides crucial information on the
financial status of the organisation. However, valuation within organisations also allows the
inception of changes whenever they are needed.
Financial Decisions
Organisations face challenges in financing, with one of the most common of them being the
outcomes of financial decisions. Competitiveness in organisations is influenced by the financial
decisions that managers and other stakeholders make. In any industry, financial decisions affect
the outcomes of the interactions between different factors. The financial decisions in an
organisation are also under the influence of other factors such as the valuation in these
organisations. A business in any industry or market must use capital as one of the main factors
in its operations, with this strategy bringing about the cost of capital.
Currently, there are no perfect markets in contemporary organisations. Hence, capital is not
always put to the intended use. A perfect business environment is the only place where capital
can be put to its planned use. However, conditions that are necessary for a perfect market are
hard to achieve. Nevertheless, if it were possible, the perfect world would have an excess
supply of capital. A perfect capital market might mean that the available unlimited capital is
only dependent on the risk of the project being undertaken (Spiegel, & Tookes 2013).

Aside from the perfect capital market, uncertainties, variables, and friction characterise the
existing real-world capital markets. The availability of tax as one of the variables in an
imperfect world ensures that organisations adopt strategies such as debts. An example of such
strategies is when an organisation operates in a capital structure with about 100% of debt
because of the positive corporate tax rate (Spiegel, & Tookes, 2013). Other factors that exist in
an imperfect world to introduce a relationship between valuations and financing include agency
costs, financial distress costs, and information asymmetries (Spiegel, & Tookes, 2013).
The financial position of an organisation ensures that the organisation can persist in an
environment where competition is an evident factor. Valuation effects that financial position of
an organisation. The reverse is also true. The decisions made in an organisation relating to the
financial positions of the organisation may be based on the valuation that is provided for this
organisation.
Weighted Average Cost of Capital
The calculation of the cost of capital is an intricate process that requires the participation of all
stakeholders. The cost of capital is calculated through the estimation of the proportion of debt
that a project consumes against the equity that is absorbed in the respective project (Massari,
Roncaglio & Zanetti 2008). The weighted average cost of capital (WACC) is calculated through
a formula that incorporates the market value of equity and debt (Massari, Roncaglio & Zanetti
2008). These values are adjusted using the costs of debt and equity. For a single firm, the
WACC is calculated as a single unit where the firm is the reference. The organisation, in this
case, is considered a single unit, with the results being for a single project.
The Weighted Average Cost of Capital is an indicator of the financial performance of an
organisation because it indicates the financial position of the organisation under discussion.
Any organisation with sound financial decisions has a favourable WACC, which is considered
a strength in these organisations. The calculation and use of WACC in financial discussions
and problem-solving is challenging for some financial analysts and other financial decision-
makers in organisations. Therefore, it is important to have a discussion on the correct use of
WACC and its implications on the financial decisions in organisations.
The other difficulty in the calculation and use of WACC is tax calculation. Different finance
officers use different methods of calculating the variables (Sabalı 2009). Financing and
investment decisions interact through taxes. WACC is an important concept in evaluating this

interaction. The formula that is used in the calculation of WACC refers to the organisation of
company as a whole upon incorporating the different aspects in financial decisions in the firm.
Therefore, this formula is effective for the “average project” where the right discount rate is
produced (Massari, Roncaglio & Zanetti 2008). Hence, the formula is incorrect when used in
the calculation of WACC for the safer and riskier projects (Magni 2012). The inaccuracy while
using this formula mainly stems from the different sections that individuals calculate in an
organisation, especially where the organisation has different departments.
Capital Structure and Valuations
Capital structure in a firm is a factor that affects valuations in these organisations. The effects
depend on the existing capital structure. According to Sabalı (2009), financing decisions
typically affect value within organisations. Some of the ways that boost value in a firm with
respect to its financing decisions is through the adjustment of the discount rate and the present
value (Massari, Roncaglio & Zanetti 2008).
The discount rate in most organisations is typically adjusted downwards, with the aim being to
account for the existing tax shields (Massari, Roncaglio & Zanetti 2008). Financing decisions
also affect value in organisations through adjusting the present value in these organisations
(Massari, Roncaglio & Zanetti 2008). According to Spiegel and Tookes (2013), the base case
is first calculated with the assumption that it is all equity financed.
Capital structure in organisations affects the value of the organisation from its first year of
operation. The capital structure in organisations is variable depending on several factors such
as the capital debt and the type of industry within which a firm is located. The tax on a firm is
a major factor with reference to its capital value, especially because the tax determines the debt
status of an organisation (Sabalı 2009).
The initial cash that is invested into a firm in the first year affects the value of an organisation
during this year. Most of the organisations that invest significant amounts of capital into their
operations end up being successful in the first year. Over the years that follow, the WACC
formula is highly applicable, as the organisational debts and equities change.
Capital structure in most organisations is affected by the financial decisions made by the
executive. Hence, the value of organisations is dependent on the type of managers that an
organisation keeps. The value of organisation changes with any financial decision made, since
the debt and equities change with these decisions (Massari, Roncaglio & Zanetti 2008).

The value of a firm may be calculated through the estimation of the WACC, which is later used
to discount the FCFF from the debt holders and equity capital contributors (Massari, Roncaglio
& Zanetti 2008). The use of WACC in the estimation of a firm’s value is very effective by far
compared to other methods of value estimation. This finding indicates a relationship between
the value of organisations and the WACC. The WACC is in turn related to the financial
decisions in an organisation. Hence, valuation is related to the financial decisions in the
organisation.
Impact of Tax Shields on WACC
According to Massari, Roncaglio, and Zanetti (2008), tax is a variable in an organisation that
affects the value of these organisations. Interest in organisations is one of the expenses that are
usually considered as tax-deductible expense (Massari, Roncaglio & Zanetti 2008). The
calculation of WACC incorporates tax as a major form of expense. This strategy determines
the value of organisations. However, tax shields in organisations may affect the calculation of
WACC. The effects of tax shields on WACC depend on the business and individuals who are
responsible for financial management in the respective institutions.
The tax shields cause changes on WACC in a number of ways. However, while these effects
are dependent on the type of organisation, the main effect is that the WACC increases with a
reduction in tax shields. Most organisations seek tax shields to lower their WACC and in effect
influence the value and competitiveness of their respective industries. A common result of tax
shields is a downward adjustment of the discount rate to account for any changes in this area
(Massari, Roncaglio & Zanetti 2008). The downward adjustment of discount rates in
organisations allows decisions to be made on the WACC and its overall effect on the firm’s
value.
Tax shields help organisations save their available financial resources, including the provision
of future resources. In areas where tax shields are effectively applied, firms report better results,
performance, and competitiveness compared to areas where these policies are scantily applied.
Adjusting the discount rate downwards is one of the ways that tax shields are accounted for.
The result of this case is a change on the value of firms (Massari, Roncaglio & Zanetti 2008).
The relationship between value of an organisation and tax shields may be demonstrated by the
inherent differences between organisations that operate in different regions with different tax
shield regimens. According to Massari, Roncaglio, and Zanetti (2008), adjustment of WACC
should affect the value of a firm through the effect of this move on the value of the organisation.

Therefore, managers should make sound decisions when it comes to applying for tax shields in
their area.
How Tax Shields affect Firm Value
Tax shields in an organisation affect the firm’s value in a number of ways as indicated above.
A common understanding is that tax is one of the factors that affect WACC, and in effect the
value of an organisation. The worth of any business is affected by the financing decisions in
the organisations, including the availability of tax shields. The discount rate constitutes one of
the factors that may be adjusted to accommodate changes in the value of organisations. Mintz
and Currim (2013) observe that downward adjustment of discount rate accounts for tax shields.
This downward adjustment results in the increase in value of organisations.
Organisations that use the discount rate to effect changes in their firm value often report success
in the use of the method. When an organisation is awarded tax shields, the value changes to
correspond to the changes introduced through the adjustment of the discount rates. Most
organisations can be described as having debts because of the tax shields that they intend to
acquire.
Therefore, contemporary organisations are prone to debts in their quest to attain tax shields
from the respective authorities. The differences in the contemporary organisations arise from
the different capabilities in the use of their debts. Most organisations whose debt status is high
attain significant tax exemptions. They are valued at higher rank compared to organisations
that have a lower debt position. The tax shields in an organisation, therefore, affect the firm
value in organisations.
Mistakes in Using WACC
Several mistakes are established in literature in the use of WACC. The first mistake is in the
calculation of this variable. In fact, some individuals use variables that are not commonly
applied in the formula. The computation of WACC is tedious due to the many variables that
are necessary for the calculation process. This situation makes the calculation difficult to the
extent that some individuals opt for shortcuts that may not be accurate. The other mistake is
that some individuals assume that the formula may be used in the calculation of WACC for a
particular section of the organisation. They forget that this formula considers the firm a single
unit (Mian & Velez-Pareja 2007).

WACC is useful in providing discount for businesses only where they are applied to
organisations or projects with a similar undertaking to the firm under consideration. For
organisations that differ from the firm under consideration, the formula may not be applicable
or provide useful results. WACC may be useful in most of the calculations where the firm under
consideration has the same size as that of other firms that were initially considered. For projects
that are safer or riskier compared to the original organisation, the calculated WACC may be
inaccurate and in some cases incorrect.
The other mistake that individuals make in the use of WACC is the assumption that it can be
applied as a single variable in the determination of a firm’s value. According to Mian and Velez-
Pareja (2007), organisations require the use of many variables to calculate their value. A single
variable may be deceptive depending on the industry within which the firm is located.
Therefore, there is a need to consider a number of variables in the calculation of a firm’s value
as using WACC alone may be inaccurate. Some of the other mistakes that individuals make in
the use of WACC include miscalculation of the debt and equities that are eventually used in the
calculation of this variable.
Adjusting the WACC
The adjustment of WACC may be done through a number of ways depending on the debt ratios
and the business risks (Mintz & Currim 2013). Adjusting the WACC when the risk of the firm’s
debt ratio and the business risk differ from those of the new project is important in the
calculation of a business’ WACC.
The adjustment of WACC is important when the debt ratios and business risks differ in
organisations. The differences between these two variables result from the changes that are
inherent in the organisations. The three main steps that should be followed when adjusting the
WACC include calculation of the opportunity cost, estimation of the cost of the organisations
debt, and recalculation of the WACC using the obtained new values (Mian & Velez-Pareja
2007).
The adjustment of this value allows the correct calculations where the estimated WACC is
obtained against the real WACC. In cases where the WACC is adjusted, the value of the firm’s
debts and opportunity costs are considered the main reasons for the adjustments. There are
many reasons for the adjustments, with the main one being to increase the accuracy of the final
WACC that is obtained for any given firm. WACC is an indicator of the financing side effect
in an organisation. It is a good indicator of value in organisations (Mintz & Currim 2013).

These financing side effects include the value of interest tax shields on debts (Massari,
Roncaglio & Zanetti 2008). Adjustment of the WACC is also important where the actual value
of a firm is to be estimated.
Valuation in Organisations
Valuation affects the financial decisions that are made in organisations. Most of the decisions
that are important in organisations are made only through the consideration of the value of the
organisation since most managers tend to focus on increasing this value. The many valuation
approaches that are currently in use stem from the extensive research done in this area. These
approaches affect the financing decisions in organisations. The methods of valuation affect the
final variable.
Hence, most of these methods have sub approaches within them. Discounted cash flow is
among the most popular methods that are used in the valuation. This strategy focuses on the
financing decisions in the organisation (Massari, Roncaglio & Zanetti 2008). According to
Dong, Hirshleifer, and Teoh (2012), the main ways of estimating the discounted cash flow
include discounting the cash flow at a risk-adjusted discount (Sabalı 2009). This formula is one
of the four main methods that are used in the discounting cash flows. Using these methods
produces significant results.
Although different methods are in use in the valuation of companies, the same results may be
achieved if the assumptions are withheld for each of the methods. The similarity of these
methods ensures that the result is compatible with the businesses for which it was attempted
first. The different proponents for the different approaches in the valuation methods assume
that their methods are the most accurate. The results indicate that these methods are closely
similar. In relative valuation, which is considered one of the most important valuation methods,
the researchers who proposed the method adopted the assumption of individual assets.
However, these methods have similar results when the different assumptions are withheld.
Conclusion
In conclusion, based on the detailed expositions that have been made in the paper, it is clear
that valuation and financing are closely related when consideration for the financial state of an
organisation is made. Valuation may be estimated in organisations using several methods. Some
of these methods have been stated in this essay. The existence of valuation in financial decisions
allows the organisations to make decisions that coincide with their immediate needs.

The paper has proposed that a relationship between valuation and financial decisions in
organisations. This relationship is affected by other factors such as taxation. The WACC is an
important factor to consider when deducing the relationship between valuation and financial
decisions. The available research proves that this concept is applicable in an organisation’s
financial decisions. The essay has looked at the relationship between WACC and valuation in
organisations and the relationship that exists between these two variables and financial
decisions in an organisation. The paper has proved a positive relationship between these
concepts.
Valuation
The valuation of any organisation allows future decision-making to ensure that it is operating
as per the expectations. Different methods are used in valuation, including those that are
supported by theories and contemporary methods. The present models that are deployed in the
evaluation process are a product of extensive research, with many researchers describing them
before their application in management and finance. What are the motives of company
valuation? Different schools of thought exist as to why company valuation is important.
One of the motives for the evaluations of a company is to make decisions in the organisation.
Depending on the decision that is reached after valuation, the involved individuals may decide
on the future of the organisation and the interventions for the areas that are found faulty.
Motives in company valuation may be characterised in different ways, including decision-
dependent and decision-independent motives (Ishakian, Knebusch & Rowen 2013). The other
category of motives is the transaction based vs the non-transaction-based motives (Ishakian,
Knebusch & Rowen 2013). The other class of motives, as described throughout the literature
on valuation, is the dominated vs the non-dominated decision (Ishakian, Knebusch & Rowen
2013).
Valuation serves different functions depending on the concerned firm or organisation. These
functions can be categorised further into minor and major functions. The main functions of
valuation in organisations include decision-making and consultation. According to Ishakian,
Knebusch, and Rowen (2013), managers and other stakeholders use valuation information in
an organisation to make decisions on the future of the organisation with the aim of improving
the organisational performance. Different firms operate on different grounds. They use
different methods of valuation to make financial and other forms of decisions in the
organisation.

The other function of valuation, according to Koziol (2014), is mediation where the firm uses
information from valuation to mediate between concepts, decisions, and individuals.
Hundsdoerfer, Kruschwitz, and Loren (2008) assert that mediation in an organisation provides
crucial information on the financial position of the organisation. Valuation also serves as a
means of argumentation. Using information from valuation, managers and other organisational
stakeholders can argue on the position of the organisation. The information is used to provide
details on the organisational performance, which is important in making a case for any
argument.
Apart from the main functions of valuation, valuation serves other auxiliary functions. One of
these auxiliary functions is information where the parties within an organisation gather
information on this organisation, including its performance and future expectations. Valuation
may also be used as a means of tax measurement where authorities determine the tax that an
organisation should forward over a given period. Many organisations where valuation has been
conducted were found to have some tax measurements, not in line with the expected values
(Mian & Velez-Pareja 2007). Valuation also serves the function of contract configuration where
employees and other parties in the organisation can have their contracts configured with the
expectations of the organisation.
Valuation Methods
Different valuation methods are in use in many organisations. Each of these methods provides
different results. The decision to use one of them is dependent on the firm that is being
evaluated, the financial methods in place, and the preferred approach. The most popular
approach depends on the organisation and the region where these organisations exist. Different
methods that are used in valuation are shown below.
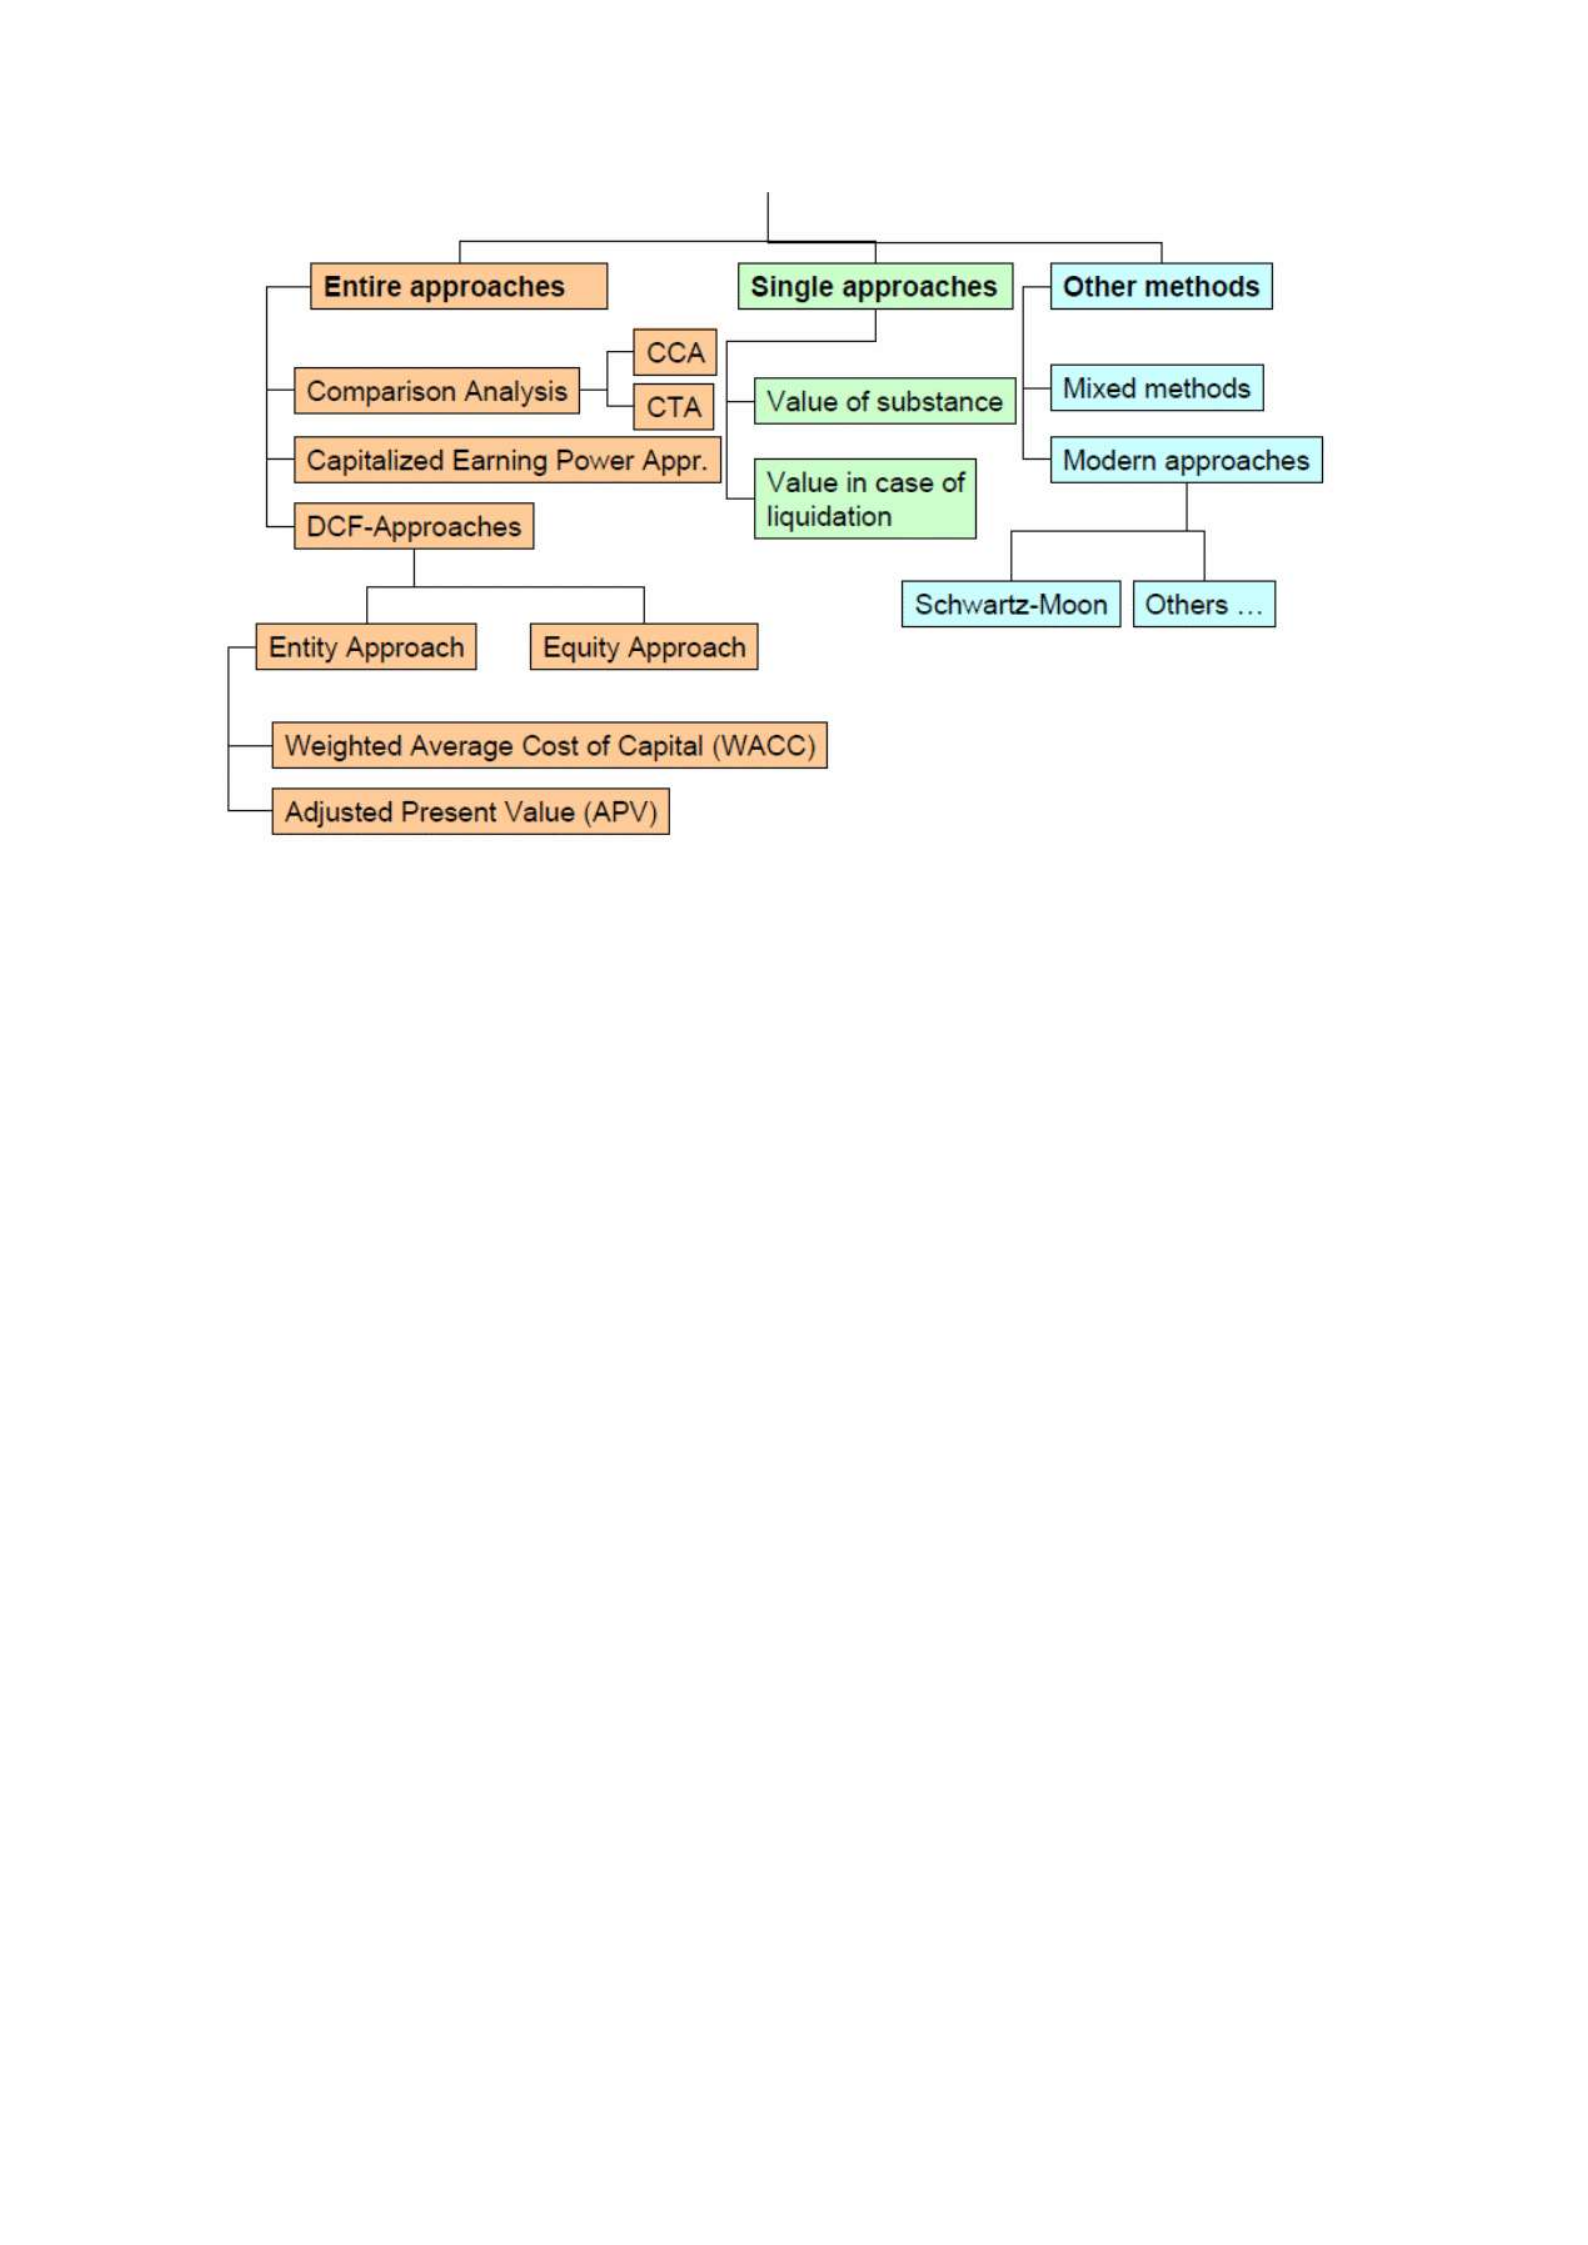
Figure 1: An Overview of Valuation Methods (Source Mian & Velez-Pareja 2007)
Different models that are applied during a valuation in organisations lead to a common result
where the organisations are able to plan for future decisions and changes. The valuation that is
obtained in organisations, irrespective of the method used, provides crucial information on the
financial status of the organisation. However, valuation within organisations also allows the
inception of changes whenever they are needed.
Financial Decisions
Organisations face challenges in financing, with one of the most common of them being the
outcomes of financial decisions. Competitiveness in organisations is influenced by the financial
decisions that managers and other stakeholders make. In any industry, financial decisions affect
the outcomes of the interactions between different factors. The financial decisions in an
organisation are also under the influence of other factors such as the valuation in these
organisations. A business in any industry or market must use capital as one of the main factors
in its operations, with this strategy bringing about the cost of capital.
Currently, there are no perfect markets in contemporary organisations. Hence, capital is not
always put to the intended use. A perfect business environment is the only place where capital
can be put to its planned use. However, conditions that are necessary for a perfect market are
hard to achieve. Nevertheless, if it were possible, the perfect world would have an excess
supply of capital. A perfect capital market might mean that the available unlimited capital is
only dependent on the risk of the project being undertaken (Spiegel, & Tookes 2013).

Aside from the perfect capital market, uncertainties, variables, and friction characterise the
existing real-world capital markets. The availability of tax as one of the variables in an
imperfect world ensures that organisations adopt strategies such as debts. An example of such
strategies is when an organisation operates in a capital structure with about 100% of debt
because of the positive corporate tax rate (Spiegel, & Tookes, 2013). Other factors that exist in
an imperfect world to introduce a relationship between valuations and financing include agency
costs, financial distress costs, and information asymmetries (Spiegel, & Tookes, 2013).
The financial position of an organisation ensures that the organisation can persist in an
environment where competition is an evident factor. Valuation effects that financial position of
an organisation. The reverse is also true. The decisions made in an organisation relating to the
financial positions of the organisation may be based on the valuation that is provided for this
organisation.
Weighted Average Cost of Capital
The calculation of the cost of capital is an intricate process that requires the participation of all
stakeholders. The cost of capital is calculated through the estimation of the proportion of debt
that a project consumes against the equity that is absorbed in the respective project (Massari,
Roncaglio & Zanetti 2008). The weighted average cost of capital (WACC) is calculated through
a formula that incorporates the market value of equity and debt (Massari, Roncaglio & Zanetti
2008). These values are adjusted using the costs of debt and equity. For a single firm, the
WACC is calculated as a single unit where the firm is the reference. The organisation, in this
case, is considered a single unit, with the results being for a single project.
The Weighted Average Cost of Capital is an indicator of the financial performance of an
organisation because it indicates the financial position of the organisation under discussion.
Any organisation with sound financial decisions has a favourable WACC, which is considered
a strength in these organisations. The calculation and use of WACC in financial discussions
and problem-solving is challenging for some financial analysts and other financial decision-
makers in organisations. Therefore, it is important to have a discussion on the correct use of
WACC and its implications on the financial decisions in organisations.
The other difficulty in the calculation and use of WACC is tax calculation. Different finance
officers use different methods of calculating the variables (Sabalı 2009). Financing and
investment decisions interact through taxes. WACC is an important concept in evaluating this

interaction. The formula that is used in the calculation of WACC refers to the organisation of
company as a whole upon incorporating the different aspects in financial decisions in the firm.
Therefore, this formula is effective for the “average project” where the right discount rate is
produced (Massari, Roncaglio & Zanetti 2008). Hence, the formula is incorrect when used in
the calculation of WACC for the safer and riskier projects (Magni 2012). The inaccuracy while
using this formula mainly stems from the different sections that individuals calculate in an
organisation, especially where the organisation has different departments.
Capital Structure and Valuations
Capital structure in a firm is a factor that affects valuations in these organisations. The effects
depend on the existing capital structure. According to Sabalı (2009), financing decisions
typically affect value within organisations. Some of the ways that boost value in a firm with
respect to its financing decisions is through the adjustment of the discount rate and the present
value (Massari, Roncaglio & Zanetti 2008).
The discount rate in most organisations is typically adjusted downwards, with the aim being to
account for the existing tax shields (Massari, Roncaglio & Zanetti 2008). Financing decisions
also affect value in organisations through adjusting the present value in these organisations
(Massari, Roncaglio & Zanetti 2008). According to Spiegel and Tookes (2013), the base case
is first calculated with the assumption that it is all equity financed.
Capital structure in organisations affects the value of the organisation from its first year of
operation. The capital structure in organisations is variable depending on several factors such
as the capital debt and the type of industry within which a firm is located. The tax on a firm is
a major factor with reference to its capital value, especially because the tax determines the debt
status of an organisation (Sabalı 2009).
The initial cash that is invested into a firm in the first year affects the value of an organisation
during this year. Most of the organisations that invest significant amounts of capital into their
operations end up being successful in the first year. Over the years that follow, the WACC
formula is highly applicable, as the organisational debts and equities change.
Capital structure in most organisations is affected by the financial decisions made by the
executive. Hence, the value of organisations is dependent on the type of managers that an
organisation keeps. The value of organisation changes with any financial decision made, since
the debt and equities change with these decisions (Massari, Roncaglio & Zanetti 2008).

The value of a firm may be calculated through the estimation of the WACC, which is later used
to discount the FCFF from the debt holders and equity capital contributors (Massari, Roncaglio
& Zanetti 2008). The use of WACC in the estimation of a firm’s value is very effective by far
compared to other methods of value estimation. This finding indicates a relationship between
the value of organisations and the WACC. The WACC is in turn related to the financial
decisions in an organisation. Hence, valuation is related to the financial decisions in the
organisation.
Impact of Tax Shields on WACC
According to Massari, Roncaglio, and Zanetti (2008), tax is a variable in an organisation that
affects the value of these organisations. Interest in organisations is one of the expenses that are
usually considered as tax-deductible expense (Massari, Roncaglio & Zanetti 2008). The
calculation of WACC incorporates tax as a major form of expense. This strategy determines
the value of organisations. However, tax shields in organisations may affect the calculation of
WACC. The effects of tax shields on WACC depend on the business and individuals who are
responsible for financial management in the respective institutions.
The tax shields cause changes on WACC in a number of ways. However, while these effects
are dependent on the type of organisation, the main effect is that the WACC increases with a
reduction in tax shields. Most organisations seek tax shields to lower their WACC and in effect
influence the value and competitiveness of their respective industries. A common result of tax
shields is a downward adjustment of the discount rate to account for any changes in this area
(Massari, Roncaglio & Zanetti 2008). The downward adjustment of discount rates in
organisations allows decisions to be made on the WACC and its overall effect on the firm’s
value.
Tax shields help organisations save their available financial resources, including the provision
of future resources. In areas where tax shields are effectively applied, firms report better results,
performance, and competitiveness compared to areas where these policies are scantily applied.
Adjusting the discount rate downwards is one of the ways that tax shields are accounted for.
The result of this case is a change on the value of firms (Massari, Roncaglio & Zanetti 2008).
The relationship between value of an organisation and tax shields may be demonstrated by the
inherent differences between organisations that operate in different regions with different tax
shield regimens. According to Massari, Roncaglio, and Zanetti (2008), adjustment of WACC
should affect the value of a firm through the effect of this move on the value of the organisation.

Therefore, managers should make sound decisions when it comes to applying for tax shields in
their area.
How Tax Shields affect Firm Value
Tax shields in an organisation affect the firm’s value in a number of ways as indicated above.
A common understanding is that tax is one of the factors that affect WACC, and in effect the
value of an organisation. The worth of any business is affected by the financing decisions in
the organisations, including the availability of tax shields. The discount rate constitutes one of
the factors that may be adjusted to accommodate changes in the value of organisations. Mintz
and Currim (2013) observe that downward adjustment of discount rate accounts for tax shields.
This downward adjustment results in the increase in value of organisations.
Organisations that use the discount rate to effect changes in their firm value often report success
in the use of the method. When an organisation is awarded tax shields, the value changes to
correspond to the changes introduced through the adjustment of the discount rates. Most
organisations can be described as having debts because of the tax shields that they intend to
acquire.
Therefore, contemporary organisations are prone to debts in their quest to attain tax shields
from the respective authorities. The differences in the contemporary organisations arise from
the different capabilities in the use of their debts. Most organisations whose debt status is high
attain significant tax exemptions. They are valued at higher rank compared to organisations
that have a lower debt position. The tax shields in an organisation, therefore, affect the firm
value in organisations.
Mistakes in Using WACC
Several mistakes are established in literature in the use of WACC. The first mistake is in the
calculation of this variable. In fact, some individuals use variables that are not commonly
applied in the formula. The computation of WACC is tedious due to the many variables that
are necessary for the calculation process. This situation makes the calculation difficult to the
extent that some individuals opt for shortcuts that may not be accurate. The other mistake is
that some individuals assume that the formula may be used in the calculation of WACC for a
particular section of the organisation. They forget that this formula considers the firm a single
unit (Mian & Velez-Pareja 2007).

WACC is useful in providing discount for businesses only where they are applied to
organisations or projects with a similar undertaking to the firm under consideration. For
organisations that differ from the firm under consideration, the formula may not be applicable
or provide useful results. WACC may be useful in most of the calculations where the firm under
consideration has the same size as that of other firms that were initially considered. For projects
that are safer or riskier compared to the original organisation, the calculated WACC may be
inaccurate and in some cases incorrect.
The other mistake that individuals make in the use of WACC is the assumption that it can be
applied as a single variable in the determination of a firm’s value. According to Mian and Velez-
Pareja (2007), organisations require the use of many variables to calculate their value. A single
variable may be deceptive depending on the industry within which the firm is located.
Therefore, there is a need to consider a number of variables in the calculation of a firm’s value
as using WACC alone may be inaccurate. Some of the other mistakes that individuals make in
the use of WACC include miscalculation of the debt and equities that are eventually used in the
calculation of this variable.
Adjusting the WACC
The adjustment of WACC may be done through a number of ways depending on the debt ratios
and the business risks (Mintz & Currim 2013). Adjusting the WACC when the risk of the firm’s
debt ratio and the business risk differ from those of the new project is important in the
calculation of a business’ WACC.
The adjustment of WACC is important when the debt ratios and business risks differ in
organisations. The differences between these two variables result from the changes that are
inherent in the organisations. The three main steps that should be followed when adjusting the
WACC include calculation of the opportunity cost, estimation of the cost of the organisations
debt, and recalculation of the WACC using the obtained new values (Mian & Velez-Pareja
2007).
The adjustment of this value allows the correct calculations where the estimated WACC is
obtained against the real WACC. In cases where the WACC is adjusted, the value of the firm’s
debts and opportunity costs are considered the main reasons for the adjustments. There are
many reasons for the adjustments, with the main one being to increase the accuracy of the final
WACC that is obtained for any given firm. WACC is an indicator of the financing side effect
in an organisation. It is a good indicator of value in organisations (Mintz & Currim 2013).

These financing side effects include the value of interest tax shields on debts (Massari,
Roncaglio & Zanetti 2008). Adjustment of the WACC is also important where the actual value
of a firm is to be estimated.
Valuation in Organisations
Valuation affects the financial decisions that are made in organisations. Most of the decisions
that are important in organisations are made only through the consideration of the value of the
organisation since most managers tend to focus on increasing this value. The many valuation
approaches that are currently in use stem from the extensive research done in this area. These
approaches affect the financing decisions in organisations. The methods of valuation affect the
final variable.
Hence, most of these methods have sub approaches within them. Discounted cash flow is
among the most popular methods that are used in the valuation. This strategy focuses on the
financing decisions in the organisation (Massari, Roncaglio & Zanetti 2008). According to
Dong, Hirshleifer, and Teoh (2012), the main ways of estimating the discounted cash flow
include discounting the cash flow at a risk-adjusted discount (Sabalı 2009). This formula is one
of the four main methods that are used in the discounting cash flows. Using these methods
produces significant results.
Although different methods are in use in the valuation of companies, the same results may be
achieved if the assumptions are withheld for each of the methods. The similarity of these
methods ensures that the result is compatible with the businesses for which it was attempted
first. The different proponents for the different approaches in the valuation methods assume
that their methods are the most accurate. The results indicate that these methods are closely
similar. In relative valuation, which is considered one of the most important valuation methods,
the researchers who proposed the method adopted the assumption of individual assets.
However, these methods have similar results when the different assumptions are withheld.
Conclusion
In conclusion, based on the detailed expositions that have been made in the paper, it is clear
that valuation and financing are closely related when consideration for the financial state of an
organisation is made. Valuation may be estimated in organisations using several methods. Some
of these methods have been stated in this essay. The existence of valuation in financial decisions
allows the organisations to make decisions that coincide with their immediate needs.

The paper has proposed that a relationship between valuation and financial decisions in
organisations. This relationship is affected by other factors such as taxation. The WACC is an
important factor to consider when deducing the relationship between valuation and financial
decisions. The available research proves that this concept is applicable in an organisation’s
financial decisions. The essay has looked at the relationship between WACC and valuation in
organisations and the relationship that exists between these two variables and financial
decisions in an organisation. The paper has proved a positive relationship between these
concepts.
References
Dong, M, Hirshleifer, D & Teoh, S 2012, ‘Overvalued Equity and Financing
Decisions’, Review Of Financial Studies, vol. 25 no. 12, pp. 3645-3683.
Hundsdoerfer, J, Kruschwitz, L & Lorenz, D 2008, ‘Investment Valuation with Tax-optimised
Financing Decisions and a Tax-optimised Default Alternative’, Business Research, vol. 1 no.
1, pp. 9-24.
Ishakian, Z, Knebusch, M & Rowen, L 2013, ‘Dominance and Transmissions in Supertropical
Valuation Theory’, Communications In Algebra, vol. 41 no. 7, pp. 2736-2782.
Koziol, C 2014, ‘A simple correction of the WACC discount rate for default risk and
bankruptcy costs’, Review Of Quantitative Finance & Accounting, vol. 42 no. 4, pp. 653-666.
Magni, C 2012, ‘In Search of the “Lost Capital”. A Theory for Valuation, Investment Decisions,
Performance Measurement’, Frontiers In Finance & Economics, vol. 9 no. 1, pp. 87-147.
Massari, M, Roncaglio, F & Zanetti, L 2008, ‘On the Equivalence between the APV and the
WACC Approach in a Growing Leveraged Firm’, European Financial Management, vol. 14
no. 1, pp. 152-162.
Mian, M & Velez-Pareja, I 2007, ‘Applicability of the Classic WACC Concept in
Practice’, Latin American Business Review, vol. 8 no. 2, pp. 19-40.
Mintz, O & Currim, I 2013, ‘What Drives Managerial Use of Marketing and Financial Metrics
and Does Metric Use Affect Performance of Marketing-Mix Activities?’, Journal Of
Marketing, vol. 77 no. 2, pp. 17-40.

Sabalı, J 2009, ‘On the Applicability of WACC for Investment Decisions’, GCG: Revista De
Globalisación, Competitividad & Gobernabilidad, vol. 3 no. 2, pp. 80-88.
Spiegel, M & Tookes, H 2013, ‘Dynamic Competition, Valuation, and Merger
Activity’, Journal Of Finance, vol. 68 no. 1, pp. 125-172.

