


FAMA-FRENCH 5-
FACTOR MODELS
CAPM
COMPARING
MGTF 415 FINAL PROJECT
YELLOW GROUP 9
AND
Presented by: Mohammed Alshaghathirah , Dhiren Rawal, Diksha
Surana, Linyang Xie, Xiaoyun Li, Xiangyu Li.
UNDERSTANDING STOCK RETURNS:
CAPM VS FAMA-FRENCH
OBJECTIVE:
WHY IT
MATTERS:
SCOPE:
Compare the explanatory power of CAPM and
Fama-French 5-Factor Models.
Helps investors understand stock return
variability, crucial for asset management
decisions.
Analysis of 20 companies over 30 years
(1993-2023).
D S
DATA COLLECTION
AND PREPARATION
•Company Data: Monthly stock prices from
Wharton Research Data Services.
• Fama-French Factors: Market risk
premium, size, value, profitability,
investment and Risk-free rate from Ken
French Data Library
D Preparation
•Used Python Programming Language
•Removed missing values, aligned datasets.
•Calculated excess returns
•Run OLS regression for CAPM model and Fama -
French five factor model.
CAPM
COMPARING MODELS
Uses Market
Risk Premium
(Mkt-RF) to
explain
returns.
F -F 5-F
M
Adds size (SMB), value
(HML), profitability
(RMW), and
investment (CMA)
M U
R² values,
coefficient
significance for
both models.
VIF for Fama-
French 5 factor
model
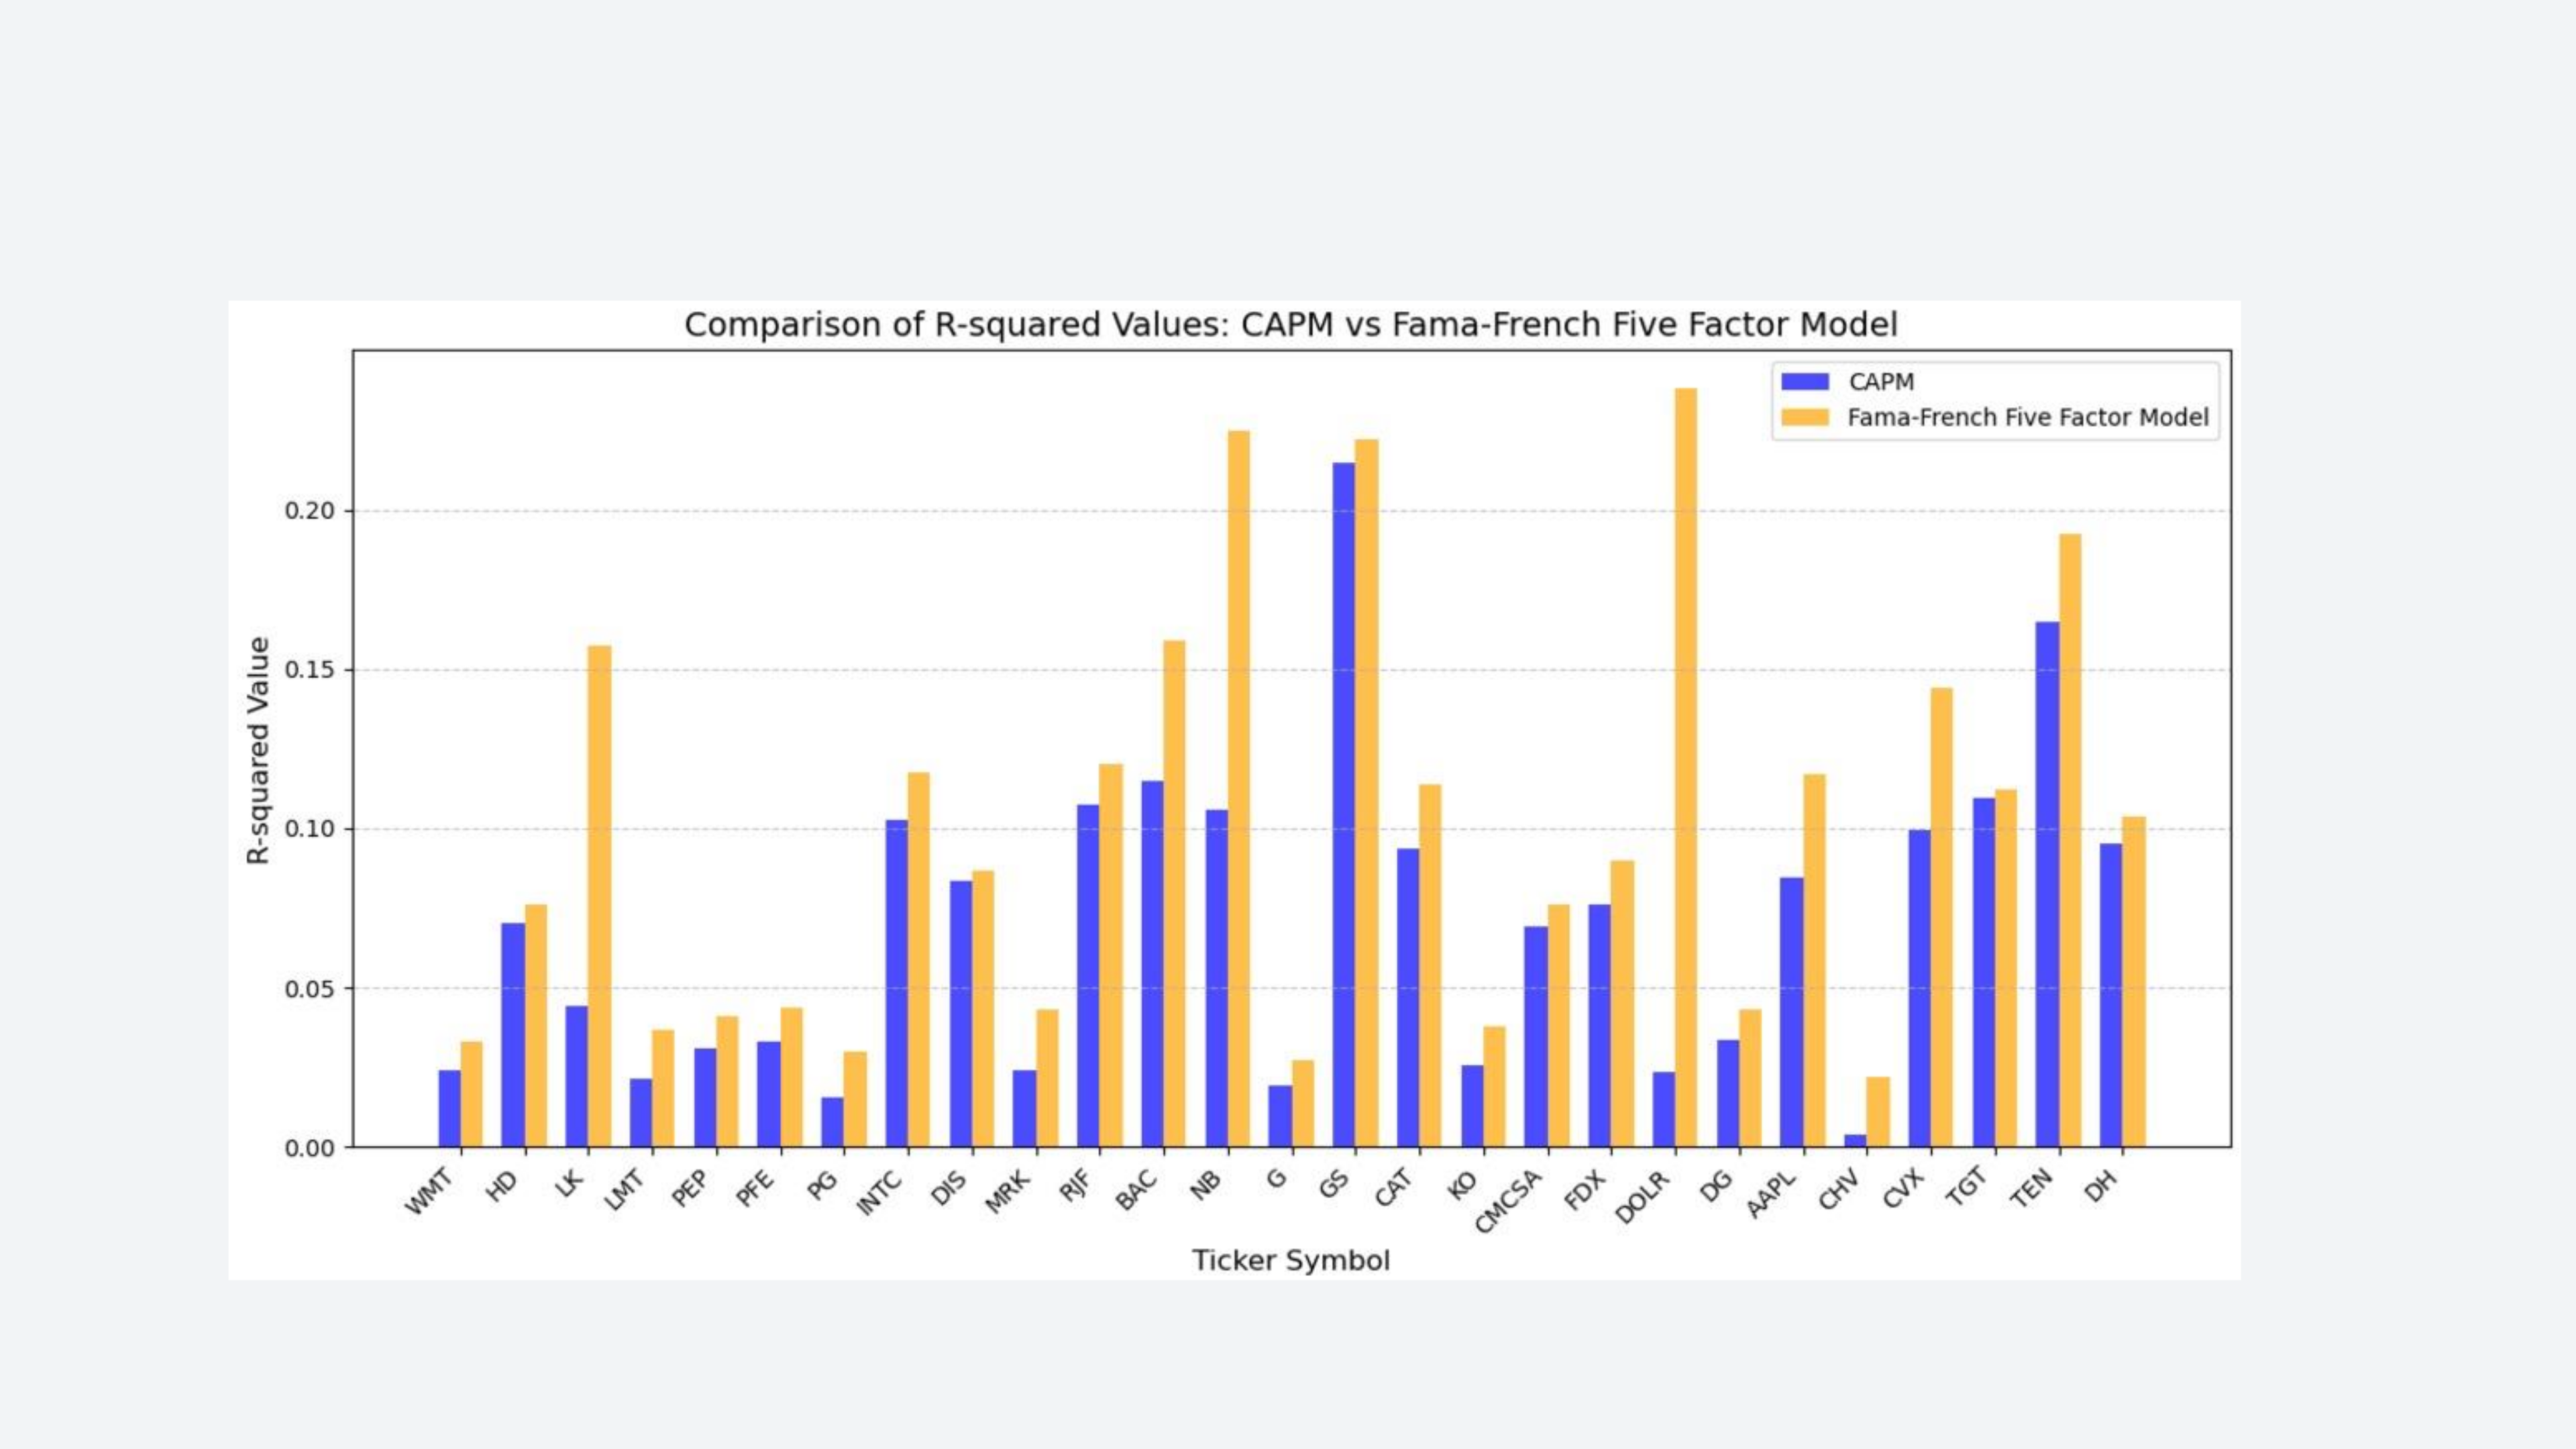
Comparison
of
R-squared
Values:
CAPM
vs
Fama-French
Five
Factor
Model
mam
CAPM
™
Fama-French
Five
Factor
Model
0.20
-
wv
=
0.15
-
>
oO
v
oC
=
“
0.10
-
co
0.05
-
0.00
)
)
,
ECE
OF
TS
EEE
E
FEES
F
OCEFS
EEF
SF
SF
Pe
FACES
¥
Co
Ticker
Symbol
Comparison of CAPM and Fama-French Model R² Values
FAMA-FRENCH VS
CAPM - KEY
RESULTS
Fama-French consistently
outperformed CAPM in explaining
stock returns.
Chart: Comparison of average R²
values (Fama-French: 0.22, CAPM: 0.14).
Insight: Higher R² and low VIF suggest
Fama-French captures more variation
in returns due to additional factors.
F VIF
Constant 1.1077
Mkt-Rf 1.2997
SMB 1.3326
HML 2.0211
RMW 1.6395
CMA 1.9707
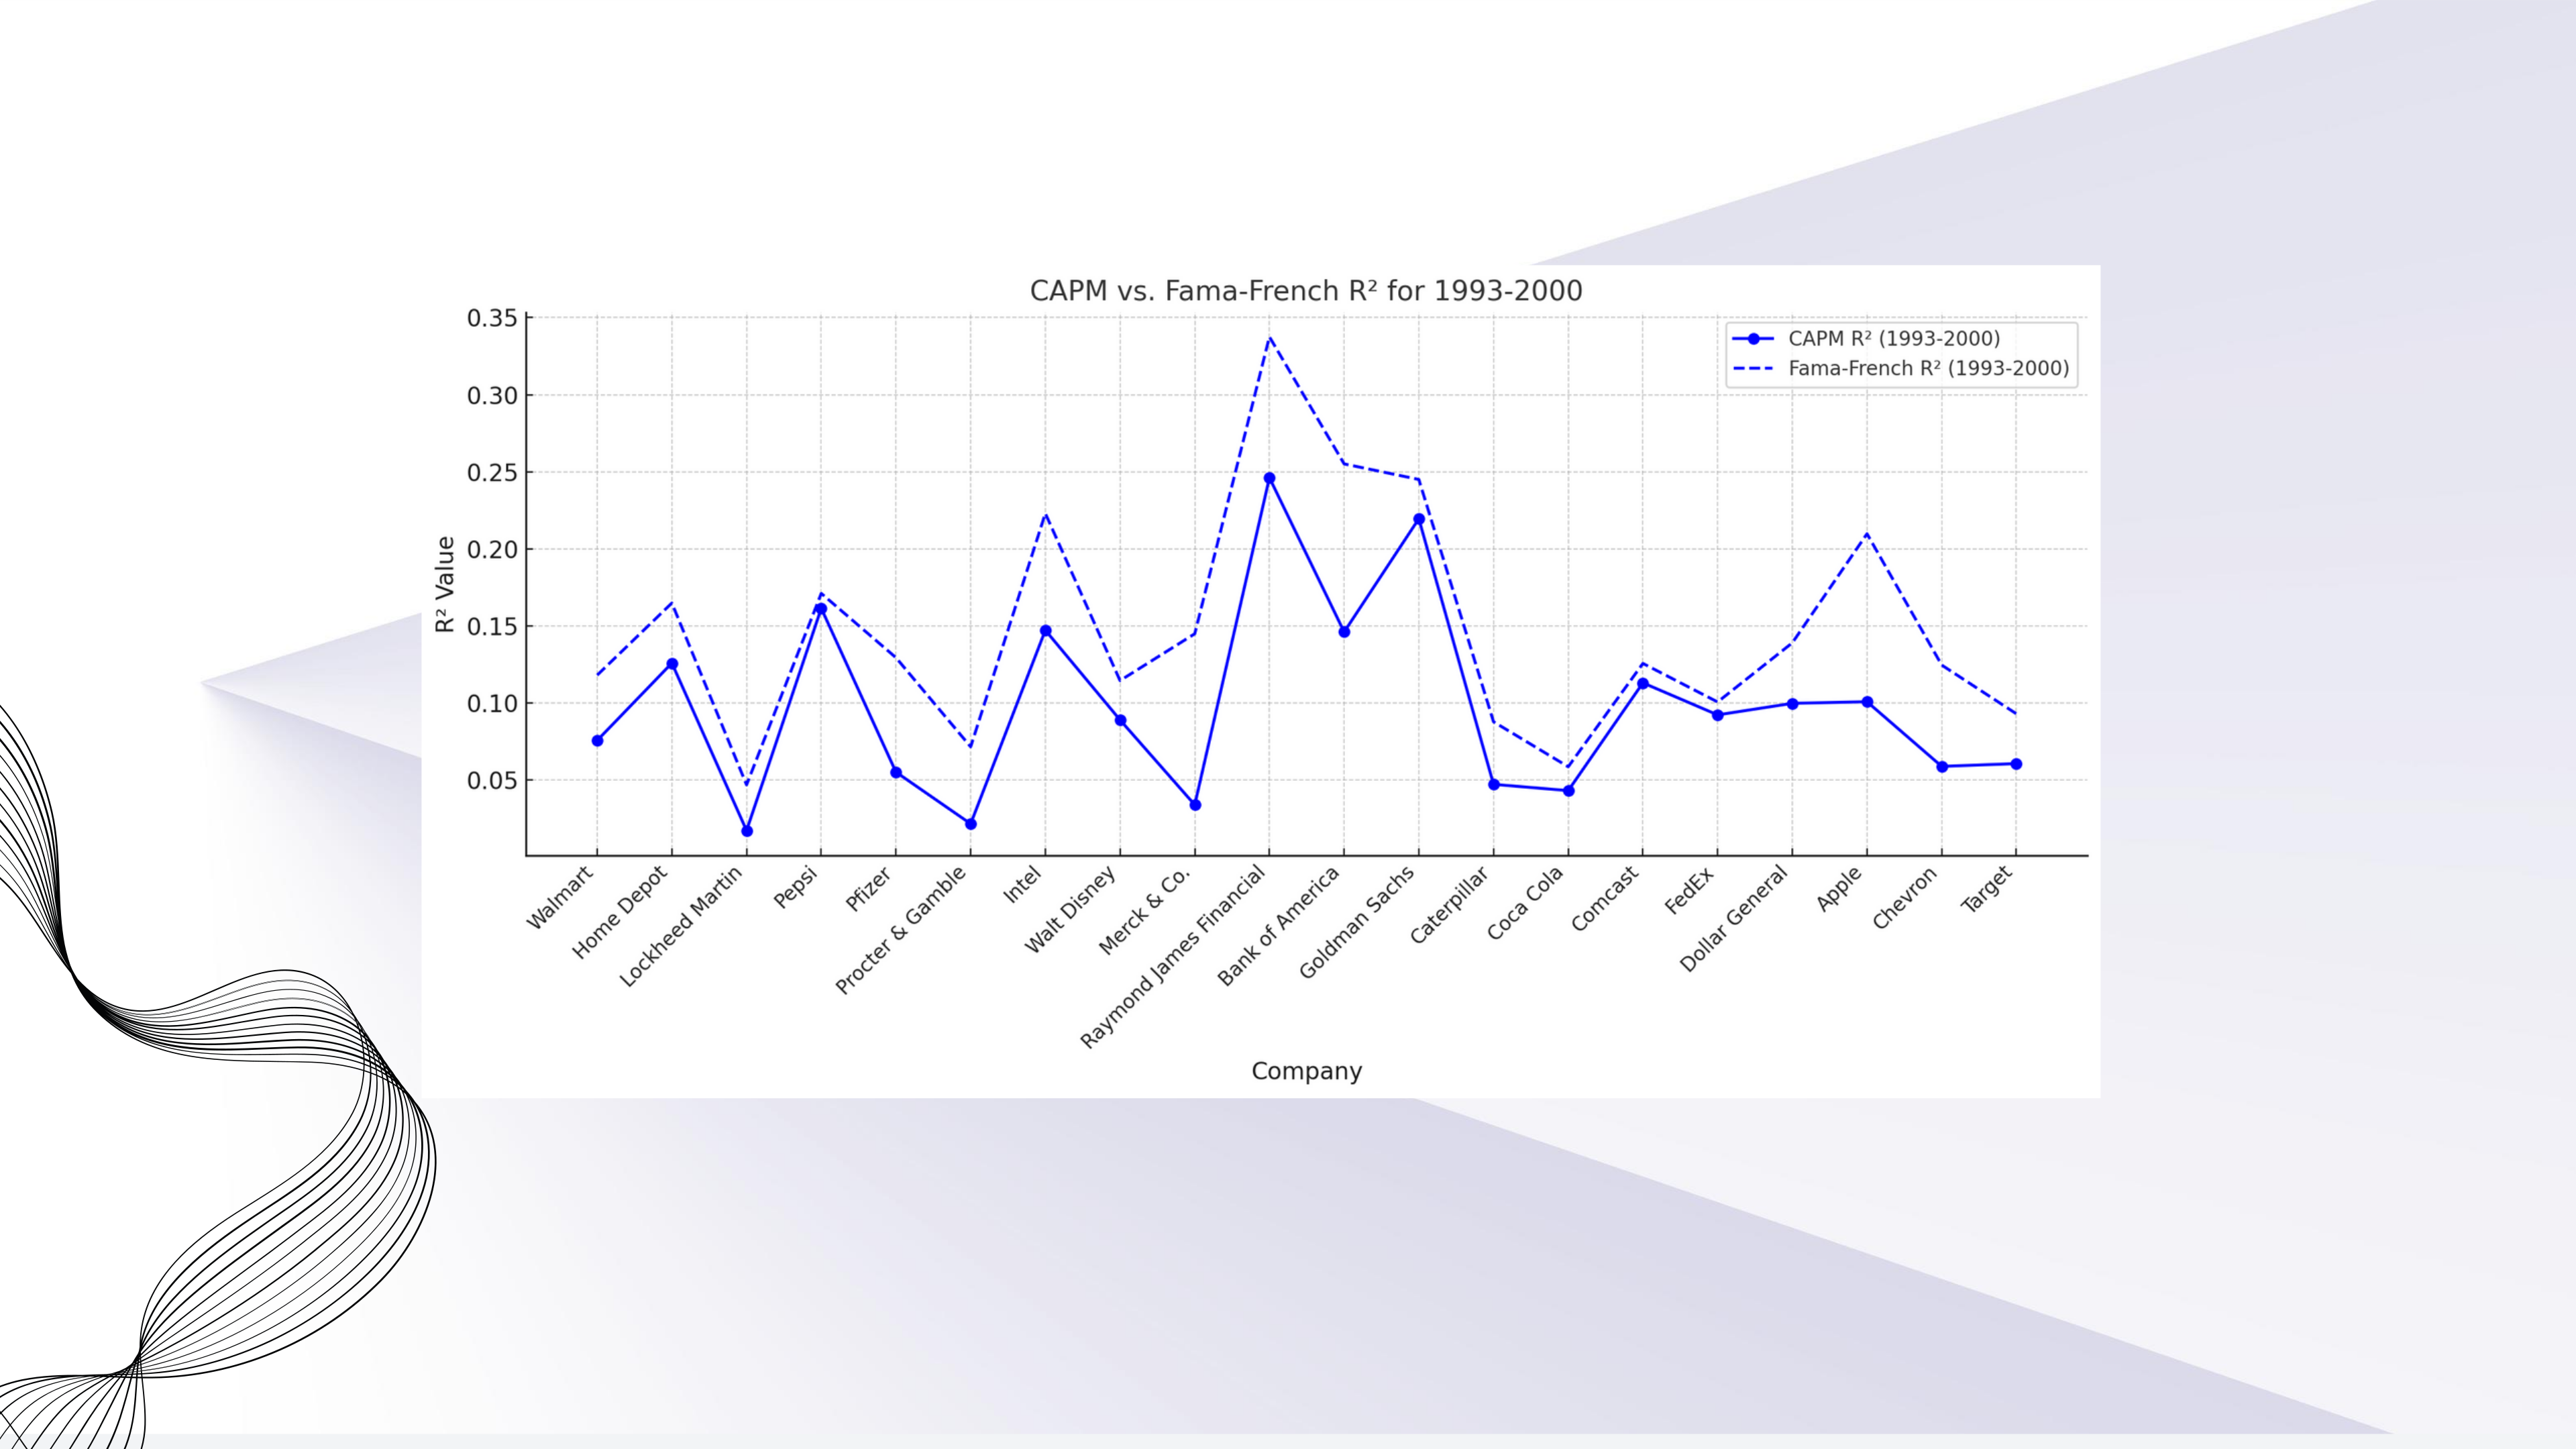
1993-2000
(Economic Boom)
•Dominant Factors: SMB
and HML (small-cap and
value).
•CAPM Underperformed
compared to Fama-
French.
Dominant Factors:
Profitability (RMW)
and Conservative
Investment (CMA).
MODEL PERFORMANCE IN
DIFFERENT ECONOMIC PERIODS
2001-2008 (Financial Crisis)
2009-2023 (Recovery)
High Profitability
became a key
driver of returns.
•Dominant Factors: SMB and HML (small-cap and value).
•CAPM Underperformed compared to Fama-French.
1993-2000 (Economic Boom)
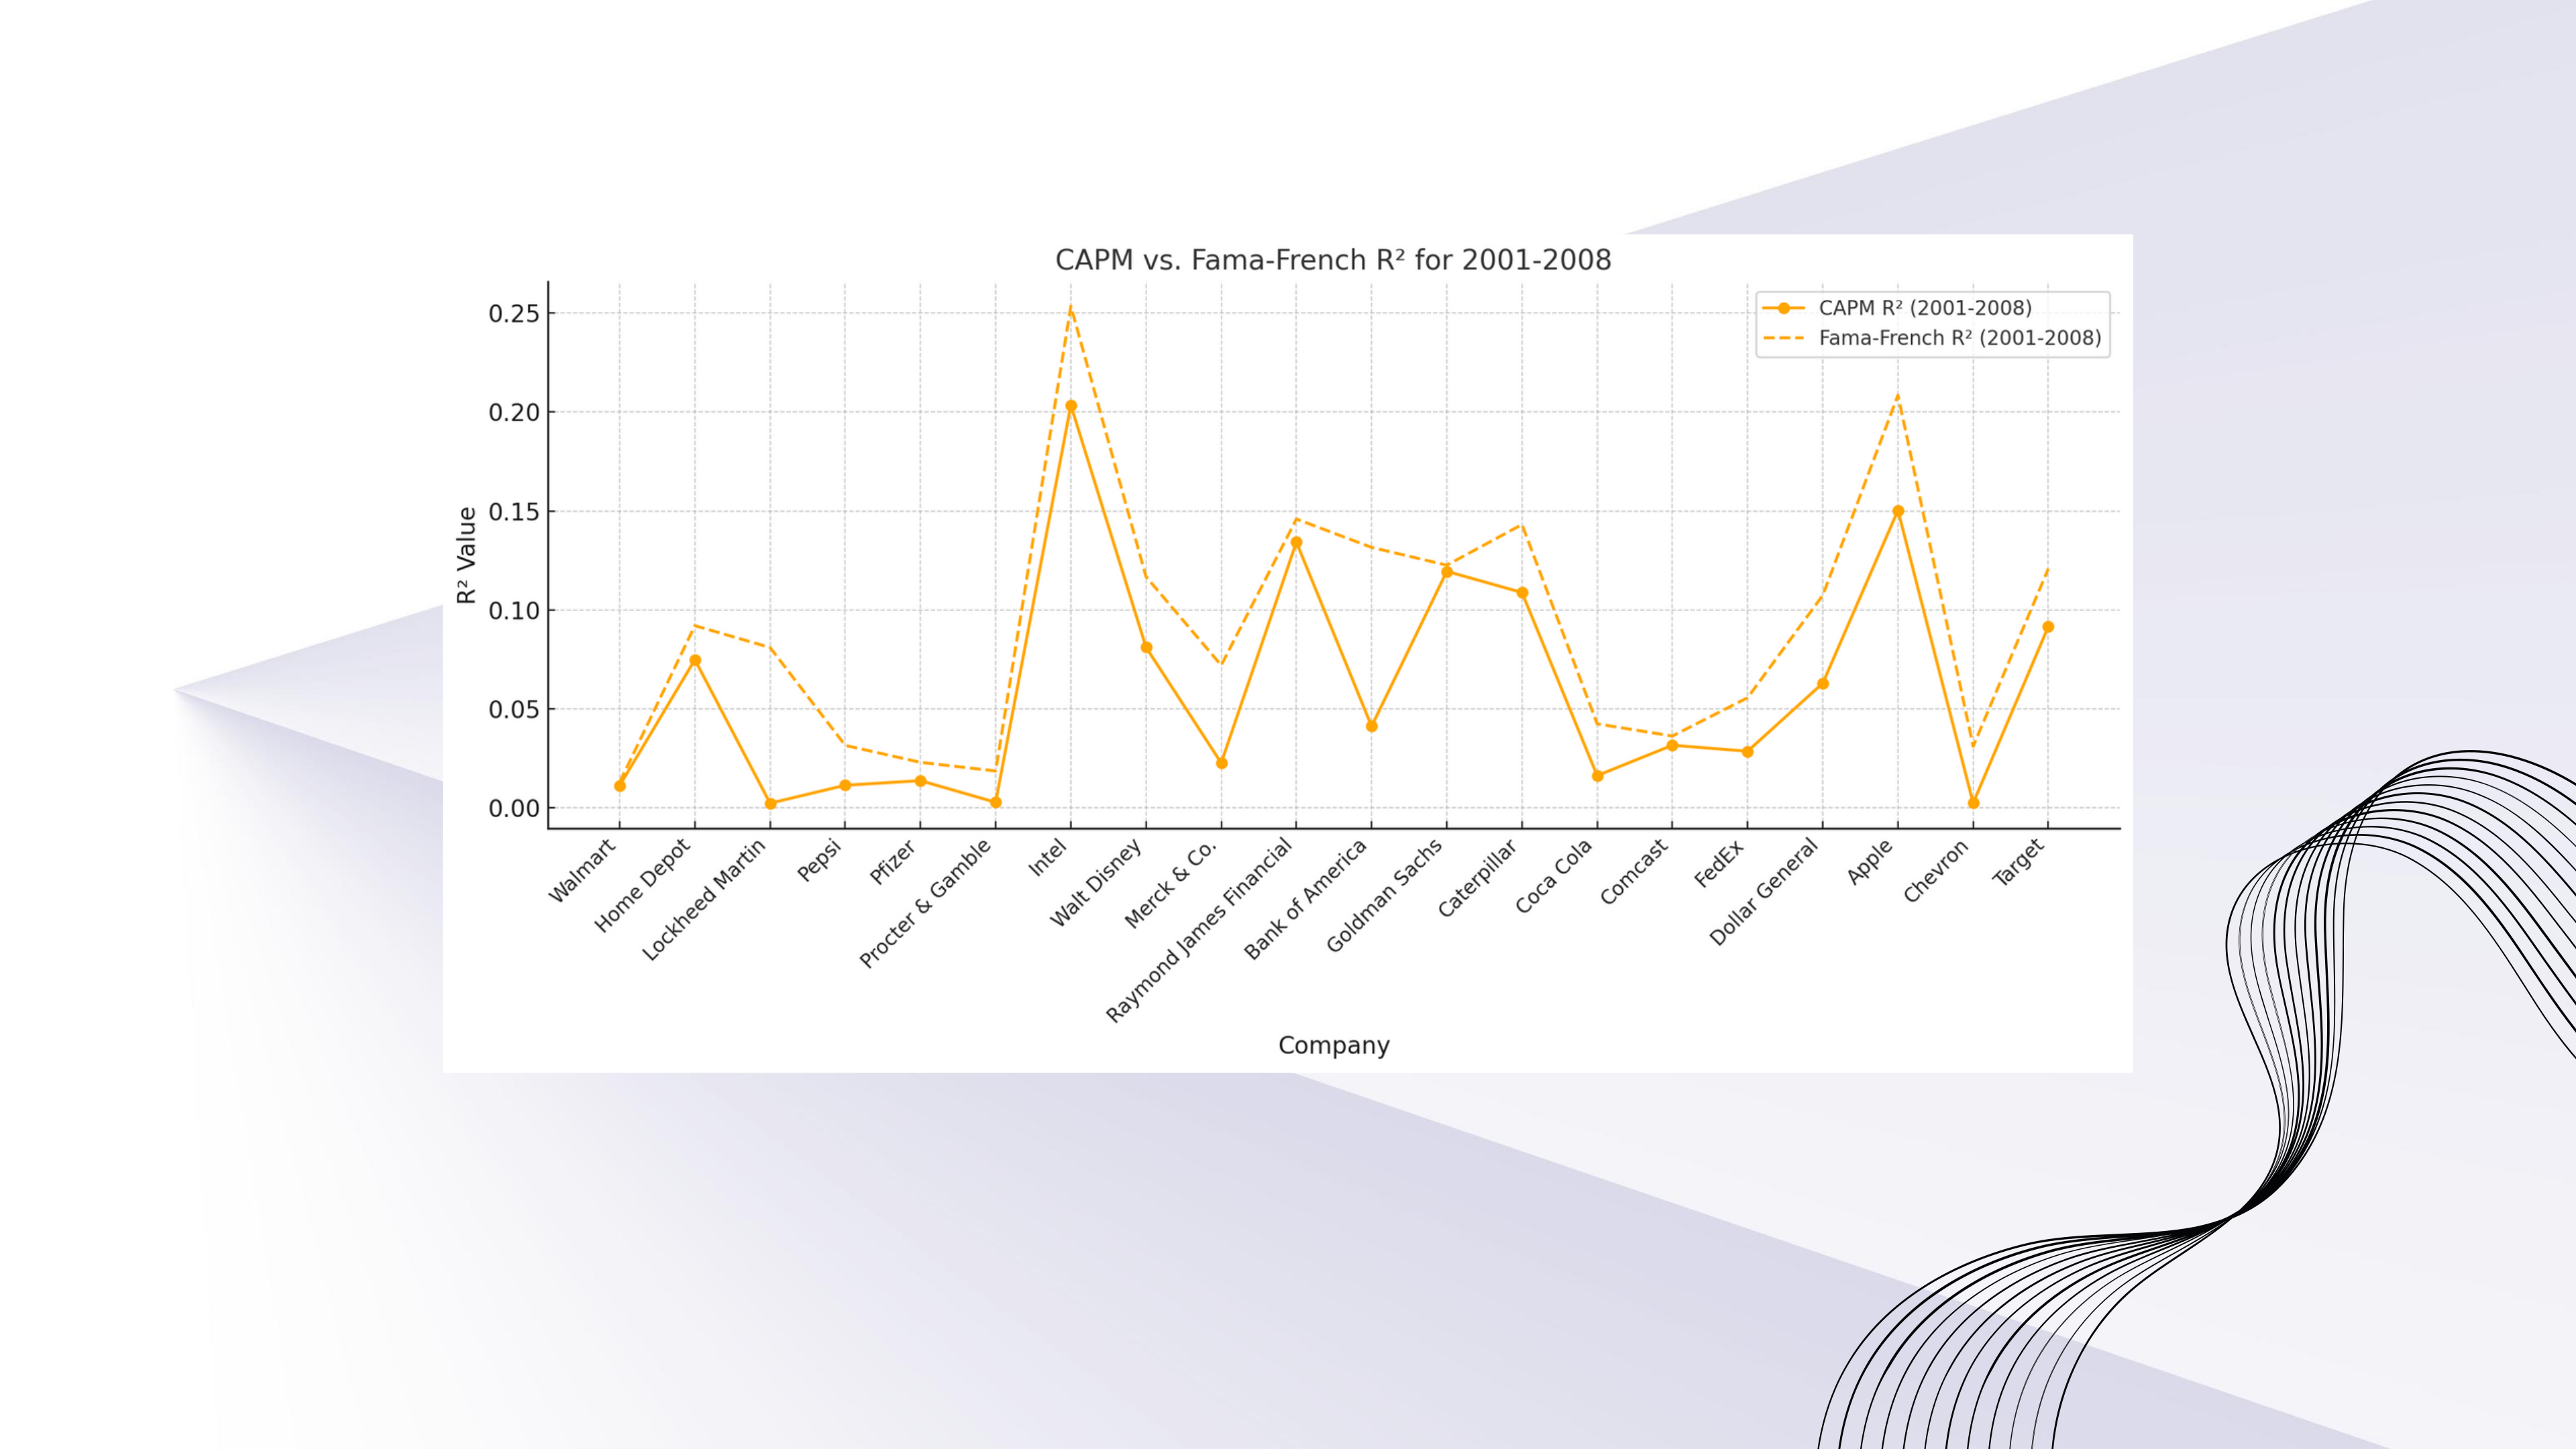
2001-2008 (Financial Crisis)
Dominant Factors: Profitability
(RMW) and Conservative
Investment (CMA).
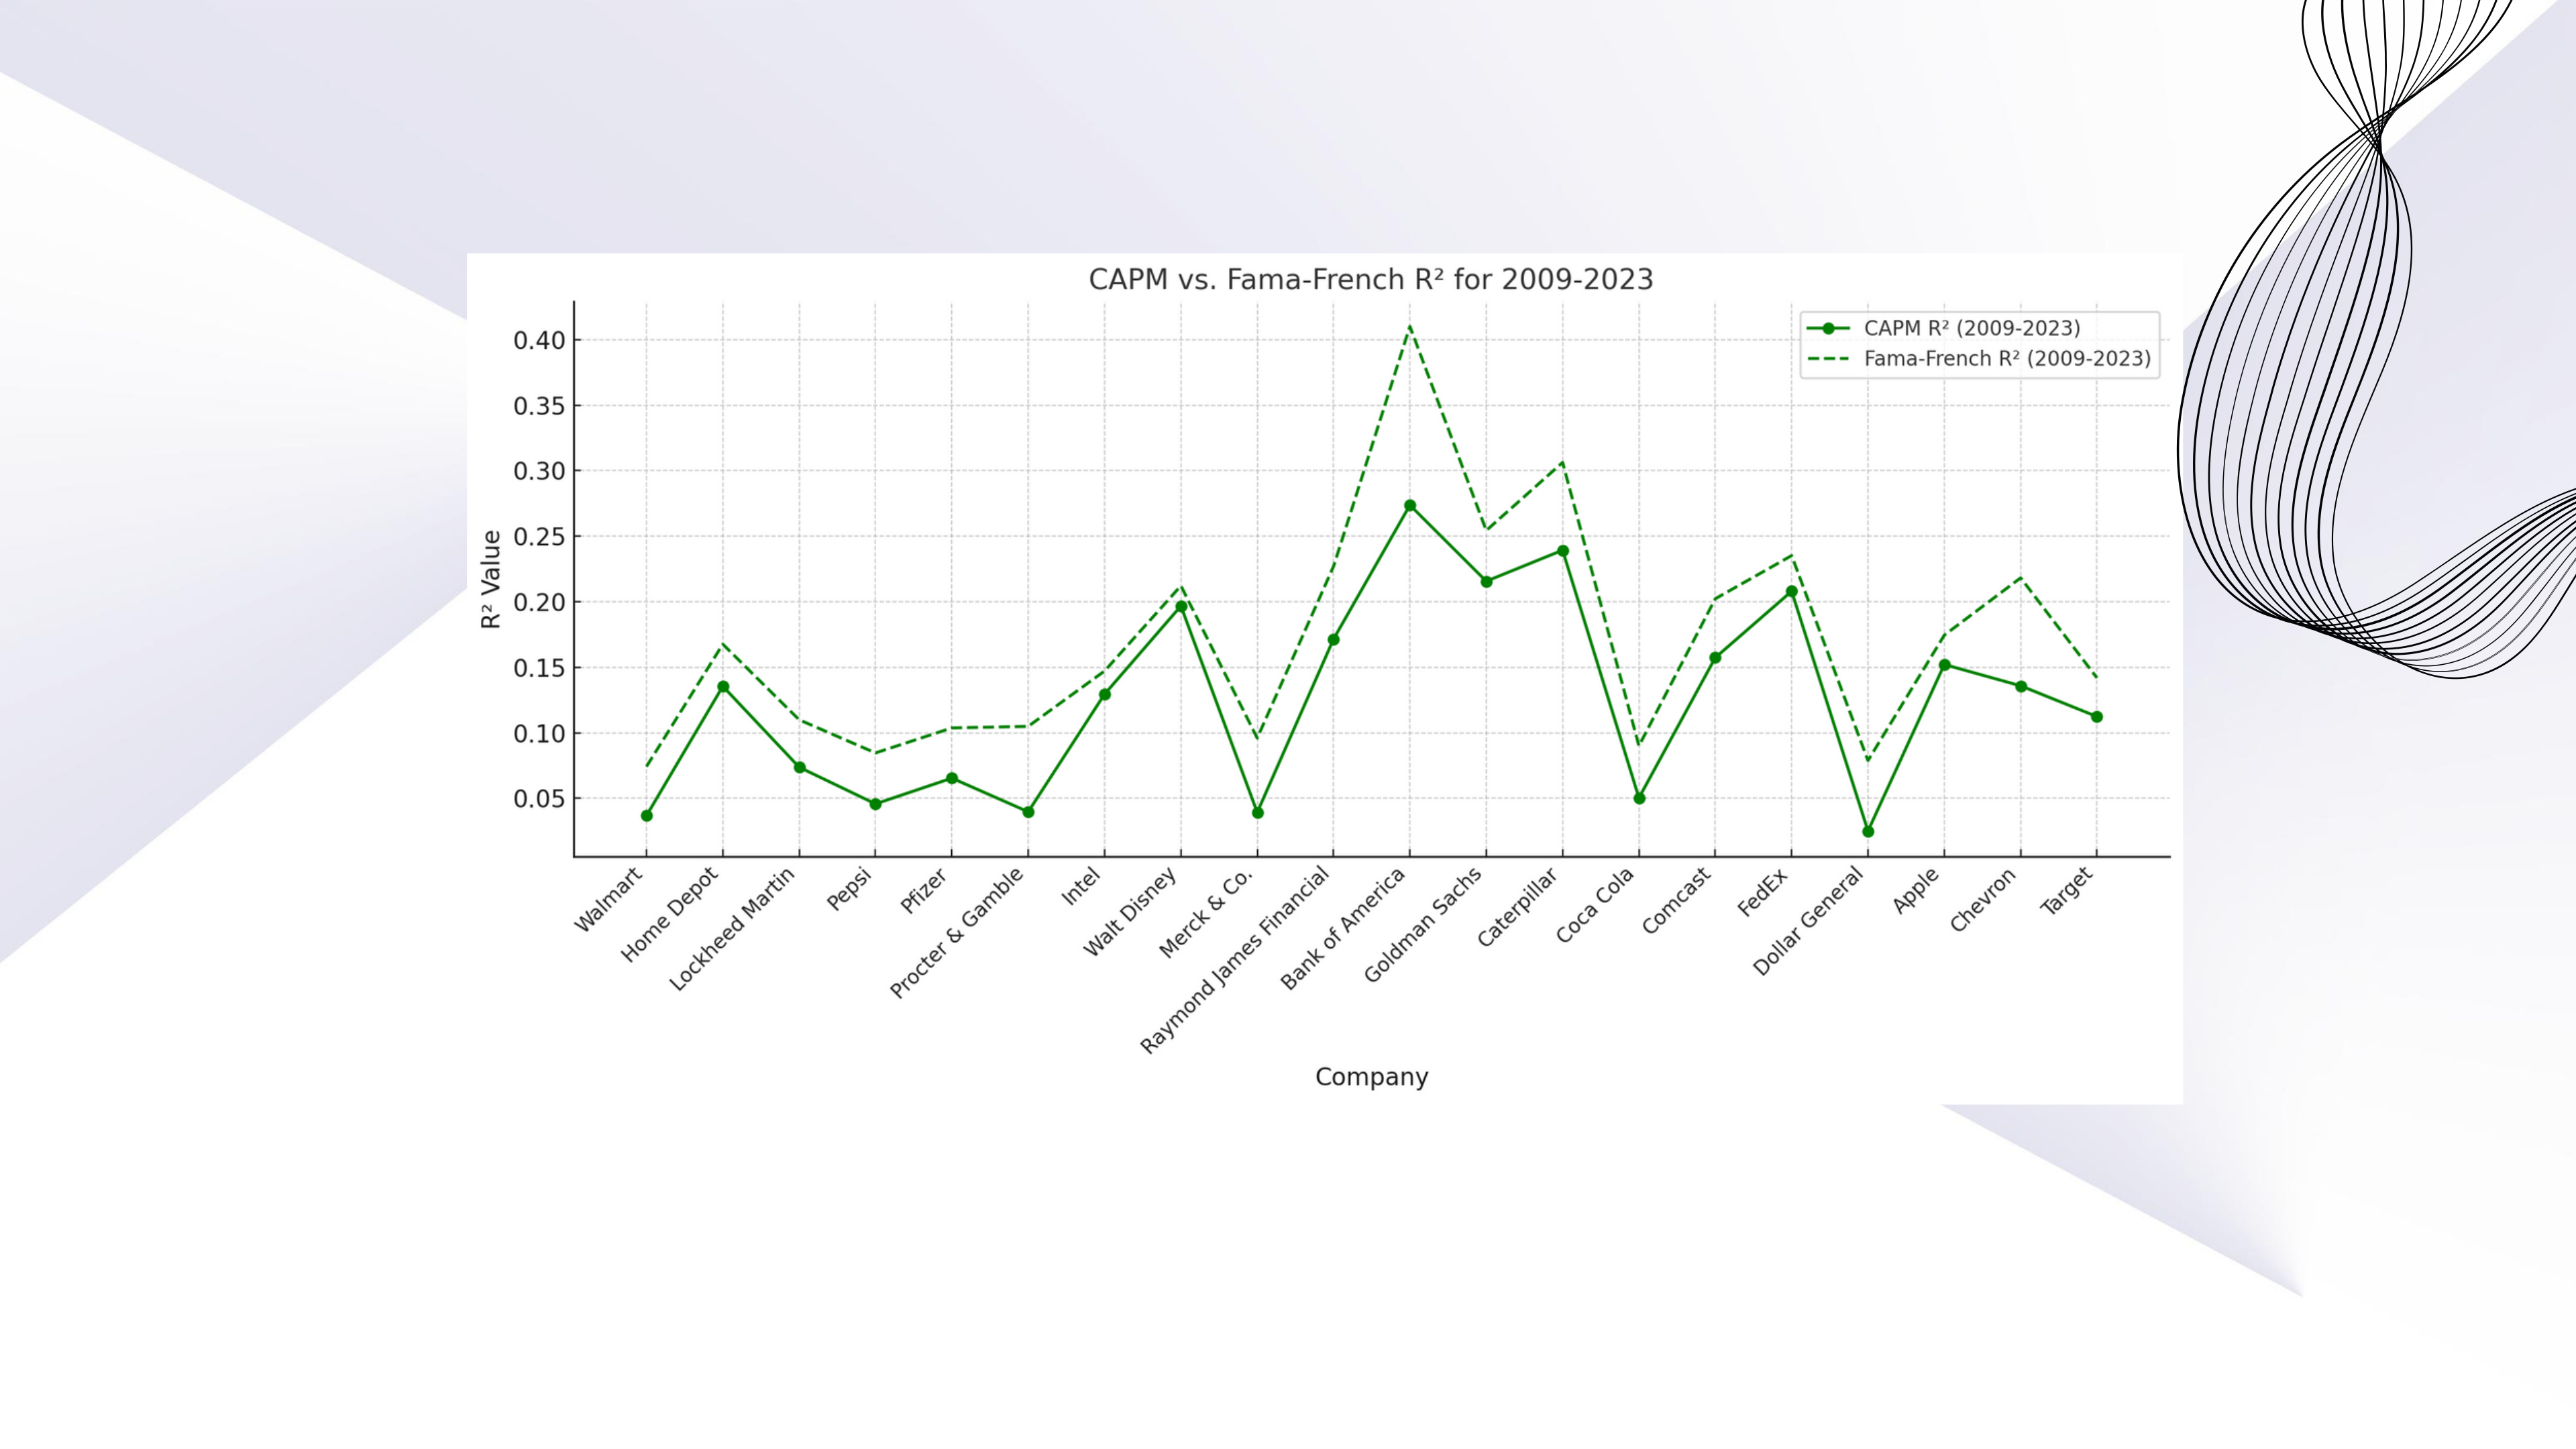
2009-2023 (Recovery)
High Profitability
became a key driver
of returns.
ASSET MANAGEMENT INSIGHTS
INVESTMENT
STRATEGY
MODEL
SELECTION
•Economic Downturns: Focus on profitable
and conservative firms.
•Boom Periods: Emphasize small-cap and
value stocks.
Fama-French is better suited for complex
economic environments.
F -F
SUMMARY & KEY TAKEAWAYS
E
A M
Provides better
explanatory power
for stock returns
compared to CAPM.
Different factors are
important during
booms vs. crises.
Can use these
insights to build
dynamic
investment
strategies for
improved
returns.
THANK YOU

