


RunningHead:MEMO1
ACC405FinalProjectTwo
ACC405
SNHU
August13,2022
MEMO2
Date:August12,2022
Subject:Splittingofprofitsamongthebusinesspartnersfromyearoneofthe business
Inthepartnershipbusinesscontext,clarityintermsofprofitdistributionandthepaymentof
salariedisvital.Theseelementshavethepotentialtoensurethatallthepartnersareabletoderiveva
luefromthebusinessandthepartnershipconcerncanfunctionsmoothly(Duetal.,2018).Themem
oisdesignedtohelpanewclientinvolvingthreepartnerssothatthefirst-
yearprofitscanbedistributedamongthem.
AllocationofProfits
(A)Inthespecificpartnershipbusinesscontext,thefirstyear’sprofitsamountingtoUSD1,50,000
mustbeevenlydistributedbetweenthethreepartners.Itisbecauseeachofthemembersiscontribut
ingtothepartnershipintheformofcash,day-to-
daybusinessoperationsandusingexperienceandattractingnewclients.Thus,basedonthediverse
contributionsmadebyAlan,Bob,andCarol,theymustbeallocatedUSD50,000ofthebusinesspro
fits.
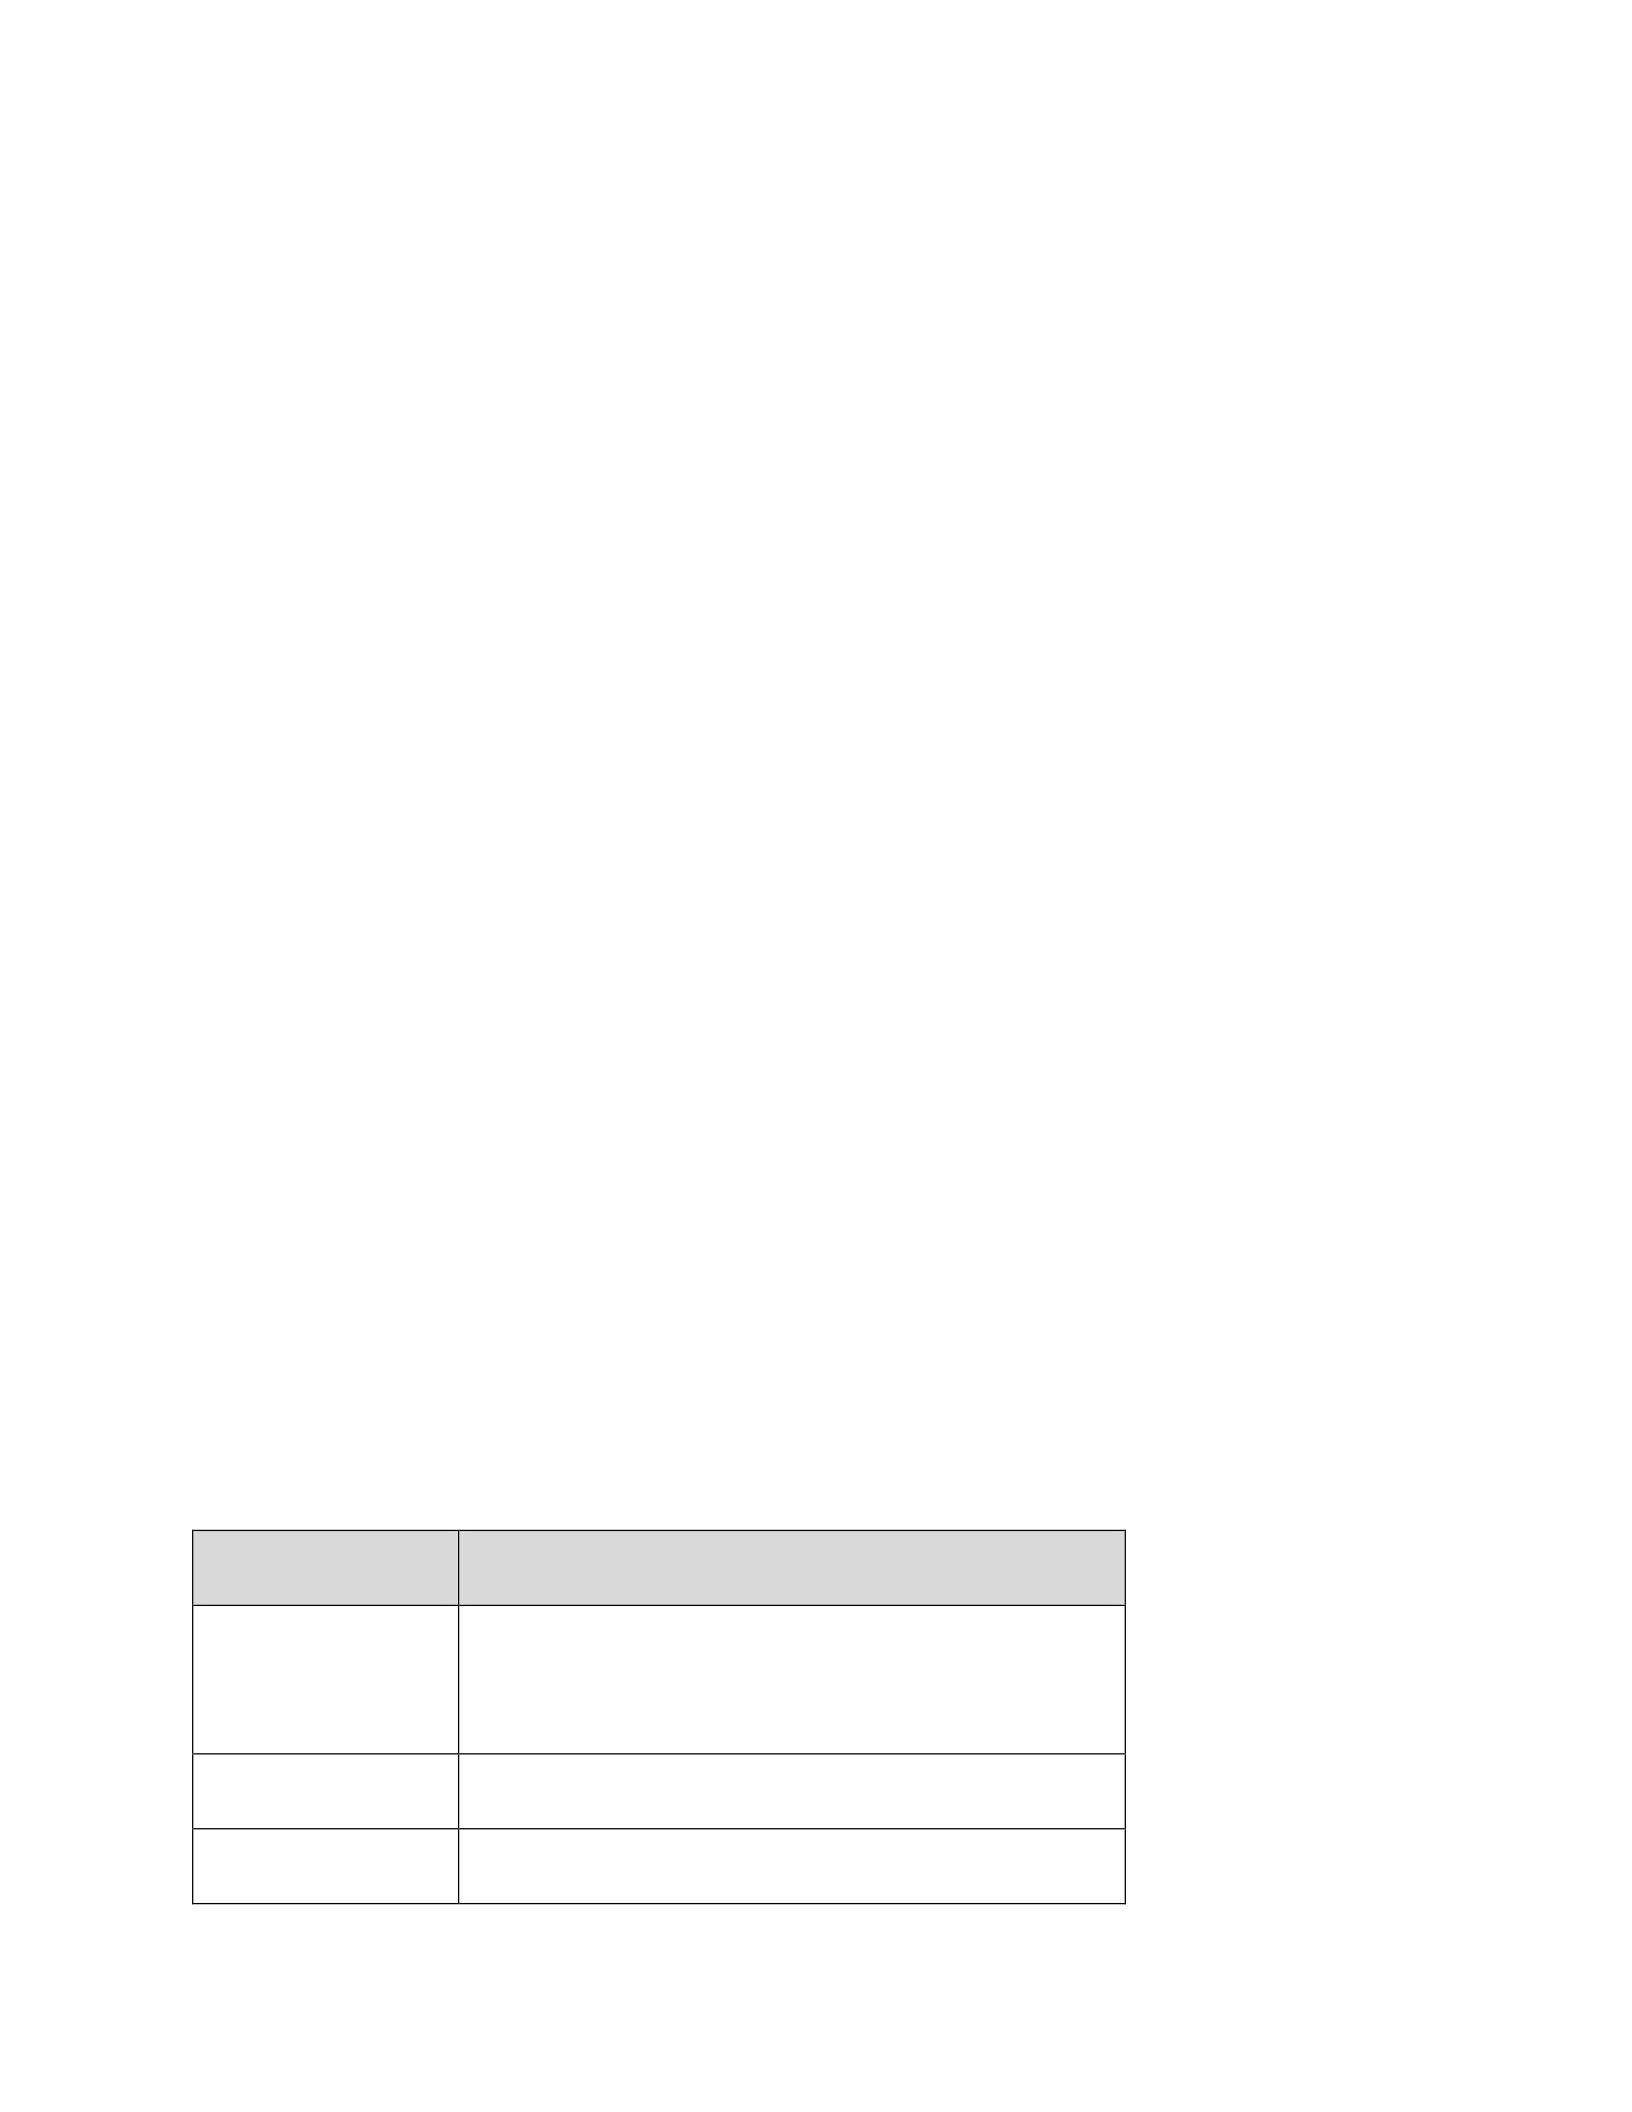
(B)Ifthebusinessprofitswereallocatedevenlyamongthethreepartnersofthebusiness,thevalue
ofeachpartner’scapitalaccountattheyear-endwouldbeasfollows:
Partners
CapitalAccountValue(inUSD)
Alan
=10,00,000(investment)+50,000allocatedprofit
=10,50,000
Bob
=50,000allocatedprofit
Carol
=50,000allocatedprofit
MEMO3
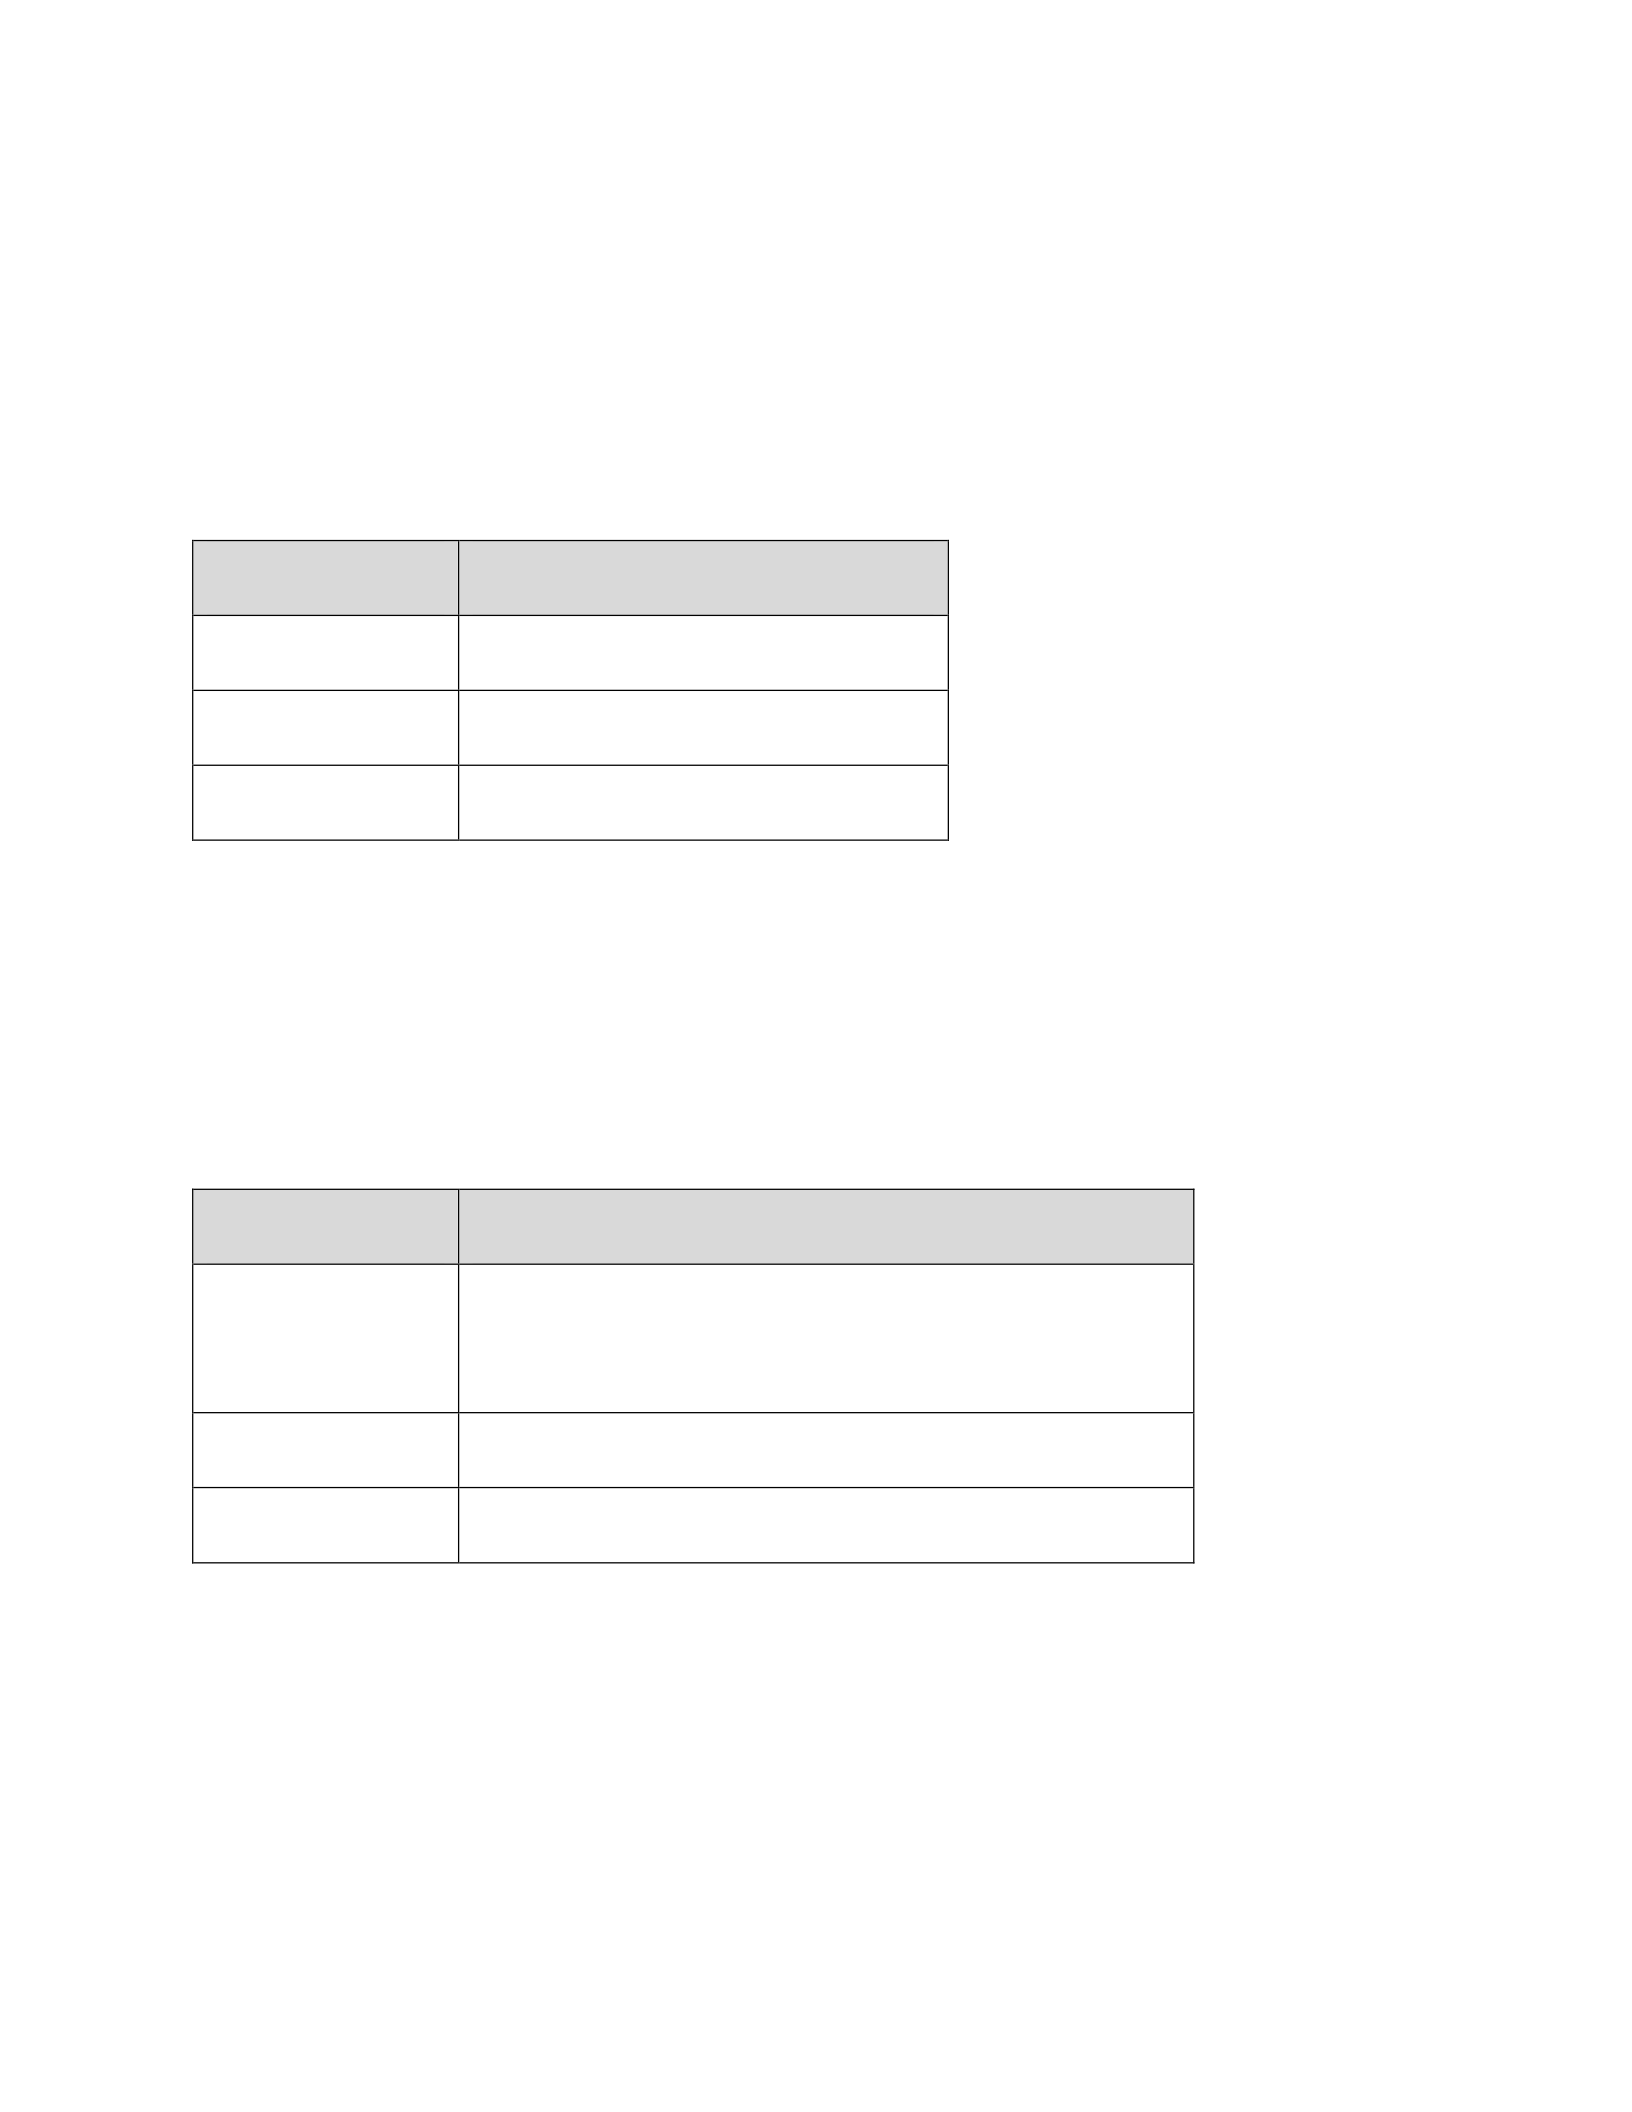
(C)Incaseanalternativemethodofprofitallocationwasadoptedwhere80%oftheprofitsweregiv
entothecashinvestor,i.e.,Alan,andthebalanceamountwassplitevenlybetweenCarolandBob,t
hentheindividualprofitsharewouldbeasfollows:
Partners
Shareinprofit(inUSD)
Alan
=80%of1,50,000=1,20,000
Bob
=10%of1,50,000=15,000
Carol
=10%of1,50,000=15,000
(D)Incasethealternativeallocationmethodwasadoptedinthebusinesscontext,thevalueofeach
partner’scapitalaccountattheendoftheyearwouldvarysignificantly.Thetablepresentedbelowc
apturesthenewcapitalaccountvaluebasedonthealternativeprofitallocationfigures.
Partners
CapitalAccountValue(inUSD)
Alan
=10,00,000(investment)+1,20,000allocatedprofit
=11,20,000
Bob
=15,000allocatedprofit
Carol
=15,000allocatedprofit
PaymentofSalary
(A)Partnerremunerationisavitalelementthatmustbetakenintoconsiderationinthespecificpartn
ershipbusinesscontext.Partnerscanbecategorizedintovaryingtypesbasedontheirspecificroles.

MEMO4
Inthepartnership,BobandCarolareactivepartnerssincetheytakepartinthedailyoperationsofth
ebusiness.Ontheotherhand,Alanisasleepingordormantpartnerashedoesnotparticipateinthe
usualanddailyfunctioningofthebusiness(Moneyandmanagementrelatedarticlesonfinance.Mo
neyandmanagementrelatedarticlesonfinance,2021).AsBobandCarolworkandcontributetono
rmalbusinessoperations,theymustreceiveasalary fortheirroles.Partnersmustbegivencompens
ationbasedontheirresponsibilities(Palaveev,2012).Thus,thesalarycomponentoftheworkingpa
rtnersmustbedeductedfromtheprofits,andthebalanceprofitsmustbeallocatedequallyorbyusin
gthealternativemethod.
(B)Ifthenon-
investorsreceivedasalary,thentheircapitalaccount wouldbeimpactedsinceitwouldincreaseowi
ngtothereceivedsalaryaswellastheallocationof profits.Similarly,iftheywouldmakewithdraw
alsfromtheircapitalaccount,thentheamountintheaccountwouldbereduced.Incaseofapotentia
lfutureliquidationorbuyout,theassetswouldbedistributedamongadiverserangeofstakeholders.
The secured creditorswouldbethefirsttoreceivetheirdue.Thentheunsecuredcreditorswouldbe
givenpreference,andultimately,theremainingassetswillbedistributedamongthepartnersofthe
business(Hyndman,2021).
(C)Theshareoftheprofitsbetweenthecashinvestorandtheworkingpartnersmustbebasedonthe
specificpartnershipagreementthathasbeenagreedupon.So,thecashinvestorshouldnotgetahigh
ershareoftheprofitsorothersharingoptions.Thus incase,theagreementdoesnotconsidertheinv
estmentof1millionbyAlan,itisimmaterialwhilesharingprofits.
(D)Incasethecashinvestorwouldgetasalary,hiscapitalaccountwouldbeimpactedsincehisnew
capital account would be USD 10,24,000. Theamountincludeshisinitialinvestmentandsalarywo
MEMO5
rthUSD24,000.Incasethereisapotentialfutureliquidationorbuyout,Alan’scapitalaccountwill
haveahigherbalanceascomparedtothatofCarolandBobsinceitincludestheinvestmentamount.
(E)Thepaymentofsalarytothepartnersandtheallocationofprofitwouldhaveamajorimpactont
hepartnership’sentriesanditsfinancialbottomline.Astheprofitswouldbedistributedamongthe
partners,thebottomlineofthebusinesswoulddecline.
(F) Forincreasingtheeffectivenessofsalarypaymentsandprofitallocationforthethreepartners,e
venandfairdistributionapproachmustbeadopted.Ascenariotoensurefaircompensationforallth
ethreepartnersispresentedwhereCarolandBobmustreceivesalaryascompensationfortheirinvo
lvementindailyoperations,andAlanmustbegiveninterestforhisinvestmentcontribution.
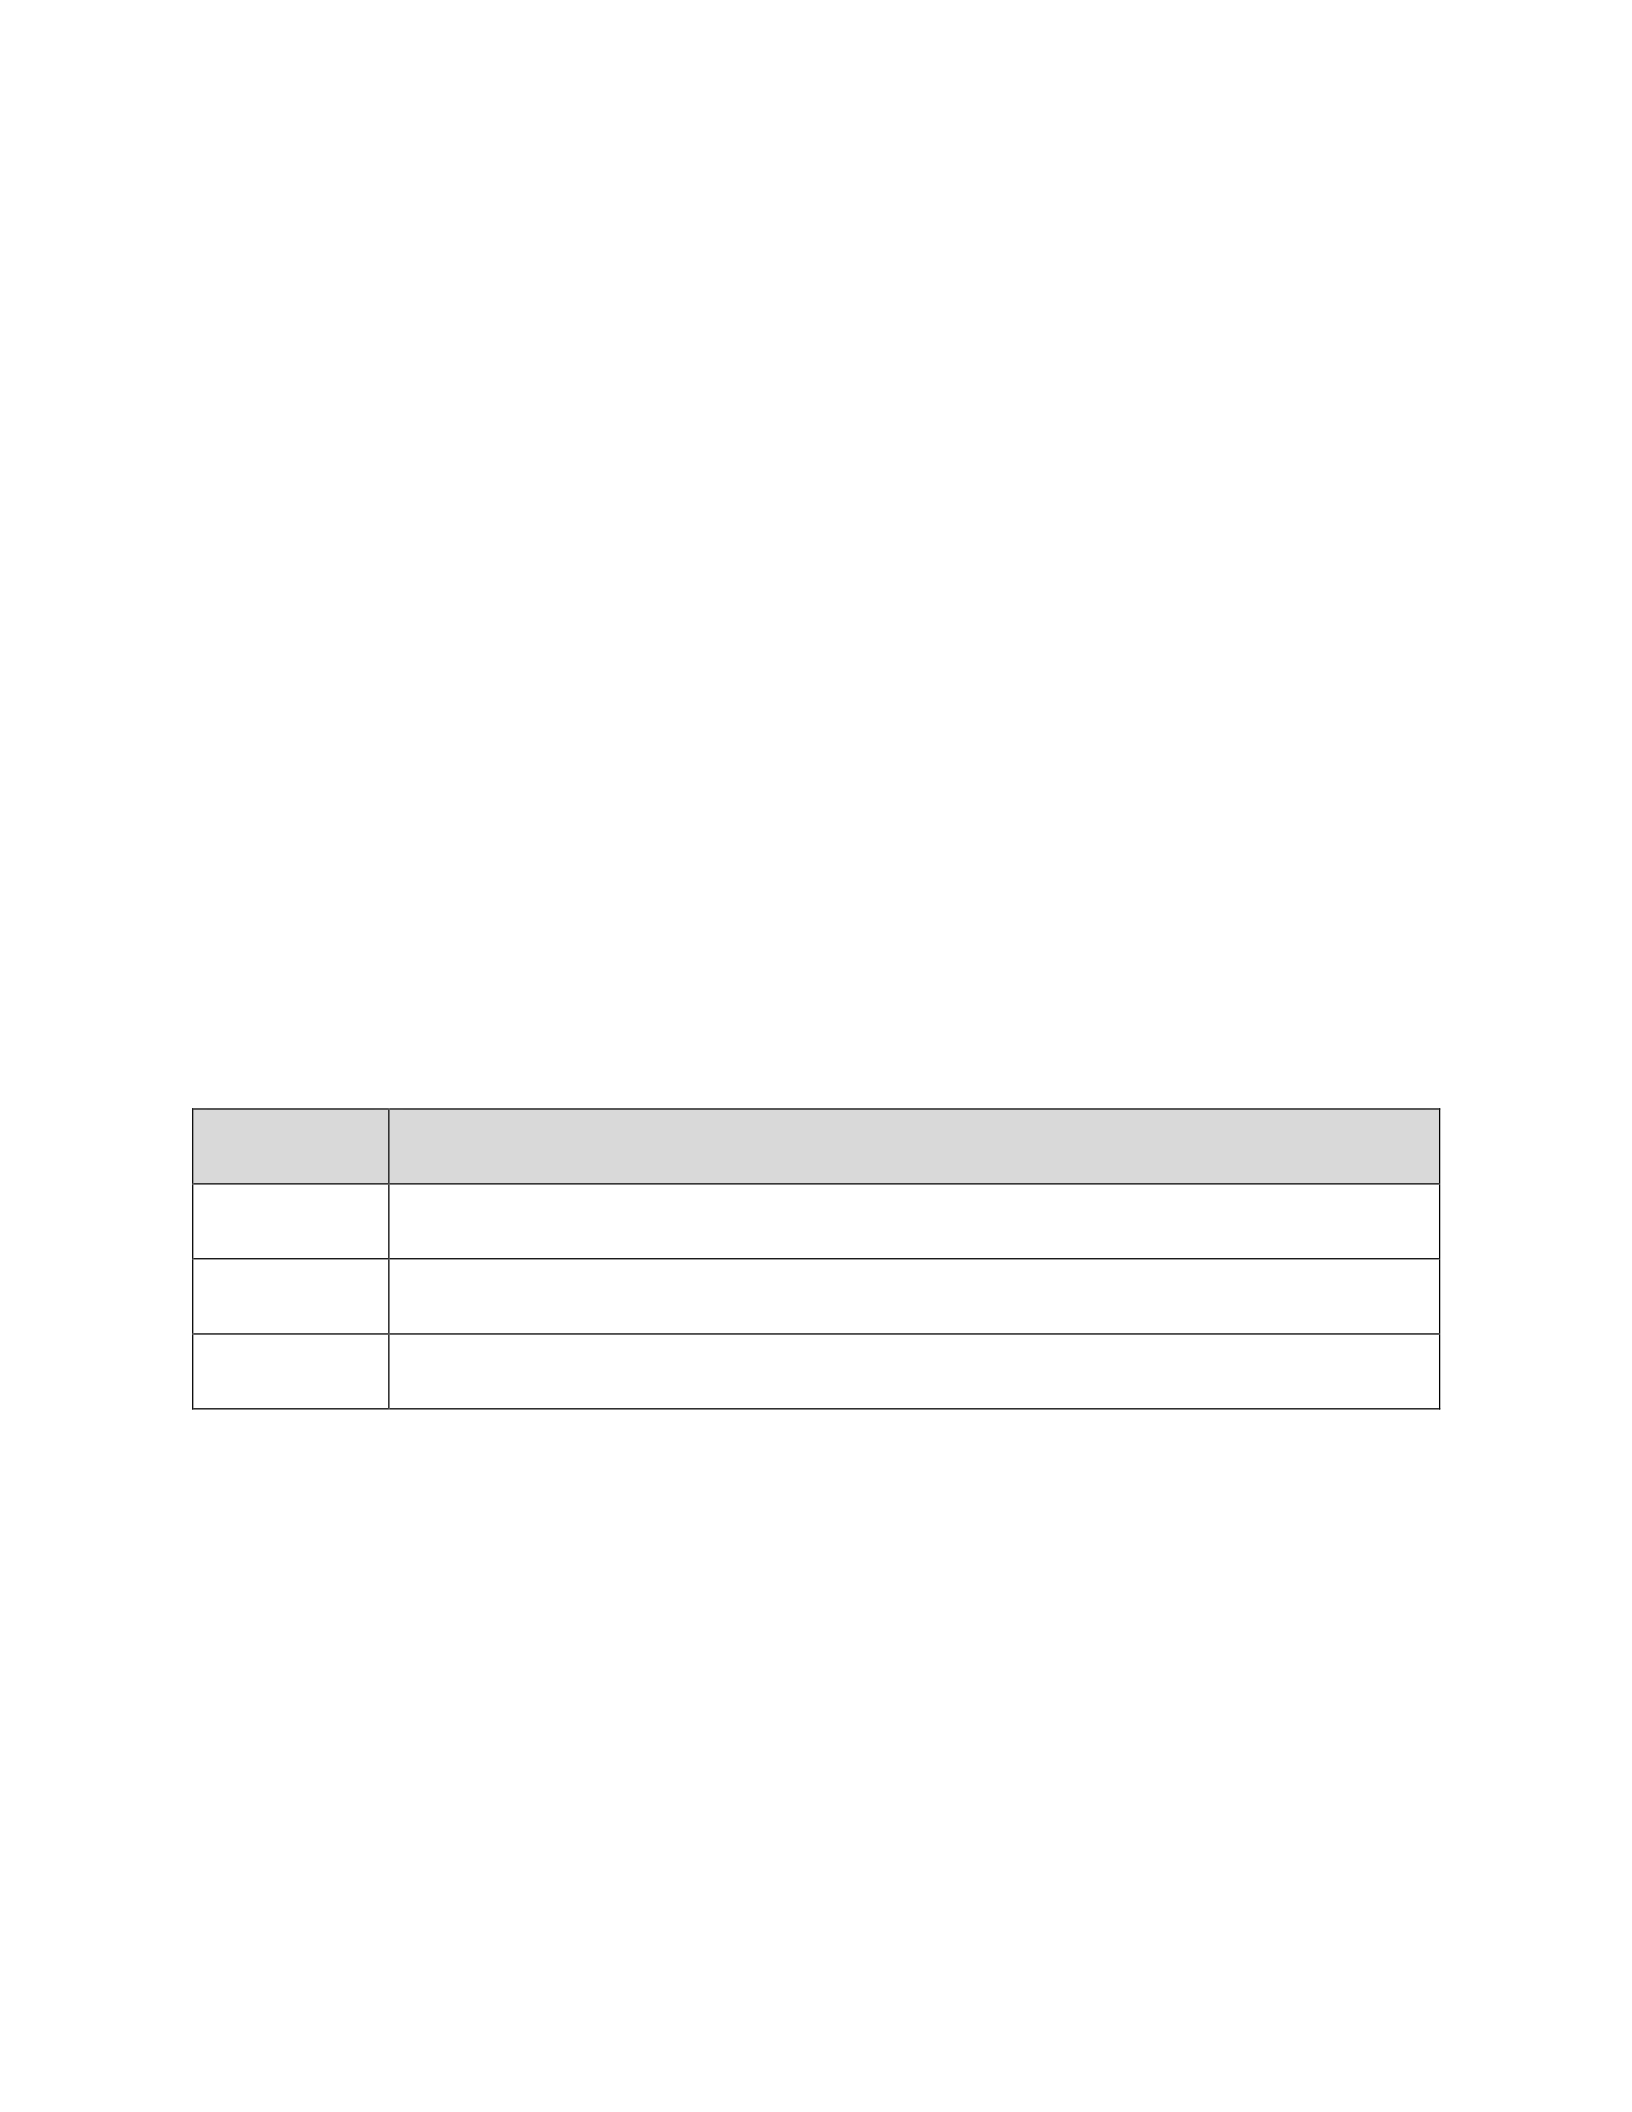
(G)Iftheproposedfairallocationmethodwasfollowed,thevalueofeverypartner’scapitalaccount
at the year-end would be as follows:
Partners
CapitalAccountValue(inUSD)
Alan
=1,50,000+50,000interestandsharedprofitsalongwithinvestmentof1million
Bob
=50,000sharedprofits
Carol
=50,000sharedprofits
ThankYou
References
Du,J.,Wu,H.,&Zhu,L.(2018).Influencingfactorsonprofitdistributionofpublic-
privatepartnershipprojects:privatesector’sperspective.AdvancesinCivilEngineering,201
8.

MEMO6
Hyndman,K.(2021).Dissolvingpartnershipsunderrisk:Anexperimentalinvestigation.Journalof
Economic Behavior & Organization, 185, 702-720.
Moneyandmanagementrelatedarticlesonfinance.Moneyandmanagementrelatedarticlesonfin
anc.(2021).RetrievedAugust12,2022,fromhttps://accountlearning.com/types-of-partners-
in-a-business-partnership/
Palaveev,P.(2012).PartnerResponsibilitiesandPartnerCompensation.10.1002/9781118531914.
ch6.

