


Running Head: MEMO a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a 1
ACC 405 Final Project Two
ACC 405
SNHU
August 13,2022
MEMO a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a
a a a a a a a a a a a a a a 2
Subject: Splitting of profits among the business partners from year one of the business
In the partnership business context, clarity in terms of profit distribution and the payment
of salaried is vital. These elements have the potential to ensure that all the partners are able to
derive value from the business and the partnership concern can function smoothly (Du et al.,
2018). The memo is designed to help a new client involving three partners so that the first-year
profits can be distributed among them.
Allocation of Profits
(A) In the specific partnership business context, the first year’s profits amounting to USD
1,50,000 must be evenly distributed between the three partners. It is because each of the members
is contributing to the partnership in the form of cash, day-to-day business operations and using
experience and attracting new clients. Thus, based on the diverse contributions made by Alan,
Bob, and Carol, they must be allocated USD 50,000 of the business profits.
(B) If the business profits were allocated evenly among the three partners of the business, the
value of each partner’s capital account at the year-end would be as follows:
Partners
Capital Account Value (in USD)
Alan
= 10,00,000 (investment) + 50,000
allocated profit
=10,50,000
Bob
= 50,000 allocated profit
Carol
= 50,000 allocated profit
MEMO a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a
a a a a a a a a a a a a a a 3
(C) In case an alternative method of profit allocation was adopted where 80 % of the profits were
given to the cash investor, i.e., Alan, and the balance amount was split evenly between Carol and
Bob, then the individual profit share would be as follows:
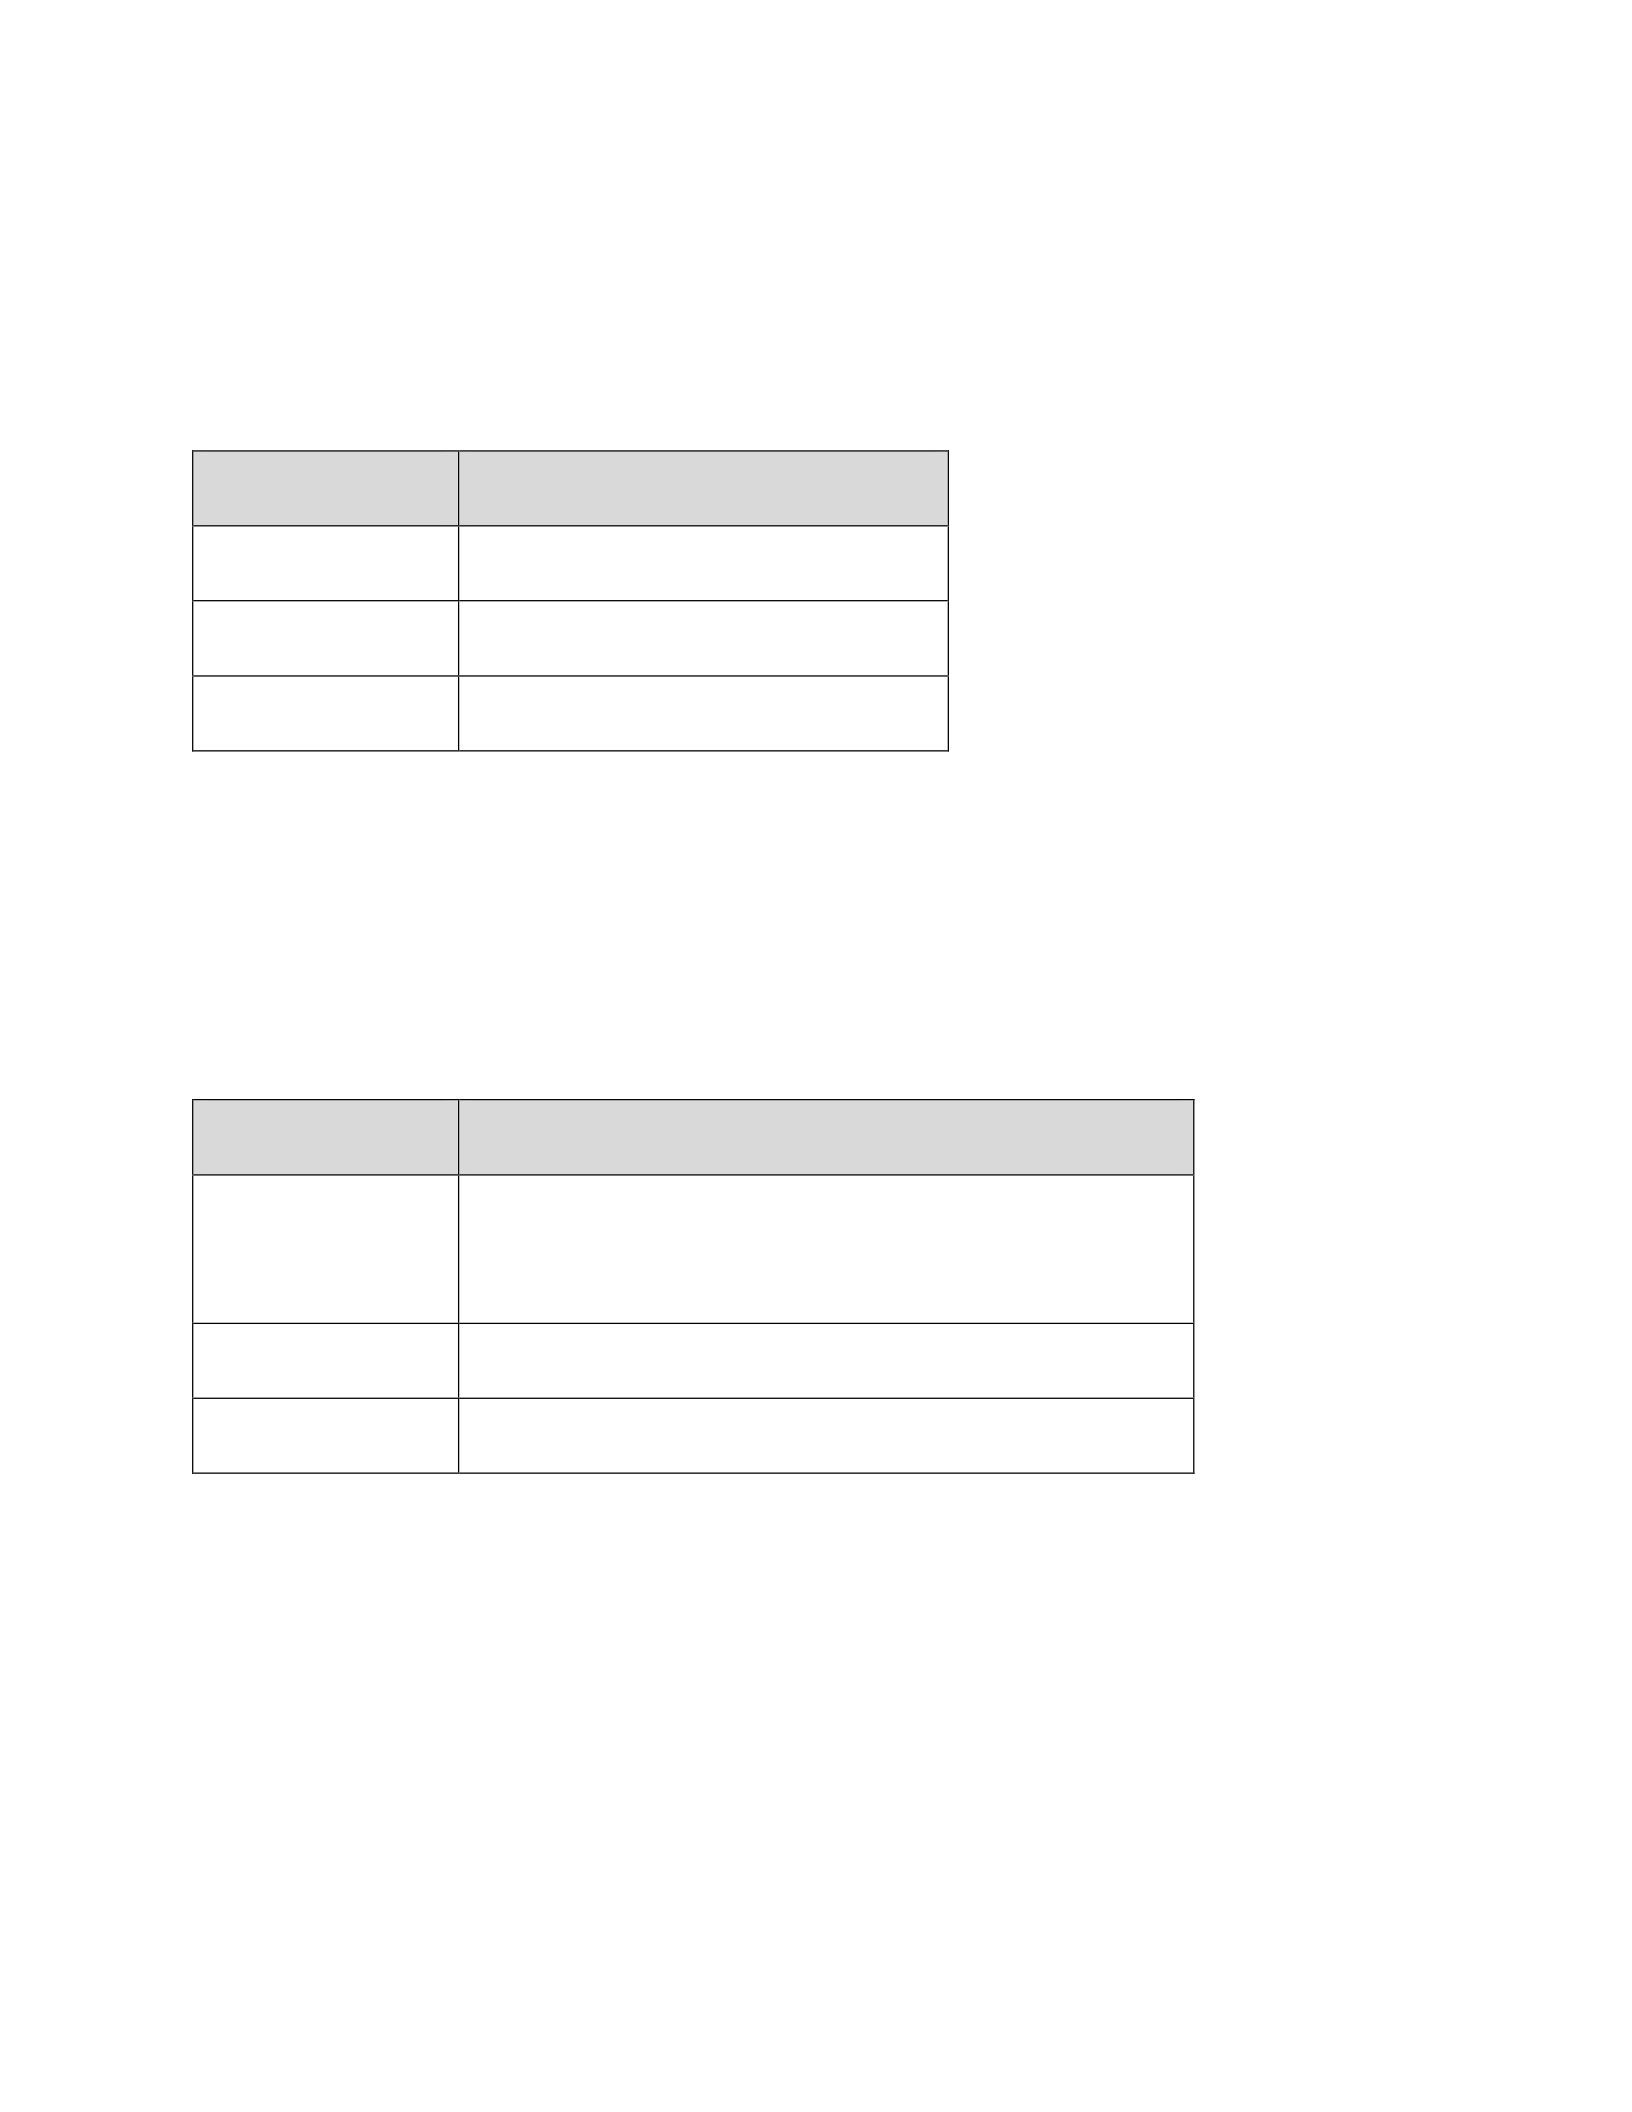
Partners
Share in profit (in USD)
Alan
= 80 % of 1,50,000 = 1,20,000
Bob
= 10 % of 1,50,000 = 15,000
Carol
= 10 % of 1,50,000 = 15,000
(D) In case the alternative allocation method was adopted in the business context, the value of
each partner’s capital account at the end of the year would vary significantly. The table presented
below captures the new capital account value based on the alternative profit allocation figures.
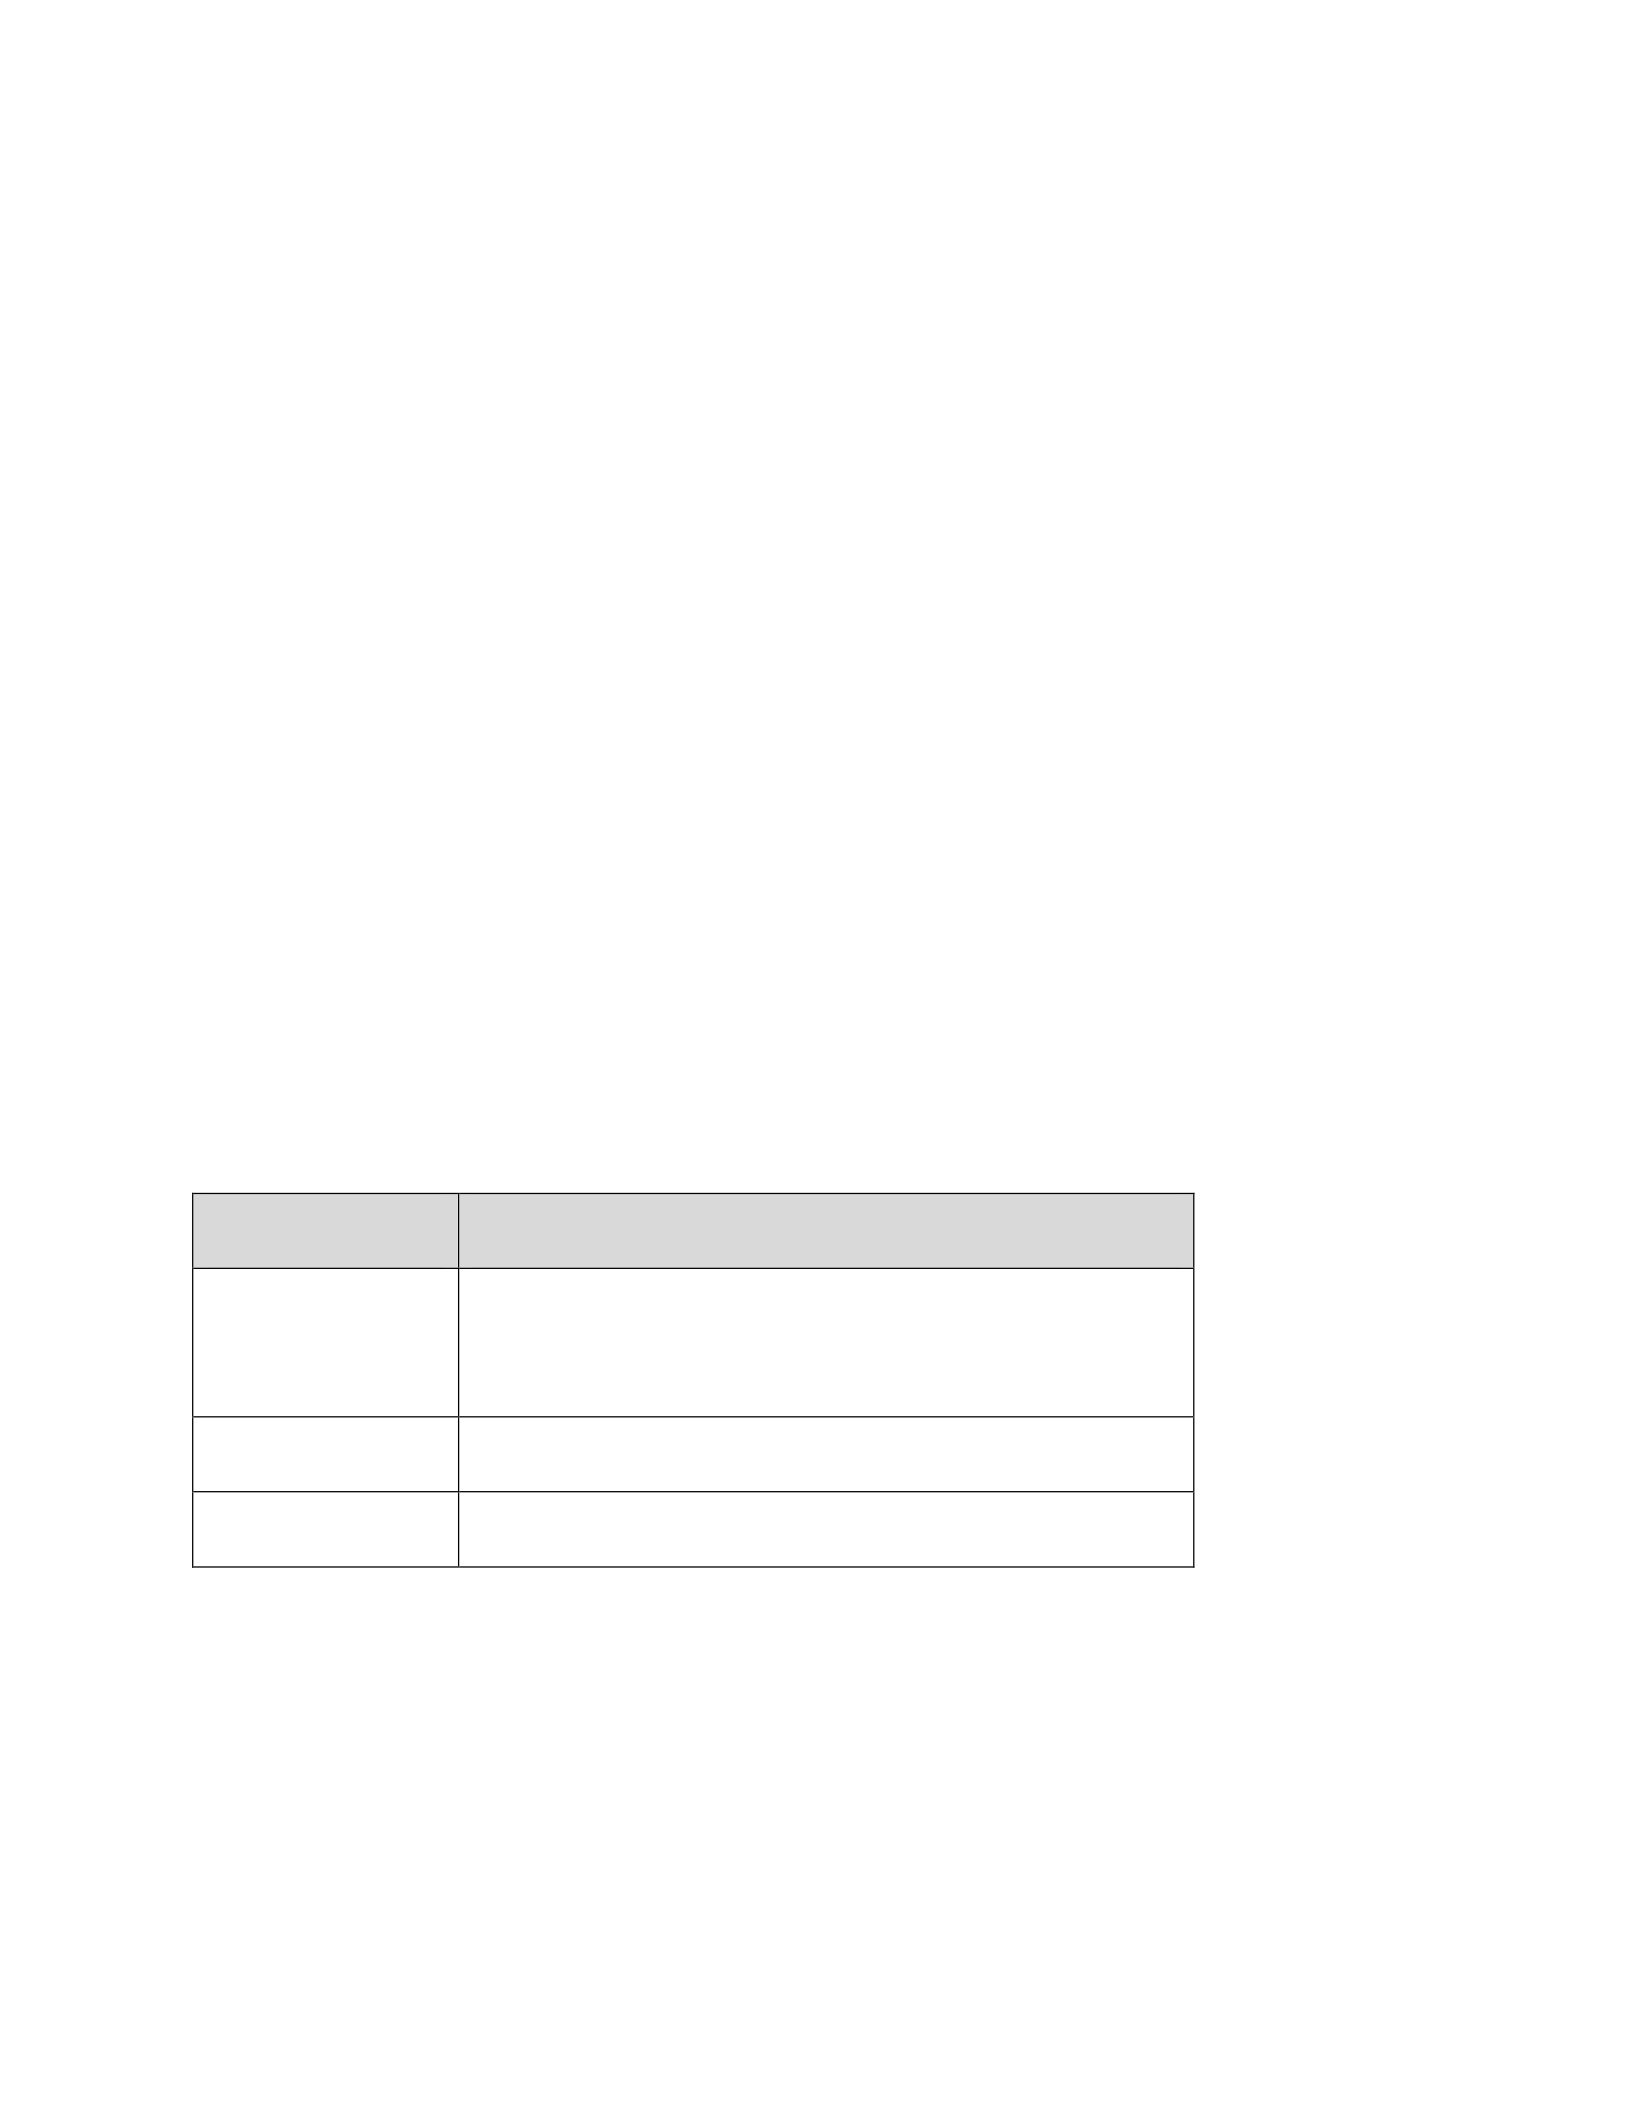
Partners
Capital Account Value (in USD)
Alan
= 10,00,000 (investment) + 1,20,000 allocated profit
=11,20,000
Bob
= 15,000 allocated profit
Carol
= 15,000 allocated profit
Payment of Salary
(A) Partner remuneration is a vital element that must be taken into consideration in the specific
partnership business context. Partners can be categorized into varying types based on their
specific roles. In the partnership, Bob and Carol are active partners since they take part in the daily

MEMO a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a
a a a a a a a a a a a a a a 4
operations of the business. On the other hand, Alan is a sleeping or dormant partner as he does not
participate in the usual and daily functioning of the business (Money and management related
articles on finance. Money and management related articles on finance, 2021). As Bob and Carol
work and contribute to normal business operations, they must receive a salary for their roles.
Partners must be given compensation based on their responsibilities (Palaveev, 2012). Thus, the
salary component of the working partners must be deducted from the profits, and the balance
profits must be allocated equally or by using the alternative method.
(B) If the non-investors received a salary, then their capital account would be impacted since it
would increase owing to the received salary as well as the allocation of profits. Similarly, if they
would make withdrawals from their capital account, then the amount in the account would be
reduced. In case of a potential future liquidation or buyout, the assets would be distributed among
a diverse range of stakeholders. The secured creditors would be the first to receive their due. Then
the unsecured creditors would be given preference, and ultimately, the remaining assets will be
distributed among the partners of the business (Hyndman, 2021).
(C) The share of the profits between the cash investor and the working partners must be based on
the specific partnership agreement that has been agreed upon. So, the cash investor should not get
a higher share of the profits or other sharing options. Thus in case, the agreement does not
consider the investment of 1 million by Alan, it is immaterial while sharing profits.
(D) In case the cash investor would get a salary, his capital account would be impacted since his
new capital account would be USD 10,24,000. The amount includes his initial investment and
salary worth USD 24,000. In case there is a potential future liquidation or buyout, Alan’s capital
MEMO a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a
a a a a a a a a a a a a a a 5
account will have a higher balance as compared to that of Carol and Bob since it includes the
investment amount.
(E) The payment of salary to the partners and the allocation of profit would have a major impact
on the partnership’s entries and its financial bottom line. As the profits would be distributed
among the partners, the bottom line of the business would decline. a
(F) For increasing the effectiveness of salary payments and profit allocation for the three partners,
even and fair distribution approach must be adopted. A scenario to ensure fair compensation for
all the three partners is presented where Carol and Bob must receive salary as compensation for
their involvement in daily operations, and Alan must be given interest for his investment
contribution.
(G) If the proposed fair allocation method was followed, the value of every partner’s capital
account at the year-end would be as follows:
Partners
Capital Account Value (in USD)
Alan
= 1,50,000 + 50,000 interest and shared profits along
with investment of 1 million
Bob
= 50,000 shared profits
Carol
= 50,000 shared profits
Thank You
References

MEMO a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a a
a a a a a a a a a a a a a a 6
Du, J., Wu, H., & Zhu, L. (2018). Influencing factors on profit distribution of public-private
partnership projects: private sector’s perspective. Advances in Civil Engineering, 2018.
Hyndman, K. (2021). Dissolving partnerships under risk: An experimental investigation. Journal
of Economic Behavior & Organization, 185, 702-720.
Money and management related articles on finance. Money and management related articles on
financ. (2021). Retrieved August 12, 2022, from https://accountlearning.com/types-of-
partners-in-a-business-partnership/
Palaveev, P. (2012). Partner Responsibilities and Partner Compensation.
10.1002/9781118531914.ch6.

