


FINANCIAL EXERCISE THREE 1
Planning and Controlling
School of Nursing, Liberty University
Author Note
Crystal Anthony
I have no known conflict of interest to disclose.
Correspondence concerning this article should be addressed to Crystal Anthony
Email: Cranthony1@liberty.edu
FINANCIAL EXERCISE THREE 2
Planning and Controlling
1. How does pay for performance (P4P) or value-based purchasing (VBP) affect staffing?
P4p or VBP was created in the early 2000s to pay hospitals and health care providers
based on their performance, rather than what the facility or provider would charge to provide
care. This system offers incentives to providers as a result of the quality care that was
provided in certain area such as financial performance, patient outcome, or internal
processes. This payment system causes increased financial pressure on health care facilities
because of potential declining of reimbursements. Facilities are pressured to improve
performance and productivity, while possibly working with less staff (Jones et. al., 2019).
The goal for value-based purchasing is that Centers for Medicare and Medicaid Services
(CMS) holds a specific percentage of payments for eligible hospitals at the beginning of the
fiscal year, and then redistributes these funds to facilities based on quality performance; and
also assist patients to compare when shopping for hospitals in the CMS’s Hospital Compare.
The hospital’s initial reduction that is earned back is based on the Total performance score
that calculates the hospitals’ final adjustment (Izon & Pardini, 2018). Even though increasing
nurse-to patient ration improves patient care and nurse burnout rates, it has a negative impact
on costs. As a resolution, nurse leaders must account for variability in the patient census. To
provide quality care efficiently that will reimburse hospitals for their performance while
budgeting expenses, decisions reviewed should be how many nurses are needed to meet
demands of patient acuity and staff accordingly and have access to trained float pool when
staffing does not accommodate floor (Maass et al., 2017). This way, there is a safe nurse-to-
patient ratio that would improve safety and enhance performance, and too many nurses
FINANCIAL EXERCISE THREE 3
would not be staffed which would increase unnecessary expenses. When there is a shortage,
a float pool nurse can be used as a resource.
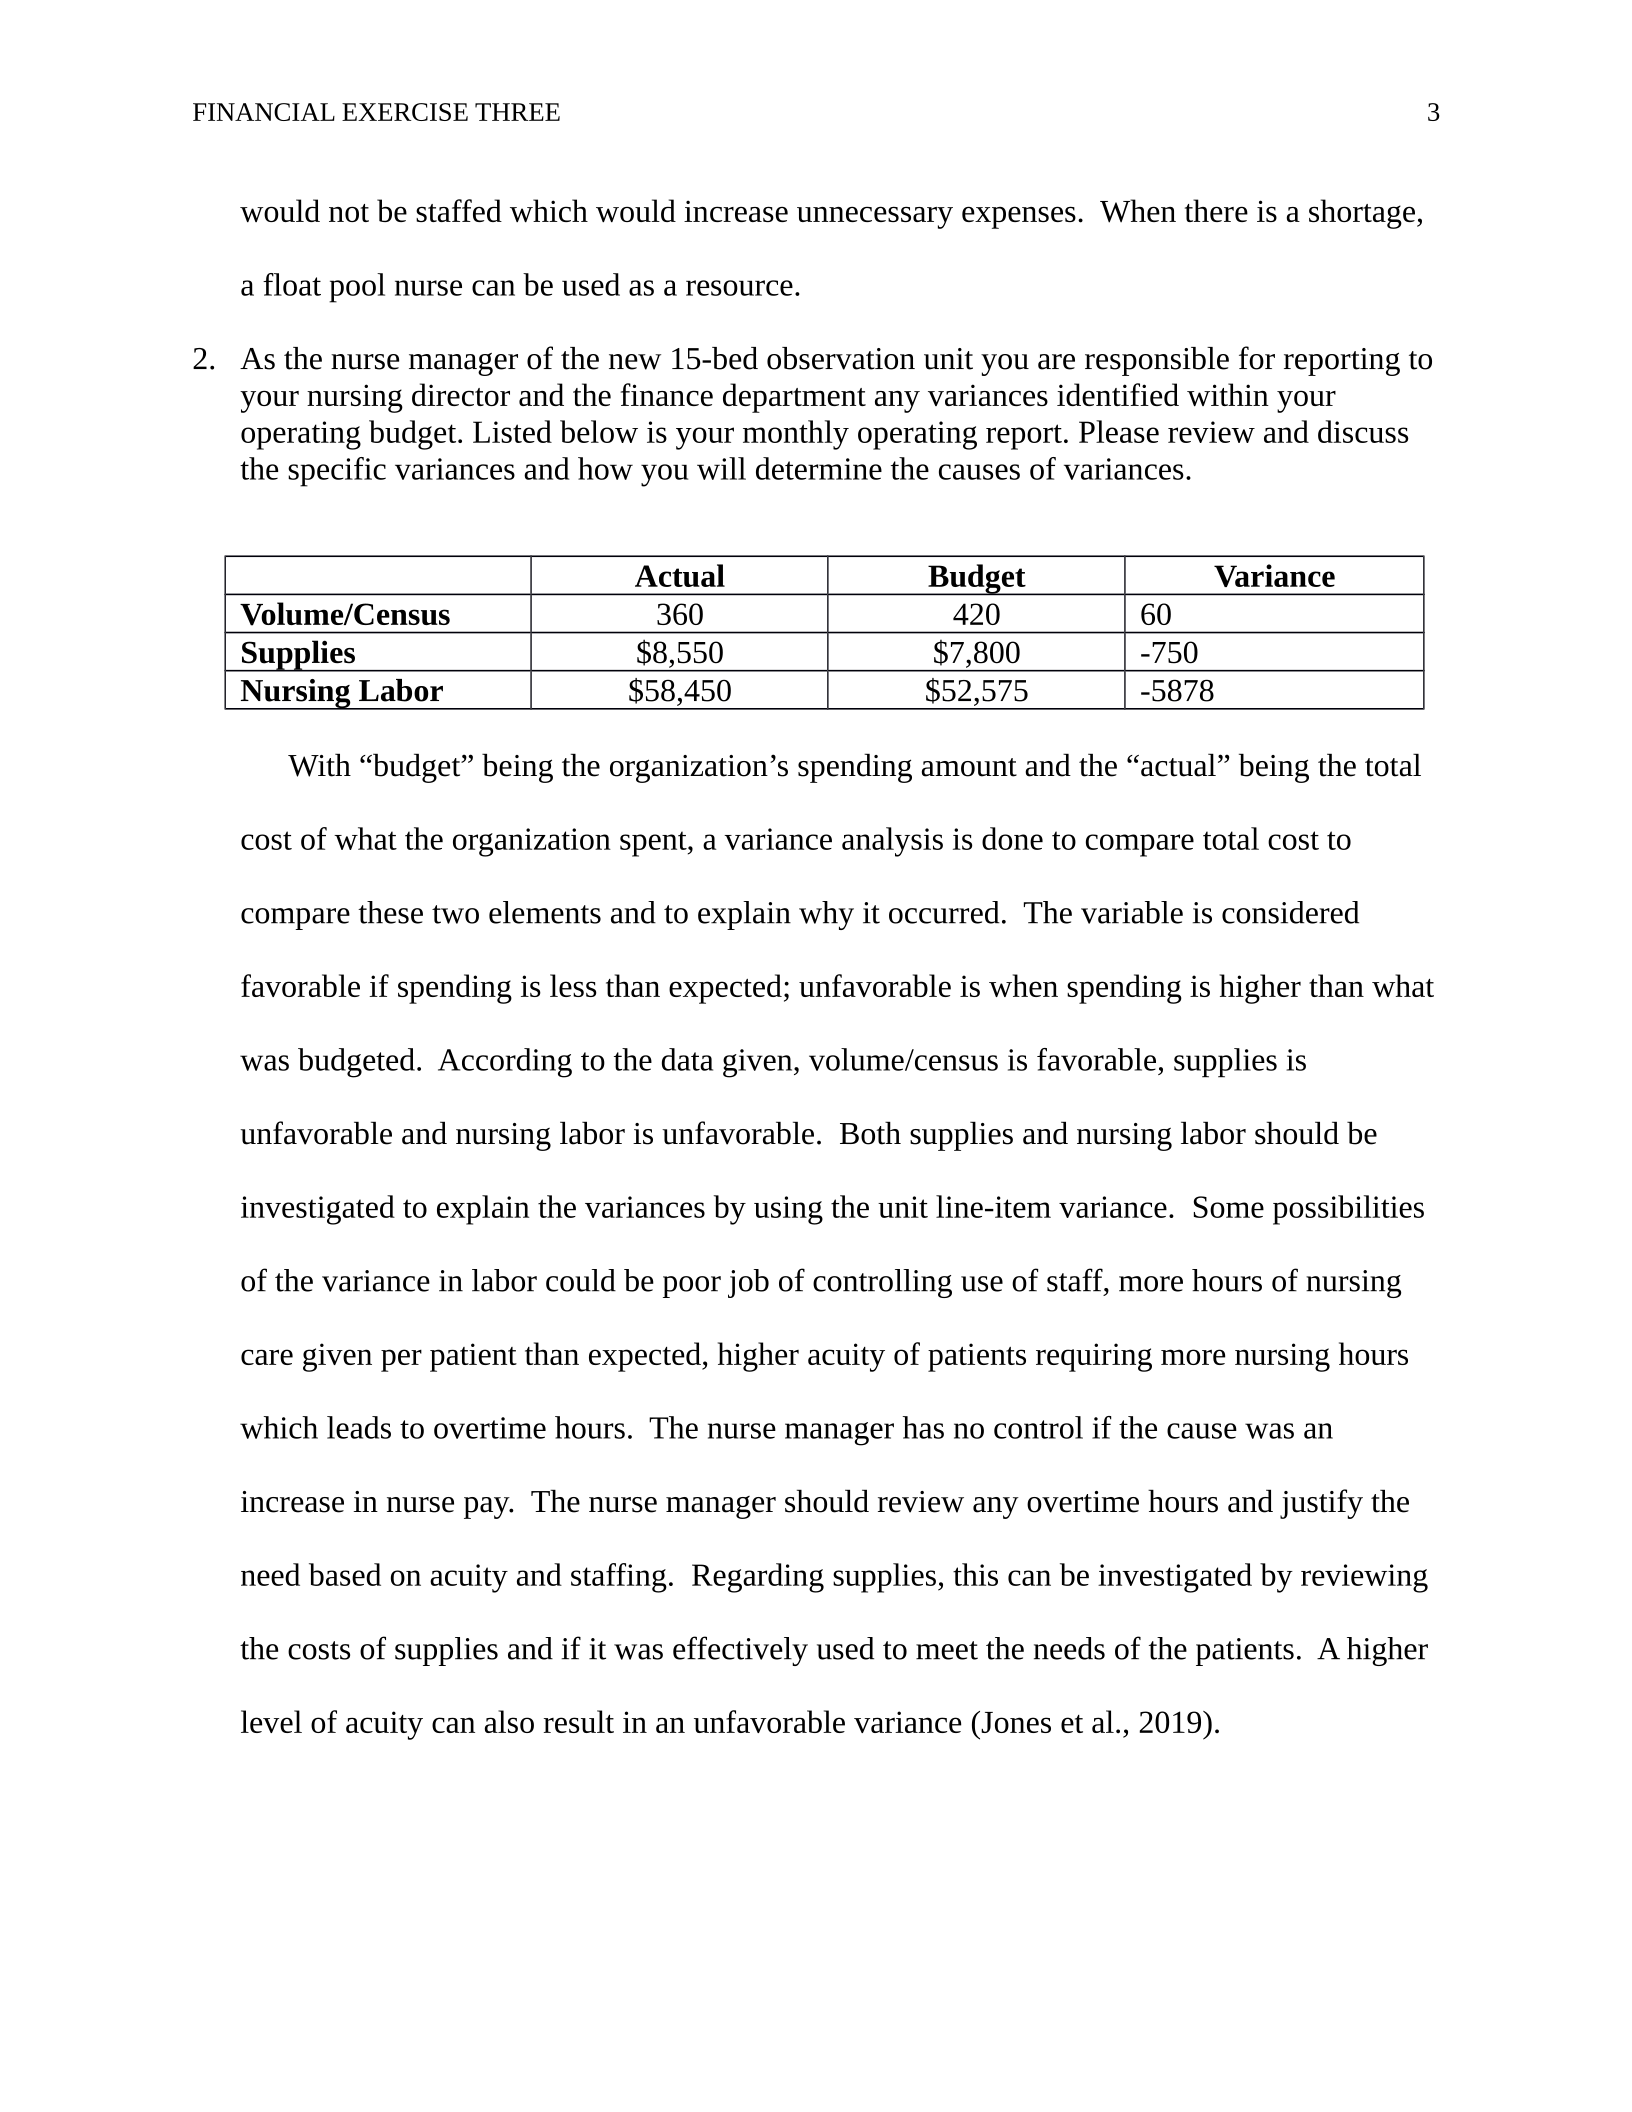
2. As the nurse manager of the new 15-bed observation unit you are responsible for reporting to
your nursing director and the finance department any variances identified within your
operating budget. Listed below is your monthly operating report. Please review and discuss
the specific variances and how you will determine the causes of variances.
Actual Budget Variance
Volume/Census 360 420 60
Supplies $8,550 $7,800 -750
Nursing Labor $58,450 $52,575 -5878
With “budget” being the organization’s spending amount and the “actual” being the total
cost of what the organization spent, a variance analysis is done to compare total cost to
compare these two elements and to explain why it occurred. The variable is considered
favorable if spending is less than expected; unfavorable is when spending is higher than what
was budgeted. According to the data given, volume/census is favorable, supplies is
unfavorable and nursing labor is unfavorable. Both supplies and nursing labor should be
investigated to explain the variances by using the unit line-item variance. Some possibilities
of the variance in labor could be poor job of controlling use of staff, more hours of nursing
care given per patient than expected, higher acuity of patients requiring more nursing hours
which leads to overtime hours. The nurse manager has no control if the cause was an
increase in nurse pay. The nurse manager should review any overtime hours and justify the
need based on acuity and staffing. Regarding supplies, this can be investigated by reviewing
the costs of supplies and if it was effectively used to meet the needs of the patients. A higher
level of acuity can also result in an unfavorable variance (Jones et al., 2019).
FINANCIAL EXERCISE THREE 4
3. As the nurse manager, you will now need to determine the staff mix based on budgeted full-
time equivalents (FTEs). Consider the formula below:
Actual Price per FTE x Actual Total Number of FTEs = Budgeted Cost
Using the figure in the table above for nursing labor, calculate the Actual Cost and how you
will divide the nursing labor expense based on skill mix. Consider safe staffing requirements,
quality of care and operational needs to meet the demands of the new unit. Provide a detailed
rationale of why and how you arrived at your decision.
A one to three nurse ratio is considered safe for a telemetry unit, so 5 RNs are needed to
accommodate this 15-bed unit. The assumed patient budget per month is 420 and the nurse
labor budget expense is 52,575 for the 15-bed unit. To find the actual price per FTE
52,575/420=125.18 and multiply 15 the actual total number of FTE. According to the
formula above 125.2*15=$1,878 budgeted cost.
4. The productivity standards for your new observation unit are set. You must meet the
minimum target of 95% with a maximum target of 105%. Keep in mind that volume drives
productivity in a positive direction. Using the formulas provided in your assigned textbook
readings, determine the number of patients you need to admit to meet budgeted volumes.
Consider the type of unit you are managing. An observation unit has a minimal stay of six (6)
hours and a maximum stay of forty-eight (48) hours. Most patients are admitted into an
appropriate next level of care (inpatient admission) or discharged home within 24 hours of
admission into an observation unit. This demonstrates a unit with rapid turnover. Also
include in your discussion how nursing labor/staffing will be managed when census/volume
drops.
According to the text, the productivity formula was used. The maximum product target is
105% at the budgeted level. Productivity = Total Outputs/Maximum hours. With this
information, we can plug number in formula to find productivity.
105%=1.05
1.05=x/48hrs
X=0.0218 or 2.18 per hours
FINANCIAL EXERCISE THREE 5
To find the number of patients that need to be admitted at budgeted volume is budgeted
volume/Total output per hour. The assumed budget volume is 420. This equation is 420/2.18
per hour= 192.66=193. Therefore, 193 patients are needed to meet budgeted volumes (Jones
et al., 2019). When the census or volume drops, the requirements to meet patient needs will
decrease.
FINANCIAL EXERCISE THREE 6
References
Izón, G.,M., & Pardini, C. A. (2018). Association Between Medicare's Mandatory
Hospital Value-Based Purchasing Program and Cost Inefficiency. Applied Health
Economics and Health Policy, 16(1), 79-90.
http://dx.doi.org.ezproxy.liberty.edu/10.1007/s40258-017-0357-3
Jones, C. B., Kovner, C. T., Finkler, S. A., & Mose, J. (2019). Financial management for
nurse managers and executives (5th ed.). St. Louis, MO: Elsevier
Maass, K. L., Maass, K. L., Liu, B., Liu, B., Daskin, M. S., Daskin, M. S., . . . Schapiro,
H. (2017). Incorporating nurse absenteeism into staffing with demand
uncertainty. Health Care Management Science, 20(1), 141-155.
doi:10.1007/s10729-015-9345-z
Powered by TCPDF (www.tcpdf.org)

