


Textbook/Essay Assignment 2:
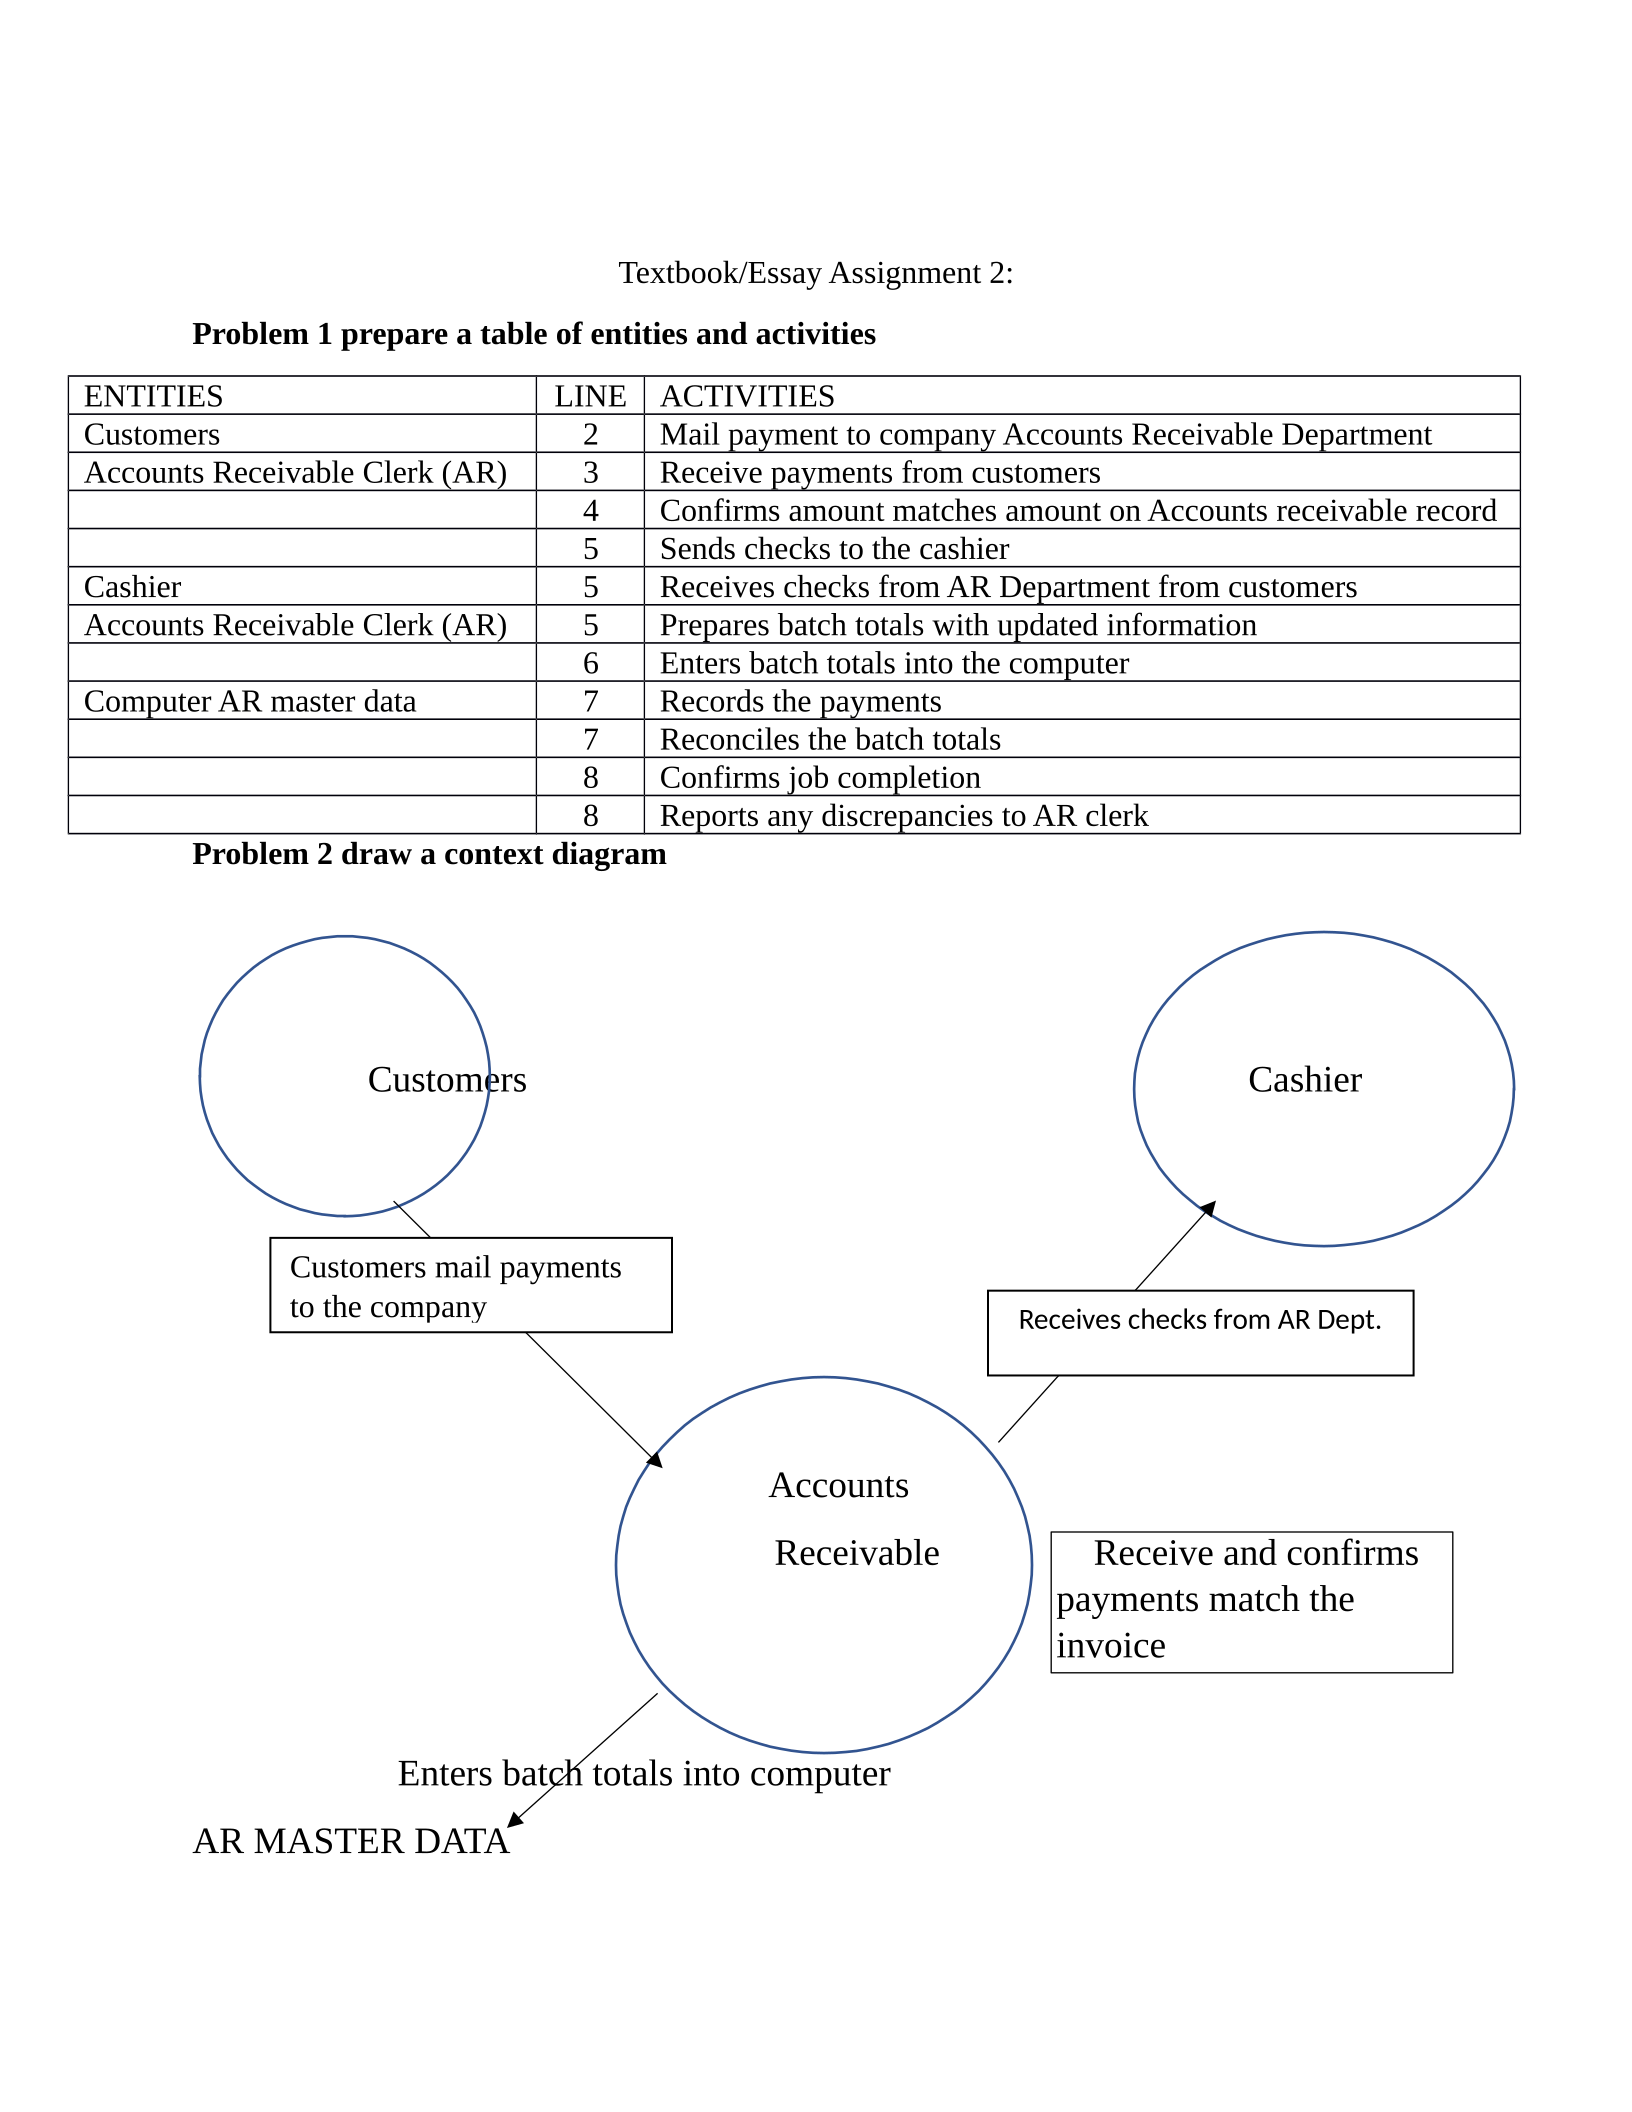
Problem 1 prepare a table of entities and activities
ENTITIES LINE ACTIVITIES
Customers 2 Mail payment to company Accounts Receivable Department
Accounts Receivable Clerk (AR) 3 Receive payments from customers
4 Confirms amount matches amount on Accounts receivable record
5 Sends checks to the cashier
Cashier 5 Receives checks from AR Department from customers
Accounts Receivable Clerk (AR) 5 Prepares batch totals with updated information
6 Enters batch totals into the computer
Computer AR master data 7 Records the payments
7 Reconciles the batch totals
8 Confirms job completion
8 Reports any discrepancies to AR clerk
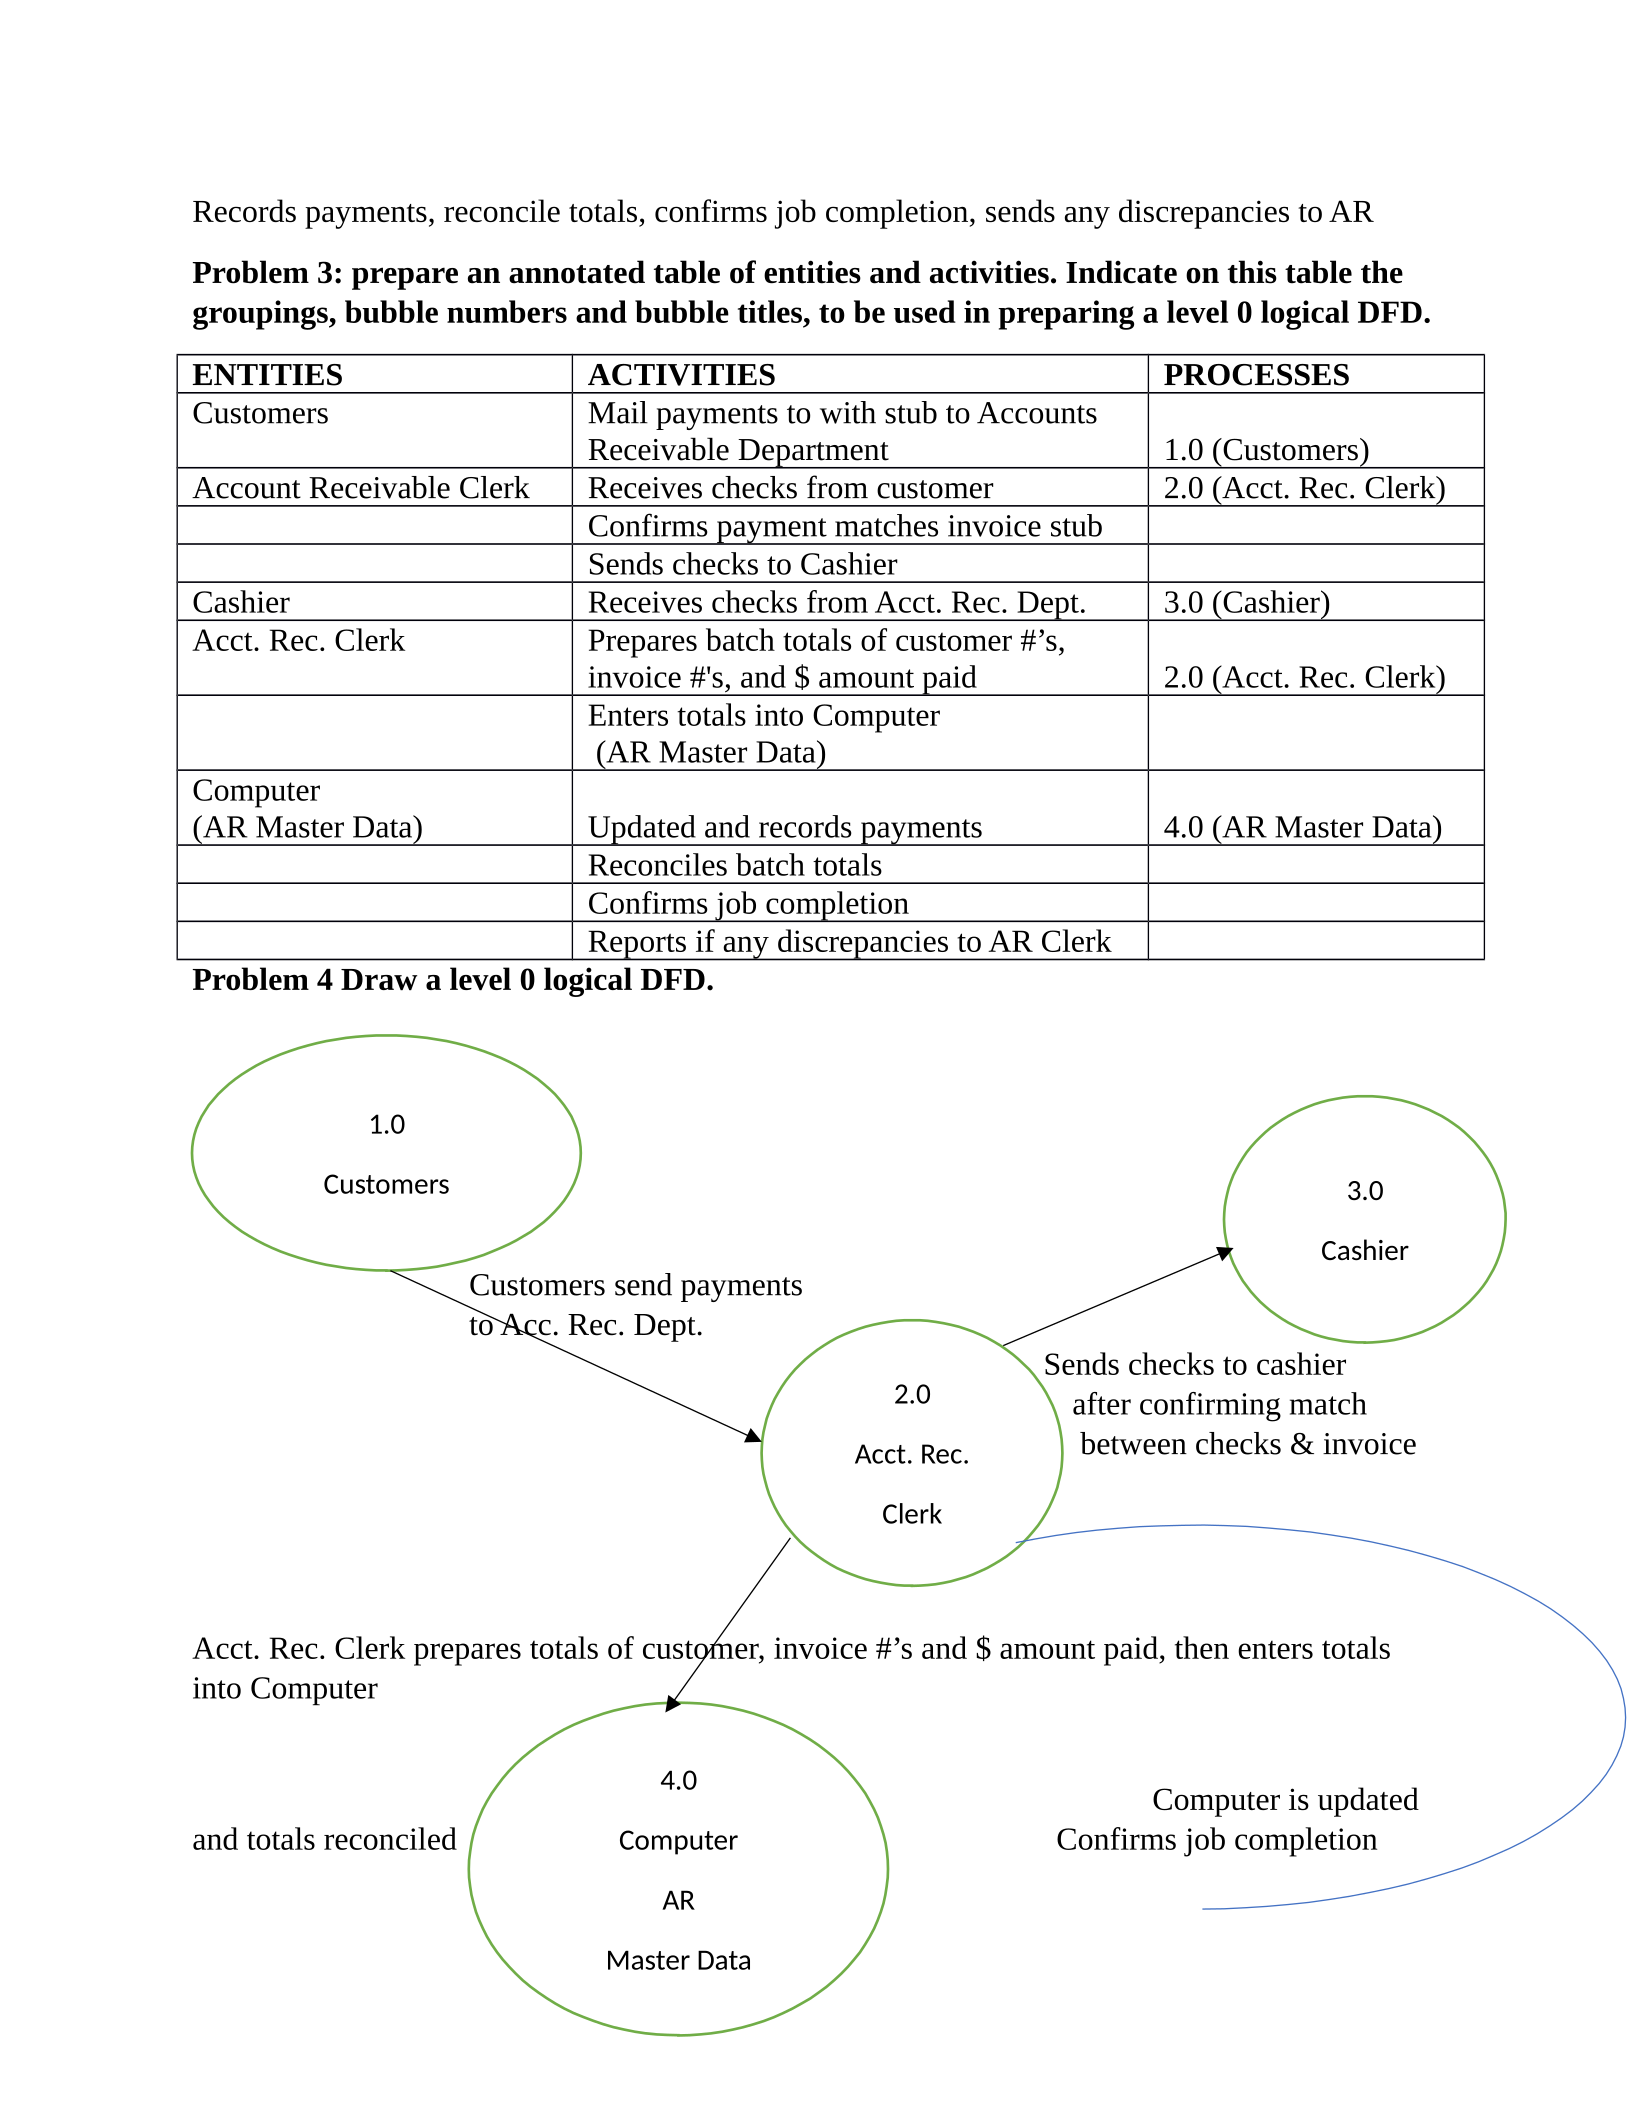
Problem 2 draw a context diagram
Customers Cashier
Accounts
Receivable Receive and confirms
payments match the
invoice
Enters batch totals into computer
AR MASTER DATA
Customers mail payments
to the company
Receives checks from AR Dept.
Records payments, reconcile totals, confirms job completion, sends any discrepancies to AR
Problem 3: prepare an annotated table of entities and activities. Indicate on this table the
groupings, bubble numbers and bubble titles, to be used in preparing a level 0 logical DFD.
ENTITIES ACTIVITIES PROCESSES
Customers Mail payments to with stub to Accounts
Receivable Department 1.0 (Customers)
Account Receivable Clerk Receives checks from customer 2.0 (Acct. Rec. Clerk)
Confirms payment matches invoice stub
Sends checks to Cashier
Cashier Receives checks from Acct. Rec. Dept. 3.0 (Cashier)
Acct. Rec. Clerk Prepares batch totals of customer #’s,
invoice #'s, and $ amount paid 2.0 (Acct. Rec. Clerk)
Enters totals into Computer
(AR Master Data)
Computer
(AR Master Data) Updated and records payments 4.0 (AR Master Data)
Reconciles batch totals
Confirms job completion
Reports if any discrepancies to AR Clerk
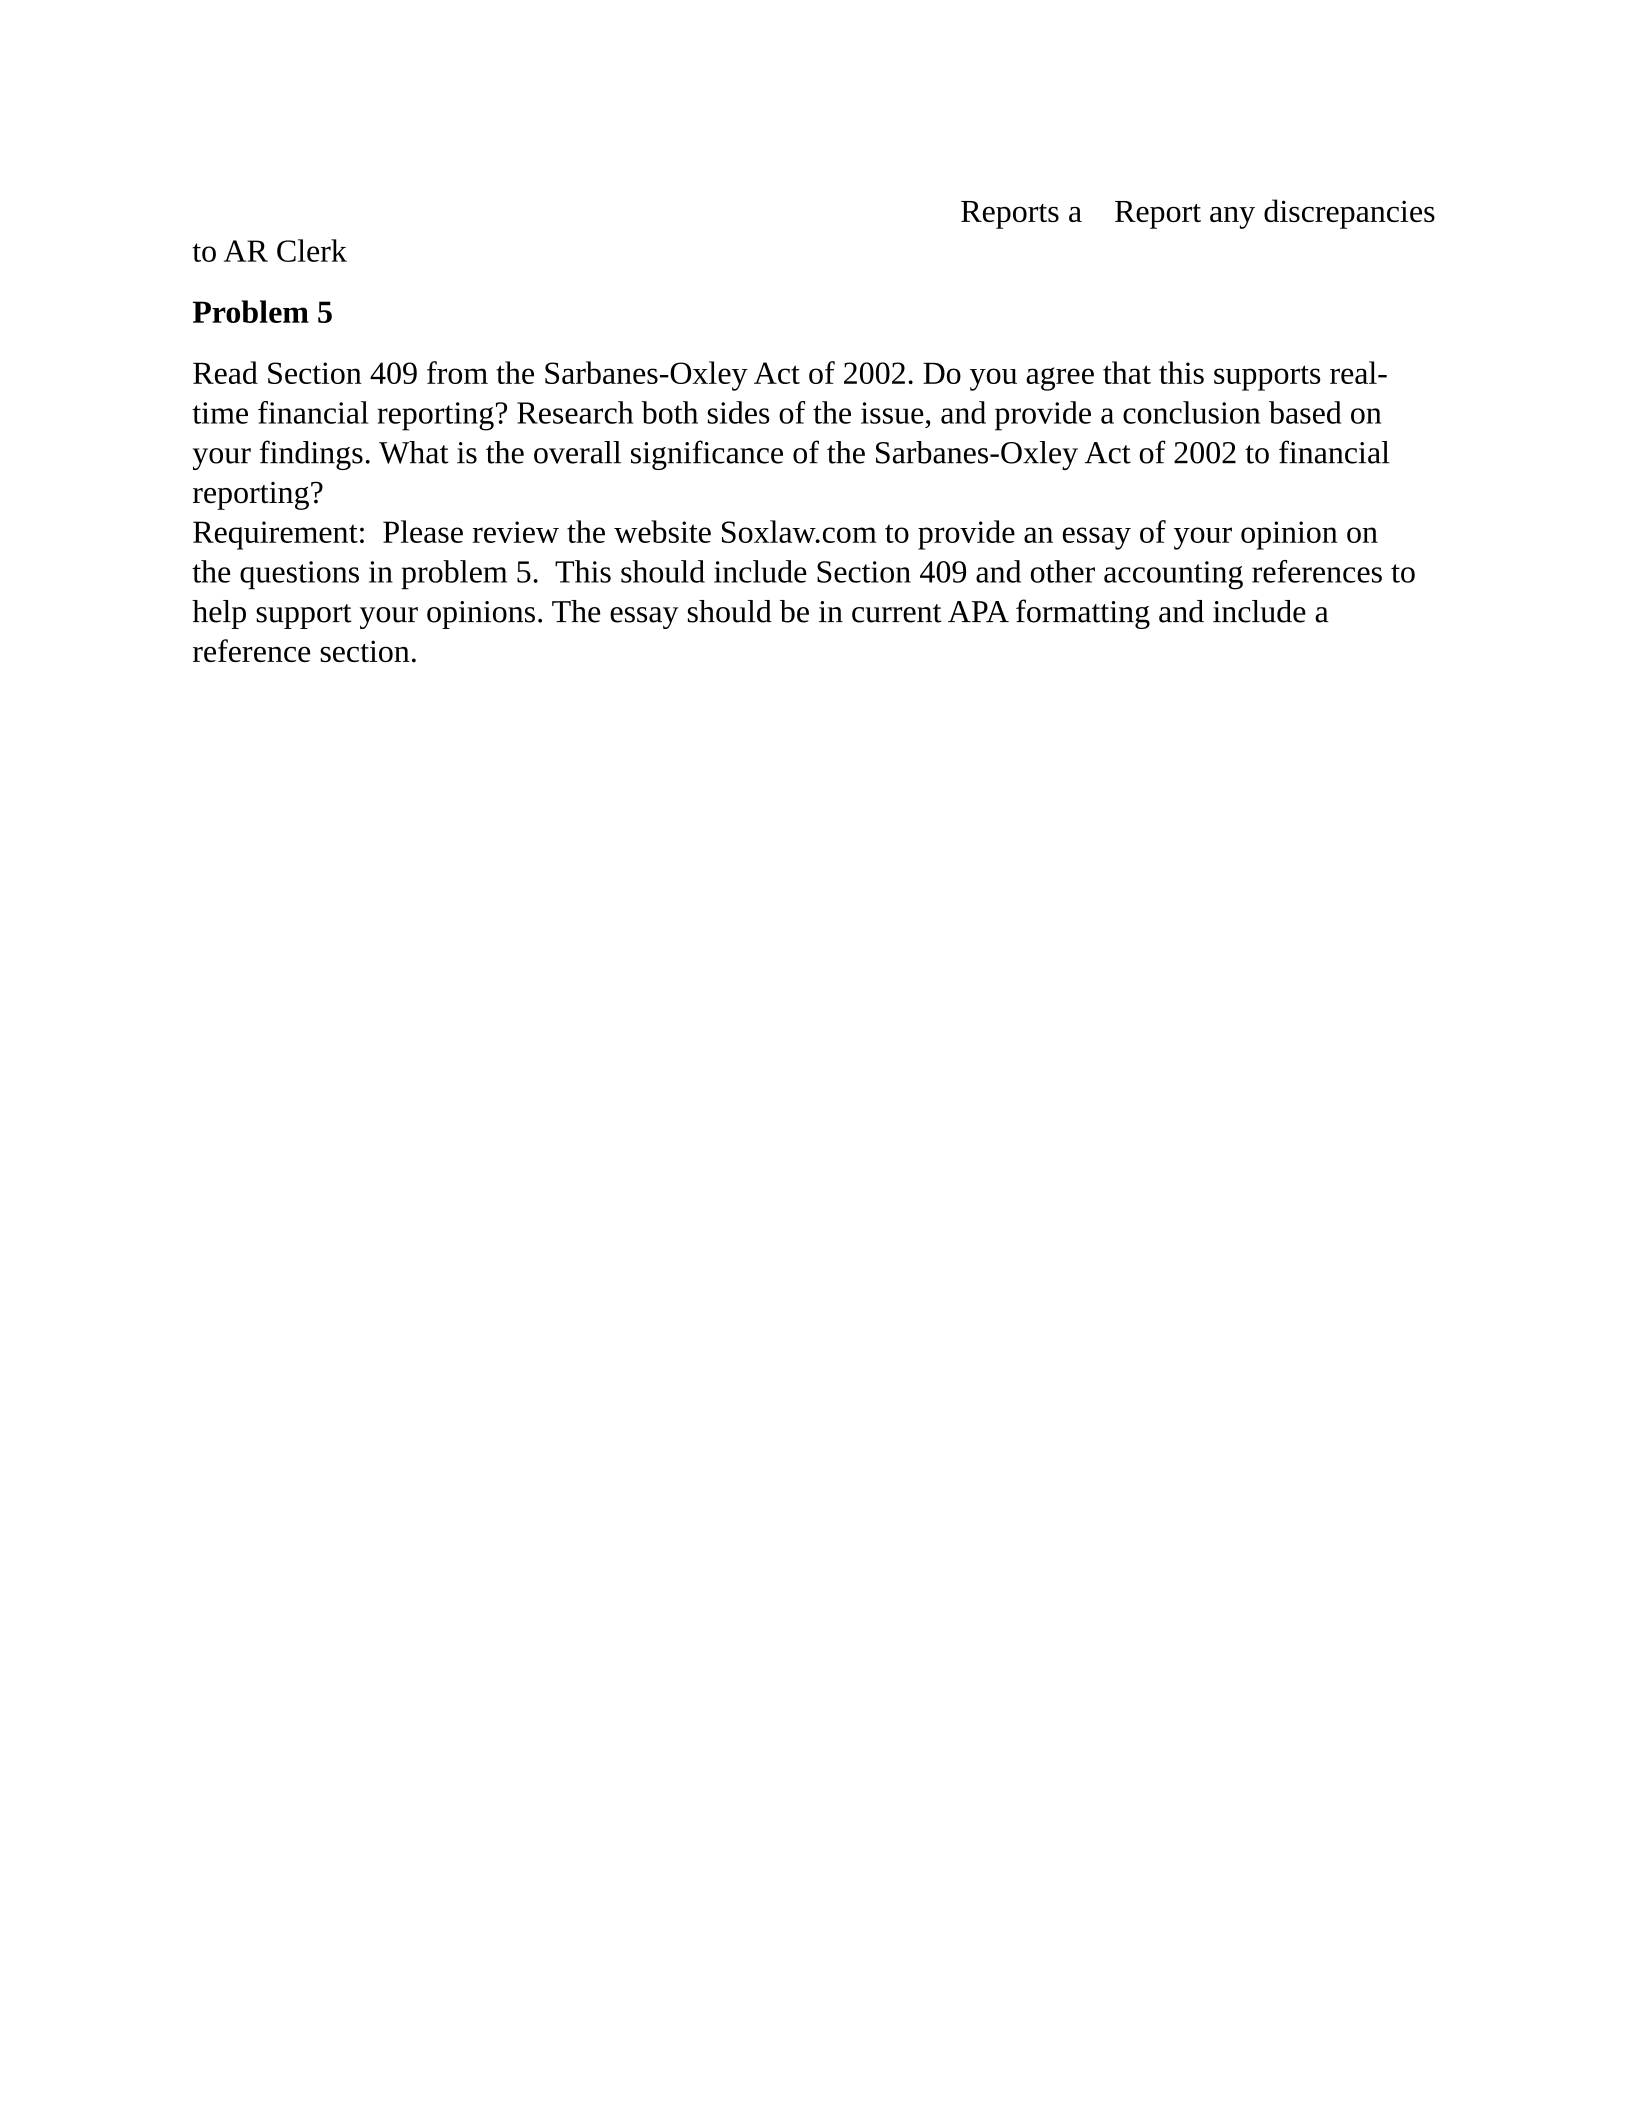
Problem 4 Draw a level 0 logical DFD.
Customers send payments
to Acc. Rec. Dept.
Sends checks to cashier
after confirming match
between checks & invoice
Acct. Rec. Clerk prepares totals of customer, invoice #’s and $ amount paid, then enters totals
into Computer
Computer is updated
and totals reconciled Confirms job completion
4.0
Computer
AR
Master Data
3.0
Cashier
2.0
Acct. Rec.
Clerk
1.0
Customers
Reports a Report any discrepancies
to AR Clerk
Problem 5
Read Section 409 from the Sarbanes-Oxley Act of 2002. Do you agree that this supports real-
time financial reporting? Research both sides of the issue, and provide a conclusion based on
your findings. What is the overall significance of the Sarbanes-Oxley Act of 2002 to financial
reporting?
Requirement: Please review the website Soxlaw.com to provide an essay of your opinion on
the questions in problem 5. This should include Section 409 and other accounting references to
help support your opinions. The essay should be in current APA formatting and include a
reference section.
The Sarbanes-Oxley Act of 2002 (SOX) came into law following Enron declaring bankruptcy,
which was one of the largest scandals in the world [ CITATION Sox22 \l 1033 ]. This law put in place
many controls that would hopefully enable the public to understand how corporations were being run
and make it easier for investors to make decisions on what corporations would provide the best return on
the money invested in that organization. There are many regulations that corporations must adhere to,
but in this case, Section 409 is the point for discussion.
Section 409 of SOX is referred to as the “Real Time Issuer Disclosures” which states that
corporations must disclose any information that changes in organizations’ financial conditions as
changes happen instead of just when records are released to the public [ CITATION Sox221 \l 1033 ].
This information must be given to the public in plain language so that anyone can understand when
something changes as many things can affect an organization. When the information is made available in
a timely manner, investors or potential investors would be able to make informed decisions on whether
or not to support that company.
Some organizations would rather not follow Section 409 of the Sarbanes-Oxley Act, especially if
the corporation does not conduct their business ethically. This act says that crucial information cannot be
withheld or hid from shareholders or the public. In any company, there is a need for management to
oversee financial information and to provide reports that adhere to the law. When things are done
ethically and an organization has nothing to hide, the public and shareholders will be more comfortable
with investing in that business [ CITATION Sox22 \l 1033 ]. Small public corporations feel that some
sections of this act make it more difficult for them to follow SOX. If the smaller companies choose not
to adhere to SOX, they may have to spend more money to comply with internal controls to honestly
promote their businesses.
Section 409 of the Sarbanes-Oxley Act does support real-time financial reporting if the company
does adhere to the law. When a company reports that there may be financial difficulties in the near future
instead of trying to hide the problems, the public may pull away in the short term; but many investors
may stay with the company if they see that information is given before trouble happens. In Proverbs
11:3, it is written; “The integrity of the upright shall guide them: but the perverseness of transgressors
shall destroy them.” [ CITATION KJV971 \l 1033 ]. This means if a business and the management
conduct business ethically and honestly, God will guide them; but dishonesty can destroy the business.
References
KJV. (1997). Holy Bible. Grand Rapids: World Publishing.
Soxlaw. (2022, December 4). SOX Section 409: Real Time Issuer Disclosures.
https://www.sarbanes-oxley-101.com/SOX-409.htm
SoxLaw. (2022, December 4). The pros and cons of the Sarbanes-Oxley Act.
https://www.soxlaw.com/the-pros-and-cons-of-the-sarbanes-oxley-act/

