


Client Interview
Leah Andersen
Liberty University
April 20, 2024
Introduction
This estate planning session is for a “newly” wedded couple. Andrew and Lynn. The purpose of this memo is to
discuss their blended family’s current financial situation and determine how best to meet their needs and goals
for an estate plan.

Summary of the Interview
I have met with my new clients Andrew and Lynn today who are in need of many changes to be made in their
estate. They were married seven years ago; it is Lynn’s first marriage and Andrew’s second. Both parties have
life insurance policies, but it was revealed that Andrew’s life insurance policy through his work still lists his
first wife as the beneficiary. First thing, Andrew’s life insurance policy needs to be updated to list Lynn as the
beneficiary. The reason for their visit with me was to obtain help from a financial expert to better prepare
money-wise for any future uncertainties. In addition, Lynn has investments, and has given a substantial amount
of money to charities. Due to this, I suggest setting up a Charitable Trust for her. Andrew paid for his children’s
undergraduate schooling and a used car once graduated. Lynn, on the other hand, purchased a golf cart for her
dad. The biggest problem they’ve encountered, and the reason they came to me for financial planning, is that
Andrew’s first wife did not have a will. In closing with them, I told them to start thinking about assigning a
power of attorney just in case they run into unfortunate circumstances. Also, Lynn and Andrew need to consider
setting up a budget plan, to properly set up life insurance policies, which will bank draft each month. All in all, I
need to work on organizing and setting up financial policies for each party.
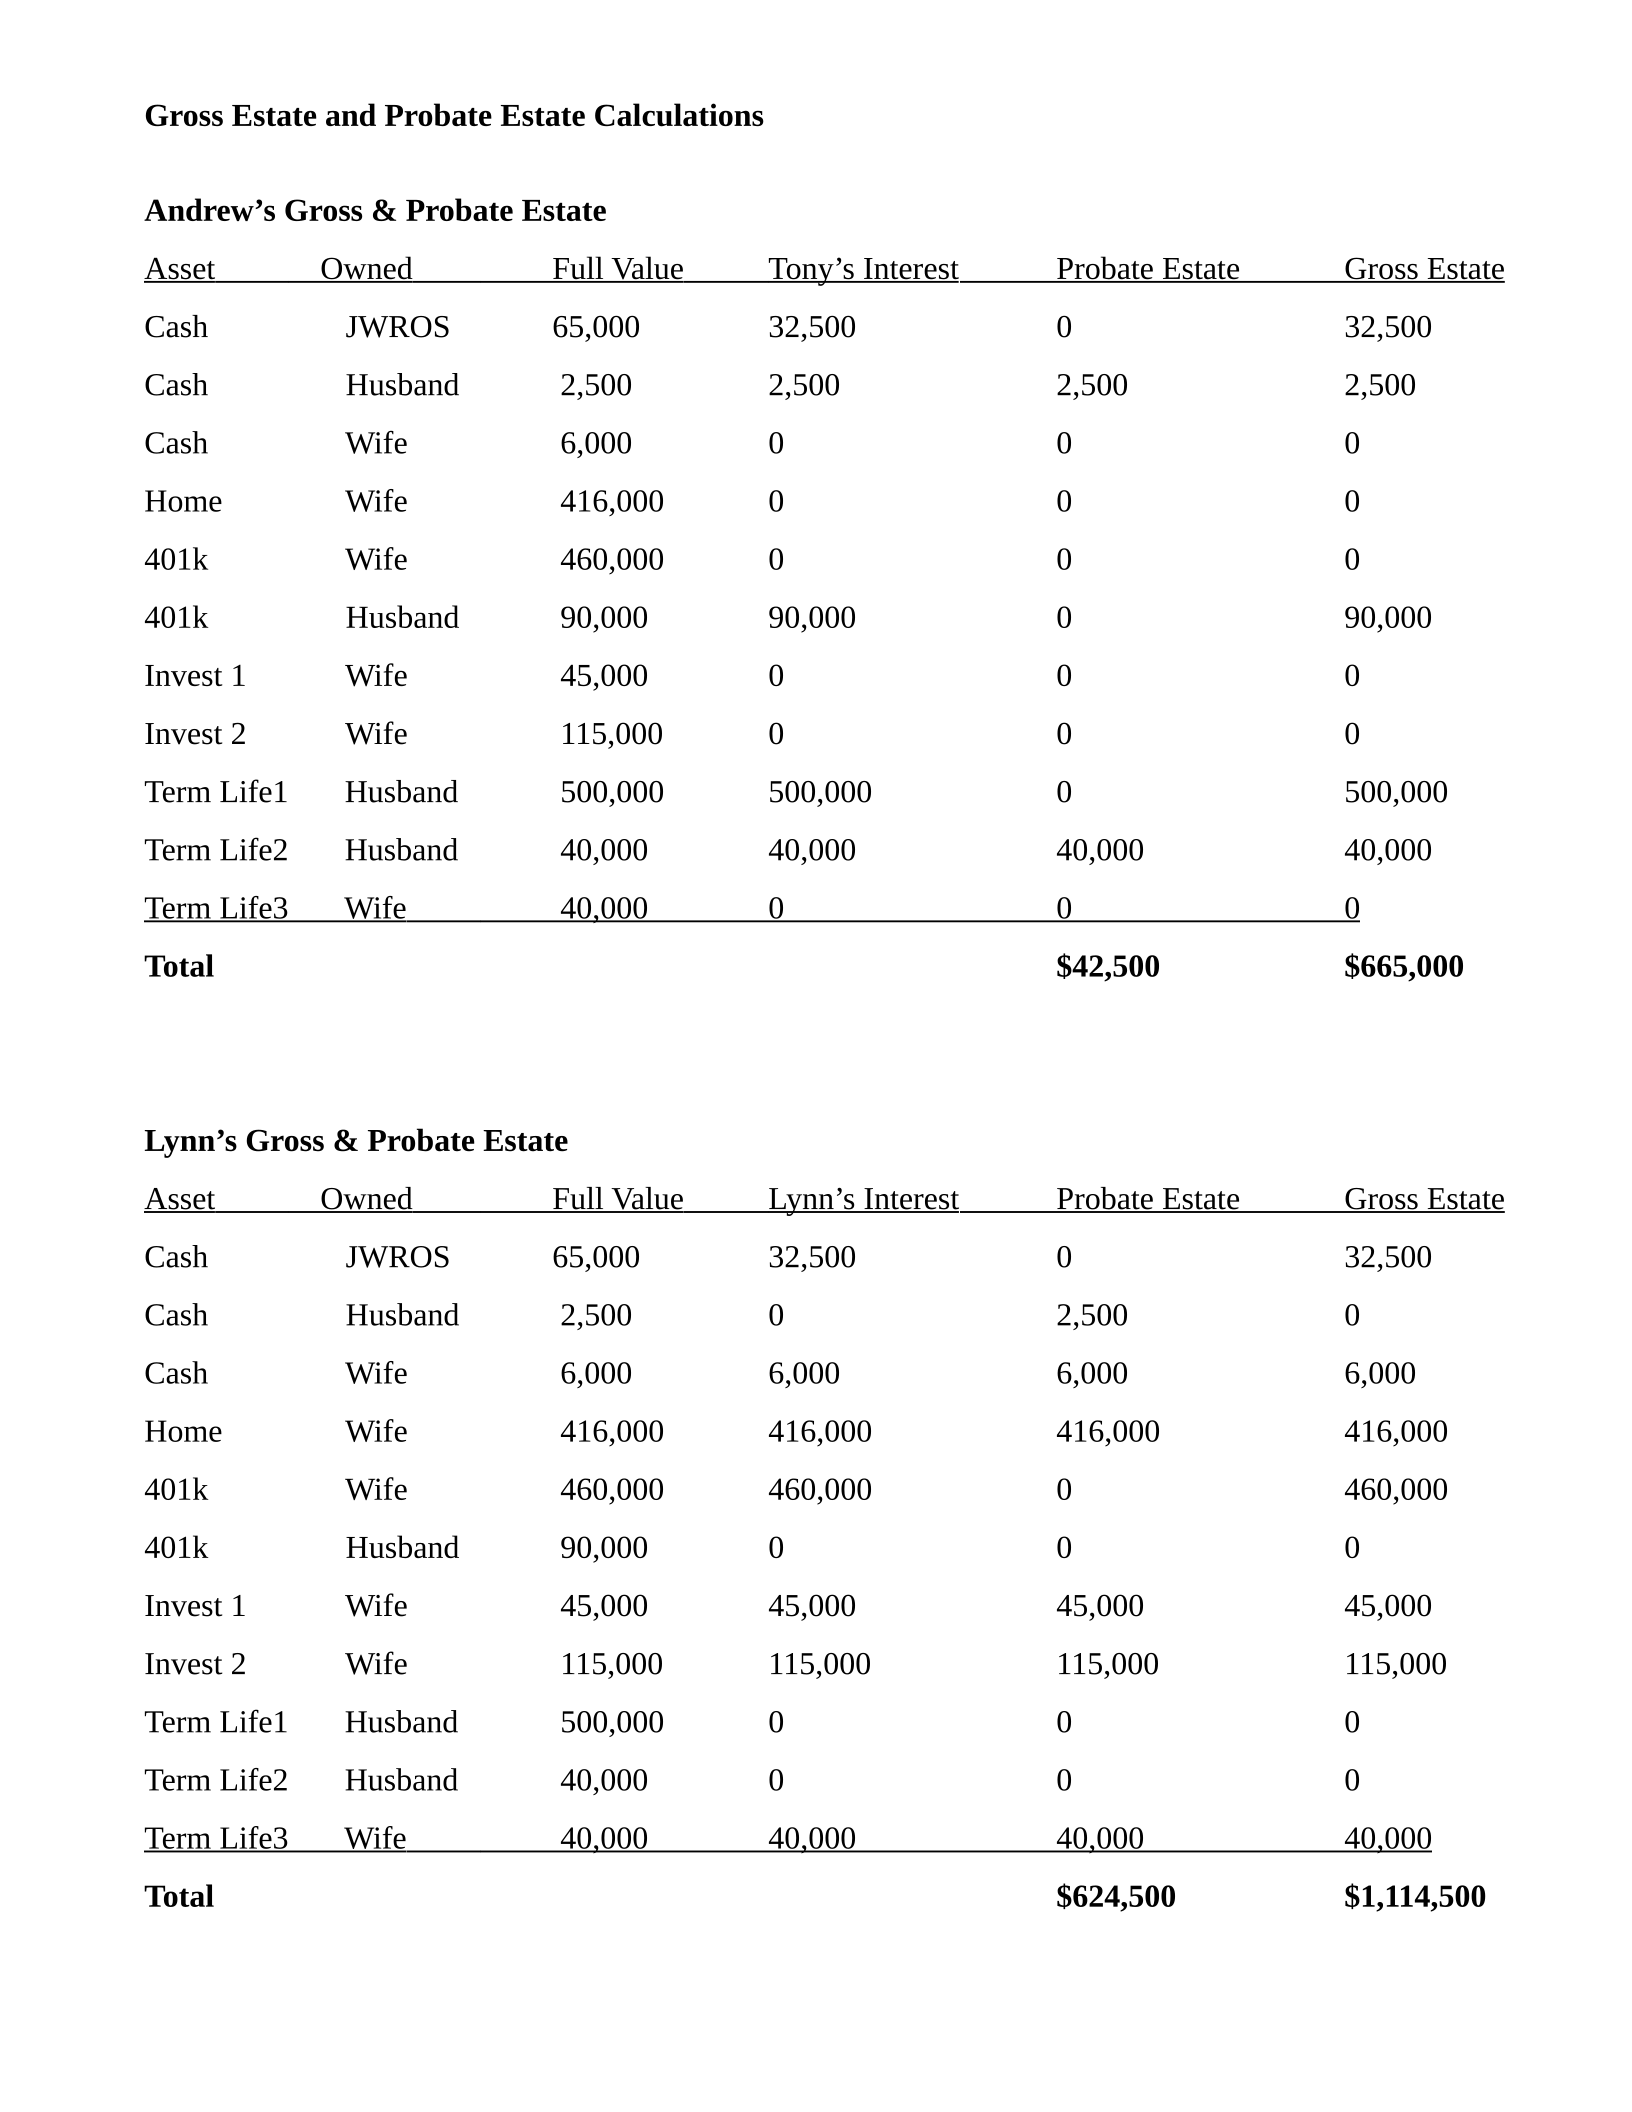
Gross Estate and Probate Estate Calculations
Andrew’s Gross & Probate Estate
Asset Owned Full Value Tony’s Interest Probate Estate Gross Estate
Cash JWROS 65,000 32,500 0 32,500
Cash Husband 2,500 2,500 2,500 2,500
Cash Wife 6,000 0 0 0
Home Wife 416,000 0 0 0
401k Wife 460,000 0 0 0
401k Husband 90,000 90,000 0 90,000
Invest 1 Wife 45,000 0 0 0
Invest 2 Wife 115,000 0 0 0
Term Life1 Husband 500,000 500,000 0 500,000
Term Life2 Husband 40,000 40,000 40,000 40,000
Term Life3 Wife 40,000 0 0 0
Total $42,500 $665,000
Lynn’s Gross & Probate Estate
Asset Owned Full Value Lynn’s Interest Probate Estate Gross Estate
Cash JWROS 65,000 32,500 0 32,500
Cash Husband 2,500 0 2,500 0
Cash Wife 6,000 6,000 6,000 6,000
Home Wife 416,000 416,000 416,000 416,000
401k Wife 460,000 460,000 0 460,000
401k Husband 90,000 0 0 0
Invest 1 Wife 45,000 45,000 45,000 45,000
Invest 2 Wife 115,000 115,000 115,000 115,000
Term Life1 Husband 500,000 0 0 0
Term Life2 Husband 40,000 0 0 0
Term Life3 Wife 40,000 40,000 40,000 40,000
Total $624,500 $1,114,500
Plan/Next Steps
Goal 1 – both parties need to establish a will
Andrew and Lynn both need to establish a will; this needs to be addressed once they come to an
agreement on designation of general power of attorney.
Goal 2 – both parties must obtain sufficient life insurance
Andrew and Lynn need to form a budget so I can best determine the amount of life insurance
coverage they each need. I need to look at their monthly allowance for life insurance and determine what
each person can afford each month for life insurance coverage.
Goal 3 – Lynn’s request to keep her assets separate from Andrew’s assets
Lynn needs to establish a trust to ensure that her assets are separated from Andrew. A trust should
be established “when there is a split interest in property (i.e., income interest to spouse with remainder
interest to children) and when the individual has reservations about the heir’s ability to manage, control,
or preserve the assets” (Dalton & Langdon, 2018).
Goal 5 – Lynn’s request to contribute her assets to charities at death.
In a QPRT, “the grantor contributes a personal residence to a trust and instead of receiving the
trust income, the grantor of the QPRT receives use of the personal residence as the income component”
(Dalton & Langdon, 2018). This method would remove the asset from the gross estate. However, “if the
grantor dies before the expiration of the trust term, the fair market value of the residence is included in
the grantor’s gross estate” (Dalton & Langdon, 2018).
Lynn has listed four separate charities for the beneficiary of her 401(k). “If the desire is to
transfer assets to qualifying charities, it is usually wise to consider transferring tax-advantaged funds
(IRAs, annuities) to these charities because these funds do not receive a step-to fair market value in
adjusted basis at the decedent’s death and are considered taxable income eligible for the Income in
Respect of the Decedent deduction to taxable recipients” (Dalton & Langdon, 2018). However,
assuming Lynn has a basic need for the financial accounts, I would advise the establishment of a CRUT.
Once determined, it would accomplish Lynn’s desire for charitable giving both now and later.
Goal 7 – Andrew’s desire to leave assets to his children
Given that the majority of Andrew’s gross estate would originate from the proceeds of the life
insurance policy that he owns at work, I would advise that he create a binding life insurance trust (ILIT)
with Crummey provisions to transfer ownership of the two policies that he owns. “If the trust owns the
policy, the proceeds will not be included in the insured’s gross estate even though the insured created the
trust and set forth the terms for distribution of trust assets (the death benefit on the life insurance policy)
to the beneficiaries” (Dalton & Langdon, 2018).
References
Dalton, M.A., & Langdon, T. P. (2018). Estate planning(12th ed.). Me, Money Education.
Flynn, K. (2022, January 6). Tuition Gift Tax Exclusion. Savingforcollege.com.
https://www.savingforcollege.com/article/tuition-gift-tax-exclusion.
IRS. (2024). What’s New – Estate and Gift Tax. Internal Revenue Service.
https://www.irs.gov/businesses/small-businesses-self-employed/whats-new-estate-and-gift-tax.
Jarvis, K. (2017, June 14). Five reasons to use a trust. FTAdviser.com.
https://www.ftadviser.com/tax-efficient-investments/2017/07/14/five-reasons-to-use-a-trust/.
Powered by TCPDF (www.tcpdf.org)

