


INDIVIDUAL LEARNING PROJECT – DATA DRIVEN FRAUD DETECTION 1
Mahogany Reyes
Acct 654- Fraud Examination
Individual Learning Project – Data-Driven Fraud Detection
Liberty University
April 5, 2024

Individual Learning Project – Data Driven Fraud Detection 2
Abstract
As computational power has increased and developed, data-driven auditing approaches
have grown in importance and necessity as a fraud detection tool. Originally, complex, and time-
consuming calculations had to be performed by hand, rendering useful formulas inaccessible.
Power auditing tools, including Excel, Access, IDEA, and SAS, have made it easier to generate
valuable formulas that can help uncover anomalies in data sets. These anomalies can then be
utilized to guide audits in the right direction. To better understand data-driven fraud detection
theories, this paper will define the term, describe the methods used, and explain the analysis
process.:(Albrecht, W. S., et al, 2019)
The three case studies that follow will also be examined in this essay. Case Studies 2 and
3 (Purchase & Vendors, Short Case 8: Benford's Law, and Purchase & Vendors). Every case
study will go into further detail on the methods used to investigate fraud and analyze data. The
phases involved in the data analysis will be outlined in a summary, along with the findings of any
fraud, anomalies, or red flags. To better understand data-driven fraud detection theories, this
paper will define the term, describe the methods used, and explain the analysis process.:

Individual Learning Project – Data Driven Fraud Detection 3
Data-Driven Fraud Detection
Fraud is not limited to a single sector, one scheme, or one sum of money. When someone
satisfies their need for attention, they will find a means to conduct fraud. One of the most
common crimes in the corporate sector is fraud, which is thought to cause an annual loss of about
$6.3 billion worldwide. (Mangala, D., & Kumari, P., 2017) Because of the rapid advancements in
information technology, fraud schemes are always changing and expanding, therefore auditors
need to have a toolbox full of techniques to assist them spot fraud. In the past, sampling
approaches were used in traditional fraud detection procedures. These sampling techniques aided
auditors in uncovering corporate transaction fraud (Albrecht, W. S., et al, 2019). Data-driven
fraud detection has emerged as the go-to technique for detection because of the development and
advancement of information technology. The process of "using data, usually through the mining
of those data, to identify patterns, anomalies, etc. to find possible fraud symptoms" is known as
data-driven fraud detection (Albrecht, W. S., et al, 2019). Using a proactive strategy, auditors go
through multiple phases of data transformation, cleansing, modeling, and inspection.:
(Nigrini, M. J., 2020). Auditors employ various quantitative analytical formulas on the entire
data set to find any information that could help identify irregularities and fraudulent activity,
providing advice on conclusions, and assisting in decision-making.:
(Nigrini, M. J., 2020). The advantage of data-driven fraud detection methods over traditional
approaches is their ability to identify and detect fraud tendencies early on, allowing auditors and
firms to stop responding to the signs of fraud. (Mangala, D., & Kumari, P., 2017).

Individual Learning Project – Data Driven Fraud Detection 4
Data Analysis Techniques and Process
It's time to examine the newly produced data set for any transactions that correspond with
the selected identifiable data once the auditing team has retrieved and deposited the data into the
analysis program of their choice.:(Albrecht, W. S., et al, 2019). Auditors need to employ a variety
of procedures when analyzing data because no single methodology will be able to find every
anomaly. There are several methods for analyzing the chosen data collection while implementing
data-driven fraud detection. These methods include time trend analysis, fuzzy matching,
financial statement analysis, stratification and summarization, digital analysis such as Benford's
Law, outlier inquiry with statistical z-score computation, and real-time and time trend analysis
(Albrecht, W. S., et al, 2019).
"The art of analyzing the digits that makeup number sets" is the initial method of digital
analysis (Albrecht, W. S., et al, 2019). Of them, Benford's Law is the most widely used and well-
known. "The first digit of random data sets will begin with a 1 more often than with a 2, a 2 more
often than with a 3, and so on," according to Benford's Law (Albrecht, W. S., et al, 2019).
Benford's Law works well when used to naturally occurring numbers, such as invoice totals; but
it is ineffectual when applied to artificial numbers, such as invoice sequences.:(Nigrini, M. J.,
2020). Benford's Law is typically not followed by human-generated numbers, which makes this
method effective for detecting fraud.: (Nigrini, M. J., 2020).
Finding outliers and generating the statistical z-score are steps in the second digital
analysis technique. By looking at outliers, auditors can ascertain whether any examples within
the data set differ from the average. One way to identify these outliers is to compute the z-score.
This data-driven analysis technique for identifying outliers is quite effective and rather easy to
use.:(Nigrini, M. J., 2020). Data conversion to a standard scale and distribution is the aim of the

Individual Learning Project – Data Driven Fraud Detection 5
statistical z-score computation. Z- Score = (Value – Mean) / Standard Deviation is the formula
used to get the statistical z-score.:(Albrecht, W. S., et al, 2019).
Fuzzy matching, time trend analysis, and stratification and summarization comprise the
next group of digital analysis approaches. "Splitting of complex data sets into groupings" is the
definition of stratification.:(Albrecht, W. S., et al, 2019). This is a way to generate groups that are
easier to study since most data sets include an infinite amount of information. After stratification,
summarization takes the groupings and performs additional computations on the data subsets to
generate a single record for each (Albrecht, W. S., et al, 2019). "A summarization approach that
produces a single number that describes each graph" is the temporal trend analysis.:(Albrecht, W.
S., et al, 2019). The auditor can then determine which graphs require additional human scrutiny
based on the sorted results. By using fuzzy matching, "searches that will find matches between
some text and entries in a database that are less than 100 percent identical" can be conducted.
(Albrecht, W. S., et al, 2019).
Real-time analysis and financial statement analysis are the last two digital analysis
techniques. Even while the potential value of data-driven analysis in identifying fraud is
beginning to become apparent, it is often used in specific contexts, such as investigations or
recurring audits. Additionally significant is the real-time analysis, which analyzes transactions as
they happen.:(Albrecht, W. S., et al, 2019). Due to the constant need for indication updating and
modification, this technique may be labor-intensive. To identify fraud, financial statements from
a given time can also be examined; auditors will concentrate on any unexpected changes during
this procedure. (Albrecht, W. S., et al, 2019). When this analysis is unavailable, the fraud must be
big enough to potentially have an impact big enough for the analysis to pick it up.:
The process of analyzing data is inherently proactive. Fraud investigators no longer need to wait
Individual Learning Project – Data Driven Fraud Detection 6
around for a tip about where to look when they use this approach. Now that they have a theory,
investigators can use the data to test it. The six steps of the data analysis procedure are as
follows: familiarizing yourself with the company, identifying potential fraud that may exist,
cataloging potential fraud symptoms, gathering data using data analysis software, analyzing the
results, and finally looking into any possible fraud symptoms.:(Albrecht, W. S., et al, 2019)
Short Case 8: Benford's Law
In Short Case 8 Benford's Law, a list of 10 checks written out to different vendors for
different bills is shown to us. The check numbers are listed in sequential sequence from 2001 to
2010. In this case, Benford's Law will be used to analyze the first-digit frequency of the check
amounts. Using Column A for the Amount, Column B for the Description, and Column C for the
Check Number, we first input the data into Excel. For any value in Column D, we can extract the
first digit by using the function formula = LEFT(A2,1). After that, we duplicate this for each
record. The research findings from this section are shown in the table below, which shows the
first digit for each record.:
AMOUNT/ CHECK # DESCRIPTION FIRST
DIGIT
$ 235.65 PAYMENT TO U.S. WEST FOR PHONE BILL
2001
2
$ 654.36 JOHN’S HEATING AND COOLING FOR FIXING A/C IN
DECEMBER
2002
6
$ 4,987.36 SHARKY’S USED CAR DEALERSHIP FOR YUGO TRUCK
2003
4
$ 339.13 SALT RIVER PROJECT FOR POWER IN DECEMBER
2004
3
$ 475.98 ARIZONA DEPARTMENT OF INTERNAL REVENUE FOR
TAXES
4
Individual Learning Project – Data Driven Fraud Detection 7
2005
$ 254.14 GRAINGER CORP. FOR POWER TOOLS
2006
2
$ 504.17 HOME DEPOT FOR OUTDOOR CARPORT
2007
5
$ 171.54 STEELIN’S CONSULTING FOR HELP WITH COMPUTER
NETWORK
2008
1
$ 326.45 PAYMENT TO U.S. WEST FOR PHONE BILL IN JANUARY
2009
3
$ 477.67 BANK OF AMERICA FOR LOAN PAYMENT
2010
4
To ascertain the frequency of every first-digit number, we must next apply the function formula
COUNTIF. The equation =COUNTIF ($D$2: $D$11, F2) is what I use to count the instances of
each number 1–9. This procedure is then repeated along each row for each record to determine
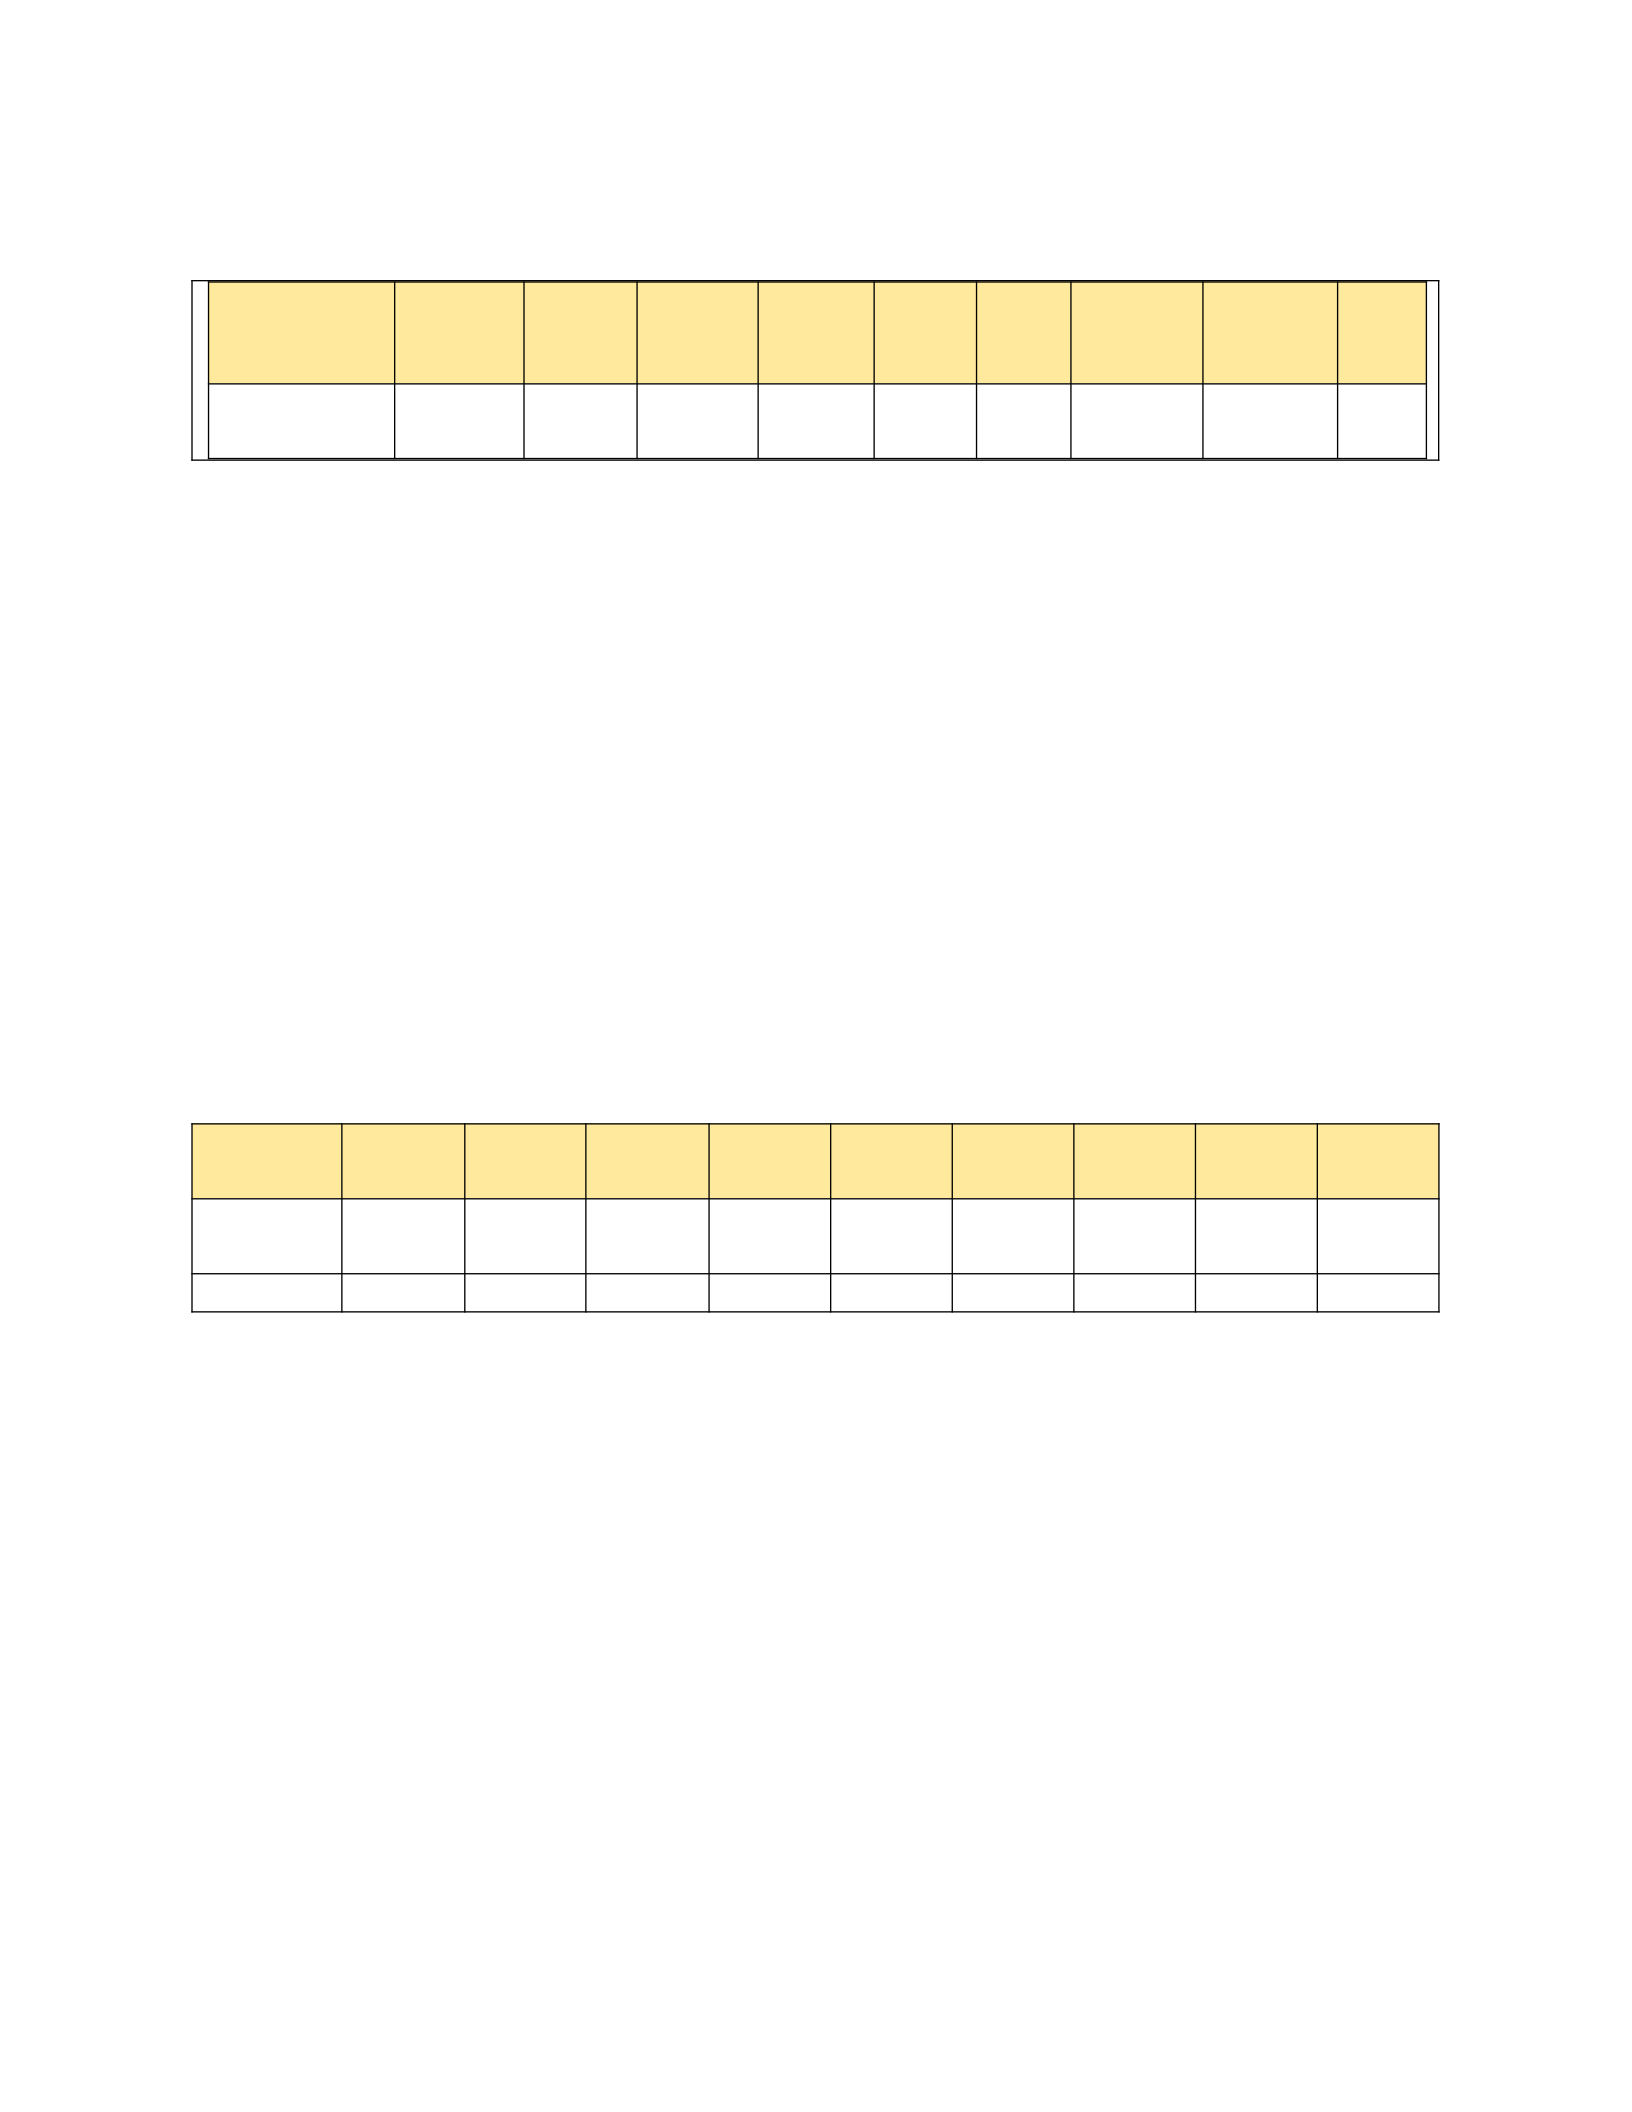
our frequency for each first digit. As can be observed in the chart below, number four has the
most frequency, occurring three times.
Individual Learning Project – Data Driven Fraud Detection 8
First Digit 1 2 3 4 5 6 7 8 9
Freg 1 2 2 3 1 1 0 0 0
According to Benford's Law, in an organic data collection, the number 1 will be the leading digit
30.1% of the time, the number 2 17.6% of the time, and so on. Benford's Law of first-digit
frequency as a percentage may be found in the graphic below. (J. C. Collins, 2017) Benford's
Law states that 9.7% of the time, the number 4 will be the initial digit. Thirty percent of the time
in this data collection, the number 4 is the initial digit. You use the frequency and total number of
records in the data set to determine the percentage for the set. The percentage frequencies for
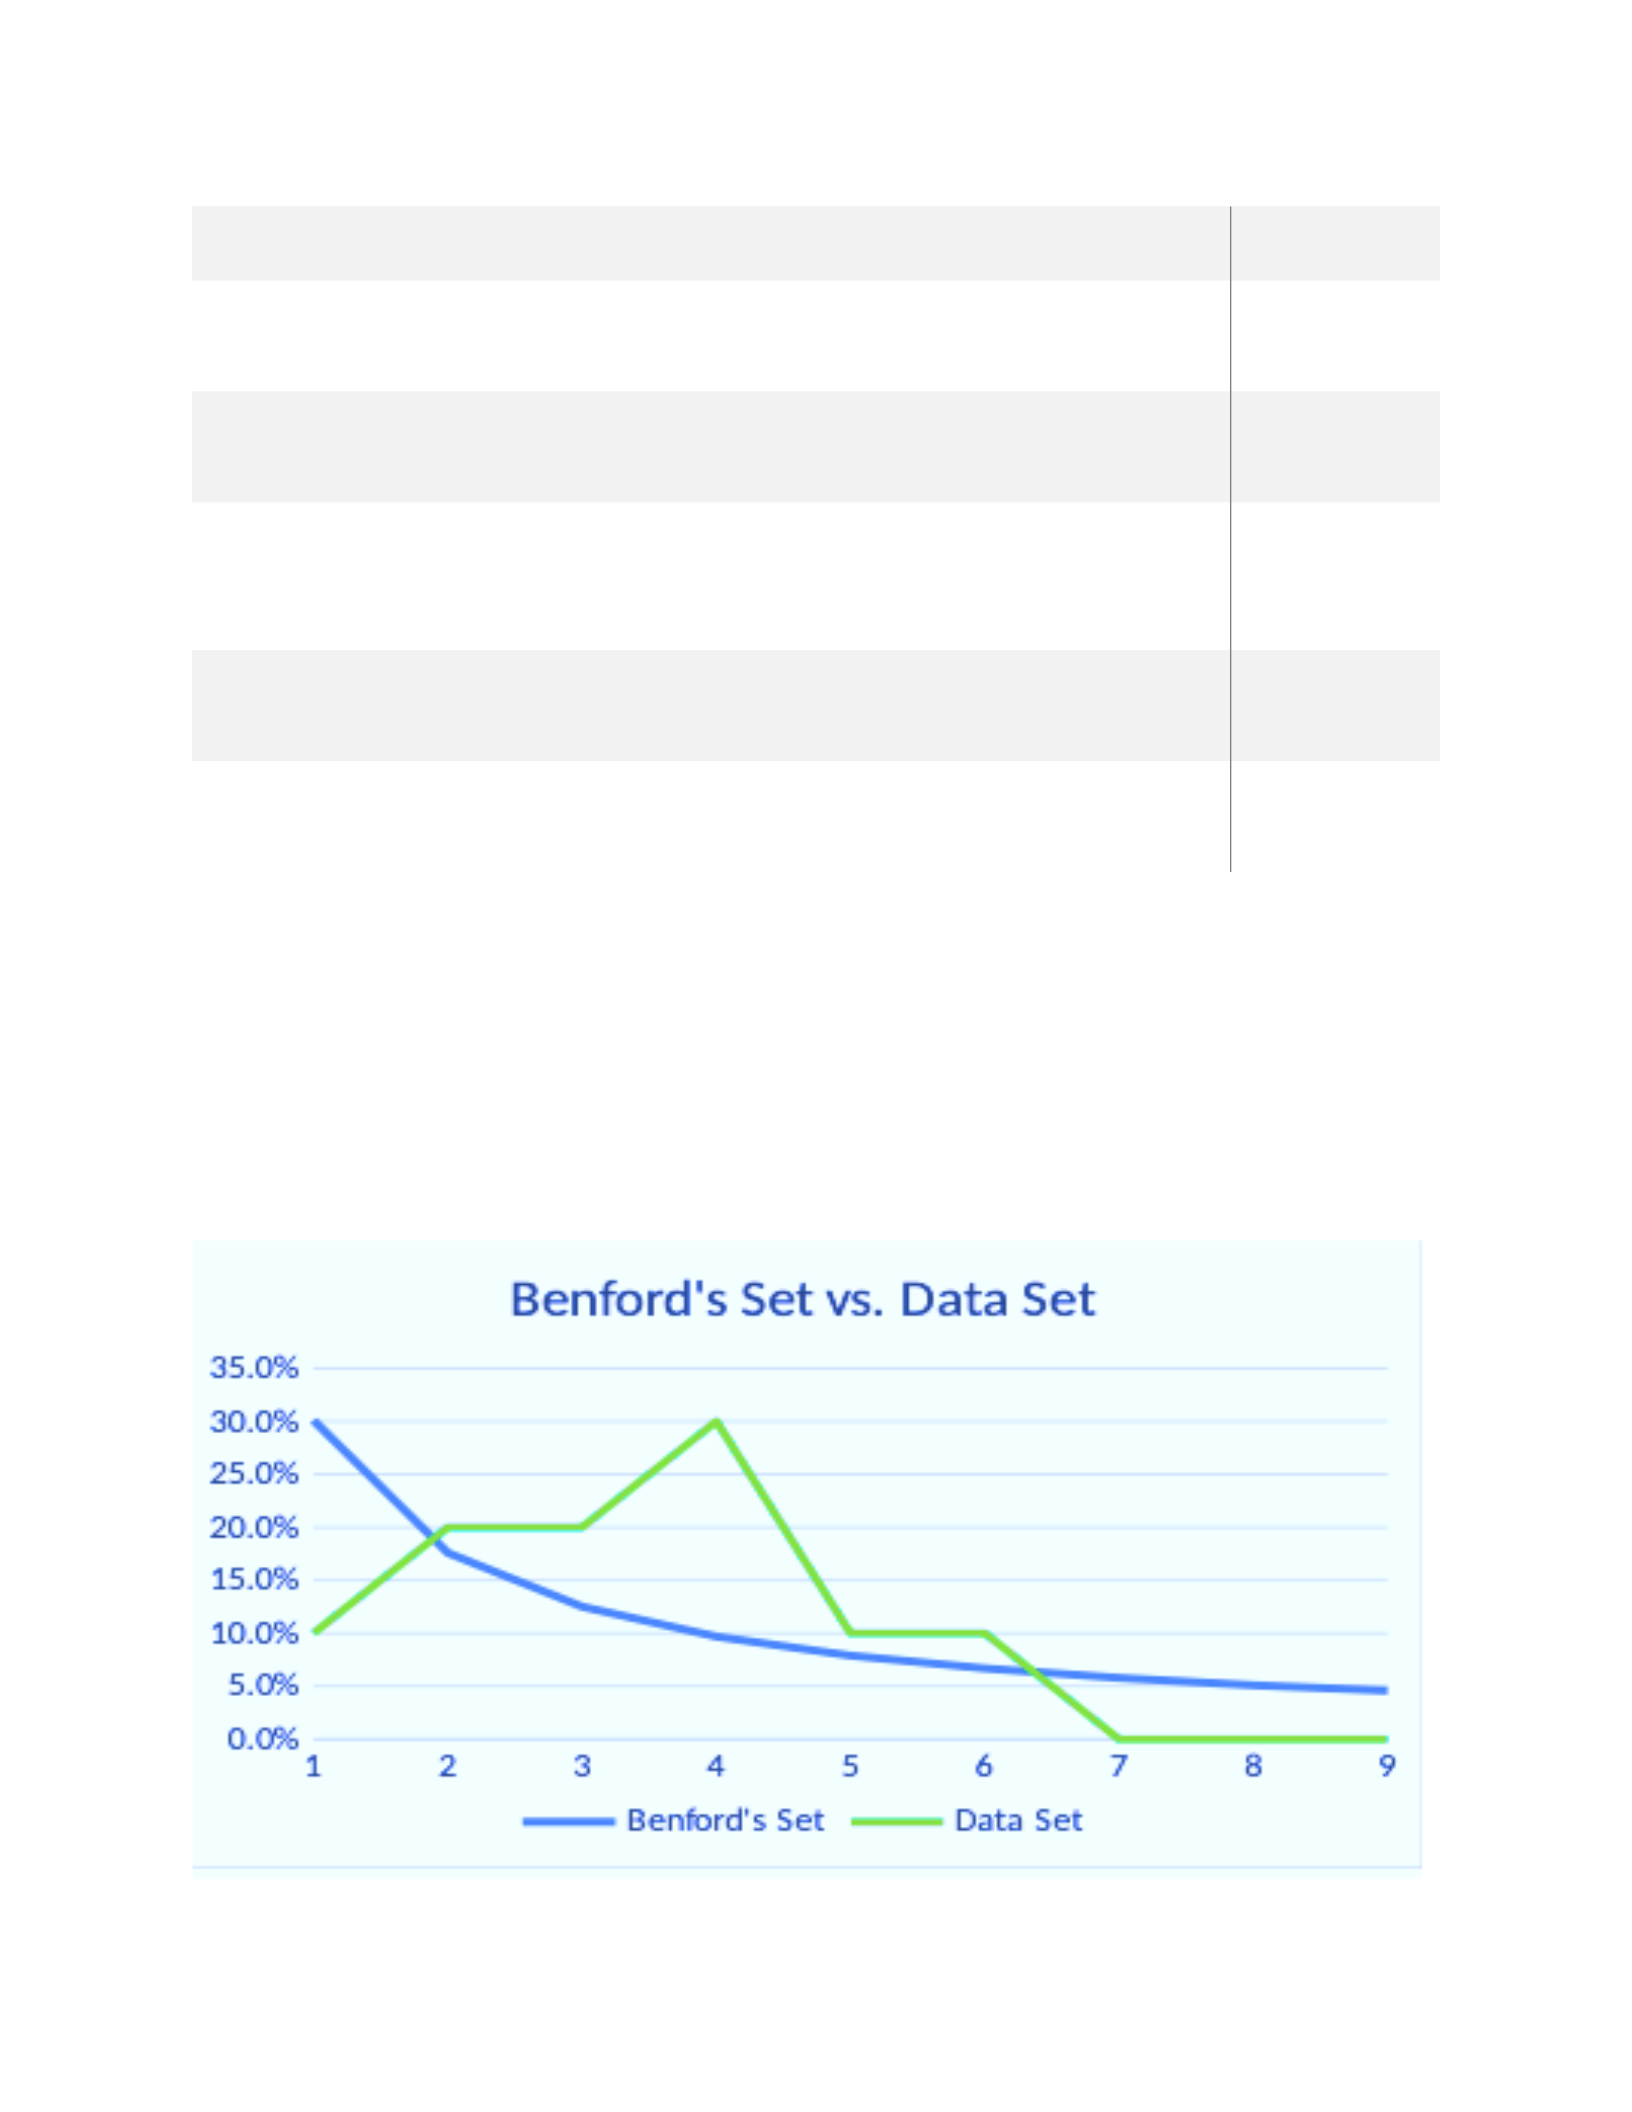
Benford's set and the Data Set are displayed below, first in chat form and subsequently in graph
form.
First
Digit
1 2 3 4 5 6 7 8 9
Binford’s
Set
30.1% 17.6 12.5% 9.7% 7.9% 6.7% 5.8% 5.1% 4.6%
Data 10% 20% 20% 30% 10% 10% 0% 0% 0%
Since there are just 10 records in the data set, it is not possible to infer with certainty that fraud
exists. However, as the statistics show, there is a considerable difference between the estimated
and real rates based on this data set. We were able to identify these variations as anomalies and a
starting point for our investigation into possible fraud by using the Benford's Law test (Goh, C.,
2020). We can infer from Benford's Law test that there is an unusual usage of amounts beginning
with 4. To determine if this is an anomaly or just a case of insufficient data, the organization
might think about extending the date range and including more records to obtain a more accurate

Individual Learning Project – Data Driven Fraud Detection 9
analysis. Investigations of any invoices with amounts that begin with the number 4 should be
initiated whether more data is supplied, as this irregularity may indicate that fraud is taking place
in the organization.:
Case Study 2: Janitorial Purchases
Our new place of employment in Case Study 2 is Cleaning Purchases, a sizable company that
handles cleaning services for various businesses. We were part of the internal auditing team as
soon as we joined the organization. Owing to the nature of their business, they have a sizable
purchasing department that manages the ordering of all the various goods needed to clean the
buildings of their clients. We have been asked to conduct a data-driven analysis of the purchase
data to identify any potential fraud because of the department's size and the quantity of things
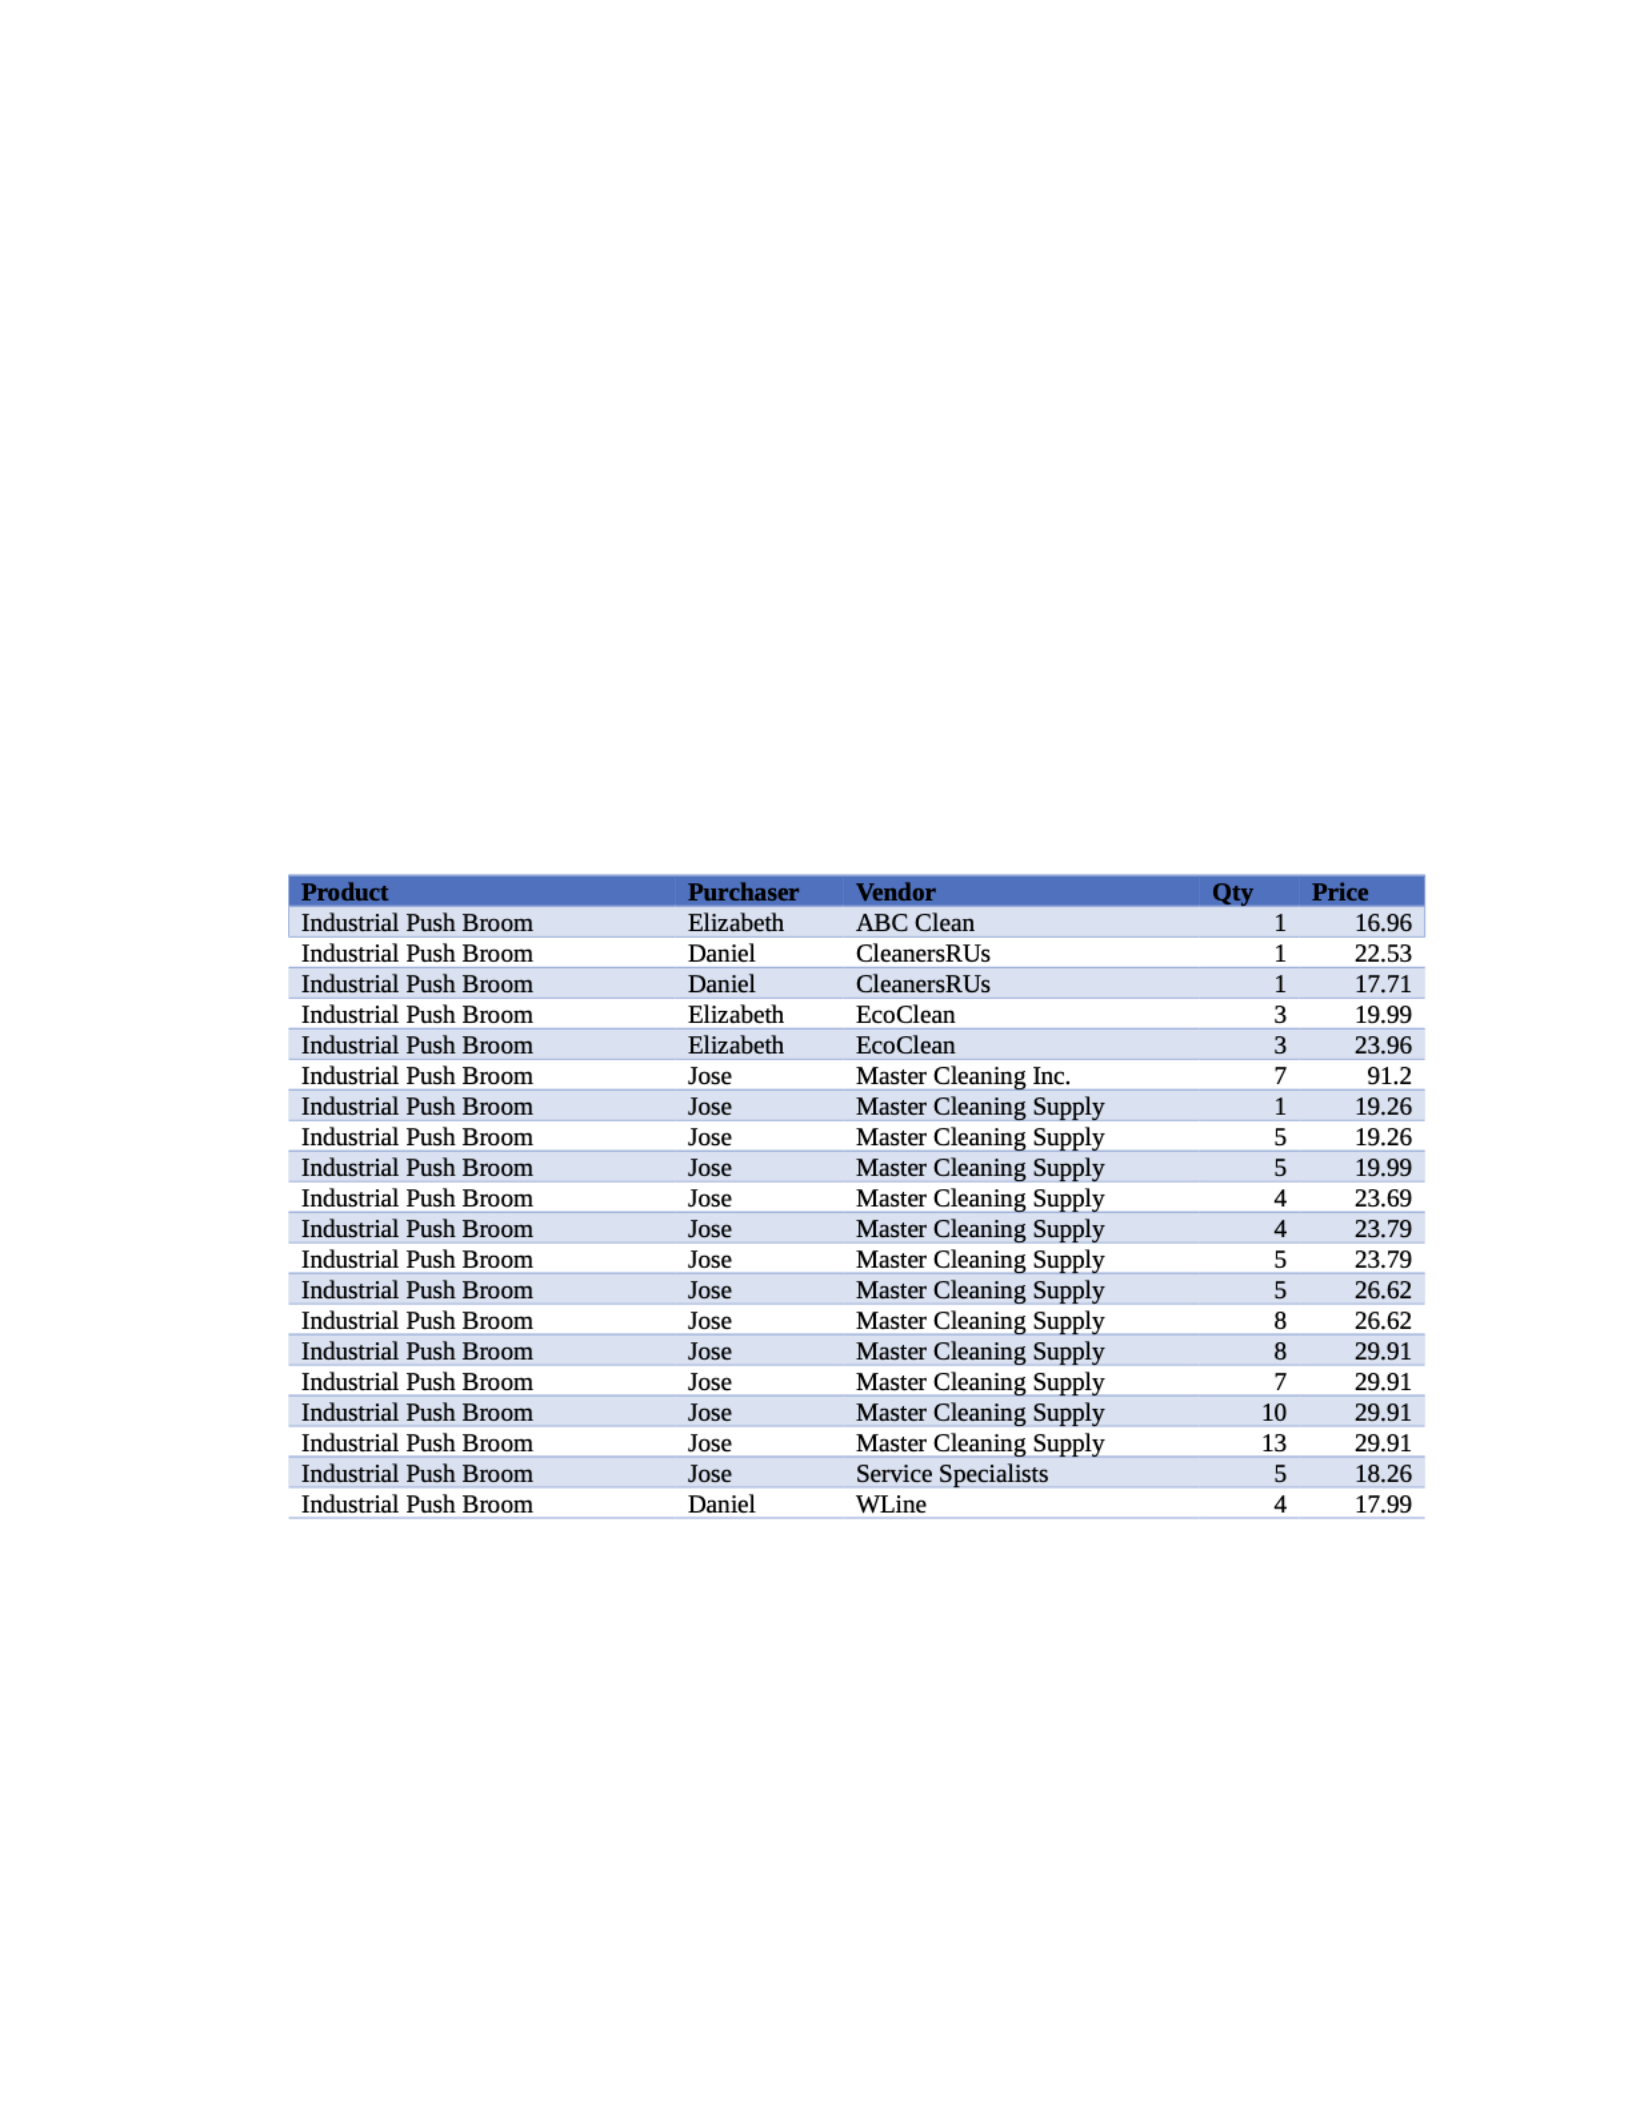
purchased.:We can find the following information using the fuzzy matching data analysis
technique with the provided data set.:The vendor Master Cleaning Inc., whose Record ID is
1823, has purchased seven industrial push brooms for $91.20 each. This vendor's name sounds a
lot like Master Cleaning Supplies, which buys industrial push brooms regularly all year long.
When compared to similar purchases, the price of $91.20 per broom is excessively high; the
prices of all other purchases are $29.91 or less per broom. For $29.91 per broom, Master
Cleaning Supplies acquired seven industrial push brooms, as documented in Record ID 1787.
This transaction is unusual, and the vendor Master Cleaning Inc. may be a ghost vendor because
of the anomalies of similar names, a single purchase, and the high cost per item for this
vendor.:The price of the Industrial Push Broom varies depending on the vendor when comparing
the different vendors and the cost per item. ABC Clean $16.96, Cleaners Rus $20.12, EcoClean
$21.98, Master Cleaning Inc $91.20, Master Cleaning Supply $26.76, Service Specialists $18.26,
and Wine $17.99 are the average prices per broom for each vendor. The seller from whom 100
Individual Learning Project – Data Driven Fraud Detection 10
brooms were acquired is the second anomaly that stands out from this data: 18 of the brooms
were purchased from a combination of the other vendors, with 75 coming from Master Cleaning
Supply and 7 from Mater Cleaning Inc. The fact that Master Cleaning Supply has 12 records
while the other vendors only have 1 or 2 is another anomaly. Additionally, the cost of the brooms
that were bought from Master Cleaning Supply has been rising over time. The last anomaly in
this data set is that Jose is identified as the buyer for every transaction completed with Master
Cleaning Supply and Mater Cleaning Inc. We can identify a potential kickback arrangement
between the buyer, Jose, Master Cleaning Supply, and Mater Cleaning Inc. through this data
analysis.
After the data analysis using an Excel pivot table to get the average prices for each product, we
can conclude that, in comparison to Daniel, Elizabeth, and Jose, Sally does pay a higher average
price for the All-Purpose Wipers. Sally pays lower or average prices on other things, whereas one
of her coworkers pays a slightly higher price when you check at other average costs for different
products and carry on with the data analysis. Thus, we can conclude that additional research is

Individual Learning Project – Data Driven Fraud Detection 11
not required.:We can quickly confirm in Excel that every purchase is included in the data set. As
the questioner pointed out, the ID sequence number would have been eliminated if the purchase
had been omitted. You may quickly and simply determine whether any records are missing by
downloading the Kutools Excel plugin. Upon installing the program and opening the data set in
Excel, all you need to do is choose the data in the ID column and execute the test by going to
Kutools > Insert > Find Missing Sequence Number. Following the test, we can see that record ID
1560 is absent from the list. We may examine and validate the amount and total columns using
Excel. There is a single record in the quantity column with a value of zero. This is transaction ID
1677 for all-purpose wipers from WLine, which Sally purchased for $9.73 apiece. Additionally,
this transaction is the only one in the Total column that is anomalous. Naturally, the total would
be 0 since the quantity was zero. Although the transaction appears suspicious because it shows a
zero value, indicating that no purchase was made, it's also possible that Sally typed it incorrectly.
This transaction must be extracted and examined in further detail.:
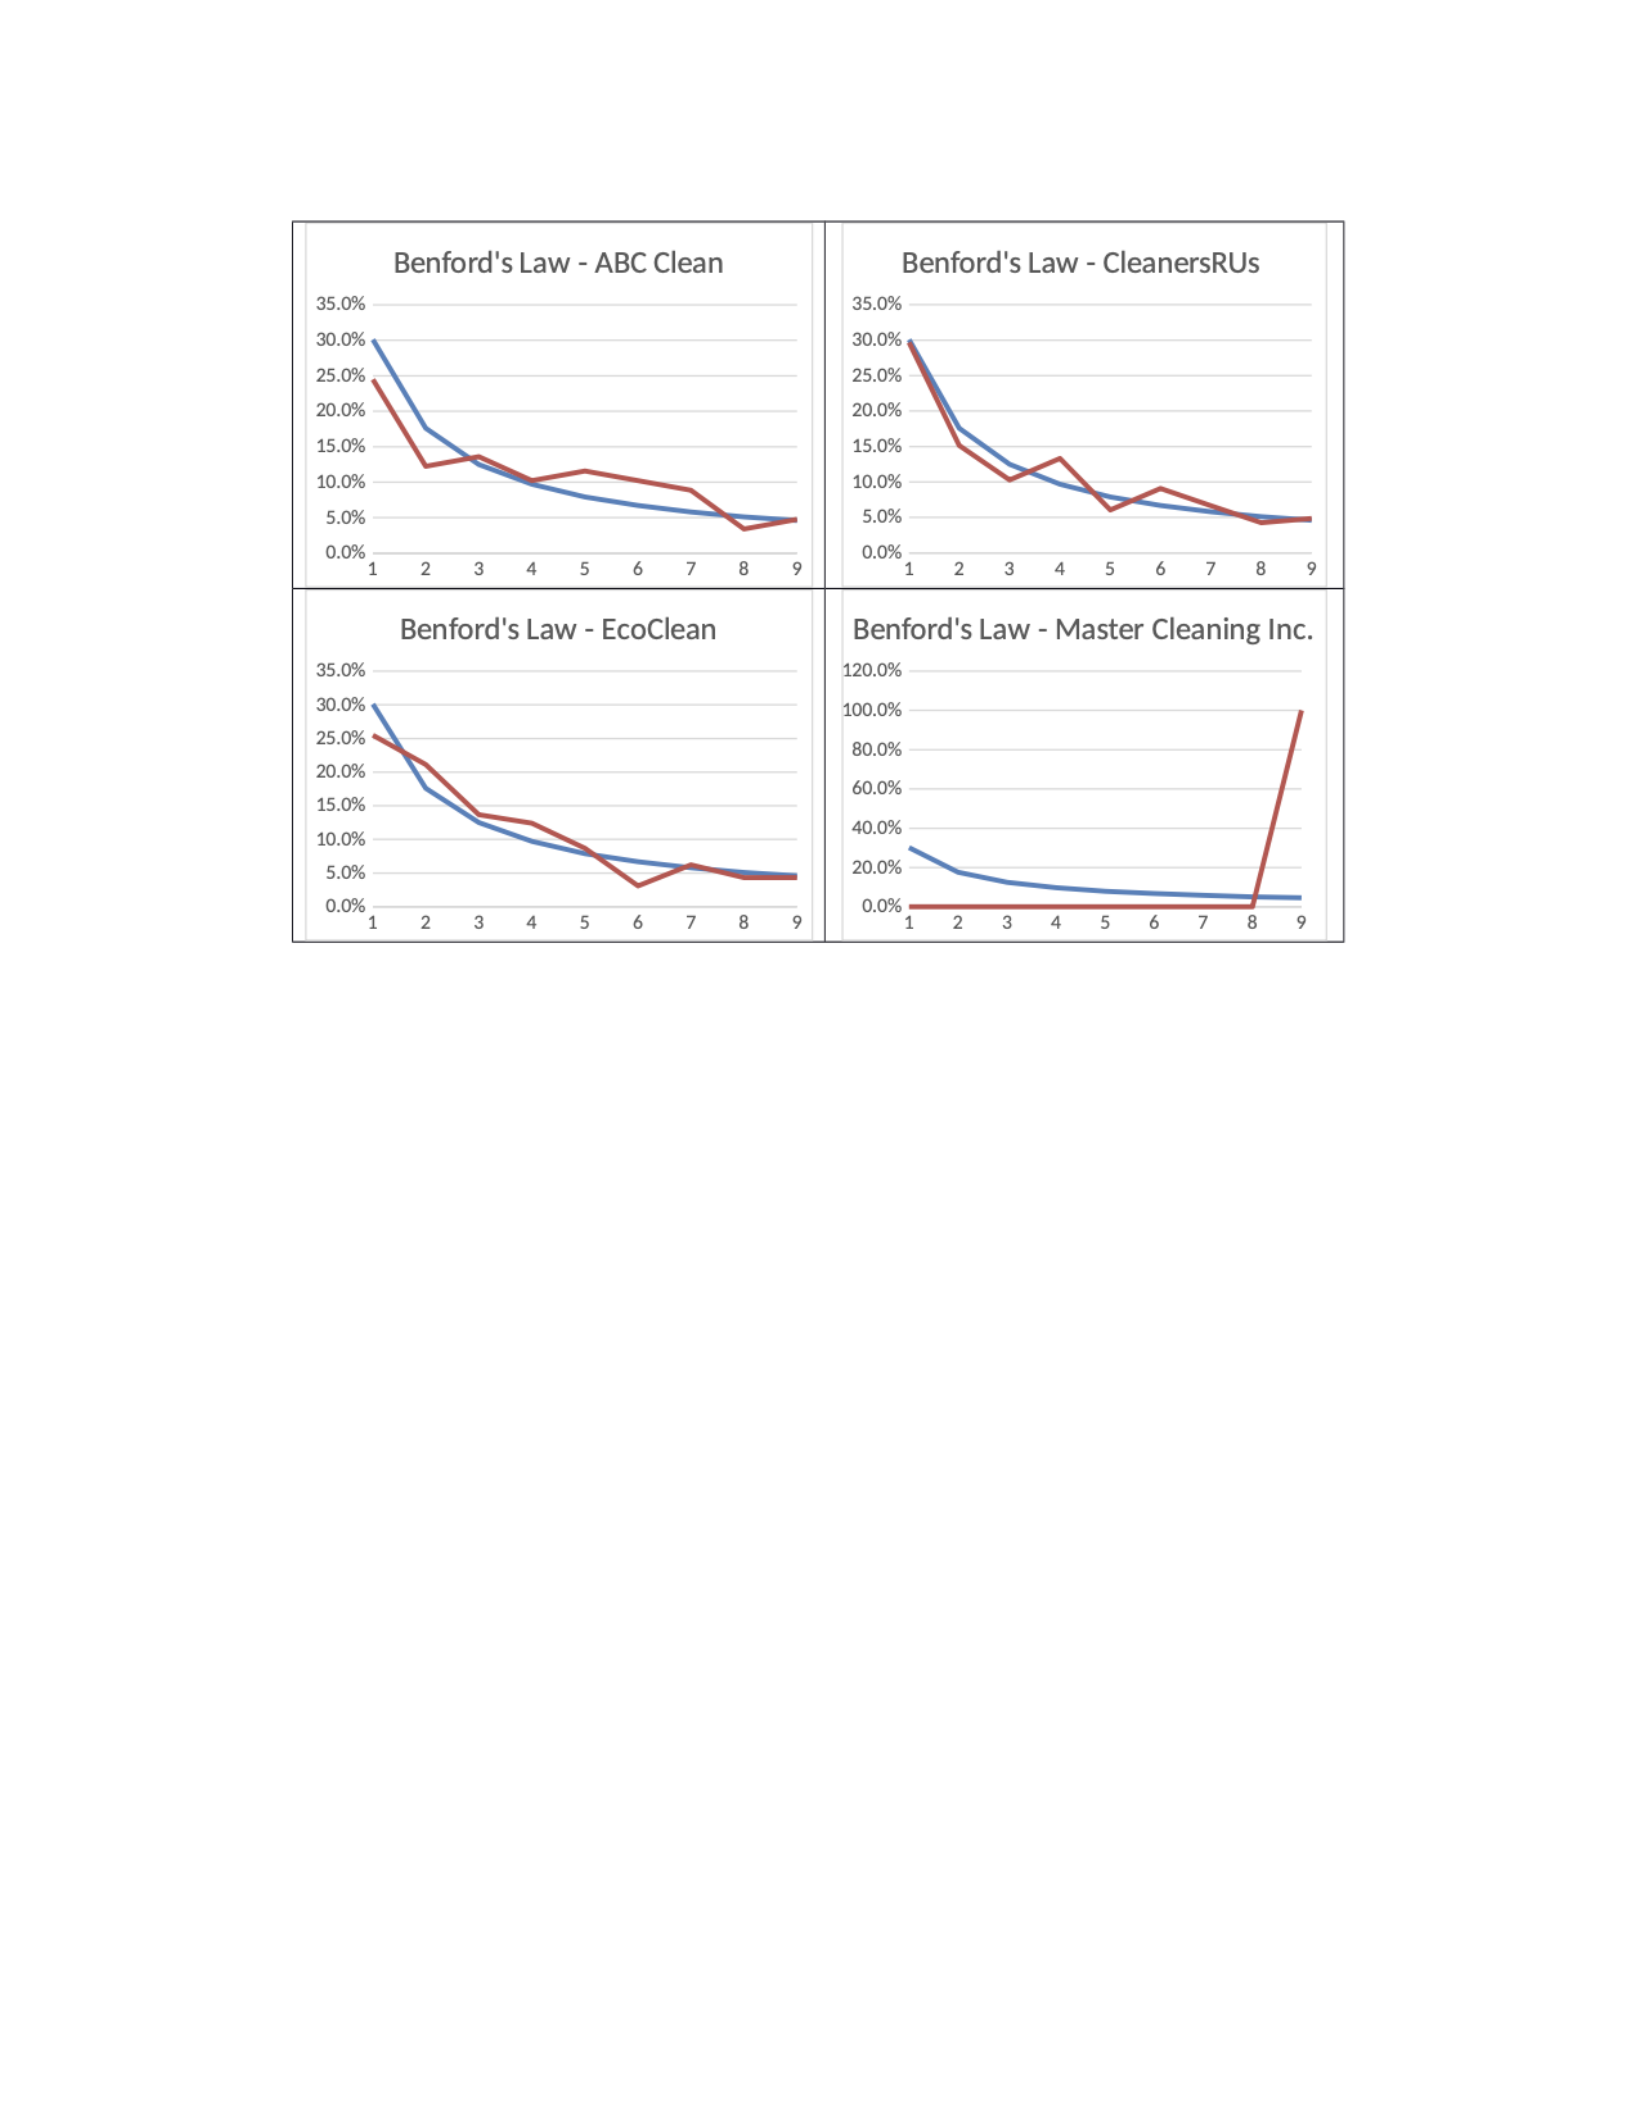
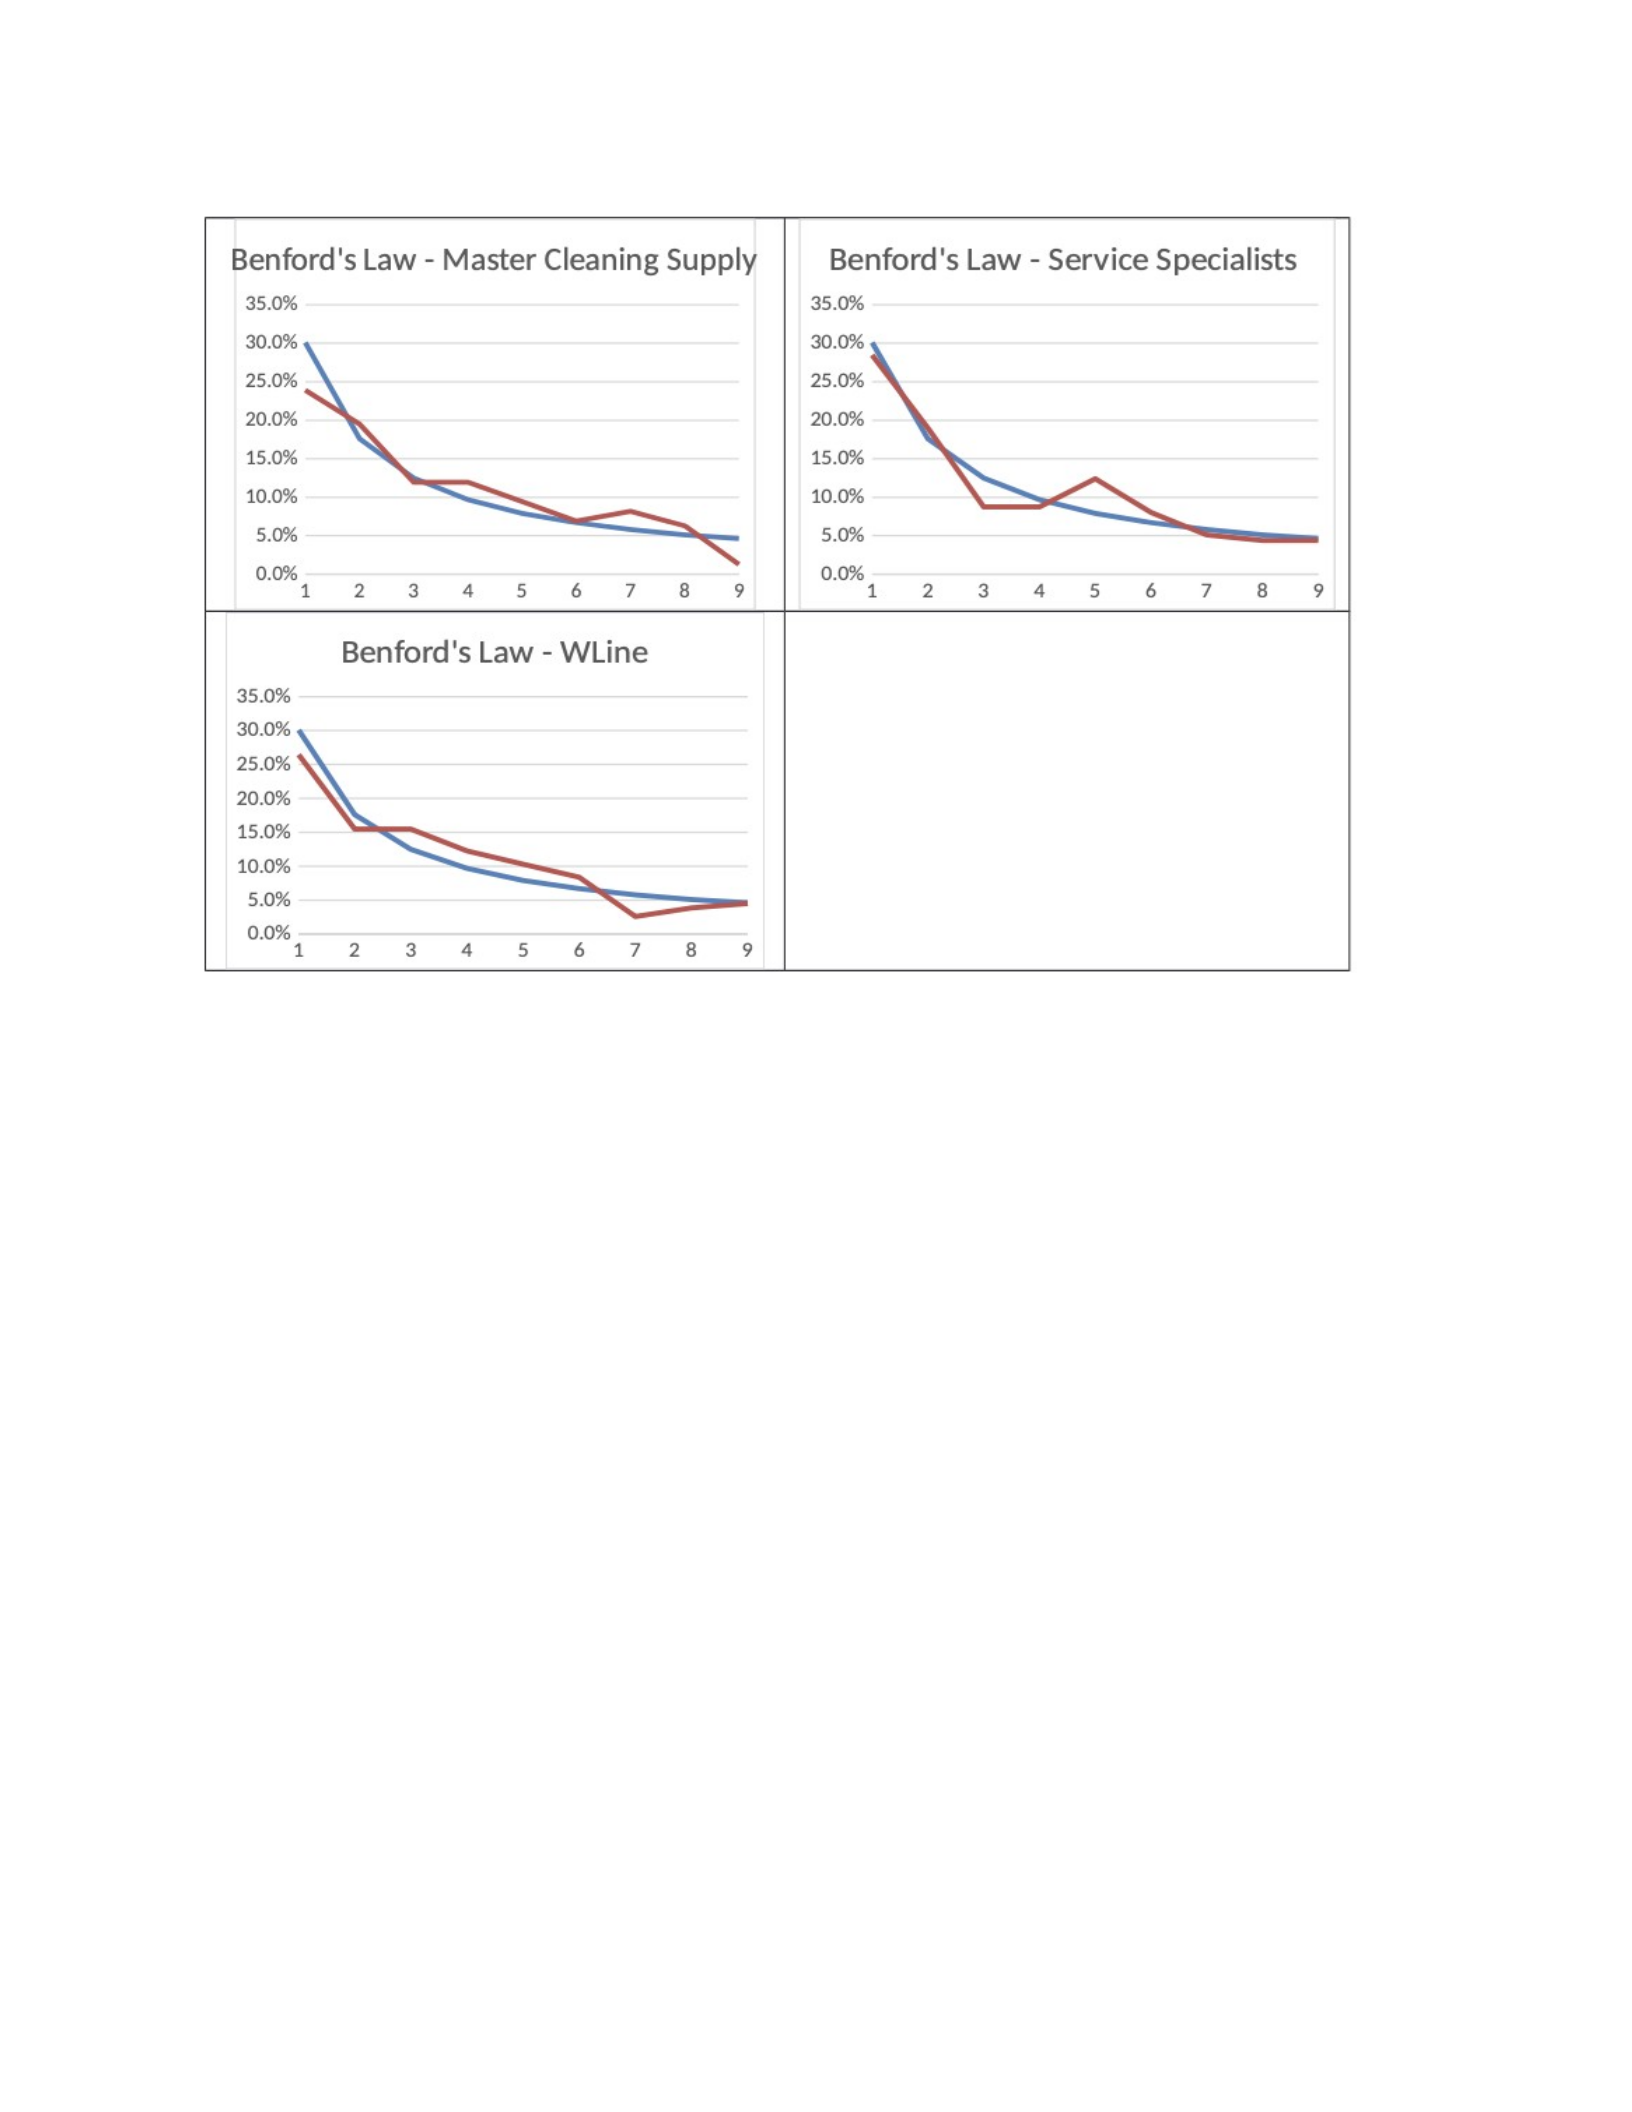
We have already gone over how to apply Benford's Law to a collection of data by
following the same procedures as in Short Case 8 Benford's Law, which is mentioned above. The
data for each computation is displayed in a graph below. This gives us a visual representation of
our presumption that one Mater Cleaning Inc. record is anomalous and requires additional
auditing. For service professionals, there is also a notable peak at the first number 5, indicating
that those records need to be retrieved for additional examination. Interestingly, Master Cleaning
Supply generally complies with Benford's Law, which allays our worries about possible
fraud.:This demonstrates how additional sampling and analysis are not always required, even in
the unlikely event that the first-digit test yields a true organic sample.
Benford's
Law
-
ABC
Clean
Benford's
Law
-
CleanersRUs
35.0% 35.0%
30.0% 30.0%
25.0% 25.0%
20.0% 20.0%
15.0% 15.0%
10.0% 10.0%
5.0% 5.0%
0.0% 0.0%
1 2
3
4
5
6 7
1
2 3
4
5
6 7 8
9
Benford's
Law
-
EcoClean
Benford's
Law
-
Master
Cleaning
Inc.
35.0%
120.0%
30.0%
100.0%
25.0% 80.0%
20.0%
60.0%
15.0%
10.0%
40.0%
5.0%
20.0%
0.0% 0.0%
1 2
3
4
5
6 7
1
2
3
4
5 6 7 8
9
Individual Learning Project – Data Driven Fraud Detection 12
Individual Learning Project – Data Driven Fraud Detection 13
Case Study 3: Purchase & Vendors
Two data sets are provided to us in this case study. A list of authorized vendors is one data
collection that purchasing department staff members can utilize to make necessary purchases.
Only the alphanumeric code provided to each approved vendor is available to us in this data set.
The purchasing department's past purchases are listed in detail in the second data set. We are
given additional information in this data collection, including the invoice number, date, buyer,
vendor code, and amount.:We may use Access, a data analysis program, to examine the data for
this case study.:To work with the data sets, we must first import them into Access. We may use
the New Data Source option under the External Data tab to add the two data sets once the
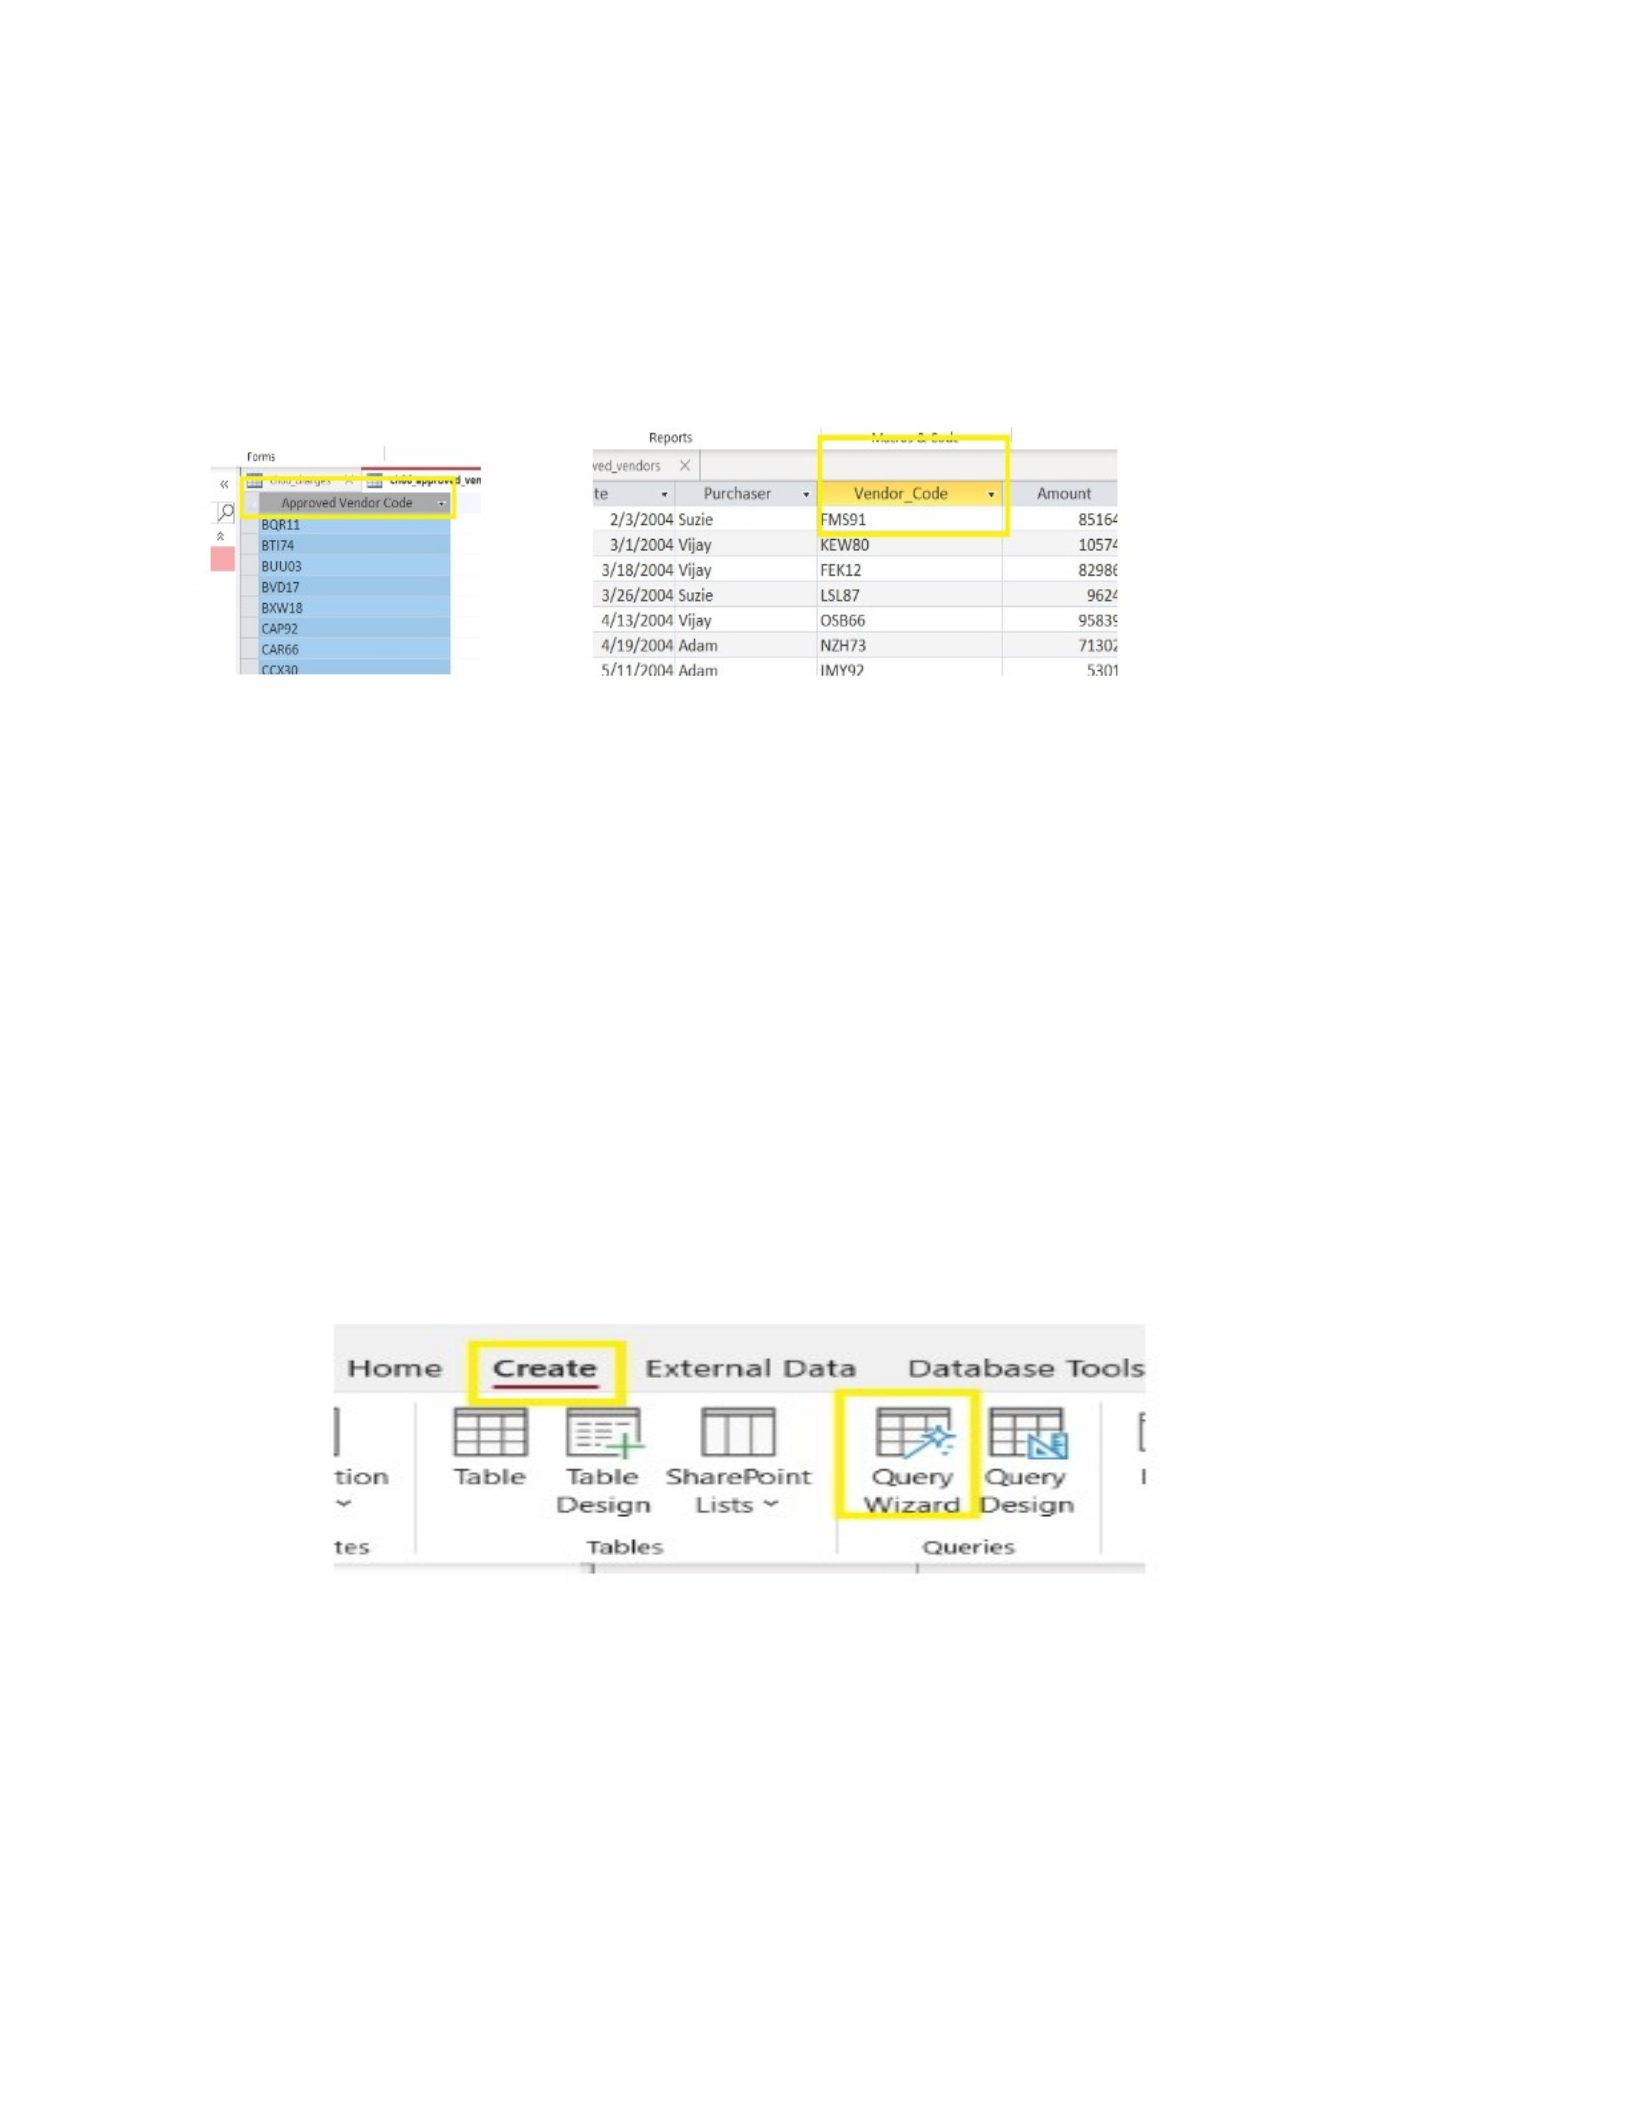
program has been opened. After reviewing the data in Access, I decided to slightly alter the name
to make it more understandable in the next procedures. Since there is a field named Vendor Code
Individual Learning Project – Data Driven Fraud Detection 14
in the other data set as well, I modified the name of the vendor data on approved vendors from
Vendor Code to Approved Vendor Code.:
Now is the time to use the data to generate a query. According to Alexander, M., and
Kusleika, D. (2018), "questions are the tools that enable you...to extract data from multiple
tables, combine it in useful ways, and present it to the user as a datasheet, on a form, or as a
printed report." We can create a new object using the Query Wizard under the Create Tab. The
Find Unmatched Query Wizard preset query is available here. According to Alexander, M., and
Kusleika, D. (2018), this query will evaluate the data sets and display records from one data set
that do not have a corresponding record in the other data set.:We will be able to determine
whether any unapproved vendors are being employed by using this data analysis technology.:
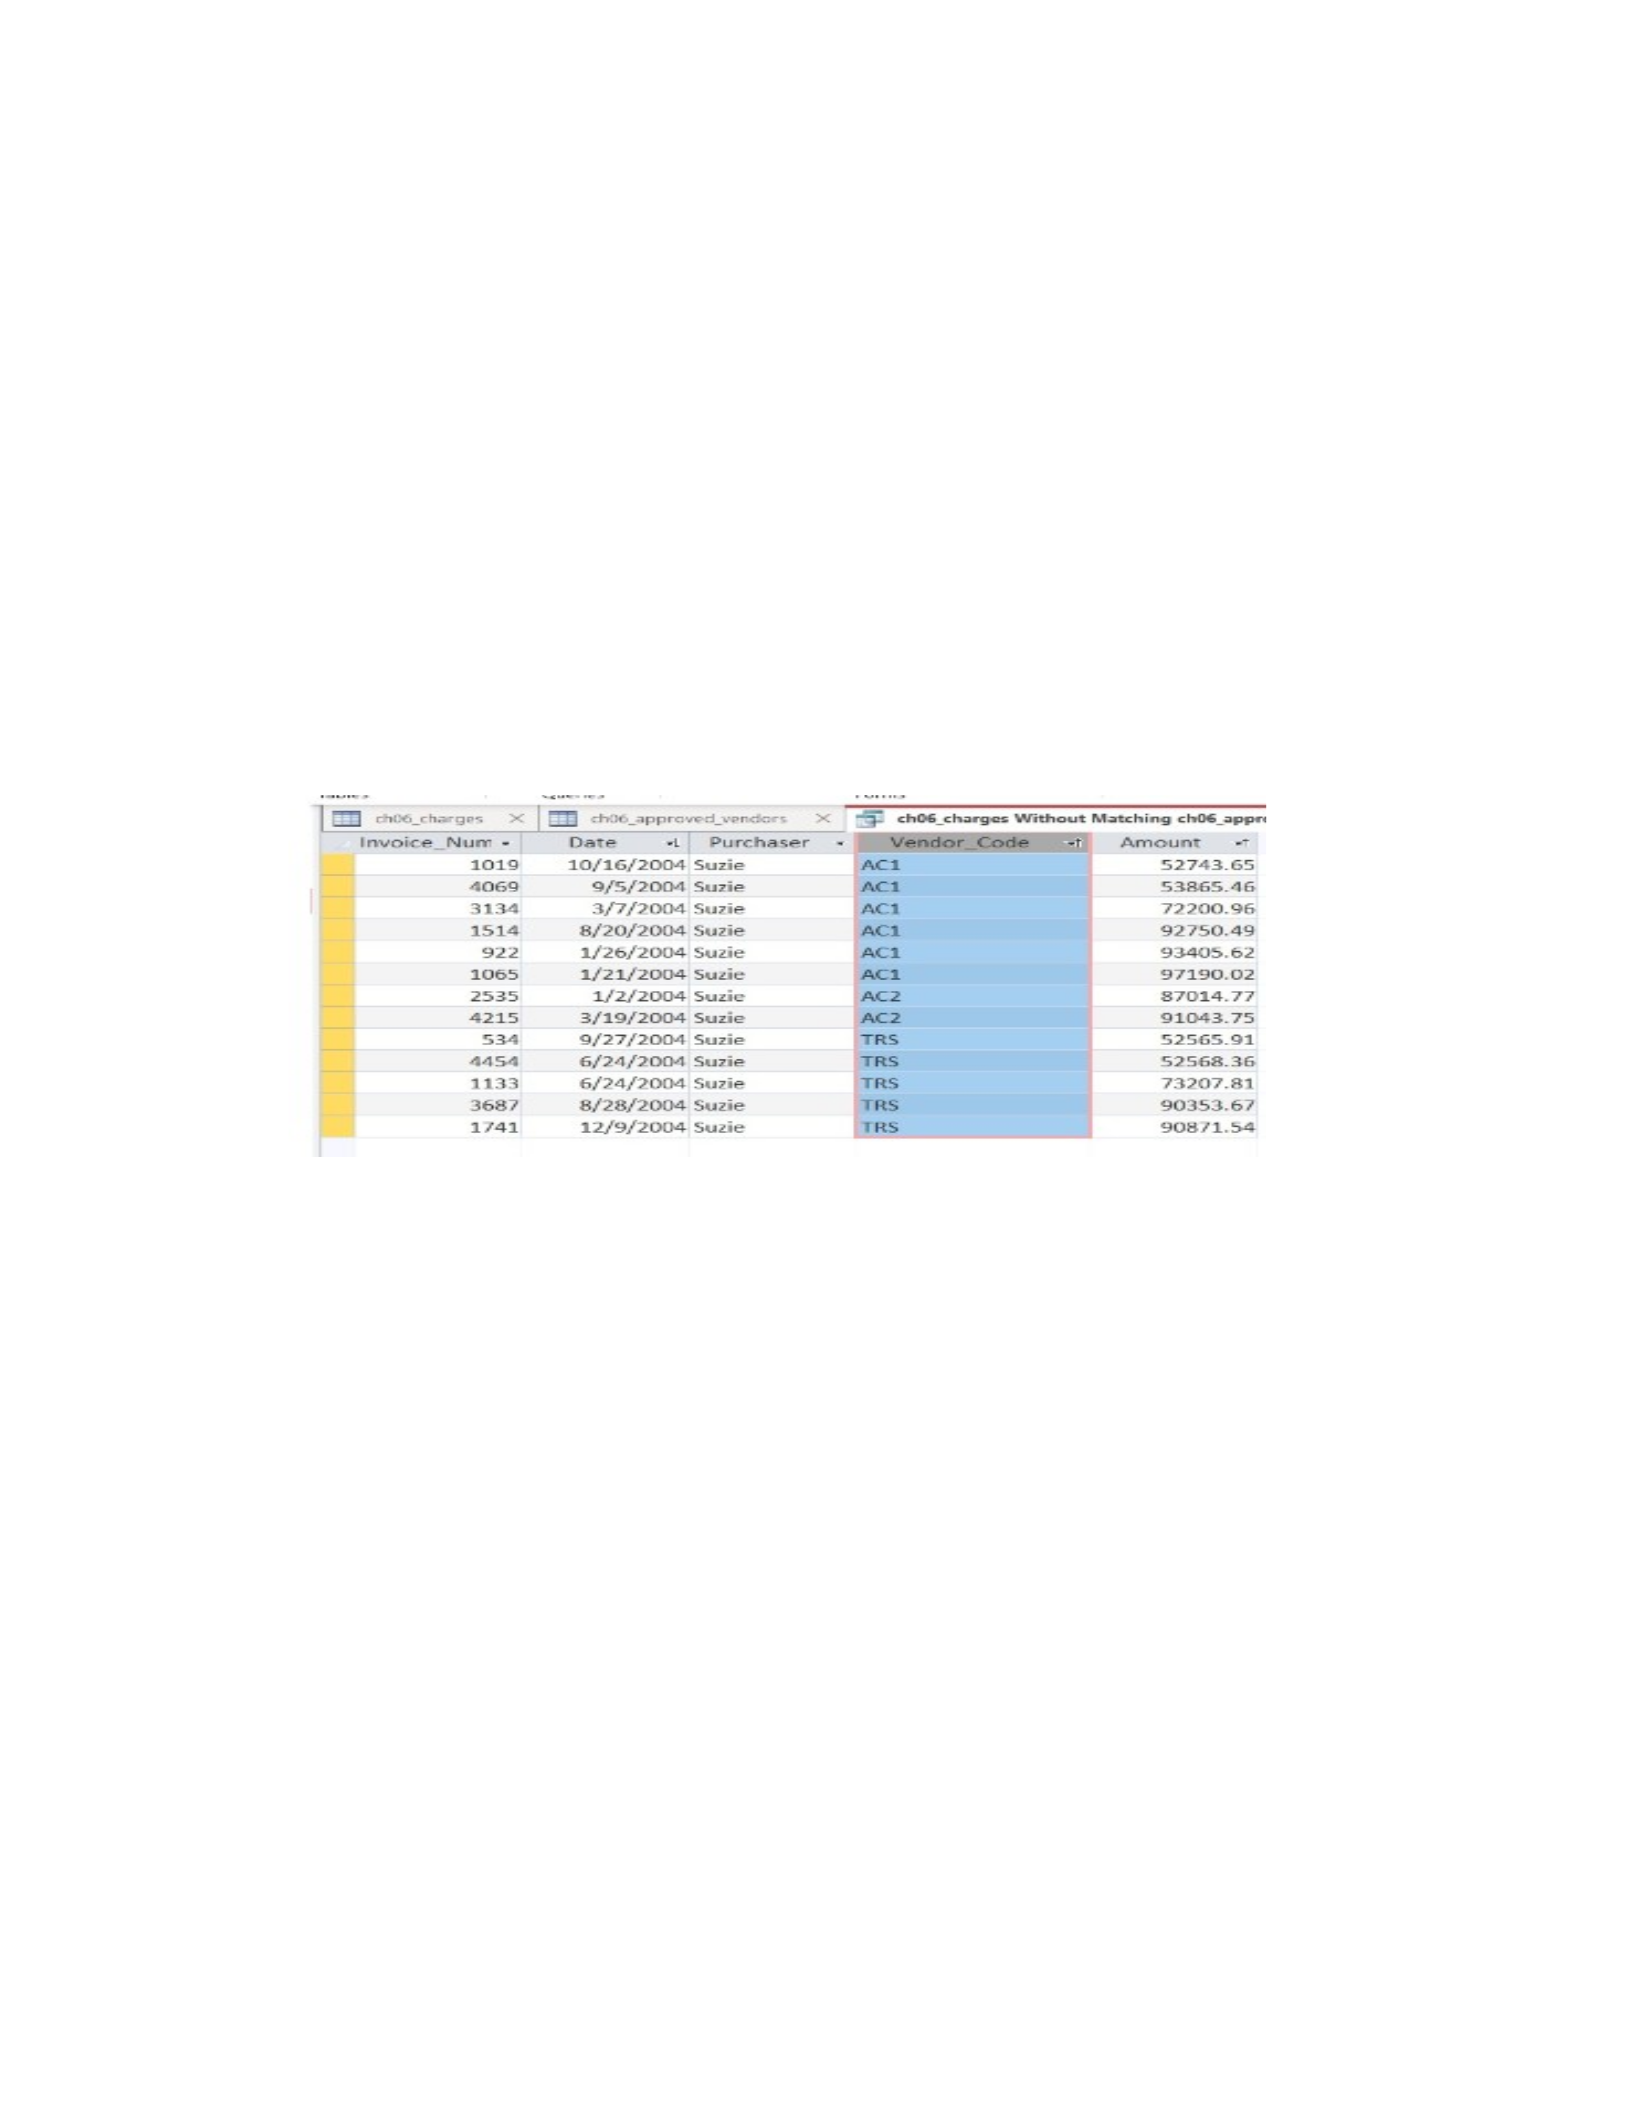
Access can expedite the computation required for us to evaluate the required data. Among
other extremely concerning results, the query led us to 13 records in which the buying
department employed an unapproved vendor. Due to the information provided, we only have
their "approved code" and not their full firm name, making AC1, AC2, and TRS the non-
Individual Learning Project – Data Driven Fraud Detection 15
approved vendors. Additionally, we can observe that Suzie, the purchasing staff, processed all 13
records.:The vendor clearance codes themselves raise another red flag; the ones in the search
results appear to be fictitious, as genuine approved vendors have codes consisting of two digits
and three letters, whereas these three only have three characters. A further red signal is the
invoice dates, some of which are for the same vendor on the same date or very near to it. The last
warning sign is the transaction amounts. The amounts range from $52,000 to $97,000, for a total
of slightly under $1 million, albeit we are not told what the corporation is buying. The data is
displayed below.:
Now that the data analysis has been completed, it is time to begin further data analysis to
look for any possible fraud. The audit team must look at the three invoices more thoroughly. To
enable each to conduct a more thorough audit, the investigators should gather all relevant
documentation for these records as well as any supporting documents. Additionally, an inquiry is
required to identify these businesses. What are their whole company names, what products do
they offer, what was purchased each time, etc.:Finding out who created the non-approved vendor
codes and seeing if they have additional information about the purpose of the vendors would be
crucial, thus interviewing the employee in charge of vendor approval would also be a crucial
assignment. In addition to the responsibilities, Suzie must be interviewed as soon as possible.

Individual Learning Project – Data Driven Fraud Detection 16
She probably has the most information to share because she was the one who produced the
records.
What would happen next would depend on how the probe turned out. If Suzie was able to
design and carry out a significant fraud plan, then a thorough investigation, intervention from
law enforcement, the filing of criminal charges, and Suzie's firing would be necessary. Whether
or not this proves to be fraud, the business needs to improve personnel training and controls.
Retraining staff on corporate policy is necessary to make sure purchasing staff members are
aware of the rules regarding orders from unapproved and non-preferred vendors. Workers should
be informed that making purchases from unapproved vendors has repercussions because their
actions may have a detrimental effect on the business.:A few drawbacks include the possibility
that they will purchase goods at exorbitant costs rather than at a reduced negotiated price, which
would be costly to the business. Higher purchase quantities may surpass budgeted amounts for
purchases. The purchasing department may also be inadvertently making duplicate purchases
because no one is aware that these transactions are coming from unapproved vendors.:
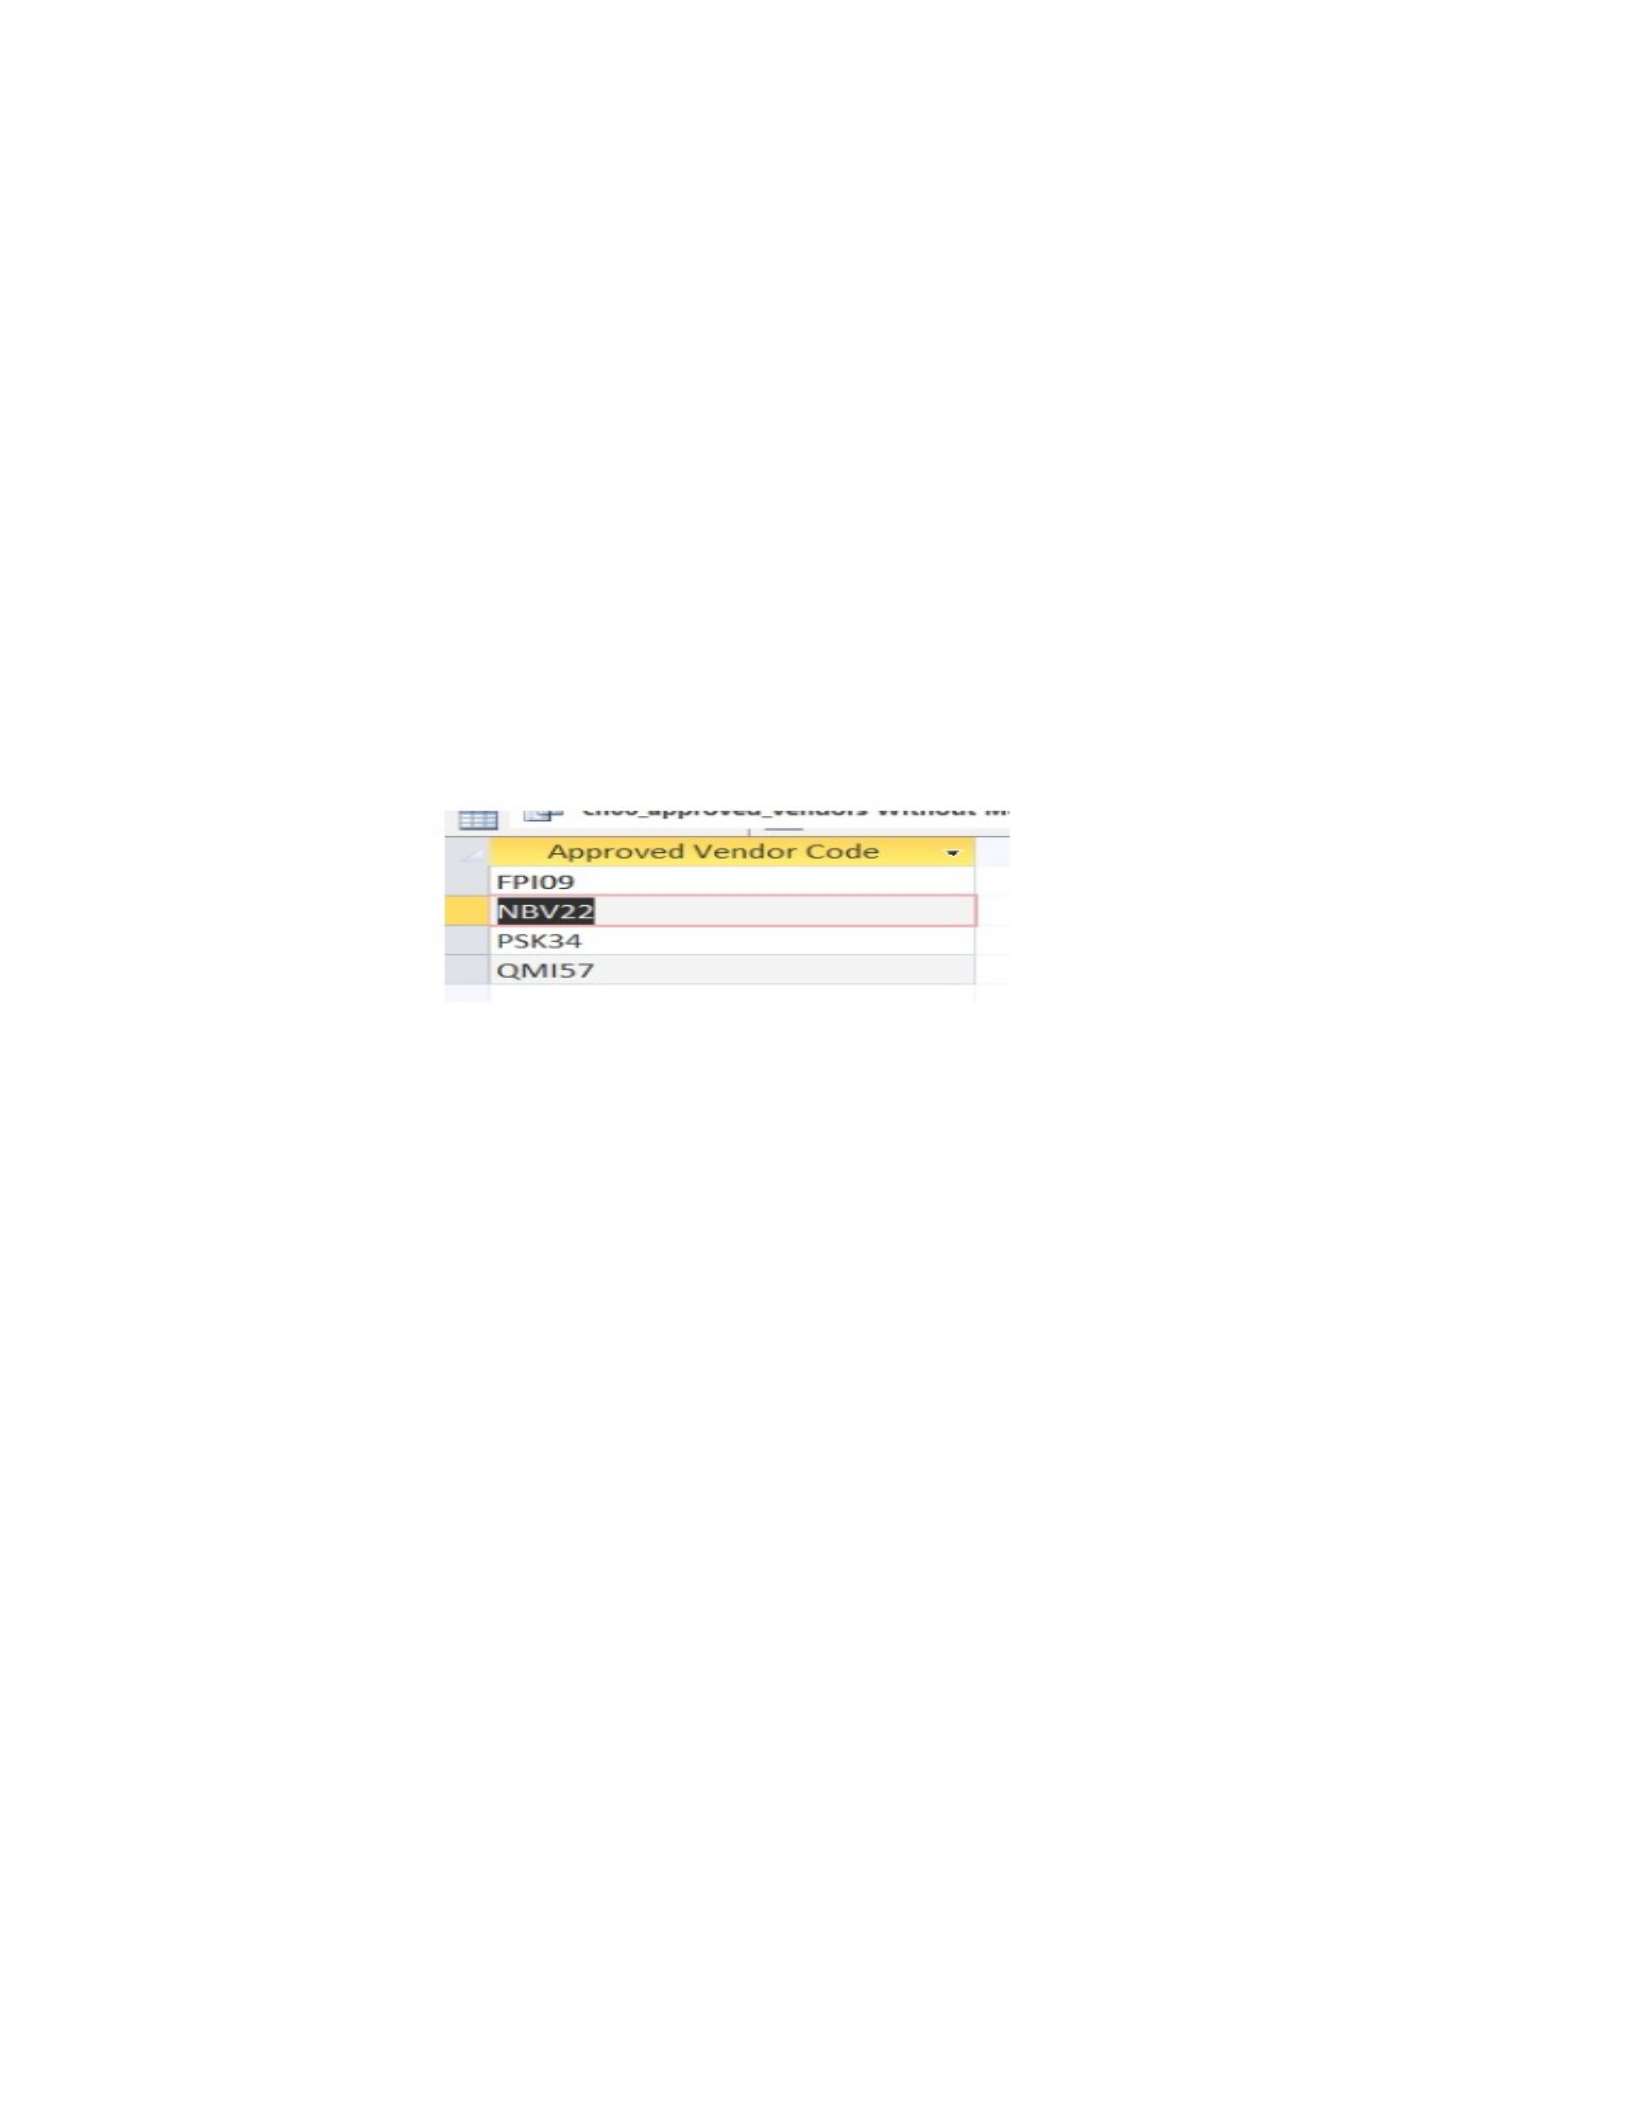
The purchasing staff must then run a second query to see whether any permitted vendors
are not being used. We can construct a new object using the Query Wizard once more under the
construct Tab. We can utilize the Find Unmatched Query Wizard preset query once more in this
situation. Upon completion of Access's quick computations, we see that the following authorized
vendors—FPI09, NBV22, PSK34, and QMI57—were not utilized. We can investigate the subject
more now that we have this knowledge. Why didn't the business use these vendors, and why?
Has the vendor experienced any changes or is their business no longer operational? In this
instance, the vendor must be taken off the approved vendor list if the business is no longer
making purchases from them or if they are no longer in operation. There's a potential that an
Individual Learning Project – Data Driven Fraud Detection 17
employee will find these vendors and create their fraud scheme if they stay on the approved
vendor list. This is an excellent illustration since, as we all know, not every company survived
COVID-19. Businesses with lists of allowed vendors ought to audit them to make sure that
employees have access to the most recent version of the approved vendor list.:Due to supply
changes over the past few years, many businesses have had to switch around their long-term
suppliers. This is an efficient control that lists like these are reviewed to prevent fraudulent
opportunities or incorrect purchases.
Conclusion
With the advent of robust data analysis programs like SAS, Excel, Access, and IDEA,
auditors may now do useful calculations at their fingertips. Thanks to advancements in
computing power, length calculations are now simple and may be completed in a matter of
seconds. Consider Benford's Law Short Case No. 8. Pen and paper calculations could be
completed quickly for the data set in this example, but what if your data set had hundreds or tens
of thousands of records? That is too much for anyone to calculate by hand. This would not be an
issue now that Excel has basic formulas.:Benford's Law's conclusion might be obtained by the
investigator in a matter of seconds using rapid and simple data analysis. From there, it would be
simple for investigators to go to more difficult tests that will help them focus on specific
anomalies within the data set. Due to the quick availability of information, auditors and
investigators are now able to evaluate massive data sets of records swiftly and effectively,

Individual Learning Project – Data Driven Fraud Detection 18
leading to the production of more accurate data findings. The business can then use the data's
conclusions to address possible fraud and enhance internal control.:
We now know that investigators and auditors serve as shareholders' watchdogs. They
assist businesses in preventing numerous fraud techniques from stealing the investments made by
each stakeholder. Even while auditors put in a lot of effort to do their part, some people will
always risk everything to create a profitable fraud scheme. As stated in Proverbs 13:11 in the
English Standard Version Bible, "dishonest money dwindles, but he who gathers money little by
little makes it grow." (Proverbs 13:11 (NIV), n.d.) A person who is prepared to violate their oath
to deceitfully amass vast sums of money may enjoy the fruits of their labor for a little while, but
their wealth will vanish as soon as their scheme is exposed and exposed by the diligent work of
the auditors.:Those who ultimately decide to act dishonestly and against God's rule will find
themselves in much more of a mess than when they first started.:

Individual Learning Project – Data Driven Fraud Detection 19
Reference
Albrecht, W. S., Albrecht, C. O., Albrecht, C. C., & Zimbelman, M. F. (2019). Fraud
Examination. 6th Edition. Boston, MA: Cengage.
Alexander, M., & Kusleika, D. (2018). Access the 2019 Bible. John Wiley & Sons, Inc.
Collins, J. C. (2017, April 1). Using Excel and Benford's Law to Detect Fraud. Journal of
Accountancy. Retrieved April 2, 2022, from https://bi-gale-
com.ezproxy.liberty.edu/global/article/GALE%7CA491719181? u=vic_liberty&sid=summon
English Standard Version Bible. (2001). ESV Online. https://esv.literalword.com/
Goh, C. (2020). Applying visual analytics to fraud detection using Benford's law. The Journal of
Corporate Accounting & Finance, 31(4), 202-208. https://doi.org/10.1002/jcaf.22440
Mangala, D., & Kumari, P. (2017). Auditors' Perceptions of the Effectiveness of Fraud
10(2), 118-
142. http://dx.doi.org/10.1177/0974686217738683
Nigrini, M. J. (2020). Forensic analytics: Methods and Techniques for Forensic Accounting
Investigations (2 edition). Hoboken, NJ: John Wiley & Sons, Inc.
Proverbs 13:11 (NIV). (n.d.). Bible Gateway.:https://www.biblegateway.com/passage/?search=Proverbs
%2013%3A11&version=NIV

