


Case 4-4
Accountants had advocated two types of income statements based on differing views of the
concept of income: the current operating performance and all-inclusive concepts of income.
Required:
a.Discuss the general nature of these two concepts of income.
b.How would the following items be handled under each concept.
i.Cost of Goods Sold
ii.Selling Expenses
iii.Prior Period Adjustments
Discussion Board: Case 6-3
ACCT 632 Advanced Financial Accounting Theory
Julie Mather
Liberty University

Current Operating Performance Concept
Income Statement Formats
The FASB’s SFAC No. 8 defines that the purpose of financial reporting is to provide
financial information about the reporting entity that is useful for equity investors, lenders, and
other creditors making decisions about providing funding or other resources to that entity.
Because of this, the income statement is very important to financial users as they depend on the
predictive nature of the report in determining cash flows, measurements of management
efficiency, and completion of corporate goals. Discussion of the two income statement concepts,
the current operating performance and all-inclusive formats will be discussed here.
The current operating performance concept includes income that is controlled or affected
by changes by management. It includes only normal or recurring income, also known as
sustainable income, that drive profit directed activities should be included in net income. All
other profit or loss activities would be included because they do not affect the day to day
corporate performance. Kanagaretnam, Mathieu, and Ramanan (2009) suggest that the for
investment managers the use of the current operating performance income statement approach
encourages executives to be proactive in their investment decisions because their compensation
is directly related to the day to day performance of that company (pg 27). While third parties do
depend on financial statements to determine their funding, lending, or investment decisions, they
are not largely influenced on where revenues, expenses, gains and losses are included on the
statements, but only that they are visible for evaluation. Net income is driving factor for many
financial decisions and the current operating performance concept allows users to see changes in
revenues and expenses over time which can be indicative for financial forecasting.
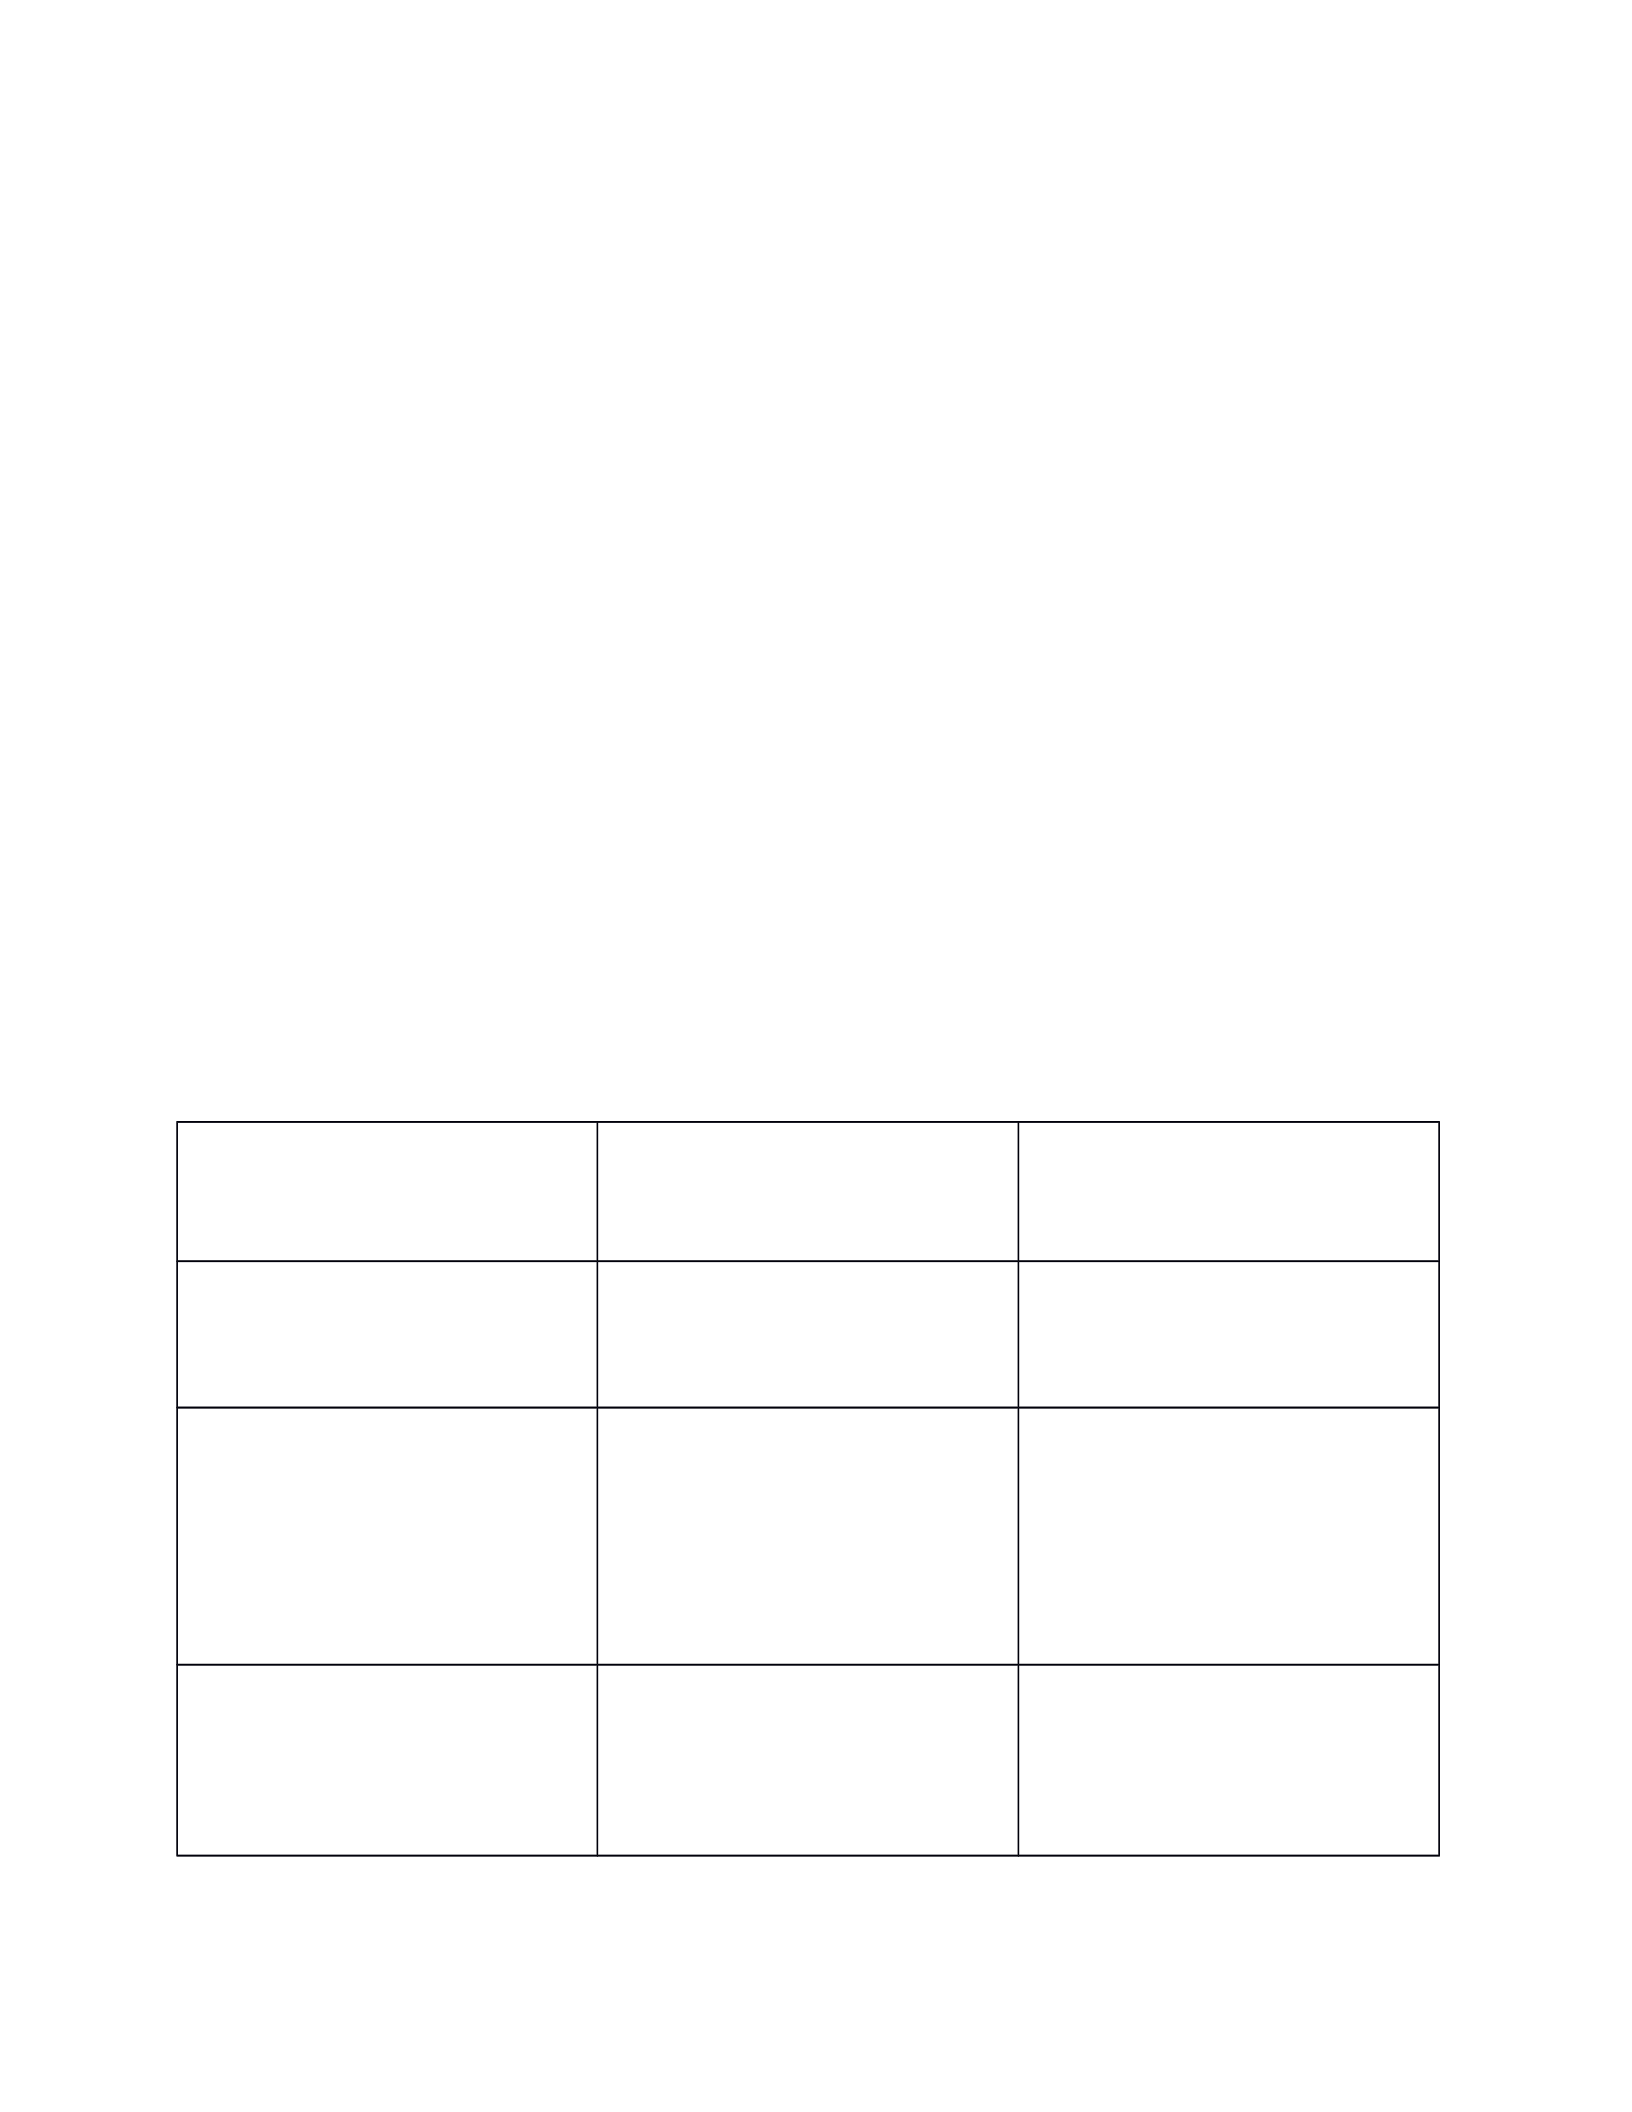
All-Inclusive
Selling Expenses
Cost of Goods Sold
Prior Period Adjustments
Current Operating
Performance Concept
Recorded as an expense and
included in net income.
If usual, included in net
income under current
operating expenses. If
unusual, included in the
retained earnings statement.
Disclosed in the financial
statement, but not included in
net income.
Included as a part of
comprehensive income.
All-Inclusive Concept
Recorded as an expense and
included in net income.
Recorded as expense and
included in net income.
Contrary to the current operating performance concept, the all-inclusive income
statement format reflects all items that directly affected stockholder’s equity during a set period
excluding capital transactions. “A company's disclosure on the face of the statement, in the
statement of changes in equity or in notes to the financial statement of accumulated balances of
each component of accumulated other comprehensive income should correspond to the
classifications used in other financial statements for components of comprehensive income”
(Luecke & Meeting, 1998) In 1966, the AICPA issued Opinion No. 9 affirming the adoption of
the comprehensive income statement and FASB SFAC No. 130 divides income into net income
and other comprehensive income. Examples of non-recurring items of income that would be
included on the all-inclusive income statement format are non-recurring gains and losses, income
from discontinued operations and extraordinary items.

Biblical Integration
As Christians we are challenged daily to put on Christ. Choosing to align ourselves with
our Heavenly Father and His plans for our lives puts us in a place where blessings are bestowed
upon us because we are His righteousness. 2 Corinthians 5:21 says, “For our sake he made him
to be sin who knew no sin, so that in him we might become the righteousness of God.” His love
is an all-inclusive unconditional love that knows no bounds. Psalm 86:5 tells us, “You, Lord are
forgiving and good, abounding in love to all who call to you.” We serve a God who is all-
knowing and seeks our hearts daily. As professionals who serve the Lord and our communities,
we should be in alignment first with Him and then in agreement with those around us.
Resources
FASB, Financial Accounting Standards Board. (n.d.). Retrieved from
https://www.fasb.org/jsp/FASB/Page/SectionPage&cid=1176154526495
Kanagaretnam, K., Mathieu, R., & Ramanan, R. (2009). Stock option grants, current operating
performance and deferral of earnings. International Journal of Management, 26(1), 26-32.
Luecke, R. W., & Meeting, D. T. (1998). How companies report income. Journal of Accountancy,
185(5), 45-52.

Reply 1:
Thanks for sharing your thoughts on case 5-4 this week, Robert! I appreciated your
insightful answers to the questions presented. You thoroughly discussed the GAAP definitions of
costs, expenses and losses used in financial reporting. An important note you made was the
difference between purchases (a cost) that produce revenue and are expensed when the “cost” is
expired where as a loss is not an expiration of costs, but rather the failure to produce revenue in
exchange for those costs. As an example, my employer builds custom automation machines that
are very costly (labor and custom materials) and as a result the COGS line for our custom
product line is extremely high. We are willing to risk a huge loss on custom project because the
profit margins are so high; however, if the product does not operate the way the customer wants,
we can incur re-work expenses that increase the level of costs we were willing to apply to this
job. Because of this, the financial preparation for uncollected accounts receivable is bad debt
expense. As custom jobs ship to the customer and pass the factory acceptance test (FAT) the
revenue can be fully recognized and not affect our reserve for bad debt. If equipment did not
meet the customer standard, an increase in the reserve for bad debt would ensure those over-
budget costs were accounted for. All costs associated with equipment would be considered
product cost as you discussed in the second question and directly run to the P&L account (Profit
and Loss) which has an immediate impact on the balance sheet (Ilcus, 2017). The Bible teaches
in the Gospel of Matthew chapter 6 (English Standard Version) that we should not worry about
tomorrow, but that the His grace and provision extend to the next day. In relation to this
discussion, opportunity costs in life should be examined, but our trust should remain in Him.

Ilcus, A. M. (2017). Period cost and its impact on financial statement. Revista De Management
Comparat International, 18(3), 315-325.
Thanks for sharing your thoughts on case 5-1 this week, Erika! I appreciated your
insightful answers to the questions presented about income smoothing. Management can be
incentivized to increase earnings when period earnings are low and decrease earnings when
period earnings are high; however, by doing so they remove the visibility of seasonality and
outside economic influences on revenues. An important reason management might be inclined to
apply income smoothing to their financials is for cash flow projections as company revenue
forecasts can be determined from historical cash flows. According to their survey completed by
Cahan, Liu, and Sun (2008), “78 percent of U.S. managers use their discretion to smooth the
income stream over time, and document strong evidence that income smoothing enhances
earnings informativeness, suggesting that on average the benefits associated with efficient
communication of private information dominate the costs associated with income garbling due to
opportunism, at least, in the U.S.” (pg.2) There are legitimate and illegitimate ways to maximize
company earnings and include completion estimates of long-term projects. Management uses
their professional judgment to recognize revenue as a percentage of work completed on a project
which can be used to more evenly distribute earnings through each financial period. In contrast,
manipulating those earnings to reflect more work completed than at the period ending would be
considered an illegal method of income smoothing. As Christians our integrity is of most
importance because we should be a reflection of Christ in our daily lives. 1 Peter 3:16 (English
Standard Version) tells us, “having a good conscience, so that, when you are slandered, those
Reply 2:

who revile your good behavior in Christ may be put to shame.” Using income smoothing should
only be utilized if it is in compliance with U.S. GAAP and with a clear conscience.
Cahan, S. F., Liu, G., & Sun, J. (2008). Investor protection, income smoothing, and earnings
informativeness. Journal of International Accounting Research, 7(1), 1-24.

