


ACCT 531 - ACCOUNTING
INFORMATION SYSTEMS - Fair
Value Measurement
Question Bank - Set 3
Liberty University
Question 1
Question
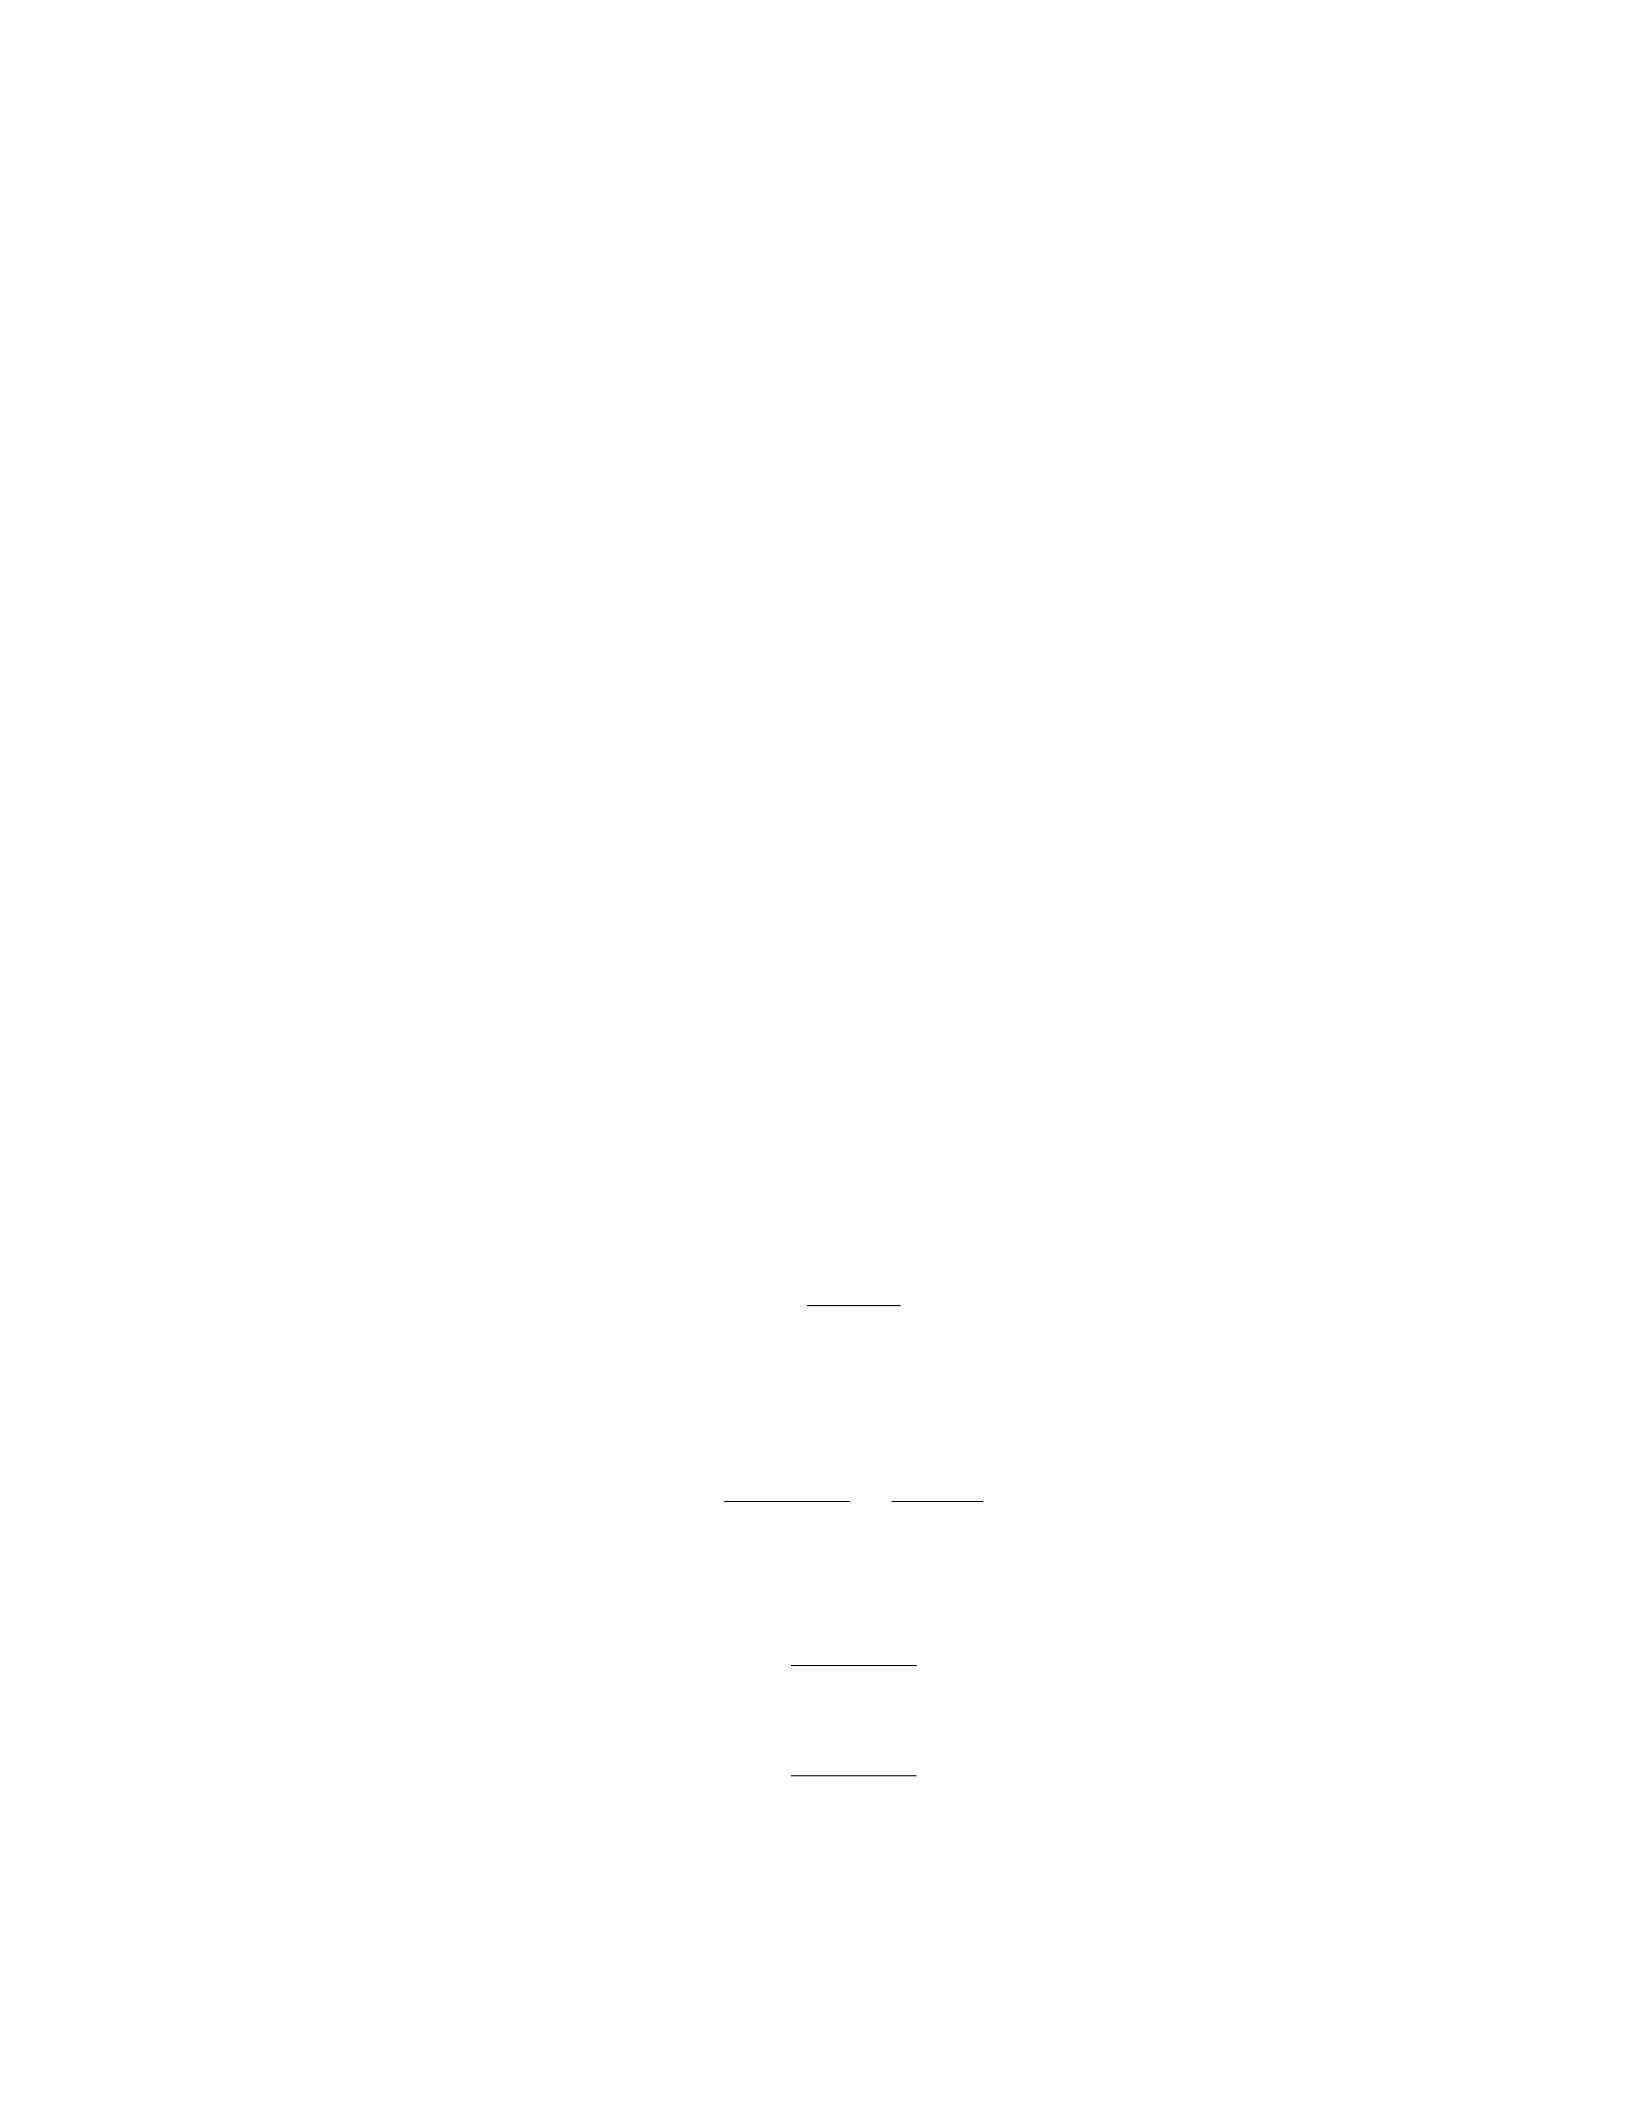
A company is trying to determine the fair value of an investment property using
the income approach. The property is expected to generate a net operating
income of 100,000peryearf orthenext5years.T hediscountrateis8
Solution
Step 1: Calculate the present value of the net operating income for each year.
We can use the formula for present value of an annuity:
P V =CF
(1 + r)n
where: - CF is the cash flow for each year, - ris the discount rate, and - nis
the number of years.
Using CF =100,000, r= 8% = 0.08, and n= 1 for each year:
P V =100,000
(1 + 0.08)1=100,000
1.08
Step 2: Calculate the present value of the net operating income for each
year. Repeat Step 1 for each year from 1 to 5: For year 2:
P V =100,000
(1 + 0.08)2
For year 3:
P V =100,000
(1 + 0.08)3
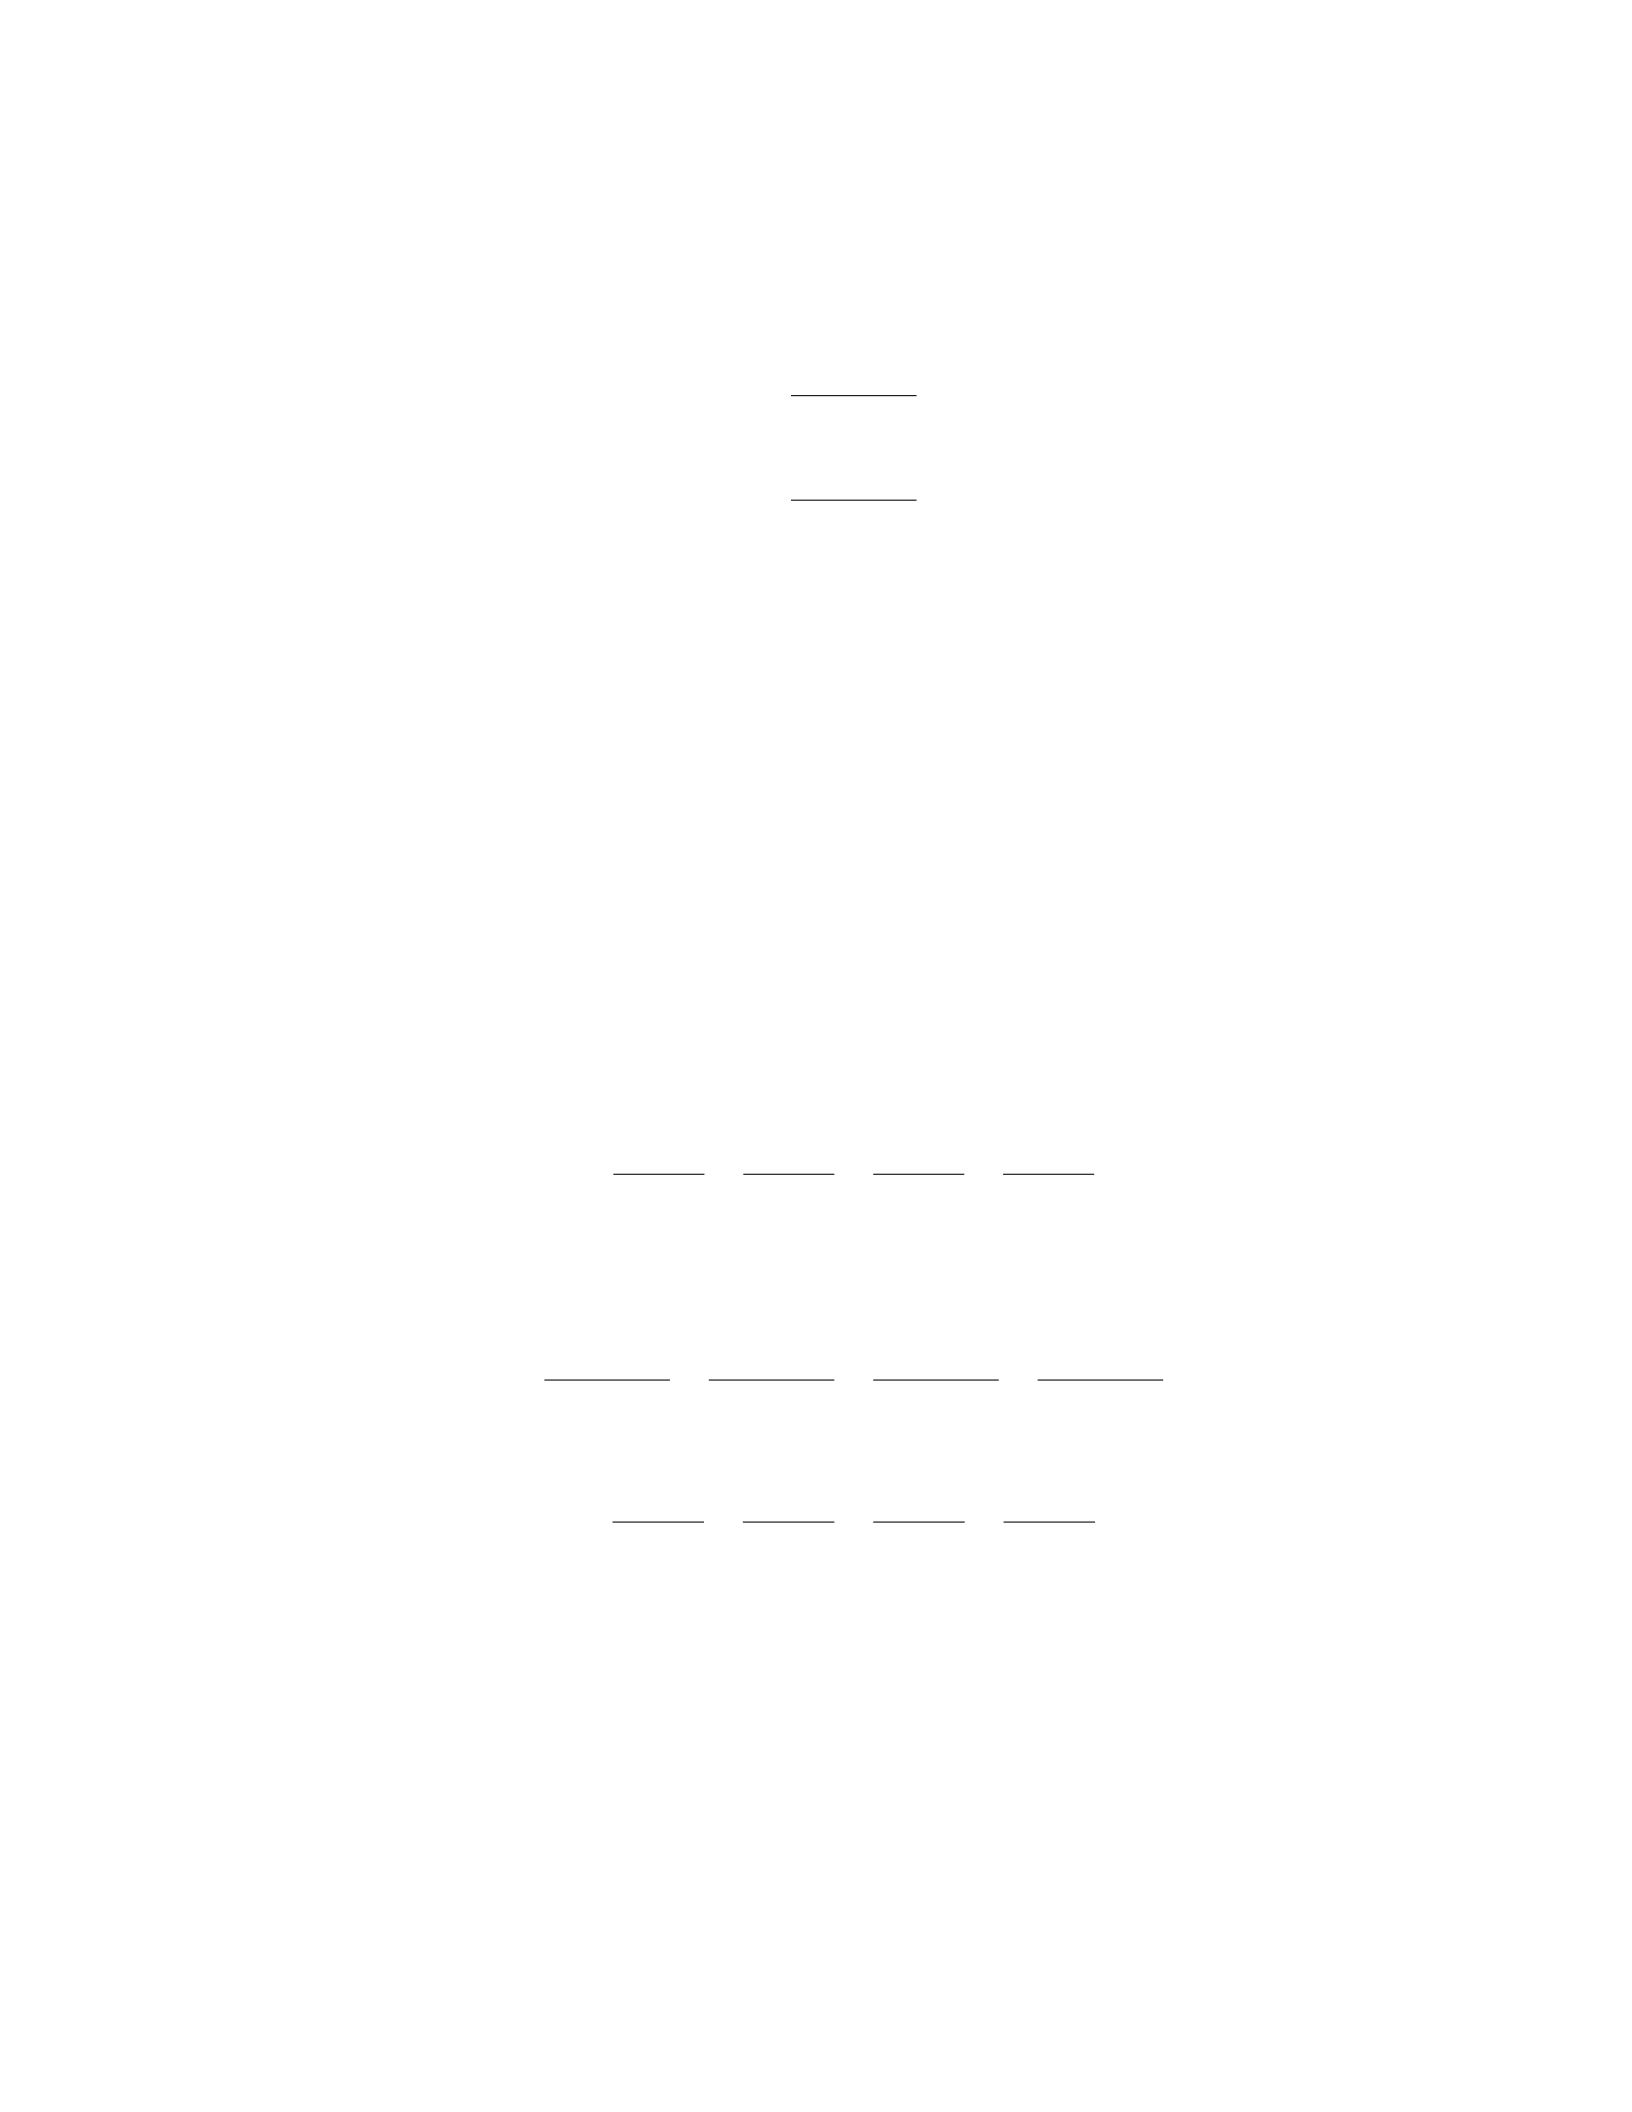
For year 4:
P V =100,000
(1 + 0.08)4
For year 5:
P V =100,000
(1 + 0.08)5
Step 3: Calculate the total fair value of the investment property. Sum up all
the present values from Step 2 to get the fair value of the investment property:
F airV alue =P V1+P V2+P V3+P V4+P V5
Question 2
Question
Company XYZ holds an investment in a privately held company. The fair
value of the investment is determined using the income approach. The discount
rate used is 10Year 1: 100,000Y ear2 :150,000 Year 3: 200,000Y ear4 :250,000
Calculate the fair value of the investment using the income approach.
Solution
Step 1: Calculate the present value of future cash flows. The present value
formula is given by:
P V =CF1
(1 + r)1+CF2
(1 + r)2+CF3
(1 + r)3+CF4
(1 + r)4
where: P V = Present value of the investment CFi= Cash flow in year i r =
Discount rate
Substitute the given values:
P V =100,000
(1 + 0.10)1+150,000
(1 + 0.10)2+200,000
(1 + 0.10)3+250,000
(1 + 0.10)4
Step 2: Compute the present value.
P V =100,000
1.10 +150,000
(1.10)2+200,000
(1.10)3+250,000
(1.10)4
P V = 90,909.09 + 123,966.94 + 160,220.47 + 189,433.47
P V = 564,529.98
Therefore, the fair value of the investment using the income approach is
564,529.98.
2
Question 3
Question
A company holds an investment property that it measures at fair value. The fair
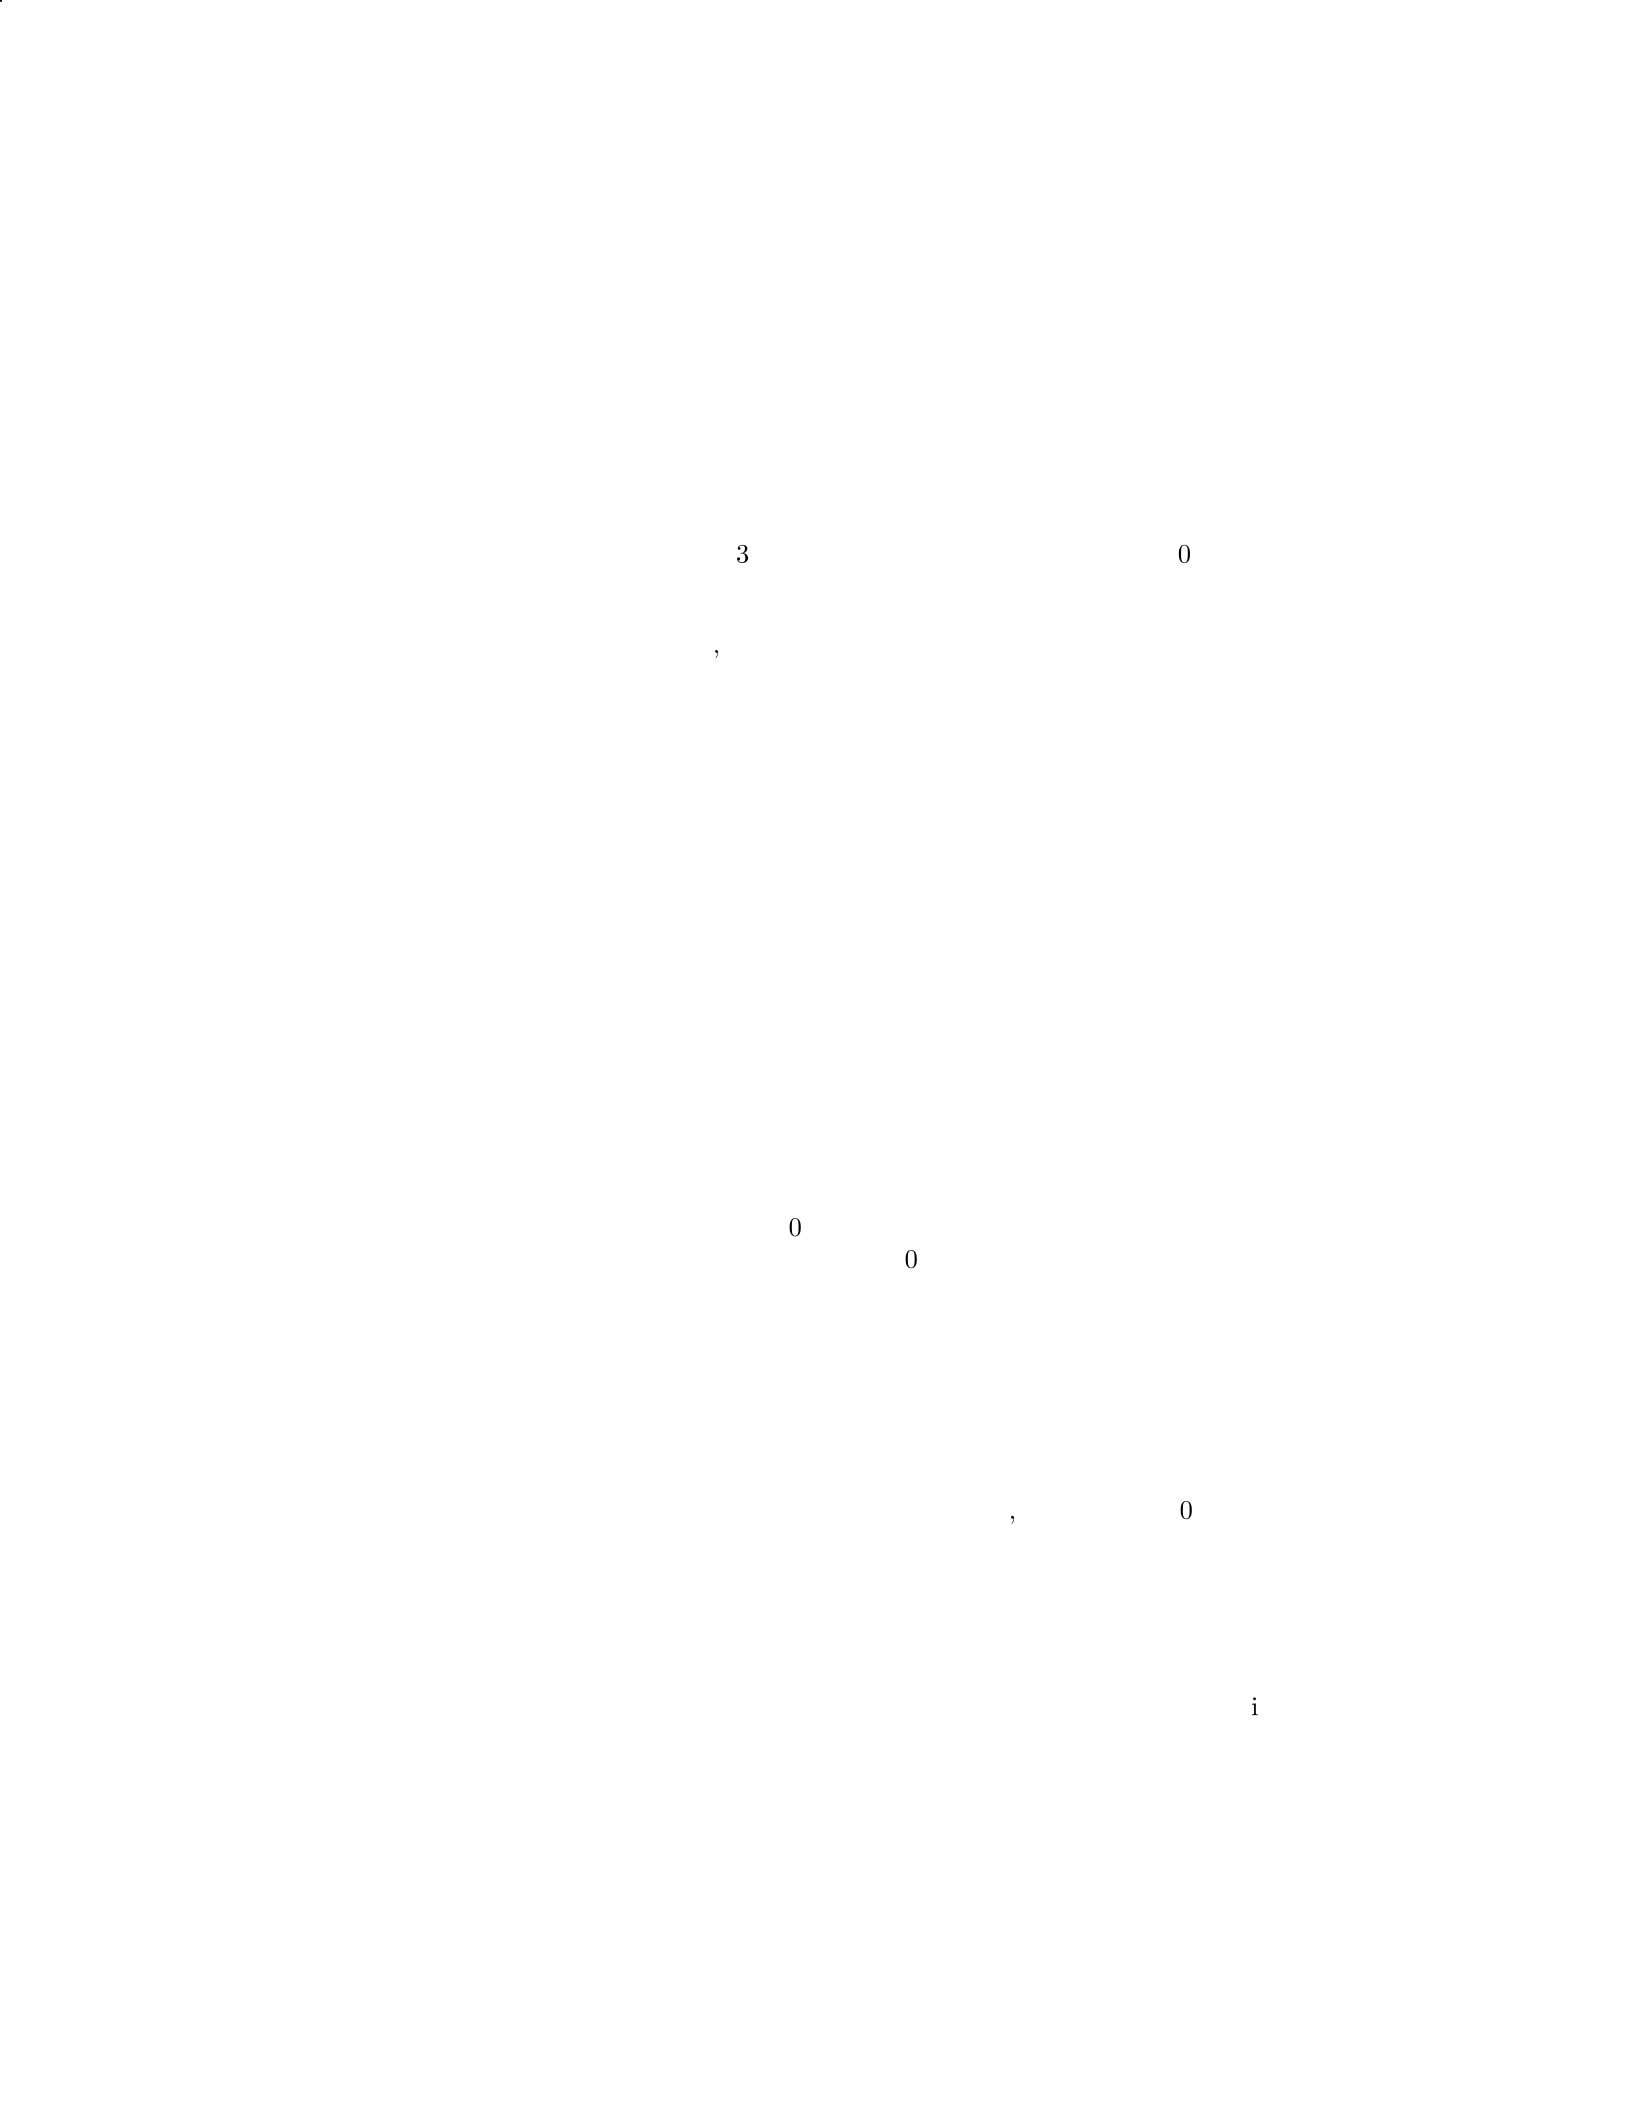
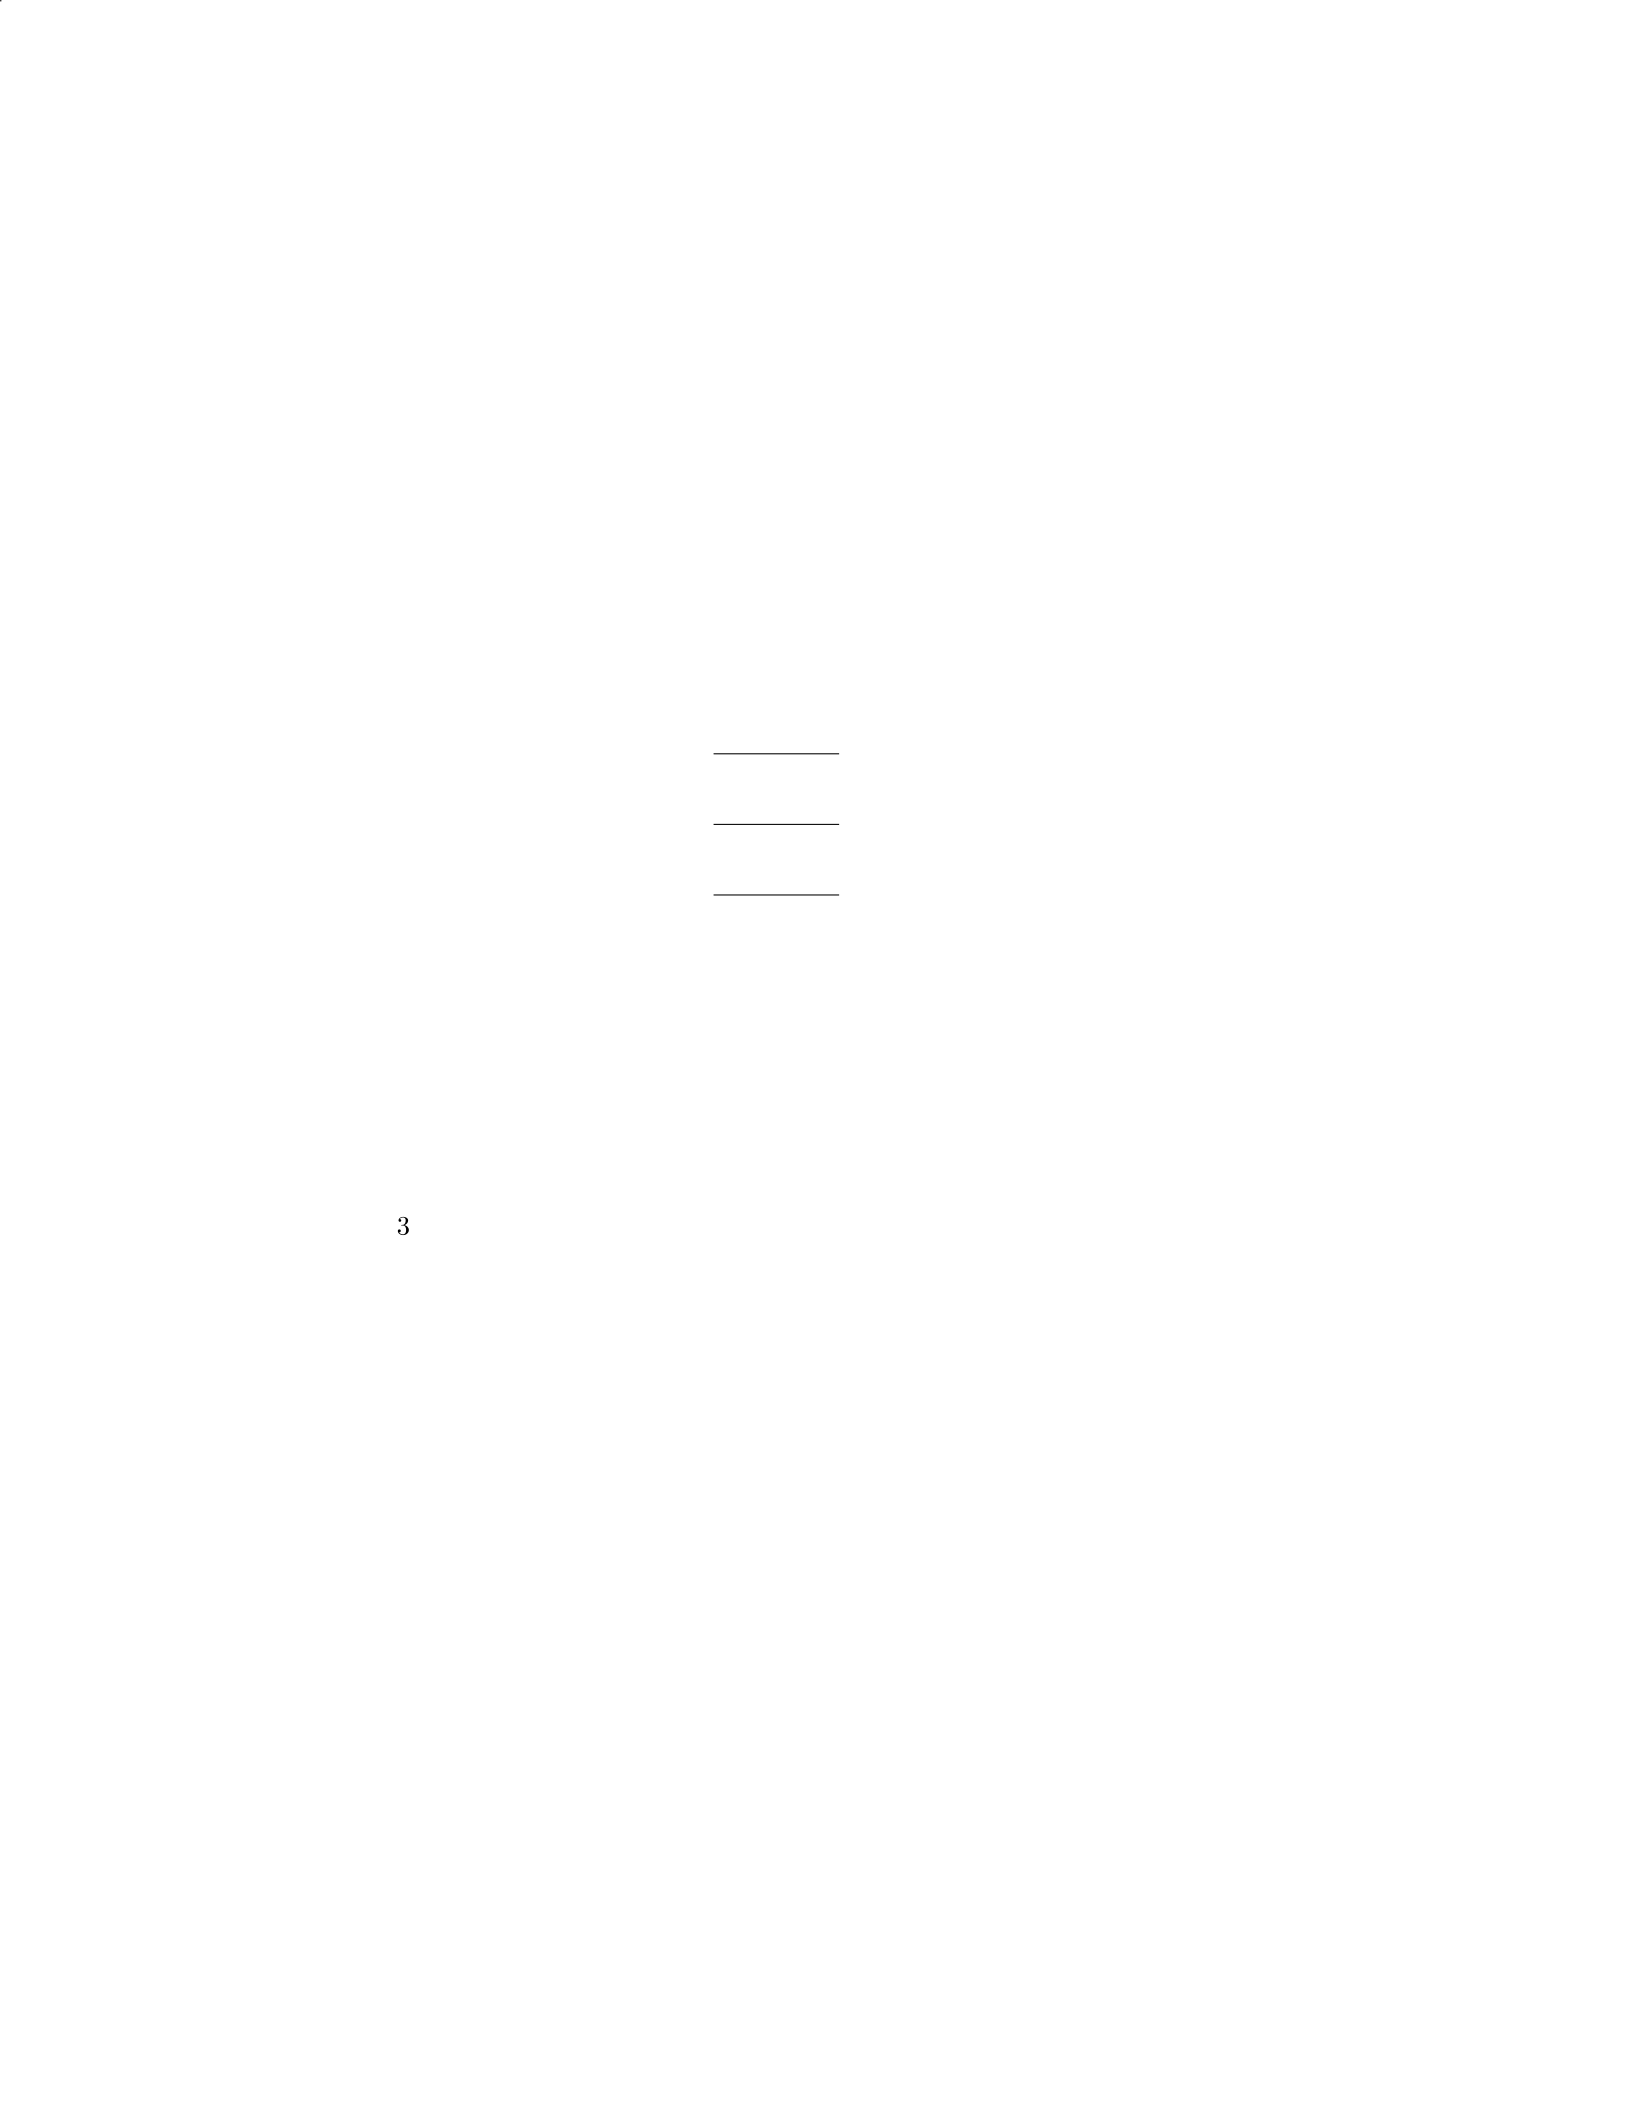
value of the property at the end of the reporting period is 500,000.Duringthereportingperiod, thecompanyreceivedrentalincomeof40,000
from the property. In addition, the property incurred operating expenses of
15,000.Determinethegainorlossrecognizedinthecompany′sincomestatementrelatedtotheinvestmentproperty.
Solution
To determine the gain or loss recognized in the company’s income statement
related to the investment property, we need to calculate the net gain or loss.
Step 1: Calculate the net gain or loss. The net gain or loss is calculated as
follows:
Net gain or loss = Fair value at the end−Fair value at the beginning−Rental income+Operating expenses
Given that fair value at the end of the reporting period is 500,000, fairvalueatthebeginningisnotprovidedinthequestion.Soweassumeitisthesameasthef airvalueattheend.Hence :
Net gain or loss =500,000 - 500,000−40,000 + 15,000
Net gain or loss = −
25,000
Step 2: Analyze the result. The negative net gain of −25,000indicatesalossrecognizedinthecompany′sincomestatementrelatedtotheinvestmentproperty.
Question 4
Question
Company XYZ owns an investment property that is reported at fair value. At
the end of the reporting period, the fair value of the property is
$
2,500,000.
During the next reporting period, the fair value of the property has increased
to
$
2,800,000. What journal entry should Company XYZ make to account for
this increase in fair value?
Solution
To account for the increase in fair value of the investment property, Company
XYZ will need to recognize a gain in its financial statements. The journal entry
will involve debiting the Investment Property account and crediting the Fair
Value Adjustment account.
Step 1: Calculate the increase in fair value:
Increase in fair value = $2,800,000 −$2,500,000 = $300,000
3

Step 2: Make the journal entry:
Debit Investment Property $300,000
Credit Fair Value Adjustment $300,000
This journal entry reflects the recognition of the gain in the fair value of the
investment property.
Question 5
Question
Suppose a company holds an investment in a financial asset that is required to
be measured at fair value through profit or loss. The fair value of the asset
increased by 15
Solution
To analyze the impact of the 15
Step 1: Determine the impact on the Balance Sheet - The 15- The
increase in fair value will result in a higher valuation of the financial asset
under the fair value measurement category. - As a result, the total assets of the
company will increase by the amount of the fair value increase.
Step 2: Identify the affected accounts - The impacted accounts on the
balance sheet will include: - Financial Asset account: This account will reflect
the higher fair value of the financial asset. - Fair Value Adjustment account:
This account will capture the unrealized gains on the financial asset.
Step 3: Assess the impact on the Income Statement - The increase in
fair value will lead to a recognition of unrealized gains in the income statement. -
The unrealized gains will be recognized as ”Fair Value Gains” under the ”Other
Income” or ”Gain/Loss” section of the income statement. - This will result in
a higher net income for the current reporting period.
In conclusion, the 15
Question 6
Question
Company X recently acquired a piece of land for development. The fair value of
the land was determined to be 1,500,000.Duringthedevelopmentprocess, CompanyXincurredadditionalcostsof200,000.
At the end of the reporting period, the fair value of the land was reassessed to be
1,600,000.Calculatethef airvalueofthelandtoberecognizedinthefinancialstatementsattheendof thereportingperiod.
4
Solution
Step 1: Calculate the carrying amount of the land The carrying amount of the
land is the initial fair value plus any additional costs incurred. Carrying amount
= Initial fair value + Additional costs Carrying amount = 1,500,000+200,000
Carrying amount = 1,700,000
Step 2: Determine the fair value gain or loss The fair value gain or loss is
the difference between the reassessed fair value and the carrying amount. Fair
value gain/loss = Reassessed fair value - Carrying amount Fair value gain/loss
= 1,600,000−1,700,000 Fair value loss = -100,000
Step 3: Recognize the fair value in the financial statements Since a fair
value loss was incurred, the fair value recognized in the financial statements will
be the lower of the carrying amount and the reassessed fair value. Fair value
recognized = Min(Carrying amount, Reassessed fair value) Fair value recognized
= Min(1,700,000,1,600,000) Fair value recognized = 1,600,000
Therefore, the fair value of the land to be recognized in the financial state-
ments at the end of the reporting period is 1,600,000.
Question 7
Question
Company XYZ holds an investment with a fair value of
$
50,000 at the end of
the year. During the year, the fair value increased by 10%. If the company
uses the Level 1 fair value measurement technique, what is the fair value of the
investment at the beginning of the year?
Solution
Step 1: Understand the Level 1 fair value measurement technique. Level 1 fair
value measurements are based on quoted prices (unadjusted) in active markets
for identical assets or liabilities that the entity can access at the measurement
date.
Step 2: Use the formula for calculating fair value after an increase. Let
F Vinitial be the fair value of the investment at the beginning of the year. Since
the fair value at the end of the year was $50,000 and increased by 10%, the fair
value at the beginning of the year can be calculated as:
F Vinitial =F Vend
1 + increase%
Step 3: Substitute the given values and calculate.
F Vinitial =$50,000
1+0.10 =$50,000
1.10 = $45,454.55
Therefore, the fair value of the investment at the beginning of the year using
the Level 1 fair value measurement technique is
$
45,454.55.
5

Question 8
Question
A company has an investment in a financial instrument classified as a Level 3
fair value measurement. The company uses unobservable inputs to determine
the fair value of the financial instrument. Explain the key considerations and
challenges the company may face in determining the fair value of this investment.
Solution
To determine the fair value of a financial instrument classified as a Level 3
fair value measurement using unobservable inputs, the company may encounter
several key considerations and challenges. Here are the steps outlining these:
Step 1: Understand Level 3 Fair Value Measurement Level 3 fair
value measurements involve significant unobservable inputs, also known as Level
3 inputs. These inputs require management’s judgment and involve a high
degree of subjectivity. Understanding the nature of Level 3 measurements is
crucial for the company.
Step 2: Valuation Techniques and Inputs The company must carefully
select appropriate valuation techniques to estimate the fair value of the financial
instrument. Since Level 3 inputs are unobservable, determining the reliability
and reasonableness of these inputs can be a challenge.
Step 3: Use of Financial Models Financial models are often used to
estimate the fair value of Level 3 financial instruments. However, the complexity
of these models and the assumptions made can introduce additional challenges
in arriving at a fair value that reflects market conditions.
Step 4: Consideration of Market and Economic Factors The com-
pany must assess how market and economic factors impact the fair value of the
financial instrument. Changes in market conditions can make it challenging to
determine the fair value accurately.
Step 5: Disclosure Requirements Given the subjectivity and complexity
involved in Level 3 fair value measurements, the company must provide extensive
disclosures in the financial statements. This includes detailing the valuation
techniques used, the inputs considered, and the sensitivity of the fair value to
changes in these inputs.
Step 6: Independent Verification To enhance credibility and reliability,
the company may consider engaging independent valuation specialists to review
and validate the fair value measurement process. This can help address concerns
about the objectivity of the valuation.
By carefully navigating these considerations and challenges, the company
can strive to determine a reliable fair value for its investment in the financial in-
strument despite the inherent difficulties associated with Level 3 measurements
based on unobservable inputs.
6

Question 9
Question
Explain the concept of fair value measurement and discuss the factors that may
influence the determination of fair value.
Solution
Step 1: Concept of Fair Value Measurement Fair value measurement is the
process of determining the value of an asset or liability based on the price that
would be received to sell an asset or paid to transfer a liability in an orderly
transaction between market participants at the measurement date. Fair value is
a market-based measurement, not an entity-specific measurement. It represents
the price that would be received to sell an asset or paid to transfer a liability in
an orderly transaction between market participants at the measurement date.
Step 2: Factors Influencing Fair Value Determination There are sev-
eral factors that may influence the determination of fair value: 1. Market con-
ditions: Fluctuations in market conditions can impact the fair value of assets
and liabilities. For example, changes in interest rates, economic conditions, and
market volatility can all affect fair value. 2. Availability of data: The avail-
ability of relevant and reliable data is essential for determining fair value. If
there is limited information about comparable transactions or market prices,
it may be challenging to determine fair value accurately. 3. Assumptions and
inputs: Fair value measurements often involve making assumptions and using
inputs based on available data. The choice of assumptions and inputs can affect
the final fair value estimate. 4. Level of judgment: Fair value measurements
require a significant amount of judgment, particularly when there is limited
market activity for the asset or liability being valued. The level of judgment
used can impact the reliability of the fair value measurement. 5. Complexity of
the asset or liability: The complexity of the asset or liability being valued can
also influence fair value determination. More complex assets or liabilities may
require more sophisticated valuation techniques, which can affect the accuracy
of the fair value measurement.
Question 10
Question
A company holds an investment in bonds classified as available-for-sale with a
fair value of 450,000.Duetomarketconditions, thefairvalueof thebondsdecreasesto420,000
at the end of the reporting period. The company decides to recognize the de-
crease in fair value. If the company reports unrealized losses in other compre-
hensive income, how would this affect the company’s financial statements?
7
Solution
1. The company recognizes the decrease in fair value of the bonds as an unreal-
ized loss. This is recorded as a decrease in the fair value of the bond investment
and an increase in unrealized loss.
2. The journal entry to recognize the decrease in fair value is as follows:
Available-for-sale bonds
$
30,000Unrealized loss on bonds
$
30,000
3. This journal entry would affect the balance sheet by decreasing the
available-for-sale bonds by
$
30,000.
4. When the company reports unrealized losses in other comprehensive in-
come, the income statement is not directly impacted. However, the accumulated
other comprehensive income section of the equity portion of the balance sheet
would decrease by the amount of the unrealized loss.
5. The company’s statement of comprehensive income would reflect the
change in other comprehensive income due to the recognition of the unrealized
loss.
6. Overall, the company’s financial position would show a decrease in total
comprehensive income due to the recognition of the unrealized loss, which would
impact the company’s equity and overall financial health.
Question 11
Question
Company X holds an investment in a security that is classified as a Level 3 asset
under fair value hierarchy. At the end of the reporting period, the fair value of
the security was estimated to be
$
1,200,000. During the next reporting period,
the fair value of the security increased to
$
1,400,000. Company X has a policy
of recognizing unrealized gains or losses on Level 3 assets directly in profit or
loss. Calculate the unrealized gain or loss that Company X should recognize in
the next reporting period.
Solution
Step 1: Calculate the unrealized gain or loss in the next reporting period. Given
that the fair value of the security increased from
$
1,200,000 to
$
1,400,000, the
unrealized gain or loss can be calculated using the formula:
Unrealized Gain or Loss = Ending Fair Value −Beginning Fair Value
Unrealized Gain or Loss = $1,400,000 −$1,200,000 = $200,000
Therefore, Company X should recognize an unrealized gain of
$
200,000 in
the next reporting period.
8
Question 12
Question
Company XYZ is considering investing in a new project and needs to determine
the fair value of the project for financial reporting purposes. The project is ex-
pected to generate cash flows of 10,000inthefirstyear,15,000 in the second year,
and 20,000inthethirdyear.T hediscountrateis8%.Calculatethef airvalueof theprojectusingthediscountedcashflowmethod.
Solution
Step 1: Calculate the present value of each cash flow.
P V1=10,000
(1 + 0.08)1= $9,259.26
P V2=15,000
(1 + 0.08)2= $12,938.02
P V3=20,000
(1 + 0.08)3= $15,873.79
Step 2: Calculate the fair value of the project by summing up the present
values of all cash flows.
F air V alue =P V1+P V2+P V3
= $9,259.26 + $12,938.02 + $15,873.79
= $38,070.07
Therefore, the fair value of the project using the discounted cash flow method
is
$
38,070.07.
Question 13
Question
You are a financial analyst working for a consulting firm. You have been tasked
with determining the fair value of a private equity investment held by one of
your clients. The investment has limited market activity and no actively traded
comparable securities. Discuss the challenges you may face in determining the
fair value of this private equity investment.
Solution
To determine the fair value of a private equity investment with limited market
activity and no actively traded comparable securities, several challenges may
arise. Below are the challenges you may face in this scenario:
9

Step 1: Lack of Observable Market Data Since the investment has
limited market activity, there may be insufficient observable market data avail-
able to determine a fair value. This lack of data makes it difficult to assess the
investment’s value accurately.
Step 2: Subjectivity in Valuation In the absence of comparable se-
curities or market transactions, fair value measurement may rely heavily on
subjective assumptions and judgments. Different analysts may come up with
different valuations based on their interpretation of available information.
Step 3: Reliance on Management Estimates When market data is
scarce, the valuation process may require significant reliance on management
estimates. This dependence on management’s projections can introduce bias
and lack of objectivity in the valuation process.
Step 4: Illiquidity and Lack of Marketability Private equity invest-
ments are typically illiquid and lack marketability. The lack of a ready market
for these investments can further complicate the determination of fair value,
as there may be limited opportunities to sell or liquidate the investment to
ascertain its true market worth.
Step 5: Complex Valuation Models Given the unique characteristics of
private equity investments, such as long investment horizons, complex capital
structures, and varying exit strategies, the valuation process may require the
use of sophisticated and complex models. These models may involve significant
assumptions and inputs that can impact the final valuation.
In conclusion, determining the fair value of a private equity investment with
limited market activity and no actively traded comparable securities poses sig-
nificant challenges, including the lack of observable market data, subjectivity in
valuation, reliance on management estimates, illiquidity, and complexity in val-
uation models. It is essential for analysts to carefully consider these challenges
and make sound judgments to arrive at a reasonable fair value estimate.
Question 14
Question
Company XYZ holds an investment in a private company which is carried at fair
value through profit or loss. At the end of the reporting period, the fair value of
the investment is determined to be 85,000.Duringthenextreportingperiod, informationbecomesavailableindicatingasignif icantincreaseinvalueof theprivatecompany.T hefairvalueisestimatedtobe110,000.
Given this scenario, explain how Company XYZ should account for the in-
crease in fair value of the investment in the next reporting period.
Solution
Step 1: Initially Recognized and Recognized at Fair Value - The investment
in the private company was initially recognized and measured at fair value.
When an entity initially recognizes a financial asset at fair value, any difference
between the transaction price and the fair value (if any) is recognized in profit
10
or loss. - In this case, since the investment was recognized at fair value, any
change in fair value after the initial recognition should also be recognized in
profit or loss.
Step 2: Increase in Fair Value - When the fair value of the investment in-
creases to 110,000inthenextreportingperiod, CompanyXY Zshouldrecognizethe25,000
increase in fair value as a gain in profit or loss. - This gain reflects the change
in fair value of the investment from 85,000to110,000.
Step 3: Accounting Entry - The accounting entry to recognize the increase
in fair value of the investment would be:
Profit or Loss 25,000
Investment in Private Company 25,000
Step 4: Disclosures - Company XYZ should disclose the fair value of the
investment in the financial statements along with the changes in fair value that
have been recognized in profit or loss. This provides transparency to the users
of the financial statements regarding the changes in fair value of the investment.
Question 15
Question
A company holds an investment in equity securities that are measured at fair
value through other comprehensive income (FVOCI). At the end of the reporting
period, the fair value of the investment has decreased by
$
15,000 compared to
its initial cost. The company considers this decrease to be temporary. How
should the company account for this decrease in fair value?
Solution
Step 1: Since the company considers the decrease in fair value to be tempo-
rary, it should recognize this decrease in fair value as an adjustment to other
comprehensive income.
Step 2: Calculate the adjustment amount. The adjustment amount is the
difference between the initial cost of the investment and the new fair value at
the end of the reporting period. In this case, the adjustment amount is
$
15,000.
Step 3: Prepare the journal entry to recognize the adjustment in fair value:
Other Comprehensive Income Dr. $15,000
Investment in Equity Securities Cr. $15,000
Step 4: After preparing the journal entry, the company’s total comprehensive
income will decrease by
$
15,000. The investment in equity securities account
will be adjusted to reflect the decrease in fair value.
Step 5: It’s important to note that the adjustment in fair value is recognized
in other comprehensive income and does not impact net income for the pe-
riod. The company should continue to monitor the fair value of the investment
11

and assess whether the decrease in fair value remains temporary or becomes
permanent.
Question 16
Question
Company XYZ holds an investment in a private company that is not publicly
traded. The investment is classified as a Level 3 asset under fair value measure-
ment. Company XYZ determines that there has been a significant decrease in
the financial performance of the private company. Explain how the decrease in
financial performance may impact the fair value measurement of the investment.
Solution
Step 1: The decrease in financial performance of the private company may im-
pact the fair value measurement of the investment as follows: - As per fair value
measurement guidelines, the fair value of a Level 3 asset is determined using
unobservable inputs, such as proprietary models or management’s estimates. -
The decrease in financial performance of the private company could result in
a reassessment of the assumptions and inputs used in the fair value measure-
ment process. - The decrease in financial performance may lead to a revision
of expected future cash flows, discount rates, or other key inputs used in the
valuation model.
Step 2: Specifically, the impact of the decrease in financial performance on
the fair value measurement of the investment could include: - A decrease in ex-
pected future cash flows due to lower revenue projections, increased expenses,
or other adverse financial indicators. - An increase in the discount rate used to
value the investment to reflect the higher risk associated with the private com-
pany’s deteriorating financial condition. - A change in the probability weighting
of different scenarios or outcomes, with a greater emphasis placed on downside
risks given the decrease in financial performance.
Step 3: Overall, the decrease in financial performance of the private com-
pany may lead to a lower fair value measurement of the investment due to the
increased perceived risk or lower expected future cash flows associated with the
investment. It is important for Company XYZ to carefully consider the impact
of the decrease in financial performance on the fair value measurement and make
any necessary adjustments to reflect the current economic conditions accurately.
Question 17
Question
Company XYZ holds an investment in a publicly traded company, which is
classified as available-for-sale. At the end of the reporting period, the fair value
12
of the investment is $500,000, and the cost of the investment is $450,000. If
the fair value of the investment decreases to $480,000 at the end of the next
reporting period, how would this change be accounted for in Company XYZ’s
financial statements?
Solution
Step 1: Calculate the gain or loss on the decrease in fair value of the investment.
Initial fair value of the investment: $500,000
Fair value of the investment at the end of the next reporting period:
$480,000
Gain (Loss) on the decrease in fair value: $480,000−$500,000 = −$20,000
Step 2: Determine the impact on Company XYZ’s financial statements.
The decrease in fair value of $20,000 results in a loss for Company XYZ.
Since the investment is classified as available-for-sale, this loss is recog-
nized in other comprehensive income (OCI).
Step 3: Record the journal entry to reflect the loss on the decrease in fair
value.
Debit: Unrealized Holding Loss (OCI): $20,000
Credit: Investment: $20,000
Step 4: Update the carrying amount of the investment on the balance sheet.
The carrying amount of the investment on the balance sheet will now be
$450,000 −$20,000 = $430,000.
Step 5: Disclose the reclassification adjustment in the financial statements.
The reclassification adjustment of $20,000 from OCI to net income should
be disclosed in the financial statements.
Therefore, the decrease in fair value of the investment would result in a
loss of $20,000 being recognized in other comprehensive income (OCI) and a
corresponding adjustment to the carrying amount of the investment on the
balance sheet.
Question 18
Question
A company is required to determine the fair value of an investment property
on its financial statements. The property was purchased three years ago for
$
500,000 and has since undergone significant revaluation with an independent
appraiser valuing it at
$
700,000. Additionally, the property generates annual
rental income of
$
40,000. If the company uses an appropriate discount rate of 8
13
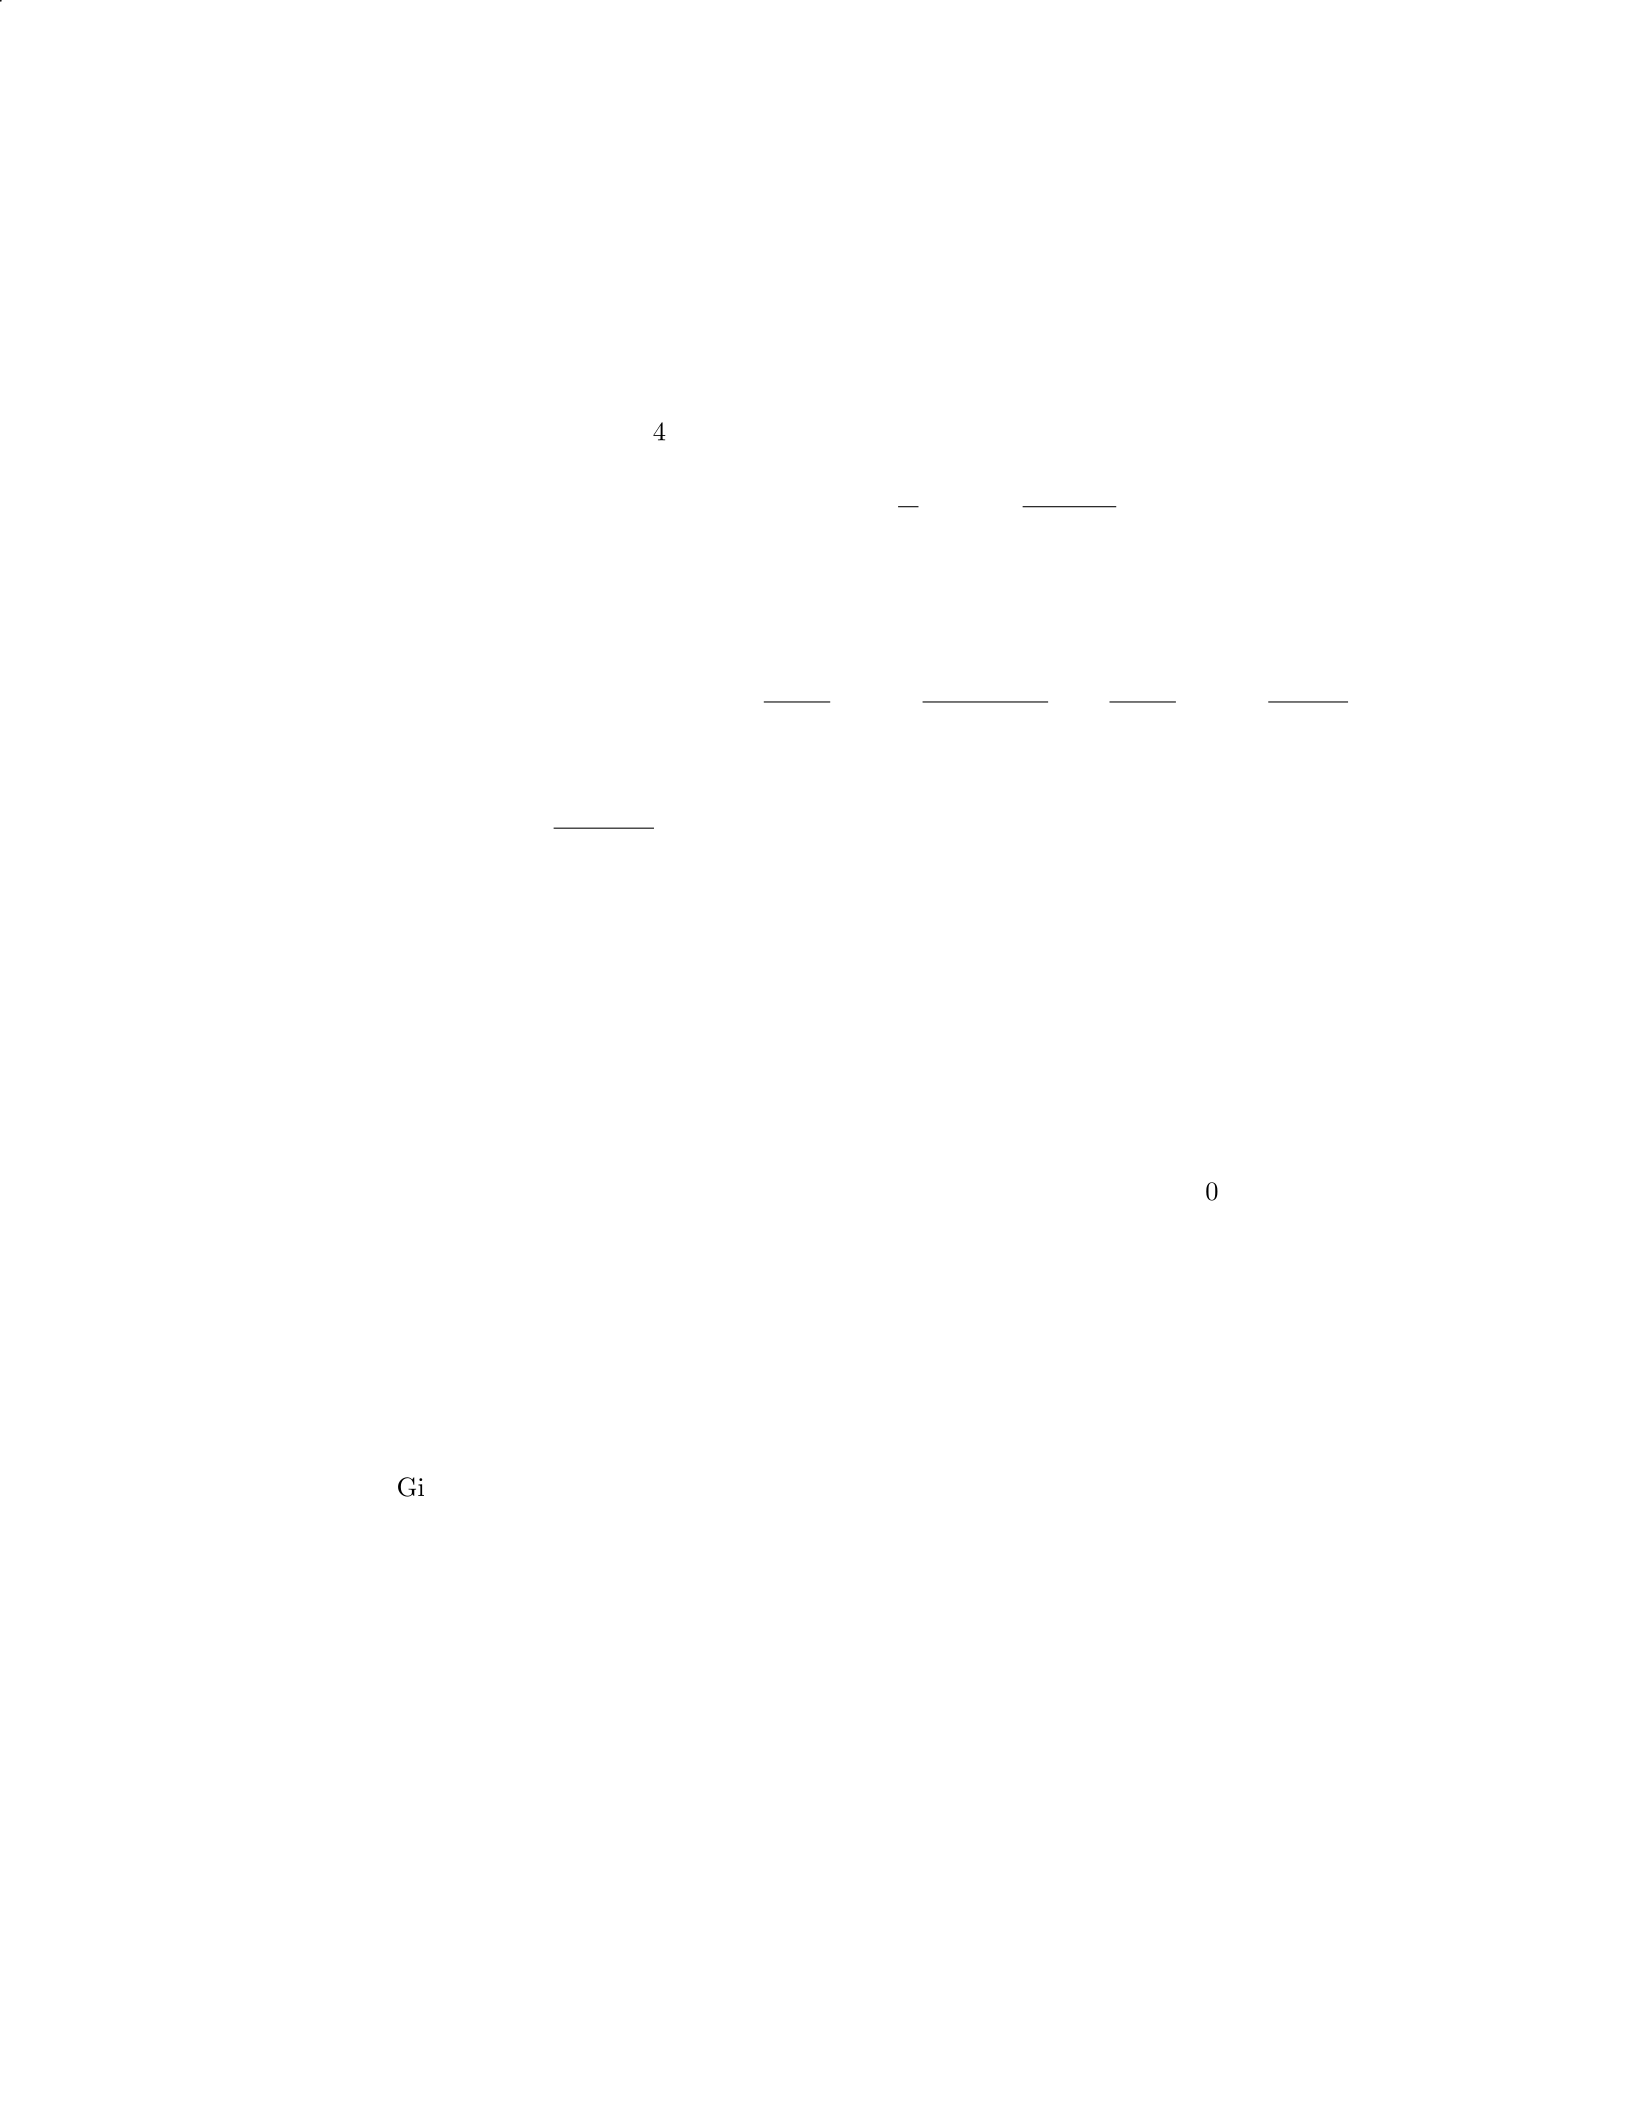
Solution
Step 1: Calculate the present value of the annual rental income. Given an
annual rental income of
$
40,000 and a discount rate of 8
Present Value of Rental Income = R
r×1−1
(1 + r)n
where: - R= $40,000 - r= 0.08 - n= 3 (since the rental income is for three
years)
Present Value of Rental Income = 40000
0.08 ×1−1
(1 + 0.08)3=40000
0.08 ×1−1
(1.08)3
= 500000×1−1
1.259712≈500000×(1−0.79383) = 500000×0.20617 ≈$103,085.01
Step 2: Calculate the fair value of the investment property. The fair value
of the investment property is the sum of the present value of the rental income
and the revaluation amount:
Fair Value = Present Value of Rental Income + Revaluation Amount
Fair Value = $103,085.01 + $700,000 = $803,085.01
Therefore, the fair value of the investment property is approximately
$
803,085.01.
Question 19
Question
Company XYZ holds an investment in a financial instrument classified as a level
3 fair value measurement. At the end of the reporting period, the fair value of the
financial instrument is determined to be 150,000, butthereissignif icantunobservableinputuncertaintyinvolvedinthevaluationprocess.CompanyXY Zhashistoricallyusedaweightedaveragecostofcapital(W ACC)of10
Given this information, determine the fair value of the financial instrument
using the method prescribed by IFRS 13.
Solution
To determine the fair value of the financial instrument using the method pre-
scribed by IFRS 13, we will calculate the fair value based on the present value of
expected cash flows discounted using current market-based observable inputs.
Step 1: Identify the relevant cash flows associated with the financial instru-
ment. The relevant cash flow associated with the financial instrument are the
14
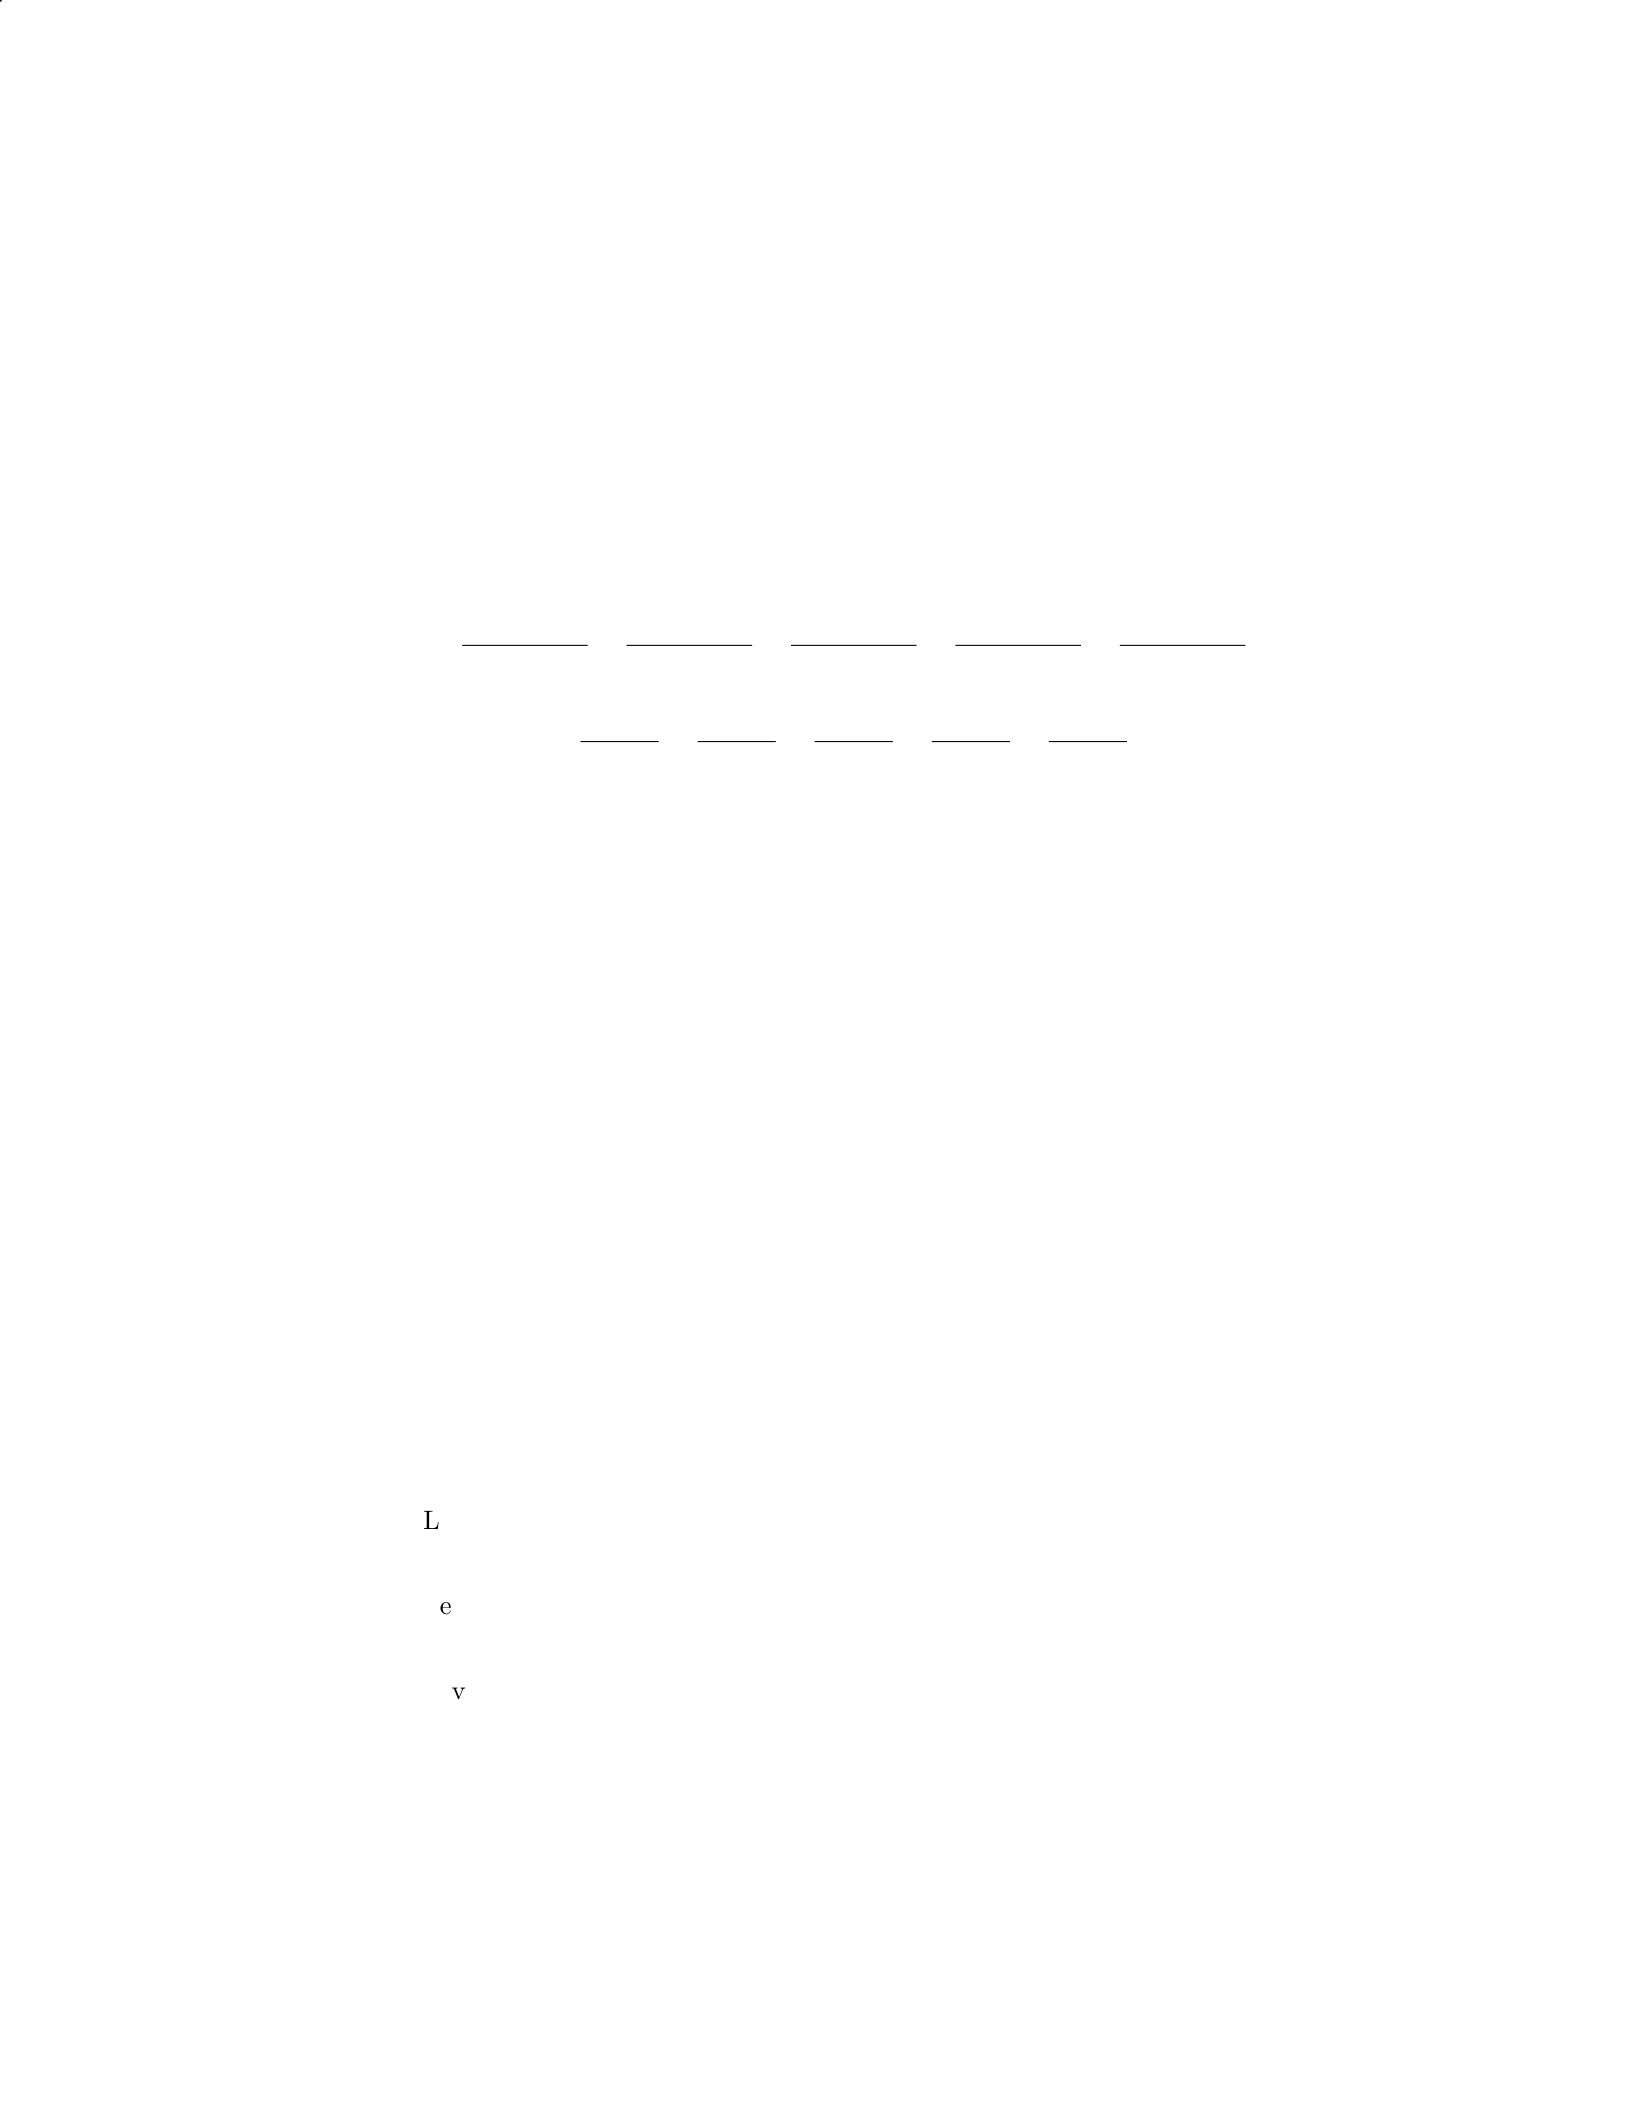
expected future cash flows Company XYZ expects to receive from holding the
investment.
Step 2: Determine the applicable discount rate. Given that Company XYZ
historically uses a WACC of 10
Step 3: Calculate the present value of expected cash flows. Let’s assume
that the expected future cash flows from the investment are as follows: Year 1:
30,000Y ear2 :40,000 Year 3: 50,000Y ear4 :60,000 Year 5: 70,000
Calculating the present value of these cash flows using the WACC of 10
P V =30,000
(1 + 0.10)1+40,000
(1 + 0.10)2+50,000
(1 + 0.10)3+60,000
(1 + 0.10)4+70,000
(1 + 0.10)5
P V =30,000
1.10 +40,000
1.102+50,000
1.103+60,000
1.104+70,000
1.105
P V ≈30,000×0.9091+40,000×0.8264+50,000×0.7513+60,000×0.6830+70,000×0.6209
P V ≈27,273 + 33,056 + 37,565 + 40,980 + 43,463 = 182,337
Therefore, the fair value of the financial instrument based on present value
of expected cash flows is approximately 182,337.
Question 20
Question
A company has an investment in a financial asset classified as a Level 3 fair
value measurement. The fair value of the investment was determined using
unobservable inputs. Explain how the company should disclose information
about the fair value measurement in its financial statements.
Solution
Step 1: The company should disclose the inputs used to determine the fair value
of the investment. These inputs are categorized into three levels:
Level 1 inputs: Observable inputs like quoted prices in active markets for
identical assets.
Level 2 inputs: Inputs other than quoted prices included in Level 1 that
are observable for the asset.
Level 3 inputs: Unobservable inputs based on the company’s own assump-
tions.
15
Step 2: The company should disclose the valuation techniques used to deter-
mine the fair value. This may include the use of discounted cash flows, market
multiples, or option pricing models.
Step 3: The company should disclose the quantitative information about the
fair value measurement. This includes the carrying amount of the investment,
the fair value measurement at the reporting date, and any changes in fair value
recognized in the income statement.
Step 4: If there are significant unobservable inputs used in the fair value
measurement, the company should disclose the sensitivity of the fair value to
changes in these inputs.
Step 5: The company should provide a qualitative description of the val-
uation process, including any assumptions made and judgments exercised in
determining the fair value measurement.
Step 6: Finally, the company should disclose any transfers between levels
of the fair value hierarchy and the reasons for such transfers. This information
helps users understand how the fair value measurement has changed over time.
Question 21
Question
A company owns an investment property that is measured at fair value through
profit or loss. The fair value of the investment property at the end of the
reporting period is
$
750,000, and the company incurs
$
10,000 in transaction
costs to sell the property. How should the company account for the transaction
costs in relation to the fair value measurement of the investment property?
Solution
1. Transaction costs should not be deducted from the fair value of the investment
property when measuring it at fair value through profit or loss, according to
IFRS 13 Fair Value Measurement.
2. The fair value of the investment property should be reported at
$
750,000
without deducting the transaction costs.
3. The transaction costs incurred to sell the investment property should be
recognized in profit or loss in the period in which they are incurred.
Therefore, the company should account for the
$
10,000 transaction costs sep-
arately in the profit or loss statement and report the fair value of the investment
property at
$
750,000 without deducting the transaction costs.
16
Question 22
Question
A company is required to determine the fair value of an investment property
using the income approach. The property is expected to generate an annual
rental income of
$
100,000 for the next 5 years. The entity uses a discount rate
of 8% for such investments. If the property is expected to be sold after 5 years
for
$
500,000, what is the fair value of the investment property?
Solution
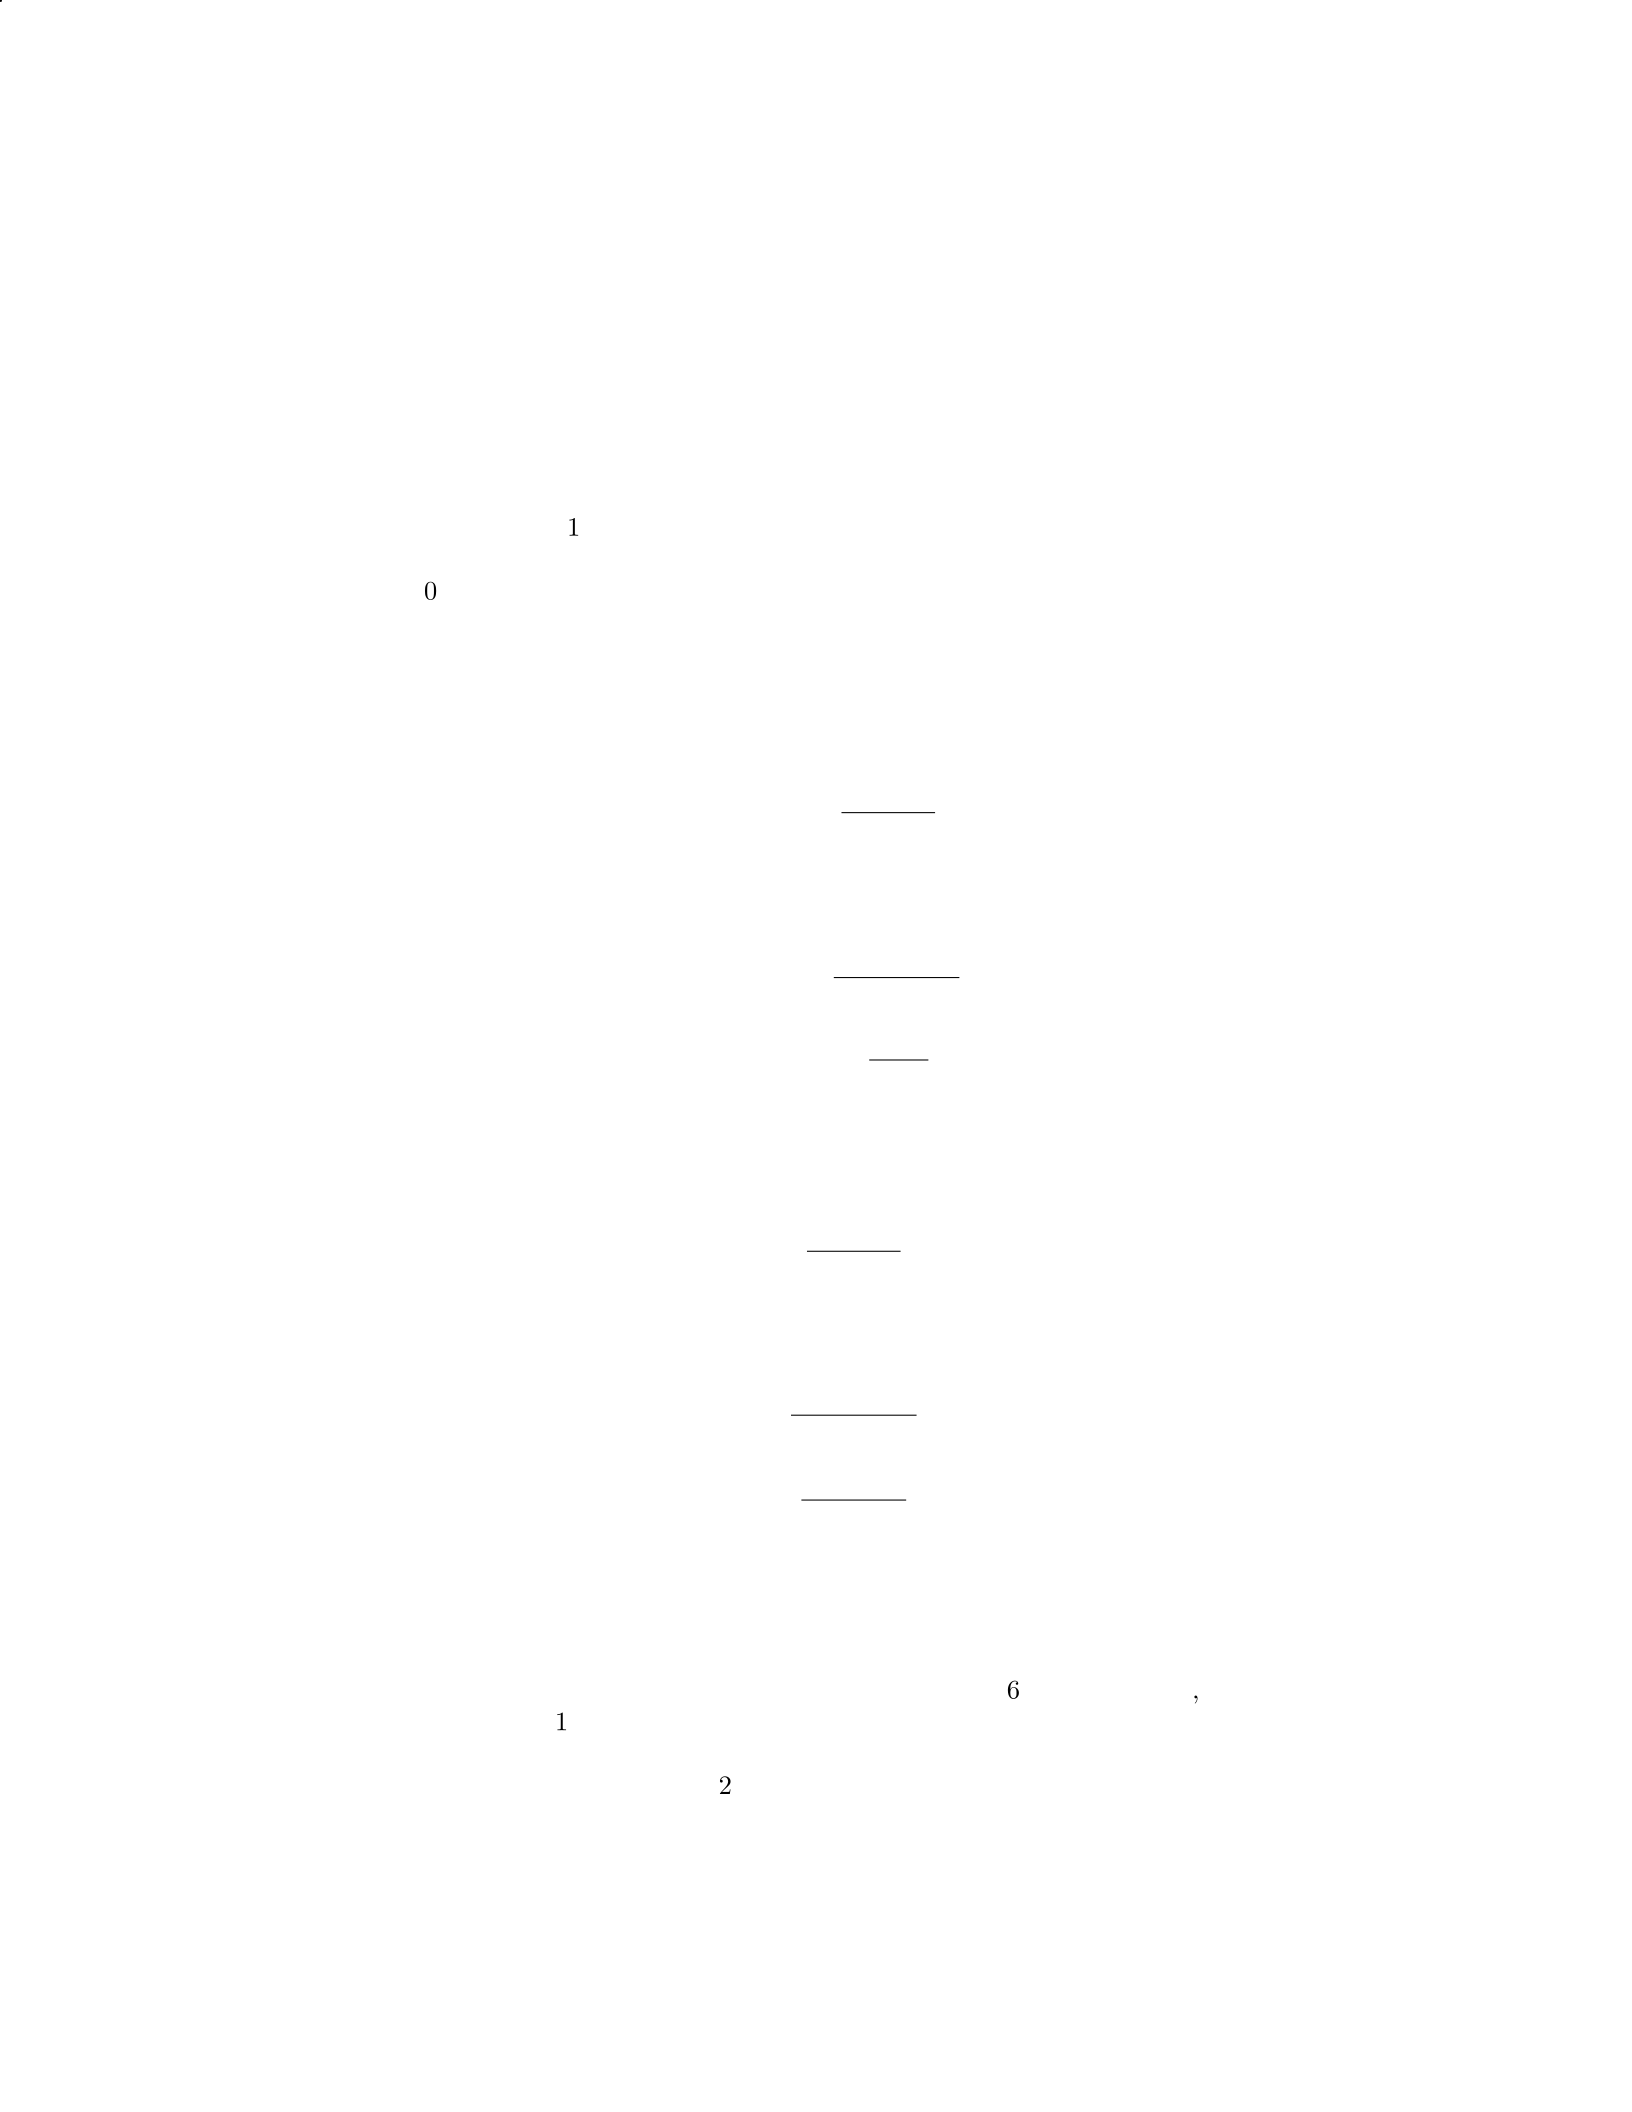
Step 1: Calculate the present value of the expected rental income. The present
value of an annuity formula is given by:
P V =P mt ×1−1
(1 + r)n∇ · r
where: P mt = $100,000, r= 0.08, n= 5 years
Plugging in the values:
P V = $100,000 ×1−1
(1 + 0.08)5∇ · 0.08
P V = $100,000 ×(1 −1
1.085)∇ · 0.08
P V $376,957.38
Step 2: Calculate the present value of the expected selling price after 5 years.
The present value of a single cash flow formula is given by:
P V =F V
(1 + r)n
where: F V = $500,000, r= 0.08, n= 5 years
Plugging in the values:
P V =$500,000
(1 + 0.08)5
P V =$500,000
1.085
P V $303,170.43
Step 3: Calculate the fair value of the investment property. The fair value of
the investment property is the sum of the present values of the expected rental
income and the expected selling price: Fair Value = Present Value of Rental
Income + Present Value of Selling Price Fair Value
$
376,957.38 +
$
303,170.43
Fair Value
$
680,127.81
Therefore, the fair value of the investment property using the income ap-
proach is approximately
$
680,127.81.
17
Question 23
Question
A company holds an investment in a financial asset classified as fair value
through other comprehensive income. At the end of the current reporting pe-
riod, the fair value of the investment is 150,000.Duringtheyear, thefairvalueof theinvestmentincreasedby20,000
due to changes in market conditions. Additionally, the company received divi-
dends of 5,000fromtheinvestmentduringtheyear.Calculatethetotalcomprehensiveincomerelatedtothisinvestmentf orthecurrentreportingperiod.
Solution
Let’s break down the total comprehensive income related to the investment into
its components.
Step 1: Calculate the gain or loss recognized in other comprehen-
sive income
The fair value of the investment at the beginning of the year was 150,000−20,000
= 130,000.T herefore, thegainrecognizedinothercomprehensiveincomeduetochangesinfairvalueis150,000
- 130,000 =20,000.
Step 2: Calculate the dividends recognized in other comprehensive
income
The dividends received during the year were 5,000.Dividendsreceivedareincludedinothercomprehensiveincomef orinvestmentsaccountedf oratfairvaluethroughothercomprehensiveincome.
Step 3: Calculate the total comprehensive income related to the
investment
Total comprehensive income = Gain or loss recognized in other compre-
hensive income + Dividends recognized in other comprehensive income
Total comprehensive income = 20,000+5,000 = 25,000.
Therefore, the total comprehensive income related to this investment for the
current reporting period is 25,000.
Question 24
Question
A company holds an investment classified as available-for-sale financial asset.
The fair value of this investment at the end of the reporting period is 200,000.T hecompany′smanagementisconsideringreclassif yingthisinvestmentasheldf ortradingtotakeadvantageofshort−
termpricemovements.If thef airvalueisexpectedtoincreaseto220,000 in the near
future, what impact would this decision have on the company’s financial state-
ments? Justify your answer with reference to Fair Value Measurement.
18

Solution
To answer this question, we need to consider the implications of reclassifying
the investment from available-for-sale to held for trading in terms of Fair Value
Measurement.
Step 1: When an investment is reclassified from available-for-sale to held
for trading, any unrealized gains or losses in the available-for-sale reserve must
be recognized in the income statement immediately.
Step 2: In this case, since the fair value of the investment is expected to in-
crease to 220,000inthenearfuture, thereisanunrealizedgainof 20,000 (220,000−200,000).
Step 3: If the company reclassifies the investment as held for trading, this
20,000unrealizedgainwillbeimmediatelyrecognizedintheincomestatementundergainsoninvestments.
Step 4: The reclassification will not affect the balance sheet directly, as the
asset will still be presented at fair value on the balance sheet.
Step 5: However, the income statement will show an increase in net income
due to the recognition of the 20,000gain.
Step 6: Overall, the reclassification of the investment from available-for-sale
to held for trading will result in a positive impact on the company’s financial
statements by increasing its reported net income for the period.
Question 25
Question
A company holds an investment in a financial instrument categorized as a Level
3 fair value measurement. At the end of the reporting period, the fair value of the
investment is 250,000.T hecompany′smanagementneedstodetermineiftherehavebeenanychangesinthefairvalueof theinvestmentcomparedtothebeginningof thereportingperiod.P rovideastep−
by−stepguideonhowthecompanycananalyzeandreportthechangesinthef airvalueoftheinvestment.
Solution
To analyze and report the changes in the fair value of the investment categorized
as a Level 3 fair value measurement, the company can follow these steps:
Step 1: Review the Valuation Techniques - The company should review
the valuation techniques used to determine the fair value of the investment at
the beginning of the reporting period. This may include market approaches,
income approaches, and cost approaches.
Step 2: Assess Changes in Inputs - Management should assess if there
have been any changes in the inputs used in the valuation techniques. Inputs
may include market data, interest rates, credit spreads, etc. Changes in these
inputs can significantly impact the fair value of the investment.
Step 3: Determine Fair Value Changes - Calculate the change in fair
value by comparing the fair value of the investment at the end of the reporting
period (250,000)tothefairvalueatthebeginningof thereportingperiod.T hiswillgivethecompanytheabsolutechangeinf airvalue.
19
Step 4: Analyze the Reason for Changes - Management should analyze
the reasons for the changes in fair value. This could include changes in market
conditions, economic factors, or specific events related to the investment.
Step 5: Disclose in Financial Statements - Finally, the company should
disclose the changes in fair value of the investment in the financial statements.
This disclosure should include the amount of change, the nature of the invest-
ment, and the reasons for the changes.
By following these steps, the company can properly analyze and report any
changes in the fair value of the investment categorized as a Level 3 fair value
measurement.
Question 26
Question
Calculate the fair value of an investment using the market approach. You are
provided the following information:
Comparable assets: 3 similar investments with market values of
$
1,200,
$
1,400, and
$
1,100.
Subject investment: Similar risk profile as the comparable assets but has
generated a higher return of 8%.
Solution
To calculate the fair value of the subject investment using the market approach,
we will need to adjust the market values of the comparable assets based on the
difference in return.
Step 1: Calculate the average rate of return for the comparable
assets
Given market values:
M1= 1200, M2= 1400, M3= 1100
The average rate of return (ravg ) of the comparable assets can be calcu-
lated as:
ravg =M2−M1
M1
+M3−M1
M1
ravg =1400 −1200
1200 +1100 −1200
1200 =200
1200 −100
1200 =100
1200 = 0.0833
Step 2: Adjust the comparable asset values for the subject invest-
ment
Given return on the subject investment: 8%
20
Adjusted value for subject investment can be calculated as:
F Vsubject =1+0.08
1 + ravg
×M1
F Vsubject =1.08
1.0833 ×1200 ≈1193.50
Therefore, the fair value of the subject investment using the market approach
is approximately
$
1193.50.
Question 27
Question
Company XYZ is assessing the fair value of an investment property using
the income approach. The property is expected to generate rental income of
120,000peryearf orthenext10years.T hediscountrateis8
Solution
Step 1: Calculate the present value factor using the formula: P V F =1−(1+r)−n
r,
where ris the discount rate and nis the number of years.
Using r= 0.08 and n= 10,
P V F =1−(1 + 0.08)−10
0.08
P V F =1−0.4632
0.08
P V F ≈0.5368
0.08
P V F ≈6.710
Step 2: Calculate the present value of the rental income using the formula:
P V =Rental Income ×P V F .
Using Rental Income = $120,000 and P V F = 6.710,
P V = $120,000 ×6.710
P V = $803,200
Therefore, the fair value of the investment property using the income ap-
proach is
$
803,200.
21

Question 28
Question
A company holds an investment in a private equity fund. The company classifies
the investment as a Level 3 fair value measurement. At the end of the reporting
period, the fair value of the investment has significantly increased due to posi-
tive financial performance of the investee companies. How should the company
account for this increase in fair value in their financial statements according to
fair value measurement standards?
Solution
Step 1: Under fair value measurement standards, changes in fair value for Level
3 investments are recognized in the income statement. The increase in fair value
of the investment should be recognized as a gain in the income statement. This
gain is reported as part of the company’s net income for the period.
Step 2: The gain recognized in the income statement is also disclosed in the
notes to the financial statements to provide users with additional information
about the nature and impact of fair value changes on the company’s financial
performance.
Step 3: It is important for the company to carefully document and disclose
the inputs and valuation techniques used in determining the fair value of the
investment to ensure transparency and comparability for financial statement
users.
Therefore, the company should recognize the increase in fair value of the
investment as a gain in the income statement and disclose relevant information
in the notes to the financial statements.
Question 29
Question
A company holds an investment in a privately held startup company. The
company values the investment using the fair value measurement model. The
fair value measurements are categorized as Level 3 inputs. What are Level 3
inputs and how are they used in the fair value measurement model?
Solution
Step 1: Level 3 inputs refer to inputs that are unobservable for the asset or
liability being valued. These inputs are used when there is little or no market
activity for the asset or liability, requiring the entity to use its own assumptions
about the inputs that market participants would use when pricing the asset or
liability. Level 3 inputs are typically based on management’s own estimates and
valuations.
22

Step 2: In the fair value measurement model, Level 3 inputs are used to
determine the fair value of assets or liabilities when Level 1 and Level 2 inputs
are not available. This often occurs when the assets or liabilities being valued
are not traded in active markets.
Step 3: When using Level 3 inputs, entities must make significant judgments
and utilize estimation techniques to determine the fair value of the asset or
liability. This may involve developing cash flow projections, utilizing option
pricing models, or other valuation techniques to estimate the fair value.
Step 4: The use of Level 3 inputs introduces measurement uncertainty and
subjectivity into the fair value measurement process. As a result, it is important
for entities to disclose the inputs, assumptions, and methodologies used when
valuing assets or liabilities with Level 3 inputs to provide users of the financial
statements with transparency about the valuation process.
Question 30
Question
Company XYZ has an investment in a financial instrument classified as held for
trading. At the end of the reporting period, the fair value of the financial instru-
ment is 250,000.However, therearecertainobservablef actorsthatsuggestthef airvaluemaynotbereliable.DiscussthestepsCompanyXY Zshouldtake, inaccordancewithIF RS13F airV alueMeasurement, todeterminethef airvalueof thefinancialinstrument.
Solution
To determine the fair value of the financial instrument in question when the fair
value may not be reliable, Company XYZ should follow specific steps outlined
in IFRS 13 Fair Value Measurement. The steps are as follows:
Step 1: Identify the Asset or Liability Identify the specific financial
instrument for which the fair value is to be determined. In this case, it is the
financial instrument classified as held for trading in Company XYZ.
Step 2: Determine the Appropriate Valuation Technique Select the
appropriate valuation technique that is suitable given the nature of the financial
instrument, the characteristics of the market, and other relevant factors. For
example, Company XYZ could consider using a discounted cash flow (DCF)
model to determine the fair value of the financial instrument.
Step 3: Collect Relevant Data Gather all relevant data related to the
financial instrument, the market, and other factors that may affect its fair value.
This includes observable market inputs such as interest rates, credit spreads, and
market prices.
Step 4: Assess the Data Quality Evaluate the quality of the data col-
lected to ensure it is reliable and relevant for the valuation. If there are observ-
able factors that suggest the fair value may not be reliable, consider adjusting
the data or applying additional techniques to verify the fair value.
Step 5: Perform the Valuation Apply the selected valuation technique
using the collected data to determine the fair value of the financial instrument.
23
This may involve making adjustments or using alternative methods to ensure a
reliable estimate of fair value.
Step 6: Review and Disclose Review the valuation process and results
to ensure they are consistent with the requirements of IFRS 13. Disclose the
key assumptions, uncertainties, and other relevant information in the financial
statements to provide transparency to users.
By following these steps, Company XYZ can determine the fair value of
the financial instrument in a manner that is consistent with the principles of
IFRS 13 Fair Value Measurement, even when the fair value may not be readily
observable or reliable.
Question 31
Question
Company X holds an investment in a private equity fund. At the reporting date,
the fair value of the investment is determined to be $1,200,000. During the year,
the fair value of the investment increased by $150,000. However, Company X
noted that the private equity fund has experienced financial difficulties after
the reporting date. As a result, the fair value of the investment is expected to
decrease by $100,000 before the financial statements are authorized for issuance.
Calculate the fair value adjustment that Company X should recognize in its
financial statements.
Solution
Step 1: Calculate the initial increase in fair value. The initial increase in fair
value is $150,000.
Step 2: Calculate the expected decrease in fair value. The expected decrease
in fair value is $100,000.
Step 3: Calculate the net fair value adjustment. The net fair value adjust-
ment is the initial increase minus the expected decrease:
$150,000 −$100,000 = $50,000
Therefore, Company X should recognize a fair value adjustment of $50,000
in its financial statements.
Question 32
Question
A company holds an investment in financial asset A which is classified as a
level 3 investment under fair value hierarchy. The fair value of financial asset
A increased by
$
20,000 during the financial period. In the balance sheet, how
should this increase in fair value be accounted for?
24
Solution
To account for the increase in fair value of financial asset A, we need to under-
stand the fair value hierarchy and how changes in fair value are recognized in
the financial statements.
Step 1: Understand Fair Value Hierarchy
Level 1 assets: These are financial assets that have quoted prices in ac-
tive markets, such as listed stocks or bonds. Their fair value is easily
determined.
Level 2 assets: These are financial assets that do not have quoted prices
in active markets, but their fair value can be determined using observable
market inputs, such as similar assets or benchmark prices.
Level 3 assets: These are financial assets that do not have readily de-
terminable fair values and require more subjective estimation. They are
valued using unobservable inputs.
Given that financial asset A is classified as a level 3 investment, any changes
in fair value will lead to adjustments in the financial statements.
Step 2: Accounting for the Increase in Fair Value When the fair value
of financial asset A increased by
$
20,000, the company needs to account for this
change in the financial statements.
For level 3 investments, changes in fair value are recognized in the income
statement as unrealized gains or losses. In this case, the increase in fair value
of
$
20,000 will be recognized as an unrealized gain in the income statement.
Therefore, the increase in fair value of financial asset A of
$
20,000 will be
accounted for as follows:
Income Statement:
Unrealized Gain on Financial Asset A $20,000
This adjustment reflects the increase in fair value of financial asset A during
the financial period and is reported in the income statement.
Question 33
Question
Company XYZ holds an investment in a private equity fund. The fair value of
this investment is determined using Level 3 inputs. Explain what Level 3 inputs
are and discuss the challenges associated with using Level 3 inputs for fair value
measurements.
25

Solution
Step 1: Level 3 inputs
Level 3 inputs are unobservable inputs for an asset or liability that are used
when determining its fair value. These inputs are based on the best informa-
tion available in the circumstances, which may include the reporting entity’s
assumptions about the assumptions market participants would use in pricing
the asset or liability.
Step 2: Challenges associated with Level 3 inputs
1. Subjectivity: Level 3 inputs are the most subjective of the three levels
of fair value measurement inputs. They require significant judgment and esti-
mation by the reporting entity. As a result, different entities may use different
assumptions leading to different fair value measurements.
2. Lack of market data: Since Level 3 inputs are unobservable, there is
often a lack of market data available to corroborate the fair value estimates.
This lack of market data can make it difficult to assess the reliability of the fair
value measurements based on Level 3 inputs.
3. Sensitivity to assumptions: Fair value measurements using Level
3 inputs can be sensitive to changes in assumptions. Small changes in key
assumptions can result in significant changes in the fair value of the asset or
liability, leading to potential volatility in financial statements.
4. Regulatory scrutiny: Given the subjectivity involved in using Level
3 inputs, fair value measurements based on these inputs are often subject to
increased regulatory scrutiny. Regulators may challenge the reporting entity’s
fair value measurements and assumptions, leading to potential adjustments or
restatements.
In conclusion, while Level 3 inputs are necessary for valuing certain assets
and liabilities, they come with challenges such as subjectivity, lack of market
data, sensitivity to assumptions, and regulatory scrutiny. It is important for
reporting entities to exercise caution and transparency when using Level 3 inputs
for fair value measurements.
Question 34
Question
Company XYZ holds a financial asset that is measured at fair value through
profit or loss. The fair value of the asset at the end of the reporting period is de-
termined to be 600,000.Duringtheyear, theassetgeneratedcashflowsof 50,000.
Additionally, the market risk premium of similar assets was estimated to be 6
Solution
Step 1: Calculate the discount rate using the formula:
Discount Rate = Risk-Free Rate + Market Risk Premium
26
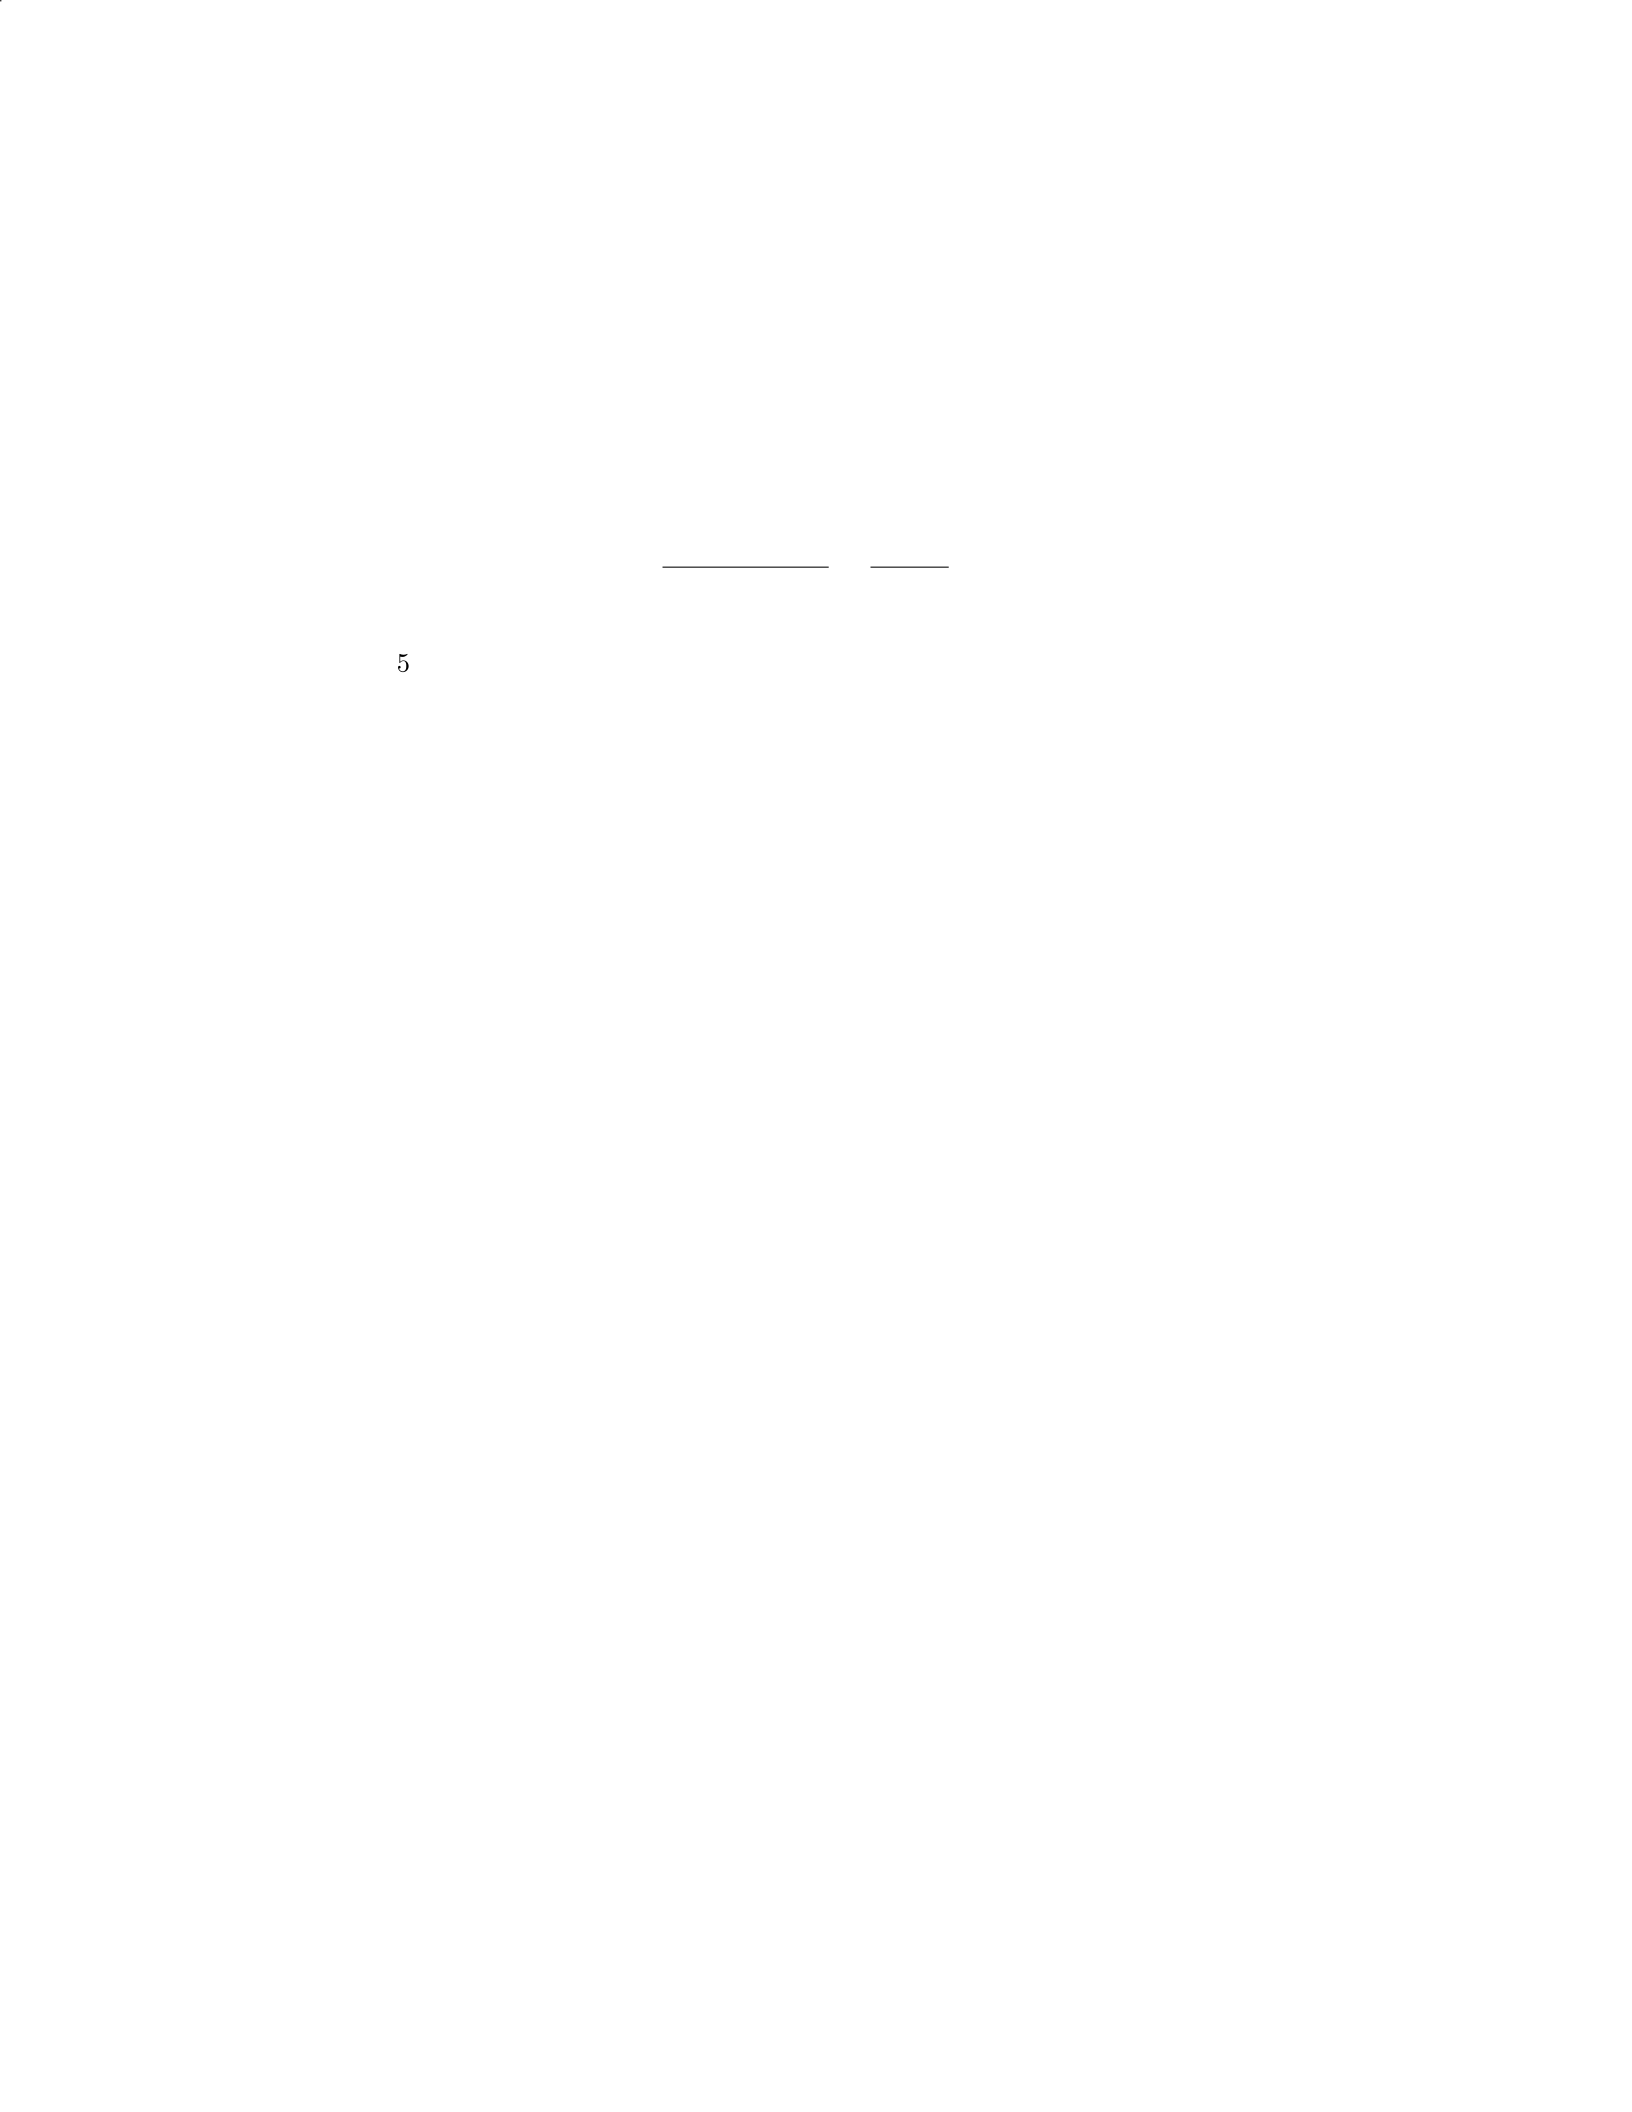
Given that the risk-free rate is 3
Discount Rate = 3% + 6% = 9%
Step 2: Use the discounted cash flow (DCF) formula to find the fair value
of the asset:
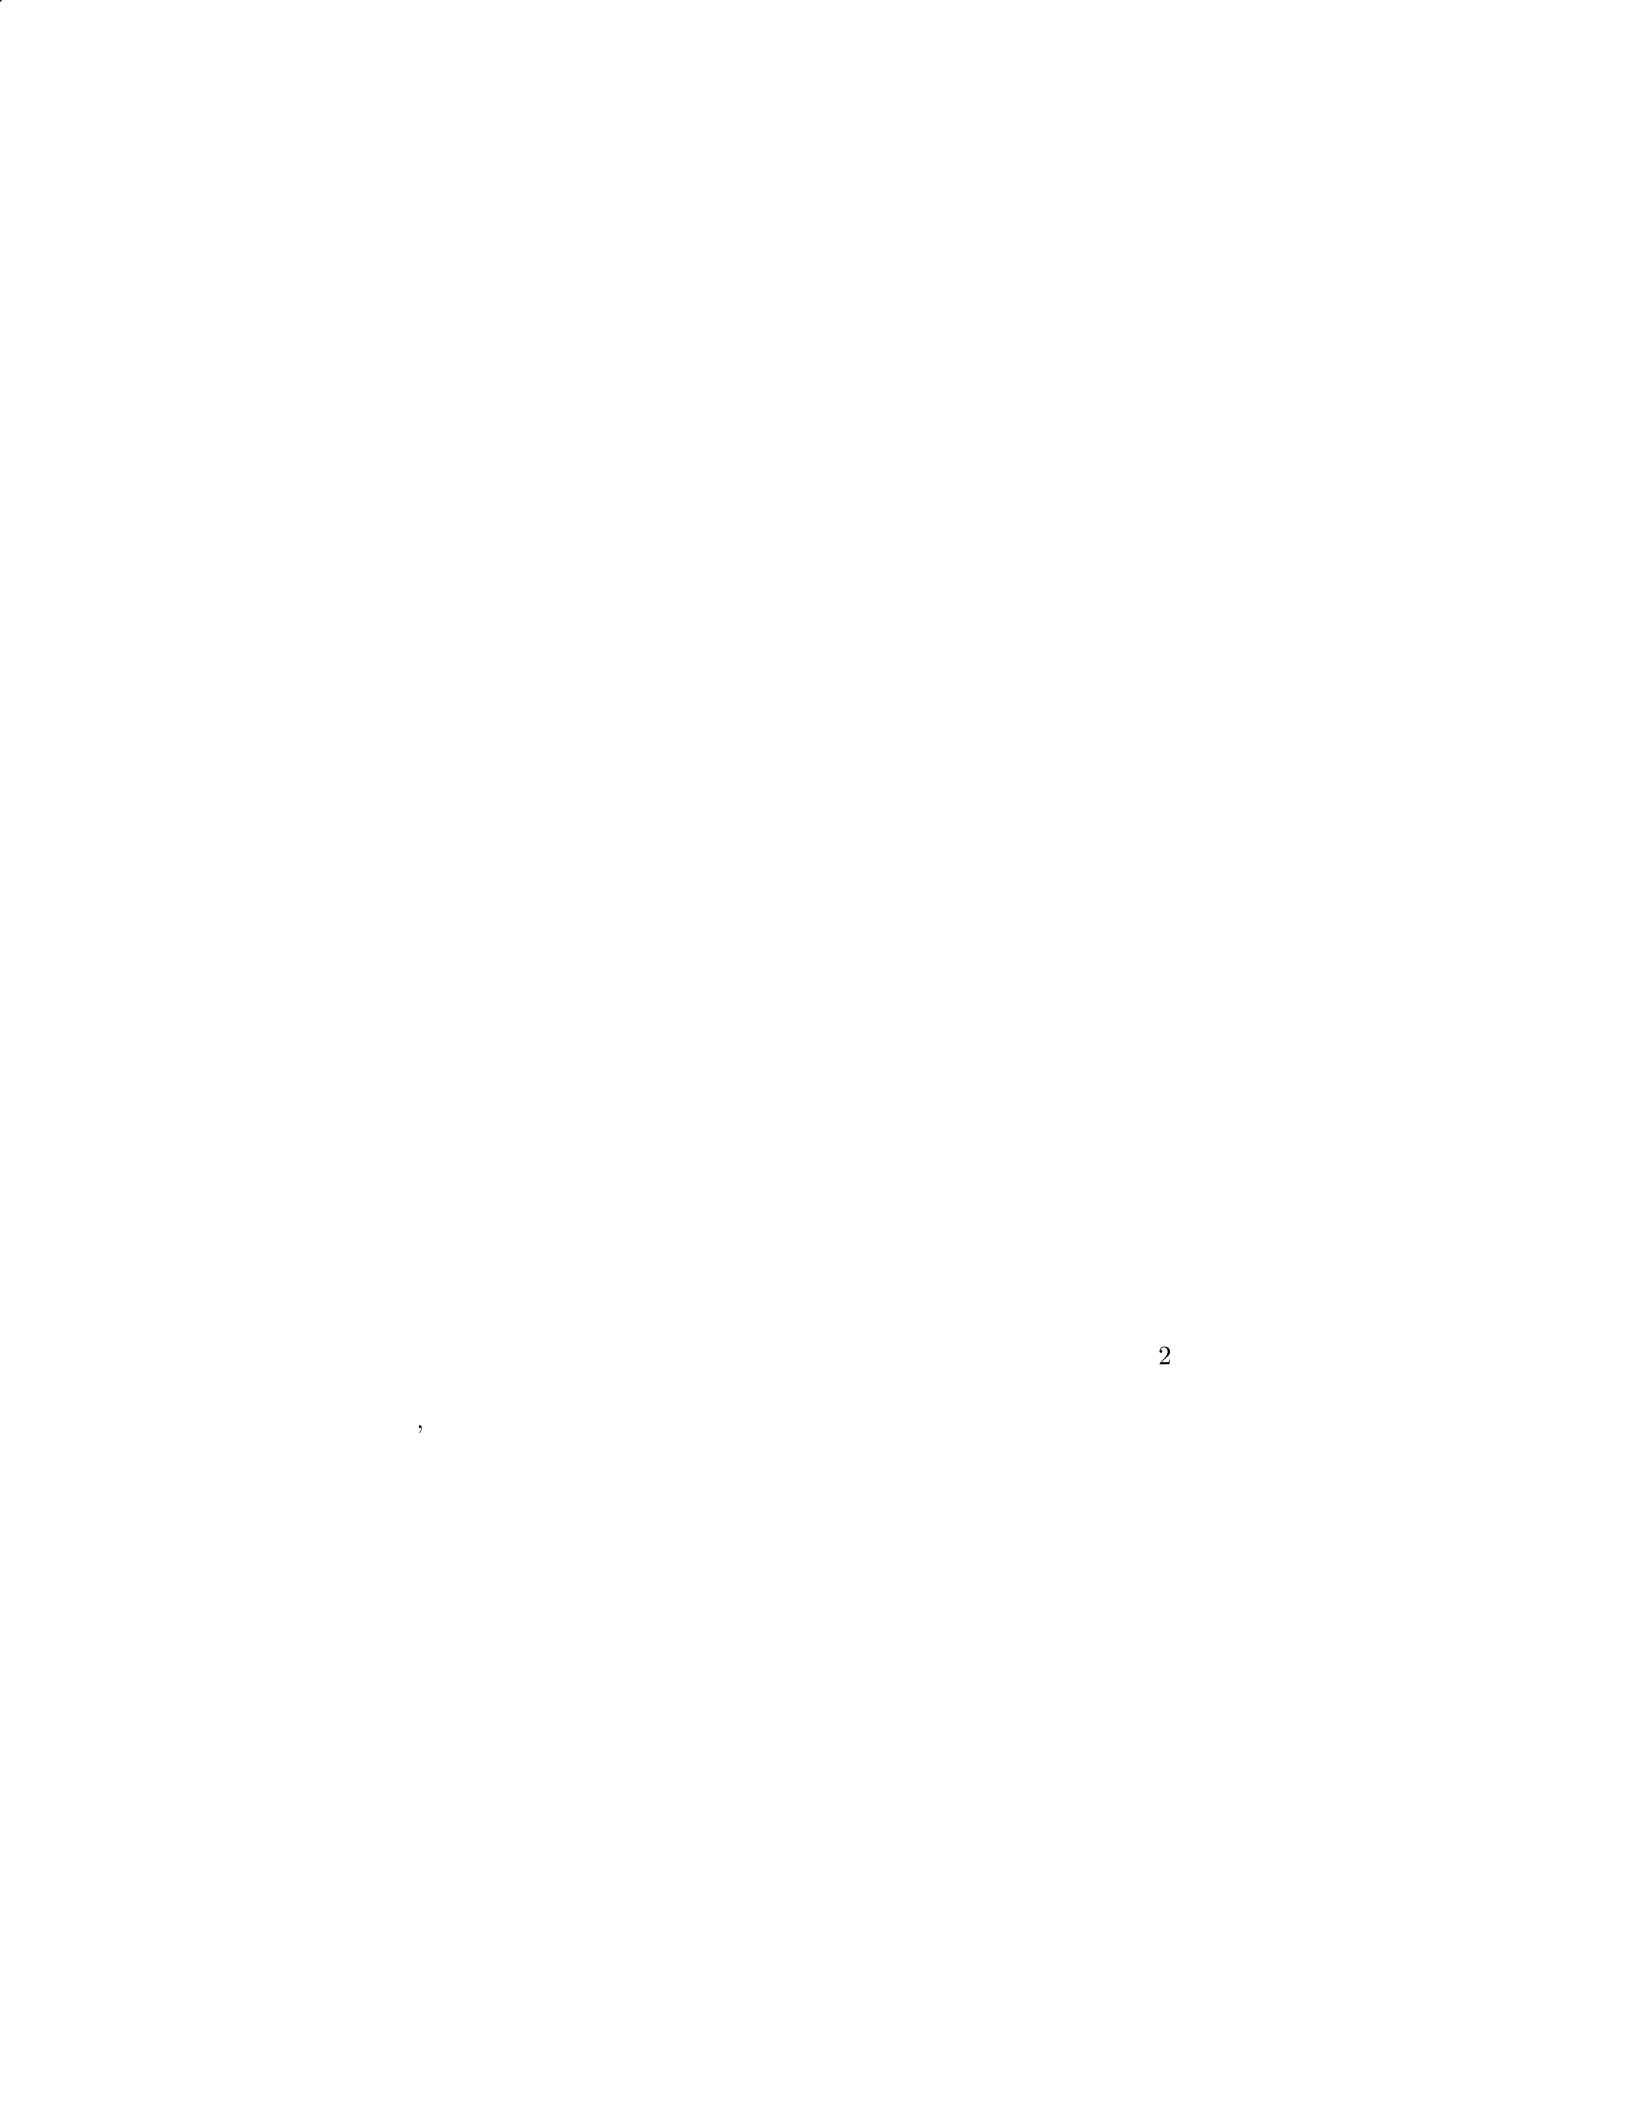
Fair Value = Cash Flows
Discount Rate =50,000
0.09 = $555,555.56
Therefore, the fair value of the asset using the discounted cash flow method
is
$
555,555.56.
Question 35
Question
Suppose a company needs to determine the fair value of an investment property.
The company has gathered relevant information and identified the following
three approaches to estimate the fair value: 1. Cost Approach - The cost to
replace the property. 2. Market Approach - Prices of similar properties in the
market. 3. Income Approach - Expected future cash flows from the property.
Explain how each of these approaches can be used to estimate the fair value
of the investment property. Additionally, discuss the advantages and disadvan-
tages of each approach in the context of fair value measurement.
Solution
Step 1: Cost Approach The Cost Approach to fair value measurement involves
determining the current cost to replace the property. This approach assumes
that the fair value of the property should not exceed the cost of acquiring or
constructing a substitute property with equivalent utility.
Advantages: - Useful when reliable market data is not available. - Provides
a straightforward estimation based on replacement cost.
Disadvantages: - Does not consider the property’s specific market conditions
or demand. - Does not reflect potential earning capacity or future cash flows of
the property.
Step 2: Market Approach The Market Approach to fair value measure-
ment involves comparing the subject property to similar properties in the market
that have been recently sold. This approach relies on the principle of substi-
tution, which states that an informed buyer would pay no more for a property
than the cost of acquiring a similar property.
Advantages: - Reflects actual market transactions and prices. - Considers
current supply and demand conditions.
Disadvantages: - Relies on the availability of comparable market data. -
Assumes properties are identical or very similar.
27
Question 3
Question
A company holds an investment property that it measures at fair value. The fair
value of the property at the end of the reporting period is 500,000.Duringthereportingperiod, thecompanyreceivedrentalincomeof40,000
from the property. In addition, the property incurred operating expenses of
15,000.Determinethegainorlossrecognizedinthecompany′sincomestatementrelatedtotheinvestmentproperty.
Solution
To determine the gain or loss recognized in the company’s income statement
related to the investment property, we need to calculate the net gain or loss.
Step 1: Calculate the net gain or loss. The net gain or loss is calculated as
follows:
Net gain or loss = Fair value at the end−Fair value at the beginning−Rental income+Operating expenses
Given that fair value at the end of the reporting period is 500,000, fairvalueatthebeginningisnotprovidedinthequestion.Soweassumeitisthesameasthef airvalueattheend.Hence :
Net gain or loss =500,000 - 500,000−40,000 + 15,000
Net gain or loss = −
25,000
Step 2: Analyze the result. The negative net gain of −25,000indicatesalossrecognizedinthecompany′sincomestatementrelatedtotheinvestmentproperty.
Question 4
Question
Company XYZ owns an investment property that is reported at fair value. At
the end of the reporting period, the fair value of the property is
$
2,500,000.
During the next reporting period, the fair value of the property has increased
to
$
2,800,000. What journal entry should Company XYZ make to account for
this increase in fair value?
Solution
To account for the increase in fair value of the investment property, Company
XYZ will need to recognize a gain in its financial statements. The journal entry
will involve debiting the Investment Property account and crediting the Fair
Value Adjustment account.
Step 1: Calculate the increase in fair value:
Increase in fair value = $2,800,000 −$2,500,000 = $300,000
3

Step 2: Make the journal entry:
Debit Investment Property $300,000
Credit Fair Value Adjustment $300,000
This journal entry reflects the recognition of the gain in the fair value of the
investment property.
Question 5
Question
Suppose a company holds an investment in a financial asset that is required to
be measured at fair value through profit or loss. The fair value of the asset
increased by 15
Solution
To analyze the impact of the 15
Step 1: Determine the impact on the Balance Sheet - The 15- The
increase in fair value will result in a higher valuation of the financial asset
under the fair value measurement category. - As a result, the total assets of the
company will increase by the amount of the fair value increase.
Step 2: Identify the affected accounts - The impacted accounts on the
balance sheet will include: - Financial Asset account: This account will reflect
the higher fair value of the financial asset. - Fair Value Adjustment account:
This account will capture the unrealized gains on the financial asset.
Step 3: Assess the impact on the Income Statement - The increase in
fair value will lead to a recognition of unrealized gains in the income statement. -
The unrealized gains will be recognized as ”Fair Value Gains” under the ”Other
Income” or ”Gain/Loss” section of the income statement. - This will result in
a higher net income for the current reporting period.
In conclusion, the 15
Question 6
Question
Company X recently acquired a piece of land for development. The fair value of
the land was determined to be 1,500,000.Duringthedevelopmentprocess, CompanyXincurredadditionalcostsof200,000.
At the end of the reporting period, the fair value of the land was reassessed to be
1,600,000.Calculatethef airvalueofthelandtoberecognizedinthefinancialstatementsattheendof thereportingperiod.
4
Solution
Step 1: Calculate the carrying amount of the land The carrying amount of the
land is the initial fair value plus any additional costs incurred. Carrying amount
= Initial fair value + Additional costs Carrying amount = 1,500,000+200,000
Carrying amount = 1,700,000
Step 2: Determine the fair value gain or loss The fair value gain or loss is
the difference between the reassessed fair value and the carrying amount. Fair
value gain/loss = Reassessed fair value - Carrying amount Fair value gain/loss
= 1,600,000−1,700,000 Fair value loss = -100,000
Step 3: Recognize the fair value in the financial statements Since a fair
value loss was incurred, the fair value recognized in the financial statements will
be the lower of the carrying amount and the reassessed fair value. Fair value
recognized = Min(Carrying amount, Reassessed fair value) Fair value recognized
= Min(1,700,000,1,600,000) Fair value recognized = 1,600,000
Therefore, the fair value of the land to be recognized in the financial state-
ments at the end of the reporting period is 1,600,000.
Question 7
Question
Company XYZ holds an investment with a fair value of
$
50,000 at the end of
the year. During the year, the fair value increased by 10%. If the company
uses the Level 1 fair value measurement technique, what is the fair value of the
investment at the beginning of the year?
Solution
Step 1: Understand the Level 1 fair value measurement technique. Level 1 fair
value measurements are based on quoted prices (unadjusted) in active markets
for identical assets or liabilities that the entity can access at the measurement
date.
Step 2: Use the formula for calculating fair value after an increase. Let
F Vinitial be the fair value of the investment at the beginning of the year. Since
the fair value at the end of the year was $50,000 and increased by 10%, the fair
value at the beginning of the year can be calculated as:
F Vinitial =F Vend
1 + increase%
Step 3: Substitute the given values and calculate.
F Vinitial =$50,000
1+0.10 =$50,000
1.10 = $45,454.55
Therefore, the fair value of the investment at the beginning of the year using
the Level 1 fair value measurement technique is
$
45,454.55.
5

Question 8
Question
A company has an investment in a financial instrument classified as a Level 3
fair value measurement. The company uses unobservable inputs to determine
the fair value of the financial instrument. Explain the key considerations and
challenges the company may face in determining the fair value of this investment.
Solution
To determine the fair value of a financial instrument classified as a Level 3
fair value measurement using unobservable inputs, the company may encounter
several key considerations and challenges. Here are the steps outlining these:
Step 1: Understand Level 3 Fair Value Measurement Level 3 fair
value measurements involve significant unobservable inputs, also known as Level
3 inputs. These inputs require management’s judgment and involve a high
degree of subjectivity. Understanding the nature of Level 3 measurements is
crucial for the company.
Step 2: Valuation Techniques and Inputs The company must carefully
select appropriate valuation techniques to estimate the fair value of the financial
instrument. Since Level 3 inputs are unobservable, determining the reliability
and reasonableness of these inputs can be a challenge.
Step 3: Use of Financial Models Financial models are often used to
estimate the fair value of Level 3 financial instruments. However, the complexity
of these models and the assumptions made can introduce additional challenges
in arriving at a fair value that reflects market conditions.
Step 4: Consideration of Market and Economic Factors The com-
pany must assess how market and economic factors impact the fair value of the
financial instrument. Changes in market conditions can make it challenging to
determine the fair value accurately.
Step 5: Disclosure Requirements Given the subjectivity and complexity
involved in Level 3 fair value measurements, the company must provide extensive
disclosures in the financial statements. This includes detailing the valuation
techniques used, the inputs considered, and the sensitivity of the fair value to
changes in these inputs.
Step 6: Independent Verification To enhance credibility and reliability,
the company may consider engaging independent valuation specialists to review
and validate the fair value measurement process. This can help address concerns
about the objectivity of the valuation.
By carefully navigating these considerations and challenges, the company
can strive to determine a reliable fair value for its investment in the financial in-
strument despite the inherent difficulties associated with Level 3 measurements
based on unobservable inputs.
6

Question 9
Question
Explain the concept of fair value measurement and discuss the factors that may
influence the determination of fair value.
Solution
Step 1: Concept of Fair Value Measurement Fair value measurement is the
process of determining the value of an asset or liability based on the price that
would be received to sell an asset or paid to transfer a liability in an orderly
transaction between market participants at the measurement date. Fair value is
a market-based measurement, not an entity-specific measurement. It represents
the price that would be received to sell an asset or paid to transfer a liability in
an orderly transaction between market participants at the measurement date.
Step 2: Factors Influencing Fair Value Determination There are sev-
eral factors that may influence the determination of fair value: 1. Market con-
ditions: Fluctuations in market conditions can impact the fair value of assets
and liabilities. For example, changes in interest rates, economic conditions, and
market volatility can all affect fair value. 2. Availability of data: The avail-
ability of relevant and reliable data is essential for determining fair value. If
there is limited information about comparable transactions or market prices,
it may be challenging to determine fair value accurately. 3. Assumptions and
inputs: Fair value measurements often involve making assumptions and using
inputs based on available data. The choice of assumptions and inputs can affect
the final fair value estimate. 4. Level of judgment: Fair value measurements
require a significant amount of judgment, particularly when there is limited
market activity for the asset or liability being valued. The level of judgment
used can impact the reliability of the fair value measurement. 5. Complexity of
the asset or liability: The complexity of the asset or liability being valued can
also influence fair value determination. More complex assets or liabilities may
require more sophisticated valuation techniques, which can affect the accuracy
of the fair value measurement.
Question 10
Question
A company holds an investment in bonds classified as available-for-sale with a
fair value of 450,000.Duetomarketconditions, thefairvalueof thebondsdecreasesto420,000
at the end of the reporting period. The company decides to recognize the de-
crease in fair value. If the company reports unrealized losses in other compre-
hensive income, how would this affect the company’s financial statements?
7
Solution
1. The company recognizes the decrease in fair value of the bonds as an unreal-
ized loss. This is recorded as a decrease in the fair value of the bond investment
and an increase in unrealized loss.
2. The journal entry to recognize the decrease in fair value is as follows:
Available-for-sale bonds
$
30,000Unrealized loss on bonds
$
30,000
3. This journal entry would affect the balance sheet by decreasing the
available-for-sale bonds by
$
30,000.
4. When the company reports unrealized losses in other comprehensive in-
come, the income statement is not directly impacted. However, the accumulated
other comprehensive income section of the equity portion of the balance sheet
would decrease by the amount of the unrealized loss.
5. The company’s statement of comprehensive income would reflect the
change in other comprehensive income due to the recognition of the unrealized
loss.
6. Overall, the company’s financial position would show a decrease in total
comprehensive income due to the recognition of the unrealized loss, which would
impact the company’s equity and overall financial health.
Question 11
Question
Company X holds an investment in a security that is classified as a Level 3 asset
under fair value hierarchy. At the end of the reporting period, the fair value of
the security was estimated to be
$
1,200,000. During the next reporting period,
the fair value of the security increased to
$
1,400,000. Company X has a policy
of recognizing unrealized gains or losses on Level 3 assets directly in profit or
loss. Calculate the unrealized gain or loss that Company X should recognize in
the next reporting period.
Solution
Step 1: Calculate the unrealized gain or loss in the next reporting period. Given
that the fair value of the security increased from
$
1,200,000 to
$
1,400,000, the
unrealized gain or loss can be calculated using the formula:
Unrealized Gain or Loss = Ending Fair Value −Beginning Fair Value
Unrealized Gain or Loss = $1,400,000 −$1,200,000 = $200,000
Therefore, Company X should recognize an unrealized gain of
$
200,000 in
the next reporting period.
8
Question 12
Question
Company XYZ is considering investing in a new project and needs to determine
the fair value of the project for financial reporting purposes. The project is ex-
pected to generate cash flows of 10,000inthefirstyear,15,000 in the second year,
and 20,000inthethirdyear.T hediscountrateis8%.Calculatethef airvalueof theprojectusingthediscountedcashflowmethod.
Solution
Step 1: Calculate the present value of each cash flow.
P V1=10,000
(1 + 0.08)1= $9,259.26
P V2=15,000
(1 + 0.08)2= $12,938.02
P V3=20,000
(1 + 0.08)3= $15,873.79
Step 2: Calculate the fair value of the project by summing up the present
values of all cash flows.
F air V alue =P V1+P V2+P V3
= $9,259.26 + $12,938.02 + $15,873.79
= $38,070.07
Therefore, the fair value of the project using the discounted cash flow method
is
$
38,070.07.
Question 13
Question
You are a financial analyst working for a consulting firm. You have been tasked
with determining the fair value of a private equity investment held by one of
your clients. The investment has limited market activity and no actively traded
comparable securities. Discuss the challenges you may face in determining the
fair value of this private equity investment.
Solution
To determine the fair value of a private equity investment with limited market
activity and no actively traded comparable securities, several challenges may
arise. Below are the challenges you may face in this scenario:
9

Step 1: Lack of Observable Market Data Since the investment has
limited market activity, there may be insufficient observable market data avail-
able to determine a fair value. This lack of data makes it difficult to assess the
investment’s value accurately.
Step 2: Subjectivity in Valuation In the absence of comparable se-
curities or market transactions, fair value measurement may rely heavily on
subjective assumptions and judgments. Different analysts may come up with
different valuations based on their interpretation of available information.
Step 3: Reliance on Management Estimates When market data is
scarce, the valuation process may require significant reliance on management
estimates. This dependence on management’s projections can introduce bias
and lack of objectivity in the valuation process.
Step 4: Illiquidity and Lack of Marketability Private equity invest-
ments are typically illiquid and lack marketability. The lack of a ready market
for these investments can further complicate the determination of fair value,
as there may be limited opportunities to sell or liquidate the investment to
ascertain its true market worth.
Step 5: Complex Valuation Models Given the unique characteristics of
private equity investments, such as long investment horizons, complex capital
structures, and varying exit strategies, the valuation process may require the
use of sophisticated and complex models. These models may involve significant
assumptions and inputs that can impact the final valuation.
In conclusion, determining the fair value of a private equity investment with
limited market activity and no actively traded comparable securities poses sig-
nificant challenges, including the lack of observable market data, subjectivity in
valuation, reliance on management estimates, illiquidity, and complexity in val-
uation models. It is essential for analysts to carefully consider these challenges
and make sound judgments to arrive at a reasonable fair value estimate.
Question 14
Question
Company XYZ holds an investment in a private company which is carried at fair
value through profit or loss. At the end of the reporting period, the fair value of
the investment is determined to be 85,000.Duringthenextreportingperiod, inf ormationbecomesavailableindicatingasignif icantincreaseinvalueof theprivatecompany.T hef airvalueisestimatedtobe110,000.
Given this scenario, explain how Company XYZ should account for the in-
crease in fair value of the investment in the next reporting period.
Solution
Step 1: Initially Recognized and Recognized at Fair Value - The investment
in the private company was initially recognized and measured at fair value.
When an entity initially recognizes a financial asset at fair value, any difference
between the transaction price and the fair value (if any) is recognized in profit
10
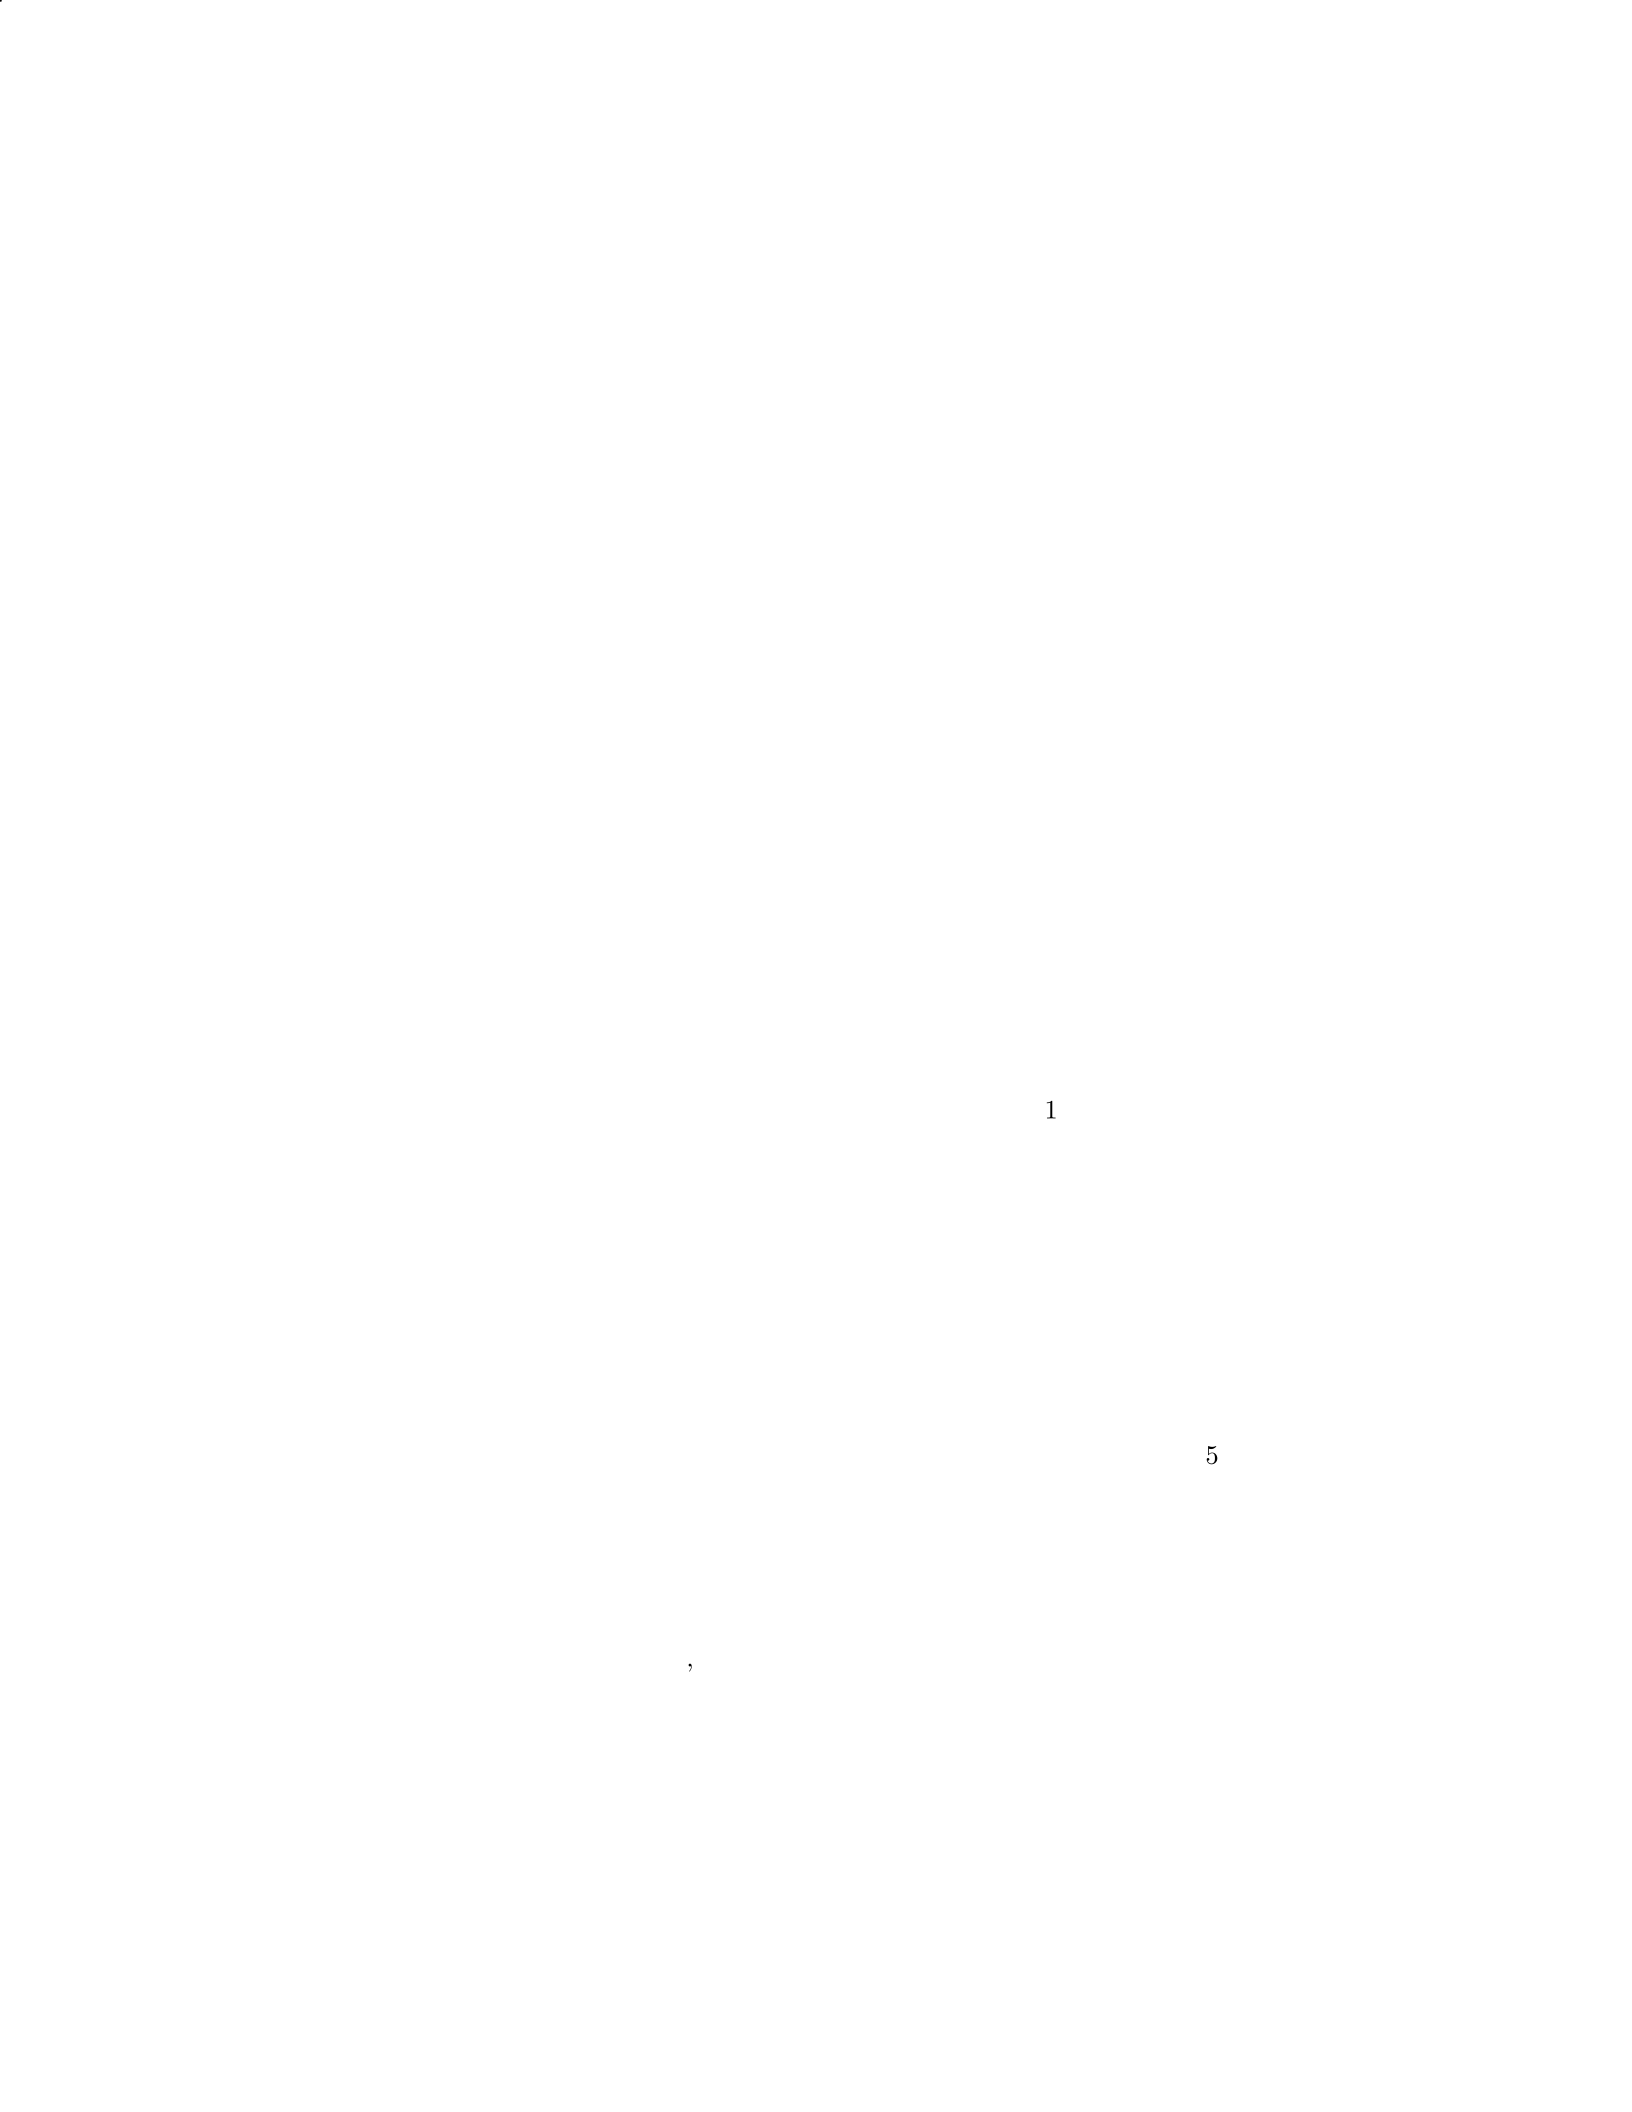
or loss. - In this case, since the investment was recognized at fair value, any
change in fair value after the initial recognition should also be recognized in
profit or loss.
Step 2: Increase in Fair Value - When the fair value of the investment in-
creases to 110,000inthenextreportingperiod, CompanyXY Zshouldrecognizethe25,000
increase in fair value as a gain in profit or loss. - This gain reflects the change
in fair value of the investment from 85,000to110,000.
Step 3: Accounting Entry - The accounting entry to recognize the increase
in fair value of the investment would be:
Profit or Loss 25,000
Investment in Private Company 25,000
Step 4: Disclosures - Company XYZ should disclose the fair value of the
investment in the financial statements along with the changes in fair value that
have been recognized in profit or loss. This provides transparency to the users
of the financial statements regarding the changes in fair value of the investment.
Question 15
Question
A company holds an investment in equity securities that are measured at fair
value through other comprehensive income (FVOCI). At the end of the reporting
period, the fair value of the investment has decreased by
$
15,000 compared to
its initial cost. The company considers this decrease to be temporary. How
should the company account for this decrease in fair value?
Solution
Step 1: Since the company considers the decrease in fair value to be tempo-
rary, it should recognize this decrease in fair value as an adjustment to other
comprehensive income.
Step 2: Calculate the adjustment amount. The adjustment amount is the
difference between the initial cost of the investment and the new fair value at
the end of the reporting period. In this case, the adjustment amount is
$
15,000.
Step 3: Prepare the journal entry to recognize the adjustment in fair value:
Other Comprehensive Income Dr. $15,000
Investment in Equity Securities Cr. $15,000
Step 4: After preparing the journal entry, the company’s total comprehensive
income will decrease by
$
15,000. The investment in equity securities account
will be adjusted to reflect the decrease in fair value.
Step 5: It’s important to note that the adjustment in fair value is recognized
in other comprehensive income and does not impact net income for the pe-
riod. The company should continue to monitor the fair value of the investment
11

and assess whether the decrease in fair value remains temporary or becomes
permanent.
Question 16
Question
Company XYZ holds an investment in a private company that is not publicly
traded. The investment is classified as a Level 3 asset under fair value measure-
ment. Company XYZ determines that there has been a significant decrease in
the financial performance of the private company. Explain how the decrease in
financial performance may impact the fair value measurement of the investment.
Solution
Step 1: The decrease in financial performance of the private company may im-
pact the fair value measurement of the investment as follows: - As per fair value
measurement guidelines, the fair value of a Level 3 asset is determined using
unobservable inputs, such as proprietary models or management’s estimates. -
The decrease in financial performance of the private company could result in
a reassessment of the assumptions and inputs used in the fair value measure-
ment process. - The decrease in financial performance may lead to a revision
of expected future cash flows, discount rates, or other key inputs used in the
valuation model.
Step 2: Specifically, the impact of the decrease in financial performance on
the fair value measurement of the investment could include: - A decrease in ex-
pected future cash flows due to lower revenue projections, increased expenses,
or other adverse financial indicators. - An increase in the discount rate used to
value the investment to reflect the higher risk associated with the private com-
pany’s deteriorating financial condition. - A change in the probability weighting
of different scenarios or outcomes, with a greater emphasis placed on downside
risks given the decrease in financial performance.
Step 3: Overall, the decrease in financial performance of the private com-
pany may lead to a lower fair value measurement of the investment due to the
increased perceived risk or lower expected future cash flows associated with the
investment. It is important for Company XYZ to carefully consider the impact
of the decrease in financial performance on the fair value measurement and make
any necessary adjustments to reflect the current economic conditions accurately.
Question 17
Question
Company XYZ holds an investment in a publicly traded company, which is
classified as available-for-sale. At the end of the reporting period, the fair value
12
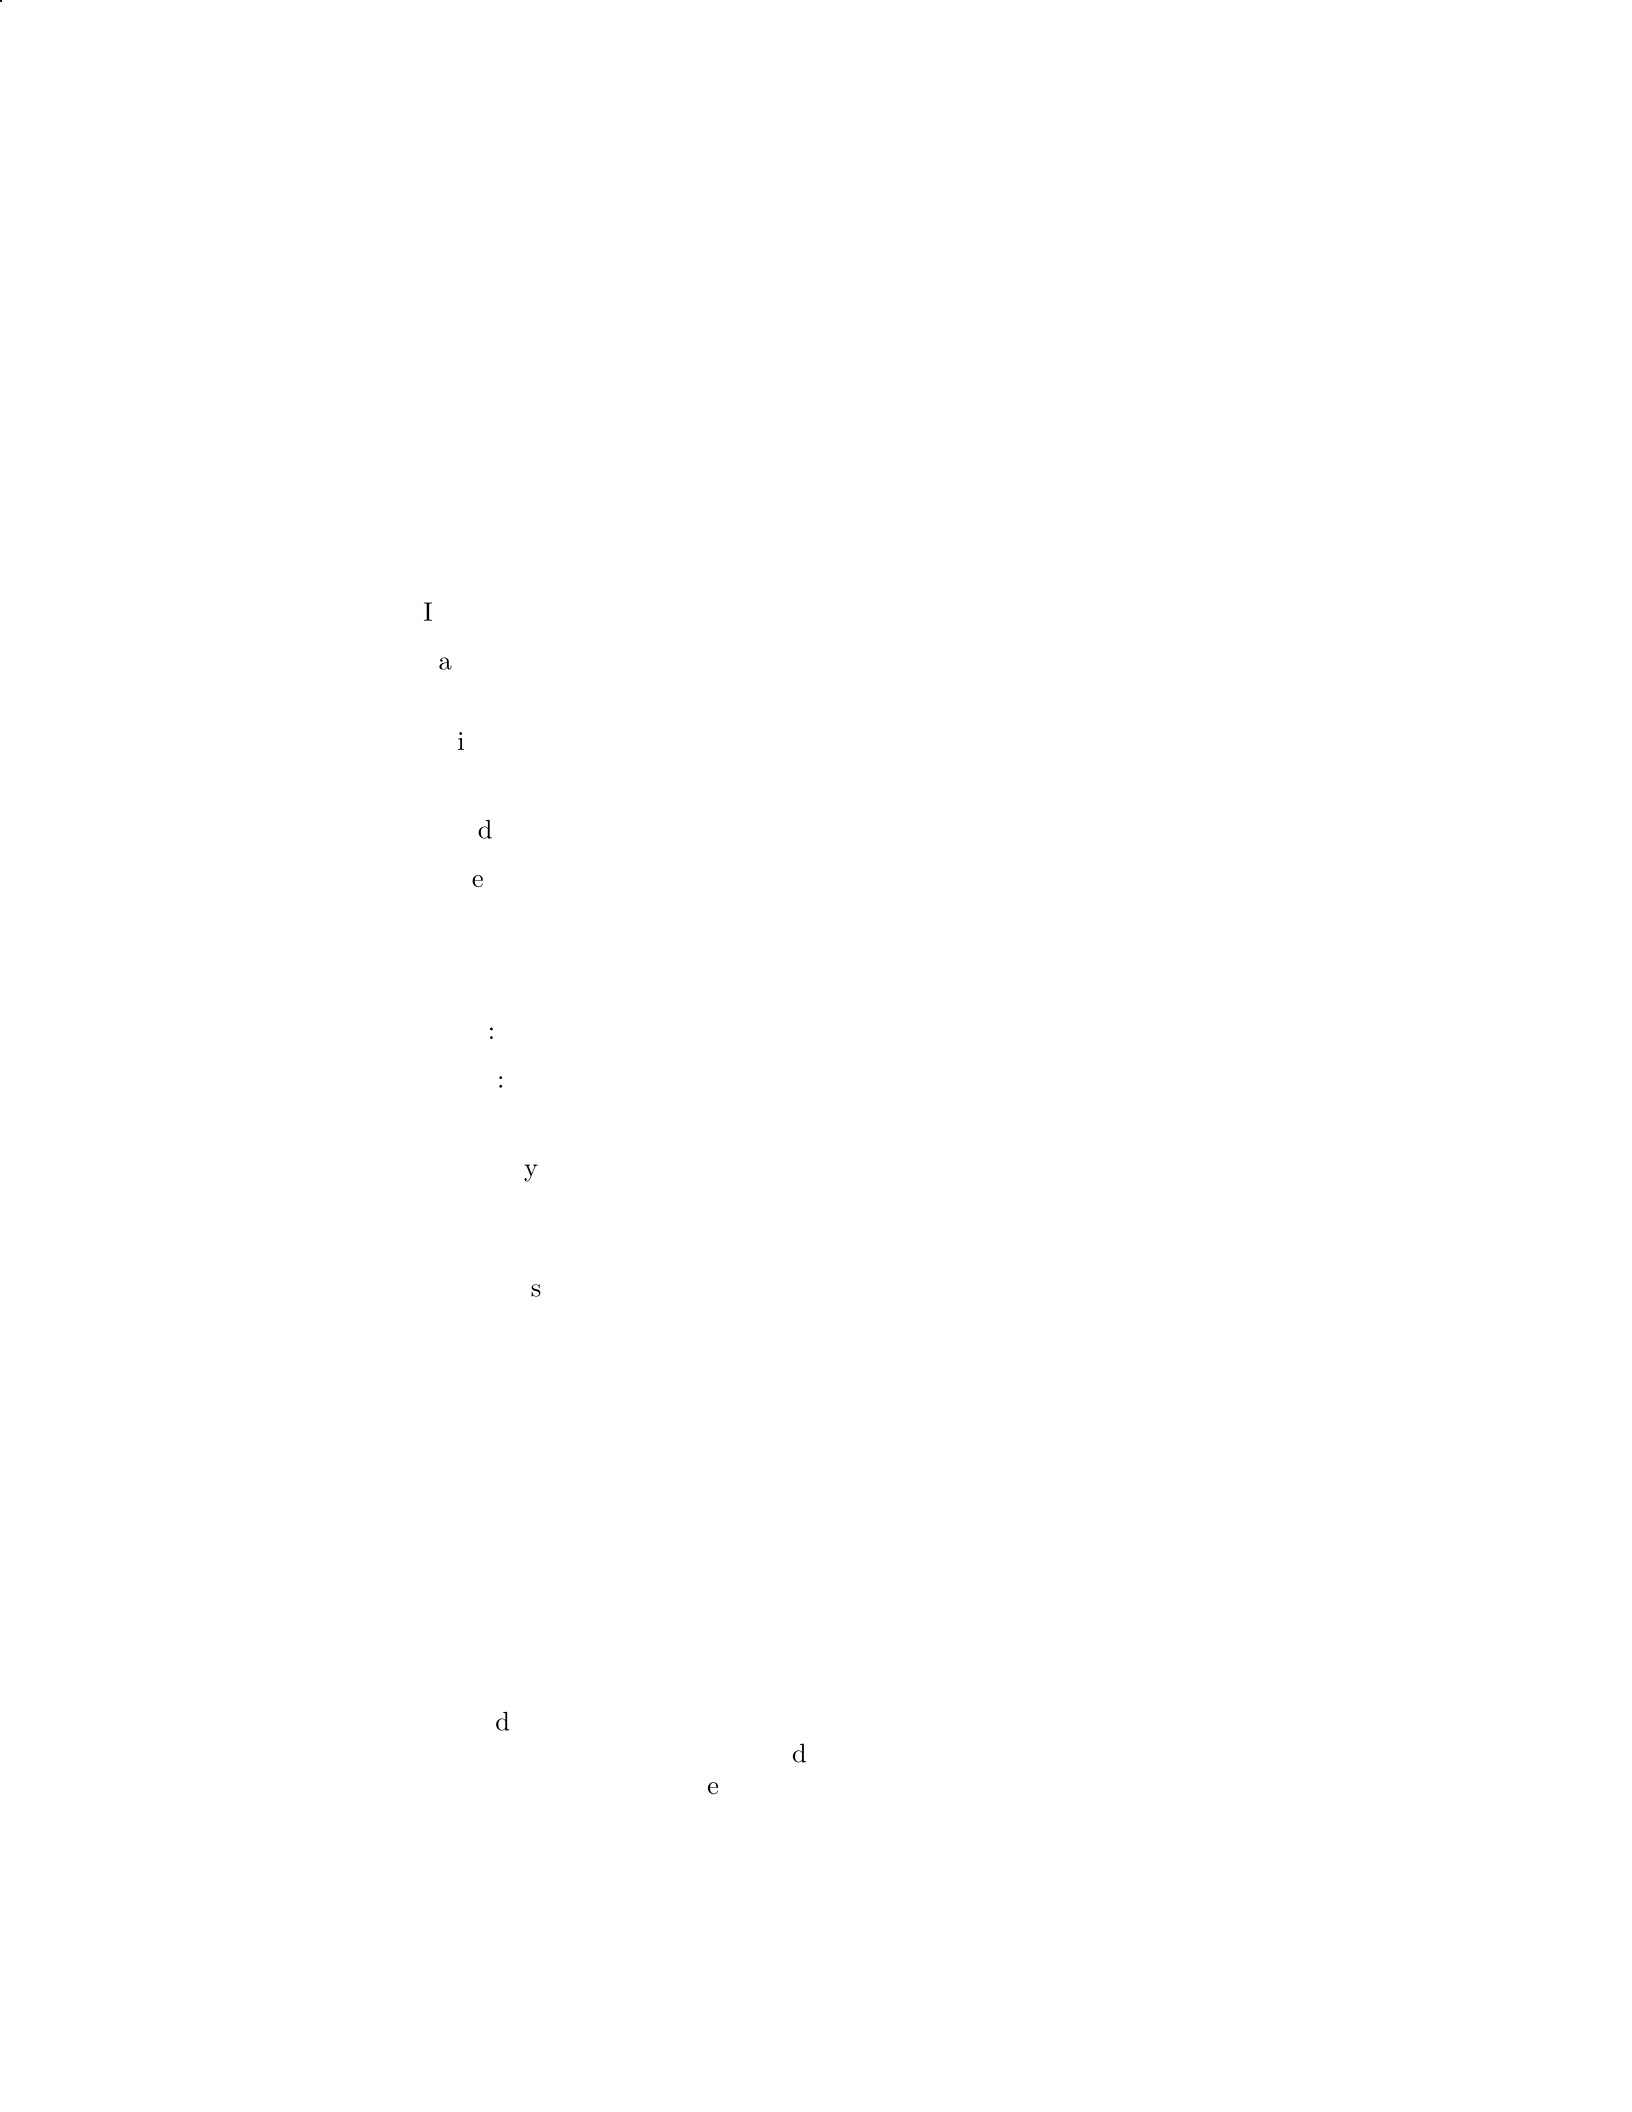
of the investment is $500,000, and the cost of the investment is $450,000. If
the fair value of the investment decreases to $480,000 at the end of the next
reporting period, how would this change be accounted for in Company XYZ’s
financial statements?
Solution
Step 1: Calculate the gain or loss on the decrease in fair value of the investment.
Initial fair value of the investment: $500,000
Fair value of the investment at the end of the next reporting period:
$480,000
Gain (Loss) on the decrease in fair value: $480,000−$500,000 = −$20,000
Step 2: Determine the impact on Company XYZ’s financial statements.
The decrease in fair value of $20,000 results in a loss for Company XYZ.
Since the investment is classified as available-for-sale, this loss is recog-
nized in other comprehensive income (OCI).
Step 3: Record the journal entry to reflect the loss on the decrease in fair
value.
Debit: Unrealized Holding Loss (OCI): $20,000
Credit: Investment: $20,000
Step 4: Update the carrying amount of the investment on the balance sheet.
The carrying amount of the investment on the balance sheet will now be
$450,000 −$20,000 = $430,000.
Step 5: Disclose the reclassification adjustment in the financial statements.
The reclassification adjustment of $20,000 from OCI to net income should
be disclosed in the financial statements.
Therefore, the decrease in fair value of the investment would result in a
loss of $20,000 being recognized in other comprehensive income (OCI) and a
corresponding adjustment to the carrying amount of the investment on the
balance sheet.
Question 18
Question
A company is required to determine the fair value of an investment property
on its financial statements. The property was purchased three years ago for
$
500,000 and has since undergone significant revaluation with an independent
appraiser valuing it at
$
700,000. Additionally, the property generates annual
rental income of
$
40,000. If the company uses an appropriate discount rate of 8
13
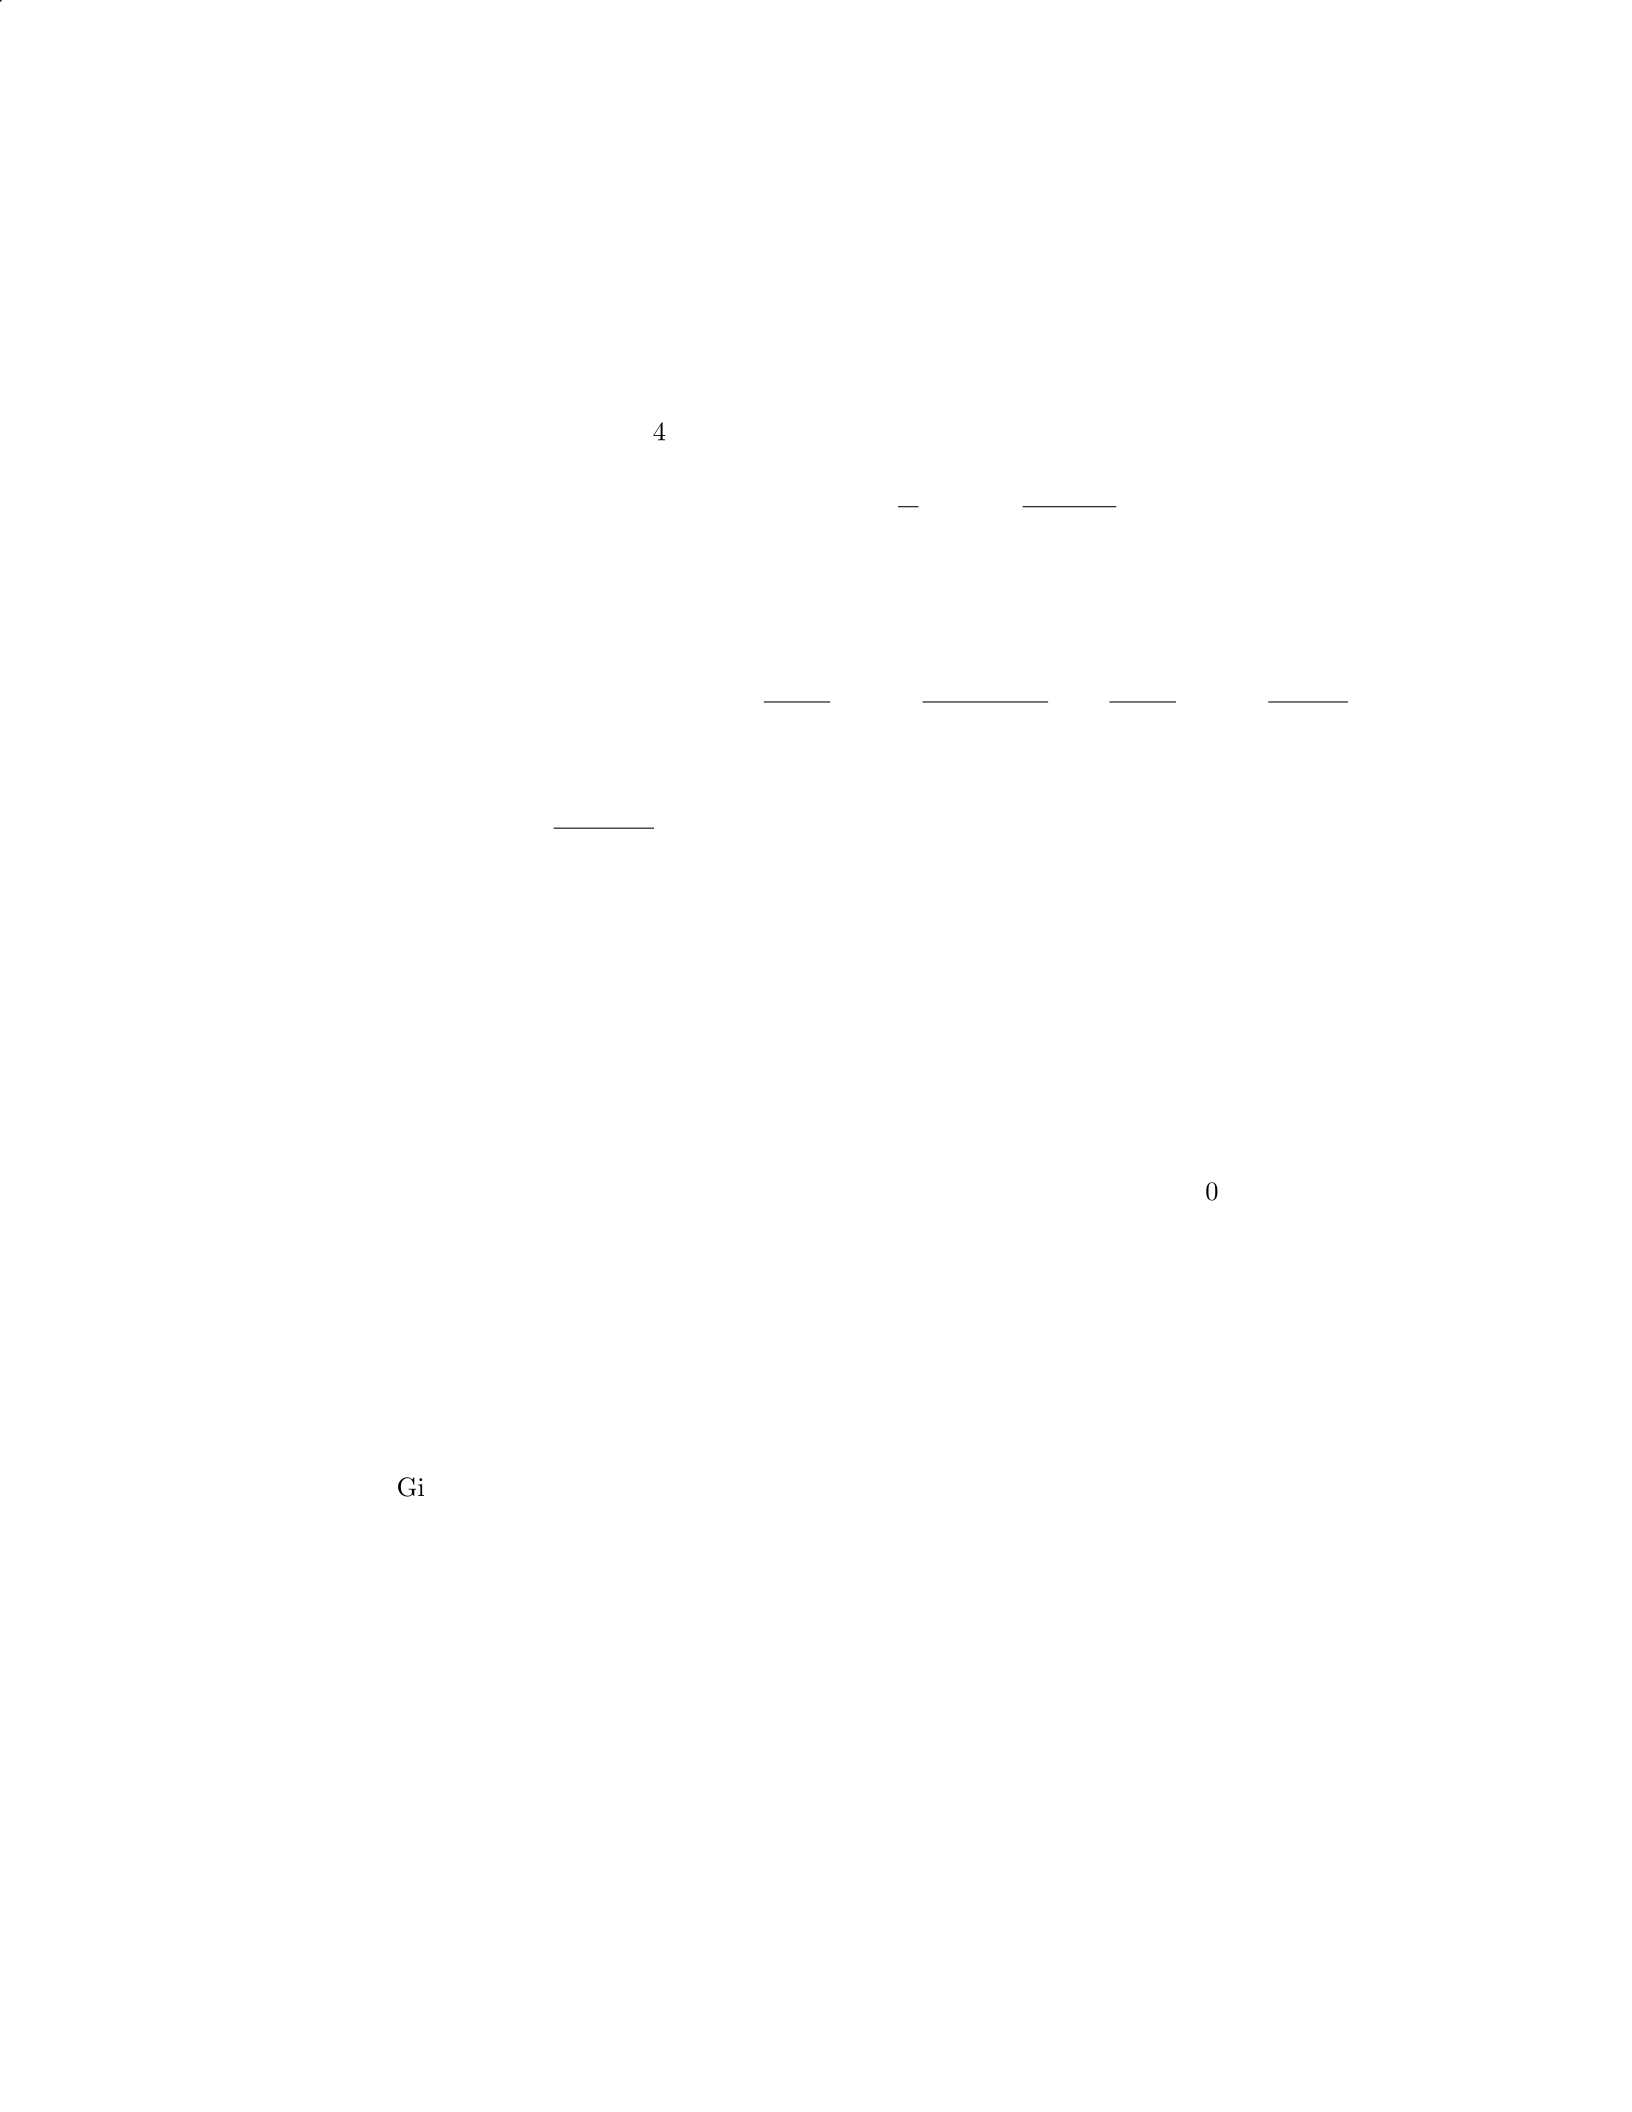
Solution
Step 1: Calculate the present value of the annual rental income. Given an
annual rental income of
$
40,000 and a discount rate of 8
Present Value of Rental Income = R
r×1−1
(1 + r)n
where: - R= $40,000 - r= 0.08 - n= 3 (since the rental income is for three
years)
Present Value of Rental Income = 40000
0.08 ×1−1
(1 + 0.08)3=40000
0.08 ×1−1
(1.08)3
= 500000×1−1
1.259712≈500000×(1−0.79383) = 500000×0.20617 ≈$103,085.01
Step 2: Calculate the fair value of the investment property. The fair value
of the investment property is the sum of the present value of the rental income
and the revaluation amount:
Fair Value = Present Value of Rental Income + Revaluation Amount
Fair Value = $103,085.01 + $700,000 = $803,085.01
Therefore, the fair value of the investment property is approximately
$
803,085.01.
Question 19
Question
Company XYZ holds an investment in a financial instrument classified as a level
3 fair value measurement. At the end of the reporting period, the fair value of the
financial instrument is determined to be 150,000, butthereissignif icantunobservableinputuncertaintyinvolvedinthevaluationprocess.CompanyXY Zhashistoricallyusedaweightedaveragecostofcapital(W ACC)of10
Given this information, determine the fair value of the financial instrument
using the method prescribed by IFRS 13.
Solution
To determine the fair value of the financial instrument using the method pre-
scribed by IFRS 13, we will calculate the fair value based on the present value of
expected cash flows discounted using current market-based observable inputs.
Step 1: Identify the relevant cash flows associated with the financial instru-
ment. The relevant cash flow associated with the financial instrument are the
14
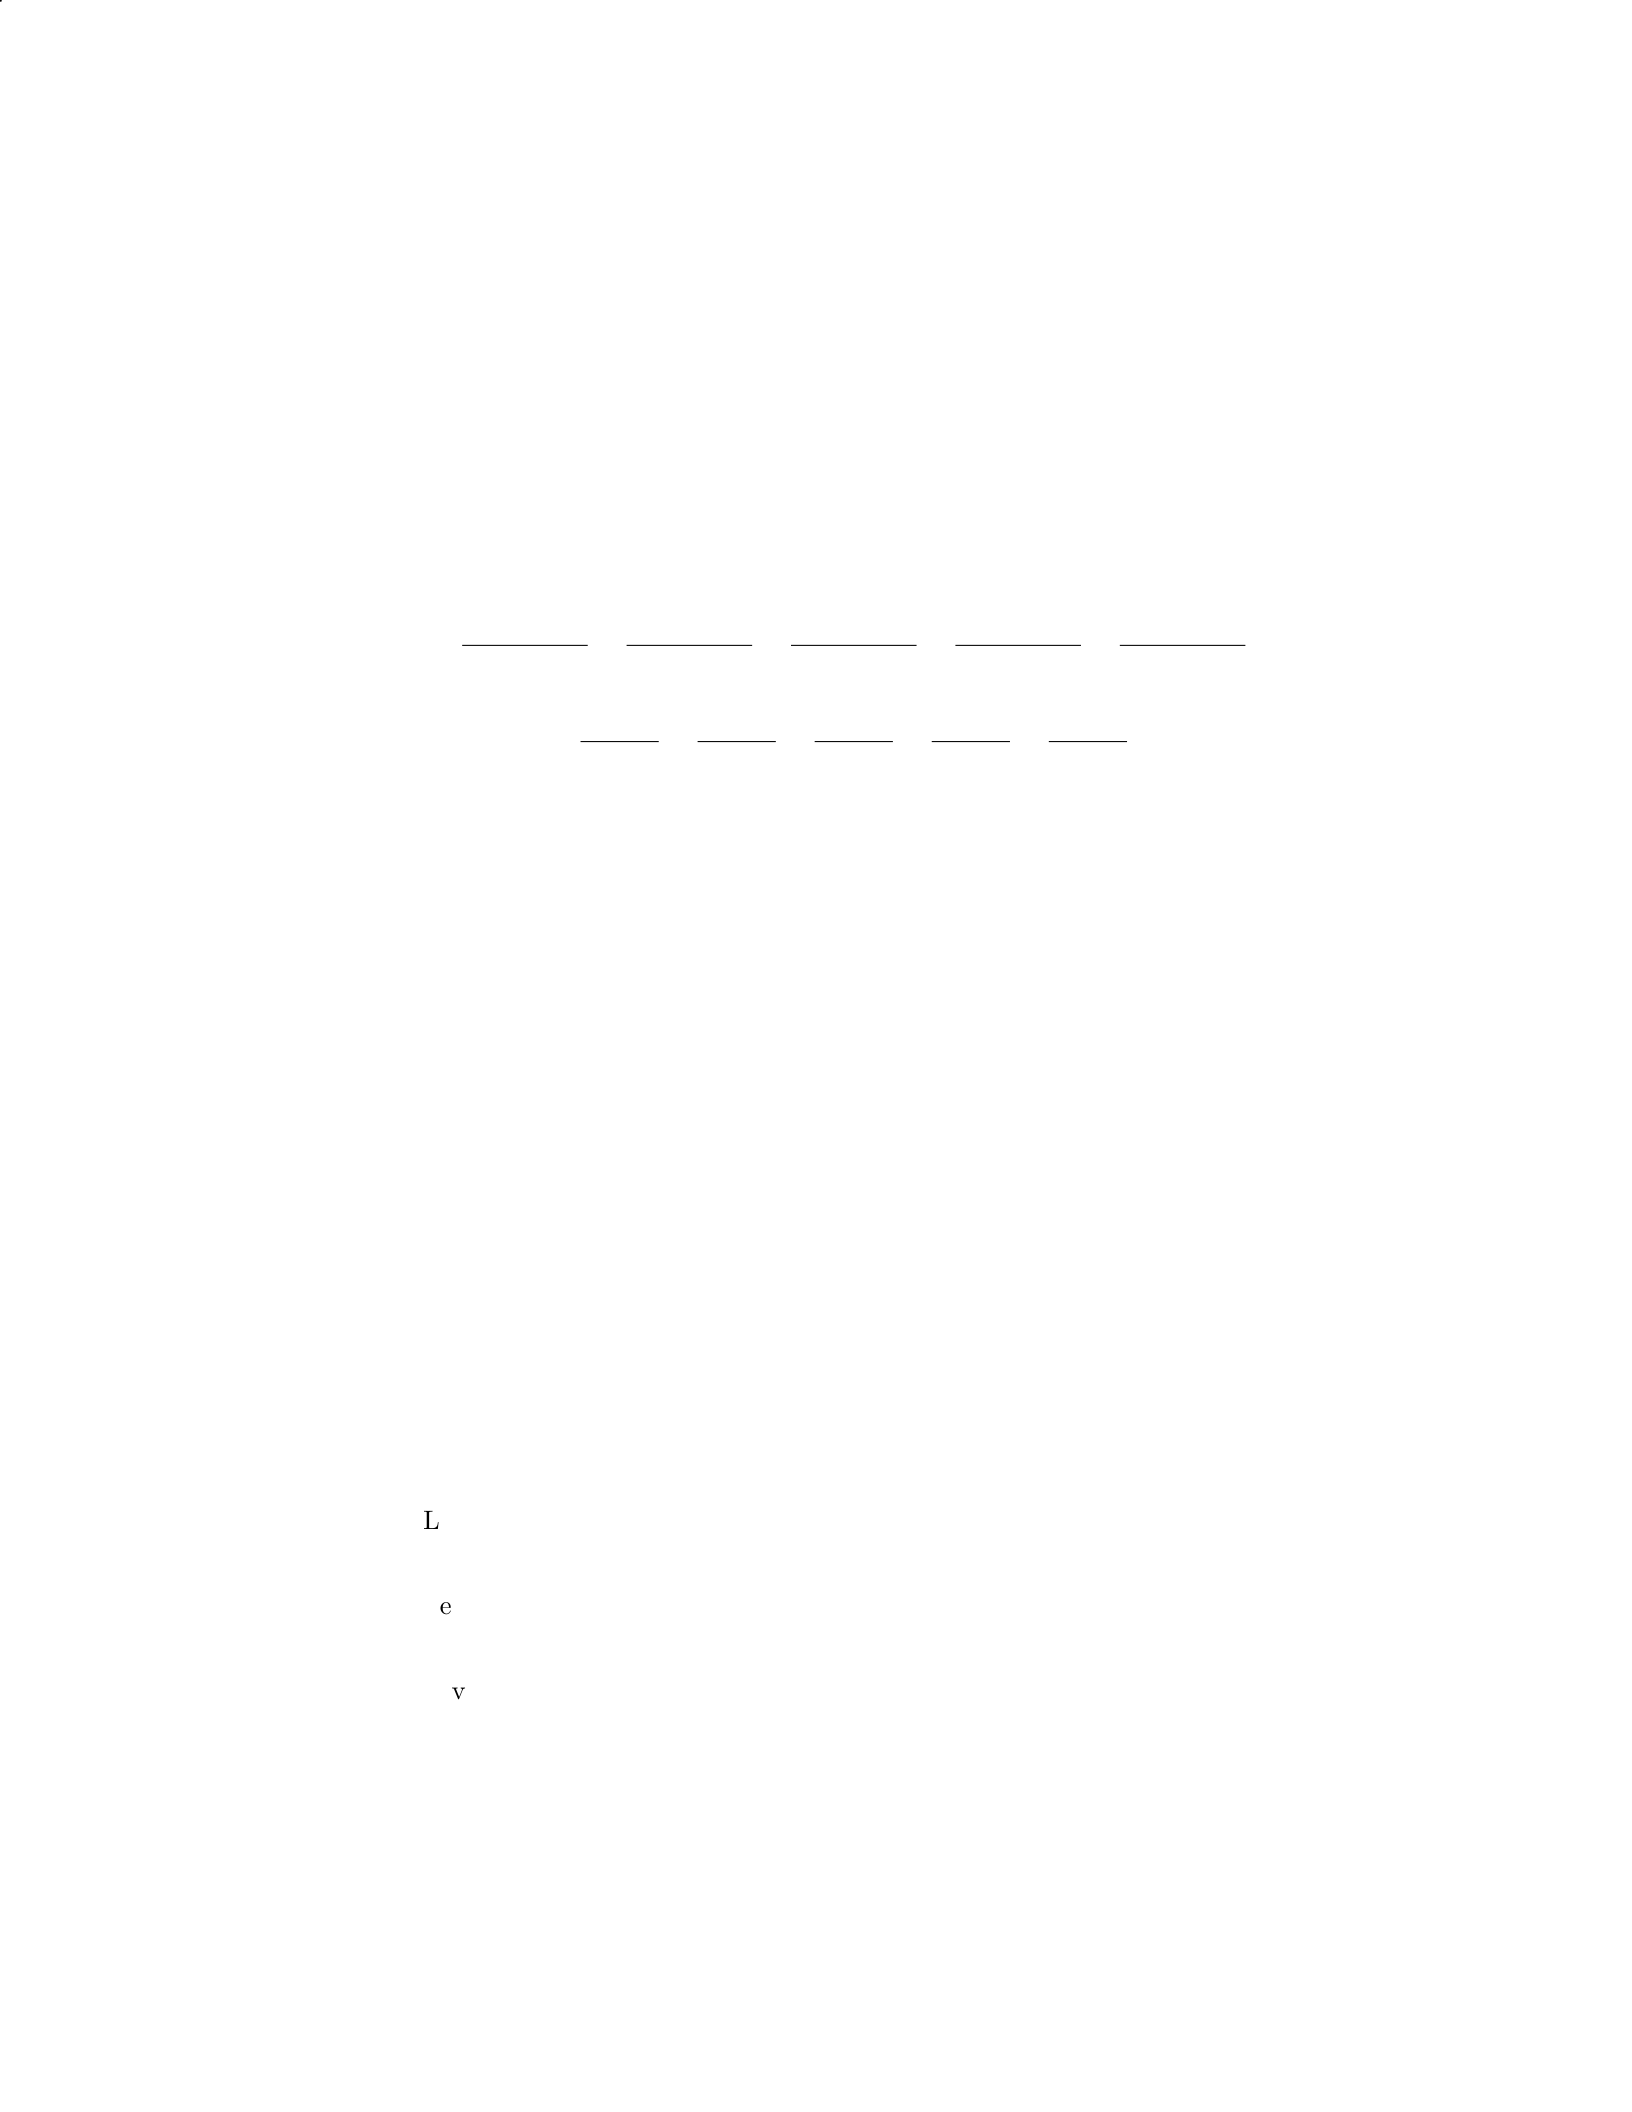
expected future cash flows Company XYZ expects to receive from holding the
investment.
Step 2: Determine the applicable discount rate. Given that Company XYZ
historically uses a WACC of 10
Step 3: Calculate the present value of expected cash flows. Let’s assume
that the expected future cash flows from the investment are as follows: Year 1:
30,000Y ear2 :40,000 Year 3: 50,000Y ear4 :60,000 Year 5: 70,000
Calculating the present value of these cash flows using the WACC of 10
P V =30,000
(1 + 0.10)1+40,000
(1 + 0.10)2+50,000
(1 + 0.10)3+60,000
(1 + 0.10)4+70,000
(1 + 0.10)5
P V =30,000
1.10 +40,000
1.102+50,000
1.103+60,000
1.104+70,000
1.105
P V ≈30,000×0.9091+40,000×0.8264+50,000×0.7513+60,000×0.6830+70,000×0.6209
P V ≈27,273 + 33,056 + 37,565 + 40,980 + 43,463 = 182,337
Therefore, the fair value of the financial instrument based on present value
of expected cash flows is approximately 182,337.
Question 20
Question
A company has an investment in a financial asset classified as a Level 3 fair
value measurement. The fair value of the investment was determined using
unobservable inputs. Explain how the company should disclose information
about the fair value measurement in its financial statements.
Solution
Step 1: The company should disclose the inputs used to determine the fair value
of the investment. These inputs are categorized into three levels:
Level 1 inputs: Observable inputs like quoted prices in active markets for
identical assets.
Level 2 inputs: Inputs other than quoted prices included in Level 1 that
are observable for the asset.
Level 3 inputs: Unobservable inputs based on the company’s own assump-
tions.
15
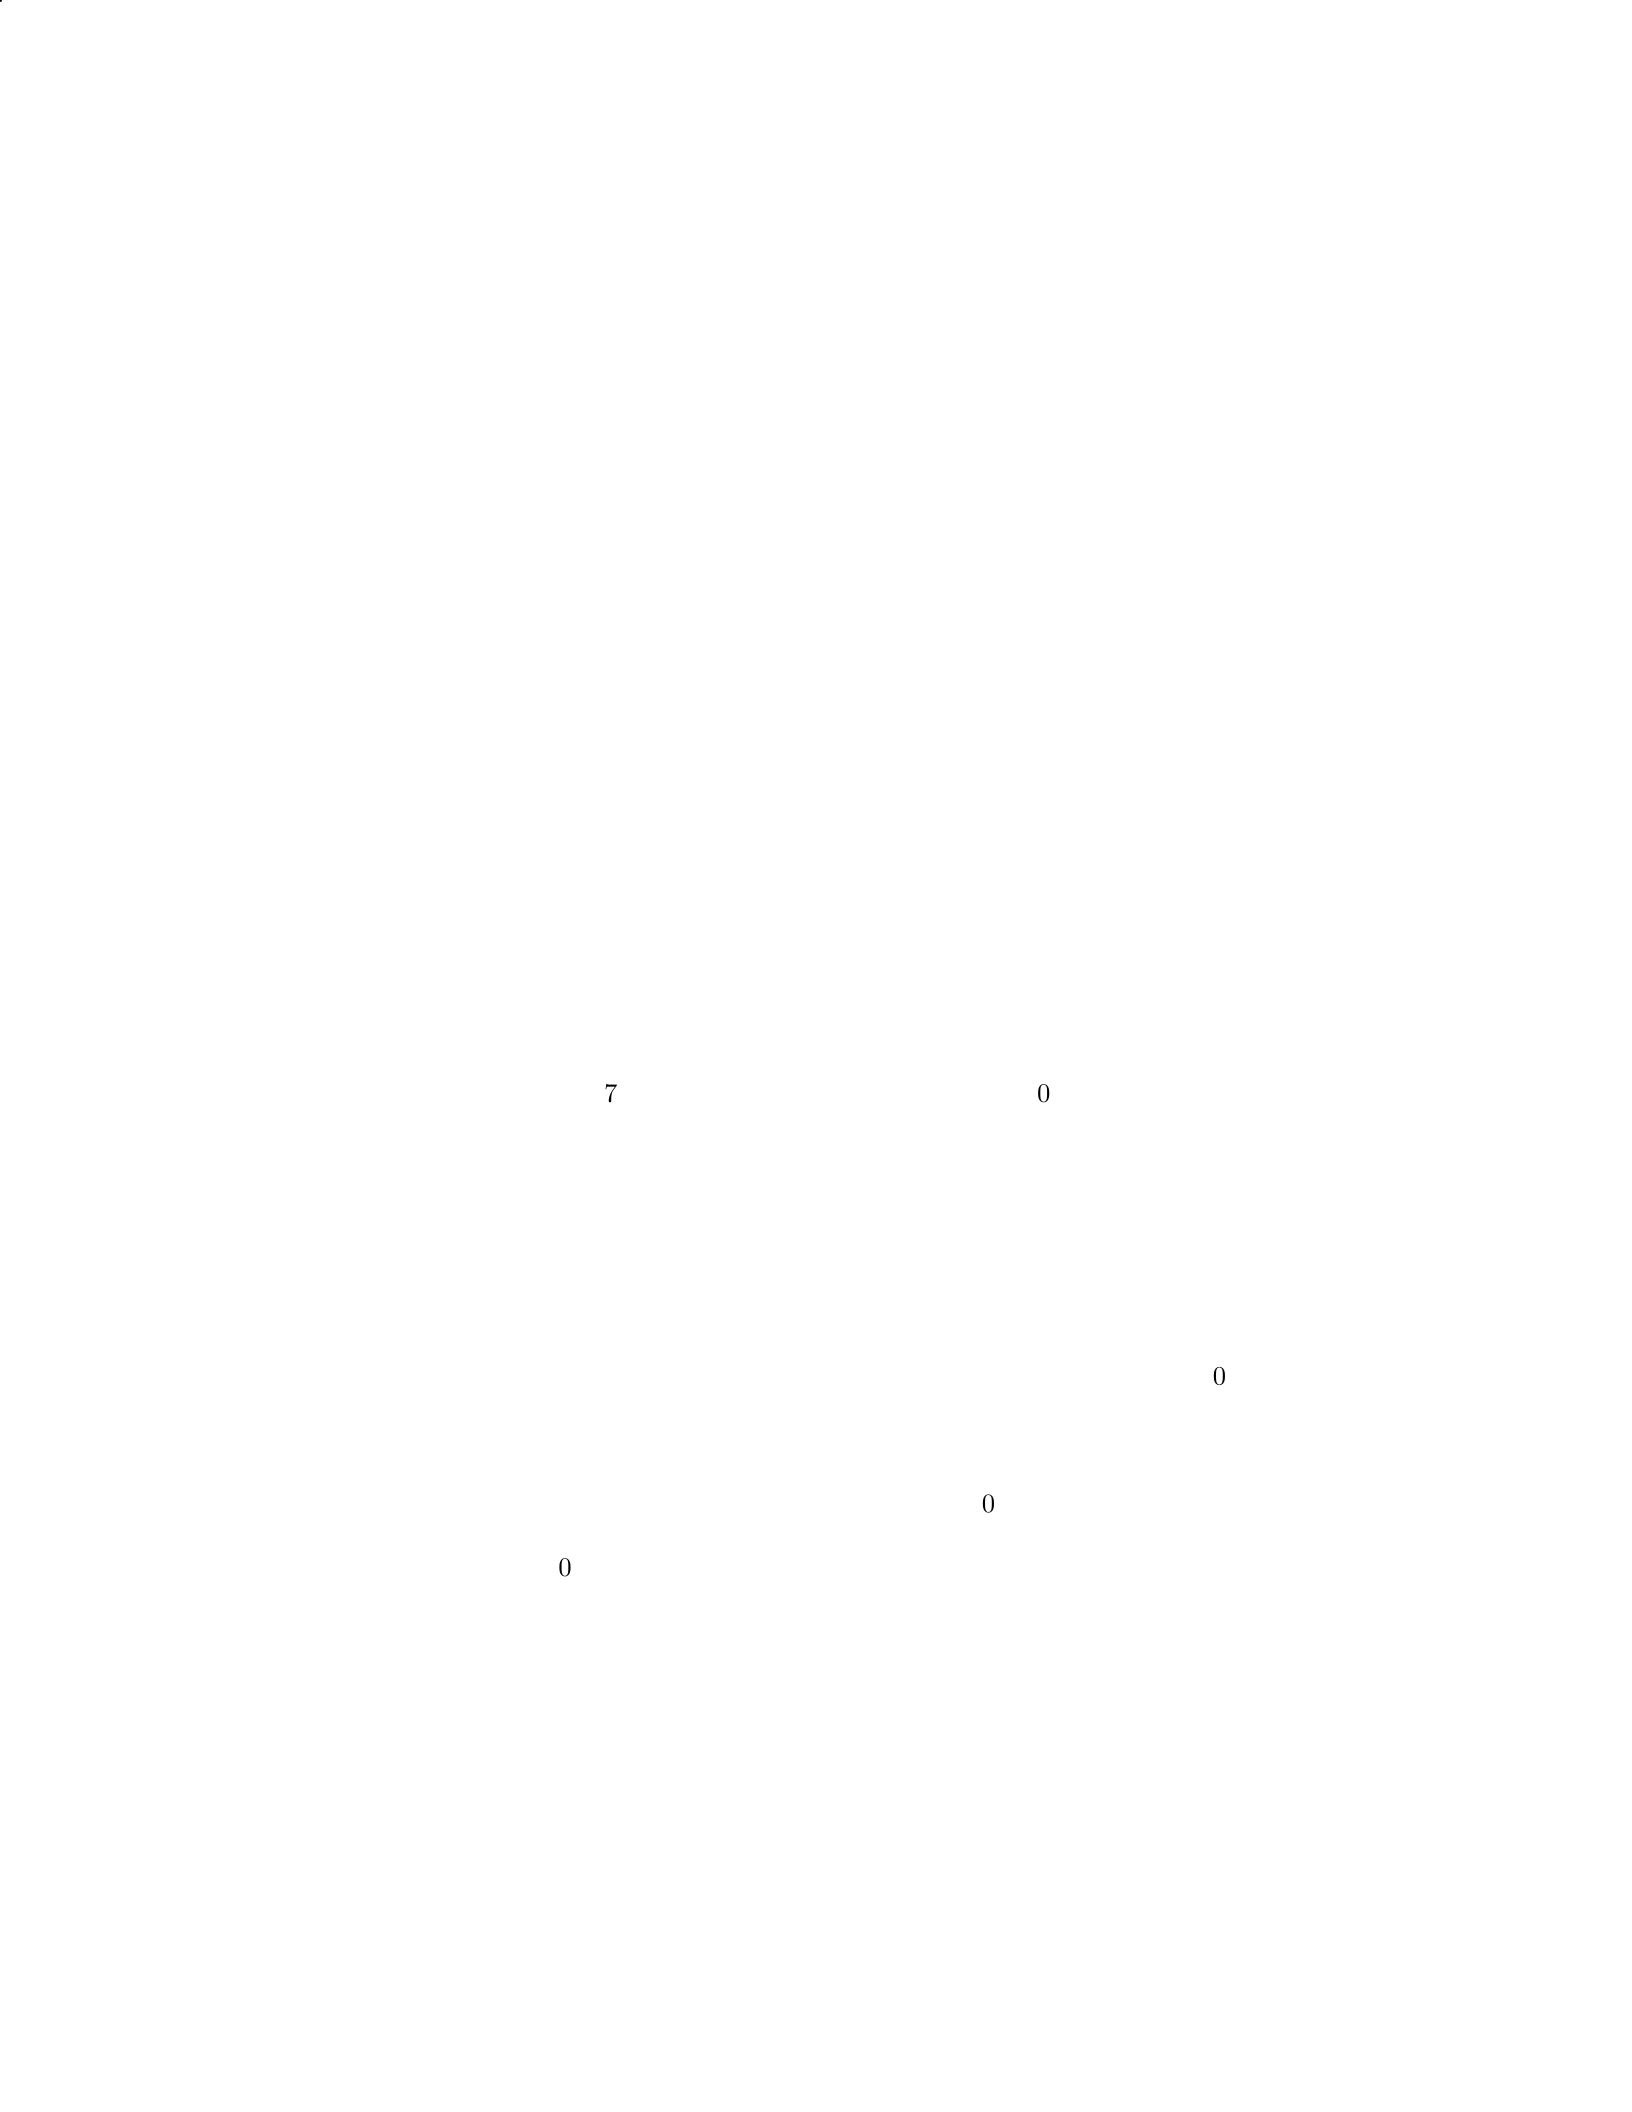
Step 2: The company should disclose the valuation techniques used to deter-
mine the fair value. This may include the use of discounted cash flows, market
multiples, or option pricing models.
Step 3: The company should disclose the quantitative information about the
fair value measurement. This includes the carrying amount of the investment,
the fair value measurement at the reporting date, and any changes in fair value
recognized in the income statement.
Step 4: If there are significant unobservable inputs used in the fair value
measurement, the company should disclose the sensitivity of the fair value to
changes in these inputs.
Step 5: The company should provide a qualitative description of the val-
uation process, including any assumptions made and judgments exercised in
determining the fair value measurement.
Step 6: Finally, the company should disclose any transfers between levels
of the fair value hierarchy and the reasons for such transfers. This information
helps users understand how the fair value measurement has changed over time.
Question 21
Question
A company owns an investment property that is measured at fair value through
profit or loss. The fair value of the investment property at the end of the
reporting period is
$
750,000, and the company incurs
$
10,000 in transaction
costs to sell the property. How should the company account for the transaction
costs in relation to the fair value measurement of the investment property?
Solution
1. Transaction costs should not be deducted from the fair value of the investment
property when measuring it at fair value through profit or loss, according to
IFRS 13 Fair Value Measurement.
2. The fair value of the investment property should be reported at
$
750,000
without deducting the transaction costs.
3. The transaction costs incurred to sell the investment property should be
recognized in profit or loss in the period in which they are incurred.
Therefore, the company should account for the
$
10,000 transaction costs sep-
arately in the profit or loss statement and report the fair value of the investment
property at
$
750,000 without deducting the transaction costs.
16
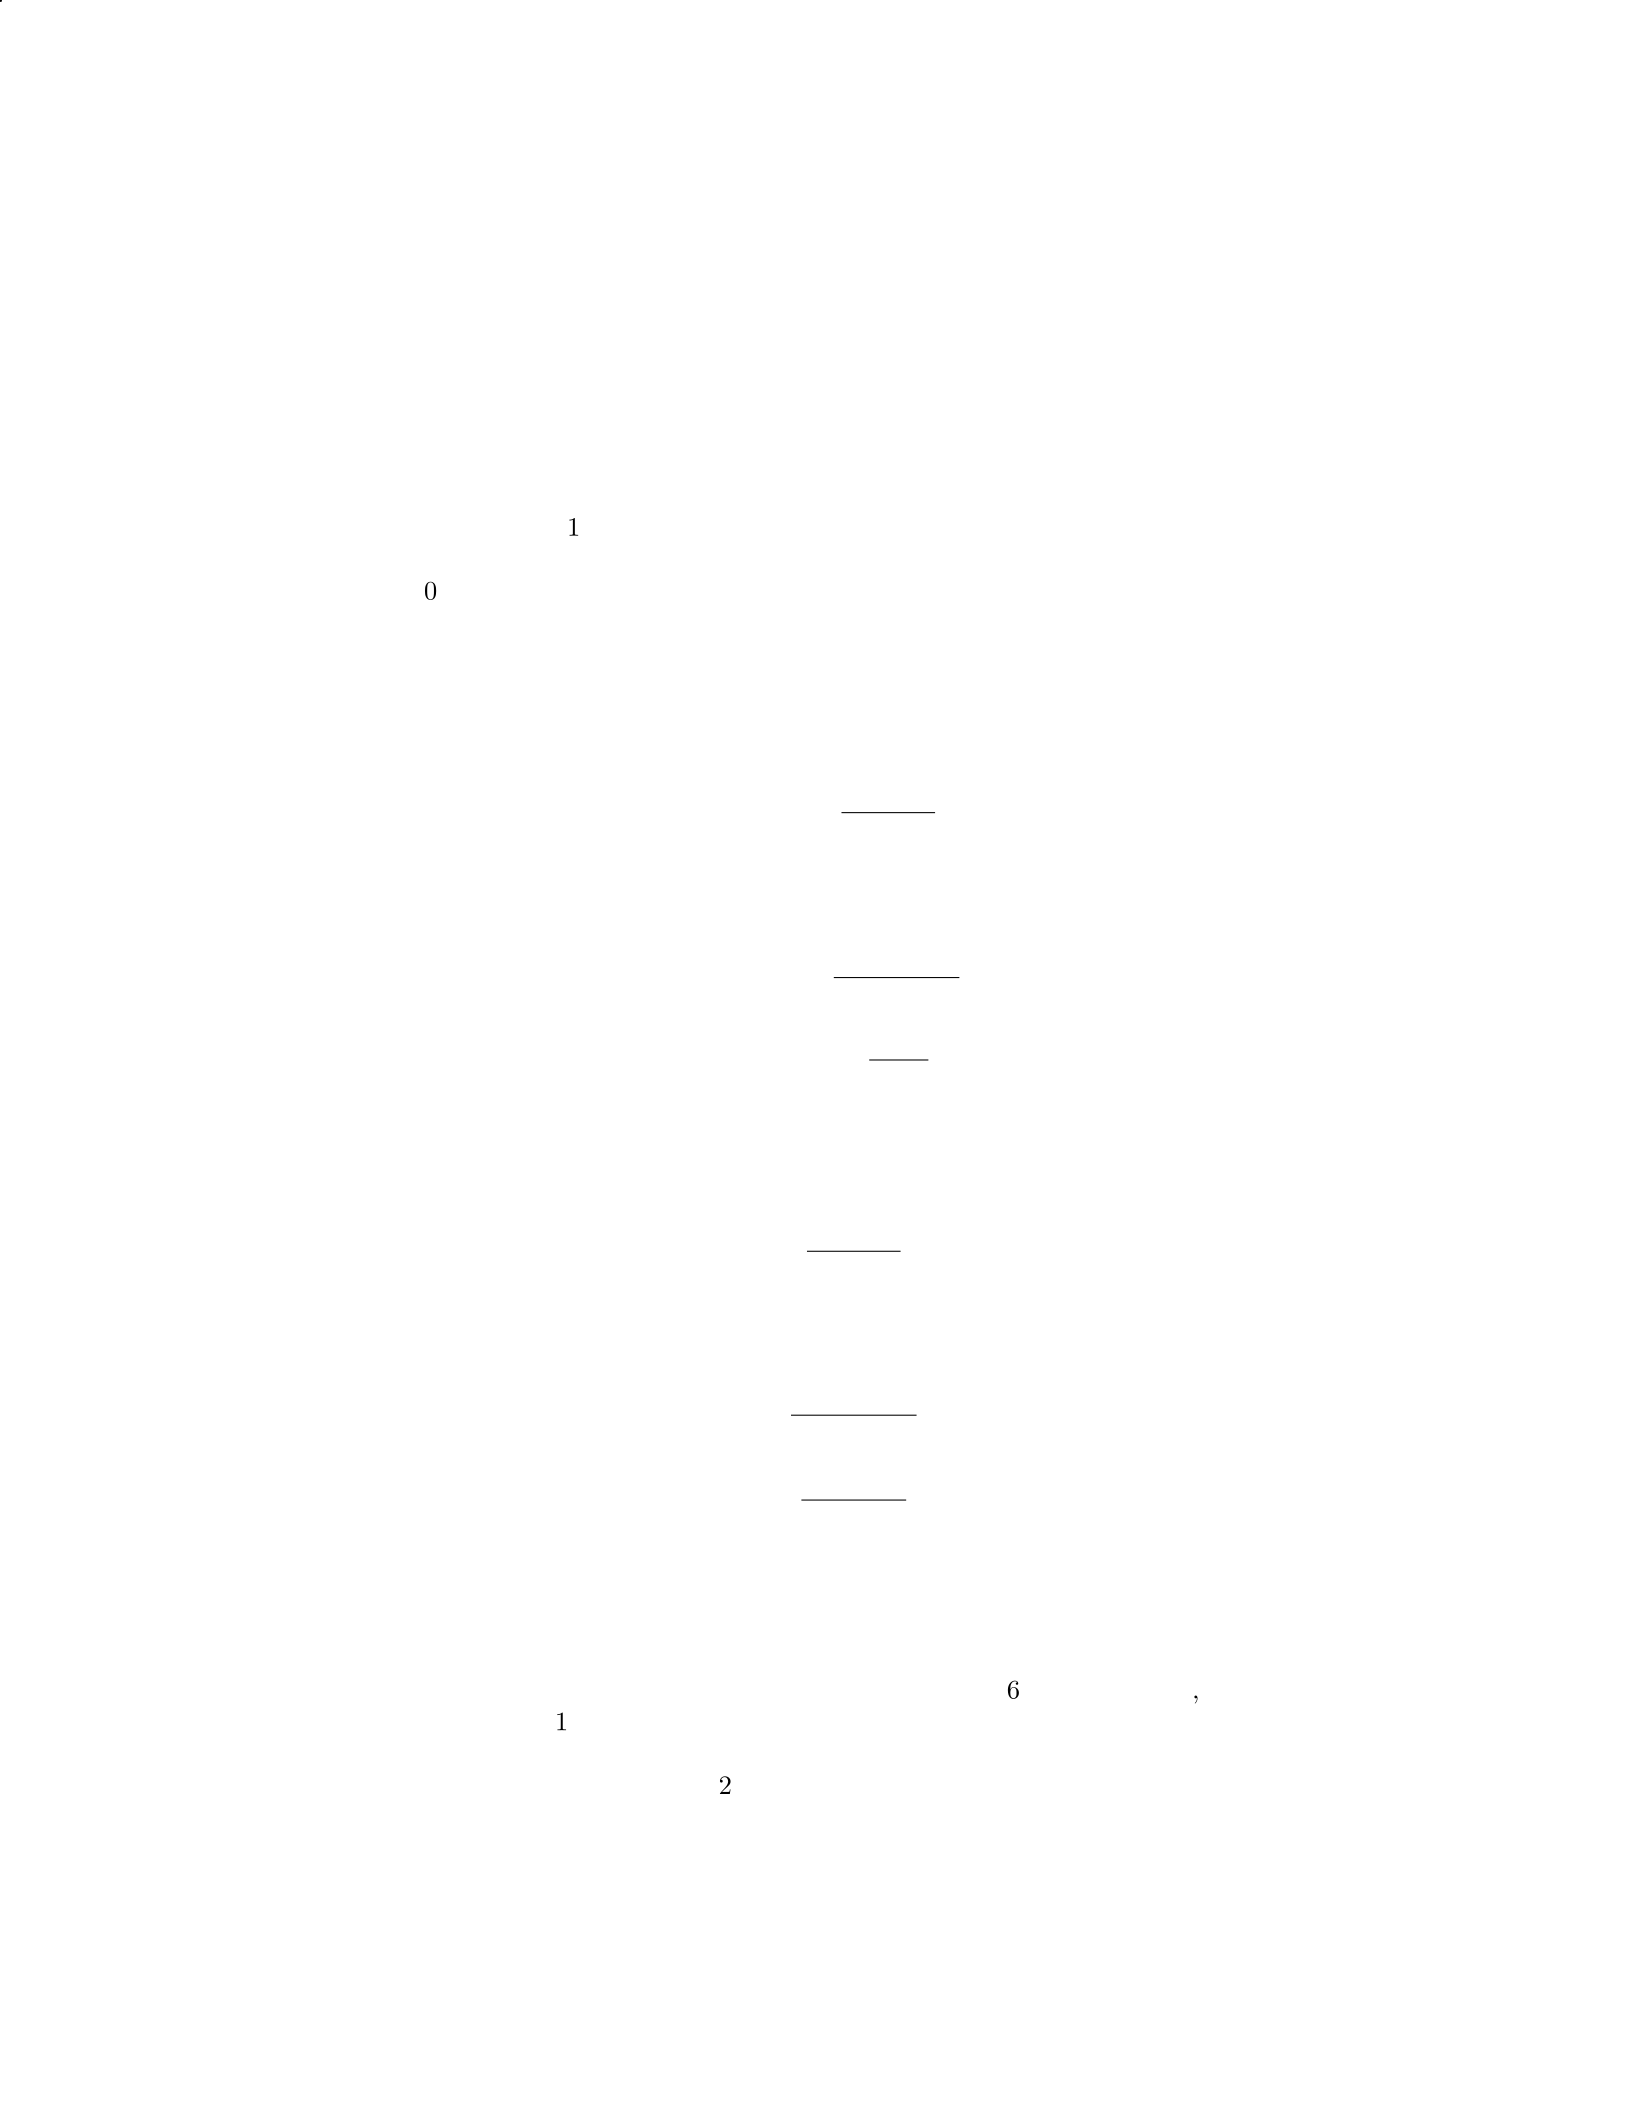
Question 22
Question
A company is required to determine the fair value of an investment property
using the income approach. The property is expected to generate an annual
rental income of
$
100,000 for the next 5 years. The entity uses a discount rate
of 8% for such investments. If the property is expected to be sold after 5 years
for
$
500,000, what is the fair value of the investment property?
Solution
Step 1: Calculate the present value of the expected rental income. The present
value of an annuity formula is given by:
P V =P mt ×1−1
(1 + r)n∇ · r
where: P mt = $100,000, r= 0.08, n= 5 years
Plugging in the values:
P V = $100,000 ×1−1
(1 + 0.08)5∇ · 0.08
P V = $100,000 ×(1 −1
1.085)∇ · 0.08
P V $376,957.38
Step 2: Calculate the present value of the expected selling price after 5 years.
The present value of a single cash flow formula is given by:
P V =F V
(1 + r)n
where: F V = $500,000, r= 0.08, n= 5 years
Plugging in the values:
P V =$500,000
(1 + 0.08)5
P V =$500,000
1.085
P V $303,170.43
Step 3: Calculate the fair value of the investment property. The fair value of
the investment property is the sum of the present values of the expected rental
income and the expected selling price: Fair Value = Present Value of Rental
Income + Present Value of Selling Price Fair Value
$
376,957.38 +
$
303,170.43
Fair Value
$
680,127.81
Therefore, the fair value of the investment property using the income ap-
proach is approximately
$
680,127.81.
17
Question 23
Question
A company holds an investment in a financial asset classified as fair value
through other comprehensive income. At the end of the current reporting pe-
riod, the fair value of the investment is 150,000.Duringtheyear, thefairvalueof theinvestmentincreasedby20,000
due to changes in market conditions. Additionally, the company received divi-
dends of 5,000fromtheinvestmentduringtheyear.Calculatethetotalcomprehensiveincomerelatedtothisinvestmentf orthecurrentreportingperiod.
Solution
Let’s break down the total comprehensive income related to the investment into
its components.
Step 1: Calculate the gain or loss recognized in other comprehen-
sive income
The fair value of the investment at the beginning of the year was 150,000−20,000
= 130,000.T herefore, thegainrecognizedinothercomprehensiveincomeduetochangesinf airvalueis150,000
- 130,000 =20,000.
Step 2: Calculate the dividends recognized in other comprehensive
income
The dividends received during the year were 5,000.Dividendsreceivedareincludedinothercomprehensiveincomef orinvestmentsaccountedf oratfairvaluethroughothercomprehensiveincome.
Step 3: Calculate the total comprehensive income related to the
investment
Total comprehensive income = Gain or loss recognized in other compre-
hensive income + Dividends recognized in other comprehensive income
Total comprehensive income = 20,000+5,000 = 25,000.
Therefore, the total comprehensive income related to this investment for the
current reporting period is 25,000.
Question 24
Question
A company holds an investment classified as available-for-sale financial asset.
The fair value of this investment at the end of the reporting period is 200,000.T hecompany′smanagementisconsideringreclassif yingthisinvestmentasheldf ortradingtotakeadvantageofshort−
termpricemovements.If thef airvalueisexpectedtoincreaseto220,000 in the near
future, what impact would this decision have on the company’s financial state-
ments? Justify your answer with reference to Fair Value Measurement.
18

Solution
To answer this question, we need to consider the implications of reclassifying
the investment from available-for-sale to held for trading in terms of Fair Value
Measurement.
Step 1: When an investment is reclassified from available-for-sale to held
for trading, any unrealized gains or losses in the available-for-sale reserve must
be recognized in the income statement immediately.
Step 2: In this case, since the fair value of the investment is expected to in-
crease to 220,000inthenearfuture, thereisanunrealizedgainof 20,000 (220,000−200,000).
Step 3: If the company reclassifies the investment as held for trading, this
20,000unrealizedgainwillbeimmediatelyrecognizedintheincomestatementundergainsoninvestments.
Step 4: The reclassification will not affect the balance sheet directly, as the
asset will still be presented at fair value on the balance sheet.
Step 5: However, the income statement will show an increase in net income
due to the recognition of the 20,000gain.
Step 6: Overall, the reclassification of the investment from available-for-sale
to held for trading will result in a positive impact on the company’s financial
statements by increasing its reported net income for the period.
Question 25
Question
A company holds an investment in a financial instrument categorized as a Level
3 fair value measurement. At the end of the reporting period, the fair value of the
investment is 250,000.T hecompany′smanagementneedstodetermineiftherehavebeenanychangesinthefairvalueof theinvestmentcomparedtothebeginningof thereportingperiod.P rovideastep−
by−stepguideonhowthecompanycananalyzeandreportthechangesinthef airvalueoftheinvestment.
Solution
To analyze and report the changes in the fair value of the investment categorized
as a Level 3 fair value measurement, the company can follow these steps:
Step 1: Review the Valuation Techniques - The company should review
the valuation techniques used to determine the fair value of the investment at
the beginning of the reporting period. This may include market approaches,
income approaches, and cost approaches.
Step 2: Assess Changes in Inputs - Management should assess if there
have been any changes in the inputs used in the valuation techniques. Inputs
may include market data, interest rates, credit spreads, etc. Changes in these
inputs can significantly impact the fair value of the investment.
Step 3: Determine Fair Value Changes - Calculate the change in fair
value by comparing the fair value of the investment at the end of the reporting
period (250,000)tothefairvalueatthebeginningof thereportingperiod.T hiswillgivethecompanytheabsolutechangeinf airvalue.
19
Step 4: Analyze the Reason for Changes - Management should analyze
the reasons for the changes in fair value. This could include changes in market
conditions, economic factors, or specific events related to the investment.
Step 5: Disclose in Financial Statements - Finally, the company should
disclose the changes in fair value of the investment in the financial statements.
This disclosure should include the amount of change, the nature of the invest-
ment, and the reasons for the changes.
By following these steps, the company can properly analyze and report any
changes in the fair value of the investment categorized as a Level 3 fair value
measurement.
Question 26
Question
Calculate the fair value of an investment using the market approach. You are
provided the following information:
Comparable assets: 3 similar investments with market values of
$
1,200,
$
1,400, and
$
1,100.
Subject investment: Similar risk profile as the comparable assets but has
generated a higher return of 8%.
Solution
To calculate the fair value of the subject investment using the market approach,
we will need to adjust the market values of the comparable assets based on the
difference in return.
Step 1: Calculate the average rate of return for the comparable
assets
Given market values:
M1= 1200, M2= 1400, M3= 1100
The average rate of return (ravg ) of the comparable assets can be calcu-
lated as:
ravg =M2−M1
M1
+M3−M1
M1
ravg =1400 −1200
1200 +1100 −1200
1200 =200
1200 −100
1200 =100
1200 = 0.0833
Step 2: Adjust the comparable asset values for the subject invest-
ment
Given return on the subject investment: 8%
20
Adjusted value for subject investment can be calculated as:
F Vsubject =1+0.08
1 + ravg
×M1
F Vsubject =1.08
1.0833 ×1200 ≈1193.50
Therefore, the fair value of the subject investment using the market approach
is approximately
$
1193.50.
Question 27
Question
Company XYZ is assessing the fair value of an investment property using
the income approach. The property is expected to generate rental income of
120,000peryearf orthenext10years.T hediscountrateis8
Solution
Step 1: Calculate the present value factor using the formula: P V F =1−(1+r)−n
r,
where ris the discount rate and nis the number of years.
Using r= 0.08 and n= 10,
P V F =1−(1 + 0.08)−10
0.08
P V F =1−0.4632
0.08
P V F ≈0.5368
0.08
P V F ≈6.710
Step 2: Calculate the present value of the rental income using the formula:
P V =Rental Income ×P V F .
Using Rental Income = $120,000 and P V F = 6.710,
P V = $120,000 ×6.710
P V = $803,200
Therefore, the fair value of the investment property using the income ap-
proach is
$
803,200.
21

Question 28
Question
A company holds an investment in a private equity fund. The company classifies
the investment as a Level 3 fair value measurement. At the end of the reporting
period, the fair value of the investment has significantly increased due to posi-
tive financial performance of the investee companies. How should the company
account for this increase in fair value in their financial statements according to
fair value measurement standards?
Solution
Step 1: Under fair value measurement standards, changes in fair value for Level
3 investments are recognized in the income statement. The increase in fair value
of the investment should be recognized as a gain in the income statement. This
gain is reported as part of the company’s net income for the period.
Step 2: The gain recognized in the income statement is also disclosed in the
notes to the financial statements to provide users with additional information
about the nature and impact of fair value changes on the company’s financial
performance.
Step 3: It is important for the company to carefully document and disclose
the inputs and valuation techniques used in determining the fair value of the
investment to ensure transparency and comparability for financial statement
users.
Therefore, the company should recognize the increase in fair value of the
investment as a gain in the income statement and disclose relevant information
in the notes to the financial statements.
Question 29
Question
A company holds an investment in a privately held startup company. The
company values the investment using the fair value measurement model. The
fair value measurements are categorized as Level 3 inputs. What are Level 3
inputs and how are they used in the fair value measurement model?
Solution
Step 1: Level 3 inputs refer to inputs that are unobservable for the asset or
liability being valued. These inputs are used when there is little or no market
activity for the asset or liability, requiring the entity to use its own assumptions
about the inputs that market participants would use when pricing the asset or
liability. Level 3 inputs are typically based on management’s own estimates and
valuations.
22

Step 2: In the fair value measurement model, Level 3 inputs are used to
determine the fair value of assets or liabilities when Level 1 and Level 2 inputs
are not available. This often occurs when the assets or liabilities being valued
are not traded in active markets.
Step 3: When using Level 3 inputs, entities must make significant judgments
and utilize estimation techniques to determine the fair value of the asset or
liability. This may involve developing cash flow projections, utilizing option
pricing models, or other valuation techniques to estimate the fair value.
Step 4: The use of Level 3 inputs introduces measurement uncertainty and
subjectivity into the fair value measurement process. As a result, it is important
for entities to disclose the inputs, assumptions, and methodologies used when
valuing assets or liabilities with Level 3 inputs to provide users of the financial
statements with transparency about the valuation process.
Question 30
Question
Company XYZ has an investment in a financial instrument classified as held for
trading. At the end of the reporting period, the fair value of the financial instru-
ment is 250,000.However, therearecertainobservablef actorsthatsuggestthef airvaluemaynotbereliable.DiscussthestepsCompanyXY Zshouldtake, inaccordancewithIF RS13F airV alueMeasurement, todeterminethef airvalueof thefinancialinstrument.
Solution
To determine the fair value of the financial instrument in question when the fair
value may not be reliable, Company XYZ should follow specific steps outlined
in IFRS 13 Fair Value Measurement. The steps are as follows:
Step 1: Identify the Asset or Liability Identify the specific financial
instrument for which the fair value is to be determined. In this case, it is the
financial instrument classified as held for trading in Company XYZ.
Step 2: Determine the Appropriate Valuation Technique Select the
appropriate valuation technique that is suitable given the nature of the financial
instrument, the characteristics of the market, and other relevant factors. For
example, Company XYZ could consider using a discounted cash flow (DCF)
model to determine the fair value of the financial instrument.
Step 3: Collect Relevant Data Gather all relevant data related to the
financial instrument, the market, and other factors that may affect its fair value.
This includes observable market inputs such as interest rates, credit spreads, and
market prices.
Step 4: Assess the Data Quality Evaluate the quality of the data col-
lected to ensure it is reliable and relevant for the valuation. If there are observ-
able factors that suggest the fair value may not be reliable, consider adjusting
the data or applying additional techniques to verify the fair value.
Step 5: Perform the Valuation Apply the selected valuation technique
using the collected data to determine the fair value of the financial instrument.
23
This may involve making adjustments or using alternative methods to ensure a
reliable estimate of fair value.
Step 6: Review and Disclose Review the valuation process and results
to ensure they are consistent with the requirements of IFRS 13. Disclose the
key assumptions, uncertainties, and other relevant information in the financial
statements to provide transparency to users.
By following these steps, Company XYZ can determine the fair value of
the financial instrument in a manner that is consistent with the principles of
IFRS 13 Fair Value Measurement, even when the fair value may not be readily
observable or reliable.
Question 31
Question
Company X holds an investment in a private equity fund. At the reporting date,
the fair value of the investment is determined to be $1,200,000. During the year,
the fair value of the investment increased by $150,000. However, Company X
noted that the private equity fund has experienced financial difficulties after
the reporting date. As a result, the fair value of the investment is expected to
decrease by $100,000 before the financial statements are authorized for issuance.
Calculate the fair value adjustment that Company X should recognize in its
financial statements.
Solution
Step 1: Calculate the initial increase in fair value. The initial increase in fair
value is $150,000.
Step 2: Calculate the expected decrease in fair value. The expected decrease
in fair value is $100,000.
Step 3: Calculate the net fair value adjustment. The net fair value adjust-
ment is the initial increase minus the expected decrease:
$150,000 −$100,000 = $50,000
Therefore, Company X should recognize a fair value adjustment of $50,000
in its financial statements.
Question 32
Question
A company holds an investment in financial asset A which is classified as a
level 3 investment under fair value hierarchy. The fair value of financial asset
A increased by
$
20,000 during the financial period. In the balance sheet, how
should this increase in fair value be accounted for?
24
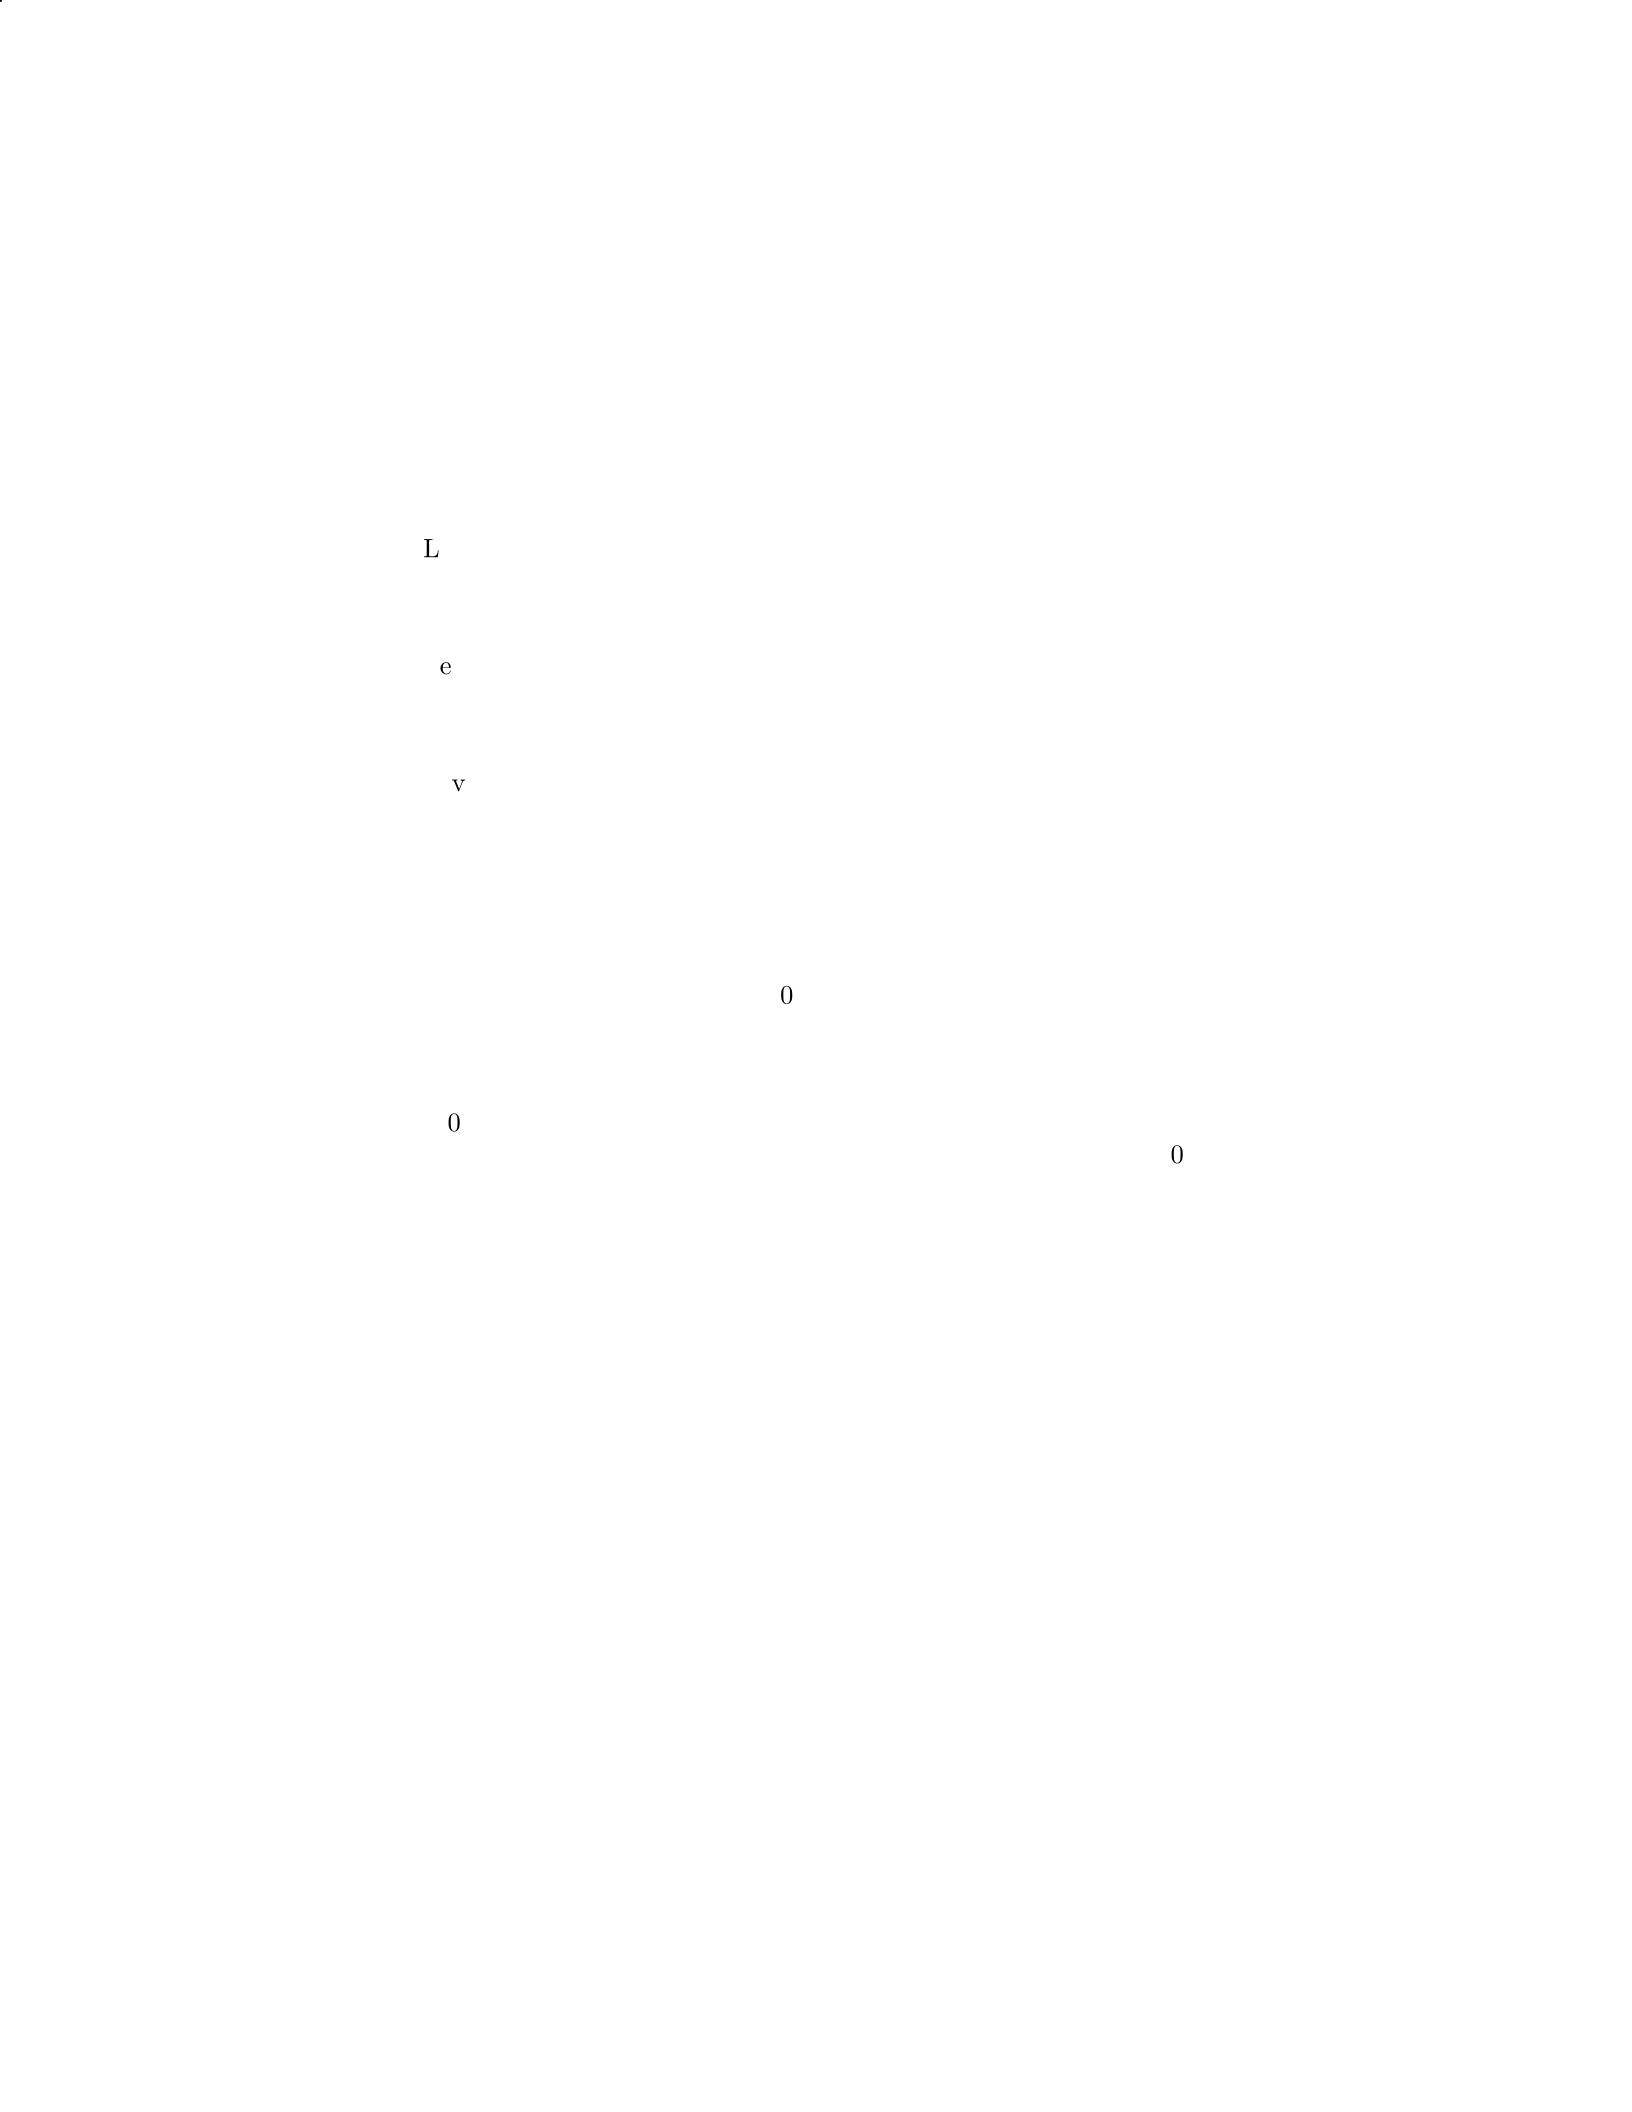
Solution
To account for the increase in fair value of financial asset A, we need to under-
stand the fair value hierarchy and how changes in fair value are recognized in
the financial statements.
Step 1: Understand Fair Value Hierarchy
Level 1 assets: These are financial assets that have quoted prices in ac-
tive markets, such as listed stocks or bonds. Their fair value is easily
determined.
Level 2 assets: These are financial assets that do not have quoted prices
in active markets, but their fair value can be determined using observable
market inputs, such as similar assets or benchmark prices.
Level 3 assets: These are financial assets that do not have readily de-
terminable fair values and require more subjective estimation. They are
valued using unobservable inputs.
Given that financial asset A is classified as a level 3 investment, any changes
in fair value will lead to adjustments in the financial statements.
Step 2: Accounting for the Increase in Fair Value When the fair value
of financial asset A increased by
$
20,000, the company needs to account for this
change in the financial statements.
For level 3 investments, changes in fair value are recognized in the income
statement as unrealized gains or losses. In this case, the increase in fair value
of
$
20,000 will be recognized as an unrealized gain in the income statement.
Therefore, the increase in fair value of financial asset A of
$
20,000 will be
accounted for as follows:
Income Statement:
Unrealized Gain on Financial Asset A $20,000
This adjustment reflects the increase in fair value of financial asset A during
the financial period and is reported in the income statement.
Question 33
Question
Company XYZ holds an investment in a private equity fund. The fair value of
this investment is determined using Level 3 inputs. Explain what Level 3 inputs
are and discuss the challenges associated with using Level 3 inputs for fair value
measurements.
25

Solution
Step 1: Level 3 inputs
Level 3 inputs are unobservable inputs for an asset or liability that are used
when determining its fair value. These inputs are based on the best informa-
tion available in the circumstances, which may include the reporting entity’s
assumptions about the assumptions market participants would use in pricing
the asset or liability.
Step 2: Challenges associated with Level 3 inputs
1. Subjectivity: Level 3 inputs are the most subjective of the three levels
of fair value measurement inputs. They require significant judgment and esti-
mation by the reporting entity. As a result, different entities may use different
assumptions leading to different fair value measurements.
2. Lack of market data: Since Level 3 inputs are unobservable, there is
often a lack of market data available to corroborate the fair value estimates.
This lack of market data can make it difficult to assess the reliability of the fair
value measurements based on Level 3 inputs.
3. Sensitivity to assumptions: Fair value measurements using Level
3 inputs can be sensitive to changes in assumptions. Small changes in key
assumptions can result in significant changes in the fair value of the asset or
liability, leading to potential volatility in financial statements.
4. Regulatory scrutiny: Given the subjectivity involved in using Level
3 inputs, fair value measurements based on these inputs are often subject to
increased regulatory scrutiny. Regulators may challenge the reporting entity’s
fair value measurements and assumptions, leading to potential adjustments or
restatements.
In conclusion, while Level 3 inputs are necessary for valuing certain assets
and liabilities, they come with challenges such as subjectivity, lack of market
data, sensitivity to assumptions, and regulatory scrutiny. It is important for
reporting entities to exercise caution and transparency when using Level 3 inputs
for fair value measurements.
Question 34
Question
Company XYZ holds a financial asset that is measured at fair value through
profit or loss. The fair value of the asset at the end of the reporting period is de-
termined to be 600,000.Duringtheyear, theassetgeneratedcashflowsof 50,000.
Additionally, the market risk premium of similar assets was estimated to be 6
Solution
Step 1: Calculate the discount rate using the formula:
Discount Rate = Risk-Free Rate + Market Risk Premium
26
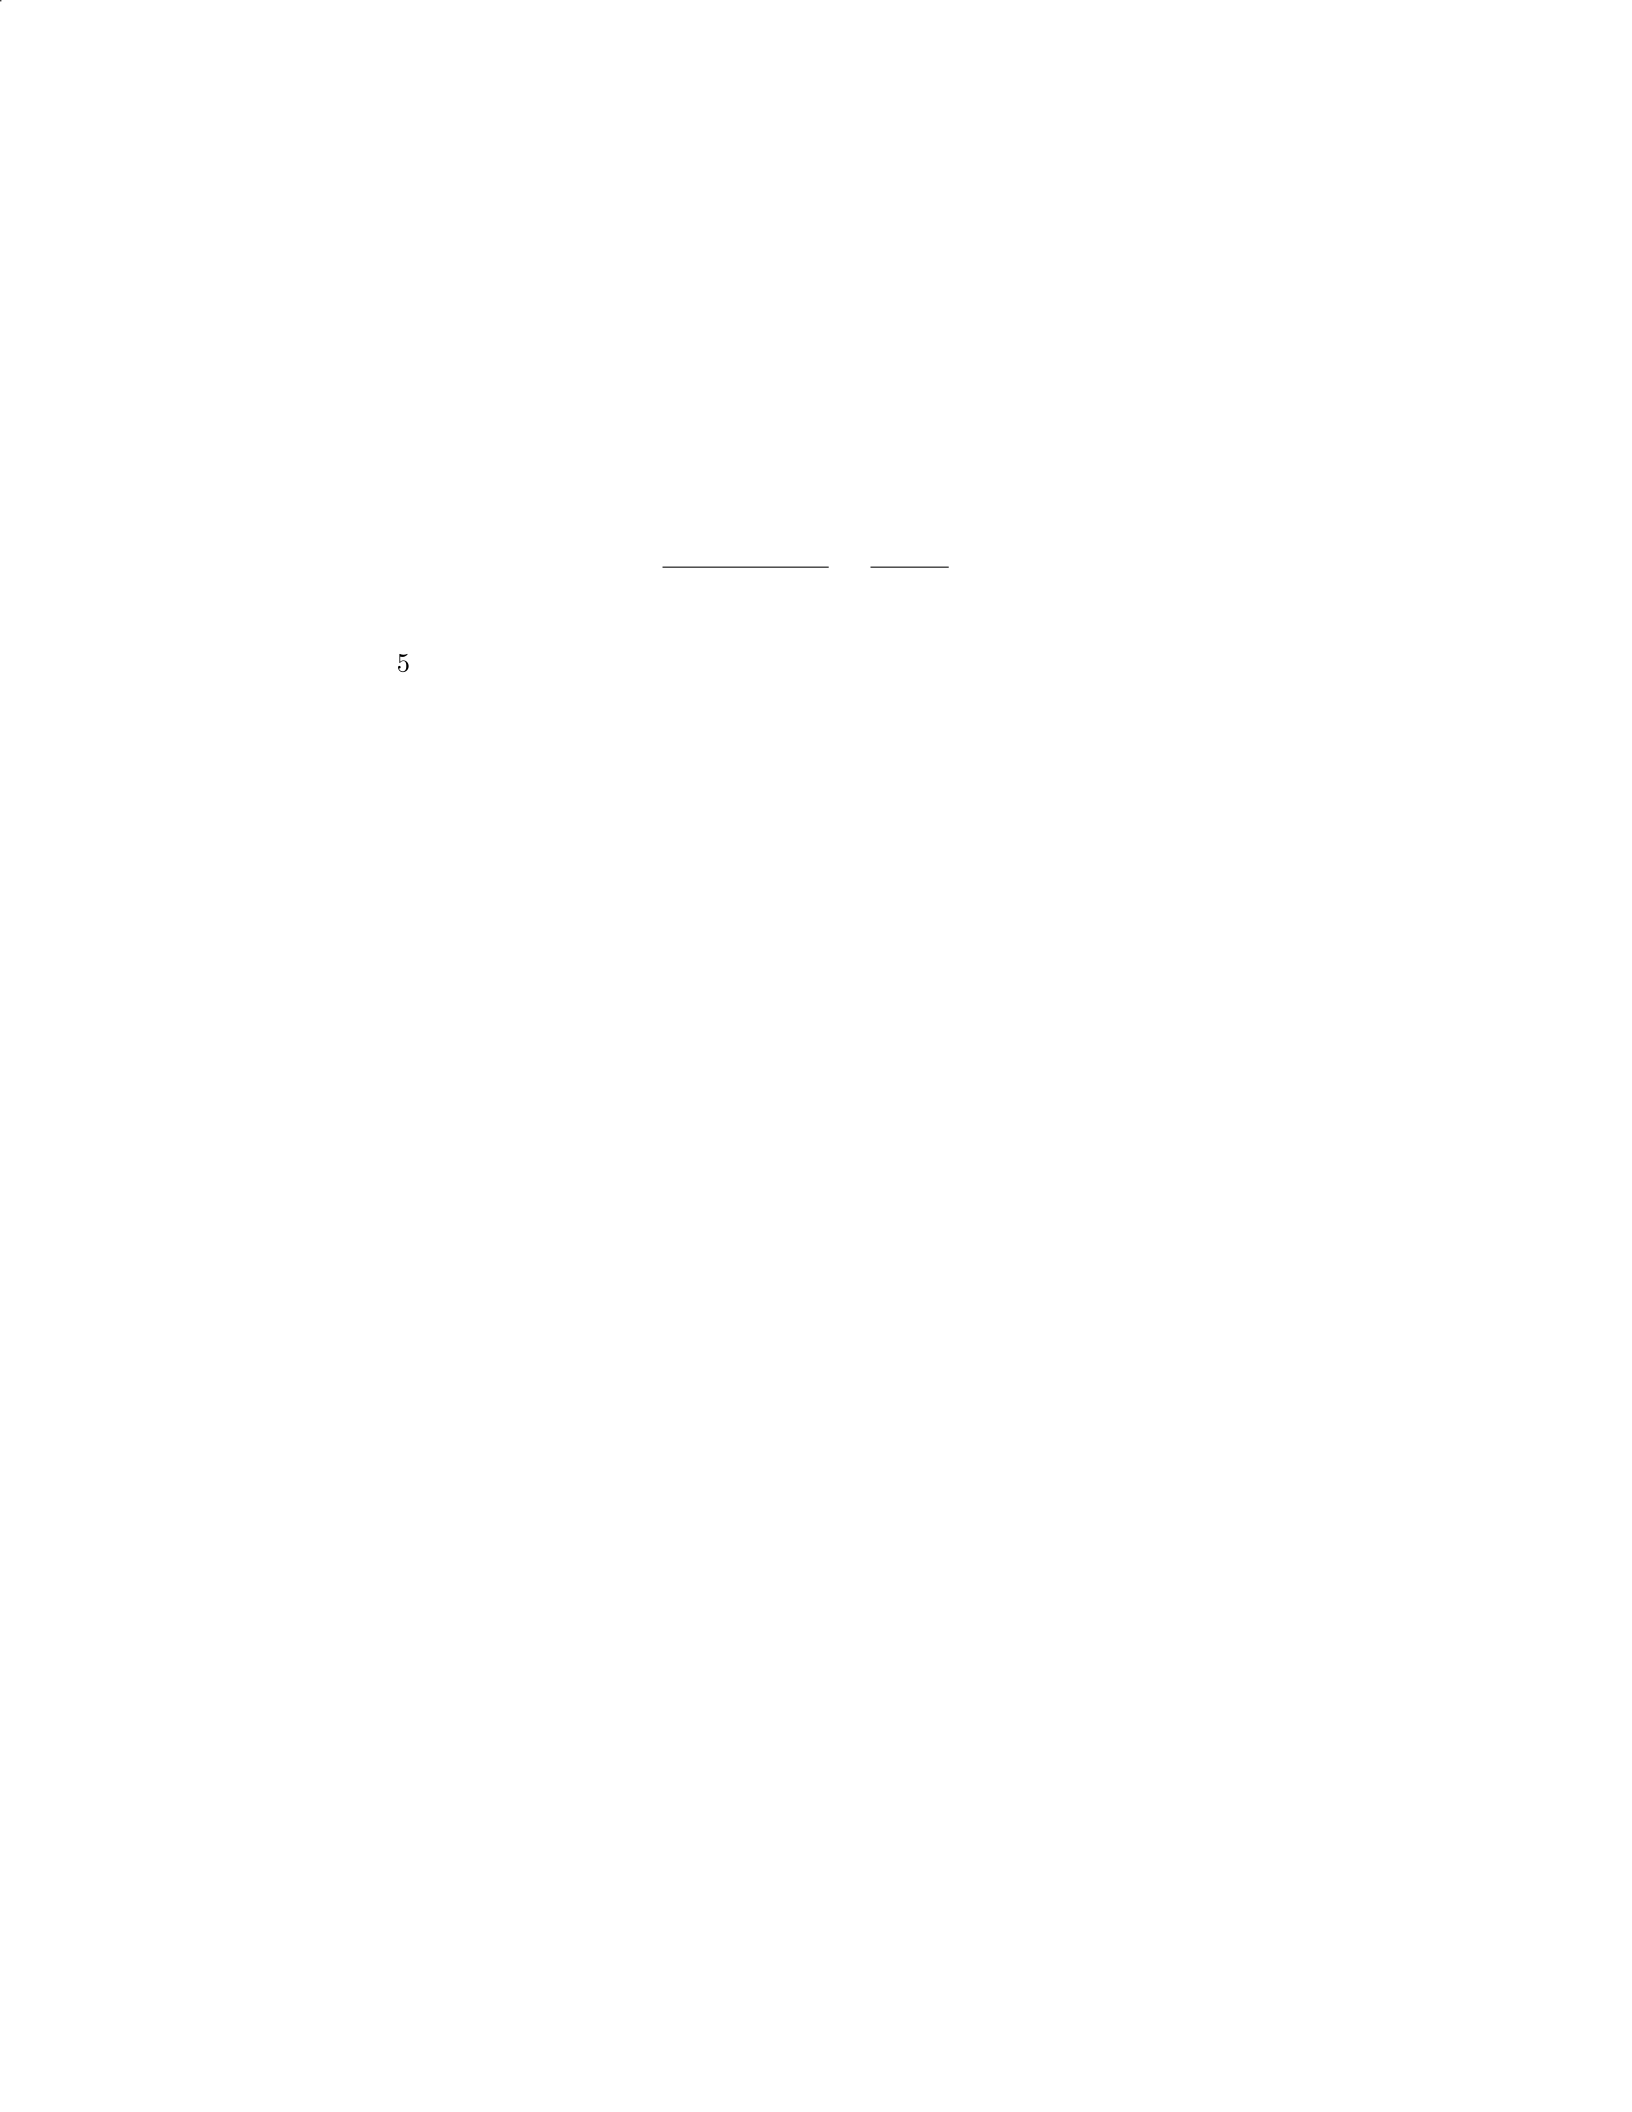
Given that the risk-free rate is 3
Discount Rate = 3% + 6% = 9%
Step 2: Use the discounted cash flow (DCF) formula to find the fair value
of the asset:
Fair Value = Cash Flows
Discount Rate =50,000
0.09 = $555,555.56
Therefore, the fair value of the asset using the discounted cash flow method
is
$
555,555.56.
Question 35
Question
Suppose a company needs to determine the fair value of an investment property.
The company has gathered relevant information and identified the following
three approaches to estimate the fair value: 1. Cost Approach - The cost to
replace the property. 2. Market Approach - Prices of similar properties in the
market. 3. Income Approach - Expected future cash flows from the property.
Explain how each of these approaches can be used to estimate the fair value
of the investment property. Additionally, discuss the advantages and disadvan-
tages of each approach in the context of fair value measurement.
Solution
Step 1: Cost Approach The Cost Approach to fair value measurement involves
determining the current cost to replace the property. This approach assumes
that the fair value of the property should not exceed the cost of acquiring or
constructing a substitute property with equivalent utility.
Advantages: - Useful when reliable market data is not available. - Provides
a straightforward estimation based on replacement cost.
Disadvantages: - Does not consider the property’s specific market conditions
or demand. - Does not reflect potential earning capacity or future cash flows of
the property.
Step 2: Market Approach The Market Approach to fair value measure-
ment involves comparing the subject property to similar properties in the market
that have been recently sold. This approach relies on the principle of substi-
tution, which states that an informed buyer would pay no more for a property
than the cost of acquiring a similar property.
Advantages: - Reflects actual market transactions and prices. - Considers
current supply and demand conditions.
Disadvantages: - Relies on the availability of comparable market data. -
Assumes properties are identical or very similar.
27
Question 3
Question
A company holds an investment property that it measures at fair value. The fair
value of the property at the end of the reporting period is 500,000.Duringthereportingperiod, thecompanyreceivedrentalincomeof40,000
from the property. In addition, the property incurred operating expenses of
15,000.Determinethegainorlossrecognizedinthecompany′sincomestatementrelatedtotheinvestmentproperty.
Solution
To determine the gain or loss recognized in the company’s income statement
related to the investment property, we need to calculate the net gain or loss.
Step 1: Calculate the net gain or loss. The net gain or loss is calculated as
follows:
Net gain or loss = Fair value at the end−Fair value at the beginning−Rental income+Operating expenses
Given that fair value at the end of the reporting period is 500,000, fairvalueatthebeginningisnotprovidedinthequestion.Soweassumeitisthesameasthef airvalueattheend.Hence :
Net gain or loss =500,000 - 500,000−40,000 + 15,000
Net gain or loss = −
25,000
Step 2: Analyze the result. The negative net gain of −25,000indicatesalossrecognizedinthecompany′sincomestatementrelatedtotheinvestmentproperty.
Question 4
Question
Company XYZ owns an investment property that is reported at fair value. At
the end of the reporting period, the fair value of the property is
$
2,500,000.
During the next reporting period, the fair value of the property has increased
to
$
2,800,000. What journal entry should Company XYZ make to account for
this increase in fair value?
Solution
To account for the increase in fair value of the investment property, Company
XYZ will need to recognize a gain in its financial statements. The journal entry
will involve debiting the Investment Property account and crediting the Fair
Value Adjustment account.
Step 1: Calculate the increase in fair value:
Increase in fair value = $2,800,000 −$2,500,000 = $300,000
3

Step 2: Make the journal entry:
Debit Investment Property $300,000
Credit Fair Value Adjustment $300,000
This journal entry reflects the recognition of the gain in the fair value of the
investment property.
Question 5
Question
Suppose a company holds an investment in a financial asset that is required to
be measured at fair value through profit or loss. The fair value of the asset
increased by 15
Solution
To analyze the impact of the 15
Step 1: Determine the impact on the Balance Sheet - The 15- The
increase in fair value will result in a higher valuation of the financial asset
under the fair value measurement category. - As a result, the total assets of the
company will increase by the amount of the fair value increase.
Step 2: Identify the affected accounts - The impacted accounts on the
balance sheet will include: - Financial Asset account: This account will reflect
the higher fair value of the financial asset. - Fair Value Adjustment account:
This account will capture the unrealized gains on the financial asset.
Step 3: Assess the impact on the Income Statement - The increase in
fair value will lead to a recognition of unrealized gains in the income statement. -
The unrealized gains will be recognized as ”Fair Value Gains” under the ”Other
Income” or ”Gain/Loss” section of the income statement. - This will result in
a higher net income for the current reporting period.
In conclusion, the 15
Question 6
Question
Company X recently acquired a piece of land for development. The fair value of
the land was determined to be 1,500,000.Duringthedevelopmentprocess, CompanyXincurredadditionalcostsof200,000.
At the end of the reporting period, the fair value of the land was reassessed to be
1,600,000.Calculatethef airvalueofthelandtoberecognizedinthefinancialstatementsattheendof thereportingperiod.
4
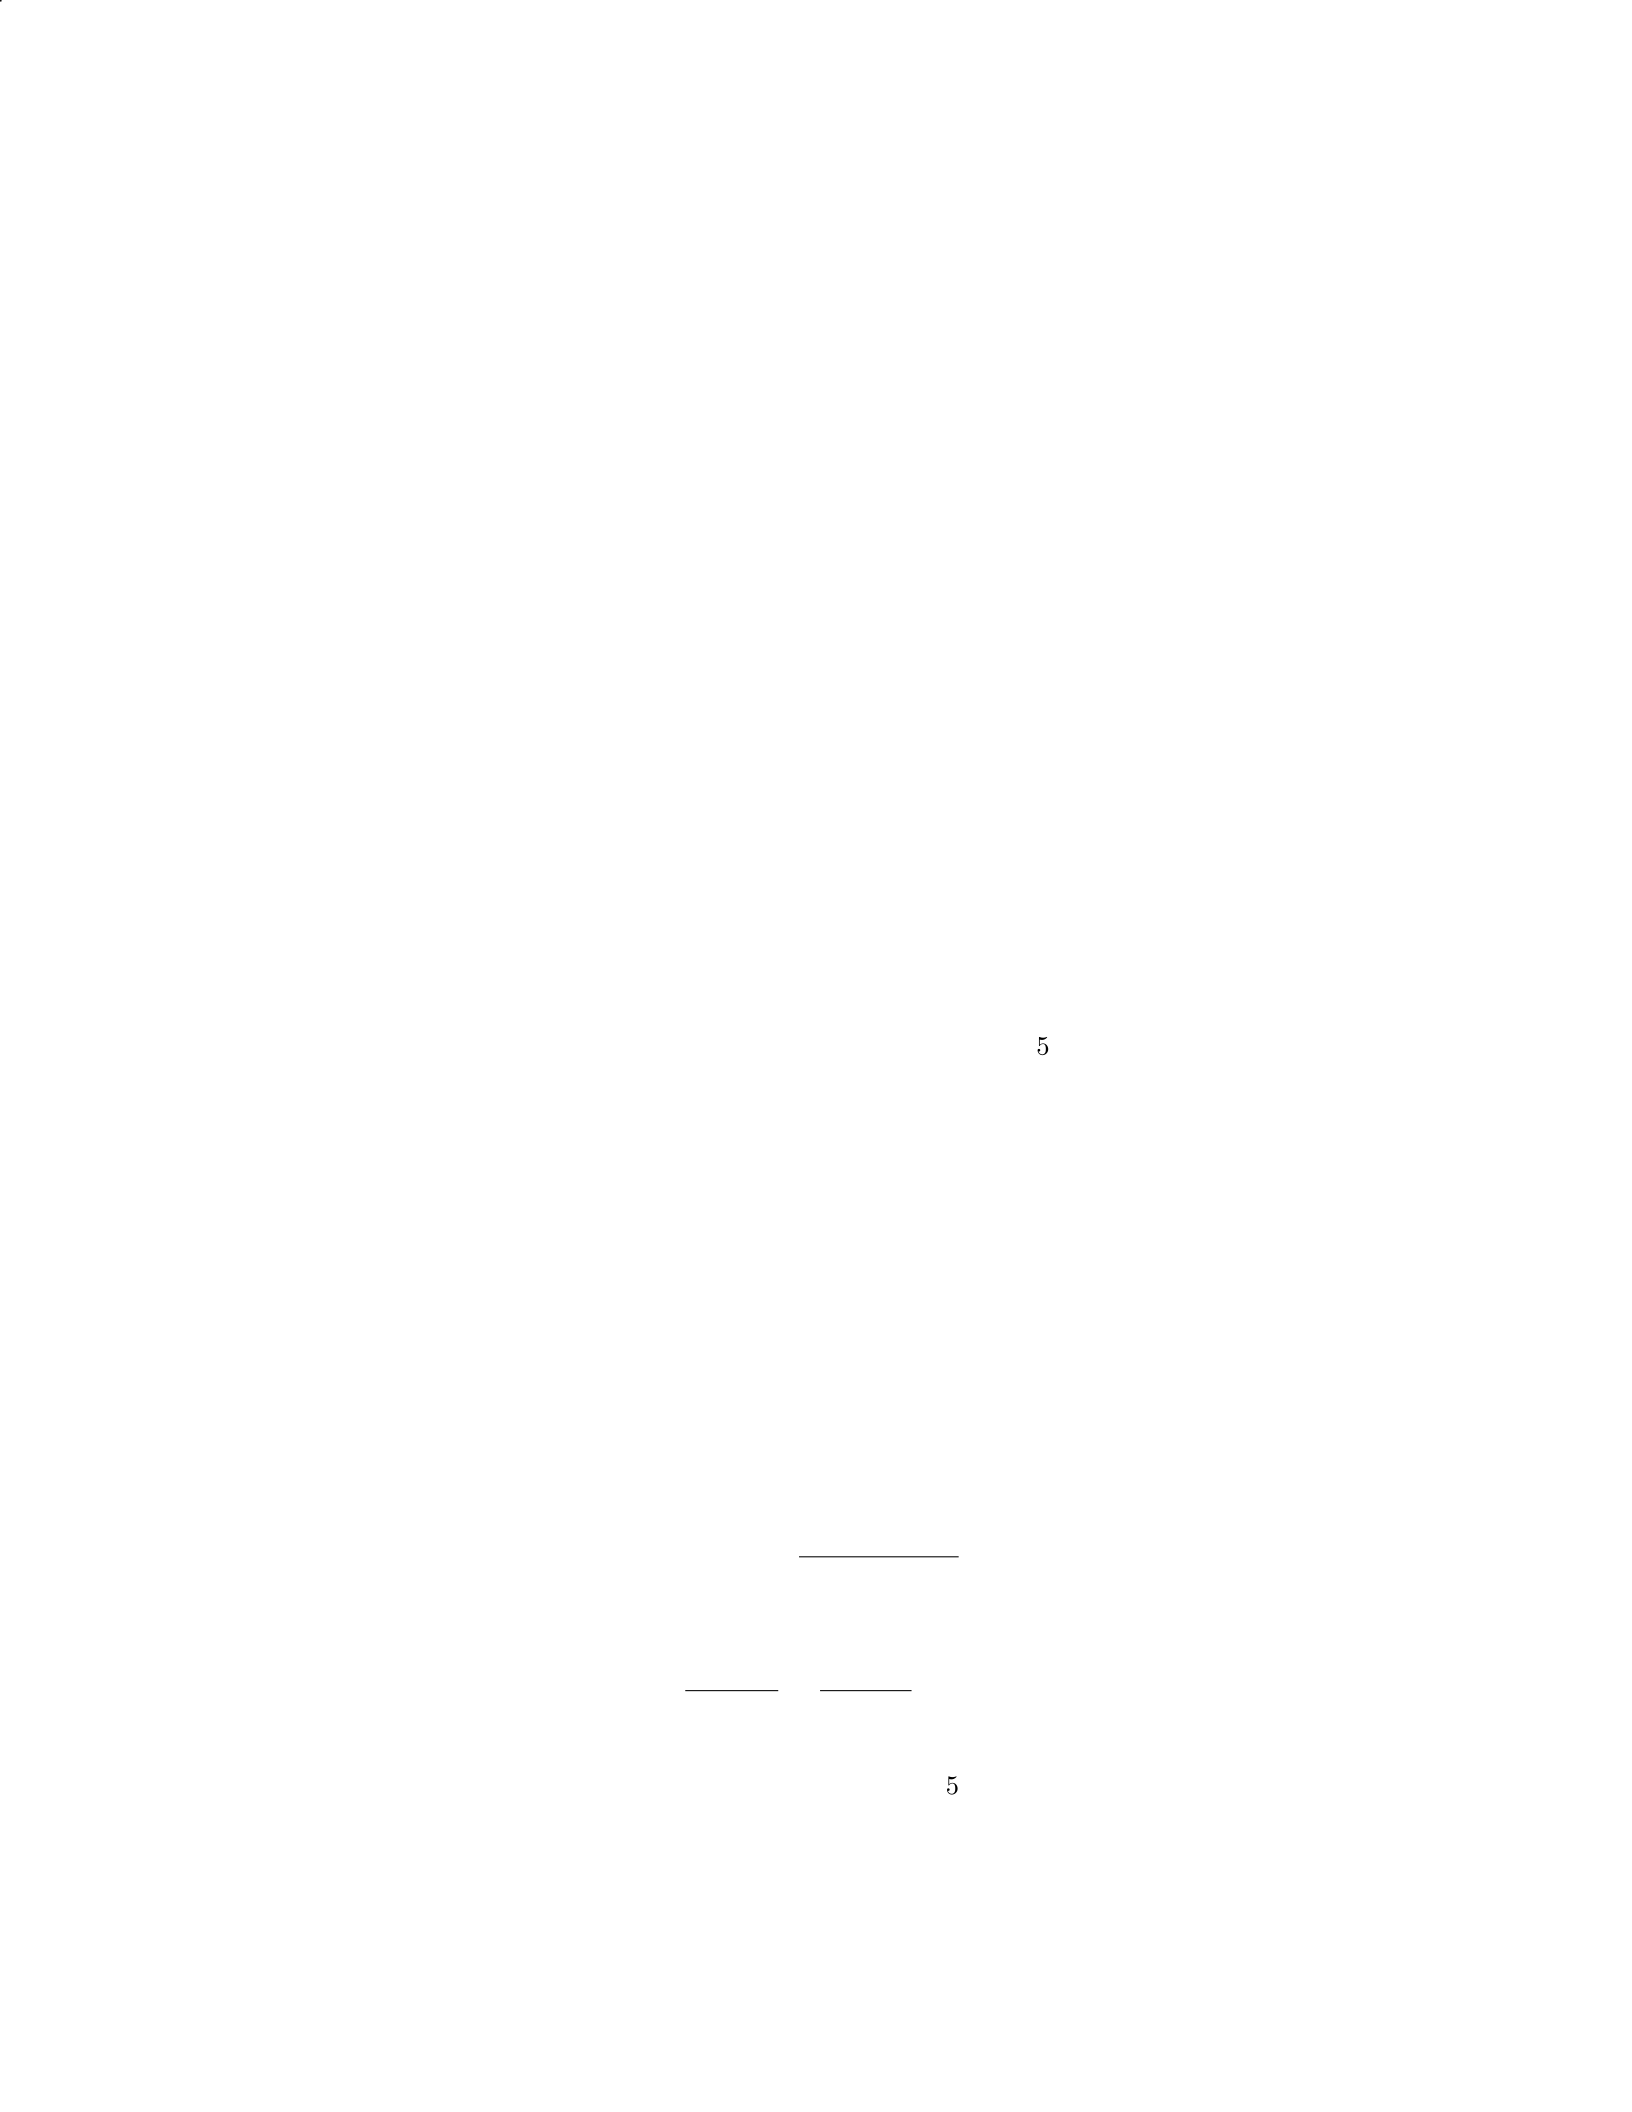
Solution
Step 1: Calculate the carrying amount of the land The carrying amount of the
land is the initial fair value plus any additional costs incurred. Carrying amount
= Initial fair value + Additional costs Carrying amount = 1,500,000+200,000
Carrying amount = 1,700,000
Step 2: Determine the fair value gain or loss The fair value gain or loss is
the difference between the reassessed fair value and the carrying amount. Fair
value gain/loss = Reassessed fair value - Carrying amount Fair value gain/loss
= 1,600,000−1,700,000 Fair value loss = -100,000
Step 3: Recognize the fair value in the financial statements Since a fair
value loss was incurred, the fair value recognized in the financial statements will
be the lower of the carrying amount and the reassessed fair value. Fair value
recognized = Min(Carrying amount, Reassessed fair value) Fair value recognized
= Min(1,700,000,1,600,000) Fair value recognized = 1,600,000
Therefore, the fair value of the land to be recognized in the financial state-
ments at the end of the reporting period is 1,600,000.
Question 7
Question
Company XYZ holds an investment with a fair value of
$
50,000 at the end of
the year. During the year, the fair value increased by 10%. If the company
uses the Level 1 fair value measurement technique, what is the fair value of the
investment at the beginning of the year?
Solution
Step 1: Understand the Level 1 fair value measurement technique. Level 1 fair
value measurements are based on quoted prices (unadjusted) in active markets
for identical assets or liabilities that the entity can access at the measurement
date.
Step 2: Use the formula for calculating fair value after an increase. Let
F Vinitial be the fair value of the investment at the beginning of the year. Since
the fair value at the end of the year was $50,000 and increased by 10%, the fair
value at the beginning of the year can be calculated as:
F Vinitial =F Vend
1 + increase%
Step 3: Substitute the given values and calculate.
F Vinitial =$50,000
1+0.10 =$50,000
1.10 = $45,454.55
Therefore, the fair value of the investment at the beginning of the year using
the Level 1 fair value measurement technique is
$
45,454.55.
5

Question 8
Question
A company has an investment in a financial instrument classified as a Level 3
fair value measurement. The company uses unobservable inputs to determine
the fair value of the financial instrument. Explain the key considerations and
challenges the company may face in determining the fair value of this investment.
Solution
To determine the fair value of a financial instrument classified as a Level 3
fair value measurement using unobservable inputs, the company may encounter
several key considerations and challenges. Here are the steps outlining these:
Step 1: Understand Level 3 Fair Value Measurement Level 3 fair
value measurements involve significant unobservable inputs, also known as Level
3 inputs. These inputs require management’s judgment and involve a high
degree of subjectivity. Understanding the nature of Level 3 measurements is
crucial for the company.
Step 2: Valuation Techniques and Inputs The company must carefully
select appropriate valuation techniques to estimate the fair value of the financial
instrument. Since Level 3 inputs are unobservable, determining the reliability
and reasonableness of these inputs can be a challenge.
Step 3: Use of Financial Models Financial models are often used to
estimate the fair value of Level 3 financial instruments. However, the complexity
of these models and the assumptions made can introduce additional challenges
in arriving at a fair value that reflects market conditions.
Step 4: Consideration of Market and Economic Factors The com-
pany must assess how market and economic factors impact the fair value of the
financial instrument. Changes in market conditions can make it challenging to
determine the fair value accurately.
Step 5: Disclosure Requirements Given the subjectivity and complexity
involved in Level 3 fair value measurements, the company must provide extensive
disclosures in the financial statements. This includes detailing the valuation
techniques used, the inputs considered, and the sensitivity of the fair value to
changes in these inputs.
Step 6: Independent Verification To enhance credibility and reliability,
the company may consider engaging independent valuation specialists to review
and validate the fair value measurement process. This can help address concerns
about the objectivity of the valuation.
By carefully navigating these considerations and challenges, the company
can strive to determine a reliable fair value for its investment in the financial in-
strument despite the inherent difficulties associated with Level 3 measurements
based on unobservable inputs.
6

Question 9
Question
Explain the concept of fair value measurement and discuss the factors that may
influence the determination of fair value.
Solution
Step 1: Concept of Fair Value Measurement Fair value measurement is the
process of determining the value of an asset or liability based on the price that
would be received to sell an asset or paid to transfer a liability in an orderly
transaction between market participants at the measurement date. Fair value is
a market-based measurement, not an entity-specific measurement. It represents
the price that would be received to sell an asset or paid to transfer a liability in
an orderly transaction between market participants at the measurement date.
Step 2: Factors Influencing Fair Value Determination There are sev-
eral factors that may influence the determination of fair value: 1. Market con-
ditions: Fluctuations in market conditions can impact the fair value of assets
and liabilities. For example, changes in interest rates, economic conditions, and
market volatility can all affect fair value. 2. Availability of data: The avail-
ability of relevant and reliable data is essential for determining fair value. If
there is limited information about comparable transactions or market prices,
it may be challenging to determine fair value accurately. 3. Assumptions and
inputs: Fair value measurements often involve making assumptions and using
inputs based on available data. The choice of assumptions and inputs can affect
the final fair value estimate. 4. Level of judgment: Fair value measurements
require a significant amount of judgment, particularly when there is limited
market activity for the asset or liability being valued. The level of judgment
used can impact the reliability of the fair value measurement. 5. Complexity of
the asset or liability: The complexity of the asset or liability being valued can
also influence fair value determination. More complex assets or liabilities may
require more sophisticated valuation techniques, which can affect the accuracy
of the fair value measurement.
Question 10
Question
A company holds an investment in bonds classified as available-for-sale with a
fair value of 450,000.Duetomarketconditions, thefairvalueof thebondsdecreasesto420,000
at the end of the reporting period. The company decides to recognize the de-
crease in fair value. If the company reports unrealized losses in other compre-
hensive income, how would this affect the company’s financial statements?
7
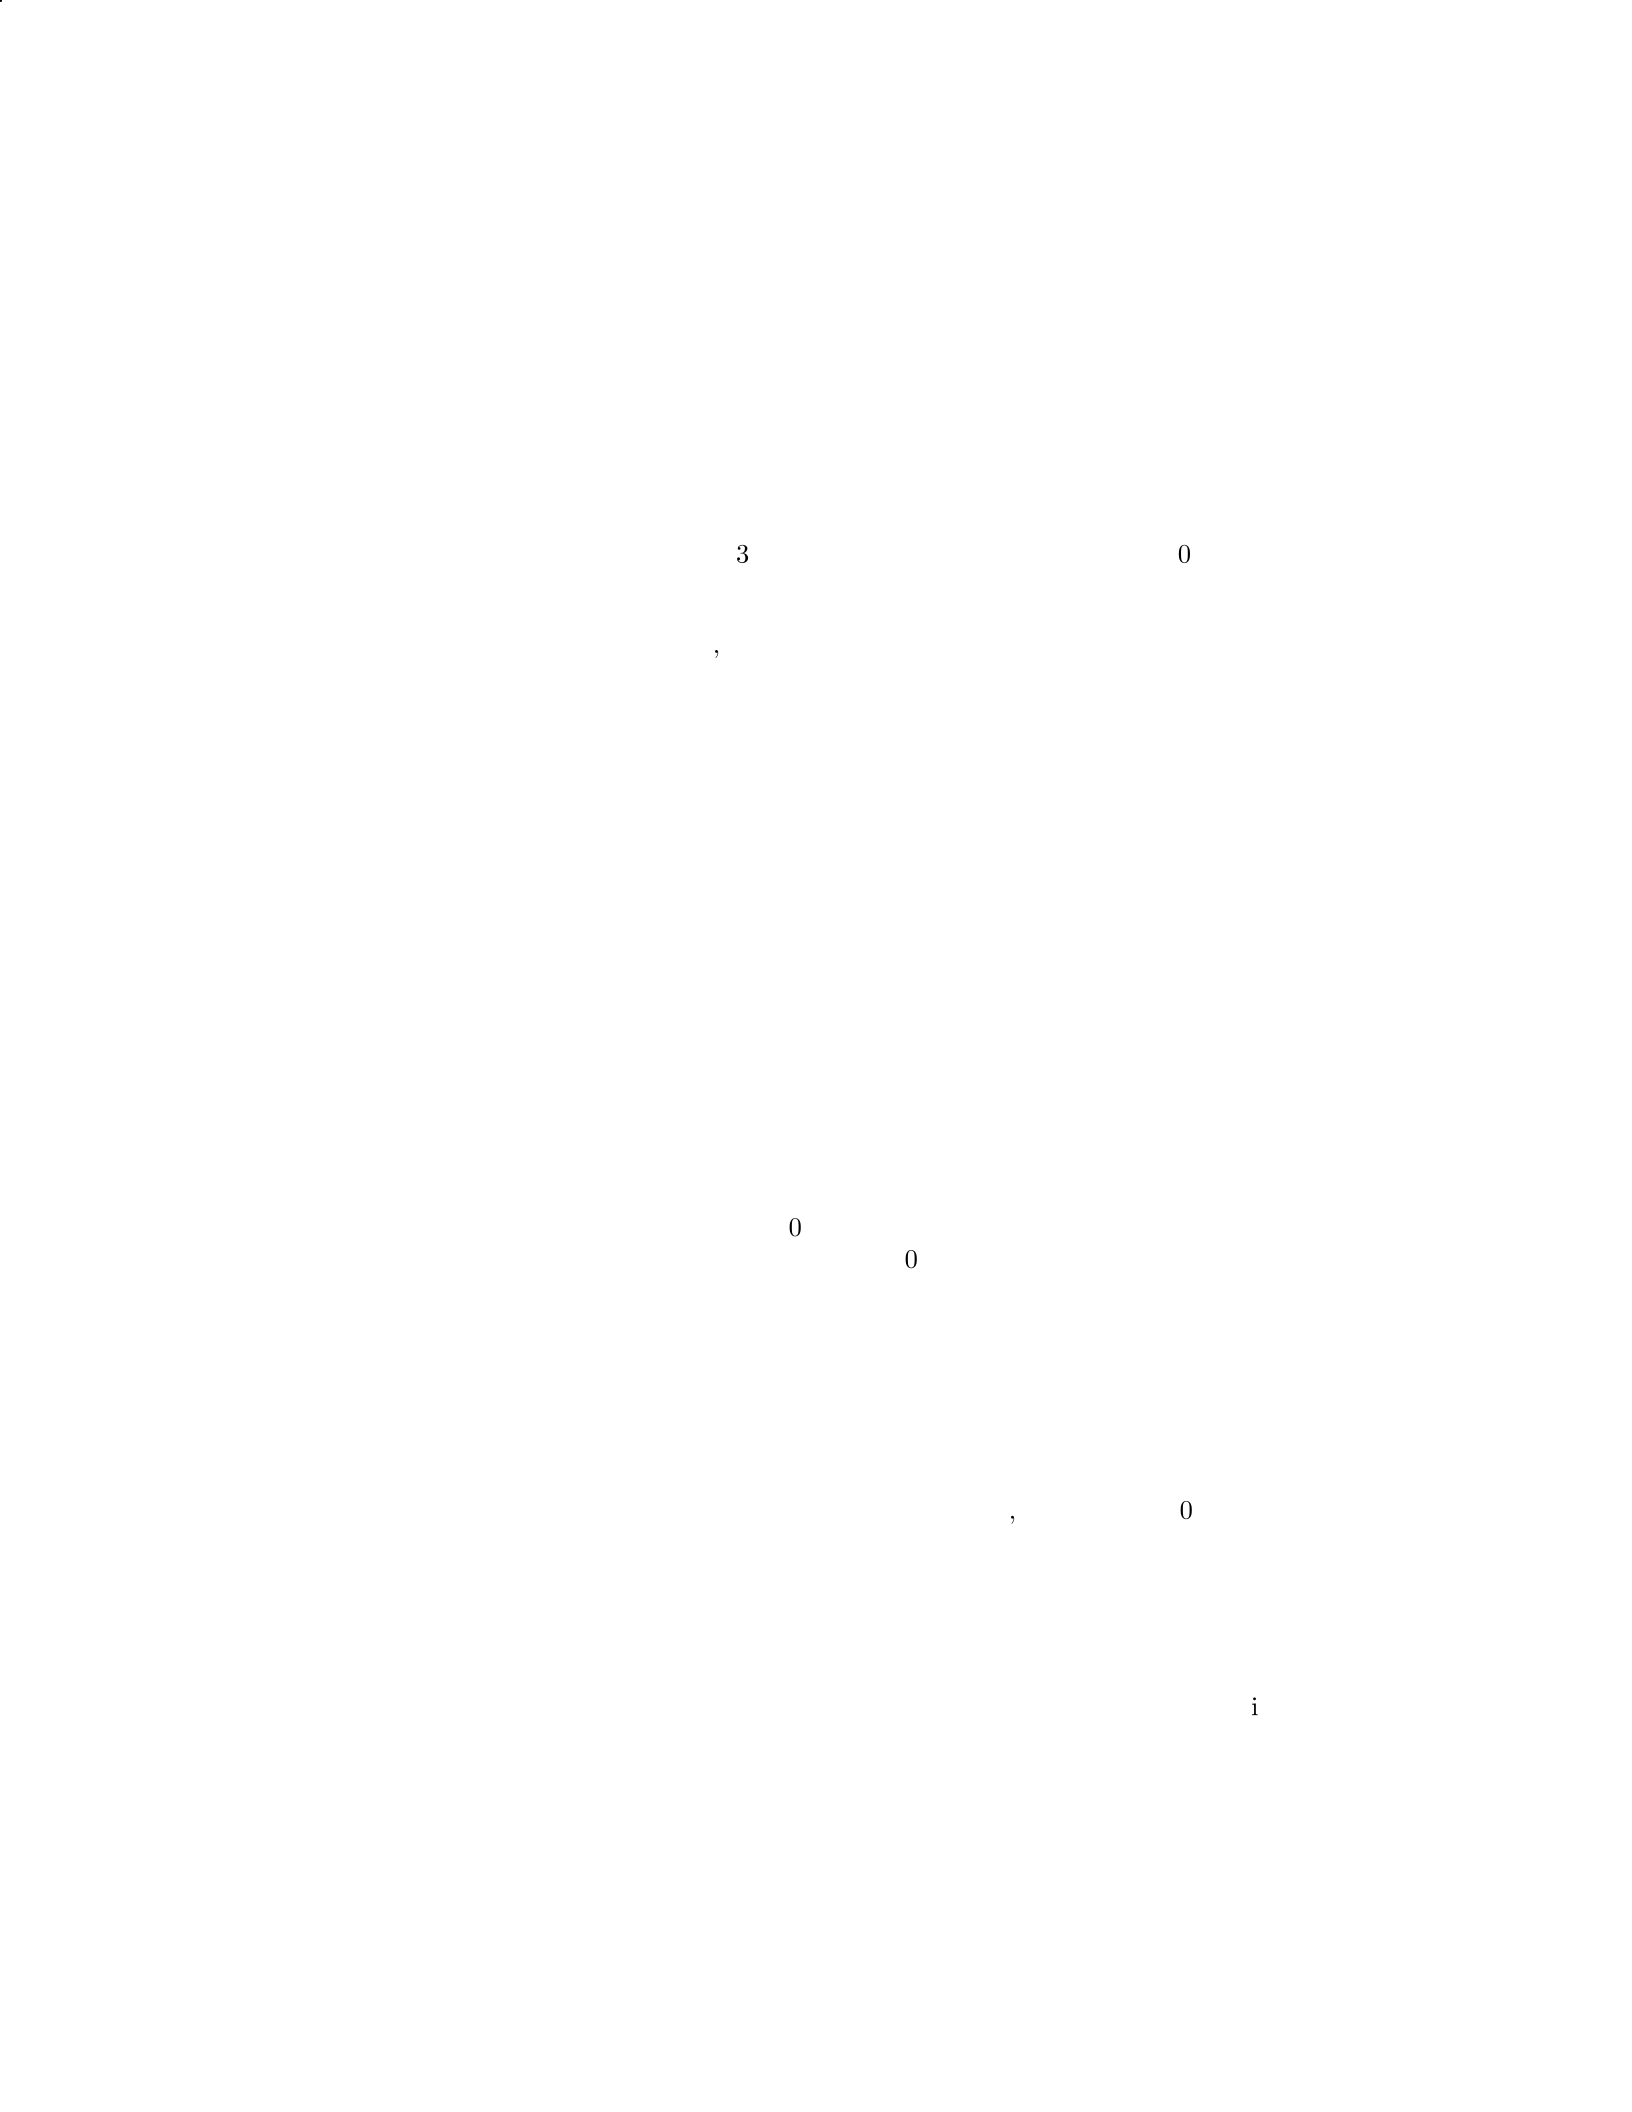
Solution
1. The company recognizes the decrease in fair value of the bonds as an unreal-
ized loss. This is recorded as a decrease in the fair value of the bond investment
and an increase in unrealized loss.
2. The journal entry to recognize the decrease in fair value is as follows:
Available-for-sale bonds
$
30,000Unrealized loss on bonds
$
30,000
3. This journal entry would affect the balance sheet by decreasing the
available-for-sale bonds by
$
30,000.
4. When the company reports unrealized losses in other comprehensive in-
come, the income statement is not directly impacted. However, the accumulated
other comprehensive income section of the equity portion of the balance sheet
would decrease by the amount of the unrealized loss.
5. The company’s statement of comprehensive income would reflect the
change in other comprehensive income due to the recognition of the unrealized
loss.
6. Overall, the company’s financial position would show a decrease in total
comprehensive income due to the recognition of the unrealized loss, which would
impact the company’s equity and overall financial health.
Question 11
Question
Company X holds an investment in a security that is classified as a Level 3 asset
under fair value hierarchy. At the end of the reporting period, the fair value of
the security was estimated to be
$
1,200,000. During the next reporting period,
the fair value of the security increased to
$
1,400,000. Company X has a policy
of recognizing unrealized gains or losses on Level 3 assets directly in profit or
loss. Calculate the unrealized gain or loss that Company X should recognize in
the next reporting period.
Solution
Step 1: Calculate the unrealized gain or loss in the next reporting period. Given
that the fair value of the security increased from
$
1,200,000 to
$
1,400,000, the
unrealized gain or loss can be calculated using the formula:
Unrealized Gain or Loss = Ending Fair Value −Beginning Fair Value
Unrealized Gain or Loss = $1,400,000 −$1,200,000 = $200,000
Therefore, Company X should recognize an unrealized gain of
$
200,000 in
the next reporting period.
8
Question 12
Question
Company XYZ is considering investing in a new project and needs to determine
the fair value of the project for financial reporting purposes. The project is ex-
pected to generate cash flows of 10,000inthefirstyear,15,000 in the second year,
and 20,000inthethirdyear.T hediscountrateis8%.Calculatethef airvalueof theprojectusingthediscountedcashflowmethod.
Solution
Step 1: Calculate the present value of each cash flow.
P V1=10,000
(1 + 0.08)1= $9,259.26
P V2=15,000
(1 + 0.08)2= $12,938.02
P V3=20,000
(1 + 0.08)3= $15,873.79
Step 2: Calculate the fair value of the project by summing up the present
values of all cash flows.
F air V alue =P V1+P V2+P V3
= $9,259.26 + $12,938.02 + $15,873.79
= $38,070.07
Therefore, the fair value of the project using the discounted cash flow method
is
$
38,070.07.
Question 13
Question
You are a financial analyst working for a consulting firm. You have been tasked
with determining the fair value of a private equity investment held by one of
your clients. The investment has limited market activity and no actively traded
comparable securities. Discuss the challenges you may face in determining the
fair value of this private equity investment.
Solution
To determine the fair value of a private equity investment with limited market
activity and no actively traded comparable securities, several challenges may
arise. Below are the challenges you may face in this scenario:
9

Step 1: Lack of Observable Market Data Since the investment has
limited market activity, there may be insufficient observable market data avail-
able to determine a fair value. This lack of data makes it difficult to assess the
investment’s value accurately.
Step 2: Subjectivity in Valuation In the absence of comparable se-
curities or market transactions, fair value measurement may rely heavily on
subjective assumptions and judgments. Different analysts may come up with
different valuations based on their interpretation of available information.
Step 3: Reliance on Management Estimates When market data is
scarce, the valuation process may require significant reliance on management
estimates. This dependence on management’s projections can introduce bias
and lack of objectivity in the valuation process.
Step 4: Illiquidity and Lack of Marketability Private equity invest-
ments are typically illiquid and lack marketability. The lack of a ready market
for these investments can further complicate the determination of fair value,
as there may be limited opportunities to sell or liquidate the investment to
ascertain its true market worth.
Step 5: Complex Valuation Models Given the unique characteristics of
private equity investments, such as long investment horizons, complex capital
structures, and varying exit strategies, the valuation process may require the
use of sophisticated and complex models. These models may involve significant
assumptions and inputs that can impact the final valuation.
In conclusion, determining the fair value of a private equity investment with
limited market activity and no actively traded comparable securities poses sig-
nificant challenges, including the lack of observable market data, subjectivity in
valuation, reliance on management estimates, illiquidity, and complexity in val-
uation models. It is essential for analysts to carefully consider these challenges
and make sound judgments to arrive at a reasonable fair value estimate.
Question 14
Question
Company XYZ holds an investment in a private company which is carried at fair
value through profit or loss. At the end of the reporting period, the fair value of
the investment is determined to be 85,000.Duringthenextreportingperiod, inf ormationbecomesavailableindicatingasignif icantincreaseinvalueof theprivatecompany.T hef airvalueisestimatedtobe110,000.
Given this scenario, explain how Company XYZ should account for the in-
crease in fair value of the investment in the next reporting period.
Solution
Step 1: Initially Recognized and Recognized at Fair Value - The investment
in the private company was initially recognized and measured at fair value.
When an entity initially recognizes a financial asset at fair value, any difference
between the transaction price and the fair value (if any) is recognized in profit
10
or loss. - In this case, since the investment was recognized at fair value, any
change in fair value after the initial recognition should also be recognized in
profit or loss.
Step 2: Increase in Fair Value - When the fair value of the investment in-
creases to 110,000inthenextreportingperiod, CompanyXY Zshouldrecognizethe25,000
increase in fair value as a gain in profit or loss. - This gain reflects the change
in fair value of the investment from 85,000to110,000.
Step 3: Accounting Entry - The accounting entry to recognize the increase
in fair value of the investment would be:
Profit or Loss 25,000
Investment in Private Company 25,000
Step 4: Disclosures - Company XYZ should disclose the fair value of the
investment in the financial statements along with the changes in fair value that
have been recognized in profit or loss. This provides transparency to the users
of the financial statements regarding the changes in fair value of the investment.
Question 15
Question
A company holds an investment in equity securities that are measured at fair
value through other comprehensive income (FVOCI). At the end of the reporting
period, the fair value of the investment has decreased by
$
15,000 compared to
its initial cost. The company considers this decrease to be temporary. How
should the company account for this decrease in fair value?
Solution
Step 1: Since the company considers the decrease in fair value to be tempo-
rary, it should recognize this decrease in fair value as an adjustment to other
comprehensive income.
Step 2: Calculate the adjustment amount. The adjustment amount is the
difference between the initial cost of the investment and the new fair value at
the end of the reporting period. In this case, the adjustment amount is
$
15,000.
Step 3: Prepare the journal entry to recognize the adjustment in fair value:
Other Comprehensive Income Dr. $15,000
Investment in Equity Securities Cr. $15,000
Step 4: After preparing the journal entry, the company’s total comprehensive
income will decrease by
$
15,000. The investment in equity securities account
will be adjusted to reflect the decrease in fair value.
Step 5: It’s important to note that the adjustment in fair value is recognized
in other comprehensive income and does not impact net income for the pe-
riod. The company should continue to monitor the fair value of the investment
11

and assess whether the decrease in fair value remains temporary or becomes
permanent.
Question 16
Question
Company XYZ holds an investment in a private company that is not publicly
traded. The investment is classified as a Level 3 asset under fair value measure-
ment. Company XYZ determines that there has been a significant decrease in
the financial performance of the private company. Explain how the decrease in
financial performance may impact the fair value measurement of the investment.
Solution
Step 1: The decrease in financial performance of the private company may im-
pact the fair value measurement of the investment as follows: - As per fair value
measurement guidelines, the fair value of a Level 3 asset is determined using
unobservable inputs, such as proprietary models or management’s estimates. -
The decrease in financial performance of the private company could result in
a reassessment of the assumptions and inputs used in the fair value measure-
ment process. - The decrease in financial performance may lead to a revision
of expected future cash flows, discount rates, or other key inputs used in the
valuation model.
Step 2: Specifically, the impact of the decrease in financial performance on
the fair value measurement of the investment could include: - A decrease in ex-
pected future cash flows due to lower revenue projections, increased expenses,
or other adverse financial indicators. - An increase in the discount rate used to
value the investment to reflect the higher risk associated with the private com-
pany’s deteriorating financial condition. - A change in the probability weighting
of different scenarios or outcomes, with a greater emphasis placed on downside
risks given the decrease in financial performance.
Step 3: Overall, the decrease in financial performance of the private com-
pany may lead to a lower fair value measurement of the investment due to the
increased perceived risk or lower expected future cash flows associated with the
investment. It is important for Company XYZ to carefully consider the impact
of the decrease in financial performance on the fair value measurement and make
any necessary adjustments to reflect the current economic conditions accurately.
Question 17
Question
Company XYZ holds an investment in a publicly traded company, which is
classified as available-for-sale. At the end of the reporting period, the fair value
12
of the investment is $500,000, and the cost of the investment is $450,000. If
the fair value of the investment decreases to $480,000 at the end of the next
reporting period, how would this change be accounted for in Company XYZ’s
financial statements?
Solution
Step 1: Calculate the gain or loss on the decrease in fair value of the investment.
Initial fair value of the investment: $500,000
Fair value of the investment at the end of the next reporting period:
$480,000
Gain (Loss) on the decrease in fair value: $480,000−$500,000 = −$20,000
Step 2: Determine the impact on Company XYZ’s financial statements.
The decrease in fair value of $20,000 results in a loss for Company XYZ.
Since the investment is classified as available-for-sale, this loss is recog-
nized in other comprehensive income (OCI).
Step 3: Record the journal entry to reflect the loss on the decrease in fair
value.
Debit: Unrealized Holding Loss (OCI): $20,000
Credit: Investment: $20,000
Step 4: Update the carrying amount of the investment on the balance sheet.
The carrying amount of the investment on the balance sheet will now be
$450,000 −$20,000 = $430,000.
Step 5: Disclose the reclassification adjustment in the financial statements.
The reclassification adjustment of $20,000 from OCI to net income should
be disclosed in the financial statements.
Therefore, the decrease in fair value of the investment would result in a
loss of $20,000 being recognized in other comprehensive income (OCI) and a
corresponding adjustment to the carrying amount of the investment on the
balance sheet.
Question 18
Question
A company is required to determine the fair value of an investment property
on its financial statements. The property was purchased three years ago for
$
500,000 and has since undergone significant revaluation with an independent
appraiser valuing it at
$
700,000. Additionally, the property generates annual
rental income of
$
40,000. If the company uses an appropriate discount rate of 8
13
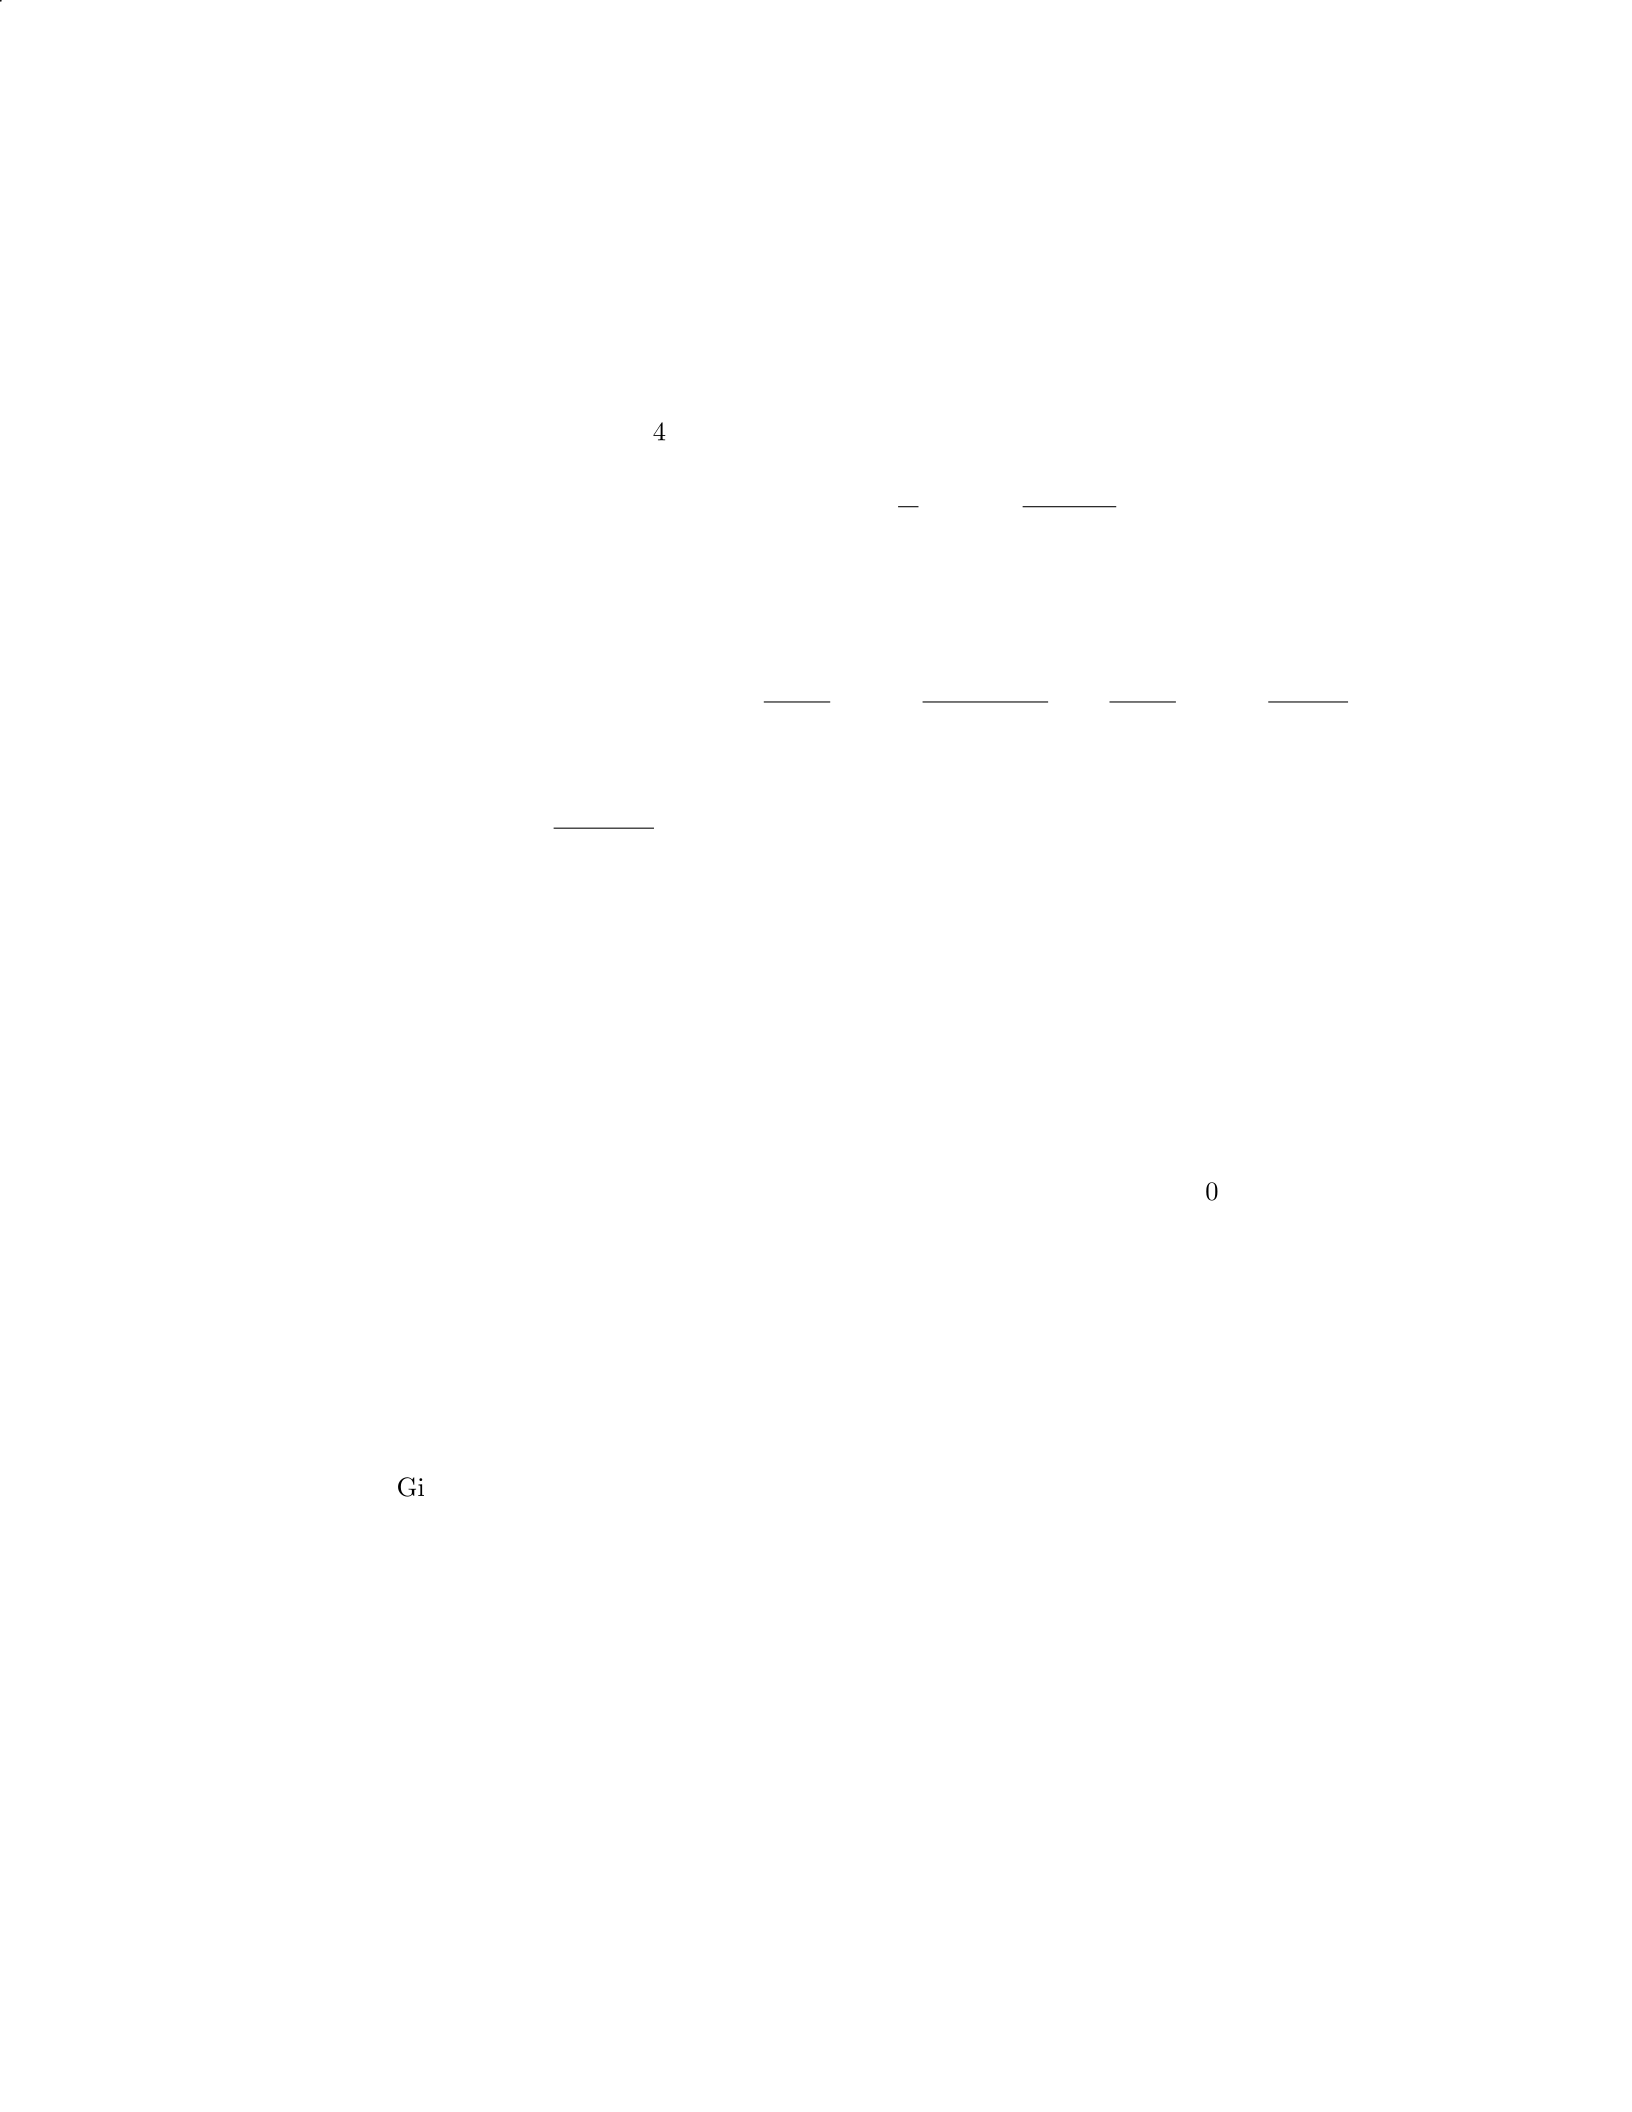
Solution
Step 1: Calculate the present value of the annual rental income. Given an
annual rental income of
$
40,000 and a discount rate of 8
Present Value of Rental Income = R
r×1−1
(1 + r)n
where: - R= $40,000 - r= 0.08 - n= 3 (since the rental income is for three
years)
Present Value of Rental Income = 40000
0.08 ×1−1
(1 + 0.08)3=40000
0.08 ×1−1
(1.08)3
= 500000×1−1
1.259712≈500000×(1−0.79383) = 500000×0.20617 ≈$103,085.01
Step 2: Calculate the fair value of the investment property. The fair value
of the investment property is the sum of the present value of the rental income
and the revaluation amount:
Fair Value = Present Value of Rental Income + Revaluation Amount
Fair Value = $103,085.01 + $700,000 = $803,085.01
Therefore, the fair value of the investment property is approximately
$
803,085.01.
Question 19
Question
Company XYZ holds an investment in a financial instrument classified as a level
3 fair value measurement. At the end of the reporting period, the fair value of the
financial instrument is determined to be 150,000, butthereissignif icantunobservableinputuncertaintyinvolvedinthevaluationprocess.CompanyXY Zhashistoricallyusedaweightedaveragecostofcapital(W ACC)of10
Given this information, determine the fair value of the financial instrument
using the method prescribed by IFRS 13.
Solution
To determine the fair value of the financial instrument using the method pre-
scribed by IFRS 13, we will calculate the fair value based on the present value of
expected cash flows discounted using current market-based observable inputs.
Step 1: Identify the relevant cash flows associated with the financial instru-
ment. The relevant cash flow associated with the financial instrument are the
14
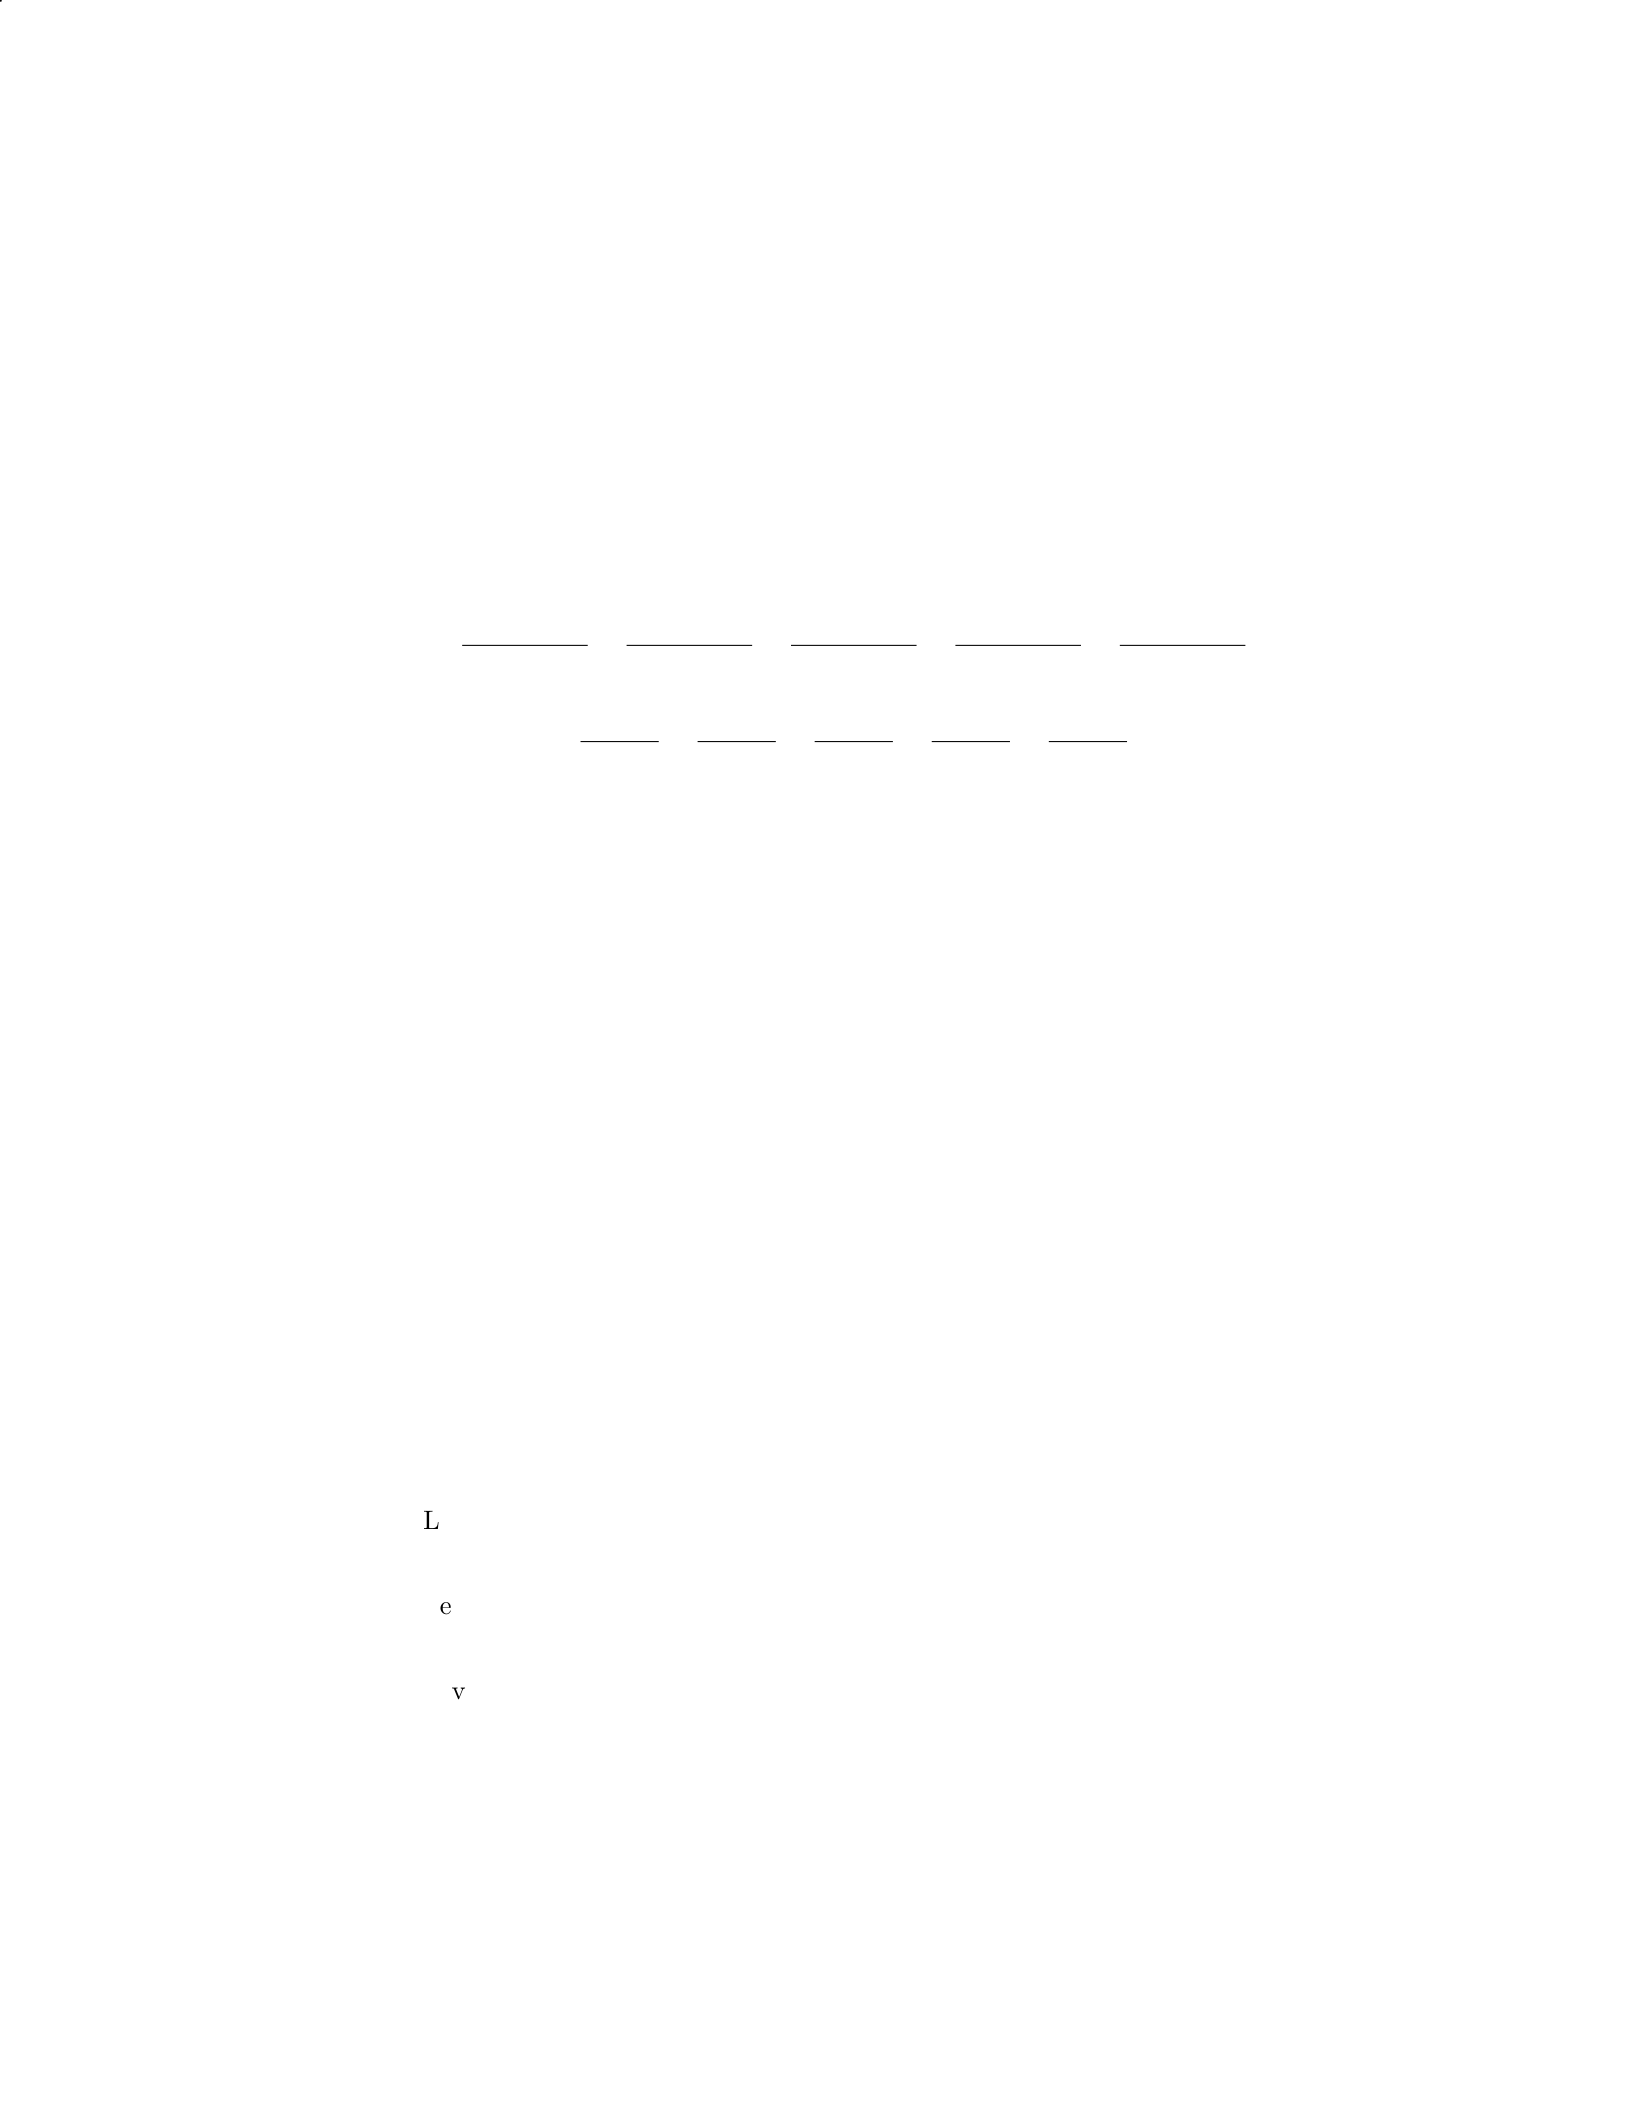
expected future cash flows Company XYZ expects to receive from holding the
investment.
Step 2: Determine the applicable discount rate. Given that Company XYZ
historically uses a WACC of 10
Step 3: Calculate the present value of expected cash flows. Let’s assume
that the expected future cash flows from the investment are as follows: Year 1:
30,000Y ear2 :40,000 Year 3: 50,000Y ear4 :60,000 Year 5: 70,000
Calculating the present value of these cash flows using the WACC of 10
P V =30,000
(1 + 0.10)1+40,000
(1 + 0.10)2+50,000
(1 + 0.10)3+60,000
(1 + 0.10)4+70,000
(1 + 0.10)5
P V =30,000
1.10 +40,000
1.102+50,000
1.103+60,000
1.104+70,000
1.105
P V ≈30,000×0.9091+40,000×0.8264+50,000×0.7513+60,000×0.6830+70,000×0.6209
P V ≈27,273 + 33,056 + 37,565 + 40,980 + 43,463 = 182,337
Therefore, the fair value of the financial instrument based on present value
of expected cash flows is approximately 182,337.
Question 20
Question
A company has an investment in a financial asset classified as a Level 3 fair
value measurement. The fair value of the investment was determined using
unobservable inputs. Explain how the company should disclose information
about the fair value measurement in its financial statements.
Solution
Step 1: The company should disclose the inputs used to determine the fair value
of the investment. These inputs are categorized into three levels:
Level 1 inputs: Observable inputs like quoted prices in active markets for
identical assets.
Level 2 inputs: Inputs other than quoted prices included in Level 1 that
are observable for the asset.
Level 3 inputs: Unobservable inputs based on the company’s own assump-
tions.
15
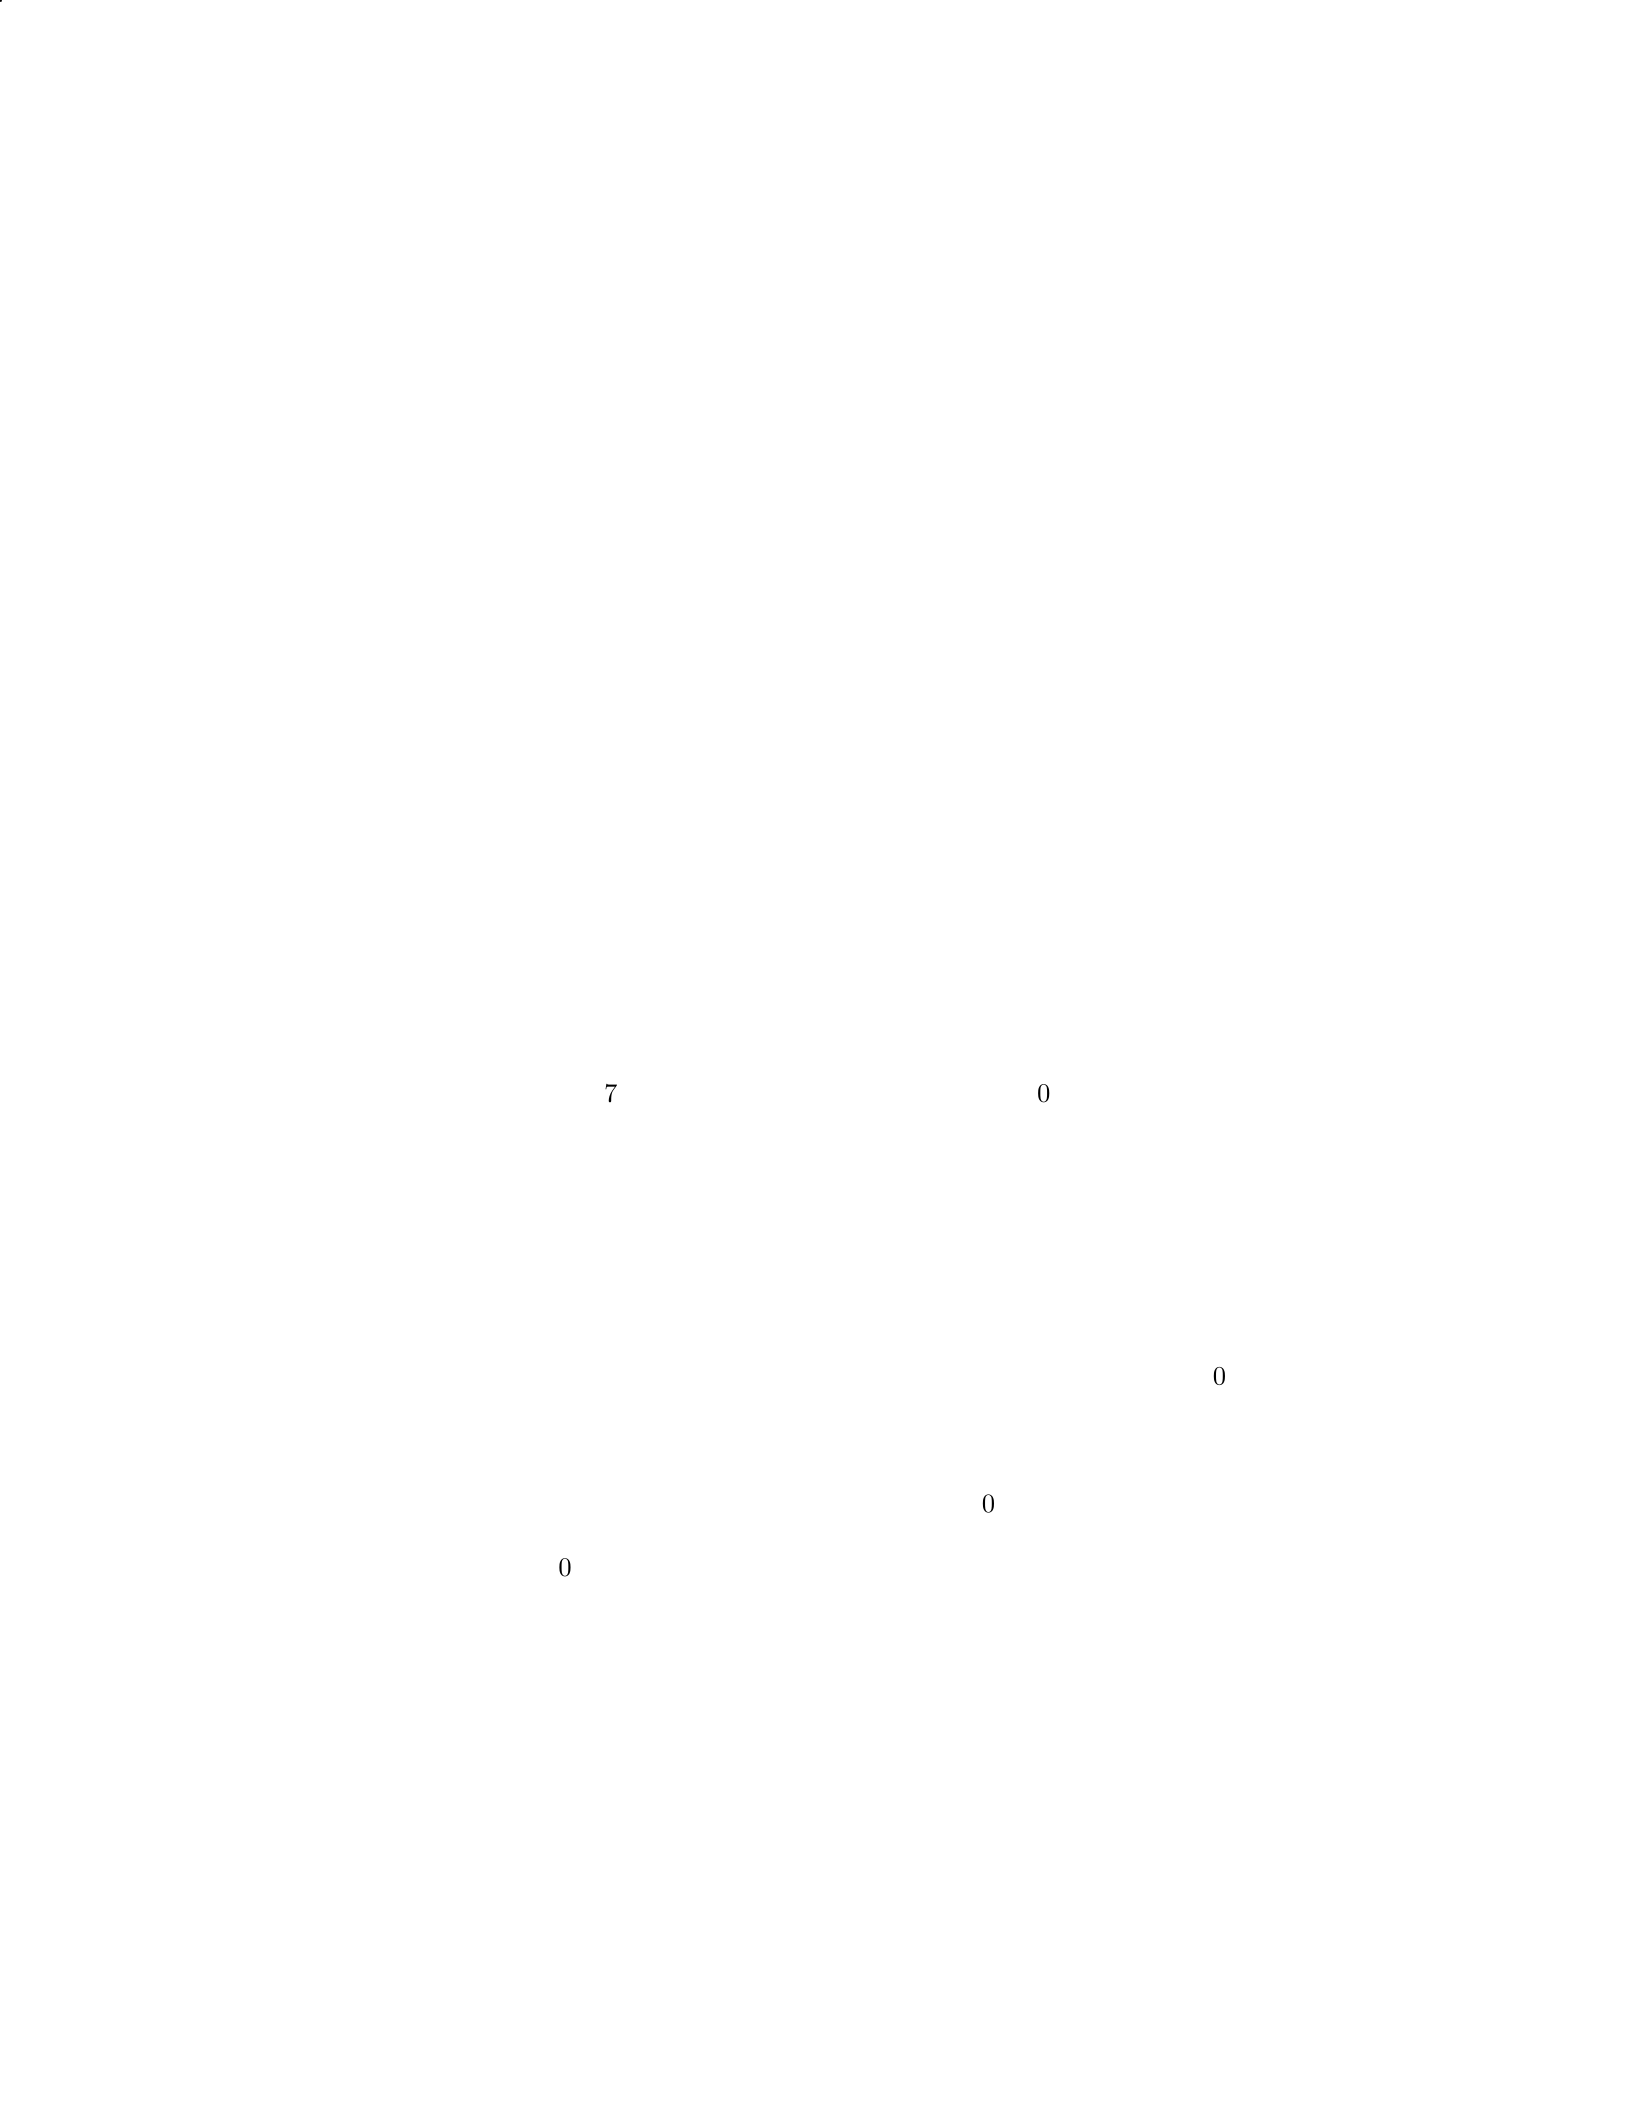
Step 2: The company should disclose the valuation techniques used to deter-
mine the fair value. This may include the use of discounted cash flows, market
multiples, or option pricing models.
Step 3: The company should disclose the quantitative information about the
fair value measurement. This includes the carrying amount of the investment,
the fair value measurement at the reporting date, and any changes in fair value
recognized in the income statement.
Step 4: If there are significant unobservable inputs used in the fair value
measurement, the company should disclose the sensitivity of the fair value to
changes in these inputs.
Step 5: The company should provide a qualitative description of the val-
uation process, including any assumptions made and judgments exercised in
determining the fair value measurement.
Step 6: Finally, the company should disclose any transfers between levels
of the fair value hierarchy and the reasons for such transfers. This information
helps users understand how the fair value measurement has changed over time.
Question 21
Question
A company owns an investment property that is measured at fair value through
profit or loss. The fair value of the investment property at the end of the
reporting period is
$
750,000, and the company incurs
$
10,000 in transaction
costs to sell the property. How should the company account for the transaction
costs in relation to the fair value measurement of the investment property?
Solution
1. Transaction costs should not be deducted from the fair value of the investment
property when measuring it at fair value through profit or loss, according to
IFRS 13 Fair Value Measurement.
2. The fair value of the investment property should be reported at
$
750,000
without deducting the transaction costs.
3. The transaction costs incurred to sell the investment property should be
recognized in profit or loss in the period in which they are incurred.
Therefore, the company should account for the
$
10,000 transaction costs sep-
arately in the profit or loss statement and report the fair value of the investment
property at
$
750,000 without deducting the transaction costs.
16
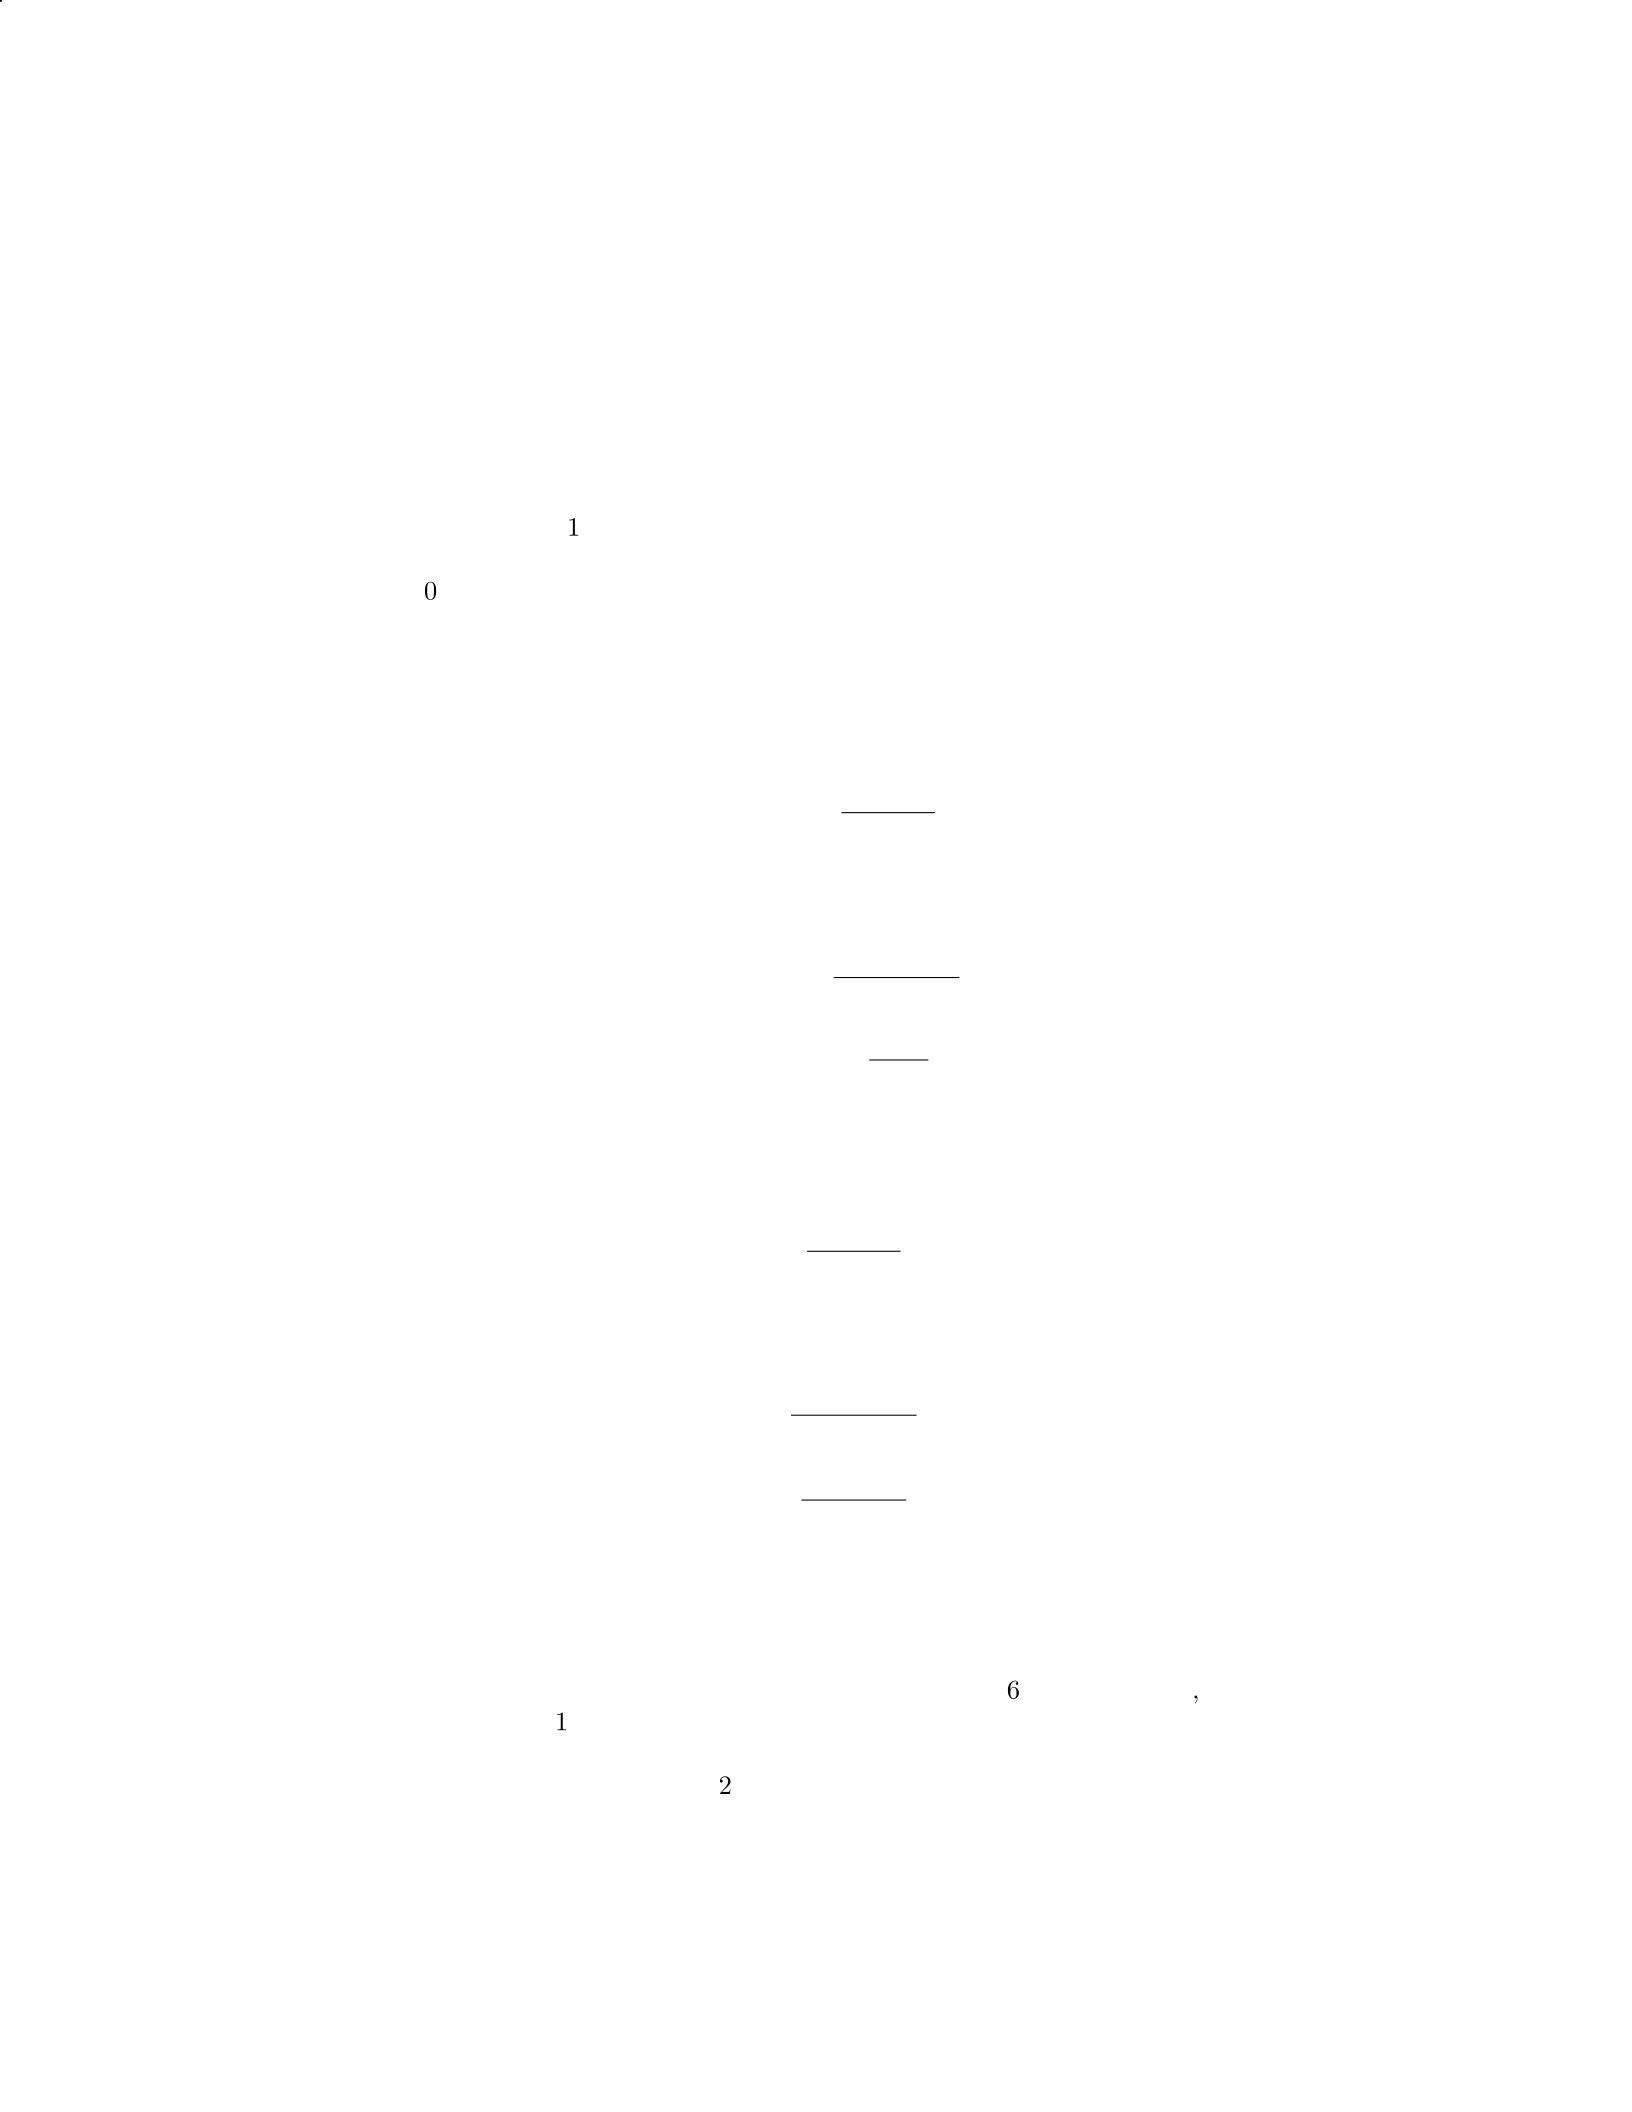
Question 22
Question
A company is required to determine the fair value of an investment property
using the income approach. The property is expected to generate an annual
rental income of
$
100,000 for the next 5 years. The entity uses a discount rate
of 8% for such investments. If the property is expected to be sold after 5 years
for
$
500,000, what is the fair value of the investment property?
Solution
Step 1: Calculate the present value of the expected rental income. The present
value of an annuity formula is given by:
P V =P mt ×1−1
(1 + r)n∇ · r
where: P mt = $100,000, r= 0.08, n= 5 years
Plugging in the values:
P V = $100,000 ×1−1
(1 + 0.08)5∇ · 0.08
P V = $100,000 ×(1 −1
1.085)∇ · 0.08
P V $376,957.38
Step 2: Calculate the present value of the expected selling price after 5 years.
The present value of a single cash flow formula is given by:
P V =F V
(1 + r)n
where: F V = $500,000, r= 0.08, n= 5 years
Plugging in the values:
P V =$500,000
(1 + 0.08)5
P V =$500,000
1.085
P V $303,170.43
Step 3: Calculate the fair value of the investment property. The fair value of
the investment property is the sum of the present values of the expected rental
income and the expected selling price: Fair Value = Present Value of Rental
Income + Present Value of Selling Price Fair Value
$
376,957.38 +
$
303,170.43
Fair Value
$
680,127.81
Therefore, the fair value of the investment property using the income ap-
proach is approximately
$
680,127.81.
17
Question 23
Question
A company holds an investment in a financial asset classified as fair value
through other comprehensive income. At the end of the current reporting pe-
riod, the fair value of the investment is 150,000.Duringtheyear, thefairvalueof theinvestmentincreasedby20,000
due to changes in market conditions. Additionally, the company received divi-
dends of 5,000fromtheinvestmentduringtheyear.Calculatethetotalcomprehensiveincomerelatedtothisinvestmentf orthecurrentreportingperiod.
Solution
Let’s break down the total comprehensive income related to the investment into
its components.
Step 1: Calculate the gain or loss recognized in other comprehen-
sive income
The fair value of the investment at the beginning of the year was 150,000−20,000
= 130,000.T herefore, thegainrecognizedinothercomprehensiveincomeduetochangesinf airvalueis150,000
- 130,000 =20,000.
Step 2: Calculate the dividends recognized in other comprehensive
income
The dividends received during the year were 5,000.Dividendsreceivedareincludedinothercomprehensiveincomef orinvestmentsaccountedf oratfairvaluethroughothercomprehensiveincome.
Step 3: Calculate the total comprehensive income related to the
investment
Total comprehensive income = Gain or loss recognized in other compre-
hensive income + Dividends recognized in other comprehensive income
Total comprehensive income = 20,000+5,000 = 25,000.
Therefore, the total comprehensive income related to this investment for the
current reporting period is 25,000.
Question 24
Question
A company holds an investment classified as available-for-sale financial asset.
The fair value of this investment at the end of the reporting period is 200,000.T hecompany′smanagementisconsideringreclassif yingthisinvestmentasheldf ortradingtotakeadvantageofshort−
termpricemovements.If thef airvalueisexpectedtoincreaseto220,000 in the near
future, what impact would this decision have on the company’s financial state-
ments? Justify your answer with reference to Fair Value Measurement.
18

Solution
To answer this question, we need to consider the implications of reclassifying
the investment from available-for-sale to held for trading in terms of Fair Value
Measurement.
Step 1: When an investment is reclassified from available-for-sale to held
for trading, any unrealized gains or losses in the available-for-sale reserve must
be recognized in the income statement immediately.
Step 2: In this case, since the fair value of the investment is expected to in-
crease to 220,000inthenearfuture, thereisanunrealizedgainof 20,000 (220,000−200,000).
Step 3: If the company reclassifies the investment as held for trading, this
20,000unrealizedgainwillbeimmediatelyrecognizedintheincomestatementundergainsoninvestments.
Step 4: The reclassification will not affect the balance sheet directly, as the
asset will still be presented at fair value on the balance sheet.
Step 5: However, the income statement will show an increase in net income
due to the recognition of the 20,000gain.
Step 6: Overall, the reclassification of the investment from available-for-sale
to held for trading will result in a positive impact on the company’s financial
statements by increasing its reported net income for the period.
Question 25
Question
A company holds an investment in a financial instrument categorized as a Level
3 fair value measurement. At the end of the reporting period, the fair value of the
investment is 250,000.T hecompany′smanagementneedstodetermineiftherehavebeenanychangesinthefairvalueof theinvestmentcomparedtothebeginningof thereportingperiod.P rovideastep−
by−stepguideonhowthecompanycananalyzeandreportthechangesinthef airvalueoftheinvestment.
Solution
To analyze and report the changes in the fair value of the investment categorized
as a Level 3 fair value measurement, the company can follow these steps:
Step 1: Review the Valuation Techniques - The company should review
the valuation techniques used to determine the fair value of the investment at
the beginning of the reporting period. This may include market approaches,
income approaches, and cost approaches.
Step 2: Assess Changes in Inputs - Management should assess if there
have been any changes in the inputs used in the valuation techniques. Inputs
may include market data, interest rates, credit spreads, etc. Changes in these
inputs can significantly impact the fair value of the investment.
Step 3: Determine Fair Value Changes - Calculate the change in fair
value by comparing the fair value of the investment at the end of the reporting
period (250,000)tothefairvalueatthebeginningof thereportingperiod.T hiswillgivethecompanytheabsolutechangeinf airvalue.
19
Step 4: Analyze the Reason for Changes - Management should analyze
the reasons for the changes in fair value. This could include changes in market
conditions, economic factors, or specific events related to the investment.
Step 5: Disclose in Financial Statements - Finally, the company should
disclose the changes in fair value of the investment in the financial statements.
This disclosure should include the amount of change, the nature of the invest-
ment, and the reasons for the changes.
By following these steps, the company can properly analyze and report any
changes in the fair value of the investment categorized as a Level 3 fair value
measurement.
Question 26
Question
Calculate the fair value of an investment using the market approach. You are
provided the following information:
Comparable assets: 3 similar investments with market values of
$
1,200,
$
1,400, and
$
1,100.
Subject investment: Similar risk profile as the comparable assets but has
generated a higher return of 8%.
Solution
To calculate the fair value of the subject investment using the market approach,
we will need to adjust the market values of the comparable assets based on the
difference in return.
Step 1: Calculate the average rate of return for the comparable
assets
Given market values:
M1= 1200, M2= 1400, M3= 1100
The average rate of return (ravg ) of the comparable assets can be calcu-
lated as:
ravg =M2−M1
M1
+M3−M1
M1
ravg =1400 −1200
1200 +1100 −1200
1200 =200
1200 −100
1200 =100
1200 = 0.0833
Step 2: Adjust the comparable asset values for the subject invest-
ment
Given return on the subject investment: 8%
20
Adjusted value for subject investment can be calculated as:
F Vsubject =1+0.08
1 + ravg
×M1
F Vsubject =1.08
1.0833 ×1200 ≈1193.50
Therefore, the fair value of the subject investment using the market approach
is approximately
$
1193.50.
Question 27
Question
Company XYZ is assessing the fair value of an investment property using
the income approach. The property is expected to generate rental income of
120,000peryearf orthenext10years.T hediscountrateis8
Solution
Step 1: Calculate the present value factor using the formula: P V F =1−(1+r)−n
r,
where ris the discount rate and nis the number of years.
Using r= 0.08 and n= 10,
P V F =1−(1 + 0.08)−10
0.08
P V F =1−0.4632
0.08
P V F ≈0.5368
0.08
P V F ≈6.710
Step 2: Calculate the present value of the rental income using the formula:
P V =Rental Income ×P V F .
Using Rental Income = $120,000 and P V F = 6.710,
P V = $120,000 ×6.710
P V = $803,200
Therefore, the fair value of the investment property using the income ap-
proach is
$
803,200.
21

Question 28
Question
A company holds an investment in a private equity fund. The company classifies
the investment as a Level 3 fair value measurement. At the end of the reporting
period, the fair value of the investment has significantly increased due to posi-
tive financial performance of the investee companies. How should the company
account for this increase in fair value in their financial statements according to
fair value measurement standards?
Solution
Step 1: Under fair value measurement standards, changes in fair value for Level
3 investments are recognized in the income statement. The increase in fair value
of the investment should be recognized as a gain in the income statement. This
gain is reported as part of the company’s net income for the period.
Step 2: The gain recognized in the income statement is also disclosed in the
notes to the financial statements to provide users with additional information
about the nature and impact of fair value changes on the company’s financial
performance.
Step 3: It is important for the company to carefully document and disclose
the inputs and valuation techniques used in determining the fair value of the
investment to ensure transparency and comparability for financial statement
users.
Therefore, the company should recognize the increase in fair value of the
investment as a gain in the income statement and disclose relevant information
in the notes to the financial statements.
Question 29
Question
A company holds an investment in a privately held startup company. The
company values the investment using the fair value measurement model. The
fair value measurements are categorized as Level 3 inputs. What are Level 3
inputs and how are they used in the fair value measurement model?
Solution
Step 1: Level 3 inputs refer to inputs that are unobservable for the asset or
liability being valued. These inputs are used when there is little or no market
activity for the asset or liability, requiring the entity to use its own assumptions
about the inputs that market participants would use when pricing the asset or
liability. Level 3 inputs are typically based on management’s own estimates and
valuations.
22

Step 2: In the fair value measurement model, Level 3 inputs are used to
determine the fair value of assets or liabilities when Level 1 and Level 2 inputs
are not available. This often occurs when the assets or liabilities being valued
are not traded in active markets.
Step 3: When using Level 3 inputs, entities must make significant judgments
and utilize estimation techniques to determine the fair value of the asset or
liability. This may involve developing cash flow projections, utilizing option
pricing models, or other valuation techniques to estimate the fair value.
Step 4: The use of Level 3 inputs introduces measurement uncertainty and
subjectivity into the fair value measurement process. As a result, it is important
for entities to disclose the inputs, assumptions, and methodologies used when
valuing assets or liabilities with Level 3 inputs to provide users of the financial
statements with transparency about the valuation process.
Question 30
Question
Company XYZ has an investment in a financial instrument classified as held for
trading. At the end of the reporting period, the fair value of the financial instru-
ment is 250,000.However, therearecertainobservablef actorsthatsuggestthef airvaluemaynotbereliable.DiscussthestepsCompanyXY Zshouldtake, inaccordancewithIF RS13F airV alueMeasurement, todeterminethef airvalueof thefinancialinstrument.
Solution
To determine the fair value of the financial instrument in question when the fair
value may not be reliable, Company XYZ should follow specific steps outlined
in IFRS 13 Fair Value Measurement. The steps are as follows:
Step 1: Identify the Asset or Liability Identify the specific financial
instrument for which the fair value is to be determined. In this case, it is the
financial instrument classified as held for trading in Company XYZ.
Step 2: Determine the Appropriate Valuation Technique Select the
appropriate valuation technique that is suitable given the nature of the financial
instrument, the characteristics of the market, and other relevant factors. For
example, Company XYZ could consider using a discounted cash flow (DCF)
model to determine the fair value of the financial instrument.
Step 3: Collect Relevant Data Gather all relevant data related to the
financial instrument, the market, and other factors that may affect its fair value.
This includes observable market inputs such as interest rates, credit spreads, and
market prices.
Step 4: Assess the Data Quality Evaluate the quality of the data col-
lected to ensure it is reliable and relevant for the valuation. If there are observ-
able factors that suggest the fair value may not be reliable, consider adjusting
the data or applying additional techniques to verify the fair value.
Step 5: Perform the Valuation Apply the selected valuation technique
using the collected data to determine the fair value of the financial instrument.
23
This may involve making adjustments or using alternative methods to ensure a
reliable estimate of fair value.
Step 6: Review and Disclose Review the valuation process and results
to ensure they are consistent with the requirements of IFRS 13. Disclose the
key assumptions, uncertainties, and other relevant information in the financial
statements to provide transparency to users.
By following these steps, Company XYZ can determine the fair value of
the financial instrument in a manner that is consistent with the principles of
IFRS 13 Fair Value Measurement, even when the fair value may not be readily
observable or reliable.
Question 31
Question
Company X holds an investment in a private equity fund. At the reporting date,
the fair value of the investment is determined to be $1,200,000. During the year,
the fair value of the investment increased by $150,000. However, Company X
noted that the private equity fund has experienced financial difficulties after
the reporting date. As a result, the fair value of the investment is expected to
decrease by $100,000 before the financial statements are authorized for issuance.
Calculate the fair value adjustment that Company X should recognize in its
financial statements.
Solution
Step 1: Calculate the initial increase in fair value. The initial increase in fair
value is $150,000.
Step 2: Calculate the expected decrease in fair value. The expected decrease
in fair value is $100,000.
Step 3: Calculate the net fair value adjustment. The net fair value adjust-
ment is the initial increase minus the expected decrease:
$150,000 −$100,000 = $50,000
Therefore, Company X should recognize a fair value adjustment of $50,000
in its financial statements.
Question 32
Question
A company holds an investment in financial asset A which is classified as a
level 3 investment under fair value hierarchy. The fair value of financial asset
A increased by
$
20,000 during the financial period. In the balance sheet, how
should this increase in fair value be accounted for?
24
Solution
To account for the increase in fair value of financial asset A, we need to under-
stand the fair value hierarchy and how changes in fair value are recognized in
the financial statements.
Step 1: Understand Fair Value Hierarchy
Level 1 assets: These are financial assets that have quoted prices in ac-
tive markets, such as listed stocks or bonds. Their fair value is easily
determined.
Level 2 assets: These are financial assets that do not have quoted prices
in active markets, but their fair value can be determined using observable
market inputs, such as similar assets or benchmark prices.
Level 3 assets: These are financial assets that do not have readily de-
terminable fair values and require more subjective estimation. They are
valued using unobservable inputs.
Given that financial asset A is classified as a level 3 investment, any changes
in fair value will lead to adjustments in the financial statements.
Step 2: Accounting for the Increase in Fair Value When the fair value
of financial asset A increased by
$
20,000, the company needs to account for this
change in the financial statements.
For level 3 investments, changes in fair value are recognized in the income
statement as unrealized gains or losses. In this case, the increase in fair value
of
$
20,000 will be recognized as an unrealized gain in the income statement.
Therefore, the increase in fair value of financial asset A of
$
20,000 will be
accounted for as follows:
Income Statement:
Unrealized Gain on Financial Asset A $20,000
This adjustment reflects the increase in fair value of financial asset A during
the financial period and is reported in the income statement.
Question 33
Question
Company XYZ holds an investment in a private equity fund. The fair value of
this investment is determined using Level 3 inputs. Explain what Level 3 inputs
are and discuss the challenges associated with using Level 3 inputs for fair value
measurements.
25

Solution
Step 1: Level 3 inputs
Level 3 inputs are unobservable inputs for an asset or liability that are used
when determining its fair value. These inputs are based on the best informa-
tion available in the circumstances, which may include the reporting entity’s
assumptions about the assumptions market participants would use in pricing
the asset or liability.
Step 2: Challenges associated with Level 3 inputs
1. Subjectivity: Level 3 inputs are the most subjective of the three levels
of fair value measurement inputs. They require significant judgment and esti-
mation by the reporting entity. As a result, different entities may use different
assumptions leading to different fair value measurements.
2. Lack of market data: Since Level 3 inputs are unobservable, there is
often a lack of market data available to corroborate the fair value estimates.
This lack of market data can make it difficult to assess the reliability of the fair
value measurements based on Level 3 inputs.
3. Sensitivity to assumptions: Fair value measurements using Level
3 inputs can be sensitive to changes in assumptions. Small changes in key
assumptions can result in significant changes in the fair value of the asset or
liability, leading to potential volatility in financial statements.
4. Regulatory scrutiny: Given the subjectivity involved in using Level
3 inputs, fair value measurements based on these inputs are often subject to
increased regulatory scrutiny. Regulators may challenge the reporting entity’s
fair value measurements and assumptions, leading to potential adjustments or
restatements.
In conclusion, while Level 3 inputs are necessary for valuing certain assets
and liabilities, they come with challenges such as subjectivity, lack of market
data, sensitivity to assumptions, and regulatory scrutiny. It is important for
reporting entities to exercise caution and transparency when using Level 3 inputs
for fair value measurements.
Question 34
Question
Company XYZ holds a financial asset that is measured at fair value through
profit or loss. The fair value of the asset at the end of the reporting period is de-
termined to be 600,000.Duringtheyear, theassetgeneratedcashflowsof 50,000.
Additionally, the market risk premium of similar assets was estimated to be 6
Solution
Step 1: Calculate the discount rate using the formula:
Discount Rate = Risk-Free Rate + Market Risk Premium
26

Given that the risk-free rate is 3
Discount Rate = 3% + 6% = 9%
Step 2: Use the discounted cash flow (DCF) formula to find the fair value
of the asset:
Fair Value = Cash Flows
Discount Rate =50,000
0.09 = $555,555.56
Therefore, the fair value of the asset using the discounted cash flow method
is
$
555,555.56.
Question 35
Question
Suppose a company needs to determine the fair value of an investment property.
The company has gathered relevant information and identified the following
three approaches to estimate the fair value: 1. Cost Approach - The cost to
replace the property. 2. Market Approach - Prices of similar properties in the
market. 3. Income Approach - Expected future cash flows from the property.
Explain how each of these approaches can be used to estimate the fair value
of the investment property. Additionally, discuss the advantages and disadvan-
tages of each approach in the context of fair value measurement.
Solution
Step 1: Cost Approach The Cost Approach to fair value measurement involves
determining the current cost to replace the property. This approach assumes
that the fair value of the property should not exceed the cost of acquiring or
constructing a substitute property with equivalent utility.
Advantages: - Useful when reliable market data is not available. - Provides
a straightforward estimation based on replacement cost.
Disadvantages: - Does not consider the property’s specific market conditions
or demand. - Does not reflect potential earning capacity or future cash flows of
the property.
Step 2: Market Approach The Market Approach to fair value measure-
ment involves comparing the subject property to similar properties in the market
that have been recently sold. This approach relies on the principle of substi-
tution, which states that an informed buyer would pay no more for a property
than the cost of acquiring a similar property.
Advantages: - Reflects actual market transactions and prices. - Considers
current supply and demand conditions.
Disadvantages: - Relies on the availability of comparable market data. -
Assumes properties are identical or very similar.
27

Step 3: Income Approach The Income Approach to fair value measure-
ment estimates the present value of expected future cash flows generated by the
property. This approach requires forecasting the property’s income stream and
applying a discount rate to calculate the present value.
Advantages: - Takes into account the property’s income-generating poten-
tial. - Considers the time value of money through discounted cash flows.
Disadvantages: - Relies on accurate forecasting of future cash flows. - Re-
quires a reliable discount rate estimation.
In conclusion, each approach to fair value measurement has its own strengths
and weaknesses. The choice of approach depends on the availability of data,
the specific characteristics of the property, and the purpose of the fair value
estimation.
28

