


ACCT 531 - ACCOUNTING
INFORMATION SYSTEMS - Fair
Value Measurement
Question Bank - Set 1
Liberty University
Question 1
Question
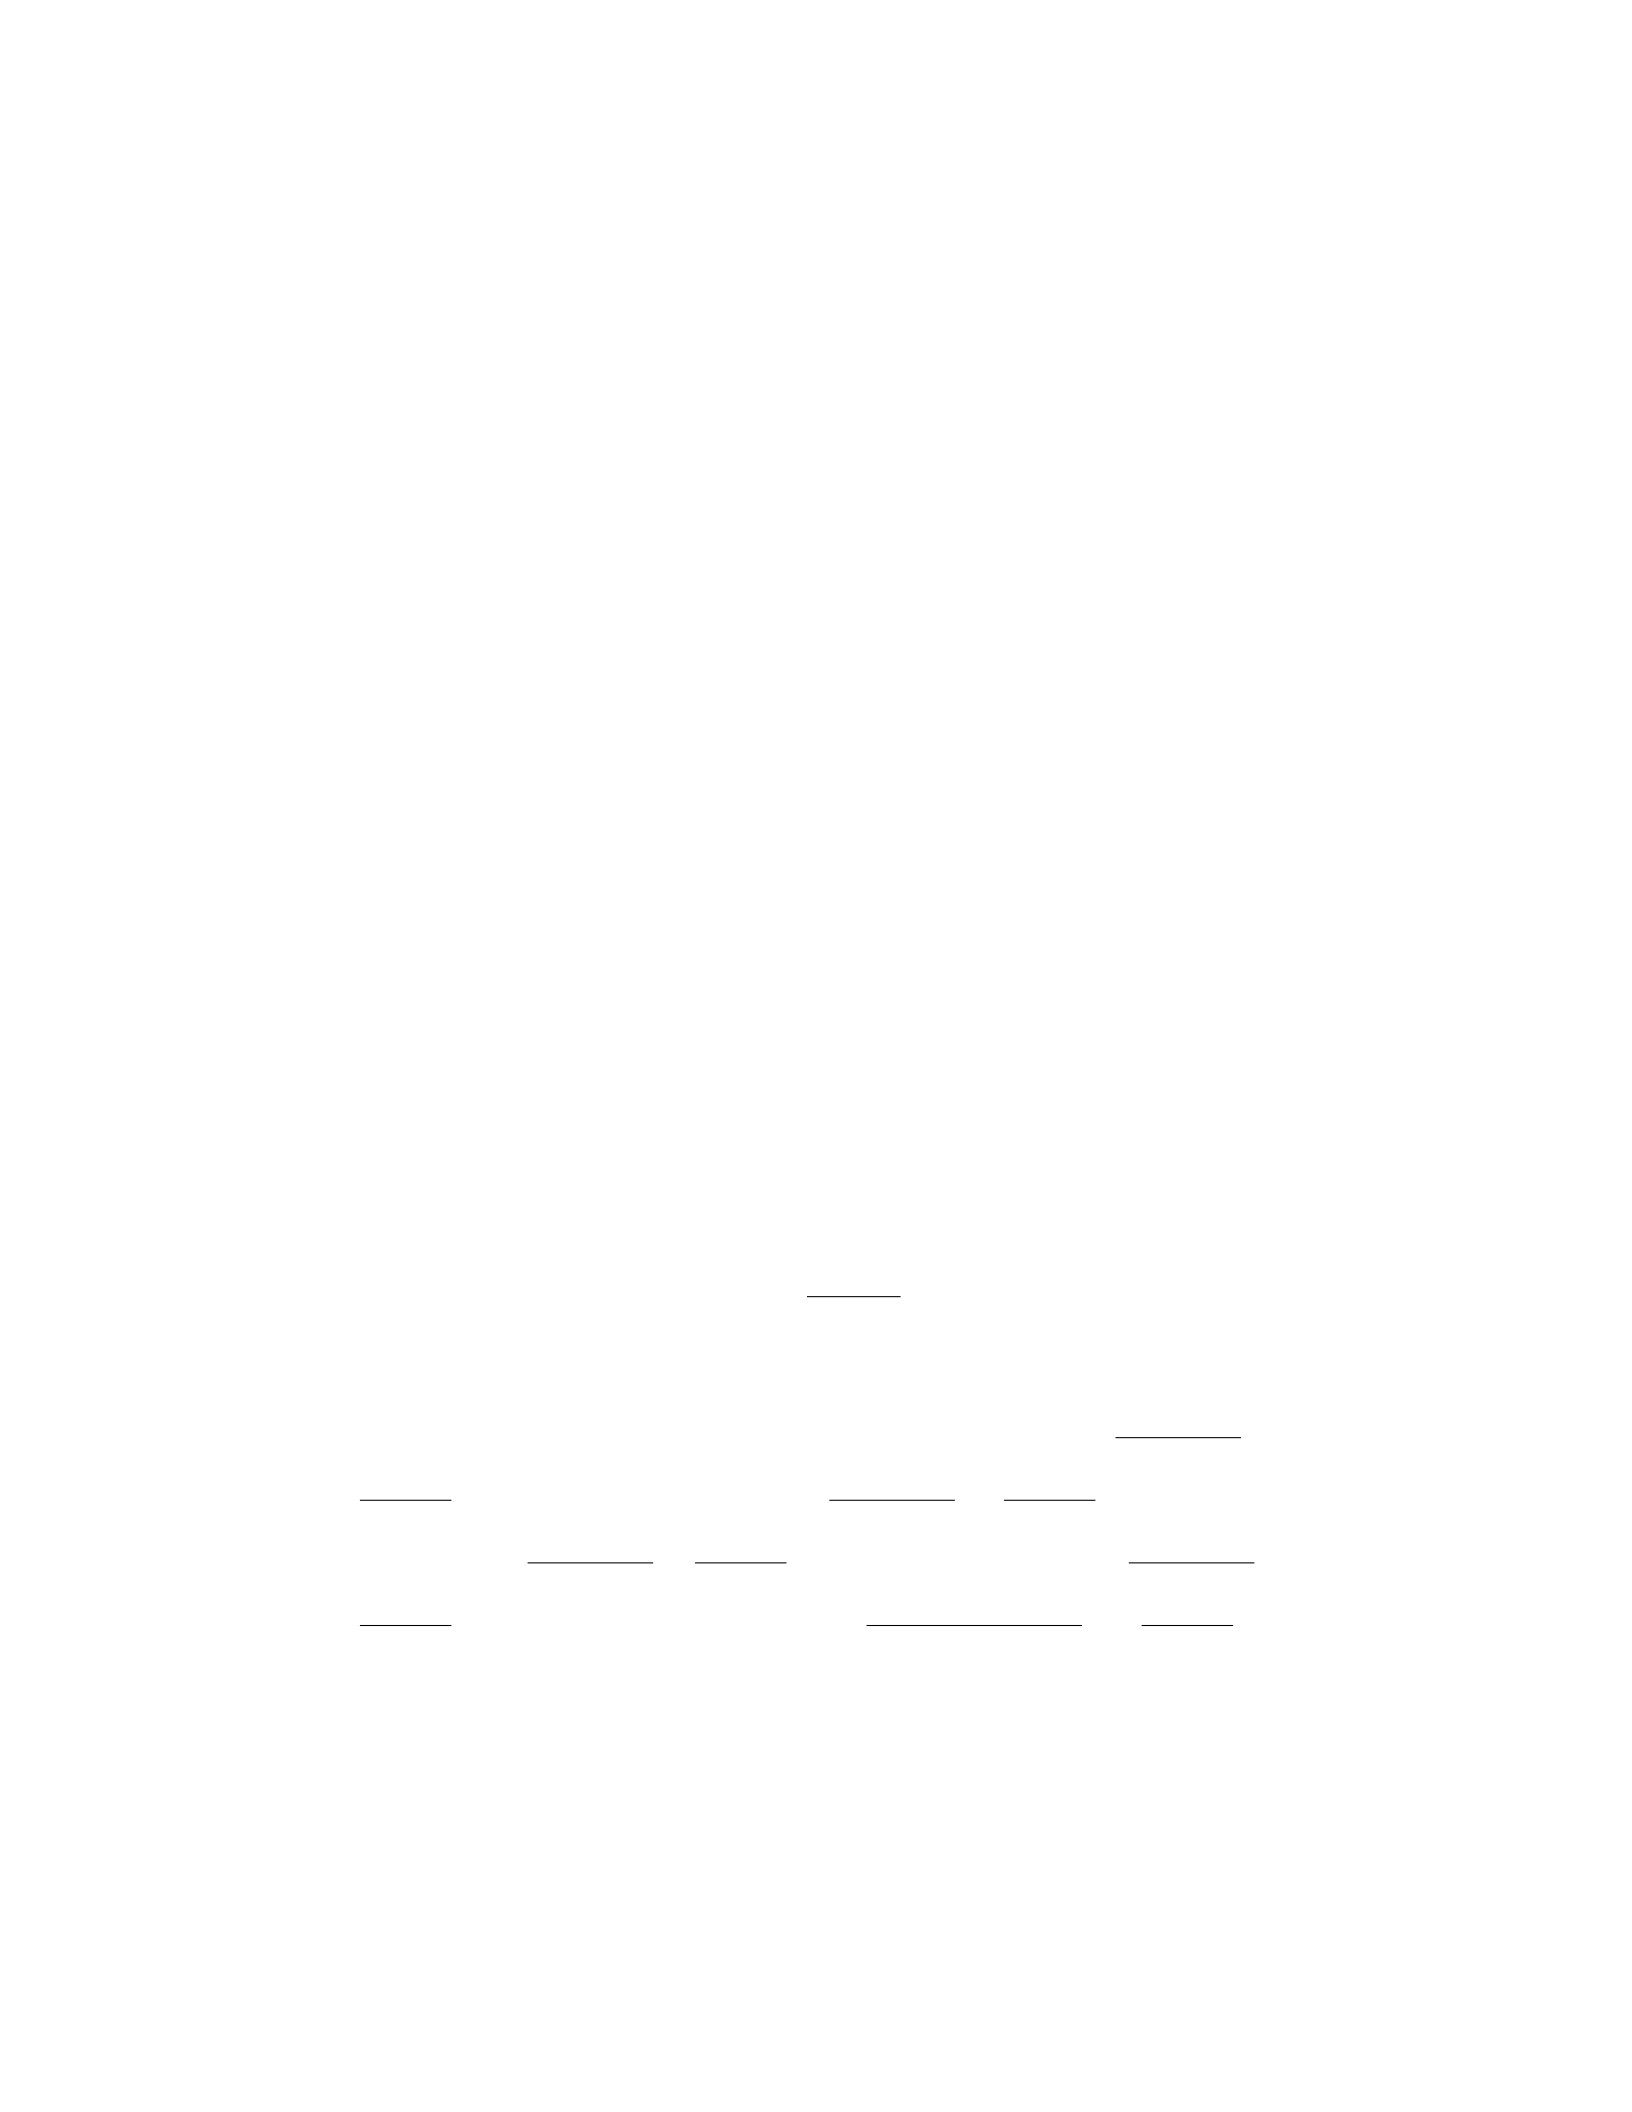
A company is assessing the fair value of a particular asset using the income ap-
proach. The asset has an expected future cash flow of 100,000peryearf orthenext5years, andaterminalvalueof500,000
at the end of year 5. The company uses a discount rate of 8
Solution
Step 1: Calculate the present value of the cash flows for each year using the
formula for present value of a single cash flow:
P V =CF
(1 + r)n
where: - CF is the future cash flow, - ris the discount rate, and - nis the
number of years in the future.
Calculating the present value for each year: - Year 1: P V =100,000
(1 + 0.08)1=
100,000
1.08 ≈92,593.07 - Year 2: P V =100,000
(1 + 0.08)2=100,000
1.1664 ≈85,681.41 -
Year 3: P V =100,000
(1 + 0.08)3=100,000
1.2597 ≈79,365.08 - Year 4: P V =100,000
(1 + 0.08)4=
100,000
1.3605 ≈73,529.41 - Year 5: P V =100,000 + 500,000
(1 + 0.08)5=600,000
1.4693 ≈
408,333.33
Step 2: Add up the present values of all cash flows to obtain the fair value
of the asset:
F air V alue =XP V = 92,593.07+85,681.41+79,365.08+73,529.41+408,333.33 ≈739,501.3

Therefore, the fair value of the asset using the income approach is approxi-
mately 739,501.30.
Question 2
Question
A manufacturing company is required to report the fair value of its inventory for
financial reporting purposes. The company uses Level 3 inputs to determine the
fair value of its inventory. Explain what Level 3 inputs consist of and provide
an example of a Level 3 input that could be used in determining the fair value
of inventory.
Solution
Step 1: Level 3 Inputs Level 3 inputs are unobservable inputs used in fair value
measurements that are supported by little or no market activity. These inputs
are based on the best information available, which may include management’s
own assumptions about the assumptions that market participants would use in
pricing an asset or liability.
Step 2: Example of Level 3 Input An example of a Level 3 input that
could be used in determining the fair value of inventory is a company’s own
internal pricing model. For instance, a manufacturing company may use a pro-
prietary model that takes into account factors like production costs, anticipated
demand, and potential obsolescence to estimate the fair value of its inventory.
Since this information is not publicly available and relies heavily on manage-
ment’s judgment, it would be classified as a Level 3 input in the fair value
measurement process.
Question 3
Question
A company has an investment in a financial instrument classified as a Level 3
fair value measurement. The fair value hierarchy ranks three levels in order of
reliability, with Level 3 being the least reliable. The company is required to
disclose the techniques and significant unobservable inputs used in developing
the fair value. Discuss the challenges and implications of using Level 3 fair value
measurements in financial reporting.
Solution
To address the challenges and implications of using Level 3 fair value measure-
ments, it is important to understand the characteristics of Level 3 fair value
2

measurements and their impact on financial reporting. Here are the key points
to consider:
Step 1: Definition of Level 3 fair value measurements - Level 3
fair value measurements represent financial instruments whose fair values are
determined primarily using unobservable inputs based on the company’s own
assumptions. - These inputs are not based on market data, making Level 3 fair
value measurements the least reliable of the three hierarchy levels.
Step 2: Challenges of using Level 3 fair value measurements - The
most significant challenge of using Level 3 fair value measurements is the sub-
jectivity involved in determining the fair value. - Companies may use different
assumptions and valuation techniques, leading to potential inconsistencies and
lack of comparability between different entities. - The use of significant unob-
servable inputs increases the risk of bias and manipulation in determining the
fair value, which can result in misleading financial statements. - There may be
limited market data available for assets or liabilities classified as Level 3, making
it difficult to assess the reasonableness of the fair value estimates.
Step 3: Implications of using Level 3 fair value measurements - The
use of Level 3 fair value measurements can impact the transparency and reli-
ability of financial reporting. - Stakeholders, including investors and analysts,
may have concerns about the reliability of financial statements that heavily rely
on unobservable inputs. - Companies using Level 3 fair value measurements are
required to disclose the valuation techniques and significant unobservable inputs
used, providing additional information for stakeholders to assess the reliability
of the fair value estimates. - Regulatory scrutiny and audit attention are typ-
ically higher for Level 3 fair value measurements to ensure the reasonableness
and accuracy of the reported values.
In conclusion, the challenges and implications of using Level 3 fair value
measurements emphasize the importance of transparency, disclosure, and con-
sistent application of valuation techniques to ensure the reliability and relevance
of financial information disclosed in the financial statements.
Question 4
Question
Company XYZ holds an investment in a security which is classified as a Level 2
fair value measurement. The security has a quoted price of 105perunit, butthebid−
askspreadiswideduetoilliquidity.T hebestestimateofthef airvalueof thesecurity, basedonthebidpriceprovidedbyabroker, is103
per unit. The observable input used in the valuation is the bid price. Calculate
the fair value of the investment using the bid price approach.
Solution
Step 1: Determine the fair value adjustment - Since the security is classi-
fied as a Level 2 fair value measurement, the fair value is determined us-
3
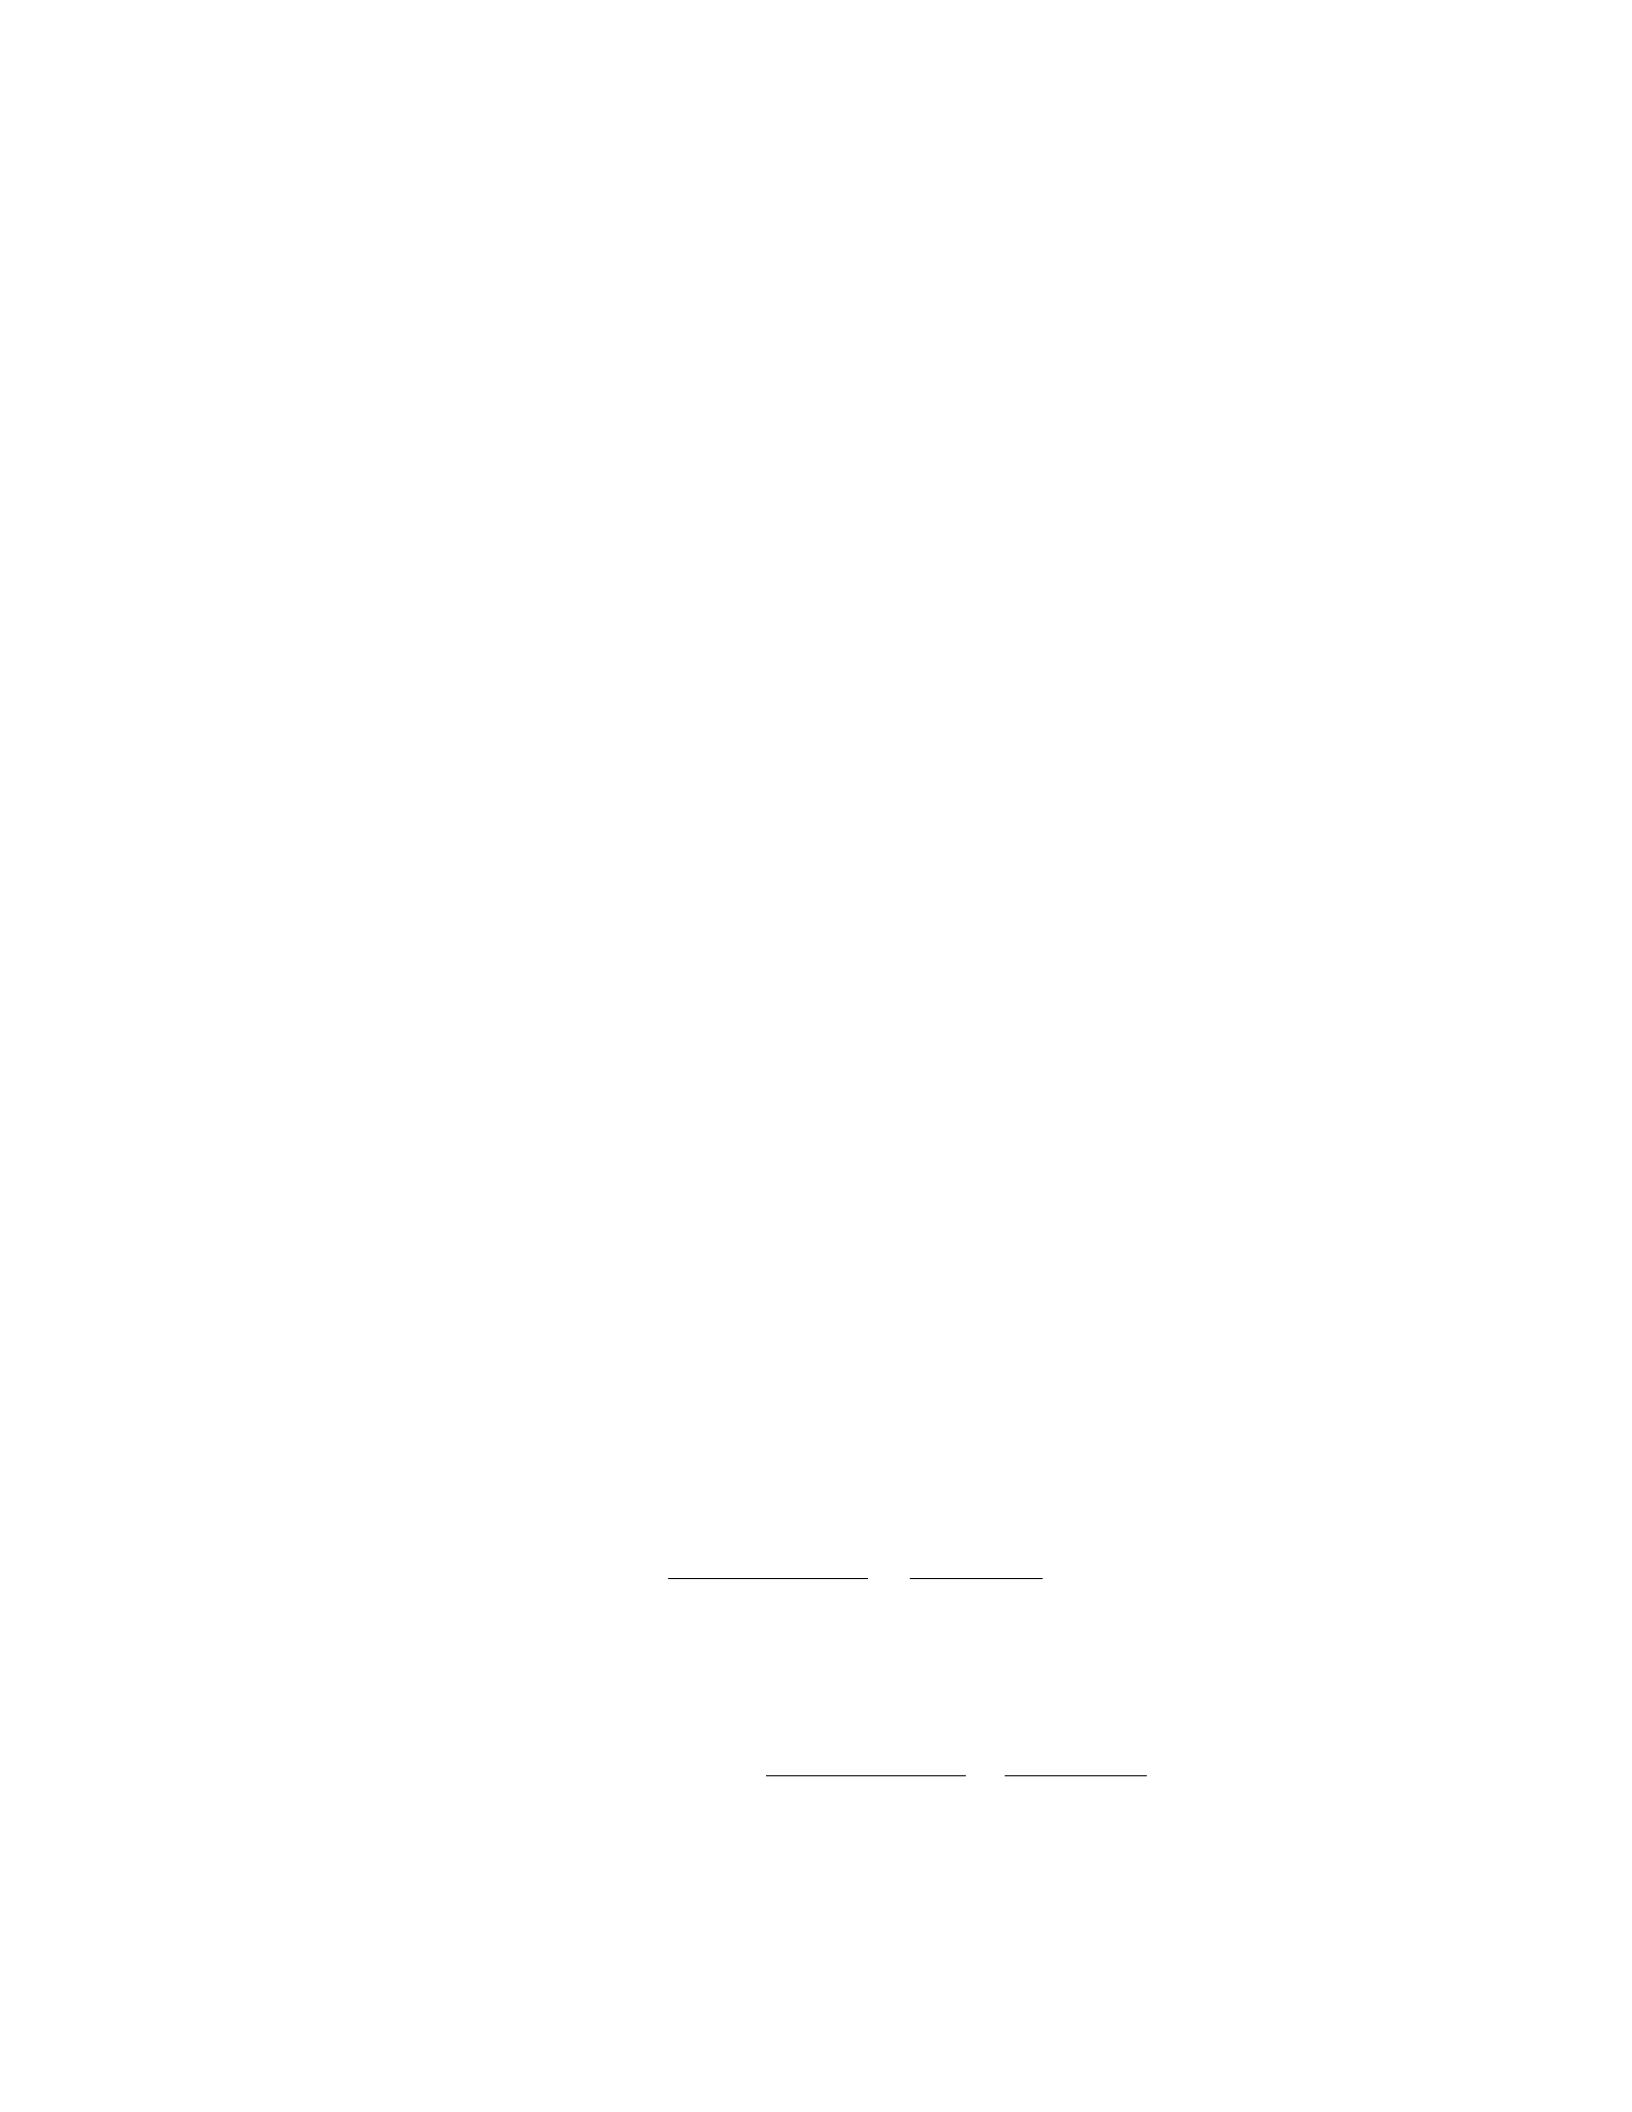
ing observable inputs, which in this case is the bid price of 103perunit. −
T hefairvalueadjustmentisthedif ferencebetweentheobservablebidpriceandthequotedprice.T heref ore, thefairvalueadjustmentis :
F air V alue Adjustment =Bid P rice −Quoted P rice
=
103 - 105 = −2
Step 2: Calculate the fair value of the investment using the bid price ap-
proach - The fair value of the investment is calculated by adjusting the quoted
price by the fair value adjustment.
F air V alue =Quoted P rice +F air V alue Adjustment
F air V alue =
105 - 2 =103
Thus, the fair value of the investment using the bid price approach is 103perunit.
Question 5
Question
Company XYZ holds an investment in a bond that is classified as a Level 2 fair
value measurement. The bond has a quoted price of 980, butthemarketforthisbondisnotveryactive.T oestimatethefairvalueofthebond, CompanyXY Zusesinputsotherthanquotedpricesthatareobservableforsimilarbonds.If theyieldonsimilarbondsis5.2
Solution
To estimate the fair value of the bond using a Level 2 fair value measurement
approach, Company XYZ will use observable market inputs other than quoted
prices. Given that the quoted price of the bond is 980andtheyieldonsimilarbondsis5.2
Step 1: Calculate the annual interest payment on the bond. The annual
interest payment can be calculated using the formula:
Interest Payment = Face Value ×Coupon Rate
Since the quoted price of the bond is 980, thef acevalueis1,000 (at par). The
coupon rate is not given in the question, so we need to calculate it:
Coupon Rate = Interest Payment
Face Value =980 ×0.052
1,000 = 0.5096
Step 2: Calculate the estimated fair value of the bond. The estimated fair
value can be calculated by discounting the future cash flows (interest payments
and face value) using the yield on similar bonds (5.2
Estimated Fair Value = Interest Payment
(1 + Yield) +Face Value
(1 + Yield)n
4
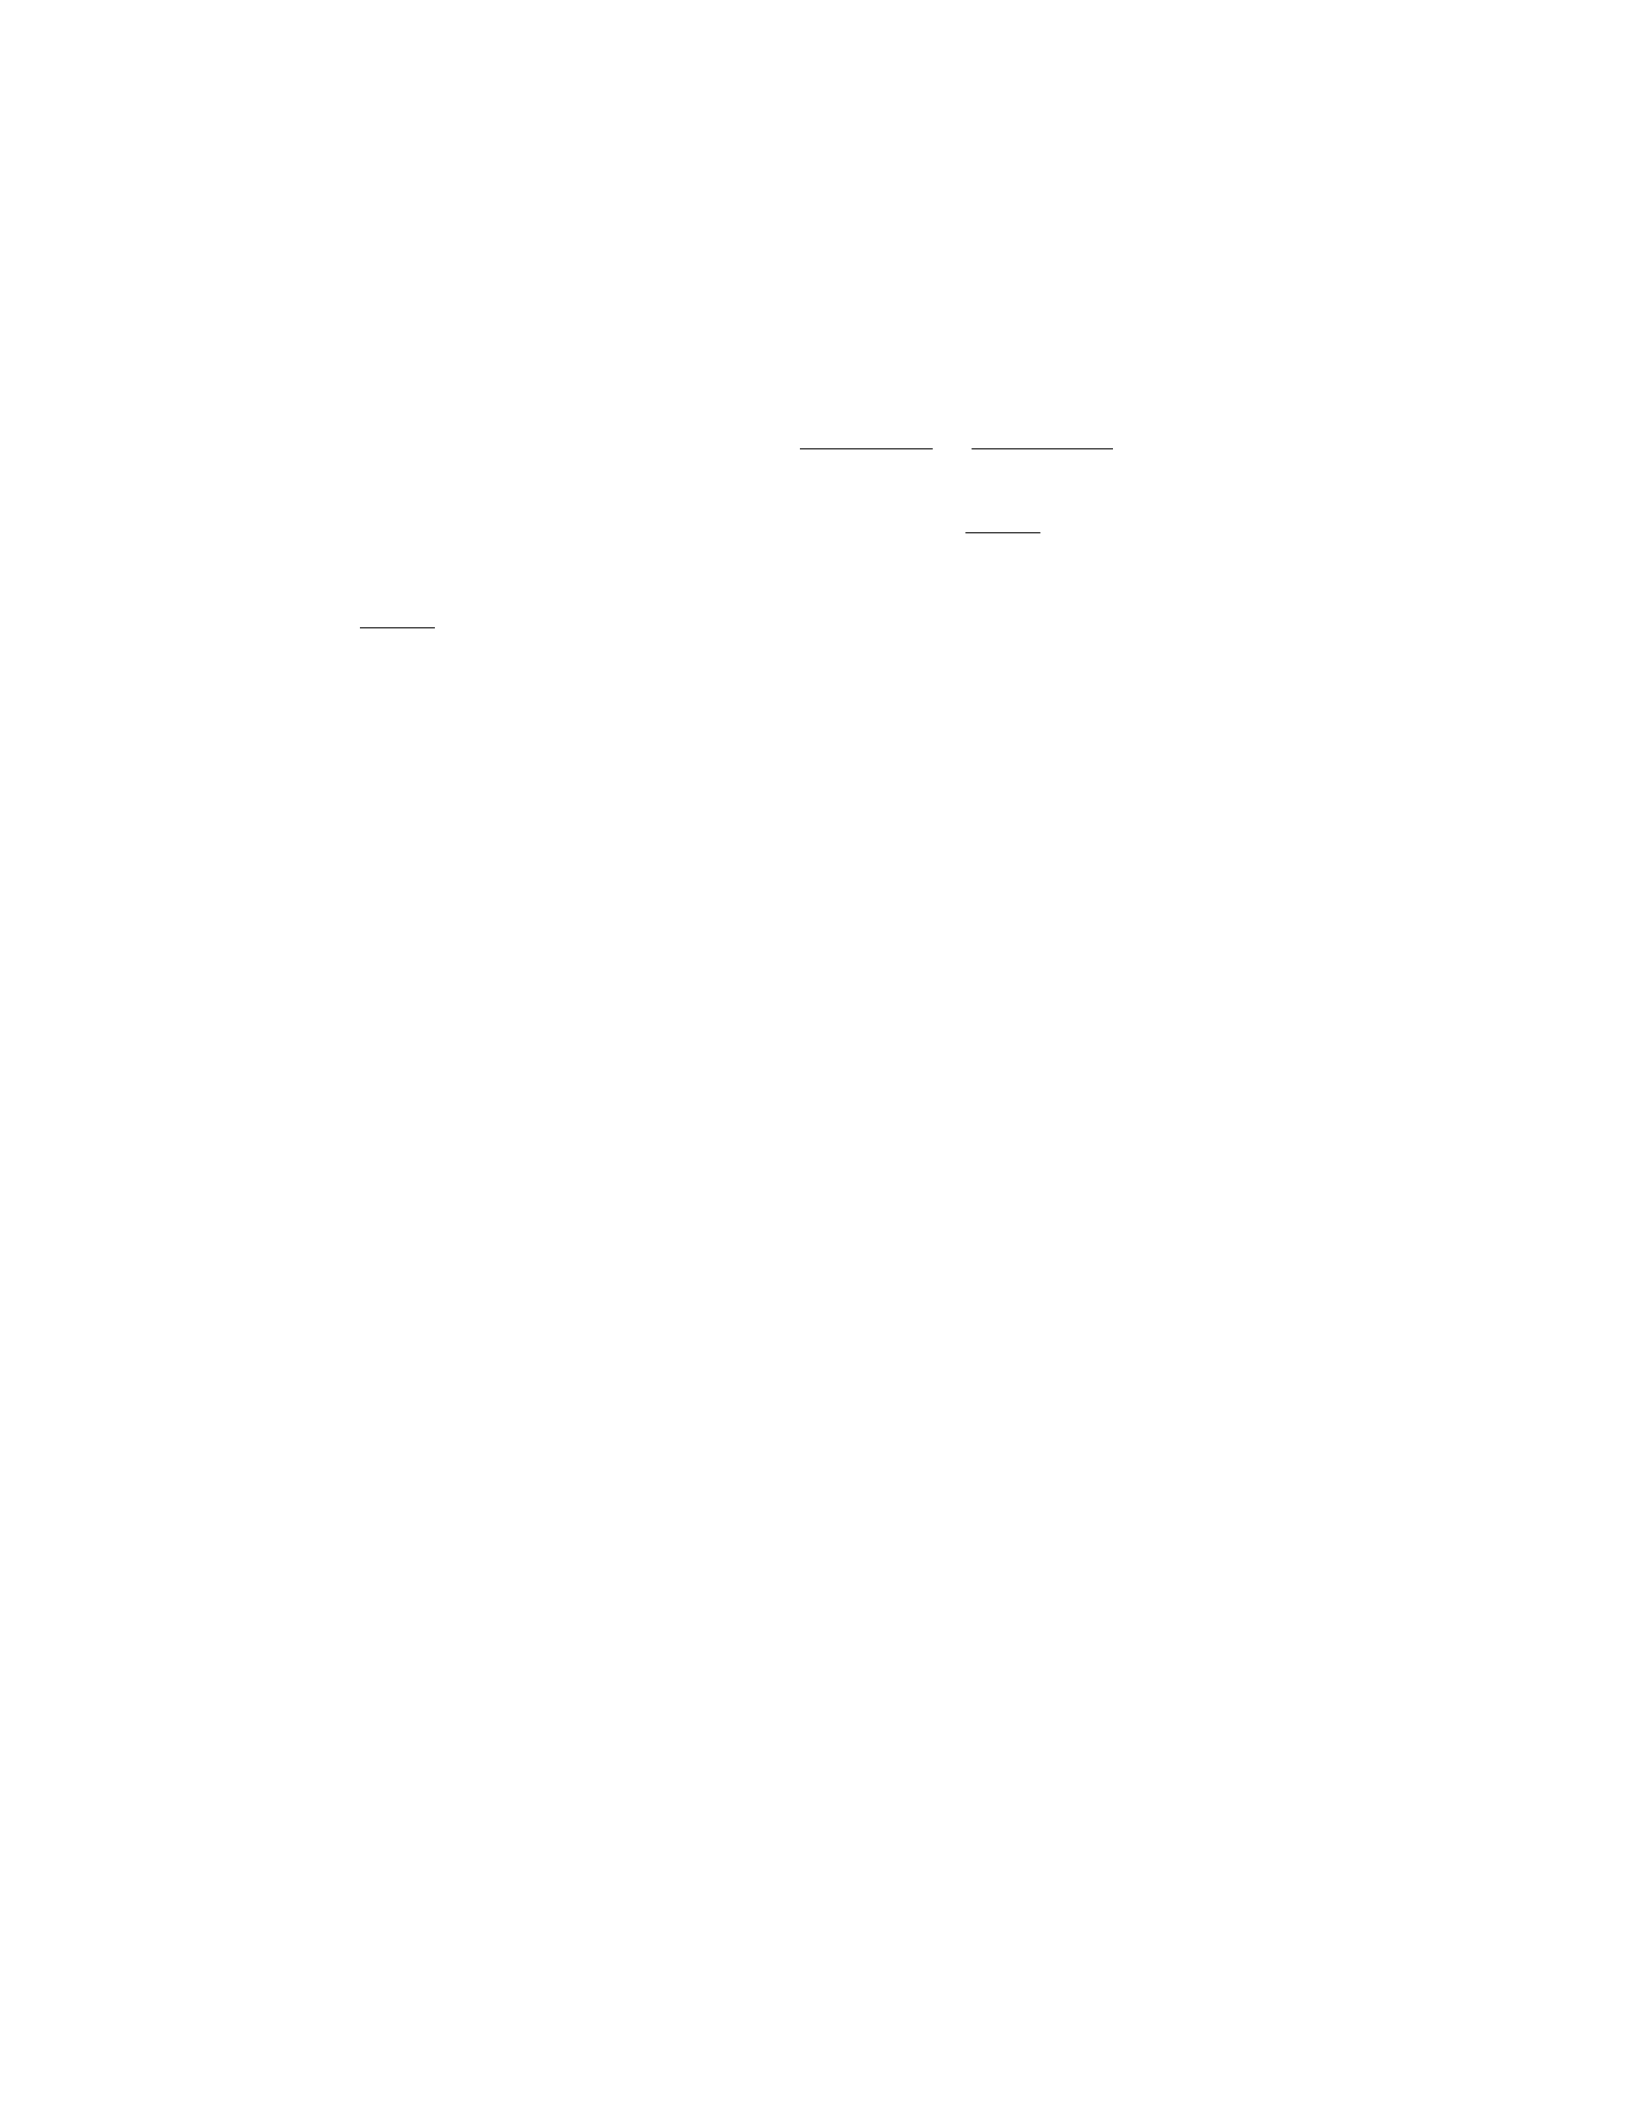
where nis the number of periods until the bond matures.
Step 3: Substitute the values into the formula and calculate.
Estimated Fair Value = 980 ×0.052
1+0.052 +1,000
(1 + 0.052)n
Estimated Fair Value = 51.04 + 1,000
1.052n
Thus, the estimated fair value of the bond held by Company XYZ is 51.04 +
1,000
1.052n.
Question 6
Question
Company XYZ holds an investment property whose fair value needs to be deter-
mined for financial reporting purposes. The property has a cost of $750,000 and
a current fair value of $825,000. Company XYZ also incurred $5,000 in trans-
action costs to acquire the property. Calculate the fair value of the investment
property for financial reporting purposes.
Solution
Step 1: Calculate the cost of the investment property including transaction
costs.
Total Cost = Cost of Property+Transaction Costs = $750,000+$5,000 = $755,000
Step 2: Determine the fair value adjustment based on the cost of the prop-
erty.
Fair Value Adjustment = Fair Value−Total Cost = $825,000−$755,000 = $70,000
Step 3: Calculate the fair value of the investment property for financial
reporting purposes.
Fair Value = Total Cost+Fair Value Adjustment = $755,000+$70,000 = $825,000
Therefore, the fair value of the investment property for financial reporting
purposes is $825,000.
Question 7
Question
A company holds an investment in a financial asset classified as available-
for-sale. At the end of the reporting period, the fair value of the asset is
1,500.However, duetomarketuncertainties, thecompany′smanagementbelievesthatthef airvaluemayf luctuatesignificantlyinthenearf uture.Howshouldthecompanyaccountf orthef airvaluemeasurementofthisfinancialassetinitsfinancialstatements?
5

Solution
1. Initial Recognition: The company should initially recognize the financial
asset at cost. In this case, the cost of the asset will be the initial purchase price.
2. Subsequent Measurement at Fair Value: As the financial asset is
classified as available-for-sale, subsequent measurement should be at fair value.
At the end of each reporting period, the company should measure the fair value
of the asset.
3. Recognition of Unrealized Gains or Losses: Any unrealized gains
or losses resulting from changes in fair value should be recognized in other
comprehensive income (OCI) until the asset is derecognized from the balance
sheet or the fair value change represents an impairment.
4. Impairment Testing: If there are indicators of impairment, such as
a significant decline in the fair value of the asset below its cost, the company
should perform impairment testing. If the asset is impaired, the company should
recognize the impairment loss in its income statement.
5. Disclosure: The company should disclose the fair value hierarchy of the
financial asset, the valuation techniques used, and any significant unobservable
inputs.
Therefore, the company should account for the fair value measurement of
the financial asset by measuring it at fair value at the end of each reporting
period and recognizing any unrealized gains or losses in OCI until the asset is
derecognized or impaired.
Question 8
Question
A company holds an investment in a private company that is not traded on any
public market. The fair value of the investment is determined using Level 3
inputs. Explain what Level 3 inputs are and provide an example of such inputs
in the context of fair value measurement.
Solution
Step 1: Fair value measurements can be categorized into three levels based on
the inputs used in the valuation process. Level 3 inputs are unobservable inputs
that are used when observable data is not available. These inputs are based
on the company’s own assumptions and estimates, and can have a significant
impact on the fair value measurement.
Step 2: An example of Level 3 inputs in the context of fair value measurement
for an investment in a private company could be the use of a discounted cash
flow (DCF) model. In this case, the company would need to estimate future
cash flows of the private company, determine an appropriate discount rate, and
make assumptions about the growth rate and terminal value. These inputs are
6

all based on the company’s own assessments and are not readily observable in
the market.
Step 3: The use of Level 3 inputs in fair value measurement introduces
subjectivity and potential bias into the valuation process. It is important for
companies to disclose the nature and impact of Level 3 inputs in their financial
statements to provide transparency to investors and other stakeholders.
Question 9
Question
A company holds an investment in a privately held company that specializes
in renewable energy projects. The fair value of this investment must be deter-
mined for financial reporting purposes. Discuss the key considerations and steps
involved in applying fair value measurement techniques for this investment.
Solution
To determine the fair value of the investment in the privately held company
specializing in renewable energy projects, several key considerations and steps
must be taken into account. Below are the key considerations and steps involved
in applying fair value measurement techniques for this investment:
Step 1: Understand Fair Value Measurement Fair value is defined as
the price that would be received to sell an asset or paid to transfer a liability in
an orderly transaction between market participants at the measurement date.
It is important to have a clear understanding of this concept before proceeding
with the fair value measurement process.
Step 2: Determine the Valuation Techniques Select appropriate val-
uation techniques based on the nature of the investment. Common valuation
techniques include market approach, income approach, and cost approach. In
this case, a combination of techniques may be necessary to arrive at a reliable
fair value estimate.
Step 3: Gather Relevant Data Collect all relevant information about
the renewable energy projects company, such as financial statements, cash flow
projections, market comparables, industry data, and any other pertinent infor-
mation that can assist in the valuation process.
Step 4: Adjust for Market and Company-Specific Factors Consider
the impact of market conditions and company-specific factors on the fair value of
the investment. Adjust the valuation based on these factors to ensure a realistic
fair value estimate.
Step 5: Reconcile and Review Reconcile the information gathered and
the valuation results to ensure consistency and accuracy. Review the assump-
tions made and the methodologies used in the valuation process to validate the
fair value estimate.
7
Step 6: Disclose the Fair Value Measurement Finally, disclose the
fair value measurement of the investment in the financial statements in accor-
dance with the applicable accounting standards. Provide detailed information
about the valuation techniques used, key assumptions made, and any significant
uncertainties surrounding the fair value estimate.
By following these key considerations and steps, the company can effectively
apply fair value measurement techniques to determine the fair value of its invest-
ment in the privately held company specializing in renewable energy projects
for financial reporting purposes.
Question 10
Question
You are a financial analyst tasked with determining the fair value of a complex
derivative instrument. The instrument has several components with unique
characteristics that affect its value. Explain what factors you would consider
when determining the fair value of this derivative instrument.
Solution
To determine the fair value of a complex derivative instrument, several factors
need to be considered. Below are the key factors:
Step 1: Identify the Components
Identify and understand each individual component of the derivative in-
strument, such as options, forwards, swaps, etc.
Determine the specific terms and conditions of each component, including
exercise prices, expiration dates, underlying assets, etc.
Step 2: Market Variables
Evaluate current market conditions and variables that may impact the
value of the derivative instrument, such as interest rates, volatility, credit
spreads, etc.
Consider how changes in these market variables would affect the value of
the derivative instrument.
Step 3: Risk Factors
Assess the different types of risk associated with the derivative instrument,
including market risk, credit risk, liquidity risk, etc.
Quantify the impact of these risks on the fair value of the instrument.
Step 4: Valuation Models
8
Select an appropriate valuation model based on the characteristics of the
derivative instrument, such as Black-Scholes model for options, discounted
cash flow analysis for swaps, etc.
Input the relevant data and assumptions into the valuation model to cal-
culate the fair value of the derivative instrument.
Step 5: Documentation and Disclosure
Document the assumptions, methodologies, and models used in determin-
ing the fair value of the derivative instrument.
Ensure proper disclosure of the fair value measurement process in financial
reports to provide transparency to stakeholders.
By considering these factors and following a structured approach, the fi-
nancial analyst can accurately determine the fair value of a complex derivative
instrument.
Question 11
Question
Company XYZ holds an investment in a private company whose fair value is not
readily determinable. The management of XYZ is required to estimate the fair
value of this investment for financial reporting purposes. Discuss the different
valuation techniques that can be used by XYZ to determine the fair value of
this investment.
Solution
To estimate the fair value of an investment when it is not readily determinable,
Company XYZ can use a variety of valuation techniques. Here are some common
methods that can be considered:
Step 1: Market Approach
XYZ can use the market approach by comparing the investment to similar
investments that have observable market prices. This method involves us-
ing market multiples or transaction prices of comparable assets to estimate
the fair value.
For example, XYZ could look at recent transactions of similar private
companies or use publicly traded companies in the same industry to derive
a valuation multiple which can then be applied to the financial metrics of
the investment.
Step 2: Income Approach
9
XYZ can also utilize the income approach, such as the discounted cash flow
(DCF) method, to estimate the fair value of the investment. This method
involves forecasting the future cash flows expected from the investment
and discounting them back to present value using an appropriate discount
rate.
The DCF method takes into account the timing and risk associated with
the cash flows, providing a comprehensive estimate of the investment’s fair
value.
Step 3: Cost Approach
Another technique that XYZ can consider is the cost approach. This
method involves estimating the fair value of the investment by determining
the cost to replace or reproduce the investment.
XYZ would consider the cost of acquiring or developing a similar invest-
ment with the same functionality, condition, and utility. This approach
can be particularly useful for assets with no comparable market data.
By considering these different valuation techniques, Company XYZ can make
a reasonable estimate of the fair value of its investment in the private company,
even when the fair value is not readily determinable.
Question 12
Question
Company XYZ holds an investment in a privately-held company that operates
in a niche market. The investment is classified as Level 3 under the fair value
hierarchy. Company XYZ has determined the fair value of this investment
using a discounted cash flow (DCF) model. Discuss the key considerations
and challenges in applying the DCF model for fair value measurement in this
scenario.
Solution
To determine the fair value of the investment in the privately-held company
using a discounted cash flow (DCF) model, several key considerations and chal-
lenges need to be addressed:
Step 1: Understand the Nature of the Investment It is crucial to
have a deep understanding of the privately-held company’s operations, financial
performance, market dynamics, growth potential, and risks. Since this company
operates in a niche market, obtaining accurate and reliable information may be
challenging.
10

Step 2: Forecasting Cash Flows One of the main challenges in applying
the DCF model is accurately forecasting the future cash flows of the privately-
held company. This requires making assumptions about revenue growth, oper-
ating expenses, capital expenditures, working capital requirements, and other
relevant factors. In the case of a niche market, forecasting cash flows can be
even more challenging due to limited available data and market trends.
Step 3: Determining the Discount Rate The discount rate used in the
DCF model is a critical input that reflects the risk associated with the invest-
ment. Estimating an appropriate discount rate for a privately-held company
operating in a niche market requires considering factors such as market risk
premium, company-specific risk factors, and the illiquidity of the investment.
Step 4: Adjusting for Illiquidity Since the investment in the privately-
held company is not publicly traded, its illiquidity needs to be taken into account
when determining the fair value. Adjustments may need to be made to the
discount rate or the cash flow projections to reflect the lack of marketability of
the investment.
Step 5: Sensitivity Analysis Given the uncertainties and challenges in-
volved in using the DCF model for fair value measurement in this scenario,
conducting sensitivity analysis is crucial. By varying key assumptions such as
revenue growth rates, discount rates, and terminal values, Company XYZ can
assess the impact on the fair value estimate and understand the range of possible
outcomes.
In conclusion, applying a DFC model for fair value measurement of an in-
vestment in a privately-held company operating in a niche market requires a
thorough understanding of the investment, accurate forecasting, careful consid-
eration of discount rates, adjustments for illiquidity, and sensitivity analysis to
account for uncertainties.
Question 13
Question
A company owns an investment property that is measured at fair value. The
fair value of the property increased by 15
Solution
Let xbe the original fair value of the property.
Step 1: Calculate the fair value after the 15The fair value after the increase
is x+ 0.15x= 1.15x.
Step 2: Set up an equation to represent the fair value gain. Since the fair
value increased by 15%, the fair value after the increase is 1.15x. The fair value
gain is 1.15x−x= $50,000.
Step 3: Solve the equation for x.
1.15x−x= 0.15x= 50000
11
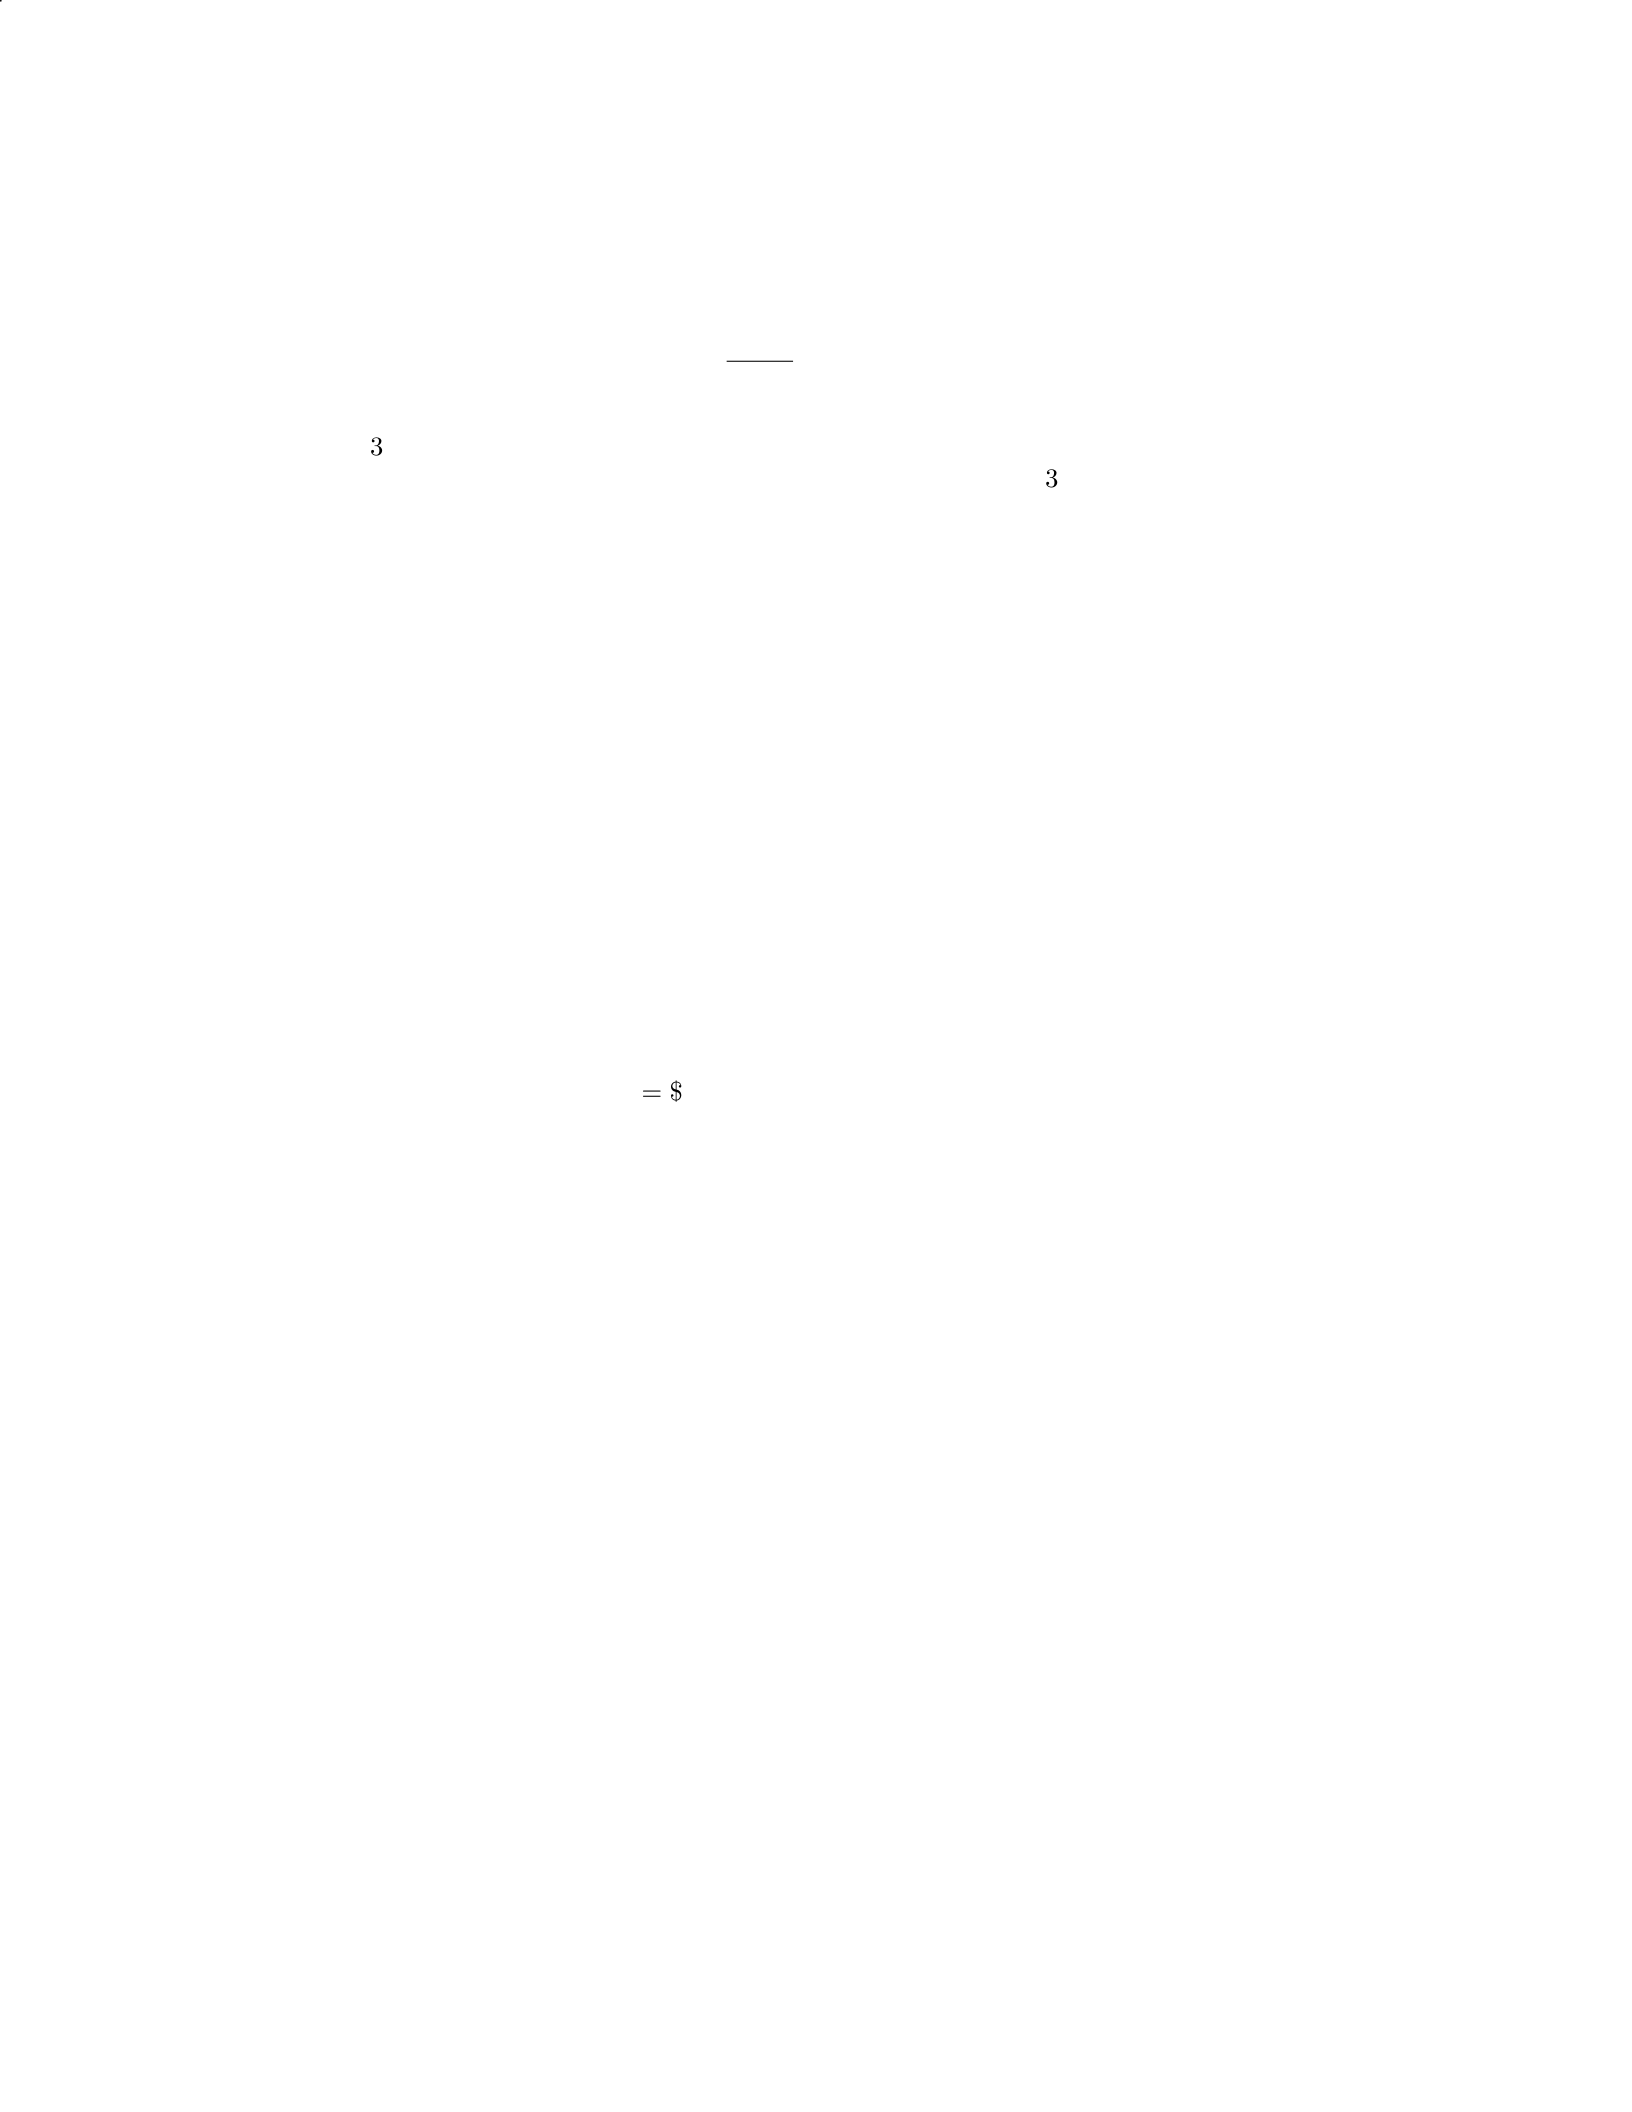
x=50000
0.15 = 333,333.33
Step 4: Check the solution. If the original fair value of the property was
$
333,333.33, a 15
Therefore, the original fair value of the property was
$
333,333.33.
Question 14
Question
A company is valuing its investment property using the fair value model. At
the end of the reporting period, the property was appraised at $2,500,000.
During the next reporting period, the property value increased to $2,700,000.
The property was held as an investment to earn rental income. The company
recognizes changes in fair value in profit or loss. Calculate the fair value gain or
loss to be reported in the company’s income statement for the second reporting
period.
Solution
Step 1: Calculate the fair value gain or loss.
Fair Value Gain or Loss = Fair Value at the end of the second reporting period −Fair Value at the end of the first reporting period
= $2,700,000 −$2,500,000
= $200,000
Therefore, the fair value gain to be reported in the company’s income state-
ment for the second reporting period is $200,000.
Question 15
Question
A company holds an investment in a private equity fund. The fair value of
the investment is determined using the income approach, which estimates fair
value based on the present value of estimated future cash flows. The company’s
discount rate used in the present value calculation is 12- Year 1: 500,000 −
Y ear2 :600,000 - Year 3: 700,000Ifthef airvalueof theinvestmentattheendof Y ear3is1,800,000,
calculate the total present value of the estimated future cash flows.
Solution
Step 1: Calculate the present value of each cash flow using the given discount
rate of 12
12
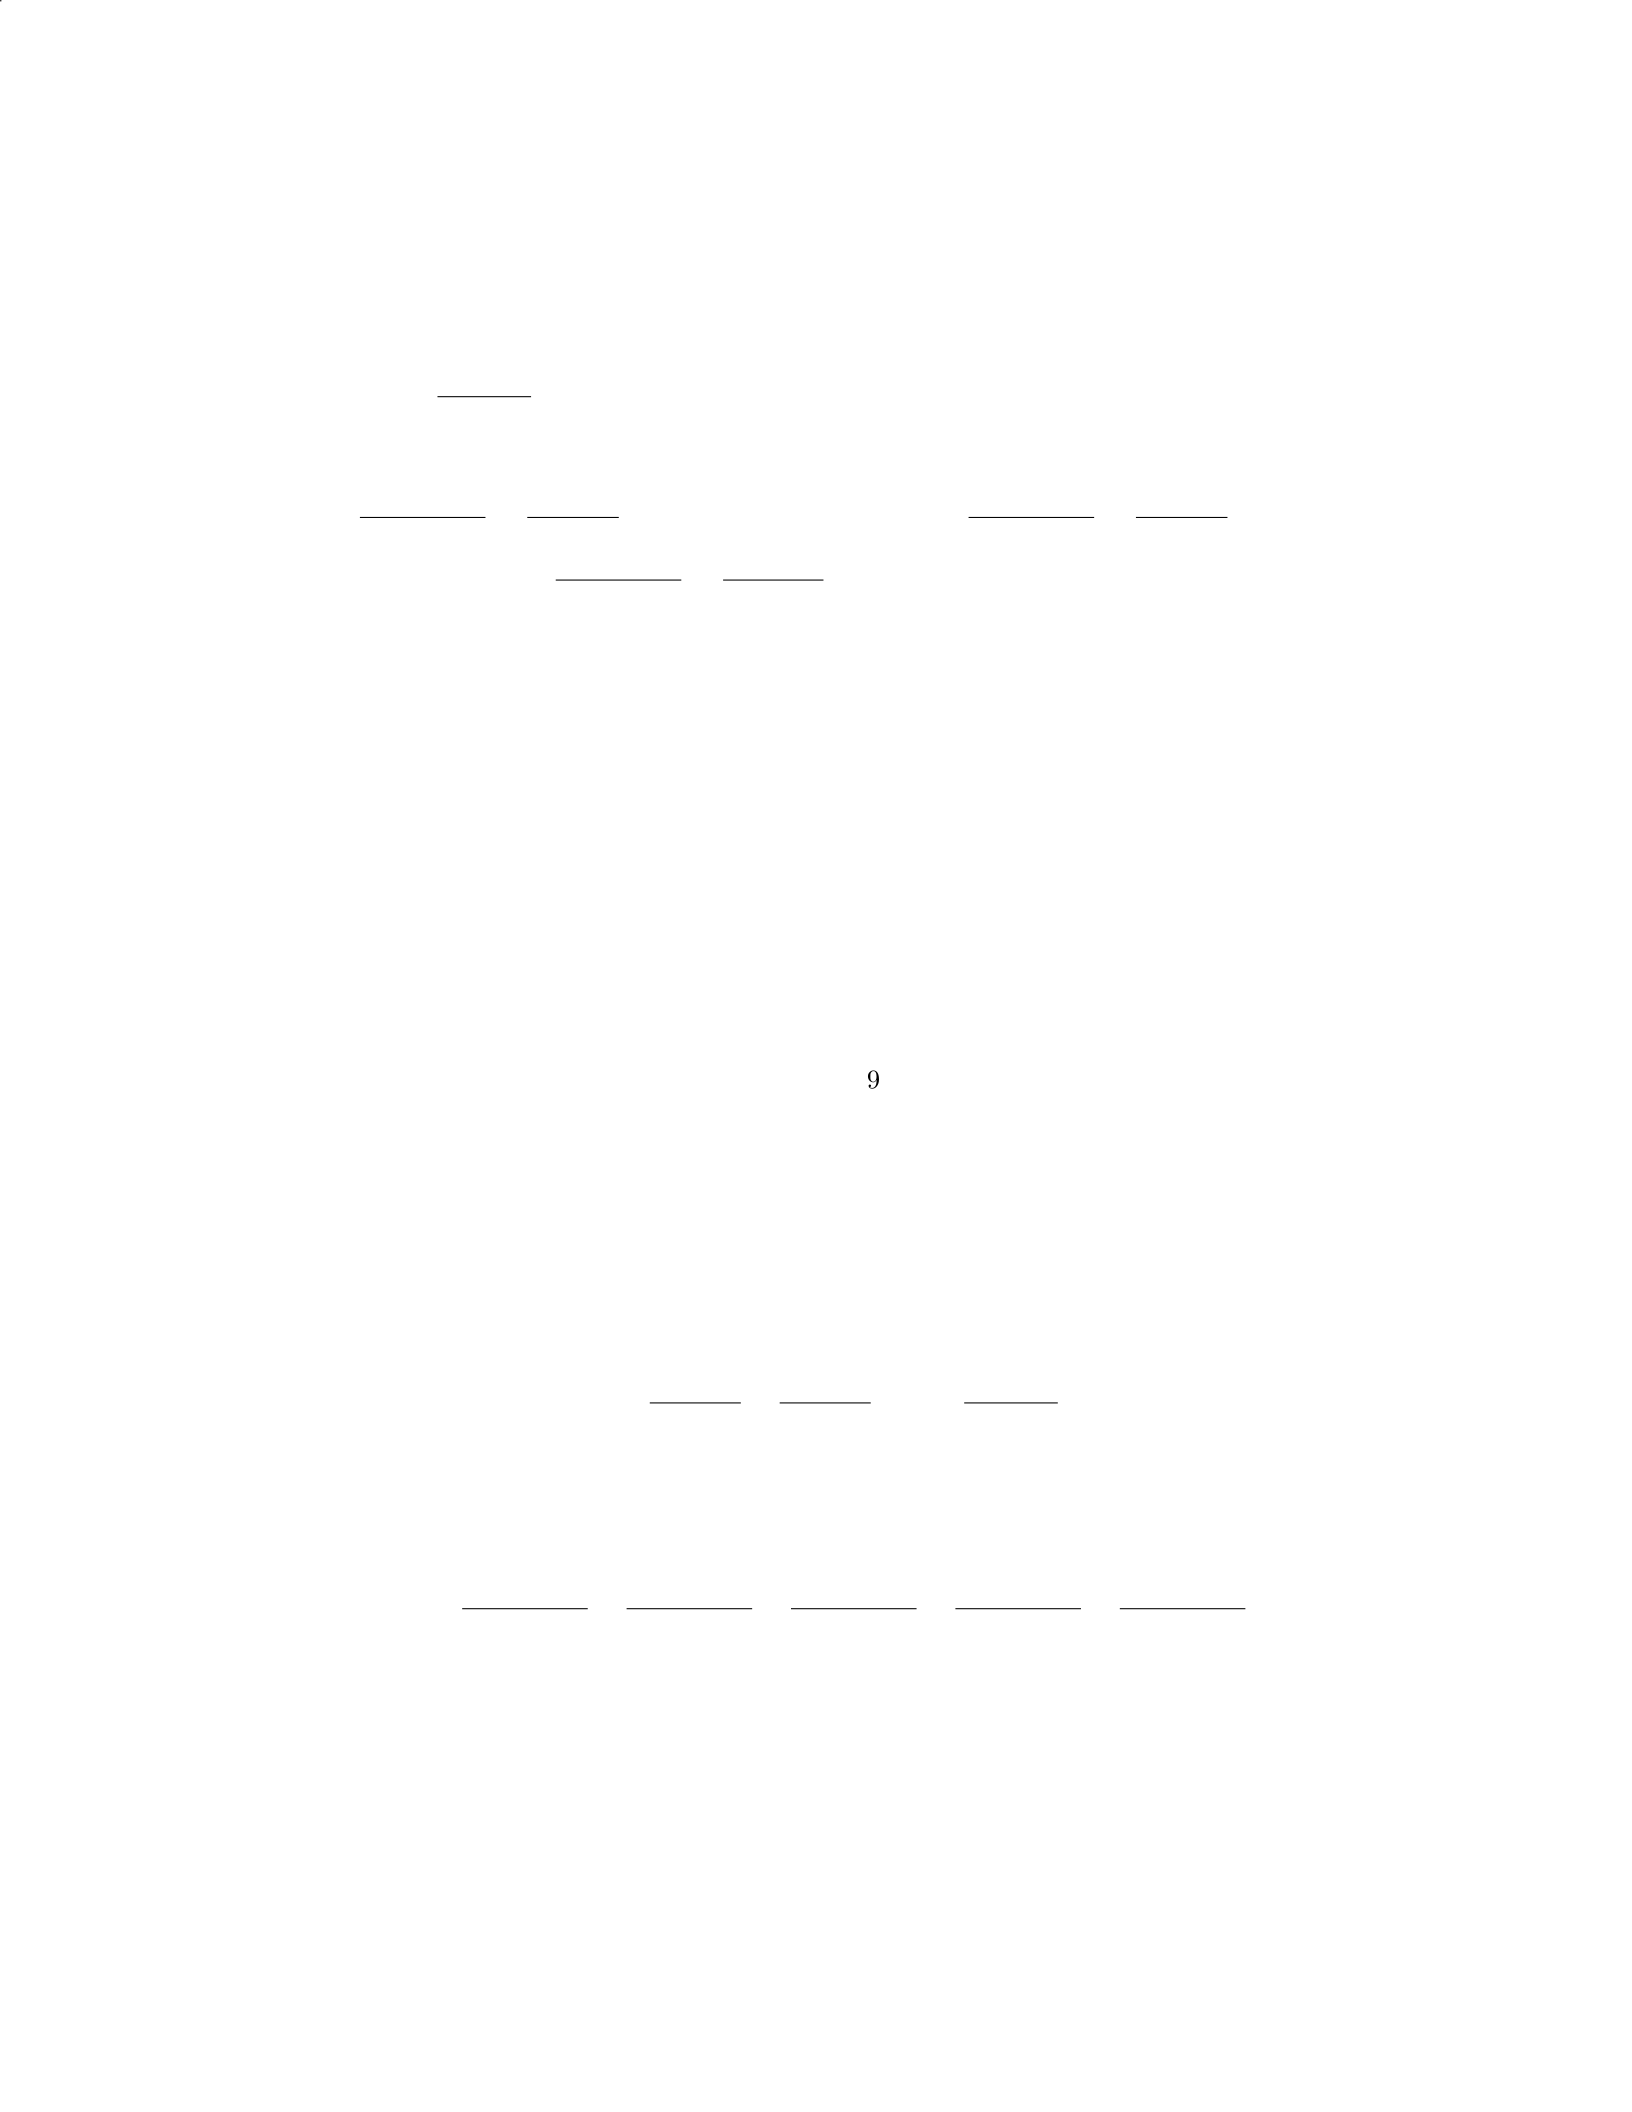
Step 2: We can use the formula for present value of a single cash flow:
P V =CF
(1 + r)n, where CF is the cash flow, ris the discount rate, and nis the
time period.
Step 3: Calculate the present value of each cash flow: - Year 1: P V1=
500,000
(1 + 0.12)1=500,000
1.12 ≈446,428.57 - Year 2: P V2=600,000
(1 + 0.12)2=600,000
1.2544 ≈478,915.66
- Year 3: P V3=700,000
(1 + 0.12)3=700,000
1.404928 ≈498,266.90
Step 4: Calculate the total present value of the estimated future cash flows
by summing up the present values of each cash flow. T otalP V =P V1+P V2+
P V3≈1,423,611.13.
Therefore, the total present value of the estimated future cash flows is ap-
proximately 1,423,611.13.
Question 16
Question
Company XYZ holds an investment in a financial instrument classified as a
Level 3 fair value measurement. The fair value hierarchy defines Level 3 inputs
as unobservable inputs, meaning that they are not based on market data.
The company’s management has estimated the following inputs for the fi-
nancial instrument: - Expected cash flows:
$
90,000 - Discount rate: 8- Expected
holding period: 5 years
Calculate the fair value of the financial instrument using the discounted cash
flow method.
Solution
Step 1: Calculate the present value of expected cash flows. The formula for
present value using discounted cash flow is:
P V =CF1
(1 + r)1+CF2
(1 + r)2+... +CFn
(1 + r)n
where: - P V = present value - CFi= cash flow in year i-r= discount rate -
n= number of years
Plugging in the values:
P V =90,000
(1 + 0.08)1+90,000
(1 + 0.08)2+90,000
(1 + 0.08)3+90,000
(1 + 0.08)4+90,000
(1 + 0.08)5
Step 2: Calculate the fair value of the financial instrument. The fair value
of the financial instrument is the sum of the present value of the expected cash
flows.
Fair value = P V
13
Calculating the present value:
P V =90,000
1.08 +90,000
(1.08)2+90,000
(1.08)3+90,000
(1.08)4+90,000
(1.08)5
P V = 83333.33 + 77160.49 + 71536.68 + 66404.12 + 61725.65
P V = 360160.28
Therefore, the fair value of the financial instrument using the discounted
cash flow method is
$
360,160.28.
Question 17
Question
A company is assessing the fair value of its investment in a private company. The
estimated fair value at the end of the year is 150,000.T hecompanyalsoestimatesa20
Solution
Step 1: Calculate the expected value using the formula:
Expected Value =
n
X
i=1
Probabilityi×Fair Valuei
Step 2: Substitute the given probabilities and fair values into the formula:
Expected Value = 0.20 ×130,000 + 0.50 ×150,000 + 0.30 ×170,000
Step 3: Calculate the expected value:
Expected Value = 26,000 + 75,000 + 51,000
Expected Value = 152,000
The expected value of the investment is 152,000.
Question 18
Question
Company A holds an investment in Company B, which is classified as an eq-
uity security. At the end of the year, Company A determines the fair value of
the investment to be $120,000. However, due to recent market volatility, there
is uncertainty about the reliability of the inputs used in the fair value mea-
surement. As a result, Company A is considering using a valuation technique
that takes into account this uncertainty to determine the fair value. Explain how
Company A should adjust its fair value measurement to address the uncertainty
surrounding the inputs.
14
Solution
Step 1: Evaluate the reliability of inputs used in the initial fair value measure-
ment. - Company A should assess the reliability of the inputs used in the fair
value measurement of the investment in Company B. If there is uncertainty
surrounding the inputs, the fair value measurement may not accurately reflect
the true value of the investment.
Step 2: Consider using a valuation technique that incorporates the uncer-
tainty. - Given the uncertainty surrounding the inputs, Company A should con-
sider using a valuation technique that takes into account this uncertainty. One
such technique is an option pricing model, such as the Black-Scholes model,
which considers market volatility and other factors that may impact the fair
value of the investment.
Step 3: Adjust the fair value measurement using the chosen valuation tech-
nique. - Company A should apply the chosen valuation technique to adjust the
fair value measurement of the investment in Company B. This adjustment may
result in a fair value that better reflects the uncertainty surrounding the inputs
and provides a more accurate representation of the investment’s value.
Step 4: Disclose the use of the valuation technique and the rationale behind
it. - It is important for Company A to disclose in its financial statements
the use of the valuation technique to adjust the fair value measurement of the
investment in Company B. The disclosure should include the rationale behind
the adjustment and how it addresses the uncertainty surrounding the inputs
used in the initial fair value measurement.
Question 19
Question
Company XYZ holds an investment in a financial instrument classified as a Level
3 fair value measurement. At the end of the reporting period, the instrument has
a fair value of 450,000.Duringtheperiod, theinstrumentgeneratedcashf lowsof 50,000,
and the discount rate used to calculate the fair value of the instrument is 8
Solution
Step 1: Calculate the present value of the cash flows generated by the finan-
cial instrument during the reporting period. Given: Cash flows generated =
50,000Discountrate = 8
The present value of cash flows can be calculated using the formula:
P V =CF
(1 + r)n
Where: P V = Present value of cash flows CF = Cash flows generated r=
Discount rate n= Number of periods
15
In this case, since the cash flows occurred during the period, there is only
one period. Therefore,
P V =50,000
(1 + 0.08)1
P V =50,000
1.08
P V ≈46,296.30
Step 2: Calculate the change in fair value during the reporting period. Given:
Fair value at the end of the period = 450,000P resentvalueof cashflows =46,296.30
The change in fair value can be calculated as:
Change in fair value =F Vend −P V
Change in fair value = 450,000 −46,296.30
Change in fair value ≈403,703.70
Step 3: Calculate the fair value of the financial instrument at the beginning
of the period. The fair value of the financial instrument at the beginning of the
period is the fair value at the end of the period minus the change in fair value
during the period.
F Vbeginning =F Vend −Change in fair value
F Vbeginning = 450,000 −403,703.70
F Vbeginning ≈46,296.30
Therefore, the fair value of the financial instrument at the beginning of the
period was approximately 46,296.30.
Question 20
Question
A company holds an investment in a financial asset classified as available-for-
sale. At the end of the reporting period, the fair value of the investment is
$4,500. The company has determined that there have been some observable
price changes for similar investments in the market since the acquisition of the
asset, and these changes are not temporary.
Given this information, calculate the fair value of the financial asset on the
acquisition date if the company decides to account for the change in fair value
using the fair value model.
16

Solution
To calculate the fair value of the financial asset on the acquisition date using
the fair value model, we need to consider the change in fair value and work
backward to find the original fair value.
Step 1: Determine the change in fair value from the acquisition date to the
reporting date.
Change in Fair Value = Fair Value on Reporting Date −Fair Value on Acquisition Date
= $4,500 −Acquisition Date Value
Step 2: Since the change in fair value is not temporary, we need to adjust
the acquisition date value to reflect this change. Let’s denote the acquisition
date value as x.
Change in Fair Value = $4,500 −x
x= $4,500 −Change in Fair Value
Step 3: Substitute the given fair value on the reporting date into the equa-
tion.
x= $4,500 −($4,500 −Change in Fair Value)
x= Change in Fair Value
Step 4: Calculate the fair value of the financial asset on the acquisition
date.
x= $4,500
Therefore, the fair value of the financial asset on the acquisition date, if the
company decides to account for the change in fair value using the fair value
model, is $4,500.
Question 21
Question
Company XYZ holds an investment in a publicly traded company with a fair
value of 450,000attheendofthereportingperiod.T hef airvaluemeasurementincludesLevel1inputs.Duringthenextreportingperiod, thef airvalueof theinvestmentincreasedto500,000.
If Company XYZ uses the fair value option for measuring this investment, how
will the changes in fair value be recognized in the financial statements?
Solution
1. When the fair value of the investment increased from 450,000to500,000, the
following journal entry will be recorded to reflect the change in fair value:
Debit: Unrealized Gain on Investment
17

Credit: Investment in Equity Securities
2. The Unrealized Gain on Investment account is a temporary account that will
be closed at the end of the reporting period. 3. The Unrealized Gain on Invest-
ment will be reported on the income statement as part of comprehensive income.
4. The Investment in Equity Securities account will be reported on the balance
sheet at the fair value of 500,000.5.T headjustmentisnecessarytoensurethattheinvestmentisrecordedatitsf airvalueattheendof thereportingperiod.
Question 22
Question
A company recently acquired a new subsidiary and needs to determine the
fair value of the subsidiary’s intangible assets for financial reporting purposes.
The subsidiary’s intangible assets include patents, trademarks, and customer
relationships. Discuss the steps involved in determining the fair value of these
intangible assets.
Solution
To determine the fair value of the intangible assets (patents, trademarks, and
customer relationships) of the subsidiary for financial reporting purposes, the
following steps need to be taken:
Step 1: Identify the Intangible Assets Identify and list all the intangible
assets of the subsidiary, such as patents, trademarks, and customer relationships.
Step 2: Gather Relevant Information Obtain detailed information
about each intangible asset, such as the nature of the asset, the expected cash
flows it will generate, any legal protection, and market conditions.
Step 3: Select an Appropriate Valuation Approach Choose the most
appropriate valuation approach based on the nature of the intangible asset.
Common valuation approaches for intangible assets include the cost approach,
market approach, and income approach.
Step 4: Apply the Chosen Valuation Approach Implement the cho-
sen valuation approach to determine the fair value of each intangible asset. For
example: - For patents, the cost approach may involve estimating the cost to
develop a similar patent. - For trademarks, the market approach may involve
analyzing the prices of similar trademarks in the market. - For customer rela-
tionships, the income approach may involve forecasting future cash flows from
the customers.
Step 5: Consider Discount Rates and Risk Factors Take into account
discount rates and risk factors associated with each intangible asset to reflect
the time value of money and the level of risk involved in generating expected
cash flows.
Step 6: Finalize Fair Value Estimates Combine the fair value estimates
of each intangible asset to determine the total fair value of the subsidiary’s
18

intangible assets for financial reporting purposes. Ensure that the estimates are
reasonable, supported by relevant data, and comply with accounting standards.
Question 23
Question
Company XYZ owns a rare piece of artwork that is considered a Level 3 fair
value measurement. The artwork has a quoted price of
$
400,000 in an active
market. However, there is a lack of observable market data for similar artworks
to use as inputs for the valuation model. Company XYZ decides to use a present
value technique to estimate the fair value of the artwork, with an appropriate
discount rate of 8% per annum. Calculate the fair value of the artwork using
the present value technique.
Solution
Step 1: Calculate the present value factor using the discount rate of 8% per
annum and the appropriate number of periods.
The present value factor can be calculated using the formula:
P V F =1
(1 + r)n
Where: - r= 0.08 (8% per annum) - nis the number of periods
In this case, since the fair value of the artwork is for the present time (Year
0), n= 0. Thus, the present value factor is:
P V F =1
(1 + 0.08)0=1
1= 1
Step 2: Calculate the fair value of the artwork using the present value tech-
nique.
The fair value of the artwork can be calculated as:
F air V alue =Quoted P rice ×P V F
Substitute the values:
F air V alue = $400,000 ×1 = $400,000
Therefore, the fair value of the artwork using the present value technique is
$
400,000.
19

Question 24
Question
Explain the concept of fair value measurement and discuss how it is applied in
the financial reporting of assets and liabilities.
Solution
Step 1: Definition of Fair Value Measurement
Fair value measurement is a principle used in accounting and finance to
determine the value of assets and liabilities. It is defined as the price that
would be received to sell an asset or paid to transfer a liability in an orderly
transaction between market participants at the measurement date.
Step 2: Application in Financial Reporting
In financial reporting, fair value measurement is used to provide relevant
and reliable information to users of financial statements, such as investors and
creditors. It is commonly applied in the following ways: - Fair value measure-
ment is used to initially recognize certain assets and liabilities at fair value, such
as derivatives and financial instruments. - Investments held by a company are
typically reported at fair value in the financial statements, providing a more ac-
curate representation of their current worth. - Impairment testing of assets also
often involves fair value measurement. If the fair value of an asset is less than its
carrying amount, an impairment loss is recognized in the financial statements.
Step 3: Challenges in Fair Value Measurement
While fair value measurement provides valuable information, there are chal-
lenges associated with its application. One challenge is the subjectivity involved
in determining fair value, especially for assets and liabilities that do not have
active markets. This can lead to potential manipulation or misrepresentation
of asset values. Another challenge is the impact of market volatility on fair
value measurements, as fluctuations in market conditions can result in signifi-
cant changes in reported values.
Step 4: Disclosure Requirements
To address these challenges and provide transparency to users of financial
statements, companies are required to provide extensive disclosure regarding
their fair value measurements. This includes descriptions of the valuation tech-
niques used, inputs into the valuation process, and sensitivity analyses to show
the effect of changes in assumptions on the fair value of assets and liabilities.
These disclosures help stakeholders better understand the basis for the reported
fair values and assess the reliability of the information provided.
20

Question 25
Question
A company purchased an investment property for 500,000.T hefairvalueofthepropertyincreasedto600,000
at the end of the year. The company recognized a gain of 20,000inprofitorlossandarevaluationsurplusof80,000
in other comprehensive income. Calculate the carrying amount of the invest-
ment property at the end of the year.
Solution
Step 1: Calculate the carrying amount of the investment property before revalu-
ation. The carrying amount before revaluation is the initial cost of the property,
which is 500,000.Carryingamountbef orerevaluation :500,000
Step 2: Calculate the revaluation gain. The revaluation gain is the difference
between the fair value of the property at the end of the year and the carrying
amount before revaluation. Revaluation gain = Fair value - Carrying amount
before revaluation Revaluation gain = 600,000−500,000 Revaluation gain =
100,000
Step 3: Allocate the revaluation gain between profit or loss and other com-
prehensive income. The gain recognized in profit or loss is 20,000, sotheremaininggainof 80,000
is recognized in other comprehensive income.
Step 4: Calculate the carrying amount of the investment property at the end
of the year. The carrying amount at the end of the year is the sum of the initial
cost and the revaluation gain recognized in profit or loss. Carrying amount at
the end of the year = Initial cost + Gain recognized in profit or loss Carrying
amount at the end of the year = 500,000+20,000 Carrying amount at the end
of the year = 520,000
Therefore, the carrying amount of the investment property at the end of the
year is 520,000.
Question 26
Question
Company XYZ holds an investment in a financial instrument that is classified as
a Level 2 asset. The company’s analysts are uncertain about one of the inputs
used to value the asset. Explain how the uncertainty surrounding this input
could affect the fair value measurement of the investment.
Solution
Step 1: First, let’s understand what a Level 2 asset is in the context of fair
value measurement. Level 2 assets are those whose fair value is determined
using inputs other than quoted prices in active markets for similar assets. These
21
inputs may include observable market data from similar assets, interest rates,
or other economic indicators.
Step 2: In this case, the analysts are uncertain about one of the inputs
used to value the asset. This uncertainty can have a significant impact on the
fair value measurement of the investment. Here are a few ways in which the
uncertainty surrounding this input could affect the fair value measurement:
Step 3: If the uncertain input has a significant impact on the valuation
model, the fair value of the investment could be materially different depending
on the actual value of the input. This could result in a wide range of possible
fair values, leading to increased uncertainty in the reported value of the asset.
Step 4: The uncertainty surrounding the input could also affect the reliability
of the fair value measurement. If the input is not verifiable or based on subjective
assumptions, it could be difficult to assess the accuracy of the valuation and the
degree of uncertainty associated with it.
Step 5: Moreover, the uncertainty in the input could lead to a higher risk
of misstatement in the financial statements. If the input is later found to be
significantly different from the estimated value, it could result in restatements
and impact the company’s credibility with investors and regulators.
Step 6: In conclusion, the uncertainty surrounding the input used to value
the asset can have a profound impact on the fair value measurement of the
investment. It is crucial for analysts and accountants to carefully consider and
disclose such uncertainties to provide a clear picture of the financial position of
the company.
Question 27
Question
A company holds an investment in a private equity fund. The investment is
classified as a Level 3 financial instrument and is measured at fair value. The
fair value of the investment increased by
$
500,000 during the current reporting
period. Discuss how this change in fair value would impact the company’s
financial statements and what disclosures would be required in the notes to the
financial statements.
Solution
Step 1: The increase in fair value of the investment would result in a gain for
the company, which would be recognized in the income statement. This gain
would increase the company’s net income for the current reporting period. The
journal entry to record the gain would be:
Income Statement →Gain on Investment : $500,000
Step 2: The increase in fair value of the investment would also impact the
company’s balance sheet. The fair value of the investment would be adjusted
22

upwards, resulting in an increase in the company’s assets. This increase would
be reflected in the balance sheet under the ”Investments” or ”Financial Assets
at Fair Value Through Profit or Loss” category.
Step 3: In the notes to the financial statements, the company would be re-
quired to disclose information about the investment in the private equity fund.
This would include details about the nature of the investment, the fair value
measurement techniques used, and the significant unobservable inputs (if ap-
plicable). Additionally, the company would need to provide information about
the impact of the change in fair value on the financial statements, including the
amount recognized in the income statement and where it is classified.
Step 4: The company would also need to disclose any significant assumptions
made in determining the fair value of the investment, as well as any sensitivity
analysis conducted to assess the impact of changes in these assumptions on the
fair value measurement.
Step 5: Overall, the increase in fair value of the investment would lead
to changes in the company’s financial statements, impacting both the income
statement and the balance sheet. Additionally, the company would need to
provide detailed disclosures in the notes to the financial statements to explain
the change in fair value and the related effects on the financial statements.
Question 28
Question
Assume a company is reporting its financial statements under IFRS 13. The
company holds an investment in a private company that does not have a quoted
market price and is not actively traded. The company’s management needs
to determine the fair value of this investment for financial reporting purposes.
Discuss the steps the company should take to measure the fair value of this
investment.
Solution
To measure the fair value of an investment in a private company for financial
reporting purposes, the company should follow the steps outlined below:
Step 1: Identify the Asset or Liability Identify the investment in the
private company that needs to be valued.
Step 2: Determine the Principal Market, if any Determine whether
there is a principal market for the investment. If there is, use the quoted price
in that market to measure fair value. If not, proceed to the next step.
Step 3: Identify Comparable Transactions Look for comparable trans-
actions involving similar investments in private companies to provide guidance
on valuation.
Step 4: Estimate Fair Value Using Valuation Techniques If there are
no comparable transactions, estimate the fair value using valuation techniques
23
such as discounted cash flow analysis, net asset value method, market multiple
approach, or option pricing model.
Step 5: Consider Control and Marketability Issues Adjust the es-
timated fair value for any control or marketability issues associated with the
investment.
Step 6: Review and Document the Process Review the valuation
process and ensure it complies with IFRS 13 requirements. Document all as-
sumptions, inputs, and methods used in determining the fair value.
Following these steps will help the company accurately measure the fair value
of its investment in a private company for financial reporting purposes.
Question 29
Question
Company XYZ holds an investment in a financial asset classified as a Level 3 fair
value measurement. The fair value of the investment at the end of the reporting
period is 350,000.T hecompany′smanagementwantstodetermineif therehavebeenanychangesinthefairvalueoftheinvestmentduringthereportingperiod.
Given the following information: - Opening fair value of the investment:
320,000 −Investmentincomereceivedduringthereportingperiod :10,000 - Loss
on fair value measurement during the reporting period: 5,000−Closingfairvalueof theinvestment :350,000
Calculate the fair value change during the reporting period and determine
if it’s an unrealized gain or loss.
Solution
Step 1: Calculate the fair value change during the reporting period.
Fair value change = Closing fair value−Opening fair value−Investment income
Fair value change = $350,000 −$320,000 −$10,000 = $20,000
Step 2: Determine if the fair value change is an unrealized gain or loss. Given
that the fair value change is positive (
$
20,000), it is considered an unrealized
gain. Therefore, during the reporting period, Company XYZ experienced an
unrealized gain of
$
20,000 on the investment.
Question 30
Question
A company holds an investment in a startup company that it classifies as an
equity investment. The fair value of the investment at the end of the reporting
period is $85,000. During the next period, the fair value decreases to $75,000.
How should this decrease in fair value be accounted for in the financial state-
ments according to fair value measurement guidelines?
24

Solution
Step 1: When the fair value of an equity investment decreases, the decrease
should be recognized as a loss in the income statement.
Step 2: The decrease in fair value from 85,000 to 75,000 amounts to 85,000−
75,000 = $10,000.
Step 3: This 10,000lossshouldbereportedintheincomestatementof theperiodinwhichthef airvaluedecreaseoccurred.
Therefore, the decrease in fair value of the investment should be accounted
for by recognizing a 10,000lossintheincomestatementof theperiod.
Question 31
Question
Company XYZ holds an investment in a private equity fund. The fair value of
this investment needs to be determined for the financial statements. The fund
is not publicly traded, so the fair value cannot be easily determined. Describe
the steps involved in determining the fair value of this investment, including
any assumptions that need to be made.
Solution
To determine the fair value of an investment in a private equity fund, several
steps need to be followed. The fair value measurement will require making
assumptions and using valuation techniques to arrive at a reasonable estimate.
Step 1:Understand the characteristics of the investment: First, it is
essential to understand the nature of the investment in the private equity fund,
including any restrictions on selling the investment and its expected cash flows.
Step 2:Consider the market and economic conditions: Evaluate the
current market and economic conditions that may impact the fair value of the
investment, such as interest rates, industry trends, and market volatility.
Step 3:Utilize valuation techniques: Choose appropriate valuation
techniques to estimate the fair value of the investment. Common techniques
include the market approach, income approach, and cost approach.
Step 4:Estimate the expected cash flows: Estimate the expected cash
flows from the investment, considering factors such as the fund’s performance,
industry outlook, and economic conditions.
Step 5:Determine discount rate: Calculate an appropriate discount
rate to determine the present value of the expected cash flows. The discount
rate should reflect the risks associated with the investment.
Step 6:Consider market data: If available, consider any market data
on similar investments or transactions to corroborate the estimated fair value.
Step 7:Review and reassess assumptions: Review all assumptions
made in the fair value measurement process and reassess them for reasonable-
ness.
25

Step 8:Finalize fair value measurement: After completing the above
steps, finalize the fair value measurement of the investment in the private equity
fund. Disclose the valuation methods used and the key assumptions made in
the financial statements.
By following these steps and utilizing appropriate valuation techniques, the
fair value of an investment in a private equity fund can be reasonably estimated
for financial reporting purposes.
Question 32
Question
A company acquired a piece of land for development purposes. The fair value of
the land was determined to be 500,000.Overthenextyear, thecompanyspent50,000
on clearing the land and preparing it for development. At the end of the year, the
company reassessed the fair value of the land and determined it had increased to
550,000.Howshouldthecompanyaccountf orthechangesinf airvalueof thelandinitsfinancialstatementsaccordingtoF airV alueM easurementstandards?
Solution
Step 1: Initially Recognized Fair Value - When the company acquired the land,
Fair Value Measurement standards required the land to be initially recognized
at its fair value of 500,000.
Step 2: Recognizing Changes in Fair Value - Changes in fair value should be
recognized in the company’s financial statements. - Here, since the fair value
of the land increased from 500,000to550,000, the company needs to recognize a
gain.
Step 3: Accounting for the Gain - The gain due to the increase in fair value
should be recognized in the company’s income statement. - The entry to reflect
the gain is: - Debit: Land 50,000 −Credit :Gainonrevaluationof land50,000
Step 4: Wrapping Up - By following Fair Value Measurement standards,
the company properly accounts for changes in the fair value of the land in its
financial statements.
Question 33
Question
A company holds an investment in a private equity fund as a Level 3 fair value
measurement, where the fair value is determined using a discounted cash flow
model. The carrying amount of the investment at the beginning of the year was
2,500,000.Duringtheyear, thefairvalueoftheinvestmentdecreasedto2,200,000 due
to changes in market conditions. At the end of the year, the fair value of the in-
vestment increased to 2,800,000asaresultof improvedmarketconditions.Calculatethegainorlossontheinvestmentrecognizedinthecompany′sincomestatementfortheyear.
26
Solution
Step 1: Calculate the loss on the investment when the fair value decreased.
Loss = Beginning fair value −Fair value decrease
Loss = $2,500,000 −$2,200,000 = $300,000
Step 2: Calculate the gain on the investment when the fair value increased.
Gain = End fair value −Beginning fair value
Gain = $2,800,000 −$2,500,000 = $300,000
Step 3: Calculate the net gain or loss on the investment for the year.
Net gain or loss = Gain - Loss
Net gain or loss = $300,000 −$300,000 = $0
Therefore, the gain or loss on the investment recognized in the company’s
income statement for the year is
$
0.
Question 34
Question
Company XYZ holds an investment in bonds classified as available-for-sale. At
the end of the reporting period, the fair value of the bonds is $475,000, while the
amortized cost is $500,000. Calculate the unrealized gain or loss that Company
XYZ should recognize in its income statement.
Solution
Step 1: First, we need to determine the amount of unrealized gain or loss.
Step 2: The unrealized gain or loss is calculated as the difference between
the fair value and the amortized cost.
Unrealized Gain or Loss = Fair Value −Amortized Cost
Unrealized Gain or Loss = $475,000 −$500,000
Unrealized Gain or Loss = −$25,000
Step 3: Since the unrealized gain or loss is negative, it means there is an
unrealized loss of $25,000 on the investment. Company XYZ should recognize
this unrealized loss in its income statement.
Therefore, Company XYZ should recognize an unrealized loss of $25,000 in
its income statement.
27

Therefore, the fair value of the asset using the income approach is approxi-
mately 739,501.30.
Question 2
Question
A manufacturing company is required to report the fair value of its inventory for
financial reporting purposes. The company uses Level 3 inputs to determine the
fair value of its inventory. Explain what Level 3 inputs consist of and provide
an example of a Level 3 input that could be used in determining the fair value
of inventory.
Solution
Step 1: Level 3 Inputs Level 3 inputs are unobservable inputs used in fair value
measurements that are supported by little or no market activity. These inputs
are based on the best information available, which may include management’s
own assumptions about the assumptions that market participants would use in
pricing an asset or liability.
Step 2: Example of Level 3 Input An example of a Level 3 input that
could be used in determining the fair value of inventory is a company’s own
internal pricing model. For instance, a manufacturing company may use a pro-
prietary model that takes into account factors like production costs, anticipated
demand, and potential obsolescence to estimate the fair value of its inventory.
Since this information is not publicly available and relies heavily on manage-
ment’s judgment, it would be classified as a Level 3 input in the fair value
measurement process.
Question 3
Question
A company has an investment in a financial instrument classified as a Level 3
fair value measurement. The fair value hierarchy ranks three levels in order of
reliability, with Level 3 being the least reliable. The company is required to
disclose the techniques and significant unobservable inputs used in developing
the fair value. Discuss the challenges and implications of using Level 3 fair value
measurements in financial reporting.
Solution
To address the challenges and implications of using Level 3 fair value measure-
ments, it is important to understand the characteristics of Level 3 fair value
2

measurements and their impact on financial reporting. Here are the key points
to consider:
Step 1: Definition of Level 3 fair value measurements - Level 3
fair value measurements represent financial instruments whose fair values are
determined primarily using unobservable inputs based on the company’s own
assumptions. - These inputs are not based on market data, making Level 3 fair
value measurements the least reliable of the three hierarchy levels.
Step 2: Challenges of using Level 3 fair value measurements - The
most significant challenge of using Level 3 fair value measurements is the sub-
jectivity involved in determining the fair value. - Companies may use different
assumptions and valuation techniques, leading to potential inconsistencies and
lack of comparability between different entities. - The use of significant unob-
servable inputs increases the risk of bias and manipulation in determining the
fair value, which can result in misleading financial statements. - There may be
limited market data available for assets or liabilities classified as Level 3, making
it difficult to assess the reasonableness of the fair value estimates.
Step 3: Implications of using Level 3 fair value measurements - The
use of Level 3 fair value measurements can impact the transparency and reli-
ability of financial reporting. - Stakeholders, including investors and analysts,
may have concerns about the reliability of financial statements that heavily rely
on unobservable inputs. - Companies using Level 3 fair value measurements are
required to disclose the valuation techniques and significant unobservable inputs
used, providing additional information for stakeholders to assess the reliability
of the fair value estimates. - Regulatory scrutiny and audit attention are typ-
ically higher for Level 3 fair value measurements to ensure the reasonableness
and accuracy of the reported values.
In conclusion, the challenges and implications of using Level 3 fair value
measurements emphasize the importance of transparency, disclosure, and con-
sistent application of valuation techniques to ensure the reliability and relevance
of financial information disclosed in the financial statements.
Question 4
Question
Company XYZ holds an investment in a security which is classified as a Level 2
fair value measurement. The security has a quoted price of 105perunit, butthebid−
askspreadiswideduetoilliquidity.T hebestestimateofthef airvalueof thesecurity, basedonthebidpriceprovidedbyabroker, is103
per unit. The observable input used in the valuation is the bid price. Calculate
the fair value of the investment using the bid price approach.
Solution
Step 1: Determine the fair value adjustment - Since the security is classi-
fied as a Level 2 fair value measurement, the fair value is determined us-
3
ing observable inputs, which in this case is the bid price of 103perunit. −
T hefairvalueadjustmentisthedifferencebetweentheobservablebidpriceandthequotedprice.T heref ore, thefairvalueadjustmentis :
F air V alue Adjustment =Bid P rice −Quoted P rice
=
103 - 105 = −2
Step 2: Calculate the fair value of the investment using the bid price ap-
proach - The fair value of the investment is calculated by adjusting the quoted
price by the fair value adjustment.
F air V alue =Quoted P rice +F air V alue Adjustment
F air V alue =
105 - 2 =103
Thus, the fair value of the investment using the bid price approach is 103perunit.
Question 5
Question
Company XYZ holds an investment in a bond that is classified as a Level 2 fair
value measurement. The bond has a quoted price of 980, butthemarketforthisbondisnotveryactive.T oestimatethefairvalueofthebond, CompanyXY Zusesinputsotherthanquotedpricesthatareobservableforsimilarbonds.If theyieldonsimilarbondsis5.2
Solution
To estimate the fair value of the bond using a Level 2 fair value measurement
approach, Company XYZ will use observable market inputs other than quoted
prices. Given that the quoted price of the bond is 980andtheyieldonsimilarbondsis5.2
Step 1: Calculate the annual interest payment on the bond. The annual
interest payment can be calculated using the formula:
Interest Payment = Face Value ×Coupon Rate
Since the quoted price of the bond is 980, thef acevalueis1,000 (at par). The
coupon rate is not given in the question, so we need to calculate it:
Coupon Rate = Interest Payment
Face Value =980 ×0.052
1,000 = 0.5096
Step 2: Calculate the estimated fair value of the bond. The estimated fair
value can be calculated by discounting the future cash flows (interest payments
and face value) using the yield on similar bonds (5.2
Estimated Fair Value = Interest Payment
(1 + Yield) +Face Value
(1 + Yield)n
4
where nis the number of periods until the bond matures.
Step 3: Substitute the values into the formula and calculate.
Estimated Fair Value = 980 ×0.052
1+0.052 +1,000
(1 + 0.052)n
Estimated Fair Value = 51.04 + 1,000
1.052n
Thus, the estimated fair value of the bond held by Company XYZ is 51.04 +
1,000
1.052n.
Question 6
Question
Company XYZ holds an investment property whose fair value needs to be deter-
mined for financial reporting purposes. The property has a cost of $750,000 and
a current fair value of $825,000. Company XYZ also incurred $5,000 in trans-
action costs to acquire the property. Calculate the fair value of the investment
property for financial reporting purposes.
Solution
Step 1: Calculate the cost of the investment property including transaction
costs.
Total Cost = Cost of Property+Transaction Costs = $750,000+$5,000 = $755,000
Step 2: Determine the fair value adjustment based on the cost of the prop-
erty.
Fair Value Adjustment = Fair Value−Total Cost = $825,000−$755,000 = $70,000
Step 3: Calculate the fair value of the investment property for financial
reporting purposes.
Fair Value = Total Cost+Fair Value Adjustment = $755,000+$70,000 = $825,000
Therefore, the fair value of the investment property for financial reporting
purposes is $825,000.
Question 7
Question
A company holds an investment in a financial asset classified as available-
for-sale. At the end of the reporting period, the fair value of the asset is
1,500.However, duetomarketuncertainties, thecompany′smanagementbelievesthatthef airvaluemayf luctuatesignificantlyinthenearf uture.Howshouldthecompanyaccountf orthef airvaluemeasurementofthisfinancialassetinitsfinancialstatements?
5

Solution
1. Initial Recognition: The company should initially recognize the financial
asset at cost. In this case, the cost of the asset will be the initial purchase price.
2. Subsequent Measurement at Fair Value: As the financial asset is
classified as available-for-sale, subsequent measurement should be at fair value.
At the end of each reporting period, the company should measure the fair value
of the asset.
3. Recognition of Unrealized Gains or Losses: Any unrealized gains
or losses resulting from changes in fair value should be recognized in other
comprehensive income (OCI) until the asset is derecognized from the balance
sheet or the fair value change represents an impairment.
4. Impairment Testing: If there are indicators of impairment, such as
a significant decline in the fair value of the asset below its cost, the company
should perform impairment testing. If the asset is impaired, the company should
recognize the impairment loss in its income statement.
5. Disclosure: The company should disclose the fair value hierarchy of the
financial asset, the valuation techniques used, and any significant unobservable
inputs.
Therefore, the company should account for the fair value measurement of
the financial asset by measuring it at fair value at the end of each reporting
period and recognizing any unrealized gains or losses in OCI until the asset is
derecognized or impaired.
Question 8
Question
A company holds an investment in a private company that is not traded on any
public market. The fair value of the investment is determined using Level 3
inputs. Explain what Level 3 inputs are and provide an example of such inputs
in the context of fair value measurement.
Solution
Step 1: Fair value measurements can be categorized into three levels based on
the inputs used in the valuation process. Level 3 inputs are unobservable inputs
that are used when observable data is not available. These inputs are based
on the company’s own assumptions and estimates, and can have a significant
impact on the fair value measurement.
Step 2: An example of Level 3 inputs in the context of fair value measurement
for an investment in a private company could be the use of a discounted cash
flow (DCF) model. In this case, the company would need to estimate future
cash flows of the private company, determine an appropriate discount rate, and
make assumptions about the growth rate and terminal value. These inputs are
6

all based on the company’s own assessments and are not readily observable in
the market.
Step 3: The use of Level 3 inputs in fair value measurement introduces
subjectivity and potential bias into the valuation process. It is important for
companies to disclose the nature and impact of Level 3 inputs in their financial
statements to provide transparency to investors and other stakeholders.
Question 9
Question
A company holds an investment in a privately held company that specializes
in renewable energy projects. The fair value of this investment must be deter-
mined for financial reporting purposes. Discuss the key considerations and steps
involved in applying fair value measurement techniques for this investment.
Solution
To determine the fair value of the investment in the privately held company
specializing in renewable energy projects, several key considerations and steps
must be taken into account. Below are the key considerations and steps involved
in applying fair value measurement techniques for this investment:
Step 1: Understand Fair Value Measurement Fair value is defined as
the price that would be received to sell an asset or paid to transfer a liability in
an orderly transaction between market participants at the measurement date.
It is important to have a clear understanding of this concept before proceeding
with the fair value measurement process.
Step 2: Determine the Valuation Techniques Select appropriate val-
uation techniques based on the nature of the investment. Common valuation
techniques include market approach, income approach, and cost approach. In
this case, a combination of techniques may be necessary to arrive at a reliable
fair value estimate.
Step 3: Gather Relevant Data Collect all relevant information about
the renewable energy projects company, such as financial statements, cash flow
projections, market comparables, industry data, and any other pertinent infor-
mation that can assist in the valuation process.
Step 4: Adjust for Market and Company-Specific Factors Consider
the impact of market conditions and company-specific factors on the fair value of
the investment. Adjust the valuation based on these factors to ensure a realistic
fair value estimate.
Step 5: Reconcile and Review Reconcile the information gathered and
the valuation results to ensure consistency and accuracy. Review the assump-
tions made and the methodologies used in the valuation process to validate the
fair value estimate.
7
Step 6: Disclose the Fair Value Measurement Finally, disclose the
fair value measurement of the investment in the financial statements in accor-
dance with the applicable accounting standards. Provide detailed information
about the valuation techniques used, key assumptions made, and any significant
uncertainties surrounding the fair value estimate.
By following these key considerations and steps, the company can effectively
apply fair value measurement techniques to determine the fair value of its invest-
ment in the privately held company specializing in renewable energy projects
for financial reporting purposes.
Question 10
Question
You are a financial analyst tasked with determining the fair value of a complex
derivative instrument. The instrument has several components with unique
characteristics that affect its value. Explain what factors you would consider
when determining the fair value of this derivative instrument.
Solution
To determine the fair value of a complex derivative instrument, several factors
need to be considered. Below are the key factors:
Step 1: Identify the Components
Identify and understand each individual component of the derivative in-
strument, such as options, forwards, swaps, etc.
Determine the specific terms and conditions of each component, including
exercise prices, expiration dates, underlying assets, etc.
Step 2: Market Variables
Evaluate current market conditions and variables that may impact the
value of the derivative instrument, such as interest rates, volatility, credit
spreads, etc.
Consider how changes in these market variables would affect the value of
the derivative instrument.
Step 3: Risk Factors
Assess the different types of risk associated with the derivative instrument,
including market risk, credit risk, liquidity risk, etc.
Quantify the impact of these risks on the fair value of the instrument.
Step 4: Valuation Models
8
Select an appropriate valuation model based on the characteristics of the
derivative instrument, such as Black-Scholes model for options, discounted
cash flow analysis for swaps, etc.
Input the relevant data and assumptions into the valuation model to cal-
culate the fair value of the derivative instrument.
Step 5: Documentation and Disclosure
Document the assumptions, methodologies, and models used in determin-
ing the fair value of the derivative instrument.
Ensure proper disclosure of the fair value measurement process in financial
reports to provide transparency to stakeholders.
By considering these factors and following a structured approach, the fi-
nancial analyst can accurately determine the fair value of a complex derivative
instrument.
Question 11
Question
Company XYZ holds an investment in a private company whose fair value is not
readily determinable. The management of XYZ is required to estimate the fair
value of this investment for financial reporting purposes. Discuss the different
valuation techniques that can be used by XYZ to determine the fair value of
this investment.
Solution
To estimate the fair value of an investment when it is not readily determinable,
Company XYZ can use a variety of valuation techniques. Here are some common
methods that can be considered:
Step 1: Market Approach
XYZ can use the market approach by comparing the investment to similar
investments that have observable market prices. This method involves us-
ing market multiples or transaction prices of comparable assets to estimate
the fair value.
For example, XYZ could look at recent transactions of similar private
companies or use publicly traded companies in the same industry to derive
a valuation multiple which can then be applied to the financial metrics of
the investment.
Step 2: Income Approach
9
XYZ can also utilize the income approach, such as the discounted cash flow
(DCF) method, to estimate the fair value of the investment. This method
involves forecasting the future cash flows expected from the investment
and discounting them back to present value using an appropriate discount
rate.
The DCF method takes into account the timing and risk associated with
the cash flows, providing a comprehensive estimate of the investment’s fair
value.
Step 3: Cost Approach
Another technique that XYZ can consider is the cost approach. This
method involves estimating the fair value of the investment by determining
the cost to replace or reproduce the investment.
XYZ would consider the cost of acquiring or developing a similar invest-
ment with the same functionality, condition, and utility. This approach
can be particularly useful for assets with no comparable market data.
By considering these different valuation techniques, Company XYZ can make
a reasonable estimate of the fair value of its investment in the private company,
even when the fair value is not readily determinable.
Question 12
Question
Company XYZ holds an investment in a privately-held company that operates
in a niche market. The investment is classified as Level 3 under the fair value
hierarchy. Company XYZ has determined the fair value of this investment
using a discounted cash flow (DCF) model. Discuss the key considerations
and challenges in applying the DCF model for fair value measurement in this
scenario.
Solution
To determine the fair value of the investment in the privately-held company
using a discounted cash flow (DCF) model, several key considerations and chal-
lenges need to be addressed:
Step 1: Understand the Nature of the Investment It is crucial to
have a deep understanding of the privately-held company’s operations, financial
performance, market dynamics, growth potential, and risks. Since this company
operates in a niche market, obtaining accurate and reliable information may be
challenging.
10

Step 2: Forecasting Cash Flows One of the main challenges in applying
the DCF model is accurately forecasting the future cash flows of the privately-
held company. This requires making assumptions about revenue growth, oper-
ating expenses, capital expenditures, working capital requirements, and other
relevant factors. In the case of a niche market, forecasting cash flows can be
even more challenging due to limited available data and market trends.
Step 3: Determining the Discount Rate The discount rate used in the
DCF model is a critical input that reflects the risk associated with the invest-
ment. Estimating an appropriate discount rate for a privately-held company
operating in a niche market requires considering factors such as market risk
premium, company-specific risk factors, and the illiquidity of the investment.
Step 4: Adjusting for Illiquidity Since the investment in the privately-
held company is not publicly traded, its illiquidity needs to be taken into account
when determining the fair value. Adjustments may need to be made to the
discount rate or the cash flow projections to reflect the lack of marketability of
the investment.
Step 5: Sensitivity Analysis Given the uncertainties and challenges in-
volved in using the DCF model for fair value measurement in this scenario,
conducting sensitivity analysis is crucial. By varying key assumptions such as
revenue growth rates, discount rates, and terminal values, Company XYZ can
assess the impact on the fair value estimate and understand the range of possible
outcomes.
In conclusion, applying a DFC model for fair value measurement of an in-
vestment in a privately-held company operating in a niche market requires a
thorough understanding of the investment, accurate forecasting, careful consid-
eration of discount rates, adjustments for illiquidity, and sensitivity analysis to
account for uncertainties.
Question 13
Question
A company owns an investment property that is measured at fair value. The
fair value of the property increased by 15
Solution
Let xbe the original fair value of the property.
Step 1: Calculate the fair value after the 15The fair value after the increase
is x+ 0.15x= 1.15x.
Step 2: Set up an equation to represent the fair value gain. Since the fair
value increased by 15%, the fair value after the increase is 1.15x. The fair value
gain is 1.15x−x= $50,000.
Step 3: Solve the equation for x.
1.15x−x= 0.15x= 50000
11
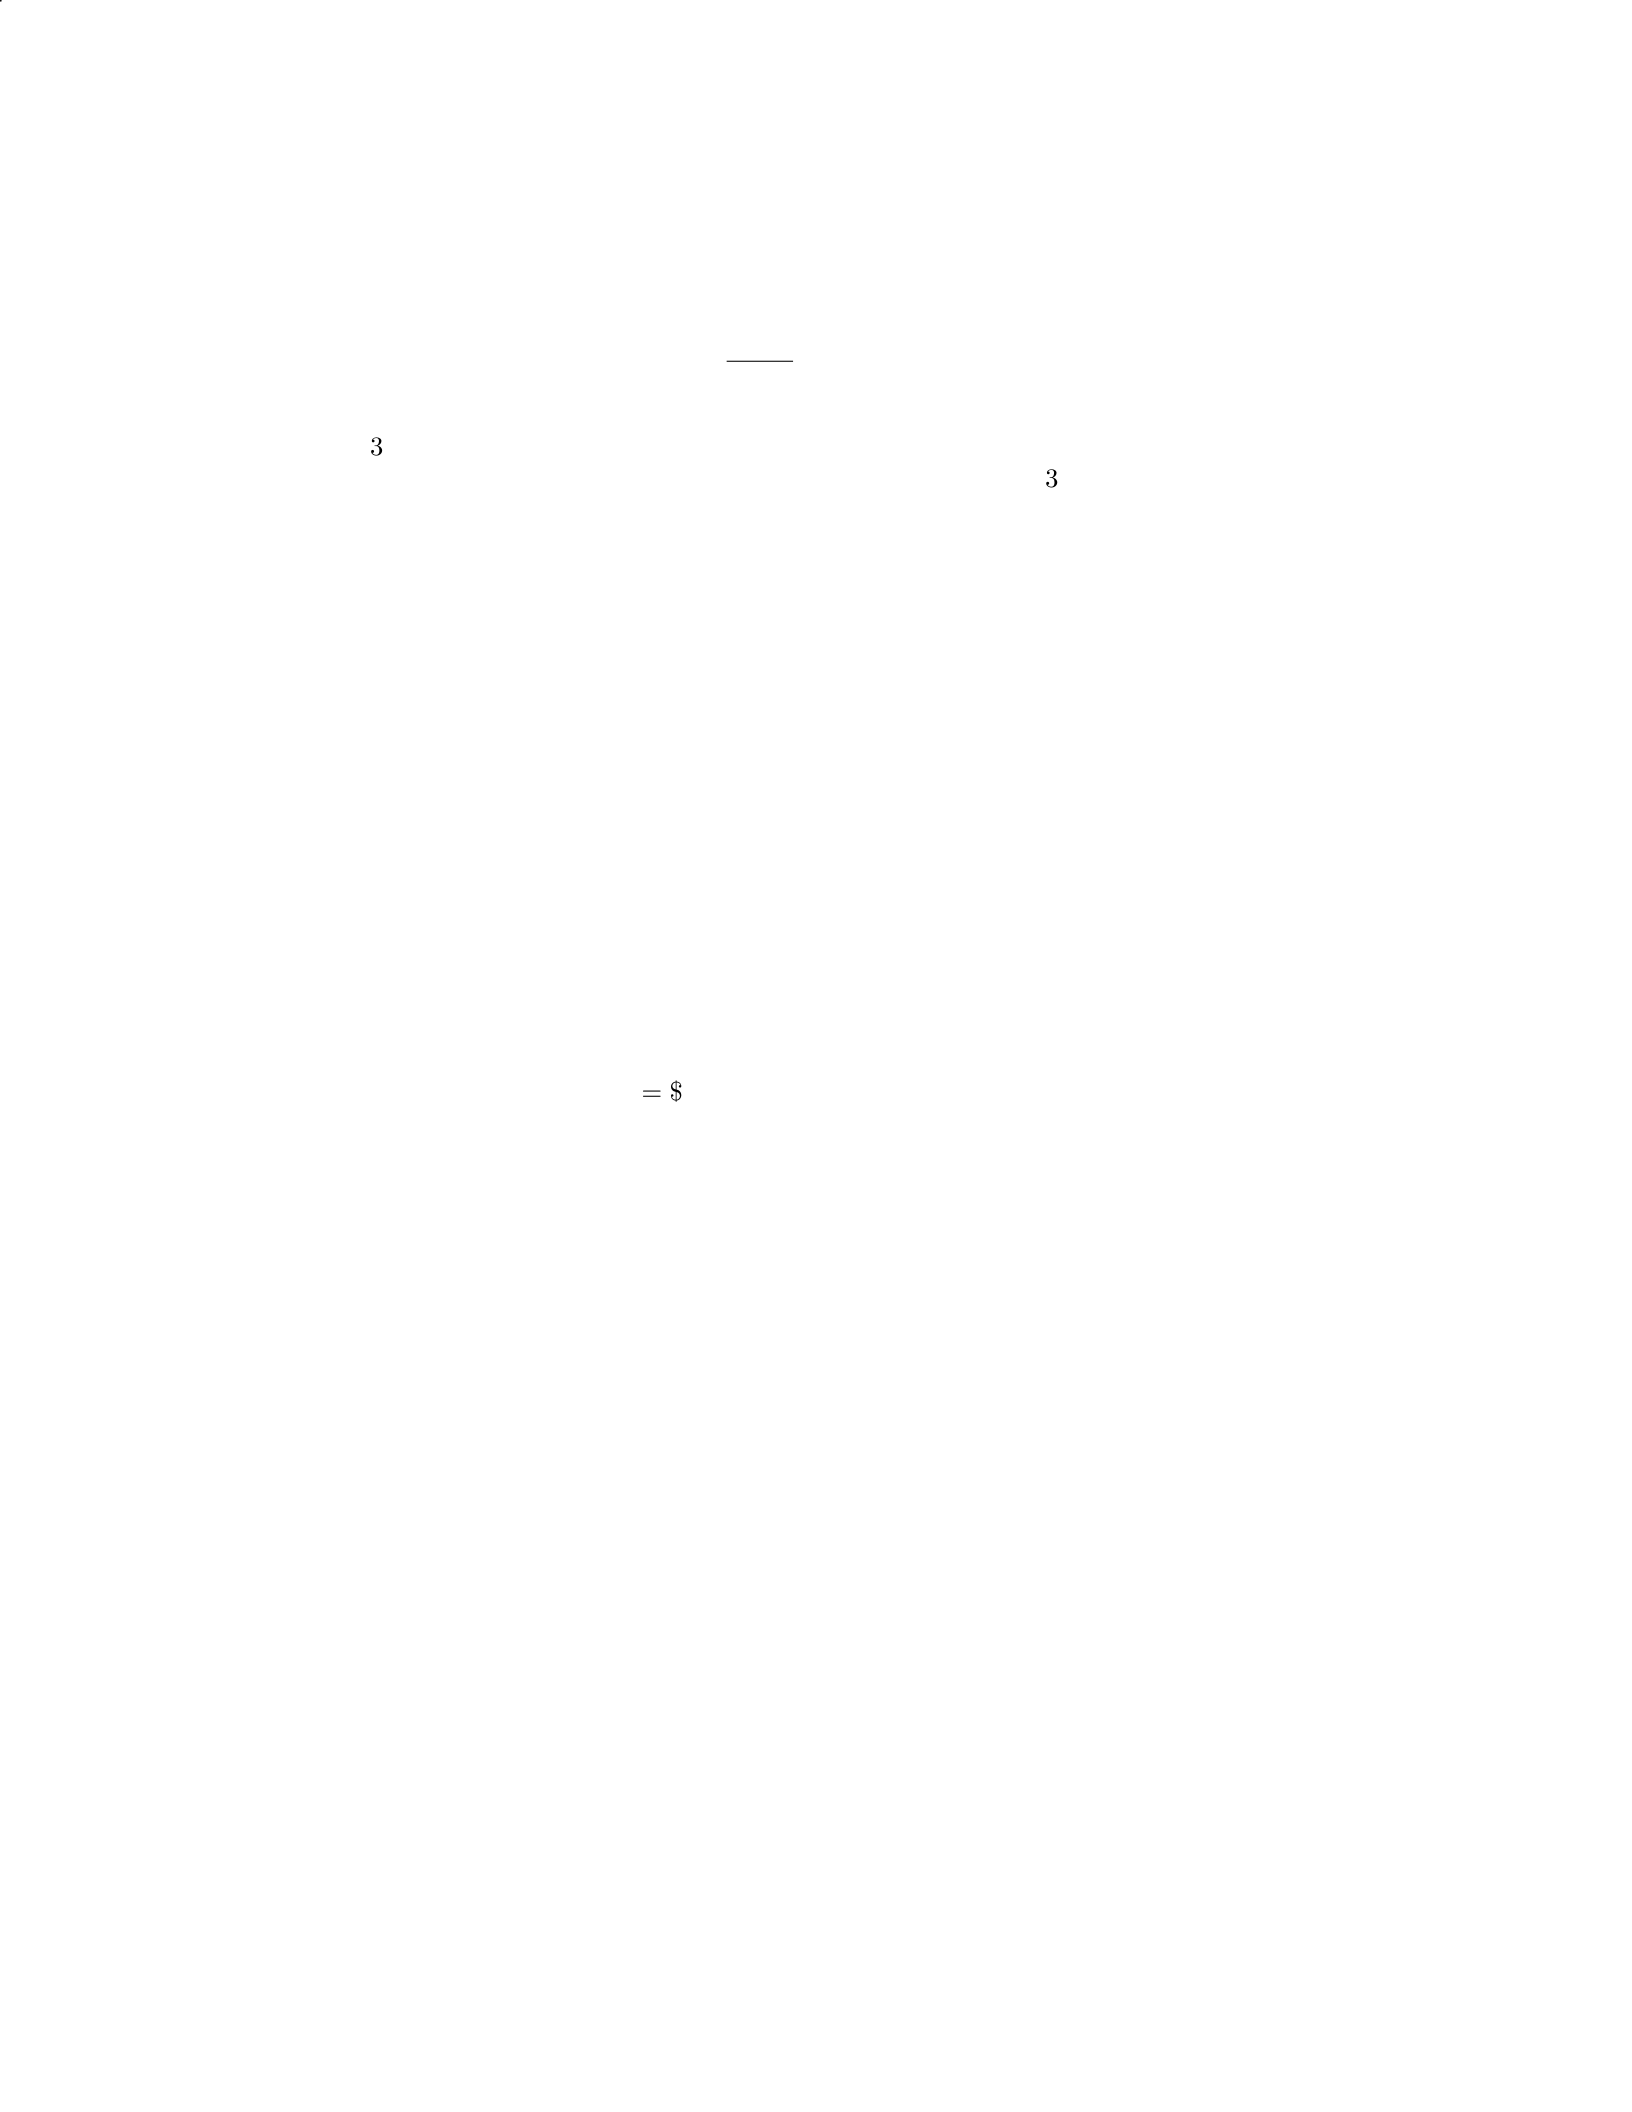
x=50000
0.15 = 333,333.33
Step 4: Check the solution. If the original fair value of the property was
$
333,333.33, a 15
Therefore, the original fair value of the property was
$
333,333.33.
Question 14
Question
A company is valuing its investment property using the fair value model. At
the end of the reporting period, the property was appraised at $2,500,000.
During the next reporting period, the property value increased to $2,700,000.
The property was held as an investment to earn rental income. The company
recognizes changes in fair value in profit or loss. Calculate the fair value gain or
loss to be reported in the company’s income statement for the second reporting
period.
Solution
Step 1: Calculate the fair value gain or loss.
Fair Value Gain or Loss = Fair Value at the end of the second reporting period −Fair Value at the end of the first reporting period
= $2,700,000 −$2,500,000
= $200,000
Therefore, the fair value gain to be reported in the company’s income state-
ment for the second reporting period is $200,000.
Question 15
Question
A company holds an investment in a private equity fund. The fair value of
the investment is determined using the income approach, which estimates fair
value based on the present value of estimated future cash flows. The company’s
discount rate used in the present value calculation is 12- Year 1: 500,000 −
Y ear2 :600,000 - Year 3: 700,000Ifthef airvalueof theinvestmentattheendof Y ear3is1,800,000,
calculate the total present value of the estimated future cash flows.
Solution
Step 1: Calculate the present value of each cash flow using the given discount
rate of 12
12
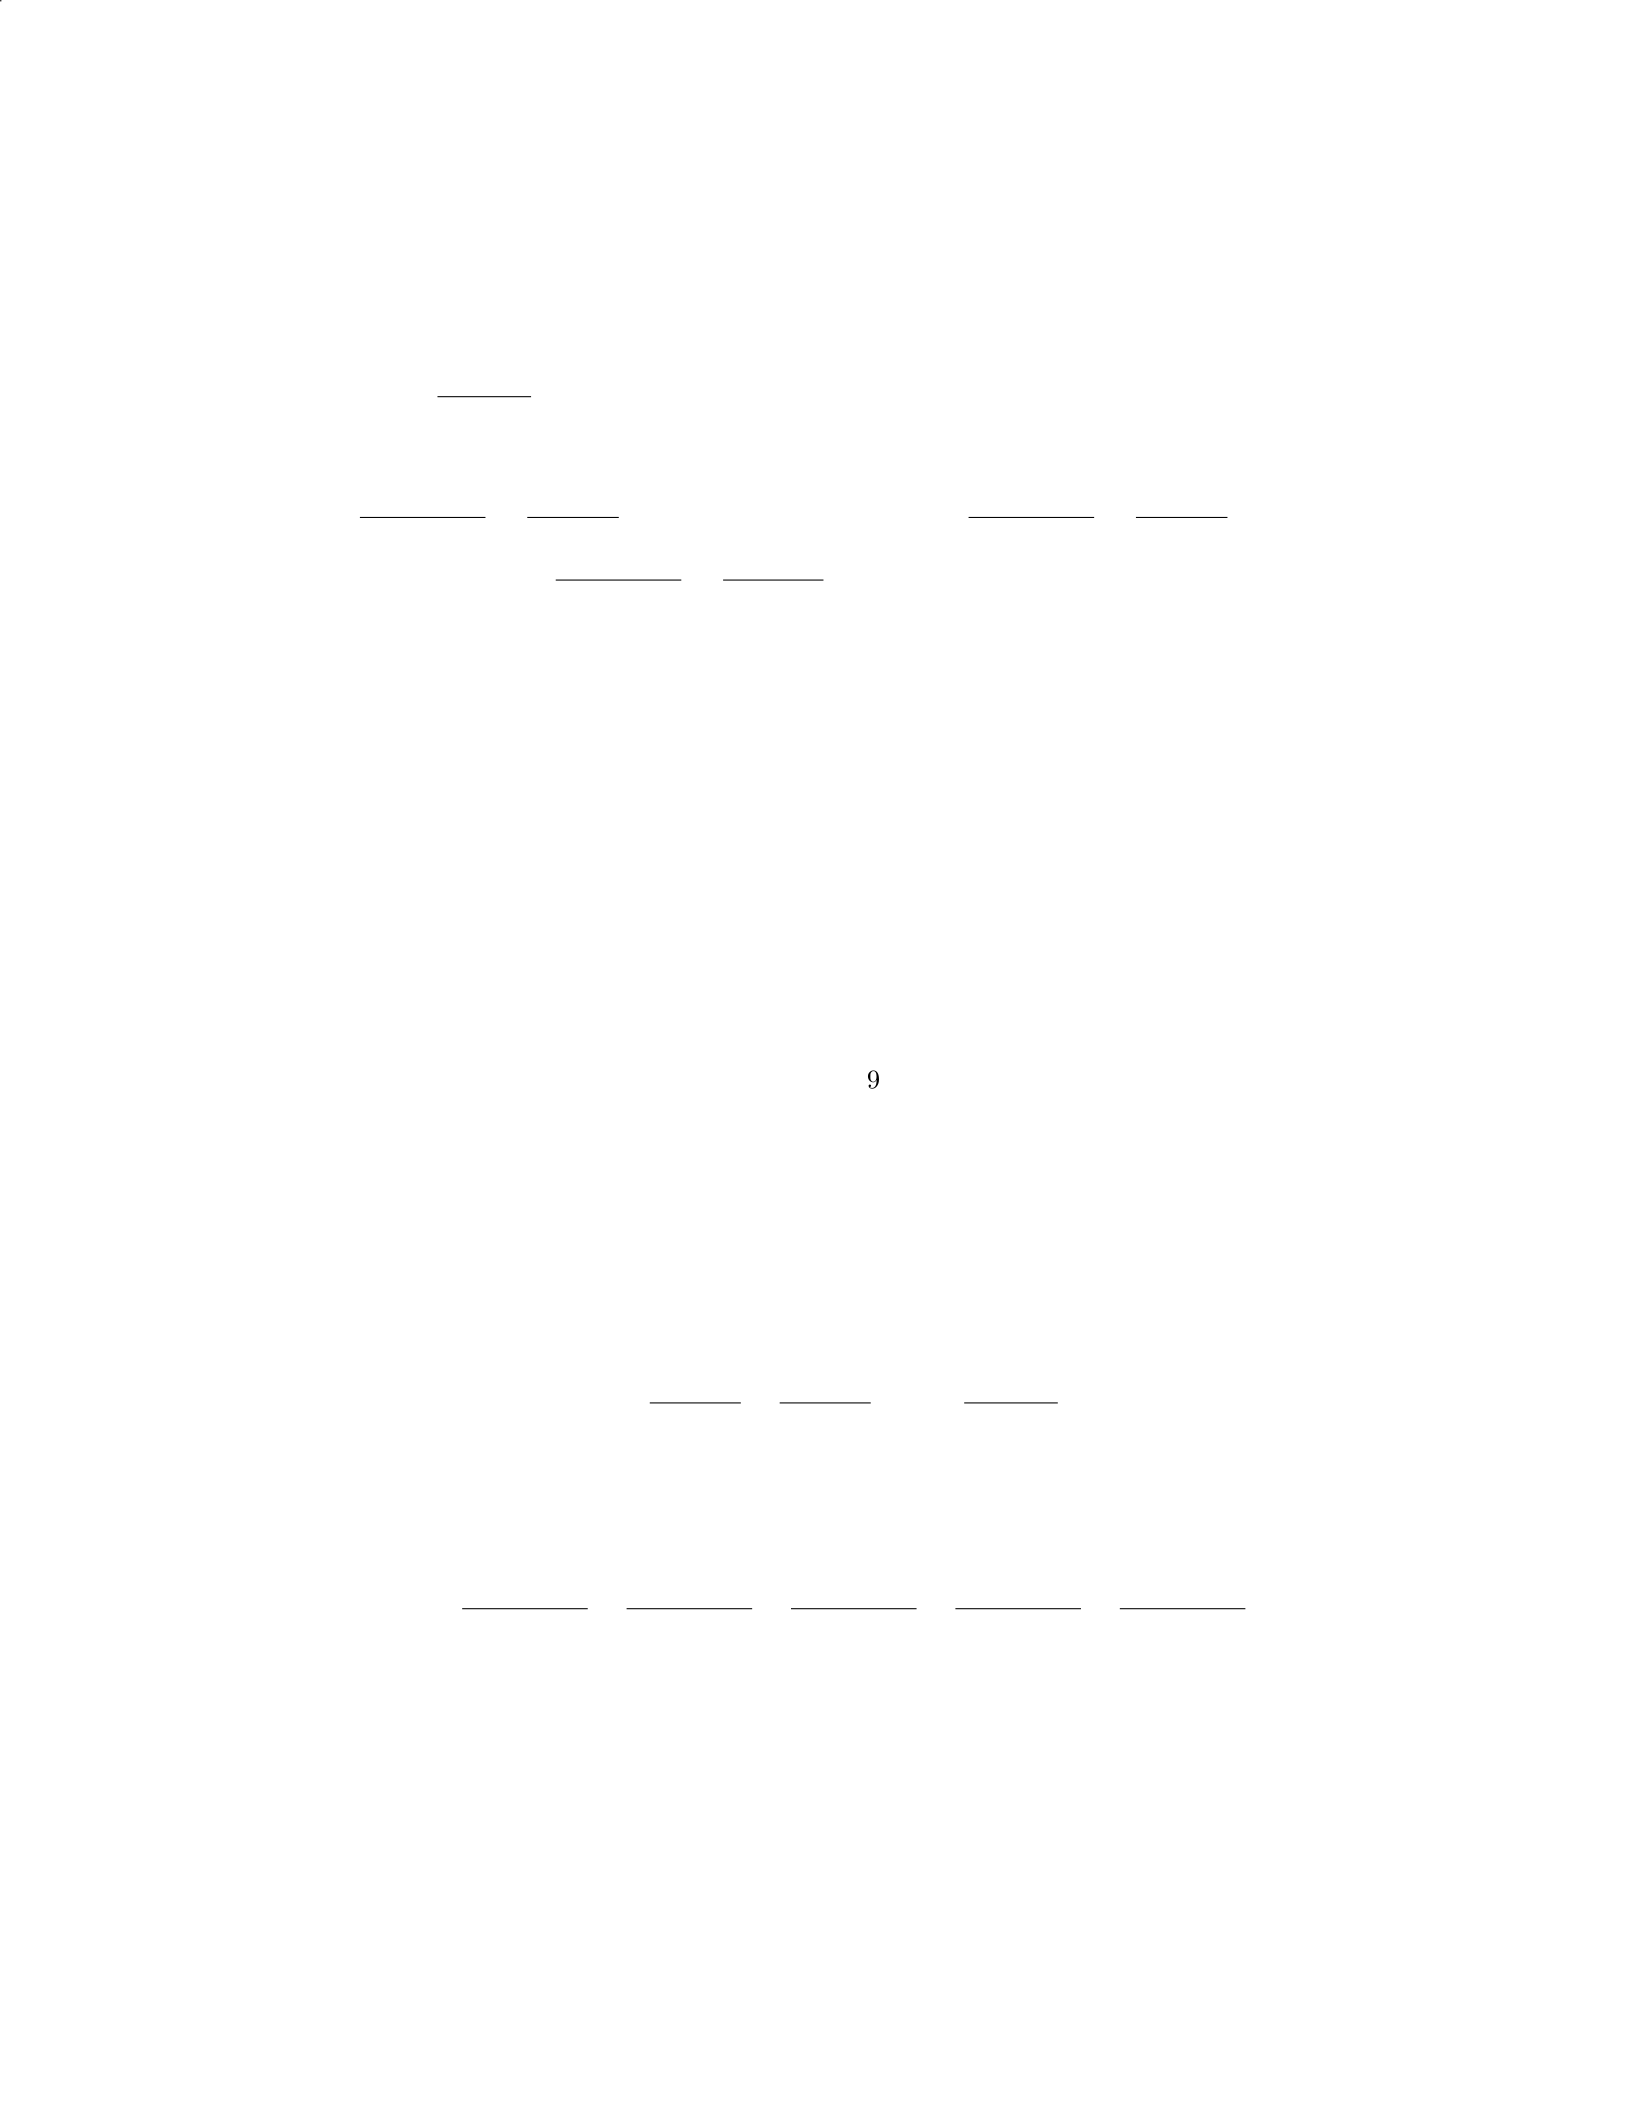
Step 2: We can use the formula for present value of a single cash flow:
P V =CF
(1 + r)n, where CF is the cash flow, ris the discount rate, and nis the
time period.
Step 3: Calculate the present value of each cash flow: - Year 1: P V1=
500,000
(1 + 0.12)1=500,000
1.12 ≈446,428.57 - Year 2: P V2=600,000
(1 + 0.12)2=600,000
1.2544 ≈478,915.66
- Year 3: P V3=700,000
(1 + 0.12)3=700,000
1.404928 ≈498,266.90
Step 4: Calculate the total present value of the estimated future cash flows
by summing up the present values of each cash flow. T otalP V =P V1+P V2+
P V3≈1,423,611.13.
Therefore, the total present value of the estimated future cash flows is ap-
proximately 1,423,611.13.
Question 16
Question
Company XYZ holds an investment in a financial instrument classified as a
Level 3 fair value measurement. The fair value hierarchy defines Level 3 inputs
as unobservable inputs, meaning that they are not based on market data.
The company’s management has estimated the following inputs for the fi-
nancial instrument: - Expected cash flows:
$
90,000 - Discount rate: 8- Expected
holding period: 5 years
Calculate the fair value of the financial instrument using the discounted cash
flow method.
Solution
Step 1: Calculate the present value of expected cash flows. The formula for
present value using discounted cash flow is:
P V =CF1
(1 + r)1+CF2
(1 + r)2+... +CFn
(1 + r)n
where: - P V = present value - CFi= cash flow in year i-r= discount rate -
n= number of years
Plugging in the values:
P V =90,000
(1 + 0.08)1+90,000
(1 + 0.08)2+90,000
(1 + 0.08)3+90,000
(1 + 0.08)4+90,000
(1 + 0.08)5
Step 2: Calculate the fair value of the financial instrument. The fair value
of the financial instrument is the sum of the present value of the expected cash
flows.
Fair value = P V
13
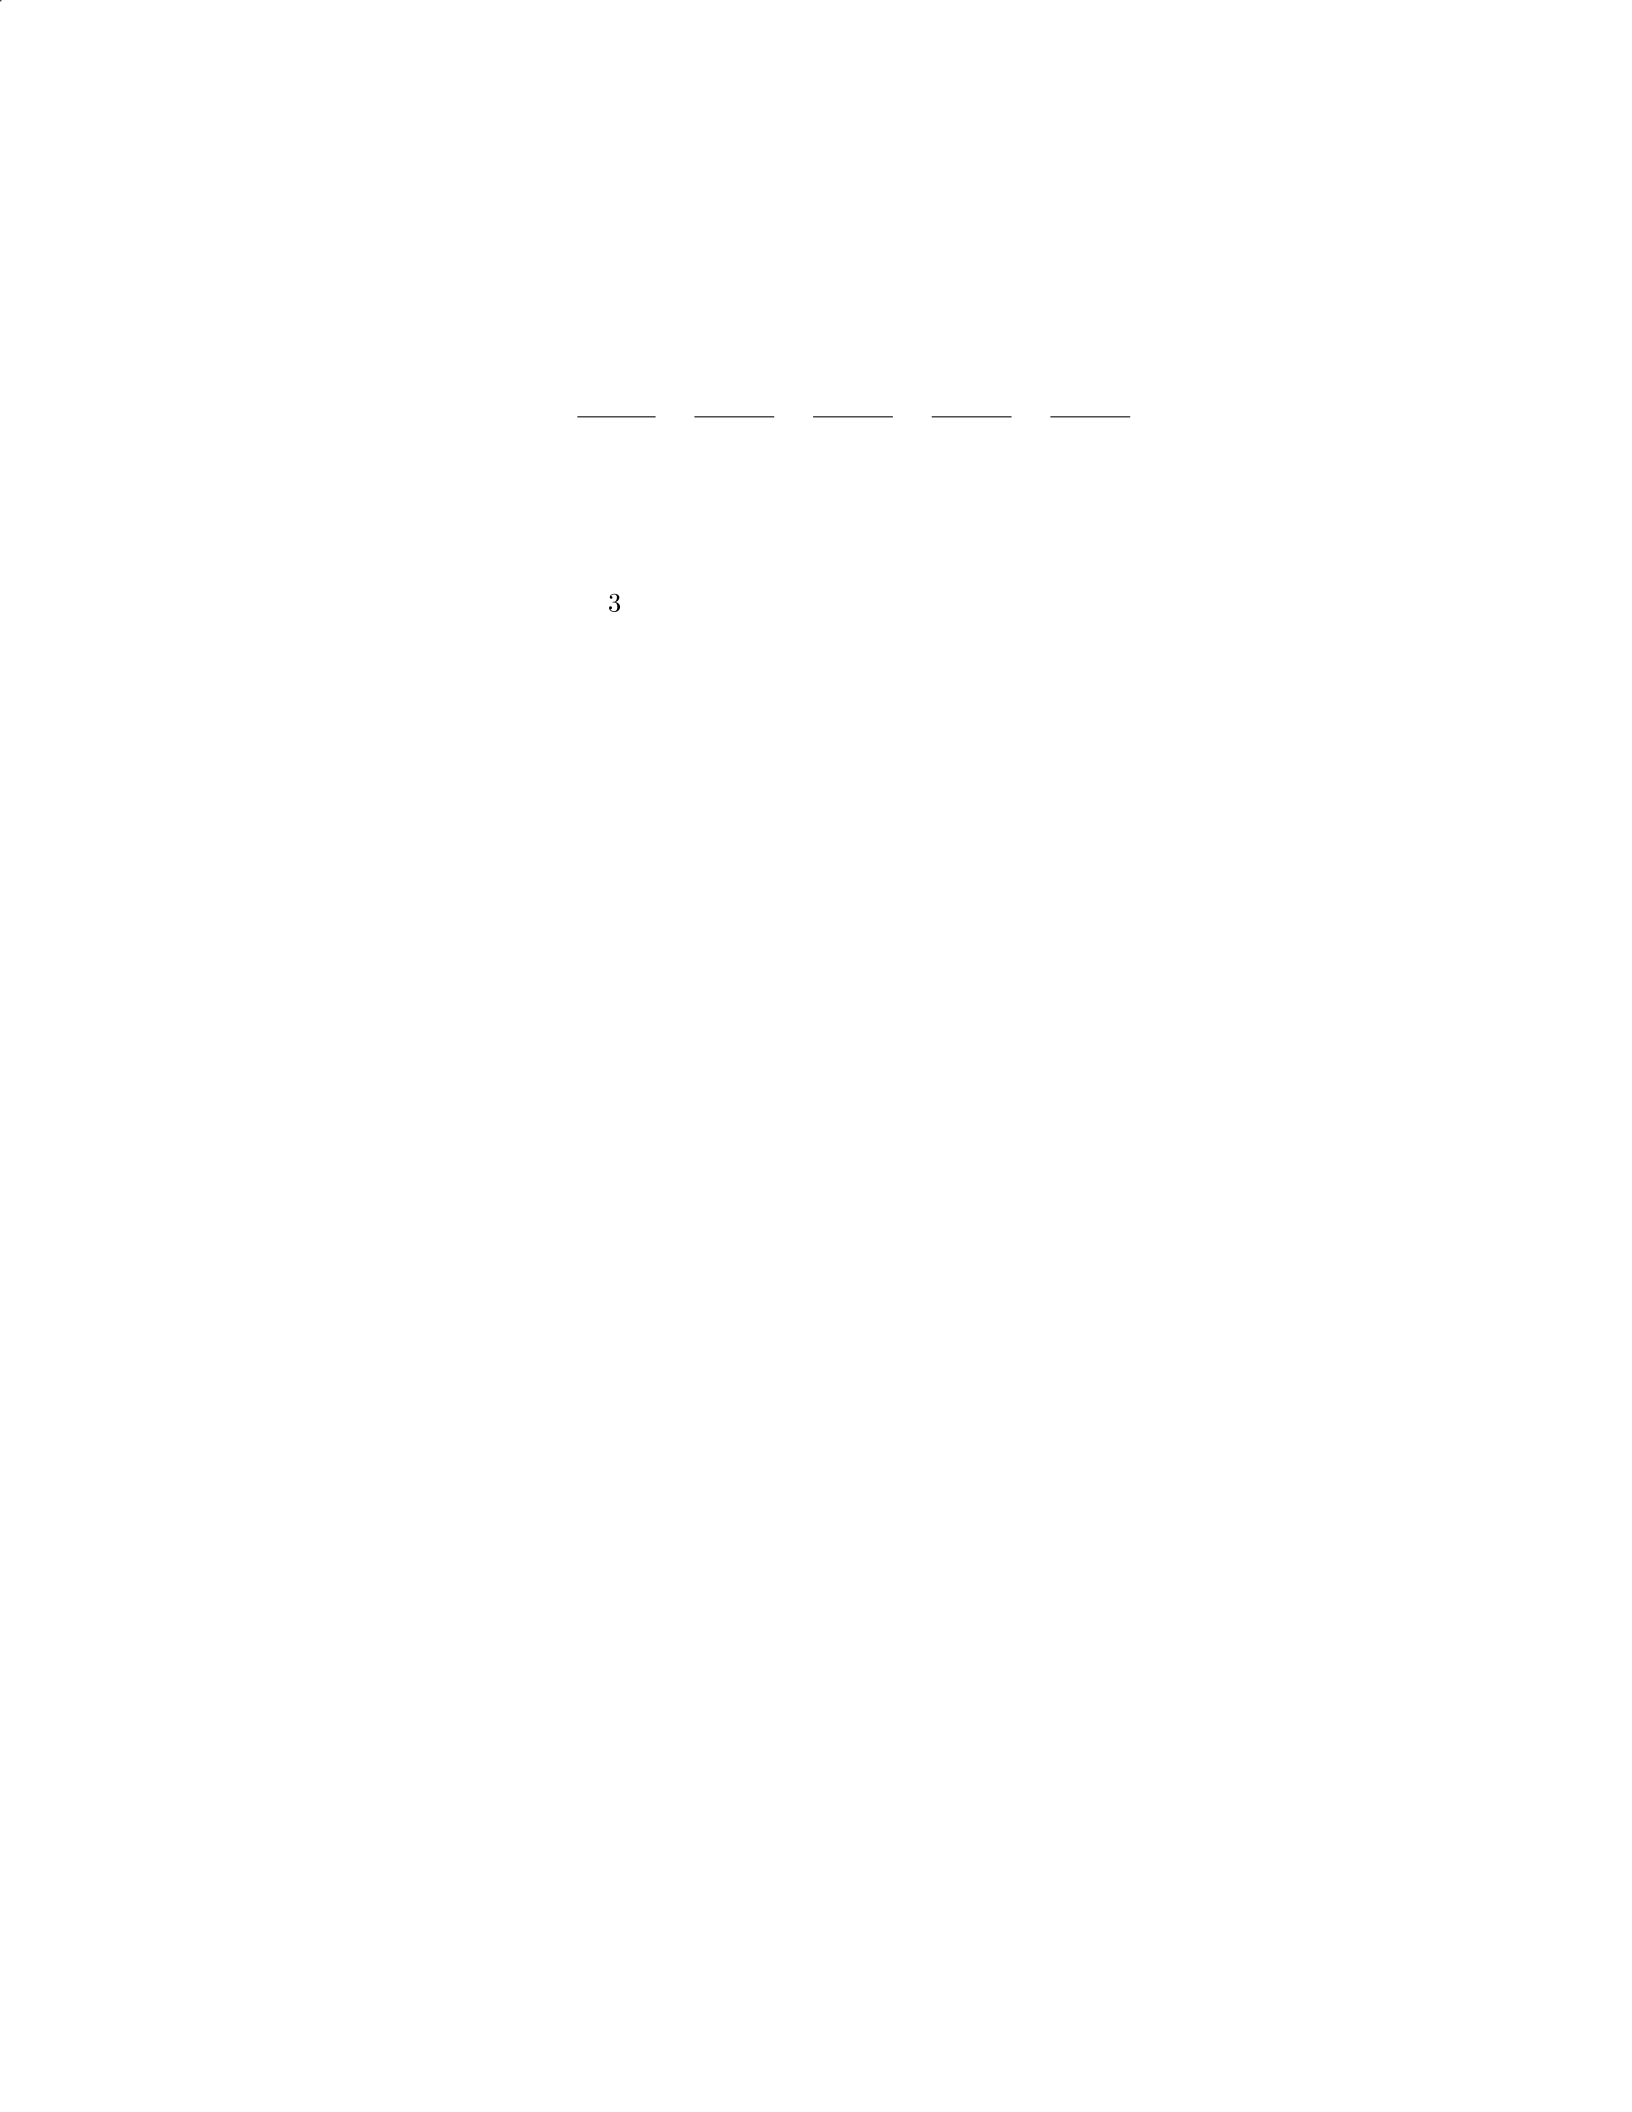
Calculating the present value:
P V =90,000
1.08 +90,000
(1.08)2+90,000
(1.08)3+90,000
(1.08)4+90,000
(1.08)5
P V = 83333.33 + 77160.49 + 71536.68 + 66404.12 + 61725.65
P V = 360160.28
Therefore, the fair value of the financial instrument using the discounted
cash flow method is
$
360,160.28.
Question 17
Question
A company is assessing the fair value of its investment in a private company. The
estimated fair value at the end of the year is 150,000.T hecompanyalsoestimatesa20
Solution
Step 1: Calculate the expected value using the formula:
Expected Value =
n
X
i=1
Probabilityi×Fair Valuei
Step 2: Substitute the given probabilities and fair values into the formula:
Expected Value = 0.20 ×130,000 + 0.50 ×150,000 + 0.30 ×170,000
Step 3: Calculate the expected value:
Expected Value = 26,000 + 75,000 + 51,000
Expected Value = 152,000
The expected value of the investment is 152,000.
Question 18
Question
Company A holds an investment in Company B, which is classified as an eq-
uity security. At the end of the year, Company A determines the fair value of
the investment to be $120,000. However, due to recent market volatility, there
is uncertainty about the reliability of the inputs used in the fair value mea-
surement. As a result, Company A is considering using a valuation technique
that takes into account this uncertainty to determine the fair value. Explain how
Company A should adjust its fair value measurement to address the uncertainty
surrounding the inputs.
14
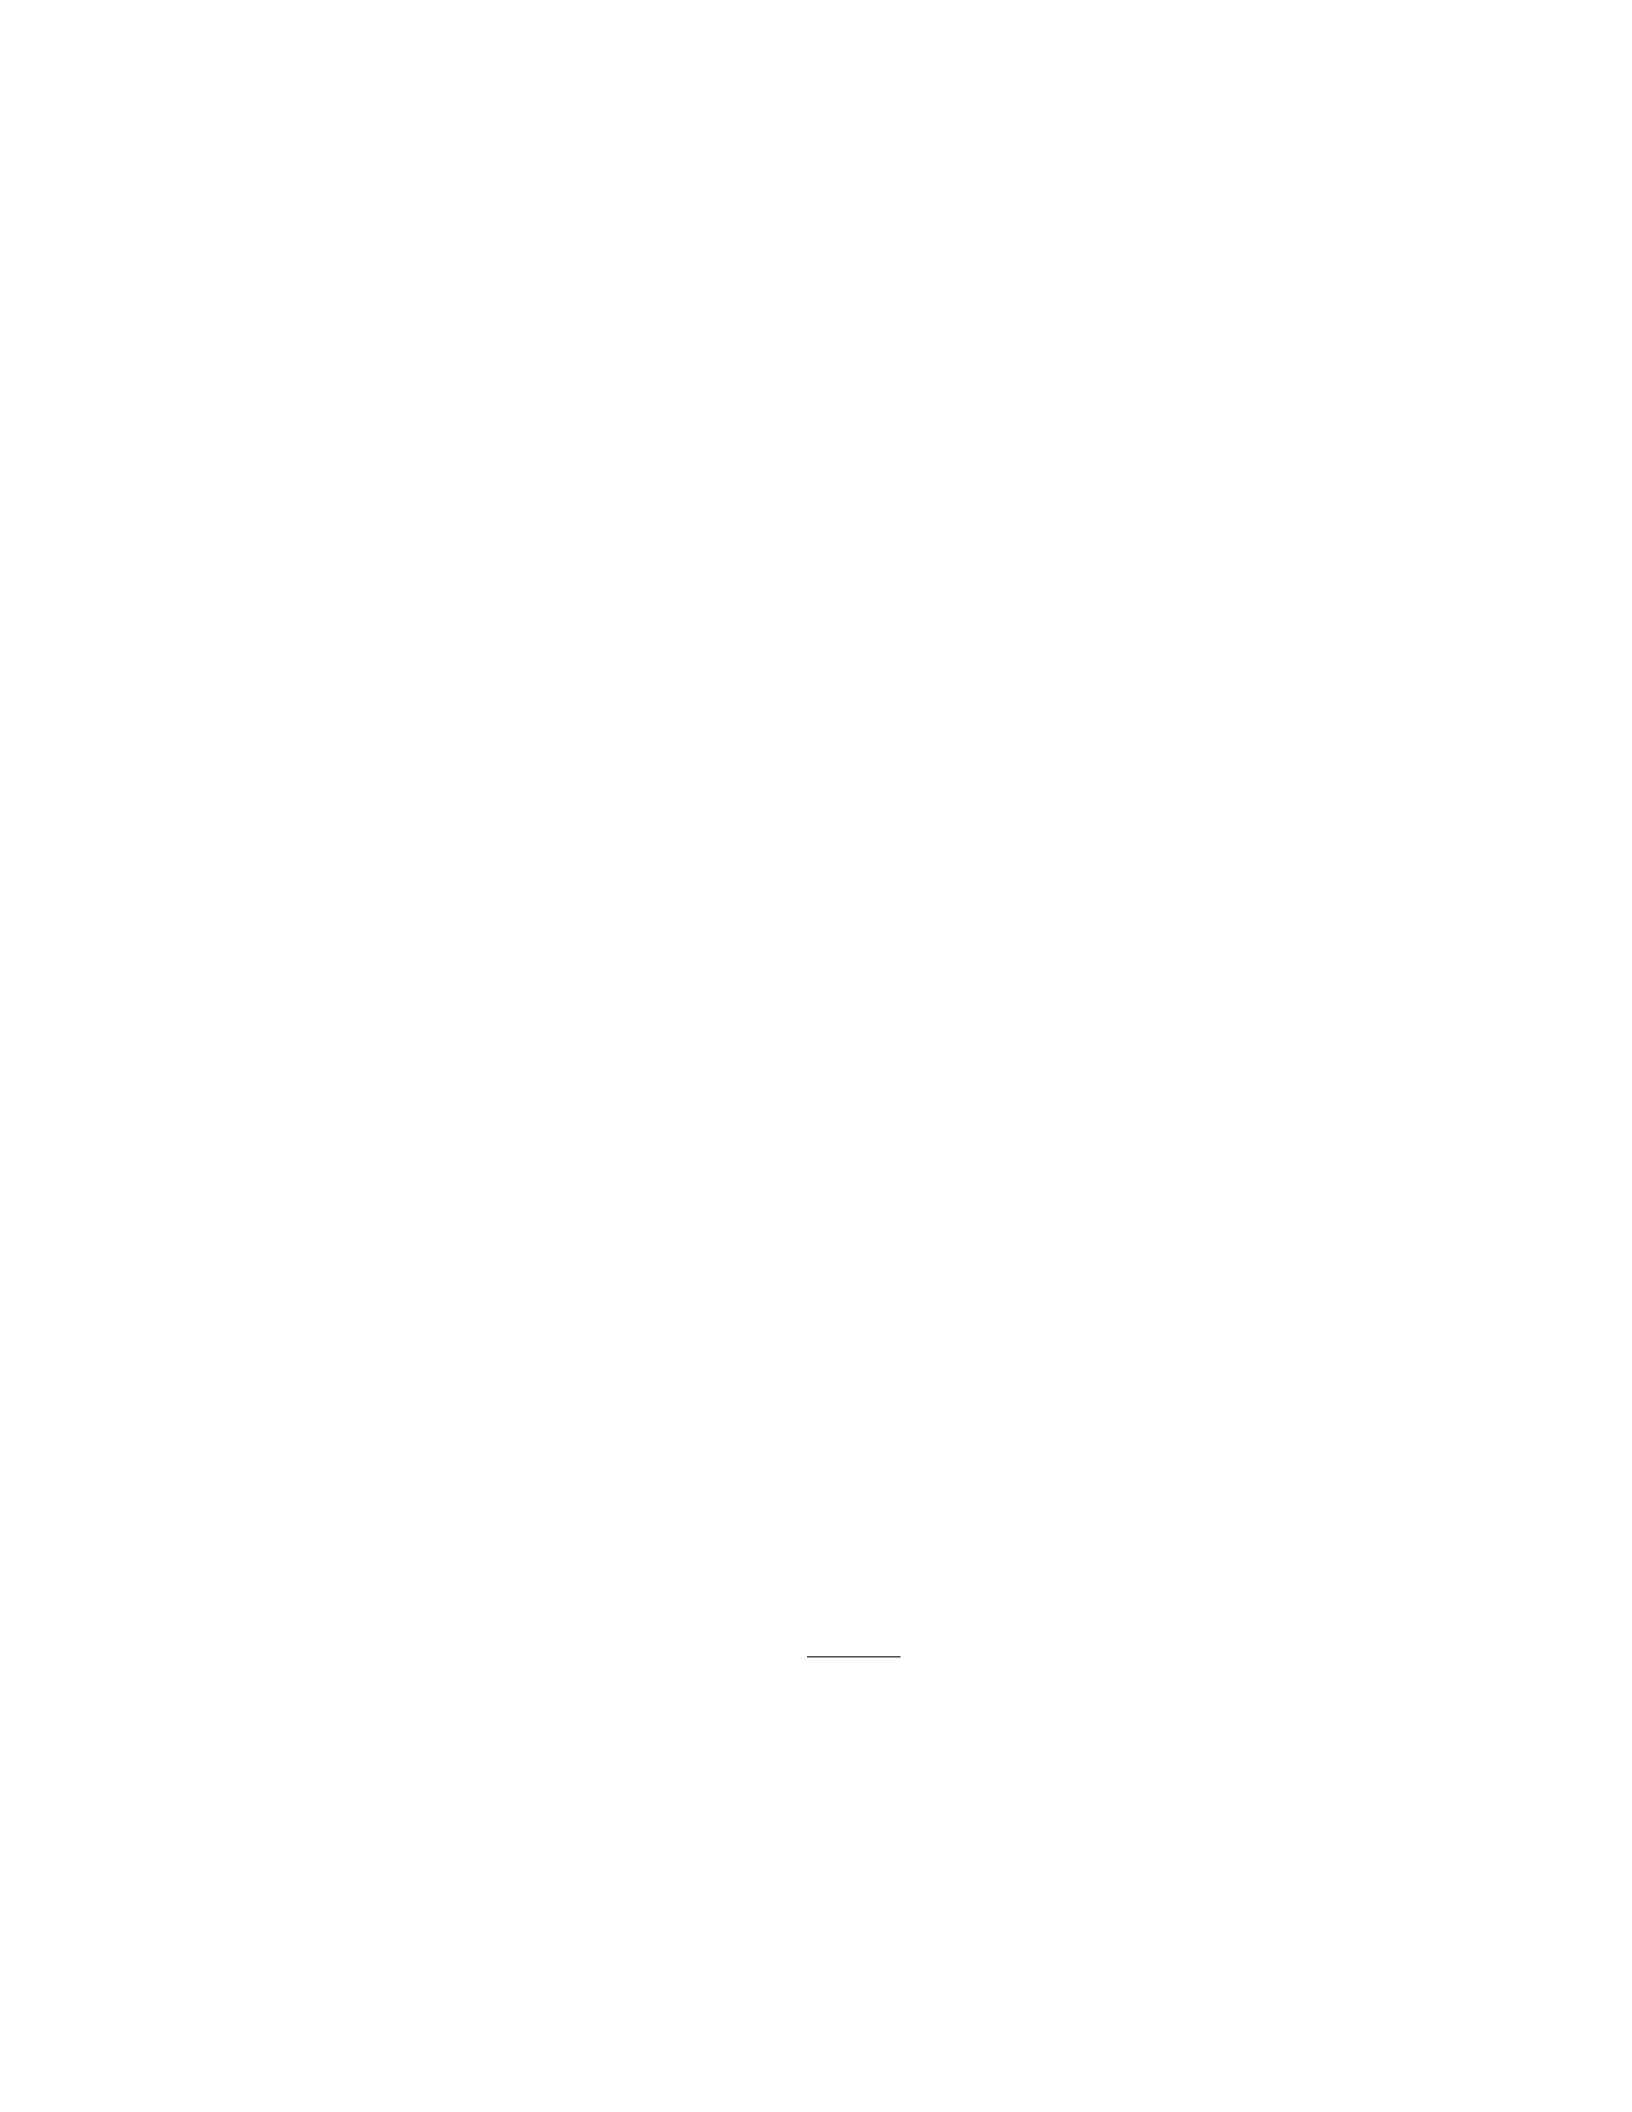
Solution
Step 1: Evaluate the reliability of inputs used in the initial fair value measure-
ment. - Company A should assess the reliability of the inputs used in the fair
value measurement of the investment in Company B. If there is uncertainty
surrounding the inputs, the fair value measurement may not accurately reflect
the true value of the investment.
Step 2: Consider using a valuation technique that incorporates the uncer-
tainty. - Given the uncertainty surrounding the inputs, Company A should con-
sider using a valuation technique that takes into account this uncertainty. One
such technique is an option pricing model, such as the Black-Scholes model,
which considers market volatility and other factors that may impact the fair
value of the investment.
Step 3: Adjust the fair value measurement using the chosen valuation tech-
nique. - Company A should apply the chosen valuation technique to adjust the
fair value measurement of the investment in Company B. This adjustment may
result in a fair value that better reflects the uncertainty surrounding the inputs
and provides a more accurate representation of the investment’s value.
Step 4: Disclose the use of the valuation technique and the rationale behind
it. - It is important for Company A to disclose in its financial statements
the use of the valuation technique to adjust the fair value measurement of the
investment in Company B. The disclosure should include the rationale behind
the adjustment and how it addresses the uncertainty surrounding the inputs
used in the initial fair value measurement.
Question 19
Question
Company XYZ holds an investment in a financial instrument classified as a Level
3 fair value measurement. At the end of the reporting period, the instrument has
a fair value of 450,000.Duringtheperiod, theinstrumentgeneratedcashf lowsof 50,000,
and the discount rate used to calculate the fair value of the instrument is 8
Solution
Step 1: Calculate the present value of the cash flows generated by the finan-
cial instrument during the reporting period. Given: Cash flows generated =
50,000Discountrate = 8
The present value of cash flows can be calculated using the formula:
P V =CF
(1 + r)n
Where: P V = Present value of cash flows CF = Cash flows generated r=
Discount rate n= Number of periods
15
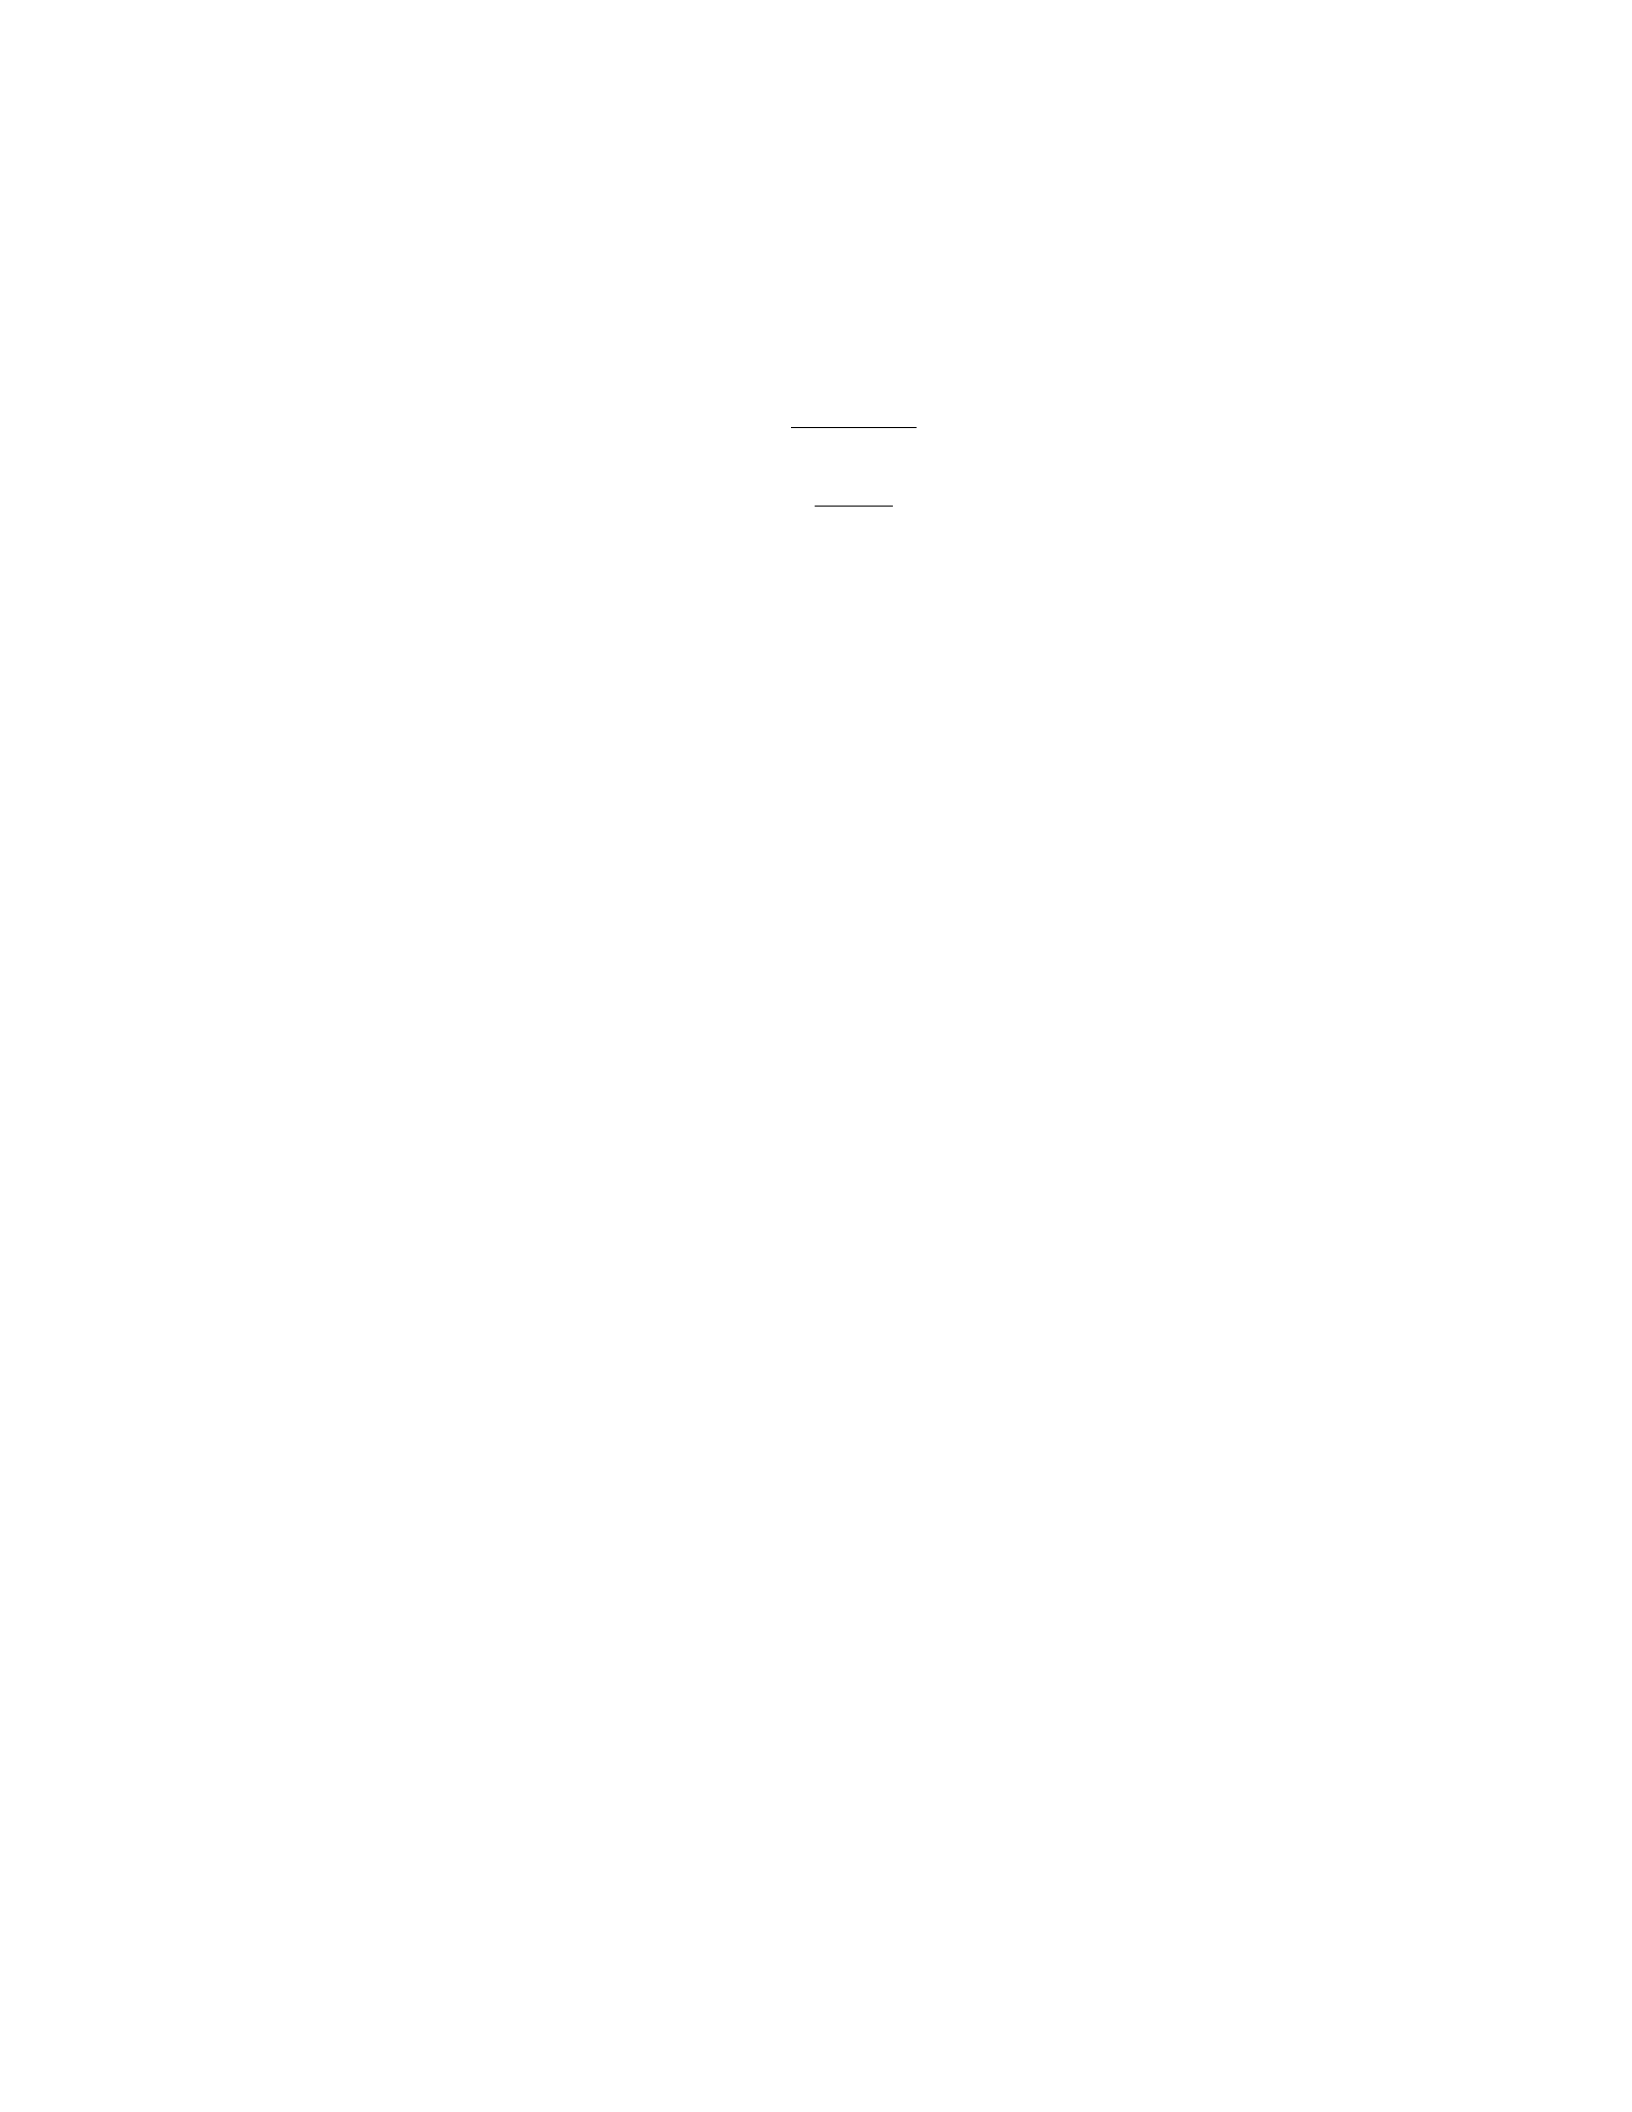
In this case, since the cash flows occurred during the period, there is only
one period. Therefore,
P V =50,000
(1 + 0.08)1
P V =50,000
1.08
P V ≈46,296.30
Step 2: Calculate the change in fair value during the reporting period. Given:
Fair value at the end of the period = 450,000P resentvalueof cashflows =46,296.30
The change in fair value can be calculated as:
Change in fair value =F Vend −P V
Change in fair value = 450,000 −46,296.30
Change in fair value ≈403,703.70
Step 3: Calculate the fair value of the financial instrument at the beginning
of the period. The fair value of the financial instrument at the beginning of the
period is the fair value at the end of the period minus the change in fair value
during the period.
F Vbeginning =F Vend −Change in fair value
F Vbeginning = 450,000 −403,703.70
F Vbeginning ≈46,296.30
Therefore, the fair value of the financial instrument at the beginning of the
period was approximately 46,296.30.
Question 20
Question
A company holds an investment in a financial asset classified as available-for-
sale. At the end of the reporting period, the fair value of the investment is
$4,500. The company has determined that there have been some observable
price changes for similar investments in the market since the acquisition of the
asset, and these changes are not temporary.
Given this information, calculate the fair value of the financial asset on the
acquisition date if the company decides to account for the change in fair value
using the fair value model.
16

Solution
To calculate the fair value of the financial asset on the acquisition date using
the fair value model, we need to consider the change in fair value and work
backward to find the original fair value.
Step 1: Determine the change in fair value from the acquisition date to the
reporting date.
Change in Fair Value = Fair Value on Reporting Date −Fair Value on Acquisition Date
= $4,500 −Acquisition Date Value
Step 2: Since the change in fair value is not temporary, we need to adjust
the acquisition date value to reflect this change. Let’s denote the acquisition
date value as x.
Change in Fair Value = $4,500 −x
x= $4,500 −Change in Fair Value
Step 3: Substitute the given fair value on the reporting date into the equa-
tion.
x= $4,500 −($4,500 −Change in Fair Value)
x= Change in Fair Value
Step 4: Calculate the fair value of the financial asset on the acquisition
date.
x= $4,500
Therefore, the fair value of the financial asset on the acquisition date, if the
company decides to account for the change in fair value using the fair value
model, is $4,500.
Question 21
Question
Company XYZ holds an investment in a publicly traded company with a fair
value of 450,000attheendofthereportingperiod.T hef airvaluemeasurementincludesLevel1inputs.Duringthenextreportingperiod, thef airvalueof theinvestmentincreasedto500,000.
If Company XYZ uses the fair value option for measuring this investment, how
will the changes in fair value be recognized in the financial statements?
Solution
1. When the fair value of the investment increased from 450,000to500,000, the
following journal entry will be recorded to reflect the change in fair value:
Debit: Unrealized Gain on Investment
17

Credit: Investment in Equity Securities
2. The Unrealized Gain on Investment account is a temporary account that will
be closed at the end of the reporting period. 3. The Unrealized Gain on Invest-
ment will be reported on the income statement as part of comprehensive income.
4. The Investment in Equity Securities account will be reported on the balance
sheet at the fair value of 500,000.5.T headjustmentisnecessarytoensurethattheinvestmentisrecordedatitsf airvalueattheendof thereportingperiod.
Question 22
Question
A company recently acquired a new subsidiary and needs to determine the
fair value of the subsidiary’s intangible assets for financial reporting purposes.
The subsidiary’s intangible assets include patents, trademarks, and customer
relationships. Discuss the steps involved in determining the fair value of these
intangible assets.
Solution
To determine the fair value of the intangible assets (patents, trademarks, and
customer relationships) of the subsidiary for financial reporting purposes, the
following steps need to be taken:
Step 1: Identify the Intangible Assets Identify and list all the intangible
assets of the subsidiary, such as patents, trademarks, and customer relationships.
Step 2: Gather Relevant Information Obtain detailed information
about each intangible asset, such as the nature of the asset, the expected cash
flows it will generate, any legal protection, and market conditions.
Step 3: Select an Appropriate Valuation Approach Choose the most
appropriate valuation approach based on the nature of the intangible asset.
Common valuation approaches for intangible assets include the cost approach,
market approach, and income approach.
Step 4: Apply the Chosen Valuation Approach Implement the cho-
sen valuation approach to determine the fair value of each intangible asset. For
example: - For patents, the cost approach may involve estimating the cost to
develop a similar patent. - For trademarks, the market approach may involve
analyzing the prices of similar trademarks in the market. - For customer rela-
tionships, the income approach may involve forecasting future cash flows from
the customers.
Step 5: Consider Discount Rates and Risk Factors Take into account
discount rates and risk factors associated with each intangible asset to reflect
the time value of money and the level of risk involved in generating expected
cash flows.
Step 6: Finalize Fair Value Estimates Combine the fair value estimates
of each intangible asset to determine the total fair value of the subsidiary’s
18
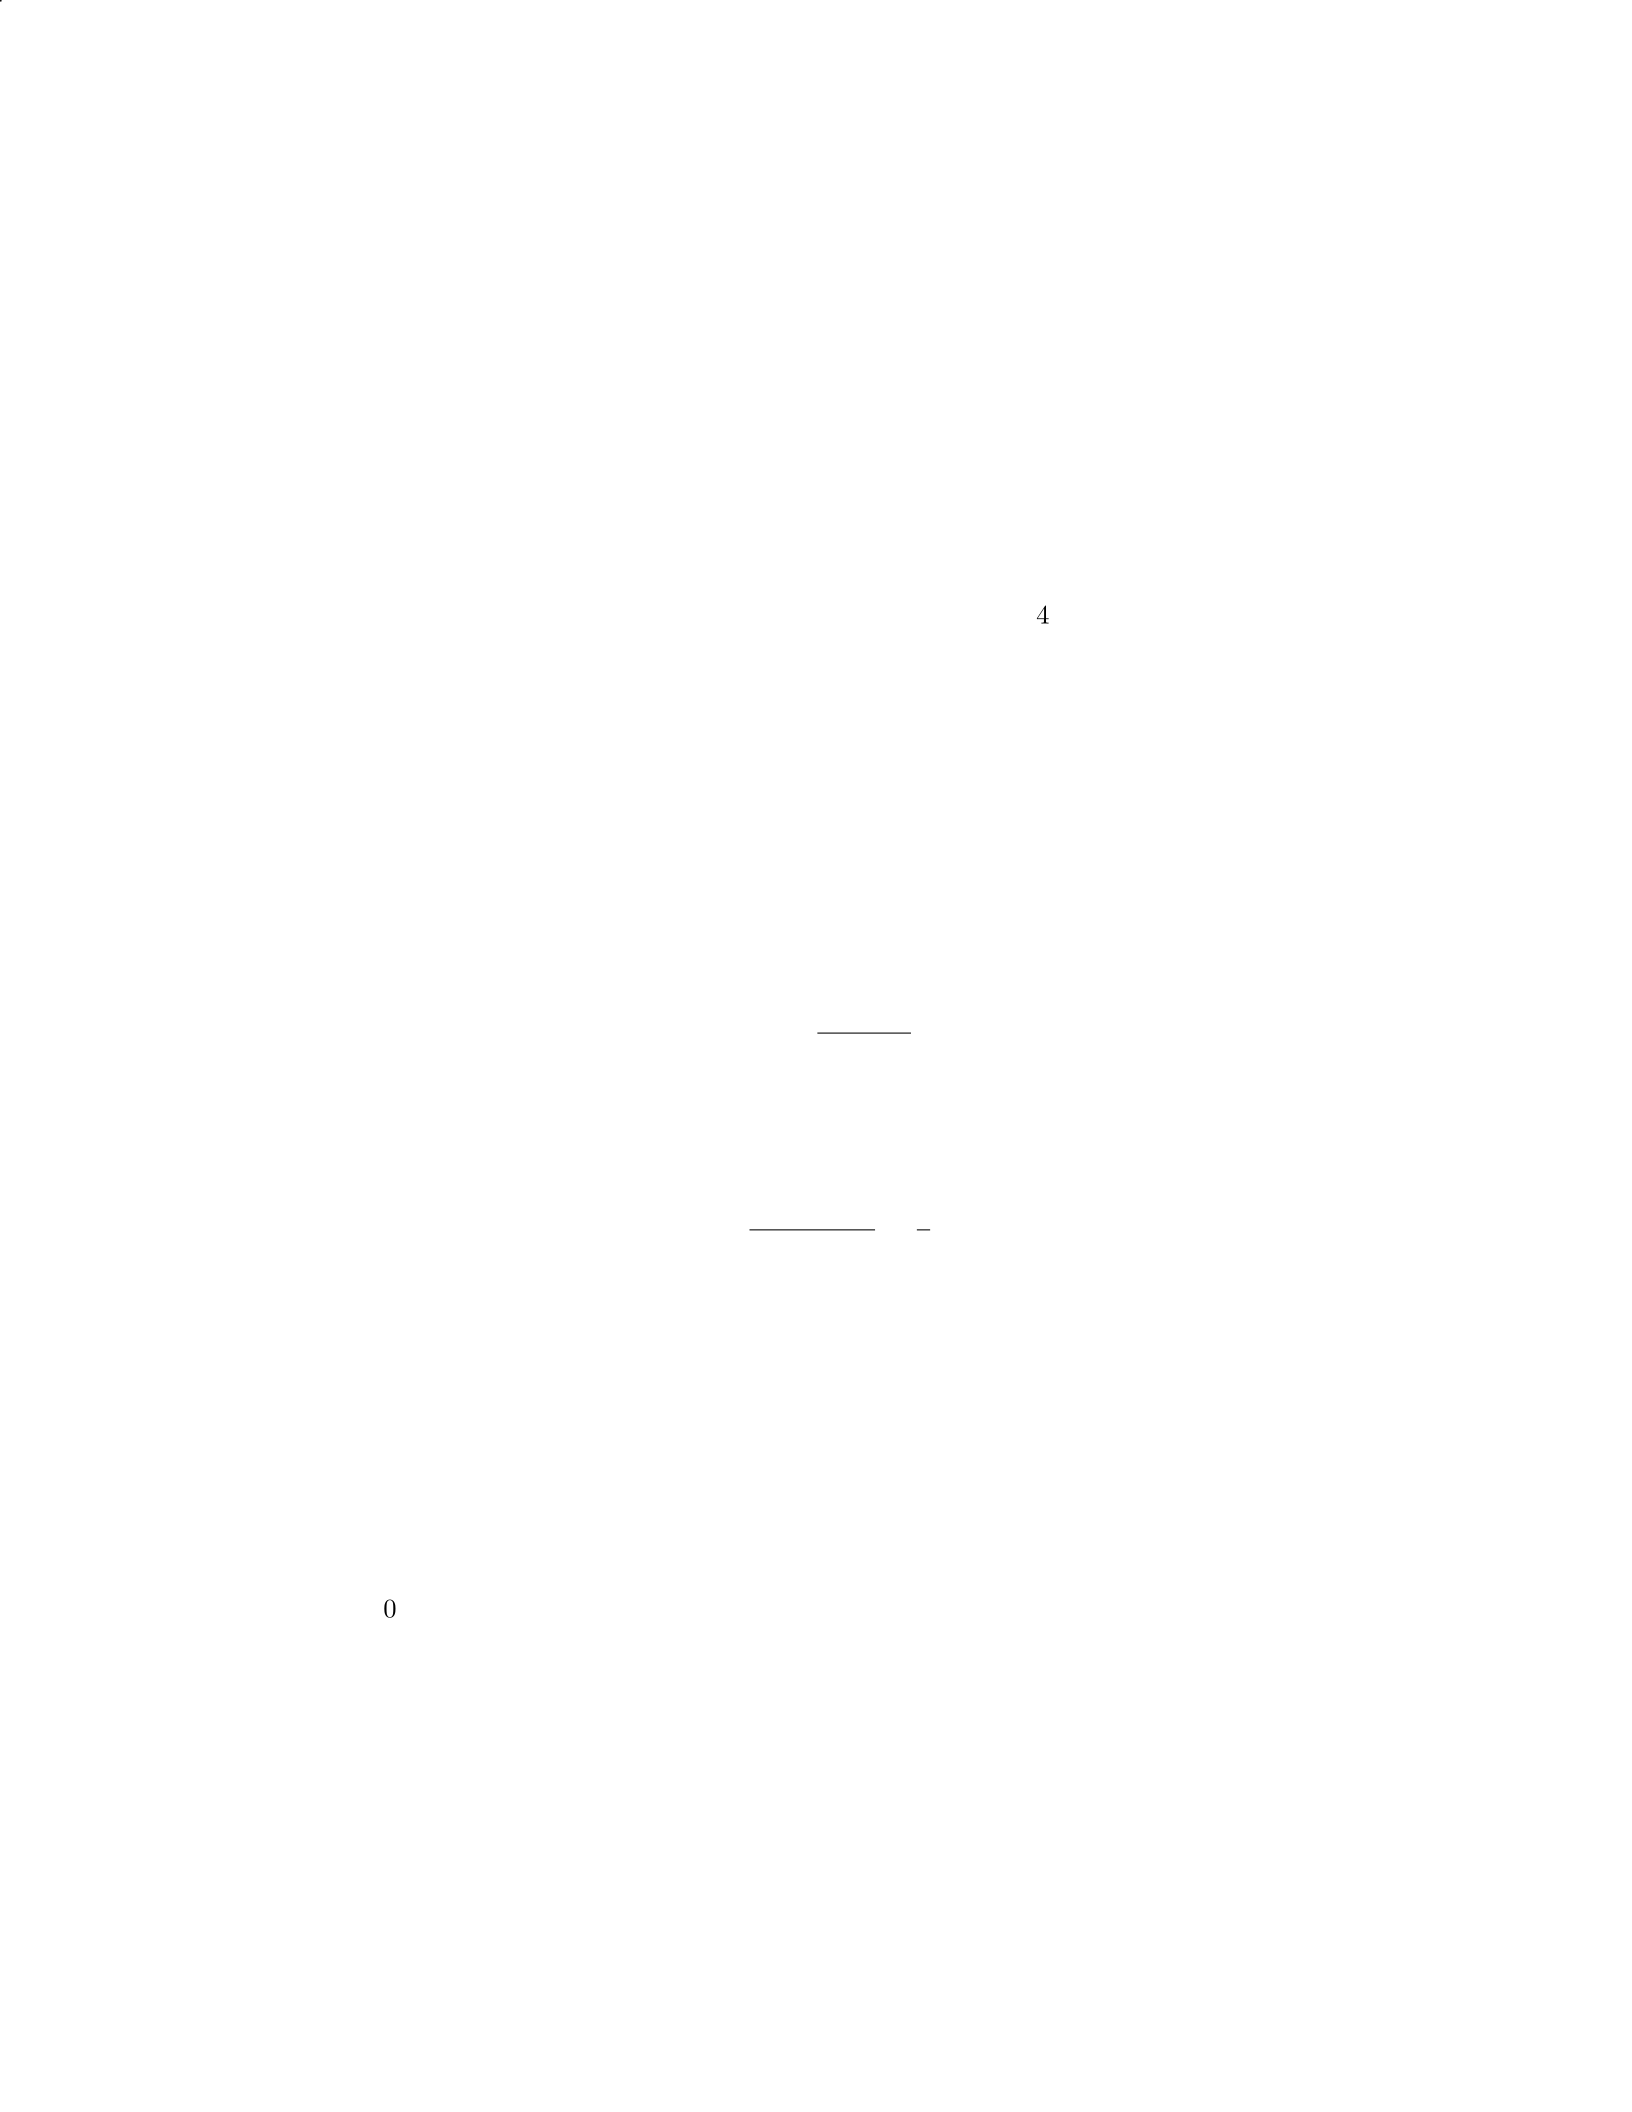
intangible assets for financial reporting purposes. Ensure that the estimates are
reasonable, supported by relevant data, and comply with accounting standards.
Question 23
Question
Company XYZ owns a rare piece of artwork that is considered a Level 3 fair
value measurement. The artwork has a quoted price of
$
400,000 in an active
market. However, there is a lack of observable market data for similar artworks
to use as inputs for the valuation model. Company XYZ decides to use a present
value technique to estimate the fair value of the artwork, with an appropriate
discount rate of 8% per annum. Calculate the fair value of the artwork using
the present value technique.
Solution
Step 1: Calculate the present value factor using the discount rate of 8% per
annum and the appropriate number of periods.
The present value factor can be calculated using the formula:
P V F =1
(1 + r)n
Where: - r= 0.08 (8% per annum) - nis the number of periods
In this case, since the fair value of the artwork is for the present time (Year
0), n= 0. Thus, the present value factor is:
P V F =1
(1 + 0.08)0=1
1= 1
Step 2: Calculate the fair value of the artwork using the present value tech-
nique.
The fair value of the artwork can be calculated as:
F air V alue =Quoted P rice ×P V F
Substitute the values:
F air V alue = $400,000 ×1 = $400,000
Therefore, the fair value of the artwork using the present value technique is
$
400,000.
19

Question 24
Question
Explain the concept of fair value measurement and discuss how it is applied in
the financial reporting of assets and liabilities.
Solution
Step 1: Definition of Fair Value Measurement
Fair value measurement is a principle used in accounting and finance to
determine the value of assets and liabilities. It is defined as the price that
would be received to sell an asset or paid to transfer a liability in an orderly
transaction between market participants at the measurement date.
Step 2: Application in Financial Reporting
In financial reporting, fair value measurement is used to provide relevant
and reliable information to users of financial statements, such as investors and
creditors. It is commonly applied in the following ways: - Fair value measure-
ment is used to initially recognize certain assets and liabilities at fair value, such
as derivatives and financial instruments. - Investments held by a company are
typically reported at fair value in the financial statements, providing a more ac-
curate representation of their current worth. - Impairment testing of assets also
often involves fair value measurement. If the fair value of an asset is less than its
carrying amount, an impairment loss is recognized in the financial statements.
Step 3: Challenges in Fair Value Measurement
While fair value measurement provides valuable information, there are chal-
lenges associated with its application. One challenge is the subjectivity involved
in determining fair value, especially for assets and liabilities that do not have
active markets. This can lead to potential manipulation or misrepresentation
of asset values. Another challenge is the impact of market volatility on fair
value measurements, as fluctuations in market conditions can result in signifi-
cant changes in reported values.
Step 4: Disclosure Requirements
To address these challenges and provide transparency to users of financial
statements, companies are required to provide extensive disclosure regarding
their fair value measurements. This includes descriptions of the valuation tech-
niques used, inputs into the valuation process, and sensitivity analyses to show
the effect of changes in assumptions on the fair value of assets and liabilities.
These disclosures help stakeholders better understand the basis for the reported
fair values and assess the reliability of the information provided.
20

Question 25
Question
A company purchased an investment property for 500,000.T hefairvalueofthepropertyincreasedto600,000
at the end of the year. The company recognized a gain of 20,000inprofitorlossandarevaluationsurplusof80,000
in other comprehensive income. Calculate the carrying amount of the invest-
ment property at the end of the year.
Solution
Step 1: Calculate the carrying amount of the investment property before revalu-
ation. The carrying amount before revaluation is the initial cost of the property,
which is 500,000.Carryingamountbef orerevaluation :500,000
Step 2: Calculate the revaluation gain. The revaluation gain is the difference
between the fair value of the property at the end of the year and the carrying
amount before revaluation. Revaluation gain = Fair value - Carrying amount
before revaluation Revaluation gain = 600,000−500,000 Revaluation gain =
100,000
Step 3: Allocate the revaluation gain between profit or loss and other com-
prehensive income. The gain recognized in profit or loss is 20,000, sotheremaininggainof 80,000
is recognized in other comprehensive income.
Step 4: Calculate the carrying amount of the investment property at the end
of the year. The carrying amount at the end of the year is the sum of the initial
cost and the revaluation gain recognized in profit or loss. Carrying amount at
the end of the year = Initial cost + Gain recognized in profit or loss Carrying
amount at the end of the year = 500,000+20,000 Carrying amount at the end
of the year = 520,000
Therefore, the carrying amount of the investment property at the end of the
year is 520,000.
Question 26
Question
Company XYZ holds an investment in a financial instrument that is classified as
a Level 2 asset. The company’s analysts are uncertain about one of the inputs
used to value the asset. Explain how the uncertainty surrounding this input
could affect the fair value measurement of the investment.
Solution
Step 1: First, let’s understand what a Level 2 asset is in the context of fair
value measurement. Level 2 assets are those whose fair value is determined
using inputs other than quoted prices in active markets for similar assets. These
21
inputs may include observable market data from similar assets, interest rates,
or other economic indicators.
Step 2: In this case, the analysts are uncertain about one of the inputs
used to value the asset. This uncertainty can have a significant impact on the
fair value measurement of the investment. Here are a few ways in which the
uncertainty surrounding this input could affect the fair value measurement:
Step 3: If the uncertain input has a significant impact on the valuation
model, the fair value of the investment could be materially different depending
on the actual value of the input. This could result in a wide range of possible
fair values, leading to increased uncertainty in the reported value of the asset.
Step 4: The uncertainty surrounding the input could also affect the reliability
of the fair value measurement. If the input is not verifiable or based on subjective
assumptions, it could be difficult to assess the accuracy of the valuation and the
degree of uncertainty associated with it.
Step 5: Moreover, the uncertainty in the input could lead to a higher risk
of misstatement in the financial statements. If the input is later found to be
significantly different from the estimated value, it could result in restatements
and impact the company’s credibility with investors and regulators.
Step 6: In conclusion, the uncertainty surrounding the input used to value
the asset can have a profound impact on the fair value measurement of the
investment. It is crucial for analysts and accountants to carefully consider and
disclose such uncertainties to provide a clear picture of the financial position of
the company.
Question 27
Question
A company holds an investment in a private equity fund. The investment is
classified as a Level 3 financial instrument and is measured at fair value. The
fair value of the investment increased by
$
500,000 during the current reporting
period. Discuss how this change in fair value would impact the company’s
financial statements and what disclosures would be required in the notes to the
financial statements.
Solution
Step 1: The increase in fair value of the investment would result in a gain for
the company, which would be recognized in the income statement. This gain
would increase the company’s net income for the current reporting period. The
journal entry to record the gain would be:
Income Statement →Gain on Investment : $500,000
Step 2: The increase in fair value of the investment would also impact the
company’s balance sheet. The fair value of the investment would be adjusted
22

upwards, resulting in an increase in the company’s assets. This increase would
be reflected in the balance sheet under the ”Investments” or ”Financial Assets
at Fair Value Through Profit or Loss” category.
Step 3: In the notes to the financial statements, the company would be re-
quired to disclose information about the investment in the private equity fund.
This would include details about the nature of the investment, the fair value
measurement techniques used, and the significant unobservable inputs (if ap-
plicable). Additionally, the company would need to provide information about
the impact of the change in fair value on the financial statements, including the
amount recognized in the income statement and where it is classified.
Step 4: The company would also need to disclose any significant assumptions
made in determining the fair value of the investment, as well as any sensitivity
analysis conducted to assess the impact of changes in these assumptions on the
fair value measurement.
Step 5: Overall, the increase in fair value of the investment would lead
to changes in the company’s financial statements, impacting both the income
statement and the balance sheet. Additionally, the company would need to
provide detailed disclosures in the notes to the financial statements to explain
the change in fair value and the related effects on the financial statements.
Question 28
Question
Assume a company is reporting its financial statements under IFRS 13. The
company holds an investment in a private company that does not have a quoted
market price and is not actively traded. The company’s management needs
to determine the fair value of this investment for financial reporting purposes.
Discuss the steps the company should take to measure the fair value of this
investment.
Solution
To measure the fair value of an investment in a private company for financial
reporting purposes, the company should follow the steps outlined below:
Step 1: Identify the Asset or Liability Identify the investment in the
private company that needs to be valued.
Step 2: Determine the Principal Market, if any Determine whether
there is a principal market for the investment. If there is, use the quoted price
in that market to measure fair value. If not, proceed to the next step.
Step 3: Identify Comparable Transactions Look for comparable trans-
actions involving similar investments in private companies to provide guidance
on valuation.
Step 4: Estimate Fair Value Using Valuation Techniques If there are
no comparable transactions, estimate the fair value using valuation techniques
23
such as discounted cash flow analysis, net asset value method, market multiple
approach, or option pricing model.
Step 5: Consider Control and Marketability Issues Adjust the es-
timated fair value for any control or marketability issues associated with the
investment.
Step 6: Review and Document the Process Review the valuation
process and ensure it complies with IFRS 13 requirements. Document all as-
sumptions, inputs, and methods used in determining the fair value.
Following these steps will help the company accurately measure the fair value
of its investment in a private company for financial reporting purposes.
Question 29
Question
Company XYZ holds an investment in a financial asset classified as a Level 3 fair
value measurement. The fair value of the investment at the end of the reporting
period is 350,000.T hecompany′smanagementwantstodetermineif therehavebeenanychangesinthefairvalueoftheinvestmentduringthereportingperiod.
Given the following information: - Opening fair value of the investment:
320,000 −Investmentincomereceivedduringthereportingperiod :10,000 - Loss
on fair value measurement during the reporting period: 5,000−Closingfairvalueof theinvestment :350,000
Calculate the fair value change during the reporting period and determine
if it’s an unrealized gain or loss.
Solution
Step 1: Calculate the fair value change during the reporting period.
Fair value change = Closing fair value−Opening fair value−Investment income
Fair value change = $350,000 −$320,000 −$10,000 = $20,000
Step 2: Determine if the fair value change is an unrealized gain or loss. Given
that the fair value change is positive (
$
20,000), it is considered an unrealized
gain. Therefore, during the reporting period, Company XYZ experienced an
unrealized gain of
$
20,000 on the investment.
Question 30
Question
A company holds an investment in a startup company that it classifies as an
equity investment. The fair value of the investment at the end of the reporting
period is $85,000. During the next period, the fair value decreases to $75,000.
How should this decrease in fair value be accounted for in the financial state-
ments according to fair value measurement guidelines?
24

Solution
Step 1: When the fair value of an equity investment decreases, the decrease
should be recognized as a loss in the income statement.
Step 2: The decrease in fair value from 85,000 to 75,000 amounts to 85,000−
75,000 = $10,000.
Step 3: This 10,000lossshouldbereportedintheincomestatementof theperiodinwhichthef airvaluedecreaseoccurred.
Therefore, the decrease in fair value of the investment should be accounted
for by recognizing a 10,000lossintheincomestatementof theperiod.
Question 31
Question
Company XYZ holds an investment in a private equity fund. The fair value of
this investment needs to be determined for the financial statements. The fund
is not publicly traded, so the fair value cannot be easily determined. Describe
the steps involved in determining the fair value of this investment, including
any assumptions that need to be made.
Solution
To determine the fair value of an investment in a private equity fund, several
steps need to be followed. The fair value measurement will require making
assumptions and using valuation techniques to arrive at a reasonable estimate.
Step 1:Understand the characteristics of the investment: First, it is
essential to understand the nature of the investment in the private equity fund,
including any restrictions on selling the investment and its expected cash flows.
Step 2:Consider the market and economic conditions: Evaluate the
current market and economic conditions that may impact the fair value of the
investment, such as interest rates, industry trends, and market volatility.
Step 3:Utilize valuation techniques: Choose appropriate valuation
techniques to estimate the fair value of the investment. Common techniques
include the market approach, income approach, and cost approach.
Step 4:Estimate the expected cash flows: Estimate the expected cash
flows from the investment, considering factors such as the fund’s performance,
industry outlook, and economic conditions.
Step 5:Determine discount rate: Calculate an appropriate discount
rate to determine the present value of the expected cash flows. The discount
rate should reflect the risks associated with the investment.
Step 6:Consider market data: If available, consider any market data
on similar investments or transactions to corroborate the estimated fair value.
Step 7:Review and reassess assumptions: Review all assumptions
made in the fair value measurement process and reassess them for reasonable-
ness.
25

Step 8:Finalize fair value measurement: After completing the above
steps, finalize the fair value measurement of the investment in the private equity
fund. Disclose the valuation methods used and the key assumptions made in
the financial statements.
By following these steps and utilizing appropriate valuation techniques, the
fair value of an investment in a private equity fund can be reasonably estimated
for financial reporting purposes.
Question 32
Question
A company acquired a piece of land for development purposes. The fair value of
the land was determined to be 500,000.Overthenextyear, thecompanyspent50,000
on clearing the land and preparing it for development. At the end of the year, the
company reassessed the fair value of the land and determined it had increased to
550,000.Howshouldthecompanyaccountf orthechangesinf airvalueof thelandinitsfinancialstatementsaccordingtoF airV alueM easurementstandards?
Solution
Step 1: Initially Recognized Fair Value - When the company acquired the land,
Fair Value Measurement standards required the land to be initially recognized
at its fair value of 500,000.
Step 2: Recognizing Changes in Fair Value - Changes in fair value should be
recognized in the company’s financial statements. - Here, since the fair value
of the land increased from 500,000to550,000, the company needs to recognize a
gain.
Step 3: Accounting for the Gain - The gain due to the increase in fair value
should be recognized in the company’s income statement. - The entry to reflect
the gain is: - Debit: Land 50,000 −Credit :Gainonrevaluationof land50,000
Step 4: Wrapping Up - By following Fair Value Measurement standards,
the company properly accounts for changes in the fair value of the land in its
financial statements.
Question 33
Question
A company holds an investment in a private equity fund as a Level 3 fair value
measurement, where the fair value is determined using a discounted cash flow
model. The carrying amount of the investment at the beginning of the year was
2,500,000.Duringtheyear, thefairvalueoftheinvestmentdecreasedto2,200,000 due
to changes in market conditions. At the end of the year, the fair value of the in-
vestment increased to 2,800,000asaresultof improvedmarketconditions.Calculatethegainorlossontheinvestmentrecognizedinthecompany′sincomestatementfortheyear.
26
Solution
Step 1: Calculate the loss on the investment when the fair value decreased.
Loss = Beginning fair value −Fair value decrease
Loss = $2,500,000 −$2,200,000 = $300,000
Step 2: Calculate the gain on the investment when the fair value increased.
Gain = End fair value −Beginning fair value
Gain = $2,800,000 −$2,500,000 = $300,000
Step 3: Calculate the net gain or loss on the investment for the year.
Net gain or loss = Gain - Loss
Net gain or loss = $300,000 −$300,000 = $0
Therefore, the gain or loss on the investment recognized in the company’s
income statement for the year is
$
0.
Question 34
Question
Company XYZ holds an investment in bonds classified as available-for-sale. At
the end of the reporting period, the fair value of the bonds is $475,000, while the
amortized cost is $500,000. Calculate the unrealized gain or loss that Company
XYZ should recognize in its income statement.
Solution
Step 1: First, we need to determine the amount of unrealized gain or loss.
Step 2: The unrealized gain or loss is calculated as the difference between
the fair value and the amortized cost.
Unrealized Gain or Loss = Fair Value −Amortized Cost
Unrealized Gain or Loss = $475,000 −$500,000
Unrealized Gain or Loss = −$25,000
Step 3: Since the unrealized gain or loss is negative, it means there is an
unrealized loss of $25,000 on the investment. Company XYZ should recognize
this unrealized loss in its income statement.
Therefore, Company XYZ should recognize an unrealized loss of $25,000 in
its income statement.
27

Question 35
Question
Company XYZ holds an investment in a private company that is classified
as a Level 3 fair value measurement. The investment was initially valued at
500,000.Attheendoftheyear, thef airvalueof theinvestmentdecreasedto450,000.
Company XYZ uses the income approach to estimate fair value. Calculate the
unrealized loss that should be recognized in the financial statements.
Solution
Step 1: Calculate the Unrealized Loss. The unrealized loss is the difference
between the initial investment value and the new fair value.
Unrealized Loss = Initial Investment Value −New Fair Value
Unrealized Loss =
500,000 - 450,000 =50,000
Step 2: Recognize the Unrealized Loss in the Financial Statements. The un-
realized loss of 50,000shouldberecognizedintheincomestatementasalossoninvestment.T hislosswilldecreasethevalueof theinvestmentreportedonthebalancesheet.
28

