


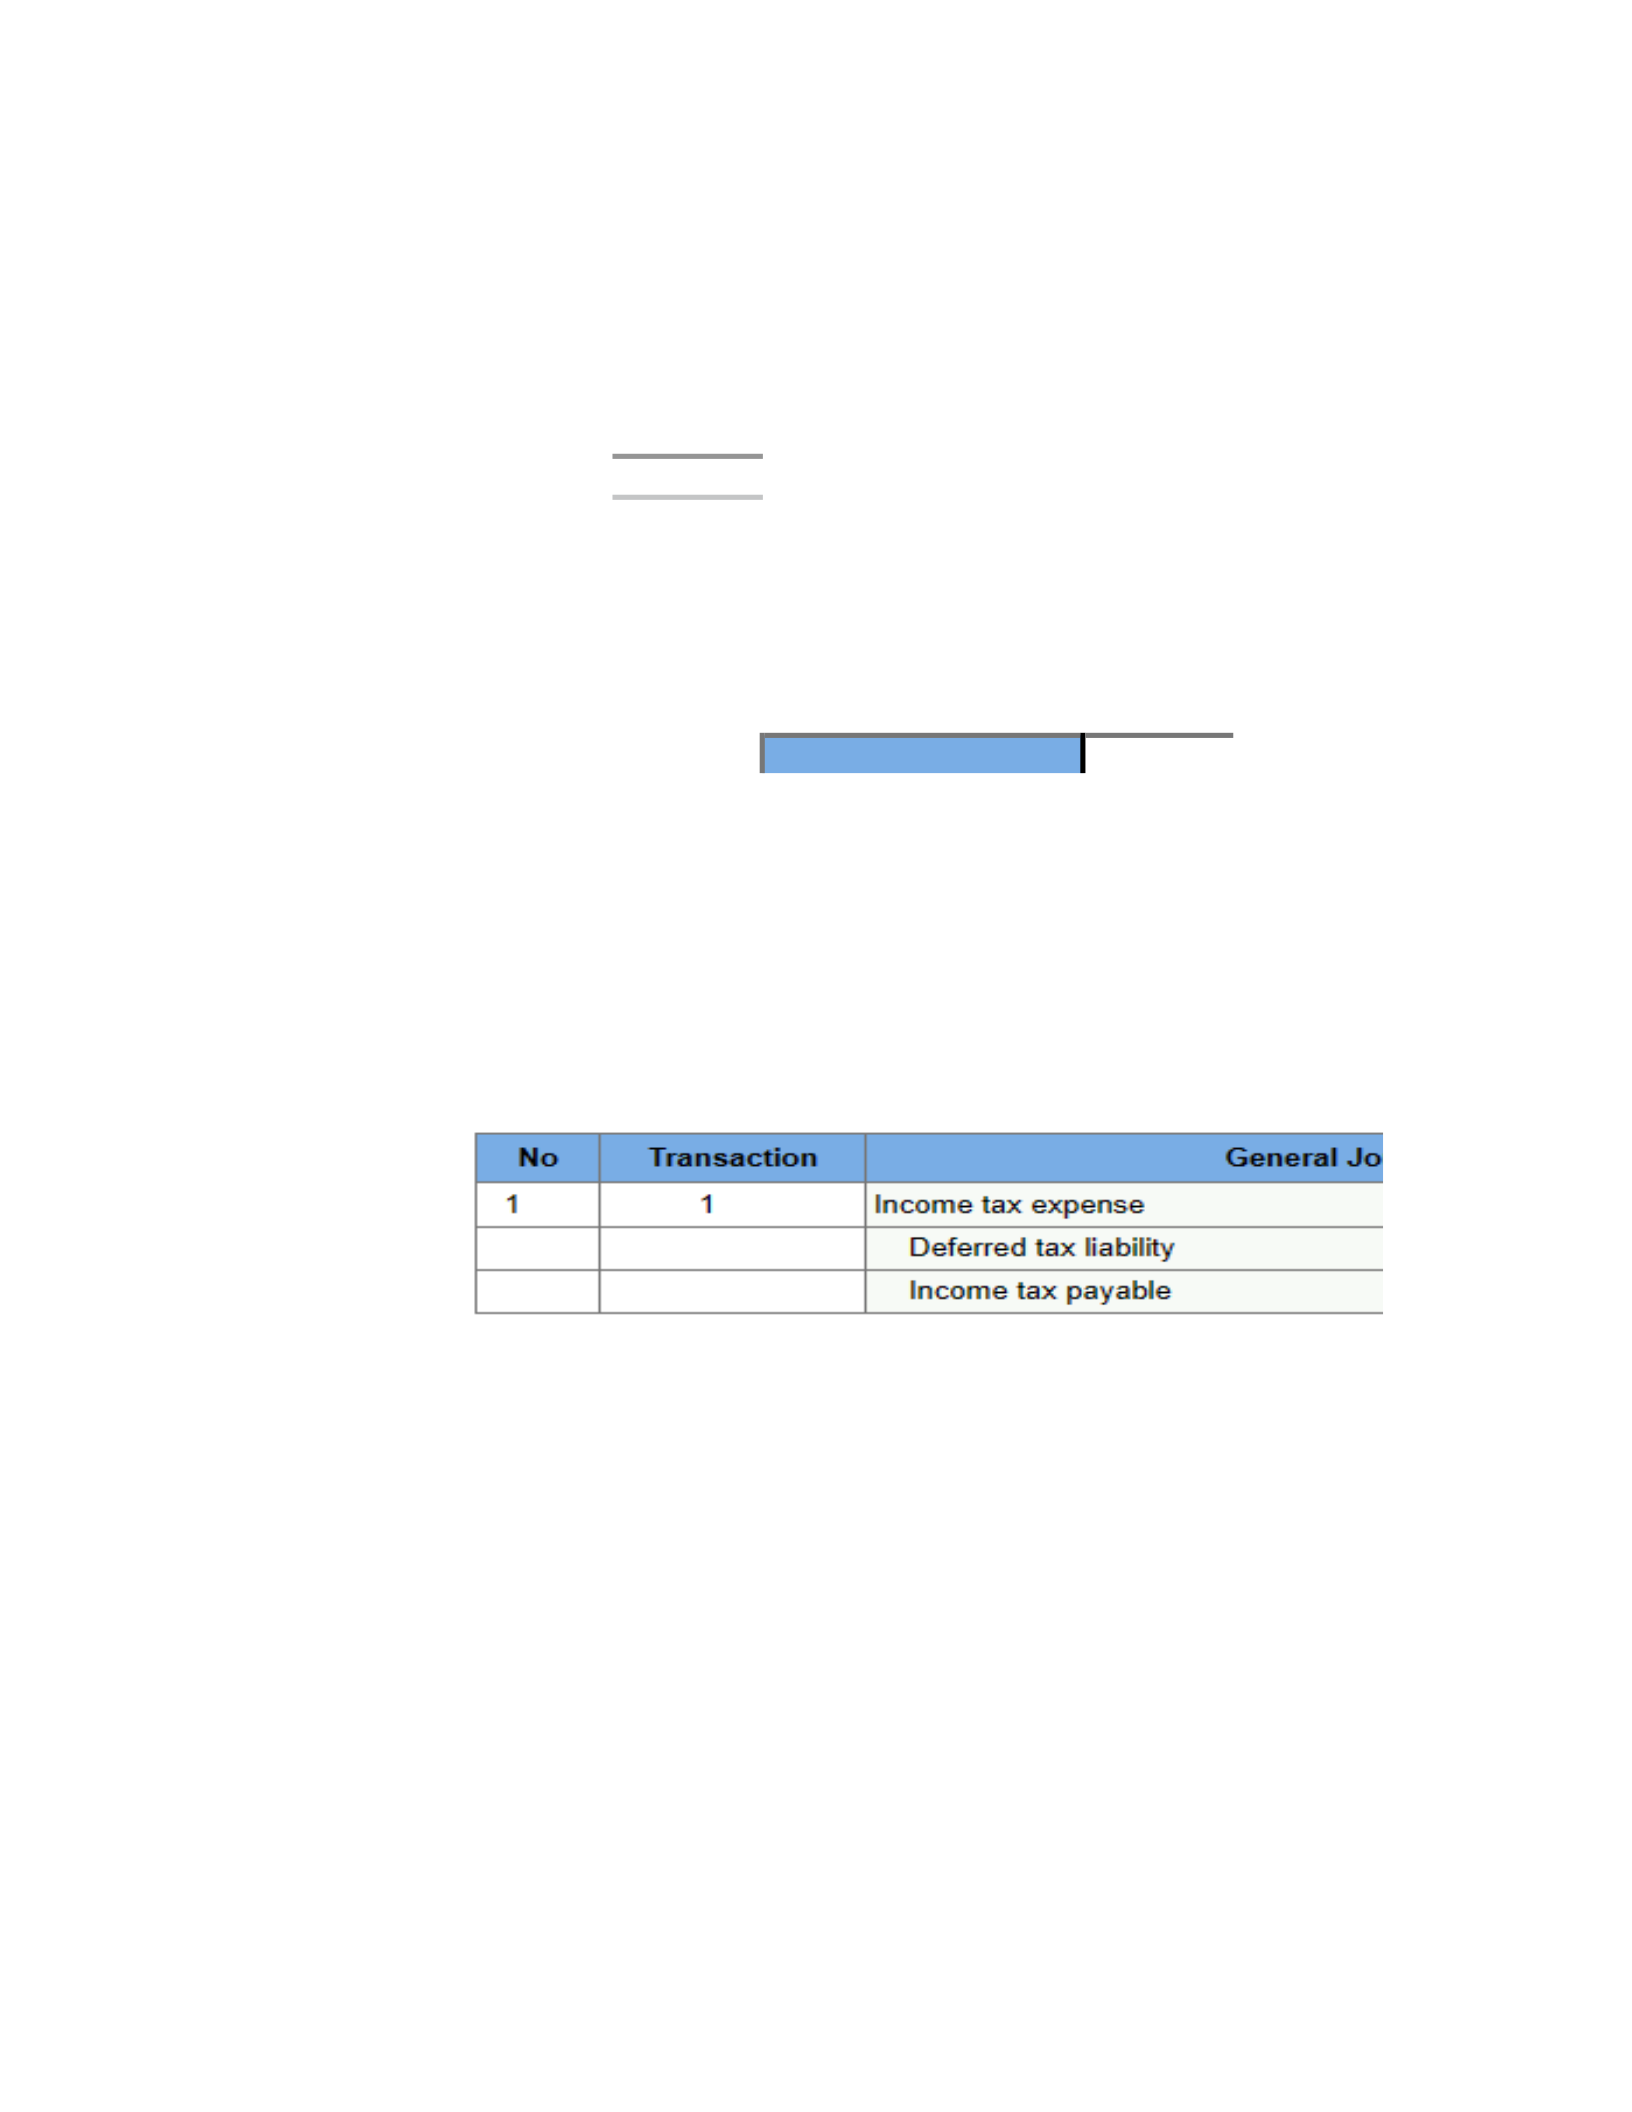
Kara Fashions uses straight-line depreciation for financial statement reporting and MACRS for income tax reporting. Three years after its purchase, one of Kara’s buildings has a book value of $680,000 and a tax basis of $510,000. There were no other temporary differences and no permanent differences. Taxable income was $5 million and Kara’s tax rate is 25%.
What is the deferred tax liability to be reported in the balance sheet? Assuming that the deferred tax liability balance was $27,000 the previous year, prepare the appropriate journal entry to record income taxes this year.
Explanation
Since tax depreciation to date has been $170,000 more than depreciation for financial reporting purposes, there will be fewer tax deductions for depreciation in the future, and future taxable amounts will be higher as the temporary difference reverses. This means a deferred tax liability should be reported to reflect the future tax consequences of the temporary difference. At this point, that amount is $170,000 times 25%, or $42,500.
If the balance of the deferred tax liability was $27,000 last year, we need an increase of $15,500.
Deferred Tax Liability
Debit Credit
27,000
15,500
42,500
Step 1: Tax payable: $1,250,000
Step 2: Deferred tax liability end balance: $42,500
Step 3: Deferred tax liability change: $15,500
Step 4: Tax expense plug: $1,265,500
Deferred tax liability ($42,500 − $27,000) = $15,500
Income tax payable ($5,000,000 × 25%) = $1,250,000
Shannon Polymers uses straight-line depreciation for financial reporting purposes for equipment costing $500,000 and with an expected useful life of four years and no residual value. Assume that, for tax purposes, the deduction is 40%, 30%, 20%, and 10% in those years. Pretax accounting income the first year the equipment was used was $600,000, which includes interest revenue of $10,000 from municipal governmental bonds. Other than the two described, there are no differences between accounting income and taxable income. The enacted tax rate is 25%.
Prepare the journal entry to record income taxes.
Note: If no entry is required for a transaction/event, select "No journal entry required" in the first account field.
Explanation
Current year
Future taxable amount
Pretax accounting income $600,000
Permanent difference:
Governmental bond interest -10,000
Temporary difference:
Depreciation
(75,000)*Footnote asterisk
$75,000
Taxable income (tax return) $515,000
Enacted tax rate 25% 25%
Tax payable currently $128,750
Deferred tax liability $18,750
Deferred Tax Liability
Debit Credit
0
18,750
18,750
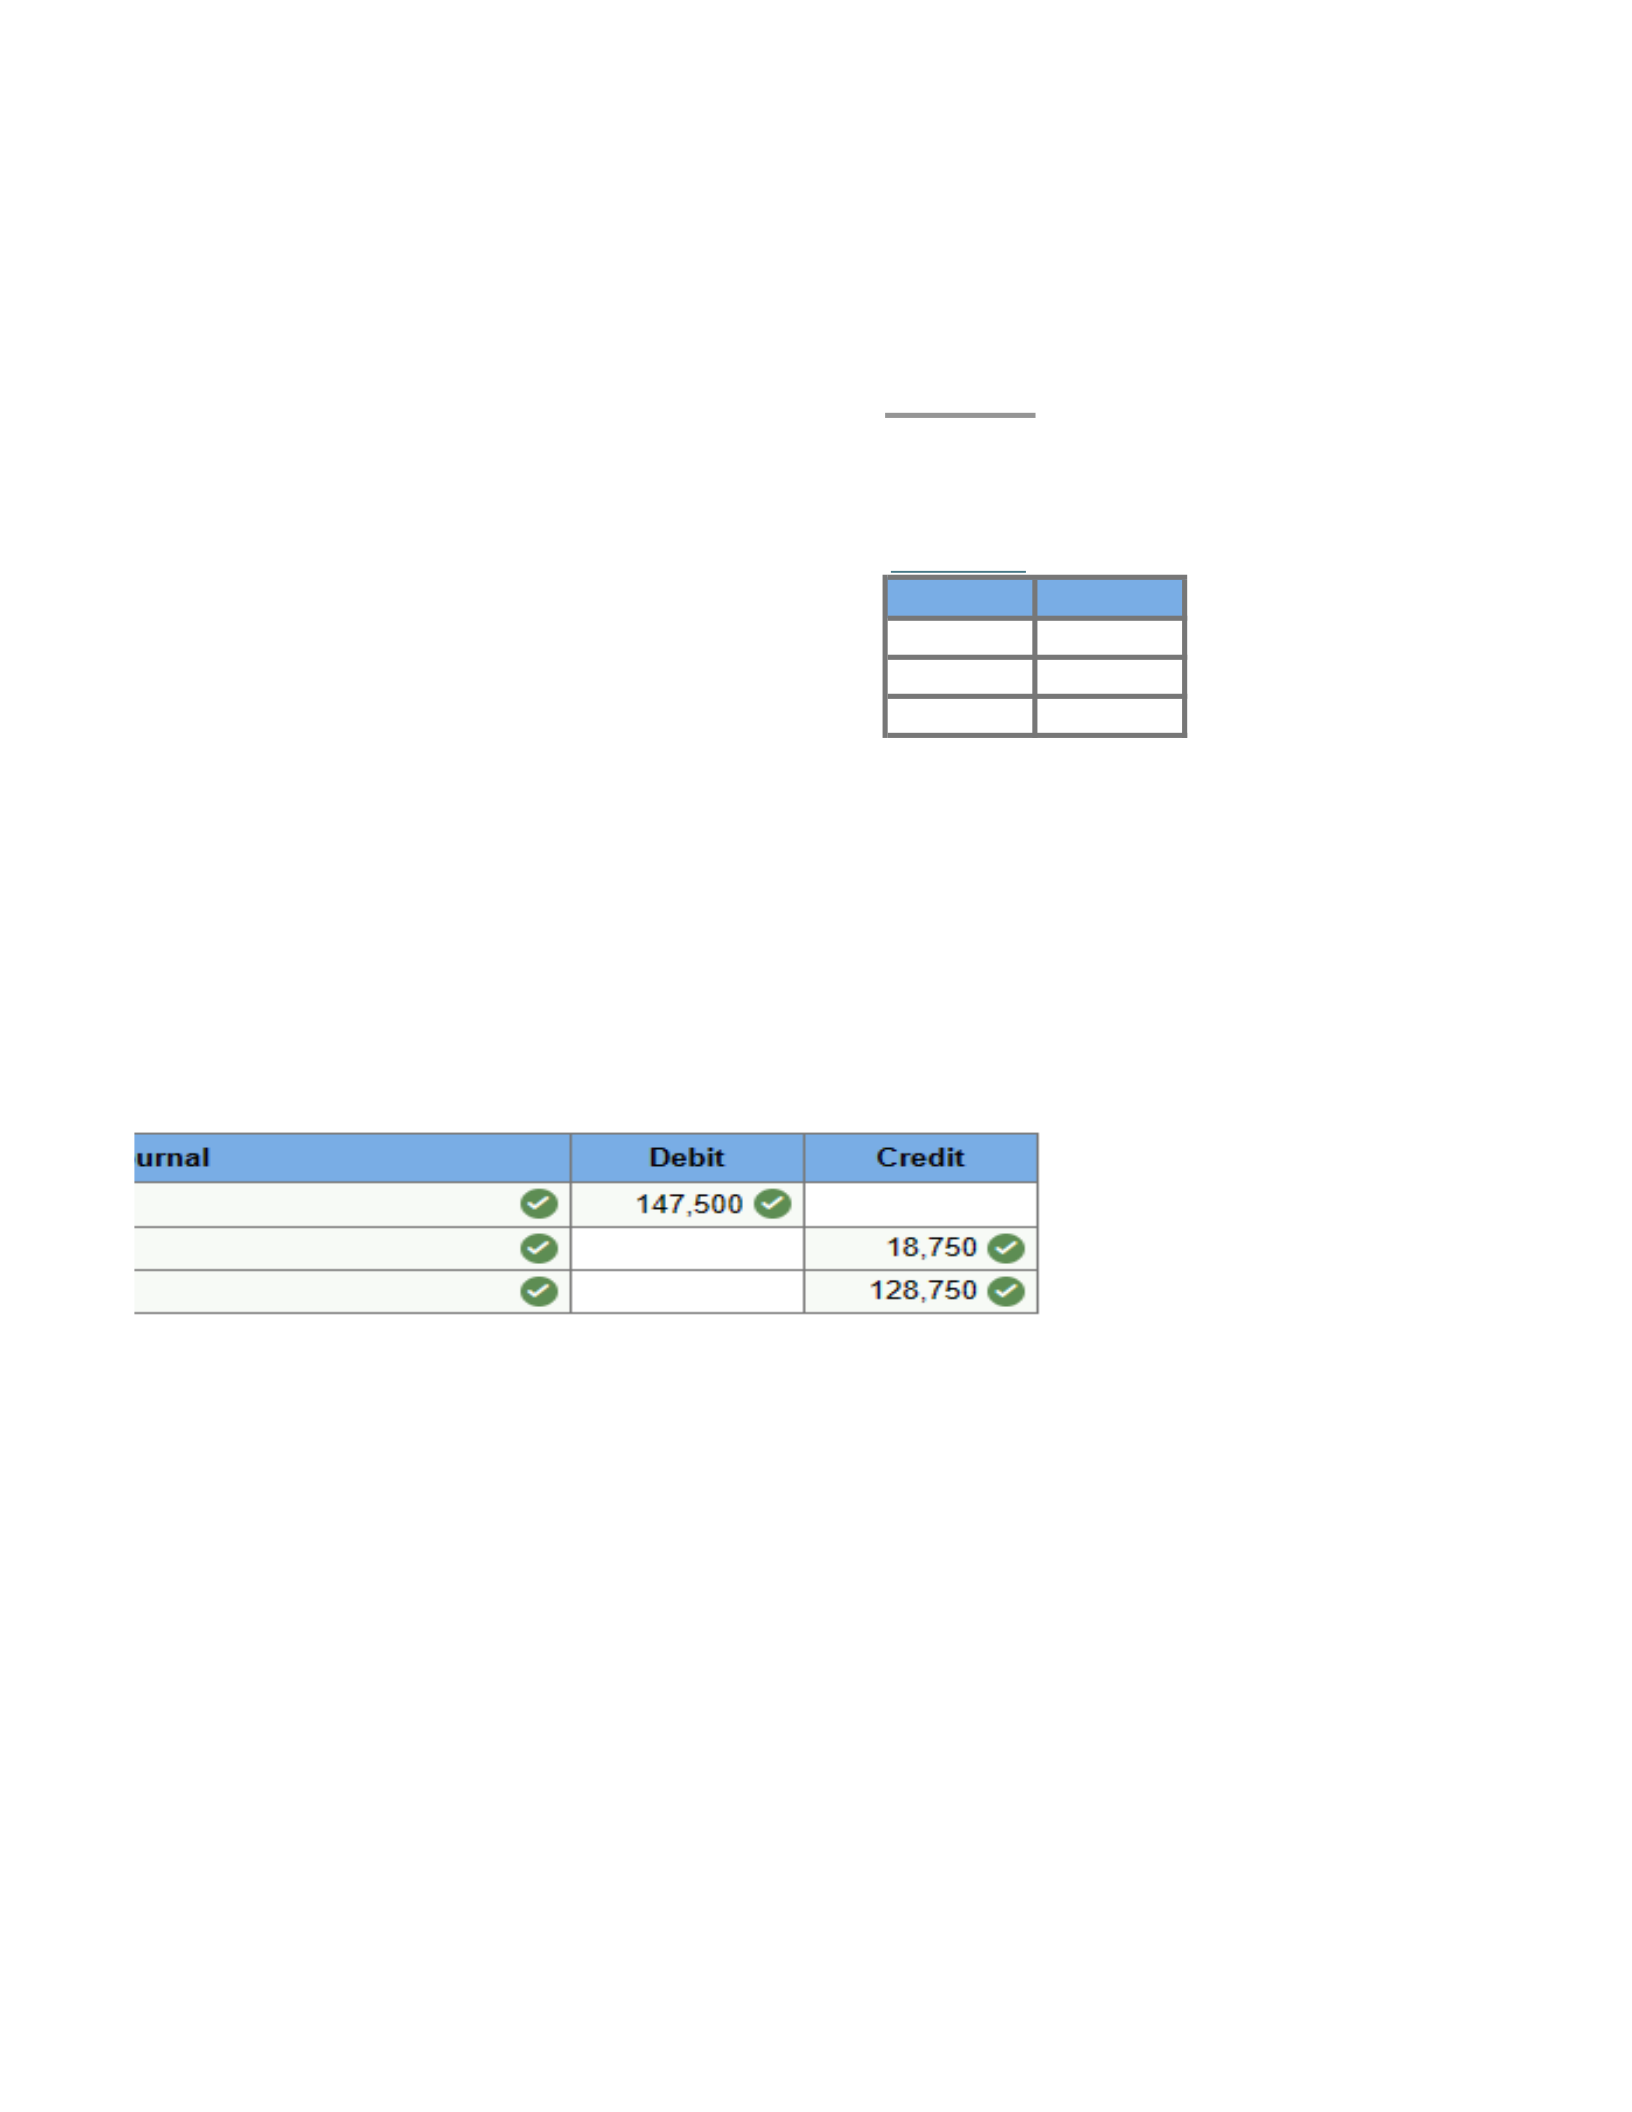
Step 1: Tax payable: $128,750
Step 2: Deferred tax liability end balance: $18,750
Step 3: Deferred tax liability change: $18,750
Step 4: Tax expense plug: $147,500
Deferred tax liability ([$75,000 × 25%] − $0) = $18,750
*Footnote asterisk Tax depreciation: $500,000 × 40%
$200,000
Straight-line depreciation: $500,000 ÷ 4 years
-125,000
Difference the first year $75,000
LossCo reported a net operating loss of $23 million for financial reporting and tax purposes. Taxable income last year and the previous year, respectively, was $24 million and $19 million. The enacted tax rate each year is 25%. Assume that LossCo qualifies as a type of company that is allowed to carry back an NOL to two prior taxable years, using the earliest year first.
Prepare the journal entry to recognize the income tax benefit of the net operating loss.
Note: If no entry is required for a transaction/event, select "No journal entry required" in the first account field. Enter your answers in whole dollars.
Explanation
NOL carrybacks are not allowed for most companies, except for property and casualty insurance companies as well as some farm-related businesses. Here, we are told that LossCo is one of those businesses, and that it carries back an NOL.
Because the net operating loss is less than the previous two years taxable income, LossCo cannot get back all taxes paid those two years. It can reduce taxable income from two years ago by $19 million (to zero) and last year’s taxable income by $4 million and get a refund of $5.75 million of the taxes paid those years.
Receivable—Income tax refund ($23 million × 25%) = $5,750,000.
Southeast Airlines had pretax earnings of $55 million. Included in this amount is income from discontinued operations of $10 million. The company’s tax rate is 25%.
What is the amount of income tax expense that Southeast would report in its income statement for continuing operations?
Note: Enter your answer in millions rounded to 2 decimal place (i.e., i.e., 5,500,000 should be entered as 5.50). Amount to be deducted should be indicated with a minus sign.
Explanation
Intraperiod tax allocation means the total income tax obligation for a reporting period is allocated among the income statement items that gave rise to the income tax. The following items should be reported net of their respective income tax effects:
Income (or loss) from ordinary, continuing operations.
Discontinued operations.
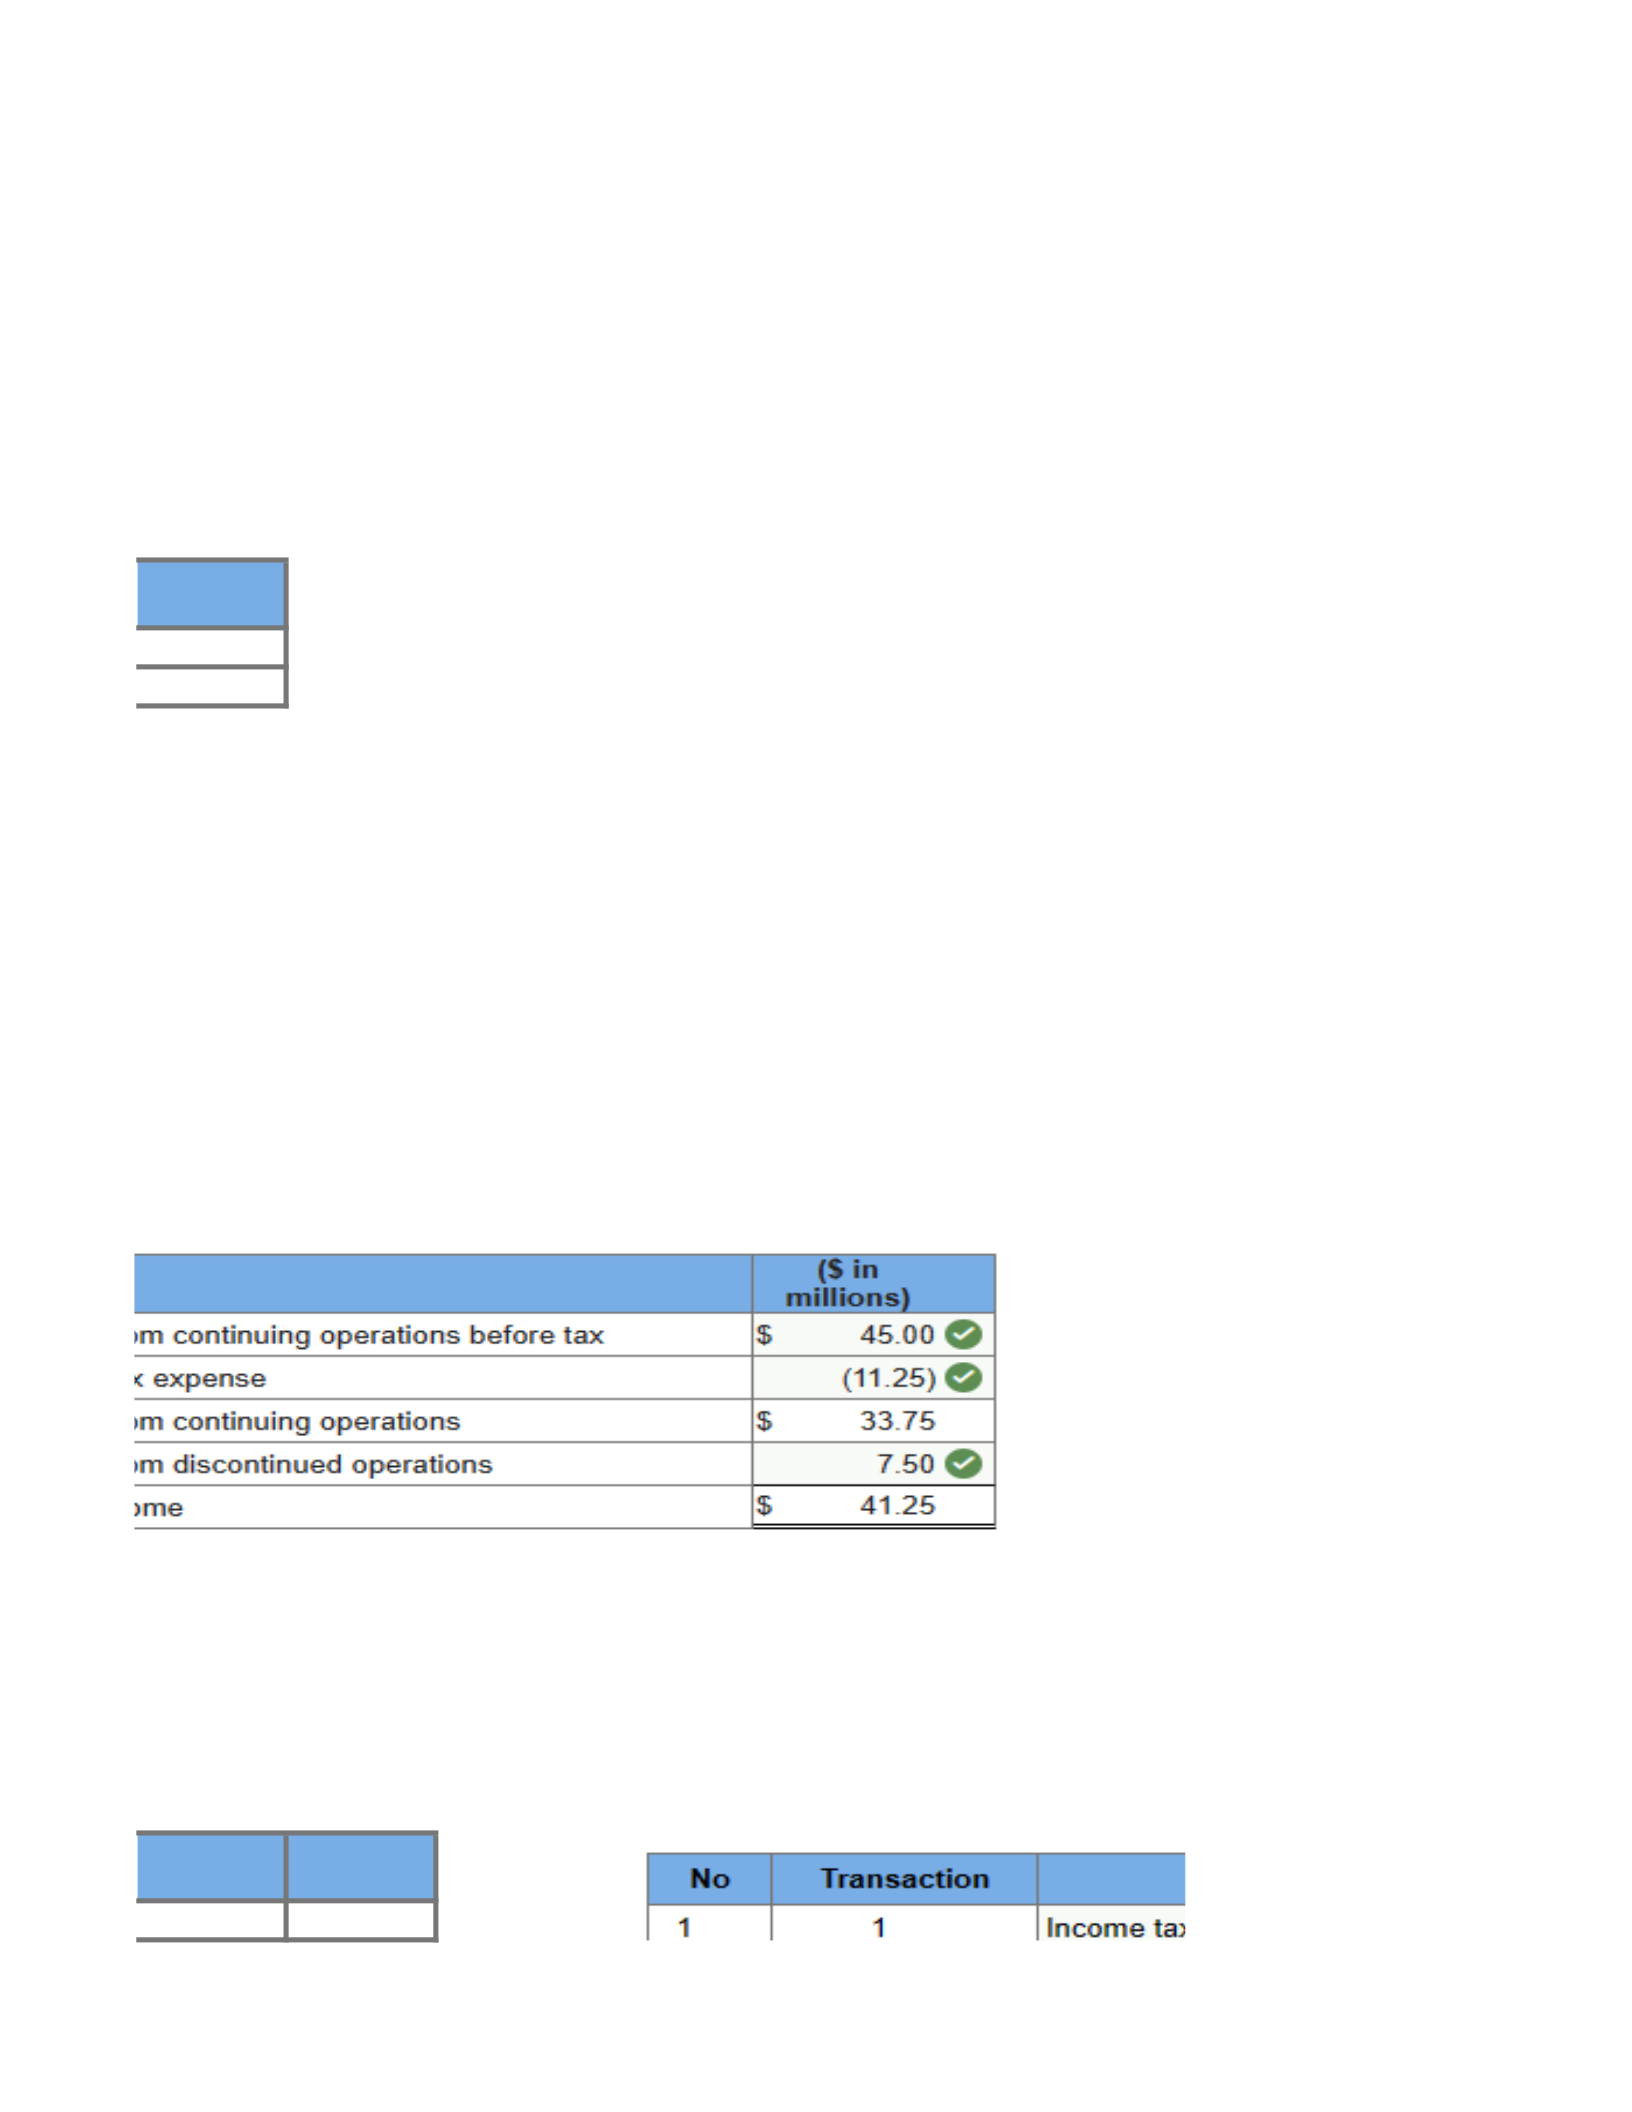
Southeast Airlines had income from continuing operations of $45 million before the income from discontinued operations of $10 million. Since the company’s tax rate is 25%, the amount of income tax expense that Southeast should report as part of income from continuing operations is $45 million × 25%, or $11.25 million. The income from discontinued operations should be reported
Lance Lawn Services reports warranty expense by estimating the amount that eventually will be paid to satisfy warranties on its product sales. For tax purposes, the expense is deducted when the warranty work is completed. At December 31, 2024, Lance has a warranty liability of $2 million and taxable income of $75 million. At December 31, 2023, Lance reported a deferred tax asset of $459,000 related to this difference in reporting warranties; it’s only temporary difference. The enacted tax rate is 25% each year.
Required:
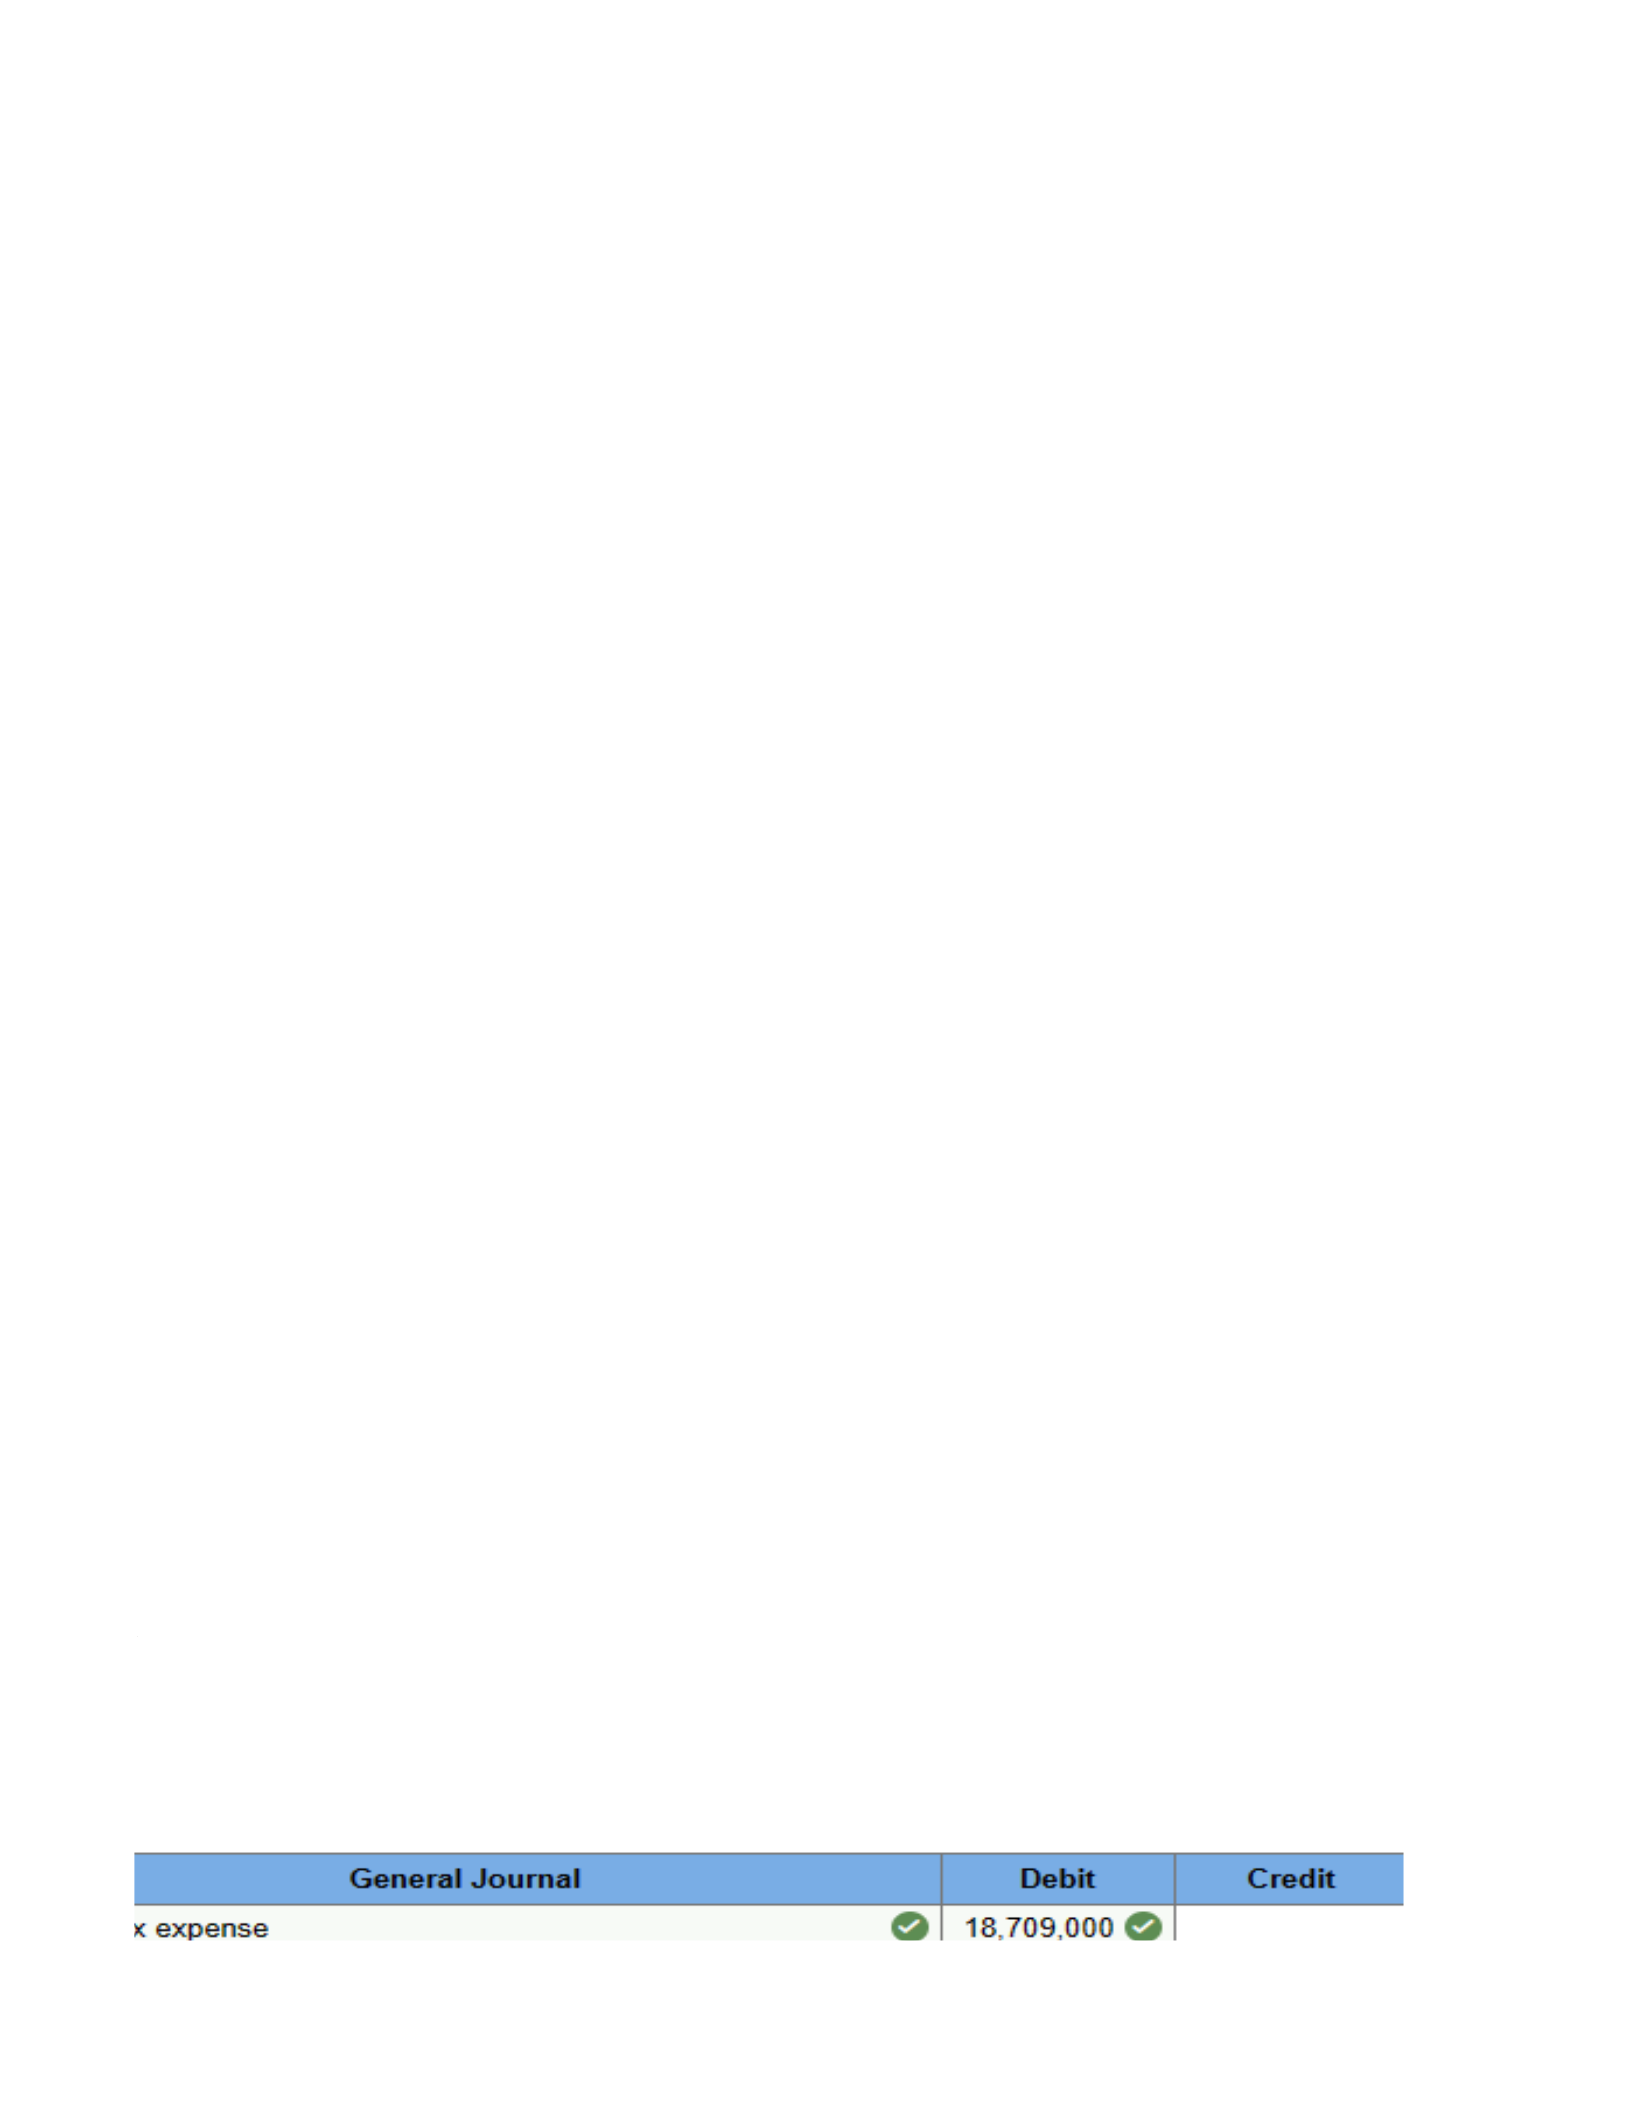
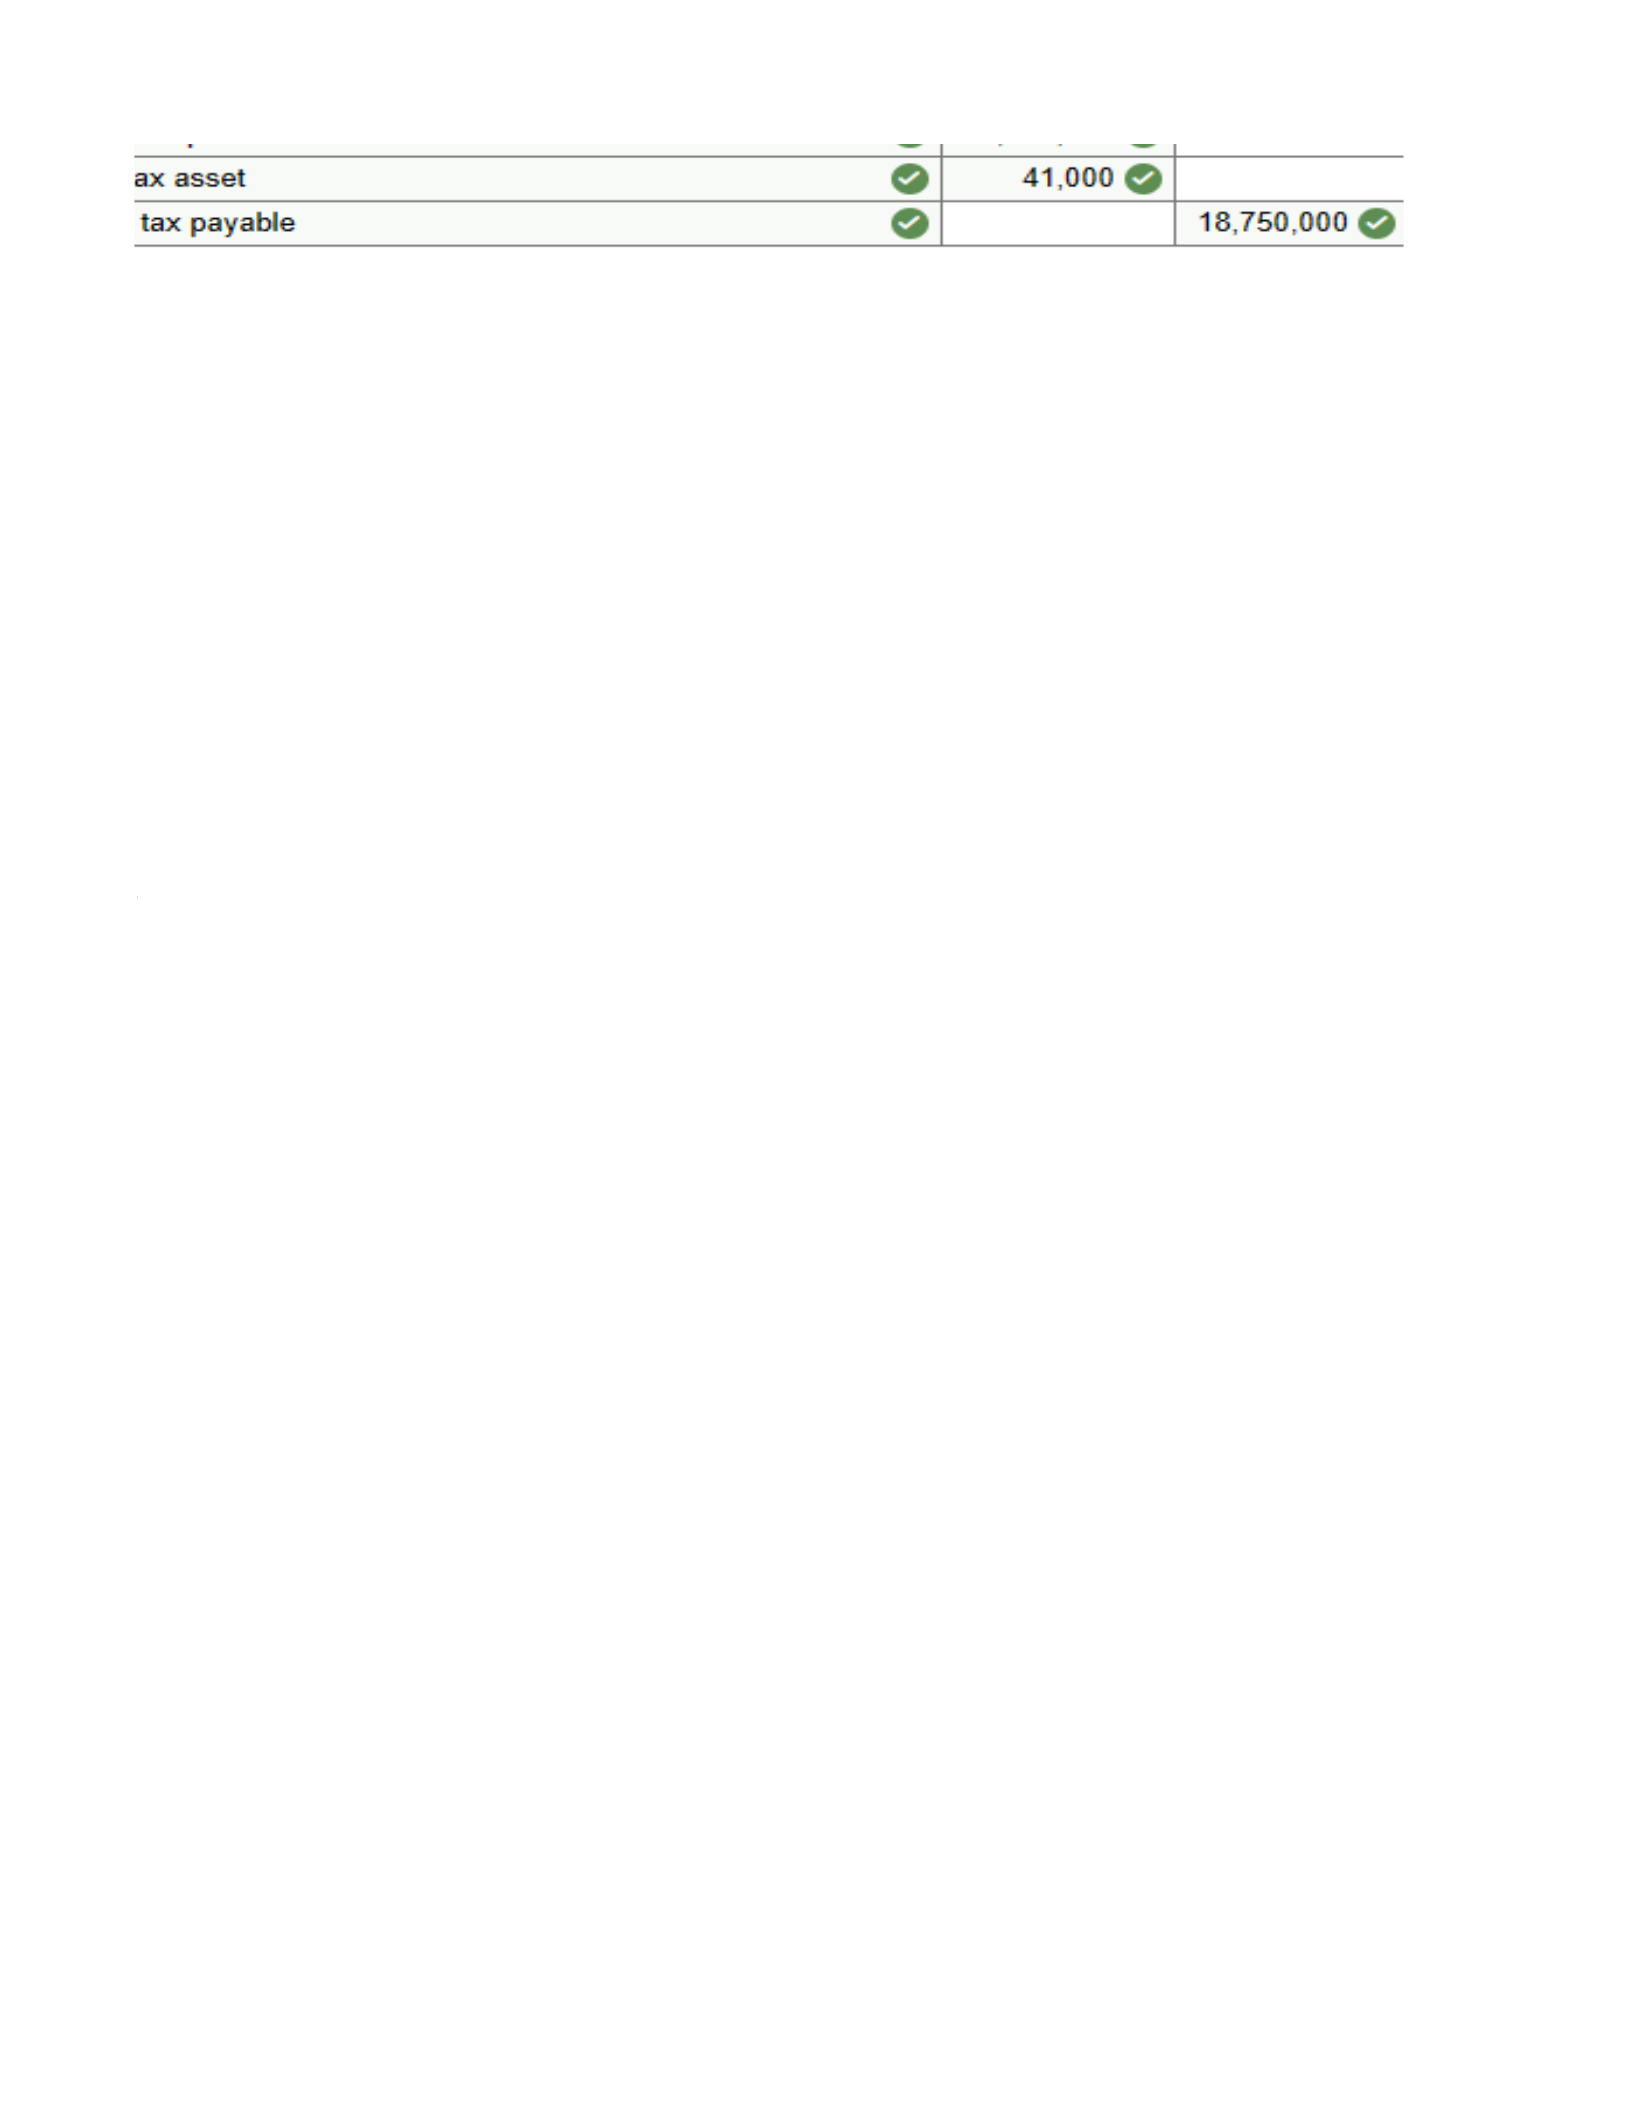
Prepare the appropriate journal entry to record Lance’s income tax provision for 2024.
Note: If no entry is required for a transaction/event, select "No journal entry required" in the first account field. Enter your answers in whole dollars.
Explanation
Deferred tax asset ([$2 million × 25%] − $459,000) = $41,000
Income tax payable ($75 million × 25%) = $18,750,000
Deferred Tax Asset
Debit Credit
459,000
41,000
500,000
Step 1: Tax payable: $18,750,000
Step 2: Deferred tax asset ending balance: $500,000*Footnote asterisk
Step 3: Deferred tax asset change: $41,000
Step 4: Tax expense plug: $18,709,000
*Footnote asterisk$2 million × 25%
Southern Atlantic Distributors began operations in January 2024 and purchased a delivery truck for $40,000. Southern Atlantic plans to use straight-line depreciation over a four-year expected useful life for financial reporting purposes. For tax purposes, the deduction is 50% of cost in 2024, 30% in 2025, and 20% in 2026. Pretax accounting income for 2024 was $200,000, which includes interest revenue of $28,000 from municipal governmental bonds. The enacted tax rate is 25%.
Assuming no differences between accounting income and taxable income other than those described above:
Required:
1. Complete the following table and prepare the journal entry to record income taxes in 2024.
2. What is Southern Atlantic’s 2024 net income?
Explanation
1. ($ in thousands)
Future Taxablem Amounts
Tax Rate
Pretax accounting income $200,000
Permanent difference -28,000
Income subject to taxation $172,000
Temporary Difference -10,000 10,000 25.00%
Income taxable in current year $162,000 25.00%
Deferred Tax Liability
Debit Credit
0
2,500.00
2,500.00
Step 1: Tax payable: $40,500.0
Step 2: Deferred tax liability ending balance: $2,500.0
Step 3: Deferred tax liability change: $2,500.0
Step 4: Tax expense plug: $43,000
2.
($ in thousands)
Pretax accounting income $200,000
Income tax expense -43,000
Net income $157,000
The information that follows pertains to Esther Food Products:
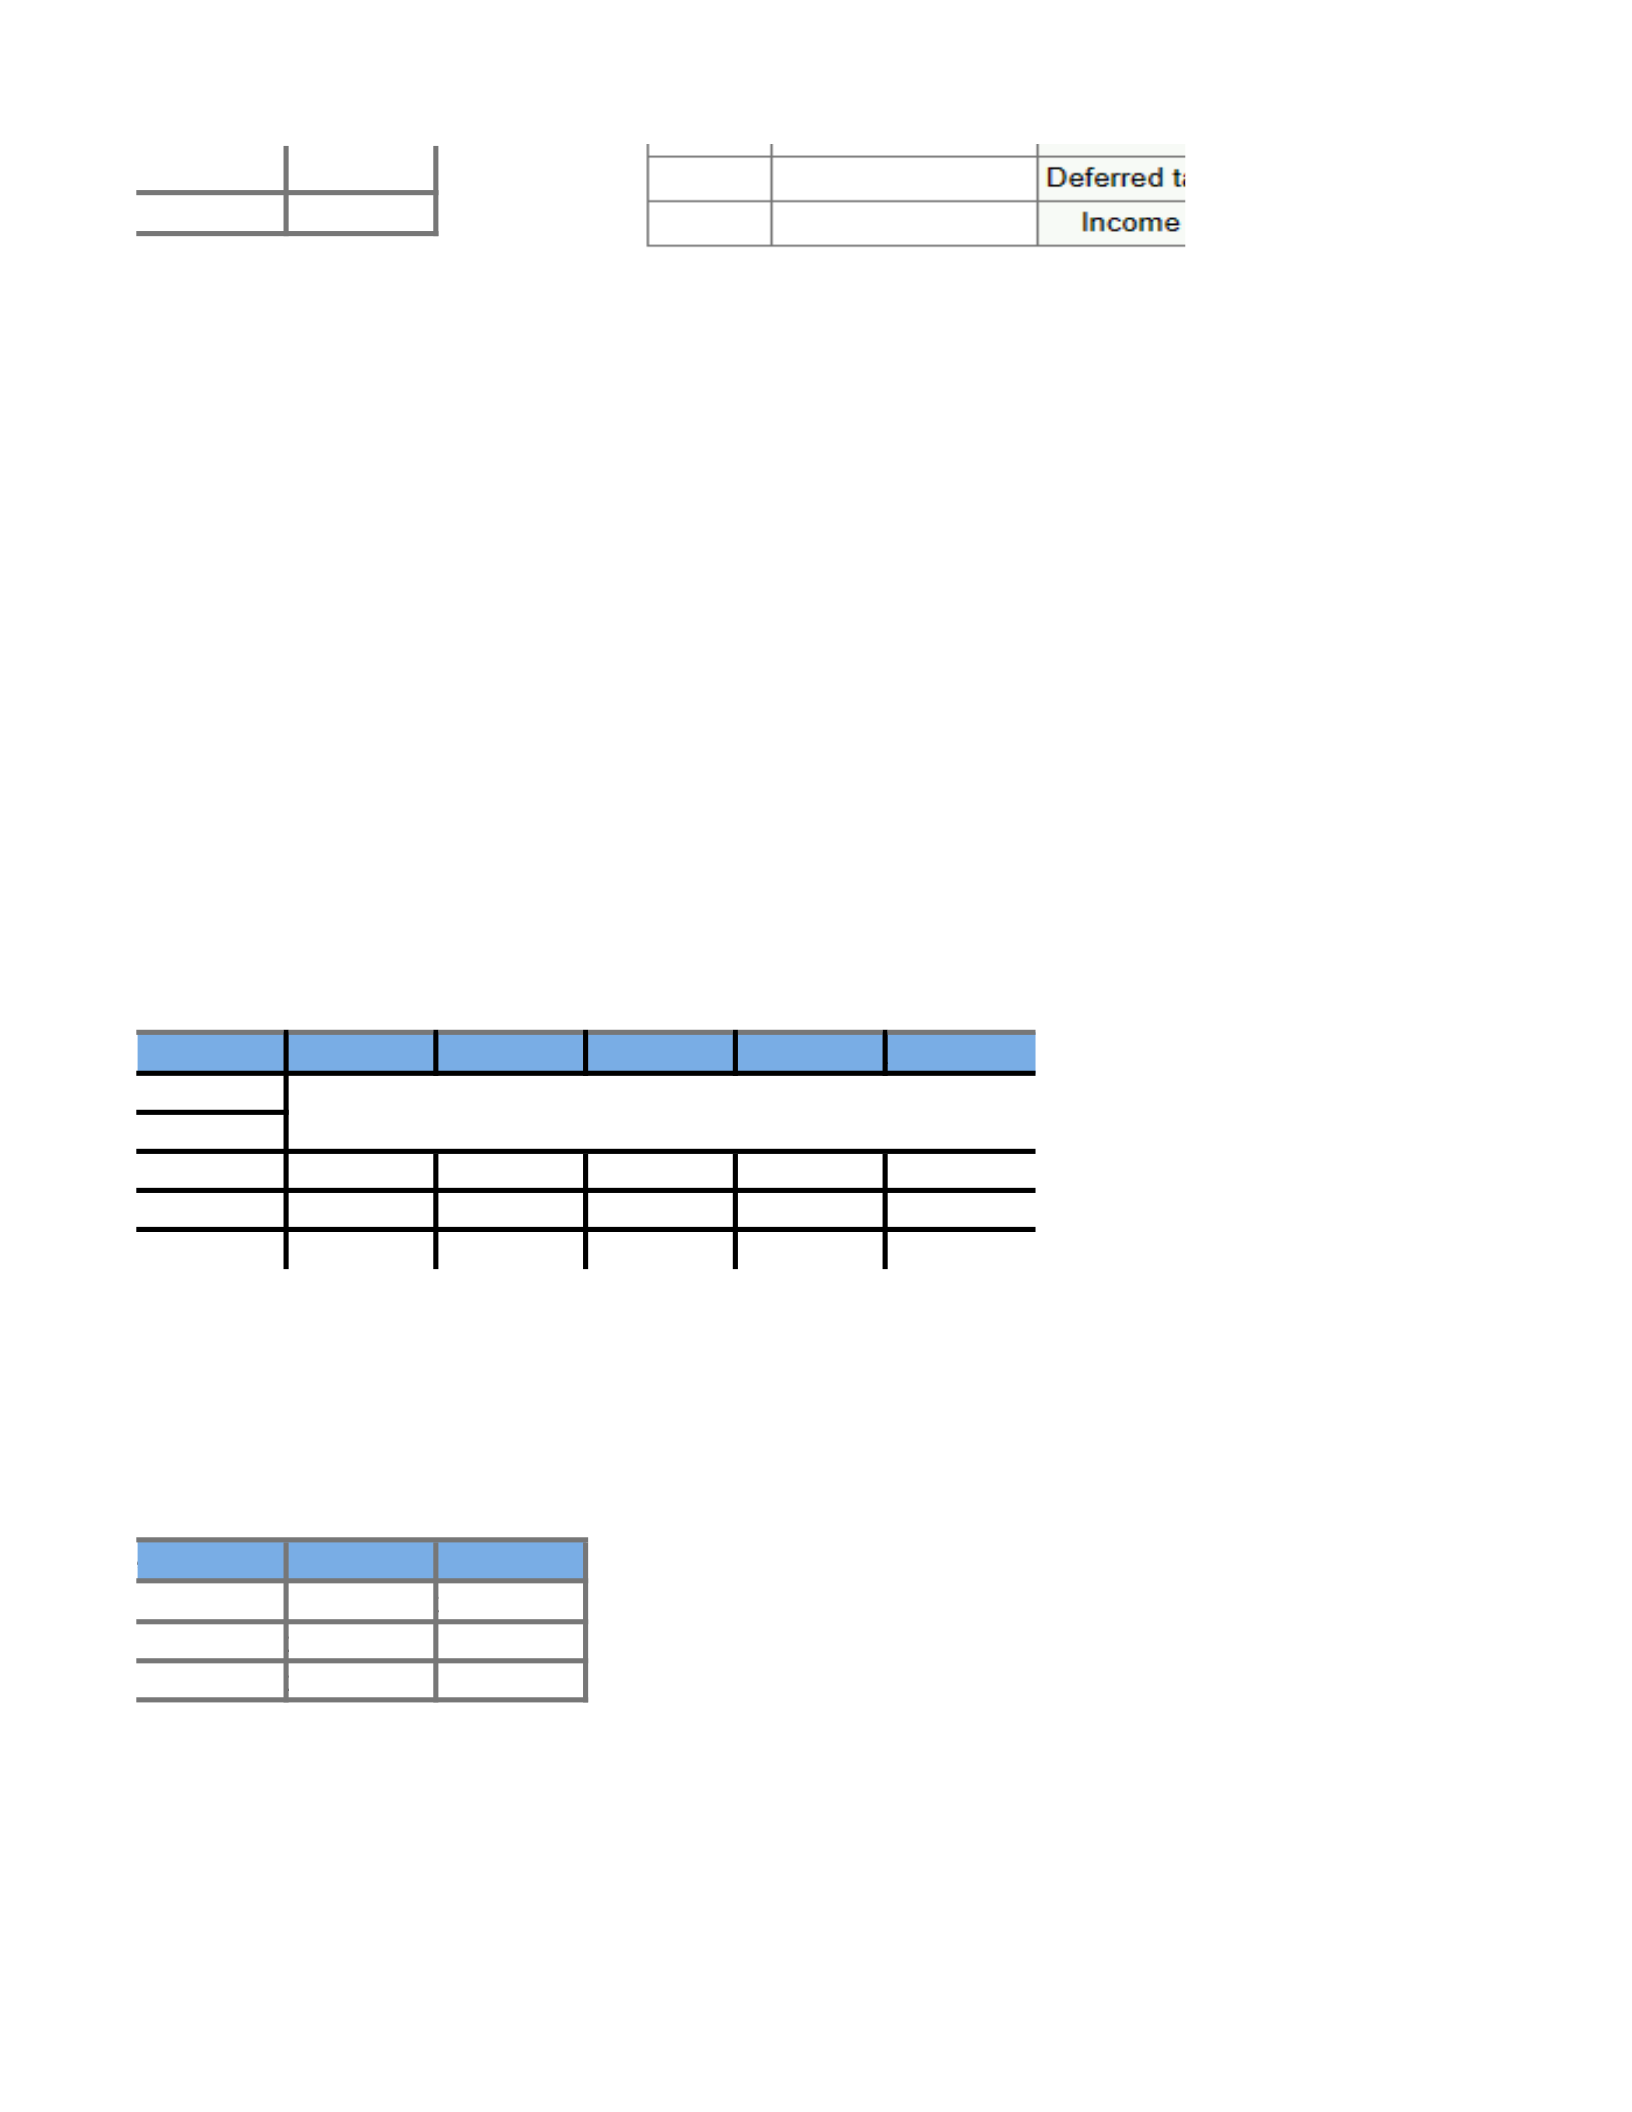
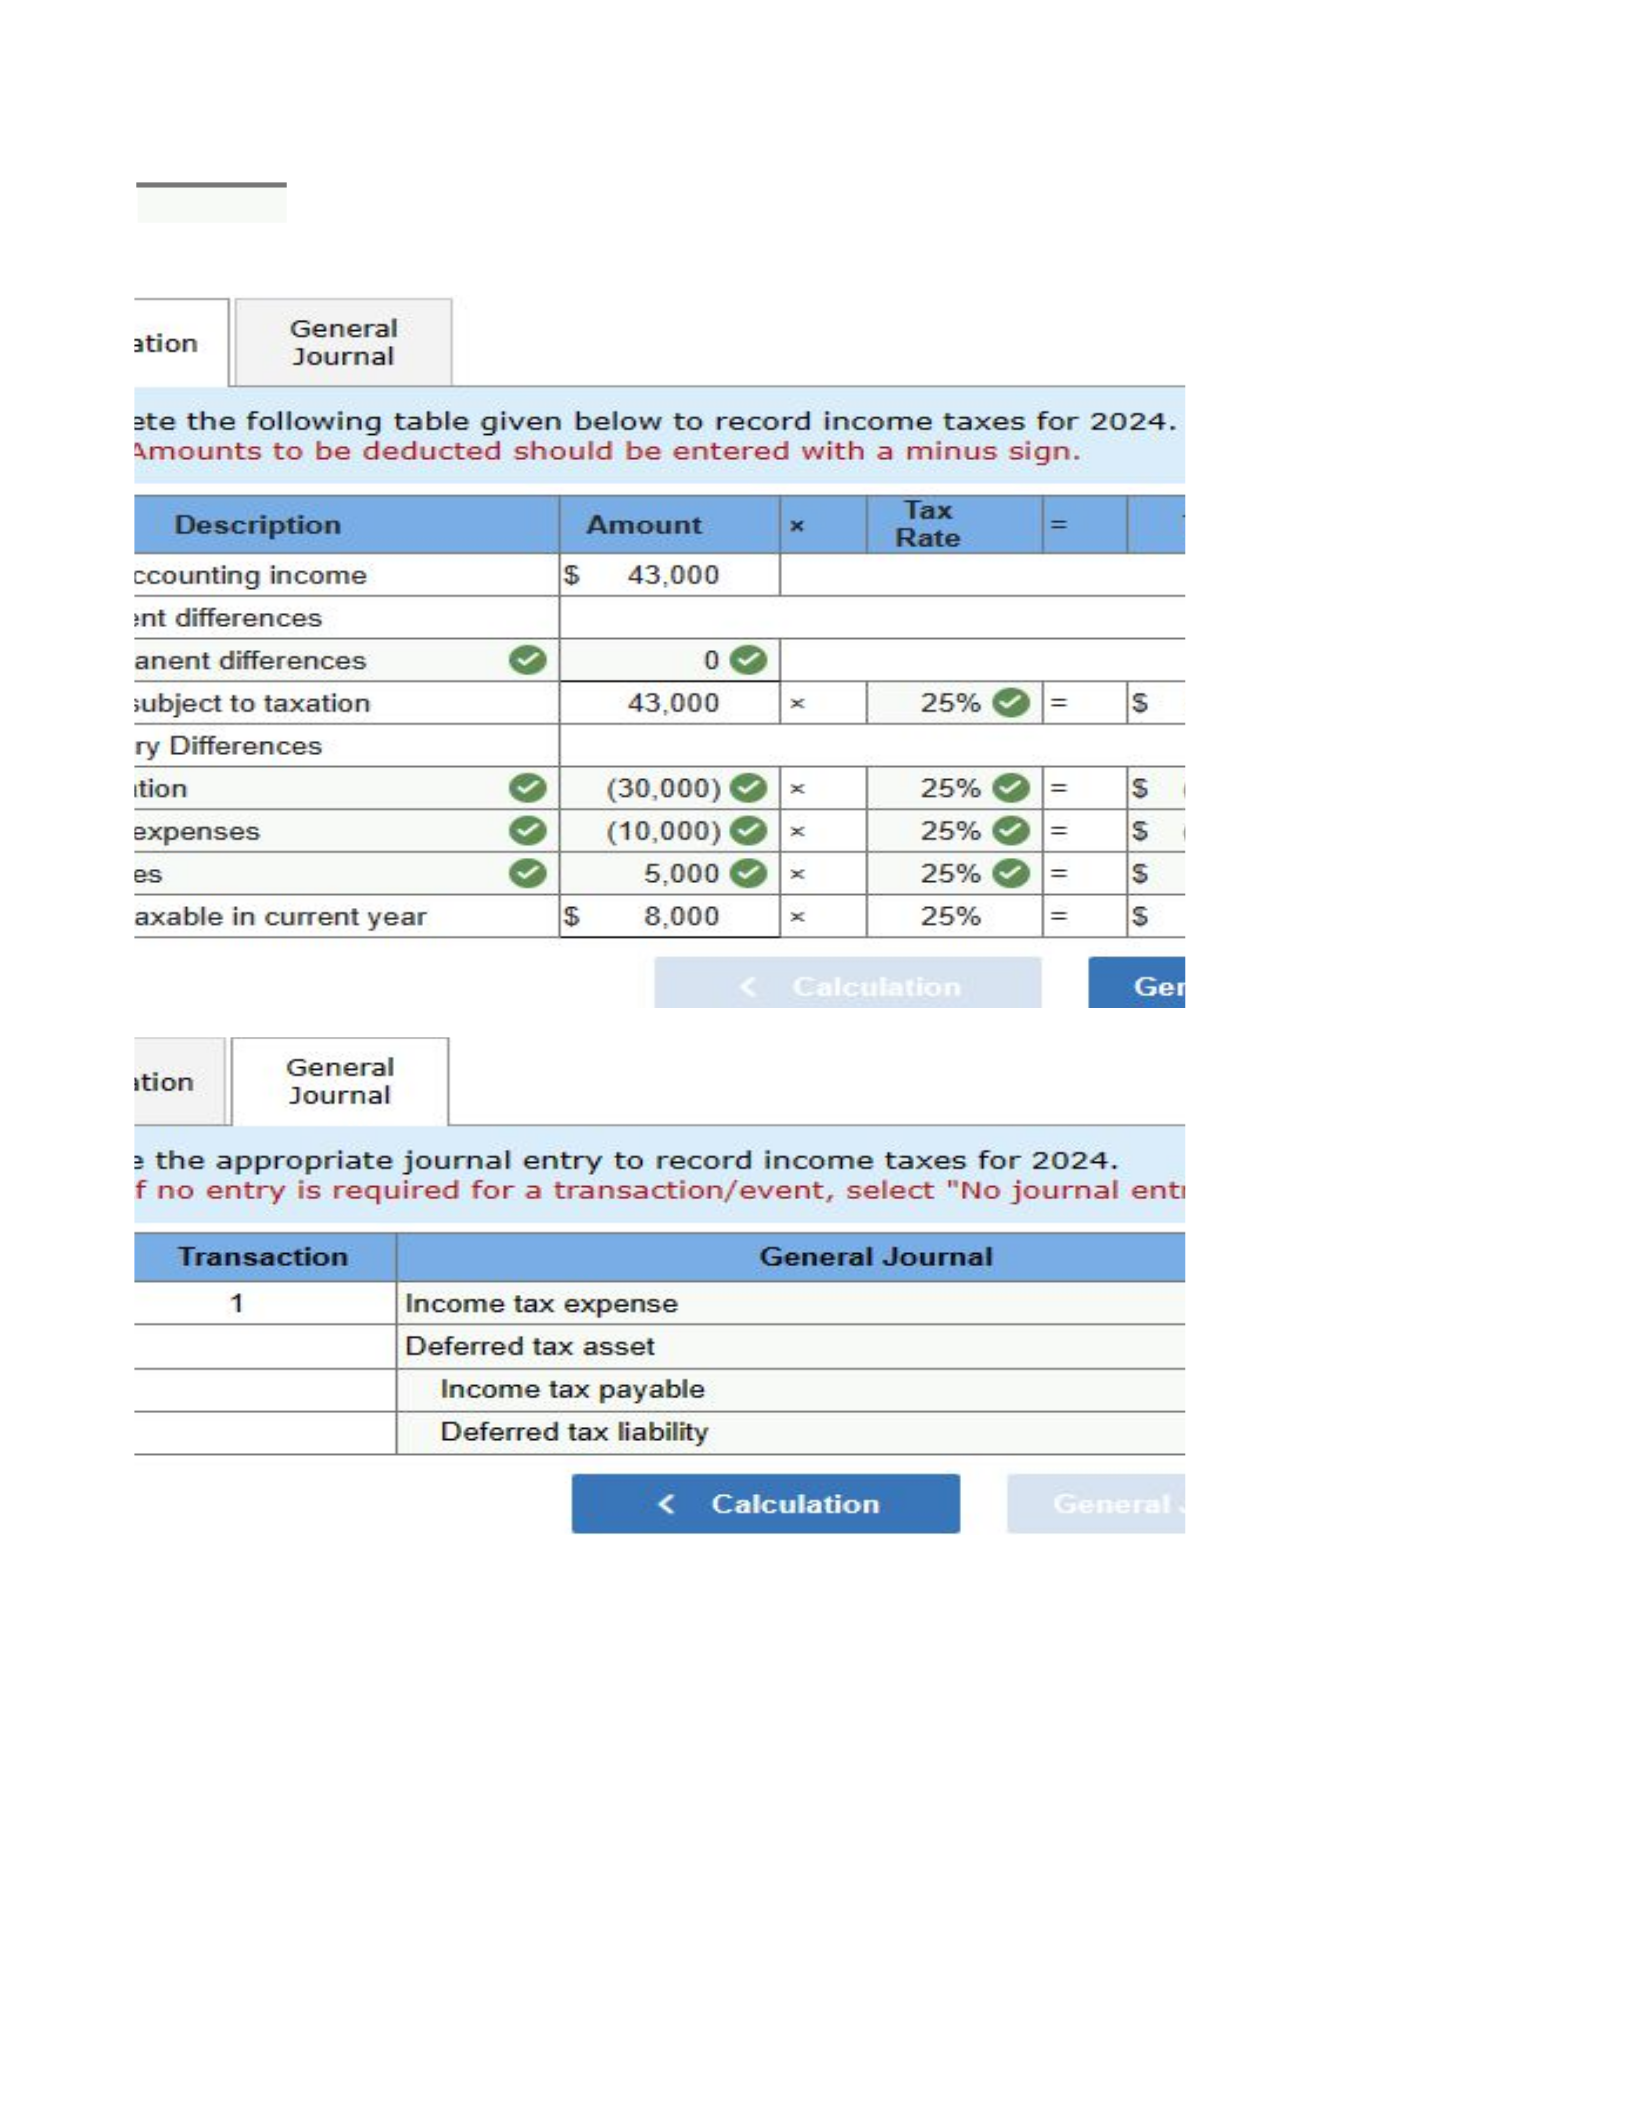
a. At December 31, 2024, temporary differences were associated with the following future taxable (deductible) amounts:
Depreciation $30,000
Prepaid expenses 10,000
Warranty expenses -5,000
b. No temporary differences existed at the beginning of 2024.
c. Pretax accounting income was $43,000 and taxable income was $8,000 for the year ended December 31, 2024.
d. The tax rate is 25%.
Required:
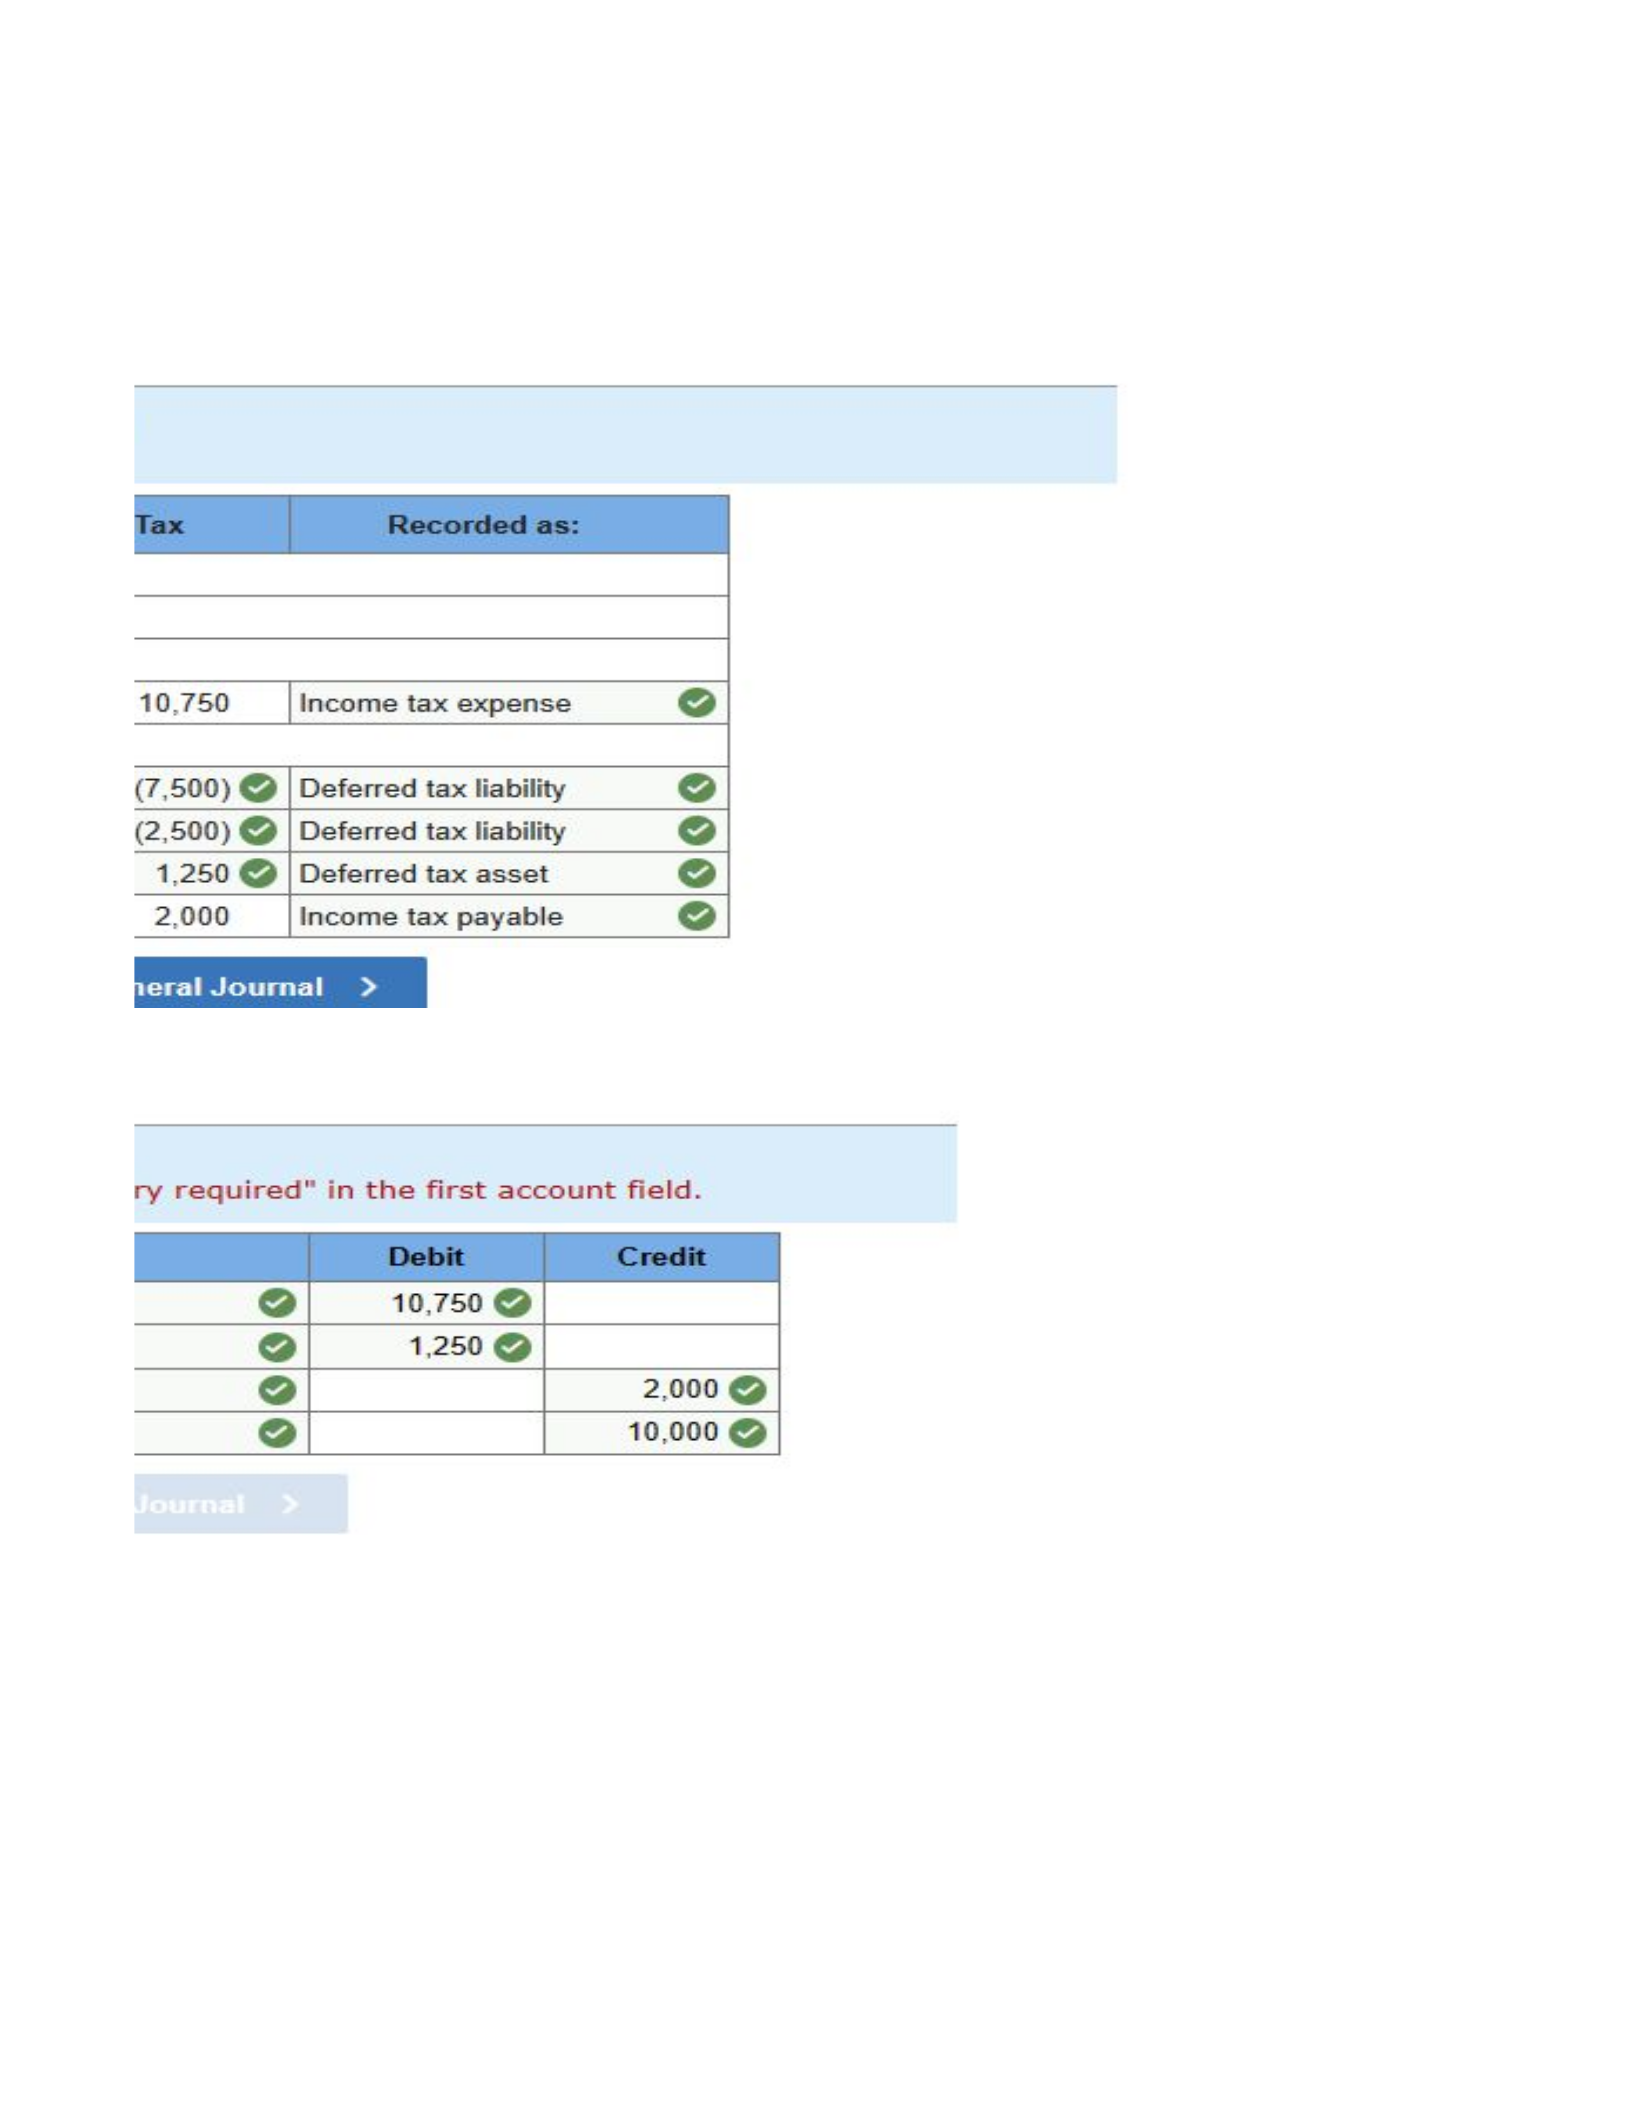
Complete the following table given below and prepare the appropriate journal entry to record income taxes for 2024.
Explanation
Deferred tax asset ($5,000 × 25%) = $1,250
Deferred tax liability (($30,000 + 10,000) × 25%) = $10,000
Income tax payable ($8,000 × 25%) = $2,000
Sherrod, Incorporated, reported pretax accounting income of $68 million for 2024. The following information relates to differences between pretax accounting income and taxable income:
a. Income from installment sales of properties included in pretax accounting income in 2024 exceeded that reported for tax purposes by $6 million. The installment receivable account at year-end 2024 had a balance of $8 million (representing portions of 2023 and 2024 installment sales), expected to be collected equally in 2025 and 2026.
b. Sherrod was assessed a penalty of $4 million by the Environmental Protection Agency for violation of a federal law in 2024. The fine is to be paid in equal amounts in 2024 and 2025.
c. Sherrod rents its operating facilities but owns one asset acquired in 2023 at a cost of $56 million. Depreciation is reported by the straight-line method, assuming a four-year useful life. On the tax return, deductions for depreciation will be more than straight-line depreciation the first two years but less than straight-line depreciation the next two years ($ in millions):
Income
Statement Tax Return
Differenc
e
2023 $14 $18 ($4)
2024 14 22 -8
2025 14 8 6
2026 14 8 6
$56 $56 $0
d. For tax purposes, warranty expense is deducted when costs are paid. The balance of the warranty liability was $3 million at the end of 2023. Warranty expense of $5 million is recognized in the income statement in 2024. $4 million of cost is paid in 2024, and another $4 million of costs are anticipated to be paid in 2025. At December 31, 2024, the warranty liability is $4 million (after adjusting entries).
e. In 2024, Sherrod accrued an expense and related liability for estimated paid future absences of $14 million relating to the company’s new paid vacation program. Future compensation will be deductible on the tax return when actually paid during the next two years ($8 million in 2025; $6 million in 2026).
f. During 2023, accounting income included an estimated loss of $2 million from having accrued a loss contingency. The loss is paid in 2024, at which time it is tax deductible.
Balances in the deferred tax asset and deferred tax liability accounts at January 1, 2024, were $1.25 million and $1.50 million, respectively. The enacted tax rate is 25% each year.
Required:
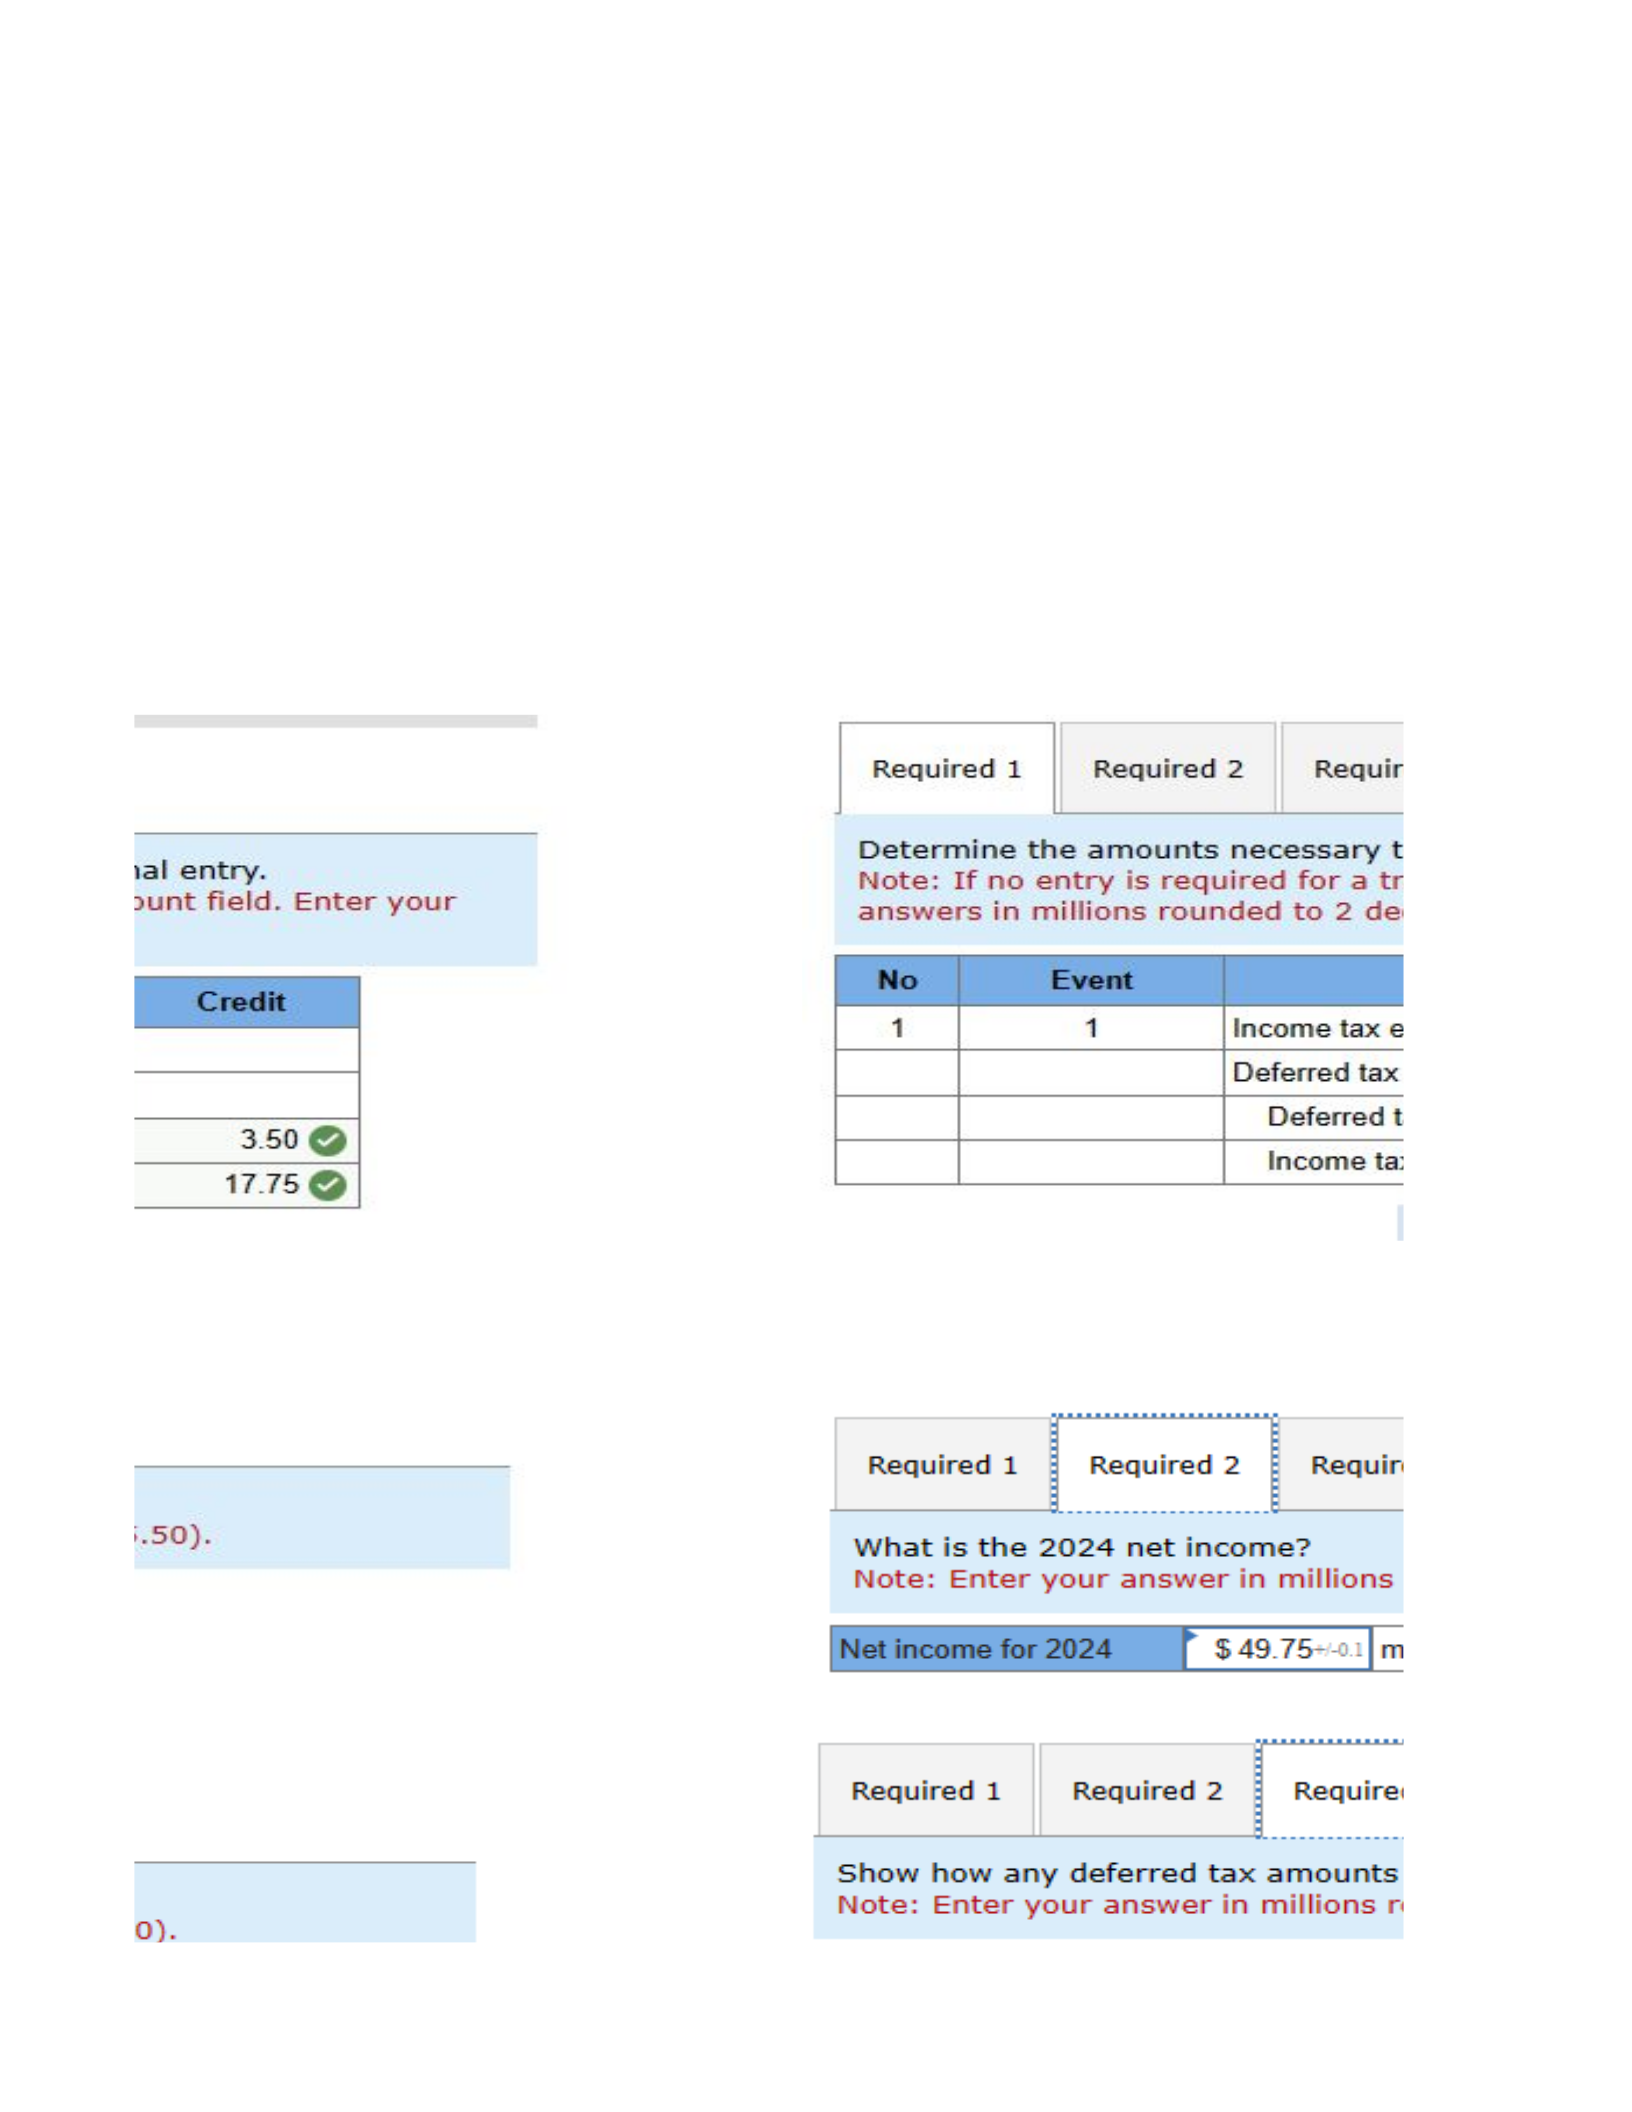
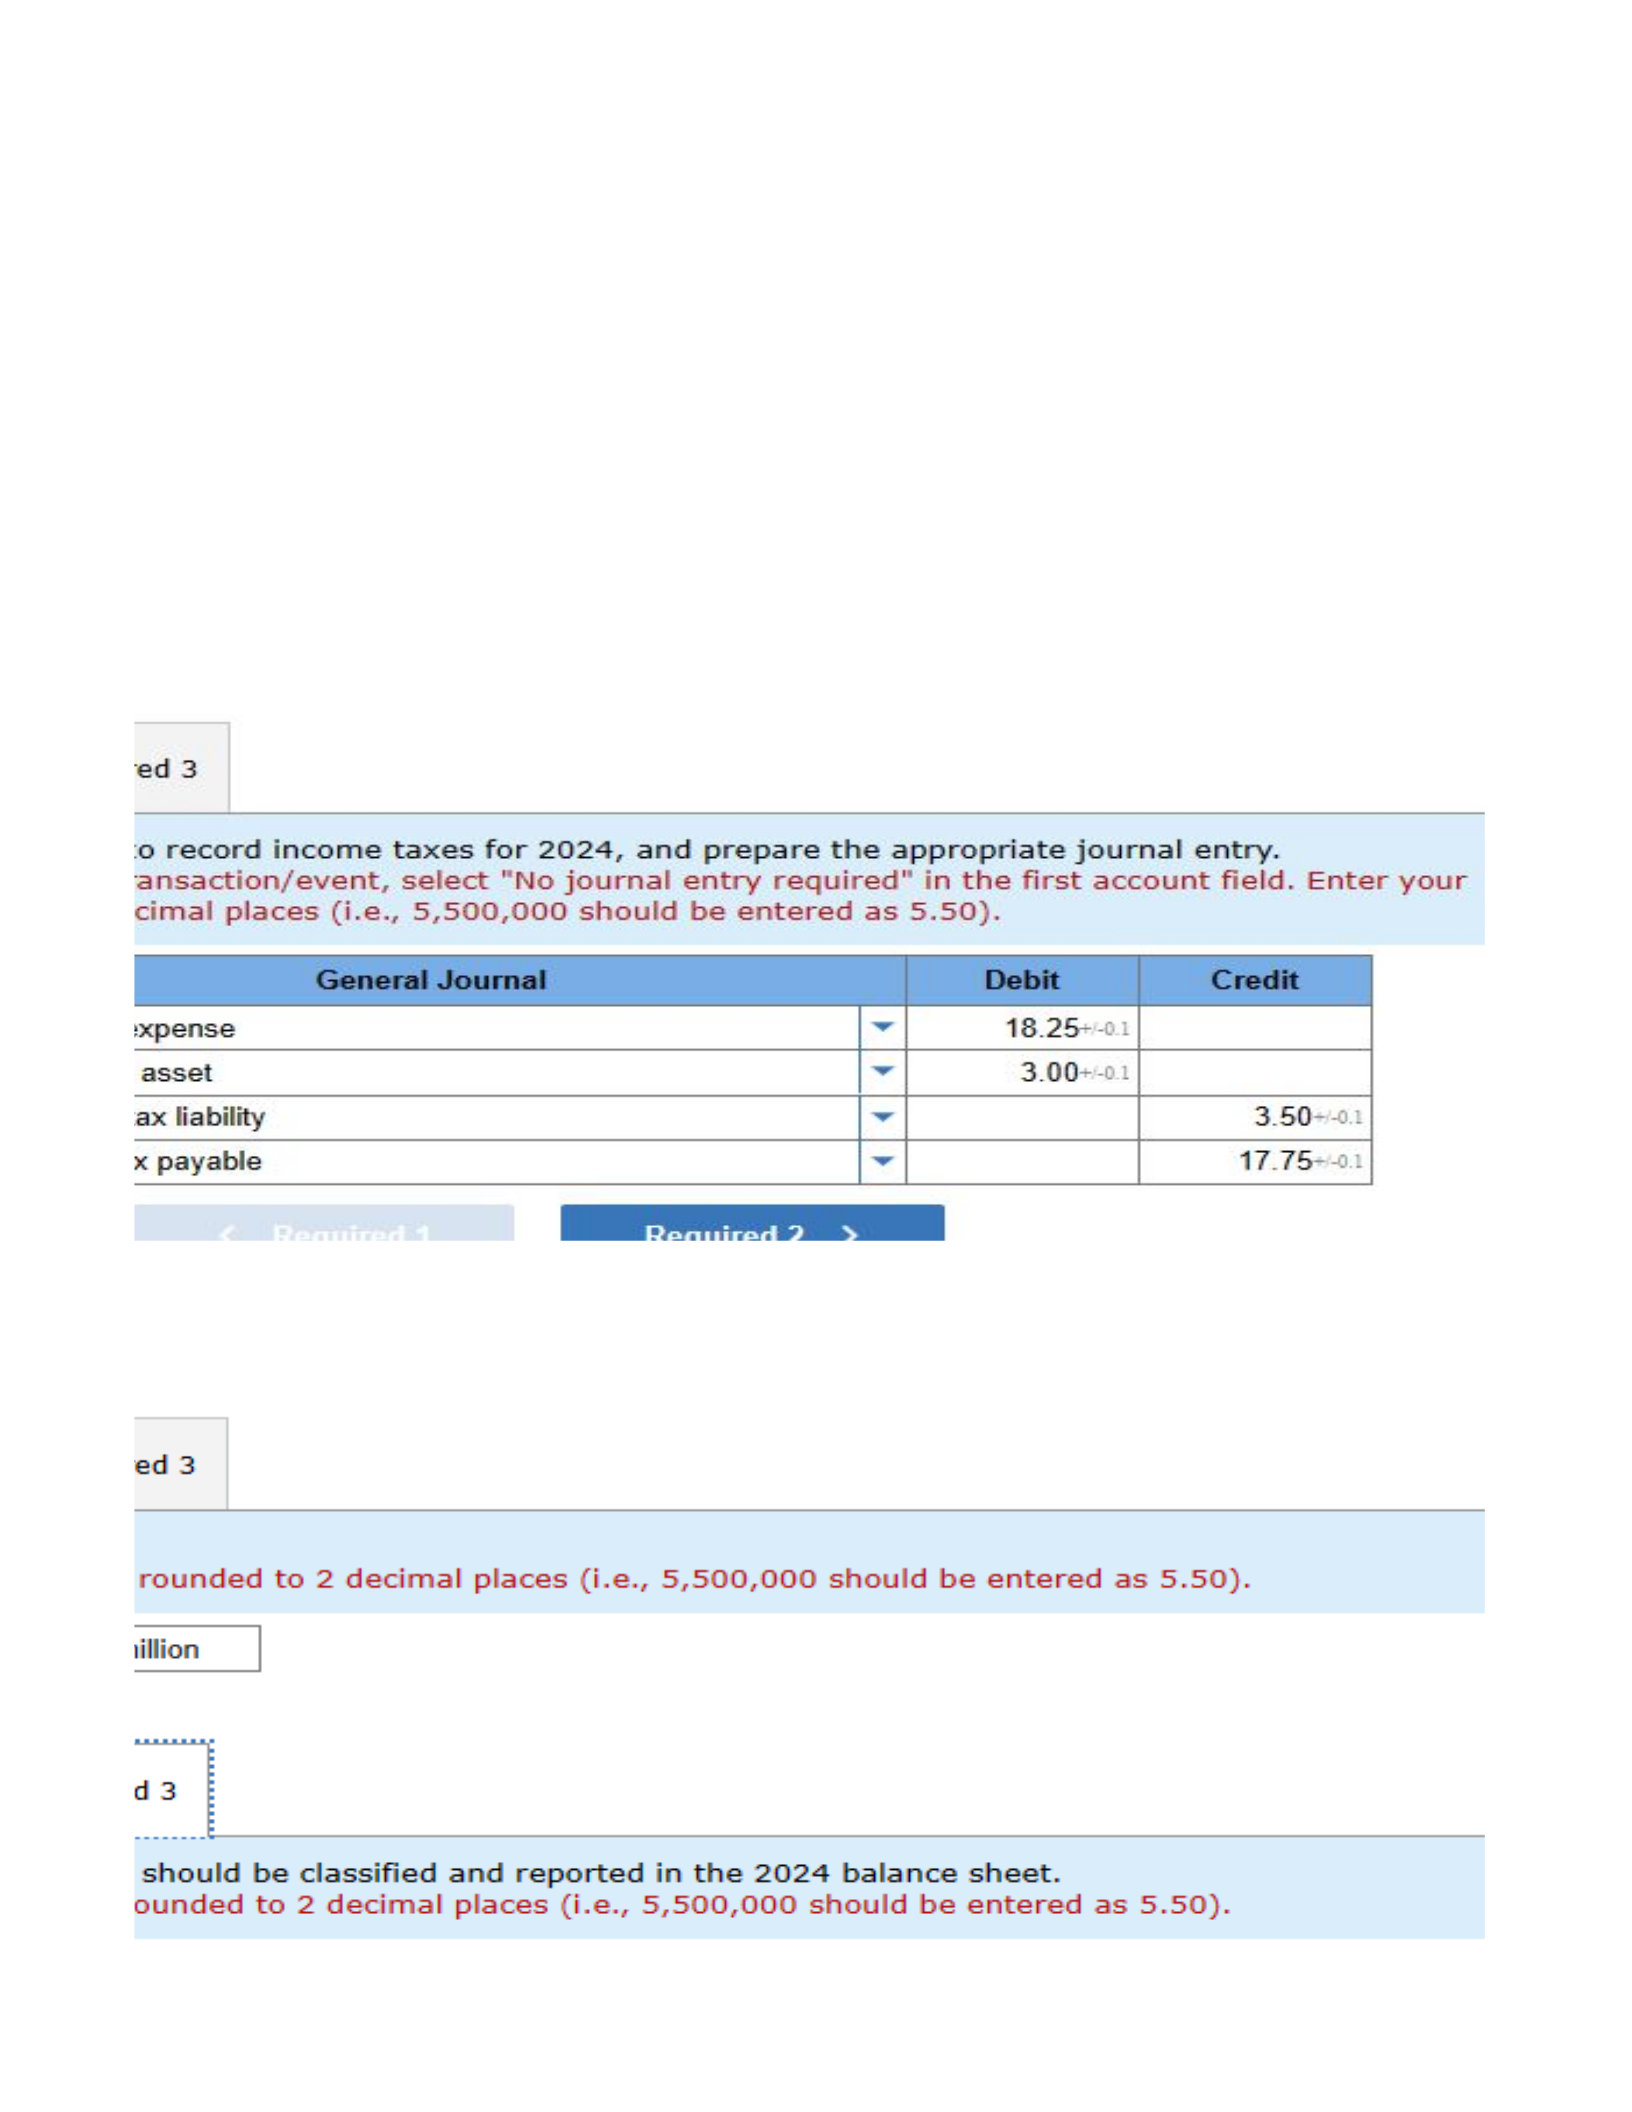
1. Determine the amounts necessary to record income taxes for 2024, and prepare the appropriate journal entry.
2. What is the 2024 net income?
3. Show how any deferred tax amounts should be classified and reported in the 2024 balance sheet.
Explanation
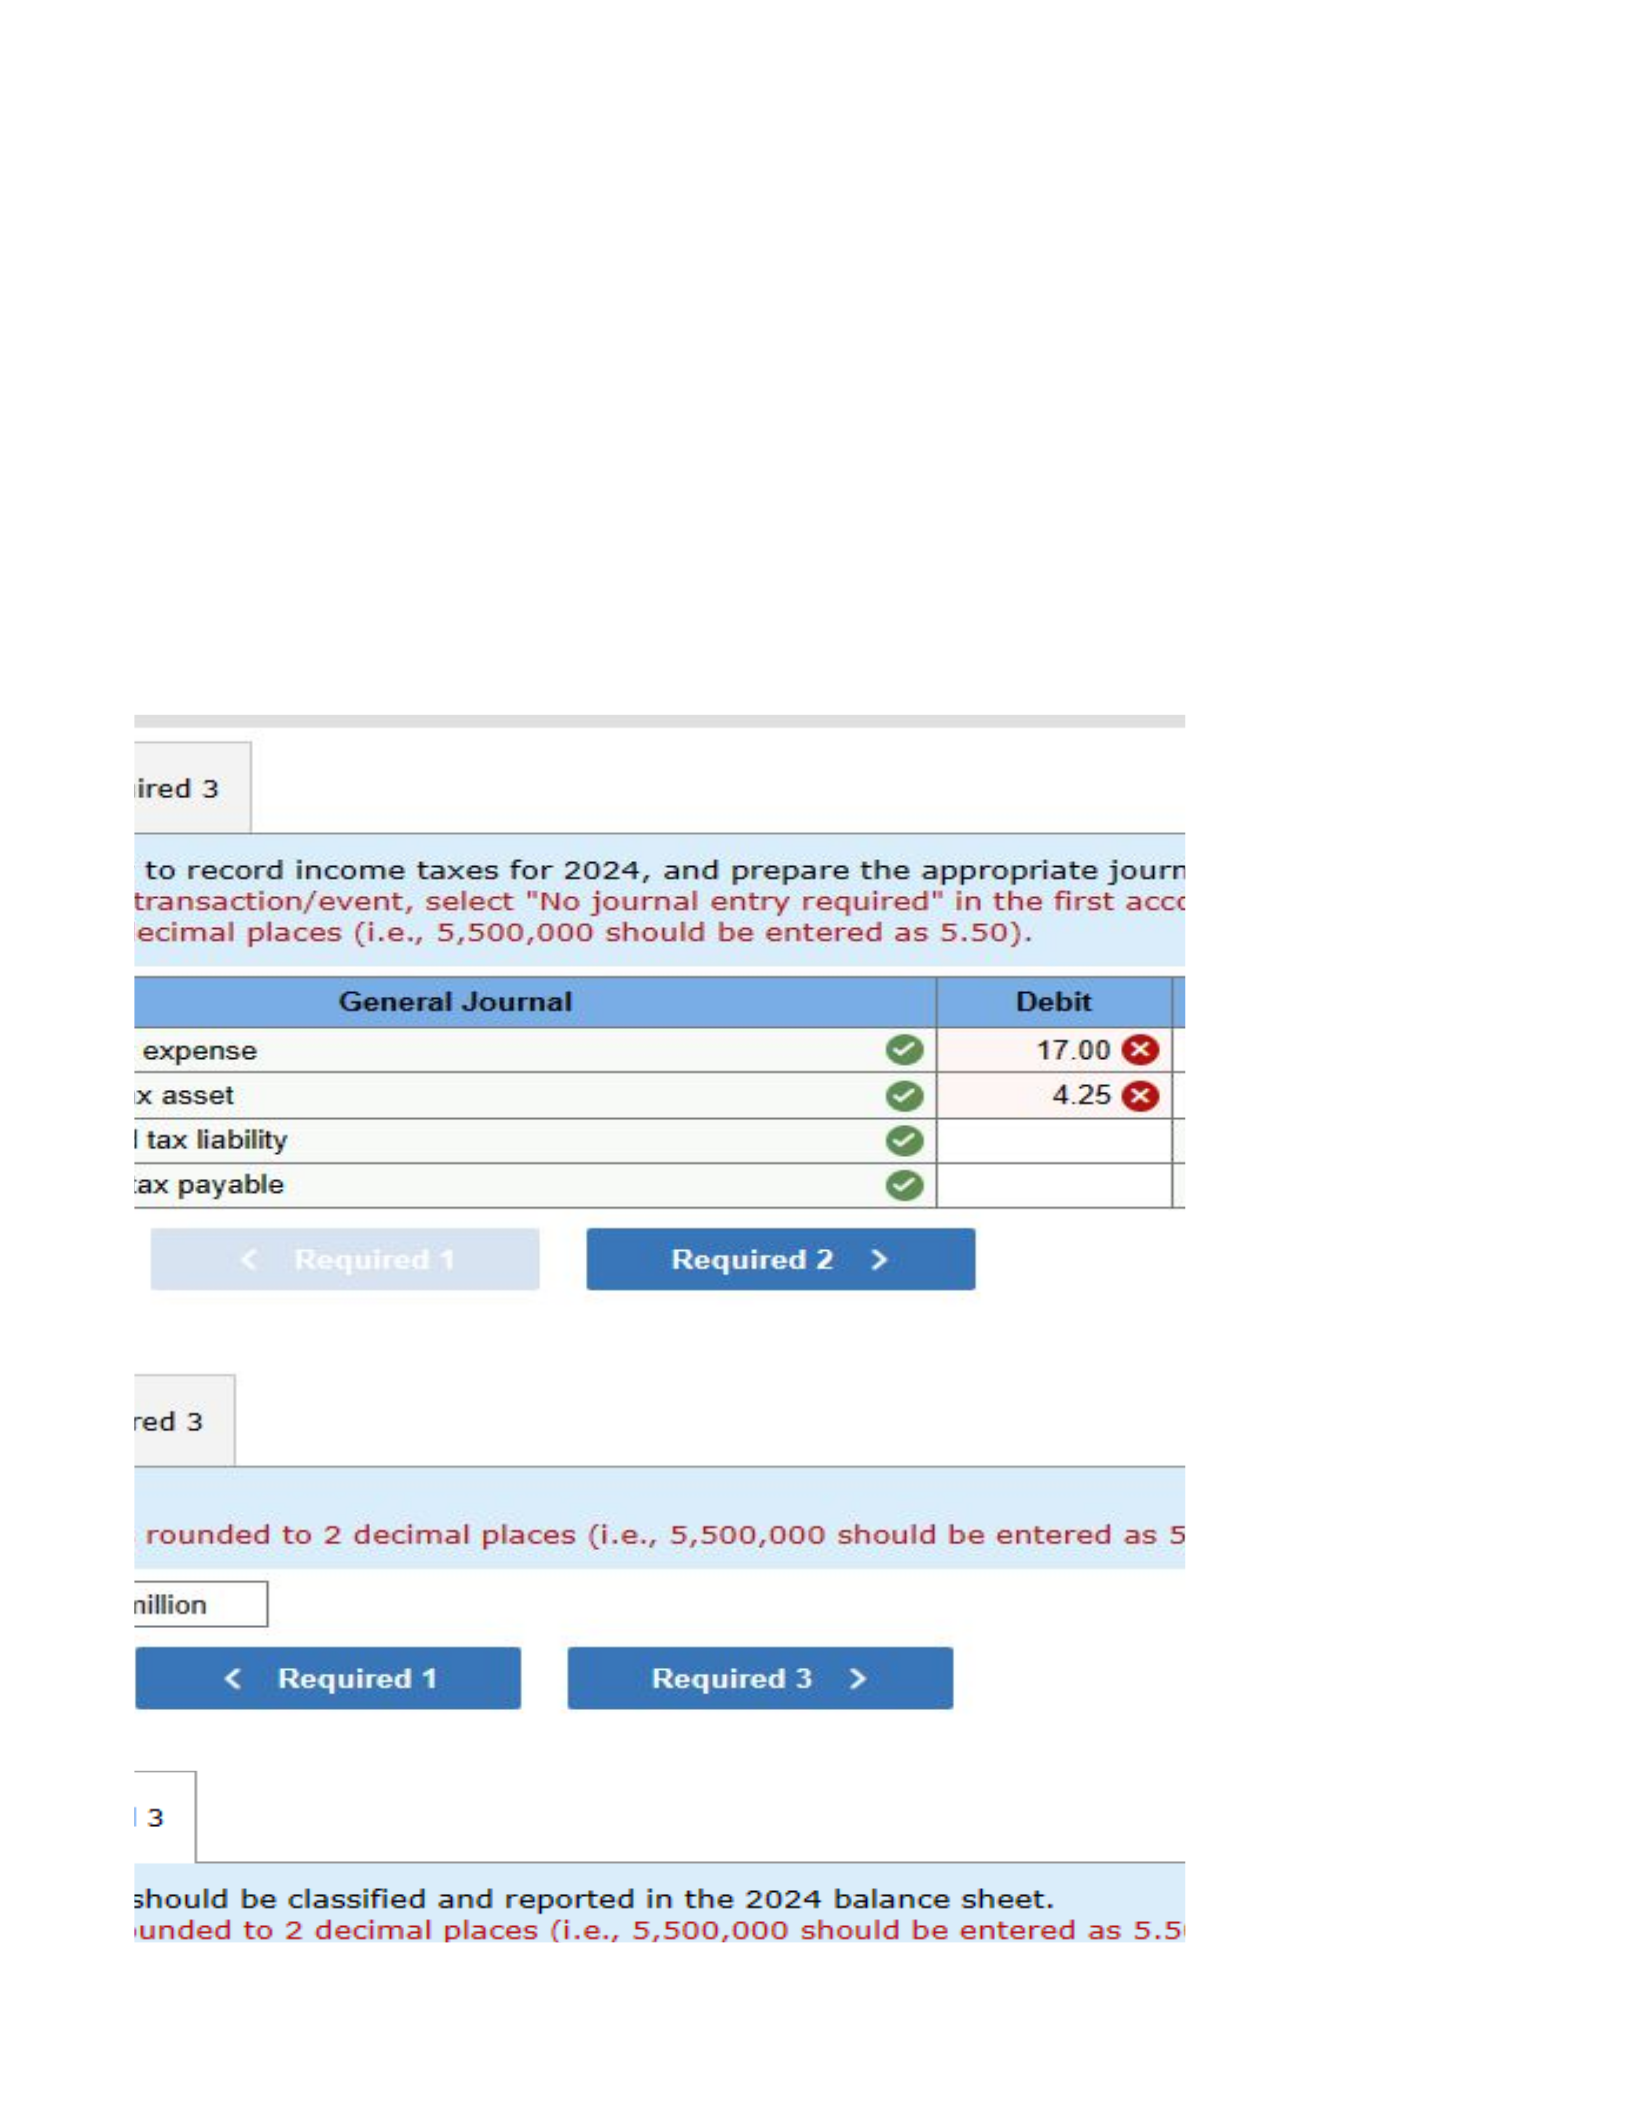
1. ($ in millions)
Current Year 2024
Future Taxable (Deductible) Amounts
2025 2026
Pretax accounting income $68
Permanent difference:
Federal fine not deductible 4
Temporary differences:
Installment sales -6 $4 $4
Depreciation -8 6 6
Warranties 1 -3
Paid future absences 14 ($8) ($6)
Loss contingency -2
Taxable income (tax return) 71
Enacted tax rate 25%
Tax payable currently $17.75
Deferred tax liability
Deferred tax asset
Deferred Tax Liability
Debit Credit
1.5
3.5
5
Deferred Tax Asset
Debit Credit
1.25
3
4.25
Step 1: Tax payable: $17.75
Step 2: Deferred tax asset end balance: $4.25
Deferred tax liability end balance: $5.00
Step 3: Deferred tax asset change: $3.00
Deferred tax liability change: $3.50
Step 4: Tax expense plug: $18.25
2.
($ in millions)
Income before income tax $68.00
Income tax expense -18.25
Net income $49.75
3. Net noncurrent deferred tax liability ($5.00 − $4.25) = $0.75
Corning-Howell reported taxable income in 2024 of $152 million. At December 31, 2024, the reported amount of some assets and liabilities in the financial statements differed from their tax bases as indicated below:
Carrying Amount Tax Basis
Assets
Current
Net accounts receivable $40 million
$44
Prepaid insurance 52 million 0
Prepaid advertising 36 million 0
Noncurrent
Investments in equity securities
(fair value)*Footnote asterisk
36 million 0
Buildings and equipment (net) 392 million 312
Liabilities
Current
Deferred subscription revenue 44 million 0
Long-term
Liability—compensated future
absences
626 million 0
*Footnote asterisk
Gains and losses taxable when investments are sold.
The total deferred tax asset and deferred tax liability amounts at January 1, 2024, were $172.25 million and $25 million, respectively. The enacted tax rate is 25% each year.
Required:
1. Determine the total deferred tax asset and deferred tax liability amounts at December 31, 2024.
2. Determine the increase (decrease) in the deferred tax asset and deferred tax liability accounts at December 31, 2024.
3. Determine the income tax payable currently for the year ended December 31, 2024.
4. Prepare the journal entry to record income taxes for 2024.
Explanation
1. Temporary Differences ($ in millions)
Future Taxable
Amounts
Future Deductible
Amounts
Net accounts receivable ($4)
Prepaid insurance $52
Prepaid advertising 36
Investment in equity securities 36
Buildings and equipment (net) 80
Deferred subscription revenue -44
Liability—compensated future
absences
-626
Totals 204 -674
Tax rate 25% 25
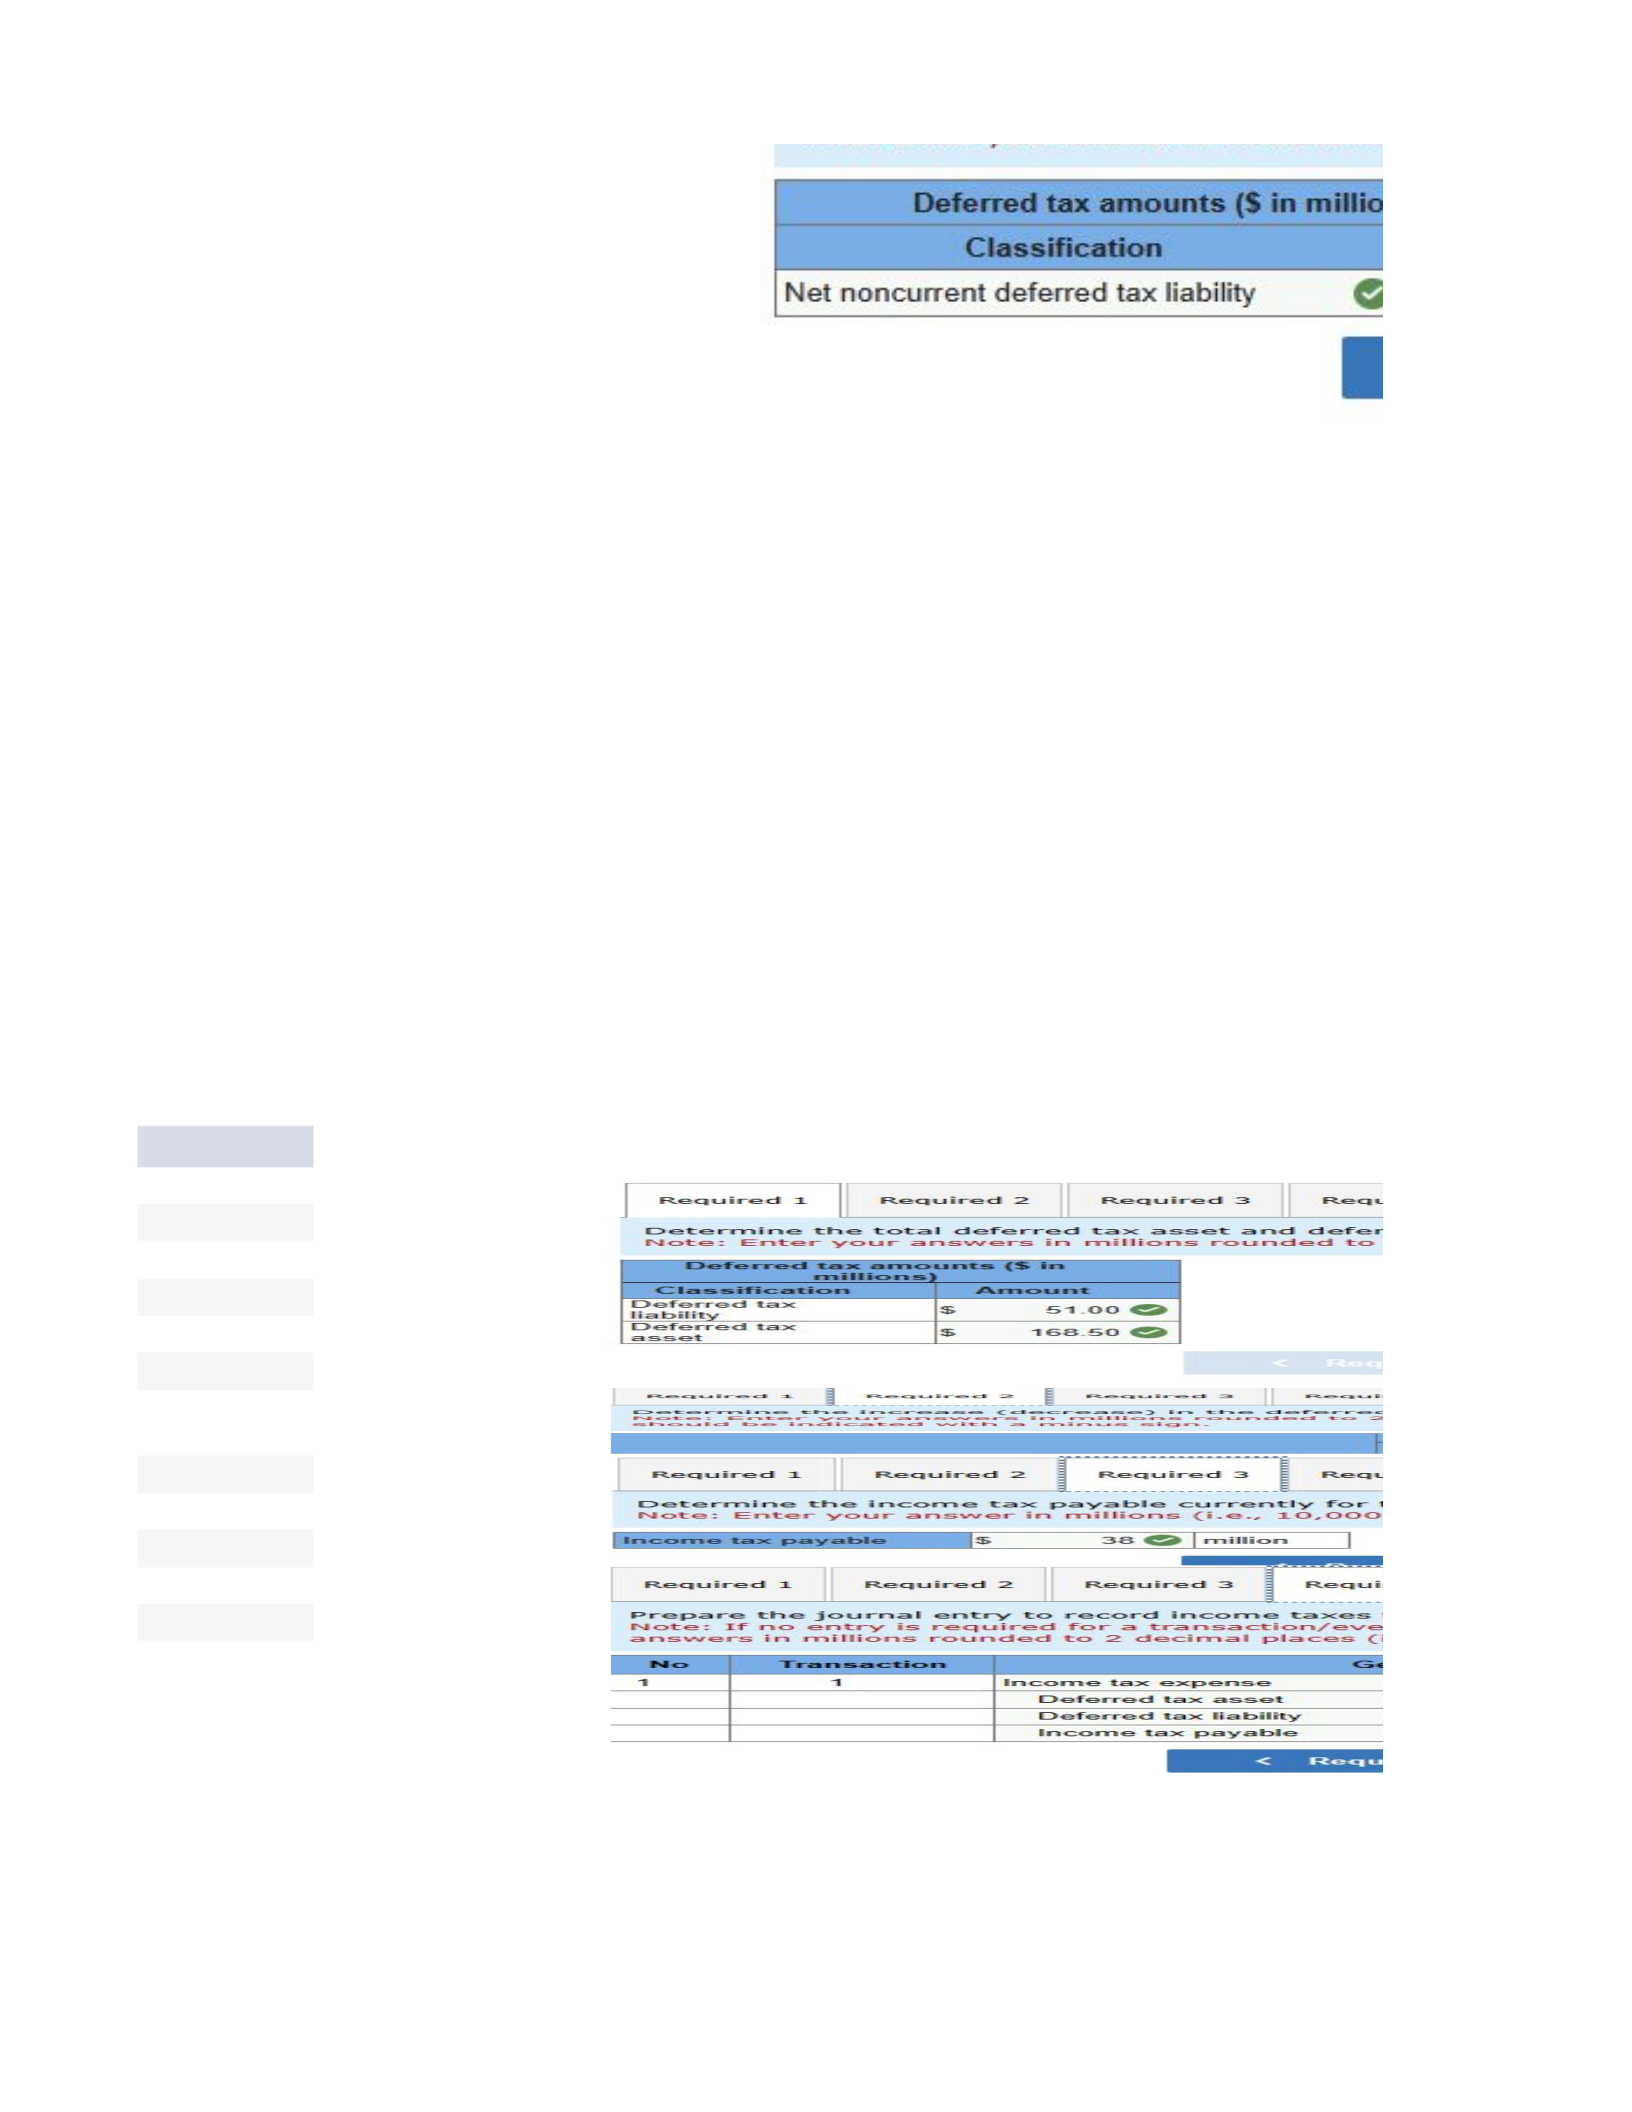
Deferred tax liability $51.00
Deferred tax asset ($168.50)
2. Deferred Tax Liability
Debit
Credit
$25.00
26
$51.00
Deferred Tax Asset
Debit
Credit
$172.25
$3.75
$168.50
Step 1: Tax payable: $38
Step 2: Deferred tax asset end balance: $168.5
Deferred tax liability end balance: $51.0
Step 3: Deferred tax asset change: $(3.75)
Deferred tax liability change: $26.0
Step 4: Tax expense plug: $67.75
3. Taxable income times tax rate equals income tax payable
$152 million × 25% = $38 million
Fore Farms reported a pretax operating loss of $168 million for financial reporting purposes in 2024. Contributing to the loss were (a) a penalty of $4 million assessed by the Environmental Protection Agency for violation of a federal law and paid in 2024 and (b) an estimated loss of $20 million from accruing a loss contingency. The loss will be tax deductible when paid in 2025.
The enacted tax rate is 25%. There were no temporary differences at the beginning of the year and none originating in 2024 other than those described above. Taxable income in Fores’s two previous years of operation was as follows:
2022 $76 million
2023 $52 million
Required:
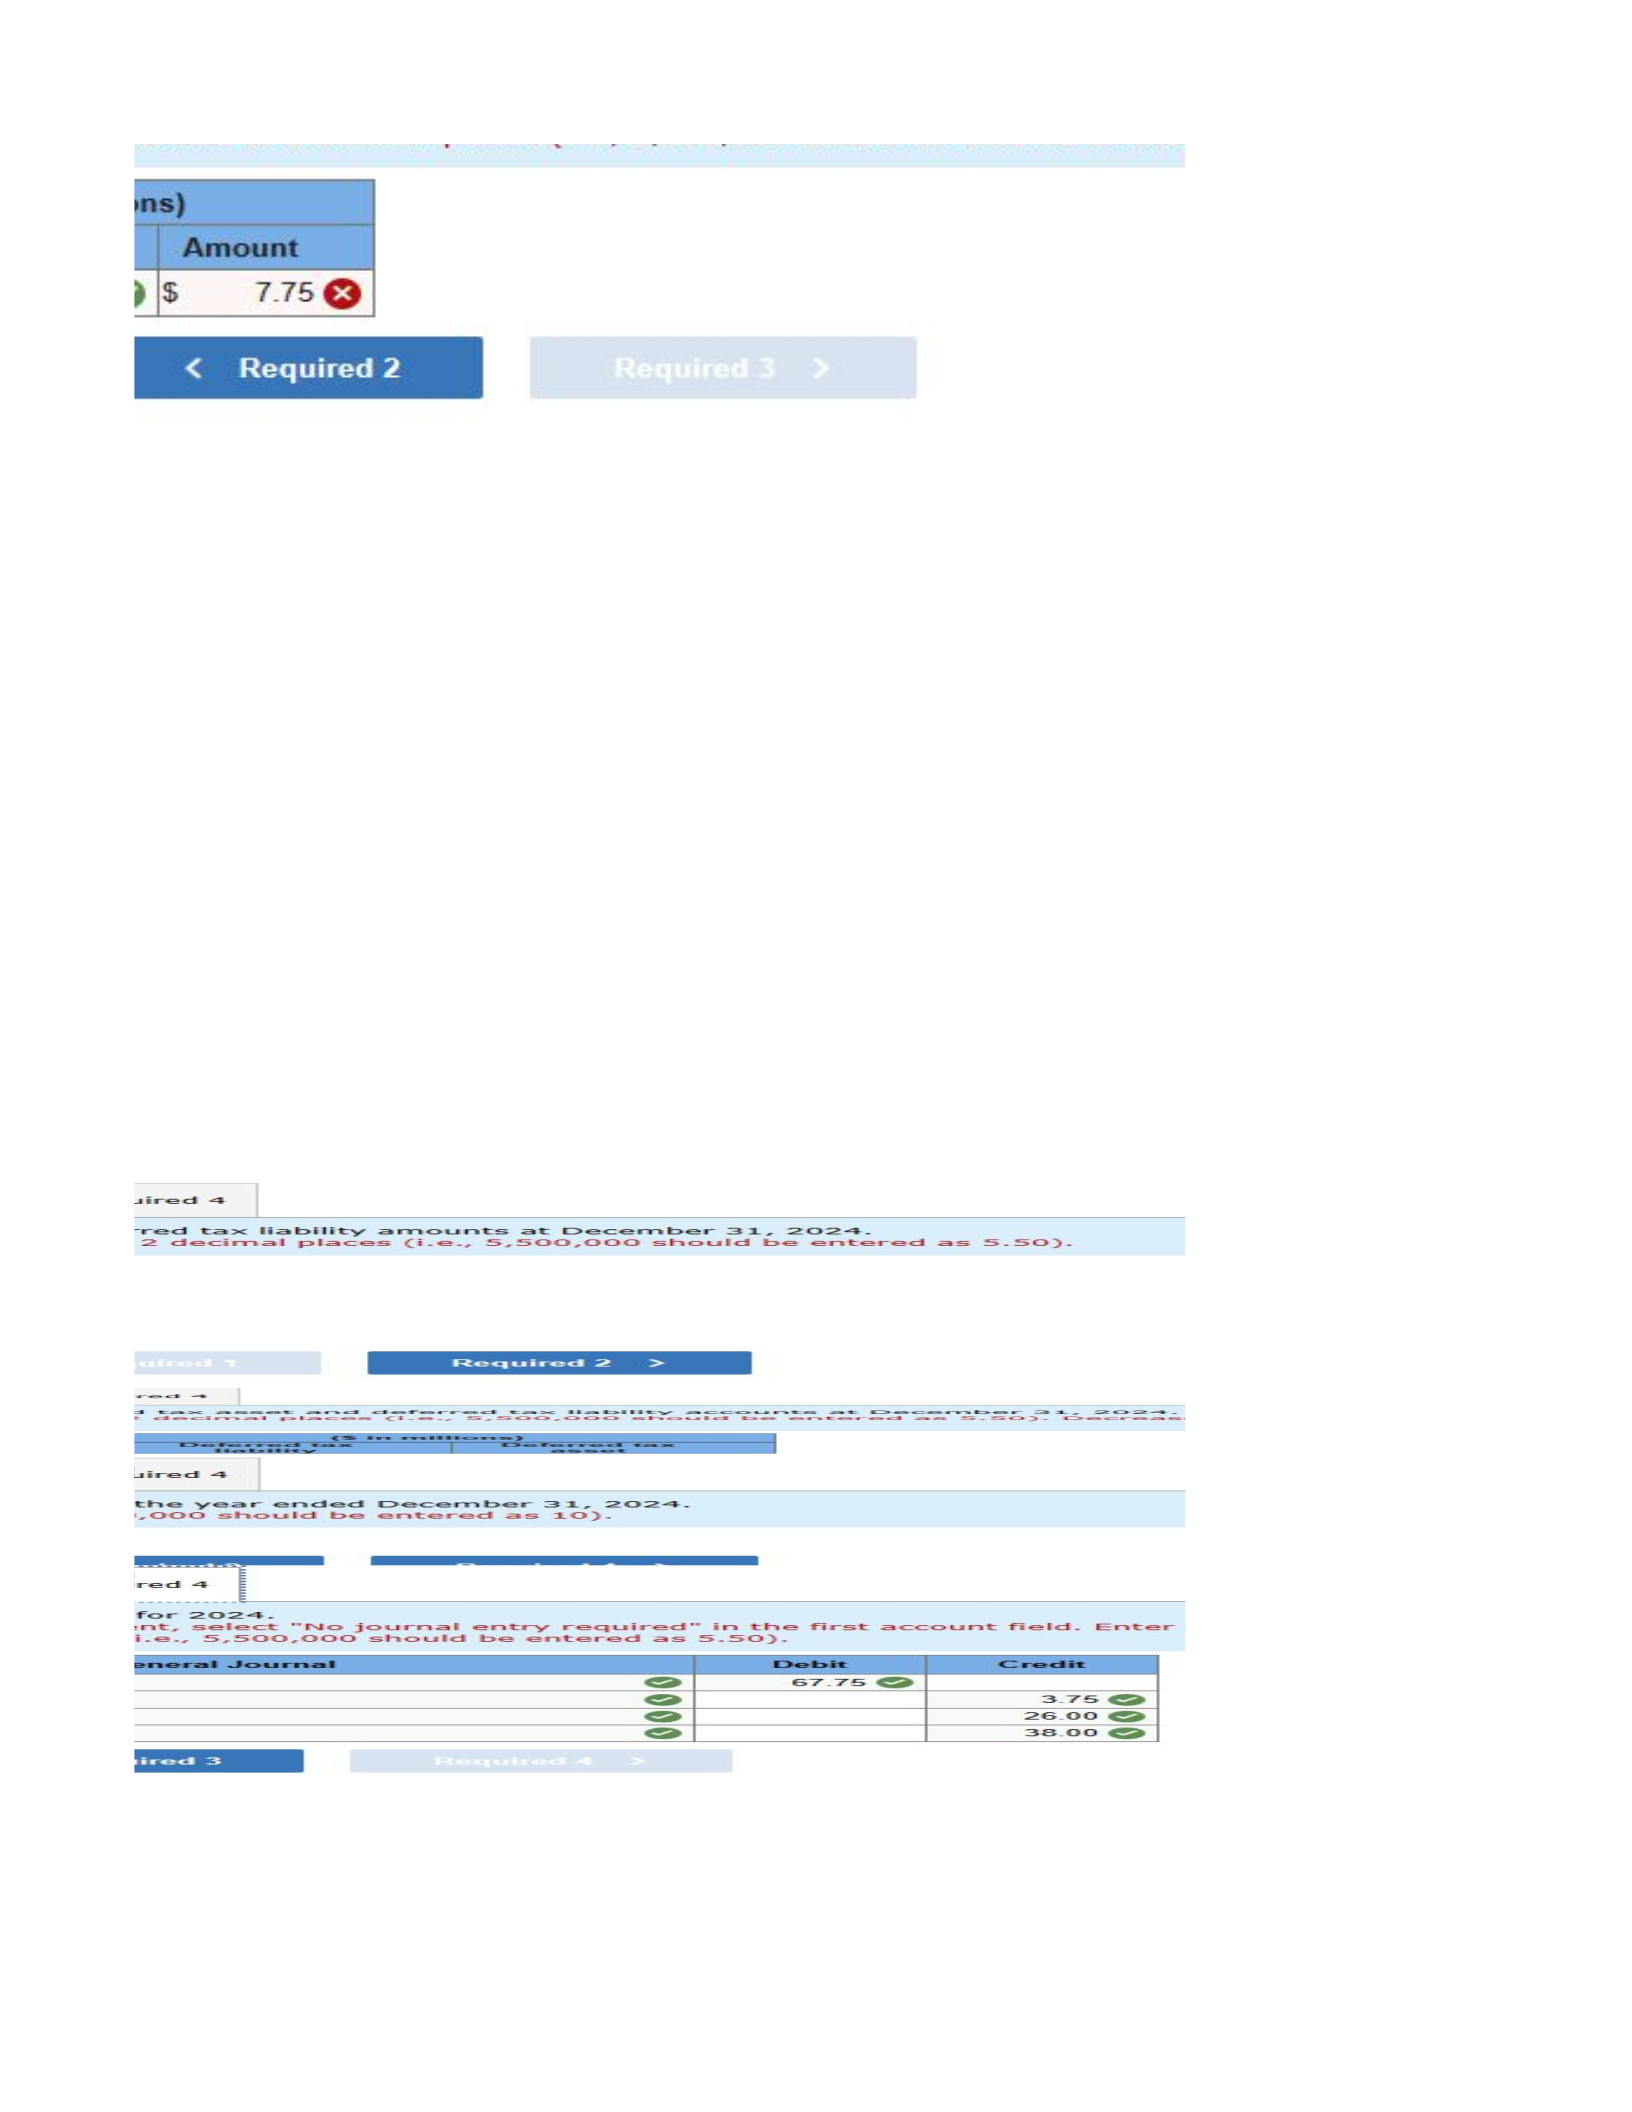
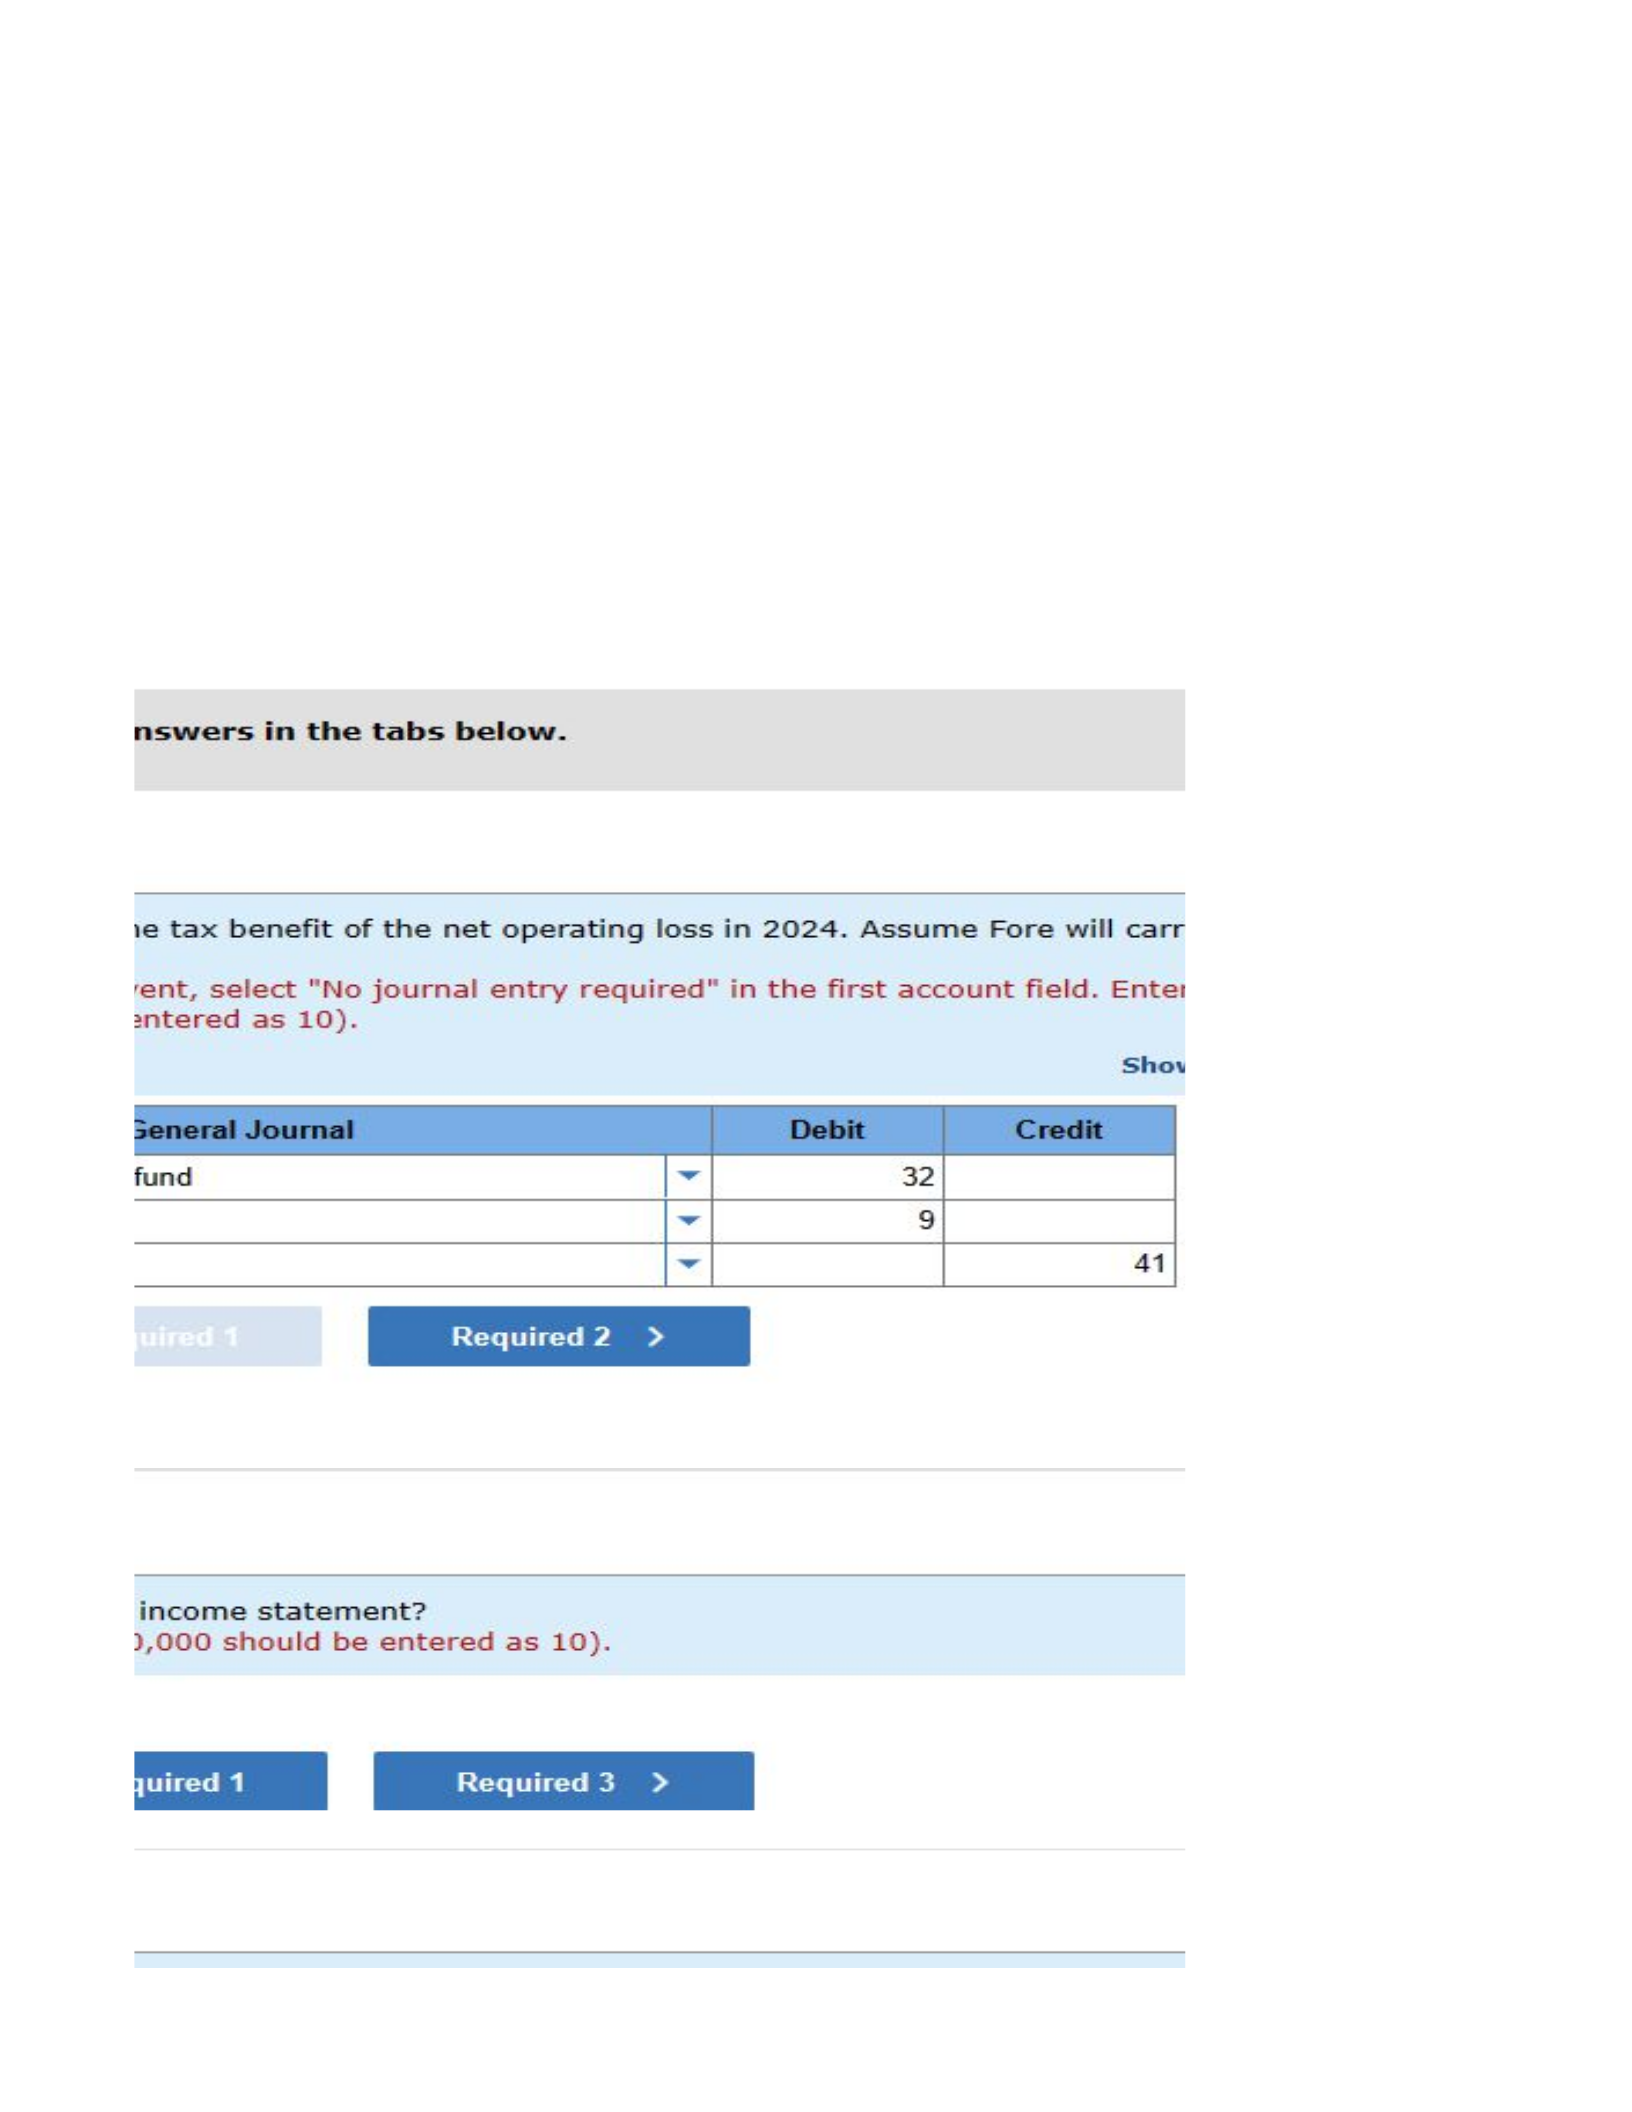
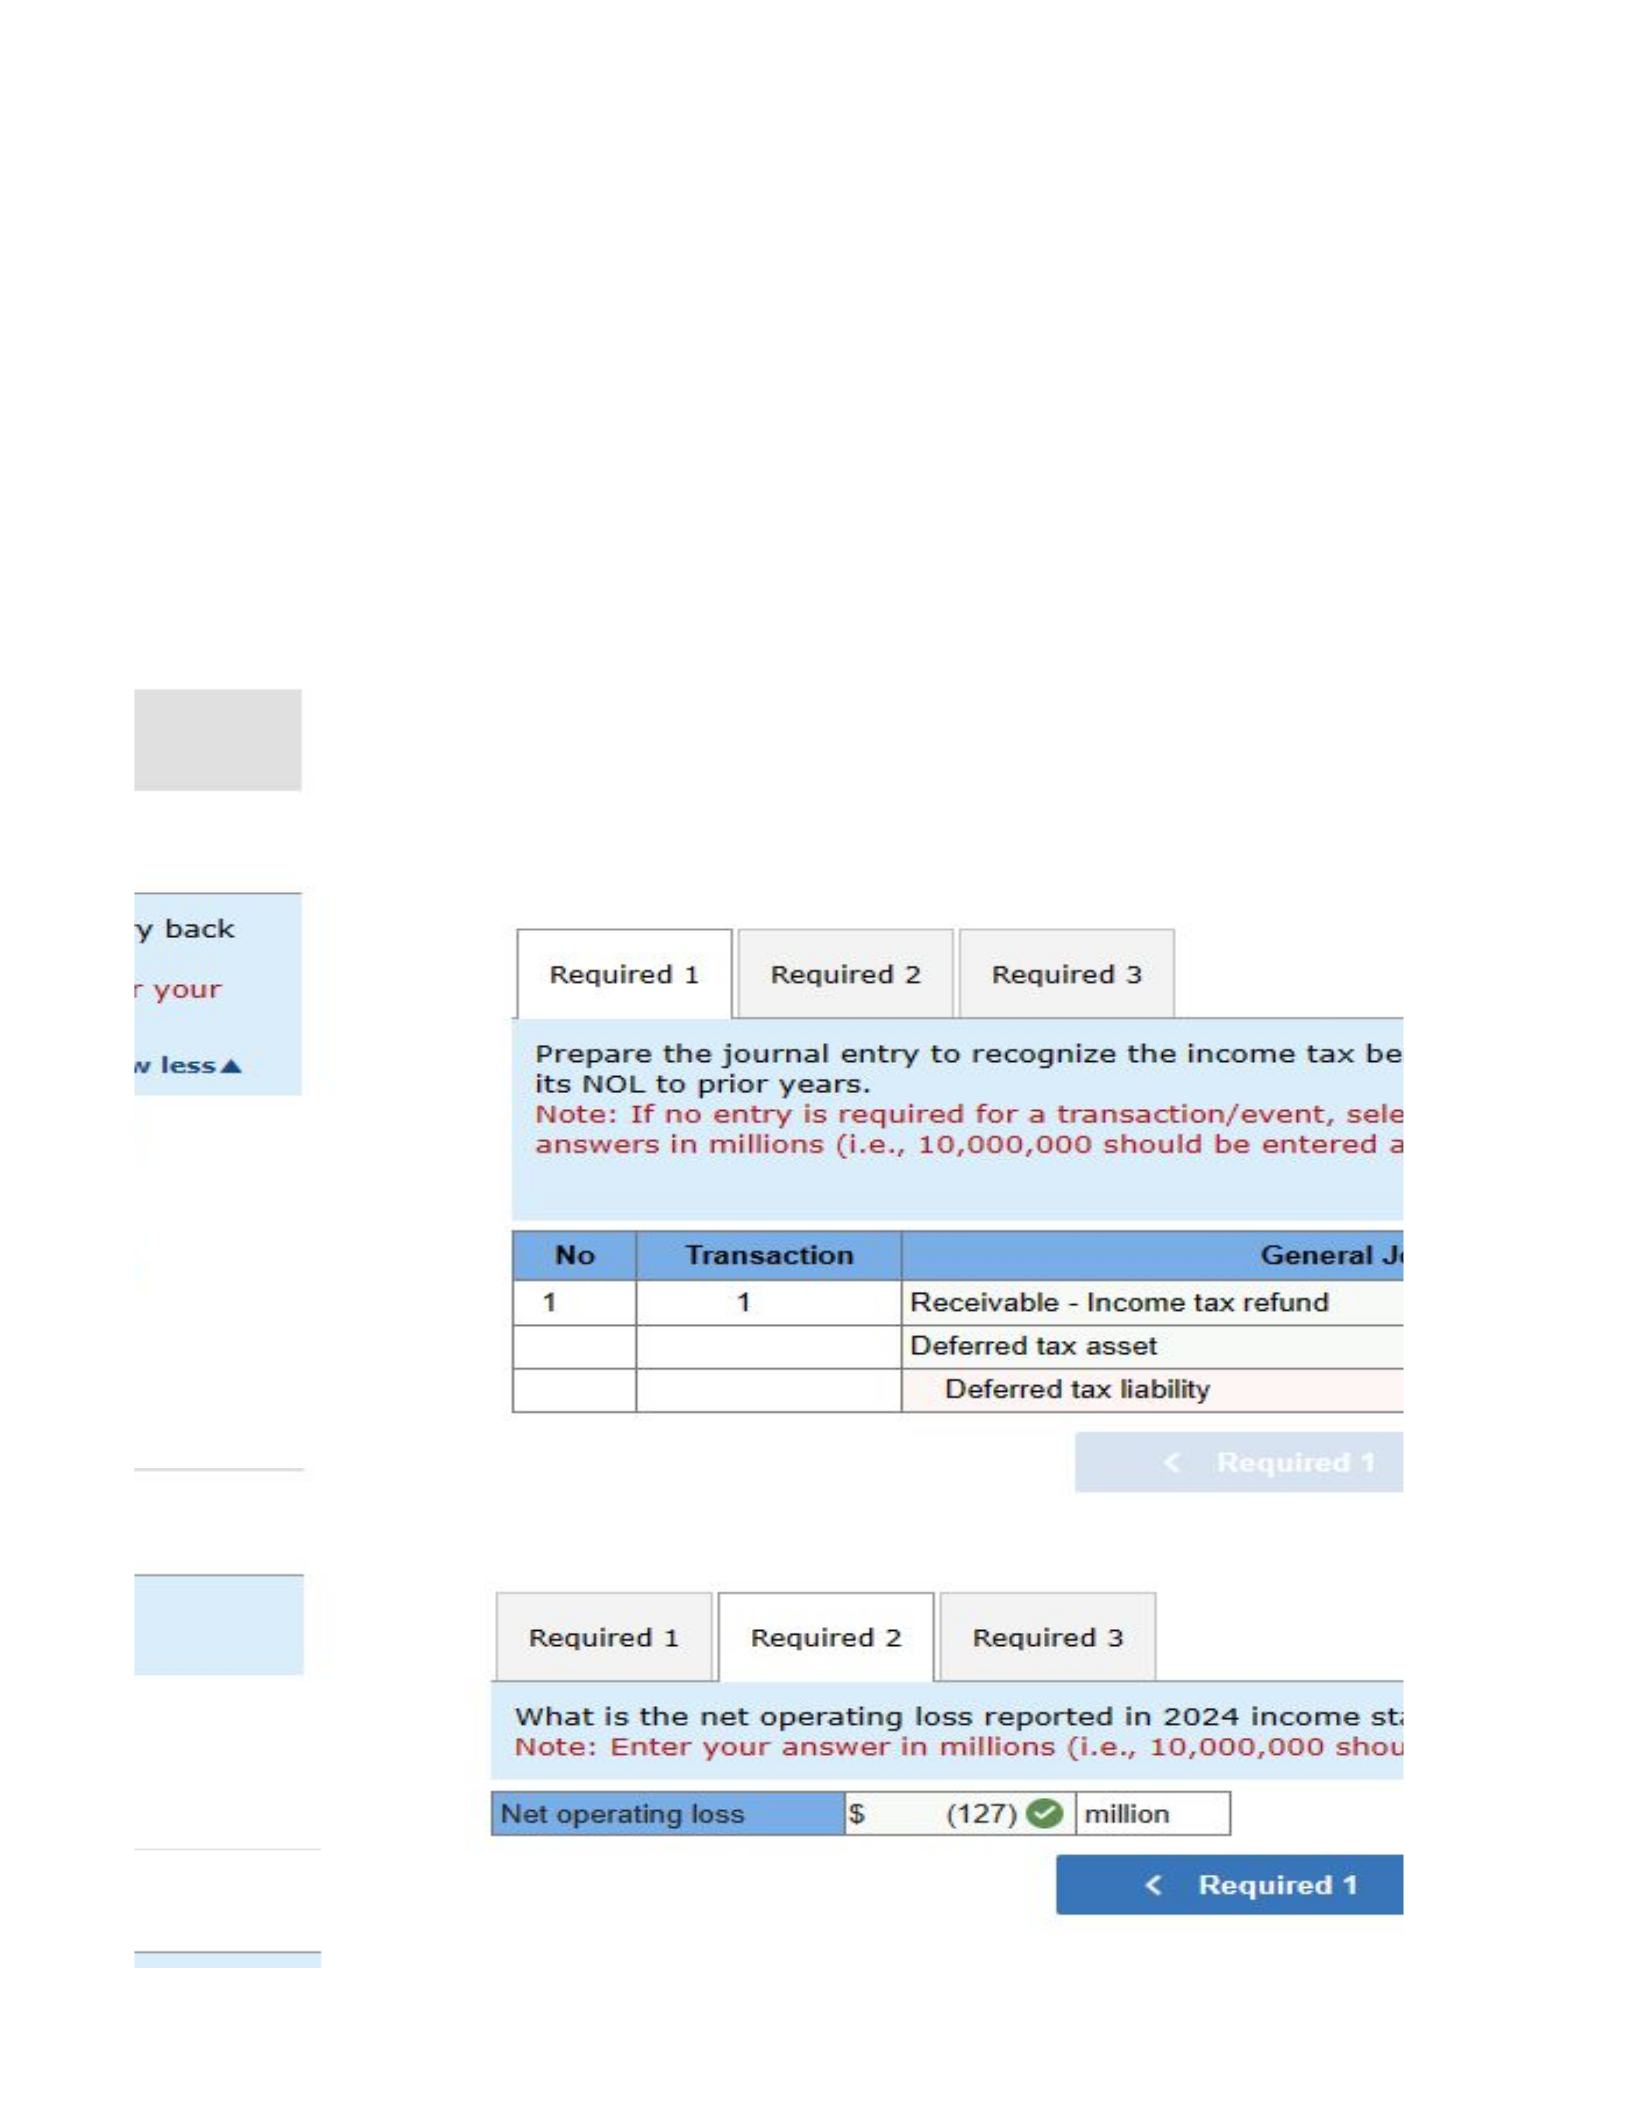
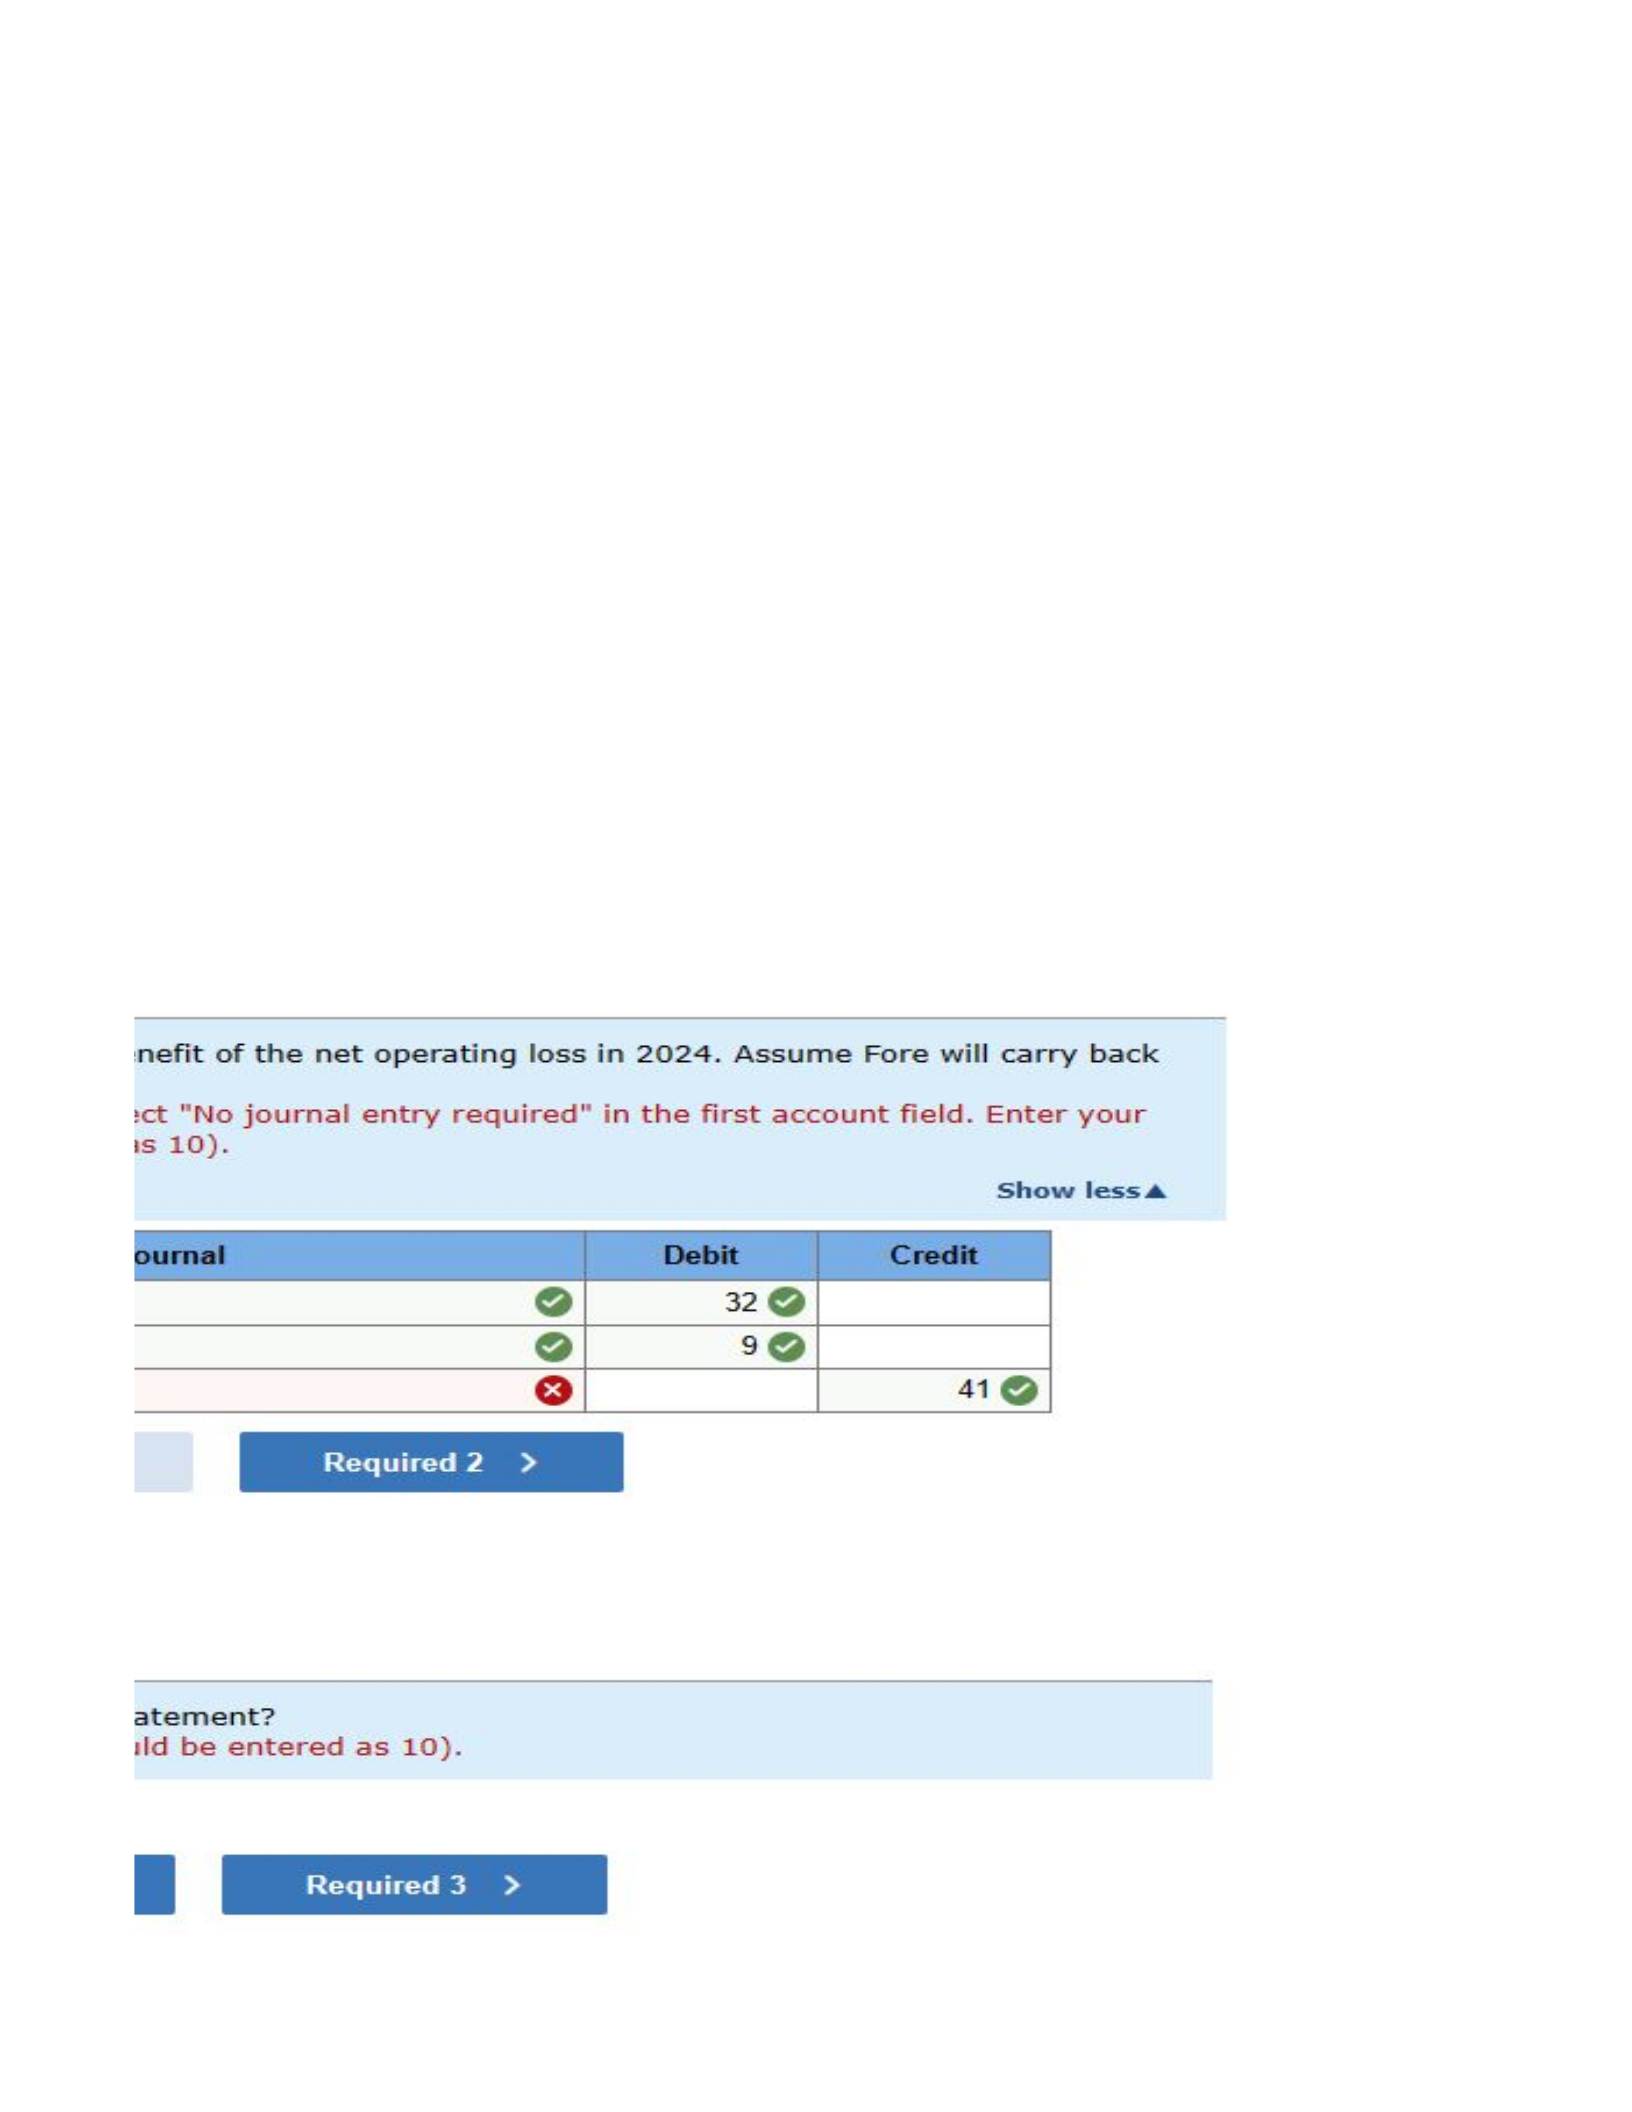
1. Prepare the journal entry to recognize the income tax benefit of the net operating loss in 2024. Assume Fore will carry back its NOL to prior years.
2. What is the net operating loss reported in 2024 income statement?
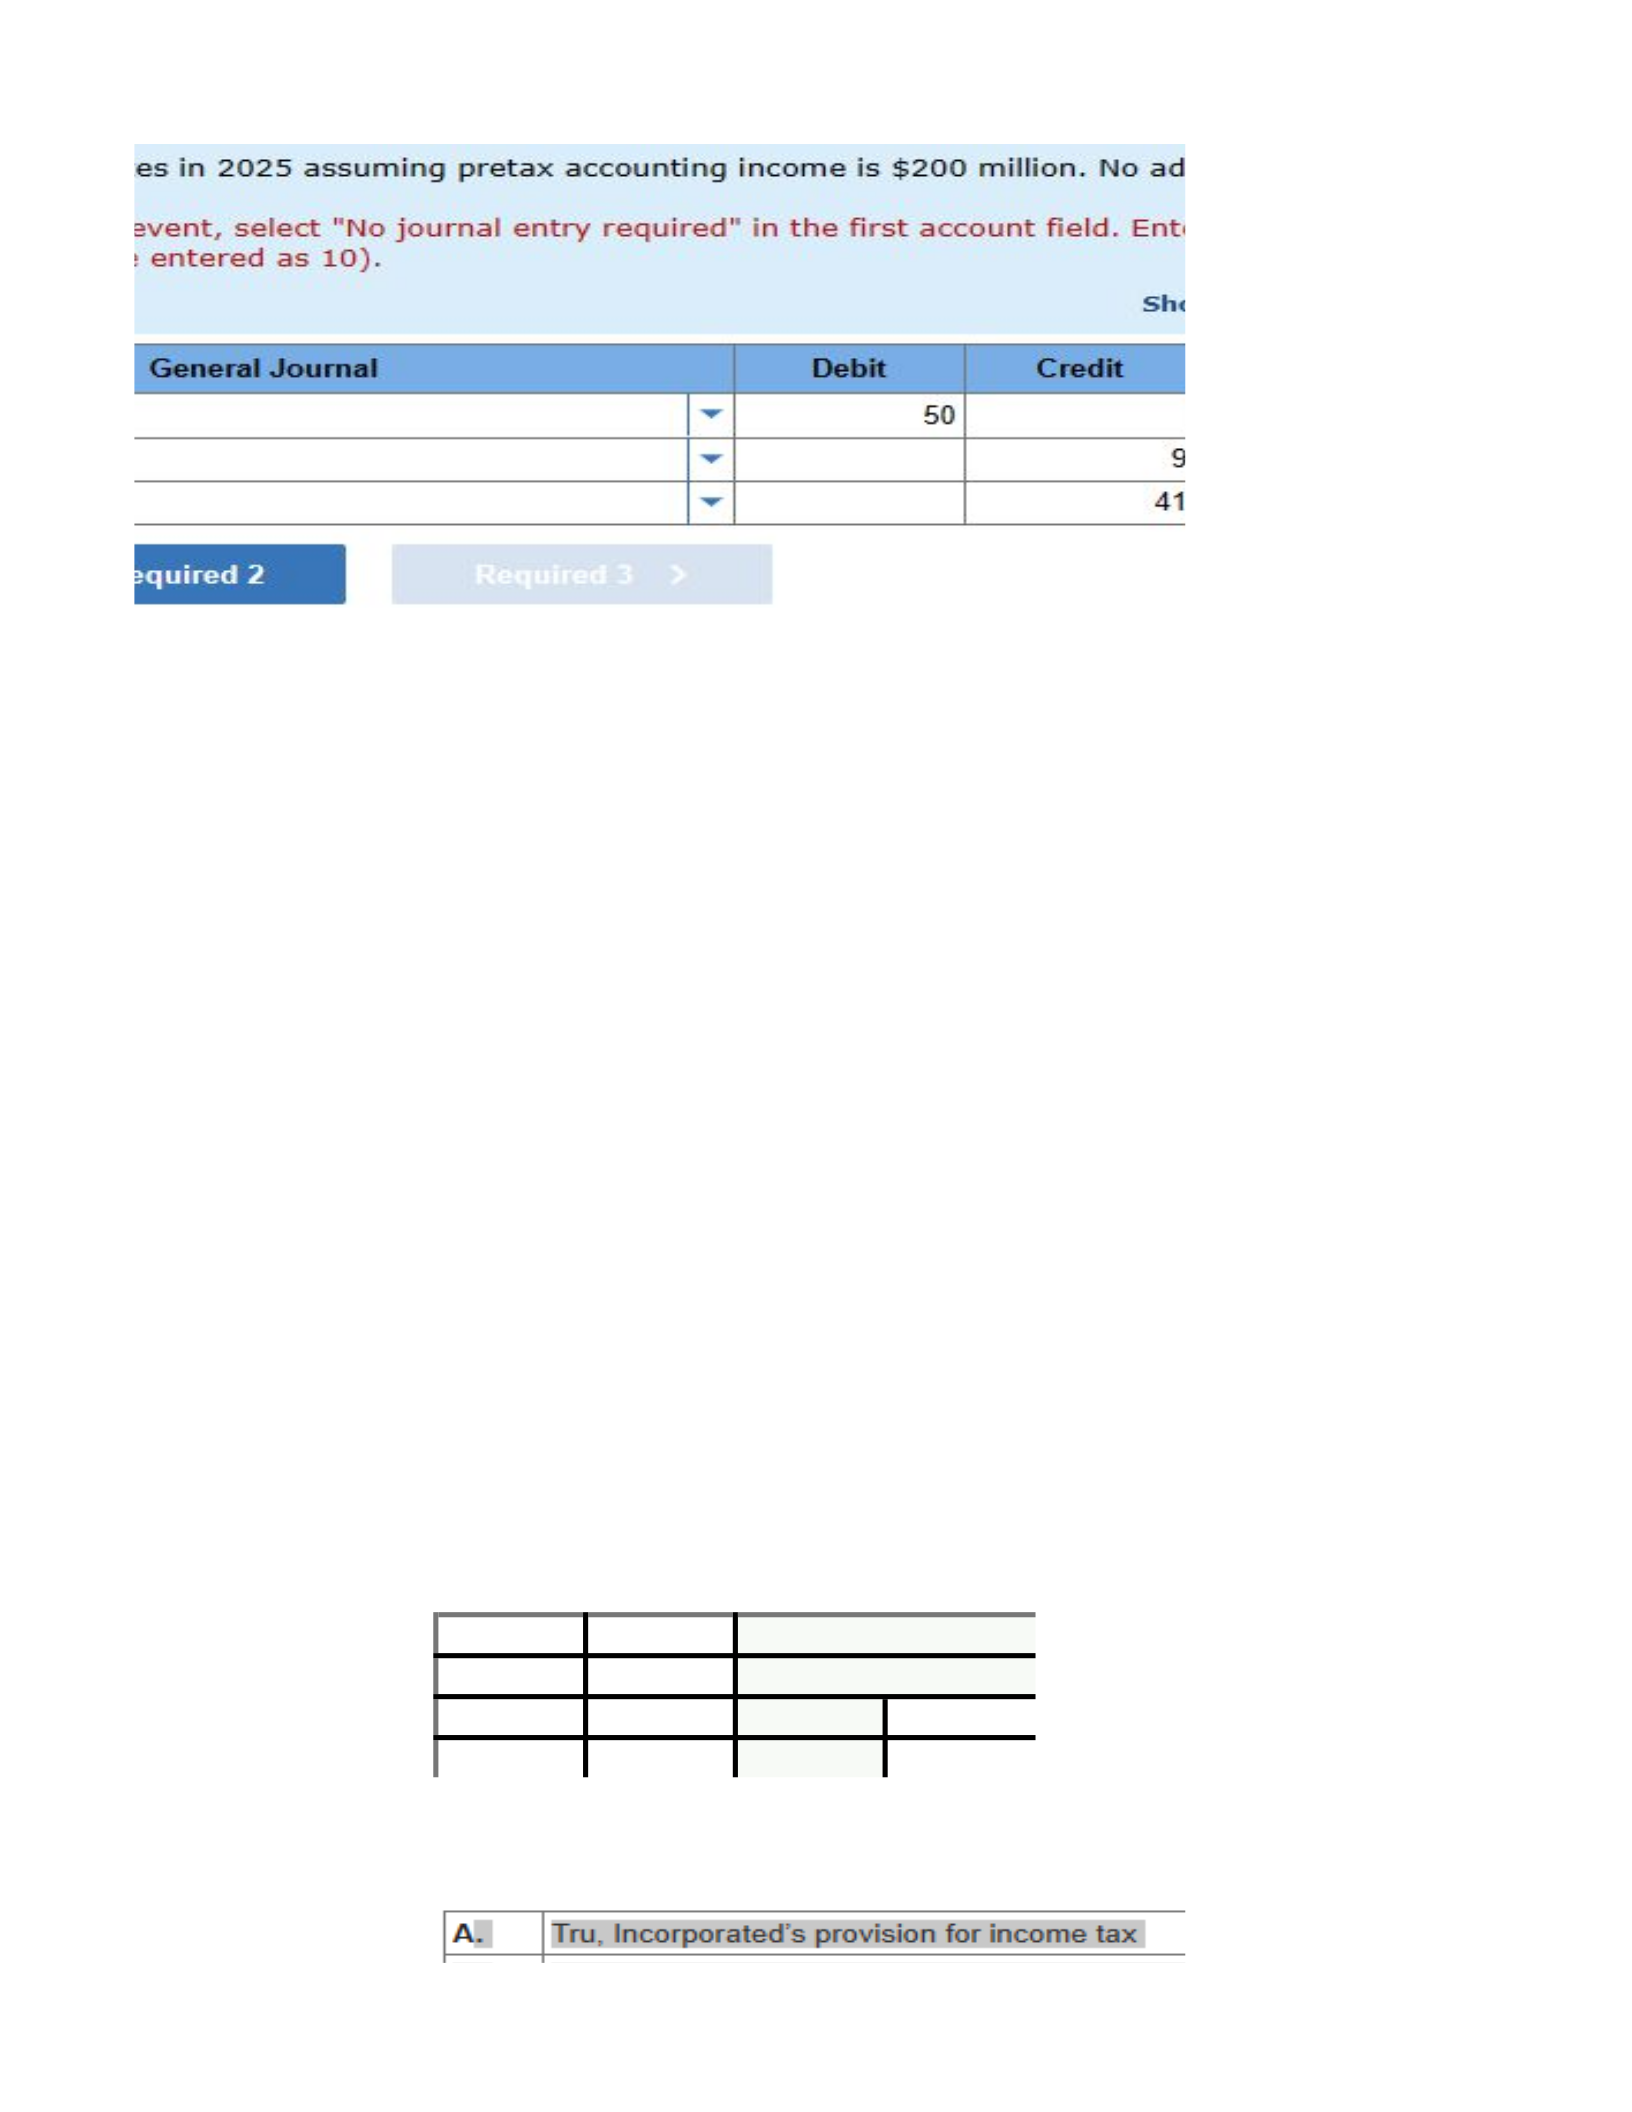
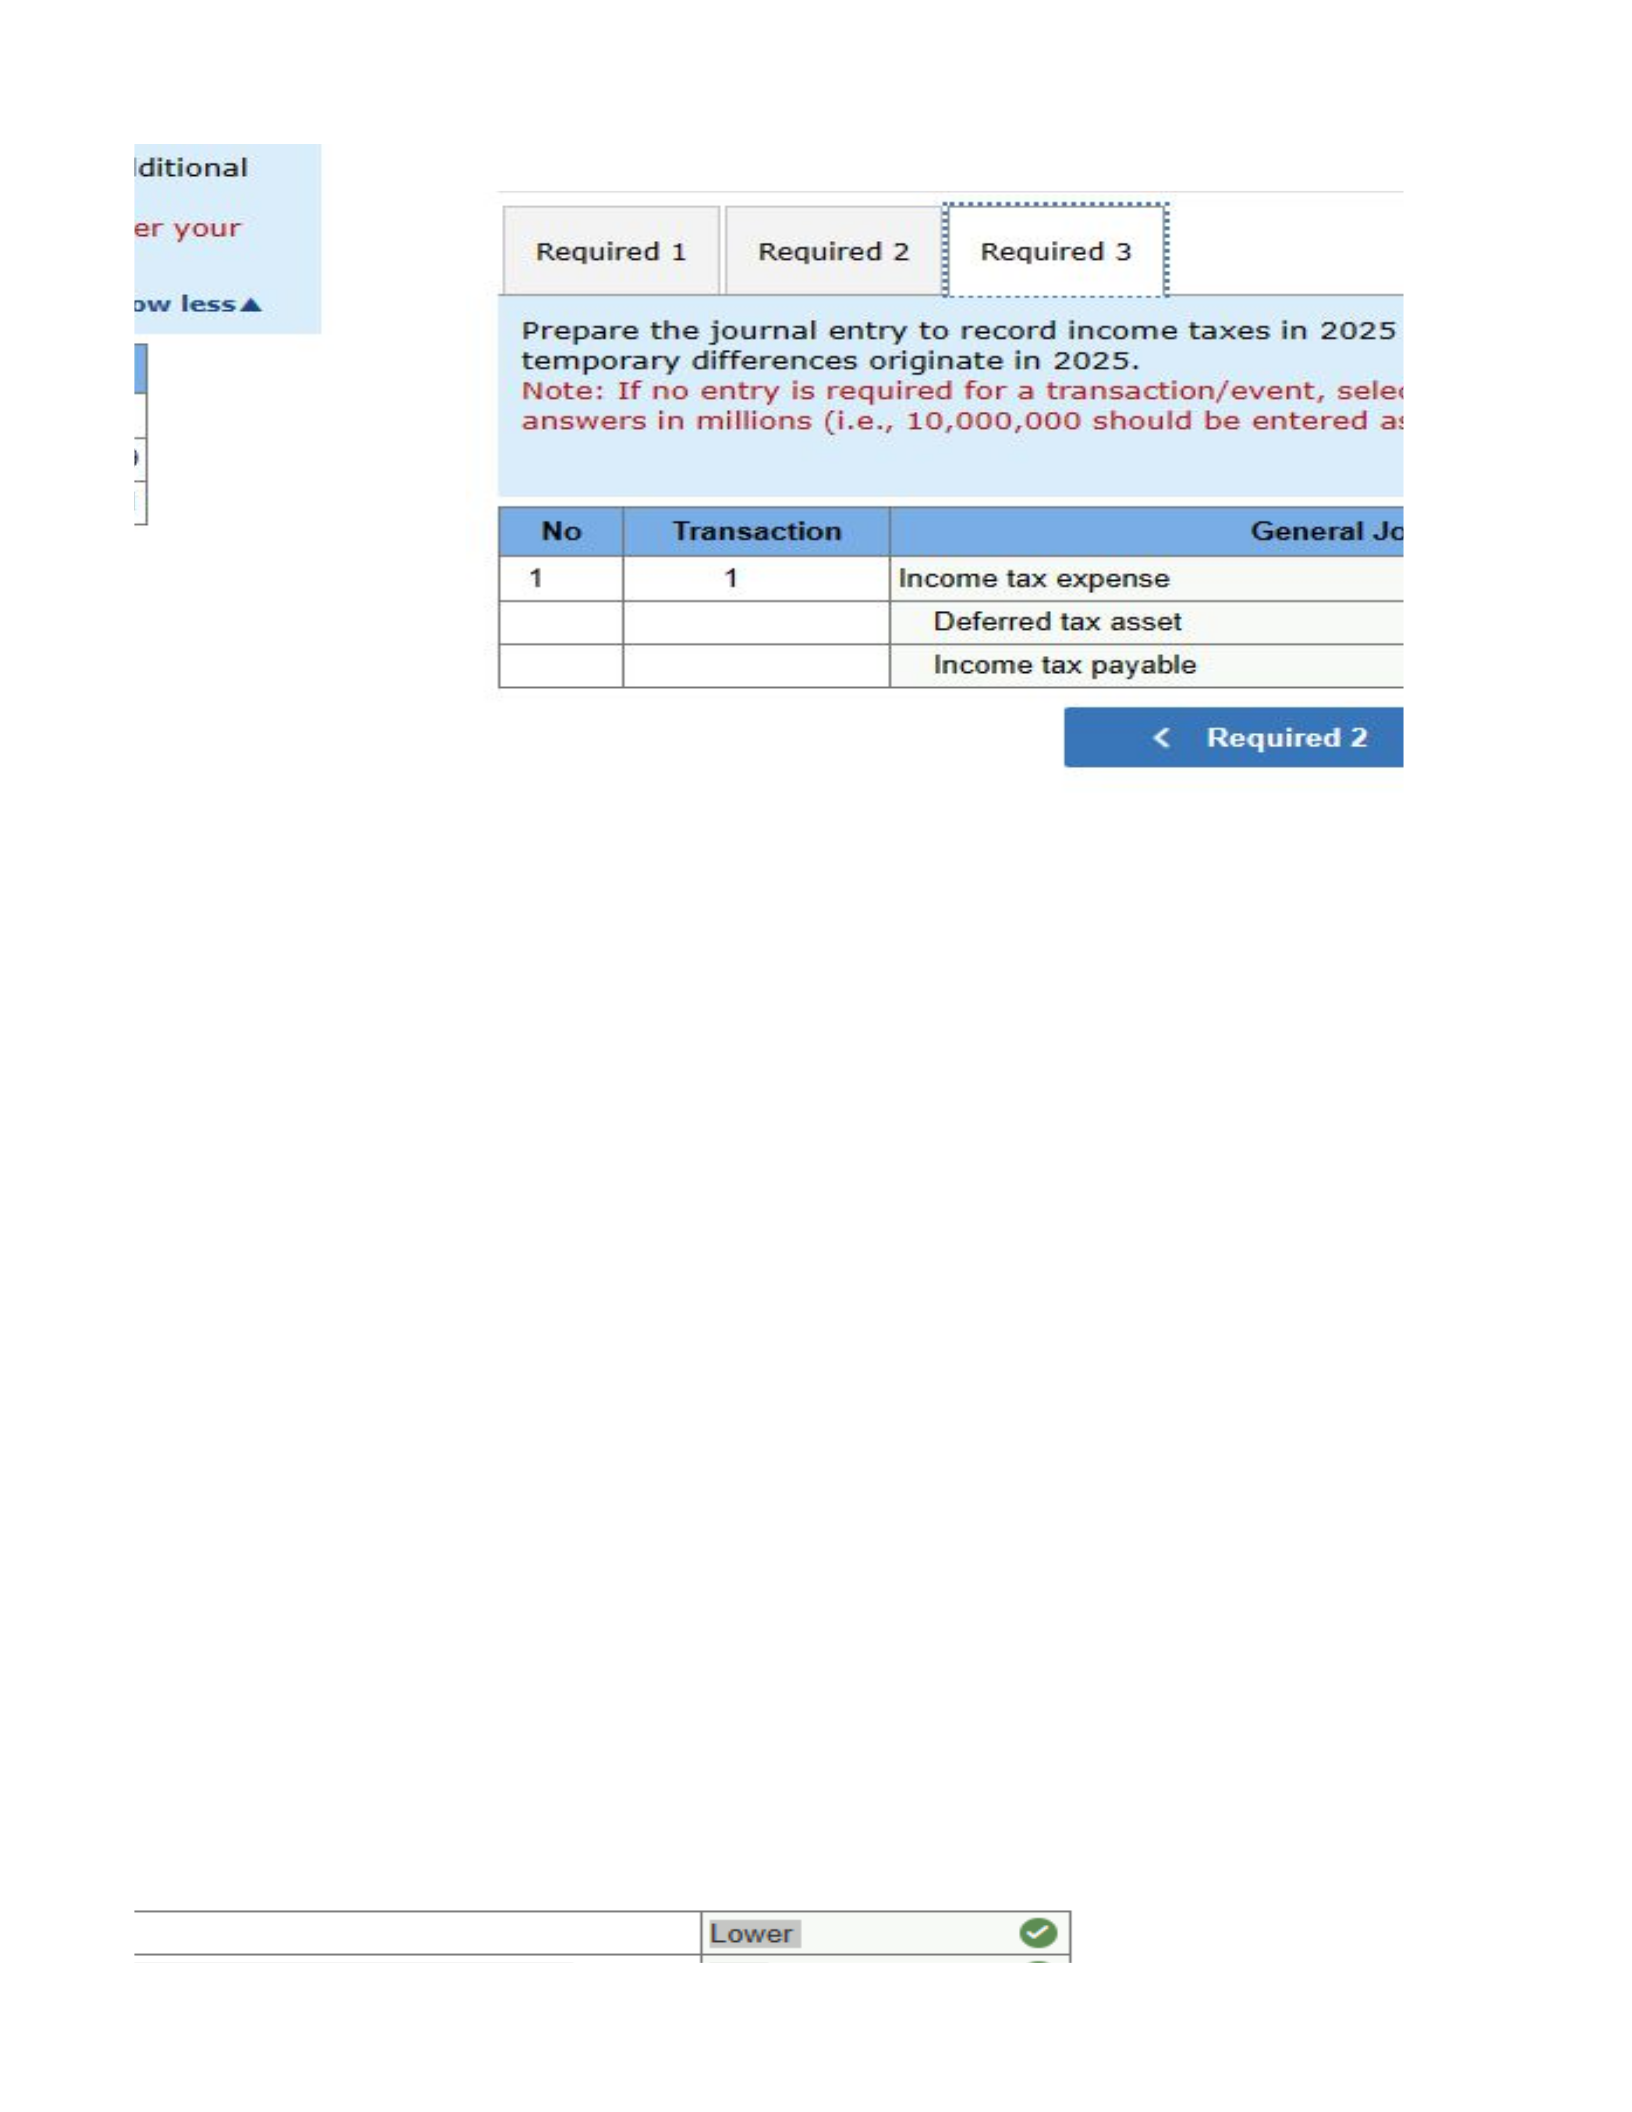
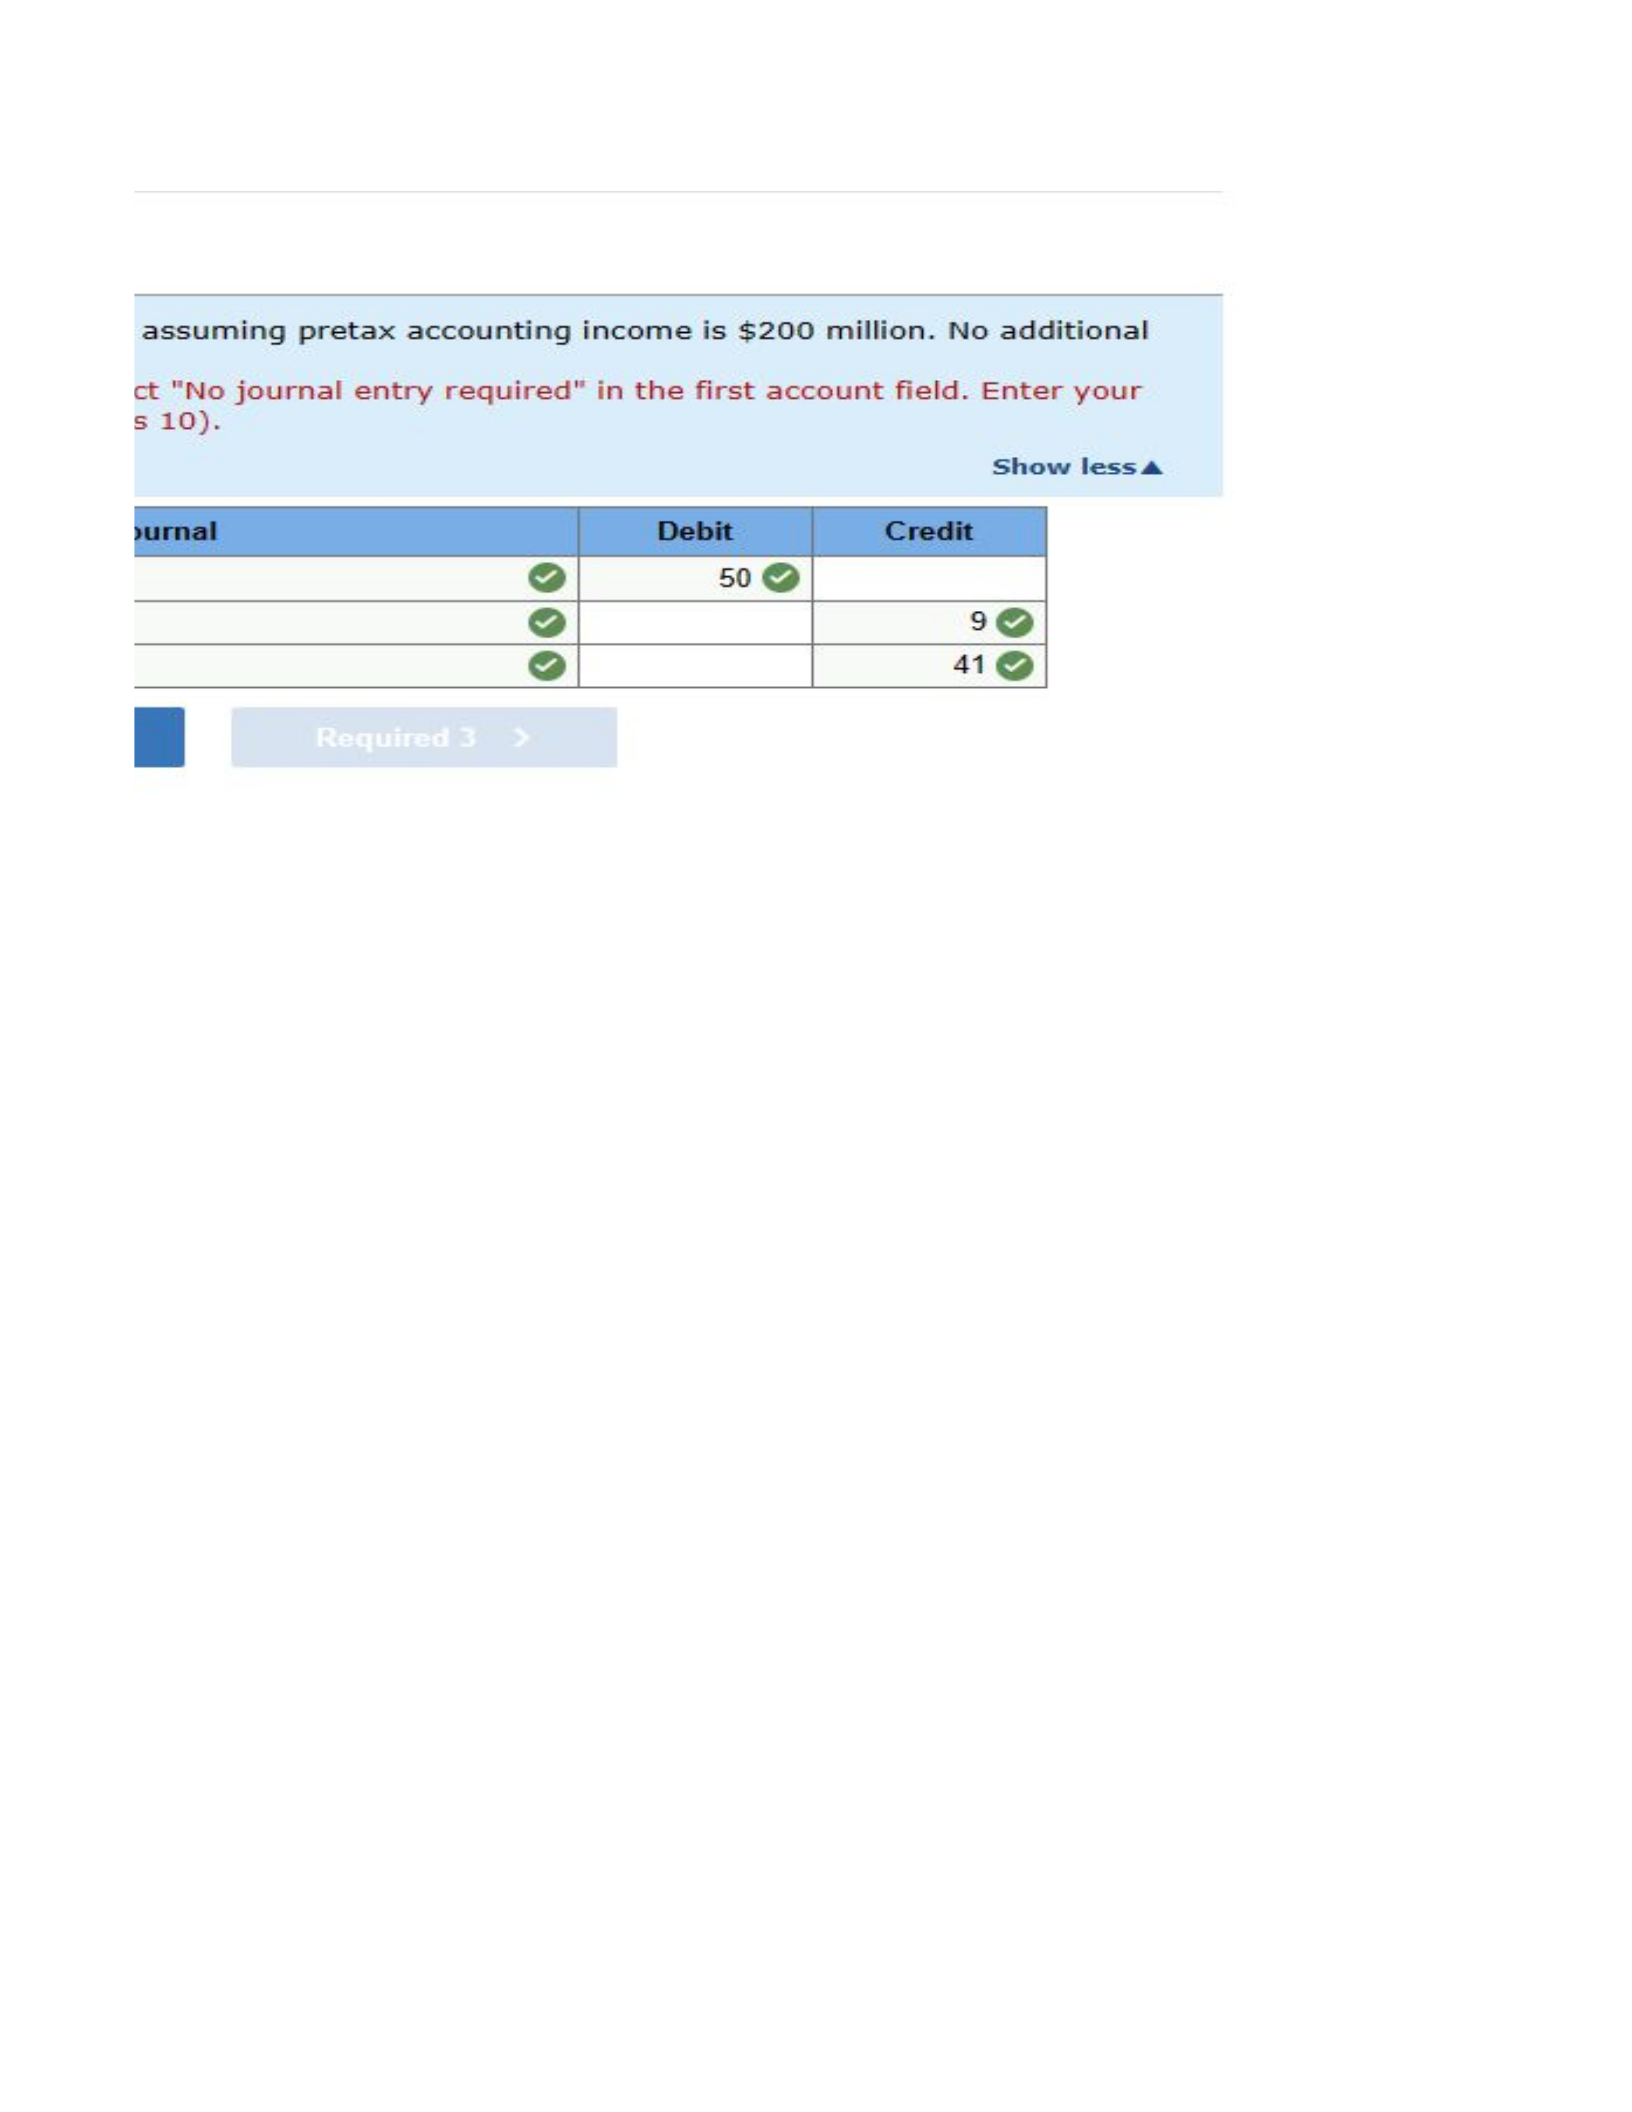
3. Prepare the journal entry to record income taxes in 2025 assuming pretax accounting income is $200 million. No additional temporary differences originate in 2025.
Explanation
1. NOL carrybacks are not allowed for most companies, except for property and casualty insurance companies as well as some farm-related businesses. Here, we are told that Fore is one of those businesses, and that it elects an NOL carryback option.
($ in millions) Prior Years
Current Year 2024
2022 2023
Accounting loss ($168)
Permanent difference:
Federal fine not deductible 4
Temporary differences:
Loss contingency 20
Taxable loss -144
NOL carryback ($76) ($52) 128
NOL carryforward 16
0
Enacted tax rate 25% 25% 25%
Tax payable (refundable) ($19) ($13) $0
Deferred tax asset
Deferred Tax Asset
Debit Credit
0
9
9
Step 1: Tax payable (receivable): $(32)
Step 2: Deferred tax asset end balance: $9
Step 3: Deferred tax asset change: $9
Step 4: Tax expense (benefit) plug: $41
2. ($ in millions)
Operating loss before income taxes ($168)
Income tax benefit:
Tax refund from NOL carryback $32
Tax savings from NOL carryforward
9 41
Net loss ($127)
3. ($ in millions)
Current Year 2025
Future Deductible Amounts
Pretax accounting income $200
Temporary differences:
Loss contingency -20
NOL carryforward -16
Taxable income (income tax return)
164 $0
Enacted tax rate 25% 25%
Tax payable $41
Deferred tax asset $0
Deferred Tax Asset
Debit Credit
9
9
0
Step 1: Tax payable: $41
Step 2: Deferred tax asset end balance: $0
Step 3: Deferred tax asset change: $(9)
Step 4: Tax expense plug: $50
Deferred Taxes and the Tax Cuts and Jobs Act of 2017 [LO16-4]
In the prior chapters’ Applying Tableaus, you examined two (hypothetical) publicly traded companies, GPS Corporation and Tru, Incorporated, as to their pattern of leasing facilities, their transition to the new lease accounting standard in 2019, and the effect of that transition on debt covenants. In this case, you examine the effect of the Tax Cuts and Jobs Act of 2017 on these companies’ operations and financial position.
Tableau Instructions:
For this case, you will create calculations to determine the effective tax rate so you can compare and contrast the effect of the 2017 Tax Act on the two companies.
Follow these steps to create the charts you’ll use for this case:
1. Download the Excel file “GPS_Tru_Financials.”
2. Open Tableau and connect to the Excel file.
3. Click on the Sheet 1 tab, at the bottom of the canvas, to the right of the Data Source at the bottom of the screen. Drag “Company” and “Year” to the Columns shelf. Change “Year” to
4. Drag “Provision for income tax” and “Deferred income taxes” under Measure Names into the Rows shelf.
5. Add labels to the bars by clicking on "Label" under the Marks card and clicking the box "Show mark labels." Format the labels according to preference and, if desired, edit the color of the years on the "Marks card" by dragging "Year" from tables (not columns) on to the Color Marks card.
6. Change the title of the sheet to be "Provision for Income Taxes and Deferred Tax Liability Trend 2012–2021" by double-clicking the tab at the bottom of the page and typing the new title.
7. Click on the New Worksheet tab on the lower left (“Sheet 2” should open) and follow the procedure outlined above for the company and year. Drag "Provision for income taxes" and "Income from continuing operations" under Measure Names into the Rows shelf. Change each to discrete by right-clicking and selecting "Discrete."
8. Create a calculated field by clicking the "Analysis" tab at the top of the screen and selecting "Create Calculated Field." Name the calculation "Effective Tax Rate." In the Calculation Editor window, drag "Provision for income taxes" and type a division sign. Then type "(", drag "Income from continuing operations," type an addition sign, drag "Provision for income taxes," and type ")" from the Rows shelf. Make sure the calculation is valid and click OK.
9. Drag the newly created "Effective Tax Rate" to the Rows shelf. Click on the "Show Me" and select "side-by-side bars." Add labels to the bars by clicking on "Label" under the Marks card and clicking the box "Show mark labels." Format the labels according to preference and edit the color on the Marks card if desired. If you want to see a line chart instead of the bars, click on Automatic under the Marks card and select Line.
10. Change the marks to percentages by right-clicking on AGG(Effective Tax Rate) in the Rows Shelf and clicking Format. When the format bar appears on the left, choose Pane. Under default, format the number as Percentage with 2 decimal places.
11. Change the title of the sheet to be "Effect of the Tax Cuts and Jobs Act of 2017" by double-clicking the tab at the bottom of the page and typing the new title.
12. Format all other labels according to preference.
13. Save your work.
Required:
Based upon your output, answer the following questions:
A. Is Tru, Incorporated’s provision for income tax (a) higher, (b) lower, or (c) roughly the same over the period 2018-2021 than in previous years?
B. Did Tru, Incorporated’s deferred tax liability appear to benefit from the Tax Act?
C. What is the effective tax rate for GPS in 2017?
D. What is the effective tax rate for GPS in 2018?
Explanation
Your Tableau analysis should produce the bar chart. Click here to view the bar chart 1.
Your Tableau analysis should produce the bar chart. Click here to view the bar chart 2.
A. Tru, Incorporated’s provision for income tax is lower over the period 2018-2021 than in previous years (and also for GPS Corporation). The Tax Act reduced the corporate income tax rate from 35% to 21% beginning in 2018.
B. Yes. Tru, Incorporated’s deferred tax liability appears to benefit from the Tax Act (and also for GPS Corporation). Not only did the Tax Act reduce income tax expense significantly each year, companies also benefited from remeasuring their deferred tax liabilities based on the new lower rate at which those liabilities will be paid.
C. The effective tax rate for GPS in 2017 was 35%.
D. The effective tax rate for GPS in 2018 was 21%.
Kara Fashions uses straight-line depreciation for financial statement reporting and MACRS for income tax reporting. Three years after its purchase, one of Kara’s buildings has a book value of $680,000 and a tax basis of $510,000. There were no other temporary differences and no permanent differences. Taxable income was $5 million and Kara’s tax rate is 25%.
What is the deferred tax liability to be reported in the balance sheet? Assuming that the deferred tax liability balance was $27,000 the previous year, prepare the appropriate journal entry to record income taxes this year.
Since tax depreciation to date has been $170,000 more than depreciation for financial reporting purposes, there will be fewer tax deductions for depreciation in the future, and future taxable amounts will be higher as the temporary difference reverses. This means a deferred tax liability should be reported to reflect the future tax consequences of the temporary difference. At this point, that amount is $170,000 times 25%, or $42,500.
Complete this question by entering your answers in the tabs below.
Balance Sheet
General Journal
What is the deferred tax liability to be reported in the balance sheet?
Note: Enter your answer in whole dollars.
Deferred tax liability $42,500
Shannon Polymers uses straight-line depreciation for financial reporting purposes for equipment costing $500,000 and with an expected useful life of four years and no residual value. Assume that, for tax purposes, the deduction is 40%, 30%, 20%, and 10% in those years. Pretax accounting income the first year the equipment was used was $600,000, which includes interest revenue of $10,000 from municipal governmental bonds. Other than the two described, there are no differences between accounting income and taxable income. The enacted tax rate is 25%.
Note: If no entry is required for a transaction/event, select "No journal entry required" in the first account field.
LossCo reported a net operating loss of $23 million for financial reporting and tax purposes. Taxable income last year and the previous year, respectively, was $24 million and $19 million. The enacted tax rate each year is 25%. Assume that LossCo qualifies as a type of company that is allowed to carry back an NOL to two prior taxable years, using the earliest year first.
Note: If no entry is required for a transaction/event, select "No journal entry required" in the first account field. Enter your answers in whole dollars.
NOL carrybacks are not allowed for most companies, except for property and casualty insurance companies as well as some farm-related businesses. Here, we are told that LossCo is one of those businesses, and that it carries back an NOL.
Because the net operating loss is less than the previous two years taxable income, LossCo cannot get back all taxes paid those two years. It can reduce taxable income from two years ago by $19 million (to zero) and last year’s taxable income by $4 million and get a refund of $5.75 million of the taxes paid those years.
No Transaction General
Journal
Debit
1 1
Receivable—Income tax refundselected answer correct
5,750,000selected answer correct
Income tax expenseselected answer correct
not attempted
Southeast Airlines had pretax earnings of $55 million. Included in this amount is income from discontinued operations of $10 million. The company’s tax rate is 25%.
What is the amount of income tax expense that Southeast would report in its income statement for continuing operations?
Note: Enter your answer in millions rounded to 2 decimal place (i.e., i.e., 5,500,000 should be entered as 5.50). Amount to be deducted should be indicated with a minus sign.
Intraperiod tax allocation means the total income tax obligation for a reporting period is allocated among the income statement items that gave rise to the income tax. The following items should be reported net of their respective income tax effects:
Southeast Airlines had income from continuing operations of $45 million before the income from discontinued operations of $10 million. Since the company’s tax rate is 25%, the amount of income tax expense that Southeast should report as part of income from continuing operations is $45 million × 25%, or $11.25 million. The income from discontinued operations should be reported
($ in millions)
Income from continuing operations before tax
$45.00selected answer correct
Income tax expense
(11.25)selected answer correct
Income from continuing operations
0
Income from discontinued operations
7.50selected answer correct
Net income 0
Lance Lawn Services reports warranty expense by estimating the amount that eventually will be paid to satisfy warranties on its product sales. For tax purposes, the expense is deducted when the warranty work is completed. At December 31, 2024, Lance has a warranty liability of $2 million and taxable income of $75 million. At December 31, 2023, Lance reported a deferred tax asset of $459,000 related to this difference in reporting warranties; it’s only temporary difference. The enacted tax rate is 25% each year.
Note: If no entry is required for a transaction/event, select "No journal entry required" in the first account field. Enter your answers in whole dollars.
No Transactio
n
General
Journal
1 1
Income tax expenseselected answer correct
Deferred tax assetselected answer correct
Income tax payableselected answer correct
Southern Atlantic Distributors began operations in January 2024 and purchased a delivery truck for $40,000. Southern Atlantic plans to use straight-line depreciation over a four-year expected useful life for financial reporting purposes. For tax purposes, the deduction is 50% of cost in 2024, 30% in 2025, and 20% in 2026. Pretax accounting income for 2024 was $200,000, which includes interest revenue of $28,000 from municipal governmental bonds. The enacted tax rate is 25%.
Assuming no differences between accounting income and taxable income other than those described above:
Required 1 Calculation
General Journal
Required 2
Complete the following table to record income taxes in 2024.
Note: Amounts to be deducted should be indicated with a minus sign. Enter your answers in whole dollars.
Tax $
Recorded as:
Description
Pretax accounting income
Permanent difference
= $ 2,500.0
Deferred tax liability
Income subject to taxation
= $ 40,500.0
Income tax payable
Temporary difference
Income taxable in current year
General Journal
Required 2
Prepare the journal entry to record income taxes in 2024.
Note: If no entry is required for a transaction/event, select "No journal entry required" in the first account field. Enter your answers in whole dollars.
No
Transaction
1 1
Required 2
What is Southern Atlantic’s 2024 net income?
Note: Enter your answer in whole dollar.
Net income
a. At December 31, 2024, temporary differences were associated with the following future taxable (deductible) amounts:
c. Pretax accounting income was $43,000 and taxable income was $8,000 for the year ended December 31, 2024.
Complete the following table given below and prepare the appropriate journal entry to record income taxes for 2024.
Sherrod, Incorporated, reported pretax accounting income of $68 million for 2024. The following information relates to differences between pretax accounting income and taxable income:
a. Income from installment sales of properties included in pretax accounting income in 2024 exceeded that reported for tax purposes by $6 million. The installment receivable account at year-end 2024 had a balance of $8 million (representing portions of 2023 and 2024 installment sales), expected to be collected equally in 2025 and 2026.
b. Sherrod was assessed a penalty of $4 million by the Environmental Protection Agency for violation of a federal law in 2024. The fine is to be paid in equal amounts in 2024 and 2025.
c. Sherrod rents its operating facilities but owns one asset acquired in 2023 at a cost of $56 million. Depreciation is reported by the straight-line method, assuming a four-year useful life. On the tax return, deductions for depreciation will be more than straight-line depreciation the first two years but less than straight-line depreciation the next two years ($ in millions):
d. For tax purposes, warranty expense is deducted when costs are paid. The balance of the warranty liability was $3 million at the end of 2023. Warranty expense of $5 million is recognized in the income statement in 2024. $4 million of cost is paid in 2024, and another $4 million of costs are anticipated to be paid in 2025. At December 31, 2024, the warranty liability is $4 million (after adjusting entries).
e. In 2024, Sherrod accrued an expense and related liability for estimated paid future absences of $14 million relating to the company’s new paid vacation program. Future compensation will be deductible on the tax return when actually paid during the next two years ($8 million in 2025; $6 million in 2026).
f. During 2023, accounting income included an estimated loss of $2 million from having accrued a loss contingency. The loss is paid in 2024, at which time it is tax deductible.
Balances in the deferred tax asset and deferred tax liability accounts at January 1, 2024, were $1.25 million and $1.50 million, respectively. The enacted tax rate is 25% each year.
1. Determine the amounts necessary to record income taxes for 2024, and prepare the appropriate journal entry.
Future Taxable Amounts [total]
Future Deductible Amounts [total]
$8
12
-3
($14)
20 -17
25% 25%
$5.00
($4.25)
Corning-Howell reported taxable income in 2024 of $152 million. At December 31, 2024, the reported amount of some assets and liabilities in the financial statements differed from their tax bases as indicated below:
million
million
The total deferred tax asset and deferred tax liability amounts at January 1, 2024, were $172.25 million and $25 million, respectively. The enacted tax rate is 25% each year.
2. Determine the increase (decrease) in the deferred tax asset and deferred tax liability accounts at December 31, 2024.

Fore Farms reported a pretax operating loss of $168 million for financial reporting purposes in 2024. Contributing to the loss were (a) a penalty of $4 million assessed by the Environmental Protection Agency for violation of a federal law and paid in 2024 and (b) an estimated loss of $20 million from accruing a loss contingency. The loss will be tax deductible when paid in 2025.
The enacted tax rate is 25%. There were no temporary differences at the beginning of the year and none originating in 2024 other than those described above. Taxable income in Fores’s two previous years of operation was as follows:
1. Prepare the journal entry to recognize the income tax benefit of the net operating loss in 2024. Assume Fore will carry back its NOL to prior years.
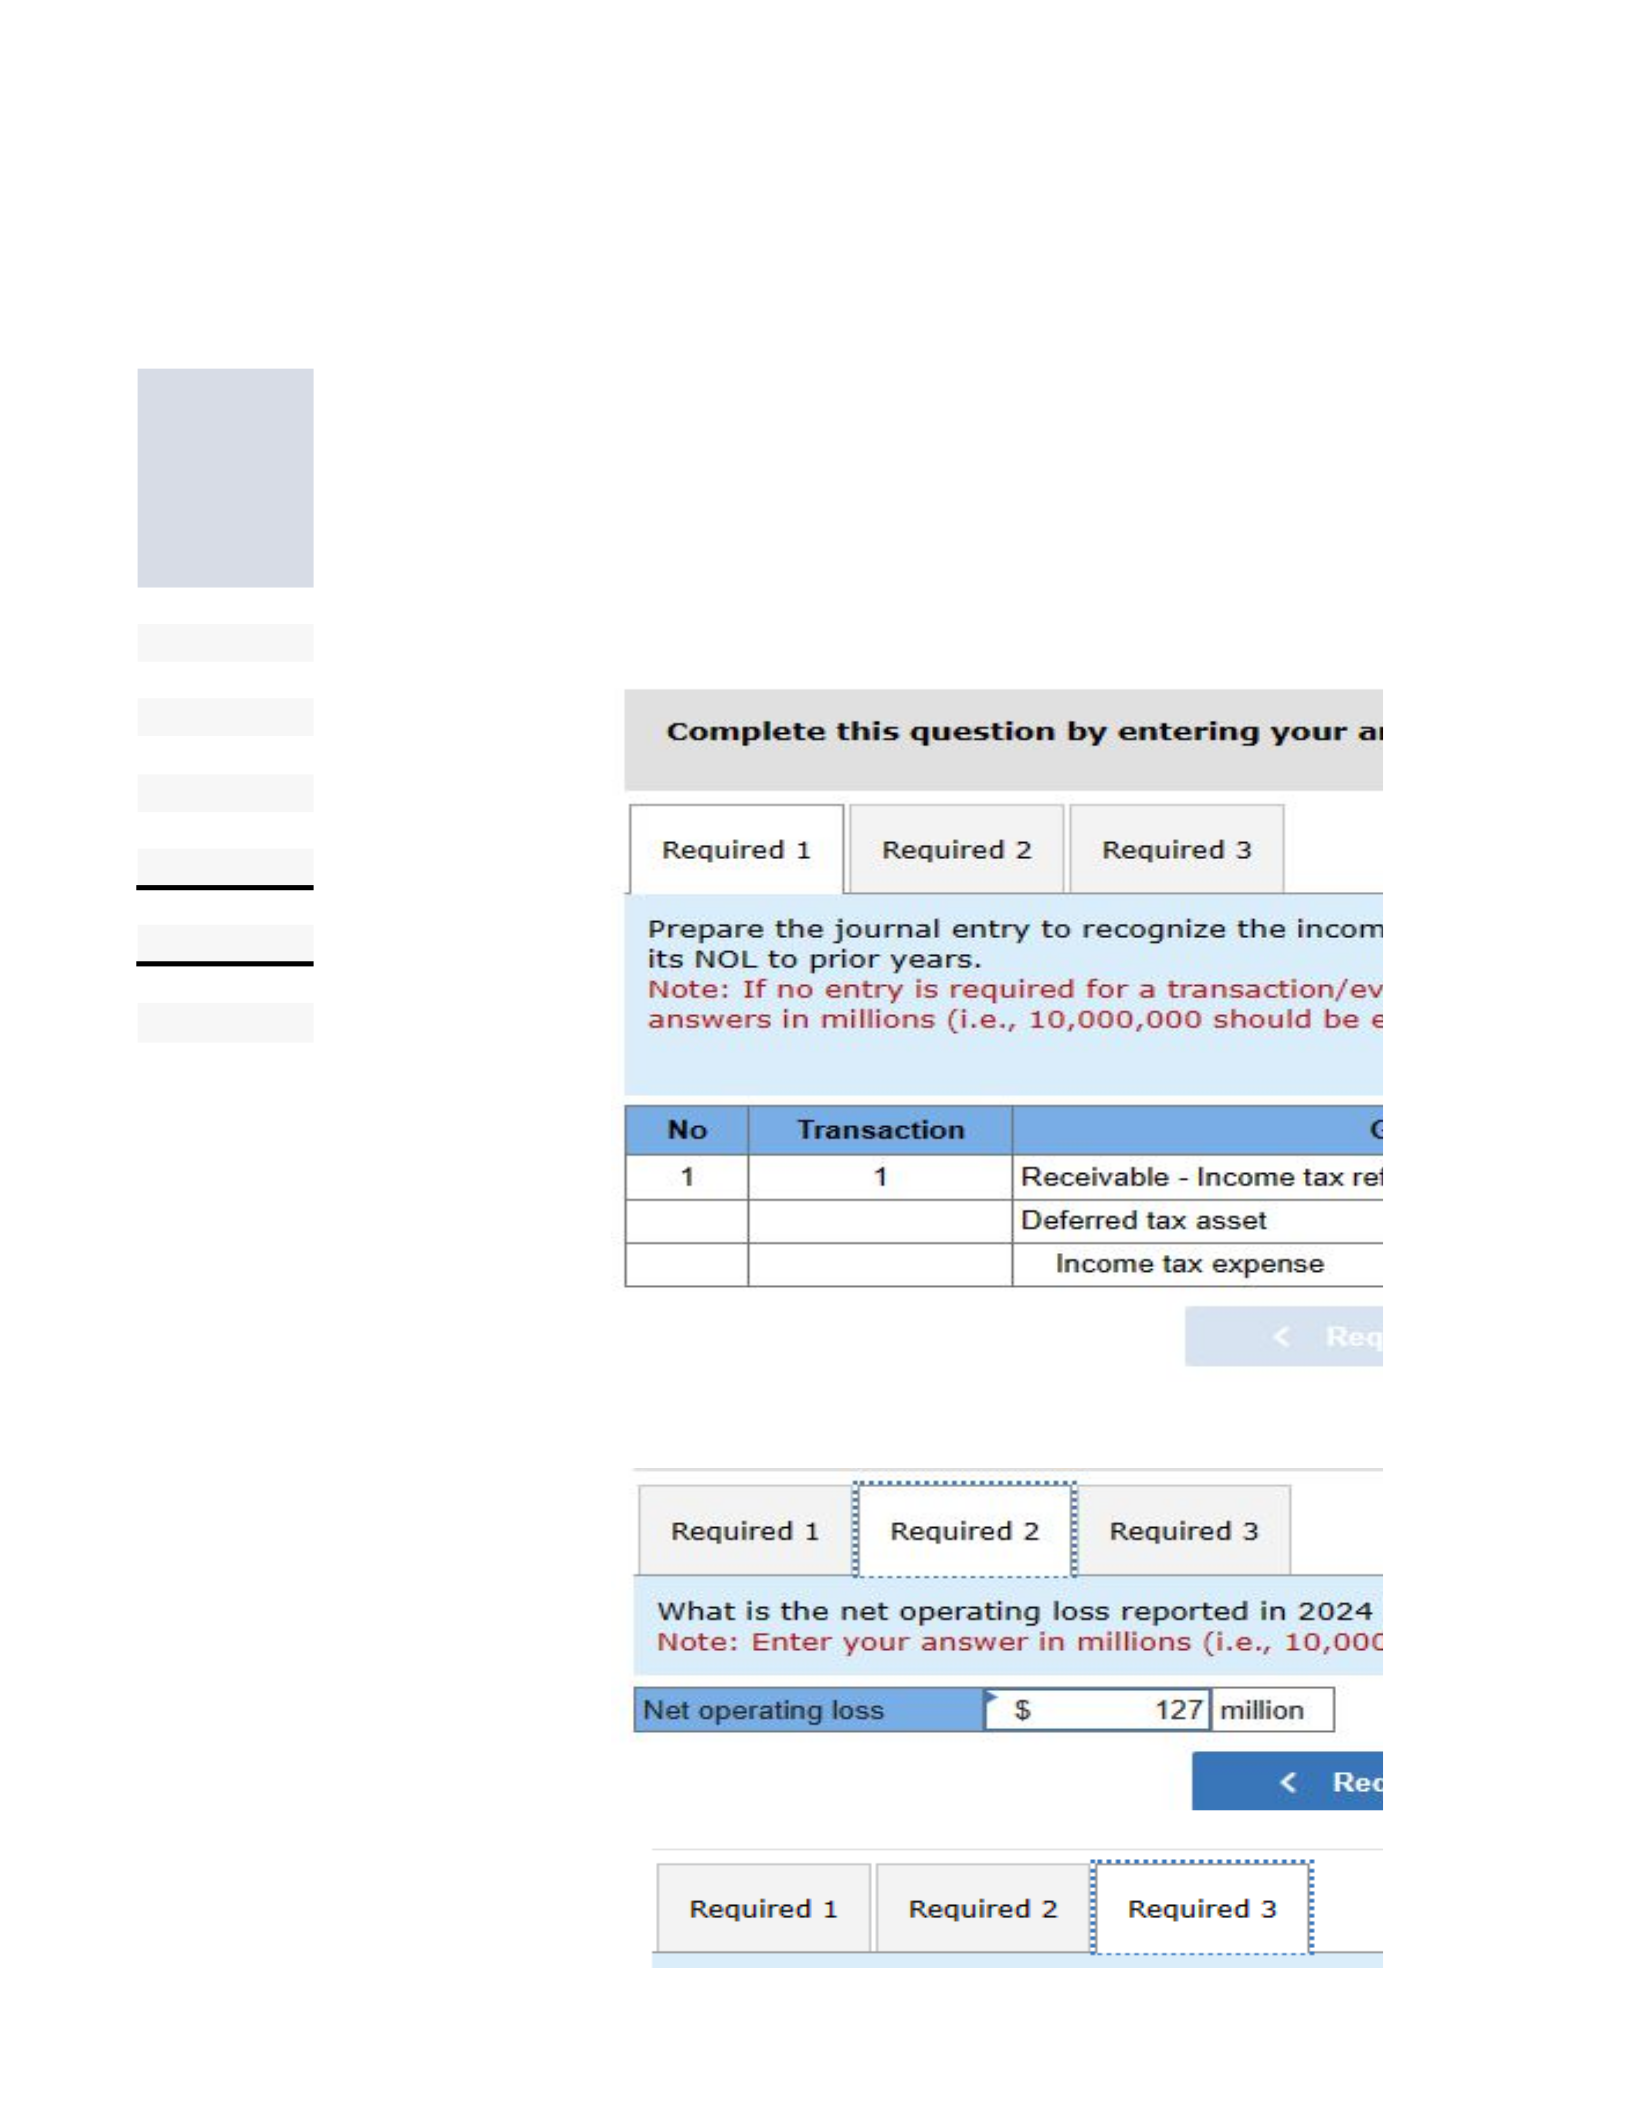
3. Prepare the journal entry to record income taxes in 2025 assuming pretax accounting income is $200 million. No additional temporary differences originate in 2025.
1. NOL carrybacks are not allowed for most companies, except for property and casualty insurance companies as well as some farm-related businesses. Here, we are told that Fore is one of those businesses, and that it elects an NOL carryback option.
Future Deductible Amounts [total]
($20)
-16
-36
25%
($9)
In the prior chapters’ Applying Tableaus, you examined two (hypothetical) publicly traded companies, GPS Corporation and Tru, Incorporated, as to their pattern of leasing facilities, their transition to the new lease accounting standard in 2019, and the effect of that transition on debt covenants. In this case, you examine the effect of the Tax Cuts and Jobs Act of 2017 on these companies’ operations and financial position.
For this case, you will create calculations to determine the effective tax rate so you can compare and contrast the effect of the 2017 Tax Act on the two companies.
3. Click on the Sheet 1 tab, at the bottom of the canvas, to the right of the Data Source at the bottom of the screen. Drag “Company” and “Year” to the Columns shelf. Change “Year” to
discrete
by right-clicking and selecting “Discrete.”
4. Drag “Provision for income tax” and “Deferred income taxes” under Measure Names into the Rows shelf.
5. Add labels to the bars by clicking on "Label" under the Marks card and clicking the box "Show mark labels." Format the labels according to preference and, if desired, edit the color of the years on the "Marks card" by dragging "Year" from tables (not columns) on to the Color Marks card.
6. Change the title of the sheet to be "Provision for Income Taxes and Deferred Tax Liability Trend 2012–2021" by double-clicking the tab at the bottom of the page and typing the new title.
7. Click on the New Worksheet tab on the lower left (“Sheet 2” should open) and follow the procedure outlined above for the company and year. Drag "Provision for income taxes" and "Income from continuing operations" under Measure Names into the Rows shelf. Change each to discrete by right-clicking and selecting "Discrete."
8. Create a calculated field by clicking the "Analysis" tab at the top of the screen and selecting "Create Calculated Field." Name the calculation "Effective Tax Rate." In the Calculation Editor window, drag "Provision for income taxes" and type a division sign. Then type "(", drag "Income from continuing operations," type an addition sign, drag "Provision for income taxes," and type ")" from the Rows shelf. Make sure the calculation is valid and click OK.
9. Drag the newly created "Effective Tax Rate" to the Rows shelf. Click on the "Show Me" and select "side-by-side bars." Add labels to the bars by clicking on "Label" under the Marks card and clicking the box "Show mark labels." Format the labels according to preference and edit the color on the Marks card if desired. If you want to see a line chart instead of the bars, click on Automatic under the Marks card and select Line.
10. Change the marks to percentages by right-clicking on AGG(Effective Tax Rate) in the Rows Shelf and clicking Format. When the format bar appears on the left, choose Pane. Under default, format the number as Percentage with 2 decimal places.
11. Change the title of the sheet to be "Effect of the Tax Cuts and Jobs Act of 2017" by double-clicking the tab at the bottom of the page and typing the new title.
A. Is Tru, Incorporated’s provision for income tax (a) higher, (b) lower, or (c) roughly the same over the period 2018-2021 than in previous years?
A. Tru, Incorporated’s provision for income tax is lower over the period 2018-2021 than in previous years (and also for GPS Corporation). The Tax Act reduced the corporate income tax rate from 35% to 21% beginning in 2018.
B. Yes. Tru, Incorporated’s deferred tax liability appears to benefit from the Tax Act (and also for GPS Corporation). Not only did the Tax Act reduce income tax expense significantly each year, companies also benefited from remeasuring their deferred tax liabilities based on the new lower rate at which those liabilities will be paid.
Kara Fashions uses straight-line depreciation for financial statement reporting and MACRS for income tax reporting. Three years after its purchase, one of Kara’s buildings has a book value of $680,000 and a tax basis of $510,000. There were no other temporary differences and no permanent differences. Taxable income was $5 million and Kara’s tax rate is 25%.
What is the deferred tax liability to be reported in the balance sheet? Assuming that the deferred tax liability balance was $27,000 the previous year, prepare the appropriate journal entry to record income taxes this year.
Since tax depreciation to date has been $170,000 more than depreciation for financial reporting purposes, there will be fewer tax deductions for depreciation in the future, and future taxable amounts will be higher as the temporary difference reverses. This means a deferred tax liability should be reported to reflect the future tax consequences of the temporary difference. At this point, that amount is $170,000 times 25%, or $42,500.
Complete this question by entering your answers in the tabs below.
General Journal
Assuming that the deferred tax liability balance was $27,000 the previous year, prepare the appropriate journal entry to record income taxes this year.
Note: If no entry is required for a transaction/event, select "No journal entry required" in the first account field. Enter your answers in whole dollars.
What is the deferred tax liability to be reported in the balance sheet?
Show less
No
Transaction
1 1
Shannon Polymers uses straight-line depreciation for financial reporting purposes for equipment costing $500,000 and with an expected useful life of four years and no residual value. Assume that, for tax purposes, the deduction is 40%, 30%, 20%, and 10% in those years. Pretax accounting income the first year the equipment was used was $600,000, which includes interest revenue of $10,000 from municipal governmental bonds. Other than the two described, there are no differences between accounting income and taxable income. The enacted tax rate is 25%.
LossCo reported a net operating loss of $23 million for financial reporting and tax purposes. Taxable income last year and the previous year, respectively, was $24 million and $19 million. The enacted tax rate each year is 25%. Assume that LossCo qualifies as a type of company that is allowed to carry back an NOL to two prior taxable years, using the earliest year first.
NOL carrybacks are not allowed for most companies, except for property and casualty insurance companies as well as some farm-related businesses. Here, we are told that LossCo is one of those businesses, and that it carries back an NOL.
Because the net operating loss is less than the previous two years taxable income, LossCo cannot get back all taxes paid those two years. It can reduce taxable income from two years ago by $19 million (to zero) and last year’s taxable income by $4 million and get a refund of $5.75 million of the taxes paid those years.
Credit
not attempted
5,750,000
Intraperiod tax allocation means the total income tax obligation for a reporting period is allocated among the income statement items that gave rise to the income tax. The following items should be reported net of their respective income tax effects:
Southeast Airlines had income from continuing operations of $45 million before the income from discontinued operations of $10 million. Since the company’s tax rate is 25%, the amount of income tax expense that Southeast should report as part of income from continuing operations is $45 million × 25%, or $11.25 million. The income from discontinued operations should be reported
Lance Lawn Services reports warranty expense by estimating the amount that eventually will be paid to satisfy warranties on its product sales. For tax purposes, the expense is deducted when the warranty work is completed. At December 31, 2024, Lance has a warranty liability of $2 million and taxable income of $75 million. At December 31, 2023, Lance reported a deferred tax asset of $459,000 related to this difference in reporting warranties; it’s only temporary difference. The enacted tax rate is 25% each year.
Debit Credit
18,709,000selected answer correct
not attempted
41,000selected answer correct
not attempted
not attempted
18,750,000
Southern Atlantic Distributors began operations in January 2024 and purchased a delivery truck for $40,000. Southern Atlantic plans to use straight-line depreciation over a four-year expected useful life for financial reporting purposes. For tax purposes, the deduction is 50% of cost in 2024, 30% in 2025, and 20% in 2026. Pretax accounting income for 2024 was $200,000, which includes interest revenue of $28,000 from municipal governmental bonds. The enacted tax rate is 25%.
Complete the following table to record income taxes in 2024.
Note: Amounts to be deducted should be indicated with a minus sign. Enter your answers in whole dollars.
Amount × Tax Rate Tax
Recorded as:
$200,000
$(28,000)selected answer correct
200000 ×
25%selected answer correct
= #NAME?
Income tax expenseselected answer correct
$(10,000)selected answer correct
× 25% = ($2,500)
Deferred tax liabilityselected answer correct
200000 × 25% = #NAME?
Income tax payableselected answer correct
Prepare the journal entry to record income taxes in 2024.
Note: If no entry is required for a transaction/event, select "No journal entry required" in the first account field. Enter your answers in whole dollars.
General Journal
Debit Credit
Income tax expenseselected answer correct
43,000selected answer correct
not attempted
Income tax payableselected answer correct
not attempted
40,500selected answer correct
Deferred tax liabilityselected answer correct
not attempted
2,500
What is Southern Atlantic’s 2024 net income?
Note: Enter your answer in whole dollar.
$157,000selected answer correct
a. Income from installment sales of properties included in pretax accounting income in 2024 exceeded that reported for tax purposes by $6 million. The installment receivable account at year-end 2024 had a balance of $8 million (representing portions of 2023 and 2024 installment sales), expected to be collected equally in 2025 and 2026.
c. Sherrod rents its operating facilities but owns one asset acquired in 2023 at a cost of $56 million. Depreciation is reported by the straight-line method, assuming a four-year useful life. On the tax return, deductions for depreciation will be more than straight-line depreciation the first two years but less than straight-line depreciation the next two years ($ in millions):
d. For tax purposes, warranty expense is deducted when costs are paid. The balance of the warranty liability was $3 million at the end of 2023. Warranty expense of $5 million is recognized in the income statement in 2024. $4 million of cost is paid in 2024, and another $4 million of costs are anticipated to be paid in 2025. At December 31, 2024, the warranty liability is $4 million (after adjusting entries).
e. In 2024, Sherrod accrued an expense and related liability for estimated paid future absences of $14 million relating to the company’s new paid vacation program. Future compensation will be deductible on the tax return when actually paid during the next two years ($8 million in 2025; $6 million in 2026).
Required
2
aired
=e
cre
FT
ta
Liability
Sere
eS Se
eee
eee
ees
Sa
eee
See
ed
eo
ed
OD
eae
eS
SS
Cf
eS,
SS
Soe
eo
Sie
ot
he
Ser
ber
Sd
aS
SS
oye
So
|
a
ee
ee
me
ee
ee
ee
Be
Se
es
a
ee
me
pe
em
me
ee
a
em
ee
fe
—e
See
eo
sO
SO
1,
OR
See
Be
Eee
Seer
eS
Oe
SC
re
Bee
Oa
coe
ee
ete
ge
le
Ee
PS
eee
SE
Ee
LOS
ra
i_{]_.
Soe
ee
Seo
he
Se
rier
Sod
aS
SL
Sop
=
er
75
aa
000
N
alain
000
Corning-Howell reported taxable income in 2024 of $152 million. At December 31, 2024, the reported amount of some assets and liabilities in the financial statements differed from their tax bases as indicated below:

Fore Farms reported a pretax operating loss of $168 million for financial reporting purposes in 2024. Contributing to the loss were (a) a penalty of $4 million assessed by the Environmental Protection Agency for violation of a federal law and paid in 2024 and (b) an estimated loss of $20 million from accruing a loss contingency. The loss will be tax deductible when paid in 2025.
The enacted tax rate is 25%. There were no temporary differences at the beginning of the year and none originating in 2024 other than those described above. Taxable income in Fores’s two previous years of operation was as follows:
1. NOL carrybacks are not allowed for most companies, except for property and casualty insurance companies as well as some farm-related businesses. Here, we are told that Fore is one of those businesses, and that it elects an NOL carryback option.
In the prior chapters’ Applying Tableaus, you examined two (hypothetical) publicly traded companies, GPS Corporation and Tru, Incorporated, as to their pattern of leasing facilities, their transition to the new lease accounting standard in 2019, and the effect of that transition on debt covenants. In this case, you examine the effect of the Tax Cuts and Jobs Act of 2017 on these companies’ operations and financial position.
by right-clicking and selecting “Discrete.”
5. Add labels to the bars by clicking on "Label" under the Marks card and clicking the box "Show mark labels." Format the labels according to preference and, if desired, edit the color of the years on the "Marks card" by dragging "Year" from tables (not columns) on to the Color Marks card.
7. Click on the New Worksheet tab on the lower left (“Sheet 2” should open) and follow the procedure outlined above for the company and year. Drag "Provision for income taxes" and "Income from continuing operations" under Measure Names into the Rows shelf. Change each to discrete by right-clicking and selecting "Discrete."
8. Create a calculated field by clicking the "Analysis" tab at the top of the screen and selecting "Create Calculated Field." Name the calculation "Effective Tax Rate." In the Calculation Editor window, drag "Provision for income taxes" and type a division sign. Then type "(", drag "Income from continuing operations," type an addition sign, drag "Provision for income taxes," and type ")" from the Rows shelf. Make sure the calculation is valid and click OK.
9. Drag the newly created "Effective Tax Rate" to the Rows shelf. Click on the "Show Me" and select "side-by-side bars." Add labels to the bars by clicking on "Label" under the Marks card and clicking the box "Show mark labels." Format the labels according to preference and edit the color on the Marks card if desired. If you want to see a line chart instead of the bars, click on Automatic under the Marks card and select Line.
10. Change the marks to percentages by right-clicking on AGG(Effective Tax Rate) in the Rows Shelf and clicking Format. When the format bar appears on the left, choose Pane. Under default, format the number as Percentage with 2 decimal places.
.
Tru, Incorporated’s provision for income tax
Lower
B.
Did Tru, Incorporated’s deferred tax liability appear to benefit from the Tax Act?
Yes
C.
Effective tax rate for GPS in 2017
35 %
D.
Effective tax rate for GPS in 2018
21 %
Did
Tru,
Incorporated's
deferred
tax
liability
apr
Effective
tax
rate
for
GPS
in
2017
Effective
tax
rate
for
GPS
in
2018
A. Tru, Incorporated’s provision for income tax is lower over the period 2018-2021 than in previous years (and also for GPS Corporation). The Tax Act reduced the corporate income tax rate from 35% to 21% beginning in 2018.
B. Yes. Tru, Incorporated’s deferred tax liability appears to benefit from the Tax Act (and also for GPS Corporation). Not only did the Tax Act reduce income tax expense significantly each year, companies also benefited from remeasuring their deferred tax liabilities based on the new lower rate at which those liabilities will be paid.
Kara Fashions uses straight-line depreciation for financial statement reporting and MACRS for income tax reporting. Three years after its purchase, one of Kara’s buildings has a book value of $680,000 and a tax basis of $510,000. There were no other temporary differences and no permanent differences. Taxable income was $5 million and Kara’s tax rate is 25%.
Since tax depreciation to date has been $170,000 more than depreciation for financial reporting purposes, there will be fewer tax deductions for depreciation in the future, and future taxable amounts will be higher as the temporary difference reverses. This means a deferred tax liability should be reported to reflect the future tax consequences of the temporary difference. At this point, that amount is $170,000 times 25%, or $42,500.
Assuming that the deferred tax liability balance was $27,000 the previous year, prepare the appropriate journal entry to record income taxes this year.
Note: If no entry is required for a transaction/event, select "No journal entry required" in the first account field. Enter your answers in whole dollars.
General Journal Debit Credit
Income tax expense 1,265,500
Deferred tax liability 15,500
Income tax payable 1,250,000
Shannon Polymers uses straight-line depreciation for financial reporting purposes for equipment costing $500,000 and with an expected useful life of four years and no residual value. Assume that, for tax purposes, the deduction is 40%, 30%, 20%, and 10% in those years. Pretax accounting income the first year the equipment was used was $600,000, which includes interest revenue of $10,000 from municipal governmental bonds. Other than the two described, there are no differences between accounting income and taxable income. The enacted tax rate is 25%.
LossCo reported a net operating loss of $23 million for financial reporting and tax purposes. Taxable income last year and the previous year, respectively, was $24 million and $19 million. The enacted tax rate each year is 25%. Assume that LossCo qualifies as a type of company that is allowed to carry back an NOL to two prior taxable years, using the earliest year first.
Because the net operating loss is less than the previous two years taxable income, LossCo cannot get back all taxes paid those two years. It can reduce taxable income from two years ago by $19 million (to zero) and last year’s taxable income by $4 million and get a refund of $5.75 million of the taxes paid those years.
Southeast Airlines had income from continuing operations of $45 million before the income from discontinued operations of $10 million. Since the company’s tax rate is 25%, the amount of income tax expense that Southeast should report as part of income from continuing operations is $45 million × 25%, or $11.25 million. The income from discontinued operations should be reported
net
of its tax expense: $10 million less 25% of $10 million, (or $2.50 million), which nets to $7.50 million. So, the total income tax obligation of $13.75 million ($55 million × 25%) is allocated between the income statement items that gave rise to the income tax.
Lance Lawn Services reports warranty expense by estimating the amount that eventually will be paid to satisfy warranties on its product sales. For tax purposes, the expense is deducted when the warranty work is completed. At December 31, 2024, Lance has a warranty liability of $2 million and taxable income of $75 million. At December 31, 2023, Lance reported a deferred tax asset of $459,000 related to this difference in reporting warranties; it’s only temporary difference. The enacted tax rate is 25% each year.
Southern Atlantic Distributors began operations in January 2024 and purchased a delivery truck for $40,000. Southern Atlantic plans to use straight-line depreciation over a four-year expected useful life for financial reporting purposes. For tax purposes, the deduction is 50% of cost in 2024, 30% in 2025, and 20% in 2026. Pretax accounting income for 2024 was $200,000, which includes interest revenue of $28,000 from municipal governmental bonds. The enacted tax rate is 25%.
Note: Amounts to be deducted should be indicated with a minus sign. Enter your answers in whole dollars.
Income tax expenseselected answer correct
Deferred tax liabilityselected answer correct
Income tax payableselected answer correct
Note: If no entry is required for a transaction/event, select "No journal entry required" in the first account field. Enter your answers in whole dollars.
a. Income from installment sales of properties included in pretax accounting income in 2024 exceeded that reported for tax purposes by $6 million. The installment receivable account at year-end 2024 had a balance of $8 million (representing portions of 2023 and 2024 installment sales), expected to be collected equally in 2025 and 2026.
c. Sherrod rents its operating facilities but owns one asset acquired in 2023 at a cost of $56 million. Depreciation is reported by the straight-line method, assuming a four-year useful life. On the tax return, deductions for depreciation will be more than straight-line depreciation the first two years but less than straight-line depreciation the next two years ($ in millions):
d. For tax purposes, warranty expense is deducted when costs are paid. The balance of the warranty liability was $3 million at the end of 2023. Warranty expense of $5 million is recognized in the income statement in 2024. $4 million of cost is paid in 2024, and another $4 million of costs are anticipated to be paid in 2025. At December 31, 2024, the warranty liability is $4 million (after adjusting entries).
e. In 2024, Sherrod accrued an expense and related liability for estimated paid future absences of $14 million relating to the company’s new paid vacation program. Future compensation will be deductible on the tax return when actually paid during the next two years ($8 million in 2025; $6 million in 2026).
et
noncurrent
deferred
tax
liability

Fore Farms reported a pretax operating loss of $168 million for financial reporting purposes in 2024. Contributing to the loss were (a) a penalty of $4 million assessed by the Environmental Protection Agency for violation of a federal law and paid in 2024 and (b) an estimated loss of $20 million from accruing a loss contingency. The loss will be tax deductible when paid in 2025.
y
back
yaa
Required
1
Required2
Required 3
een
Prepare
the
journal
entry
to
recognize
the
income
tax
be
its
NOL
to
prior
years.
Note:
If
no
entry
required
for
a
transaction/event,
sele
lions
(i.2.,
10,000,000
should
be
entered
a
1 1
Receivable
-
Income
tax
refund
Deferred
tax
asset
Deferred
tax
liability
Required
1
Required
2
Reauired
3
What
is
the
net
operating
loss
reported
in
2024
income
sti
Note: Enter
your
answer
in
millions
(i.e.,
10,000,000
shou
In the prior chapters’ Applying Tableaus, you examined two (hypothetical) publicly traded companies, GPS Corporation and Tru, Incorporated, as to their pattern of leasing facilities, their transition to the new lease accounting standard in 2019, and the effect of that transition on debt covenants. In this case, you examine the effect of the Tax Cuts and Jobs Act of 2017 on these companies’ operations and financial position.
7. Click on the New Worksheet tab on the lower left (“Sheet 2” should open) and follow the procedure outlined above for the company and year. Drag "Provision for income taxes" and "Income from continuing operations" under Measure Names into the Rows shelf. Change each to discrete by right-clicking and selecting "Discrete."
8. Create a calculated field by clicking the "Analysis" tab at the top of the screen and selecting "Create Calculated Field." Name the calculation "Effective Tax Rate." In the Calculation Editor window, drag "Provision for income taxes" and type a division sign. Then type "(", drag "Income from continuing operations," type an addition sign, drag "Provision for income taxes," and type ")" from the Rows shelf. Make sure the calculation is valid and click OK.
9. Drag the newly created "Effective Tax Rate" to the Rows shelf. Click on the "Show Me" and select "side-by-side bars." Add labels to the bars by clicking on "Label" under the Marks card and clicking the box "Show mark labels." Format the labels according to preference and edit the color on the Marks card if desired. If you want to see a line chart instead of the bars, click on Automatic under the Marks card and select Line.
sear
to
benefit
from
the
Tax
Act?
Yes’
3
2e
Be
B. Yes. Tru, Incorporated’s deferred tax liability appears to benefit from the Tax Act (and also for GPS Corporation). Not only did the Tax Act reduce income tax expense significantly each year, companies also benefited from remeasuring their deferred tax liabilities based on the new lower rate at which those liabilities will be paid.

Since tax depreciation to date has been $170,000 more than depreciation for financial reporting purposes, there will be fewer tax deductions for depreciation in the future, and future taxable amounts will be higher as the temporary difference reverses. This means a deferred tax liability should be reported to reflect the future tax consequences of the temporary difference. At this point, that amount is $170,000 times 25%, or $42,500.
Assuming that the deferred tax liability balance was $27,000 the previous year, prepare the appropriate journal entry to record income taxes this year.
Note: If no entry is required for a transaction/event, select "No journal entry required" in the first account field. Enter your answers in whole dollars.
Shannon Polymers uses straight-line depreciation for financial reporting purposes for equipment costing $500,000 and with an expected useful life of four years and no residual value. Assume that, for tax purposes, the deduction is 40%, 30%, 20%, and 10% in those years. Pretax accounting income the first year the equipment was used was $600,000, which includes interest revenue of $10,000 from municipal governmental bonds. Other than the two described, there are no differences between accounting income and taxable income. The enacted tax rate is 25%.
of its tax expense: $10 million less 25% of $10 million, (or $2.50 million), which nets to $7.50 million. So, the total income tax obligation of $13.75 million ($55 million × 25%) is allocated between the income statement items that gave rise to the income tax.
Lance Lawn Services reports warranty expense by estimating the amount that eventually will be paid to satisfy warranties on its product sales. For tax purposes, the expense is deducted when the warranty work is completed. At December 31, 2024, Lance has a warranty liability of $2 million and taxable income of $75 million. At December 31, 2023, Lance reported a deferred tax asset of $459,000 related to this difference in reporting warranties; it’s only temporary difference. The enacted tax rate is 25% each year.
Southern Atlantic Distributors began operations in January 2024 and purchased a delivery truck for $40,000. Southern Atlantic plans to use straight-line depreciation over a four-year expected useful life for financial reporting purposes. For tax purposes, the deduction is 50% of cost in 2024, 30% in 2025, and 20% in 2026. Pretax accounting income for 2024 was $200,000, which includes interest revenue of $28,000 from municipal governmental bonds. The enacted tax rate is 25%.
ed3
‘0
record
income
taxes
for
2024,
and
prepare
the
appropriate
journal
entry.
‘ansaction/event,
select
"No
journal entry
required"
in
the
first
account
field.
Enter
your
cimal
places
(i.¢.,
5,500,000
should
be
entered
as
5.50).
expense
=
18.25+
asset
~
3.00--01
ax
lial
~
350-0
x
payable
~
IT.15-.
ed
3
rounded
to
2
decimal
places(i.e.,
5,500,000
should
be
entered
as
5.50).
3
should
be
classified
and
reported
in
the
2024
balance
sheet.
ounded
to
2
decimal
places(i.e.,
5,500,000
should
be
entered
as
5.50).
50.1
CeCe
inefit
of
the
net operating
loss
in
2024.
Assume
Fore
will
carry
back
set
"No
journal
entry
required’
15
10).
the
first
account
field.
Enter
your
Show
lessa
32@
30
16
Peete
atement?
tld
be
entered as
10).
i
Required
3
>
In the prior chapters’ Applying Tableaus, you examined two (hypothetical) publicly traded companies, GPS Corporation and Tru, Incorporated, as to their pattern of leasing facilities, their transition to the new lease accounting standard in 2019, and the effect of that transition on debt covenants. In this case, you examine the effect of the Tax Cuts and Jobs Act of 2017 on these companies’ operations and financial position.
8. Create a calculated field by clicking the "Analysis" tab at the top of the screen and selecting "Create Calculated Field." Name the calculation "Effective Tax Rate." In the Calculation Editor window, drag "Provision for income taxes" and type a division sign. Then type "(", drag "Income from continuing operations," type an addition sign, drag "Provision for income taxes," and type ")" from the Rows shelf. Make sure the calculation is valid and click OK.
9. Drag the newly created "Effective Tax Rate" to the Rows shelf. Click on the "Show Me" and select "side-by-side bars." Add labels to the bars by clicking on "Label" under the Marks card and clicking the box "Show mark labels." Format the labels according to preference and edit the color on the Marks card if desired. If you want to see a line chart instead of the bars, click on Automatic under the Marks card and select Line.

Shannon Polymers uses straight-line depreciation for financial reporting purposes for equipment costing $500,000 and with an expected useful life of four years and no residual value. Assume that, for tax purposes, the deduction is 40%, 30%, 20%, and 10% in those years. Pretax accounting income the first year the equipment was used was $600,000, which includes interest revenue of $10,000 from municipal governmental bonds. Other than the two described, there are no differences between accounting income and taxable income. The enacted tax rate is 25%.

of its tax expense: $10 million less 25% of $10 million, (or $2.50 million), which nets to $7.50 million. So, the total income tax obligation of $13.75 million ($55 million × 25%) is allocated between the income statement items that gave rise to the income tax.

