


Running Head: Misapplied Overhead 1
Misapplied overhead and its implications on the accounting process
Elana Richardson
Liberty University
Overhead is a predetermined rate used to estimate actual overhead coats at the end of the
accounting period and assume that actual overhead costs will be proportional to the actual

Running Head: Misapplied Overhead 2
amount of the location base for the period. The difference between actual overhead and applied
overhead is called misapplied overhead. Misapplied overhead can take one of two forms: overap-
plied and underapplied. Overapplied and underapplied overhead is the difference between over-
head applied to Work in Process Inventory and actual overhead costs incurred (Garison et. al.,
2015). Both have long lasting consequences that can effect years worth of financial statements.
The size of the amount that has been misapplied will be labeled as either significant or immate-
rial the journal entries to close them are to different accounts. What is classified at immaterial
and significant depends of the company and the size of their operations. $500 for one company
may be a drop in the bucket but for another this amount is a significant error that can have vast
consequences if not corrected properly. And while these errors may self correct over time it is
imperative that they be corrected manually in order to avoid intentional fraud or discovery by au-
ditors.
Overhead accounts can take several forms depending on the type of business using them.
Companies which manufacture goods for sale will have manufacturing overhead, otherwise
known as factory overhead. Businesses which do not manufacture goods will not have manufac-
turing overhead. Both types of companies will have administrative overhead, which concerns ad-
ministrate office jobs and their expenses. Manufacturing overhead is comprised of expenses that
are not easily traced to a specific product but are incurred when making goods and products.
These expenses consist of indirect costs which can include the salaries of employees that do not
work directly on specific products like floor managers, small material such as nuts and bolts, the
depreciation of assets and equipment, utilities for the factory, maintenance, repairs and other mis-
cellaneous expenses (Wild & Shaw, 2015). The predetermined overhead rate is calculated by di-

Running Head: Misapplied Overhead 3
viding estimated overhead by the estimated activity of the allocation base. The difference be-
tween actual overhead incurred and overhead applied is an overhead cost variance. Depending on
which way the variance swings it will be either favorable or unfavorable for the company. For
expenses a favorable variance is where actual expense was less than budgeted and an unfavor-
able variance is where actual expense was more than budgeted. It is the opposite where revenue
is concerned. Companies will attempt to get an overall favorable variance which may necessitate
unfavorable variances in overhead.
Administrative and Manufacturing overhead both have distinct and important roles to
play for businesses and as such they will also have different ways in which they are allocated.
Administrative overhead is much easier to allocate and correct than Manufacturing overhead.
The differences between budgeted and actual Administrative Overhead is a simple variance and
is corrected at the end of the period as appropriate. Administrative overhead tends to include all
office work when connected to a manufacturing company as these jobs are mainly support of
other functions and do not generate any profit for the company. Administrative overhead is con-
sidered a period cost and is directly allocated to Selling and Administrative expense on the In-
come Statement each period. Administrative overhead consists of office supplies, outside legal
and auditing fees, utilities, travel and entertainment expenses, and administrative salaries (Bragg,
2015).
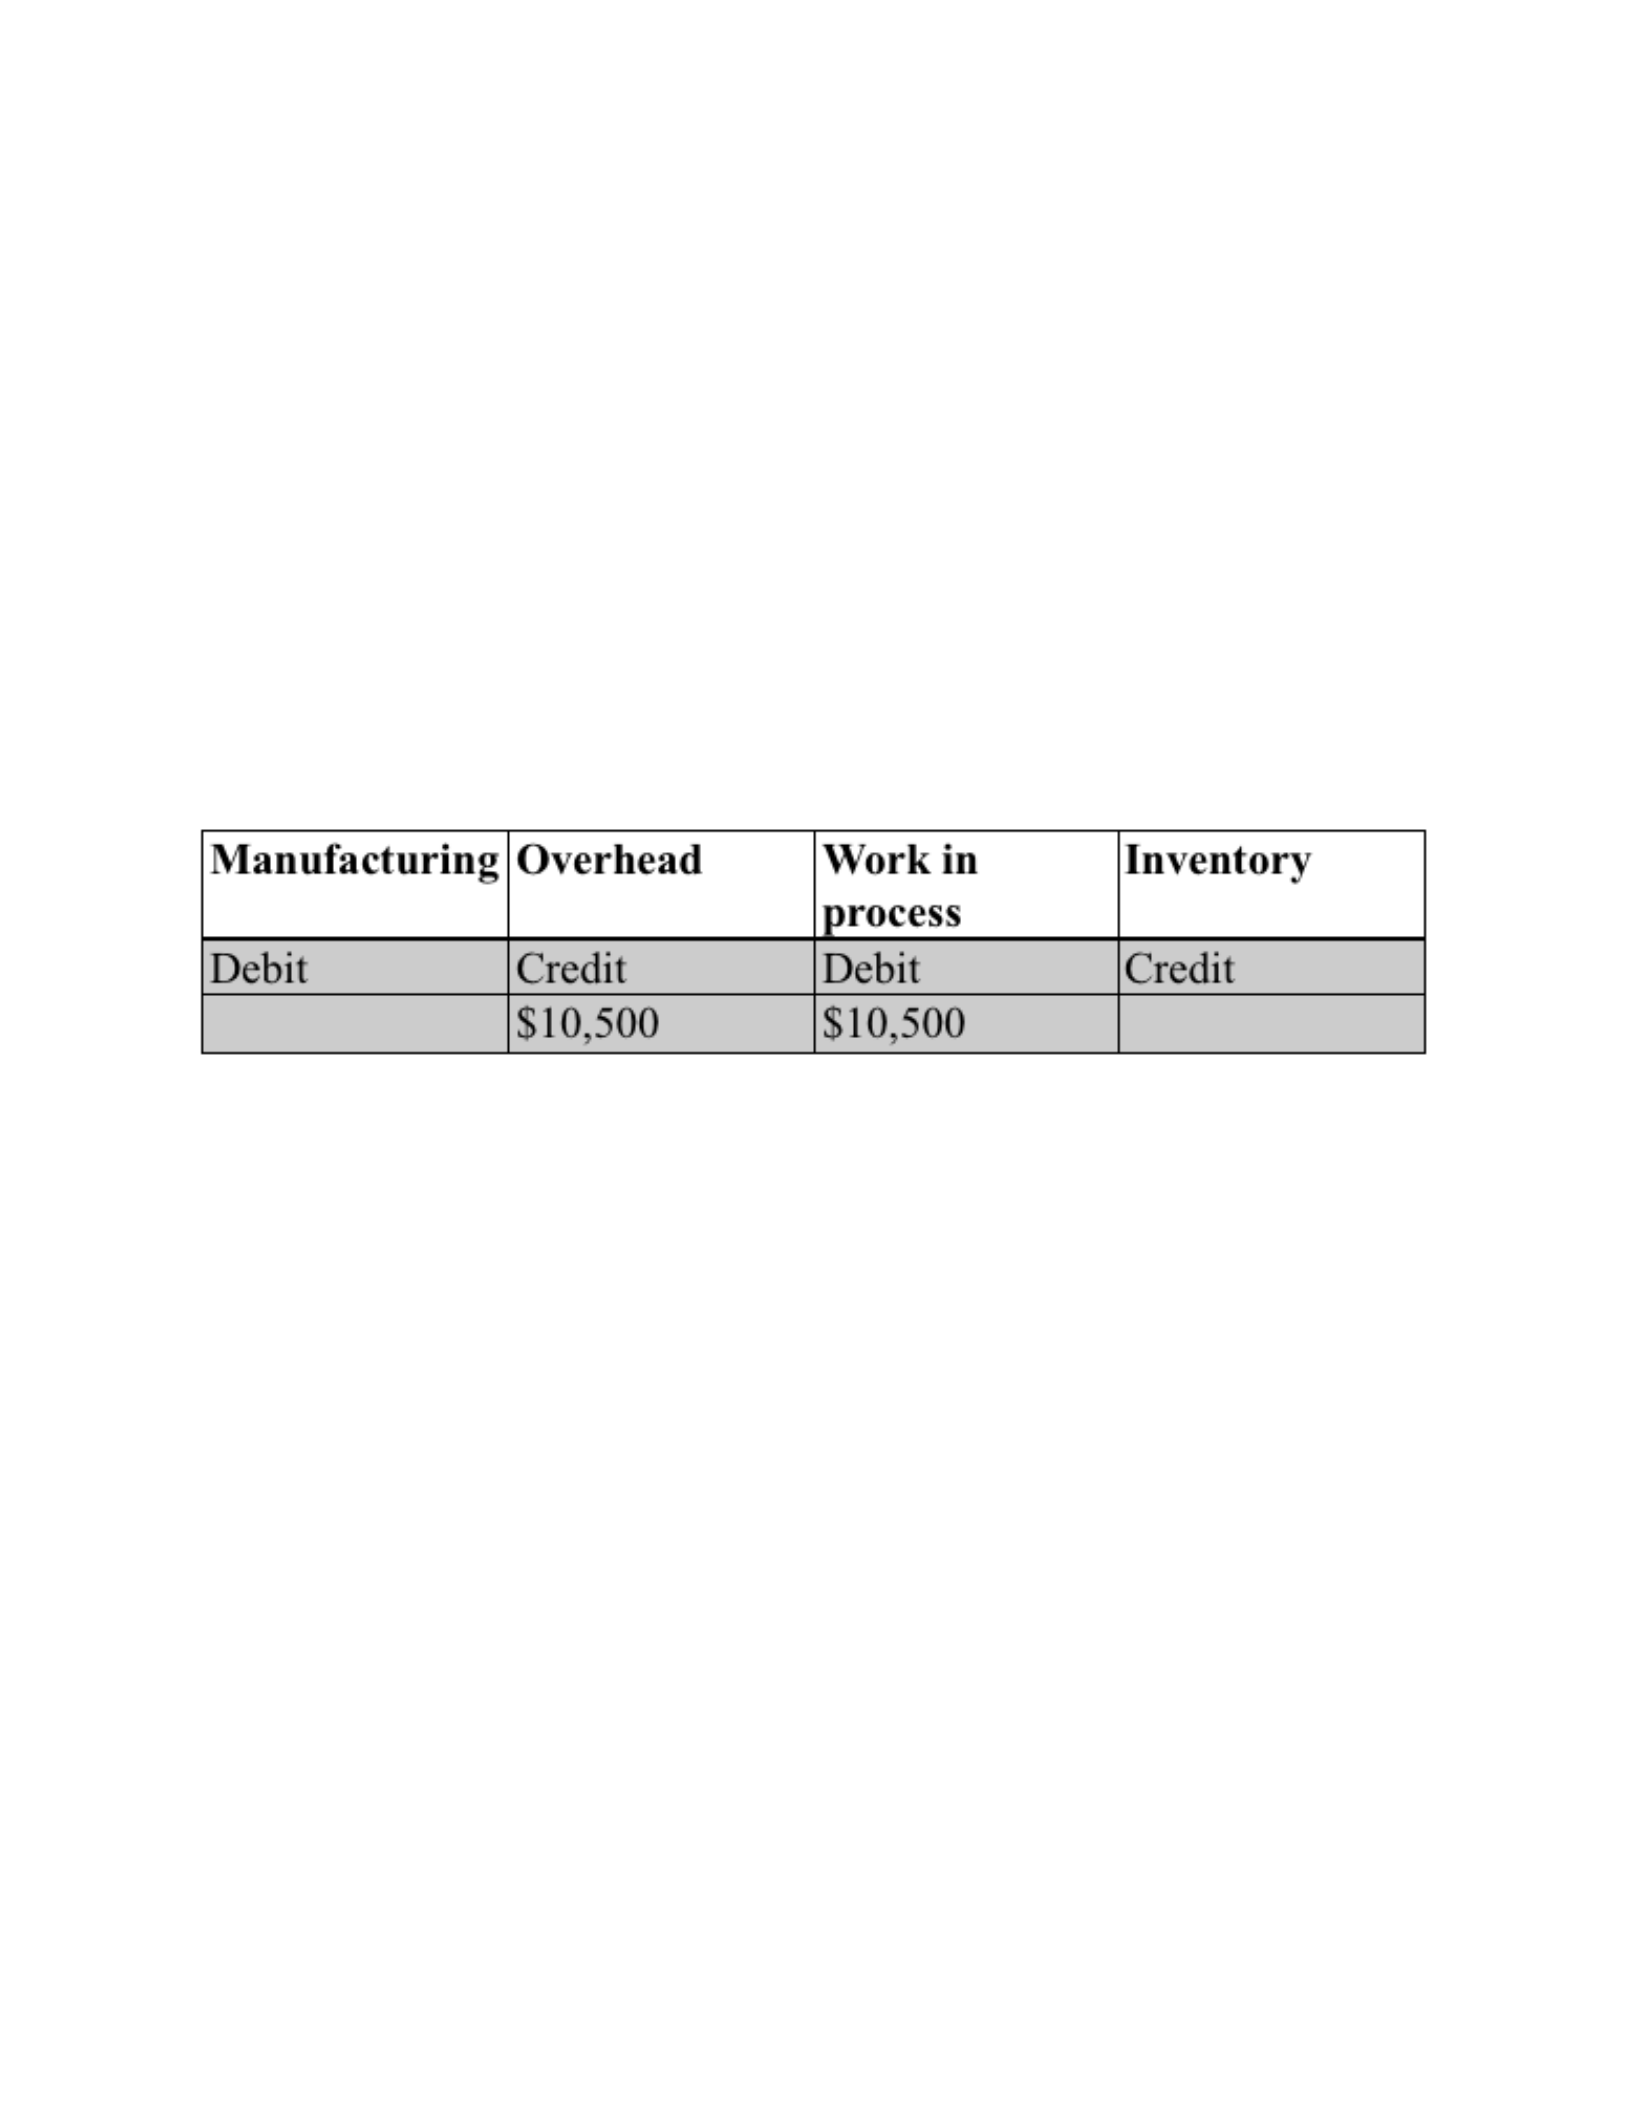
Manufacturing overhead when properly applied is connected to two different T-accounts.
The first is Work in Process inventory. Manufacturing overhead is applied to work in process ac-
cording to the predetermined rate and the allocation base. This same amount is then added to the
manufacturing overhead account. Say Company A has a predetermined manufacturing overhead
Running Head: Misapplied Overhead 4
rate of $3.50 and an allocation base of machine hours. Over the course of the period they incur
3,000 machine hours. This would mean Company A has manufacturing overhead of $10,500 to
apply to the Work in Process inventory and Manufacturing Overhead T-accounts. This allocated
overhead is a stand in for actual overhead that will be calculated at the end of the period. In order
to apply the overhead to the necessary amounts there must be a debit to work in process inven-
tory and a credit to manufacturing overhead. When actual overhead is calculated as more or less
than the allocated overhead is where adjusting entries must be made. The type of adjustments
necessary will depend on how large of a difference there is between actual and allocated over-
head.
Overapplied overhead is created when the actual overhead is less than the estimated over-
head. When this happens managers have actually managed to go “under budget” and save money
on expenses creating a favorable variance. The excess of allocated overhead must be removed in
order to have the correct amounts in the ending inventory, and overhead accounts. Should the
overapplied overhead not be discovered the ending inventory will be artificially high leading to
other accounting errors in income in future years. If at all possible managers will attempt to have
overapplied overhead at the end of the period.

Running Head: Misapplied Overhead 5
Underapplied overhead is the product of applied overhead being less than actual over-
head. This difference in applied and actual overhead insinuates that management has gone over
budget with their expenses and is an unfavorable variance. This under allocated overhead must
be rectified in order for all relevant accounts to be correct. With underapplied overhead ending
inventory will be lower than it should. This will also cause other accounting errors in income.
Both of these errors in inventory should self-correct, also known as counterbalancing,
within two years if not discovered (Delaney & Whittington, 2010). Overstating inventory in the
year 20X1 would also overstate the income of year 20X1 and understate the income of year
20X2. However the opposite would be true if inventory was understated due to an error in manu-
facturing overhead. In this case inventory in year 20X1 would be understated cause income in
20X1 to be understated and the income of year 20X2 to be overstated before leveling to normal
in year 20X3. It should be noted however that even though these errors correct themselves over
time they should be manually corrected when found in order to comply with Generally Accepted
Accounting Principles (GAAP). Without the manual correction of these errors it would be con-
sidered fraud by an auditor.
There are two main ways to adjust the T-accounts in order to rectify any differences be-
tween allocated overhead and actual overhead. The first of these is for immaterial amounts.
These amounts are relatively small in relation to the size of the business in question. To close an
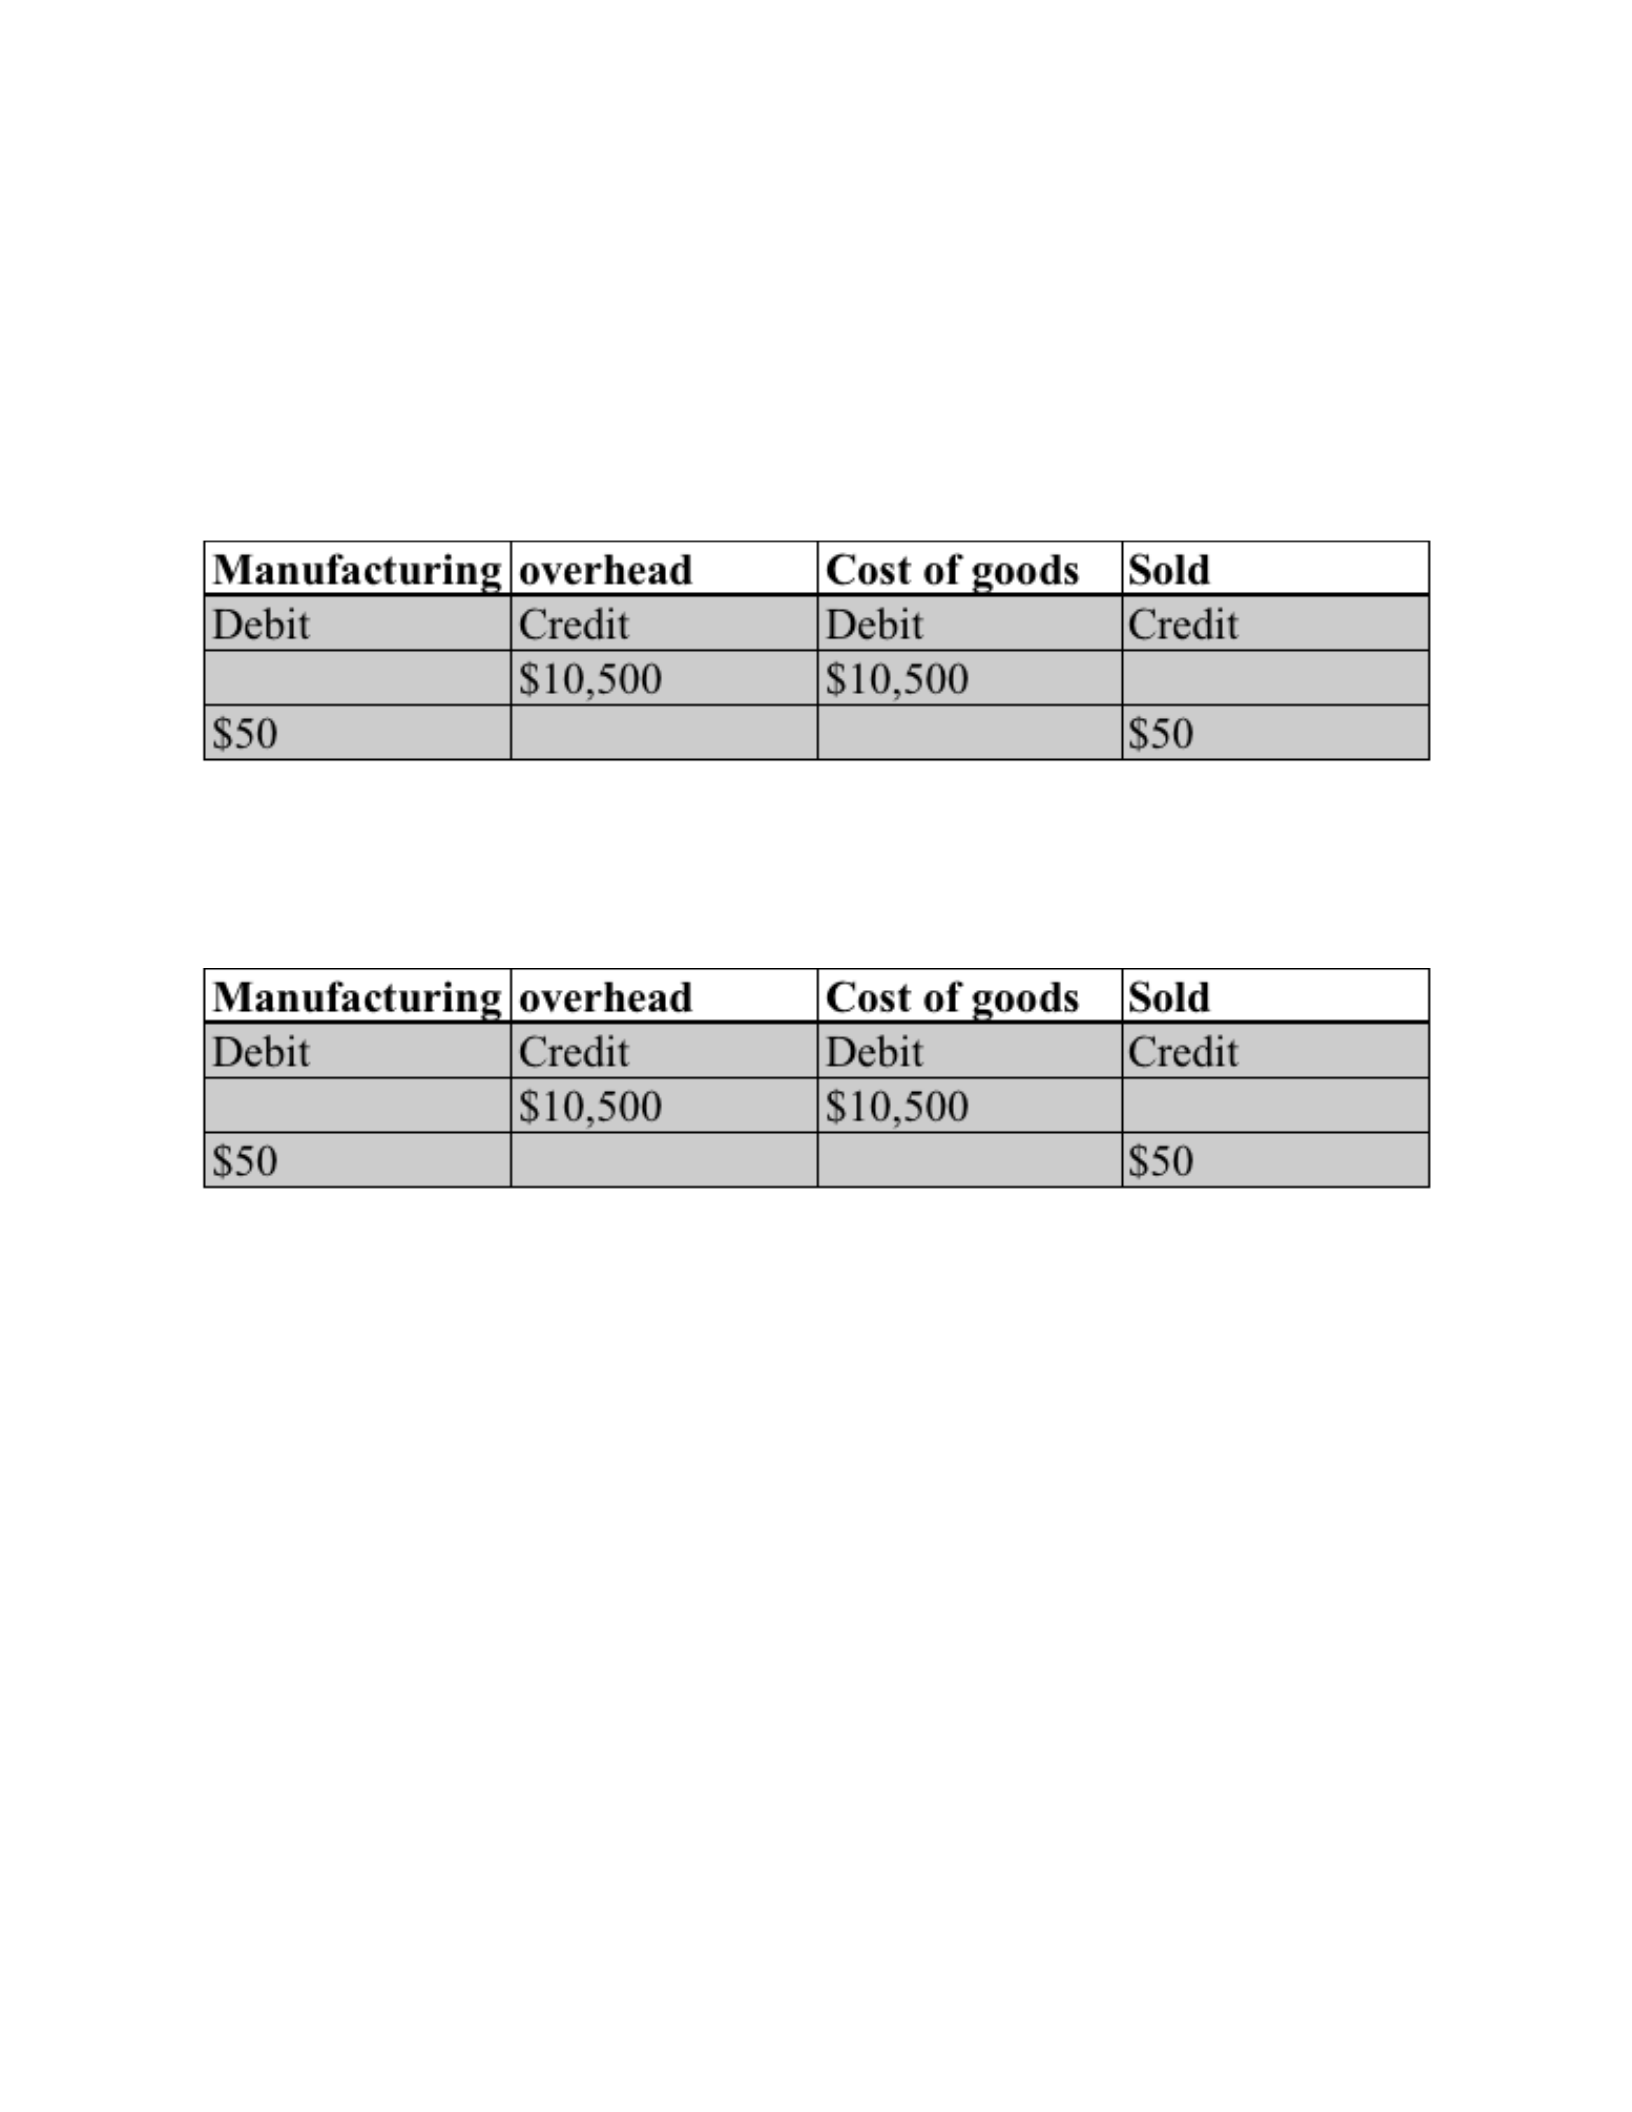
immaterial amount of misapplied overhead the Manufacturing overhead and Cost of Goods Sold
T-accounts are used. Taking the example from earlier Company A has allocated $10,500 of over-
head to the Work in Process and Manufacturing overhead accounts. At the end of the period the
goods produced have been sold. Should company A find they have an immaterial amount of
Running Head: Misapplied Overhead 6
overapplied overhead of $50 the journal entries to correct this error would be as follows: a debit
to Manufacturing Overhead of $50 and a credit to Cost of Goods Sold for $50. If instead Com-
pany A found an immaterial amount of undersupplied overhead the journal entries would include
a debit to Cost of Goods Sold and a credit to Manufacturing Overhead.
Entries to correct overapplied overhead:
Entries to correct undersupplied overhead:
However, there is a different process should the amount of misapplied overhead be
deemed significant. A significant amount of over or underapplied overhead means that the bal-
ance is vastly different from what it should have been if overhead was applied correctly (Putra,
2018). In this case the excess or undersupplied overhead must be allocated between Work in
Process Inventory, Finished Goods Inventory, and Cost of Goods Sold. Should Company A find
at the end of the period that the actual overhead incurred is $15,500 instead of the applied

Running Head: Misapplied Overhead 7
$10,500 this would be considered a significant underappliction. In order to rectify this account-
ing error Company A must divide the $5,000 of undersupplied overhead between Work in
Process Inventory, Finished Goods Inventory, and Cost of Goods Sold. There should be debits to
Work in Process Inventory, Finished Goods Inventory, and Cost of Goods Sold based on their re-
spective ending balances but in total equalling $5,000 and a credit to Manufacturing overhead for
$5,000. If however the actual overhead incurred was $5,500 Manufacturing Overhead should be
debited $5,000 and Work in Process Inventory, Finished Goods Inventory, and Cost of Goods
Sold should be credited according to their ending balances.
The main difference between immaterial and significant amounts of misapplied overhead
is how they are reallocated in order to correct any errors. What each company regards as an im-
material cost will vary depending on how large the company is and how much they normally
send on overhead and other expenses. However, despite the major differences between what
companies count as immaterial the process is the same. Significant amounts of overhead are allo-
cated between multiple T-accounts according to their ending balances in order to ensure that the
correct amount of expense is attached to each product produced. Without these differences for
immaterial and significant amounts of misapplied overhead it would be possible to still have an
incorrect amount of ending inventory.
While it has been mentioned that the errors inherent with misapplying overhead will
eventually self correct it is imperative that they not be allowed to lay and must be adjusted.
GAAP requires the errors be corrected upon their discovery. If the error is covered in the prior
period while creating the current periods statements a restatement of the prior periods financial
statements must be made. The reissuance of the financial statements must also include a disclo-

Running Head: Misapplied Overhead 8
sure note reporting the effect of the error correction on each line item affected. And the cumula-
tive effect of the change on retained earnings. These steps must be taken to avoid any future
problems with auditors. The correction of overhead errors should take place as soon as they are
found in order to prove the most up to date financial information as well as comply with GAAP.
Both manufacturing and administrative overhead have their roles to play in the account-
ing process. They allow management to reasonably predict the amount of money necessary to
pay for expenses in any given period. While there may be errors due to differences in actual costs
of expenses included in overhead the original calculations give companies a reasonable estimate
of what to expect based off of past periods. Without overhead expense accounts it would be im-
possible to determine the amount of expenses attached to each completed product. And without
these complete expenses it would be hard to judge the proper selling price in order to create rev-
enue for the company. The correction of misapplied overhead is essential to ensuring companies
maintain the correct ending inventory amounts. While the errors caused by overapplied and un-
derapplied overhead are self-correcting or counterbalancing companies should make efforts to
ensure the undiscovered errors are minimal and the errors discovered are correctly adjusted. De-
termining whether or not the misapplication of overhead is immaterial or significant will be de-
termined by each company individually. The delineation of how these two types of misapplied
overhead are handled is important in order to maintain the proper amount of ending inventory.
Having correct overhead amounts will allow a company to release their financial statements
without worry of needing to rerelease them later with corrections. While companies may attempt
to fudge their overhead in order for their revenues to look larger internal and external audits are a
Running Head: Misapplied Overhead 9
large deterrent. It is in a companies best interest to correctly apply and report overhead, both
manufacturing and administrative.
References
Bragg, S. (2015, January 27). Administrative overhead. Retrieved October 13, 2017, from
https://www.accountingtools.com/articles/what-is-administrative-overhead.html
Delaney, P. R., & Whittington, O. R. (2010). Wiley CPA Exam Review 2011, Financial Account-
ing and Reporting. John Wiley & Sons.
Running Head: Misapplied Overhead 10
Garrison, R. H., Noreen, E. W., & Brewer, P. C. (2015). Managerial accounting (16th ed.). New
York: McGraw-Hill Education.
Putra, L. D. (2008, November). Disposition Of Underapplied And Overapplied Overhead Cost.
Retrieved October 15, 2017, from http://accounting-financial-tax.com/2008/11/disposi-
tion-of-underapplied-and-overapplied-overhead-cost/
Wild, J. J., & Shaw, K. W. (2015). Managerial Accounting (5th ed.). McGraw-Hill Education.

