


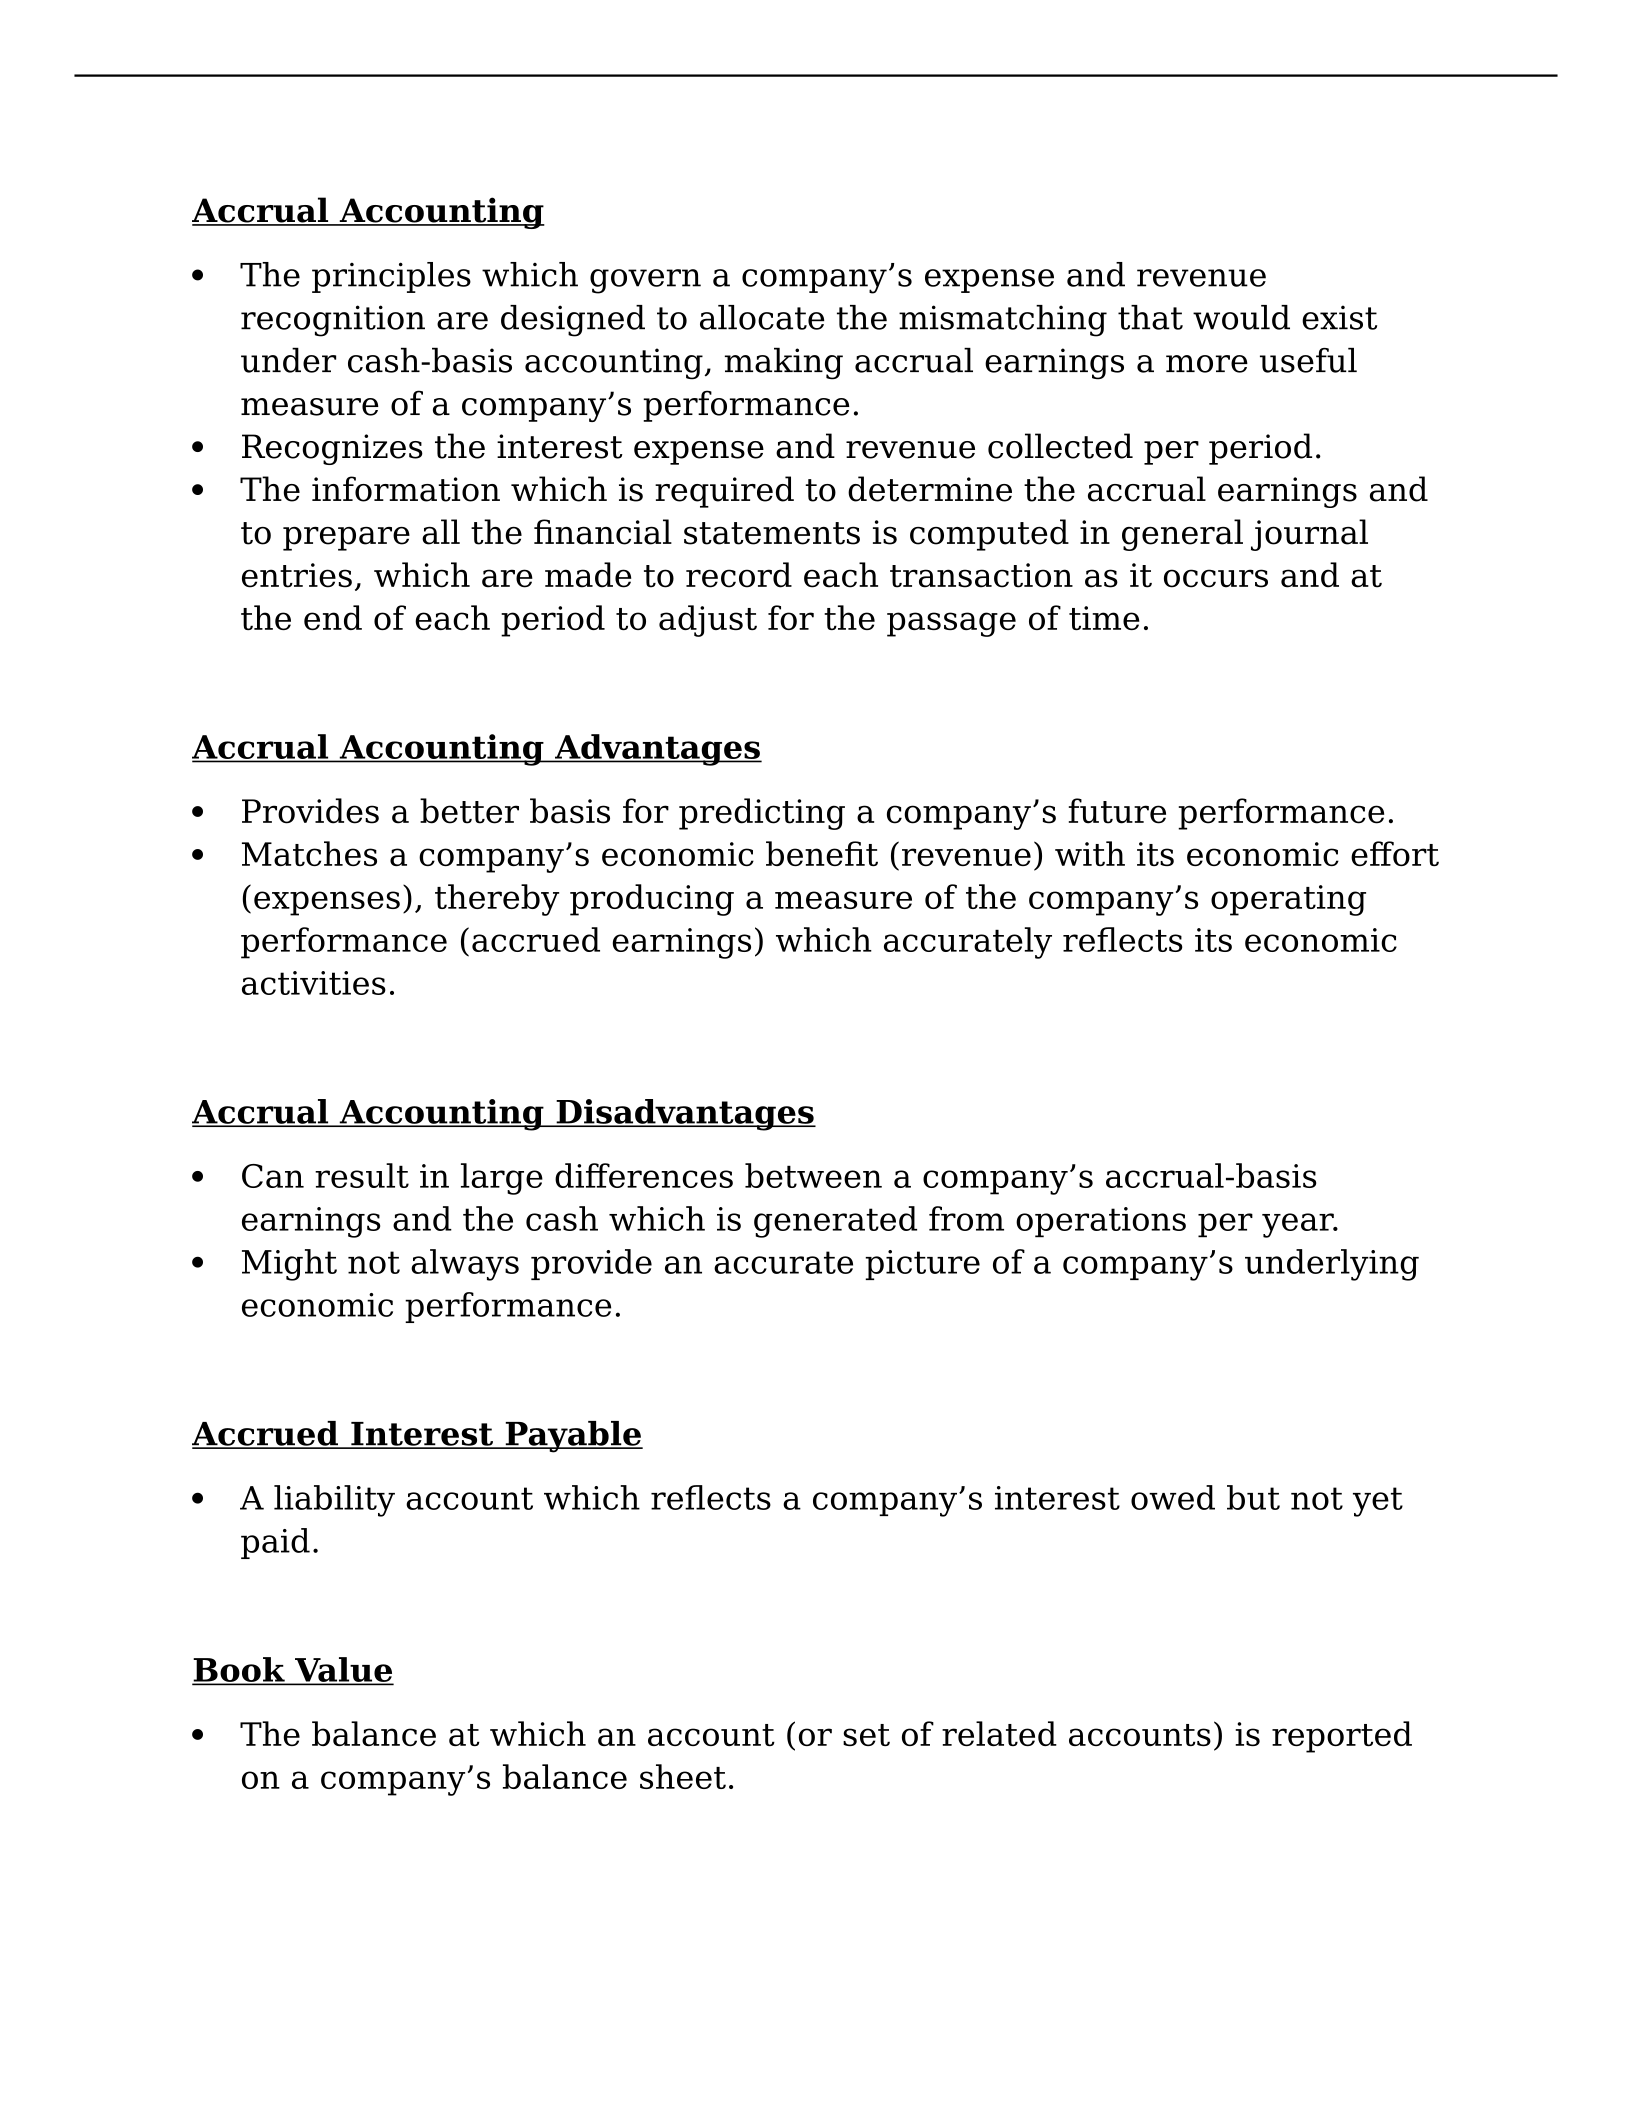
Accrual Accounting
The principles which govern a company’s expense and revenue
recognition are designed to allocate the mismatching that would exist
under cash-basis accounting, making accrual earnings a more useful
measure of a company’s performance.
Recognizes the interest expense and revenue collected per period.
The information which is required to determine the accrual earnings and
to prepare all the financial statements is computed in general journal
entries, which are made to record each transaction as it occurs and at
the end of each period to adjust for the passage of time.
Accrual Accounting Advantages
Provides a better basis for predicting a company’s future performance.
Matches a company’s economic benefit (revenue) with its economic effort
(expenses), thereby producing a measure of the company’s operating
performance (accrued earnings) which accurately reflects its economic
activities.
Accrual Accounting Disadvantages
Can result in large differences between a company’s accrual-basis
earnings and the cash which is generated from operations per year.
Might not always provide an accurate picture of a company’s underlying
economic performance.
Accrued Interest Payable
A liability account which reflects a company’s interest owed but not yet
paid.
Book Value
The balance at which an account (or set of related accounts) is reported
on a company’s balance sheet.
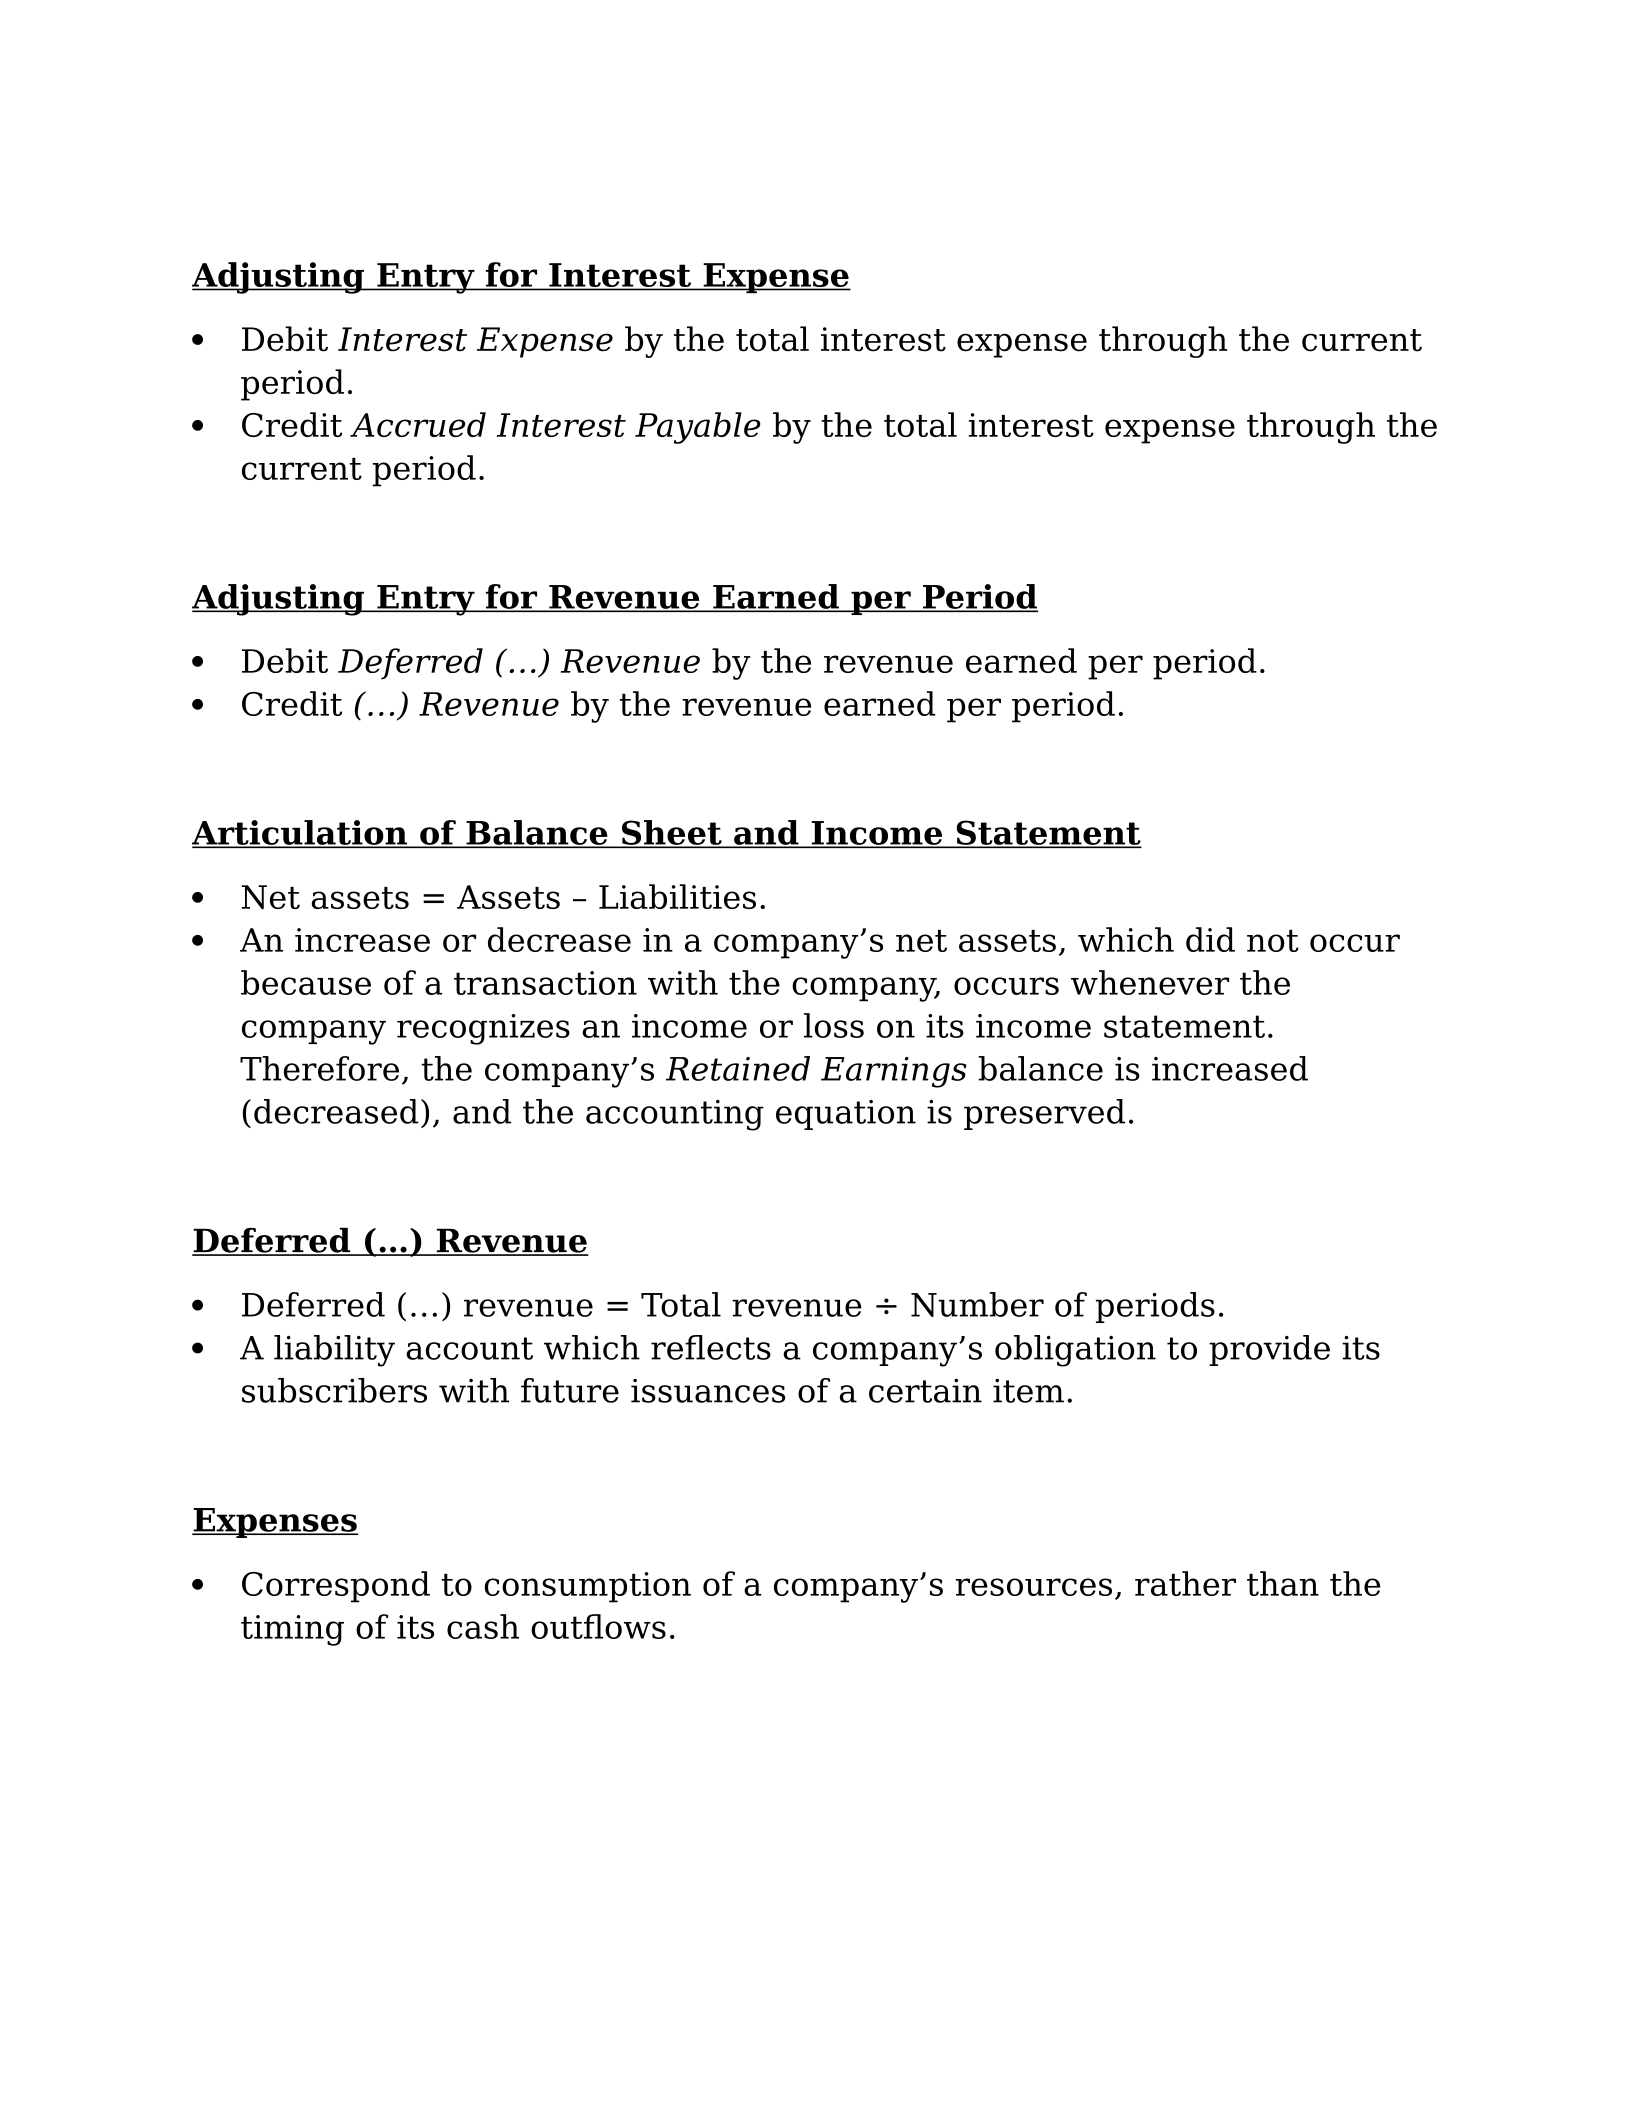
Adjusting Entry for Interest Expense
Debit Interest Expense by the total interest expense through the current
period.
Credit Accrued Interest Payable by the total interest expense through the
current period.
Adjusting Entry for Revenue Earned per Period
Debit Deferred (…) Revenue by the revenue earned per period.
Credit (…) Revenue by the revenue earned per period.
Articulation of Balance Sheet and Income Statement
Net assets = Assets – Liabilities.
An increase or decrease in a company’s net assets, which did not occur
because of a transaction with the company, occurs whenever the
company recognizes an income or loss on its income statement.
Therefore, the company’s Retained Earnings balance is increased
(decreased), and the accounting equation is preserved.
Deferred (…) Revenue
Deferred (…) revenue = Total revenue ÷ Number of periods.
A liability account which reflects a company’s obligation to provide its
subscribers with future issuances of a certain item.
Expenses
Correspond to consumption of a company’s resources, rather than the
timing of its cash outflows.
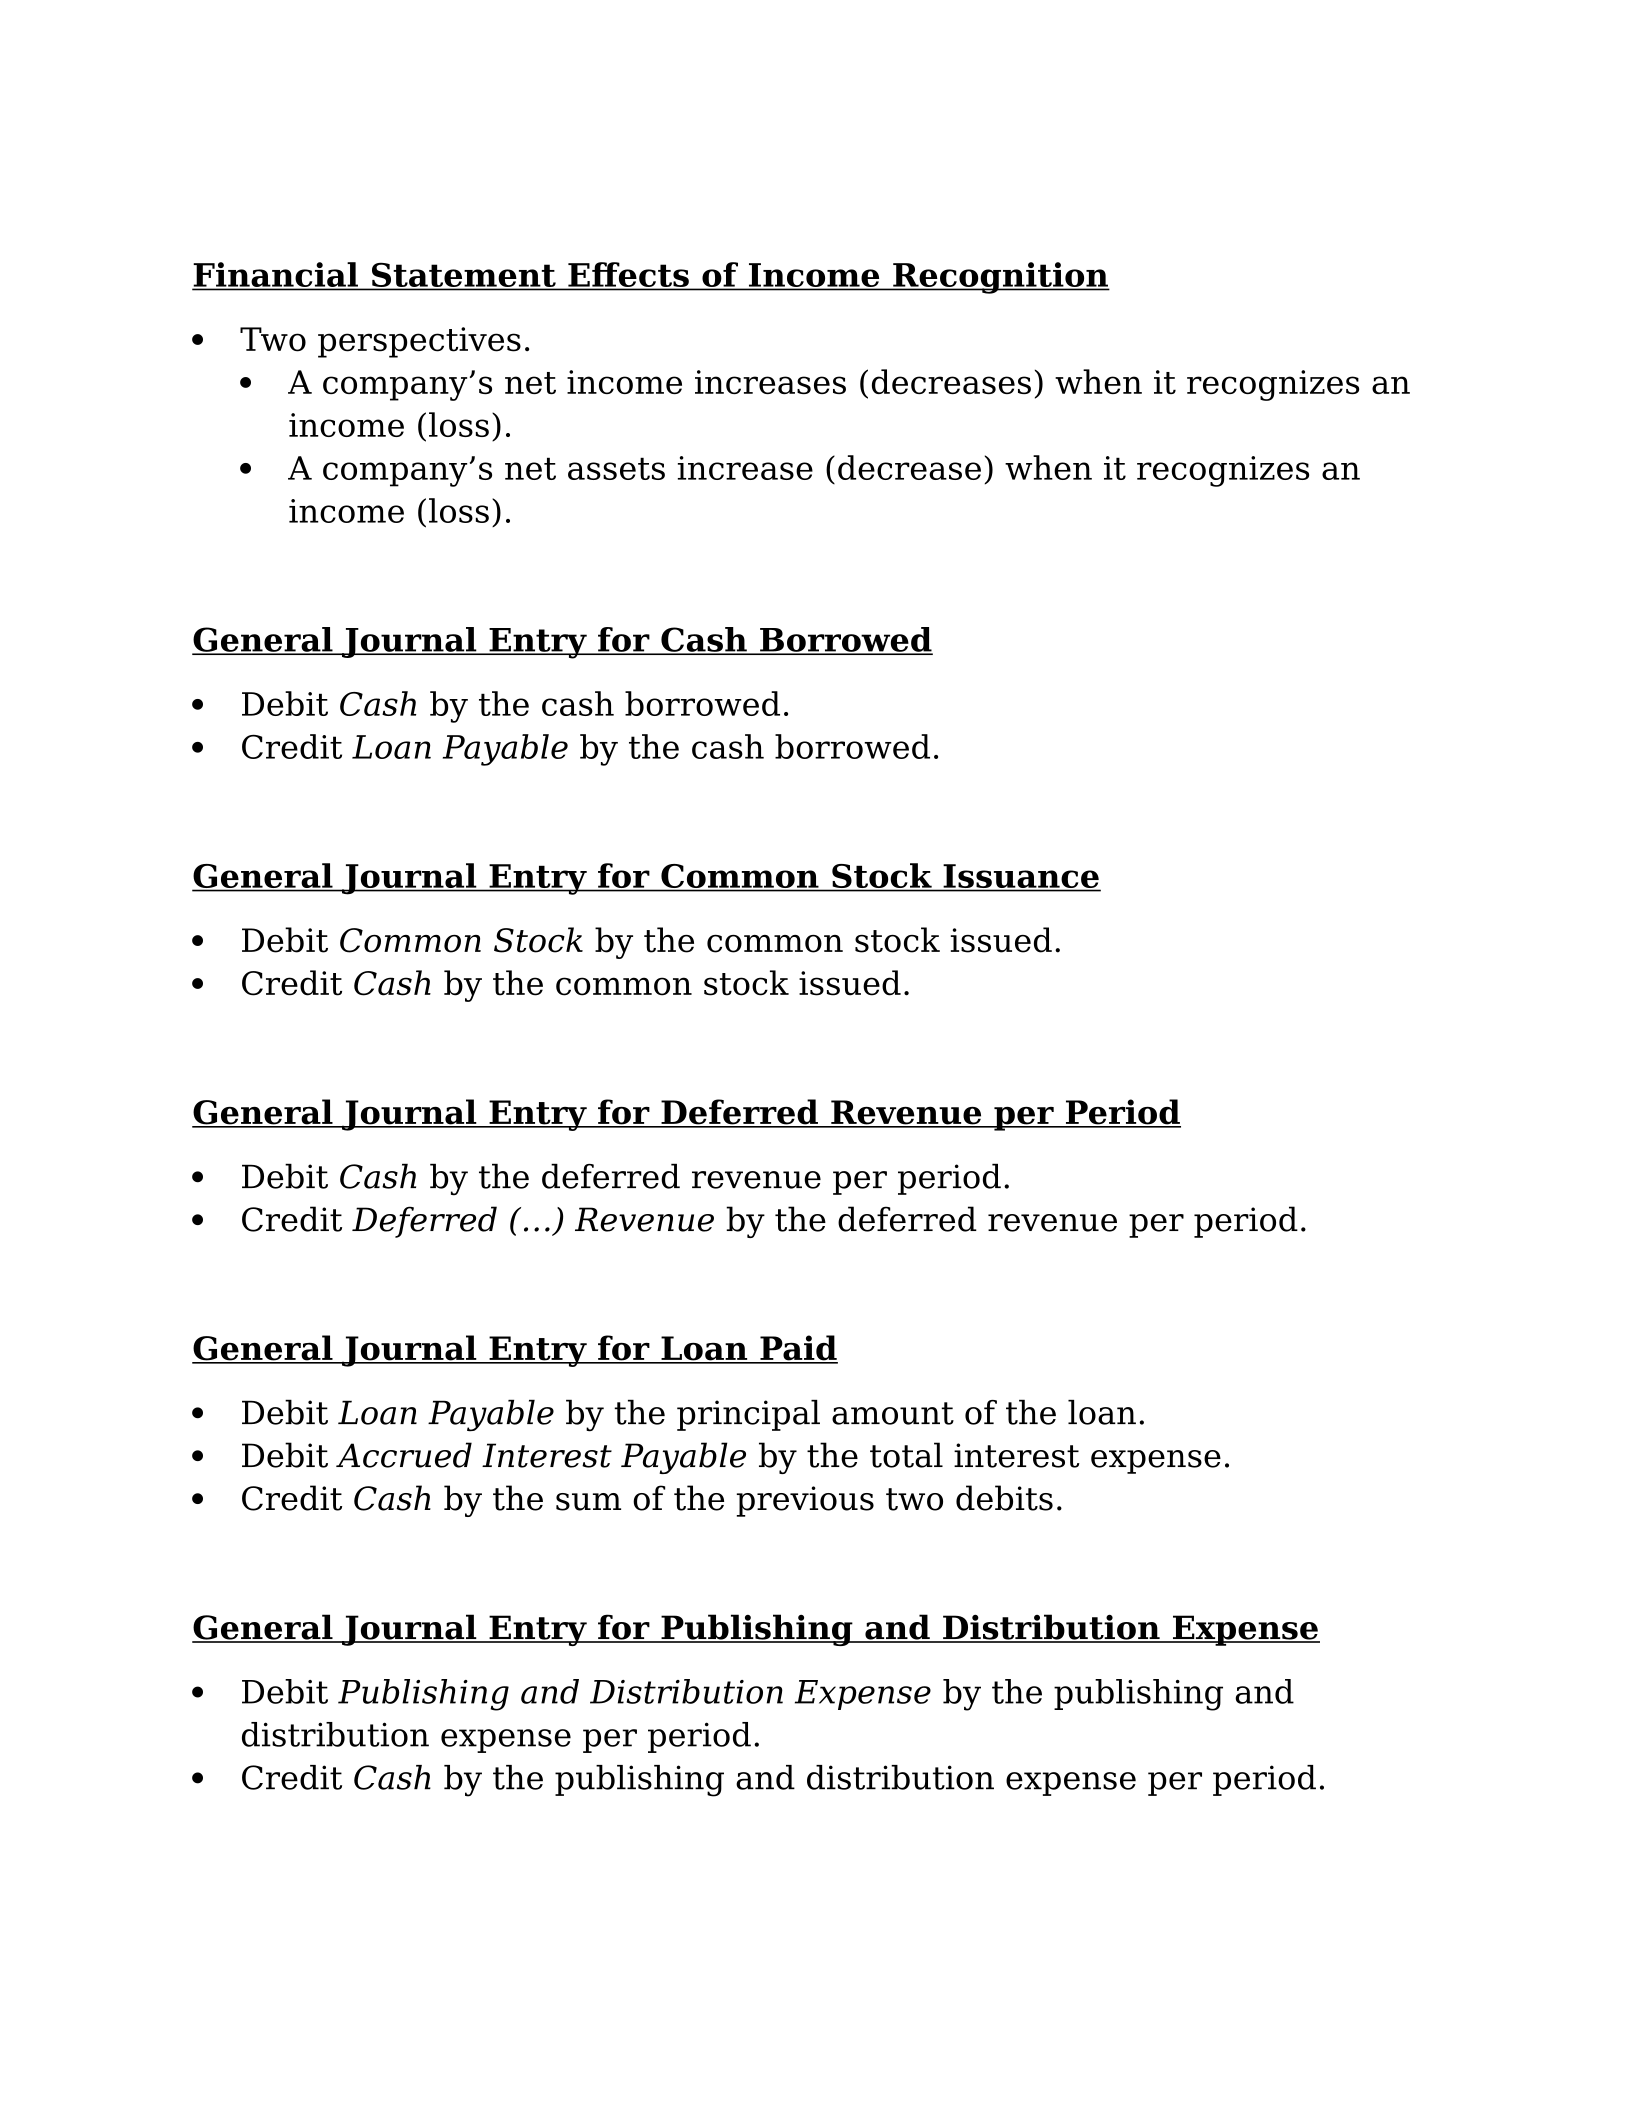
Financial Statement Effects of Income Recognition
Two perspectives.
A company’s net income increases (decreases) when it recognizes an
income (loss).
A company’s net assets increase (decrease) when it recognizes an
income (loss).
General Journal Entry for Cash Borrowed
Debit Cash by the cash borrowed.
Credit Loan Payable by the cash borrowed.
General Journal Entry for Common Stock Issuance
Debit Common Stock by the common stock issued.
Credit Cash by the common stock issued.
General Journal Entry for Deferred Revenue per Period
Debit Cash by the deferred revenue per period.
Credit Deferred (…) Revenue by the deferred revenue per period.
General Journal Entry for Loan Paid
Debit Loan Payable by the principal amount of the loan.
Debit Accrued Interest Payable by the total interest expense.
Credit Cash by the sum of the previous two debits.
General Journal Entry for Publishing and Distribution Expense
Debit Publishing and Distribution Expense by the publishing and
distribution expense per period.
Credit Cash by the publishing and distribution expense per period.
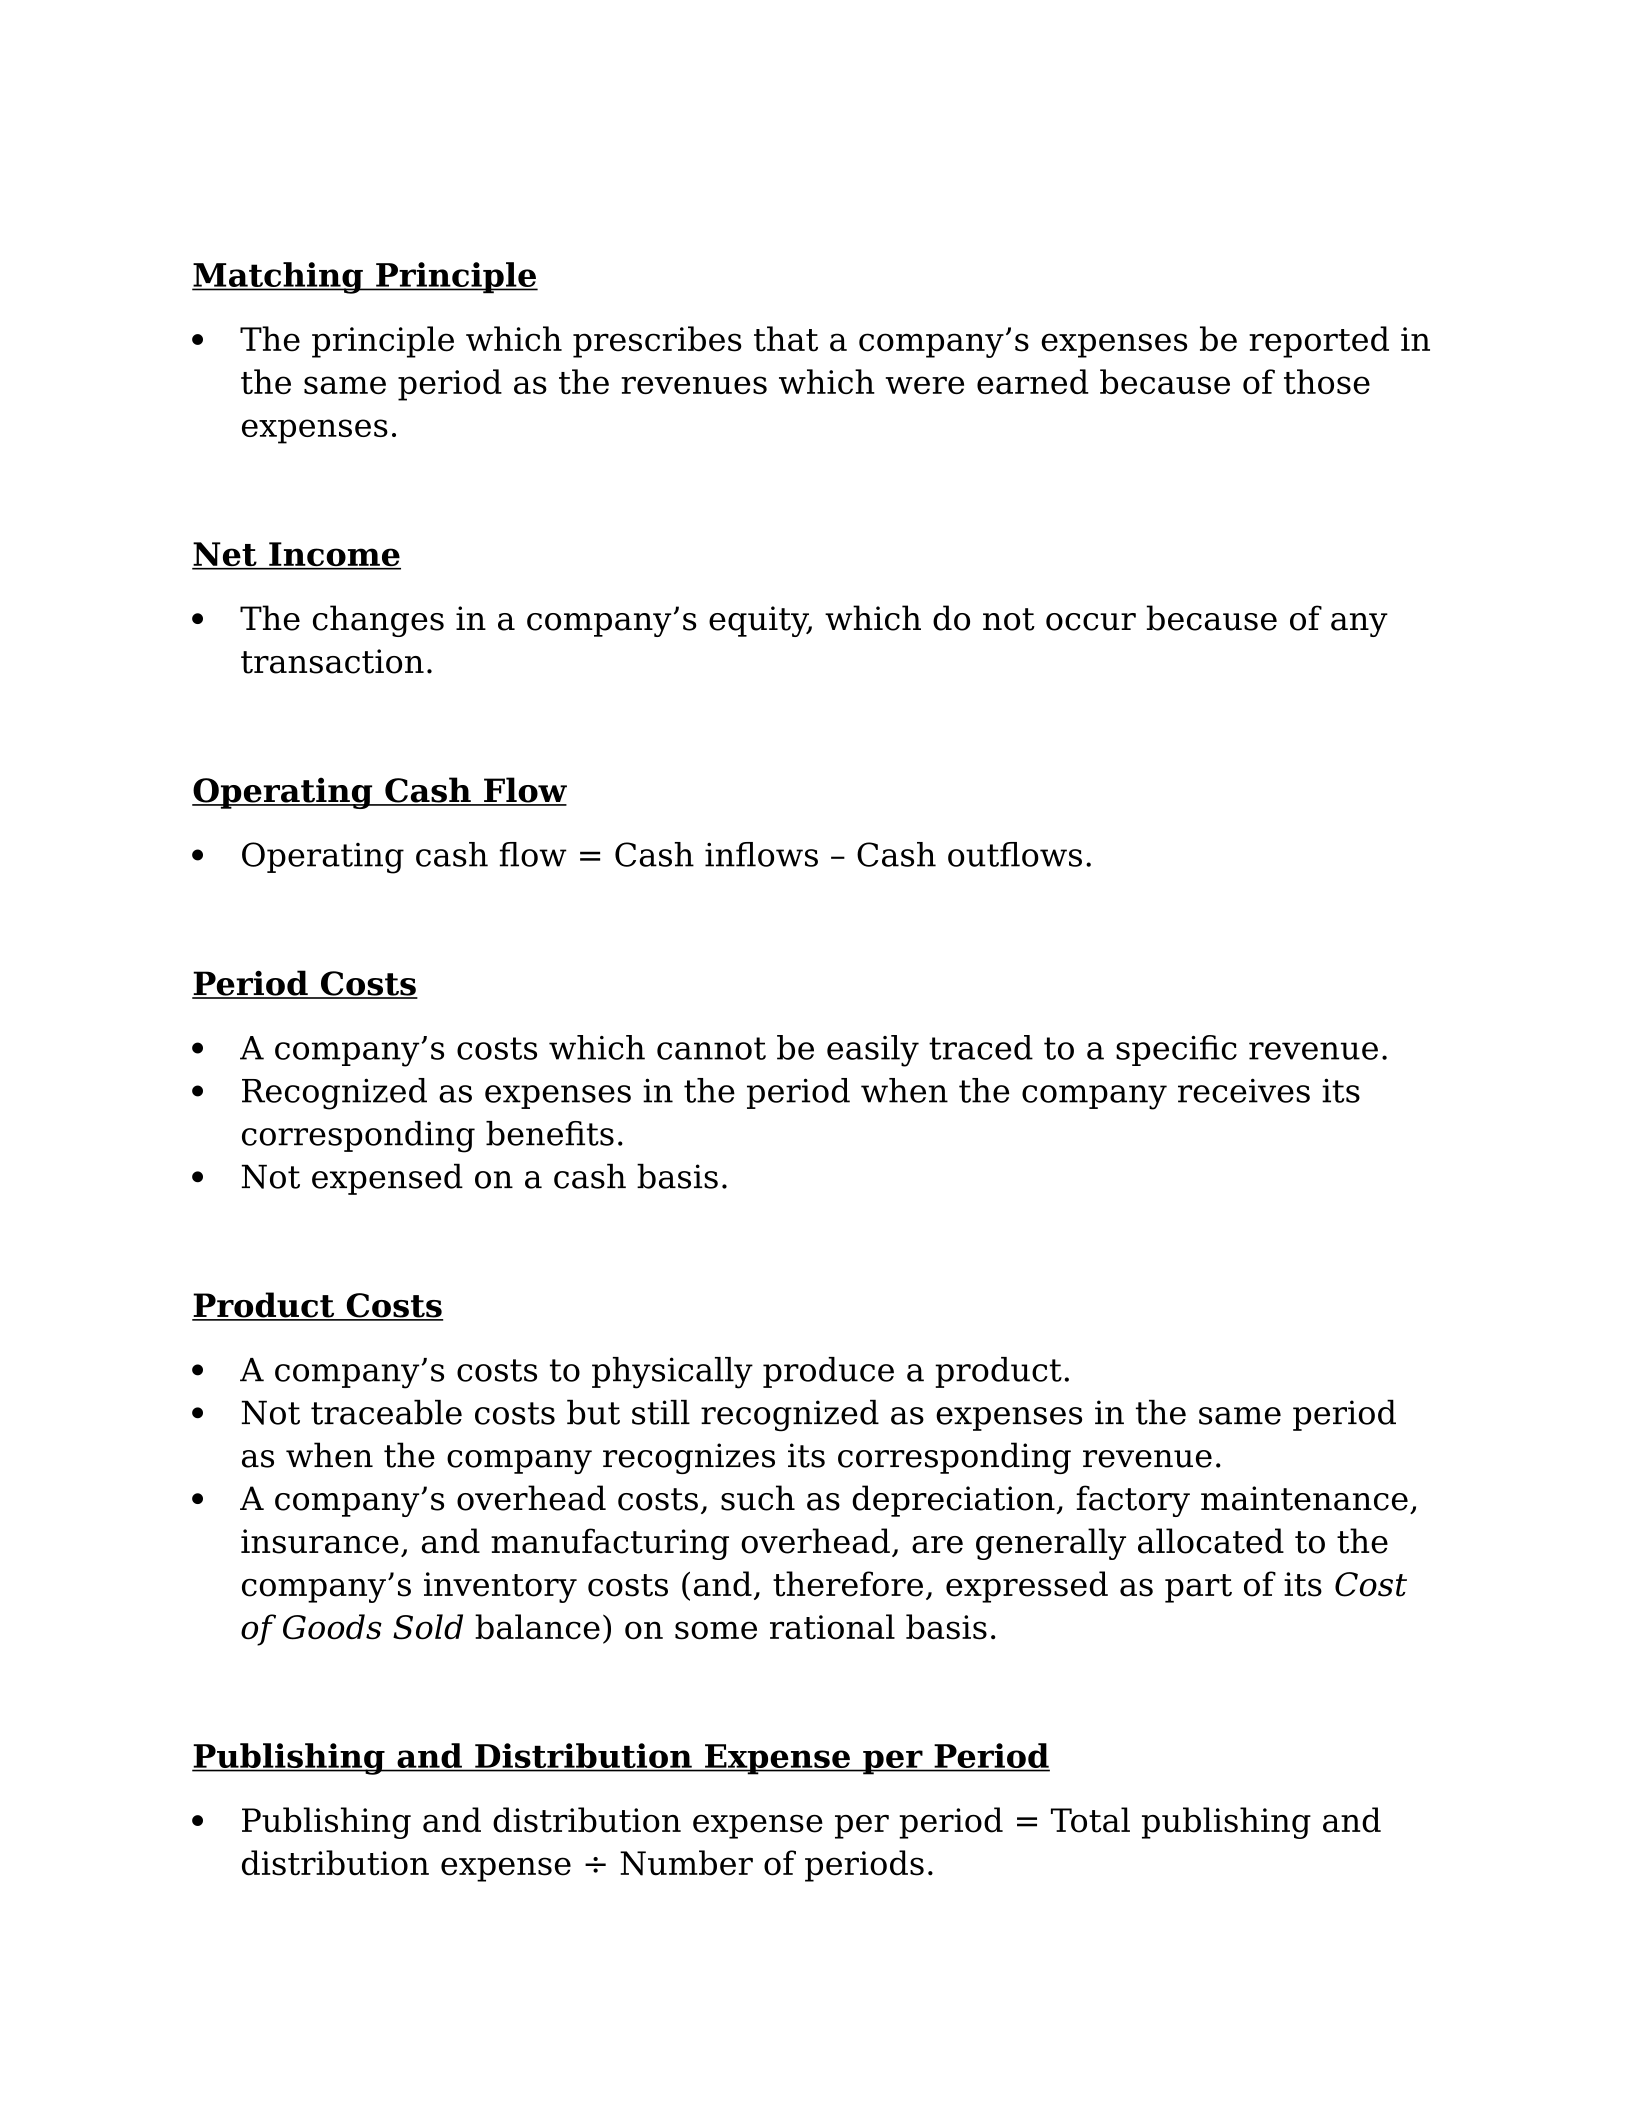
Matching Principle
The principle which prescribes that a company’s expenses be reported in
the same period as the revenues which were earned because of those
expenses.
Net Income
The changes in a company’s equity, which do not occur because of any
transaction.
Operating Cash Flow
Operating cash flow = Cash inflows – Cash outflows.
Period Costs
A company’s costs which cannot be easily traced to a specific revenue.
Recognized as expenses in the period when the company receives its
corresponding benefits.
Not expensed on a cash basis.
Product Costs
A company’s costs to physically produce a product.
Not traceable costs but still recognized as expenses in the same period
as when the company recognizes its corresponding revenue.
A company’s overhead costs, such as depreciation, factory maintenance,
insurance, and manufacturing overhead, are generally allocated to the
company’s inventory costs (and, therefore, expressed as part of its Cost
of Goods Sold balance) on some rational basis.
Publishing and Distribution Expense per Period
Publishing and distribution expense per period = Total publishing and
distribution expense ÷ Number of periods.
Retained Earnings
An equity account.
Represents all a company’s earnings since its inception, net of its
dividends.
Revenues
The cash which a company receives from its sales.
Recognized when a company has satisfied its contractual obligations to
provide goods or services to a customer by transferring control over
those goods or services to the customer.
Correspond to a company’s products delivered or services performed,
rather than its cash receipts.
Revenue Earned per Period
Revenue earned per period = Total revenue ÷ Number of periods.
Total Interest Expense
Total interest expense = (Principal amount of loan + Interest expense for
previous periods) × Interest rate.
Traceable Costs
A company’s costs which can be easily traced to a specific revenue.
Recognized as expenses in the same period as when the company
recognizes its corresponding revenue.
Powered by TCPDF (www.tcpdf.org)

