


Corporate Political Activity And Media Coverage Effects On
Strategic Change And Firm Performance
INTRODUCTION
Existing studies examining the relationship between corporate political activities and firm
performance come from various disciplines such as strategic management, economics, political
science, sociology and finance. Corporate political activities, defined as corporate attempts to
influence government policy in a way that favors the firm (Baysinger, 1984), are commonly used
by firms in various countries (Hillman, Keim, & Schuler, 2004). In the U.S., there is a rich
literature examining corporate political activities. Studies have shown that the majority (over
63%) of Washington lobbyists are hired by firms and trade associations (Baumgartner & Leech,
2001), showing the pervasive interest of businesses in influencing public policy. The dominant
view in management and political science literature is that a company’s corporate political
activities are positively associated with firm performance (Pfeffer & Salancik, 1978; Boyd, 1990;
Hillman, Keim, & Schuler, 2004). Such activities can directly increase firm performance by
influencing legislatures to pass laws that change market structures to a firm’s competitive
advantage
(Peltzman, 1976; Stigler, 1971), by getting government contracts (Blumentritt, 2003), by
obtaining licenses and permits to operate, and even by restraining the abilities of potential or
current competitors in the market. Corporate political activities can also indirectly lead to higher
firm performance by influencing public policy and creating an environment that favor its core

business, or by reinforcing social relationships between business executives and public officials,
thereby maintaining favorable business conditions (Clawson et al., 1998). Theories such as
resource dependence theory and industrial-organization economics support this view.
However, another research stream holds an opposite view; several recent empirical studies
propose that corporate political activities are negatively associated with financial performance
(Igan, Mishra, & Tressel, 2009; Aggarwal, Meschke, & Wang, 2012), and a firm’s political
contribution is negatively associated with market performance (Hadani et al., 2013). Despite
extensive research on both sides, scholars haven’t reached an agreement on this issue, and the
relationship between corporate political activities and firm performance remains complex and
unclear.
It is indisputable that firms are actively engaging in political activities not only in
Washington, but also globally, but most of the existing studies are U.S-centric or mainly focus on
Western countries, such as those in the European Union (Coen, 1997; Skippari, 2003), and Russia
(Kubicek, 1996). Few studies focus on Eastern countries like Japan (Angel, 2000; Broadbent,
2000) and South Korea (Kang, 2002), with even fewer focusing on China. Hillman and Keim
(1995) and North (1990) have proposed that the relationship between business and government,
more specifically politicians on the board of directors and firm performance, are likely to be
different in different institutional contexts. For example, in China, out of the 2,985 deputies in
the 10th National People’s Congress (2003-2008), 417 could be identified as business leaders of
companies, which means in the whole Congress, nearly 14% deputies were CEOs, CFOs, COOs
and general managers of companies.

The National People’s Congress (NPC) is the national legislature in China, with the ultimate
right to legislate, oversee government operations, and elect major government officers (Li &
Liang, 2015). Unlike other corporate political activities that “indirectly” influence public policy,
having a CEO in the Congress is the most effective and essential way to influence public policy
because in such a situation the business leader is simultaneously manager and policy maker.
Through legislation proposals, business leaders are able to propose nation-wide or region-wide
legislation to shape government regulations and produce a more favorable business environment
(Truex, 2014). According to the report of the 10th NPC, over 80% of the deputies’ proposals were
resolved in some way, and 50% resulted in policy improvement.
According to Forbes (2013), 71% of the top 500 richest Chinese business people have
political appointments. In contrast, in the U.S. 115th Congress (2017-2018), there were only 37
former CEOs in the House and 10 in the Senate (Manning, 2017). In the U.S., it is not
uncommon for current or former CEOs to be represented on presidential task forces or special
committees.
For example, in the G.W. Bush Administration, corporate executives had seats on the President’s
Energy Task Force and the Department of Commerce-led Advisory Committee on Trade Policy
Negotiations (Hillmann et al., 2004). Currently, however, there is no CEO on-the-job that is also
in either the House or the Senate (Manning, 2017).
The active participation of Chinese business leaders in political activities offers a dramatic
context in which to examine the relationship between a firm’s corporate political activities and its
performance. In China, the reforms and opening-up, the expanded institutional regulation and the

increase in the number of political interest groups have all stimulated corporate political activity,
especially in the past 20 years. As the role of the government and the scope of its regulatory
policies change over time, businesses must learn coping strategies for dealing with the
corresponding uncertainty in the system. In addition, given the unique political and economic
system of China, and the increasingly important political and economic roles that emerging
markets like China play in the world today, it is both important and interesting to explore firms’
political activities in the institutional context of China. By doing so, we can test current theories
and empirical findings from the Western context, expanding them into a totally different
institutional context. We can also gain a better understanding of the relationship between
business and government in China, which is in such a dramatic era of change.
Therefore, in this study, the relationship between corporate political activities and firm
performance will be explained through the lens of Chinese business leaders’ political
appointments, especially their legislation behavior in the Congress.
Further, we examine the relationship between having a business leader’s legislation
proposal(s) in the Congress and strategic change. Strategic change has been defined as the overall
change in a firm’s pattern of resource allocation in multiple key strategic dimensions (Finkelstein
& Hambrick, 1990; Carpenter, 2000), such as advertising intensity (advertising/sales), research
and development intensity (R&D/sales), plant and equipment newness (net P&E/gross P&E), non-
production overhead (selling, general, and administrative [SGA] expenses/sales), inventory levels
(inventories/sales) and financial leverage (debt/equity).

The reasons that we want to focus on the relationship between corporate political activity and
strategic change are as follows. First, this is the area that has received the least amount of attention
for at least two decades (Hillman et al., 2004). That is, companies’ efforts to better understand
internal procedures and routines related to effective implementation of corporate political activities
remain unclear. Second, timely strategic change is crucial as it reflects a company’s ability to
anticipate and respond to environmental change, which contains both opportunities and hazards.
According to Wiersema and Bantel (1992), possessing this ability is one of the most important
ways in which a company’s competitiveness and viability are ensured, but surprisingly, to our best
knowledge, there is no study examining the relationship between corporate political activity and
strategic change.
Last, we want to focus on “fame and fortune”. Media coverage of business leaders has
significantly increased in recent decades (Halff, 2013); CEOs in the Congress are “superstars”.
Recent empirical studies propose that media coverage of CEOs significantly increases firm value.
Nguyen (2015) has found that firms with the highest levels of CEO media coverage outperform
those with the lowest levels by 8% in abnormal stock returns. Russell Reynolds Associates (2003)
have surveyed institutional investors and have found that the presence of a “high-profile” CEO is
one of the factors influencing investment decisions. Hamilton and Zeckhauser (2004) have found
that as firm sales increase, the number of relevant articles in the New York Times increases, while
the overall percentage mentioning the CEO declines. However, earlier works such as that by Cutler
et al. (1989) examining the relationship between media coverage and movement of stock prices
find no evidence supporting the notion that media coverage could explain stock prices or aggregate

price movements. In other words, the media play on a small role, repeat only already-known news,
and do not convey useful information (Bendisch et al., 2013).
Despite the increasingly important role the media play in influencing business, scholars still
have not reached an agreement on this topic. Moreover, the relationship between a business
leader’s media coverage and a firm’s strategic change remains unclear.
This paper proceeds as follows. We first introduce the National People’s Congress of China,
its function and how CEOs and other business leader deputies are elected. Then we review the
existing theories and empirical studies examining the effects of business leaders’ legislation
behavior and media coverage on firm performance and strategic change. We then discuss our
study’s data and method. Lastly, we present our findings and conclude this study by explaining its
contribution to the literature.
Background information on Chinese business leaders’ political appointments
In this section, we describe the setup of the National People’s Congress of China (NPC), the
manner in which business leaders are appointed as deputies to the NPC and how they influence
public policy through legislation proposals.
The NPC is the national legislature of the People’s Republic of China. Under China’s current
Constitution, the NPC is structured as a unicameral legislature, a legislature that consists of only
one chamber or house. The NPC has the power to legislate and amend the Constitution if needed,
to oversee the operations of the government, to approve the Annual Report of Government Work,

and to elect the major officers of state, including the country’s President and the Premier of the
State Council.
There are People’s Congresses at five administrative levels: national, provincial, prefectural,
county and township. Representatives at the county level and below are elected directly by the
people, whereas the higher-level deputies are elected by the deputies of the congress directly
below them. In our sample, the NPC deputies, serving for a term of five years, were elected by
deputies serving at the provincial level. The whole NPC, which had 2,987 deputies in 2016,
meets once a year in Beijing for two to three weeks. Similar to the U.S. House of
Representatives, the NPC allocates seats to each province in proportion to its population, ranging
from 13 representatives for Taiwan to 175 representatives for Shandong.
The political appointment ratio of Chinese publicly listed private firms increased from around
22% in 1995 to 41% in 2012 (Li & Liang, 2015, see Figure 1). The ratio is defined as the number
of listed private firms whose CEOs or Chairs are People’s Congress or People’s Political
Consultative Conference (PPCC) members, divided by the total number of listed private firms.
--------------------------------------- Insert Figure 1
Here
---------------------------------------
There are also criticisms that the NPC is a “rubber stamp”, by which is meant an institution
that by law has considerable power but in fact has very little power. This “rubber stamp” label
implies that the entity rarely or never disagrees with more powerful institutions. In China, the more
powerful institution is the Chinese Communist Party (CCP). Political scientists such as O’Brien

(1990) believe that by the time a bill is placed before the NPC, the major content has already been
decided by the CCP or the government and the NPC deputies are expected to simply just vote it
through; the more powerful government organ uses the NPC to endorse and formalize laws in order
to create the superficial appearance of legislative process. One piece of evidence raised in support
of the “rubber stamp” label regarding the NPC is that it has seldom, if not never, rejected a law
brought to it by the government.
However, the NPC is not completely without influence; on the contrary, its influence is
increasing. The reason we rarely see any laws rejected by the NPC is because the manner in which
deputies attempt to influence the policy process is non-confrontational. This is partially due to the
deputies’ Chinese cultural background. Chinese people rarely criticize others openly and directly.
Even if they do so, they have to do it in in a very polite way that involves specific expressions (i.e.,
mianzi, or “saving face” for oneself and for the person being criticized), especially as it relates to
one’s social standing, prestige and reputation.
As a pro-economic development regime, the Chinese state is ideologically oriented toward
business (Kennedy, 2005). The CCP has written in its Party Constitution that “development is the
first priority of our Party in governing and rejuvenating the country”, and that “we shall continue
to make economic development the central task and stick to the pursuit of comprehensive,
coordinated and sustainable development.”
Business development is central to accomplishing these Party goals; business often “educates”
government officials, helping them to see problems from a business perspective, and business
cooperates with the government to achieve outcomes that benefit the company, the government

and the country as a whole. Often with authoritative and first-hand knowledge of the economy and
industry, business leaders in the NPC have earned a “privileged position” at the policy-making
table.
THEORY AND HYPOTHESES
Business leaders’ proposal(s) and firm performance
Pfeffer and Salancik’s (1978) publication, The External Control of Organizations: A
Resource Dependence Perspective, is recognized as the pioneering and foundational work on
resource dependence theory, which proposes that resources are key to organizational success and
that access and control over resources is a basis of power: “The organization, through political
mechanisms, attempts to create for itself an environment that is better for its interest”, and
“organizations may use political means to alter the condition of the external economic
environment.” Therefore, business leaders in the NPC actively seek to create their environment
by trying to shape government regulations to produce a more favorable environment for their
firms.
However, we believe that scholars holding this view ignore the very critical fact that in the
NPC, business leaders’ proposals are mainly industry- or sector-specific laws. In other words,
business leaders are interested in policies that affect their own sector or the whole industry.
Business leaders almost never propose legislations that could only benefit their own firms, such
as obtaining licenses and permits to operate, getting loans etc. The obvious reason is that they do
not want to be considered “selfish”, since by definition they are the deputies of the people, not

their own companies. Also, in order for a proposal to be presented to and considered by the NPC,
a minimum number of 30 deputies are required to sign off on the proposal, which significantly
adds to the difficulty of proposing legislation that only benefits one company.
Evidence has shown that Chinese CEO and business leader deputies propose and advance
policies that favor their industries. For example, during the annual NPC conference in 2015, the
CEO of Tencent Technology, Ma Huateng, proposed motions regarding legislation on the Internet
and digital industry, Tencent’s industry. The CEO of Geely Holding Group, Li Shufu, proposed
motions on green energy automobiles, driverless cars and automatic driving at the NPC annual
conference in both 2016 and 2017. He also called for reforms of the taxi services in the country.
Geely is a Chinese multinational automotive manufacturing company whose main products are
automobiles, taxis, motorcycles, engines, and transmissions. It sells passenger cars under the
Geely and Volvo brands and taxis under the London Taxi brand. Although there is no information
revealed at the national level regarding the result of each individual proposal, we can observe
that the digital industry and the industry of electric and eco-friendly automobiles have received
substantial financial support from the government in recent years. The proposals by Mr. Ma and
Mr. Li thus benefit the industries they are in, not just Tencent and Geely.
Therefore, we believe that having proposals in the NPC will only lead to firm performance
conformity, that is, “typical performance” among peer firms.
Hypothesis 1: A business leader with NPC proposal(s) is positively associated with
performance conformity.

Business leaders’ proposal(s) and strategic change
Regarding proposed legislation, most draft laws circulate between the NPC, the State Council,
and relevant government ministries for months, some even for several years, before they are
finalized and made publicly available. The average time it takes for proposed legislation to be
finalized and made law is around 2 to 5 years, with very rare exceptions. This period of time is
extremely valuable to firms with their business leaders in the NPC because they can change their
business strategies and adjust their business practices based on their understanding of the
formulation and execution of future policy changes. This early access to important legislation
information provides these firms with a great “insider’s advantage”, which cannot be easily
achieved by non-NPC firms, or the “outsiders”.
Timely strategic change is crucial as it reflects a company’s ability to anticipate and respond
to environmental change, but such change could contain both opportunities and dangers. As the
legislation process is a long one that usually lasts years and involves a large degree of uncertainty,
business leaders who have proposals in the NPC know that change is coming but cannot be sure
when and to what extent. This uncertainty drives them to maintain the status quo, or as the old
Chinese saying goes: 以不变应万变 (“counter changes with changelessness”). Therefore, they
are less likely to engage in strategic change, at least during their congressional tenure.
Another relevant factor is called the “distraction effect”. The NPC deputies are all part-time
deputies and almost all of them have full-time jobs. The whole NPC only meets once a year, but it
is not the yearly two-week meeting that decides the fate of any particular legislation bill. Rather, it
is expected that any disagreements should be resolved ahead of time and consensus should be

reached behind closed doors months or even longer before the annual meeting convenes. NPC
deputies and government officials initiate direct contact long before any official policies are
adopted. Such exchanges can be initiated by either side during the proposition and consideration
of specific regulations and laws (Kennedy, 2005). In the case of economic- or business-related
legislation, the government may ask for a meeting regularly with business leader deputies from
certain industries, and in order to finalize proposals, business leaders can also invite government
officials to attend certain meetings of industry or business associations over policy issues. There
are also many other forms of direct interaction between deputies from industry and the government.
For example, the NPC often sends delegations to meet with local governments, scholars and
researchers, business associations, companies or even employees in various cities, to gain opinions
on certain legislation, or investigate policy issues. This study, research and investigation process
is a very critical regulatory duty of deputies. In 2016, more than 1,700 NPC deputies participated
in such activities, and the total number of legislation proposals in 2016 was 8,239 (Annual Report
of NPC Standing Committee, 2016). Ministries at the national and regional level can hold formal
or informal hearings to get opinions from industry, and industry leaders often invite deputies to
visit their companies or even participate in press conferences and new product announcements,
using these occasions to bring up development and policy issues. Contrary to popular belief,
deputies’ policy proposals calling for new legislation or revision of existing laws are taken quite
seriously by the CCP and the government, because deputies have been in their fields for a long
time, during which they have investigated and researched issues; legislation proposals are
considered first-hand resources, and therefore can significantly affect ultimate policy changes

(Jiang, 2003). According to Truex (2014), 77% of the deputy proposals are resolved in some way,
and 50% result in policy improvement.
The research and investigation process occupies a large amount of business deputies’ time and
therefore causes business leaders to be distracted and less likely to focus on strategic change.
Therefore, we propose that if a business leader has NPC proposal(s), his or her company is less
likely to engage in strategic change.
Hypothesis 2: A business leader with NPC proposal(s) is negatively associated with strategic
change.
The effects of business leaders’ media coverage on firm performance and strategic change
Ego identity theory (Erikson, 1968) is a major individual development theory. The theory
proposes that the ultimate purpose for individual development is self-fulfillment. Business leaders
in the NPC have dual roles, and some have even more. They represent both the NPC and their
companies, and most importantly, they represent themselves. Their multiple roles require them to
focus on fulfilling a deputy’s responsibilities, increasing firm performance and achieving personal
goals. According to this theory, business leaders seek political appointments mainly for self-
benefit. Before entering the NPC, business leaders focus on firm performance as it is a major and
critical component of their self-benefit. However, after achieving business success and entering
the NPC, business leaders move to a different life stage: from self-orientation to social orientation,
a life stage with the ultimate purpose of serving others and society.

In a recent study by Li and Liang (2015), those two scholars find that in China, the more socially
motivated successful individuals are, the more they feel obligated to contribute to the greater
good of society. Therefore, business leaders are more likely to spend resources and effort in
pursuing political appointments, such as NPC membership. Once the business leaders enter the
NPC, they have already proved that they were successful business leaders and they have
received recognition from the government, and the political activities offer less marginal
economic benefits. The next stage is self-fulfillment, which is a socially-oriented life stage.
Furthermore, studies have shown that CEOs with prominent media profiles are likely to
prioritize their personal achievement and own success above that of the company (Collins,
2001); this is especially the case for our “business stars” in the NPC.
Taking all of this together, we expect that a greater volume of business leaders’ media coverage
is likely to lead companies towards “typical performance”, or performance conformity, and that
media coverage is negatively associated with strategic change, mainly because when business
leaders move to the self-fulfillment life stage and are actively involved in political activities, they
may be inclined to maintain the status quo of business, as it has proved successful in the past.
Hypothesis 3: Business leaders’ media coverage is positively associated with performance
conformity.
Hypothesis 4: Business leaders’ media coverage is negatively associated with strategic
change.
Figure 2 captures the hypothesized relationships in this study.

--------------------------------------- Insert Figure 2
Here
---------------------------------------
DATA AND METHODS
Sample
We analyzed a large firm-level dataset provided by the National Bureau of Statistics (NBS) of
China for the period 2002-2009, containing an average of 289,600 firms each year. NBS conducted
annual surveys of all state-owned enterprises and those non-state-owned enterprises with annual
sales above 5 million RMB, or 762,000 USD. The dataset covers 37 manufacturing industries all
over China. In 2004, for example, the firms in the dataset accounted for over 95% of China’s total
industrial value, produced over 90% of its output, generated 97.5% of its exports and employed
over 72% of its industrial workforce.
From the dataset, we generated a sample of 365 firms with business leaders in the National
People’s Congress, which account for 87.5% of the total firms that have business leaders in the
NPC. We define a business leader as a chairman, CEO, CFO, COO or a general manager of the
company.
The information reported to NBS should be quite reliable (Cai & Liu, 2009; Brandt et al.,
2012). There are several reasons why scholars believe this to be so. Firstly, the purpose of the
NBC survey is to calculate the country’s Gross Domestic Product (GDP). Every industrial
company is required by the government to file an annual report of basic company information,

production activities, accounting and financial information etc. Since 1995, NBS has established
strict collection, calculation and double-checking procedures regarding this dataset. NBS also
assigns every firm a legal identification number and tracks each company’s ownership changes.
Secondly, NBS’s policies clearly state that “the use of materials regarding units and individuals
collected in the economic census shall be strictly limited to the purpose of the economic census
and shall NOT be used by any unit as the basis for imposing penalties on respondents of the
economic census.” Therefore, companies do not have clear incentives or motivations to misreport
their information to NBS, because such information should not and cannot be used against them
by other government agencies such as the tax authorities. Thirdly, we understand that the
misreporting of statistical data from China is a concern, but most misreporting occurs with local
GDP data provided by local governments (Cai & Liu, 2009). This dataset, however, was directly
collected by the central NBS, and therefore we can reasonably believe that it is less likely to have
been manipulated by local governments.
Sometimes a firm receives a new ID as a result of restructuring, merger or acquisition. We
created numerical IDs to manually link firms over time, using information such as firm name,
address, industry, major product and establishment date to link them. Finally, we obtained a sample
of 2,212 observations of 365 companies.
Demographic information regarding the NPC deputies was collected from the official NPC
deputy database, which provides deputy information such as name, age and educational
background, as well as all other important background information. Additional information
regarding the deputies, such as tenure in the company, tenure in the Congress, and whether the

business leader was the company founder, was collected from deputies’ official company websites,
and also from Baidu Encyclopedia (www.baidu.com), which is the Chinese version of Wikipedia.
Similar to Wikipedia, Baidu has profiles of NPC deputies and major company leaders.
Measures
Performance conformity. According to Hiller and Hambrick (2005), conformity refers to the
extent to which a focal firm behaves like a “typical firm” in the industry or among its peers and
avoids deviation from industry standards or norms. To measure performance conformity, we
calculated a firm’s return on assets (ROA) and compared it with the average ROA of the sample.
If the performance of the focal firm is within 10% of the average of the all firms in the sample,
variable Performance conformity was coded “1”.
Strategic change. Following Finkelstein and Hambrick (1990) and Zhang (2010), we used five
key strategic dimensions to generate a composite measure of changes in allocation of resources:
R&D intensity, advertising intensity, nonproduction overhead expenses, inventory levels and
financial advantage.
Media coverage was measured as the natural logarithm of the number of media reports. We
used Python3 software to collect and content-analyze business leaders’ media reports from Sina
Finance. Sina (http://www.sina.com.cn) is the largest website in China and has over 100 million
registered users worldwide. Sina Finance is believed to be the most comprehensive website
containing company financial information, business leaders’ news reports and other business
related news and reports. The other reason we used Sina Finance to search business leaders’

media reports was that by doing so we could significantly reduce duplicated news reports and
therefore avoid double-counting of news. Unlike Google or Baidu Encyclopedia
(www.baidu.com), Sina Finance rarely has duplicated reports on business leaders. To quantify
business leaders’ exposure to media and in order to make sure the search results were accurate,
we did the following. We counted the number of articles that reported a business leader’s
activities. In the report, the role of a business leader could be a leader of a company, a deputy of
the NPC, or both. We used the following combinations to search the media: a business leader’s
full name and his or her company name; a business leader’s full name and the abbreviation of his
or her company name; a business leader’s full name and “NPC member” (ren da dai biao). The
time range was from 2002 to 2009: starting one year before their Congress membership started
and ending one year after their membership ended. Also, because the “key words” we searched
were in Chinese, we needed to encode the string of new features to “GB2312”, the code format in
“search.sina.com.cn”. Through Python3, we were able to run the codes and export the search
results to an excel sheet. We also manually cross checked at least half of the results and found
them to be very satisfactory.
Proposal was measured as a binary variable, coded “1” if a business leader in the observation
year submitted a legal proposal as the primary sponsor to the NPC and “0” if not.
To control for any confounding effects of business leaders’ personal characteristics, we also
controlled for their age, tenure, level of education, founder status, international experience,
status of being a former official and gender. Vast research has shown that those demographic
traits relate to business leaders’ cognition and influence firms’ decisions. Additionally, we also

included government ownership, coded as “1” if the government had any ownership of the focal
firm and “0” if otherwise.
Analysis and results
Given the unbalanced panel data, both fixed-effects and random-effects models were
considered. To decide between fixed or random effects, we ran a Hausman test (Hausman, 1978)
after regressing the dependent variables on all other variables, where the null hypothesis was that
the preferred model was the random-effects model and the alternative the fixed-effects model
(Greene, 2008). The Hausman test showed that there were no systematic differences of coefficients
between the fixed and random models. Therefore, random-effects models were appropriate for
testing all three hypotheses.
A Wald test showed the presence of heteroskedasticity after running simple OLS
regressions for all three dependent variables. Therefore, our analyses used robust standard errors
to correct for heteroskedasticity (Huber, 1972; White, 1982).
Table 1 shows the descriptive statistics including means, standard deviations and
correlations among the variables. The mean of the natural logarithm of media coverage was 2.171,
which was about 145 times the number of media reports in numeric terms. In any given year, about
4.4% of business leaders submitted at least one proposal to the NPC. The average age of business
leaders in our sample was about 53 years old, they had on average held the position for about 18
years, and on average had a college degree. Nearly 10% of them were former government officials,

45% of them had some international experience, and 8% of them were female. Among all firms,
about 10% were owned or partially owned by the government.
To assess the multicollinearity among the variables, we calculated variance inflation factors
(VIFs) after conducting a simple OLS regression for each of the dependent variables. For both
models, the mean of the VIFs and the VIF for each variable were below the conventional criteria
(VIF < 10) (O’Brien, 2007). Therefore, we included all variables in the model as there was no
indication of multicollinearity concerns.
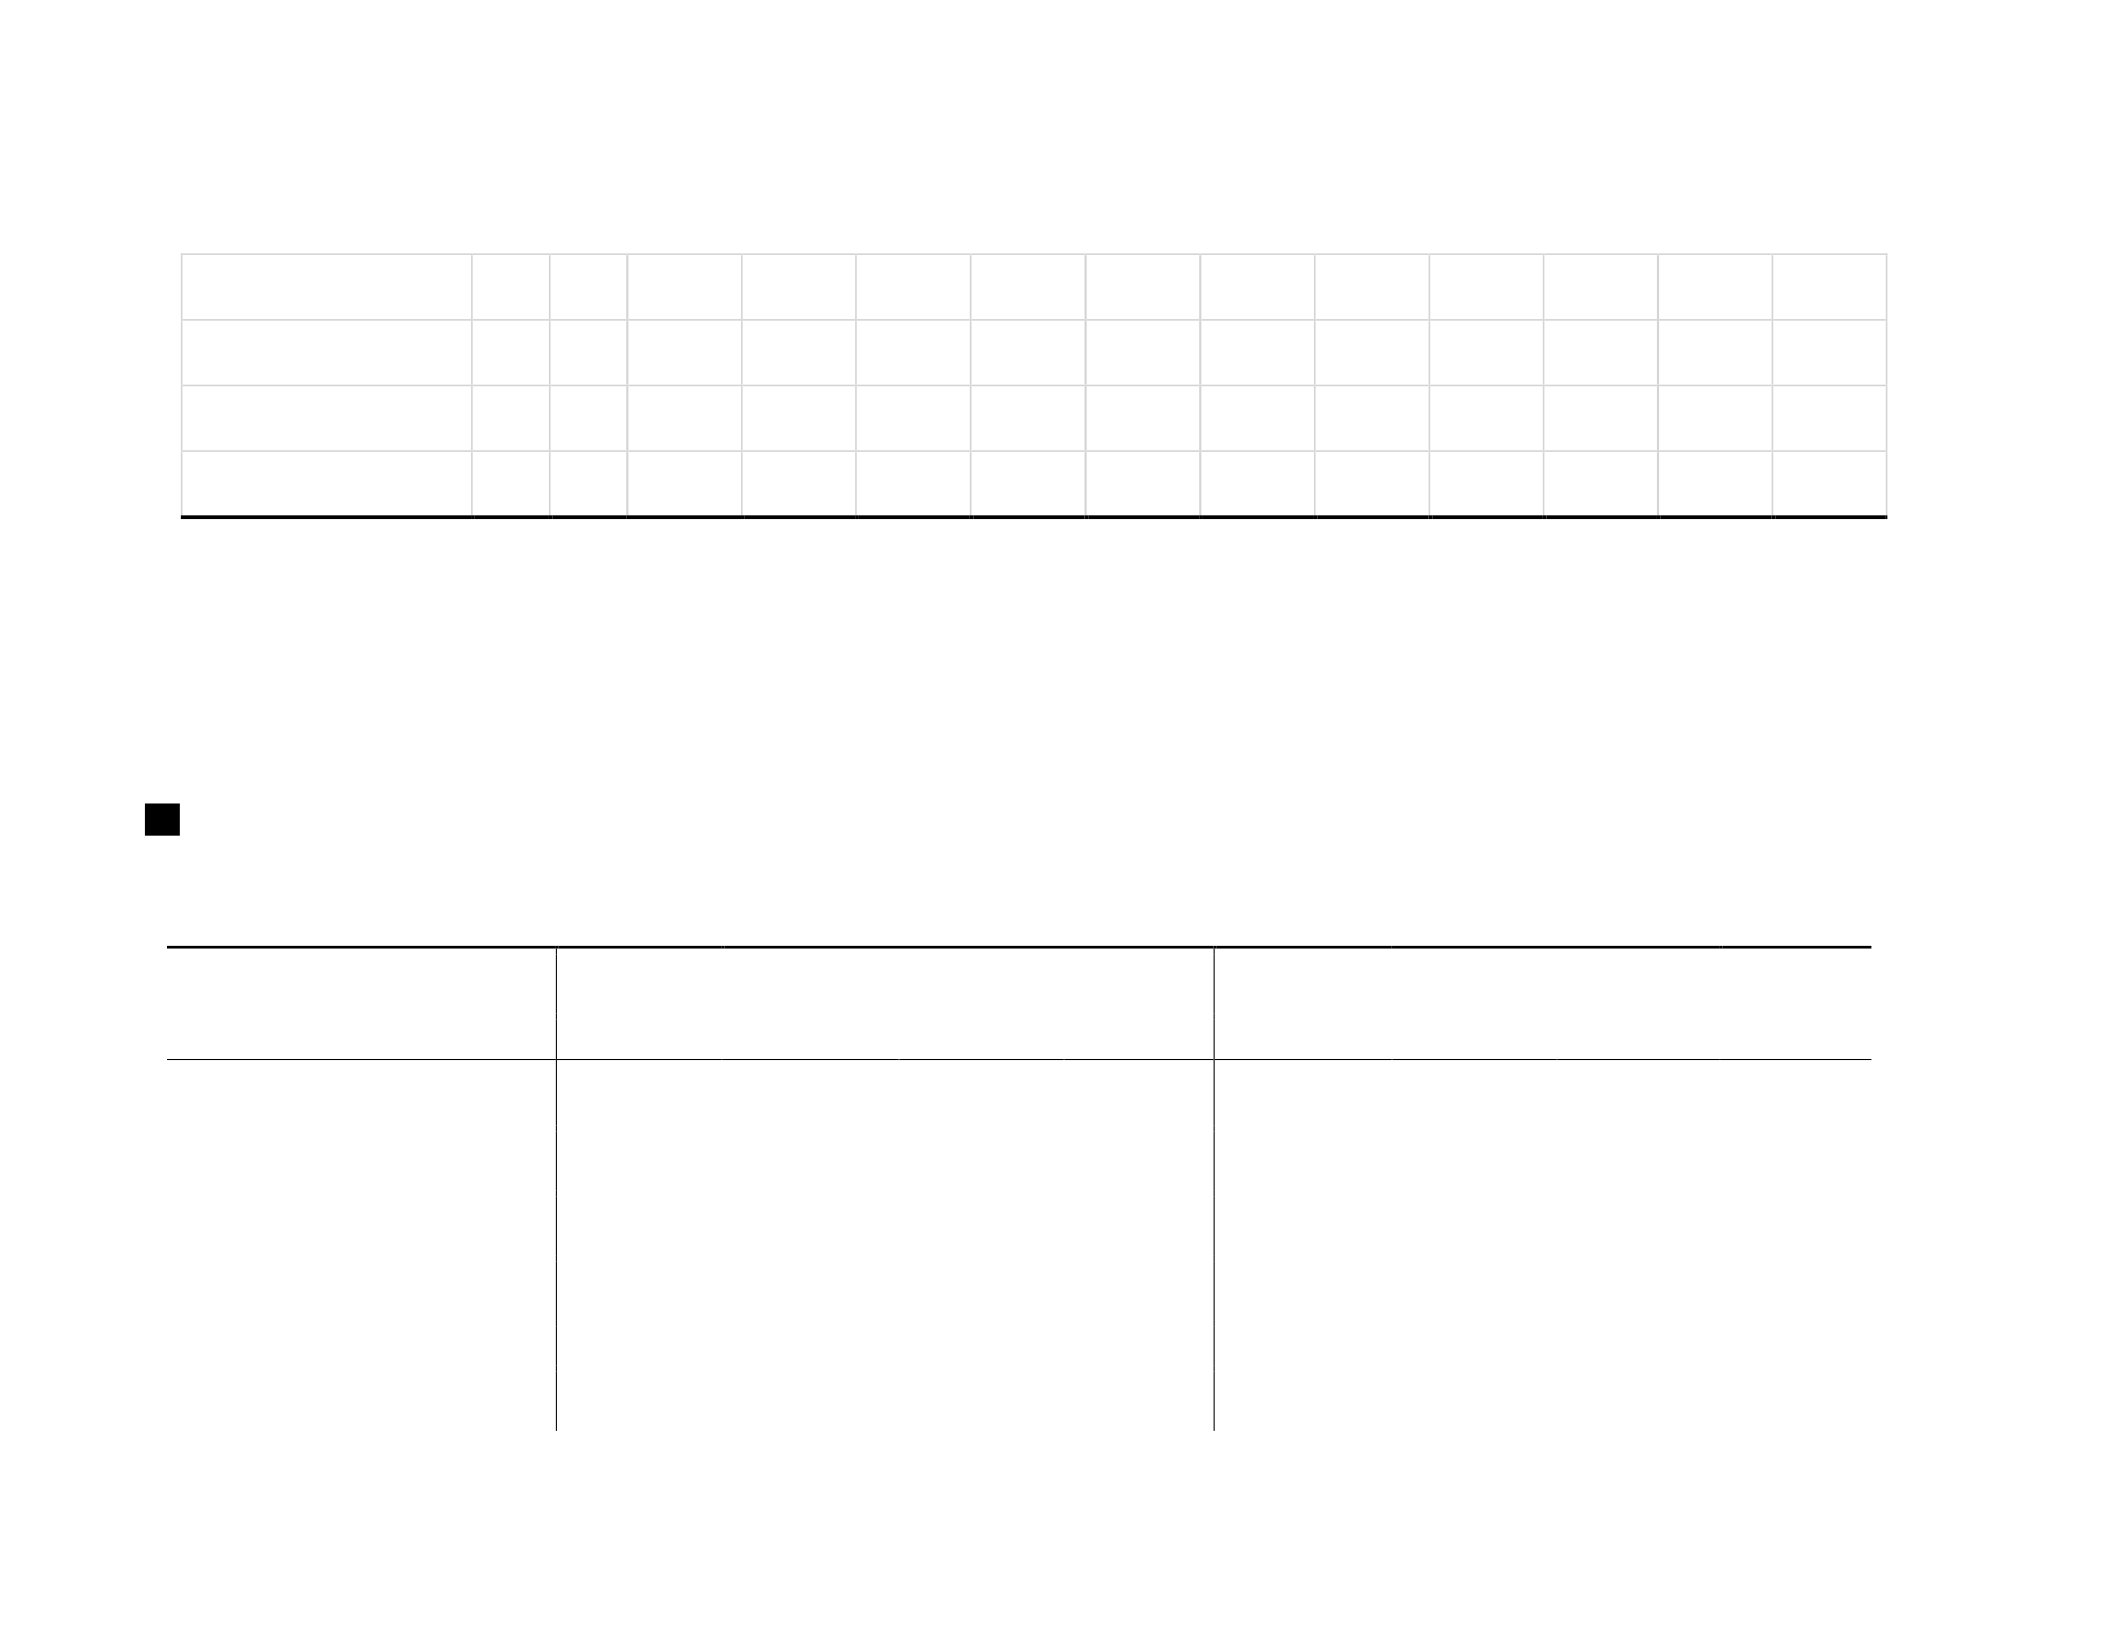
As shown in Table 2, we developed eight sets of random-effects regression models. Models
1-4 are logit models where the dependent variable is performance conformity. Model 1 includes
only control variables (business leader and firm characteristics). Models 2-4 add the independent
variables to examine the effects of media coverage and proposal on performance conformity.
Similarly, Models 5-8 examine the effects of our independent variables on strategic change. Model
5 includes control variables only, and Models 6-8 include the independent variables.
-----------------------------------------------------
Insert Table 1 and Table 2 here
-----------------------------------------------------
H1 is not supported. As shown in Models 2 and 4 in Table 2, the coefficient for proposal was
not significant. In H2, we hypothesized a positive relationship between media coverage and
performance conformity. Models 3 and 4 examine this proposed relationship. We found that media
coverage was positively associated with firm performance conformity and that the coefficient for
media coverage was significant (p < .050), providing support for Hypothesis 2.

Both H3 and H4 are supported. As shown in Models 6-8, the coefficient was negative and
significant for both proposal (p < .050) and media coverage (p < .001), suggesting that business
leaders who submitted proposals to the NPC or received a high level of media coverage would
make fewer changes to their organizations.
CONCLUSION & DISCUSSION
We examined the intriguing phenomenon that an increasing number of Chinese business
leaders, both from state-owned and private-owned enterprises, are seeking political appointments
in the NPC. This study contributes to the literature on corporate political activity and firm
performance. This research helps us to better understand the consequences of Chinese business
leaders’ political appointments in the NPC, especially the effects of their legislation behaviors on
firm performance and strategic change.
By collecting and analyzing a sample of 365 business leaders in the NPC, we were able to
apply and expand Western individual development theories, such as Ego identity theory (Erikson,
1968), to an ancient Eastern culture and the unique institutional context of China.
We also contributed to the literature on business leaders’ media coverage and its consequences
on firm performance and strategic change.
Future research could explore the following questions: What are the antecedents of Chinese
business leaders’ political appointments? We understand that a business leader in the Congress
has reach a new life stage and firm performance may not be their top priority, but what exactly
drives business leaders to seek political appointments? Also, can we apply findings regarding the

relationship between corporate political activities and firm performance in Western countries
such as the U.S. and the U.K. to China (i.e., creating a matching sample of firms with/without
CEOs in the Congress, and investigating the effects of congressional membership on firm
performance)?
Furthermore, industry-level variables have received little attention. Research has shown that
some firms in heavily regulated industries are more critically affected by public policies than
others (Lang & Lockhart, 1990). This suggests that although business leaders’ political
appointments may be beneficial for all firms, these linkages are even more important for those in
heavily regulated industries. So the question becomes: what kind of firms and industries would
benefit more from such political appointments?
Other industry-level variables, such as industry concentration and competitors’ political
activities, could also impact firm’s corporate political activities. Concentration within an industry
generally refers to the degree to which a small number of firms provide a major portion of the
industry’s total production. If concentration is low, then the industry is considered to be
competitive. If the concentration is high, then the industry will be viewed as oligopolistic or
monopolistic. In a highly concentrated industry, because of the fewer total number of firms and the
presence of only a few dominant firms, firms should be more motivated to seek political attachment
and gain influence on public policies since the political payoffs are much higher than those for
firms in fragmented and less-concentrated industries. In addition, competitors’ political activities
could also influence a business leader’s motivation to seek political appointment. Schuler et al.
(2002) have found that in the U.S., firm-level political activities are positively associated with

overall industry-level political activities. Hersch and McDougall (2000) report that American and
Japanese automakers regularly match each other’s political donations. Skippari (2003) examines
how firms in Finland both competed and cooperated with rivals to gain favorable political
outcomes, which also suggests that intra-industry dynamics play a very important role in
influencing corporate political activities. In China, we expect to find similar phenomena. For
example, in the IT industry, almost all of the CEOs from major dominant firms have political
appointments.
Meanwhile, future research could also examine relationship between location and the
antecedents and consequences of political appointment. That is, are firms from certain parts of
China more willing to build such connections with the government? Are companies in certain
districts greater beneficiaries of political appointments? What are the differences across different
districts?
Lastly, it would be very interesting to investigate the impact of different Congress levels on
the relationship between political appointment and firm performance. There are five
administrative levels of Congress in China (national, provincial, prefectural, county and
township), and it is relatively difficult and takes a longer time for business leaders to propose
legislation at the national level. Would it be relatively easier to propose similar legislation at the
provincial or county level? These questions have important practical implications and are left for
future research for answer.
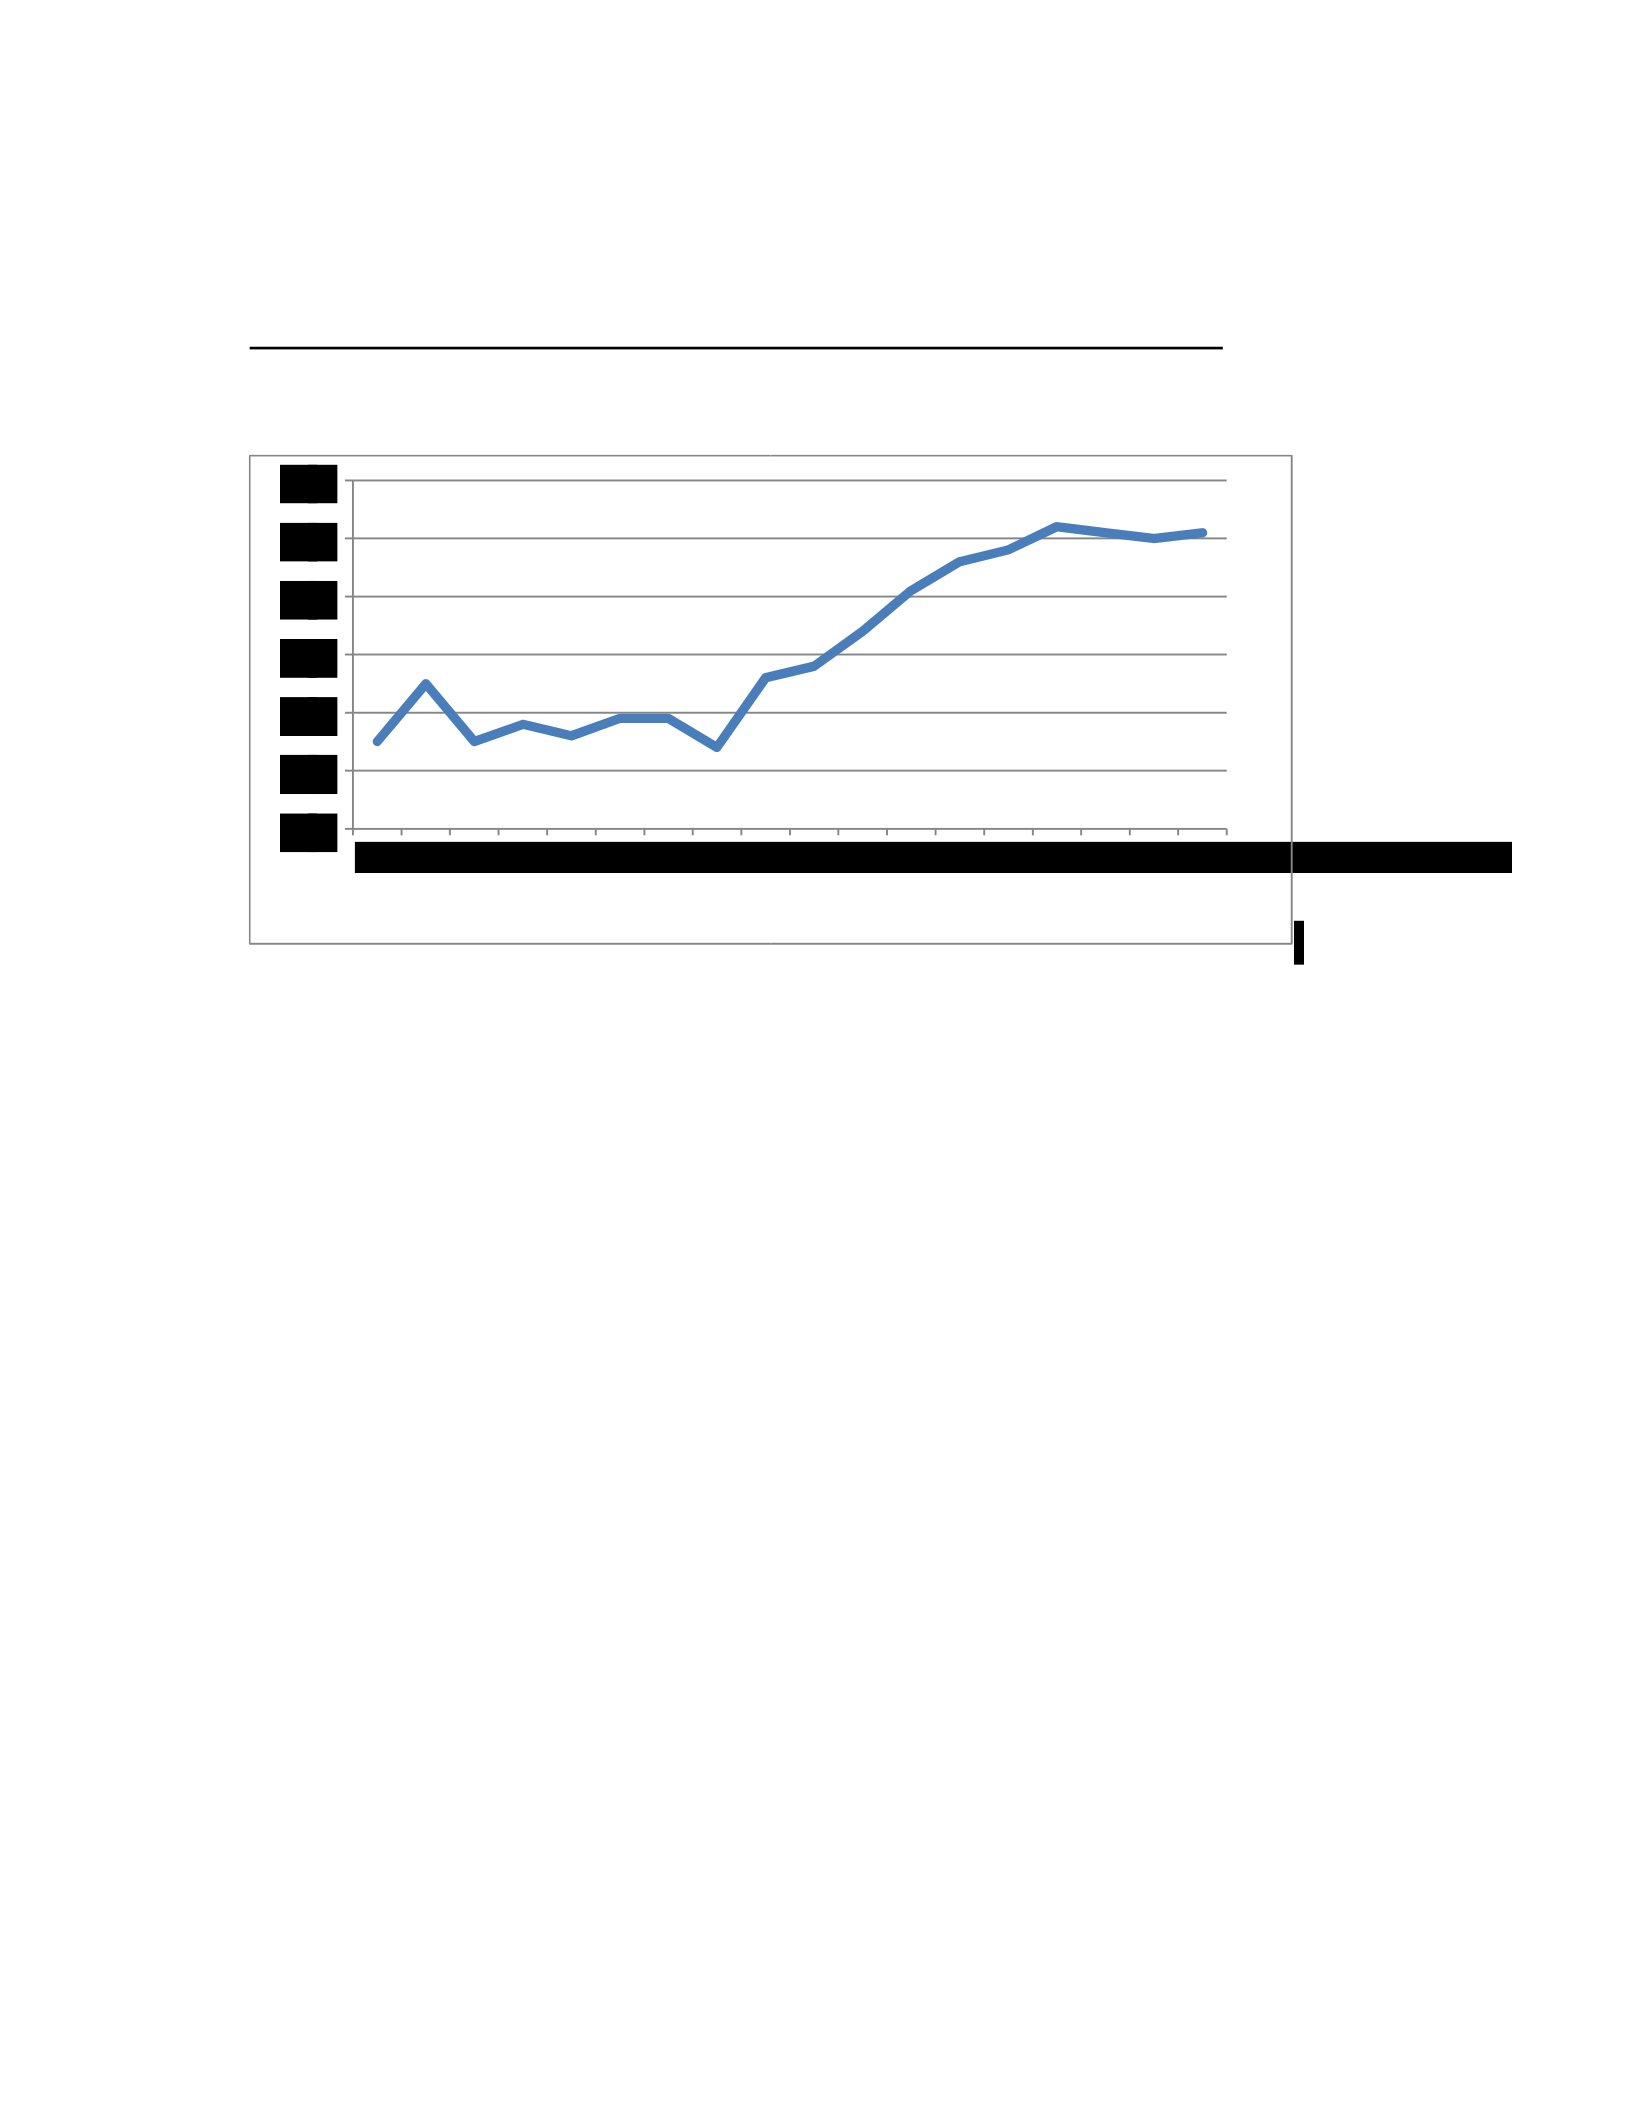
Figure 1
Political Appointment Ratios in Chinese Publicly Listed Private Firms, 1995-2012
Political Appointment Ratio = Number of listed private firms whose CEOs or Chairs were PC or PPCC members /
Total number of listed private firms
Data from Li & Liang (2015)
15
%
20
%
25
%
30
%
35
%
40
%
45
%
199519961997199819992000200120022003200420052006200720082009201020112012
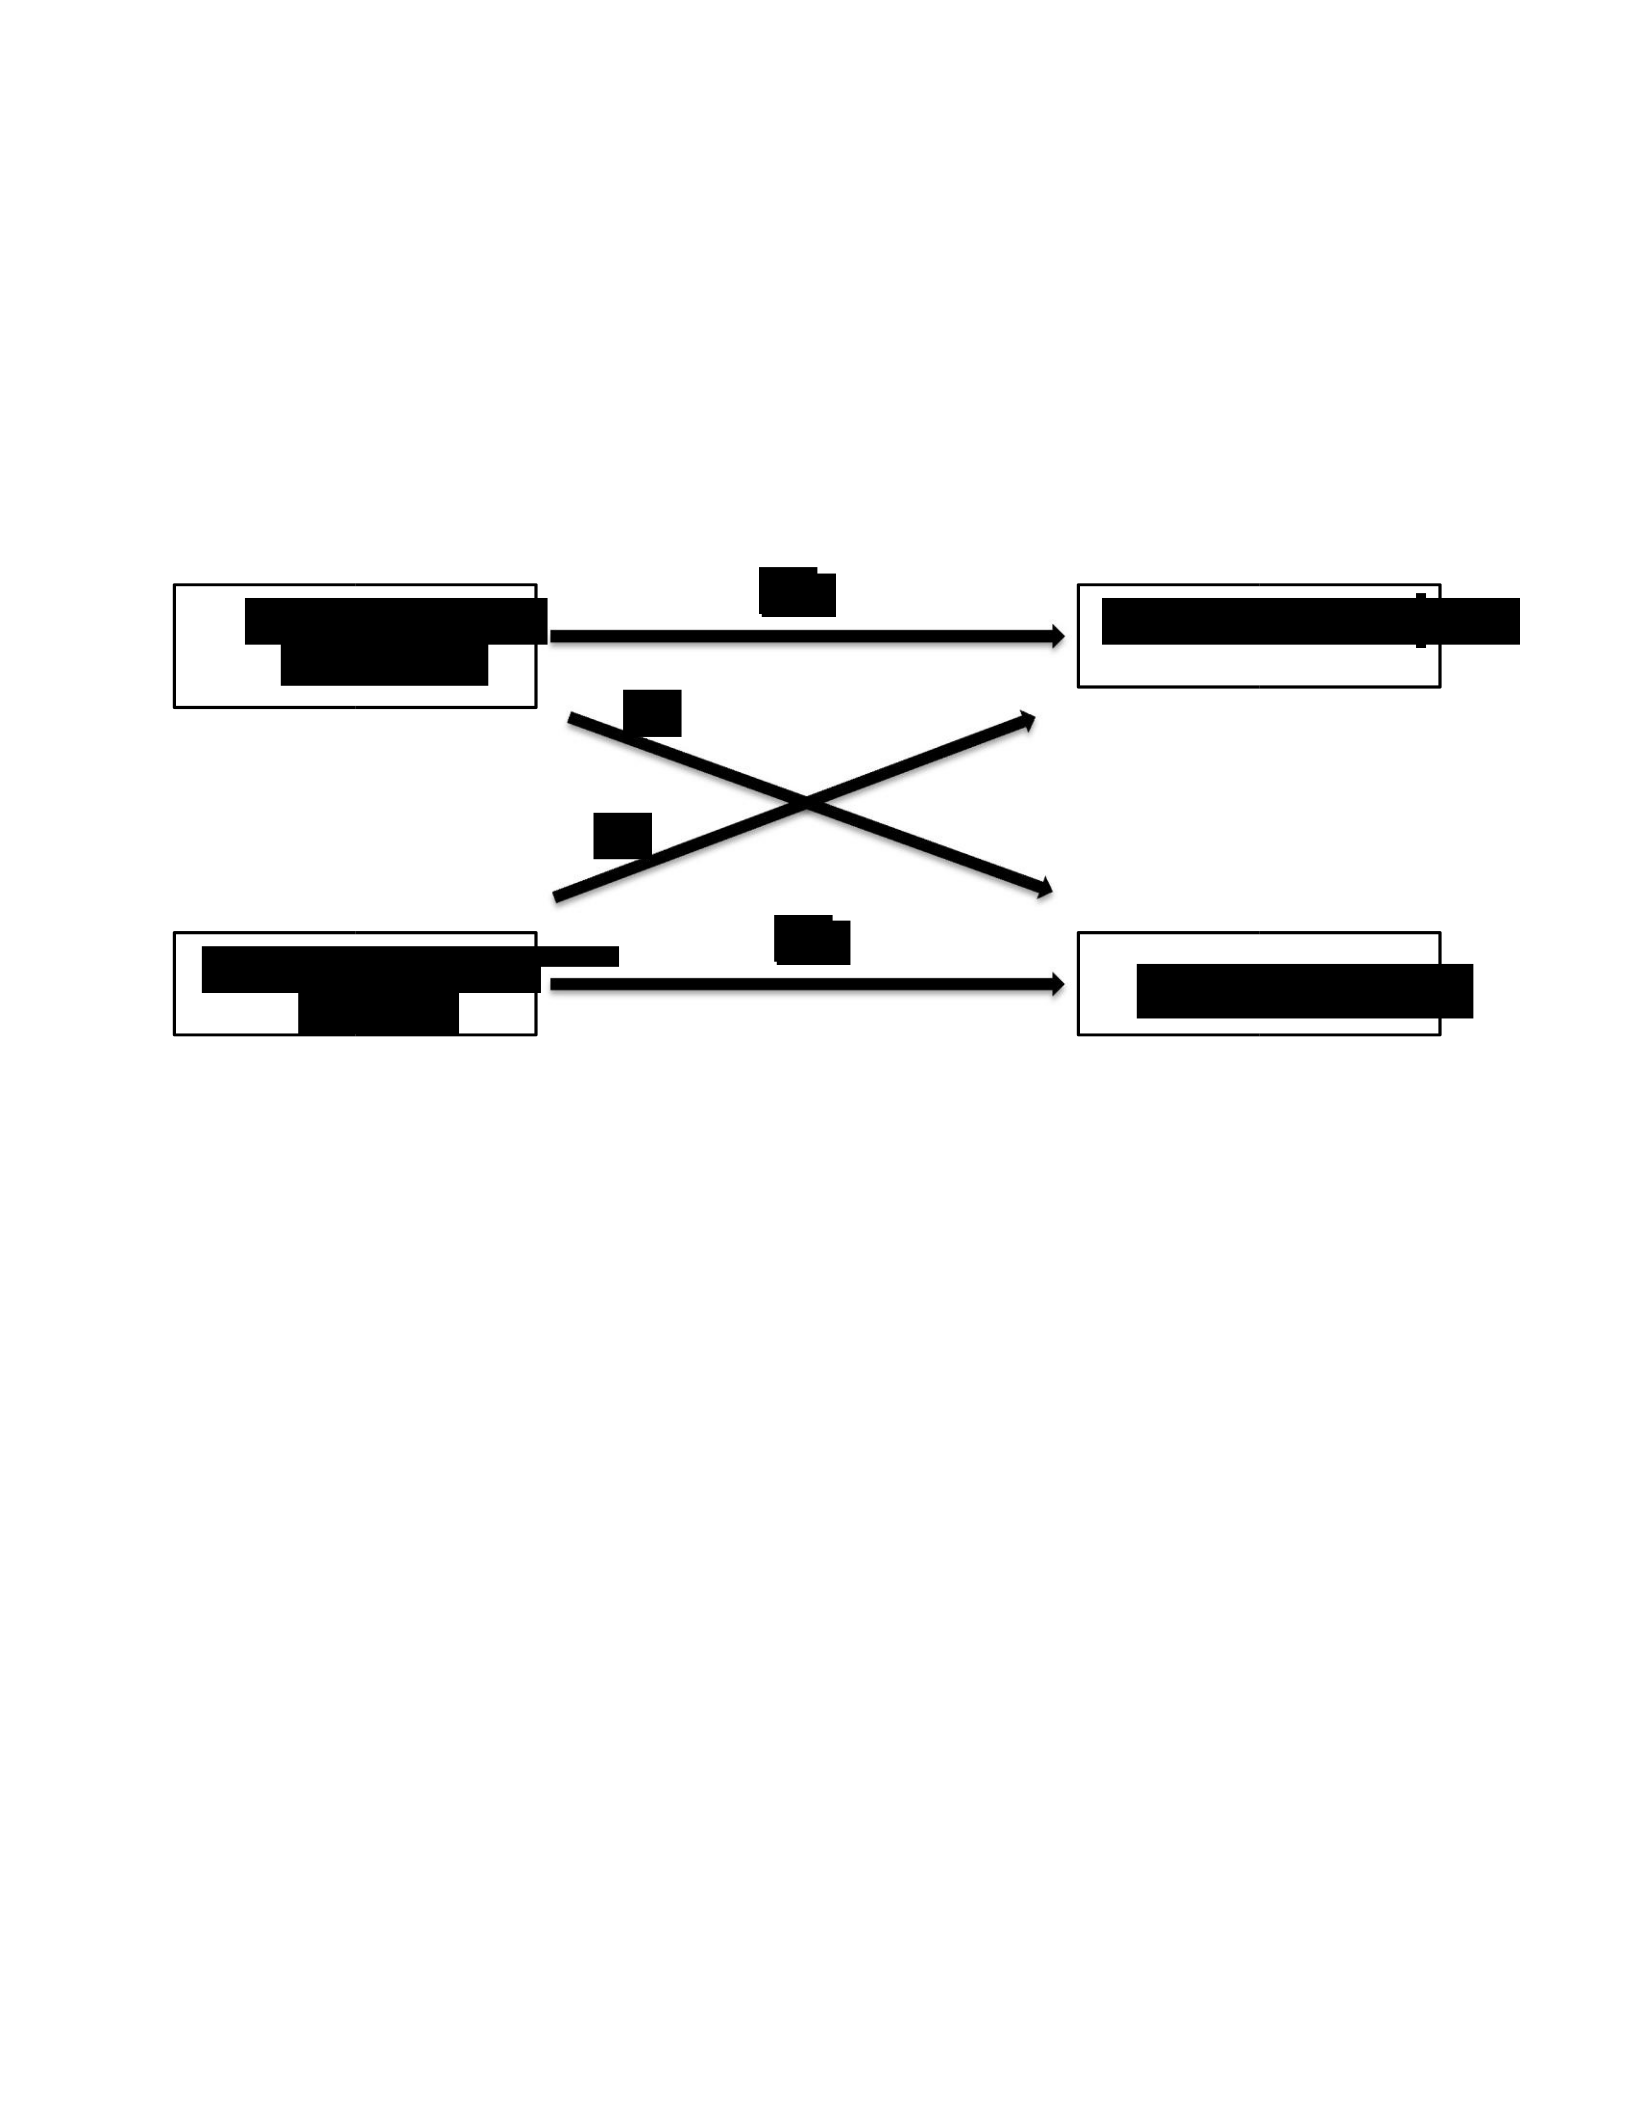
FIGURE 2
Theoretical Model
Business leader’s media
coverage
Business leader’s
proposal(s)
Performance conformity
Strategic change

25
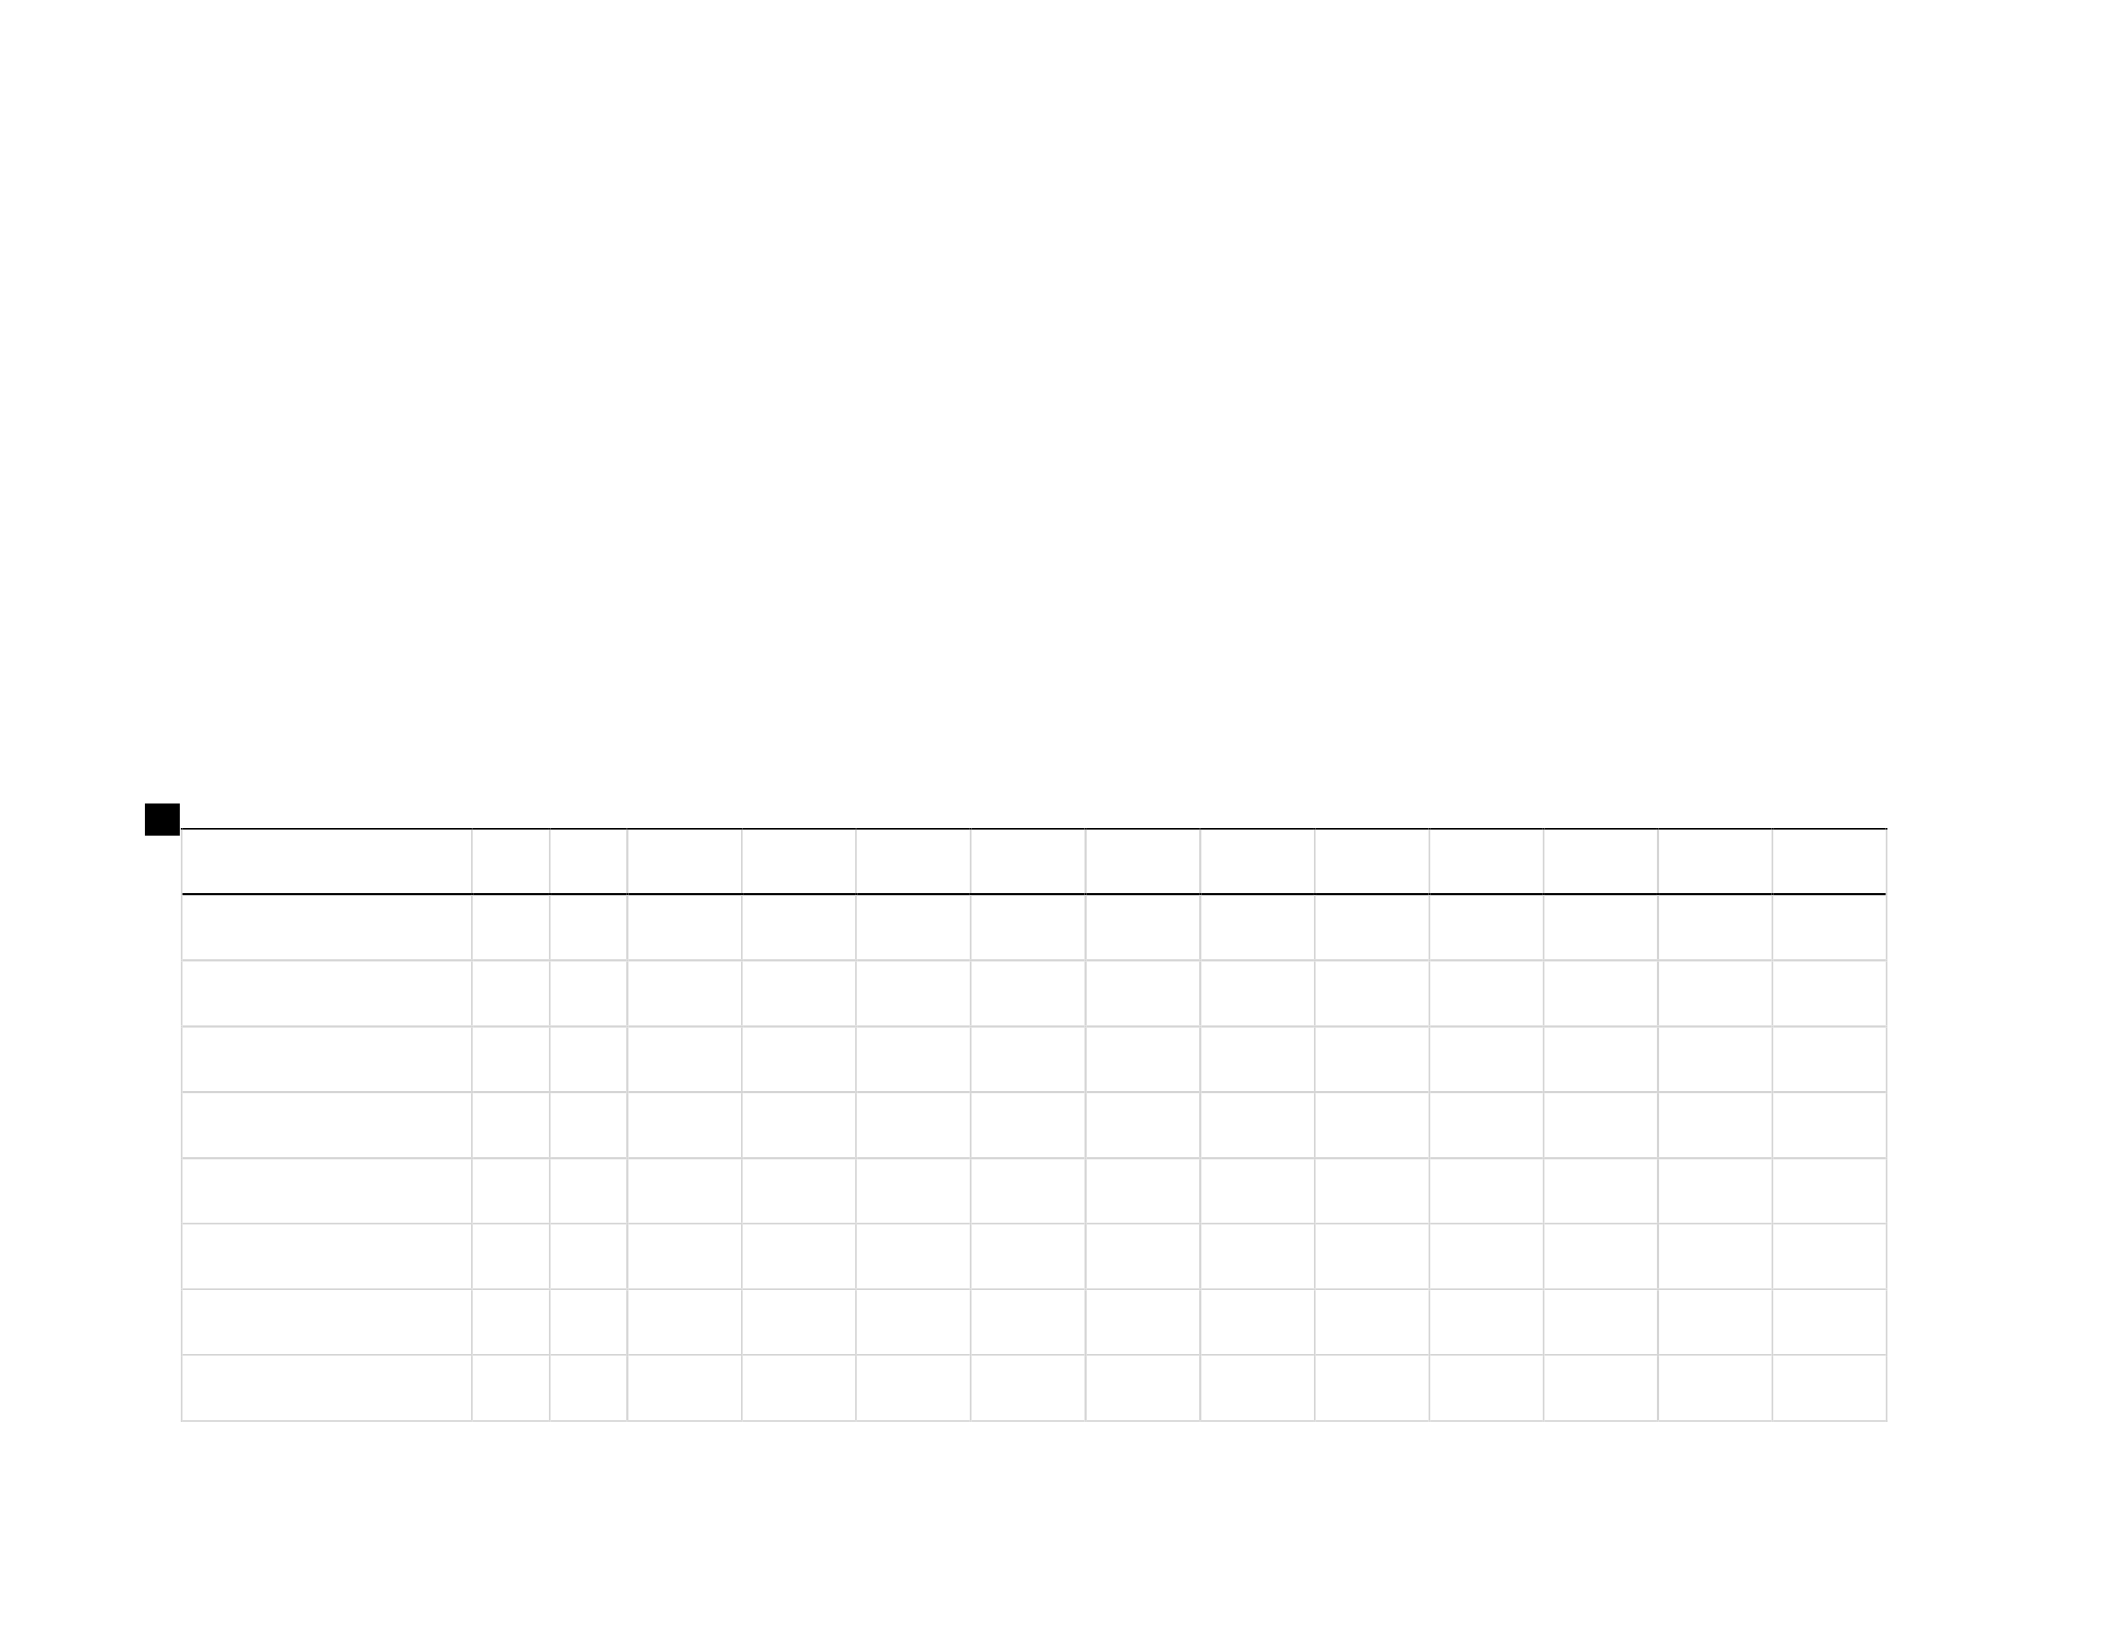
Table 1. Descriptive Statistics
Mean
S.D.
1
2
3
4
5
6
7
8
9
10
11
1. Performance Conformity
0.031
0.174
2. Strategic Change
0.835
1.764
-0.0145
3. Media Coverage
2.171
1.169
0.0482*
-0.166***
4. Proposal
0.044
0.205
-0.0135
-0.0351
0.0559**
5. Founder
0.335
0.472
-0.00243
0.0119
0.0796***
0.0727***
6. Age
52.682
7.379
0.0489*
-0.163***
-0.0404
-0.0460*
-0.107***
7. Tenure
18.612
9.865
0.0278
-0.117***
-
0.0701***
-0.0525*
-0.292***
0.394***
8. Education Level
2.125
0.845
-0.0416*
0.0156
0.137***
-0.0650**
-0.128***
-0.267***
-
0.0893***
9. Government Ownership
0.107
0.309
0.00418
0.00562
-0.0049
-0.0392
-0.206***
0.0860***
0.0730***
0.107***
10. Former Official
0.120
0.325
-0.00312
-0.00803
-0.0211
-0.0525*
-0.123***
0.0463*
-0.154***
0.0134
-0.0217
11. International Experience
0.454
0.498
0.0935***
0.0129
0.192***
0.0653**
0.0781***
0.0139
-0.00141
-
0.0937***
-0.0361
-
0.0733***
12. Female
0.081
0.273
0.00319
-0.0141
-0.0361
0.0953***
0.0899***
0.0133
0.0195
-0.108***
-0.0395
-0.109***
-0.00233
n = 2212. † p < 0.1, * p < 0.05, ** p < 0.01, *** p < 0.001 (two-tailed tests).
Table 2. Regression Results
Dep. = Performance Conformity
Dep. = Strategic Change
Model 1
Model 2
Model 3
Model 4
Model 5
Model 6
Model 7
Model 8
Proposal
-0.592
-0.603
-4.864*
-3.974*
(0.76)
(0.76)
(1.89)
(1.85)
Media Coverage
0.459**
0.460**
-4.434***
-4.406***
(0.17)
(0.17)
(0.40)
(0.40)
Founder
-0.044
-0.037
-0.054
-0.049
-2.111†
-2.092†
-1.307
-1.297
(0.32)
(0.32)
(0.33)
(0.33)
(1.14)
(1.14)
(1.16)
(1.16)
Age
0.028
0.027
0.025
0.024
-0.612***
-0.623***
-0.624***
-0.632***
(0.02)
(0.02)
(0.02)
(0.02)
(0.07)
(0.07)
(0.08)
(0.08)
Tenure
0.005
0.004
0.007
0.006
-0.231***
-0.238***
-0.256***
-0.262***
(0.02)
(0.02)
(0.02)
(0.02)
(0.06)
(0.06)
(0.06)
(0.06)
Education Level
-0.185
-0.192
-0.259
-0.267
-1.479*
-1.570*
-0.469
-0.548
(0.18)
(0.18)
(0.19)
(0.19)
(0.62)
(0.62)
(0.64)
(0.64)
Government Owned
0.106
0.101
0.135
0.132
1.708
1.682
1.553
1.532
(0.44)
(0.44)
(0.44)
(0.44)
(1.52)
(1.52)
(1.51)
(1.52)
Former Official
0.154
0.141
0.246
0.230
-1.533
-1.696
-1.803
-1.935
(0.44)
(0.44)
(0.45)
(0.45)
(1.60)
(1.61)
(1.63)
(1.63)
International Experience
1.101***
1.109***
1.015***
1.020***
0.736
0.854
3.033**
3.115**
(0.30)
(0.30)
(0.30)
(0.30)
(1.00)
(1.00)
(1.03)
(1.04)
Female
0.008
0.052
0.070
0.120
-1.290
-0.964
-2.022
-1.751
(0.50)
(0.51)
(0.51)
(0.52)
(1.87)
(1.88)
(1.90)
(1.91)
Constant
-5.642***
-5.551***
-7.474***
-7.370***
49.162***
50.209***
56.586***
57.380***
(1.33)
(1.33)
(1.49)
(1.49)
(4.30)
(4.32)
(4.35)
(4.37)
n = 2212. † p < 0.1, * p < 0.05, ** p < 0.01, *** p < 0.001 (two-tailed tests).

30
REFERENCES
Aggarwal RK, Meschke F, & Wang TY. 2011. Corporate political donations: Investment or
agency? Business and Politics 14: 1469–3569.
Anderson AR, & Lee EY-c. 2008. From tradition to modern: Attitudes and applications of
guanxi in Chinese entrepreneurship. Journal of Small Business and Enterprise
Development 15(4): 775–787.
Baumgartner F, & Leech B. 2001. Interest niches and policy bandwagons: Patterns of interest
group involvement in national politics. Journal of Politics 63: 1191–1213.
Baysinger B. 1984. Domain maintenance as an objective of business political activity: An
expanded typology. Academy of Management Review 9: 248–258.
Bendisch F, Larsen G, & Trueman M. 2013. Fame and fortune: A conceptual model of CEO
brands. European Journal of Marketing 47(3/4): 596–614.
Boyd B. 1990. Corporate linkages and organizational environment: A test of the resource
dependence model. Strategic Management Journal 11: 419–430.
Blumentritt TP. 2003. Foreign subsidiaries’ government affairs activities: The influence of
managers and resources. Business and Society 42: 202–233.
Broadbent, J., 2000. The Japanese network state in US comparison: does embeddedness
yield resources and influence? Asia/Pacific Research Center, Institute for
International Studies, Stanford University.
Cai H, & Liu Q. 2009. Competition and corporate tax avoidance: Evidence from Chinese
industrial firms. Economic Journal 119: 764–795.
Carpenter MA. 2000. The price of change: The role of CEO compensation in strategic
variation and deviation from industry strategy norms. Journal of Management 26:
1179–1198.
Caves R, & Porter M. 1977. From entry barriers to mobility barriers: Conjectural decisions
and contrived deterrence to new competition. Quarterly Journal of Economics
91(2): 421–441.
Clawson D, Neustadtl A, & Weller M. 1998. Dollars and Votes: How Business Campaign
Contributions Subvert Democracy. Philadelphia, PA: Temple University Press.

31
Collins J. 2001. Good to Great. Why Some Companies Make the Leap… and Others Don’t.
Harper Collins: New York, NY.
Cutler D, Poterba J, & Summers L. 1989. What moves stock prices? Journal of Portfolio
Management 15: 4–12.
Erikson EH. 1968. Identity: Youth and Crisis. New York, NY: Norton.
Esty DC, & Caves RE. 1983. Market structure and political influence: New data on political
expenditures, activity, and success. Economic Inquiry 21(1): 24–38.
Ferguson, T. and Voth, H.J., 2008. Betting on Hitler—the value of political connections in
Nazi Germany. The Quarterly Journal of Economics, 123(1), pp.101-137.
Finkelstein S, & Hambrick DC. 1990. Top-management team tenure and organizational
outcomes: The moderating role of managerial discretion. Administrative Science
Quarterly 35: 484–503.
Halff, G. 2013. The Presentation of CEOs in Economic Downturn. Corporate Reputation
Review 16(3): 234–243.
Hamilton J, & Zeckhauser R. 2004. Media Coverage of CEOs: Who? What? Where? When?
Why? Paper presented to Workshop on the Media and Economic Performance.
Hansen W, & Mitchell N. 2000. Disaggregating and explaining corporate political activity:
Domestic and foreign corporations in national politics. American Political Science
Review 94: 891–903.
Hersch P, & McDougall G. 2000. Determinants of PAC contributions to house incumbents:
Own versus rival effects. Public Choice 104: 329–343.
Hillman A, & Keim G. 1995. International variation in the business-government interface:
Institutional and organizational considerations. Academy of Management Review 20:
193–214.
Hillman A, & Hitt M. 1999. Corporate political strategy formulation: A model of approach,
participation and strategy decisions. Academy of Management Review 24: 825–842.
Hillman AJ, Keim GD, & Schuler DA. 2004. Corporate political activity: A review and
research agenda. Journal of Management 30: 837–857.
Hillman A. 2003. Determinants of political strategies in US multinationals. Business &
Society 42: 455–484.

32
Hofstede G. 1981. Culture and organizations. International Studies of Management &
Organization 10(4): 15.
Igan D, Mishra P, & Tressel T. 2009. A fistful of dollars: Lobbying and the financial crisis.
IMF working paper. Available at: www.imf.org/external/pubs/ft/wp/2009/
wp09287.pdf. (28 June 2012).
Jiang JS. 2003. The National People’s Congress of China. Beijing: Foreign Languages Press.
Jonsson B. 2007. Does the size matter? The relationship between size and profitability of
Icelandic firms. Bifrost Journal of Social Science 1: 43–55.
Kang, D.C., 2002. Bad loans to good friends: money politics and the developmental state in
South Korea. International organization, 56(1), pp.177-207.
Kennedy S. 2005. The Business of Lobbying in China. Cambridge, MA: Harvard University
Press.
Kubicek, P., 1996. Variations on a corporatist theme: Interest associations in post soviet
Ukraine and Russia. Europe-Asia Studies, 48(1), pp.27-46.
Laat M, Lally V, Lipponen L, & Simons R-J. 2007. Investigating patterns of interaction in
networked learning and computer-supported collaborative learning: A role for Social
Network Analysis. Computer Supported Learning 2: 87–103.
Lang J, & Lockhart D. 1990. Increased environmental uncertainty and changes in board
linkage patterns. Academy of Management Journal 33: 106–128.
Lee J. 2009. Does size matter in firm performance? Evidence from US public firms.
International Journal of the Economics of Business 16(2): 189–203.
Li X, & Liang X. 2015. A Confucian social model of political appointments among Chinese
private-firm entrepreneurs. Academy of Management Journal 58(2): 592–617.
Liu H, & Roos LU. 2006. Managing strategic planning paradigms in China. Marketing
Intelligence & Planning 24(5): 432–45.
Mahon J, & Murray E. 1981. Strategic planning for regulated companies. Strategic
Management Journal 2: 251–262.
Manning J. 2017. Membership of the 115th Congress: A Profile. Congressional Research
Service. Available at: www.crs.gov

33
Mishel L, Bivens J, Gould E, & Sheirholz H. 2012. The State of Working America. 12th
Edition, Ithaca, NY: Cornell University Press.
Nguyen B. 2015. Is more news good news? Media coverage of CEOs, firm value, and rent
extraction. Quarterly Journal of Finance 5(4): 1–38.
Nie H, Jiang T, & Yang R. 2012. The Journal of World Economics.
North D. 1990. Institutions, Institutional Change and Economic Performance. New York, NY:
Cambridge University Press.
O’Brien K. 1988. China’s National People’s Congress: Reform and its limits. The China
Quarterly 13: 343–74.
O’Brien K. 1990. Reform without Liberalization: China’s National Congress and the Politics
of Institutional Change. New York, NY: Cambridge University Press.
Olson M. 1965. The Logic of Collective Action. Cambridge, MA: Harvard University Press.
Park S, & Luo Y. 2001. Guanxi and organizational dynamics: Organizational networking in
Chinese organizations. Strategic Management Journal 22(5): 455–477.
Peltzman S. 1976. Toward a more general theory of regulation. Journal of Law and Economics
19: 211–240.
Peni E. 2014. CEO and chairperson characteristics and firm performance. Journal of
Management & Governance 18: 185–205.
Pfeffer J, & Salancik GR. 1978. The External Control of Organizations: A Resource
Dependence Perspective. New York, NY: Harper and Row.
Porter ME. 1979. The structure within industries and company performance. Review of
Economics and Statistics 61(2): 214–227.
Russell Reynolds Associates. 2003. Formula for Confidence: Resetting Investment Criteria.
Singh J, House R, & Tucker D. 1986. Organizational change and organizational mortality.
Administrative Science Quarterly 32: 367–386.
Schuler D, Rehbein K, & Cramer R. 2002. Pursuing strategic advantage through political
means: A multivariate approach. Academy of Management Journal 45: 659–672.

34
Scherer FM. 1973. The determinants of industrial plant sizes in six nations. Review of
Economics and Statistics 55(2): 135–145.
Shepherd WG. 1972. The elements of market structure. Review of Economics and Statistics.
54(1): 25–37.
Skippari M. 2003. Process Theory Approach to Corporate Political Strategies: A Research
Agenda. Presented at the 2003 Academy of Management Meeting. Seattle, WA.
Stigler G. 1971. The theory of economic regulation. Bell Journal of Economics and
Management Science 2: 3–21.
Thompson J. 1967. Organizations in Action. New York, NY: McGraw-Hill.
Truex, R., 2014. The returns to office in a “rubber stamp” parliament. American Political
Science Review, 108(2), pp.235-251.
Wiersema MF, & Bantel KA. 1992. Top management team demography and corporate
strategic change. Academy of Management Journal 35(1): 91–121.
Williamson O. 1984. Corporate governance. Yale Law Journal 93: 1197–1229.

35
Essay 2: Chinese CEOs in the National People’s Congress (NPC):
A Moderated Mediation Framework
INTRODUCTION
Research over the past two decades has yielded substantial evidence indicating that a
close relationship exists between corporate political strategies and firm performance (Getz,
1993; Hillman, 1999; Hillman, 2005; Sun et al., 2012). It has been proposed in some studies
that such relationship is positive (Truex, 2014; Zheng et al., 2015), and the core assumption
is that improving firm performance indicates that firms implement different corporate
political strategies (North, 1990; Lux et al., 2011). Meanwhile, it is also proposed in existing
studies that such relationship was negative (Hadani and Schuler, 2013; Igan, Mishra, and
Tressel, 2009; Aggarwal et al., 2012; Boubakri et al., 2008). In the literature it remains unclear
how effectively and under what conditions corporate political strategies increase or decrease
firm performance. One particular reason is scholars’ lack of understanding of the mechanisms
in this relationship (Truex, 2014). Through this study we address this gap and contribute to
the literature by opening the “black box”, that is, the various mediators between corporate
political strategies and firm performance. Particularly, we are interested in CEOs’ personal
service in political entities, and how such service or political appointment influences firm
performance, especially return on assets (ROA) and market share. As one important
component of corporate political strategies, CEOs’ personal service in political entities has

36
gained substantial attention (Getz 1993; Hillman, 1999; Hillman, 2005). Hillman (1999) used
the event-study methodology to study business leader’s personal service, especially having a
firm representative serve in the federal cabinet and elected to the U.S. House of
Representatives and Senate. The findings suggest that such personal service positively affects
firm value. About a decade ago, scholars began to switch the focus from developed countries
to emerging economies (Zheng et al., 2015).
It is indisputable that firms are actively engaging in political activities not only in
Washington, but also globally. However, most existing studies are U.S.-centric or mainly
focus on Western countries, such as those in the European Union (Skippari, 2003), and Russia
(Kubicek, 1996). Few studies focus on Eastern countries like Japan (Broadbent, 2000) and
South Korea (Kang, 2002), with even fewer focusing on China. Hillman and Keim (1995),
and North (1990) proposed that the relationship between business and government is likely
to be different in different institutional contexts. In this study, we also tested and expanded
current theories and empirical findings from Western research to a totally different
institutional context—China. By doing so, we could gain a better understanding of the
relationship between business and government, especially in China, a country in such a
dramatic era of change.
According to Forbes (2013), 71% of the top 500 richest Chinese business people have
political appointments. Out of the 2,985 deputies in the 10th National People’s Congress
(NPC, 2003-2008), 417 could be identified as business leaders of companies. The active

37
participation of Chinese business leaders in political activities offers a dramatic context in
which to examine the relationship between a firm’s corporate political strategies and firm
performance. In China, the economic reform, the expanded institutional regulation and the
increase in the number of political interest groups, have all stimulated corporate political
strategy, especially in the past two decades. As the role of the government and the scope of
its regulatory policies change over time, businesses must learn coping strategies for dealing
with the corresponding uncertainty in the system. In addition, given China’s unique political
and economic system and the increasingly important political and economic roles that
emerging markets like China play in the world today, it is both important and interesting to
explore firms’ political activities in the Chinese institutional context.
The structure of this paper is as follows: we begin by looking at the theoretical
background and existing literature on the relationship between corporate political strategies
and firm performance, especially CEOs’ personal service in political entities and its influence
on firm performance. Then, we introduce the National People’s Congress of China and CEO
deputies in the Congress. Next, we formulate our research hypotheses and describe the data
collection process and the methods we used. Finally, we present our findings and conclude
with a discussion of implications for future research.
THEORY AND HYPOTHESES DEVELOPMENT

38
Corporate political strategies and firm performance
Corporate political strategies, or corporate political activities (CPAs), are relatively
widespread (Faccio, 2006; Sun et al., 2012). CPA is an important component of firm
nonmarket strategy (Lux et al., 2011). Such strategies are designed and implemented to
manage the institutional or societal context of economic competition, and to create a more
favorable environment for the firm. Getz (1993) grouped corporate political strategies into
seven broad categories: lobbying, reporting research results, reporting research results,
testifying, legal action, service by corporate leaders and constituency building. The
underlying assumption is that firms engage in CPAs to improve firm performance (North,
1990), which is also the dominant view in management and political science literature. This
view is supported in existing research, through which evidence is shown that corporate
political strategies directly increase firm performance by influencing legislatures to pass laws
that change market structures to a firm’s competitive advantage (Peltzman, 1976; Stigler,
1971) by getting government contracts (Blumentritt, 2003), by obtaining licenses and permits
to operate, and even by restraining the abilities of potential or current competitors in the
market. Corporate political strategies can also indirectly lead to higher firm performance by
influencing public policy and creating an environment that favors a firm’s core business, or
by reinforcing social relationships between business executives and public officials, thereby
maintaining favorable business conditions (Clawson et al., 1998). Ferguson and Voth (2008)
examined Germany before World War II. They collected monthly stock prices from official

39
publications of the Berlin stock exchange, and their results showed that politically affiliated
firms outperformed the stock market by 5% to 8%, and account for a large part of the market’s
rise. They attributed the reasons to the willingness of investors to pay higher prices for
affiliated firms, and investors recognized the special value that politically connected firms
had.
Meyer and Rowan’s pioneering work (1977) of contemporary institutional research,
Institutionalized organizations: Formal structure as myth and ceremony, provided a
theoretical perspective that explains why firms implement corporate political strategies. A
fundamental question that defines institutional theory is: why do firms look alike? The
answer is the different institutional forces that push firms in industries toward similar, or
isomorphic, practices (DiMaggio & Powell, 1983). In response, many firms follow the
industry leader and adopt certain practices. Hillman (2003) examined the determinants of
political strategies used by U.S. multinationals in Europe and found that institutional
variables explain the choice of political strategy, including the approach, participation and
strategy. In their meta-analysis study, Lux and colleagues (2011) suggested that institutional
forces could shape corporate political strategies. The research analyzed 78 studies with a
sample size of 72,265 and found that corporate political strategies are related to
performance and that firms are “forced” to engage in political activities if they want to
compete with firms that already engage in such activities.

40
Personal services as corporate political strategy
Corporate political strategies are largely comprised of Political Action Committee (PAC)
contribution and lobbying (Lux et al., 2011). Scholars from different disciplines agreed that
lobbying was the primary political strategy, and PAC contribution was the complementary
action (Kaiser, 2009), and perhaps this is the reason that attention has focused heavily on these
two political strategies. However, as one important component of corporate political strategies
(Getz, 1993; Hillman, 1999; Hillman, 2005), personal service by CEOs in the government
has been ignored for a long time, especially in those studies that focused on the U.S..
In his study, Getz (1993) proposed that corporate leaders’ personal service in official
government posts provides potential political benefits for the corporation. In the U.S.,
executives may serve at the federal cabinet level, in executive and administrative departments,
or as consultants or members of special committees. In Table 1, we summarized research in
the past two decades on the antecedents and consequences of CEOs’ political appointment.
--------------------------------------- Insert Table 1 Here
---------------------------------------
Hillman and colleagues (1999) found that firm performance would be positively affected
if a link were established between a firm and the government through personal service. In the
study, they used Scholes-Williams’ event-study methodology and limited personal service to
political appointments at federal cabinet level and elections to the Senate and U.S. House of

41
Representatives. Zheng and colleagues (2015) found political ties can improve both firm
survival (labeled “buffering”) and performance (labeled “enabling”), with weaker firms
gaining more from buffering and stronger firms gaining more from enabling.
What about China?
As we have discussed earlier, 417 out of the 2,985 deputies in the 10th National People’s
Congress (2003-2008) could be identified as business leaders of companies, which means in
the whole Congress, nearly 14% of deputies were CEOs, CFOs, COOs and general
managers of companies. In contrast, this number is zero in the U.S. In other words, there is
no CEO on-the-job that is also in either the House or the Senate (Manning, 2017).
The National People’s Congress is the national legislature of the People’s Republic of
China. Under China’s current Constitution, the NPC is structured as a unicameral
legislature, a legislature that consists of only one chamber or house. The NPC has the power
to legislate and amend the Constitution if needed, to oversee the operations of the
government, to approve the Annual Report of Government Work, and to elect the major
officers of state, including the country’s President and the Premier of the State Council.
Unlike other corporate political strategies that “indirectly” influence public policy, having a
CEO in the Congress is the most effective way to influence public policy because in such a
situation the business leader is simultaneously manager and policymaker. Through

42
legislation proposals, business leaders are able to propose nation-wide or region-wide
legislation to shape government regulations and produce a more favorable business
environment (Truex, 2014). A seat in the Congress also allows firms to access a valued set
of resources, such as bank loans, government subsidies, and so on, that indirectly help
improving their performance and expand market share. We will elaborate on NPC firms’
access to resources later in the paper.
Before an NPC firm formally “uses” its influence, the NPC membership itself already
sends a strong and clear signal to the outside world that the firm is currently well-run, has
achieved a certain level of status and received recognition from the government in the form
of political appointment and access to other political connections that also come with
membership in the NPC (Sun et al., 2011; Yang et al., 2017). Truex (2014) studied the
relationship between NPC membership announcements and stock market reaction. He
observed the average stock prices for NPC firms and non-NPC firms over a short time
window starting a few weeks before NPC membership was announced and ending after the
announcement. After conducting a formal weighted fixed effect analysis, he found that NPC
membership brings an increase in share price ranging from three to four RMB (Chinese
currency, equal to 0.43-0.58 USD), depending on the balancing model and window of time
studied.
Although substantial evidence indicates corporate political strategy, especially CEO’s
personal service in political entities, could lead to higher firm performance, firms eventually

43
have to come back to market and face market competition. Tian and Deng (2007) proposed
that relative market share in a firm’s industry will influence variance of political strategy
choice. Schuler (1996) found that market changes are positively associated with firms’
political involvement, especially competitive pressures from foreign imports, or import
penetration, and declining consumption in the domestic market is positively associated with
a firm’s political involvement. Both scenarios suggest firms’ attempts to respond to market
changes. However, to our best knowledge, there is no existing study that empirically
examines the direct impact of political strategy on market share. Deng and colleagues
(2010) suggest that the purpose of firms’ engaging in political strategy is to shape a better
external environment for firms’ market strategy and strengthen firms’ competitive position
in a given industry. Therefore we argue that NPC membership could help expand firm’s
market share.
Taking all of this into account, we propose:
Hypothesis 1: NPC membership is positively associated with firm performance.
Hypothesis 2: NPC membership is positively associated with market share.
Access to Resources
Network strategy helps an organization overcome the lack of valuable resources that it
needs in order to grow (Zhang & Zhang, 2006). These resources include soft resources (such

44
as policy preference, etc.) and hard resources (such as material resources, bank loans,
government subsidies, etc.). Studies have shown that in China scarce resources are allocated
according to guanxi rather than based on bureaucratic rules (Park and Luo, 2001). Guanxi,
pronounced gwan-see, translates into “social connection”, or “relationship”, and is the
informal connections essential to gaining approval or access to just about everything in China
(Shaw & Meier, 1994): resources, valuable information, and licenses or permits to operate in
certain industries. The two Chinese characters guan and xi literally translate into “a gate” or
“a door” and “to connect” or “to attach”. According to Park and Luo (2001), guanxi is a
cultural characteristic that has strong implications for interpersonal and inter-organizational
dynamics in Chinese society. It refers to the concept of drawing on a web of connections to
secure favors in personal and organizational relations. There is a rich literature (e.g. Buttery
& Leung, 1998) in which it is proposed that cultivating personal connections and establishing
a personal guanxi network is the very first thing that foreigners seeking to do business in
China should do. CEOs’ political appointment or attachment with government officials is
considered an important type of guanxi (Park & Luo, 2001). Building such political guanxi
with government (Li & Liang, 2015) could lead to access, or lower cost to access specific
resources that may be leveraged to influence firm performance. Substantial studies have been
undertaken to examine Chinese CEOs’ attachment with government officials at various levels
of governmental, bureaucratic, and regulatory agencies and their access to various types of
resources (Luo & Chen, 1997; Peng & Luo, 2000). Pearce and Robinson (2000) proposed that

45
guanxi could increase sales, help avoid fines or taxes, and maintain a competitive advantage.
Although guanxi itself cannot be bought or sold at a certain price, it can provide individuals
and companies with the opportunity to acquire valuable resources and win them competitive
advantage over others (Braendle et al., 2005). Khwaja and Mian (2005) found similar
preferential treatment in Pakistan. They analyzed a loan-level data set of more than 90,000
companies that represents the universe of corporate lending in Pakistan. The results showed
that politically connected firms receive substantial preferential treatment by being provided
with greater access to credit. Such firms receive 45% larger loans than non-politically
connected firms. Claessens and colleagues (2007) found that Brazilian firms with larger
campaign contribution substantially increased their bank leverage relative to a control group
after each election, showing their preferential access to bank financing. Similar evidence for
lending patterns is also found in India (Cole and Duflo, 2004) and Thailand (Charumilind et
al., 2006). Yu and Pan (2008) found that Chinese firms with political connections get more
bank loans and longer loan maturity than those without political relations. Wang and Ni (2012)
analyzed the data of Chinese-listed private firms from 2006 to 2009, and found that political
connection is negatively associated with the cost of bank loans.
Regarding another critical resource, government subsidy, there are several reasons why
governments grant such aid: to support certain industries or firms, to support certain
developing regions, to encourage R&D, to help domestic firms compete in the global market,
and so on. U.S. state governments have been awarding financial subsidies to individual

46
companies, example such as Exxon Mobil in Texas, Amazon and Boeing in Washington, and
most recently the 4.1 billion US dollars from the state of Wisconsin to Foxconn. The question
was and will always be: who gets subsidies, or who has priority? In a recent study, Aobdia
and colleagues (2018) analyzed publicly traded companies in the U.S. that received a subsidy
from at least one state during 2000 through 2014, and found that political contributions
increase both the likelihood that a company is awarded a state subsidy and the dollar value of
subsidy awarded. Just like the state governments of the U.S., the Chinese government has a
long history of awarding financial subsidies to individual corporations, state owned or
privately owned. For example, through government subsidies, the manufacturing capacity of
China’s solar panel industry grew tenfold, leading to a vast global oversupply (Haley & Haley,
2013). A surge in exports of Chinese panels depressed world prices by 75%. In 2012, China’s
top six solar companies had debt ratios of over 80%. The subsidies took the form of free or
low-cost loans; artificially cheap raw materials, components, energy, and land; and support
for R&D and technology acquisitions. Zhang and colleagues (2014) analyzed firm-level data
related to manufacturing companies listed in China. The results show that state owned firms
can obtain more subsidies than private owned enterprises because of their unique connection
with government.
Taking all of this into account, we propose:
Hypothesis 3: NPC membership is negatively associated with bank loan costs.

47
Hypothesis 4: NPC membership is positively associated with government subsidy.
Labor efficiency
Sullivan and Sheffrin (2003) define economic efficiency as a concept of resource
utilization, a concept that refers to the production of goods and services from a certain quantity
of resources. If we apply this concept to labor resources, then labor efficiency increases as the
labor-to-revenue ratio decreases. Labor-to-revenue ratio shows how much a company spends
on its employees to generate revenue. Lower ratio is generally good for business as it indicates
a higher level of utilization and productivity of labor resources (Stuebs & Sun, 2010).
There has been a growing interest in the degree that human resource systems influence
labor efficiency or productivity (Datta et al., 2005). Delery and Shaw (2001) proposed two
features that distinguish Strategic Human Resource Management (SHRM) from traditional
HR management: (1) SHRM focuses on the strategic role that HR plays in increasing
organizational productivity and firm performance; (2) SHRM studies have focused on
organizational-level analysis. Jackson, Schuler and Jiang (2014) define SHRM scholarship as
the study of HRM systems (and/or subsystems) and their interrelationships with other
elements comprising an organizational system, including the organization’s external and
internal environments, the multiple players who enact HRM systems, and the multiple
stakeholders who evaluate the organization’s effectiveness and determine its long-term
survival. Such definition reminds us of the important interrelationship between an

48
organization’s external environment and HRM system. Collins and Clark (2003) examined
the relationships between a set of HR practices, top management teams’ (TMT) external and
internal social networks, and firm performance. They found that TMT’s external and internal
social networks are positively associated with firm performance, and such social networks
mediate the relationship between HR practice and firm performance. In their study,
government agencies are critical components of firms’ external environment. To our Chinese
CEOs, the Congress is a great platform that increases their social networks in size, range, and
strength. Such large, broad and strong-tied networks can in turn influence HR practices, either
the “best practices” proposed by the universalistic perspective, or the strategic contingency
proposed by the contingency perspective (Delery & Doty, 1996).
NPC membership can also increase labor productivity and brings labor efficiency
benefits. Stuebs and Sun (2010) found that business reputation is positively associated with
improved labor efficiency and labor productivity. As we have discussed earlier, a seat in the
Congress sends a strong and clear signal to the outside world that the firm is currently well-
run, has achieved a certain level of status and has special guanxi with government. Such status
or reputation could attract and motivate employees. Good employees are attracted to NPC
firms and they may be willing to accept less compensation to exchange for other benefits the
employment opportunity brings. Employees’ competing for careers with NPC firms creates a
larger labor supply which in turn, decreases compensation. In addition, employee productivity
increases as employees are motivated to work harder for reputable NPC firms. Such

49
motivation could be intrinsic, including pride, enjoyment, accomplishment, and skill
development, which are not necessarily associated with monetary rewards. To sum up, labor
inefficiency is expected to decrease as labor costs go down and labor productivity goes up,
therefore we propose a negative relationship between NPC membership and labor
inefficiency.
Hypothesis 5: NPC membership is negatively associated with labor inefficiency.
Strategic Change
The reason we focus on strategic change is because it has been proven to be a critical
antecedent of CEOs’ influence on firm performance (Wiersema & Bantel, 1992; Zhang &
Rajagopalan, 2010). Le and Kroll (2017) proposed a positive relationship between CEOs’
international experience and firm performance, both directly and mediated through the greater
strategic change fostered by these CEOs. In management literature, strategic change has been
defined as the overall change in a firm’s pattern of resource allocation in multiple key strategic
dimensions (Finkelstein & Hambrick, 1990; Zhang & Rajagopalan, 2010): R&D intensity,
advertising intensity, nonproduction overhead expenses, inventory levels and financial
advantage. Following existing research, we define strategic change as the change over time
of a firm’s pattern of resource allocation in multiple key strategic dimensions that goes beyond
industry-wide changes in those dimensions.

50
Timely strategic change is crucial as it reflects a company’s ability to anticipate and
respond to environmental change, but such change could contain both opportunities and
dangers. Changing firm strategy involves great risk, especially in the cases when established
ways of conducting business are abandoned, or current patterns of resource allocation are
changed, because in those cases, payoffs are not always guaranteed. Such risks are even
greater for CEO deputies in the Congress as almost all of the firms in the Congress are
successful firms. In order to be elected as deputies in the Congress, CEOs must prove that
they have been successful business leaders. For them, there is no need to change either the
overall firm strategy or the pattern of resource allocation, as they already have a well-
established track record and their strategy worked fairly well in the past. This is especially
true for state-owned firms. We will elaborate on the impact of ownership in later sections.
Also, the uncertainty associated with political appointment increases dramatically as CEOs
join in the politicians’ club. Uncertainty could be regarding the future of the business, or the
future of a CEO’s personal career. Such uncertainty drives CEOs to maintain the status quo,
or as the old Chinese saying goes: “meet all changes with constancy”.
Another reason why CEOs are less likely to engage in strategic change is because of the
totally new career that Congress membership brings. Being a Congress member is very
different from being a business manager. This is a completely new identity and a totally
different career path. Even if NPC deputies are all part-time based and the whole NPC meets
only once during the two-week annual meeting, deputies are not just working for two weeks

51
during the whole year. For example, proposing legislation bills, the most important duty of
deputies, cannot be done in just two weeks. It is not the two-week yearly meeting that decides
the fate of any particular legislation bill. On the contrary, it is expected that any disagreements
should be resolved ahead of time and consensus should be reached behind closed doors,
months or even longer before the annual meeting convenes. NPC deputies and government
officials initiate direct contact long before any official policies are adopted. There are also
many other forms of required interaction between deputies from industry and the government.
For example, the NPC often sends delegations to meet with local governments, scholars and
researchers, business associations, companies or even employees in various cities, to gain
opinions on certain legislation, or to investigate policy issues. The research and investigation
are critical regulatory duties of deputies. In 2016, more than 1,700
NPC deputies participated in such activities, and the total number of legislation proposals in
2016 was 8,239 (Annual Report of NPC Standing Committee, 2016). Such research and
investigation process could occupy a large amount of business deputies’ time and therefore
cause business leaders to be distracted and less likely to focus on strategic change. We also
call this “distraction effect”.
Hypothesis 6: NPC membership is negatively associated with strategic change.

52
Mediating effects
In the previous sections, we have argued that NPC membership has a positive effect on
both ROA and market share. We have also reasoned that NPC membership has a positive
impact on government subsidy, and negative impact on loan cost, labor inefficiency and
strategic change. We also posit that lower bank costs could help firms increase performance
and expand market share. Jin and colleagues (2018) used firm-level data related to listed
manufacturing companies in China from 2011 to 2015 and found that receiving government
subsidies improves firm performance. Zhang et al. (2013) found that government subsidies,
in both long and short terms, have significant positive effects on the financial performance of
wind energy manufacturing companies. One early study by Brander and Spencer (1985)
proposed that government subsidies, especially export subsidies, could be attractive policy
tools because they improve the relative position of a domestic firm in non-cooperative
rivalries with foreign firms, enabling it to expand its market share and improve its financial
performance. In recent studies, such as that of Buts and Jegers (2013), a sample of 13,000
Belgian firms was analyzed and a significant and positive influence of fixed asset subsidies
on market shares was found. Regarding the relationship between strategic change and firm
performance and market share, there has been ongoing debate in existing studies for decades.
One effect is adaptive and another is disruptive. In the adaptive view, which is also the
dominant view, strategic change can have positive effects on both firm performance and
market share because strategic change represents the firm’s bold thinking and novel strategic

53
initiatives (Zhang & Rajagopalan, 2010), and therefore it may allow the firm to align with the
external environment and increase performance and expand market share. Regarding the
relationships between labor efficiency and firm performance and market share, positive links
have been established in various studies, specifically that labor efficiency can increase
organizational outcomes such as firm performance and market share.
Hypothesis 7: Bank loan costs mediate the positive relationship between NPC membership
and ROA.
Hypothesis 8: Bank loan costs mediate the positive relationship between NPC membership
and market share.
Hypothesis 9: Government subsidy mediates the positive relationship between NPC
membership and ROA.
Hypothesis 10: Government subsidy mediates the positive relationship between NPC
membership and market share.
Hypothesis 11: Labor inefficiency mediates the positive relationship between NPC
membership and ROA.
Hypothesis 12: Labor inefficiency mediates the positive relationship between NPC
membership and market share.
Hypothesis 13: Strategic change mediates the positive relationship between NPC membership
and ROA.
Hypothesis 14: Strategic change mediates the positive relationship between NPC membership
and market share.
The moderating role of firm ownership
In 2014, 19 out of 20 of the largest enterprises in China were state-controlled or state-
owned enterprises (SOEs). Chinese industry includes a total of 17,830 state-owned or state-
controlled enterprises, which is more than half the total number of all enterprises in China

54
(National Bureau of Statistics of China, 2014). Among all SOEs, near 20% are directly
controlled by the central government. All SOEs are supervised by China’s State Asset
Supervision and Administration Commission (SASAC), whose main job is performing
investors’ responsibilities and supervising and managing the state-owned assets of the
enterprises. The SASAC reports to the State Council, which puts SOEs under direct
supervision of the central government. In other words, SOEs and governments (whether
central or local governments), have such unique “blood ties”, which give SOEs advantages
that private firms seldom enjoy. The influence of Chinese firms’ ownership on bank loan
costs is an issue of great interest and complexity. In China, lenders are exposed to lower
failure and bankruptcy risks when they issue loans to SOEs (Luo et al., 2018). This is the
reason banks prefer to lend more money to SOEs at lower costs rather than give loans to
private firms, and, moreover, almost all of the commercial banks in China are state-owned.
Transferring money from banks to SOEs is similar to transferring money from the
government’s left pocket to the right. Unlike SOEs, private firms normally don’t enjoy this
preferential treatment. Therefore Congress membership is more “meaningful” to private
firms because with it, private firms join the club that they were previously excluded from, a
club whose members enjoy many advantages, including lower loan costs.
Hypothesis 15: Firm ownership moderates the negative relationship between NPC
membership and bank loan cost, resulting in such relationship being experienced more
strongly by private firms.

55
The same logic applies to the case of government subsidy. O’Connor et al. (2006) found
that on average Chinese SOEs receive more subsidies than private firms. They further
argued that the reason is that the government wants to use subsidies to pursue sociopolitical
objectives such as creating job opportunities and stabilizing local economies. If a firm is an
SOE and its CEO is a Congress member, such sociopolitical objectives are more likely to be
set for this firm, and government subsidies are more likely to be given to this type of firm.
Hypothesis 16: Firm ownership moderates the positive relationship between NPC
membership and government subsidy, resulting in such relationship being experienced more
strongly by SOEs.
We have reasoned that NPC membership leads to less strategic change in general. This is
especially true for SOEs. If a firm is owned by the central government, its CEO is appointed
by the State Asset Supervision and Administration Commission. In other words, the CEO is
appointed by the government and reports to the government. He or she is more of a politician
than a businessperson. There is no need for such CEOs to change the pattern of resources
allocation since they have well-established track records and their strategy worked fairly well
in the past, this also being the reason they were appointed in the first place. However, CEOs
from private firms are quite different. The National People’s Congress provides them with a

56
great platform from which to get easy access to resources and information, resources they are
not used to having and information that would not have been shared with them previously.
For example, the average time for a legislation proposal to be finalized and made law is around
two to five years, with very rare exceptions. This period of time is extremely valuable to
private firms in the Congress because they can change their business strategies and adjust
their business practices based on their understanding of the formulation and execution of
future policy change. This early access to important legislation information provides private
firms a great “insider’s advantage”, which cannot be easily achieved by non-NPC firms, or
“outsiders”. Since SOEs are “insiders” from their first day of operation, such insider’s
advantage is more salient for private firms.
Hypothesis 17: Firm ownership moderates the negative relationship between NPC
membership and strategic change, resulting in such relationship being positive for private
firms.
For decades, both scholars and government have been criticizing labor inefficiency and
poor HR management practices of Chinese SOEs. The “cradle to grave socialism”, lifetime
employment and heavy burden social welfare all put SOEs in a disadvantaged position when
competing against private firms. Since 1994, the central government urgently called for
reforms and reorganization of SOEs. Increasing labor efficiency is one of the objectives.

57
Compared to private firms, SOEs have a higher level of labor inefficiency and we expect
SOEs that have CEOs in the NPC to experience stronger negative relationship between NPC
membership and labor inefficiency. In other words, they increase labor efficiency to a larger
extent than private firms do.
Hypothesis 18: Firm ownership moderates the negative relationship between NPC
membership and labor inefficiency, resulting in such relationship being experienced more
strongly by SOEs.
Figure 1 presents our theoretical framework.
-------------------------------------- Insert Figure 1
Here
--------------------------------------
METHODS
Data collection
We analyzed a large firm-level dataset provided by the National Bureau of Statistics
(NBS) of China for the period 2002-2013. NBS conducted annual surveys of all state-owned
enterprises and those private enterprises with annual sales above 5 million RMB, or 762,000

58
USD. The dataset covers 37 manufacturing industries all over China. The dataset ranges from
181,542 firms in 2002 to 345,101 firms in 2013, with an average of 321,722 firms per year
throughout the sample period. In 2004, for example, the dataset contains 279,092 firms which
accounted for over 95% of China’s total industrial value, produced over 90% of its output,
generated 97.5% of its exports and employed over 72% of its industrial workforce.
Excluding the missing data, we generated a sample of 366 firms with business leaders in
the National People’s Congress, which account for 88% of the total firms that have business
leaders in the NPC. We define a business leader as a chairman, CEO, CFO, COO or a general
manager of the company. To link a business leader to the firm, we also collected their
demographic information from the official NPC deputy database, which provides deputy
information such as name, age and educational background, as well as all other important
background information. We also crosschecked company websites and Baidu Encyclopedia
(www.baidu.com) to make sure of information accuracy.
In order to make a valid comparison between firms whose CEOs were in the NPC and
those whose CEOs weren’t, we created a matching sample set using the Coarsened Exact
Matching (CEM) method. CEM is a monotonic imbalance reducing matching method which
means that the balance between the treated and control groups is determined by ex ante user
choice rather than discovered through the usual laborious process of checking after the fact,
tweaking the method, and repeatedly re-estimating (Blackwell et al., 2010). CEM also assures
that adjusting the imbalance on one variable has no effect on the maximum imbalance of any

59
other. We used year, firm size, location and industry as criteria to create a matching sample of
44,894 firms that have no CEOs in the NPC.
Measures
Return on assets (ROA). ROA is defined as net income divided by total assets. After we
calculated the ratios, we accounted for industry effects by subtracting the industry median
changes in these ratios.
Market share. To calculate a firm’s market share, we looked at the ratio of the firm’s total
revenue divided by the total revenue of the top 20 firms in the industry.
NPC. If a focal firm has a business leader in the 10th National People’s Congress
(2003-2008), the variable NPC was coded “1”, otherwise it was coded “0”.
Bank loan costs. To calculate bank loan costs, we looked at the ratio of total interest a
focal firm paid for long-term debt divided by the amount of total debt (Francis et al., 2013).
Government subsidy. We used the ratio of total government subsidy a focal firm received
divided by the total subsidy the whole industry received. We also accounted for industry
effects by subtracting the industry median changes in these ratios.
Labor inefficiency. To calculate labor inefficiency, we first added the total compensation
and benefits a focal firm paid to its employees, and subtracted the total from the industry
median. We then divided this number by the total revenue to get the labor-to-revenue-ratio.

60
Strategic change. Following Finkelstein and Hambrick (1990), and Zhang and
Rajagopalan (2010), we used five key strategic dimensions to generate a composite measure
of changes in allocation of resources: advertising intensity (advertising/sales), research and
development intensity (R&D/sales), fixed assets intensity (fixed assets/total assets), non-
production overheads (selling, general, and administrative expenses/sales), inventory levels
(inventories/sales) and financial leverage (debt/equity). We took into account the differences
between a firm’s current pattern of resource allocation and its own pattern in the previous
year. We also compared such differences to the industry’s central tendency.
We accounted for exogenous influences on ROA, market share and bank loans by
including relevant control variables: firm size, rule of law, industry concentration and
government market control. It has been show in vast amounts of research that these
variables relate to corporate political strategy, firm performance and market share. Take
industry concentration for example, Schuler and colleagues (2002) propose that firms in
concentrated industries are more motivated to implement political strategies as the political
payoffs are higher for those firms. The authors further suggest that large firms also have
stronger incentives to engage in political strategy as large firms are affected by the
government and public policy changes to a greater extent than smaller firms.
ANALYSIS AND RESULTS
We test the proposed moderated mediation framework in several ways. We first follow
the causal steps approach proposed by Baron and Kenny (1986), and then we use normal

61
theory based framework (Preacher et al., 2007) for testing moderated mediation. Pre-
regression analysis indicates that there are no serious violations of the major regression
assumptions. Table 2 shows the descriptive statistics, including means, standard deviations
and correlations among the variables.
-------------------------------------- Insert Table 2 Here
--------------------------------------
As shown in Table 3, we first perform multiple random-effects regression models to check if
the framework complies with Baron and Kenny’s (1986) requirements. According to their
approach, establishing a mediation effect requires first, that the independent variable
significantly affects the dependent variable; second, that the independent variable
significantly affects the mediator; and third, when independent variable and mediator are
added to the model simultaneously, the mediator significantly accounts for variability in the
dependent variable and the effect of the independent variable on the dependent variable is
significantly reduced.
Model 1 shows the effects of control variables on ROA and Model 2 adds the main effects
of the moderating variable—firm ownership. Model 3 adds the main effect of independent
variable NPC membership on ROA and the results show that NPC membership has a positive
and statistically significant effect on ROA (β = 7.45, p < 0.001), so Hypothesis

62
1 is supported. Models 4 to 6 examine the effects of NPC membership on market share. Model
4 shows the control variables only and Model 5 adds the main effects of the moderating
variable. Model 6 shows that NPC membership has a positive and statistically significant
effect on market share (β = 1.33, p < 0.001). Hypothesis 2 is also supported. These results
satisfy the first requirement of Baron and Kenny’s (1986) approach. We then develop Models
7 to 10 to test the effects of NPC membership on mediators. NPC membership has a positive
and statistically significant effect on government subsidy (β = 0.42, p < 0.05), and a negative
and statistically significant effect on the cost of loans (β = -20.04, p < 0.001). However, the
effects of NPC membership on strategic change and labor inefficiency are not statistically
significant. Therefore, Hypotheses 3 and 4 are supported, but Hypotheses 5 and 6 are not.
Next, we examine the effects of mediators on dependent variables. Following existing studies
(Kenny, 2009), we add mediators to the regression models separately when they have high
correlations. Models 11 to 14 show that government subsidy has a positive and statistically
significant effect on ROA (β = 0.33, p < 0.001), strategic change has a positive and statistically
significant effect on ROA (β = 0.05, p < 0.001), and labor inefficiency has a negative and
statistically significant effect on ROA (β = -0.10, p < 0.001). However, the effect of loan cost
is not significant (p > 0.10). Models 15 to 18 show that government subsidy has a positive
and statistically significant effect on market share (β = 0.09, p < 0.001), and labor inefficiency
has a negative and statistically significant effect on market share (β = -0.002, p < 0.001).
However, the effects of loan cost and strategic change on market share are not significant (p

63
> 0.10). These findings suggest that government subsidy mediates the relationship between
NPC membership and ROA, and the relationship between NPC membership and market
share, therefore Hypotheses 9 and 10 are supported.
-------------------------------------- Insert Table 3 Here
--------------------------------------
We then test the moderation hypotheses in Models 19 to 22. Model 21 suggests a positive
and significant effect of the interaction between NPC membership and firm ownership on
strategic change (β = 10.56, p < 0.01). Hypothesis 17 is therefore supported. Model 22 shows
a positive and significant effect of the interaction between NPC membership and firm
ownership on labor inefficiency (β = 9.37, p < 0.05). Hypothesis 18 is therefore supported.
However, the interaction between NPC membership and firm ownership does not
significantly affect loan cost and government subsidy. Figure 2 shows the statistically
significant interaction effects.
-------------------------------------- Insert Figure 2
Here
--------------------------------------
To further explore how the indirect effects of NPC membership on ROA and market share
differ depending on firm ownership, we follow Preacher and colleagues’ (2007) normal theory
based theoretical framework for moderated mediation. To compute the conditional indirect

64
effects, we calculate regression coefficients from two different sets of models: one set of
models with mediators as the response variables and another set of models with the dependent
variables as the response variables. Conditional indirect effects are obtained by multiplying
coefficients from the models along with the values of the moderator. Table 4 presents the
conditional indirect effects of NPC membership on ROA (Table 5 for market share) for private
and state-owned firms. Both provide 95% confidence level intervals for these effects. These
findings are in line with our previous random-effects regression analysis.
-------------------------------------- Insert Table 4 Here
--------------------------------------
--------------------------------------
Insert Table 5 Here
--------------------------------------
Discussion and conclusion
The purpose of this study is to investigate the effects of NPC membership on return on
assets (ROA) and market share, and examine various mediators among these relationships.
The results suggested that NPC membership has positive effects on ROA and market share,
also government subsidy mediates the positive effects NPC membership have on ROA and
market share, respectively. Furthermore, NPC membership is positively associated with
government subsidy and negatively associated with bank loan costs. When adding the
interaction effects of firm ownership, the results showed that private firms experience a

65
positive relationship between NPC membership and strategic change, and state-owned firms
have a stronger negative relationship between NPC membership and labor inefficiency.
Our study offers a number of contributions to the growing literature of corporate political
strategy. First, to our best knowledge, this study is the first one to open up the black box, that
is, the various mediators between corporate political strategy and firm performance. Lacking
of understanding of the mechanisms in this relationship is the major reason that it still remains
unclear how effectively and under what conditions that corporate political strategies increase
firm performance (Truex, 2014). Second, we developed a theoretical framework and found
empirical evidence suggesting that NPC membership is positively associated with firm
performance and market share. Our study supported the hypotheses proposed by various
scholars (North, 1990; Lux et al., 2011). Third, by introducing a moderated mediation
framework, we provided insights into the interaction effects of NPC membership and firm
ownership on various mediators, and their influence on firm performance and market share
eventually. These relationships have not been established in previous research.
Future research could further investigate other underlying mechanisms and a more
comprehensive analysis is needed to consider both how and when corporate political strategy
could improve firm performance. Meanwhile, scholars have been focusing on the
consequences of corporate political strategy, little attention has been paid to the antecedents
of political strategy, especially CEO’s personal service in political entities. So what leads to
the Congress membership? What kinds of firms are likely to get the membership? What kinds

66
of business leaders are more likely to be elected or re-elected and stay in the Congress for a
long time? Also industry-level variables need to be thoroughly analyzed. Research has shown
that firms in heavily regulated industries are more critically affected by public policies than
others (Lang & Lockhart, 1990), therefore firms in such industries are more interested in
political strategy. Other industry-level variables, such as industry growth, industry
concentration and competitors’ political strategy, could also have impact on firm’s
engagement and choice of various corporate political strategies. Take the “control variable”-
industry concentration for example: concentration within an industry generally refers to the
degree to which a small number of firms provide a major portion of the industry's total
production. If concentration is low, then the industry is considered to be competitive. If the
concentration is high, then the industry will be viewed as oligopolistic or monopolistic. In a
high concentrated industry, because of the fewer total number of firms and only a few
dominant firms, firms should be more motivated to seek political attachment and gain
influence on public policies since the political payoffs are much higher than that in a
fragmented and lower concentrated industry. Also the focal firm’s position in the industry and
competitors’ political strategy could also influence firm or a CEO’s motivation to engagement
in political strategy. Schuler and colleagues (2002) found that in the U.S., firm-level political
activities are positively associated with overall industry-level political activities. Hersch and
McDougall (2000) report that US and Japanese automakers regularly match each other’s
political donations. Skippari (2003) examines how firms in Finland both competed and

67
cooperated with rivals to gain favorable political outcomes, which also suggests that intra-
industry dynamics play a very important role. In China, we are expecting a similar
phenomenon. In the IT industry, for example, almost all of the CEOs from major dominant
firms are members of NPC or other political organizations.
Meanwhile, future research could also examine the location differences in the
antecedents and consequences of CEO’s political appointment. That is, are firms from
certain provinces more willing to build such connections with government? Do companies
from certain districts benefit more (or less) from political appointments? What are the
differences across different locations?
Lastly, it will be very interesting to explore the impact of different Congress levels on
the relationship between CEO’s political appointment and firm performance. We now know
there are five administrative levels of Congress in China: national, provincial, prefectural,
county, and township. Will it be relatively easier to seek appointment at the provincial or
county level? As long as the firm’s business is regional, it can still benefit from such
legislation changes. These questions have important practical implications and are left for
future research.
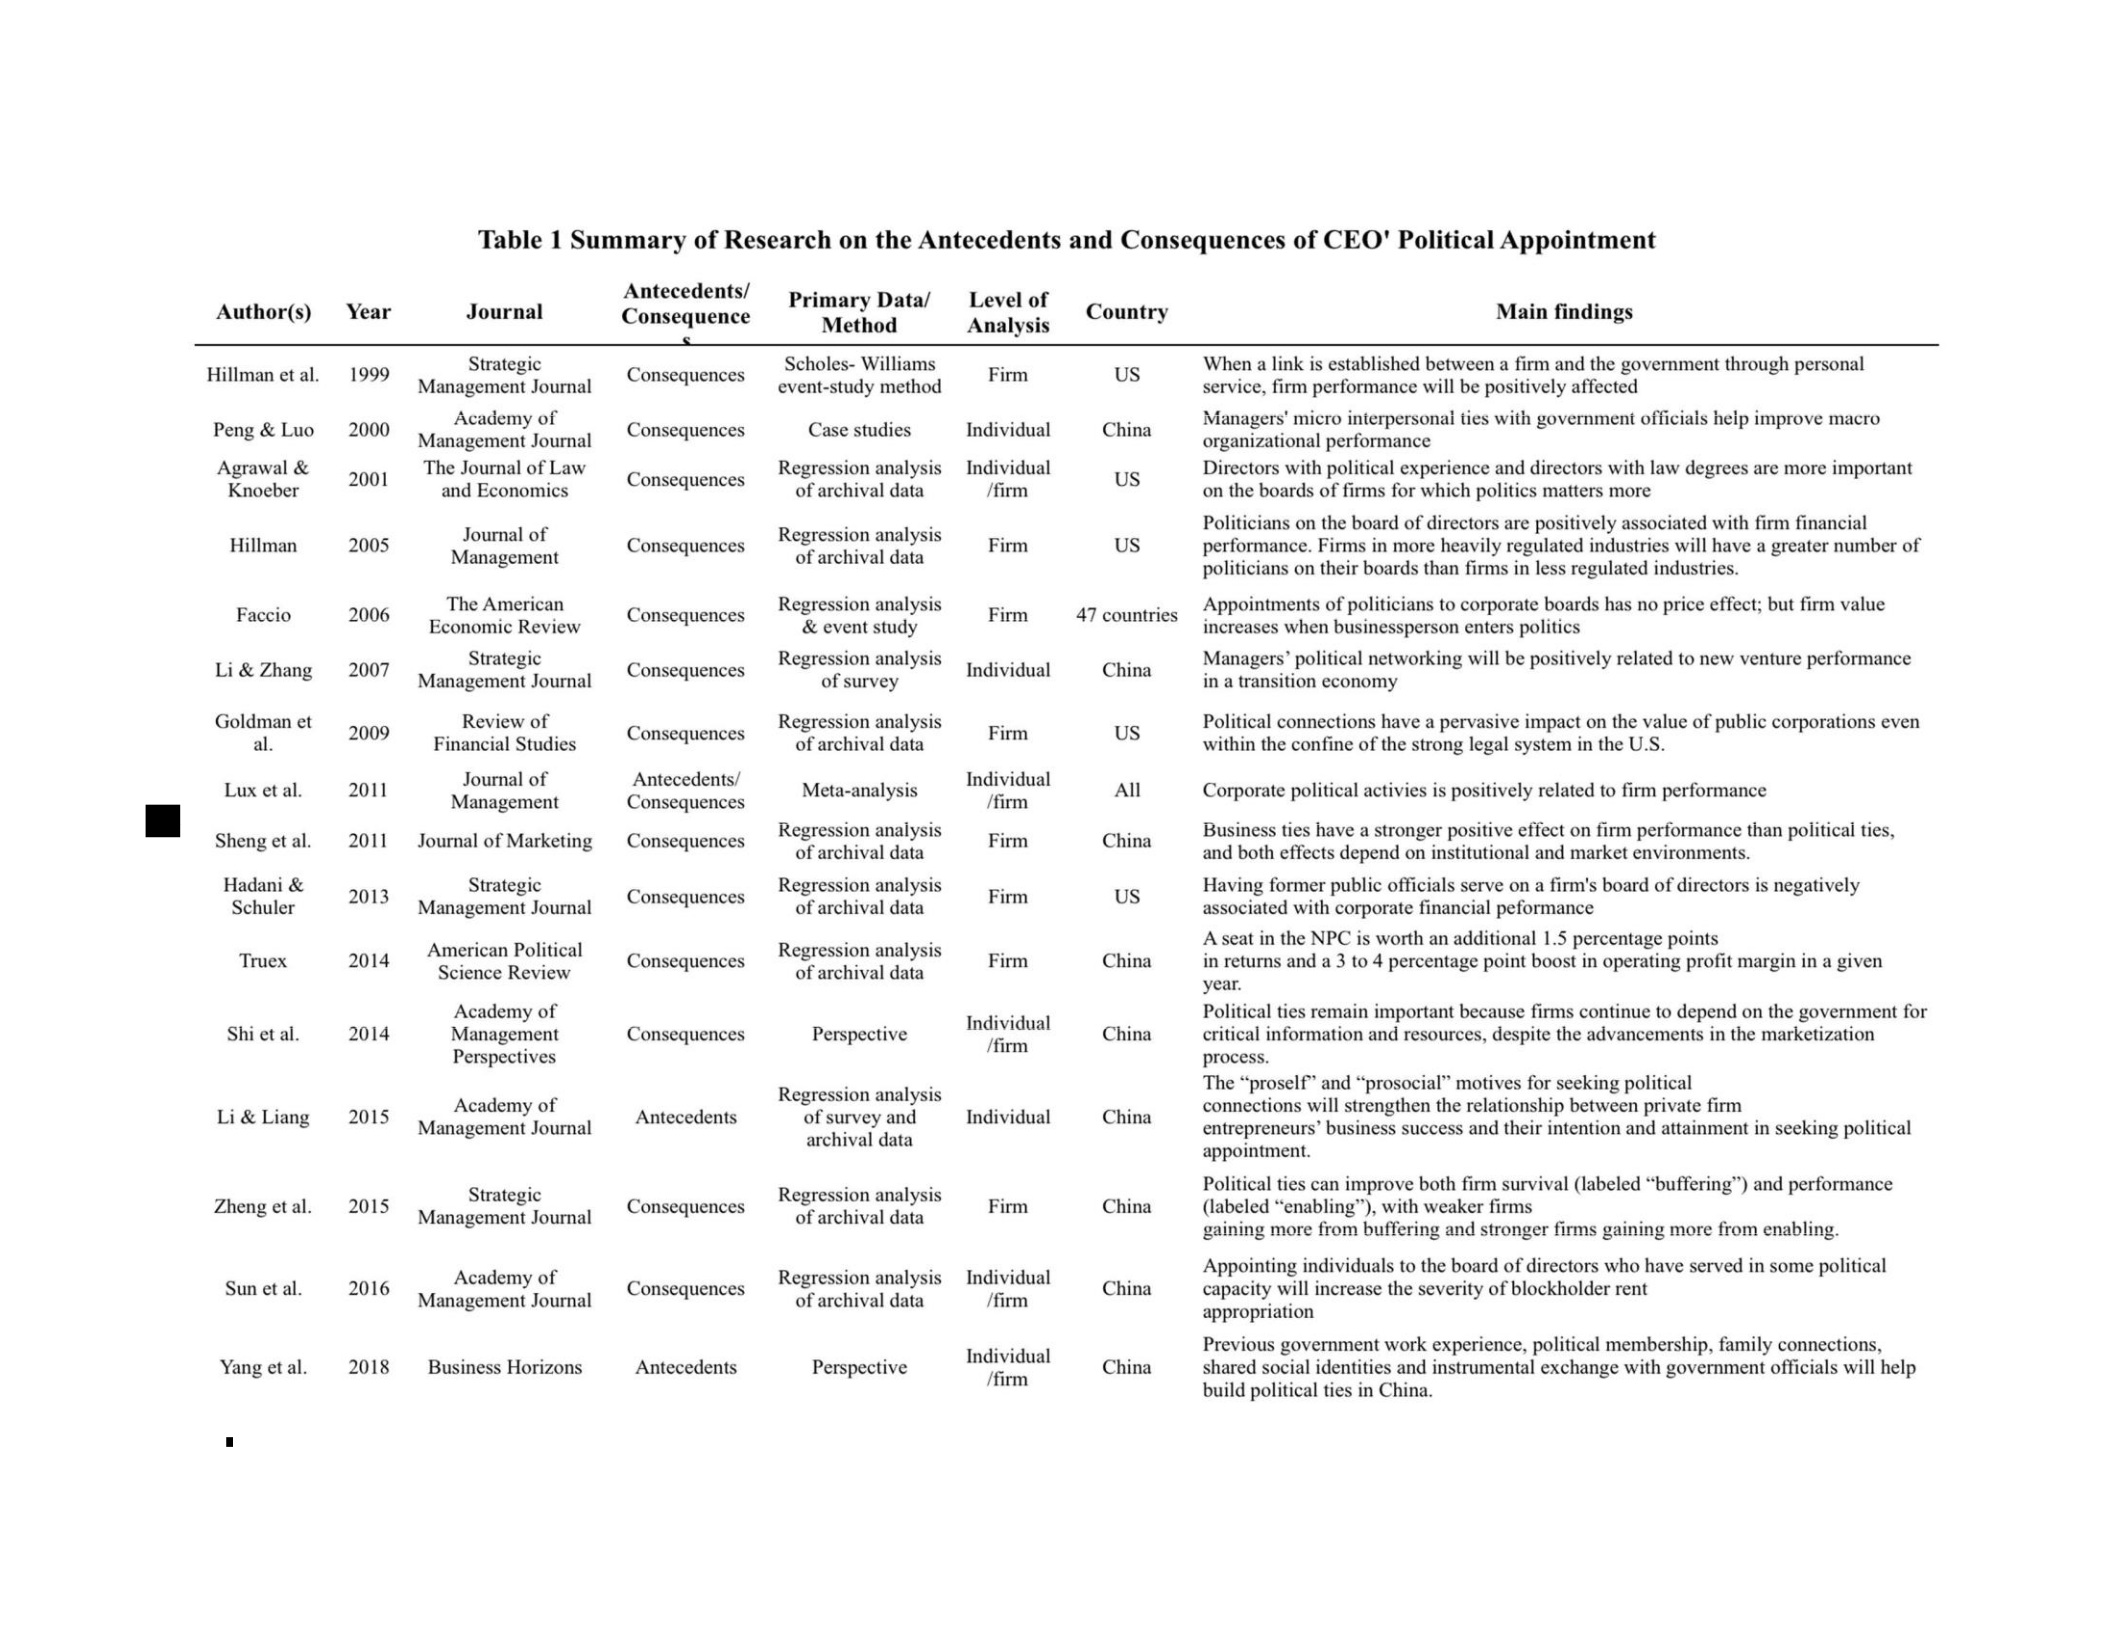
S9
Table
1
Summary
of
Research
on
the
Antecedents
and
Consequences
of
CEO'
Political
Appointment
Antecedents/
pj
rimary
Data/
Level
of
; ‘
Author(s
Year
Journal
g
Count
Main
findings
(s)
Consequence
Methad
Analysis
ry
g
Hillman
et
al.
1999
Strategic
Consequences
Scholes-
Williams
Firm
US
When
a
link
is
established
between
a
firm
and
the
government
through
personal
Management
Journal
event-study
method
service,
firm
performance
will
be
positively
affected
Peng
&
Luo
2000
Academy
of
Consequences
7
Individual
China
Managers
micro
interpersonal
ties
with
government
officials
help
improve
macro
ManagementJournal
organizational
performance
Agrawal
&
2001
The
Journal
of
Law
Cone
‘siti
Regression
analysis
Individual
US
Directors
with
political
experience
and
directors
with
law
degrees
are
more
important
Knoeber
and
Economics
nea
of
archival
data
/firm
on
the
boards
of
firms
for
which
politics
matters
more
: .
Politicians
on
the
board
of
directors
are
positively
associated
with
firm
financial
.
Journal
of
Regression
analysis
;
:
: é : 3 :
Hillman
2005
Consequences
;
Firm
US
performance.
Firms
in
more
heavily
regulated
industries
will
have
a
greater
number
of
Management
of
archival
data
ee
: : ‘ A
politicians
on
their
boards
than
firms
in
less
regulated
industries.
Faccio
2006
The
American
Consequences
Regression
analysis
Finn
47
comnrtion
Appointments
of
politicians
to
corporate
boards
has
no
price
effect;
but
firm
value
Economic
Review
&
event study
increases
when
businessperson
enters
politics
Li&
Zhang
2007
Strategic
Consequences
Regression
analysis
Individual
China
Managers
Political
networking
will
be
positively
related
to
new
venture
performance
Management
Journal
of
survey
in
a
transition
economy
Goldman
et
Review
of
Regression
analysis
;
Political
connections
have
a
pervasive
impact
on
the
value
of
public
corporations
even
al.
2009
Financial
Studies
CO™S©dueNces
Of
archival
data
ene
US
within
the
confine
of
the
strong
legal
system
in
the
U.S.
Journal
of
Antecedents/
:
Individual
ve
eae
ss
Lux
et
al.
2011
Management
Consequences
Meta-analysis
/firm
All
Corporate
political
activies
is
positively
related
to
firm
performance
5
Regression
analysis
: ,
Business
ties
have
a
stronger
positive
effect
on
firm
performance
than
political
ties,
eee
—
ES
of
archival
data
—_
_aen
and
both
effects
depend
on
institutional
and market
environments.
Hadani
&
Strategic
Regression
analysis
‘
Having
former
public
officials
serve
on
a
firm's
board
of
directors
is
negatively
2013
Consequences
A
Firm
US
3 Q :
Schuler
Management
Journal
of
archival
data
associated
with
corporate
financial
peformance
.
we
.
.
A
seat
in
the
NPC
is
worth
an
additional
1.5
percentage
points
Truex
2014
nineteen
Political
Consequences
Regression
analysis
Firm
China
in
returns
and
a 3
to
4
percentage
point
boost
in
operating
profit
margin
in
a
given
Science
Review
of
archival
data
year.
Academy
of
Individual
Political
ties
remain
important
because
firms
continue
to
depend on
the
government
for
Shi
et
al.
2014
Management
Consequences
Perspective
en
China
critical
information
and
resources,
despite
the
advancements
in
the
marketization
Perspectives
process.
R
‘
;
The
“proself”
and
“prosocial”
motives
for
seeking
political
egression
analysis
: ; : : :
.
‘
Academy
of
—
,
connections
will
strengthen
the
relationship
between
private
firm
Li
&
Liang
2015
Antecedents
of
survey
and
Individual
China
Sia
ie
: :
;
.
ii
ManagementJournal
adohival
deka
entrepreneurs’
business
success
and
their
intention
and
attainment
in
seeking
political
appointment.
‘
,
‘
Political
ties
can
improve
both
firm
survival
(labeled
“buffering”)
and
performance
Strategic
Regression
analysis
‘ :
a
sncsiga
com
Zheng
et
al.
2015
Consequences
.
Firm China
(labeled
“enabling”),
with
weaker
firms
Management
Journal
of
archival
data
as
A
gs
;
gaining
more
from
buffering
and
stronger
firms
gaining
more
from
enabling.
‘ 3 a 5
Appointing
individuals
to
the
board
of
directors
who
have
served
in
some
political
Academy
of
Regression
analysis
Individual
: :
ans
.
Sun
et
al.
2016
Consequences
:
China
capacity
will
increase
the
severity
of
blockholder
rent
Management
Journal
of
archival
data
/firm
ba
appropriation
Individual
Previous
government
work
experience,
political
membership,
family
connections,
Yang
et
al.
2018
Business
Horizons
Antecedents
Perspective
pie
China
shared
social
identities
and
instrumental
exchange
with
government
officials
will
help
build
political
ties in
China.
Figure 1 Theoretical framework
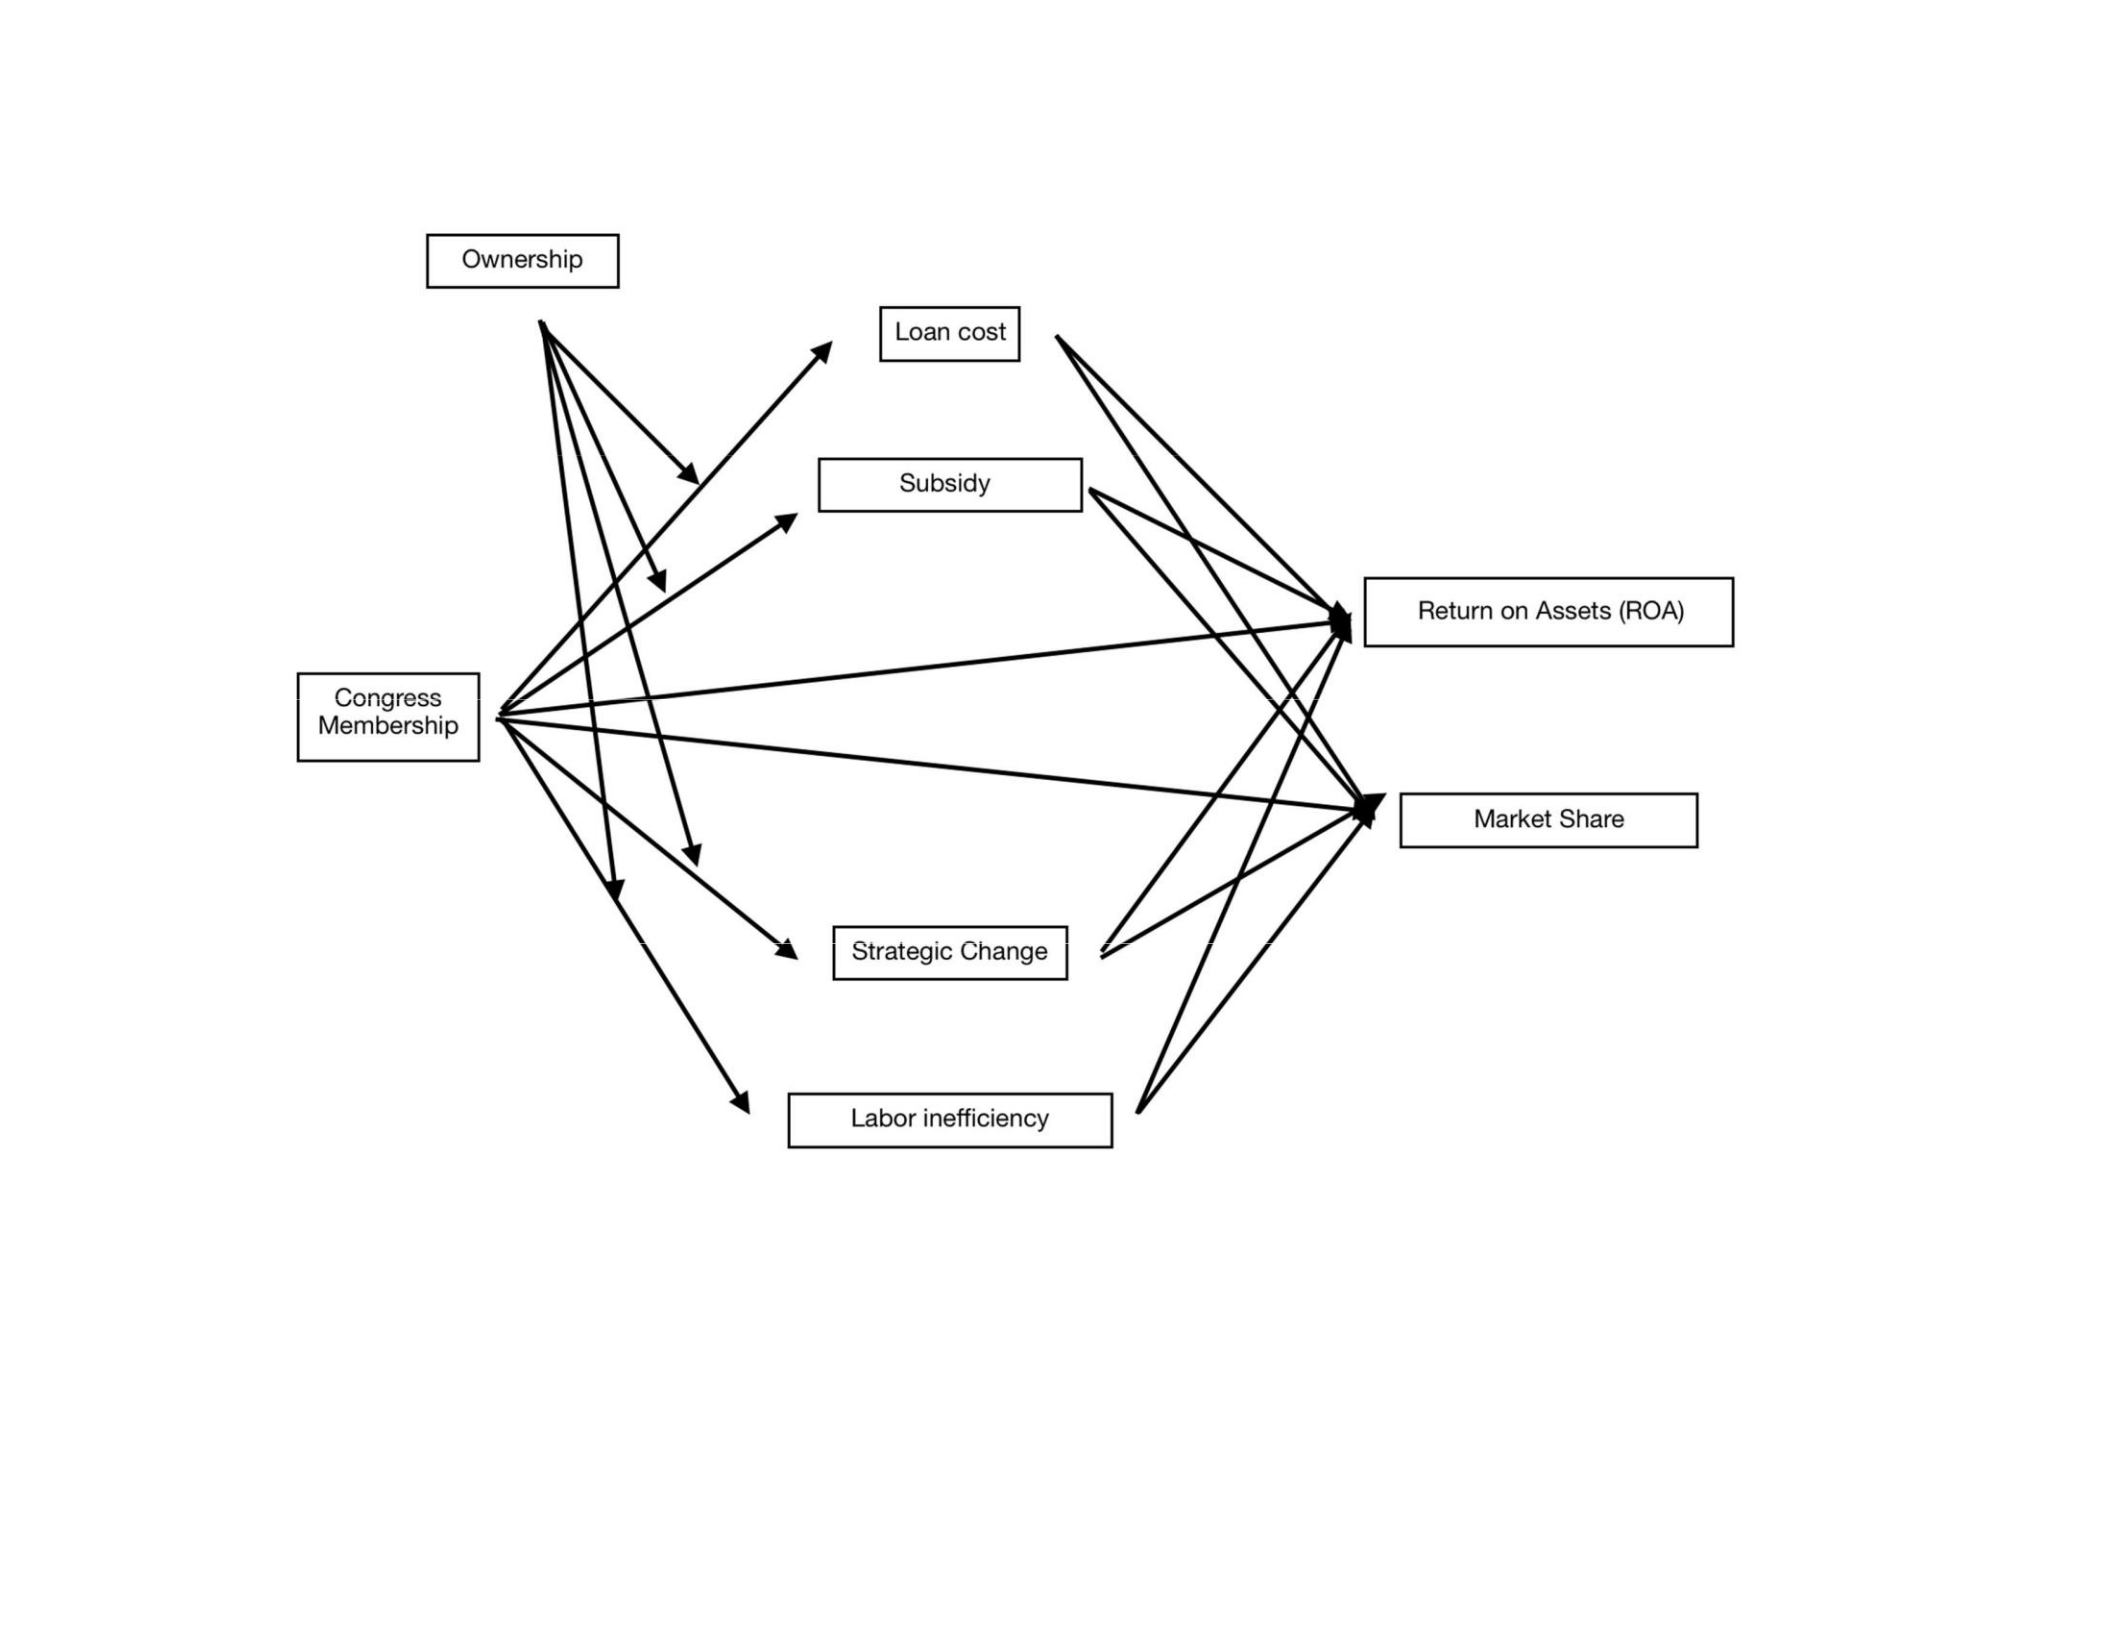
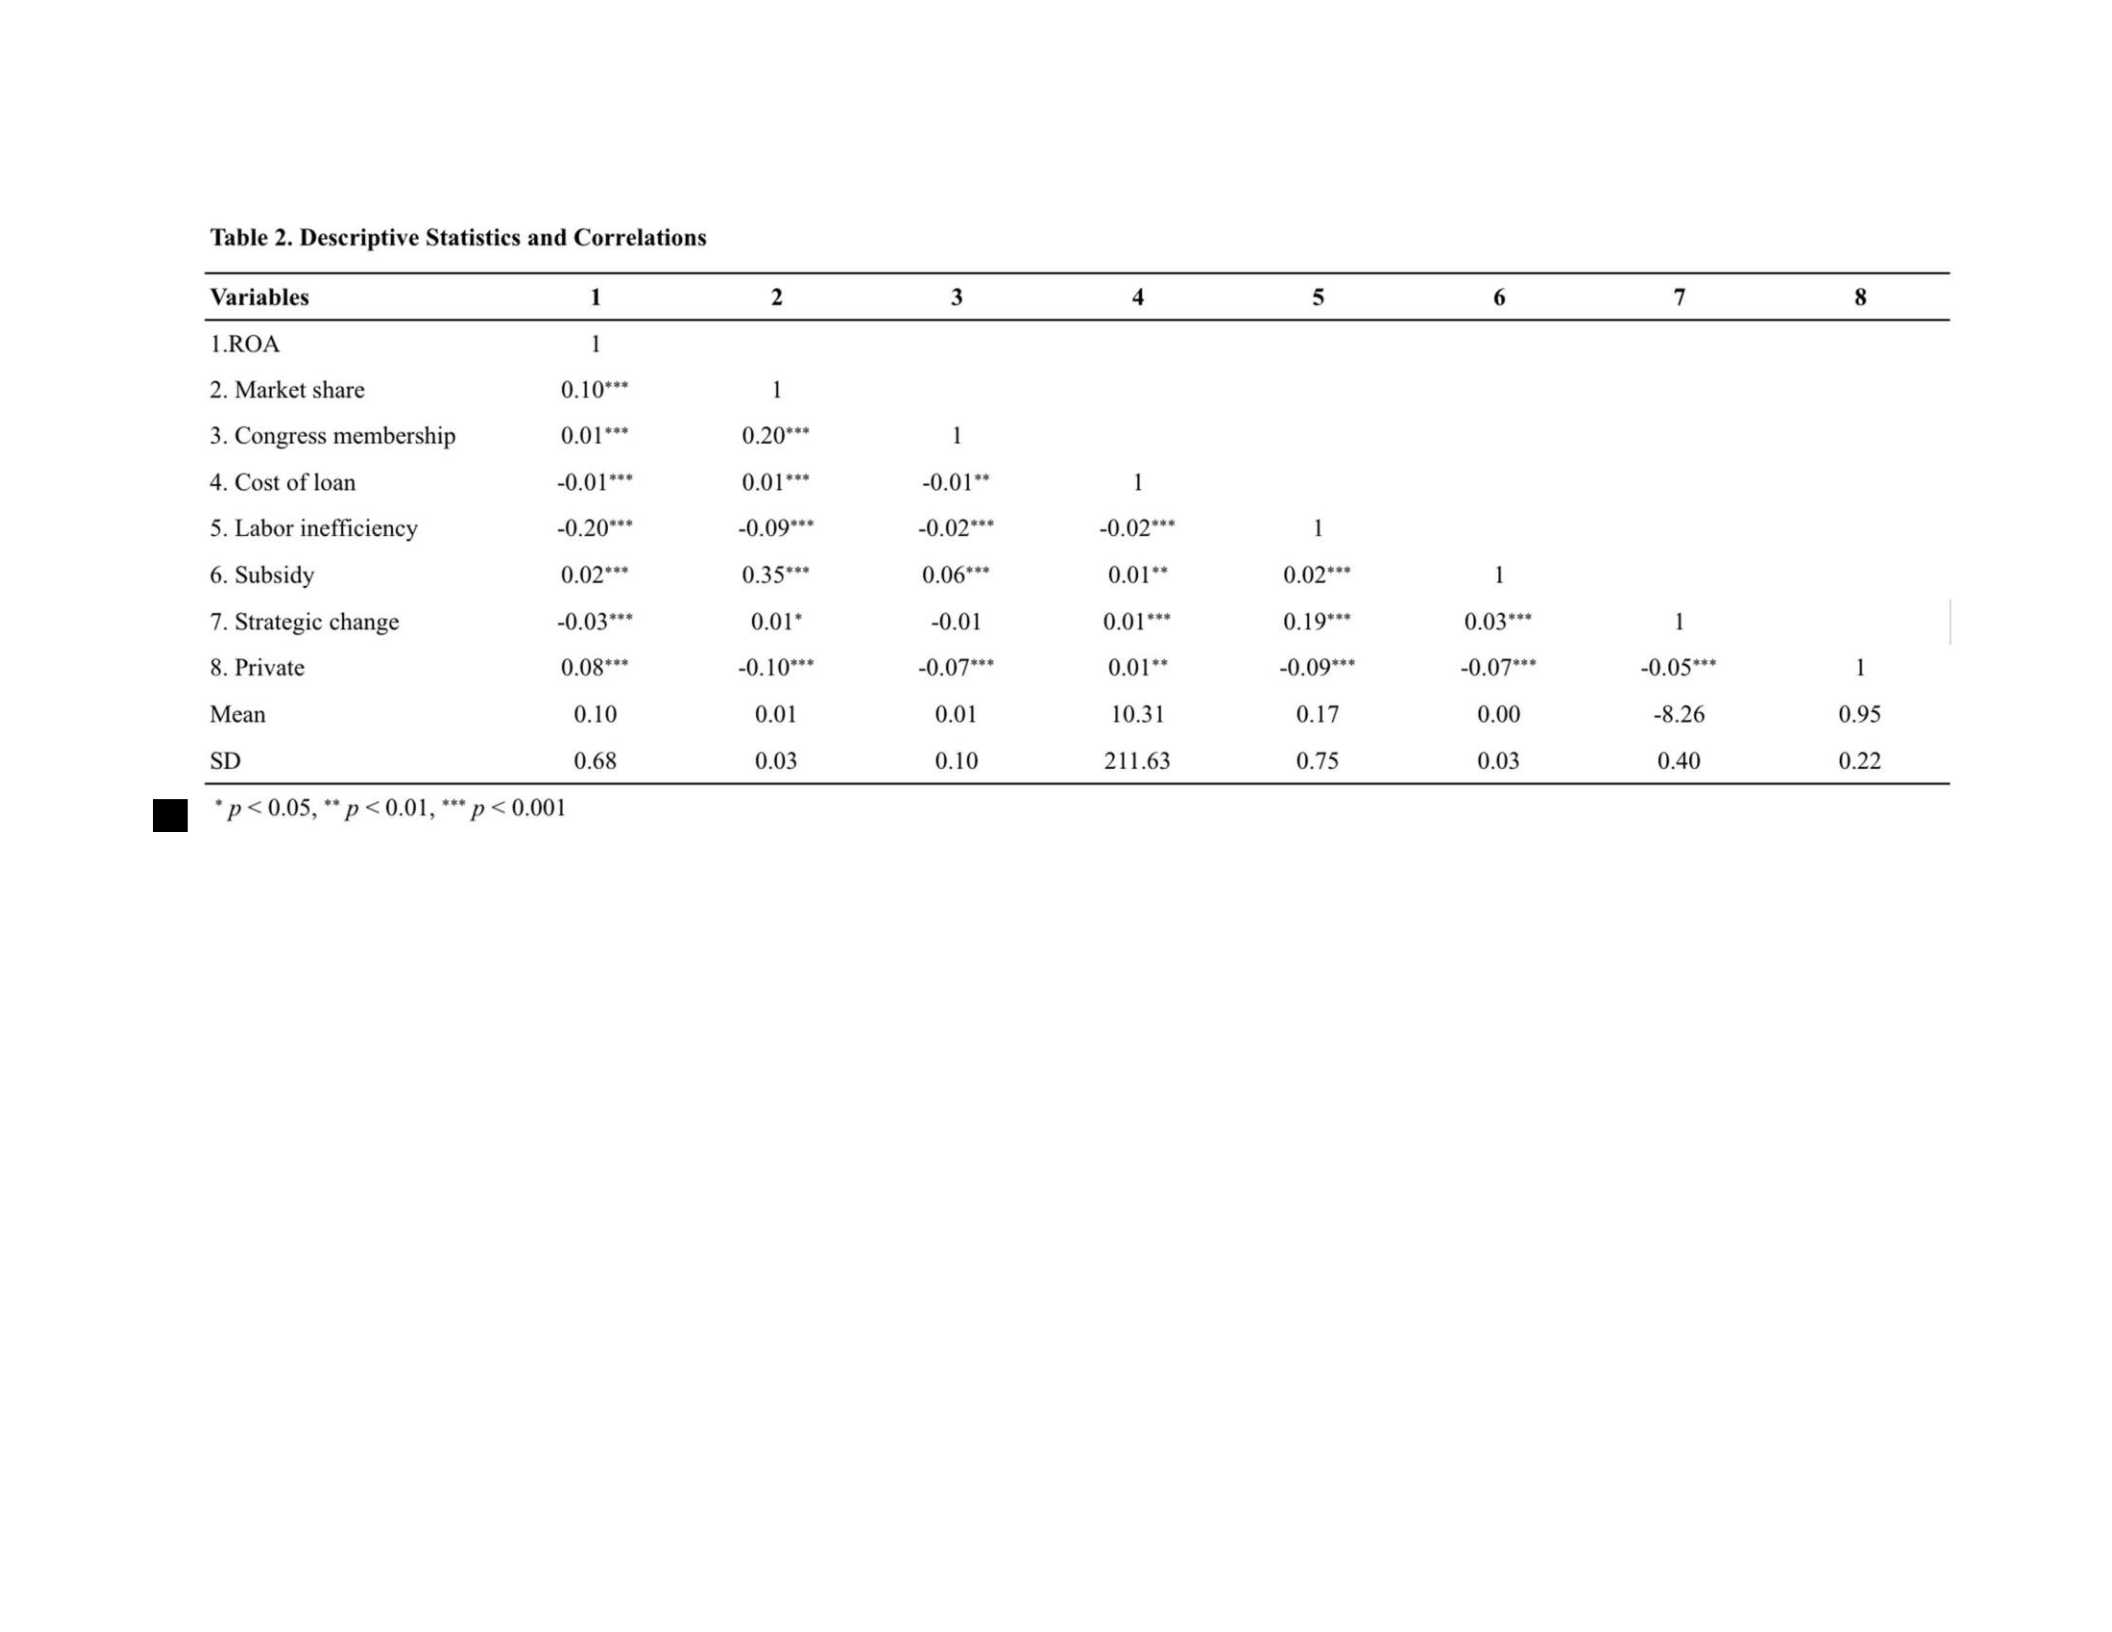
Table 3 Results of Regression Analysis
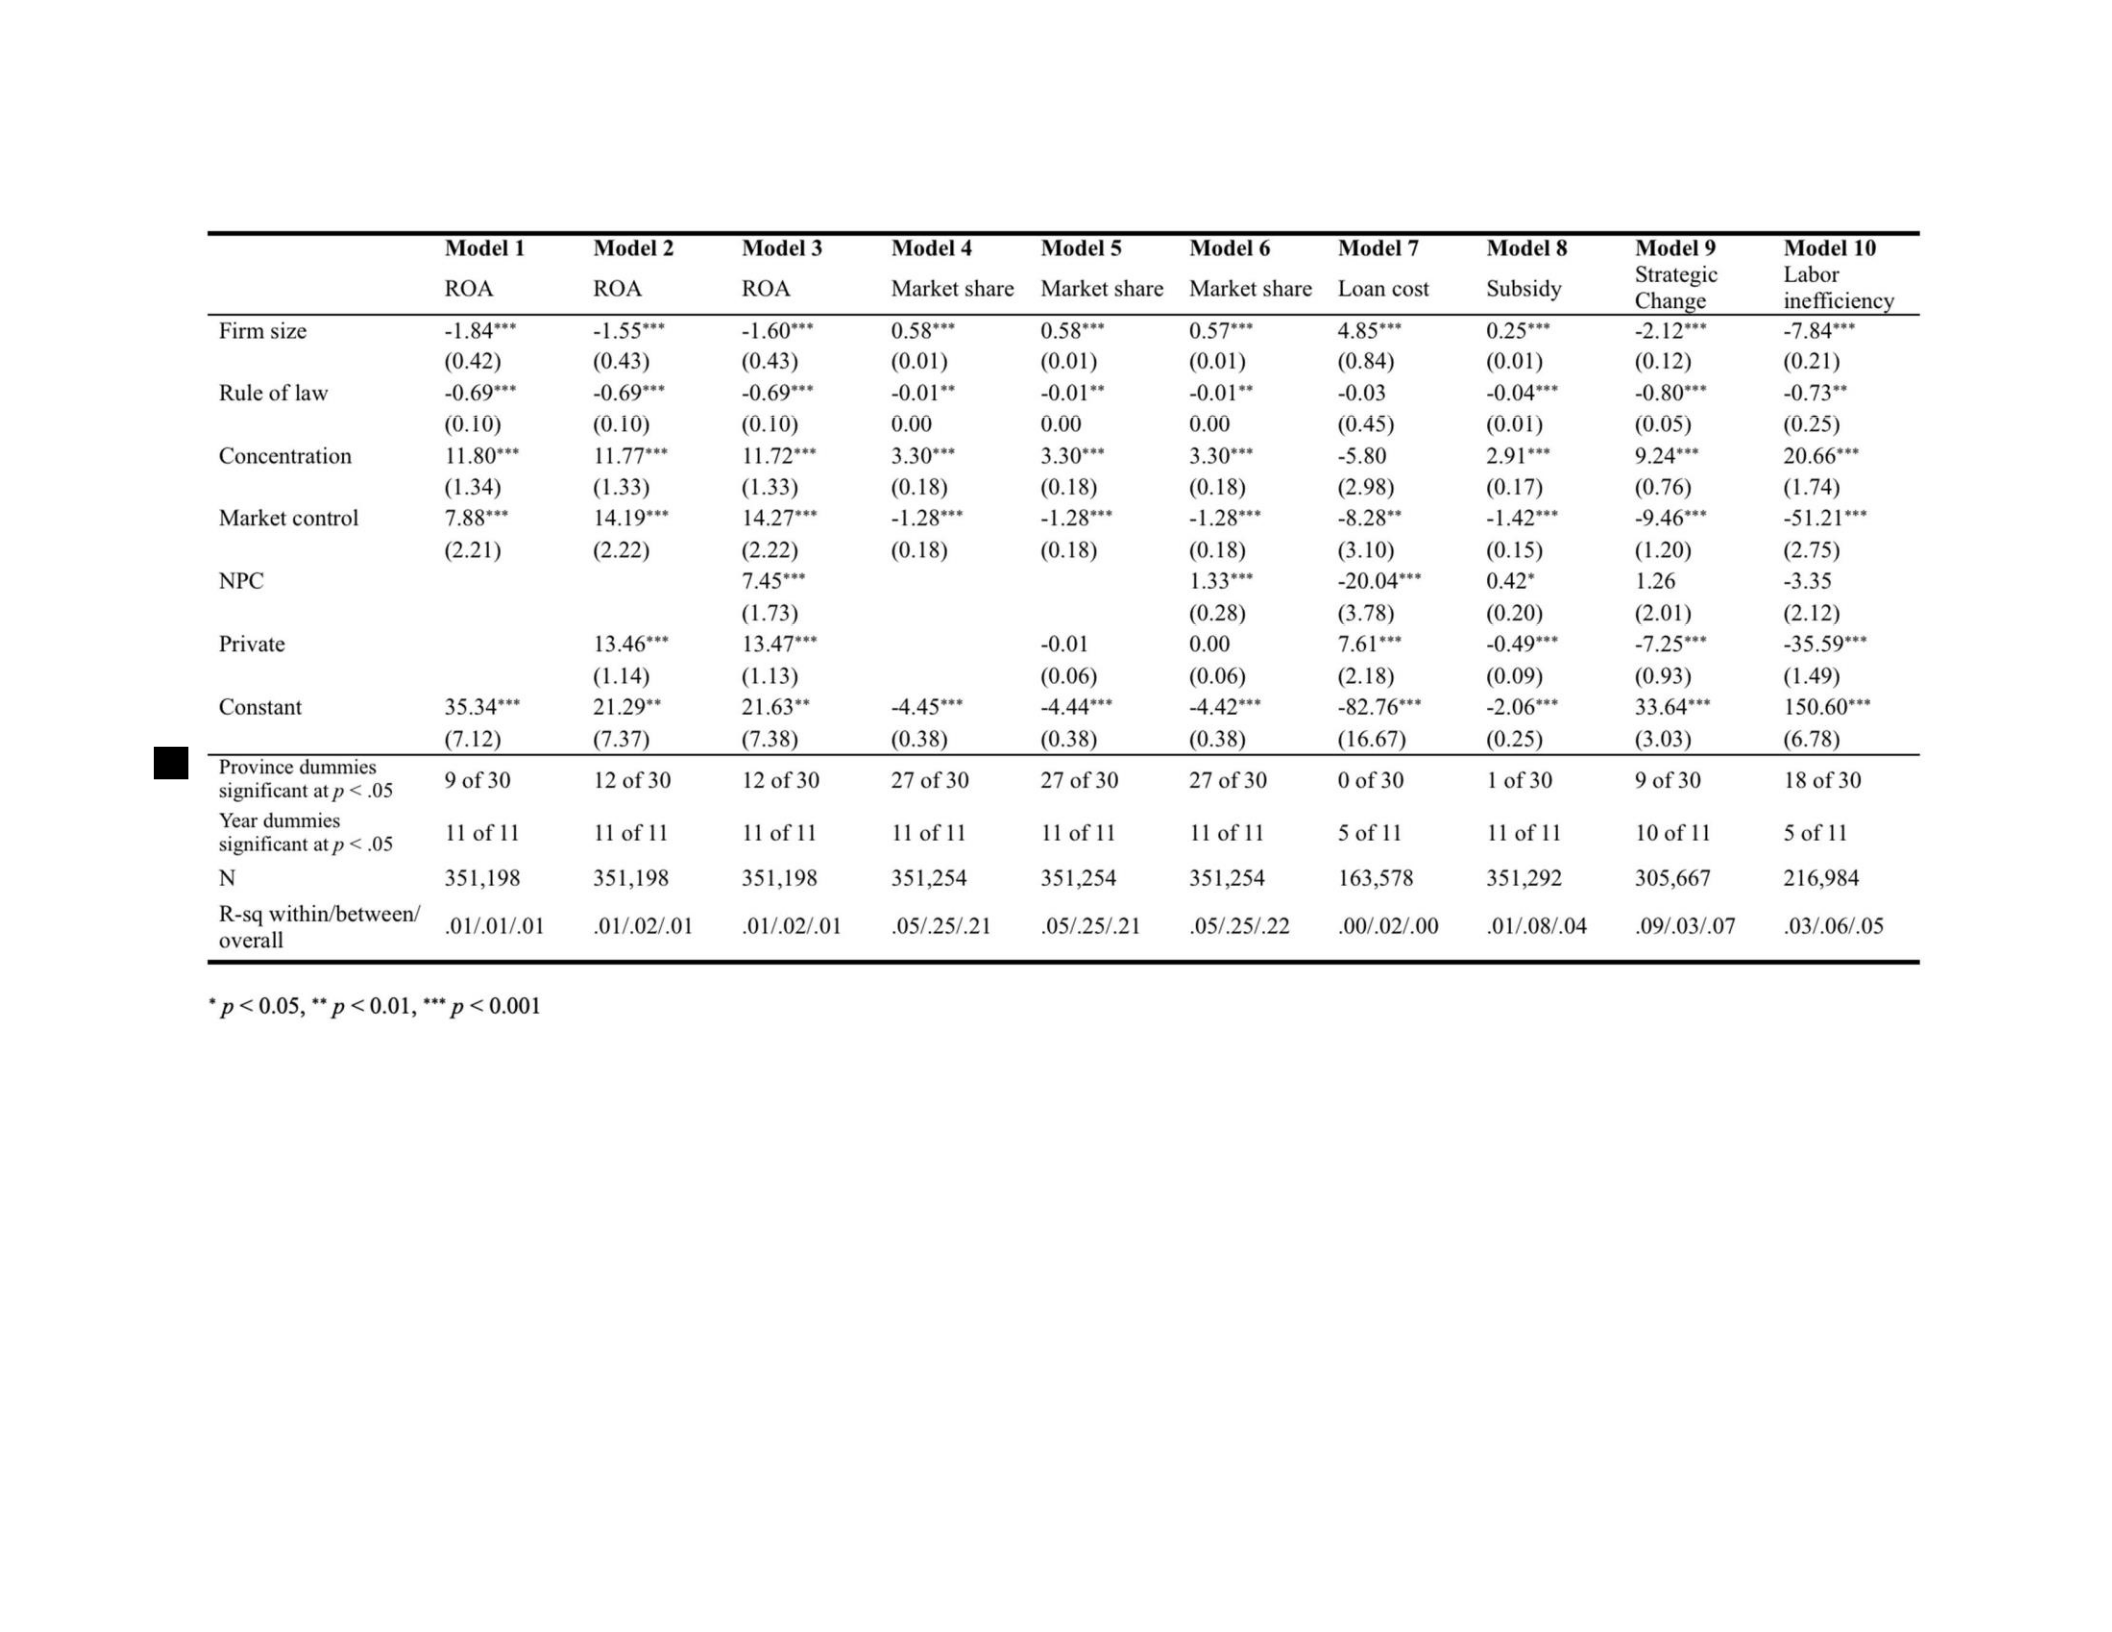
Table 3 Results of Regression Analysis (Continued)
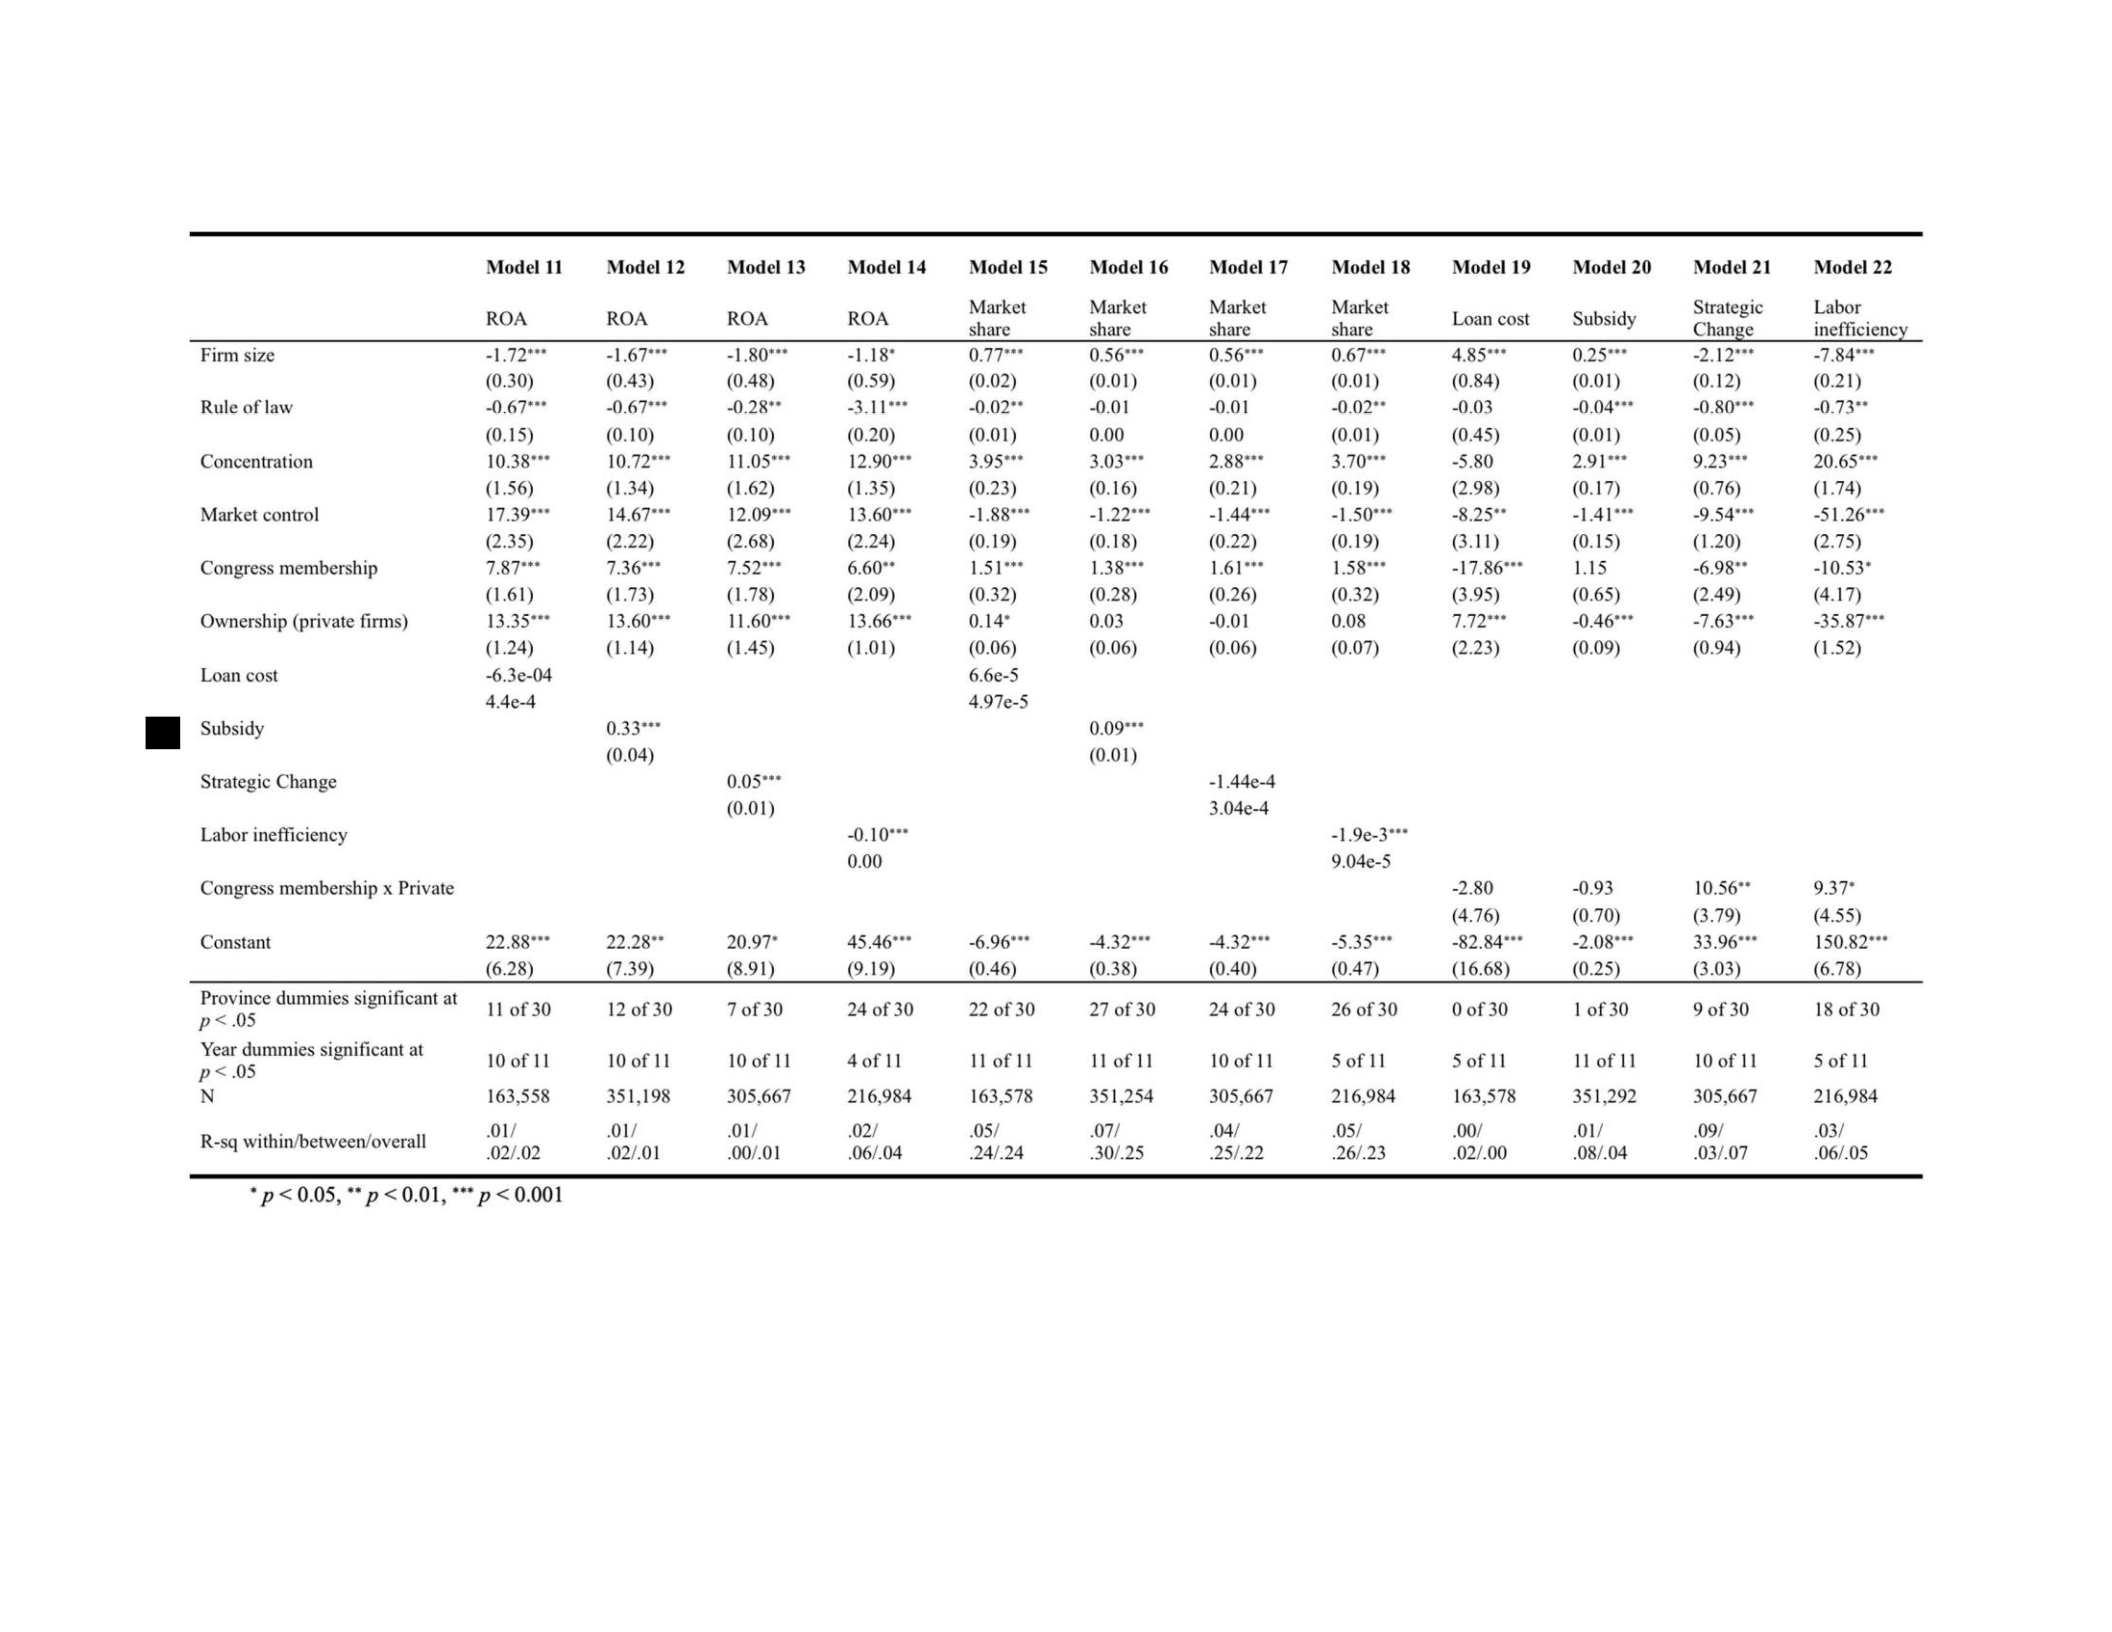
69
Model
11
Model
12
Model
13
Model
14
Model
15
Model
16
Model
17
Model
18
Model
19
Model
20
Model
21
Model
22
ROA
ROA
ROA
ROA
Market Market Market
Market
inaneoe
Subsidy
Strategic
Labor
share share
share
share
Change
inefficiency
Firm
size
-1.72°** -1.67°** -1.80°**
-1.18"
O77
0.56°**
0.56***
0.67***
4.85°**
025"
~zAZ
-7.84°""
(0.30) (0.43) (0.48) (0.59) (0.02)
(0.01)
(0.01)
(0.01)
(0.84) (0.01) (0.12) (0.21)
Rule
of law
-0.67*** -0.67°**
-0.28**
ooo
L
LS
-0.02**
-0.01
-0.01
-0.02**
-0.03
-0.04°"* -0.80°**
-0.73**
(0.15)
(0.10)
(0.10)
(0.20)
(0.01)
0.00 0.00
(0.01)
(0.45) (0.01) (0.05) (0.25)
Concentration
10.38°**
10.72°**
11.05°*°
12.90°*°
35.95***
3:03"
2.88°** 3.70°**
-5.80
291°"
9:25"""
20.65***
(1.56) (1.34) (1.62) (1.35) (0.23) (0.16) (0.21)
(0.19)
(2.98) (0.17) (0.76) (1.74)
Market
control
17.39°**
14.67°** 12.09°** 13.60°**
-1.88°"* -1.22°"°
-1.44°""°
-1.50°**
-8.25**
-1.41°"* -9.54°"*
-51.26***
(2.35) (2.22) (2.68)
(2.24)
(0.19) (0.18) (0.22)
(0.19)
(3.11)
(0.15) (1.20) (2.75)
Congress
membership
7.87°**
7.36°"*
732"
6.60°*
1.51°**
1.38°°*
1.61°** 1.58°**
-17.86***
1.15
-6.98"*
-10.53*
(1.61) (1.73) (1.78)
(2.09)
(0.32)
(0.28)
(0.26)
(0.32)
(3.95) (0.65) (2.49) (4.17)
Ownership
(private
firms)
13:35*""
13.60°**
11.60°**
13.66°**
0.14°
0.03
-0.01
0.08
V2
-0.46°** -7.63***
-35.87°**
(1.24) (1.14) (1.45) (1.01) (0.06) (0.06) (0.06)
(0.07)
(2.23) (0.09) (0.94) (1.52)
Loan
cost
-6.3e-04
6.6e-5
4.4e-4
4.97e-5
Subsidy
033°"
0.09°**
(0.04) (0.01)
Strategic
Change
0.05***
-1.44e-4
(0.01)
3.04¢-4
Labor
inefficiency
-0.10°"*
-1.9e-3"**
0.00
9.04e-5
Congress
membership
x
Private
-2.80
-0.93
10.56°*
9.37°
(4.76) (0.70) (3.79) (4.55)
Constant
22.88°**
22.28°*
20.97°
45.46°"°
-6.96""* -4.32°"° -4.32°""
-5.35***
-82.84°"*
-2.08°"*
33.96°**
150.82°**
(6.28) (7.39) (8.91)
(9.19)
(0.46) (0.38) (0.40)
(0.47)
(16.68)
(0.25) (3.03) (6.78)
oe
dummies
significant
at
11
4639
120f30
7
0f 30
240f30
22 of
30.»
270f30
240f
30
26
of
30
O
of 30
1
of 30
9
of
30
18
of
30
se
10
of
11
10
of
11
lOofll
4
of
I
M1
of
11
Hof
11
10
of
11
5
of
11
5
of
11
M1
of
11
10
of
11
5
of
11
N
163,558
351,198 305,667
216,984
163,578
351,254 305,667
216,984
163,578
351,292
305,667
216,984
R-sq
within/between/overall
.O1/
O1/ O1/
.02/
.05/
.07/
.04/
.05/ .00/
O1/
.09/
.03/
.02/.02
.02/.01 .00/.01
.06/.04 .24/.24
.30/.25
.25/.22
.26/.23
.02/.00 .08/.04 .03/.07
.06/.05
*
p<
0.05,
*
p<
0.01,
**
p<
0.001
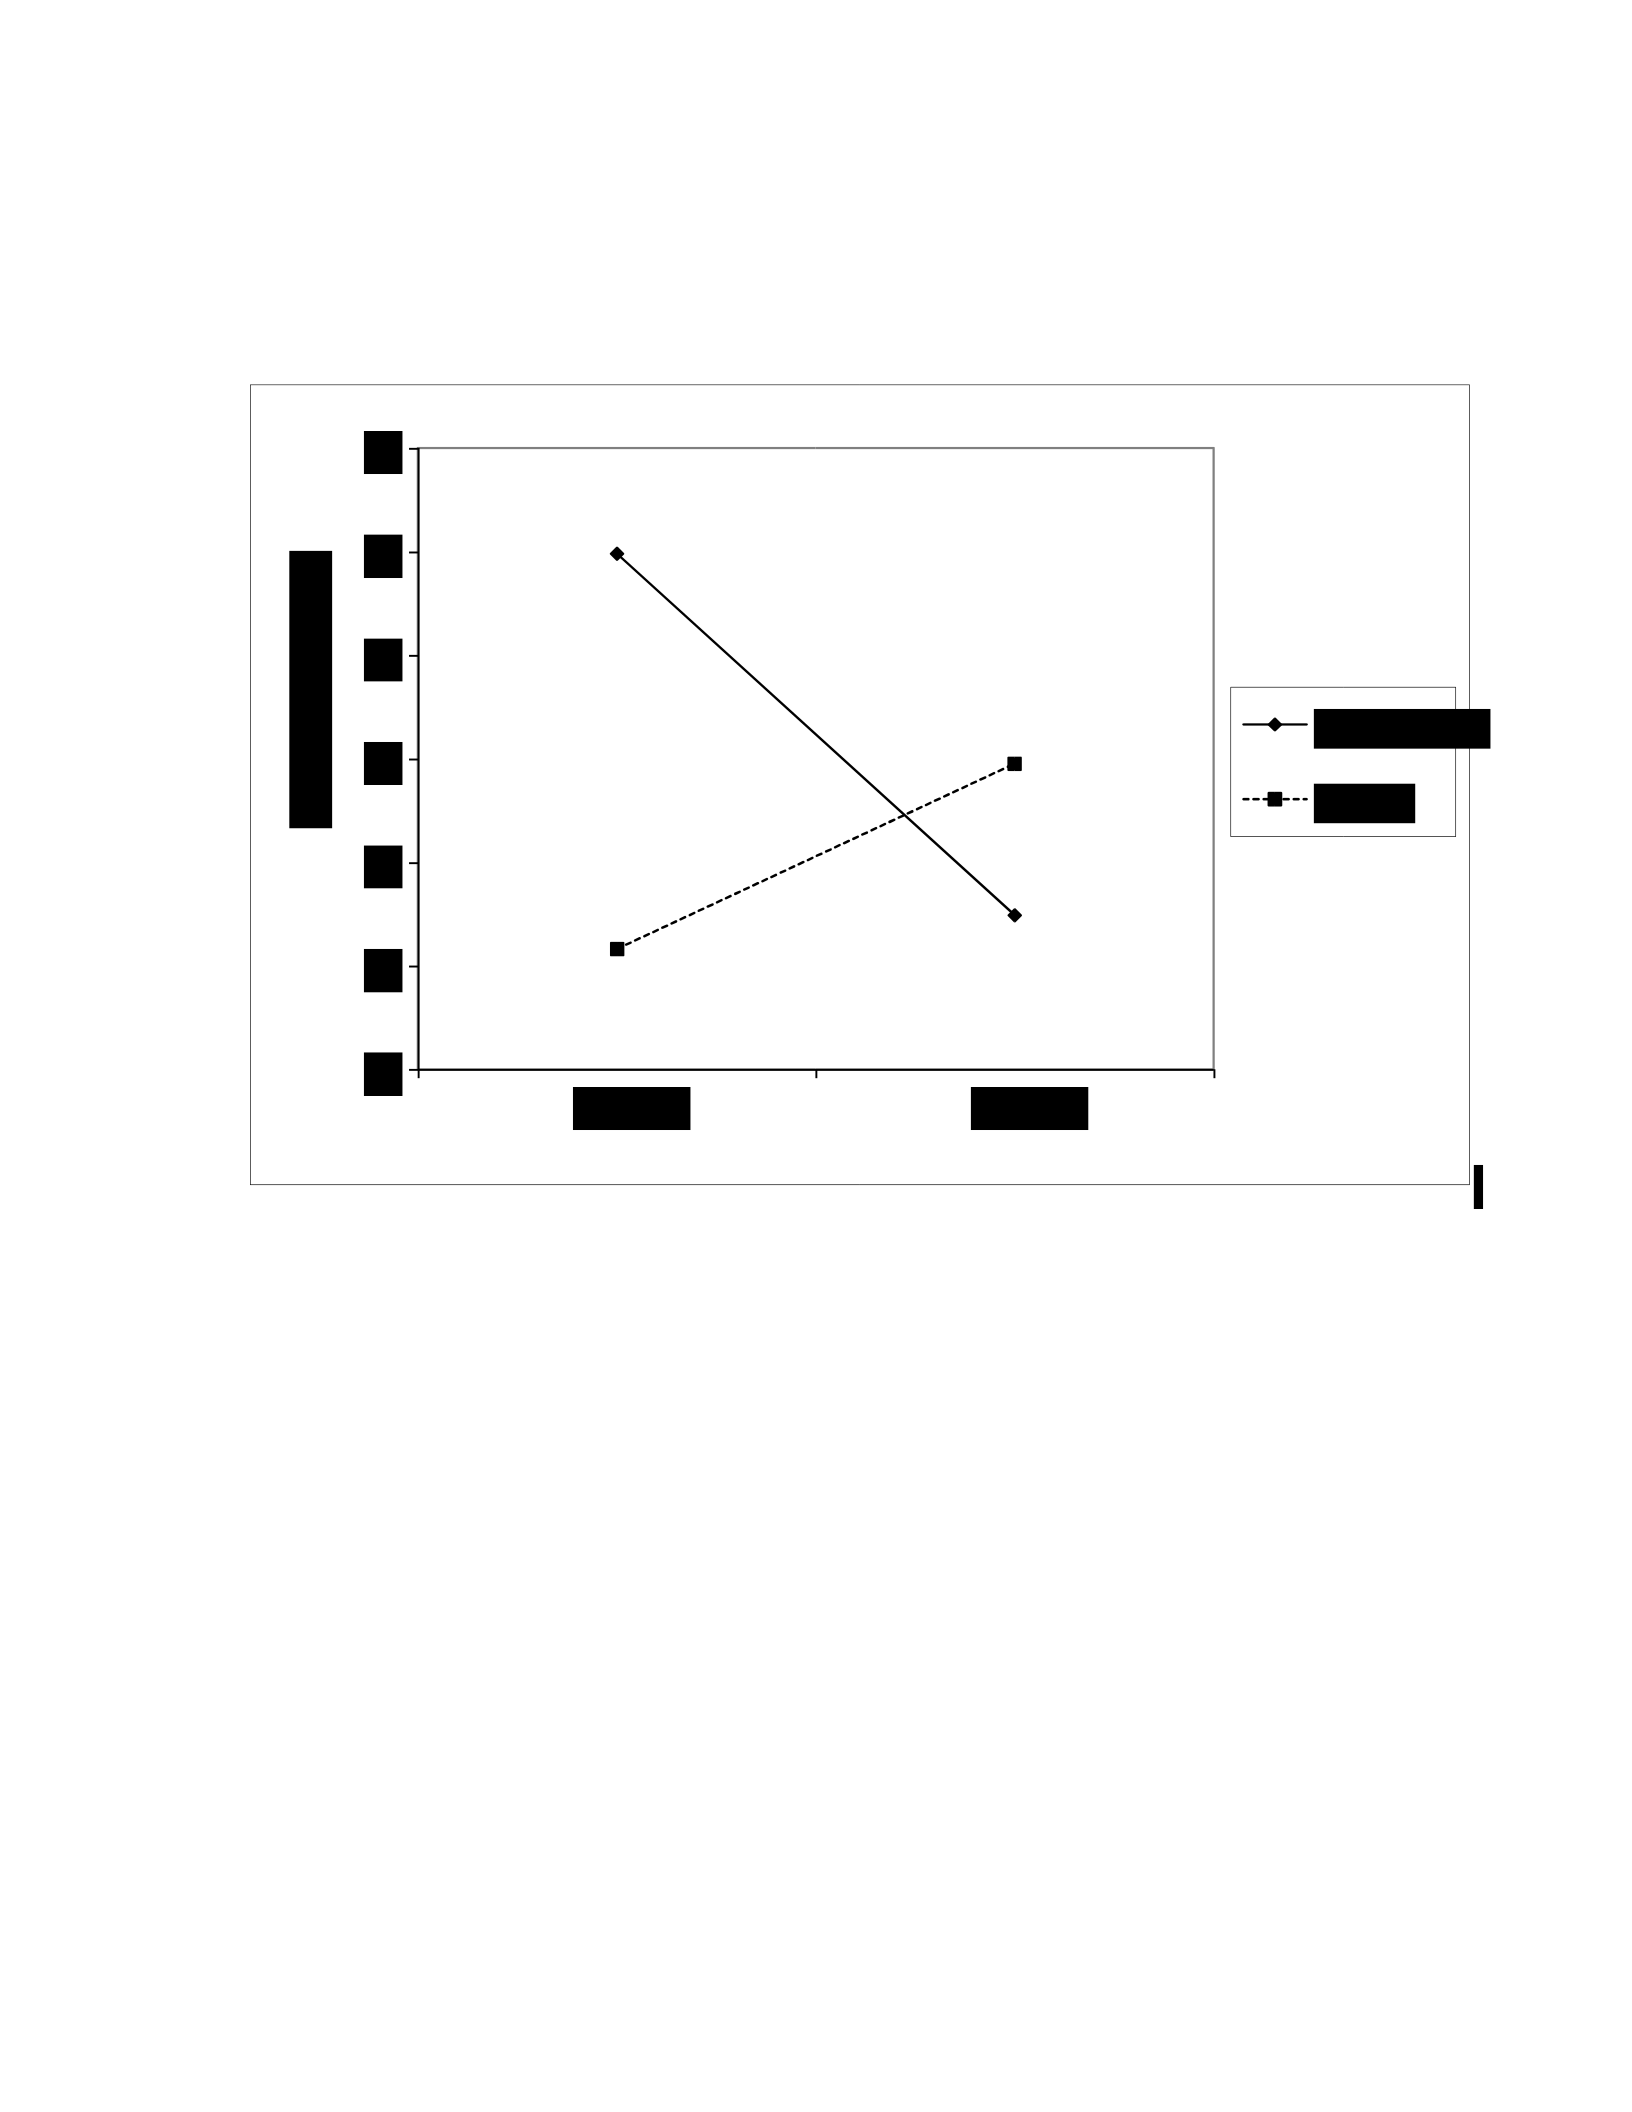
Figure 2 Plots of interaction effects
24
26
28
30
32
34
36
NPC=0
NPC=1
State owned
Private
70
100
110
120
130
140
150
160
NPC=0
NPC=1
State owned
Private

