


Risk Management During Financial Crisis in the US
IEE 454 - Risk Management
Arizona State University-Tempe
December 11, 2024

Abstract
Banks and other financial institutions forming part of
the financial system contribute greatly to the
development of any economy. Business and industrial
enterprises look for increased financial support from
these institutions, since they can develop and introduce
innovative financial products and services. Because of
the nature of products and services handled by the
financial institutions, they are exposed to different
types of financial risks. There has been increased
exposure of financial institutions to various risks before
and during the recent financial crisis.
In this context, this research extends to the examination
of risk management under conditions of the financial
crisis. The study covers the classification of risks and the
salient aspects of risk management. Different risk
assessment models and their deficiencies are also
focused. The research engages qualitative case studies
of the risk management failures in Lehman Brothers and
2007/2008 subprime financing to report on the
implications of risk management on the financial
institutions. Suggestions on concrete measures for
improving risk management in financial institutions are
not included in the scope of this study.
Introduction

The word risk originates from the Italian
word risicare meaning ‘to dare’. Webster’s Dictionary
(1989) defines the word risk to mean
• expose to the chance of injury or loss
• a hazard or dangerous chance
• the hazard or chance of loss
• the degree of probability of such loss
The understanding of risk, measuring it and analyzing its
consequences has made risk-taking as one of the drivers
of the modern Western industrial development.
Economic growth, improved quality of life and
technological advancements – all have been the positive
outcomes of risk-taking. In the traditional setting, codes,
predetermined standards, and fixed hardware
requirements guided the carrying out of hazardous
activities. In the modern world, there is a complete
change in the focus were with the functional orientation
what is interesting is the result to achieve, rather than
the solutions or guidelines to achieve the desired end.
In such a functional system, the ability to address risk
becomes the key element. Therefore identifying and
categorizing risks is of critical importance for providing
decision support for making suitable choices of
arrangements and measures to achieve what is planned.

Risk Management – An Overview
While risk is the potential loss that occurs because of
natural or human activities, the potential losses are “the
adverse consequences of such activities in the form of
loss of human life, adverse health effects, loss of
property, and damage to the natural environment”
(Modarres, 2006). Risk analysis, therefore, is a process,
which characterizes, manages and informs others about
the existence, nature, magnitude, and prevalence of
potential losses in any situation. The process also
describes and cautions on the contributing factors and
uncertainties connected with such potential losses.
In engineering systems comprising of hardware,
software, and human organizations potential losses due
to the associated risks may arise externally to the
system or losses caused by the system to the humans,
organization, assets and/or environment. The loss may
also occur internally resulting in damages to the system
only. From an engineering perspective, the risk or
potential loss results in exposure of recipients to
hazards and such hazards normally extend to “injury or
loss of life, reconstruction cost, loss of economic activity
and environmental losses”. In engineering systems, risk
analysis is undertaken to measure the extent of the
potential loss as well as to identify the elements of the

system, which are most responsible for causing such
losses.
The risk management system thus signifies the ability to
define the probable future course of events, making
closer to a realistic assessment of the associated risks
and uncertainties and to enable decision-making among
the available alternatives. Risk management extends
the decision-making ability to several varied social,
economic, business and political issues. Based on an
evaluation of several quantitative and qualitative
factors interconnected with the issues under
consideration, the best alternative giving the highest
probability needs to be selected in any decision-making
process. In business situations, choosing a specific
alternative depends on the consideration of associated
costs and other key performance measures as well as a
careful assessment of risk and uncertainties to ensure
positive outcomes. However, it cannot be ruled out that
there might also result in some negative outcomes; but
positive outcomes should be visualized as the overall
outcomes. This is the essence of risk assessment and the
process of risk management.
Risk analysis has its intellectual roots traced back to a
hundred years, yet this discipline is developed into an
organized body of knowledge only within the past two

decades. Risk analysis is undertaken to serve several
purposes such as determination of environmental and
health hazards associated with several activities or
substances or for comparing new and existing
technologies or for determining the effectiveness of
different control and mitigation techniques designed to
reduce risks (Cohrssen & Covello, 1999). Risk analysis is
also undertaken to set the priorities of the management
in choosing one among several activities for regulatory
or corrective action.
Risk assessment, on the other hand, is the technical
assessment of the nature and magnitude of risk. Both
the terms risk analysis and risk assessment are mostly
used synonymously. Risk management uses information
and data gathered from risk assessment and analysis
and assimilate such information with information on
technical resources, social, economic and political
values for choosing the control or response options. Risk
management is resorted to determine means of
reducing the risk or getting rid of the risk. The difference
between risk management and risk assessment is
subject to wider debates and is not within the purview
of this report. However, risk perceptions have a large
influence on both risk management and risk
assessment.

People have different perceptions about risks and such
perceptions are affected by different elements such as
the persons or things likely to be affected, nature,
familiarity and magnitude of perceived effects. The
perceptions often also based on the likely benefits to
accrue from acceptance of the risks. Because risk is
ubiquitous, risk analysis techniques are used to analyze
several phenomena having different magnitudes. Risk
analysis makes use of a wide variety of techniques,
which are used in situations where the solutions are not
explicitly available and where the information on the
potential losses is ambiguous and uncertain. Risk
analysis uses various disciplines like science,
engineering, and statistics for analyzing the risk-related
information and for making estimation and evaluation
of the probability and magnitude of the associated risks.
Problem Definition
In any economy, business houses and industrial
enterprises depend on the financial institutions for their
financial support, as these institutions develop and
provide innovative financial products and services.
Given the nature of products being dealt with by the
banks and financial institutions as also the nature of
transactions the institutions are exposed to different
kinds of risks. Some activities carry risks of complex

nature like the case of illiquid and proprietary assets
being held by the banks (Santomero & Trester, 1997).
Financial institutions need to adopt systems for
identification; assessment and management of risks to
their operations and these risks may arise because of
the influence of external and internal factors. These risk
mitigation initiatives are considered important to
enhance the ability of the financial institutions to
respond to movements in the financial markets, which
are quick and unexpected. The efficiency of risk
management of a financial institution depends partly on
the effectiveness of corporate governance practices of
the institution, which focus on risk mitigation across the
institution. There are different types of risks faced by
financial institutions, which influence their risk
management practices.
The risk management in the financial institutions
centers around two basic issues as to the impact of risk
on the functioning of the financial institutions and how
the institutions can work to mitigate the potential risks
involved which form an integral part of the products of
the financial institutions (Stulz, 1984). The available
literature points out four distinct reasons for practicing
risk management in any financial institution. They are
(a) self-interest of the managerial people involved in the

business processes of the financial institutions, (b)
impact of taxation, (c) the cost of financial distress and
the resultant economic losses and (d) capital market
imperfections (Santomero, 1995). In each of the above
instances, the profits are volatile, which may result in a
reduction of the firm’s value to some of the
stakeholders. Anyone of the above reasons would have
the effect of motivating the management to make a
careful assessment of the risks associated with the
different products and techniques for risk mitigation.
Risk management in the financial service industry has
assumed greater importance in the wake of a balanced
economic development of the nation. An intrusive risk
management system is considered very much essential
given the concern about the safety and soundness of the
financial service industry. However, the advancement in
the information and communication technology, the
enlargement in the financial services industry, the
ambiguity in the distinction of banking and non-banking
financial institutions and the creation and offering of
numerous financial service products have put the
banking system in a state of perpetual change and
instability. Thus, the transformation of the industry into
a highly competitive and dynamic environment has
made the system incompatible with traditional risk
management systems. The key question remains that

whether at all it is possible to adopt appropriate risk
management systems meeting the needs of the
increasingly competitive environment of the banking
systems.
In the years leading up to the recent financial crisis,
some of the authorities have recognized that and
intimated several investment banks, that they have not
implemented efficient risk mitigation initiatives. Despite
the advice from the regulators, these institutions have
not taken any steps to remove these weaknesses in their
risk management systems such as making changes in the
system of risk assessments, until the crisis occurred. This
is because these institutions reported a strong financial
position. Based on such reporting, the senior
management had presented the plans for change in
their risk management plans. In some instances, the
authorities themselves were not convinced about the
existence of deficiencies in the risk management until
such time the institutions were affected financially by a
lack of proper risk mitigating plans because of the recent
financial crisis. Authorities have accepted their heavy
reliance on the risk reports of the top management of
investment banks. This makes the necessity of the
senior management of the financial institutions
especially the commercial banks understanding the risk
assessment and management under the financial crisis

an important and significant task. This thesis studies the
issue of risk management under conditions of financial
crisis and challenges faced by the financial institutions
to mitigate risks, which will add to the existing
knowledge on risk management of financial institutions.
Research Objective
Examining risk management under conditions of the
financial crisis and the challenges faced by financial
institutions is the central aim of this study. In achieving
this central aim, the stud attempts to achieve the
following other objectives.
• To study and make an in-depth report on the
concept of risk, the rationale for risk management
risks faced by the financial institutions and methods
of measuring risk
• To make an in-depth study of the deficiencies in risk
management by financial institutions during the
recent financial crisis
• To report on the effects of the deficiencies in
managing risk effectively
The study will achieve other objectives incidental to the
above objectives.
Research Questions

Based on the theoretical observations from case
studies, the research will find answers to the following
research questions.
1. What are the salient aspects of risk management by
financial institutions under conditions of the
financial crisis?
2. What are the deficiencies in the risk assessment
and risk management techniques followed by the
financial institutions during the recent financial
crisis?
3. What are the effects of the deficiencies in managing
risks effectively by the financial institutions?
Research Methodology
This research has been undertaken to examine the
salient aspects of risk management under conditions of
the financial crisis and the challenge of financial
institutions functioning in the United States in this
respect.
Denzin and Lincoln (1998) state the researcher is
independent to engage any research approach, so long
as the method engaged enables him to complete the
research and achieve its objectives. To achieve its
objectives, this research proposes to use the deductive
or qualitative approach. The qualitative research

method is also referred to as ‘naturalistic’ research
(Bogdan and Biklen (1982); Lincoln and Guba (1985);
Patton (1990); Eisner (1991). According to Marshall and
Rossman (1995), qualitative research is based on the
collection of data from different sources and the data
already collected forms the basis for reporting the
findings of the study and making recommendations. Yin
(1984) identified different sources like “archival records,
direct observations, interviews, and observation of the
participants,” for data collection to conduct qualitative
research.
The research design of the case study was adopted for
the study. Case study design can be considered as the
appropriate one, as this method allows an examination
in depth (Burns, 2000 p. 461). According to Burns
(2000), using a case study method, the researcher will
be able to undertake an intensive analysis of the
research topic to get deep insights on the subject
studied (p. 461). Punch (1998) observes that the case
study allows for a variety of research questions and
purposes, which enables the researcher to gather a full
understanding of the case to the extent possible,
(p.150). However, the case study may be considered as
more subjective. Burns (2000) points out that the case
study may turn the researcher to be selective in
interpreting the results. This makes the observations

and interpretations devoid of easy checking or
verification. The case study allows an opportunity for
the researcher to advance personal causes (Burns, 2000,
p 474). The research will use secondary data for
researching literature review and case studies.
Collection of Secondary Data
According to Al-Mashari, Zahir & Zairi (2001), because of
“a lack of methodological research constructs” it
becomes important that an in-depth review of the
relevant literature is undertaken. Therefore, an
extensive literature review will be attempted using
professional journals and other research publications
containing articles on risk management by financial
institutions and factors affecting risk mitigation. The
research will review the theoretical contributions of
several research scholars and practitioners to form the
theoretical base for the research.
Data Analysis Method
Since the information gathered is qualitative, there will
be no statistical methods used to analyze the data
collected. An in-depth analysis of the factors and their
comparison with the oretical findings will be undertaken
to achieve the research objectives.
One of the serious limitations of this research is the
smaller number of samples that will be selected for the

case study. Generalization of the deficiencies in
managing risk effectively during the financial crisis,
based on the findings of this research, using the case
study of Lehman Brothers and 2007/2008 subprime
mortgage, may not be possible and to this extent, this
study suffers a serious limitation. Another limitation of
the study was the availability of an abundance of
literature on the topic of risk management by financial
institutions. Considerable time has to be spent on
reviewing the available literature and extracting the
relevant ideas for inclusion in the thesis. This has
impeded the progress of the research to some extent.
The case study will cover the failure of effective risk
management in Lehman Brothers and 2007/2008
subprime mortgage, to assess and report on risk
management during times of financial crisis. Secondary
research was used to collect information on risk
management under the circumstances of the financial
crisis. The scope of the current research is limited to
assess the deficiencies in risk management by financial
institutions in the context of the United States and has
not been extended to suggesting ways of improving risk
management by financial institutions during the
financial crisis.
Thesis Structure

To make a comprehensive presentation, this thesis is
structured to have five chapters. This Chapter, while
presenting a background of the research issue, also laid
the objectives of the study as well as the research
method, aims, and structure of the thesis. Chapter Two
presents a review of the recent literature on risk
management to add to the existing knowledge on the
effect of deficiencies of managing risk effectively by the
financial institutions during the financial crisis. Chapter
Three provides a brief description of the research
method followed for the research. Chapter Four
contains case studies on risk management practices of
Lehman Brothers and 2007/2008 Subprime mortgage
and a discussion on the findings of the case studies.
Chapter Five is the concluding chapter, which contains a
summary of the most important findings of the research
and answers to the research questions. This chapter also
contains a few recommendations for further research in
the field.
Literature Review
The objective of this chapter is to present an analytical
discussion of the relevant prior research work in the
area of risk management by financial institutions to add
to the current knowledge on the research topic. The
added knowledge will enable an in-depth understanding

of the implications of the findings of the current
research.
Financial Service Industry
Risk management in the financial service industry has
assumed greater importance in the wake of a balanced
economic development of the nation. Efficient risk
management is considered very much essential because
of the concern about the safety and soundness of the
financial service industry. However, the advancement in
the information and communication technology, the
enlargement in the financial services industry, the
ambiguity in the distinction of banking and non-banking
financial institutions and the creation and offering of
numerous financial service products have put the
financial system in a state of perpetual change and
instability.
Thus, the transformation of the industry into a highly
competitive and dynamic environment has made the
system incompatible with the traditional risk
management models and their application to the
industry. The key question remains that whether at all it
is possible to adopt a risk management model mitigating
all types of risks associated with the operations of
financial institutions in the increasingly competitive
environment of the financial system. This review

examines different aspects of risks faced by banking and
other financial institutions.
In the present day business environment to enhance the
competitive strength, the firms constantly look for
information and knowledge relating to the shift in the
market conditions and also enabled services for putting
forth the financial and other transactions. In this sphere,
the services by the financial services organizations are
extremely important and necessary for the business
houses to accomplish their financial objectives.
However, the products and services being dealt with by
the financial service organizations are so vulnerable that
these firms are exposed to different kinds of risks while
operating in the market. Hence, the firms in the financial
services industry attach more importance to risk
management in their organizations. Risk management
in the financial services organizations is necessitated
due to various reasons.
The most important reason is the potential economic
losses to which the firms will be exposed in case they
had to meet with some unforeseen risk and it may erode
the entire capital of the firm. There are other reasons
for undertaking risk management in these firms like the
tax implications of the transactions, movement in the
capital and stock markets and the persistent fear of the

people managing the financial services businesses that
their decisions may be proved wrong by the course of
business events. In any risk, being faced by the financial
service firm there is the potential danger of the firm
losing profits, which in turn would result in the decline
of the firm value for some of the stakeholders. Similarly,
all or any of these reasons for managing the risk may
force the management of the firm to make an
assessment of the risks involved and take necessary
corrective or preventive action to protect the firm
against the risks identified. In this article, the different
kinds of risks to which the financial institutions are
exposed and how the firms can protect them against
these risks are discussed.
Methods to Protect Against Risks
The financial institutions adopt several ways of
protecting them against the risks associated with their
businesses. In general, the organizations can find out
the best business practices in the industry concerning
risk management and adopt them in their organizations.
Alternatively, the organizations can find convenient
ways of transferring the risks to other players in the
market or the organizations can employ specialized risk
management programs at their organizational level to

protect them against any financial loss resulting from
the risks.
The best practices in the industry are the normally
adopted risk management procedure by most of the
organizations in which the organizations take actions
like underwriting and reinsurance of risk so that the risks
will be spread among the operators which have the
effect of reducing the risks of apparent risks associated
with the business. Also, the financial institutions may
undertake hedging of their balance sheet items to
protect any possible financial risks due to change in
interest rates or exchange rates if the assets and
liabilities are held in foreign companies. The basic
objective behind these measures can be seen from the
fact that the organizations do not want to carry the risks,
which are part of the businesses undertaken by them
and to maintain the level of total risks under
controllable levels.
There are systemic risks that can be eliminated by a
proper assessment of the risks and taking risk protection
programs to safeguard the financial interests of the
organizations. Similarly, in the case of risks that the
organizations may face due to the frauds committed by
the staff and employees, losses arising out of oversights
and mistakes of the employees due to limited control by

senior-level management – known as operational risks
– the organizations can find suitable ways to minimize
these risks. In any case, it must be noted that the
organizations would suffer from possible erosion of
profits due to excessive protective measures being
taken by them to control the risks. However, it may be
possible for the organizations to make a cost
justification for the extended risk management
measures and communicate them to the stakeholders
to make them agree for the reduced earnings.
A significant part of the risks of the financial institutions
is getting transferred to other willing counterparts by a
method called ‘Risk transfer’ where the assets created
by the financial institutions are transferred to other
business counterparts on a fair market value mutually
agreed by both the parties.
Such transfers are commonly accepted by the
organizations if they find that keeping the assets may
not bring any additional financial advantage to them
rather than increasing the associated risks. There are
specialized markets and players to deal with such claims
issued or other financial assets created by the
organizations. Individuals and organizations acquire
such kind of assets as a part of diversification programs
of their portfolios.

Yet another bundle of risks connected with the business
of the financial institutions, which have the
characteristic feature of being inherently associated
with the transactions and which need constant
monitoring and control by the institutions. There is no
other alternative available to the organizations to shirk
away from the responsibility for these risks except to
take and provide for the losses arising out of these risks.
However, the organizations can employ aggressive
techniques of risk management, which may entail
additional resources for engaging such risk
management techniques. These risks in a way are out of
the ordinary and carry certain special features, which
make them distinct requiring special attention from the
organizations to control the damage on their account.
• As found in the case of some defined pension and
other retirement benefits schemes, there are some
equity claims in respect of which the financial
institutions are accountable for a fiduciary liability
where it is not possible to trade in or hedge against
the specific claims even if the investors would like
to do so. In these cases, the organization should
take adequate precautions and protective
measures to minimize their risk exposure on these
accounts.

• The other areas where such kinds of risks operate
are the illiquid and proprietary assets being owned
by financial institutions like banks. Such risks are
very complex demanding aggressive risk
management techniques to be employed by the
organizations.
• There are transactions where there are elements of
moral hazard forcing the financial institutions to
undertake strong measures of risk management to
protect the interests of the stakeholders. The
application of such risk management techniques
forms part of the operating procedures of the
organizations and all the risk management
programs are considered an integral part of the
business of the financial institutions.
What Are Financial Services?
The basic functions of banks, stockbrokers, insurance
companies and other financial service providers
comprise of services relating to:
• Collecting the savings of the people to provide
them compensation in the form of interest for
foregoing the current utility of those savings and
• Providing fiancé to those people, firms and even
governments who have the intention of investing
the finance so provided which will enable them to

pay back the institutions the financing and other
service charges in the future.
Another service provided by the financial institutions is
the use of money or other financial instruments to
realize the payments due on purchases of goods and
services on behalf of the customers. To perform this
function efficiently the banks and the financial
institutions have developed instruments like checks,
wire transfers, credit and debit cards including smart
cards and a host of other instruments which are known
as the payment mechanism of the economy.
Yet another addition to the financial services includes
the provision of guidance to the potential savers on how
effectively use their savings to reap a good return on
their investment which service is recognized as asset
management and treasury management. (The
Environment)
The financial services have taken the provision of a fifth
service, which is the risk management to both the
investors and savers. Risk management in its traditional
form covered only the insurance of buildings, workers’
lives, and property. However, the present-day concept
of insurance has extended its horizon to cover a wide
range of activities including financial derivatives to
manage “price, interest rate, exchange rate, and even

credit risks apart from covering the property, accidents,
and self. Thus, financial services encompass the
following mechanisms:
1. Mechanisms or instruments that enable the
potential savers to park their savings safely and
profitably
2. Mechanisms which provide the needy investors or
borrowers the required funds to fund their projects
3. Mechanisms that govern the payments on behalf of
the customers and
4. Provision of advice to the savers as to the manner
of dealing with their financial needs, as well as
managing the assets of the investors and savers and
5. Mechanisms to protect and manage the life,
property, and finances of the constituents
The Environment
The US financial system consists of an array of financial
institutions that provide any of the abovementioned
financial services. Despite being the most developed
and extensive in the world, financial service institutions
face several risks in providing the above services. This
review will cover risk management from the perspective
of financial institutions providing all the above services
and products.

Concept of Risk
This section elaborates on the concept of risk as it is
applied in the context of financial institutions. The word
‘concept’ is considered appropriate because the risk is
not a directly observable and objective phenomenon of
the natural world. The greatest challenge of risk
management is that risk is to be construed by the people
directly affected by the phenomenon.
Although the studies relating to risk are, varied and wide
still there has not been evolved a comprehensive
definition that covers all the aspects of risk. Quite often
risk is perceived as incidents or happenings which have
unwanted or unfavorable consequences. But such a
definition results in accepting misleading concepts of
risk being viewed as having negative and positive
consequences alike and secondly risk not only covers
single events but also relates itself to the future project
directions. There are chances that the project
conditions may change in a favorable or unfavorable
direction. The point here is that it is difficult to predict
the course of the future project direction at the
beginning of the project life cycle. Moreover, there are
plenty of chances that the prevailing conditions change
during the period at which the project progresses. The

risk here is that the conditions are diverse and might be
potentially severe far more than the estimations.
It so happens in the investment management process
the risks that are already identified as certain and
definite are only analyzed to prevent the impact of such
risks hampering the returns from such investments.
Risks follow the path of either that they will happen or
they may not happen and the impact of the risk is largely
influenced by the conditions prevalent at the time of the
happening of the risk. (Ward and Chapman, 2003; Artto,
and Kähkönen, 2000) The quality of the analysis of risk
depends on the variability and the degree of uncertainty
connected with future scenarios. (Turner, 1999) This is
the reason that there has been a recommendation by
many researchers that the term ‘risk’ needs to be
replaced by the term ‘uncertainty’ which has more
neutral quality as compared to ‘risk’. The term
‘uncertainty’ also has a larger scope than that is covered
by ‘risk’. The term ‘uncertainty’ has more capabilities to
replace the term risk as the variability and ambiguity
connected with risk can be accommodated in
uncertainty (Ward and Chapman, 2003).
Artto and Kähkönen (2000) point out the risk has a
dimensional perception which implies that risk could be
adverse and significant for the same may turn out to be

an opportunity or less significant for someone else
(Artto, and Kähkönen 2000). Risk perception is regarded
as one of the major development in the area of risk
management practices. Kahkonen identifies that it is
possible to localize the definition of risk in a way that it
could define the risk more precisely in individual cases.
(Kähkönen, K. in Artto, K., Kähkönen (2000)
It is possible that the risks can be categorized in several
ways based on the degree of details involved or based
on a particular viewpoint selected for the purpose. The
risk categorizations may take the form of a risk list or it
may as well present the sources of risks, which depend
on the phase or the type of the project. A typical risk
categorization may take the following form as
advocated by Artto and Kähkönen (2000):
• Pure Risks are the ones, which are caused by factors
like natural calamities or weather conditions;
• Financial Risks take the form of either difficult cash
flow situations or credit risks and the like;
• Business Risks encompass any kind of risks that may
affect the progress of the project,
• Political Risks are identified as the one which covers
extreme political situations like war which has a
serious impact on the project process.

Turner (1999) suggested the categorization of risks as
business risks, insurable risks, external risks, and
internal risks depending on the impact of the risks of the
location of the control over the risks. Bad weather may
be cited as an example of the external risk on which the
project manager does not have any control. Similarly,
the business risks are those risks, which generally have
to be faced by any venture to take advantage of a likely
opportunity, which can be a positive outcome of
business risk.
Approaches to Risk Mitigation
There are there general methods of mitigating the risks
in financial institutions:
1. The firms can employ simple business practices
which have the capabilities of eliminating or
avoiding risks
2. The firms can try to transfer the risks to other
market participants and
3. There can be an active risk management programs
at the firm level
In the first of the above three methods, the practice of
risk avoidance reduces the chances of the firms
accumulating losses by the elimination of risks which are
superfluous to the business processes. The financial

institutions follow actions like underwriting standards,
hedging to match the assets and liabilities, reinsurance
or syndication to spread the risks and due diligence
investigation. In these actions, the main objective is to
make the firm get rid of the risks that are not part of the
financial services provided or to absorb only an
optimum level of a particular risk.
In the case of systematic risks, it is possible to reduce
the risks that are not required to continue to do the
business by avoiding them altogether. Similarly, in the
case of operational risks, the firms can adopt different
ways to reduce the different kinds of risks including
fraud, oversight failure, lack of control and managerial
limitations. However, it must be noted that aggressive
risk avoidance measures in these areas may result in
lowering the profitability to some extent but enough
cost justification can be communicated to the
shareholders for the reduction in the earning.
Risk transfer is another method of mitigating a
substantial part of the risks. Risk transfer is achieved by
the firms by transferring the assets created by the
financial institutions at fair market value at the open
market. The firms undertake the transfer of these assets
if they find no incremental benefit in providing for the
mitigation of risks associated with the keeping of such

assets. Usually, there exists a market for the claims
issued and are assets created by many of the financial
institutions and there are individual market participants
who undertake to acquire these assets for
diversification of portfolios.
There is another set of risks, which are inbuilt in the
operations of the financial institutions and the firms
themselves must absorb these risks. In these cases, the
firms should practice aggressive risk management
techniques and the firms are expected to employ
additional resources for managing these risks. These
risks possess certain special characteristics:
1. There are the stakeholders for whom the
institutions own financial responsibility. The claims
of these people cannot be treated otherwise even
by the people who have invested in financial
institutions. Example in this connection is the
defined pension plans schemes.
2. Some activities carry risks of complex nature like
the case of illiquid and proprietary assets being held
by the banks (Santomero and Trester, 1997).
3. The existence of moral hazard in which the
stakeholders’ interests need to be protected by
adopting different risk management techniques as
part of the operating procedures.

4. Any risk management process is central to business
purposes.
Risks Associated with Financial Services Products
Before an analysis of the risks associated with the
financial services products and the ways of mitigating
them, it becomes important that an overview of the
financial services being provided by the financial
institutions is undertaken. The financial services
provided by the institutions can be categorized under
the following groups (Merton 1995; Merton and Bodie,
1995):
1. Origination – involving location, evaluation, and
creation of new financial claims issued by the
institutions’ clients. The originator depending on
his plans to retain the ownership of the new asset
or sell the product he takes the position of the
principal while retaining the ownership and an
agent while trying to sell the asset. An example of
the originating function is that of the mortgage
banker.
2. Distribution – represents the act of selling newly
originated products to different customers who can
finance them. The institution may act as a broker or
as a principal. In this case, the financial institutions
do not take ownership of these assets but act to

place the assets in the portfolio of the potential
investors.
3. Servicing – facilitates the collecting the payments
due from the issuers and settling the claimants. The
service provider in this process maintains records of
payments, monitors the financial contracts, and
takes necessary action in case of defaults. This kind
of activity is more prominent in developed nations.
In this case, the same institution holds most of the
assets.
4. Packaging – is of recent origin and involves the
collection of individual financial assets into
common pools, and then is repackaged to increase
the liquidity or meet the cash flow requirements of
specific customers.
5. Intermediating – is the most popular financial
service undertaken by the institutions, which
involves the practice of issuing and purchasing of
different financial claims to a single financial entity.
There are three different kinds of financial
intermediating that are common; they are (i)
insurance underwriting (ii) loan underwriting and
(iii) security underwriting which involves the
acquiring of securities as principal to distribute to
different investors.

6. Market Making – is an activity where a dealer buys
and sells identical financial instruments. However,
the market maker does not become the principal in
the transactions. A market maker becomes an
intermediary when it finances the transactions by
issuing its claims and acquires financial assets.
In all the above transactions, a distinction must be made
between the “principal and agency activities”. This is
because the accompanying “risks and incentives” vary
from each other for the two positions. While a principal
commits a capital risk in terms of both time and money,
the agent works for someone and hence there is the risk
of time only. In the agency business, the capital
investment is modest whereas in the case of the
principal activity there is a heavy investment of capital
outlay. Since the principal owns a portfolio there is the
systematic and idiosyncratic risk. In the case of an
agency, there is only the idiosyncratic risk.
Risk Management by Financial Institutions
Any financial institution is subject to risks. Managing
risks is a complex proposition for any financial
institution. Risk management has become an
increasingly important phenomenon, in the current
global economic scenario where there is a close link
among the financial systems of different economies.
Effective risk management has been prescribed by the
global financial institutions and banking regulators, as
an important element in the long-term success of the
financial institutions. The management of financial
institutions and regulators focus on improving the
ability of the organizations to manage future risks
instead of evaluating the current or historical financial
performance. Risk management in the case of financial
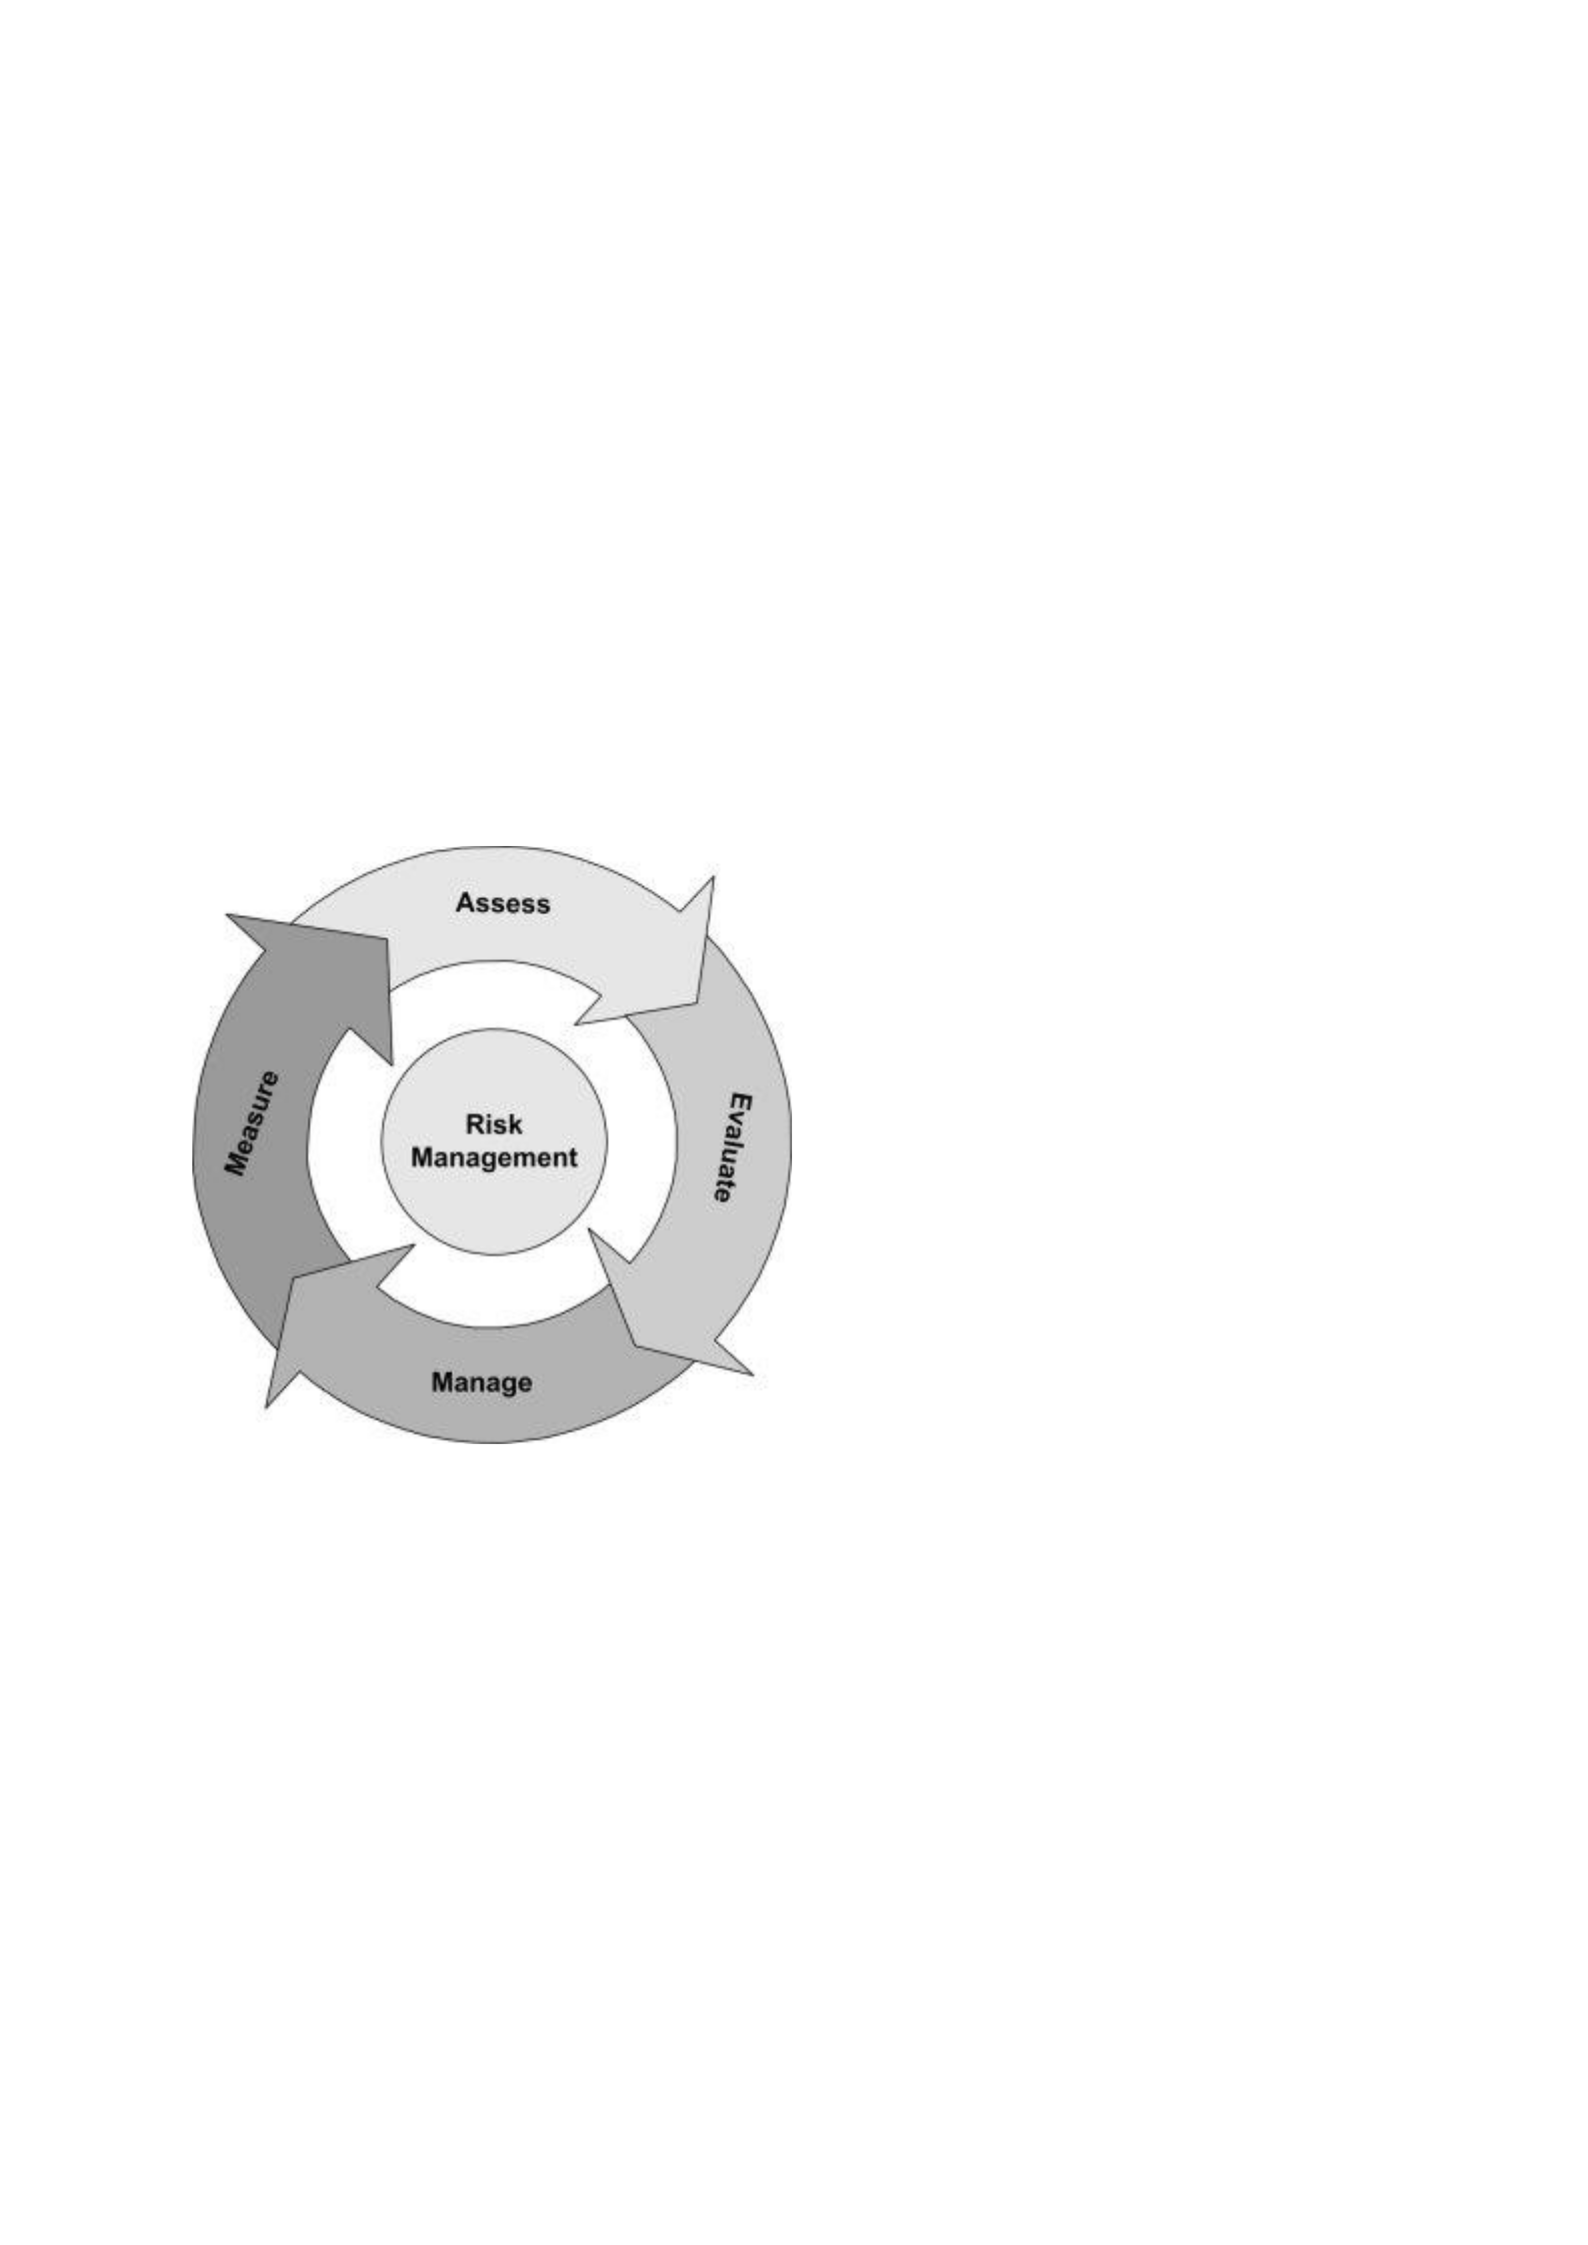
institutions takes the following form.
From the above figure, it may be observed that the risk
management framework in the financial institutions
includes assessing, evaluating, managing and measuring
risks to which the institutions are exposed. Risk
management must be a continuous process providing
the feedback to the management on the potential
losses that are likely to occur because of the exposure
to different types of risks.

The management and regulators consider the
management of future risks as the best predictor of
long-term success. The financial institutions, receive
several benefits out of efficient risk management.
• The foremost advantage of risk management is that
it serves as an early warning for potential problems
of financial institutions. With a systematic process
of evaluation and measurement of risks, the
financial institutions will be able to identify the
problems at an earlier stage, before these problems
become larger and affect the efficiency in the
performance of the financial institutions. An early
warning signal prevents the drain of the
management time and resources of the financial
institutions. When the financial institutions can
identify the problems earlier they have to spend
only lesser time fixing problems and they can spend
more time productively on their growth.
• With an efficient risk management plan in place,
the financial institutions will be able to allocate
their resources more efficiently. The resources here
represent the cash and capital available with the
financial institutions. “A good risk management
framework allows management to quantitatively
measure risk and fine-tune capital allocation and

liquidity needs to match the on and off-balance
sheet risks faced by the institutions and to evaluate
the impact of potential shocks to the financial
system or institution” (GTZ, 2000). The financial
institutions must engage effective treasury
management, as the primary objective of the
financial institutions is to maximize the earnings by
channelizing their investments in portfolios having
the minimum risk of loss.
• A risk management system, when it functions
efficiently within a financial institution, can provide
to the institution better and quality information on
potential consequences, which may be both
positive and negative. Effective risk management
can establish a proactive and forward-thinking
organizational culture within a financial institution.
It also helps managers in identifying and assessing
new market opportunities and it enhances the
ability of the managers to foster continuous
improvement of existing operations of the financial
institutions, resulting in the effective alignment of
performance incentives with the strategic goals of
the organization.
In the case of financial institutions, better risk
management yields similar benefits, as they do in the

case of traditional banking institutions. With the
continuous growth and expansion of the financial
institutions, they have to serve more customers and
attract mainstream investment capital and funds for
their successful operation. For achieving this, the
financial institutions have to strengthen their internal
capabilities to identify and anticipate potential risks.
This ability will enable the financial institutions to avoid
the unexpected drain of their resources and there may
not be any surprises or shocks to the organization.
Creating an efficient risk management framework
within the organization has to be the priority of the
financial institutions; once they can identify the
individual risks such as credit risk, market risk, and
liquidity risk, (following sections discuss different types
of risks faced by financial institutions). Financial
institutions should also have clarity about the roles and
responsibilities of managers and board members,
concerning the risk management of the institution,
which will enable the organization, build stronger
organizations. “A comprehensive approach to risk
management reduces the risk of loss, builds credibility
in the market place and creates new opportunities for
growth,” (GTZ, 2000 p. 5).

A risk management framework for a financial institution
represents a consciously designed system implemented
to protect the organization from unexpected and
undesirable surprises (there are denoted as downside
risks) and enables the organization to derive the
advantages of opportunities available to the
organization. The following are the potential
advantages of an effective risk management framework
as it applies to a financial institution. Since effective risk
management will avoid most of the delinquencies in the
financial institutions, a discussion on the risk
management for the financial institutions becomes
important.
Effective Risk Management Can:
1. Integrate the operations of the financial institutions
into a set of systematic processes. This systematic
process enables the identification, measurement,
and monitoring of different types of risks faced by
the financial institutions by helping the
management to have a close watch on the
organizational functions in a global way
2. Provide continuous feedback between measuring
and monitoring and between internal controls and
reporting. Such a framework also provides for an
active oversight by the senior leaders of the

organization and the directors on the operations of
the financial institution. This also enables the
organization and its top management to respond
swiftly to changes in internal and external
environments of the financial institution
3. Provide an overview of the situations in which the
management can have an overview, where
different risks interact with each other and they can
exacerbate one another in adverse situations.
4. Allocate the responsibility for risk management and
organizational preparedness to the domain of the
senior management and that of the board
5. Promote efficient use of resources and decision-
making in the most cost-effective way
6. Create an internal organizational culture in which
there is a possibility of ‘self-supervision’, which will
be able to identify and monitor risks much before
the outside stakeholders or regulators could
identify them.
Importance of Risk Management to Financial
Institutions
Some reasons make a more sophisticated risk
management framework and improved approaches are
important to financial institutions. In the present day

context, the financial institutions have grown to larger
proportions, serving a large number of customers and
broader geographic areas. They offer a wide range of
financial services and products. In practice, the internal
risk management of the financial institutions is found to
be a step or two behind the scale and scope of their
operations. This makes an effective risk management an
important factor to sustain their growth. Secondly, for
meeting the requirements of enlarged lending activities,
financial institutions have to rely increasingly on
market-driven sources of funds.
The funds are generally drawn from external investors
or as deposits from the savings of clients. If the financial
institutions have to preserve the access to such funding
sources it requires the maintenance of good financial
performance and avoid unexpected losses. Third, the
organizational structures and operating environments
pose exclusive problems to the management. “They
may be very decentralized or too centralized (both can
be a risk), tend to be labor and transaction-intensive
have concentration risk in certain regions or sectors
(e.g. agriculture) due to their mission and often operate
in volatile and less mature financial markets.” Finally,
financial institutions have to establish financial viability
through operations, which are efficient and cost-
effective. This calls for effective risk management to

achieve better resource management without exposing
the institution to undue risk.
Rationale for Risk Management
The importance of risk analysis can be found in dealing
with increasingly complex financial transactions. For
example in derivative transactions, several innovative
products and services have developed over the period,
which enlarges the risk of the financial institutions in
these fields. The complexity is enhanced as a natural
evolution process, although it is not a universal
phenomenon. For instance, with sophisticated
information and communication techniques number of
people dealing with the financial institutions from
different geographical locations increase, which also
enhances the risk element for the financial institutions.
As a concurrent development, with the increase in
information and knowledge of the public, there is the
demand and need for higher levels of service quality and
the risk increases because of the increased complexity
of the systems. Therefore, it becomes important for
financial institutions to understand and meet the
investors’ demand by making their policies consistent
with such demands. In recent periods risk analysis is one
important and powerful tool to address risk

management issues by the financial institutions and to
develop sound and safety policies and design strategies.
Thus, economic challenges, market uncertainties, and
difficult value trade-offs among competing goals have
made it difficult to arrive at a consensus on the policies
to be followed to manage the potential hazards,
dangers and losses to financial institutions. However,
suitable policies must be developed and implemented
to achieve the desired outcomes in the matter of
protecting the interest of the financial institutions. It is
therefore important that the use of risk analysis to
improve risk management decisions and policies
resorts.
The demand for risk analysis can be seen from the
significance of eliminating all risks associated with an
activity. Risks must be weighed in terms of (i) risks of
alternative activities to that which is being considered
and (ii) trade-offs between the benefits likely to accrue
from the incremental efforts taken to mitigate the
particular risks and the cost of such efforts in getting the
resultant benefits. Here lies the demand for risk
analysis. Risk analysis provides the information needed
to weigh the alternatives and analyzing the tradeoffs
between costs and benefits. This is more so when there
is ambiguity surrounding the available information and

the information is uncertain and not obvious to make a
decision. Risk assessment techniques become handy in
providing a means of presenting the relevant
information in an organized way and estimating the
impact of adverse consequences.
However, the analysis conducted using risk assessment
techniques may be able to provide precision to the
information only to a certain degree, because of the
tentative nature of the underlying assumptions and
uncertainties, which are inherent in the risk assessment.
In such cases, there is the demand for risk analysis and
efforts may be taken to arrive at a balance by
considering what constitutes acceptable risk by using
any risk assessment tools. Thus to meet the demand for
risk analysis, individuals and corporate decision-makers
identify levels of risk which are within the tolerance limit
in the light of several other factors like cost of risk
reduction, perceived risks and benefits of the
technology applied, activity, or substance that poses the
risk and the available alternatives for the activity or
substance, (Covello et al 1988; Travis et al 1987; Travis
and Hattermer-Frey, 1988).
Classification and Measurement of Risk
To manage their risks, financial institutions must have
complete knowledge about the risks affecting their

operations. Acquiring the knowledge about the risks
involves assigning the methodologies to measure them
based on a perceived and classified expression of risks.
Thus, there are different steps involved in the process of
identifying and measuring the risks. They are: (i)
classification of risks into meaningful and observable
types of risks, (ii) selection of an appropriate model-
based methodology for measuring the risks belonging to
the individual classification made and finally, (iii) use of
the selected methodology to generate a measurement
of the specific risks affecting the financial institutions.
Once the financial institutions acquire the knowledge
relating to the risks affecting their operations, the
management can start applying various policies to
assess, mitigate or transfer the risks identified by them.
This section provides a review of the commonly used
classification of the risks and the fundamental current
risk management and measurement methods.
Out of the above classification of the financial
institutions, the originators, distributors, service
providers, and packagers can be considered as having
the agency characteristics and the intermediaries and
market makers represent principal business makers.
The agency services act to provide market access to the
buyers and sellers of financial instruments and hence
expose the service provider to a minimum of risks. The

businesses where the service providers act as principals
place a significant amount of capital on the interaction
between the buyers and sellers.
In fact in these areas that the financial institutions
expose themselves to major risks and hence there is the
need for an effective risk management program. Both
the intermediary and the market maker are not covered
entirely for the risks associated with their activities and
hence it may be necessary that its investors may have to
bear some part of the risks associated with the activities
of these financial institutions. The risks borne by these
institutions can be broken down into three general
categories of risks, which are (i) market risk, (ii) credit
risk and (iii) liquidity risk. Apart from these risks, there is
a liquidity risk, which is often mentioned as a major
separate risk category. There are other non-financial
risks, which includes strategic and business risk, which
also needs consideration by the financial institutions.
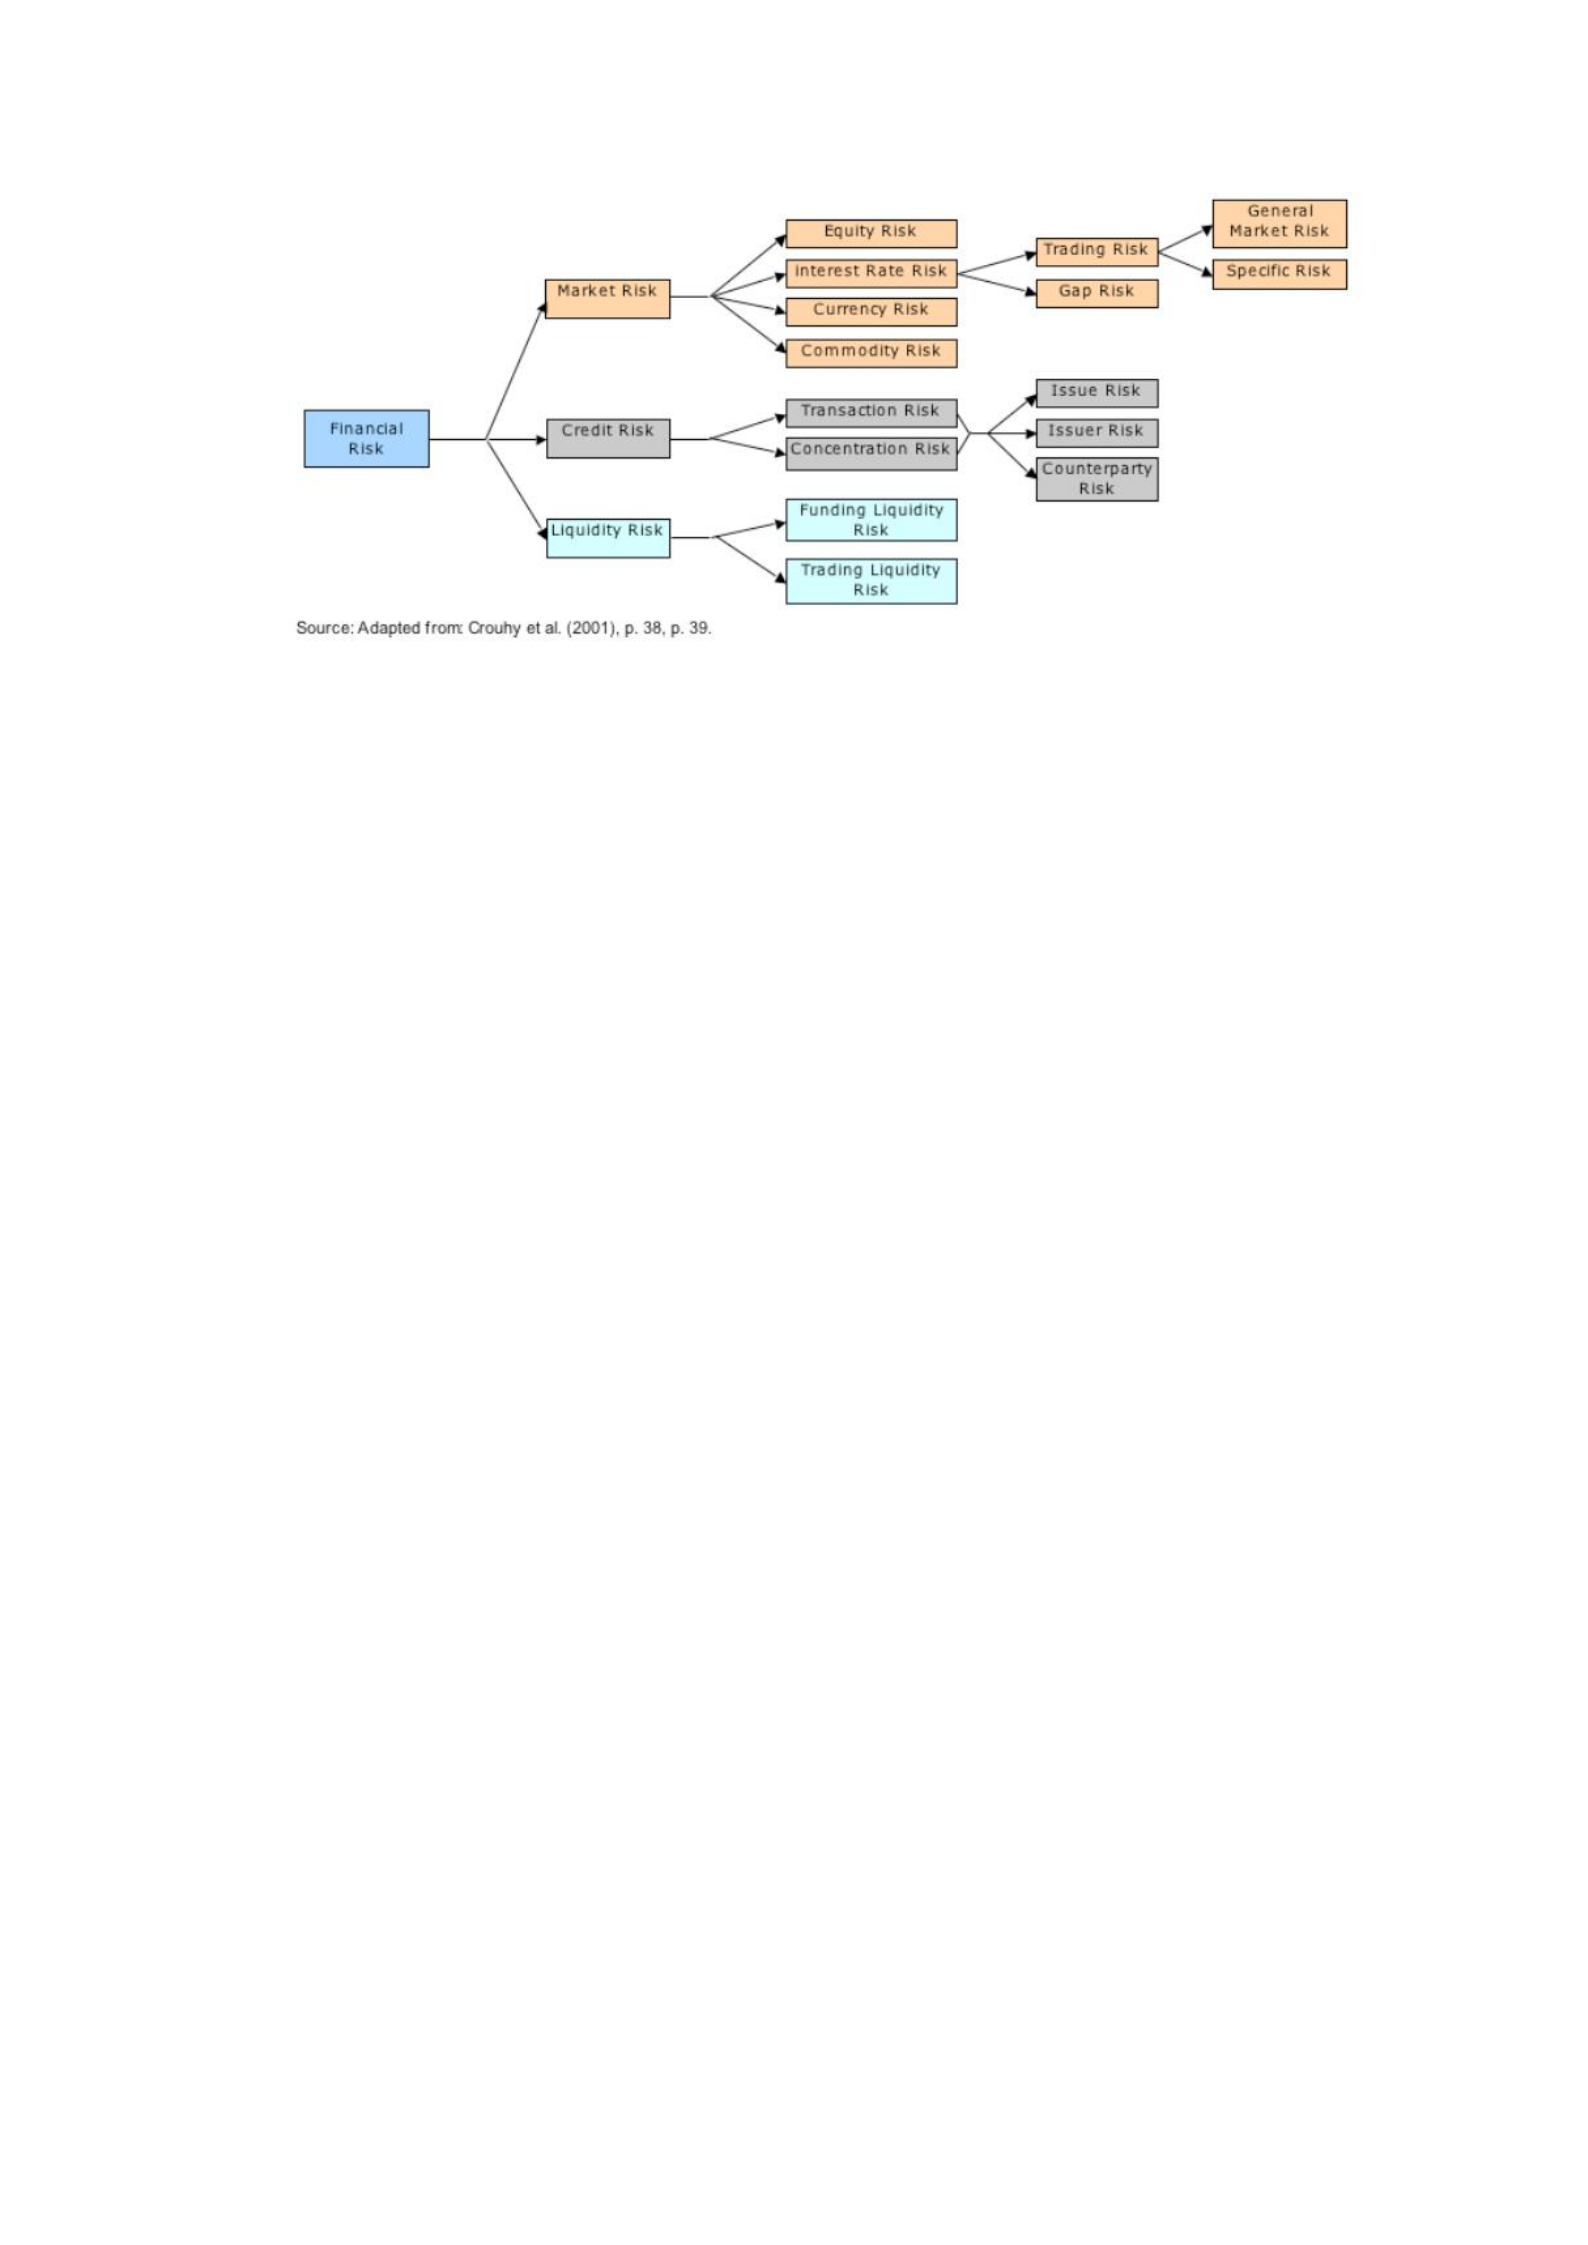
Figure: Financial Risk and Major Categories
The three main categories of financial risk can be
subdivided into other subcategories as depicted in the
above figure. However, there may be varying
classifications of the risks facing financial institutions in
the literature. Since the financial institutions must have
a thorough knowledge of the major risks affecting their
financial standing and profitability, studying the
classification becomes important and it also helps them
to design and apply appropriate risk management
policies to overcome the potential losses arising from
the risks.
Market Risks
Market risks have a financial orientation and these risks
arise because of frequent changes in the domestic
financial system. The disparity in values of properties
and claims against a financial institution can lead to the
facing of market risk by the financial institutions. Market

risks are likely to become more pertinent when the
financial institutions become larger in size and
operations and complex in terms of assets and liabilities
possessed by them. The varying proportions of
properties and claims of the financial institutions pose
challenges of market risk to the financial institutions
because fluctuations in the market, which affect the
value of such properties and claims.
Changes in conditions of the market, in which the
financial institutions are operating, though may be
external to the financial institutions influence the
functioning of the financial institutions favorably or
unfavorably. Therefore, these are considered as market
risks for financial institutions. There are three important
market risks for the financial institutions and the
following sections deal with these different types of
market risks. Market risk can be subdivided into “equity
risk, interest rate risk, currency risk, and commodity
risk.”
Interest Rate Risk
Interest rate risk can be defined as the current or
prospective changes in the earnings and capital caused
by periodic movements in the interest rates.
“Depending on the interest rate risk profile of banks,
such as the extent to which individual banks are net

lenders or net borrowers in the interbank market, their
profitability will be affected to different degrees” (Yam,
2006). The major risk being faced by the banks and the
financial institutions is the risk posed by the change in
the interest rates. The interest rate risk for the financial
institutions emanates from the financial intermediation
services being undertaken by them.
The risk is caused by the difference in the maturity
values of the assets and liabilities of the banks. The
interest rate sensitivity differences often expose the
equity of the banks and other institutions to changes in
the interest rates, which ultimately affects the
profitability of the institutions. The unexpected changes
in the interest rates make the balance sheet hedging
activity of the bank, which is normally undertaken based
on the maturities of assets and liabilities at the expected
maturity values shown in the balance sheets of the
firms. When there are changes in the interest, which
affect the valuation of assets and liabilities negatively
the banks and other institutions are bound to get a
beating of the earnings. The other forms of interest rate
risks are the refinancing risk and reinvestment risks.
Techniques Used to Protect Against Interest Rate Risk
A forward contract with the interest rate changes as the
base is known as ‘forward rate agreement’ (FRA). The

FRA consists of an inter-bank traded contract to buy or
sell interest payments on a future date and the interest
is to be calculated on a notional principal. Under the
forward trade agreement, the buyer gets a right to
specify a certain rate of interest for an agreed term,
which is set to start on a future date. The interest
amount will be arrived based on an assumed principal
amount. Similar to the currency forward contracts, the
FRAs also are entered into with maturity periods of
1,3,6,9 and 12-month periods.
Interest rate futures, on the other hand, are largely used
by the finance and treasury managers of non-financial
companies in contrast to the currency futures (Bodnar
& Gebhardt, 1999; Eiteman et al., 2000). The enhanced
usage may be because interest rate futures are having
relatively high liquidity, are simple to use and the
interest rate exposures of the firms are standardized.
However, Phillips, (1995) and Mallin et al., (2001) are of
the view that the interest rate futures are not popular
among firms to manage their interest rate risks.
The interest rate swap is a dealing between two entities
wherein one party settles interest to the other on fixed
dates, but with varying interest calculations. ‘Plain
Vanilla’ is the common arrangement where one part of
the payments is set and the other part of the payment

is maintained at varying rates. This type of swap
contracts has become the most popular financial
arrangement in the global context.
Interest rate options are just like forward rate
agreements. In the interest rate options, instead of
being bound by a firm commitment to receive interest
at one rate and make payment of the interest on
another, a right is given to the holder to receive interest
at one rate and make payment of the interest on
another.
Currency Risk
Currency risk or foreign exchange risk is a natural
consequence of international business dealings, where
the value of the currency of one country moves up and
down against that of another. International firms
usually enter into some contracts that require payment
in different currencies. This risk arises because of a
change in the domestic currency value of a firm’s assets
and liabilities caused by the changes in the rates at
which the currencies of different countries are counted.
The exchange rate exposure may be positive or negative
(Banking and Finance, 2000).
Firms that deal in currencies of different countries face
the risk of gaining or losing in the value of assets and
liabilities or respect of their revenue or outflows

because of sudden unanticipated changes in currency
exchange rates (Sivakumar & Sarkar, 2007). Economic
globalization has made the business organizations
spread their wings across the geographical locations and
use low-cost locations for improving their profitability
and sales growth. This has necessitated the movement
of foreign exchange from one country to another in the
form of capital movements and the profits repatriated
to the country of origin. However, due to frequent and
major changes in the domestic and international
financial markets, the firms have been exposed to two
kinds of foreign exchange risks. These are exchange rate
risks and interest rate risks. The firms adopt several
measures to protect against currency fluctuations.
Techniques Used to Manage Currency Risks
One of the earliest methods adopted without involving
any derivative instrument is the forward contracts in
foreign currencies in which they are dealing it. However,
this method of mitigating the foreign exchange risks did
not prove to be effective whenever there was a
favorable movement of the foreign currency and the
firms are often exposed to loss of profits, which they
would have otherwise earned had they not entered into
the forward contracts. After the introduction of the
various forms of financial derivatives, they started

covering their foreign exchange exposure by resorting
to financial derivatives.
Using Derivatives for Managing the Currency Risks
Out of the above methods of mitigating the foreign
exchange risk, the forward contract is the oldest and
most popular one used by the business firms to manage
the financial risks. A forward contract is “a cash market
transaction in which delivery of the commodity is
deferred until after the contract has been made.
Although the delivery is made in the future, the price is
determined on the initial trade date.” (Investopedia,
2009) Under the forward contract, the firm agrees to
buy and deliver a certain amount of a specified foreign
currency at a future date. The rate at which the currency
is to be delivered is decided at the present point of time.
If the actual currency value on the date the amount is
due is more, the firm makes a profit out of the deal and
if the currency value is less than the contracted value a
loss results out of the deal.
A futures contract is defined as “A standardized,
transferable, exchange-traded contract that requires
delivery of a commodity, bond, currency, or stock index,
at a specified price, on a specified future date.” (Investor
Words, n.d.) Under the futures contract, the firm is
obligated to buy certain specified currencies at specified

exercise exchange rates. In this type of contract, the risk
to the holder of the instrument is rather high and
unlimited as there is always used to exist an asymmetry
in the payment pattern. The risk of the seller is unlimited
as well.
Under the currency swap contract, the buyer and seller
or the other parties involved in the contract are
obligated to provide for predefined remittances at the
appointed payment dates. A swap contract comprises a
series of forwarding contracts put together for covering
the foreign exchange risks. Under this system, the
parties provide each other with the difference in the
interest payments covering the amount contracted in
the different currencies. An option “Like other options,
an option on a futures contract is the right but not the
obligation, to buy or sell a particular futures contract at
a specific price on or before a certain expiration date.
These grant the right to enter into a futures contract at
a fixed price,” (Investopedia, 2010c).
Credit Risks
Generally “Credit risk is the risk that a change in the
credit quality of a counterparty will affect the value of a
bank’s [or other financial institution’s; note of the
author] position,” (Crouhy et al. 2001). Credit risks arise
due to the non-performance of a debtor and these risks

usually arise either the debtor is unwilling or unable to
perform according to the already committed contract
terms. This has its effect on the lender who underwrote
the loan, other people who advanced money to the
creditor as well as the shareholders of the debtor
himself. A major part of credit risk is the culmination of
the systematic risks and the unusual losses associated
with these risks pose a problem for the creditors despite
the benefits of diversification from the whole
uncertainty. This applies especially to the creditors who
advance amounts in the local market against the
security of the illiquid assets (Morsman, 1993).
Credit risk has a close association with the lending of the
financial institutions and is an important risk that any
financial institution could face. Whenever a financial
institution lends money to a borrower, there is an
inherent risk that the borrower may commit default in
repaying the amounts to the institutions. Where there
is a potential chance that the borrower fails to pay back
the borrowed amount the situation is known as the
credit risk. “Credit risk is simply the possibility of the
adverse condition in which the clients do not pay back
the loan amount” (India Microfinance News, 2010). This
type of risk is the popular one among the financial
institutions. Credit risk becomes important for the
financial institutions, as these institutions have a diverse

clientele. Financial institutions derive their funds and
fund their portfolio through external borrowings or
deposits from the public and by subscribing to their
capital. Advancing a loan by the financial institutions
also puts these sources of funds under risk.
Credit risk is inbuilt to the transactions undertaken by
any investment or commercial bank. It is a fact that
financial institutions can neither are too conservative in
their approach towards lending, (as this approach would
be a deterrent on their growth) nor can they act over-
enthusiastically. If they act in an over-enthusiastic
manner, the organization may face the danger of
incurring potential losses. Therefore, it becomes
essential that the financial institutions have to institute
appropriate risk-mitigating initiatives, to ensure
sustained profitability avoiding the negative impact of
different risks affecting the business beyond reasonable
levels. Credit risk arises because of elements affecting
the operations present both within and outside the
financial institution.
There are different forms of credit risk and the
subcategories include the sovereign, political and
country risks. All these categories include exposures to
losses because of cross-border business connected with
decisions of foreign governments and regulatory bodies.

Settlement risk is another category of credit risk, where
there is a failure of a two-way payment transaction.
Settlement risk occurs when one of the persons dealing
under a transaction defaults after the other party has
performed his part in the transaction.
Managing credit risk form a major responsibility for the
banks, as lending is the core business for the banks.
Banks mainly adopt (i) portfolio diversity, (ii)
conservative underwriting and account management
and (iii) aggressive collection procedures as the
techniques to mitigate credit risk (Dorsey, 2007). The
best way banks manage their credit risk is by dividing
their total amount of lending by companies, industries
or geographical locations. This enables the banks to
have a cushioning effect in the matter of credit risk
management. If the bank experiences a higher credit
risk exposure in one of the geographical locations, it will
be offset by the safe lending in other areas. This way the
banks can spread their credit risk over different
portfolios of lending.
When the banks lend to firms in any sector, they can
protect themselves against credit risk by evolving
efficient procedures for risk mitigation. The focus of risk
management in respect of credit risk lies in avoiding
writing bad loans. If a loan appears to be doubtful, the

banks take all possible efforts to realize the loan. The
banks, which develop the skills for better managing
credit risk, can have a higher competitive ability than
the others are. Establishment of sound credit approval
systems and processes supplement this ability of the
banks to mitigate the credit risk more efficiently.
Since lending becomes the major activity for the banks,
they establish detailed systems and procedures for
assessing the risks and rewards of its credit risk
settlement activities. An efficient credit analysis would
help banks to mitigate their credit risk largely. This way
the banks would be able to eliminate credit risk without
lowering their level of activities in credit trading by
making their settlement practices more efficient. The
trading patterns of the banks also have an impact on the
mitigation of their credit risk largely.
Liquidity Risk
Asset liability management is important for any
organization, especially for financial institutions. “Asset
liability management is, therefore, a process through
which an organization has to match maturing of its
assets (that is when they can be turned into cash) with
maturing of its liabilities (that when they are falling due
for poor payments)” (India Microfinance News, 2006).

“If an organization does not have sufficient assets
maturing to fulfill its liabilities falling due then there is a
risk that the organization may not be able to honor its
committed obligation and this risk is called Liquidity
Risk. Assets, maturing within one year period are
termed as Current Assets, while liabilities which are
falling due within one year period are called Current
Liabilities,” (India Microfinance News, 2006).
“Liquidity management is, therefore, basically
managing current assets and currents liabilities. If an
organization’s current liabilities are more than current
assets than such an organization has an immediate
liquidity risk. Liquidity risk in financial institutions is
considered to be one of the most sensitive issues and a
risk of high priority,” (India Microfinance News, 2006).
“As liquidity problem can result in a financial institution
failing to honor its obligations, it can result in loss of
reputation, loss of credibility among lenders and
depositors and has the potential to snowball into a big
crisis” (India Microfinance News, 2006). If a financial
institution is unable “to pay back savings of depositors
when they come for withdrawal because they do not
have enough cash then it can immediately give the
wrong signal in the market,” (India Microfinance News,
2006). The news will flow in the market that either

financial institution does not intend to repay the
depositors or the institution is insolvent and unable to
meet its financial commitments. “Spread of this news
with other depositors can result in the panic situation
who may also come for withdrawal and this could lead
to a situation called to run on savings, where everyone
wants to withdraw their savings compounding the
entire problem,” (India Microfinance News, 2006). Also,
defaults committed by the financial institution in
making repayments to its lenders will lead to reduced
confidence not only of the present lending agencies but
also other prospective lending agencies. Because of this,
the credit rating of the financial institution will fall,
making any further rising of funds difficult for the
institution.
It is also not advisable that the financial institution
always keeps high liquidity with sufficient cash at all
times to face emergencies. It is important to understand
that liquidity entails a cost on the organization and if the
financial institution decides to maintain all of its assets
as a liquid, it may not be possible for it to earn any fee
or interest. It is always in the interest of the organization
to avoid idle assets. Since the income of the financial
institution arises from lending the money, it will fail to
earn the interest income if it maintains all its assets in
cash form with it. Additionally, the financial institution

“has to pay interest on its borrowing as well as deposits
irrespective of the fact that they are deployed in loans
or not,” (India Microfinance News, 2006). Therefore,
“while high liquidity brings the profitability and
sustainability of a financial institution down, insufficient
liquidity results in the risk of defaulting on obligations”
(India Microfinance News, 2006). The financial
institutions must institute appropriate risk mitigation
plans, within the financial institution to enable the
organization to conduct its business transactions
smoothly.
Operational Risk
The operational risks take the form of errors in record
keeping, computing errors in calculating the payments,
processing system failures and non-compliance with
some regulatory requirements. The operational risks
result in issues relating to processing, settling and
providing, and securing delivery of trades in exchange
for cash. Thus through individual operating issues pose
smaller risks to the well-managed organizations, they
may sometimes expose these firms to larger exposure
of economic losses.
Operational risks arise from human or computer error.
These risks may arise when the financial institution
serves the clients during its business. Operational risks

may be found in any division or product of the financial
institution. “This risk includes the potential that
inadequate technology and information systems,
operational problems, insufficient human resources or
breaches of integrity (i.e. fraud) will result in
unexpected losses,” (GTZ, 2000).
Traditionally any other uncertainty, which could not be
classified into the ambit of another major risk group,
was included in the group of operational risk. However,
the Basel Committee on Banking Supervision has
provided a new definition of operational risk. This
definition includes any loss occurring to the financial
institution from a lack of internal control or inefficiency
of systems and procedures. It also includes loss arising
from the operation of external events. This definition
has provided for a different category of risks connected
with the operations of the financial institutions, which is
the “strategic risk”.
There has been increased importance attached to
operational risk in recent years, because of the
proliferation of information and communication
technology usage in the financial institutions and
because of the recognition of the increased role of
human resources in the operation of these institutions.
Another feature of operational risk is that it can emerge

in all the departments across the institution because of
the presence of human resources and technology in all
the functional areas of the financial institutions.
In the present day’s context, the financial markets and
banking institutions and system has changed
dramatically with the increased use of technologies.
Also, enterprises across the globe have recognized the
importance of human resources. Financial institutions
have also adopted these larger changes and the
operations of the financial institutions are carried out
using modern-day technological measures. This has
given rise to several operational risks to which the
financial institutions are exposed. “Strong internal
processes, systems, good human resource and
preparedness against external events are needed for
managing the operational risk. Operational risk is
enhanced by increased dependence on technology, low
human and business ethics, competition, weak internal
systems in particular weak internal controls,” (India
Microfinance News, 2006a).
The operational risks to which a financial institution is
exposed can be grouped under five different categories
–
I. human risks including errors, frauds, collections,
and animosity,

II. Process risks including lack of clear procedures on
operating such as disbursements, repayments, day-
to-day operations, accounting, data recording and
reporting, cash handling and auditing,
III. system and technology risks like a failure of
software, computers and power failures,
IV. relationship risks like client dissatisfaction,
dropouts, loss to competition and poor products
and
V. asset loss and operational failure due to external
events, loss of property and other assets or loss of
work due to natural disasters, fires, robberies,
thefts, riots.
Other Categories of Risk
There are some other categories of risk, which can be
listed including reputational risk and strategic risk.
Reputational impairment to the financial institution
causes reputational risk.
“Perceived incompetence, negligence or misconduct of
the institution” is the major cause of reputational risk.
Strategic risk arises because of the strategic choices of
top management. The following sections discuss other
categories of risk.
Systematic Risks

Systematic risk is the risk of changes in the asset values,
which are the result of systemic factors. The institutions
can at best hedge against most of these risks but cannot
completely do away with them. The systematic risks are
faced by the institutions because of the impact of the
economic conditions on the values of assets owned or
claims issued by the institutions. The best example of
the systematic risk is the difference occurred in the
worth of properties and claims because of the changes
in the interest rates. Due to fluctuations in the market
rate of interests, unpredictable differences occur in the
worth of properties and claims. Similarly, large-scale
changes in weather may influence the value of real
estate assets.
The institutions that may experience a significant
impact on their balance sheets due to systematic risks
try to mitigate these risks by a careful estimation of the
impact of the particular systematic risks and limit their
sensitivity to these risk factors, which cannot be
avoided. This forces those institutions which are
exposed to a larger fixed income market take efforts to
monitor the interest rate movements closely and adjust
their exposures accordingly (Esty, Tufano, and Headly
(1994) and Santomero (1997). They do it more
rigorously than those firms, which have very little
exposures to risks in their portfolios.

Counterparty Risks
The counterparty risks result from the failure of one of
the parties to the transaction to carry out his part of the
contract. The trading partner may refuse to perform
either due to an adverse price movement caused by the
operation of the systematic risks or due to any other
political or legal constraint that was not expected to
happen by the actors. The non-systematic counterparty
risks can be mitigated by undertaking diversification on
a wide scale. Though counterparty risk can be equated
with the credit risks, it can be considered as a transient
financial risk resulting from trading activity, different
from the default of a debtor. There may be several other
reasons for the counterparty risk to arise other than the
credit issue.
Legal Risks
Legal risks are distinct from the legal impacts of other
kinds of risks like credit, counterparty and operational
risks dealt with above. These risks stem from the
operation of new statutes, court rulings, or new
regulations, which have the effect of making even the
previously properly done transactions to contentious
ones. These risks appear even when all the parties who
performed well in the past and can perform better in the
future. For example, the introduction of new

bankruptcy laws may create new risks for corporate
bondholders. Similarly, there may be significant impacts
on real estate values due to changes in environmental
regulations. There is yet another kind of legal risk, which
may arise due to the institution’s management practices
or the action of its employees. Accounting and other
frauds, violations of securities laws and other misdeeds
can result in large economic losses.
Risk Measurement Methodologies
Next to the classification of risks into different
categories is choosing the appropriate model-based
methodology to measure the specific risks. The purpose
of risk measurement methods is to specify the risk
factors and risk exposures that need to be captured and
quantified for serving as inputs for the calculation of the
extent of risk. The selected method specifies the
particular risk factors and risk exposures that need to be
captured. Capital Asset Pricing Model, Value at Risk
(VaR), and Arbitrage Pricing Theory and Fama-French
Three Factor Model are some of the quantitative
methods used for measuring risks of financial
institutions.
Capital Asset Pricing Model (CAPM)
This model developed by William F. Sharpe and John
Lintner for the valuation of security. This method has

been adopted for the valuation of shares of a firm by
many analysts due to its simplicity and the real-world
applicability. This method takes into account the
association between the threat of loss and anticipated
income from each security. This model assumes that
based on the behavior of the risk-averse investor there
is implied an equilibrium relationship between risk and
expected return from the prospective investments
planned by the investor.
In the market equilibrium, security will be expected to
provide a return following the risk, which is inbuilt
within the security and hence impossible to avoid. This
risk is the one that cannot be avoided by diversifying the
investment portfolio. With larger unavoidable risk
inbuilt in a security, the person investing in that security
will expect a larger return from that particular security.
The association between anticipated income and inbuilt
risks forms the basis for valuing the securities under the
CAPM model. (Van Horne, 2004) This model has several
assumptions for its offering the proper results. The
method also has several significant repercussions.
“CAPM implies that investing in individual stocks is
pointless because you can duplicate the reward and risk
characteristics of any security just by using the right mix
of cash with the appropriate asset class”. (Moneychimp)

Value at Risk
“Value at Risk (VaR) is a technique used to estimate the
probability of portfolio losses based on the statistical
analysis of historical price trends and volatility. VaR is
commonly used by banks, security firms and companies
that are involved in trading energy and other
commodities. VaR can measure risk while it happens
and is an important consideration when firms make
trading or hedging decisions” (Investopedia, 2010).
“Value at Risk (VAR) is a statistical measure of downside
risk based on current positions and for a given position”
(Jorion, 2007, p 105), and for a given position can be
defined as “the worst loss over a target horizon such
that there is a low prespecified probability that the
actual loss will be larger” (Jorion, 2007, p 106). The
various definitions include two parameters, which are
required to be chosen based on specific circumstances
– which are a holding period or target horizon and a
prespecified probability or confidence level. Besides
these two parameters, there is a need to mark the
current position on the market. VaR provides a simple
and easy-to-drive measure that allows aggregation of
risks at the level of the whole firm. The VaR may be
derived as either nonparametric, parametric or Monte
Carlo VaR.

“In the nonparametric approach to VaR, no parameters
of the forward distribution are estimated or assumed
from theoretical reasoning. Instead, the distribution is
simulated from (recent) empirical returns data.
Historical simulation is the main example of a
nonparametric VaR method,” (Dowd, 2002, p 57).
Nonparametric VaR does not involve the presumption
of a certain type of forwarding distribution, which is an
advantage. However, the problem with this measure is
that the results are dependent on the sample period
used. Parametric VaR approaches work based on the
estimate of the parameters of the underlying
distribution by fitting a distribution to the observed
data.
Multifactor Model
“A financial model that employs multiple factors in its
computations to explain market phenomena and/or
equilibrium asset prices. The multi-factor model can be
used to explain either an individual security or a
portfolio of securities. It will do this by comparing two
or more factors to analyze relationships between
variables and the security’s resulting performance”
(Investopedia, 2010a).
Factors involved in this model are calculated using the
following formula.

“Ri = ai + βi(m) Rm + βi(1)F1 + βi(2)F2 +…+βi(N)FN + ei
Where:
Ri is the returns of security i
Rm is the market return
F(1,2,3…N) is each of the factors used
β is the beta with respect to each factor including the
market (m)
e is the error term
a is the intercept” (Investopedia, 2010a).
“Multi-factor models are used to construct portfolios
with certain characteristics, such as risk, or to track
indexes,” (Investopedia, 2010a). However, it is difficult
to estimate precisely the nature and number of factors
that need to be included. For example, Fama and French
Model suggest the inclusion of factors like “size of firms,
book-to-market values and excess return on the
market” (Investopedia, 2010a). The techniques will be
graded on past results, which do not facilitate the
accurate prediction of estimated results.
“Multi-factor models can be divided into three
categories: macroeconomic, fundamental and statistical
models. Macroeconomic models compare a security’s
return to such factors as employment, inflation, and

interest. Fundamental models analyze the relationship
between a security’s return and its underlying financials
(such as earnings). Statistical models are used to
compare the returns of different securities based on the
statistical performance of each security in and of itself”
(Investopedia, 2010a).
There are different models like Arbitrage Pricing Theory
and the Fama-French Three-Factor Model, which can be
grouped under multi-factor models.
Possible Deficiencies in Risk Management Models
The previous sections contained the salient aspects of
risk management and classification of risks into
different categories. This section discusses the
deficiencies of the risk management models and the
additional risks the models create because of the
deficiencies. These deficiencies account for all the
possibilities where the risk management may not yield
the desired results to the financial institution. When the
financial institution relies on these models for assessing
and managing their risks, these deficiencies in the
models constitute new risks for the institutions. These
deficiencies can be termed as “model risks” and they do
not arise from the underlying phenomenon themselves
but form the perceptions and reactions of the
institutions on the models of risk measurement. In

general, model risk can be categorized as a subtype of
operational risk.
Unreliability of risk management models might arise
because of two factors. First, technological and
methodological imperfections might vitiate the utility of
some of the risk measurement models. Secondly,
changes from exogenous risk to endogenous risk result
in the happening of extreme market events leading to
changes in market reality and thereby affect the use of
risk management to the financial institution. There have
been criticisms that risk management is less than fully
scientific. The discussion of model risk suggests that
model risk might lead to serious deficiencies in financial
risk management and the institutions must not put
undue reliance on the results on any single risk model.
Inapplicability of Risk Management Modeling
Applying the risk management models under
circumstances, where there is no way of using the
models is the most basic model risk that the financial
institutions might encounter. It many cases it may not
be possible to know certain issues precisely. Essential
uncertainty connected with such issues cannot be
reduced to quantifiable risks and consequently, it may
not be possible to mitigate them using the risk
management models. In some instances, the risk

management model may make the uncertainty appear
as a risk quantifiable. However, in such cases engaging
in any risk management model and relying on the results
of such a model will prove to be another major risk.
According to Derman (2003), “In terms of risk control,
you’re worse off thinking you have a model and relying
on it than simply realizing there isn’t one” (p. 134).
Use of Incorrect Risk Management Model
The next model risk evolves from the fact that the
financial institutions are likely to make incorrect
methodological decisions while engaging a specific risk
management model. These methodological issues and
possible missteps may lead to the application of an
incorrect model.
The models may fail to provide a correct assessment of
risk because of various reasons. The following are some
of the reasons why these methodological issues may
arise. The financial institutions might
a. chose a one-factor model where a multi-factor
model would be more appropriate,
b. confuse stochastic with deterministic variables,
c. pick an unsuitable distribution,
d. overlook correlations between certain factors,

e. use outdated or otherwise currently invalid
assumptions,
f. use a theoretical model that assumes frictionless
markets in actual markets,
g. use a correct model that relies on mistaken data
estimates, and
h. continue using a previously correct model after the
market context has changed (Derman, 2003, p 134-
135).
Problems With Var Model
Several criticisms have been raised against the use of
the VaR model. According to Dowd, “there is compelling
evidence that model risk is a major problem with VaR
models,” (Dowd, 2006, p. 185). Part of the model risk
arises because of some arguable deficiencies inherent in
the model and part of the problems is because of the
implementation issues associated with the model.
Incorrect uses to which the VaR model is applied also
gives rise to methodological issues. By frequent
reference to three different studies, literature has
shown that different VaR models or “even different
implementation of similar VaR models” are likely to
produce inconsistent results affecting the risk
management decision of enterprises. According to the
study by Beder (1995), “… the magnitude of the

discrepancy among these methods is shocking, with
VAR results varying by more than 14 times for the same
portfolio. These results illustrate the VAR’s extreme
dependence on parameters, data, assumptions, and
methodology,” (Beder, 1995, p. 12).
The study by Marshall/Siegel has shown that differences
in the implementation of even a single VaR model could
produce significant VaR results. The third study by
Berkowitz/O’Brian was based on the examination of VaR
models of six commercial banks in the jurisdiction of the
United States. The authors report, “Our findings
indicate that banks’ 99th percentile VaR forecasts tend
to be conservative, and, for some banks, are highly
inaccurate,” (Berkowitz & O’Brian, 2002). These studies
and others report that high sensitivity of VaR results
produces considerable model risk based on the
specification of VaR methodologies and implementation
details.
There are more issues associated with model risk of VaR
methods, which are technical are found by different
studies. Artzner et al. (1999) think that VaR is “not an
ideal risk measure.” Based on the findings of their study,
the authors have attributed two basic reasons for
rejecting the VaR measure of risks. They are:

a. ” value at risk does not behave nicely concerning
the addition of risk, even independent ones,
thereby creating severe aggregation problems.
b. the use of value at risk does not encourage and,
indeed, sometimes prohibits diversification
because the value at risk does not take into account
the economic consequences of the events, the
probabilities of which it controls” (Artzner et al.
1999, p. 218).
Point (a) remarks that the VaR does not possess the
characteristic of subadditivity, which adds an
incoherent nature to the risk measure. The second point
indicates that VaR as a risk measure will not be able to
recognize the concentration of risks. A similar use of VaR
across different institutions is likely to create feedback
effects, which might lead to “a breakdown of
correlations and are a source of systemic risk.” Another
criticism is that general VaR models are not able to
consider liquidity risks explicitly. Despite the number of
approaches to include liquidity effects in the VaR model,
liquidity risk remains a serious issue.
Use of Correct Model and Incorrect Solution
The third important model risk identified by Derman
(2003) is the use of a correct risk management model
but arriving at an incorrect solution despite the use of

the correct model. According to Derman (2003), “You
can make a technical mistake in finding the analytic
solution to a model. This can happen through subtlety
or carelessness. … It takes careful testing to ensure that
an analytic solution behaves consistently for all
reasonable market parameters,” (Derman, 2003, p.
135). This model risk is self-explanatory, where
organizations may not be able to make use of the
incorrect solutions provided by the risk management
models, even though they have engaged the
appropriate model that needs to be used considering
the circumstances.
Use of Correct Model and Inappropriate Use
The fourth category of model risk as identified by
Derman (2003) is the use of a good model outside the
intended purview of the application of the model.
Dermon (2003) states, “There are always implicit
assumptions behind a model and its solution method.
But human beings have limited foresight and a great
imagination, so that, inevitably, a model will be used in
ways its creator never intended,” (Derman, 2003, p.
135). This model risk is essentially an example of
implementation risk, which is similar to the situation of
using a correct model to arrive at incorrect solutions to
manage the risk.

Summary
Risk management enables improvement in
“organizational monitoring, control and performance
appraisal by top management, shareholders, debt-
holders, regulators and other stakeholders.” From the
perspective of the relationship between a principal and
agent, risk management creates additional knowledge
at various levels. It helps ensure that agents act meeting
the interests of the principal. Additional transparency
created by efficient risk management processes helps in
reducing the overall monitoring costs. However, such
reduction depends on the cost involved in instituting
risk management measures. Finally, there is a need for
appropriate regulations, which prescribe risk
management practices for avoiding or lessening the
“negative impact of a market failure at the
macroeconomic level.”
Research Methodology
The objective of this chapter is to describe the
methodology adopted for meeting the aims and
objectives of this study. “In the discussion of the
selection of a problem suggests valuable criteria:
1. novelty of the problem,
2. investigator’s interest in the problem,

3. practical value of the research to the investigator,
4. worker’s special qualification,
5. availability of the data,
6. cost of investigation, and
7. time required for the investigation,”(Watkins
(1994) quoted by Reyes, (2004); Burns and Grove,
(2005).
While considering all these aspects one of the most
important issues in conducting social research is to find
a way of getting the focus on the different aspects like
the problem statement, conceptualizing the theory and
choosing the research design. “Focus provides the
integration of seeming diversity of the elements of the
process from the presentation of the problem to the
scope of research, conceptual framework, related
literature, instrumentation, appropriate statistical
methods to be used as well as the design and
methodology used,” (Reyes, 2004, p 3).
Denzin and Lincoln (1998) state the researcher is
independent to engage any research approach, so long
as the method engaged enables him to complete the
research and achieve its objectives. However, the
researcher must consider the nature of the research
inquiry and the variables that have an impact on the

research process. The researcher has to evaluate the
appropriateness of the methodology as to its ability to
find plausible answers to the research questions within
the broad context of the nature and scope of the
research issue. For the current research on risk
management and its implications for financial
institutions during the financial crisis, considering the
research issue under study, the qualitative research
approach of the case study was engaged. This chapter
presents a description of the research method and
discusses the salience, merits, and demerits of the
method adopted. The justification of the research
method also forms part of the chapter.
The research methodology is not just about data
collection and the rules for evidence; it is more about
the nature of explanation and how the explanations are
produced. How knowledge is developed from these
explanations depends on the methodology used.
Research design, on the other hand, provides the plan
and structure as to how explanations can be obtained.
This chapter explains the research methodology and
design adopted. This research was conducted in two
phases. In Phase 1 (exploratory study), several research
questions were developed based on the review of the
literature relevant to the research inquiry. In Phase 2

case studies on the 2007/2008, subprime mortgage and
risk management failures in Lehman Brothers were
carried out.
A descriptive research method such as the case study
should be treated as complementary to the secondary
research method used for collecting the required data.
If properly utilized, the case study approach could
provide important insights into the risk management
practices and their implications on financial institutions
during the financial crisis.
Problem Statement, Research Objective, and Research
Questions
Financial institutions need to adopt systems for
identification; assessment and management of risks to
their operations and these risks may arise because of
the influence of external and internal factors. These risk
mitigation initiatives are considered important to
enhance the ability of the financial institutions to
respond to fluctuations in the financial system, which
are quick and unexpected. The risk management in the
financial institutions centers around two basic issues as
to the impact of risk on the functioning of the financial
institutions and how the institutions can work to
mitigate the potential risks involved which form an
integral part of the products of the financial institutions.

Risk management in the financial service industry has
assumed greater importance in the wake of a balanced
economic development of the nation. An intrusive risk
management system is considered very much essential
given the concern about the safety and soundness of the
financial service industry. However, the advancement in
the information and communication technology, the
enlargement in the financial services industry, the
ambiguity in the distinction of banking and non-banking
financial institutions and the creation and offering of
numerous financial service products have put the
banking system in a state of perpetual change and
instability.
In the years leading up to the recent financial crisis,
some of the regulators have recognized that and
intimated investment banks, that they have not
implemented efficient risk mitigation initiatives. Despite
the advice from the regulators, these institutions have
not taken any steps to remove these weaknesses in their
risk management systems such as making changes in the
system of risk assessments, until the crisis occurred. In
this context, this thesis studied the issue of risk
management under conditions of financial crisis and
challenges faced by the financial institutions to mitigate
risks.

Examining risk management under conditions of the
financial crisis and the challenges faced by financial
institutions is the central aim of this study. In achieving
this central aim, the stud attempted to achieve the
following other objectives.
• To study and make an in-depth report on the
concept of risk, the rationale for risk management
risks faced by the financial institutions and methods
of measuring risk
• To make an in-depth study of the deficiencies in risk
management by financial institutions during the
recent financial crisis
• To report on the effects of the deficiencies in
managing risk effectively
The study will achieve other objectives incidental to the
above objectives.
Based on the theoretical observations and findings from
case studies, the research will find replies to the
following research issues.
1. What are the salient aspects of risk management by
financial institutions under conditions of the
financial crisis?
2. What are the deficiencies in the risk assessment
and risk management techniques followed by the

financial institutions during the recent financial
crisis?
3. What are the effects of the deficiencies in managing
risks effectively by the financial institutions?
Methodological Framework
The methodological framework includes the research
process, research philosophy and research approach
used for conducting this research.
Research Process
The research process encompasses different elements
involved in the research methodology, in which the
process specifies the limits of the research. These
boundaries take the form of the research philosophy
and approach. The research strategy including the
research techniques and data collection methods also
are the components of the research process. Within the
boundaries of the research process, the time spheres for
completing the study are also included. The elements of
research philosophy, research approach, research
strategies, and data collection methods are discussed
within this chapter under different sections. All the
selected components under these heads are collectively
known as the research design.

The design for further research can be formed by stating
the research issue clearly. When the research problem
is well defined, it will automatically point towards the
appropriate method of investigation. However, there
can be no single research method that can be used for
all research issues. There are some research techniques,
which are available to the choice of the researcher. In
many instances, the researcher has to make many
compromises, in the process of choosing a suitable
research technique. For example, the researcher has to
compromise in the quality of information, if he has to
consider the cost of data collection and analysis. In
some other cases, time constraints may be the
prominent force driving the researcher to choose a
particular research technique. Therefore, the design of
a research process is always influenced by both budget
and time factors in arriving at the research technique.
The research design may be categorized into descriptive
or causal. Descriptive studies will provide complete
details on the research inquiry. The purpose of causal
studies is to find the effect of one variable on another.
Research Philosophy
The research approach has the role of observing the
progress of the research, which in turn depends on the
research philosophy chosen as the basis for conducting

the research. The ways of collecting information,
interpreting and analyzing the information are covered
by the phenomenon of research philosophy (Saunders
et al., 2003).
The scope of this study is to explore the implications of
risk management practices on financial institutions
during the financial crisis. Based on the review of the
relevant literature, a theoretical framework has been
evolved to extend the knowledge on risk management
principles and practices. Because of the nature of the
research issue and the need for a substantial amount of
information to be collected, interpreted and analyzed to
present the real situation, the study adopted the
research philosophy within a ‘phenomenological’
philosophical approach. According to this approach, it is
a common phenomenon that all individuals hold certain
assumptions, beliefs, and attitudes. However, for
completing the current study the phenomenological
approach cannot be adopted fully.
According to Flinders and Mills (1993), the
phenomenological approach, the beliefs and attitudes
are held to be the individual views forming part of the
conceptualization process. This approach has a role in
the creation of meaning in the surrounding world while
directing the actions of an individual within the context

of the world. By using this approach, the study would be
able to embark on an outcome that considers the
perceptions of the individuals, who were the
participants to the research inquiry. The process also
takes into account the meaning of their actions created
by the participants based on their outlook and
responses on the actions of the people in the world
around them.
Ontology is one of the philosophies underlying social
researches. The objective of the ontological perspective
is to provide an account of the research issue in an
elementary way. Mason (2002) posits that the
ontological perspective necessitates the researcher to
acquire the ability to understand how his perceptions
influence the process of the research. According to Scott
and Usher (2000), “… philosophical issues are integral to
the research process… what researchers ‘silently think’
about research.” Therefore, the purpose of engaging a
philosophical perspective to any social research is to
understand the awareness and opinions of people, their
perceptions, explanations, practices, and dealings,
which reflect meaningful visions of social realism. It is
the responsibility of the researcher to see how these
actions would influence the outcome of the research
and to assess the influence of the research philosophy
on the overall research process.

‘Epistemology’ is another philosophical approach to
social research, which spells out and explains different
research philosophies that can be applied to the
research process. Epistemology covers issues that
are known to be factual. Doxology is the opposite view
of Epistemology. Doxology implies issues that
are believed to be factual. Thus, the goal of
epistemology is the creation of a set of rules for knowing
things now someone claims the existence of a factual
thing or issue. Epistemology also checks on the validity
of such a claim (Scott and Usher, 2000). The goal of any
scientific or social research is to convert the research
issue from the position of being believed to be true into
the position of known values. Epistemology emphasizes
the factors that enable the researcher to distinguish
between valid knowledge and assumptions constituted
by opinions or beliefs (Scott and Usher, 2000).
Apart from the phenomenological approach, this
research follows a combined positivist epistemology
and objective ontology approach. The adoption of these
philosophical approaches enables that data collected
are not biased with the personal perceptions of the
researcher. The information and data required for
completing this study will be collected from case studies
of specific events where risk management has failed
during the financial crisis. The sources and nature of

data make objective ontology as an appropriate
philosophy for this research.
Research Approach
The research follows a qualitative and deductive
research approach. The salience of the research
approach is explained in the following sections.
Qualitative Method
Being one of the principal methods in conducting
researches in the realm of social science the qualitative
method involves examining the viewpoints, outlooks,
and experiences of the individuals taking part in
research from the points of view of the informants. As
against the quantitative research method, the
qualitative research method does not make use of
quantitative data and statistical analyses. Logical
deductions to infer information concerning the human
element forms the basis of the qualitative method. A
major criticism against the qualitative method is that it
always has a smaller sample size, which makes
generalization difficult.
The qualitative method makes use of data collection and
analysis methods, which do not involve the collection of
quantitative information (Lofland & Lofland, 1984). The
qualitative research method has been identified to
focus on “quality” instead of “quantity” of information.

Some of the researchers believe that the qualitative
method uses a subjective methodology and makes the
researcher substitute as the major research instrument
(Adler and Adler, 1987). Past literature is abundant in
qualitative research methods. The qualitative research
method is also referred to as ‘naturalistic’ research
(Bogdan and Biklen (1982); Lincoln and Guba (1985);
Patton (1990); Eisner (1991). These researchers have
identified several distinguishing features of the
qualitative research method.
Patton states one of the requirements of the qualitative
method is that the researcher has to locate the natural
surrounding for taking up the process of data collection.
It is also important that the researcher maintain
emphatic neutrality throughout the research process. If
the researcher is keen on deriving the optimal outcome
from the qualitative research, he has to make a proper
definition of the natural surrounding and its boundaries.
There is the likelihood of the researcher becoming a
research instrument himself. The qualitative method
makes use of the inductive process for analyzing the
collected information.
Eisner admires the qualitative method for using vivid
reports with a communicative language and
comprehensive and meaningful research report. Hoepfl

(1997) states that qualitative research adopts
‘trustworthiness’ as the fundamental factor that
influences its process. The qualitative research enables
the researcher to acquire an interpretative
temperament, which in turn helps him find out the
meanings of the happenings conveyed to the people,
who deal with them (the happenings). Qualitative
research gives the researcher also, the ability to
interpret these meanings. Lincoln and Guba (1985)
found the interconnection between these characteristic
features. Its emergent nature forms one of the salient
features of qualitative research.
Patton (1990) observes that qualitative research suffers
from a drawback in that the researcher can arrive at the
research strategies after he starts with the process of
data collection. This is because the researcher has to
adhere to the systematic followup and understanding of
the meanings of the information and data in respect of
the background in which they are collected. Under the
qualitative method, it becomes essential that the
researcher spell out the primary questions to be
examined in advance and subsequently to proceed to
formulate the strategies for collecting the required data.
Deductive Approach

Deductive and inductive approaches are the usual
research approaches that are used in social science
researches. According to Saunders et al. (2003), the
deductive technique requires the researcher to
formulate different hypotheses and engage a research
strategy to test the hypotheses. The deductive approach
starts with the formation of a general idea on the
research issue. Based on the idea generated the
researcher forms hypotheses, which can be tested using
appropriate research techniques and tools to support
the general idea generated. If the hypotheses are
supported, it implies that the initial idea generated
about the research issue is correct. Social research often
uses the deductive approach rather than the inductive
approach.
In the inductive approach, the researcher starts the
process with data collection and once the data is
collected, he develops a theory based on the analysis of
the data collected earlier. Creswell (1994) observes that
the inductive approach investigates research topics,
which are relatively noticeable and exciting as well as
contentious.
Saunders et al. (2003) identify the goal of the inductive
approach is to get a better understanding of meaning
attached by human beings to events. The inductive

approach also provides an in-depth knowledge of the
research context. The inductive approach also
comprises the process of data collection for a qualitative
study. When the researcher uses the inductive
approach, there is the likelihood that the researcher can
change the research emphasis as the approach
encompasses flexible formation that facilitates changes.
However, the major concern about the inductive
approach is that the approach does not possess the
requirement of generalization. Saunders et al. (2003)
identify the purpose of the research approach as the
indication of whether the commitment of “… the theory
is explicit within the research design”. Mason (2002)
states the goal of the research approach is “deciding
what theory does for your arguments”. The appropriate
research approach will help the researcher in choosing
the research design, which will facilitate the research
process most.
This study uses a deductive research approach since
different research questions have been developed
before engaging a research strategy.
Research Design
This study follows the research design of a case study. In
recent years, the roles of descriptive and qualitative
research methodologies, which include case studies,

participant observation, informant and respondent
interviewing and document analysis have been
emphasized and pursued (Scapens, 1990). In these
approaches, the researcher is required to have closer
involvement with the organizations under study. Based
on the detailed examination of the organizations
concerned, research findings are described instead of
being prescribed.
One qualitative method, which seems to offer at least a
partial solution to the currently unsatisfactory research,
is the case study approach. In contrast to simplistic and
superficial findings of the quantitative method, the case
study provides the opportunity for the research to
develop better theories in risk management and control
systems, which are based on real-world managerial
practices. Also, the case study allows the flexibility to be
interpretative of the findings. The research, for
example, is not restricted to his/her original theory, but
most often is encouraged to come up with new
theoretical discoveries.
The case study has been used as a research tool for
several types of research. “Case study is an ideal
methodology when a holistic, in-depth investigation is
needed” (Feagin et al. 1991). Different exploratory
studies in the discipline of social studies have made use

of the case study method for collecting relatable
information about the topics researched. The following
case study as the research tool facilitates the researcher
to follow well -developed techniques to meet the
requirements of data collection for any kind of
investigation. “Whether the study is experimental or
quasi-experimental, the data collection and analysis
methods are known to hide some details,” (Stake,
1995). However, the case study method has the unique
capability of retrieving additional information from
different perspectives drawn using multiple sources of
data.
There are varying kinds of case studies, which can be
engaged in conducting studies in different settings.
These are exploratory case studies, explanatory case
studies, and descriptive case studies. Stake (1995) took
note of other forms of case studies. An intrinsic case
study is one in which the researcher has a concern in the
case being studied. The instrumental case study enables
the researcher to explore additional information that is
understandable to the normal observer. A collective
case study is concerned with the study of a group of
cases.
The case study method cannot be construed as sampling
research. However, to derive optimum benefit from the

case study, the researcher has to select the appropriate
case. Case study as a research tool has often faced
criticism because of its lack of the ability to provide for
generalization of the findings. It is a common
condemnation of the case study method that the
findings cannot be applied widely in actual situations.
Yin (1984) has answered the criticism by offering a well
made out explanation on the distinction between
“analytic generalization” and “statistical
generalization”. “In analytic generalization, the
previously developed theory is used as a template
against which to compare the empirical results of the
case study” (Yin, 1984).
Yin has led the way in making the case study as one of
the prominent methods of conducting social research.
After Yin (1984), several professionals and academics
have provided new insights into the case study method
and made it become one of the preferred research tools
in social researches. Case study becomes an attractive
research tool because of its ability to study the research
issue in natural surroundings, which is the core element
of any qualitative research. This capability makes the
case study a practicable research tool.
Data Analysis

According to Marshall and Rossman (1995), qualitative
research is based on the collection of data from
different sources and the data already collected forms
the basis for reporting the findings of the study and
making recommendations. Yin (1984) identified
different sources like “archival records, direct
observations, interviews, and observation of the
participants,” which can be used in conducting
qualitative research. Quantitative research uses tools
like surveys for data collection. The data collection
methods for the current research include the collection
of secondary data and information retrieval from
archival records, and other documents for completing
the research. The quality of data collected determines
the validity and reliability of the research findings. Thus,
“qualitative modes of data analysis provide ways of
discerning, examining, comparing and contrasting, and
interpreting meaningful patterns or themes.
Meaningfulness is determined by the particular goals
and objectives of the project at hand.” (Boojihawon,
2006)
Any of the following data collection methods can be
used in following the case study research approach.
They are; “(i) documents, (ii) archival records, (iii)
interviews, (iv) direct observation, (v) participant
observation and (vi) artifacts.” Either the researcher can

use a single or a combination of these or other methods
for data collection and the selection of data collection
method rely on the nature of research proposed to be
undertaken.
There are only a few tenets, which define the mission of
data collection. Each research study has to use a data
collection method, which fits into the research
methodology chosen by the researcher. The goals of
both quantitative and qualitative research studies are to
make the most of the responses from the participants
and to enhance the accuracy of the results to the
maximum extent possible.
Taylor-Powell & Renner (2003) explain that qualitative
research depends on expressions and observations as
compared to quantitative research based on numbers.
Analysis of qualitative data requires creativity,
discipline, and a systematic approach. They further
illustrate that there is no single way to analyze the
qualitative data however the basic approach is to users
‘content analysis.
Summary
This chapter presented a detailed account of the
research approach, research philosophy, and research
design apart from providing the methodological
framework of the current research. Data and

information collected from the exploratory study and
the case studies are presented in the subsequent
chapters. The next chapter presents the findings from
the exploratory study. These will be secondary data and
information collected through a review of the literature
analyzed to provide an in-depth understanding of the
implications of risk management in financial institutions
during the financial crisis. The contents of this chapter
are the findings from the case study. The analysis of the
findings from the case forms part of this chapter.
Case Study, Findings and Discussion
This chapter presents case studies on the risk
management approaches of Lehman Brothers and the
financial institutions when they were dealing with a
subprime mortgage during 2007-08. The case studies
will reveal the risk management failures, which led to
the downfall of the company Lehman Brothers and
several other financial institutions because of poor risk
management practices during the financial crisis.
Case Study of Risk Management in Lehman Brothers
This section discusses the failure in the risk
management practices, which led to the bankruptcy of
Lehman Brothers.
Lehman Brothers – An Overview

Lehman Brothers Inc was the fourth largest investment
bank in the world, which filed for bankruptcy during
September 2008. The company started as a small dry
goods store in the year 1844 grew to one of the leading
investment banks in the US. Lehman Brothers had a
strong position in dealing with fixed-income products.
Later on, it diversified into investment banking
activities.
Just before 2007, Lehman Brothers was making a
considerable proportion of their earnings from the
business of issuing securitized assets like mortgage
loans. When the collapse of the US subprime mortgage
industry started, it resulted in a large-scale credit crisis.
It also led to an increase in mortgage default rates,
which in turn led to the disappearance of the demand
for these securities. This situation has made Lehman
face a situation of having billions of dollars worth of
depreciating securities in its balance sheet. This has
made the company to take up large write-offs and write-
downs. Finally, the efforts of the company to shed its
risky assets proved futile. The investors liquidated
stocks of Lehman Brothers in the stock market on the
consideration that Lehman might not be able to transact
its business as it did before.

On September 2, 2008, the state-owned Korean
Development Bank confirmed its proposed move to buy
25% of the stakes in Lehman Brothers. However, the
deal did not go through. In the following weekend,
Lehman Brothers put up itself for sale. An urgent
meeting of the officials of Wall Street conducted by the
US Federal Reserve urged them to extend necessary
financial help to Lehman Brothers. “Bank of America
(BAC) and Barclays (BCS)” being the contenders for the
stocks of Lehman Brothers backed out on the refusal of
the federal government to consider writing off the
future liabilities of the company against government
revenue. At the final stage, Lehman Brothers had no
prospective buyers. Therefore, the company chose to
file for bankruptcy protection under Chapter 11 on
September 15, 2008. With the filing of bankruptcy, the
long history of the company ended. The petition filed by
Lehman Brothers was the huge petition for insolvency
filing on record.
There were several causes for the decline of the
business of Lehman Brothers. During the years 2003 and
2004, when the housing boom in the United States was
in the peak, Lehman acquired five companies engaged
in the business of mortgage lending. The acquisition of
these companies first appeared prescient with the
company earning record revenues from its real estate

business. The business of the company in realty assets
helped the company to record high revenue growth of
56% in the capital markets within two years between
2004 and 2006. This business growth was a record
considering the growth of other entities in the same
sector. In the year 2006, Lehman securitized $ 1.46
billion of mortgages, which accounted for a 10%
increase over the previous year. “Lehman reported
record profits every year from 2005 to 2007. In 2007,
the firm reported net income of a record $4.2 billion on
revenue of $19.3 billion” (Investopedia, 2010b).
During February 2007, the stock price of Lehman
Brothers reached a record high of $ 86.18. This gave the
company a market capitalization of $ 60 billion.
“However, by the first quarter of 2007, cracks in the U.S.
housing market were already becoming apparent as
defaults on subprime mortgages rose to a seven-year
high” (Investopedia, 2010b). “On 14 March 2007, one
day after the firm’s stock had its biggest one-day drop in
five years on concerns that rising defaults would affect
Lehman’s profitability, the firm reported record
revenues and profit for the first fiscal quarter” (Teng,
2010). The CFO of the company reported that the
company has taken care of the rising risks posed by the
increased home delinquencies. He further reported that
the rise in the delinquencies would have little impact on

the profitability of Lehman Brothers. The CFO also
reported that he did not anticipate the problem of the
subprime market affecting the rest of the housing
market or affecting the US economy.
The share prices of Lehman dropped drastically during
mid-2007 when two of the hedge funds operated by
Bear Stearns failed. The company announced the
closure of many other offices in three states. “Even as
the correction in the U.S. housing market gained
momentum, Lehman continued to be a major player in
the mortgage market” (Investopedia, 2010b). In 2007,
the company underwrote a high volume of mortgage-
backed securities than has been done by any other firm.
The company accumulated $85 billion portfolios, which
was equivalent to four times the equity of the
shareholders. “In the fourth quarter of 2007, Lehman’s
stock rebounded, as global equity markets reached new
highs and prices for fixed-income assets staged a
temporary rebound. However, the firm did not take the
opportunity to trim its massive mortgage portfolio,
which in retrospect, would turn out to be its last chance”
(Investopedia, 2010b).
“Hurtling Toward Failure Lehman’s high degree of
leverage – the ratio of total assets to shareholders
equity – was 31 in 2007, and its huge portfolio of

mortgage securities made it increasingly vulnerable to
deteriorating market conditions” (Ritholtz, 2010). “On
17 March 2008, following the near-collapse of Bear
Stearns, the second-largest underwriter of mortgage-
backed securities, Lehman’s share price fell 48%” (Teng,
2010). “Confidence in the company returned to some
extent in April, after it raised $4 billion through an issue
of preferred stock that was convertible into Lehman
shares at a 32% premium to its price at the time”
(Investopedia, 2010b). However, with the skepticism of
the hedge fund managers, about the valuation of the
mortgage portfolio, the stock prices of the company
continued to fall.
During June 2008, the company reported a loss of $ 2.8
billion out of its operations for the second three months
period. The company reported that it had raised
another six billion US Dollars from the investing public.
The company announced that it had raised its liquidity
pool to an estimated $ 45 billion reducing its exposure
to residential and commercial mortgages by 20% and
cutting down the leverage factor of 32 to almost 25.
However, none of these efforts proved useful and
ultimately the company filed for bankruptcy protection
under Chapter 11 in September 2008.
Risk Management Failure in Lehman Brothers

According to the report made by the court-appointed
examiner in the Lehman Brothers bankruptcy case, the
firm had ignored its risk management limits, since it
pursued a high growth strategy. The following is an
excerpt from the report.
“In 2006, Lehman made the deliberate decision to
embark upon an aggressive growth strategy, to take on
significantly greater risk, and to substantially increase
leverage on its capital. In 2007, as the subprime
residential mortgage business progressed from problem
to crisis, Lehman was slow to recognize the developing
storm and its spillover effect upon commercial real
estate and other business lines. Rather than pull back,
Lehman made the conscious decision to “double down,”
hoping to profit from a counter‐cyclical strategy. As it
did so, Lehman significantly and repeatedly exceeded its
internal risk limits and controls,” (Wheelhouse Advisors,
2010).
Although, many analysts point out that the lack of
efficient risk assessment in the recent crisis, as
responsible for the downfall of Lehman Brothers, there
are ample of evidence to prove that the management of
the company failed to recognize the warnings about
risks, which were made explicit from the risk-mitigating
procedures of the company.

“During this period of aggressive growth, Lehman
developed significant exposures to risky subprime
lending, commercial real estate, structured products,
and high-risk lending for leveraged buyouts” (U.S.
Department of the Treasury, 2010). In the process, the
company had made repeated breaches of its risk
concentration limits in meeting the objective of
achieving high earnings.
Common business sense demands that the executive
leaders take the responsibility for effective risk
management based on the information from different
sources for their probability of making successful
business decisions.
“Lehman had a risk management staff that was devoted
entirely to conducting an array of ‘stress tests’ to
accurately determine the potential consequences of an
‘economic shock’ about their assets and investments.
Lehman substantially reduced their decision-making
effectiveness when they disregarded, according to the
report, its risk managers, its policies, and its risk limits.
The report also suggests that management removed
their Chief Risk Officer and its head of the Fixed Income
Division, because of their opposition to managements
growing accumulation of illiquid and risky investments”
(Cotton, 2010).

Another reason for the bankruptcy of Lehman Brothers
is the model risk. The company mostly used the Value at
Risk (VaR) model invented by J.P. Morgan Chase & Co.
While this model
allows the traders to make real money with their
business, it reduces the worries of the top management
about the risk that the traders are taking to make their
earnings. The model makes several mathematical
assumptions, which are “provably false in real life,” and
provides an assessment of 99% confidence limit of the
loss likely to occur at each trading point at most 1% of
the time.
“One big problem with this approach to managing risk is
that it does not tell you what can happen the other 1%
of the time when the VAR limit is exceeded. But the top
managers of the investment banks were lulled into
believing that the other 1% did not matter: After all,
they came to believe, if it was only a 1% probability, how
dangerous could it be. However, since VAR was
calculated from daily price movements, that 1% was
quite important. The other problem with VAR is that, in
most cases, it depends on an assessment of the
“volatility” of the security concerned – how much that
security bounces around. However, volatility is by

definition low in quiet markets and much higher in
turbulent markets” (Hutchinson, 2008).
Hence, the assessment of risk is low in quiet markets,
which encourage the traders to accumulate assets and
then the risk zooms up when the market turns another
way, at which point, the traders may not be able to
unwind the previously established positions. Therefore,
the use of VaR as a risk measurement model may not
ensure “a culture of risk management at every level.”
When the company indulged in using more leverage to
augment the funding, the risk becomes significant.
Case Study of 2007/2008 Subprime Mortgage
The subprime mortgage crisis can be considered as one
of the most serious economic disturbances affecting the
United States during the period after the Great
Depression of the 1930s. The issues relating to rewards
and pitfalls of subprime financing are fundamental to
the elements of risk-bearing, sharing, and transfers, in
the realm of financial markets and institutions affecting
the world economies. The purpose of the analysis is to
provide a critical review and understanding of the
rewards and pitfalls of effective risk management
policies so that the designing of new and efficient
policies to reduce the adverse impact of the current
crisis and to prevent the occurrence of such future

events. The case study analyzes the subprime financing
as a major financial market innovation and provides a
list of issues raised and lessons learned in the process of
innovation from the perspective of risk management.
Subprime Lending – A Financial Innovation
Innovations in the financial market are most likely to
occur in the context of the following fundamental
conditions.
1. The market should consist of borrowers and
investors who are previously underserved.
Subprime borrowers who were otherwise denied
prime credits were keen on using subprime
financing to finance the purchase of vehicles. The
investors worldwide with a glut in savings could not
earn higher returns for their investments and this,
in turn, made them turn to subprime lending to
earn relatively higher rates of returns.
2. The advancement in technology and expertise
acted as the catalyst to create sophisticated
subprime mortgage creation using state-of-the-art
tools ensuring the design of security and
management of financial risks.
3. The regulatory environment that prevailed in the
United States was not only benign but also helped
the origination of subprime lending. Despite the

presence of a complex network of federal and state
regulations, only a few of these regulations
impeded the growth of subprime financing.
“Furthermore, the existing system of commercial
bank capital requirements provided banks with
strong incentives to securitize many of the
subprime mortgage loans they originated.”
(Spence, Amez, & Buckly, 2009)
Financial innovations have most of the time been
proved to be risky undertakings. This is all the more so
when the innovations resulted in the creation of new
classes of loans and securities which are risky. Even
though each of the innovations led to some sort of a
crisis, modified forms of innovations such as subprime
auto financing have proved to be of significant benefits
even in today’s economic scenario. Therefore, it is
reasonable to assume that subprime financing
innovations, when reformed and refined would be able
to help the subprime borrowers with enough
opportunities to meet their financing needs.
Lessons Learned From Financial Crisis Caused by
Subprime Lending
There have been several issues connected with the
subprime financing and its impact on the economy as a

whole and the financial markets and institutions. These
issues can be categorized as:
• Issues directly associated with subprime lending
• Issues connected with the securitization of
subprime mortgages
• Issues connected with the operations of financial
markets and institutions, which were engaged in
subprime lending
Issues Directly Associated with Subprime Mortgage
Lending
Issues directly associated with subprime mortgage
lending include:
A. Subprime financing has helped several young and
minority households to acquire homes much
needed to improve their status and other important
social purposes. The increased purchase of homes
has stimulated the lending by the investment banks
through various intermediaries.
B. Intense competition in the market should generally
work out to the advantage of uninformed
borrowers by protecting their interest, but
subprime lending has worked in the opposite
direction and revealed a serious market failure in
this respect. There is a strong need for

improvements in regulations, even considering the
exhaustive regulatory measures, as they exist
today. However, it must be ensured that there is no
creation of destructive regulations, which would
work to end all the subprime lending activities.
C. Traditionally there has been reluctance among the
lenders, dealers and other service providers to
modify the terms of the loans, even when
requested by the borrowers. Contractual
limitations also acted to restrict the chances of any
modifications. Now under different circumstances,
the lenders and borrowers are found to be
amenable to governmental reform plans
characterized as one-time emergency plans, when
the damage is already done. It was unfortunate a
large number of subprime borrowers were beyond
such help. Unfortunately, in the case of subprime
financing, the resultant default rates are high
despite some modifications carried out.
D. The costs imposed by the subprime loan
foreclosures are limited because the defaulting
borrowers simply surrender the houses when they
are unable to meet the payments. This would work
to reduce the credit rating of the borrowers,
disabling them to access a new mortgage for

several future years. However, steps can be taken
to reduce even these costs to the borrower.
Issues Connected With Securitization Of Subprime
Loans
A. According to the report by President’s Working
Group on Financial Markets (2008), the incomplete
disclosures and the process of securitization have
duped the investors to purchase high-risk subprime
mortgage securities and only renowned and
sophisticated institutional investors have
purchased these mortgage (President’s Working
Group on Financial Markets, 2008). The meaning
and significance of the term “subprime” is also clear
to understand the ramifications of the subprime
transactions, which existed even from the late
1990s. Therefore, it is reasonable to assume that
the securitization process cannot by itself be
considered as a source of a subprime mortgage
crisis, more particularly in the case of auto financing
B. The credit rating agencies also had a major role to
play in the subprime lending crisis. The agencies
systematically under-estimated the risk of
subprime mortgage pools, depending too much on
the FICO scores. The rating agencies also erred by
underestimating the degree of risk on

Collateralized Debt Obligations (CDOs), which were
backed, by subprime securitization tranches.
C. One of the most important reasons for the
investors to suffer huge losses is linked directly with
their tendency to concentrate the risks by
leveraging their positions with borrowed funds.
Furthermore, many of the investors depended on
short-term loans to finance subprime lending
transactions.
Issues Connected with Operations of Financial Markets
and Institutions
The breakdown in the financial market trading and
liquidity allowed the market prices of many subprime
mortgages to fall considerably lower levels than their
fundamental values. This has resulted in a serious
subprime crisis for both home loans as well as for
automobile financing. The opaque nature of the
instruments covering the undervalued subprime
securities and CODs discouraged the investors from
purchasing these instruments. The investment banks
also remained silent in reporting the declines in their
investment portfolios, which added to the liquidity
issues connected with subprime mortgage securities.
Credit Rating Agencies and Their Role in Subprime
Crisis

It is being argued that the credit rating agencies are
responsible for turning the risky house mortgages into
securities, which were considered suitable for investors.
Normally the investors had no means of verifying the
quality of the securities, which in this case is the house
mortgages. To determine whether a mortgage is safe
the details of the owner of the property, the income of
the owner and his/her credit history need to be studied.
However, in the absence of such details, the investors
relied on the ‘AAA’ rating given by rating agencies like
Moody’s. Over the period starting from the year 1996
Moody’s and its principal competitors, Standard &
Poor’s and Fitch Rating have started this business of
rating the mortgage securities, which were believed by
the investors as an unquestionable basis for
investments. For the rating agencies, it was a new
business and more profits. By turning the house
mortgages as a source of funding, the agencies
transformed mortgages – which otherwise had no
means of recognition – as a strong base for writing new
loans by the mortgage banks.
With the support of the ratings by the credit rating
agencies, the volume of such loans tripled to $ 2.5
trillion in the year 2006 being mortgages issued to
subprime borrowers. Almost all the entire subprime
loans were converted into securitized pools, and sold to

Wall Street, with heavy trading going on such
securitized pools.
The most important point here is that the investors had
no knowledge, nor they had any means of making their
judgments on the quality of these mortgages, the equity
covered by the properties, and many other usual
investment considerations. Al they did before investing
is to rely on the credit ratings offered by the renowned
rating agencies. Thus, the credit agencies have assumed
the role of the de-facto watchdog of the mortgage
industry.
However, the credit rating agencies deny accepting the
fact that they should have been more vigilant in rating
these mortgages by offering an argument that it was the
mortgage holders who have defaulted are to be blamed,
as most of them obtained the loans by telling lies to the
financial institutions originally sanctioned the loans.
However, the fact remains that the rating agencies have
erred in rating the mortgages with more credible
ratings. This is evident from the fact that Moody’s,
Standard & Poor’s and Fitch Rating have downgraded
the ratings of a large number of mortgage securities
after the housing collapse. The rating agencies contend
that even though it is true that the credit rating agencies
did not have access to the individual loan files of all the

borrowers to verify the information provided by the
borrowers, the investment banks provided them with
spreadsheets containing data on borrowers’ credit
histories based on which the ratings have been made.
Most of the ratings were based on the expertise of the
rating agencies as statisticians and an aggregate basis.
Therefore, they argue that there was no means of
verifying the credibility of each borrower before
awarding the ratings.
Moreover, in the United States, many classes of
investors are not allowed to make investments in any
non-investment grade bonds. This has forced the issuers
to urge the rating agencies to grade various bonds
covering the subprime mortgages. The rating agencies
are free to charge such issuers for their rating services.
This also has increased the number of ratings given by
the rating agencies. Though it was a smart way to carry
on the business, such smartness has created conflicts
among different agencies (Roger Lowenstein, 2008).
In the case of structured finances like bank loans, the
situation is much worse and complicated, because few
banks would come again and again to the rating
agencies for grading the securities to which they are
getting exposed and for such rating the banks pay hefty
fees to the rating agencies like for example Moody’s.

However, the banks will only pay the fees when the
agency offers the rating as desired by the banks. In case
of a strained relationship with Moody’s for example, the
client bank can try its luck with the competitor Standard
& Poor for getting the desired rating. This practice is
being described as ‘rating shopping’. This is another
factor that needs to be considered in the role of credit
rating agencies in the subprime mortgage crisis.
Risk Management Failures in Subprime Lending
The subprime crisis is an example of illustrating the
implications of various risks of financial risk
management.
First, the risk management models adopted by the
financial institutions have not served their purposes and
led to a serious financial crisis during 2008. According to
Danielsson (2008), “… the current crisis took everybody
by surprise despite all the sophisticated models, all the
stress testing, and all the numbers” (Danielsson 2008, p.
4). The investment bankers Merrill Lynch in their annual
report for the year 2007 stated,
“As a result of the unprecedented credit market
environment during 2007, in particular the extreme
dislocation that affected U.S. subprime residential
mortgage-related and ABS CDO positions, VaR, stress
testing and other risk measures significantly

underestimated the magnitude of actual loss.
Historically, these AAA-rated ABS CDO securities had
not experienced a significant loss of value” (Merrill
Lynch, 2008, p. 62-63).
This goes to prove that the risk management models
have not performed as expected. The remarks by Merrill
Lynch mention two issues – “reliance on rating/rating
agencies and the role of historical simulation in
assessing the risks of new products.”
As per the discussion earlier, the ratings provided by the
rating agencies were very unreliable. The investors who
used the ratings as inputs in their risk assessment
models were misled in arriving at the extent of risk.
There might be different reasons for the agencies to
provide unreliable ratings. They are (i) the agencies used
different proprietary models for rating asset-backed
securities and most of these models suffered from some
common deficiencies affecting their risk assessments.
(ii) Secondly, the problematic issue as pointed out by
Danielsson. He argues that rating agencies
“… underestimated the default correlation in
mortgages, assuming that mortgage defaults are fairly
independent events. Of course, at the height of the
business cycle that may be true, but even a cursory
glance of history reveals that mortgage defaults become

highly correlated in downturns. Unfortunately, the data
samples used to rate SIVs often were not long enough
to include a recession,” (Danielsson 2008, p. 2).
(iii) the third issue is the conflict of interest among the
rating agencies. According to Rosner (2007),
“The problem was that the rating agencies faced a huge
conflict of interest. Not only were they vouching for the
securities’ credit soundness, but they were also being
paid large fees by the issuers of the securities to do so.
… the more deals they could justify rating highly, the
better their earnings – and the less incentive they had
to rate conservatively,” (Rosner, 2007, p. 15).
Relying on these unreliable ratings will have significant
consequences in risk assessment. Crockett states
“Asset-backed commercial paper was regarded as
among the most liquid of instruments. So liquid that the
issuing banks charged very little for the liquidity
enhancement features they offered and did not regard
the contingent liability they faced as requiring much if
any set-aside capital. The liquidity originated in the fact
that the borrowing entities were highly creditworthy,
and the valuation of the underlying collateral was
regarded as well-founded (using ratings provided by
rating agencies)” (Crockett, 2008, p. 15).

Taleb & Martin (2007) state “The recent subprime
mortgage debacle illustrates the risks faced by low-
probability, high-impact events,” (p. 188). Any type of
risk measurement model will not be able to predict the
extent of risks because of the “uncertainty, complexity
and tight coupling” involved in the creation of such
models.
The subprime mortgage crisis outlined the importance
of endogenous risk and how the endogenous risk makes
risk, management models unreliable. Danielson
remarks that one cannot ignore endogenous risks
during the financial crisis and therefore the risk
assessment models fail if there are endogenous risks.
According to Adrian and Shin (2008), mark-to-market
accounting and risk management systems combine to
generate “balance sheet-driven pro-cyclical leverage of
financial institutions.” Leverage is a major element,
which has a large influence on the reactions of the
institutions in a real or perceived crisis such as the
subprime mortgage crisis.
The recent financial crisis is an indication of how
liquidity is endogenously affected. The subprime
mortgage highlights that “liquidity in markets and for
individual intermediaries is much more interdependent
than often realized. Markets are dependent on back-up

liquidity lines from financial institutions, and institutions
are dependent on continuous market liquidity to
execute their risk management strategies,” (Crockett,
2008, p. 14). Adrian and Shin (2008) point out that credit
lines provided by financial institutions to vehicles
invested in MBS and CDOs “made it difficult to contract
balance sheets and caused banks to reduce their
engagements in unrelated segments where this was
possible.”
Discussion
The delinquencies in subprime mortgage loans and the
number of foreclosures in the home loan market-giving
rise to the need for serious economic, social and
regulatory measures had a serious impact on the US
economy. The credit needs of the low-income
individuals are often met with ‘predatory lending’,
which comprises of several financial practices. These
changed financial practices represent the new
dimensions of risk management. This kind of lending has
become increasingly predominant in rural areas.
Predatory lending usually takes the form of payday
loans to check cashing and car title loans, which
threaten the income and assets of the borrowers by the
higher rate of interest and stringent repayment
conditions.

The subprime mortgage market was nothing but an
extension of this lending practice prevalent in the
housing market. Subprime mortgage loans carried
interest rates much higher than the prime loans to cover
the additional risk exposure of the lenders in extending
credit to the borrowers who had a bad loan track and
were defaulters in repayments. With the increase in
subprime lending, the rate of failures had also
considerably increased, as most of the people, who
obtained the loans, were those who did not have the
adequate means to repay the loans. When such failures
reached a greater proportion, “investors have started
scrutinizing subprime loans more carefully and, in turn,
lenders have tightened underwriting standard,”
(Bernanke, 2007). Banks and financial institutions
undertook certain other measures including credit
spreads over subprime securitizations to control the
rate of delinquencies.
Although the term ‘subprime mortgage’ was used to
indicate the loans offered to those borrowers whose
credibility is doubtful, the term “subprime’ does not
signify the character of the loan itself but characterizes
the borrower meaning the borrower has a substandard
credit status. The term ‘subprime’ is one of the
innovative inclusions in the financial language of the
Twenty-first Century. Lack of good credit history and

habitual defaults in repayments make the borrowers get
into the status of subprime borrowers. Subprime
mortgages were provided using several instruments.
The expansion in the subprime mortgage has made the
home-ownership possible for those borrowers who
otherwise would not have been able to qualify for any
borrowing. There has been a sharp increase in the
subprime mortgage in recent years. “In 1996, subprime
lenders reported $90 billion in lending. By 2004, the
subprime mortgage market had grown to $401 billion”
(Carsey Institute, 2006). “Last year, 13.5 percent of
mortgages originated in the U.S. were subprime,
according to the Mortgage Bankers Association,
compared to 2.6 percent in 2000. Overall, the subprime
market was $600 billion in 2006, 20 percent of the $3
trillion mortgage market, according to Inside Mortgage
Finance. In 2001, subprime loans made-ups just 5.6
percent of mortgage dollars” (Kratz 2007).
“For these mortgages, the rate of serious delinquencies
– corresponding to mortgages in foreclosure or with
payments ninety days or more overdue – rose sharply
during 2006 and recently stood at about 11 percent,
about double the recent low seen in mid-2005”
(Bernanke, 2007)

With the increase in the subprime mortgage market, the
concerns over the adverse effects of the predatory loans
have also increased. Indirectly forcing borrowers to take
loans with very higher rates of interest and processing
and other fees than they were eligible and afford was
one of the components of predatory lending often
adopted by the lenders. “It has been estimated that as
many as half of all subprime loan borrowers could
qualify for conventional rate mortgages” (Fannie Mae
and Freddie Mac, 2004). According to the U.S.
Department of Treasury guidelines issued in 2001,
“Subprime borrowers typically have weakened credit
histories that include payment delinquencies and
possibly more severe problems such as charge-offs,
judgments, and bankruptcies. They may also display
reduced repayment capacity as measured by credit
scores, debt-to-income ratios, or other criteria that may
encompass borrowers with incomplete credit histories”.
A highly automated origination system, which facilitated
faster credit scoring and risk-based pricing algorithms,
was instrumental for the rapid growth and
consolidation of the mortgage industry (Collins, Belsky,
& Case, 2005). The growing use of credit scores in
mortgage lending and the creation of automated
underwriting systems also helped the new origination
system very well (Brueggeman & Fisher, 2004; Kendall

& Fishman, 1996; Fabozzi & Modigliani, 2002). These
were the obvious changes required to develop new risk
management perspectives during the mid to late 2000s.
“The advent of risk-based pricing meant that rather than
charging a single rate to all qualified borrowers, the
mortgage market classified borrowers into risk buckets
based on factors such as their demonstrated ability to
handle debt repayment, the stability of employment,
the extent of documentation of their financial
information and the loan-to-value ratio” (Apgar &
Herbert, 2005).
How subprime lending transactions took place, fully
explains the impact of changes in the risk management
practices during the period. There has been a complete
change in the system of originating the loans. Unlike the
traditional way of originating the loans from the bank
branch located in the same area, any of the three
available channels – retail, correspondent or through
brokers originated the loans. Retail activity resembled
the traditional lending where the employees of the bank
or mortgage institution reached the potential
customers and complete the formalities for sanctioning
the loan. Subprime lending business took place through
the branch operations and sometimes institutions close
the loans over the telephone or the Internet. After
funding, the commercial bank may decide to hold the

retail loan in the portfolio. Alternatively, it may decide
to transfer the portfolio to another lender. Yet another
way is to package the loans and sell them to another
secondary market. This will enable the banks to shift
their exposure to the buyer of the mortgage.
The subprime crisis has taken the toll with at least 25
large subprime lenders declaring bankruptcy and
substantial losses being announced by many financial
institutions, bond insurers, and special purpose
enterprises. The impact on the US economy is significant
resulting in lower levels of consumer spending, subdued
levels of consumer confidence, lessened asset prices,
and a significant decline in the projected growth levels
and a considerable rise in the unemployment level.
(AMUNC Background Paper, 2008)
When the crisis hit the subprime mortgage and credit
markets the impact on the credit markets was that the
markets dried up with deal volumes going to
significantly low levels and this made the financial
services firms start thinking on their alternative moves.
One of the victims of the crisis is Lehman Brothers,
which was made to file bankruptcy. Other institutions
like Washington Mutual had to increase the loan-loss
reserves up to $ 2.2 billion to cover the mortgage
exposure. Same is the case with some of the major

financial services firms with five of them (Merrill Lynch
($ 3.4 billion), UBS ($ 3.3 billion), Citigroup ($ 3.1 billion),
Deutsch Bank ($ 2.4 billion) and Morgan Stanley,
JPMorgan Chase and Bank of America put together $ 3
billion) made to write-down $ 17 billion collectively.
(Berkshire Capital Securities, 2007)
While the impact of the subprime crisis on the
traditional long-only assets market is mixed, the biggest
impact was felt on the alternative investment vehicles
of hedge funds and private equity.
The foremost effect of extending the subprime lending
to less creditworthy customers was the increased
foreclosures in the case of home loans as well as auto
finance. This development was unintentional at the
time, lending institutions considered granting of loans
on a large scale to a large number of customers.
However, this outcome was not surprising because most
of the borrowers, who obtained the loans, were low-
income group people and they were not in a position to
meet the mortgage payments in time. Some lower-
wealth brokers could not protect the mortgages by
making timely mortgage payments. This led to more
delinquencies and defaults in subprime loans.
Another side effect of the increase in subprime lending
was the decline in the price levels of homes and used

automobiles. This is because much of the home loans
under subprime lending were given to under-served
lower-income borrowers who concentrated buying
homes in lower-income neighborhoods where the
housing market is more fragile with very few takers of
homes either on foreclosure or on sale. This buying
pattern coupled with abusive marketing and origination
practices led to the concentration of foreclosures
resulting in a contagion effect where foreclosures above
some threshold level could bring down prices in an area
and stimulate a further cycle of foreclosures and
decline.
Studies have proved beyond doubt the connection
between the increase in foreclosures and the
phenomenal growth in subprime lending. Cutts &
VanOrder, (2003), researchers at Freddie Mac
estimated the serious delinquency rate for conventional
prime loans at 0.55 percent as of mid-2002.
Contrastingly, the serious delinquency rate in respect of
subprime loans was at 10.44 percent, which is nearly 20
times higher than that in respect of conventional prime
loans. In the case of riskier loans, the delinquency rate
was at 21 percent. Subprime mortgage loans were the
most default-prone mortgage segment of the home
loan market. The data collected from Freddie Mac
suggests that delinquencies in respect of subprime loans

constituted more than 50 percent of the total seriously
delinquent loans, while prime loans accounted for 25
percent of the seriously delinquent loans.
The rapid growth in the subprime lending market in
extending credit to risky borrowers coupled with the
changes in the economic climate pushed the level of
delinquency loans at the national level to a higher level.
Collins, Belsky, & Case, (2004) observe that the serious
delinquency rates in subprime loans and foreclosures in
the segment almost doubled between the years 1998
and 2001, only to fall off slightly after 2001. Apgar and
Herbert (2005) believe that “higher foreclosures among
subprime loans are a natural outgrowth of the lower
credit quality that characterizes the subprime market.
This effect is reinforced by the fact that collateral value
in the subprime market is generally weaker” (Apgar &
Herbert, 2005).
There were several factors responsible for the onset of
the financial crisis during 2007-2008. In general, the
macroeconomic policies implemented in the United
States and the rest of the industrially advanced nations
were the main contributing factor for the crisis.
Economic policies concerning fiscal adjustments
resulted in a reduction of saving volumes in the United
States. Even the country allowed a not so stringent

monetary policy to be in force for a longer period. “In
Japan, the mix of monetary and fiscal policies distorted
the global economy and financial system” (Truman,
2009).
Easy monetary policies followed by many other
countries including the Asian countries contributed
their part to the global meltdown. “The impressive
accumulation of foreign exchange reserves by many
countries also distorted the international adjustment
process, including but not limited to taking some of the
pressure off of the macroeconomic policies of the
United States and other countries” (Truman, 2009).
With the result, there were increased activities in the
housing sector not only in the United States but also in
many other countries coupled with the increased
availability of market credit resulting in a steep hike in
the stock values and other symptoms of unorthodox
financial practices, ultimately leading to the financial
Tsunami. The role of inadequate financial sector
supervision and regulation has also to be taken into
consideration for the financial Tsunami.
Irrespective of the causes, there are some distinguishing
features of the crises, which need consideration to
discuss the effects and challenges the financial tsunami

has created to affect the global economy in the context
of risk management.
“First, the proximate origins of the crisis were in the
United States” (Truman, 2009), large and the actions of
the financial institutions functioned in the country were
the main reason for the emergence of the crisis.
“Second, if the largest economy in the world, whose
currency and institutions are at the core of the global
financial system, stops functioning, the fact that the
resulting crisis becomes global should not be
surprising,” (Truman, 2009). Finally, it is but natural that
an economic shock, when started in the financial
market, would first affect the real economy. Adverse
impact on the real economy, in turn, would influence
the financial market further, ultimately affecting the
real economy again.
“The reduction in growth has not been limited to the
advanced economies” (Truman, 2009). The reduction
suffered is similar for developed countries, transition
and developing countries and the countries located in
Western Hemisphere. The expected fall in growth for
the years 2008-2010 on an average is 11 percent for the
advanced economies and 12.8 percent for other
economies. Another lesson learned from the crisis,
which is broader in scope is that the globalization of

trade, financial globalization, and globalization in
exchange for labor has united the countries larger than
it was in the earlier century. The repercussion of
extension of this unity is that any economic shock that
influences a larger nation or cluster of nations in the
global financial system will lead to some effect, mostly
undesirable on the remaining nations.
Pitfalls of Subprime Mortgages
There were two important pressing issues from the
perspectives of the borrowers, which emerged as a
result of the subprime mortgage crisis, that apply
equally to subprime auto financing.
1. The first one is the predatory lending practices,
which arise when the borrowers are persuaded to
opt for mortgage loans that did not work in their
best interests. The borrowers would not have taken
up those loans when there was complete disclosure
of the actual terms of the loans and a clear
understanding of the terms. It is the function of a
well-functioning and competitive market to protect
the uninformed borrowers. The problems that
accompanied this issue were:
2. The mortgages were made to be quite complex
with choices of fixed and adjustable rates and
switching from fixed to floating rates over time

3. The mortgage brokers were in an advantageous
position to receive their fees immediately on the
origination of the mortgage and this prevented
most of them to act in utter disregard of their future
reputation
4. Frauds had started in the origination process with
intentional overstating of the incomes by the
borrowers, which ultimately proved to be
detrimental to both the investors and the
borrowers when the loans default.
5. Loan defaults and foreclosures created by the
excessive subprime lending process directly hit
both the borrower and the lender, which resulted
in a lose-lose situation. Lack of thinking in the
direction of modifying the loan terms to such level
which the borrower can manage, to avoid a
mortgage default was another important issue that
was responsible for the economic havoc created by
the subprime lending practices.
Thus, from the foregoing issues relating to subprime
mortgage borrowers, the following pitfalls of subprime
lending have been identified.
•
• The real source of income of the borrower
guaranteeing the repayment of the subprime auto

loan is of prime importance, which was greatly
ignored while granting subprime auto loans
• The absence of regulatory and institutional
infrastructure, which could have moderated the
costs associated with borrower defaults. This
implies the formation of a mechanism to provide
for loan modifications that would avert loan
defaults
• Lack of consumer protection legislation to operate,
when the subprime mortgage market expanded
and loans were provided to rather relatively
inexperienced and uninformed consumer
borrowers such as people belonging to young ages
and minority communities
• Mortgage loans have been traditionally associated
with unavoidable risks, which raised the possibility
of large-scale loan losses. There was no anticipation
of such eventual risks. There were no suitable
regulations, which could govern the creation of
suitable capital requirements by banks and various
other financing institutions indulged in subprime
lending activities. There were also no plans for
dealing with distressed institutions
• The forces of mortgage market innovations and
increased mortgage lending had resulted in a

boom-bust automobile financing cycle, which went
unanticipated by all the agencies and institutions
connected with financial market operations
including Federal Reserve as the controlling
authority.
“Responsibility for the subprime mortgage crisis is more
properly shared among the market participants—
lenders, investors, and the credit rating agencies—since
they all failed to recognize that their actions relating to
subprime mortgage lending were creating a house price
boom that almost surely would end in a crisis” (Spence,
Amez, & Buckly, 2009).
Today, more than ever, organizational leaders are
increasingly faced with the momentous task of steering
their respective organizations to financial independence
and efficiency against a backdrop of repetitive economic
downturns and upheavals (Melton, 2009). The latest
round of economic crisis has not fully subsided financial
institutions have not fully recovered for the recession.
The global economy recedes into a pronounced
meltdown, if not an absolute recession (Rubin &
Buchanan, 2008). The latest round of financial
meltdown thought to have been occasioned by the US
housing market crash and subprime mortgage lending
crisis, have destabilized organizations more than any

other recession since the Great Depression of the 1930s
(Kotz, 2009).
In the US alone, big multinational organizations such as
Merrill Lynch, Bear Stearns, AIG, and the Lehman
Brothers have fallen under the heavyweight of the
ongoing global financial upheavals, sending thousands
of employees into unproductiveness (Lowe-Lee, 2008).
According to the UN News Centre (2009), the latest
economic crisis continues to push the world’s most
susceptible individuals into the periphery of abject
poverty, starvation, and early death. Mass layoffs and
salary reductions have become the buzzwords for many
organizations today.
Many organizations continue to be strong in the face of
economic adversity (Blankenburg & Palma, 2009).
Organizations that continue to stay stronger in this hit-
economy have evidenced a strong relationship between
performance and leadership. As large conglomerates
such as Merrill Lynch and Bear Stearns bows towards
bankruptcy suits and acquisitions, others such as
Proctor and Gamble, Hewlett-Packard, Dell, Google, and
Microsoft persist to register impressive performance
under similar economic conditions (Long, 2009;
Gladkova, 2008).

This kind of scenario calls for a paradigm shift in the way
risk management is looked upon as a key determinant
of the performance of the organizations. Williams
(2009) posited that the world’s assiduous and
conscientious managers are best known in tough
economic times. During the many economic recessions
that have rocked the world’s economic scene,
organizations have been able to stand the test of time
due to efficient risk management, which helped them to
weather the economic storm (Long, 2009).
Consequently, the answer to why some organizations
continue to perform remarkably well while others fail in
hard economic situations may inarguably lie in the
efficiency of their risk management practices.
Conclusion and Recommendations
This chapter presents concluding remarks and
recommendations for further research.
Conclusion
This thesis presented an overview of (i) the
conceptualization of risk faced by financial institutions,
(ii) risk management by financial institutions by
engaging different risk management models and (iii) the
implications of the risk management models in
mitigating the risks of financial institutions. The case
studies on Lehman Brothers and the 2007/2008

subprime crisis provided an illustrative discussion on the
implications of risk management models. The purpose
of the study is to assess the need for financial
institutions to adopt systems for identification,
assessment, and management of risks to their
operations. The study observes that these risks may
arise because of the influence of external and internal
factors. According to the findings of the study, these risk
management systems are considered important to
enhance the ability of the financial institutions to
respond to the rapid and unexpected changes in the
financial markets.
The study finds that the phenomenon of risk
management in the financial institutions center around
two basic issues as to the impact of risk on the
functioning of the financial institutions and how the
institutions can work to mitigate the potential risks
involved in the products and services of the financial
institutions. Risk management in the financial service
industry has assumed greater importance in the wake of
a balanced economic development of the nation. The
study finds that an intrusive risk management system is
very much essential given the concern about the safety
and soundness of the financial service industry.
However, the advancement in the information and
communication technology, the enlargement in the

financial services industry, the ambiguity in the
distinction of banking and non-banking financial
institutions and the creation and offering of numerous
financial service products have put the banking system
in a state of perpetual change and instability. This
requires new perspectives on risk management to cover
the risks of financial institutions.
The study finds that in the years leading up to the recent
financial crisis, some of the regulators have recognized
that and intimated large and complex financial
institutions, that they have not implemented efficient
risk management systems. Despite the advice from the
regulators, these institutions have not taken any steps
to remove these weaknesses in their risk management
systems such as making changes in the system of risk
assessments, until the crisis occurred. In this context,
this thesis studied the issue of risk management under
conditions of financial crisis and challenges faced by the
financial institutions to mitigate risks.
The research was undertaken to achieve the objective
of examining risk management under conditions of the
financial crisis and the challenges faced by financial
institutions. The review of the literature which formed
part of the research and the case studies on Lehman
Brothers and 2007/2008 subprime crisis, has provided

added knowledge on the salient aspects of risk
management under conditions of the financial crisis.
The next objective of the study was to study and make
an in-depth report on the concept of risk, the rationale
for risk management, risks faced by the financial
institutions and methods of measuring risk.
The research-based on the review of the related
literature has discussed these aspects relating to risk
management at length and achieved this objective of
the study. The research covered the classification of the
risks faced by the financial institutions and the methods
of mitigating them. The research had the objective of
making an in-depth study of the deficiencies in risk
management by financial institutions during the recent
financial crisis. The study observed that the risk
management models like VaR and CAPM suffer from
basic shortcomings, which make the risk management
deficient to protect the financial institutions from their
exposure to various risks. The study observed from the
case
study of Lehman Brothers that the company used the
VaR model of risk assessment, which proved ineffective
in assessing the exposure of the company to different
risks resulting from the financial crisis. The study

achieved the objective of reporting on the implications
of the deficiencies in managing risk effectively.
Based on the theoretical observations and findings from
case studies, the research answered the research
question on the salient aspects of risk management by
financial institutions under conditions of the financial
crisis and the deficiencies in the risk assessment and risk
management techniques followed by the financial
institutions during the recent financial crisis. The
question on the effects of the deficiencies in managing
risks effectively by the financial institutions was also
answered through the findings from the case study on
the subprime crisis, as the financial tsunami caused by
subprime crisis has been the result of the failure of risk
management strategies adopted by the financial
institutions.
Recommendations
The research observes that the financial institutions
must not neglect the negative side of the risk
management while drawing the research management
strategies. It is also important that the regulators must
take the potential negative side effects of the modes of
risk management, which they prescribe to the financial
institutions. For instance, the regulators while
prescribing measures like minimum capital ratios must

consider the negative side effects of such a measure on
the capital adequacy of the financial institutions.
Prescribing concrete measures for risk mitigation by the
financial institutions is beyond the scope of this paper.
However, the study suggests that increased awareness
of risk management at the institutional level will be of
great help in improving the cognitive biases in adopting
the relevant risk management model. It is the opinion of
the researcher that adding further regulation in the
quest of taming the financial
market risk may not produce the desired result unless
there is complete awareness among the financial
institutions on the necessity of understanding the
implications of effective risk management to introduce
effective risk assessment models in their respective
organizations. It is also important that the institutions
quantify the impact of various risks as a part of risk
management in individual organizations. However, it
needs to be understood that the quantification cannot
be done with any degree of precision with the help of
available risk management models.
The managers have to expect certain limitations from
the existing models and they have to make suitable
provision for such model risks in their risk mitigation
initiatives. Finally, the experience from the subprime

crisis makes it clear that historical simulations based on
“normal” market environments may prove dangerously
wrong when there are changed market circumstances
and therefore such simulations have to be considered as
having limited predictive power in helping the manager
forming their risk management strategies. It is
necessary to consider the fact that incentive risk arising
from risk-adjusted-performance assessments can result
in significant damage to the institutions’ financial
standing.
Therefore, the managers have to consider these risks
seriously in their risk management proposals. Finally, it
has to be stated that risk management has an important
role to play in helping the financial institutions to avoid
accidental blow-ups. However, it is also important that
the cost of providing for risk management initiatives is
also an important consideration in deciding on the
proper course of action. The study discussed several
areas under the classification of risks, where the
managers have to focus, to ensure that the institutions
engage best risk management practices to protect their
exposures to different types of financial risks.
References

Adler, P. A. & Adler, P., 1987, Membership roles in field
research Newbury Park, CA: Sage, ISBN 978-
0803927605.
Al-Mashari, M. and Zairi, M., 2001, “Revisiting BPR: a
holistic review of practice and Development.’’ Business
Process Management Journal, Vol. 6 No. 1, 10-42.
AMUNC Background Paper, 2008, ‘The Role the IMF can
play in reducing the Fallout from the US Subprime
Mortgage Market’ Asia-Pacific Model United Nations
Conference 2008. Web.
Apgar, W. C., & Herbert, C. E., 2005,.Subpirme Lending
and Alternative Financial Services Providers. Web.
Artto, K., Kähkönen, K., 2000, Unknown Soldier
Revisited: A Story of risk Management, Project
Management Association Finland, Helsinki, 114p
Artzner, P.; Delbaen, F.; Eber, J.-M.; Heath, D., 1999,
Coherent Measures of Risk, in: Mathematical Finance,
Vol. 9, No. 3, July 1999, pp. 203-228.
Banking and Finance, 2000. Hedging Foreign Exchange
Risk – Isn’t is also a Risk. Web.
Beder, T. S., 1995, VAR: Seductive but Dangerous,
in: Financial Analysts Journal, Vol. 51, No. 2,
September/October 1995, pp. 12-24.
Berkowitz, J.; O’Brian, J., 2002, How Accurate Are Value-
at-Risk Models at Commercial Banks?, in: Journal of
Finance, Vol. 57, No. 3, June 2002, pp. 1093-1111.
Berkshire Capital Securities ‘Impact of Subprime Crisis is
Mixed for Asset Management Industry’. Web.
Bernanke, B. S., 2007, ‘The Subprime Mortgage
Market’ (Remarks by Mr. Ben S Bernanke, Chairman of
the Board of Governors of the US Federal Reserve
System, at the Federal Reserve Bank of Chicago’s 43rd
Annual Conference on Bank Structure and Competition,
Chicago, 2007). Web.
Blankenburg, S., & Palma, J.G., 2009. Introduction: The
global financial crisis. Cambridge Journal of Economics,
Vol. 33, No. 4, pp. 531-538.
Boojihawon, D.K., 2006, International entrepreneurship
strategy and managing network dynamics: SMEs in the
UK advertising sector In: Fai, Felicia M. and Morgan,
Eleanor J. eds. Managerial issues in international
business Academy of international business. New York,
NY, USA: Palgrave Macmillan.
Bodnar, G.M. & Gebhardt, G., 1999. Derivatives used in
Risk Managment by US and German Non-Financial
Firms. Journal ofInternational Financial Accounting,
10(3), pp.103-33.

Bogdan, R C and S K Biklen., 1982, Qualitative research
for education: An introduction to theory and
methods. Boston : Allyn and Bacon Inc.
Brueggeman, W. B., & Fisher, J., 2004, Real Estate
Finance and Investments. London: McGraw-Hill
Professional.
Burns, R.B., 2000, Introduction to Research
Methods (4th edition) London: Sage.
Burns, N and K Grove., 1993, The practice of nursing
research: Conduct, critique and utilization (5th ed.).
Philadelphia: Saunders.
Carsey Institute, 2006, ‘Subprime and Predatory Lending
in Rural America: Mortgage lending practices that can
trap low-income rural people’ Policy Brief No 4 Fall
2006. Web.
Cohrssen, J. J. & Covello, V. T., 1989, Risk Analysis: A
Guide to principles and methods for analyzing health
and environmental risks. Washington, D.C.
Collins, M., Belsky, E., & Case, k. E., 2005,. Exploring the
welfare effects of risk based pricing in the subprime
mortgage market. In Building Assets, Building Credit:
Creating Wealth in Low-Income Communities. 138-152.
N. Retsinas and E. Belsky, eds. Cambridge MA: Joint
Center for Housing Studies, Harvard University.

Cotton, Gregory, 2010, Behind Lehman’s multi-billion
dollar risk management failure, Web.
Covello, V.T., D. McCallum, and M. Pavlova (Eds.).
1988. Effective Risk Communication. Plenum Press, New
York.
Creswel, J., 1994, Research Design: Quantitative &
Qualitative Approaches. Thousand Oaks NJ: Sage
Publications.
Crouhy, M.; Galai, D.; Mark, R., 2001, Risk Management,
McGraw Hill: New York
Cutts, A. C., & VanOrder, R. A., 2003. On the Economics
of Subprime Lending. Web.
Denzin, N K and Y S Lincoln., 1998, Strategies of
qualitative inquiry. Thousand Oaks CA: Sage
Publications.
Derman, E., 2003, Model Risk, in: Warwick, B. (ed.), The
Handbook of Risk, Hoboken (New Jersey) 2003, pp. 129-
142
Dorsey, P., 2007. The Five Rules For Successful Stock
Investing. Morningstars Guide To Building Wealth And
Winning in the Stock Market. UK: Wiley & Sons.
Dowd, K., 2002, Measuring Market Risk, Chichester
(West Sussex) et al. 2002.

Dowd, K., 2006, Retrospective Assessment of Value at
Risk, in: Ong, M. K. (ed.), Risk Management: A Modern
Perspective, Amsterdam et al. 2006, pp. 183-203.
Eiteman, D.K., Stonehill, A.I. & Moffett, M.H.,
2000. Multinational Business Finance. USA: Addison –
Wesley.
Eisner, E W., 1991, The enlightened eye: Qualitative
inquiry and the enhancement of educational
practice. New York NY: MacMillan Publishing Company.
Esty, B., P. Tufano, and J. Headley, “Banc One
Corporation: Asset and Liability Management,” Journal
of Applied Corporate Finance, (7)5.
Fabozzi, F. J., & Modigliani, F., 2002, Capital Markets,
Institutions and Instruments Italy: Prentice Hall
Fannie Mae and Freddie Mac, 2004, Separate and
Unequal Predatory Lending in America. ACORN:
Washington, DC.
Feagin, J, A Orum and G Sjoberg., 1991, A Case for Case
Study. Chapel Hill NC: University of North Carolina Press.
Flinders, D.J. and Mills, G.E., 1993, Theory and concepts
in Qualitative Research, Perspective from the field New
York: Teachers College Press.
Gladkova, S., 2008. Google will do well even in a
recession. Web.
GTZ, 2000, ARisk Management Framework for
Microfinance Institutions. Web.
Hoepfl M.E., 1997, Choosing Qualitative Research: A
Primer for Technology Education Researchers, Journal
of Technology Education 9(1).
Hutchinson, Martin, 2008, How Lehman Brothers’ Own
Risk Management Strategy May Cause it to Fail, Web.
India Microfinance News, 2006, Microfinance Risks –
Market Risk – Part 3, Web.
India Microfinance News, 2006a, Microfinance Risks –
Operational Risk – Part 2, Web.
India Microfinance News, 2010, Types of Risks faced by
Microfinance Institutions – Part 1, Web.
Investopedia, 2009. Forward Contract. Web.
Investopedia, 2010, Value at Risk – VaR, Web.
Investopedia, 2010a, Multi-Factor Model, Web.
Investopedia, (2010b). Case Study: The Collapse of
Lehman Brothers, Web.
Investopedia, (2010c). CFA Level 1 – Exchange Traded
Options, Web.
Jorion, P., 2007, Value at Risk: The New Benchmark for
Managing Financial Risk, 3rd ed., New York et al. 2007.

Kendall, L. T., & Fishman, M. J., 1996, A Primer on
Securitization. Cambridge MA: MIT Press.
Kratz, Ellen Florian, 2007, ‘The Risk in Subprime’ Fortune
Article CNN Money.com. Web.
Lincoln, Y., & Guba, E., 1985, Naturalistic inquiry New
York: Sage.
Lofland, J., & Lofland, L. H., 1984, Analyzing social
settings Belmont, CA: Wadsworth Publishing Company,
Inc.
Long, S., 2009. Against all odds: How power leaders
achieve the impossible. Business Leadership Review,
Vol. 6, No.3. Web.
Lowe-Lee, F. (2008). US financial turmoil and impact on
Korea’s economy. Web.
Mallin, C., Ow-Yong, K. & Reynolds, M., 2001.
Derivatives Usage in UK Non-financial Listed
Companies. European Journal of Finance, 7, pp.63-71.
Marshall, C & Rossman, G. B., 1985, Designing
qualitative research (2nd Ed.) Newbury Park, CA: Sage.
Mason, J., 2002, Qualitative Researching (2nd ed.).
London: Sage Publications.

Melton, W.R., 2009, How to eliminate fear of global
economic recession and terrorism. Fix Bay Inc
Publishing. ISBN: 9780578004556.
Merton, R.C., 1995, Financial Innovation and the
Management and Regulation of Financial
Institutions, Journal of Banking and Finance 19, 461–
481.
Merton, R.C. and Bodie, Z., (1995). A Conceptual
Framework for Analyzing the Financial System. Chapter
1 in Crane et al. (1995).
Modarres, M., 2006, “Risk Analysis in Engineering“,
Taylor & Francis.
Morsman, E., 1993. Commercial Loan Portfolio
Management. Philadelphia: Robert Morris Associates.
Patton, M Q., 1990, Qualitative Evaluation and Research
Methods (2nd ed.). Park CA: Sage Publications.
Phillips, A., 1995. Derivatives Practice and Instrument
Survey. Financial Management, 24(2), pp.115-25.
President’s Working Group on Financial Markets.,
2008. Policy Statement on Financial Market
Developments. Washington DC.
Punch, F. K., 1998, Introduction to social research,
Quantitative and Qualitative approaches. London: Sage
publication.
Reyes, M., 2004, Social Research; A Deductive
Approach. USA: Rex Bookstore Inc.
Ritholtz, Barry, 2010. Dick Fuld’s Fanstastic
Revisionism, Web.
Roger Lowenstein, 2008, ‘The Subprime Bust in
Microcosm: The Saga of a Failed Mortgage Security’
International Herald Tribune 2008, Web.
Rubin, J., & Buchanan, P., 2008. What’s the real cause of
global recession? CIBC World Markets Inc. Web.
Saunders, M, P Lewis and A Thornhill, 2003. Research
Methods for Business Students. Harlow: Prentice Hall.
Santomero, A., 1995, Financial Risk Management: The
Whys and Hows, Financial Markets,Institutions, and
Instruments, 4: l-14.
Santomero, A., 1997, Commercial Bank Risk
Management: An Analysis of the Process.” Journal of
Financial Services Research 12(2-3):83-115.
Santomero, A. M. and Trester, J. J., 1997, Structuring
Deposit Insurance for a United Europe. European
Financial Management, 3: 135–154.
Scapens, R. W., 1990, ‘Researching Management
Accounting Practice: The Role of Case Study
Methods’, British Accounting Review, 22, 259-281.

Scott, D. and Usher R., 2000, Researching Education
Data, Methods and Theory in Educational
Enquiry London: Continuum.
Sivakumar, A. & Sarkar, R., 2007. Corporate Hedging for
Foreign Exchange Risk in India. Web.
Spence, M., Amez, P. C., & Buckly, R. M.
(2009). Urbanization and Growth. Web.
Stake, R., 1995, The Art of Case Research. Newbury
Park: Sage Publications.
Taylor-Powell, E. and Renner, M., 2003, “Analyzing
Qualitative Data”, Bulletin G3658-12, University of
Wisconsin-Extension, Cooperative Extension, Program
Development & Evaluation, Madison, Wisconsin, 2003.
Teng, Jiulin, 2010. Lehman Brothers Holdings Inc. (the
text-only version of my case study report for Behavioural
Management Control), Web.
Travis, C. C., E. Crouch, R. Wilson, E Klema., 1987. Cancer
risk management: A review of 132federal regulatory
decisions. Environmental Science and Technology, Vol
21, No. 5, 415 – 420.
Travis, C.C. and Hattermeyer-Frey, H.A., 1988.
Determining an acceptable level of risk, Environmental
Science and Technology, 22(8): 873-876.

Truman, E. M., 2009, The Global Financial Crisis: Lessons
Learned and Challenges for Developing Countries. Web.
Turner, J.R., 1999, The Handbook of Project-Based
Management: Improving the processes for achieving
strategic objectives, 2nd edition, McGraw-Hill, London,
529p
UN News Centre., 2009. No end in sight to economic
crisis for hard-hit developing world – UN Report. Web.
U.S. Department of the Treasury, 2010, Treasury
Secretary Tim Geithner Written Testimony before the
House Financial Services Committee, Web.
VanHorne, J. C., 2004. Financial Management Policy XII
Edition. New Delhi India: Prentice-Hall of India Private
Limited.
Ward, S., Chapman, C., 2003, Transforming project risk
management into project uncertainty
management, International Journal of Project
Management, Vol.21, pp. 97-105.
Watkins, J M., 1994, A Post Modern Critical Theory of
Research: Knowledge and Policy. London: Falmer.
Webster’s Dictionary of English Usage. 1989. Edited by
E. Ward Gilman. Springfield, Mass.: Merriam-Webster
Wheelhouse Advisors, 2010, Ignoring Risk Management
at Lehman Brothers, Web.

Williams, R.B. (2009). Why do some leaders succeed in
tough economic times and others fail. Web.
Yam, J., 2006. Managing Interest Rate Volatility. Web.
Yin, R., 1984, Case Study Research: Design and
Methods. Beverly Hills CA: Sage Publishing.

