


INTRODUCTION Energy is an essential part of our daily
The Importance of Energy
Energy is an essential part of our daily lives, economic development, and social stability.
Reliable and affordable energy is indispensable for industry, agriculture, critical infrastructure,
transportation, health, and modern communication systems. Energy has allowed governments,
public sectors, and private entities to improve manufacturing and services, living conditions,
prosperity, and the well-being of people across the globe. Energy is also a source of power
and influence, which can lead to competition, drive for innovation, and technological
development while presenting one of the greatest challenges for global environmental
security. The demand for energy is expected to increase, albeit more environmentally friendly
energy sources will be utilized. Therefore, uninterrupted access and control over energy
resources to meet growing demand will continue to be a challenge for both developed and
developing countries.
Energy resources, such as oil and gas, are also considered as commodities and financial assets
linking national and international markets. Oil and natural gas are transported via pipelines
crossing national borders, and Liquefied Natural Gas (LNG) and oil tankers are sailing the
world and creating an energy web.2 These energy networks and systems have become a
connecting tissue between countries and continents. Oil and natural gas pipelines serve as a
means of connecting producers and customers, delivering energy to the end users.
The production, transport, and consumption of energy resources are generally based on
supply and demand dynamics determined by market interactions at national, regional, and
global levels. While energy is a large expenditure for importing countries, it is a major source
of income and revenue for producing and transit countries. On the one hand, consumer
countries are concerned with the security of supply. On the other hand, producing countries
are concerned with the security of demand. Transit countries, between producers and

consumers, are interested in becoming an energy hub to negotiate cheaper prices and gain
political leverage.
1.2. Why the Subject Matters
Energy has become an indispensable part of economic development and social stability.
Security of energy supplies remains one of the most critical aspects for maintaining the
western way of life as well as the national security of concerned countries. Thus, energy
security is a “deeply political concept shaped by factors beyond the materiality of energy
systems” and continues to be at the forefront of political, economic, social, technological, and
environmental discussions. Possession of, or control over, energy resource increases the
power and geopolitical influence of nations. In international relations, power is defined as
“the capacity to do things and in social situations to affect others to get the outcome we want.”
In other words,
“It is the ability of one nation to influence the behavior of other nations…A nation’s command
of physical power, notably through its control over primary energy resources such as oil, not
only shapes its economic development but also its national security and military strength.”
Russia’s natural gas supply to Europe has been at the center of a geopolitical clash. Oil
exports allowed for a rapid economic recovery in Russia. However, Marshall Goldman argues
that “natural gas and monopoly control of the gas pipelines…transformed Russia…into a
robust energy superpower with restored political muscle.” Why is building a direct natural gas
pipeline from Russia to Germany so controversial amongst exporting, transit, and consumer
countries and other powers such as the US? For example, if it were construction of a pipeline
from Norway to Germany, the focus would be on the economics and environmental issues, not
over geopolitics. On the contrary, the European-Russia energy relationship, from the very
beginning during the Cold War to today, has been affected by geopolitical considerations due
to Russia’s use of energy relations as an extension of its foreign policy. From the Soviet Union

era to today’s Russia, western decision-makers have always debated whether Russia could use
energy interdependence as an instrument of geopolitical power and influence or if this
relationship is based on market driven supply and demand dynamics. In most cases, this
relationship is driven by both considerations and has evolved over time based on geopolitical
and economic dynamics. Therefore, the views on energy relations depend in the eyes of the
beholder, reflecting either the producer, consumer, or transit countries’ position and interests.
The main question this paper seeks to answer is to what extent Russia could use natural
gas/energy supplies to leverage political outcomes. In other words, under what conditions can
Russia leverage energy power to support its foreign policy objectives? European energy
dependency on imports has increased due to depleting energy resources since the beginning of
the 2000s. Therefore, to what extent Europe is dependent on Russian energy supplies is
another area this paper aims to answer. Russia’s threat of energy flow disruption or the
awareness of this potential cut off could affect Europeans’ sense of security. How have the EU
energy policy and strategy evolved to address increasing geopolitical concerns due to a high
level of dependency on Russia? Could the US and other LNG-exporting countries provide
alternative sources of supply to meet European natural gas demand? What would be the role
of the
Caucasus and Central Asia’s energy resources to becoming a viable alternative to Russian
supplies?
While market dynamics are likely to dominate the energy/natural gas relationship based on
interdependence, I argue that the Soviet Union, then Russia, have used energy relations as a
natural extension of their foreign policy. However, Russia’s ability to create and use energy as
a weapon relates directly to the level of European dependency on external resources, in
particular, energy imports from Russia. Energy security concerns, whether real or perceived,

are directly related to national security and vary by nation according to the extent of their
dependency on a single source. While the Russian foreign and energy policy approach to
Europe has significantly been influenced by realist worldview and ‘zero-sum game’ thinking,
I also argue that Russia is concerned to maintain its market share and reputation as a reliable
supplier of energy to Western Europe, as fossil fuel revenues are critical to support its
government’s budget.
The Soviet Union, later Russia, has become one of the main suppliers of fossil fuels to
Europe, creating a high level of dependency for several countries, especially those in Central
and Eastern Europe and the Baltics, that either were part of the Soviet Union or were former
Soviet satellites. With the independence of former Soviet Republics and increased Western
and Chinese economic relations, Russia has increasingly been dissatisfied and would like to
increase its influence over the former Soviet-space or its “near abroad”,. The Russian
approach to its near abroad is not expected to change in the near future. Additionally, recent
events, such as Russia’s invasion of Ukraine, are driven by more a nationalistic sentiment than
realist thinking. Realist approaches are rational and always monitor balance of power
dynamics using a cost-benefit analysis. On the other hand, nationalist approaches are not open
to reason that makes their actions more dangerous as they tend to take risks. As long as
Russia’s ‘zero-sum game’ understanding continues, it will struggle to preserve influence over
Central Asia and the Caucasus region through diplomatic pressure, covert economic
dominance, and regional
integration efforts.
Central Asia and the Caucasus emerged as another source of energy supplies for global
markets. While Russia has been seeking to assert its influence over the region, Central Asian
Republics and the Caucasus are in search of access to the international markets. Europe,
Russia and Central Asia/the Caucasus represent an energy triangle. The recent events in the

Central Asia and the Caucasus have allowed Russia to increase its influence over the region.
First, Russia’s role in the ceasefire agreement between Azerbaijan and Armenia cemented its
security interests and legalized the deployment and presence of Russian peacekeepers.
Second, Russia has intervened in Kazakhstan after the protests turned into a violent uprising.
Under the premises of the Collective Security Treaty Organization (CSTO), Russian-led
military troops entered the country to restore order. Reports suggest that troops redeployed
after stability was established.
These developments have increased Moscow’s regional standing and supported its objective
to reintegrate post-Soviet space under its sphere of influence. While Central Asia has the
capacity, Russia’s increased power would affect its energy relations with the West. It is not
known if Russia would allow Central Asian and Caucasus energy projects that could both
threaten its market share and its geopolitical influence in Europe. In this context, for the
diversification of energy supplies, to what extent could energy reserves in Central Asia and
the Caucasus region provide a credible resource alternative for the EU’s energy needs, thereby
reducing its dependence on Russia? Thus, Central Asia’s ability to be a source of reliable
energy supply is also reviewed.
The Russia-Ukraine gas crisis in 2006 was perceived as a “wake-up call” for the EU energy
sector. Likewise, the disruption of gas flow in the beginning of 2009 caused a humanitarian
emergency in the Balkans and significant economic problems in Eastern
European countries that rely on the Russian gas flow through Ukraine. The Russia-Ukraine
energy relations are also influenced by geopolitical concerns driven by both cooperation and
conflict. While Russia and Ukraine had disputes in 2006 and 2009 over gas prices, payments,
and tariffs for the transit of Russian gas to Europe, the following Ukrainian conflict resulted in
Russia’s illegal annexation of Crimea in 2014, which was about power not energy.

The European approach to energy relations is driven by liberal thinking. At the European
Commission and throughout Western Europe, creating a single liberalized energy market
through regulatory frameworks would increase competition and open up markets to multiple
suppliers. The European view of interdependence and trade allow nations to address issues by
defining their mutual interests, but have to be reviewed under the light of recent
developments, especially Russia’s invasion of Ukraine. Europe and Russia have mutual
interests in the areas of energy, trade, technology transfer, finance and joint projects that
require cross-border cooperation. The European liberal approach that seeks to increase trade
and economic relations in multiple areas, has not supported regional stability and failed to
improve democratization in Russia. These recent examples provide evidence that it may be
time to revisit the role of interdependence in liberal thinking.
Additionally, the differences in the EU member states’ understanding and articulation
of energy security have been a challenge for the development of a common energy policy.
The European Commission’s efforts to regulate this relationship, develop an EU Energy
Security Strategy, common Energy Policy, and open up the European energy market for
greater competition have been successful albeit they have limits as in the Nord Stream 2 case.
While Russian gas supplies continue across the borders, diverging national interests of
member nations will shape pipeline politics even though they are not aligned with the
European policy and regulations. In my view, Europe will remain vulnerable against Russia’s
destabilization strategy using energy supply, especially natural gas, to leverage political
outcomes at the time of its choosing.
While Europe started getting energy resources from external sources in the second half of the
20th Century, the EU has become a net energy importer of crude oil, natural gas, uranium, and
solid fossil fuels, since the early 2010s. In 2018, Russia provided 30% of oil, almost 40% of
natural gas, and 40% of coal to Europe. The EU is likely to remain one of the main energy

markets for Russia over the next two decades. This high level of energy imports from Russia
creates an asymmetric interdependency that can be exploited by Russia for geopolitical
purposes at a time of its choosing. A sudden disruption of a high proportion of the energy
flow, in particular natural gas, would have tremendous economic, social, and political
setbacks for the European countries that are members of the European Union and NATO.
Finally, I also argue that diversification of energy resources could reduce vulnerability of
European countries and the EU/NATO members, thus lessening Russian influence. While
Europe is in search for alternatives, Central Asia and the Caucasus have emerged as energy
producers and have promising potential for the diversification of resources and routes for
European energy security, especially after the Soviet Union disbanded. Due to their vast
energy resources, Central Asia and the Caucasus have been one of the most important areas of
Russian foreign and energy policy since the dissolution of the Soviet Union. Central Asia and
the
Caucasus region are also important for European and Asian neighbors with potential non-
Russian, non-OPEC energy resources.
1.3. Contribution to the Literature
This paper contributes to the literature by applying competing theories to the existing
challenges at different levels of actors: supranational, national, and industry (i.e., European
Commission, member states, multinational corporations and industry), highlighting the
differences between the EU, member states, and industries as well as their priorities in
understanding and approaches to energy security. Additionally, it provides insight on how
parties involved in an asymmetric interdependence, such as Russia and its European
counterparts, might have contrary views on the same relationships. This interdependence
relates to how energy could be utilized as part of an instrument of national power to deter, if
not to influence, decisions and political outcomes on other parties. Russia, an emerging energy

powerhouse, has been exploiting European energy dependency and using energy as part of its
hybrid warfare tools aligned with its long-term strategy to paralyze the EU, NATO, and
Western decision-making.
Energy security is defined as a “wicked problem that is not aligned with traditional linear,
analytical approaches.” European-Russian natural gas relations involve multiple actors, such
as states; non-state actors such as multinational corporations; and state-owned enterprises,
international and supranational organizations. The interdependence between Europe and
Russia encompasses a complex relationship between producer, transit, and consumers at
multiple levels with converging and diverging interests that even changes over time. The
debate over energy interdependence and reliance on Russian energy supply goes back to the
Cold War period. Goldman argues, “Reagan understood the geopolitical risks that such a
pipeline would create…Germany might someday find itself held hostage to Soviet demands.”
Europeans, led by Margaret Thatcher, ignored the sanctions and exported compressors and
pipes-xii necessary to build the pipeline network. Soviet gas was delivered to Austria in 1968,
followed by an agreement with West Germany in 1970.17 Today, a vast gas pipeline network
has been developed since the first Soviet-European agreement in the middle of the Cold War,
and Russian gas exports to Europe have grown significantly “over five decades to become
(along with gas from the North Sea) one of the foundations of Europe’s energy economy.”
There are two competing views that posit to explain European-Russian energy relations,
especially the supply of natural gas that is highly dependent on pipeline infrastructure. The
first view argues that energy trade and international economic cooperation have a positive
influence on international relations, and gas flow remained stable over the last five decades,
surviving several crises and strategic shocks including “…the fall of the Soviet Union and rise
of Russian President Vladimir Putin’s authoritarian state; outright warfare in Ukraine and
elsewhere; massive experiments in deregulation; and the rise of environmentalism.”19 This

view is aligned with the liberal, market-driven, and pluralist approach that suggest
interdependence and economic relations will contribute stability that would allow
uninterrupted flow of natural gas. On the other hand, the realist view suggests that the energy
relation is a zero-sum game, linking it with national security of the countries involved and
balance of power dynamics between producing, transit, and consumer countries. The EU,
NATO Alliance, and the member nations have been troubled by Russia’s attempt to use energy
to leverage political outcomes against countries in the former Soviet Space, in particular
Ukraine and Georgia. Russia could also use energy/natural gas supply to further create a
wedge amongst European countries that are members of the EU and NATO.
The neoliberal and realist approaches, as well as the Copenhagen School, were used to
explain the European-Russian energy relationship in the literature. However, a multipronged
approach that focuses on the EU, member states, and industry, with different perspectives and
diverging priorities was not provided. The EU, as a supranational international organization,
has ambitions to establish a single energy market based on liberal principles. The member
states of the EU maintain power and influence in deciding on their energy mix and energy
contracts that are driven by both liberal and realist schools of thought. The member states
have diverging views and different schools of thought in regard to European energy
interdependence to Russia; while some focus on market dynamics, others view it as a
vulnerability and a zero-sum game.
From the Russian perspective, priorities are aligned with foreign policy objectives albeit
Gazprom abides certain market regulations. This paper would provide an analysis that could
help Wester policy-makers and energy experts to identify their policy priorities to counter
Russian strategy. The subject of accessing a stable, abundant and uninterrupted supply of
energy has been perceived as an existential threat especially by those countries in Central and
Eastern Europe. The threat narrative was used by the political elite as well as government

representatives, securitizing the energy security issue due to the high level of European
dependence on Russian natural gas delivery. The sensitivity and vulnerability interdependence
of these countries could be perceived as a national security concern. Central and Eastern
members of the EU especially perceive their vulnerability as a vital security concern that
brings the securitization aspect, the Copenhagen school’s approach to energy security into the
discussion. Securitization of energy security will be discussed; however, in-depth analysis of
the core elements of the Copenhagen school’s approach is not included in the literature
review. At the same time, newly independent countries of the Central Asia and Caucasus
region have had limited success in developing greater cooperation to establish a
corresponding foreign and security policy approach that could allow them to develop a
coordinated and mutually acceptable strategy to transmit their energy resources to
international markets. While they have a common history, shared geography, intertwined
social and political structures, there are several reasons for this failure, such as competing
national interests, a struggle for leadership, and a lack of supporting institutions affecting
interstate relationships amongst regional countries. There are no mechanisms to curb
competition amongst regional countries. Central
Asia is a landlocked region, its geography has increased costs of building pipelines, and the
accomplishment of an agreed regime/structure has been another factor for the failure of the
development of export pipelines. The drivers for competition ranged from achieving energy
security to geopolitics, as well as domestic dynamics driven by autocratic leadership,
nepotism, and corruption.
The ethnic, cultural, religious and language convergences and divergences of Central Asia
and the Caucasus regional countries are considered as part of the key factors for social
instability, and civil and interstate wars. Other factors include, albeit limited but continuous,
Russian influence and race for domination and control of the region by internal and external

stakeholders including China, the US, the EU, Turkey, and Iran. As a result, the absence of an
energy security regime in Central Asia and the Caucasus region, as well as a lack of
international institutions, have amplified the emergence of power politics and the balance of
power dynamics.
1.4. Energy Security – An Overview
Energy Security is a contested, multifaceted, highly politicized, and one of the most disputed
issues in international relations. While energy security is widely discussed and debated in
governments, international organizations, and academic circles, there is no agreed definition.
Recent studies indicate that more than 80 different definitions of energy security exist; some
of these will be listed in the following chapter.22 One of the experts, Daniel Yergin, defined
energy security as “the availability of sufficient supplies at affordable prices.”23 The
International Energy Agency’s (IEA) definition includes:
‘uninterrupted availability’ of resources, such as oil and gas, highlighting the
differences between short and long-term aspects. While “long-term energy security
mainly deals with timely investments to supply energy in line with economic
developments and environmental needs…short-term energy security focuses on the
ability of the energy system to react promptly to sudden changes in the supply-demand
balance.” Owing to its multi-dimensional nature, there is no widely accepted and
internationally agreed upon definition of energy security.
The views on the definition of energy security differ based on one’s place in the supply chain
from production to transit and receiving countries. Energy Charter Secretariat highlights that
“the most distinctive difference in energy security concepts is found between energy importers
and exporters, resulting from the emphasis on security of supply for the former and security of
demand for the latter.”25 Additionally, there are internal differences amongst the energy
exporters/producing countries such as the Organization of the Petroleum Exporting Countries
(OPEC) and non-OPEC countries such as Russia, Kazakhstan, Azerbaijan, Brunei and
Malaysia. It should also be noted that exporters/producing countries have both demand and
supply security concerns considering their domestic consumption. While producing and

consumer countries differ in motivation, energy security is reliant on the context and is highly
dependent on infrastructure, especially oil and gas pipeline systems, that allows transit
countries to influence supply and demand dynamics and physical security.
Energy security concerns are also derived from different risk factors including manmade or
natural disasters, geopolitical tensions, conflicts, and accidents as well as other issues such as
resource nationalism, price volatility, and high-level of dependency to a single source. All
these concerns create vulnerabilities and anxieties for energy consumers over the security of
supply. Based on these factors, Pascal and Elkind argued that the simple terms affordability
and dependable supply are not sufficient to define energy security. They suggested that “[T]he
notion of energy security hinges on perspective: the temporal choices we make and the way
we balance economic, national security, and environmental concerns.” For example, the rapid
changes in energy prices, whether it is a sharp increase or a decline, not only threaten energy
markets but also destabilize the global economy. It was argued that the oil price peak of $148
in 2008, driven by speculative actions of investors, might have contributed to the economic
recession. Finally, the energy relationships between producer and consumer countries are also
open for exploitation as experienced during the recent Russia- Ukraine gas crisis in 2006 and
2009. The increased importance of supply security might allow producing countries to
weaponize energy dependency to dictate political or security related impositions on transit and
consumer countries.
1.5. Dimensions of the Energy Security Concept
Energy has been a central element of human activities from primitive human groups to more
industrial societies. Klare argues that “without adequate supplies of basic fuels, a complex
society cannot maintain a high rate of industrial output, provide a decent standard of living to
its citizens, or defend itself against computing powers.” While energy resources are perceived
as financial commodities, oil has been distinguished for its role in the economy and way of

life in the West. With the recent movement to replace coal consumption, natural gas has
become the second largest energy source for Europe following oil since the mid-1990s. This
has become a concern due to the increasing role of natural gas in Russia-European energy
relations. The definition of energy security remains vague and does not cover every aspect of
the concept of energy security. The energy security concept encompasses the following
additional dimensions: first, critical infrastructure protection, including physical security
aspects from production and the supply chain to the end users; second, access to energy
resources including investment, exploration, development and production; third, preserving a
coherent energy security system that includes national policies and international organization
to address disruptions and other emergencies in a timely manner; and finally, maintenance of
trust that encourages long-term investment for exploration and development of infrastructure
to move resources to the end users. Taking into consideration all these dynamics involving
states, stateowned enterprises, multinational corporations and international institutions
increases the complexity of energy security.
The concept of energy security has evolved over time. Initial energy security concerns
focused on providing supply to armies, addressing crises such as the 1973/74 oil embargo, and
disruptions of gas supplies, and stabilization of oil prices to ensure affordability. The
evolution of energy security is explained by the four ‘A’s of energy security: availability,
accessibility, affordability and acceptability. Further analysis investigates the following
questions: security for whom? Security for which values? From what threats? Cherp and
Jewell also provide alternative approaches that focus on vital energy systems and their
vulnerabilities as well as political construct and securitization of energy security. Dannreuther
argues that “energy security involves differing and unequal relations of political power,
divergent understandings of justice, fairness, and conflicts over differing values.”33 These
views further emphasize the complexity of energy security as a concept and its relations with

a wide variety of actors that include state and non-state actors such as supranational and
international organizations, as well as multinational corporations with either diverging or
converging interests depending on the situation.
1.6. European Energy Security
The EU has become one of the major importers of energy over the last two decades. While
energy security appears an abstract concern, the EU is vulnerable to energy shocks due to its
dependence on external energy sources, especially natural gas. The European Energy Security
Strategy highlights that “The European Union's prosperity and security hinges on a stable and
abundant supply of energy.” However, the uninterrupted flow of energy is not an exclusive
requirement for the EU member states; both developed and developing countries need energy
to sustain their economic growth and prosperity while maintaining social stability.
During the Cold War, the Union of Soviet Socialist Republics (USSR) was reputed as being a
reliable supplier of energy to Western Europe. However, since the collapse of the Soviet
Union, this situation has changed owing to the “complex relations between Moscow and its
former republics, most of which were heavily dependent on Russian energy.”35 With the
ascension of Central and Eastern European countries to the EU membership, the energy
dependency to Russia has significantly increased. Baltic and other CIS countries were subject
to price increases and supply interruptions during the 1990s. Recent developments indicate
that energy security has become increasingly important for European countries, members of
the European Union (EU), and the North Atlantic Treaty Organization (NATO), in regard to
their economy, industry, society, and sustainability of daily life of their people.
European energy dependency has increased with the decline of domestic production and the
situation has worsened with the extension of the European Neighborhood policy to include
Ukraine, Belarus, and Moldova in 2009. The EU introduced the Third Energy Package

consisting of the separation of energy supply and generation from the operation of
transmission networks (unbundling), non-discriminatory access to energy infrastructure, and
independence of national energy regulators. These regulatory measures and increasing
environmental concerns brought political pressures on development and control of the
pipelines. This resulted in an increasing Russian resistance to the EU’s energy policies and
development of more assertive actions against the former Soviet space. Thus, the US and
Western concerns over the political consequences of high-level European dependence on
Russia has gained more validity compared to the Cold War period.37
Energy-related relationship is fundamentally an interaction between suppliers and consumers;
it could also include a group of consumers such as members of the EU with diverging national
interests. While there is agreement on the security of supply, views differ significantly over
the concerns of the securitization of energy security. EU member states agree upon several
key issues such as intensifying cooperation, strengthening emergency mechanisms, sharing
risk assessment data, protecting critical infrastructure, increasing incentives for renewables
and coordinating energy policies. In this regard, the Juncker Commission identified a resilient
“Energy Union” as one of their top ten priorities when they took office in 2014. After a year-
long consultation, the Commission adapted an Energy Union
Strategy that “has five dimensions:
- security of supply, solidarity and trust
- a fully integrated energy market
- energy efficiency
- decarbonization of the economy, and
- research, innovation and competitiveness.”39
A unified EU approach to energy policy, especially towards Russia, has evolved over the last
two decades albeit significant differences remain between member states. European-Russia

energy relations, especially natural gas, have political, institutional, legal and regulatory
dimensions that involves “social-technical assemblages, infrastructure, commercial
transactions, and contractual relations.”
Increase in energy demand and security of energy supplies have become integral parts of
national security for EU members with a high level of dependency to a single supplier. The
EU has been seeking ways to compel Russia closer to its perspective on energy relations and
to diversify energy resources to reduce high level of dependency to a single supplier. The
Caspian region countries, Azerbaijan, Kazakhstan and Turkmenistan, with proven oil and gas
reserves are identified as potential suppliers. Central Asia and Caucasus countries with vast
energy resources have been exploring transmission networks to access the international
markets in order to turn these valuable reserves into benefits to support their economic and
social development.
Looking into all the parameters of the Normandy Index: from climate change, economic
crisis, hybrid threats, terrorism, violent conflicts, cybersecurity, disinformation, fragile states,
and trans-border crime to weapons of mass destructions, the EU is “being more at risk in the
area of energy security than the rest of world.”
Figure 1: The European Union Global Strategy vs Eleven Threats
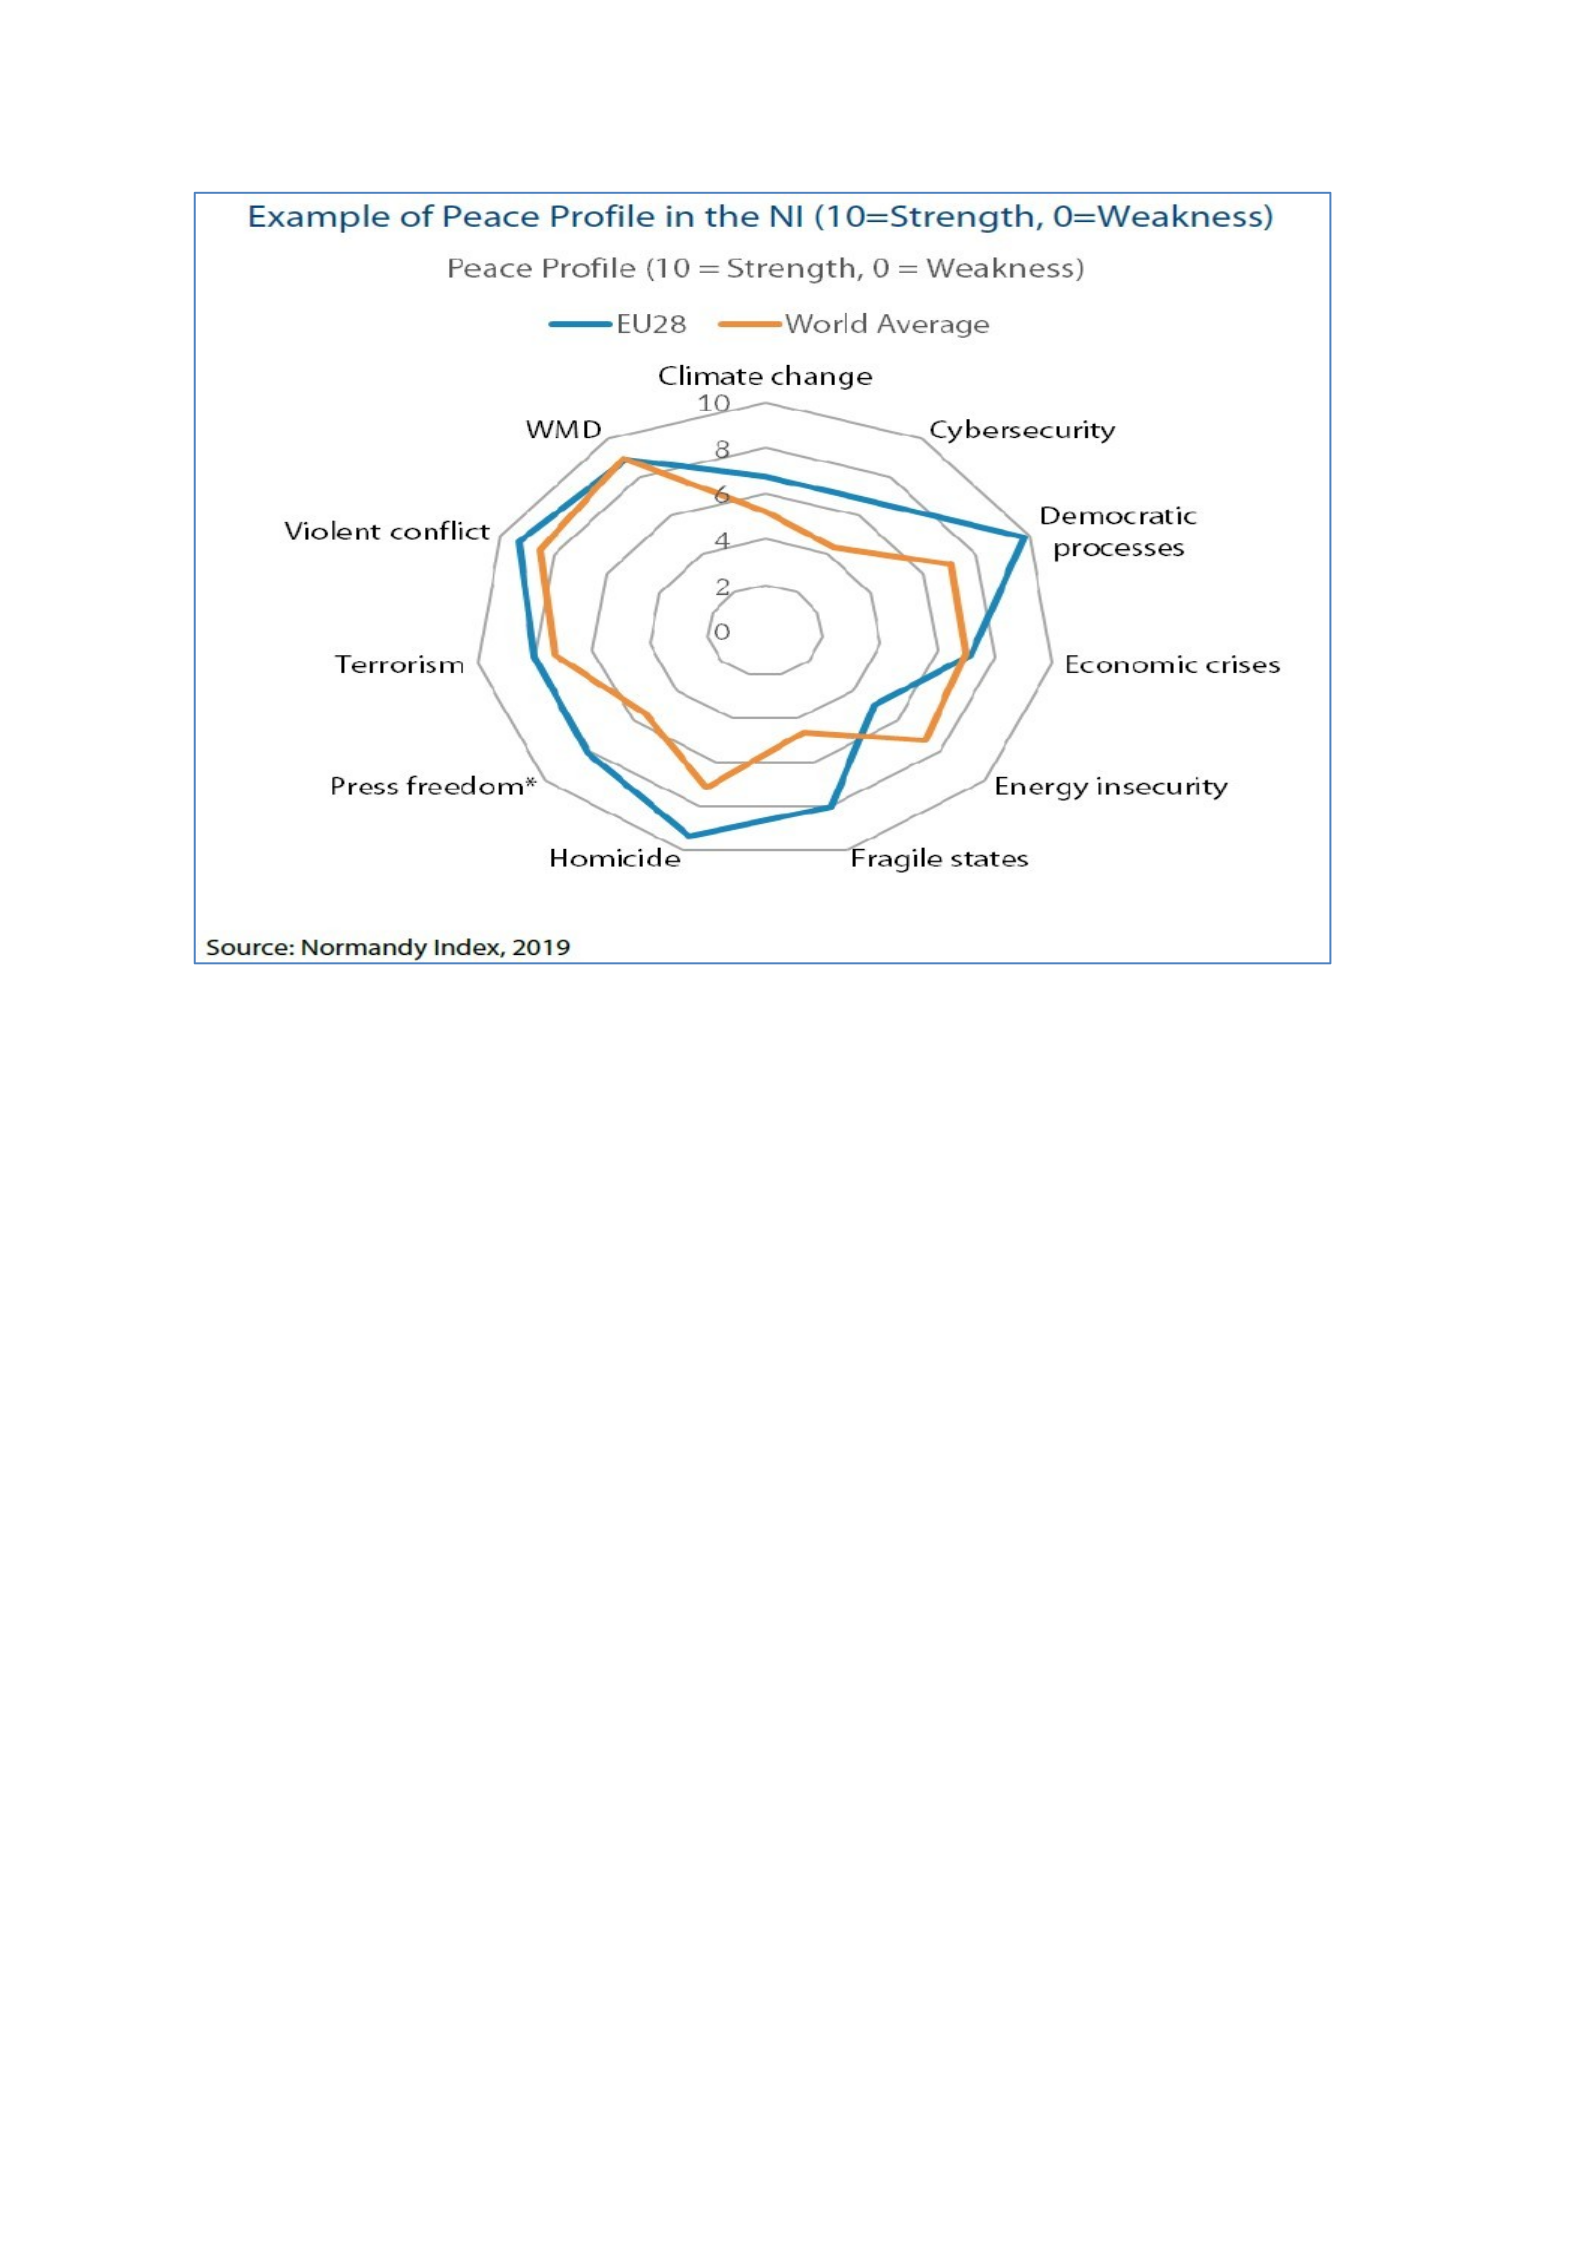
Source: European Parliament, “Mapping Threats to Peace and Democracy Worldwide,” Introduction
to the Normandy Index,
1.7. Russia – An Emerging Energy Power
Russia’s relationship with the West has been increasingly complex and deteriorating since the
beginning of the 21st Century. Russian foreign policy has increasingly been assertive, driven
by the balance of power and sphere of influence approaches influenced by a zero-sum game
geopolitical mindset. Putin has continued to rely on Russia’s vast energy resources such as oil
and gas as well as pipeline networks, to gain/regain Russia’s influence around the world and
uphold its aspirations for great power status. Russian foreign policy, reinforced by its energy
policy and strategy, supports Putin’s ambitions to strengthen Russia’s standing to balance
American power.

Russian foreign policy is closely intertwined with its energy policy. “The objective of the
energy policy [is]…to maximize the effective use of natural energy resources and the potential
of the energy sector to sustain economic growth, improve the quality of life of the population
and promote strengthening of foreign economic positions of the country.”46 Unlike Iran and
Venezuela, Russia has not overtly threatened supply disruptions to achieve political ends.
However, Russia has taken steps to use energy “resources as a political tool to either punish or
coerce its customers.” These measures include: consolidation of state control over energy
resources; establishment of control over transit pipelines and distribution networks; and, using
coercive and punitive measure such as threat, price hikes and disruptions. Thus, disrupting
natural gas supplies is one method of utilizing energy resources for political power. Russia’s
relations with the affected parties, before and after the incident, such as the gas disruptions to
Ukraine in 2006 and 2009, require further analysis to determine whether any coercive actions
were taken.48 The interaction between Russian foreign and energy policies has evolved over
time and it is argued that “…the Nexus between economic capabilities and strategic ends has
influenced Putin’s thinking since even before his ascension.”
In the mid-2000s, Russia regained economic strength, owing to high oil and natural gas
prices, and began seeking ways to increase its sphere of influence in the post-Soviet space.
Although the Russian leadership denied using energy as a ‘weapon,’ its use of gas and oil to
seek influence around the world was proven with its actions in Ukraine. Renz and Smith argue
that “…during the post-Soviet era, Russia has more than once felt the need forcefully to exert
its position in the post-Soviet region (by military means, but also by using the ‘energy
weapon,’ enforcing trade deals, regional integration, Eurasian civilization arguments,
educational influence, promotion of Russian language, etc.)” Russia has been exporting oil,
natural gas, coal, and nuclear material to Europe as one of the main suppliers. In this context,
natural gas differs strongly from oil in its physical and political characteristics, and

uninterrupted natural gas supply and determination of pipeline routes have become the most
critical issues. While the EU focusing on supply security, Russia emphasized demand security
by obtaining long-term contracts as well as acquiring and controlling European/Eurasian
pipeline networks and other downstream assets.
1.8. Central Asia/Caucasus and New Geopolitics of Energy
Central Asia and the Caspian region have emerged as one of the key areas of the world’s
proven oil and gas reserves. While these hydrocarbon reserves are relatively small compared
to the rest of the world, “they are considered of major geopolitical importance by external
powers, as they are not controlled by the Organization of Petroleum Exporting Countries
(OPEC) or by the Russian Federation.” Central Asia and the Caspian region is landlocked;
transporting oil and gas is complicated due to geopolitical, financial and technological
reasons. Therefore, availability of these energy supplies for the EU and other energy
consumers such as China depends on the development of export and transportation
infrastructure connecting growing energy outputs to international markets. The capacity of
Central Asia to provide alternatives for Russian energy has resulted in both cooperation and
competition between and amongst regional countries as well as other stakeholders such as
Russia, China, Turkey, Iran, and the EU.
While geography and energy infrastructure are presented as two of the key obstacles for
access to international markets, there are other fundamental challenges resulting from the
historical, economic, demographic, and most importantly geopolitical experiences of regional
countries. The Central Asia and Caucasus countries recently gained their independence
following the collapse of the Soviet Union, and they are highly dependent on Russia.
Additionally, these countries do not possess institutions, experiences, technology, and most
importantly financial resources to develop large energy projects. They rely on Western
countries, financial institutions, and private industry with technology and know-how. The

involvement of states, multinational corporations, financial institutions, and state-owned
enterprises further complicates the problem.
Central Asia and the Caucasus have witnessed a geopolitical struggle between Russia and the
West in determination of energy transportation routes since the late 1990s and early 2000s.
For example, Russia was critical of the Baku-Tbilisi-Ceyhan (BTC) pipeline project, stating
that it is a political venture rather than an economic one that aims to isolate Russia and Iran.
The Kremlin argued that existing pipeline infrastructure through Russian territory would have
been much cheaper for the Western consumers. The BTC pipeline became operational in
2006; it connects Baku, Azerbaijan to Ceyhan, Turkey on the Mediterranean coast, passing
through Georgian territory. Without the U.S. backing, BTC could not be constructed. The US
and the EU proposed several energy routes, such as the Nabucco pipeline project, which was
similar to the BTC pipeline, bypassing Russian territory. This project was “weakening both
Russia's monopoly in Europe and its monopsony in Central Asia.”54 Russia, using a state-
owned company, Gazprom, initiated a competing project called South Stream. At the end, the
Nabucco pipeline project did not materialize while the original South Stream changed
direction and became the Turk Stream project. Russia sees its foreign and energy policies as
closely intertwined and economic aspects can be sacrificed for political objectives to ensure
that it can continue to wield its power to influence energy routes, domestic and international
affairs of
Central Asian countries, as well as its relations with Europe.
1.9. Methodology and Paper Structure
In support of this study, qualitative and quantitative data were collected from the following
sources: The International Energy Agency (IEA), the Energy Information Agency (EIA), IHS,
the European Union, BP, Gazprom, and the Oxford Institute for Energy, as well as other
academic studies. The combination of qualitative and quantitative data allows in-depth

exploration of energy relations between the European Union and Russia. The analysis is
supported by face-to-face interviews with individuals from some of these organizations such
as IEA, IHS, BP, and the European Union. The data presented in this paper aims to explain
cause and effect relationships in the arguments, and the findings are depicted by using
supporting graphs, maps, tables and relevant charts as required.
The main question this paper seeks to answer is to what extent Russia could use natural
gas/energy supplies to leverage political outcomes in Europe. The most critical aspects of
energy relations, interdependence and diversification, have been at the heart of energy
security and are the focus of this paper. In this regard, a review of different aspects of the
main question will be provided: To what extent is Europe dependent upon Russian natural
gas? Under what conditions can Russia leverage economic/energy interdependence for the
purposes of national security? As Russia remains one of the main suppliers of energy, why are
natural gas pipelines/networks so important for exporting, transit, and consumer countries?
Additionally, to diversify energy supplies, to what extent energy could reserves in Central
Asia and the
Caucasus region provide a credible resource alternative for the EU’s energy needs, thereby
reducing its dependence on Russia.
While overall energy security issues have been studied to explain changes in energy mix,
consumption, and evolution of European energy policies, the main focus remains on natural
gas reserves, production capacity, and pipeline networks due to the high level of competition,
politicization, and securitization of the overall natural gas system. Pipelines account for 78%
of natural gas trade while the rest transported as liquefied natural gas (LNG) via ocean going
tankers, and their “infrastructures are extremely costly to build and require long-term horizons
and predictable economic and political context.” Therefore, while the energy security analysis
of European countries includes fossil fuels, oil, gas, coal, nuclear, and renewables in energy

mix, the focus will be on natural gas, especially on pipeline systems and energy distribution
networks. The analysis also focuses on policy changes over time such as
Germany’s decision to phase-out nuclear power and coal power plants that affect Germany’s
energy mix and to some extent other EU members with significant consequences on their
dependency to external energy sources, especially on natural gas.
The following three components are studied: the first component is the review of European
Union energy dependence with a particular focus on Russia. This review will include whether
European-Russian energy relations could be defined as mutual or asymmetric
interdependence; vulnerability and sensitivity analysis of the EU; and select members’
relationship with Russia as a single point of failure. How has this energy interdependence
evolved and how will it shape the European-Russia relations in the future? In this context, the
following areas will also be investigated: to what extent will energy security concerns become
a national security priority for the EU member countries? What is the role of a transit country?
How did the state’s role in the gas trade evolve? Will there be regional/country differences in
the EU based on geography and their level of dependency to a single source? And how will
these differences affect the EU’s approach to Russian energy/natural gas supply?
The EU has been attempting to regulate energy trade, develop policies and set rules for
market structures. A Third legislative Energy Package for an internal EU gas and electricity
market was adopted in July 2009. Directive 2009/73/EC provides rules for the transmission,
distribution, supply, and storage of natural gas. The package covers areas such as
“unbundling,” “independent regulators” and “cross-border cooperation” aimed at limiting
Russian influence by separating energy supply and generation from the operation and
transmission networks.57 How was European energy policy evolved and shaped? What were
the underlying concerns and challenges over time? Are these efforts and market-based
principles sufficient for European energy security for the 21st Century? How will Russian grey

zone activities affect the EU and NATO’s cohesion, and to what extent are individual
members of the EU vulnerable against Russian coercion?
A combined historical literature review and a case study - Nord Stream II – discusses the
underlying reasons for supporting and opposing views, different viewpoints between the
Eastern/Central and Western European countries. This will be followed by an analysis of the
Russia-Ukraine crisis that focuses on long-term Russian strategic objectives to diversify
export routes by circumventing Ukraine through new pipelines, Nord Stream I-II, Blue
Stream, and Turk Stream.
The following hypothesis is reviewed to explore European-Russia energy relations from a
European perspective:
- H1: The decline in European domestic production and growing consumer demand
increases EU member states’ dependency on Russian natural gas and pipeline
networks, making them more vulnerable against Russian coercion, ensuring to a
more assertive Russia. The higher the European dependency, the more Russia has
the ability to use energy power to influence political outcomes. Thus, Russia
exploits European energy vulnerability to leverage political outcomes and uses
energy as a weapon.
Russia is the largest supplier of energy resources to Europe. While there are alternatives for
oil supply, natural gas transported via pipelines is difficult to diversify in case of a longterm
disruption due to political, economic, technological, or other reasons. In this context, the
following areas will also be explored: the higher the Russian control of gas and oil pipeline
networks, the less leverage Europe has on Russia; the more dependent European countries are
on a single energy source, the less secure they feel; the more diversified the European energy
resources, the less vulnerable against energy supply disruptions; the more alternative energy
resources are available for Europe, the more competitive pricing is available; the more

cooperative/cohesive within the EU members, the less vulnerable from Russian coercion.
The second component will focus on Russia’s natural resources, oil and natural gas, and its
dependency on European markets. Russian natural gas supply to Europe is not new. In this
part, I will cover how Russia-European natural gas relations have evolved since the 1960s,
including the Cold War period. Energy income has been very important if not vital for the
Soviet Union and later Russia’s economy. Income through energy exports has been a subject
for controversy as the Soviet’s, then Russia, used these resources for defense procurement,
supporting its assertive actions that undermine the liberal world order; achieving Russia’s
global ambitions to become a great power; and providing a lifeline to first Soviet and now for
Putin’s regime.
Russia’s natural gas reserves, production and distribution networks are also very important
for its domestic consumption, sustaining economy and growth as well as daily lives of the
people. Without exports to European markets, domestic production could falter and might not
be supported due to high level subsidies for Russian market. While energy inputs are so
crucial to its economy and regime survival, under what condition could Russia use energy to
leverage political outcomes in Europe? Looking from the Russian perspective will allow a
comprehensive assessment supported by the following hypothesis:
- H2: Russia is dependent on energy revenues in particular from Europe that has the
largest share in oil and gas exports. Moscow views energy demand security as the
foundation of European-Russia energy relations while maintaining asymmetric
energy interdependence through high-level dependence of EU member states to a
single source. The higher the Russian dependence on access to European markets,
the more Russia seeks control over pipeline networks and to increase its influence
over the transit countries, its near abroad, and European consumers.

Energy markets have become very competitive. Cheaper natural gas delivery to European
markets is key for Russia to maintain competitive prices thus requires construction and
control of the pipeline networks as well as long-term contracts. In this context the following
areas will also be investigated: the cheaper Russian natural gas, the less desire European
countries will drive for diversification; the higher the energy production and export, the more
income for the Russian economy; the higher the Russian oil and gas revenues, the higher the
political support for Putin his power vertical; the more diversified Russian gas and oil
markets, the less affected Russia will be from US and European sanctions.
The analysis of Russia-European energy relations will be followed by a study of Central Asia
and the Caucasus capacity to contribute to energy security for Europe. This part focuses on
the availability of Central Asia’s energy resource at an affordable price. The availability of
energy resources depends on the level of fossil fuel reserves in Central Asia and the Caucasus.
The affordability is linked with several factors including required investment for exploration
and development of transport pipelines as well as the level of cooperation amongst regional
countries. The level of cooperation amongst regional countries depends on their historical,
social, economic and energy, political, and security interests, but is also linked to their
structural relations with Russia.
Energy reserves in Central Asia and the Caucasus region could provide a credible resource
alternative for the EU’s energy needs, thereby reducing its dependence on Russia. Therefore,
the third hypothesis aims to study the energy reserves and transmission networks from Central
Asia and the Caucasus to Europe in order to become a viable alternative:
- H3: Central Asia and the Caucasus region has sufficient oil and natural gas
reserves that could provide alternative source of energy. The higher the capacity of
central Asian Republics to access international/European markets, the more they
have the potential for diversification by providing alternative energy supplies.

The EU is also concerned with political stability, human rights, and international democratic
standards of suppliers; the better the political stability and democratic institutions in regional
countries, the more they can be an alternative supply source. Central Asia and the Caucasus
region have sufficient energy resources. However, access to international markets has been a
challenge due to geography and lack of infrastructure. Therefore, the following supporting
areas are also considered to ensure comprehensive research is conducted to explore the
problem: the higher the oil and gas production of Central Asia, the more developed the
pipeline system, the more Central Asia can serve as an alternative; the more price competitive
Central Asian energy is, the more likely it can be an alternative.
Recognizing that one size fits all is very difficult for Central Asia and the Caucasus, so the
EU, a regional entity itself, adapted a three-prong approach: bilateral, regional, and wider
regional. Energy relations along these lines are based on mutual cooperation, cost-benefit
analyses of diversifying energy networks, while encouraging political stability and economic
prosperity through regional cooperation. The findings shed light on whether the
diversification of energy supply sources, such as the building of a natural gas pipeline through
the Southern Corridor, increases European supply security.
The EU approach to the region is based on two principles: first, coordination of EU policy in
areas such as good governance, natural resources, security, and transportation; the second,
seeking synergies in specific areas such as energy, security, and sustainable development.
While several other factors drive the EU’s approach, energy security represents one of the
priorities of the EU strategy for the region. A closer energy relation with Central Asia and the
Caucasus will allow the EU to access non-OPEC and non-Russian energy
resources.

The final component of this paper is conclusions that focuses on the findings of previous
chapters that examines the energy relationship among the EU, Russia, and Central Asia and
the Caucasus.
The dependent variable of this study is the Russia’s ability to use energy/natural gas supply
to leverage political outcomes. Energy concerns are directly related to national security and
varies by nation to the extent that their dependency is on a single source. The perception of
insecurity directly relates to the stability of respective countries and regions. This paper
examines the differences amongst the member countries of the EU and the divergence of
national security concerns that explains why energy security is likely to remain as a major
challenge for the EU for the foreseeable future.
The first independent variable is European countries dependence on Russian natural gas
supplies. There is a significant difference between Western and Eastern Europe in their
understanding of energy security, especially dependence on Russia’s natural gas. Dependency
could be further divided into two groups: first, dependency to a single source and the second,
dependency due to the volume of imported gas. The level of dependency of European
countries varies by whether they have potential for diversification to an alternative supplier,
such as the case for Poland and Lithuania that have built LNG degasification facilities. In this
context, a dependency analysis of European countries is provided in the study.
The second independent variable is Russia’s relations with the Central Asian and Caucasus
countries, as they become a potential energy provider for Europe. Central Asian and the
Caucasus Republics relied on a collaborative approach for the development of energy
resources and transporting them to world markets. Although this approach was fruitful in
some cases, such as the construction of the Baku-Tbilisi-Ceyhan pipeline, it was always
challenged both commercially and politically by Russia that pursues establishing a sphere of
influence over former Soviet space that is generally referred as its ‘near abroad.’

The key question to consider with Russian relations is what would Russia’s reaction be if the
Southern Corridor increasingly reduced Gazprom’s share in the European markets? In this
context, the ability of Central Asia and the Caucasus countries to provide a credible
alternative for the diversification of the European energy resources, in particular natural gas
will be studied. While Central Asia and the Caucasus could be defined as a single geographic
region, it consists of several countries with different historical, ethnic, political, economic,
and national security interests. There are a number of important indicators/variables that
might impact the capacity of the region by varying degrees.
The third independent variable is EU relations with Central Asia and the Caucasus. This
relationship was driven by the European desire to diversify energy resources while
constrained by issues ranging from human rights and civil society development to
environmental concerns and good governance. Europe needs energy security more than ever
as improving resilience and green energy take priority to recover from the impacts of the post
COVID-19 economic crisis. Under current circumstances, increasingly revisionist Russia
could leverage energy security for political outcomes that are likely to influence EU strategy
towards the Central Asia and
Caucasus region.
The following provides an overview of the structure of the paper. In Chapter II, a literature
review and the theoretical framework is covered. The chapter starts with the definition of
energy security and explains what energy security means for energy producers, transit
countries, and consumers? The concept of energy security is evolving continuously and the
views differ based on an understanding of international relations. This chapter provides
analysis of realist and liberal theories and their approaches to energy security; sensitivity and
vulnerability interdependence in an energy security context; and varying definitions and the
evolution of the concept of energy security. Other dynamics that affect energy security will

also be reviewed to understand how changes in energy supply and demand would affect
energy security. Finally, the evolution of the concept of energy security is further examined
using different lenses.
Chapter III covers how European energy security has evolved including intra-European
energy relations and the EU member’s relations with the Soviet Union and later with Russia.
An analysis on the development of the natural gas trade (issues, concerns, supply and demand,
and market dynamics) is discussed, as well as vulnerabilities over European dependency on a
single source; this analysis will be based on the data of EU 27, which some cases include the
UK and the EU candidate countries. The most recent policy developments and initiatives,
such as the establishment of the single European market and its impact on natural gas
enterprises, show that progress has been achieved for the EU’s Energy Union concept. While
the role of the new pipeline structures, such as Nord Stream 2 is included, it will also be
presented as a case study in a stand-alone chapter.
Chapter IV provides an analysis of Russia’s energy reserves, pipeline systems, and potential
future projects that have direct impact on the evolution of its foreign and energy policies. In
this context, the Russia-European energy security relationship will be reviewed and an in-
depth analysis provided. What does ‘Third Energy Package’ mean for Russia? How were
state-owned enterprises, in particular Gazprom, affected by the implementation of
regulations? The impact of the Russia-Ukraine gas crisis and other political constraints will
also be reviewed as energy resources are being used in Russia’s hybrid warfare toolbox.
Russia is generally concerned over ensuring demand security. While maintaining market share
in Europe, other alternatives, such as exports to China and other countries in the South and
Southeast Asia, will be reviewed. The role of energy income in the Russian economy and how
potential Central Asian and the Caucasus exports to Europe might affect European
dependency will also be discussed. Therefore, this chapter also covers Russia’s efforts to

undermine Western support on projects that could transport oil and gas from Central Asia and
the Caucasus through the Southern Corridor.
Chapter V is dedicated to the case study of the controversial Nord Stream pipelines, in
particular Nord Stream 2. This discussion starts with the facts and figures of Nord Stream 1
that was also debated and heavily criticized by Central and Eastern European countries.
Supporters and opponents of these projects’ present arguments on the grounds that economic
interdependence brings stability versus a zero-sum game approach driven by national security
concerns. This chapter also covers Russia’s natural gas exports to European countries and
pipeline infrastructure/network used for the delivery.
In this context, the positions of key stakeholders - Germany, Poland, the United States, and
Russia - are explained. NS 1 and 2 create a single point of failure resulting an increased
vulnerability for Germany while minimizing Russian reliance on Soviet legacy pipeline
networks transiting through Central and Eastern European countries. When Nord Stream 2 is
fully operational, Russia will be able to negotiate with both Western and Central and Eastern
European countries from a position of strength due to increased pipeline capacity. This will
allow Russia to yield energy power to leverage political outcomes.
Chapter VI focuses on Central Asia and the Caucasus geography and history, starting from
the Russian Empire period through the Soviet Union to current day. It explains the concept of
‘wider Central Asia’ and involvement of regional and global stakeholders that is also called
the “New Great Game.” Geopolitics of the region provide a better understanding of the way
that actors are behaving today. Putting history and geography into perspective would also
increase our understanding of how some of the findings could be applied to current
circumstances. This chapter focuses on regional countries’ energy reserves, production
capacity, and energy-related infrastructure developments, in particular oil and gas pipeline

systems. An analysis of the Central Asia and Caucasus region’s proven oil and gas reserves
and capacity to provide sufficient means to Europe to diversify energy resources is covered.
There are certain challenges and opportunities for Central Asia and the Caucasus countries
regarding their ability to produce and export energy to international markets. One of the key
questions is to what extent does existing infrastructure support their ambitions to export, given
that in some areas they continue to depend on old Soviet infrastructure controlled by Russia?
This chapter also includes new energy projects for production and pipelines that enable an
increase in Central Asia and the Caucasus export capacity to international markets in the
West such as the Trans-Anatolian Natural Gas Pipeline (TANAP) and the Trans-Adriatic
Pipeline (TAP), as well as those directed to the East such as China and other neighboring
countries.
Finally, Chapter VII provides a summary of the conclusions derived from the analyses in the
previous chapters of the paper. The focus is devoted on energy security relations as well as on
overall security considerations for Europe, Russia, and Caucasus-Central Asia triangle.
CHAPTER 2
LITERATURE REVIEW: THEORETICAL FRAMEWORK, DEFINITION AND
EVOLUTION OF THE ENERGY SECURITY CONCEPT
2.1. Theoretical Framework
The energy relationship between states is a source of inter-state cooperation and/or conflict.
This relationship also involves non-state actors: international and supranational organizations,
such as the International Energy Agency (IEA) and the European Union (EU) respectively,
national and international energy companies, and financial institutions. Therefore, there are
competing theoretical frameworks that aim to explain energy relations and the concept of
energy security. Dannreuther argues that “distinction between a geopolitical or mercantilist

conceptualization of energy security and a liberal, market-driven and pluralist approach…map
onto the classical divide in International Relations theory between realism and liberalism.”
Energy security, in general, is perceived as part of national security while different approaches
are influenced by ideological and normative frameworks. While realist and liberalist
approaches represent main divisions in the way the concept of energy security is perceived,
the changes in technology and environment have increased the way policies are developed.
A realist approach argues that energy security is a zero-sum game, linking it with the balance
of power dynamics. On the other hand, a liberal approach, based on complex interdependence
theory, suggests highlighting the importance of market dynamics, global governance
structures, and the role of international organizations, norms, as well as other dynamics such
as increasing concerns over climate change, to explain this relationship. Additionally, energy
security was deliberated as part of international regimes. Proponents of the international
regimes are linked with realist and liberal tradition while their understanding of these theories
differs: on the one hand liberals suggest that regimes remain the normal state of affairs in the
international system; on the other hand, realists argue that regimes are difficult to create and
maintain in the face of alterations in underlying national power capabilities. Krasner refers to
a “modified structural approach” that “accepts the basic analytic assumptions of structural
realist approaches, which posit an international system of functionally symmetrical, power-
maximizing states acting in an anarchic environment.” Adding to this complexity, cooperation
or confrontation/competition involves not only state actors but also multinational
corporations, state-owned enterprises, and international organizations. Before going into detail
on how evolution of European Union and market dynamics have shaped European-Russia
energy relations and how geography, history and culture have influenced the
Central Asia/Caucasus region’s relationships with Russia, the following international relations
theories are reviewed as to their approach to energy security: realism and liberalism.

2.2. Realism and Energy Security
Morgenthau argues that “politics is governed by objective laws that have their roots in
human nature.” Human nature has not changed. Energy is and will remain an important aspect
of life and prosperity for humanity. Mearsheimer suggests that realists have a pessimistic view
of international politics, and their views are shaped by three main assumptions: first, states are
the principal actors in international relations and great powers dominate and shape
international politics; second, behavior of states and great powers are influenced by their
external environment, not by domestic reasons; third, power dominates states thinking, and
states compete for power. In Waltz’s view “two elements of the structure of the international
system are constant: the lack of an overarching authority means that its ordering principle is
anarchy, and the principle of self-help means that all of units remain functionally alike.” In the
realist view, states, as principal actors in the international system, seek survival, focus on their
own security, pursue their own national interests, and compete for power in an anarchic
system.
These goals are potentially in conflict with other states’ political interests and the resolution of
a conflict of interest is generally linked with material capabilities.
During the Cold-War, the Union of Soviet Socialist Republics (USSR) was one of two global
superpowers that had been engaged in a “zero-sum” competition for power and influence
against the United States and NATO. According to Tsygankov, “Realists have typically argued
that the Soviet leaders, while employing a revolutionary ideology and acting under a
totalitarian system of government, defended Russia’s traditional interests.” He suggests that
“Realism seems to work when the actual policies at play are of a zero-sum nature, but it errs
when the zero-sum reality is not in place,”68 and there are fundamental changes in Russia’s
foreign policy that present opportunity for cooperation with Western nations. However, this
assertion contradicts what Morgenthau argues that states cannot trust anyone but themselves,
and this foundation breeds hostility and war in international relations. Morgenthau also argues
that “International politics, like all politics, is a struggle for power. Whatever the ultimate
aims of international politics, power is always the immediate aim; … the ultimate aim …to
promote one’s interest by changing the mind of the opponent.” He also suggests that power
politics and balance of power are the defining characteristics of international order that
reduces the possibility of cooperation among states.70
It could be assumed that the following are commonly accepted realist core assumptions:
a generally pessimistic view of human nature; the centrality of states as actors in
international relations; an emphasis of material capabilities of states; the essential
insecurity of states; the uncertainty of states’ intentions; a prevailing condition of
anarchy in the international order; an emphasis on the structure and polarity of the
international system; the pursuit of power; and the struggle to ensure security in this
environment.
Keohane and Nye highlight the inadequacy of realist assumptions to explain the changing
conditions of world politics. They suggest complex interdependence comes closer to reality
than realism. In Keohane and Nye’s view, political processes under main realist assumptions
could be listed as follows in Table 1:
Table 1: Political Processes Under Realist Assumptions
Political Processes Realism
Actors’ objectives The high politics of military security dominates economic and social
affairs. Defending state’s territory and interest will be the key
objective.
State policy instruments Military national instrument of power will be the most effective,
although other national instruments of power such economic and
diplomacy will also be used.
Agenda development Potential shifts in the balance of power dynamics and emerging
security threats will set agenda in high politics and will strongly
influence other agendas.
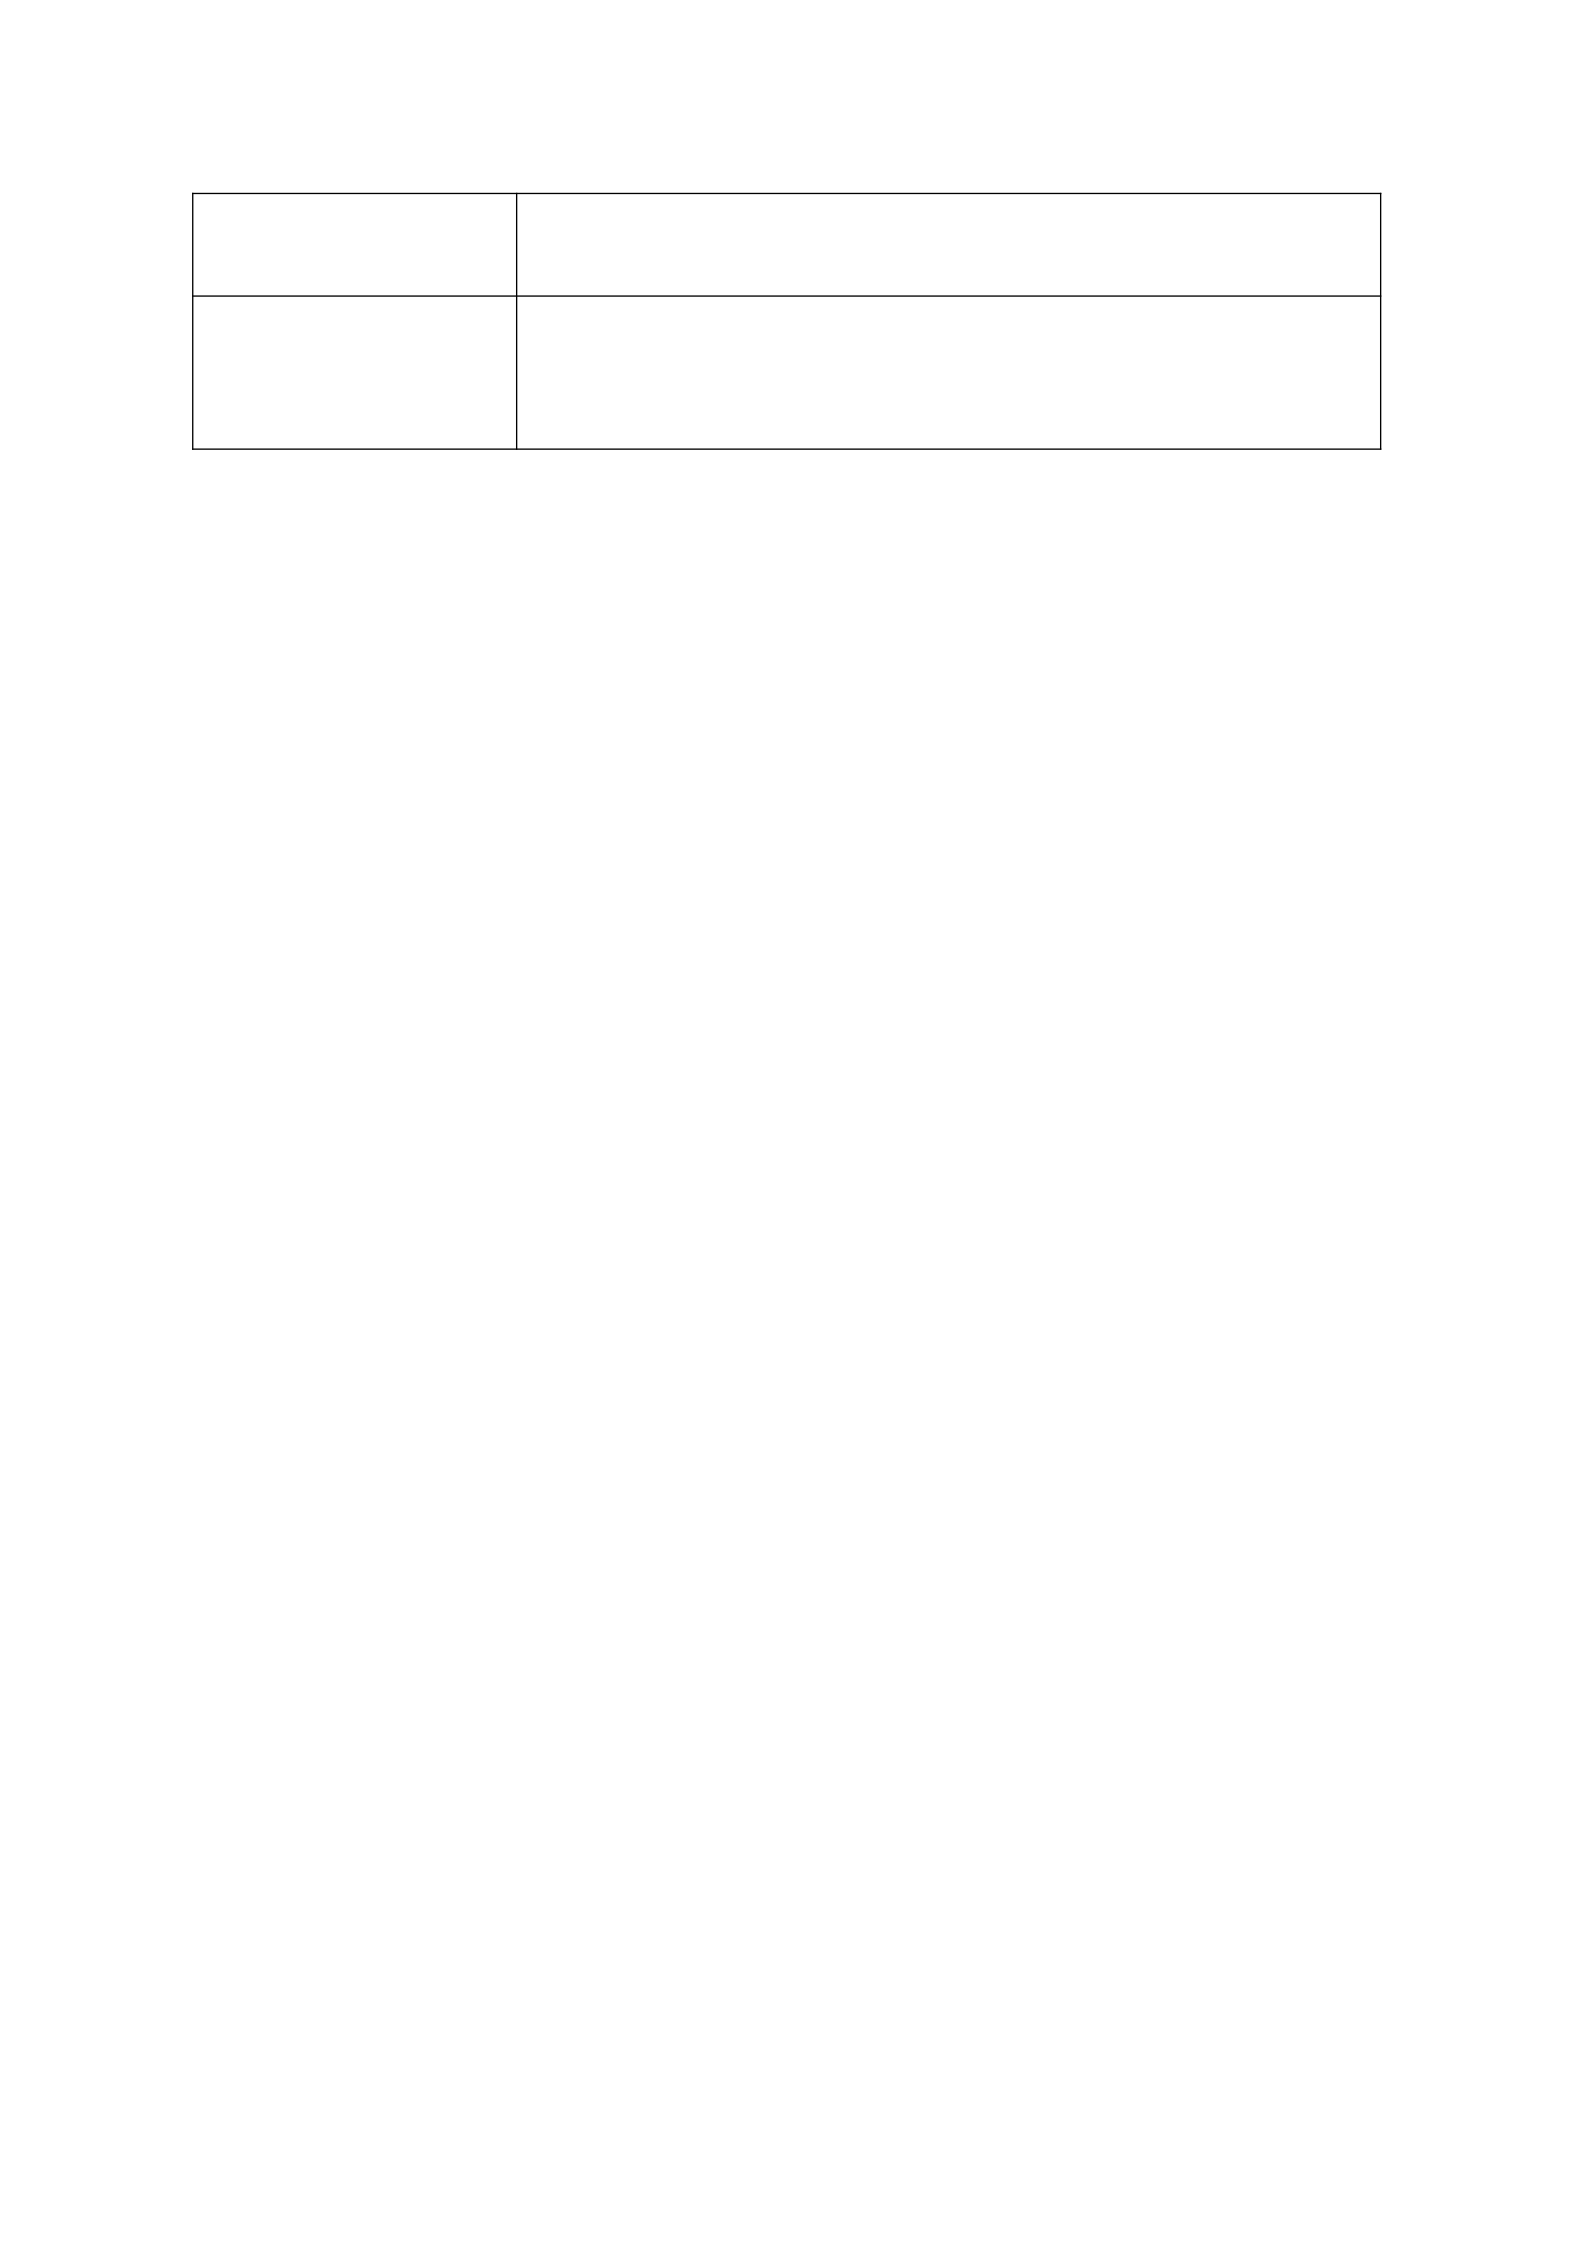
Linkages Linkages will be key to reduce differences in outcomes among issue
areas that reinforce international hierarchy.
International
Organizations’ Roles
States are the main actors and focuses their self-interests. International
organizations will play minor roles, while state power and the military
force remain dominant.
Source: Keohane and Nye, Power and Interdependence, Third Edition, pages 20-32
Klare argues that during the Cold War, the West relied on market dynamics rather than state-
driven approaches in the area of energy security. The Soviet Union was perceived a reliable
supplier of energy. European leaders, specifically German Chancellor Willy Brandt, promoted
energy policies that allowed West Germany to import 20% of its gas supplies from the Soviet
Union, owing to much cheaper prices compared to Western Allies. However, the situation has
evolved and key decisions have been taken by governments which are increasingly shaped by
market dynamics, even though private energy companies have played an important role since
the end of the Cold War.74 Dannreuther argues that most popular writers, including Klare, have
adopted a realist framework to explain energy security relationships, albeit not always
explicitly stated. According to Dannreuther “The ideological struggles between capitalism and
communism of the Cold War era have now been replaced by a geopolitical struggle for access
and control of natural resources.” Additionally, the realist view suggests that states seek the
use of force to reduce vulnerability due to dependency on natural resources. Contrary to what
was argued by Samuel Huntington that the post-Cold War period is defined by the clash of
civilizations, Klare argues that “There is a high correlation between areas of conflict and
concentration of critical materials.”76 In his analysis of the conceptual motivation for the Iraq
War, Yetiv suggests that Iraqi WMD programs, Iraq’s ties to terrorism, and democratization of
Iraq were not the main arguments. There were possible alternative motivations such as oil
security and reducing dependency to Saudi Arabia by controlling Iraqi reserves. As this

example suggests, resources are one of the main causes of contemporary conflicts, and they
are “…vital ingredients of national power and prosperity, and that states inevitably compete
for access to resources and are willing…to contemplate military action.” The realist
approach to energy security is widely accepted as it relates to the fundamental role of state
actors, competition to gain superiority over other actors, and anarchical nature of international
relations. Esakova argues that “Energy resources are a power resource and one of the major
measures for a state’s influence and power both on the national and international level. Nation
states strive to provide their individual energy security acting as coherent units and dominant
actors in energy politics and representing their sovereign interests.” Energy security is
considered as a key element of national security, a source of power that is based on material
factors, including energy resources required to support the economy and the military.
Under the realist view to energy security, pursuing a multilateral approach and acquiring
cooperation with other state actors are limited. Additionally, empowering international
organizations and institutions for multilateral cooperation on energy issues, based on legal
foundations and market dynamics, will be difficult. Energy resources are perceived as a
source of geopolitical power, key for economic development and social stability. Therefore,
military force is considered to be one of the fundamental instruments of access and control of
energy resources by consumer and producer states, as part of their energy security strategy.
Similar to the use of military instruments, economic sanctions are also considered measures
applied under realist conditions. Therefore, security dilemma is applied as a state’s defensive
measure, ensuring its energy security could be regarded as a direct threat by other parties.80
There are diverging views on how relative gains affect the distribution of energy related
transactions. The realist approach to energy security proposes a zero-sum game, suggesting
that the finite nature of energy resources requires one party’s gain could only be possible at
another party’s loss. Therefore, state control of energy resources and distribution networks is

critical and allows influence other parties’ policy choices. Those that adopt realist thinking
tend to encourage establishment of a monopoly, such as Gazprom, to ensure Russian foreign
policy objectives are considered in relations with the other countries. This approach is also
driven by geographical advantages and disadvantages associated with the ability to secure the
flow of oil and gas reserves through pipelines and choke points. On the contrary, Esakova also
argues that “The energy field may also be seen as a non-zero-sum game, because a single
power cannot win all as some other powers are likely to benefit one way or another.”
In the last decade, Gazprom has increased its share in the European gas market. The growing
gas trade between Russia and Europe, at 37% in 2018 compared to 27% in 2011, will increase
energy security concerns over security of gas supplies. The Russian state controls over 50%
share of Gazprom, one of the largest gas producing companies in the world. The
Russian natural gas sector is still largely controlled by several state-owned enterprises, with
Gazprom having the highest share in this sector. Victor, Jaffe and Hayes argue that “Countries
that commit to importing large volumes of gas place the security of their energy system partly
in the hands of others.”84 Therefore, Gazprom’s efforts to develop, build, and own pipeline
networks are generally aligned with Russian foreign policy objectives.
Following Ukraine’s democratization and establishing relations with the West, Russia has
made significant investments, both politically and economically, to develop several pipeline
networks, such as Nord-Stream 1 and 2, Blue-Stream, and Turk-Stream, that circumvent
(bypass) Ukraine and other Eastern European countries. As a result, pipeline networks,
especially those carrying natural gas, have been a focus of Russia’s energy relations with
Europe, driven by and aligned with Russian foreign policy objectives. While one might argue
that the Russia-Ukraine gas dispute is driven by price adjustments and late payments, Russian
attempts to undermine improving Ukraine - EU relations and maintaining Russian sphere of
influence, in other words the realist worldview, is the main cause.

2.3. Liberalism and Energy Security
Keohane and Nye argue that a new era has emerged and the traditional realist approach to
international relations is not sufficiently explaining the changing nature of world politics.
Welch and Nye suggest that transnational economic development of the 1960s and 1970s
increased interest in liberal theories. In this regard, liberal thinking aligned with economic
interdependence posits three main strands, political, social, and economic, that help to
explain the international system. Political aspects further break-down into two related parts,
institutions and democracy. While these aspects, individually, could help to describe the
international system, their convergence allows a comprehensive analysis of change and actual
situations.
Dannreuther argues that liberalism accepts the fundamental realist assumption of anarchy.
However, he suggests that “Liberalism differs from realism asserting that realism presents
only a partial and incomplete picture of the international system.”87 For example, the
economic strand is highly relevant to explain energy context as it relates to trade and
interdependence between states.
Trade encourages states to address issues by defining their mutual interest in economic
terms, avoiding securitization and militarization of energy security. “Trade offers states a way
to transform their position through economic growth rather than through military conquest.”
In his early 2000s assessment, Lo suggested that under Putin, “The Kremlin is anxious to
depoliticize foreign economic policy as much as possible; the implicit message being that the
business of money-making – whether in relation to Caspian Sea energy development
pipelines, or arms sales – is too important to be muddled by the baggage of geopolitical
pretentions.”89

Lo also noted that Putin’s maximalist finance-driven approach towards the energy sector,
particularly oil and gas, has important implications for Russia’s role as a global actor. Keeping
strict control of the gas market by using Gazprom allows Russia to maintain gas delivery
under exclusive purview of the state. This situation has changed as the long-term contracts
“where the state dominates the economy and international trade in gas is backed by state-to-
state agreements.” Hayes and Victor defined this system as the “old world” that is in contrast
the gas trade system defined as the “new world” where the role of states shifts to the market
institutions.91
Liberalism also suggests that person to person contact increases social interactions which
support understanding, thereby reducing the potential for conflict. Transnational and trans-
governmental relations through multiple channels of contacts further blur the distinction
between domestic and international politics, while creating conditions for complex
interdependence. These social and business interactions take place in different contexts, from
student exchanges to tourist visits and joint business ventures, allowing diverging views on
contentious issues and a better understanding of different perceptions. While proponents of
this view argue that the world is different from the beginning of the 20th Century, uncertainty
remains amongst foreign policy experts due to the similarity in conditions of today to pre-
World
War I conditions that did not prevent conflict between European powers. In the same context,
Gustafson argues that natural gas was at the center when European-Russian business relations
flourished in the early 1990s. For a time, normal economic ties were expected to foster normal
political relations, and vice versa, “But natural gas has now become part of the problem, for
reasons that could never have been anticipated during the Cold War.”93
Exploration, development and production of energy resources require large investments and
advanced technology of energy companies operating in global markets. These companies,

excluding state-owned enterprises, are rarely influenced by state policies and generally
operate independently from the political space. Dannreuther argues that “The international oil
market is globally integrated and fungible and the historical trajectory is, if anything, towards
enhanced transparency and openness to market forces…Global gas markets appear to be
moving in a similar direction.”95 Several energy ventures are joint projects involving Russian
state-owned enterprises and Western companies, such as Nord-Stream I and II, Turk-Stream,
Blue-Stream, and others. While these projects promoted cooperation in certain regions, they
did not prevent certain developments such as Russia’s illegal annexation of Crimea,
interference in Eastern Ukraine, or the Russia-Georgian War.
In addition to social interactions, international institutions have the potential to reduce the
difficulty of the security dilemma created by NATO and EU expansion. The Alliance gave the
highest priority to NATO’s enlargement and expected Russia to “play a unique role” within
the framework of the NATO-Russia Founding Act on Mutual Relations (establishment of
NATO-Russia Council [NRC]); Cooperation and Security on the basis of common interest;
and reciprocity and transparency to achieve a lasting and inclusive peace. However, the signs
of resentment in Russia started emerging from the very beginning as former Warsaw Pact and
Soviet Republics were becoming members of NATO and the European Union. Russia was
against NATO and EU expansion and perceived its exclusion from the enlargement process as
losing influence over its near abroad. The institutions directly related with energy and
security, such as the NRC, the Organization for Security and Co-operation in Europe (OSCE),
and The
Energy Charter Treaty (ECT), have little impact to tame Russian and Western concerns.
International and non-governmental energy related organizations and civil society have
played significant roles to influence state behavior, albeit in some cases in a negative sense for
the liberal international order, such as the oil embargo imposed by the Arab members of the

Organization of Petroleum Exporting Countries (AOPEC) against the United States, the
Netherlands, Portugal, and South Africa. The embargo resulted in huge reductions in oil
production and banned exports to targeted countries. International organizations in this regard
affected state decisions. In response to AOPEC’s oil embargo, another autonomous
organization, the International Energy Agency (IEA) was created to coordinate a collective
response to any major oil supply disruptions. While oil security continuously remains as one
of the key aspects of the IEA’s agenda, it also focuses on global dialogue for reliable,
affordable, and clean energy.
These two organizations represent different parts of the energy relationship. While OPEC
represents the interests of oil producing countries, the IEA offers measures for secure and
sustainable energy supplies to its members. Their influence on international politics and the
national security of its member states cannot be ignored. The ECT went into force in 1998 as
a legally binding document that formulates the relationship between foreign investors and host
states, protects their rights against the host states, while providing a framework for their
activities. The international organizations have been and are likely to remain part of the
supply and demand equilibrium as influential key actors. However, their efficiency and ability
to influence outcomes depend on the level of commitment of the parties involved.
2.3.1. Interdependence - Mutual vs Asymmetric Interdependence
Keohane and Nye define interdependence as “mutual dependence.” They argue that
“interdependence in world of politics refers to situations characterized by reciprocal effects
among countries or among actors in different countries.” Keohane and Nye continue to
explain the effects as a result of these transactions as flow of money, goods, people, and
messages across international borders. As the world becomes more interconnected, they
suggest that “the effects of transactions on interdependence will depend on the constraints, or
costs, associated with them.”

Different views on economic interdependence and political conflict were also presented by
Mansfield and Pollins. Their first view is “heightened interdependence fosters cooperative
political relations.” On the other hand, critics of this view suggest that “rather than fostering
cooperation, increased interdependence generates political discord.” Another group believes
“…that economic exchange has no strong bearing on the high politics of national security.”
Montesquieu is quoted as saying, “…the natural effect of commerce is to lead to peace. Two
nations that trade together become mutually dependent: if one has an interest in buying, the
other has an interest in selling; and all unions are based on mutual needs.” Mansfield and
Pollins continue to explain this liberal position, making reference to Buzan who suggests that
“a liberal economic order makes a substantial and positive contribution to the maintenance of
international security.”
On the other hand, dependency has been explained differently from the way it was described
in “economic development and dependency.” Baldwin makes reference to Duvall’s point on
the meanings of the dependence by stating, “The distinction [is] often made between
‘sensitivity interdependence’ and ‘vulnerability interdependence.’ While the first meaning
implies mere ‘contingency,’ the second implies ‘need fulfilment that would be costly to
forego.”’ The concepts of sensitivity and vulnerability interdependence are the cornerstones of
the interdependence theory105 introduced by Robert O. Keohane and Joseph S. Nye. Therefore,
two different consequences exist for breaking the dependence as shown in the analysis
provided by Keohane and Nye. Baldwin suggests that:
“The crucial difference between the first and second meaning of “dependence” has to
do with the ease of breaking the relationship: “sensitivity interdependence” implies
nothing about the cost of altering the relationship whereas vulnerability
interdependence defined as “necessary,” “ineluctable,” “inevitable,” “inextricable,” or
“unavoidable,” is grounds for suspicion that the author has in mind a relationship that
would be costly to break.”106
Keohane and Nye, in their seminal work Power and Interdependence, argue that complex
interdependence affects behavior of states and international relations with the following key
assumptions:107
- Actors. There are multiple actors in the international system other than states.
These entities and other trans-governmental channels create interactions involving
individuals, international organizations and transnational/multinational companies. -
Issues. There is no arranged hierarchy among issues. Therefore, military security is
not predominant at all times. The domestic and foreign policy issues are blurred, and
domestic policy issues might require varying degrees of coordination involving
several levels. Lack of coordination on issues requires cross-governmental policy
which might result in significant costs.
- Role of Military Force. Use of military force depends on the issues and
governmental relations with other regional governments influenced by the existence
of complex interdependence. “Military force could be irrelevant to resolving
disagreements on economic issues among members of an alliance, yet at the same
time be very important for that alliance’s political and military relations with a rival
bloc.”108
Esakova highlights the following characteristics of the political processes of complex
interdependence that are relevant to energy security relations. The changes in distribution of
power resources within issue areas shape the status of international regimes and political
agendas. Changes to the roles and functions of international actors also affect linkages from
International Economic System”) the distinction is also found in an earlier article by Kenneth Waltz (“The Myth of
Interdependence” in The International Corporation, ed. Charles Kindleberger [Cambridge, Mass.: The MIT Press,
1970], p. 210.)
105 Keohane and Nye, Power and Interdependence, 10.
106 Baldwin, “Interdependence and Power,” 477.
107 Keohane and Nye, Power and Interdependence, 20-22.
108 Ibid.
other issues. For example, “Linkages by the strong states are more difficult since force is
ineffective…Linkages by weak states take place through international organizations.” The
existence of multiple channels allows international organizations to play a more important
role compared to state-focused realist assumptions. “Multiple channels connect societies,
including: informal ties between government elites as well as forma foreign office
arrangements.”110 International organizations play a significant role, i.e., set agendas, induce
coalition formation, and act as arenas for political action by weak states. The following table
is a summary of
Keohane and Nye’s point of view political processes under liberal assumptions.
Table 2: Political Processes Under Complex Interdependence Assumptions111
Political Processes Complex Interdependence
Actors’ objective Objectives of the states will be aligned with their national interests.
Transgovernmental politics will shape and influence definition of objectives.
Transnational actors will follow their own objectives.
State policy
instruments
National instruments of power relevant to issue areas will play the most
relevant role. International organizations, transnational actors and the way
interdependence managed will play important roles.
Agenda
development
The changes in the distribution of power resources in issue areas will shape the
agenda development; the status of international regimes; changes in the
importance of international actors; linkages from other issues; and
politicization as a result of increasing sensitivity interdependence.
Linkages Strong states will find it more difficult to establish linkages due to
ineffectiveness of force. On the other hand, linkages by weak states through
international organizations will erode rather than reinforce hierarchy.
International
Organizations’
Roles
International organizations will use their ability to choose an issue and to
mobilize votes as an important political resource. They will set agendas,
encourage coalition-formation and allow weak states to play political role.
Source: Keohane and Nye, Power and Interdependence, Third Edition, pages 20-32
2.3.2. Sensitivity and Vulnerability Interdependence in the Energy Security Context Keohane
and Nye argue that to understand the role of power in interdependence, it is necessary to
distinguish sensitivity and vulnerability interdependence. While framework remains the same,
sensitivity involves how quickly a policy change in one country could bring costly changes to
another in terms of volume and associated costs. Keohane and Nye refer to the:
“example of sensitivity interdependence that the United States, Japan and Western
Europe that was affected by increased oil prices in 1971 and again in 1973-1975…
The United States was less sensitive than Japan to petroleum price rises, because a
smaller proportion of its petroleum requirements was accounted for by imports, but as

rapid price increases and long lines at gasoline stations showed, that the United States
was indeed sensitive to the outside change.”
This could be explained by oil’s role as a global commodity. The demand increase in other
parts of the world has impacts on other consumers due to their sensitivity to rapid changes,
even if their dependence to outside sources is limited. Stulberg refers to Keohane, Nye, and
Hirschman and highlights that ‘sensitivity’ is “measured in terms of the volume and
distribution of specific resources exchanged, refers to the extent to which a country is affected
by the actions of another.” In this context, he defines Russia’s ability to leverage and control
the Turkmen gas exports to the CIS countries and the European markets as an asymmetry.
Finally, sensitivity interdependence is not limited to energy domain; it can be social,
economic, or even political. Keohane and Nye suggest that consideration should be given to
“what the situation would be if the framework of policies could be changed. If more
alternatives were available…what would be the costs of adjusting to the outside change?” If
such alternatives differ from one country to another, policies and availability of other less
costly options reflect the level of a country’s vulnerability interdependence. An example of
this would be two countries, both importing the same percentage of oil from external sources,
but one of them could shift to domestic resources in case of a rapid increase in energy prices.
As Keohane and Nye mentioned, while they are both sensitive to the change in oil prices, one
without domestic or other alternatives will be more vulnerable than the other. “The
vulnerability dimension of interdependence rests on relative availability and costliness of the
alternatives.” Based on this foundation, Esakova further elaborates on this energy-based
relationship:
- The level of sensitivity interdependence implies the relative volume of
imported energy in the overall energy demand of an energy importing country;
- The level of vulnerability interdependence is measured by the alternatives to
imported energy and the costs of switching to possible alternatives.

The sensitivity and vulnerability interdependence are also closely linked with the supply and
demand relationship. Farrell and Bozon argue that when uncertainty and anxiety dominates
energy markets, prices are likely to increase. Energy producing and exporting countries are
less concerned on “security of demand” while energy prices are high, in the same way energy
importers are not troubled with the “security of supply” when prices are low. Geopolitical
considerations become “a key factor encompassing everything, from the vigorous use of
energy as a foreign- policy tool, to persistent strikes and unrest and instabilities in certain
energy producing countries such as Russia and Venezuela...to rising instability in the Middle
East.”
These geopolitical concerns, especially for importing countries, are directly linked with the
‘security of supply.’
On the other hand, security of demand, mostly an issue for producing and exporting
countries, is affected by economic recession, especially in the largest oil importing countries,
or policy changes that shape the energy mix of countries aiming to reduce CO2 emission. If
any oil and gas exporting country does not have alternative markets, it is more vulnerable to
demand shocks compared to other energy exporting countries. For example, Uzbekistan is a
landlocked gas producer with no outlet to international markets. While it has abundant gas
reserves, it is a net oil importer. Uzbekistan uses its natural gas resources to produce oil and
reduce its vulnerability by decreasing its import from regional countries. This attempt will
shape
Uzbekistan’s sensitivity and vulnerability interdependence by using its own resources.
The following factors will influence Uzbekistan’s energy policies:
- Diversification of energy mix;
- Reducing import dependence and increasing potential for fuel substitution;
- Supporting domestic market and price stability;

- Reducing the impact of price volatility in international markets.
2.3.3. Sensitivity and Vulnerability Interdependence - Analysis of Europe-Russia In order to
understand European-Russian relations, it is important to understand not only
geopolitical concerns but also economic ones, in particular energy, as well as
impediments in these relationships. Therefore, a good start for this analysis is to
understand European levels of energy dependence, as suggested by Esakova that
“Sensitivity and vulnerability interdependence are the starting points for analysis of
energy relationships, as such analysis helps to measure the level of dependence of each
of the actors and the overall interdependence between the actors.” The EU Energy
Security Strategy is focused on its collective response to the energy crises considering
the Union’s overall energy dependency on external resources. However, energy
security issues have been considered an integral part of individual members’ national
security agenda at national levels, without taking into account a more collective
approach and interdependence amongst the other members of the EU. This outcome is
aligned with the understanding suggest that “The study of the characteristics and
development of an energy-based relationship should begin with the analysis of the
sensitivity and vulnerability interdependence of each of the actors.” In recent
years, Russia - EU energy relations evolved around the two different perspectives of
the parties involved. The foundation of these differences is reflected in the two
different worldviews, based on realist and liberal approaches to energy security. It
should also be noted that European-Russian energy relations have, in fact, evolved
over time. During the Cold War, Russia presented itself as a reliable partner. At the end
of the Cold War, there were high expectations based on previous experience assuming
Russia would remain as a reliable partner for energy cooperation. These expectations
were reflected with the initiation of the EU-Russia

Energy Dialogue regime in 2000. However, Russia’s approach and commitment to
the EU-Russia Energy Dialogue changed with geopolitical developments in Russia
and former Soviet space since 2003.
With the Putin administration’s centralization policies, Russian foreign policy has also
changed as a response to developments such as “the second wave of the North Atlantic Treaty
Organization (NATO) enlargement in Eastern Europe, the 2004 EU enlargement and ‘colored
revolutions’ in Ukraine and Georgia in 2003 and 2004.”123 These developments changed
Russian attitudes toward rapprochement and created a sea change in Russian foreign energy
policy. Compounded by economic growth driven by high oil prices, Russia further distanced
itself from the West, thus increasing the potential for conflict. As a result, Russia took a more
confrontational approach with the West, including the 2006 and 2009 gas crises with Ukraine,
the 2008 war against Georgia, the 2013 -2015 illegal annexation of Crimea, the support of the
separatist movement in Eastern Ukraine, and the involvement in the war in Syria since 2013.
These geopolitical developments have second and third order effects on energy security
considerations and brought up concerns regarding the reliability of Russia as a partner.
Esakova argues that sensitivity analysis of the EU against Russia could be measured by short-
term supply disruptions. Umbach highlights that Russia perceives this relation as asymmetric
interdependence and “Russia can live at least one year without any European/Western
investments and technologies; Europe cannot survive even 30 days without
Russian gas.” While this claim may not be the case with EU’s recent reverse flow and other
resilience measures, it reflects the potential that the EU’s sensitivity interdependence could be
regarded as high. Esakova, based on IEA principles, highlights the following parameters that
could be used to measure the degree of a country’s sensitivity interdependence: “diversity of
the primary fuel mix, import dependence and fuel substitutability, market concentration and
share of politically unstable regions in imports.”126 These metrics are useful and provide

insights measuring a country’s sensitivity interdependence, the differences between member
countries could be an area for exploitation by Russia.
In regard to vulnerability interdependence of the EU, Esakova argues long-term threats
should be considered, such as the EU’s inability to diversify energy supplies and pipeline
networks.127 Additionally, efforts to increase energy efficiency, to improve market
liberalization and to use alternative sources such as liquefied natural gas are investigated in
the analysis. A lack of coherent energy policy could continue to hinder Europe to address
these comprehensive challenges. Finally, pipelines and Liquefied Natural Gas (LNG)
infrastructures are extremely expensive, and who can bear these costs affects national
decisions. Russia’s attempts to engage European Union members individually using state-
owned enterprises are expected to undermine any common strategy that reduces vulnerability
interdependence.
2.3.4. Sensitivity and Vulnerability Interdependence - Analysis of Central Asia and
Caucasus-Russia
The relationship between Russia and Central Asia could also be defined as complex
interdependence as it has the following three main characteristics:
- Multiple channels to connect societies exist, such as but not limited to,
informal ties between governmental, non-governmental, international, and business
elites. In addition to a systemic Soviet division of labor to enable production of
material dependent upon Russia and other republics, there is a large Russian
population in Central Asia, though with varying numbers from republic to republic.
Ethnic Russians are generally in a position to influence the key decision-making
systems of Central Asian societies.
- There are multiple issues that dominate the agenda of interstate relations;
however, for Russia, energy security is one of the most important priority items in

their agenda. These issues could be categorized into three main areas: first, high-
level political relationships; second, security co-operation in the region; and third, its
range of investment in energy projects in these countries. Therefore, military security
does not dominate the agenda.
- During the annexation of Central Asia, the Russian empire used military force
to control Central Asia. Although coercion might be part of Russia-Central Asia
relations during the Soviet period, use of military force was not part of the
relationship during the Cold War. Since the end of the Cold War, Russian attempts to
establish security frameworks similar to the Warsaw Pact have not been successful.
Central Asia/Caucasus and Russia relationship is as complex as European-Russian
relationship. Russian policy since the end of the Cold War, led by its giant state own enterprise
Gazprom, “to retain, as far as possible, control over Central Asian exports, and to limit
attempts by Central Asian producers to open up export routes either to China and other Asian
destinations or to Europe by routes that avoid Russia.” During that period Russia controlled
and influenced gas prices whether they are delivered to Russian consumers, CIS countries or
European markets. Russian dominance over Turkmen gas exports was challenged with the
construction of the Turkmen-Kazakh-Chinese natural gas pipeline in 2007. Turkmenistan and
China reached a gas deal in 2006 allowing export of up to 30 Bcm/year Turkmen gas to China
in 2011. These developments, including potential export of Central Asian gas to Europe via
Azerbaijan and Turkey, increased pressure on Russia. As a result, Gazprom agreed to accept
purchase agreements at European price levels with the Turkmen, Kazakh, and Uzbek national
gas companies.
Central Asia and the Caucasus sensitivity interdependence to Russia has three dimensions:
first export depends on the balance amongst Russian production capacity, domestic customers’
consumption, and availability of markets for Russian gas export. The second, the availability
of Russian pipeline networks for Central Asian gas deliveries to less desirable markets such as
Ukraine that pay lower prices compared to European markets. Russia plays the transit country
role in this context. Finally, Central Asian countries are highly dependent on the revenues
whether they are from Russia, CIS countries, or European markets that are available through
pipeline transit from Russia.
The alternatives have increased since the 2010s whether markets in the East or in the West,
albeit remains limited in terms of Central Asian/Caucasus capacity to deliver natural gas.
Therefore, vulnerability interdependence of Central Asian and Caucasus countries to Russia
has decreased due to availability of alternative markets. However, there would be not only
economic but also security consequences should any of the republics attempt to break up the
relationship with Russia as it was the case during the Russian Empire then USSR periods.
2.4. Energy Security Definition – An Overview
A vague definition of energy security connotes different meanings for different people,
depending on their role and function in the energy supply chain. This large variation of
diverging understanding of the definition has further security consequences from global level
issues such as climate change, to regional and national energy security concerns. Table 3 lists
definitions that provide the convergence and divergence of the main aspects of energy
security.
Table 3: Energy Security Definitions - Evolution of Factors132
Serial Definition Sources
1 The availability of energy at all times in various forms, in sufficient
quantities and at affordable prices, without unacceptable or irreversible
impact on the environment. These conditions must prevail over the long
term. Energy security has both a producer and a consumer side.
Anderson et
al.133
2 To assure adequate, reliable supplies of energy at reasonable prices and in
ways that do not jeopardize major national values and objectives.
Andrews134
3 The ability of an economy to guarantee the ability of energy resource
supply in a sustainable and timely manner with the energy price being at a
level that will not adversely affect the economic performance of the
economy. Thus, there are several factors that can influence the “security” of
energy supply, such as: (1) the availability of fuel reserves, both
domestically and by external suppliers; (2) the ability of an economy to
acquire supply to meet projected energy demand; (3) the level of an
economy’s energy resource diversification and energy supplier
diversification; (4) accessibility to fuel resources, in terms of the
availability of related energy infrastructure and energy transportation
infrastructure; and (5) geopolitical concerns surrounding resource
acquisition.
Asia Pacific
Energy
Research
Centre135
132 Sovacool, Routledge Handbook, 4-6.
133 Anderson, Coelho, Doucet, Freudenschuss-Reichl, Jefferson, Jochem, and Karekezi et al. "World Energy," 42.
134 Andrews, “Energy Security,”17, reference to Yergin, “Energy Security.” 135 A Quest for Energy Security, 5.
53
Table 3 (Continued)
Serial Definition Sources
4 A condition in which a nation and all, or most, of its citizens and businesses
have access to sufficient energy resources at reasonable prices for the
foreseeable future, free from serious risk of major disruption of service.
Barton et al
5 Measures taken to reduce the risks of supply disruptions below a certain
tolerable level. Such measures should be balanced to ensure that a supply of
affordable energy is available to meet demand. Security of energy supply
thus encompasses both issues of quantity and price.
Bazilian,
O’Leary,
Howley and
Gallachóir
6
Reliable and adequate supply of energy at reasonable prices… it simply
means uninterrupted supply that fully meets the needs of the global
economy.
Bielecki138
7
Loss of welfare that may occur as a result of a change in price or availability
of energy.
Bohi, D. and
Michael A.
Toman139
8 Adequate energy supply and affordable prices as well as social and cultural
sustainability and environmental preservation.
Brown and
Sovacool140
9 “Low vulnerability of vital energy systems” opens a road towards more
detailed specifications of
(a) vital energy systems; and
(b) their vulnerabilities, composed of exposure to risks and resilience.
Cherp and
Jewell141
10 Diversity of supply; clean fuels that are affordable and readily available;
stability; smarter use of energy resources; reliability; electrification of
ground transport; bio-based mobility fuels.
CNA
11 Accelerate the transition to a low carbon economy requires urgent and
ambitious action at home and abroad…
• save energy;
• develop cleaner energy supplies; and
• secure reliable energy supplies at prices set in competitive markets.
Our strategy continues to be based on the principle that independently
regulated, competitive energy markets, are the most cost-effective and
efficient way of delivering our objectives
Department of
Trade and
Industry, UK143
12 To convey the connection between the economic activity that occurs in both
domestic and international energy markets and the foreign policy response
of nations (apart from the fundamental connection between national
security and a healthy economy).
Deutch
13 Threats to security often come in the form of low probability but
highconsequence events (failure of Russian gas exports, or a nuclear
accidentcausing similar reactors to close).
Doczy, Borner,
MacKerron
Serial Definition Sources
54
Table 3 (Continued)
14 To ensure that energy supplies are available, sufficient, affordable and
sustainable. This will mean taking a broad range of measures: conserving
and raising energy efficiency; rationalizing pricing and taxation systems;
improving energy sector governance; and diversifying energy supplies, in
particular making greater use of alternative and renewable resources.
Economic and
Social
Commission for
Asia and the
Pacific, United
Nations
(ESCAP, UN)
15 To ensure the uninterrupted physical availability of energy products and
services on the market, at a price which is affordable for all consumers
(private and industrial), while contributing to the EU's wider social and
climate goals.
European
Commission146
16 Reliable and affordable access to energy supplies – is inextricably tied up
with military and national security.
Florini
17 The availability of energy at all times in various forms, in sufficient
quantities, and at affordable prices. Goldemberg
18 The way of equitably providing available, affordable, reliable, efficient,
environmentally benign, proactively governed, and socially acceptable
energy services to end-users, which is gaining ever more prominence on
contemporary policy agendas. Energy security has supply-side and
demandside components.
Goldthau,
Sovacool
19 A methodology that can be used to explain energy security…four Rs:
review (understanding the problem), reduce (using less energy), replace
(shifting to secure sources), and restrict (limiting new demand to secure
sources).
Hughes
20 The ability of a nation to muster the energy resources needed to ensure its
welfare. In a narrower meaning it refers to territorial energy autonomy.
Consequently, energy supply security is a matter of both domestic policy
and international relations.
International
Atomic Energy
Agency
21 The uninterrupted availability of energy sources at an affordable price.
Energy security has many aspects: long-term energy security mainly deals
with timely investments to supply energy in line with economic
developments and environmental needs. On the other hand, short-term
energy security focuses on the ability of the energy system to react
promptly to sudden changes in the supply-demand balance.
International
Energy Agency
(IEA)
22 The term may be defined in terms of access to secure, stable, and reliable
supplies of efficient and modern energy supplies and appliances at prices
that are affordable and in amounts adequate to meet demands for basic
energy services in full to ensure human health and well-being and without
detriment to the environment
International
Institute of
Applied Systems
Analysis
Serial Definition Sources
23
Air pollution and global warming are two of the greatest threats to human
and animal health and political stability. Energy insecurity and rising prices
of conventional energy sources are also major threats to economic and
political stability…energy-related solutions to global warming, air
pollution mortality, and energy security while considering impacts of the
solutions on water supply, land use, wildlife, resource availability,
reliability, thermal pollution, water pollution, nuclear proliferation, and
undernutrition.
Jacobson
55
Table 3 (Continued)
24 Proposes to use the term energy services security (ESS) instead of energy
security…refers to the certainty level at which the population in a defined
region can have access to affordably and competitively priced,
environmentally-acceptable energy services of adequate quality.
Jansen155
25 Assurance of the ability to access the energy resources required for the
continued development of national power ... it is the provision of
affordable, reliable, diverse, and ample supplies of oil and gas and their
future equivalents and adequate infrastructure to deliver these supplies to
market.
Kalicki and
Goldwyn
27 Energy-based indicator set can cover most relevant sustainability issues.
This simplifies the formal modelling of the framework; interdependences
and interactions between components or the selected indicators can be
modelled…In this set, economic activity, climate change, poverty, equity,
energy resources, energy efficiency, and air pollution will be covered.
Kemmler and
Spreng
28 • Development of flexible, transparent and competitive energy markets,
including gas market;
• Diversification of energy fuels, sources and routes, and encouragement of
indigenous sources of energy supply;
• Reducing our greenhouse gas emissions, and accelerating the transition to
a low carbon economy, as a key contribution to enduring energy security;
• Enhancing energy efficiency in supply and demand, and demand
response management;
• Promoting deployment of clean and sustainable energy technologies and
continued investment in research and innovation;
• Improving energy systems resilience by promoting infrastructure
modernization and supply and demand policies that help withstand
systemic shocks and cyberattacks;
• Putting in place emergency response systems, including reserves and fuel
substitution for importing countries, in case of major energy disruptions;
a host of factors must be considered from both domestic and international
perspectives, including: ensuring domestic access to energy, securing the
electric grid, encouraging the development of global markets, and
supporting alliances and partnerships that strengthen energy security.
Kenderdine 158
Serial Definition Sources
56
Table 3 (Continued)
29 Secure, reliable and affordable energy supplies are fundamental to
economic stability and development (IEA, 2006); the availability of energy
at all times in various forms, in sufficient quantities, and at affordable
prices (The World Energy Assessment, 2000:11); The key principles:
• Diversification of energy supply sources is the starting point for energy
security;
• A “security margin” consisting of spare capacity, emergency stocks and
redundancy in critical infrastructure is important;
• Relying on flexible markets and avoiding the temptation to micromanage
them can facilitate speedy adjustment and minimize longterm damage;
• Understand the importance of mutual interdependence among companies
and governments at all levels;
• Foster relationships between suppliers and consumers in recognition of
mutual interdependence;
• Create a proactive physical security framework that involves both
producers and consumers;
• Provide good quality information to the public before, during and after a
problem occurs;
• Invest regularly in technological change within the industry;
• Commit to research, development and innovation for longer-term energy
balance and transitions;
Kessels, Bakker
and Wetzelaer
30 A future where abundant, reliable, and affordable energy is produced with
little impact on the environment and no dependence on the goodwill of
hostile nations (P.V. Domenici, The Chairman of the Senate Energy and
Natural Resources Committee [2004])
Kessels, Bakker
and Wetzelaer
31 The five Ss: supply, having resources, such as fossil fuels, alternative
energy, and renewable energy; sufficiency, adequate quantity of fuel and
services from these sources; surety, having access to them; survivability,
resilient and durable sources of energy in the face of disruption or damage;
and sustainability, reducing waste and limiting damage to the environment.
Kleber
32 The ability to assure adequate, sustainable supply of energy at a reasonable
cost, including externalities. One might also think about energy security as
a process, an ebbing and rising flow:
• The flow of primary energy from its varied sources and the shifts
from one source to another over time;
• The flow of energy products across energy infrastructure and the
shifts in the patterns of flows in this infrastructure;
• The flow of energy across private and government channels and
the shifting balance between these flows;
• The flow of energy across international borders and the shifting
balance of regional and national power and control over these flows.
Konoplyanik162
Serial Definition Sources
57
Table 3 (Continued)
33 From the viewpoint of a consumer and net importer of energy sources,
energy security denotes the right to use reliable sources of energy at
competitive prices produced by an environmentally sustainable and safe
means. It also includes the absence of physical disruptions and volatile
increases in prices. On the other hand, energy security is in the perspective
of a producer and net exporter of energy resources, signifying the security
of supply as well as security of demand.
Kurian and
Vinodan
34 The traditional definition of sufficiency, reliability, and affordability now
seems incomplete. Environmental sustainability, geopolitical factors, and
social acceptability are clearly elements that need to be added to our
calculus.
Logan
Venezia164
and
35 Rests on three pillars:
1) Making domestic energy infrastructure, notably electric and gas grids,
resilient; 2Phasing out, not expanding, vulnerable facilities and unreliable
fuel sources; Ultimately eliminating reliance on oil from any source.
Lovins165
36 The concept of maintaining a stable supply of energy at a “reasonable”
price to avoid the macroeconomic costs associated with interruption of
energy supply or increases in energy price.
Medlock166
37 Provision of reasonably priced, reliable, and environmentally friendly
energy (references to the IEA and EC definitions).
Mueller-
Kraenner
38 Security of energy supply is the resilience of the energy system to unique
and unforeseeable events that threaten the physical integrity of energy
flows or that lead to discontinuous energy price rises, independent of
economic fundamentals.
An external and an internal dimension of energy supply security are of
importance…The external dimension is mainly defined by concerns about
import dependence from potentially unstable countries. The internal
dimension instead is about creating appropriate incentive mechanisms and
frameworks to allow public and private actors to invest in adequate levels
of production and transport capacity that provide continuous access to
energy services at stable prices.
Nuclear Energy
Agency
39 Provision of adequate, affordable, efficient, and reliable energy services
with minimal adverse impacts on the environment Omorogbe
40 Energy policy objectives…securing energy supply continuity, securing
properly functioning energy markets and promoting energy efficiency,
energy savings, and promotion of new and renewable energy resources.
Scheepers,
Seebregts, Jong,
Maters
41 Analyzed in terms of changes in net energy import dependency of the
power sector (NEID) and diversification of energy resources used to
generate electricity (SWI).
Shrestha, Farooq
and Kumar
Serial Definition Sources
58
Table 3 (Continued)
42 Energy technologies are judged according to five criteria:
• technical feasibility, meaning that such systems must be commercially
developed and available to enter the American energy market;
• cost, in terms of whether their use would increase or decrease electricity
prices for consumers;
• negative externalities, in terms of their impact on human health and the
environment;
• reliability, in terms of how dependable such technologies are at generating
and delivering electricity; and,
• security, or how safe and immune such technologies are from attack or
accident. The use of such criteria—while they may appear as common
sense to many—reveals some surprising results.
Sovacool
43 The threats of supply and price disruptions arising from risks associated with
the sources of gas supplies, the transit of gas supplies and the facilities
through which gas is delivered. There are two major dimensions of these
risks:
• short-term supply availability versus long-term adequacy of supply
and the infrastructure for delivering this supply to markets;
• operational security of gas markets, i.e., daily and seasonal stresses
and strains of extreme weather and other operational problems versus
strategic security, i.e., catastrophic failure of major supply sources and
facilities.
Stern
44 Over the last decade it has become one of the government’s priorities.
Physical supply of electricity and gas, i.e., ensuring there is no interruption
in energy flows (concretely: to avoid power cuts, for example).
Price security or stability, i.e., ensuring that energy sources are sufficiently
diverse to protect consumers from sudden price hikes.
The Switch174
45 Focuses on the geographical location of energy resources, political stability
of producing and consuming countries, and availability of fuel substitutes.
This view sees energy supply as a key component of national security and
correct policy becomes a matter of maintaining economic vitality and
military strength.
Tonn et al
46 Availability of usable energy supplies, at the point of final consumption, in
sufficient quantity and timeliness so that, given due regard for encouraging
energy efficiency, the economic and social development of the country is not
materially constrained
US Agency for
International
Development
47 Capacity to avoid adverse impact of energy disruptions caused either by
natural, accidental, or intentional events affecting energy and utility supply
and distribution systems
US Department of
Defense
Source: Author’s compilation from multiple sources
59
Table 3 (Continued)
2.5.
Energy Security Definition – An Analysis of Energy and Security
The Energy security phrase could be further analyzed by looking into the ‘energy’ and
‘security’ terms separately. The Oxford English Dictionary defines energy as “the strength and
vitality required for sustained physical or mental activity and/or power derived from the
Serial Definition Sources
48 Access to affordable, reliable and sustainable energy. Modern energy
is essential to reach other SDGs and is at the center of efforts to tackle
climate change.
World Bank
49 An umbrella term that covers a range of issues linking energy,
economic growth and political power, such as the security of energy
supply, the level and quality of access, and uncertainty over prices.
World Economic
Forum
- Global Energy
Architecture
50 Autonomy, energy supply that is within the control of a country and
free from disruption by external agents; reliability, or distribution that
is safe and meets demand without interruption; affordability, or prices
commensurate with the buying power of consumers; and sustainability,
or sufficient supply of energy to support a high quality of life without
damaging the environment.
World Economic
Forum - Global Risks
2009
51 Reliable, stable and sustainable supply of energy at affordable prices
and social costs. Exploring and implementing long-term sustainable
solutions in this complex field are vital to promote peace and economic
growth.
World Economic
Forum
- “Global Agenda
Counsel”
52 The absence of, protection from, or adaptability to threats that are
caused by or have an impact on energy supply chain.
Winzer
53 From a European perspective, as a significant energy consumer and net
importer of oil and gas, energy security means access to reliable
sources of energy, at competitive prices, produced in environmentally
responsible and safe manner. From an Algerian perspective, as a
significant energy producer and net exporter of both oil and gas to
Europe, the concern is not so much about security of supply, but
security of demand.
Witton183
54 The availability of sufficient supplies at affordable prices. Yergin184

60
utilization of physical or chemical resources, especially to provide light and heat or to work
machines.” Energy should also be perceived as part of a system that helps individuals to
continue maintaining their standard of living and societies to develop and prosper. Energy
supports “the basic necessities of modern human life, industry, and transportation.” Goldthau
and Savacool define energy as:
…the socio-technical system in place to convert energy fuels and carriers into services
—thus not just technology or hardware such as power plants and pipelines, but also
other elements of the ‘fuel cycle’ such as coal mines and oil wells in addition to the
institutions and agencies such as electric utilities or transnational corporations that
manage the system. It’s not only extracting natural riches from the ground but
processing in a responsible way is crucial for how we use the energy.187
Security is defined as “the activities involved in protecting a country, building or person
against attack, danger or threat.”188 While the absence of threats could also be used as an
approach to describe security, it is generally related to “an actor, activity, technology, or
system.”189 Protection against attacks, such as terrorism or piracy, could easily be rendered
into using military means to ensure uninterrupted flow of resources and the physical
protection of exploration, production, transition and distribution of supplies. This could be
alluded to external and/or internal factors that could be measured against objective criteria.
However, an individual’s perception of security is subjective. While it is difficult to measure,
subjective security could be an important aspects of policy development. The external and
internal threats might originate resource nationalism and energy exporting countries control
over the resources to utilize supplies achieving political ends or poor infrastructure and
inefficient markets. The energy security definitions lead us several ways to cluster and
categorize energy security. Securitization of energy along national and state centric lines
encompasses vulnerability of energy dependent countries, concerns over the international
balance of power and national security, protection of state and its functions. The human
security viewpoint focuses on “safety from chronic threats such as hunger, disease and
repression; and protection from sudden and harmful disruptions in the pattern of daily life”
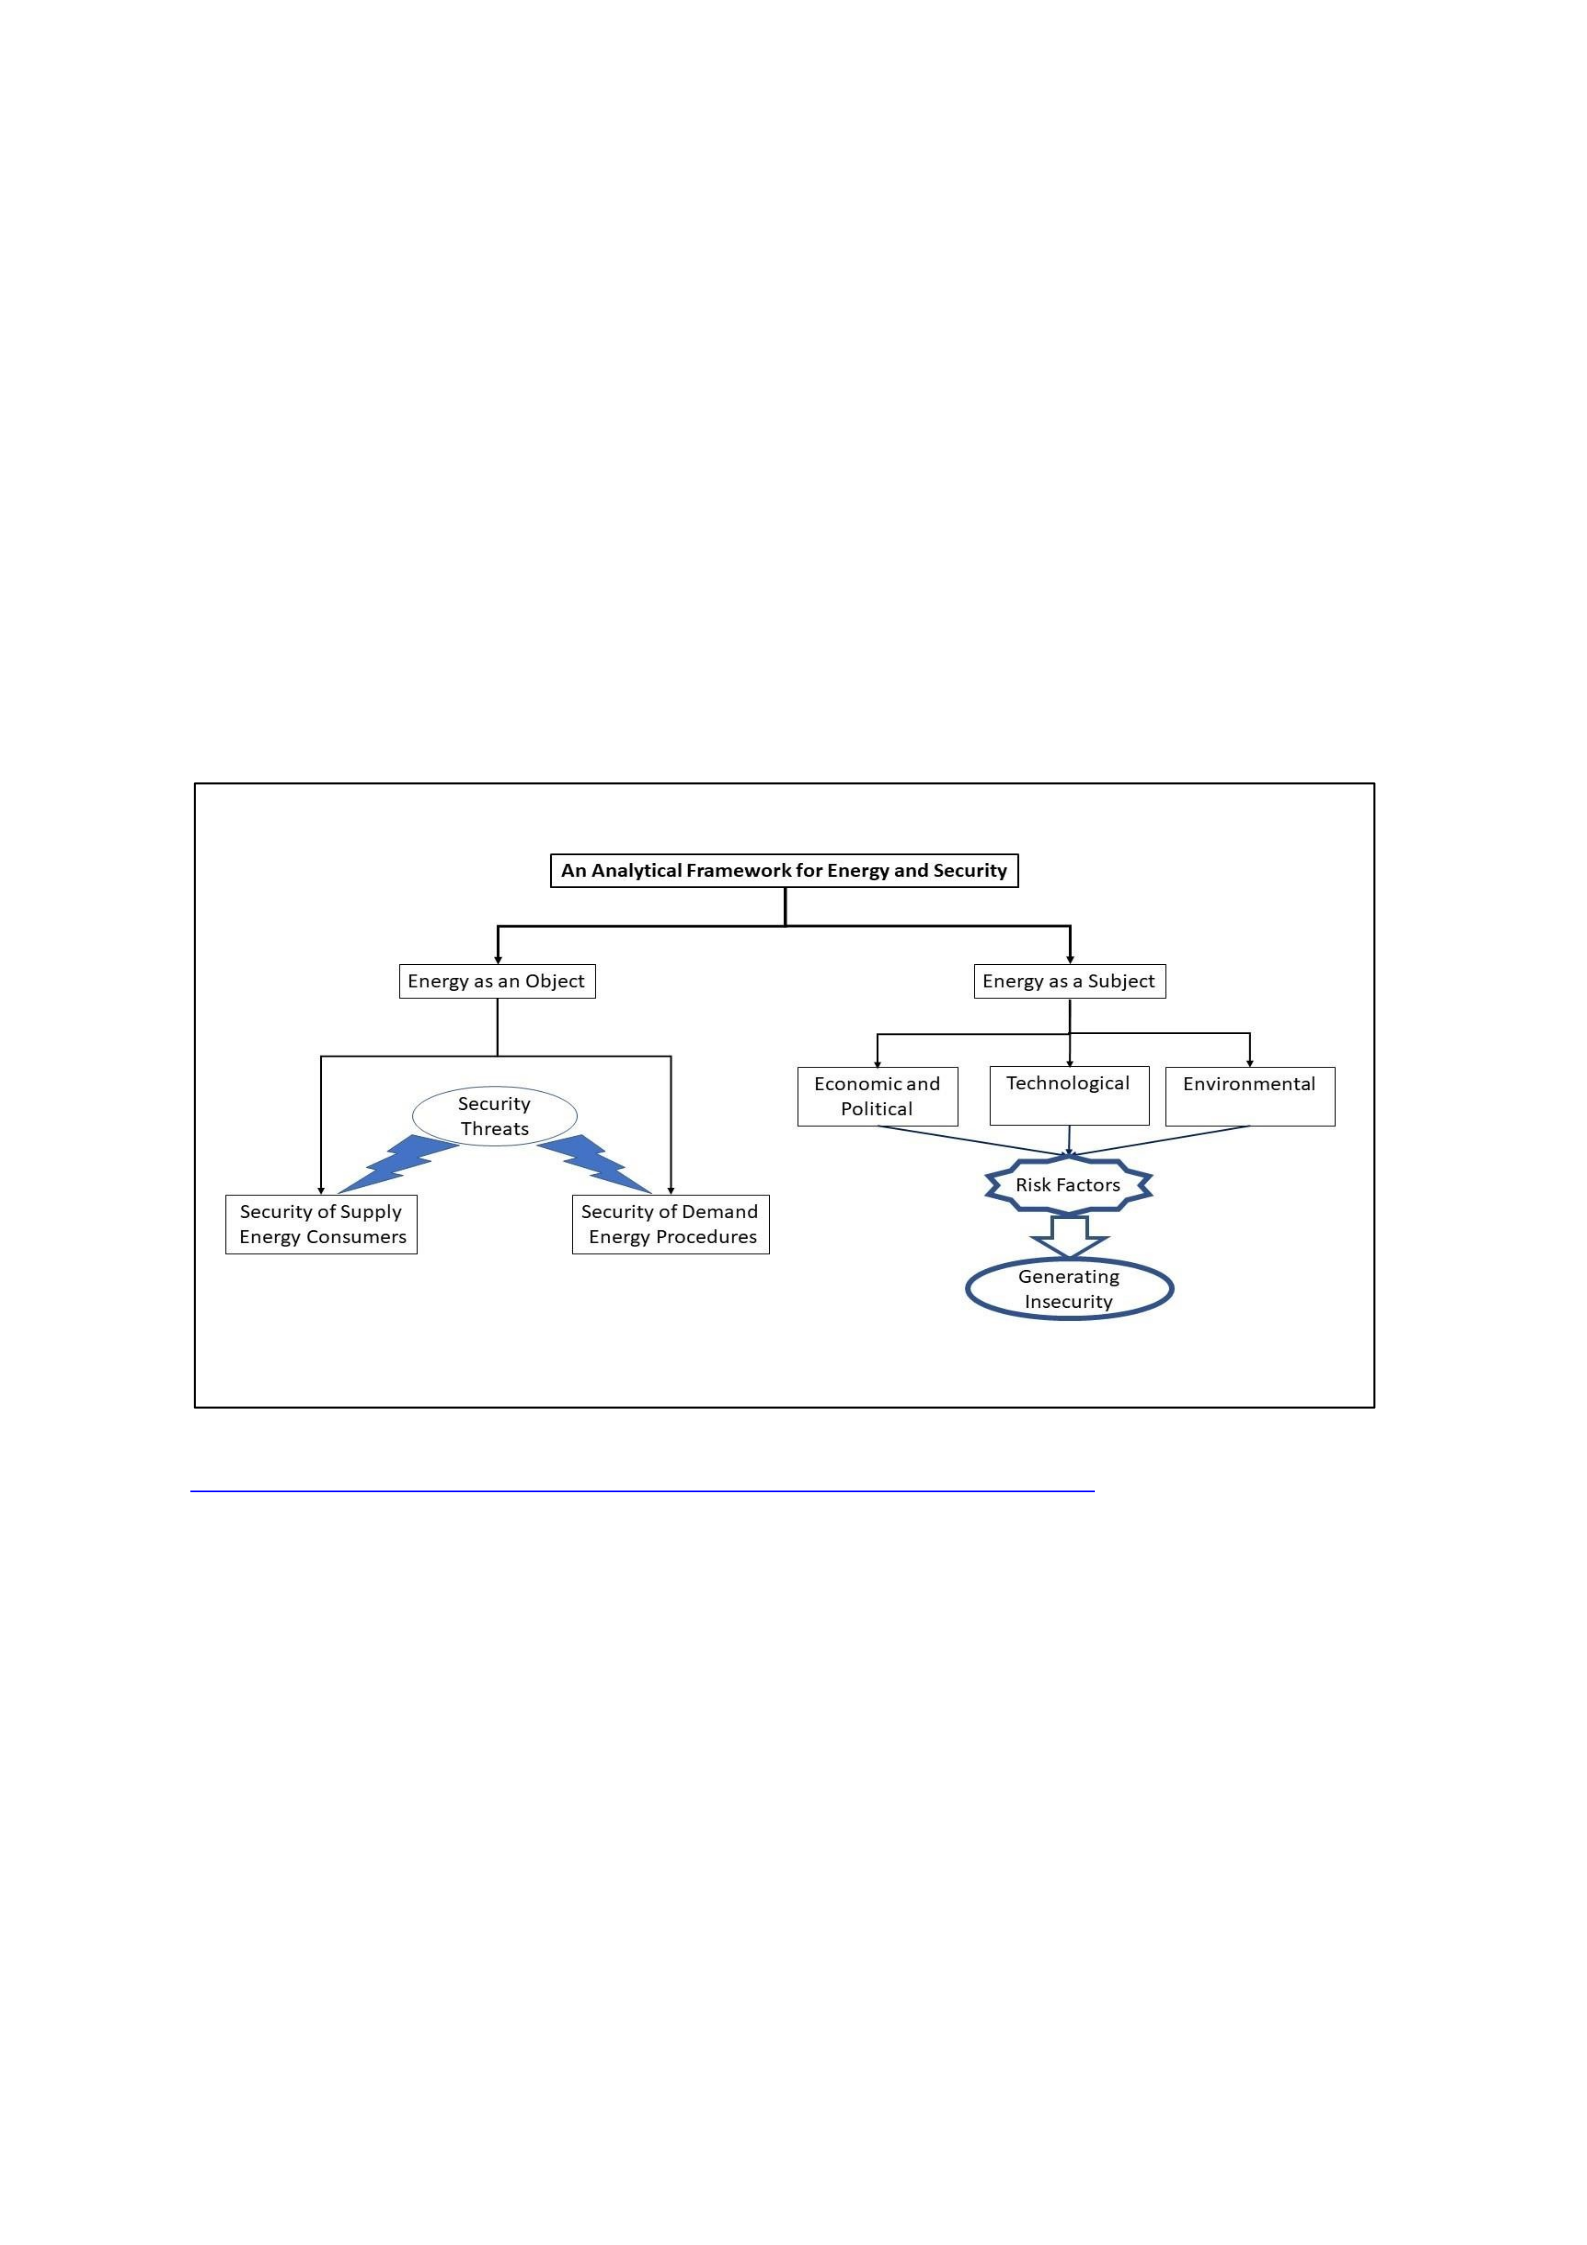
61
that addresses security concerns of individuals. Energy security could be part of any
discussions along these lines. As depicted in Figure 2, Johansson uses two main frameworks
to cluster and categorize key aspects of energy security:
- First, energy system as an object with a focus on energy supply and demand
security;
- Second, energy system regarded as a subject generating insecurity and acting
as a threat multiplier.
Figure 2: Analytical Framework to Study Energy and Security Relations192
Source: Bengt Johansson, A broadened typology on energy and security,
https://www.sciencedirect.com/science/article/pii/S0360544213001886?via%3Dihub
An energy system includes a set of technical and non-technical components that allow
delivery of energy from production to the end-users. The first framework, energy as an object,
is further bifurcated into two angles, security of supply and security of demand. Johansson
argues, “A well-functioning energy system has at least two aspects, security of supply and
security of demand.” While these two perspectives differ significantly based on one’s place in
an energy system, there is a fundamental relationship between securing energy supply and

62
demand based on market dynamics. Energy systems as an object are vulnerable against
external and internal threats, and they need to be protected to ensure they deliver services for
individuals and society to accomplish their functions.
Security of supply consists of a system from exploration, extraction, preparation
(liquefaction), transportation using pipelines or other means, refining, and distribution to the
end users. External and internal, man-made, and natural threats could affect this system any
time, resulting in potential disruption of the supplies. Energy interruption, price shocks, and
long-term high price levels are considered threats to security of supply. Uninterrupted and
stable supply of energy resources is a key prerequisite for provision of supply security that is
mostly a concern for energy importers. Most of the EU members fall into this category due to
their dependency on energy imports. Therefore, the EU energy strategy focuses on resilience,
protection of the critical energy infrastructure, resource availability, and market-based supply
and demand relationships.
Energy exports are a key source of income for the economy and the national budgets of
energy producers and exporters. In order to maintain a stable income, security of demand is a
major concern for these countries as the energy sector’s share is large in their industrial
production. For example, oil and gas revenues contributed to 36% of the Russia’s federal
budget in 2016, and fossil fuels accounted for as much as 63.2% of Russia’s export in 2017.
While consumer countries would like to push prices low as much as possible, exporting
countries benefit from the high energy prices. An increase in oil prices between 2003 and
2008 caused a global financial crisis which allowed Putin to build Russia’s public finances
before the global economic meltdown. Based on IEA and BP reports, “Russia is the world’s
largest exporter of energy resources: #2 for oil exports, #1 for gas exports, and #3 for coal
exports in the world in

63
2017.”196 Security of demand is critical for the Russian economy as well as Central Asian and
Caucasus countries.
Price volatility and energy competition are considered as external threats against the energy
system and cause concern not only for consumers but also for producers. Stable energy prices
and security of transportation networks form mutual interests shared with the energy
importing and exporting countries. Energy exporters also focus on the protection of their
market shares. Russia has provided alternative gas pipeline projects to reduce interest in the
Nabucco project, moving gas from Turkmenistan and Azerbaijan through Turkey to Europe.
Russia uses every overt and covert means to prevent, delay, and when possible, control
Central Asian and the Caucasus region’s access to international markets. Putin was successful
for the cancellation of the Nabucco projects. Russia’s gas supply to Europe has been at the
heart of a geopolitical competition and one of the key drivers for the Russian intervention in
Ukraine.
As a subject, energy systems could generate security concerns or could become a threat
multiplier in several ways based on: economic and political, technological, and environmental
risk factors.197 Energy systems are highly politicized and contested. Large projects such as
Nord Stream 1 and 2 have become contentious, involving major powers, international
organizations, industry, state-owned enterprises and financial institutions. For example, due to
US sanctions, the Nord Stream 2 project was delayed when it reached the final phase of
construction. Political and economic aspects, such as Western sanctions due to Russia’s illegal
annexation of Crimea, affected technology transfer to the Russian energy sector. Critical
energy infrastructure has been targeted over the years, and it will continue to be targeted by
not only physical means but also cyber-attacks. Sovacool lists countries that were subject to
attacks on critical infrastructure:
Afghanistan, Angola, Argentina, Bolivia, Brazil, Chile, Cyprus, Egypt, El Salvador,
Germany, Guatemala, France, India, Iran, Ireland, Iraq, Israel, Italy, Japan, Korea,

64
Kuwait, Lebanon, Libya, Mozambique, Netherlands, Nicaragua, Nigeria, Portugal,
Puerto Rico, Qatar, Saudi Arabia, Singapore, Spain, Sweden, Syria, Taiwan, Turkey,
Uganda, United Kingdom, United States, Vietnam, and Zimbabwe.
The most recent attacks occurred in Eastern Europe and the Baltics, where Ukrainian and
Estonian energy infrastructure were targeted by technology-based threats. Growing use of
electronic, digitized and internet/intranet-based control mechanisms and management systems
have increased vulnerability of energy systems against individuals, non-state and state actors.
While these points establish a foundation for initial analysis using both qualitative and
quantitative data, parameters and indicators measuring energy security might change over
time. For example, increased focus on decarbonization and change in climate related policies
over energy mix could also affect prioritization at individual, local, national, and global
levels. Changes in market dynamics, extreme weather events, technical and operational
deficiencies could influence production capacity resulting in supply interruptions. These
external and internal factors have direct influence on supply and demand dynamics and
relations between energy producers, transit countries and consumers.
2.5.1. Key Elements of Energy Security – Availability, Reliability, Affordability, and
Sustainability
Energy security definitions listed above in Table 3 could be further categorized based on
traditional factors that are mostly perceived as the lowest common denominator: availability,
reliability, affordability, and sustainability.
- Availability: the physical existence of energy resources and services, oil, gas,
coal etc. and users/consumers ability to acquire what they need. Elkind argues
that:

65
oAvailability requires the existence of commercial energy markets in which
buyers and sellers trade energy goods and services, markets that take shape
only when parties agree on terms that accommodate the commercial,
economic,
political, strategic, and other interests of buyers, sellers, and shippers.
Mutuality of interest among players in the value chain is therefore a prerequisite for
energy security. o While many energy resources are available in nature, such as the
Arctic region which holds 13% of the world's undiscovered oil and 30% of its
undiscovered gas,200 they require extensive investments, advanced technology, and
physical conditions to explore and extract them. These resources are available, but
they are costly and difficult to extract. Additionally, the creation of markets requires
legal and regulatory frameworks that are acceptable to all parties involved.
Therefore, availability involves multi-stakeholders and mechanisms based on
markets and regulations to allow users/consumers to secure these resources. -
Reliability: Disruption of energy supplies is a major concern for
users/consumers as well as producers and exporting countries. Uninterrupted energy
flow is an essential part of market dynamics as well as maintenance of basic services
such as heating homes, offices, and schools; operating factories and supporting
industry; and providing power for hospitals and transportation. The disruption of
energy systems could be a result of external and internal threats that include man-
made and naturel causes. For example, recent hurricanes Katrina, Rita, and Sandy
have undermined US domestic supply chains while terrorist or cyber-attacks have
disrupted supplies in other countries. The following measures enhance reliability
while improving energy security:

66
o“Diversification of sources of supply, o diversification of supply chain used
for processing, transporting, and distributing energy, o resilience or the ability
to handle shocks and recover from failures, o reducing energy demand to ease
the burden on infrastructure, o redundancy in case failures occur (especially in
energy infrastructure), o creating emergency stocks, o disseminating timely
information to markets.”
- Affordability: Energy prices affect users/consumers choices, and if energy is
not affordable, it cannot be used. IEA data shows 1.1 billion people do not
have access to electricity worldwide; this is also referred to as energy poverty.
The affordability aspect of energy security is not only related with the high or
low levels compared to consumers’ income levels; the volatility of price is
also a concern. Consumers naturally prefer low energy prices. However low
prices could motivate an increase in energy consumption and might have
negative impacts on the energy mix of countries. Governments might focus on
short term benefits and delay environmentally friendly and technologically
advanced energy solutions due to higher costs of such policy choices. Elkind
argues that getting energy prices at the right level is one of the central
requirements for improving energy security.
- Sustainability/Acceptability: This mainly addresses environmental concerns
related to energy systems/industry and is also referred to as acceptability. In
recent years, increased attention has been directed to adverse effects of
climate change and environmental security. The use of fossil fuels, coal,
hydrocarbon gas liquids, natural gas, and petroleum have caused greenhouse
gas emissions. Growing public pressure and changes in environment have
increased emphasis on environmental sustainability with implications for coal

67
power plants to the automobile industry, air travel, and other areas that drive
energy consumption. Climate change will continue to increasingly affect the
energy mix of countries. The most recent European Commission analysis
highlights achieving climate neutrality by 2050 under its green resilience
objective. This report states, “This entails eliminating our dependency on
fossil fuels, reducing our impact on natural resources…changing lifestyles,
production and consumption patterns, and climate proofing infrastructure.”
Elkind highlights that energy infrastructure typically is long-lived and past
decisions are expected to remain valid for another decade or more.204
Therefore, climate change related policies and decisions will affect energy
security approaches from both consumer and producer countries driven by
supply and demand dynamics. Technologies used to increase energy security
will also be driven by climate change policies as governments’ taxes and
subsidies are expected to be shaped by public concerns.
- These key elements of energy security will be affected by a number of
components that are shaped by threats to energy security. These threats vary
from increasing extraction costs to national policies, legal regulatory or
environmental concerns as well as man-made or natural disasters, political and
military
interventions.
2.5.2. Key Elements of Energy Security – Alternative Approaches
The definition of energy security depends on one’s place in the energy system and it means
different things to different people under different circumstances and situations. Additionally,
energy security as a concept is extended to areas such as climate change and energy poverty

68
that are related to energy policy issues. While there are different definitions, the meaning of
energy security also depends on the problems that are being considered. The differences are
largely driven by national priorities of respective countries in the energy system. Pundits of
social scientists, in particular those studying energy security, provide clarity and increase
explanatory and predictive force by not trying to eliminate the differences in energy security
definitions.206
Alternative approaches to define energy security go beyond availability, reliability,
affordability, sustainability/acceptability and posit the following three questions:
- Security for whom?
- Security for which values?
- From what threats?
In their analysis, Cherp and Jewell reinforce Buzan’s argument that a concept of security that
fails to ask Security for whom? makes little sense. While early energy security studies of the
1970s are clear in their explanation of referent object as oil-importing industrialized nations,
“the scope of contemporary energy security studies goes beyond OECD oil importers to
include nations of all levels of development that extract, import, export and use a variety of
energy sources and carriers.”207 Energy security systems also involve private consumers, other
non-state actors such as industry and businesses, energy companies, and in particular state-
owned enterprises, that have increased their influence on policy development as well as
prioritization of energy related investment. Early energy security definitions address concerns
of oil/gas importing countries/nations, which have a different interpretation of energy security,
Affordability for whom? This was not explained well especially to private consumers,
industry, and businesses. Household and private consumers would like energy prices low
compared to their income, and businesses would like to maintain a competitive edge and

69
maintain low energy prices. On the other hand, energy companies focus on profitability and
business continuity.
The second key question is Security for which values? This investigates whether energy
security definitions analyze the link between energy security and relations with human values.
Cherp and Jewell argue that in the 20th century, “the classic energy security studies proceeded
from the strong, self-evident and implicit connection between national values such as political
independence and territorial integrity and a particular energy system: oil supplies.”209
However, in the 21st century, energy security concerns extend beyond oil to other energy
sectors such as natural gas. It also moves beyond traditional geopolitical values and is
connected with social, environmental and political values. Therefore, energy security metrics
move beyond geopolitical issues but include environmental and other concerns that might be
more interested to the public and drive policy development.
The final question is From what threats? This question elaborates on the differences between
potential risk to disrupt energy supply/systems and resilience to maintain business continuity
in case a disruption occurs. Resilience-enhancing policies, including green resilience, have
become a strategic focus for the European Commission’s post-COVID 19 recovery agenda.
Understanding sensitivities and vulnerabilities of the energy systems could enable alternative
approaches and further contextualization of energy security. Cherp and Jewel suggest that
“low vulnerability of vital energy systems” could describe energy security and allow
conceptualization of recent developments and potential future energy systems.
2.6. Evolution of Energy Security Concept
There are two different narratives in regard to the development of the energy security
concept. The first narrative focuses on how exponential transition from human power in
premodern agrarian societies transformed to fuel-based industrial societies. Once scarce and
expensive energy resources have become widely accessible and used by large populations,

70
providing prosperity and development to Western countries. This monumental change in
human condition is driven by availability and affordability of energy resources. While the
better human conditions get, the demand for energy increases. The increase in demand is
directly correlated with the increases in human population and condition. The second
narrative agrees on the effects of the energy driven transition in societies. However, it
questions equal and fair distribution of “the resulting economic and political conditions,
highlighting the structural inequalities and the unevenness of global development.” 211
The rapid economic growth in the 1950s and 1960s in Europe and in Japan increased demand
for oil and “had a transformative impact on the world energy scene and on global politics…
commercial competition could turn into a national rivalry that cast in terms of threats and
security, disrupting the working relationships that the world economy requires.”212 During the
1973 Arab-Israel War, in protest to US support of Israel, Arab states stopped exporting oil
shipments to the U.S. and its allies. The oil shortage has caused economic, social and political
problems that resulted in further securitization of the subject. The most recent examples are
Russia’s cutting gas delivery to Ukraine in 2006 and 2009 to leverage political outcomes. The
effects were felt not only in Ukraine, but also in Europe, and exacerbated concerns in Eastern
European and Baltic countries that have higher dependence on Russian energy resources.
The concept of energy security is also closely linked with geopolitics and national security
concerns of the parties involved. This is not a new phenomenon. Securitization of energy goes
back to 1911 when British ships using coal were converted to using oil. This change enabled
the British to increase their ships’ speed and allowed more space for weapons and
ammunition; however, it created another problem: finding a secure oil supply. Although
securitization of energy is commonplace, the source of national concerns differs significantly,
increasing the complexity of the subject. The following are a few different examples of how

71
energy security is achieved or considered as a market-driven relationship based on global
governance mechanism:
- After its independence in 1990, Lithuanian leadership recognized that total
reliance on Russian resources undermined their national security. They
adopted a policy to diversify energy supply both in oil and gas.214
- Retired Admiral Dennis Blair, in his testimony to the US Senate, argued that
excessive dependence on oil for transportation was inconsistent with the U.S
national security strategy. He was concerned for the increased reliance on a
volatile region of the world.215
- The U.S. limited oil exports to China after the communist revolution in 1949
and then cut oil supplies with the outbreak of the Korean War, affecting
Chinese military operations. This development still echoes today and has
pushed China for self-reliance for defense and economic development,
resulting in energy security becoming a crucial aspect of Chinese national
strategy.216
- Oil and gas have powered the Russian economy since the collapse of the
Soviet Union, and they have become the engine of recovery and growth, the
number one source of government revenues, while heavy reliance on oil and
gas has also created vulnerabilities. During a NATO organized international
conference in 2012, in Zagreb,
NATO and EU members complained about the security of energy supply and Russia’s
actions to cut gas flow through Ukraine in 2006 and 2009. The Russian Ambassador
stated that demand security is their biggest concern.
- To avoid the Russian sphere of influence in Central Asia and the Caspian
region with its vast energy resources, the US and the West focused on

72
potential reintegration of the region into the world energy market to increase
diversification and contribute energy security. Regional countries were not in
a position to disengage from Russia, “as the Azeri national security advisor
put it, ‘Oil is our strategy, it is our defense, it is our independence.”’218
- Kazakhstan had similar complex post-Cold War geopolitical struggles in
relations with Russia, striking a balance between re-definition of former Soviet space a
new Russian near abroad strategy – and the rest of world. The geography of Central
Asia was an additional challenge in getting oil and gas to global markets due to a lack
of sufficient infrastructure, excluding those controlled by Moscow.219
- In addition to Central Asian and the Caucasus countries, players included
Russia, the U.S., the EU, China, Iran, and Turkey, with different objectives
and priorities. Where those objectives converged and were supported by the
markets, energy and pipeline politics produced positive outcomes, while
struggle and competition continued elsewhere.
Is energy security being perceived as a military concept or an economic one? Does it make
any difference whether it is a military or economic concept? These questions were reviewed
by Esakova, who concluded that “In purely economic terms, energy security is measured as
the physical supply interruption and non-emergency price level. In military terms, energy
security is defined as an equivalent to national security, i.e., an essential element guaranteeing
a country’s military security.” The gas crises in 2006 and 2009 between RussiaUkraine started
as an economic crisis, then evolved into a military conflict in 2013 and 2014. Physical supply
interruption was used to coerce other parties to achieve political ends. Therefore, it is difficult
to differentiate whether energy security is in an economic or security context. This issue has
also been reflected at the EU and NATO. While it deploys military forces against piracy and
terrorist threats, the EU perceives energy security as an economic issue and develops

73
strategies to deal with challenges by utilizing market forces. NATO is more concerned with
the high-level dependency of its members on foreign energy suppliers and distribution
networks. NATO member nations are also interested in energy supply chains spreading across
the globe that increase potential for disruption by state and non-state actors.
European Energy Security Strategy highlights that energy security is a market-driven
economic concept and should be dealt with by cooperation and the energy development of
internal markets with increased interconnections.222 However, this approach has not been
followed by Russia. Dellecker and Gomart argue that “…in Eurasia as anywhere, energy and
geopolitics are closely intertwined…Russia’s official energy strategy to 2020 urges the state
to be deeply involved in the energy sector so as to protect the country from both internal and
external threats...the official strategy notes that “energy security is the most important element
in Russia’s national security.”’223
Energy security is perceived to be part of national security for any state. Esakova argues that
“Energy resources are a power resource and one of the major measures for a state’s influence
and power both on the national and international level.” As a consequence, states highly
dependent upon imported energy perceive this dependency as a source of national
vulnerability and follow an increasingly geopolitical approach. The consumer states sense of
vulnerability is exacerbated due to location of natural resources in volatile regions such as the
Middle East and Central Asia, “where weak and fragile states with multiple internal sources
of conflict”225 and a lack of institutions that help to alleviate distrust while setting conditions
for cooperation exist.
The Russian approach to Ukraine and Europe has significantly been influenced by realist
thinking. Esakova argues that “…the realist conditions in [the] energy context suggest that
survival in the international system of anarchy is possible only by means of securing the
state’s individual access to energy resources.” The realist-oriented energy security framework

74
is widely supported and accepted as one of the key dynamics of competition and conflict
between the United States and China. However, gaining energy independence and becoming a
major supplier of oil and gas after the shale gas and oil revolution, United StatesChina
relations in the energy domain has been influenced by market dynamics, while competition
shifted other areas such as technology and trade.
Competition for resources has also changed the way states approach energy security. Central
Asia and the Caucasus (Caspian Sea basin) has emerged as a potential area with vast untapped
resources which has instigated the New Great Game to access and control energy resources of
the region.227 Dannreuther also suggests that “The perception of Russia’s stranglehold on
Europe has similarly influenced Western perception Russia’s policies towards Ukraine.
Popular and elite discourse have resurrected the idea of a renewed post-Cold War
‘great game’ in Central Asia …as part of a geopolitical struggle between China, [the] West
and Russia over oil, gas, and mineral resources of these regions.” Based on Collier and
Hoeffler’s research on the causes of post-Cold War civil conflicts, Dannreuther highlights that
the main cause of these conflicts are not grievance issues as generally perceived, but rather
driven by “greed and material rewards offered in particular by control of natural resources.”229
2.7. Conclusions
Energy security is contested, multifaceted, and highly politicized, and it is likely to remain
one of the most disputed issues in international relations. There is no agreed definition of
energy security or a shared understanding of the energy security concept. The strategic and
geopolitical role of energy will continue as the concerns for security of supply occupy
decisionmakers agendas along the lines of the four ‘A’s – availability, accessibility,
affordability and acceptability. While energy disruption could happen for a variety of reasons
such as failures of technology, natural or man-made disasters, extreme weather events, using
oil as a political weapon like what happened in the 1973 AOPEC oil embargo caused a

75
haunting damage on the long-term legacy of energy supply and demand dynamics. Russia-
Ukraine gas crises in 2006 and 2009 resulted in supply cut-offs to Europe albeit they were for
economic reasons, as an outcome of price and debt disputes. Russia’s illegal annexation of
Crimea and ongoing intervention in Eastern Ukraine, as well as attempts to establish pipeline
networks circumventing Ukraine, brought energy security concerns to the agenda of Western
decisionmakers, especially those of energy dependent European Union members.
The literature is dominated by two competing views centered on realist and liberalist schools
of thought that explain energy relations between Europe and Russia, the world’s largest
importer and the largest exporter of gas. The realist view securitizes the issue by using
geopolitical and energy security lenses while liberals argue that interdependence is based on
economic relations, efficiency, norms, and the role of institutions. These diverging views on
energy security, based on national, economic and/or business interests, are reflected
differently in two geographic zones: Western and Central/Eastern Europe that includes
countries in Baltics and Balkans. In Western Europe, economy and efficiency tends to
predominate the views on European-Russia natural gas relations while in Central/Eastern
Europe, national security concerns come to the forefront. This might directly relate to Baltic,
Balkan and Central/Eastern
Europe’s proximity to Russia. However, Russian strategy to eliminate energy transit countries
and utilize energy prices or cut-offs to leverage political outcomes have also influenced the
development of a negative perception. As Gustafson argues, Europe, Germany in particular,
should not be perceived as a homogeneous entity in terms of views on European-Russia
energy relations. There are two different camps operating with different opinions:232 “For the
first community, economics and efficiency are the paramount explanations of events and the
surest guides to policy…For the other community, the Russian-German gas trade is

76
fundamentally about geopolitics and security, particularly the threat of gas as a weapon for
Russian political and strategic ends.”
These competing views go beyond the literature and create diverging perspectives between
and within countries, amongst energy companies, financial and economic institutions, security
and policy think tanks, as well as government ministries of countries. Albeit these differences,
European-Russia energy relations have evolved over-time since the first gas trade started in
the 1960s. This relationship survived fundamental geopolitical and geoeconomics changes
such as the end of the Cold War, re-unification of Germany, the collapse of the Soviet Union,
EU enlargement in 1995, 2004, 2007, and 2013, and NATO expansion including former
Soviet states. Russia’s illegal annexation of Crimea and intervention in Eastern Ukraine was a
watershed moment for increasing tendencies for a geopolitical approach to the
EuropeanRussian energy relations.
The EU stands out one of key players to regulate energy markets by introducing competition
doctrine and the market-based innovations for transforming and reforming the European gas
sector. Over the last six decades, European - Russia energy relations, in particular gas, have
become more complex with the involvement of transnational energy companies, stateowned
enterprises, international and supranational organizations, increasingly complex legal
requirements, as well as construction of a web of pipelines, connectors that carry gas to all
parts of Europe. The following chapter will study European-Russia energy relations but will
also include neighboring and EU aspiring countries that have a transit role such as Ukraine.
Additionally, the United States-led shale gas revolution will be discussed with its increasing
share in international markets.
CHAPTER 3
EUROPEAN ENERGY SECURITY

77
3.1. Introduction
In response to the critics of the Royal Navy’s decision to convert battleships from coal to oil,
Churchill told them the fundamental principles of energy security: “On no one quality, on no
one process, on no one country, on no one route, and no one field must we be
dependent.” In another occasion, he said, “Safety and certainty in oil lie in variety and variety
alone.” While energy concerns focused on supplying military forces, armies, and navies, in the
beginning of the 20th Century, there has been a shift towards using energy to support rapid
industrialization and development after World War II. The idea of diversification has been the
cornerstone of European energy security.
Initially, natural gas was seen as a by-product of oil and was paid little attention as a
commercially valuable energy source due to challenges to transport natural gas over
longdistances. A gradual change of natural gas use as a source of energy coincided with the
end of the war. Oil industrialists realized natural gas could be used as an energy source on its
own and started building pipelines. Natural gas became one of the main drivers for optimism
and postwar economic growth between the mid-1940s and the AOPEC oil embargo in 1973.238
The energy crisis brought energy security concerns to the public eye and policy makers’
attention due to increasing pressure to reduce energy dependency on external resources,
especially to a single source. Hogselius argued that, “Mentioning energy and geopolitics in
the same sentence evokes memories of dramatic international events and crises such as the
1973 oil embargos,
Russia’s alleged use of natural gas as a foreign policy tool.”
In this chapter, I will explain the evolution of natural gas in Europe and increasing
dependency on external sources, especially to Russian natural gas. I will start with the
development of the European natural gas market and initial Soviet Union exports headed for
Europe in late 1960s during the Cold War. This will be followed by the evolution of European

78
as a single market as Central and Eastern European countries joined the European Union and
NATO, which resulted with a significant impact on the EU’s gas dependency to a single
source. At the same time, Russia’s growing desire to control pipeline networks to increase its
leverage over the former satellite or Soviet republics - in its ‘near abroad’- where energy
dependency is generally higher.
I will also review the EU’s search for a common energy policy and creation of an Energy
Union initiative to counter Russian influence. In this context, the differences between Western
and Central/Eastern European countries and the latter’s energy security concerns are studied.
European attempts to meet increasing demand for natural gas and to reduce dependency to a
single source by diversifying natural gas imports whether via pipelines or LNG terminals will
be reviewed.
3.2. European-Soviet Union Energy Relations - Natural Gas in Europe
3.2.1. Cold War Period – Eastern Europe
European-Soviet Union, later European-Russian, energy relations started with oil transactions
and have evolved over time with the first gas trade which started in the late 1960s. The Soviet
Union had large oil, natural gas, and coal reserves and had the capacity to provide cheap gas
in large volumes. There were two trends, at the time, which made Soviet gas attractive for
Western Europe, especially for Austria, Southern Germany, France, and Northern Italy. First,
there were large Soviet gas reserves discovered in Tyumen, West Siberia, in the early 1960s.
The second, relaxation in East-West relations. While the remoteness of these natural gas
reserves caused intense political debates in Moscow due to lengthy transport distances, they
were new and untouched. The following map shows the East and West Siberian, Turkmen,
and Azerbaijan oil and gas production fields and connecting pipelines.
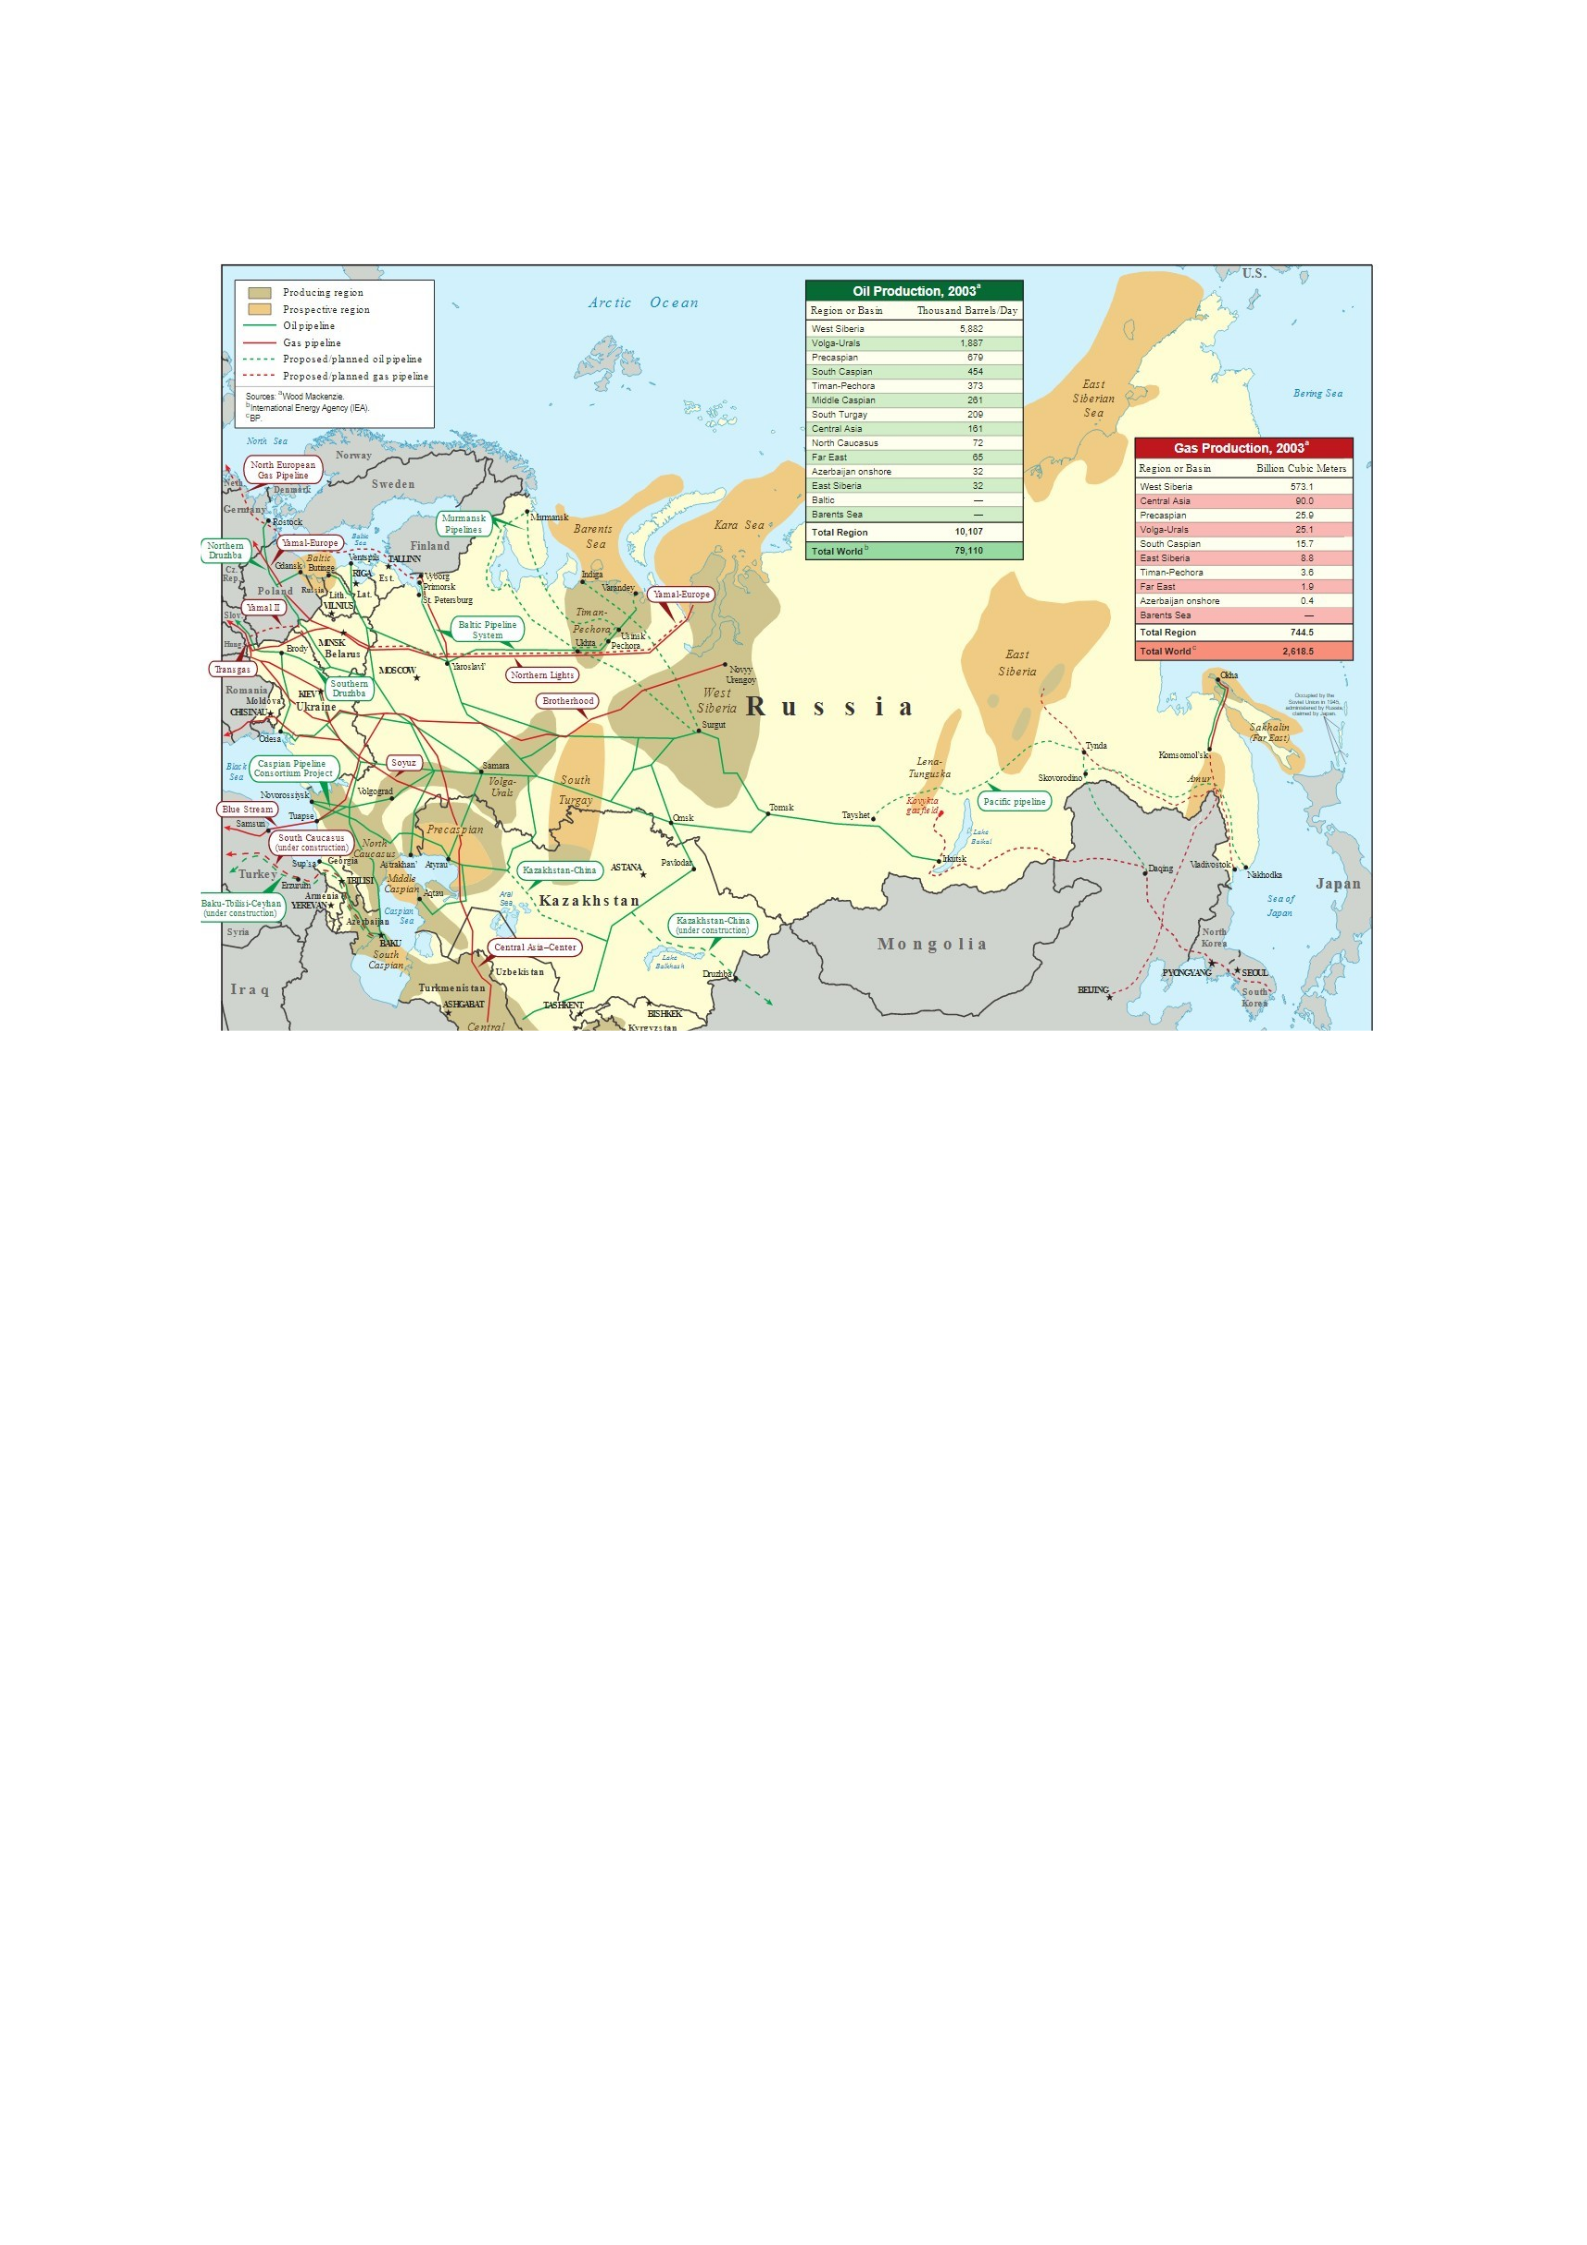
79
Figure 3: Selected Oil and Gas Pipeline Infrastructure in the Former Soviet Union
Source: US Energy Information Agency, http://www.eia.doe.gov/cabs/Russia/images/fsu_energymap.pdf
Soviet desire for increasing energy exports was driven by finding hard currency for trade
with the West. Stern highlights that, “The countries of Eastern Europe were heavily dependent
upon the USSR for supplies of oil and gas. No East European country, except Romania,
produced more than negligible quantities of oil, although Poland and Hungary are modest gas
producers.” By the mid-1960s, Moscow was able to supply oil and gas to Eastern European
countries. Grigas writes that, “Russia began using oil as an instrument of soft power,
particularly in Eastern Europe…initially supplying oil at very low prices, Russia was able
shift dependence of eastern Europe’s heavy industry sector from cheap coal to cheaper oil.”
However, by the end of the 1960s and early 1970s, when oil prices increased during the crisis,
Eastern Europe was encouraged to get oil from the Middle East in exchange for manufactured
goods and technology. The growing dependency on Soviet energy, a lack of integrated and

80
transparent pricing mechanisms, and the alleged exploitation of Eastern European importers
through price discrimination resulted in growing concern in Eastern Europe. Additionally, the
1973 Oil crisis had a devastating effect on Eastern Europeans as their purchasing power
decreased significantly.
The AOPEC oil embargo was one of the main reasons for the strategic decision for Western
Europe to establish energy relations with the Soviet Union. European countries were seeking
for other sources to diversify their energy supply. Esakova argues that while Europe
considered developing future energy relations with the Soviet Union, that was the beginning
of realizing its energy producing potential, while still being required to make major
investments in its energy sector. Therefore, their dependence on Soviet energy was
strengthened.
Soviet gas sector development was closely linked with the increasing demand in Europe.
Natural gas exports to Poland started after World War II, in the late 1940s, with very small
quantities. This was followed by exports to other Eastern European countries,
Czechoslovakia, and further extended to the south to Bulgaria and to the north to the German
Democratic Republic (GDR). Competition for pipelines in Eastern Europe started as early as
the 1960s. In referencing Harrison, Gustafson states, “In 1964, Ulbricht250 demanded that
Khrushchev commit to building a pipeline to the GDR and to begin gas deliveries by 1969.”
Ulbricht used the fact that pipelines were being built to Poland and Czechoslovakia as the
foundation of his argument. Solving natural gas transport challenges was an essential step to
move Soviet gas from giant gas fields in Urengoy, Yamburg and Medvezhe, initially to
Eastern then to Western Europe.253 Finally, Khrushchev accepted construction of the gas
pipeline to the GDR and provided economic support to save the socialist cause by avoiding
any negative comparison with West Germany. However, Khrushchev was later blamed by

81
East European socialist leaders for favoring the GDR while other Eastern European countries
requested economic support for their problems.254
The Soviet planned to extend pipeline networks from Eastern Europe to the West. In this
context, the Soviets contacted with Poland and East Germany for increasing diameters of the
pipeline and building an expansion to export Soviet gas to West Germany. This proposal was
met with strong opposition by East Germans, and Soviets were forced to cancel their demand
using a large diameter pipe. The Central and Eastern countries become large importers of
Soviet natural gas, by 1973, Poland, Czechoslovakia, and East Germany, Bulgaria in 1974,
and in 1975 Hungary were all connected to the Soviet pipeline network. Therefore, “all Soviet
satellites except Romania had become importers.”255 According to Gustafson, “This early
episode shows that the Soviets already had a larger goal in mind - to transit gas through the
satellite countries to Western Europe.” Additionally, it also indicates political relations took
precedence over economic relations, as the GDR relinquished transit benefits through gas
flow to the West.
3.2.2. Cold War Period – Western Europe
In Western Europe, natural gas was discovered and industrialized after WWII. This area
benefited from the existing infrastructure that was supporting the so-called “town gas” and
“coke gas.” Additionally, public and private players have gained experience in how to handle
natural gas. However, the development was slow and different in each country. Italy was the
first exception with major finds in Po Valley, and pipelines were built to support the
production. France had a similar breakthrough with a small discovery. LNG from the US and
Algeria become a major source for the UK natural gas supply.
In Germany, coke gas and town gas were the main sources to support consumption, managed
by municipality-owned utilities, until major discoveries of natural gas in Groningen in the
Netherlands that changed the European gas industry and set the foundation for today’s gas

82
interactions. The main European focus was shifted to the Netherlands and its giant Slochteren
gas field in Groningen. The idea of building trans-border gas pipelines started with
applications made by West German energy companies to “build a pipeline from the Dutch
border to Germany’s industrial heartlands.” This was a starting point for exporting gas via
pipelines and international gas trade. In the 1960s, the discovery of Groningen in the
Netherlands was followed by British and Norwegian discoveries of large reserves in the North
Sea. These developments coincided with the discoveries made in Soviet West Siberia and the
Algerian Southern Saharan Desert.
Austria was the first Western country that received Soviet natural gas in 1968, shortly after
negotiations started in 1967, and “it would become more dependent on deliveries from the
East than any other nation in continental Western Europe.”261 Gustafson highlights the
significance of Austria as a crucial step for showcasing that “gas exports across the ‘Iron
Curtain,’ despite ideological differences and recurring diplomatic tensions, could be
conducted reliably on straightforward commercial principles.” Austrian domestic gas
production was small and in decline. To meet increasing gas demand, Austrians were
watching the development of Soviet so-called Bratstvo (Brotherhood) Pipeline. The first
natural gas exports to Europe originated from Soviet territories closer to European borders,
such as Ukraine and the central region of Russia where initial pipelines were constructed.
Even after the Ukrainian and Easterncentral Russian gas resources were depleted, pipelines
continued to be used to transport Siberian gas to Europe. This resulted in Ukraine becoming a
transit hub for Soviet, then Russian, natural gas exports.
Extending Soviet gas from the Czechoslovak terminus in Bratislava to Vienna required
construction of 55 kilometers of new pipeline; this was more geographically advantageous
than supplies from any other source.265 Soviet gas exports to Austria made commercial sense.
However, Cold War geopolitics were also involved in the selection of Austria as an example.
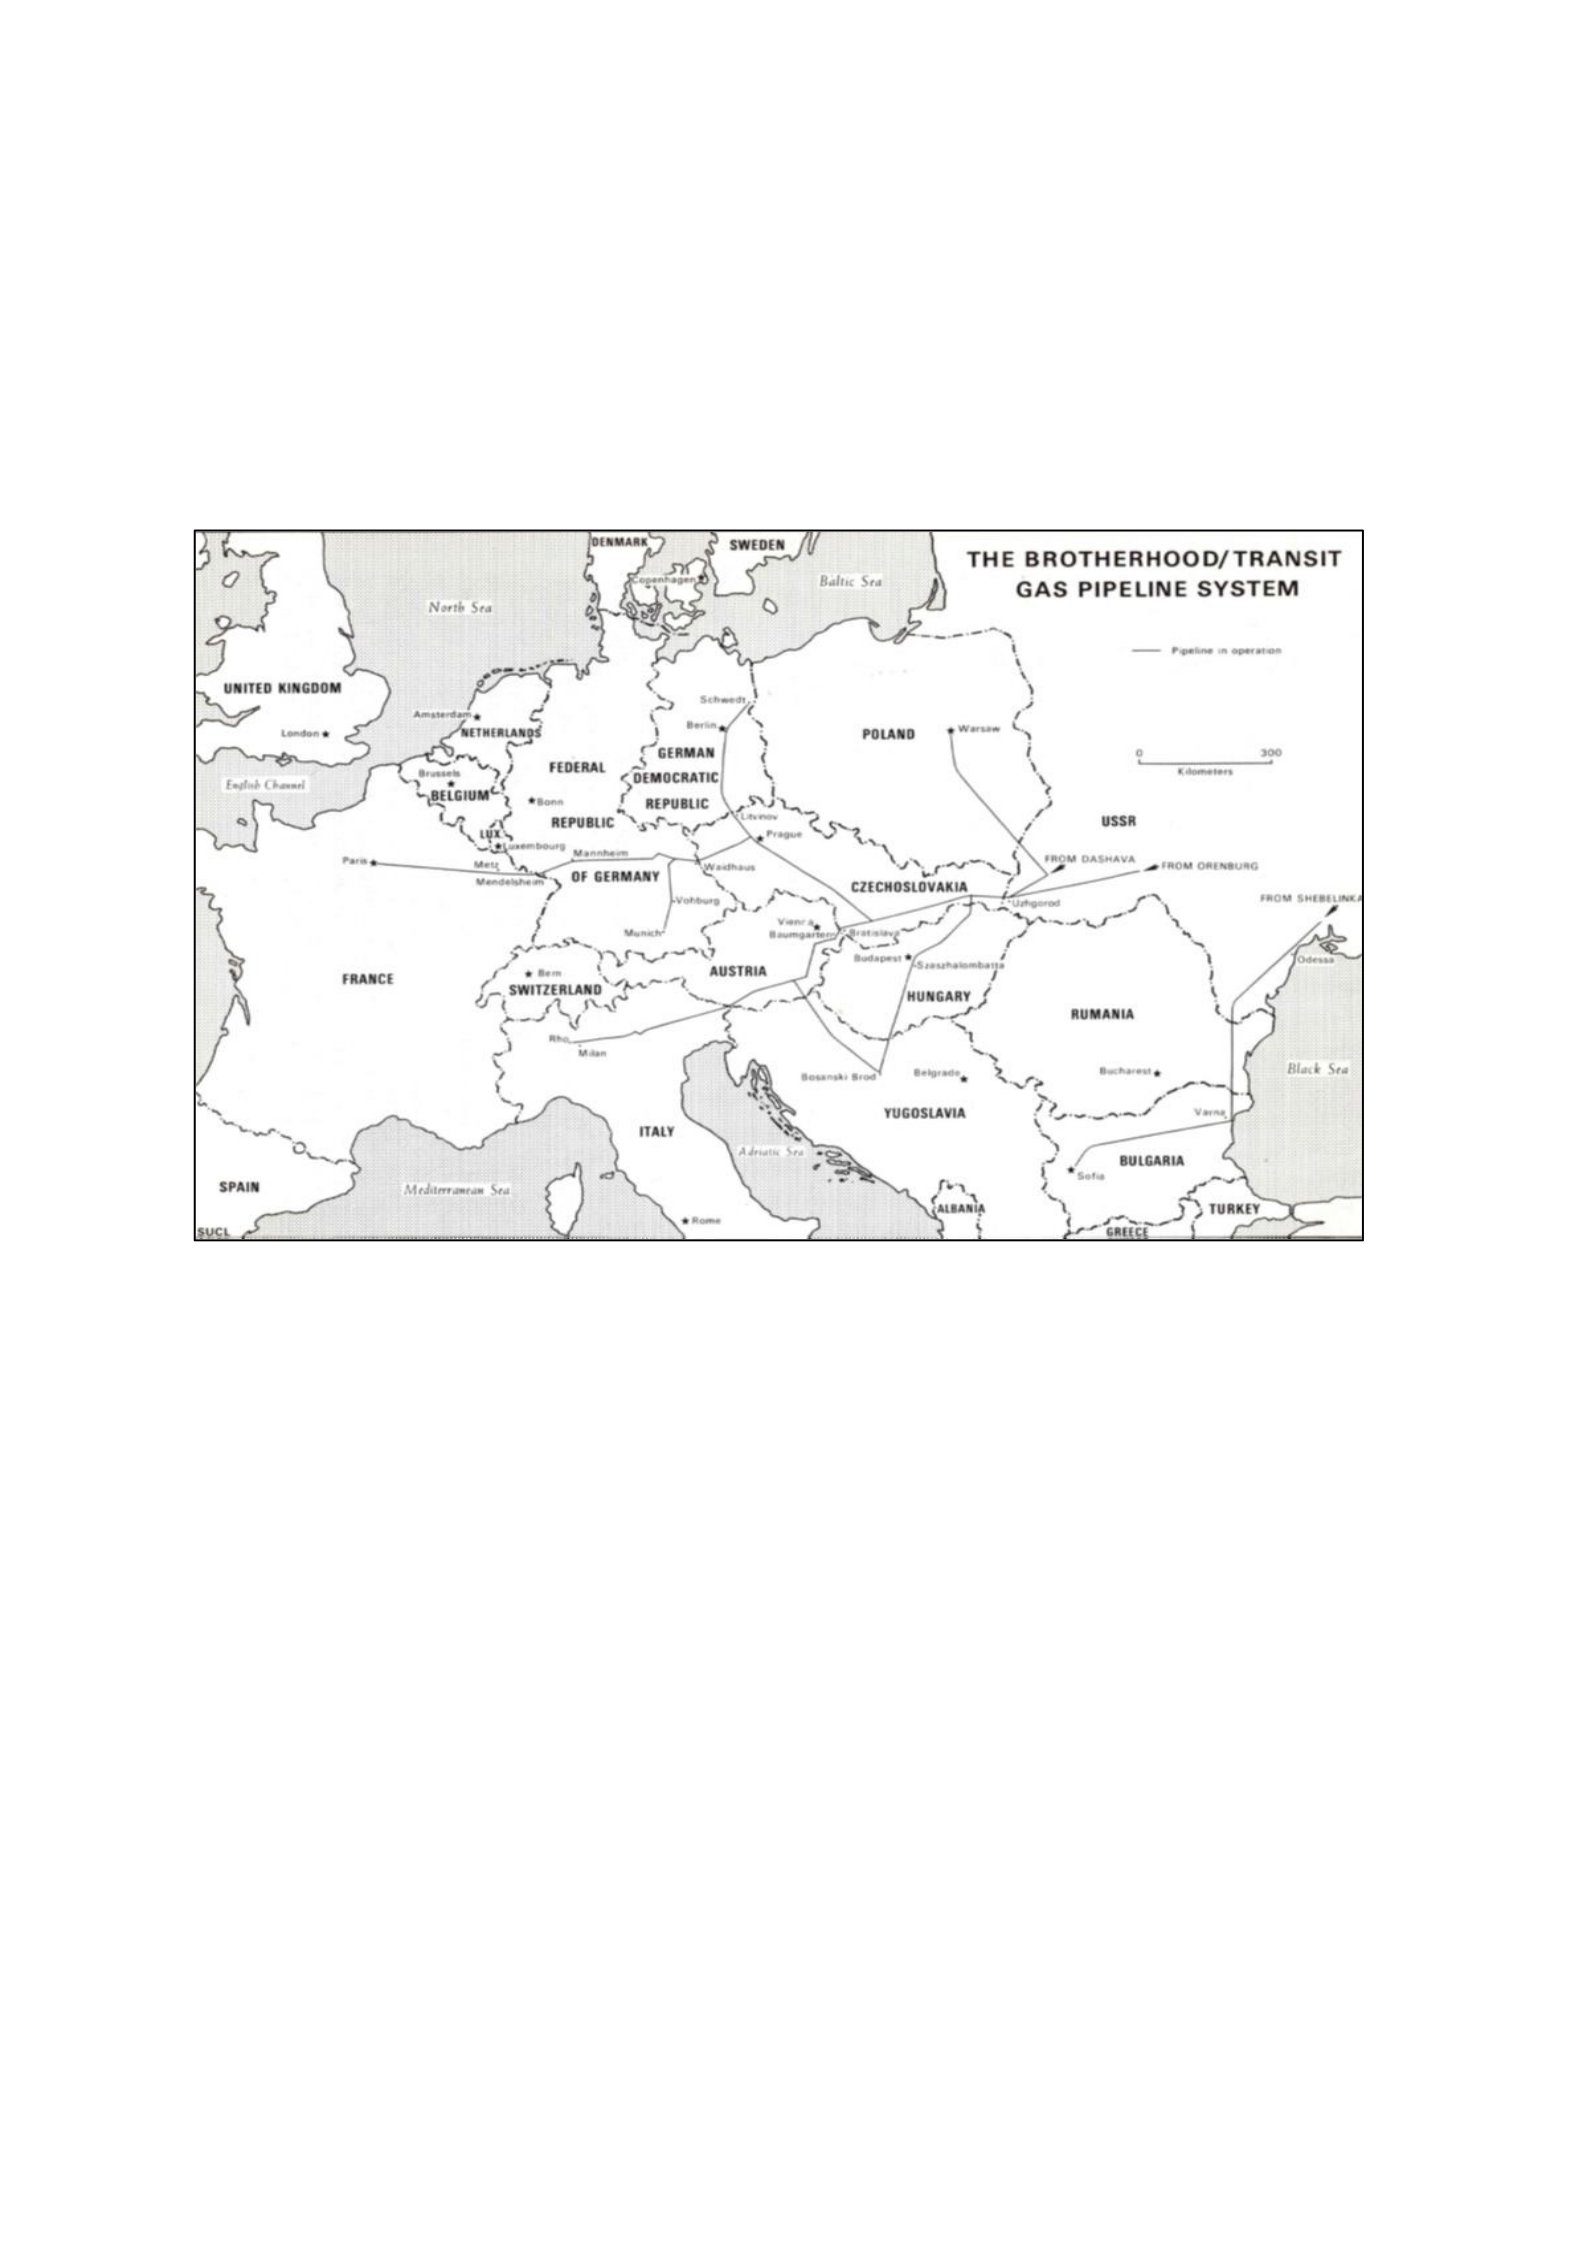
83
The Soviets wanted Austria to maintain its neutrality and were increasingly concerned about
growing attraction of the European Economic Community (EEC). Additionally, Austria
opened up potential exports to Italy while setting an example for the rest of Western
Europe.266
Figure 4: Soviet Bratstvo (Brotherhood) Pipeline
Source: Stern, Soviet Natural Gas Development to 1990, p. 60
In the early 1960s, the Federal Republic of Germany (FRG), or West Germany, was excluded
from Moscow’s export strategy due to the overall political relationship and the “antiGerman
policies formed [as] part of a broader Soviet strategy aimed at disturbing West European
integration efforts.”268 The Soviets viewed NATO and other Western organizations, such as the
European Coal and Steel Community, the European Atomic Energy Community
(EURATOM), and the European Economic Community (EEC), as anti-Soviet
establishments.269 West Germany – Soviet gas relations had multiple dimensions, and key
individuals, including both West German and Soviet experts and negotiators, government

84
officials as well as Gazprom and Ruhrgas representatives, played important roles in
overcoming diplomatic and commercial challenges. Ruhrgas signed a twenty-year contract for
Soviet gas imports. The Chancellor of West Germany, Willy Brandt, approached German-
Soviet gas relations as a geopolitical strategy that could help reducing tensions between the
West and the East. Hogselius highlights that “In a speech to the European Council in January
1967, Willy Brandt pointed at Germany’s historical role as a ‘bridge between Western and
Eastern Europe’ and…his government intended to rebuild this bridge, which had been
destroyed by the Cold War.”272
Without the role Brandt played, Gustafson argues that the first gas deal would not have
happened. This gas deal was part of larger geopolitical approach adopted by Brandt called
Ostpolitik that remained the foundation of West German foreign policy in the following
decades. Throughout the Cold War, cooperation started with gas-for-pipe deals and the
“economic sphere was perceived as a major element of détente and ‘change through
rapprochement.’”275 The European Community and Moscow signed the first strategic
agreement in 1970. “This agreement,” Esakova argued, was based on the fact that “the USSR
needed Western financing and technology, while Western European countries - West
Germany, France, Austria, Italy, and Belgium - looked to diversify their gas supply.”276 On the
other hand, Stern highlights that, “When the first contract was concluded in 1970, there was a
certain amount of alarm in government circles about possible dependency. Two more deals, in
addition to Trilateral agreement, have been completed; however, and the original fears of
Germans seem to have been allayed.” Apparently, political drivers over Brandt’s Ostpolitik
encouraged companies with subsidies and financial support to agree on the gas deal. This
agreement started as a state-to-state level deal; however, over time, while Soviet level
engagement was directed by top government officials and state-owned enterprises, Western
engagement was mostly dictated by market dynamic and private companies.
85
Highlighting the importance of the West German-Soviet gas deal in 1970, Gustafson argues
that if “The Soviet-Austrian contract of 1968 had shown that an East-West gas deal was
feasible…a loophole… the Soviet–West German contract was a breakthrough, the beginning
of a breach in the Iron Curtain that would only grow larger over the following decades.”278
When the deal was reached, German state level involvement had ended with the signing of the
contract, but the Soviet, then Russian, top leadership were always involved in setting strategic
directions and managing geopolitical issues. In the mid-60s, while the demand for Soviet gas
was not significant and could not economically be justified, at the time the contract was
concluded, the demand for natural gas was growing between 30 to 60% a year. To this day,
Germany remains the largest buyer of Russian gas in Europe. The following table depicts
Soviet Natural Gas Exports in 1970s, including imports from Iran and Afghanistan.
Table 4: Soviet Natural Gas Export in 1970s, Including CMEA and the West (Bcm)
Year 1970 1973 1974 1975 1976 1977 1978
CMEA countries
Poland 1.0 1.7 2.1 2.5 2.5 2.8 2.9
Czechoslovakia 1.4 2.4 3.2 3.7 4.3 4.9 5.0
Table 4 (Continued)
Year 1970 1973 1974 1975 1976 1977 1978
Bulgaria - - 0.3 1.2 2.2 3.0 3.0
German Democratic Republic - - 2.9 3.3 3.4 3.6 3.7
Hungary - - - 0.6 1.0 1.0 1.2
Other Countries Total
Austria 1.0 1.6 2.1 1.9 2.8 2.8 3.0
Federal Republic of Germany - 0.4 2.2 3.1 4.0 5.8 6.0
Italy - - 0.8 2.3 3.7 5.5 5.5
France - - - - 1.0 2.0 2.0
Finland - - 0.4 0.7 0.8 0.8 1.0
Total a 3.3 6.1b 14.0 19.3 25.8 31.3 33.3

86
Data Source: Jonathan F. Stern, Soviet Natural Gas Development to 1990, Table 2-15 a
Numbers may not sum to totals due to rounding.
b Stern highlights that the statistical yearbook gives an export of 6.8 bcm without any explanation of the discrepancy
of 0.7 bcm.
The first European-Soviet gas trade agreements were based on trading goods not money.
According to Gustafson, “The Soviets needed steel, technology, and finance; the East
Europeans needed energy; and the West Europeans needed export markets. For all sides, gas
was a currency, a substitute for money.” Gas was used as a currency during this exchange, in
fact, it was very difficult to determine the actual price of the gas due to gas invoice settlement
through arbitrarily priced goods and politically priced credit, especially in Soviet-German gas
trade in the1980s.282
The Reagan administration urged Europe to consider over-reliance to Soviet natural gas while
Europe agreed to build East-West or widely known as Yamal – the world’s largest pipeline at
the time. The US offer to Europe to use coal as an alternative fuel for natural gas was not
widely supported. In 1981, the US responded with sanctions against the Soviet Union when
the USSR introduced martial law in Poland. While in 1982, US sanctions included
American-made and -licensed energy equipment that could be used in development of the
West Siberian pipeline to Western Europe. However, the Reagan administration’s efforts
failed to gain traction in West Germany and other European countries. The pipeline network,
called the
Brotherhood, served as the primary transport means for Soviet, then Russian, gas exports to
Europe and Ukraine during the Cold War. With the collapse of the Soviet Union, the dynamics
changed overnight between Russia and Ukraine, and the latter become the main transit

87
country while the former remained the supplier. Today, the division of industry infrastructure
and Brotherhood Network continues to be part of geopolitical struggle between
Russia and Ukraine with severe consequences for Europe.
3.2.3. Cold War Period – European Gas, Groningen and North Sea Reserves
There were two major natural gas discoveries during the Cold War period in Europe; the first
one was a huge gas field in the Groningen in the Netherlands in 1959. This discovery, laying
in at a great depth, encouraged companies and geologists to continue exploring the North Sea
region, close to the British Coast. Large natural gas deposits were discovered in the British
sector of the North Sea, at West Sole, in 1965, that was followed by the biggest oil and gas
discovery at the Norwegian sector of the North Sea in 1969. While Europe had a web of
pipelines crossing the continent like a few strands of string in the 1960s supporting local gas
markets, Yergin argues that, “The real European gas market only began with the development
of the Groningen field in Holland.”286 The Groningen discovery is also important that it
helped the development of the:
…doctrine for pricing gas that has been used in every European gas contract
practically down to the present day. The basic idea is that gas should be priced
according to its value to the user, not its cost to the producer… the price of gas must
not exceed that of competing fuels at the point of consumption… it logically leads to
the idea that the price at the wellhead should be the “netback” - that is, the price to the
consumer minus the costs of transportation and distribution.
The Norwegian gas industry has extensive challenges similar to those in Soviet industry.
However, there were significant differences between the Norwegian state socialism directed
capitalist approach and the Communist system on the following areas: ownership and control
was the first area; the Norwegian approach to industrial and technology policy; and the way
Norway established relationships with the European Union and the resulting business models
under which gas was exported to Europe, especially the way contracts were put in place.
Norwegian industry, in contrast with the Soviet gas industry, was developed “primarily on

88
commercial principles, based on a close partnership between the state and private-sector
capital and expertise, especially international oil companies.”289 On the contrary, Soviet
leaders were skeptical of foreign companies’ involvement to the degree that they managed the
whole process. They were also concerned and worried about Washington’s involvement in
creating a dependency for technology.
While in both cases support from foreign companies were crucial for successful development
of the gas networks, the Norwegian case involved foreign companies from the very
beginning. The Norwegian model, compared to the Soviet Gazprom model, enabled a
“company-state relationship, open to the outside world and aimed at developing cooperative
relations with international companies offshore, under the benevolent but watchful eye of the
Norwegian government.” Additionally, Norway allowed Phillips to negotiate a gas contract
with European companies led by Ruhrgas, using the classic Groningen contract model and gas
pricing that had become the norm by that that time and was also used by the Soviets in their
first contracts with Austria and Germany. The ‘Norpipe’ pipeline, 443 kilometers in length,
was commissioned in 1977, four years after the contract was signed. Through these pipelines,
Norway became one of the main suppliers of natural gas to European markets while the UK’s
North Sea fields were used to support its domestic market and consumers.
To present alternative gas resources for Continental Europe, the Reagan administration urged
Norwegians to develop Sleipner and Troll gas fields as potential competitors against Soviet
gas (See Figure-5: Norwegian Gas Fields and Pipelines to both Continental Europe and the
UK). This was an example of how commercial interests intertwined with geopolitics. The
United States “imposed a unilateral embargo that prohibited companies from
exporting…equipment that was essential to the construction and operation of the West Siberia
Pipeline. The Europeans, however, were as determined as the Soviets to go ahead.”293
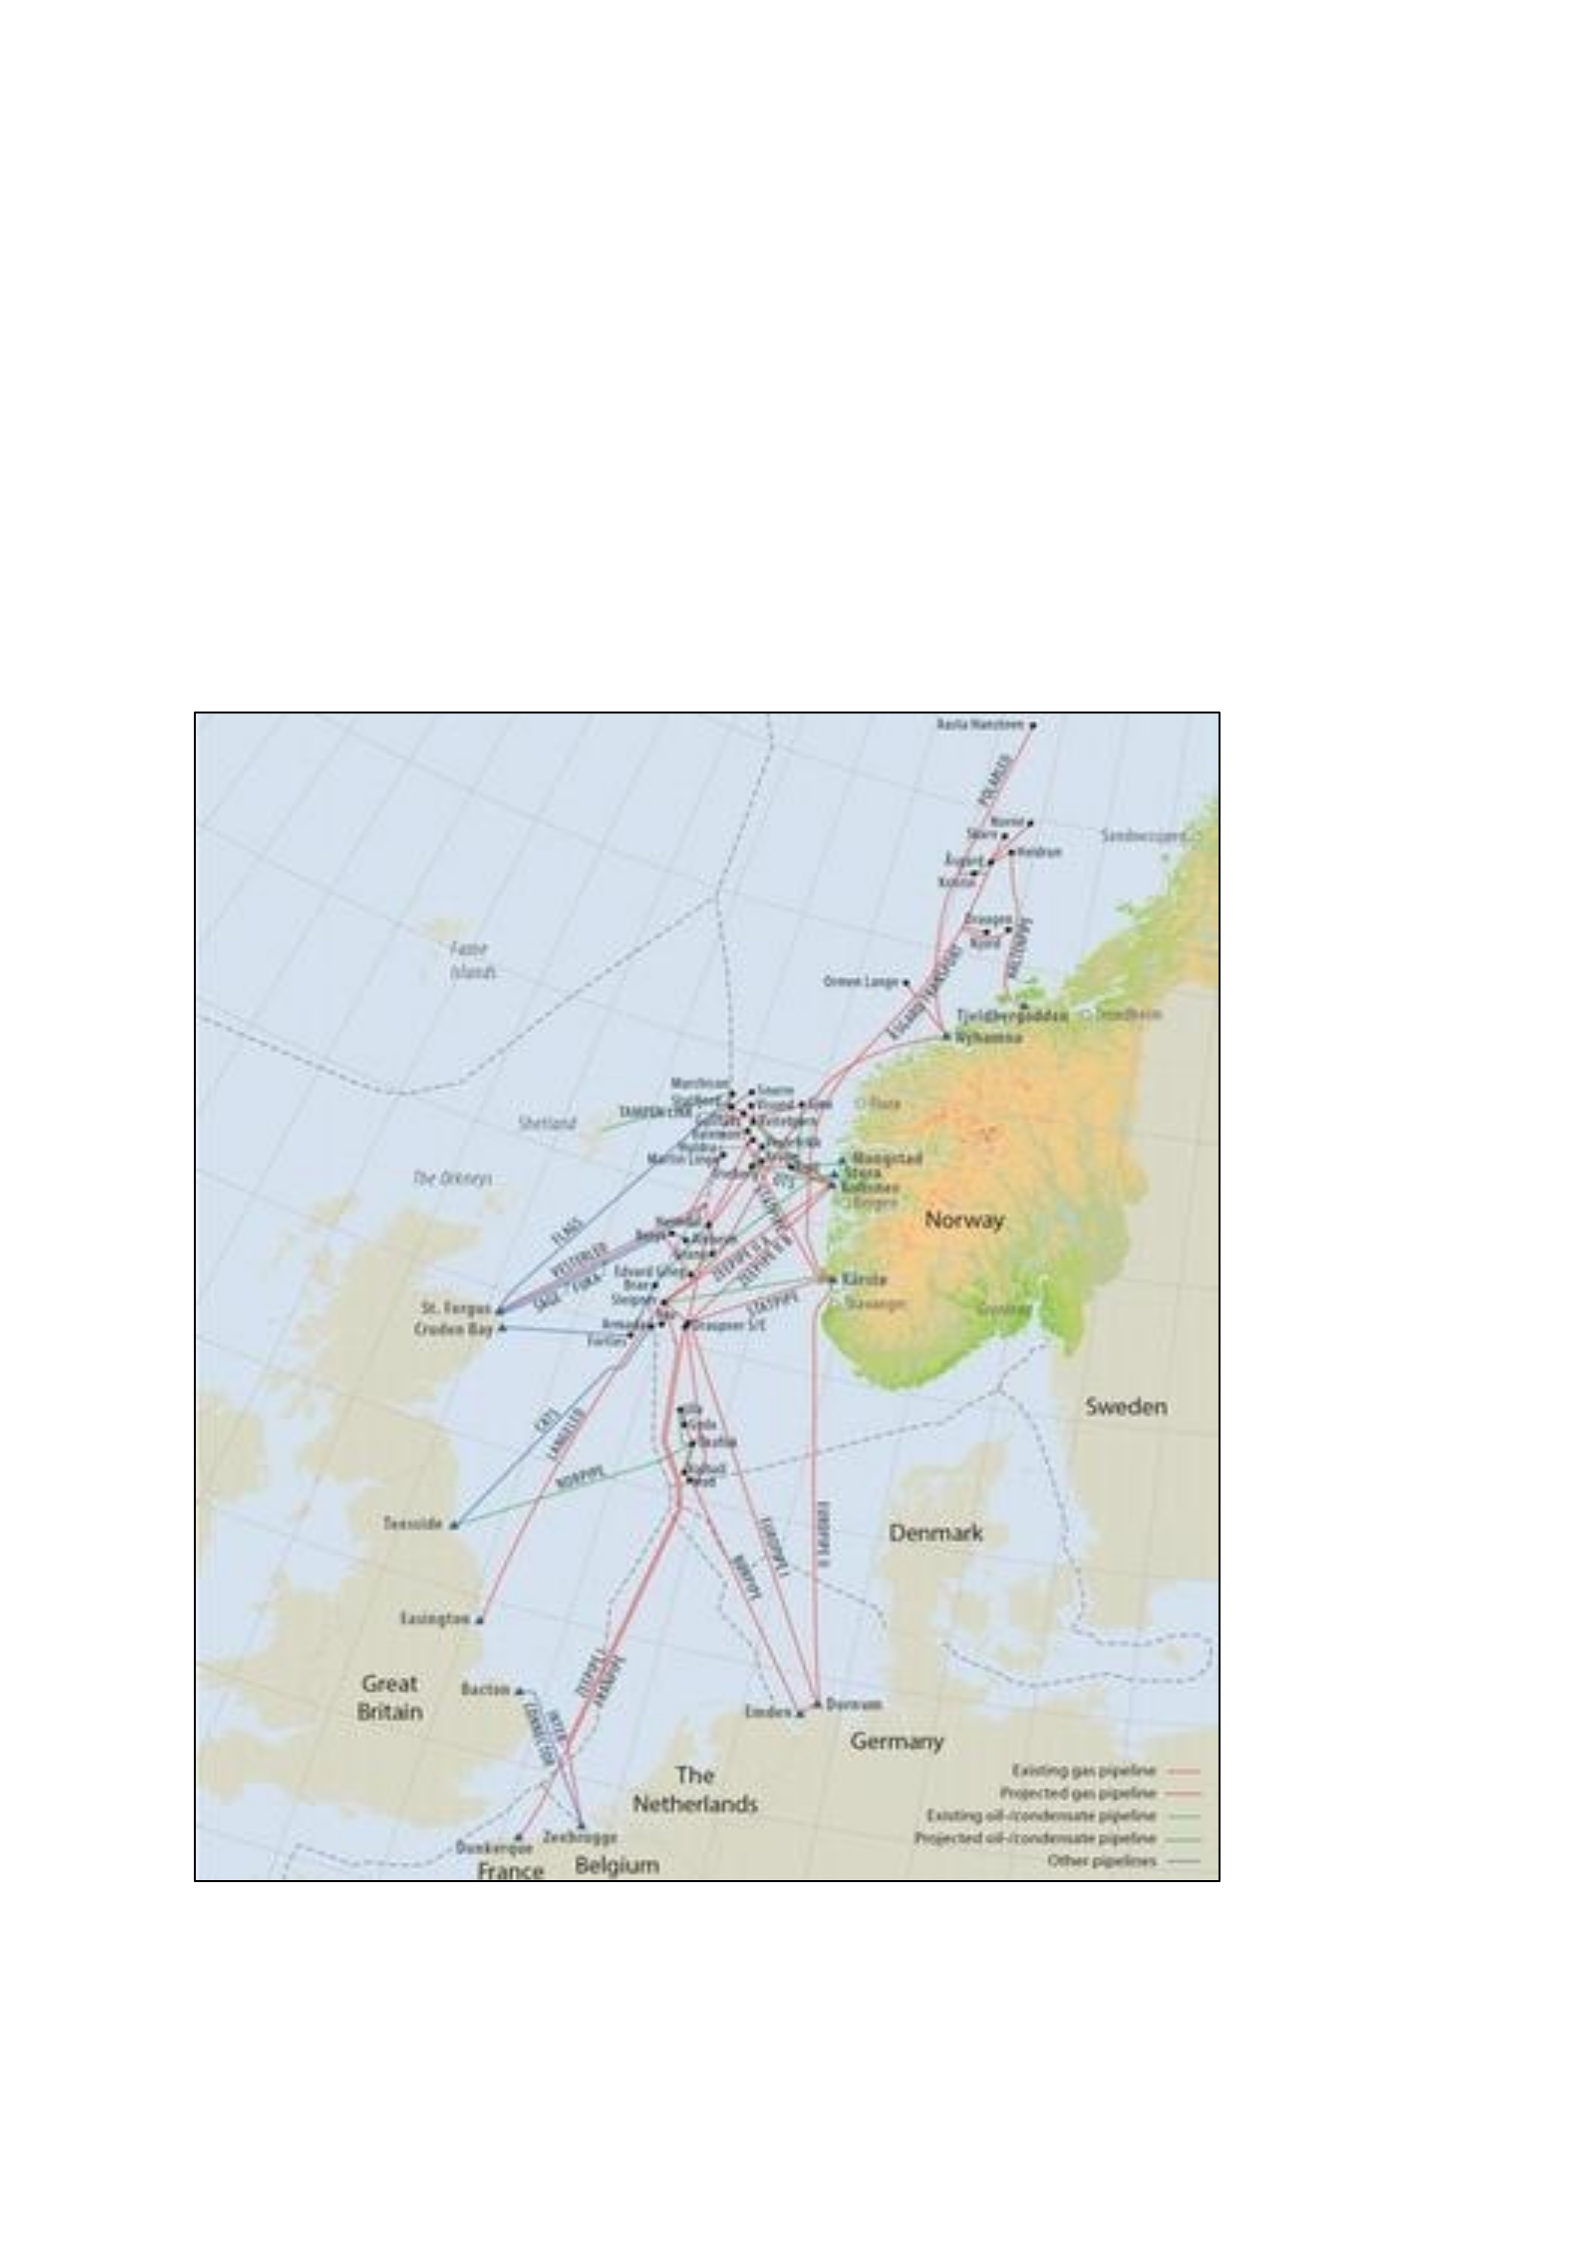
89
Figure 5: Norwegian Gas Fields and Pipelines to both Continental Europe and the UK
Source: US Energy Information Agency, with permission from the Norwegian Petroleum Directorate
https://www.eia.gov/international/analysis/country/NOR/background

90
The West Siberia Pipeline and Soviet gas would allow Europe to diversify away from the
unstable Middle East resources as well as reduce coal in its energy mix. With Thatcher
leading the UK’s opposition for domestic reasons, the Reagan embargo collapsed. While the
US administration was not successful in convincing the Allies, the two arguments presented
for the embargo remain valid still today even after the end of the Cold War and the collapse of
the Soviet Union. The following argument raised by Stern in the 1980s reinforces the US
position at the time and remains as a major challenge even for today’s Russian-German
energy relations:
“The major concern about Soviet gas exports to the West is that, while oil deliveries
can be replaced by fuel from other source, a country that becomes dependent on
Soviet natural gas will find it difficult, if not impossible, to substitute fuel in the event
of an embargo. Thus, in case of natural gas, the dependence relationship between
importer and supplier is very great.”
3.2.4. Cold War Period – Energy Security and Interdependence
During the Cold War period, Western Europe’s perception of the USSR was as a reliable and
politically stable partner compared to the Middle East that was affected by political instability
and presented as unstable supply source.296 In 1980, Stern predicted that “by 1990, natural gas
will have equaled and possibly overtaken oil in importance in the Soviet fuels production
balance…irrespective of possible deliveries to the West, Soviet natural gas will command
considerable attention over the next decade.”297 This analysis has proven valid even for today
as Russian gas export dependency of Central and Eastern European countries remain not only
an economic but also a geopolitical concern. He also suggested that “Natural gas will be an
extremely important energy export of the USSR and will be the most significant energy
export to the hard currency.” Esakova brings up the main concern regarding the
interdependence as an outcome of this energy relationship between Europe and Russia. She
suggested that the “mutual interdependence” relations might mean for Europe a worst-case

91
scenario – a total halt in gas deliveries. However, at the time, the impact in terms of the level
of sensitivity and vulnerability interdependence of Western Europe was considered as
reasonable due to the available alternatives, spare and storage capacities.
Major West Siberia discoveries in the early 1980s boosted Soviet production, making them
the largest gas producer of the world. However, to transport West Siberia’s gas required
Western involvement as it was highlighted “No Western pipe, equipment, and finance, no
West Siberian gas.” Gustafson noted that “There was much anxiety in Washington and the
European capitals about whether the Soviets would use gas as a weapon in the Cold War.”
However, this project went ahead as planned. The West Europe-Soviet relationship was
perceived as mutual interdependence due to the Soviet’s reliance on the West’s support and
the importance of Western technology and finance to develop the West Siberia Pipeline.
The interdependence remained as one of the key aspects of European-Soviet Union relations
by the end of the Cold War. Thus, mutual interdependence meant different things for Europe
and the Soviet Union. A total interruption of the Soviet gas supply could be defined as worst
case scenario for Western Europe, but the impact was manageable, and disruption could be
short-term because of a natural gas storage and spare capacity provided by alternatives such
as coal, oil, and nuclear power. However, the long-term impacts could be managed by
reprioritization of energy supply. On the other hand, the short-term impact on the Soviet
Union would be neglectable albeit the long-term impact would be grave due to a lack of
energy cooperation with Europe and losing the most profitable markets.
In development of the pipeline networks, former Soviet satellite states emerged as “transit
countries,” and with the sudden collapse of the Soviet Union, newly independent states joined
the transit country group including Ukraine, Belarus, Moldova, Poland, the Czech Republic,
Hungary, Lithuania, Latvia, and Estonia. These countries are located in Central and Eastern
Europe, and several of them have joined the European Union and become members of the

92
NATO Alliance. These countries have imported energy from Russia, or earlier the Soviet
Union. They received a high level of gas subsidies, benefited from transit fees, and used
Russian dependency to export to Europe as a leverage in their relations with Russia. This
toxic relationship between Russia and its former satellites and newly independent republics
changed the energy security landscape, resulting in economic and political disputes that
continue today. The US administration under President Reagan was concerned by increasing
Soviet gas exports to West Europe. The US had, at that time, two valid arguments; first,
natural gas could continue to provide hard currency for financing the Soviet military
industrial complex. The US was working with NATO Allies to counter Soviet military
expansion by increasing the
Alliance’s military capabilities. Allowing Soviets to allocate more defense funds through
income gained via European gas money did not make any sense. The second, increased
Western dependency on Soviet natural gas could be used as a leverage to create a wedge
within the Alliance. These two arguments are still legitimate concerns within European-
Russian energy relations.
The European-Soviet relations started as a state-to-state relationship covering both economic
and geopolitical contexts. Over time, European considerations were shifted, weighing over the
economic aspects of interdependence. As argued by Hogselius, “The Iranian revolution, the
second oil price shock, the Soviet Union’s invasion of Afghanistan, the Polish crisis of 1981–
1982, and Reagan’s new confrontative policy toward Moscow did not affect the increasing
trends of natural imports from the USSR to Europe in the 1980s. However, Soviet decisions
were always taken at the political level, putting long-term perspectives and security dynamics
into consideration, utilizing price and pipeline routes to support their position. The Cold War
period set the conditions for the Russian approach to shape the natural gas landscape that

93
continued for some time after the Cold War, until the European Union’s energy market gained
strength to challenge the status-quo.
3.3. European Energy and Natural Gas Markets
3.3.1. Initial Steps - the Directive on Transit of Natural Gas
In the 1980s, there was a shift in Europe toward establishment of a ‘Single European Market’
that enabled “abolition of barriers of all kinds, harmonization of rules, approximation of
legislation and tax structures, strengthening of monetary cooperation, and the necessary
flanking measures to encourage European firms to work together.” The Commission’s white
paper on a Single Market focused on the internal European market; it had no mention of
energy. However, when implementation of these measures started, it was apparent that single
market measures have fundamental effects shaping energy markets, especially the natural gas
market. Grigas argued that, “Possibly the greatest regulatory and policy undertaking of the EU
institutions to date is to attempt to merge the separate national energy markets into a single
EU market.”307 The white paper, COM (85) 310, initiated this challenging endeavor that is still
being tested today with Russian attempts to create a wedge within the EU.
While Single European Market started as an internal market liberalization and privatization
effort, consequences affected and continue to influence European relations with the Russian
gas behemoth, Gazprom. Although the timetable set by the Commission required completion
of the programmed by the end of 1992, the gas sector in Europe resisted a change in business
practices and greater liberalization. This resulted in the step-by-step introduction of measures
as Energy Packages; other political and environmental developments such as German
unification, the collapse of the Soviet Union, EU and NATO expansion, the Ukraine crisis,
and climate change will continue to affect the energy landscape.
Boersma provided a holistic view of the natural gas system that is comprised of four
elements:

94
…markets, infrastructural companies, governmental institutions, and regulatory
authorities. The marketplace is where the producers, suppliers, traders, and consumers
operate. This is where natural gas is supplied to both small consumers (retail) and
large energy-intensive industries, and where traders operate at energy exchanges and
increasingly trade short-term (spot market) and long-term (futures) products.
The way contracts are developed is key to ensure market liberalization efforts are
materialized. However, in the early 1990s, the European natural gas system was still
maintaining traditional gas trade rules that were started in Groningen in the 1960s. The so-
called ‘old system’ was based on long-term contracts, managed markets, and inter-fuel
pricing.
At the same time, other areas and regions such as North America, Australia, and Great Britain
were adopting new market approaches that offered short-term (spot market) trade, so called
the “new system” that allowed “liberalized pipeline access, greater stress on market signals,
and the beginning of gas-on-gas competition.”310 While implementation of the programmed
was not completed in time, Gustafson references gas expert Simon Blakey, who suggested
that “The Commission’s impact on national-level decision-makers…can genuinely be said to
have changed the playing field on which gas industry conducts its business.” The White Paper
did not have an immediate effect on natural gas businesses, especially industry practices such
as gas-on-gas competition.
While member states, especially Germany, kept their positions to resist liberalization efforts,
there was a “pushback against the application of competition law to the energy sector.”
Natural gas usage continued to increase in Europe, and it has gained a larger share than coal
in total primary energy consumption in 1994. Gas and electricity networks were not regulated
in Europe, and in Germany, the gas industry was mainly a private-sector business. Electricity
and gas industries are generally perceived as national assets due to their role as part of
national critical infrastructure that remain within national borders. Governments wanted to
control the critical energy infrastructure due to their importance for security as well as their

95
high level of dependence on electricity and gas supply. The main focus of these efforts was to
achieve “security of supply and environment protection.”
The Directive on the Transit Gas through grids (91/296/EEC)315 highlighted the importance of
greater integration of the European energy market; the role of natural gas as an essential part
of European energy balance; and the requirement for greater reliance on natural gas for
diversification of energy resources. Gustafson highlighted that the Directive “met strong
resistance in Germany and the Netherlands. This was mainly due to member states’ natural
gas industry monopolies’ resistance to change, in particular in Germany, and to some extent in
France, as well as other countries in continental Europe.
Member states were not moving away from the “old system” of traditional gas markets and
long-term supply contracts (LTSCs). The reluctance was due to the requirement for structural
changes that the industry, local state governments, and utility services were resisting to
accept. For example, “Of the forty-three companies covered by the Transit Directive,
twentynine were German…more than twenty of them were either customers, suppliers, or
joint-
venture subsidiaries of Ruhrgas.”316 Members states’ failed to fully agree on third-party
access to transmission pipelines, so the Transit Directive remained as a “procedural document
with no provisions on transit tariffs, capacity allocation, and congestion management.”
Yafimava highlights Stern’s point suggesting that, “Russian gas only becomes the property of
European buyers once it has reached its delivery point(s) at their national borders as specified
in their LTSCs concluded with Gazprom.”318 Jirusek and Vlcek refer to the main elements of
LTSCs summarized by Konoplyanik:
- “They provide demand security that facilitates for upstream investment and
field development;
- The values of natural gas both domestic consumers and export are aligned with
the fuel oil replacement value;
- Regular price review both within at the given contract pricing formula and
review of the formula itself;
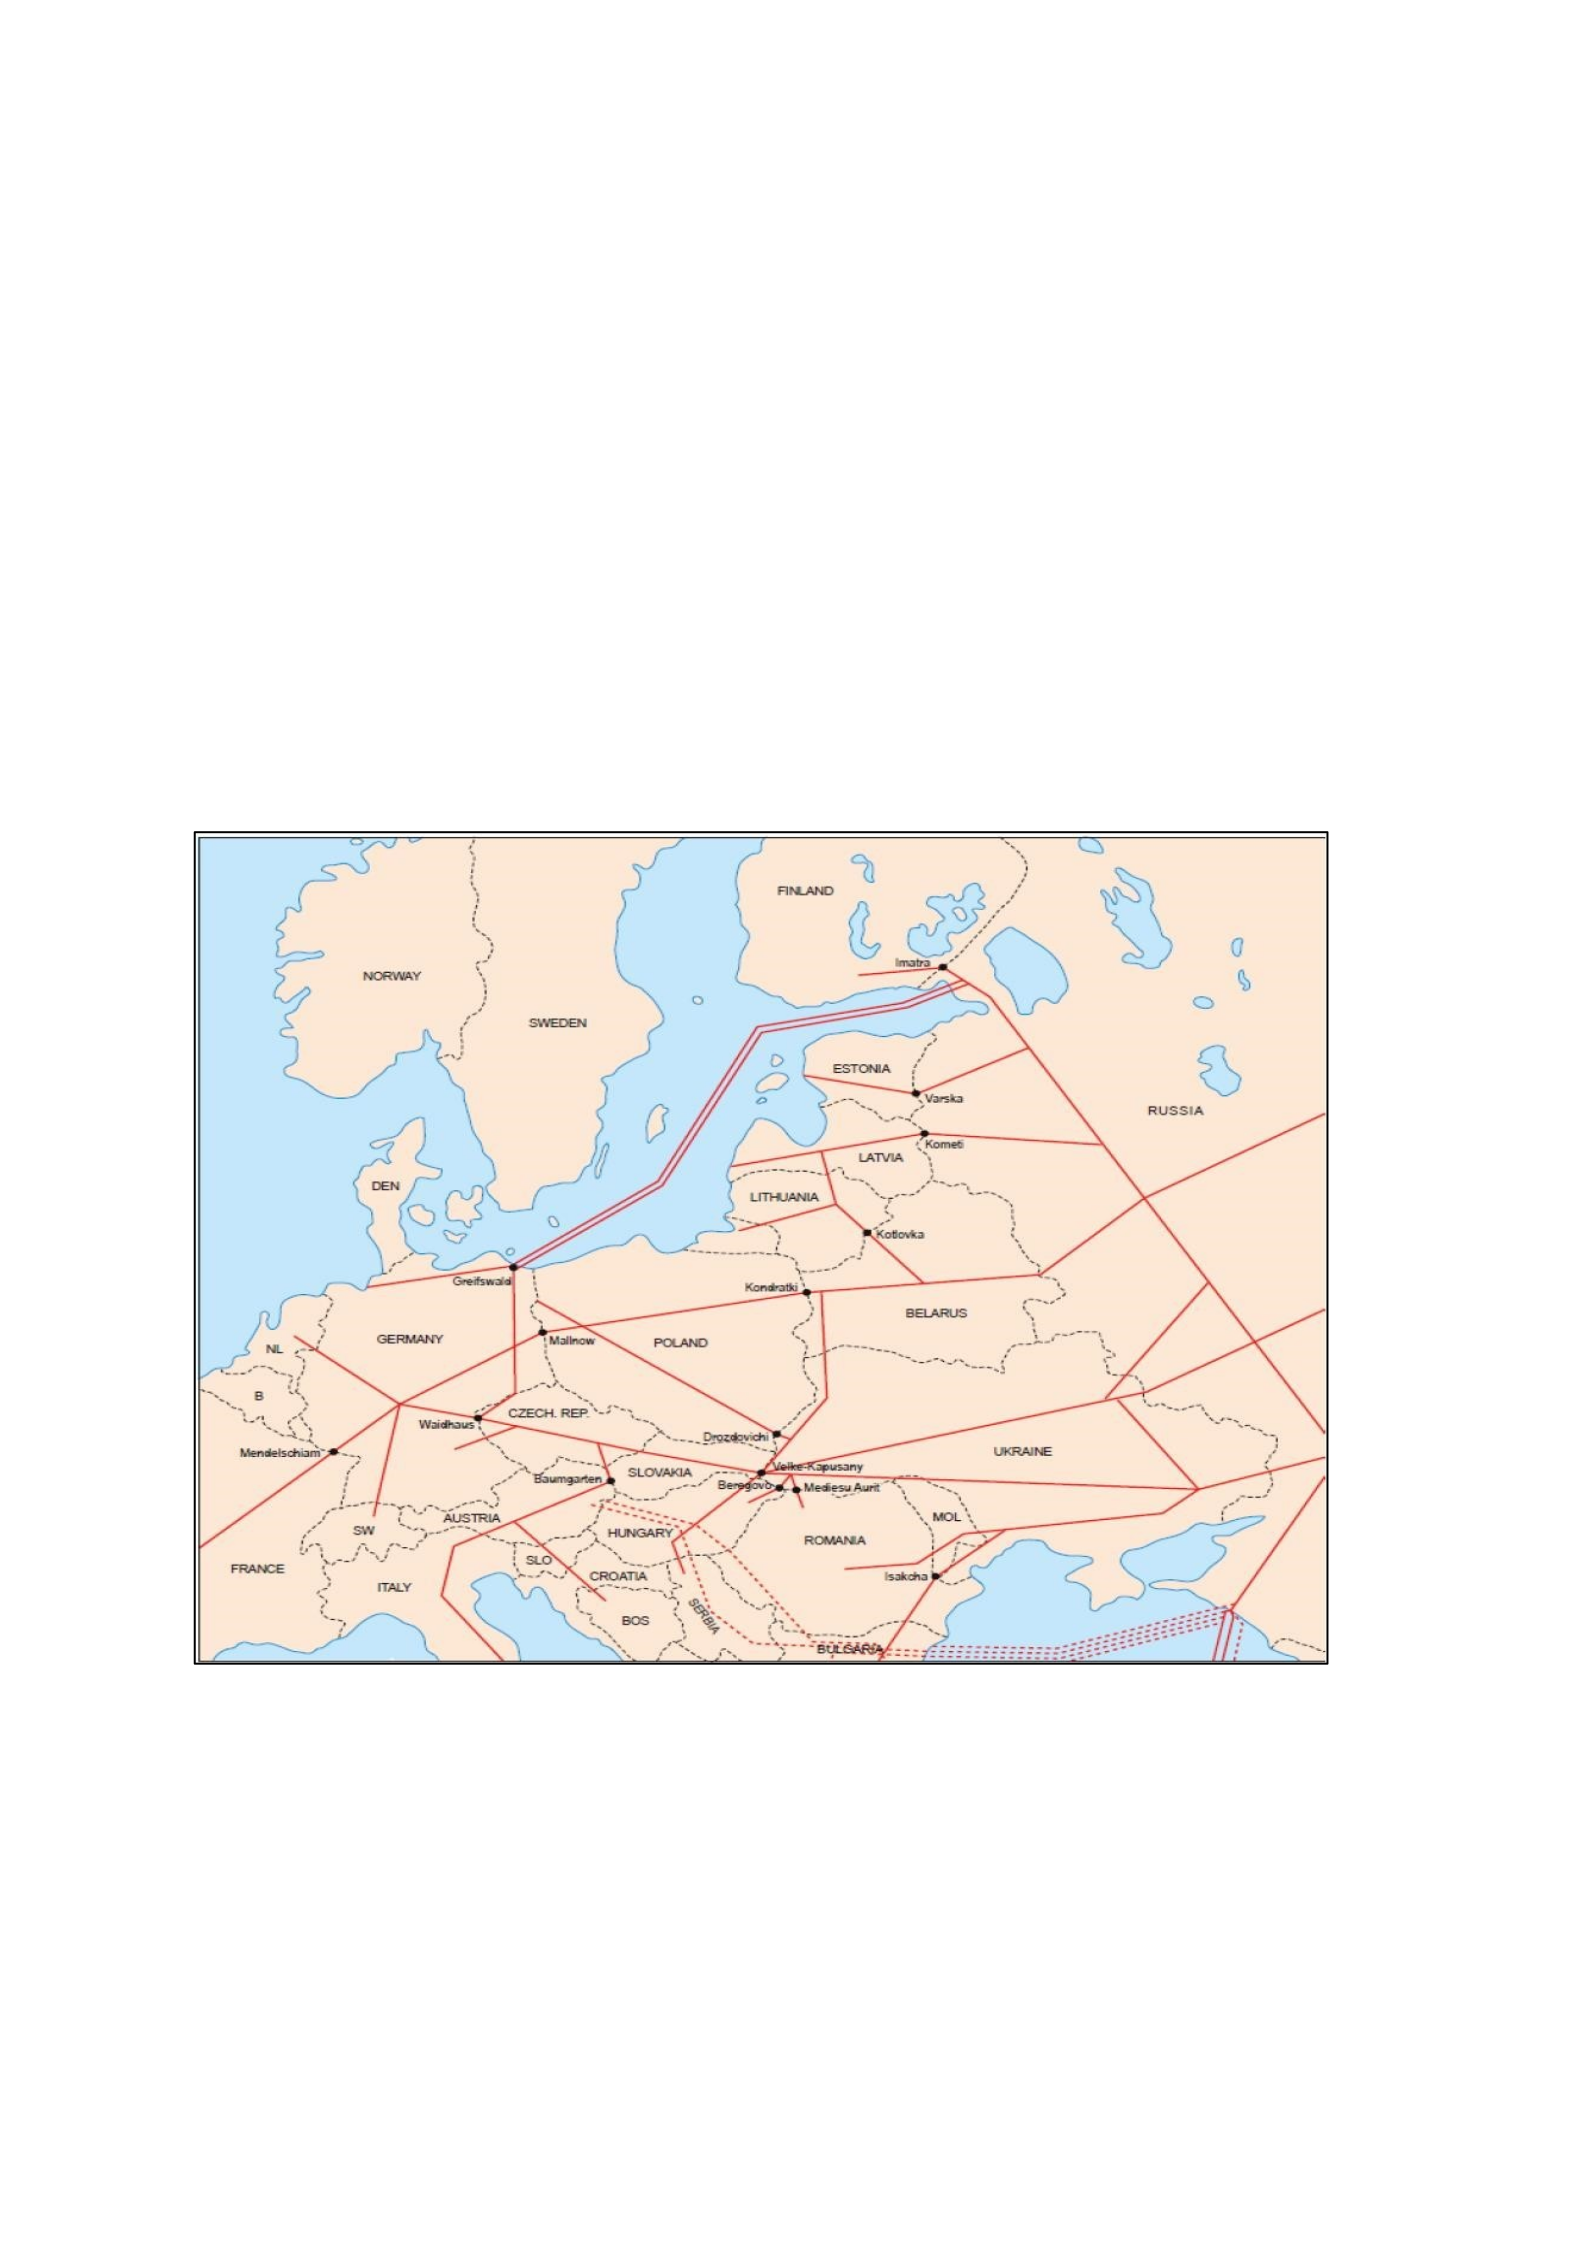
96
- Net-back price to delivery point;
- The system was designed to remain stable and predictable by reducing the
number of actors in the market and limited cross border gas
competition due to fragmentation of national markets.”
Therefore, measures identified in the Transit Gas Directive and following the EU Directive
and Regulations will only matter after these border points of entry. The following map clearly
shows that the geographical location of delivery points where pipelines enter German territory
is far beyond the Russian border, due to a Cold War legacy division of “East” and “West”
borders.
Figure 6: Russian Gas Supplies to Europe: Borders and Delivery Points
Source: Katja Yafimava, The EU Third Energy Package for Gas and the Gas Target Model, OIES,
3.3.2. The First Gas Directive – Prolonged Move to Energy Markets

97
The First Gas Directive was released in 1998, setting common rules for the internal market in
natural gas. The changes towards liberalization and privatization enabled the European
Commission to introduce regulatory measures for the development of the energy sector. The
Directive on trans-European networks in the energy sector (96/391/EC) laid down a series of
measures aimed at creating a more favorable context, such as the realization of projects of
common interest in connection with the development of trans-European networks in the
energy sector. The Commission, with this Directive, focused on common projects in
development of trans-European energy networks and achieving community-wide
interoperability. Technical cooperation for proper functioning of interconnectors and
cooperation for projects reducing delay were identified as favorable for common interests and
eligible for funding support.
The Commission continued its efforts to set the rules for the internal market in natural gas.
Directive 98/30/EC “lays down the rules relating to the organization and functioning of the
natural gas sector, including liquefied natural gas (LNG), access to the market, the operation
of systems, and the criteria and procedures applicable to the granting of authorizations for
transmission, distribution, supply, and storage of natural gas.” The Directive also established
common rules for the natural gas systems. Several other key issues were also covered, such as
guaranteeing non-discriminatory access to member-states markets; developing minimum
technical standards for storage and distribution facilities; requirements for integrated natural
companies to maintain separate accounts for gas and non-gas activities; accommodating
thirdparty access (TPA); gradual market opening and reduced market domination.
The First Gas Directive introduced harmonization by setting common rules for generation,
supply and transmission, unbundling, and negotiated third-party access. This was one of the
key initial steps for the establishment of a natural gas market albeit with little materialized
effect on issues such as third-party access, transparency, and unbundling. Member states

98
continue to use the Directive on the Transit Gas and the First Gas Directive together and had
to choose between regulated and negotiated third-party access. Gustafson noted that these
three issues emerged as the key battleground for achieving a single gas market: “exclusive
rights; third-party access; and unbundling that were all related to gas transit.” It should also be
noted that the First Gas Directive was released before the Central, Eastern European, Balkan,
and Baltic countries joined the European Union. Although it focused on Western Europe, little
progress was achieved on the key issues, further delaying Europe’s achievement of a single
gas market before the EU enlargement. With the participation of these countries, there were
increased energy security concerns due to a high level of dependency of new members.
3.3.3. The Second Gas Directive – Establishing Common Rules
The Commission released the Second Gas Directive 2003/55/EC in 2003, repealing the
Directive on Transit Gas and the First Gas Directive, recognizing the limited progress
achieved with the previous Directive 98/30/EC and highlighting its shortcomings on the
desired completion of the single natural gas market. The Second Directive aimed at
establishing harmonization and market integration that advanced rules on national regulators.
However, it failed to provide a level of competition for a flourishing energy market. In the
wake of the First Directive, Gustafson emphasized two examples of progress achieved during
the period: first, the UK-Belgium Interconnector pipeline that brought gas from the liberalized
UK market to Europe, established a bridge between spot and continental long-term contract
prices; second, an increased utilization of the European Commission’s power through
implementation of competition and antitrust policies of the Directorate-General for
Competition (DG-COMP). The Second Gas Directive “eliminated the notion of transit and
awarded an identical treatment to all gas flows in the European Union, irrespective of whether
they were cross-border(s).” The Second Directive focused on establishing common rules for
the transmission, distribution, supply, and storage of natural gas. The Directive focused on the

99
unbundling of transmission system operators highlighting that transmission system operator
“shall be independent at least in terms of its legal form, organization, and decision making
from other activities not relating to transmission.” The Second Directive also identifies
transmission system operators responsible for “ensuring the long-term ability of the system to
meet reasonable demands for the transportation of gas.” Boersma summarizes key aspects of
the second Gas Directive:
The new directive also aimed to improve the access of new suppliers to the market and
gave consumers the ability to switch freely between gas suppliers… a number of
measures were recorded in the directive to ensure among others transparent contract
conditions and dispute settlement mechanisms…prompted member states…to appoint
independent regulators to monitor transparency, discrimination, the level of
competition and the tariffs used by system operators.
With the Second Gas Directive and Gas Regulation 1775, DG-COMP started setting
precedence by increasingly enforcing competition rules. While liberalization and privatization
are seen as appealing areas for policymakers to focus in energy systems, other crucial areas
such as exclusive rights, third-party access, and unbundling were not attractive areas to tackle
due to resistance from member states. Boersma argued that Commission policy makers
believed at the time “there was no incentive at the member state level to collaborate on these
matters: infrastructure investments and designing of regulatory regimes.”335 These sensitive
areas were accepted as national business and should be regulated by nations.
In 2005, the DG-COMP initiated Energy Sector Inquiry (ESI) to identify critical
shortfalls of the existing Directive and Regulations to achieve a competitive and transparent
gas market. The findings of the ESI showed that EU competition law did not provide
sufficient means for access or changing the legacy transportation contracts that were
incompatible with the new regulation. Additionally, “access to transit pipelines, transit
congestion, and transparency of access to transit networks could not be tackled effectively
solely through application of competition law.” Boersma confirms these findings and

100
suggests, “The EC concluded that these rules and measures did not provide the necessary
framework for achieving the objective of a well-functioning internal market.”
On the other hand, the Commission was very keen to address the shortfalls in the
establishment of the European energy market. Gustafson refers to DG-COMP Neelie Kroes’
2006 statement in Vienna:
Despite the two waves of liberalization…a single competitive European energy market
is still not a reality…Shortly after coming into office, I was pleased that my
Commission colleagues backed my suggestion for an in-depth assessment of energy
markets. Over the past nine months, we have used a new tool – the sector inquiry-to
find out the barriers to free competition in energy.
3.3.4. The Third Energy Package – Natural Gas Markets
The Third Energy Package, Directive 2009/73/EC, was proposed in 2007, approved in 2009,
and became law in the EU in March 2011. It is the most incisive and comprehensive change
and a significant step forward in completing and adding new impetus for the transformation of
the EU gas market structure and single European energy market: aiming to deliver real choice
for all consumers of the EU; providing new business opportunities and more cross-border
trade; achieving efficiency gains, competitive prices, and higher standards of service; and
contributing to security of supply and sustainability.341 The excerpt are depicted in the
following pages. However, the 2003 Directive did not sufficiently address the following
challenges:
There are obstacles to the sale of gas on equal terms and without discrimination or
disadvantages…non-discriminatory network access and an equally effective level of
regulatory supervision…the present rules and measures do not provide the necessary
framework for…a well-functioning internal market …Without effective separation of
networks from activities of production and supply (effective unbundling), there is a
risk of discrimination.
The First and the Second Energy Packages were introduced before the EU enlargements in
2004 and 2007. Western Europe reunited with the eight countries of central and Eastern
Europe: Czechia, Estonia, Hungary, Latvia, Lithuania, Poland, Slovakia and Slovenia. While

101
accession of the new members finally ended the division of Europe, it significantly changed
the
European Union’s energy landscape. New members of the EU included the former satellites
and members of the Soviet Union. The general perception in these countries, especially in
Poland, suggested that the EU energy policy before the 2004 enlargement had not sufficiently
addressed Europe’s overdependence on energy imports. European-Russian energy relations
have been a major challenge for the EU integration.344 In parallel to Russia’s efforts to
eliminate transit countries and raise energy prices, tensions increased in Ukraine, Belarus, and
Baltic
states.345
These concerns, especially dependency on Russian gas, were brought to energy security
discussions in the development of the Third Energy Package. “It was largely Polish efforts
that led to energy solidarity language being inserted into the Lisbon Treaty…Poland has
lobbied to get European funds to build its energy infrastructure.” Poland is also recognized
with its high-level “securitization” approach to energy policy, oftentimes framing it as a
national security issue and an existential threat. The Lisbon Treaty sets energy security as one
of the objectives of EU energy policy that provided a legal basis for EU actions.
Figure 7: The EU Energy Packages - Evolution of Energy and Gas Markets
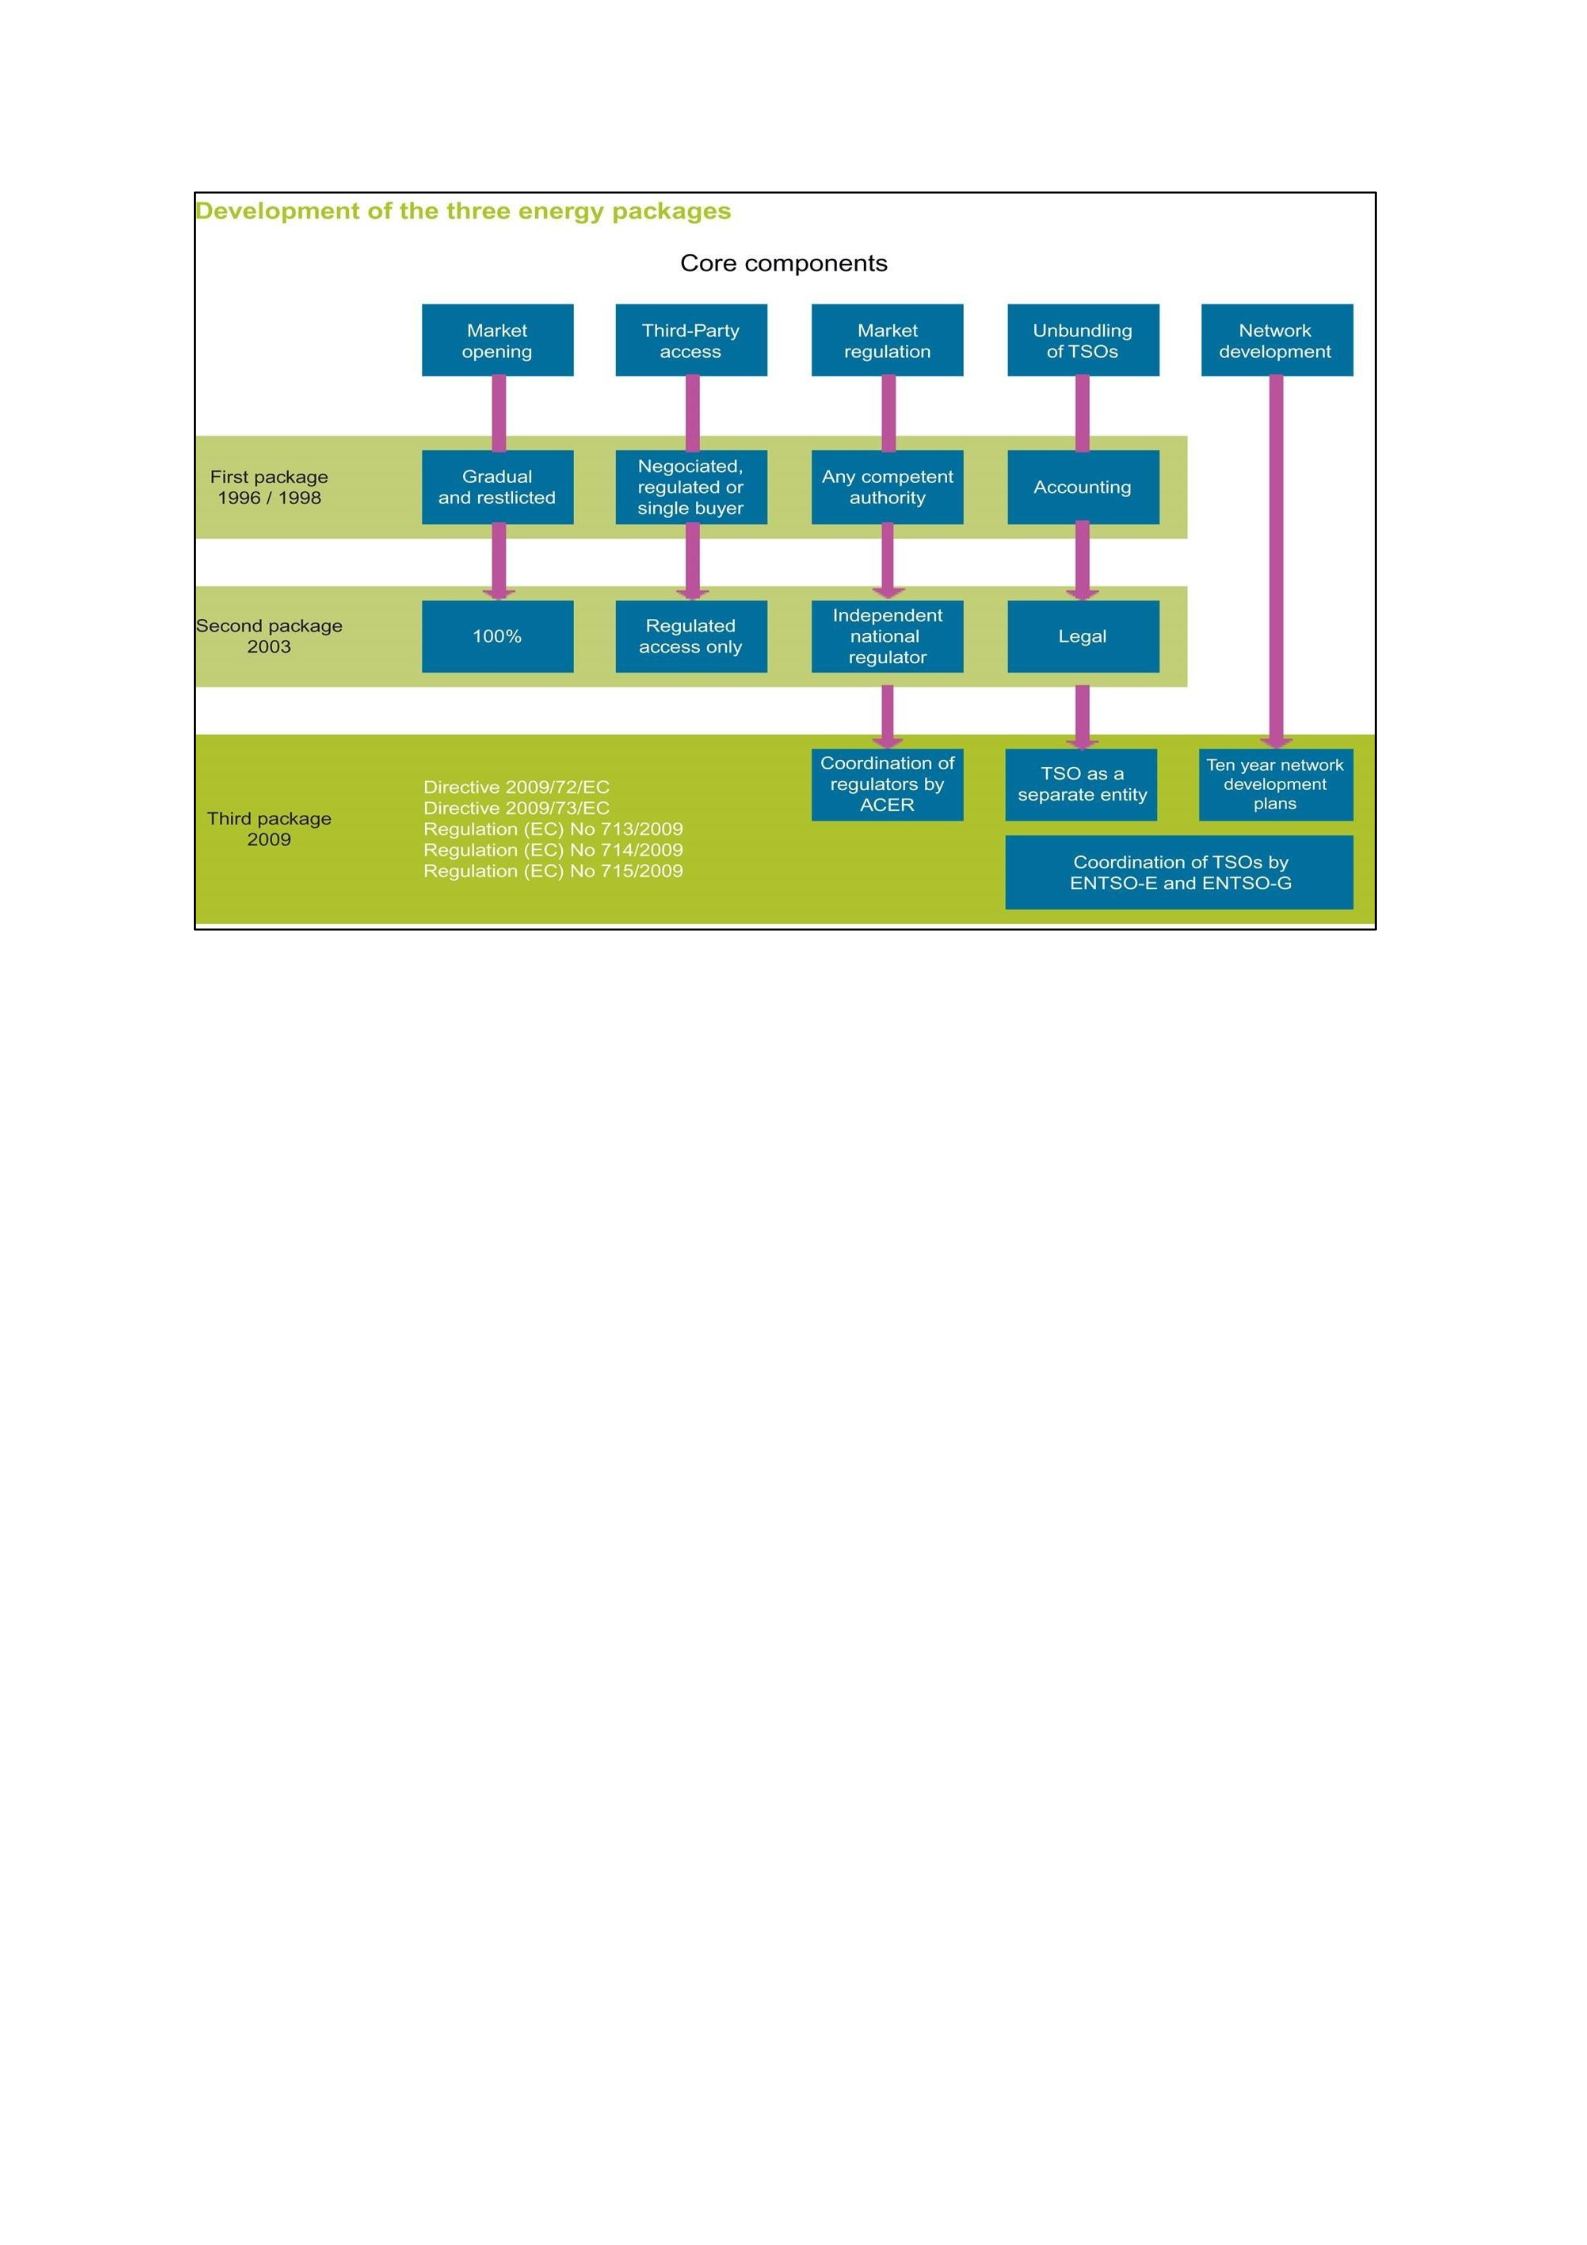
102
Transmission System Operators (TSO); Agency for Cooperation of Energy Regulators (ACER); European Network of
Transmission System Operators (ENTSO); ENTSO-E (in electricity); ENTSO-G (in gas)
The EU’s natural gas market packages have two prongs as highlighted by Grigas: “first, they
include directives, decisions, regulations, and infringement procedures that are specifically
tailored for [the] energy sector; second, they invoke competition law.”350 In 2015, Boersma
argued that “European institutions have been reforming European gas markets with the aim to
increase competition and create one single market, yet this proves to be a lengthy and
complex task that has not been completed to date.” He also suggested that insufficient
implementation of the legislation by member states is another reason for lack of progress to
achieve effective competition. Additionally, member states were hesitant to delegate authority
to Brussels for the unbundling of integrated energy companies, especially countries with
protectionist behavior were holding back. Yafimava agrees with this sentiment suggesting,
“Despite the avalanche of Directives and Regulations adopted since the early 1990s, the EU

103
single liberalized gas market had failed to make serious progress; the EC began to use EU
Competition law.” However, with the introduction of the Third Energy Package, the EU has
“unilaterally changed the regulatory framework, inducing more-short term elements. The
outcome increased institutional mismatches at the regulatory, contractual and commercial
levels.”355
In this environment, with diverging views on energy security, the Third Energy Package
focused on addressing shortcomings of the Second Energy Package. The package introduced
significant reforms on the implementation of more stringent unbundling; ensured more
independent regulators for application of the rules; established Agency for the Cooperation
of Energy Regulators (ACER) to help the different national regulators to cooperate and ensure
the smooth functioning of the internal energy market; enhanced transparency and cross
border cooperation for ensuring electricity and natural gas is effectively transported through
pipelines and grids by National transmission system operators; and finally, set the rules to
protect European energy consumers’ rights by creating open and fair retail markets that allow
choice, or changing of suppliers, without extra charges and receiving information on energy
consumption.
The European gas market should not be perceived as a homogeneous entity. It comprised of
several national gas markets with different characteristics. 1990 marked an important
development for the German gas market, Gazprom and BASF-Wintershall established a joint
venture called Wingas. The joint venture agreement allowed Gazprom to enter West European
in particular German gas markets. The German-Russian natural gas relationship was
perceived as a strategic partnership between the early 1990s that become a “new Ostpolitik”
in the early 2000s, succeeding at the idea of “rapprochement through interdependence.” This
cooperation also expanded building a new pipeline system, interacting with local utilities, and

104
giving Gazprom opportunity to market Russian gas directly to East Germany as part of the
joint venture.359
According to Gustafson, “The continued growth of the Gazprom-Wintershall Alliance, right
down to the present participation of Wintershall and OMV in today’s joint consortium to build
the Nord Stream 2 pipeline from Saint Petersburg to north Germany.”360 Gazprom has an
important role in the German market. However, with the introduction of the Third Energy
Package, German-Russian natural relations could not be addressed bilaterally without taking
into consideration the EU that established regulatory frameworks. In this context, the Nord
Stream 2 will be discussed in detail as a case study further in the paper.
The EU Energy Commissioner (DG-Energy), Andris Piebalgs, was attempting to
address energy issues along the following main areas: “sustainability, security of supply, and
competition” while giving priority for a common European energy policy development,
market liberalization, and privatization. DG-Energy, in close coordination with the DG-
COMP, followed a two-prong approach to address market reform in the electricity and gas
industries. While DG-COMP focused on implementation of competition law, DG-Energy
established a forum to “explore the technical and political issues, and get the buy-in of the
companies under the eye of government representatives.”362 Both approaches were essential
and complemented each other with the Commission’s vision achieving sustainability, security
of supply and
competition. According to Stent:
The sustainability issue focuses on the environment and the climate change… security
of supply means focusing on new sources of energy, such as renewables, and reducing
dependence on imports…in terms of competitiveness, the EU will table a strategic
plan for research into new technologies.
In response to Lithuania’s complaints, DG-COMP started an investigation against

105
nearly two dozen subsidiaries and affiliates of Gazprom in 2011. Contrary to expectations,
these developments did not lead to another gas crisis or a cut-off. The investigation continued
for three-and-a-half years and was followed by negotiations between Gazprom and DG-
COMP, lasting another three years. Gazprom conceded to comply with the regulations.
Gustafson concludes that DG-COMP’s success against Gazprom sets a precedence on both
symbolic and practical levels and marks the completion of the liberalization of the European
gas market.364
The DG-COMP affair finally came to a close, with an amicable settlement that did not
conceal the essential outcome: a sweeping victory by DG-COMP and a wholesale
series of concessions by Gazprom. As a result, the marketization revolution has finally
spread to Eastern Europe and—after stiff resistance—has been accepted by
Gazprom.365
The traditional method of gas market exchange was a preferred “modus operandi” for
Gazprom and could be further described by two key characteristics. This model based on long
term contracts “strengthens the position of fundamental gas suppliers, providing them with
tools to exert market and political power. It also prevents any significant changes of status
quo, cementing the position of these companies.” The following figure highlights the key
aspects of the Third Energy Package that brought significant regulatory measures for
European energy market with important consequences on Gazprom’s efforts to control
transmit ad downstream assets.
Figure 8: The Third Energy Package
106
The Third Energy Package (Excerpts explaining key concepts)
Aim: The previous round of EU energy market legislation, known as the Third Energy Package, aims at
improving the functioning of the internal energy market and resolving certain structural problems. Scope:
The package covers the following five areas: 1) unbundling, 2) independent regulators, 3) Agency for the
Cooperation of Energy Regulators (ACER), 4) cross-border cooperation, and 5) open and fair retail
markets.
1) Unbundling:
Unbundling is the separation of energy supply and generation from the operation of transmission
networks. If a single company operates a transmission network and generates or sells energy at the same
time, it may have an incentive to obstruct competitors' access to infrastructure. This prevents fair
competition in the market and can lead to higher prices for consumers. Unbundling must take place in one
of three ways, depending on the preferences of individual EU countries:
•ownership unbundling
•independent system operator
•independent transmission system operator – (All important decisions must be made
independently of the parent company.) 2) Independent regulators:
A competitive internal energy market cannot exist without independent regulators who ensure the
application of the rules. The requirements for national regulators have undergone a number of
changes, specifically:
•Regulators must be independent from both industry interests and government. They must be their
own legal entity and have authority over their own budget. National governments must also
supply them with sufficient resources to carry out their operations
•Regulators can issue binding decisions to companies and impose penalties on those that do not
comply with their legal obligations
•Electricity generators, gas network operators, and energy suppliers are required to provide
accurate data to regulators
•Regulators from different EU countries must cooperate with each other to promote competition,
the opening-up of the market, and an efficient and secure energy network system.
3) Agency for the Cooperation of Energy Regulators (ACER)
In order to help the different national regulators to cooperate and ensure the smooth functioning of the
internal energy market, the EU established the ACER. It is independent from the Commission, national
governments, and energy companies. ACER's work involves:
•drafting guidelines for the operation of cross-border gas pipelines and electricity networks
•reviewing the implementation of EU-wide network development plans
•deciding on cross-border issues if national regulators cannot agree or if they ask it to intervene
•monitoring the functioning of the internal market including retail prices, network access for
electricity produced from renewables, and consumer rights.
4) Cross-border cooperation
National transmission system operators are responsible for ensuring electricity and natural gas is
effectively transported through pipelines and grids. Due to the cross-border nature of Europe's energy
market, they must work together to ensure the optimal management of EU networks. They also coordinate
the planning of network investments and monitor the development of new transmission capabilities.
5) Open and fair retail markets
The third package includes rules designed to benefit European energy consumers and protect their rights.
They include the right to choose or change suppliers without extra charges, receive information on energy
consumption, and quickly and cheaply resolve disputes.
Source: Table is exact words from the key points derived from the European Commission’s webpage.
The traditional gas market system used to allow Soviets, then Russia/Gazprom charging
unfair prices through price manipulation, controlling cross-border gas sales through destination
clauses, and including conditional clauses to obtain unrelated commitments from wholesalers.

107
These practices allowed Gazprom to leverage consumers. The Third Energy Package have started
to change the status quo, or the existing architecture of the EU gas market, by bringing structural
and behavioral transformation.
DG-COMP has increasingly used legal and regulatory framework for establishing such a
functioning market. Examples of this have already appeared with the DG-COMP’s handling
of Lithuania’s complaint against Gazprom for anticompetitive behavior. The complaints
highlighted Gazprom’s abusive long-term supply contracts against Central and Eastern
European countries with limited or no viable alternatives. DG-COMP highlighted the
following preliminary charges:
“Gazprom is breaking EU antitrust rules by pursuing an overall strategy to partition
Central and Eastern European gas markets with the aim of maintaining an unfair
pricing policy in several of those Member States… Gazprom implemented its strategy
in three different ways, first, by hindering cross-border gas sales through so-called
destination clauses; second, by charging unfair prices; and third, by making gas
supplies conditional on obtaining unrelated commitments from wholesalers.”
According to the Commission, eight member countries of the EU were specifically targeted;
these countries are located in Central Europe, Eastern Europe, and the Baltic and Balkan
regions. They were “largely cut off not only from the rest of the European gas system but also
from each other.” They were previously part of the Council for Mutual Economic Assistance
(COMECON), or the Soviet Union itself, and were connected to Russia and Russian gas
through the old Soviet system.
The DG-COMP case against Gazprom was successfully settled in 2018. First,
DGCOMP and Gazprom accepted gas “swaps” into so-called gas islands, countries that
Russia is the only supplier to such as the Baltics and Bulgaria. The second, establishing spot
prices used in European hubs as a key benchmark instead of using oil-indexed gas prices. This
is very significant, especially for the Central and Eastern European countries that do not have
an easy alternative access to natural gas. While oil-indexed prices were not completely
abandoned, Gazprom made significant concessions over its long-held pricing system.

108
Gustafson highlights that, “The settlement of the DG-COMP investigation, which was
achieved in the middle of one of the most serious crises in East-West relations since the end of
the Cold War, showed both the power and persistence of DG-COMP as well as the ability of
the Russian side to adapt to the regulatory and commercial framework created by the three
Gas and Power Directives over the previous thirty years.” While Russia continues to focus on
increasing its European market-share and rent-maximization, the EU is concerned with
growing energy security in the area of natural gas supply.
3.3.5. The Fourth Energy Package – Clean Energy for All Europeans
In 2016, the EC published a proposal, “Clean Energy for All Europeans,” that reflects the
influence of the Energy Union established in 2015. The EU recognized that the common
energy market and climate policies, two key pillars related with energy, were in fact two sides
of the same coin and cannot be addressed separately. The Fourth Energy Package lays out an
integrated climate and energy policy that focuses on achieving energy and climate targets but
also supports the proposed reforms “to market design and network operation to adapt to
renewable generation, which is more variable, more distributed and requires greater
flexibility.”
In 2019, the EU completed its energy policy framework that is aligned with the
climate change targets by moving away from fossil fuels and reducing greenhouse gas
emissions. The package is expected to be turned into law within the next few years and will
provide benefits to the environment, customers, and the markets/economy. This package will
set the foundation for the EU’s long-term strategy for achieving carbon neutrality by 2050.
The Clean Energy Package aims to achieve European climate and energy targets. It consists
of eight legislative proposals including Energy Union governance, electricity market design,
rules for the ACER, and security of supply. It has not provided a specific natural annex or
amendment. The package has addressed five main focus areas of the European Energy Union:

109
energy security; the internal energy market; energy efficiency; decarbonization of the
economy; and research, innovation, and competitiveness. The Energy Union and its effects on
European Energy Policy and Energy Strategy will be covered in the following paragraphs.
The
Clean Energy Package will have implications on member states’ national energy mix; in other
words, the fuel choices of the member states will be shaped by the requirements to achieve
the European Union’s commitments to the Paris Agreement measures. Szulecki and Westphal
argue that, “It is now a necessity under the Paris Agreement’s framework to restore the EU’s
soft power, linking it to the Sustainable Development Goals agenda, and securing global
leadership in sustainability transition.”376
3.4. Natural Gas Supply Disruption to Europe
3.4.1. Russia – Ukraine Gas Crises of 2006 and 2009
With the collapse of the Soviet Union, Russia and Ukraine recognized that Russia has the gas
and Ukraine has the pipelines.377 The system functioned despite several problems because it
was divided into two parts that required a compromise and mutual sacrifices to continue.
Except for gas deliveries to Finland and Turkey, Russian exports to Europe were transported
through three transit countries: Ukraine, Belarus, and Moldova. Owing to historical evolution
of the natural gas pipeline system, Ukraine occupied the most important position with more
than 80% of the gas transported through its territory. According to Stern, the
RussianUkrainian gas relationship in 1990s was characterized by:
“Ukrainian inability to pay for up to 50 Bcm/year which it imported from Russia,
leading to very high levels of debt and unpaid bills which led to reduction of Russian
gas supplies to Ukraine for short periods of time, aimed at restoring payment
discipline which in turn led to…unauthorized diversions of the volumes in transit to
European countries.”
Increased gas prices and accumulating debt resulted in a reduction in gas delivery to Ukraine.
At the same time, Russian intimidation was increased to control, and if possible, acquire
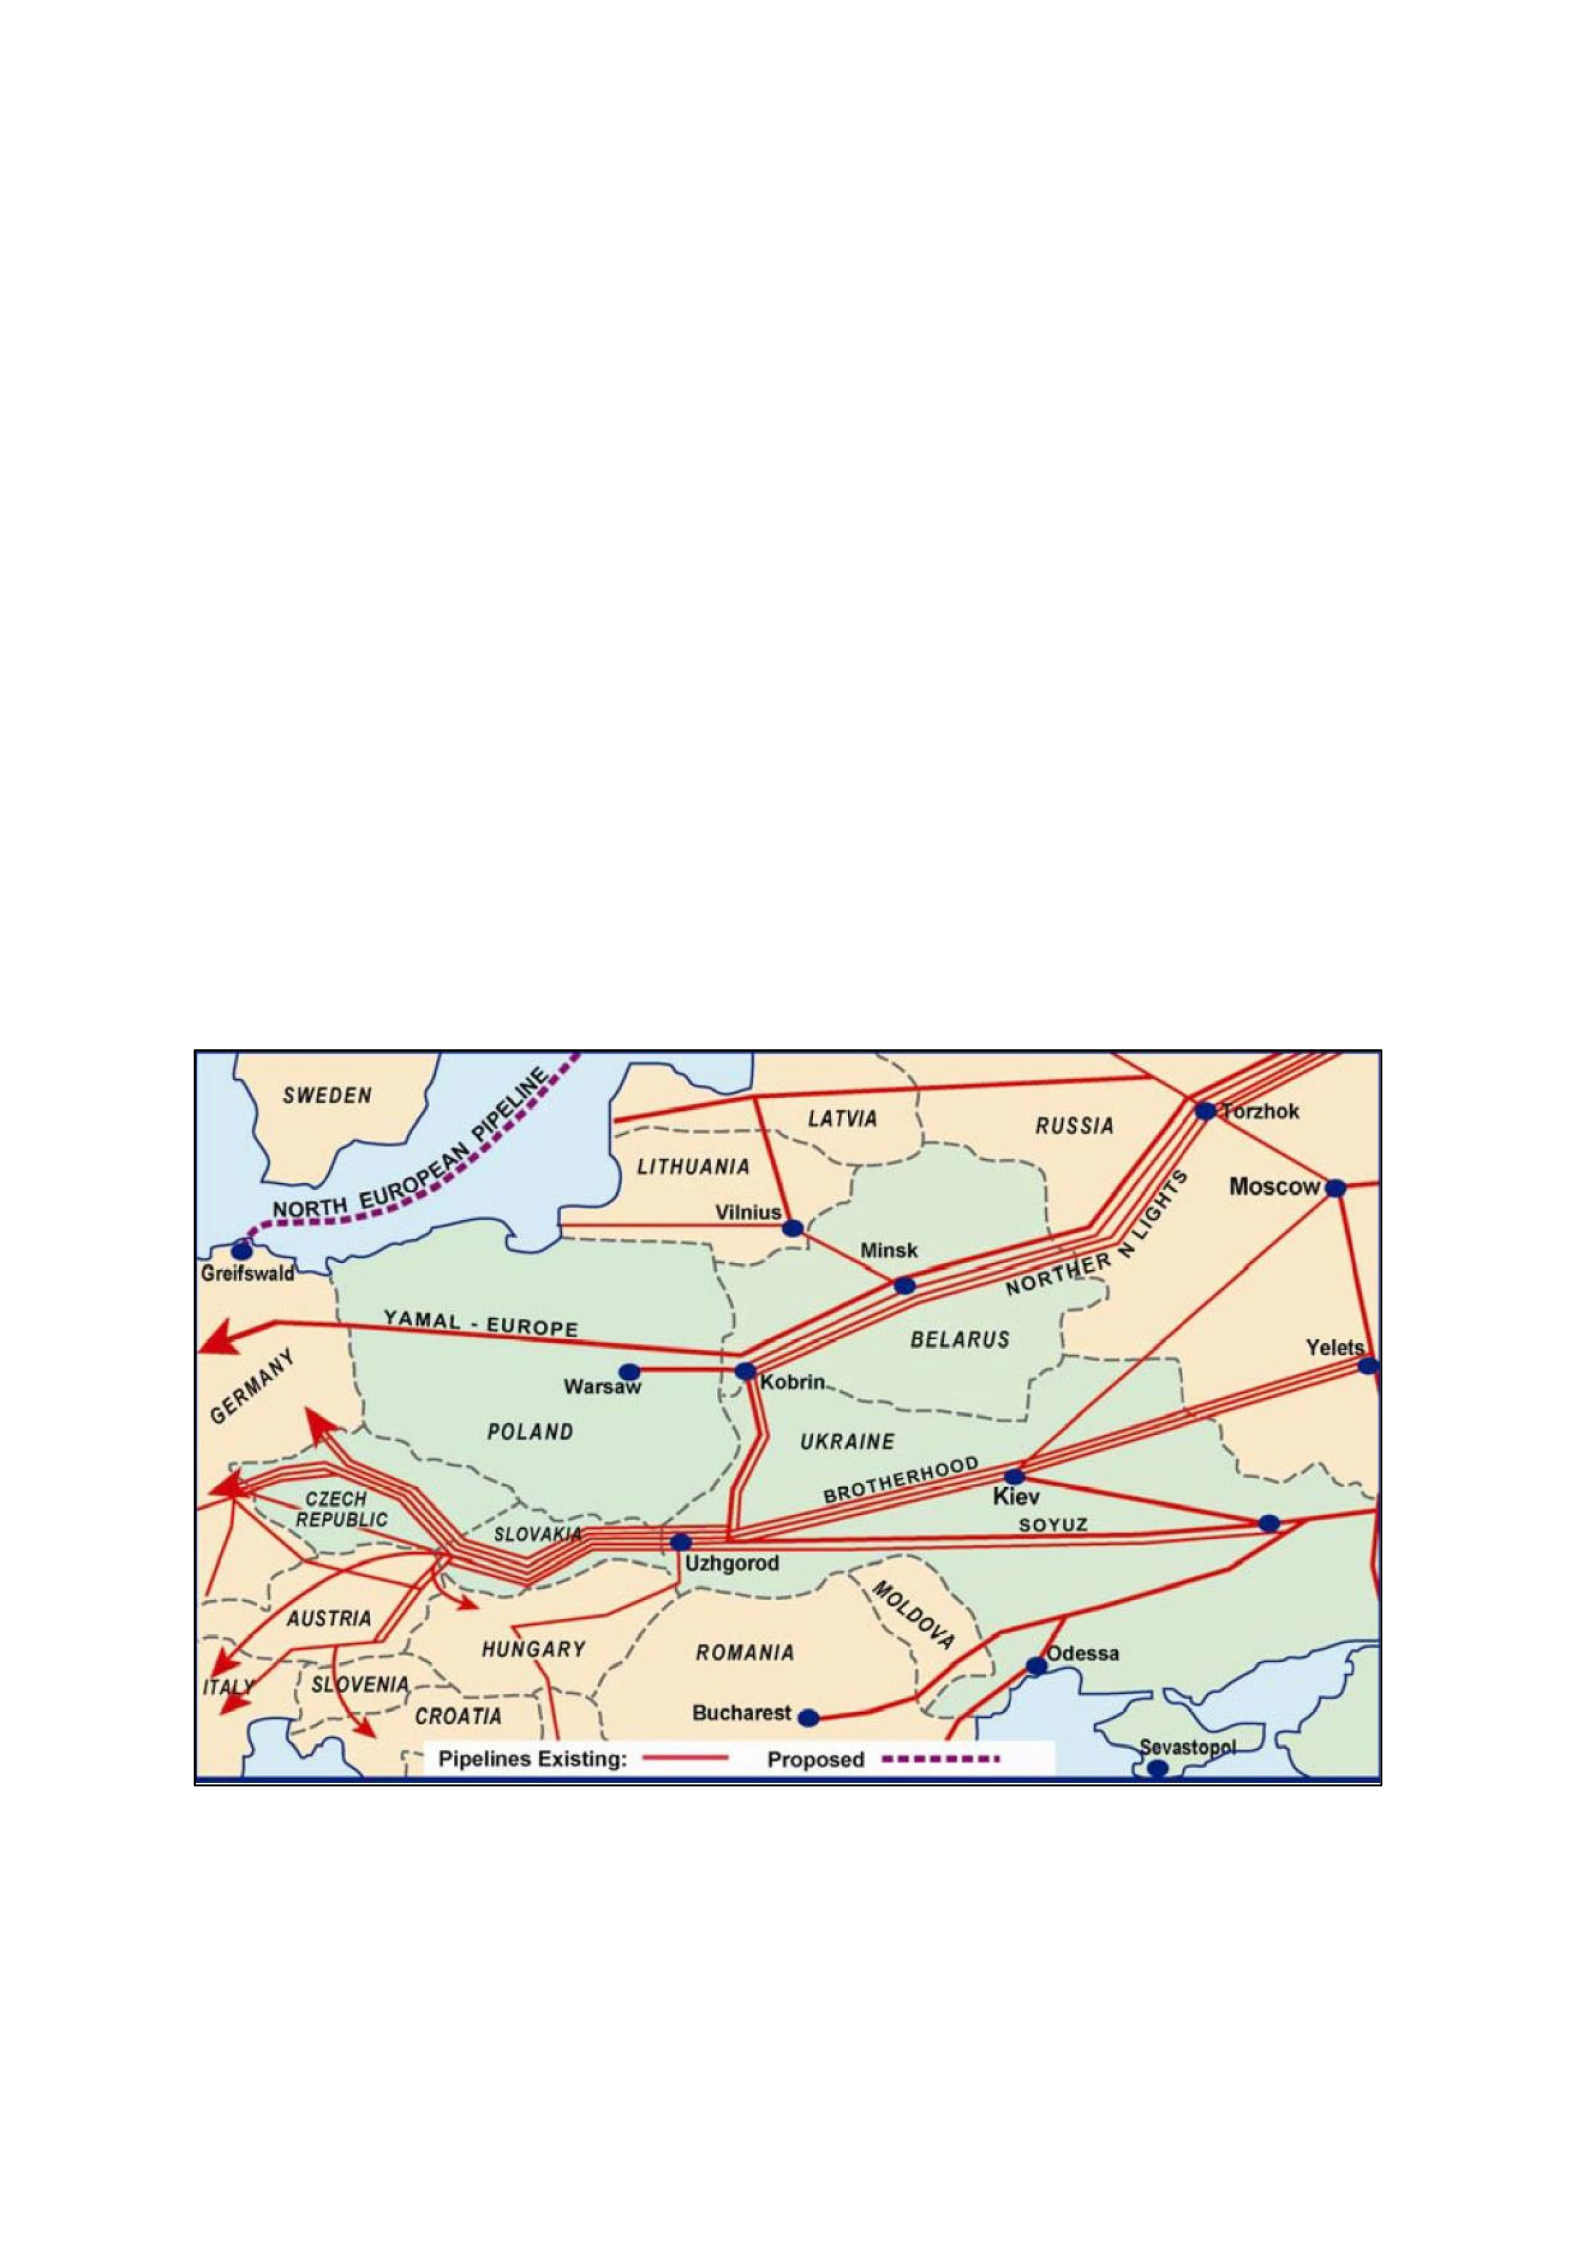
110
geopolitically important strategic facilities such as the Naval base in Sevastopol and most
importantly the natural gas pipeline networks. Over time, Russia, Ukraine, and their natural
gas companies have become increasingly confrontational due to pricing, debt, tariffs, and
overall ownership of the energy infrastructure, especially pipelines.379 While Russia was able
to secure a lease for the Sevastopol Naval Base, the main base of the Russian Black Sea Fleet,
the Ukrainian parliament was against handing over control of the pipeline system and
consistently vetoed this as a betrayal of national sovereignty. More importantly, Russian
leaders were frustrated with the political developments in Ukraine. However, the 2006 and
2009 crises could be attributed to pricing and debt issues. The details of the Russia-Ukraine
crisis will be analyzed in the following chapter. The following map depicts the importance of
the Ukrainian pipeline networks for Russian gas exports to Europe.
Figure 9: Ukraine's Pipeline Network for Russian Natural Gas Exports to Europe
Source: Jonathan Stern, OIES, The Russian-Ukrainian gas crisis of January 2006

111
Although the EU has made progress in improving its energy security after the initial Russia-
Ukraine crises of 2006 and 2009, Europe’s energy dependence on Russia has been rising
rather than falling. Russia continues to provide one third of the EU’s oil and gas. The EU
statistics office suggests that the EU reliance on imported energy increased from 63.4% in
2009 to 65.8% in 2012. Alarmed with the severe impact of reduced gas flow and the potential
for further disruptions, the EU convened an Energy Council meeting on 19 February 2009.
This was the first regular meeting since the gas crisis between Russia and Ukraine in January
2009. While oil stocks were reviewed, the main concern was the security of the natural gas
supply. A press release stated that:
During the crisis, the EU demonstrated that it could speak with one voice and was be
able to act quickly and resolutely…sending monitors to remote locations in Ukraine
and Russia… Mitigation measures…allowed most countries to manage the situation
successfully. Solidarity measures…were swiftly implemented… However, the
weaknesses of EU energy security and the EU's energy situation were also identified.
It confirmed that the EU urgently needs to continue the development of the internal
market, to improve energy interconnections for security of supply, to reinforce its
emergency mechanisms and to strengthen its negotiating position vis-à-vis our major
suppliers.
The Energy Council meeting adapted measures to allow the EU to address emerging
challenges. The process also enabled the EU to lay out a strategy encompassing not only
energy security issues but also establishing a single market and climate change mitigation
measures.
This eventually led to the development of the EU Energy Security Strategy that highlights the
EU’s energy import dependency on Russia.
3.4.2. European Support to Ukraine in Dealing with Russia
Ukraine has been a special interest for European energy security as the main transit hub for
natural gas transport. The 2006 and 2009 natural gas supply disruptions caused concerns not
only at the EU but were also widely condemned by NATO. Energy supply security was
discussed at the NATO Bucharest Summit in 2008, highlighting that “energy developments

112
could have major security implications for Allies and the Alliance. After all, in particular for
some of NATO’s new members that were burdened with serious energy vulnerabilities, energy
security was a question of national security.” Russia’s actions were described as part of its
hybrid warfare toolbox that is used to coerce Ukraine towards the Russian sphere of
influence. On the other hand, EU support to Ukraine included offering guarantees for its debt
to Gazprom in 2014; facilitating arrangements for receiving gas from EU countries such as
Slovakia at a reasonable price; mediating the Ukraine-Russia transit agreement in 2019 with
favorable terms for Kyiv.
One of the fundamental reasons for the Russia-Ukraine gas crisis was the Kremlin’s
perceived threat of color revolutions. The Rose Revolution in the newly independent Georgia
and the Orange Revolution in Ukraine not only represented the potential for waves of
democratization that could spread to Russia, but they also meant that the Kremlin was losing
control of the Ukrainian gas pipeline network that transported more than 80% of Europe’s
natural gas. Therefore, the 2009 natural gas cut-off was a defining moment for Russia-
Ukraine relations, and both parties had so much to lose. Gazprom, with the potential threat of
losing its four-decades-old reputation of being a reliable supplier, could not have decided this
by itself.
Gustafson argues that, “Putin had been personally involved in every stage of Russian gas
policy from the moment he took office, and consequently he can surely have had no illusions
about how Europe would react to a cut-off.” This example shows that the leadership in the
Kremlin, whether Soviet or Russian, has always considered geopolitical context when making
decisions on large projects such as the Nord Stream 2 and always sought to exploit the
differences amongst the EU members and NATO Alliance, especially with the old members
represented by Western Europe and new members that are part of Central, Eastern Europe, the
Baltics, and the Balkans.

113
Recent developments in Ukraine have shown that “energy has come to symbolize the
geopolitics of the 21st century, reflecting countries’ diminishing reliance on military and
political power,” argues Peterson and Barysch. Russia’s annexation of Crimea has been
motivated by changing its geopolitical priorities; however, a lack of unified European
response to Russia has been driven by increasing energy security concerns and asymmetric
energy interdependency of members of the European Union to Russia. While Eastern
European countries such as Poland and Lithuania wanted to see a strong NATO military
response, Western European countries preferred to pursue a diplomatic solution to this crisis.
The main reason for this diverging response was the considerable level of interdependency
between Russia and Western European members of the EU, in particular in the areas of trade
and energy supply.
3.5. European Energy Policy and Strategy
3.5.1. The Development of Energy Policy for the Enlarged EU
In 2003, the European Commission released an Energy Policy that was focused on energy
relations of the enlarged EU with its neighbors and most important geographical partners,
including Russia, Ukraine, and regions such as the Caspian Basin, the Mediterranean, and
North Africa. This policy emphasized completeness of the internal energy market and security
of energy supplies of the EU by establishing regulations within the “Wider Europe”
geographical scope that includes Southeast Europe and the Caspian Sea Regions. The policy
objectives were identified as enhancing the security of energy supplies; strengthening the
internal energy market; supporting modernization of energy systems including partner
countries; and facilitating major infrastructure projects.
A policy paper written by the European Commission identifies natural gas security of supply
as a major challenge and expects that the import requirements will increase due to demand
from an enlarged European Union. This policy paper was written before Eastern European

114
countries and the Baltics, then Balkans, had joined the EU. The gas had to come from areas
that were geographically further away from the European Union. In order to get natural gas
from these regions, new infrastructure, new pipelines, would be required. In the context of the
EU-Russia Energy Dialogue:
For the European Union, it is important to maintain and enhance Russia’s role as a
supplier of gas and oil and to strengthen Russia as a secure and reliable supplier
through technology transfers and investments to upgrade Russia’s energy
infrastructure…a new political impetus…by working together towards a strategic
European Union-Russia energy partnership…ensuring adequate energy supplies and
appropriate prices for economic development…of the European continent, and the
long-term nature of investments in energy production and transport.
The policy paper recognized the mutual dependence in the energy sector and planned an
energy dialogue platform between the European Union and Russia. The Commission policy
also laid out key issues including “identification of energy infrastructure projects of common
interest and the central role of long-term gas supply contracts in securing the conditions for
the Internal Energy Market by facilitating investments.” The policy paper also recognized the
different regulatory systems for gas in Russia and suggested that a common regulatory space
would increase business opportunities as well as lead to secure and efficient gas supplies. The
Commission’s long-term intent for Russia was a step-by-step market integration and a
balanced market interpenetration, similar to the other external gas suppliers to the EU.
Ukraine was recognized as the most important transit country as 80% - 90% of the total
Russian gas exports to Europe moved over Ukrainian territory. Ukraine has one of the most
extensive natural gas infrastructures in Europe, with around 14,000 km of pipeline that has the
capacity to move 175 bcm per year and has 30 bcm storage capacity. Most of the
infrastructure was built during the Soviet Union timeframe. The policy paper recognizes the
challenge to guarantee the overall performance, safety, and security of the Ukrainian network.
The Policy paper also mentions the EU’s interest in the Caspian Basin region with its
extensive oil and gas reserves that could contribute to European security of supply. It lists

115
reserves and production of the regional countries of Kazakhstan, Azerbaijan, and Iran. The oil
and gas resources of the Central Asian and Caspian regions, as well as their potential for
diversification of energy resources for Europe, is covered in the following chapters. The
policy paper identifies whether these resources are transported to Europe, either through
Russia or through other transport routes, and states that “secure and safe export routes for
Caspian oil and gas will be important for the EU’s security of energy supply as well as crucial
for the development of the Caspian region.” Iran and Turkey were identified as potential
routes for what will be called later as ‘Southern Corridor Pipeline.’
Esakova refers to Westphal and Aalto’s analysis of EU energy policy that suggests three main
principles that characterize the European Union’s energy policy: “first, market rules and
competitiveness, which reproduces the core idea and the strongest sector of the EU
integration, the Single Market; second, sustainable development, which comprises such issues
as environmental protection and fight against climate change, energy saving, increased energy
efficiency and utilization of renewable energy resources; and finally, security of energy
supplies.’ Energy directives and other regulatory measures focus on addressing these
challenging issues. However, differences amongst member states’ priorities in implementation
of regulatory measures and determining their energy mix as well as interaction with Russia
and transit countries remained as a source of contention.
3.5.2. Energy 2020 - A strategy for competitive, sustainable, and secure energy
In 2010, European Commission released Energy Strategy 2020 that identified the following
energy policy objectives: “To ensure the uninterrupted physical availability of energy
products and services on the market, at a price which is affordable for all consumers (private
and industrial), while contributing to the EU's wider social and climate goals. The central
goals for energy policy are now laid down in the Lisbon Treaty.”398 The strategy paper
recognized the progress achieved on security of supply, competitiveness, and sustainability,

116
albeit slowly, and expressed concerns over the slow adaptation of energy systems, outdated
infrastructure, and less competitive energy economies. This strategy paper does not address
any issues related with Russia, Ukraine, or other potential sources for resources that were part
of the 2003 policy paper. This was potentially due to European decision-makers lack of a
clear way ahead for how to handle Russia after the 2006 and 2009 Russia-Ukraine gas crises.
2010 Strategy focused on internal markets and pointed out some significant shortfalls
mentioned in the Second and Third Energy Packages in the following areas: fragmented
internal energy market; shortfalls on transparency, accessibility, and choice; different national
rules and practices that still dominates the growing companies within and beyond national
borders; lack of full implementation of internal market legislation; and finally, albeit limited
but remaining barriers to open and fair competition. The high number of investigations into
anti-competitive behavior in the energy sector was mentioned as a significant concern that
emerged as part of the Commission’s Energy Sector inquiries.
Natural gas was mentioned with the assumption that supply will remain stable and that it
“will continue to play a key role in the EU’s energy mix in the coming years, and gas can gain
importance as the back-up fuel for variable electricity generation.” It touches upon the
interconnectedness and diversification of pipeline and LNG networks as well as domestic
networks with external sources. Strategy highlights that:
Energy security is closely intertwined with the EU’s foreign and security priorities.
Diversification of fuels, sources of supply and transit routes is essential for EU
security as are good governance, respect for the rule of law and protection of EU and
foreign investments in energy producing and transit countries…EU policy will pay
particular attention to safety and security of oil, natural gas pipelines...by combining
energy policy and CFSP instruments.
2010 Strategy also highlighted the challenges to achieve the 20/20/20 climate targets on
greenhouse gas emission reductions, share of renewables, and energy efficiency efforts that
were adopted in 2007. However, Europe has not only achieved but also gone beyond its
greenhouse gas emission reduction targets in 2020, falling to 24% below 1990 levels in 2019.

117
In terms of share of renewables, European renewable energy share represented 19.7% of
energy consumed, only 0.3% short of the 2020 target.
3.5.3. European Energy Security Strategy (2014)
The European Commission’s European Energy Security Strategy highlights that, “The
European Union's prosperity and security hinges on a stable and abundant supply of
energy.”404 It continues, stating that:
In the winters of 2006 and 2009, temporary disruptions of gas supplies strongly hit EU
… was a stark “wake-up call” … a lot has been done … strengthen the EU's energy
security in terms of gas supplies and to reduce …dependent on one single supplier…
The EU needs…a hard-headed strategy for energy security … resilience to these
shocks and disruptions to energy supplies in the short term and reduced dependency
on particular fuels, energy suppliers and routes in the long-term.
European energy security concerns, in general, could be defined as supply security and
member nation’s high-level dependence on a single external supplier. The EU imports more
oil (almost 90%) than natural gas (66%); however, dependence on natural gas has become a
major source of concern due to lack of potential energy sources for diversification. Several
member states rely on natural gas from Russia as a single supplier, and some members still
import electricity from Russia to sustain support for the increasing power demand of their
economies. Strategy papers highlight that, “Energy security issues are addressed only at [the]
national level without taking fully into account the interdependence of member states.”
The EU Energy Security Strategy also outlined short- and long-term measures. In the short-
term measures that were focused on overcoming a major disruption during the winter
2014/15, “particular attention [was] paid to vulnerable areas, to [enhance] storage capacity, to
[develop] reverse flows, and to [develop] security of supply plans at [the] regional level and to
[exploit] more [of] the potential of Liquefied Natural Gas.” The so-called stress test
mentioned in the strategy was carried out by EU member states as well as neighboring
countries in August and September 2014. The outcome of the stress test that simulated

118
different energy supply disruption scenarios for a period of one or six months were as follows:
first, a complete halt of Russian gas imports to the EU, and the second, a disruption of
Russian gas imports through the Ukrainian transit route.408
As reflected in the findings and press release of the Commission, cooperation is the key to
mitigate the impact of the supply disruption. However, the results of the stress test clearly
show Europe’s vulnerability to the disruption of the supply from Russia. It suggests that “a
prolonged supply disruption would have a substantial impact on the EU. Eastern EU countries
and Energy Community countries would be particularly affected.” The outcome of the
worstcase scenario, interruption of all Russian gas supplies for six months, suggests that
Hungary, the Balkans, the Baltic States, and Finland would have a severe shortfall by
February even with gas sharing and other measures mitigating the impact. In order to address
supply challenges and increase energy security, the EU’s long-term measures should include
diversifying supplier countries and routes.
There are a few issues that would shed a light on the future of European-Russian energy
relations based on the findings of the ‘Stress Test.’ While the Commission analysts used
periods of one month and six months for each case, it does not define the length of the
disruption that would have a substantial impact. The findings are based on individual national
simulations, taking into account the situation in neighboring countries. While nations focus on
avoiding a national crisis, the report draws upon analysis of national responses that concludes
that a cooperative approach could significantly reduce the impact in the most affected
countries. That result might be true during an exercise or a stress test that involves reactions
by national technocrats and bureaucracy; however, ongoing vaccine distribution and
pandemic measures determined by political leaders have been extremely uneven and
problematic within the EU member states, even between countries such as Germany and

119
Austria due to border closures or test requirements that could never have been imagined. In a
real disruption, the situation could be much worse than the test outcome suggests.
In case of a major supply disruption, there will be a rush to meet domestic demand and a
market-based approach as suggested as a potential solution of the test would never satisfy
those countries in need. There will be pressure for the release of strategic shocks, forced fuel
switching, and demand curtailing, but these measures will be uneven throughout the EU
member states. Due to different levels of dependence on Russian natural gas and diverging
national priorities, the stress test might not reflect potential conditions in a real crisis situation.
With the Energy Security Strategy, the Commission is looking into taking a stronger political
role, which is a step forward creating the Energy Union that is explained below. The Third
Energy Package has caused major changes to the German domestic energy markets as well as
to the gas industry’s relations with Russia, in particular with Gazprom. While the future of the
European natural gas demand remains uncertain, owing to climate change measures and
technology advancements, European and U.S. sanctions over the Ukraine crisis limits
Germany’s policy choices for further discussions over security of gas supply matters and gas
market design beyond the Third Energy Package.
Bros, Mitrova and Westphal argue, “The ‘geopolitical burden’ on natural gas stems from
Russia's strong position in the natural gas market in the EU. Russia's natural resource
endowment in such close proximity to the EU is no longer seen without bias as being an asset
to the EU or Germany.” Central and Eastern European and the Baltic members of the EU have
been vocally criticizing Germany “for placing its economic interests first, at the expense of
the EU, whereas Russia has been perceived as trying to weaken the EU by using German-
Russian ties.” The Nord Stream 1 and 2 projects are perceived as Russia’s geopolitical
approach to natural gas supply, increasing its market share in Western Europe. Additionally,

120
Russian attempts to bypass Ukraine as a transit country allows leveraging future natural gas
supply to increase its power and influence.
3.5.4. European Energy Union
Following the release of the European Energy Security Strategy in 2014, the Junker
Commission identified establishment of an Energy Union as one of its key priorities. Energy
Union strategy identifies five intertwined and mutually reinforcing dimensions: ensuring
energy security by diversifying Europe’s energy sources through cooperation between EU
countries; fully integrated internal energy markets that enables the free flow of energy without
regulatory or technical barriers; improving energy efficiency that will reduce energy import
dependency, lower emission, and drive growth and employment; retaining Europe’s
leadership in renewable energy and maintaining climate targets by decarbonizing the
economy; and finally, supporting research, innovation, and development for a breakthrough in
clean energy low-carbon technologies that drive energy transition and allow maintaining
competitiveness. The Energy Union provided an umbrella concept to address several
challenging issues from energy security to achieving climate targets. One of the most
important aspects of the
Energy Union is that it offers an excellent opportunity to complete the internal gas market.
The Energy Union could increase EU energy infrastructure investment to address key issues
such as member states’ dependence on a single source, namely Russia. While this is mostly a
concern for Central and Eastern European countries, there are certain steps to increase
accessing alternative energy resources such as initiatives by Poland and Lithuania to build
LNG terminals. As highlighted by Boersma, despite the political desire to achieve energy
independence, member nations are likely to be required to pay a premium due to competitive
pricing of Russian gas via pipeline. Although the Energy Union was introduced as a drastic
reform and major change in the European approach to Russia, in particular energy relations

121
and natural gas trade, the objectives identified in the Energy Union have yet to be
accomplished due to diverging national interests of Western, Central, and Eastern Europe.
The most recent report on the state of the Energy Union, The Fifth Report on the Progress
Achieved, released in October 2020 focuses on COVID-19 recovery efforts. The report
highlights the EU’s new focus on the European Green Deal that aims “to transform the EU
into a fair and prosperous society and combines policies to tackle climate change, to protect
and restore biodiversity, eliminate pollution, to move to a circular economy, and to ensure that
no one is left behind in the green transition.” Natural gas will have important role for the
EU’s transition to achieve 2050 climate targets. In that regards, the EU’s dependence on
Russian natural gas is expected to increase and natural gas is perceived as a transition fuel as
Europe continues to reduce coal plants and phase out nuclear power.
The Fifth Progress Report is also accompanied by assessment of the final national energy and
climate action plans. Each EU member state provides its own assessment of the five main
areas identified in the Energy Union strategy and shares their best practices. For example,
Lithuania provided the following assessment in the area of energy security:
Maintaining high levels of security of supply is a priority in the ongoing
transformation of the energy system, with the objectives by 2030 of 45% renewables
powered electricity and increasing the share of domestic renewable energy for
electricity generation to 70% to replace imports… When considering risks…projects
that focus on interconnectors with neighboring countries for both gas and electricity.
However, the generation capacities of the neighboring countries are not sufficiently
taken into account…As regards diversification of sources and routes, the plan
specifies measures and key objectives for diversification and to reduce import
dependency for gas and electricity, but not for oil.”
These reviews and annual assessments allow the Commission and member nations to
coordinate energy security efforts and concerns, especially joint projects, as Europe targets a
carbon-neutral economy in accordance with the European Green Deal.
3.6. The EU-Russia Energy Cooperation Mechanisms – Multilateral Frameworks
3.6.1. Energy Charter Treaty

122
With the collapse of the Soviet Union in 1991, the European Economic Community (ECC)
promoted international energy cooperation with former Soviet satellites and new republics in
Eastern Europe and Central Asia, based on a shared interest in secure energy supply and
sustainable economic development. This process allowed development of the Energy Charter
Treaty (ECT) that was signed in 1994 and went into force in 1998. ECT is a legally binding
document that provides framework for foreign investors’ activities and protect their rights in
the host states. The treaty focuses on the following main areas:
…the protection of foreign investments; non-discriminatory conditions for trade in
energy materials, products and energy-related equipment and provisions to ensure
reliable cross-border energy transit flows through pipelines, grids and other means of
transportation; the resolution of disputes between participating states and host states;
the promotion of energy efficiency and attempts to minimize the environmental
impact of energy production and use.419
There are fifty-six members of the ECT. While Russia signed the document in 1994, the
Russian Parliament did not ratify the treaty due its Protocol on Transit that would allow
freedom of transit without distinction of origin, destination of ownership, and
nondiscriminatory pricing.420 In other words, it would allow unlimited third-party access to
Russia’s pipeline network that is still debated between Russia and the EU. ECT was the first
attempt to challenge Gazprom’s monopoly; if it were approved, ECT would enforce
multilateral regulations over Russia’s pipeline network. For example, Gazprom’s role as buyer
and reseller of Central Asia and Caspian gas would cease, and Turkmens would sell their gas
to Europe or other former Soviet states at European prices. Additionally, ratification of the
Charter would allow European companies to participate in Russia’s upstream and in
ownership of Russia’s transit energy infrastructure. These concessions, from the Russian point
of view, are against Moscow’s approach seeking to revise post-Cold War era arrangements
and increase
its influence its “near abroad.”

123
The Energy Charter is still in effect for solving European and International investorstate
disputes. At the time of this writing, around 135 cases were introduced under the premises of
the Charter’s obligations. However, there is increasing pressure for a review of the Treaty due
to changes in investment law and environmental objectives. Brauch argues, “The special
protections that the Energy Charter Treaty gives to fossil fuel investors and their investments
go in the opposite direction of what is needed for the world to decarbonize its energy matrix
and fight the climate emergency.”
3.6.2. EU-Russia Energy Dialogue
There were different expectations when a bilateral EU-Russia Energy Dialogue was
introduced during the EU-Russia Summit in 2000 in Paris. Based on the developments in the
1990s, there were high expectations, assuming Russia would remain as a reliable partner for
energy cooperation. These expectations were reflected with the initiation of the EU-Russia
Energy Dialogue regime covering some of the Energy Charter Treaty principles. The joint
declaration refers to rigorous implementation of the Partnership and Cooperation Agreement
(PCA) in the economic and social spheres. Additionally, it states that:
The EU and Russia have decided to institute, on a regular basis, an Energy Dialogue ...
will provide an opportunity to raise all the questions of common interest relating to the
sector, including the introduction of cooperation on energy saving, rationalization of
production and transport infrastructures, European investment possibilities, and
relations between producer and consumer countries. The planned ratification of the
Energy Charter Treaty by Russia and the improvement of the investment climate will
be important aspects in this context.
The dialogue initially contributed to confidence building and problem solving such as
recognizing mutual dependence and establishing joint ventures. It has not progressed as
planned and failed to fully integrate the Russian and European energy systems.424
Russia’s approach and commitment to the EU-Russia Energy Dialogue changed with
the geopolitical developments in Russia and the former Soviet space since 2003. With the
Putin administration’s centralization policies, Russian foreign policy has also changed as a

124
response to the developments such as “the second wave of the North Atlantic Treaty
Organization
(NATO) enlargement in Eastern Europe, the 2004 EU enlargement, ‘colored revolutions’ in
Ukraine and Georgia in 2003 and 2004.” These developments changed Russian
rapprochement attitude and created a sea change in Russian foreign energy policy.
Additionally, Russia realized that individual European countries prefer to deal with Russia
bilaterally such as the Nord Stream and South Stream projects indicated. Since Central and
Eastern European countries preferred a common EU policy, it was not possible to align
national priorities, especially amongst the old members of the EU and the new members,
mostly former Soviet satellites or new republics.426
3.7. European – Russia Energy Relations
3.7.1. Energy Demand and European Energy Security– An Overview
Over the last three decades, European energy policy evolved around two main objectives:
first, ensuring greater energy security in the natural gas system by building resilience and the
establishment of a single gas market for the EU. The second, addressing climate change
concerns by decarbonization, increasing energy efficiency, and increasing support for
renewable energy. In 2016, Maroš Šefčovič, Vice President and Commissioner of the Energy
Union, reflected the core message of the European Union’s strategy adopted by
the European Commission in February 2015:428
The EU continues to be dependent on importing energy. It imports about 53% of its
energy at a cost of around €400 billion annually, making it the largest energy importer
in the world. The EU remains vulnerable to external energy shocks no matter what the
roots for this are. A fragile international context, combined with overdependence of
some Member States on one particular source or supplier, calls for reinforced efforts
to reduce its dependency on particular fuels, energy suppliers and routes.429

125
What Vice President Šefčovič highlighted in his statement and is suggested by an analysis of
global and European energy trends, European demand for energy, especially for natural gas, is
expected to increase over the next few decades. Europe will increasingly be vulnerable to
energy shocks, such as the instability in oil and gas exporting countries, manmade or natural
disasters, resource nationalism, and geopolitical conflict. Europe, especially the Central and
Eastern European countries, and former Soviet republics, will be susceptible to political
manipulation due to the high-level dependence on a single source - Russia.
The World Energy demand continues to increase driven by economic development, especially
in the Indo-Pacific region. The level of economic activity is one of the key determinants of the
energy trends. In the World Energy Outlook 2015 Report, the International Energy Agency
(IEA) identified three core scenarios: The New Policies Scenario; the Current Policies
Scenario; and the 450 Scenario. The New Policies scenario, the IEA’s central scenario
identified in 2015, takes into account climate pledges by countries toward implementing
measures in accordance with the Paris Agreement.431 Article 2 of the Agreement sets a goal
aiming to limit global warming compared to the pre-industrial levels in the context of global
response to the threat of climate change, thereby reaching global peak of greenhouse gas
emissions as soon as possible to achieve climate neutrality by mid-century.
While European energy supply remains stable and the global share of the EU 27’s energy
supply is around 10%,432 the new European Green Deal targets net-zero greenhouse gas
emissions by 2050. The Commission developed an Action Plan and turned it into a “European
Climate Law” that emphasizes its “ambition to make Europe the first climate-neutral
continent by 2050.” Therefore, climate targets will also bring additional stress to European
energy markets and security of supply, as well as relations between Brussels and member
nations, in particular on the member nations’ policy choices that shape the energy mix of the
respective countries. For example, one of biggest energy users in Europe, Germany, will

126
phase-out its nuclear plants in 2022. Germany has also established a target to end coal-fired
power generation by 2038, with a potential option to bring it forward by 2035. These policy
choices will result in an increase of gas share in energy mix over the mid-term. Germany’s gas
demand will increase significantly as its domestic production has been in decline since 2004.
Russia’s role will be growing as Germany is directly linked to Russia via pipeline networks
that will be used to import natural gas.435
While climate mitigation measures will have significant consequences on European energy
demand and European-Russian energy relations by 2050, Europe will continue to remain
import dependent on fossil fuels for the foreseeable future. Central and Eastern
European countries have similar challenges and depend upon the gas supply from Russia.
Grigas highlights that, “Until recently, many countries, especially, Central and Eastern Europe
and the Caucasus, have been 100% dependent on a single gas pipeline, a single gas-producing
country, and even a single company, such as the Russian gas giant Gazprom…Russia [has]
likewise been dependent on a fixed set of pipeline export routes and consumers.”
There has been a growing demand for oil and natural gas in Europe while concerns increased
dependency on Russia. The EU, together with the countries aspiring to be part of the
European Union, has become the largest importer of gas. As a result of depleting European
production, the EU 27 natural gas import dependency was more than 80% in 2018, around a
20% increase compared with what it was in 2000. The following figure depicts the world total
energy supply by region in 2020.
Figure 10: World Total Energy Supply by Region
127
Source: European Commission, Directorate-General for Energy, EU energy in figures: statistical pocketbook 2020,
Publications Office, 2020, https://data.europa.eu/doi/10.2833/75283
3.7.2. European Energy Import Dependence
In 2014, EU Energy Security Strategy stated that:
The EU imports 53% of the energy it consumes. Energy import dependency relates to
crude oil (almost 90%), to natural gas (66%), and to a lesser extent to solid fuels
(42%) as well as nuclear fuel (40%) …Six Member States depend [on] Russia as
single external supplier for their entire gas imports and three of them use natural gas
for more than a quarter of their total energy needs. In 2013 energy supplies from
Russia accounted for 39% of EU natural gas imports or 27% of EU gas consumption;
Russia exported 71 % of its gas to Europe with the largest volumes to Germany and
Italy.440
The following map shows European energy import dependency by country. Most of Europe is
more than 50% dependent at the aggregate level.
Figure 11: Europe Energy Import Dependence – 2018
10
22.5
15.6
18.6
5.3
5.9
5.3
3
15.8
World Total Energy Supply by Region
EU27_2020
China
United States
Asia*
Russian Federation
Africa
Middle East
World Bunkers**
Rest of the World
* non OECD and OECD Asia, excluding China
** International aviation and international navigation
128
Source: Julian Wettengel, Clean Energy Wire “Germany’s Dependence on Imported Fossil Fuel.”
Europe, members of the EU, the UK, and Turkey depend greatly on energy imports “for their
energy supply, none of them having a positive energy trade balance...Intra-EU energy flows
[are] treated as domestic”442 Most energy experts’ views converge on the EU’s ‘increased
dependency on imports of oil, gas, and coal supplies, while renewable and nuclear power is
estimated [as] not being able to meet this shortfall/deficit.”
The European Union’s energy dependency on Russia has changed in parallel with the
developments of the European political landscape in the post-Cold War era, especially with
the EU enlargements in 1995, 2004, 2007, and 2013. With the ascension of former Soviet
satellites and former Soviet republics into the EU, the level of dependency has increased
significantly due to the new members higher rates of energy dependency on both resources
and infrastructure, in particular natural gas pipelines. The dependency of the member states
129
is based on not only resources such as oil, natural gas, coal, and electricity, but also on the
infrastructure such as pipelines and power lines/grids on which the energy supply is
transported. While the EU has taken certain regulatory measures with several Energy
Packages including directives to establish an internal energy/natural gas market, Grigas
argues, “The differences among EU members will likely to persist in terms of their
dependence on Russian gas, as will differences in degrees [of] energy security and energy
vulnerability, complicating efforts to develop a common approach.”
The following figures depict EU imports of crude oil, natural gas, and coal by country.
Russia is by far the biggest provider of energy in oil, natural gas, and coal to Europe. Figure
12: EU Oil Imports by Country
Source: Julian Wettengel, Clean Energy Wire, based on Eurostat data
Figure 13: EU Natural Gas Imports by Country
29.8
8.7
7.4 7.2 7.2 7.1 6.1
4.6 3.9 3.9
2.4
11.6
0
5
10
15
20
25
30
35
Russia Iraq Saudi
Arabia
Norway Kazakhstan Nigeria Libya Azerbaijan Iran United
Kingdom
United
States
Others
Percentage by Partners - 2018
Shares based on thousand tonnes
Imports from not specified countries excluded
Source: Eurostat
EUROPEAN UNION CRUDE OIL IMPORTS - 2018
130
Source: Julian Wettengel, Clean Energy Wire, based on Eurostat data
Figure 14: EU Solid Fossil Fuel Imports by Country
Source: Julian Wettengel, Clean Energy Wire, based on Eurostat data
While net import dependency aggregate data shows an overall situation of respective
countries, detailed distribution of energy mix and usage provide a more complex and
troublesome picture. For example, countries that appear to be a net energy exporter, such as
40.1
18.5
11.3
4.5
25.6
0
5
10
15
20
25
30
35
40
45
Russia Norway Algeria Qatar Others
Percentage by Partners -
2018
Shares based on million cubic meters
Imports from not specified countries excluded
Source:Eurostat
EUROPEAN UNION NATURAL GAS IMPORTS - 2018
42.3
18.3
13.4 11.6
4
10.5
0
5
10
15
20
25
30
35
40
45
Russia United States Colombia Australia Indonesia Others
Percentage by Partners - 2018
EUROPEAN UNION SOLID FUEL IMPORTS - 2018

131
the case for the Netherlands in the 1970s due to its vast natural gas reserves, but it was
dependent on crude oil imports. As we have seen in the previous chapter, energy is a system
and energy exporting countries are also dependent on foreign nations for technology,
equipment, processes, and resources that are required to explore, transit, and process energy
resources.
Europe, as a net energy importer, depends on raw material but has the technology, equipment,
and resources that allow producer countries to extract and make raw materials available for
export. This interdependence set the foundation for European-Soviet energy relations during
the Cold War. While the situation has changed and technology advancements for conventional
resource extraction allow Russia to operate and utilize existing reserves, there are areas such
as the Arctic that still require Western technology to explore resources. In other words, the
interdependence which has set the initial foundation still survives albeit increased complexity
due to changes in the actors and linkages.
As highlighted by Grigas, the EU is a unique entity, neither a nation state nor an international
organization. It is an evolving supranational organization that is “primarily an economic union
of states, aggregating functions formerly reserved for national governments, with internal
politics, foreign policy, and energy relationships continuously evolving.” However, each
member state has its own national interests that might be in conflict with the other members.
Energy security, especially natural gas relations with Russia, is one of the most evident
fissures in the EU between the Western and Central/Eastern European members. While
attempts to overcome these differences still occupy the Commission’s agenda leading to the
development of the Energy Union under the Junker Presidency, national interests and
priorities still prevail over the common European position such as the debate over Nord
Stream 2.
3.7.3. European Natural Gas Consumption by Country

132
The European Commission statistics indicate that natural gas gross inland consumption of
the EU increased by 4.2% in 2019 compared to 2018. The increases were observed in Spain
(14.1%), Greece (9.0%), and Germany (7.7%), while the largest drops were observed in
Latvia (-8.4%), Estonia (-8.0%), and Denmark (-6.7%). As depicted in Figure 15 below,
natural gas demand is mainly concentrated in North-West Europe. Germany, Italy, and France,
followed by the Netherlands, Spain, and Poland, are the main consumers of natural gas in the
European Union. The UK and Turkey also import large amounts of natural gas. At the same
time, EU domestic natural gas production continued to decrease, falling by 11.0% compared
to 2018.
The drops in output were observed in the Netherlands, Denmark, Ireland, Croatia, Italy,
Hungary, and Austria, varying from (-25.4%) to (-9.2%). A slight increase of (0.5%) was
achieved in natural gas production in Poland.
European domestic gas production is projected to decline. This projection is supported by
IHS Markit’s most recent analysis in “Outlook for Natural Gas” that also suggests the
European natural gas demand is expected to decline over the long-term after 2030, pending
“on the progress in electrification, implementation of renewable power generation and the use
of renewables to replace fossil fuel emissions.” IHS also argued that natural gas pipelines and
additional gas infrastructure, such as the Nord Stream 2 pipeline, would be beneficial for
Europe. Chief natural gas strategist of IHS stated, “It is in the interest of European consumers
to have abundant choice of import infrastructure from both price and security of supply
considerations - especially if the infrastructure investments and risks are born by private
companies.”
Figure 15: Gross Inland Consumption of Natural Gas EU27, 2018-2019
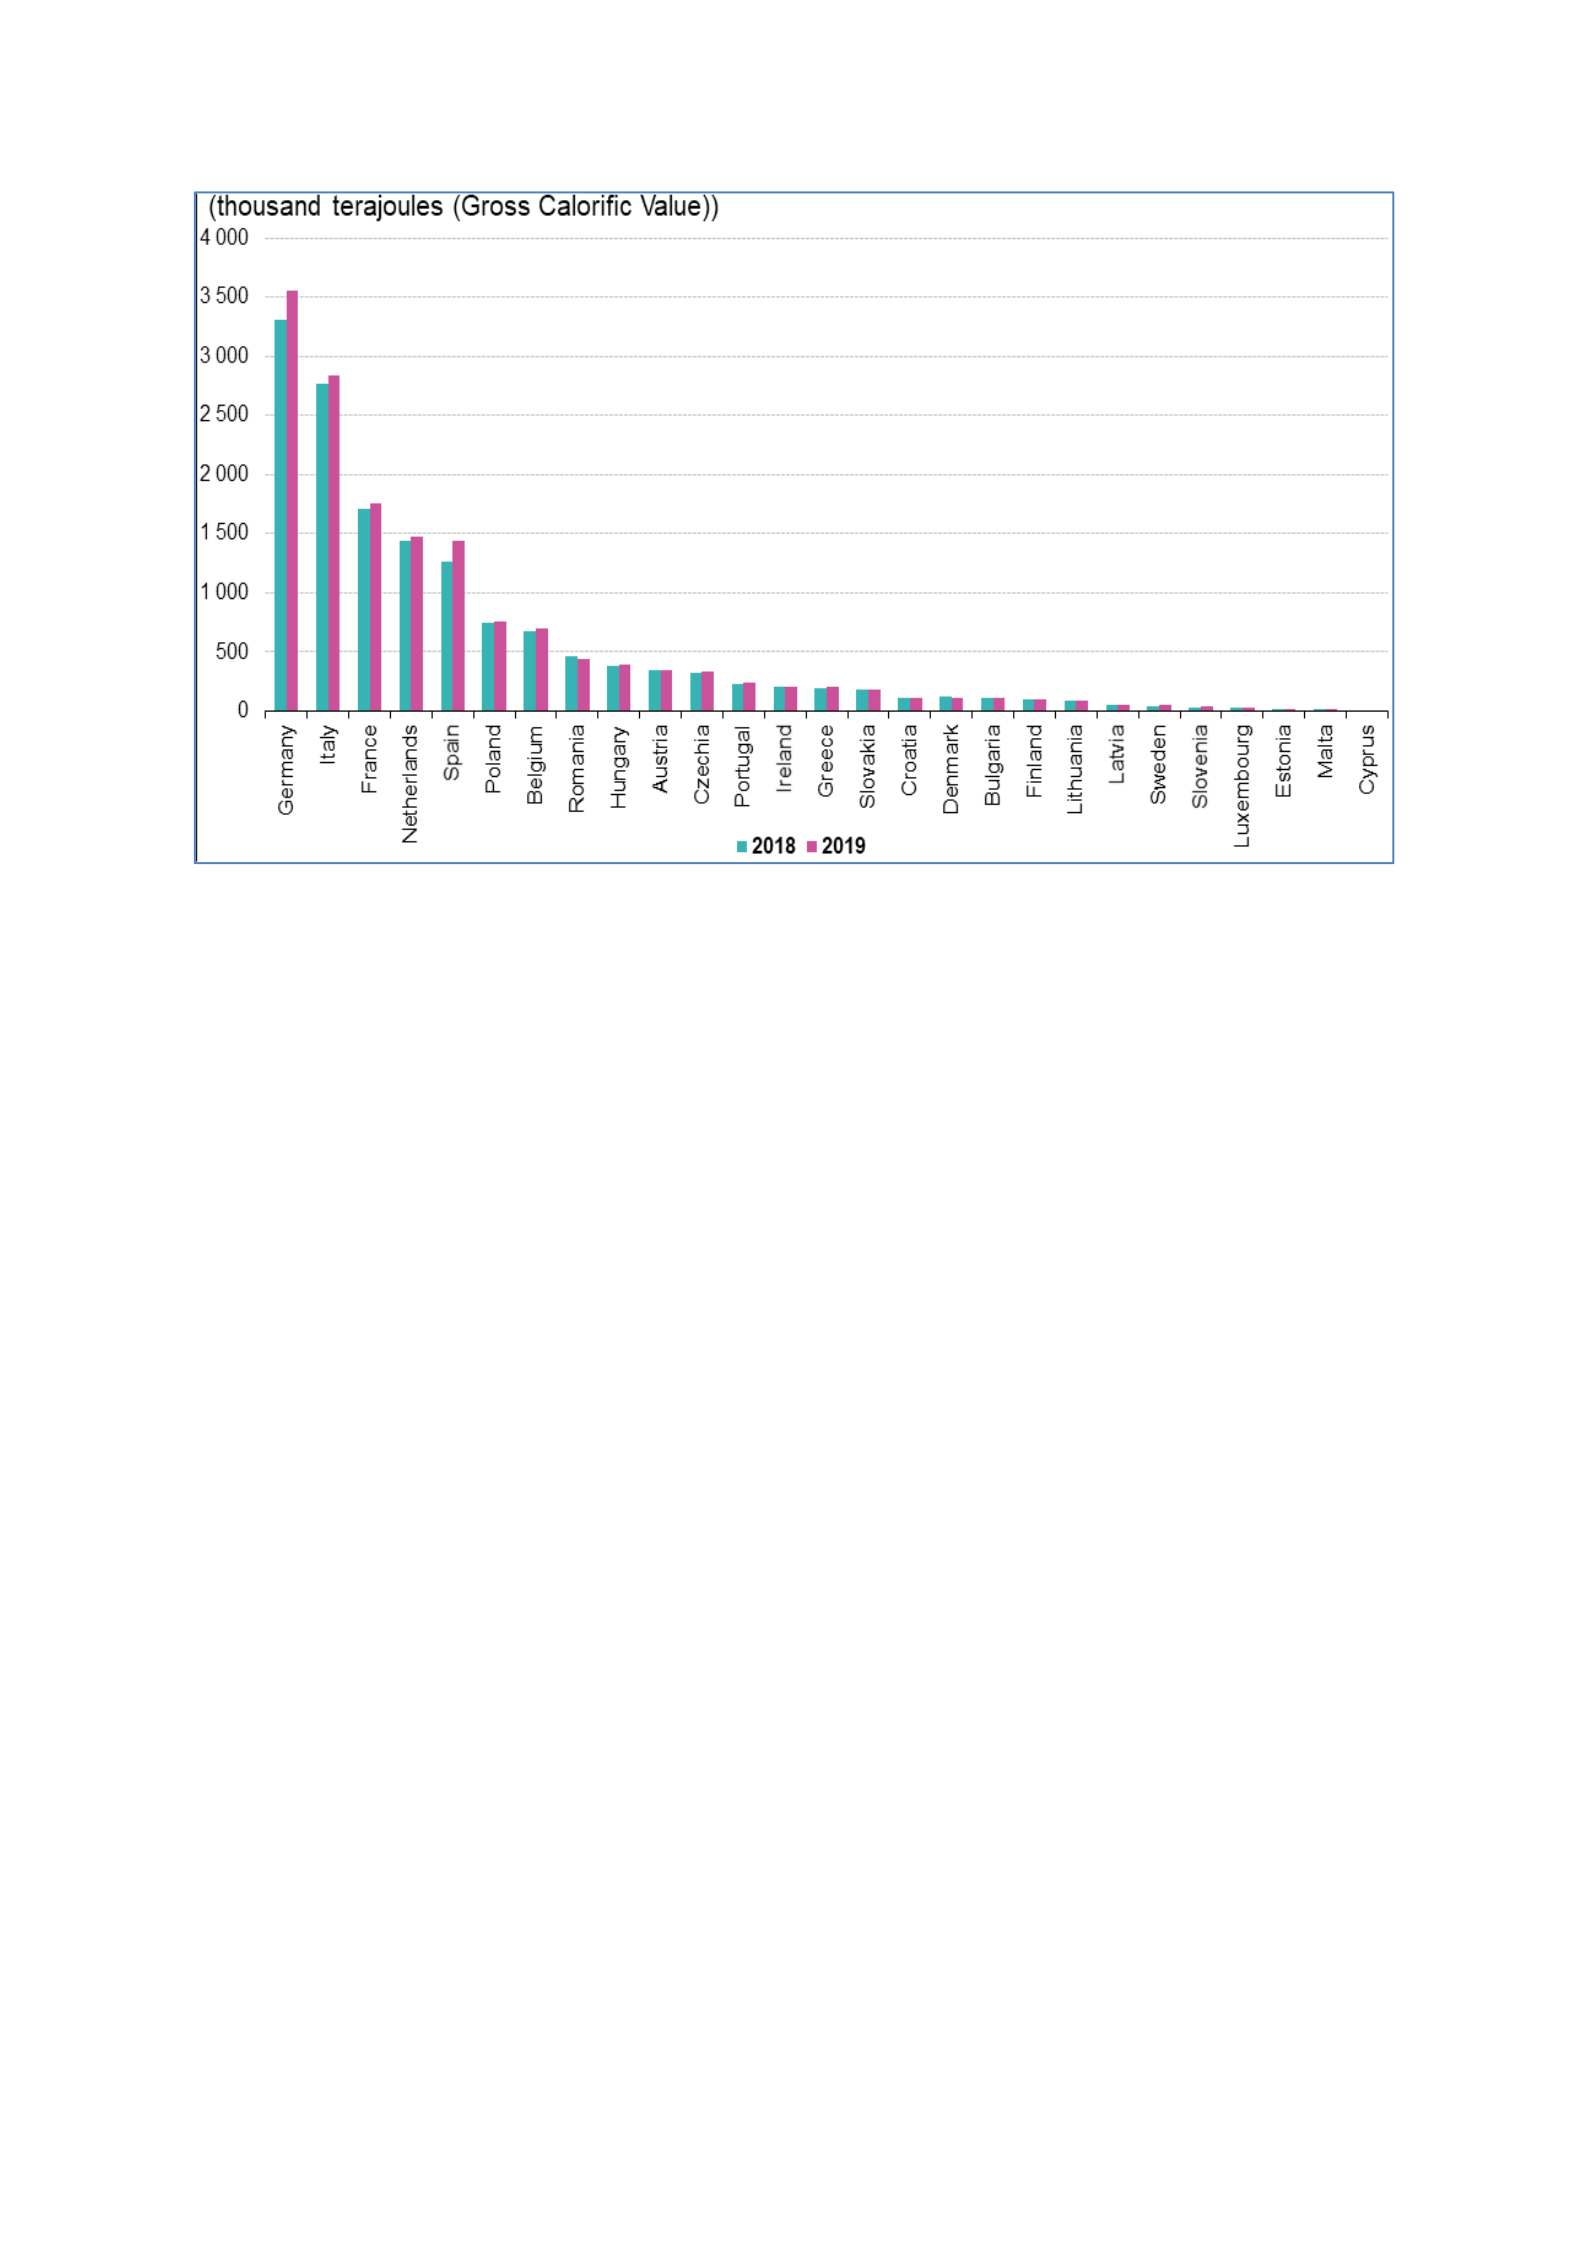
133
Source: EC, Eurostat, Gross Inland Consumption of Natural Gas by Country
https://ec.europa.eu/eurostat/statisticsexplained/index.php?
title=Natural_gas_supply_statistics#Consumption_trends
3.7.4. European Natural Gas Demand – Russian Gas Supply
Since the end of the Cold War, there has been an increasing demand for natural gas in
Europe. While the demand is increasing, European domestic production is in decline. While
there are diverging views on the future of these two trends, the IEA estimates that natural gas
demand at global level could decrease 5% in 2020 due to the COVID 19 pandemic’s impact
on the global economy and societies. While this change represents the largest drop in
consumption since the 2009 financial crisis, European gas demand is expected to recover
during the second half of 2021 and remain stable out to 2025.
In a 2014 study, the outlook for natural gas demand in Europe, Honore argued that the future
of gas demand is uncertain after the crippling energy demand in 2009. Based on his scenario
analysis, demand first falls by 2020 and then picks up and grows between 2020-2030 when
the nuclear phase out is completed and coal starts losing its share in the energy mix. This

134
analysis is supported by Grigas who suggested, “the EU’s long-term focus on renewable and
efficiency policies is reaping results and contributing to declining gas demand…In addition
and in contrast to environmental objectives, since the US shale boom, cheap American coal
exports to Europe have also contributed to a decline in gas usage.” While assessments
converge on the uncertainty of the future of European gas demand, especially on Russian gas,
due to a number of factors affecting not only European-Russian relations but also global
concerns such as climate change. One of the most important and increasingly central factors is
the political context that will be influenced by Russia-Ukraine relations.
Natural gas has also an increasing share in the energy mix of the EU. While the share of
different energy resources varies considerably amongst the member states, petroleum products
occupy the largest share (36%), followed by natural gas (21%), and solid fossil fuels (15%).
Renewable energy shares have also increased to solid fossil fuel level (15%) and are expected
to continue to increase its share in the energy mix. Nuclear energy provides (13%), and its
share is expected to decrease with the phasing out of German nuclear plants, but it also
occupies the largest share in France and Sweden. The future of natural gas demand should
also be considered with several other factors such as the EU transition to a low-carbon
economy, decreased economic activity due to the pandemic and associated economic crisis,
and the increased share of renewable energy in post-COVID 19 recovery.
There are several factors that will determine the future of natural gas demand in Europe.
First, the pace of economic recovery after the COVID 19 pandemic. At the time of writing,
COVID variants are affecting Europe and returning to a new normal will significantly vary
amongst the members of the European Union, depending on the individual countries’
economic resilience and strength. The second, changes in natural gas usage in major sectors,
such as residential, industry, and power generation, based on the requirements for achieving
climate change targets, will influence natural demand. If Europe focuses on achieving a rapid

135
economic recovery, natural gas usage in industry and power generation is likely to increase.
However, the Commission’s continued focus on green resilience might affect the transition
from coal to natural gas and renewables. The third, political considerations, such as Russia-
Ukraine relations and Western sanctions led by the US and the EU will shape security and the
political landscape and affect natural gas usage. An increasingly assertive Russia will drive
EU members to increase their focus on alternative energy resources either by increasing
investment to import and using LNG or increasing the emphasis on renewables. Finally,
continued change in the energy mix will affect the demand for natural gas. The phasing out of
nuclear power plants by 2022 and reducing dependency on coal-fired power generation will
affect the amount of natural gas imports. For example, a recent German study outlines how
Germany will adapt its power generation to achieve the renewable energy share of 65% by
2030.
The following chart depicts the EU 27’s natural gas imports between the 1990s to 2018.
The steadily increasing trend between the 1990s and the early 2000s become stable around
2010. While there is an observed growth towards 2017/8, that increase was due to
maintenance of other power generation capacity such as nuclear plants in Europe. Therefore, a
slight increase is expected due to the phasing out of nuclear and coal-based power generation
by 2030, and the demand is likely to remain stable in the 2030s.
Figure 16: EU Natural Gas Imports since the Cold War (1990-2018) EU27
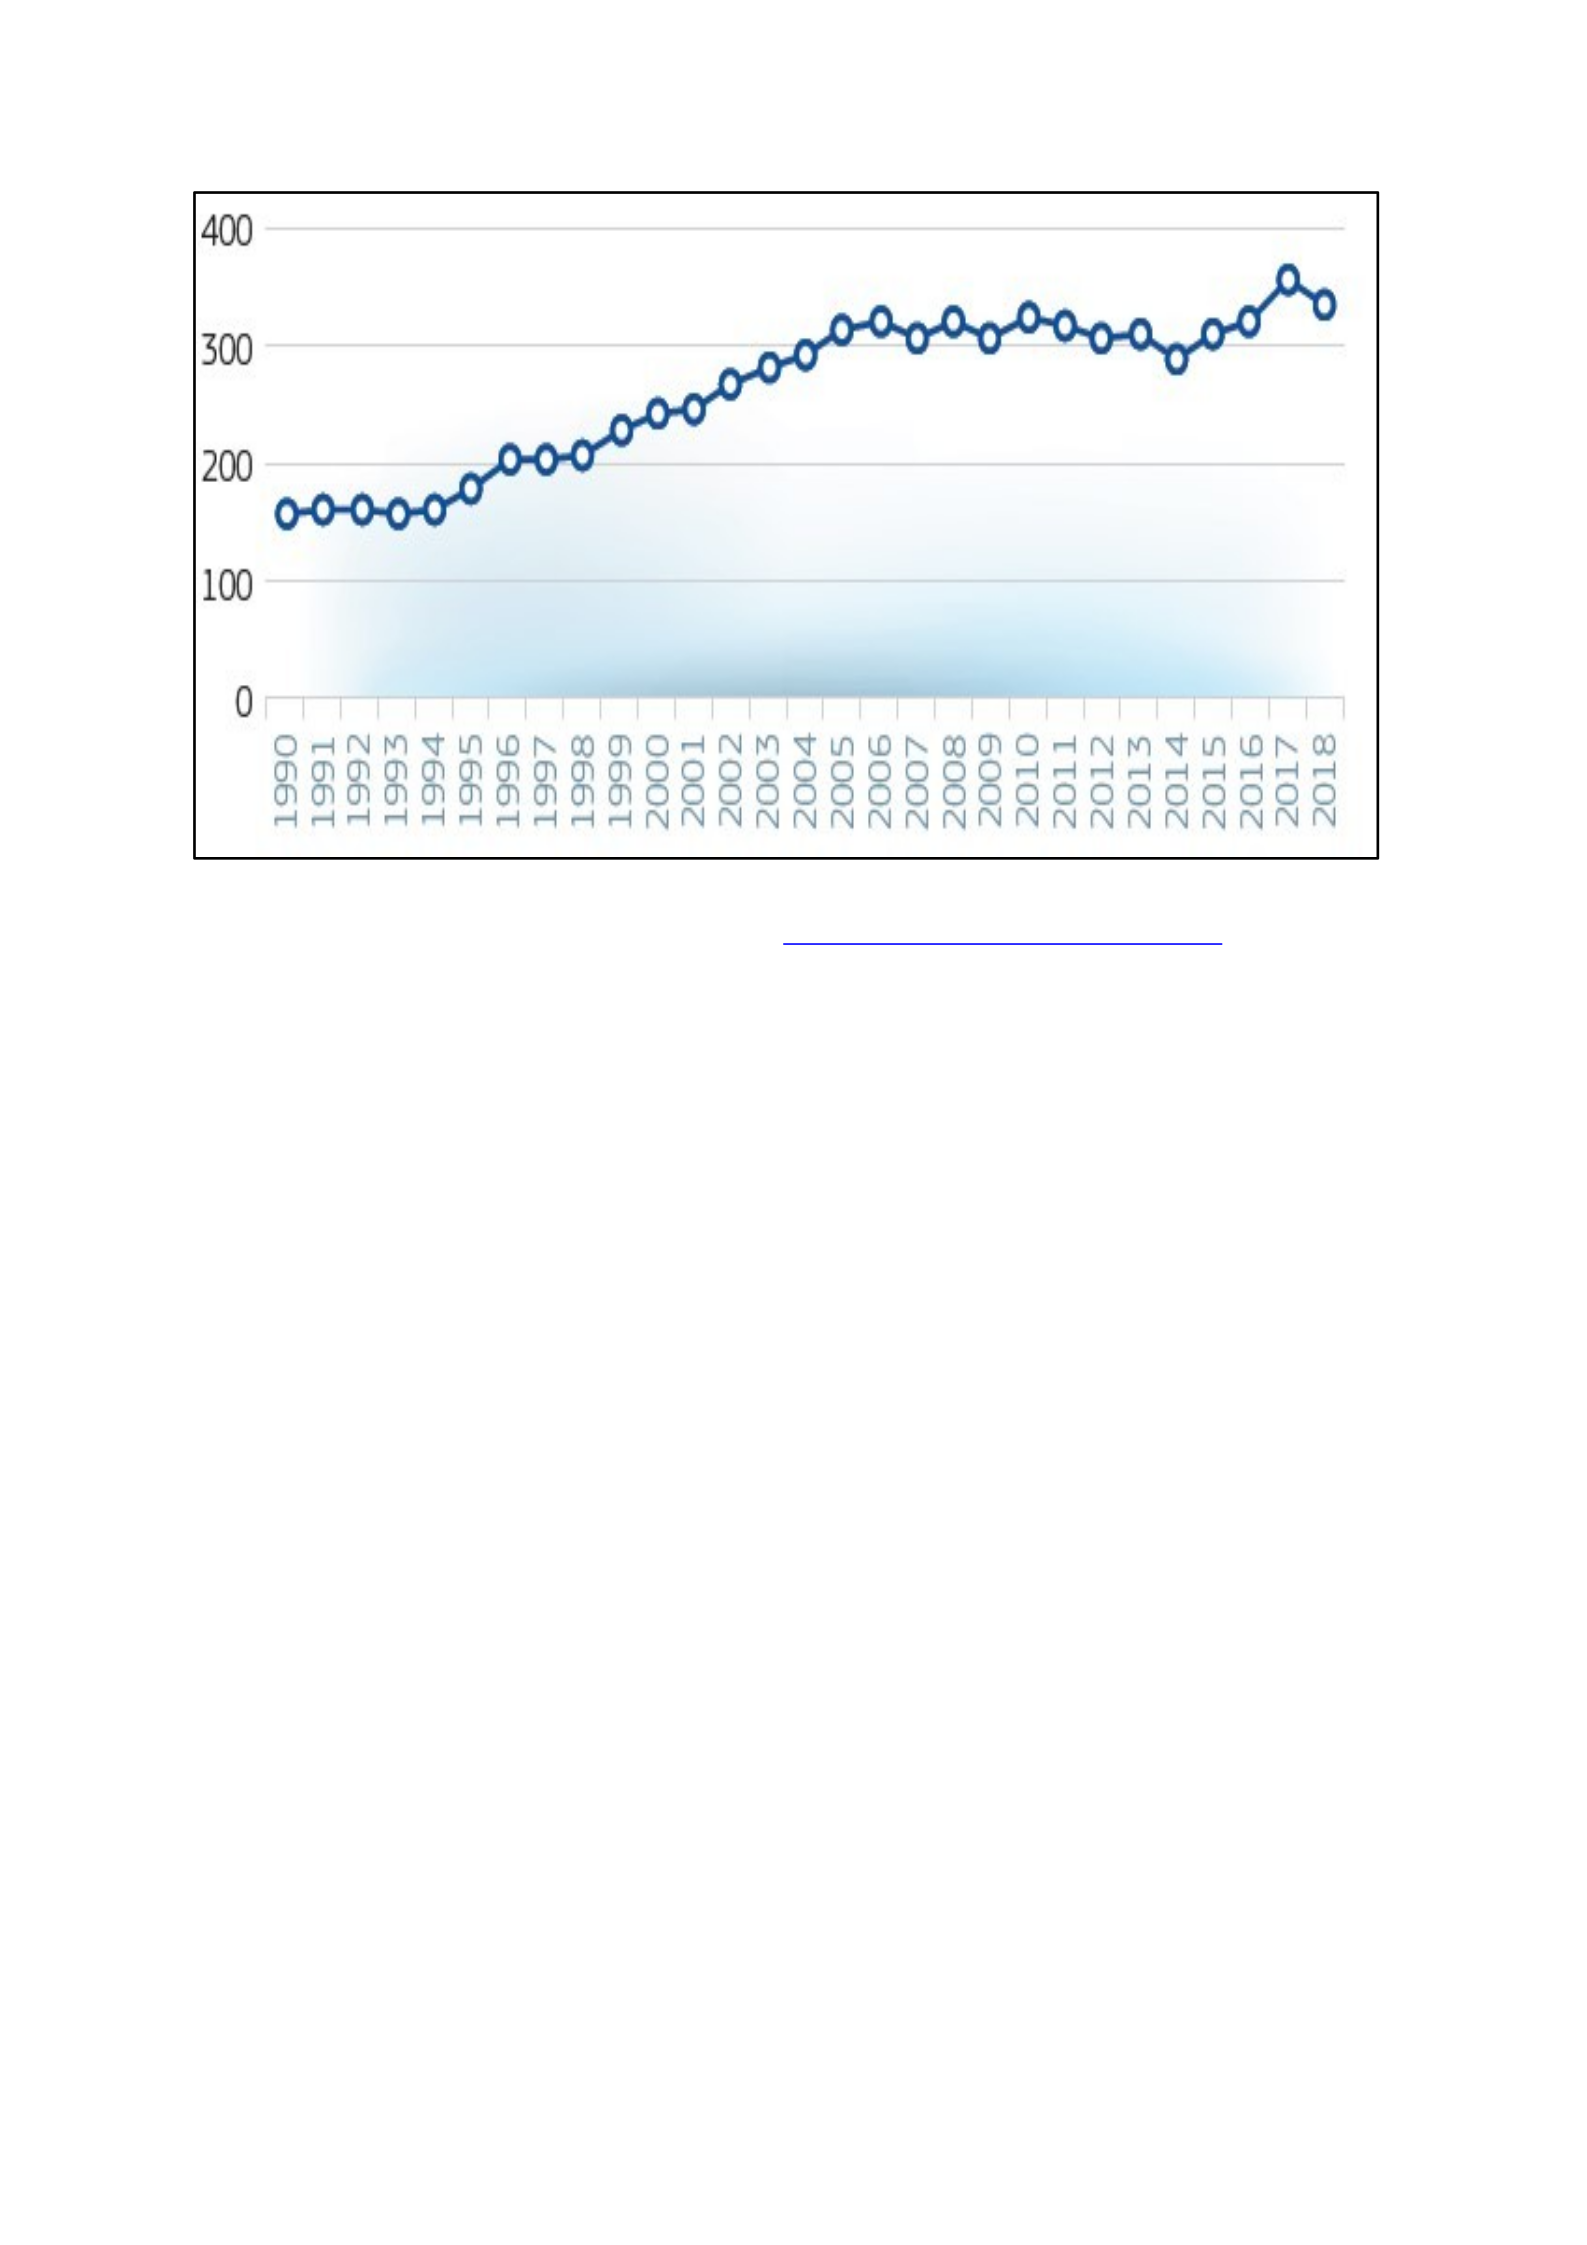
136
Source: EU Energy in Figures, European Commission, Directorate-General for Energy, EU energy in figures:
statistical pocketbook 2020, Publications Office, 2020, https://data.europa.eu/doi/10.2833/75283
Oil is a fungible commodity, and the oil market is a liquid international market. However,
natural gas, excluding LNG, is transported via pipeline networks, “facing more challenges
due to the inflexibility of pipelines and risks associated with the transit countries.”458 Natural
gas supplies to Europe are provided a small group of suppliers and the majority of the gas is
transported via pipeline networks. The following figure depicts EU natural gas imports by
country. The largest share of gas is provided by Russia followed by Norway and Algeria.
The share of domestic production is expected to decline. While the percentage of Russia’s
share is expected to remain around 40% in overall natural gas imports, the volume of gas
imported by the EU is expected to grow modestly by 2025 and remain stable afterwards. The
following figure depicts the European Union’s main natural gas trading partners.
Figure 17: Natural Gas Imports from Main trading Partners, EU27, 2019/20
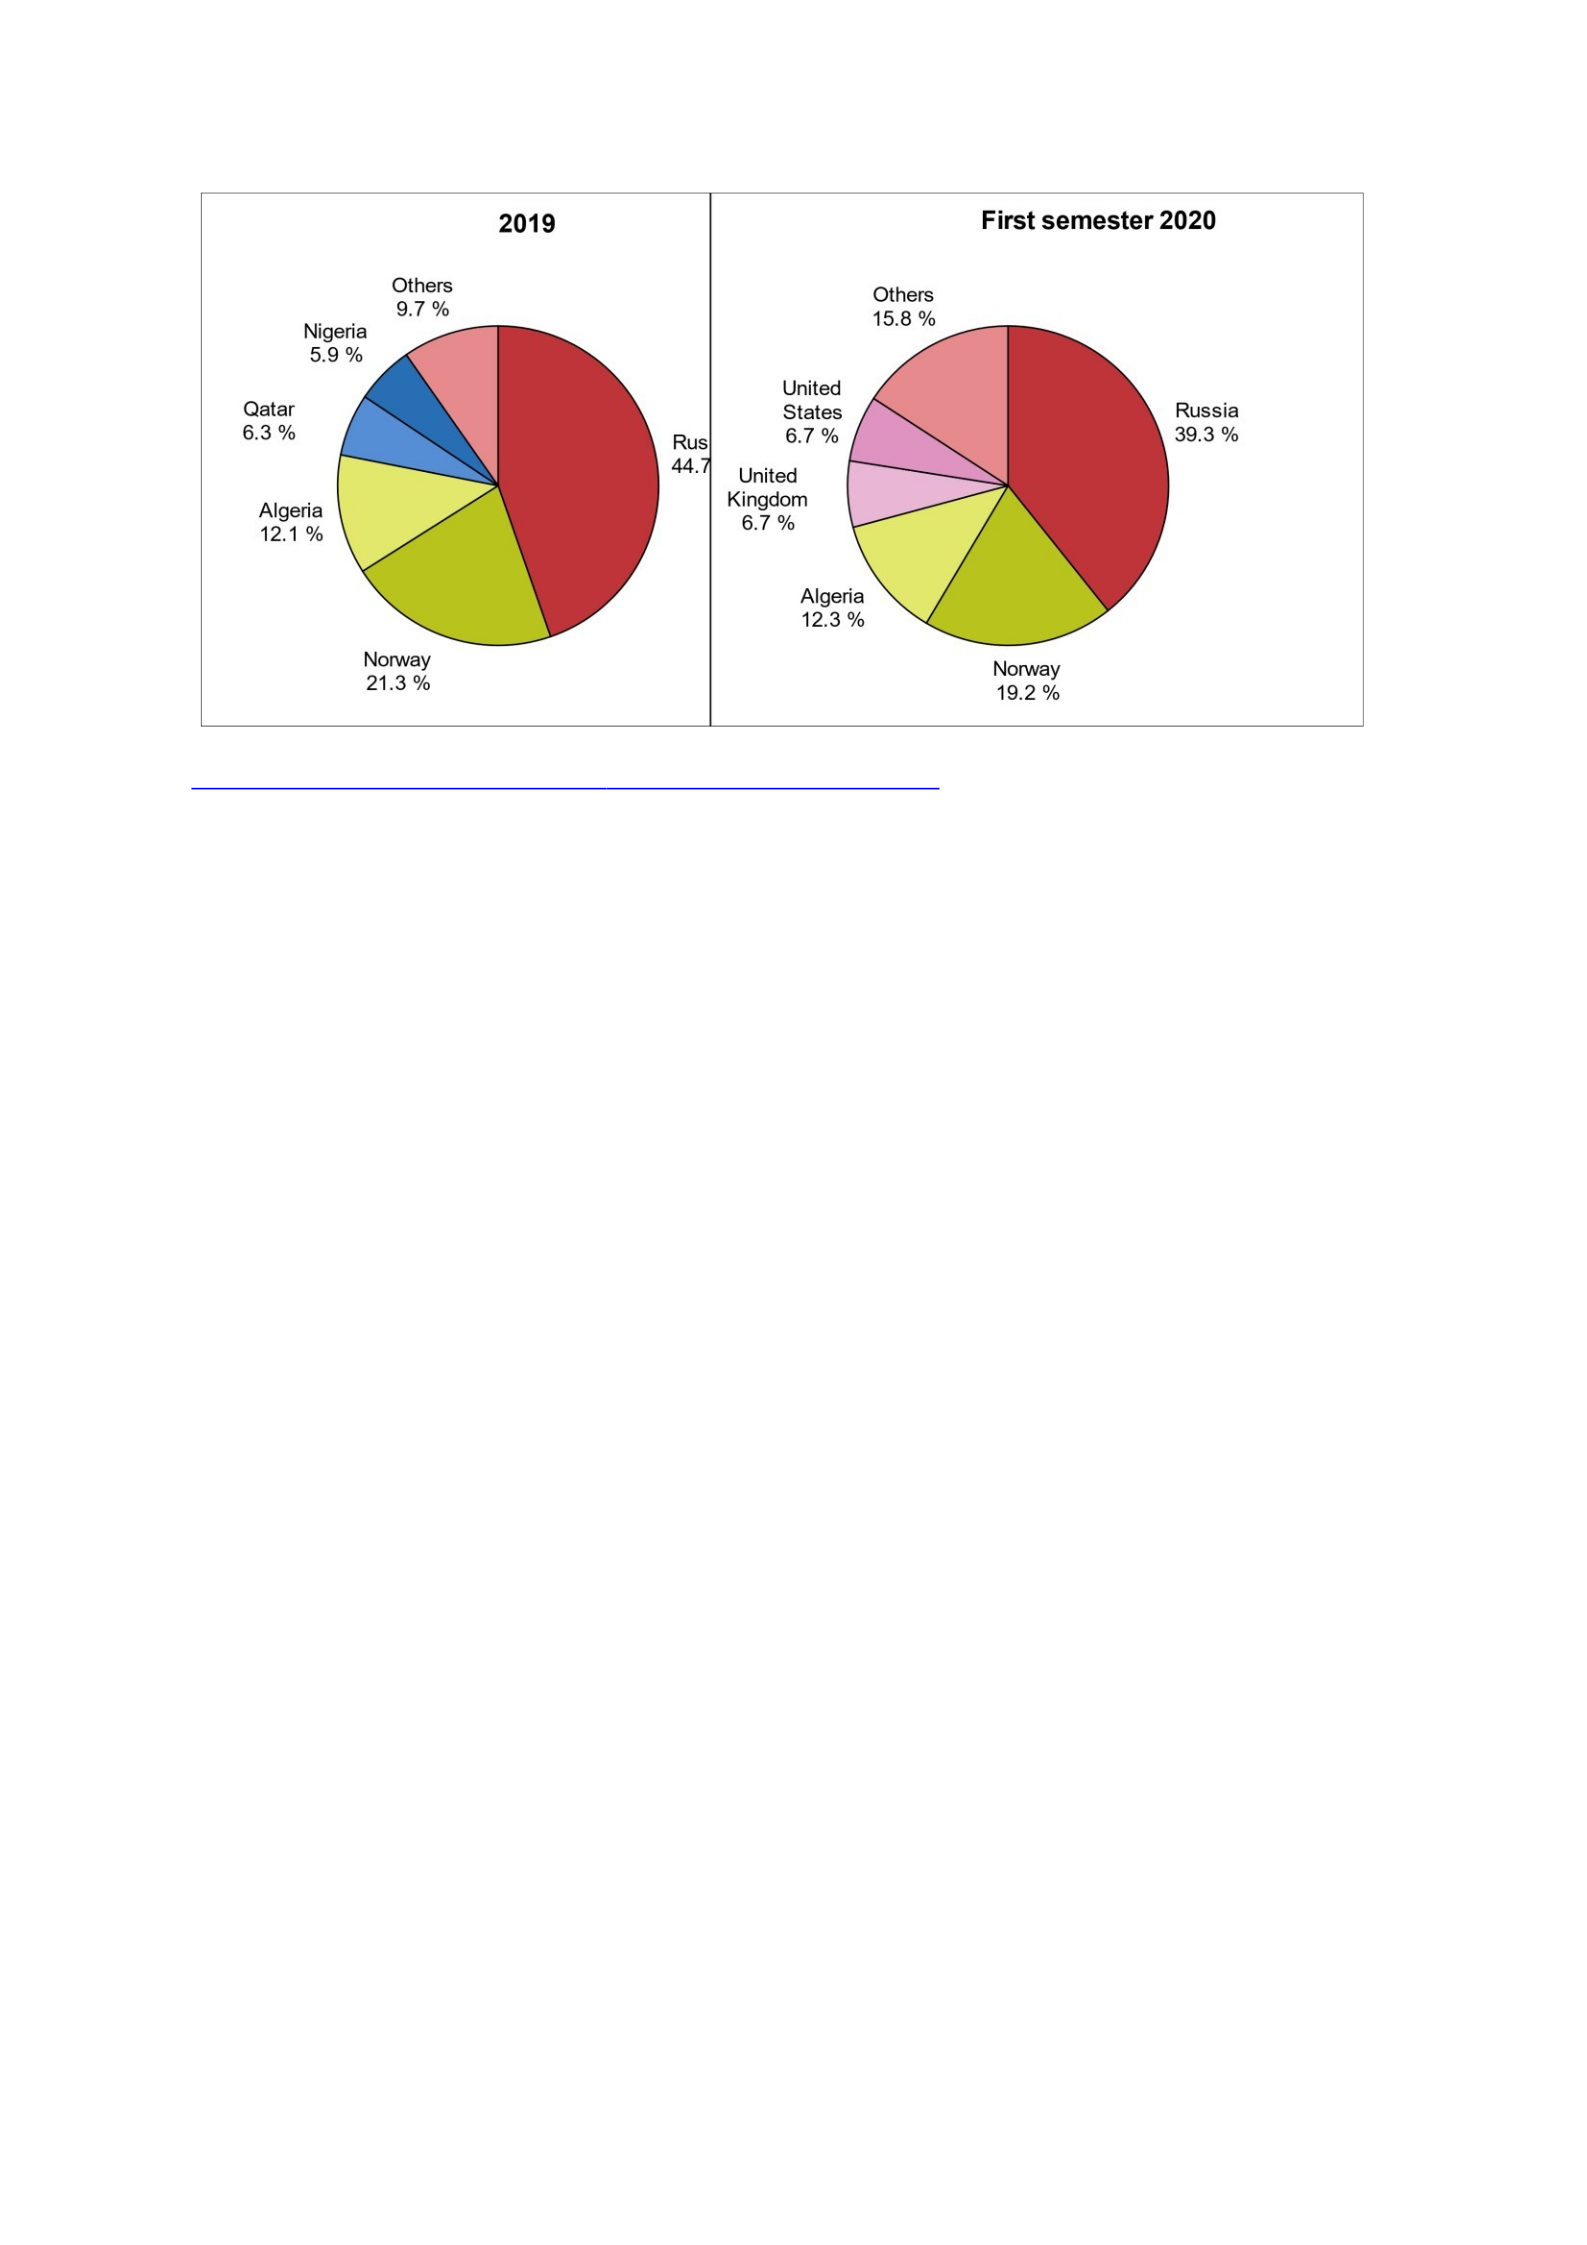
137
Source: European Commission, Eurostat, October 2020, 4.
https://ec.europa.eu/eurostat/statistics - explained/pdfscache/46126.pdf
3.7.5. Increasing share of LNG and infrastructure development
LNG is perceived to be an insurance policy against potential natural gas supply disruptions or
sudden changes in the energy demand. The delivery of LNG is more flexible compared to the
pipelines. The IEA “Gas 2020” estimate suggests that LNG remains the main driver of the
international gas trade, and it is becoming increasingly fluid and competitive.461 LNG imports
have become an important source for Europe to diversify gas supplies. While LNG’s share in
natural gas imports is still low, European LNG import is expected to surge with a sizeable
increase in LNG import volumes by 2030.
The US has become the biggest natural gas producer in the world, owing to the shale
revolution. The growing gas production in the US and significant investment increasing LNG
export infrastructure would drive natural gas exports to Europe. There are already signs of a
huge increase in US exports to Europe. While 10% of the US global LNG exports went to
Europe in 2017/2018, it jumped to 36% in 2019, and is expected to maintain an upward trend
based on the July 2018 Trump-Junker agreement. The increasing export of LNG from the US
to Europe, along with other LNG supplies, increased competition with Russian gas. Yergin

138
argues, “European buyers now had multiple options and choices, which meant diversification
of supply - the keystone of energy security.” To support increasing LNG imports, there are
several LNG infrastructures projects underway.
Esakova highlights the difficulty and higher costs of transporting and storing natural gas
compared to oil. Additionally, lack of sufficient regasification capacity due to limited number
of terminals, especially in Western Europe, has been identified as a vulnerability. Lithuania
opened a liquefied natural gas floating storage and regasification terminal in Klaipeda in
2014, to reduce their dependence and vulnerability against a single supplier. Yergin refers to
Lithuania’s energy minister who said, “We have had many historical challenges with Russia.
But now, as a result of opening of the country’s LNG importing facility, gas supply has been
depoliticized.” The same approach was followed by Poland that inaugurated its new
Świnoujście LNG import terminal in 2015/16. While the price of LNG is more expensive than
the pipeline gas, LNG competition is helping to keep Russian gas prices low as suggested by
Poland and Lithuania.
The EU has a number of LNG terminals; most of them are located in Southern Europe. As a
result, most of these facilities are under-utilized at almost one third of the real capacity.
European gas distribution networks are not sufficiently integrated to make full use of the LNG
capacity. Additionally, pipeline networks have not developed to transport gas from the South
to the North where Russian gas is the main source. For instance, “Spain has nearly one-third
of the EU's import capacity, but interconnecting pipelines are not sufficient to transport large
quantities of gas from Spain to France, and from there to Eastern Europe.”466 These LNG
import facilities will increasingly gain economic and geopolitical importance by 2030 as
European imports, in particular German, are expected to peak.
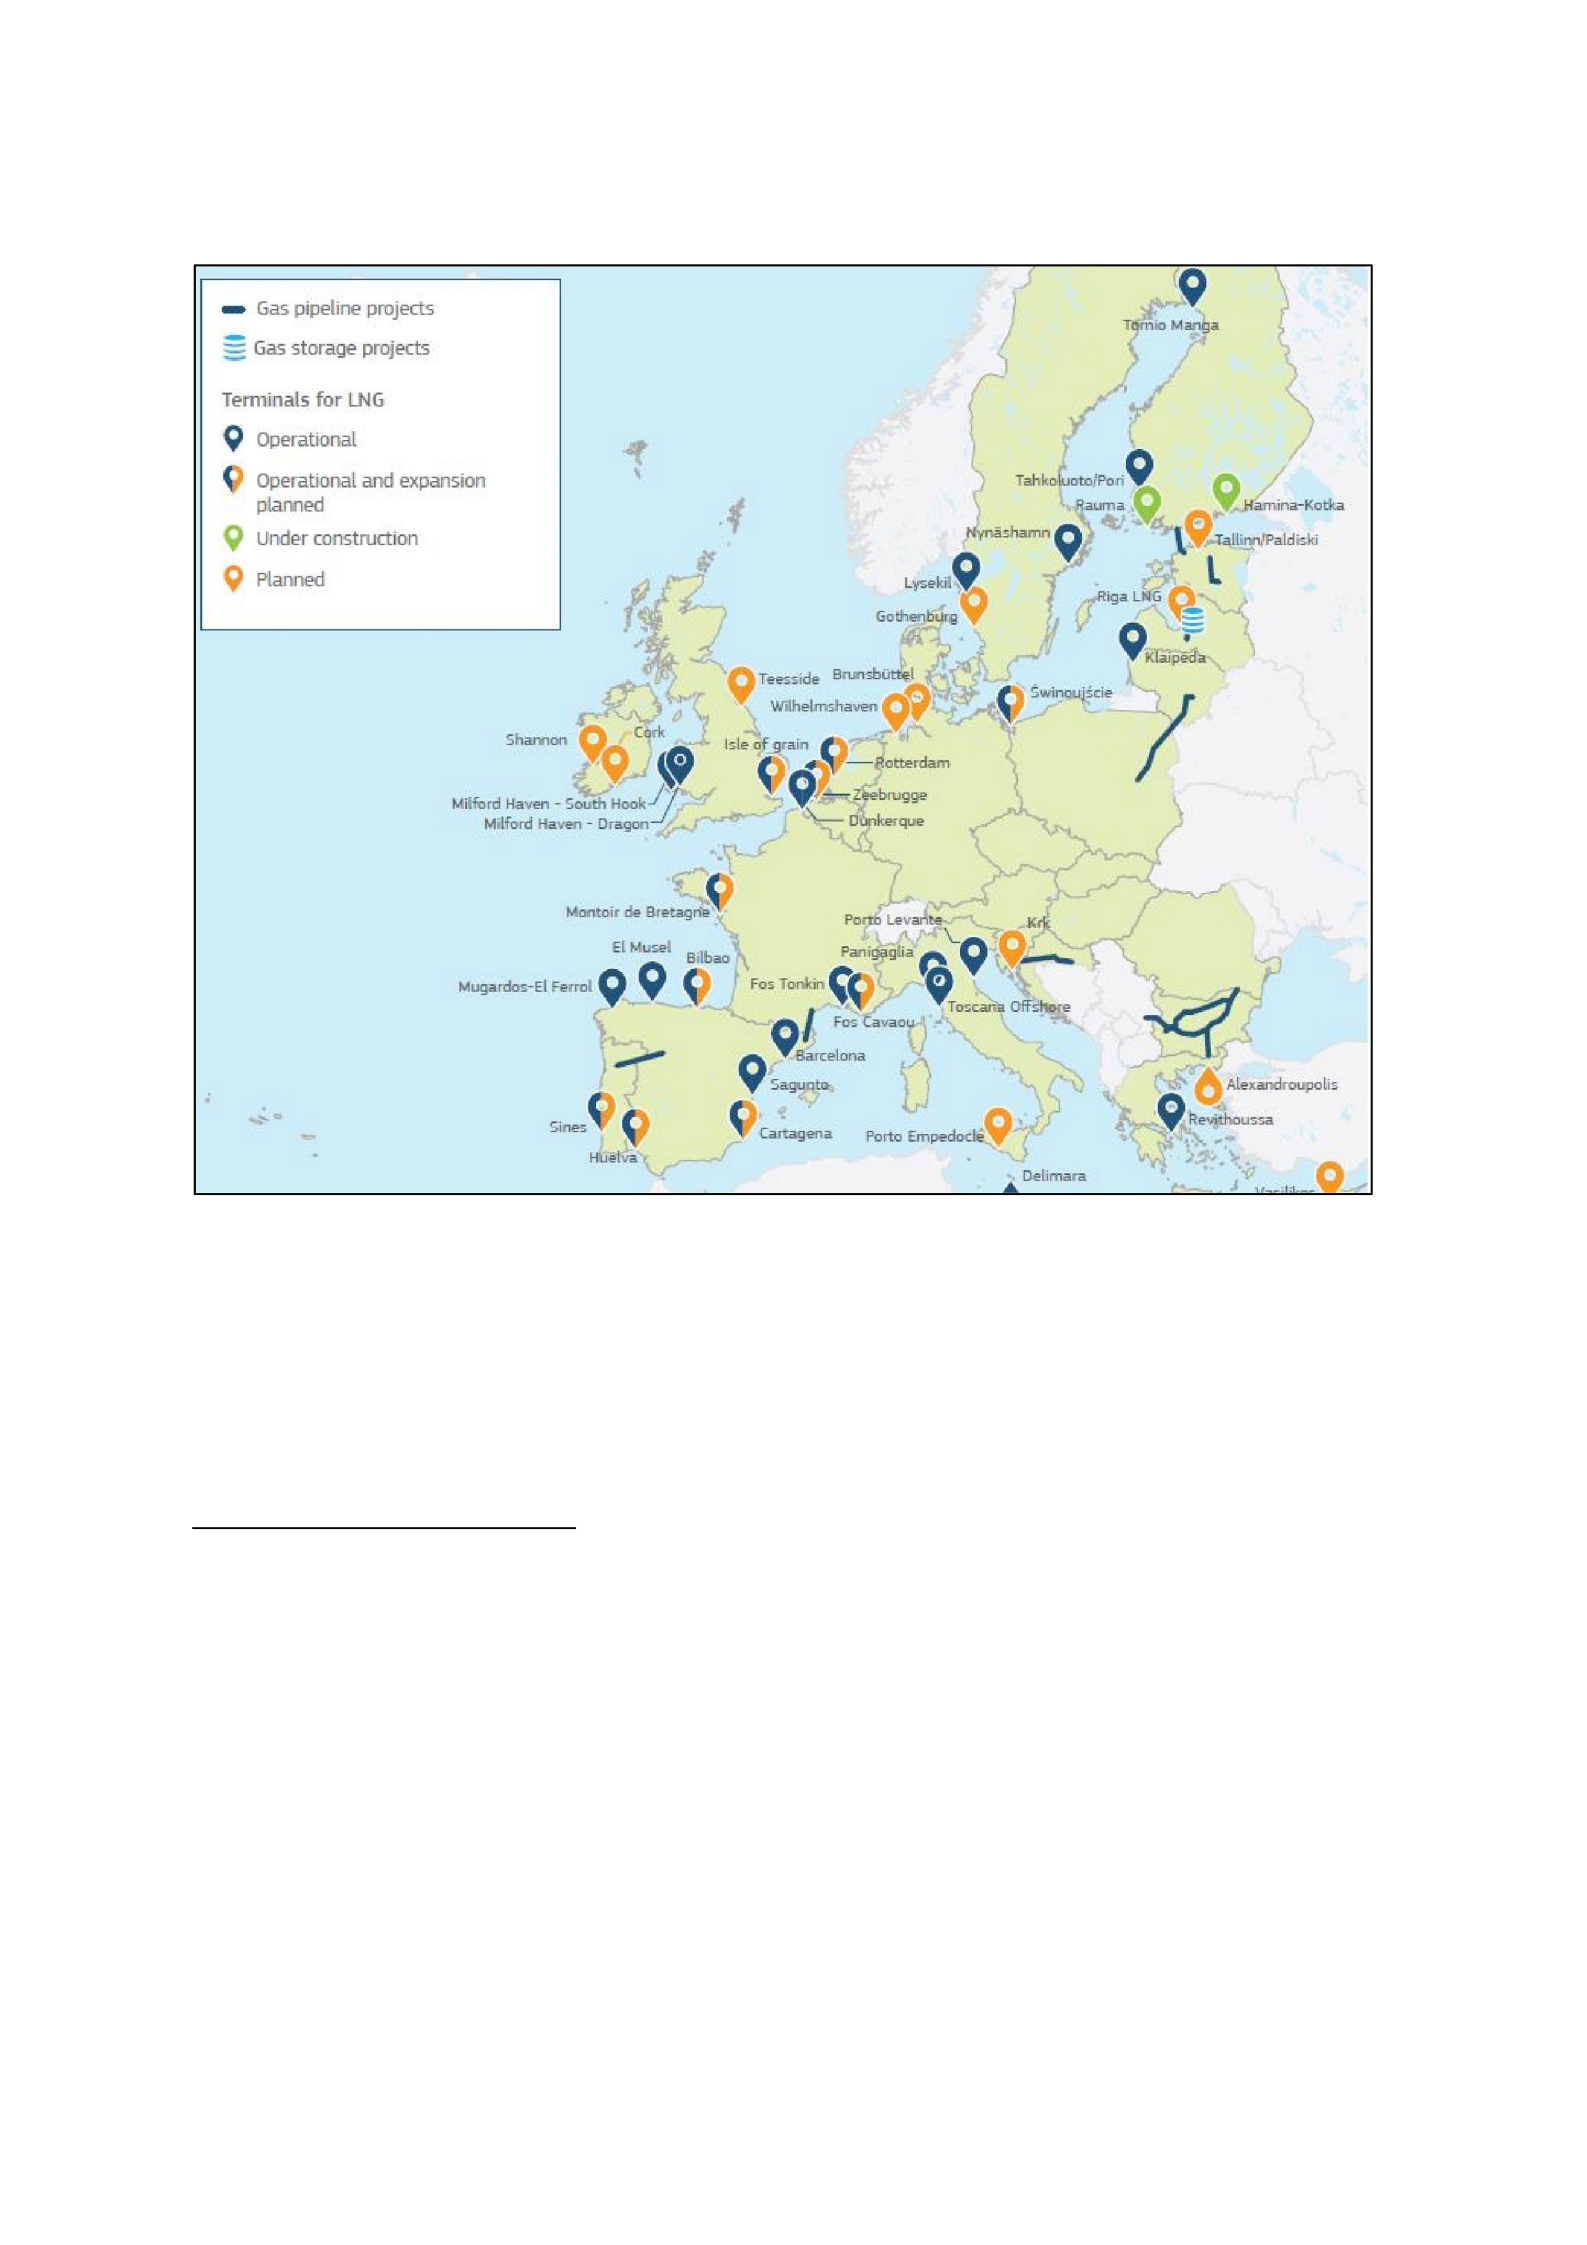
139
Source: European Commission, 8 Jan 2020, https://ec.europa.eu/energy/sites/ener/files/eu-us_lng_trade_folder.pdf
466 Russell, “Energy Security in the EU’s External Policy,” 6,7.
467 European Commission, ‘EU-U.S. LNG Trade,’ Data Source, European Commission, 8 Jan 2020,
https://ec.europa.eu/energy/sites/ener/files/eu-us_lng_trade_folder.pdf
As seen on the above map, there are several other LNG projects and supporting infrastructure
underway, and several others are planned. While LNG appears as an alternative to pipeline
gas, there are some inherent challenges and constraints for LNG to become a real substitute.
LNG causes more environmental concerns compared to natural gas transported via pipeline
due to additional emissions generated during liquefaction and shipping. LNG transport
requires special, expensive, and purpose-built ships for carrying LNG over long distances.
Figure 18: The European LNG Infrastructure 467
140
Degasification and other land-based infrastructure including pipeline networks for distribution
are huge investments, and these new pipelines should be coordinated with several countries.
3.7.6 European Natural Gas Imports and Import Dependency
There are a number of fundamental factors that define a country’s dependency on imports and
suppliers. While the level of dependency to a single supplier is one of the most important
factors, the volume of imports from a single supplier is also one the determinants of defining
interdependence between supplier and consumers. In other words, it outlines sensitivity and
vulnerability interdependence of EU and member states. The following table is based on 2020
data and depicts Russia’s share of European oil and gas imports.
Table 5: Russia’s Share in Oil and Gas Imports to EU27, 2020
Share (%) of Russia in national extra- EU27
imports
Country Petroleum oils Natural gas
Belgium 25-50 0-25
Bulgaria 50-75 75-100
Czechia 25-50 75-100
Denmark 0-25 0-25
Germany 25-50 50-75
Estonia 75-100 75-100
Ireland 0-25 0-25
Greece 0-25 25-50
Table 5 (Continued)
Country
Share (%) of Russia in national extra- EU27
imports
Petroleum oils Natural gas
Spain 0-25 0-25
France 0-25 0-25
Croatia 0-25 0-25
Italy 0-25 25-50
Cyprus 0-25 0-25
Latvia 0-25 75-100
Lithuania 50-75 25-50
Luxembourg 0-25 0-25
Hungary 75-100 75-100
141
Malta 0-25 0-25
Netherlands 25-50 0-25
Austria 0-25 75-100
Poland 50-75 50-75
Portugal 0-25 0-25
Romania 25-50 75-100
Slovenia 0-25 75-100
Slovakia 75-100 75-100
Finland 75-100 75-100
Sweden 0-25 25-50
Source: Eurostat database (Comext) and Eurostat estimates
The largest importers of oil were Germany, Spain, Italy, and the Netherlands while the share
of imports in Estonia, Hungary, Slovakia, and Finland were between 75-100%. Both factors
are critical in each countries’ assessment of sensitivity and vulnerability interdependence to
Russia. The share of Russian oil imports in Spain, France, and Italy was less than 25%.
Additionally, ten EU Member States (Bulgaria, Czechia, Estonia, Latvia, Hungary, Austria,
Romania, Slovenia, Slovakia, and Finland) imported more than 75 % of their natural gas from
Russia. Excluding Austria, Finland, and Slovakia, these countries are either former Soviet
satellites or republics and are in close proximity to Russia. In respect to natural gas, the
largest natural gas importers were Germany, Spain, France, Italy, and the Netherlands.
However, Russian natural gas imports share was less than 25% for Spain, France, and the
Netherlands; for Germany it remains between 50-75%.
The following table depicts the amount of natural gas imports and the share of these imports
within the EU members based on a comparison of data between 2000 and 2018. First, an
increase in the amount of natural gas imports is noticeable for almost all the main importers,
such as Germany’s import increased from 61.1 Mtoe to 70.5 Mtoe, while its share in Europe
has decreased from 25.4% to 21.4%. Italy remains one of the biggest importers of natural gas,
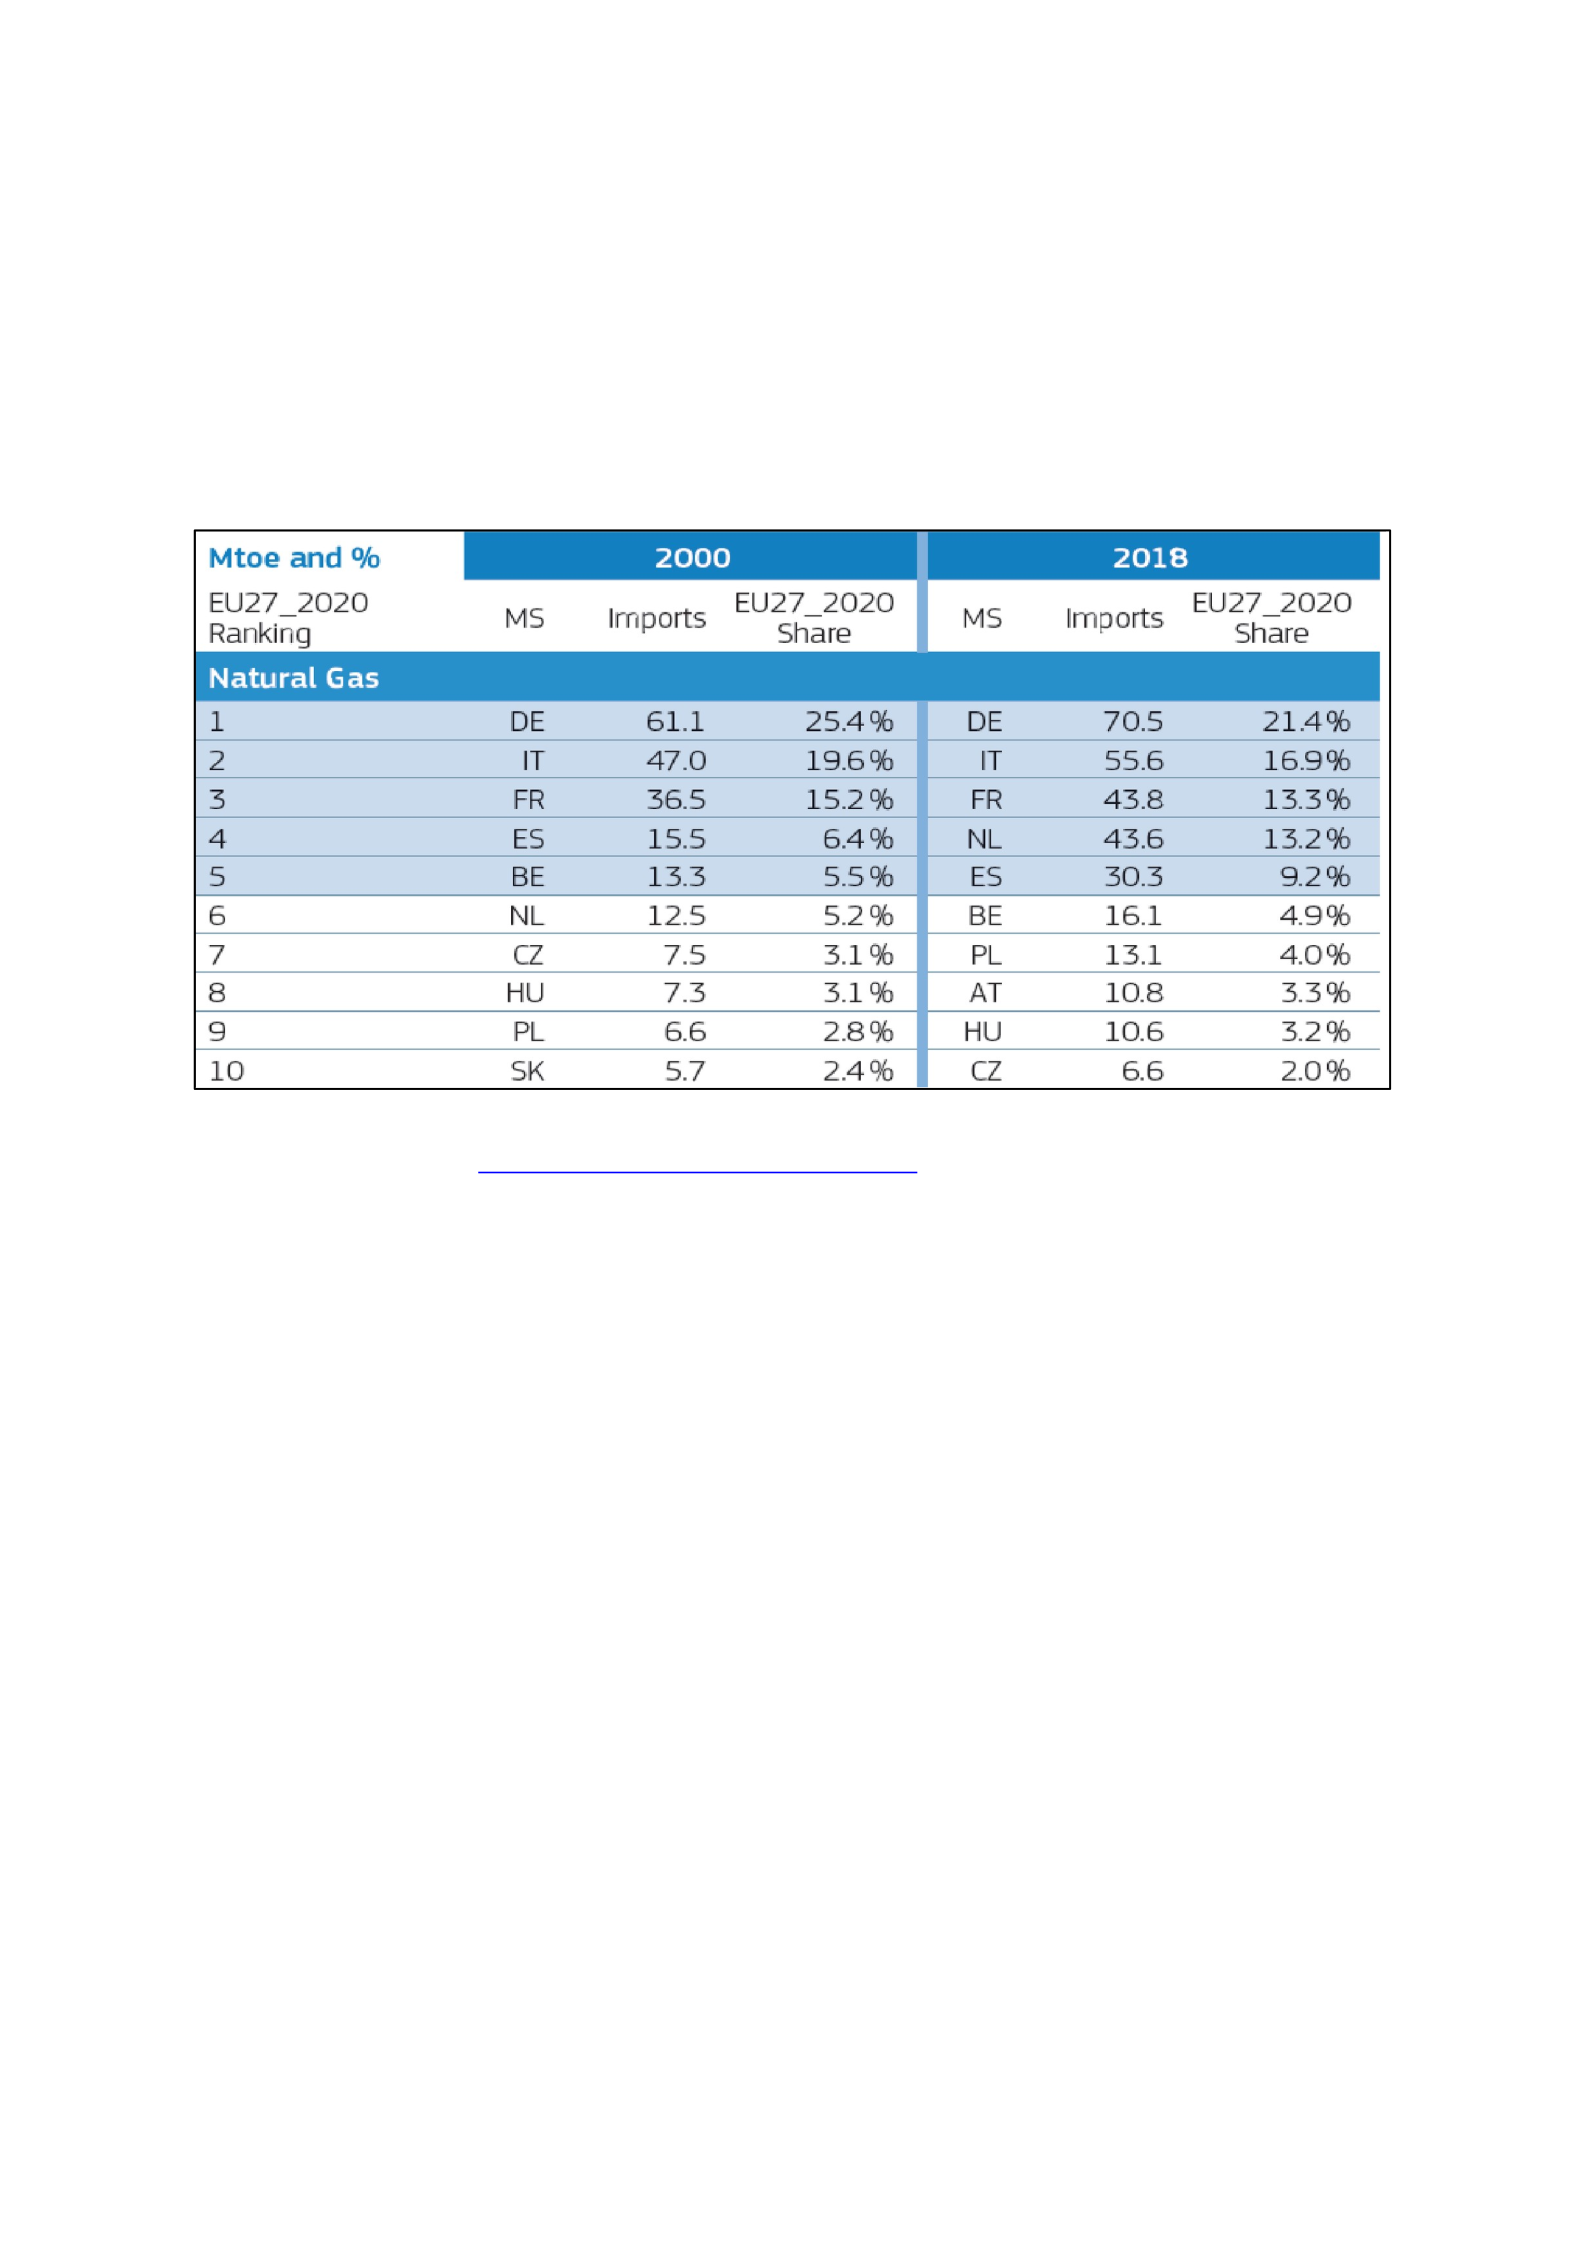
142
and its share within the EU follows a similar pattern. However, the biggest changes were
observed in imports of the Netherlands and Spain.
Table 6: Natural Gas Imports by Country (Top 10) and Their Share in EU27
Source: European Commission, Directorate-General for Energy, EU energy in figures: statistical pocketbook 2020,
Publications Office, 2020, https://data.europa.eu/doi/10.2833/75283
In parallel with the decline in indigenous gas production, the Netherlands has also become a
major importer of natural gas. The Netherlands imports have increased from 12.5 Mtoe to
43.6 Mtoe, and Spain has also doubled its imports. They are part of the group of countries
whose share within the EU imports have increased significantly. It should also be noted that
while the member nations share within the EU was decreasing, the import volume of gas
increased. The following table clearly shows the changing trends in natural gas imports and
domestic EU production.
The tables above highlight the differences of EU member states in their dependence on
Russia’s oil and natural gas supplies. The level of dependence has also been influenced by
other factors, such as geography - member states proximity to Russia; history - whether they

143
were former Soviet satellites and republics; the level of economic interactions and trade
relations; and cultural ties. Esakova highlights the two diverging policy approaches that
divides the EU.
The first group perceives Russia as a potential partner that could be dealt with within the
European rules and norms. They also believe Russian could be drawn into the EU’s orbit
“involving Russia in as many institutions as possible and encouraging Russian investment in
the EU’s energy sector and striking bilateral energy deals with Russia, even if Russia
sometimes breaks the rules.”
The other side of the spectrum, the second group, perceives Russia as a threat.472
Esakova references Leonhard and Popescu’s analysis that defines other group’s view that
suggests a series of policy actions: “Russian expansionism and contempt for democracy must
be rolled back through a policy of ‘soft containment’ that involves excluding Russia from the
G8, expanding NATO to include Georgia and Ukraine, supporting anti-Russian regimes in the
neighborhood, building missile shields, developing an ‘Energy NATO,’ and excluding
Russian investment from the Western European energy sector.” This analysis was conducted
before
Russia’s aggressive actions in the Caucasus and Ukraine.
The Russia-Georgia war and illegal annexation of Crimea, as well as ongoing intervention in
Eastern Ukraine, has moved many countries from the first group to second group. Russia’s
G8 membership was suspended after the Ukraine crisis and the illegal and illegitimate
annexation Crimea. Russia’s military posture has increasingly become more assertive. While
the EU and Europe supported US led sanctions on Russia, some key members of the EU, such
as Germany, Italy, and France, still advocate and encourage bilateral relations with Russia.

144
Under US leadership, NATO has taken certain steps, such as establishing a missile defense
system and deploying several battle groups to Eastern Europe and the Baltics, to stop
Russian expansionism in particular efforts to increase influence over Central and Eastern
Europe, the Baltics, and the Balkans.
3.8. EU – Russia Interdependence Analysis
3.8.1. The IEA Model of Short‐Term Energy Security (MOSES)
Figures 16-18 and Tables 6 and 7 show to what extent Europe is dependent upon Russian
energy, in particular natural gas, as well as transport pipeline networks. The IEA has
developed a Model of Short‐Term Energy Security (MOSES) that “takes an energy systems
approach, dealing with all parts of the energy system from supply to transformation,
distribution and end‐use energy services.”474 This model is based on the most prominent and
widely cited energy security studies that are reviewed in detail in Chapter 2. This approach
allows understanding of vulnerabilities of energy systems by interpreting indicators relevant
to the fuel types.475 MOSES uses the following indicators in the assessment process: net
import dependence; political stability of suppliers; number of entry points (LNG ports and
pipelines); diversity of suppliers; proportion of offshore production; daily send-out capacity
from underground and LNG storage; and finally, natural gas intensity. These indicators are
further categorized based on their origins, external or internal, and their relevance to risks or
resilience capacity.
While qualitative analysis is widely used to understand sensitivity and vulnerability analysis,
quantifying some of the key variables would allow comparison of different countries. Each
factor is quantified from political stability of supplying countries to diversity of suppliers,
natural gas intensity, etc. Then each country’s energy (natural gas) security profile is
developed based on the number of pipelines and/or LNG ports/terminals, supplier diversity,
natural gas storage capacity, and their ability to meet over 50% peak-daily demand. Then
145
countries are categorized into three levels of domestic or external risk exposure: low, medium,
and high risk. Their resilience capacity is measured by diversity of suppliers and entry points
such as pipelines. Doing this level of quantitative analysis is outside of the scope of this
paper; the following table shows how these natural gas indicators are reflected in the analysis:
Table 7: Natural Gas - Dimensions of Energy Security Indicators477
Risks Resilience
External External risks:
•import dependency
•political stability of suppliers
External resilience:
•entry points: Liquified natural gas (LNG) ports
•entry points: pipelines
•diversity of suppliers
Domestic Domestic risks:
• offshore production
Domestic resilience:
• send-out capacity from natural gas storage •
gas intensity
Source: IEA, Jewell, 2011, The IEA Model of Short-term Energy Security (MOSES), Primary Energy Sources
and Secondary Fuels. All Rights Reserved.
According to the IEA, the most important indicator in terms of natural gas supply
security is net import dependence. EU member states fall into three categories:
- low import dependency (≤10%) and net exporters: Belgium, Denmark, Ireland, Spain,
France, Croatia, Cyprus, Luxembourg, Malta, the Netherlands, and Portugal.
- moderate import dependency (30%‐40%): Greece, Italy, Lithuania, Sweden
- and high import dependency (≥70%): Germany, Poland (50-75%), Bulgaria, Czech
Republic, Estonia, Latvia, Hungary, Austria, Romania, Slovakia, Slovenia, and
Finland (75-100%).
IEA categorization is not aligned with the way that the EU categorized the level of
dependence of its member states. Some of the member states in the low import category might
be well over 10% dependent on Russian gas supply. Low import reflects 0-25%, moderate
reflects 25-50% dependency, and those whose dependency is over 50% are registered as high
import dependent countries.

146
3.8.2. Sensitivity and Vulnerability Interdependence
European-Russia energy relations have multiple dimensions; therefore, it is important to
understand not only geopolitical concerns but also economic impediments of these
relationships. As a result, a good start for this analysis is to understand their level of
dependence, as suggested by Esakova:
Sensitivity and vulnerability interdependence are the starting points for analysis of
energy relationships, as such analysis helps to measure the level of dependence of each of the
actors and the overall interdependence between the actors. Thus, the study of the
characteristics and development of an energy-based relationship should begin with the
analysis of the sensitivity and vulnerability interdependence of each of the actors. In an
earlier part of this chapter, energy and natural gas dependency of the EU member states to
Russia was reviewed. Future prospects suggest that the EU’s dependence on Russia is
expected to continue over the short to mid-term albeit other sources of energy will become
available over time. The Roadmap to EU-Russia Energy Cooperation until 2050 highlights
that “Natural gas is of immense importance in the energy relationship between the EU and
Russian Federation. While it is not as large – in energy and financial terms – as the trade in
crude oil and oil products, its importance for many EU member states is greater because of the
high level of dependence on Russian gas.” The high-level of dependence on Russia was
recognized in the ‘Roadmap’ that was signed by the EC Energy Commissioner and Minister
of Energy of the Russian Federation. Based on a 2016 estimate, the European Commission
expects that a continued decline in domestic gas production and increasing consumption will
drive natural gas demand. The EC forecast suggests that “by 2050, the EU will need to
import 87% of its gas needs, compared to 70% at present.”481
Using the theory framework provided by Keohane and Nye and indicators identified by the
IEA, Esakova argues that the EU’s sensitivity interdependence could be defined as high,
especially for the short-term supply interruptions. Esakova used the following criteria, based
on IEA indicators, to measure the degree of sensitivity interdependence for short-term supply
disruptions: “the share of oil and gas in the EU energy mix; the import dependence of the EU
on fossil fuels and potential substitutes; Russia’s share in EU’s energy imports; EU’s
dependence on pipeline supplies, capacity to store large quantities of gas or to substantially

147
increase imports of LNG supplies; and, instabilities in the major European transit
countries.”482 While the Russia-Ukraine gas disputes will be reviewed in the following
chapter, it is important to determine Europe’s readiness for supply interruptions, such as the
ones that took place in the early 2000s. There have been three major natural gas supply
interruptions in 2006, 2009, and 2014 between Russia and Ukraine that effected natural gas
flow to Europe. The 2006 disruption showed Europe was unprepared for such an event;
Hungary lost 40% and other Eastern European countries lost around one third of their
supplies. France and Italy were also affected, losing around over one-quarter of their supply.
The 2006 disruption was short, only three days, but severe, and Gazprom was quick to restore
export levels to sustain supply
security.
The similar scenario was repeated in late 2008 and early 2009, “when Russian gas producer
Gazprom halted supplies through Ukraine, leaving several Southeastern European countries
including Moldova, Bulgaria and Romania with a severe shortage of gas for nearly two weeks
in the depths of winter.” It should be noted that all these supply cuts were targeting Ukraine,
not Europe or any of its member states. These supply disruptions brought up the key concern
of “What will happen if Russian gas supplies are interrupted this winter?” These concerns led
the European Commission to conduct a stress test to measure and identify concrete measures
to mitigate the impacts of supply disruptions. While the report suggests that cooperation is the
key and a market-based approach should be the guiding principle, the EU’s sensitivity
interdependence remains high even after the measures taken by the Third Energy Package that
further regulated European Natural Gas market dynamics.
Led by Poland and Lithuania, Central and Eastern European countries have been raising
concerns over increasing dependency on Russian energy supplies, in particular natural gas.

148
They also raised concerns over the degree of the EU’s growing vulnerability interdependence
on Russian gas. In a 2012 analysis, Esakova argues that:
The degree of sensitivity interdependence is not as important as the degree of
vulnerability interdependence…The vulnerability interdependence of the EU can be
measured by looking not only on the proportion of the EU’s needs and costs in case of
a cut off of energy supplies, but also at the alternatives to imported energy and the
costs of switching to possible alternatives. Thus, the EU’s vulnerability
interdependence in the relationship with Russia should be seen in the terms of long-
term threats, such as the inability of the EU to provide for a long-term diversification
of energy routes and energy supplies, more investments into increased energy
efficiency and alternative energy technologies, as well as more market
liberalization.486
Since 2012, the EU has supported development of natural gas interconnectors, such as the
ongoing work to connect Lithuania and Poland and has used reserve gas flow from the West
to the East to support Central and Eastern Europe, including Ukraine. An example of this is
the test in 2014 which pumped gas from Slovakia to Ukraine to reduce dependency on Russia.
While these measures have provided relief for a short duration of supply disruption in 2014, it
does not change the fact that the EU is highly dependent on natural gas pipeline supplies and
does not have sufficient capacity to store large quantities of gas or to substantially increase
imports of LNG in the event of a cut-off of Russian supplies.
According to Esakova, the following factors define the EU’s energy relations with
Russia in terms of vulnerability interdependence:
- The IEA long term outlook suggest that the EU energy mix will continue to
include a large share of oil and gas;
- The EU energy import dependency will continue, especially for natural gas due
to phasing out of nuclear and coal power plants;
- European domestic natural gas production will continue to decline, increasing
reliance on Russian natural gas to fill the void;
- Diversification of supply via new pipeline construction has become costly
while increasing political instability in the North Africa and Middle East
regions are limiting their role as a reliable energy supply source;
- The number of LNG terminals are likely to continue to increase, but they are
far from the level they could be substitute pipeline volume.
- The Asia-Pacific region, especially China, Japan and India, will compete for
LNG imports. Esakova refers to Stern who argues that increasing LNG trade
and exports reduce incentives for long-distance multi-country pipeline

149
projects. The LNG market provides inherent diversity and flexibility which is
not possible with a pipeline system. China’s energy demand increases
competition for Central Asian energy resources, especially for natural gas,
thus, reducing the attractiveness of European markets.
- Finally, the IEA estimates that high levels of European dependence on Russian
gas will continue until at least 2040.
3.8.3. Sensitivity and Vulnerability Interdependence – Differences between EU Members and
Implications on EU policy
A European Parliament study emphasized that the “dependence on energy imports is perhaps
the EU's main external vulnerability, weakening its position vis-à-vis supplier countries such
as Russia.” Both Esakova and the IEA’s analyses suggest that the EU’s sensitivity and
vulnerability interdependence in energy transactions to Russia, in particular gas transactions,
have increased since the 2000s. As mentioned in earlier parts of this chapter, the
EU member states’ natural gas import dependency varies considerably as their relations with
Russia vary. Esakova argues, “There are significant differences between the levels of
vulnerability and sensitivity interdependence between Russia and Western European
countries, and Russia and Eastern European transit states.” As Yergin highlighted that
agreeing on a common policy on energy:
was very hard to come by with twenty-eight different countries, with different
interests, different endowments, different needs – and different attitudes toward
Russia. West European generally welcomed Russian gas imports. Eastern and Central
European countries, much more dependent on Russian gas, saw their reliance as a
source of vulnerability, reminding them of their former thralldom to Moscow when
they were satellites of Soviet Union.
Additionally, differences exist amongst the Central and Eastern European countries. In 2017,
the EU 27 was the largest importer of energy, including oil, natural gas, and coal), ahead of
China and the United States.493 Russia was the primary supplier of energy to Europe. Esakova
suggests, “One of the major concerns for the energy security of the EU is its incoherent
external energy policy…bilateral deals with Russia in the energy sphere have undermined the

150
EU’s ability to secure key political goal.”494 While the EU is the world’s largest importer of
energy, member nations are responsible for the relationships with third parties for the nature
of the contracts, means of distribution, as well as energy price. With the introduction of the
Third Energy Package, the EU aims to use its regulatory power and create a common energy
market while subsequently reducing differences through bilateral deals. However, Russia
continues to engage member states bilaterally, by developing long term contracts/deals
including joint natural gas infrastructure projects that undermine the EU’s energy security
strategy.
Lithuania and Poland made natural gas infrastructure investments to reduce their dependency
on a single source-Russia, and single means-pipelines, by establishing LNG terminals and
distribution networks. As a result, their dependency level on Russian gas has decreased,
allowing them to stand up against Gazprom’s price manipulation and cut-off threats. Potential
for diversification, albeit limited, has helped in the Baltics and Eastern Europe; “Poland
claims that the LNG imported through its new Świnoujście terminal (opened in 2016) is 20-
30% cheaper than Russian gas.” Poland and Lithuania also get better natural gas prices from
Russia, supported Belarusian opposition, and acted as strong advocates for a change in
Belarus after the rigged elections in 2020.
The EU energy security policy should address the weakest points that Russia could exploit.
Esakova argues that the EU’s energy security policy and strategy should also be aligned and
be consistent with:
The EU’s broader foreign policy objectives such as conflict prevention and
resolution, nonproliferation, and promoting human rights…formulating a common
external energy policy that draws on the full range of the EU’s internal and external
capabilities, would substantially reinforce Europe’s position when speaking to key
suppliers such as Russia or OPEC.”496
However, as Russell underlined, the EU’s high level of dependence and reliance on energy
imports constrains its ability to promote interest and values. The EU’s top oil and gas

151
suppliers, excluding Norway, are authoritarian states that do not meet international democratic
standards.
3.9. Conclusions
Europe will continue to depend on external energy resources and Russia will remain
Europe’s main supplier of energy, especially natural gas. Energy has become one of the most
existential factors for the European way of life. The critical importance of a stable and
abundant supply of energy for European prosperity and security is emphasized in the
European Energy Security Strategy. The decline in domestic production compounded by the
growing demand for natural gas increased Russian exports to Europe.
The 1973 AOPEC oil embargo, the energy crisis, left enduring legacies: first, it
showed how market dynamics could be overturned and be challenged by political instability,
how a little-known cartel at the time could affect oil distribution and prices. Second, it started
a public policy debate over the role of the state(s) and the markets in ensuring energy
security.499 While the debate over the definition of energy security and concept continued,
there were no major supply disruptions until the 2006 and 2009 Russia-Ukraine gas crises that
were a wake-up moment for Europe. Since then, energy security has become a source of
major concern for the EU and NATO Alliance.
The Normandy Index of 2019 suggests that energy insecurity is perceived as the
highest risk for the EU due to the high-level dependency to external suppliers, especially to
Russia.
Russia’s illegal annexation of Crimea and intervention in Eastern Ukraine was a watershed
moment with international borders were violated by the use of force Russian aggression in
Ukraine shows the return of power politics in Euro-Atlantic region. Using power politics
should be regarded as part of overall Russian efforts to bypass the Soviet legacy pipeline
networks in Central and Eastern Europe reducing dependence on transit countries.

152
The European-Soviet Union/Russian energy relationship was begun in late 1960s, when the
pipeline networks were built during the Cold War. Initially, energy trade was based on barter
arrangements that started with oil and gas being traded for steel and equipment. Over time,
barter arrangements were replaced by long-term contracts based on bilateral relations and
market dynamics. The shale gas revolution, increasing LNG trade and competition, and
development of spot market and liberalization of pipeline access have together transformed
the long-term contracts and the way contracts are designed.
A reduction in the cost of solar panels and wind turbines, driven by technology
advancements, have led to a growing share of renewables in the European energy mix.
However, concerns over geopolitical influence, a high level of dependency both in terms of
volume and a lack of diversity, as well as long-term contract-based energy transactions,
remain at the core of Europe-Russia energy relations through private trader-intermediaries to
more conventional monetary and commercial relations.
The European approach to energy relations is based on market dynamics as framed by the
liberalism school of thought. The role of the European Union and its objective establishing
liberalization and marketization of the European gas system originated in the UK and moved
to the Netherlands and Belgium. The European Commission led the development of a single
energy market. Initially, there were several directives and regulations released by the
Commission, which ultimately led to the Third Energy Package, introduced to achieve a
single, comprehensive European energy market. The biggest challenge came from Germany
and France due to resistance of their energy industry to transform changing business practices,
such as breaking down monopolies and moving away from long-term contracts to spot
markets.
However, the European Commission was successful with the implementation of the Third
Energy Package: unbundling, ensuring independence of regulators, establishment of the

153
Agency for Cooperation of Energy Regulators ACER, increasing cross-border cooperation
that benefit energy consumers.
Liberalization of the markets as a trend progressed eastward to Central and Southern Europe.
It continued to expand toward Eastern Europe, the Balkans and the Baltics, and finally
reached Ukraine, becoming a wave of economic and political reforms. With the legacy
longterm contract system, Central and Eastern Europe had been subject to Gazprom’s strategy
of implementing unfair pricing, interrupting cross-border sales, and obtaining unrelated
commitments. With increasing power of the Commission, Europe was able to make progress
albeit slow to achieve a single European gas market. While Russia had been accommodating
the requirements of the European energy regulations and adopting the changing market
dynamics due to liberalization, issues such as exclusive rights, third-party access and
unbundling presented challenges to the Russian gas giant Gazprom, specifically its long-term
strategy to establish a vertical monopoly to control both upstream and downstream assets.
These issues have not stopped Europe from moving market liberalization and integrating
Central and Eastern Europe into a liberalized European natural gas market. The most
important step was the Third Energy Package, presenting new measures and regulations that
have started to change the status quo by introducing structural and behavioral changes in the
energy market. When Europe, the members of the EU, and Russia started to implement these
changes presented by the Third Energy Package, the first fundamental challenge originated
from the perspective of each party involved on how these regulations were to be
implemented. While progress has been achieved, there remain diverging views between
Europe and Russia, as well as differences among the members of the EU on certain issues that
led the development of new pipelines such as Nord Stream II. Russia, while accepting certain
terms of the Third Energy Package, continues to view energy security through geopolitical
lenses. Gazprom uses every means to circumvent and bend the rules of the single energy

154
market established by the Third Energy Package. EU member states are divided on their
approaches to energy relations with Russia. Western European members of the EU place
economic concerns over geopolitics while Central Europe, Eastern Europe, the Baltic, and the
Balkan members are concerned with national security in the context of energy security.
The cooperation mechanism and multilateral frameworks, such as the Energy Charter Treaty
(ECT) and EU-Russia Energy Dialogue, have not delivered desired effects for providing
multilateral solutions to address increased securitization of energy relations. Russia’s
withdrawal from the ECT remains one of the biggest setbacks for its full integration into
European energy markets. Russia will continue to pursue bilateral approaches and
government to government deals that allow development of long-term contracts. This bilateral
approach also allows Russia to use energy relations as part of its hybrid warfare toolbox to
increase its influence at different levels, from the EU to member states and multinational
corporations/companies.
Another major difference between Europe and Russia is the political leadership’s
involvement in the decisions over energy infrastructure development and other energy
security issues. During the Cold War, Chancellor of West Germany Willy Brandt supported
establishment of energy relations as part his ‘Ostpolitik’ and UK’s Prime Minister Margaret
Thatcher supported construction of pipeline linking Siberia to West Germany albeit the United
States’ political opposition. Recently, German Chancellors Schröder and Merkel supported
construction of Nord Stream I and II pipelines, respectively highlighting that their decisions
are based on economic not geopolitical imperatives.
On the contrary, Soviet and Russian leadership have remain ultimately involved in the
development of gas relationships at almost every level and used energy relations, in particular
national gas pipelines, as part of its geopolitical toolbox. However, Gustafson argues that

155
while gas provides Russia a leverage and Putin was involved in decisions, gas as a weapon
was not used in Ukraine:
The key to understanding the Russian-Ukrainian gas relationship is that gas gives
Russia a powerful geopolitical lever, which it has repeatedly used to manipulate
Ukrainian politics and to bind Ukraine to its sphere of influence. There is no question
but that under President Putin Russia has indeed pursued these objectives. But there is
a problem with the gas weapon part of the narrative. Whenever Russia has really
sought to influence Ukrainian politics or policy, it has for the most part not used gas as
a weapon.
However, there are competing views on Russia’s use of natural gas supply cuts against
Ukraine to leverage political outcomes. The gas weapon - cutting gas off from Ukraine - was
used for a very short period of time in 2006 and 2009, under the disguise of debt and pricing
conflicts between Naftogaz (Ukraine) and Gazprom. While Gustafson’s observations are true,
it is also important to recognize that the geopolitical approach followed by Russia to establish
new pipelines, Nord Stream I and II, Blue Stream, and Turk Stream, will minimize if not
completely eliminate Ukraine’s role as the transit country. Transit countries between Europe
and Russia not only benefit from transit fees but also gain advantages against Russia. The
development of multiple pipelines to circumvent Ukraine will not only prevent transit
revenues, but will minimize the leverage Ukraine holds over Russia.
The competition between European Union and Russian control over pipelines will continue.
While the European Commission continues to execute measures of the regulations identified
in the Third Energy Package and follow-on guidance, Russia, through Gazprom, will continue
to establish joint ventures and other means to work around these measures. For the time
being, strategic approach allowed Russia to increase its control over pipeline networks by
construction of Nord Stream and Turk Stream. We can argue that Russia has gained a position
of strength for any future negotiations not only in the area of energy, but also in geopolitics.
We can also argue that Ukraine has become a prey to Russian aggression as it lost the value of
the largest transit country that Russia relied on for its exports.

156
While the European Commission calculates risks and opportunities at aggregate level for the
Union, it was obvious that during the 2014 stress test that some members were more
vulnerable than others. These member states will continue to conduct cost-benefit analysis in
their interaction and relations with Russia. The increased dependency of Europe, specifically
the nations, with either high level or high volume of natural gas importers, will securitize
energy and view this dependency as a national security concern. Finally, the Kremlin should
also conduct a cost benefit analysis in regards to using energy as part of power politics due to
high level dependency on energy export revenues that will be covered in the next chapter.

157
CHAPTER 4
RUSSIAN FEDERATION ENERGY STRATEGY AND FOREIGN POLICY
4.1. Introduction
As the world’s largest country by landmass, Russia holds vast amounts of raw materials and
natural resources. These minerals and raw materials include fossil fuels, such as oil, gas and
coal; precious metals, such as gold, platinum, polymetallic ores, and diamonds; and rare earth
elements. While Russia’s oil industry emerged much earlier in the nineteenth century, in
Baku, Azerbaijan and on the other side of the Caspian Sea in Kazakhstan, natural gas
exploration started later in the early 1920s. The production in the Caspian basin oil fields
around Groznyi and Baku allowed Russia to become one of the largest producers of oil in the
world in 1898, and overtaking the United States. However, “Russian oil production suffered
badly in the turmoil of the decade leading up to World War I.” The Bolshevik Revolution, the
nationalization of the oil industry, a failed energy policy, and purges of the Stalin regime
caused dwindling oil production in the 1930s. In the early part of the twentieth century,
especially during World War II, the Soviet Union, once an oil exporter, had to import fuel,
particularly for aviation, from the United States. Gaddy and Ickes highlight that in the postwar
period, the growth of oil and gas revenues began to play a bigger role changing “the structure
of the Soviet economy and led to the dependence on resource rents that still dominate the
economic system today.”
The Soviet Union, then Russia, has been one of the biggest energy suppliers in the world
since World War II. As highlighted previously, Russia’s latest Energy Strategy documents,
natural resources, and the energy sector are critical “to sustain economic growth, improve the
quality of life of the population and promote strengthening of foreign economic positions of
the country.” In this context, oil and natural gas pipelines have been a central element for the

158
Soviet Union’s energy strategy to ensure long-term foreign policy objectives that are reflected
in relations with Western Europe, Central and Eastern European countries, as well as the
Caucasus and Central Asian republics.
While energy strategy and foreign policy are closely intertwined, it is also important to
recognize that both Soviet Union, and then Russia, achieved separating energy trade and
geopolitics when it served their purpose. For example, the first Soviet gas export agreement
was signed and deliveries started from Czechoslovakia to Austria on September 1, 1968,
despite the Warsaw Pact invasion of Czechoslovakia ten days earlier on 20-21 August 1998.508
Similarly, construction of the Nord Stream 2 (NS 2) pipeline was discussed and negotiated
albeit the illegal annexation of Crimea and the Ukraine crisis were affecting Russian-
European and Russian-NATO relations.
The United States and European Union imposed sanctions following the Russian
intervention in Ukraine and the shooting down of a Malaysian airliner by the Russian-
supported separatists. The sanctions became “the centerpiece of the international response to
Russia’s actions in Ukraine.” Russia continued with the NS 2 project while sanctions were
supported by Germany with a strong backing of Chancellor Merkel and most business groups.
However, the NS 2 pipeline project was not part of the initial EU sanctions until renewed
tougher bipartisan US sanctions were introduced in June 2020. While Eastern European
countries led by Poland were very vocal and had valid concerns over Russia’s increased
assertiveness, construction went ahead when the Biden administration waived the sanctions.
In this chapter, I argue that energy resources, in particular oil and natural gas, have been
central to the Soviet Union, then Russia’s, national security due to their role on foreign policy
and economy. The energy strategy and foreign policy are intertwined and have been used as
geopolitical and economic leverage to maintain the unity of the Soviet Union. Following the
collapse of the Soviet Union, energy security has remained as a core interest for Russia,

159
enabling its economic recovery, regime survival, and its return to the international scene in the
beginning of the 21st Century. Russia’s energy strategy aims “to maximize the effective use of
natural energy resources and the potential of the energy sector to sustain economic growth,
improve the quality of life of the population, and promote strengthening of foreign economic
positions of the country.” While strategy focuses on long-term development for the energy
sector, Russia has continued to use oil and natural gas resources against its former satellites in
Central and Eastern Europe and the former Soviet Union (FSU) countries for rewarding,
punishing, threatening, and coercion.
I will start with the evolution of the oil and natural gas sectors during the Soviet Union’s
timeframe and then focus on Russian Energy Security Strategy and Foreign Policy as well as
how they are intertwined and are implemented holistically. Analysis of the Soviet Union
period will cover three different dimensions: domestic politics - competition between the oil
and gas sectors; challenges over construction of pipelines and energy relationships with the
members of the Council for Mutual Economic Assistance (CMEA); the consequences of the
high level interdependence between the Soviet Union and its satellite countries; the effects of
increasing dependence of Western European countries on Russian natural resources and
resulting concerns over relations within the European Community, NATO and the EU, in
particular Germany-US relations. This will be followed by an analysis of Russian Federation
Foreign Policy and Energy Strategy using a similar approach that focuses on energy as an
instrument of Russian foreign policy, relations with the FSU countries, central and eastern
Europe, and Western Europe. The impact of the Russia-Ukraine gas crisis and other political
constraints will also be reviewed as an example of how energy resources are being used as
part of Russia’s hybrid warfare toolbox.
I will provide an overview of Russia’s energy reserves, pipeline systems, and potential future
projects that have direct impact on the evolution of its foreign and energy policies. Russia is

160
generally concerned with ensuring demand security, which will be further elaborated on to
gain insights as to how Russia perceives energy security. Due to the fundamental role of
energy income for its economy, Russia will use every asset to reduce any potential
competition from European markets. Moreover, Russian efforts to diversify energy markets
will be reviewed in its relations with the Asia/Pacific countries and efforts on improving its
LNG exports. Russia’s efforts to maintain and expand market share in Europe while
developing other alternatives, such as exports to China and other countries in South and
Southeast Asia, will also be reviewed.
Finally, this chapter covers Russia’s efforts to undermine Western support on projects that
could transport oil and gas from Central Asia and the Caucasus through the Southern
Corridor.
4.2. Soviet Union Energy Strategy and Foreign Policy
Soviet energy strategy was a top priority for the political leadership and economic planners.
Between World War II until the collapse of the USSR, Soviet leadership used energy
resources for developing its industry; gaining hard currency as a main income for the
economy; providing fuel to the military activities and operations; supporting foreign policy
objectives; establishing relationships with the West, increasing their dependency to Russian
energy supplies; and supporting Soviet people by increasing their living standards.
Khrushchev believed that “the country’s oil and gas resources and chemical materials as
significant assets for modernizing the Soviet economy and raising the people’s standard of
living.”
The Western Europe-Soviet natural gas cooperation started at the end of the 1960s that
allowed construction of complex trunk pipelines to deliver gas from Siberia to Austria, West
Germany, Italy, and France. These complex long-distance pipeline networks provided Europe
an alternative to the energy from unstable regions of the Middle East that was proven to be

161
unreliable following the Organization of Arab Petroleum Exporting Countries (OAPEC)
embargo of 1973. The European-Soviet gas deals was based on long-term contracts that
enabled the delivery of natural gas at the lowest cost transported via high pressure long-
distance largediameter trunk pipelines. These enormous projects were several thousand
kilometers and required multi-billion-dollar investments.514 Thus, “the Soviet’s early long-
term contracts were agreed to between governments and were based on barter exchange. This
barter model was rudimentary but effective.”515 The agreements designed fair risk sharing for
investment amongst the parties who were ideologically separated by an “Iron Curtain.” The
natural gas trade benefited both sides: providing cheap and clean fuel to Europe, allowing first
the USSR then Russia to use export revenues to import European goods and technology while
balancing its state budget through revenues.516
The Soviet Union’s energy strategy was influenced by several factors from domestic issues to
energy and trade relations with its satellites and Western European countries, including global
energy players that have large energy reserves, such as the Middle East countries and the US.
Perovic argues that “the Soviet Union needed to produce energy in everlarger quantities, not
only to fuel industrialization and modernization, but also to sustain its ambitions as a great
power…The various Soviet oil and gas campaigns from Stalin to Brezhnev were designed to
support the needs of the country’s military and its energy-intensive economy.” While this
overall direction was clear, domestic competition between oil and natural gas industries
delayed the development of natural gas exploration and construction of pipelines due to
allocation of resources for oil exports.518
Perovic argues that “In East-West relations, Soviet energy was at times a cause of tension and
confrontation, but much more a political ‘softener’” Energy resources were also a source of
competition and conflict between the Soviets and CMEA countries due to diverging priorities,
debt issues and increasing demands for subsidies. While energy was used and served as a

162
connecting tissue to attract Central and Eastern European satellites, oil and gas represented
main export items to Western Europe for hard currency and were also utilized for transfer of
Western technology for modernization of the Soviet industry and development of the
economy.520 This situation resulted in a dilemma for the Soviet leadership, whether to export
energy resources to Western Europe or maintain influence over its satellites by providing
subsidized oil and natural gas.
Soviet leaders, from Khrushchev to Gorbachev, had given exports to Western Europe a
precedence over its satellites and followed a long-term strategy in development of the
pipelines. In this regard, between the second half of the 1950s and the first half of the 1960s,
Khrushchev’s foreign policy concept was based on “the principle of ‘peaceful coexistence’
and economic competition between capitalism and socialism…” Utilizing massive amounts of
natural resources, Khrushchev’s “main economic objective […] to catch up with and overtake
the most advanced capitalist countries in the shortest possible time in terms of per capita
production.”
While there is no defined energy strategy for the Soviet Union, the approach followed by
Khrushchev and following leaders set the foundation of Russia’s energy strategy that aims to
use natural resources to acquire hard currency in order to maintain economic development,
support technology transfer, finance military capability development, and increase the quality
of life for Soviet citizens. Perovic argues that “the Soviet Union was a rather reluctant energy
power.” Vavilov and Trofimov highlight the importance of long-term contracts for the early
period of gas trade in Europe for the development of pipeline networks that relied on “the
parties’ commitments on the terms of trade as a basis for long-term investment upstream and
midstream.” The long-term natural gas contracts were especially important for the Soviet
energy exports that were dealt at the government level focusing on the exchange of pipes,

163
compressors, and other technical support for gas deliveries that were also essential for
domestic pipeline network construction.
Soviet oil and gas exploration, extraction and transport became a success story, and exports to
Eastern and Western Europe increased exponentially, making the Soviet Union one of the
energy powers in the world. However, Perovic suggests that “the issue of energy was more
often a burden rather than an asset.” He also claims that:
The image portrayed in the West during the Cold War about the Soviet Union trying to
use energy as a political weapon, as a way to tighten its grip over its Eastern European
allies and counter American influence in Western Europe, is at least partly misleading
and in need of revision…In East–West relations, Soviet energy was at times a cause of
tension and confrontation, but much more often a political “softener.” The Iron Curtain
was a dividing line between East and West, but nowhere was this curtain more porous
than in the domain of energy flows.526
These points were brought up several times by other experts such as Gustafson who argues
that natural gas symbolizes a bridge between the Soviet Union and the West. He suggests that
“over the years the gas bridge has served a shared economic interest that has stood the test of
time.” Per Hogselius argues that “economic considerations were always more important than
political ones in bringing about and sustaining the gas flow between East and West.” Due to a
lack of pipeline capacity and frequent technical failures, Soviet leadership had to give priority
to exports for Western Europe over domestic consumers resulting in large scale scarcity in the
Soviet Union. Therefore, proving be a reliable supplier cost domestic sacrifice, human
suffering, and diminished industrial productivity.
These different analyses denote that a blanket approach does not address concerns of the
Central and Eastern European countries, or those countries that have a higher level of
dependency. Per Hogselius argues that East-West natural gas system-building was a political
activity; this was true not only as far as the Soviet Union was concerned, but also in terms of
West European interests.” Thus, energy relations were a catalyst for German “Ostpolitik,” that
led to setting conditions for détente. However, energy relations did not produce the same
outcome for Soviet satellites, such as Czechoslovakia. In August 1968, the Warsaw Pact

164
forces invaded Czechoslovakia that provided an initial natural gas bridge to Western Europe
through Austria. This two-pronged energy strategy towards Western Europe and Soviet
satellites continued throughout the Cold War and was later adopted by Russia with the
collapse of the
Soviet Union.
4.2.1. Evolution of Oil and Natural Gas Sectors - Domestic Dimension
The real journey of Russia becoming an energy powerhouse started with the Soviet
Union during the Cold War in the 1960s. While the Soviet Union was perceived as a
middlelevel power, the ascendancy of Stalin to leadership led increasing acceptance of
traditional power politics in the 1930s. World War II was a major event that “radically altered
the structure of international politics” and changed Soviet foreign policy. Possession of large
energy resources was one of the pillars of the Soviet’s return to power politics. According to
Stern, the Soviet Union was the only self-sufficient major industrialized country in energy
resources throughout the 1970s. After the discovery of the super-giant Romashkino field in
the Volga Ural region, Grace argues that “the organizational power of a command economy
concentrated massive resources…[and] raised oil at an unprecedented rate. Plentiful oil
delivered record domestic economic growth and added a strategic new tool to Soviet foreign
economic policy.”534
New oil field developments in the Volga-Ural region allowed the Soviets to regain market oil
market share from the late 1950s and early 1960s that caused concerns over
“Moscow’s growing influence over European affairs, prompting the North Atlantic Treaty
Organization (NATO) to advise its members to show restraint in purchasing Soviet oil… The
aim was to torpedo projects such as the Druzhba (“Friendship”) oil pipeline that was built to
transport Soviet oil via the Soviet republics of Ukraine and Belorussia to Poland, Hungary,

165
Czechoslovakia, and the German Democratic Republic (GDR) and, hence, to the borders of
Western Europe” The embargo on sale of the larger diameter steel pipes and relevant pipeline
technology caused varying reactions from the European allies. This was the first US attempt
to influence Western Europe to reduce dependence on the Soviet/Russian energy resources.
However, the embargo imposed on the Soviets was lifted a few years later in November 1966,
when the debates in the West shifted from the “Red Oil" to increasing concerns over “a
possible Soviet oil shortage in the near future, caused by declining growth rates, increasing
domestic demand, and existing supply commitments to East European satellites.”
The Soviet attempts to extract natural resources were driven by the need to support military
activities and operations as well as funding the development of the industry and support
capabilities improving social standards. Perovic argues that “Soviet energy exports also
served as an important tool in Moscow’s project to integrate the socialist states of Eastern
Europe into a single economic space…energy also served as an important tool in Moscow’s
project to integrate the socialist states of Eastern Europe into a single ‘energy space’ through
the construction of an extensive pipeline system.”537 Soviet attempts to create a single
economic space were ultimately supported by its energy resources that were used to create
dependency. Where possible, The Soviets used hydropower energy that was considered cheap
compared to other forms of energy in republics such as Tajikistan. Oil and natural gas
pipelines were built like neural networks to support this system, allowing Russia to control
resources and their distribution.
Figure 19: Soviet Oil Pipelines in the 1960s
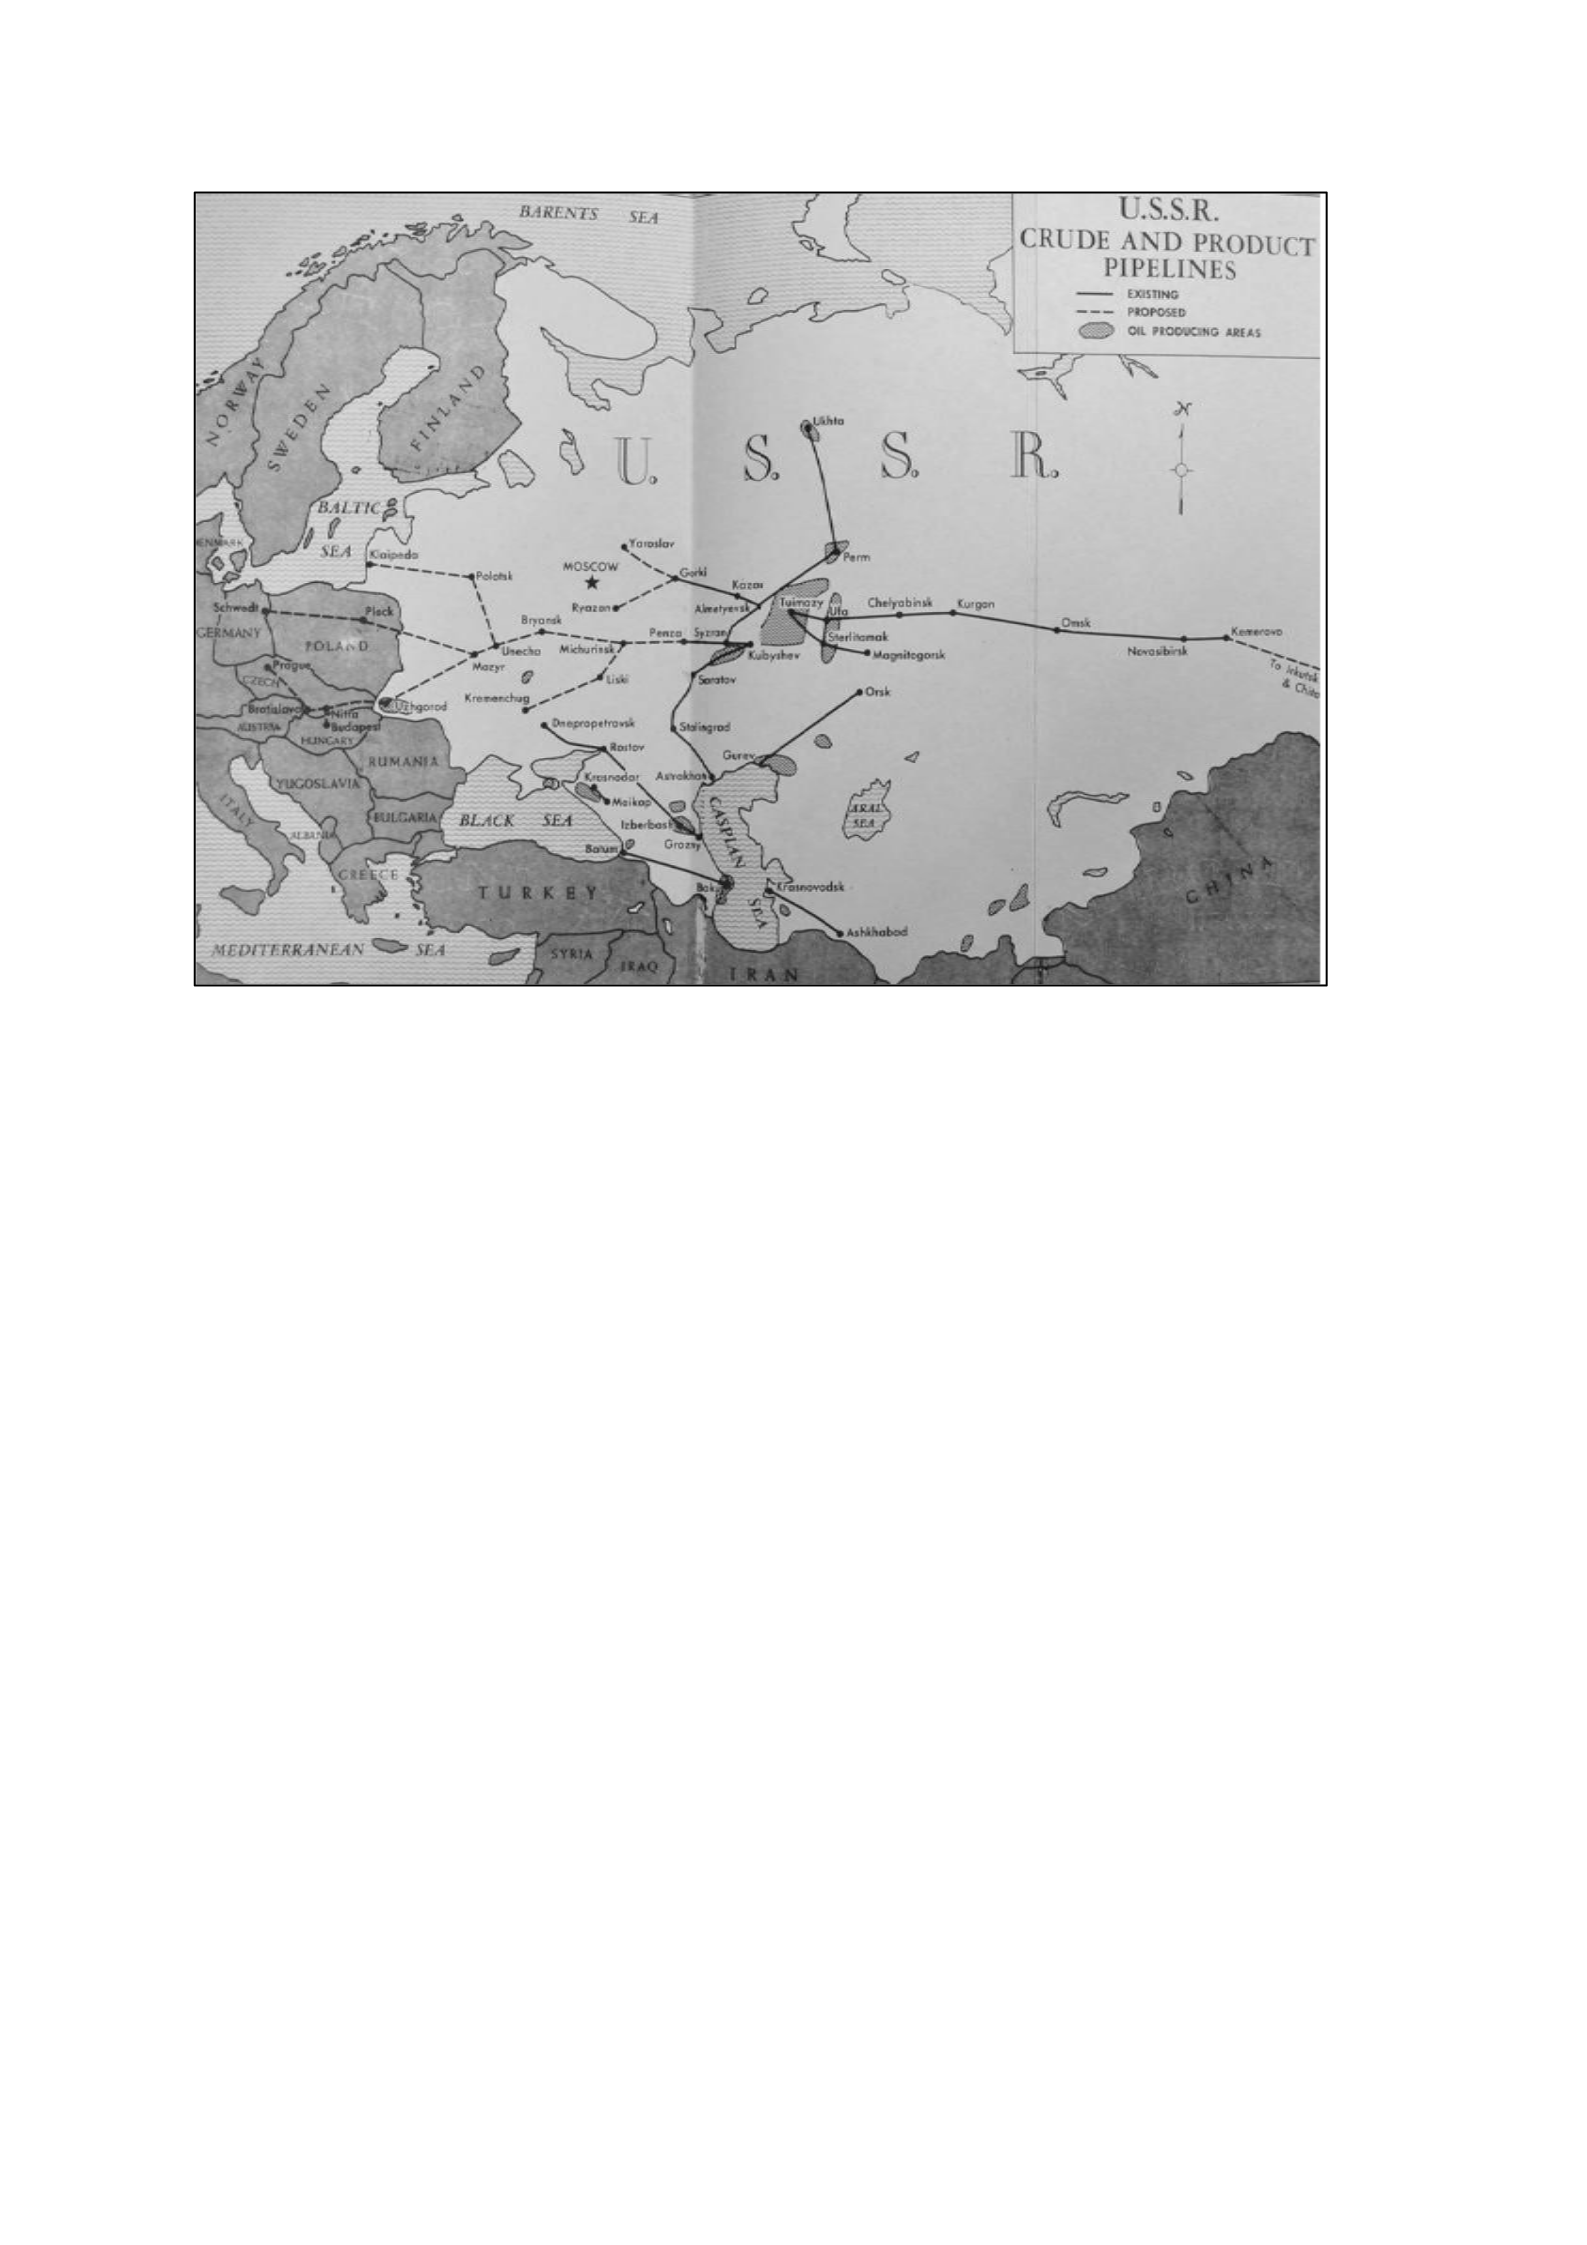
166
Source: Cantoni, R. Debates at NATO and the EEC in Response to the Soviet “Oil Offensive” in the Early 1960s
With the discovery of natural gas reserves in the Shebelinka region of eastern Ukraine, a
long-distance natural gas pipeline was built to carry the Volga region’s resources to Moscow
and Leningrad. This was followed by efforts to transport North Caucasus gas to the same
destinations, first Moscow, then Leningrad. Pipeline networks were further extended to the
Baltic Republics through Belarus. In the second half of the 1950s, the rapid development of
the Soviet gas industry took place under Khrushchev, who was a true believer of the future of
the natural gas development. However, Khrushchev “had to deal with influential interest and
lobby groups representing different sectors.”540 These interest groups included those supported
by oil, coal, natural gas, nuclear and hydropower. The competition amongst interest groups
started during the Soviet Union, and the early gas industry grew out of the oil industry that
goes back to the 1930s. The natural gas was introduced during World War II with the

167
discoveries of the reserves near Saratov, southeast of Moscow, and development of the Galicia
gas field by the construction of the pipeline from Dashava to Kiev in 1948, then to Moscow in
1951, albeit overall contribution and overall energy production in the Soviet Union remained
limited until the early 1960s.
Gustafson highlights one of the most ironic facts of the natural Russia-Ukraine gas issues,
considering the current crisis, that “the modern Soviet natural gas industry originated in
Ukraine, or to be more precise, in what was at the time Polish Galicia.” Then, the discovery of
new gas fields in eastern Ukraine resulted in the construction of the Bratstvo (Brotherhood)
pipeline carrying gas from Ukraine to Eastern Europe, then to Austria and Western Europe.
While attempts to bring West Siberian natural gas were delayed due to the diverging views of
the leadership of the Soviet establishment, this had two major consequences: first, overuse of
Ukrainian gas. The second, “a long hesitation in organizing for exports, even though the gas
sector badly needed imported pipe and technology.” As a result, the Ukrainian gas fields were
the first depleted gas reserves due to support for the Soviet economy and the first gas exports
to Europe.
The Soviet Union had to gain hard currency to obtain Western technology and equipment to
sustain development of its industry and support modernization of the domestic economy. In
that respect, energy exports played a crucial role as a stimulus for economic growth. Stern
emphasizes that another area where hard currency was used was in financing grain imports
when the Soviet harvest was poor. Therefore, raw material exports, especially oil and natural
gas, were central to the Soviet economy and foreign policy. The following table depicts
exponential increase in Soviet Oil and Natural Gas production and exports during the Cold
War.
168
Table 8: Soviet Oil and Natural Gas Production and Exports
Years Oil production
(Millions of Tonnes) Oil exports
(Millions of Tonnes)
Gas production
(bcm) Gas exports (bcm)
1950 37.9 0.3 5.8 0.05
1955 70.8 2.9 9.0 0.16
1960 147.9 17.8 45.3 0.24
1965 242.9 43.4 127.7 0.39
1970 353.0 66.8 197.9 3.3
1975 489.3 93.1 289.3 19.3
1980 603 159.0 435 57.2
1985 595 164.9 643 71.0
Sources: Andreas Heinrich, and H. Pleines. "Introduction: Export Pipelines in Eurasia." Reference to Block,
Herbert: Energy syndrome, Soviet version, in: Annual Review of Energy, 1977 (vol. 2), pp. 455-497, here pp.
482,486; Bethkenhagen, Jochen: Soviet energy: rapid rise in output and exports, in: Economic Bulletin, 1988 (vol.
24), no. 12, pp. 7-13, here pp. 8, 11.
While the Soviet Union was one of two global superpowers, it was largely closed to world
markets and highly dependent on exports of natural resources for hard currency to sustain its
economy. The OAPEC crisis of 1973 shook the western world; however, it was beneficial for
the Soviet Union in economic terms, bringing $2 billion extra in hard currency for a smaller
amount of oil.548 The Soviets benefited from both the change in oil prices and an increase in
production. “World oil prices rose from $1.80 a barrel in current dollars in 1970 to $36.83 a
barrel in 1980. Soviet oil exports rose from 1.9 million bpd in 1970 to 3.2 million bpd in
1978.” According to Nogee and Donaldson, the Arab oil embargo resulted in challenges and
opportunities: “On the positive side for Moscow were the gaping split in Western unity, the
likelihood of increasing nationalization of Western oil interests in the area, and the higher
prices that the Soviets were able to get for their own oil exports.” The key concerns could be
identified as the increasing role of Saudi Arabia, rather an anticommunist state, leading the
boycott against Western powers and “the cutbacks in the delivery of the Mideast oil to Eastern
Europe [which] had forced Soviets to divert some of their own exports from Western to
Eastern
169
Europe.”551
4.2.2. Russian Relations with the Council for Mutual Economic Assistance
(CMEA/COMECON) Countries
After World War II, the Soviet oil industry had recovered with the “new production in the
Volga-Urals region and then the discovery of vast new supplies in West Siberia.” Therefore,
the Soviet oil production base moved from the Baku region to the Volga Urals which
represented more than 50% of oil production by the mid-1950s. With this shift in production
regions and the substantial increase in oil output, pipeline systems evolved to deliver output
from these new fields to the domestic and international markets, namely Western Europe.
The Soviet oil pipeline network doubled between 1950 and 1955, reaching 10,400 kilometers
and expanded to 16,700 kilometers within a decade. This resulted in 85% of Soviet oil being
transported via pipelines. Around the same time period, the discovery and exploration of the
natural gas reserves in the same region made the Soviet Union self-sufficient in energy terms
and a major oil and natural gas exporter to Europe. Energy exports connected the Soviet
Union to world markets, something that characterizes this period. The following table depicts
increasing oil production while a corresponding growth of oil exports between 1965 and
1989, the year of the collapse of the Soviet Union.
Table 9: Oil Production and Exports (million tonnes) in the USSR, 1965-1989
Year Total Oil Exports Oil Output Share of Total Oil Exports in Oil Output (%)
1965 75.7 242.9 31.2
1970 111.4 353 31.6
1975 150.5 490.8 30.7
1980 182.5 603.2 30.3
1985 193.5 596.7 32.4
1989 215.6 607.2 35.5
Source: Sergei Ermolaev. "The Formation and Evolution of the Soviet Union’s Oil and Gas Dependence." Carnegie
Moscow Center 29 https://carnegieendowment.org/2017/03/29/formation - and - evolution - of - soviet - union - s - oil -
and gas - dependence - pub - 68443

170
By the end of the 1950s, crude oil was transported via rail and ship to the CMEA countries.
In December 1958, the CMEA signed an agreement for construction of the first large oil
export pipeline “Druzhba” (Friendship), replacing cost-intensive transport and establishing a
trunk pipelines system to carry Volga-Urals crude oil to Poland, East Germany,
Czechoslovakia and Hungary. The construction of the Druzhba pipeline network was started
in
1960 and completed in 1964. “The completion of the Druzhba oil pipeline also had impacts on
energy relations with individual West European countries, because Soviet crude oil could now
be transported to the West faster, cheaper, and in greater quantities.”557
While the USSR was expecting to increase its energy exports to gain hard currency, there was
one major limitation – the high-level of dependence on Eastern Europe for Soviet oil and
natural gas. Central and Eastern European countries, members of the Council for Mutual
Economic Assistance, were highly dependent on subsidized oil and natural gas exports linking
their economies in a vulnerable way to the Eastern Bloc. Soviet energy supplies and trade was
a key lever to achieve political submission for the Warsaw Pact. Jaffe and Soligo refer to
Rosner’s argument that “The Soviet energy grid is a tangible manifestation of Soviet energy
diplomacy, which found its roots in the Brezhnev doctrine of restricted sovereignty.”
The relationships between the Soviet and CMEA were very complex and had multiple
dimensions, including competition between the CMEA states for resources as well as their
considerations on relations with the West such as the German Democratic Republic’s (GDR)
concerns over Soviet energy exports to West Germany. Stern highlights that the major
concern for these countries, even during the Cold War, had to be greater dependence on the
Soviet
171
Union “unless they can import oil and gas from elsewhere.”561 The following table depicts the
increasing natural gas dependency of the CMEA members that had become a growing
concern for the Soviets, especially for their rising oil and natural gas demand. In order to
maintain domestic stability of the CMEA countries, the Soviets had to divert larger quantities
of fuel/energy resources to support its allies. These oil and gas supplies could have also been
exported to Western European countries for hard currency.
Table 10: Unit prices a of Soviet Oil and Gas Exports, 1973-1976
Year 1973 1974 1975 1976
Fuel Type Oil Gas Oil Gas Oil Gas Oil Gas
Bulgaria 14.6 15.2 13.5 34.2 29.4 37.5 33.4
German Democratic Republic 14.2 18.8 13.4 28.2 13.4 32.1 24.6
Poland 17.3 12.3 20.6 12.3 39.5 24.9 42.0 28.5
Czechoslovakia 16.4 13.1 16.3 13.6 30.9 22.3 34.1 30.7
Hungary 17.9 20.9 41.0 26.6 44.7 30.2
France 17.0 61.9 58.2 65.0 22.8
Federal Republic of Germany 36.6 13.0 66.8 12.6 62.3 17.8 80.9 20.2
12.5Italy 17.7 58.2 7.0 50.7 14.6 58.2 12.5
Aust29.8ria 22.9 9.3 63.2 12.1 58,7 27.0 65.5 29.8
Finland 22.1 67.0 42.5 61.9 41.7 66.4 42.1
Data Sources: Data Source: Jonathan F. Stern, Soviet Natural Gas Development to 1990, Table 3-2. Calculated from
Vneshnyaya Torgovlya SSSR for respective years.
a (rubles per million tons of oil equivalent)
Soviet energy exports, especially oil, to the CMEA countries were part of the overall Soviet
strategy to maintain a sphere of influence over Central and Eastern Europe. Romania was the
only exception with sufficient oil production capacity. Other central and eastern European
countries were critically dependent upon the Soviet Union as their oil and natural gas source
for their energy. Stern highlights that in 1965, CMEA countries had no doubts that “Moscow
could and would supply the great majority of the oil and gas requirements of the countries of

172
Eastern Europe.” However, CMEA countries had witnessed a change in energy commitment
and supply position of Moscow around 1976-1780.564
The Kremlin was encouraging Eastern Europeans to seek alternative markets to at least get
some of their oil for their consumption from elsewhere, such as the Middle East. One of the
main drivers for the change in oil policies of Moscow was a fourfold increase in energy prices
in the aftermath of the oil crisis. To benefit from the increase in oil prices, Moscow intended
to discontinue subsidizing CMEA energy supplies. “With skyrocketing world market prices
for oil, the existing price system, in place since 1958, had become highly unfavorable to the
Soviet
Union as the main energy exporter in the CMEA area.” Therefore, Soviet satellites have
become an economic liability as Kansikas argued:
On the one hand, Soviet oil and gas financed the economic system of the socialist
bloc. On the other hand, however, energy resources also fueled the pattern of
interdependency in both East–East and East–West trade. The extent of
interdependency created through the energy trade during the 1970s became clear in
the mid-1980s…, By the late 1980s, Soviet allies had become hugely indebted to
Western creditors, and the Soviet Union was now both unwilling and unable to assist
them economically. The empire had become a liability.
The Russians, according to Gustafson, had complaints that the CMEA countries were getting
underpriced natural gas and oil exports. The price of energy goods had always been debated
between the Soviets and its satellites, such as the argument Ulbricht and Khrushchev had in
the 1960s. The result was a widening gap between the Soviets and CMEA countries due to
subsidized oil and natural exports traded with Eastern European overpriced and lowquality
products. While technocrats such as Kosygin and Baibakov were against subsidized delivery
of the energy exports, Brezhnev and members of the Politburo were concerned with de-
stabilization of the Eastern European satellites and directed low prices to continue.568
However, low-priced energy exports to the CMEA countries reduced Soviet hard currency

173
income and might have been one of the key factors that contributed to the collapse of the
Soviet economy.
To address Soviet burden sharing concerns, Eastern Europeans were asked “to invest in
energy resource and development projects on Soviet soil, which was a further condition for
receiving increased Soviet deliveries.” In 1970, oil and petrochemical export to the Socialist
Nations was about 54% of total exports. In 1980, this increased to 65% while total oil export
also increased 50% (From 111.4 to 182.5 million barrels). If Kosygin and Baibakov were
successful on the cancellation of energy subsidies to allies, Ermolaev argues that “this would
diminish the loyalty of these nations and make them start market reforms earlier than they did.
As many of their products were not competitive on the world market, production would have
started to decrease much earlier.”
On the one hand, oil and natural gas allowed the Soviet Union to create a dependency of the
CMEA countries. However, as noted by Kansikas, “energy was not an easy weapon to be used
in exploiting or controlling allies…Oil was in high demand in both socialist and capitalist
markets.”571 Soviet efforts to change pricing mechanisms, to request CMEA countries to find
alternative energy sources, and to divert oil imports to the Middle East markets caused
resistance and discontent on the part of Eastern European allies.
On the other hand, with these current pricing mechanisms and raw material trade with low-
quality Eastern European goods, such as machinery, the Soviets experienced significant
losses. However, the Soviet Union continued to provide subsidized oil to its allies as long as
CMEA countries were important for Moscow and “it considered the alliance to be its number
one priority... This ceased to be the case at the end of the 1980s. In a radical change of
priorities, the Soviet leadership no longer considered the East European part of its empire to
be paramount…The dissolution of the Soviet bloc in late 1989 can partly be explained by the

174
Soviet Union’s decision—due to the external shock created by a drop in oil export revenues—
no longer to support its alliance.” Several arguments were made regarding the collapse of

