


CH 8 BONDS
BONDS: long term debt securities issued by corporations and governmental agencies.
● Are typically registered, meaning that they have a record of ownership
● Typically thought of as a safer investment than common stock.
SECURED BONDS: have collateral
● If you took out a loan for a car, the car would be the collateral
● Meaning if the bond has collateral then their is some form of asset tied to it
UNSECURED BONDS are called DEBENTURE and sometimes subordinated debentures
● No collateral tied to this
● Suppose this year you bought 1 bond from a company and it was unsecured (debenture)
next year to raise more money the company sells more. Now if the company were to get
into financial trouble, wouldn’t it make sense that you should be able to get your bond
first(since it was sold first)?
○ What happens typically is since your bond would have seniority those newer
ones would be subordinated bonds (would be riskier). As a bond becomes riskier
the return it needs to pay goes up
○Junk Bonds come from here, all they are greatly subordinated bonds
■Just means it’s a riskier higher yielding bond
BEARER BONDS have no record of ownership
● Meaning if it was stolen, you wouldn’t be able to get it back, it’s like cash.
INDENTURE: are the listed conditions of a bond (information packet).
1. Rights of all parties:
a. company that sold the bonds (one party: issuer), have the right to use your
money for that specified time frame (but they have to pay you the interest every
year).
b. You (another party: bond holder) who bought the bond, have the right to receive
the interest. You can sell it anytime though (don’t have to keep it)
c. The trustee(third party: neutral), would most likely a be a bank, where the
company chooses it and pays them to make sure that everyone does as there
supposed to do.
2. Restrictive provisions: if you bought a secured bond that has collateral, therefore the
company can’t sell the collateral cause then it would no longer be a secured bond.
a. Call Feature w/ Restrictive Provisions: one would be that the company can’t call
back any bonds till 5 years or they can’t call more than 20% of them in a year.
3. Sinking fund: if a company sells $100 million dollars worth of bonds that mature in 20
years, would it be nice to know if the company has a plan to start saving money, so by
the end of the 20 years they have enough money to pay everyone back.
4. Call feature: if the bond is callable, that means the company can force you to sell the
bond back to them. Investors don’t like this feature but companies do.
a. What the company is doing here is refinancing.
5. Convertible feature: feature where if you buy a convertible bond, you have the option to
convert that bond into a specified number of common stock
a. Preferred Stock can also sometimes be converted into Common Stock.
6. Terms: coupon rate, par value, maturity
a. COUPON RATE: the interest rate the bond is set to pay
i. Normally a fixed rate, not going to change.
b. PAR VALUE: most corporate bonds have a par value of $1000 (can be anything
though just example)
i. EXAMPLE: Coupon Rate of 6% with a par value of $1000 means the bond
pays $60 a year till it matures.
ii. Most bonds semi annual interest, so the $60 would be split in half for
every 6 months (so $30 every 6 months).
c. MATURITY: time frame of the bond (specific date in real life).
*THIN MARKETS FOR REGULAR INVESTORS, because most of us don't buy bonds and don’t see
them.
*More mutual funds and pension plans that buy a lot of bonds.
CONVERTIBLE BOND:
●Example: purchase a bond for $970 that has a $1000 par value. You can convert the
bond into 25 shares of common stock which is currently selling for $30 a share (you
would think it would be the $1000 par value you would pay the $1000 but when interest
rates in the economy go up and down, and when they change the price of bonds
change).
● *There is an opposite relationship between bond prices and interest rates
●CONVERSION PRICE = Par / Conversion Ratio = 1000/25 = $40 per share
●CONVERSION RATIO = Par / Conversion Price = 1000/40 = 25 shares
●CONVERSION VALUE = Stock Price x Conversion Ratio = $30 x 25 = $750
●CONVERSION PREMIUM = Bond Price - Conversion Value = $970 - 750 = $220
TYPES OF BONDS:
●CORPORATE: are issued by firms to raise capital. Typically, par is $1000 (what we
assume) and the maturity is 10-30 years
●TREASURY BONDS: issued and guaranteed by the US Gov (which the largest issuer of
debt securities in the world). Interest received is state tax exempt
○ One benefit is our states do not tax the interest we receive from them
●GOVERNMENT AGENCY BONDS: are issued and guaranteed by the particular agency of
the government: HUD, Federal Home Loan Mortgage Corp., Student Loan Marketing
Assoc., Federal National Mortgage Assoc. (Fannie Mae). FHA, VA…
○ They are usually guaranteed by the particular agency of the government.
●MUNICIPAL BONDS: issued by states, counties, school districts… Interest received is
federal tax exempt and usually state tax exempt also.
○ Aka “Munies”.
○TAX EQUIVALENT YIELD = interest rate (or the yield)/ (1- tax rate)
○ Local to your area
○ As a taxpayer or property tax payer we are paying a fee to pay the interest of
these bonds (if you are a property owner)
○ One Benefit is (huge for people in the highest tax brackets) federal and state
gov’s don’t tax the interest.
○ One of the reasons why it’s tax exempt, is whoever is issuing the bonds (school
district, city…) they pay a lower interest rate because the investors don’t pay
taxes on the interest they receive so it’s cheaper for them.
●ZERO COUPON BONDS: purchase a bond at a very large discount with no interest
payments being made until maturity.
○ Implies the bond pays no interest, in theory it really does, they just don’t send
the interest to you.
○EXAMPLE: If you want to buy a $1000 savings bond, you pay about half price,
and then when the bond matures they give you full value. You don’t receive
anything in between because the government is applying the interest to the price
to the savings bond every year.
○ At maturity they give you par value, even though you didn’t get a check for the
interest every year, you still technically get it.
○ BOND VALUE = PAR VALUE (PVIF)
■Use Table D3
Inverse Relationship between the current market interest rate (investor’s required rate of
return) and bond values.
○ When interests go up, bond prices fall allow you to purchase a bond at a discount
○ When interest rates go down, bond prices go up which means you are willing to
pay a premium.
BOND RISKS:
●DEFAULT RISK: chance of losing your capital
○ Because you’re not the owner but rather a lender
●CALL RISK: applies to callable bonds, possibility of the company forcing you to sell the
bond back to them, they tend to give you a premium though (a bonus) up to one years
worth of interest, as an “apology” of sorts.
●INTEREST RATE RISK: refers to that inverse relationship between interest rates and bond
prices.
○ Let’s say you have a bond with a 20 yr maturity if interest rates go up and down,
the price of that bond will fluctuate a lot more than a bond with a 5 year
maturity.
●BOND LADDERING: investing in bonds with varying maturity dates to reduce interest
rate risk (besides diversifying in investing in multiple companies).
○ Although this is diversifying just by maturity dates than multiple companies.
BOND RATINGS: all publicly traded bonds are rated
● Standard & Poor’s “AAA” best
○ They get paid by the companies that they rate, so there is a wonder if there is a
conflict of interest going on since you’re being paid by the company you’re rating.
● Moody’s “Aaa” ratings
BOND VALUATION: what would you be willing to pay for a $1000 par, 20 year maturity bond
with an 8% coupon rate when the current market rate is 10%? (Interest rates are above the
coupon so the price must sell below par).
● Because the current market rate(or investors required rate of return) is more than the
coupon we know the bond will sell at a discount.
BOND VALUE = Interest (PVIFA) + Par (PVIF)
USE TABLE D4
(20 yr) $830 = 80 (8.514) + 1000(0.149)
*if you paid $830 for this bond and for the next 20 years you receive 80 interest over those
years ($1600). But instead of the 80 in the last year the company pays you back the $1000,
you’ve made $1600 in interest (over the 20 years), and they give you the $830 back but they
gave you 1000, so $1000 par - $830 = $170 in capital gain. You’re making a 10% annual return.
(10 yr) $878 = 80 (6.145) + 1000(0.386)
(1 yr) $982 = 80(0.909) + 1000(0.909)
1000 - 982 = $18 (cap gain) + $80 (interest for the year) = 98/982 (what you’re selling
for) = 0.099 or 10%
Can only do this for a 1 yr bond, not any more than this.
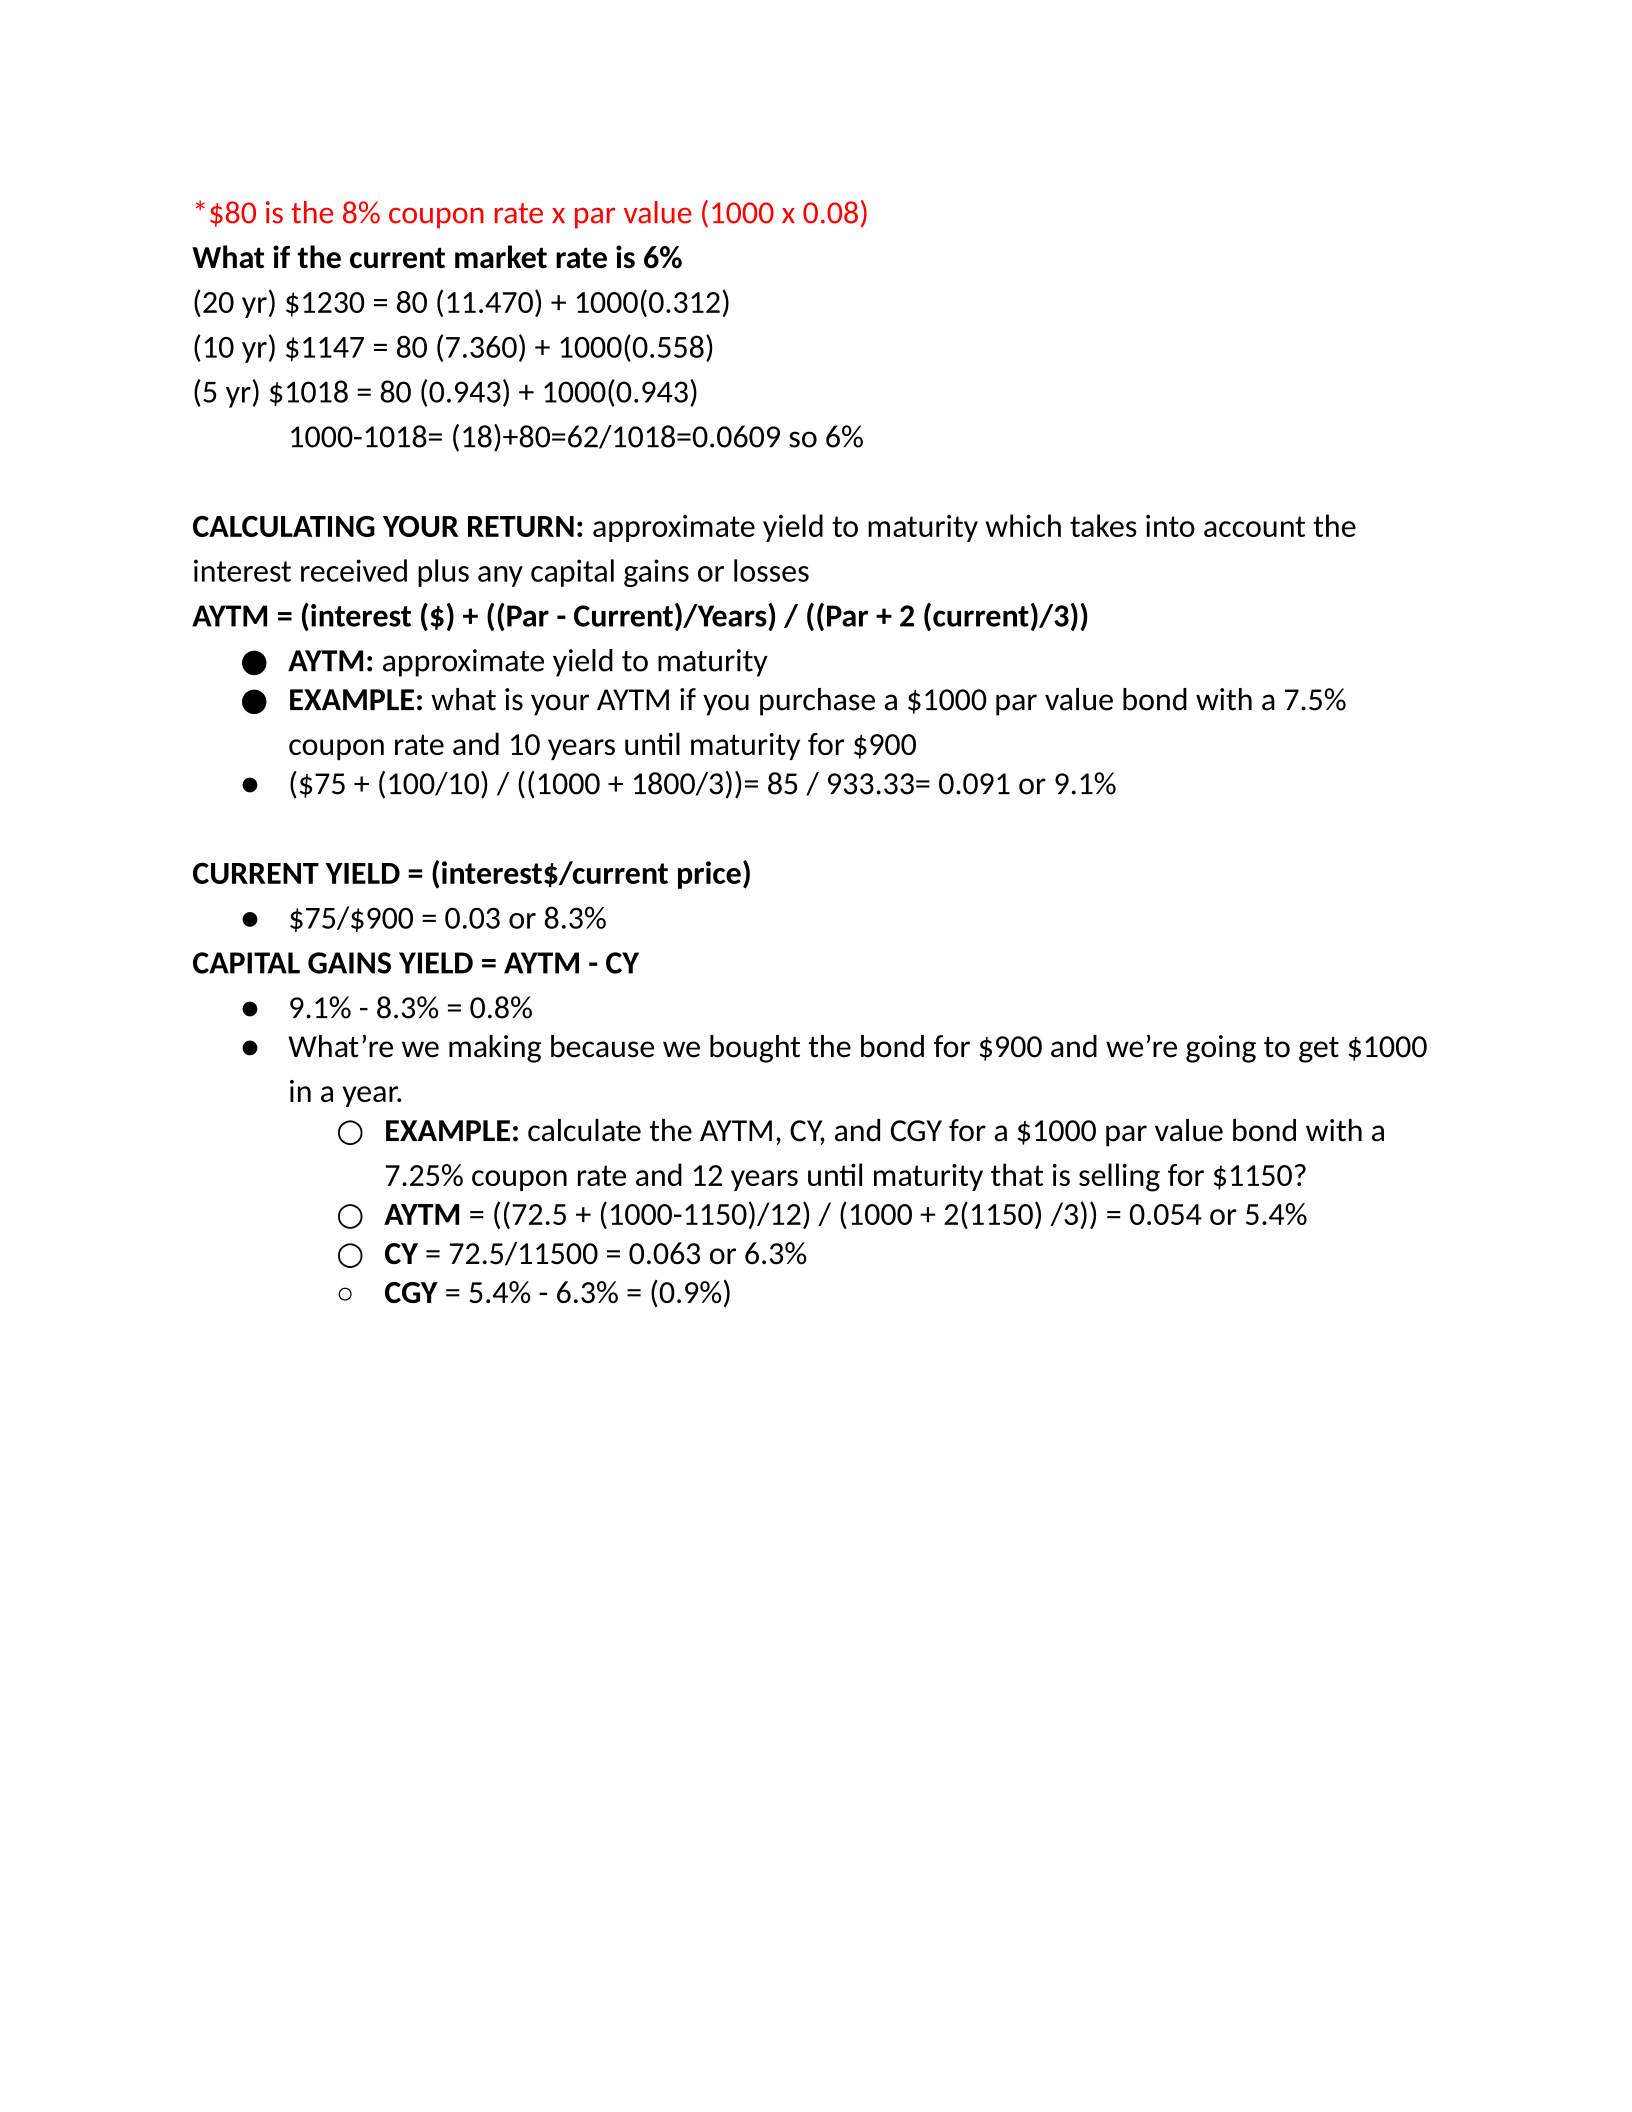
*$80 is the 8% coupon rate x par value (1000 x 0.08)
What if the current market rate is 6%
(20 yr) $1230 = 80 (11.470) + 1000(0.312)
(10 yr) $1147 = 80 (7.360) + 1000(0.558)
(5 yr) $1018 = 80 (0.943) + 1000(0.943)
1000-1018= (18)+80=62/1018=0.0609 so 6%
CALCULATING YOUR RETURN: approximate yield to maturity which takes into account the
interest received plus any capital gains or losses
AYTM = (interest ($) + ((Par - Current)/Years) / ((Par + 2 (current)/3))
●AYTM: approximate yield to maturity
●EXAMPLE: what is your AYTM if you purchase a $1000 par value bond with a 7.5%
coupon rate and 10 years until maturity for $900
● ($75 + (100/10) / ((1000 + 1800/3))= 85 / 933.33= 0.091 or 9.1%
CURRENT YIELD = (interest$/current price)
● $75/$900 = 0.03 or 8.3%
CAPITAL GAINS YIELD = AYTM - CY
● 9.1% - 8.3% = 0.8%
● What’re we making because we bought the bond for $900 and we’re going to get $1000
in a year.
○EXAMPLE: calculate the AYTM, CY, and CGY for a $1000 par value bond with a
7.25% coupon rate and 12 years until maturity that is selling for $1150?
○AYTM = ((72.5 + (1000-1150)/12) / (1000 + 2(1150) /3)) = 0.054 or 5.4%
○CY = 72.5/11500 = 0.063 or 6.3%
○CGY = 5.4% - 6.3% = (0.9%)

