


CASH FLOW
At this point, we are ready to discuss perhaps one of the most important pieces of
financial information that can be gleaned from financial statements: cash flow. By cash
flow, we simply mean the difference between the number of dollars that came in and the
number that went out. For example, if you were the owner of a business, you might be
very interested in how much cash you actually took out of your business in a given year.
How to determine this amount is one of the things we discuss next.
There is no standard financial statement that presents this information in the way
that we wish. We will therefore discuss how to calculate cash flow for U.S. Corporation
and point out how the result differs from that of standard financial statement
calculations. There is a standard financial accounting statement called the statement of
cash flows, but it is concerned with a somewhat different issue that should not be
confused with what is discussed in this section.
From the balance sheet identity, we know that the value of a firm’s assets is equal
to the value of its liabilities plus the value of its equity. Similarly, the cash flow from the
firm’s assets must equal the sum of the cash flow to creditors and the cash flow to
stockholders (or owners):
Cash flow from assets = Cash flow to creditors + Cash flow to stockholders
This is the cash flow identity. It says that the cash flow from the firm’s assets is equal
to the cash flow paid to suppliers of capital to the firm. What it reflects is the fact that a
firm generates cash through its various activities, and that cash is either used to pay
creditors or paid out to the owners of the firm. We discuss the various things that make
up these cash flows next.
Cash flow from assets
Cash flow from assets involves three components: operating cash flow, capital
spending, and change in net working capital. Operating cash flow refers to the cash flow
that results from the firm’s day-to-day activities of producing and selling. Expenses
associated with the firm’s financing of its assets are not included because they are not
operating expenses.
As we discussed in Chapter 1, some portion of the firm’s cash flow is reinvested in
the firm. Capital spending refers to the net spending on fixed assets (purchases of fixed
assets less sales of fixed assets). Finally, change in net working capital is measured as
the net change in current assets relative to current liabilities for the period being
examined and represents the amount spent on net working capital. The three
components of cash flow are examined in more detail next.
Operating cash flow
To calculate operating cash flow (OCF), we want to calculate revenues minus costs,
but we don’t want to include depreciation because it’s not a cash outflow, and we don’t
want to include interest because it’s a financing expense. We do want to include taxes,
because taxes are, unfortunately, paid in cash.
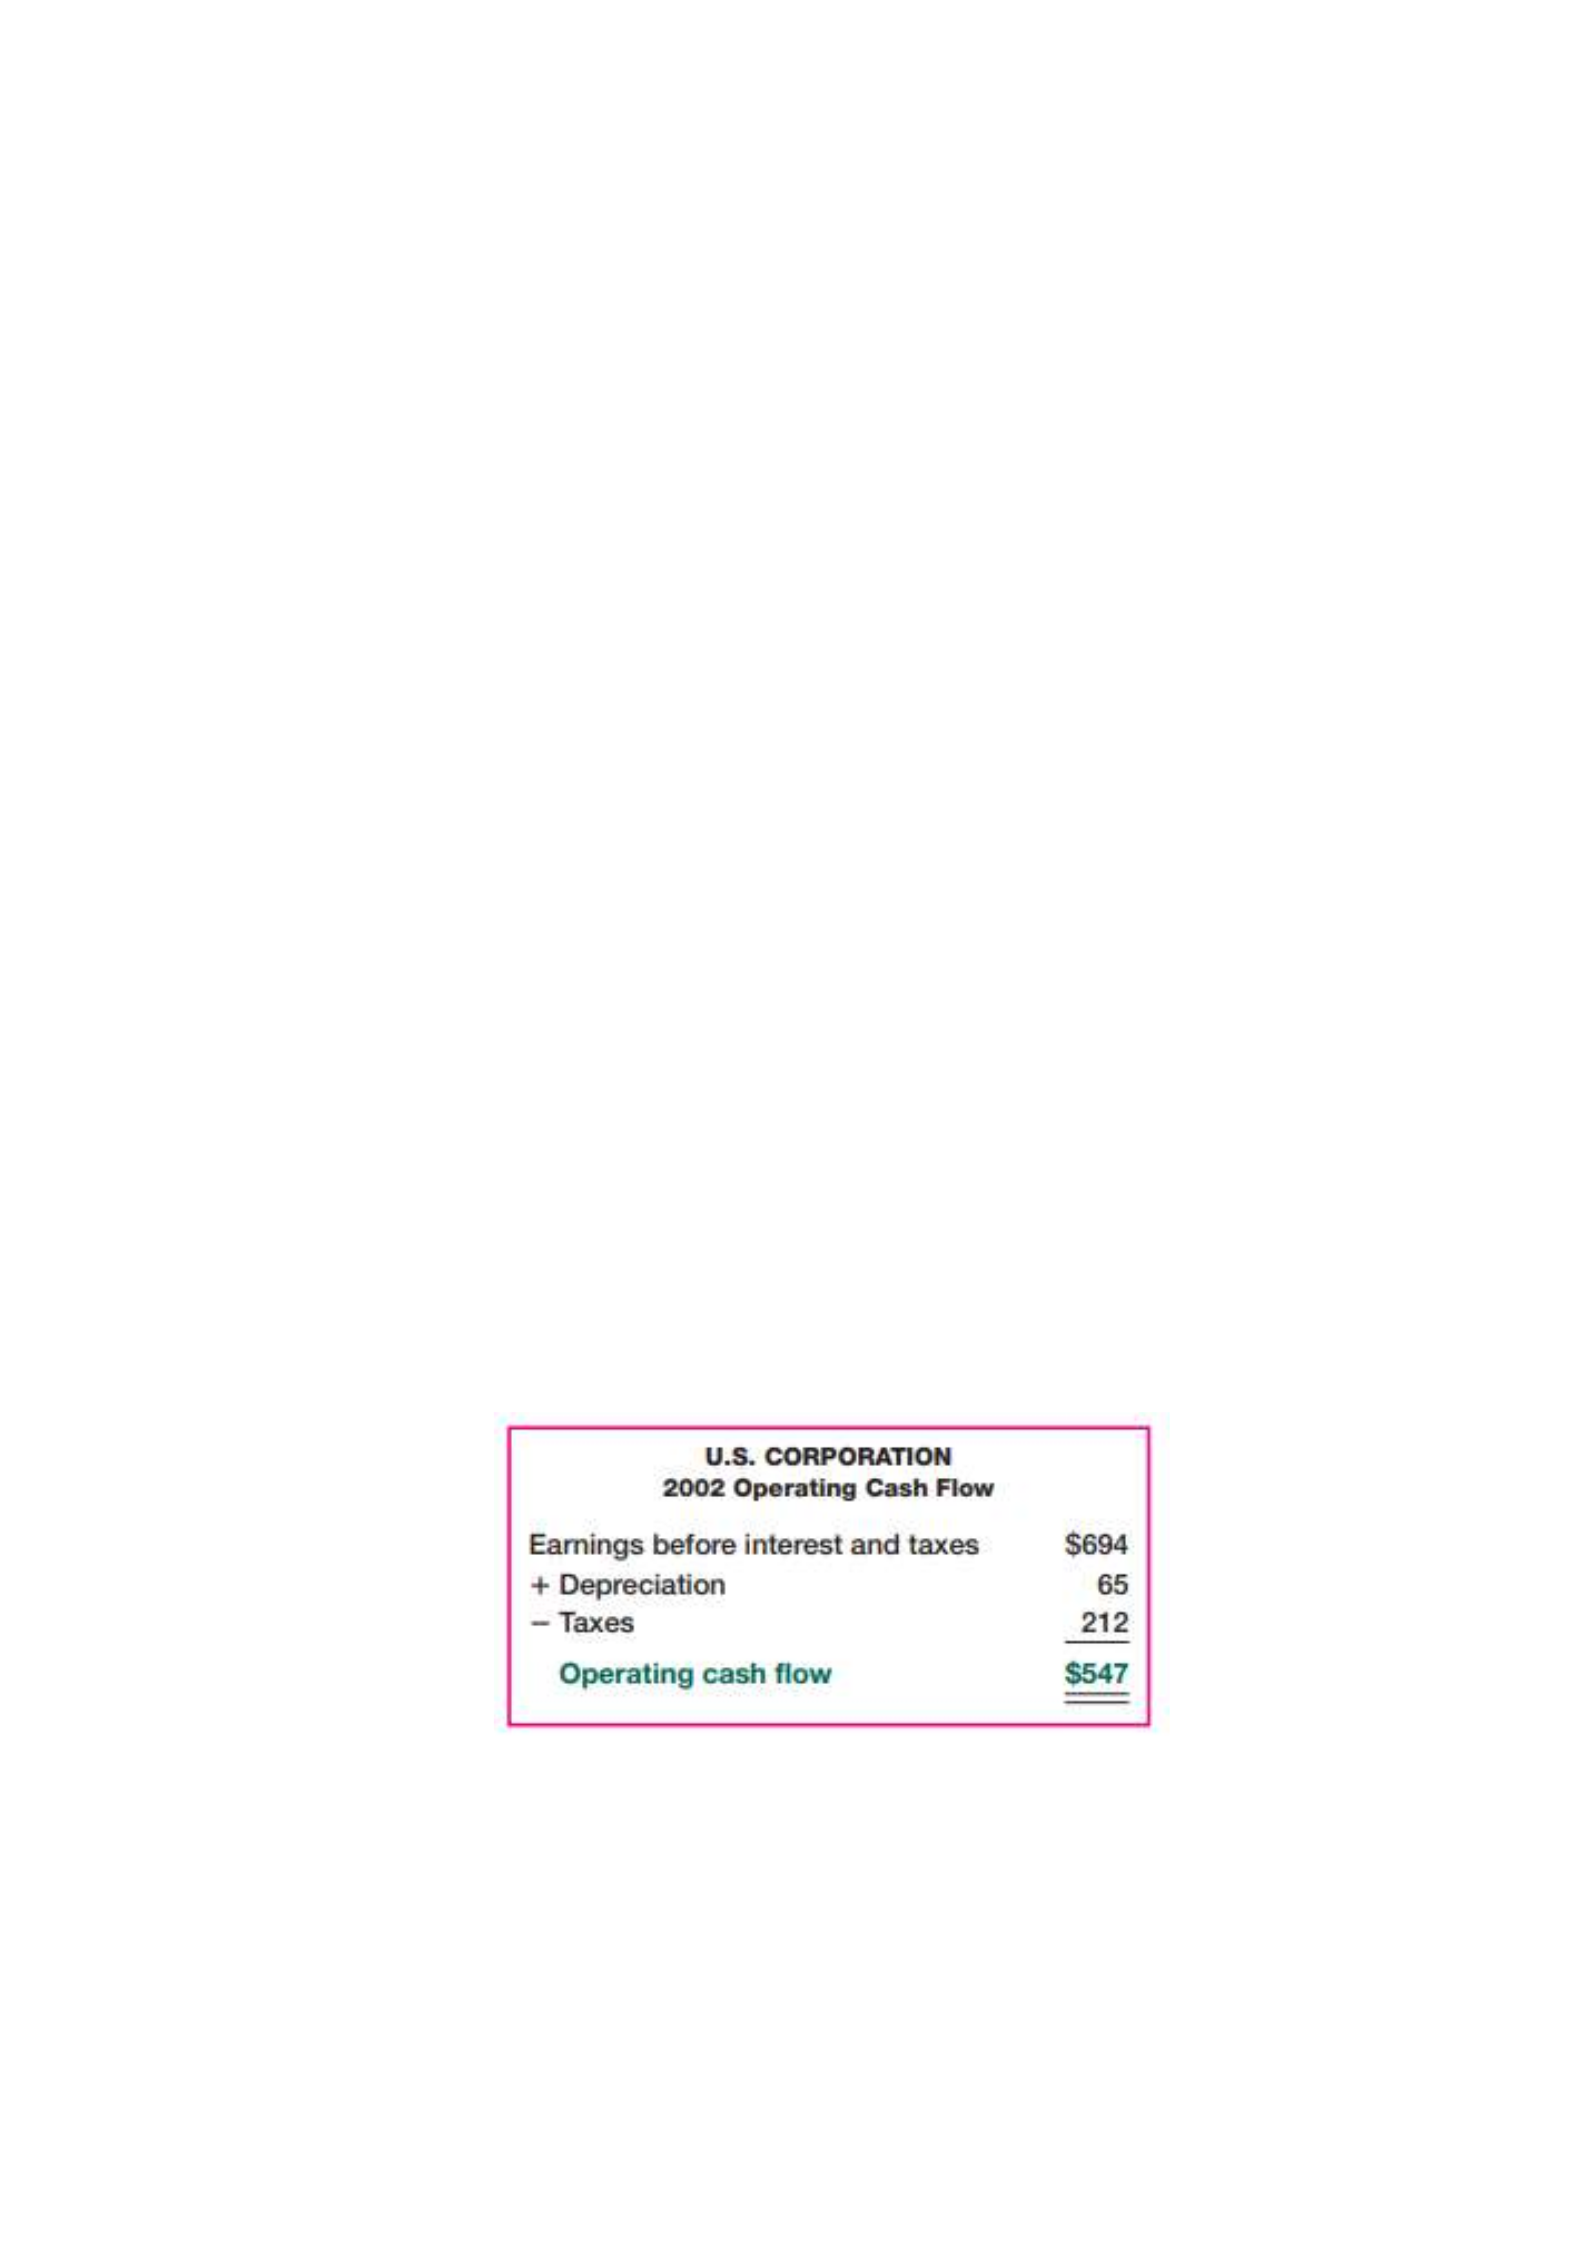
If we look at U.S. Corporation’s income statement (Table 2.2), we see that earnings
before interest and taxes (EBIT) are $694. This is almost what we want since it doesn’t
include interest paid. We need to make two adjustments. First, recall that depreciation is
a noncash expense. To get cash flow, we first add back the $65 in depreciation because
it wasn’t a cash deduction. The other adjustment is to subtract the $212 in taxes because
these were paid in cash. The result is operating cash flow:
Operating cash flow is an important number because it tells us, on a very basic
level, whether or not a firm’s cash inflows from its business operations are sufficient to
cover its everyday cash outflows. For this reason, a negative operating cash flow is often
a sign of trouble.

There is an unpleasant possibility of confusion when we speak of operating cash
flow. In accounting practice, operating cash flow is often defined as net income plus
depreciation. For U.S. Corporation, this would amount to $412 + 65 = $477.
The accounting definition of operating cash flow differs from ours in one important
way: interest is deducted when net income is computed. Notice that the difference
between the $547 operating cash flow we calculated and this $477 is $70, the amount of
interest paid for the year. This definition of cash flow thus considers interest paid to be an
operating expense. Our definition treats it properly as a financing expense. If there were
no interest expense, the two definitions would be the same.
To finish our calculation of cash flow from assets for U.S. Corporation, we need to
consider how much of the $547 operating cash flow was reinvested in the firm. We
consider spending on fixed assets first.

