


THE SCOPE FOR MONETARY AUTONOMY IN HONG KONG AND
SINGAPORE
Chapter 1 Introduction
The standard trilemma analysis is typically presented in the form that if a country has a credibly
fixed exchange rate and no capital controls, then it cannot also have an independent monetary
policy. This is clearly true for the long term because in the long-term countries must have a
balance of payments adjustment mechanism and these are the three main methods of adjustment.
The trilemma is sometimes described as being an implication of the standard Mundell-Fleming
open economy macro model. This is correct, however, for the short run only if capital mobility is
perfect so that any attempt at independent monetary policy will be offset by sufficient capital
flows to keep the money supply unchanged. If capital mobility is imperfect, however, then
sterilized intervention in the foreign exchange market can loosen the trilemma constraint in the
short term. This is especially true for economies that have considerable international reserves so
that they can finance short term payments imbalances. See Aizenman (2013) and Steiner (2017).
While international capital mobility is certainly high for many countries this does not necessarily
imply that it is so high that a number of countries cannot engage in considerable short term
sterilization and indeed there is a sizeable literature that finds that this is often done. However,
these studies have typically not taken into account the extent of these countries' capital controls
and degree of exchange rate flexibility, thus they are not direct tests of whether the trilemma
constraints can be violated in the short run.
1
Hong Kong presents us with a rare opportunity to analyze this possibility directly. As He and
McCauley (2013) describe it, "Hong Kong has an exchange rate link to the dollar and capital
account openness" (p. 9.) Of course, a pegged rate may not meet the trilemma requirements if it
is not credible, but Hong Kong has followed a hard rather than soft peg and there have been few
occasions in which the credibility of the peg has been seriously questioned. Furthermore, Hong
Kong has a well-developed financial market and is clearly well integrated into global financial
markets. Its "natural" rate of capital mobility is clearly quite high and its monetary and financial
conditions are clearly heavily affected by international developments. This does not logically
imply that the capital mobility facing Hong Kong is so high that it has no potential for any
degree of monetary autonomy. This is an empirical question which this dissertation is designed to
address.
A number of studies have found that despite the absence of significant capital controls there is a
less than one to one pass through from changes in interest rates in the U.S. to those in Hong
Kong indicating that capital mobility is less than perfect. Some studies, however, have found
pass-through to be close to 1. Thus, based on the previous literature it is an open question
whether there is sufficient imperfect asset substitutability to give Hong Kong scope for some
degree of short-run monetary autonomy.
Goh Lim, E. G., & Goh, S. K. (2016). Is Malaysia exempted from the impossible trinity? An empirical analysis for
an emerging market. Macroeconomics and Finance in Emerging Market Economies, 9(2), 131-147. .
Even if there is some scope for sterilization, the monetary authorities might still be institutionally
constrained from using it such as in a pure currency board. Furthermore, even if it is not so
constrained, a country might choose not to use this option. In a strict currency board arrangement
2
sterilization is not allowed and changes in the monetary base automatically follow from changes
in international reserves. Like many currency boards, however, Hong Kong's currency board
arrangements are not so strict. The level of international reserves acts as a constraint on how
much the monetary base can be expanded so that full convertibility is assured, but reserve
increases do not automatically force expansions of the monetary base. Indeed, currently
international reserves substantially exceed the monetary base. Thus, at present and throughout
most of its experience with a currency board, Hong Kong's reserve constraint has not been
binding and the effective constraint on sterilization is the degree of capital mobility.
One measure of international capital mobility is the extent to which changes in interest rates in a
core country affect interest rates in other countries, i.e, the extent to which there is interest rate
pass-through. Consistent with most of the previous studies for Hong Kong we find that most of
our estimates suggest that there is substantial but less than full pass-through, suggesting high but
less than perfect capital mobility.
Unlike studies on interest rate interdependence, we are not aware of studies that have looked
directly at the ability of Hong Kong to sterilize the effects of international reserve changes on its
monetary base. We find robust estimates that the Hong Kong Monetary Authority (HKMA) has
been able to undertake partial monetary sterilization and thus enjoys some degree of monetary
autonomy, thus allowing it to operate outside of the trilemma constraints in the short run.
3

Another challenge the monetary trilemma faces is the effectiveness of flexible exchange rates in
helping countries insulate the domestic economy from overseas monetary shocks. Rey (2013)
argued, "The global financial cycle transforms the trilemma into a 'dilemma' or an 'irreconcilable
duo': independent monetary policies are possible if and only if the capital account is managed."
This dissertation examines the argument by comparing Hong Kong and Singapore's monetary
autonomy. Hong Kong and Singapore are comparable small and open economies. However, they
choose different exchange rate regimes – Hong Kong adopts a hard peg against the U.S. dollar
while Singapore carries on a managed floating exchange rate regime. Suppose there is no
significant difference in the monetary autonomy scope between Hong Kong and Singapore. In
that case, it means that flexible exchange rates are not effective in helping small open economies
to maintain monetary autonomy. We estimate the responses of Singapore interest rates to changes
in their U.S. counterparts in the periods between Jan. 1998 through Feb. 2021 and the extent to
which foreign exchange interventions are sterilized between Jan. 1992 and Jun. 2021. As
predicted by the trilemma, the estimated interest rate pass-through from the U.S. to Singapore is
lower than that to Hong Kong, and international reserve flows in Singapore are sterilized more
intensively than those in Hong Kong. The findings suggest that Singapore has more scope for
monetary autonomy than Hong Kong, implying that the weak form of the monetary trilemma
still holds.
The remainder of this dissertation is organized as follows. The theoretical framework is
presented in Chapter 2. The past literature on the measures of monetary autonomy is reviewed in
Chapter 3. The economic backgrounds and monetary and exchange rate policies of Hong Kong
and Singapore are introduced in Chapter 4. The methodology is shown in Chapter 5. The
4

estimated interest rate pass-through is presented and explained in Chapter 6. The estimated offset
and sterilization coefficients are shown and explained in Chapter 7. The robustness check is
presented in Chapter 8. The concluding remarks are made in Chapter 9.
5
Chapter 2 Theoretical Framework
This dissertation studies monetary insulation in small open economies based on the international
interest rate pass-through model and the offset and sterilization coefficients model. They are
presented, respectively, in the following subsections.
Section 2.1 The Interest Rate Pass-Through Model
The domestic interest rates of a small open economy are determined by foreign interest rates,
market expectations on the local currency depreciation and the degree of capital mobility. The
model is written as follows.
𝐸" − 𝐸
∆𝑅 = ∆𝑅∗ + + 𝜌
(2.1)
𝐸
where
∆𝑅 = the change in the domestic interest rate from last period;
∆𝑅∗= the change in the foreign interest rate from last period;
𝐸"= the expected exchange rate of the home currency against the foreign currency;
𝐸 = the spot exchange rate of the home currency against the foreign currency;
𝜌 = the degree of capital mobility.
In the case of fixed exchange rates, the market expects no change in the exchange rate of the
local currency against the base currency. Thus, 𝐸" = 𝐸, and the term .#!$#/ = 0. #
6
When the home and foreign assets can substitute with each other perfectly, there is no risk
premium between the domestic and foreign interest rates. In this case, 𝜌 = 0.
Therefore, the domestic interest rates are dominated by foreign interest rates under fixed
exchange rates (#!$# = 0) and perfect capital mobility (𝜌 = 0). Theoretically, there is
no #
monetary autonomy in this case.
If the capital mobility is not perfect (𝜌 ≠ 0), the international interest rate pass-through will be
less than one for one even under a hard peg.
Given the degree of capital mobility, the interest rate pass-through to an economy with floating
exchange rates is lower than that to a hard peg. There are more scopes for monetary autonomy
under a floating exchange rate than that with a fixed regime.
Section 2.2 The Offset and Sterilization Coefficients Model
The domestic money supply of an open economy is endogenous to cross-border capital flows
under pegged exchange rates. The interactions between domestic monetary policy and capital
flows are modelled with capital flows equation (eq. 2.2) and policy reaction function (eq. 2.3)
simultaneously. They are shown as follows.
∆𝑁𝐹𝐴 = 𝛼% + 𝛼&∆𝑁𝐷𝐴 + 𝑍’𝐴
(2.2)
∆𝑁𝐷𝐴 = 𝛽% + 𝛽&∆𝑁𝐹𝐴 + 𝑋’𝐵
(2.3)
where
7

∆𝑁𝐹𝐴 = the change in the net foreign assets on the balance sheet of the economy’s central
bank; ∆𝑁𝐷𝐴 = the change in the net domestic assets on the balance sheet of the economy’s
central bank.
𝛼& is the offset coefficient. It measures the degree of capital mobility. When capital mobility is
perfect, any discretionary monetary policy that leads to a change in the net domestic assets will
result in an interest rate differential between home and foreign economies. The capital flows
driven by the interest rate differential can offset the effect of the independent monetary policy on
the domestic money supply completely. In this case, 𝛼& = −1. When capital is completely
immobile across border, there will be no change in the net foreign assets and the independent
monetary policy will be fully effective. In this case, the offset coefficient is zero.
𝛽& is the sterilization coefficient. It measures the extent to which the monetary effect of foreign
exchange interventions is sterilized. The success of sterilization is subject to imperfect capital
mobility. The sterilization coefficient is supposed to be zero when capital mobility is perfect
(𝛼& = −1).
The simultaneous equations indicate that the net foreign and domestic assets are endogenous to
each other. If each coefficient is estimated with a single equation, the result can be biased due to
an endogeneity issue. Thus, the offset and sterilization coefficients are estimated together by
previous empirical work with instrumental variables that affect one variable and are exogenous
to another one, such as the lags of the variable, to address the problem. Nevertheless, the
8

sterilization coefficient is a more reliable estimate than the offset coefficient as previous
literature has found.
Chapter 3 Literature Review
This chapter summarizes the important empirical literature that has estimated the parameters
relevant to testing various aspects of the monetary trilemma.
Section 3.1 The Interest Rate Pass-Through under Fixed Exchange Rates and No Capital
Controls
Previous literature has examined the corner solution of the monetary trilemma. Borenzstein et al.
(2001) have investigated 8 economies for the period between 1994 and 2000 and used the vector
autoregression model. They estimated the reaction of Hong Kong interest rates to US monetary
policy shocks. Although they argued that the response is one for one, the equality has not been
tested. We choose the least squares model to emphasize the causal-effect relationship between
the US and Hong Kong interest rates and finds the pass-through less than one for one.
Frankel et al. (2004) used the monthly 91-day interest rates of 46 countries and the US from Jan.
1970 to Mar. 1999 and estimated the interest rate pass-through with the autoregressive distributed
lag (ARDL) model. They estimated that the level relationship between the US and Hong Kong
interest rates is 0.91. Frankel’s study uses levels which are subject to serious problems of
common determinants of the interest rates. This study estimates the first-differenced interest rate
pass-through to measure the response of local rates to changes in the US rates which is more
appropriate and finds that the interest rate pass-through is lower than the past work.
9

Previous literature also has used different samples for the estimation. Cheng and Rajan (2020)
have investigated 88 countries for the period from 1973 to 2014. They found that the interest rate
pass-through under peg and no capital controls is 0.94. But it has not been tested whether the
coefficient is statistically equal to one. Besides, the sample comprises both advanced and
emerging market economies with pegged exchange rate regimes, which can bias the result.
Empirical studies have found that the interest rate pass-through to advanced economies (AEs) is
higher than that to emerging market/developing economies (EMEs). Klein and Shambaugh
(2015) have used a sample of 44 countries from 1973 to 2011 and estimated interest rate
passthrough from the US to these countries. They found the pass-through is 0.94 to pegged AEs
but 0.72 to pegged EMEs. Albagli et al. (2019) have investigated the 2-year Treasury yield
passthrough from the US to 12 AEs and 12 EMEs between 2003 and 2016 and estimated that the
pass-through is 0.263 to AEs but 0.160 to EMEs. Obstfeld et al. (2015) have used both short- and
long-term interest rates of 34 countries during the period from 1989 to 2013 to estimate the
passthrough. Their results find that the pass-through to pegged AEs can be higher than 0.9 while
it is not significant to pegged EMEs. Caceres et al. (2016a) have used a sample of 43 emerging
and advanced economies between 2000 and 2015 and estimated both short- and long-term
interest rate pass-through with a VAR model. They found that the short-term interest rate pass-
through is 0.23 to AEs but 0.14 to EMEs. The difference becomes smaller in terms of long-term
interest rates—the long-term rate pass-through is 0.67 to AEs and 0.65 to EMEs. The pass-
through to AEs is slightly higher than that to EMEs though.
10

The higher interest rate pass-through to AEs than that to EMEs can be explained with the
comovement of the US and other advanced economies’ monetary policy as the economies are
interdependent to a higher extent than with EMEs and capital mobility is likely to be higher than
with EMEs. The endogeneity issue makes the interest rate pass-through overestimated with the
samples comprising advanced economies.
This study focuses on small open economies (Hong Kong and Singapore) which have negligible
influence over the world economy. The US interest rate is exogenous to the local rates in Hong
Kong and Singapore. Therefore, the endogeneity issue is addressed. We find that the estimated
interest rate pass-through to the small open economies is less than one for one.
Bleaney et al. (2013) have used the annual data of 126 countries from 1990 to 2005 and found
that although the interest rate pass-through is 0.4 and statistically less than one for general pegs
without capital controls, the pass-through is statistically equal to one for credible pegs. The
credibility is defined as low inflation differential in one way, and hard pegs in another way. The
authors used an interaction term of the foreign interest rate and a dummy variable for pegs to
examine the effect of credible pegs on the interest rate pass-through compared to non-pegs. The
result is puzzling as the coefficient on the foreign interest rate is statistically less than one and
the coefficient on the interaction term is not statistically significant—it fails to reject the
hypothesis that the coefficient is zero, but the combination of the coefficients on the foreign
interest rate and the interaction term, which represents the pass-through to credible pegs, is
statistically equal to one. It is puzzling that the interest rate pass-through is estimated to be one
for one under credible pegs that include both hard and soft pegs with low inflation. This study
11

estimates the pass-through to Hong Kong and Singapore and finds distinct responses of the two
economies to foreign monetary policy. The pass-through to a soft peg is significantly lower
than one for one.
The earlier work that found the interest rate pass-through to economies is one for one under fixed
exchange rates and no capital controls has not distinguished the influence of conventional
monetary policy from the unconventional monetary policy that has been implemented since the
Global Financial Crisis. Takats and Vela (2014) have estimated the policy rate responses of 20
emerging market economies to US monetary policy for the periods from the first quarter of 2000
to the third quarter of 2013 and from the first quarter of 2008 to the third quarter of 2013,
respectively, and found significant and different changes in the interest rate pass-through
between the full sample period and the subperiod of the GFC and its aftermath across different
countries. The estimated interest rate pass-through declines from 1.08 to 0.66 but remains
significant in the case of Brazil; it increases from insignificant 0.07 to significant 0.3 in the case
of Hungary; and the pass-through decreases from significant 0.53 to -0.14 but insignificant in the
case of Russia. The author has not examined the policy rate response under a hard peg to the
unconventional monetary policy. This study estimates and compares the interest rate passthrough
from the US to Hong Kong before and after the GFC, and finds that the policy rate passthrough
is estimated to decline from one for one to 0.577.
Unlike previous literature that all used short-term interest rates to examine the corner solution of
the monetary trilemma, the long-term bond yields have been used to examine the change in the
interest rate pass-through before and after the GFC. Gilchrist et al. (2016) have used the 2-year
12

and 10-year nominal government bond yields of 12 countries to estimate the response of local
government bond yields to the US monetary policy shocks during the periods from Feb. 6, 1992
to Nov. 24, 2008, and from Nov. 25, 2008 to Apr. 30, 2014. They found changes in the interest
rate pass-through to emerging market economies but the changes do not have a clear direction.
The magnitude of the response increases in Brazil, Mexico and Thailand but decreases in
Singapore. The study did not examine the effect of exchange rate regimes on the interest rate
pass-through under the unconventional monetary policy. Curcuru et al. (2018) have estimated the
10-year government bond yield pass-through from the US to 3 advanced economies and 3
emerging market economies from Jan. 2002 to Dec. 2017. Their results show an increase in the
pass-through to Germany, U.K., Korea, Mexico and Brazil and a slight decrease in the response
of Canada. Albagli et al. (2019) have found the 2- and 10-year interest rate pass-through declines
to developed economies and increases to emerging market economies from the pre-Oct. 2008
period to the post-Oct. 2008 period. Miyajima et al. (2014) have estimated the responses of
domestic short- and long-term interest rates to changes in the US 10-year bond yield using the
monthly data of five Asian economies for two periods between Jan. 2003 and Dec. 2007 and
between Jun. 2009 and Dec. 2013. Their estimates show a positive and more persistent response
in the post-GFC period than that prior to the GFC.
The past work shows unclear direction of changes in the interest rate pass-through before and
after the GFC. It is attributed to the absence of exchange rate regime variable in the models. This
study estimates both short- and long-term interest rate pass-through to Hong Kong and finds a
decrease in the monetary transmission in the aftermath of the GFC to the small open economy
under fixed exchange rates.
13

Bluedorn and Bowdler (2010) have used the daily and monthly overnight money market rates of
37 countries, including the Eurozone, from 1973 to 2000 to estimate the response of domestic
interest rates to unanticipated and exogenous US monetary policy changes versus expected
policy changes. They used the market prices of the federal funds futures and calculated a FOMC
meeting-based series of unanticipated and exogenous US monetary policy changes and found
that the interest rate pass-through is one for one when the policy is unanticipated but less than
one when the policy change is expected. As the measurement is based on market expectations, it
may underestimate the scope for monetary autonomy that a local monetary authority has with
policy rates and sterilization. This study uses the 3-month government bond yields to test for the
corner solution and finds that the 3-month interest rate pass-through is less than one for one
during the period from 1991 throughout 2023.
Previous literature has shown that domestic interest rates respond to US monetary tightening and
easing differently. Han and Wei (2018) have considered the asymmetry exists only under flexible
exchange rates. Azad and Serletis (2020) also have shown the asymmetric responses of 6
emerging market economies with inflation targets with a VAR model. Cheng and Rajan (2020)
have estimated the asymmetry under different exchange rate regimes and financial openness.
They have found that the interest rate pass-through under pegs and no capital controls is one
when the US rate rises and 0.87 when the US rate decreases. But the difference has not been
tested statistically. This study estimates the interest rate pass-through to Hong Kong in
subperiods each of which is identified with a particular US monetary policy and finds that Hong
14

Kong interest rates do not necessarily respond to the US monetary tightening to a greater extent
than to monetary easing.
The following sections summarize the literature with respect to their findings on each of the most
important aspects of this dissertation.
Section 3.2 The Interest Rate Pass-Through across Different Exchange Rate Regimes
under No Capital Controls
Flexible exchange rates have been questioned regarding their effect on the scope for monetary
autonomy under free capital flows. Rey (2015) has observed the correlations of different types of
capital flows among different regions all over the world and argued for a “global financial cycle”
due to which an economy cannot have monetary autonomy without capital controls no matter
what exchange rate regime the economy chooses. The international interest rate pass-through
was not estimated by the author for her argument. But there has been previous literature
estimating the interest rate pass-through to examine the effect of pegged exchange rates on the
loss of monetary autonomy, which are with or against the argument.
Peg vs. Non-Peg
The earlier work has employed a binary classification of exchange rate regimes into pegs and
non-pegs and created a dummy variable that takes a value of 0 for non-pegs and 1 for pegs to
examine the effect of a pegged exchange rate regime versus a floating exchange rate regime on
the international interest rate pass-through. Different models have been constructed with the
dummy variable.
15

Shambaugh (2004) has used the monthly interest rates of 155 countries from 1973 to 2000 and
segmented the sample into four subsamples with respect to exchange rate regime and capital
controls. The interest rate pass-through is estimated to be 0.67 under pegged exchange rates and
0.56 under non-pegged regime, given no capital controls. The difference between the estimates is
not tested but the effect of pegs is examined in another model with the dummy variables of pegs
and no capital controls. The coefficient on the dummy variable of pegs is around .3 and
statistically significant. However, the effect may be underestimated because the model does not
include an interaction term of the dummy variables of pegs and no capital controls. Without the
interaction term, the model assumes that the difference in the interest rate pass-through between
pegs and non-pegs remains the same between with and no capital controls. An interaction term of
the dummy variables is employed to explain the response to base interest rates and the coefficient
on the term is 0.45 and statistically significant.
Miniane and Rogers (2007) have used the monthly interest rates of 26 countries from Jan. 1975
to Dec. 1998 and a vector autoregressive (VAR) model to estimate the response of domestic
interest rates to the US monetary policy shocks under fixed versus floating exchange rates
following the binary classification of exchange rate regimes by Shambaugh (2004). They found
that fixers have a greater and more persistent interest rate response to the US monetary policy
changes than floaters. As discussed in the last subsection, the VAR model has an endogeneity
issue that the domestic and US rates are assumed to be endogenous to each other.
Han and Wei (2018) have used the monthly policy rates and 10-year government bond yields of
28 countries and the US between Jan. 1990 and Jun. 2014 to estimate the interest rate
16

passthrough under fixed versus flexible exchange rates and with versus without capital controls.
They found the pass-through is the highest under fixed exchange rates and no capital controls
and the pass-through under flexible exchange rates without capital controls is the second highest
in the four categories. Although the magnitudes of the interest rate pass-through are different
between fixed and flexible exchange rates under no capital controls, the difference has not been
tested. Besides, the model have all four dummy variables that identify observations in terms of
exchange rate regimes and the existence of capital controls. As there is not a category excluded
from the specification, there is multicollinearity issue in the estimation.
In contrast to the literature that has found evidence that substantiates the effect of pegged
exchange rates on the loss of monetary autonomy, Hofmann and Takats (2015) have used the
short- and long-term interest rates of 30 emerging market and small advanced economies from
the first quarter of 2000 to the fourth quarter of 2014 and found significant but less than one for
one interest rate spillovers from the US to the economies under non-pegged exchange rates. The
effect of pegs which is examined with an interaction term of a dummy variable of peg and the
US interest rate is not statistically significant. The degree of capital controls is not controlled for
in the estimation, which can make the spillover underestimated.
Obstfeld (2015) has used the 3-month and 10-year government bond yields of 34 countries
between the third quarter of 1989 and the fourth quarter of 2013 and estimated the short- and
long-run interest rate pass-through with developed and developing economy subsamples. An
interaction term of the dummy variable of pegs and the US interest rate is employed to examine
the effectiveness of pegs on the interest rate pass-through. The author found that the coefficients
17

on the US rate and the interaction term are not significant for developing countries but
significant for advanced economies. Similar with Hofmann and Takats (2015), capital controls
are not controlled for in the work.
Previous literature has found inconclusive evidence on the effect of exchange rate flexibility on
the scope for monetary autonomy with the binary classification of exchange rate regimes. The
classification does not measure the exchange rate flexibility precisely and may bias the results as
both hard and soft pegs are classified into the category of pegs. In that case, the interest rate
passthrough can be overestimated and the loss of monetary autonomy is overstated under a soft
peg.
This problem has been addressed by earlier work creating an additional category for soft pegs to
the binary classification of exchange rate regimes.
Hard Peg vs. Soft Peg
In the comparison between hard and soft pegs, previous literature has presented inconclusive
evidence.
The first strand of literature has found that managed floating limits the scope for monetary
autonomy as strictly as hard pegs. Frankel et al. (2004) have estimated the 90-day interest rate
pass-through from the US or Germany to 46 countries under fixed versus intermediate regimes
by decade from Jan. 1970 to Mar. 1999. They found that the US T-bill rate pass-through to
developing countries in 1990s is statistically equal to one regardless of exchange rate regimes.
18

Besides, the authors have estimated the pass-through to individual economies. They found both
Hong Kong under a fixed regime and Singapore with an intermediate regime have statistically
unity level interest rate relationship with the US in the 1990s. On the other hand, Frankel et al.
(2004) have estimated that the local interest rate responsiveness to US T-bill rate is statistically
equal to one but less than one under intermediate regimes. As explained in the earlier subsection,
the level interest rate relationship can overestimate the interest rate pass-through.
The second strand of literature has found significant differences in the interest rate pass-through
between hard and soft pegs. Obstfeld and Taylor (2004) and Obstfeld, Shambaugh, and Taylor
(2005) have estimated the interest rate pass-through to multiple countries under gold standard,
the Bretton Woods system, and in the post-Bretton Woods period. They found the average
interest rate pass-through in the post-Bretton Woods period is 0.68 under occasional pegs and
0.93 under pegs. But the authors have not tested difference in the pass-through between pegs and
occasional pegs.
Ricci and Shi (2016) have estimated the policy rate pass-through is 0.799 under pure peg to the
US and 0.1867 under mixed exchange rate regimes. Both are statistically significant. But there is
no evidence for open financial accounts since capital controls are not controlled in their work.
Georgiadis and Zhu (2019) estimated that the interest rate pass-through under limited exchange
rate flexibility and capital controls is 0.76. And Klein and Shambaugh (2015) have estimated that
the interest rate pass-through under soft pegs is 0.32 and significantly lower than pegs by 0.19.
19
The past work shows the distinct scope for monetary autonomy under intermediate regimes from
that under pegs or non-pegs, but the estimates are divergent. The divergence could be accounted
for by the different exchange rate classifications employed by the previous literature to
distinguish pegs, soft pegs, and free floats.
The measure of exchange rate flexibility has been developed by Ahmed (2021), finding the
coexistence of significant and insignificant interest rate pass-through under intermediate regimes
by constructing an index of peg intensities with six categories. The author has estimated the
interest rate pass-through in each category and found that the US monetary shocks statistically
significantly impact the interest rates of countries with peg intensities of 0.7 or higher but do not
significantly impact countries with peg intensities of .5 or less. In the subsample of advanced
economies, the interest rate pass-through remains statistically significant except with the peg
intensity of .3. In contrast to advanced economies, emerging market economies are unaffected by
US monetary shocks except those with peg intensities of .9 and 1.
The earlier work has provided inconclusive evidence on the scope for monetary autonomy with
an exchange rate regime on the middle ground. The models used by the previous literature have
assumed that exchange rate flexibility remains constant under an exchange rate regime or that the
exchange rate stability (the variation in spot exchange rates) is equivalent to the peg intensity.
This study, however, finds that given a managed floating exchange rate regime/crawling band,
the degree of exchange rate flexibility is low when the currency is under depreciation pressure
20
and foreign exchange interventions (FXIs) are intensive. It is high when there is no depreciation
pressure on local currency and foreign exchange interventions are not intensive. The scopes for
monetary autonomy under intermediate regimes can change as the intensity of foreign exchange
interventions changes. Earlier literature has not captured the effect of FXIs on the interest rate
pass-through.
The third strand of literature has found no loss of monetary autonomy under the intermediate
regimes. Shambaugh (2004) have found that occasional pegs have a lower interest rate
relationship with the US interest rate than pegged and non-pegs. Klein and Shambaugh (2015)8
have found that the influence of changes in base interest rates is not statistically significant on
the interest rates of emerging market economies with soft pegs. Ahmed (2021) have found that
the monetary spillover from the US to emerging market economies is not statistically significant.
These empirical results show that countries do not lose any monetary autonomy with managed
floats and open financial accounts.
The past work used panel data from multiple countries with different measures on international
capital transactions.
Case Studies
Goh and McNown (2015) have found no integration between Malaysia and the US interest rates
in the managed floating eras, suggesting no loss of monetary autonomy in the long run under
managed floating.
21
Keil et al. (2004) have investigated the interest rate pass-through from the US to Korea before
and after Asian Financial Crisis (AFC) and found that the pass-through is 1.736 prior to the AFC
with a pegged exchange rate regime and 0.179 in the post-AFC period with a floating regime.
Capital mobility in the cases of Malaysia and Korea is generally thought to be not so high as for
Hong Kong and Singapore, which can underestimate the difference in the interest rate
passthrough between a hard peg and a managed floating.
This study focuses on Singapore with no significant capital controls and finds that the interest
rate pass-through is statistically significant from the US to Singapore. It suggests that the interest
rate of Singapore is affected by changes in the US monetary policy. The small open economy
does not have complete monetary independence under managed floating exchange rates.
Hong Kong vs. Singapore
The VAR Model
Previous literature that estimated the impulse responses of Hong Kong and Singapore to the US
monetary shocks with VAR models has found that both economies respond to the foreign
monetary shocks and Hong Kong has a greater and more persistent response than Singapore.
22

Borensztein (2001) has found that the response of Hong Kong is three times larger than that of
Singapore to US monetary shocks. The response is 0.2-0.4 bps and later rises to 0.6 for a 1bp
shock in the case of Singapore but it is unity and later rises to 1.5 in the case of Hong Kong.
Bowman et al. (2015) have investigated 10-year sovereign bond yields between Jan. 2006 and
Dec. 2013 and found that in response to a 25-bp decrease in the US 10-year yield, Hong Kong
lowers its interest rates by 13 bps after around 45 days and Singapore interest rates decline by 9
bps after 90 days. This is equivalent to a passthrough coefficient of .54 for HK and .36 for
Singapore.
Fong et al. (2015) have estimated that the interest rate pass-through is 0.74 to Hong Kong and
0.46 to Singapore. Caceres et al. (2016a) have estimated that Hong Kong short-run interest rate
rises by 65 bps in response to a 100-bp rise in the federal funds rate, and Singapore short-run rate
rises by 46 bps in response to the same shock. The interest rate pass-through for long term assets
is higher than pass through for short term assets. The long-term interest rate pass-through is
estimated to be 1.05 to Hong Kong and 0.74 to Singapore.
The Least Squares Model
Valente (2009) has estimated the interest rate response of Hong Kong and Singapore to the US
monetary policy announcements using 3-month, 1-, 5-, and 10-year government debt security
yields between Oct. 1996 and Jun. 2004. The results show that the pass-through is higher to
Hong Kong than that to Singapore, and the short-run rate pass-through is higher than the longrun
interest rate pass-through. This study extends the sample coverage and includes the period after
23

the 2008 Global Financial Crisis. We find that in contrast to the previous literature, the interest
rate pass-through increases as the maturity increases.
Takats and Vela (2014) have estimated the policy rate pass-through from the US to Singapore is
0.49 during the period from the first quarter of 2000 throughout the third quarter of 2013 and
0.05 for the period from the first quarter of 2008 to the third quarter of 2013. The latter is
estimated with the US shadow rate. The long-term interest rate pass-through is 1.28 to Hong
Kong and 0.67 to Singapore from Jan. 2000 to Sep. 2013 and declines in the post-GFC period.
The long-term pass-through is 0.88 to Hong Kong and 0.58 to Singapore between Jan. 2008 and
Sep. 2013. All estimated pass-throughs are statistically significant. This study, however, finds
that Singapore does not have a policy rate but carries an exchange-rate-centered monetary policy
framework that have domestic interest rates adjusted to foreign rates through managing a policy
band for the Singapore dollar nominal effective exchange rate (S$NEER). Thus, we use the
government bond yields to estimate the interest rate pass-through to Singapore instead of policy
rates.
The case studies of the offset and sterilization coefficients are reviewed in the following
subsections.
Section 3.3 The Offset Coefficients under Free Capital Flows
Previous literature has estimated the offset coefficient for economies without major capital
controls. Gilal et al. (2016) have investigated the case of Pakistan from Jan. 1982 to Dec. 2013
24

and estimated that the offset coefficient of Pakistan is -0.8155. The authors argued for perfect
asset substitutability with the estimate.
Akikina and AI-Hohan (2003) have studied the case of Saudi Arabia without capital controls
during the period between 1960 and 1994 and estimated that the offset coefficient of Saudi
Arabia is -1.22 and statistically equal to -1.
Trinh (2018), Ouyang et al. (2008) and Ouyang and Rajan (2011) also have found that the offset
coefficients are almost -1 in the cases of Vietnam, Taiwan, and Singapore, respectively, but they
argued that the capital mobility is not perfect.
The estimates for perfect capital mobility are biased due to an endogeneity issue. The net
domestic assets, which are the independent variable, are endogenous to the net foreign assets,
which are the dependent variable, in a reduced-form capital flow equation. Previous literature
has pointed out the issue and addressed it by using the two-stage-least-square (2SLS) approach.
The offset coefficient is estimated with the sterilization coefficient in simultaneous equations.
However, the estimates of the offset coefficient from the 2SLS model can be biased as
instrumental variables seem not to fix the endogeneity issue perfectly. For instance, one of the
instrumental variables that have been commonly used in the estimation of the offset coefficient is
the net domestic assets for the last period. The instrumental variable can be endogenous to
expectations on the net foreign assets for the current period and thus make the offset coefficient
overestimated. Therefore, this study uses both interest rate pass-through and the offset coefficient
to measure the capital mobility in Hong Kong and finds that although the capital mobility is not
25

perfect, the offset coefficient is close to one. The coefficient does not measure the degree of
capital mobility precisely.
Section 3.4 The Sterilization Coefficients under Free Capital Flows
General Models
There have been three models constructed by previous literature to estimate the sterilization
coefficient. The first model is the reduced-form approach which estimates the sterilization
coefficient with the capital flows equation. The approach has been used by Herring and Marston
(1977), Obstfeld (1983), Kwack (2001), Cavoli and Rajan (2006), Aizenman and Glick (2009),
Khemraj and Pasha (2011), and Hassan et al. (2013). As discussed in Chapter 2, there is an
endogeneity issue in this approach. The second model is the simultaneous equations which
estimate the offset and sterilization coefficients with the 2SLS or 3SLS approach. The model has
been discussed by Roubini (1988) and Brismiss et al. (2001) on the loss function of central
banks. This study employs the second model and modifies the loss function for a monetary
authority under pegged exchange rates based on reviews on the previous literature. Our review is
shown in the chapter of methodology. The last model is the VAR model. It has been employed by
Cavoli and Rajan (2006).
Under Fixed Exchange Rates
Earlier literature has estimated the sterilization coefficient for economies under fixed exchange
rate regimes and without major capital controls. Gilal et al. (2016) and Akikina and AI-Hohan
(2003) have found sterilization at a low level with high capital mobility in Pakistan and Saudi
Arabia but Khemraj and Pasha (2011) and Hassan et al. (2013) found intensive sterilization in
26

Caribbean economies and Gulf Corporation Council (GCC) countries without capital controls.
Under Managed Floating Rates
Past work has investigated Singapore regarding sterilization. Ouyang, Rajan, and Willett (2008)
have modified the BGT model by taking money multipliers into account and used the panel data
of eight Asian economies for the period between the first quarter of 1990 and the third quarter of
2005 during which the crisis period from the second quarter of 1997 to the that of 1998 is
excluded. The authors estimated that with the assumption of perfect foresight, the sterilization
coefficient is -0.796 for the pre-crisis period and -0.601 for the post-crisis period; for static
expectations, the sterilization coefficient is -0.838 for the pre-crisis period and -0.514 for the
post-crisis period. The sterilization coefficient of each individual economy was not estimated.
There has been previous literature focusing on case studies of Singapore with respect to
sterilization (Kwack, 2001; Aizenman and Glick, 2009; Ouyang and Rajan, 2011; Cavoli and
Rajan, 2015 & 2017). They have found almost full sterilization in the case of Singapore in the
1990s or earlier and the first decade of 2000s. This study extends the sample coverage to 2021
and the sterilization after the 2008 Global Financial Crisis is investigated.
Overall Summary
There is considerable previous literature relevant to various aspects of the monetary trilemma.
They use a range of methodologies and samples. The results tend to differ considerably resulting
from differences in samples, methodologies and whether exchange rate regimes and capital
controls are included and, when they are, how they are measured.
27

Given the difficulties in getting good classifications for exchange rate regimes this dissertation
has chosen to focus on two countries that have absence of significant capital controls and their
exchange rate regimes are clear cut to test some important aspects of the international monetary
trilemma.
28
Appendix
Table 3.1 Details of the Least Squares Model Literature (Relevant Variables to the Review)
Author(s) Country(s)/Frequency &
Sample Coverage
Interest Rates Other Variables
Frankel et al.
(2004)
46 countries (18 industrial
and 28 developing) and
the U.S.
M: 1970M1-1999M3
90-day money market
rates and
U.S./German 90-day
T-bill rate
Inflation rate
Keil et al.
(2004)
Korea
M: 1990M1-2003M6
Money market rate
Obstfeld and
Taylor (2004)
15 countries
Y: 1870-2000
Short-term interest
rates
Dummy: Peg
Shambaugh
(2004)
155 countries M:
1973-2000
Money market
(overnight) or
(3month) Treasury bill
rates
Dummy: Peg
Di Giovanni
and
Shambaugh
(2008)
152 countries
1973-2002
Base GDP growth;
Inflation; Dummy: peg
Valente
(2009)
Hong Kong, Singapore,
and the US
M: 1994M2-2004M6
3-month, 1-, 5-, and
10-year sovereign
bond yields
Bluedorn and
Bowdler
(2010)
37 countries (including
the Eurozone)
M and D:
1973:M22000:M12
Overnight money
market rate
Dummy: peg
Takats and
Vela (2014)
20 EME countries
Q: 2000Q1-2013Q3
Policy rates; longterm
rates
Inflation rate; output gap
Hofmann and
Takats (2015)
22 emerging market
economies and 8 smaller
open advanced economies
Q: 2000Q1-2014Q4
Policy rate;
threemonth interbank
rate; and 10-year
government bond
yield
VIX; domestic and U.S.
macroeconomic
variables: year-on-year
inflation and real GDP
growth; Dummy: peg
Klein and
Shambaugh
(2015)
44 countries,
consistent with Klein
(2012) Y: 1973-2011
Output growth;
Inflation; Dummy: peg
Obstfeld
(2015)
34 countries Q:
1989Q3-2013Q4
Three-month Treasury
bill rates and 10-year
government bond
yields
VIX; Dummy: peg
29
Gilchrist et
al. (2016)
12 countries
D: Feb. 6, 1992 – Apr. 30,
2014 (143 FOMC
announcements)
Federal Funds Rate;
market interest rates;
2- and 10-year bond
yields
Ricci and Shi
(2016)
Advanced and emerging
market economies
M: not found
Policy rate; 3-month,
2-year, and 10-year
government bond
yields; interbank rates;
bank deposit and
lending rates
VIX; inflation
Curcuru et al.
(2018)
Germany, Canada, UK,
Korea, Mexico and Brazil
D: 2002M1-2017M12
10-year government
bond yields
Han and Wei
(2018)
28 countries and the US
M: 1990M1-2014M6
Policy rate; 10-year
bond yields
GDP growth; Inflation;
VIX
Albagli et al.
(2019)
12 developed countries
and 12 emerging market
economies
M: 2003M1-2016M12
2- and 10-year
Treasury yields
Table 3.2 Details of Results in the Least Squares Model Literature (Relevant Results to the
Review)
Author(s) LR/SR
(interest
rates)
Precrisis/postcrisis AE/EME Pegs/nonpegs Open/closed
financial
accounts
Results
Frankel et
al. (2004)
SR Both Both -0.52—
1.26
Keil et al.
(2004)
SR Both Both 0.179—
1.736
Obstfeld and
Taylor
(2004)
SR All Both -0.05—
0.61
Shambaugh
(2004)
SR Both All All 0.27—
0.67
Di Giovanni
and
Shambaugh
(2008)
Both 0.172—
0.4
Valente
(2009)
Both 0.162—
0.657
30
Bluedorn and
Bowdler
(2010)
SR Both 0.08—0.78
Takats and
Vela (2014)
Both Full/postcrisis EME -0.84—
1.52
Hofmann and
Takats (2015)
Both Both 0.34—0.59
Klein and
Shambaugh
(2015)
Both All All 0.18—0.94
Obstfeld
(2015)
Both Both Both 0.26—
0.938
Gilchrist et
al. (2016)
Both Both Both 0.364—
1.733
Ricci and Shi
(2016)
SR Both Both 0.1363—
0.799
Curcuru et al.
(2018)
LR Both Both 0.156—
0.692
Han and Wei
(2018)
Both Both Both 0.251—
0.796
Albagli et al.
(2019)
Both Both 0.1—0.318
Table 3.3 Details of the ECM Literature (Relevant Variables to the Review)
Author(s) Country(s)/Frequency &
Sample Coverage
Interest Rates Other Variables
Frankel et al.
(2004)
46 countries (18 industrial
and 28 developing) and
the U.S.
M: 1970M1-1999M3
90-day money market
rates and U.S./German
90-day T-bill rate
Inflation rate
Keil et al.
(2004)
Korea
M: 1990M1-2003M6
Money market rate
Obstfeld and
Taylor (2004)
15 countries
Y: 1870-2000
Short-term interest rates Dummy: Peg
Shambaugh
(2004)
155 countries
M: 1973-2000
Money market
(overnight) or (3-month)
Treasury bill rates
Dummy: Peg
Edwards
(2015)
Chile, Colombia, and
Mexico
Policy rate (level, change) Inflation variables;
Exchange rate
31
M: 2000M1-2008M6 expectation; global
perceptions of
country risk
Goh and
McNown
(2015)
Malaysia
M: 1991M1-2012M11
The US Federal Funds
rate and Malaysian
interbank rates
Ricci and Shi
(2016)
Advanced and emerging
market economies M:
not found
Policy rate; 3-month,
2year, and 10-year
government bond yields;
interbank rates; bank
deposit and lending rates
VIX; inflation
Table 3.4 Details of Results in the ECM Literature (Relevant Results to the Review)
Author(s) LR/SR
(interest
rates)
Precrisis/
postcrisis
Pegs/
nonpegs
Open/closed
financial
accounts
Level
relationship
Adjustment
Coefficient
Frankel et
al. (2004)
SR All 0.72—24.5 0.05—
0.78
Keil et al.
(2004)
SR Post-crisis 0.236 -0.241
Obstfeld
and Taylor
(2004)
SR Both -1.15—1.1 -0.7-- -0.03
Shambaugh
(2004)
SR All All -1.65—
1.36
-0.26-- -
0.05
Edwards
(2015)
SR 0.32—0.74
Goh and
McNown
(2015)
SR Pegs Open -0.44 -0.62
Ricci and
Shi (2016)
SR -0.05
32
Table 3.5 Details of the VAR Model Literature (Relevant Variables to the Review)
Author(s) Country(s)/Frequency
& Sample Coverage
(Local) Interest
Rates
Endogenous
Variables
Foreign Factors
Borensztein
(2001)
8 economies
D and M: 1994-2000
3-month T-bill
rate, interbank
rate, bank bill
rate, Pre-1 rate,
deposit rate,
and CETES
rate.
Domestic
interest rates,
Emerging
Market Bond
Index (EMBI),
log of the
exchange rate
U.S. monetary
policy ( the US
federal funds
futures rates or
90-day
Treasury Bill
rate)
Canova (2005) 8 Latin American
countries
Q: 1990:Q1-2002:Q4
90-day market
rates (or
lending/deposit
90-180-day
rates)
Output, inflation,
trade,
competitiveness,
interest rate
variables
U.S. monetary
policy, index
of world
commodity
prices, EMBI,
EMEI
Miniane and
Rogers (2007)
26 countries
M: 1975M1-
1998M12
Domestic
interest rates
Price, output,
interest rate,
exchange rate,
and reserve
variables
US monetary
policy shocks
Moreno (2008) 10 countries
D: 2001:01:01-
2006:09:30
Short-term
(overnight or
interbank) rates
and 1-, 3-, 5-
and 10-year
rates
Domestic long-
and short-term
rates
Foreign (U.S.)
rate of similar
maturity
Jain-Chandra
and Unsal
(2014)
8 emerging Asian
economies M:
2000:M1-
2010:M11
3-month, 1year,
and 10year
government
bond yields
Output, inflation,
exchange rate,
capital flows
variables
The 10-year US
Treasury yield,
VIX,
foreign demand
Miyajima et al.
(2014)
5 small open Asian
economies
M: 2003M12007M12
and
2009M6-2013M12
Domestic
overnight and
5-year bond
yield
Output,
inflation, and
domestic
interest rates
variables
The US 10year
Treasury yield
Bowman et al.
(2015)
17 Emerging Market
Economies (EMEs)
M: 2006M1-
2013M12
10-year
sovereign bond
yields
Sovereign bond
yields, exchange
rates, and
headline stock
US monetary
policy shocks
33
indexes
Fong et al.
(2015)
11 largest AsiaPacific
economies
M: 2004M10-
2014M2
10-year local
sovereign bond
yields
The domestic
3month
interbank
interest rate, the
5-year domestic
sovereign CDS
spread, the risk
reversal of the
US dollar
against the local
currency
The 10-year
US Treasury
yield
Caceres,
CarriereSwallow,
Demir, et al.
(2016) a
43 emerging and
advanced countries
M: 2000M1-
2015M10
The short-term
and long-term
government
bond yields in
local currency
Domestic
interest rates in
the small open
economies
The US federal
funds rate or
10-year
Treasury bond
yield, VIX
Caceres,
Carriere-
Swallow and
Gruss (2016) b
6 advanced small
open economies with
highly flexible
exchange rates26 and
40 advanced and
emerging economies
The 3- and
6month
Treasury
bill rates
Domestic
interest rates,
inflation and
output
The US federal
funds rate
M: 1998M1-2009M6
Belke et al.
(2018)
12 economies
D: 2003:05:14-
2016:09:02
10-year
government
bond yields
Logs of daily
VIX (CBOE
Volatility Index)
and oil prices
Long-term
interest rates in
core countries
Azad and
Serletis (2020)
12 emerging
economies
M: 1994M2-2018:M4
Monetary
policy rates
The policy rate
of the emerging
economy
The monetary
policy rate in
the United
States and the
logged change
in the exchange
rate
of the emerging
economy
34
Table 3.6 Details of Results in the VAR Model Literature (Relevant Results to the Review)
Author(s) LR/SR
(interes
t rates)
Precrisis/
postcrisis
AE/
EME
Pegs/
nonpegs
Open/
closed
financial
accounts
Results
Borensztei
n (2001)
SR Both 0.2—1.5 bps/1
bp change in the
base rate
Canova
(2005)
SR 5% -- 68% of
variability in
domestic rates
explained by the
U.S. shocks
Miniane
and
Rogers
(2007)
Both Both 5 – 20 bps/25
bps increase in
the US rate
Moreno
(2008)
LR EME -5 – 5 (units and
shocks
unknown)
Jain-
Chandra
and Unsal
(2014)
LR EME Contemporaneo
us correlation:
0.65 Variance
explained:
10%-- 70%
Miyajima
et al.
(2014)
LR Both -0.2%--0.4%/1%
point increase in
U.S. 10-year
bond yield
Bowman et
al. (2015)
LR EME 14 bps—19
bps/25 bps
decrease in the
U.S. 10-year
yield
Fong et al.
(2015)
LR -0.5—1.5 (units
unknown)
Caceres et
al. (2016a)
Both Both 0.05—2.31 bps/ 1
bp change in the
U.S. rate
Caceres et
al. (2016b)
SR Both 20-60 bps/100
bps increase in
the U.S. policy
35
rate.
Belke et al.
(2018)
LR 0.03%--34.94%
Azad and
Serletis
(2020)
SR EME -15%--15% (units
and impulse
unknown)
Table 3.7 Previous Literature on the Sterilization Coefficient
Author(s) Country(s)
Frequency
& Sample
Coverage
Model Variables Objective
Functions
Offset
Coefficient
(on d.NDA)
Capital
Flow
Equation
Sterilization
Coefficient
(on d.NFA)
Monetary
Policy
Reaction
Function
Wang et
al. (2019)
China
M:
2000M1—
2017M12
BGT, Ouyang Table 3 P5/19 Tables 6—
7
-0.188—-
-.222
Tables 6—7
-0.813—-
1.054
Trinh
(2018)
Vietnam
Q:
2000Q3—
2014Q4
Ouyang and
Rajan (2011)
P10/21
Eq. 3-4
Table 4
Table 6 -
0.903
Table 6 -
0.775
Lim and
Goh
(2016)
Malaysia
M:
1991M1—
2009M12
BGT, Ouyang Eq. 4 and
5
P9/18
Appendix
1
Eq. 3a
P5/18
Table 2 -
0.5583
Table 3 -
0.7794
Ouyang
and Rajan
(2011)
Singapore
and Taiwan
Q:
1990Q1—
2008Q4
BGT,
2SLS,
3SLS
Eq. 2a and
2b Table 1
A1
P17/18
Tables 3 and
4 -0.922—-
0.861
Tables 3 and
4 -1.09—-
1.049
Ouyang et
al. (2010)
China M:
2000M6—
2008M9
Modified
BGT
Eq. 4 and
5
Table 1
A1 Tables 4 and
5 -0.721—-
0.517
Tables 4 and
5 -1.001—-
1.234
Ouyang et
al. (2008)
Eight Asian
economies
Q:
1990Q1—
2005:Q3
BGT Eq. 15 a
and b
Table 4
Eq. 4 Table 8
-0.838—-
0.514
Table 8
-1.265—-
0.846
36
Djedaiet
and Ayad
(2017)
Algeria M:
2002M1—
2016M12
ARDL
approach
P7/14 Eq.
6
Table 3 -
0.994
Cavoli
(2017)
Six Asian
economies
Q:
1994Q1—
2012Q1
Kalman
Filter
Estimates
Appendix
Table
Annex 1:
Simple
Stylized
Model A8
Figure 4
Table 2
0.89—1.02
Gilal et al.
(2016)
Pakistan M:
1982M1—
2013M12
Cumby and
Obstfeld
(1981) 2SLS.
GMM
Eq. 2 and
3
Table 2
-0.8155—
1.632
Table 1
-0.3754—0
Cavoli and
Rajan
(2015)
Six Asian
Economies
(same with
Cavoli,
2017)
1994-2012
Table 1
0.89—1.02
Figure 3
Hassan et
al. (2013)
GCC
countries Q:
1990:2—
2008:3
Reducedfor
m approach
(using
reaction
functions of
central
banks.)
Eq. 6 Estimate
interest rate
differentials
Tables 3 and
4 -0.96—-
0.17
Khemraj
and Pasha
(2011)
Eight
Caribbean
economies
Q:
1993:Q1—
2008:Q2
Reducedform
approach.
Huang
(1995)
Eq. 1 Table 1
Fixed
exchange
rate
regimes
Dual
nominal
anchors
Table 3
-1.03—-
0.16
Aizenman
and Glick
(2009)
15
countries
in Asia and
Latin
America
Q:
1984Q2—
2007Q2
Reducedform
approach
Eq. 1
P8/41
Tables 1-2
37
Cavoli
(2007)
Five Asian
countries M:
1990:M1—
1997M5
VAR
Interest rate
model OLS,
TSLS
Eq. 9 Table 4 Table 3.
Cavoli
and Rajan
(2006)
Same with
Cavoli
(2007)
Reducedform
approach,
VAR
Eq. 10 Table 4
Akikina
and
AlHoshan
(2003)
Saudi
Arabia
A: 1960-
1994
Modified
monetary
approach to
the BoP:
DC=BP+…
Eq. 10 -1.22 (-1)
(CF=DC…)
-0.31
(DC=BP…)
Kwack
(2001)
Seven
Asian
Countries36
1985-1996
Herring and
Marston
(1977),
Obstfeld
(1983)
Reduced
form
approach
Eq.s
1113,
Table
2
Table 2 -0.9
or higher
Chapter 4 Monetary Policy and Exchange Rate Configurations of Hong
Kong and Singapore
The monetary policy configurations of Hong Kong and Singapore are discussed in this chapter.
Both Hong Kong and Singapore are small open economies and emphasize exchange rate
stability. In spite of the similarities, the two economies manage exchange rates differently: Hong
Kong chooses a hard peg against the U.S. dollar while Singapore employs a managed floating
exchange rate regime. Given the exchange rate policy setting, Hong Kong and Singapore have
monetary autonomy in different degrees.
Section 4.1 Economic Backgrounds of Hong Kong and Singapore
38
Hong Kong and Singapore make up a negligible proportion of the world economy. The GDP of
each economy accounts for 0.41% of the world GDP in 2020. The low impact determines that
there does not exist a substantial endogeneity issue in the estimation of interest rate pass-through
to measure monetary independence for the two economies.
Hong Kong and Singapore have high trade and financial openness. The sum of exports and
imports was 360% of GDP for Hong Kong and 338.3% for Singapore in 2021. They do not
impose major controls on international capital transactions. Trade and financial liberalization
means that the economies are highly affected by external monetary shocks.
The major difference between the two economies is that Singapore has greater domestic products
and firms proportion in international trade and finance. The exports of domestic products made
up less than 2% of total exports for Hong Kong but 45.56% for Singapore in 2021. Over 80% of
the total market capitalization was attributed to foreign companies on the Hong Kong Exchange
(HKEX) in 202140. Foreign companies, however, accounted for less than 20% of the total market
capitalization on the Singapore Exchange (SGX) in 2021. This difference helps explain why
Hong Kong simply focuses on exchange rate stability while Singapore additionally takes
inflation stability into account in their monetary policy configurations.
Section 4.2 The Exchange Rate Regimes of Hong Kong and Singapore
The Hong Kong Monetary Authority (HKMA) carries on a Linked Exchange Rate System
(LERS) to the U.S. dollar. Under the LERS, the spot exchange rate of Hong Kong dollars is
39
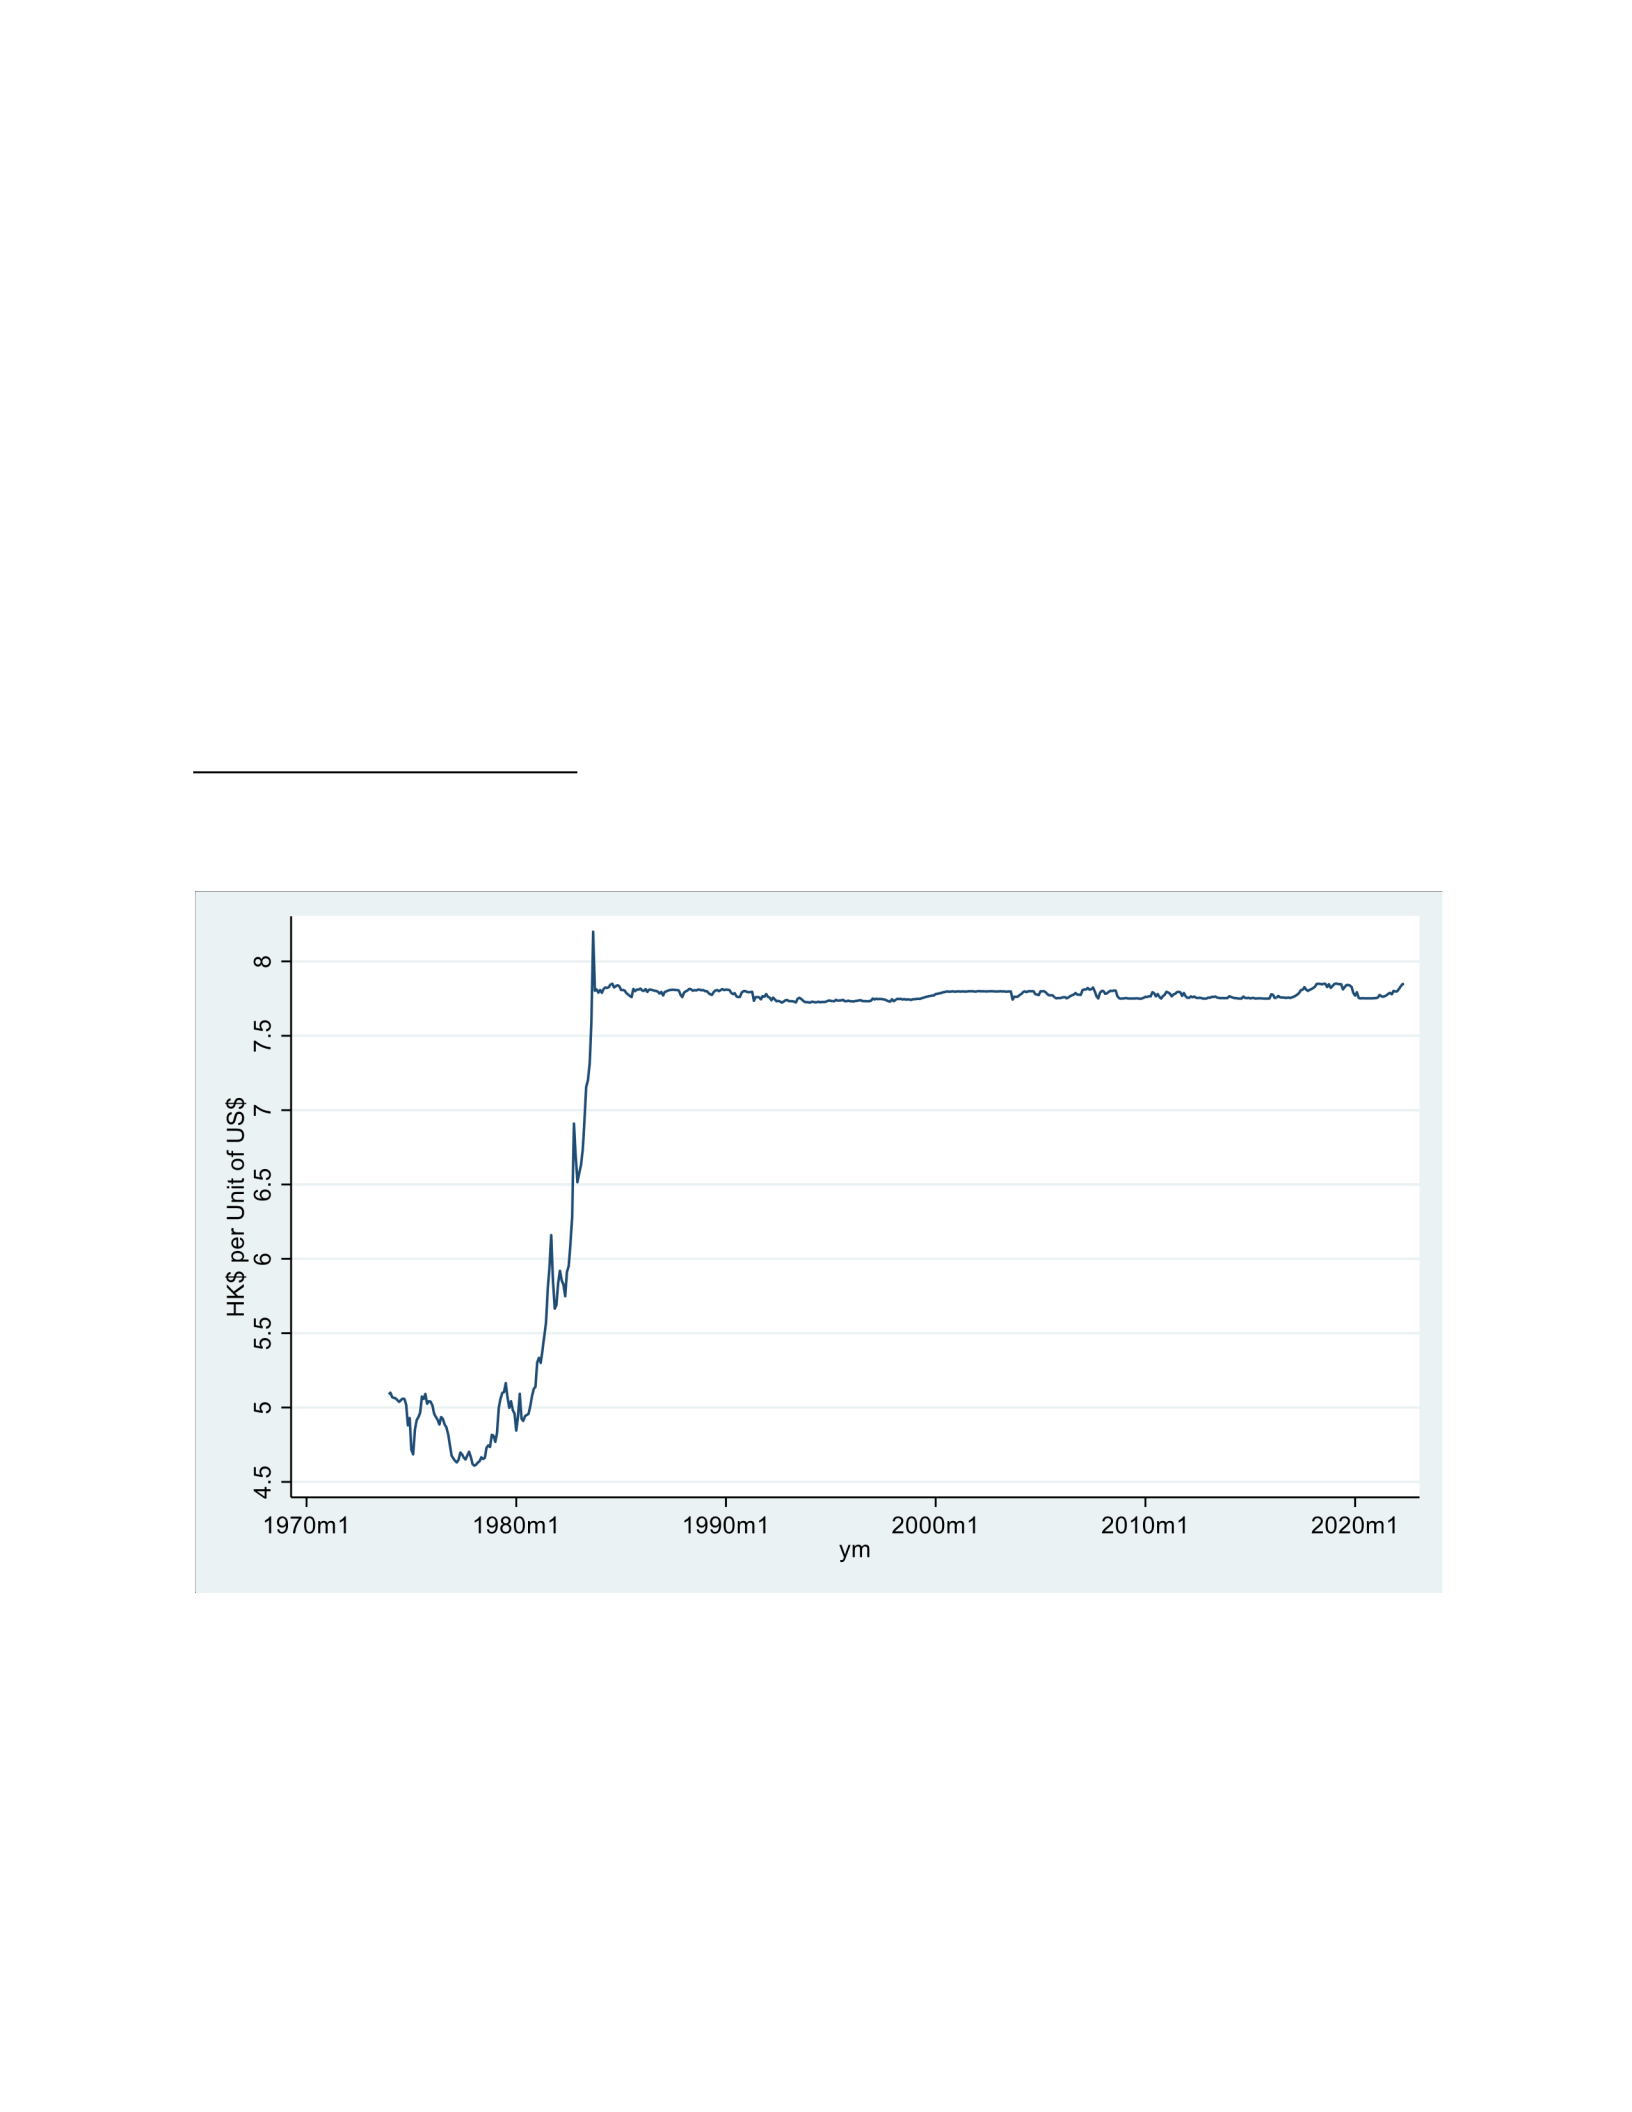
allowed to fluctuate within a very narrow band between HK$7.75/US$ and HK$7.85/US$. If the
spot exchange rate reaches the upper or lower limit, the HKMA will intervene in the foreign
exchange market. The variation in the spot exchange rate of Hong Kong dollars against U.S.
dollars is less than 2% throughout the period from May 2005 to Feb. 2021.
Figure 4.1 The Spot Exchange Rate of Hong Kong Dollar against US dollar between Dec.
1973 and May 2022
40
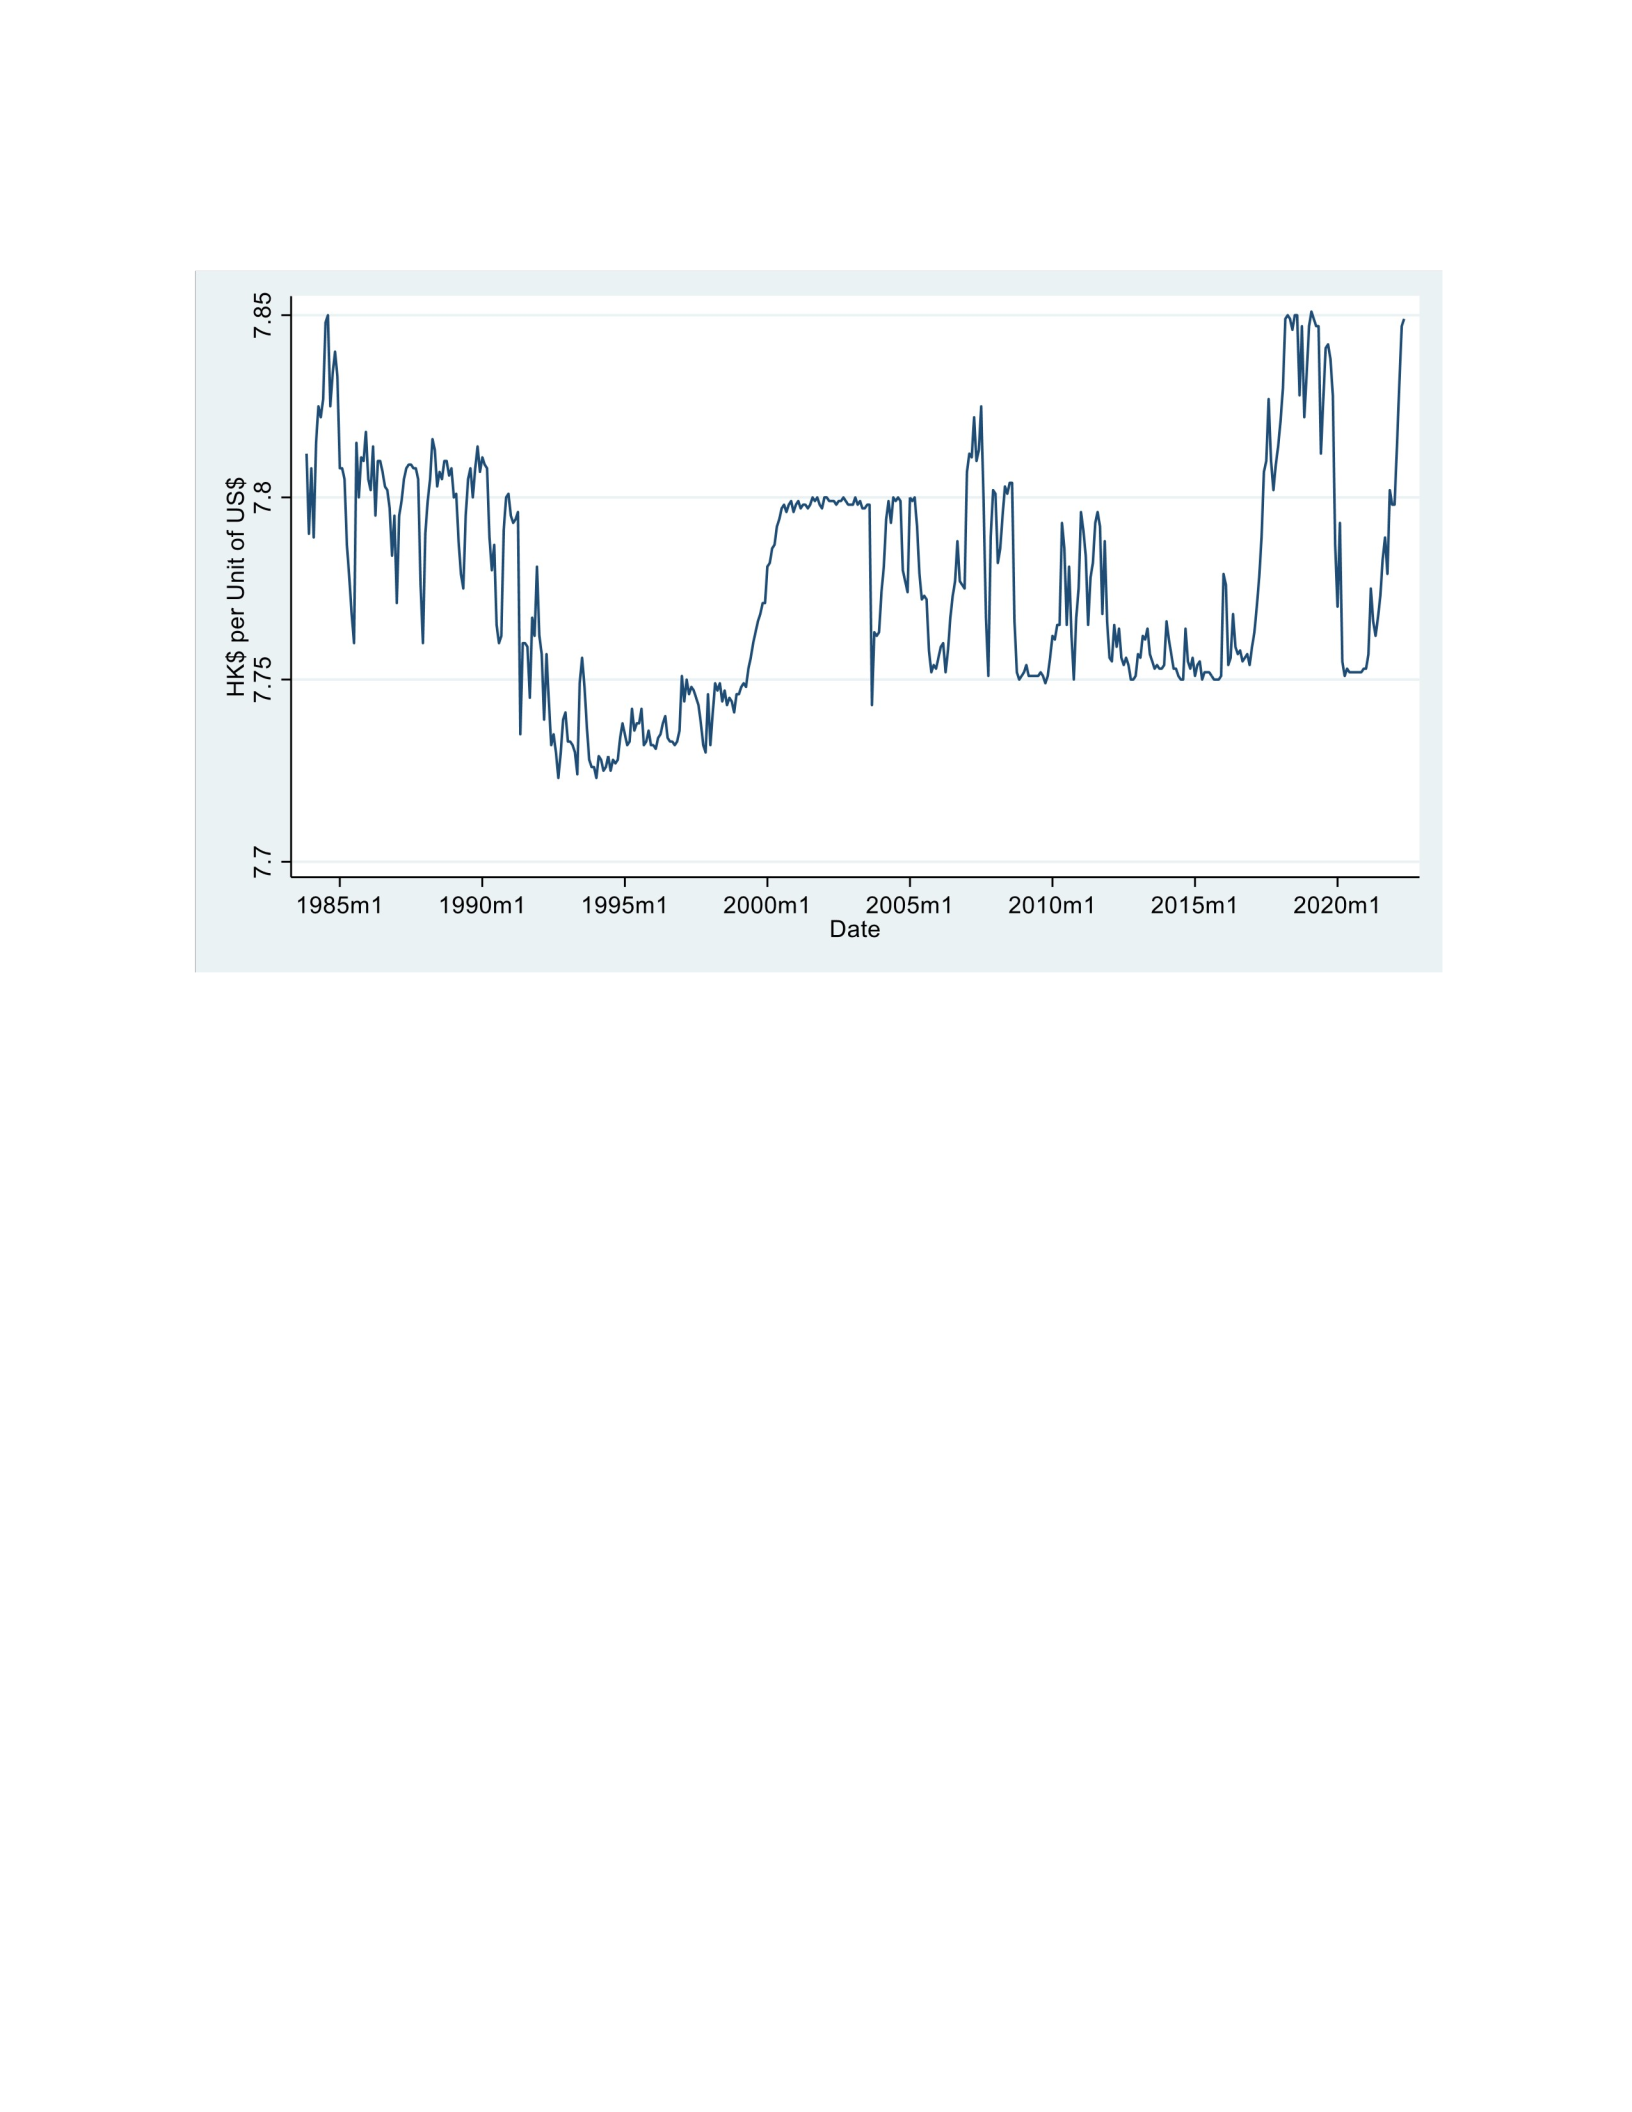
Figure 4.2 The Spot Exchange Rate of Hong Kong Dollar against US dollar between Nov.
1983 and May 2022
The LERS is a type of currency board arrangement. It requires the monetary base of Hong Kong
dollars to be fully backed by the U.S. assets. Although there is a minimum requirement on
reserves held by the HKMA, it is not required that the monetary base and money supply change
one for one with changes in international reserves as is required with a full currency board. The
backing ratio of reserve assets to the monetary base is over 100% and varies over time. The
outstanding Exchange Funds Bills and Notes, which are debt securities issued by the HKMA, are
included in the monetary base, which makes reserve money comprising cash in circulation and
bank liquidity change differently from the monetary base.
The Monetary Authority of Singapore (MAS) chooses a managed floating exchange rate regime.
The Singapore Dollar Nominal Effective Exchange Rate (S$NEER) is managed against a basket
of currencies and moves within a policy band. That is much wider than the narrow band of the
41
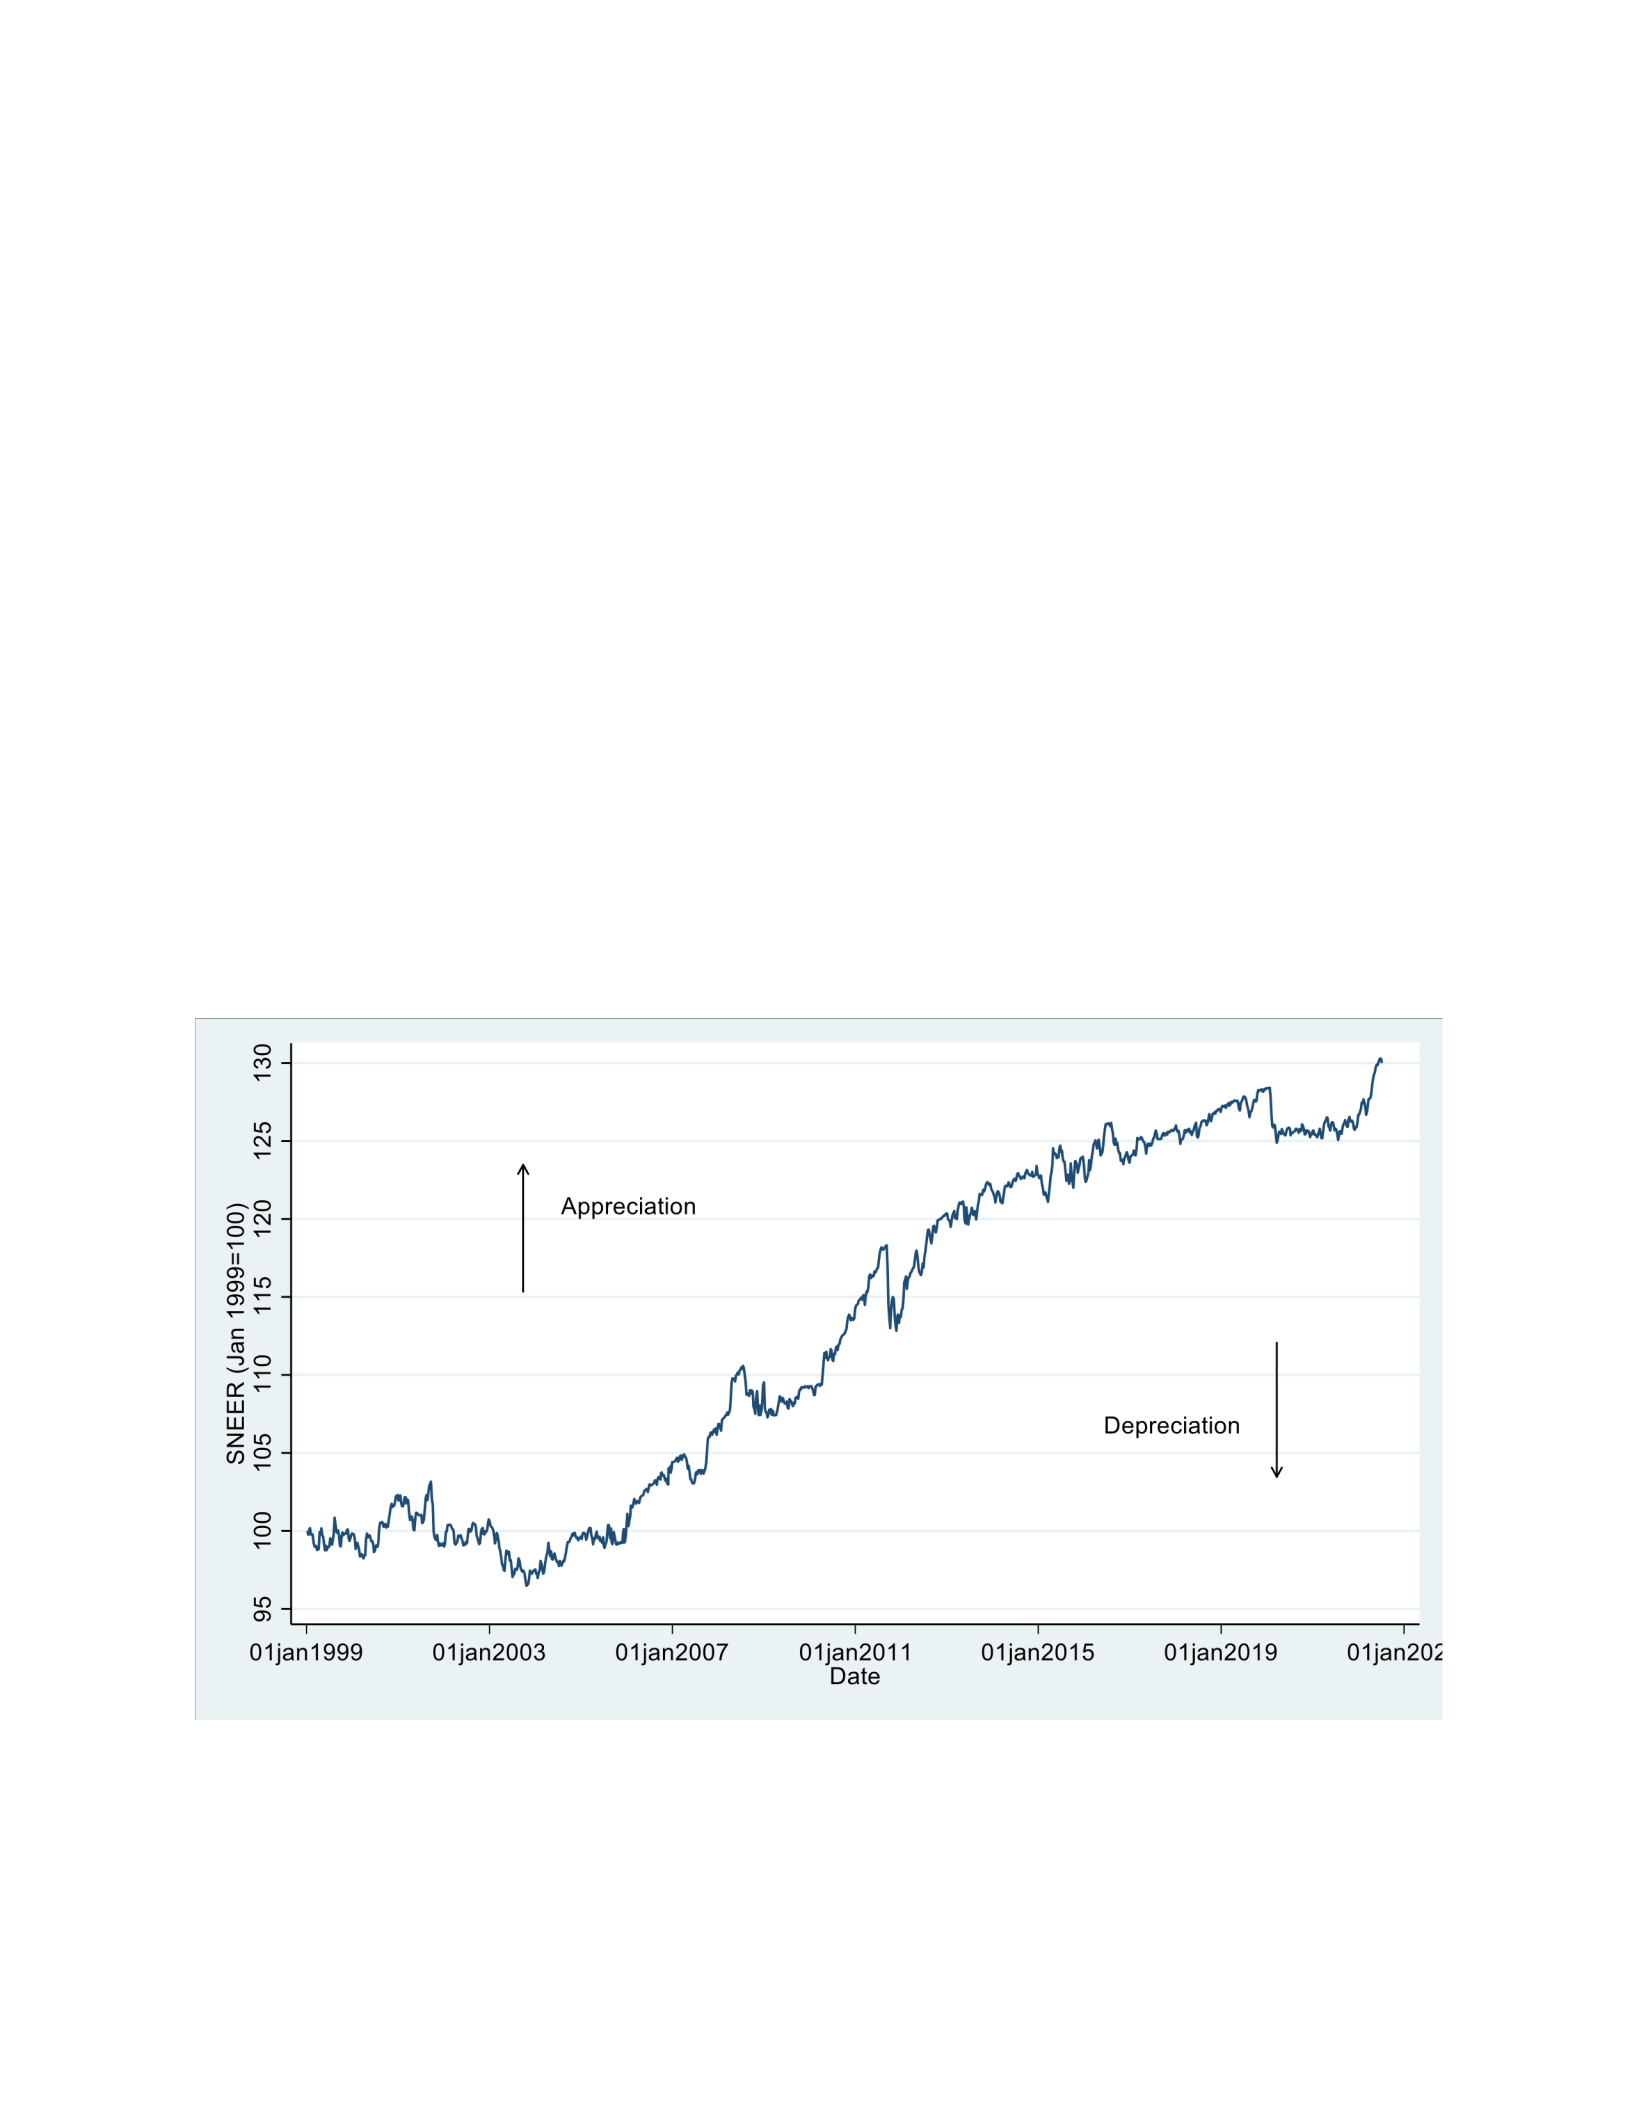
Hong Kong fixed rate. The band is reviewed semi-annually. The MAS adjusts the center, slope,
and width of the policy band as necessary: when the economic uncertainty increases, the band
will be widened; when there is a rapid increase (decrease) in economic growth or an abrupt
increase (decrease) in the inflation rate, the band center will rise (drop); and when a tightening
(easing) monetary policy is needed, the band will be steeper (flatter). The slope of the band will
not be negative. If a devaluation is needed, the MAS will lower the band's center point instead of
making it downward sloping. Thus, the managed floating exchange rate regime could be
classified as a crawling band. See a summary of announced changes in the policy band setting in
appendix.
Figure 4.3 Singapore Dollar Nominal Effective Exchange Rate (S$NEER) (Jan. 1999 = 100)
42
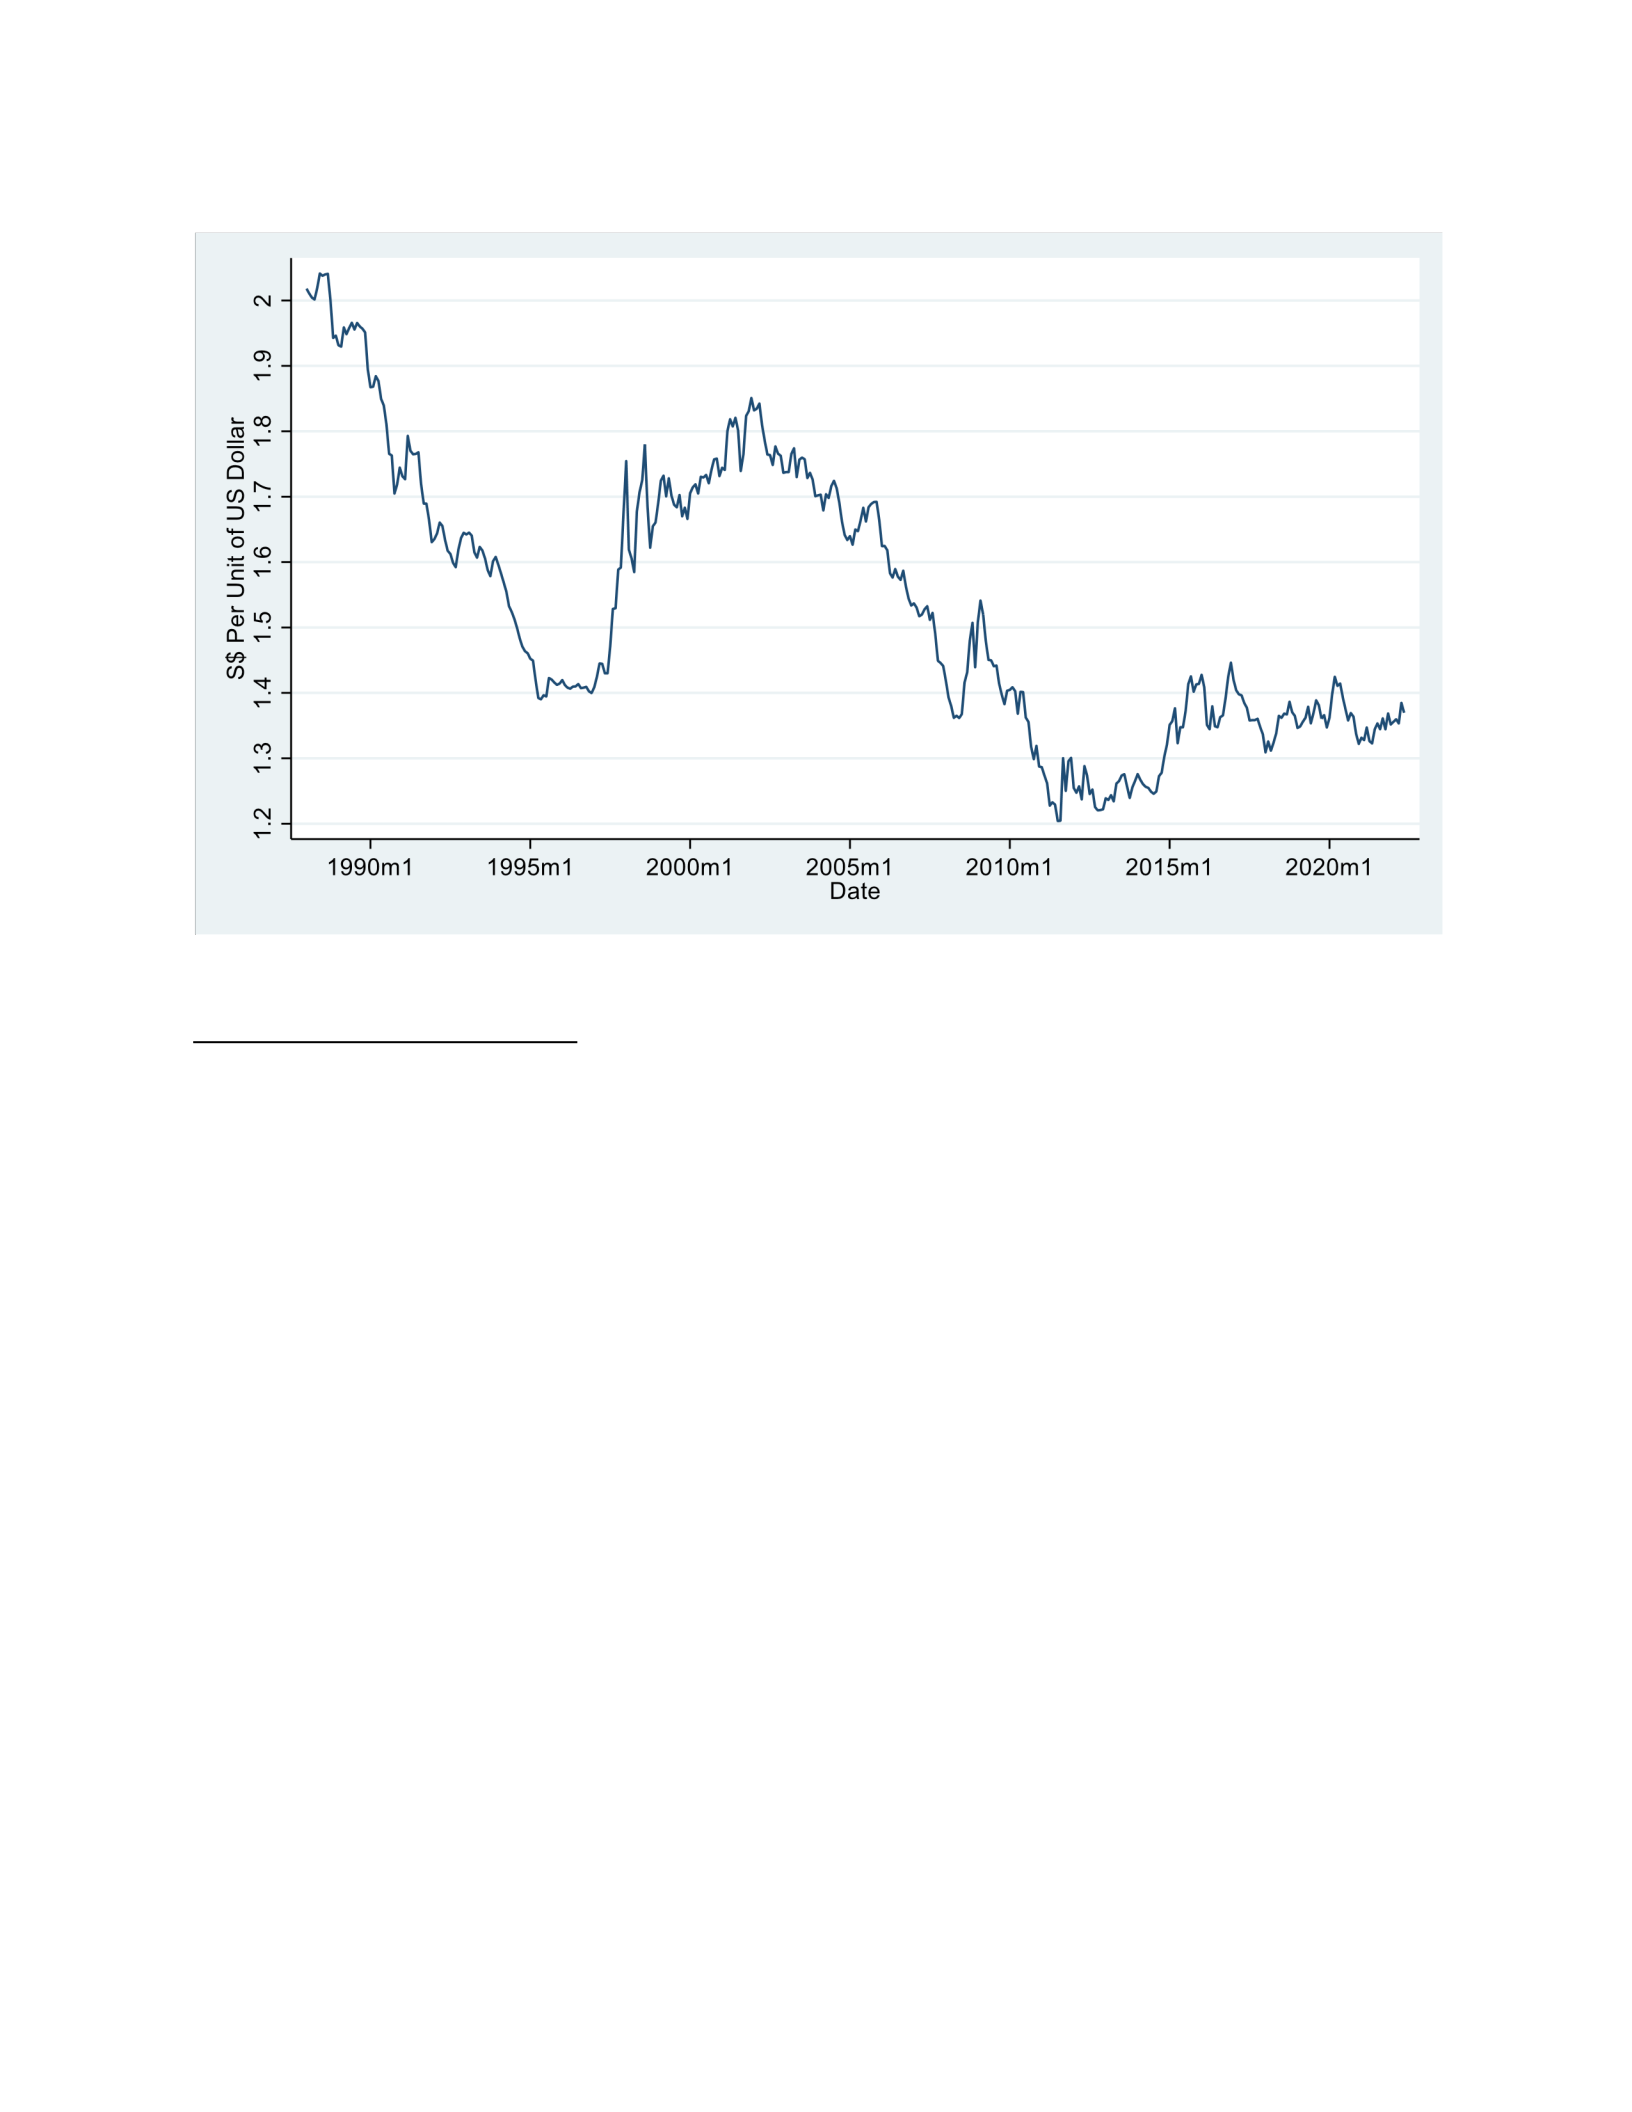
Figure 4.4 The Spot Exchange Rate of Singapore Dollar against US dollar
The exchange rate regime of Singapore dollars is thus much more flexible than that of Hong
Kong dollars. The coefficient of variation in spot exchange rates is 0.21 for Hong Kong and 0.27
for Singapore. The average ratio of percentage change in foreign exchange reserves to
percentage change in spot exchange rate is -1.01 for Singapore with the standard deviation of
14.98 while the average ratio is -56.70 with the standard deviation of 438.76 for Hong Kong as
calculated with monthly data from Jan. 1997 to Dec. 2022.
43
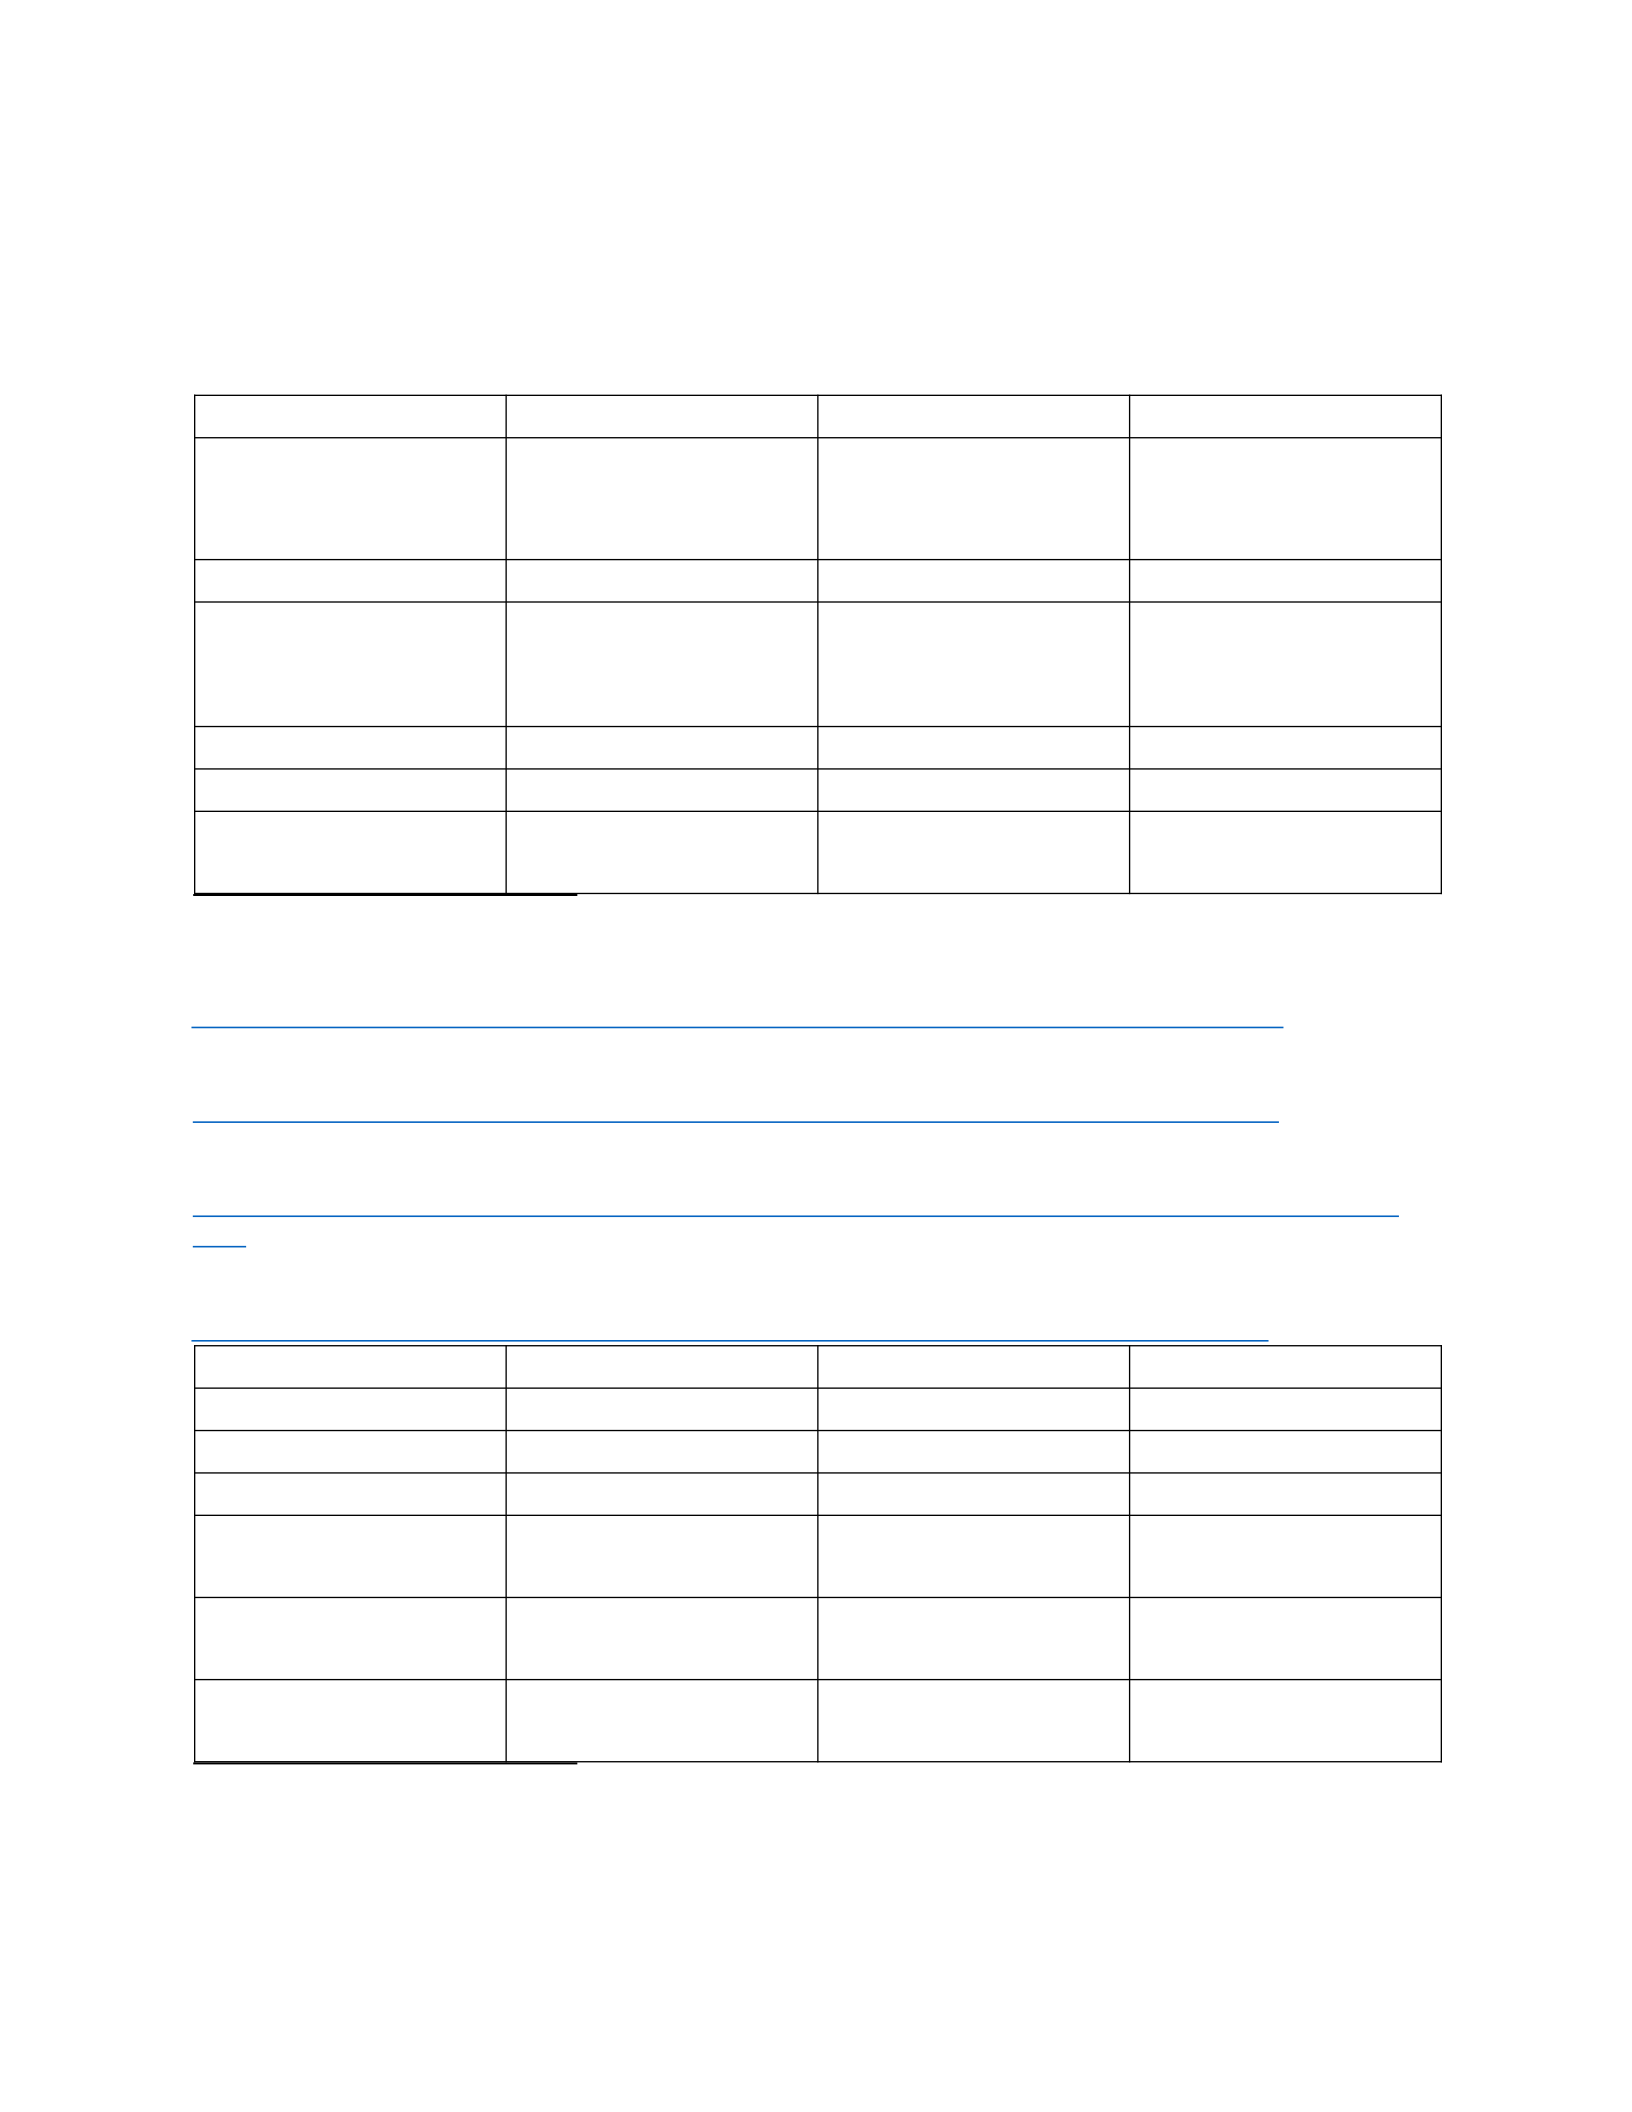
Appendix
A. Singapore Exchange Rate Policy Band Table 4.3 The Exchange-Rate Policy Band
Changes over Time (S$NEER, End of Period Figure, Jan. 1999=100)
Date43 Slope Width Center
Jul. 2001 Horizontal44 (neutral
policy stance, 0% of
appreciation)
Oct. 2001 Wider45
Jan. 2002 Narrower46 Dropped to around
99.22.
(depreciation)
Jul. 2003 Dropped to 97.04
Apr. 2004 Upward49
Oct. 2007 Steeper and upward
sloping
43 The earliest Monetary Policy Statement released by the MAS was for Feb. 2001. Before Jul. 2001, the MAS
maintained a policy stance of allowing a modest and gradual appreciation. Source:
https://www.mas.gov.sg/news/monetary-policy-statements/2001/monetary-policy-statement-22-feb-01 44 The
MAS announced, “MAS has therefore shifted to a neutral exchange rate policy stance, with a policy band
centered on a zero percent appreciation of the S$NEER.” in the Monetary Policy Statement for Jul. 2001. Source:
https://www.mas.gov.sg/news/monetary-policy-statements/2001/monetary-policy-statement-12-jul-01
45 The MAS announced, “...widen the policy band to allow greater flexibility in managing the exchange rate.” in the
Monetary Policy Statement for Oct. 2001. Source:
https://www.mas.gov.sg/news/monetary-policystatements/2001/mas-press-statement-on-monetary-policy-10-oct-
2001
46 The MAS announced, “We are also restoring a narrower policy band, as market and economic conditions have
become less volatile.” in the Monetary Policy Statement for Jan. 2002. Source:
https://www.mas.gov.sg/news/monetary-policy-statements/2002/monetary-policy-statement-2-jan-02
Apr. 2008 Rose to 107.7551
Oct. 2008 Horizontal 52
Apr. 2009 Dropped to 107.4353
Apr. 2010 Upward54 Rose to 109.3955
Oct. 2010 Steeper and upward
sloping56
Wider
Apr. 2011 Rose to somewhere
below 115.32
Oct. 2011 Flatter and upward
sloping
51 The MAS announced, “… re-center the exchange rate policy band at the prevailing level of the S$NEER.” in the
Monetary Policy Statement for Apr. 2008. Since the S$NEER stayed in the upper half of the policy band, the
center was raised at this review. The S$NEER was 107.75 on Apr. 4, 2008 which was the last observation of the
44
S$NEER before Apr. 10, 2008 on which the Monetary Policy Statement was released. Thus, the center of the
policy band is estimated to increase to around 107.75. Source: https://www.mas.gov.sg/news/monetary-
policystatements/2008/monetary-policy-statement-10-apr-08
52 The MAS announced, “…is shifting its policy stance to a zero percent appreciation of the S$NEER policy band.”
in the Monetary Policy Statement for Oct. 2008. Source: https://www.mas.gov.sg/news/monetary-
policystatements/2008/monetary-policy-statement-10-oct-08
53 The MAS announced, “… re-center the exchange rate policy band to the prevailing level of the S$NEER.” in the
Monetary Policy Statement for Apr. 2009. Since the S$NEER had stayed in the lower half of the policy band since
Oct. 2008, the center was lowered at this review. The S$NEER was 107.43 on Apr. 9, 2009 which was the last
observation of the S$NEER before Apr. 14, 2009 on which the Monetary Policy Statement was released. Thus, the
center of the policy band is estimated to drop to 107.43. Source: https://www.mas.gov.sg/news/monetary-
policystatements/2009/monetary-policy-statement-14-apr-09
54 The MAS announced, “…will shift the policy band from that of a zero percent appreciation to one of modest and
gradual appreciation.” in the Monetary Policy Statement for Apr. 2010. Source:
https://www.mas.gov.sg/news/monetary-policy-statements/2010/monetary-policy-statement-14-apr-10
55 The MAS announced, “… re-center the exchange rate policy band at the prevailing level of the S$NEER.” in the
Monetary Policy Statement for Apr. 2010. Since the S$NEER stayed in the upper half of the policy band in the
past six months before the announcement, the center was raised. The S$NEER was 109.39 on Apr. 9, 2010 which
was the last observation of the S$NEER before Apr. 14, 2010 on which the Monetary Policy Statement was
released.
Thus, the center of the policy band is estimated to increase to around 109.39. Source:
https://www.mas.gov.sg/news/monetary-policy-statements/2010/monetary-policy-statement-14-apr-10 56 The MAS
announced, “…the slope of the policy band will be increased slightly...” in the Monetary Policy Statement for Oct.
2010. Source: https://www.mas.gov.sg/news/monetary-policy-statements/2010/monetary-policystatement-14-oct-10
Apr. 2012 Steeper and upward
sloping60
Narrower61
Oct. 2015 Flatter and upward
sloping62
Apr. 2016 Horizontal63
Apr. 2018 Upward64
Oct. 2019 Flatter and upward
sloping65
Apr. 2020 Horizontal 66
Oct. 2021 Upward67
Apr. 2022 Steeper and upward
sloping
Rose to 128.0669
Jul. 2022 Rose to 130
60 The MAS announced, “The slope will be increased slightly...” in the Monetary Policy Statement for Apr. 2012.
Source: https://www.mas.gov.sg/news/monetary-policy-statements/2012/monetary-policy-statement-13-apr-12 61
The MAS announced, “...restoring a narrower policy band.” in the Monetary Policy Statement for Apr. 2012.
Source: https://www.mas.gov.sg/news/monetary-policy-statements/2012/monetary-policy-statement-13-apr-12
62 The MAS announced, “...the rate of appreciation will be reduced slightly.” in the Monetary Policy Statement for
Oct. 2015. Source: https://www.mas.gov.sg/news/monetary-policy-statements/2015/monetary-policy-
statement14oct15
45
63 The MAS announced, “...set the rate of appreciation of the S$NEER policy band at zero percent...” in the
Monetary Policy Statement for Apr. 2016. Source:
https://www.mas.gov.sg/news/monetary-policystatements/2016/mas-monetary-policy-statement-14apr16
64 The MAS announced, “...increase slightly the slope of the S$NEER policy band, from zero percent previously.” in
the Monetary Policy Statement for Apr. 2018. Source:
https://www.mas.gov.sg/news/monetary-policystatements/2018/mas-monetary-policy-statement-13apr18
65 The MAS announced, “...reduce slightly the rate of appreciation of the S$NEER policy band.” in the Monetary
Policy Statement for Oct. 2019. Source:
https://www.mas.gov.sg/news/monetary-policy-statements/2019/masmonetary-policy-statement-14oct19
66 The MAS announced, “...will adopt a zero percent per annum rate of appreciation of the policy band starting at the
prevailing level of the S$NEER.” in the Monetary Policy Statement for Apr. 2020. Source:
https://www.mas.gov.sg/news/monetary-policy-statements/2020/mas-monetary-policy-statement-30mar20 67 The
MAS announced, “...raise slightly the slope of the S$NEER policy band, from zero percent previously.” in the
Monetary Policy Statement for Oct. 2021. Source:
https://www.mas.gov.sg/news/monetary-policystatements/2021/mas-monetary-policy-statement-14oct21
B. An Analysis of the Monetary Base Elements of Hong Kong Dollars
In the case of Hong Kong, if the change in the monetary base (MB) is dominated by the change
in the net foreign assets (NFA) and the change in the net domestic assets (NDA) counters the
monetary effect, it suggests partial sterilization. If the NDA changes in the same direction with
the NFA and MB, the foreign monetary influence will be amplified in domestic sectors. If the
change in the MB is dominated by the change in the NDA, it implies that the monetary authority
makes an independent monetary policy from the foreign monetary policy. Table 4 shows the
different categories for observations with respect to monetary autonomy.
Table 4.4 Three Categories with Respect to Monetary Autonomy for Hong Kong
∆𝑴𝑩 × ∆𝑵𝑫𝑨
< 𝟎 > 𝟎
∆𝑴𝑩 ×
∆𝑵𝑭𝑨
> 𝟎 Category I: Partial
Sterilization
Category II: Foreign
Policy Amplifier
< 𝟎 N.A. Category III:
Independent Monetary
Policy
46
Table 4.5 The Distribution of Periods between Jan. 2000 and May 2022 across three
Categories
∆𝑵𝑭𝑨 > 𝟎 ∆𝑵𝑭𝑨 < 𝟎 Total
Category I 95 35 130
Category II 36 15 51
Category III 56 44 100
47

Chapter 5 Methodology
This chapter shows models, data, and variables we use to estimate the interest rate pass-through
and the offset and sterilization coefficients.
Section 5.1 Estimation of Interest Rate Pass-Through
The interest rate pass-through is estimated with the least squares model, and the autoregressive
distributed lags model.
First-Differenced Regression Model
The least squares model is expressed as follows:
∆𝑟( = 𝛼% + 𝛼&∆𝑟)*,( + 𝜀((5.1)
where 𝑟( is an economy’s interest rate at time t. 𝑟)*,( is the U.S. counterpart interest rate at time t.
∆ indicates the change in a variable from the last period t-1. The coefficient 𝛼& measures the
degree of interest rate pass-through from the U.S. to the economy in the current period. If the
coefficient lies between zero and one, it suggests that the domestic interest rate follows the
movement of the U.S. counterpart but is not fully adjusted to the U.S. rate.
In addition to the effect of the U.S. rate in the prevailing period, the influence of lagged U.S.
interest rates on the domestic interest rate is estimated using the following specification:
.
∆𝑟( = 𝛼% + I 𝛼,-&∆𝑟)*,($, + 𝜀((5.2)
,/%
where 𝑝 is the lag length of the U.S. interest rate.
48
If the domestic interest rate is under the influence of the U.S. interest rate from the previous
periods, at least one coefficient in 𝛼0, … , 𝛼($. is statistically significant.
The interest rate pass-through is estimated with eq. 5.2 for robustness check.
Error Correction Model
The error correction model assumes that there is an equilibrium level relationship between the
domestic and U.S. interest rates, and estimates how fast the domestic interest rate is adjusted to
the equilibrium. Frankel et al. (2004) have constructed an autoregressive distributed lag (ARDL)
model, which is written as follows:
1-& 3-&
𝑟( = 𝛾% + I 𝛾&.𝑟($. + I 𝛾02𝑟)*,($2 + 𝜐((5.3)
./& 2/%
where (P+1) is the lag order of an economy’s interest rate and (Q+1) is the lag order of the US
interest rate, 𝑃 ≥ 1 𝑎𝑛𝑑 𝑄 ≥ 1. 𝛾02 measures the long-run level relationship in interest
rates between an economy and the US.
Rewriting equation (3) yields the following error correction model:
1 3
∆𝑟( = I Υ&.∆𝑟($. + I Υ02∆𝑟)*,($2 − 𝛿W𝑟($& − 𝜃% − 𝜃&𝑟)*,($&Y + 𝜐(
(5.4)
./& 2/%
∑1./& 𝛾&.. 𝜃% = 45" and 𝜃& = ∑$%&5’ 4#$. 𝛿 is the adjustment
coefficient measuring where 𝛿 = 1 −
the speed of the interest rate relationship deviation in the short run converging to the long-run
equilibrium.
49
In addition, Shin et al. (2014) developed a non-linear ARDL (NARDL) model. The model is
employed to examine the effects of the U.S. rate on the domestic rate in upward and downward
trends, separately. The specification reads:
1 3
∆𝑟( = I Υ&.∆𝑟($. + I(Υ0-2(∆𝑟)*- ,($2 + Υ0$2’∆𝑟)*$ ,($2) − 𝛿W𝑟($& − 𝜃% − 𝜃&𝑟)*,($&Y
+ 𝜐((5.5)
./& 2/%
Let 𝜃$.
Where 𝜃- represents the long-run relation between the domestic rate the US rate in an upward
trend and 𝜃$ denotes the long-run relation between the domestic rate and the US rate in a
downward trend.
We use the NARDL model to estimate the interest rate pass-through for robustness checks.
Data and Variables
Daily and monthly data of interest rates are used to estimate the models presented in equations
(1), (2), (4), and (5). Since HK and SGP are one day ahead of the US, the time variable for HK
and SGP’s daily data is adjusted from “t” to “t-1”. The monthly data is the interest rate for the
last day with data available in a month. The full sample period from Jun. 10, 1991 to Feb. 26,
2021 is divided into six phases: the pre-AFC, AFC, pre-GFC, GFC, ZLB, and post-ZLB periods.
The corresponding time periods to these subsamples are shown in the following table:
Table 5.1 Subperiods for the Estimation of Interest Rate Pass-Through
Pre-AFC AFC Pre-GFC GFC ZLB Post-ZLB
Daily Jun. 30,
1997 and
Before
Jul. 1,
1997—
Dec. 31,
Jan. 1,
2000—Jul.
31, 2007
Aug. 1,
2007—
Dec. 16,
Dec. 17,
2008—
Dec. 16,
Dec. 17,
2015—
Feb. 26,
50
1999 2008 2015 2021
Monthly Jun. 1997
and before
Jul.
1997—
Dec. 1999
Jan.
2000—Jul.
2007
Aug.
2007—
Nov. 2008
Dec.
2008—
Nov. 2015
Dec.
2015—
Feb. 2021
Hong Kong Interest Rates
The interest rate pass-through estimation uses the yields of Exchange Fund Bills and Notes
(EFBNs) and Government Bonds of maturities from 1 month to 10 years. The data of the debt
securities yields are available in the Monthly Statistical Bulletin of the Hong Kong Monetary
Authority. The earliest period with data availability is Jun. 10, 1991, and the sample end period is
Feb. 26, 2021. See the interest rates in the following list:
Table 5.2 Hong Kong Interest Rate Variables and Labels
Interest Rate Label
EFB_30day 30-day Exchange Fund Bill Rate
EFB_91day 91-day Exchange Fund Bill Rate
EFB_182day 182-day Exchange Fund Bill Rate
EFB_364day 364-day Exchange Fund Bill Rate
EFN_2yr 2-year Exchange Fund Note Rate
EFN_3yr 3-year Exchange Fund Note Rate
EFN_5yr 5-year Exchange Fund Note Rate
EFN_7yr 7-year Exchange Fund Note Rate
EFN_10yr 10-year Exchange Fund Note Rate
gb_2yr 2-year Government Bond Yield
gb_3yr 3-year Government Bond Yield
gb_5yr 5-year Government Bond Yield
gb_10yr 10-year Government Bond Yield
The interest rates are available in different time periods as shown in the following table.
Table 5.3 Data Availability in the Subperiods for Interest Rate Pass-Through Estimation for
Hong Kong
Pre-AFC AFC Pre-GFC GFC ZLB Post-ZLB
Daily Jun. 30,
1997 and
Before
Jul. 1,
1997—
Dec. 31,
Jan. 1,
2000—Jul.
31, 2007
Aug. 1,
2007—
Dec. 16,
Dec. 17,
2008—
Dec. 16,
Dec. 17,
2015—
Feb. 26,
51
1999 2008 2015 2021
Monthly Jun. 1997
and before
Jul.
1997—
Dec. 1999
Jan.
2000—Jul.
2007
Aug.
2007—
Nov. 2008
Dec.
2008—
Nov. 2015
Dec.
2015—
Feb. 2021
EFB_30day Jun. 10,
1991--
X X X X X
EFB_91day Jun. 10,
1991--
X X X X X
EFB_182day Jun. 10,
1991--
X X X X X
EFB_364day Jun. 10,
1991--
X X X X X
EFN_2yr Nov. 19,
1991--
X X X X X
EFN_3yr Oct. 26,
1993--
X X X --Feb. 27,
2015
N.A.
EFN_5yr Sep. 27,
1994--
X X X --Feb. 27,
2015
N.A.
EFN_7yr Nov. 28,
1995--
X X X --Feb. 27,
2015
N.A.
EFN_10yr Oct. 29,
1996--
X X X --Feb. 27,
2015
N.A.
gb_2yr N.A. N.A. N.A. N.A. Sep. 2,
2009—
Mar. 10,
2015
N.A.
gb_3yr N.A. N.A. N.A. N.A. Nov. 2,
2011--
X
gb_5yr N.A. N.A. N.A. N.A. Nov. 2,
2009--
X
gb_10yr N.A. N.A. N.A. N.A. Jan. 11,
2010--
X
Note: “X” represents available. “N.A.” is the abbreviation of “Not Available”.
Singapore Interest Rates
The yields of Singapore Government Securities (SGS) are used to estimate the US-SGP interest
rate pass-through. The sample includes the securities whose maturities range from 3 months to
10 years. The data is available on the website of the Monetary Authority of Singapore. The
52
earliest date for available data of the SGP interest rates is Jan. 2, 1998. The end date for the
sample is Feb. 26, 2021. The labels and availabilities of the interest rates are shown in the
following tables.
Table 5.4 Singapore Interest Rate Variables and Labels
Interest Rate Label
sgs_3m 3-month Singapore Government Security Yield
sgs_6m 6-month Singapore Government Security Yield
sgs_1yr 1-year Singapore Government Security Yield
sgs_2yr 2-year Singapore Government Security Yield
sgs_5yr 5-year Singapore Government Security Yield
sgs_7yr 7-year Singapore Government Security Yield
sgs_10yr 10-year Singapore Government Security Yield
Table 5.5 Data Availability in the Subperiods for Interest Rate Pass-Through Estimation for
Singapore
AFC Pre-GFC GFC ZLB Post-ZLB
Daily Jan. 2,
1998—
Dec. 31,
1999
Jan. 1,
2000—Jul.
31, 2007
Aug. 1,
2007—
Dec. 16,
2008
Dec. 17,
2008—
Dec. 16,
2015
Dec. 17,
2015—
Feb. 26,
2021
Monthly Jan.
1998—
Dec. 1999
Jan.
2000—Jul.
2007
Aug.
2007—
Nov. 2008
Dec.
2008—
Nov. 2015
Dec.
2015—
Feb. 2021
sgs_3m X X X -- Sep. 18,
2013
N.A.
sgs_6m N.A. N.A. N.A. Jul. 9,
2012—Jun.
26, 2014
Jun. 27,
2019--
sgs_1yr X X X X X
sgs_2yr X X X X X
sgs_5yr X X X X X
sgs_7yr X X X --Jan. 31,
2011
N.A.
sgs_10yr Jun. 29,
1998--
X X X X
Note: “X” represents available. “N.A.” is the abbreviation of “Not Available”.
53
The U.S. Interest Rates
We use the U.S. Treasury bond yields in the estimation of the interest rate pass-through. The
Federal Funds Target Rate is employed to estimate the policy rate pass-through from the U.S. to
Hong Kong for robustness checks. The policy rate pass-through is not presented as main results
because Singapore does not have the policy rate for its monetary policy framework and there is
not policy rate pass-through for Singapore estimated and compared to the case of Hong Kong.
Previous literature also used the 3-month money market rate in addition to short-run and longrun
government bond yields. But the money market rate is not considered in this study focusing on
the government bond yields. The data source of the U.S. interest rates is Federal Reserve
Economic Data (FRED). The interest rates are listed as follows:
Table 5.6 The U.S. Interest Rate Variables and Labels
Interest Rate Label
TCM_1m 1-month Treasury Constant Maturity
TCM_3m 3-month Treasury Constant Maturity
TCM_6m 6-month Treasury Constant Maturity
TCM_1yr 1-year Treasury Constant Maturity
TCM_2yr 2-year Treasury Constant Maturity
TCM_3yr 3-year Treasury Constant Maturity
TCM_5yr 5-year Treasury Constant Maturity
TCM_7yr 7-year Treasury Constant Maturity
TCM_10yr 10-year Treasury Constant Maturity
To estimate the interest rate pass-through, the start date of the U.S. interest rate sample is
consistent with those of the HK and SGP interest rate samples, respectively.
The period for available data of the U.S. interest rates is longer than that for the HK and SGP
interest rates. Thus, the start date of the U.S. interest rate sample is the earliest date of the
available HK and SGP data.
54
Table 5.7 Data Availability in the Subperiods for Interest Rate Pass-Through Estimation for
the U.S.
Pre-AFC AFC Pre-GFC GFC ZLB Post-ZLB
Daily Jun. 10,
1991—Jun.
30, 1997
and Before
Jul. 1,
1997—
Dec. 31,
1999
Jan. 1,
2000—Jul.
31, 2007
Aug. 1,
2007—
Dec. 16,
2008
Dec. 17,
2008—
Dec. 16,
2015
Dec. 17,
2015—
Feb. 26,
2021
Monthly Jun.
1991—Jun.
1997
Jul.
1997—
Dec. 1999
Jan.
2000—Jul.
2007
Aug.
2007—
Nov. 2008
Dec.
2008—
Nov. 2015
Dec.
2015—
Feb. 2021
TCM_1m N.A. N.A. Aug. 1,
2001--
X X X
TCM_3m X X X X X X
TCM_6m X X X X X X
TCM_1yr X X X X X X
TCM_2yr X X X X X X
TCM_3yr X X X X X X
TCM_5yr X X X X X X
TCM_7yr X X X X X X
TCM_10yr X X X X X X
Section 5.2 Estimation of the Offset and Sterilization Coefficients
The offset and sterilization coefficients are estimated with simultaneous capital flows equation
and monetary policy reaction function under a joint framework developed by Brissimis, Gibson,
and Tsakalotos (2002) and modified by the author.
The Original BGT Model
Brissimis, Gibson, and Tsakalotos (2002) developed the following model to estimate the offset
and sterilization coefficients. It assumes that a monetary authority has the following loss function
with exchange rate stability as the only policy objective:
55
𝐿( = 𝛼(𝑠( − 𝑠(7)0 + 𝜀W𝜎*,(Y0
(5.6)
where 𝑠( denotes the spot exchange rate of home currency per unit of a foreign currency at time
t. 𝑠(7 represents the target exchange rate. 𝜎*,( stands for the exchange rate volatility at time t.
𝛼 𝑎𝑛𝑑 𝜀 are parameters.
The monetary authority tends to minimize the loss function in equation (5.6). The minimization
problem is subject to the following constraints:
∆𝑁𝐹𝐴( = 𝐶𝐴 + ∆𝑁𝐾(
(5.7)
(5.8)
∆𝑟( = −𝜓∆𝑁𝐷𝐴(𝜓 > 0
(5.9)
𝜎*,( = 𝜅𝜎*,($& − 𝜁(∆𝑁𝐹𝐴( − 𝑑0∆𝑁𝐹𝐴()
𝜅, 𝜁 > 0
(5.10)
where 𝐶𝐴 represents the current account and is assumed to be exogenous. 𝑁𝐾( denotes net
capital inflows at time t. The capital inflows are determined by the degree of capital mobility
measured by 1/c and the uncovered interest rate parity deviation. 𝐸(𝑠(-& stands for the
expectations for the spot exchange rate of period t+1 at time t. 𝑟( is the domestic interest rate.
𝑟(∗ indicates the foreign interest rate. 𝑑0 is a dummy variable with the value of 2 when ∆𝑁𝐹𝐴(
< 0 and 0 when ∆𝑁𝐹𝐴( > 0. That is, (∆𝑁𝐹𝐴( − 𝑑0∆𝑁𝐹𝐴() indicates the absolute value
of ∆𝑁𝐹𝐴(.
56
Using equations (5.7)-(5.9) yields
𝑠( = 𝑐∆𝑁𝐹𝐴( − 𝑐𝐶𝐴 + 𝑠($& + 𝜓∆𝑁𝐷𝐴( + ∆(𝐸(𝑠(-& + 𝑟(∗)
(5.11)
Substituting equations (5.10) and (5.11) for 𝑠(and 𝜎*,( in eq. (5.6) and taking derivatives
of the loss function with respect to NDA and NFA yield the following capital flow equation and
monetary reaction function:
∆𝑁𝐹𝐴( = − j(𝛼𝑐0𝛼𝜓𝑐+ 𝜀𝜁0)𝛼𝑐0𝛼𝑐 7)
k ∆𝑁𝐷𝐴( + l(𝛼𝑐0 + 𝜀𝜁0)m 𝐶𝐴 − j(𝛼𝑐0 + 𝜀𝜁0)k (𝑠($&
− 𝑠(
(𝛼𝑐 𝛼𝑐 ∗) − j 0𝜅𝜀𝜁+ 𝜀𝜁0)k (𝑑0 − 1)𝜎*,($&
(5.12) − j 0 + 𝜀𝜁0)k ∆(𝐸(𝑠(-& + 𝑟((𝛼𝑐
𝑐 𝑐 1 1
∆𝑁𝐷𝐴( = − j𝜓k ∆𝑁𝐹𝐴( + j𝜓k 𝐶𝐴 𝜓 𝜓
(5.13) where − n oon ∆𝑁𝐷𝐴( in eq. (5.12) is the
offset coefficient measuring the degree of capital mobility. − n o on ∆𝑁𝐹𝐴( in eq. (5.13) is
the sterilization coefficient, measuring the effectiveness of the short-term monetary policy.
57

The parameter of each control variable in the equations (5.12) is explained as follows: Holding
the other things constant, 1) the current account balance has a positive effect on the net foreign
assets. When the current account is in surplus, there is appreciation pressure on the local
currency. The monetary authority will buy foreign assets with the home currency in the foreign
exchange market to prevent the home currency from appreciating. Therefore, the net foreign
assets increase with a current account surplus; 2) the deviation of the spot exchange rate from the
official pegged rate has a negative effect on the net foreign assets. A depreciation pressure can
reduce the net foreign assets.
The Modified Model for Hong Kong and Singapore
As analyzed in Chapter 2, it is possible that small open economies have some room for shortterm
monetary autonomy with the objective of exchange rate stability. Therefore, the loss function for
Hong Kong and Singapore is modified as follows:
𝐿( = 𝛼(∆𝑠()0 + 𝛿W𝜎?,(Y0
(5.14)
where ∆𝑠( denotes the change in spot exchange rate of home currency per unit of a foreign
currency from last period at time t. 𝜎?,( stands for domestic interest rate volatility at time t.
𝛼 𝑎𝑛𝑑 𝛿 are parameters.
Constraints follow the BGT model with a modification for the current account variable. In the
original model, the current account is assumed to be exogenous. We assume this variable to be a
function of spot exchange rate against the dollar, cyclical income, and domestic prices. With its
limited fluctuations we do not expect the exchange rate to be important but have included it for
completeness. The constraints are as follows:
58
∆𝑁𝐹𝐴( = 𝐶𝐴( + ∆𝑁𝐾(
(5.15)
𝐶𝐴( = −𝜃𝑠( + 𝜅𝑌:,( + 𝜆∆𝑝(, 𝜃, 𝜅, 𝜆 > 0
(16)
Y@,A = φ&(∆NFAA + ∆NDAA) + φ0Y@,A$& ,
φ&, φ0 > 0
(5.17)
∆pA = π&(∆NFAA + ∆NDAA) + π0∆pA$& ,
π&, π0 >
0
(5.18)
(5.19)
(5.20)
𝜎?,( = 𝜂𝜎?,($& − 𝜉(∆𝑁𝐷𝐴( − 𝑑&∆𝑁𝐷𝐴()
𝜂, 𝜉 > 0
(5.21) where Y@,A denotes cyclical income at time t. ∆pA represents
inflation rate. 𝑑& is a dummy variable with the value of 2 when ∆𝑁𝐷𝐴( < 0 and 0 when
∆𝑁𝐷𝐴( > 0. That is, (∆𝑁𝐷𝐴( − 𝑑&∆𝑁𝐷𝐴() the absolute value of ∆𝑁𝐷𝐴(.
Deriving capital flows equation and monetary reaction function yields
∆𝑁𝐹𝐴( = (𝑐𝑐𝜅(1φ−& +𝜅φ𝑐𝜆& π−&𝜆−π&𝜓)) ∆𝑁𝐷𝐴( − 𝑐(1 − 𝜅φ𝑐𝜃& − 𝜆π&)
𝑠($& + 𝑐(1 − 𝜅𝑐𝜅φφ&0− 𝜆π&) Y@,A$&
59
𝑐𝜆π01
(5.22)
(1 − 𝜅φ& − 𝜆π&)
∆𝑁𝐷𝐴 𝑁𝐹𝐴(
− [𝜉0𝛿(1 − 𝑑&)0𝑐𝜃𝛼(1 −(𝑐𝜅𝑐𝜃φ)&0+−𝑐𝜆𝛼(π𝑐𝜅& −φ&𝜓+)
𝑐𝜆π& − 𝜓)0] 𝑠($&
+ [𝜉0𝛿(1 − 𝑑&𝑐𝜅)0φ(10𝛼−(𝑐𝜃𝑐𝜅)φ0&−+𝛼𝑐𝜆(𝑐𝜅π&φ−&
+𝜓)𝑐𝜆π& − 𝜓)0] Y@,A$&
+ [𝜉0𝛿(1 − 𝑑&𝑐𝜆)0(π10𝛼−(𝑐𝜅𝑐𝜃φ)0&−+𝛼𝑐𝜆(𝑐𝜅π&φ−&
+𝜓)𝑐𝜆π& − 𝜓)0] ∆pA$&
𝜉𝛿(1 − 𝑐𝜃)0𝜂
+ [𝜉0𝛿(1 − 𝑑&)0(1 − 𝑐𝜃)0 − 𝛼(𝑐𝜅φ& + 𝑐𝜆π& − 𝜓)0] (1
− 𝑑&)𝜎?,($&
(5.23)
In summary, the capital flow equation is written as follows:
∆NFAA = 𝜑% + 𝜑&∆NDAA + 𝜑0𝑌:,($& + 𝜑B∆pA$& + 𝜑C𝑒($& + 𝜑D∆(𝐸(𝑒(-&
+ 𝑟(∗) (5.24) where
𝑒( stands for the spot exchange rate in the unit of home currency per foreign currency. 𝜑& is the
offset coefficient. Its value ranges between -1 and 0. The value of 0 indicates complete capital
60
immobility and -1 denotes perfect capital mobility. The closer the coefficient is to -1, the higher
the estimated capital mobility.
The monetary reaction function is
∆NDAA = 𝜙% + 𝜙&∆NFAA
+ 𝜙E(1 − 𝑑&)𝜎?,($&
(5.25)
where 𝜙& is the sterilization coefficient with the value range of [-1, 0]. The value of -1 suggests
full sterilization and 0 implies no sterilization. The extent of sterilization increases from 0 to -1.
3SLS Model for Robustness Check
We also the Three-Stage-Least-Squares (3SLS) to estimate the offset and sterilization
coefficients for a robustness check. The model is written as follows:
For the capital flow equation,
∆NFAA = 𝜑% + 𝜑&∆NDAA + 𝜑0𝑌:,($& + 𝜑B∆pA$& + 𝜑C𝑒($& + 𝜑D∆(𝐸(𝑠(-& + 𝑟(∗)
(5.26)
C B
∆NDAA = ∆NFAA + I ∆NFAA$F + I ∆NDAA$F
(5.27)
,/& ,/&
For the monetary reaction function,
∆NDAA = 𝜙% + 𝜙&∆NFAA
𝜙E(1 − 𝑑&)𝜎?,($&
(5.28)
∆NFAA = ∆NDAA + ∑B,/& ∆NDAA$F + ∑C,/& ∆NFAA$F
61

(5.29)
Data and Variables
Monthly data in a sample from Jan. 1999 to Jun. 2021 are collected to estimate the offset and
sterilization coefficients of Hong Kong. The source of data is the Economic & Financial Data for
Hong Kong on the website of the HKMA and the Census and Statistics Department of Hong
Kong. The Singapore sample covers the period from Jan. 1992 to Jun. 2021. The monthly data of
SGP are collected from the Singapore Department of Statistics and the Monetary Authority of
Singapore. The 3-month U.S. Treasury Bill rate is collected from the FRED. Since the 3-month
Singapore Inter-Bank Offered Rate (SIBOR) discontinued from Jan. 2014, the Singapore
Overnight Rate Average (SORA) is instead used in the estimation for the period after 2013.
Measures of Net Domestic Assets
With the balance sheet structure, we derive the following equation:
𝑀𝐵 = (𝐹𝐴 − 𝐹𝐿) + (𝐷𝐴 − 𝐷𝐿)
(5.30)
Rewriting equation (5.30) yields:
𝑀𝐵 = 𝑁𝐹𝐴 + 𝑁𝐷𝐴
(5.31)
where NFA indicates net foreign assets and NDA represents net domestic assets.
62
Net domestic assets is derived using the following equation:
𝑁𝐷𝐴 = 𝑀𝐵 − 𝑁𝐹𝐴
(5.32)
When conducting sterilization studies, it is important, however, to look carefully at the
institutional characteristics of the countries being studied. For example, for some countries
changes in reserve requirements can be an important method of sterilization, not just open
market operations. However, changes in reserve requirements are not important in Hong Kong.
For Hong Kong, the important unusual characteristic of the monetary authorities’ operations is
that for the HKMA the monetary base of HK dollars includes the Exchange Fund Bills and Notes
(EFBN) outstanding, which is different from standard definition of reserve money. These central
bank-issued debt securities are purchased by banks and become domestic liabilities for the
HKMA.
While we place primary weight on the HKMA’s definition of the base we also provide estimates
using the conventional definition. The monetary base of HK dollars according to the
conventional definition is comprised of cash, bank reserves, and the outstanding debt securities
repurchased by the HKMA, which is written as follows:
𝑅𝑀 = 𝐶𝑎𝑠ℎ + 𝐴𝐵 + 𝐸𝐹𝐵𝑁GHIJ
(5.33)
where RM stands for the reserve money defined by the IMF. Cash represents the currency in
circulation including the indebtedness of certificates and coins issued by the SAR government.
63
AB stands for the aggregated balance of banks in Hong Kong with the HKMA. 𝐸𝐹𝐵𝑁GHIJ
indicates the Exchange Fund Bills and Notes held by the HKMA.
Using the conventional definition to calculate the NDA variable, we have the following equation:
𝑁𝐷𝐴 + 𝑁𝐹𝐴 = 𝐶𝑎𝑠ℎ + 𝐴𝐵 + 𝐸𝐹𝐵𝑁GHIJ
(5.34)
That is,
𝑁𝐷𝐴K* = 𝐶𝑎𝑠ℎ + 𝐴𝐵 + 𝐸𝐹𝐵𝑁GHIJ − 𝑁𝐹𝐴
(5.35) In addition to the components
of reserve money under the IMF definition, the HKMA includes the rest of outstanding
Exchange Fund Bills and Notes in its monetary base, which is expressed as follows:
𝑀𝐵 = 𝐶𝑎𝑠ℎ + 𝐴𝐵 + 𝐸𝐹𝐵𝑁GHIJ + 𝐸𝐹𝐵𝑁LMKN*
(5.36)
where MB denotes the whole monetary base of HK dollars as measured by the HKMA.
𝐸𝐹𝐵𝑁LMKN* denotes the Exchange Fund Bills and Notes held by institutions other than
HKMA.
We have “banks” in the subscript because available data for this variable is the amount of
outstanding EFBNs held by banks. We assume that the outstanding debt securities not held by the
HKMA are held by banks.
Table 5.8 The Simplified Balance Sheet of the Hong Kong Monetary Authority
Assets Liabilities
Foreign Assets (FA) Monetary Base (MB)
Certificate of Indebtedness + Coins (𝐶𝑎𝑠ℎ)
64
Aggregate Balance (𝐵𝑎𝑛𝑘 𝑅𝑒𝑠𝑒𝑟𝑣𝑒𝑠)
Outstanding Exchange Fund Bills and Notes
repurchased by the HKMA (𝐸𝐹𝐵𝑁GHIJ)
Outstanding Exchange Fund Bills and Notes
held by banks (𝐸𝐹𝐵𝑁LMKN*)
Domestic Assets (DA)
Domestic Liabilities (DL)
Foreign Liabilities (FL)
Using the HKMA’s definition, we have the following equation:
𝑁𝐷𝐴 + 𝑁𝐹𝐴 = 𝐶𝑎𝑠ℎ + 𝐴𝐵 + 𝐸𝐹𝐵𝑁GHIJ + 𝐸𝐹𝐵𝑁LMKN*
(5.37) The NDA variable
derived with the HKMA’s definition of the monetary base is thus written as follows:
𝑁𝐷𝐴* = 𝐶𝑎𝑠ℎ + 𝐴𝐵 + 𝐸𝐹𝐵𝑁GHIJ + 𝐸𝐹𝐵𝑁LMKN* − 𝑁𝐹𝐴
(5.38)
To distinguish the two NDA variables, we the standard measure (𝑁𝐷𝐴K*) to denote the one
calculated with the conventional definition of the base and displayed in eq. 5.35. We use the
HKMA measure (𝑁𝐷𝐴*) to indicate the one defined by the HKMA and presented in eq. 5.38.
The data and variables for the estimation of the offset and sterilization coefficients are shown in
Tables 5.9 and 5.10.
Table 5.9 Data and Variables for the Offset and Sterilization Coefficients Estimation
Variable Label Note
𝐹𝐴( Foreign assets
65
𝐹𝐿( Foreign liabilities
𝐺𝐷𝑃( Real Gross Domestic
Product
𝑀𝐵( Monetary Base
𝐷𝐸𝐵𝑇( Bank-held Exchange Fund
Bills and Notes
Only for Hong Kong
𝐶𝑃𝐼( Consumer Price Index
𝑒( Spot exchange rate against
the dollar
𝑟(∗ 3-month Treasury Bill rate
𝑟( 3-month domestic interest
rate
𝑟( Singapore Overnight Rate
Average
Only for Singapore
Table 5.10 Variables and Labels for the Offset and Sterilization Coefficients Estimation
Variable Label Formula
𝑁𝐹𝐴(
∆NFAA Year-over-year change in the
net foreign assets in
percentage of real GDP
𝑁𝐹𝐴( − 𝑁𝐹𝐴($&0
𝐺𝐷𝑃(
NDAO,A Standard net domestic assets 𝑀𝐵( − 𝑁𝐹𝐴(
∆NDAO,A Year-over-year change in the
HKMA measure of the net
domestic assets in percentage
of real GDP
𝑁𝐷𝐴*,( − 𝑁𝐷𝐴*,($&0
𝐺𝐷𝑃(
NDAPO,A The standard measure of the
net domestic assets in
percentage of real GDP
𝑀𝐵( − 𝑁𝐹𝐴( − 𝐷𝐸𝐵𝑇(
∆NDAPO,A Year-over-year change in the
non-standard net domestic
assets in percentage of real
GDP
𝑁𝐷𝐴K*,( − 𝑁𝐷𝐴K*,($&0
𝐺𝐷𝑃(
𝑇𝑅𝐸𝑁𝐷( HP-filtered trend of real GDP
𝑦:,($& Cyclical component of real
GDP
𝐺𝐷𝑃( − 𝑇𝑅𝐸𝑁𝐷(
𝑌:,($& Cyclical component of real
GDP in percentage of the
GDP trend
𝑦:,($&
66
𝑇𝑅𝐸𝑁𝐷(
∆pA$& Year-over-year percentage
change in the consumer price
index
𝐶𝑃𝐼( − 𝐶𝑃𝐼($&0
𝐶𝑃𝐼($&0
𝑒($& First lag of the spot exchange
rate of local currency against
the dollar
𝐸(𝑠(-& Perfect expectation on the
percentage change in the spot
exchange rate of local
currency against the dollar
ln (𝑒(-&)
∆(𝐸(𝑠(-& + 𝑟(∗) Change in the expectation on
the spot exchange rate and the
foreign interest rate from the
last period
(𝐸(𝑠(-& + 𝑟(∗) − (𝐸($&𝑠(
+
𝑟(∗$&)
𝑑& Dummy variable indicating if
domestic money market is in
surplus or deficit
=0 if ∆NDAA >0; =2 if
∆NDAA<0
𝜎?,($& Volatilities in the domestic
interest rate
𝑠𝑡𝑑(𝑟()
(1 − 𝑑&)𝜎?,($& Absolute value of the
volatilities in the domestic
interest rate for the last period
The stationarity of variables is examined with Augmented Dickey Fuller (ADF) test. The results
are presented in Tables 5.11 and 5.12. Based on the test statistics, the null hypothesis of a unit
root is rejected. The data series is stationary.
Table 5.11 The Augmented Dickey Fuller Test Results for Hong Kong
Variable ADF test statistic (with drift)
∆NFAA -2.26**
∆NDAA -3.26***
𝑌
-4.352***
-2.842***
𝑒($& -3.306***
∆(𝐸(𝑠(-&
+ 𝑟(∗)
-11.059***
(1 − 𝑑&)𝜎?,
($&
-11.322***
67
* P <0.1, ** P<0.05, *** P<0.01
Table 5.12 The Augmented Dickey Fuller Test Results for Singapore
Variable ADF test statistic (with drift)
∆NFAA -1.628*
∆NDAA -1.852**
𝑌 -3.848***
-2.602***
𝑒($& -1.330*
∆(𝐸(𝑠(-&
+ 𝑟(∗)
-12.502***
(1 − 𝑑&)𝜎BQ,
($&
-8.626***
(1 − 𝑑&)𝜎*R?M,
($&
-5.179***
* P <0.1, ** P<0.05, *** P<0.01
68

Chapter 6 Estimated Interest Rate Pass-Through
The estimates of interest rate pass-through with equation 5.1 are presented in this chapter. We
find that the asset substitutability between the United States and Hong Kong is not perfect. The
interest rate pass-through from the US to Hong Kong is less than one for one in most cases. It is
estimated to be 0.769 on average. And there is a large variation in the pass-through over time and
across maturities, suggesting imperfect capital mobility between Hong Kong and the US.
The interest rate pass-through from the US to Singapore is also estimated and presented
following the estimates for Hong Kong. By comparing the estimated pass-through between Hong
Kong and Singapore, we find that the pass-through from the US to Singapore is lower than that
to Hong Kong in every subsample with which both are estimated to be statistically significant,
substantiating that a managed floating exchange rate regime is more effective to insulate the
monetary autonomy of a small open economy than a hard peg under free capital flows.
Nevertheless, the small open economy is not completely protected from foreign monetary shocks
with managed floating as the interest rate pass-through from the US to Singapore is statistically
significant and positive in most cases.
Our estimates of interest rate pass-through show that there are limits to arbitrage. One likely
reason is that investors may be risk averse in the financial markets of Hong Kong and Singapore,
which makes capital mobility imperfect in normal times; 2) In a financial crisis that originates
from the base country, a credit crunch can make the degree of capital mobility decrease
dramatically and reduce the strength of the international monetary transmission; 3) In the
69
aftermath of the crisis, the capital mobility can be lower than its pre-crisis level as investors
become more risk averse and with unconventional monetary policy, which allows domestic
interest rates to deviate from the base rates to a greater extent.
Investors are risk averse in the financial markets of Hong Kong and Singapore. The estimated
interest rate pass-through from the US to Hong Kong increases from 0.0656 to 0.621 at daily
frequency as the interest rate maturity increases from 1 month to 10 years. Similarly, the
passthrough to Singapore is estimated to be not statistically significant with 3- or 6-month
interest rates at daily frequency. The daily interest rate pass-through that is estimated to be
statistically significant increases from 0.08 to 0.305 as the maturity of interest rates rises from 1
year to 10 years in the case of Singapore. The results indicate that investors are more likely to
take arbitrage of long-term assets, which is less risky, than short-term assets within one day.
In addition to the daily estimates, the 1-month interest rate pass-through to Hong Kong that is
estimated to be significant is much lower than the estimates of interest rates with longer
maturities than one month in all samples at monthly frequency. It means that investors are less
likely to take the arbitrage of a one-month asset than that with a longer maturity even though
investors have one month to take the arbitrage.
The credit crunch in the 2008 global financial crisis negatively affected the short-term asset
substitutability between the US and the small open economies. The 1- and 3-month interest rate
pass-through to Hong Kong is estimated to be not significant for the GFC period at daily
70
frequency. Similarly, the 3-month and 1-year interest rate pass-through to Singapore is not
statistically significant at daily frequency for the crisis period. When foreign assets are not
available in the financial markets in crisis, investors cannot take the arbitrage and domestic
interest rates can, therefore, deviate from the long-run relationship with the base rates in a very
short period.
Investors can be more risk averse in the aftermath of a financial crisis. The highest interest rate
pass-through to Hong Kong for the pre-Asian Financial Crisis (AFC) period is estimated to be
0.885 with the 5-year interest rates at daily frequency. In the subperiods after the AFC, the
estimated 10-year interest rate daily pass-through is found to be the highest. At monthly
frequency, the 1-year interest rate pass-through to Hong Kong is estimated to be the highest in
the subperiods prior to the Global Financial Crisis (GFC) period and the highest pass-through for
the ZLB period is found with the 7-year interest rates. The maturity of interest rates with the
highest asset substitutability increases to 10 years for the post-ZLB period. The change in the
assets with the highest substitutability is also related to unconventional monetary policy which
involves long-term Treasury bond yields. As a result, the estimated interest rate pass-through to
Hong Kong decreases from the pre-GFC period to the post-ZLB period.
The estimated interest rate pass-through from the US to Hong Kong is less than one for one and
has a heterogenous pattern across different subperiods and maturities. The estimates show the
risk aversion of investors in the Asian financial markets in normal time and the aftermath of a
financial crisis, the credit crunch in the crisis, and unconventional monetary policy that all make
71

the capital mobility imperfect and allows the small open economy to have some scopes for
monetary autonomy partially in the short run.
The interest rate pass-through to Singapore is estimated to be lower than for Hong Kong when
both are statistically significant in the whole period and each subperiod, with the interest rates of
each maturity, and at both monthly and daily frequencies.
The extra scope for monetary autonomy in Singapore than Hong Kong increases when the MAS
does not make foreign exchange interventions (FXIs) intensively. The gap increases from the
GFC period to the ZLB period, indicating that more transmission fell on exchange rates in
Singapore after the financial crisis. The market expected the local currency to appreciate, and
investors did not seek for the yields of foreign assets in the aftermath.
The gap in monetary autonomy is narrowed between Hong Kong and Singapore when the MAS
takes intensive FXIs. The estimated interest rate pass-through to Singapore increases from the
pre-GFC period to the post-ZLB period. In contrast, the estimated interest rate pass-through to
Hong Kong declines before and after the GFC and ZLB periods. It indicates that less
transmission falls on exchange rates and investors are more likely to take arbitrage for the rise in
the US rates in Singapore in the post-ZLB period.
The estimated interest rate pass-through is shown as follows in detail.
72

Section 6.1 The Estimated US-Hong Kong Interest Rate Pass-Through
Tables 6.1 and 6.2 show that the international pass-through from the U.S. to HK estimated using
the 1-month interest rates is significant for the pre-GFC and post-ZLB periods but not significant
for the GFC and ZLB periods. The daily pass-through is estimated to be significant at a 99.9%
confidence level with the magnitude of .2 prior to the GFC but not significant from the GFC
period. At a monthly frequency, the estimated pass-through is significant in the pre-GFC and
post-ZLB periods. From the time period before the GFC to that after the ZLB, the magnitude of
the pass-through is estimated to decrease from .377 to .277.
The monthly variation of the HK 1-month rate explained by the US counterpart decreases from
6.4% in the pre-GFC period to 1.4% in the post-ZLB period as suggested by the adjusted
Rsquares of the regression models based on the two subsamples. The daily variation explained
by the US 1-month rate is 2.2% for the pre-GFC period. Using the 1-month interest rates, the
U.S. interest rate is estimated to explain 2.2% variation of the HK counterpart in the pre-GFC
period at a daily frequency.
Tables 6.3 and 6.4 show that the substitutability of the U.S. 3-month Treasury security for the HK
3-month EFN is estimated to be statistically significant in the subsamples except the AFC and
GFC periods. The estimation for the periods before the GFC has a higher confidence level of
99.9% than for the ZLB and post-ZLB periods. At a monthly frequency, the pass-through keeps
declining from the pre-AFC period to the ZLB period. The magnitude of the estimated monthly
pass-through is .875 in the pre-AFC phase, .586 for the pre-GFC era, and .35 for the ZLB period.
It increases to .51 in the post-ZLB period. At a daily frequency, the pass-through is .487 before
73

the AFC, .252 after the AFC and before the GFC, .0715 in the ZLB era, and .218 in the postZLB
period.
The proportion of variation in the HK 3-month interest rate pass-through explained by the US
3month interest rate has similar changes over time with the magnitude of the estimated
passthrough. It decreased from the pre-AFC period to the ZLB era and then increased in the most
recent period. The proportion for the post-ZLB phase remains lower than that for the pre-AFC
period. At a monthly frequency, the U.S. interest rate explained 26.1% variation in the HK rate
prior to the AFC. The proportion declined to 13% for the pre-GFC period, 2.7% for the ZLB
period, and 13.2% in the post-ZLB period. At a daily frequency, 5% of daily variation in the HK
rate is explained by the US rate in the pre-AFC phase. The proportion is 3.9% for the pre-GFC
phase, .5% for the ZLB era, and 1.5% in the post-ZLB period.
Tables 6.5 and 6.6 show that the estimated US-HK pass-through regarding 6-month interest rate
is significant at a monthly frequency in the pre-AFC, pre-GFC, and post-ZLB periods, and at a
daily frequency based on the subsamples except the AFC and post-ZLB periods. The estimated
pass-through decreases over time. The estimated monthly pass-through is .994 for the pre-AFC
period, .816 for the pre-GFC period, and .601 for the post-ZLB phase. The estimated daily
passthrough is .685 for the pre-AFC phase, .454 for the pre-GFC period, .126 for the GFC
period, and .113 for the ZLB era.
The estimation of the interest rate pass-through with the 6-month interest rates shows a decline in
the variation of the HK rate explained by the US rate. The monthly variation explained by the US
74

rate was 41.3% prior to the AFC, 27.2% after the AFC and before the GFC, and 19.8% for the
post-ZLB period. The proportion of daily variation in the HK rate explained by its U.S.
counterpart was 12.2% in the pre-AFC era, 10.2% in the pre-GFC period, 1.4% in the GFC
phase, and 1.5% in the ZLB era.
Table 6.7 and 6.8 show that the 1-year interest rate pass-through from the US to HK is estimated
to be significant at a monthly frequency in the sample period except the AFC and ZLB phases
and at a daily frequency based on the subsamples except the AFC period. The estimated monthly
pass-through remains higher than .9 before the ZLB period. It is in particular one for one for the
GFC period. In the post-ZLB phase, the pass-through decreased to .596. The estimated daily
pass-through begins to decline before the GFC period. It is .743 for the pre-AFC phase, .581 for
the pre-GFC period, .233 for the GFC phase, .171 for the ZLB era, and .22 for the post-ZLB
period.
The proportion of monthly variation in the HK rate explained by its US counterpart is higher than
40% in the pre-AFC and pre-GFC periods, 34.2% in the GFC period, and 23.5% in the postZLB
period. The proportion of daily variation is greater than 20% in the pre-AFC and pre-GFC
periods and drops to 4% or less in the GFC, ZLB, and post-ZLB periods.
Tables 6.9-6.12 show that the estimated pass-through of the 2-year interest rate is statistically
significant in all the periods except the AFC era from both monthly and daily data. All the
significant estimates have the confidence level of 99.9%. The estimated pass-through remains
higher than .95 for the pre-AFC, pre-GFC, and GFC periods, declines to .463 in the ZLB period,
75

and rebounds to .539 in the post-ZLB period from the monthly data. The estimated daily
passthrough begins to decrease from the pre-GFC period. It is .806 for the pre-AFC period, .681
for the pre-GFC period, .563 for the GFC, and around .4 for the ZLB and post-ZLB period.
The proportion of monthly variation in the HK rate explained by the US rate is greater than 52%
prior to the ZLB period and less than 26% in the ZLB and post-ZLB periods. The explained
proportion of daily variation remains between 31.3% and 37% throughout the pre-AFC period to
ZLB period and declines to 14% in the post-ZLB.
Tables 6.13-6.16 show that the estimated 3-year interest rate pass-through is statistically
significant at the significance level of .1% from the pre-AFC period to the post-ZLB period
except the AFC period at both daily and monthly frequencies. The estimated pass-through from
the monthly data increases slightly over time prior to the ZLB phase. It is .884 for the pre-AFC
period, .928 for the pre-GFC period, and 1.023 for the GFC period. The estimated pass-through
decreases to .756 in the ZLB period. The pass-through is also estimated using the HK
government bond yield for the ZLB and post-ZLB periods. It is .783 for the ZLB period and .591
for the post-ZLB period.
The estimated daily pass-through decreases throughout the six sub-periods. It is .848 for the
preAFC period, .684 for the pre-GFC period, .578 for the GFC period, .512 for the ZLB period.
The estimate with the government bond yield is .558 for the ZLB period and .421 for the post-
ZLB period.
76

The proportion of variation in the HK rate explained by the US rate remains stable between 57%
and 68.8% at the monthly frequency. The proportion for the government bond yield is lower than
that for the EFN rate. It is 43.7% in the ZLB period and 31.7% in the post-ZLB period. The
proportion at the daily frequency ranges between 35% and 47.5% for the EFN rate. It is 29.7%
for the ZLB period and 14.2% for the post-ZLB period with the government bond yields.
Tables 6.17-6.20 show the estimated daily and monthly 5-year interest rate pass-through is
statistically significant at the 99.9% confidence level based on the six sub-samples except the
AFC period. The estimated monthly pass-through ranges between .752 and .889 using the EFN
rate until Feb. 2015 and is around .7 using the government bond yield for the ZLB and post-ZLB
periods. The estimated daily pass-through decreases before and after the GFC. It is .885 for the
pre-AFC period, .718 for the pre-GFC period, and around .55 for the GFC and ZLB periods. The
daily pass-through estimated using the government bond yield is slightly below .5 for the last
two periods.
The adjusted R-square of the monthly estimate is higher than 60% and less than 65% for the
periods with the significant estimates except the GFC period. It is 49% in the crisis period. The
R-square of the monthly estimate using the government bond yield is 52.4% for the ZLB period
and 44% for the post-ZLB period. The R-square of the daily estimate is around 50% in the
periods with significant estimates except the GFC period with the R-square of 43%. The Rsquare
of the daily estimate with the government bond yield is 30.5% for the ZLB period and
20.5% for the post-ZLB period.
77

Tables 6.21 and 6.22 show that the estimated 7-year interest rate pass-through is statistically
significant at the 99.9% confidence level for the periods by Feb. 27, 2015 except the AFC period.
The estimated monthly pass-through varies over time. It is greater than .9 for the pre-AFC and
GFC periods, .861 for the pre-GFC period, and .773 for the ZLB period. The estimated daily
pass-through decreases over time. It is .847 for the pre-AFC period, .734 for the pre-GFC period,
.597 for the GFC period, and .539 for the ZLB period.
The U.S. rate explains more than 50% of variation in the HK rate except in the GFC period. The
proportion of daily variation explained by the US rate is 43.6% in the GFC phase and around
52% for the rest of subsamples with significant pass-through. The proportion of monthly
variation explained by the US rate is 48.3% in the GFC period and around 64% in the other
subsamples except the AFC period.
Tables 6.23-6.26 show that the estimated 10-year interest rate pass-through is statistically
significant for the six periods except the AFC period. The confidence level of daily estimates is
99.9% while the confidence level of monthly estimates is 99.9% for the pre-GFC, ZLB, and
post-ZLB periods, 99% for the GFC period, and 95% for the pre-AFC period.
The estimated monthly pass-through increases from the pre-AFC phase to the pre-GFC period
and declines slightly in the periods after the GFC. It is .617 for the pre-AFC period, .845 for the
pre-GFC period, .805 for the GFC period, and .768 for the ZLB period. The estimated
78

passthrough using the government bond yield is .692 for the ZLB period and .789 for the post-
ZLB period.
The estimated daily pass-through decreases over time. It is .845 for the pre-AFC period, .777 for
the pre-GFC period, .67 for the GFC, and .565 for the ZLB period. The estimate with the
government bond yield is around .5 for the ZLB and post-ZLB periods.
The adjusted R-square of the monthly estimate is around 60% for the pre-GFC, ZLB, and
postZLB periods, and 37.6% on average for the pre-AFC and GFC period. The R-square of the
estimate with the government bond yield is 54% for the ZLB period and 58.1% for the post-ZLB
period.
The adjusted R-square of the daily estimate ranges between 52.1% and 53.9% from the pre-AFC
period to the ZLB period except the GFC period with the R-square of 41.8%. The R-square of
the estimate with the government bond yield is 39.8% for the ZLB period and 21.5% for the
post-ZLB period.
Tables 6.41-6.53 show the US-HK interest rate pass-through estimated with the ARDL model.
On average, the speed of adjustment is less than 3 days for the interest rates of maturities shorter
than one year, including 1-, 3-, and 6-month rates, and longer than three days for the interest
rates of maturities equal to or longer than one year, including 1-, 2-, 3-, 5-, 7-, and 10-year rates.
The average of the half-life increases as the maturity increases for the short-run interest rates
79

whose adjustment takes less than three days. For the interest rates whose adjustment takes more
than three days, the 2-year rate takes the least time of around 3 days. Following the 2-year rate,
the 3- and 5-year rates take less than four days but longer than 3 days to make the adjustment.
Both 1- and 10-year rates take around 4 days for the adjustment on average. The 7-year rate
spends more than 5 but less than 6 days as the interest rate with the slowest adjustment speed.
Besides, the HK interest rates are adjusted to their US counterparts in most of periods but not
every period. The significant proportion of the adjustment coefficients is less than 100% for
every interest rate in the samples.
The estimated interest rate relationship from the whole sample increases from .709 to 1.697 as
the maturity increases from 30 days to 10 years. In addition to the estimates from the EFBN data,
the relation is also estimated with the long-run government bond yields. The estimated
government bond yield pass-through remains between .72 and .79 (footnote: the sample coverage
of the government bond yields is shorter than that of the EFBNs.). The adjustment time increases
from 2.22—5.57 days to 6.31—9.25 days as the maturity increases from being equal to one year
or less to being longer than one year. In the interest rates of maturities less than two years, the
adjustment time increases as the maturity increases from one month to one year. In the interest
rates of maturities longer than one year, the adjustment time remains less than seven days for the
2-year rate, more than eight but less than nine days for 3- to 7-year rates, and more than nine
days for the 10-year rate. The government bond yields take more than one and less than four
days to complete the adjustment.
In the pre-AFC period, the long-run equilibrium in the interest rate relationship between the US
and HK remains around 1 for the 3-, 6-month, 1-, and 2-year rates. The level relationship of the
80

3-year rate is .887 while the 10-year rate relationship is 1.184. The 7-year interest rates do not
have a significant relation in this sample. The short-term dynamics converge to the long-run
equilibrium in the interest rates except the 5- and 7-year rates. The 6-month, 1-, and 2-year rate
takes less than one day to make the adjustment; and the 3-month and 3-year rates take more than
one but less than two days to be adjusted to the US counterpart.
The relationship between the US and HK interest rates is not statistically significant for the AFC
period. The adjustment coefficients, however, are significant for the interest rates whose maturity
is 3 years or shorter. The interest rates with significant adjustment coefficients take no longer
than 2 days to complete the adjustment.
The HK interest rates maintain significant long-run equilibrium relationship with their US
counterparts for the pre-GFC period. The level relationship increases from .846 to 1.1 as the
maturity increases from one month to two years. The 2- and 3-year rate relationships remain
around 1.1. The relations of 5-, 7-, and 10-year interest rates are greater than 1.1 and increase
with the maturity increasing. The adjustment of the local interest rates to the corresponding US
rates are effective for this period except the 7- and 10-year rates. The adjustment time ranges
between three and seven days. The 1- and 3-month rates take more than three and less than five
days to make the adjustment. The time spent in the rest of interest rates is more than five and less
than seven days.
The level interest rate relationship between HK and the US is statistically significant for the GFC
phase except the 1-month rate. The 3- and 6-month rate relations are .71 and .779, respectively;
The relations of 1-, 2-, 3-, and 5-year rates are around 1; And the 7- and 10-year rate relations are
81

greater than 1.2. The 1-, 3-, and 6-month rates take less than one day but some time to make the
adjustment while the rest of interest rates of longer maturities are immediately adjusted to the US
counterparts during the GFC period.
The US-HK interest rate level relationship is effective in the interest rates for the ZLB period
except the 3-, 6-month, and 1-year rates. The significant long-run relationship is .552 in the
1month rate and increases from .518 to .917 as the maturity increases from 2 years to 10 years.
The relationship estimated with the government bond yields ranges between .468 and .888 and
rises with the maturity increasing from 2 years to 10 years. The adjustment of interest rates of
maturities less than two years increases from .75 day to 3.12 days as the maturity increases from
1 month to 1 year. The adjustment of interest rates of maturities equal or greater than 2 years
range between 1.6 and 2.5 days from the EFN data. The adjustment of the government bond
yields takes more than three days in terms of the 10-year rate and less than two days regarding
the rest of interest rates.
The long-run equilibrium relationship between HK and the US interest rates remains effective for
the post-ZLB period. The estimated level relations with the EFBN yields from the highest to the
lowest is .815 in the 6-month rates, .807 in the 3-month rates, .803 in the 1-year rates, .749 in the
2-year rates, and .737 in the 1-month rates. The estimated relations from the government bond
yields decrease from .74 to .7 as the maturity increases from 3 years to 10 years. The 1-year rate
takes the longest 3 days to make the adjustment to the US rate. The 2-year rate follows the 1year
rate and takes around 2.86 days to complete the adjustment. The 2-, 5-, and 10-year government
bond yields also take more than two and less than three days to be adjusted to the long-run
82

equilibrium relationship with the US rate. The short-run interest rates of maturities less than one
year take 2 days or less to make the adjustment.
Section 6.2 The Estimated US-Singapore Interest Rate Pass-Through
The interest rate pass-through from the United States to Singapore is estimated to be lower than
the US-HK interest rate pass-through. The SGP estimates range between .43 and .645 from the
monthly data while the HK monthly estimates range between .692 and .845. The estimated daily
pass-through is within the range between .119 and .367 in the case of Singapore while the daily
estimate is between .481 and .777.
The SGP estimates do not have values greater than one but have negative values. There are seven
negative estimates in the SGP results. In contrast to 7 out of 8 negative estimates from the AFC
sample in the case of HK, 5 out of 7 negative estimates are from the ZLB sample and the
remainder is from the AFC sample in the case of Singapore. In addition, the SGP estimates have
a statistically significant negative pass-through while the HK estimates do not have one. The
USSGP 3-month rate pass-through estimated from the daily data is statistically significant at
95% confidence level for the AFC period.
Tables 6.27 and 6.28 show that the 3-month interest rate pass-through from the US to SGP is
effective in the AFC and pre-GFC samples. The estimate is statistically significant at 95%
confidence level from the daily data for the AFC period and at 99% confidence level from the
monthly data and 99.9% confidence level from the daily data for the pre-GFC period. The
significant estimates range between -3 and .4. They are -2.77 for the AFC period, .121 from the
83

daily data and .379 from the monthly data for the pre-GFC period. The proportion of variation in
the SGP rate explained by the US corresponding rate is less than 11% and the proportion
estimated from the monthly data is greater than that from the daily data. The proportion is .6%
for the AFC period, 1.7% at the daily frequency for the pre-GFC period and 10.9% at the
monthly frequency for the pre-GFC period.
The statistically significant estimates of the 3-moth interest rates in the case of SGP are lower
than their corresponding estimates in the case of Hong Kong for the pre-GFC period regarding
magnitude and adj. R-square. The HK estimates are .252 from the daily data and .586 from the
monthly data. The adjusted R-squares of the HK estimates are 3.9% at the daily frequency and
13% at the monthly frequency.
Tables 6.29 and 6.30 show that the 6-month interest rates have an effective pass-through from the
US to SGP in the post-ZLB period at the significance level of 1% at the monthly frequency. The
estimate is .589. It is slightly lower than the HK estimate of .601. The proportion of variation
explained by the US rate is more in the case of SGP than that in the case of HK. The adjusted R-
square of the SGP estimate is 44% while the percentage for the HK estimate is
19.8%.
Tables 6.31 and 6.32 show that the US-SGP pass-through of the 1-year interest rates is effective
for the pre-GFC and post-ZLB periods. The significant estimate is .375 from the monthly data. It
is statistically significant at the significance level of 1%. The estimate from the daily data
is .0997 for the pre-GFC period and .153 for the post-ZLB period. The significance level is .1%
for the pre-GFC estimate and 1% for the post-ZLB estimate.
84

The estimates are all lower than their HK counterparts. The HK estimate is .976 from the
monthly data for the pre-GFC period, and .581 for the pre-GFC period and .22 for the post-ZLB
period at the daily frequency.
Tables 6.33 and 6.34 show that the 2-year interest rate pass-through from the US to SGP could be
effective in every period. The daily pass-through is statistically significant at 95% confidence
level for the AFC period; Both daily and monthly pass-throughs are significant at 99.9%
confidence level for the pre-GFC period; The pass-through for the GFC period is significant at
the confidence level of 95% from the monthly data and 99.9% from the daily data; The daily
pass-through is significant at 99.9% confidence level for the ZLB period; The pass-through for
the post-ZLB period is significant at 99% confidence level from the monthly data and 99.9%
confidence level from the daily data.
The significant estimates of the US-SGP pass-through of the 2-year interest rates are overall
lower than the corresponding HK estimates. The SGP estimates range between .273 and .371
from the monthly data while the monthly pass-through from the US to HK is estimated to be
within a range from .463 to .962. The significant daily estimates range between .133 and .239 in
the case of SGP while they range between .429 and .681 in the case of HK. However, the SGP
rates are not necessarily less related to the US rates than the HK rates. In the AFC period, the
US-HK pass-through is not statistically significant while the US-SGP pass-through is significant.
Besides, the HK estimates decreases from the GFC period to the post-ZLB period while the SGP
estimates increase over time.
85

Tables 6.35 and 6.36 show that the 5-year interest rate pass-through from the US to SGP is
effective in every period but the significance level of the estimate varies across the different
periods. It is .1% for the pre-GFC and post-ZLB periods, 1% for the ZLB period, and 5% for the
GFC period from the monthly data; The daily estimate has the significance level of 1% for the
AFC period and .1% for the rest of periods. The monthly estimate peaks at .608 in the GFC
period and remains .358 and .301 for the pre-GFC and ZLB periods, respectively. From the ZLB
period to the post-ZLB period, the estimate increases to .426. The daily pass-through estimates
range between .122 and .299. It is the lowest in the AFC period and the highest in the post-ZLB
period. The estimate for the pre-GFC period is as high as that for the post-ZLB period. It
decreases from .294 to .188 from the pre-GFC period to the GFC period and increases to .222 for
the ZLB period.
The SGP estimates are overall lower than the HK counterparts. The minimum values of the HK
estimates are greater than the maximum values of the SGP estimates. The HK estimates are
greater than .675 from the monthly data and .466 from the daily data while the SGP estimates are
less than .608 from the monthly data and .3 from the daily data.
Tables 6.37 and 6.38 show that the estimated 7-year interest rate pass-through from the US to
SGP is statistically significant for the pre-GFC period at 99.9% confidence level and the GFC
period at 95% confidence level at the monthly frequency. The daily pass-through is effective in
the AFC period with the significance level of 5% and the rest of periods with the significance
level of .1%. The monthly estimates are .439 for the pre-GFC period and .602 for the GFC
period. The daily estimate remains the lowest at .0948 for the AFC period, peaks at .313 for the
86

pre-GFC period, and decreases to .186 for the GFC period, and .157 for the ZLB period. The
variation of the SGP rate explained by the US rate remains around 31% at the monthly frequency
in the two periods with significant estimates while it drops from 17.8% in the pre-GFC period to
7.9% for the GFC period and 5.4% for the ZLB period.
The US-SGP pass-throughs of the 7-year interest rates are lower than the corresponding US-HK
pass-throughs. The HK estimates are higher than .861 for the pre-GFC and GFC periods from the
monthly data while the SGP estimates are lower than .602. The HK estimates are greater than .53
from the daily data while the SGP estimates are lower than .32. But the US-SGP pass-through is
effective in the AFC period at the daily frequency in contrast that the US-HK pass-through is not
statistically significant in this period.
Tables 6.39 and 6.40 show that the US-SGP pass-through of the 10-year interest rates is effective
from the AFC period to the post-ZLB period. The estimate is statistically significant at 99.9%
confidence level in the periods except the AFC period with the estimates whose significance
levels are higher than 5% from the monthly data and less than 1% from the daily data and the
GFC period with the significance level of 5%. The monthly pass-through increases after the GFC
happened. The estimate is .43 for the pre-GFC period. It increases to .645 for the GFC period and
stays at on average .54 for the ZLB and post-ZLB periods. The daily pass-throughs for the crisis
periods are lower than those in normal time. The estimates are .119 for the AFC period and .217
for the GFC period while the estimates range between .3 and .37 for the pre-GFC, ZLB and post-
ZLB periods.
87

Tables 6.54-6.60 show that the US-SGP interest rate pass-through estimated with the ARDL
model.
Table 6.54 shows that the 3-month interest rate pass-through from the US to Singapore is
estimated to be significant for the full sample and subperiods except the AFC and post-ZLB
periods. The highest level relationship is estimated to be 0.484 for the GFC period. The local
interest rate is adjusted to the US rate in the full sample and subperiods except the AFC period. It
takes around 4 days to complete the adjustment on average in the full sample.
Table 6.55 shows that the 6-month SGP interest rate is statistically significantly affected by the
US counterpart in the post-ZLB period. The estimated level relationship between SGP and the
US is higher than that between HK and the US. The estimate is .921 from the SGP sample while
it is .815 from the HK sample. The SGP interest rate, however, does not have significant
adjustment to the long-run relationship with the US rate for both the ZLB and post-ZLB phases.
Table 6.56 shows that the 1-year interest rate of SGP has long-run equilibrium relationship with
the corresponding US rate for the pre-GFC, GFC, and post-ZLB periods. The estimated relations
are between .45 and .49 for the pre-GFC and GFC phases and .718 for the post-ZLB period. The
local interest rate is adjusted to the long-run equilibrium effectively for the three periods. The
time spent on adjustment in the case of SGP is shorter than that in the case of HK for the preGFC
and post-ZLB periods. The adjustment of the SGP rate takes around three days in the preGFC
sample while the HK rate takes around six days. The adjustment time is less than three days in
the SGP rate but around three days in the HK rate for the post-ZLB period. Although the
88

adjustment coefficients are smaller than -1 in both cases for the GFC period, suggesting both the
SGP and HK rates are adjusted instantly in this period, the coefficient of HK is greater than that
of SGP in magnitude, implying a quicker response to changes in the US counterpart.
Table 6.57 shows that the US-SGP 2-year interest rate relationship is statistically significant for
the periods except the AFC and ZLB eras. The significant level relationship is .511 for the
preGFC period, .465 for the GFC period, and .673 for the post-ZLB period. Recall that the level
relationship between HK and the US rates is 1.1 for the pre-GFC period, .979 for the GFC
period, and .749 for the post-ZLB period. Compared to the considerable difference in the
relationship between SGP and HK for the pre-GFC and GFC periods, the estimated equilibrium
relations of SGP and HK with the US rate are closer in the post-ZLB period. The SGP rate is
adjusted more quickly than the HK rate for the pre-GFC, GFC, and post-ZLB periods. The
adjustment of the SGP rate costs around 3.43 days for the pre-GFC period while the HK rate
takes more than five days to make the adjustment. For the GFC period, the adjustment coefficient
in the case of SGP is larger than that in the case of HK, suggesting a quicker adjustment occurred
to the SGP rate than the HK rate. The adjustment coefficient of SGP is -1.83 and the coefficient
of HK is -1.67. The time spent on adjustment is 2.29 days in the SGP rate and
2.86 days in the HK rate for the post-ZLB period.
Table 6.58 shows that the US-SGP relationship in the 5-year interest rate is effective for the
preGFC, GFC, and post-ZLB periods. The estimated relations are between .553 and .598 for the
preGFC and GFC periods, respectively, and .788 for the post-ZLB period. The relations are
lower than the corresponding US-HK estimates. The short-term dynamics of the SGP rate
89

converge to the long-run equilibrium for the AFC, pre-GFC, and post-ZLB periods. The SGP rate
take less time than the HK rate to be adjusted to the US rate for the AFC and pre-GFC periods
but more time for the post-ZLB period. The time spent on the adjustment of the SGP rate is .18
day for the AFC period, 2.61 days for the pre-GFC period, and 4.27 days for the post-ZLB
period. In contrast, the HK rate is not adjusted to the US rate for the AFC period, and takes 6.71
days and
2.31 days to make the adjustment for the pre-GFC and post-ZLB periods, respectively.
Table 6.59 shows that the 7-year interest rate relationship between SGP and the US is estimated
to be statistically significant for the pre-GFC and GFC periods. The estimated relations remain
around .6 for the two periods. Although the SGP rate does not necessarily own long-run
equilibrium relationship with the US rate for every period, it is adjusted to the US rate for every
period from the AFC to the ZLB phases. It takes less than one day and 2.86 days to make the
adjustment for the AFC and pre-GFC periods. In contrast, the HK rate is not adjusted to the US
rate for the two periods. For the GFC period, the HK rate completes the adjustment more quickly
than the SGP rate. The coefficient adjustment is -2.626 in the case of SGP and -.573 in the case
of HK for the GFC period, implying that the SGP rate takes .81 day to be adjusted to the US rate
while the HK rate makes the adjustment immediately. The adjustment takes .69 day in the SGP
rate for the ZLB period while the HK rate adjustment takes around 2 days for this period.
Table 6.60 shows that the 10-year interest rate of SGP is effectively affected by the US rate for
the pre-GFC and post-ZLB periods. The estimated relations are .727 and .736 for the two
periods, respectively. The estimate for the pre-GFC period is lower than the US-HK estimate of
90

1.51 while the US-SGP estimate for the post-ZLB period is higher than the US-HK estimate
of .7. In contrast to the HK rate that is not adjusted to the US rate for the AFC and pre-GFC
periods, the SGP rate is actively adjusted to the US rate for the two periods. In addition to the
two periods, the SGP rate is adjusted to the US rate for the GFC and post-ZLB period. There is
no significant adjustment found for the ZLB period. The time spent on the adjustment from the
longest to the shortest is 2.96 days for the pre-GFC phase, 2.63 days for the post-ZLB era, .67
day for the GFC period, and .45 day for the AFC period. Compared to the SGP rate, the HK rate
costs less time, instantly and 2.19 days, to make the adjustment for the GFC period and the
postZLB period, respectively.
The results of estimated interest rate pass-through substantiate that the capital mobility is not
perfect in Hong Kong. The interest rate pass-through from the US to Hong Kong is less than one
for one under the hard peg. It means some scope for monetary autonomy in Hong Kong in the
short run. The estimates also show that Singapore has more scope for monetary autonomy than
Hong Kong as the estimated interest rate pass-through from the US to Singapore is lower than
for Hong Kong.
91

