


Chapter 1
Introduction
My thesis consists of three essays in the field of international economics. The
first two essays examine trade growth during periods of large growth in inter-
national trade over the past 60 years. I use bilateral trade data to decompose
trade growth across goods classifications during rapid growth episodes and find
that trade growth is granular — the majority of overall trade growth between
given country-pairs is accounted for by a small number of goods classifications
exhibiting large growth in trade, while most goods exhibit small or negligible
growth. In the first essay (Chapter 2), I ask whether standard “Melitz-style”
international trade models, when supplemented with productivity and tariff
changes imputed from trade data, can generate the observed level of granu-
larity in bilateral trade data. In the second essay (Chapter 3), I add a choice
among multiple distribution technologies for exporting firms, with differing
fixed and variable costs, to quantify the model’s ability to match the observed
granularity of trade growth. The third essay (Chapter 4) examines how varia-
tion in transportation methods, which I denote “the supply network”, impacts
price dispersion across locations. I use a unique data set on weekly gasoline
1

2
prices across 44 Canadian cities to quantify how differences the available meth-
ods of transporting gasoline between locations (by pipeline, marine tanker, rail
or truck) account for observed mean and weekly price differences across cities.
International trade has grown nearly twice as fast as world GDP over the
past 60 years. For most countries, this growth in trade has occurred in a small
number of rapid growth episodes. Standard international trade models have
significantly under-predicted this large growth in international trade during
these periods of rapid growth. As such, recent Melitz-style trade models have
investigated the role of heterogeneity in trade growth across various industries
and goods. Chapter 2 analyzes bilateral trade data, at the 5-digit SITC classi-
fication level for Canada, Germany, Mexico, Japan, U.S., and U.K. (accounting
for 20–25% of global trade) between 1989 and 1999, in order to to decompose
the patterns of trade growth across various goods classifications. I find that
bilateral trade growth during these rapid growth episodes is granular — less
than 5% of goods classifications account for over 65% of overall bilateral trade
growth while the majority of goods exhibit little to no growth in trade.
Trade theory suggests that disproportionately large growth in this small
number of goods categories may be accounted for by the goods experiencing
the largest reductions in tariff rates. However, I find that tariff reductions
cannot account for the granularity of bilateral trade growth. Further, I find
that production growth and increases in trade intensity (defined as the share
of domestic production that is exported) are both significant factors in these
large-growth goods classifications.
I use a Melitz-style trade model, featuring heterogeneous productivity firms

3
facing CES demand under monopolistic competition, calibrated to match bilat-
eral trade flows, to quantify the predictions for trade growth across goods clas-
sifications during growth episodes. I find that for reasonable parameter values,
the model predicts less granular trade growth, generating only about 10% of
the granularity in the data, as measured by the share of total trade growth
accounted for by various quantiles of goods classifications. To better match
the observed granularity, I augment this standard model by incorporating het-
erogeneous productivity changes and tariff reductions imputed from the U.S.
production and export data. Doing so, I find that the model predicts roughly
70% of the granularity across goods observed in the trade data.
To account for the remaining heterogeneity of trade growth in the bilat-
eral trade data, I examine the role of heterogeneity in exporting methods in
accounting for differences in observed levels of trade and trade growth across
goods. Firms often choose between alternate methods of exporting their goods
to foreign countries. Generally, these can be grouped into two broad categories
— methods with high fixed costs and low variable costs, and those with low
fixed costs and high variable costs.
In Chapter 3, I use the standard Melitz-style model from Chapter 2, and
add a choice among multiple distribution technologies for exporting firms —
one low-fixed, high-variable cost option, and one high-fixed, low-variable cost
option. Solving the model, I find that, following productivity or tariff changes,
firms that switch from not-traded to traded, or from the low-fixed to high-fixed
cost method exhibit disproportionately larger growth than non-switching firms,
generating higher granularity in trade growth in the model. To quantify the
effect of this mechanism on trade growth granularity, I calibrate and simu-
late the model, incorporating heterogeneous productivity and tariff changes
4
imputed from trade data, to match data on bilateral trade flows and trade
growth. I find that the model with multiple distribution technologies increases
the predicted granularity of trade growth across goods to 90–95% of the level
observed in the data, as opposed to the 70% generated by a model with a single
distribution technology in Chapter 2.
Chapter 4 investigates how variation in available transportation methods
impacts observed price differences across locations in the Canadian gasoline
market. Price dispersion is often attributed to transportation costs — the
larger the costs of transporting goods between locations, the larger the price
gaps that can be sustained over time. Many studies use geographic distance
as a proxy for transportation costs.1However, little is known about the quan-
titative impact of variation in the methods used to transport goods between
locations on these relative price differences.
I use a unique data set on weekly average gasoline prices in 44 Canadian
cities between 2001 and 2017, as well as differences in the four main modes of
transporting gasoline — via pipeline, marine tanker, rail or truck — to quan-
tify the impact of the supply network on relative price differences between
locations. Controlling for distance, regional and market effects, I find that the
supply network has a significant impact on price dispersion in the Canadian
gasoline market. City-pairs connected via pipeline — a faster, lower cost-per-
unit method — exhibit 3.5% less mean-price dispersion than those connected
by higher cost-per-unit methods like rail or truck. Further, the existence of
pipelines connecting cities has the effect of reducing weekly price differences
by the equivalent of a 53% reduction in geographical distance, while a seaport
connection between cities reduces the effective distance by 38%, compared to
1See, for example, Burdett and Judd (1983), Crucini, Telmer and Zachariadis (2003), or
Engel and Rogers (1996).

5
land-route alternatives.
A brief case study of supply disruptions at the refinery level indicates that
unplanned refinery shut-downs result in price spikes that are higher in regions
closest to these supply disruptions, and that retail price shocks have lower
variation in cities that share a pipeline connection than in those that do not.
These results reinforce the finding that the structure of the supply network is
significant in accounting for observed price dispersion across locations.
1.1 References
BURDETT, K. AND K.L. JUDD (1983). “Equilibrium Price Dispersion”, Econo-
metrica , Vol. 51, No. 4, pp. 955-–969
CHANEY, T. (2008). “Distorted Gravity: The Intensive and Extensive Margins
of International Trade”. American Economic Review, 98:4, 1707–1721.
CRUCINI, M., C. TELMER AND M. ZACHARIADIS (2003). “Price Dispersion:
The Role of Borders, Distance and Location”, Tepper School of Business, Paper
490
ENGEL, C. AND J. ROGERS (1996). “How Wide Is the Border?”, American Eco-
nomics Review, Vol 86 No 5, pp. 1112–1125
MELITZ, M.J. (2003). “The Impact of Trade on Intraindustry Re-allocations
and Aggregate Industry Productivity.” Econometrica, Vol. 71.6 (2003): 1695–1725.
Chapter 2
Decomposing Episodes of Large
Growth in International Trade
2.1 Introduction
Over the past 50 years, international trade has grown nearly twice as fast as
world GDP.1For most countries, this growth has not been smooth and constant
over time, but rather occurred over a small number of rapid growth episodes.2
For some countries, episodes of large growth follow implementations of trade
liberalization, such as the North American Free Trade Agreement (NAFTA)
in the early 1990s. However, episodes of large trade growth also occur in the
absence of formal trade liberalizations.3
It is well-documented that in many instances, trade models significantly
1Source: IMF WEO 2012
available at: http://www.imf.org/external/pubs/ft/weo/2012/02/weodata/index.aspx.
2Figure A.1 shows bilateral trade for several countries over the past 30-–60 years, where
an average of roughly 70-–90% of overall growth over this period is accounted for by periods
spanning only 10% of the time span (i.e. 5 years).
3For example, between 1990 and 1999, Mexican exports to Canada quintupled, from $0.4
billion to $2.1 billion. By contrast, Mexico’s GDP grew by only 70% during this same period.
Over the same period, German exports to the U.S. grew from $25 billion to $49 billion while
German GDP grew by only 50%.
6
7
under-predicted the magnitude of trade growth during these episodes.4More
recently, papers like Melitz (2003) and Chaney (2008) have focused on the role
of heterogeneity in accounting for trade growth across industries and goods. As
a result, trade literature has examined responses to trade liberalization across
various types of goods and industries: previously-traded goods that become
traded in larger values — the intensive margin — and previously not-traded
goods that become traded — the extensive margin.5
Several questions remain to account for the large growth during these rapid
growth episodes:
1. What is the distribution of growth across goods during growth
episodes? What proportion of overall trade growth is attributable to
intensive margin growth as opposed to extensive margin growth? Kehoe
and Ruhl (2013) find evidence that the extensive margin is in fact large
and significant in accounting for overall trade growth. Further, within
these margins, is trade growth widely dispersed across a large number
of different goods, or is trade growth granular — i.e. is trade growth
concentrated in a small number of goods accounting for the majority of
overall trade growth?6
4For example, see Kehoe(2005) for a detailed examination of the erroneous predictions of
trade models following NAFTA.
5Although the terms “goods” and “industries” may have different connotations in other eco-
nomic literature, for brevity I will hereafter use the term “goods” to refer to various industries
and the goods they produce and trade.
6The use of the term “granular” in the literature is relatively recent and sparse — papers
like Gabaix (2011), DiGiovanni and Levchenko (2014) and DiGiovanni, Levchenko and Mejean
(2017) use granularity to refer to the “incompressible grains of economic activity” that result
from the idiosycratic shocks to the upper end of the fat-tailed distribution of firms within an in-
dustry, that pervade to aggregate economy-level shocks. For the purposes of this dissertation, I
extend my connotation of granularity to include two main properties: (1) the level of disaggre-
gation in cross-sectional trade that identifies idiosyncratic behavior across industries in a given
period, similar to Gabaix and others (as opposed to homogeneous behaviors across industries or
focusing on aggregate values, and (2) idiosyncratic behavior in trade growth across industries
8
2. What accounts for heterogeneity of growth across different goods?
Do tariff reductions account for overall trade growth for each good? Is
trade growth a function of production growth or increases in trade in-
tensity (or both)? That is, does trade growth for each good coincide with
increases in domestic production, with a constant share of output being
traded, or does the share of domestic output being traded increase?
3. Are the predictions of Melitz-style models consistent with the level
of granularity observed in international trade data? Do the mech-
anisms for tariff reductions and productivity changes in these models de-
liver similar patterns of trade growth across goods as observed in the
data?
In this paper, I document new data facts on bilateral trade growth across
goods during rapid growth episodes. I analyze 5-digit Standard International
Trade Classification (SITC) bilateral trade data, between 1989 and 1999, for
6 countries (Canada, Germany, Japan, Mexico, USA and UK) accounting for
20–25% of global trade during this period. Although data limitations restrict
the sample to this 10-year period, it does include the implementation of the
North American Free Trade Agreement (NAFTA) and the Canada-US Free
Trade Agreement (CUSFTA) in the early-to-mid 1990s, thus allowing a com-
parison of growth for trade-liberalization and non-liberalization country-pairs.7
I supplement this data with 8-digit Harmonized Tariff Schedule (HTS) data
— industries react differently across the distribution of trade, even from similar previous levels
of trade. The latter property contrasts with the connotation of terms like “lumpiness” of trade
(as in Armenter and Koren (2014), among others) which denotes the concentration of trade and
trade growth at the upper end of the distribution, where the majority of trade growth would
similarly be accounted for by those industries accounting for the majority of previous trade.
7Numerous papers, such as Caliendo and Parra (2014), Gould (1998), Romalis (2007), etc.,
examine the overall impact of NAFTA and CUSFTA, providing a large, diverse literature.
9
on U.S. tariff rates and 6-digit North American Industry Classification Sys-
tem (NAICS) data on U.S. manufacturing production. The U.S. tariff data is
matched to U.S. import data to analyze the impact of changes in tariff rates
on the growth in trade across goods classifications. U.S. manufacturing data
is matched to U.S. export data to decompose trade growth into changes in pro-
duction and changes in trade intensity.
I document four key facts during these rapid trade growth episodes:
1. Bilateral trade growth is granular across time and across goods — over
70% of total trade growth over time is accounted for by 10% of the total
time period (i.e. 5 of 50 years), and less than 5% of goods classifications
account for 65–110% of total bilateral growth across country-pairs8
2. Changes in tariffs do not account for episodes of large trade growth
3. Increases in trade intensity and domestic production each account for
large growth in trade across goods
4. The extensive margin is significant for overall bilateral trade, but is driven
by a relatively small number of extensive margin goods (<20%) that ac-
count for the majority of overall extensive margin growth
Across all bilateral country-pairs, trade growth is granular across time and
goods. Over the past 50 years, most of the total growth in bilateral trade is
accounted for by a small number of rapid growth episodes. Examining growth
for each year, the 5 largest-growth years (i.e 10% of the total time span) ac-
count for over 70% of the total growth in bilateral trade over the past 50 years.
8These goods can account for over 100% of trade growth due to negative growth in some
goods classifications.
10
Cross-sectionally, the majority of total bilateral trade growth is accounted for
by a small number of goods classifications exhibiting disproportionately large
growth.9Nearly all these large-growth goods had non-zero levels of trade prior
to rapid growth. Large growth from goods categories with zero previous trade
is rarely observed. Further, among this set of large-growth goods, there is large
variation in their level of trade prior to rapid growth.
Reductions in trade barriers alone are unable to account for these large-
growth goods categories which comprise the majority of trade growth across
country-pairs. Many episodes of trade growth occur in goods whose tariff rates
do not change, while most changes in tariff rates do not result in large trade
growth for those goods. As a result, there is no statistically significant corre-
lation between reductions in U.S. tariffs rates and U.S. bilateral trade growth
across goods categories. Of the 100 goods contributing the largest shares of bi-
lateral trade growth, over half exhibit no reduction in their ad valorem equiva-
lent (AVE) tariff rate. Further, of the goods with the largest reductions in tariff
rates, few (10-–20%) exhibit substantial growth in trade.
Examining U.S. manufacturing data, I find that episodes of large growth in
bilateral trade coincide with increases in both trade intensity and production.10
Controlling for changes in domestic production, observed increases in trade
9On average, across country-pairs, roughly 1% of goods classifications account for approxi-
mately 60% of total trade growth.
10To clarify this distinction, global growth of new technologies like smart-phones and laptop
computers, employed on a global scale, necessitates increased production of semi-conductors,
the key foundation of internal circuitry for modern electronics. A large increase in exports
for goods like semi-conductors may therefore be proportional to increases in their overall pro-
duction, with trade intensity (the share of domestic production that is exported) remaining
relatively constant. Alternatively, episodes of trade liberalization resulting in decreased bar-
riers to trade may lead to a larger share of domestic production being exported to a given
destination, representing an increase in trade intensity, even in the absence of large increases
in gross production.
11
intensity account for 35–90% of total bilateral trade growth across country-
pairs.11 Conversely, holding trade intensity constant, production growth ac-
counts for 30–40% of observed trade growth for some country-pairs, while for
others it accounts for virtually none of the overall bilateral trade growth.
Extensive margin growth is measured as changes in trade accounted for
by the goods classifications representing the bottom 10% of initial trade.12 I
find extensive margin growth is significant to overall bilateral growth for all
country-pairs. Additionally, within the extensive margin, large growth in a
small number of goods accounts for the majority of overall extensive margin
growth, mirroring the granularity of trade growth across goods in the intensive
margin, for trade-liberalizing and non-liberalizing countries alike.
I quantitatively compare these empirical findings on trade growth across
goods to the predictions of Melitz-style trade models. As in Melitz(2003), Help-
man, Melitz and Yeaple (2004) or Chaney (2008), these models typically feature
heterogeneous productivity firms, monopolistic competition pricing, and CES
demand, as well as fixed and variable costs of exporting. Since I am interested
in the quantitative results, I use reasonable parameter values and calibrate
this “standard model” to match observed trade flows and quantitatively assess
the model’s ability to match the observed granularity in bilateral trade data for
two main cases:
11Due to the data limitations of only having U.S. production data, I only consider 5 country
pairs — U.S. exports to Canada, Mexico, Japan, Germany and the U.K.
12This paper adopts the Kehoe and Ruhl (2013) definition of the extensive margin—the set
of goods that account for the bottom 10% of initial trade. This is due to reporting issues in
international trade—shipments with sufficiently low values need not be declared on Customs
reports for many countries, so distinguishing true zero-trade goods from small trade goods can
cause issues. For similar reasons, I follow the Kehoe and Ruhl approach of using the bottom
decile of goods, according to initial trade value to represent the extensive margin.

12
1. Standard model with uniform tariff reductions. A standard Melitz-
style model featuring firms with fixed productivities drawn from a Pareto
distribution, where trade liberalization takes the form of a uniform reduc-
tion in tariffs across all goods, a common approach in the trade literature.
2. Standard model with heterogeneous productivity changes and
tariff reductions. A standard Melitz-style which I augment by incorpo-
rating heterogeneous changes in productivity across goods imputed from
U.S. production data, as well as heterogeneous tariff reductions across
goods matched from U.S. import data.
I find that the predictions of the standard model with uniform tariff reduc-
tions do not match the stylized facts observed in the data. With a Pareto distri-
bution of productivities, and a fixed and variable cost of exporting, this model
produces much less granularity of trade growth than found in the data. In equi-
librium, goods are stratified into traded goods (those with sufficiently high pro-
ductivity to cover the fixed cost of exporting) and goods that are not-traded (i.e.
those where the fixed cost exceeds the potential profits from exporting). Fol-
lowing a uniform reduction in trade costs for all goods, the increase in exports
of previously traded is proportional to their productivities. As a result, growth
in the intensive margin of trade is smooth across previously-traded goods, not
granular. Extensive margin growth arises from a shift in the productivity cut-
off, resulting in some goods that were previously not-traded becoming traded,
as the reduction in variable cost makes it profitable to pay the fixed cost of
exporting.
The key result delivered by this standard mechanism is the smoothness
of trade growth — exports grow proportionally to the uniform reduction in

13
trade costs and proportionally to their productivity. The only disproportion-
ate growth in the standard model comes from extensive margin goods, jumping
from zero trade to non-zero levels. However, these goods become traded in such
small values (as a result of their relatively low productivities), that they ac-
count for a small proportion (<20%) of overall trade growth. This implies that
across goods, goods with similar initial levels of trade are predicted to grow
in similar magnitudes, and trade growth is only slightly more granular than
cross-sectional trade in any given period. Conversely, in the data trade growth
is highly granular and trade growth is substantially more granular than cross-
sectional trade.
Matching both the levels of cross sectional bilateral trade and the observed
level of granularity from the data is important for several reasons. For policy
analysis, it is necessary to identify the disparity in trade growth across indus-
tries so as to assess the welfare impact of trade policy across income distribu-
tions. It is important that the model capture the granularity of observed trade
to provide insight into heterogeneous responses across industries to policy pro-
posals such as trade liberalization. Matching the granularity of trade across
goods may also be important for quantifying the impact of shocks (both cyclical
and secular) on trade flows, sectoral output dynamics and the reallocations of
inputs across industries.
To attempt to better match the level of granularity observed in the data, I in-
troduce into the model heterogeneous tariff and productivity changes imputed
from U.S. manufacturing and export data. Heterogeneous productivity changes
across goods allow for large jumps in productivity for some goods classifications
that generates disproportionately large trade growth for these goods. Hetero-
geneous tariff reductions similarly allow for disproportionately large growth

14
in the goods exhibiting the largest tariff reductions, while goods experiencing
smaller reductions in trade costs exhibit much smaller growth.
To quantify this mechanism, I calibrate the standard model including het-
erogeneous productivity and tariff changes to match U.S. export data and com-
pare the granularity of trade growth across goods in the model to that in the
data. I find that incorporating these productivity and tariff changes signifi-
cantly increases the granularity of trade growth predicted in the model. Mea-
suring the proportion of overall bilateral trade growth accounted for by various
quantiles of large-growth goods, I find that this augmented model generates
roughly 70% of the granularity observed in the trade data, a marked improve-
ment from the 10% generated by the standard model with uniform tariff reduc-
tions.
2.2 Related Literature
Several empirical papers document the “lumpiness” of trade — a majority of
international trade in a given period is accounted for by a relatively small num-
ber of goods traded in large volumes, while a large proportion of domestically-
produced goods are not exported. Armenter and Koren (2010) suggest that
the concentration of large amounts of total bilateral trade in a small number of
goods categories may be systematic of the sparseness of trade data — in a given
period, the fact that there are relatively few international shipments (balls)
compared to the large number of potential goods classifications (bins) necessar-
ily results in this inherent “lumpiness” of trade across goods categories, with a
large number of goods being not-traded or traded in very small amounts, while
the majority of bilateral trade is concentrated in a small number of large-trade

15
goods. However, Blum, Claro and Horstmann (2016) argue that a key underly-
ing assumption driving the balls and bins model — that export shipment size
is randomly allocated across good categories, and is independent of firm size
— is inconsistent with shipment data and invalidates the Armenter and Koren
model’s findings. Alternatively, Fernandes et al (2015) argue that the granu-
larity of trade growth, particularly on the intensive margin, may arise from
a log-normal productivity distribution, as opposed to the Pareto distribution
commonly assumed in Melitz-style trade models, which causes firms to react
disproportionately in response to trade liberalization that lowers variable costs
of exporting. Alessandria, Kaboski and Midriggan (2010) attribute the lumpi-
ness of trade to economies of scale in transportation and delivery lags. They
find that large costs associated with international transportation of goods leads
firms “stock up” with larger and less frequent shipments, accounting for the
lumpiness of trade across goods and time.
While these papers focus on the patterns of cross-sectional trade, a cen-
tral contribution of this chapter is to document the fact that trade growth is
granular. Further, I find that the set of large-growth goods accounting for the
majority of trade growth is uncorrelated with the set of goods in which per-
period trade is concentrated. Finally, I find that trade growth is more granular
than cross-sectional trade, and that the level of trade growth across goods is
uncorrelated with initial levels of trade.
A large literature (e.g. Krugman (1979), Lancaster (1980), Deardorff (1984),
etc) documents recent growth in international trade. Most germane to this
chapter is the documented fact that the ratio of trade to GDP has increased
over the past 50 years. Bergoeing and Kehoe (2001) document key trade growth
16
facts and investigate the ability of standard trade models to quantitatively cap-
ture the patterns observed in international trade data. This chapter documents
that this trade growth is highly concentrated in a small number of rapid growth
episodes over this period.
This chapter is also related to empirical work identifying the effects of trade
liberalizations on bilateral trade flows. Romalis (2007) uses a difference-in-
difference approach to exploit variation between trade liberalizing and non-
trade liberalizing countries to estimate elasticities of traded goods. He reports
that trade liberalization has a significant impact on volume, but small impact
on prices and welfare. This chapter extends these data facts by investigating
trade growth variation across individual goods, and develops a model that can
deliver the patterns of trade observed in the data, which standard models do
not produce.
Kehoe and Ruhl (2013) find that the extensive margin plays a significant
role in accounting for bilateral trade growth, with a 10% increase in trade
between country-pairs being accompanied by a 36% increase in the extensive
margin, on average.13 While I find similar results on the impact of the overall
extensive margin, this chapter adds to Kehoe and Ruhl by decomposing exten-
sive margin growth between goods that were previously not traded and those
that were traded in very small amounts. I document that extensive margin
growth is quite granular, with less than 5% of extensive margin goods account-
ing for over 25% of growth in the extensive margin.
Many papers have used standard international trade models to examine the
impact of trade liberalizations (and other structural change) on trade volumes
13Kehoe and Ruhl’s interpretation of the extensive margin varies from the theoretical defini-
tion identified in Chaney (2008) — Kehoe and Ruhl classify the extensive margin as the growth
in trade among the set of least-traded goods, classified as the bottom decile of goods sorted by
initial trade value.

17
and the patterns of trade growth. However, these models do not produce the
high level of granularity of trade growth observed in the data. Melitz (2003)
introduces heterogeneous productivity across firms with a fixed cost of entry to
a model with monopolistic competition, which predicts that intensive margin
growth is smooth across goods. Chaney (2008) builds on the Melitz framework
to isolate the role of the extensive margin in trade growth, identifying the set
of goods that enter the exporting market following reductions in trade barriers.
However, in this framework, extensive margin growth is smooth across exten-
sive margin goods. Arkolakis (2010) builds a model of market penetration, in
which firms essentially choose their fixed cost in order to penetrate a market
and then face increasing marginal costs to reach additional consumers. How-
ever these models, whether employing a single fixed-cost export technology (as
in Melitz, Chaney), or a continuum of fixed cost options (as in Arkolakis), do not
produce the non-convexity of trade growth across goods observed in the data.
This chapter extends the literature by adding heterogeneous productivity and
tariff changes to investigate whether this standard framework can generate
the level of granularity of trade growth observed in the data across both the
intensive and extensive margins.
2.3 Data
2.3.1 Stylized Facts
I use data on bilateral trade values, ad valorem tariff rates, and manufacturing
data to decompose trade growth between the intensive and extensive margins
across goods classifications. Four key facts emerge from the data:
1. Trade growth is highly granular across time and across goods
18
classifications.
a. Across countries, bilateral trade growth over time occurs in short
periods of rapid growth. Rather than smooth, consistent growth
over time, growth is concentrated in a small number of rapid growth
episodes. Over the past 50 years, the 5 largest-growth years account
for roughly 75% of overall trade growth.
b. Across goods classifications, trade growth is concentrated in a small
number of goods classifications, with 5% of classifications accounting
for roughly 65–110% of total bilateral trade growth by country-pair.
In all bilateral pairs, there are many goods classifications that begin
with zero trade, and remain so over time.14 Goods that switch from
zero reported trade to positive trade remain at low values. The ma-
jority of goods that are initially traded grow very little — it is only
a small number of goods, growing from low levels of initial trade to
high levels of final trade, or from high levels of initial trade to very
high levels of final trade, that account for the majority of the growth
in bilateral trade.
2. Reductions in tariffs coincide with only 10–20% of the large-growth
goods.
Tariff reductions do not account for the granularity in trade growth. Among
the subset of large-growth goods which account for the majority of trade,
large decreases in tariff rates accompany only a small number (10–20%)
of these goods, while the remaining goods exhibit no change or small in-
creases in their ad valorem equivalent tariff rate.
14While this property is consistent across country-pairs, it is not true that it is the same set
of goods with zero trade across all country pairs. One good with zero trade for one country-pair
may be highly traded across other country-pairs, and vice-versa.

19
3. Trade intensity and production growth both account for large
growth in bilateral trade
Controlling for growth in production across goods classifications, increases
in trade intensity account for 35–90% of total observed trade growth across
various U.S. bilateral pairs. Conversely, fixing trade intensity at initial
levels, growth in domestic production accounts for 30–40% of U.S. export
growth to certain countries (such as Canada and Japan), whereas pro-
duction growth accounts for virtually none of the observed bilateral trade
growth in others (Germany, Mexico, U.K.).
4. Extensive margin growth is granular and a significant factor in
total bilateral trade growth The rise in trade growth of the least-
traded goods accounting for the bottom decile of initial bilateral trade is
significant in accounting for overall trade growth. A 10% increase in bilat-
eral trade is accompanied by a 24% increase in the extensive margin, on
average across country-pairs. Extensive margin growth is granular, with
a small number of extensive margin goods (<5%) accounting for roughly
25% of total extensive margin growth, but less granular than total bilat-
eral growth.
2.3.2 Data Sources
To study and decompose bilateral trade growth, I use annual UN Comtrade
data on bilateral trade from 1989–1999, at the 5-digit Standard International
Trade Classification (SITC) level, for 6 countries — Canada, Germany, Japan,
Mexico, U.S.A, and U.K. Trade between these country-pairs accounts for roughly
20–25% of global trade during this period. At the 5-digit SITC code level there
20
are 1836 different goods classifications.15 Since the 1989–1999 period includes
the implementation of NAFTA and CUSFTA — episodes of trade liberalization
for some country-pairs (Canada, Mexico, U.S.A.) but not for others (Germany,
Japan, U.K.) — I am able to examine the differential effects of trade liberaliza-
tion on trade growth across country-pairs.16
I use data on U.S. tariff rates and U.S. imports from Canada, Germany,
Japan, Mexico, and the U.K. to investigate the impact of trade liberalization,
and heterogeneous changes in tariff on trade growth across goods. The U.S. tar-
iff rate data is from the NBER database on international trade and reports the
ad valorem equivalent (AVE) tariff rates on U.S. imports between 1989–1999 at
the Harmonized Tariff Schedule (HTS) 8-digit level.17 This includes estimates
of AVE rates for all Most-Favored-Nation-status (MFN) trading partners, such
as Germany, Japan and U.K., as well as the tariff schedules for Canada and
Mexico following the implementation of NAFTA. I match this tariff data, with
data on U.S. imports, resulting in approximately 8000–10000 different goods
categories, depending on the import source country.18
15The UN uses a lexicographic ordering of SITC codes, with a parent category divided into up
to 10 subcategories at each stage of disaggregation — thus a 3 digit code 782 may be subdivided
into 7821 and 7822, and 7822 may be subdivided into 78221, 78223, 78225, 78227 and 78229,
etc. This may invokes concerns of endogeneity in the classifications — goods with larger trade
values may enable or necessitate more subdivisions, while goods with less trade may be lumped
into one broader parent category. However, the SITC codes underwent their most recent rounds
of revisions in 1986 and 2006 respectively — since the data in this work focuses on the time
periods 1989–1999, this concern should be reasonably mitigated. This is similarly true for the
NAICS and HTS classification systems. For a more detailed methodology, consult the United
Nations Statistic Divisions reports, available at http://unstats.un.org/unsd/family/default.asp.
16This trade data is particularly appropriate as it represents a subset of the Kehoe and Ruhl
(2013) data set, allowing for a comparison of the results on trade liberalizations and extensive
margin growth found in that paper.
17This data set is compiled by Feenstra, Romalis and Schott (NBER working paper), avail-
able at http://www.johnromalis.com/publications/.
18U.S. import data comes from a dataset on U.S imports and exports compiled by Pe-
ter Schott, containing data on U.S. imports at the 10-digit HTS level, which is then ag-
gregated up to the 8-digit level over the same time period, 1989–1999, available at http :
//faculty.som.yale.edu/peterschott/subinternational.htm.
21
To identify the relationship between trade and gross domestic production, I
include matched data on U.S. manufacturing and U.S. exports. I compile pro-
duction data from the NBER-CES Manufacturing Industry database to provide
data on 473 goods classifications at the 6-digit North American Industry Classi-
fication System (NAICS) level between 1989 and 1999. I match the production
data to U.S. export data at the 6-digit NAICS level for the same destination
countries as the tariff and bilateral trade data.19
Since international trade data often suffers from issues of sparseness and
lumpiness in shipments, I use a 3-yr average to control for reporting errors
in the timing of shipments, or instances of shipment and Customs reports be-
ing dispersed over multiple years. I classify the initial level of trade as the
1989–1991 average and the final level of trade as the 1997–1999 average for
each good classification. The difference in these 3-yr averages therefore repre-
sents the growth in trade over this period.
Descriptive Statistics
Tables 2.1 and 2.2 present summary statistics, for NAFTA country-pairs and
non-NAFTA country-pairs respectively, of the 5-digit SITC bilateral trade data.
There are three key facts to note. First, on average, the initial level of trade
for NAFTA and non-NAFTA pairs is approximately the same (roughly $36B),
in total shipment value in $US, while the average final level of trade is higher
in NAFTA country-pairs ($75B) than in non-NAFTA pairs ($57B). This reflects
the larger average growth in total trade for NAFTA country-pairs of 148%,
while non-NAFTA pairs average 63% growth over the same period. Second, the
bottom decile of goods, ordered by initial trade value, grow to account for 18%
19The NBER data comes from a database compiled by Becker, Gray and Marvakov, available
at http://www.nber.org/nberces/, while the export data comes from the Schott database (Ibid.).
22
of final trade in NAFTA country-pairs, while accounting for 13% of final trade
in non-NAFTA pairs. This implies a slightly larger role for the extensive mar-
gin in trade-liberalizing countries. Third, the 10 largest-growth goods in each
country pair (out of 1836 total good classifications) accounts for approximately
50% of total trade growth in NAFTA and non-NAFTA country-pairs alike. Sim-
ilarly, the 100 largest-growth goods account for 101% of total trade growth in
non-NAFTA countries, and 90% of total trade growth in NAFTA country-pairs.
Together, these three facts suggest that trade growth is highly concentrated
in a small number of goods classifications. This pattern is consistent across
all country-pairs, although it is slightly more prominent in trade-liberalization
country-pairs.
Table 2.1: Summary Statistics: NAFTA country-pairs
Bilateral Trade Statistics: 5-digit SITC codes
Variable Can-Mex Mex-Can Can-Usa Usa-Can Mex-Usa Usa-Mex NAFTA Avg
Initial trade 452451 1711096 83278894 71313846 28298716 25796112 35141852
Final trade 880883 5537384 160144152 123700777 93734628 70447948 75740962
Total trade growth 428432 3826288 76865257 52386931 65435912 44651836 40599109
%∆ in trade 94.7% 223.7% 92.3% 73.5% 231.2% 173.1% 148%
Share of trade growth 94.7% 61.3% 41.1% 29.4% 42.5% 29.6 51.9%
from 10 largest growers
Share of trade growth 136.5% 95.0% 77.6% 68.5% 85.2% 71.2% 91.8%
from 100 largest growers
Extensive margin 25.7% 26.4% 15.6% 11.5% 17.5% 13.3% 18.3%
share of final trade
Number of goods 1836
(All trade values in thousands of $US)
Table 2.2: Summary Statistics: Non-NAFTA country-pairs
Bilateral Trade Statistics: 5-digit SITC codes
Variable Ger-Usa Usa-Ger Jpn-Usa Usa-Jpn UK-Usa Usa-UK Non-NAFTA Avg
Initial trade 25828198 21430441 93940987 48749684 18021847 19532210 37917228
Final trade 47977038 34737504 124383525 67346115 33471956 34286200 57033723
Total trade growth 22148840 13307063 30442537 18596431 15450108 14753990 19116495
%∆ trade growth 85.7% 62.1% 32.4% 38.1% 85.7% 75.5% 63.3%
Share of trade growth 52.0% 56.1% 57.8% 58.1% 41.1 38.7% 50.6%
from 10 largest growers
Share of trade growth 85.3 107.9% 121.1% 118.7% 87.2% 85.9% 101.1%
from 100 largest growers
Extensive margin 13.0% 12.9% 12.3% 12.4% 11.9% 14.5% 12.8%
share of final trade
Number of goods 1836
(All trade values in thousands of $US)
23
2.3.3 Granularity of Trade Growth
Granularity Across Time
Over the past 50–60 years, trade growth across NAFTA and non-NAFTA country-
pairs exhibit similar patterns.20 All country-pairs show large overall growth
over this period, but exhibit large variation in the rate of growth between pe-
riods. In most cases, the majority of the overall trade growth over time is
accounted for by a small number of episodes of rapid growth.
To quantify the granularity in trade growth over time, I calculate the share
of total trade growth accounted for by each year, and calculate the proportion
of overall trade growth accounted for by the top 5, 10 and 15 years of growth.
Table 2.3 reports that the top 5 years of growth (representing only 10% of the
total time frame) account for roughly 75% of overall trade growth across time.21
The top 10 and 15 years of growth account for roughly 150% and 200%, re-
spectively, of total bilateral trade over this period, suggesting that most of the
overall growth over time is concentrated in a small number of rapid growth
episodes.
Table 2.3: Proportion of total bilateral trade from “X” top-growth years
Proportion of trade growth from top X%years
(5-digit SITC codes)
1-yr intervals 2-yr intervals 3-yr intervals
Country-Pair 5 yrs (10%) 10 yrs (20%) 15 yrs (30%) 3 yrs (10%) 6yrs (20%) 9yrs (30%) 2 yrs (10%) 4 yrs (20%) 6 yrs (30%)
Mex-Can 0.6856 0.9931 1.1836 0.7257 1.0360 1.1356 0.7146 0.9552 1.0612
Usa-Jpn 0.6781 1.0553 1.3400 0.6000 0.9775 1.2586 0.5747 0.8556 1.0261
Jpn-Usa 0.9172 1.5070 1.9293 0.8442 1.2970 1.5322 0.6426 0.9776 1.2874
Mean 0.7603 1.1852 1.4843 0.7233 1.1035 1.3088 0.6440 0.9295 1.1249
20Figure A.1 plots total bilateral trade values for exports over the past 50 years for Mexican
exports to the U.S. and Canada, as well as U.S. exports to Japan and Japanese exports to the
U.K. For some countries in the data set, such as Mexico, the data only extends back to 1980. For
brevity, only 4 countries are plotted here, but other the country-pairs exhibit similar growth
patterns over time.
21It should be noted that these need not be concurrent years, but rather the 5 individual
years demonstrating the largest growth across the entire time period.
24
Due to the inherent lumpiness and variability in reporting of international
shipments, using single year intervals to measure growth may potentially over-
estimate trade growth in any given year. I therefore repeat the exercise by
using 2-year and 3-year intervals for the length of each period in calculating
trade growth. I find similar results to those using 1-year intervals, with a high
degree of granularity across time periods, with the top 10% of time periods
accounting for 70–75% of total trade growth. This reinforces the finding that
trade growth is not smooth and uniform across time, but highly concentrated
in a small number of episodes of rapid growth.
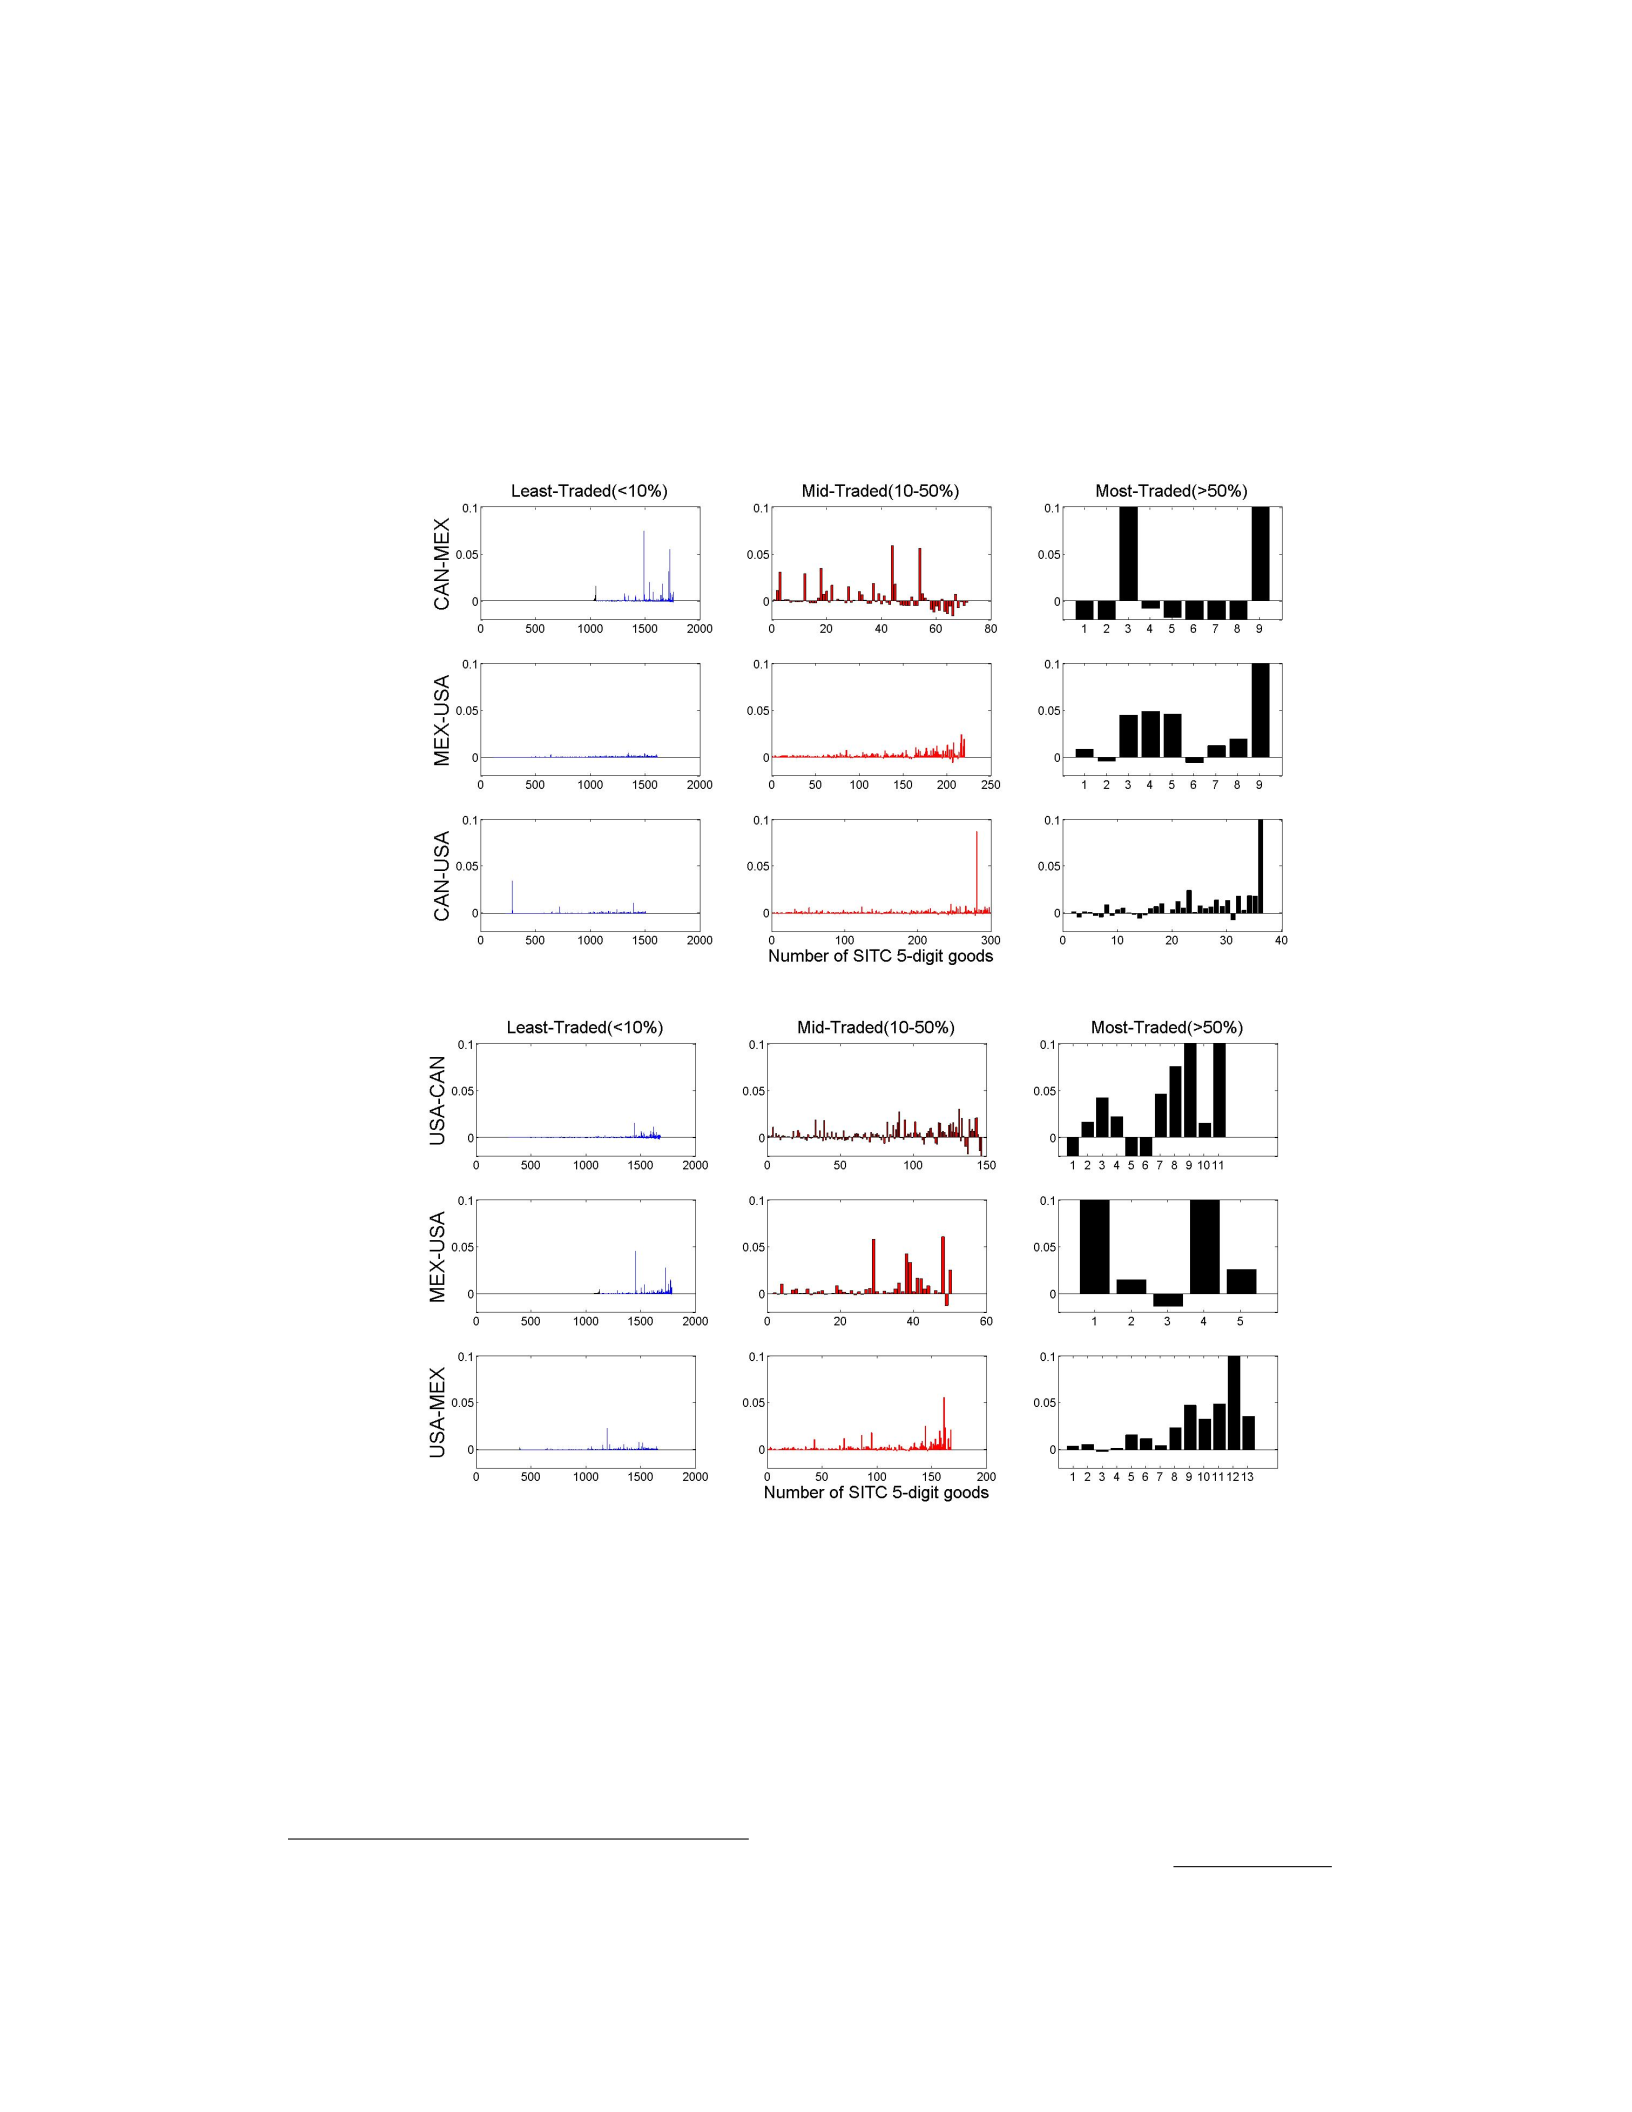
Granularity across goods
To identify the properties of trade growth, I examine the share of total trade
growth accounted for by each good for each country pair. I arrange goods, in
ascending order, by initial value of exports for each bilateral pair and calcu-
late each good’s corresponding share of the total growth in bilateral trade. For
ease of exposition, I separate goods into 3 groupings — the least-traded goods
(comprising the bottom decile of total initial exports, by 5-digit SITC code); the
mid-traded goods (comprising the second through fifth deciles); and the most-
traded goods (comprising the top 50% of initial exports).. Across the various
bilateral country-pairs, the least-traded goods make up 75–90% of the goods
classifications. Roughly half of these categories are goods with zero reported
trade.22 The set of most-traded goods comprises a small number (5–40 of 1836)
of good classifications. This reflects the “lumpiness” in cross-sectional trade
data — many goods are not-traded or traded in small quantities, while a small
number of highly-traded goods accounts for a large portion of total bilateral
22Due to the fact that most countries exclude very small shipments (i.e. less than $2000)
from customs duties and reports, the term “not-traded” is used in this paper to refer to goods
with no recorded trade value in these customs reports.
25
trade in any given period.
Figure 2.1: Growth by Good: 5-digit SITC bilateral trade
(b) NAFTA county-pairs
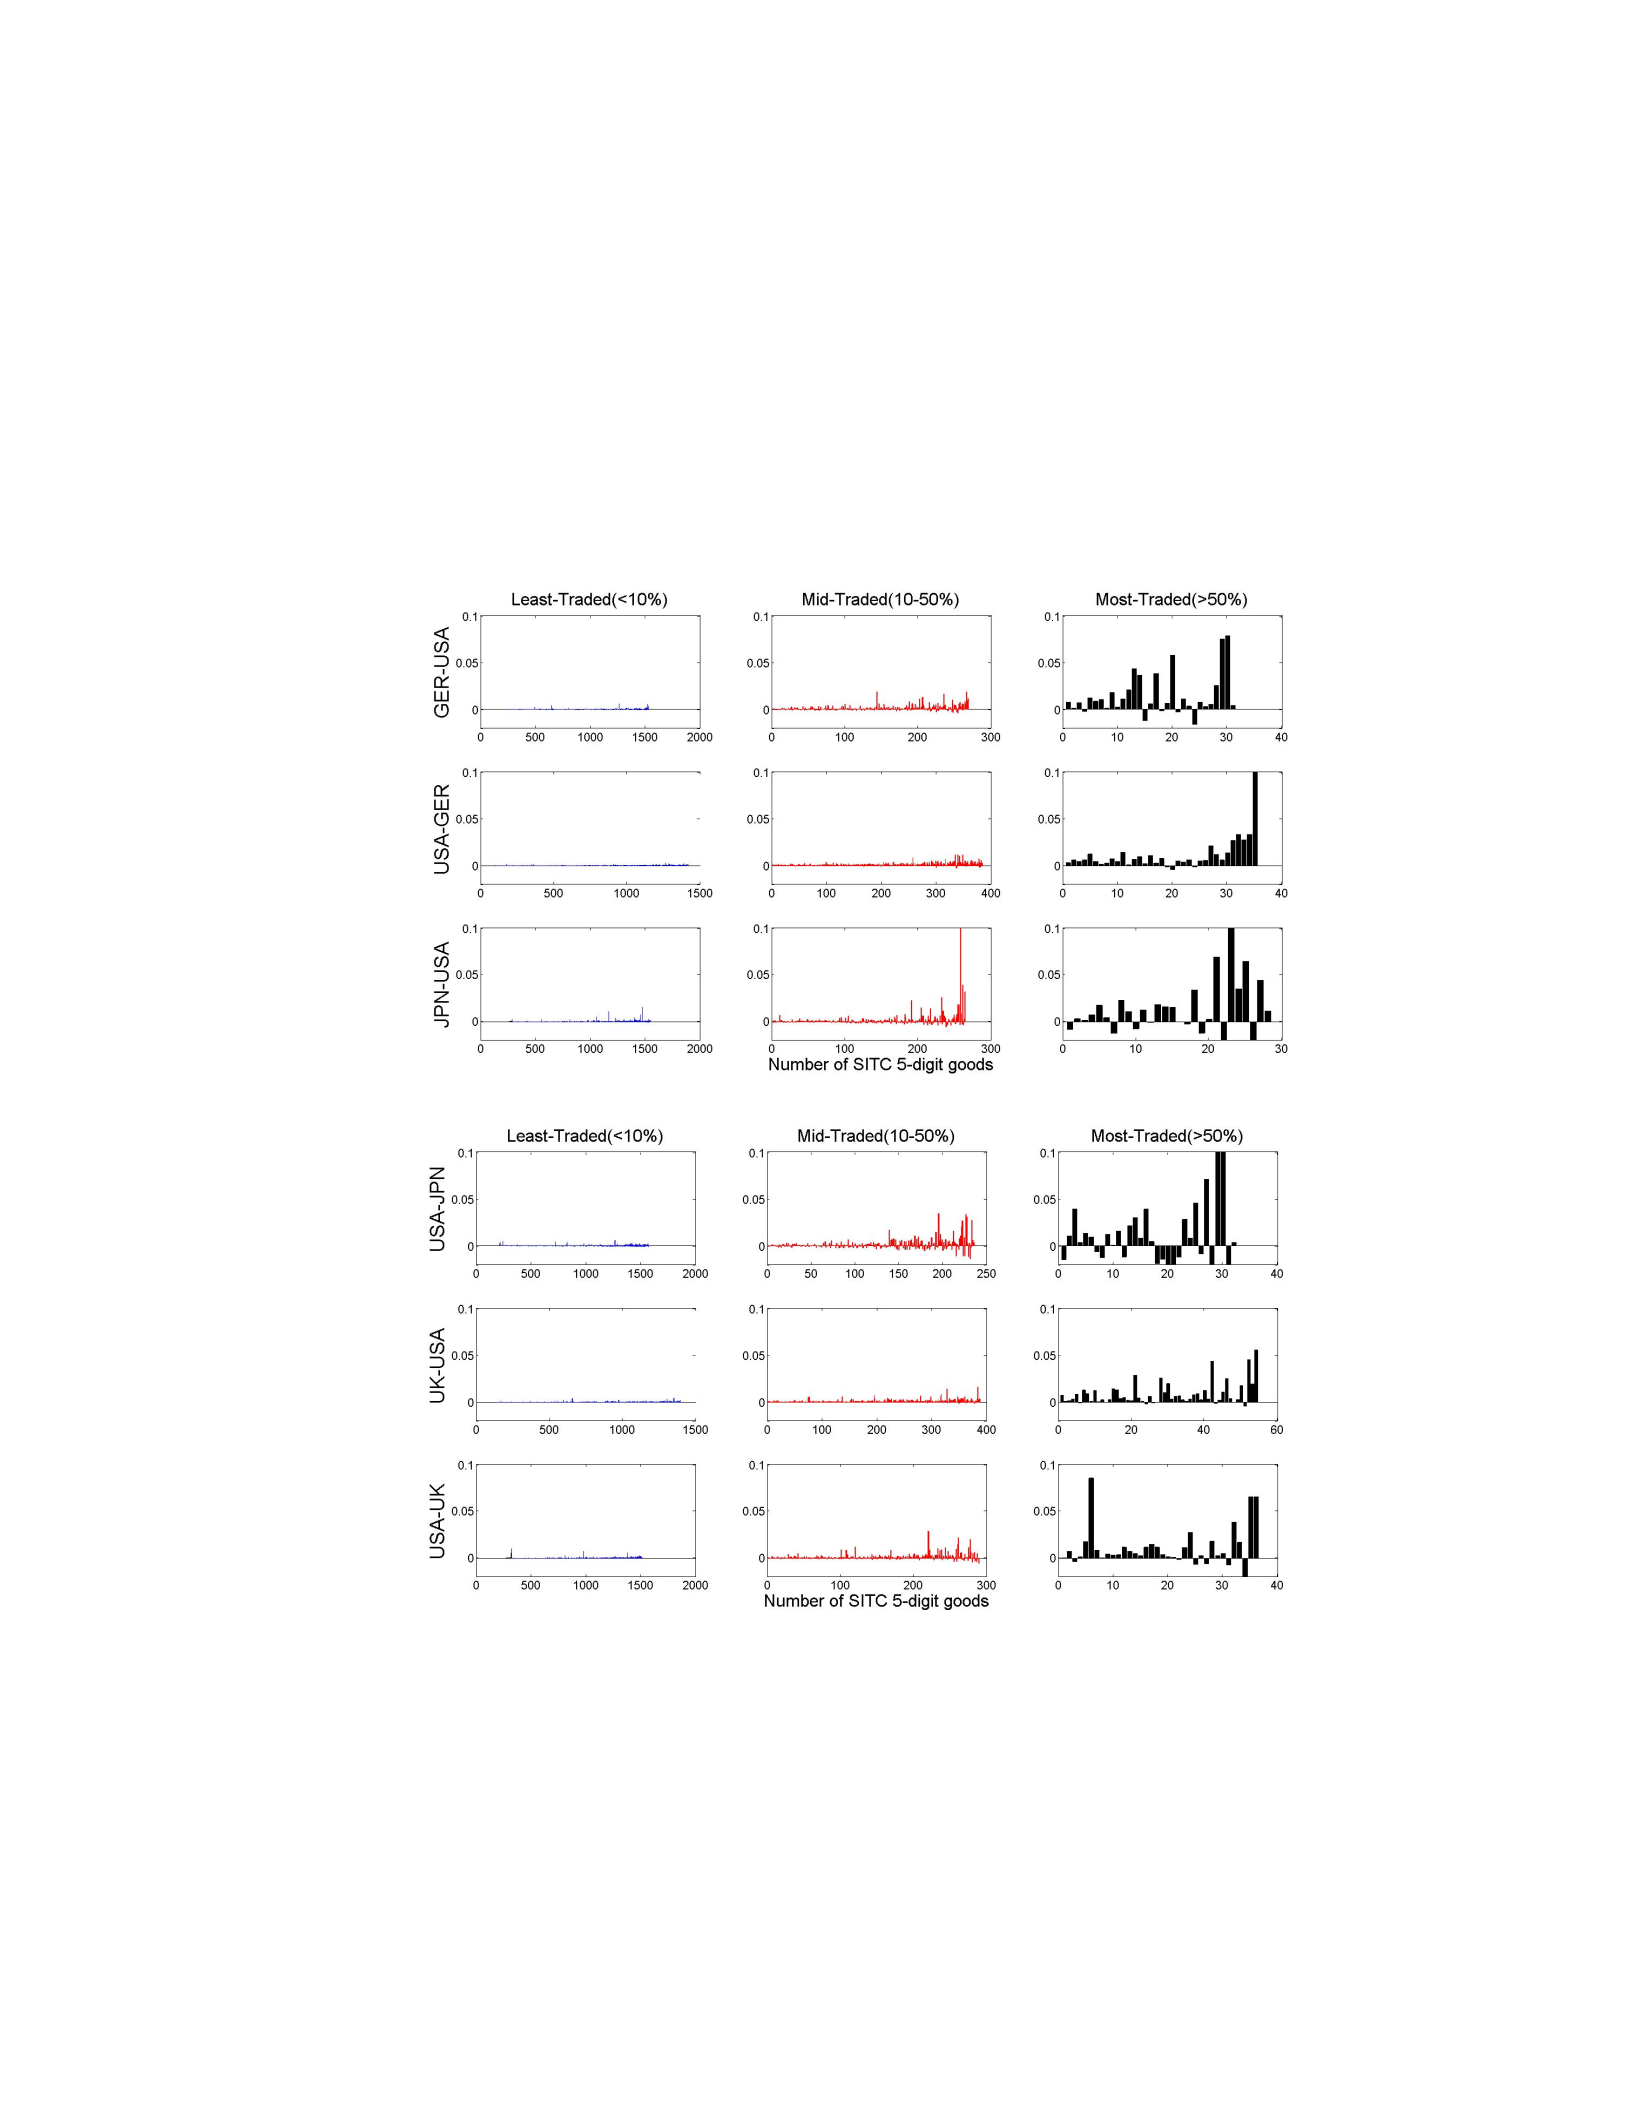
To decompose trade growth across goods, I plot the trade growth accounted
for by each good as a share of total bilateral trade growth in Figures 2.1–2.2.23
The height of each bar represents that good’s contribution to the total growth
23Formally, the y-axis of Fig. A.2–2.2 is measured, for each good i, as: ∆Exports(i)
Pj∆Exports(j).
26
Figure 2.2: Growth by Good: 5-digit SITC bilateral trade
(b) Non-NAFTA county-pairs
27
in trade for that country-pair.24
Bilateral trade growth is highly granular, with a small number of goods
exhibiting large increases in trade values accounting for the vast majority of
total trade growth. Most of these goods originate from the mid- or most-traded
categories, and almost never from the least-traded category. The remaining
goods (90–95% of all goods classifications) exhibit small (<0.05% of total trade),
zero, or negative growth.
This finding can be summarized as follows: many goods begin and remain
not-traded; some not-traded goods become traded in small amounts, but al-
most never go from zero to large amounts of trade; most traded goods grow
very little; a small number of goods grow from small amounts of trade to large
amounts, or from large amounts to even larger amounts, the two cases that
account for the majority of trade growth between country-pairs.
The goods exhibiting large growth that account for the majority of trade
growth come from varying levels of initial trade across bilateral pairs. That
is, large growth goods (“growers”) do not all begin with similar levels of initial
trade, and goods with similar initial levels of trade do not necessarily grow in
similar proportions.25 Further, goods that begin with zero trade do not typically
become traded in large values, if they become traded at all.
To quantify this relationship, I calculate the share of total bilateral trade
growth accounted for by these high-growth goods. Table 2.4 lists the proportion
of overall trade growth accounted for by the top 1% of large-growth goods, as
24To more clearly illustrate the patterns of trade growth, I also plot groupings of goods indi-
vidually, as seen in Figures A.2–A.4. These figures represent the case for Canadian exports to
Mexico; Figures 2.1–2.2 show similar results for all country-pairs.
25One possible exception to this might be the U.S.-Canada pairing, which seems to exhibit
less concentration of trade growth and smoother growth in trade, according to initial value of
trade by good.
28
well as the top 2%, 5% and 10% of goods.26 The mean values, across all country-
pairs, identify the granularity in trade growth, with the top 1% of goods ac-
counting for 62% of total trade growth, while the top 2%, 5% and 10% of goods
accounting for 76%, 93% and 105% of total bilateral trade growth, respectively.
There is variability in the degree of granularity across country-pairs — the top
1% of Canadian exports to the U.S. account for 108% of total growth in trade,
while the top 1% of U.S. exports to Mexico account for only 39% of total trade
growth. However, all country-pairs exhibit granularity of trade growth across
goods, with a disproportionately high concentration of trade growth in a small
number of goods.
Table 2.4: Proportion of total bilateral trade concentrated in top “X00%of goods
Proportion of growth from top X%of goods
(5-digit SITC codes)
Country-Pair 1% (18 goods) 2% (36 goods) 5% (91 goods) 10% (183 goods)
Can-Usa 1.081 1.223 1.355 1.410
Can-Mex 0.491 0.606 0.760 0.884
Ger-Usa 0.589 0.692 0.837 0.955
Jpn-Usa 0.722 0.940 1.189 1.313
Mex-Can 0.718 0.818 0.940 1.004
Mex-Usa 0.551 0.681 0.836 0.935
Usa-Can 0.373 0.478 0.665 0.815
Usa-Ger 0.710 0.882 1.062 1.167
Usa-Jpn 0.753 0.928 1.165 1.311
Usa-Mex 0.396 0.518 0.692 0.834
Usa-UK 0.492 0.647 0.841 0.972
UK-Usa 0.516 0.653 0.853 0.974
Mean 0.616 0.756 0.933 1.048
While this pattern of granularity of trade growth is pervasive across all
country-pairs, it is not the same goods categories that account for the major-
ity of trade growth across different country-pairs. Rather, there is significant
26As there are 1836 goods classifications, the top 1% of goods consists of the top 18 goods
classifications, the top 2% consisting of 36 goods, etc.
29
Table 2.5: Common large-growth goods across all countries
Number of Goods with X% of Trade Growth
5-digit SITC codes (1836 goods)
Countries >3% >1% >0.5% >0.1%
All 0 1 2 9
Pass. Autos Switches/Fuses Unhardened rubber
Other auto parts Pipe valves
Metal mountings
Peripheral units
TV transmitters
Static converters
Elec. microcircuits
Gas instruments
Polarizing lenses
heterogeneity in which goods account for the majority of trade growth across
country-pairs. Table 2.5 shows that of the 1836 SITC 5-digit classifications,
none account for at least 3% of total trade growth in every country-pairs. Only
one category, passenger automobiles (excluding buses), accounts for at least 1%
of trade growth in every country-pair. Further, only a dozen of the 1836 goods
classifications account for at least 0.1% of total trade growth in every country-
pair. Examining bilateral pairs, of the small number of goods categories ac-
counting for the majority of trade growth, only a small proportion (roughly
5–20%) are common to both countries’ trade growth. Table 2.6 demonstrates
that for each bilateral pair, of the 1–6 goods categories accounting for at least
5% of bilateral trade growth for each country, none or only 1 of them is common
to both countries. Similarly, of the roughly 20–30 goods each accounting for at
least 1% of total bilateral trade growth, only 4–8 of these goods are common to
both countries.
30
Table 2.6: Common large-growth goods across country-pairs
Number of Goods with X% of Trade Growth
5-digit SITC codes (1836 goods)
Country >5% >3% >1% >0.5% >0.1%
Same Same Same Same Same
Canada 6 9 21 40 103
Mexico 4 117 118 426 6107 27
Canada 1 4 14 34 176
USA 1 012 115 532 15 202 108
Mexico 2 6 21 35 138
USA 1 016 118 836 15 190 76
Germany 2 3 12 31 165
USA 4 121 126 844 17 139 72
Japan 3 5 31 57 146
USA 3 121 325 853 19 178 62
UK 3 6 19 47 159
USA 3 014 222 642 18 182 91
2.3.4 Tariff Rates
Trade theory suggests that reductions in import tariffs should lower barriers to
trade and increase trade for those goods. To examine the relationship between
changes in tariff rates and corresponding trade growth across goods, I match
data on U.S. tariff rates to U.S. import data at the 8-digit HTS code level.27 I
calculate the change in the tariff rate for each good as the difference between
the initial and final ad valorem equivalent (AVE) tariff values calculated by
Romalis (2007). For each bilateral U.S. trade partner, I match the AVE tariff
change to the corresponding growth share in U.S. imports for each good. Across
all goods, the tariff changes show a wide range of values, from large increases
27To examine tariff data at the most disaggregated level available, I use 8-digit HTS data,
which has significantly more goods classifications than the 5-digit SITC data (>8000 vs. 1836)
— however, I find the pattern of trade growth granularity, while slightly more pronounced in
the HTS classifications, displays similar patterns of the concentration of trade growth as the
5-digit SITC code data. As in the 5-digit SITC data, trade growth is also slightly more granular
in NAFTA countries (Canada and Mexico) than it is in non-liberalizing countries (U.K.).
31
to no change to large decreases. Tariff changes are generally larger and more
negative in the trade liberalizing countries of Canada and Mexico than those
for Most Favored Nation (MFN) status countries like the U.K. However, for
each country-pair, the correlation between import growth and the change in
tariff rates across all goods is not significantly different from zero. Isolating
each set of least-, mid- and most-traded goods, this lack of correlation holds.28
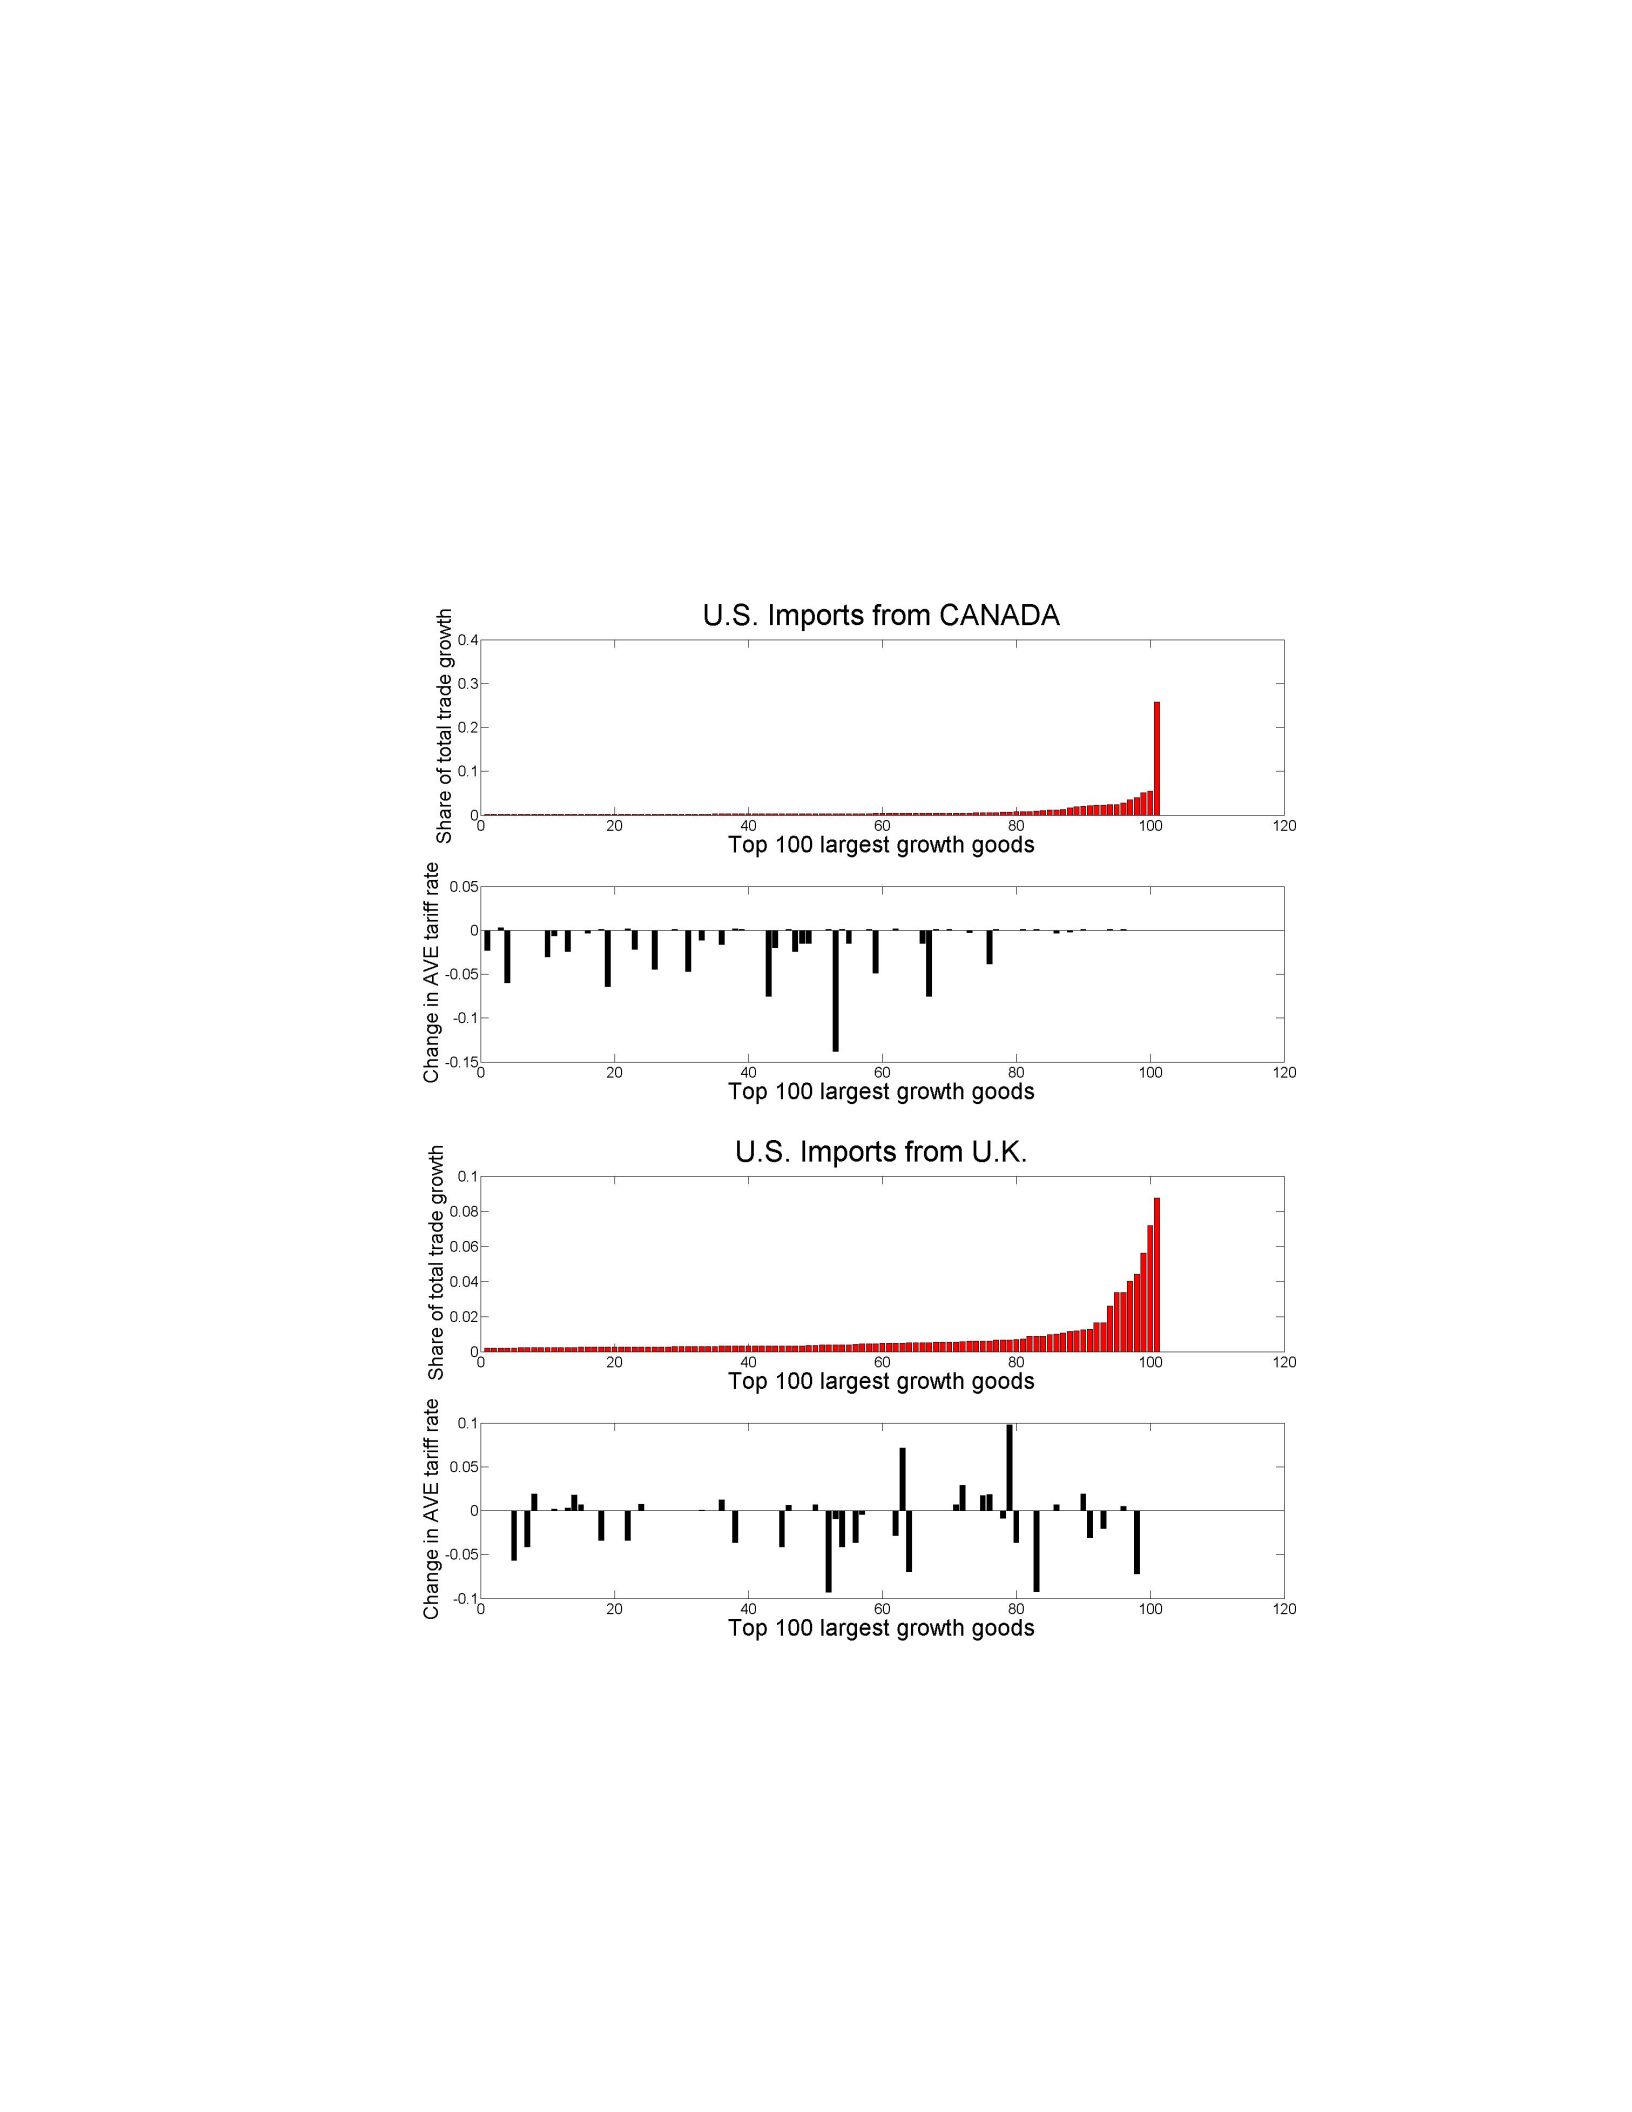
Due to the granularity of trade growth across goods, I isolate the subset of
largest-growth goods contributing the majority of total trade growth and ex-
amine their corresponding tariff changes. Figure 2.3 plots the 100 goods clas-
sifications that contribute the most to import growth (accounting for ≈80% of
total growth). These large-growth goods display a wide range of tariff changes
— depending on the country-pair. Only 10 to 30 of these 100 largest “growers”
exhibit notable decreases in the AVE tariff rate. The remaining goods reflect no
change or an increase in the AVE rate, suggesting that tariff decreases alone
cannot account for the granularity in trade growth across goods.
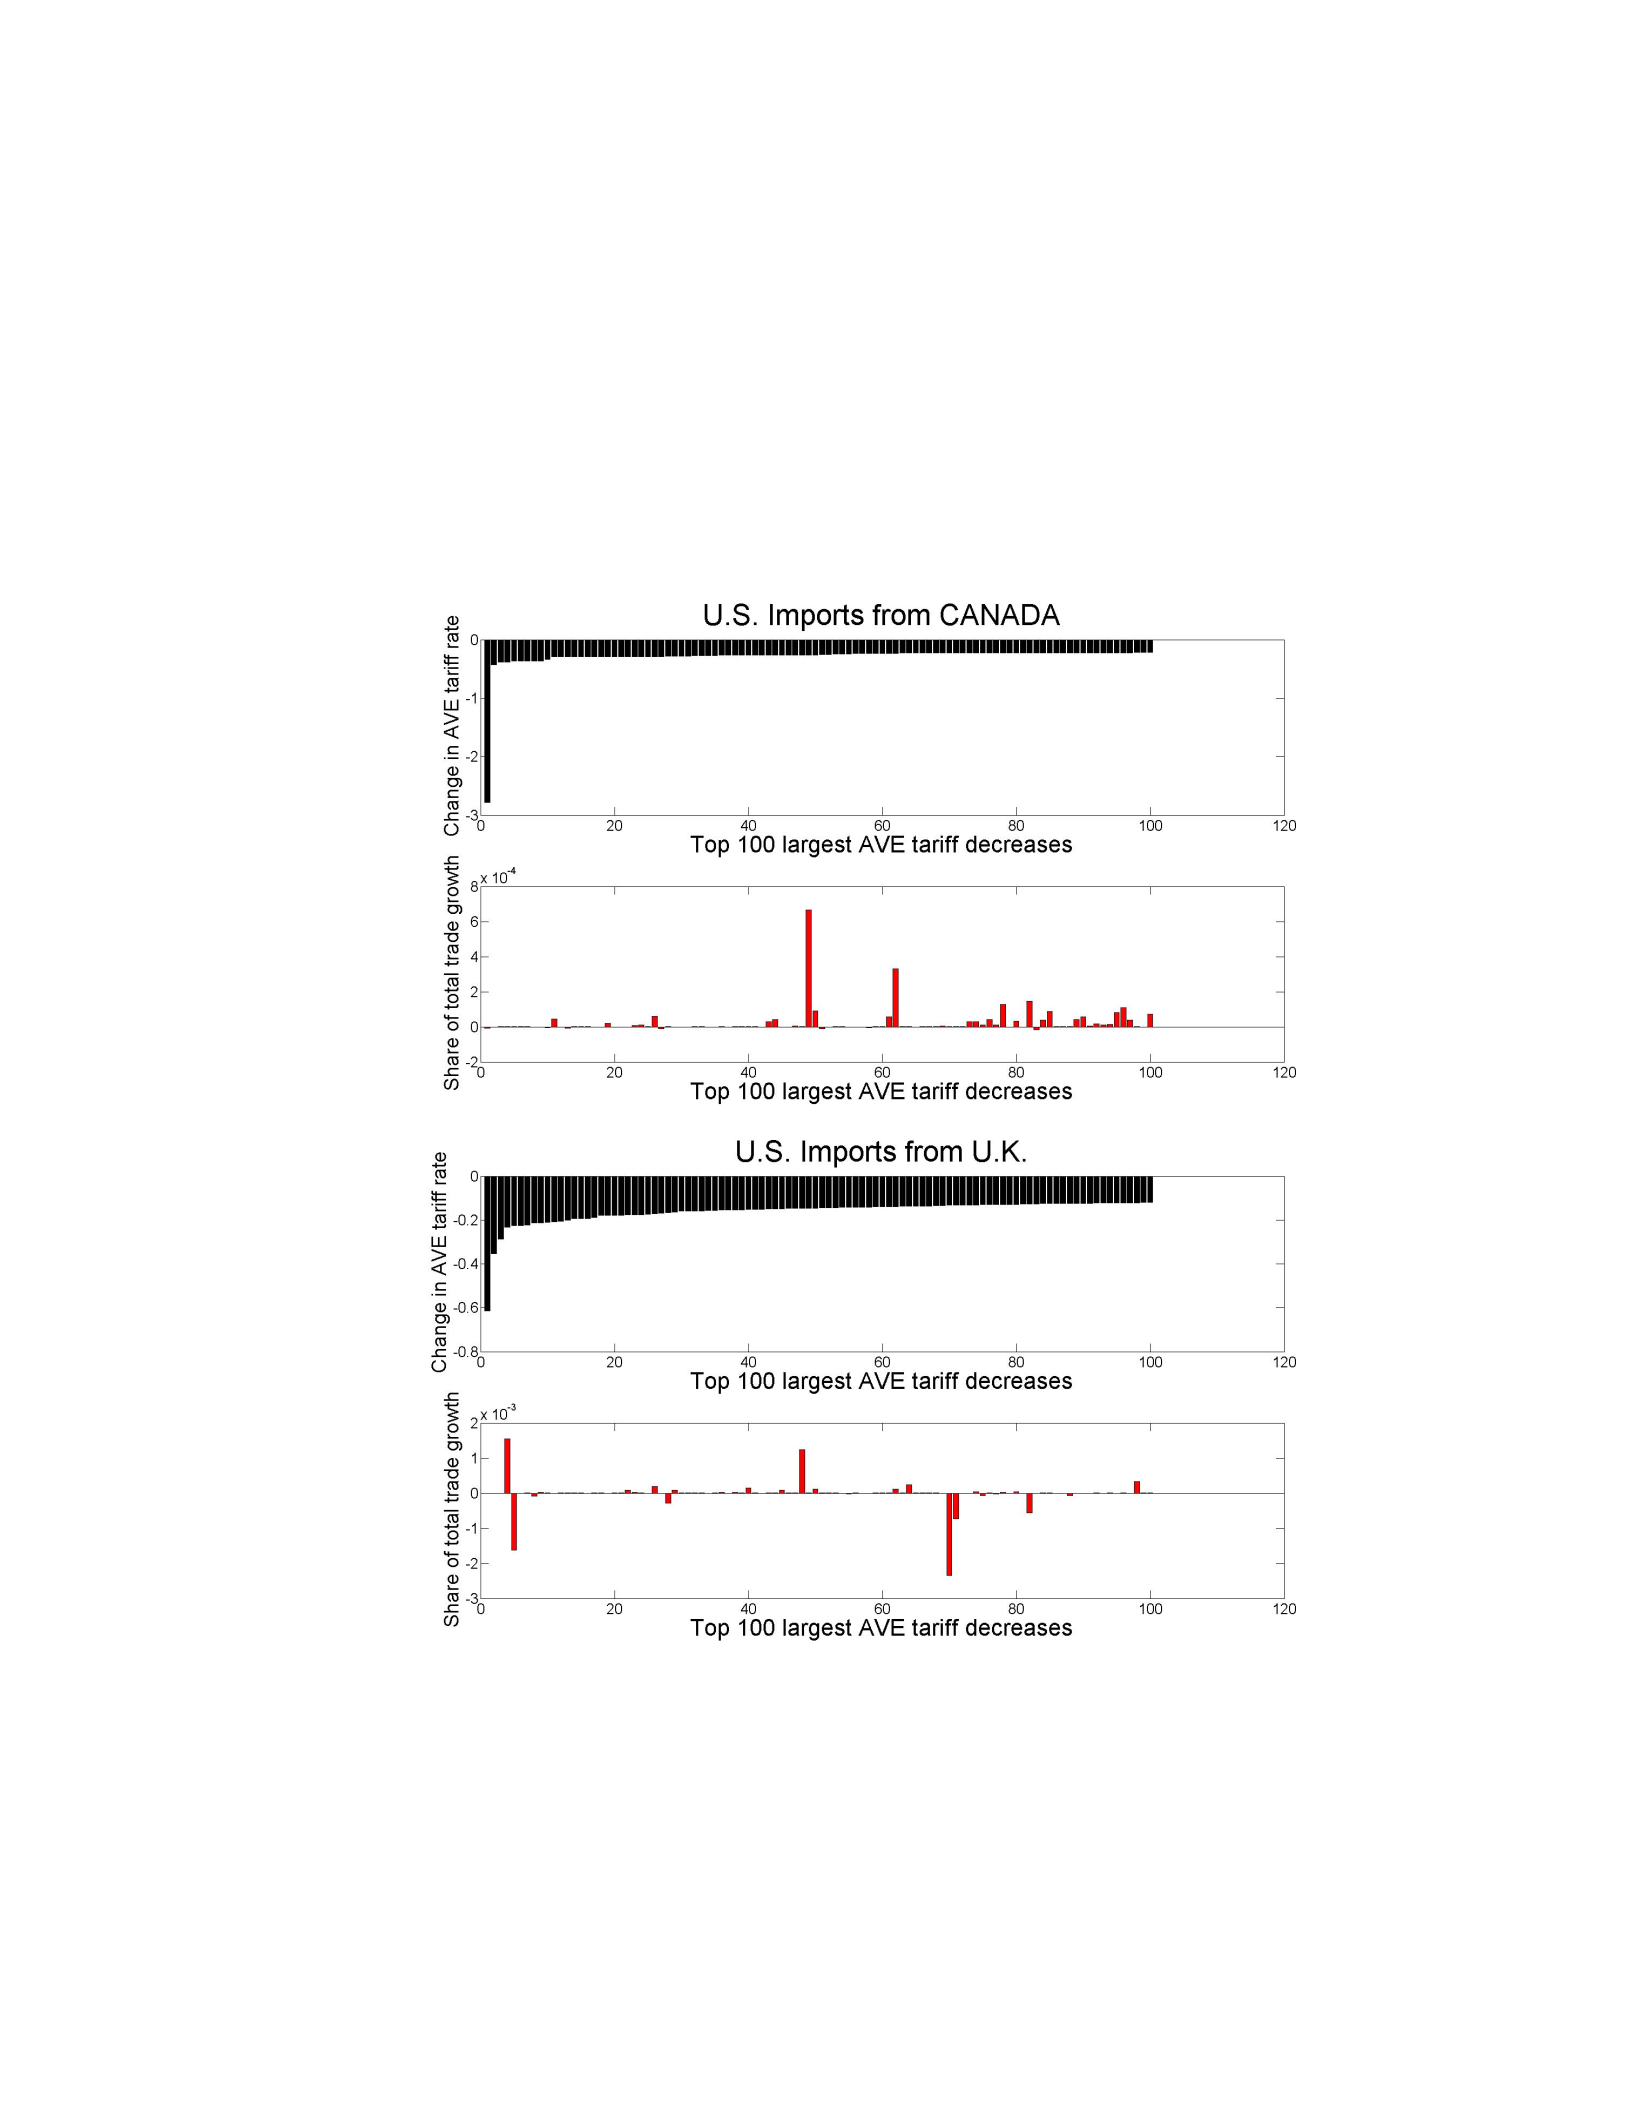
Alternatively, in Figure 2.4, I isolate the subset of goods that exhibit the
largest decreases in tariff rates to examine their corresponding share of trade
growth. Roughly one-third of the goods experiencing the largest tariff reduc-
tions exhibit positive growth in trade. However, few of these goods (<10–15%)
contribute significant shares to the overall increase in imports. The majority of
goods with the largest tariff reductions exhibit no growth or slight decreases in
imports from initial to final trade levels, coinciding with the lack of statistically
significant correlation between tariff changes and import growth.
28Refer to Figures A.5–A.7.
32
Figure 2.3: Large-growth goods: Imports vs. Tariff changes
33
Figure 2.4: Large tariff decrease goods: Imports vs. Tariff changes
34
2.3.5 Production Growth and Trade Intensity
Trade theory predicts that increases in trade across goods may be related to
increases in overall domestic production, with the share of domestic production
being exported staying constant. Alternatively, increases in exports may be
driven by an increase in trade intensity — exporting a proportionally larger
share of domestic production, independent of the level of domestic production.
To examine the relationship between bilateral trade growth and domestic
production, I focus on U.S. data, due to the availability of U.S. production data
from the NBER manufacturing database at the 6-digit NAICS code level. The
trade data is therefore confined to U.S. exports to Canada, Germany, Japan,
Mexico, and U.K. I concord the U.S. export data from the 5-digit SITC codes to
the 6-digit NAICS classifications and match it to the corresponding production
data. This less disaggregated 6-digit NAICS code level results in less classifi-
cations (473 goods) than the 5-digit SITC level (1836 goods).29
One possibility is that these large-growth goods that account for the major-
ity of trade are simply due to large increases in domestic production, with a
constant share of domestic production being exported. To determine whether
these goods exhibit similar granularity in their domestic production, I calcu-
late the share of domestic production growth accounted for by each good. To be
consistent, I group the production data into the same categories of least-, mid-
and most-traded goods, that are arranged in the same fashion as the export
data. Specifically, the goods are grouped according to their initial trade levels,
and then analyzed for their growth in production. Thus, the “bottom decile”
29As seen in Figures A.9(a)–2.2 and 2.5. U.S. export data exhibits similar granularity at
the less disaggregated 6-digit NAICS code level as at the 5-digit SITC code level. Extensive
margin growth, represented by the set of least-traded goods, is still significant; however, due
to the less disaggregated data, the extensive margin accounts for a smaller fraction of final
bilateral trade (≈14%) than it does in the SITC data.
35
of production goods account for the bottom 10% of initial trade, and may not
account for the bottom 10% of initial domestic production.
Production growth is concentrated in a small number of goods for each
country-pair, but is less granular in the production data than in the export
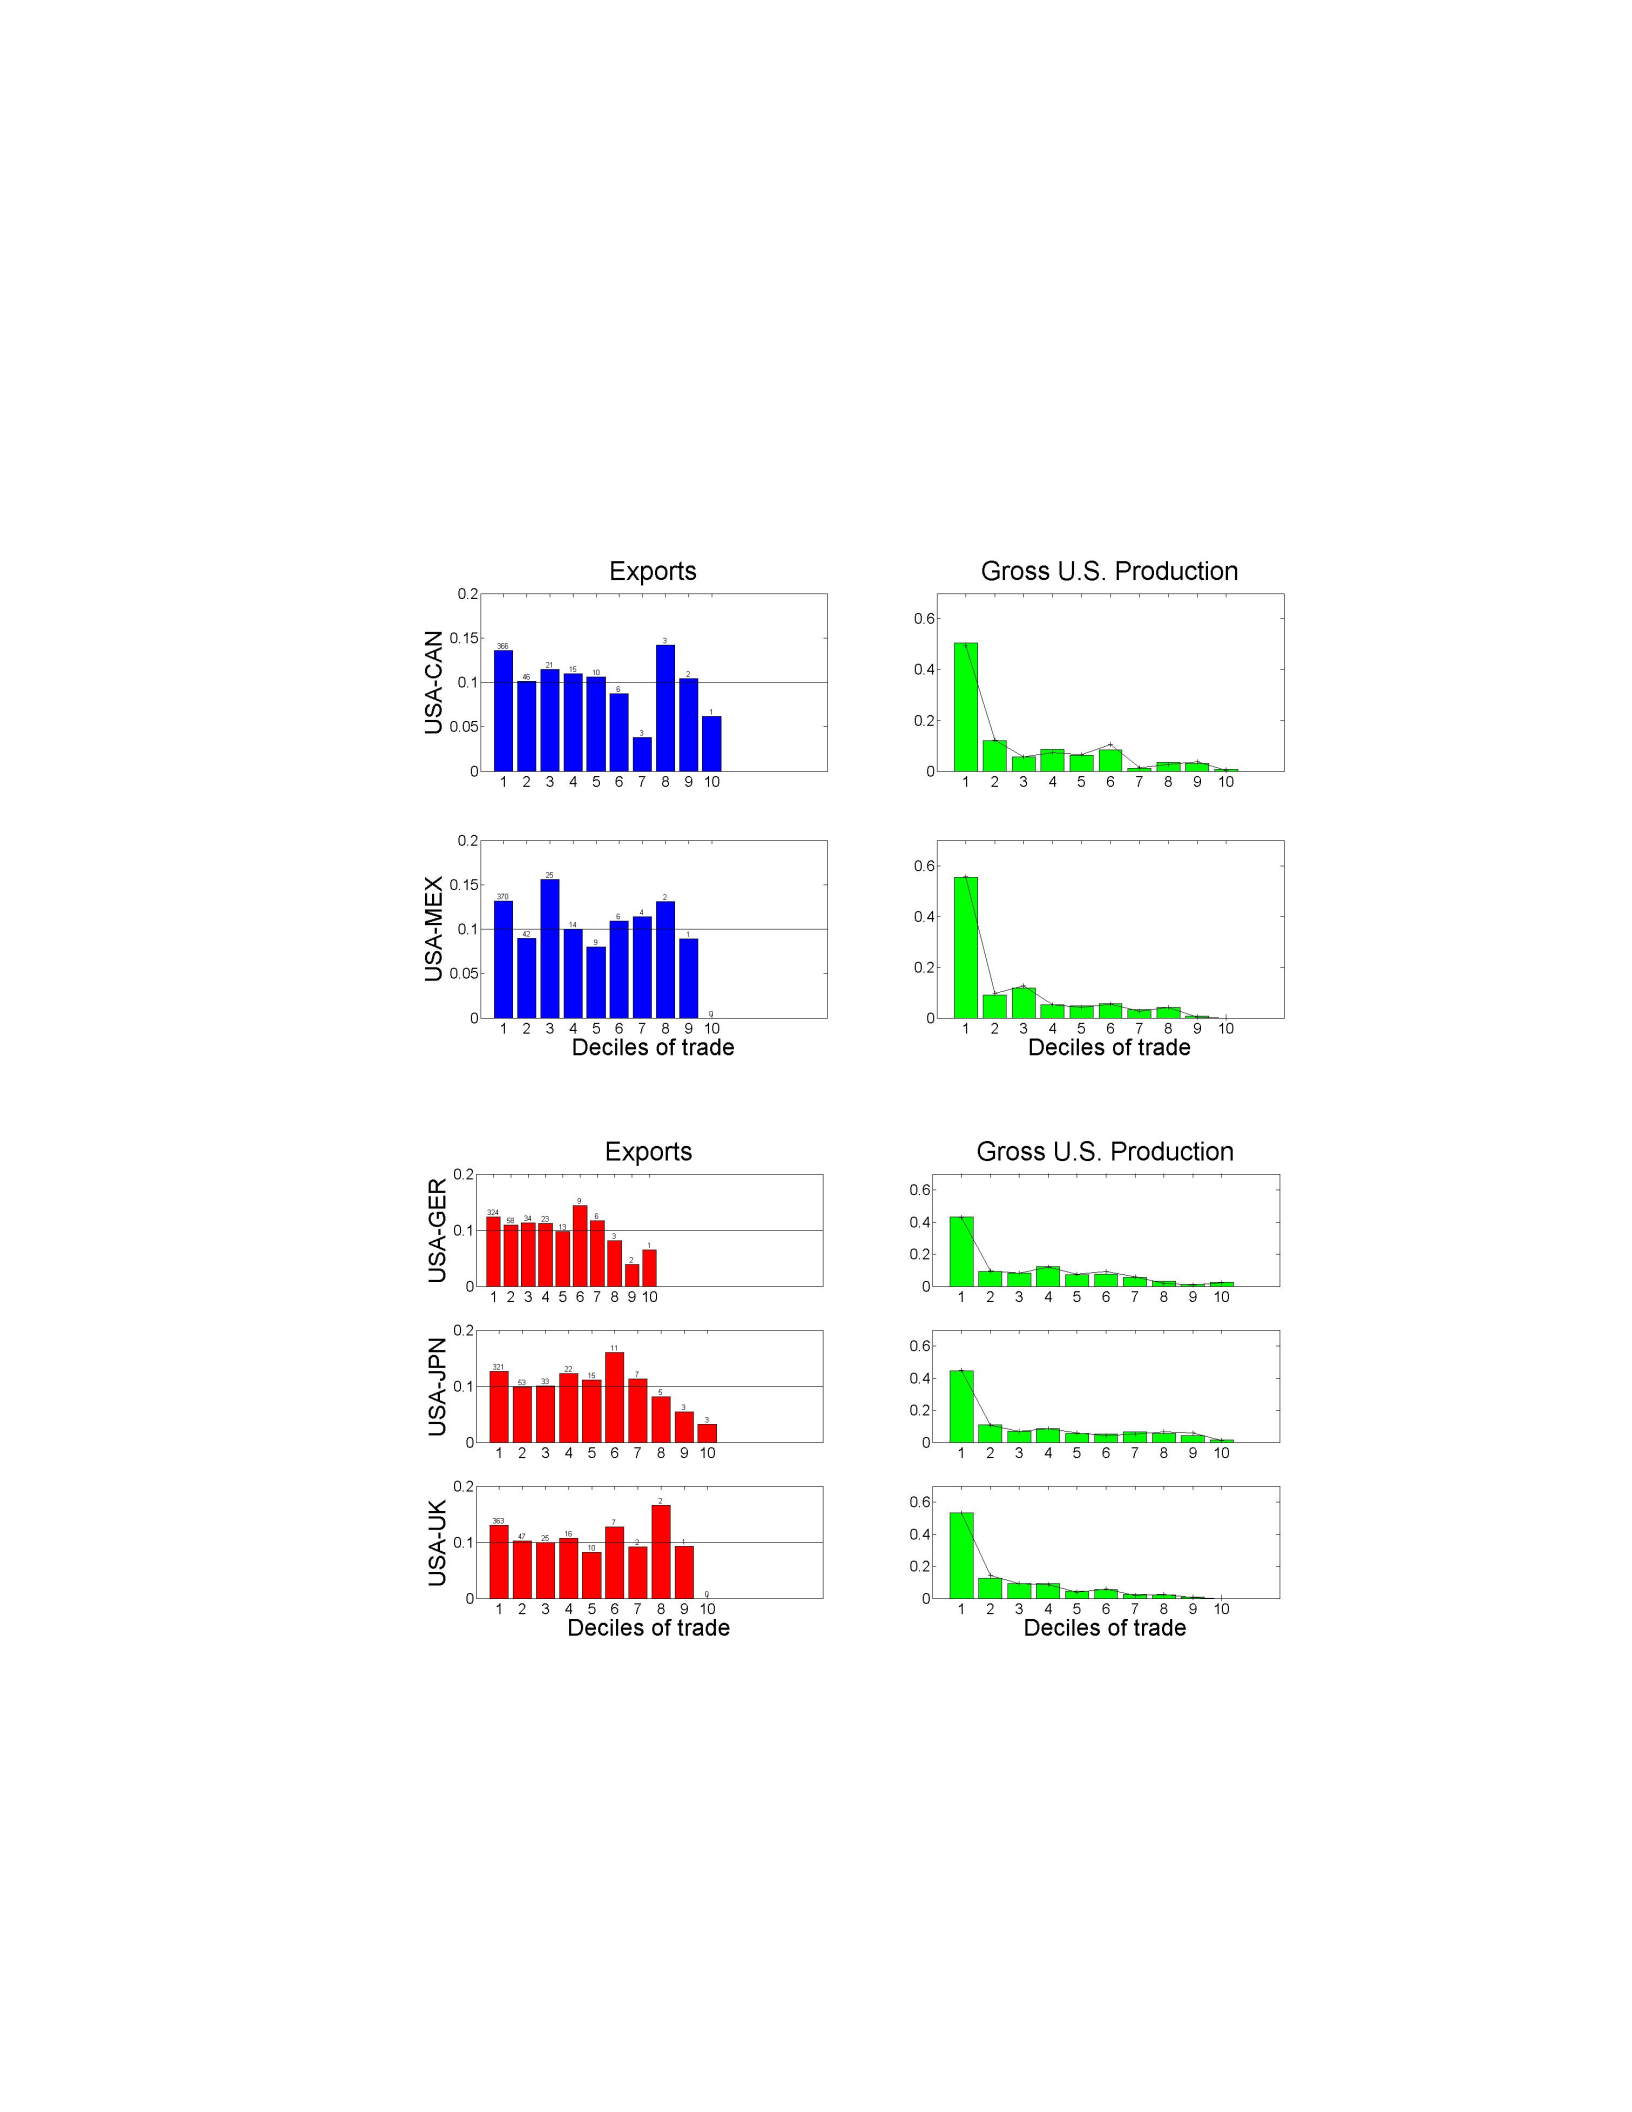
data, particularly among the mid- and most-traded goods sets.30 Examining
the deciles of U.S. production, each decile primarily remains at its initial levels
in the final production data. In Figure 2.5, the value of final production appears
as the height of each bar, with the initial value plotted as the “+” in each decile.
Most deciles, across all country-pairs, demonstrate small to no change in their
fraction of total production from initial to final levels. Also, the bottom decile in
each country-pair accounts for a large share of overall production, both in ini-
tial and final levels, reflecting the fact that many domestically-produced goods
are not traded between each country-pair.
The production data suggests that the granularity in trade growth is not
merely a function of domestic production. To examine the effect of changes in
total production and changes in trade intensity in accounting for bilateral trade
growth, I construct the exports-to-production ratio for each good, for both ini-
tial and final levels of trade. I then create two separate measures to decompose
the effects of changes in trade intensity and production growth in contributing
to trade growth:
1. Holding production constant at initial levels, and multiplying by the final
level of trade intensity, I calculate the share of trade growth that can be
attributed to growth in trade intensity
2. Holding the trade intensity fixed at the initial level, and multiplying by
the final level of production, I calculate the share of trade growth that can
30See Figures A.9(a)–A.9(b).
36
Figure 2.5: Decile Growth (6-digit NAICS) bilateral trade
(a) NAFTA country-pairs
(b) Non-NAFTA country-pairs

37
be attributed to production growth
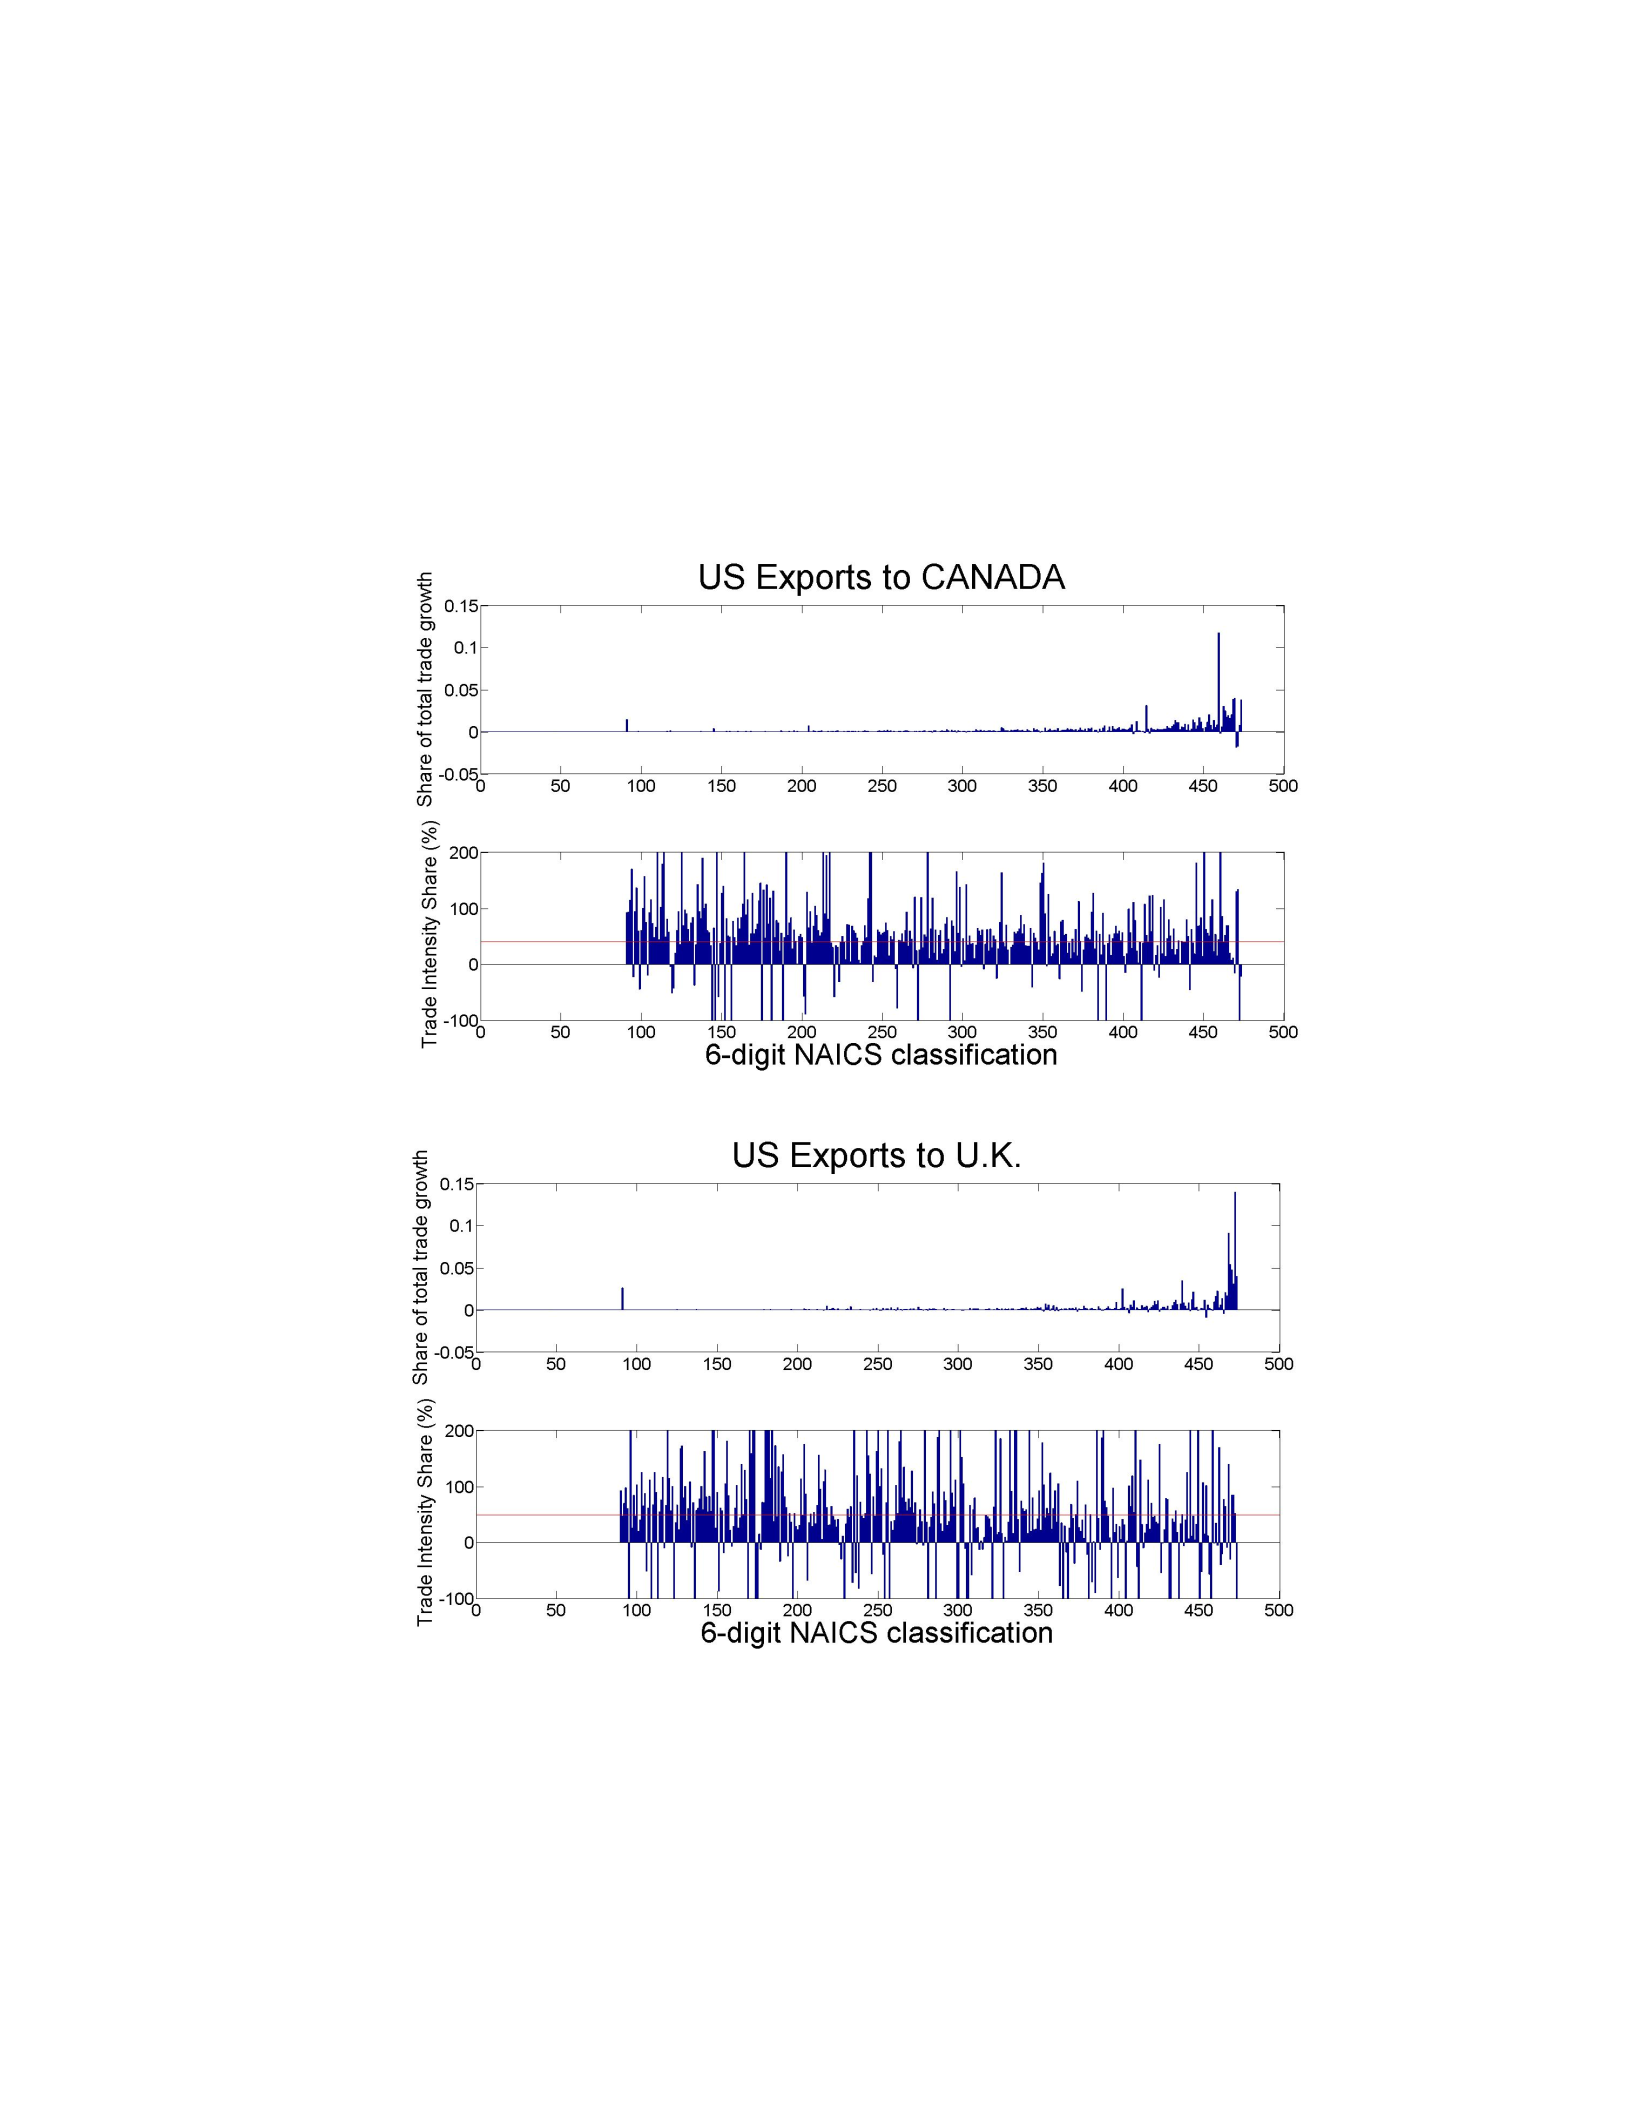
To illustrate this decomposition, Figure 2.6 plots the share of total trade growth
(in the top row of each figure) along with the corresponding trade intensity
share for each of the 473 6-digit NAICS goods classifications. Across all goods,
increases in trade intensity account for, on average, 30% to 72% of the observed
trade growth across country-pairs. However, there is little correlation between
the share of trade growth accounted for by each good and the corresponding
trade intensity share, as reported in Table 2.7. There is similarly no signifi-
cant correlations between initial trade values and the resultant trade intensity
share across goods.
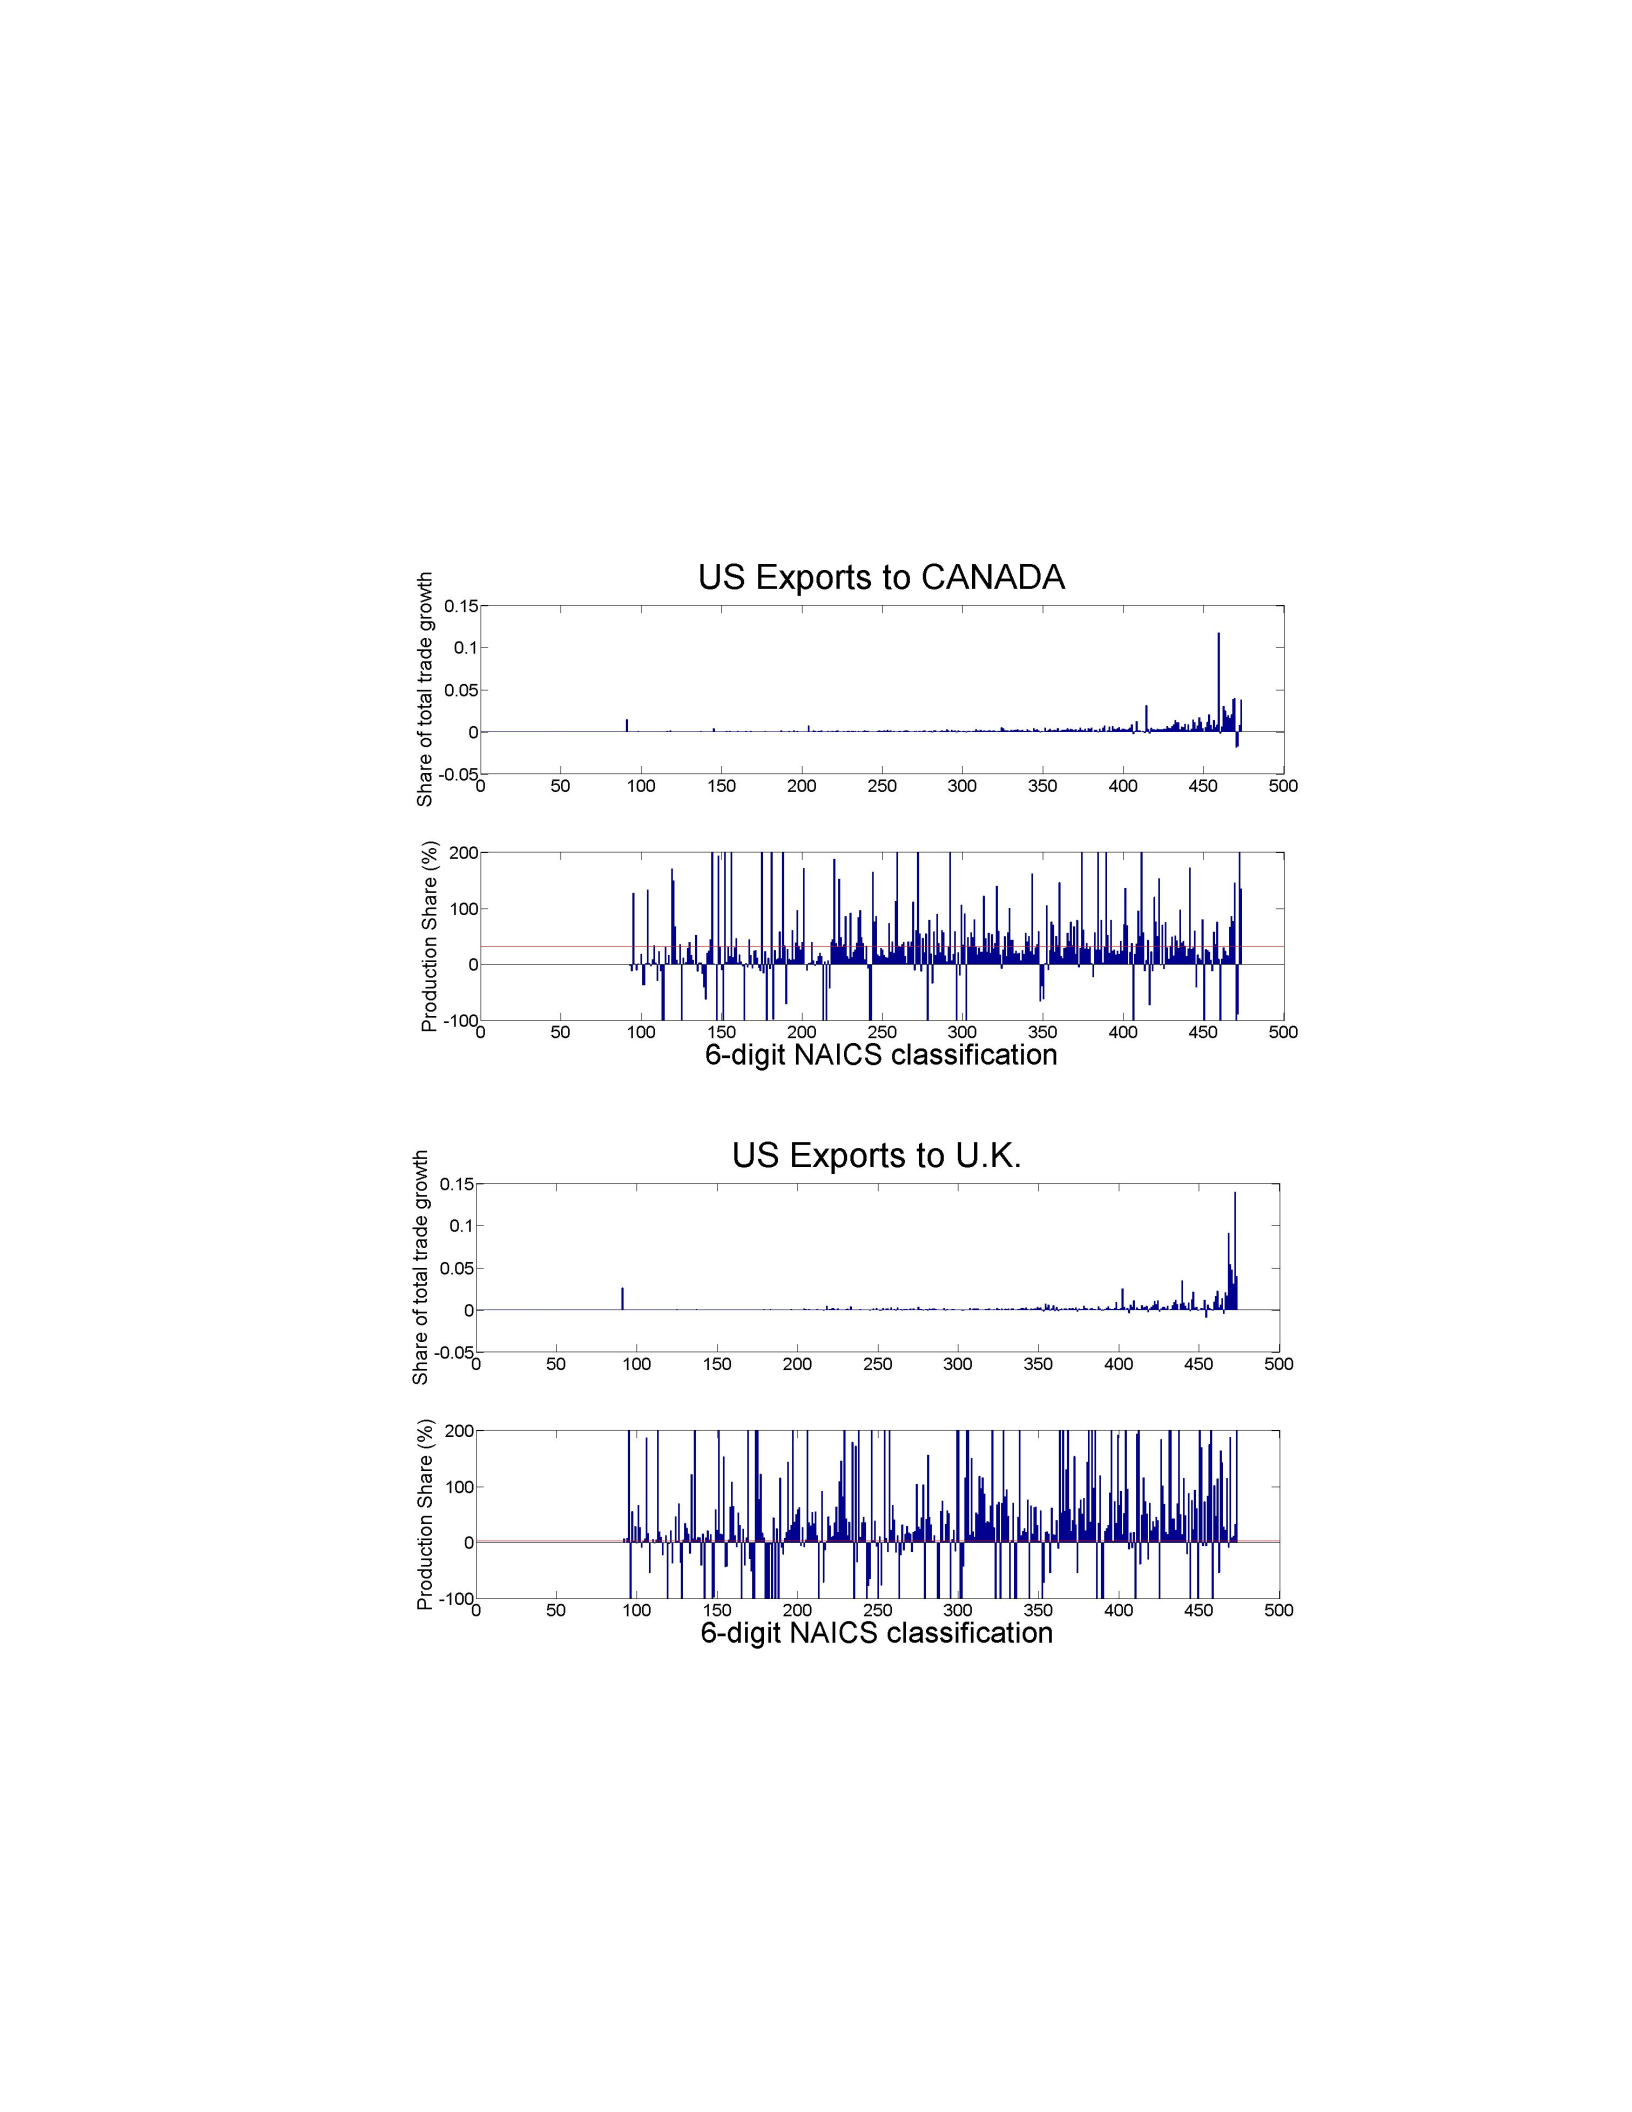
Similarly, increases in production account for, on average, -5% to 33% of the
observed trade growth across country-pairs. For some destination countries
(Canada and Japan), production growth accounts for large portions of total
trade growth (30–40%), while for others (Germany, Mexico, U.K.) production
growth accounts for virtually none of the overall growth in trade, on average,
as seen in Figure 2.7. Across goods there is little correlation between the share
of trade growth and the corresponding production growth share for each good,
as reported in Table 2.7. However, unlike the trade intensity shares, goods with
higher initial trade values generally have higher production growth shares.
On average, increases in trade intensity are significant factors in account-
ing for episodes of large growth in bilateral trade across all country-pairs. Pro-
duction growth shares vary more widely across destination countries in their
significance in accounting for trade growth. There is no discernible difference
between trade-liberalizing destination countries and non-liberalizing destina-
tion countries for both the mean trade intensity and production growth shares.
38
Figure 2.6: Trade Intensity Share vs. Share of Trade Growth
(a) U.S.-Canada
(b) U.S.-U.K.
39
Figure 2.7: Production Growth Share vs. Share of Trade Growth
(a) U.S.-Canada
(b) U.S.-U.K.
40
Table 2.7: Correlations: Trade Intensity & Production Growth Shares vs.
Share of Trade Growth
Correlation US-Can US-Ger US-Jpn US-Mex US-UK
Trade Intensity Share vs
Share of Trade Growth -0.007 -0.052 -0.010 -0.015 -0.006
Production Growth Share vs
Share of Trade Growth 0.023 0.053 0.015 0.032 0.023
2.3.6 Extensive Margin Growth
Kehoe and Ruhl (2013) find that the extensive margin is significant in account-
ing for overall bilateral trade growth. Due to inconsistencies in the reporting
of small shipment values in international trade data, Kehoe and Ruhl examine
the set of least-traded goods in each bilateral country pair, represented by the
subset of goods accounting for the bottom decile of initial trade. Examining the
growth in the share of final trade accounted for by this set of least-traded goods
then gives a proxy for extensive margin growth in bilateral trade data.
To quantify the contribution of new or previously not-traded goods to over-
all trade growth, I calculate extensive margin growth in bilateral trade data
following the methodology of Kehoe and Ruhl (2013). Due to the large number
of goods that are not traded (30–50% of the 1836 classifications for most coun-
tries) between any given country-pair, it takes 75–90% of all goods classifica-
tions to account for 10% of initial trade. Mirroring Kehoe and Ruhl’s findings, I
find the extensive margin is significant in accounting for bilateral trade growth
across country-pairs in the 5-digit SITC trade data. Across all country-pairs,
the set of least-traded goods accounts for an average of approximately 16% of
41
final trade. A 10% growth in total trade between country-pairs is accompa-
nied by a 24% increase in the share of final trade accounted for by these goods.
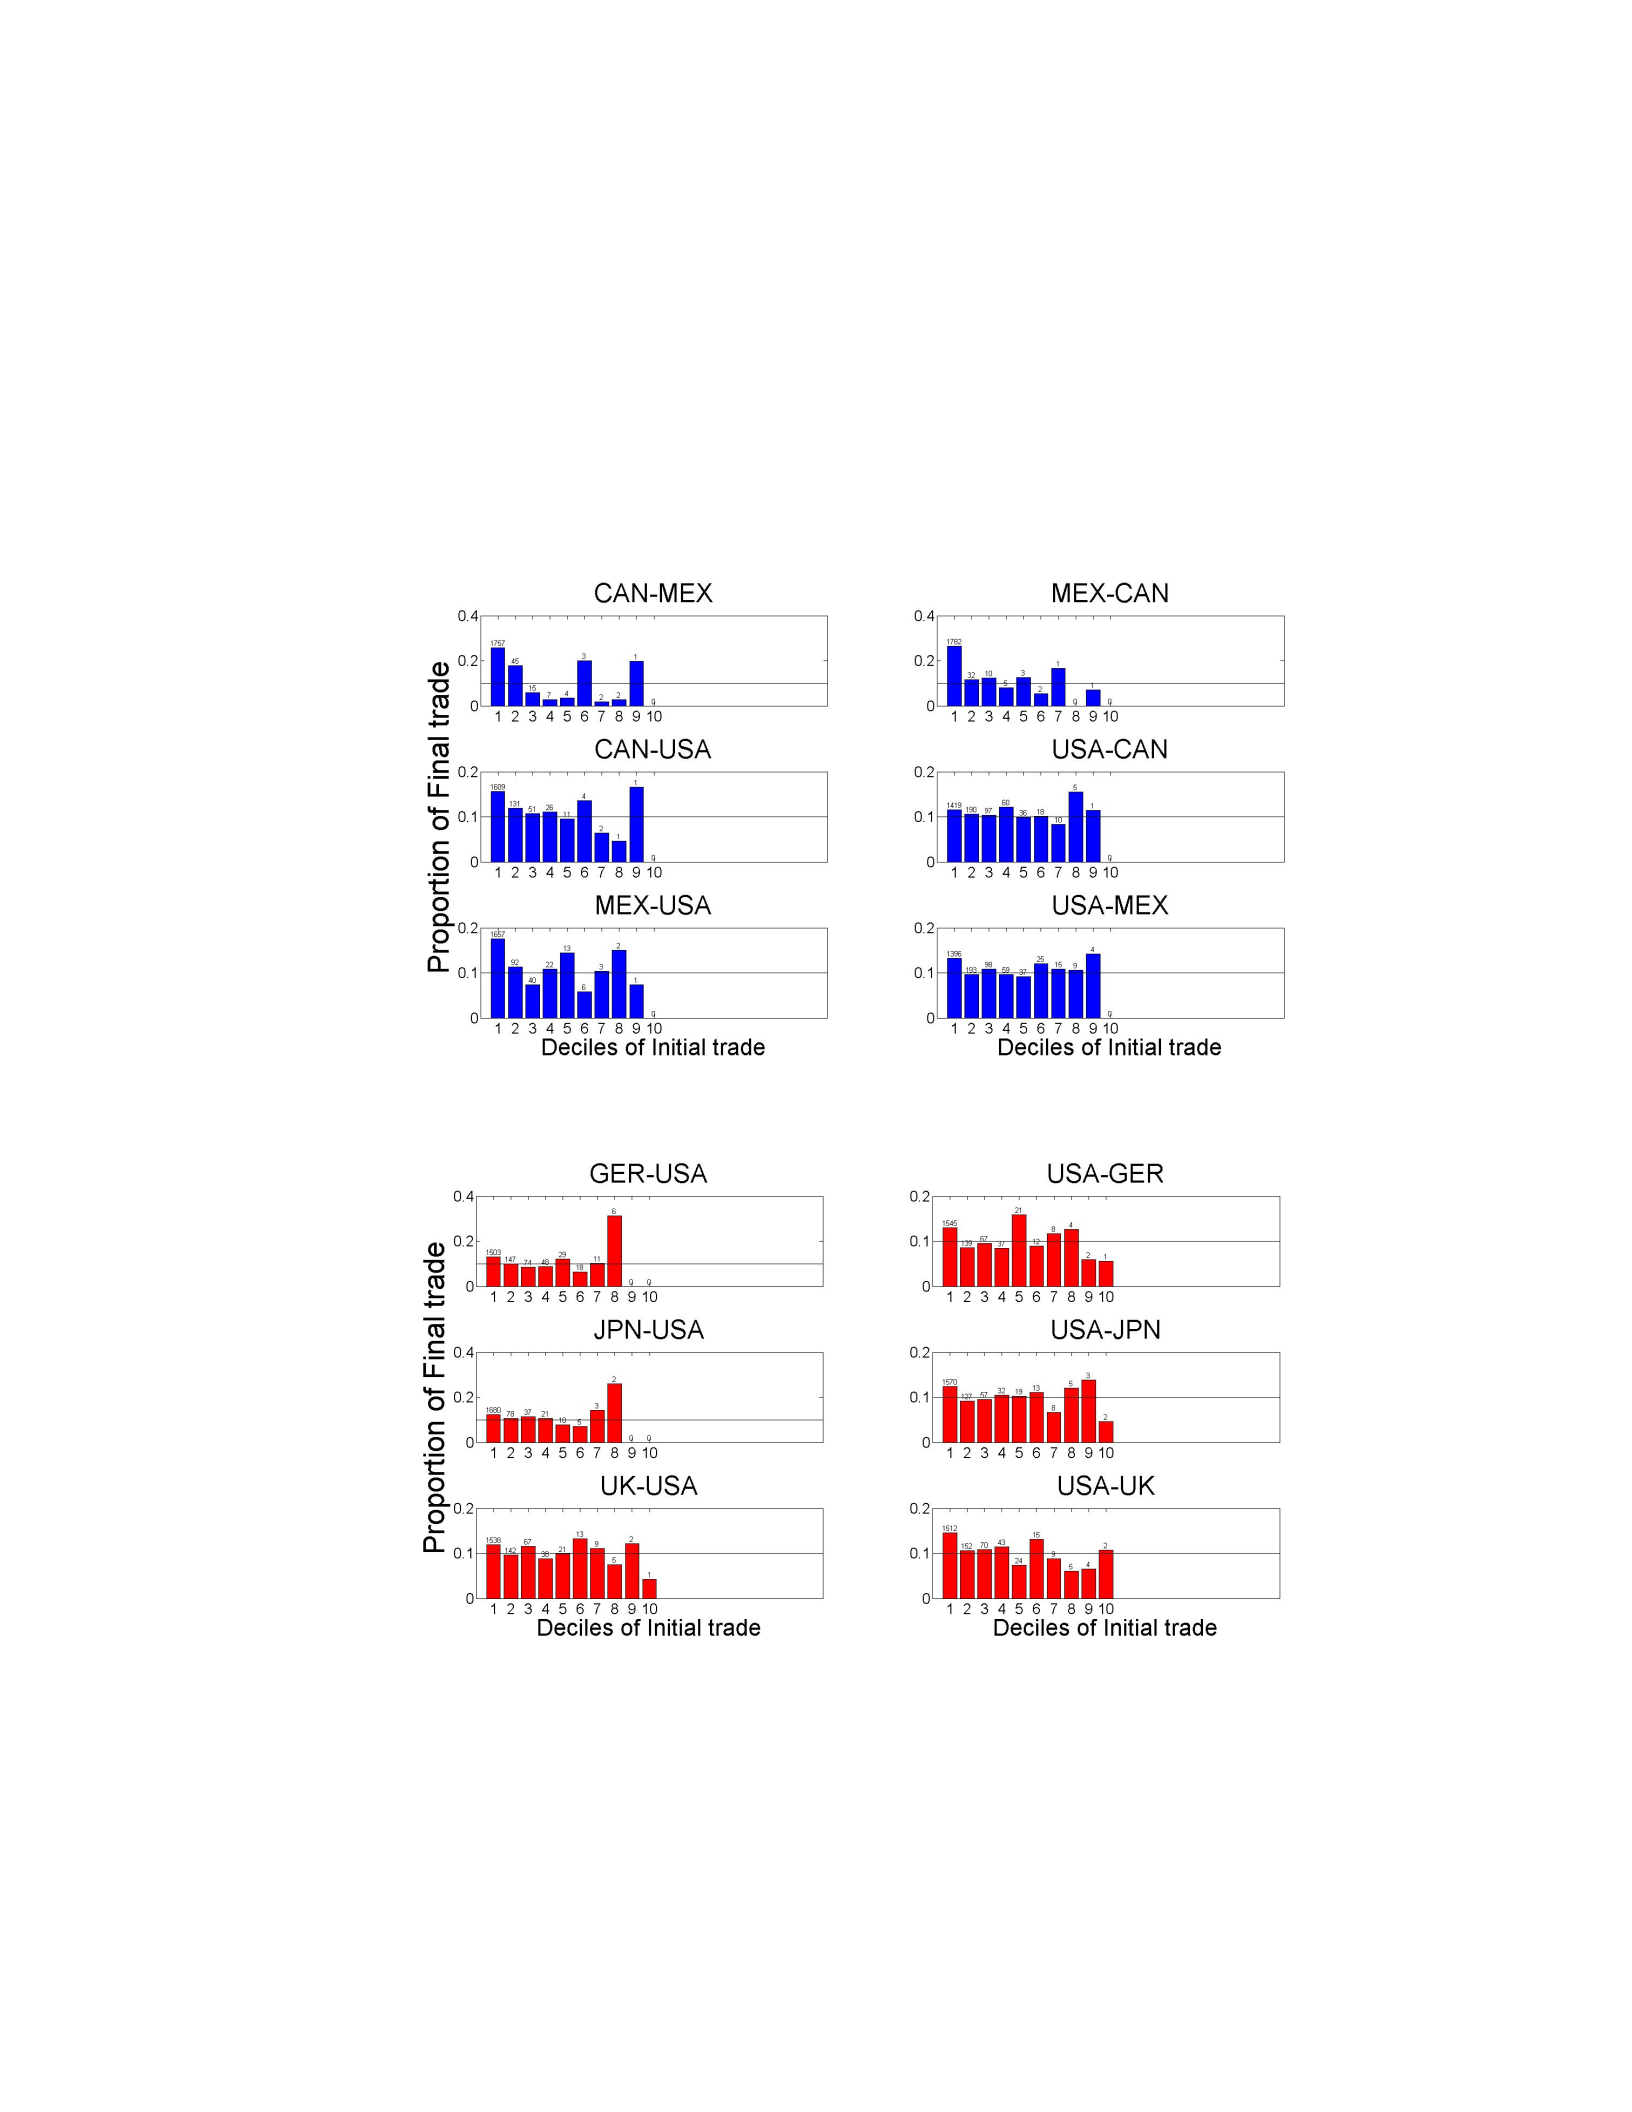
However, there is also significant growth in other deciles by country-pair. For
example, the 6th decile of Canadian exports to Mexico grows to account for
over 20% of final trade, and the 5th decile of U.S. exports to Germany grows to
account for 18% of final trade, as seen in Figure 2.8.
Kehoe and Ruhl (2013) examine the overall role of the extensive margin in
contributing to total bilateral trade growth. I extend their findings by identi-
fying that within the set of least-traded goods, the majority of extensive mar-
gin growth comes from a small number of goods growing from small values to
slightly larger values of trade, not from not-traded goods becoming traded in
large amounts. Nearly half of the goods classifications contained within this
set of least-traded goods begin as not-traded.31 The majority of these remain
not-traded, while those that become traded only do so in small amounts. A
small number of goods (<10% of all extensive margin goods classifications) in
each bilateral pair exhibit relatively large growth, from a small value of initial
trade to large values of final trade. This result shows the granularity of trade
growth within the extensive margin that mirrors that in the intensive margin.
However, due to the exceedingly large number of goods classifications exhibit-
ing small growth, these large-growth extensive margin goods only contribute
5–25% of total extensive margin growth.
2.4 Model
I now ask whether the predictions of standard Melitz-style trade models are
consistent with the empirical findings in the data. The term “standard” here
31Refer to Figure A.2.
42
Figure 2.8: Decile Growth: 5-digit SITC bilateral trade
(a) NAFTA country-pairs
(b) Non-NAFTA country-pairs

43
refers to recently used models where firms differ in productivity, face fixed
and variable costs of exporting (as in Melitz (2003), Chaney (2008), etc.) and
CES demand under monopolistic competition. Specifically, I ask whether these
models, for reasonable parameter values, generate the high level of granularity
of trade growth across goods classifications observed in the data, in response
to both uniform and heterogeneous tariff reductions, and when incorporating
heterogeneous productivity changes imputed from the data.
I analyze a two-country model with firms indexed by heterogeneous produc-
tivities, facing CES demand under monopolistic competition, with fixed and
variable costs of exporting. I characterize the equilibrium objects for profit-
maximizing firms in their export decisions, and identify the stratification of
goods as exported or not-traded. I then introduce trade liberalization, repre-
sented as a reduction in the variable costs of exporting, for two main cases,
in order to determine the implications for bilateral trade growth across goods
classifications, to compare to the empirical findings. First, I follow an approach
common to many trade models, with firms exhibiting heterogeneous productiv-
ities that are fixed across periods, where trade growth is generated by trade
liberalization that takes the form of a uniform proportional reduction in tariff
rates across goods. Second, I augment this standard approach by incorporat-
ing heterogeneous tariff reductions, matched from global tariff data, as well as
heterogeneous productivity changes, imputed from U.S. production data, across
goods.
I find that the standard model with uniform tariff reductions does not cap-
ture the granularity of trade growth — the model predicts trade growth is
widely dispersed across a large number of goods classifications. Additionally,
growth in the extensive margin, as represented by the set of least-traded goods,
44
does not match the pattern of growth in previously not-traded goods or the
small subset of goods growing from small values of trade to much larger val-
ues. Adding heterogeneous productivity changes and tariff reductions allows
the model to to better match the lumpiness of initial trade values across goods
seen in the trade data, as well as predicting significantly more granularity in
trade growth across goods. This version of the model also better captures the
granularity of growth within the extensive margin, as well as better capturing
the contribution of the extensive margin to overall trade growth.
2.4.1 Model Set-up
The model builds on the standard trade model framework, with 2 symmetric
countries, Home(H) and Foreign(F).32 Firms are heterogeneous in their labor
productivity, with each firm producing a differentiated good using only labor as
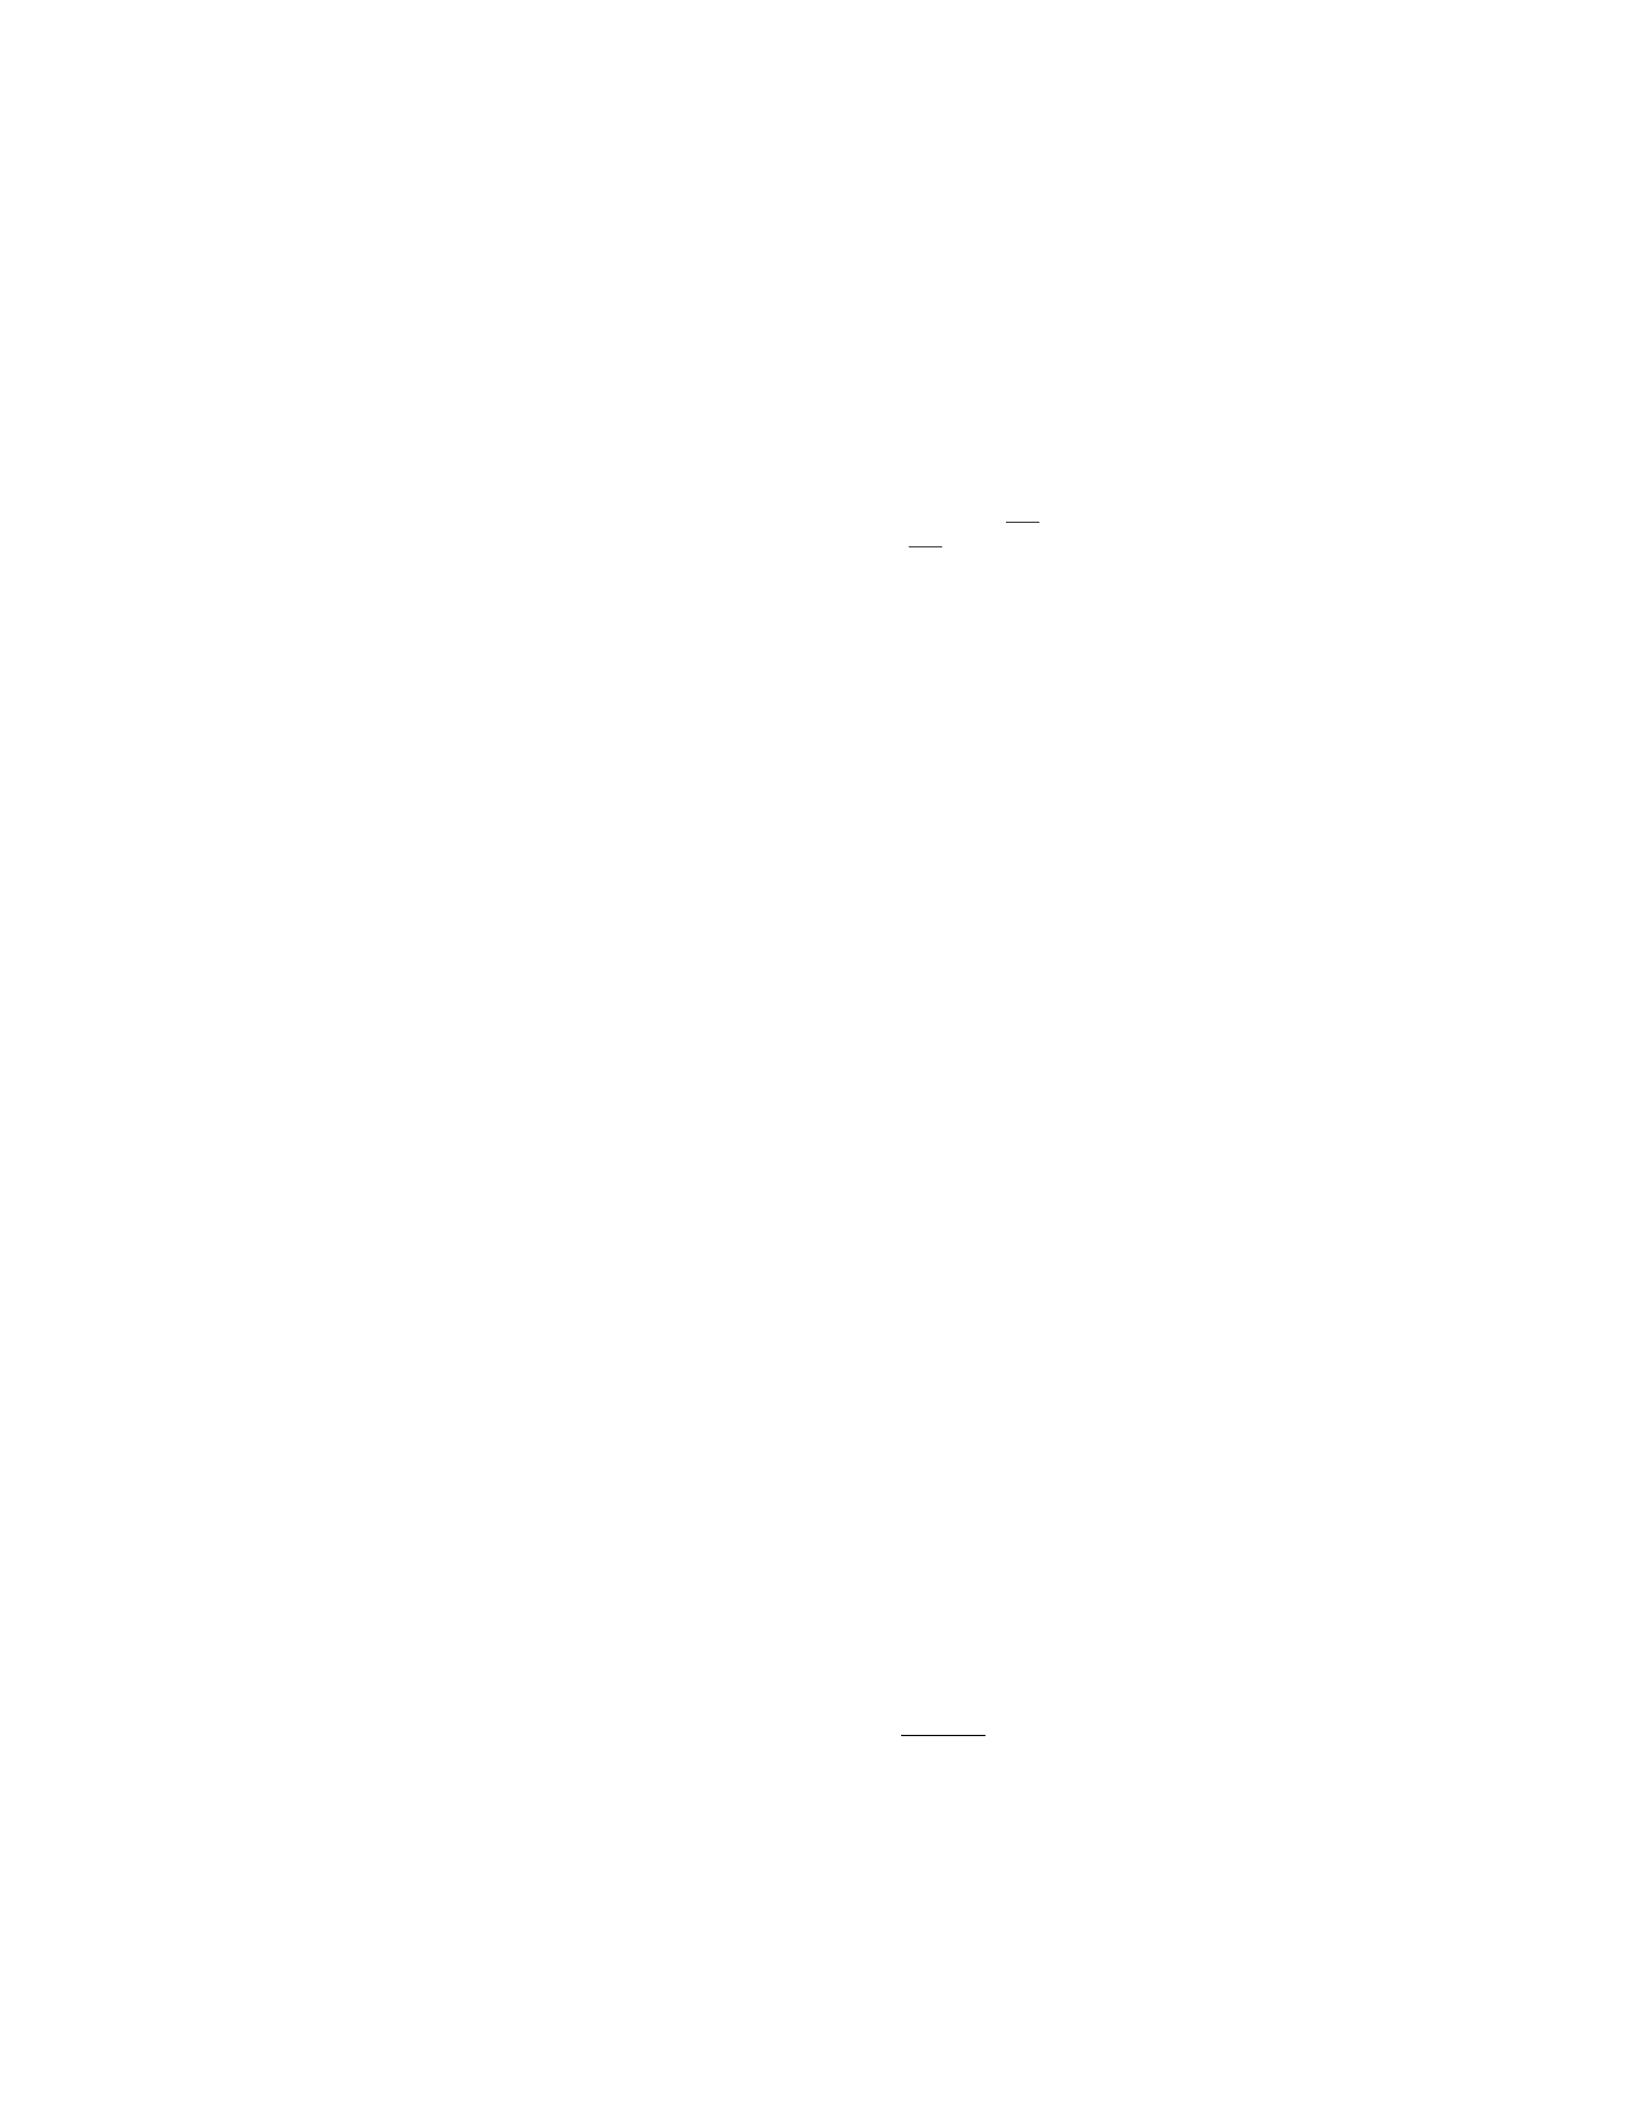
an input. Firms are indexed by their productivity, 1
a, where ais the amount of
labor required to produce one unit of output. Pricing follows the Dixon-Stiglitz
(1977) model of monopolistic pricing with firms facing CES demand in both a
home and foreign country. Firms may sell in the domestic market only, or may
choose to also export to the foreign market via a common distribution technol-
ogy that requires a fixed cost of exporting, and an iceberg variable cost per unit
shipped to the destination market. Following the literature, episodes of trade
liberalizations can be represented by a uniform reduction in the variable cost
of exporting in the second period.
32For brevity, I will consider the problem of Home’s exports to Foreign — by symmetry, the
Foreign country faces the same problem as the Home country in its exporting decisions.
45
Consumers
Preferences of consumers in country i∈ {H, F }can be represented by the CES
utility function
Ui=Za∈A
c(a)−1
da
−1
(2.1)
where c(a)is consumption of good variety a,is the elasticity of substitution
across goods ( > 1) and Ais the set of available goods.
Firms
I assume firms maximize profits under monopolistic competition pricing, as
in Dixon-Stiglitz (1977) while facing this CES demand. Firms first draw their
labor requirement from a Pareto distribution, G(a), which they hire at domestic
wage rate, ωiin country i. Firms then choose whether or not to service the
foreign market by paying a fixed cost of exporting, f, and a variable cost of
exporting, τin the form of an iceberg transportation cost.
2.4.2 Characterizing Equilibrium
Demand
Due to the symmetry of the two-country model, I consider only the demand
from Foreign for product varieties produced in Home, and set aside the de-
mand from the domestic market. For utility-maximizing consumers with this
common CES utility specification, the demand in Foreign for Home variety a
is:
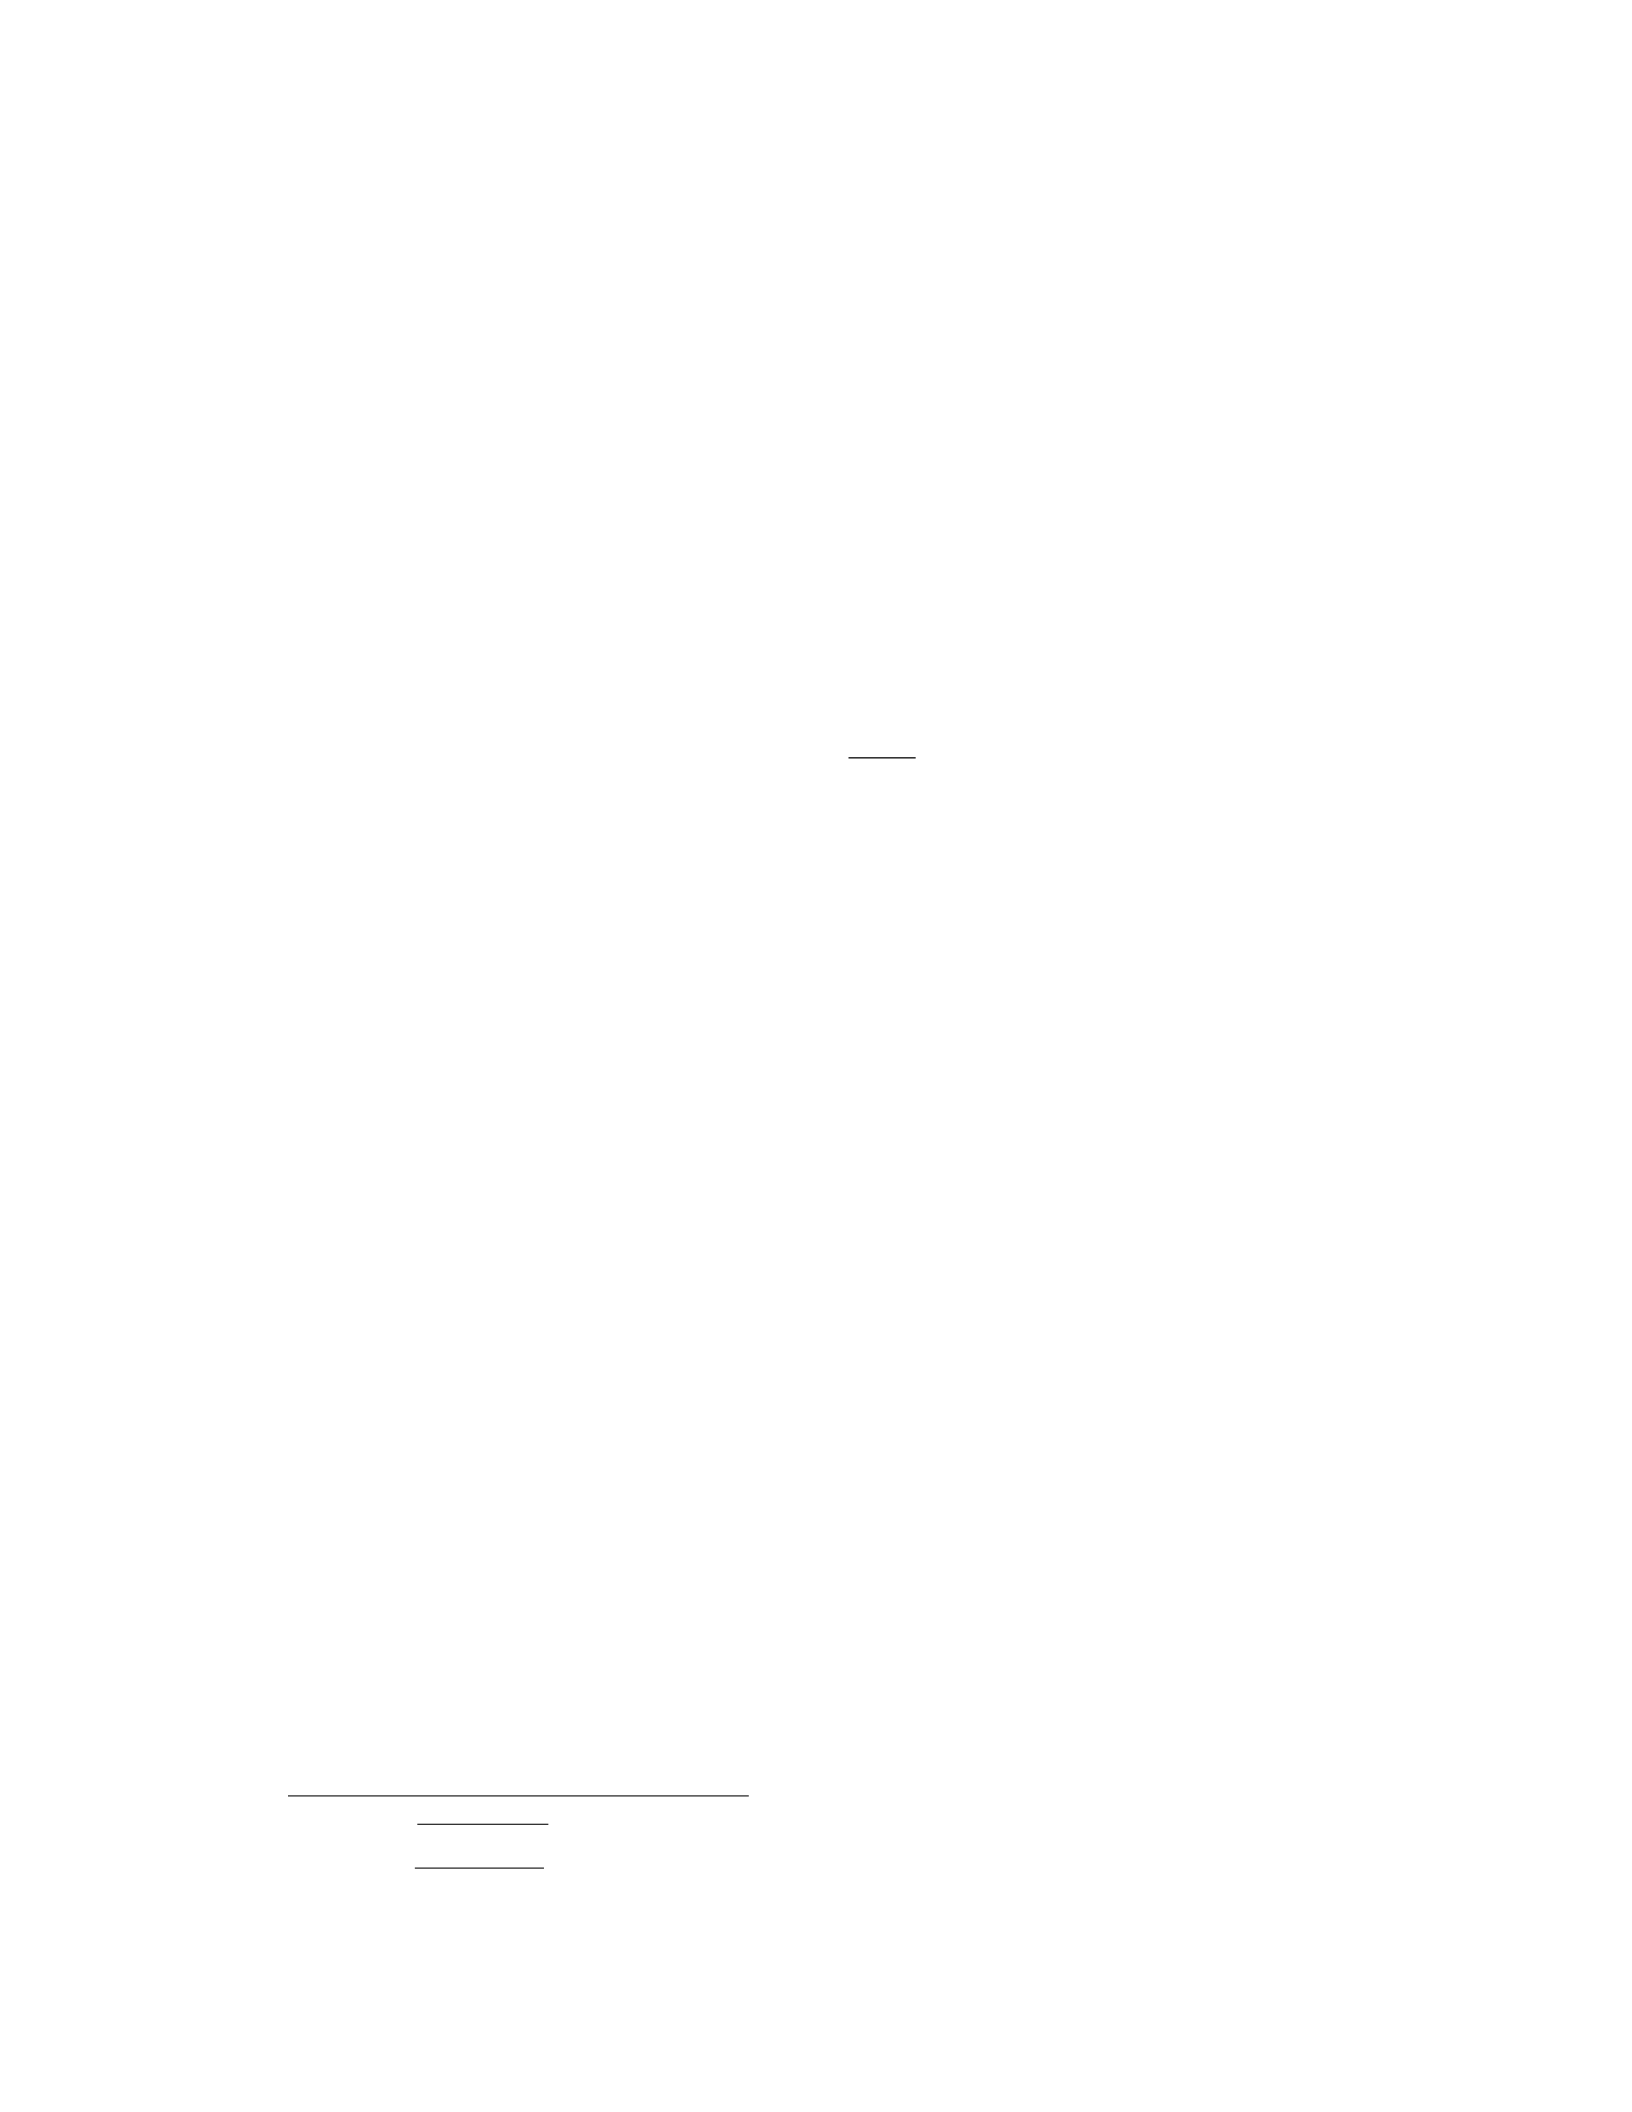
cF(a) = EFp(a)−
PF1−(2.2)
where EFis national income in Foreign and PFis the Foreign aggregate price
level.
46
Firm’s Decision
Under monoplistic competition, firms price at a constant mark-up over marginal
cost. In the Home market, the marginal cost of production is ωHa, while the
marginal cost for firm ato service the foreign market is ωHτa, as each exporting
firm must pay the additional variable export cost τper unit. This results in a
price in Foreign for variety aproduced in Home of
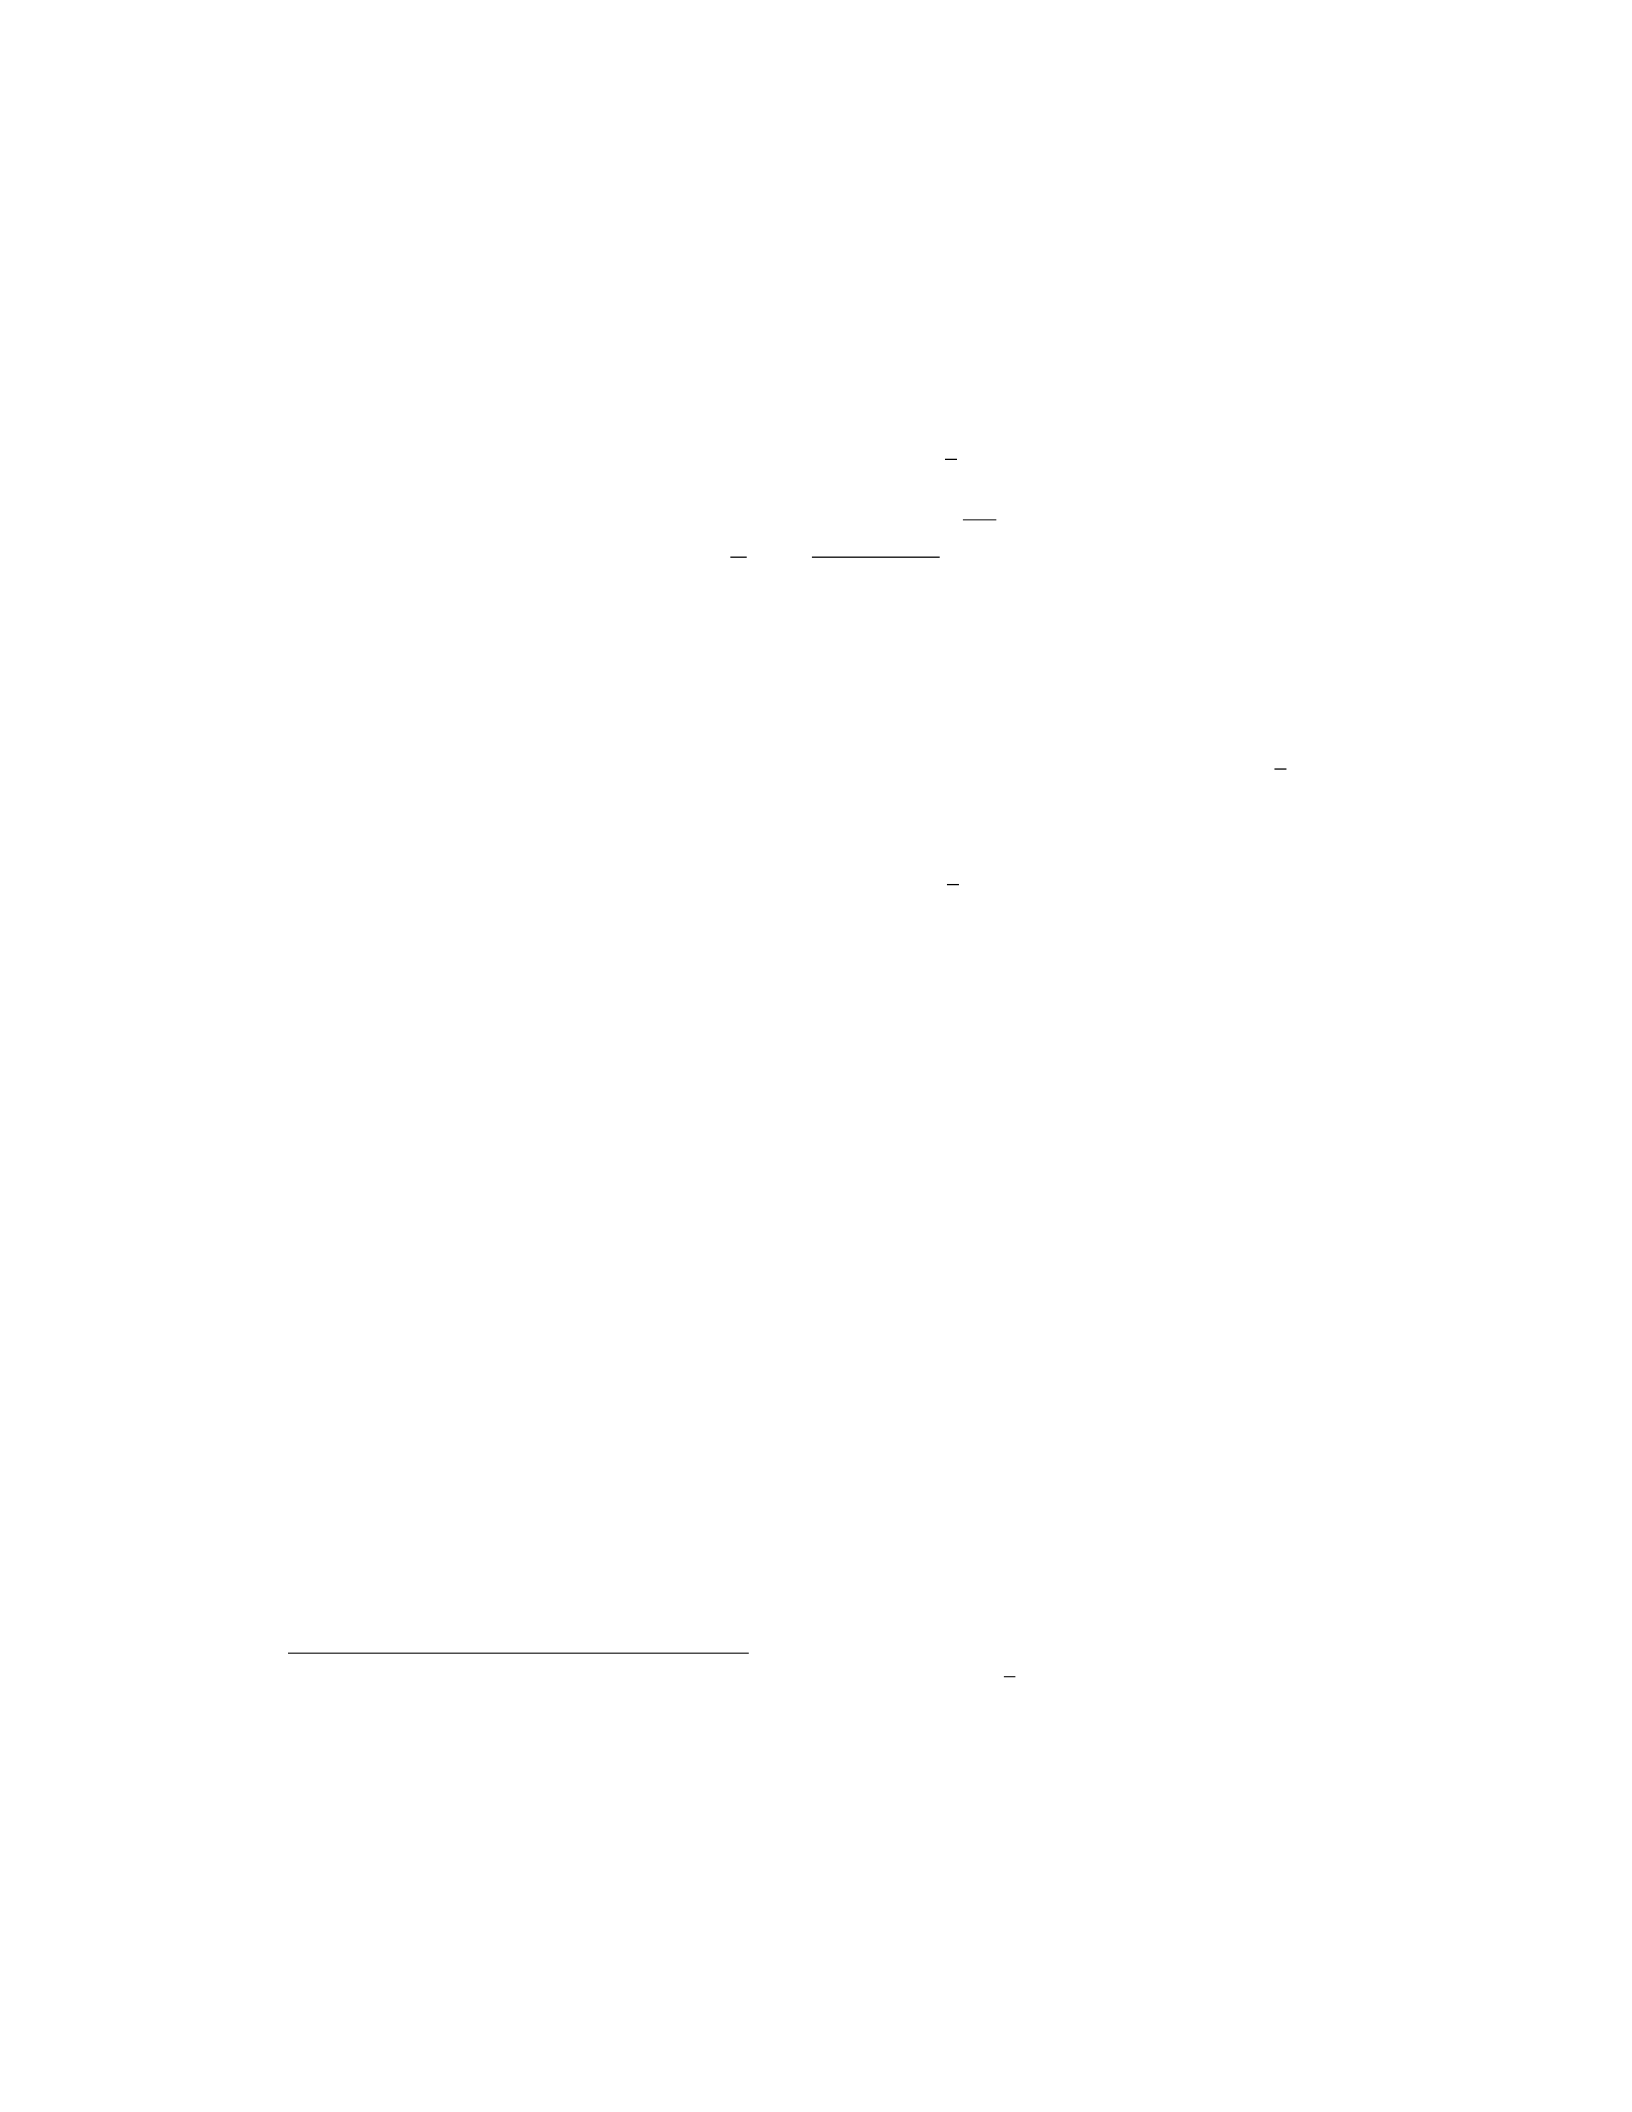
pF(a) =
−1ωHτa (2.3)
For a firm with labour requirement a, domestic profits for profit maximizing
firms are:33
πD(a)=(ωHa)1−DH(2.4)
Under CES demand and monopolistic competition pricing, these profits are
proportional to the firm’s productivity.
For a firm with labour requirement a, the additional profits from exporting
are:
πX(a) = (ωHτa)1−DF−ωHf(2.5)
That is, firms generate sales that are proportional to their productivity and
the variable transportation costs τ, but must pay the fixed cost, f, in order to
access the foreign market. 34
Productivity thresholds
These profit functions result in productivity thresholds dictating which firms
will choose to export and which will only be produced domestically. With no
33DH=EH−
[PH(−1)]1−and is a constant w.r.t. a.
34DF=EF−
[PF(−1)]1−.
47
fixed cost of entry, domestic profits are always non-negative, so all firms choose
to produce domestically.35 To export, additional profits must be non-negative:
πX(a)≥0. This leads to productivity cut-off, 1
¯a, that satisfies:
1
¯a=ωHfτ −1
DF
1
−1
(2.6)
The productivity cut-off for exporting is increasing in both fand τ.
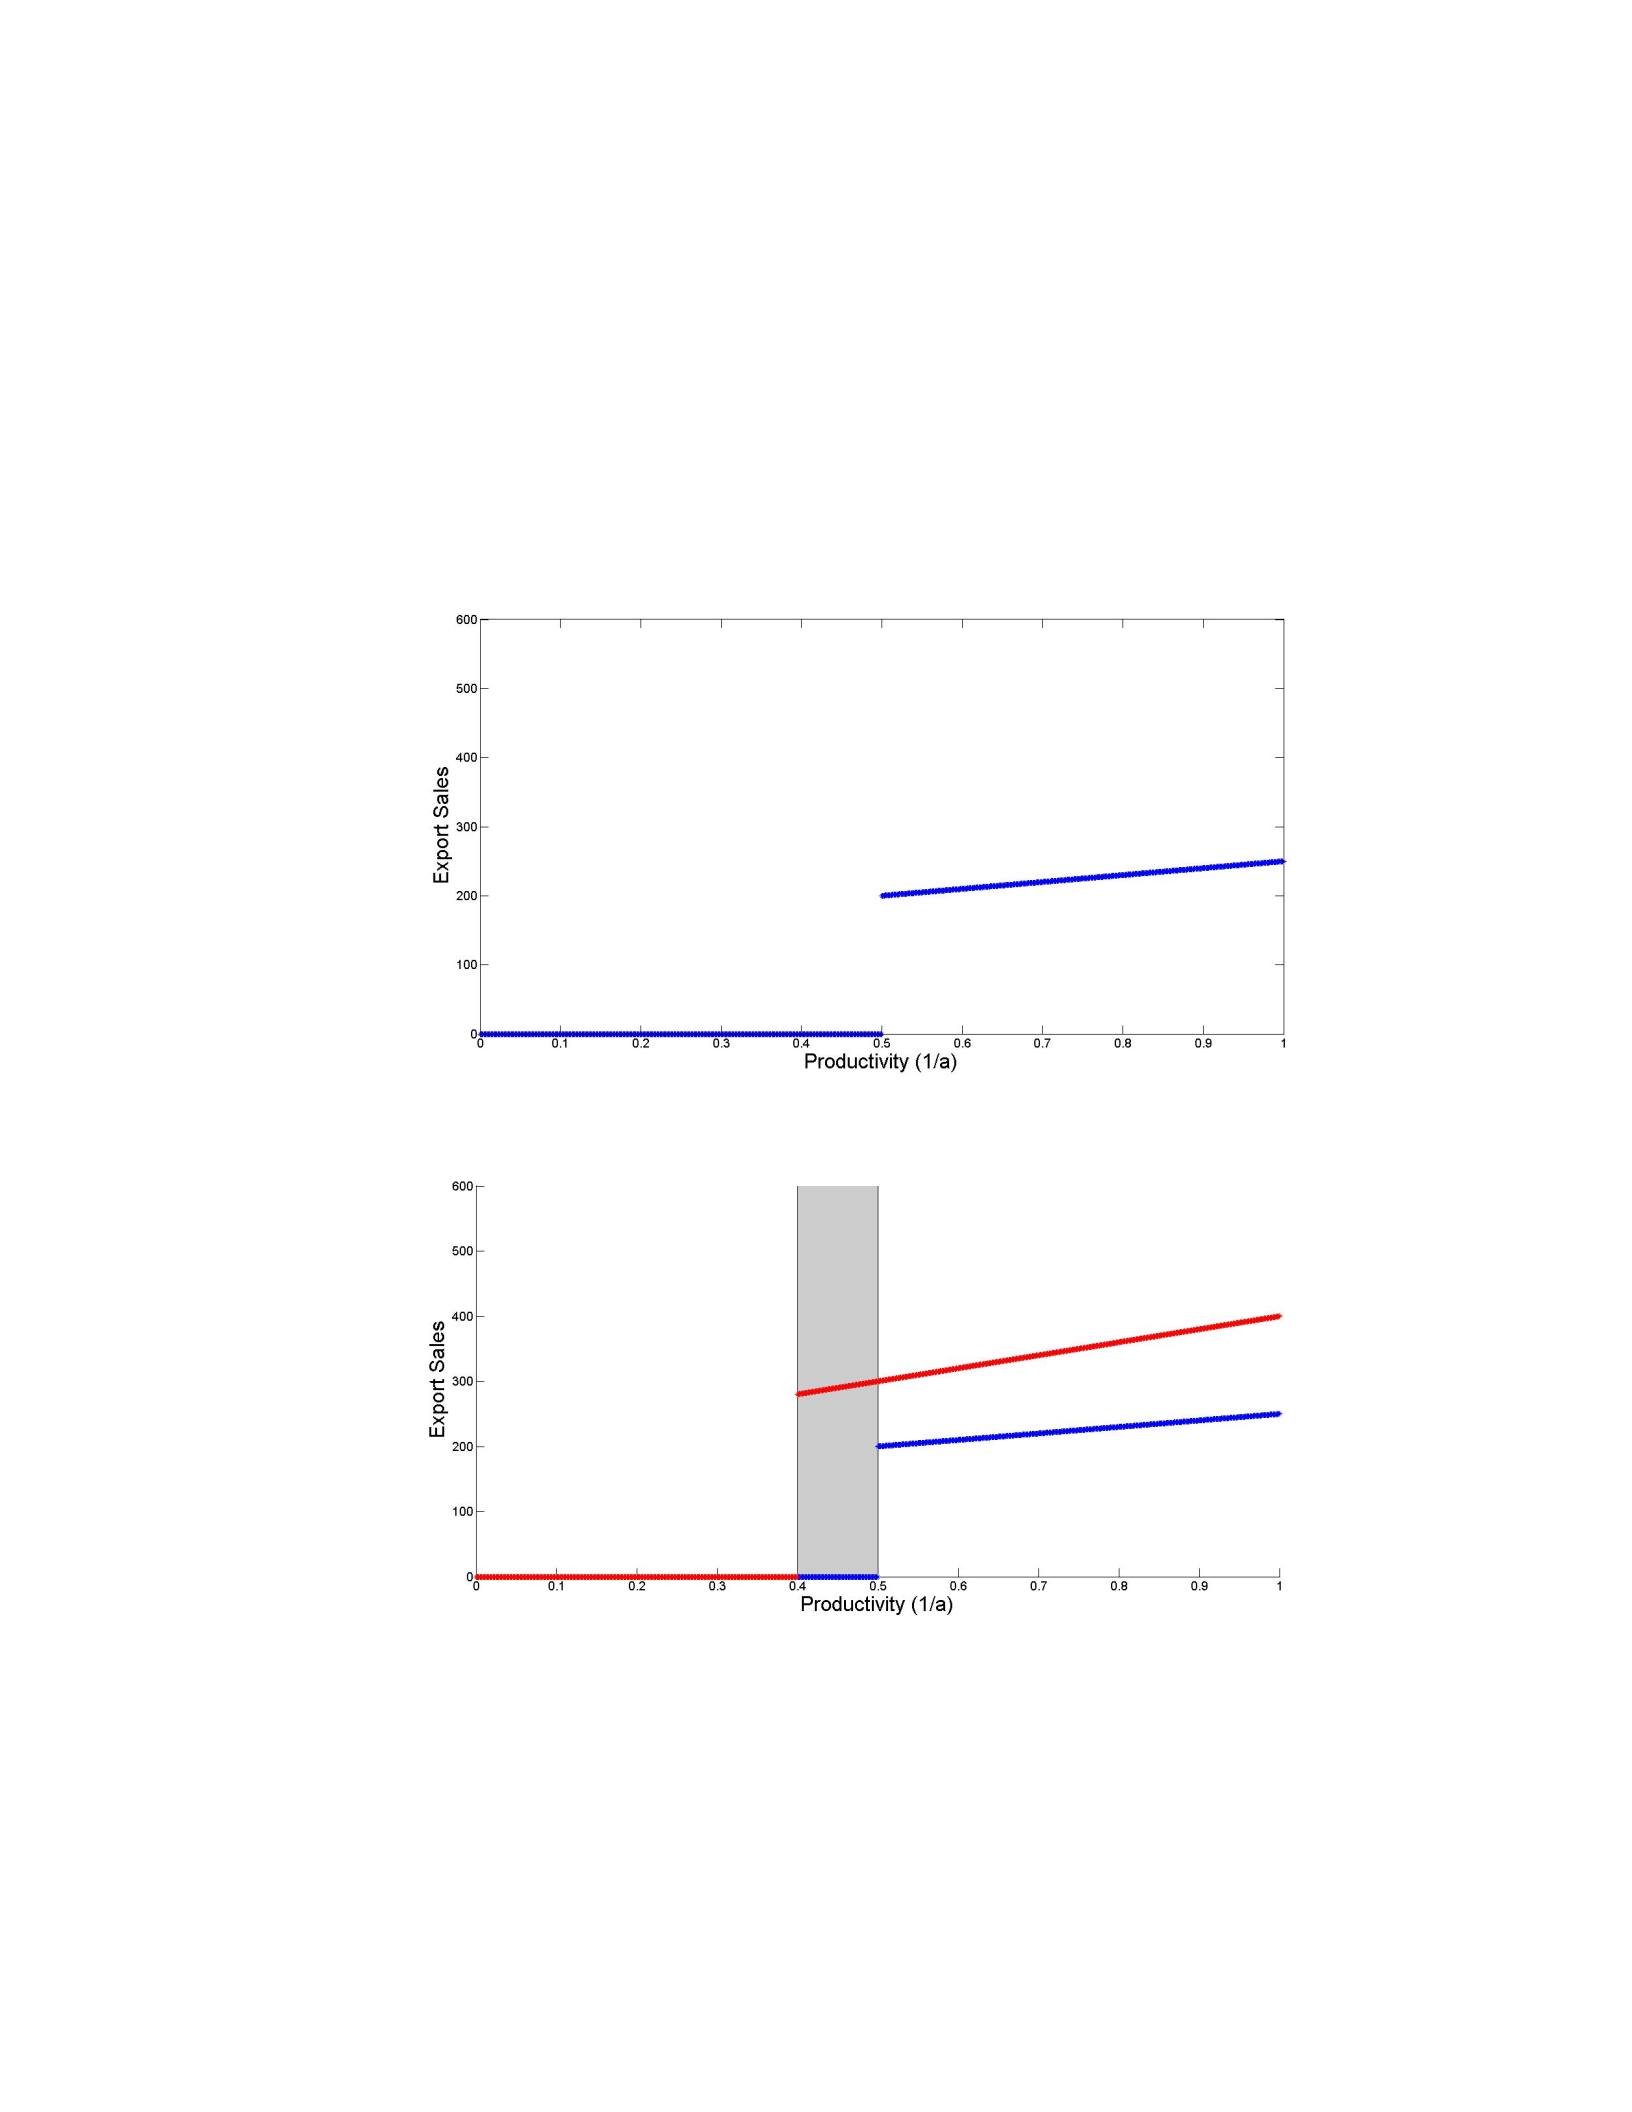
The top panel of Figure 2.9 shows the stratification of goods according to
the exporting choice. Arranging goods by increasing productivity 1
a, the least
productive goods will only be produced for domestic consumption. Firms pro-
ducing good awith productivity higher than 1
¯awill choose to export.
2.4.3 Trade Liberalization
In order to examine whether the standard model can match observed patterns
of trade growth in the data, I characterize equilibrium in the static standard
model in two cases: an “initial” period and a “final” period. I categorize the
difference in the equilibrium trade values for each good across periods as the
corresponding growth in trade for each good. Following the trade growth lit-
erature, I consider the counter-factual of an episode of trade liberalization be-
tween periods, represented as a reduction in the variable cost of exporting, to
determine the patterns of trade growth across goods.36
A fall in iceberg transportation costs lower the marginal cost of servicing
the foreign market. This results in a lower price offered to the foreign market.
35πD(a)=(ωHa)1−DH≥0implies productivity cut-off 1
a= 0.
36The work here addresses a period of trade liberalization in the standard context of reducing
τ. However, it is noted that τ, the variable cost of exporting, can be decomposed into τ=M C +
tar, where MC represents the distribution costs of production and transportation to reach the
foreign market, and tar is the tariff rate. Thus examining a decrease in τprovides insight
into cases of pure trade liberalization, captured by a decrease in tar or cases like technological
improvements in the distribution network, MC.
48
Figure 2.9: Standard model with uniform tariff reductions
(a) Initial export sales
(b) Final export sales

49
With an elasticity of substitution greater than 1, this generates an increase
in export sales for all exported goods that is proportional to the fall in tariffs
and the firm’s productivity — this is growth in the intensive margin. Addition-
ally, the decrease in variable costs lowers the productivity threshold, as the
increase in variable profits resulting from the lower marginal costs of reaching
the foreign market allow a subset of goods that were previously not-traded to
overcome the fixed cost of exporting and enter the foreign market — this is
growth in the extensive margin.
The bottom panel of Figure 2.9 demonstrates the change in export sales re-
sulting from a decrease in trade costs for the standard model with uniform tar-
iff reductions. First, all previously exported goods increase their export sales
due to the direct decrease in variable costs, proportional to their productivity.
The model predicts that the largest intensive margin growth will occur among
goods with the largest initial level of trade, with goods traded at lower lev-
els exhibiting smaller growth in trade. Second, as the productivity threshold
shifts to the left, lower productivity firms enter the export market, represent-
ing the extensive margin. As these were the marginally excluded firms before
the trade liberalization, the model predicts the final level of trade for these
goods to be similar to that of the goods previously least-traded. As these goods
all previously accounted for zero export sales, the model predicts the growth in
trade for the extensive margin goods to be relatively larger than that of other
previously traded goods with similar productivities, i.e. those previously just
above the cut-off.

50
Implications for trade growth
The standard model predictions for growth in bilateral trade are inconsistent
with the empirical findings. Growth is smooth across all previously traded
goods, and neither the intensive nor extensive margins display the high level
of granularity of a small number of goods accounting for the majority of trade
observed in the data.
First, the standard model delivers much less granularity of trade growth
than observed in the data. The model predicts that trade growth for previously
traded goods will be much less concentrated, as the growth in trade is pro-
portional to the initial level of trade, reflecting each good’s productivity. With
a common fixed and variable cost of exporting, goods with similar productiv-
ities, and thus similar initial levels of trade, will have similar levels of trade
following homogeneous reductions in trade costs, and thus contribute similar
shares of total trade growth. Additionally, no goods with low levels of initial
trade exhibit disproportionately large growth, as seen in the data. Further, all
goods with high initial levels of trade grow similarly, with none of these goods
exhibiting zero or negligible trade growth as seen in the data.
Second, growth in the extensive margin does not match the stylized facts
from the data. The model predicts that most extensive margin growth, in terms
of the Kehoe-Ruhl representation of the set of least-traded goods, comes from
large increases in previously not-traded goods becoming traded in relatively
high values. All previously-traded goods within the extensive margin grow
proportionally to their productivity and the reduction in tariffs, similar to in-
tensive margin goods. The standard model predicts that due to the relatively
large growth in the intensive margin, the extensive margin accounts for a small
portion of overall total trade growth.

51
Finally, standard models often use the simplifying assumption that trade
liberalization takes the form of a decrease in the marginal cost of exporting
that is constant and proportional across all goods. The tariff data shows that
periods of trade liberalization tend to exhibit high levels of heterogeneity in the
magnitude of AVE tariff reductions across goods, which will not be captured by
a homogeneous reduction of the marginal costs of exporting across all goods in
the model.
2.5 Numerical Exercises: Trade Growth
Characterizing equilibrium in the standard model generates smooth growth
across goods, which is proportional to each firm’s productivity and the reduc-
tion in variable costs from trade liberalization. The standard model does not
generate the granularity of trade growth observed in the data. To quantify the
level of granularity generated by the standard model, I use reasonable param-
eters from trade literature to calibrate the standard model. I compare both the
level of granularity in trade growth and the correlations of trade growth with
production growth and trade intensity predicted in the model against those
observed in the data.
I simulate the model for two main cases:
1. The standard model with uniform tariff reductions.
Firms in the model exhibit productivities drawn from a Pareto distribu-
tion, which are fixed for each good category across the initial and final
periods. As is common in may standard trade models, trade growth is
driven by trade liberalization between the initial and final periods that
takes the form of a uniform proportional reduction in tariffs across all
52
goods.
2. The standard model with heterogeneous productivity changes and
tariff reductions.
Firms again take Pareto productivities in the initial period. However, fi-
nal period productivities are calculated by incorporating heterogeneous
productivity changes to the Pareto distribution as calculated by the im-
puted changes in productivity backed out from the U.S. production data.
This simulation also introduces trade liberalization between periods by
incorporating heterogeneous tariff reductions across goods, imputed from
tariff data.
2.5.1 Parameterization and Calibration
The numerical strategy is to select reasonable parameter values for the elas-
ticity of substitution across goods classifications, productivity parameters, and
fixed and variable costs of exporting, within the estimated ranges of the leading
trade literature.
The model predictions are compared to those of the 5-digit SITC bilateral
trade data with 1836 goods classifications, as well as the 6-digit NAICS data,
with 473 classifications, in order to match production data. To represent these
goods in the model, I draw each firm’s productivity from a Pareto distribution,
and map each firm to the production of one good.37 I arrange firms according
37The Pareto distribution is commonly used in a vast literature on international, (i.e. Melitz
(2003), Chaney(2008), Gabaix (2008), Helpman, Melitz and Rubenstein (2008), among many
others), both for its computational expediency and its ability to match certain stylized facts,
such as the upper-right tail of the firm distribution, which motivates the choice of a Pareto
distribution employed here. However, although not employed in this chapter, recent work has
begun to explore alternate distributions, such as log-normal (Eeckhout (2004), Fernandes et
al(2014), etc) or a mixed distribution of the two (Nigai (2017) that match other salient proper-
ties of firm-level productivity distributions.
53
to their heterogeneous productivity levels, in ascending order.38 The iceberg
cost, representing the variable cost of exporting, is set at 2.0. The elasticity of
substitution across goods in the CES demand function is set toward the high
end of estimated values in the literature, at 6.0, in order to give the model a
better chance to match the granularity of growth across traded goods observed
in the data.39
The fixed cost in the model determines the productivity threshold beyond
which firms will enter into the exporting market. As such, the fixed cost is
calibrated to match the number of non-exported goods classifications in each
bilateral trade pair. Finally, DF, the constant which contains foreign income
and price levels as well as other constants in the model set-up, is calibrated to
match the total level of initial bilateral trade for each country-pair.
For the standard model with uniform tariff reductions, I calibrate the pro-
portional reduction in tariffs (as represented by a reduction in the variable
costs of exporting) necessary to match the total growth in exports for each coun-
try.40
For the standard model with heterogeneous productivity and tariff changes,
I first determine the distribution of productivity changes across goods classifi-
cations imputed from U.S. production data. I use the 6-digit NAICS data to
38Thus “good 1” will be least productive firm, “good 2” will be the next least-productive firm,
etc.
39See, for example, Imbs and Mejean(2010), who estimate elasticities for more than 30 coun-
tires between 1 and 7.5, and supported by McDaniel and Balistreri (2003) who summarize
the literature’s findings that estimated elasticities are higher with more highly disaggregated
data.
40Specifically, I take the observed change in AVE tariff rates from the data, and scale them
by the factor necessary to match the observed change in exports for each bilateral country
pair. This method implicitly assumes that DFis constant across periods, thus all growth is
generated via the uniform tariff reduction. However, since I am concerned with the share of
trade growth accounted for by each good category, this method is computationally equivalent
to choosing a set reduction in tariffs (i.e. 10%) and calibrating DFto match the overall level of
trade growth.
54
back out the implied productivities for each good in the U.S. production data,
in both the initial and final periods. I then calculate the growth in productivity,
and apply the imputed productivity change onto the initial Pareto distribution
of firms in the model, in order to calculate the new productivities for the final
period. I then determine the distribution of tariff changes across goods im-
puted from tariff data from U.S. export destinations (e.g. Canada, Germany,
Mexico, Japan and the U.K.). I normalize this distribution of tariff changes
and calibrate it to match the overall level of bilateral trade growth for each
country-pair, as in the case of the uniform tariff distribution, given the produc-
tivity changes already imposed.41
2.5.2 Standard Model with Uniform Tariff Reductions
Figure 2.10 presents the results of the model simulation for Canadian exports
to Mexico using the 5-digit SITC data.42 In the bottom row of each column, the
standard model specification is unable to match the patterns of trade observed
in the actual bilateral trade data presented in the top row. The overall gran-
ularity of trade growth, with the majority of growth concentrated in a small
number of goods is not produced in the standard model with uniform tariff re-
ductions. The model delivers smooth growth across goods, with each previously
traded goods experiencing trade growth proportional to its initial level of trade,
reflective of its productivity. Further, growth in the extensive margin, repre-
sented by the bottom decile of initial trade, occurs solely in previously traded
goods (represented in blue), with virtually none of the overall trade growth
41Similar to the case of uniform tariff reductions, for the sake of calculating the share of trade
growth across goods, this method is computationally equivalent to calibrating DFto match the
overall level of trade growth, or scaling the productivity changes proportionally to match the
observed trade growth.
42All other country-pairs present similar results, and are omitted here for brevity.
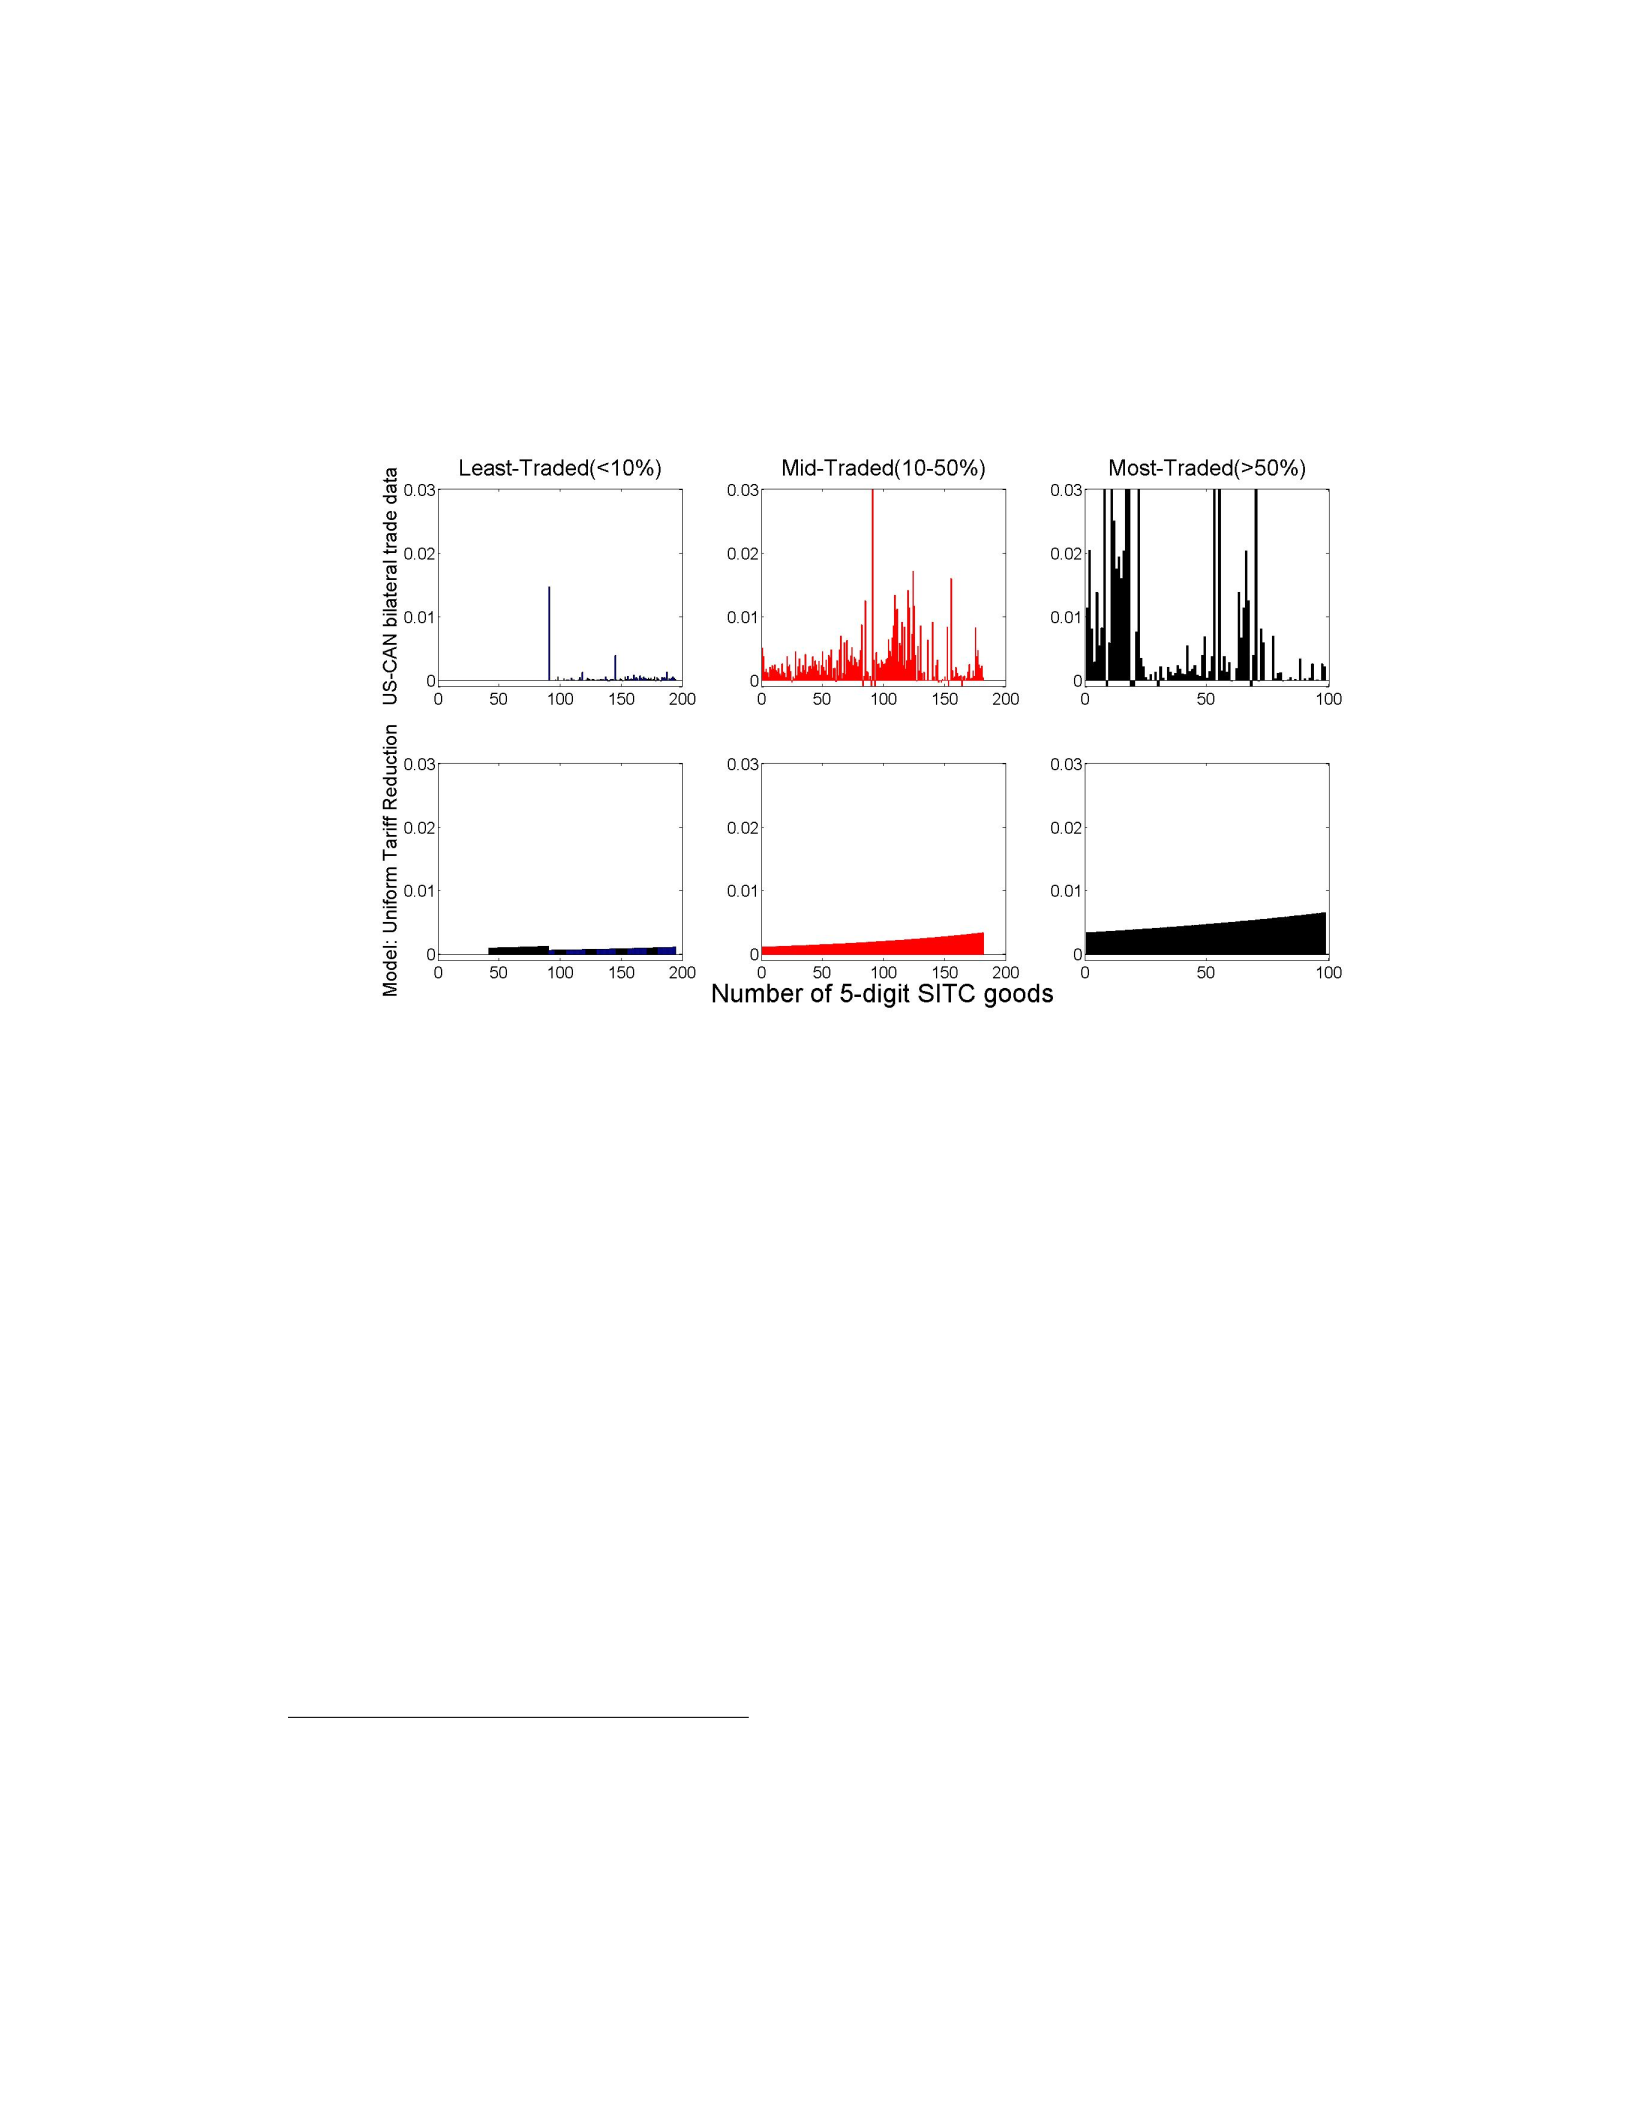
55
attributable to previously not-traded goods becoming traded.
Figure 2.10: Standard Model with uniform tariff reductions (Can-Mex)
To quantify the degree of granularity of trade growth, Table 2.8 reports
the proportion of overall trade growth accounted for by various quantiles of
goods classifications. On average, across country-pairs, the top 1% of goods
classifications accounts for 32% of overall trade growth in the data, but only 3%
of overall trade growth in this model simulation.43 The standard model with
uniform tariff reductions delivers only roughly 10% of the granularity observed
in the data, as measured by the fraction of overall trade growth accounted for
by the various quantiles of largest-growth goods.
This lack of granularity is not surprising — by construction, with all firms
exhibiting fixed productivities and a uniform reduction in tariffs across goods,
the majority of trade growth is evenly dispersed across previously traded goods.
43It should be noted that this level of concentration is less than the 65% of trade growth
accounted for by the top 1% of goods in the 5-digit SITC data. This is mainly due to the
necessity of switching to the less disaggregated NAICS data (with only 473 goods) in order to
impute productivities from U.S. production data, where 1% of goods is only 5 goods, as opposed
to 18 goods in the SITC classification data.
56
Table 2.8: Standard Model with Uniform Tariff Reductions
Proportion of growth from top X%of goods
(6-digit NAICS codes)
Model 1% (5 goods) 2% (10 goods) 5% (24 goods) 10% (47 goods) 20% (94 goods)
Data 0.318 0.473 0.696 0.852 0.988
Standard 0.032 0.062 0.143 0.259 0.4490
The only disproportionate growth comes from the extensive margin — firms
which cross the productivity threshold switch from not-traded to trade, but
become traded only in relatively small volumes. Trade growth from these ex-
tensive margin goods is outweighed in the share of total trade growth by the
increases in goods at the upper ends of the productivity distribution. In all
cases, growth is smooth and proportional to productivity, and fails to produce
the granularity of trade growth observed in the data.
2.5.3 Standard Model with Heterogeneous Productivity
Changes and Tariff Reductions
The standard model with uniform tariff reductions fails to generate the granu-
larity in trade growth found in the trade data due to the smoothness in the pro-
ductivity distribution, and the uniformity of tariff reductions with are common
across all goods. A possible solution is adding heterogeneity in the productivity
distribution and in the reductions in tariff rates across goods. If some goods
categories experience large increases in productivity, it may lead to dispropor-
tionately larger growth in production and trade for those goods. Similarly, large
decreases in tariff rates for some goods may lead to disproportionately larger
growth in those categories. Combining these effects may be able to generate
the level of granularity observed in the data, due to the large growth in a small
subset of goods experiencing the complementarity of these effects. I re-simulate
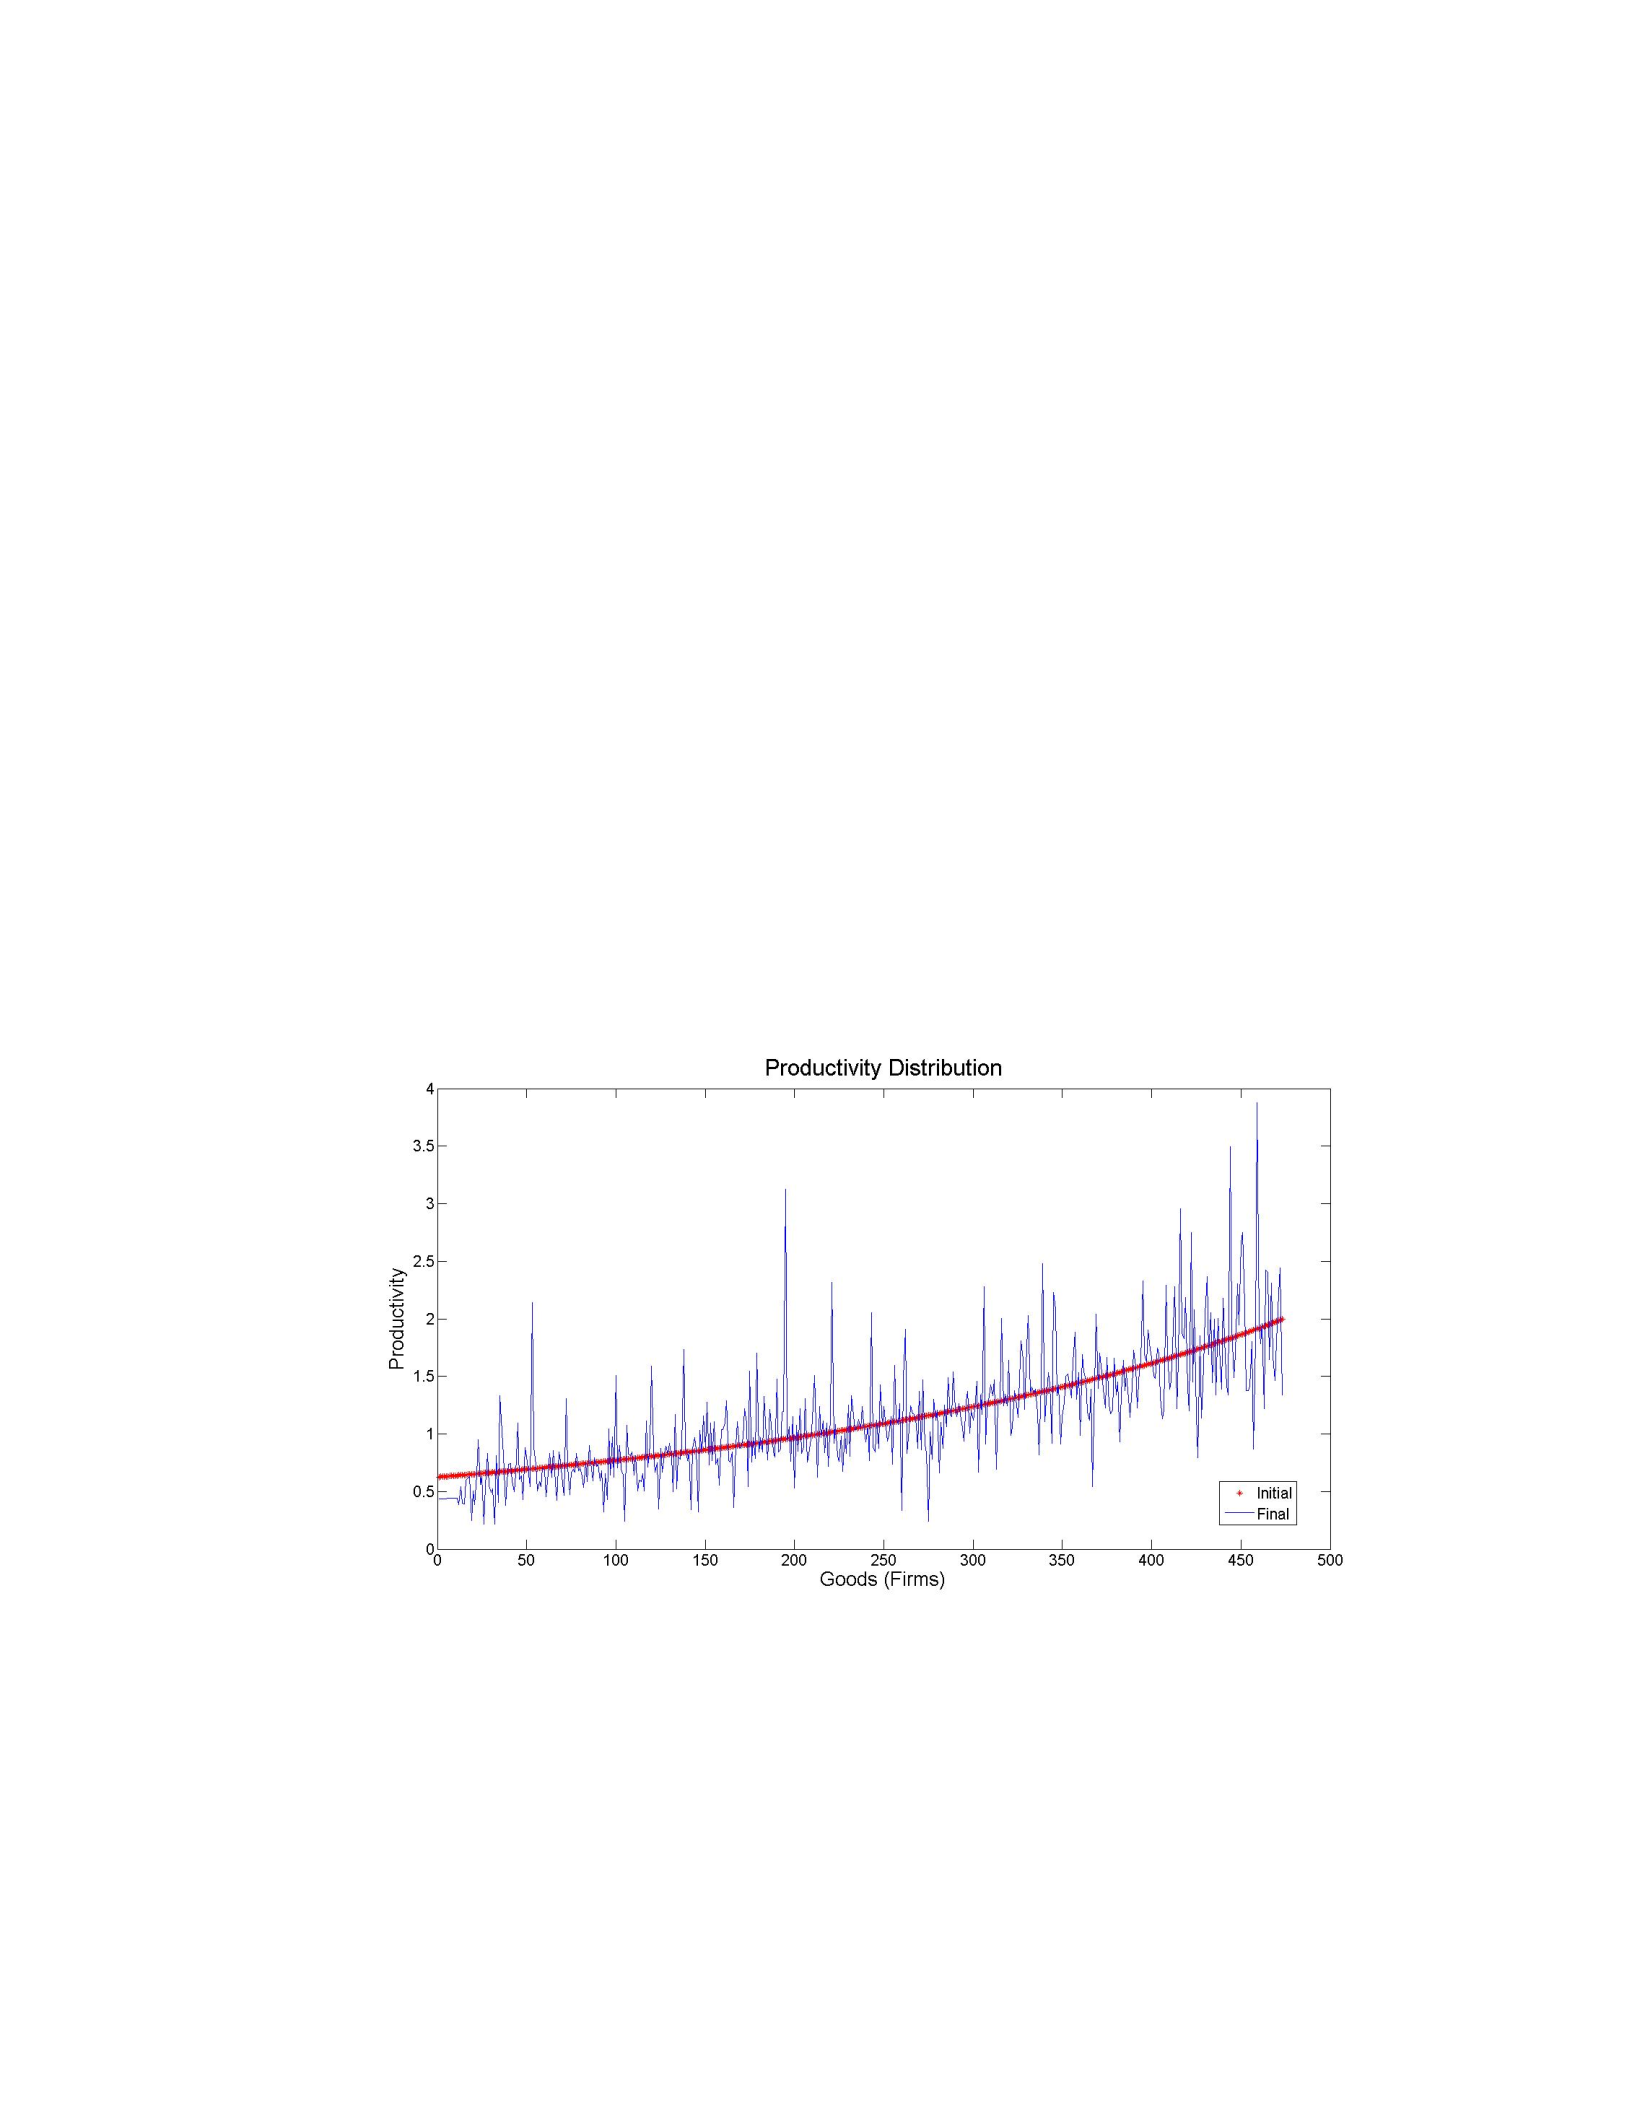
57
the standard model incorporating heterogeneous productivity changes and tar-
iff reductions imputed from U.S. production and export data, to determine if
this augmented standard model can produce the documented patterns of trade
growth.
Figure 2.11 demonstrates the distribution of productivity changes imputed
from U.S. production data. There is a great deal of heterogeneity across the
final distribution (in blue), once applied to the initial Pareto distribution (in
red). This suggests there may be some ability for the model to capture a higher
degree of granularity of trade growth as in the data, due to the relatively small
number of goods exhibiting disproportionately large productivity shocks, aris-
ing from varying levels of initial trade.
Figure 2.11: Productivity Distributions: Productivity Shocks
Once applied to the standard model, the heterogeneous productivity changes
and tariff reductions generate a larger degree of granularity in trade growth,
similar to that in the data. As can be seen in the bottom row of Figures
2.12(a)–2.12(b), the standard model with productivity shocks generates much

58
more heterogeneity across goods in the level of trade growth than the standard
model, due primarily to the large degree of heterogeneity in the productivity
shocks. Contrasting with the observed patterns of trade growth in the bilat-
eral trade data in the top row, there are typically a larger number of large
growth goods in the most-traded goods, and fewer large spikes among the mid-
traded goods in the model than what is observed in the data. This model sim-
ulation does appear to generate similar patterns of trade growth among the
least-traded goods, although there is a larger role of the traditional extensive
margin goods — those switching from not-traded to traded — in the model
than is observed in the data. Overall, there appear to be a larger number of
goods exhibiting relatively large growth in the model, such that the degree of
concentration of a large proportion of overall trade growth in a small number
of goods is slightly less than in the data, and thus the magnitude of growth
concentrated in each large-growth good is less in this model simulation.
Table 2.9 quantifies the degree of granularity generated in this model sim-
ulation. Across various country-pairs, including heterogeneous productivity
changes and tariff reductions greatly improves the standard model’s ability to
generate the granularity observed in the data. Analyzing the share of trade
growth accounted for by various quantiles of large-growth goods, the model
now generates roughly 70% as much granularity as in the data, a marked im-
provement from the 10% generated in the standard model with uniform tariff
reductions. In many cases, this improves to 80–90% of the granularity ob-
served in the data as more goods are included (i.e. the top 10% or 20% of
largest-growth goods).
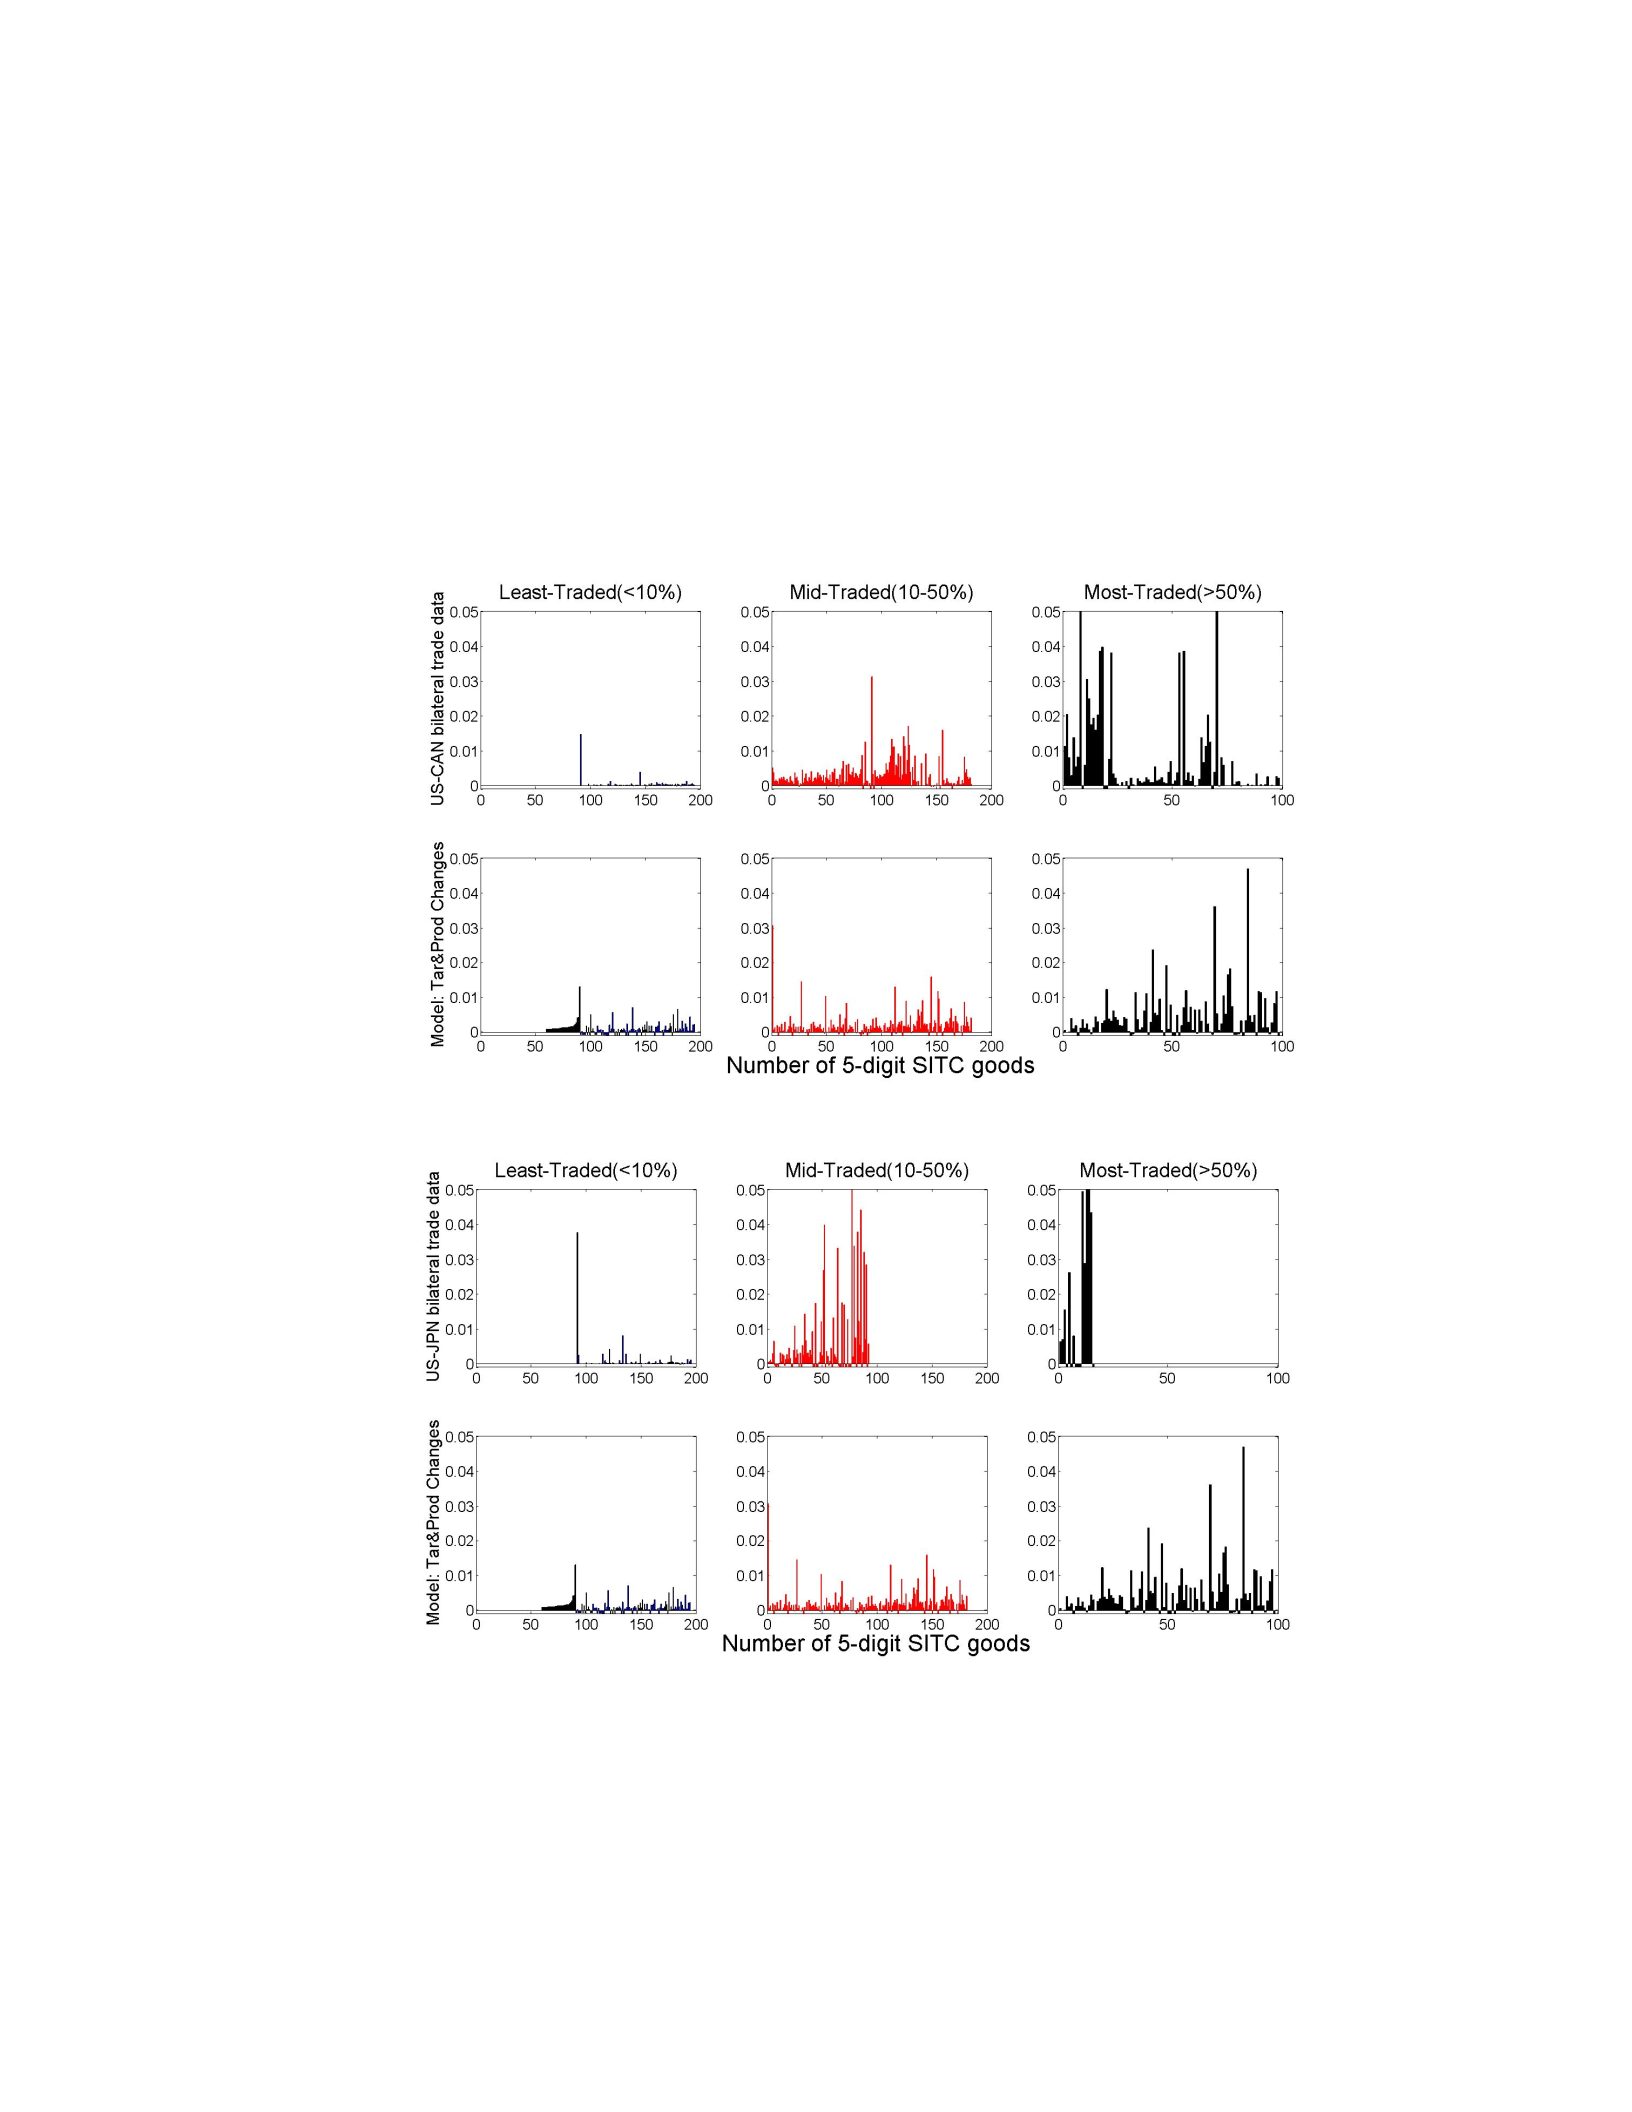
59
Figure 2.12: Standard Model with Heterogeneous Productivity Changes and
Tariff Reduction
(a) U.S.-Canada
(b) U.S.-Japan
60
Table 2.9: Heterogeneous Productivity Changes and Tariff Reductions
Share of growth from top X%of goods
(6-digit NAICS codes)
US Exports to Mexico
Model 1% 2% 5% 10% 20%
Data 25% 36% 57% 74% 89%
Productivity &
Tariff Changes 18% 26% 39% 53% 71%
US Exports to Canada
Model 1% 2% 5% 10% 20%
Data 26% 38% 56% 71% 86%
Productivity &
Tariff Changes 14% 22% 39% 58% 80%
US Exports to Japan
Model 1% 2% 5% 10% 20%
Data 37% 56% 86% 101% 114%
Productivity &
Tariff Changes 25% 37% 60% 82% 105%
2.5.4 Quantitative Analysis
To further illustrate the granularity generated by the standard model, I plot
the histograms of the share of total trade growth accounted for by each good, for
each of the various iterations of the model, in Figure 2.13. For all country-pairs,
the high level of granularity in the trade data results in a bimodal distribution,
with large spikes at small positive values, and at the top end of the distribution.
This reflects the empirical findings that most goods grow very little, and the
majority of trade growth is concentrated in a small subset of goods exhibiting
large growth.
The standard model with uniform tariff reductions produces a flatter, smoother
distribution of trade growth shares, reflecting much less granular growth across
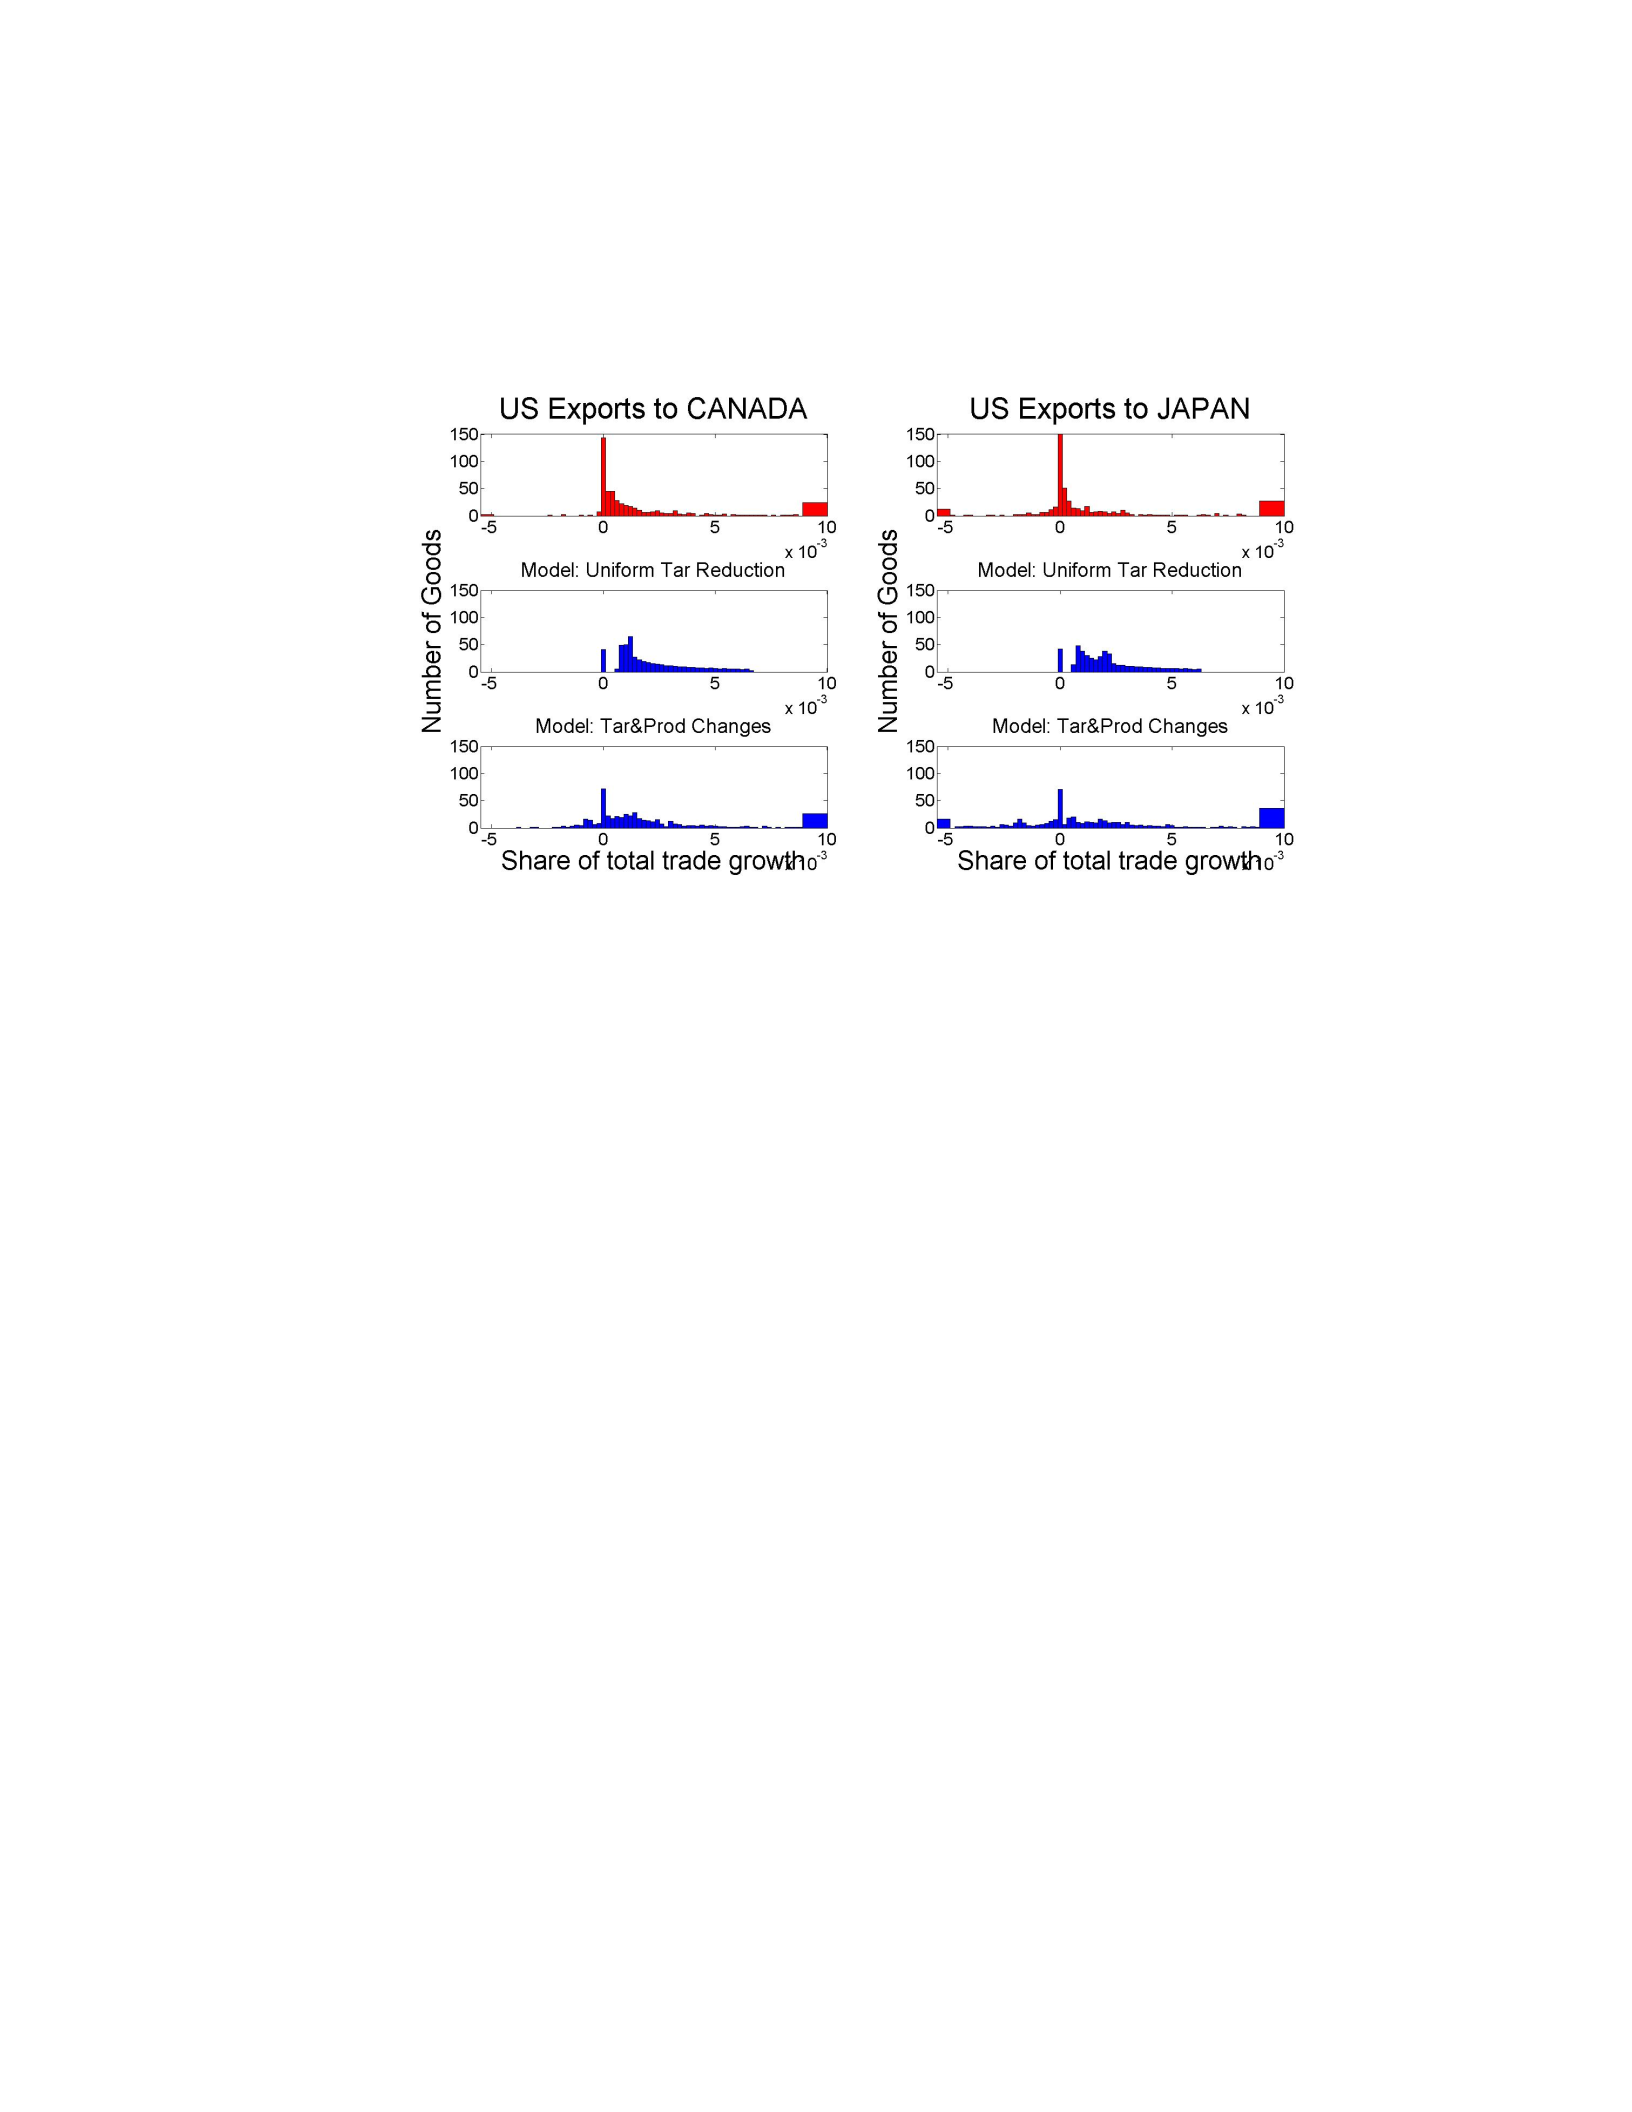
61
Figure 2.13: Histograms of Trade Growth by Goods
goods, and much less growth at the top end of the distribution. The stan-
dard model with heterogeneous productivity changes and tariff reductions pro-
duces comparable growth at the top end of the distribution, reflecting the large
growth among the small subset of goods accounting for the majority of trade
growth. However, the remainder of the distribution is less granular than in
the data, with growth more evenly dispersed across the remaining goods.
To quantify this dispersion of growth across goods, Table 2.10 provides sum-
mary statistics of trade growth across goods classifications for the various it-
erations of the model. The standard deviation gives an idea of the dispersion
across goods in the share of trade growth accounted for by each good, while the
kurtosis provides insight into the steepness of the distribution, both of which
reflect the granularity of trade growth. Notably, the variation across goods in
their share of total trade growth is higher in the data than in any of the model
iterations, and the kurtosis is significantly higher. The standard model with
heterogeneous productivity changes and tariff reductions performs best, with
a standard deviation 65% as large and a kurtosis 45% of that of the data. The
62
Table 2.10: Summary Statistics: Growth by Goods — Data vs. Models
Standard Deviation and Kurtosis
Model US/Can US/Ger US/Jpn US/Mex US/UK
Data Std 0.0072 0.0094 0.0107 0.0065 0.0092
Kurt 142.2410 34.0410 89.1526 62.6012 127.3663
Standard Std 0.0016 0.0015 0.0015 0.0017 0.0016
Kur 3.0950 3.0340 3.0825 3.0545 3.1281
Prod. shock Std 0.0043 0.0077 0.0072 0.0037 0.0052
Kur 39.9845 42.2558 42.2955 37.3227 41.5337
standard model with uniform tariff reductions generates standard deviations
and kurtosis that are much lower than those observed in the data.
Table 2.11 reports correlation coefficients between the initial level of trade
for each good and the resultant share of total trade growth accounted for by
each good. In the data, this correlation is statistically insignificant, ranging
from -0.02 to 0.05 across country-pairs, signifying that the high degree of con-
centration of growth in a small subset of goods is independent of those goods’
initial trade values. In the standard model with uniform tariff reductions, in
which goods have fixed productivities, this correlation is very high, greater
than 0.85 for all country-pairs. This characterizes the “smooth” productivity
distribution in the model, which results in all goods growing proportionally to
the tariff decrease and their initial productivity. The model with heterogeneous
productivity changes perform better, though the correlation coefficients are still
statistically non-zero, and in some countries much higher than observed in the
data. Again, the inherent smoothness in the initial productivity distribution
passes through in at least some degree to the levels of initial and final trade,
even when including heterogeneous productivity changes, generating stronger
correlation between initial trade levels and trade growth across goods.
63
Table 2.11: Correlations: Initial Trade vs Share of Total Trade Growth
Model US/Can US/Ger US/Jpn US/Mex US/UK
Data -0.0113 -0.0063 -0.0193 0.0453 -0.0155
Standard 0.9795 0.9114 0.9255 0.9869 0.9674
Prod. shock 0.3620 0.1715 0.1886 0.4405 0.2903
2.6 Conclusions
This chapter identifies key facts of trade growth during episodes of large growth
in bilateral trade. Bilateral trade growth is granular across goods classifica-
tions, with less than 5% of goods categories accounting for over 65% of total
trade growth during these periods. Tariff changes do not account for the large
growth in this subset of large growth goods, and many goods experiencing large
drops in their AVE tariff rates exhibit little to no growth. For all U.S. exporting
partners, increases in trade intensity, on average, account for a large share of
total trade growth, while production growth, on average, accounts for signifi-
cant portions of trade growth for some country-pairs, but virtually none of the
overall trade growth for others.
Characterizing the predictions of the a Melitz-style model with uniform tar-
iff reductions shows that it does not generate the granularity observed in the
data. Trade growth is much less granular in this model, generating only 10%
as much granularity as in the data, as measured by the share of total trade
growth accounted for by various quantiles of goods classifications. Adding het-
erogeneous productivity changes and tariff reductions to the model generates
a higher degree of granularity in trade growth in the model, capturing approx-
imately 70% of the granularity observed in the data.
Further research is needed to match the model to the level of granularity

64
generated by the data. More detailed data on tariff and production levels, for
a larger collection of countries, at this level of disaggregation across goods may
improve the model’s ability to match the observed level of granularity. Simi-
larly, examining non-tariff trade barriers may help to account for the remaining
25–30% of trade growth concentrated in a small subset of large-growth goods.
Finally, examining variation in the methods of transportation and distribution
of exported goods may help account for the granularity of trade growth, as
goods exported via different distribution methods may respond differently to
trade liberalization, leading to a larger degree of granularity generated when
these factors are considered in a Melitz-style model environment.
2.7 References
ABEL-KOCH, J. (2013) “Who Uses Intermediaries in International Trade? Ev-
idence from Firm-level Survey Data,” The World Economy. 36(8),1041–1064.
AHN, J., A. KHANDELWAL,AND S. WEI (2011). “The Role of Intermediaries in
Facilitating Trade,” Journal of International Economics, 84(1), 73–85.
ALESSANDRIA, G., J. KABOSKI AND V. MIDRIGAN (2010). “Inventories, Lumpy
Trade, and Large Devaluations”. American Economic Review, 58(Dec), 2304–39.
ANDERSON, J.E. AND E. VAN WINCOOP (2003). “Gravity with Gravitas: A
Solution to the Border Puzzle”. American Economic Review. 93(1). 170–192
ARKOLAKIS, C. (2010). “Market Penetration Costs and the New Consumers
Margin in International Trade”. Journal of Political Economy, 118(Dec), 1151–99.
ARMENTER, R., AND M. KOREN (2010). “A Balls-and-Bins Model of Trade”.
American Economics Review (forthcoming).
BERGOEING, R., AND T. KEHOE (2001). “Trade Theory and Trade Facts”. Fed-
eral Reserve Bank of Minneapolis, Research Department.
CALIENDO, L. AND F. PARRA (2014). “Estimates of the Trade and Welfare
Effects of NAFTA”. The Review of Economics Studies. rdu035.
CHANEY, T. (2008). “Distorted Gravity: The Intensive and Extensive Margins
of International Trade”. American Economic Review, 98:4, 1707–1721.

65
DORNBUSCH, R., S. FISCHER,AND P. SAMUELSON (1977). “Comparative
Advantage, Trade, and Payments in a Ricardian Model with a Continuum of
Goods”. American Economic Review, 67(5)823–39.
FEENSTRA, R., J. ROMALIS,AND P. SCHOTT “U.S. Imports, Exports and Tariff
Data, 1989–2001”, NBER Working Paper 9387.
FERNANDES, A.M., P. KLENOW, S. MELESHCHUK, M.D. PIEROLA,AND A.
RODRGUEZ-CLARE (2015) “The Intensive Margin in Trade: Moving Beyond
Pareto”, Working Paper.
GABAIX, X. (2011) “The Granular Origins of Aggregate fluctuations.” Econo-
metrica 79(3): 733–772.
GOULD, D.M. (1998). “Has NAFTA Changed North American Trade?” Eco-
nomic Review- Federal Reserve Bank of Dallas 12–23.
HELPMAN, E., M.J. MELITZ,AND Y. RUBINSTEIN (2008). “Estimating Trade
Flows: Trading Partners and Trading Volumes.” The Quarterly Journal of Eco-
nomics 123(2): 441–487.
HELPMAN, E., M.J. MELITZ AND S. YEAPLE (2004). “Export Versus FDI with
Heterogeneous Firms”. American Economic Review, 94(1), 300–316.
HORNOK, C., AND M. KOREN (2015). “Per-shipment Costs and the Lumpiness
of International Trade.” Review of Economics and Statistics. 97(2), 525–530.
IMBS, J., AND I. MJEAN (2010) “Trade Elasticities” Paris School of Economics,
unpublished mimeo.
KEHOE, T. (2005). “An Evaluation of the Performance of Applied General Equi-
librium Modes on the Impact of NAFTA”, in Frontiers in Applied General Equi-
librium Modeling: Essays in Honor of Herbert Scarf, edited by Kehoe, Srini-
vasan and Whalley, 341–77. New York: Cambridge University Press.
KEHOE, T. AND K. RUHL (2013). “How Important is the New Goods Margin in
International Trade?”. Journal of Political Economy, 121 (2013), 358–92.
KRUGMAN, P. (1980). “Scale economies, product differentiation, and the pat-
tern of trade.” The American Economic Review, 950–959.
MCDANIEL, C., AND E. BALISTRERI (2003) “A Review of Armington Trade
Substitution Elasticities.” Economie internationale (2) 301–313.
MELITZ, M.J. (2003). “The Impact of Trade on Intraindustry Reallocations and
Aggregate Industry Productivity.” Econometrica, Vol. 71.6 (2003): 1695–1725.
NAGURNEY, A. (2010). “Optimal Supply Chain Network Design and Redesign
at Minimal Total Cost and with Demand Satisfaction”. International Journal

66
of Production Economics. 128, 200–208.
NIGAI, S. (2017). “A Tale of Two Tails: Productivity Distribution and the Gains
from Trade.” Journal of International Economics (104): 44–62.
PIERCE, J. AND P. SCHOTT (2012). “A Concordance Between Ten-Digit U.S.
Harmonized System Codes and SIC/NAICS Product Classes and Industries”.
Journal of Economic and Social Measurement, 37(1–2), 61–96.
ROMALIS, J. (2007). NAFTAs and CUSFTAs Impact on International Trade,
Review of Economics and Statistics, 89(3), pp.416–435.
SANTOSO, T., S. AHMED, M. GOETSCHALCKX,AND A. SHAPIRO (2005). “A
Stochastic Programming Approach for Supply Chain Design Under Uncertainty”.
European Journal of Operation Research, 167, 95–115.
SCHOTT, P. (2008). “The Relative Sophistication of Chinese Exports ”. Eco-
nomic Policy, 53, 5–49.
Chapter 3
The Role of Multiple Distribution
Technologies in Accounting for
Trade Growth
3.1 Introduction
Fixed and variable costs of exporting have been found to play a significant
role in accounting for international trade flows.1A wide literature establishes
the role of geographic barriers, international borders, and tariffs and quotas
in accounting for variation in bilateral trade growth across countries.2It is
well-documented, in papers like Anderson (1979), or Parsley and Wei (1996),
that trade flows generally decrease with distance — the larger the geographic
distance, the higher the presumed transportation costs of shipping goods to
foreign locations, resulting in smaller trade flows, ceteris paribus.
While a large literature examines the impact of transportation costs in ac-
counting for bilateral trade flows across countries, many studies assume a
1See, for example Melitz (2003), Chaney (2008), or Bernard et al (2007) for prominent
examples.
2See Eaton, Kortum (2002), Engel, Rogers (1996), among others.
67
68
singular exporting technology, with a common fixed and variable cost. How-
ever, when exporters ship their goods internationally, they typically compare
the costs of multiple available technologies to choose their optimal distribution
networks.3In many cases, these can be divided into two broad categories: (1)
methods with low-fixed and high-variable costs, and (2) methods with high-
fixed and low-variable costs. For example, firms exporting large volumes may
opt to build their own infrastructure, complete with marine or air transport and
offices at home and abroad to handle shipments, incurring large fixed costs, but
relatively low per-unit costs. Conversely firms with relatively small or infre-
quent shipments may choose to export using an intermediary like FedEx, with
minimal fixed costs, but higher per-unit costs incurred.
One of the main findings of Chapter 2 is that trade growth is granular —
that the majority of bilateral trade growth is accounted for by a small number
of large-growth goods classifications. I find that using a standard Melitz-style
trade model, and including heterogeneous productivity and tariff changes im-
puted from U.S. production and tariff data, generates roughly 70% as much
granularity as in bilateral trade data. Can incorporating heterogeneity in
available exporting technologies help account for the remainder of this gran-
ularity? How do the differences in available transportation options, and their
associated costs, affect suppliers exporting decisions and account for increased
granularity in trade growth across goods?
To answer these questions, I build a model of bilateral trade with standard
features such as heterogeneous productivities across firms, CES preferences
and monopolistic competition pricing similar to Chapter 2. In this chapter, I
3For a general overview of recent developments in the strategic supply network formation
literature, see Mills, Schmitz and Frizelle (2004), or work on optimal supply network design,
such as Nagurney, Dong and Zhang (2004).

69
add a choice for exporters among multiple distribution technologies — one low-
fixed, high variable cost method, and one high-fixed, low-variable cost method
— to examine how variation in the available distribution technologies impacts
bilateral trade flows and trade growth across goods classifications. This model
framework generates three main channels for generating large trade growth
across goods:
1. Large increases in productivity that lower the marginal costs of produc-
tion
2. Large reductions in tariff rates that lower the marginal costs of servicing
the foreign market
3. The ability for firms to switch distribution technologies, from a high vari-
able cost method to a lower variable cost method
The contribution of this chapter is to examine the impact of this third chan-
nel. In Chapter 2, I find that a Melitz-style generates only 70% as much gran-
ularity in trade growth as bilateral trade data. Including this “switching”
mechanism may allow the model to bridge this gap, which requires a higher
concentration of overall trade growth in a smaller number of goods exhibiting
disproportionately larger growth.
With CES demand and monopolistic competition pricing, the fixed costs of
exporting generate productivity thresholds — the least productive firms do
not export, firms with sufficiently high productivities export via the low-fixed
cost method, and the most productive firms find it profitable to export via the
higher-fixed cost method. As trade barriers fall (commonly represented by re-
ductions in the variable costs of exporting), the productivity thresholds shift —
some previously not-traded goods now become exported, and some previously
70
traded goods switch from the low-fixed/high-variable cost method, to the high-
fixed/low-variable cost method. These “switchers” may exhibit disproportion-
ately larger trade growth, due to double effect of the original reduction in trade
costs, combined with the switch to a lower variable cost exporting method.
To quantitatively assess the ability of this channel to generate granularity
in trade growth, I calibrate the model to match observed trade shares across
goods in bilateral trade data. As in Chapter 2, I use 6-digit North American In-
dustry Classification System (NAICS) data on U.S. exports to Canada, Japan,
and Mexico between 1989 and 1999, to determine the share of cross-sectional
trade and trade growth accounted for by each good category.4I target the level
of granularity in trade growth, which I quantify by calculating the share of
bilateral trade growth accounted for by each of the 473 NAICS goods classifica-
tions. I find that trade growth is highly granular in the data, with the top 5% of
large-growth goods accounting for, on average, 66% of bilateral trade growth.5
Most goods account for very little of the overall growth in trade — it is only a
small number of goods, growing from small initial levels of trade to large levels
of trade, or from large initial levels to much larger levels, that account for the
majority of growth.
4The analysis in this chapter is confined to these three destination countries due to data
limitations — in order to include heterogeneous productivity changes at this disaggregated
level of goods classifications, I use 6-digit NAICS production data for the United States, mak-
ing the U.S. the only source country for bilateral trade; in order to include heterogeneous tariff
reductions at this level of disaggregation, I use 8-digit Harmonized Tariff Schedule (HTS) im-
port tariff data, corcorded to 6-digit NAICS classifications, that is only available during this
period for Canada, Japan and Mexico.
5Further, I find that trade growth is more granular than cross-sectional trade — that is, the
top 5% of large-trade goods categories accounts for 52% of trade in a given period, but the top
5% of large-growth categories accounts for, on average, 66% of trade growth across countries.
Note: these top 5% categories need not be the same — the top 5% of traded goods in one period
are not necessarily the largest growth goods in the next period.
71
I quantitatively assess whether this model with multiple distribution tech-
nologies can generate the high degree of granularity observed in the data. As
in Chapter 2, each firm produces a single, unique good using labour as the
sole input, indexed by its productivity, 1
a, where ais the per-unit labor require-
ment, facing CES demand with monopolistically competitive markets. In this
chapter, I add a discrete choice among multiple distribution technologies for
exporting firms — X1: a low-fixed, high-variable cost method (f1, τ1), and X2: a
high-fixed, low-variable cost method (f2, τ2). Given a productivity drawn from a
Pareto distribution, firms profit maximize by deciding whether to export, and
if so, choosing their optimal distribution technology.
Characterizing equilibrium, I find that with CES preferences, foreign de-
mand for each good produced in the home country is inversely proportional
to that good’s price offered in the foreign market. Monopolistic competition be-
tween firms implies that each good is priced in the foreign market at a constant
mark-up over marginal cost. This marginal cost has multiple components —
the marginal cost of domestic production, a, which is a function of each firm’s
productivity; and the marginal cost of reaching the foreign market, which itself
has two components — the variable costs of the distribution method employed,
τ, and any tariffs imposed by the destination country, which is treated similar
to a change in the variable transportation cost. However, with multiple dis-
tribution technologies, the variable distribution cost can take two values — τ1
or τ2, allowing for greater heterogeneity across goods in the growth in trade
generated by productivity changes or trade liberalization.
Exporting profits are thus a function of the firm’s productivity and the fixed
and variable costs of the chosen distribution method. The existence of fixed

72
costs of exporting generates productivity thresholds — only goods with suffi-
ciently high productivities will find it profitable to export, and only goods with
productivities high enough to cover the higher fixed cost will find it profitable
to export via method X2, while all other exported goods will be exported via
the lower-fixed cost method X1. Goods are stratified in the model according to
their optimal distribution choice, and trade flows are a function of the relative
productivities and export costs across goods.
To quantify the granularity of trade growth generated by this model, I first
solve the model for given values of fixed and variable costs, productivities and
tariff rates, to determine export sales and optimal distribution choices across
goods. To analyze growth in this static model, I follow a common approach
of representing trade liberalization as a fall in trade costs which reduce the
variable costs of exporting, and then re-solve the model to determine changes
in the model’s predictions for export sales and distribution choice.
With CES demand, monopolistic competition pricing, and a single distri-
bution technology, a fall in trade costs results in a proportional increase in
exports for each previously-traded good. However, with multiple distribution
technologies, the fall in variable costs also shifts the productivity thresholds for
the high- and low-fixed cost distribution methods. Some previously not-traded
goods become traded, as the reduction in variable costs makes paying the fixed
cost to export profitable. This is extensive margin growth, and leads to dispro-
portionately larger growth than the size of the tariff reduction for these goods,
as they grow from zero to larger share of total trade by crossing the exporting
threshold. Further, some goods previously traded via the low-fixed cost method
now profitably switch to the higher-fixed cost method, accessing the lower vari-
able cost. These “switchers” exhibit disproportionately larger export growth
73
due to a double effect — the direct effect of a reduction in the variable costs
due to tariff decreases, and the indirect effect of switching to a distribution
method with a lower variable cost.
To compare the predictions of the multiple distribution technologies model
to the data, I calibrate and simulate the model and calculate the share of to-
tal trade growth accounted for by each good. I first simulate the model with
each good classification drawing a heterogeneous productivity from a Pareto
distribution, and determine the share of trade accounted for by each good. I re-
simulate the model, adding heterogeneous productivity changes for each good
that I impute from U.S. production data, and heterogeneous tariff reductions
concorded from destination-country tariff data. The changes in the model’s pre-
dictions for each good’s level of exports between the two simulations are then
compared to the changes in trade for each good in the data.
A key issue is how to calibrate the fixed and variable costs, f1, f2and τ1, τ2.
Since data on direct measures of shipping and distribution costs is limited at
this level of disaggregation, I calibrate the fixed and variable costs in the initial
simulation to match the granularity of cross-sectional trade in the data for
the 1989–1991 average for each country-pair. For a given τ1, the lower fixed
costs, f1is calibrated to match the number of not-traded goods categories.6The
higher fixed cost, f2and lower variable cost τ2are calibrated to best match the
granularity in cross-sectional trade, as measured by the share of total trade
accounted for by top quantiles of goods categories (i.e. the top 2, 5, and 10%)
in a given period. I retain these values for the fixed and variable costs in the
second simulation.
Simulating the model, I find the multiple distribution technologies model
6This is determined by the equation for the lower productivity cut-off, Eq.(5).
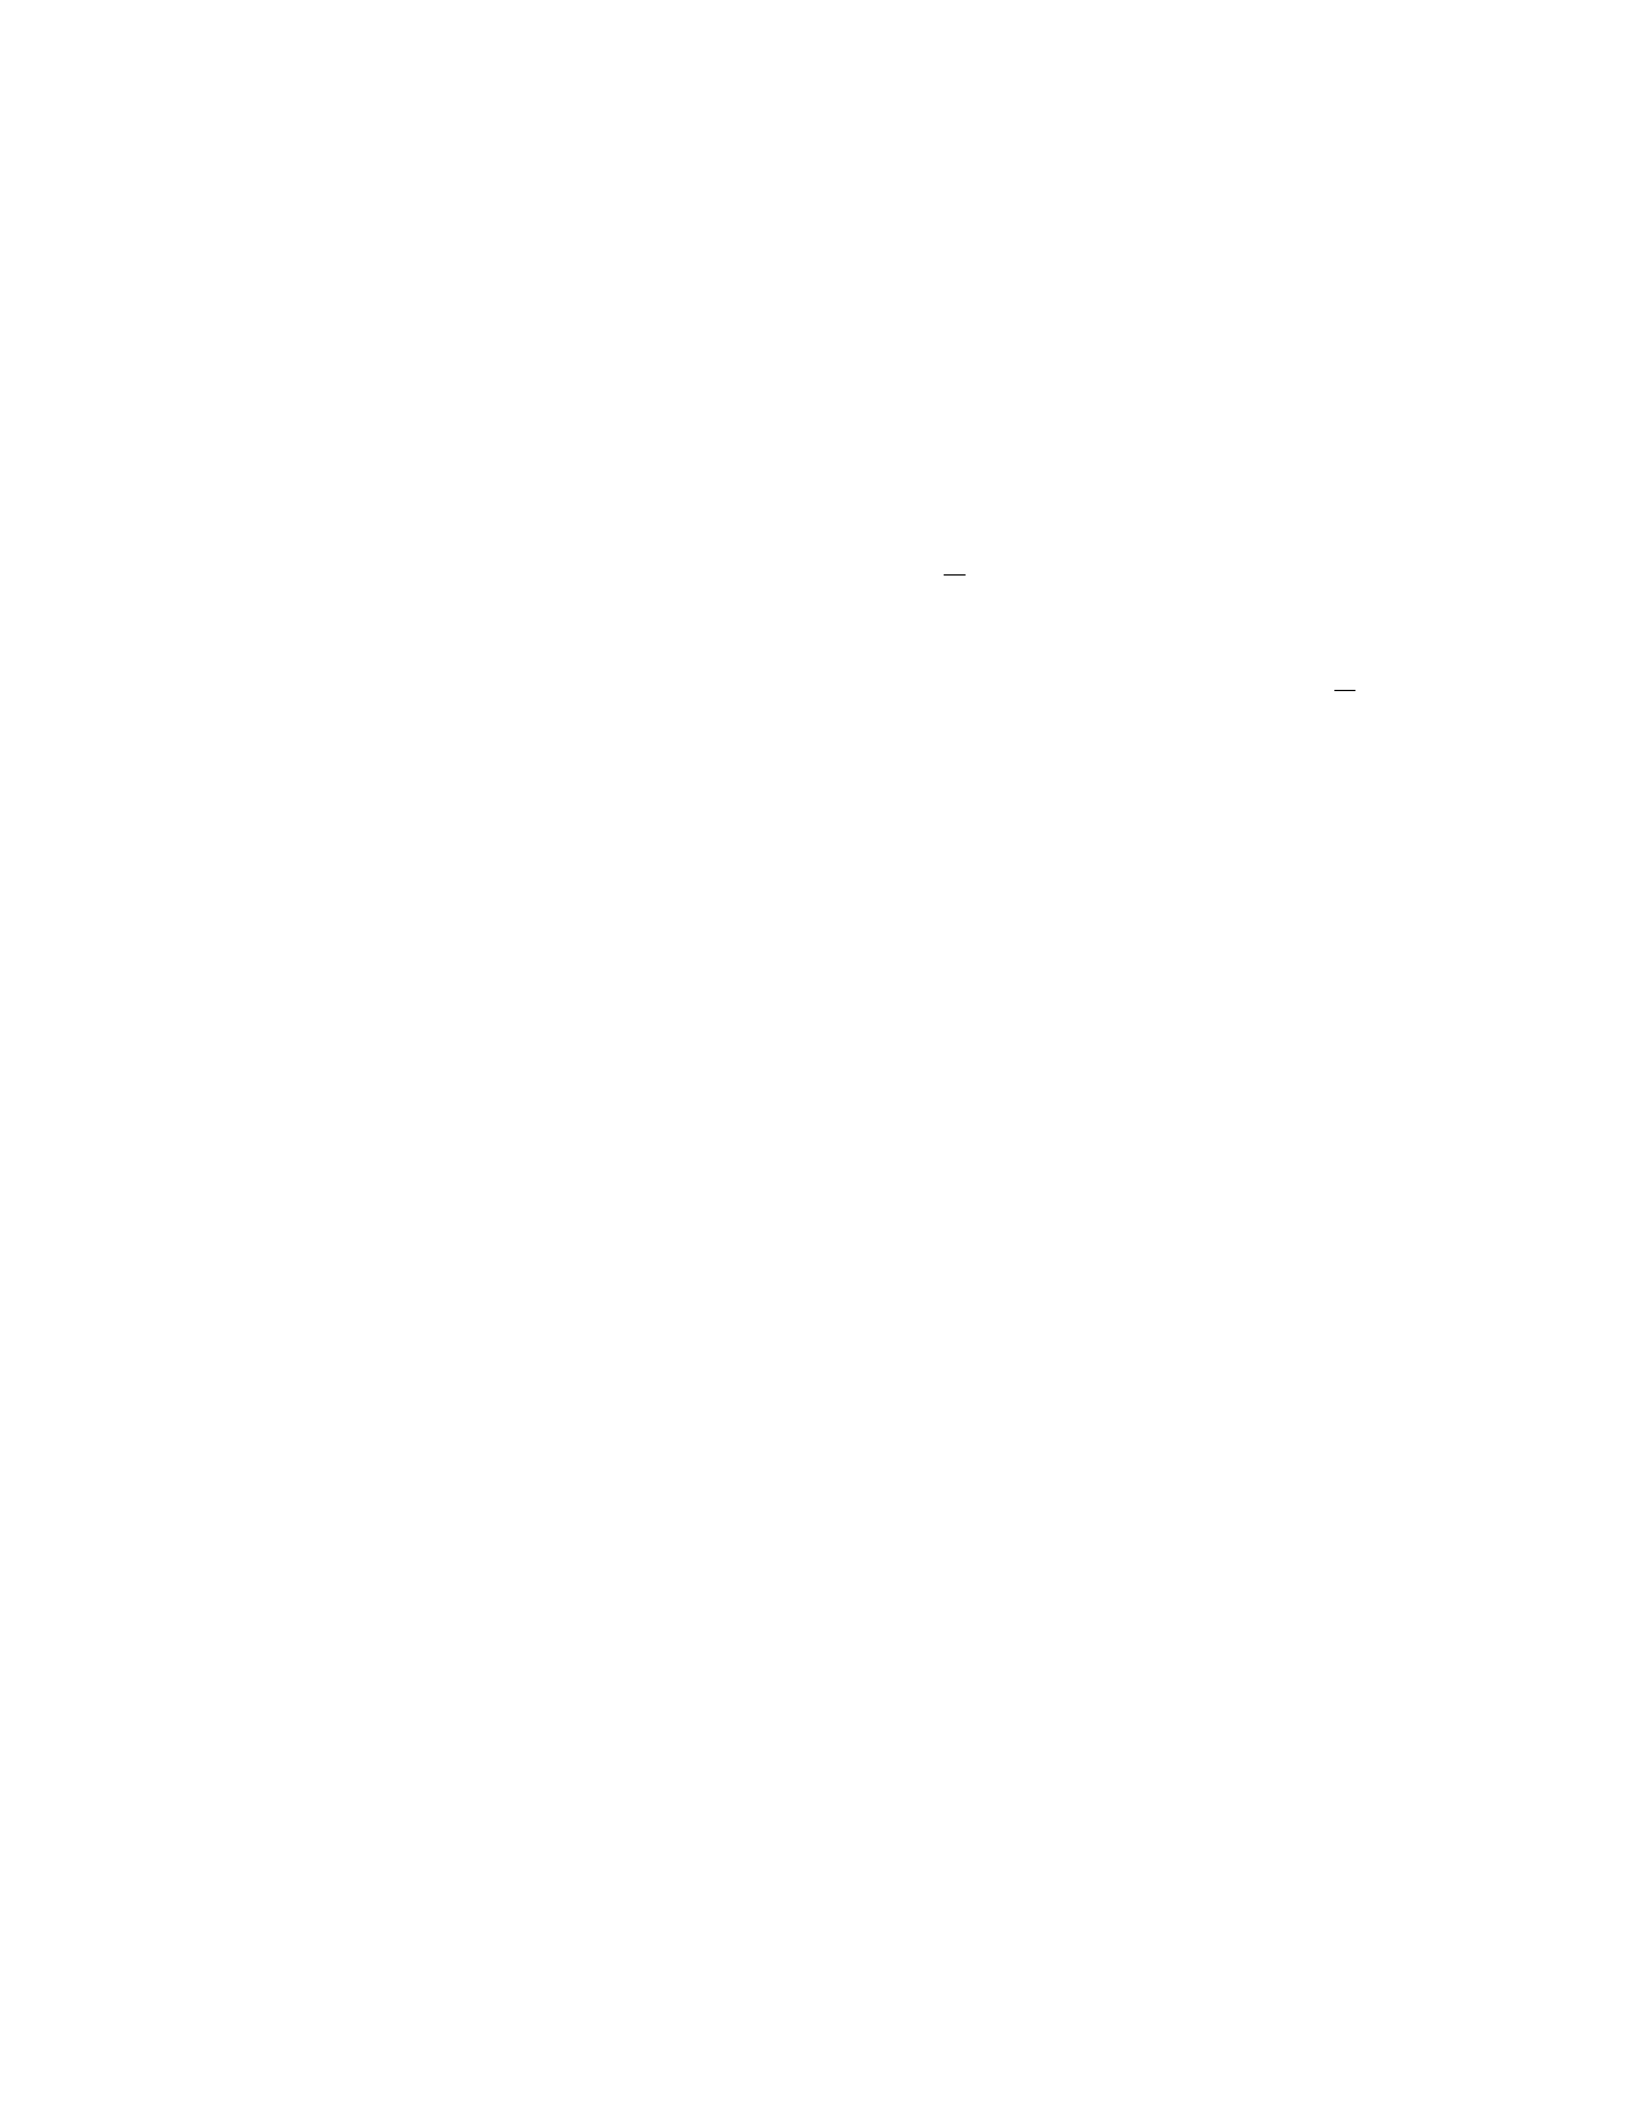
74
closely matches the degree of granularity in cross-sectional trade. On average
across country-pairs, the top 2, 5 and 10% of goods categories, respectively,
account for 33, 56 and 64% of cross-sectional trade, as compared to 35, 52 and
67% of cross-sectional trade in the data. Achieving this granularity requires
a relatively high ratio of fixed costs, with f2
f1calibrated anywhere from 670
for U.S. exports to Mexico, up to 1840 for U.S. exports to Japan. The ratio of
variable costs for the two methods is fairly consistent, calibrated near τ2
τ1=0.60
for all country-pairs.
I find that the two-method model generates a higher degree of granularity,
with the top quantiles of goods categories accounting for roughly 90–95% of the
share of total trade growth as in the corresponding trade data. Specifically, the
top 2, 5 and 10% of goods categories account for 43, 57 and 81%, respectively,
of total trade growth in the two-method model, compared to 43, 66 and 82% in
the data. Conversely, performing similar model simulations with only a single
distribution technology, as in Chapter 2, accounts for only 23, 46 and 64% of
total trade growth, roughly 60–70% of the granularity observed in the data.
Examining the choices of distribution methods in the simulations, I find
that switching behaviour generates increased granularity in trade growth in
the model. Goods that begin and remain traded via method X1account for an
average of less than 0.01% of total trade growth. Goods that begin and remain
traded via method X2contribute a larger share of total trade growth, on aver-
age 0.40% of total trade growth for each good in this group. However, goods
that switch from not-traded to traded via either method contribute an average
of 0.39% of total trade growth, while goods that switch distribution methods
from X1to X2contribute an average of 0.60% of total trade growth. This sup-
ports the theory that the ability for firms to choose among multiple distribution
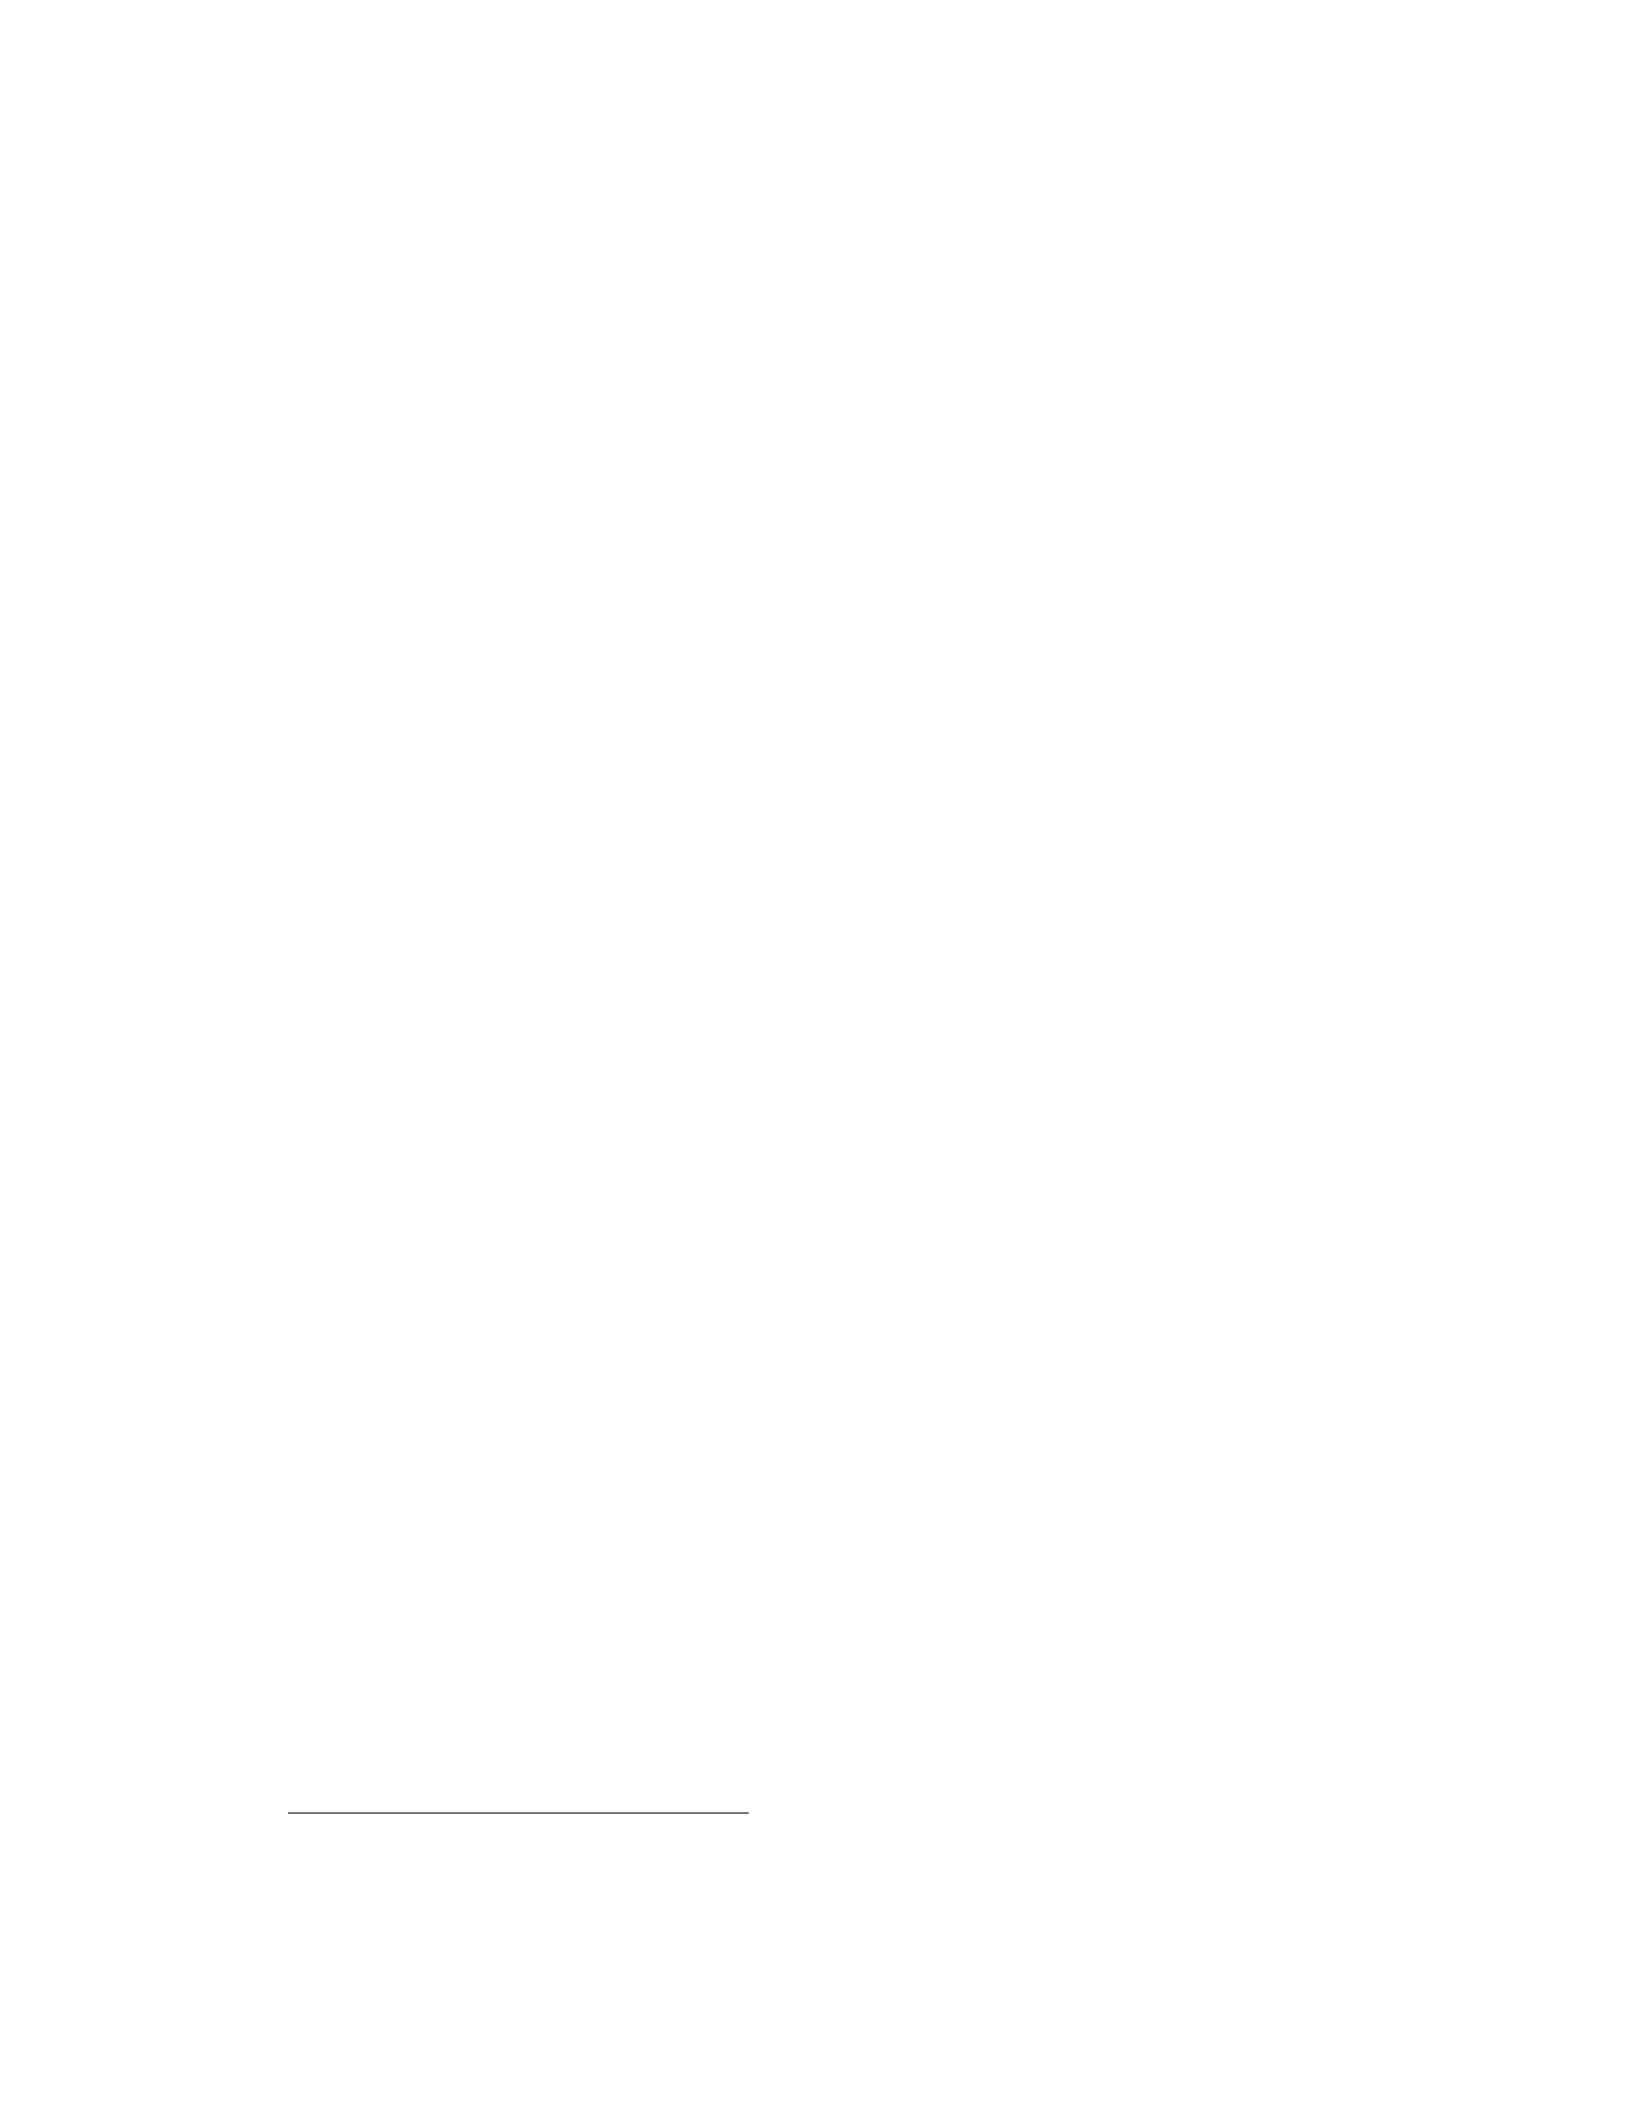
75
technologies in the exporting process increases the granularity predicted by
the model, more closely matching the level of granularity observed in bilateral
trade data.
3.2 Related Literature
As in Chapter 2, this chapter contributes to the “trade lumpiness” literature, in
multiple ways.7First, this chapter provides a novel mechanism of incorporat-
ing multiple exporting technologies into a standard Melitz-style trade model,
that is capable of matching a high degree (roughly 90–95%) of the granularity
of cross-sectional trade observed in the data. Second, a central contribution
of Chapter 2 was to document the fact that trade growth is more granular
than cross-sectional trade, and that the set of large-growth goods is uncorre-
lated with the set of goods that were previously most highly traded. Including
multiple exporting technologies in the model generates a mechanism whereby
firms may switch distribution technologies, leading to disproportionately larger
trade-growth than non-switching firms, and helping to account for the granu-
larity of both cross-sectional trade and trade growth over time.
This chapter builds a framework similar to that of Helpman, Melitz and
Yeaple (2004), in which firms face a choice of exporting versus foreign direct in-
vestment (FDI). In their model, firms face different fixed costs of exporting and
FDI, and become stratified: domestic-only producers, firms productive enough
to pay the relatively lower fixed costs of exporting, and firms that are most
productive and can pay the relatively higher fixed costs of FDI to profit from
the lower marginal costs of production in FDI rather than exporting. However,
7See Armenter, Koren (2010), Hornok, Koren (2015) or Alessandria, Kaboski and Midraggan
(2010), for example.

76
since FDI is not observed in trade data as exports, this mechanism would not
be present in accounting for the granularity of export growth. This chapter
introduces a similar mechanism, with goods stratified according to their opti-
mal distribution technology, but which allows for the model to account for the
granularity of trade growth observed in export data.
A wide literature investigates optimal supply network design, to identify
how firms choose their distribution networks when confronted with options
across multiple distribution technologies. Nagurney (2010), and subsequent
papers related to this work, investigate the formation, and potential re-optimization,
of firms’ optimal supply networks. This work focuses on channels such as the
role of excess capacity — firms strategically choose distribution network capac-
ity and usage, to dynamically optimize around potential changes in the econ-
omy. Similarly, Santoso et al (2005) propose an algorithmic approach, similar
to Nagurney, for solving optimal supply network design across firms. While
this chapter abstracts from innovation in new supply network design or ca-
pacity constraints, it contributes to the supply network literature by quantita-
tively assessing the impact of distribution options in accounting for observed
patterns of trade growth.
Another literature related to optimal distribution networks focuses on the
role of wholesalers as intermediaries in international trade. Abel-Koch (2013)
uses firm-level data to empirically examine the relationship of firm size and
production to the use of trade intermediaries in Turkish exporting firms, and
find that intermediary use is decreasing in firm size, and that newly traded
goods are more likely to use trade intermediaries to export their products. Ahn,
Khandlwal and Wei (2011) incorporate an intermediary sector into a model
with heterogeneous firms, and find that firms are stratified into non-traded,

77
use of trade intermediary, and direct exporting firms, according to productivity.
This chapter finds a similar result of the stratification across the multiple tech-
nologies in firms’ distribution choice; however, these previous works largely
seek to match data on cross-sectional trade, not on trade growth. Further, they
primarily focus on matching which firms employ each method of trade, and do
not examine the possible change in these optimal choices following a reduc-
tions in trade barriers and the resultant impact on trade growth across firms.
This chapter extends this literature by allowing for possible changes in distri-
bution choice across multiple exporting technologies as trade barriers fall or
other structural changes may take place.
A large literature highlights the role of heterogeneity in accounting for
trade growth in international trade models. However, the focus of these models
is typically in matching overall trade flows and growth in trade. This chapter
focuses not only on matching overall bilateral trade growth, but also the distri-
bution of growth across goods, in matching the observed granularity of bilateral
trade data. Melitz (2003) and Chaney (2008), both pre-eminent works in this
literature, document the role of heterogeneous productivities across firms, as
well as fixed and variable costs of exporting, to identify the roles of the inten-
sive and extensive margins in accounting for overall trade growth. Freund and
Pierola (2015) empirically determine that the majority of cross-sectional trade
can be attributed to a small number of the largest firms in a given sector, which
can account for variation in the sectoral distribution of exports relative to in-
come across countries. Arkolakis (2010) focuses on market penetration, build-
ing a model in which firms essentially choose their fixed cost in order to access
a foreign market. Depending on this choice of fixed costs, they then face vary-
ing options of increasing marginal costs to reach additional consumers and in-
crease sales. However, as documented in Chapter 1, even adding heterogeneous

78
productivity and tariff changes to these types of models does not generate suf-
ficient granularity of trade growth. By adding a discrete choice across multi-
ple distribution technologies in the exporting process, allowing some firms to
switch technologies and leading to disproportionately larger growth for these
goods, the model in this chapter is better able to match the granularity of trade
growth across goods observed in the data.
3.3 Data
To decompose trade growth across goods, I use 6-digit North American Indus-
try Classification System (NAICS) data for U.S. exports to Canada, Mexico and
Japan, from 1989 to 1999. Unlike Chapter 2, the bilateral trade data is con-
fined to this subset of country-pairs by data limitations. In order to include het-
erogeneous productivity changes imputed from production data, I confine the
analysis to U.S. exports, as data at this level of disaggregation is only avail-
able for U.S. production. Similarly, in order to include heterogeneous tariff
changes across goods, I confine the analysis to U.S. exports to Canada, Mexico
and Japan, as tariff data at this level of disaggregation is only available for
this subset of the countries used in Chapter 2 for this time period.
To combine these disparate data sources, I map all data to the 6-digit NAICS
classification system. While these limitations restrict the analysis to a smaller
set of countries, I am still able to analyze trade growth across goods at a rel-
atively high level of disaggregation, and for countries that experience formal
trade liberalization (U.S.-Canada, U.S.-Mexico) as well as those that do not
(U.S.-Japan).
In Chapter 2, I used 5-digit Standard International Trade Classification

79
(SITC) data to document the granularity of trade growth across goods. One
key distinction between the two goods classification systems is the level of dis-
aggregation — there are 1836 goods categories in the 5-digit SITC data, while
the NAICS data is less disaggregated, with only 473 goods classifications. Since
the level of disaggregation has a potential impact on the level of granularity, I
re-calculate the shares of total trade growth accounted for by top quantiles of
goods categories for each country-pair in the 6-digit NAICS data.
As in Chapter 2, I use a 3-year average for measuring trade flows, to account
for issues such as shipping delays and customs reporting irregularities. For
each 6-digit NAICS good, I calculate the average export value from 1989–1991,
which I label as the “initial” trade value, and similarly calculate the average
export value from 1997–1999, which I label as the “final” trade value. Trade
growth is thus measured as the difference in these three-year averages for each
good.
3.3.1 Bilateral Trade Data
Descriptive Statistics
Table 3.1 presents summary statistics for U.S. exports to Canada, Mexico and
Japan, between 1989 and 1999. Countries experiencing formal trade liberal-
ization (U.S./Canada, U.S./Mexico around NAFTA) exhibit larger total growth
in trade than those non-liberalizing countries (U.S./Japan). Additionally, this
trade growth represents a larger percentage increase in trade over initial lev-
els, with U.S. exports to Canada and Mexico growing by 115% and 189% re-
spectively, while U.S. exports to Japan grew by 44% over this period.
80
Table 3.1: Summary Statistics: Bilateral Trade Data
(6-digit NAICS codes)
Variable USA-CAN USA-MEX USA-JPN
Initial Trade 65196.99 24536.51 34976.65
Final Trade 139880.12 70818.53 50320.17
Trade Growth 74683.13 46282.01 15343.51
%∆ in Trade 115% 189% 44%
Share of initial trade from top X%of goods
2% 37% 27% 41%
5% 53% 45% 59%
10% 66% 62% 74%
Share of trade growth from top X%of goods
2% 38% 36% 56%
5% 56% 57% 86%
10% 72% 74% 102%
Median share of 0.05% 0.03% 0.03%
trade growth
Number of goods: 473
(All trade values in thousands of $US)
81
Trade Growth Granularity
I re-calculate the share of total trade growth between country-pairs that is ac-
counted for by each 6-digit NAICS classification. Table 3.1 reports the share of
total trade growth accounted for by the top 2, 5 and 10% of goods. At this lower
level of disaggregation, trade growth remains granular, with a small number
of goods (roughly 10, 25 and 50 goods) accounting for 43%, 66% and 82% of
total trade growth, respectively, but is not as pronounced as in the 5-digit SITC
data from Chapter 2.8However, trade growth is still highly concentrated in
a small number of goods, while the majority of goods account for very little of
the overall growth in trade. Further, for each country-pair, the median share
of trade growth per good (0.03–0.05%) is well below the mean share of trade
growth (2.1% for each of the 473 goods categories), signifying a highly skewed
distribution of trade growth across goods. Finally, trade growth remains more
granular than cross-sectional trade — the top 2, 5 and 10% of goods categories
account for 43%, 66%, and 82% of trade growth, but only 35%, 52% and 67% of
trade in the initial period.9
Figure 3.1 illustrates the granularity of trade growth across goods at this
lower level of disaggregation. As in Chapter 2, this is shown by the small num-
ber of spikes representing goods exhibiting large growth shares, while most
goods exhibit little negligible growth shares.10 Further, trade growth shares
remain uncorrelated with initial levels of trade — the small number of goods
8For example, in the SITC data, the top 1% of goods categories accounted for roughly 60%
of total trade growth, on average across country-pairs — accounting for 60% of trade growth in
the NAICS data would require 2–5% of largest-growth goods categories.
9These 2,5 and 10% of goods categories need not be the same in accounting for trade growth
versus cross-sectional trade — that is, the most-traded goods in the initial period are not nec-
essarily the same goods that exhibit the largest growth in trade.
10Figure 3.1 illustrates this case for U.S. exports to Canada — similar examples for U.S.
exports to Mexico and Japan can be found in Appendix B.
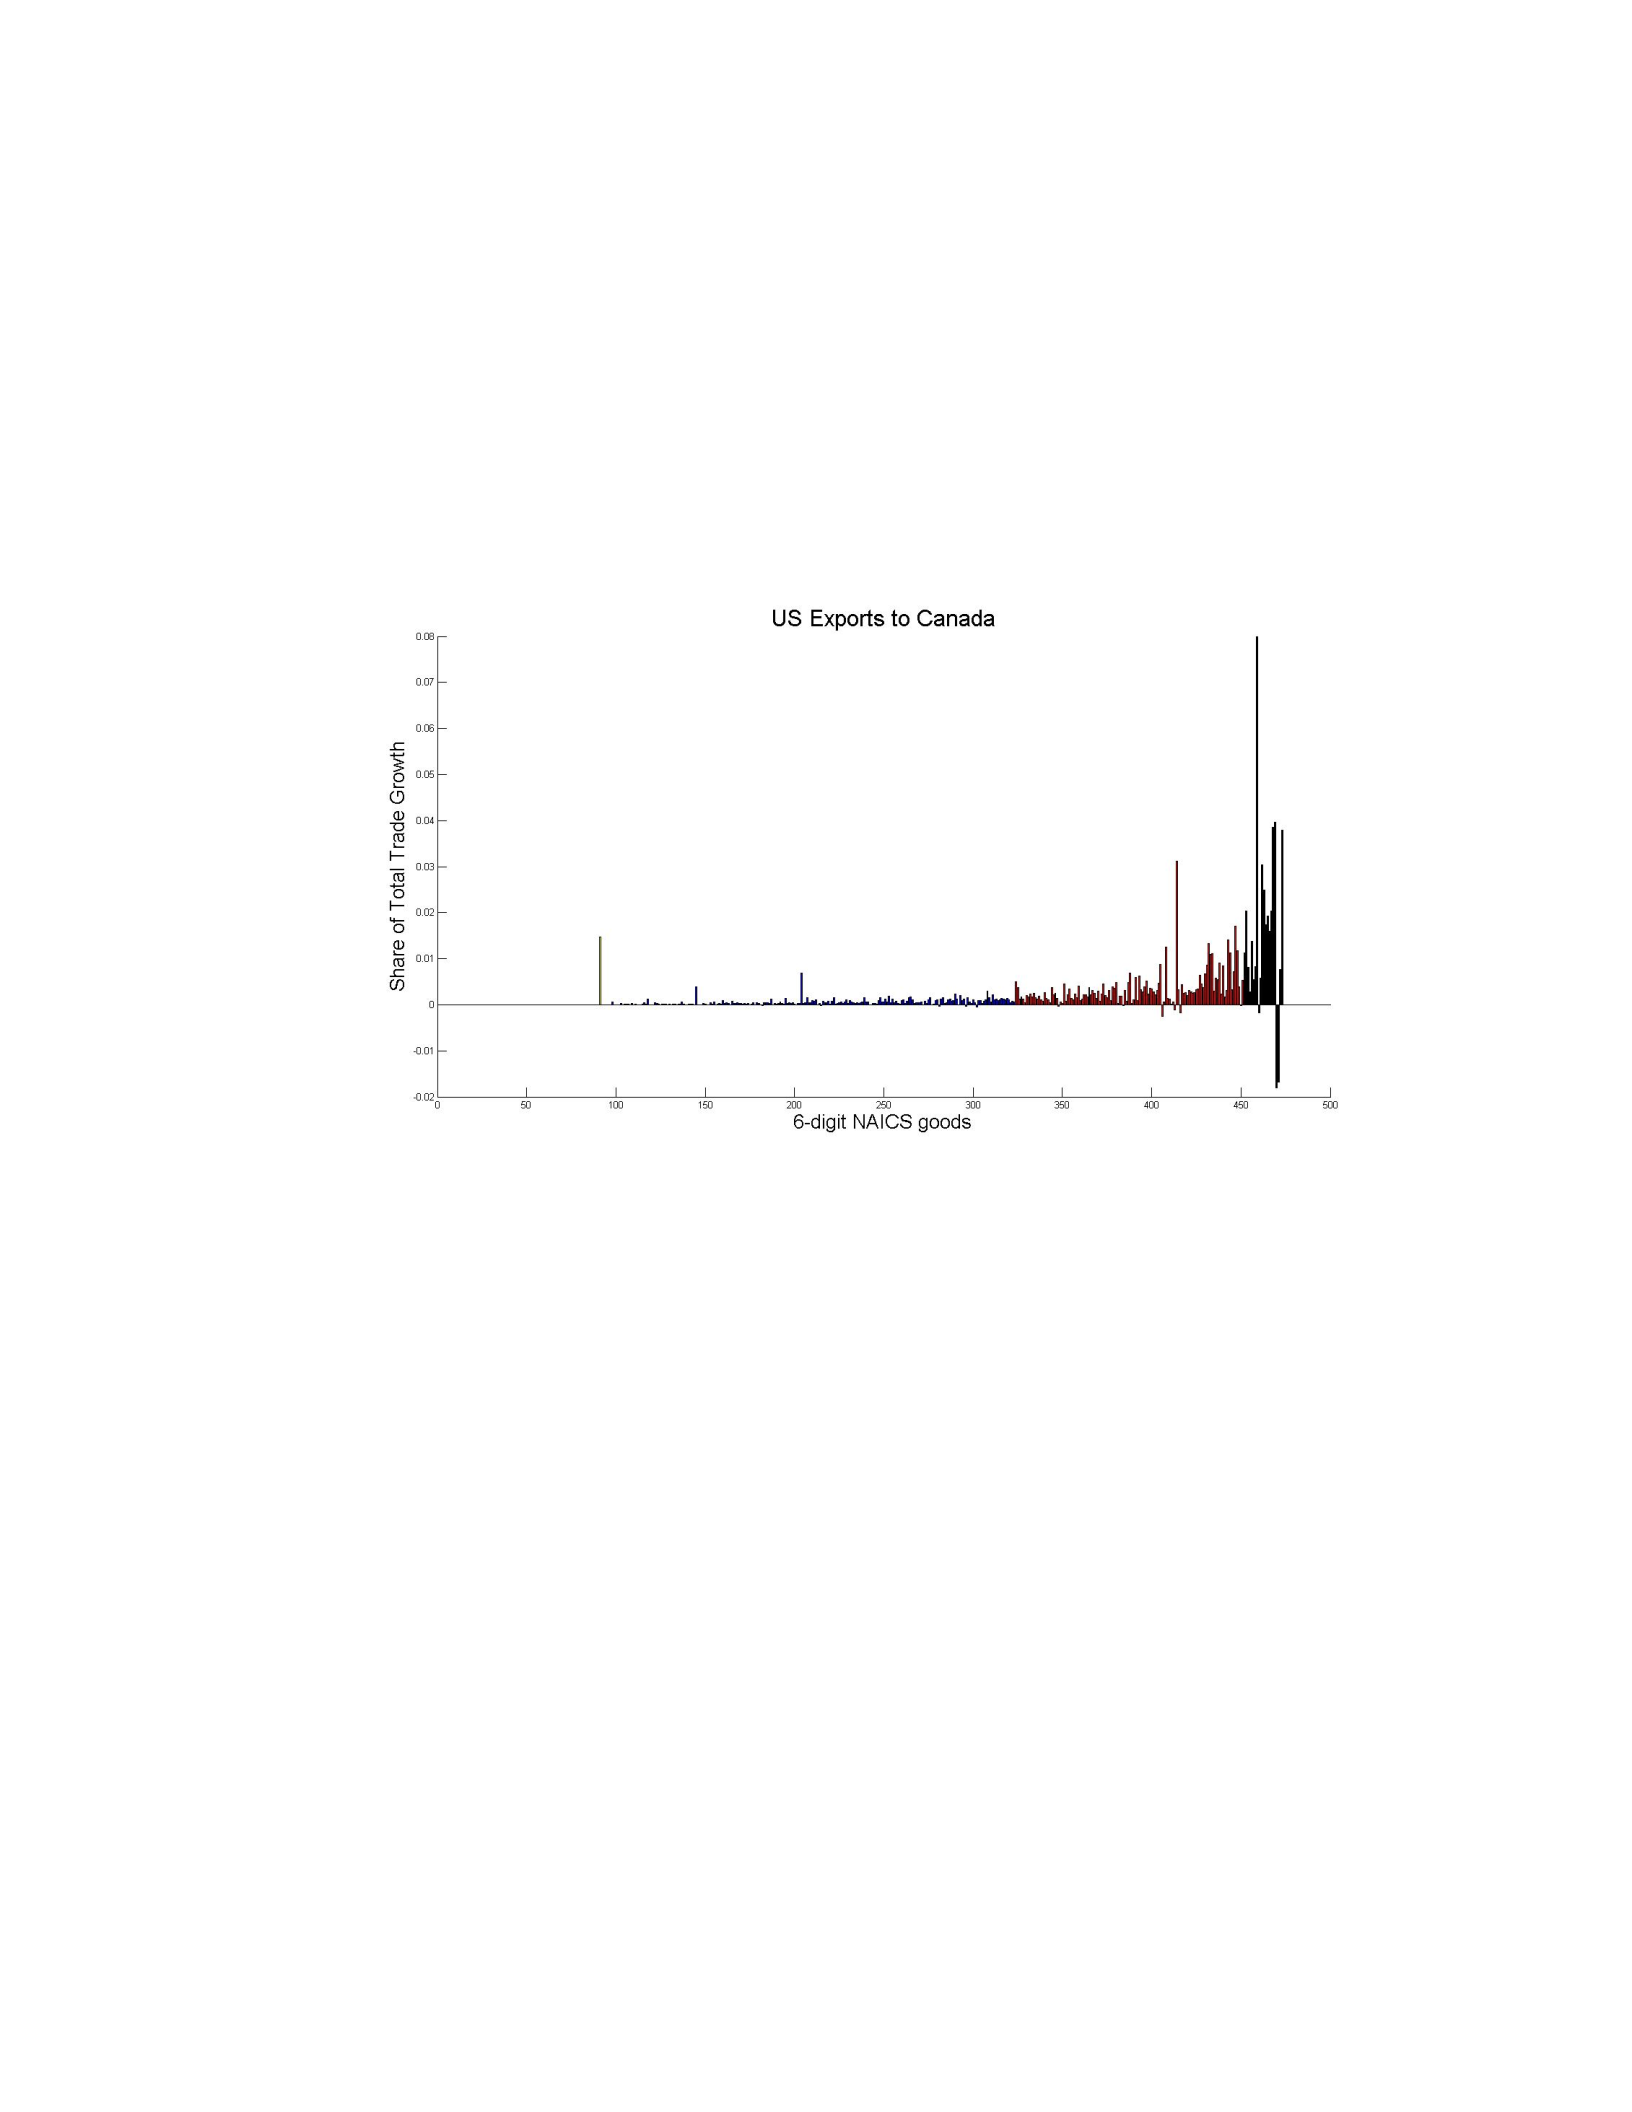
82
accounting for the majority of overall trade are not necessarily just the largest,
or smallest, initially traded-goods, but rather arise from varying levels of ini-
tial trade.
Figure 3.1: Growth by Goods Category: US Exports to Canada
3.3.2 Production Data
To quantitatively assess the the model’s predictions for the trade growth across
goods, I include heterogeneous productivity changes, imputed from U.S. pro-
duction data, and compare the granularity of trade growth predicted by the
model to that observed in the bilateral trade data. I use 6-digit NAICS data
on U.S. production from the NBER-CES Manufacturing Industry Database,
for the initial period (1989–1991 average) and the final period (1997–1999 av-
erage), to calculate the changes in imputed productivity between periods. I
match the changes in productivity to the data on bilateral trade growth for
each 6-digit NAICS good category.
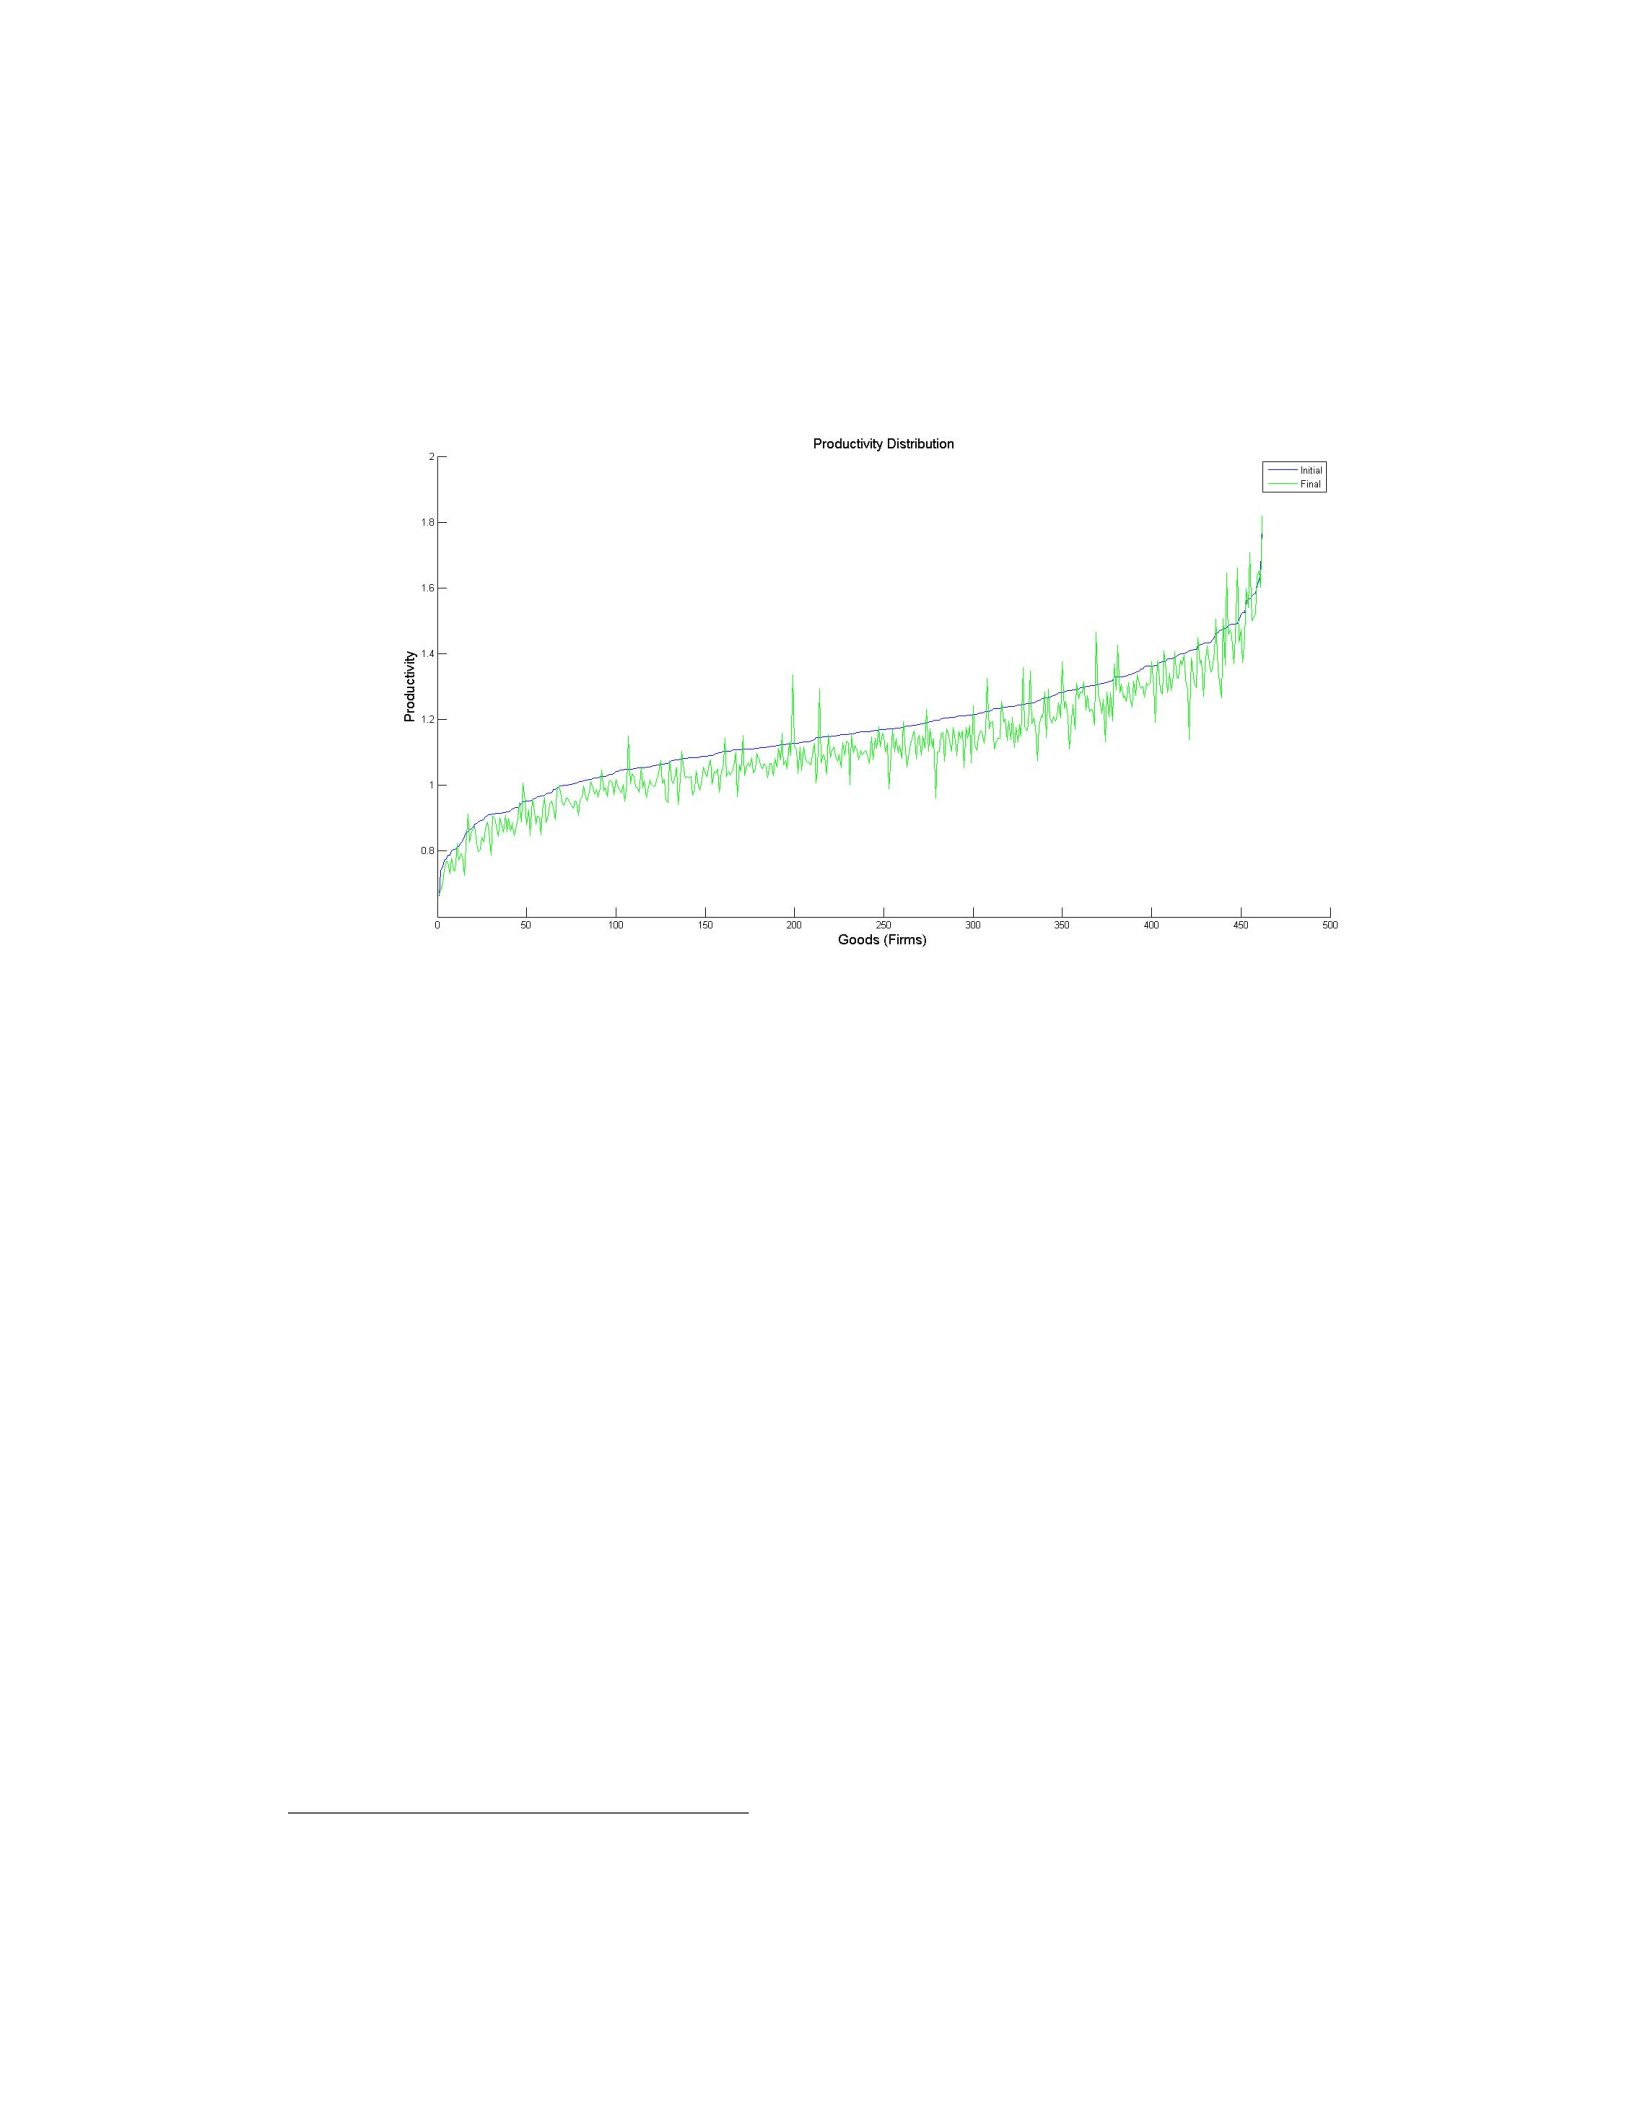
83
Figure 3.2: Productivity Distributions: Implied Productivities
Figure 3.2 demonstrates the changes in the imputed productivities for U.S.
production. For each good category, I use the observed level of domestic produc-
tion to back out the implied productivity from the production function for the
initial period and arrange goods in order of ascending productivity. I repeat
the process for the final period and map the change in imputed productivity
to each corresponding good from the initial period productivity distribution.11
There is a large degree of heterogeneity of productivity changes across goods.
Further, the changes in productivity are uncorrelated with the initial produc-
tivities — that is, it is not just the most productive firms that become even
more productive, or vice-versa.
11I also normalize the changes in productivity to mean zero to highlight the heterogeneity in
productivity changes across goods, rather than merely an increase in mean productivity.
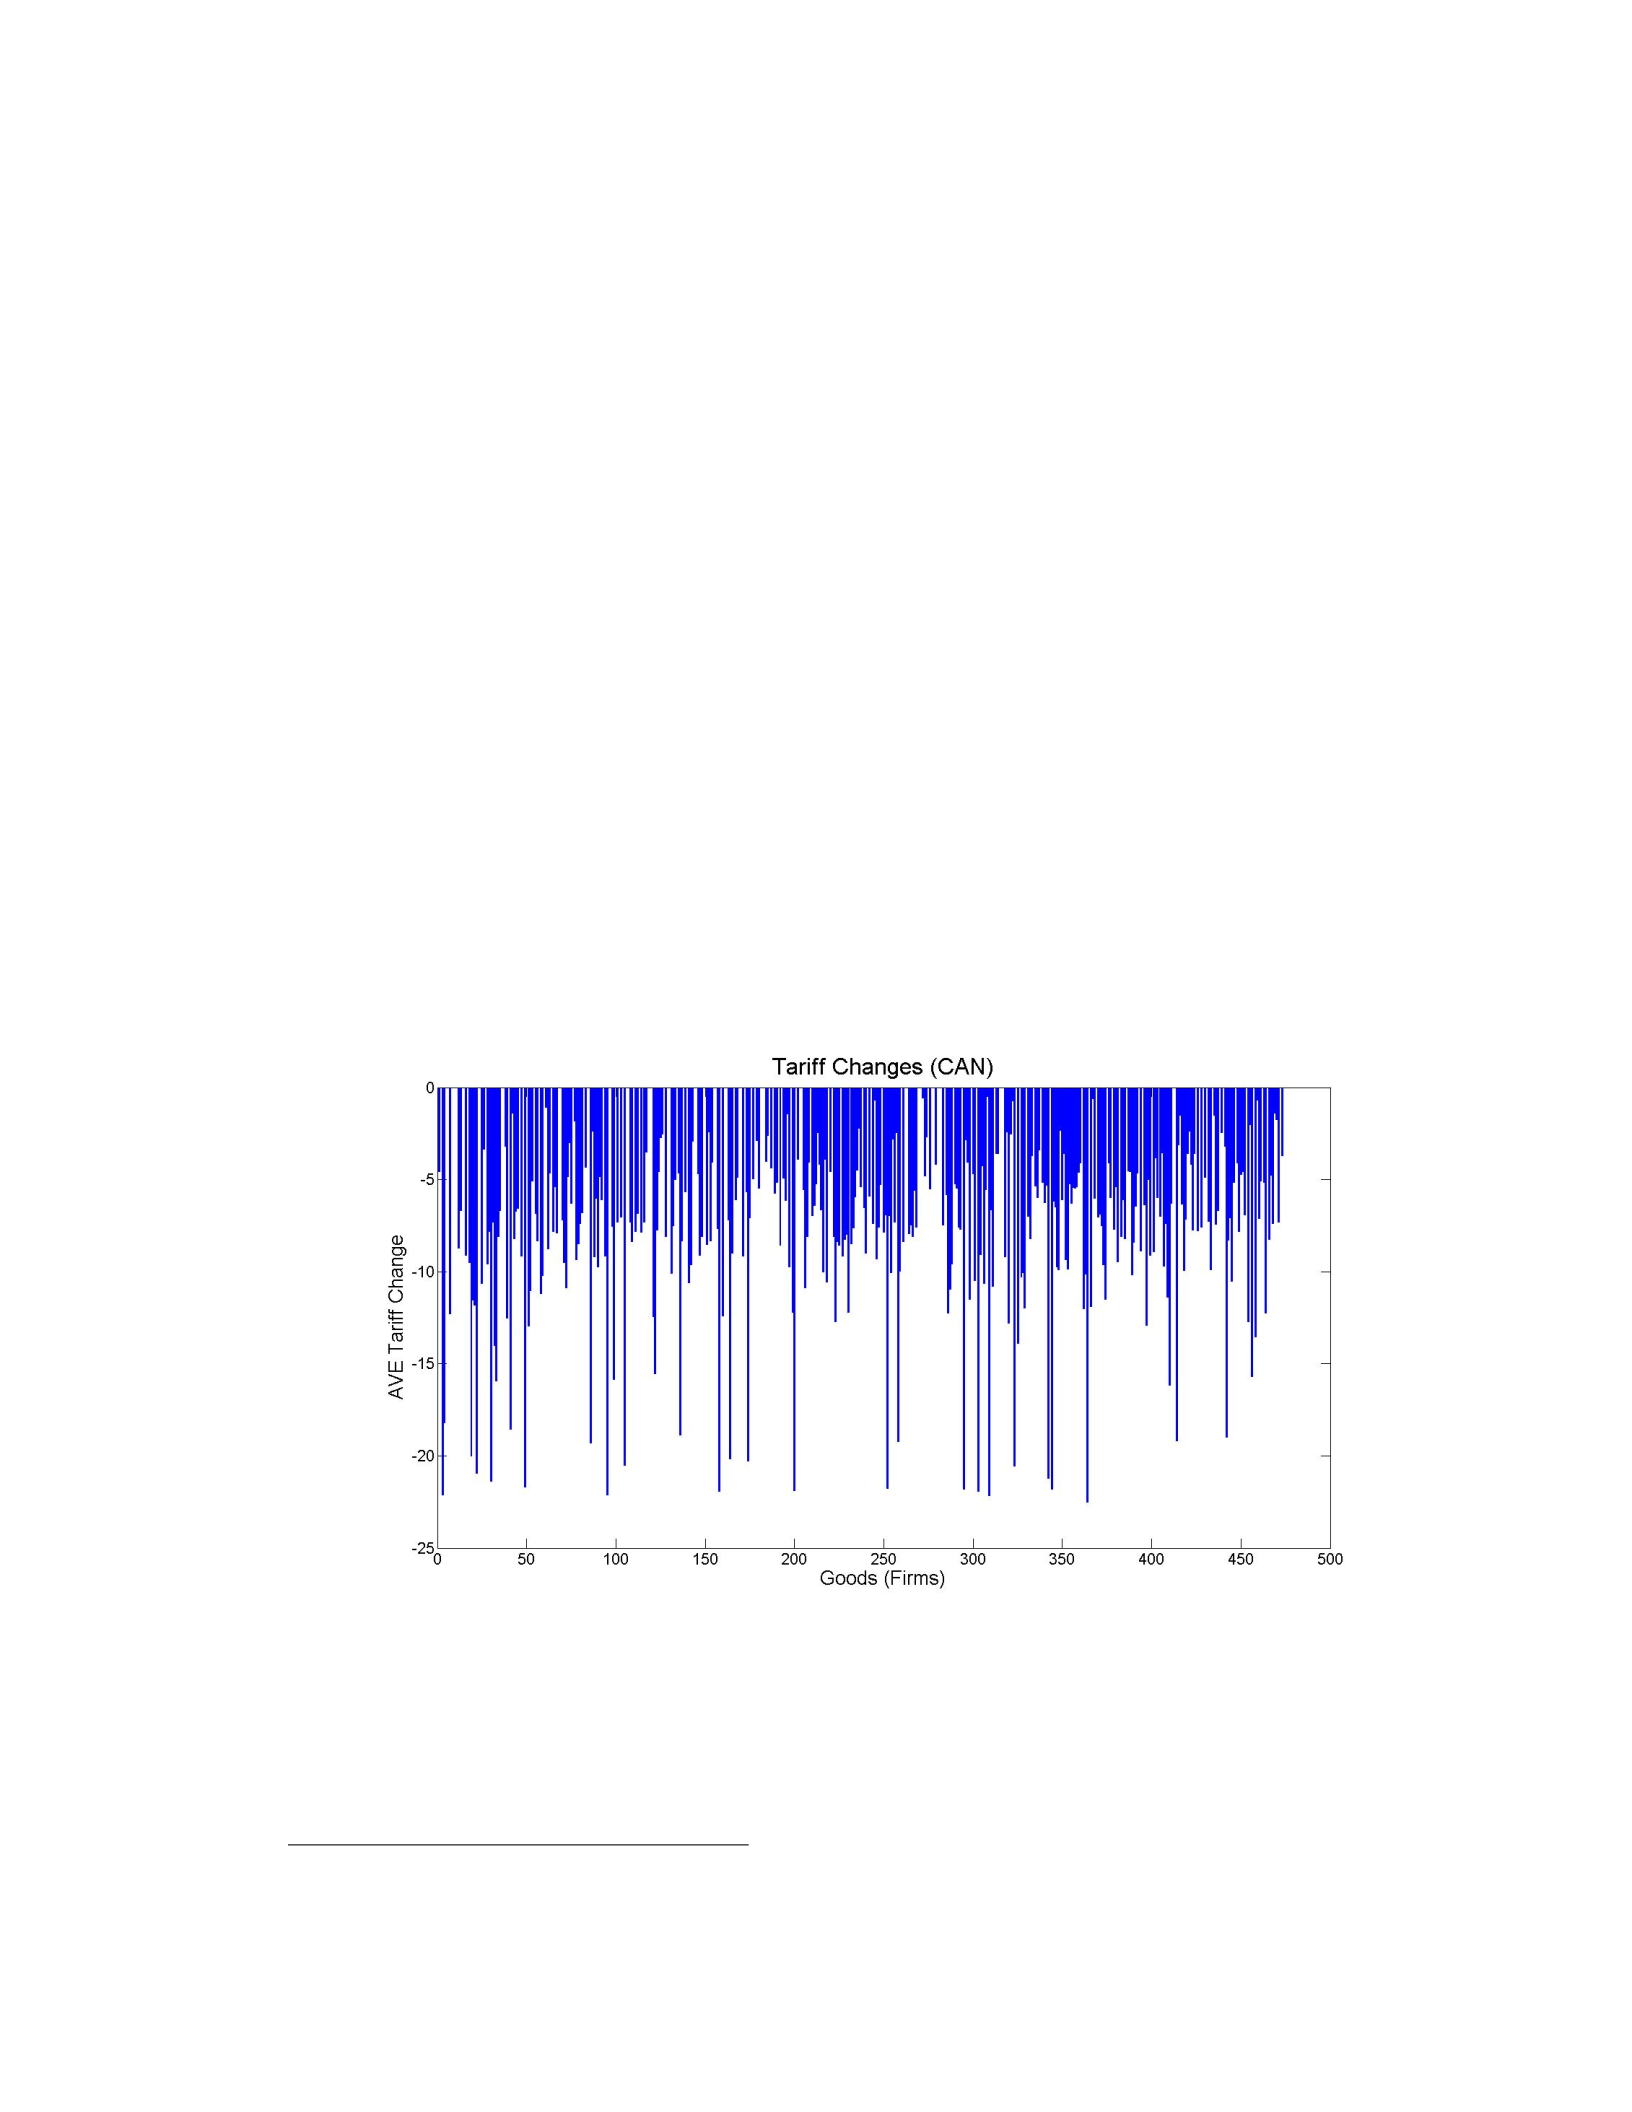
84
3.3.3 Tariff Data
As in Chapter 2, I analyze the role of heterogeneous tariff changes in account-
ing for trade growth granularity in a standard trade model. To do so, I map
changes in the ad valorem equivalent (AVE) tariff rates for U.S. export desti-
nations to each good category in the model. I use 8-digit Harmonized Tariff
Schedule data from the World Bank’s World Integrated Trade Solution (WITS)
database on AVE import tariff rates on U.S. exports for Canada, Mexico and
Japan, from 1989–1991 and 1997–1999 to match the initial and final periods
in the bilateral trade data. I use concordances provided by Pierce and Schott
(2012) to map the 8-digit HTS tariff rates to the 6-digit NAICS classifications.
Figure 3.3: Heterogeneous Tariff Changes: Canada
Figure 3.3 shows the changes in the AVE tariff rates between the initial
and final periods for each concorded 6-digit NAICS good category for Canada.12
12Similar tariff changes for Mexico and Japan are shown in Figures B.4–B.6.
85
There is a large degree of heterogeneity across goods in the AVE tariff changes,
with most goods falling somewhere in the range between zero change and a
25% reduction tariffs.13 The mean reduction in tariffs are largest in Canada,
followed by Mexico and finally Japan, reinforcing that countries engaged in for-
mal trade liberalization policy over this period (U.S./Canada, U.S./Mexico) have
larger overall reductions in tariffs than those countries that lack a formal trade
liberalization agreement (U.S./Japan). Further, there are a larger proportion
of goods categories exhibiting large decreases in tariffs for Canada and Mexico,
and relatively more goods with small or zero reductions in tariffs for Japan.
3.4 Model
To account for the granularity of trade growth in the data, I extend the Melitz-
style model framework from Chapter 2 by including a choice among two ex-
porting technologies — one low-fixed, high-variable cost method, and one high-
fixed, low-variable cost method. The model includes heterogeneous produc-
tivities across firms, monopolistic competition, and CES preferences for con-
sumers. I characterize consumer demand and firms’ profit maximization in
equilibrium, including firms’ export decisions and distribution method choice.
As in Chapter 2, I use a static two-country model, and characterize par-
tial equilibrium to predict export sales of home-produced goods in the foreign
market. To analyze growth in this static environment, I solve the model for
two cases: first, I solve the model with a Pareto distribution of firms facing
CES demand, under monopolistic competition, given a choice among the two
13There is a notable exception, with an outlier of Mexican tariffs on U.S. exports of NAICS
311213 — “Malt Manufacturing, from barley, rye or other grains” rising by over 130%.

86
distribution technologies— this will serve to represent the “Initial period”; sec-
ond, I re-solve the model, incorporating heterogeneous productivity and tariff
changes across goods, under the same choice of distribution methods for export-
ing firms — this will serve as the “Final period”. Trade growth for each good
is calculated as the changes in the model’s predictions for exports between the
two cases.
In the Initial period, I find that the model generates productivity thresh-
olds for exporting, and goods are stratified according to their initial produc-
tivities. The least productive goods are not exported, as the fixed costs of ex-
porting make exporting unprofitable regardless of distribution method. Goods
with sufficiently high productivity find it profitable to export via the low-fixed,
high variable cost method. The most productive goods exhibit the largest ex-
port sales, finding it more profitable to export the high-fixed, low-variable cost
method.
In the Final period, I find that adding productivity and tariff changes across
goods generates a large degree of heterogeneity in trade growth across goods.
The model produces three channels for disproportionately larger growth in cer-
tain goods, generating the granularity of trade growth:
1. Goods with large increases in productivity
2. Goods with large decreases in tariffs, represented by a reduction in the
variable costs of exporting
3. The ability for firms to switch distribution technologies, from a high-
variable to a low-variable cost method
With productivity increases or tariff reductions (or a combination of the two),
some goods that were previously not-traded now find exporting profitable, via
87
the low-fixed cost method, or via the high-fixed cost method if these shocks
are sufficiently large. Similarly, some goods that were previously exported via
the low-fixed cost method now find it profitable to switch to the high-fixed cost
method, with a corresponding reduction in variable costs. These “switching”
goods exhibit disproportionately larger growth, as they benefit directly from
the productivity increase or tariff reduction, but also indirectly from the choice
of switching to a lower-variable cost method, leading to larger export sales.
This “switching” mechanism generates more granularity than the standard
model with a single distribution technology, as a larger share of total trade
growth is concentrated in these disproportionately larger-growth goods.
3.4.1 Model Set-up
The model builds on the standard Melitz-style framework, adding a discrete
choice among multiple exporting technologies. I use a static, two-country model
with symmetric countries, Home (H) and Foreign (F). As in Chapter 2, firms are
heterogeneous in their productivities, 1
awhere ais the per-unit labour require-
ment. Firms engage in monopolistic competition pricing, facing CES prefer-
ences generating consumer demand from each country. Firms choose whether
to sell to the foreign market by utilizing one of two distribution methods — one
with a lower fixed and higher variable (iceberg) cost of exporting, and the other
with a higher fixed and lower variable cost of exporting.
Firms
I assume each firm produces a differentiated good, so that each good category
in the model is synonymous with one firm, indexed by its per-unit labour re-
quirement, a. Firms use labour as the single input, paying the domestic wage
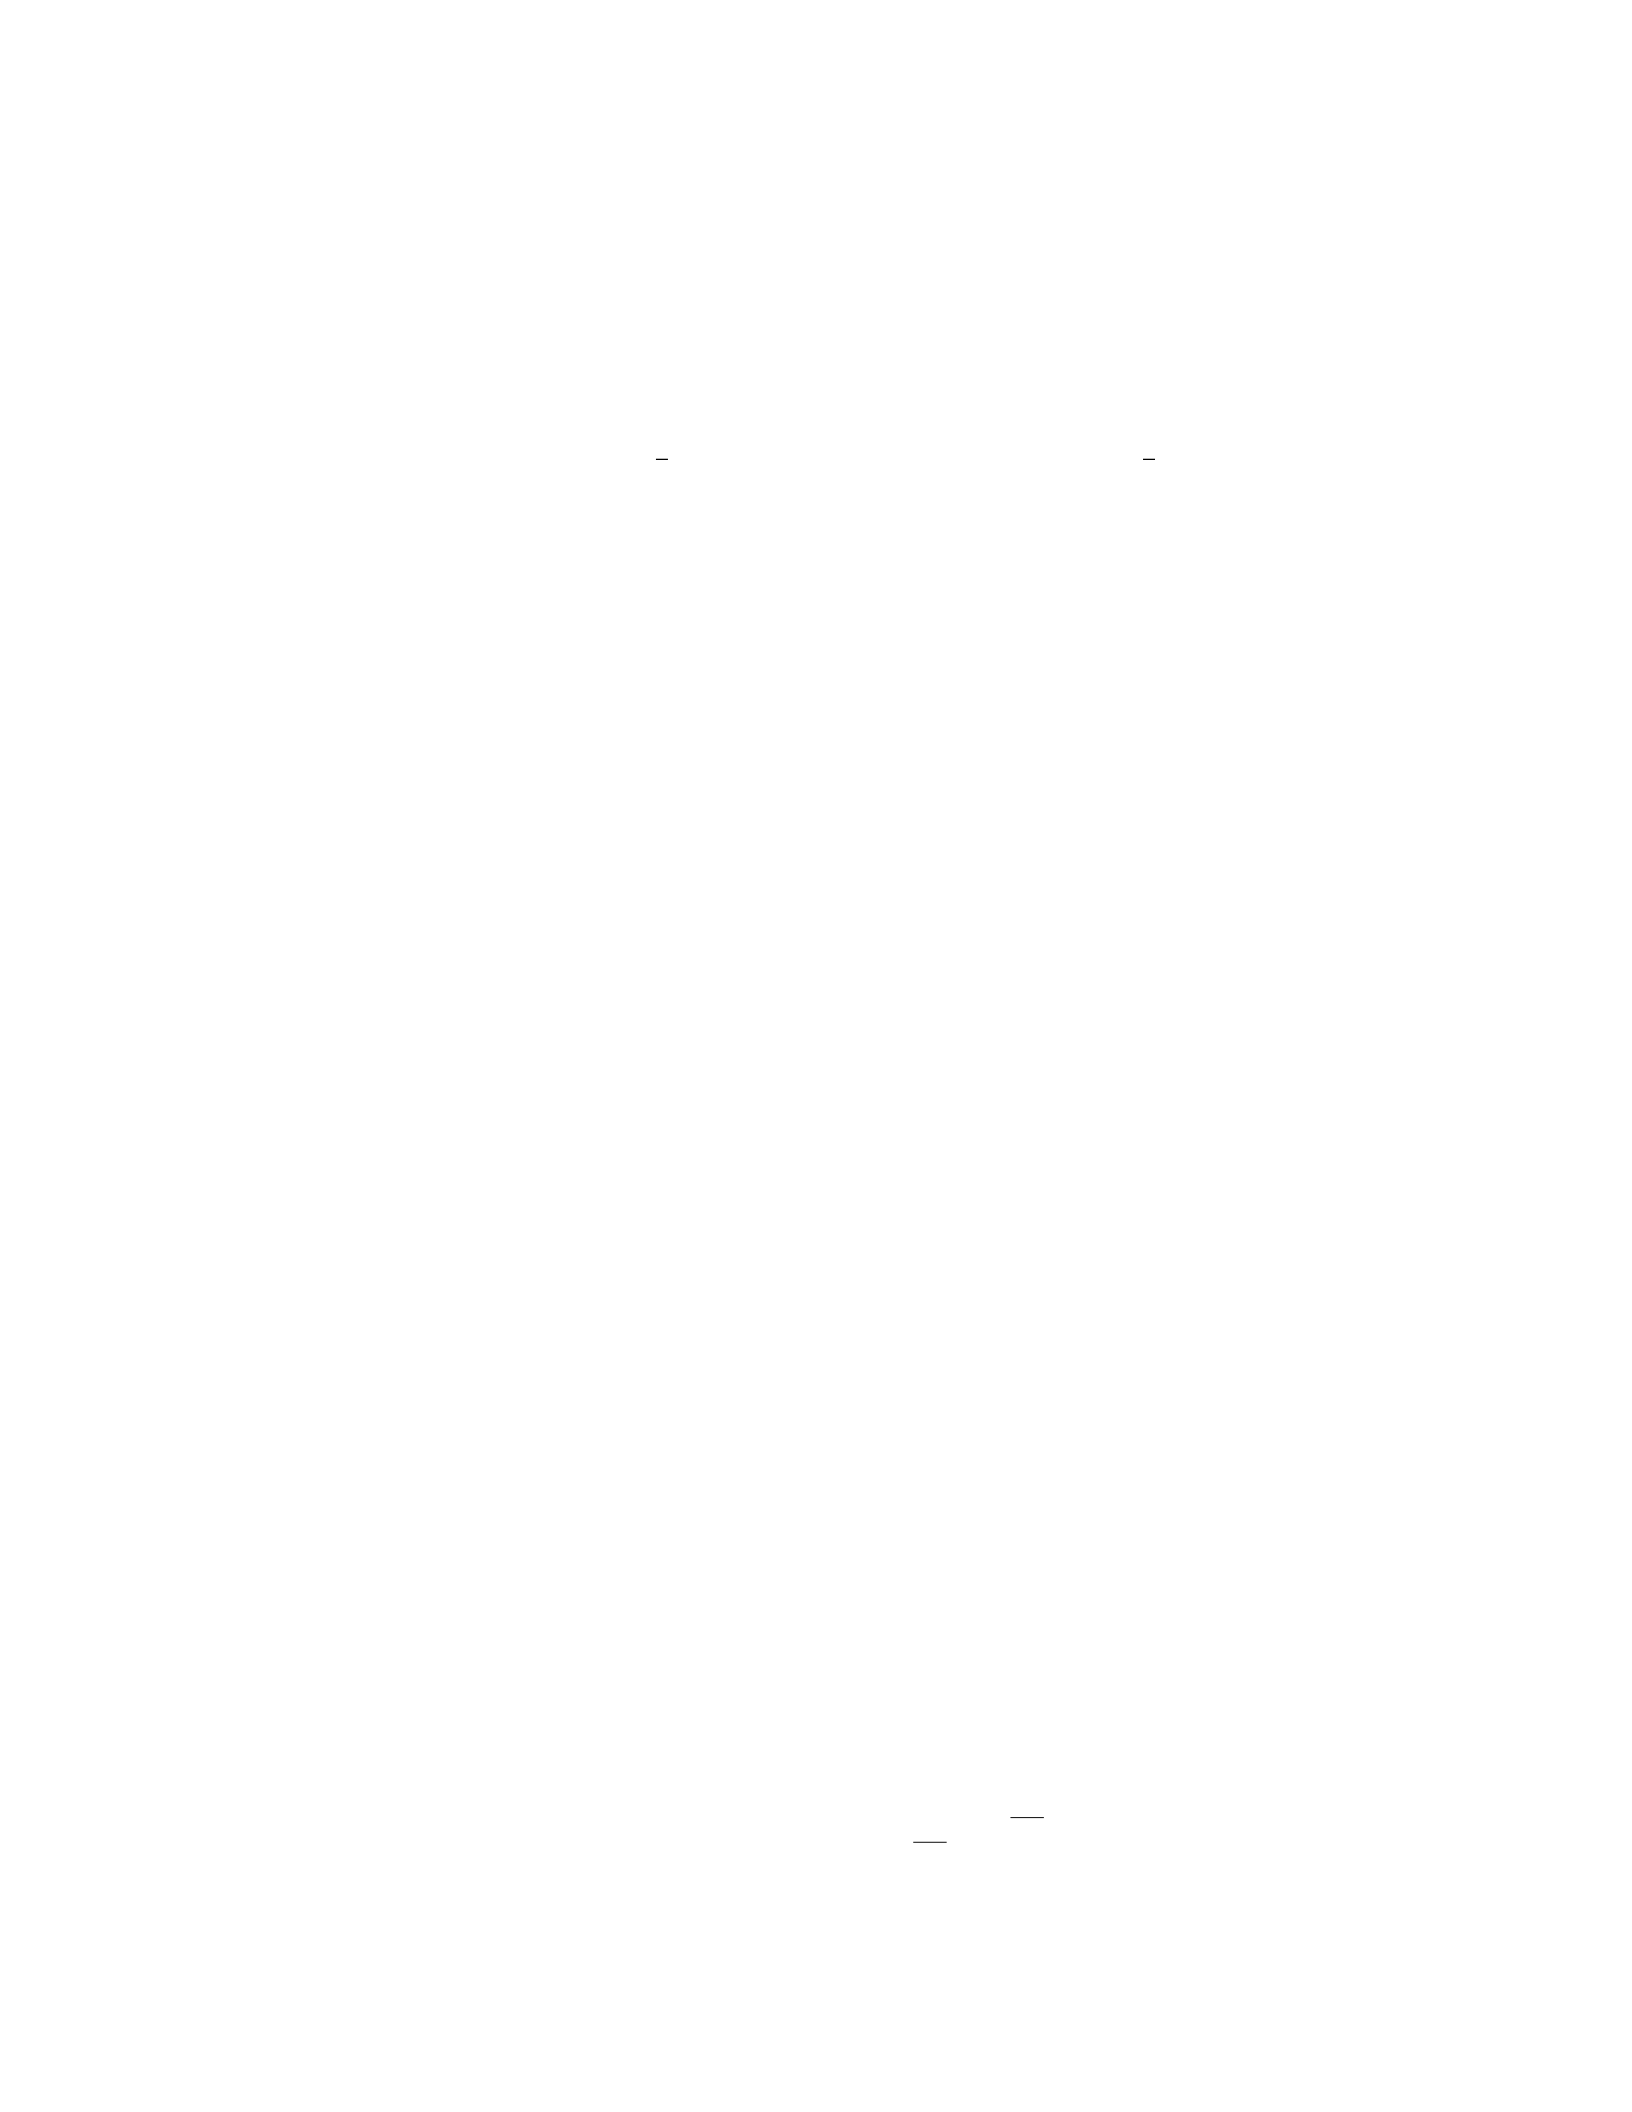
88
rate ωito produce in country i∈ {H, F }. For simplicity, I consider the case of
Home exports to Foreign, though the symmetric problem is equivalent. Firms
draw their productivity, 1
a, from a Pareto distribution, G(1
a). Firms engage in
monopolistic competition pricing, as in Dixit-Stiglitz (1977), facing CES de-
mand from each country. Given foreign demand for their product, cF(a), firms
choose whether or not to service the foreign market. If they choose to export,
firms must choose their optimal distribution technology among:
1. Method X1(f1, τ1): a low-fixed, high-variable cost option
2. Method X2(f2, τ2): a high-fixed, low-variable cost option
For a firm with labour requirement a, given foreign demand cF(a), the firm’s
profit maximization problem is:
max
Xj,j∈{1,2}{max
p(a){p(a)cF(a)−h(a, Xj)cF(a)}} (3.1)
where h(a, Xj)is the cost function, depending on the choice of distribution
method Xj, j ∈ {1,2}. These costs include the fixed cost of exporting, fj, as well
as the marginal cost of exporting, which embeds the marginal cost of produc-
tion, ωHa, and the variable cost of exporting, τj. The variable cost can be further
decomposed into two components: the shipping costs of physically transporting
goods between locations, and trade barrier costs, such as tariffs. By assump-
tion, there is no fixed cost for domestic production.
Consumers
Preferences of consumers in country i∈ {H, F }are represented by the CES
utility function,
Ui=Za∈A
ci(a)−1
da
−1
(3.2)
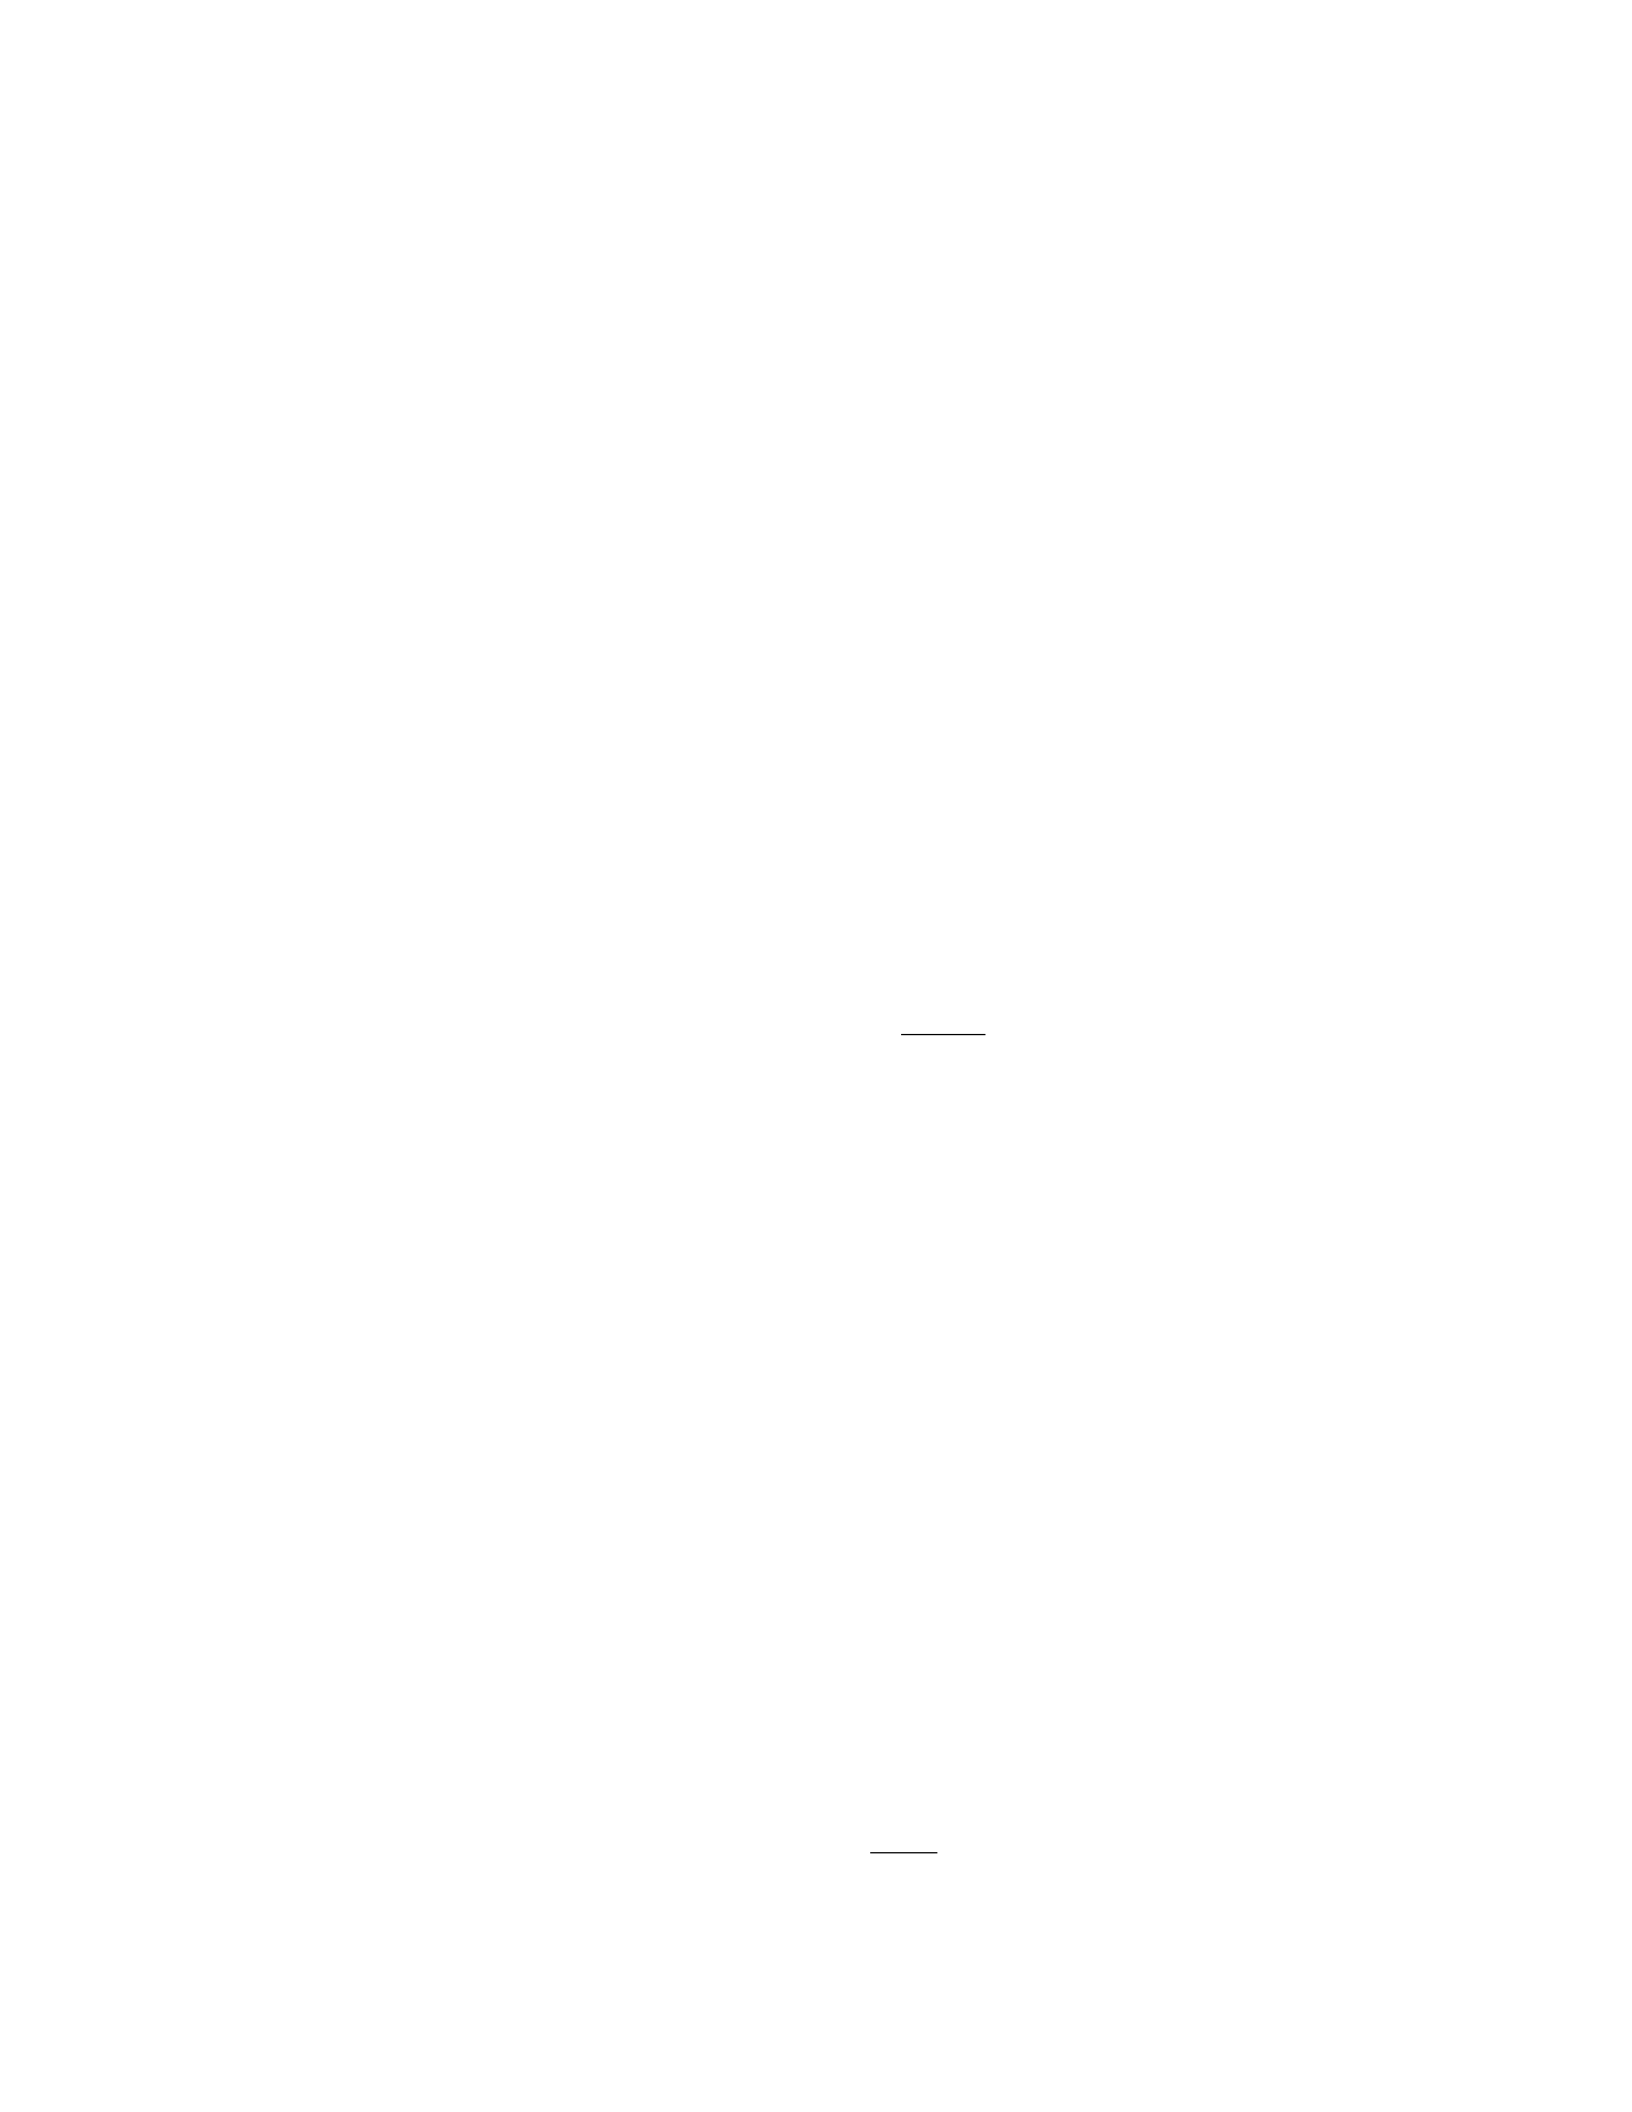
89
where ci(a)is consumption of good variety a,is the elasticity of substitution
across goods ( > 1) and Ais the set of available goods. Since the two countries
are symmetric, I solve the case of Home exports to Foreign, and therefore only
consider the utility function UFto derive demand for Home-produced goods in
the Foreign market, cF(a).
3.4.2 Characterizing Equilibrium
I solve the model to characterize equilibrium export flows for all goods vari-
eties, a∈A. With no fixed cost of production, all goods are produced in Home,
and consumers in Foreign have demand for these varieties that is given by the
well-known demand function for CES preferences:
cF(a) = EFp(a)−
PF1−(3.3)
where EFis national income in Foreign and PFis the aggregate price level
in Foreign. With > 1, demand in the Foreign market, cF(a), is inversely
proportional to the price offered in the Foreign market for each Home-produced
good.
Monopolistic competition implies that firms price at a constant mark-up
over marginal cost. The marginal cost of servicing the foreign market has mul-
tiple components. The marginal cost of domestic production is ωHa— how-
ever, in order to have a full unit reach the foreign market, the firm must ship
τ > 1units (where τis commonly referred to as the iceberg transportation cost).
Thus the marginal cost of exporting is ωHτja, where j∈ {1,2}depending on the
distribution method employed by the firm. This results in a price in Foreign
for Home-produced variety aof:
pF(a, Xj) =
−1ωHτja(3.4)
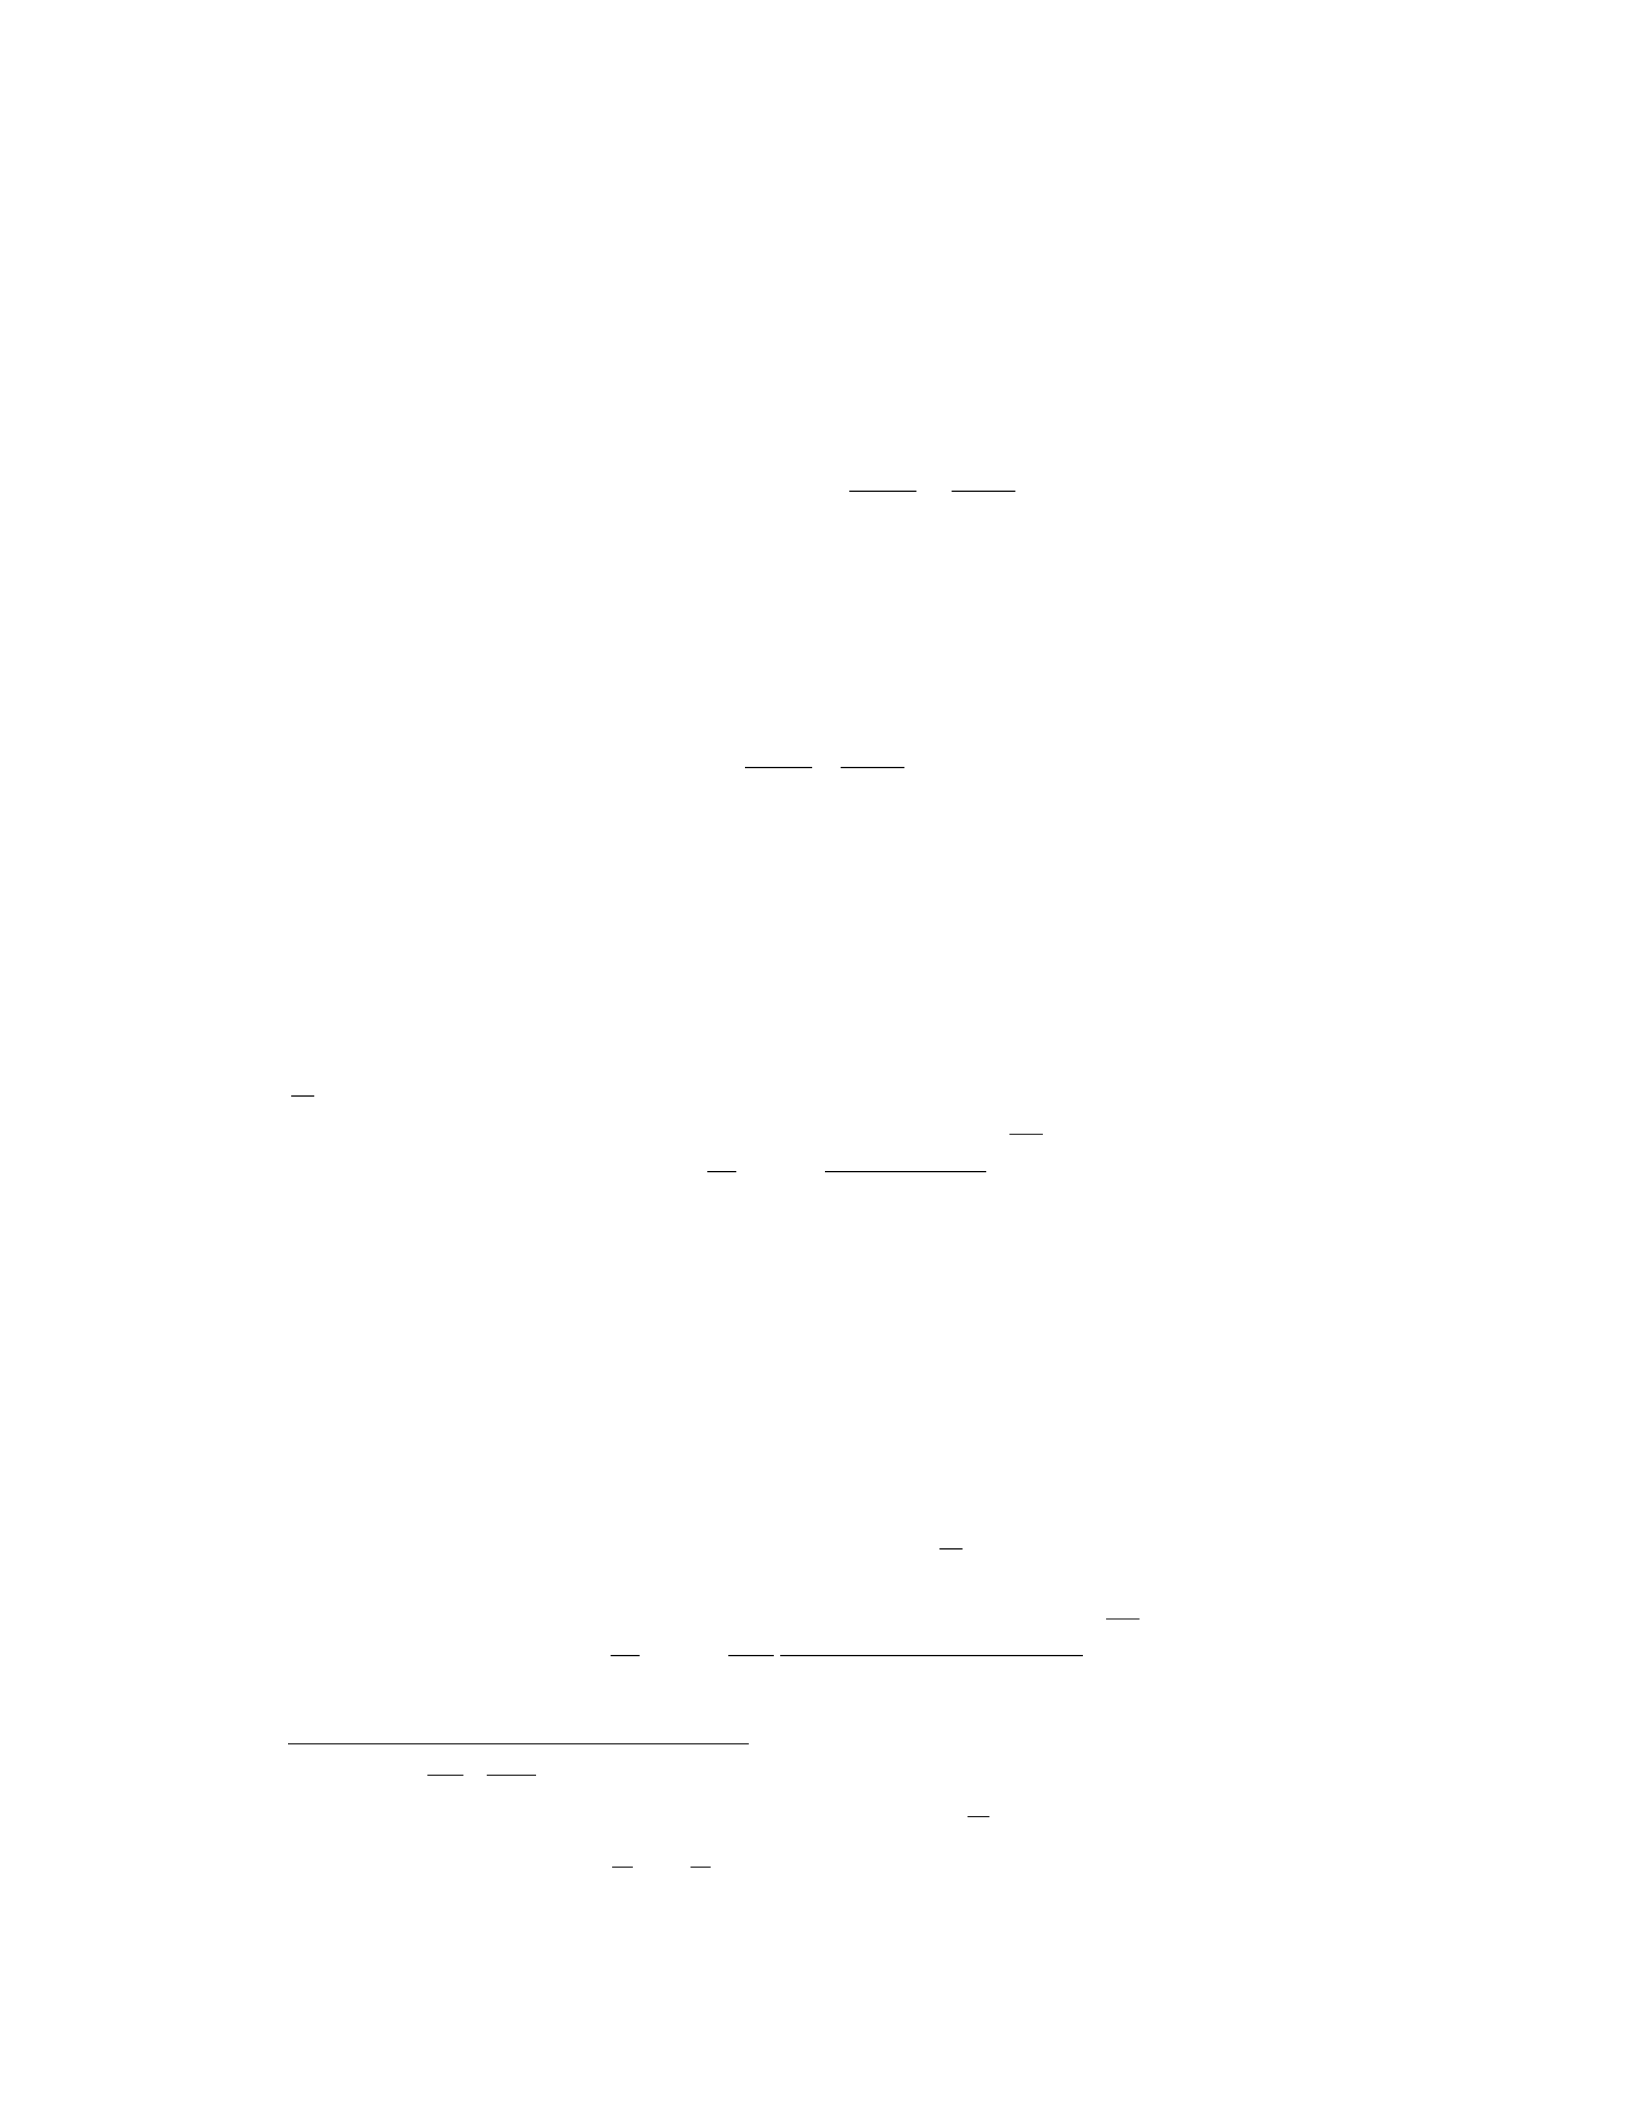
90
Export sales, pF(a, Xj)cF(a), are proportional to productivity and inversely
proportional to the variable cost of exporting:
ExSales(a, Xj) =
−1EF
P1−
F
[ωHτja]1−(3.5)
The exporting profits for a firm with labour requirement ausing distribution
technology Xj, j ∈ {1,2}with associated fixed cost fjand variable cost τjare:
π(a, Xj) = 1
−1EF
P1−
F
[ωHτja]1−−ωHfj(3.6)
Productivity thresholds
To export via either distribution method, exporting profits must be non-negative:
π(a, Xj)≥0. Re-arranging the profit function yields a productivity threshold
1
¯a1, that satisfies:
1
¯a1=(ωH)f1τ−1
1
DF
1
−1
(3.7)
where DFis a constant with respect to a.14 This implies that firms must be
sufficiently productive to cover at least the lower fixed cost of exporting, f1, to
make exporting profitable.15
There is also a threshold that determines which firms will choose to export
via method X2rather than method X1, where π(a, X2)> π(a, X1). Solving this
inequality yields the productivity threshold 1
¯a2, that satisfies:
1
¯a2=ωH
DF
(f2−f1)
(ωHτ2)1−−(ωHτ1)1−
1
−1
(3.8)
14DF=h1
−1iEF
P1−
F
15It is assumed that (f1, τ1)and (f2, τ2)are such that 1
¯a1is lower for method X1than method
X2. Thus, by assumption, f1
f2<τ2
τ1−1.
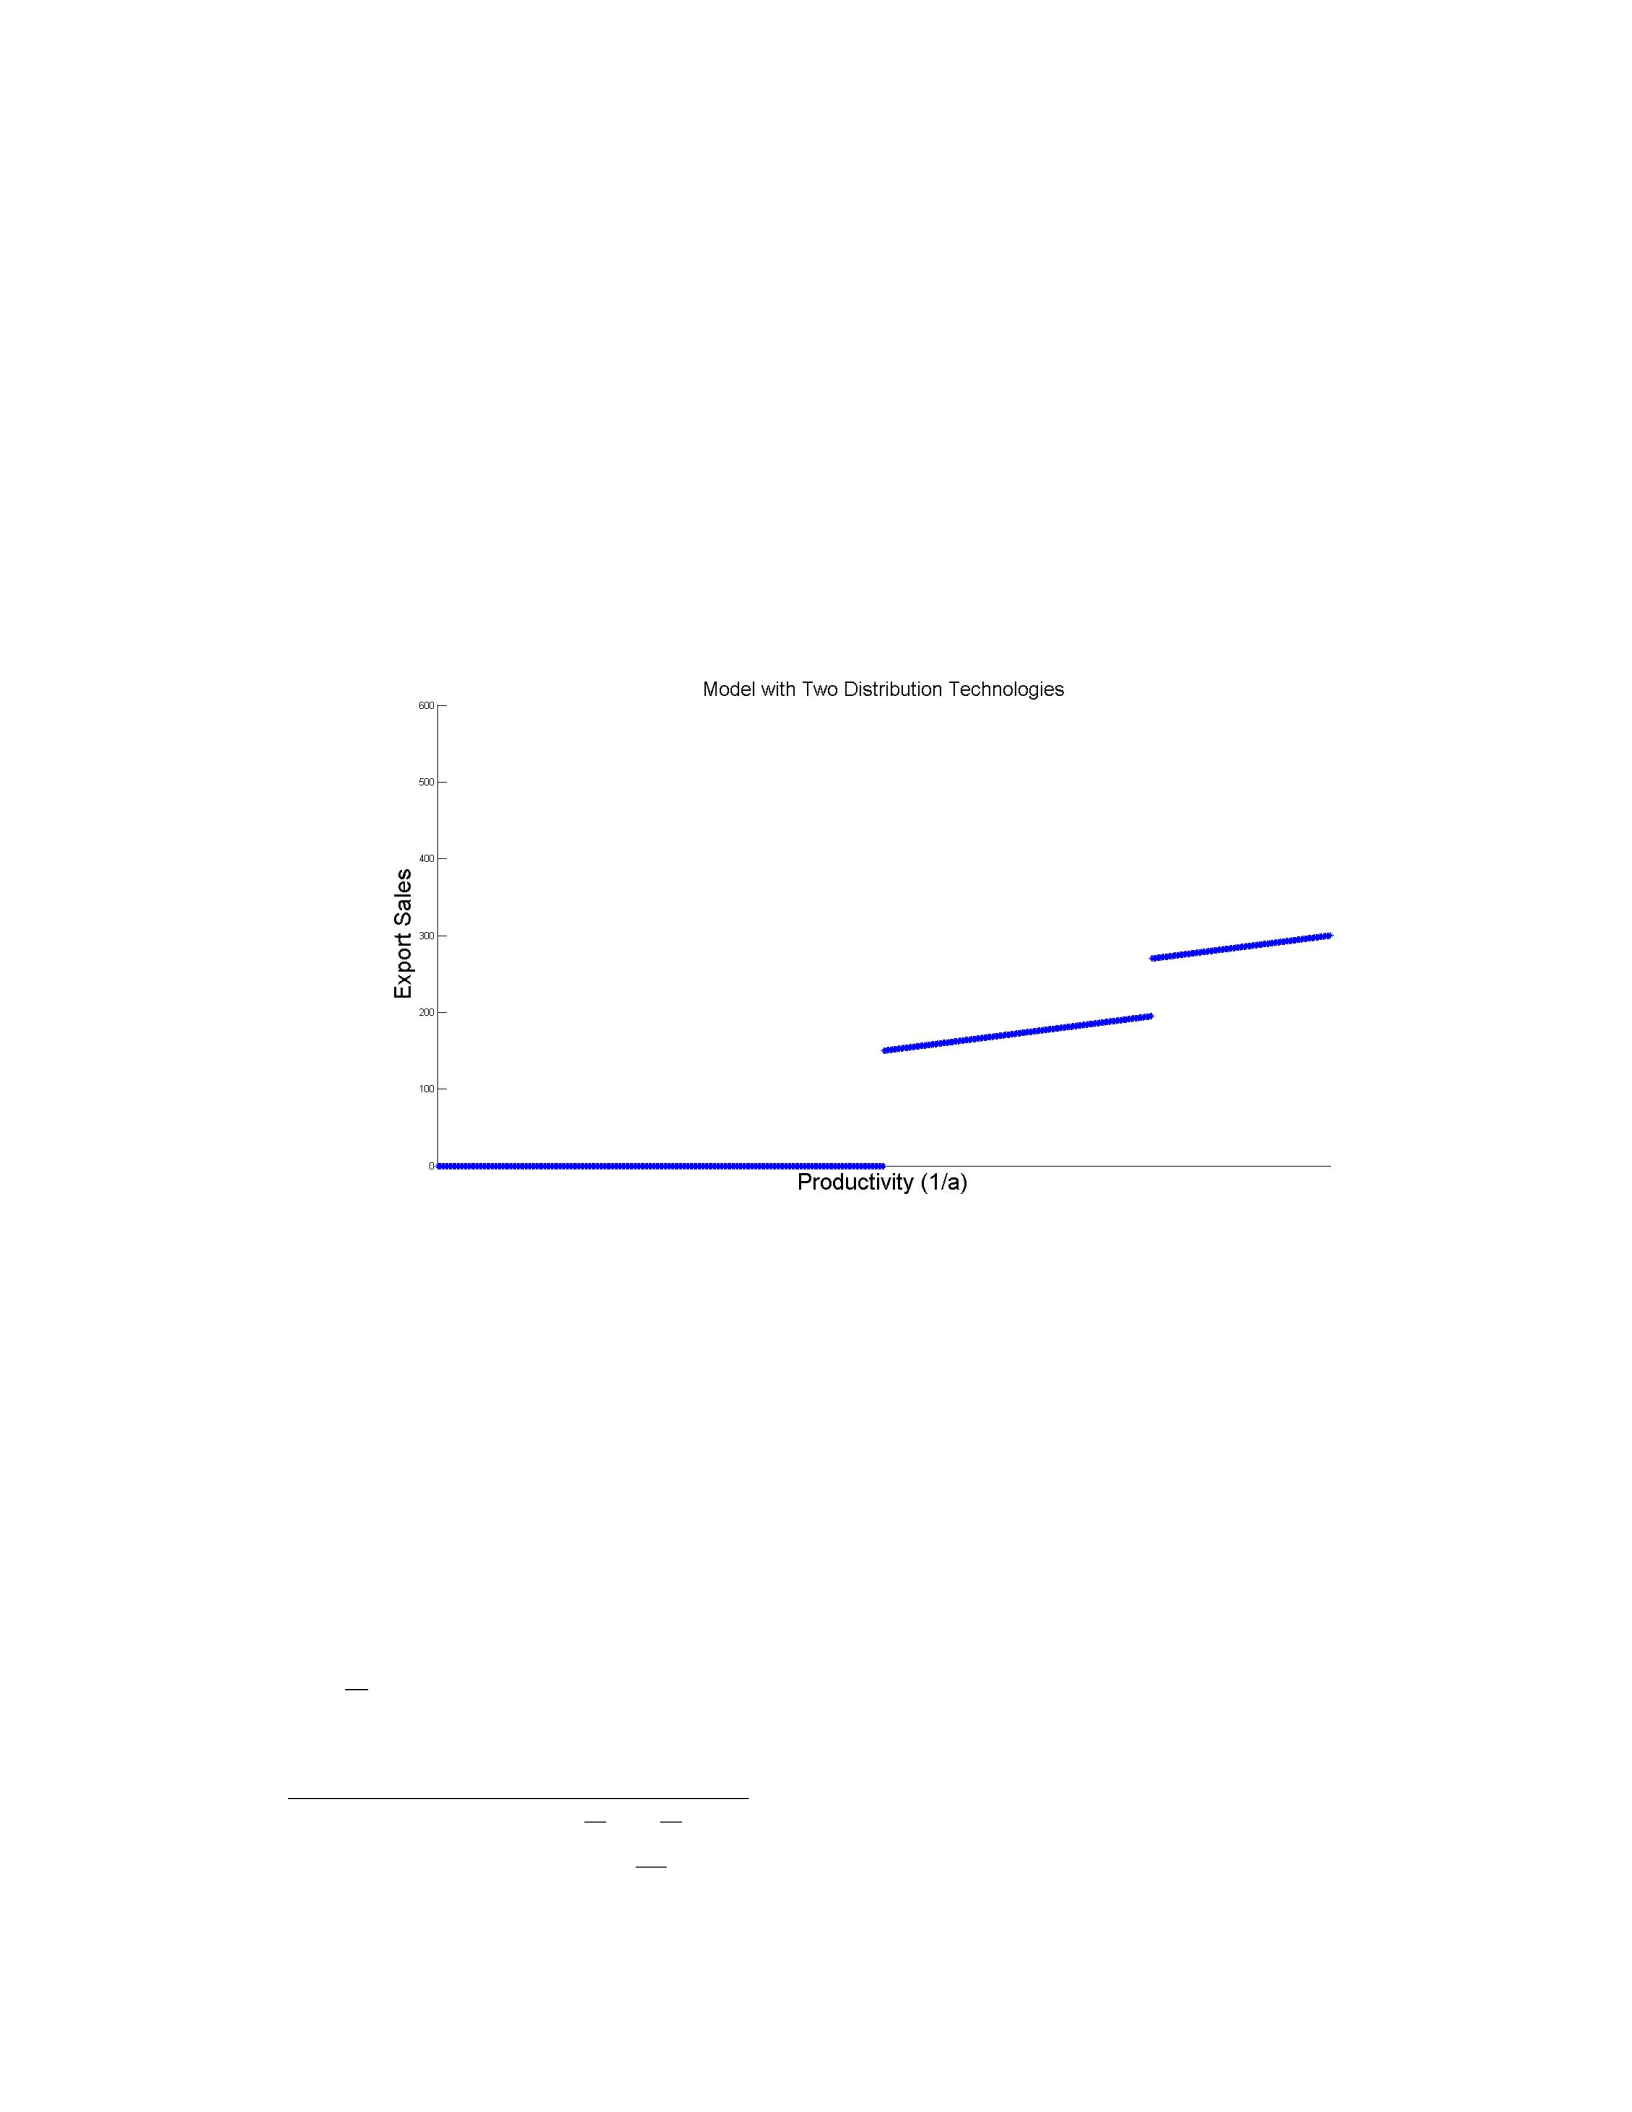
91
Firms with sufficiently high productivity will choose to export via the higher-
fixed cost method, X2, while firms with lower productivity will choose to export
via method X1, as long as their productivity is such that paying the lower-fixed
cost of exporting still yields positive exporting profits.16
Figure 3.4: Initial level of export sales
Figure 3.4 demonstrates the stratification of export sales across goods, by
productivity. Firms with low productivity draws do not export. Firms with suf-
ficiently high productivity find exporting profitable after paying the fixed cost,
with sales increasing in productivity. The less productive of these firms will ex-
port via method X1, while the more productive firms will export via method X2.
There is a discontinuous jump in export sales at the upper productivity thresh-
old 1
¯a2, with the more productive firms benefiting from the lower variable cost,
leading to higher export sales.
16It is assumed that 1
¯a2>1
¯a1, which further disciplines the relationship of the fixed and
variable costs: f2> f1h1−τ1
ωH−1τ1−
2−τ1−
1i.
92
3.4.3 Comparative Statics: Tariff and Productivity Changes
To analyze trade growth in the static model, I solve the model twice — for
an “Initial” period and for a “Final” period. I calculate the difference in pre-
dicted export sales across the two cases to represent trade growth for each
good. To determine the Initial period’s export sales, I solve the model with a
random productivity draw from a Pareto distribution for each firm producing
good variety aand solve for each firm’s profit maximization export decision and
distribution method choice. To determine the Final period’s export sales, I re-
solve the model while incorporating heterogeneous changes in productivity and
tariffs across goods, imputed from bilateral trade data. I impute the changes
in productivity from U.S. production data between 1989–1991 and 1997–1999,
and apply the corresponding change directly to the productivity of each good,
1
afrom the Initial period. Similarly, I impute changes in AVE tariff rates for
each good from U.S. export destination tariff rates, which takes the form of a
proportional reduction in the variable costs of exporting, τ1or τ2, relative to the
Initial period’s values.
Across goods, an increase in productivity or a decrease in tariffs lowers the
price offered in the foreign market, as given in Equation 3.4. The direct ef-
fect is a proportional increase in exports, as given by Equation 3.5 due to the
heterogeneous changes in productivity and tariff rates across goods.
Changes in productivity and tariff rates also have an indirect effect on ex-
port sales by altering the productivity thresholds that dictate the optimal dis-
tribution choice for each good. Equations 3.7 and 3.8 show that a reduction
in tariffs which decreases the variable costs of exporting, τ1and τ2, lowers the
productivity thresholds, 1
¯a1and 1
¯a2. This allows some goods that were below the
exporting threshold, 1
¯a1, to become exported, and some goods that were below
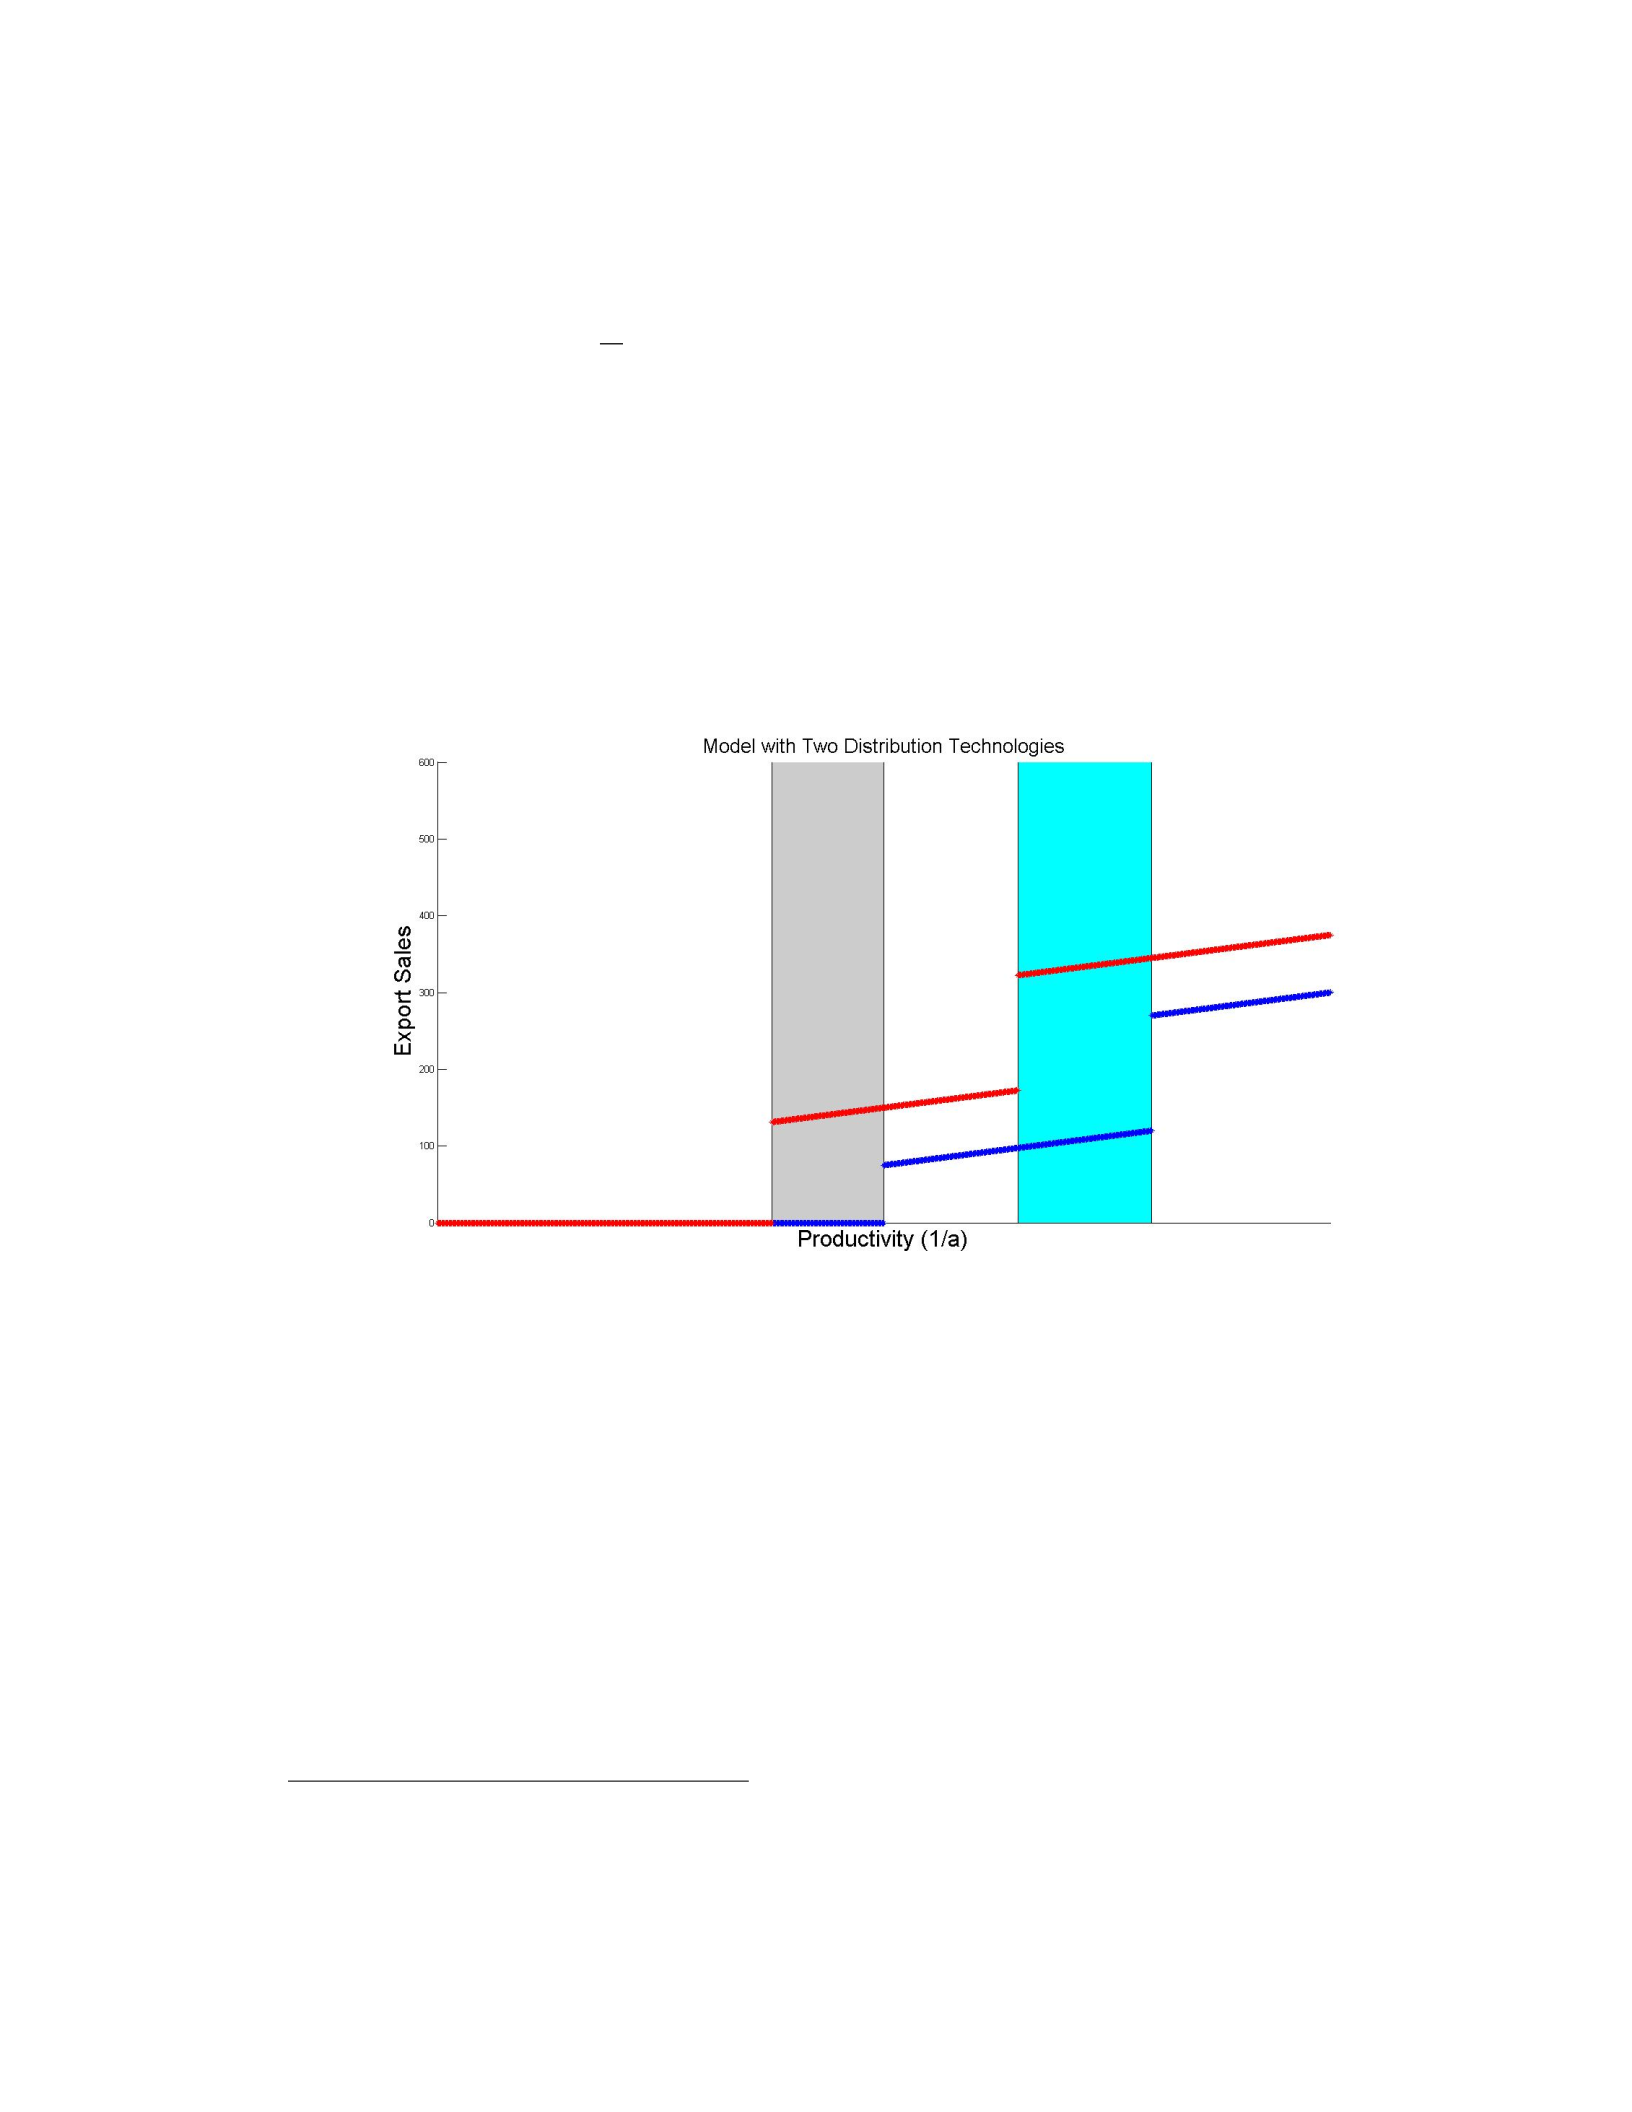
93
the upper threshold, 1
¯a2, to switch from exporting via method X1to X2. The for-
mer is categorized as extensive margin growth— previously not-traded goods
become exported. For the latter, firms that switch from X1to X2also benefit
from the reduction in variable costs by moving from τ1to τ2, bringing a sec-
ondary increase in export sales, as in Equation 3.5.17
Figure 3.5: Final level of export sales
With three distribution possibilities, {0, X1, X2}in each period, there are 9
potential combinations for distribution method choice across the two periods.
Figure 3.5 shows the stratification of these possibilities. With a reduction in
the variable costs of exporting from a decrease in tariffs, export sales will in-
crease proportionally across the productivity distribution for each method. Ad-
ditionally, the productivity thresholds will shift, as represented by the shaded
regions in Figure 3.5. Trade growth can be decomposed as follows: Goods that
17It should be noted that if productivity decreases or tariffs increase, the converse is true—
the productivity thresholds increase and sales decrease, with firms potentially “switching
down” in their distribution choices.
94
begin with and retain the lowest productivities will remain not-traded. Some
previously traded goods will increase export sales proportionally to the reduc-
tion in tariffs, while continuing to use the same distribution method, either X1
or X2. However, some previously not-traded goods may now cross the lower
productivity threshold and become exported via method X1.18 Similarly, with
the reduction in variable costs of exporting, some goods that were previously
traded via method X1now find it profitable to switch to method X2(as shown
in the blue shaded region). This increase in export sales is disproportionately
larger than it would be at similar productivity levels where the choice of distri-
bution method does not change (as in the white shaded regions to the left and
right).
Adding changes in productivity moves firms across the productivity distri-
bution, which potentially generates more granularity in trade growth. Firms
with a sufficiently large increase in productivity may “jump” across a produc-
tivity threshold in Figure 3.5. For example, a firm with low productivity may
choose not to export in the initial period, but an increase in productivity may
move them into a region of the distribution where exporting becomes profitable
via X1, or via X2if the increase in productivity is sufficiently large. Similarly,
goods initially exported via X1may receive a sufficient increase in productiv-
ity to move to a portion of the distribution where switching to X2is profitable,
bringing a disproportionately larger growth in trade than the direct effect of
the productivity increase.19
The model now provides three channels for generating heterogeneity in
18While not shown explicitly in 3.5, it is theoretically possible for goods to jump from not-
traded to exported via method X2if the tariff reductions are sufficiently large.
19Again, it should be noted that although the cases presented here deals with tariff decreases
and productivity increases, the converse holds for cases of tariff increases and productivity
decreases and the resultant decreases in export sales across goods.

95
trade growth across goods. First, heterogeneous tariff changes, represented
as changes in the variable cost of exporting for both distribution technologies,
changes the price offered in the foreign market and results in proportionally
larger export sales for the goods exhibiting the largest tariff reductions. Sec-
ond, heterogeneous productivity changes, represented as changes to the vari-
able cost of domestic production, similarly result in heterogeneous changes in
the price offered in the foreign market and proportionally larger export sales
for the goods exhibiting the largest productivity increases. Third, these first
two channels may lead to certain goods crossing the productivity thresholds,
resulting in disproportionately larger growth for these “switchers” — goods
that switch from not-traded to traded via either technology, or switching from
method X1to X2. This occurs due to the combined effect of these goods ex-
hibiting increases in export sales proportional to the growth in the first two
channels being magnified by a switch to a lower-variable cost method, ampli-
fying the growth in trade. The larger growth exhibited by this subset of goods
increases the granularity of trade growth predicted by the model, compared to
the model with a singular distribution technology.
3.5 Quantitative Analysis
To quantitatively assess the model’s ability to match the granularity in the
data, I calibrate and simulate the model with multiple distribution technolo-
gies to match bilateral trade flows. I first simulate the model and calibrate the
fixed and variable costs of exporting to match U.S. exports to Canada, Mex-
ico and Japan, for the 3-year average from 1989–1991, representing the “Ini-
tial period”. I re-simulate the model, adding heterogeneous productivity and
tariff changes imputed from U.S. data, to match bilateral trade data for each

96
country-pair over a three-year average from 1997–1999, representing the “Fi-
nal period”. I calibrate the distribution of tariff reductions for the Final period
to match the overall growth in trade for each country-pair between 1989–1991
and 1997–1999 averages.
One key issue in simulating the model is how to implement the fixed and
variable costs (f1, τ1;f2, τ2) associated with the different distribution methods
available to exporters. Since direct data on variations in shipping rates across
goods is highly limited at this level of disaggregation, I calibrate these pa-
rameters to match the granularity of cross-sectional trade flows. Specifically,
I calibrate the relative fixed and variable costs for the two methods, X1and
X2, to match the shares of total trade accounted for by the top 2, 5 and 10%
of goods categories in the Initial period. I then take these costs as given when
re-simulating the model for the Final period.
In Chapter 2 I found that including heterogeneous productivity and tar-
iff changes in the Melitz-style model accounted for roughly 70% of the ob-
served granularity of trade growth in bilateral trade data. Adding a choice
among multiple distribution technologies to this model framework, I find that
the model now captures roughly 90–95% of the granularity in the data. Fur-
ther, I find evidence of switching behaviour in the model simulations, which
increases the level of granularity in predicted trade growth. Although a rel-
atively small number firms choose to switch technologies, with the majority
of overall trade growth occurring from goods retaining their distribution choice
across periods, I find evidence that on average, each switching firm accounts for
a greater share of trade growth (0.5–1.0% per good) than each non-switching
firm (0–0.5% per good), increasing the granularity of trade growth across goods.
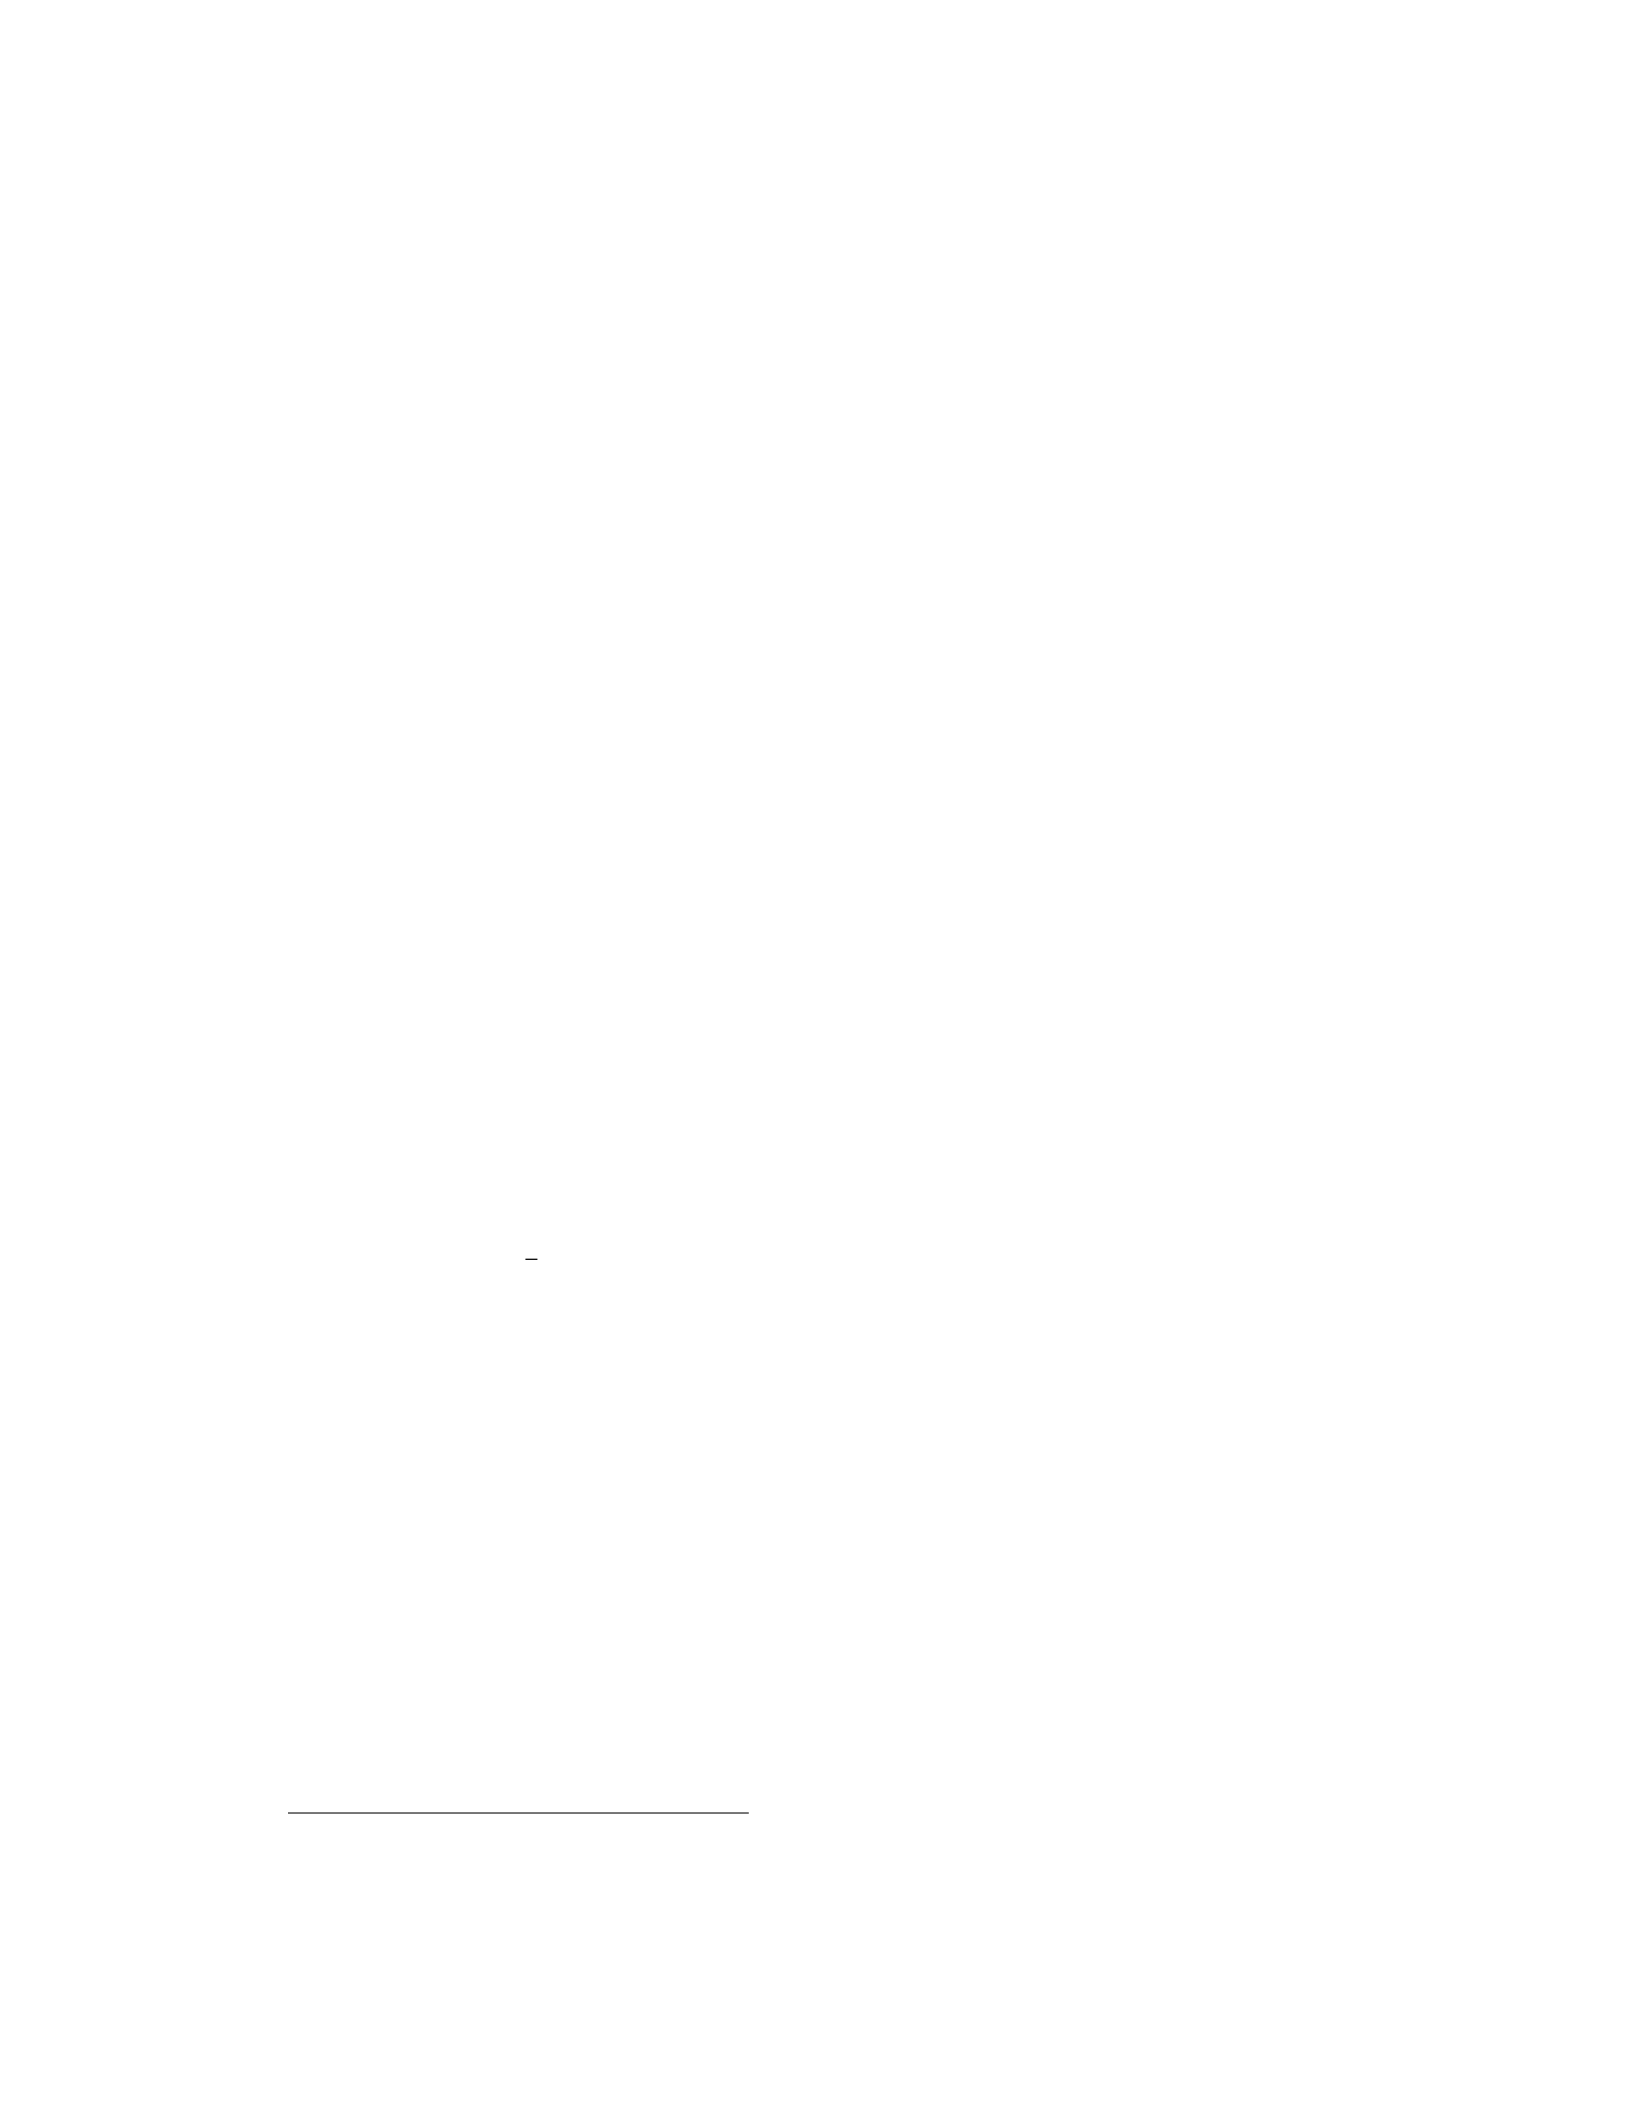
97
3.5.1 Parameterization and Calibration
The calibration strategy in this chapter is similar to that of Chapter 2, with one
notable exception — I now have two additional free parameters to calibrate: f2
and τ2, the costs associated with the second distribution option X2. As in Chap-
ter 2, I first parameterize and calibrate the model to match bilateral trade
data on U.S. exports to Canada, Mexico and Japan for the 3-year average from
1989–1991, which I classify as the Initial period. To analyze changes in trade
flows across goods, I re-simulate the model, adding heterogeneous productivity
and tariff changes imputed from U.S. data, and calibrating the model to match
bilateral flows for U.S. exports to Canada, Mexico and Japan for 1997–1999,
which I classify as the Final period. To incorporate these heterogeneous pro-
ductivity and tariff changes, I calibrate the model to match data at the 6-digit
North American Industry Classification System (NAICS) level, resulting in 473
distinct goods classifications.
For the Initial period, I draw each firm’s initial productivity from a Pareto
distribution, G(1
a), mapping each firm to a single good category, and set the
elasticity of substitution, , at 6.0.20 Since my variable of interest is the share
of growth accounted for by each good category (not the absolute level of trade
flows for each category), I begin with τ1, the higher variable cost, as a free
parameter, as in Chapter 2. For a given τ1, the lower fixed cost, f1, which de-
termines the lower productivity threshold for exporting, is calibrated to match
the number of not-traded goods in the data. I then simultaneously calibrate
the higher fixed cost f2, and lower variable cost, τ2, to match the cross-sectional
trade flows accounted for by the top 2, 5 and 10% of goods in the Initial period
20Refer to Chapter 2, Section 5.2.1 for a discussion on these parameter choices and
implications.
98
(1989-1991 average for each destination country in the data).21
Similar to Chapter 2, I use U.S. manufacturing data to impute changes
in productivity across goods between the Initial and Final periods, and apply
these changes to the productivity distribution from the Initial period simu-
lation.22 I use 8-digit Harmonized Tariff Schedule (HTS) data, which I con-
cord to 6-digit NAICS classifications, to determine the changes in ad valorem
equivalent (AVE) tariff changes for Canada, Mexico and Japan between the
1989–1991 and 1997–1999 periods.23 I scale the distribution of tariff changes
to match total trade growth for each U.S. export destination for the Final pe-
riod, 1997–1999, retaining the same set of fixed and variable cost options cali-
brated in the Initial period, to determine exports, distribution choice, and share
of total trade growth accounted for by each good category.24
3.5.2 Initial Period
Table 3.2 presents the results of the model calibration for each destination
country. For the top 2, 5, and 10% of goods categories, the model captures
93–95% of the overall granularity in cross-sectional trade, on average across
21Specifically I grid search over a range of all plausible values of f2and τ2consistent with
the literature, to determine the parameter values that minimize the loss function over various
quantiles of trade, k~rdata −~rmodelk, where the ~r’s are vectors of the proportion of total trade ac-
counted for by the top 2, 5 and 10% of goods. Therefore, in keeping with the focus on matching
the share of trade growth accounted for across goods in the data, the calibration determines
the ratio of fixed and variable costs between methods X1and X2.
22Figure B.3 shows the distribution of Initial productivities along with the applied produc-
tivity changes.
23Figures B.4–B.6 show the distribution of tariff changes across goods classifications. Of
note, the mean tariff decreases are larger in Canada and Mexico, due to the formal trade
liberalization of NAFTA, as opposed to Japan. However, while there are many more goods
exhibiting large AVE decreases for Canada and Mexico, there are still large AVE reductions
for some goods categories in Japan, in the absence of formal trade liberalization agreements.
24As in Chapter 2, this is computationally equivalent to calibrating DFto match the overall
level of trade growth.
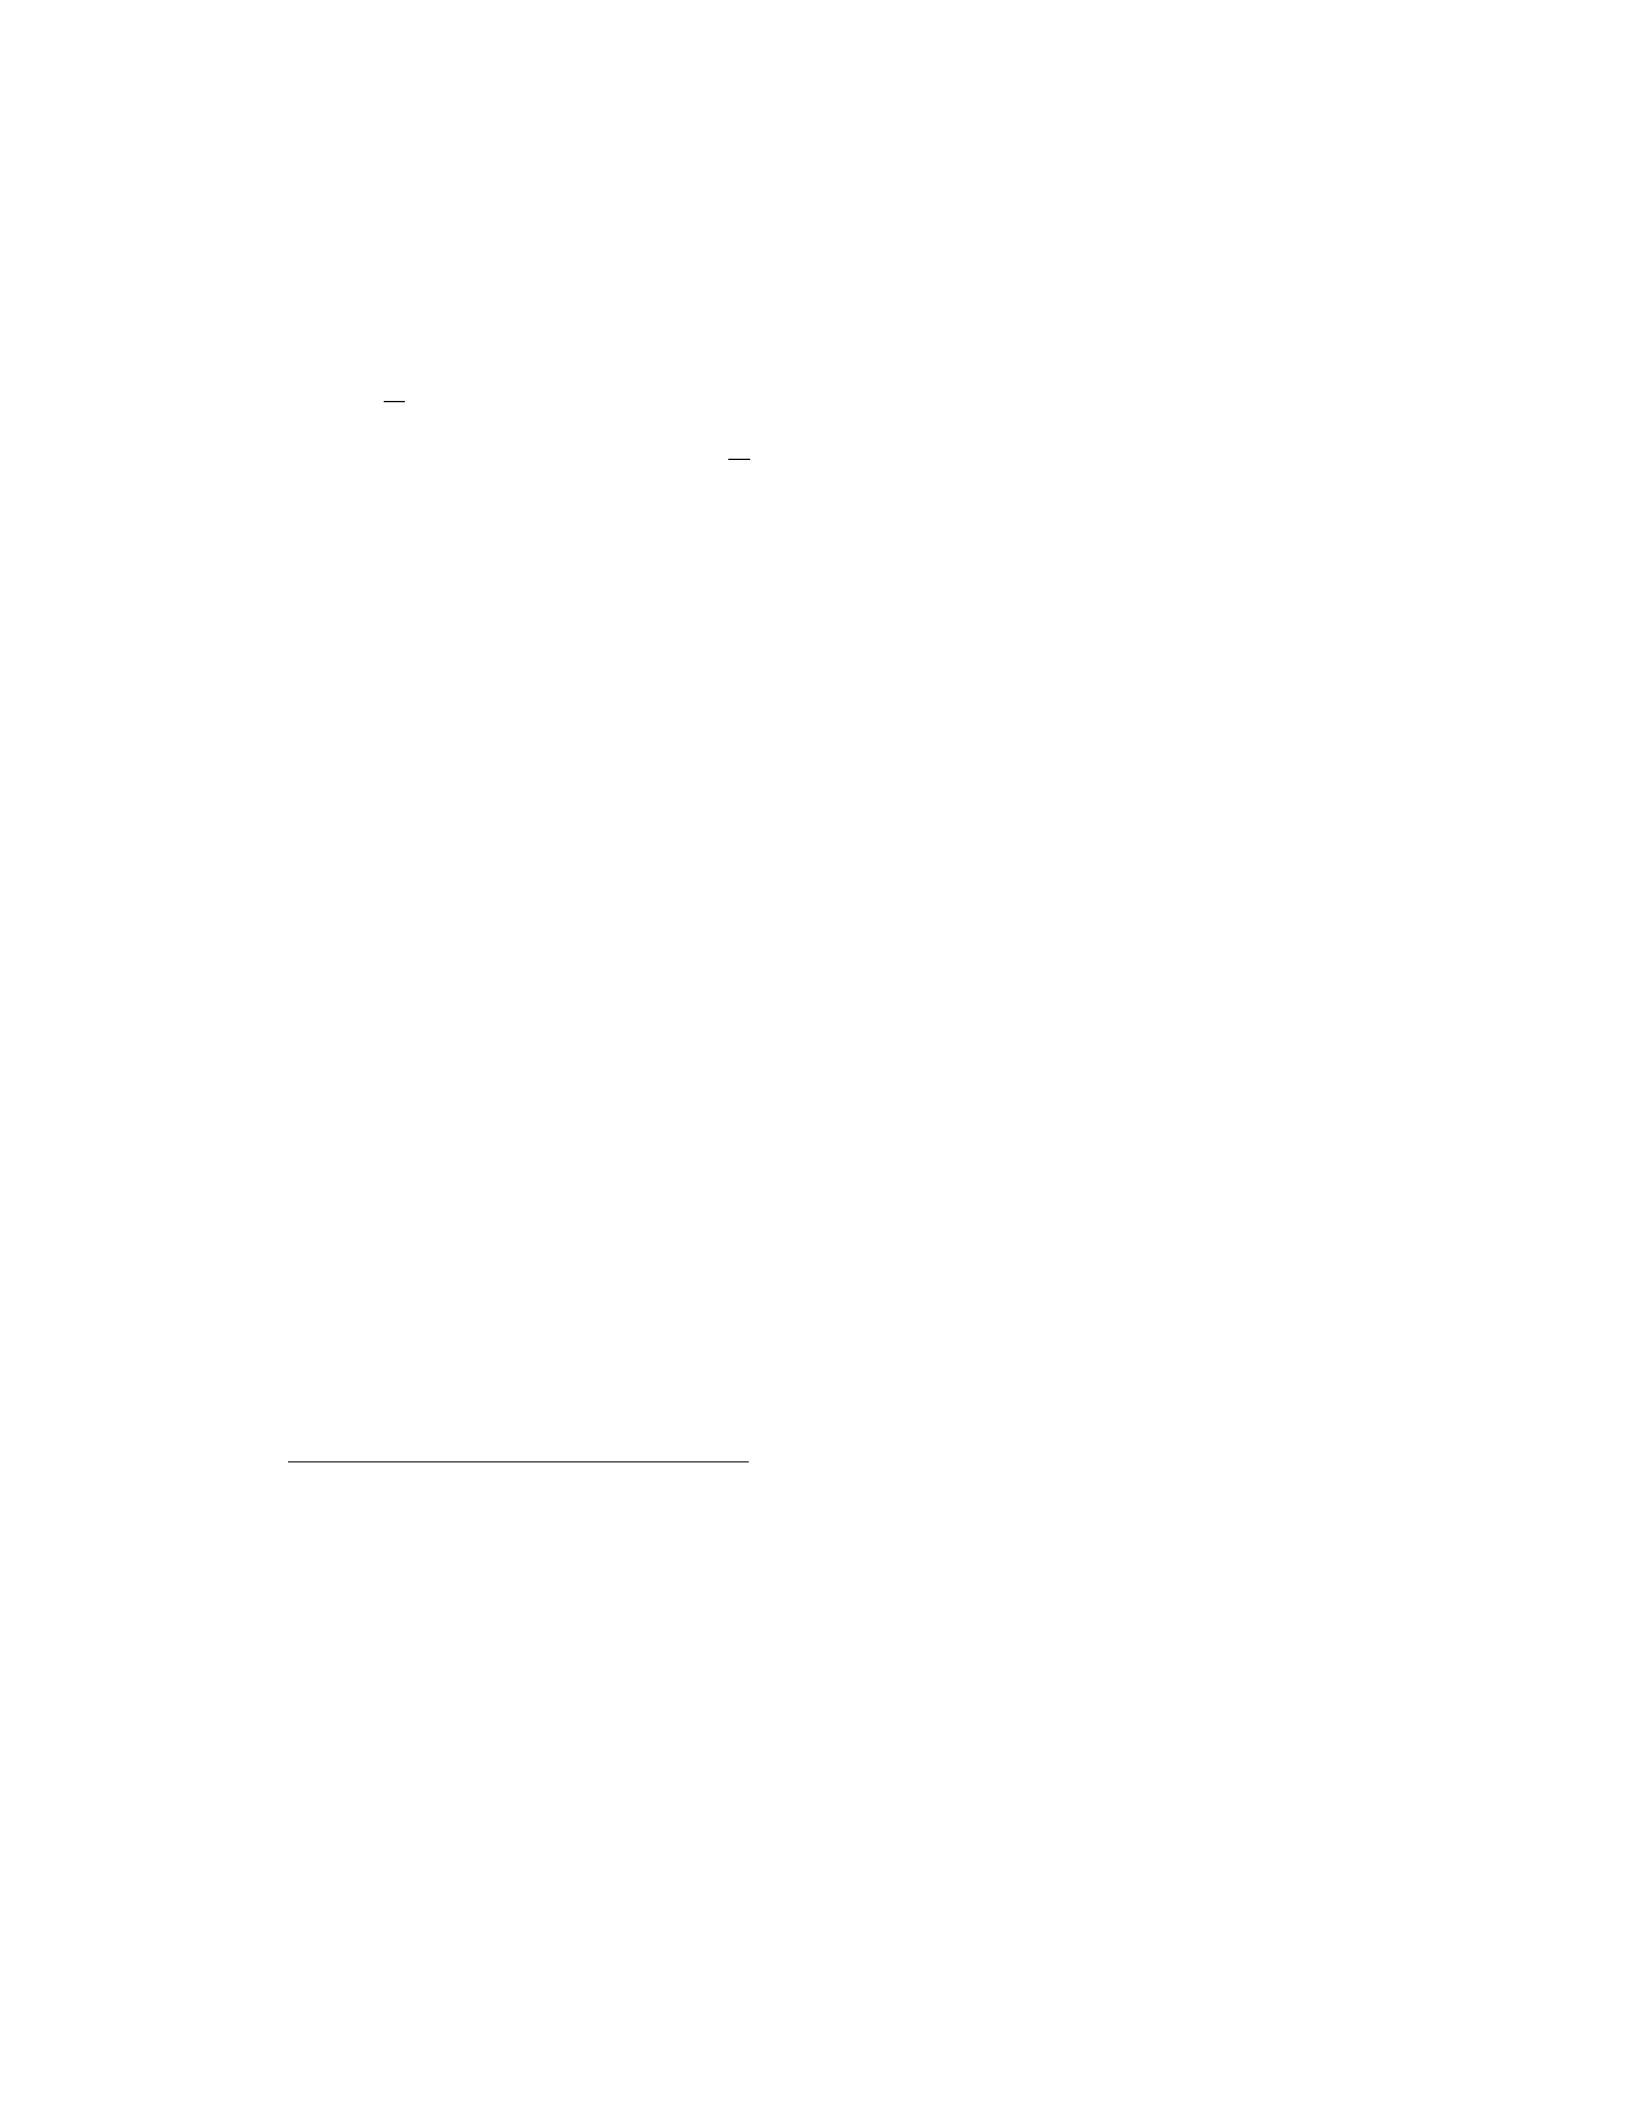
99
country-pairs. For all country-pairs, the ratio of the two calibrated variable
costs, τ2
τ1, is consistently between 0.55–0.65.25 There is more variation in the
ratio of calibrated fixed costs, f2
f1, across country-pairs. For U.S. exports to Mex-
ico, where the top quantiles of goods account for lower shares of Initial trade,
the ratio is lower, at 670. For U.S. exports to Canada and Japan, where the
trade shares accounted for by the upper quantiles of goods is higher, the ratio
of fixed costs is higher, at 1430 and 1840, respectively.26 These results suggest
that a higher fixed cost ratio creates a higher productivity threshold for firms
using method X2, which, combined with a lower variable cost τ2, concentrates
a larger share of Initial trade in a smaller proportion of goods categories at the
top end of the distribution.
3.5.3 Final Period
Table 3.3 reports the share of trade growth accounted for by quantiles of largest-
growth goods categories for each U.S. export destination. The share of trade
growth accounted for by the top 2, 5 and 10% of goods is roughly 90–95% as
high as that observed in the data, on average across country-pairs. This marks
an improvement from the roughly 70% of granularity generated by the model
with a single distribution technology, as in Chapter 2.
25With the higher variable cost, τ1, set as a free parameter at 2.0, this results in values for τ2
across countries of 1.12–1.32, consistent with the interpretation in the literature of the iceberg
costs shipping, where τrepresents the number of units necessary to ship to result in 1 unit
arriving at the destination country.
26Due to the scarcity of direct measures of the fixed costs of exporting, it is difficult to as-
sess the appropriateness of these fixed cost ratios — the vast majority of the relatively small
literature that seeks to directly measure distribution and transportation costs in international
trade goes no deeper than identifying total costs, without decomposing the shares of fixed vs.
variable costs, and virtually all assume a common distribution technology. However, Kropf
and Saure (2014) estimate variation across Swiss firms in fixed costs per shipment, and find
logged values that range from -3 to 9 — thus the fixed cost ratios I calibrate between 670 and
1840 correspond to logged differences of 6.5 to 7.5, which arguably fall within realistic ranges
of those imputed by Kropf and Saure.
100
Table 3.2: Cross-Sectional Granularity: Initial Period
Share of trade from top X%of goods
(6-digit NAICS codes)
USA-CAN USA-JPN USA-MEX
Model Data Model Data Model Data
2% 37 37 41 41 21 27
5% 57 53 63 59 49 45
10% 62 66 68 74 62 62
20% 71 81 75 88 71 79
40% 84 94 87 97 84 94
f2
f11430 1840 670
τ2
τ10.59 0.56 0.66
Additionally, I track the distribution choice for each good across the two sim-
ulations to quantitatively assess the ability of the model’s “switching” mecha-
nism to account for trade growth granularity. Figure 3.6 plots the distribution
choice across goods, arranged by ascending initial productivity. Firms are ini-
tially stratified according to productivity, with the least productive firms not
exporting, the most productive firms exporting via method X2, and those in
between the productivity thresholds exporting via method X1, represented by
the starred levels. After including the productivity and tariff changes from the
data, and simulating the model, the bars represent the new distribution choice
for each good. Many previously not-traded goods remain not-traded, but some
now become traded via X1or X2(as reflected by the bars ascending to 1 or 2).
Similarly, a large proportion of goods previously traded via method X1remain
traded via X1; however, some now switch to method X2(as reflected by the bar
ascending above the starred line) while others no longer export (as reflected by
a blank space for that good). The same is true for goods initially traded via X2,
where the majority remain traded via X2, but some goods switch to either X1
101
Table 3.3: Trade Growth Granularity: Second Period
Share of growth from top X%of goods
(6-digit NAICS codes)
CAN-USA JPN-USA MEX-USA
Model Data Model Data Model Data
2% 33 38 59 56 37 36
5% 48 56 74 86 50 57
10% 75 71 97 102 70 74
20% 92 86 116 114 87 89
40% 111 99 138 123 104 101
f2
f11430 1840 670
τ2
τ10.59 0.56 0.66
(a space down to level 1) or not-traded (a space down to 0).
Comparing across the two simulations, I find that firms switching from dis-
tribution technology 1 to 2 account for a larger shares of total trade growth
than the traditional extensive margin of firms switching from non-traded to
traded. Table 3.4 reports the shares of trade growth accounted for by each of
the 9 possible combinations of distribution choices across the two simulations.
While there are a smaller total number of firms switching from not-traded to
traded, or from method X1to X2than there are firms that retain the same
distribution choice, these switching firms account for relatively larger shares
of trade growth, on average. Firms switching from not-traded to traded ac-
count for an average of roughly 0.3–0.7% of total trade growth per good, while
firms switching from X1to X2account for an average of 0.5–1.0% of total trade
growth per good, across the various country pairs. Conversely, firms that re-
tain X1in both simulations account for virtually none of the total trade growth,
and while firms that retain X2account for 50–60% of the total trade growth,
the fact that there are relatively so many of these firms (140–150 per country)
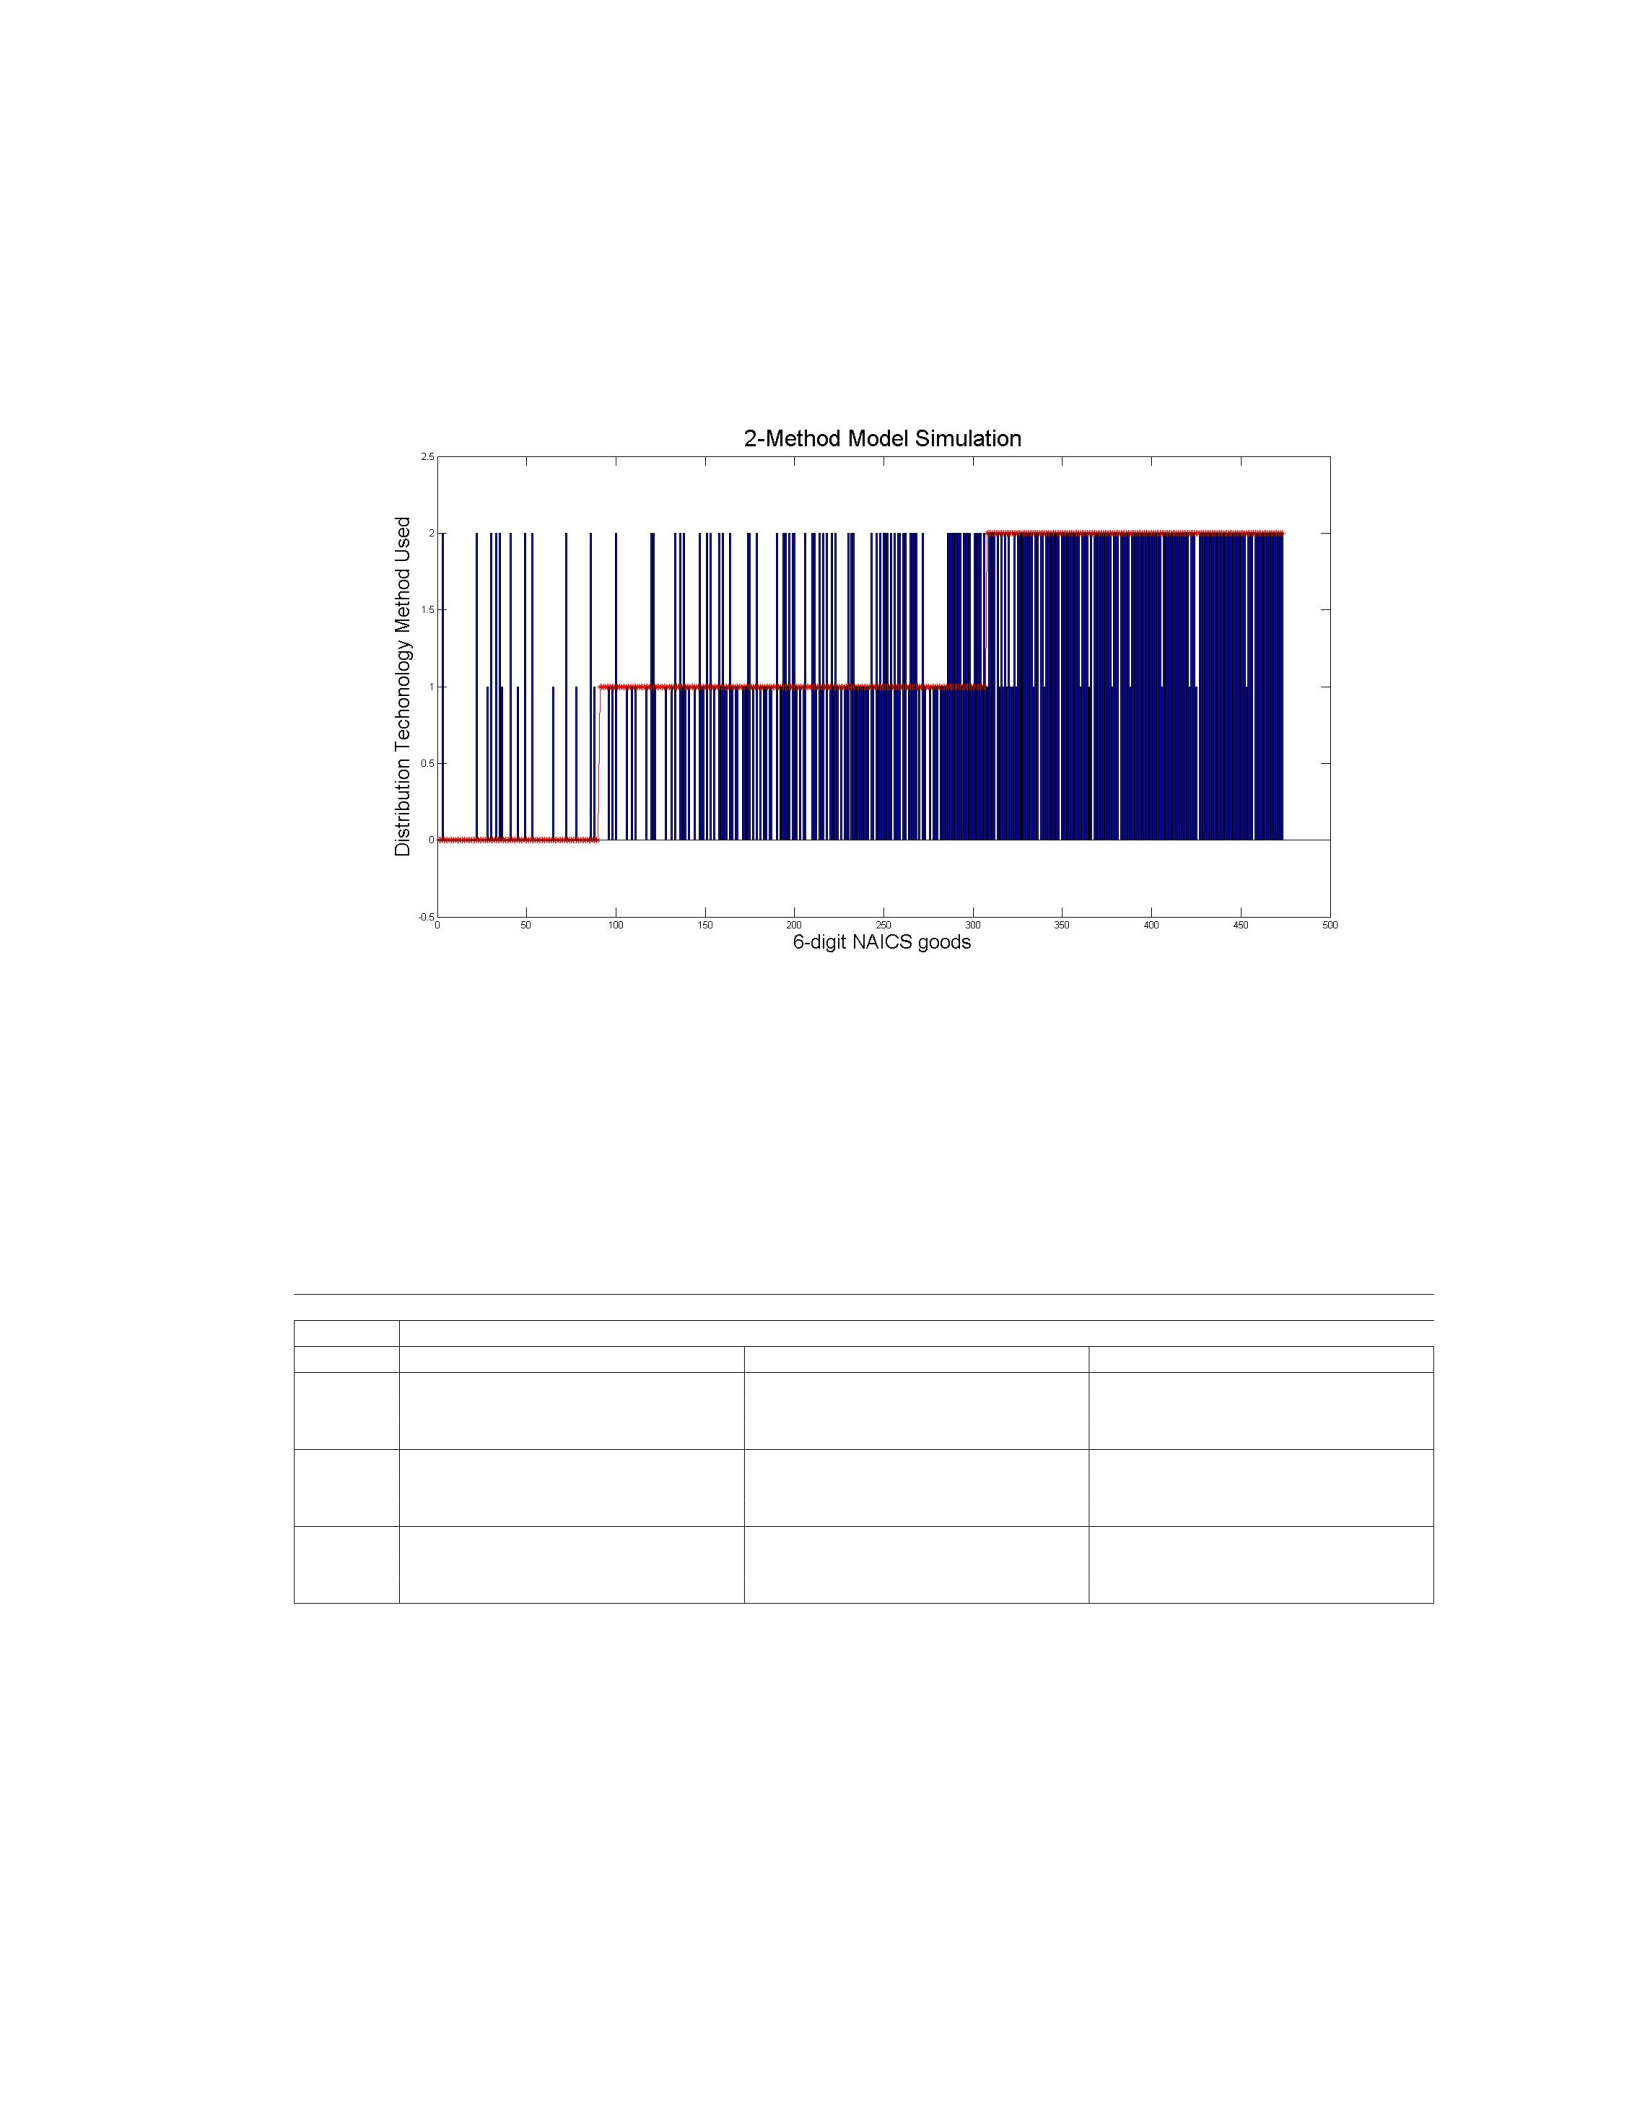
102
Figure 3.6: Model Simulation: Optimal Distribution Choice
means that on average, they account for only 0.3–0.5% of total trade growth
per good.
Table 3.4: Optimal Distribution Method Choice
Proportion of total trade growth
U.S.-Canada U.S.-Japan U.S.-Mexico
Methods Tot. Share # goods Avg. Share Tot. Share # goods Avg. Share Tot. Share # goods Avg. Share
0→0 0% 74 0% 0% 78 0% 0% 74 0%
0→X10.03% 6 0.00% 0.03% 6 0.01% 0.05% 6 0.01%
0→X26.14% 10 0.61% 8.98% 7 1.28% 4.60% 10 0.46%
X1→0 -0.27% 77 0.00% -0.50% 81 -0.01% -0.36% 78 0.00%
X1→X10.08% 74 0.00% -0.08% 67 0.00% 0.32% 71 0.00%
X1→X239.61% 66 0.60% 61.41% 62 0.99% 32.22% 69 0.47%
X2→0 -3.31% 7 -0.47% -6.34% 5 -1.27% -1.99% 7 -0.28%
X2→X1-7.06% 17 -0.42% -15.88% 15 -1.06% -3.95% 16 -0.25%
X2→X264.78% 142 0.46% 52.39% 152 0.34% 69.11% 142 0.49%
It is also important to note that in Table 3.4 it is possible for firms to “switch
down” in the model — firms with decreases in productivity or increases in tar-
iffs may choose to switch from X2to X1following the inverse rationale of firms

103
that “switch up”, or may even decide to stop exporting altogether. While there
are a smaller number of these types of down-switching firms than up-switching
firms, their presence in the model serves to amplify the granularity of trade
growth, as the up-switching firms account for an even larger share of total
trade growth when these decreases in exports from down-switching firms are
taken into consideration.
3.6 Conclusions
This chapter extends the literature by identifying a novel mechanism that
helps account for the high degree of granularity of trade growth observed in
bilateral trade data. I use data U.S. exports to Canada, Mexico and Japan,
between 1989 and 1999, at the 6-digit NAICS level, to determine the distribu-
tion of trade growth shares across goods. I find that trade growth is granular
— a small number of goods categories accounts for a majority of total bilateral
trade growth- specifically, the top 5% of goods accounts for roughly 66% of over-
all trade growth, on average across country-pairs. Further, I find that trade
growth is more granular than cross-sectional trade, and that trade growth is
uncorrelated with previous levels of trade.
To match this level of granularity in the data, I use a standard trade model
framework, and add a discrete choice among multiple distribution technologies
for firms in the exporting process. I introduce a low-fixed, high-variable cost
exporting technology, and a high-fixed, low-variable cost exporting technology,
and include heterogeneous productivity and tariff changes, imputed from trade
data, to analyze the predictions for trade growth across goods in the model. I
calibrate the fixed and variable costs, and the distribution of productivity and
tariff changes, to match overall bilateral trade flows, and simulate the model

104
to determine the distribution of growth in export sales predicted by the model.
I find that the model simulation generates roughly 90–95% of the observed
granularity of trade growth in the bilateral trade data, as measured by the
share of total trade growth accounted for by the top quantiles of goods cate-
gories. The model with multiple distribution technologies increases the gran-
ularity of trade growth in the model, as compared to a standard model with a
single distribution technology, which generates only 60–70% as much granu-
larity as the data. In the model, I find evidence that goods that switch their
distribution technology in response to heterogeneous productivity changes and
tariff reductions account for a relatively larger share of total trade growth than
non-switching goods. This occurs as a result of the double effect of a direct re-
duction in variable costs of exporting from tariff reductions and productivity
increases, combined with an indirect effect of switching to a lower variable cost
method of exporting, resulting in disproportionately higher growth, accounting
for the observed granularity of trade growth.
3.7 References
ABELKOCH, J. (2013). “Who Uses Intermediaries in International Trade? Ev-
idence from Firmlevel Survey Data”. The World Economy. 36(8), 1041–1064.
AHN, J., A. KHANDELWAL,AND S. WEI (2011). “The Role of Intermediaries in
Facilitating Trade,” Journal of International Economics. 84(1), 73–85.
ALESSANDRIA, G., J. KABOSKI AND V. MIDRIGAN (2010). “Inventories, Lumpy
Trade, and Large Devaluations”. American Economic Review. 58(Dec), 2304–39.
ANDERSON, J.E. (1979). “A Theoretical Foundation for the Gravity Equation”.
The American Economic Review. 69(1), 106–116.
ANDERSON, J.E. AND E. VAN WINCOOP (2003). “Gravity with Gravitas: A
Solution to the Border Puzzle”. American Economic Review. 93(1). 170–192
ANDERSON, J.E. & Y.V. YOTOV (2010). “The Changing Incidence of Geogra-
phy,” American Economic Review, American Economic Association. Vol. 100(5),

105
pages 2157–86
ARKOLAKIS, C. (2010). “Market Penetration Costs and the New Consumers
Margin in International Trade”. Journal of Political Economy. 118(Dec), 1151–99.
ARMENTER, R. AND M. KOREN (2014). “A Balls-and-Bins Model of Trade”.
The American Economic Review. 104(7), 2127–2151.
BERGOEING, R., AND T. KEHOE (2001). “Trade Theory and Trade Facts”. Fed-
eral Reserve Bank of Minneapolis, Research Department.
BERNARD, A.B., J. EATON, J.B. JENSEN,AND S. KORTUM (2003). “Plants and
productivity in international trade”. The American Economic Review. 93(4),
1268–1290.
BLUM, B., S. CLARO,AND I. HORSTMANN (2016). “A Balls-and-Bins Model of
Trade: Comment.” American Economic Review 106(3), 843–51.
CALIENDO, L. AND F. PARRA (2014). “Estimates of the Trade and Welfare
Effects of NAFTA”. The Review of Economics Studies. rdu035.
CHANEY, T. (2008). “Distorted Gravity: The Intensive and Extensive Margins
of International Trade”. American Economic Review. 98:4, 1707–1721.
CRUCINI, M., C. TELMER AND M. ZACHARIADIS (2003). “Price Dispersion:
The role of borders, distance and location”, Tepper School of Business. Paper
490
DORNBUSCH, R., S. FISCHER,AND P. SAMUELSON (1977). “Comparative
Advantage, Trade, and Payments in a Ricardian Model with a Continuum of
Goods”. American Economic Review. 67(5)823–39.
EATON, J. AND S. KORTUM (2002). “Technology, Geography, and Trade”. Econo-
metrica, 70(5), 1741–1779.
ENGEL, C. AND J. ROGERS (1994). “How Wide is the Border?” American Eco-
nomic Review. 86(5), 1112–1125.
FEENSTRA, R., J. ROMALIS,AND P. SCHOTT. (2002). “U.S. Imports, Exports
and Tariff Data, 1989–2001”, NBER Working Paper 9387.
FERNANDES, A.M., P. KLENOW, S. MELESHCHUK, M. DENISSE PIEROLA
AND A. RODRIGUEZ-CLARE (2015). “The Intensive Margin in Trade: Moving
Beyond Pareto”, Working Paper.
FREUND, C. AND M. PIEROLA (2015). “Export Superstars” Review of Eco-
nomics and Statistics, 97(5), pp. 1023–1032
GOULD, D. (1998). “Has NAFTA Changed North American Trade?” Economic
Review- Federal Reserve Bank of Dallas 12–23.

106
HELPMAN, E., M.J. MELITZ AND S. YEAPLE (2004). “Export Versus FDI with
Heterogeneous Firms”. American Economic Review, 94(1), 300–316.
HORNOK, C., AND M. KOREN (2015). “Per-shipment Costs and the Lumpiness
of International Trade.” Review of Economics and Statistics. 97(2), 525–530.
KEHOE, T. (2005). “An Evaluation of the Performance of Applied General Equi-
librium Modes on the Impact of NAFTA”, in Frontiers in Applied General Equi-
librium Modeling: Essays in Honor of Herbert Scarf, edited by Kehoe, Srini-
vasan and Whalley, 341–77. New York: Cambridge University Press.
KEHOE, T. AND K. RUHL (2013). “How Important is the New Goods Margin in
International Trade?”. Journal of Political Economy, 121 (2013), 358–92.
KROPF, A., AND P. SAUR (2014). “Fixed costs per shipment.” Journal of Inter-
national Economics 92(1): 166–184.
KRUGMAN, P. (1980). “Scale Economies, Product Differentiation, and the Pat-
tern of Trade.” The American Economic Review, 950–959.
MELITZ, M.J. (2003). “The Impact of Trade on Intraindustry Reallocations and
Aggregate Industry Productivity.” Econometrica, Vol. 71.6 (2003): 1695–1725.
MILLS, J., J. SCHMITZ,AND G. FRIZELLE (2004). “A Strategic Review of Sup-
ply Networks”. International Journal of Operations & Production Manage-
ment, 24(10), 1012–1036.
NAGURNEY, A. (2010). “Optimal Supply Chain Network Design and Redesign
at Minimal Total Cost and with Demand Satisfaction”. International Journal
of Production Economics. 128(1), 200–208.
NAGURNEY, A., J. DONG AND D. ZHANG (2002). “A Supply Chain Network
Equilibrium Model”. Transportation Research Part E: Logistics and Trans-
portation Review. 38(5), 281–303.
PARSLEY, D.C., AND S.J. WEI (1996). “Convergence to the Law of One Price
Without Trade Barriers or Currency Fluctuations”. The Quarterly Journal of
Economics, 111(4), 1211–1236.
PIERCE, J. AND P. SCHOTT (2012). “A Concordance Between Ten-Digit U.S.
Harmonized System Codes and SIC/NAICS Product Classes and Industries”.
Journal of Economic and Social Measurement, 37(1–2), 61–96.
ROMALIS, J. (2007). NAFTAs and CUSFTAs Impact on International Trade,
Review of Economics and Statistics, 89(3), pp.416–435.
SANTOSO, T., S. AHMED, M. GOETSCHALCKX AND A. SHAPIRO (2005). “A
Stochastic Programming Approach for Supply Chain Design Under Uncertainty”.
European Journal of Operation Research, 167, 95–115.

107
SCHOTT, P. (2008). “The Relative Sophistication of Chinese Exports ”. Eco-
nomic Policy, 53, 5–49.
SHEN, Z.J.M. (2006). “A Profit-Maximizing Supply Chain Network Design
Model with Demand Choice Flexibility”. Operations Research Letters, 34(6),
673–682.
Chapter 4
The Supply Network and Price
Dispersion in the Canadian
Gasoline Market
4.1 Introduction
Policymakers and consumers have long sought to understand why prices for
identical goods differ across locations. Many studies use geographic distance,
as a proxy for transportation costs, to account for large price differences of ho-
mogeneous goods across locations.1However, little is known about the impact
of variation in the methods used to transport goods between locations on these
relative price differences. In this chapter, the term “supply network” refers
to the different modes of transporting products between locations. For sup-
pliers servicing various locations, the associated transportation costs will be a
function of not just the geographical distance covered, but also of the costs as-
sociated with the various methods of transportation for reaching each potential
destination. The structure of the supply network therefore plays a key role in
1See Burdett and Judd (1983), Crucini, Telmer and Zachariadis (2003), or Engel and Rogers
(1996) among others.
108
109
limiting arbitrage opportunities and determining what level of price dispersion
can be sustained across locations over time.
This chapter quantifies the impact of the supply network on relative price
dispersion in the Canadian gasoline market. The Canadian gasoline indus-
try is large — the average Canadian household spends over $2000 per year
on gasoline for transportation, accounting for over 3% of household spending.2
Gasoline is a homogeneous good for which consumers make purchasing deci-
sions based largely on price and accessibility, with varying brands being ar-
guably indistinguishable in their physical composition.3Further, there is sub-
stantial data on gasoline prices, at various levels of aggregation, provided by
various data sources, allowing for a more thorough breakdown of demand-side
and supply-side effects that are common to, and differ across, locations.
There are four methods of transportation for gasoline products employed
across Canada: pipeline, marine tanker, rail and transport truck. Pipelines
are generally the safest and most cost-effective means of transporting large
volumes. Marine tankers similarly offer large capacity, but are limited to lo-
cations with access to seaports, while rail and truck offer access to a greater
number of locations, but at much smaller scales.
While most studies use geographic distance as a proxy for transportation
costs, few studies have quantified the impact of the structure of the supply
network on price dispersion. Locations that are linked by fast, low-cost and
large-scale methods may exhibit lower price dispersion than locations that are
linked by more costly or smaller-scale technologies that can sustain larger price
gaps. As such, the existence of pipelines or seaports between locations may be
2Statistics Canada, Survey of Household Spending, 2015.
3While there is an extensive literature examining the role of distance, location and compe-
tition on price dispersion witin cities, this paper focuses on differences in city-wide average
prices across cities. See Marvel (1976), Chandra, Tappata (2011), Lewis (2011), among others.
110
expected to decrease arbitrage opportunities for suppliers and result in smaller
relative price dispersion than locations with only road or rail connections.
To quantify the impact of the supply network on price dispersion in the
Canadian gasoline market, I use a unique data set, compiled from Kent Mar-
keting Services, on weekly average gasoline prices from 44 Canadian cities,
between 2001 and 2017. One source of price dispersion arises from differences
in provincial and municipal gasoline taxes that may distort retail prices faced
by consumers across Canada, even after controlling for transportation costs. I
therefore use pre-tax prices for gasoline in each location, to control for varia-
tion in taxes and isolate the true prices received by suppliers that discipline
the arbitrage conditions when price gaps arise between locations.
Examining the data provides several key facts about gasoline prices across
locations over time. Price levels are highly correlated across locations, while
changes in price are less highly correlated. Intra-regional prices are more
highly correlated and exhibit smaller mean differences than inter-regional prices.4
The coefficient of variation for weekly prices is small and stable, both nationally
and at the regional level. Finally, the location of the minimum and maximum
weekly prices rarely changes within Canada.
Regressing measures of price dispersion on distance, region, market size
and supply network variables, I find that that the supply network is signifi-
cant in explaining observed price dispersion across Canadian cities. I find that
cities connected by pipeline exhibit 3.5% less mean-price dispersion than cities
only connected by road or train. Using weekly relative prices, I find that the ex-
istence of a pipeline connection between cities reduces weekly-price dispersion
by 2.2%, while a maritime connection reduces weekly-price dispersion by 1.6%.
4Regions are broken down according to the natural supply orbits of the Canadian gasoline
market: West, Ontario, Quebec and Atlantic.

111
A pipeline connection has the equivalent effect on weekly price dispersion as a
53% reduction in the geographical distance separating the two locations. Sim-
ilarly, a seaport connection has the equivalent effect as a 38% reduction in
geographic distance.
To put these findings into context, consider two cities such as London, ON
and Halifax, NS, of roughly similar total population and density. These two
cities are roughly 1850km apart, and at present share no pipeline or maritime
connection, with a mean-price difference of approximately 1 ¢/L, with standard
deviation of 3.5 ¢/L and a range of weekly-price differences between 0 and 14
¢/L. The regression analysis suggests that a pipeline built between these two
cities would effectively “move” Halifax to Quebec City — that is, the effect on
weekly price differences between these two cities would be the equivalent of
having the city of Halifax moved 50% closer in geographic distance to London.
Ignoring this impact of the supply network would bias the evaluations of sup-
pliers or policymakers considering potential infrastructure projects or policy
assessments, if they considered only geographic distance as a proxy for trans-
portation costs.
To check the robustness of these results, I consider two alternative cases
— omitting city-pairs subject to price regulation, and omitting geographically
remote cities. Some locations, like Quebec and the Atlantic provinces, impose
regulations on weekly gasoline prices. Omitting all city-pairs containing a Que-
bec or Atlantic city, I find the supply network variables remain significant and
become slightly larger in magnitude. Similarly, omitting Whitehorse and Yel-
lowknife, which may be outliers due to their extreme geographic remoteness,

112
I find little change in the regression coefficients, with the supply network re-
maining significant in accounting for mean and weekly relative price disper-
sion across locations.
To further isolate the role of the supply network in accounting for observed
price dispersion, I consider “supply shocks”, in the form of disruptions to the
gasoline production and distribution process. I analyze several instances of
refinery shut-downs to examine the effects on production volumes and retail
prices across locations. I find that retail prices increase relatively more in re-
gions closest to refinery shut-downs than in those further away, indicating that
prices are most significantly impacted within the supply orbit of the affected re-
finery. Further, I find that price dispersion is lower across locations that share
pipeline connections than those that do not, suggesting that arbitrage oppor-
tunities arising from supply disruptions are more constrained when locations
are connected by faster, cheaper methods of transportation. Both of these find-
ings reinforce the result that the structure of the supply network, not solely
geographical distance between locations, is significant in determining the level
of price dispersion that can be supported between locations.
4.2 Related Literature
A large and diverse literature examines violations of the Law-of-One-Price
(LOP) to determine the causes of price dispersion across locations over time.
Papers like Stahl (1982), Crucini, Telmer and Zachariadas (2003), and Crucini,
Shintani and Tsurugu (2012) all examine various sources of price dispersion,
113
such as distance between locations (typically serving as a proxy for transporta-
tion costs), market effects and border effects.5Recent work such as Crucini and
Yilmazkuday (2014) integrates the role of productivity and wage differences,
along with distance and border effects, in accounting for LOP violations. Kano,
Kano and Takechi (2013) estimate a model of iceberg-type transportation costs
to determine that geographic barriers are a significant contributor to failures
of the LOP in Japanese wholesale agricultural markets. This chapter extends
this literature by quantifying these types of effects on a particular market, re-
tail gasoline, across Canadian cities. Further, this chapter considers not just
geographic distance as a proxy for transportation costs, but also examines vari-
ation in transportation methods to account for observed price dispersion across
locations in the Canadian gasoline market.
A separate literature examines supply networks formation and equilibrium
structures.6Shen (2006) investigates how firms strategically construct their
supply networks, by choosing which groups of customers to serve in a profit-
maximizing competitive environment. Nagurney, Dong and Zhang (2004) in-
troduce a more general model of supply network equilibrium which is adapt-
able to different implementations of decision-makers and their independent
behaviours. Although this chapter abstracts from strategic decisions regarding
the formation of the gasoline supply network, it contributes to this literature by
examining the effects of the existing supply network on retail price behaviour.
This chapter is unique in its quantitative measure of the impact of the existing
5This literature ultimately branches back to the seminal work of Stigler (1961), which iden-
tifies the role of incomplete information and search in accounting for price dispersion across re-
tailers, followed by works like Burdett and Judd’s (1983) work on multiple equilibria in models
with imperfect information, many of which can support long-run price dispersion, and provide
a basis for the role of distance, as it relates to acquiring costly information, in accounting for
relative price differences across locations.
6For a general overview of the strategic supply network formation literature, see Mills,
Schmitz and Frizelle (2004).

114
supply network on retail price dispersion across locations.
A large literature has examined the oil and gasoline industry, at various
levels of disaggregation, across a large number of locations, and across vari-
ous shipping and retailing methods. Marvel’s (1976) empirical analysis of the
gasoline market examines the role of consumer responses to costly, imperfect
information in explaining price dispersion across locations and price variabil-
ity over time. Adams (1997) argues that, compared to other less homogeneous
goods purchased in convenience stores, the relatively low search and informa-
tion costs of gasoline explain a large degree of price dispersion in highly local-
ized markets. Similarly, Pennerstorger et al (2015) use gas station-level data
to test a model of costly information acquisition in the localized retail gasoline
market and find that allowing for spatial variation in the share of informed con-
sumers sampling gasoline prices along their commuting routes helps account
for observed price dispersion across locations.
This chapter expands on the gasoline literature in multiple ways. First,
these papers largely focus on demand-side effects, like consumer search costs,
in accounting for price dispersion. While this chapter also considers demand-
side market and regional effects, it extends the existing literature by adding a
quantitative analysis of the impacts of supply-side effects in explaining price
dispersion across locations. Second, this literature predominantly examines
price dispersion within local markets, on a station-to-station basis. This chap-
ter quantifies the effects of transportation costs and supply network variables
on price dispersion on a larger geographic scale, accounting for city-level mean
prices across more geographically diverse locations.
Eckert (2011) surveys the literature on gasoline retailing, including supply
side effects related to gasoline pricing. Among these are numerous studies on

115
the relationship of crude oil prices to retail prices, and the asymmetries of price
movements to increases and decreases in crude oil prices. Feyrer, Mansur and
Sacerdote (2016) investigate the transmission of income shocks generated by
the fracking revolution in the crude gasoline industry and find that wage and
income shocks are most strongly transmitted to areas that are most closely
connected, both geographically and along the supply network, to the fracking
sites. One of the most closely related studies in the recent literature comes
from Yilmazkuday and Yilmazkuday (2012), who attempt to attribute relative
price differences between locations to difference stages of the production pro-
cess. They determine that price dispersion across locations within a city can
be decomposed as attributable to 50% from crude oil prices, 33% from refinery
costs, 12% from taxes, 10% from mark-ups, and only 4% from spatial factors.
While this chapter does not decompose the contributing factors of price disper-
sion in a manner similar to these papers, it does extend the price dispersion
literature by quantifying the relationship of the supply network structure to
observed price dispersion across locations.
4.3 Supply Network
A common approach in price dispersion literature is to use a measure of geo-
graphic distance as a proxy for the associated transportation costs that govern
the arbitrage conditions sustaining price gaps between locations. However, if
transportation costs differ across locations, or vary depending on factors like
the method of transportation employed, geographic distance alone may be a
biased measure. The potential profits for suppliers seeking to buy product at
lower price locations and transport to higher price locations for resale depend
116
on the per-unit costs associated with the transportation methods available be-
tween those locations. Observed price dispersion will therefore be a function
not only of geographic distance, but also of the characteristics of the trans-
portation options that suppliers can employ between retail locations.
In this chapter the term “supply network” refers to the various methods
available for transporting oil products, such as refined gasoline, between loca-
tions across Canada. There are four primary modes of transportation: pipeline,
marine tanker, rail, and truck. Pipelines are the most prominently used method
of transporting bulk quantities, with approximately 750 million barrels of re-
fined oil products being shipped annually via pipeline. Alternatively, approxi-
mately 95 million barrels of refined products are transported by marine tanker,
both domestically and via import, into Canadian ports annually. Put into
perspective, the amount of oil products transported daily across Canada via
pipeline would necessitate the equivalent of 4200 rail cars, or 15,000 trucks.
Pipelines are the most cost-effective means of transporting large quanti-
ties of gasoline products, followed in order by tanker, rail and truck.7How-
ever, pipeline and sea transport face obvious limitations of geography and pre-
existing infrastructure, as pipelines and sea routes are less prevalent than the
extensive rail and highway networks throughout Canada. Therefore, locations
that share existing pipeline or sea route connections may reflect different rel-
ative pricing patterns than locations that do not have access to these shipping
options.
The Canadian gasoline supply network begins with crude oil reserves and
imports. The vast majority of domestic crude production occurs in Western and
7For a detailed breakdown of the crude oil and petroleum products infras-
tructure in Canada, refer to Natural Resources Canada report, available at:
http://www.nrcan.gc.ca/energy/sources/infrastructure/1490.
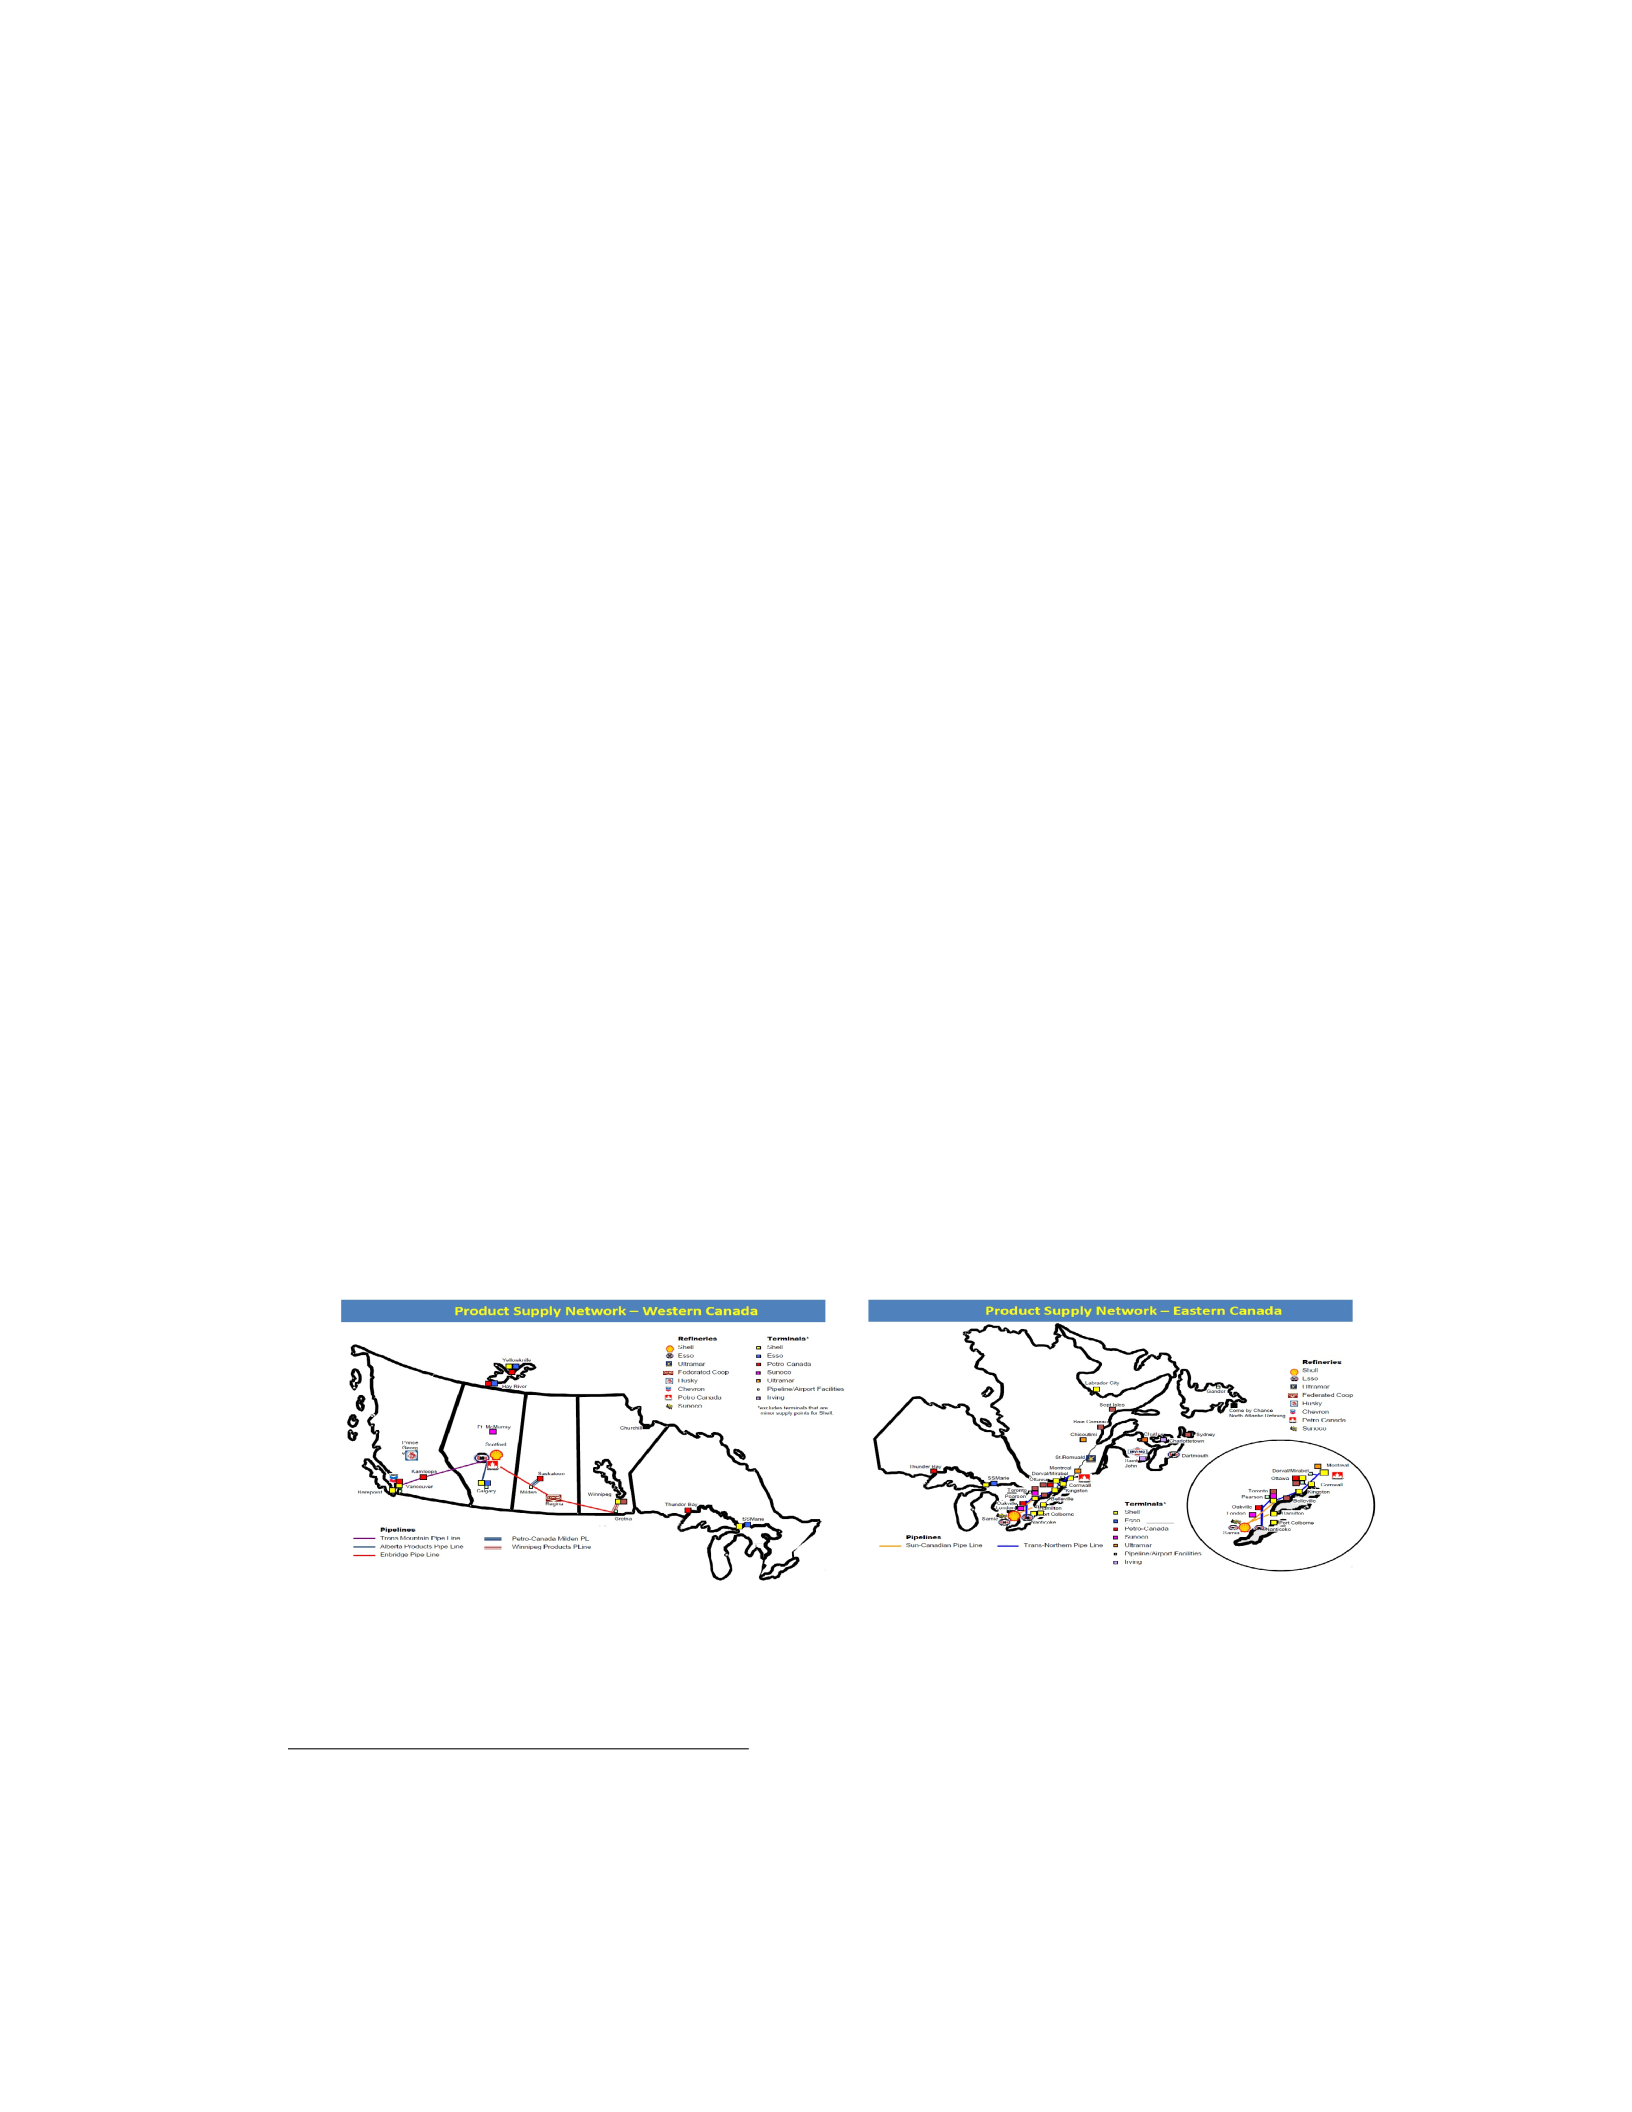
117
Northern Canada, with the remainder mainly occurring in offshore reserves
in the North Atlantic Ocean.8Crude oil is transported to refineries to be pro-
cessed into finished petroleum products via two primary methods: in Western
and Central Canada, where crude comes mainly from domestic production, this
occurs via pipeline; in the East and Quebec, where most crude comes from off-
shore reserves or imports, this occurs primarily via marine tanker.9This leads
to a natural division of Canadian cities into distinct supply regions: Western
Canada, Ontario, Quebec, and Atlantic Canada — in this chapter, I use the
term “regions” to refer to these 4 distinct supply regions of the Canadian gaso-
line market.
Once the crude oil is transported from the source, it is converted into fin-
ished oil products at one of 19 Canadian refineries, 16 of which produce finished
gasoline products, that are located in all Canadian provinces with the excep-
tions of PEI, Manitoba and the northern territories. The locations of these
refineries are shown in Figure 4.1.
Figure 4.1: North American Oil Pipeline Infrastructure
(a) Western Canada (b) Eastern Canada
8Energy Information Administration, United States Department of Energy, report in Oil
and Gas Journal, December 2011, available at: www.eia.doe.gov/oiaf/ieo/index.html.
9There are an estimated 250,000km of liquids pipeline infrastructure across Canada.
Source: Canadian Energy Pipeline Association.
118
Once refined, gasoline is shipped to regional terminals for distribution to
retail outlets. Shipping from refineries to terminals can occur by pipeline, ma-
rine tanker, rail or truck. Once delivered to terminals, the refined gasoline may
first receive additives to create unique blends that are specific to retail brands,
or be shipped directly to retail outlets, which is always done by truck. To take
advantage of economies of scale, retail brands often use the same terminals for
distribution to retail outlets, through reciprocal purchase agreements.10 This
minimizes total transportation costs for refined products, resulting in a rela-
tively small number of terminals supplying large geographic regions for any
number of distinct retail brands.
The supply network figures most prominently between the refinery and ter-
minal stages, where methods of transportation are most varied. Pipelines, fol-
lowed by ports, are more cost-effective than rail and truck, but are more limited
by geography and terrain. Although pipelines have the lowest per-unit ship-
ping cost, their construction is also the most expensive. Industry rule-of-thumb
suggests that it requires approximately 15–20 years of pipeline operation to re-
coup the fixed costs of building a pipeline.11
Since the methods of transportation and their associated costs are common
to all locations for most links in the supply network (crude to refinery, ter-
minal to final outlet), any variation in transportation costs between locations
10Source: Natural Resource Canada, Ibid.
11Source: Canadian Energy Pipeline Association.
119
can be assumed to be a function of the methods employed between refinery-
to-terminal across locations.12 Therefore in quantifying the impact of the sup-
ply network on price dispersion across locations, I use variation in the supply
network at the terminal-to-refinery stage, in conjunction with geographic dis-
tance, as a proxy for the transportation costs associated with supplying various
locations.
The Impact of the Supply Network on Price Dispersion
For some intuition as to why the supply network may impact price dispersion in
the gasoline market, consider two cities located Xkm apart that exhibit differ-
ent pre-tax gasoline prices. Any observed price difference theoretically reflects
the cost of arbitraging this price gap for potential suppliers. Suppliers would
need to find it profitable to purchase gasoline at the lower price location and
transport it to the higher price location for resale. However, the arbitrage op-
portunity depends on the existing supply network — the costs of transporting
bulk quantities will depend not just on the distance between the two locations,
but also on the available methods of transportation and their associated costs.
In my quantitative analysis, I supplement data on traditional measures of ge-
ographic distance between locations with data on supply network variables to
get an unbiased estimate of the quantitative impact of both distance and sup-
ply network variation on price dispersion across locations.
Pipelines are widely agreed to be the safest, quickest, and cheapest means of
transporting large quantities of gasoline products between locations. Although
12Due to the mostly partitioned aspect of the crude-to-refinery stage of the production pro-
cess, any difference between pipeline and seaport supply methods could be assumed to be
captured by regional effects between the West, Ontario and Quebec/Atlantic regions — these
divisions concur with the assertions made in the Natural Resources Canada report on gasoline
supply infrastructure that define these regions as natural “supply orbits”.

120
cost may vary depending on location, transporting oil products by pipeline
generally costs between $3–6 per barrel, and move at speeds between 5 and
20km/hr. Since pipelines are generally laid underground, they tend to follow
direct routes between locations and are largely indifferent to terrain. Once
pipelines are constructed connecting locations, they can be used with relatively
little cost of coordination, for large volumes of product — analogous to “flipping
a switch” and sending the products to their desired location. However, one
drawback of pipeline use is that the large capital and fixed costs associated
with their construction mean the limited number of existing pipelines are typ-
ically run at or near capacity and accommodating large increases in demand is
often difficult.
Conversely, consider the alternative of transportation by land, typically
done by rail for large volumes of product. Although freight train shipping is
typically faster once set in motion (roughly 30–35km/hr), the per-unit costs are
higher, typically between $10–15/barrel, and shipping routes may not be as
direct, historically following roadways, and are often impeded by the surround-
ing terrain. Additionally, it is estimated that the amount of oil product shipped
through pipelines on a daily basis in Canadian pipeline infrastructure would
require approximately 4200 rail cars to transport. Thus, setting up large ship-
ments by rail would be much more costly to arrange and would require a longer
time frame to organize than with pipelines, potentially missing opportunities
for arbitraging price differences. Similarly, shipping by marine tanker imposes
geographical limitations, requiring ports for both locations, and faces higher
variable costs and coordination time than shipping by pipeline.
Observed price gaps between two locations may therefore reflect differences
in the supply network: locations connected via pipeline may exhibit smaller
121
ceteris paribus price differences than those that are not, with similar effects
expected for locations connected by seaport, as opposed to land. For these rea-
sons, the supply network may be significant in determining what price gaps
can be sustained over short periods of time, reflected by weekly relative price
differences. However, over time, using mean price differences, the supply net-
work may not play as large a role as arbitrage opportunities may be reduced or
eliminated over time.
4.4 Data
Gasoline Price Data This paper uses a unique data set compiled from gaso-
line price data collected by the Kent Group, a downstream data collection and
marketing services firm.13 The Kent group performs weekly random surveys
of gas stations to produce a snapshot of city-level average retail prices across
Canada. The relevant data is compiled from weekly average price data for reg-
ular unleaded gasoline across a city-wide sampling of independent gas stations
located in 44 Canadian cities between January 2001 and May 2017. Together
they comprise 905 weeks of observations for a total of 39,820 independent city-
average retail price observations.
Since this paper investigates the role of the supply network on price disper-
sion across locations, I examine pre-tax price data, controlling for variation in
provincial and municipal gasoline taxes, to identify the price that would actu-
ally be received by suppliers, which governs the arbitrage condition. Summary
statistics for the pre-tax price data at the national, as well as regional levels
can be found in Table 4.1. The four regions correspond to the natural divisions
suggested by the structure of the supply network. There is large variation at
13Available at http://www.kentmarketingservices.com/dnn/PetroleumPriceData.aspx.
122
the national level, with weekly pre-tax prices ranging from 14 ¢/L up to 128.5
¢/L between 2001 and 2015, with a mean price of 67 ¢/L. The mean and stan-
dard deviation are consistent across the various regions, with the West typ-
ically exhibiting the highest mean prices and largest min-max spread, while
the Atlantic region exhibits the smallest min-max spread.
Table 4.1: Pre-tax Weekly Unleaded Gasoline prices
Summary Statistics
(¢/L)
Region Mean Std. Dev. Min Max Median
Canada 67.4 19.2 14.1 128.5 67.4
West 70.0 19.7 14.1 128.5 70.2
Ontario 65.8 19.2 20.9 113.5 66.4
Quebec 65.6 18.8 23.5 112.3 65.8
Atlantic 66.2 18.3 27.2 108.7 66.2
This retail price data is consistent with data collected by Statistics Canada,
with the added benefit of more frequent observations (weekly rather than monthly)
which allows for a more accurate accounting of responses to price gaps that
arise (and may disappear) between locations across shorter periods of time.
Further the 44 cities in this data set (as opposed to the 18 in the StatsCan
data) cover a more geographically diverse set of locations across Canada, and
include more variation in the available supply network between locations, al-
lowing for a stronger analysis of the impact of the supply network on price
dispersion in the Canadian gasoline market.
4.4.1 Descriptive Statistics from Pre-Tax Data
The data provides several key insights into pricing behaviour. Pre-tax prices
are highly correlated across cities, both in price levels and, to a lesser extent,
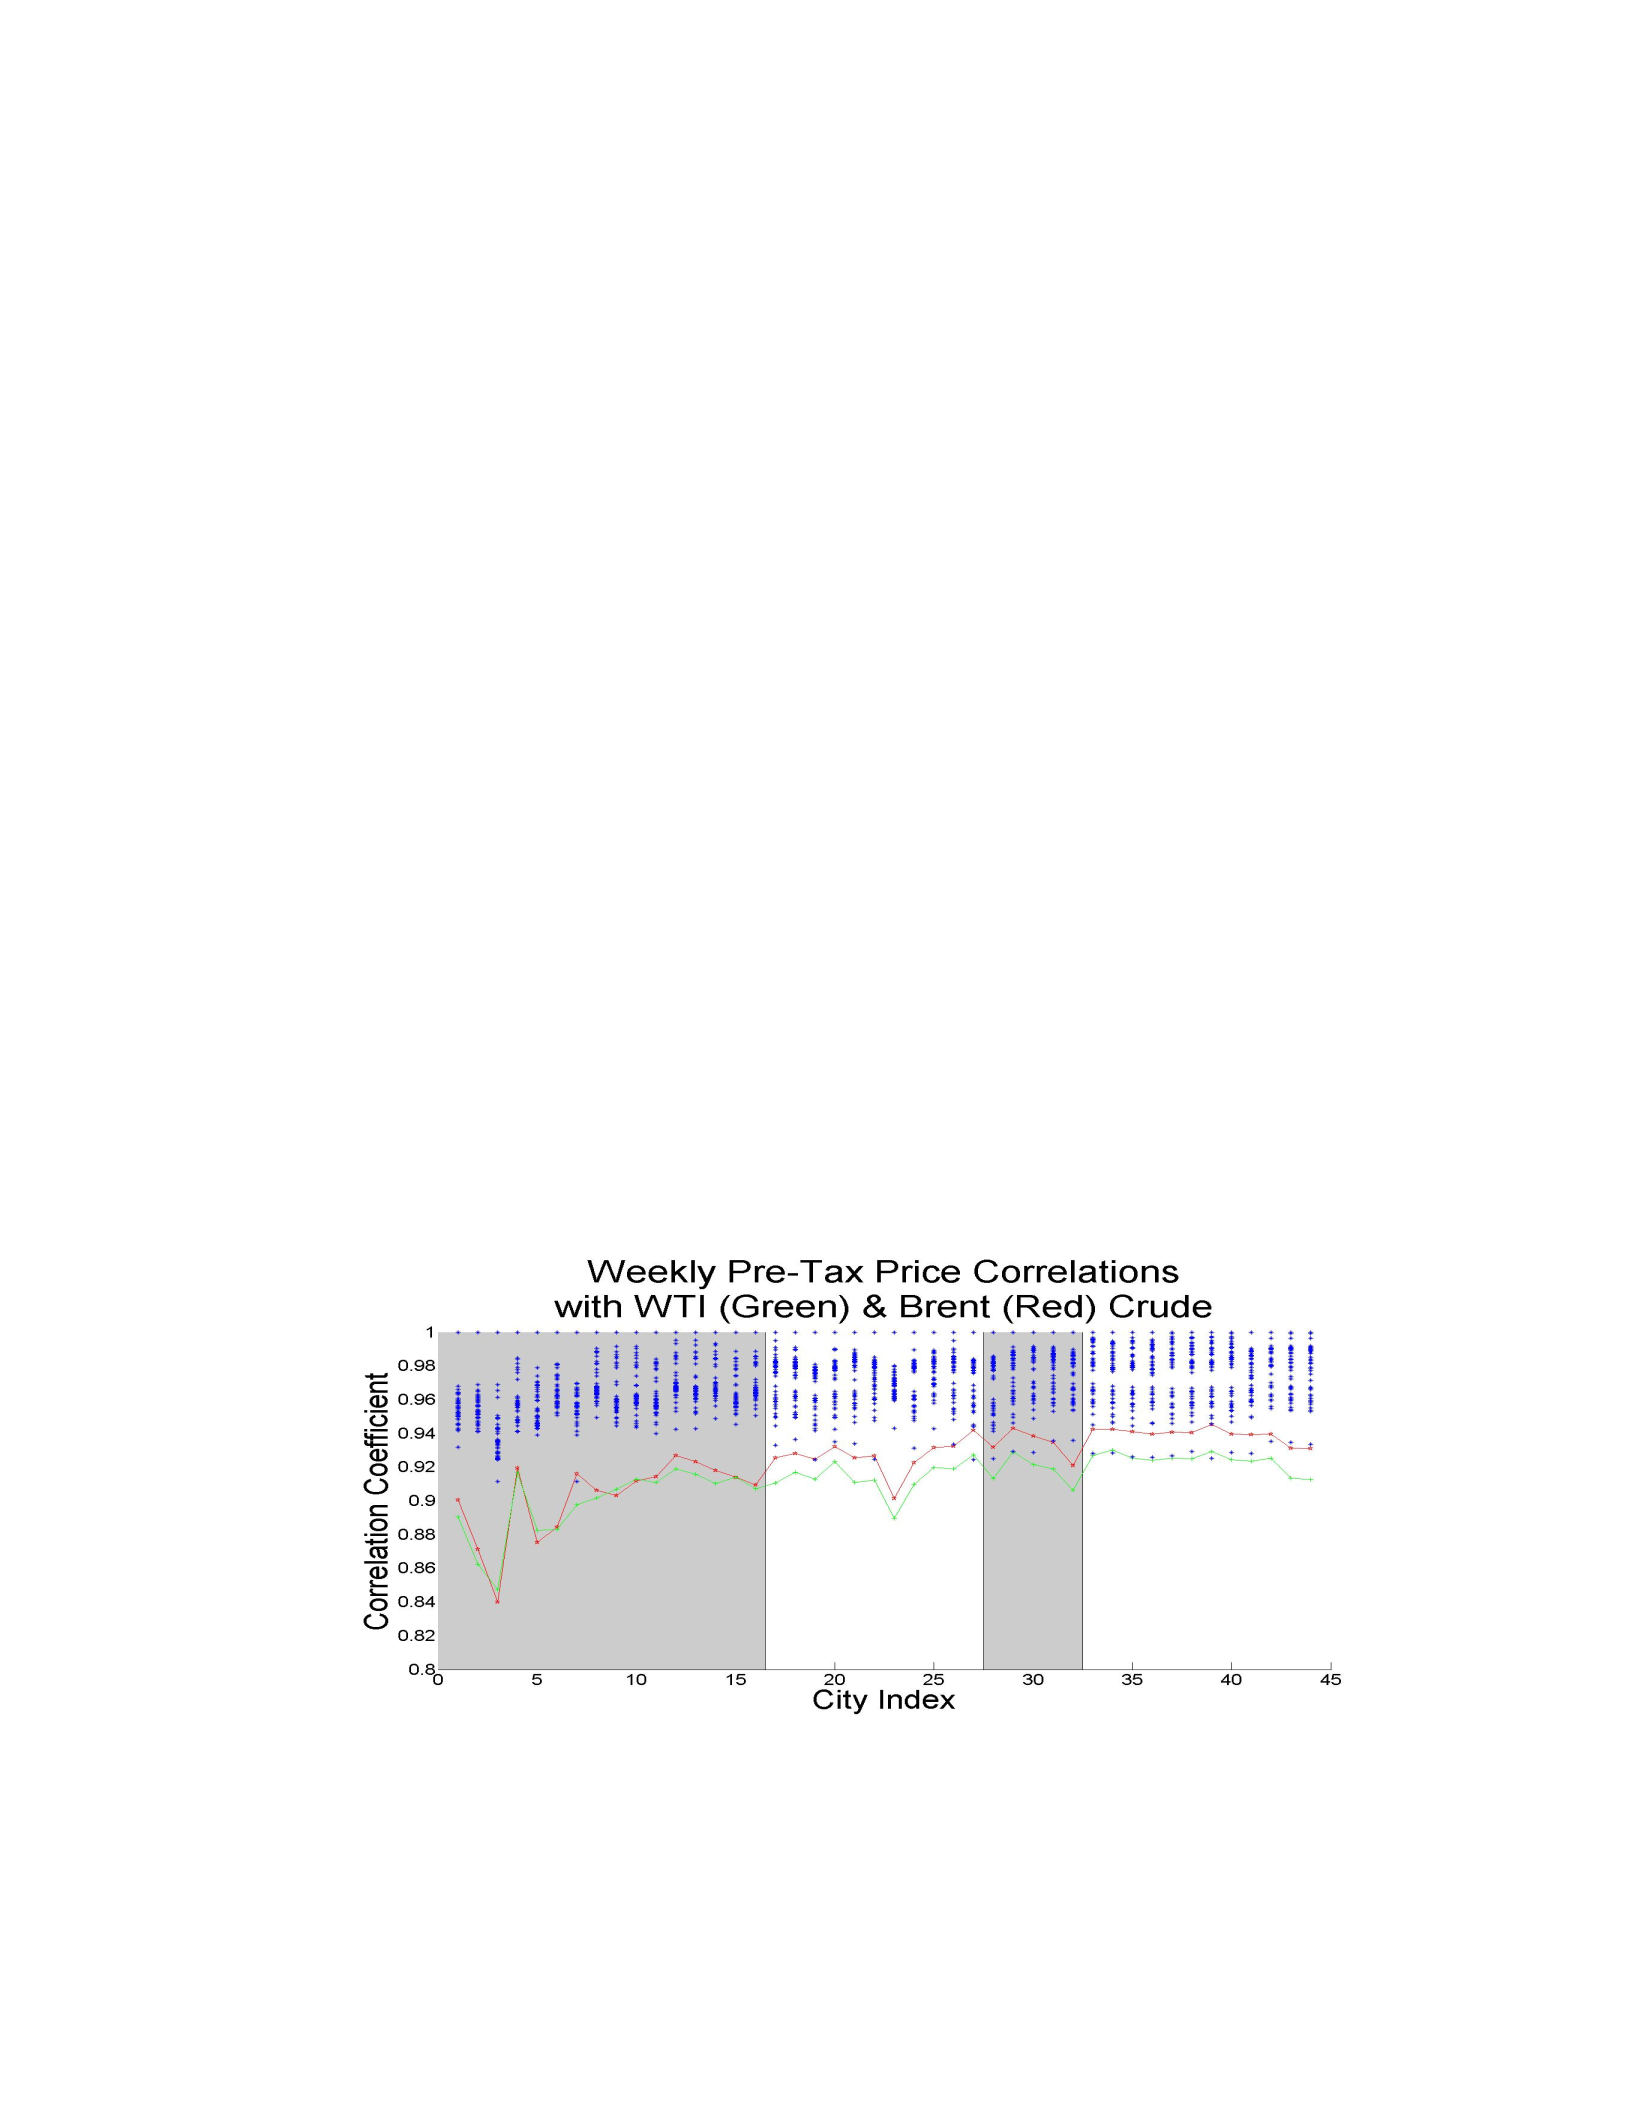
123
changes in price. These correlations are strongest between cities within supply
regions, which also exhibit smaller mean-price differences than inter-regional
city-pairs. Relative prices change little across cities and variation across loca-
tions is small and stable.
1a. Pre-tax prices are highly correlated across locations
Over the 17 year period spanned by the data, pre-tax gasoline prices are highly
correlated for all city-pairs. Figure 4.2 shows that most correlation coefficients
for city-pairs are above 0.95, and all are above 0.90, indicating a high level
of correlation in weekly prices over time. These prices are even more highly
correlated across city-pairs than they are with crude oil prices, both with Brent
crude, which is typically used as a price gauge in Eastern and Central Canada,
as well as with West Texas Intermediate (WTI), which is used more in the
United States and Western Canada.
Figure 4.2: Weekly Price Correlations: Levels
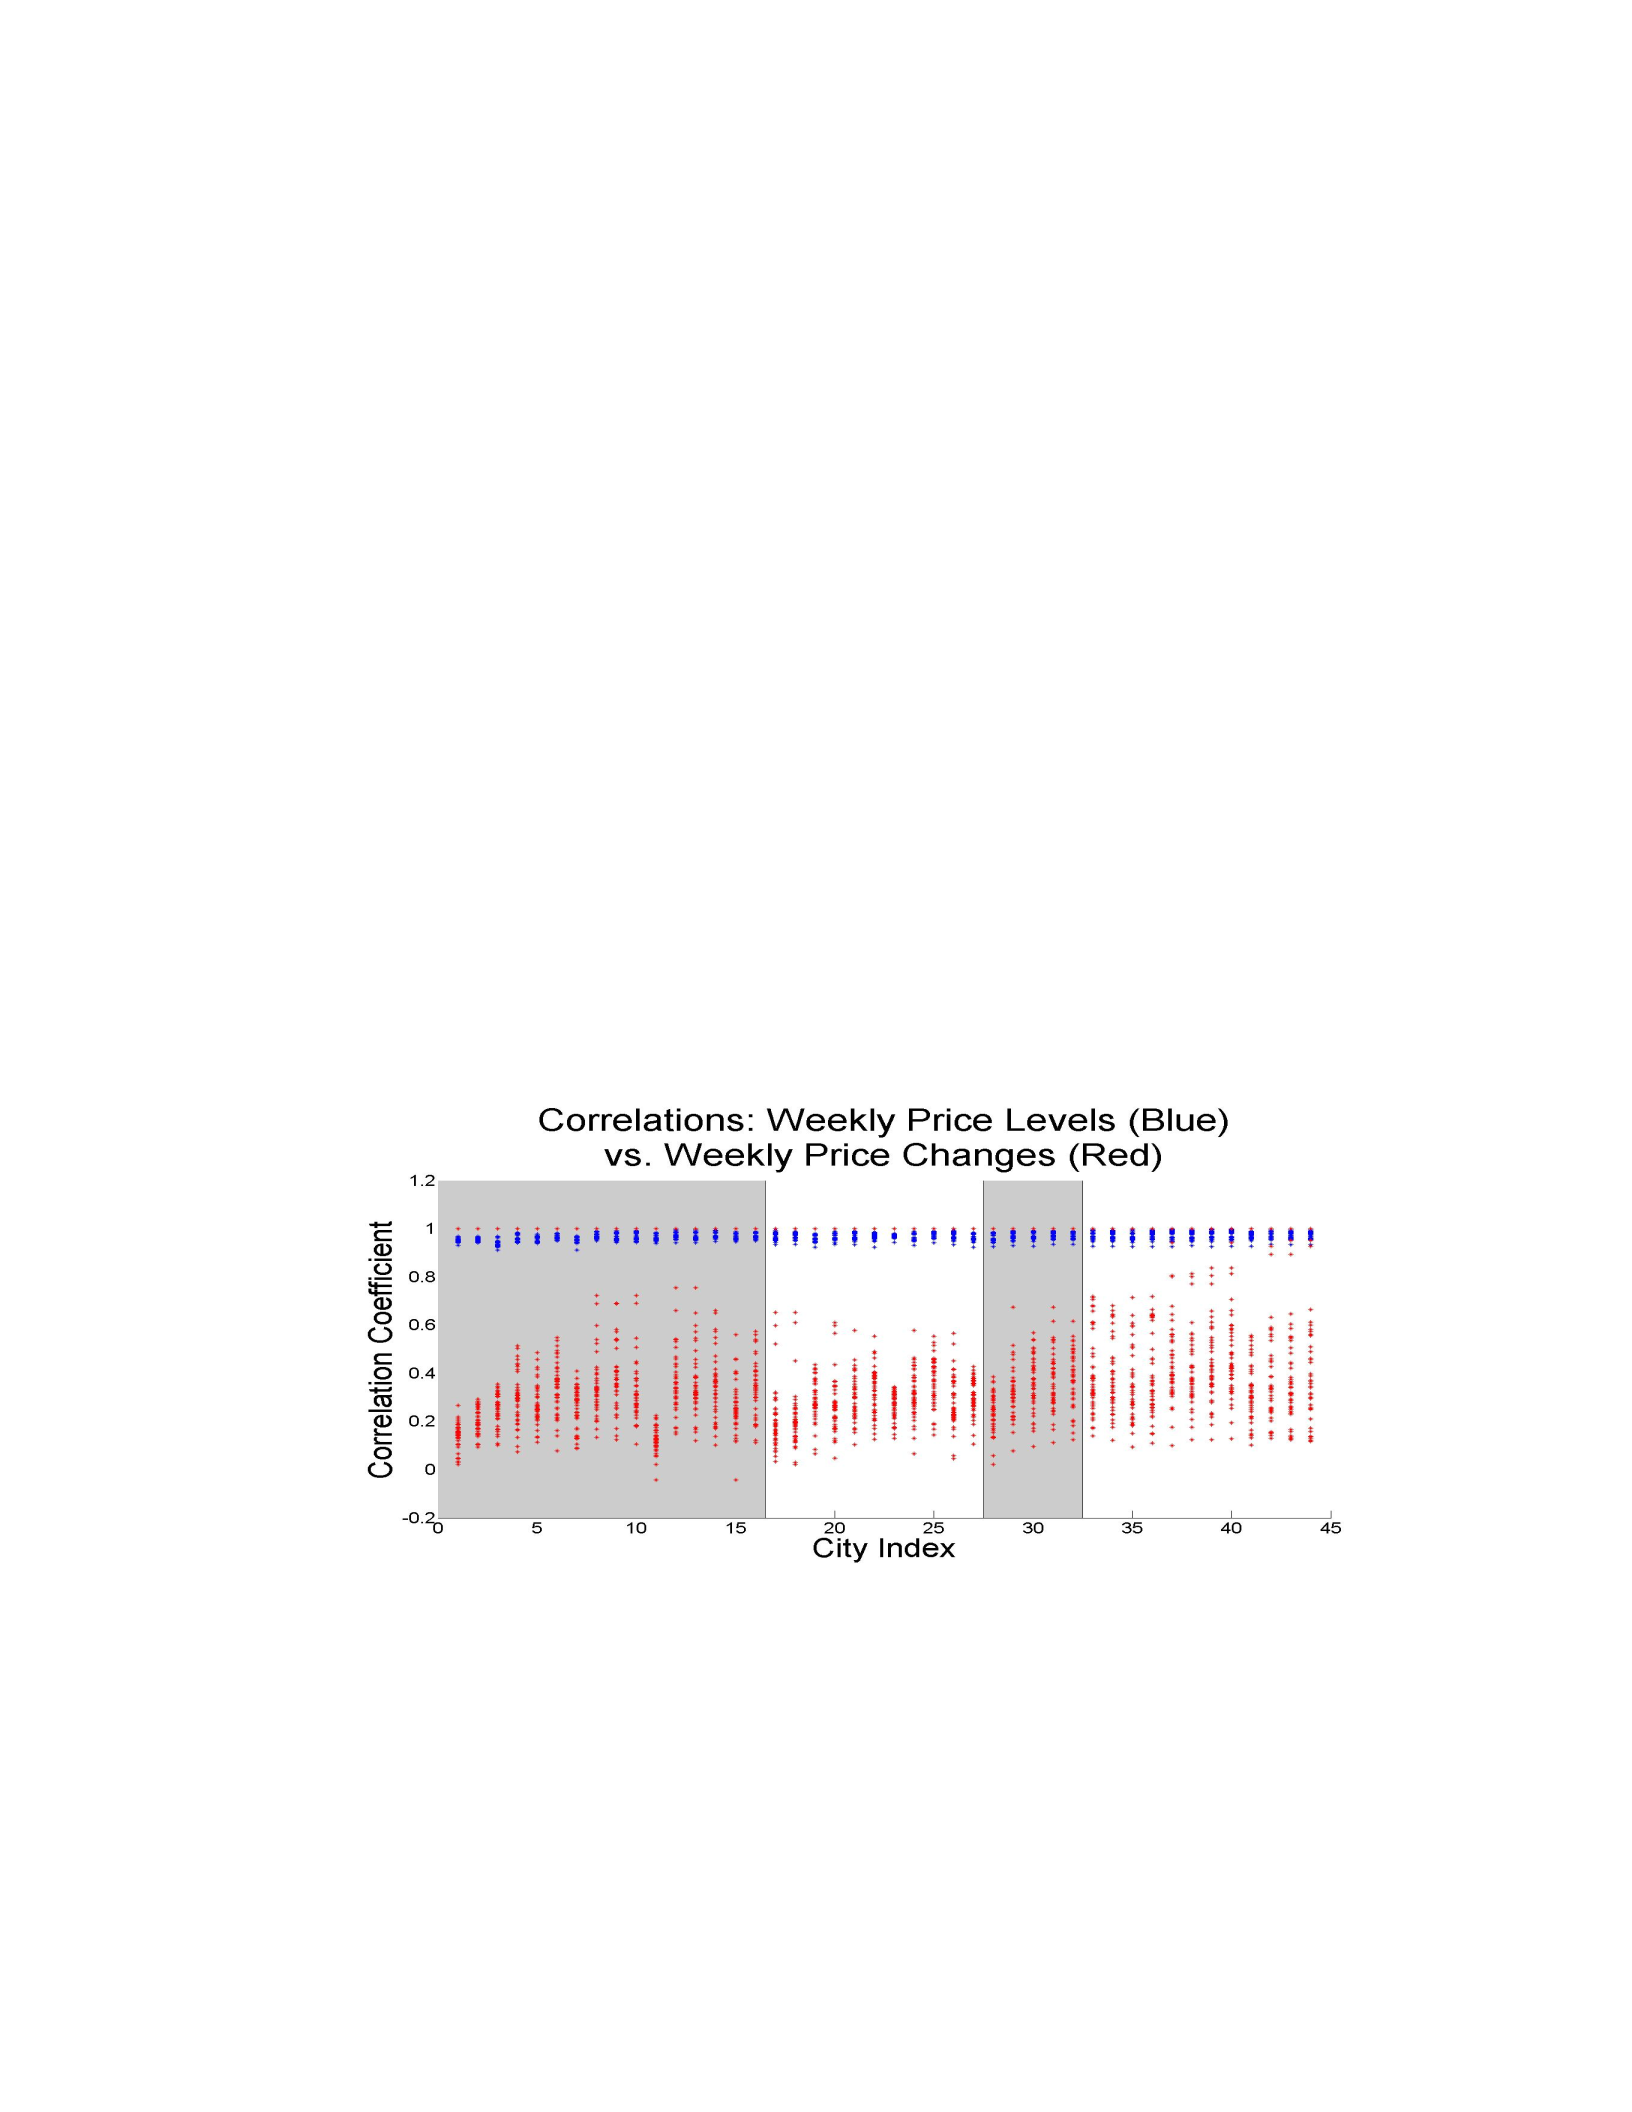
124
1b. Pre-tax price changes are less highly correlated across locations
Though the pre-tax prices exhibit high correlations across locations, the changes
in weekly pre-tax prices are less highly correlated. Figure 4.3 plots the corre-
lation coefficients for all city-pairs for the change in the pre-tax price from the
previous week’s value. These correlations, most of which are in the range of
0.15–0.60, are smaller than those of the price levels (0.90–0.99). This discrep-
ancy between the high level of correlations between price levels and the lower
level of correlation between price changes raises questions about the responses
of retail prices to shocks across locations. Differences in market size, location-
specific demand shocks, or variation in the available supply network may be
significant in accounting for these retail price movements.
Figure 4.3: Weekly Price Correlations: Weekly Changes
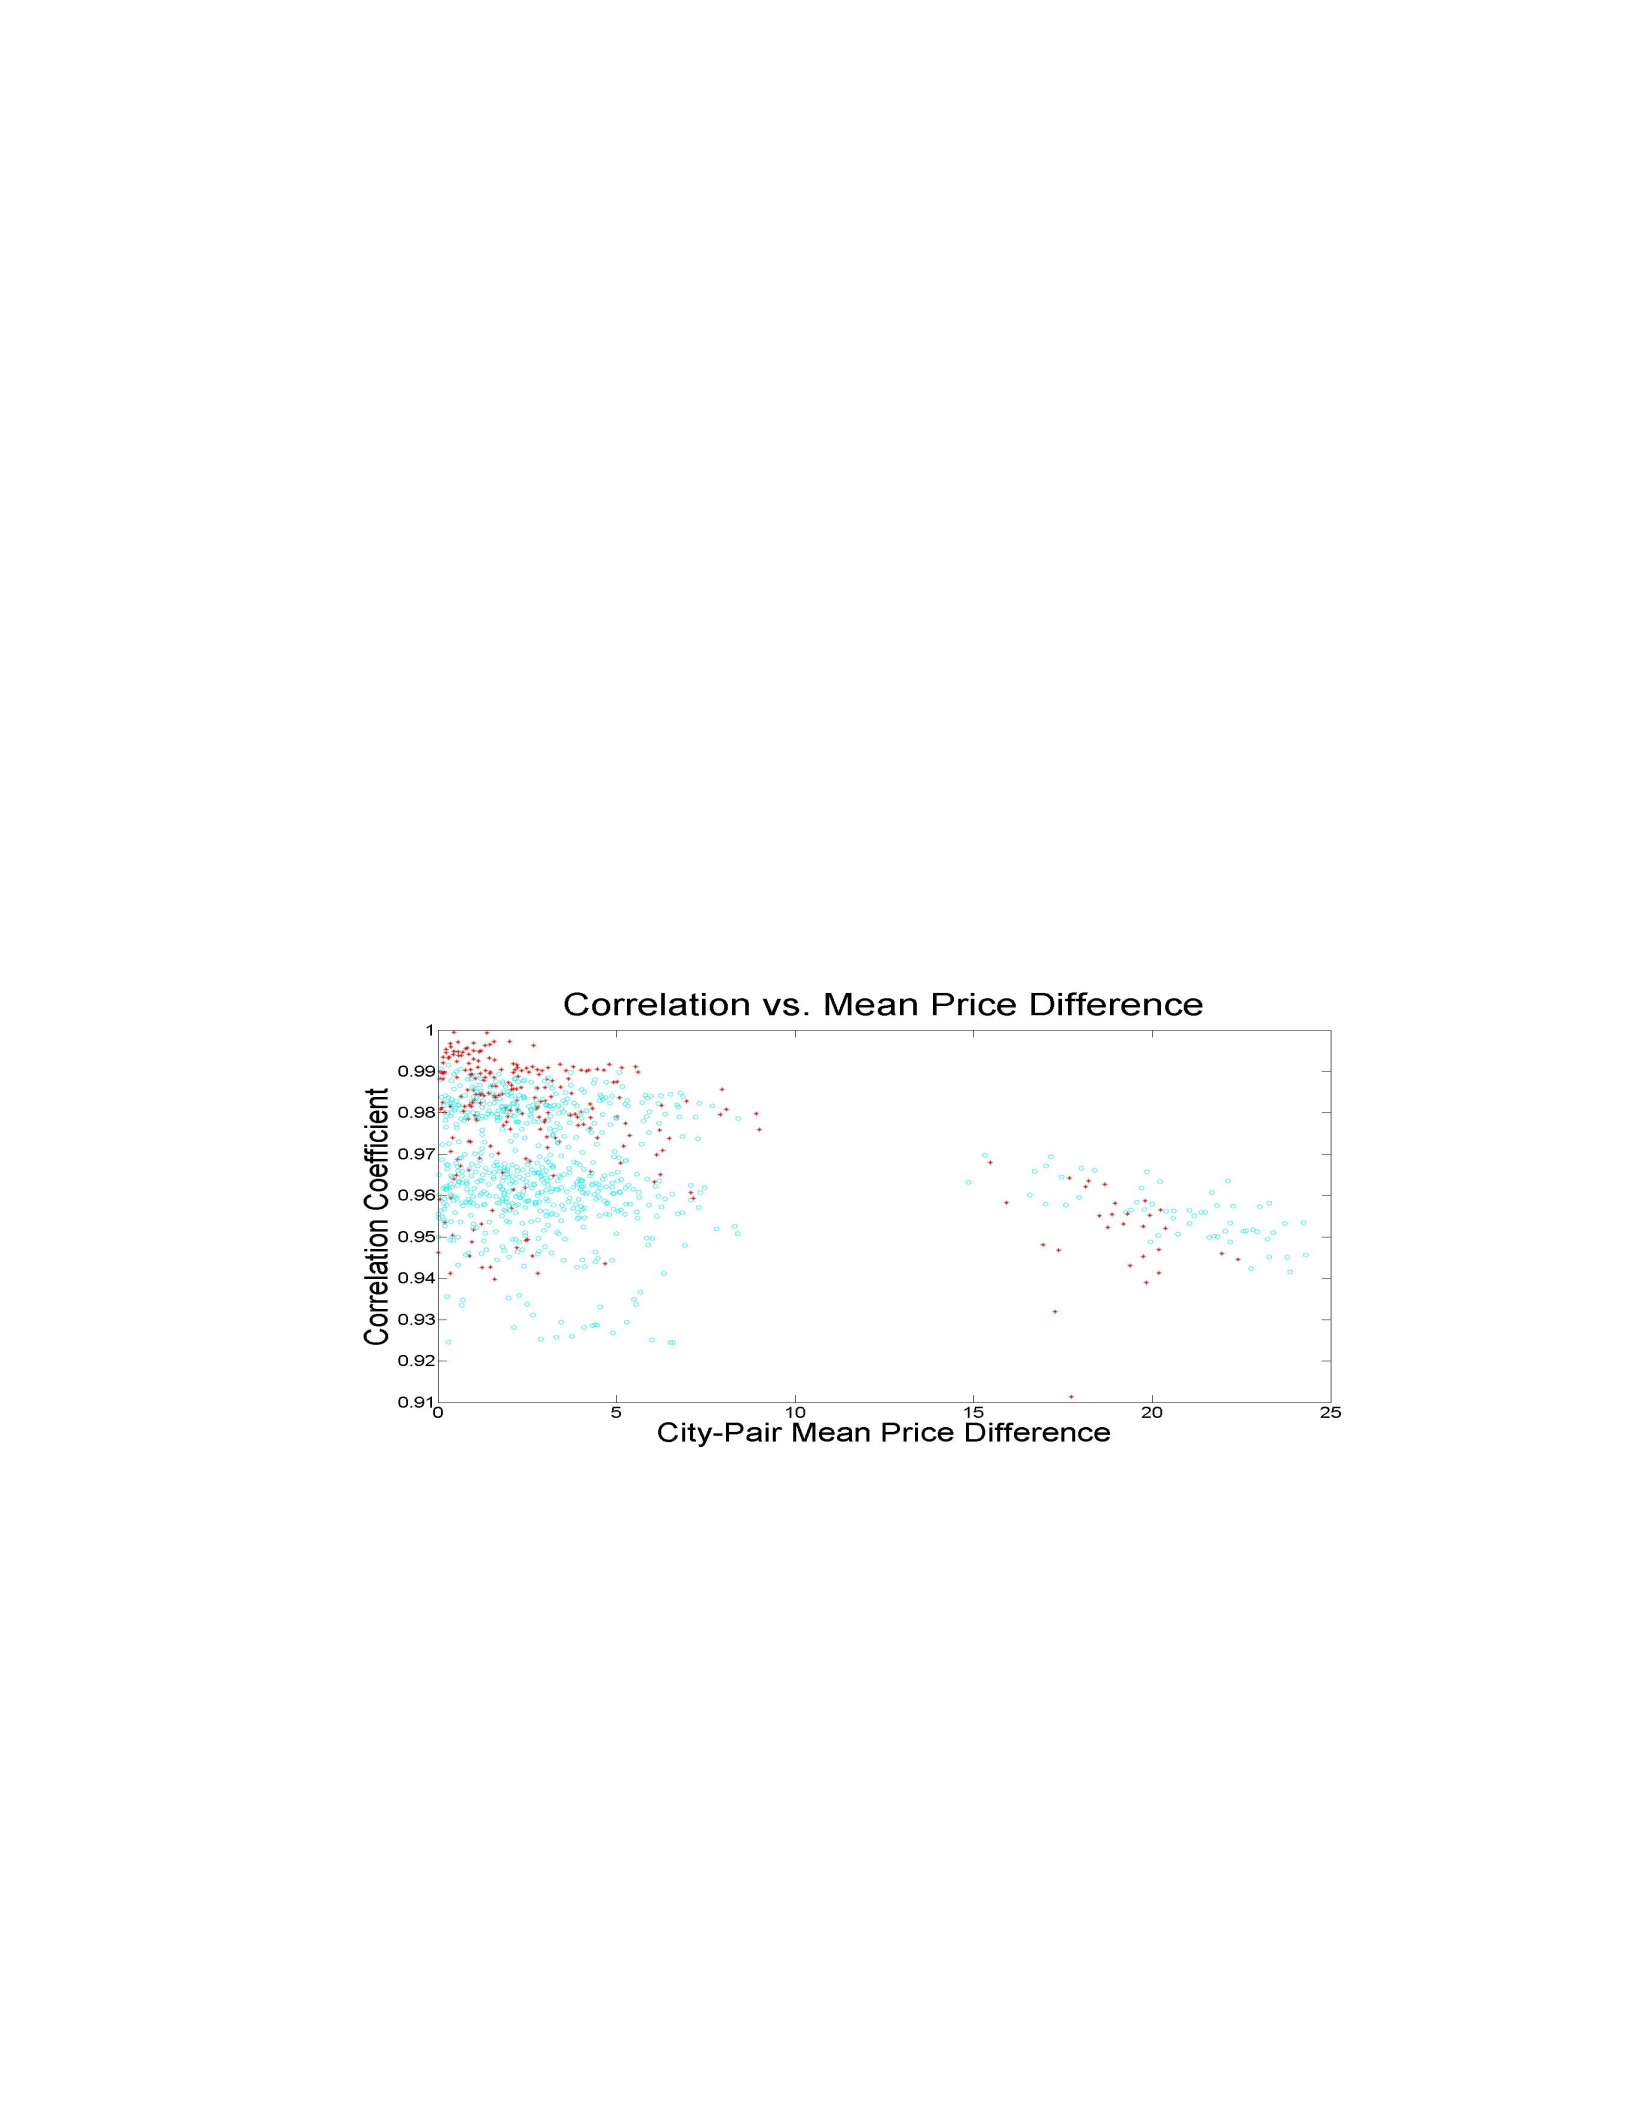
125
2a. Intraregional pre-tax prices are more highly correlated
Pre-tax prices are more highly correlated for city-pairs within the same region
than for interregional pairs. In Figure 4.4, all city-pairs display high correla-
tion coefficients, above 0.90; however, while most intraregional city-pairs, seen
in red, have coefficients between 0.96 and 0.99, the majority of interregional
correlation coefficients, seen in blue, are generally lower, falling between 0.94
and 0.98. This property holds within each of the four regions across Canada,
with intraregional city-pairs displaying higher correlations than interregional
pairs.
Figure 4.4: Retail Price Correlations vs. Mean Price Differences: National
2b. Intraregional pre-tax prices exhibit smaller mean-price differences
Intraregional city-pairs also exhibit a smaller mean price difference than in-
terregional pairs, regardless of the Canadian region in which they occur. With
the notable exception of a grouping of points from city-pairs involving White-
horse or Yellowknife (which may potentially be outliers due to their northern

126
isolation), most intraregional city-pairs exhibit lower mean-price differences,
in the range of 0–5 ¢/L differences. Although many interregional city-pairs
also exhibit low mean-price differences in this range, a larger proportion of in-
terregional pairings display differences in the range of 5–10 ¢/L. This property
is true within each region as well. These findings reinforce the relevance of
regional effects in accounting for retail price dispersion.
3. Coefficient of variation for pre-tax prices is small and stable
Pre-tax prices display a level of variation across Canada that remains small
and stable over time. The coefficient of variation for weekly pre-tax prices lies
in the range from 0.04 to 0.20 over the span of January 2001 to May 2017, the
majority of which occur below 0.10, and exhibits few large changes. Figure 4.5
shows that as the mean national price changes and trends higher over time,
the coefficient of variation remains small, reflecting a fairly stable relationship
of prices across the country over time. Notable is the increase in mean prices
during the crisis of 2008 (around week 400), with correspondingly low varia-
tion, and the ensuing spike in the coefficient of variation as the mean prices
finally decreased in late 2008, indicative of national prices rising symmetri-
cally, but declining at different rates in the ensuing periods. Across regions,
the coefficient of variation is consistently low and stable.
4. Minimum and maximum prices’ location rarely changes
Although weekly gasoline prices across Canada change frequently for each city,
the location of the minimum and maximum weekly prices across Canada rarely
changes. Over the 905 week period spanned by the data, only 3 of the 44 differ-
ent cities assume the place of maximum pre-tax price, with the vast majority
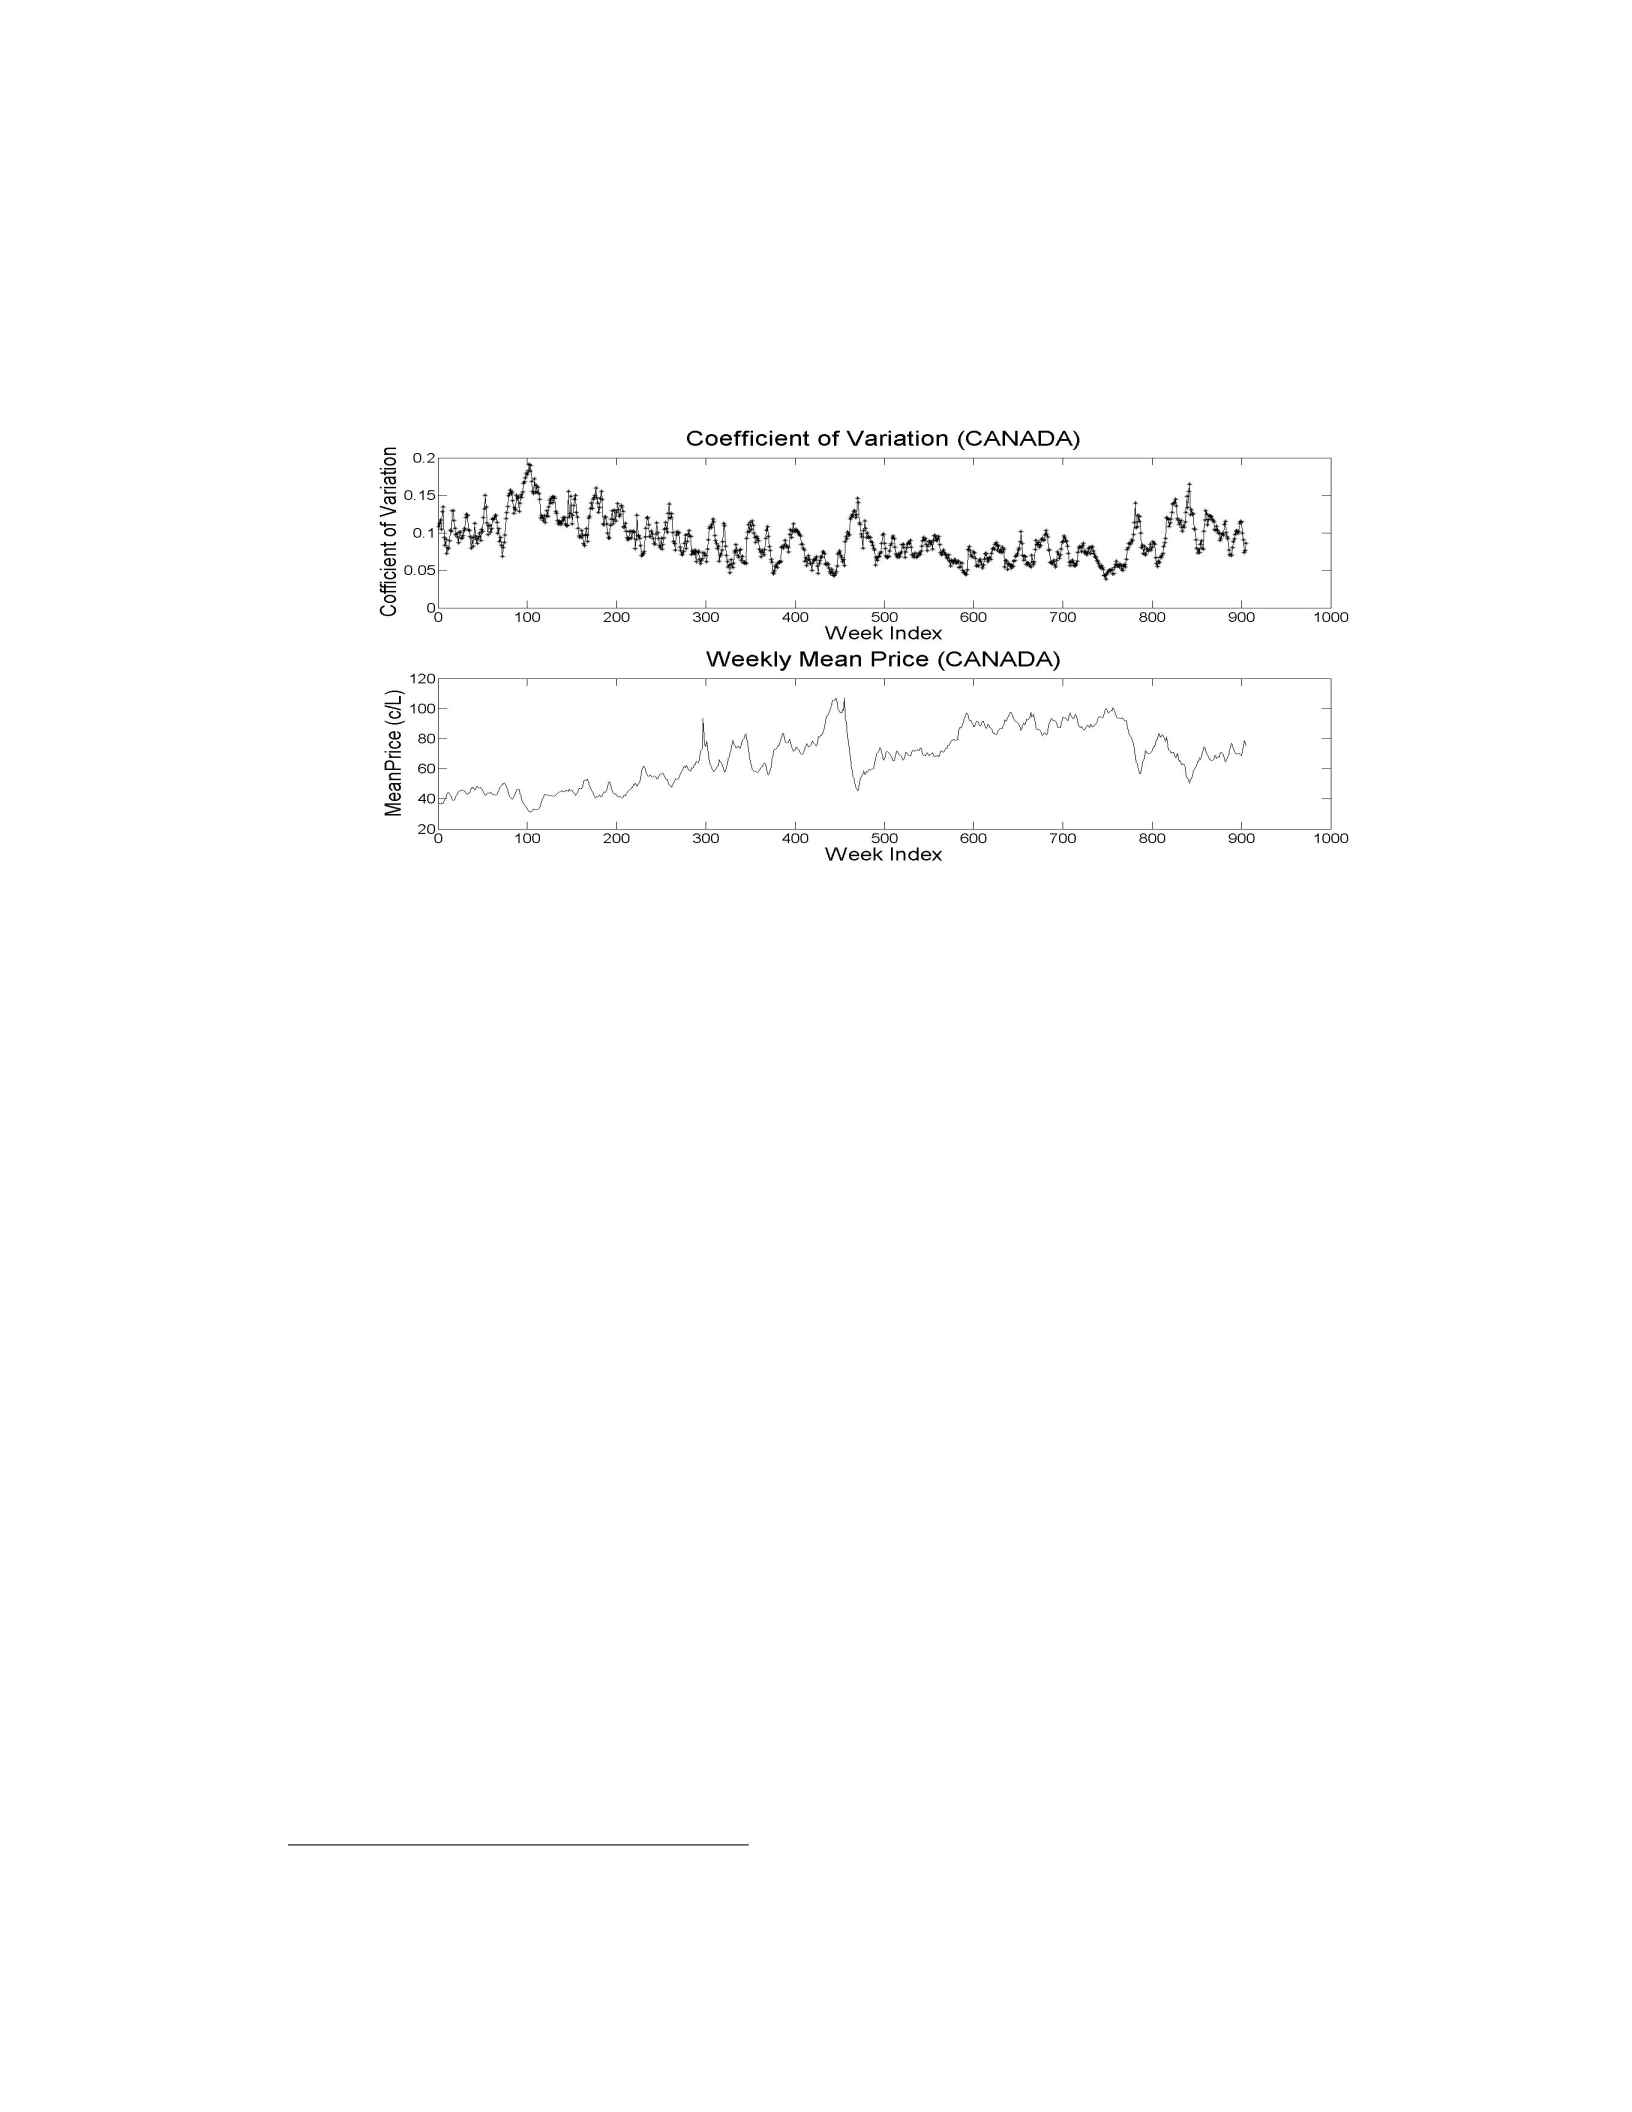
127
Figure 4.5: Coefficient of Variation: National
of these occurrences being split between the two most geographically isolated
cities, Yellowknife, NWT., and Whitehorse, YK.14 The location of the minimum
pre-tax price changes more frequently than the maximum, but a small number
of cities, such as Windsor, Quebec City, Montreal, Ottawa, Edmonton and Van-
couver, account for the majority of minimum weekly prices. The histogram in
Figure 4.6 plots the frequency of these occurrences.
The minimum and maximum weekly pre-tax prices also follow a stable re-
lationship with the mean weekly price. The maximum price typically falls in
a range of 120–150% of that of the mean national price, while the minimum
price falls in the range of 75–90% of the mean national price, as seen in the top
panel of Figure 4.7. This leads to a steady min-max spread that resides mainly
between 30–70% of the mean price, as shown in the bottom panel of Figure 4.7.
14Corner Brook, NL accounts for the maximum price in only a few weeks.
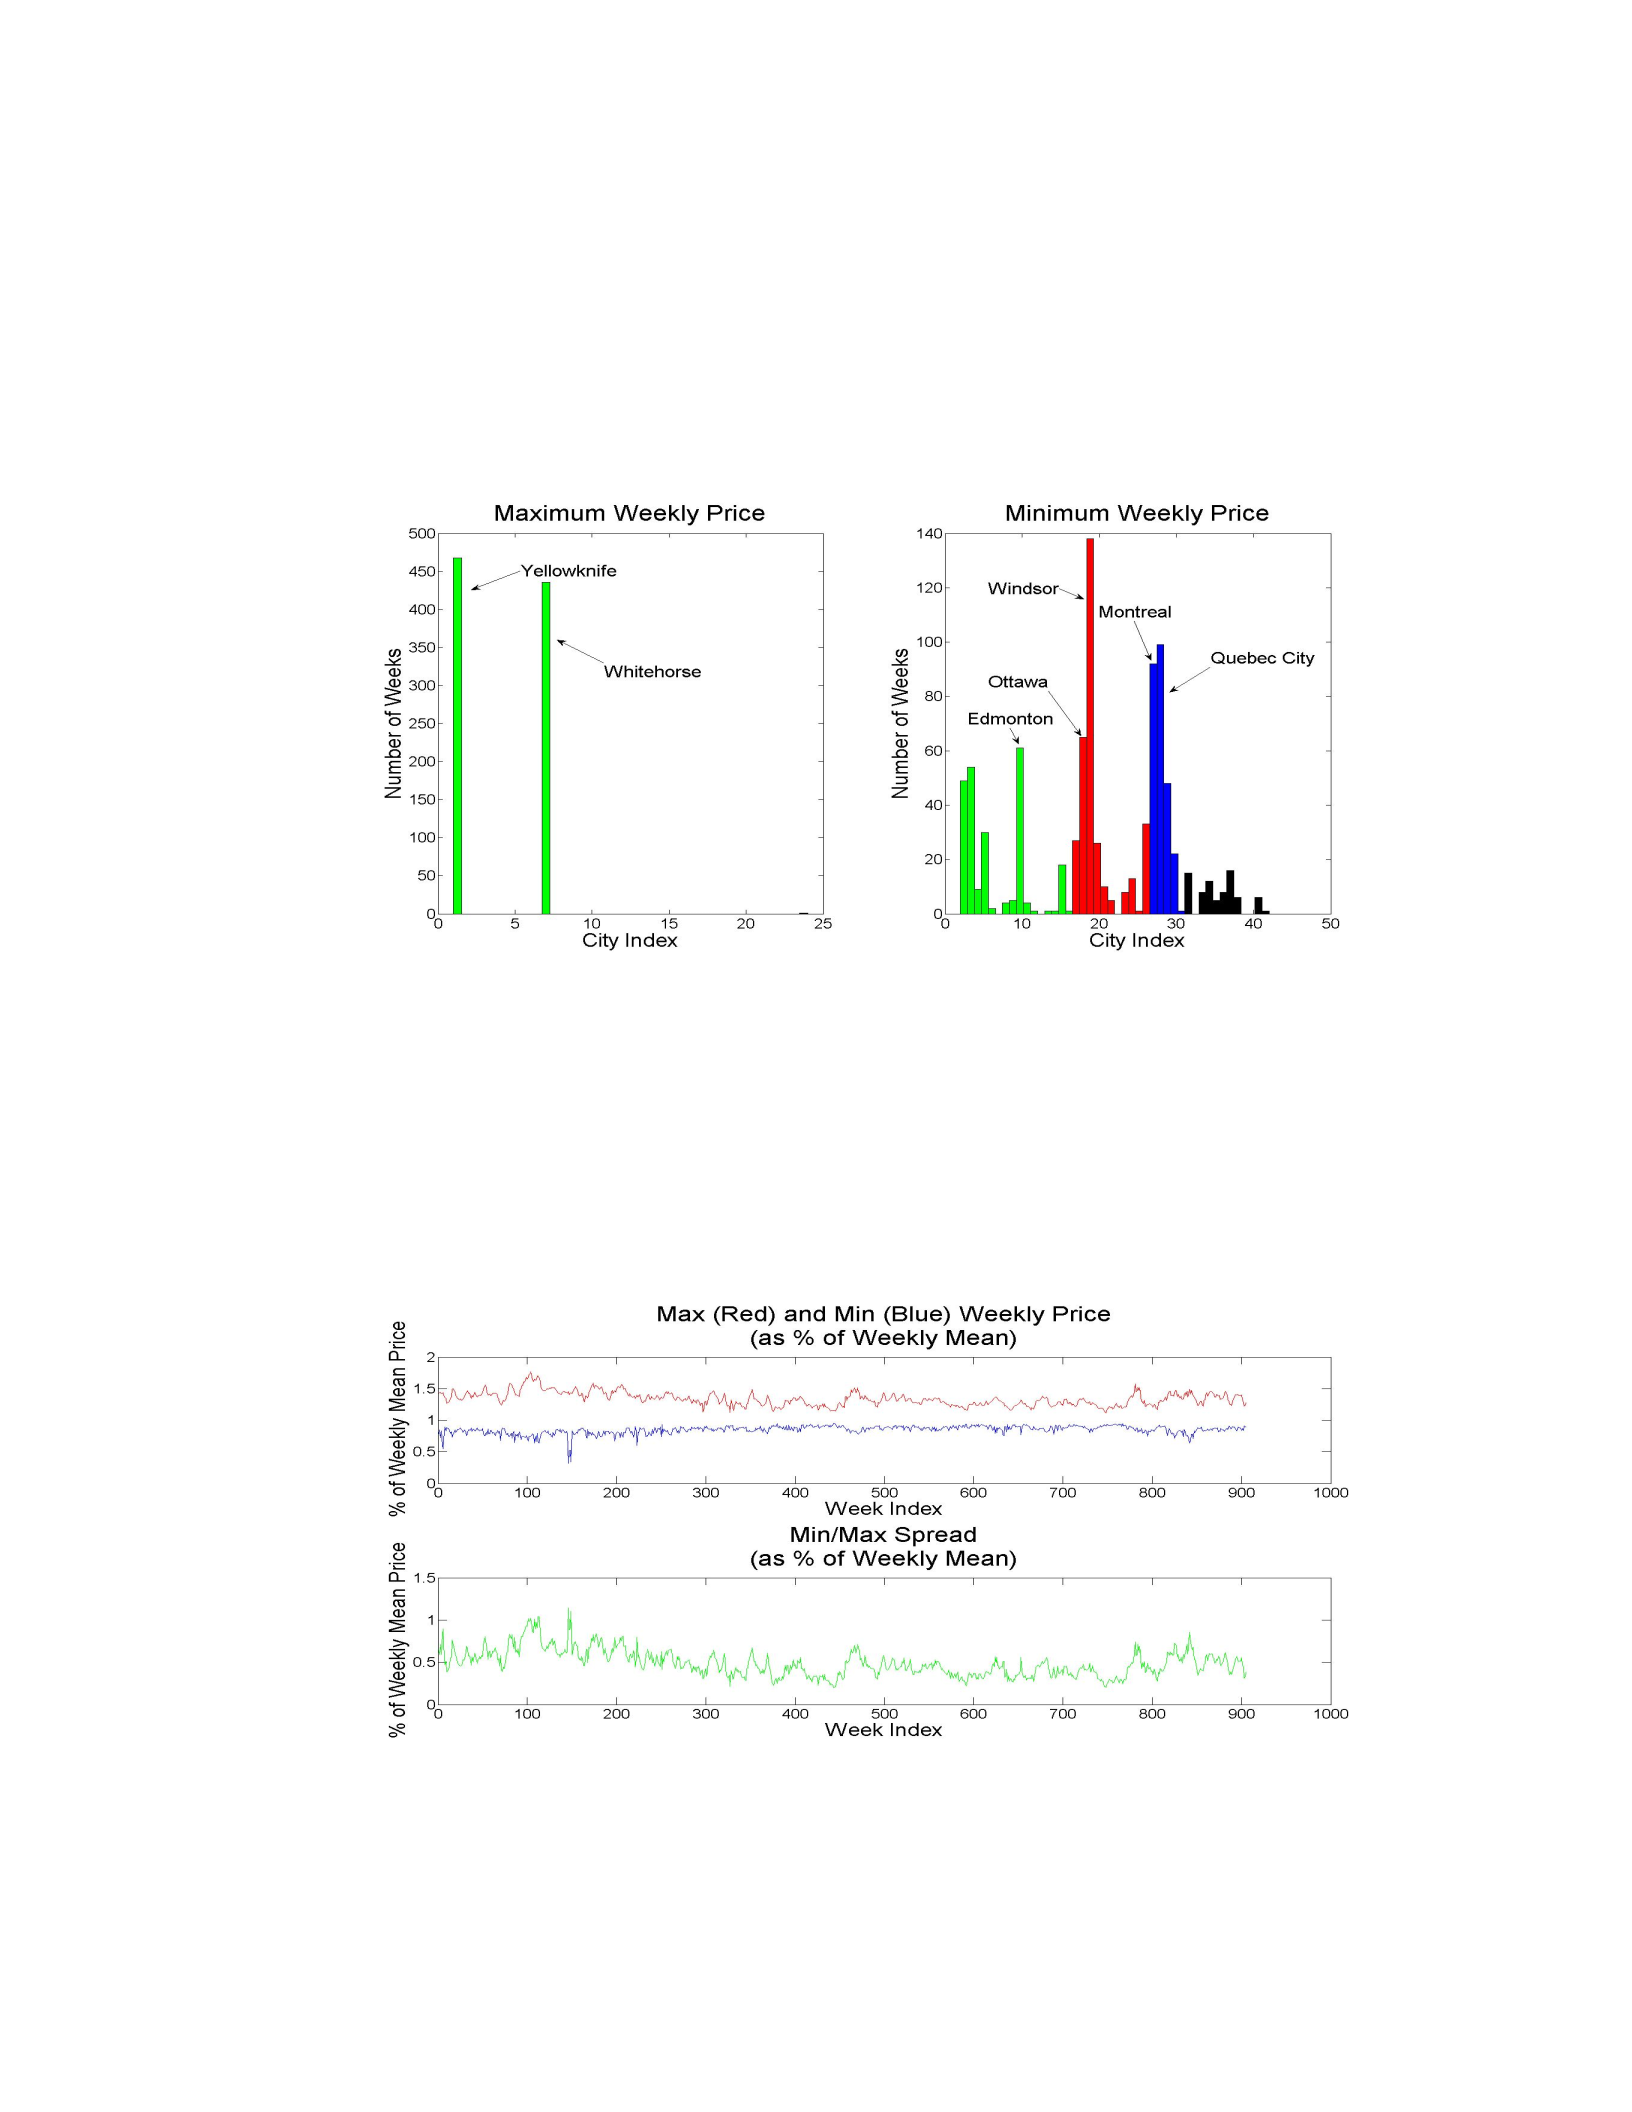
128
Figure 4.6: Max/Min histogram
Figure 4.7: Min/Max spread and Mean Price
129
4.5 Empirical Analysis
I use regression analysis to quantify the impact of the structure of the sup-
ply network, as well as other explanatory variables, on price dispersion across
Canadian cities. I regress measures of mean and weekly relative prices across
Canadian cities on explanatory variables such as distance, region and market
size, and also include supply network variables — specifically, I use dummy
variables for the existence of a pipeline or seaport connection linking locations,
as well as distances from each city to the closest supply terminal.15
Testing for Stationarity
To determine how the supply network and other explanatory variables impact
price dispersion across locations over time, I follow the literature on Law-of-
One-Price (LOP) deviations and test for stationarity in the weekly price data
for each city, as well as relative prices between city-pairs, to rule out long-run
convergence to parity of prices across locations.16 I use a standard Dickey-
Fuller test of the AR(1) process with constant and time trend, of the form
∆Pjt =α0+α1t+δPjt−1+ut(4.1)
Table 4.2 shows that the null hypothesis of a unit root (δ= 0) can be rejected
at the 95% confidence level for 19 of the 44 Canadian cities. I find that the more
geographically isolated a city, the more likely is its weekly price data to be non-
stationary — for example, northern cities such as Yellowknife, Whitehorse,
many prairie cities and all of the Atlantic cities appear to be non-stationary,
15Source for terminal distance data: http://www.essomaps.ca/terminals.
16For example, see Ceglowski (2003) or Parsley and Wei(1996).

130
while most of Ontario and Quebec, as well as large Western cities like Vancou-
ver and Victoria, appear to be stationary.
However, since the arbitrage opportunity is a function of the relative price
between cities, I also test the time series of weekly relative prices across all
city-pairs for stationarity. For each city-pair, ij, I test the AR(1) process of the
form
∆|log(Pit)−log(Pjt)|=α0+α1t+δ|log(Pit−1)−log(Pjt−1)|+ut(4.2)
With 44 Canadian city-pairs, I find that all 946 possible relative price se-
ries can reject the null hypothesis of a unit root at the 99% confidence level.
This indicates that while each individual city’s price series may or may not be
stationary over time, the high degree of correlation between city-pair prices
generates a stationary time series for each potential weekly relative price se-
ries. This result suggests that OLS regression, using weekly relative prices
as the dependent variable is suitable for quantifying the impact of the supply
network on price dispersion across locations.
131
Table 4.2: Testing for Stationarity of Time-Series Data
Stationary at the X% confidence level?
99% 95% 99% 95%
WEST Region
Whitehorse No No Red Deer No No
Vancouver Yes Yes Edmonton No Yes
Victoria Yes Yes Lethbridge No Yes
Prince George No No Regina No No
Kamloops No Yes Saskatoon No No
Kelowna No No Prince George No No
Yellowknife No No Winnipeg No No
Calgary No Yes Brandon No No
ONTARIO Region
Toronto Yes Yes Thunder Bay No Yes
Ottawa No Yes North Bay Yes Yes
Windsor Yes Yes Timmons No No
London No Yes Hamilton No Yes
Sudbury Yes Yes St. Catherines No Yes
Sault Ste. Marie No Yes
QUEBEC Region
Montreal Yes Yes Gaspe No No
Quebec City No Yes Chicoutimi No Yes
Sherbrooke No No
ATLANTIC Region
Saint John No No Yarmouth No No
Fredericton No No Truro No No
Moncton No No Charlottetown No No
Bathurst No No St. Johns No No
Halifax No No Gander No No
Sydney No No Cornerbrook No No
132
Empirical Approach
To quantify the impact of the supply network on pre-tax gasoline price disper-
sion across Canadian cities, I use OLS regressions with two different measures
of price dispersion between city iand city jas the dependent variable:
1. The absolute mean-price difference between city-pairs, |log(¯
Pi)−log(¯
Pj)|.
2. The weekly relative price between cities, |log(Pit)−log(Pjt)|.
These measures capture different aspects of price dispersion across locations:
mean city-pair differences examine systemic price variation across cities, while
weekly relative prices examine how prices move and react to shocks differently
across locations.
The explanatory variables include measures of distance, market size, and
supply network variables. For each city-pair, distance is measured as the
shortest driving route (in thousands of kilometres) between the two cities,
distij .17 This measure highlights the distinction between transporting prod-
ucts by pipeline and sea versus the default alternative of land routes used by
train and truck, which may impose geographical limitations. Market size vari-
ables include a regional dummy, Regij , which takes the value of 1 if both cities
are in the same region (as defined by the supply network regions) and zero oth-
erwise, and two population measures, popij . The first measure is the difference
in population between city-pairs, |totpopi−totpopj|.18 The second measure is the
difference in population density between city-pairs, |densi−densj|, measured
as population per square kilometer, in order to control for rural and urban
17See Appendix C.1 for a detailed discussion of data measures.
18The population measured used here is the population within city limits, as measured by
Statistics Canada.
133
differences such as land prices that may be passed-through to pre-tax gasoline
prices. The supply network variables include two dummy variables for pipeline
connection, P ipeij , and seaport connection, Seaij , which are set to 1 if the two
cities share a pipeline connection or traversable seaports, respectively, and zero
otherwise. 19 Finally, the variable termij represents the difference between the
distance to the closest supply terminal for the two cities.20
With yrepresenting one of the two dependent variables, the regression spec-
ification is then:
y=α+βlog (distij )+γRegij +δP ipeij +λSeaij +θlog (popij )+ψlog(termij )+ij (4.3)
All non-dummy variables are log-transformed to compensate for potential
heteroskedasticity issues with prices, distance and population differences be-
tween pair-wise locations. For both mean- and weekly-prices, clustered stan-
dard errors are used to control for correlation between observations of relative
prices that share at least one city in common.21
4.5.1 Mean Price differences
The coefficient estimates with city-pair mean price differences as the depen-
dent variable can be found in Table C.1. The supply network has a significant
impact on pre-tax mean-price differences across locations. The coefficients for
19Potential problems with endogeneity may arise with the pipeline variable, as it may be
argued that the choice of locations for pipeline construction may be influenced by relative prices
across those locations. However, since the pipelines employed in this study were constructed
well before the time span of the retail price data, it is assumed in this chapter that these
pipeline connections are predetermined as explanatory variables for pre-tax price dispersion.
20For example, if city iis 100km from its nearest terminal and city jis 75km from its nearest
terminal, termij would be 25km.
21Specifically, errors are clustered in groups g= 1, ..., G, where all elements of group gcontain
a relative price that includes city iin |log(¯
Pi)−log(¯
Pj)|for mean-price differences, or city iin
period tin |log(Pit)−log(Pjt)|for weekly-price differences.
134
the dummy variables on pipeline and seaport connections both have the ex-
pected negative sign, implying that retail prices are less dispersed across lo-
cations sharing these connections. However, the estimates for seaport are not
significantly different from zero at a 90% confidence interval, as opposed to
a 99% confidence level for the pipeline dummy. The coefficient on pipeline
(δ=−0.0353) in the preferred specification in regression 1, indicates that,
ceteris paribus, cities connected by a pipeline exhibit 3.5% less dispersion in
their mean prices. I also find that while statistically significant, doubling the
difference in distances from the nearest terminal would increase mean-price
dispersion by only 0.3%.
Distance and region have statistically significant coefficients. Interpreting
these coefficients, with (β= 0.0374), two cities that are 100% further apart (in
km) exhibit 3.7% more price dispersion in their mean prices. Intuitively, this
means that if City X and City Y are identical in every way, but City X happens
to be twice as far away from City Z as is City Y, then we would expect the
difference in mean prices between City X and City Z to be 3.7% larger than
that between City Y and City Z, ceteris paribus.22 The region coefficient is
positive, predicting that prices are 6.3% more dispersed for city-pairs that are
within the same region than for those that are not. This may potentially be
due in part to demand side effects, indicating that demand shocks are highly
localized over time, and not necessarily dispersed across entire regions.
Finally, the population coefficients are both found to be significant, but
small. City-pairs with 100% larger population differences exhibit 0.5% more
22While this result may seem small in magnitude relative to the percentage increase in dis-
tance between locations, a country as geographically scattered as Canada suggests such large
variations in distance, with a coefficient of variation for the distance variable of 0.6817, com-
pared to coefficient of variations for pre-tax prices Canada-wide with a mean value of 0.0943.

135
mean-price dispersion, while cities with 100% larger differences in popula-
tion density also exhibit 0.5% more mean-price dispersion. While distance,
region and pipeline are significant factors in predicting mean price differences,
the value of the estimated coefficients changes very little across regressions
as other explanatory variables such as seaports and population measures are
added.
4.5.2 Weekly relative prices
The supply network also impacts relative weekly-price differences. Table C.2
presents the results of the regression analysis with weekly relative prices as
the dependent variable. Controlling for distance and market effects, the supply
network variables for pipeline and seaport connects are statistically significant
and negative. In the baseline specification in Reg. 1, the existence of a pipeline
connecting two cities (δ=−0.0221) amounts to a 2.2% lower weekly relative
price difference, while locations that share a seaport connection (λ=−0.0160)
display to a 1.6% reduction in relative weekly price dispersion. Distance, re-
gion and market size variables are also all significant explanatory variables
in this specification. A 100% increase in distance between two locations in-
creases the weekly relative price gap by 4.2%, while a 100% increase in ei-
ther total population differences or population density differences amounts to
a 0.5% greater spread in relative prices. Again, intraregional relative prices
are more dispersed than interregional prices, by approximately 5.6%. Using
these parameter estimates, the existence of a pipeline between two locations
produces an analogous effect on relative prices as would a 53% reduction in
distance between them, while the existence of a maritime shipping link pro-
duces the effect of a 38% reduction in land route distance.

136
The distance coefficient estimates are stable across most regression specifi-
cations, although the coefficients suggest that omitting supply network charac-
teristics from any regression analysis of these weekly relative prices may bias
the predicted results. The omitted supply network variables may bias the dis-
tance coefficients upwards by roughly 5% across specifications, and ignoring re-
gional effects (where region boundaries are defined with supply network arcs)
can bias distance coefficients by upwards of 35%. Taken in conjunction with the
results obtained from the mean-price difference specifications in Section 4.5.1,
this suggests that arbitrage opportunities that may arise in any given period
by the presence of a pre-tax price gap across locations are not merely limited
by the geographical distance between locations. Rather, they are a function
of the effective distance between locations, which takes into account both the
geographical distance and the available supply network linking the two. The
regression coefficients support the intuition that pipelines are potentially able
to curtail arbitrage opportunities to a greater extent due to the speed and ease
of coordination of shipping via pipeline, while larger price variations may be
sustainable across locations connected by truck or rail, due to the larger time
and monetary costs of coordinating the resources necessary to ship large quan-
tities via these modes of transportation.
4.5.3 Robustness
To check the robustness of these results, I consider two alternative cases of the
regression analysis: (1) omitting Quebec and Atlantic Canada cities from the
data, and (2) omitting Whitehorse and Yellowknife from the data.
Case (1): While the Federal government does not regulate gasoline prices
in Canada, several provinces do enforce some form of price regulation. Quebec
137
sets a minimum weekly price, dependent on estimated acquisition and trans-
portation costs, while New Brunswick sets a maximum weekly price, indexed
to crude prices and retail margins. Nova Scotia, Price Edward Island and New-
foundland and Labrador all set the weekly price of gasoline in their province
following similar standards based on spot crude prices and relative to esti-
mated transportation costs.23 This raises the possibility that the estimates in
Tables C.1–C.2 are biased. I therefore perform the regression analysis while
omitting all city-pairs that include at least one of the cities in the Quebec and
Atlantic regions, effectively leaving only the Ontario and West regions.
Case (2): Due to their relatively extreme geographic remoteness, Yellowknife,
NWT. and Whitehorse, YK may be outliers in the Canadian gasoline market.
While theoretically possible, it may not be practical to consider that suppliers
explore arbitrage opportunities between Yellowknife and St. John’s, NFLD,
in the same light as they would explore potential arbitrage opportunities be-
tween Edmonton and Calgary, AB, for example. I therefore repeat the regres-
sion analysis while omitting all city-pairs that include either Whitehorse or
Yellowknife.
Omitting Quebec and Atlantic
In Table C.3, omitting Quebec and the Atlantic provinces produces relatively
little change on the impact of the supply network on mean-price differences.
The coefficient on pipeline remains significant and negative, while its value
increases slightly — the existence of a pipeline connecting cities now results
in a 4.1% reduction in price dispersion. The seaport coefficient is still statisti-
cally insignificant at the 90% confidence level, and the coefficient on terminal
23A more detailed description can be found at the Consumer Council of Canada:
http://www.consumerscouncil.com/index.cfm?id=13904.

138
distance becomes statistically insignificant as well once these cities have been
omitted. The coefficient on distance remains significant, and rises slightly, with
a 50% increase in distance between cities resulting in a 2.6% larger difference
in mean-prices.
In Table C.4, the impact of the supply network on weekly price dispersion
increases when omitting Quebec and Atlantic cities. A pipeline connection
reduces weekly price dispersion by 3.0%, and a seaport connection reduces
price dispersion by 4.3%. This change may be a function of the fact that for
the remaining cities, in the West and Ontario regions, there are a larger va-
riety of employed transportation methods, with pipelines in particular being
more prominent. Contrarily, the omitted Quebec and Atlantic cities tend to be
mainly connected by seaports and lack much pipeline infrastructure. The coef-
ficient on distance increases, with a 50% increase in distance resulting in 2.7%
less weekly price dispersion across locations.
Omitting Whitehorse and Yellowknife
In Table C.5, the supply network remains significant in impacting mean-price
dispersion when omitting Whitehorse and Yellowknife. A pipeline connection
between locations reduces mean-price dispersion by 1.6%, and a seaport con-
nection between locations reduces mean-price dispersion by 1.0%, and the sea-
port variable now becomes significant at a 95% confidence level. Perhaps not
surprisingly, removing the two cities that are the most extremely geographi-
cally located reduces the magnitude of the distance and region coefficients. A
50% increase in distance between cities results in only 0.2% less mean-price
dispersion, and locations in the same region exhibit only 0.7% less price dis-
persion than city-pairs that span multiple regions.

139
In Table C.6, omitting Yellowknife and Whitehorse decreases the impact of
the supply network on weekly price dispersion. The pipeline and seaport coef-
ficients are still statistically significant, but smaller, with a pipeline connection
reducing weekly relative price dispersion by only 0.4% while a maritime con-
nection reduces weekly price dispersion by 1.3%. The distance coefficient, while
still statistically significant, also decreases, with a 50% increase in distance re-
sulting in a 0.6% increase in price dispersion between cities.
4.5.4 Summary: Impact of Supply Network on Price Dis-
persion
I find that mean price differences are functions of distance, as a proxy for trans-
portation costs, and market-specific factors that limit arbitrage opportunities
and allow price gaps to be sustained in mean prices over time. I also find that
the supply network, both in regional supply effects and the existing pipeline
infrastructure, significantly impact mean price differences. Weekly price dif-
ferences are also significantly impacted by the structure of the supply network
for both pipeline and marine transportation. Pipeline connections between lo-
cations limit weekly-price dispersion by the equivalent of a 53% reduction in
distance, while seaport connections are akin to a 38% reduction in distance
across locations. This suggests that the costs of arbitraging price gaps are sig-
nificantly affected by the differences in the supply network’s structure, with
lower variable-cost methods (like pipelines) reducing the effective distance be-
tween locations more than alternative methods with higher per-unit shipping
costs.

140
4.6 Case Studies of Supply Shocks
An alternative approach to identify how the supply network impacts retail
prices in the Canadian gasoline market is how “supply shocks” affect retail
price dispersion across locations. This paper specifically considers disruptions
in production at the refinery level. This aspect of the supply chain is chosen for
several reasons:
1. There are a relatively small number (16) of refineries that operate across
Canada, and therefore occurrences of refinery shutdowns can be more
easily identified via newspaper and petroleum industry reports;
2. Products are moved from refineries to terminals for distribution via all
four modes of transportation, and therefore the variation in the trans-
portation availability across geographic locations is larger than for the
retail level, where all transportation is done by truck;
3. It allows for consideration of reactions in price to supply disruptions that
may be felt by a group of cities within a geographic proximity to a par-
ticular refinery, but not necessarily at either the national level, or the
extremely localized level.
Intuitively, one might expect that a shortage in supply caused by a tempo-
rary shutdown of a refinery in a particular region may impact relative prices
for nearby cities, but not necessarily all cities nationwide. Further, one might
expect that the ability of suppliers in a certain location to respond to supply
shortages to depend on the available modes of transportation in their regions.
Therefore, one way to investigate this conjecture is to examine cases of ob-
served refinery shutdowns, to determine responses in production levels, net
141
imports and retail price changes that occur as a result. However, since refiner-
ies are such vital links in the supply chain, there are large incentives to keep
them operating and resolve any disruptions as quickly as possible, regardless
of repair costs. Thus it is difficult to find a large number of instances of re-
fineries remaining closed for any prolonged period of time, in order to perform
a thorough quantitative analysis.
The small number of shutdowns can be classified in one of two ways: planned
shutdowns, defined as a scheduled, forecast shutdown of refinery operations,
typically for maintenance purposes, performed during seasons when gasoline
demand is lowest; and unplanned shutdowns, defined as an unexpected disrup-
tion caused by accidents or acts of nature. Examples of planned and unplanned
shutdowns are listed in Table 4.3.
Table 4.3: Refinery Shutdowns
Refinery Date Reason Capacity % of Reg.
(bpd) capacity
Planned shutdowns
Calgary Jun/Jul 2006 Maintenance 110,000 18.7
Saint John Nov/Dec 2008 Maintenance 300,000 59.5
Edmonton Aug 2009 Maintenance 135,000 23.0
Unplanned shutdowns
Nanticoke (ON) Feb 2007 Fire 112,000 29.2
Edmonton Aug 2008 Cat. Conv. 135,000 23.0
Scotsford (AB) Sept 2009 Unplanned maint. 100,000 17.0
Dartmouth (NS) Sept 2010 Hurricane 89,000 17.6
In order to examine the effects of these shutdowns on refinery production
volumes, data from Statistics Canada is employed for the period January 2001
to May 2017. This data is categorized by Statistics Canada into provincial
aggregate levels, as well as regional levels, which can then be matched into the
142
regions suggested by the supply network infrastructure. Specifically, refinery
data is grouped into the Atlantic provinces, Quebec and Ontario — the only
notable exception is that the Western provinces are not aggregated together
into one region, but rather by individual province. The one shortcoming of this
data is that figures are withheld for refinery production in Saskatchewan and
British Columbia, in accordance with confidentiality requirements.24 However,
as there are no refineries in Manitoba or the territories, and by capacity, the
B.C. and Saskatchewan refineries make up relatively small portions of the total
capacity of the region (less than 15%), the Alberta refinery data can serve as a
reasonable approximation for the Western region. Summary statistics for the
refinery data can be found in Table 4.4.
Table 4.4: Refinery Production
Summary Statistics
(cubic metres per month)
Region Mean Std. Dev. Min Max Median
Canada 824670 116810 443136 1131445 829380
West 793820 107930 443136 970013 808240
Ontario 894240 128600 528807 1131445 872330
Quebec 796200 84740 513483 976323 807000
Atlantic 814410 112890 443624 995657 838090
4.6.1 Stylized Facts from the data
Production Planned shutdowns have minimal effect on refinery production
volumes at the regional level. Planned shutdowns at the Saint John and Ed-
monton refineries coincided with 2% and 1% decreases in production levels
24Refer to the Canadian Statistics Act, available for viewing at:
http://www.statcan.gc.ca/about-apercu/act-loi-eng.htm.

143
from their seasonal (monthly) averages in their respective regions, while the
Calgary shutdown coincides with a 4% increase in the regional production lev-
els relative to the season average. The size of these deviations, in terms of
standard deviations from the mean, are -0.26, -0.10 and +0.19 for Saint John,
Edmonton and Calgary, respectively. Refinery production for the Alberta re-
gion can be seen in Figure 4.8 with the period 1 week prior to 6 weeks after the
beginning of the shutdown highlighted. At the time of the planned shutdown,
production in the Alberta region actually increases, and remains slightly above
its seasonal average.
Conversely, unplanned shutdowns appear to have larger negative effects on
regional production volumes. Unplanned shutdowns at the Nanticoke, Edmon-
ton and Scotsford refineries coincide with 23.9%, 27.7% and 21.7% decreases in
regional production relative to seasonal averages, which are analogous to -1.64,
-2.80 and -1.85 standard deviations from their respective means. Refinery pro-
duction for the Ontario region can be seen in Figure 4.9 with the period 1 week
prior to 6 weeks after the beginning of the shutdown due to the Nanticoke fire
highlighted. In this case, at the time of the fire, the region experience a notable
decline in production and remains below its seasonal average in the following
weeks.
Inventories Planned shutdowns typically correspond with increases in in-
ventories in the month prior to the shutdown and little to no change in inven-
tories during the shutdown period, relative to their seasonal averages. Con-
versely, unplanned shutdowns display no discernible pattern in inventories for
the preceding month, with large decreases in inventories during the time of
the shutdown, relative to seasonal averages. This suggests that suppliers may
ramp up production near the end of the month preceding a scheduled closure
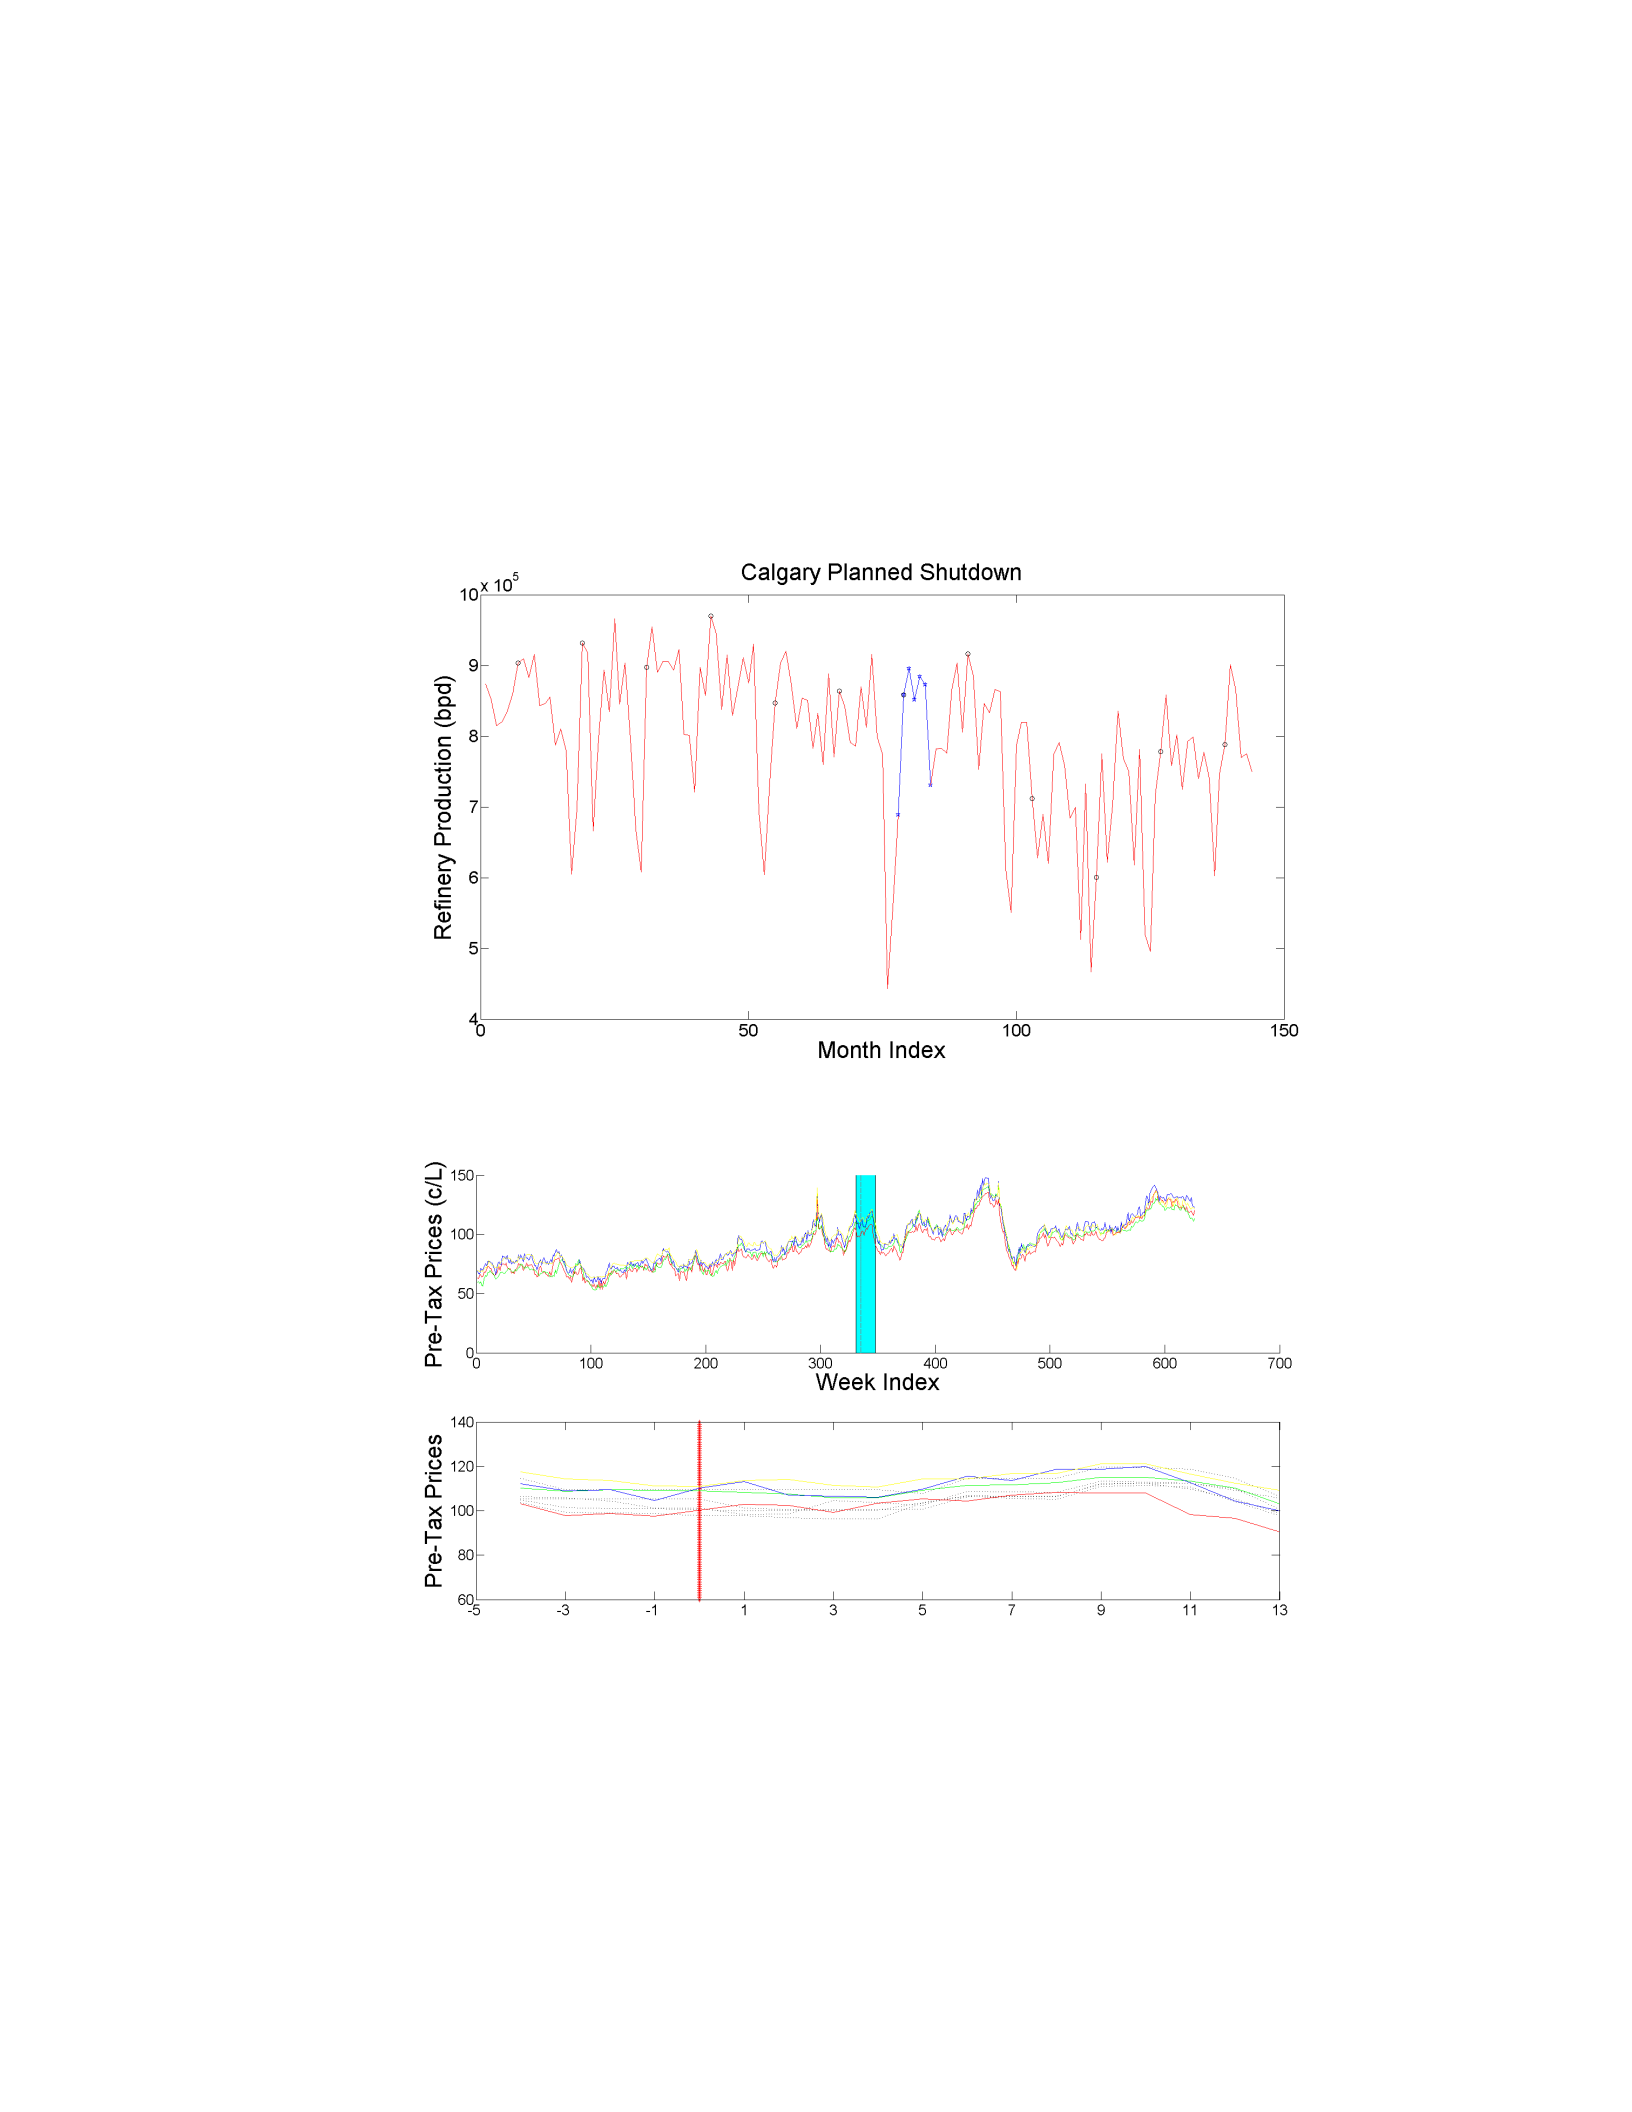
144
Figure 4.8: Calgary Planned shutdown
(a) Refinery Production
(b) Retail Prices
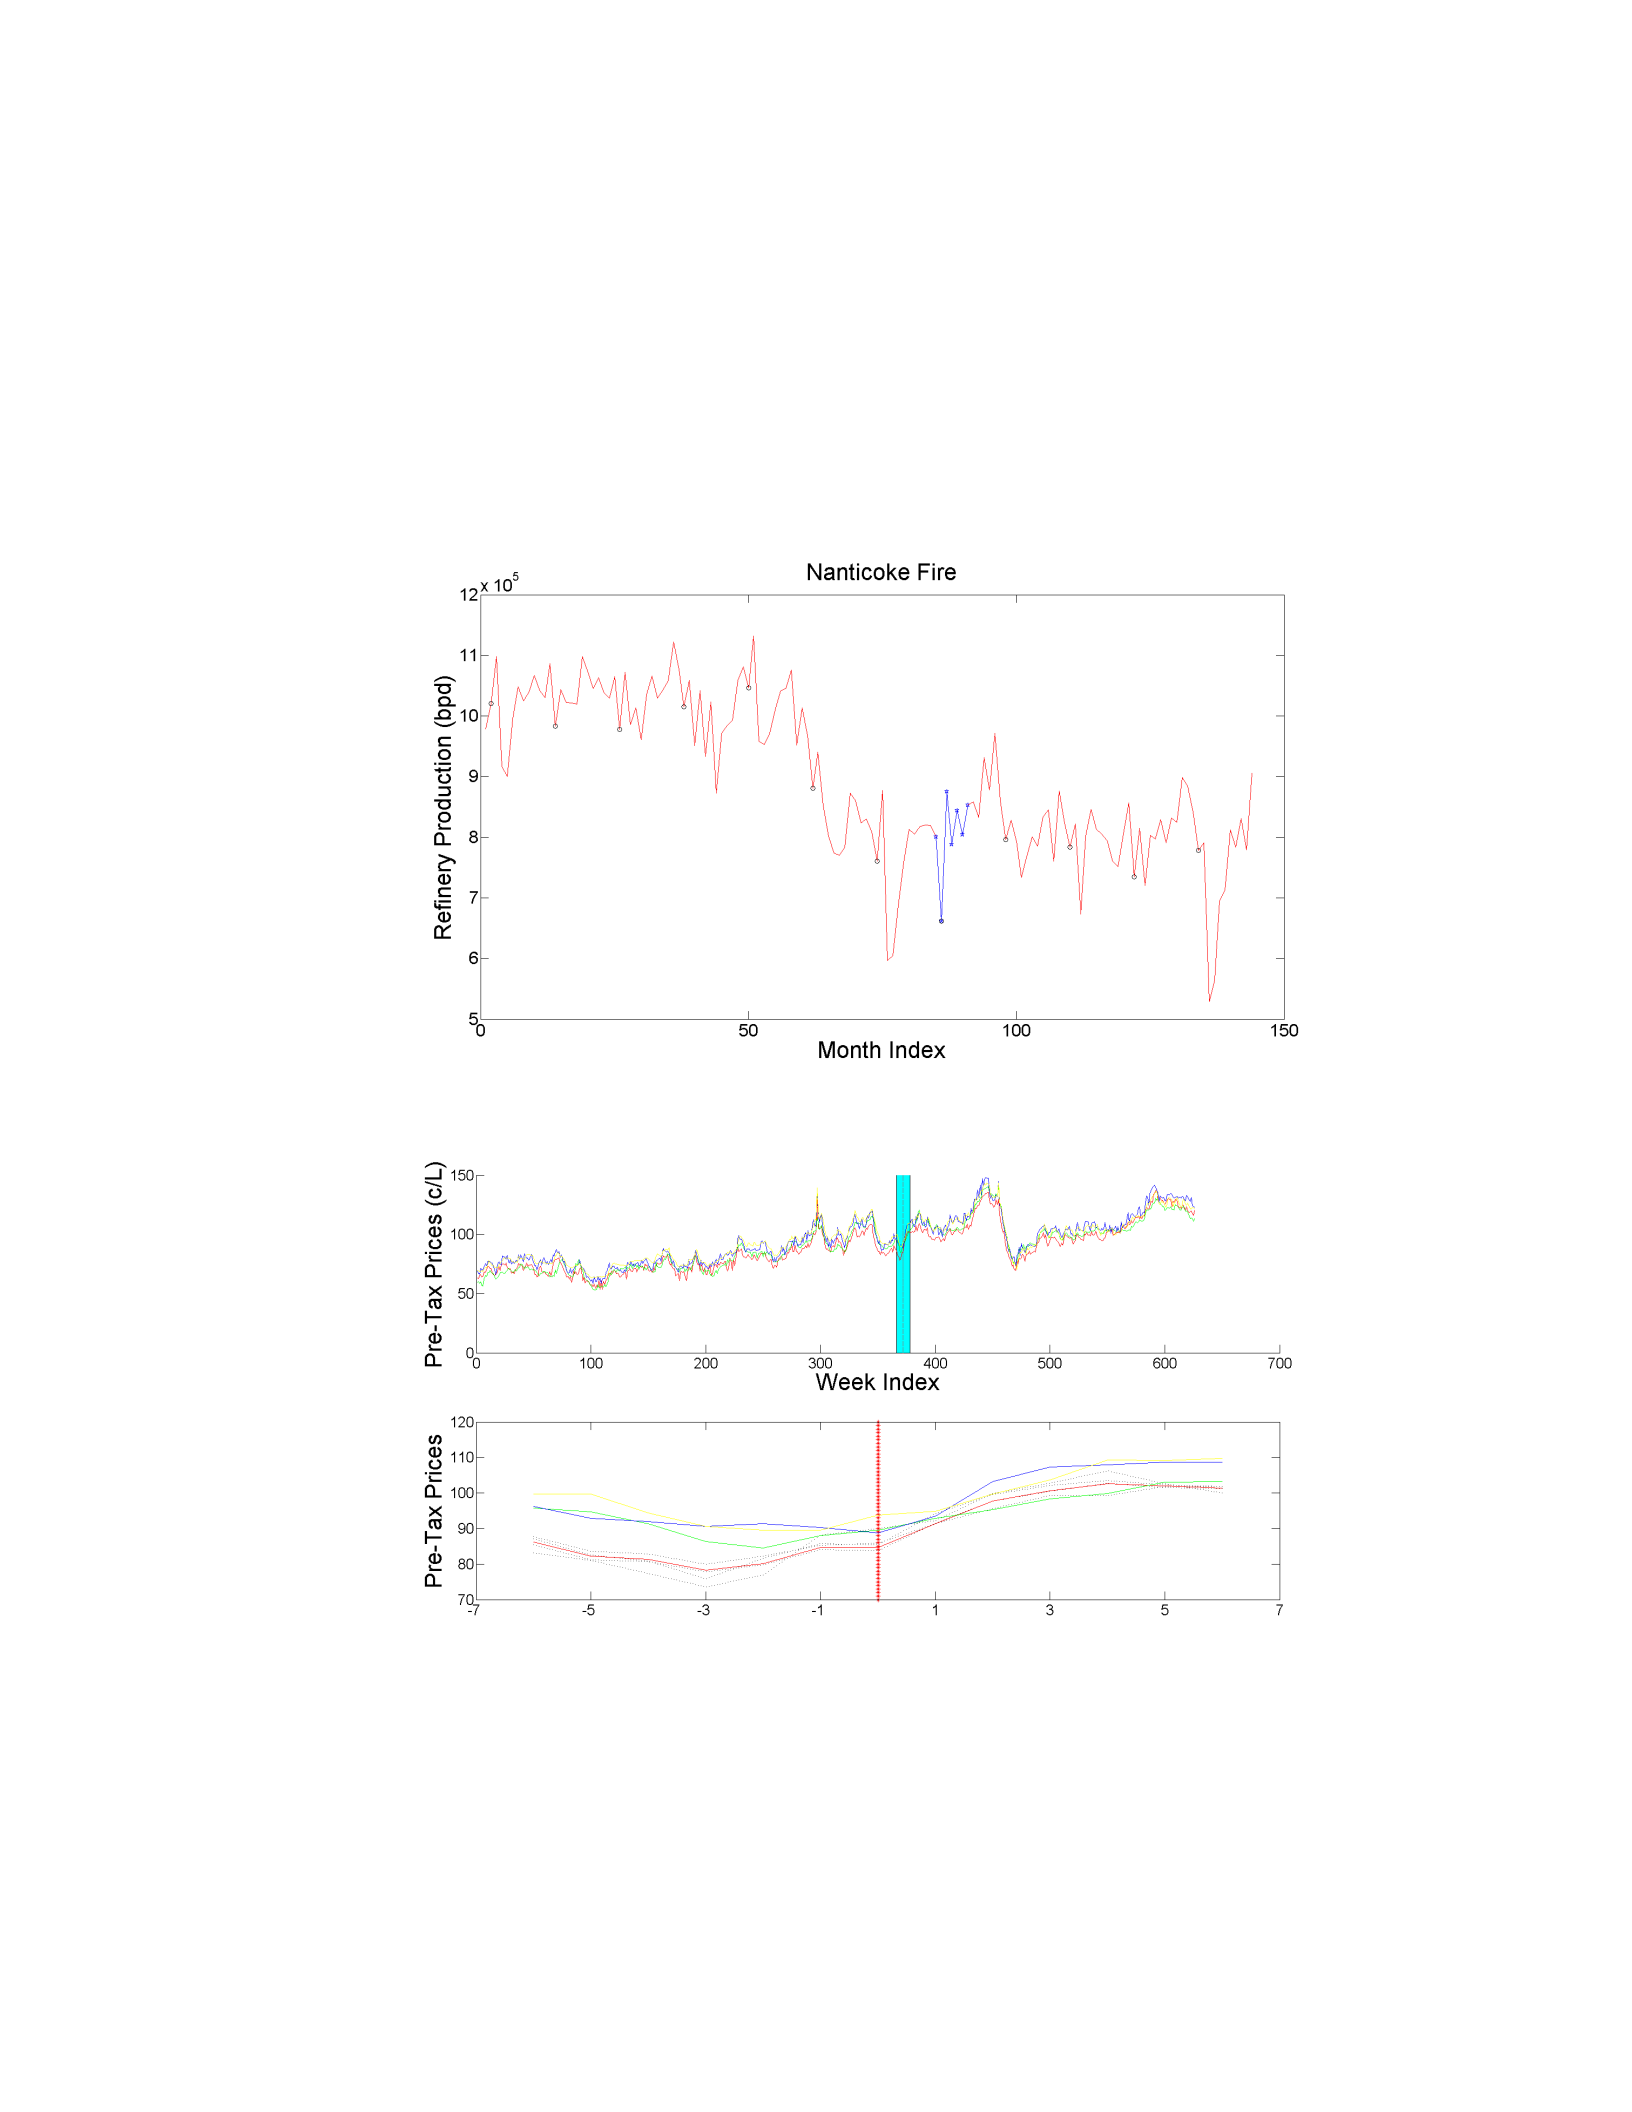
145
Figure 4.9: Nanticoke Unplanned shutdown
(a) Refinery Production
(b) Retail Prices

146
in order to utilize some of the additional inventories to cover production short-
ages, while this strategy is simply not available for suppliers who cannot pre-
dict the unplanned shutdowns, thus inventories must decrease to accommodate
these unplanned decreases in production. Figure 4.10 shows the changes in net
inventories during both planned and unplanned shutdowns.
Net Imports Planned shutdowns do not noticeably impact net imports in
a region, relative to the seasonal average, while unplanned shutdowns tend
to coincide with increases in regional net imports during periods of decreased
production. This suggests that suppliers may be able to compensate for re-
gional production shortages by increasing net imports into the region when
unplanned shutdowns occur, while net imports may not be affected during pe-
riods of planned shutdowns, as prior planning may be able to adequately com-
pensate for these production shortages and not necessitate additional net im-
ports over seasonal averages. Figure 4.11 shows changes in net imports during
both planned and unplanned shutdowns.
Taken together, these facts from the data suggest a narrative in which the
scenarios of planned vs. unplanned shutdowns induce different responses from
suppliers. Since planned shutdowns are generally scheduled for periods when
demand is at its lowest, suppliers may be able to mitigate any decreases in cur-
rent production by using previously increased inventories to account for any
shortages. Further, as these planned shutdowns are scheduled and known, net
imports can be pre-arranged to compensate for any further shortages in net
production, so that net imports during planned shutdowns do not vary from
seasonal averages. However, when unplanned disruptions occur, suppliers may
resort to covering supply shortages by increasing net imports above seasonal
averages. Suppliers’ ability to adjust quickly to these unplanned shortages
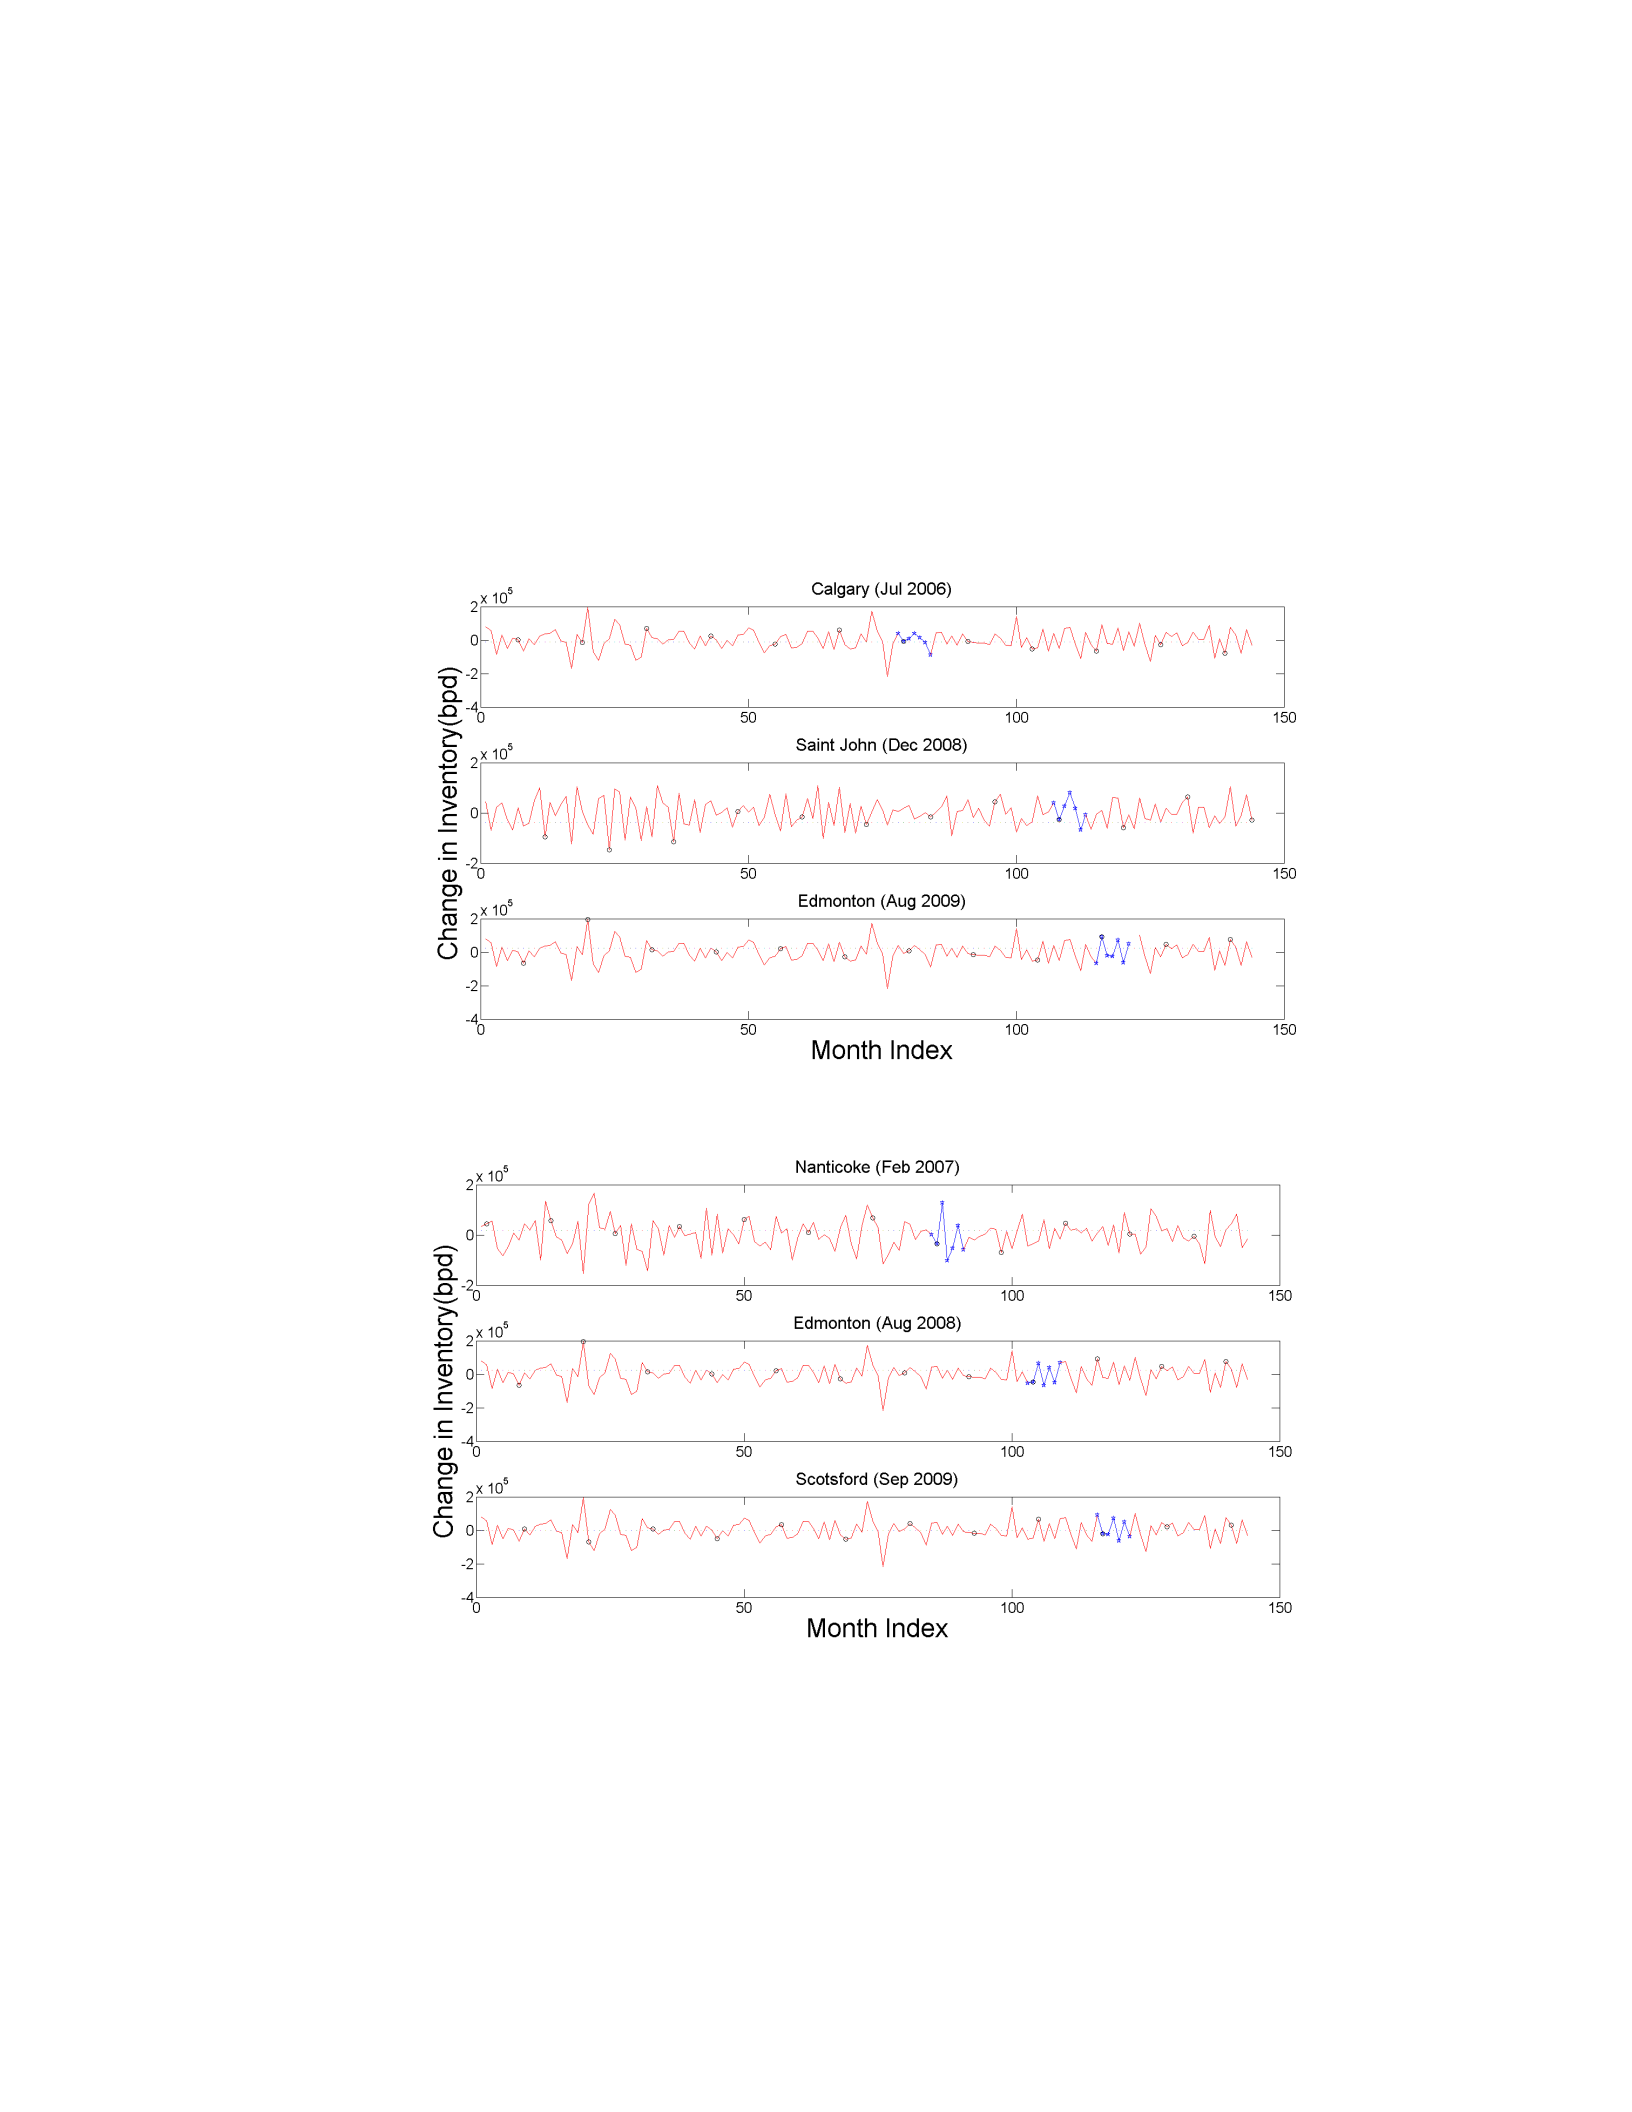
147
Figure 4.10: Refinery Inventories
(a) Planned Shutdowns
(b) Unplanned Shutdowns
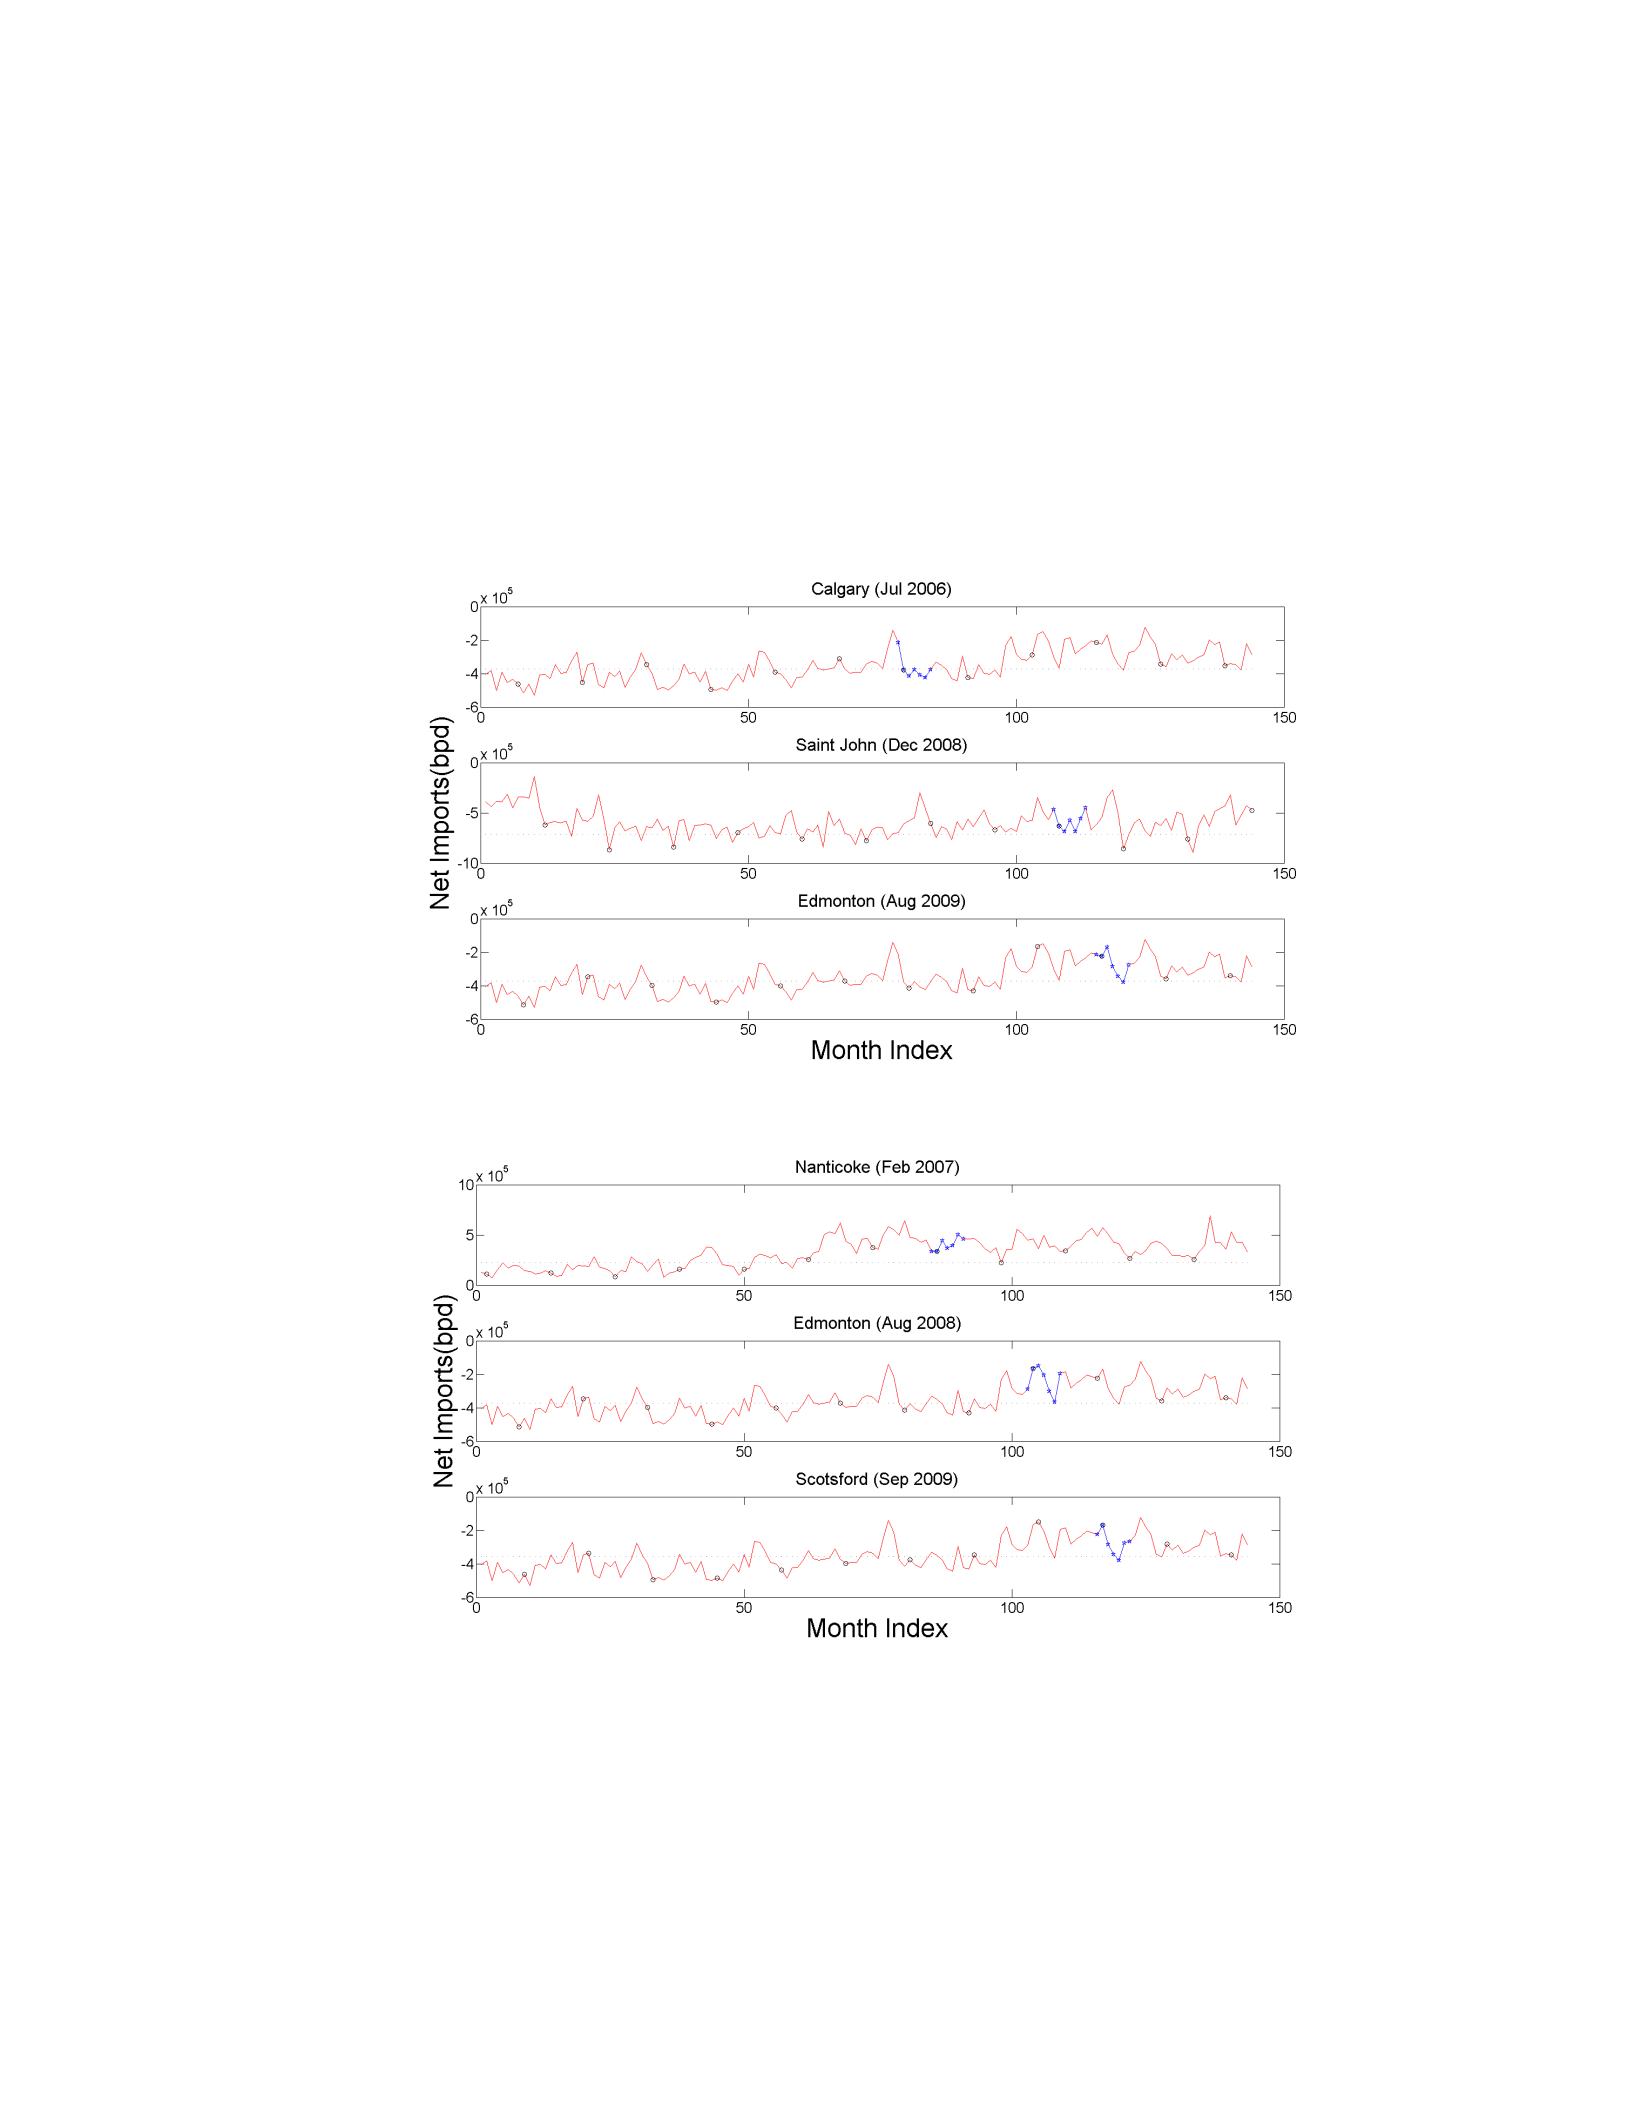
148
Figure 4.11: Refinery Net Imports
(a) Planned Shutdowns
(b) Unplanned Shutdowns

149
will therefore be constrained by the existing supply network available to move
product across and within each region. Therefore the structure of the supply
network may have a large influence on the capability and speed at which sup-
ply shocks can be dissipated in the retail market.
4.6.2 Retail prices
As there are so few instances of prolonged refinery-level shutdowns, this paper
focuses on two specific example: a planned maintenance shutdown in Calgary
in late June/early July 2006 and an unplanned shutdown due to a fire at the
Nanticoke, ON refinery in February 2007. These two cases studies were cho-
sen for closer examination due to each refinery’s relatively similar share of re-
gional production capabilities, ranging from 20–30% of their respective region’s
typical gasoline production and the relatively central location of each refinery
within their regional supply hub.
A preliminary look at retail prices following these supply shocks indicates
that retail prices spike slightly more in locations in closer proximity to the
refinery that is shutdown than in other regions following an unplanned shut-
down. However, following unplanned shutdowns, prices generally move in sim-
ilar fashions across all regions, and these supply shocks do not appear isolated
to local prices. Further, locations close to the shutdown refinery that share
pipeline connections tend to exhibit less variation in price changes than those
locations with no pipeline access. Once again, this suggests that the supply in-
frastructure impacts retail price dispersion, as locations connected via pipeline
are separated by a smaller effective distance, ceteris paribus, and can therefore
disseminate supply shocks more quickly, resulting in less variation in retail
price.
150
In the case of the Nanticoke fire, over the three week period following the
refinery shutdown, the Ontario average retail price spiked by 15.3% while the
Canadian average price increased by 12.6% and Western and Atlantic prices
grew by only 6.4% and 6.3% respectively.25 Additionally, the standard deviation
of price spikes for Ontario cities that share a common pipeline connection is
0.0263, whereas that of cities without pipeline access was 0.0384. Conversely,
in the case of a planned shutdown in Calgary, in the three week period following
the shutdown, the Western average retail price decreased by 0.01% while the
Canadian average price decreased by 0.03% and the Quebec and Ontario aver-
ages changed by -0.02% and +0.03% respectively, all of which reflect almost no
change in prices and minimal differences across regions.26 Contrasting these
two case studies provides preliminary evidence to reinforce the significance of
the supply network in impacting the way in which supply shocks are transmit-
ted into retail price changes across locations.
4.7 Conclusions
The supply network has a significant impact on relative price dispersion in the
Canadian gasoline market, limiting arbitrage opportunities that arise from
price gaps across locations. Like previous studies on price dispersion, geo-
graphic distance and market size are found to be significant factors in account-
ing for price gaps and violations of the law of one price for a homogeneous
good like gasoline. However, the contribution of this chapter is to determine
that variation in the available methods of transportation of gasoline products,
via pipeline or seaport connections, also significantly impacts price differences
25These results can be seen in the bottom panel of Figure 4.10(b).
26These results can be seen in the bottom panel of Figure 4.9(b).

151
across locations. Pipelines decrease weekly price dispersion by the equivalent
of a 53% reduction in distance, while seaport connections reduce price disper-
sion by the equivalent of a 38% reduction in geographical distance.
This result is reinforced by a case study of supply shocks in the supply chain
for gasoline during refinery shutdowns. Examining these incidents suggests
that unplanned refinery shutdowns coincide with decreased regional produc-
tion levels that are accompanied by spikes in retail prices. These price spikes
are larger (in percentage terms) in areas closer to the shutdown, and also ex-
hibit less variation across locations that are connected by pipelines than across
those that are not. Planned shutdowns, however, exhibit minimal changes to
production levels and no clear price spikes, regardless of geographic location or
proximity to the refinery shutdown.
While this chapter offers some initial insight into the role of the supply
network on price dispersion in the Canadian gasoline market, more extensive
data on pre-tax and retail price dispersion across a larger number of locations,
of varying market size, would allow a more precise examination. As more cities
are included in the Kent dataset, further work may be able to exploit variation
in more remote and smaller cities, as opposed to the larger and more centrally
located cities that are currently available. Future potential work may also
focus on the role of the supply network on an international scale, by incorpo-
rating multiple countries and investigating retail price dispersion on a larger
geographic scale, including the impact of border effects. Data from American
retail gasoline markets at a level of detail comparable to the Canadian data
set could offer a first step in understanding what price differences arise when
policy and trade barriers potentially affect supply distribution and price dis-
persion across countries.

