


Corporate Social Responsibility in the United
States and Nigeria
Chapter 1: Introduction to the Study
Scholars such as Carroll and Shabana (2010), Hanlon and Fleming (2009),
Kinderman (2012), and Marens (2013) have asserted that they are witnessing a sustained
corporate effort to convince a more diverse group of stakeholders that fundamentally
capitalistic corporations are embracing CSR as a desirable business development goal and
strategy of sustainable shared values (as cited in Agudelo et al., 2019; Freeman &
Dmytriyev, 2017). Corporations have been casting aside decades of empirical evidence of
corporate irresponsibility to make a case for the inclusion of social values in their current
operations (Hanlon & Fleming 2009; Marens, 2010). Kurucz et al. (2008) explained four
business case arguments that have been pitched by corporations in support of the
proposition of performing better by giving back: (a) lowering the cost and risk of doing
business, (b) bolstering reputations and legitimacy, (c) empowering competitive
advantage, and (d) facilitating win-win quid pro quo value creation.
Concurrently, several scholars have been wary in the face of this effort, asserting
their critical interpretations of evolving corporate motivations. What the analysts argued
they could have been seeing are renewed propaganda efforts at marketing and branding
(Hanlon & Fleming 2009), a predatory grab for greater power (Marens, 2010), a
diversionary tactic or smokescreen to mislead (Banerjee, 2008), or a quid pro quo for less
regulation (Kinderman, 2012). Kurucz et al. (2008) asserted that when scholars have
examined the business pitches for CSR theoretically (Carroll, 1979; Swanson, 1999;

Wood, 1991) and empirically (Cochran & Wood, 1984; Graves & Waddock, 1994;
Mattingly & Berman, 2006; Rousso & Fouts, 1997), test results were mixed when
comparing social performance against financial performance.
A substantial number of scholars have also asserted that CSR may not be a
legitimate or credible development goal or strategy of shared values (Agudelo et al.,
2019; Freeman & Dmytriyev, 2017) in the view of internal and external multinational
corporation stakeholders in practice (Aragon-Correa et al., 2020; Haack et al., 2020;
Kurucz et al., 2008). Some observers and scholars have questioned to what extent CSR is
working for Nigerian stakeholders in the context of Nigeria, which is the sixth major
oilproducing nation in the world and contains some of Africa’s largest multinational
corporations in oil and gas such as Shell Petroleum Development Company of the United
Kingdom (Egharevba & Ovenseri-Obomo, 2019), in banking such as the First Bank of
Nigeria established as the Bank of British West Africa banking of Lagos, Nigeria
(Michael, 2014), and in diary such as Friesland Camina of the Netherlands (Ekumankama
et al.. 2019). Stakeholders in the broadest possible perspective include shareholders,
executive officers, employees, customers, suppliers, service providers, communities,
infrastructure providers, governments, and those who benefit and depend upon the
environment in which the multinational corporations work in, in the sense of
employment, economic security, safety, dispute resolution, and infrastructure
(Babatunde, 2020; Odera et al., 2020; Raimi, 2018). Clarification of this debate by
initiating an internal and external stakeholder survey in the United States and Nigeria

could enable positive social change by clarifying perceptions and validating the claims of
either side of the ongoing debate on these matters, as the following narrative reveals.
Background of the Study
There is a gap in knowledge about what should be the business case for CSR from
the stakeholder’s perspective. This is the gap between what has been pitched by internal
and external corporate stakeholders advocating CSR programs versus what has been
found in practice.
Corporate Social Responsibility Versus Capitalism
Smith has been widely considered to be the originator of the idea of modern
capitalism when he asserted that business benefits everyone in society when it is free
from hindrance in seeking profits and efficiency (as cited in Lantos, 2001). In the recent
past, Friedman’s neo-classical stance based upon Smith’s definition elevated the ethical
and lawful production of profit as the principal social responsibility of business. Smith
focused his definition of capitalism upon generating shareholder wealth through finance
and marketing models and techniques to build and operate product and services
businesses that generate profits using capital and human resources. Friedman’s
shareholder model invalidated the idea that there should be other social responsibilities
carried out by corporate employees besides making profits, claiming that these actions
could do more harm than good to society (Friedman, 1962; Lantos, 2001; Moir, 2001).
The Friedman’s shareholder model has been challenged repeatedly. Bowen (1953)
introduced a more broad-based concept of social responsibilities of business beyond the

sole focus on profit generation. This challenge initiated a debate that went on for decades
up to the present where there has been little consensus about the technicalities of what
CSR means (Carroll, 1991; Jones, 1995, 1999; Kakabadse et al., 2005; McWilliams &
Siegel, 2001). Interpretations in the place of or in addition to CSR have included some of
the following: sustainable development, business ethics, corporate social contract,
corporate accountability, business in society, corporate citizenship, and corporate
governance. These themes demonstrate the original idea's power to inspire the
development of many related but independent concepts (Carroll, 1999). However, no
consensus is needed to validate the legitimacy, value, and credibility of the concept about
an organization’s responsibility to social welfare or the environment (Lantos, 2001) even
though there is no shortage of ideas inspired, advocated, or applicable to single cases
(Agudelo, 2019).
Although there is little that all of these interpretations have in common, the CSR
paradigm as asserted by numerous corporate representatives could replace the classic and
neoclassic capitalism models by expanding their focus to also include social
responsibility models and techniques to build and operate product and service businesses
that generate profits and other benefits using capital and other resources to benefit
corporate shareholders, executive officers, employees, customers, communities, and other
general stakeholders (Moura-Leitre & Padgett, 2011; Yuan et al., 2019). Moreover,
activities could be conducted that do not directly benefit the corporation’s shareholders.
The stakes are higher now than they have ever been. There are more stakeholders (Wang
et al., 2016) and a larger number of corporate leaders both supporting and criticizing the

CSR development effort, so the scope and complexity of CSR has, in turn, expanded
(Carroll & Shibana, 2010; Kurucz et al., 2008).
Through all of these CSR development efforts over time, the net results have been
mixed (Kurucz et al., 2008; Orlitzky et al., 2003). Although there are several perennial
CSR initiatives being discussed and analyzed, such as the well-visited arguments about
doing well by doing good in theory (Swanson, 1999) and empirically (Cochran & Wood,
1984; Mattingly & Berman 2006) in both social and financial spheres. There are also new
features and business arguments about CSR’s emergence (Kurucz et al., 2008). What
appears to be different now as distinguished from decades earlier are more complex
contexts and scales of global trade and more competition (Carroll & Shabana, 2010;
Kurucz et al., 2008). Accompanying this new global complexity are fundamental changes
in the concepts of capitalism (Hanlon & Fleming, 2009; Kinderman, 2012); the changing
nature, policies, and effectiveness of the institutions of labor unions, government, and
business; as well as the associated relationships between them and other special interest
activists, stakeholders, and cultural groups (Marens, 2013).
Motivations for Corporate Origination and Participation in CSR Programs
From the corporation’s point-of-view, the primary and general reason for
engaging in CSR programs today is to do well financially by doing good socially. Kurucz
et al. (2008) translated these descriptive justifications by rewording the proposition as
improving CFP and CSP. However, in meta-analysis quantitative measurement studies,
Orlitzky et al. (2003) found generally positive correlations between CFP and CSP in
different industries and contexts, and Preston and O’Bannon (1997) found mixed results

where financial performance either preceded social performance or was explained by
positive synergies between the two.
Stakeholder Theory and Stakeholders
Freeman (2013) outlined the basic foundational elements of stakeholder theory:
(a) corporations have interactive links between stakeholders such that the decisions of
both entities affects the other, (b) there is a high level of concern upon the relationship
processes and outcomes between the corporation and its stakeholders, (c) all legitimate
stakeholder interests have value and no interests dominate the other (Clarkson, 1995;
Donaldson & Preston, 1995), and (d) there is a focus upon managerial decision making
(Donaldson & Preston, 1995).
Clarkson (1995) defined primary stakeholders as those who have risked some
form of value-based financial or human resource investment capital in a corporation to
enable ongoing operations. These stakeholders could be investors, banks and financiers,
shareholders, managers, employees, suppliers, and governments that provide
infrastructure resources. The natural environment is also a stakeholder within the
communities they operate as well as the communities themselves, which provide taxes to
fund the public services and infrastructure, and protection of the environment either in the
form of prevention or restoration of the corporation’s activities degrading impact. Starik
(1995) clarified that there are both internal and external stakeholders of the corporation.
Corporations have multiple responsibilities to their internal shareholders and employees
that are different from their stakeholder responsibilities to their external shareholders,
including customers; local communities’ benefit from job offerings, corporate giving,

governments that tax corporations and collect licensing fees and regulatory fines, and
spending that money on providing community services (municipal police, fire fighting,
regulation, and public utilities). The number and mix of stakeholders who occupy these
categories can vary substantially from corporation to corporation.
It is uncertain how multinational corporations headquatered in the United States
work with their external stakeholders in other international communities worldwide who
have different cultural norms and expectations. In summary, this study was needed
because there is a lack of agreement about the definition, credibility, value, and
legitimacy of CSR; there is uncertainty about CFP when improving CSP; and there is
insufficient knowledge about international stakeholders’ CSR attitudes about
multinational operations.
Problem Statement
The content of written CSR reporting in developing nations may not be as
legitimate as corporate stakeholders and the public had thought. In a study of published
annual reports of six major oil companies working in the Niger Delta of Nigeria, it was
found that there could be violations of accepted international CSR reporting norms and
transparency (Emezi, 2014; Odera et al., 2020). However, there have been only a few
other confirming studies (Osei-Kojo & Andrews, 2020; Uwalomwa & Jimoh, 2012) and
noncurrent, suggesting a gap in the literature. The social problem that these findings
suggest is that the current CSR paradigm so frequently characterized as credible (Ting et
al., 2019; Vu et al., 2020) in reality could be a decoupling between theory and practice
(Babatunde, 2020; Hauser & Schembera, 2019; Tashman et al., 2019). The specific

management problem was that it was unclear whether CSR in practice has been aligned
with Freeman’s (2013, 2016, 2017) CSR theories that hypothetically CSR (a) lower cost
and sustain business, (b) elevate the legitimacy of stakeholders, (c) enhance competitive
advantages, and (d) facilitate win-win quid pro quo value creation in the United States
and Nigeria.
Purpose of the Study
The purpose of this correlational research design quantitative study was to
empirically test (a) the theory of CSR positing that CSR programs are correlated with
improved CSP and CFP; and (b) the stakeholder theory, asserting the existence of a
mutually beneficial interactive correlation between corporations and all of their
stakeholders and a positive association of such links with corporate competitiveness
(CC), corporate reputation (CR), and corporate value creation (CVC) effects of CSR in
developing nations such as Nigeria. Sociodemographic control variables and a
moderating variable of the United States' national culture (NC) versus Nigeria’s were
statistically controlled in the study.
Research Questions and Hypotheses
Research Question (RQ)1: Are CSR programs associated with improved CSP and
CFP?
H011: CSR programs are not associated with improved CSP.
H111: CSR programs are associated with improved CSP.
H012: CSR programs are not associated with improved CFP.
H112: CSR programs are associated with improved CFP.

RQ2: What are the stakeholder multinational corporate connection differences
between Nigerian and U.S. multinational stakeholders in the costs and risks of doing
business, corporate reputation and legitimacy, competitive advantages, and win-win quid
pro quo value, considering the cultural differences between both nations?
H021: CSR does not have positive effects on CR, but the effects are moderated by
the national cultures of the United States and Nigeria.
H121: CSR has positive effects on CR, but the effects are moderated by the
national cultures of the United States and Nigeria.
H022: CSR does not have positive effects on CC, but the effects are moderated by
the national cultures of the United States and Nigeria.
H122: CSR has positive effects on CC, but the effects are moderated by the
national cultures of the United States and Nigeria.
H023: CSR does not have positive effects on CVC, but the effects are moderated
by the national cultures of the United States and Nigeria.
H123: CSR has positive effects on CVC, but the effects are moderated by the
national cultures of the United States and Nigeria.
Theoretical Framework
The theoretical foundation that formed the basis of this study included stakeholder
theory as described by Freeman (2013, 2016, 2017) that predicted stakeholders’ behavior
with corporations in how they interact, how their interactions affect both parties, what
both parties are most concerned about, whether one of the party’s interests dominate the
other (Clarkson, 1995; Donaldson & Preston, 1995), and what interaction there is a focus
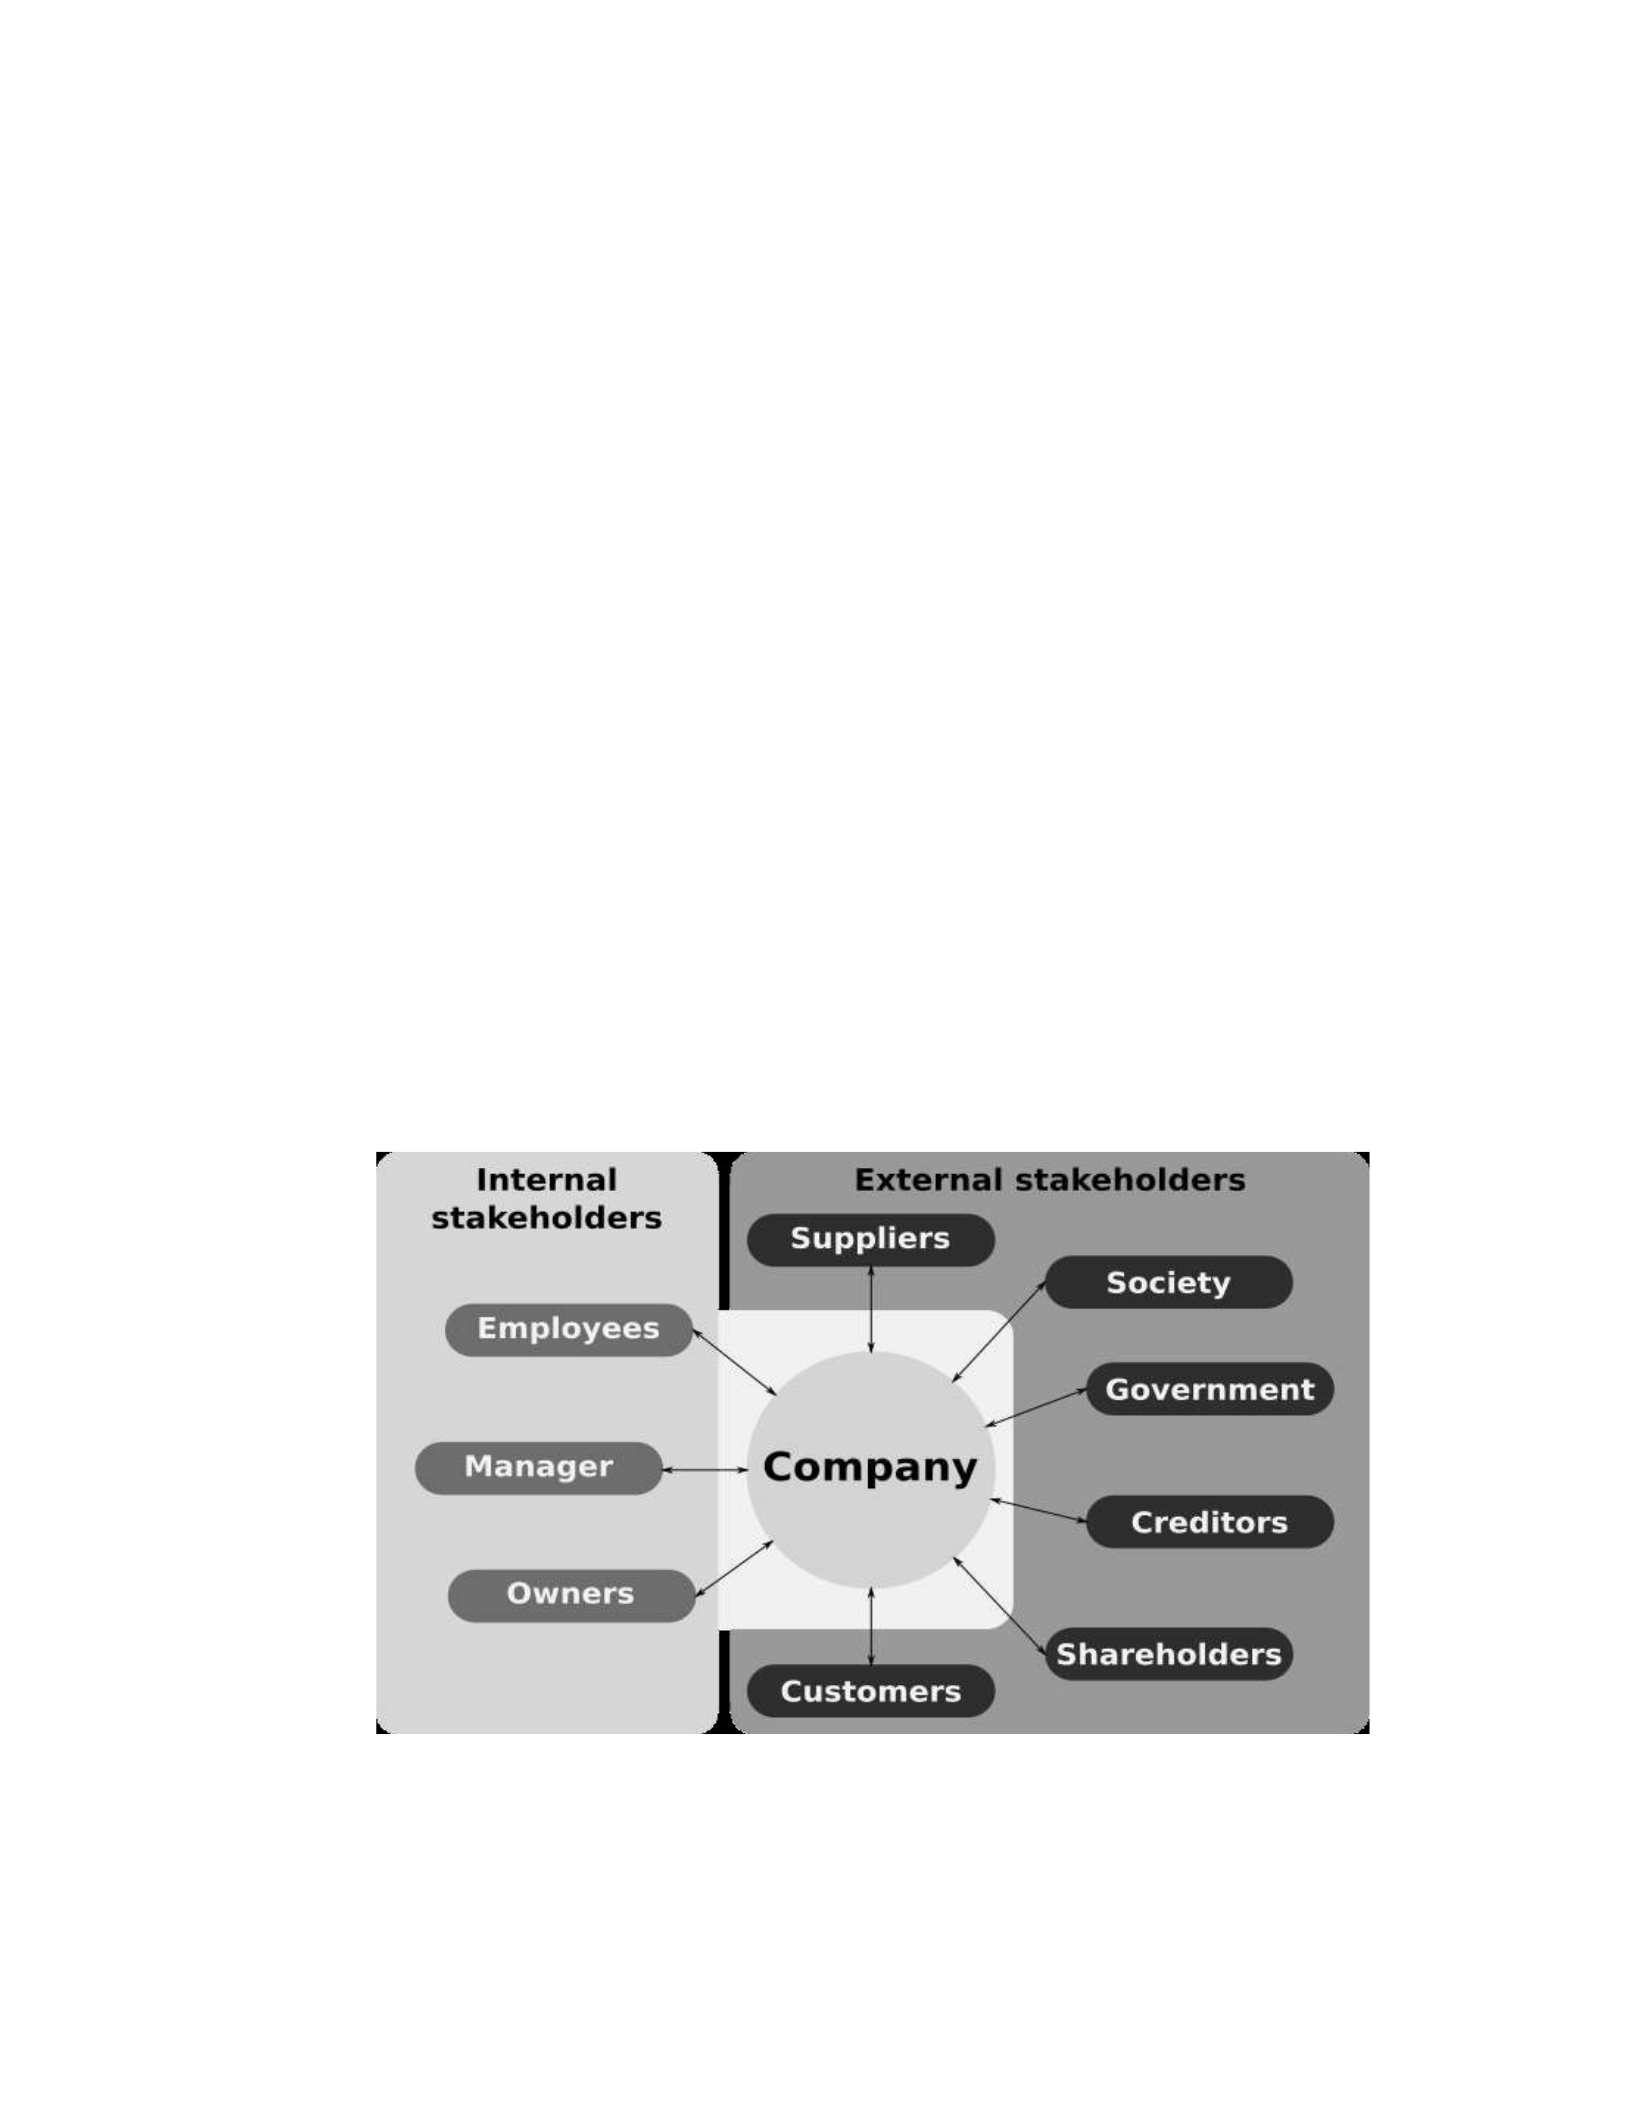
upon (Donaldson & Preston, 1995). Starik (1995) described a typology of corporate
stakeholders, making a distinction between the interests and behavior of stakeholders that
are internal (investors, banks and financiers, shareholders, managers, employees,
suppliers, and governments that provide infrastructure resources) and external
(customers, local communities that benefit from job offerings, corporate giving,
governments that tax corporations and collect licensing fees and regulatory fines,
spending that money on providing community services) to the corporation’s operations.
A diagram summarizing stakeholder theory based upon the original Freeman et al.
(2007) model that was later refined, and as shown in Figures 4 and 5 in Chapter 2 is shown
in Figure 1.
Figure 1
Illustration of Stakeholder Types in Freeman’s Stakeholder Theory
Note. Figure showing the typical stakeholders of a company. The stakeholders are
divided into internal and external stakeholders. Reprinted from Stakeholder, by
Grochim, 2008, (https://commons.wikimedia.org/w/index.php?curid=44754443 ) .
Copyright 2008 by Commons.
The following theories and concepts could have also affected this study: classical
capitalism theory, neo-capitalism theory, and CSR models. Smith asserted in his classical
capitalism model that business benefits everyone in society when it is free from hindrance
in seeking profits and efficiency. Friedman’s neoclassical capitalistic shareholder model
invalidated the idea that there should be any other social responsibilities besides making
profits carried out by corporate employees, claiming that these actions could do more
harm than good to society (Lantos, 2001; Moir, 2001).
Bowen (1953) was one of the first of many to challenge classical and neoclassical
capitalism theory by characterizing a broader-based capitalism model that included social
responsibilities beyond the sole focus upon profit generation. Kurucz et al. (2008) posited
four business case arguments in support of the basic CSR model of doing well in profits
by giving back social benefits, including (a) lowering the cost and risk of doing business,
(b) bolstering reputations and legitimacy, (c) empowering competitive advantage, and (d)
facilitating win-win quid pro quo value creation. The theory of CSR is shown in Figure
2, as it has been described and modeled (Kurucz et al., 2008), where corporate reputation
is interpreted as CSP, and company market value is interpreted as CFP.
Figure 2
Illustration of the Theory of Corporate Social Responsibility (as explained by Kurucz et
al.2008)
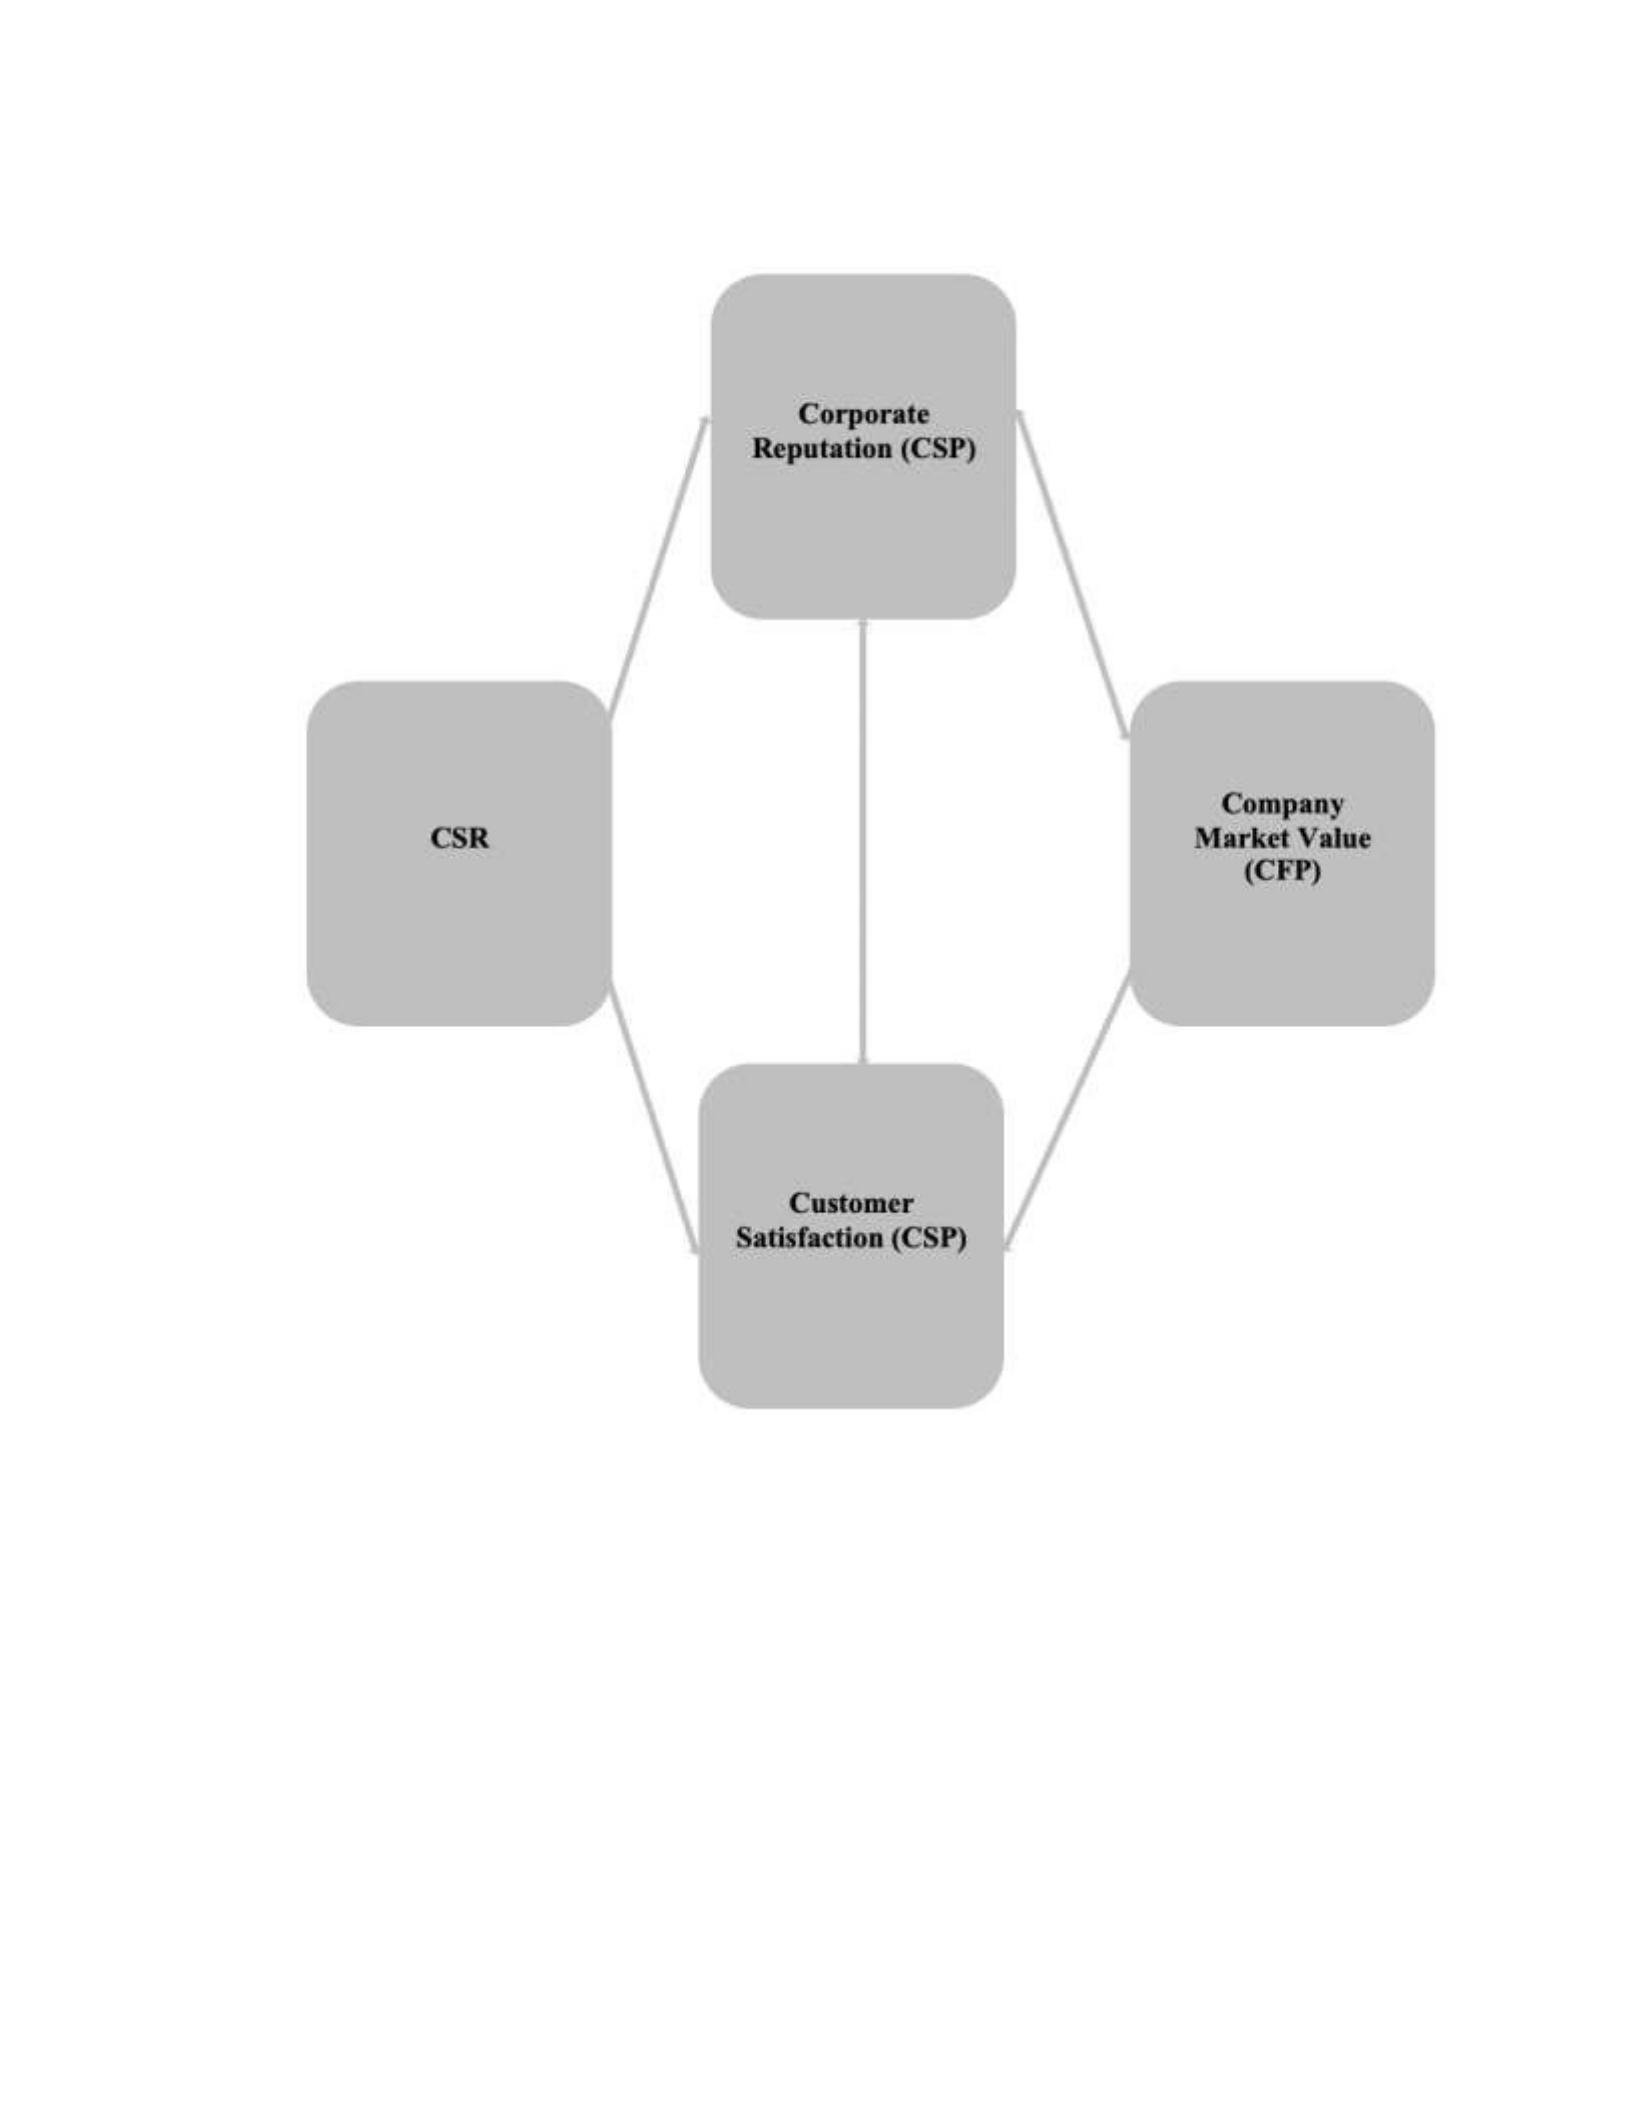
Note. Figure Illustrating the Theory of Corporate Social Responsibility. It shows the link
among CSR, corporate reputation, customer satisfaction, and company market value.
Synthesizing both models with the conceptual model of this study is shown in
Figure 3 where the antecedent CSR hypothetically leads to the distal outcomes of
company market value/ CFP, CR/ CSP, CC, corporate customer satisfaction/ CSP, and
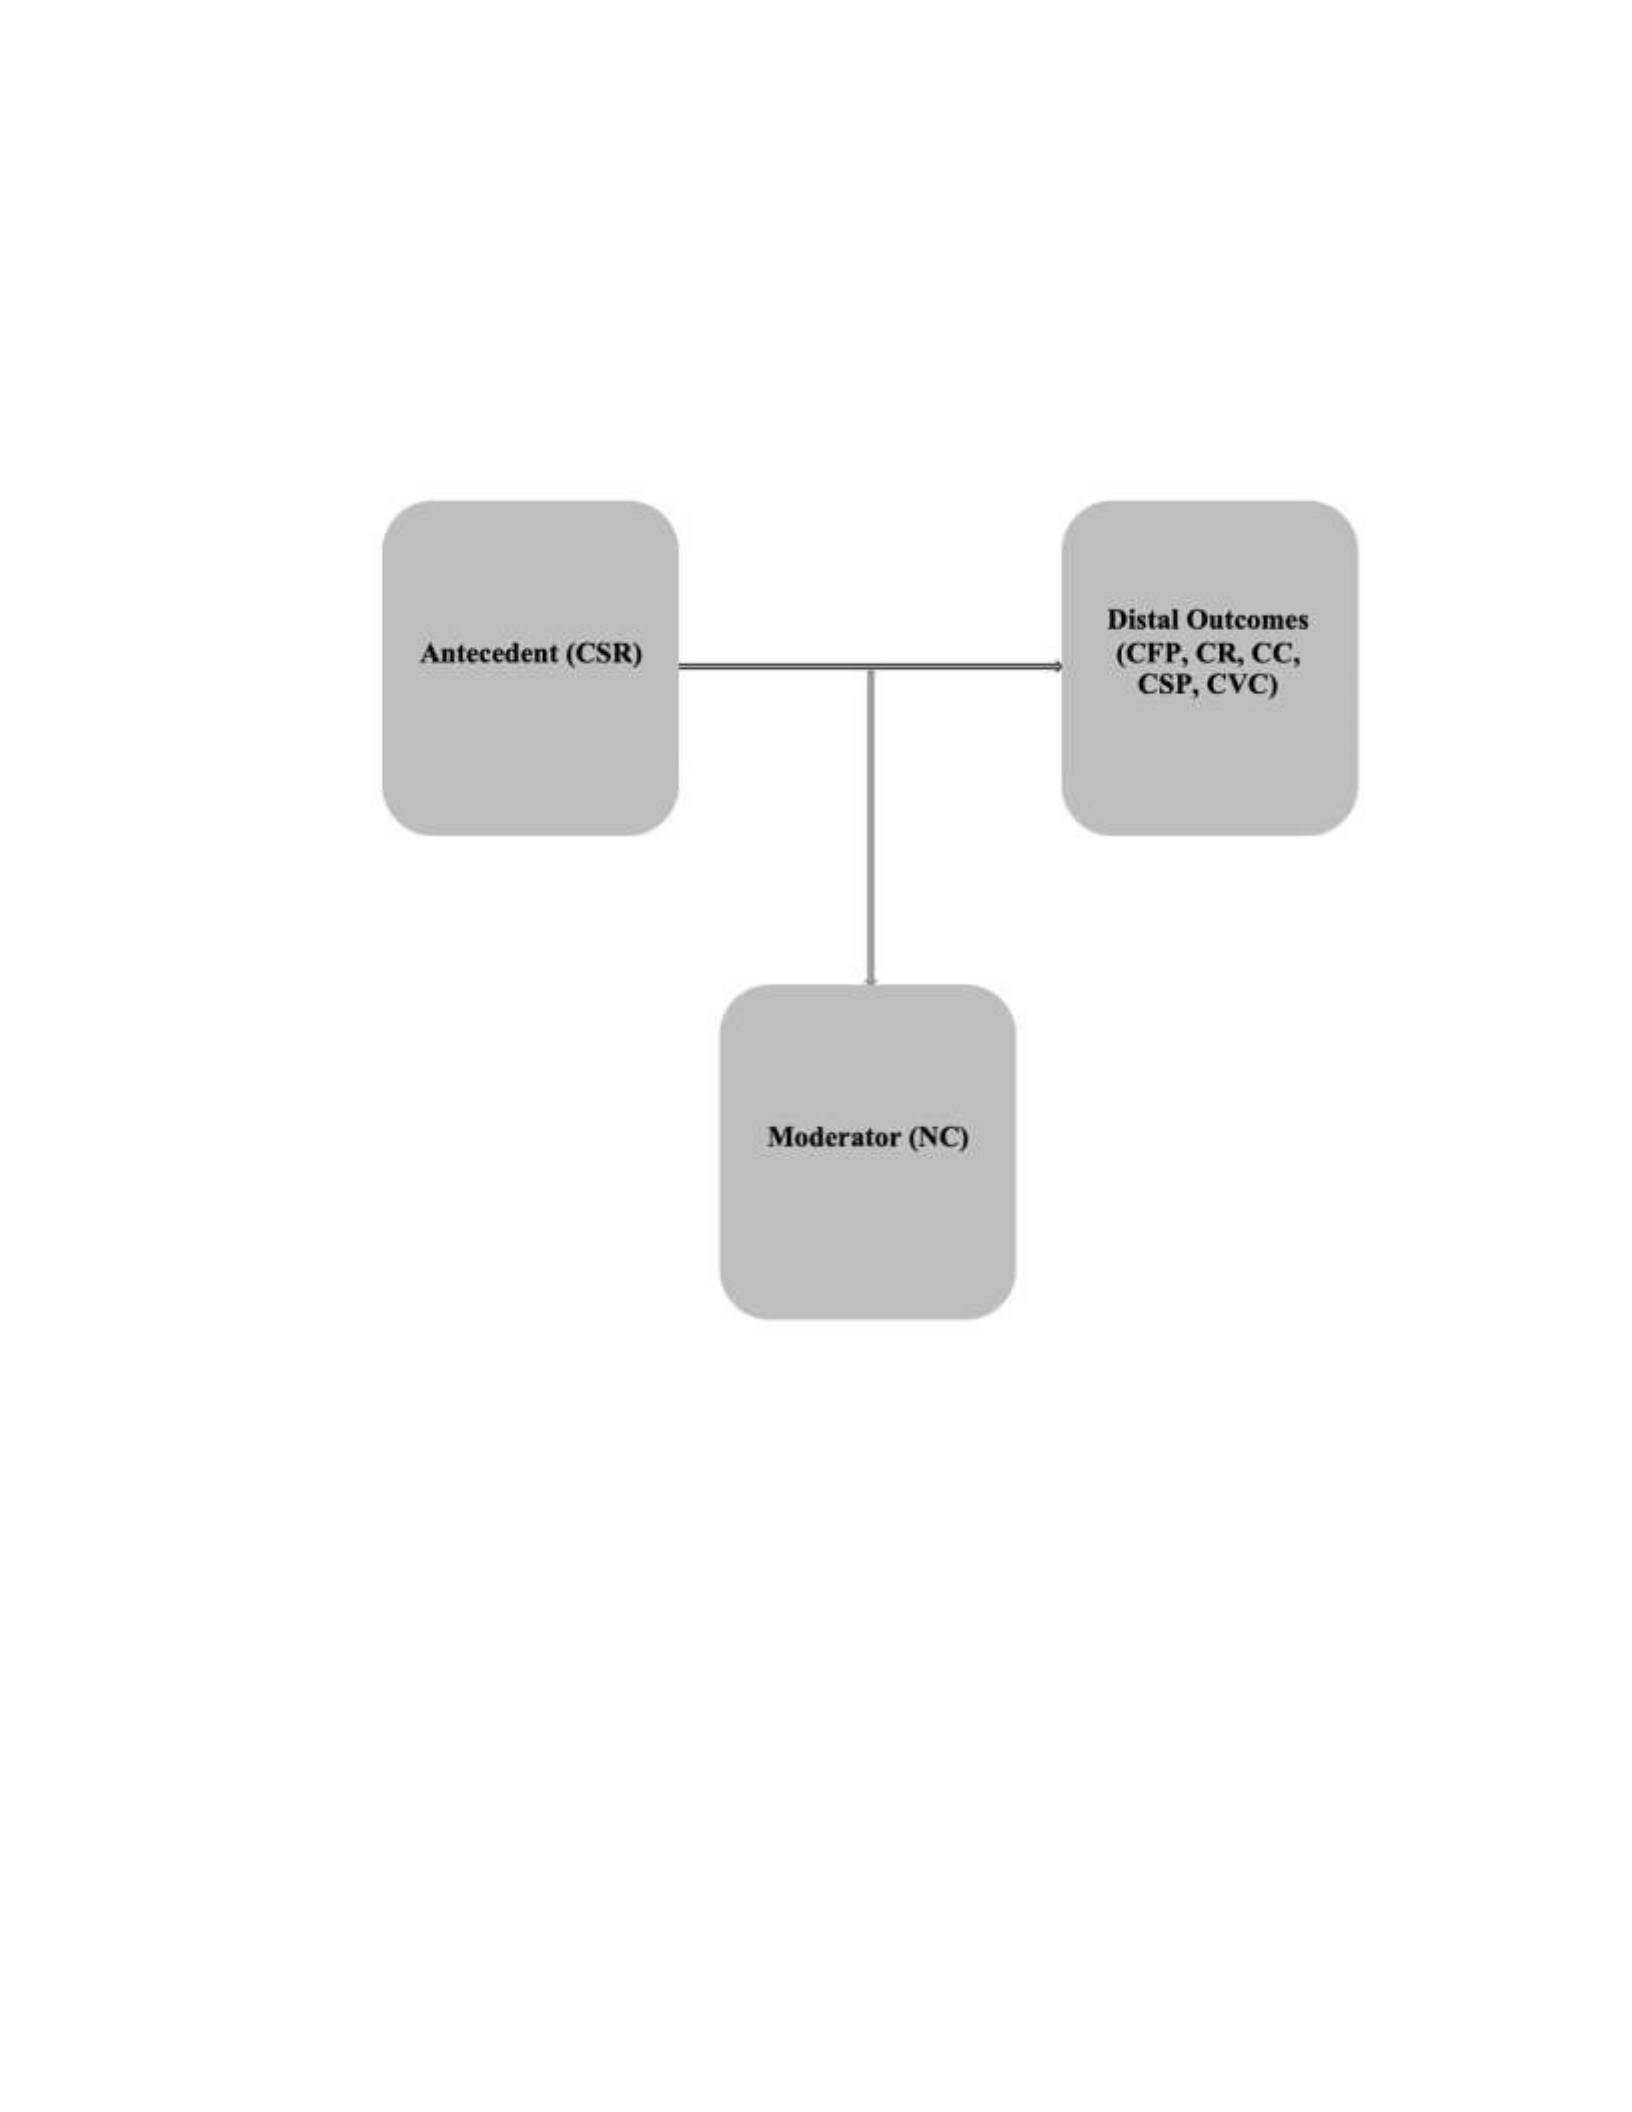
CVC/company market value all moderated by NC.
Figure 3
Conceptual Model of the Study
Note. Conceptual model of this study, where CSR is corporate social responsibility, NC is
national culture, CFP is corporate financial performance, CR is corporate reputation, CC
is corporate competitiveness, CSP is corporate social performance, and CVC is corporate
value creation/company market value.
Recent scholarly studies that provided theoretical support included Alvarez et al.
(2020), who sought to discover the dynamics of the phenomena that take place over time
as stakeholders come to the forefront and their input becomes crucial to the opportunity

formation process for entrepreneurs; Bartelmeb and Godemann (2020), who examined
how firms understood and perceived communication as a CSR dimension; Geerts and
Dooms (2020), who studied how stakeholders in the Belgian port industry viewed
sustainability reporting as a management tool for understanding where an organization is
positioned along the sustainability pathway; Crane (2018), who presented a model of
stakeholder connectedness and described the conditions in which a company’s behaviors
toward one stakeholder can erode or build trust across stakeholders; Girschik (2020), who
addressed intra-organizational pressures for organizational transformation towards more
responsible business practices by studying what part internal activists play; and Pirson et
al. (2017), who developed a contingency model for stakeholder trust formation that was
founded on the impact of stakeholder specific vulnerability and the personal values of the
trustor.
Other recent scholarly studies that provided theoretical support included Barletti
et al. (2020), who employed a realist synthesis review in examining the academic
literature on multistakeholder forums designed to support efforts towards more
sustainable land use; Saxton et al. (2020), who built a model of firm response to
stakeholders that combined the notions of CSR communication and stakeholder salience;
Liang et al. (2020), who identified six types of sustainable corporations by their
orientation towards sustainability based on the moral responsibility theory of corporate
sustainability; Brand et al. (2020), who argued that in a lot of cases, communicative
action is not a fitting regulative ideal for discussions between companies and
nongovernmental organizations (NGOs); Jia (2019), whose study extended the literature

on the relationship between CSR activities and firm performance; and Sabadoz and
Singer (2017), who explored the issues of political CSR and the challenges of corporate
deliberation.
Nature of the Study
This quantitative study employed a correlational research design. The rationale for
the selection of such research design was twofold. First, given the nature of CSR as a
phenomenon under investigation and the research questions of the study, the other three
quantitative research designs (descriptive, quasi-experimental, and experimental) were
inappropriate because the purpose of this survey study was to test empirically (a) the
theory of CSR, positing that CSR programs are correlated with improved CSP and CFP;
and (b) the stakeholder theory, asserting the existence of a mutually beneficial interactive
correlation between corporations and their stakeholders, and a positive association of
such links with CC, CR, and CVC effects of CSR in developing nations such as Nigeria.
Sociodemographic control variables and a moderating variable of the United States' NC
versus Nigeria’s were statistically controlled in the study.
Second, it was challenging to manipulate the study's dependent variables, given
how the participants were selected and the data collection methods that were used. Thus,
quasi-experimental and experimental quantitative research designs were out of the
question. In this context, the cross-sectional, correlational, survey-based research design
was an efficient research solution given the study's scope and scale. Homogenous
purposive sampling was used to test propositions of the CSR and the stakeholder theories

in the context of the United States and Nigerian national cultures. The data were collected
using two research instruments: the English language version of the Values Survey
Module (VSM) 2013 Questionnaire (Hofstede & Minkov, 2013a), and the CSR Attitudes
Questionnaire (Hofstede & Minkov, 2013b). Appropriate parts of both surveys were
combined into a single instrument and converted to an online form for more efficient data
collection using the SurveyMonkey online service.
The participants for the study were recruited through accessing the membership
base of the professional associations of business, legal, accounting, engineering, social
science, natural science, and consulting organizations. The inclusion criteria were as
follows: (a) currently working for a private, for-profit company in the United States or
Nigeria with an active CSR program, (b) currently working for a government, (c) a U.S.
or Nigerian citizen, (d) at least three years of work experience in the current position, (e)
the company’s CSR program has been in effect for at least five years as reflected in the
company’s mission statement, (f) familiarity with the company’s CSR program and
ability to comment on it, and (g) English reading comprehension. The exclusion criteria
were as follows: (a) under 18 years of age, and (b) currently studying. These exclusion
criteria allowed for the elimination of individuals lacking direct knowledge about the
topic of the current study.
These exclusion criteria allowed for the elimination of individuals lacking
knowledge about the topic of the current study or with limited understanding of the
relationships between the study variables.

To determine the sample size required to detect an effect of .8 with α = .05 for a
generalized linear model (GLM), an a priori power analysis was conducted using the
GPower 3.1 statistical tool. The power analysis indicated that the minimum required
sample size should be N = 348. All data collected in the study were analyzed using IBM
SPSS 26 statistical software. The participants’ responses were checked for completeness
using the missing values analysis (MVA). The participants' sociodemographic profiles
were analyzed using frequency analysis, which was performed on the entire sample first
and then on each country (the United States and Nigeria) and sample subgroups.
The empirical tests were conducted using CSR as the independent variable. CSP,
CFP, CR, CC, and CVC were the dependent variables. These variables were controlled
by sociodemographic variables while using the United States' NC versus Nigeria’s as a
moderating variable. The tests of normality and tests for outliers were conducted on all
variables where such tests were appropriate. The internal consistency and dimensionality
of three constructs (CA, CC, and PI) were conducted to statistically assess constructs’
reliability and to obtain Cronbach’s alphas and Pearson Correlation coefficients for each
of them. Finally, the study's hypotheses were statistically tested using the GLM modeling
approach (see Dobson & Barnett, 2018; Fox et al. 2019).
Definitions
Corporate competitiveness (CC): A multidimensional, theoretical, and relative
concept related to the market mechanism that may suggest different levels of aggregation:
individual, industrial, regional, and national organizations (Braendle et al., 2017).

Corporate financial performance (CFP): A multidimensional construct that is the
economic aftermath as a result of the interactions among an organization’s actions,
attributes, and environment (Trumpp & Guenther, 2017).
Corporate reputation (CR): The collective perception of an organization’s past
activities and expectations regarding its future activities, in view of its competence in
relation to its closest competitors (Pires & Trez, 2018).
Corporate social performance (CSP): The practices, principles, and
organization’s relationship with institutions, people, communities, businesses, societies,
and the world, regarding measured actions of the organization towards these stakeholders
as well as the unintentional externalities of their business activities (Wood, 2015).
Corporate social responsibility (CSR): Corporations taking on a responsibility to
society and a wider category of stakeholders outside its shareholders (Wang et al., 2016).
Corporate social responsibility (CSR) associations: Includes obligation to
diversity in promoting and hiring, environmental responsiveness, community
participation, support of corporate philanthropy or cultural activities, labor relations, and
consumerism (Moon et al., 2015).
Corporate value creation (CVC): In the context of CSR, when strategic corporate
social responsibility programs are implemented properly, they can aid organizations in
competing with their rivals and in turn develop added value not just for the organization
but also for the society at large (Palazzo et al., 2020).

Ethical corporate behavior: Catering to stakeholders' needs, fulfilling regulatory
obligations, making the right financial decisions, transparency, and enhanced
accountability in the corporate governance system (Elgammal et al., 2018).
Legitimacy theory: States that the more the probability of adverse changes in an
organization’s conferring public’s views of how socially responsible the organization is,
the more the interest on the organization’s part to implement legitimation strategies to
deal with these changes in social views (Ching & Gerab, 2017).
National culture (NC): Understood as the shared mental programming of the mind
from a nationwide perspective (Ansah et al., 2019).
Stakeholders: Stakeholder identification is founded on three significant
characteristics: being affected by and affecting the firm, interdependence, and the sense
of a right or an interest in the firm (Miles, 2017).
Stakeholder theory: States that the fundamental aim of a business is to create
value for the individuals and groups who can be affected by or can affect the business
(Freudenreich et al., 2020).
Social responsibility: The responsibility of organizations to improve and support
society while also going about their business legitimately (Carroll, 1979).
Sustainability: The concept has to do with economic developmental activities that
meet the needs of the present without hindering the capability of future generations to
meet their own needs, in which there are three equal elements and pillars holding up the
concept:

environment, economy, and equity (Portney, 2015).
Assumptions
Several assumptions were believed to be true but were not able to be proven. It
was assumed that people who are most likely to know something about stakeholder
relationships with corporations should be the ones answering questions. This, in turn,
meant that people who are most familiar with business and money matters in the largest
multinational companies could be the best candidates. It was also assumed that the most
likely places to access these kinds of knowledgeable senior people would be in nonprofit,
professional associations, such as national chambers of commerce, national bar
associations, national managerial associations, and national certified accounting
associations. Professional associations were also likely to be the best places to recruit 350
or more volunteers to participate in the study by using their information distribution
software and websites.
It was also assumed that the best participation in the survey would be achieved
using online survey software such as Survey Monkey for people who were computer
literate. With these assumptions in mind, it was also logical that the online software
should be able to handle all of the functions that are required to be fulfilled to recruit
potential survey participants, which are: able to present an institutional review board
(IRB) informed consent document to explain the reasons for the project, obtain their
signature after reading measures to protect their confidentiality, screen in and screen out
prospective participants using inclusionary and exclusionary criteria, conduct the study
survey, conduct an exit survey about the ease of taking the survey, compile the data,

enable monitoring and spot-checking of how many people have completed the survey
prior to reaching the targeted population sample desired, and send the completed data to
my computer for statistical analysis. It was also assumed that the final number of people
recruited would exceed the value of the sample size to fulfill the sample size required by
the statistical power equation due to missing data and having to omit incomplete surveys.
Scope and Delimitations
The measures taken to use an existing validated survey instrument for most of the
survey questions included selecting a sample size to keep bias below 5%, selecting
standard statistical methods to analyze the data, asking demographic questions to check
that the inclusion and exclusion criteria were followed, checking for interaction of threats
to internal validity, including an exit interview to receive participant feedback, and using
Survey Monkey to pretest and standardize the procedures expected to minimize the
problems with internal validity. Specific independent variables that were tested in the
study against the dependent variable of CSR legitimacy and credibility in the perception
of internal and external stakeholders included four business case arguments that have
been pitched by corporations to support the CSR case: (a) lowering the cost and risk of
doing business, (b) bolstering reputations and legitimacy, (c) empowering competitive
advantage, and (d) facilitating win-win quid pro quo value creation.
The measures taken to screen and target the study population with inclusion and
exclusion criteria were expected to result in a population who was knowledgeable about
stakeholder issues, working for a for-profit company at least three years, working for a
governmental organization, a citizen of the United States or Nigeria, familiar with the

employer’s CSR program that has been in effect for at least five years, and a
stakeholder in at least one category (employee, shareholder, customer, member of the
community where company offices are located, supplier to a company with a CSR
program that has been in effect for at least five years, and former employee of a
government that provides infrastructure to the employer or supplier). The measures
taken to recruit the population within professional associations in both the United States
and Nigeria containing senior, seasoned businesspersons who were likely to qualify in
multiple ways as internal and external stakeholders were expected to decrease external
sources of validity. The greatest source of external validity was expected to be making
appropriate and consistent generalizing based on the study’s results.
Limitations
The study procedures analyzed the effects of participants’ attitudes towards the
CSR programs specific to multinational corporations they are associated with, in the
broader context of the United States versus Nigerian national cultures. In this case, the
internal validity is the degree to which the independent variables singularly or in
combinations explain the participants' attitudes towards CSR legitimacy and credibility
compared to other undetermined variable influences. Preassessing what could be a threat
to the internal validity other than construct validity, none of the following potential
threats described in the literature were believed to be threats: maturation, history, testing,
instrumentation, statistical techniques, selection, sample depletion, and interaction of
threats (Edmonds & Kennedy, 2017). The selection and validation of statistical models
was driven by the nature of the study's constructs and the hypothesized relationships

among them. The validity of statistical models included testing underlying assumptions
and descriptive validity diagnostics that addressed all threats to internal validity posed by
the statistical techniques used in the study, so no threats were anticipated. Covariate
analysis and linear filtering were performed during data analysis as statistical quality
control measures (see van Etten, 2009).
Two principal threats to construct validity for this survey approach were thought
to be assessment reactivity (social desirability bias) and the timing of the measurement.
Assessment reactivity means the survey participants did not answer truthfully about how
they feel, an unlikelihood given that responses were kept confidential. The likely
probability that the survey would be run in a time just following something scandalous
reported in the news related to CSR was very low. Confounding variables could exist but
were unlikely to be uncovered during the study unless the participants expressed
questions admitting to or knowing about them, so this could have been a study weakness;
however, it was expected to be minimal. Again, anonymity could have been the best
countermeasure protecting the study from these possibilities.
Significance of the Study
The primary significance of this study was that it could contribute new insights to
theory and practice and bring about positive social change regarding stakeholder attitudes
concerning CSR policies that have been put into effect by U.S. multinational corporations
operating in the United States and Nigeria, among other countries. CSR was introduced
by Bowen (1953), but no settled consensus has been reached about its definition as part

of the makeup of modern corporations, including among those who have claimed to be
the corporation’s stakeholders. Focus upon one and only one type of stakeholder and
beneficiary, the owner, was the concern written about in the “Wealth of Nations” in 1776
by the Scottish economist philosopher Smith (Smith, 1991).
Smith described what has come to be known as classical capitalism, which was to
be followed decades later in modern times by Friedman (1970), who supported Smith’s
conception with an updated clarification that became known as neo-classical capitalism
(Lantos, 2001; Moir, 2001). Stakeholder theory was created relatively soon after
acknowledging the concept of multiple corporate stakeholders (Clarkson, 1995;
Donaldson & Preston, 1995; Freeman, 1984) as part of CSR conceptual models that have
inspired scholarly debates for several decades.
Significance to Theory
Classical capitalism (Smith, 1991) and neoclassical capitalism theory (Friedman,
2002) both conceive of one category of corporation stakeholder – the shareholder(s), the
owner(s) who is (are) the principal beneficiary (beneficiaries) of the corporate profits.
The concept of CSR has been a concept portraying multiple stakeholders, and with that,
multiple beneficiaries, including shareholders, employees, customers, suppliers, service
providers, communities, infrastructure providers, governments, and the environment.
Profits and losses under this conception are more widely shared and spread among the
stakeholders. This study provided theoretical insights into the wider conception of
corporate-stakeholder interaction – if corporations can do well by doing good. It could fill
a gap in knowledge about stakeholder attitudes towards the legitimacy, credibility,

practicality, and sustainability of CSR policies as a departure from classical and
neoclassical capitalism theories and stakeholder theory as it relates to various conceptions
of CSR.
Related to these matters are how stakeholders, such as employees, shareholders,
suppliers, consumers, service providers, communities, infrastructure providers, and
governments in various roles within nations such as Nigeria with different cultural values,
regarded the endeavors of United States based multinational organizations – their CSR
policies, ethics, reputation, and marketing. Study participants provided theoretical
insights on whether NC provides a moderating role in a CSR conceptual model of
multinational corporations from countries of origin such as the United States, of “doing
well by doing good” in other nations where they have a substantial presence through the
location of their multinational corporations in developing nations such as Nigeria.
Significance to Practice
Study participants provided insights in this study concerning the general CSR
conceptual framework about four potential practice benefits frequently asserted by
representatives of many multinational corporations in many past studies to be made
possible by using the basic CSR model of doing well in profits by giving back social
benefits in all locations where corporations are doing business, and in the international
contexts, including (a) lowering the cost and risk of doing business, (b) bolstering
reputations and legitimacy, (c) empowering competitive advantage, and (d) facilitating
win-win quid pro quo value creation (Kurucz et al., 2008). The participants’ responses to
these kinds of questions could determine whether CSR is a sustainable concept in

Nigeria. Underlying the participants’ responses to these questions is the extent to which
the stakeholders have a stake in the company. I expected that many stakeholders would
fill more than one stakeholder role. It may also be true that the more stakeholder roles
that are filled by each stakeholder, the greater that person’s or group’s commitment is to
the corporation, which could lead to greater corporation success at fulfilling its mission.
Significance to Social Change
The world’s population and operational systems have become orders of
magnitude larger and much more complex since Smith published his classic economic
and philosophical theory of capitalism in the Wealth of Nations in 1776 (Lantos, 2001). It
is now understood that corporations through their stakeholders can generate far greater
positive outcomes as well as negative externalities upon the individuals, communities,
environments, and nations they serve than once thought was the province of just one
category of stakeholder – the shareholder (Chernev & Blair, 2015; Suarez, 2020). It also
is now widely perceived that large corporations and large multinational corporations
could have a positive social change impact upon communities and developing nations
based upon the content, scale, capital, financial stability, human resources (Harrison et al.
(2015), access to technology, connectedness to global resources (Crane, 2018), and
unique tacit knowledge of industrial development logistics (Freeman et al., 2007).
Producing more knowledge as to how, where, and how much this can work to
produce positive social change could be the ultimate value of this study. As far as CSR
has been developed as a concept, it is still in its infancy in terms of how to build effective
detailed CSR policies and implementation plans so that they fulfill the promise of the

four pillars (Harrison et al., 2015), and moderating factors have been identified as being
potential drivers of successful social change outcomes in this study.
Summary and Transition
In Chapter 1, I introduced and outlined the background of the study. The research
problem was stated, and the nature, theoretical foundation, assumptions, scope and
delimitations, limitations, and significance of the study were explained. The purpose
statement, research questions, and hypotheses were presented, and the definition of key
terms were provided. There has been a concerted effort by corporations to convince their
colleagues, skeptical scholars, stakeholders, and others that they are setting aside
neoclassic capitalism and embracing the CSR paradigm. This spirited and contentious
debate in which corporations have asked many to set aside decades of corporate
irresponsibility and belief that corporations will now integrate social values into their
current operations is ongoing. The corporations’ principal pitch of doing well by doing
good has been captured in a four-point paradigm that CSR will lower the cost and sustain
business, elevate the legitimacy of stakeholders, enhance competitive advantages, and
facilitate win-win quid pro quo value creation in the United States and Nigeria.
The problem is it is unclear whether potential CSR stakeholders will agree and go
along with this paradigm, including the stakeholders who reside in nations in which U.S.
multinational corporations provide products and services. There have only been a few
confirming studies and noncurrent research, suggesting a gap in the literature. There is
also a gap in knowledge about whether CSR in practice is aligned with the CSR paradigm
described in scholarly journal articles. The purpose of this quantitative study was to

empirically test (a) the theory of CSR positing that CSR programs are correlated with
improved CSP and CFP; and (b) the stakeholder theory, asserting the existence of a
mutually beneficial interactive correlation between corporations and their stakeholders,
and a positive association of such links with CC, CR, and CVC effects of CSR in
developing nations such as Nigeria. Sociodemographic control variables and a
moderating variable of the United States' NC versus Nigeria’s were statistically
controlled in the study.
Chapter 2 provides a detailed literature overview of the theoretical foundations of
capitalism theory, neo-capitalism theory, stakeholder theory, and the contentious debate
over the CSR paradigm, showing the relationship between the four independent variables,
moderating variable, and the dependent variable of doing well by doing good, the
rationale for the inclusion of these variables, and what is known about the variables. A
detailed description follows, describing the major hypotheses and delineation of the
assumptions.
Chapter 2: Literature Review
The past and current literature are inconclusive whether the CSR paradigm is
legitimate and credible in the view of multinational corporation stakeholders in the
United States and Nigeria. It is unclear whether CSR in practice is aligned with
Freeman’s CSR theories that (a) lowers cost and sustains business, (b) elevates the
legitimacy of stakeholders, (c) enhances competitive advantages, and (d) facilitates
winwin quid pro quo value creation in the United States and Nigeria.

The purpose of this quantitative study was to test empirically (a) the theory of
CSR, positing that CSR programs are correlated with improved CSP and CFP; and (b) the
stakeholder theory, asserting the existence of a mutually beneficial interactive correlation
between corporations and their stakeholders, and a positive association of such links with
CC, CR, and CVC effects of CSR in developing nations such as Nigeria.
Sociodemographic control variables and a moderating variable of the United States' NC
versus Nigeria’s were statistically controlled in the study.
In this chapter, I present the theoretical framework of stakeholder theory in
relation to capitalism and CSR, a review of literature on capitalism, CSR, and stakeholder
constructs, the study methodology, the literature of the variables at play, how these
variables were selected, what remains controversial, and what remains to be studied.
Literature Search Strategy
The literature search was conducted within several databases, including Thoreau
Multi-Database, EBSCO, ProQuest Dissertations, Walden University Dissertations, and
Google Scholar. Keywords used were capitalism, corporate social responsibility,
stakeholder theory, doing well by doing good, stakeholder interaction with corporations,
corporate social responsibility, corporate social performance versus corporate financial
performance, and stakeholder theory. Providing the literature for review in this study
were peer-reviewed journals, many of which were published within the last 5 years.
There were other noteworthy journals that enhanced the structure of the study and the
understanding of key concepts presented in the study. The keywords were also used in
combination to discover if more applicable search results could be obtained.

Theoretical Framework
Even though CSR and corporate capitalism were important conceptual models in
this study, stakeholder theory (Freeman, 1984) was the primary theoretical foundation of
the study because stakeholder theory could predict how CSR and corporate capitalism
could be defined or redefined as it pertains to these two nations. In other words, given the
setup of this study, the national cultures of the United States and Nigeria that determine
how stakeholder theory unfolds in each country were set up as the operational
independent variables of the study and CSR, and corporate capitalism effects or impacts
of these independent variables were the operational dependent variables. I assumed that
stakeholders in the United States and Nigeria generally understand and conceptualize
CSR and capitalism in different ways although the details of exactly how they differ have
not been described in the literature.
Stakeholder Theory
The roots of stakeholder theory can be traced back to the roots of capitalism and
Smith, who published The Wealth of Nations in 1776. Smith asserted that profit-making
was the source of the wealth of all nations, describing how profits were converted into
wealth. Capitalism can be thought of as the roots of stakeholder theory because
capitalism was developed over the centuries to become the foundation of the present-day
U S. corporation. Stakeholder theory derives from the fundamental business model of
modern U.S. corporations that create functions that impact and serve a series of
stakeholders that make the running of corporations possible (Lantos, 2001).

Origins of Stakeholder Theory
By the 21st century, the corporation had established the form that is commonly
known today. Along the way of its development, the corporation also had critics who
sought to improve upon the basic corporation model by suggesting fundamental structural
changes such as adding more social responsibilities and ethical standards (Bowen, 1953;
Freeman, 1984). Friedman’s (1962) neoclassical capitalistic shareholder model appeared
to many to push back on that suggestion by reaffirming Smith’s model by reasserting that
the fundamental responsibility of corporations was making profits carried out by
corporate employees, claiming that added social responsibilities could do more harm than
good to society (as cited in Friedman, 2002; Lantos, 2001; Moir, 2001). Although
Friedman’s model had a legion of followers and detractors, over time, his model may
have been misinterpreted by several critics who felt that Friedman’s model was outdated.
In 1963, “stakeholder” as a concept appeared in a 1963 internal memo at the
Stanford Research Institute (Freeman et al. 2013), today known as SRI International. A
decade later, many academics and management practitioners were developing theories to
deal with problems connected with uncertainty and change. Freeman (2010) suggested
that these problems be approached using the stakeholder idea combined with the ethical
aspects of business management based upon his background in philosophy, including
work by Barnard (1938).
In the 1980s and 1990s, Freeman used the stakeholder concept to address three
related concepts: “(a) the problem of value creation and trade in a rapidly changing and
global business context, (b) the problem of ethics in capitalism, and (c) the problem of

managerial mindset…to…better create value, and…explicitly connect business and
ethics” (Freeman et al., 2010, p. 29). The idea uniting them all together was using
stakeholder relationships as the unit of analysis – how groups of customers, suppliers,
employees, financiers (stockholders, bondholders, banks, etc.), communities and manager
interactively create and trade value. These relationships proceed and change over time.
The executives of the corporation organize, reimagine, and restructure these relationships
to create a maximum of stakeholder value, especially where there are conflicting interests
and tradeoffs, that is then decided and distributed (Freeman, 1984; Freeman et al., 2010;
Harrison et al., 2019).
Although Freeman was one of Friedman’s most persistent supporters, Freeman’s
introduction of the stakeholder model led others to believe that he was also one of
Friedman’s critics. Freeman viewed the stakeholder model as a complementary
enhancement embedded in Friedman’s capitalism model (as cited in Agle et al. 2008).
Many critics of Friedman may not have understood that Freeman’s stakeholder theory
was a push to improving the strategic management of stakeholders to enhance and
improve the capitalistic model (Agle et al. 2008; Freeman, 1984).
Freeman asserted, “The key idea about capitalism is that the entrepreneur or
manager creates value by capturing the jointness of the interests” (as cited in Agle, 2008,
p. 165). Freeman asserted further, “Stakeholder theory…is a very simple idea about how
people create value for each other. It’s a theory about what good management is” (as
cited in Agle, 2008, p. 166). Freeman and McVea (2001) later defined what they called
the six-point basic argument of stakeholders’ theory as “how could they (managers) be

more effective in identifying, analyzing, and negotiating with key stakeholder groups”
(pp. 230-231):
1. No matter what you stand for, no matter what your ultimate purpose may be,
you must take into account the effects of your actions on others, as well as
their potential effects on you.
2. Doing so means you have to understand stakeholder behaviors, values, and
backgrounds/contexts, including the societal context. To be successful over
time, it will be better to have a clear answer to the question, “What do we
stand for?”
3. Some focal points can serve as answers to the question “What do we stand
for?” or enterprise strategy.
4. We need to understand how stakeholder relationships work at three levels of
analysis: the rationale of ”organization as a whole,“ the process or standard
operating procedures: and the transactional or day-to-day bargaining.
5. We can apply these ideas to think through new structures, processes, and
business functions, and we can especially rethink how the strategic planning
process works to take stakeholders into account.
6. Stakeholder interests need to be balanced over time. (p. 231)
Freeman (2001) also proposed to reform corporation law in the interests of stakeholders:
1. The Stakeholder Enabling Principle – Corporations shall be managed in the
interests of their stakeholders, defined as employees, financiers, customers,
employees, and communities.

2. The Principle of Director Responsibility – Directors of the corporation shall
have a duty of care to use reasonable judgment to define and direct the affairs
of the corporation in accordance with the stakeholder enabling principle.
3. The Principle of Stakeholder Recourse – Stakeholders may bring an action
against the directors for failure to perform the required duty of care. (pp. 47-
48)
Stakeholders
Stakeholders have been generally defined by Clarkson (1995) as those people who
have converted their convictions into personal risk by putting some form of financial or
human resource capital into a corporation’s asset base to facilitate the corporation’s
ongoing operations. These stakeholders are in one or more of the following categories:
shareholders, investors, customers, employees, suppliers/consultants, and governments
that provide infrastructure resources, regulations, licenses to operate, and laws and
standards to guide behavior. The natural environment could also be considered a passive
stakeholder within the communities where the corporations operate in and the
communities themselves that provide taxes to fund the infrastructure and protect the
environment either in the form of prevention or restoration of the corporation’s degrading
impact. This definition was expanded by Starik (1995), who suggested that there are two
categories of stakeholders:
1. There are internal stakeholders that are defined by shareholders, investors,
banks and financiers, customers, managers, employees, suppliers/consultants,
governments, and the natural environment where the stakeholders operate.

2. There are also external stakeholders including customers; local communities
that contribute a labor pool as well as benefitting from job offerings; corporate
giving that supports community charities through monetary and human
resource voluntary efforts; and governments that tax corporations and collect
licensing fees and regulatory fines, spending that money on providing
community services and clean-up of environmental emissions that
corporations externalize (Starik, 1995, p. 215).
The number and mix of stakeholders who occupy these categories can vary
substantially from corporation to corporation. Internal to the organization, primary
stakeholders contribute monetary or human resource assets directly to the corporation,
whereas external or secondary stakeholders contribute or are affected by the firm. Over
the decades, the number of stakeholder categories and diagrams of the categories in
relation to the corporation has changed. Freeman et al. (2007) used the diagram in Figure
4 to describe the relationship between two tiers of stakeholders and the corporation.
Figure 4
The Two Categories of Stakeholders
Government
Communities Customers
Media
Competitors
The Firm
Financiers Employee
s
Suppliers
Special
Interest
Groups
Consumer
Advocate
Groups
Primary Secondary Stakeholders Stakeholders
Note. The internal primary stakeholders and the external secondary stakeholders. From
Managing for stakeholders: Survival, reputation, and success (p. 7), by Freeman et al.,
2007, Yale University Press. Copyright 2007 by Freeman et al.
In the last decade, as the interest in and support for stakeholder theory has
increasingly grown by corporations and their stakeholders, sentiment has increased for
greater engagement by stakeholders in the corporation's operations. As greater
engagement by stakeholders in the operations of corporations has grown and more
stakeholders have been identified, the corporation has been pushed out of the center of
the activity and the line separating primary and secondary stakeholders has become
blurred as stakeholders have become more integrated into the corporations' ongoing
operations, as is conceptually shown in Figure 5.
Figure 5
Multistakeholder Value Map
Industry
Society
Local NGOs Local communities government Firm
MStaukltei--
Governments Holder
Intermediaries Alliance Other
Firm
Competitors
Suppliers
Communities
Customers
Media
Joint Valu e Creation
emergen t process
Financiers Consumer
Advocate
Groups
Employees
Suppliers
Civil Society
Organizations
Special Interest
Groups
Note. Multistakeholder value map showing a joint value creation emergent process. From
Stakeholder relationships and responsibilities: A new perspective (p. 52), by C. Civera
and R. E. Freeman, 2019, Symphonya. Emerging Issues in Management, (1), pp. 40-58
(http://dx.doi.org/10.4468/2019.1.04civera.freeman ) . Copyright 2019 by Civera and
Freeman.
The following is a description of each of the major stakeholder categories:
Industry: All stakes are reciprocal in terms of potential benefits and losses,
rights, and responsibilities. All stakeholders under this category are
indispensable to the success and survival of the firm.
Communities: When local communities where the firm resides grants firms
the rights to operate their business and take advantage of local infrastructure,
they also become a stakeholder in the firm as they receive economic and
social benefits in the form of taxes and fees to support that infrastructure and

jobs to help their citizens. The firm also agrees not to create externalities in
the form of pollution that impose uncompensated costs on the community
(Freeman, 2000).
Customers: In exchange for value, customers receive values; thus, the revenue
they provide is also indispensable to the firm's success and continuation. This
revenue is necessary for reinvestment in the firm’s research and development
of new products and services. When customers and firms exchange
information about products and services as stakeholders, they can help each
other better understand how those products and services' true value can help
improve quality, delivery, and satisfaction (Freeman, 2000).
Employees: The stake that employees have is their jobs and livelihood. They
expect wages and benefits in return for skills they have that they apply to the
work, engaging work, and security (Freeman, 2000).
Firm: What is referred to as the firm are the corporation's managers and
employees who have an employment contract and a duty to protect the
corporation’s health and welfare. This means providing a balance between the
conflicting demands of its stakeholders (Freeman, 2000). Owners seek better
financial returns; customers want more research and development; employees
want higher wages and benefits, and communities want more donations for
community facilities. Demand for more benefits usually exceeds the supply of
the firm’s resources.

Owners: The owners of the corporation – families, financiers, founders,
stockholders, are those who have the financial stake in the corporation in the
form of shares of stock and have put money into the firm to receive some kind
of financial type of return (Freeman, 2000).
Suppliers: Whether a corporation produces services or products, suppliers are
indispensable to the firm's success and survival as well as the customer and
final user of the product or service. Therefore, the supplier is a stakeholder in
the firm's success and, when treated as such, will support the firm as a part of
the firm with price cuts, allowing late payment and financing (Freeman,
2000).
Society: External to the organization are other groups and organizations that
are indirectly related to the firm as context stakeholders, including civil
society organizations, consumer advocate groups, governments, media,
competitors, and special interest groups. These additional groups have been
added to the list of corporation stakeholders in recent years, representing an
expansion of thinking about stakeholder theory that has grown and
intensified in more than 30 years of focus and research on stakeholder
relationships and responsibilities (Civera & Freeman, 2019). These
additional stakeholder categories have been represented in an expanded
concept of multistakeholder initiatives (MSIs) as shown in Figure 2,
reflecting changes in thinking among researchers in the past decade that
emphasizes the interrelationships between stakeholders, interdependence of

stakeholders, cooperation between stakeholders, and uniqueness of
stakeholders superseding the long-held corporation-centric point-of-view
(McVea &
Freeman, 2005; Soundararajan & Brown, 2016).
These changes had been foreseen and previously described by Freeman (2013). In
the past few decades, many, if not all scholars with notable exceptions, have understood
the importance and value of mutual benefits shared by both the firm and its stakeholders.
Despite strongly palpable movement in this direction, some research findings have
evidence to the contrary. Mitchell et al. (1997) presented evidence that stakeholder
relationships with the corporation are very much a power relationship in which
stakeholders are subordinated based upon corporate dependence, their leveraging power
against the corporation, and the justifiability and imperative nature of their claim. In such
relationships in the corporation, it is the firm that reacts to claims and either creates social
and economic solutions that have value or not (Tashman & Raelin, 2013). Transactional
focus, as distinguished from social relationships between stakeholders, also seems most
relevant (Civera & Freeman, 2019). This concept seems to hold even if market pricing
logic used to create value does not lead to beneficial social ends (Venkatamaran, 1997).
Bridoux and Stoelbohorst (2016) asserted that this pricing logic is frequently top of mind
among stakeholders as firms are perceived as always acting in their self-interest.
In recent years multi-stake initiatives (MSIs) – private initiatives among multiple
stakeholders, some attracting a plurality of stakeholders at a corporation dealing with
social, environmental, and other pressures - integrate stakeholder theory with corporate

stakeholder ethical responsibility in (Mena & Palazzo, 2012). These initiatives are often
taken by a vanguard of innovative leaders with broad interests who have pursued
extended negotiations that provide a byproduct of norms for corporate behavior (Zeyen et
al., 2016). This kind of leadership also puts pressure on all stakeholders in a firm because
it demonstrates strong cooperation as to what is in the mutual interest of many
stakeholder groups (Strand & Freeman, 2015), and what could be as important a priority
in value creation as anything the firm puts forth (Boiral & Heras-Saizarbitoria, 2017).
Primary Elements of Stakeholder Theory
The four primary elements of stakeholder theory (Freeman, 1984) at its inception
were as follows:
1. Corporations have interactive links between stakeholders such that the
decision of both entities affects the other.
2. There is a high level of concern upon the relationship processes and outcomes
between the corporation and its stakeholders.
3. All legitimate stakeholder interests have value, and no interests dominate the
other.
4. There is a focus on management decision making. (p. 92)
Over time, stakeholder theory has been gathering increasing attention, focus, and
momentum within academia, corporations, and government. Stakeholder theory
integrates profits, purpose, social morality, and ethics (Civera & Freeman, 2019), as the
theory has described from its inception.

Profits and Purpose. Friedman (2002) emphasized that earning profits were the
primary function and purpose of business, “…as long as it stays within the rules of the
game, which is to say, engages in open and free competition, without deception or fraud”
(p. 133). Agle et al. (2008) and Freeman et al. (2010) argued that Friedman’s perspective
could be “compatible with stakeholder theory – in fact, we see Friedman as an early
stakeholder theorist” (Freeman et al., 2010, p. 10). Clarifying this position, Civera and
Freeman (2019) asserted that “for Friedman, it is within capitalism that stakeholder
interests are pursued and not within corporate social responsibilities” (p. 43). Freeman
went deeper, asserting for Friedman, earnings were primarily associated with markets and
how they work so that maximizing profits within markets brought success to corporations
(Civera & Freeman, 2019). On the contrary, Freeman was quoted as asserting that
stakeholder theory was “not a theory about the firm, but rather it is a very simple idea
about how people create value for each other (Agle et al., 2008). It’s “a theory about what
good management is” (Agle et al., 2008, p. 166). Agle et al. (2008) further posited that
businesses have multiple purposes, and one of those purposes is creating “as much value
as possible for shareholders” (p. 166). Fink (2019), CEO of Blackrock Investments, in a
letter to CEOs said,
Purpose is not the sole pursuit of profits but the animating force for achieving
them. Profits are in no way inconsistent with purpose – in fact, profits and
purpose are inextricably linked. Profits are essential if a company is to effectively
serve all its stakeholders over time – not just shareholders but also employees,
customers, and communities. (para. 5)

Social Morality and Ethics. From the beginning, Harris and Freeman (2008),
Freeman (2000), Wicks (1996), and Freeman (1994) asserted that business and morality
are intrinsically and interdependently integrated, meaning that all corporate behavior,
conduct, and actions lead to consequential and ethical outcomes. Freeman (2000), who
was a philosophy major, asserted, “Most people, most of the time, take, or want to take
responsibility for the effects of their actions on others. And, if they did not, then what we
call ‘ethics,’ or ‘morality’ would be meaningless” (p. 172). This joining of interests is the
basis of Freeman’s theoretical framework of Stakeholder theory as it describes his
conceptualization of the mutual relationships and responsibilities between corporations
and stakeholders (Strand & Freeman, 2015). This is an orientation to collaboration and
partnering, morally enabling a partnership of equals so that stakeholders become active
partners in any value creation process (Civera & Freeman, 2019). Joint value creation
means “mutually supportive contributions to value creation from multiple stakeholders
whose tasks and outcomes are highly interdependent” (Bridoux & Stoelhorst, 2016, p
229).
Corporate Social Responsibility
CSR has been in the ethics literature for a long time, especially as it applies to
stakeholder theory and has served as a part of the underpinnings of the rise of CSR
activities by corporations to the present day. The literature addresses the fundamental
questions of the far-reaching universal purposes of the corporation to serve society-
atlarge and how goals along those lines can be accomplished. Historical
conceptualization of CSR has coalesced around several different themes and keywords: to

name a few for corporate social performance (Aguinis & Glavas, 2012; Ansah et al.,
2019; Carrol, 1979;
George et al., 2019; Lins et al., 2017; Ogri et al., 2019; Wartick & Cochran, 1985; Wood,
1991), to name a few for corporate social responsiveness (Ackerman, 1973; Ackerman &
Bauer, 1976; Agao et al., 2020; Du & Viera, 2012; Sethi, 1975), to name a few for
corporate citizenship (Wood & Logsdon, 2017; Waddock, 2004), to name a few for
corporate governance (Freeman, 2016; Jones, 1980; Kahn et al. 2013; Mason &
Simmons, 2014; Sacconi, 2006; Visconti, 2019), to name a few for corporate
accountability (Cho et al., 2012; Weuster et al., 2020), to name a few for sustainability
and the triple bottom line (Ashrafi et al., 2020; Bussoli et al. 2019; Cupertino et al.
(2019); Elkington, 1997; Parvin et al., 2020; Sughra et al., 2019; Velte, 2020), and for
corporate social entrepreneurship (Austin et al., 2006).
The basic business argument for CSR, meaning pursuing the business proposition
of doing well by doing good (Chernev & Blair, 2015), is an argument for improving CFP
by improving CSP in our communities and society in general (Kurucz et al., 2008). There
have been many reviews of the business case for CSR focused on examining the
relationship between CSR and financial performance (Ackerman, 1973; Haigh & Jones,
2006; Margolis & Walsh, 2001; Salzmann et al., 2005; Smith, 2003; Vogul, 2005;
Waddock & Graves, 1997). The chorus of business critics and global business leaders
arguing for attaining this widely suggested premise has been discussed for decades by
scholars theoretically (Carroll, 1979; Swanson, 1999; Wood, 1991) and empirically
(Cochran & Wood, 1984; Graves & Waddock, 1994; Mattingly & Berman, 2006; Rousso

& Fouts, 1997).
Those who have studied the results of 120 invested trials have come away,
however, with decidedly inconclusive and unpredictable findings, which is to say
financial performance could be better, about the same, or worse for the wide range of
social programs researched (Kurucz et al. 2008; Margolis & Walsh, 2001). Although
these results have been disappointing, it hasn’t stopped government, business leaders, and
business associations from calling for an even greater amount of social and
environmental programs to be included in CSR (Wheeler & Grayson, 2001). Scholars
(Carroll & Shabana, 2010; Hanlon & Fleming 2009; Kinderman, 2012; Marens, 2013)
have put their colleagues on notice that they are witnessing a sustained corporate effort to
convince a more diverse group of stakeholders that fundamentally capitalistic
corporations are legitimately embracing CSR. Corporations are casting aside decades of
empirical evidence of corporate irresponsibility to make a case for the inclusion of
legitimate social values in their current operations (Hanlon & Fleming 2009; Marens,
2010).
Stakeholder theory, language, and rhetoric has been instrumental in assisting CSR
scholars in identifying, detailing, and building the case for the “social” aspect of CSR both
conceptually and empirically (Freeman et al., 2010) as was previously described. Despite
that, the conceptual basis of the CSR that, in principle and practice maintains a clear
separation between business and social interests as well as business and ethical behavior,
does not address the creation of value, which is at the core of what business does. This
could be a substantial self-defeating weakness of CSR that stakeholder theory could

resolve (Freeman et al., 2010). Those who have promoted the CSR concept perhaps do not
want to say how value is created because that could mean they would also have to take a
strong ethical stand that they appear reluctant, resistant, or recalcitrant to do; or they may
not want to admit that strong ethics should supersede profit-making (Freeman et al.,
2010).
Adding social responsibilities to corporate financial responsibilities poses a
structural conflict to corporations that could be unwilling to take a strong ethical position
with potentially serious consequences. Recent crises in the banking and financial
services industry, for example, have demonstrated that those firms that did not closely
integrate ethics with the way they created value, unfortunately, could not fulfill their
responsibilities to stakeholders and wound up damaging a larger amount of value for
many others as well as themselves than might have been expected (Freeman et al., 2010).
Kurucz et al., (2008) posited that four business case arguments that have been
pitched by corporations in support of the proposition of performing better by giving back:
(a) lowering the cost and risk of doing business, (b) bolstering reputations and legitimacy,
(c) empowering competitive advantage, and (d) facilitating win-win quid pro quo value
creation. Concurrently, several scholars, however, have been steadfastly wary in the face
of this effort, freely asserting their own critical interpretations of evolving corporate
motivations. What the analysts asserted they could have been seeing were renewed
propaganda efforts at marketing and branding (Hanlon & Fleming 2009), a predatory
grab for greater power (Marens, 2010), a diversionary tactic or smokescreen to mislead
(Banerjee, 2008), or a quid pro quo for less regulation (Kinderman, 2012).

As there is no settled definition of CSR (Carrol, 1999; Driver, 2006; Garriga &
Mele, 2004; Smith, 2003; Van Marrewijk, 2003), nor of corporate sustainability (CS) that
has been suggested as a surrogate of CSR as a corporate strategy (Ashrafi et al., 2020)
there could be room for an improved proposition relating CFP to CSP. Of the many
studies that made serious efforts to empirically study the link between CFP and CSP
(Ackerman, 1973; Graves & Waddock, 1994; Orlitzky et al., 2003), one stood out.
Margolis and Walsh (2001), in a meta-analysis of 95 similar empirical studies
investigating the relationship between CFP and CSP, found that over 50% of these
studies were a significant challenge to credibility due to questionable study procedures,
sample variance, operationalization of CSP and CFP, and control measures.
Another indicator of credibility concerns was how CSR scholars projected new
research on social issues requiring attention as a means of justifying CSR spending that
could take a significant amount of money away from profit maximization (Margolis &
Walsh, 2001). These were to be studies on (a) search for mediation or correlation
between CSP and CFP, and (b) using well established valid and reliable survey
instrumentation. These were studies seeking to bolster economic arguments about what
could be tense considerations in balancing the distribution decision tradeoff between
profits versus normative social demands (Freeman et al., 2010). The irony is this is
precisely what managers are engaged in when balancing stakeholder interests when
following the key tenets of stakeholder theory – a theory that integrates ethics and profits
to such an extent that corporate choices are facilitated and legitimized more seamlessly.

Summary and Conclusions
In Chapter 2, I reviewed the extant literature on the origins of stakeholder theory,
who are potential stakeholders, the primary elements of stakeholder theory, and the
historical conceptualization of CSR. Stakeholder theory is a currently applicable and
viable theory of corporation behavior originated in 1984 by R. Edward Freeman that
forms the theoretical foundation of this study in predicting how CSR and corporate
capitalism is defined, may be defined, or could be redefined as it pertains to Nigeria and
the United States. This is a theory that encompasses CSR and goes far beyond it while
also reaffirming and enhancing Smith’s model of capitalism introduced in 1776, and
Friedman’s neoclassical capitalistic shareholder model introduced in 1962 (Friedman,
2002). The Freeman model (1984) includes a model that defines both internal
(employees, customers, communities, financiers, and suppliers) and external categories of
stakeholders (government, competitors, consumer interest groups, special interest groups,
and media) linked to the corporation as it was redefined by Freeman et al. (2007). It also
encompasses recent emergent updates to the stakeholder model to include groups of
multi-stakeholders taken from these categories and others (NGOs, local governments,
civil society organizations, consumer advocate groups) that come together on occasion to
take positions on corporate governance, entrepreneurship, and value creation projects and
issues.
What is known in the literature is that many corporations worldwide have taken
up the policies espousing CSR programs, and policies for CSR programs potentially
posing substantial costs. What is unknown is whether the CSR paradigm is legitimate and

credible in the opinion of multinational corporation stakeholders in the United States and
Nigeria. It is unclear that: (a) the CSR proposition that improving CSP will improve CFP,
and (b) the stakeholder theory that corporations have interactive links between
stakeholders such that the decision of both entities affects the other.
At an even greater level of detail, it is also unclear whether the CSR: (a) truly lowers the
cost and risk of doing business, (b) bolsters customer satisfaction, reputations, and
legitimacy, (c) empowers competitive advantages, and (d) facilitates win-win quid pro
quo value creation for all stakeholders in the estimation of internal and external
multinational corporation stakeholders in the United States and Nigeria. This study could
fill at least one of the gaps in understanding the extent to which stakeholder interaction
between corporations and stakeholders exists such that the links between both entities
affect the other. Discussed in Chapter three are the details of the intended methodology,
the research design and rationale, the data collection and analysis plan, threats to validity,
and ethical procedures adhered to.
Chapter 3: Research Method
The purpose of this correlational research design quantitative study was to
empirically test (a) the theory of CSR, positing that CSR programs are correlated with
improved CSP and CFP; and (b) the stakeholder theory, asserting the existence of a
mutually beneficial interactive correlation between corporations and their stakeholders,
and a positive association of such links with CC, CR, and CVC effects of CSR in
developing nations such as Nigeria. Sociodemographic control variables and a
moderating variable of the United States' NC versus Nigeria’s have been statistically

controlled in the study. In Chapter 3, I describe the research methodology that was
selected to achieve the research purpose of the study. I explain the research design and
rationale for the study, identify the target population, sample, and sampling procedures
used, present the research instrument, and describe the data collection and data analysis
plans. Finally, the threats to validity and the standards of ethical research are discussed.
Research Design and Rationale
In this study, I used a quantitative methodology. Quantitative methods are used
widely in social sciences and the management field due to high objectivity and reliability
across various designs, diverse populations, and different interventions (Cassell et al.,
2018). The quantitative methodology was selected because it is flexible and generalizable
(Wilcox, 2019), and it can be safely relied upon to make predictions about different
phenomena (Edmonds & Kennedy, 2017).
Research Design
I used a correlational, questionnaire-based survey research design with multiple
between-group comparisons and fixed effects in this quantitative study. No variables in
the study were manipulated. Cross-sectional research designs measure variables and the
hypothesized relationships between them at the moment of data collection as long as the
variables are properly operationalized, that is, they are observable and measurable
(Edmonds & Kennedy, 2017, p. 118). In turn, correlational designs investigate
relationships between multiple variables to ascertain a possible causation or, at minimum,
the degree of association or strength of correlation between them (Edmonds & Kennedy,
2017, p. 119). The survey approach is the most common type of nonexperimental

research. Currently, the vast majority of survey-based research designs employ online
tools for sampling and especially data collection (Best & Krueger, 2019). The goal of
survey-based research designs is “to eventually generalize the findings to the entire
population or at least to a significant portion of it” (Edmonds & Kennedy, 2017, p. 133).
The study variables consisted of NC as the independent variable; CSR effects on CFP,
CR, CC, CSP, and CVC as the dependent variables; and NC as a moderating variable.
Rationale
The rationale for such a research design was twofold. First, the purpose of the
study and the research questions rendered the other three quantitative research designs
(descriptive, quasi-experimental, and experimental) inappropriate. Second, manipulation
of the dependent variables was not feasible because of the sampling procedures and data
collection methods. Thus, quasi-experimental and experimental research designs were
also unsuitable. Thus, the selected research design was the optimal investigative solution
given the study's scope and scale.
Methodology
In this section, I outline the research approach for this quantitative study. This
quantitative study used a correlational research design. Quantitative research designed
was chosen in order to establish a relationship between the independent variable and
dependent variables. An alignment of this methodology with the literature review, nature
of the study, and research questions was made.

Population
The study population was professionals both in Nigeria and in the United States
who work for large or very large private for-profit companies with active CSR programs.
I relied on the definitions by the U.S. Bureau of Labor Statistics and the U.S. Census
Bureau as classification categories. The U.S. Census Bureau defined a for-profit company
as any corporate entity, which earns profit through its operations and is concerned with its
interests as opposed to nonprofit organizations (U.S. Census, 2020). The U.S. Census
Bureau also distinguished for-profit corporations from government-sponsored enterprises,
which are quasi-governmental privately held entities established to improve or make
possible the flow of credit to specific sectors of the economy or to provide essential
services to the public (U.S. Census, 2020). In turn, the Bureau of Labor Statistics defined
a company as large if it employs 2,500 and 9,999 people and very large if it employs over
10,000 people (U.S. Bureau of Labor Statistics, 2020b).
According to the latest available data, 39.1% of the United States labor force, or
approximately 63.4 million people, were employed at either large or very large company
(U.S. Bureau of Labor Statistics, 2020a). The size of Nigeria’s total labor force in 2020
was approximately 61.4 million, but the proportion of people who have been working at
large or very large companies in Nigeria has been much less – 9.3% or about 5.7 million
in total (The World Bank, 2020). Thus, the number of people in both countries that are
employed by large or very large companies is 69.1 million. These available data have
indicated that roughly 76% of the world's highest-revenue companies have active CSR
programs (Kuna-Marszałek & Kłysik-Uryszek, 2020). Because the company size

strongly correlates with its revenue size (Greene, 2018), it is safe to extrapolate that 76%
of the highest revenue companies can be classified as either large or very large. Thus, the
estimated total size of the study population was 52.5 million.
Sample and Sampling Procedures
The participants were selected through purposive sampling, “a non-probability
sampling procedure in which the researcher utilizes specific criteria to choose members
of the population to participate in the study” (Arnab, 2017, p. 65). O employed
homogenous purposive sampling, that is, “intentionally selecting participants that are
comparable in nature and uniform across the drawn sample” (Lohr, 2019, p. 117).
Homogenous purposive sampling is used when there is “a need to conduct research to
gain an understanding of the collective experience” (Fuller, 2012, p. 238). In the current
study, homogenous purposive sampling was used to test empirically several propositions
of the current version of stakeholder theory (see Freeman, 1984, 1999; Freeman et al.,
2010; Freeman et al., 2019).
The inclusion criteria were as follows: (a) currently working for a private,
forprofit company in the United States or Nigeria with an active CSR program, (b)
currently working for a government, (c) a U.S. or Nigerian citizen, (d) at least three years
of work experience in the current position, (e) the company’s CSR program has been in
effect for at least five years as reflected in the company’s mission statement, (f)
familiarity with the company’s CSR program and ability to comment on it, and (g)
English reading comprehension. The exclusion criteria were as follows: (a) under 18

years of age, and (b) currently studying. These exclusion criteria allowed for the
elimination of individuals lacking direct knowledge about the topic of the current study.
To determine the sample size required to detect an effect of .8 with α = .05 for a
GLM, a priori power analysis was conducted using GPower 3.1 statistical software. The
results indicate that the minimum required sample size was N = 348.
Instrumentation
The data were collected using two research instruments: (a) the English language
version of the VSM 2013 Questionnaire, and (b) the CSR Attitudes Questionnaire
(CSRAQ). Both surveys were combined into a single instrument (see Appendix A) and
converted to an online form for data collection using the SurveyMonkey service.
The Values Survey Module (VSM)
The VSM 2013 is a 30-item questionnaire-based survey developed by Hofstede in
1982 for comparing culturally influenced values of respondents from two or more
countries (Hofstede & Minkov, 2013b). The VSM 2013 computes scores on six
dimensions of NC with four questions per dimension (Hofstede & Minkov, 2013a), 24
questions in total (Appendix A, Q1-24). The six dimensions (subscales) include the
following:
1. Power Distance Index (PDI; Q1-4).
2. Individualism vs. Collectivism Index (IDV; Q5-8).
3. Uncertainty Avoidance Measure (UA; Q9-12).
4. Masculinity vs. Femininity Index (MAS; Q13-16).
5. Long-term vs. short-term Orientation Index (LTO; Q17-20).

6. Indulgence vs. Restraint Index (IND; Q21-24).
The responses were measured using a uniform 5-item Likert scale indicating (a)
the degree of importance of a statement to a respondent (1 = of utmost importance, 2 =
very important, 3 = of moderate importance, 4 = of little importance, 5 = of very little or
no importance), or (b) the level of agreement with a statement (1 = strongly agree, 5 =
strongly disagree), or (c) the frequency of occurrence (1 = always, 2 = usually, 3 =
sometimes, 4 = seldom, 5 = never). The last six questions collect demographic
information (gender, age, level of education, type of job, current nationality, nationality at
birth, and kind of stakeholder; Hofstede & Minkov, 2013a).
As a research instrument, the VSM 2013 is an operationalization of Hofstede’s
cultural dimensions theory (Minkov & Hofstede, 2013). In particular, the theory posits
that a society’s culture affects the values of its members, which in turn affect group
attitudes within each culture and also to a significant degree the individual behavior of
the members of the same culture (Hofstede, 2002; Hofstede et al., 2010; Hofstede et al.,
2002). The authors of the VSM 2013 emphasized that it is “not for comparing
individuals” as it is based on “country-level correlations” and “country-level correlations
produce dimensions of NC” (Hofstede & Minkov, 2013a, p. 4). The VSM 2013 is the
latest version, and it is freely available for academic research purposes. Permission to use
the VSM 2013 is not needed. The validity and reliability of the VSM 2013 have been
extensively tested empirically, and both were found to be high (Bakir et al., 2015;
Beugelsdijk & Welzel, 2018; Eringa & Rieck, 2015; Minkov, 2018).

The CSR Attitudes Questionnaire (CSRAQ)
The CSRAQ (FleishmanHillard, 2019) is a smaller version of the National Survey
Questionnaire on CSR, developed by FleishmanHillard, a brand marketing and research
agency, to measure the attitudes of consumers, professional investors, and executives
towards CSR programs. For this study, only 12 CSRAQ questions were included in the
single research instrument (Appendix A). The 12 questions measured participants’
opinions about
1. The CSR effects on CFP (Q25-27)
2. The CSR effects on CR(Q28-30).
3. The CSR effects on CC (Q31-33).
4. The CSR effects on CSP(Q34-35).
5. The CSR effects on CVC(Q36).
The participants’ responses were measured using a 7-item Likert scale indicating
the degree of agreement with a specific statement about the CSR (1 = completely
disagree, 2 = disagree, 3 = somewhat disagree, 4 = uncertain, 5 = somewhat agree, 6 =
agree, 7 = completely agree). The authors of the CSRAQ evaluated it in over 170 studies
of the CSR, and the instrument was found to be valid and reliable, especially for the
measurement of employees’ attitudes.
The rationale for the selection of namely these 12 questions was based on the
following considerations. First, there was the sociodemographic profile of the target
population in the current study. The original CSRAQ survey contains 34 questions, while
the VSM included 24 questions. Implementing a survey with 58 questions would have
increased the risk of incomplete responses, which in turn could have complicated the
analyses. Furthermore, four of the CSRAQ questions are identical to sociodemographic
questions in the VSM. Second, the selected CSRAQ questions closely matched, without
any modification, the constructs of the current study. Third, some of the CSRAQ
questions are only applicable to the United States. business context. The focus of the
study was on the comparison between the United States and Nigeria. Last, I did not
eliminate English language proficiency as a possible factor that could affect the
participants’ responses.
Operationalization of Constructs
The constructs and their roles in the study as variables are presented in Table 1.
The five dependent variables' constructs reflect the extended typology of the business
case arguments in support of CSR programs, as proposed by Kurucz et al. (2008).
Table 1
Operationalization of Constructs and Variables of the Study
Variable Construct Operationalization
Independent
(IV) - 1
National culture (NC). A set of beliefs and values shared by the U.S. and Nigerian participants and
consisting of 6 dimensions as measured by the VSM 2013.
Dependent
(DVs) - 5
CSR effects on corporate
financial performance (CFP).
Participants’ opinions about CSR's effects on lowering the costs and risk of
doing business as measured by the CSRAQ (Q25-27).
CSR effects on corporate
reputation (CR). Participants’ opinions about CSR's reputational and legitimizing effects as
measured by the CSRAQ (Q28-30).
CSR effects of corporate
competitiveness (CC). Participants’ opinions about CSR's effects on corporate competitive
advantage as measured by the CSRAQ (Q21-33).
CSR effects on corporate social
performance (CSP).
Participants’ opinions about the influence of CSR programs on their
company's social image (Q34-35).
CSR effects on corporate value
creation (CVC). Participants’ opinions measured by the CSRAQ (Q36) about CSR's effects
as a facilitator of win-win quid pro quo value creation.
Moderating
variable (MV)
- 1
National culture (NC). A set of cultural beliefs and values of the U.S. and Nigerian participants as
measured by the VSM 2013 (Q1-24).
Control (CVs)
- 7
Gender (GEN), age (AGE), level
of education (EDU), type of job
(JOB), current nationality
(NATC), nationality at birth
(NATB), and kind of stakeholder
(SHOLD).
Constants to prevent confounding with the IV. Constructs gender (Q37), age
(Q38), level of education (Q39), job type (Q40), current nationality (Q41), and
nationality at birth (Q42) are all operationalized using the criteria of the
VSM-2013 (Hofstede & Minkov, 2013a). Construct Kind of Stakeholder
(Q43) has two dimensions – internal (2 categories – employee and manager)
and external (4 categories – service provider, supplier, government
regulator, consumer) and operationalized using criteria of Phillips et al.
(2019).
Notes. Table showing the construct and operationalization of the independent, dependent,
moderating, and control variables.
Data Collection Plan
The participants were recruited through accessing the membership bases of
several professional associations in both locations of the study. Letters explaining the
purpose of the study and requesting permission to email members were sent to the
proposed associations. Once the permission was obtained, the members received an email
soliciting their participation in the study. Upon electronically confirming their agreement
to participate in the study, the participants accessed the provided SurveyMonkey live link
to the study’s research instrument. The process of data collection took 37 days. When the
data collection was completed, the collected dataset was downloaded from the
SurveyMonkey website.

Procedures for Recruitment
The professional associations were selected to match their counterparts in each
country in terms of their organizational mission, and the size of membership in Nigeria;
the participants was recruited from prominent national business associations in both
Nigeria and the United States whose identities have been left out of this description as a
condition of participation requested by the associations.
Participation
The background research on all associations in both countries indicated that each
association united several thousands of individual members. Most of these individual
members are mid to high-level corporate professionals working in their respective
industries. According to methodological literature on internet research, the average
response rates for an online survey range between 17.2% and 23.8% (Arnab, 2017;
McNabb, 2013; Rea & Parker, 2014). Assuming the lowest bound of the range is more
likely, then the researcher can expect to recruit at least 1,500 participants. It is also likely
that up to 10% of participants will not finish the survey (Arnab, 2017).
This process will nevertheless leave enough participants for the application and
inclusion and exclusion criteria of the study. After all exclusions and attrition, the
researcher found that the number of participants was more than sufficient to satisfy the
minimum sample size requirement of 348 to detect strong effects. It was also sufficient to
detect medium and weak interactive effects that were expected in this study.

Data Analysis Plan
All data collected in the study was analyzed using IBM SPSS 27 statistical
software. The data analysis involved the following steps. First, the participants’ responses
were checked for completeness using the MVA. Depending on whether data are missing
completely at random (MCAR), missing at random (MAR), or missing not at random,
missing data were eliminated through listwise or pairwise deletion (Little & Rubin,
2019). No substitution or imputation data was done. Second, the sociodemographic
profile of the participants was analyzed using frequency analysis, which was performed
on the entire sample first and then on each country. Third, the frequency analysis of the
five constructs (CFP, CR, CC, CSP, CVC) was conducted to evaluate the vector of the
hypothesized relationships. Fourth, the hypotheses of the study were statistically
evaluated using the distributional analysis and generalized linear models (GLM). The
effects of cultural differences between Nigeria and the United States on participants’
views was examined as aggregates, then further explored using the six dimensions of NC
(Agresti, 2019). The research questions and hypotheses of the study are shown below:
RQ1: Are CSR programs associated with improved CSP and CFP?
H011: CSR programs are not associated with improved CSP.
H111: CSR programs are associated with improved CSP.
H012: CSR programs are not associated with improved CFP.
H112: CSR programs are associated with improved CFP.
RQ2: What are the stakeholder multinational corporate connection differences between
Nigerian and U.S. multinational stakeholders in the costs and risks of doing

business, corporate reputation and legitimacy, competitive advantages, and
winwin quid pro quo value, considering the cultural differences between both
nations?
H021: CSR does not have positive effects on CR, but the effects are moderated by
the national cultures of the United States and Nigeria.
H121: CSR does have positive effects on CR, but the effects are moderated by the
national cultures of the United States and Nigeria.
H022: CSR does not have positive effects on CC, but the effects are moderated by
the national cultures of the United States and Nigeria.
H122: CSR does have positive effects on CC, but the effects are moderated by the
national cultures of the United States and Nigeria.
H023: CSR does not have positive effects on CVC, but the effects are moderated
by the national cultures of the United States and Nigeria.
H123: CSR does have positive effects on CVC, but the effects are moderated by
the national cultures of the United States and Nigeria.
Threats to Validity
Validity is “the degree to which a result of a study is likely to be true and free of
bias, i.e., systematic errors” (Reichardt, 2019, p. 26). In essence, validity is a measure of
quality control, and as such, it has two aspects – external and internal validity. The
external validity concerns the external question of whether the results of a study will
remain the same if the study is replicated in other contexts and with different populations
or participants (Agresti, 2019). In contrast, the internal validity measures whether “the

research has been designed in such a way so that it truly investigates what is being
examined” (Agresti, 2019, p. 92). In turn, internal validity consists of face, content, and
construct validities. The latter is “the degree to which a research instrument actually
measures what it is supposed to be measuring” (Bandalos, 2018, p. 111).
External Validity
External validity is defined as “the extent to which the results can be generalized
to the relevant populations, settings, treatments, or outcomes” (Edmonds & Kennedy,
2017, p. 8). From this perspective, any factors that may undermine the generalizability of
research results should be treated as threats to external validity. The most common threats
to external validity include biased sampling, unique stimulus characteristics, unusual
settings, treatment variations, outcome variations, and context-dependent variation
(Edmonds & Kennedy, 2017, p. 9).
Careful consideration of various threats to external validity suggested that only
sample selection bias may pose a real problem due to purposive sampling. The
participants were recruited from professionals who were willing to participate in the
study and answer the research instrument's questions. While purposive sampling is a
nonprobability sampling procedure, willingness to participate in the survey is highly
unpredictable. Therefore, this threat to external validity is mitigated in no small degree by
the randomness of participants’ enrollment.
The effects of other threats to external validity are either non-existent or
insignificant. The study used the same research instrument for all participants, regardless
of whether they were in the United States or Nigeria. The same survey was administered

online. Thus, there is nothing unusual about the study’s settings – the online environment
was familiar to all participants. Likewise, the online survey was not considered a
treatment or an intervention. It is an instrument to measure participants’ attitudes towards
CSR. Therefore, treatment and outcome variations also were not an issue in this study.
Last, context-dependent mediation is the subject of the study, and as such, any issues
related to its differential effects between the U.S. and Nigerian contexts were fully
accounted for in the data analyses in this study (Hayes, 2018).
Internal Validity
Internal validity refers to “the extent to which the outcome was based on the
independent variable as opposed to extraneous or the effects of unaccounted-for
variables” (Edmonds & Kennedy, 2017, p. 7). The methodology literature identified the
following key threats to internal validity: maturation, history, testing, instrumentation,
statistical techniques, selection, sample depletion, and interaction of threats (Edmonds &
Kennedy, 2017, pp. 7-8). The instrumentation threats are directly related to construct
validity, which is addressed in the next section. Because the study did not focus on the
analysis of individual characteristics of participants per se, maturation, and testing did not
pose a threat to the internal validity of the study. History threats to internal validity are
“events occurring in the research environment that substantially change the conditions of
the study, affecting its outcome” (Carmines & Zeller, 1979, p. 64). The study utilized a
cross-sectional design, and therefore the attitudes of the participants were collected at a
specific point in time. So, history threats to internal validity were not an issue in the

study. No major economic policy or socio-political or legal changes occurred at the
period of data collection to affect its outcomes in any assessable way.
The study procedures analyzed the effects of participants’ attitudes towards CSR
in the larger context of national cultures (United States versus. Nigeria). The selection
and validation of statistical models was driven by the nature of the study's constructs and
the hypothesized relationships among them. The validity of statistical models included
testing underlying assumptions and descriptive validity diagnostics. The latter are
powerful tools to address all threats to internal validity posed by statistical techniques
used in the study (Verma & Abdel-Salam, 2019). The MVA was performed on the
original dataset to form the analytical sample (Molenberghs et al., 2014). The MVA
procedure addressed the selection and sample depletion threats to internal validity (Little
& Rubin, 2019). Finally, given how the threats discussed above were mitigated, it is
unlikely that they had any measurable interactive effects on the study’s outcomes. To
eliminate such possibility, covariate analysis and linear filtering were performed during
statistical quality control measures (Heeringa et al., 2017).
Construct Validity
Construct validity is defined as “the extent a generalization can be made from the
operationalization, i.e., measurement of the theoretical construct back to the conceptual
basis responsible for the change in the outcome” (Edmonds & Kennedy, 2017, p. 9).
Methodology literature identified over 20 different types of threats to construct validity
(Mayo, 2018). The majority of threats to construct validity are typically classified as
social threats (Cooper, 2017; Rea & Parker, 2014). The three most common social threats

to construct validity are hypothesis guessing, evaluation apprehension, and experimenter
expectancies. Because the study employed the survey approach with anonymous
responses, the effects of the hypothesis guessing, and evaluation apprehension were
negligible. The primary focus of the survey approach was measurement, and in this
study, it was the measurement of respondents’ attitudes and opinions about the CSR in
specific cultural contexts, so making appropriate and consistent generalizing based on the
study’s results was critical.
Thus, there are two main threats to construct validity for the survey approach: (a)
assessment reactivity (acquiescence response bias or social desirability bias), and (b)
timing of measurement (Edmonds & Kennedy, 2017, p. 134). Assessment reactivity in
survey research refers to instances when respondents “change or alter the way they
respond to items on a survey, which is different than the way they truly feel” (Edmonds
& Kennedy, 2017, p. 134). The confounding effects of assessment reactivity cannot be
entirely eliminated in survey research (Rea & Parker, 2014), but this study employed
anonymity as the effective countermeasure for this threat (Reichardt & Gollob, 1989).
The threats to construct validity stemming from the timing of measurement did not
become serious in the time in which the survey was administered. Because there were no
major corporate scandals related to the CSR, the timing of conducting the survey had no
detectable confounding effect on the results of the current study.
Ethical Procedures
The study’s research location was in the United States, though some participants
may be physically located in Nigeria. Hence, because the study was implemented in the

United States and at an American research organization, according to the federal
regulations on the ethical conduct of research, any study involving human participants,
even responding to an internet survey, must fully comply with the principles of (a)
respect for persons, (b) beneficence, and (c) justice (U.S. Department off Health and
Human Services, 2020).
Respect for persons requires that the researcher and the process of research
“should protect the participants’ autonomy or the right to self-determination” (U.S.
Department of Health and Human Services, 2020).. Thus, the researcher must ensure that
no harm will be inflicted on the research participants in the study and optimize the
benefits while minimizing the possibility of harm (Resnik, 2019). There also should be
mutual beneficence in research, i.e., “equitable distribution of the burden and the benefits
of the research between the researcher and the participants” (Lahman, 2018, p. 37).
To comply with these principles, the researcher abided by all ethical research
requirements at all stages of the study. The recruitment and selection of the participants
was carried out with full impartiality, i.e., with equal opportunity to participate,
regardless of their demographic background or socioeconomic characteristics. Respect
for persons and beneficence was ensured by using informed consent, anonymity, and
confidentiality. The IRB review was obtained and served as an additional safeguard for
the ethical conduct of the research and the IRB approval number is 04-09-21-0356520.
Informed Consent
During recruitment and data collection, all research participants received an
electronic informed consent form in which they agreed to participate in the study and take

the survey. The consent form was an online page that opened before the actual survey.
The consent form described all expectations as a participant in this research. The
participants were informed about the purpose of the study, the reason for the data
collection, key steps in data collection and analytical procedures, and applicable research
ethics standards. The participants also received an e-copy of their rights as a research
study participant if they express their desire to have one. The participants were informed
that at any time when they were responding to the survey questions, they were
completely free to discontinue their participation and withdraw from the study by simply
logging off without any ramifications for them. In this case, their responses were deemed
moot and were erased from the dataset.
Anonymity and Confidentiality
The complete and unconditional anonymity and confidentiality of all participants
was fully assured for the entire duration of the study, including the process of data
collection and data analysis. The true identities and professional profiles of the
participants was concealed by the default option of the online survey – participants were
not asked for any personally identifying information. As a result, all data collected was
depersonalized by default.
IRB Permission
Permission to conduct research involving human participants was obtained from
the IRB of Walden University. I submitted the following information to obtain the IRB
approval: (a) a summary of the study and a research proposal, (b) a statement explaining
how informed consent will be obtained from the participants, (c) a data management

plan, and (d) a “no-risk to participants” statement. The researcher did not expect, nor did
he become aware of any conflicts of interest in the study. The researcher does not occupy
any corporate position related to issues of the CSR. This study is not funded by any
corporate entity.
Summary
Chapter three presented the research methodology of the study. It discussed the
selected research design and the rationale behind such selection, described the research
population, the sample and the sampling procedures, specified approaches to data
collection and data analyses, discussed three types of threats to validity of the study and
provided necessary explanations regarding the ethical procedures of the current research.
Chapter four will present the detailed results of the statistical analyses and the outcomes
of hypotheses testing.

Chapter 4: Results
Past researchers found that CSR may be understood and practiced differently in
the developed and developing nations (Babatunde, 2020; Hauser & Schembera, 2019;
Ting et al., Tashman et al., 2019; Vu et al., 2020). This difference translates into the
specific management problem of the lack of clarity on whether CSR in practice is aligned
with Freeman's theory that CSR (a) lowers cost and sustains business, (b) provides
legitimacy to business' stakeholders, (c) enhances competitive advantages, and (d)
facilitates win-win quid pro quo value creation. Thus, the purpose of this study was to
empirically test (a) the theory that CSR programs are associated with improved CSP and
CFP; and (b) the stakeholder theory, asserting the existence of a mutually beneficial
interactive relationship between corporations and their stakeholders, and a positive
association of such links with CC, CR, and CVC effects of CSR, using Nigeria and the
United States as a cultural comparison.
The research questions of the current study were as follows: (a) RQ1: Are CSR
programs associated with improved CSP and CFP, and (b) RQ2: What are the stakeholder
multinational corporate connection differences between Nigerian and U.S. multinational
stakeholders in the costs and risks of doing business, corporate reputation and legitimacy,
competitive advantages, and win-win quid pro quo value, considering the cultural
differences between both nations?
Five main hypotheses were tested statistically. Two hypotheses addressed RQ1
(a) H111: CSR programs are associated with improved CSP, and (b) H112: CSR programs

are associated with improved CFP. Three hypotheses addressed RQ2, asserting that the
tested effects are moderated by the national cultures of Nigeria and the United States: (c)
H121: CSR has positive effects on CR, (d) H122: CSR has positive effects on CC, and (e)
H123: CSR has positive effects on CVC.
In Chapter 4, I describe the timeframe and procedures of the data collection;
present the outcomes of the missing values analysis; report baseline descriptive and
demographic characteristics of the sample; provide results of the univariate analyses of
the main variables and covariates of the study; and report the findings of the statistical
analyses, organized by research questions and hypotheses tested. Lastly, I summarize
answers to the research questions and provide transitional material from the findings to
introduce the reader to Chapter 5.
Data Collection
The study population was professionals in Nigeria and in the United States who
work for large or very large private for-profit companies with active CSR programs. The
study population was defined using the definitions by the U.S. Bureau of Labor Statistics
as classification categories. The estimated total size of the study population was
approximately 52.5 million.
The sample was drawn using homogeneous purposive sampling, that is,
intentionally selecting participants who are similar in nature and uniform across the
sample. Using the defined inclusion and exclusion criteria, participants lacking direct
knowledge about the topic of the current study were eliminated. The participants were

recruited through accessing the membership databases of 13 professional associations in
both locations of the study. Letters explaining the purpose of the study and requesting
permission to email members were sent to the associations. Once the permission had been
obtained, the members received an email soliciting their participation in the study. Upon
electronically confirming their agreement to participate in the study, the participants
accessed the provided SurveyMonkey live link to the research instrument.
The data collection lasted 37 days and took place in May to June 2021. The
minimum required sample size of 348 participants was achieved on Day 29, but data
collection continued for an additional 8 days to allow for possible data attrition as a result
of data cleaning and missing values analysis. In total, 457 individuals attempted the
survey. Considering the cumulative size of the professional associations' membership
databases of 12,318, the recruitment rate was 3.71%, which was on the low side for
internet surveys. Based on the Q1-9 of the survey, which assessed eligibility, 67
individuals terminated their participation. In total, 391 participants completed the survey.
Thus, the participation rate was 85.56%. There were no discrepancies in the data
collection from the plan presented in Chapter 3. Upon completion of the data collection,
the dataset was downloaded from the SurveyMonkey website and analyzed. All data
collected in the study have been analyzed using IBM SPSS 27 statistical software.
The drawn sample was representative of the study's target population because the
observed frequencies of categories in all variables closely reflected the corresponding
frequencies in the rosters of the professional associations' databases. In 87% of

observations, the variance was less than 5%. The exceptions were as follows: (a) two
categories (high school, associate degree) in the variable education, (b) two categories
(unemployed, generally trained laborer) in the variable job type, and (c) two categories
(government regulator, consumer) in the variable stakeholder type. These categories
showed up in the sample but were not present in the associations' rosters. Because the
initial sample size (N = 391) was ≈ 11.0% higher than the minimum required sample size,
the sample was sufficiently proportional to the study population (a) to explore the
hypothesized relationships with sufficient power, and (b) to generalize the findings of the
study to the entire population of the study and respective populations of professionals in
Nigeria and the United States.
The survey instrument also included four survey quality control questions (Q56-59).
The results overall suggested that the participants believed that the survey (a) addressed
expectations either completely (72.8%) or mostly (19.3%); (b) missed no relevant
questions (82.4%); (c) contained no inappropriate questions (98.7%); and (d) was timed
correctly (91.9%), with only 3.4% of the participants opining that the process provided
them with not enough time, and 1.6% that more time would be better. It is unclear why
5% of the participants felt that the survey required more time as the completion time was
in the range of Min = 12 min. 44 sec., Max = 51 min. 39 sec., with the mean completion
time of 38 min. 01 sec., which all were below the allotted 60 minutes.
Missing Values Analysis
The first step in the data analysis involved the MVA to check participants'
responses for completeness. The MVA results (Appendix B) indicated that the data were

missing not at random, thus requiring listwise deletion on all cases with ≥ 5% of missing
values (MVs) and prohibiting data imputation (see Little & Rubin, 2019). In total, five
cases were removed: (a) one case with three MVs (7% data loss), (b) two cases with
seven MVs (16.31% data loss), (c) one case with 12 MVs (27.9% data loss), and (d) one
case with 29 MVs (67.4% data loss). Then, five cases with one MV (2.3% data loss) and
two cases with two MVs (4.7% data loss) were kept in the dataset and were used in the
statistical analyses using pairwise deletion. Also, because two participants indicated that
they had nationality other than of Nigeria or the United States, two cases were removed
as not satisfying the group sorting criterion. After the listwise deletion of seven cases, the
dataset contained 384 cases and 16,512 observations. The cumulative data attrition was ≈
1.79%, which was within the acceptable range of ≤ 3% of all observations (see Little &
Rubin, 2019).
Sample Characteristics
The descriptive sociodemographic characteristics of the sample are presented in
Table 2. The total size of the sample size N = 384, of which 195 participants reported
their current nationality as Nigerian and 191 participants as American. Because all
covariates were categorical, then they were characterized using frequency counts. In
terms of gender, males accounted for 58.3% of the total sample, while females for41.7%.
Thus, in general, males were overrepresented in the sample by 16.6%. However, while in
the United States group, the gender representation was somewhat more balanced (55.5%
males versus 44.5% females), in the Nigeria group, the gender representation was skewed
towards males (61.1% versus 38.9%). This observation was not surprising, given the
gender gap in the management positions in both countries.
Table 2
Sociodemographic Characteristics of the Sample
Nationality
Variables Categories Measures Total
Nigeria United States
Gender
Male Count / (Total) Within
gender / (Nationality)
118 (30.7%)
52.7% (61.1%)
106 (27.6%)
47.3% (55.5%)
224 (58.3%)
100.0% (58.3%)
Female
Count / (Total) 75 (19.5%) 85 (22.1%) 160 (41.7%)
Age
Within gender / (Nationality) 46.9% (38.9%) 53.1% (44.5%) 100.0% (41.7%)
Young professionals
(20-29 y.o.)
Midcareer professionals
(30-39 y.o.)
Count / (Total)
Within age / (Nationality)
Count / (Total)
Within age / (Nationality)
14 (3.6%)
70.0% (7.3%)
75 (19.5%)
56.4% (38.9%)
6 (1.6%)
30.0% (3.1%)
58 (15.1%)
43.6% (30.4%)
20 (5.2%)
100.0% (5.2%)
133 (34.6%)
100.0% (34.6%)
Education
Senior professionals
(40-60+ y.o.)
Count / (Total) Within
age / (Nationality)
104 (27.1%)
45.0% (53.9%)
127 (33.1%)
55.0% (66.5%)
231 (60.2%)
100.0% (60.2%)
High school
Associate degree
Bachelor's degree
Count / (Total)
Within education / (Nationality)
Count / (Total)
Within education / (Nationality)
Count / (Total)
2 (0.5%)
100.0% (1.0%)
1 (0.3%)
50.0% (0.5%)
38 (9.9%)
0 (0.0%)
0.0% (0.0%)
1 (0.3%)
50.0% (0.5%)
48 (12.5%)
2 (0.5%)
100.0% (0.5%)
2 (0.5%)
100.0% (0.5%)
86 (22.5%)
Within education / (Nationality) 44.2% (19.8%) 55.8% (12.5%) 100.0% (22.5%)
Master's degree
Count / (Total) 120 (31.3%) 133 (34.7%) 253 (66.1%)
Within education / (Nationality) 47.4% (62.5%) 52.6% (69.6%) 100.0% (66.1%)
Doctorate degree*
Count / (Total) 31 (8.1%) 9 (2.3%) 40 (10.4%)
Job
type
Within education / (Nationality) 77.5% (16.1%) 22.5% (4.7%) 100.0% (20.4%)
Unemployed
Generally trained
laborer
Count / (Total)
Within job type / (Nationality)
Count / (Total)
Within job type / (Nationality)
2 (0.5%)
100.0% (1.0%)
3 (0.8%)
100.0% (1.6%)
0 (0.0%)
0.0% (0.0%)
0 (0.0%)
0.0% (0.0%)
2 (0.5%)
100.0% (0.5%)
3 (0.8%)
100.0% (0.8%)
Vocationally trained
professional
Count / (Total)
Within job type / (Nationality)
3 (0.8%)
60.0% (1.6%)
2 (0.5%)
40.0% (1.0%)
5 (1.3%)
100.0% (1.3%)
Nationality
Categories Measures Total
Nigeria United States
Stakeholder
Type
N 193 191 384
Note. * Including professional doctorates.
Academically trained
professional
Count / (Total)
Within job type / (Nationality)
42 (10.9%)
58.3% (21.8%)
30 (7.8%) 72 (18.8%) 41.7%
(15.7%) 100.0% (18.8%)
Manager of
subordinates
Count / (Total)
Within job type / (Nationality)
55 (14.3%)
51.9% (28.5%)
51 (13.3%) 106
(27.6%) 48.1% (26.7%) 100.0%
(27.6%)
Manager of managers Count / (Total)
Within job type / (Nationality)
88 (22.9%)
44.9% (45.6%)
108 (28.1%) 196 (51.0%)
55.1% (56.5%) 100.0% (51.0%)
Employee Count / (Total) 44 (11.5%) 32 (8.4%) 76 (19.8%)
Within stakeholder / (Nationality) 57.9% (22.9%) 42.1% (16.8%) 100.0% (19.8%)
Manager
Count / (Total) 131 (34.2%) 158 (41.3%) 289 (75.5%)
Within stakeholder / (Nationality) 45.3% (68.2%) 54.7% (82.7%) 100.0% (75.5%)
Service provider
Count / (Total) 14 (3.7%) 1 (0.3%) 15 (3.9%)
Within stakeholder / (Nationality) 93.3% (7.3%) 6.7% (0.5%) 100.0% (3.9%)
Government regulator
Count / (Total) 2 (0.5%) 0 (0.0%) 2 (0.5%)
Within stakeholder / (Nationality) 100.0% (1.0%) 0.0% (0.0%) 100.0% (0.5%)
Consumer
Count / (Total) 1 (0.3%) 0 (0.0%) 1 (0.3%)
Within stakeholder / (Nationality) 100.0% (0.5%) 0.0% (0.0%) 100.0% (0.3%)

In the whole sample, the age distribution of the participants was as follows: (a)
young professionals (20-29 years old) was 5.2%; (b) midcareer professionals (30-39
years old) was 34.6%, and (c) senior professionals (40-60+ years old) was 60.2%. Thus,
mature professionals cumulatively accounted for 94.8% of all respondents. The same age
distributions were observed in both country groups, with young professionals accounting
for 3.6% in the Nigeria group and 1.6% in the United States group; while in aggregate,
mature professionals accounted for 92.8% and 98.4% respectively. However, senior
professionals as a category were 12.6% higher in the United States group than in the
Nigerian group.
In terms of educational attainment, in the total sample, (a) two categories (high
school and associate degree) accounted for only 0.5% of participants each, (b) 22.5% of
all participants reported holding a bachelor's degree, (c) 66.1% of all participants reported
a master's degree, and (d) 10.4% reported a doctorate degree. Thus, the sample was
dominated by individuals with a master's degree. The distributions of educational
attainment in both national groups are roughly similar to the total sample, but the Nigeria
group has 3.5 times more respondents with a doctorate than the United States group
(8.1% versus 2.3% respectively).
Just as with education, the distribution of job types in the total sample followed
the same pattern of extremely low frequencies of some categories. Specifically,
unemployed (0.5%), generally trained laborers (0.8%), and vocationally trained
professionals (1.3%) were only marginally represented. In contrast, academically trained
professionals (18.8%), managers of subordinates (27.6%), and managers of managers

(51.0%) accounted for the bulk of the sample, with managers cumulatively representing
77.6%. In the two national groups, the distributions of the frequencies generally reflect
the that of the total sample. However, comparatively, in the Nigeria group, academically
trained professionals were overrepresented by ≈ 28.57% (i.e., 10.9% versus 7.8%
respectively), while managers of managers were overrepresented by ≈18.51% in the
United States group (28.1% versus 22.9% respectively). Regardless of these two
differences, managers as a cumulative category accounted for ≈ 74.1% in the Nigeria
group and ≈ 83.2% in the United States group.
Lastly, the participants selected a specific type of stakeholder to which they
belonged. In the total sample, government regulator (0.5%) and consumer (0.3%) were
the least represented stakeholder types, while service provider accounted for a negligible
3.9%. Employees as a type represented 19.8% of the total sample, which appears to be
closely correlated with the share of academically trained professionals as a job type. In
stark contrast with the other four categories, managers as a stakeholder type constituted a
huge proportion of the total sample – 75.5%, which was also consistent with the
proportionate weight of managers as a job type.
Taken together, these descriptive statistics suggested that the sample was (a)
goaloriented, i.e., it would allow to test the five hypotheses of the study using appropriate
statistical means; (b) accurate of the total population of the study as the vast majority of
participants were able to classify themselves based on the proposed variables and
categories; and finally, (c) balanced between the United States and Nigeria, because the
sizes of the two groups of the study differed by less than 1%.
Study Results
The next two steps in the data analysis involved conducting (a) multiple
frequency analyses to test the hypothesized vectors and the strengths of associations
between CSR programs, CSP and CFP; and then (b) inferential analyses to test the three
hypothesized relationships, moderated by national cultures of Nigeria and the United
States, between the effects of CSR programs on CC, CR, and CVC.
Associations Between CSR, CSP, and CFP
By examining the vectors and the strengths of the hypothesized relationships
between CSR, CSP and CFP, the analyses addressed RQ1 of the study. Specifically, H111
and H112 associated with RQ1 were tested by applying the method of moments to the
distributions of the observed frequencies. The participants' opinions regarding the
relationship between CSR programs and CSP were measured by Q34-35 of the research
instrument. The views of the participants regarding the relationship between CSR
programs and CFP were measured by Q25-27 of the research instrument. The responses
were measured using a 7-item Likert scale indicating the degree of participants'
agreement with a specific statement about CSR programs. On all five questions, specific
measures of central tendency (mean, mode), dispersion (standard deviation), and
posterior distribution (skewness, kurtosis) were obtained for the total sample to assess the
general picture and also separately for Nigeria and the United States groups for a
comparison (Table 3).
Table 3
Results of the Frequency Analysis (Q25-27, Q34-35)
Nationality Measures CSR
Q34:
Facilitates
social value creation
Q35:
Helps to attract
political support
Q25:
Lowers
business costs
Q26:
Lowers
business risks
Q27:
Has positive effects
on fin. bottom line
Nigeria
N = 192
Mean
STD
6.33
1.01
6.09
1.17
5.69
1.65
5.88
1.48
6.13
1.17
CV 0.17 0.19 0.28 0.25 0.19
Mode 7.00 7.00 6.00 6.00 7.00
Skewness -2.99 -2.07 -1.42 -1.82 -2.38
United
States
N = 191
Kurtosis 12.47 5.95 1.13 2.99 7.35
Mean
STD
CV
6.53
0.65
0.09
6.51
0.68
0.10
6.46
0.71
0.11
6.49
0.59
0.09
6.51
0.55
0.08
Mode 7.00 7.00 7.00 7.00 7.00
Skewness -3.34 -3.18 -2.82 -0.81 -0.51
Total
N = 384
Kurtosis 25.14 21.96 17.73 0.55 -0.85
Mean
STD
6.43
0.85
6.30
0.97
6.07
1.33
6.18
1.17
6.32
.93
CV 0.13 0.15 0.22 0.19 0.14
Mode 7.00 7.00 7.00 7.00 7.00
Skewness -3.31 -2.58 -2.12 -2.43 -2.75
Kurtosis 17.31 10.15 4.53 7.05 11.81
Note. Results of the Nigerian and U.S. frequency analysis on CSR.
Conceptually, as an alternative to the method of maximum likelihood, the method
of moments involves equating sample moments with theoretical moments (Pearson,
1936). Because it yields consistent estimators, the method of moments is particularly
appropriate for the analysis of categorical data (Diaconis, 1987). In the current analysis,
(a) mean as the first raw moment, (b) standard deviation as the derivative of the second
central moment – variance, (c) coefficient of variation CV = ) mode = 3*MED –
2*μ, (e) the two standardized moments skewness (third central moment) and kurtosis
(fourth central moment) were obtained and used to assess the location and variability in
frequency distributions of answers to each of Q25-27 and Q34-35.
In the total sample, the results revealed that for all five questions analyzed: (a) all
modes were single and = 7 (completely agree), while all means ϵ [6.07; 6.43], i.e.,
between "6 – agree" and "7 – completely agree" with all CVs substantially < 1, indicating
very low variations; (b) all coefficients of skewness G1 ϵ [-3.31; -2.12] indicating that the
data were highly negatively skewed, i.e., skewed towards higher values on the 7-item
Likert scale; and (c) all coefficients of kurtosis γ ϵ [4.53; 17.31] indicating that all
distributions were extremely leptokurtic. Taken as a whole, this evidence suggested with
high certainty that most participants were in "complete agreement" with statements about
CSR programs presented in Q25-27 and Q34-35.
In the Nigeria group, the results revealed that for all five questions analyzed: (a)
all modes were single, three modes = 7 (completely agree) and two modes = 6 ("agree"),
while all means ϵ [5.69; 6.33], i.e., answers were clustering towards stronger levels of
agreement with the questions, with all CVs substantially < 1, indicating very low
variations; (b) all coefficients of skewness G1 ϵ [-2.99; -1.42] indicating that the data
were highly negatively skewed, i.e., skewed towards higher values on the 7-item Likert
scale; and (c) coefficients of kurtosis γ ϵ [1.13; 12.47] indicating that three distributions

(Q34-35, Q27) were extremely leptokurtic, one distribution (Q26) was roughly mesokurtic (γ
= 2.99), and one distribution (Q25) was platykurtic (γ = 1.13). Taken as a whole, this
evidence suggested with high certainty that most participants were in "complete
agreement" with the statement that CSR is associated with improved CSP as measured by
Q34-35. At the same time, while most of the participants in the Nigeria group were in
"agreement" with the statement that CSR programs are associated with improved CFP as
measured by Q25-27, the participants clearly demonstrated a higher degree of diversity of
opinions compared to the total sample regarding the associations of CSR programs with
lower costs of doing business (Q25) and with lower risks of doing business (Q26). In the
United States group, the results revealed that for all five questions analyzed: (a) all modes
were single and = 7 (completely agree), while all means ϵ [6.46; 6.53], i.e., between "6 –
agree" and "7 – completely agree" with all CVs considerably < 1, indicating extremely
low variations in the opinions. The picture was more nuanced with the skewness. In
particular, the data were highly skewed towards higher values on the 7item Likert scale
for Q34 (G1 = -3.34) and for Q35 (G1 = -3.18), which measured the association between
CSR programs and CSP and for Q25 (G1 = -2.82), which measured the association
between CSR programs and CFP. For Q26 (G1 = -0.81) and Q27 (G1 = 0.51), the data were
only moderately skewed towards higher values on the 7-item Likert scale, thus
suggesting that the participants were less sure about the positive vector of the
associations between CSR programs and respectively lower costs of doing business and
the financial bottom line. Likewise, the coefficients of kurtosis varied across the United

States group. Specifically, results for Q34 (γ = 25.14) and Q35 (γ = 21.94) indicated that
both distributions were extremely leptokurtic. This result was highly consistent with the
results of the skewness analysis, i.e., that the U.S participants consistently demonstrated
"complete agreement" with the statements that CSR programs are associated with
improved CSP. Given the results for Q25-27, the participants varied in their assessments of
the association between CSR programs and the CFP. The combined evidence suggested
with high certainty that most participants were in "complete agreement" with statements
about CSR presented in Q25-27 and Q34-35.
Using cumulative results of the analyses of the total sample and the two group
analyses, and based on the preponderance of evidence, both null hypotheses H011 and
H012 were rejected; while both main hypotheses, i.e., H111: CSR programs are associated
with improved CSP and H112: CSR programs are associated with improved CFP were
accepted. Therefore, since both main hypotheses were accepted, RQ1 was answered
affirmatively.
CSR Effects on CC, CR, and CVC
The next step in the analytical sequence addressed RQ2 and involved conducting
inferential statistical analyses to test the three main hypotheses related to RQ2: H121,
H122, and H123. In particular, it was evaluated whether, and if so, then how exactly the
effects of the hypothesized relationships between CSR programs on CC, CR, and CVC
are moderated by the national cultures of Nigeria and the United States. The opinions of
the participants regarding the effects of CSR programs on (a) CC, were measured by
Q3133; (b) CR, were measured by Q28-30; and (c) CVC, by Q36 of the research instrument.

The responses were measured using a 7-item Likert scale indicating the degree of
participants' agreement with a specific statement about the effects of CSR programs.
National Culture: Nigeria Versus the United States
To measure the moderating effects of the national cultures of Nigeria and the
United States on the three hypothesized relationships of the RQ2, seven new variables
(PDI – power distance index, IDV – individualism vs. collectivism index, UAI –
uncertainty avoidance index, MAS – masculinity vs. femininity index, LTO – long vs.
short-term orientation index, IND – indulgence vs. restraint index, and HGCDI –
Hofstede's global cultural dimension index) were computed using the participants'
answers to the 24 items of the 2013 version of the Hofstede's Values Survey Module
(Hofstede & Minkov, 2013a). The six new variables reflected the six cultural dimensions
(subscales) of the VSM 2013. The scores for Nigeria and the United States were
calculated using the formulas of the VSM 2013 Manual. The composite Hofstede's global
cultural dimension index (HGCDI) was computed using the six new variables (PDI, IDV,
UAI, MAS, LTO, IND) as well as the formula and the country coefficients for Nigeria
and the United States. The HGCDI was developed by Roy in a cross-country
metaanalysis of 179 empirical studies that relied on the Hofstede's VSM as a research
instrument (Roy, 2020). The HGCDI was computed using the following formula:
HGCDI = 7 + 0.15PDI + 0.21IDV + 0.32UAI + 0.33MAS + 0.28LTO + 0.23IND.
The comparisons between Nigeria and the United States national cultures are
presented in Table 4.
Table 4
National Cultural Comparisons: Nigeria Versus the United States
Dimensions of NC Nations
Nigeria United States
PDI - Power distance index 85 39
IDV – Individualism vs. collectivism index 54 70
UAI - Uncertainty avoidance index 51 39
MAS - Masculinity vs. femininity index 55 51
LTO – Long vs. short-term orientation index 46 21
IND - Indulgence vs. restraint index 73 89
HGCDI - Hofstede's global cultural dimension index 95 83
Note. Table showing Nigeria versus the United States dimensions of NC comparisons
Figure 6
National Cultural Comparisons: Nigeria Versus the United States
HGCDI -
U.S.
Nigeria
83
89
85
21
46
51
55
51 70
73
39
39
54
Hofstede’s global cultural dimension index
IND - Indulgence index
LTO - Long-term orientation index
MAS - Masculinity index
95
UAI - Uncertainty avoidance index
IDV - Individualism Index
PDI - Power Distance Index
Note. Comparison scores of the national culture of Nigeria versus the United States in
terms of IND, LTO, MAS, UAI, IDV, and PDI indexes.
As it follows from the calculated scores, Nigeria and the United States differed on
each of the six dimensions of NC, but the sizes of the differences varied across the
dimensions. Specifically, Power distance is "the extent to which the less powerful
members of institutions and organizations within a country expect and accept that power
is distributed unequally" (Hofstede, 2002, p. 44). So, the calculated PDI for the sample
suggested that Nigeria (85) has much higher scores on this dimension than the United
States (39), implying a higher degree of acceptance of hierarchical order, which needs no
further justification. In Nigeria, hierarchy in an organization is seen as reflecting inherent
inequalities, centralization is preferable, and subordinates expect to be told what to do.
Across all six dimensions, the divergence between Nigeria and the United States on the
power distance was the second largest – by 54.12%!
In turn, individualism is "the degree of interdependency a society maintains
among its members" (Hofstede, 2002, p. 48). This cultural dimension has to do with
whether people's self-image is defined in terms of "I" or "We." In individualist societies,
people are expected to look after themselves and their immediate family only. In contrast,
in collectivist societies, people belong to "in groups" that take care of them in exchange
for loyalty. The IDV score for Nigeria was 54, which was somewhat higher than in other
studies, where such scores were ≈ 30% lower. However, comparatively, Nigeria is a

much more collectivist society than the United States (IDV = 70). The higher observed
IDV scores for Nigeria can be attributed to the demographic characteristics of the Nigeria
group, in which managers as a cumulative category accounted for ≈ 74.1%.
In terms of uncertainty avoidance, which is defined as "the extent to which the
members of a culture feel threatened by ambiguous or unknown situations and create
beliefs and institutions that try to avoid these" (Hofstede, 2002, p. 52), Nigeria received
an intermediate score of 51, suggesting no clear preference. The United States scored 39,
suggesting a relatively lower focus in this group on controlling the future and higher
tolerance of uncertainty and ambiguity.
Next, according to Hofstede (2002), the principal difference between societies
and organizations on the masculinity versus femininity dimension is the nature of
motivation, with desiring to be the best defining more masculine cultures while liking
what one does distinguishing more feminine cultures (p. 55). Nigeria scored 55, while the
United States scored 51, suggesting that both countries are more masculine than
feminine. However, females accounted for ≈ 38.9% of Nigerian participants and ≈ 44.5%
of the United States group, which can plausibly explain that the scores observed in this
study differed from scores in past studies. Regardless of the differences between the
observed and past empirical MAS cores, in general, in masculine countries, people "live
to work," managers are likely to be decisive and assertive, the emphasis is on equity,
competition, and performance and conflicts are typically resolved by fighting them out.
The long versus short-term orientation dimension describes how "a specific
societal culture maintains links with its past while dealing with contingent challenges"

(Hofstede, 2002, p. 57). Surprisingly, while the United States scored relatively low on
this dimension (21), Nigeria scored quite high (46), suggesting that participants in the
sample had more normative cultural values rather than pragmatic. These observations
were inconsistent with LTO scores obtained in past studies in which the United States
typically scored higher than Nigeria. Such reversal can possibly be explained by the
psychological effects of the COVID pandemic during which the data were collected.
Another plausible explanation could be that industries in which the participants worked
were affected differently in Nigeria and the United States by the economic slowdown due
to quarantine measures. The divergence between the two national cultures was the largest
on the LTO – 54.35%.
Last, the indulgence index measures "the extent to which people try to control
their desires and impulses" (Hofstede, 2002, p. 58). The observed IND scores were also
quite surprising. In contrast to past studies, Nigeria (73) scored 16 points lower than the
United States (89), suggesting that the latter may be a more indulgent culture than
previously thought. The IND scores specifically indicated that while both cultures
generally exhibit a willingness to realize their impulses and desires with regard to
enjoying life and having fun, individuals in both cultures possess a positive attitude and
have a tendency towards optimism, place a higher degree of importance on leisure time,
and act as they please. Indeed, the higher than usual IND scores for the United States
group can only be attributed to the psychological effects of the COVID pandemic as
people faced a major public health emergency, suffering, and death, compensating for
such eventualities by becoming more indulgent, following the dictum of carpe diem.

Overall, the observed scores highlighted the differences between the national cultures of
Nigeria and the United States, especially on the three key points of cultural divergence –
the long versus short-term orientation by ≈ 54.35%, the power distance by ≈
54.12%, and on the individualism versus collectivism index by ≈ 22.86%. At the same
time, because the six cultural dimensions have different weights in the HGCDI formula,
the cumulative cross-country difference was only ≈ 12.63% (Nigeria = 95 versus United
States = 83). However, Roy (2020) created the HGCDI more as a research implement to
facilitate statistical model-building for cross-cultural comparisons.
Moderating Effects of National Culture
The last step in the data analysis involved obtaining the estimates of the
moderating effects of the national cultures of Nigeria and the United States on the three
hypothesized relationships of RQ2. The three hypotheses (H121, H122, H123) related to
RQ2 were statistically tested using the generalized linear models (GLM). Initially,
according to the data analysis plan in Chapter 3, the effects of cultural differences
between Nigeria and the United States on the relationships between the CSR programs
and CR, CC, and CVC were first to be examined using six cultural dimensions
separately, then the same effects were to be further explored using the aggregate of
HGCDI. However, all efforts to estimate the moderating effects of national cultures
exerted by each of the six cultural dimensions had failed as models either did not hold or
had a very poor fit. In other words, it was impossible to differentiate the individual
effects of each dimension of the national cultures. The likely reason is the much weaker

effects of separate cultural dimensions compared to the nation’s aggregates. The sample
and group sizes were probably insufficient to detect medium or/and small effects, i.e., d ≤
0.5 at the selected level of significance of 5%.
Nevertheless, the estimates of the moderating effects of the national cultures as
aggregates were obtained using univariate GLMs models. All GLMs were applied
iteratively, with backward elimination of covariates and using (a) optimization of
adjusted R2 and (b) significance at α = 0.05 as concurrent elimination criteria. The final
models contained covariates that were retained as per criteria. The independent variable
(IV) in all final models was NC as measured by the HGCDI for both countries, and thus
contrasting Nigeria with the United States. in all models. The dependent variables were
CSR effects on corporate prominence (Q28), legitimacy (Q29), reputation (Q30),
productivity (Q31), customer base (Q32), competitiveness (Q33), and social value creation
(Q36). The covariates were the variables Gender, Age, Education, Job Type, and
Stakeholder Type.
The three hypotheses (H121, H122, H123) of the RQ2 were statistically tested in two
steps. First, the hypothesized positive effects of the CSR programs on CR, CC, and CVC
were established using frequency analysis and the method of moments. Second, the
estimates of the moderating effects, if any at all, of the aggregates of NC, were obtained.
The results of the frequency analysis are presented in Table 5. The results on the total
sample and the country groups were uniform and showed that (a) all modes, except in Q31
in the Nigerian group, were single and = 7, all means were clustering towards stronger
levels of agreement with the questions, with all CVs substantially < 1, indicating very
low variations; (b) all coefficients of skewness were skewed towards higher values on the
7-item Likert scale; and (c) all coefficients of kurtosis, except in Q31-33 in the United
States group, were extremely leptokurtic.
Table 5
Results of the Frequency Analysis (Q28-33, Q36)
Nationality
Measures
CSR has positive effects on corporate CR, CC, and CVC
Q28:
Prominence
Q29:
Legitimacy
Q30:
Reputation
Q31:
Productivity
Q32:
Customer
Base
Q33:
Competitiveness
Q36:
Social value
creation
Nigeria
N = 192
Mean
STD
CV
Mode
6.32
0.97
0.15
7.00
6.22
0.98
0.16
7.00
6.24
0.94
0.15
7.00
6.02
1.19
0.19
6.00
6.18
1.07
0.17
7.00
6.16
1.04
0.17
7.00
6.28
0.94
0.15
7.00
Skewness -2.97 -2.25 -2.56 -1.86 -2.34 -1.92 -2.69
United
States
N 191
Kurtosis 12.88 8.15 10.74 4.19 7.78 5.53 11.33
Mean
STD
CV
Mode
6.51
0.64
0.09
7.00
6.49
0.66
0.11
7.00
6.49
0.67
0.11
7.00
6.48
0.59
0.09
7.00
6.51
0.58
0.08
7.00
6.51
0.57
0.08
7.00
6.52
0.65
0.09
7.00
Skewness -3.32 -3.13 -3.07 -0.83 -1.05 -0.82 -3.40
Total
N = 384
Kurtosis 25.86 23.14 22.07 .52 1.77 0.67 26.41
Mean
STD
CV
Mode
6.41
0.83
0.13
7.00
6.35
0.84
0.13
7.00
6.37
0.83
0.13
7.00
6.25
0.97
0.16
7.00
6.34
0.87
0.14
7.00
6.34
0.85
0.13
7.00
6.41
0.82
0.13
7.00
Skewness -3.28 -2.64 -2.84 -2.21 -2.55 -2.15 -3.06
Kurtosis 17.71 12.42 14.53 7.22 10.85 8.08 16.05
Notes. Results of the Nigerian and U.S. frequency analysis on CSR and its impact on CR,

CC, and CVC.
In general, this evidence suggested with high certainty that most participants in
the total sample and the nation groups were in "complete agreement" with the statements
that CSR has positive effects on CR, CC, and CVC as measured by Q28-33 and Q36.
Therefore, the hypothesized positive effects of the CSR programs were established. The
estimates of the moderating effects of the national cultures are presented in Table 6. The
review of the estimates allowed to make observations. First, overall, as aggregates, the
national cultures of Nigeria and the United States do moderate the positive effects of the
CSR programs on respectively CR, CC, and CVC, regardless of specific measures
analyzed.
Second, using cross-cultural comparisons, the moderating influence appeared
stronger for the United States group in all seven models, on average by 37 points or ≈
10.2%. Third, of all covariates, only Gender (1 model), Education (1 model), and Gender
and Education together (5 models) appeared to be of any relevance to the moderating
effects of national cultures as measured by the standardized estimates of the effect size
(η2). Given this observation, a closer exploration of the interactive effects of national
culture, gender, and educational attainment will be warranted in future research as it may
bring new management insights on how these variables may change certain cultural
norms in societies and contribute to management effectiveness. Fourth, the moderating
influence of national cultures appeared to be the weakest for the positive effects of CSR
programs on corporate productivity (Q31), suggesting that other relevant factors may have
a stronger influence on it (e.g., leadership style, organizational structure, workforce
development programs, etc.). Lastly, the moderating influence of national cultures
appeared to be the strongest for positive effects of CSR programs on CR (Q28-30) and
CVC (Q36).
Using cumulative results of (a) frequency analysis that confirmed the
hypothesized positive effects of CSR programs, and (b) the estimates of the moderating
effects of Nigeria and the United States national cultures, all three null hypotheses H021,
H022, and H123 were rejected based on the compound evidence. Concurrently, all three
main hypotheses – H121, H122, and H123 were accepted. Therefore, given such outcomes,
RQ2 was answered as follows: considering the moderating effects of national cultures, the
stakeholder multinational corporate connection differences between Nigerian and
U.S. multinational stakeholders are most pronounced in the CSR positive effects on
CVC, less so on CR, and the least on CC.
Table 6
Estimates of the Moderating Effects of NC (Nigeria Versus United States)
variable Lower Upper
Q28: CSR has
pos. effects on
corp.
prominence
Education
HGCDI (U.S.)
HGCDI
(Nigeria)
.195
5.576
5.364
.069
.335
.344
2.827
16.639
15.578
.005
.000
.000
.059
4.917
4.687
.330
6.235
6.041
.021
.421
.390
Q29: CSR has Gender .232 .086 2.709 .007 .064 .400 .019
Dependent
Parameter B STE t Sig.
% CI95
η2
positive effects
on corporate
legitimacy
Education
HGCDI (U.S.)
HGCDI
.201
5.196
.069
.368
2.900
14.138
.004
.000
.065
4.473
.337
5.918
.022
.345
(Nigeria)
4.908 .374 13.107 .000 4.171 5.644 .312
Q30: CSR has
positive effects
on corporate
reputation
Gender
Education
HGCDI (U.S.)
HGCDI
.209
.244
5.024
.084
.068
.359
2.491
3.602
13.988
.013
.000
.000
.044
.111
4.318
.373
.377
5.730
.016
.033
.340
(Nigeria)
4.750 .366 12.979 .000 4.030 5.469 .308
Q31: CSR has
positive effects
on corporate
productivity
Gender
Education
HGCDI (U.S.)
HGCDI
(Nigeria)
.261
.285
4.738
.096
.078
.412
2.718
3.674
11.495
.007
.000
.000
.072
.133
3.928
.450
.438
5.549
.0
19
.0
34
.2
59
4.263 .420 10.150 .000 3.437 5.089 .2
14
Dependent Parameter
variable B STE t Sig. 95% CI η2
Lower Upper
Q32: CSR has
positive effects
on customer
base
Education
HGCDI (U.S)
HGCDI
(Nigeria)
.257
5.279
4.913
.072
.348
.358
3.589
15.172
13.741
.000
.000
.000
.116
4.595
4.210
.398
5.963
5.616
.033
.377
.332
Q33: CSR has
positive effects
on corporate
competitiveness
Gender
Education
.271
.253
.085
.069
3.179
3.675
.002
.000
.103
.118
.438
.388
.026
.034
HGCDI (U.S.)
HGCDI
4.911 .365 13.440 .000 4.192 5.629 .323
(Nigeria)
4.545 .372 12.208 .000 3.813 5.277 .282
Q36: CSR has
positive effects
on social value
creation
Gender
Education
HGCDI (U.S.)
HGCDI
.185
.180
5.398
.083
.067
.358
2.216
2.673
15.077
.027
.008
.000
.021
.048
4.694
.349
.313
6.102
.013
.019
.375
(Nigeria)
5.141 .365 14.093 .000 4.424 5.859 .344
Note. a. NNigeria = 192, NU.S. = 191; b. Adjusted R2 ϵ [0.851; 0.979]; c. Partial η2 = η2,
given DV=1.
Summary
To summarize the results of the analyses, five hypotheses in total were confirmed
in the current study. The results of descriptive and distributional analyses using the
method of moments allowed to give an affirmative answer to the first question of the
study. The obtained evidence clearly suggested that corporate social responsibility
programs are, in fact, associated with improved CSP and CFP. The results of
distributional and inferential analyses using the GLM modeling addressed the second
research question of the study by concluding that given the cross-national cultural
differences, the stakeholder multinational corporate connection differences between
Nigerian and U.S. multinational stakeholders are most pronounced in the CSR positive
effects on corporate value creation, less so on corporate reputation, and the least on
corporate competitiveness.
Chapter 5 will present an interpretation of the conclusions in the broader context
of the extant literature on corporate social responsibility, provide recommendations for

management practice and future research, and discuss broader societal implications of the
current study's findings.
Chapter 5: Discussion, Conclusions, and Recommendations The
purpose of this study was to empirically test (a) the paradigm of CSR as a desirable
business development goal and strategy of sustainable shared values (Agudelo et al.,
2019; Freeman & Dmytriyev, 2017), and (b) stakeholder theory (Freeman et al. 2019).
The CSR paradigms that have been adopted by many large corporations typically posit
that CSR programs provide greater social benefits and financial performance than
Smith’s classical capitalism and Friedman’s neoclassical capitalism. Stakeholder theory,
closely associated with but not the same as CSR, has asserted that the existence of
mutually beneficial interactions between corporations and all its stakeholders through
associated CSR competitiveness, reputation, and value creation building in developing
nations such as Nigeria is a worthy corporate strategic objective. The nature of the study
was the use of correlation research design because of the empirical testing objective of
the study of the CSR paradigm as positing positive associations with CSP and CFP; and
stakeholder theory that is positively associated with CSR competitiveness, CSR
reputation, and CSR value creation building, all of which invalidates the other three
research design options (descriptive, quasi-experimental, and experimental).
Interpretation of Findings
The findings for RQ1 were divided into two parts:

RQ1, Part 1 findings: Both Nigerian and U.S. study participants consistently
demonstrated nearly complete agreement that CSR programs were correlated with
improved corporate social performance in the response to two survey questions: (a) CSR
facilitated social value creation, and (b) CSR helped to attract political support. This
result occurred despite substantial and significant cultural differences between the U.S.
and Nigerian study participants.
RQ1, Part 2 findings: Both Nigerian and U.S. study participants agreed that CSR
programs were significantly correlated with improved CFP in the response to three
survey questions: (a) CSR lowers business costs, (b) CSR lowers business risks, and (c)
CSR has positive effects on the financial bottom line. The cumulative evidence suggested
that CSR programs were in fact associated with improved CSP and CFP.
The findings for the RQ2, Part 1 were divided into seven parts: Both Nigerian and
U.S. study participants agreed that CSR does have positive effects on corporate costs and
risks of doing business, enhancing reputation and establishing legitimacy, in the response
to five survey questions: (a) CSR facilitated prominence, (b) CSR facilitated legitimacy,
(c) CSR facilitated reputation, (d), CSR facilitated productivity, and (e) CSR customer
base, considering the cultural differences between both nations. Again, this result
occurred despite substantial and significant cultural differences between the U.S. and
Nigerian study participants.
RQ2: Part 2 findings: Both Nigerian and U.S. study participants agreed that CSR
programs do have positive effects on corporate competitiveness, in response to one
survey question about competitive advantage. Again, this cohesive result occurred despite

substantial and significant cultural differences between the U.S. and Nigerian study
participants.
RQ2: Part 3 findings: Both Nigerian and U.S. study participants agreed that CSR
does have positive effects on corporate quid pro quo win-win social value creation.
Again, this result occurred despite substantial and significant cultural differences between
the U.S. and Nigerian study participants. Given the cross-national cultural differences,
the stakeholder multinational corporate connection differences between Nigerian and
U.S. multinational stakeholders are most pronounced in the CSR positive effects on
corporate value creation, less so on corporate reputation, and the least on corporate
competitiveness.
Cultural Comparisons
All but one of the seven indices of Hofstead’s national cultural comparisons
survey questionnaire responded to by U.S. and Nigerian study participants were found to
be significantly different. The six indices found to express substantial differences in order
of the greatest differences were as follows: (a) LTO 54% different, long-term more
normative orientation in favor of Nigerian, and short term more pragmatic in favor of the
U.S. participants; (b) expectance and acceptance of PDI 54% different, greatest
expectance and acceptance by Nigerian participants, and least expectance and acceptance
by U.S. participants; (c) UAI 24% different, greatest avoidance by Nigerian participants,
least avoidance by U.S. participants; (d) IDV 23% in which Nigerian is the more
collectivist culture and the U.S. participants being more individualism oriented; (e) IND

18% where the Nigerian participants try to restrain their desires and impulses more than
the U.S. participants; (f) HGCDI was only 13% between the Nigerian participants and the
U.S. participants because all the indices have different weights in the formula; and finally
(g) masculinity versus femininity (7%), indicating both Nigerian participants and U.S.
participants share similar values as masculine cultures desiring to be the best and living to
work.
Moderating Influence of National Culture
First, Nigerian and U.S. cultures as aggregates moderated the positive effects of
the CSR stakeholder programs on CR, CC and competitive advantages, and CVC.
Second, moderating influences appeared to be higher across all seven models on average
for U.S. participants by 10.2%. Third, the data suggested that of all the covariates, only
gender, education, and gender and education together were of any relevance to the
moderating effects of national cultures. Fourth, the moderating influence of national
cultures appeared to be weakest for the positive effects of CSR programs on corporate
productivity. Fifth, the moderating influence of national cultures could be the strongest
for positive effects of CSR stakeholder programs on CR and CVC.
Interpretation Related to the Peer-Reviewed Literature
The findings in this study are unexpectedly unambiguous, unlike the diverse and
contentious views of scholars in recent decades (see Freeman, 1984 1994, 2000; Freeman
et al., 2001, 2007, 2010, 2017, 2019), who have been debating the issues surrounding
CSR and expounding on expanding stakeholder roles for several decades. Freeman et al.
(2017) recently have been moving forward, nudging and countering the views of the

freemarket and capitalism foundational scholars such as Friedman (2002, 2007) and
others such as Lantos (2001) who were inspired by Smith, author of a seminal classic
entitled The Wealth of Nations first published in 1776. On these matters, Carroll and
Shabana
(2010), Hanlon and Fleming (2009), Kinderman (2012), and Marens (2013) have placed
their skeptical and wary colleagues on notice that an increasing number of multinational
capitalistic corporations have been legitimately embracing what they have regarded as a
new paradigm of organized market behavior and strategy called CSR.
These scholars have been holding up decades of empirical evidence of egregious
corporate irresponsibility to make their case for the inclusion of a greater amount of
legitimate and ethical stakeholder social values into the profit seeking ventures and
operations of large, medium, small corporations and especially major multinational
corporations. Kurucz et al. (2008) posited that this change in corporate direction would
and should do well for corporate interests by doing good and specifically (a) lowering the
cost and risk of doing business, (b) improving corporate reputations and legitimacy, (c)
empowering competitive advantages, and (d) facilitating win-win quid pro quo value
creation.
The results of this study have provided strong supporting empirical evidence from
384 corporate professionals both in a developing economy, Nigeria, as well as corporate
professionals in the advanced economy of the United States, that CSR programs are
associated with improved CSP and CFP. Additionally, the results of this study strongly
suggest that CSR programs have positive effects on corporate reputations,

competitiveness, and value creation. The demographics of the study sample also
suggested that the people who would know best about CSR trends in their country
participated in this survey: (a) senior career professionals ages 40 to 60 made up more
than 60% of the study sample, (b) academically trained professionals made up 19%,, (c)
managers of subordinates (28%) made up 47% of the sample, (d) those with master’s
degrees (66%) or PhDs (20%) made up 86% of the study sample, and (e) females made
up 42% and males 58% of the study sample. The study sample was recruited through
professional associations, so participants were active in their professions and likely could
have used these networks to stay informed of what was really happening below the
surface in their communities.
The results of this study, while filled with superlatives and positive views, could
also be interpreted alternatively based upon literature reviews by skeptics encountered in
this study and stakeholder sampling bias.
Skeptical Literature Reviews
If the present study were reviewed by those who have written articles that have
been critical of corporate CSR, here is what might be observed. Hanlon and Fleming
(2009) may have raised the question of the extent to which corporate participants have
been engaged in using CSR in their corporate marketing and branding. These scholars
pointed out that a review of the websites and annual reports of major multinationals such
as British Petroleum (BP), Shell Oil, and others reveal major efforts to reveal their
“responsibility initiatives” (Hanlon & Fleming, 2009, p. 1). What is meant by this is that
CSR has become a substantial “marketing and branding” effort for “most large and

medium sized corporations” (Hanlon & Fleming, 2009, p. 1). BP’s oil interests were
nationalized by Nigeria in 1979, so BP is no longer engaged in Nigeria, but Royal Dutch
Shell, which was the first major corporation to discover oil in Nigeria in 1936, still has a
major presence in Nigeria and actively manages its image, especially regarding
destruction of farmlands and fishing grounds through communication about its oil spills,
gas flaring, environmental degradation, and pollution (Manzie, 2018).
Other critics such as Roberts (2003) have referred to CSR in more critical rhetoric
as an “ideological smokescreen” (see Hanlon & Fleming, 2009, p. 2). Roberts asserted,
“In this form corporate social responsibility is cheap and easy; a sort of prosthesis, readily
attached to the corporate body, that repairs its appearance but in no way changes its
actual conduct” (p. 250). Marens (2010) was less charitable, labeling marketing use of
CSR by major corporations as a predatory grab for power. Banerjee (2008) said of CSR
that its use was a diversionary tactic to mislead, while Kinderman (2012) cynically
described CSR as a quid pro quo for less regulation. This kind of commentary ordinarily
might not be regarded seriously in a low stakes environment, but in Nigeria where oil is
the primary industry that the nation depends on for much of its foreign exchange capital,
the stakes may be too high to ignore (Okotie, 2018; Ugbomeh & Atube, 2010).
Stakeholder Sampling Bias
In this cross-sectional correlational study, I focused principally on the
membership of major business professional associations whose headquarters are located
in the principal cities of Nigeria and the United States, consisting of professionals
working in private for-profit companies, although this set of criteria was dropped in an

early part of the study to allow for government employees and nonprofits. It was also
believed that this group of participants who were better educated than most of the
Nigerian and U.S. general population could likely have been better informed about local,
regional, and national events and therefore could be in a better position to evaluate issues
brought up in the study survey. A decision was also made not to target only people who
had high levels of specialized knowledge about the oil industry or the impacts of oil
industry activities because it might have skewed and biased the survey result based upon
this specialized knowledge.
These inclusion criteria decisions were principally made for study convenience as
this was an academic, low budget study, with a limited time frame. Had the study
circumstances allowed for fewer restraints, perhaps a longitudinal study with wider
participation from scholars in more countries and stakeholder categories could have
provided a better balance of interests and greater generalizability of results. An excess of
focus upon private sector participants could have overlooked corporate training bias in
which I could have attracted too many participants who had been indoctrinated in
overstating the corporation’s official positions rather than a more objective perspective,
resulting in a less disproportionate number of biased corporate positions.
Interpretation Related to the Theoretical Framework
The primary theoretical framework of the study was philosopher Freeman’s (Freeman et
al., 2010) stakeholder theory. Other theories in the background were Smith’s classical
capitalism theory, and Friedman’s neoclassical economic capitalism theory

(Friedman, 2002). It was clear from the study results that Freeman’s stakeholder theory
was what most likely led the responses. What was not clear was which stakeholders were
most in control of the responses. If Freeman’s theory was legitimately being followed,
the stakeholders would have ideally been closer to being most representative of all
stakeholders, but if Freeman’s theory was being followed as a smokescreen, as a number
of critics contended, the stakeholders most represented would likely have been the
owners, corporate officers, shareholders, consultants, and supply chain providers of
goods and services perhaps closer to Freeman’s theories because Smith’s theory would
not have been libertarian, a form of capitalism that rejects most regulatory restraints on
capitalism. Smith believed in legitimate government oversight of tax on businesses.
Friedman, on the other hand, is a step away from libertarian, as Friedman (2002) would
have espoused social libertarianism and limited financial regulation.
Limitations of the Study
There were natural limits to the outcome of the study that arose during the study
that limited the study outcome. In addition, the limitations of this study were evaluated
based on three criteria: generalizability, validity, and reliability. The study was a low
budget, student study conducted by a novice researcher. On the other hand, this was an
ambitious study measuring the behavior of a highly educated, seasoned, sophisticated,
mainly senior business decision makers as study participants residing in a large resource
rich African nation and the largest western nation by economic assets and corporate
value.

Generalizability, Validity, and Reliability
This study was limited as to generalizability in that it was a correlational
quantitative research design to empirically test whether the theory of CSR programs was
correlated with improved CSP and CFP. Correlational studies examine the strength of
relationships between variables without ascribing causation. The findings of this study
revealed that there was indeed a very strong correlation established between CSR and
CSP and a relationship of lesser strength established between CSR and CFP. The primary
limitations were suspected to be in selection of the correlation analysis that limited
causation; however, there could have been differences in the study outcome based upon
selection of the sample population used in the study, which might amount to a bias in the
selection process.
The validity and reliability of the VSM 2013 have been empirically tested, and
were found to be valid and highly reliable (Bakir et al., 2015; Beugelsdijk & Welzel,
2018; Eringa & Rieck, 2015; Minkov, 2018). The validity and reliability of the CSRAQ
(Fleishman-Hillard, 2019) instrument was also evaluated in over 170 CSR studies and
found to be valid and reliable, especially for the measurement of employees’ attitudes.
Recommendations
The findings of this study suggest that there could be a strengthening of the
viability of the CSR development goal and strategy of sustainable shared values and
stakeholder theory among senior corporate leaders in Nigeria and the United States
among the study sample population and those that resemble them in other similar
contexts. Additionally, the sample population in this study could join what has been

defined in the research literature as a growing number of those in multinational
corporations who support of the proposition of performing better by doing good.
Recommendations for Theory
More specifically, the study sample could add voices to a widening circle of
stakeholders who believe the CSR approach might result in: (a) lowering the cost and risk
of doing business, (b) bolstering reputations and legitimacy, (c) empowering competitive
advantage, and (d) facilitating win-win quid pro quo value creation. An example of these
beliefs could be the emergence of other voices in recent years since 2011 of what appears
to be a parallel movement to the CSR movement called the environment, social, and
governance (ESG) investment movement (In, et al., 2019) that is increasingly being
mentioned as a guide to financial investment into projects that have similar characteristics
as CSR projects. The rise of ESG awareness at the very least suggests that there may be a
growing appetite in the business community for additional investment in these kinds of
projects instead of just voicing opinions.
In opposition, on the other hand, are a plentiful array of critics who have made
themselves known in the research literature by expressing skepticism of the CSR/ESG
approach implying and making outright accusations that literature and sometimes even
financial support could be a patronizing kind of subterfuge or smokescreen to disguise
disingenuous intentions. They remind that self-interested resistance can be expected when
what is at stake are potentially substantial amounts of financial, natural, and human
resources at risk that could be protected by enabling delays, foot dragging, and resistance
to change in uncertain times. This apparently fertile environment of opposing

perspectives suggest that theory building could be a viable enterprise, inspiring
alternative perspectives and pushing research beyond its current boundaries to places that
ought to be visited. Nigeria could be an ideal context for doing just that as there is no
absence of financial, natural, and human resources including opposing opinions at stake
and at play.
Recommendations for Future Research
The findings in this project could gain greater credibility through further survey
research using the same research survey instrument with a wider and deeper array of
sample populations especially in Nigeria to include: more of the oil production
stakeholder community that dominates the country such as direct employees of the
multinationals, oil and oil service retail and wholesale customers, business and individual
consumers, oil service suppliers, other service providers, communities where the oil is
extracted, infrastructure equipment providers, government officials who regulate and
license the industry, and those who benefit and depend upon the environment in which
the multinational corporations work in, in the sense of employment, economic security,
safety, dispute resolution, and infrastructure. The oil industry is such a foundational
economic resource for the Nigerian nation as a power source for so many other industries
and consumers that customers and consumers make up a potentially very large customer
base. The Nigerian oil industry is also a large employer that furnishes an economic
engine with substantial economic multiplier effects that drives economic wellbeing of
many communities, regions and the nation. It could be potentially insightful to compare
the responses from the different stakeholder categories to see how similar or different the

responses are from the results of the current study as well as the differences in
perspective.
Implications
The implications of this study could be far reaching. In a curious way the study is
in-and-of-itself an investigation into a broader, deeper way of analyzing the further
reaching influential ripples of a major industry upon the social and economic fabric of a
nation. This has been done by probing the thoughts and insights of what are the potential
major stakeholders of the economic engines of a country instead of unrelated bystanders
of economic power operators which are the multinational corporations.
Implications for Positive Social Change
This study was a correlational survey of what amounted to an elite class of senior
professionals who were in the present or in the past direct or indirect stakeholders of
major multinational corporations, some of whom in the past operated in Nigeria directly
or indirectly for these major multinationals and others who serve them presently, directly
or indirectly in various capacities as: employees, service providers, infrastructure
equipment providers, community members, government regulators, consultants,
accountants, engineers, and lawyers to name a few. Still others in the United States were
knowledgeable professionals in similar occupations for other multinationals and major
corporations that could have been related in some way either by profession or by way of
being knowledgeable of the operations of industries whose operations they were familiar
with.

Methodological Implications
In addition to professional connections, these were professionals who were
familiar with CSR and/or ESG programs and practices. The fact that these study
participants were recruited in professional associations addresses their interconnections
with one another, sharing insights and information about shared experiences. Correlating
CSR programs to CSP and CFP was tapping into the routine professional and informal
interactions these professionals may have had with each other in business and social
relations over many years as colleagues, friends, and neighbors. In terms of
methodological implications, finding other professional associations to study in the future
that are associated with other CSR and stakeholder categories could also generate
interesting or insightful findings.
Theoretical Implications
The theoretical implications of the findings in this study are supportive of both
CSR and stakeholder theories and their continued growth in sectors like the oil industry
in Nigeria. Initiatives in support of these theories both in Nigeria and the United States
prove to be sustainable and not a patronizing kind of subterfuge or smokescreen as some
cynics and critics have asserted and portrayed them. Support also could be easier to come
by if there were genuine broader and deeper stakeholder engagement and satisfaction,
which in turn could have a flywheel effect upon the furtherance of CSR and stakeholder
theories. In the macro view, the legitimacy of theories ultimately depends upon a host of
known and yet, unknown factors as well as the intrinsic efficiency and efficacy of the
theories in terms of how well their tenets hold under stress, change, and testing.

Empirical Implications
What was discovered in Nigeria and the United States in this study could be
typical of what happens in other nations that are in similar circumstances. Nigeria,
although rich with an abundance of natural resource commodities such as oil, finds itself
much like other nations who are too economically dependent upon a single industry or
commodity with volatile and fluctuating resource prices, that can be damaging to the
economy and livelihoods when prices decline and are volatile. With such heavy
dependence upon the fortunes of this kind of industry, stakeholders associated with the
rise and fall sometimes must suffer losses and hardships. However, what this study also
has suggested in terms of positive social change is that having the Nigerian industries
following CSR and stakeholder programs could be a major benefit to the growing list of
new shareholder beneficiaries in the country. After all, whoever is at risk also could find
themselves better off with a seat at the corporate table because having a seat could enable
rich financial rewards and security as well along with more control over their own
destiny. The next step might be to find countries similar to Nigeria to duplicate this study
in order to discover what their industry professionals think about these kinds of
vulnerabilities.
The results gotten form this study have an important implication for positive
social change in clarifying the perceptions and validating the claims in support of both
CSR and stakeholder theories and their continued growth in sectors like the oil industry
in nations like Nigeria. Findings in this study also have a potential impact for positive
social change by contributing new insights to theory, practice, and bringing about change

regarding stakeholder attitudes concerning CSR policies that have been put into effect by
MNC’s operating in nations like Nigeria and the United States. Ultimately, the results
gotten from this study have a potential impact for positive social change by increasing the
trust and confidence of stakeholders and the general public on the other side of the
ongoing debate, which will in turn be advantageous for the MNC’s and other
corporations with CSR policies (through improved CSP and CFP), and this has a
potential of encouraging corporations especially in nations like Nigeria and the United
States to continue with their CSR programs which as the CSR and stakeholder theories
claim, will be beneficial to all involved.
Recommendations for Practice
CSR and stakeholder theories despite being in existence for several decades are
still in their infancy, because so much is still unknown and remains to be discovered
about what lies ahead. At this juncture, the findings in this study suggest that more basic
discovery appears to fall to those who practice rather than those who work in theory
development in the sense of empirically experimenting with and attempting to verify
what practices will drive CSR and stakeholder theories to greater levels of insight,
efficiency, efficacy, reliability, and legitimacy. More corporations in mineral and
commodity extraction industries experimenting with CSR and expanded stakeholder
practices in developing countries would be helpful to know more about. What remains to
be discovered about the CSR business development goals and strategy of sustainable
shared values and stakeholder theory is the extent to which stakeholder status can be
elevated in Nigeria for those that are affected by major oil companies there including US.

multinationals such as Exxon, Chevron, and Marathon and seven other major
international firms: Sinopec, PetroChina, Saudi Aramco, Royal Dutch Shell, BP, Total
SE, and PJSC Lukoil who are very active in the Nigerian oil fields.
Recommendations for elevating stakeholder status is interpreted as meaning
expanding company stakeholders beyond the standard investor base of shareholders,
bondholders, C-suite company executives, board members, employees, as well as service
providers (maintenance and repairs), infrastructure equipment providers (equipment,
maintenance supplies, and other supply chain suppliers), government regulators (federal,
regional, state, local), consultants (selected associations, scientific advisors, accountants,
engineers, lawyers) and peers (friends, colleagues, and neighbors). Stakeholders could be
given expanded communications, invitations to public hearings, voting privileges, and
invitations to participate in various longitudinal studies.
Conclusions
There was substantial agreement among both Nigerian and U.S study participants
that CSR programs improved corporate social performance by facilitating social value
creation and helping to attract political support. The participants also substantially agreed
that CSR programs improved corporate financial performance by lowering business costs
and risks and contributing positively to the financial bottom line. Additionally, they
substantially agreed that CSR had positive effects on corporate costs and risks of doing
business, enhancing reputations, and establishing legitimacy by facilitating prominence,
legitimacy, reputation, productivity, customer base, competitiveness, and quid pro quo
win-win social value creation in consideration of cultural differences between the two

nations. Given the cross-national cultural differences, the stakeholder multinational
corporate connection differences between Nigerian and U.S. multinational stakeholders
were most pronounced in the CSR positive effects upon corporate value creation, less so
on corporate reputation, and the least so on corporate competitiveness.
The findings in this project could gain greater credibility through further survey
research into a wider and deeper array of the industrial production stakeholder
community verifying what practices drive the CSR business development goals and
strategy of sustainable shared values and stakeholder theories to greater levels of insight,
efficiency, efficacy, reliability, and legitimacy. The implications of the findings in this
study are supportive of both CSR business development goals and strategy of sustainable
shared values and stakeholder theories and their continued growth if industry initiatives
in support of these theories both in Nigeria and elsewhere prove to be sustainable and not
a patronizing kind of subterfuge or smokescreen as some cynics and critics have asserted
and portrayed them.

