


A Composite Index to Measure Integration of
Global Business Citizenship
Section 1: Foundation of the Study
Corporate Social Responsibility (CSR) is a broad concept consisting of the
economic, legal, ethical, and philanthropic responsibilities of corporate leaders (Carroll,
1999). Leaders of multinational or global corporations take CSR seriously. Business
Citizenship focuses on the ethical responsibly of corporate leaders as informed by CSR
(Carroll, 1999). Ninety-seven percent of the top 100 U.S. companies operate in multiple
nations and claim to be business citizens (Fifka, 2013). Wood and Logsdon developed
the theory of Global Business Citizenship (GBC) in 2002. GBC is defined as “a business
enterprise (and its managers) that responsibly exercises its rights and implements its
duties to individuals, stakeholders, and societies within and across national and cultural
borders” (p. 4). The definition implies that these rights fall within the ethical
responsibilities of CSR. By 2006, Wood, Logsdon, Lewellyn, and Davenport expanded
the GBC theory into a four-step implementation process. The first step is to develop a
companywide overarching code of ethical conduct consistent with the definition of GBC
(VALUE). The second step is to implement the overarching code of conduct throughout
the organization and adapt it to local customs, norms, and ethical standards (IMPLE).
The third step is to analyze problem areas and experiment with solutions to remediate the
conflicts (ANALY). The fourth step is to systemize learnings from the IMPLE and
ANALY steps and institutionalize the best policies, practices, and behaviors throughout

the organization. (LEARN). These four steps are the principles of the theory of GBC. As
leaders implement each step, their companies are maturing as global business citizens.
Companies that demonstrate these four steps are following the GBC principles.
Numerous research articles referenced and built upon the GBC theory. Current
researchers continue to cite the theory (Aguinis & Glavas, 2012; Font, Walmsley,
Cogotti, McCombes, & Hausler, 2012; Godos-Díez, Fernández-Gago, &
MartínezCampillo, 2011; Hart & Sharfman, 2012; Hemphill & Lillevik, 2011). Research
citing and building upon the GBC theory indicates that researchers consider it a valid
theory. The challenge facing researchers and business practitioners is the absence of a
rating system to determine whether a company meets the definition of a business citizen
and a composite index to measure the maturity level a company has achieved toward
becoming a business citizen. The key lies in the theory of GBC. The theory simply
provided the framework, or constructs needed to assess the maturity level a company has
achieved toward becoming a business citizen.
The ultimate objective of this research was to develop a composite index to
evaluate the maturity level that a company has attained in implementing the four steps of
the GBC framework. From a methodological viewpoint, the first step was to develop a
survey with a superset of questions that capture the multiple dimensions, or complexities,
of each step of the four-step framework developed by Wood et al. (2006). In quantitative
statistics, the steps of implementing the GBC theory equate to constructs. Donna J. Wood
was the lead researcher of the GBC theory. Wood agreed that VALUE, IMPLE,
ANALY, and LEARN could be considered the four constructs of the GBC theory (D. J.

Wood, personal communication, August 14, 2014; Appendix E).The second step was to
administer the survey to a qualified sample of business executives with knowledge and
understanding of GBC. The third step was to feed the collected sample into a powerful
statistical technique called exploratory factor analysis (EFA). The EFA method
rationalized the superset of questions into a minimal subset of questions necessary to
capture each construct. EFA generates so-called eigenvalues, or weights, on each
question. The result was a consensus survey with weights on each question. The final
step was to use the eigenvalues to determine an overall score or representative index of
global business citizenship to measure each company.
Researchers have made substantial progress in developing instruments to measure
various aspects within the broad field of corporate social responsibility. The extensive
literature review for this study and a review of the literature performed by Wood in 2010
did not reveal a measure for business citizenship, corporate citizenship, or any derivation
or definition of the term. Without a measure, it is difficult to know if a company meets
the societal expectations of a global business citizen or is merely making the claim
(Shinkle & Spencer, 2012).
Background of the Problem
For 60 years, researchers have studied the social responsibilities of business
leaders (Carroll, 1999). Research shows that companies that responsibly exercise their
rights and implement their social duties may obtain legitimacy from society and increase
competitive performance (Menck & Oliveir, 2014). Legitimacy and increased
competitive performance contribute to maximizing shareholder value. As such, there was

no longer a question of whether leaders should integrate social responsibility into their
business strategies, but how (Crittenden, Crittenden, Piney, & Pitt, 2011; Shepherd,
2014). The theory of GBC contends that the answer is for companies to become global
business citizens (Wood et al., 2006).
The concept of global business, or corporate, citizenship has rapidly gained
popularity in the corporate, academic, and political arenas (Crittenden et al., 2011). In the
corporate world, major companies, such as Boeing, Dow, IBM, and Microsoft all claim
that they are business citizens (Crittenden et al., 2011). Universities are incorporating
global business citizenship into their curricula (Lilley, Barker, & Harris, 2014). The
Clinton Global Initiative recognizes companies with the Global Citizenship Award
(Clinton Global Initiative, 2013). Despite the popularity of business citizenship to
describe the ethical component of social responsibility, at the start of this study there was
no published and publicly available rating system to measure the level of global business
citizenship for a given company.
Problem Statement
In 2014, over 8,000 business leaders across 145 countries had signed the United
Nations Global Compact to demonstrate their corporations’ commitment to ethical values
and responsibilities within society (Ortas, Alvarez, & Garayar, 2015). Business
citizenship has emerged as the preeminent term to describe the ethically responsible roles
of corporations within society (Crittenden et al., 2011). Of the top 100 U.S. companies,
97% claim to be business citizens (Fifka, 2013). The general business problem was that
there was no self-administered rating system available for business leaders to report to

stakeholders the steps they had achieved toward becoming an ethically responsible
business citizen (Milne & Gray, 2013). The specific business problem was that there was
no published self-administered survey instrument, or composite index derived from such
a survey, to assess the maturity level a company had achieved toward becoming a
business citizen as defined by the GBC theory (Wood, 2010).
Purpose Statement
The purpose of this cross-sectional quantitative study was to develop Likert
survey questions (independent variables) and apply EFA to reveal factors (dependent
variables) and assign weights to questions to develop a self-administered rating system to
measure the GBC theory, which assesses the maturity level a company has attained
toward becoming a global business citizen. Development of this rating system required
four methodological steps. First, creating a survey consisting of 1 qualifying question and
22 Likert questions that are operationalizing the GBC principles of VALUE, IMPLE,
ANALY, and LEARN. Second, administering the survey to members of professional
associations who were senior executives of U.S. corporations with an understanding of
GBC. Third, applying the EFA statistical method to the data. EFA revealed the
relationship between the Likert survey questions and the factors that emerged, reduced
the questions, and assigned weights to the remaining questions. Fourth, use the EFA
assigned weights to develop a composite index. The result of this study provides a rating
system to measure a company’s GBC maturity level. This study contributes to social
change by providing practitioners, academics, and stakeholders with a rating system to

evaluate the maturity level that corporate leaders have attained toward becoming a global
business citizen.
Nature of the Study
The goal of this research was to operationalize the four high-level GBC theory
steps, or constructs, elaborated by Wood et al. (2006), into a useful survey instrument
and weighted index. These artifacts allow practitioners, academics, and stakeholders to
selfadminister a quantitatively validated survey to corporate leaders to evaluate the
maturity level they have attained in implementing the four steps of the GBC theory. The
results of the survey provide a rating system in the form of a composite index to measure
the maturity level corporate leaders have achieved toward becoming a global business
citizen.
Applying a quantitative, qualitative or even a mixed methodology could have
produced an instrument and weighted index. There are advantages and disadvantages to
each methodology. The critical decision in selecting a quantitative method for this
research was the fact that the method must be appropriate for construct operationalization
to render a weighted index based on the scores attained by the survey instrument.
Researchers often use the qualitative methodology to describe and explain a phenomenon
and discover relevant concepts to propose a theory (Gioia, Corley, & Hamilton, 2012).
Once researchers identify concepts and propose a theory, they use the quantitative
methodology to formulate constructs. These constructs are qualities that researchers can
operationalize and quantify as variables for the purpose of measurement (Gioia et al.,
2012). Because the goal of the research was to operationalize and measure the constructs

of the previously developed theory of GBC, a quantitative methodology was most
appropriate.
Of the numerous quantitative methods available, EFA was appropriate for this
study. Researchers commonly use EFA to develop and validate self-reporting assessment
instruments, especially when there is little or no a priori knowledge of the structural
model (Ruscio & Roche, 2012). The EFA quantitative method was appropriate because it
is a rigorous statistical approach. EFA provided an unbiased method for reducing the
number of factors, examining relationships between factors, and evaluating the construct
validity of a measurement scale (Williams, Brown, & Onsman, 2012). Measurements
should repeatedly produce the same results, the measurement should be stable over time,
and the measurements should be similar within a given period (Hasson & Keeney, 2011).
Using EFA should ensure reliability by establishing construct, content, and statistical
validity. The EFA technique established weighted factors that loaded to the constructs,
which described the theoretical framework, thereby ensuring construct validity. The EFA
technique determined content validity. Applying EFA demonstrated that the measure
covered the range of meanings associated with the constructs (MacKenzie, Podsakoff, &
Podsakoff, 2011; Oluwatayo, 2012; Podsakoff, MacKenzie, & Podsakoff, 2012).
Computing the scree test to determine the optimal number of factors to retain ensured
statistical validity. To mitigate time and expense constraints, five experts with the
familiarity of corporate or business citizenship assessed the face validity of the survey.
The experts determined that the questions were reasonable, unambiguous, and clear,
(Oluwatayo, 2012; Synodinos, 2003). Figure 1 depicts the EFA method to evaluate GBC
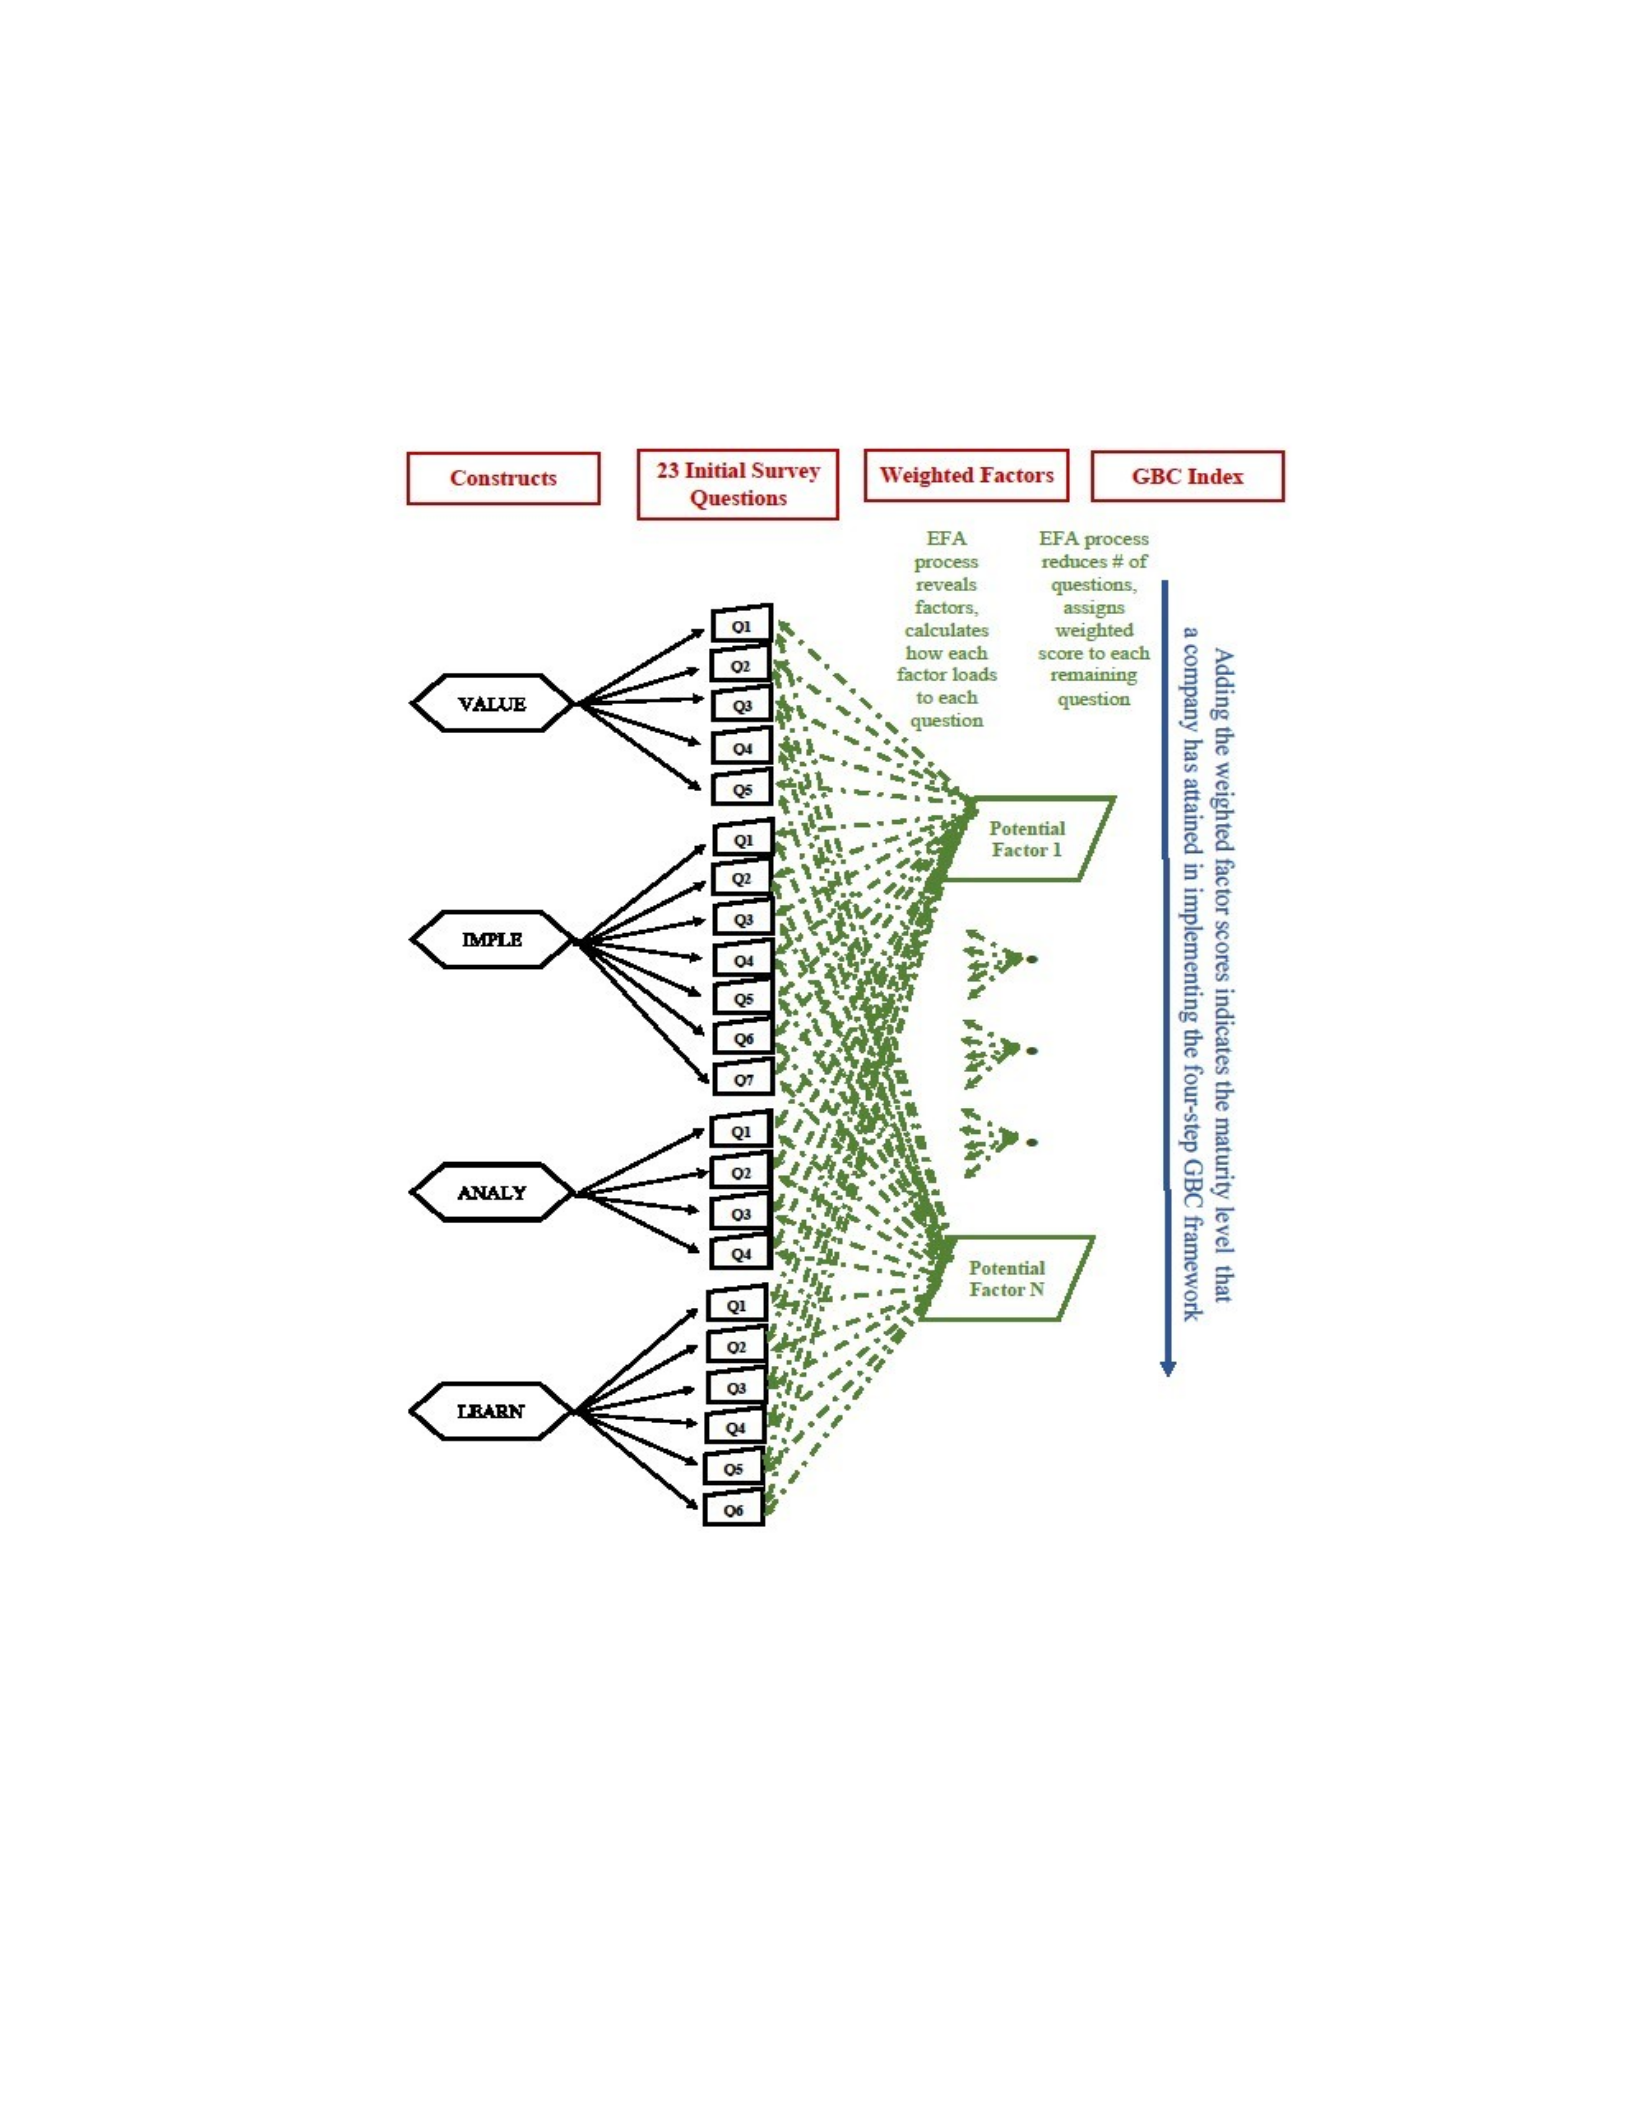
integration.

Figure 1. Schematic of EFA method to evaluate GBC integration.
The four-step GBC framework provided the assumed constructs. The constructs
were the following. First, developing overarching corporate values (VALUE). Second,
implementing the values (IMPLE). Third, analyzing problems and experimenting to
revise the values or local implementations (ANALY). Fourth, learning from the previous
steps and institutionalizing best practices (LEARN) (Wood et al., 2006). In Figure 1, the
black arrows indicate the survey questions that may describe each construct. EFA applied
to the data collected by administering the survey removed redundant questions and
assigned scores (called eigenvalues) to each question. The result is the minimal set of
questions that are necessary for the final survey and weighted factors. At a minimum, one
question should load to each construct. The blue arrows indicate this minimal question,
but the final research may yield more than one. When company leaders complete the
resulting survey, the resulting data yields weighted scores, indicating the maturity level
that they have attained in implementing the four-step GBC framework. In summary, EFA
statistical analysis was not only appropriate but also necessary to determine the critical
factors and their weightings that should comprise a standard rating system in the form of
a composite index to measure GBC.
Researchers commonly use Likert-type survey instruments to collect data for the
EFA quantitative method (Harrison & Reilly, 2011; MacKenzie, Podsakoff, &
Popsakoff, 2011). A Likert scale is a 5- or 7- point ordinal scale used to measure the
degree to which participants agree or disagree with a statement (Sullivan & Artino,

2013). Because archival data to support this type of research was not available, a survey
design was appropriate. Furthermore, a cross-sectional survey design was best suited to
collect the significant amount of data necessary for EFA (Beavers, Lounsbury, Richards,
Huck, Skolits, & Esquivel, 2013). The actual survey consists of 23 questions. The first
question was a “yes” or “no” qualifying question. The 22 Likert-type questions were
designed to attempt to capture the four constructs of the GBC theory. The study was
cross-sectional, meaning the sample represented a cross-section of the population for
which the measure was designed (MacKenzie et al., 2011). In this case, executive leaders
of multinational business organizations in the United States were the intended population
for this instrument. This cross-sectional sample should represent the population so that
the results should generalize to the broader population (MacKenzie et al., 2011).
Research Question
The purpose of the research was to develop a rationalized survey consisting of the
minimal set of survey questions required to assess the step or steps corporate leaders
have achieved in implementing the four steps of becoming a global business citizen. A
subsequently weighted index based on such questions evaluated the maturity level that
corporate leaders have attained toward becoming a global business citizen as defined by
the theory of GBC. Fundamentally, the research aimed at answering the following key
research question:
RQ: How many and what factors (dependent variables) are needed to
characterize the Likert survey questions (independent variables) to assess a company’s
GBC maturity level?

For an EFA study, such an overarching research question can be broken down
into four sub-questions given the fact that the GBC theory stipulates four key steps or
constructs:
Sub-Research question1 (SRQ1): Does the survey adequately capture the VALUE
construct of the GBC theory?
Sub-Research question 2 (SRQ2): Does the survey adequately capture the IMPLE
construct of the GBC theory?
Sub-Research question 3 (SRQ3): Does the survey adequately capture the
ANALY construct of the GBC theory?
Sub-Research question 4 (SRQ4): Does the survey adequately capture the
LEARN construct of the GBC theory?
Hypotheses
Multiple hypotheses could have been stated to operationalize the overarching RQ
and sub-research questions SRQ1-SRQ4. However, EFA is not an inferential statistical
technique and therefore when using this technique, researchers cannot stipulate
inferential hypotheses (Beavers et al., 2013). Instead, when using EFA, researchers often
stipulate so-called propositions about the number of factors to retain to capture the
relevant constructs. Given this general practice, researchers can state the propositions as
how many factors are required to represent the survey and the nomenclature k-factors to
stipulate such propositions (Henson & Roberts, 2006).
The GBC theory detailed four steps that leaders must implement to become a
global business citizen. These four steps are the GBC principles and equate to the

constructs of VALUE, IMPLE, ANALY, and LEARN (D. J. Wood, personal
communication, August 14, 2014; Appendix E). The EFA analysis revealed how many
factors emerged to best answer the question of whether a company meets the definition
of a global business citizen. The EFA analysis also yielded a measure of the maturity
level a company has achieved toward becoming a global business citizen by identifying
the step or steps leaders have implemented. Before the EFA technique, it was unknown
how many factors would emerge to answer the question of whether a company meets the
definition of a global business citizen and measures the maturity level a company has
achieved. The correct hypothesis centered around how many k-factors characterize
companies following the GBC principles. Mathematically, the following proposition
equated to the required hypotheses:
H0k: k= number of factors needed to characterize companies following GBC
principles.
Theoretical Framework
The theory of Global Business Citizenship was the basis of the theoretical
framework of this quantitative study. Researchers Logsdon and Wood developed the
GBC theory in 2002 (Logsdon & Wood, 2002; Logsdon & Wood, 2005; Wood &
Logsdon, 2002). Wood and Logsdon used a deductive, descriptive typology to develop
their theory of GBC (Wood et al., 2006). In 2006, together with Lewellyn, and
Davenport, Wood and Logsdon further developed their theory into a framework (Wood
et al., 2006). The theory describes a four-step framework. Figure 2 depicts the four-step
framework for implementing GBC within an organization. The first step was to develop a
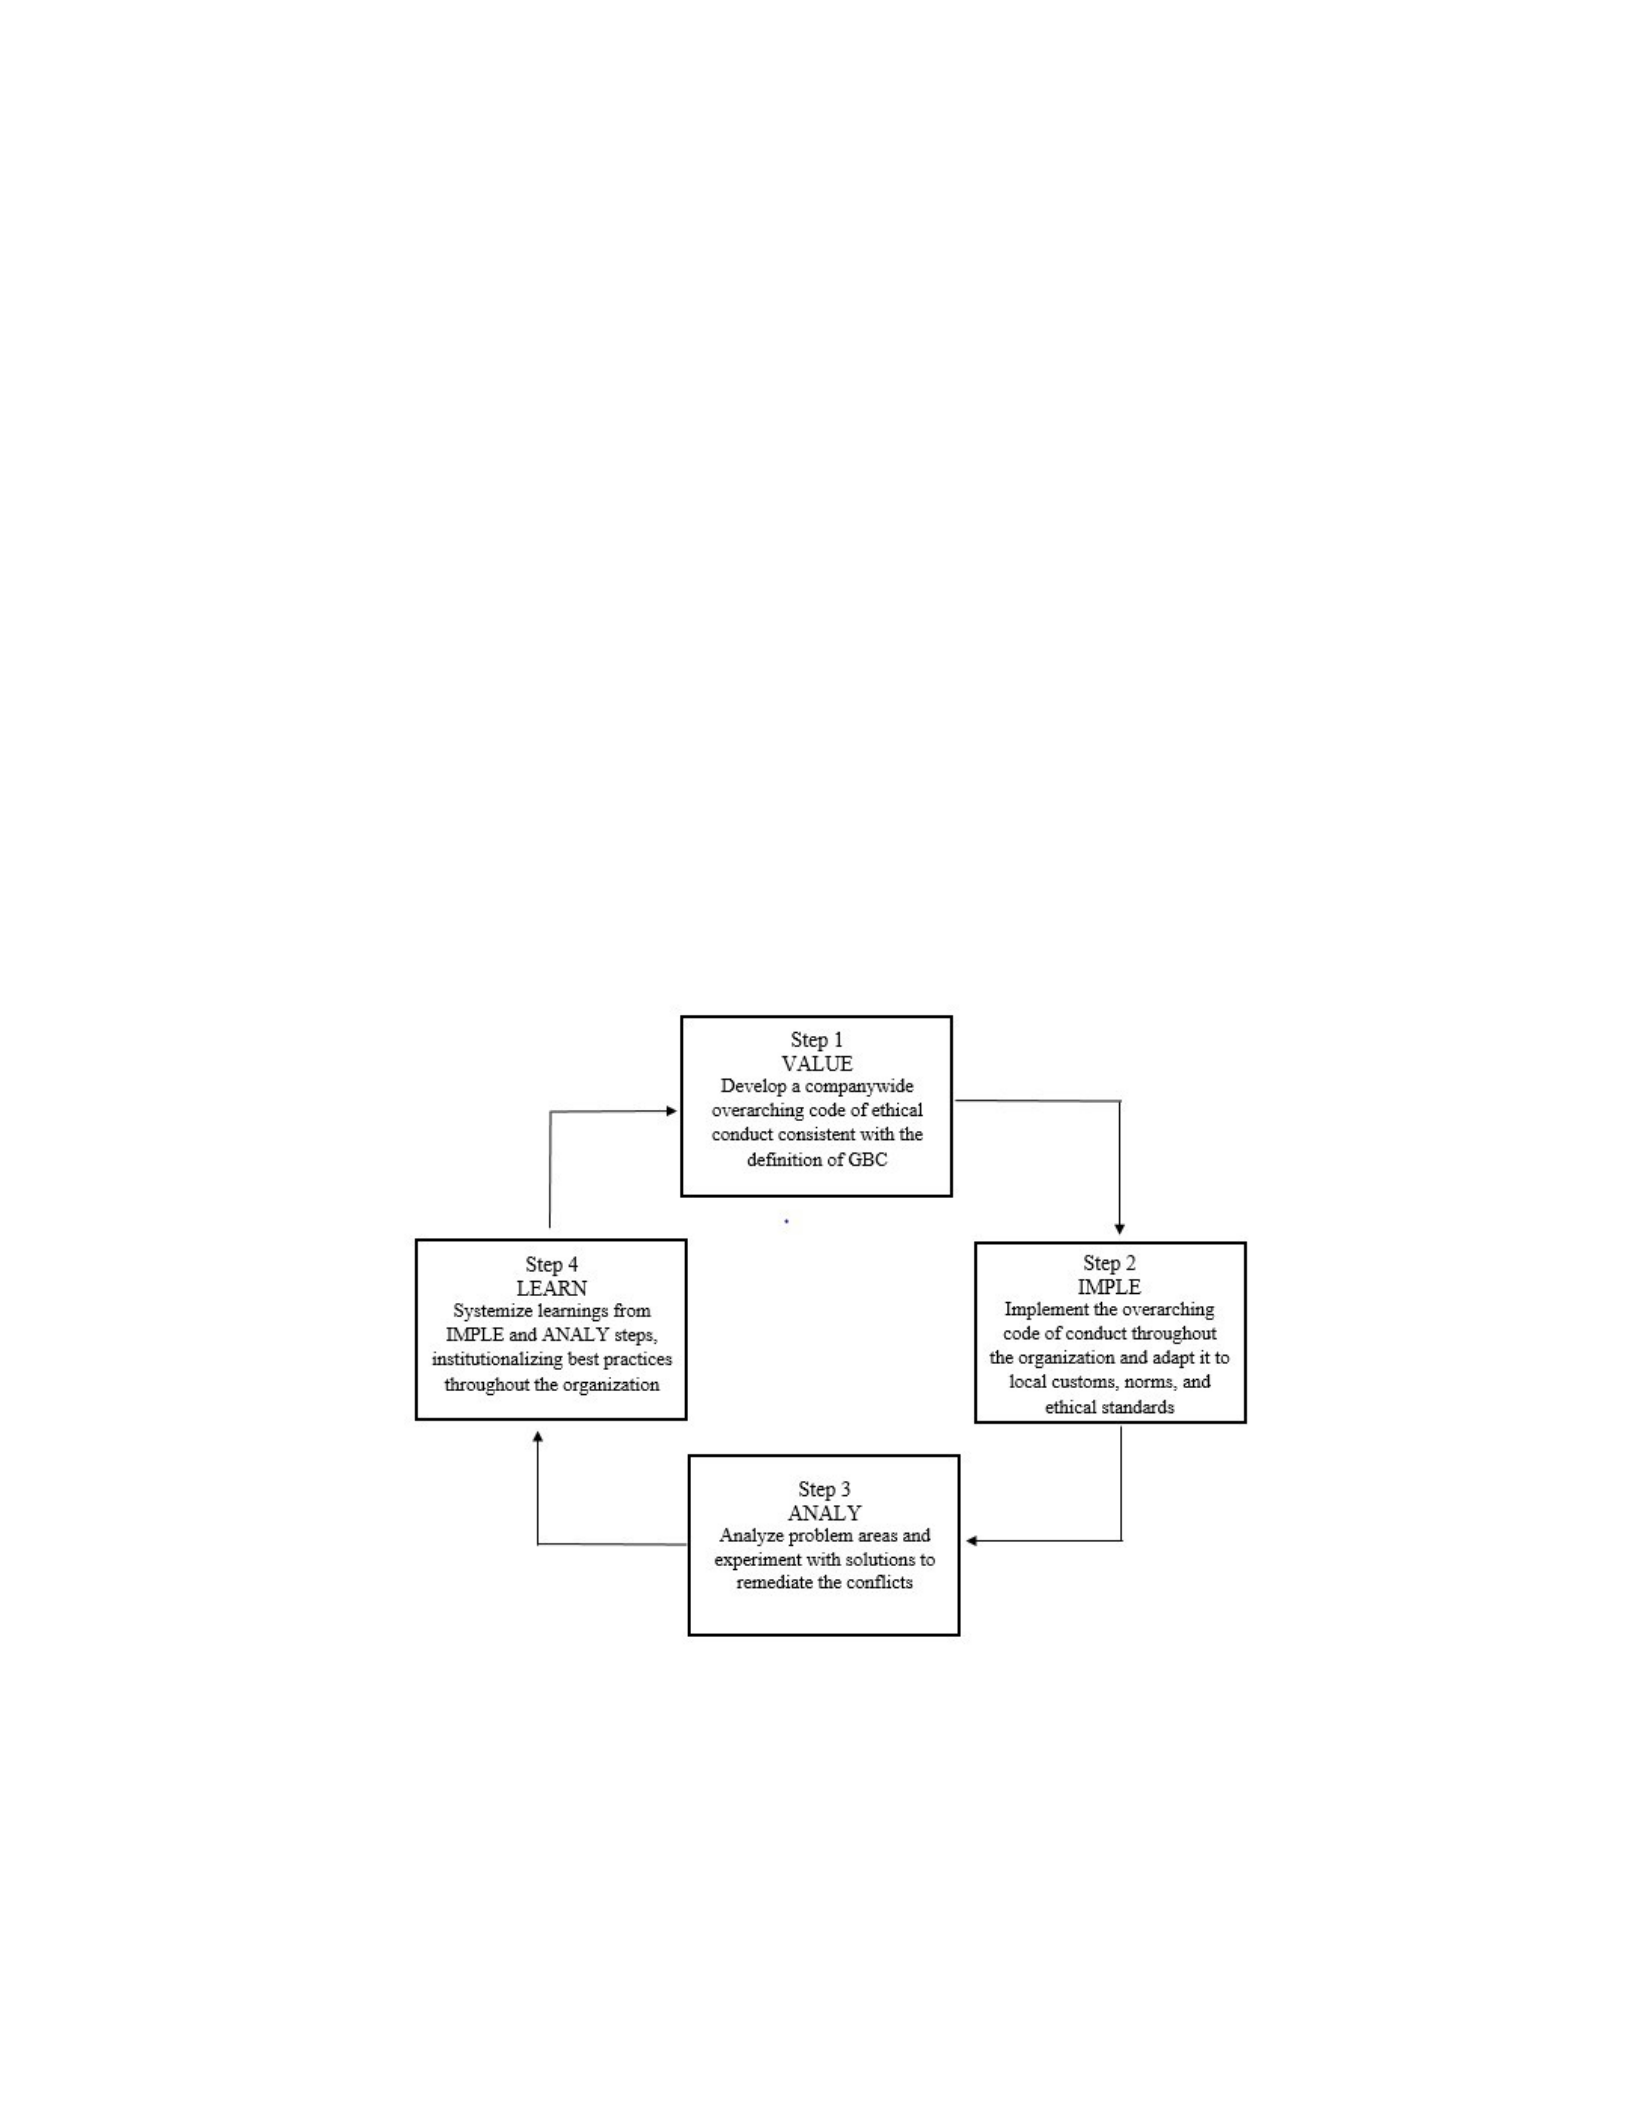
companywide overarching code of ethical conduct consistent with the definition of GBC
(VALUE). The second step was to implement the overarching code of conduct
throughout the organization and adapt it to local customs, norms, and ethical standards
(IMPLE). The third step was to analyze problem areas and experiment with solutions to
remediate the conflicts (ANALY). The fourth step was to learn from the previous steps,
systemize, and institutionalize best practices (LEARN). These four steps are the GBC
principles. Companies, academics, and politicians are using the term “corporate
citizenship” to describe the socially responsible role of businesses (Clinton Global
Initiative, 2013; Crittenden et al., 2011; Lilley et al., 2014). Because stakeholders are
using the term, the GBC theory fits to inform whether companies are business citizens.
Figure 2. The four-step framework for implementing GBC.

Operational Definitions
Corporate Social Responsibility. “Context-specific organizational actions and
policies that take into account stakeholders’ expectations and the triple bottom line of
economic, social, and environmental performance” (Aguinis & Glavas, 2012).
Global Business Citizen. “A global business citizen is a business enterprise
(including its managers) that responsibly exercises its rights and implements its duties to
individuals, stakeholders, and societies within and across national and cultural borders”
(Wood et al., 2006, p. 35).
Globalization. As a result of declining costs, the process of free trade across
borders connecting and transferring capital, goods, and people at distant locations (Bond
& O’Byrne, 2014). When referring to a “global business citizen” or “global corporation”,
globalization implies that the entity considers the entire world as a single space (Bond &
O’Byrne, 2014).
Stakeholder. “Any person, group, or organization who can affect or is affected by
the organization’s actions. Traditionally, a company’s stakeholders include investors,
employees, customers, suppliers, and the local communities. Others—governments,
NGOs, activists, the media—are also considered stakeholders today” (Wood et al., 2006,
p. 11).
Assumptions, Limitations, and Delimitations
The basis of the research for this study was the formation and administration of a

Likert-type scale instrument designed to identify the key questions that were significant
indicators of the four steps, or constructs, of GBC. The below assumptions, limitations,
and delimitations frame the study.
Assumptions
Assumptions are ideas that seem self-evident and are taken-for-granted as true
(Jansson, 2013). Researchers make assumptions about methods, design, and data (Leech,
Onwuegbuzie, & Combs, 2011). Several key assumptions underlie this research study.
The first was that the theoretical framework was measurable. The second was that
operationalization of the constructs captured the four-step GBC framework. The third
was that the instrument measured what it was intended to measure, also known as
construct validity. The fourth was that participants had sufficient knowledge of GBC to
complete the survey. The fifth was that the selected sample represented medium to large
national and multinational companies. The sixth assumption was that a survey approach
and EFA was appropriate for this study
The first assumption was that the theoretical framework was measurable. The
assumption was that a combination of some or all of the four key constructs might
measure the maturity level a company has achieved toward becoming a global business
citizen. The constructs were VALUE, IMPLE, ANALY, LEARN. This assumption may
have been limiting because this study did not consider constructs outside these four.
Mitigating the risk of this being a limiting assumption was the fact that these four
constructs are the basis of the GBC theory. Inherently, it was safe to assume that the
GBC theory included all of the constructs necessary to capture the stated definition of

business citizenship. The assumption was that the GBC theory was necessary and
sufficient for assessing an organization’s level of maturity as a global business citizen.
The second assumption was that the operationalization of the constructs into
survey questions accurately captured the four-step GBC framework. That is, the
assumption was that the survey’s 22 Likert questions adequately covered the majority of
issues that contribute to each of the four steps of the GBC framework. Three items
mitigated this potential limitation. First, the literature informed the constructs and the
specific questions. Second, the lead GBC theory author communicated her agreement.
Third, five subject matter experts (SME’s) evaluated the questions. Specifically, the
literature included the seminal studies in which Donna J. Wood and Jeannine M.
Logsdon developed the theory of GBC and the book published by the authors of the
theory of
GBC. In a personal email communication, Donna J. Wood agreed that VALUE, IMPLE,
ANALY, and LEARN captured the process of implementing the four-step GBC
framework (D. J. Wood, personal communication, August 14, 2014; Appendix E).
Additionally, five GBC subject matter experts (SMEs) reviewed the questions in the
newly developed instrument and agreed that the questions are clear and concise
(Appendix F). Applying EFA to the survey results reduced the number of questions. This
reduction identified the critical questions needed to evaluate the maturity level that a
company has attained in implementing the four-step GBC framework. The EFA process
also mapped the questions to their underlying factors, thus enabling development of a
composite index.

The third key assumption was that the instrument measured what it was intended
to measure, also known as construct validity (Cronbach & Meehl, 1955). The goal of the
research studies is for investigators to confirm or disconfirm that the instrument measures
what the investigator hypothesized it would measure (Cronbach & Meehl, 1955).
Cronbach and Meehl (1955) proposed three steps to evaluate construct validity. The
following is a summary of how instrument validity was determined. The Instrument
Validity subsection under the Data Collection section details these steps. In summary, the
first was to state the theoretical framework and assign meaning to each construct.
VALUE, IMPLE, ANALY, and LEARN were the constructs. These constructs were
informed by the literature and personal communication from Donna J. Wood, principal
researcher of the GBC theory (D. J. Wood, personal communication, August 14, 2014;
Appendix E). The survey questions were an attempt to assign meaning to each construct.
Five SME’s indicated that they felt the questions captured the meaning of the constructs
and were clear (Appendix F). The second step was to develop methods and empirically
measure how adequately the instrument substantiated the assigned construct meanings.
Some methods for examining construct validity exist. One was the multitraitmultimethod
matrix (MTMM), described by Campbell and Fiske's landmark paper
(1959). Others include factor analysis, and structural equation modeling (Marsh, Morin,
Parker, & Kaur, 2014). Using EFA satisfied this assumption. The third step was to
interpret correlations and present evidence and reasoning to show the reader why the
correlations confirmed or disconfirmed the hypothesis. EFA was the heart of this
research. Once the research was complete, the data was analyzed using the EFA

technique. Interpretation of the correlations provided evidence and reasoning to show
why the correlations confirmed or disconfirmed the hypothesis. In the case of applying
EFA, the hypothesis equates to propositions about the number of factors to retain to
capture the relevant constructs. In conclusion, the assumption of the construct validity of
the instrument was strongly satisfied via the original theory author’s confirmation, SME
confirmation, and EFA application.
The fourth assumption was that the participants possessed sufficient knowledge of
GBC to complete the survey. This assumption could have been a limiting factor because
surveys completed by participants with insufficient knowledge of GBC may not reflect
answers about which items suggest the four constructs of GBC. The first question was
designed to mitigate this potential limitation. The first question was, “I am familiar with
the concept of corporate citizenship, business citizenship, corporate social responsibility,
or the ethical responsibilities of corporations”. Participants indicated “yes” or “no” to this
question. The online survey directed participants answering “no” to this first qualifying
question to the end of the survey without answering the Likert questions. The online
survey continued to the Likert questions for participants answering “yes” to the question.
The fifth assumption was that the business leaders assembled at the Executive
Suite professional business society represent the business leaders of medium to large
national and multinational corporations. By definition, a cross-sectional sample implies
that it was representative of medium and large companies, but it may not have been true
given that the sample frame included executives belonging to this one professional
society. This study did not include businesses headquartered in countries outside the U.S.

The sixth assumption was that a survey approach and EFA was appropriate for
this study. A survey approach was best suited to collect the requisite data because
archival data to support this research was not available. This study was exploratory
versus conclusive in nature. Being exploratory allowed for exploring the dimensions of
the survey items and development of a measurement model (Williams et al., 2012).
Based on existing studies in which researchers applied exploratory surveys to develop a
composite measurement index, EFA appeared to be an appropriate methodology. In the
absence of any other quantitative studies in which researchers attempt to develop a model
to measure GBC, EFA was appropriate.
Limitations
To make research feasible, investigators limit what is under study (Bridges,
Hauber, Marshall, Lloyd, Prosser, Regier, Johnson, & Mauskopf, 2011). Limitations are
characteristics that are out of the researcher’s control but may influence the interpretation
of the findings of the study and establishment of external and construct validity (Brutus,
Aguinis, & Wassmer, 2013). Investigators may limit several areas. First, researchers may
limit the selection of elements under study. Researchers may make simplifications
necessary to produce a feasible study. Researchers may limit correlations among
elements. Alternatively, investigators may limit whether the participants generalize to the
population (Bridges et al., 2011). Several limitations to this study existed. As already
mentioned, the first was that sampling executives assembled at Executive Suite were a
subjective sample due to geography, demographics, and economic conditions.

Consequently, the results of this study may not generalize to businesses headquartered in
countries outside the United States. Replicating this study in other countries to determine
whether the results of this study generalize to other countries was an area for further
research.
A second limitation was the lack of existing academic studies specifically about
the theory of GBC and about developing a composite index to measure GBC. Leaders of
major corporations claim that their companies are business citizens (Crittenden et al.,
2011). Universities are incorporating business citizenship into their curriculums (Lilley et
al., 2014). Every year, the Clinton Global Initiative presents the International Global
Citizenship Award (Clinton Global Initiative, 2013). Despite these facts, the academic
literature was surprisingly lacking in the particular area of corporate or business
citizenship (Crittenden et al., 2011). There was abundant research going back 60 years in
the broad field of CSR, of which GBC is a subset (Carroll, 1999). While the lack of GBC
studies was a limitation, extrapolating relevant data from abundant CSR research
mitigates the limitation. This limitation also highlighted the need for this study.
A third limitation was that the operationalization of the constructs into survey
questions might have induced question redundancy or inclusion of weaker questions. The
EFA technique removed redundancy and retained the questions that were minimally
necessary to represent each factor. Applying EFA mitigated the limitation of question
redundancy or weak questions.

The EFA technique did not detect if there were missing questions in the original
survey. Thus, a fourth limitation was that in operationalizing the constructs into survey
questions, there might have been missing questions that jeopardized construct validity.
To mitigate this issue within the constraints of time and resource limits in concluding the
study, five SMEs reviewed the questions and offered suggestions for including missing
questions. The SMEs agreed that the questions were valid and did not offer suggestions
for adding additional questions.
Delimitations
Delimitations are intentional inclusionary and exclusionary boundaries that
researchers establish to guide their research and analysis process (Bartoska & Subrt,
2012). Delimitations identify the scope, or boundaries, of the study (Thomas & Magilvy,
2011). Establishing the boundaries allows future researchers to use the same data to
replicate or transfer the study (Thomas & Magilvy, 2011). The scope of this study was
limited to identifying critical factors required to measure GBC and determining the
minimal set of questions necessary to capture the factors. The four-step GBC framework
provided the assumed constructs. The constructs were the following. First, developing
overarching corporate values (VALUE). Second, implementing the values (IMPLE).
Third, analyzing problems and experimenting to revise the values or local
implementations (ANALY). Fourth, learning from the previous steps and
institutionalizing best practices (LEARN) (Wood et al., 2006). Operationalizing these
constructs, I developed a 23-question survey. Twenty-two Likert-type questions
described the four constructs. Using data from the survey, applying EFA reduced the 22

Likert questions to the minimum that were necessary, and mapped the essential questions
to an unknown number of subsets. In EFA, these subsets are known as “factors.” The
hypothesis section of this paper explains the factors. The resulting questions and factors
were those that best evaluated the maturity level that a company has attained in
implementing the four-step GBC framework. The resulting questions and factors
informed the creation of the composite index. The scope of this study was to create an
instrument that best captured the four constructs using EFA and using the EFA weights
(eigenvalues) to weight the instrument questions to compute an overall index of maturity.
Certain elements of GBC were out of the scope of this study. The study of why
business leaders do or do not implement the four-step framework of GBC was well
beyond the scope of this study. How or why stakeholders such as employees, consumers,
competitors, and non-governmental agencies pressure companies to practice business
citizenship behavior was beyond the scope of this study. Despite the importance of why
business leaders do or do not implement GBC or how or why stakeholders pressure
companies to practice GBC behavior, this study was limited to identifying factors that
described the four-step framework of GBC.
It was not within the scope of this study to assess the general views or opinions
corporate leaders had about the value of GBC. Soliciting the views about the value of the
GBC process was subjective. A qualitative study of such opinions may have value in
forwarding the academic research about the topic of GBC. Because this study was a
delimitated as described above, the study only focused on what items in the survey
described the implementation process.

This study did not cover how corporate leaders could move to implement the
four-step GBC framework. In their book, Global Business Citizenship, Wood et al.
(2006) clearly articulated how corporate leaders can apply the four-step GBC framework.
When complete, this study provided a way to measure at what point corporate leaders
have achieved in implementing the four-step framework of GBC. However, the study did
not touch upon how to apply the framework.
As already discussed, leaders at major companies such as American Electric
Power, Boeing, Dow, IBM, McAfee, McKesson, Microsoft Corp., and Nestle Waters all
claim that their companies are business citizens. The leaders claim that their companies
are business citizens because they are acting responsibly toward individuals,
stakeholders, and societies (Crittenden et al., 2011). This study did not examine how
corporate leaders that claim to be business citizens define the term or validate their claim.
Significance of the Study
CEOs at more than 80% of the U.S. Fortune 500 companies consider social
responsibility a mainstream component of their communications strategies (Taneja,
Taneja, & Gupta, 2011). As part of the communications strategies, 97% of the top 100
U.S. companies claim to be business citizens (Fifka, 2013). Research indicates that
business citizenship behavior may produce sustainable long-term economic, social, and
environmental benefits for the company and its stakeholders (Campbell, Eden & Miller,
2012; Menck & Oliveira, 2014; Wood et al., 2006). Business citizenship also provides a
moral, social, and political compass for business practice (Wood et al., 2006). Business
leaders are claiming that their companies are business citizens possibly to achieve

longterm economic, social, and environmental benefits. Business leaders are also making
the claim because stakeholders are demanding that they conduct their business as socially
responsible citizens of society (Park & Ghauri, 2015; Öberseder, Schlegelmilch, &
Gruber, 2011; Shum & Yam, 2011). The problem was that in searching the literature I
was not able to find a rating system for business citizenship, corporate citizenship, global
business citizenship, or any other derivative of the theme that business leaders can
selfadminister.
This study contributed to business practice and social change by introducing the
GBC index as a tool to quantitatively measure whether a company is a global business
citizen. Corporate leaders can use such a tool to demonstrate quantitatively to their
stakeholders the stage of maturity they have attained in becoming a global business
citizen. The following sections explain more fully the contribution to the business
practice and implications for social change.
Contribution to Business Practice
Measuring GBC was different from existing measures of CSR. The academic
literature provided several methods for measuring various aspects of CSR. The available
methods have limitations. One limitation was that measures rely on third-party data
(Glavas & Kelley, 2014). Another limitation was that reporting may not be conclusive for
comparisons between companies or countries (Panait, Voica, & Radulescu, 2014). A
final limitation was that reporting does not follow a standard format with defined
indicators that allow stakeholders to compare results within a firm over time (Berliner &
Prakash, 2014). Research by Calabrese, Costa, Menichini, Rosait, and Sanfelice (2013)

concluded that a method for assessing the stage a company had reached in overall CSR
cultural development was lacking. Most importantly, none of the CSR instruments
measured GBC. Measuring GBC is important for business leaders. Leaders who build the
reputation of being good business citizens may improve legitimacy, reduce the cost of
capital, improve access to capital, and experienced improved profitability.
Corporate leaders that build the reputation of being good business citizens
improve legitimacy in the eyes of their stakeholders (Wolf, 2014). When stakeholders
view a company as being legitimate, they provide access to essential resources (Wolf,
2014). Without essential resources, a company cannot operate (Wolf, 2014). Companies
must rely on stakeholders to obtain essential resources and maximize the value of the
corporation (Moura-Leite, Padgett, & Galán, 2014). Stakeholders are demanding that
corporate leaders conduct their business as though they are socially responsible citizens
of society (Park & Ghauri, 2015; Öberseder et al., 2011; Shum & Yam, 2011). To
conduct business and maximize corporate value, leaders must demonstrate to their
stakeholders that their companies are legitimate. Demonstrating that their companies are
business citizens indicates legitimacy (Park & Ghauri, 2015; Öberseder et al., 2011;
Shum & Yam, 2011).
Research suggested that corporate leaders that build the reputation of being good
business citizens reduced the cost of capital and improved access to capital by attracting
investors (Attig, El Ghoul, Guedhami, & Suh, 2013; Jiraporn, Jiraporn, Boeprasert, &
Chang, 2014; Oikonomou, Brooks & Pavelin, 2014). Credit ratings are an integral factor
in the rate companies pay for capital (Attig et al., 2013). Attig et al. (2013) provided

evidence that credit rating companies awarded relatively higher ratings to firms that
demonstrated business citizenship. Oikonomou et al. (2014) found that bond yield
spreads were higher for companies that demonstrated business citizenship. Oikonomou et
al. concluded that it appeared that investors perceived business citizens as having lower
credit risk and better credit quality.
Scherer and Palazzo (2011) compiled over 100 empirical studies that all
demonstrated a positive relationship between positive CSR and improved financial
performance. Researchers continue to demonstrate this positive relationship (Flammer,
2015; Gallardo-Vázqueza & Sanchez-Hernandez, 2014; Michelon, Besso, & Kumar,
2013; Torugsa, O’Donohue, & Hecker, 2013; Wang, Lu, Kweh, & Lai, 2014). As
discussed, GBC is a subset of CSR. Leaders who practice business citizenship may yield
improved profitability.
Because legitimacy, the cost of capital, and profitability are essential, it is
important for leaders to be able to demonstrate whether their companies demonstrate a
high, medium, or low level of business citizenship. Future researchers, practitioners, and
stakeholders will be able to use the GBC index as a tool to calculate the GBC score for
individual companies quantitatively. The score assesses the level of global business
citizenship for a given company. The score indicates whether individual companies
demonstrate a high, medium or low commitment to the four-step framework. The
fourstep GBC framework provided the assumed constructs. The constructs were the
following. First, developing overarching corporate values (VALUE). Second,
implementing the values (IMPLE). Third, analyzing problems and experimenting to

revise the values or local implementations (ANALY). Fourth, learning from the previous
steps and institutionalizing best practices (LEARN) (Wood et al., 2006).
Practitioners could use the GBC index to determine a baseline that would allow
them to establish goals for implementing the four-step GBC framework and chart
progress toward the goals (Wood et al., 2006). Practitioners could also use the index to
uncover areas for improvement or, conversely, identify areas of excellence to replicate
(Wood et al., 2006). By improving the GBC score, leaders would demonstrate their
commitment to GBC. A high GBC score could lead to improved legitimacy, the cost of
capital, and profitability.
Implications for Social Change
The concept of global business citizenship provides a moral, social, and political
compass (Wood et al., 2006). GBC is a process that allows companies to integrate
responsible and ethical business policies and actions that positively affect their economic,
social, and environmental performance (Wood et al., 2006). This compass may help
managers practice ethical conduct within the communities where they do business.
Practicing ethical conduct may produce sustainable long-term economic, social, and
environmental benefits for the company and its stakeholders (Wood et al., 2006). GBC is
an indicator of the level to which companies are maximizing shareholder value and
gaining a competitive advantage at the same time that they are incorporating laws, public
policies, political issues, and the interests of stakeholders. It also indicates that they are
acting ethically and responsibly for the benefit of individual managers, corporations,

industries, and society as a whole (Wood et al., 2006). The GBC index may identify
corporate leaders that apply the framework for being global business citizens.
A Review of the Professional and Academic Literature
This section focuses on a review of the literature needed to support the research.
First is an overview of the search method and instruments used to conduct the literature
review. The literature review covers the following four main themes: (a) explanation of
GBC; (b) the business and social case for GBC; (c) existing approaches to measuring
CSR; and (d) overview of EFA and its application.
This literature review begins with the seminal articles in which Wood and
Logsdon used deductive, descriptive typology to develop the theory and arrived at the
definition of GBC. Next is a presentation of the case for why corporate leaders should
integrate the GBC framework. With the definition and argument for implementing GBC,
the next section assessed current measurement approaches for CSR since none existed for
GBC. The final section presents an overview of the EFA technique and examples of how
researchers use EFA, to demonstrate the scope, strengths, and limitations of the
technique.
Literature Review, Search Methods and Search Instruments Employed
The extensive literature review began with the seminal articles published in 2002
by Donna J. Wood and Jeanne M. Logsdon, the authors of the theory of GBC. The
seminal work also included the subsequent book published by the authors in 2006. From
there, the search of the literature focused on the keywords corporate social
responsibility, CSR, corporate social performance, global business citizen, business
citizen, and corporate citizen. The search primarily included articles published in peer-
reviewed journals between 2011 and 2015 available from EBSCOhost, Emerald
Management Journals, ProQuest ABI/INFORM, SAGE Journals Online, and
ScienceDirect databases. Table 1 depicts the databases used. Automated Google Scholar
alerts for the search terms corporate social responsibility and global business citizen
yielded relevant articles appearing as advanced online publications in 2014 and 2015.
Updates to the reference section occurred as the journals publish the cited articles.
Table 1
Databases Used
EBSCOhost
Emerald Management Journals
ProQuest ABI/INFORM
SAGE Journals Online
Science Direct
The literature supported how and why the Wood and Logsdon developed the
theory of GBC. It also provided evidence for a solid case for the relevance of GBC
because when companies implement the GBC framework, they can obtain legitimacy
from society and increase competitive performance. Lastly, the literature provided
evidence that there was no rating system for GBC.
Database
Besides the core research topic, some reviewed literature provided an in-depth
understanding of the EFA research method. For this topic, the search of the literature
focused on the keywords exploratory factor analysis, EFA, and factor analysis. This
portion of the literature review provided information for an overview of factor analysis in
general and the EFA technique in particular. Researchers use EFA to test relationships,
generalize results to alternate populations, use existing scales, test the effectiveness of a
measurement instrument, or developed and/or refined a new measurement instrument.
The final section of the literature review covered EFA studies that demonstrated how
researchers used the EFA technique in these ways.
There are 175 peer-reviewed articles cited in this study. Of those, 91% of them, or
159, are references within five years of the anticipated graduation year of 2016 and 16
are older than five years. Of the 16 studies that are older than five years, two are seminal
articles published by Wood and Logsdon. Along with these two seminal studies, the book
Wood and Logsdon wrote based on their seminal studies was cited. The study referenced
two websites, and one was a government website. Overall, 89% of the references were
peer-reviewed and published within five years of the anticipated graduation year. Table 2
contains the numbers and percentages of the professional and academic literature
reviewed and all references used in the study.
Table 2
Reviewed Literature and All References Statistics
Literature 5 or fewer years Literature older Total Percentages <= 5
Literature Type old than 5 years years
Books 0 3 3 0
Dissertations 0 0 0 0
Peer-Reviewed Articles 159 16 175 91
Web Pages 2 1 3 67
Others (e.g., Gov.) 1 2 2 50
Total
Peer-Reviewed and
162 21 183 89
Dissertations <= 5 years 159 0 183 87
The Theory of Global Business Citizenship
Research into the role of business in society began in 1953 with the publication of
Howard R. Bowen’s book titled Social Responsibilities of the Businessman (Carroll,
1999). The term corporate social responsibility (CSR) emerged to describe the social
responsibility of businesses (Crittenden et al., 2011). As the society became concerned
with corporate practices such as depleting the environment, producing harmful consumer
products, and inhumane workplaces, there was a significant increase in CSR research
(Logsdon & Wood, 2002). By 1973, there was still no consensus about exactly what CSR
was, so the American Enterprise Institute sponsored a major debate about the meaning of
CSR (Carroll, 1999). In Carroll’s 1979 seminal study, he proposed a CSR model that
encompassed the economic, legal, ethical, and philanthropic responsibilities expected of
corporate leaders (Carroll, 1979). Through the 1990s, scholars introduced concepts
related to CSR. CSR concepts include corporate social performance (CSP), stakeholder
theory, business ethics theory, and corporate citizenship (Carroll, 1999; Crittenden et al.,
2011). Business leaders embraced the term “corporate citizenship” to define the ethical
component of their CSR efforts (Carroll, 1999). With this new practitioner focus, Carroll
revisited his model. He wrote, “the CSR firm should strive to make a profit, obey the
law, be ethical, and be a good corporate citizen” (Carroll, 1999, p. 289). However, there

was still no distinction or connection between CSR and corporate citizenship (Carroll,
1999; Logsdon & Wood, 2002; Wood & Logsdon, 2002). Global corporate citizenship
emerged as the prominent term on the ethically responsible role of business (Crittenden
et al., 2011). Wood and Logsdon seized the opportunity to develop a theory of corporate
citizenship that integrated CSR with the idea that businesses were citizens (Wood &
Logsdon, 2002). The researchers used the term “business” in place of “corporate” to
indicate that companies are engaged in business. Wood and Logsdon then extended the
theory to the global level. Wood and Logsdon linked global citizenship to global business
strategy by implementing broad universal principles and integrating legitimate cultural
norms, rules, and performance expectations (Logsdon & Wood, 2002).
Wood and Logsdon used a deductive, descriptive typology to develop their
theory of GBC (Wood et al., 2006). Deductive, descriptive typology is a well-established
analytical method used in social science research to reduce complexity, form concepts,
and explore dimensionality (Collier, LaPorte, & Seawright, 2012; Fiss, 2011). Wood and
Logsdon first presented the argument that the idea of citizenship translated from the
individual to a business organization (Wood & Logsdon, 2002). Wood and Logsdon then
presented strategic approaches for implementing GBC.
Wood and Logsdon (2002) began with the fact that in a globalized, free market
without a single government to establish and enforce rules, companies had new
opportunities to exploit people and the environment. Wood and Logsdon proposed that
the concept of global business citizenship would provide a moral, social, and political
compass. This compass would help managers practice prudent and ethical conduct within

the communities where they did business. Wood and Logsdon theorized that the ethical
conduct at the local level would produce sustainable long-term economic, social, and
environmental benefits for the company and stakeholders (Wood et al., 2006).
Wood and Logsdon began constructing their theory by demonstrating how the
idea of individual citizenship translated to companies. Over the past several thousand
years, philosophers have developed the notion that individuals are citizens with inherent
human rights (Logsdon and Wood, 2002). In their first seminal article, Wood and
Logsdon (2002) examined how the three most widely supported modern views of
citizenship for individuals translated to citizenship for companies. The three views of
citizenship for individuals they examined included the minimalist theory of civic
association, the communitarian model, and the universal human rights model. The
minimalist theory says that citizens are free agent residents of a common jurisdiction
striving to achieve their goals within the constraints of rules necessary to protect their
individual liberties (Wood & Logsdon, 2002). In the communitarian model, citizens unite
in a community having duties to participate in making and carrying out rules for the
welfare and preservation of the culture of the community. The universal human rights
model provides individuals the freedom to pursue their interests and has autonomy of
action while balancing that freedom with the welfare of the overall society. In this model,
the government secures and protects individualism, independence, and social welfare by
establishing rights and duties based on a set of shared values. Wood and Logsdon
analyzed whether the idea of business citizenship made sense from these three
perspectives of individual citizenship.

From the minimalist theory of civic association perspective, Wood and Logsdon
(2002) determined that companies could not be citizens. Wood and Logsdon resolved
that, within the minimalist framework, companies were a legal structure that allowed for
managers, as agents of shareholders, to negotiate contracts. Shareholders provide capital
and acquire property ownership through business activities to maximize their
selfinterests. Within this view, companies cannot be citizens because they do not act
independently of their shareholders.
Wood and Logsdon (2002) concluded that the communitarian model perspective
did provide for companies being business citizens. Wood and Logsdon determined that
because companies used the resources of the community and reflected the values of the
community, they were a part of the community yet distinct from individuals. Wood and
Logsdon argued that the business leaders tend to conform to local norms and contribute
to the welfare of the community to remain in good standing with the community. Wood
and Logsdon reasoned that the businesses thrived by helping the community thrive. In
the communitarian model, companies act as individual citizens, carrying out rules for the
welfare and preservation of the community; therefore, society considers them citizens.
Wood and Logsdon (2002) determined that the universal human rights model also
support companies as citizens, however, with weaker rights and duties than individuals.
Similar to the communitarian model, Wood and Logsdon argued that companies use the
resources of the community with the purpose of creating a surplus, thereby allowing
individuals and societies to do more with their limited resources. Companies must
become members of stakeholder networks that span multiple locales to use the resources

of local communities. Wood and Logsdon concluded that companies could be citizens
because they pursue their interests, have autonomy of action, and provide for social
welfare.
Furthering their argument for corporations as citizens, Wood and Logsdon (2002)
explained the legal and moral status of corporations. Wood and Logsdon began by
showing that corporations are legal entities with rights analogous to individuals. Wood
and Logsdon outlined how U.S. constitutional and case law recognized corporations as
artificial persons, subject to some identical criteria and protections as individuals. For
example, in the United States, both individuals and corporations enjoy the protections of
the First, Fourth, Fifth, and Fourteenth Amendments of the U.S. Constitution. Individuals
and corporations must abide by residency laws and have rights within the due process of
law to privacy, life, liberty, property, and exemption from double jeopardy. Corporations
also have the right to political participation, in the forms of lobbying and contributions to
political campaigns. Wood and Logsdon concluded that granting legal status to
companies allow them to, “better serve their human purposes and their human
constituents” (p. 83). Wood and Logsdon further concluded that since companies have
limited legal rights analogous to individuals, we should attribute limited citizenship
rights and duties to them as well, and being legal citizens comes with moral obligations.
Wood and Logsdon (2002) went on to determine the moral obligations of
companies. Wood and Logsdon outlined French’s 1979 viewpoint that since business can
behave rationally and with an intention, they have moral obligations to self-regulate,
according to the community’s moral rules. By contrast, they outlined the opposite

viewpoint put forth by Ladd in 1970. Ladd’s view was that companies lack intentionality
and autonomy. Therefore, companies are incapable of moral obligations, and regulatory
controls are necessary to achieve ethical business practices. Wood and Logsdon also
outlined middle-ground perspectives by Donaldson in 1982, Werhane in 1985, and
DeGeorge in 1999. These middle-ground perspectives included several ideas. First,
companies have a different moral agency to follow than individuals because the people
within companies collectively know more than an individual can know. Second, business
actions cannot be reduced to individual actions; therefore, businesses have some moral
obligations. Third, companies are moral actors but not moral persons because they are
not human beings with awareness of their actions. Fourth, stakeholders should not expect
companies to act morally, but should praise positive moral actions and place blame when
they violate the moral law. From the arguments about the legal and ethical obligations of
companies, Wood and Logsdon concluded that individuals form companies to further
societal satisfaction. Businesses add to societal satisfaction by creating jobs, growing the
economy, investing in research and development, and education. As such, corporations
should be subject to some of the same legal and moral rights and obligations as
individuals. However, Wood and Logsdon also concluded that it was inappropriate to
consider that companies are equivalent to individuals.
In a second seminal article, Logsdon and Wood (2002) used Aristotle’s idea that
individual citizens have duties to participate in the political process, pay taxes, and
participate in military service. Over the centuries, societies have adapted these
fundamental duties to custom and law. In their argument, Logsdon and Wood

demonstrated how these duties of individual citizens translated to corporate
responsibilities.
First in Logsdon and Wood’s (2002) argument was that individual citizens have a
responsibility to participate in the political process. Logsdon and Wood argued that
individuals participate in voting, engaging in political discourse and avoiding unfair
influences, such as bribery or coercion. Wood and Logsdon showed that while firms
cannot vote, they do participate in the political process by lobbying and avoiding unfair
influences such as bribery or coercion. Additionally, Logsdon and Wood argued that
investors and consumers sanction business activities by effectively voting with their
spending dollars.
Second in Logsdon and Wood’s (2002) argument, individual citizens are
obligated to pay taxes that benefit the collective good. Individuals also voluntarily
support social services through philanthropy. Likewise, firms are obligated to pay taxes.
Many corporations also voluntarily support social services through philanthropy.
In the final piece of Logsdon and Wood’s (2002) argument, individual citizens
have a duty to participate in the defense against common threats. Firms are required to
support their employees serving the military. Furthermore, Logsdon and Wood claimed
that corporations should “defend against enemies of the business institution whether
within or across political borders” (p. 174). Logsdon and Wood argued that capitalism
depend on laws and the moral ideas of private property and human rights. Without these
ideas, there is no ground for entering into contracts. Logsdon and Wood thus contended
that the enemies of business organizations are conditions that threaten human rights, and

firms must defend against such threats. With the understanding that companies do have
duties similar to the duties of individual citizens, Logsdon and Wood concluded that
companies meet these criteria of being citizens. Logsdon and Wood also found that
citizenship implies inherent natural human rights. The next step Wood and Logsdon took
was to define the four-step framework of the theory of GBC. The four steps were
developing corporate values (VALUE), implementation (IMPLE), problem analysis
(ANALY), and learning and institutionalizing best practices (LEARN).
Values. Logsdon and Wood (2002) began integrating the idea of global
citizenship into their theory by examining universal values of individual citizenship.
Logsdon and Wood cited the United Nations’ Universal Declaration of Human Rights as
the foundation that there was a uniform set of rights and obligations protecting the
individuals of the globe. Logsdon and Wood also cited the fact that most countries
incorporated civil and political rights into their constitutions. Logsdon and Wood “claim
that there is now a common awareness of cross-cultural conditions and a common
language of rights that help to shape the social, political, and economic forces of the
world” (p. 164). Logsdon and Wood argued that multinational companies profoundly
shape the economy, society, and politics. Therefore, companies directly affect human
rights. Articles 28–30 of the Universal Declaration of Human Rights tasks companies,
countries, other organizations, and individuals with promoting social welfare, protecting
human rights, and defending against any person or entity attempting to destroy any of the
rights outlined in the Universal Declaration of Human Rights.

Global companies have an obligation to act as citizens and uphold these universal
human rights. The theory of GBC states that the first step toward becoming a global
business citizen is to develop a companywide, overarching values in the form of a code
of ethical conduct (Wood et al., 2006). The theory of GBC suggests that corporate
leaders use the Universal Declaration of Human Rights as the foundation for developing
companywide overarching values (Wood et al., 2006). Developing overarching values is
the first step of the four-step framework of the theory of GBC (Wood et al., 2006). This
first step equates to the first construct of VALUE. The next question Logsdon and Wood
addressed was how to handle differences between overarching values and local norms.
Implementation. Logsdon and Wood (2002) argued that in today’s global
business environment, business leaders must uphold universal human rights. Logsdon
and Wood also argued that in upholding human rights, they must work within the
“norms, rules, and performance expectations” of the local communities in which they do
business
(p. 165). Logsdon and Wood first demonstrated that local norms vary among
communities, and some may even conflict with universal rights, but all have social
legitimacy within their community.
A study by Barkemeyer and Figge (2014) supported the view that corporate
leaders should incorporate local values into value codes. Barkemeyer and Figge found
that centralizing development and maintenance of CSR agendas at the corporate
headquarters did not result in optimal solutions for stakeholders outside the headquarters.

Barkemeyer and Figge called the phenomenon “headquartering” Barkemeyer & Figge
found that headquartering led to management problems at subsidiaries away from the
headquarters. Barkemeyer and Figge suggested leaders that control the CSR agenda and
do not allow for local implementation could expect one of three outcomes. First, when
there is a match of headquarter and local values, the local stakeholders will uphold the
local values. Second, when there is a mismatch of priorities, local stakeholders will
pursue their agendas. Third, when there is a mismatch of talk and action, local
subsidiaries may not implement the headquarters’ initiatives.
The language used in ethical codes is as important as the ethics themselves.
Winkler (2011) studied companies listed on the Frankfurt Stock Exchange to determine
how the language of ethical codes defined relationships between employees, line
managers, top managers, and compliance officers. The results showed that the ethical
codes placed management at the upper side of the formal hierarchy. The language
granted this group superior rights and knowledge. The codes depicted employees as
passive receivers of the codes. The language suggested that employees required ethical
monitoring and control. The language further indicated that employees were not
competent to interpret the codes nor empowered them to achieve higher morality.
However, Winkler’s results also exposed that management expected employees to
demonstrate the ethical behavior of the corporate leaders. This ambiguity leads to
indifference toward the ethical code. Winkler concluded that to have ownership for a
corporate ethical code; employees must have a stake in the code and perceive it as their
personal code of conduct. Winkler acknowledged that establishing ownership is difficult

when a company has thousands of employees spread across the globe, and the parent
company attempts to disseminate their fixed code throughout the organization.
International managers face pressure to adapt local norms if they wish to do
business in the community. Wood et al. (2006) proposed that GBC companies adopt a
“limited number of broad universal principles; a wide range of variant applications, some
acceptable, some not; and a “free space” in which norms and applications remain to be
developed” (p. 171). The free space allows international managers the ability to
incorporate local norms, rules, and performance expectations into their business
practices. Recent studies support this assumption.
Through an exploratory and descriptive case study, Proenca and Branco (2014)
demonstrated that local managers at companies in Portugal engaged in CSR activities
that aligned with their personal values and morals. Owen and Kemp (2014) argued that to
bring about positive CSR change within the mining industry, the moral sensibilities of
the local, in the trenches, employees should drive professional habits and organizational
strategies. Despite the importance of following local issues, Bondy and Starkey (2014)
found that the 37 multinational companies they researched did not incorporate local
culture into their CSR policies but adopted a unified international strategy. Bolton, Kim,
and Gorman (2011) conducted a case study to examine the initiation, implementation,
and maturation process of implementing a CSR strategy. In the end, Bolton et al.
identified a CSR strategy as a morally responsible business citizen. Bolton et al. selected
of one of the largest multinational companies with more than 102,000 employees as their
case study company. Bolton et al. found that implementing or sustaining any CSR-related

initiatives without employee engagement and an agreement was difficult. Through
analyzing the company’s “People Survey” of more than 100,000 employees around the
globe, Bolton et al. found that employees’ personal morals significantly affected the
company, both positively and negatively. It was mandatory that companies allowed
employees at the local levels to have input to creating the CSR strategy.
Logsdon and Wood (2002) argued that to uphold human rights; corporate leaders
must incorporate the norms, rules, and expectations of local communities.
Implementation of ethical codes is a long-term process that requires commitment,
communication, and integration into business practices for employees to integrate them
into organizational cultures (Erwin, 2011). Implementing the overarching values
throughout the organization and incorporating local customs, norms, and ethical
standards became the second step of the four-step framework of the theory of GBC. This
second step equates to the second construct of IMPLE.
Analyze. Wood et al. (2006) acknowledged that incorporating local norms, rules,
and performance expectations into business practices might lead to conflicts with the
overarching values or conflicts within local societies. Logsdon and Wood proposed that
international managers must experiment to determine which norms, rules, and
performance expectations to incorporate, and how. Through this experimentation, the
business adopts policies and procedures that fit the local culture, ethical tradition, and
law, and best serves the people and the firm. Analyzing problem areas and experimenting
with solutions to remediate conflicts became the third step of the four-step framework of
the theory of GBC (Wood et al., 2006). This third step equates to the third construct of

ANALY.
Learn. Logsdon and Wood further argued that, through experimentation, the
entire business must systematically learn from their successful implementation of local
business practices. Systemizing learnings from the IMPLE and ANALY steps, and
institutionalizing best practices throughout the organization became the fourth step of the
four-step framework of the theory of GBC (Wood et al., 2006). This fourth step equates
to the fourth construct of LEARN.
Wood et al. (2006) defined a global business citizen as, “a business enterprise
(including its managers) that responsibly exercises its rights and implements its duties to
individuals, stakeholders, and societies within and across national and cultural borders”
(p. 4). Within their concrete framework, the first step is to develop a companywide
overarching code of ethical conduct consistent with the definition of GBC. The second
step is to implement the overarching code of ethical conduct throughout the organization
and adapt it to local customs, norms, and local ethical standards that seem in conflict with
the overarching code of ethical conduct. The third step is to analyze areas where local
norms, rules, and performance expectations conflict with the code of ethical conduct and
experiment with creative and practical solutions to remediate the conflicts. The fourth
step is to learn from the previous steps, systemize, and institutionalize the best policies,
practices, and behaviors throughout the organization.
Grounded in an overarching code of conduct, implementing the four-step GBC
framework will orient companies in a way that enhances legitimacy through socially
acceptable behavior at the individual, organizational, and systemic levels. With their

seminal companion articles, Wood and Logsdon made a compelling case that companies
have limited legal and moral obligations analogous to individual citizens. Wood and
Logsdon showed how companies carry out rules for the welfare and preservation of the
community. Wood and Logsdon explained that corporations had autonomy to pursue
their interests and provide for social welfare. Wood and Logsdon showed that, like
individual citizens, corporations have duties to participate in the political process, pay
taxes, and participate in military service. Wood and Logsdon made the case that global
companies have an obligation to act as citizens and uphold universal human rights. When
corporations act like global business citizens, they not only meet these obligations, but
they also receive economic, social, and environmental performance benefits.
The Case for Global Business Citizenship
As we have seen, the theory of GBC integrates CSR with the concept that
companies have limited legal and moral rights and obligations as citizens (Wood &
Logsdon, 2002). The result of implementing the GBC framework’s responsible and
ethical business policies and actions positively affect a company’s economic, social, and
environmental performance. Research shows that CSR strategies have the potential to
obtain legitimacy from society and increase competitive performance (Menck & Oliveira,
2014). Wood et al. (2006) suggested that corporate leaders could integrate CSR into
business practices by identifying and implementing ethical codes of conduct, the first
step to becoming a GBC business. The benefits of CSR translate to the benefits of GBC,
therefore, in making the case for GBC it was appropriate to examine the literature related
to CSR.

Research and surveys indicate that by engaging in CSR behavior, companies have
the potential to obtain legitimacy from society and increase competitive performance
(Menck & Oliveira, 2014). Legitimacy and competitive performance directly affect
profitability. The below sections make the case for why business leaders would benefit
from implementing the GBC framework.
Legitimacy. With globalization came the loss of shared moral orientation,
widening governance gaps, and increased public awareness of the conduct of corporate
leaders (Voegtlin, Patzer, & Scherer, 2012). As such, it is more important for corporate
leaders to build their legitimacy and maintain trustful relationships with stakeholders
(Voegtlin et al., 2012). An important way for corporate leaders to obtain legitimacy from
society is by engaging in CSR activities (Menck & Oliveira, 2014; Zheng, Luo, &
Makisomov, 2014). Legitimacy is the assumption that the actions of a company are
consistent with societal norms, values, and beliefs (Du & Vieira, 2012). Legitimacy is
vital for corporations because stakeholders will only ensure a continuous flow of
essential resources to entities they perceive as legitimate and reputable (Du & Vieira,
2012). Fundamentally, a reason companies would benefit from implementing the GBC
framework is that it helps build reputation and legitimacy (Campbell, Eden & Miller,
2012).
The reputation and legitimacy of companies reside within the perceptions of
stakeholder (Bitektine, 2011). The theory of social judgments of organizations explains
that stakeholders build their perceptions of the reputation, legitimacy, and status of
corporations by five factors (Bitektine, 2011). The first is whether a firm belongs to a

category or industry. The second is whether an organization has the right to exist. The
third is whether an organization is beneficial or hazardous to individuals, social groups or
society as a whole. The fourth is the performance and behaviors exhibited by the
corporation. The fifth is how an organization ranks with similar organizations.
Stakeholder perceptions establish reputation and legitimacy (Bitektine, 2011) and CSR
strategy significantly influence stakeholder perceptions (Dilling, 2011).
Within the context of legitimacy, Parsons, Lacey, and Moffat (2014) studied how
managers conceptualized that society grants corporations a ‘social license to operate’.
Parsons et al. found that the participants conceptualized the notion of social license to
operate within the four themes of legitimacy, localization, process and continuum, and
manageability. Concerning legitimacy, the participants of the study indicated that they
focused on the community approving and accepting of the way corporate leaders do
business, rather than whether a corporation’s values aligned with societal or cultural
values. The participants evaluated corporate legitimacy.
The results of a study by Park, Lee, and Kim (2014) showed economic and legal
CSR initiatives had a significant impact on corporate reputation. Their study also showed
that ethical and philanthropic CSR initiatives did not directly affect corporate reputation.
However, these categories did indirectly affect the trust consumers had related to
corporate integrity and benevolence. The authors demonstrated that if ethical and
philanthropic CSR strategies instilled integrity and social benevolence in consumers, they
enhanced corporate reputation.

Stakeholders perceive the reputations of companies in the oil industry to be highly
controversial (Du & Vieira, 2012). As a result, one of the strategies of oil companies to
build a positive reputation is to engage in CSR initiatives (Du & Vieira, 2012). In a study
by Du and Vieira (2012), the researchers found that oil companies engaged in a broad
range of CSR initiatives and used those initiatives as public relation campaigns. Because
of the study, the researchers recommended that to build a reputation; oil companies
should stop using “CSR as public relations.” Instead, the researchers suggested that oil
companies should engage in long-term socially responsible initiatives, such as
developing renewable energy sources.
Stanaland, Lewin, and Murphy (2011) looked at the issue from the perspective of
how perceived financial performance, and ethical conduct influenced the perceptions of
firms’ CSR strategies. The results of the study showed that when consumers saw the
positive financial performance, they provided a better evaluation of CSR activities.
Similarly, when consumers saw high-quality ethics statements, they provided a better
evaluation of CSR activities. The results of their study also showed that when consumers
had a positive CSR perception, they rated corporate reputation and consumer trust and
loyalty higher while rating perceived risk lower. The authors concluded that commitment
to positive financial performance and ethical standards positively influenced perceptions
of CSR activities, which directly related to positive corporate reputation and consumer
loyalty and trust.
Dilling (2011) showed that the CSR strategies of companies significantly
influenced stakeholder perceptions. In Dilling’s study, the age of corporations and their

publishing of CSR reports significantly increased stakeholders’ perceptions of
corporations. Surprisingly, Dilling also demonstrated that CSR efforts in the areas of
cultural diversity and community development decreased stakeholders’ perceptions of
organizations.
Corporate reputation informs how stakeholders view the ethical conduct of
companies. Cian and Cervai (2014) published a study to clarify the definitions of and
relationships between the terms, “corporate image,” “projected image,” “construed
image,” “reputation,” “organizational identity”, and “organizational culture.” Cian and
Cervai provided several conclusions. One conclusion was that the perceptions of
stakeholders informed reputation. Another conclusion was that reputation was the answer
to “who we are”. Similarly, reputation was corporate culture. Reputation was also what
internal stakeholders believe external stakeholders thought about their company. Finally,
reputation was what management communicates to external audiences.
Vos, Shoemaker, and Luoma-aho (2014) demonstrated that corporate
communication was the strategic interface between both internal and external
stakeholders. The discipline of corporate communication aims to develop good will and
mutual relations while acknowledging possible conflicting interests. Vos et al.
recognized that stakeholders do not all have a shared stake in an organization.
Stakeholders will have interests’ specific to their issues and possibly even have opposing
points-of-view. Their viewpoints and expectations inform corporate reputation.
The above-cited studies showed that the perceptions stakeholders had about
CSRrelated economic and legal initiatives, ethical conduct, and publishing of CSR

reports all positively influenced corporate reputation and legitimacy. A study by
Campbell et al. (2012) confirmed that the main effect of CSR on corporate reputation
was both statistically and practically significant. Despite this finding, Campbell et al.
found that when local branches of multinational corporations were far away from the
corporate headquarters, they were less likely to engage in CSR. Local branches that were
proximate to the corporate headquarters were more likely to engage in CSR. Campbell et
al. concluded that despite the positive benefits of CSR, foreign firms at greater distances
were less willing to invest in host-country CSR.
CSR strategies have the potential to help companies obtain the legitimacy they
need to gain cooperation and necessary resources from stakeholders and conduct business
within society (Menck & Oliveira, 2014). Without legitimacy, there is no shareholder
value. Assuming that the purpose of business is to maximize the value to shareholders
within ethical and lawful means, as Carroll (1979) suggested, there is no longer a
question of whether leaders should integrate CSR into their business strategies, but how.
Wood et al. (2006) suggested that the global business leaders could integrate social
responsibility into their business practices by becoming global business citizens.
Numerous studies indicate that positive CSR increases competitive performance. CSR
increases competitive performance because it adds value to stakeholders, especially
consumers, and employees, influences the cost of doing business, in particular, the cost
of capital, and improves financial performance.
Competitive Performance. The value CSR activities add to stakeholders and the
costs associated with CSR affects the competitive performance of companies (Menck &

Oliveira, 2014). The value CSR activities add to stakeholders, especially consumers, and
employees, affect competitive performance. The following focuses on literature
informing how CSR activities add value to stakeholders, affect the cost of capital, and
affect the financial performance.
CSR Value to Stakeholders. Stakeholders significantly influence CSR activities
and business citizenship behavior (Lahouel, Peretti, & Autissier, 2014; Park & Ghauri,
2015). Corporate leaders that build the reputation of being a good business citizen
improve legitimacy in the eyes of their stakeholders (Wolf, 2014). When stakeholders
view a company as being legitimate, they provide access to essential resources (Wolf,
2014). Increasingly, stakeholders are demanding higher levels of CSR performance.
Stakeholders are demanding that corporate leaders conduct their business as though they
are socially responsible citizens of the society (Park & Ghauri, 2015; Öberseder et al.,
2011; Shum & Yam, 2011). Companies must rely on stakeholders to maximize the value
of the corporation (Moura-Leite et al., 2014). Responsible leaders must consider the
consequences of corporate actions on all stakeholders (Voegtlin et al., 2012). MouraLeite
et al. (2014) found that providing what stakeholders demanded had a significant positive
effect on corporate financial performance.
Farmer (2014) identified a shift from corporate leaders being accountable to
shareholders above all to being accountable to stakeholders, including employees,
consumers, and local communities. Farmer noted that European business leaders focus on
investing in the communities in which they do business. As Wood et al. (2006)
contended, Farmer commented that the model is more sustainable because acting in this

socially responsible way should enhance competitiveness and maximize wealth creation
to the overall society.
Carlon and Downs (2014) developed a comprehensive method to account for the
financial value stakeholders bring to a firm. In the model, the first phase was to
determine whether the firm was a stakeholder firm, meaning they were accountable to
stakeholders first, as opposed to a shareholder firm that was responsible to shareholders
first. The second phase was to assess the financial value various stakeholders bring to the
firm. In the financial valuation, Carlon and Downs included the importance of business
citizenship activities. The third phase was to account for and report on that value.
The results from the above studies indicated that stakeholders influence the CSR
behavior of companies. However, a study about stakeholders’ power to influence CSR in
China indicated a different story. Lu and Abeysekera (2014) acknowledged that in the
past few years, the Chinese government had made significant strides toward continuous
economic growth, but CSR disclosure is a relatively new practice in China. The results of
Lu and Abeysekera’s study indicated that while CSR disclosure had a positive
association with profitability, the power of stakeholders to influence CSR disclosure was
weak.
Contrarily, Park, Chidlow, and Choi (2014) found that among South Korean firms, both
primary and secondary stakeholders were able to influence CSR practices positively.
Goyal, Rahman, and Kazmi (2013) determined that between 1992 and 2011, most of the
CSR research analyzed the relationship between CSR and financial performance in

developed countries. Studying stakeholders’ power to influence CSR in developing or
government controlled countries seems to be an area warranting further research.
Consumers are arguably the most important stakeholder group for a company
(Menck & Oliveira, 2014). A company cannot stay in business without consumers
purchasing their products. Research indicated that consumer stakeholders were concerned
about price and the value products provided. Consumers are also concerned about the
meaning, or the social identity related to the product, company, or industry (Menck &
Oliveira, 2014). Surveys of by Cone Communication (2013) of 10,287 actual consumers
showed that fifty-five percent of global consumers said they had refused to buy products
in the last year because of negative social responsibility. While some research supports
direct relationships between CSR and consumers’ intentions to purchase products,
attitudes do not always predict behavior (Papaoikonomou, Ryan, & Giniesis, 2011).
Likewise, purchasing intentions do not necessarily translate into actual purchases
(Papaoikonomou et al., 2011).
In a multi-method qualitative study, Papaoikonomou et al. (2011) examined why
consumers might not make purchases aligned with their CSR concerns. Papaoikonomou
et al. found several reasons for the intention—behavior gap. One reason was that
consumers encountered a lack of comparable products produced by companies aligned
with their ethical concerns. Consumers also complained that ethical alternatives did not
meet their expectations in areas such as functionality or style. Consumers indicated that
they found it difficult to obtain information about how companies made products and felt
that CSR reporting was incomplete or of questionable quality and credibility. Another

reason for the intention—behavior gap was that consumers were on limited budgets and
companies priced ethically responsible products too high. There were also factors of
everyday life such as the “pester power” of children demanding products, the influence
of
friends and peers, and opting for the easy choice.
Mandhachitara’s (2011) quantitative study of bank customers showed that CSR
had a strong, significant positive relationship with consumers’ loyalty, suggesting repeat
patronage intentions. There was a significant and positive association between repeat
patronage intentions and service quality. Results also showed that perceived service
quality contributed to consumers’ loyalty. While CSR initiatives did not significantly
relate to repeating patronage intentions, CSR did show positive and significant
relationships with loyalty and perceived service quality. Supporting Mandhachitara’s
research, the 2013 Cone survey of 10,287 consumers showed that when companies
engaged in CSR, 96% of respondents had a more positive image. Ninety-four percent
reported they were more likely to trust those companies, and 93% indicated that they
would be more loyal to those companies. Mandhachitara concluded that the positive
associations between CSR and product loyalty and service quality had direct
consequences for banking services.
Öberseder et al., (2011) found that when consumers did not have information about
CSR, it did not play a role in their purchasing decisions. When consumers did have
relevant information, they began a complicated hierarchical process of core, central, and
peripheral factors to assess their purchasing decisions. The researchers concluded that the

complexity of the decision process hindered consumers’ purchasing decisions. Research
supports that incorporating CSR into business practices has the benefit of influencing
consumers’ purchasing intentions, however, their intentions may not translate to actual
purchasing behaviors due to a variety of complicated hierarchical factors.
Shen, Wang, Lo and Shum (2012) found that consumers indicated that they were
willing to pay a higher price for fashions produced in manners consistent with human and
environmental well-being. Their study also reported that when consumers had limited
knowledge about global sweatshop practices of fashion retailers, that lack of knowledge
prevented consumers from translating their concerns into purchases. Likewise, Marquina
and Morales (2012) found that consumers in Peru and Spain indicated that they were
willing to pay more for products from companies with good CSR reputations, including
sound labor and environmental practices.
Employees are a primary stakeholder group of all corporations (Farooq, Farooq,
& Jasimuddin, 2014). Results from a study by Evans and Davis (2014) indicated that the
more employees perceived their employers to exhibit business citizenship behavior, the
more likely they were to identify with the organization. The employees also engage in
organizational citizenship behavior and avoided the potential deviant behavior in the
workplace. CSR activities help organizations retain employees who are loyal and have
positive attitudes (Hansen, Dunford, Boss, Boss, & Angermerier, 2011; Wong & Gao,
2014). The results of a quantitative study by Hansen et al. (2011) showed that employees
who had positive CSR perceptions of their company had decreased intentions to leave.

The employees also demonstrated increased organizational citizenship behavior.
Likewise, Wong & Gao (2014) found that stakeholder related CSR activities resulted in a
significant employee commitment to the organization.
Evans and Davis (2014) conducted a study to predict whether employees’
perception of the business citizenship of their company would influence their
organizational citizenship behavior. In this study, Evans and Davis defined corporate
citizenship as how the corporate leaders were “fulfilling economic, legal, ethical, and
discretionary responsibilities imposed on the firm by its stakeholders” (p 129). Evans and
Davis measured organizational identification, organizational citizenship behaviors,
employee deviance, and socially desirable responding. The results of their study
indicated that when employees perceived their employer as exhibiting business
citizenship, they were more likely to identify with the organization, engage in
organizational citizenship behaviors, and avoid the deviant behavior.
Deviant behavior is costly and harmful to organizations (Aleassa & Zurigat,
2014). Aleassa and Zurigat conducted a study to determine how employees who
identified with their corporation and the company’s ethical values responded when faced
with unethical behaviors committed by their peers. Aleassa and Zurigat found that
employees who identified with their company were more likely to report their peers’
misconduct. The question this raises is how companies can influence how employees
identify with the company.
Farooq et al. (2014) conducted a study to determine if evaluating CSR initiatives
could predict employee behavior. The results of their study demonstrated that CSR

initiatives directed toward the community, employees, and consumers positively
influenced how the employees identified with the organization and how they shared
information. Therefore, employees will identify with companies that engage in CSR
initiatives.
Chen and Hung-Baesecke (2014) found that leaders’ participation and modeling
of CSR directly affected employees’ attitudes about CSR. In particular, Chen and
HungBaesecke found three management behaviors that directly and indirectly affected
employee CSR participation. The three management practices were role modeling or
leading by example, advocating for CSR and facilitating employee CSR participation.
Bohdanowica, Zientara, and Novotna, (2011) demonstrated a significant link
between CSR and employee engagement. Some companies are using this link to promote
their CSR activities as a way to attract employees who align with the company culture
(Bohdanowica et al., 2011). Bohdanowica et al. analyzed Hilton’s We Care! Program,
Hilton’s We Care! Program involved over 16,000 of the hotel’s employees to develop
CSR initiatives in the form of “greening” to reduce energy use and CO2 emissions.
Bohdanowica et al. showed that the program motivated 95% of the Hilton employee
participants. Ninety percent believed the program helped improve Hilton’s profitability,
and 89% replied that for them, the program improved the hotel’s image. Hilton promotes
the We Care! Program to prospective employees.
Socially responsible activities help organizations retain employees who are loyal
and have positive attitudes (Hansen, Dunford, Boss, Boss, & Angermerier, 2011; Wong
& Gao, 2014). When employees perceived their employer as exhibiting corporate

citizenship, they were more likely to identify with the organization, engage in
organizational citizenship behaviors, and avoid deviant behavior (Evans & Davis, 2014).
Likewise, employees who identified with their company were more likely to report their
peers’ deviant behavior (Aleassa & Zurigat, 2014). Companies can influence how their
employees identify with them by engaging in CSR initiatives directed toward
community, employees, and consumers (Farooq et al., 2014). When leaders participate
and model
CSR behaviors, they directly affect employees’ attitudes about CSR (Chen &
HungBaesecke, 2014). Because of the significant link between CSR and employee
engagement, some companies are promoting their CSR activities as a way to attract
employees aligned with the company culture (Bohdanowica, Zientara, & Novotna, 2011).
CSR and the cost of capital. Numerous studies indicate that CSR activities
influence investors and the cost of capital. Research suggested that positive CSR
strategies reduce the cost of capital and improve access to capital by attracting investors.
Credit ratings are an integral factor in the rate companies pay for capital (Attig et al.,
2013). A study by Attig et al. (2013) provided evidence that credit rating companies
awarded relatively higher ratings to firms with good social performance, especially CSR
that extended beyond compliance. By sampling the KLD database, Jiraporn et al. (2014)
found that firms’ credit ratings increased as much as 4.5% when they increased their
KLD CSR score by one standard deviation. Oikonomou et al. (2014) reviewed more than
3,000 bond issues by 742 firms operating in 17 industries. Oikonomou et al. found that
bond yield spreads were higher for companies that demonstrated good social performance

and companies with negative social performance paid more for capital. The authors
concluded that it appeared that good social performance led investors to perceive the
companies as having lower credit risk and better credit quality.
Strugatch (2011) determined that 82% of investors evaluate social responsibility
when making their investment decisions. Cohen, Holder-Webb, Nath, and Wood (2011)
conducted a study to determine what nonfinancial information investors used and desired
to use more of in the future. Cohen et al. found that investors placed the most importance
on economic performance followed by corporate governance and corporate social
responsibility. The respondents also indicated interest in using more nonfinancial
information in the future. Furthermore, the respondents clearly indicated their preference
for corporate social responsibility information provided by a third party. Aspara and
Tikkanen (2011) found that 85% of investors were willing to invest in a company with
lower financial returns if they identified positively with the corporate identity. Likewise,
Dhaliwal, Li, Tsang, and Yang (2011) and Xu, Liu, and Huang (2015) found that
institutional investors invested in companies with superior CSR performance. Dhaliwal et
al. (2011) found that companies that voluntarily disclosed superior CSR performance
paid less for equity capital. Additionally, these firms raised significantly more capital
than companies that did not disclose their CSR activities. Similarly, Girerd-Potin,
Jimenez-Garcès, and Louvet (2014) found that the cost of equity was lower for
companies that demonstrated social responsibility toward business stakeholders, societal
stakeholders, and financial stakeholders.
Cho, Lee, and Pfeiffer (2013) found a significant positive association between the

“bid—ask” spread and the CSR activities of the companies in which they were investing.
The authors concluded that this indicated that investors with knowledge about the CSR
performance of corporations exploited that information when valuing stock. A study by
Cheng, Ioannou, and Serafeim (2014) also indicated that companies with better CSR
performance were able to raise more financing. Dhaliwal et al. also found that companies
with superior CSR performance attracted more analyst coverage, and the analysts
produced reports with fewer forecast errors and dispersion.
Elliott, Jackson, Peecher, and White (2013) found that investors valued corporate
stock based on firm CSR performance and their assessment of the CSR performance.
Furthermore, the researchers found that investors who did not explicitly analyze CSR
performance were more willing to invest in a firm with positive perceived CSR
performance. The results of a study by Sun and Cui (2014) indicated that companies with
positive CSR did reduce the risk of default.
Investors in Bangladesh do not seem to demonstrate the level of rewarding
companies with good CSR by reducing the cost of equity as the above studies indicate.
Ahmed, Islam, Mahta, and Hasan (2014) sampled 152 companies listed on the Dhaka
Stock Exchange. Ahmed et al. found that good CSR performance had a positive, but
insignificant, relationship to the amount of money that institutional investors supplied to
those companies in Bangladesh. In summary, research indicates that CSR activities
attract investors and reduce the cost of capital, which directly affects financial
performance.

CSR and financial performance. Scherer and Palazzo (2011) compiled over 100
empirical studies that all demonstrated a positive relationship between positive CSR and
improved financial performance. For this study, the Walden Library was the resource that
enabled a comprehensive search for articles published in 2013 and 2014 that reported
results examining the relationship between CSR and financial performance. Nine articles
reported a positive relationship; one reported a peripheral positive relationship; three
articles reported no relationship, and one study of Chinese companies reported a negative
relationship.
In the following nine articles, researchers found a positive relationship between
CSR and financial performance. By studying the CSR-related proposals that shareholders
passed by a narrow margin, Flammer (2015) found the CSR activities increased
shareholder value by 1.77%. Wu and Shen (2013) found that CSR positively affected
financial performance in the banking industry. In particular, Wu and Sen found that CSR
positively affected return on assets, return on equity, net interest income, and non-interest
income. Michelon et al. (2013) analyzed the best business citizens as defined by Kinder,
Lyndenberg, Domini Analystics, Inc. (KLD). Wu and Shen found a positive relationship
between CSR and financial performance when those companies strategically aligned their
CSR initiatives to stakeholder interests. In another study using KLD data of companies in
the U.S. telecommunications industry, Wang et al., (2014) found a significant positive
relationship between KDL social rating indexes and corporate performance. Wang et al.
found that companies that implemented CSR had higher corporate efficiency. In a study
of small and medium companies, Torugsa et al. (2013) found that firms that

synergistically integrated the economic, social, and environmental dimensions of CSR
initiatives showed enhanced financial performance.
Boesso, Kumar, and Michelon (2013) studied the relationships between corporate
performance and descriptive, instrumental, and strategic approaches to CSR. Boesso et
al. found an association between all three CSR approaches and corporate performance,
but in different ways. Helpful CSR had a positive association with short-term measures
of corporate performance. Strategic CSR influenced short and medium-term corporate
performance. Descriptive CSR had no definite association with corporate performance.
Lu, Wang, and Lee (2013) demonstrated that CSR had a positive effect on the
financial performance of US semiconductor companies. Mallin, Farag, and Ow-Yong
(2014) studied 90 banks across 13 Islamic countries. Lu et al. discovered a positive
association between CSR disclosure and financial performance and those banks with
better financial performance were more inclined to disclose their CSR performance.
Gallardo-Vázqueza and Sanchez-Hernandez (2014) defined a scale to measure the social,
economic, and environmental dimensions of CSR and competitive success. The results of
sampling 67 regional divisions of medium and large firms concluded positive CSR had a
significant and positive effect on those firms’ overall competitive success, indicating
positive financial performance.
In the comprehensive search of articles published in 2013 and 2014, one studied
indicated a peripheral positive relationship between CSR and financial performance.
Chun, Shin, Choi, and Kim (2013) studied the relationship between corporate ethics and
financial performance. The results did not indicate a direct link between corporate values

and firm performance. However, the researchers did find that the corporations with
higher internal ethical standards enjoyed increased levels of collective organizational
commitment by the employees, which provided meaningful improved financial
performance.
In the comprehensive search of the literature published in 2013 and 2014, three
studies indicated no relationship between CSR and financial performance. Belu and
Manescu (2013) used a Data Envelopment Analysis model to evaluate the effects of CSR
on profitability. Their analysis did not confirm the positive relationship that the
researchers were expecting, but the result also did not find evidence to oppose a positive,
or negative, relationship. Ducassy (2013) studied whether CSR improved financial
performance during times of economic crisis. He found that at the beginning of the 2007
financial crisis, there was a significant positive effect, however after the first six months;
there was no longer a significant connection between CSR and financial performance.
Erhemjamts, Li, and Venkateswaran (2013) found that firms with better financial health,
performance, and R&D were more likely engaging in CSR activities than firms with
poorer financial health, performance, and R&D intensity.
In a review of the literature about CSR and corporate financial performance,
Goyal et al. (2013) determined that between 1992 and 2011, most of the research
analyzed the relationship in developed countries. However, Julian and Ofori-Dankwa
(2013) studied the effects of spending money on CSR initiatives to financial resource
availability in the emerging economy of sub-Saharan Africa. Contrary to developed
nations, Julian and Ofori-Dankwa found a significant negative relationship between CSR

expenditures and return on sales, return on equity, and firm net profitability. Their study
indicated that firms in developing nations were profit motivated to spend less of their
financial resources on CSR activities than were firms in developed countries.
Overview of Exploratory Factor Analysis and its Application
Factor Analysis (FA) is a statistical data reduction method. There are two types of
Factor Analyses: Confirmatory Factor Analysis (CFA) and Exploratory Factor Analysis
(EFA). Below is a summary of both CFA and EFA literature, with emphasis on EFA and
how researchers apply EFA since this was the procedure utilized in this research study.
The key term in FA is “factor”. By definition, a factor is an abstract concept or
latent variable such as intelligence. Researchers cannot directly measure abstract
concepts, such as intelligence. To measure such abstract concepts, researchers must
administer different types of questions or even tests to assess them in a holistic or
composite fashion.
The fundamental idea of both CFA and EFA is that multiple observed Likert
variables have similar patterns of responses because of their association with an
underlying latent variable (the factor) which researchers cannot easily measure. For
example, people may respond similarly to Likert questions about income, education, and
occupation, which are all associated with the latent variable “socioeconomic status.”
Factor Analysis. Factor analysis is a group of statistical methods used to understand
and simplify patterns of relationships underlying measured variables (Beavers et al.,
2013; Fabrigar, Wegener, MacCallum, & Strahan, 1999; Schmitt, 2011). For over sixty
years, social scientists have used factor analysis. Researchers use factor analysis to

develop theories, develop instruments, analyze longitudinal data, compare group means,
and evaluate the validity of measures (Beavers et al., 2013; Fabrigar et al., 1999;
Schmitt, 2011). Factor analysis is a concept that includes both exploratory factor analysis
(EFA) and confirmatory factor analysis (CFA) (Jennrich & Bentler, 2011).
CFA tests whether a known factor model can predict a set of observed data
(DeCoster, 1998). Researchers use CFA to verify or confirm hypotheses or theory
(Ruscio & Roche, 2012; Schmitt, 2011). Researchers also use CFA to establish the
validity of the factor model (Ruscio & Roche, 2012; Schmitt, 2011). CFA is used to
compare two models using the same data (Ruscio & Roche, 2012; Schmitt, 2011). CFA
is a good way to test the significance of factor loading (Ruscio & Roche, 2012; Schmitt,
2011). Researchers use CFA to test relationships between factor loadings and tests for
correlation or lack of correlation of factors (Ruscio & Roche, 2012; Schmitt, 2011).
Finally, CSA assesses the convergent and discriminate validity of measures (DeCoster,
1998).
EFA tests the number of common factors that influence measures and tests the
strength and relationship between each common factor to the corresponding measure
(DeCoster, 1998). Researchers use EFA for several reasons. First is to identify the nature
of constructs that underlie responses (DeCoster, 1998). Second is to determine sets of
items that interconnect (DeCoster, 1998). Third is to demonstrate the depth and breadth
of measurement scales (DeCoster, 1998). The fourth is to classify the most important
features of a group of items (DeCoster, 1998). Fifth is to generate factor scores that
represent the underlying constructs (DeCoster, 1998). Researchers commonly use EFA to

develop and validate self-reporting assessment instruments, especially when there is little
or no a priori knowledge of the structural model (Williams et al., 2012). Researchers also
use EFA to evaluate the construct validity of a measurement scale (Williams et al., 2012).
This statistical analysis is necessary to determine the critical factors that should comprise
a standard composite index. Therefore, EFA was the technique most appropriate for this
study. The remainder of this section provides an overview of the EFA technique and then
provides examples of published EFA studies to demonstrate how researchers apply the
technique.
To summarize, EFA allows researchers to discover constructs or concepts that are
not directly measurable by collapsing a large number of Likert variables into a few
interpretable underlying factors representing such constructs. Researchers use CFA more
often than they use its exploratory counterpart. Researchers use EFA to reduce or identify
the minimal number v of Likert variables to form a set of k factors or latent variables.
Researchers use CFA to determine the extent to which the given set of v Likert questions
measures k predefined factors. EFA is a data reduction method or an inductive theory
procedure. CFA is a procedure for testing hypotheses deduced from that theory.
Overview of the EFA technique. When using EFA appropriately, researchers
must make a series of methodological decisions and subjective judgments (Conway &
Huffcuit, 2003; Izquierdo, Olea, & Abad, 2014). Decisions and subjective judgments
directly affect results, interpretations and reporting (Conway & Huffcuit, 2003; Izquierdo
et al., 2014). In all steps of EFA, there are numerous statistical methods available
(Izquierdo et al., 2014). Using methods that are not optimal for the data can yield

misleading results (Conway & Huffcutt, 2003; Fabrigar et al., 1999; Izquierdo et al.,
2014). Fabrigar et al. demonstrated that EFA was a strong methodology that yielded
significant results, however, questionable decisions about the statistical procedures used
led to misleading results.
Exploratory factor analysis involves a series of statistical analysis steps. Beavers
et al. (2013), Schmitt (2011), and Williams et al. (2012) expanded on the five-step
process. The first is to analyze the factor analysis descriptive statistics. In this stage, the
researcher determines if the data is suitable for EFA. Assumptions about the suitability of
the data include examining correlational values and linear relationships (Beavers et al.,
2013). In EFA, there are no dependent or independent variables; therefore, normality is
not required for EFA (Beavers et al., 2013). The second step is to extract factors. The
linear combinations resulting from this first extraction are the factors (Beavers et al.,
2013). The third step is to determine which factors to retain. The researcher must decide
which factors best represent the data and the relationships, and determine which are not
statistically or theoretically relevant. Once identified, the researcher will retain only those
factors that best represent the data (Beavers et al., 2013; Schmitt, 2011; Williams et al.,
2012). Identifying the optimal number of factors to retain is crucial. Retaining too few or
too many factors affects the stability of factor patterns and interpretation (Hayton, Allen,
& Scarpello, 2004; Preacher, Zhang, Kim, & Mels, 2013). The fourth step is factor
rotation. Because there are an infinite number of solutions, the factors are rotated to
achieve a simpler structure and produce a solution that is easier to interpret (Beavers et
al., 2013; DeCoster, 1998). The fifth step is to interpret the factor structure. EFA is an

iterative process that requires the researcher to interpret both the items and the factors
(Beavers et al., 2013). Each measure linearly relates to each factor (DeCoster, 1998). The
factor loadings revealed by the factor rotation indicate the strength of the relationships
(DeCoster, 1998). DeCoster (1998) included the sixth step of constructing factor scores
for use in developing a composite index. The final seventh step is to apply the final index
to rank companies as to the maturity level of global business citizenship they have
achieved.
EFA Applications. Published EFA studies demonstrate the practical
implementation of the EFA technique. Social science investigators use EFA to research
various issue. EFA is good for testing relationships. Researchers use EFA to determine
whether an instrument developed for one population generalizes to other populations.
EFA helps researchers analyze whether existing instruments are applicable for different
purposes. EFA is good for testing the effectiveness of existing instruments. Most
importantly for this study, researchers use EFA to develop new measurement indexes.
The following EFA studies illustrate these applications of EFA.
Test relationships. Social scientists use EFA to test relationships. EFA reveals
relevant factors and reduces the number of items to those that accurately describe
relationships. Three recent studies illustrate how researchers use EFA in this context.
Rostamnezhad, Zarei, and Jalali (2014) used an EFA approach to testing the
impact of technological entrepreneurship on economic development. The authors defined
technological entrepreneurship as exploiting technological advances to create and
commercialize innovative products. The authors contended that successful technological

entrepreneurship translated to a competitive advantage both in the home country and
abroad. The authors surveyed teachers and experts familiar with technological
entrepreneurship and economic development. Rostamnezhad et al. applied EFA to
identify casual relationships and the latent structure to develop a conceptual model. The
results suggested that technological entrepreneurship had a significant positive effect on
economic development. With this study, the authors tested the relationship that
technological entrepreneurship had on the economic development.
Lizote, Verdinelli, and Silveira (2013) used EFA to determine whether
organizational factors positively related to the entrepreneurial competencies of
employees. In performing a literature review, Lizote et al. found that organizations that
promoted and developed entrepreneurial competencies had improved organizational
performance and quickly adapted to changing business environments. Lizote et al. used
Moriano et al.’s model of five dimensions of organizational factors together with Lenzi’s
model of eight entrepreneurial competencies to develop a 5-point Likert scale of 59
questions. The results of Lizote et al.’s study confirmed that organizational factors
positively related to entrepreneurial competencies. From the two models, Lizote et al.
determined that the entrepreneurial competency of the search for opportunities and
initiatives correlated with the organizational factor of support from top management.
Support from upper management also correlated significantly with demand for quality
and efficiency. Results also indicated that managers should clearly establish goals and
plans. Interestingly, a factor with no influence in any area was the use of rewards. Lizote

et al.’s research were an important initial part of a broader study to understand
relationships between organizational factors and entrepreneurial competencies.
To understand what service dimensions affect Chinese air passengers’
satisfaction, Wang, Qiu, Wang, and Wu (2014) conducted a study to determine the needs
and expectations of Chinese air passengers. After conducting a literature review, the
authors identified 16 key service areas. Wang et al. designed a questionnaire to capture
the perceptions passengers had of the service areas. The researchers administered the
survey to participants after they deplaned at Nanjing Lukou International Airport and
received 335 completed responses. Through EFA analysis, the authors identified
fivedimensional factors: in-flight comfort; flight core benefit; travel service and
flexibility price; equipment and relational benefit; and price. With this study, the authors
tested the relationship between air travel satisfaction and 16 key service areas.
Dhurup, Mafini, and Masitenyane (2014) used an EFA approach to study factors
that influenced customer satisfaction in the precision concrete products industry. Based
on an analysis of 260 responses, the researchers reduced the question to an 18-item scale
with the five factors of responsiveness, problem-solving, physical aspects, service
personnel and physical appearance. The researchers acknowledge that the result did not
generalize because the respondents were all customers of one company. However, the
study does provide insight into the relationship between the extracted factors and
customer satisfaction within the industry.

Generalizing to alternate populations. Researchers also use EFA to determine
whether an instrument developed for one population generalizes to other populations.
Zourbanos, Dimitrious, Goudas, and Theodorakis (2014) used EFA to determine whether
Lawrance’s 1989 Smoking Efficacy Scale (SES) generalized to the Greek population.
After translating the SES instrument into Greek, Zourbanos et al. (2014) administered the
survey to three samples of high school students between the ages of 16 and 17. The
researchers included 536 participants. EFA showed that the results are loaded on three
factors including opportunity, friends, and emotion. The results were consistent with
Lawrance’s original English language instrument designed for adults. Zourbanos et al.
concluded that their Greek version of the SES was a valid and reliable self-reporting
instrument to assess smoking self-efficacy in adolescents. Zourbanos et al. concluded that
SES was a promising tool to understand how to influence Greek adolescents’ ability to
resist smoking or to reduce or quit smoking once they had started.
Dardas and Ahmad (2014) validated whether the often-used World Health
Organization’s Quality of Life Questionnaire-BREF (WHOQOL-REF) was effective in
evaluating the quality of life parents of autistic children. The researchers administered the
WHOQOL-REF to 184 participants with autistic children. After applying EFA, the
researchers determined that the 4-domain model of the questionnaire be useful when they
redistributed the domains. The researchers tested the effectiveness of the existing
instrument and found it valid for the population of parents of autistic children.

Using existing scales. Researchers use existing scale instruments to conduct new
research. Researchers may use a single instrument or combine multiple instruments into
one survey. Three studies illustrate the use of EFA in this context.
Chaudhary (2014) used EFA to examine psychometric properties using the
existing Occupational Self-Efficacy Scale (OSES). The purpose was to identify an
alternative multidimensional occupational scale. Chaudhary’s EFA revealed three of the
six factors from the original scale to be consistent with self-efficacy. Chaudhary
concluded that the three-factor structure was superior to other self-efficacy measurement
models.
Kursunluoglu (2014) studied how customer service affected customer satisfaction
and loyalty. Kursunluoglu created a 51-item questionnaire by combining two existing
instruments, the ACSI scale, and the Customer Loyalty Scale. After applying EFA to the
data, Kursunluoglu removed nine items and identified eight primary factors; however,
only four of them affected customer satisfaction and loyalty. The factors that affected
satisfaction and loyalty were incentives, payment options, atmosphere, and employee
encounter.
Burchell and Tumawu (2014) combined four existing survey instruments to assess
employee motivation and work ethic in Ghana. The researchers combined the British
Household Panel Survey, the European Community Household Panel Survey, the British
Social Attitudes Survey, and the Workplace Employment Resources Survey into one
instrument. The survey assessed teachers and banking professionals’ attitudes toward
working hard to help one’s organization and their attitudes toward the importance of

work ethic. The results of the EFA suggested that employees in the private sector had a
higher level of commitment to their employers and a higher work ethic than those
employed in the public sector.
Test the effectiveness of a measurement instrument. Researchers use EFA to test
the effectiveness of an existing measurement instrument. In the state of Virginia, policy
makers based funding decisions on the Phonological Awareness Literacy Screening for
Grades 1 through 3 (PALS 1-3) (Huang, 2014). Huang set out to test three models that
could represent the factor of PALS 1-3, a one-factor model, a two-correlated factor
model, and a bifactor model. The result of the EFA indicated that the bifactor model was
the best fit and provided for the best generalizability and stability. Huang tested the
effectiveness of the instrument and found the bifactor model was the best fit.
Develop/refine a new measurement instrument. Since the focus of this research is
to use EFA to develop a new survey instrument and accompanying composite index, it is
appropriate to include studies in which researchers used EFA in this context. The
following five studies published in 2014 illustrate how researchers use EFA to develop
new instruments.
Shaw, Kristman, Williams-Whitt, Soklaridis, Huang, Côté, and Loisel (2014)
used EFA to develop a new Job Accommodation Scale. Their scale assessed temporary
job modifications for people returning to work after a medical leave for lower back pain.
Through their EFA, the authors identified five underlying factors including modification
of physical workload, modification of work, the environment, change of work schedule,

alternative work, and arranging for assistance. The authors concluded that the result
supported the applicability, reliability, and validity of their Job Accommodation Scale.
Liou and Kuo (2014) developed an instrument to measure senior high school
students’ motivation and self-regulation toward learning science via technology-based
methods versus in-person methods. Liou and Kuo used EFA to determine the validity and
reliability of the Motivation and Self-Regulation Toward Technology Learning (MSRTL)
instrument. The researchers used 909 completed surveys for their EFA analysis. The
results of the EFA confirmed seven scales for technology learning, including selfefficacy,
value, active learning strategies, environmental stimulation, goal-orientation, self-
regulation-triggering, and self-regulation-implementation. The results also indicated that
male and female participants did not tend toward the same preferences for all of the
scales.
To explore what achievements, skills, and personal attributes made college
graduates most employable, Pool, Qualter, and Sewell (2014) developed a new
CareerEDGE Employability Development Profile (EDP) instrument. With 807 student
participants, Pool et al. used EFA to determine that there were five factors. The five
factors included: emotional intelligence and self-management; academic performance
and study skills; career development learning, problem-solving skills; and work/life
experience. The authors contended that their self-assessment instrument would help
students at higher learning institutions determine the factors that would help them secure
jobs when they graduate.

Researchers have linked excessive Internet use to sleep disorders, personal injury,
depression, and poor social and academic adjustment. Jelenchick, Eickhoff, Christakis,
Brown, Zhang, Bensen, and Moreno (2014) developed the Problematic and Risky
Internet Use Screening Scale (PRIUSS). The PRIUSS applied to adolescents and young
adults and provided practitioners with a tool to help prevent such disorders. After
developing a survey and collecting data, the authors used EFA to explore the factor
structure and reduce the number of items. The final scale was an 18-item instrument.
Through rigorous EFA and CFA, the authors felt the new instrument was a reliable
representation of the theoretical framework and was a strong fit for the empirical data.
Practitioners can use the scale to screen for excessive Internet use, which can lead to
preventative care.
Fullwood, Nicholls, and Makichi (2014) sought to expand on the research about
what motivates people to blog. The researchers developed the Blogging Motivations
Questionnaire (BMQ). For the study, Full et al. also used the International Personality
Item Pool (IPIP). The IPIP provided the researchers with a reliable measure of five
personality traits including extraversion, agreeableness, conscientiousness, emotional
stability, and openness. The researchers applied EFA to the results of administering the
BMQ to 160 blogging participants. The EFA technique reduced the number of factors
and determined factor loadings. The results indicated people blog for six primary reasons
including personal revelation, an emotional outlet, creative outlet, selective disclosure,
social networking, and advertising. Correlating the BMQ results with the IPIP results, the
researchers discovered that conscientiousness predicted social networking; agreeableness

predicted selective disclosure, and openness predicted creative outlet. Fullwood et al.
developed a new instrument and combined it with an existing scale to produce new
results.
EFA has several practical uses for social scientists. Social science researchers use
EFA to test relationships, determine whether an instrument developed for one population
generalizes to other populations, use existing instruments for different purposes or test
the effectiveness of existing instruments. Most importantly for this study, researchers use
EFA to develop new measurement indexes. Using EFA was an appropriate approach to
developing a survey instrument and composite index to understand the maturity level
corporate leaders have achieved toward implementing the GBC framework.
Transition
Section 1 of this doctoral study established the background, problem, purpose,
and nature of the study. Section 1 presented the research questions, hypotheses,
theoretical framework, and significance of this study. Additionally, section 1 provided a
synthesis of the literature. The literature review included studies that supported the
development of the GBC theory, established the case for GBC, described CSR
measurement techniques, and provided an overview of EFA and published applications
of the technique. As explained in section 1, there was a clear need to establish a
measurement index for GBC. Section 2 describes the research design and quantitative
methodology used for this study.
Section 2: The Project

Research shows that responsible and ethical business policies and actions have the
potential to provide companies with legitimacy from society and increase their
competitive performance (Menck & Oliveira, 2014). Implementing the GBC framework
orients corporations in a way that enhances legitimacy by providing a common
foundation for socially acceptable behavior at the individual, organizational, and
systemic levels (Wood et al., 2006). While there have been valuable contributions toward
measuring different aspects of CSR, at the start of this study there was no
selfadministered rating system available for business leaders to report to stakeholders the
steps they have achieved toward becoming an ethically responsible business citizen
(Milne & Gray, 2013).
Purpose Statement
The purpose of this cross-sectional quantitative study was to develop Likert
survey questions (independent variables) and apply EFA to reveal factors (dependent
variables) and assign weights to questions to develop a self-administered rating system to
measure the GBC theory, which assesses the maturity level a company has attained
toward becoming a global business citizen. Development of this rating system required
four methodological steps. First, creating a survey consisting of 1 qualifying question and
22 Likert questions that operationalized the GBC principles of VALUE, IMPLE,
ANALY, and LEARN. Second, administering the survey to members of professional
associations who were senior executives of U.S. corporations with an understanding of
GBC. Third, applying the EFA statistical method to the data. EFA revealed the
relationship between the Likert survey questions and the factors that emerged, reduced

the questions, and assigned weights to the remaining questions. Fourth, use the EFA
assigned weights to develop a composite index. The result of this study provided a rating
system to measure a company’s GBC maturity level. This study contributes to social
change by providing practitioners, academics, and stakeholders with a rating system to
evaluate the maturity level that corporate leaders have attained toward becoming a global
business citizen.
Role of the Researcher
Such things as researchers’ personal bias, experiences, beliefs, and even their
approach can influence research (Hunt, 2011). In this respect, to be as transparent as
possible, I disclose no prior experience in the area of study and my interest in this field
was purely academic. My role as the researcher was to develop, administer, and collect
data from a Likert-type survey instrument and then analyze and report the results
(Croasmun, & Ostrom, 2011). Within my professional role, I had access to business
executives via Executive Suite. As part of the data collection process, participants
received an informed consent form (Appendix C) providing information, ascertaining
comprehension, and ensuring they were participating voluntarily (U.S. Department of
Health & Human Services, 1979). The protocol complied with the ethical principles for
the protection of human subjects of research, in compliance with the Belmont Report
(U.S. Department of Health & Human Services, 1979). Additionally, as the researcher, I
handled the validation and reliability of the instrument and interpretation of the data
collected.

Participants
The process of implementing the four-step GBC framework assumes that business
leaders develop corporate values, implement those values, engage in problem analysis
and experimentation, and learn from the previous steps to institutionalize best practices.
As such, business leaders with knowledge of these constructs were appropriate
participants for this research. The scope of the study focused on medium to large,
multinational business organizations headquartered in the United States.
Research shows that soliciting participants associated with professional societies
improves survey response rates significantly (Melnyk, Page, Wu, & Burns, 2012;
VanGeest & Johnson, 2011). Informed by this research, participants forming the sample
frame were business executives who were members of the Executive Suite professional
society. Executive Suite is an invitation-only, online forum for executive level business
leaders. At the time of survey distribution, Executive Suite had 298,841 members.
Members of Executive Suite should have had the knowledge of and been
competent to identify items that may demonstrate the constructs. These business leaders
should have had direct experience developing corporate values, implementing those
values, analyzing issues related to the values and implementation, and learning,
systemizing, and institutionalizing best practices.
Personalized delivery of surveys significantly improves response rates (Melnyk
et. al., 2012; Sahlqvist, Song, Bull, Adams, Preston, & Ogilvie, 2011; Sinclair, O’Toole,
Malawaraarachchi, & Leder, 2012; VanGeest & Johnson, 2011). Informed by this
research, I distributed the survey via online communication to the entire membership of

Executive Suite. All members had the opportunity to take a survey. Only those interested
in participating in the study clicked through to the online survey.
The working relationship of this study was to ensure the anonymity and
confidentially of participants. The survey did not ask for any personal information that
could identify the individual, such as name or email address. The research question was
to determine how many and what factors were needed to characterize the Likert survey
questions to assess a company’s GBC maturity level. The business leaders in this sample
had knowledge of the four constructs were able to answer the Likert survey questions.
Because the participants represented companies from a variety of industries, the results of
the study generalize to the global business community.
Research Method and Design
This quantitative research study relied on a statistical method called EFA and a
cross-sectional survey design. The design of the study was a Likert-type survey
consisting of 1 qualifying yes/no question and 22 Likert-type questions assumed to
capture the four GBC constructs. The GBC constructs were equivalent to the four-step
GBC framework. The four-step GBC framework provided the assumed constructs. The
constructs were the following. First, developing overarching corporate values (VALUE).
Second, implementing the values (IMPLE). Third, analyzing problems and
experimenting to revise the values or local implementations (ANALY). Fourth, learning
from the previous steps and institutionalizing best practices (LEARN) (Wood et al.,
2006).
In the absence of any other known quantitative studies of this kind, applying the

EFA method to the data obtained from the survey reduced the questions to a minimum
number. EFA also indicated how to group the remaining questions into subsets, called
factors. The EFA-generated eigenvalues weights on each question generated the overall
weighted formula, or index, to measure GBC implementation.
Research Method
The adopted method to develop a rating system index to measure GBC maturity
level was an extensively used statistical method called EFA (Basto & Pereira, 2012;
Izquierdo et al., 2014). Researchers commonly use EFA to develop and validate
selfreporting assessment instruments, especially when there is little or no a priori
knowledge of the structural model (Ruscio & Roche, 2012). Other quantitative
techniques could have produced a subset of questions to understand the maturity level
companies had achieved in implementing GBC. These include using Confirmatory Factor
Analysis (CFA) instead of Exploratory Factor Analysis (EFA) or the Delphi technique.
The following is an explanation of why EFA was superior to these techniques for this
study.
CFA tests whether a known factor model can predict a set of observed data
(DeCoster, 1998). CFA requires that researchers specify a particular factor structure in
advance and then designate which items load on which factor. CFA is a model in which a
specific item (question) maps to a specific construct. In contrast, EFA allows all items to
load on all factors. When there is little or no a priori knowledge of the structural model,
EFA is the preferred method to reveal the item-to-factor structure (Ruscio & Roche,

2012). As such, researchers commonly use EFA to develop and validate self-reporting
assessment instruments. Researchers use CFA to verify or confirm hypotheses or theory
(Ruscio & Roche, 2012; Schmitt, 2011). CFA is good for establishing the validity of the
factor model (DeCoster, 1998). CFA is a method well suited to comparing two models
using the same data (DeCoster, 1998). Researchers use CFA to test the significance of
factor loading, to test relationships between factor loadings, and to test for correlation or
lack of correlation of factors(DeCoster, 1998). CFA is also used to assess the convergent
and discriminate validity of measures (DeCoster, 1998). A recommendation for further
study was to conduct a CFA study to validate the results of this EFA study.
SMEs could have validated that the survey questions adequately represented the
process of implementing GBC. As an extension of this method, a group of SME may
have collected and aggregated information systematically via a Delphi technique (Hasson
& Keeney, 2011). These methods were not appropriate for several of reasons. The first
was defining the meaning of SME (Hasson & Keeney, 2011). Defining who is an expert
in GBC could be a research study itself. Secondly, recruiting a panel of supposed experts
to participate would have been challenging (Hasson & Keeney, 2011). Third, the level of
influence some SMEs may have had on other members of the panel may have skewed
results (Hasson & Keeney, 2011). Fourth, establishing anonymity of the member SMEs
would have been difficult (Hasson & Keeney, 2011). Fifth, it would have been difficult
to define what constitutes a consensus (Hasson & Keeney, 2011). Sixth, determining
what criteria to include would have been uncertain (Hasson & Keeney, 2011). Finally,

the influence of personal bias amongst the SMEs would have been a limitation (Hasson
& Keeney, 2011).
Because EFA is a multivariate statistical approach, it provided an unbiased
method for reducing the number of factors, examining relationships between factors, and
evaluating the construct validity of measurement scales (Williams et al., 2012). The EFA
method should ensure reliability. Measurements should repeatedly produce the same
results, the measurement should be stable over time, and the measurements should be
similar within a given period (Hasson & Keeney, 2011).
The quantitative EFA method was appropriate in its rigor because it involved a
series of statistical analysis steps (Basto & Pereir, 2012; Beavers et al. 2013; Schmitt,
2011; Williams et al., 2012). The following is a brief overview of the EFA method. The
Data Analysis section of this paper provides details of each step. The first step is the
planning step. During this step, the investigator determines if the data obtained by
administering the survey to a participant group is suitable for EFA (Beavers et al. 2013;
Schmitt, 2011; Williams et al., 2012). Once determined that the data be suitable, the
second step is to extract factors (Basto & Pereir, 2012; Beavers et al. 2013; Schmitt,
2011; Williams et al., 2012). These factors are the key questions that best describe each
of the four steps of implementing GBC or each of the constructs. The third step is to
identify the number of factors to retain (Basto & Pereir, 2012; Beavers et al. 2013;
Schmitt, 2011; Williams et al., 2012). The retained factors are those that best represent
the data and the relationships (Basto & Pereir, 2012; Beavers et al., 2013; Schmitt, 2011;
Williams et al., 2012). Retaining the optimal number of factors is crucial because

retaining too few or too many factors affects the stability of factor patterns and
interpretation (Hayton et al., 2004; Preacher et al., 2013). The fourth step is to rotate the
factors (Basto & Pereir, 2012; Beavers et al., 2013; Schmitt, 2011; Williams et al., 2012).
Because there are an infinite number of solutions, the EFA technique includes rotating
the factors to achieve a simpler structure and produce a solution that is more readily
interpretable (Beavers et al., 2013; DeCoster, 1998). The fifth step is to interpret the
factor structure (Beavers et al. 2013; Schmitt, 2011; Williams et al., 2012). The factor
loadings revealed by the factor rotation indicate the strength of the relationships
(DeCoster, 1998). Researchers interpret the data to find the delicate balance between
statistical significance and conceptual relevance (DeCoster, 1998). When developing a
composite index, the sixth step is to construct factor scores (DeCoster, 1998). The
EFAgenerated eigenvalues weights are multiplied with the corresponding Likert response
and then summed to obtain an overall index (DeCoster, 1998). In summary, the EFA
method provided an unbiased method for reducing the number of factors, examining
relationships between factors, evaluating the construct validity of a measurement scale,
and developing a composite index (Williams et al., 2012). A qualitative or less rigorous
quantitative method was not conducive to achieving these outcomes.
Research Design
The research question was how many and what factors (dependent variables) were
needed to characterize the Likert survey questions (independent variables) to assess a
company’s GBC maturity level? The study relied on a cross-sectional survey design
appropriate for EFA data collection to answer the research question. The survey

attempted to capture the assumed constructs of the GBC theory. A cross-section sample
was representatives of the business community familiar with the concept of GBC. The
sample also had to be large enough to apply the EFA technique.
In this research study, a cross-sectional survey design for data collection was
appropriate for the EFA method. Researchers commonly use Likert-type survey
instruments to collect data for quantitative EFA research (Harrison & Reilly, 2011;
MacKenzie et al., 2011). Researchers use cross-sectional surveys to measure constructs,
or the abstract and latent ideas or themes (MacKenzie et al., 2011). In survey research,
survey questions attempt to articulate the common characteristics of the constructs
(MacKenzie et al., 2011).
For this study, the actual survey consists of 1 qualifying yes/no question and 22
Likert-type questions. The questions were designed to attempt to capture the assumed
four constructs of the GBC implementation framework. The constructs were corporate
values (VALUE), implementation (IMPLE), problem analysis and experimentation
(ANALY) and learning and institutionalizing best practices (LEARN). Donna J. Wood,
the lead researcher who developed the theory of GBC, agreed that these were the
necessary and sufficient constructs of the GBC theory (D. J. Wood, personal
communication, August 14, 2014; Appendix E). The survey questions attempted to
articulate the common attributes/characteristics of each step, or construct, and may be
necessary to evaluate whether a company has attained implementation of each step.
Unlike constructs being necessary and sufficient, only one question may have been
necessary and sufficient to describe a construct. Alternatively, questions may have been

neither necessary nor sufficient. Unnecessary questions received low EFA loadings.
However EFA was not able to identify missing questions, and future researchers might
need to add such questions. The Data Collection Instruments section details the
development of the survey and the Likert-type questions. In summary, applying EFA to
the resulting data determined which questions were required to evaluate the maturity
level that a company has attained in implementing the four-step GBC framework.
Archival data to support this original research was not available. Even if archival
data related to business citizenship were available, use of archival data might
compromise the study. Use of archival data might have compromised the study if such
data did not match the constructs, the range of measures, scope, or breadth of this study
(Rabinovich & Cheon, 2011).
The study was cross-sectional, meaning the sample represented a cross-section of
the population for which the measure was designed (MacKenzie et al., 2011). In this
case, I developed the instrument for executive leaders of multinational business
organizations, not limited to any particular industry. The survey was deliberately short to
improve response rates (Meade & Craig, 2012; Sahlqvist et al., 2011). Since the sample
was crosssectional, it should have represented the population so that the results should
generalize to the broader population (MacKenzie et al., 2011).
Population and Sampling
It was necessary to use a representative sample to generate results that apply to
businesses. That is, the results should fulfill the requirement for a cross-sectional
representation of various business views on GBC. Given this rationale, the following

sections describe the population from which the sample came. The discussion also
calculates the required sample size required by EFA.
Population
The sample units consist of corporate leaders interested in business citizenship.
Ideally, one should sample from the worldwide population of corporate leaders, but this
was impractical due to its geographic scope and the time and expense required reaching
participants (Baltar & Brunet, 2012). Instead, sample participants were comprised of
business executives who were members of Executive Suite. Membership of this
professional society included business executives, senior professionals, and emerging
leaders, all leaders who may have an interest or at least an understanding of business
citizenship. Also, the sample size satisfied the needs of EFA.
Population aligns with the overarching research question
The overarching RQ was how many and what factors (dependent variables) were
needed to characterize the Likert survey questions (independent variables) to assess a
company’s GBC maturity level? The sample had to understand GBC to provide data that
was meaningful to answer the RQ. Of the top 100 U.S. companies, 97% claim to engage
in business citizenship activities (Fifka, 2013). Major companies such as Boeing, Dow,
IBM, and Microsoft claim that they are business citizens (Crittenden et al., 2011). Senior
executives of these and other leading U.S. corporations comprise the membership of the
Executive Suite. Therefore, the sample units had sufficient knowledge of the dimensions
or factors and their strength that comprise GBC theory to provide data to answer the
overarching RQ.

Sampling Method
Given that the intent was to use this study to generate results that apply to global
businesses, a cross-sectional representation of various business views on GBC was ideal.
A probabilistic sample was required to achieve cross-sectional representation (Trotter,
2012). In probabilistic sampling most often used with quantitative methods, one selects
cases that are together representative of the total population, even though many cases in
isolation will have a low information value (Trotter, 2012). These cases are sample units
or individual corporate leaders. Sample frames identify all of the sample units, or
members, of the target population (McLeod, Klabunde, Willis, & Stark, 2013). In this
study, the sample frame was members of Executive Suite. As previously explained, the
geographic scope and the time and expense required to reach the worldwide population
of corporate leaders interested in business citizenship was prohibitive. Therefore, the
sample units were members of Executive Suite. At the time of survey distribution,
Executive
Suite had 298,841 members. For this study, the sample frame equaled the population.
By contrast, qualitative methods often use a narrow or purposeful sample to
addresses specific purposes related to the research questions. In qualitative research, each
case is selected to address a particular set of questions. With this tight parameter, each
case has a high information content/value (Palinkas, Horwitz, Green, Wisdom, Duan, &
Hongwood, 2013; Trotter, 2012). However, such a narrow sample is usually not
representative, limiting the research findings to that particular subset of participants and
the limitation of not achieving cross-sectional representation (Palinkas et al., 2013). A

probabilistic sampling method was required to achieve the cross-sectional goal of this
study.
There are multiple probabilistic sampling methods available. Probabilistic
methods include simple random sampling, systematic random sampling, stratified
random sampling, cluster sampling, multiphase sampling, and multistage sampling
(Acharya, Prakash, Saxena, & Nigam, 2013). Researchers use a random process of
selecting participants with all of these methods (Acharya et al., 2013). In the simple
random sampling technique, every individual, or sample unit, of the sample frame have
an equal chance of being selected (Acharya et al., 2013).
Of all of the aforementioned probabilistic sampling methods, the simple random
sampling technique was the most feasible to select a sample of business leaders with
knowledge and interest in GBC. Researchers commonly use simple random sampling
when it is complex, costly, or impossible to randomize to the individual level of a
population (Welton, Madan, Caldwell, Peters, & Ades, 2014). Given a large number of
multinational corporations, it was impossible to randomize to the individual level of the
population. Leaders interested in or having an understanding of business citizenship may
have been members of Executive Suite. Selecting this professional business society as the
sample may seem to be biased sampling. However, the simple randomized sampling
method is recognized as an effective method of achieving a probabilistic sample
(Acharya et al., 2013; Baltar & Brunet, 2012; Welton et al., 2014).

Calculating sample size
For the EFA method, researchers determine sample sizes in two ways. One
method is to determine the minimum number of samples needed (N). Another method is
to determine the sample size as a function of the number of variables. Also known as the
subjects-to-variable ratio, (N:p) (Beavers et al., 2013; Guadagnoli & Velicer 1988;
Hogarty, Hines, Kromrey, Ferron, & Mumford, 2005). There are advantages, and
disadvantages, of both methods. The subjects-to-variable ratio was best suited to
determine the sample for this study. The following is a discussion of the advantages,
disadvantages, and rationale for choosing subjects-to-variable ratio.
There are studies about selecting a minimum sample size. Jung and Lee (2011)
analyzed the factor extraction outcomes using sample sizes of less than 50. Jung and Lee
analyzed the outcomes achieved by applying maximum likelihood factor analysis
(MLFA), principle component analysis (PCA) and regularized exploratory factor analysis
(REFA). The researchers found that REFA recovered acceptable factor loadings, had
smaller mean absolute differences and mean square errors, and provided stable factor
loading estimates with samples of 50 or less. Fabrigar et al. (1999) determined that
samples as small as 100 could yield stable solutions. Beavers et al. (2013) recommended
using samples of at least 150 for multivariate tools, such as EFA. Guadagnoli and Velicer
also determined that when researchers selected variables that were representative
indicators of a component, 150 observations yielded accurate solutions. At the high end
of the minimum number of samples, Guadagnoli and Velicer found that they needed 300
when few variables defined factors with moderate to low loadings.

Given this diverse range of recommended sample sizes, using a formula to
determine the appropriate sample size was appropriate. For this study, the method of
determining sample size as a function of the number of variables, (N:p), or the subject-
tovariable method, was suitable. Hogarty et al. (2005) found that a higher number of
samples were necessary when the goal of the study was to understand which factors
underlie which variables. When the study goal was to ensure that sample loadings
correlated highly with population loadings, fewer samples were necessary (Hogarty et al.,
2005). Comrey and Lee (1992) recommend a minimum of 5 observations per variable, or
ideally 20 observations per variable, for EFA. According to this empirical rule, and given
an initial survey with 22 Likert questions (22 variables), at a minimum 22*5 = 110
observations were needed to perform an EFA analysis adequately. Ideally, 22*20 = 440
observations were needed to perform an EFA analysis. Table 3 shows the minimum and
an ideal number of observations as calculated in a subject-to-variable ratio method using
22 variables. Given this wide range, the intent was to solicit the ideal sample size of 440
cases if possible but satisfy the minimum of 110 observations before undertaking the
analysis. Assuming a 10% rate for invalid surveys and an average industry response rate
of 20%, then a minimum of (110*1.10)/0.20 = 605 surveys should have been
administered. Ideally (440*1.10)/0.20=2420 surveys should have been administered.
In summary, the intended population of this study was corporate leaders of
multinational business organizations in the United States. This population was
appropriate because, collectively, the members could answer the overarching research
question. The research question was how many and what factors were needed to
characterize the Likert survey questions to assess a company’s GBC maturity level?
Members of Executive Suite were business executives. This population should have an
interest or understanding of business citizenship. Researchers recognize the simple
random sampling method as an effective method of achieving a probabilistic sample, and
other methods were cost-prohibitive or possibly even impossible. For the EFA technique,
the method of determining sample size as a function of the number of variables, (N:p), or
the subject-to-variable method, was suitable. A minimum of 110 observations was
required, with an ideal of 440 observations.
Table 3
Subject-to-Variable Ratio to Determine Sample Size
Minimum # of Ideal # of
Observations
Observations Observations
Observations per Variable 5 20
# of Observations needed ( N:p) 110 440
Number of variables (p)=22.
Ethical Research
All data collected for this study adhered to the standards set by the U.S.
Department of Health & Human Services’ Belmont Report (U.S. Department of Health
& Human Services, 1979). Additionally, all data collected complied with the standards
set by Walden University’s Internal Review Board (IRB). All participants were voluntary
and anonymous. I did not collect any data before formal IRB approval.
All participants had ample opportunity to review the informed consent form
before starting the survey. The informed consent form appears in Appendix C. The

informed consent form included information about the research procedure, the purpose,
risks, and anticipated benefits, and a statement offering participants the opportunity to
ask questions and to withdraw from the study at any time (U.S. Department of Health &
Human Services, 1979). The informed consent form contained a statement to ascertain
that participants comprehended the information (U.S. Department of Health & Human
Services, 1979). Finally, the informed consent form included a clause stating that
participants agreed to participate on a volunteer basis, free of coercion and undue
influence (U.S. Department of Health & Human Services, 1979).
Participants could withdraw from the study at any time by contacting the
researcher (U.S. Department of Health & Human Services, 1979). The informed consent
form provided the relevant contact information. However, because of the anonymous
nature of the survey, participants’ individual surveys cannot be identified. Participants
received no compensation or incentives for participating in the study. For five years from
the time of data collection, I will maintain all data in a safe, and secure location in an
anonymous format with no personal information indicated. After five years, I will
destroy the electronic data by using Secure Erase software in compliance with Walden
University’s IRB guidelines.
Data Collection Instruments
In this quantitative study, data collection begins with the instrumentation. This
section explains the construction of the 23-question instrument, Cronbach’s alpha method
to assure instrument reliability, and the methods employed to determine instrument
validity. The next step was the data collection technique. This section explains the

rationale for collecting data by personally delivering surveys to members of a
professional society. The last step was data organization techniques. This section
describes data security, retention, query approval, and destruction techniques.
Instrumentation
The first step of this quantitative research study was the construction of a
23question, 5-point Likert-type survey instrument. I constructed the instrument for use in
this study. Appendix A and Appendix B display two versions of the instrument. The
version in Appendix A shows the four constructs and the questions related to each
construct. Appendix B displays the version of the instrument for distribution to
participants.
Instrument Construction. When constructing a survey instrument, the first
consideration is the research objective and variables required to test the research
questions (Lederer, Comber, & Oswalt, 2014; Sinkowitz-Cochran, 2013; Synodinos,
2003). The ultimate objective of this quantitative study was to develop a composite index
to assess the level of global business citizenship for a given company. The literature
informed the constructs (Burton & Mazerolle, 2011; Sinkowitz-Cochran, 2013).
Specifically, the research included seminal studies and book published by the authors of
the theory of GBC. The four-step GBC framework provided the assumed constructs. The
constructs were the following. First, developing overarching corporate values (VALUE).
Second, implementing the values (IMPLE). Third, analyzing problems and
experimenting to revise the values for local implementations (ANALY). Fourth, learning
from the previous steps and institutionalizing best practices (LEARN) (Wood et al.,

2006). Donna J. Wood, the lead researcher who developed the theory of GBC, agreed
that these terms captured the process of implementing the four-step GBC framework (D.
J. Wood, personal communication, August 14, 2014; Appendix E).
When constructing a survey instrument, the second consideration was the
administration method. Administration methods include personal interviews or
selfadministered questionnaires (Sinkowitz-Cochran, 2013; Synodinos, 2003; VanGeest
& Johnson, 2011; Weigold, Weigold, & Russell, 2013). The survey construction should
fit the method of administration (Sinkowitz-Cochran, 2013; Synodinos, 2003; VanGeest
& Johnson, 2011; Weigold, Weigold, & Russell, 2013). Because the instrument for this
study was a Likert-type survey, it fell into the self-administered category. Personalized
delivery of surveys significantly improves response rates (Melnyk et al., 2012; Sahlqvist
et al., 2011; Sinclair et al., 2012; VanGeest & Johnson, 2011). The survey was an online
survey administered through Survey Monkey (Lederer et al., 2014; Synodinos, 2003). I
sent a personal online communication to all members of Executive Suite informing them
about the nature of this study and requesting their participation.
The third consideration when constructing a survey instrument is forming the
questions themselves. The factors that influence questionnaire construction include the
wording of questions, choice of response options, the sequence of questions, and the
intended audience (Synodinos, 2003). Participants tend to understand words differently
(Porter, 2011). To help participants understand the questions, the wording of the
questions should be concise and simple in structure (Lederer et al., 2014; Money, Lines,

Fernando, & Elliman, 2011; Synodinos, 2003). Additionally, each question should relate
to a single issue (Lederer et al., 2014; Money et al., 2011; Synodinos, 2003).
Response choices can include open-ended or closed-ended questions (Bartkus,
Mills, & Olsen, 2014; Lederer et al., 2014; Synodinos, 2003). Self-administered surveys
are well suited for closed-ended questions. Closed-ended questions are easier for
participants to answer, have a tendency to produce fewer missing data, and are easier to
code and analyze than open-ended questions (Sinkowitz-Cochran, 2013; Synodinos,
2003). The instrument for this study was a closed-ended Likert-type survey.
Oddnumbered Likert-type scales allow respondents to answer neutrally, which may
reduce response bias (Croasmun, & Ostrom, 2011; Sinkowitz-Cochran, 2013). The
interval Likert-type scale allowed participants the following response options: strongly
disagree, disagree, neither disagree nor agree, agree or strongly agree (Croasmun &
Ostrom, 2011). Appendix A presents the survey with questions grouped according to
each construct and their corresponding Likert-type response options.
Presenting the questions in different sequences can influence respondents’
answers (Synodinos, 2003). Some research recommends ordering questions logically,
grouping questions together within a topic, and ordering questions from general to
specific (Lederer et al., 2014; Synodinos, 2003). Other studies indicate that a presenting
the questions in a random way reduces response bias (Krumpal, 2013). In an attempt to
reduce response bias, the questions were randomized. Appendix B presents the survey in
the randomized format that participants received.

The final factor that influences questionnaire construction is the intended
audience (Porter, 2011; Sinkowitz-Cochran, 2013; Synodinos, 2003). Synodinos (2003)
noted that the researcher must be extremely well versed in the topic and understand the
capabilities of the participants. The researcher must select appropriate participants, tailor
the survey for the audience, and be able to explain why participants may not have
answered specific questions (Porter, 2011; Synodinos, 2003). Participants may not
answer questions because they did not feel the question was applicable or because they
did not understand how to respond to the question (Porter, 2011; Synodinos, 2003).
Business leaders who are members of Executive Suite represent corporate leaders
interested in business citizenship. The instrument was a short 23-question survey to
accommodate these busy executives. The first question was a qualifying question asking
participants whether they understood the concept of business citizenship, corporate
citizenship, corporate social responsibility, or the ethical responsibilities of corporations.
The yes or no answer to this question revealed the capability of participants to answer the
subsequent questions. The survey directed the participants answering “no” to this first
question to the end of the survey without answering any of the 22 Likert questions. This
information provided insight into whether unanswered questions were a result of the
participants feeling they were not applicable or their inability to answer the questions
(Synodinos, 2003).
Informed by these guidelines, the survey questions related to the four constructs
with the first question measuring each participant’s understanding of global business
citizenship. The remaining 22 Likert-type questions relate to the four constructs. The

GBC seminal studies, the book published by the theory’s authors, and an extensive
literature review informed the development of the items that may characterize each of the
constructs. Five questions related to developing a companywide overarching code of
ethical conduct consistent with the definition of GBC (VALUE). Seven questions related
to the IMPLE construct. The IMPLE construct was the implementation of the
overarching code of conduct throughout the organization and adaptation to local customs,
norms, and local ethical standards that seem in conflict with the overarching code of
ethical conduct. Four questions related to analyzing problem areas and experimenting
with creative and practical solutions to remediate conflicts (ANALY). Six questions
related to systemizing learnings from the previous steps and institutionalize the best
policies, practices, and behaviors throughout the organization (LEARN).
Instrument Reliability. In quantitative research, reliability assures that a
researcher could replicate the study by using the same methods and a similar group of
participants (Oluwatayo, 2012; Tavakol & Dennick, 2011). In this study, the burden of
reliability falls to the instrument. There are multiple methods available to test the
reliability of survey instruments. Standard alternatives include test-retest, equivalent
forms, split-half coefficients, and Cronbach’s alpha (Oluwatayo, 2012; Yang & Green,
2011).
The test-retest coefficient method assesses transient errors but requires the
researcher to administer the survey on two separate occasions (Yang & Green, 2011).
The equivalent forms coefficient also assesses transient errors but requires developing,
validating, and administering two equivalent surveys (Yang & Green, 2011). The

splithalf coefficient method uses Spearman-Brown prophecy formula to assess internal
consistency reliability, but not transient errors, from one single administration of a survey
(Yang & Green, 2011). Social scientists widely use and recommend the Cronbach’s
alpha method (Croasmun, & Ostrom, 2011; Gadermann, Guhn, & Zumbo, 2012;
Oluwatayo, 2012; Tavakol & Dennick, 2011). Cronbach’s alpha is a good test for
reliability of instruments designed to gather responses in the continuum (Croasmun, &
Ostrom, 2011; Gadermann et al., 2012; Oluwatayo, 2012; Tavakol & Dennick, 2011).
Responses in continuum include Likert scales (Croasmun, & Ostrom, 2011; Gadermann
et al., 2012; Oluwatayo, 2012; Tavakol & Dennick, 2011). The Likert scale for this study
is, strongly disagree, disagree, neither disagree nor agree, agree or strongly agree.
Because the survey for this study was Likert-type, the Cronbach’s alpha method was
appropriate to ensure the consistency and stability of the result of the scale data. After
entering the data into SPSS software, a reliability analysis of each question produced
descriptive reliability statistics for the items and the scale as well as showing the inter-
item correlations. The results of the item-total statistics indicated if removing any of the
questions would lead to higher or lower Cronbach’s alpha scores. Cronbach’s alpha
scores between 0.67 and 0.90 demonstrate acceptable reliability (Oluwatayo, 2012;
Tavakol & Dennick, 2011).
Instrument Validity. Instrument validity means determining how well an
instrument measures what it was intended to measure (Burton & Mazerolle, 2011;
Oluwatayo, 2012). There are four types of validity that inform whether of an instrument
is suitable for the intended purpose. Validity includes construct, face, content, and

criterion validity (Burton & Mazerolle, 2011; Oluwatayo, 2012). The following address
each of these types of validity.
Construct validity means that an instrument measures what it was intended to
measure (Burton & Mazerolle, 2011; Cronbach & Meehl, 1955; Oluwatayo, 2012). The
goal of the research is for the investigator to confirm or disconfirm that the instrument
measures what the investigator hypothesized it would measure (Cronbach & Meehl,
1955). Cronbach and Meehl (1955) proposed three steps to evaluate construct validity.
The first is to state the theoretical framework and assign meaning to each construct. The
second is to develop methods and empirically measure how adequately the instrument
substantiates the assigned construct meanings. The third is to interpret correlations and
present evidence and reasoning to show the reader why the correlations confirm or
disconfirm the hypothesis.
For this study, the first step in establishing construct validity involved using the
GBC theory as the theoretical framework. The set of four interrelated theoretical
concepts captured by the GBC theory informed the constructs. The four theoretical
concepts were VALUE, IMPLE, ANALY, and LEARN. As already mentioned, Donna
Wood, the
principal researcher responsible for the development of the theory, indicated that she
agreed that these were the constructs (D. J. Wood, personal communication, August 14,
2014; Appendix E). The survey questions were an attempt to assign meaning to each
construct. Five SME’s indicated that they felt the questions captured the meaning of the
constructs and were clear. Cronbach and Meehl’s (1955) second step to establish

construct validity is to develop methods and empirically measure how adequately the
instrument substantiated the assigned construct meanings. There are several methods for
examining construct validity. Validity methods include the multitrait-multimethod matrix
(Campbell & Fiske, 1959), factor analysis, and structural equation modeling (Marsh et
al., 2014). The third step is the heart of this research. The data were interpreted using the
EFA technique. Interpretation of the correlations provided evidence and reasoning to
show why the correlations confirmed or disconfirmed the hypothesis. In the case of
applying EFA, the hypothesis equated to propositions about the number of factors to
retain to capture the relevant constructs. In summary, the assumption of the construct
validity of the instrument was strongly satisfied via the original theory author’s
confirmation, SME confirmation, and EFA application.
Face validity is a subjective assessment of whether the instrument is relevant,
reasonable, unambiguous, and clear (Oluwatayo, 2012; Synodinos, 2003). Having a panel
of subject matter experts validate the questions is a recommended way to address face
validity (Burton & Mazerolle, 2011; Oluwatayo, 2012). Accordingly, five experts in the
field of CSR or with a familiarity of global corporate or business citizenship confirmed
that the 22 Likert-type questions were relevant, reasonable, unambiguous, and clear
(Appendix F).
Content validity demonstrates that the measure covers the range of meanings that
apply to the constructs (Oluwatayo, 2012). A frequently used method to address content
validity is factor analysis (MacKenzie et al., 2011; Oluwatayo, 2012; Podsakoff et al.,

2012). The research method of this study was EFA. Therefore, the data analysis validated
the content and mitigated content validity threats.
Researchers use criterion-related validity to demonstrate that the scores from the
new instrument correlate highly with scores from existing instruments that are already
determined to be valid (Oluwatayo, 2012). No existing instruments measure GBC.
Because there were no existing instruments to correlate with, it was beyond the scope of
this study to confirm criterion-related validity. Confirming criterion-related validity was
a recommended area for further research.
Data Collection Technique
The method of survey delivery can have a significant impact on response rates
(Melnyk et al., 2012). Personally delivering surveys improves response rates significantly
(Melnyk et al., 2012; Sahlqvist et al., 2011; Sinclair et al., 2012; VanGeest & Johnson,
2011). Soliciting participants from professional societies also significantly improves
survey response rates (Melnyk et al., 2012; VanGeest & Johnson, 2011). Informed by
this research, participants forming the sample frame were business executives who were
members of Executive Suite. An email Letter of Cooperation from Anthony Vlahos, the
owner of the Executive Suite society, appears in Appendix D.
I distributed the survey via online communication to the entire Executive Suite
membership. The online survey directed participants answering “yes” to the first
qualifying question to the informed consent. Participants had the opportunity to review
the conditions of the informed consent before proceeding to the Likert questions.
Appendix B displays the version of the survey that was disturbed to participants.

Appendix C presents the accompanying informed consent form.
An alternative to personally distributing surveys via electronic communication at
renowned professional societies could have been to email surveys to a distribution list of
executives. There are numerous advantages of online surveys. With online surveys, data
is instantaneously stored in a database. Delivery costs may be lower. There is the ability
to offer multiple languages. The data collection process may be faster. Questionnaires
may be user-friendly. Participants can complete surveys to suit their schedule. With
online surveys, participants answer questions in the order presented by the researcher
(Baltar & Brunet, 2012). There are also drawbacks to online surveys. One drawback may
be that participants may view email as spam and not open it (Baltar & Brunet, 2012).
Non-response rates could be significant (Baltar & Brunet, 2012). Surveys delivery is
impersonal (Baltar & Brunet, 2012). It is unclear who completes the survey (Baltar &
Brunet, 2012). A final drawback is that there may be privacy-related issues (Baltar &
Brunet, 2012). Given these drawbacks and the proven advantages of personally
delivering the surveys to members of a professional society was the data collection
technique chosen.
Data Analysis
The data analysis technique for this study was exploratory factor analysis. Before
beginning any analysis, it was appropriate to identify missing data. Mitigation required
removing individual responses with missing data. Before beginning the EFA technique, it
was appropriate to examine descriptive statistics on the Likert data. These descriptive
statistics included frequency tables, mean, median, standard deviation, the coefficient of

variation, and Cronbach’s alpha. The first step of the EFA technique was to run factor
analysis descriptive statistics including correlation matrix, Bartlett’s test of sphericity,
Kaiser-Meyer-Olkin (KMO) measure of sampling adequacy, and possibly anti-
correlation matrix. The second step was to run the initial extraction. Principal axis factor
was the most appropriate extraction technique to discover latent variables and
relationships between items to achieve the purpose of this study. The third step was a
combination of Kaiser’s eigenvalues-greater-than-1 and scree plot to determine the
factors to retain. The fourth step was using oblique Promax method of factor rotation.
The fifth step was to interpret the factor structure using EFA factor loadings and
Cronbach’s alpha. The ultimate goal of this study was to develop a composite index to
determine integration of GBC. The final step was to construct the factor scores for the
composite index. The EFA technique reduced the survey questions to the optimal number
and provided eigenvalue scores on the resulting questions. The eigenvalues multiplied
with the corresponding Likert question score and summed generated an overall index.
Below is a detailed description of each of these steps.
Step 0: Likert Data Descriptive Statistics
Before running EFA, I identified and mitigated missing data. Calculation of
descriptive statistics on the Likert data included frequency tables for each item, mean,
median, standard deviation, and coefficient of variation. Cronbach’s alpha tested the
consistency and stability of the results of the ordinal scale data

Missing data. Missing data can complicate analysis (Seaman & White, 2013;
Seaman, White & Copas, & Li, 2012). Understanding what data is missing is required to
know if mitigating techniques are required (Seaman & White, 2013; White et al., 2012).
The simplest mitigating technique is to remove the incomplete data (Seaman & White,
2013). I used the default option in SPSS to remove records with missing data.
Determining missing data in SPSS involved clicking analyze – multiple imputations –
analyze patterns – selecting the variables – selecting the options of a summary of missing
values, patterns of missing values, and variable with the highest frequency of missing
values.
Likert data descriptive statistics. Descriptive statistics recommended for ordinal
Likert-type item responses include frequency tables, mean, and median, (Boone &
Boone, 2013). Academics have long argued about whether measurements for interval
data apply to the ordinal data (Sullivan & Artino, 2013). Sullivan and Artino provide the
example of “what does the average of “never” and “rarely” really mean?” (p. 542).
Similarly, the mean may appear to be the neutral response if responses cluster around the
high and low extremes (Sullivan & Artino, 2013). However, researchers have determined
that parametric tests, such as mean, standard deviation, and coefficient of variation, are
more robust than nonparametric tests (Sullivan & Artino, 2013). Frequencies were
meaningful to determine the number of responses of each type to each question (Boone
& Boone, 2013). The coefficient of variation is a standardized frequency distribution
expressed as a percentage calculated as a ratio of the standard deviation of the mean
(Subramani & Kumarapandiyan, 2013). Mean provided information about the most

frequent responses (Boone & Boone, 2013). Median indicated the average of the range of
numbers (Boone & Boone, 2013).
Cronbach’s alpha. Social scientists widely use and recommend using
Cronbach’s alpha to test the consistency and stability of the results of the ordinal scale
data (Croasmun, & Ostrom, 2011; Gadermann, Guhn, & Zumbo, 2012; Oluwatayo, 2012;
Tavakol & Dennick, 2011). Consistency and stability indicate the reliability of the survey
instrument (Croasmun, & Ostrom, 2011; Gadermann, Guhn, & Zumbo, 2012;
Oluwatayo, 2012; Tavakol & Dennick, 2011). After entering the data into SPSS
software, a reliability analysis of each question produced descriptive reliability statistics
for the items and the scale as well as showing the inter-item correlations. The results of
the item-total statistics indicated if removing any of the questions would lead to higher or
lower Cronbach’s alpha scores. Cronbach’s alpha scores between 0.67 and 0.90
demonstrate acceptable reliability (Oluwatayo, 2012; Tavakol & Dennick, 2011).
I calculated frequency tables, mean, median, standard deviation, the coefficient of
variation, and Cronbach's alpha on the Likert items. Calculating frequencies tables, mean,
and median in SPSS involved clicking analyze – descriptive statistics – frequencies –
statistics – select mean, median, and standard deviation. The coefficient of variance was
standard deviation divided by mean. Calculating Cronbach’s alpha in SPSS involved
clicking analyze – scale – reliability analysis, then transferring the variables to the Items
section, and then selecting Model as “Alpha.”

EFA Step 1: Factor Analysis Descriptive Statistics
In the EFA method, the first step is to analyze the descriptive statics of the data to
determine if the data obtained from administering the survey instrument to a participant
group is suitable for EFA (Beavers et al. 2013; Schmitt, 2011; Williams et al., 2012).
Assumptions about the suitability of the data include correlational values, and linear
relationships (Beavers et al., 2013). In EFA, there are no dependent or independent
variables; therefore, normality is not required for EFA (Beavers et al., 2013). Generating
factor analysis descriptive statistics in SPSS involved selecting analyze – dimension
reduction – factor – selecting the variables – descriptives – selecting the options of
univariate descriptives, initial solution, coefficients, significance levels, determinant,
KMO and Bartlet’s test of sphericity, inverse, reproduced, and anti-image. This
procedure produced results to determine correlational values and linear relationships.
Correlational values. The SPSS correlations matrix from the factor analysis
descriptive statistics produced the correlations matrix to determine correlational values.
Producing and examining a correlation matrix addressed the correlational values
assumption. Correlations indicate linear relationships (Beavers et al., 2012). Correlations
that exceed .30 indicate sufficient commonality to continue the evaluation (Beavers et al.,
2013).
Linear relationship. The SPSS Bartlett’s test of Sphericity from the factor
analysis descriptive statistics produced Bartlett’s test. The assumption testing must show
that linear relationships exist (Beavers et al., 2013). Bartlett’s Test of Sphericity,
available in SPSS software, is a single number that indicates if linear combinations exist.

Data is suitable for EFA if the Bartlett’s Test of Sphericity is significant (p<.05)
(Williams et al., 2012).
Kaiser-Meyer-Olkin Measure (KMO) of Sampling Adequacy and the
AntiCorrelation matrix indicate whether the dataset produced distinct and reliable factors
(Beavers et al., 2013). A KMO value below .5 is unacceptable (Beavers et al., 2013). If
the KMO value is below .5, the anti-correlation matrix may indicate items that are
unsuitable for the EFA. Values in the anti-correlation matrix above .5 indicate the item
does not have a linear relationship and indicates removal of the item (Beavers et. al.,
2013).
EFA Step 2: Initial Factor Extraction
Once determined that the data was suitable for EFA, the second step was the
initial extraction (Beavers et al., 2013; Schmitt, 2011; Williams et al., 2012). Factor
extraction identifies the latent variables and the relationships between the measured
variables. The linear combinations resulting from this first extraction are the factors
(Beavers et al., 2013). With the first extraction, the linear combinations are independent
or uncorrelated, also known as orthogonal (Beavers et al., 2013). For EFA, there are two
primary extraction models, component analysis, and common factor model (Schmitt,
2011). There are some methods available for each of these models (Schmitt, 2011).
Component analysis method, such as principal component analysis (PCA), reduces the
number of variables while retaining as much of the original variance as possible (Conway
& Huffcutt, 2003). Researchers use a common factor method, such as principal axis
factoring (PAF), to understand the latent, or unobserved, variables and the relationships

between the measured items (Conway & Huffcutt, 2003). Principal axis factor (PAF), a
common factor model, was well suited for this purpose (Conway & Huffcutt, 2003;
Schmitt, 2011; Williams & Brown, 2012). Therefore, I used the common factor model
method PAF, which was available in the SPSS software package. Running PAF in SPSS
involved clicking analyze – dimension reduction – factor – selecting the variables –
choosing principal axis factoring – selecting the options Correlations Matrix, Scree Plot
and eigenvalues greater than 1.
EFA Step 3: Factor Retention
Factor extraction yields multiple factors. The third step was multiphase. First was
to determine which of those factors best represent the data and the relationships (Beavers
et al., 2013; Schmitt, 2011; Williams et al., 2012). The second was to determine which
factors were not statistically or theoretically relevant (Beavers et al., 2013; Schmitt,
2011;
Williams et al., 2012). Third was to retain only those factors that best represented the
data (Beavers et al., 2013; Schmitt, 2011; Williams et al., 2012). Retaining the optimal
number of factors was crucial. Retaining too few or too many factors affects the stability
of factor patterns and interpretation (Hayton et al., 2004; Preacher et al., 2013). Again,
there are multiple techniques available to determine the number of factors to retain, such
as the Kaiser’s eigenvalues-greater-than-1, scree plot, and parallel analysis (Ruscio &
Roche, 2012).
Kaiser’s eigenvalues-greater-than-1 (K1), “retains factors with eigenvalues
greater than 1” (Hayton et al., 2004, p. 193). It is the default on statistical software

programs such as SPSS (Ruscio & Roche, 2012). As the name implies, K1 sets the
threshold between large and small eigenvalues at 1 (Ruscio & Roche, 2012). Eigenvalues
greater than 1 are retained and eigenvalues less than one are not retained (Ruscio &
Roche, 2012). Hayton et al. identified three issues with K1. First, it indicates upper and
lower bound factors, but in practice, researchers use it to determine the exact number of
factors to retain. Second, it tends to lead to overestimation of the number of factors.
Third, it is arbitrary (Fabrigar et al., 1999).
The scree test produces a graphical plot of the eigenvalues in descending order
(Ruscio & Roche, 2012). The scree begins at the breakpoint or the point at which there is
an abrupt change from large to small eigenvalues (Ruscio & Roche, 202). Factors that do
not belong to the scree are retained (Hayton et al., 2004). The scree test is subjective,
especially when there is no clear break or multiple breaks; however, Hayton et al. found
the method worked well with strong factors. Likewise, Fabrigar et al. (1999) found that
the scree test worked well when underlying factors were distinct.
Parallel analysis (PA) may be an accurate method for identifying the number of
factors to retain. PA was accurate primarily because it adjusts for sampling error (Hayton
et al., 2004; Ruscio & Roche, 2012). However, social scientists underutilize PA in their
research (Hayton et al., 2004). Hayton et al. speculated that the reason researchers
underutilize PA is because it is not available in the widely used statistical packages.
In practice, many researchers use multiple methods to determine the number of
factors to retain (Hayton et al., 2004). Standard techniques that are available to determine
the number of factors to retain are the Kaiser’s eigenvalues-greater-than-1, scree plot, and

parallel analysis (Ruscio & Roche, 2012). Scree test, which is available in SPSS
software, is one acceptable method of factor retention (Beavers et al., 2013). I used
Kaiser’s eigenvalues-greater-than-1 and confirmed the number of factors to retain with
scree test. The factor extraction method mentioned above produced a scree plot to
provide a visual representation of the data.
EFA Step 4: Factor Rotation
The fourth step was to factor rotation (Beavers et al., 2013; Schmitt, 2011;
Williams et al., 2012). The factors are rotated to achieve a more simple structure and
produce a solution that is more readily interpretable (Beavers et al., 2013; DeCoster,
1998). There are two types of rotational methods: orthogonal and oblique. There are
fundamental differences between these two methods (Browne, 2001). The method used
can significantly affect the correlations between each factor, as well as how items
correlate with multiple factors, or cross-loadings (Browne, 2001).
The orthogonal rotation methods, such as varimax, quartimax, and equimax reveal
uncorrelated factors that are easy to interpret. However, these methods do not identify
correlated factors (Schmitt & Sass, 2011). As such, orthogonal methods may not
represent the underlying data structure (Schmitt & Sass, 2011). Orthogonal tools are
appropriate if the factors are conceptually independent, and the goal is to generate factor
scores (Beavers et al., 2013).
The oblique rotation methods, such as direct oblimin, Promax, Orthoblique, and
Procrustes, account for relationships, or correlations, between factors (Beavers et al.,

2013). Browne (2001) stated that the oblique rotation method is more appropriate in most
“practical situations” (p. 114) because correlated factors more accurately represent reality
and produces a simpler factor pattern.
Browne (2001) determined that without standardization, both oblique rotation and
orthogonal rotation methods could reproduce their model’s simple structure reasonably
well. When factors were uncorrelated, orthogonal and oblique rotation both resulted in
factor correlations of about zero and similar factor loadings (Floyd & Widaman, 1995 as
cited in Conway & Huffcutt, 2003). However, Browne (2001) also found that oblique
rotations yielded perfect cluster solutions with two substantial loadings per factor and
demonstrated that oblique rotation resulted in greater simplicity.
Myers, Ahn, and Jin (2013) determined that the target rotation method performed
well when there was little a priori knowledge of the structural model, and the underlying
structure was complex. In their study of target rotation, when factor loading was not low,
two or three items per factor achieved accurate results. When factor loading was low,
they obtained accurate results with sample sizes of at least 200 and four or more items
per factor.
Oblique methods produce superior results with correlated factors, and oblique and
orthogonal methods lead to the nearly identical factor loading solutions when constructs
are uncorrelated. Most social science studies involve correlated factors (Schmitt 2011).
The oblique target rotation method performed well for new model development. Schmitt
also recommended oblique rotation when developing and testing a new measurement.
Since the purpose of this research was to construct a new measurement instrument to

develop a new model, which involves identifying correlated factors, I used Promax
oblique factor rotation. Additionally, Promax oblique factor rotation it was available in
the SPSS software package. Running factor rotation in SPSS involved continuing from
the factor extraction procedures described above, by clicking on method and choosing
Promax.
EFA Step 5: Interpretation of Factor Structure
EFA is an iterative process that requires the fifth step of interpreting both the
items and the factors (Beavers et al., 2013). Each measure linearly relates to each factor
(DeCoster, 1998). The factor loadings revealed by the SPSS factor rotation output
indicated the strength of the relationships (DeCoster, 1998). Results of EFA studies
should be statistically significant (Beavers et al., 2013). However, researchers must also
use their theoretical knowledge of the data to determine the conceptual relevance of the
results (Beavers et al., 2013). The researcher must find the fine balance between
statistical significance and conceptual relevance.
I used EFA to evaluate patterns, determine constructs, and reduce the number of
questions. The first procedure was to determine the items with the highest factor loadings
from the EFA. The next procedure was to retain the items with the best factor loadings.
Statistically, items with loadings of .70 or higher that simultaneously do not load on
another factor greater than .40 are considered good identifiers of the factor (Garson, 2010
as cited in Beavers et al., 2013). The final procedure was to calculate Cronbach’s alpha
for each factor including the questions retained for each factor. Cronbach’s alpha scores
between 0.67 and 0.90 demonstrate acceptable reliability (Oluwatayo, 2012; Tavakol &

Dennick, 2011). The resulting questions were the optimal number to measure integration
of GBC.
Step 6: Construct Factor Scores for Composite Index
The purpose of this study was to develop an index to evaluate the maturity level
that a company has attained in implementing the four-step GBC framework. This sixth
step involved constructing factor scores that could be summed to create factor weights
(DeCoster, 1998). The above detailed EFA technique removed redundant questions and
assigned eigenvalue scores to each remaining question. The result was the minimal set of
questions that were necessary for the final survey and the weight assigned to each
question. The EFA-generated eigenvalues were weights that were each multiplied by the
corresponding Likert question score and summed to obtain an overall index (DeCoster,
1998). When company leaders complete the final survey, the resulting data will yield
weighted scores, indicating the maturity level that the company has attained in
implementing the four-step GBC framework.
Data Application
Future researchers can use the GBC index as a tool to capture the four-step
framework of implementing GBC. Researchers and practitioners can then use the result
to calculate, quantitatively, the GBC Composite Index score for individual companies.
The GBC Composite Index score indicates the stage individual companies have achieved
in implementing GBC. The mean GBC Composite Index indicates whether individual
companies demonstrate a high, medium or low commitment to the four-step framework.
Section 3 presents a proposed ranking scale.

The four-step GBC framework provided the assumed constructs. The constructs
were the following. First, developing overarching corporate values (VALUE). Second,
implementing the values (IMPLE). Third, analyzing problems and experimenting to
revise the values or local implementations (ANALY). Fourth, learning from the previous
steps and institutionalizing best practices (LEARN) (Wood et al., 2006).
Study Validity
Study validity includes both internal and external validity. For this study, the
validity of the instrument indicated the internal validity of the study. Tests to determine
internal validity include construct, face, content, and statistical validity. In quantitative
research, external validity means that the results generalize to the population. The
following provides additional details of establishing the internal and external validity of
this study.
Internal validity. The internal validity tests include construct, face, content, and
statistical validity. Construct validity is whether the definitions accurately reflect the
theoretical framework (Oluwatayo, 2012). In this study, the theoretical framework was
the GBC theory with the constructs of VALUE, IMPLE, ANALY, and LEARN. The
EFA technique established weighted factors that could load to the constructs, which
validated the theoretical framework, thereby ensuring construct validity. To mitigate time
and expense constraints, five experts with the familiarity of corporate or business
citizenship assessed the face validity of the survey. The experts determined that the
instrument was reasonable, unambiguous, and clear, (Oluwatayo, 2012; Synodinos,
2003). The EFA technique determined content validity. Applying EFA demonstrated that

the measure covered the range of meanings that could have been applied to the constructs
(MacKenzie et al., 2011; Oluwatayo, 2012; Podsakoff et al., 2012). Computing the scree
test to determine the optimal number of factors to retain ensured statistical validity.
Construct validity. Construct validity is whether the definitions accurately reflect
the theoretical framework (Oluwatayo, 2012). A significant threat to construct validity is
not correctly identifying the constructs. Donna J. Wood, the lead researcher who
developed the theory of GBC, agreed that the terms VALUE, IMPLE, ANALY, and
LEARN capture the process of implementing the four-step GBC framework (D. J. Wood,
personal communication, August 14, 2014; Appendix E). The EFA process ensured
construct validity.
Face validity. Face validity is a subjective assessment of whether the instrument
is relevant, reasonable, unambiguous, and clear (Oluwatayo, 2012; Synodinos, 2003). To
minimize time and cost constraints, five SMEs helped to mitigate the threats of
ambiguous or poorly worded questions (Oluwatayo, 2012). The five individuals were
SMEs in the field of CSR, and/or had sufficient familiarity of global corporate or
business citizenship. The SMEs agreed that the 22 Likert-type questions were reasonable,
unambiguous, and clear. Therefore threats to face validity were mitigated (Appendix F).
Content validity. Content validity demonstrates that the measure covers the range
of meanings applicable to the constructs (Oluwatayo, 2012). A frequently used method to
address threats to content validity is factor analysis (MacKenzie et al., 2011; Oluwatayo,
2012; Podsakoff et al., 2012). By using EFA, the data analysis validated the content and
mitigated content validity threats.

Statistical validity. Threats to statistical conclusion validity focus on whether the
interpretation and measuring of the scores derived from the instrument are valid
(Oluwatayo, 2012). For EFA, this relates to selecting the optimum number of factors.
Selecting too few or too many factors can result in significant model errors (Schmitt,
2011). Parallel analysis (PA) and minimum average partial (MAP) methods are the most
accurate methods for validating the number of factors (Schmitt, 2011). When modeling
Likert scale surveys, the distribution may be non-normal (Schmitt, 2011). Because the
PA method randomly generates eigenvalues over multiple iterations, the distribution
becomes inconsequential; therefore, the resulting data are accurate (Schmitt, 2011). To
ensure the statistical validity and mitigate threats, I determined the optimal number of
factors to retain by using SPSS software to compute a scree test.
External validity. Quantitative research conducted on samples should
demonstrate what is happening in the world (Oluwatayo, 2012). The samples should
correspond to the population. Establishing this external validity is, arguably, the most
important component of a study (Oluwatayo, 2012) because if the study is not valid, it
will not generalize to the population. The major threat to establishing external validity is
that the sample is not representative of the population. The population of this study was
business leaders of multinational companies in the United States. The sample frame was
business executives who were members of professional business societies, specifically
the Executive Suite. The assumption was that the members had an understanding of
global business citizenship and were capable of understanding and accurately completing
the questionnaire. In this case, the sample should be representative of the populations,

thereby establishing external validity. Establishing internal validity, statistical
conclusions validity, and external validity of this study should translate to the results
generalizing to the population. Therefore, the results of the study should generalize to the
global business community.
Transition and Summary
Section 2 laid out the research plan I intended to execute. The plan included the
purpose and design, methodology, sampling, and my role as the researcher. No data were
collected at this point in time, and section 2 only provided the research plan. Upon
Walden University IRB approval, I progressed to Section 3. Section 3 involved collecting
and analyzing the data, presenting the findings, indicating how the study applies to
business practice and contributes to social change and recommendations for further
actions and study.
Section 3: Application to Professional Practice and Implications for Change
This section begins with a restatement of the purpose of the study and
presentation of the findings. The study provided applications to professional practice
and implications for social change. This section describes the applications and
implications. The results of the study indicate recommendations for action and
recommendations for further research. This section explains the recommendations. I
provide reflections about my experience of the Doctor of Business Administration
doctoral study process. The study closes with the conclusion.

Introduction
The purpose of this cross-sectional quantitative study was to develop Likert
survey questions emanating from the GBC theory and apply EFA to assign importance
weights to the questions and group them into factors. The EFA process allowed me to
develop a minimal or pointed self-administered rating index to measure the maturity
level a company has attained toward becoming a global business citizen.
Presentation of the Findings
The data analysis technique for this study was exploratory factor analysis.
Participants completed 381 surveys. The first survey question was the qualification
question, “I am familiar with the concept of corporate citizenship, business citizenship,
corporate social responsibility, or the ethical responsibilities of corporations”.
Participants responded “no” to 209 surveys. These surveys were not include in further
analysis. Participants responded “yes” to 172 surveys. These data were included in the
usable results.
I then analyzed the collected survey data using IBM SPSS Statistics 21. The
remaining 22 questions of the 23-question survey were Likert-type questions. All
Likertscale responses were entered as a score of 1 to 5. A score of 1 represented strongly
disagree. A score of 2 represented disagree, 3 was neither disagree nor agree, 4 was
agree. A score of 5 represented strongly agree. This paragraph is an overview of the data
analysis procedure, followed by details of the procedures and results. The initial data
analysis step was to determine and eliminate surveys with missing data. Likert data
descriptive statistics involved analyzing responses to individual questions using

frequency distributions, mean, median, and Cronbach’s alpha. EFA was used to identify
and group interrelated variables to factors. Step 1 of the EFA technique was to examine
the factor analysis descriptive statistics. The correlations matrix, Bartlett’s Test of
Sphericity, and KMO all indicated the dataset would produce distinct and reliable factors.
Step 2 was to perform a principal axis factoring initial extraction. Step 3 was to examine
scree test and Kaiser’s eigenvalues-greater-than-1 to determine factor retention. Step 4
was Promax oblique factor rotation. Step 5 was an interpretation of the factor structure
and Cronbach's alpha to test the reliability of the determined factor structure. An
additional sixth step was to construct factor scores for the GBC composite index. The
final step was to apply the index.
Step 0: Likert Data. Missing data can complicate analysis (Seaman & White, 2013;
Seaman, White & Copas, & Li, 2012). The simplest mitigating technique is to remove
the surveys with incomplete data (Seaman & White, 2013). I used the default option in
SPSS to identify missing data. Of the 172 usable surveys, SPSS identified 153 containing
no missing data (Figure 3). I removed the 19 surveys that contained missing data. The
result was 153 surveys used for in data analyses. Since the minimum EFA sample size as
specified in Table 3 of Section 2 was determined to be 110 observations, then this
condition was fully satisfied with the sample of 153 usable surveys.
Figure 3. Missing Data.
Likert data descriptive statistics. The next step was to run descriptive statistics
on the Likert data to become familiar with the data. Descriptive statistics recommended
for ordinal Likert-type item responses include mean, median, coefficient of variation to
explain frequency, and frequency tables (Boone & Boone, 2013; Subramani &
Kumarapandiyan, 2013). Table 4 displays the descriptive statistics. Mean described the
average for each variable (Boone & Boone, 2013). The median was the measure of
central tendency indicating the value in the middle of the range of items or the most
popular response (Boone & Boone, 2013). A median of four on all items was unexpected.
In retrospect, the median responses may have indicated the positive perspective the
executives had toward their company as being a global business citizen company. The
standard deviation was used to calculate the coefficient of variation. Frequency tables
provided the number of responses to each item for each variable (Boone & Boone, 2013).
Appendix H presents the frequencies tables for each variable Q1 through Q22.
Table 4
Descriptive Statistics: Mean, Median, Standard Deviation, Coefficient of Variation
Variable
n M Mdn SD
Coefficient of
Variation
Q1 153 4.20 4.00 1.002 23.85%
Q2 153 3.47 4.00 1.142 32.89%
Q3 153 4.14 4.00 1.058 25.57%
Q4 153 3.96 4.00 1.032 26.04%
Q5 153 3.95 4.00 0.955 24.16%
Q6 153 3.73 4.00 1.008 27.06%
Q7 153 3.61 4.00 1.028 28.48%
Q8 153 3.86 4.00 1.045 27.06%
Q9 153 3.85 4.00 1.050 27.27%
Q10 153 3.88 4.00 1.000 25.75%
Q11 153 4.04 4.00 1.063 26.32%
Q12 153 3.50 4.00 1.125 32.10%
Q13 153 3.72 4.00 1.067 28.68%
Q14 153 4.16 4.00 0.862 20.70%
Q15 153 3.94 4.00 1.008 25.58%
Q16 153 4.00 4.00 1.130 28.24%
Q17 153 3.65 4.00 1.067 29.25%
Q18 153 3.61 4.00 1.101 30.46%
Q19 153 3.71 4.00 1.043 28.10%
Q20 153 3.75 4.00 1.017 27.14%
Q21 153 3.58 4.00 1.074 30.05%
Q22 153 3.92 4.00 1.118 28.55%
Cronbach’s alpha measures how items relate to each other as a group, or their
intercorrelations (Croasmun, & Ostrom, 2011; Gadermann, Guhn, & Zumbo, 2012;
Oluwatayo, 2012; Sullivan & Artino, 2013; Tavakol & Dennick, 2011). Cronbach’s
alpha will increase as the intercorrelations among test items within groups of questions,
such as those related to a construct, increase. Alpha for a related subset of questions, such
as those in a construct, are regarded as offering a reliable set of questions to measure the
construct when 0.67 < alpha < 0.90 (Oluwatayo, 2012; Tavakol & Dennick, 2011). In this
range, the researcher has increased confidence to pursue EFA analysis to weight each
question within a given construct. The Cronbach's alpha scores of .921 for the VALUE
construct, .916 for the IMPLE construct, .910 for the ANALY construct, and .932 for the
LEARN construct indicated highly acceptable reliability (Table 5).
Table 5
Reliability Statistics: Cronbach’s alpha
Construct Questions n Cronbach’s alpha
VALUE 1, 3, 4, 11, 22 5 .921
IMPLE 6, 9, 12, 13, 14, 17, 21 7 .916
ANALY 2, 5, 7, 18 4 .910
LEARN 8, 10, 5, 16, 19, 20 6 .932
Given the reliability of the data, I continued the EFA analysis. EFA analysis
identified and grouped interrelated variables to factors. EFA was the appropriate
approach to answering the research question.
Research Question. The purpose of applying EFA was to answer the research
question (RQ): how many and what factors characterized the Likert survey questions to
assess a company’s GBC maturity level? The EFA process targeted the above RQ as it
identified how the survey questions, or items, related to the four assumed constructs of
VALUE, IMPLE, ANALY, and LEARN. The following are details of the analysis. EFA
Step 1: Factor Analysis Descriptive Statistics. In the EFA method, the first step was to

calculate and interpret several key factor analysis descriptive statistics. These included
correlations matrix, Bartlett’s Test of Sphericity, and Kaiser-Meyer-Olkin Measure
(KMO) of Sampling Adequacy. These descriptive statistics were a complement to
Cronbach’s alpha in determining the appropriateness of utilizing the results from
administering the survey instrument to the participant group in an EFA analysis (Beavers
et al. 2013; Schmitt, 2011; Williams et al., 2012). The next sections present the various
factor analysis descriptive statistics.
Correlational values. Correlations indicate the common relationship, or
intercorrelation, between any pair of variables (Beavers et al., 2012). Items that are
strongly intercorrelated may represent the same underlying factor. Correlations that
exceed.30 indicate sufficient commonality to continue EFA evaluation (Beavers et al.,
2013). Table 6 shows the correlations matrix from the SPSS factor analysis descriptive
statistics. As seen from Table 6, all correlations equaled or exceeded .30. Correlations
exceeding .30 indicate that they are intercorrelated sufficiently to identify common
factors.
Table 6
Factor Analysis Descriptive Statistics: Correlation Matrix
Correlation Q1 Q2 Q3 Q4 Q5 Q6 Q7 Q8 Q9 Q10 Q11 Q12 Q13 Q14 Q15 Q16 Q17 Q18 Q19 Q20 Q21 Q22
Q1 1.000 .422 .824 .574 .532 .459 .371 .429 .523 .424 .838 .300 .509 .540 .630 .552 .320 .381 .471 .477 .404 .644
Q2 .422 1.000 .529 .519 ,575 .627 .775 .562 .614 .556 .462 .603 .650 .503 .642 .464 .580 .674 .634 .654 .583 .557
Q3 .824 .529 1.000 .650 .560 .492 .455 .499 .570 .526 .802 .351 .565 .552 .649 .622 .346 .424 .549 .547 .387 .755
Q4 .574 .519 .650 1.000 .512 .540 .569 .532 .517 .563 .715 .471 .600 .555 .542 .559 .454 .531 .552 .599 .365 .665
Q5 .532 .575 .560 .512 1.000 .547 .665 .620 .754 .683 .565 .481 .620 .593 .701 .616 .546 .690 .607 .659 .507 .631
Q6 .459 .627 .492 .540 .547 1.000 .670 .588 .564 .549 .532 .575 .705 .552 .586 .566 .588 .675 .588 .573 .536 .540
Q7 .371 .775 .455 .569 .665 .670 1.000 .666 .683 .679 .460 .730 .649 .459 .575 .487 .713 .819 .637 .710 .605 .544
Q8 .429 .562 .499 .532 .620 .588 .666 1.000 .658 .652 .490 .524 .561 .551 .654 .602 .552 .645 .627 .648 .493 .542
Q9 .523 .614 .570 .517 .754 .564 .683 .658 1.000 .579 .571 .611 .591 .602 .713 .605 .681 .724 .603 .642 .608 .611
Q10 .424 .556 .526 .563 .683 .549 .679 .652 .579 1.000 .537 .463 .598 .473 .724 .652 .504 .562 .756 .702 .400 .550
Q11 .838 .462 .802 .715 .565 .532 .460 .490 .571 .537 1.000 .396 .602 .496 .671 .652 .424 .463 .574 .563 .389 .761
Q12 .300 .603 .351 .471 .481 .575 .730 .524 .611 .463 /396 1.000 .601 .369 .456 .409 .840 .742 .545 .545 .734 .463
Q13 .509 .650 .565 .600 .620 .705 .649 .561 .591 .598 .602 .601 1.000 .523 .682 .562 .641 ,647 .660 .577 .584 .614
Q14 .540 .503 .552 .555 .593 .552 .459 .551 .602 .473 .496 .369 .523 1.000 .677 ,547 .399 .531 .448 .558 .452 .493
Q15 .630 .642 .649 .542 .701 .589 .575 .654 .713 .724 .671 .456 .682 .677 1.000 .716 .488 .602 .747 .691 .475 .603
Q16 .552 .464 .622 .559 .616 .566 .487 .602 .605 .652 .652 .409 .562 .547 .716 1.000 .442 .518 .681 .602 .325 .620
Q17 .320 .580 .346 .454 .546 .588 .713 .552 .681 .504 .424 .840 .641 .399 .488 .442 1.000 ,768 .517 .499 .816 .499
Q18 .381 .674 .424 .531 .690 .675 .819 .645 .724 .562 .463 .742 .647 .531 .602 .518 .768 1.000 .607 .623 .645 .593
Q19 .471 .634 .549 .552 .607 .588 .637 .627 .603 .756 .574 .545 .660 .448 .747 .681 .517 .607 1.000 .694 .419 .566
Q20 .477 .654 .547 .599 .659 .573 .710 .648 .642 .702 .563 .545 .577 .558 .691 .602 .499 .623 .694 1.000 .509 .600
Q21 .404 .583 .387 .365 .507 .536 .605 .493 .608 .400 .389 .734 .584 .452 .475 .325 .816 .645 .419 .509 1.000 .435
Q22 .644 .557 .755 .665 .631 .540 .544 .542 .611 .550 .761 .463 .614 .493 .603 .620 .499 .593 .566 .600 .435 1.000
Two variables computing R^2 > 0.90 indicates that one of the two variables must
be eliminated so as to avoid multicollinearity. Haitovsky’s significance test indicates
whether the correlation matrix has the issue of multicollinearity. Multicollinearity does
not exist if the result is not significant. Table 7 shows the Haitovsky’s significance test.
Since no pairs of variables compute R^2 > 0.90, and the Haitovsky’s score is not
significant, I proceeded to the next step of the analysis.
Table 7
Factor Analysis Descriptive Statistics: Haitovsky’s Significance Test
Factor Result
det .000000000108486
K 22
N 484
df 231
H .000000051512820
ɑ .05
p-value 1
H-crit 267.45
sig No
Linear relationship. I calculated two key descriptive statistics to assess the
adequacy of the sample, as shown in Table 8 below. Specifically, the Bartlett’s Test of
Sphericity assessed whether there was redundancy between the variables that could be
summarized with a few number of factors. Formally, the test checks the H0: whether the
variables are orthogonal. Researchers reject the H0 when the p-value < alpha. As shown
Table 8, the chi-square test statistic was significant χ2 (231) = 3301.755, p<.0000. Thus,
the variables were not orthogonal, indicating that I could proceed with EFA.
The Kaiser-Meyer-Olkin Measure (KMO) of Sampling Adequacy has the same
goal as Bartlett’s Test of Sphericity but proceeds differently. The KMO test checks if we
can efficiently factorize the original survey questions. KMO does this by comparing the
values of correlations between variables and those of the partial correlations, that is, it
removed the effect of the remaining variables. When KMO is close to 0, then EFA is not
relevant and should not be applied. If however, KMO is close to 1, then EFA can perform
the factorization efficiently because the variables are highly correlated. As shown in
Table 8, the KMO of 0.939 is close to 1 indicating that the sample data would produce
distinct and reliable factors and was adequate for EFA.
Table 8
Factor Analysis Descriptive Statistics: KMO and Bartlett’s Test of Sphericity
Kaiser-Meyer-Olkin Measure of .939
Sampling Adequacy
Bartlet’s Test of Sphericity Approx. Chi-Square 3301.755 df
231
Sig. .000
EFA Step 2: Initial Extraction. The second step of EFA was the initial extraction
(Beavers et al., 2013; Schmitt, 2011; Williams et al., 2012). I used principal axis
factoring (PAF) to obtain eigenvalues for each item and understand the latent variables
and the relationships between the measured items (Table 9). Table 9 shows the initial
eigenvalues before extraction and the extraction sums of squared loadings after
extraction. The extraction sums of squared loadings that occurred after extraction and
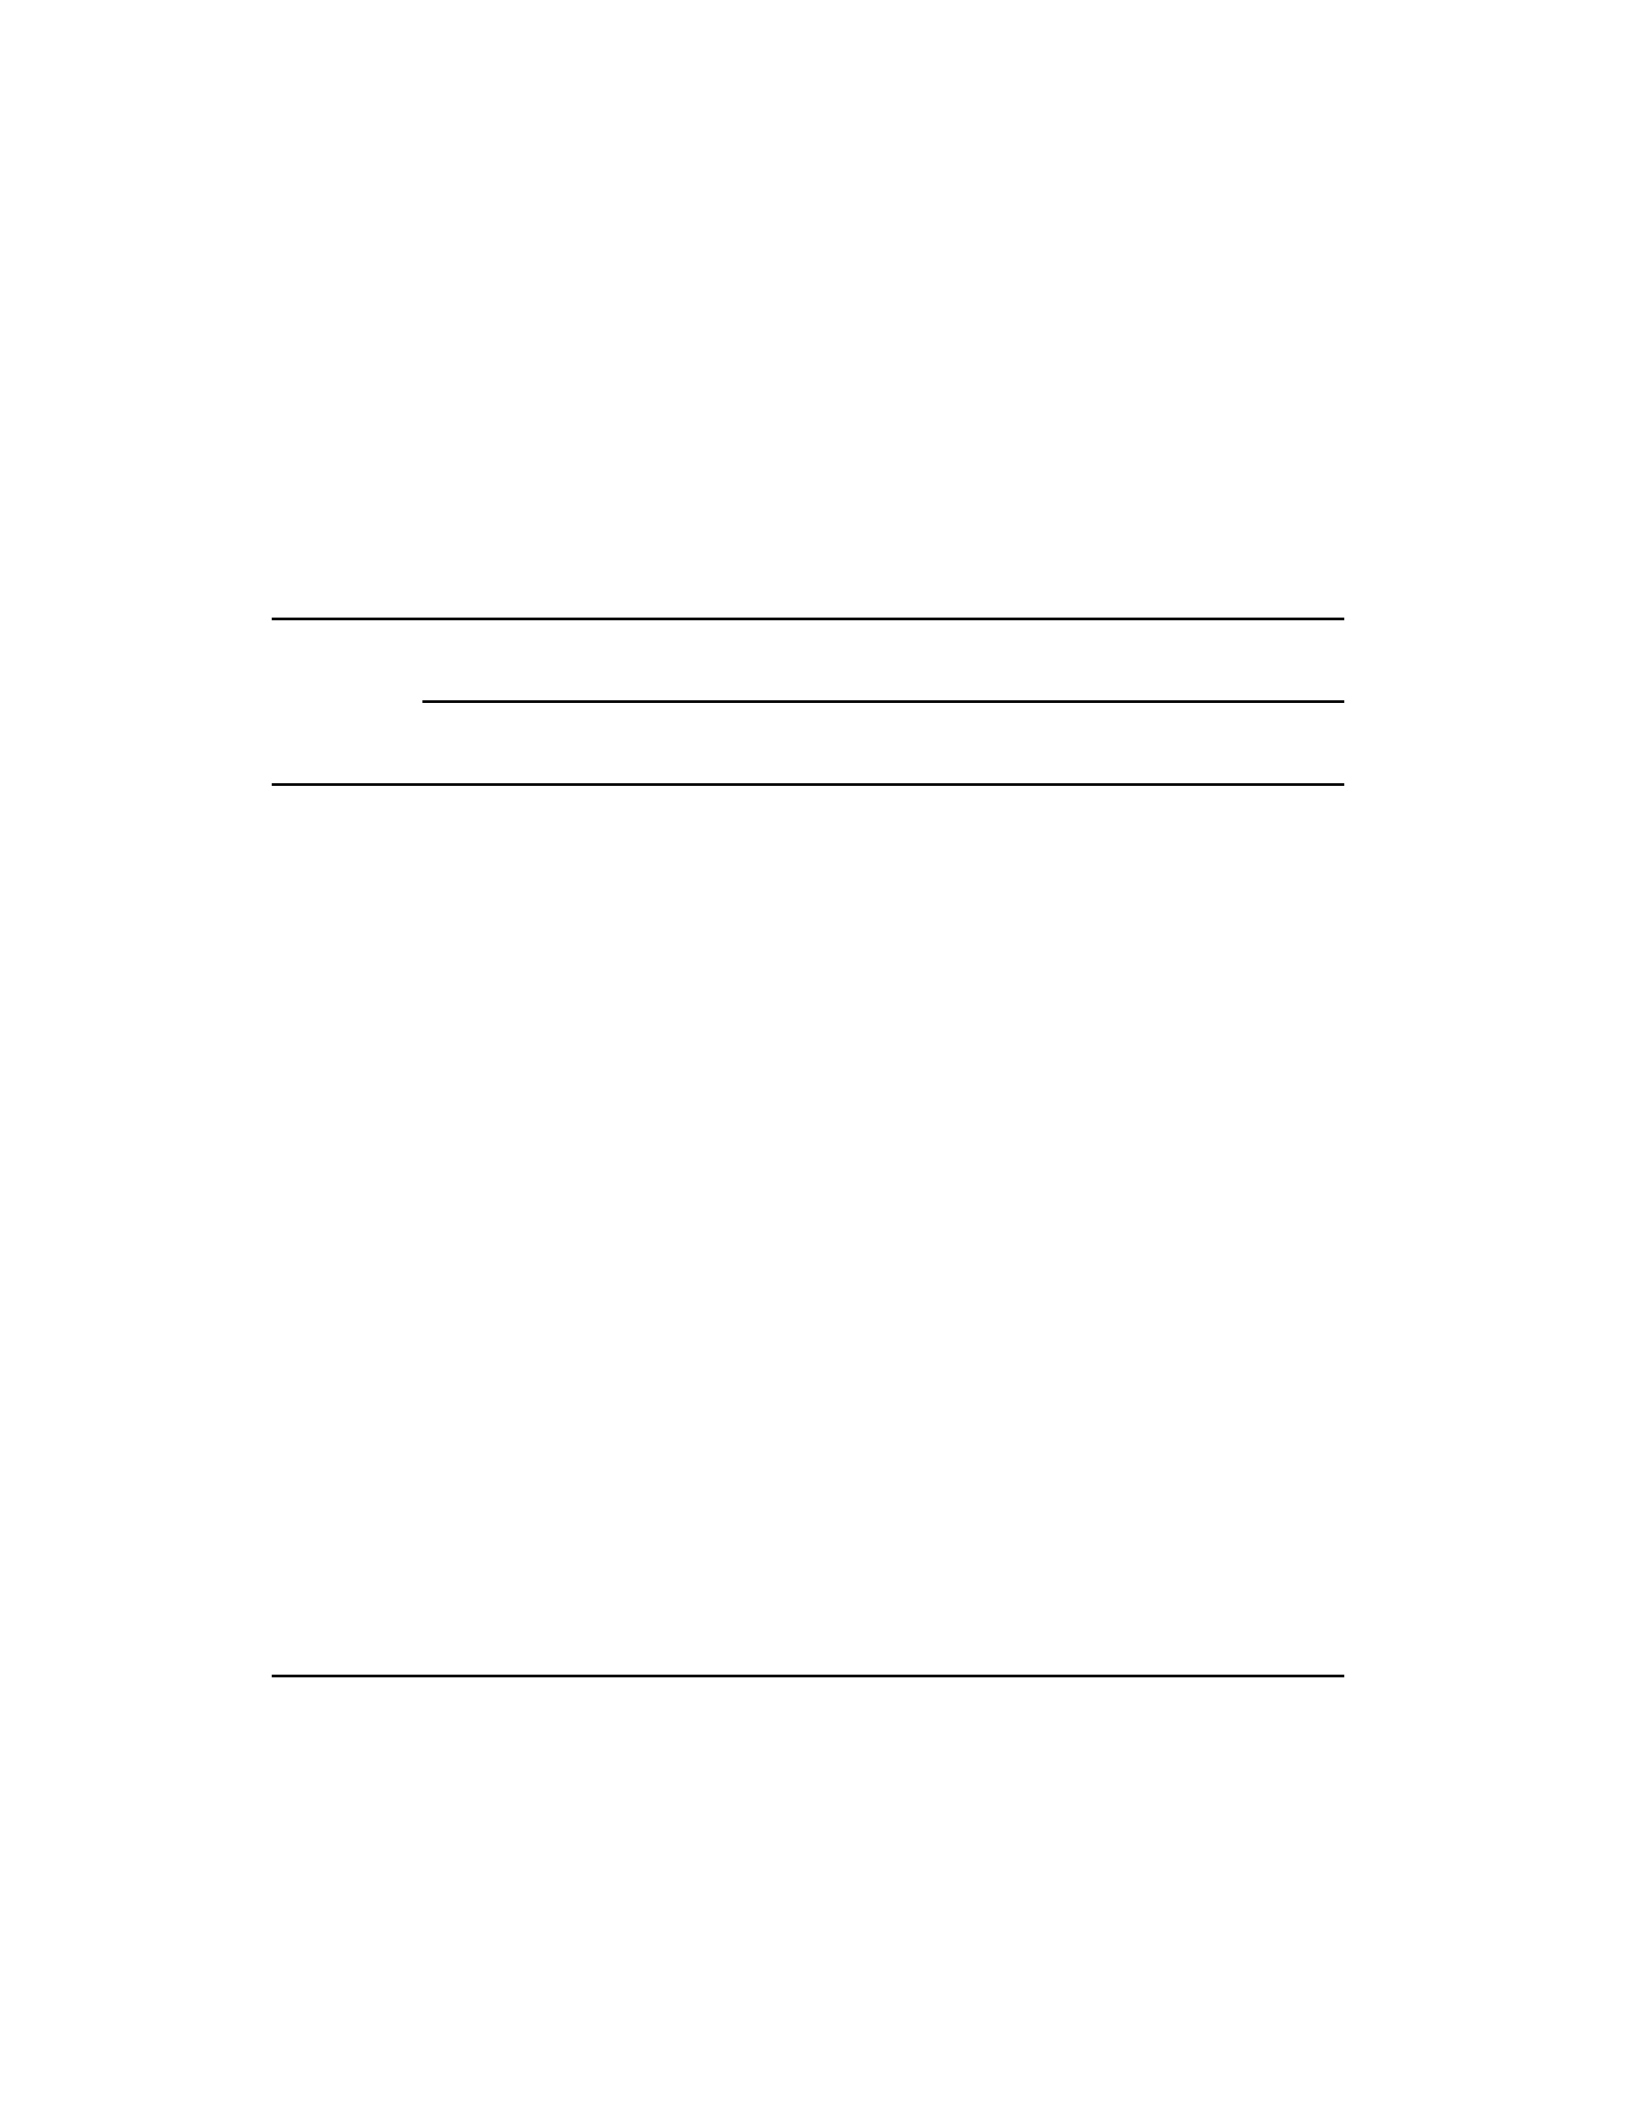
based on the eigenvalues > 1 criterion left three factors. The three factors had eigenvalue
totals over Kaiser’s criterion of 1 or higher. These three eigenvalues combined explained
69.999% of the variance (Table 9). The initial scree plot (Figure 4) showed three factors.
Table 9
EFA Initial Extraction: Initial Eigenvalues and Total Variance Explained
Factor
Initial Eigenvalues Extraction Sums of Squared
Loadings
Total % of
Variance
Cumulative
%
Total % of
Variance
Cumulative
%
1 13.104 59.566 59.566 12.806 58.208 58.208
2 2.012 9.146 68.711 1.789 8.132 66.340
3 1.064 4.836 73.547 .805 3.659 69.999
4 .739 3.357 76.905
5 .608 2.765 79.670
6 .555 2.521 82.191
7 .520 2.364 84.555
8 .444 2.018 86.573
9 .386 1.754 88.327
10 .353 1.606 89.933
11 .315 1.434 91.367
12 .298 1.353 92.720
13 .256 1.166 93.886
14 .227 1.033 94.919
15 .207 .942 95.861
16 .194 .882 96.744
17 .180 .818 97.562
18 .149 .678 98.240
19 .126 .573 98.812
20 .095 .432 99.244
21 .088 .400 99.644
22 .078 .356 100.000
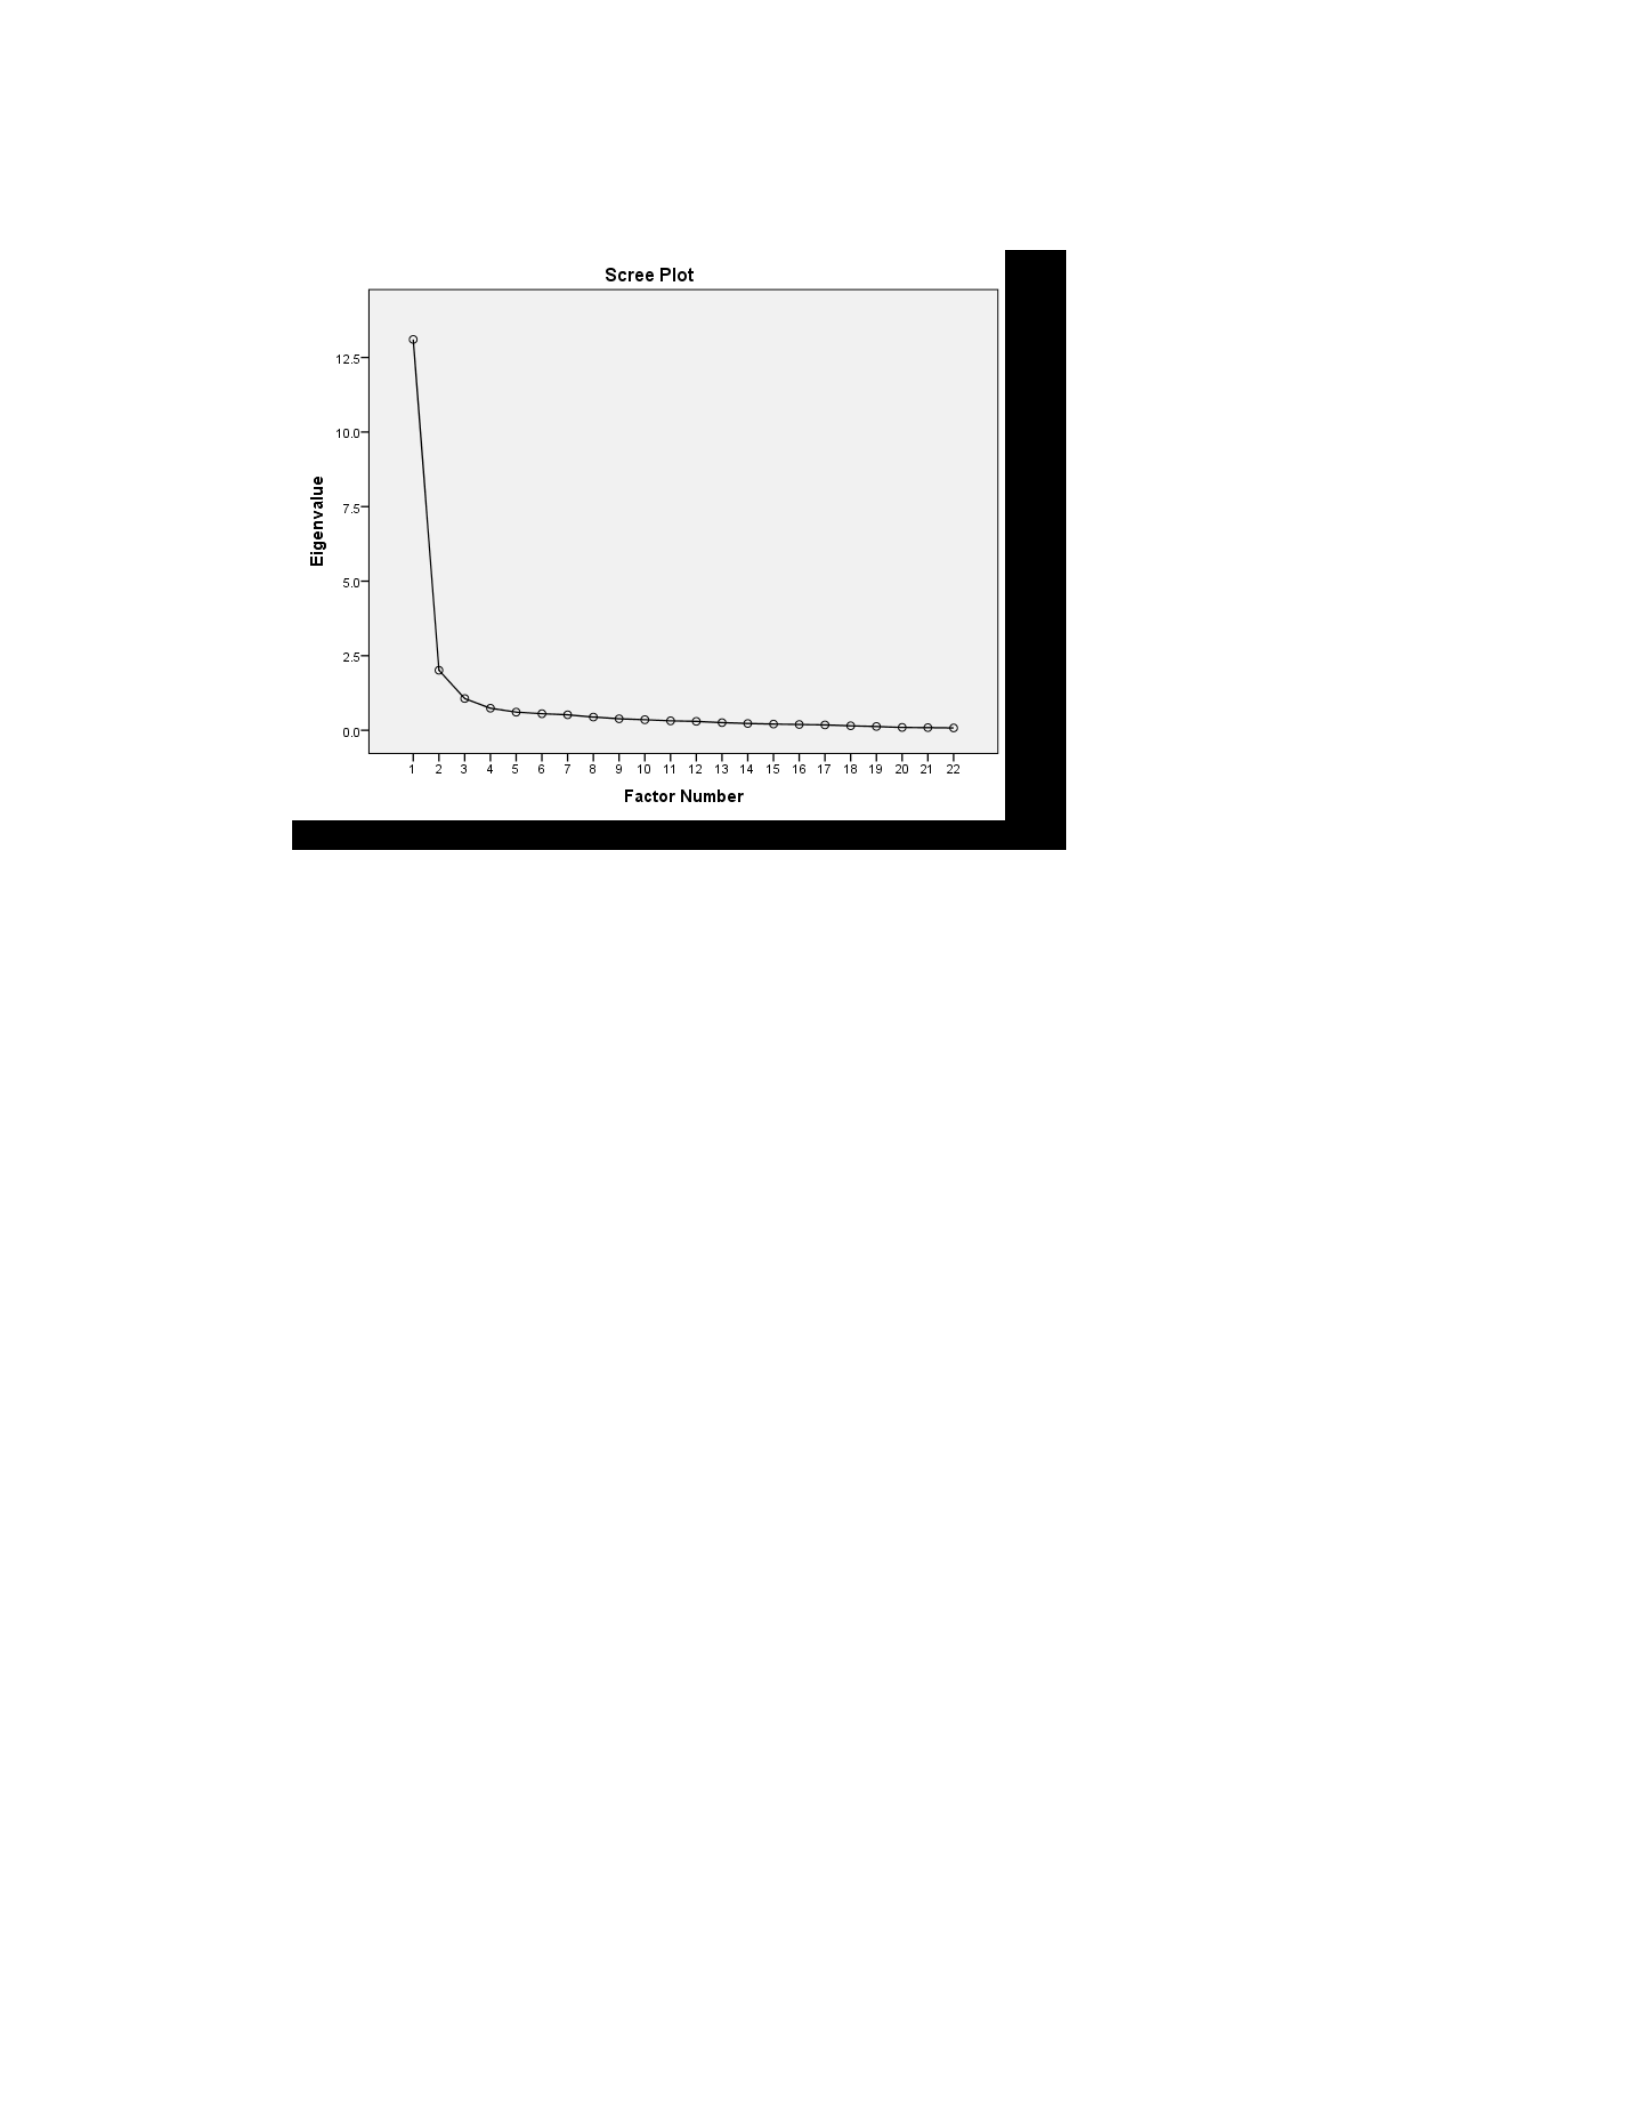
Figure 4. Initial scree plot.
EFA Step 3: Factor Retention. The next step involved generating the
communalities to evaluate the appropriateness of the Kaiser criterion. Based on Kaiser’s
rule, I extracted the recommended three factors 13.104, 2.012, and 1.064 (Table 9).
Kaiser’s rule recommends less than 30 variables, a sample size >250, the majority of
communalities >0.7 and average communality >0.6 (Field 2009). This study passably met
Kaiser's criteria with 22 variables, 153 sample size, 13 of the 22 questions with
communalities >0.7 and with the average communality of the 22 questions of 0.73 (Table
10). Communalities ranging between .60 and .80 indicate excellent congruence (Gaskin
& Happell, 2014). Kaiser criterion indicated that retaining the three factors with
eigenvalue values greater than one was appropriate.
Table 10
EFA Initial Extraction: Communalities Table
Item Initial Extraction
Q1 1.000 .846
Q2 1.000 .647
Q3 1.000 .847
Q4 1.000 .620
Q5 1.000 .678
Q6 1.000 .608
Q7 1.000 .810
Q8 1.000 .662
Q9 1.000 .696
Q10 1.000 .784
Q11 1.000 .867
Q12 1.000 .816
Q13 1.000 .668
Q14 1.000 .513
Q15 1.000 .789
Q16 1.000 .697
Q17 1.000 .864
Q18 1.000 .802
Q19 1.000 .744
Q20 1.000 .712
Q21 1.000 .788
Q22 1.000 .724
Figure 4 above shows the scree plot of the eigenvalues in descending order. The
number of factors to retain is the point at which there was an abrupt change from large to
small eigenvalues. The scree plot concurred with Kaiser’s rule in retaining three factors
(Figure 4). I continued with factor rotation using three factors.
EFA Step 4: Factor Rotation. The fourth step was Promax oblique factor rotation using
the k=3 retained factors. I used Promax oblique factor rotation because it performed well
for new model and measurement instrument development (Beavers et al., 2013; Schmitt,
2011; Williams et al., 2012). Table 11 indicated the variables that loaded to each of the
three factors.
Table 11
EFA Factor Rotation: Pattern Matrix
Note: Extraction Method: Principal Component Analysis.
Rotation Method: Promax with Kaiser Normalization.
Rotation converged in 5 iterations.
EFA Step 5: Interpretation of Factor Structure. EFA is an
iterative process that requires the fifth step of interpreting
both the items and the factors (Beavers et al., 2013). From the
Factor Rotation Pattern Matrix (Table 10), I retained ten items
with EFA factor loadings of .70 or higher that simultaneously
did not load on another factor greater than .40. Table 12
shows the retained questions that loaded to each factor. EFA
generated high factor loadings for Factor 1 with questions
Q10, Q15, Q19, and Q20. All of these questions related to the
LEARN construct; thus Factor 1 represented LEARN. EFA
generated high factor loadings for Factor 2 with questions Q12, Q17, and Q21. All of
these questions related to the IMPLE construct; thus Factor 2 represented IMPLEMENT.
EFA generated high factor loadings for Factor 3 with questions Q1, Q3, and Q11. All of
these questions related to the VALUE construct; thus Factor 3 represented VALUE.
Table 12
Component
1 2 3
Q1 -.090 -.018 .980
Q2 .397 .465 .048
Q3 .085 -.046 .887
Q4 .211 .124 .563
Q5 .595 .169 .162
Q6 .325 .425 .158
Q7 .490 .587 -.129
Q8 .691 .185 -.007
Q9 .374 .411 .191
Q10 .946 -.058 -.044
Q11 .053 .004 .895
Q12 -.002 .926 -.048
Q13 .274 .422 .272
Q14 .369 .088 .366
Q15 .704 -.029 .283
Q16 .684 -.152 .325
Q17 -.030 .954 -.015
Q18 .327 .680 -.044
Q19 .825 .030 .030
Q20 .713 .129 .069
Q21 -.213 .947 .129
Q22 .131 .164 .667
EFA Interpretation: Factor Summary
Factor Number Factor Name Questions
1 Learn Q10 Q15 Q19 Q20
2 Implement Q12 Q17 Q21
3 Value Q1 Q3 Q11
Cronbach’s alpha scores calculated for each factor and all ten retained factors was
above .9 indicating excellent reliability. Tables 13 - 15 show Cronbach’s alpha scores for
Factors 1, 2, and 3 of .911, .921, and .932 respectively. Table 16 shows Cronbach’s alpha
of .925 for all ten retained questions.
Table 13
Cronbach’s alpha: Factor 1
Cronbach’s alpha n
.911 4
Table 14
Cronbach’s alpha: Factor 2
Cronbach’s alpha n
.921 3
Table 15
Cronbach’s alpha: Factor 3
Cronbach’s alpha n
.932 3
Table 16
Cronbach’s alpha: 10 Retained Items
Cronbach’s alpha n
.925 10
The overarching RQ was how many and what factors (dependent variables) are
needed to characterize the Likert survey questions (independent variables) to assess a
company’s GBC maturity level? EFA concluded that the three factors of VALUE,
IMPLE, and LEARN are needed to assess a company’s GBC maturity level. EFA
identified ten questions that best represent these three factors. The conclusions to the
subRQs are presented in Table 17. Sub-RQs 1, 2, and 4 were met. EFA indicated
retaining no questions from the ANALY construct because no questions from the
ANALY construct had factor loadings of >0.70. The ANALY questions all involved
analyzing and experimenting with integrating the overarching principles/values with local
customs or norms. Not retaining questions from the ANALY construct aligned with the
factor retention of three factors. Table 17
Sub-RQ Conclusions
Sub-RQ Conclusion
SRQ1:
Does the survey adequately capture the
VALUE construct of the GBC theory?
Yes
SRQ2:
Does the survey adequately capture the
IMPLE construct of the GBC theory?
Yes
SRQ3:
Does the survey adequately capture the
ANALY construct of the GBC theory?
No
SRQ4:
Does the survey adequately capture the
Yes
LEARN construct of the GBC theory?
Continuing with the analysis of the three emerging factors LEARN, ANALY, and
VALUE, I identified items with the highest factor loadings and examined inter-item
correlations and Cronbach’s alpha to identify the questions that performed well for each
construct. The original survey included four questions intended to capture the ANALY
construct. EFA analysis indicated that the original survey did not adequately capture the
ANALY construct of the GBC theory. The EFA process could also have identified an
alternative explanation that GBC may be adequately measured with the three constructs
of VALUE, ANALY, and LEARN. The result was the selection of 10-questions with the
corresponding factor analysis results as shown in Table 18.
Table 18
Factor Weights for Each Question by Factor
Original
Number
Final
Number
VALUE
(f3)
IMPLE
(f2)
LEARN
(f1)
Q1 Q1 .980
Q11 Q2 .895
Q3 Q3 .887
Q21 Q4 .947
Q17 Q5 .954
Q12 Q6 .926
Q15 Q7 .704
Q19 Q8 .825
Q10 Q9 .946
Q20 Q10 .713
Table 19 displays a simplified GBC Index survey using the ten retained questions
that represented the three emerging factors. The table includes each factor and the
questions that loaded to each factor. The table includes the full questions, the original
question number of each question, and the newly assigned final question number. A
suggestion for further research is to develop different questions within the ANALY
construct. Further research would indicate whether the survey questions developed for
this study were inadequate, or whether the theory of GBC can be adequately captured and
measured with the three constructs of VALUE, IMPLE, and LEARN.
Table 19
Final Survey Questions by Factor
Question Original
Number
Final
Number
VALUE QUESTIONS (f3)
Have a written code of conduct and policies that reflect the
company’s principles/values.
Q1 Q1
Have a written code of conduct and policies that govern their
conduct everywhere they operate around the globe.
Q11 Q2
Have a written code of conduct and policies that reflect a high
degree of ethical standards.
Q3 Q3
IMPLEMENTATION QUESTIONS (f2)
Implement local variations of their principles/values based on
local customs, culture, norms, or national standards.
Q21
Q4
Engage local employees and stakeholders in establishing local
variations of company principles/values to meet local customs,
culture, norms, or national standards.
Q17 Q5
Empower local employees to establish local variations of
Q12 Q6
company principles/values to meet local customs, culture, norms,
or national standards.
LEARN QUESTIONS (f1)
Have a formal, systematic process to organize and communicate
organizational performance to facilitate learning within the
organization.
Q15
Q7
Have a formally structured knowledge bank, available to
everyone in the company, where employees can enter tacit
knowledge, questions, and lessons learned.
Q19 Q8
Institutionalize lessons learned into policies, practices, and
behaviors.
Q10 Q9
Share important lessons learned and best practices with
stakeholders and other companies outside the company.
Q20 Q10
Step 6: Construct Factor Scores for Composite Index
The purpose of this study was to develop an index to evaluate the maturity level
that a company has attained in implementing the GBC framework. The sixth step
involved constructing factor scores for the three factors VALUE, IMPLEMENT, and
LEARN and summing them to create factor weights (DeCoster, 1998). EFA generated
eigenvalues, or weights, that are each multiplied by the corresponding Likert question
score. The sum of the results from each factor equates to the overall composite index.
Multiplying the overall composite index by 2.279 normalizes the score to a scale of 100
for ease of interpretation by laypeople (Table 18). When a company representative
completes the final survey, the resulting data will yield a single weighted score,
indicating the maturity level that the company has attained in implementing three steps of
the GBC framework of VALUE, IMPLEMENT, and LEARN.
Table 20 shows the GBC Composite Index calculation for one person. An
individual would answer the final ten survey questions (Table 17). The Likert-scale
responses available to the person are as follows: 1 = strongly disagree, 2 = disagree, 3 =
neither disagree nor agree, 4 = agree, 5 = strongly agree. The response to each question
will be recorded in Table 20 and multiplied with the corresponding eigenvalue as shown
in Table 20. The resulting values are subtotaled for each factor. The sum of the subtotals
is then multiplied by 2.279 to normalize to a scale of 100. The final normalized number is
the GBC Composite Index score. The use of a weighted questions formula based on
eigenvalues is appropriate due to one key reason: all questions are Likert questions from
a scale of 1 to 5. Therefore the measurement scale across all the questions is identical and
thus can be added.
Table 20
GBC Composite Index Calculation
Eigenvalues / question /
factor Calculated Scores
Likert
Survey
Question
#
p1
Responses
f3 f2 f1
VALUE IMPLE LEARN
f3 f2 f1
weighted weighted weighted
score score score
1 5 .980 4.900
2 5 .895 4.475
3 5 .887 4.435
4 5 .947 4.735
5 5 .954 4.770
14.135 15.940
6 5 .926 4.630
7 5 .704 3.52
0
8 5 .825 4.12
5
9 5 .946 4.73
0
10 5 .713 3.56
5
Subtotal score per factor 13.810
Add Sub f3, Sub f2, Sub f1 43.885
Subtotal x 2.279 = normalized scale of 100 = final GBC Composite Index Score 100.000
Data Application
Future researchers and practitioners can use the result of this study to calculate the
GBC Composite Index score related to the factors of VALUE, IMPLEMENT, and
LEARN for individual companies. The GBC Composite Index score will indicate the
stage individual companies have achieved in implementing these three GBC constructs.
The mean GBC Composite Index will indicate whether individual companies
demonstrate a high, medium or low commitment to becoming a global business citizen.
The maximum composite score is 43.885 achieved by rating every item 5, or highly
agree. Normalized to a scale of 100 this equates to a score of 100.0 (Table 21).
Table 21
GBC Composite Index: Level 5
Likert
Survey
Question #
p1
Responses
Eigenvalues / question /
factor Calculated Scores
f3 f2 f1
VALUE IMPLE LEARN
f3 f2 f1
weighted weighted weighted
score score score
1 5 .980 4.900
2 5 .895 4.475
3 5 .887 4.435
4 5 .947 4.735
5 5 .954 4.770
6 5 .926 4.630
7 5 .704 3.520
8 5 .825 4.125
9 5 .946 4.730
10 5 .713 3.565
Subtotal score per factor 13.810 14.135 15.940
Add Sub f3, Sub f2, Sub f1 43.885
GBC Composite Index Score 100.000
The minimum composite score from scoring 1, or highly disagree, to each
question is 8.777 (Table 22). A minimum score indicates a company has not started
becoming a global business citizen.
Table 22
GBC Composite Index: Level 1
Likert
Survey
Question #
p1
Responses
Eigenvalues /
question /
factor Calculated Scores
f3 f2 f1
VALUE IMPLE LEARN
f3 f2 f1
weighted weighted weighted
score score score
1 1 .980 .980
2 1 .895 .895
3 1 .887 .887
4 1 .947 .947
5 1 .954 .954
6 1 .926 .926
7 1 .704 .704
8 1 .825 .825
9 1 .946 .946
10 1 .713 .713
Subtotal score per factor 2.762 2.827 3.188
Add Sub f3, Sub f2, Sub f1 = Score 8.777
GBC Composite Index Score 20.000
Scoring 1 on every item yields a composite score of 8.777 and a normalized score
of 20.0. Scoring 2 on every item yields a composite score of 17.554 and a normalized
score of 40.0. Scoring 3 on every item yields a composite score of 26.331 and a
normalized score of 60.0. Scoring 4 on every item yields a composite score of 35.108 and
a normalized score of 80.0. Scoring 5 on every item yields a composite score of 43.885
and a normalized score of 100.0.
Table 23 displays a proposed ranking scale. Future researchers should confirm
this ranking scale. A normalized score between the lowest possible score of 20.0 and 39.0
was assigned Level 1 indicating that a company does not qualify as a global business
citizen. A score between 39.0 and 58.0 was assigned Level 2 indicating that a company
may have started implementing few aspects of GBC but is immature. A score between
58.0 and 77.0 was assigned Level 3 indicating that a company has implemented limited
aspects of GBC and had novice experience. A score between 77.0 and 96.0 was assigned
Level 4 indicating that a company has successfully implemented several aspects of GBC
and is at an intermediate level. A score between 96.0 and the highest possible score of
100.0 indicates a company has implemented most or all of the VALUE, IMPLEMENT,
and LEARN components and was assigned as a Level 5 advanced GBC.
Table 23
GBC Maturity Level Ranking Scale
GBC Composite Index Score Range Level GBC Maturity Level
(20.0, 39.0] Level 1 Not applicable
(39.0 , 58.0] Level 2 Immature
(58.0 , 77.0] Level 3 Novice
(77.0 , 96.0] Level 4 Intermediate
(96.0 , 100.0] Level 5 Advanced
Applications to Professional Practice
Business leaders that can demonstrate to their stakeholders that they are good
business citizens may gain the benefits of improved legitimacy (Wolf, 2014), improved
cost of capital (Brooks & Pavelin, 2014), and improved profitability (Flammer, 2015).
Stakeholders are demanding that corporate leaders conduct their business as though they
are socially responsible citizens of society (Park & Ghauri, 2015). The general business
problem was that there was no self-administered rating system available for business
leaders to report to stakeholders the steps they have achieved toward becoming an
ethically responsible business citizen (Milne & Gray, 2013). The goal of this research
was to operationalize the four high-level GBC theory steps elaborated by Wood et al.
(2006), into a useful survey instrument and weighted index.
The results of the study measured three of the four steps of the GBC
implementation process. The retained survey questions, or items, related to the three
factors of VALUE, IMPLEMENT, and LEARN. The third step of the four-step GBC
implementation process involves analyzing problem areas and experimenting with
solutions to remediate conflicts between the overarching principles/values with local

customs or norms, the ANALY construct. EFA indicated that participants did not rate any
ANALY questions with enough significance to be included in the final survey.
The retained survey questions indicated that the first factor is to create a written
code of conduct that reflects a high degree of ethical standards and the principles/values
of the company. The Code governs the conduct of the company’s employees everywhere
they operate around the globe. The second factor is to implement the code at the local
level. Local employees and stakeholders are empowered to establish local variations of
the code to meet local customs, culture, norms, and national standards. The third factor is
to learn from the previous steps. Learning means organizing and communicating how the
company performs on GBC. Learning means the company institutionalizes lessons
learned into policies, practices, and behaviors and maintains a knowledge bank that is
available to everyone within the company. A mature global business citizen shares
important lessons learned and best practices with stakeholders and others outside the
company.
The artifacts resulting from this study will allow academics to conduct further
research toward the development of a quantitatively validated survey that business
leaders can self-administer. The results of this survey provided a suggested rating system
in the form of a composite index indicating the stage of creating values, implementing,
and learning that business leaders have achieved toward becoming a global business
citizen. Within the context of these three constructs, the results of this study provided a
suggested scale of 5 levels of maturity. A GBC Composite Index score between 20.0 and
39.9 equates to Level 1 indicating that a company does not qualify as a global business

citizen. A GBC Composite Index score between 39.0 and 58.0 equates to Level 2
indicating that a company may have started implementing few aspects of GBC but is
immature. A GBC Composite Index score between 58.0 and 77.0 equates to Level 3
indicating that a company has implemented limited aspects of GBC and had novice
experience. A GBC Composite Index score between 77.0 and 96.0 equates to Level 4
indicating that a company has successfully implemented several aspects of GBC
and is at an intermediate level. A GBC Composite Index score above 96.0 indicates that a
company has implemented most or all of the VALUE, IMPLEMENT, and LEARN
components and is a Level 5 advanced GBC.
The intent of this study was to provide business leaders with a tool to show
stakeholders how they rank as a global business citizen. The result was a study that
researchers can use for further research related to the ANALY construct. The question
was whether the initial survey inadequately captured the ANALY construct, or whether
the three constructs of VALUE, IMPLE, and LEARN adequately describe and measure
the theory of GBC. Follow-up research is required before final development of a
quantitatively validated tool to assess the step or steps corporate leaders have achieved in
implementing the four steps of becoming a global business citizen.
Implications for Social Change
The value of this GBC calculated index is that it provides a practical survey-based
assessment to evaluate the steps that business leaders have achieved toward transforming
their company into a global business citizen. The composite index scale provides a
number that ranks the relative adherence to the GBC steps, rather than a qualitative yes or

no answer. This ranking allows corporate leaders, stakeholders, and academics to
evaluate the progress over time of a company by utilizing the same survey and looking
for improvement in specific areas as captured by the various survey questions related to
the constructs. Business leaders will have this quantitative tool to help communicate to
their stakeholders the steps they have achieved toward becoming a global business
citizen. GBC is an indicator of the level to which companies are maximizing shareholder
value and gaining a competitive advantage at the same time that they are incorporating
laws, public policies, political issues, and the interests of stakeholders. It also indicates
that they are acting ethically and responsibly for the benefit of individual managers,
corporations, industries, and society as a whole.
Recommendations for Action
The concept of global business, or corporate, citizenship has rapidly gained
popularity in the corporate, academic, and political arenas (Crittenden et al., 2011).
Business citizenship has emerged as the preeminent term to describe the ethically
responsible roles of corporations within society (Crittenden et al., 2011). Major
companies, such as Boeing, Dow, IBM, and Microsoft all claim that they are business
citizens (Crittenden et al., 2011). Of the top 100 U.S. companies, 97% claim to be
business citizens (Fifka, 2013). Publically publishing a GBC Composite Index score
would demonstrate the maturity level corporate leaders have achieved toward becoming a
global business citizen. Further research is required to validate whether this study
inadequately captured the analysis step of the GBC four-step implementation process, or

the three factors of VALUE, IMPLEMENT, and LEARN adequately describes and
measures the theory of GBC.
I intend to conduct a follow-up study to determine whether the survey questions
related to the ANALY construct were insufficient, or whether the ANALY step of the
GBC implementation process is not required. I intend to publish the results of this study
in a peer-reviewed journal such as Corporate Social Responsibility and Environment
Management, Global Business Review, Journal of Business Ethics, or Journal of
Management. After the follow-up study, I will distribute the findings of this study and the
subsequent study to professional societies for business executives. I have personal
relationships with, and will distribute information to the following professional societies;
Dallas Business Club, Executives Club of Chicago, Executive Suite, Global Business
Development Center, Leadership Think Tank, Los Angeles Area Chamber of Commerce,
Los Angeles World Affairs Council, and Town Hall Los Angeles. Finally, Donna J.
Wood, the lead researcher responsible for the GBC theory, personally asked me to send
her a copy this study upon completion. She is retired, but I will offer to communicate the
results of this study with her contacts.
Recommendations for Further Research
Recommendations for further research include conducting follow-up research
around the ANALY construct, conducting a CFA study, confirming the proposed ranking
scale, replicating the study in countries outside the United States, and confirming
criterion-related validity. The results of this survey indicated that the sub-research
question is asking whether the survey adequately captured the ANALY construct of the

GBC theory was not met. The first suggestion for further research is to develop different
questions within the ANALY construct. Further research would indicate whether the
survey questions developed for this study were inadequate, or whether the theory of GBC
can be adequately captured and measured with the three constructs of VALUE, IMPLE,
and LEARN.
Researchers use CFA to test the significance of factor loading, to test relationships
between factor loadings, and to test for correlation or lack of correlation of factors
(DeCoster, 1998). The second recommendation for further study is to conduct a CFA
study of the simplified GBC Index survey. The simplified survey does not represent the
ANALY construct. A CFA study would validate the results of this EFA study for the
three constructs of VALUE, IMPLE, and LEARN.
Table 23 presents a suggested ranking scale for the GBC maturity level. The
ranking scale may not accurately reflect the maturity levels of not applicable, immature,
novice, intermediate, and advanced. A final recommendation for further research is to
apply the survey to numerous business leaders to confirm the proposed ranking scale.
The sample frame was a subjective sample due to geography, demographics, and
economic conditions. Consequently, the results of this study may not generalize to
businesses headquartered in countries outside the United States. An area for further
research is to replicate this study in other countries to determine whether the results
generalize to other countries.
No existing instruments measure GBC. Because there were no existing
instruments to correlate with, it was beyond the scope of this study to confirm

criterionrelated validity. Researchers use criterion-related validity to demonstrate that the
scores from the new instrument correlate highly with scores from existing instruments
that are already determined to be valid (Oluwatayo, 2012). Confirming criterion-related
validity is a recommended area for further research.
Reflections
Having worked as an executive at multi-national, multi-billion dollar companies
and as an executive and serving on boards of medium to large nonprofit companies
biased my view of the ethical responsibilities of corporate leaders. I was pleased to find
the theory of Global Business Citizenship. The concept of global business citizenship
allows corporate leaders to maximize shareholder value and gain competitive advantage
at the same time that they are integrating responsible and ethical business policies and
actions, incorporating laws, public policies, political issues, and the interests of
stakeholders. It also indicates that they are acting ethically and responsibly for the benefit
of individual managers, corporations, industries, and society as a whole (Wood et al.,
2006). I started the study firmly believing the EFA results would align with the four-step
process of implementing GBC. I was surprised that participants gave low scores to the
questions related to the third step of analyzing problem areas and experimenting with
solutions to remediate conflicts between the overarching principles/values with local
customs or norms, the ANALY construct. Participants did not rate ANALY questions
with enough significance to generate an ANALY factor or load to any of the three latent
factors. Either the survey questions related to the ANALY construct were inadequate, or
participants did not feel that the ANALY step was necessary. If the latter is the case, the

GBC theory may need revising. Further research is warranted.
Conclusion
Business leaders claim that their companies are business citizens to achieve the
possibly of long-term economic, social, and environmental benefits that may come from
being a global business citizen (Campbell, Eden & Miller, 2012; Menck & Oliveira,
2014; Wood et al., 2006). Business leaders are also making the claim because
stakeholders are demanding that they conduct their business as socially responsible
citizens of society (Park & Ghauri, 2015; Öberseder, Schlegelmilch, & Gruber, 2011;
Shum & Yam, 2011). This study provided the foundation for the first quantitative rating
system that business leaders could self-administer to measure global business citizenship.
After follow-up studies related to the analyzing step of the GBC implementation process,
the GBC Composite Index will be a tool that corporate leaders can use to demonstrate to
their stakeholders the stage of maturity they have attained in becoming a global business
citizen.

