


Estimating Degree of Market Power
With respect to the first objective, this study estimates the degree of market power
based on the three measures: the RI, OI and CQ. In order to calculate these measures,
each firm’s own-and cross-price elasticities and price-response elasticities are needed.
These elasticities are estimated by simultaneous demand-supply equations based on the
Bertrand competition assumption such that price is the strategic choice variable and firms
make their choices simultaneously. Following Cotterill (1994), this study employs the
linear approximate almost ideal demand system (LA/AIDS) proposed by Deaton and
Muellbauer (1980) to estimate the demand for canned tuna in the market and the price-
reaction functions to investigate strategic-price response among firms. The LA/AIDS is a
modification by Deaton and Muellbauer from their almost ideal demand system (AIDS)
to replace the non-linear price index with the Stone price index. Cotterill (1994) and
Vickner and Davies (1999) used the LA/AIDS in estimating the degree of market power.
Use of the Stone index in the LA/AIDS causes estimated parameters to be biased
and inconsistent (Pashardes, 1993 and Moschini, 1995). This dissertation uses the
corrected Stone index suggested by Moschini (1995) in the LA/AIDS estimation. The
results of the measures of market power found in this dissertation are consistent with
those of Cotterill (1994) and Vickner and Davies (1999) in that the leading firms which
are able to maintain high prices and market shares have high degrees of market power. In
addition, this dissertation re-estimates the simultaneous equations with the use of the
traditional Stone index in the LA/AIDS and the parameter estimates are compared to
those of the corrected version. The results from both versions are found to be very close
giving the interpretation of market power in the same fashion. This study found that
5

Starkist, the highest-market share brand, has the highest degree of market power. The
market power of Starkist and Chicken of the Sea is derived from both unilateral and
coordinated market power, whereas that of Bumble Bee is derived from its own unilateral
market power, not from coordinated market power.
Investigating Price-Response Strategies
The investigation is divided into two parts because the second objective in this
dissertation is to investigate the strategic price-response relationships among firms in the
canned tuna industry based on both static and dynamic approaches. In part one, the price
response relationships are investigated through the price-reaction functions from the
estimated simultaneous equations. This investigation is based on the static approach
because Bertrand-competition assumes that the price strategies are made simultaneously
by each firm. Starkist and Chicken of the Sea are found to respond positively to each
other. Bumble Bee seems to conduct price war against its rivals since it responds
negatively to Starkist’s and Chicken of the Sea’s price strategies. On the other hand, both
Starkist and Chicken of the Sea do not respond to Bumble Bee’s price strategy during the
same time period. However, Bumble Bee is one of the leading brands in the market;
therefore, the results in the first part raise the interesting question of whether Bumble
Bee’s price strategy in past periods may affect Starkist’s and Chicken of the Sea’s price
strategies in the current period.
The second part of this dissertation investigates further the price-response
relationships among firms based on a dynamic approach. The Bertrand-competition
assumption is replaced by an assumption that a firm in the market sets its price depending
6

on its own past prices and those of rivals. A vector autoregressive (VAR) model is
employed. The strategic-price responses are investigated using the VAR’s applications
including the Granger-causality test, the impulse response function (IRF) analysis, and
the forecast error variance decomposition (FEVD) analysis. The Granger-causality test
examines whether the dynamic price-response relationships exist. The IRF analysis
graphically reveals the direction of the effect of a one-time shock to one of the
innovations on future values of the endogenous variables, whereas the FEVD analysis
measures proportions of a brand’s price variations that can be explained by shocks to its
own price and it rivals’ prices for each forecast horizon. Although the results from part
one indicate that Starkist and Chicken of the Sea do not respond Bumble Bee’s price
strategy during the same time period, the Granger-causality results show that both
Starkist and Chicken of the Sea respond negatively to Bumble Bee’s past price. The
results from the IRF and FEVD analyses also support the Granger-causality test results
for the three-leading canned-tuna brands’ relationships.
In summary, this dissertation estimates the degree of market power and
investigates strategic-price responses among firms in the canned tuna industry in the
Knoxville, Tennessee market. The strategic-price responses are investigated using both
static and dynamic approaches. Part one estimates the degree of market power and price-
response relationships based on a static approach. Part two investigates the dynamic
price-response relationships. Overall, the results from both parts of this dissertation
provide helpful insights on the degree of market power and strategic-price responses
among firms in the canned tuna market.
7

Contributions of this Dissertation
The first contribution of this dissertation is to improve the model specification in
estimating the degree of market power as developed by Cotterill (1994) and followed by
Vickner and Davies (1999). In their studies, Cotterill (1994), and Vickner and Davies
(1999) measured the degree of market power in the carbonated soft drink industry
(Cotterill) and the spaghetti sauce industry (Vickner and Davies) by estimating the
LA/AIDS model and price reaction functions simultaneously. In this study, the corrected
Stone index suggested by Moschini (1995) is used in the LA/AIDS model.
Second, this study is the first to examine the degree of competitiveness of brands
of a manufactured food product at the local level. Work to date on food manufacture
degree of market power and pricing strategies has been conducted at the aggregate
national level (Appelbaum, 1982; Schroeter, 1988; Baker and Breshnahan, 1985; Liang,
1989; Cotterill, 1994; and Vickner and Davies, 1999). These studies have not captured
local market effects on pricing conduct and local demand. Only the studies of Cotterill
(1994), and Vickner and Davies (1999) have used scanner data in investigating the degree
of market power. Nayga (1992) suggested that due to the enormous information and the
high cost of acquisition involved with scanner data, an individual researcher may not be
able to efficiently collect or organize the volume of information. Individual researchers
might have to form a team and combine their efforts when conducting research in a
national or regional level to become cost effective. Otherwise, “individual researchers
should just focus on a local retail firm with multiple stores” (Nayga, 1992). Nayga
(1992) suggested that scanner data from supermarkets in a particular location present a
controlled situation. Therefore, the community specific results may not contribute to
8

broad regional or national inferences. This dissertation estimates the degree of market
power and strategic price response in canned tuna industry in a specific local market,
Knoxville, Tennessee. Although demographic information is not available, the study
should provide information regarding the degree of competitiveness and price strategies
among firms in a local market.
Third, this dissertation not only refines Cotterill’s, and Vickner and Davies’ work,
but also extends their research to dynamic analysis. Due to the previous work (Cotterill,
1994; and Vickner and Davies, 1999), the Bertrand price reaction model yields
information of strategic price response through the price-response elasticities. These
results show pricing behaviors among firms in a static way. In other words, a firm sets its
price responding to its rivals’ prices in the present time. In fact, firms’ strategies may
respond to one another depending not only on today’s information, but also on past
information. This study employs a vector autoregressive (VAR) model to investigate
dynamic price relationships among firms in the canned tuna market.
Regarding previous industrial-organization research in this area, Vickner and
Davies (2000) estimated strategic-price response between two leading brands in the
canned pineapple industry using the VAR and vector error correction model. The
Granger causality test and the IRF analysis were applied to investigate the price
relationships. With respect to the IRF analysis, confidence intervals are used to evaluate
the statistical reliability of the estimated results. However, confidence intervals were not
included in Vickner and Davies’ IRF analysis. This may affect the interpretation of their
empirical results. This dissertation improves the price-response study by including
confidence intervals in the IRF results to determine whether the estimated price-response
9

relationships are asymptotically and statistically significant. In addition, the FEVD
analysis, one of the useful VAR applications which measures proportions of a brand’s
price variations that can be explained by shocks to its own price and it rivals’ prices for
each forecast horizon, was not employed in the Vickner and Davies study. The FEVD
results can give additional information to the IRF and Granger-causality results in
estimating price-response effects. Therefore, this dissertation includes the FEVD
analysis to rigorously investigate pricing relationships.
Limitations and Extensions
Limitations of this dissertation mainly involve the data. First, demographic and
brands’ cost data are not included. Second, this study was not able to take into account
the effects of the use of brands’ coupons because IRI does not report the extent of their
use. Third, the time period of observations is short. Therefore, strategic-price responses
among firms in the long run may not be captured. Finally, the price-response analysis in
the second part investigates only whether the price relationships exist. The VAR’s
applications do not provide statistical magnitudes concerning the price relationships.
This dissertation can be extended in several ways. In a local market, store brands
such as Kroger and BI-LO may have some effects on the national brands’ demand and
price strategies. One extension is to include store brands as key variables in the
estimation of the degree of market power and price-response strategies among the canned
tuna brands in a local market. Another extension is to find a way to include both static
and dynamic information in the estimation of the degree of market power. Measures of
the degree of market power need information of demand and price-response elasticities
10

based on a static approach. Since this dissertation has shown that firms’ price strategies
are both static and dynamic, future studies might find a method to measure the degree of
market power that is able to take into account both static and dynamic information in
their investigations.
11

PART 1: ESTIMATING THE DEGREE OF MARKET POWER AND
PRICE-RESPONSE STRATEGIES IN THE CANNED
TUNA INDUSTRY: A STATIC APPROACH
12

Chapter One
Introduction
A firm is said to have market power if the firm is able to raise price profitably
above its marginal cost without losing its market share. One reason this can occur is
because the products are differentiated. Consumers perceive that brands in a market are
imperfect substitutes. As a result, a firm may raise its price above that of its rivals
without losing its market share. In this case, the competitive tactics of firms in the
market may use advertising to emphasize product features. However, in a product-
differentiated oligopoly, although products differ, they can be substituted. Firms are
interdependent in the way that if a firm’s price is too high compared to that of its rivals,
consumers may switch to competitors. Therefore, price is also a strategic variable in the
product-differentiated oligopoly market.
Objectives
The main objectives of this first part are to estimate the degree of market power
and to investigate strategic-price responses among firms in the canned tuna market at the
local level. The $2.1 billion canned tuna market is selected as a representative product-
differentiated oligopoly (Casamar Group, Inc., 2001). This dissertation focuses the
estimation on the local level with Knoxville, Tennessee as a representative local market.
The data are scanner data which have been actively used in food marketing and economic
research since the 1980s (Nayga, 1992). The scanner-data set in this study were collected
13

weekly by Information Resources, Incorporated (IRI) for 157 weeks over the period of
January 4, 1998 to December 31, 2000 from 134 supermarkets in Knoxville, Tennessee.
In an oligopolistic market, when a firm’s product is differentiated from the others,
a demand curve facing the firm is downward-sloping. Carlton and Perloff (2000) stated
“that if a firm faces a downward-sloping demand curve, it has market power.” The firm’s
downward-sloping demand curve becomes less elastic if the firm has high market power;
however due to the presence of substitution it is more elastic than that of a monopolist,
which is a market-wide demand curve. If the firm increases price and can influence all of
its rivals to follow its strategy, the demand curve facing the firm becomes a close
reflection of the market-wide demand curve, and the firm is said to have extremely high
market power with full collusion.
Rothschild (1942) introduced a theoretical measure of the degree of market power
called the Rothschild Index (RI). Later, Cotterill (1994) modified the RI to be more
applicable with the use of elasticities. The main idea of the RI is that it compares a
firm’s own-price elasticity of demand when none of its rivals are collusive, which is
called the non-followship demand elasticity, with the fully collusive demand elasticity.
The closer to one the RI is, the greater the degree of market power. However, the RI
measures only unilateral market power, ignoring the effects of partial collusion among
firms. Basically, firms in a product-differentiated oligopoly are interdependent.
Therefore, partial collusion exists. Cotterill introduced two more measures of market
power called the O Index (OI) and the Chamberlin Quotient (CQ) in order to take into
account market power from partial collusion of which Cotterill called coordinated market
power.
14

In order to calculate the RI, OI, and CQ, own-price and cross-price elasticities of
demand and price-response elasticities of each firm are needed. Following Cotterill
(1994), this dissertation employs the demand-supply simultaneous equations to estimate
such elasticities assuming that the canned tuna market is operated under Bertrand
competition such that price is strategic variable and firms make their decisions
simultatneousely. On the demand side, the Linear Approximate Almost Ideal Demand
System (LA/AIDS) developed by Deaton and Muellbauer (1980) is used. Price-reaction
equations represent the supply-side of the system. In their research, Cotterill (1994) and
Vickner and Davies (1999) used the Stone index in the LA/AIDS in estimating the degree
of market power. However, some studies found that the use of the Stone index in the
LA/AIDS causes estimated parameters to be biased and inconsistent (Pashardes, 1993
and Moschini, 1995). This dissertation uses a corrected Stone index suggested by
Moschini (1995) in the LA/AIDS estimation to estimate the degree of market power
among brands in the canned tuna market. In addition, the estimated price-reaction
functions are used to investigate strategic-price responses among brands in the market.
Four canned tuna brands are estimated: Starkist, Chicken of the Sea, Bumble Bee,
and Allother. The study finds consistency between firms’ market shares and their market
power in a positive way. Starkist, the brand with the highest market share, has the highest
degree of market power. Its market power is derived from both unilateral and
coordinated market power. Interestingly, Bumble Bee is able to maintain its market
power without collusion from its rivals. With respect to the price relationships, Starkist
and Chicken of the Sea respond positively to each other strategy, but they do not respond
15

to the Bumble Bee strategy. In addition, the study finds an evidence of price war on
Bumble Bee against Starkist and Chicken of the the Sea.
The remainder of this first part is organized as follows. The theoretical
framework and literature review are presented in Chapter Two. Chapter Three discusses
the scanner data followed by a presentation of the econometric method used in this
research. Chapter Four reports the estimated results and Chapter Five presents a
conclusion.
16

Chapter Two
Theoretical framework and Literature Review
The degree of market power in this study was measured in three ways: the
Rothschild and O indices, and the Chamberlin Quotient. In order to calculate these
measures, we have to estimate partial own- and cross-price elasticities, and price-
response elasticities for each brand. In this study, the partial own- and cross-price
elasticities were estimated using the Linear Approximate Almost Ideal Demand System
(LA/AIDS), whereas the price-response elasticities were estimated using price reactions
functions. This chapter reviews the relevant theoretical and empirical literature
associated with LA/AIDS and price-reaction functions. It provides a structure for
extensions of the models and associated empirical work described in subsequent chapters.
The Market Power Analysis
One of the main objectives of this dissertation is to estimate the degree of market
power in the canned tuna industry. Greer (1992) states that “market power is the ability
to influence market price and/or subdue rivals”. Greer indicates that it is market structure
that determines ability. Variations in the features of market structure cause variations in
demand and supply. Perfect competition and monopoly are the two polar cases of market
structure. In a perfectly competitive market, the demand curve facing a firm is horizontal
because each firm has no control over price. On the other hand, a monopolist’s demand
17

curve represents the market-wide demand curve because the monopolist has no
competition.
Between these two polar cases, an oligopoly market is an intermediate situation of
“rivalry” among a small number of firms. An oligopolistic firm potentially faces two
kinds of downward-sloping demand curves; a followship demand curve and a non-
followship demand curve, “neither of which is the market-wide demand curve. The firm
might face either one or both or portions of both of these demand curves, depending on
what assumptions it makes concerning its rivals’ behavior.” (Greer, 1992)
1. The followship demand curve (FD).
The FD curve facing a firm occurs if firms try to maintain their market shares. For
example, a price increase by one firm is matched by its competitors such that their market
shares are unchanged. Hence, the followship demand curve could be called a “constant
share” demand curve. Greer mentions that the followship demand curve is “a close
reflection of the market-wide demand curve” (Greer, 1992). If the firm has an ability to
influence the market price and then its rivals follow, this indicates the firm has some
market power. In economic applications with an oligopoly market, the followship
demand curve facing a firm can be viewed as the firm’s demand curve with perfectly tacit
collusion.
2. The non-followship demand curve (NFD).
The NFD curve facing a firm occurs if the firm has no power to influence the market
price. Therefore, an increase in its price is not matched by its rivals and that firms’
market share changes. The NFD curve could be called a “changing market share curve.”
The elasticity of the NFD curve is much higher than the elasticity of the FD curve in
18
absolute value because a firm will get a substantial increase in quantity sold in the market
if it cuts its price, and a considerable decrease in customers if it raises its price since its
rivals do not match the price change. The NFD curve varies in elasticity across firms
within a given market. In economic applications with an oligopoly market, the non-
followship demand curve reflects a non-collusive situation.
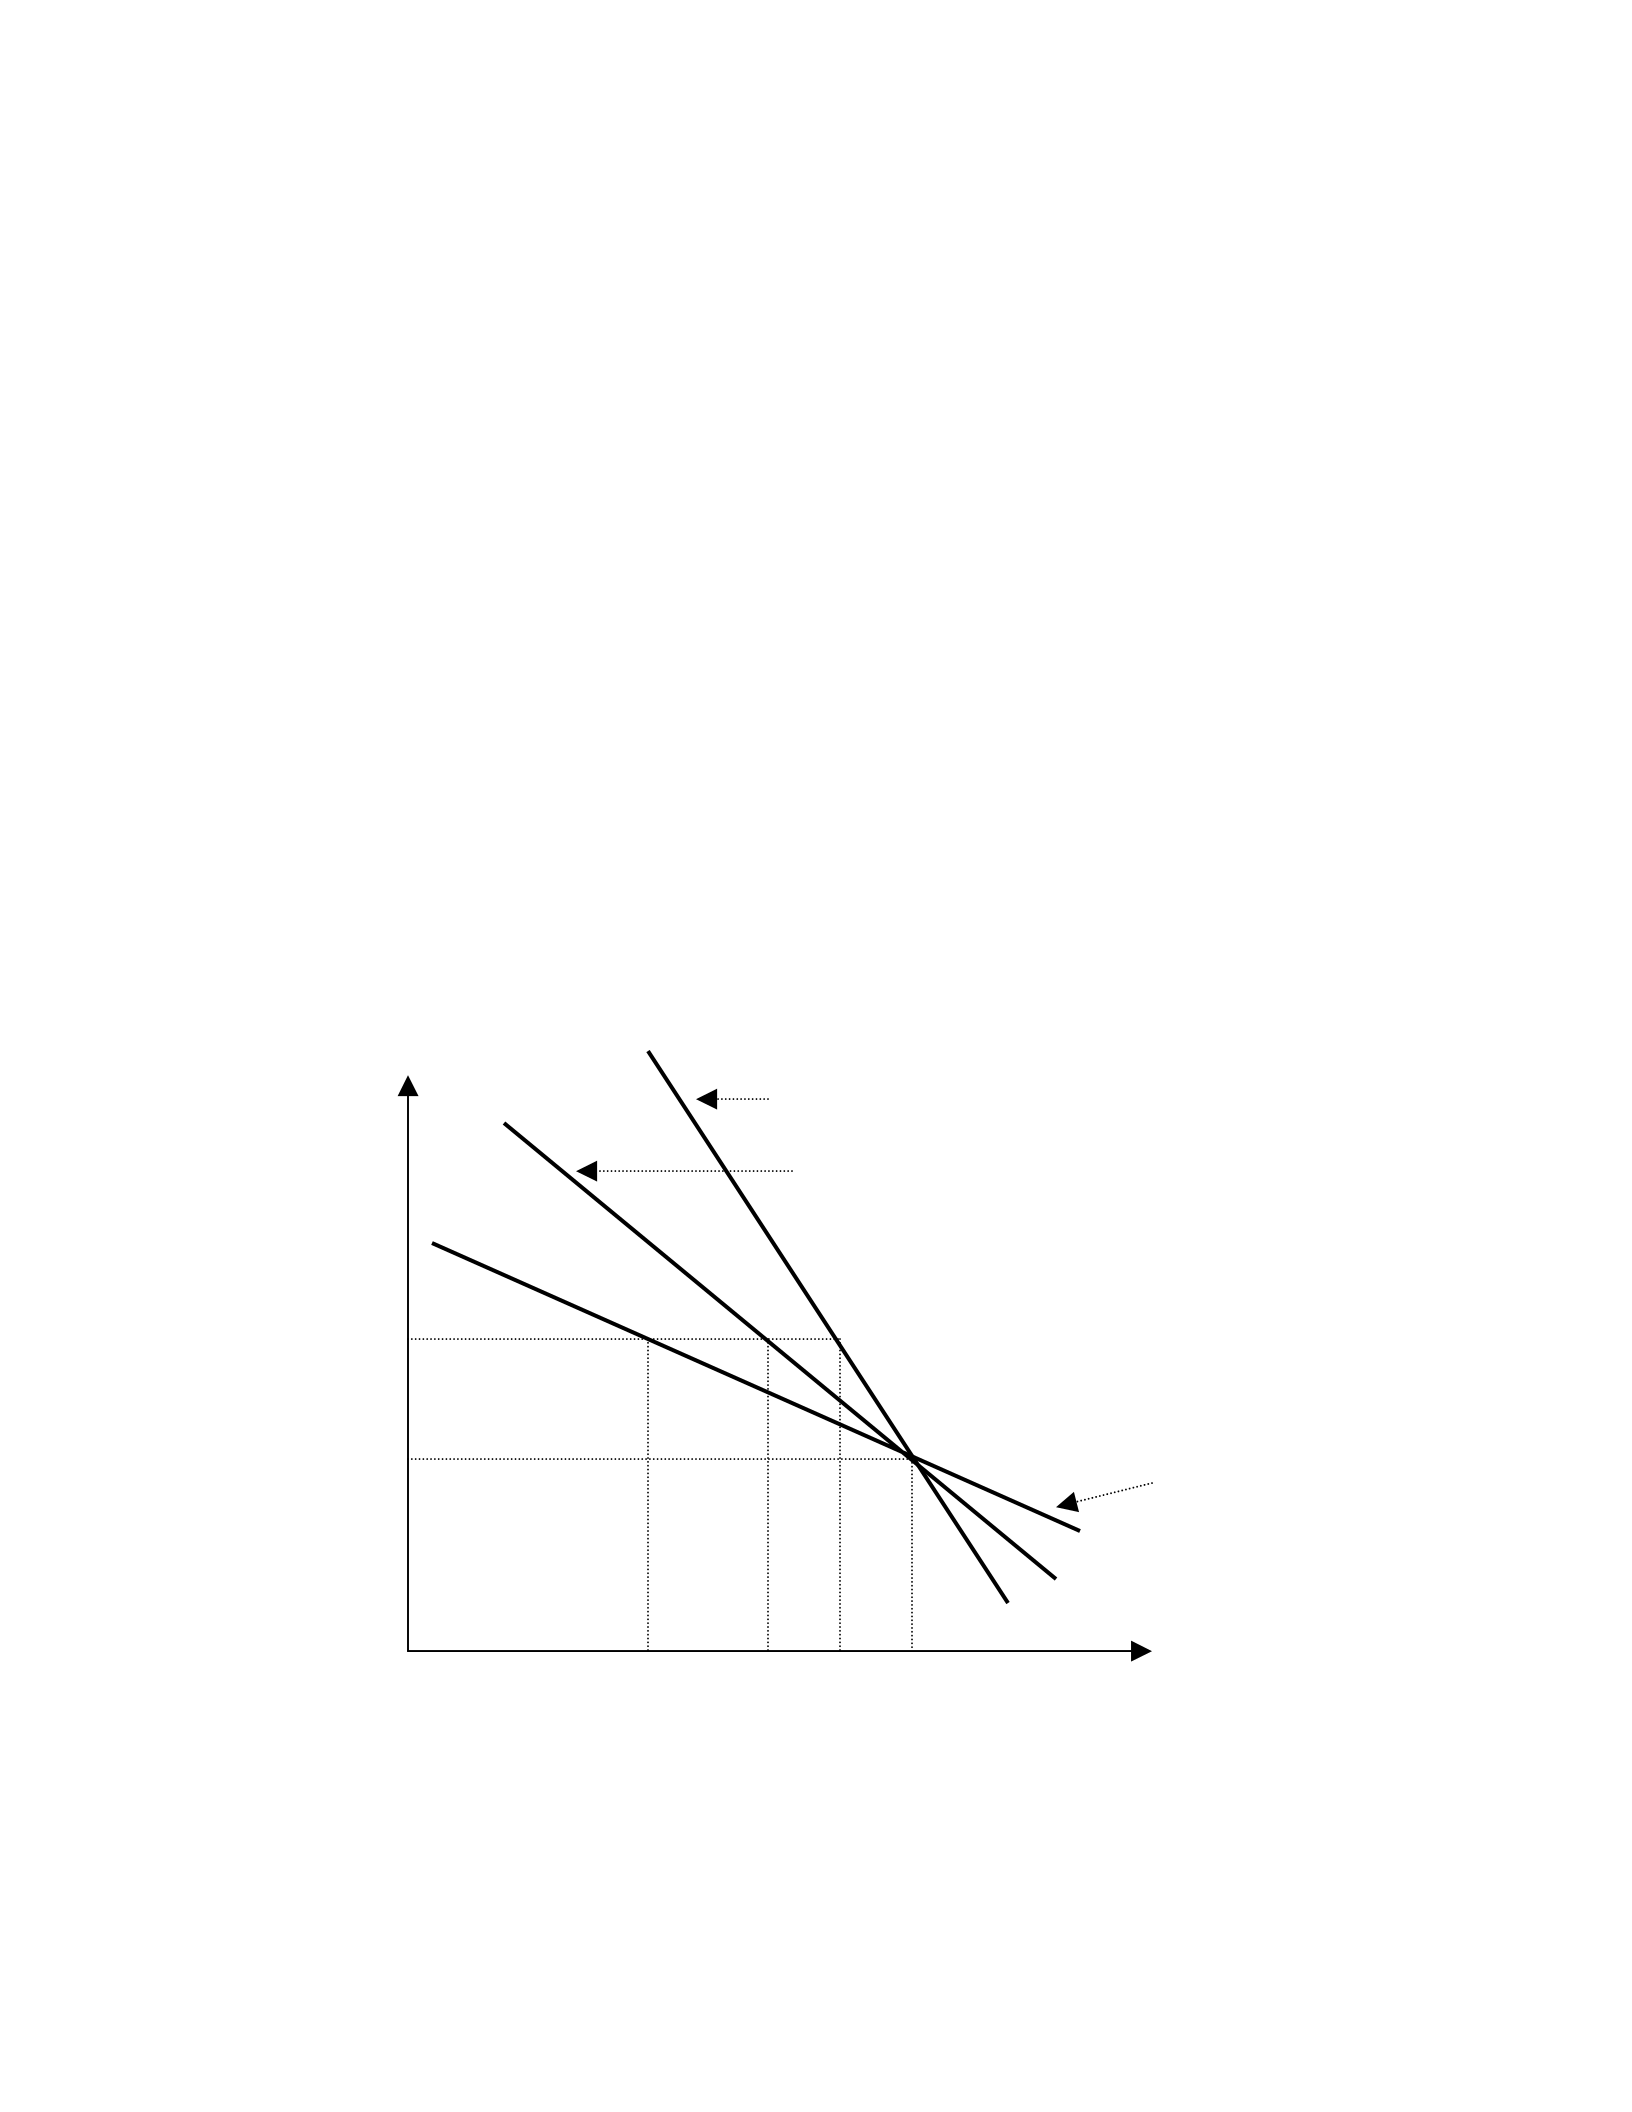
Figure 2.1 shows these demand relationships for a representative brand, namely
brand 1. Assume that demand curves are linear and the market is in equilibrium at P0 Q0.
In addition, assume that the brand 1 firm decides to raise price to P1. An increase in price
yields a decline in quantity sold to Q1.
Price Followship Demand
Observed Demand
P1
P0
Non-followship Demand
0 QNF Q1 QF Q0 Quantity
Figure 2.1 Followship, Non-Followship, and Observed Demand Curves
19

If there is perfectly tacit collusion among firms, the output will decline only to QF
because the firm has market power to influence the market price and its rivals follow, and
if there is no tacit collusion, the quantity demanded will decline to QNF implying that the
firm does not have enough market power to affect the market price and no one follows.
Rothschild (1942) introduced a theoretical measure of the degree of market power
called the Rothschild Index (RI). It is the slope of the non-followship demand curve
divided by the slope of the followship demand curve.
RI = slope of NFD curve/slope of FD curve
and 0 ≤ RI ≤ 1.
Under perfect competition the slope of NFD curve would be zero implying that a
competitive firm has no control over price and no effect on its rivals. If the NFD curve
is identical to the FD curve, the RI will be equal to 1 implying that the demand curve is
the market-wide demand curve of a monopolist. From these two extreme cases using the
measure of RI, we would be able to measure a degree of market power from an observed
demand with the RI ranging from zero to one.
Cotterill (1994) has modified the Rothschild Index (RI) to be more applicable by
converting the slope of the NFD curve and FD curve into elasticities. This approach
leads to the use of econometric methods to measure the degree of market power in
empirical research. With respect to Figure 2.1, let
∆
P be the change in price ( P1 – P0),
∆
QNFD equals the change in quantity sold (Q0 – QNF) on the NFD curve, and
∆
QFD is the
change in quantity sold (Q0 – QF) on the FD curve.
20
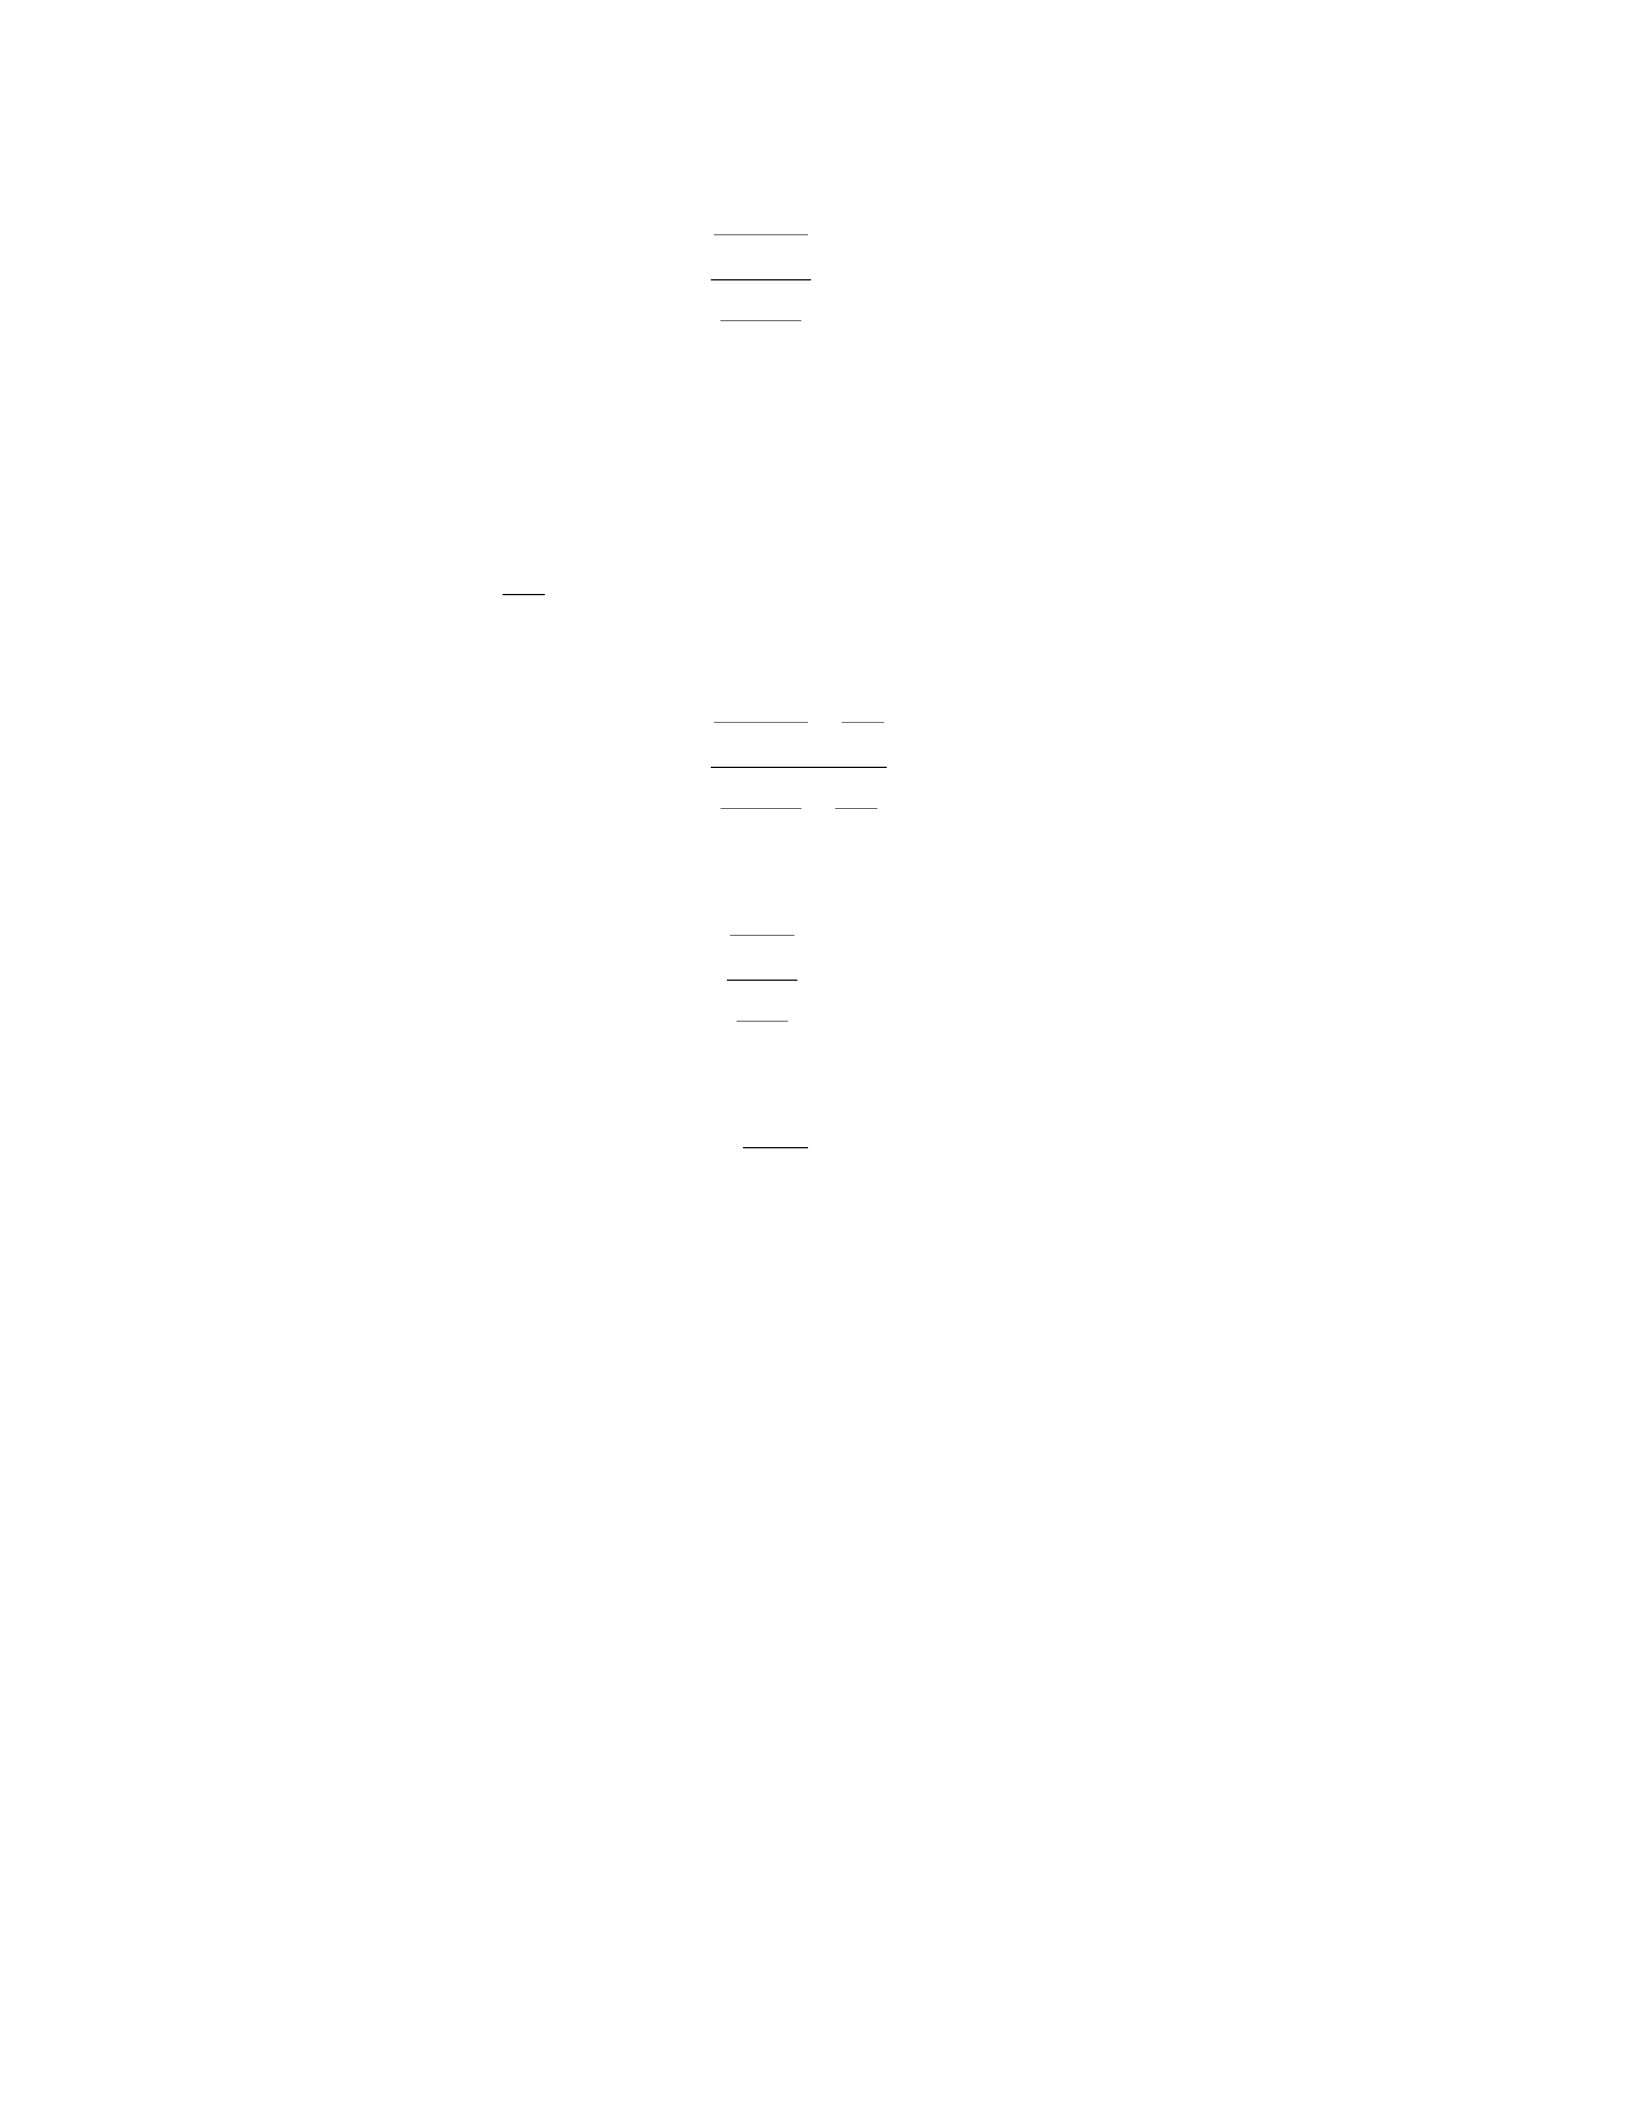
RI =
FD
NFD
Q
P
Q
P
∆
∆
∆
∆
Assume that the going price and quantity are P0 and Q0 and that the elasticities of NFD
curve and FD curve are calculated at this point. Multiplying the numerator and
denominator by
0
0
P
Q.
RI =
0
0
0
0
P
Q
Q
P
P
Q
Q
P
FD
NFD
×
∆
∆
×
∆
∆
=
FD
NFD
η
η
1
1
=
NFD
FD
η
η
,
where NFD
η
represents the non-followship demand elasticity and FD
η
represents the
followship demand elasticity. This measure of RI using elasticities retains the same
interpretation of market power as the RI did in terms of slopes. If the market is perfectly
competitive, NFD
η
will be infinitely negative, and the RI will be equal to zero. If NFD
η
is
equal to FD
η
, the RI will be equal to one, meaning that the market has monopoly power.
Baker and Breshnahan (1985) were the first to estimate the degree of market
power in a differentiated oligopoly by combining demand analysis with industrial
organization concepts. Cotterill (1994) has extended the approach by developing a brand
21
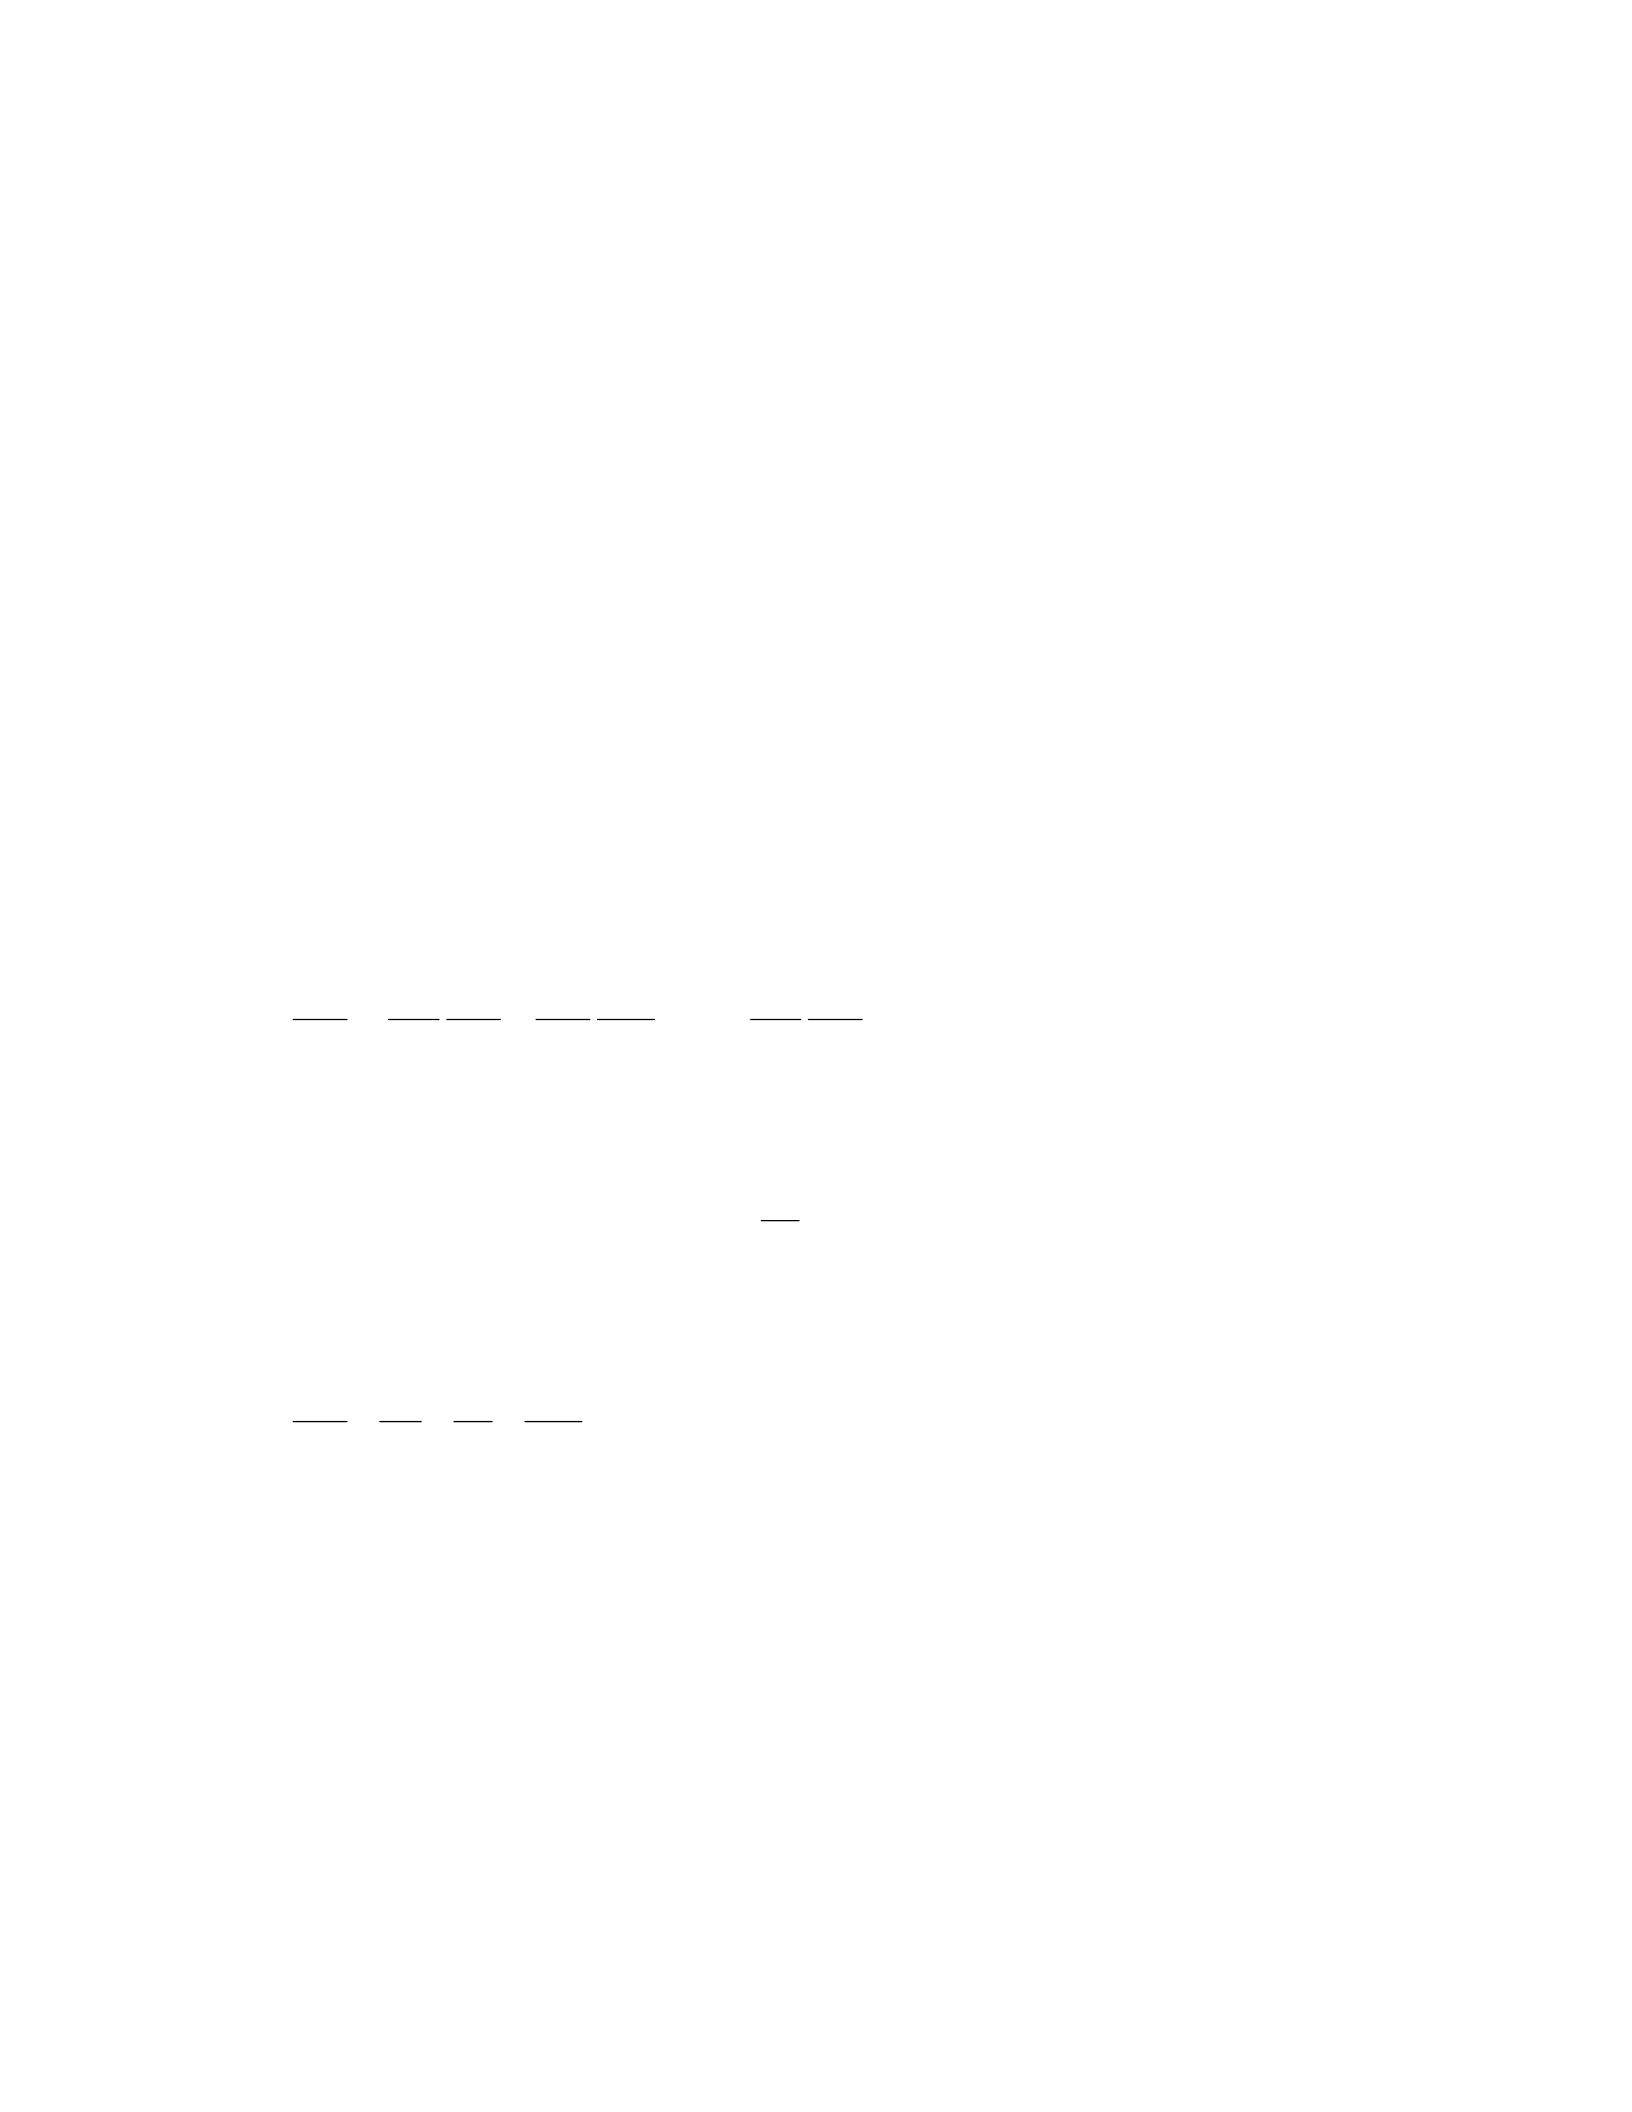
level analysis of demand and market power based upon a more general theory. He
assumed that an industry is differentiated and that Bertrand competition occurs such that
price is the strategic variable. Then the demand for brand 1 in the n-brand industry is a
function of its price and its rival’s prices, that is:
q1 = q1( p1, p2 . . . pn, D) (2.1)
where:
q1 = the quantity of brand 1,
pi = the price of brand i, i = 1,…, n, and
D = a vector of demand shift variables.
If we take the total derivative of this equation, with respect to p1, we will obtain
1
1
1
2
2
1
1
1
1
1
1
1... dp
dD
D
q
dp
dp
p
q
dp
dp
p
q
dp
dq
∂
∂
++
∂
∂
+
∂
∂
=. (2.2)
Assuming that demand shift variables are constant, the last term in equation (2.2) is equal
to zero. Multiply equation (2.2) by
1
1
q
pand use the chain rule to account for oligopolistic
price interdependence (for example, the second term of the right hand side would be
1
2
1
1
2
2
2
1
dp
dp
q
p
p
p
p
q×××
∂
∂). Some algebraic manipulation results in the following formula
for the observable price elasticity of demand:
1
2
111
0
1i
n
i
i
εηηη
∑
=
+= , (2.3)
where:
= observable price elasticity for brand 1,
0
1
η
22

11
η
= partial-own price elasticity of demand,
i1
η
= firm 1’s cross-price elasticity with respect to pi (i≠1), and
= rivals’ price response elasticity or the conjectural price response of firm i with
respect to firm 1’s price (i≠1).
1i
ε
Equation (2.3) is interpreted as follows. Brand 1’s observable price elasticity is
composed of two elements, its partial own-price elasticity and its coordinated market
power component. The partial own-price elasticity of demand for brand 1 ( 11
η
)
represents the percentage change in quantity of brand 1 demanded in response to a
percentage change in its own price when its competitors’ prices are held constant.
Therefore, the partial own price elasticity of demand can be interpreted as the non-
followship demand elasticity, which measures the unilateral market power of the brand
(Cotterill, 1994). The coordinated market power component is the summation of
products between brand 1’s cross price elasticities and its rivals’ price-response
elasticities. If there is tacit collusion among firms in a way that other brands follow a
change in brand 1’s price, will be positive. Assuming that all brands are substitutes,
though not perfect, the cross price elasticities,
1i
ε
i1
η
, are also positive. If the price-response
elasticities and the cross-price elasticities are not zero, yielding coordinated market
power, the observable price elasticity in equation (2.3) will be less elastic than the partial
own price elasticity. The followship demand elasticity ( ) can be obtained by adding
up the partial own-price elasticity and all cross-price elasticities assuming that all the
are equal to one (full collusion), . According to the fully collusive
F
1
η
1i
ε
n
i
i
F
2
1111
=
∑
=
ηηη
+
23
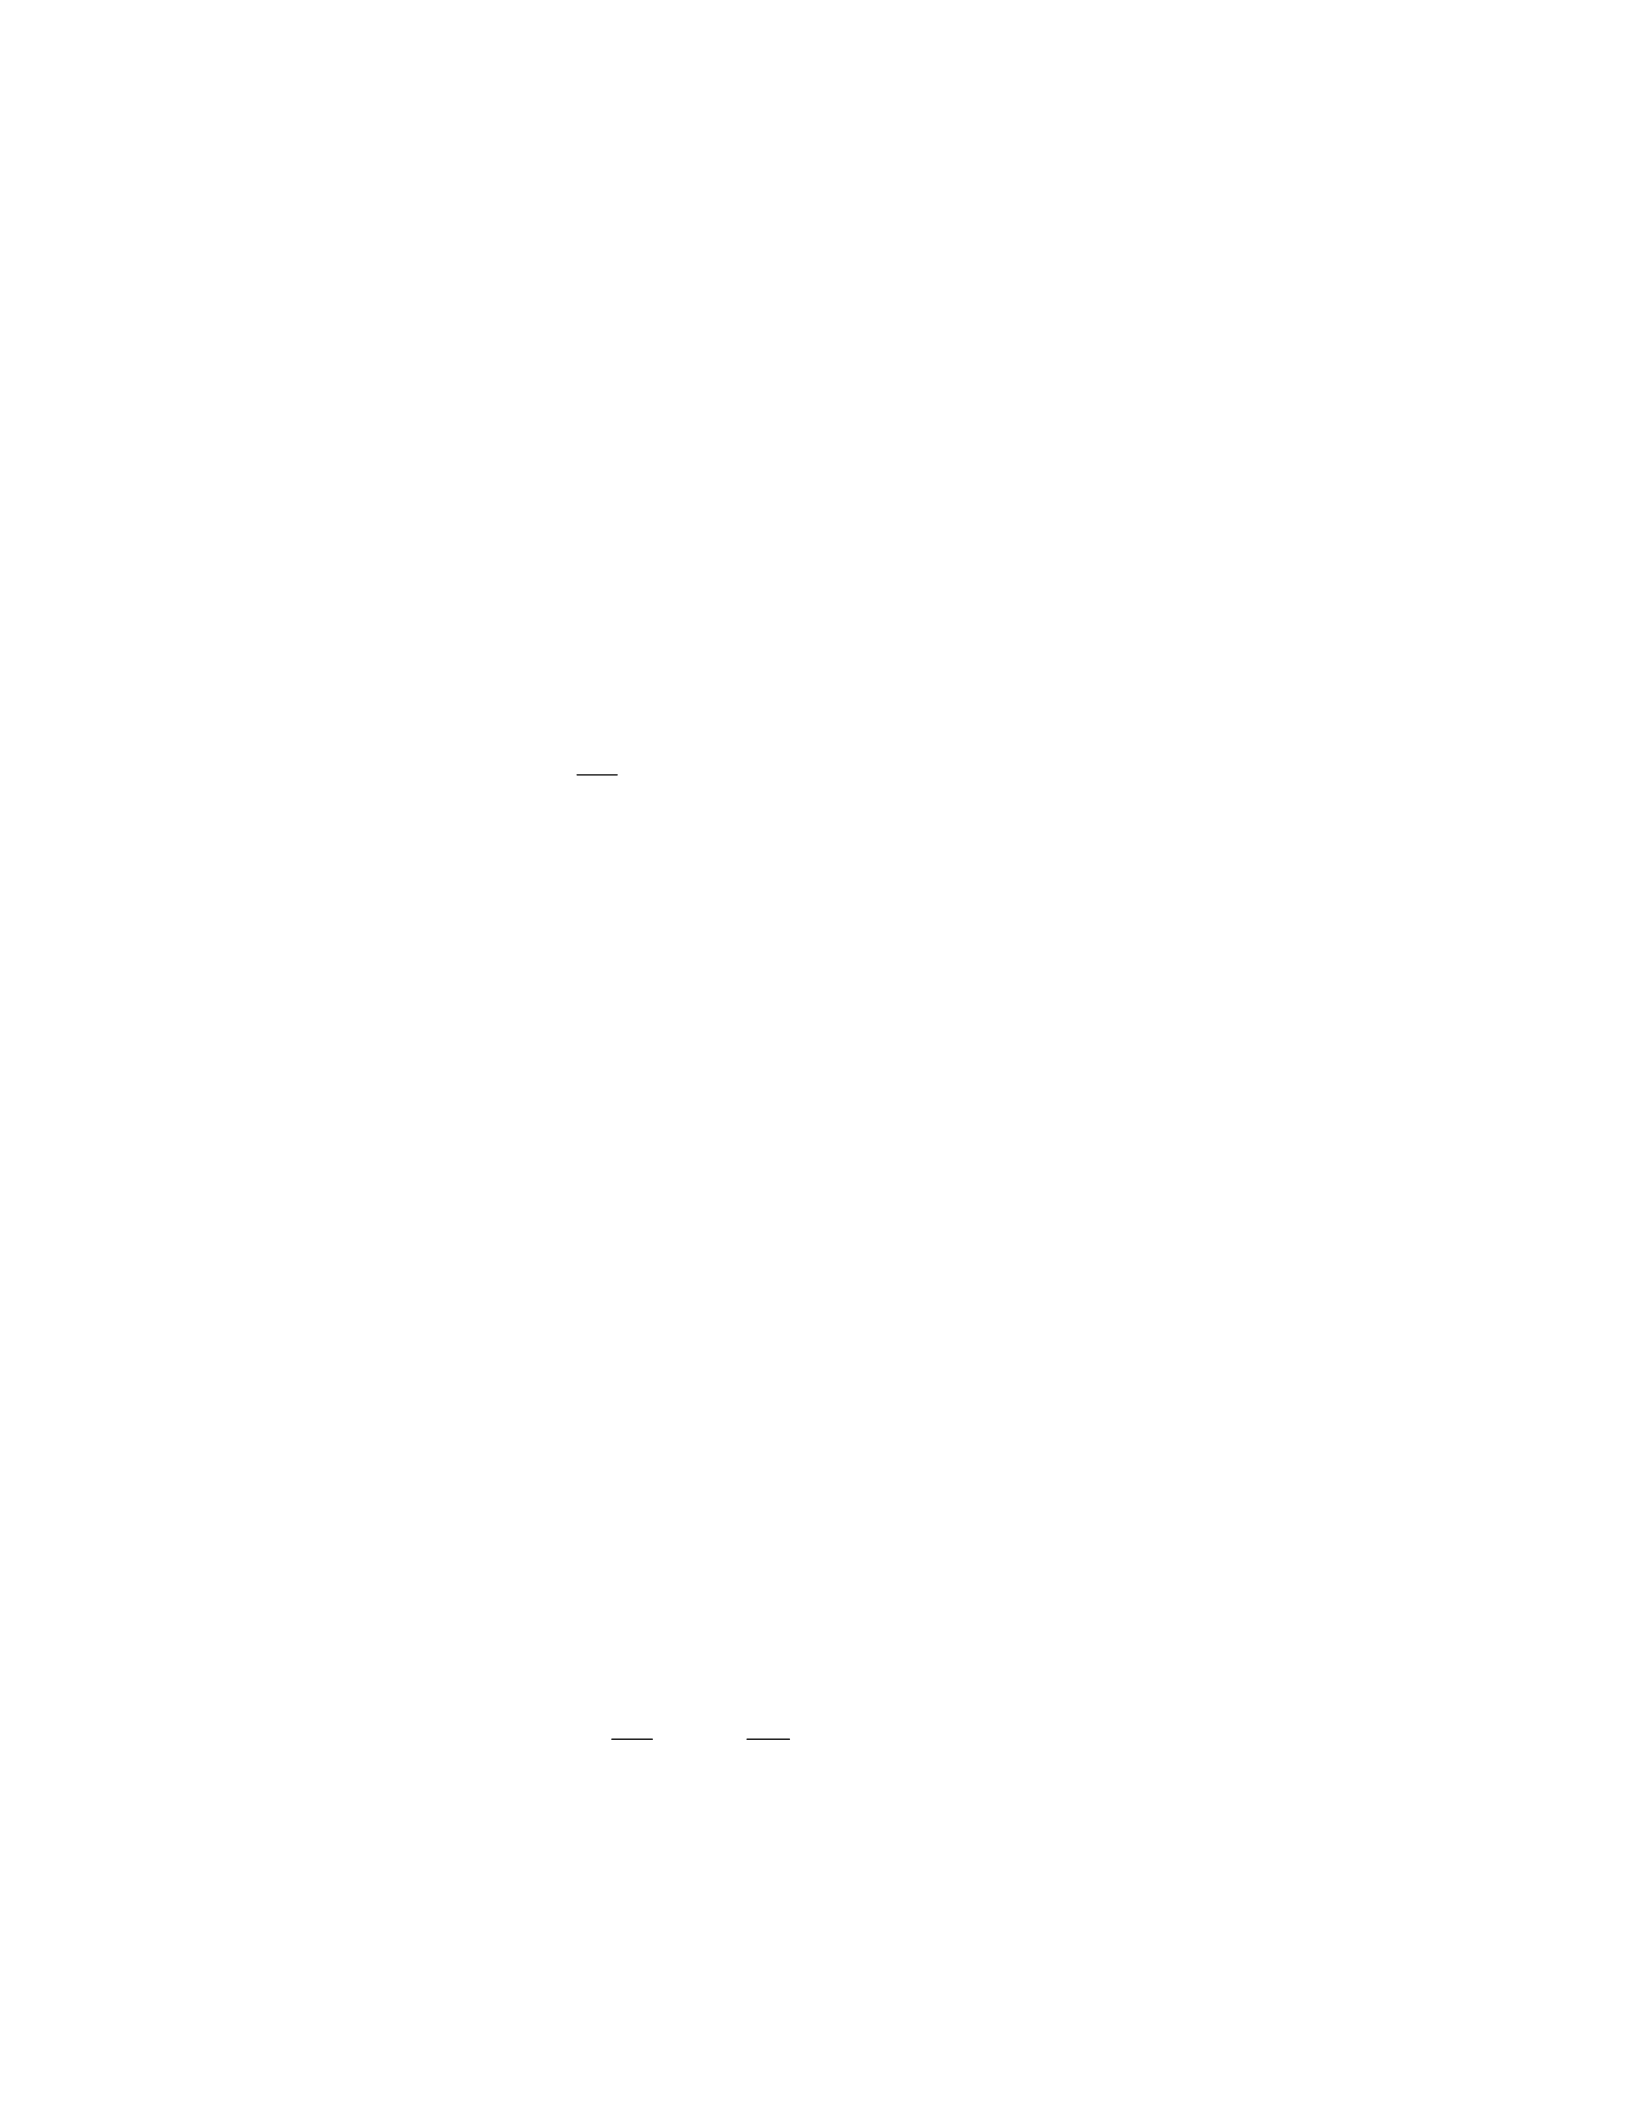
assumption, the followship demand elasticity is also called the fully collusive elasticity,
which is used for the rest of this dissertation. The RI measures a degree of unilateral
market power because it compares the fully collusive elasticity ( ) and the non-
followship elasticity(
F
1
η
11
η
).
0
1
F
1
η
η
11
η
Cotterill (1994) introduced a second measure of observed market power called the
O Index (OI). The OI can be obtained by dividing the slope of the observed demand by
the slope of the followship demand. Developed the same way as the RI Index, the OI is
OI = , and 0 ≤ RI ≤ OI ≤ 1.
In perfect competition, the OI is zero because the partial own price elasticity or the non-
followship elasticity ( ) is infinitely negative (and so is the observable price elasticity),
and there is no coordinated market power. If the market is perfectly collusive, the
observed demand elasticity will be equal to the fully collusive elasticity resulting in the
OI equal to one. Unlike the RI, the OI measures a degree of bilateral market power
because the observed demand elasticity ( ) in the OI accounts for both unilateral and
coordinated market power. Moreover, since the observable price elasticity is less elastic
than the partial own price elasticity, the OI of the observed demand is always greater than
or equal to the RI. The closer to one the OI is, the greater the degree of market power.
0
1
η
In addition, Cotterill (1994) presented a new measure of market power called the
Chamberlin Quotient (CQ).
CQ = 1 – OI
RI = 1 –
11
0
1
η
η
24

and 0 ≤ CQ ≤ 1.
The CQ measures the fraction of market power of the observed demand due to tacit
collusion. The higher are levels of tacit collusion in a market, the lower is the observed
demand elasticity ( ) than the partial own-price elasticity (
0
1
η
11
η
), and, therefore, the
higher the CQ.
The Demand System
In order to measure the degree of market power in any industry using the RI, OI,
and CQ, the partial own- and cross-price elasticities, and price-response elasticities of
each brand in the industry must be estimated. In this study, the partial own- and cross-
price elasticities were estimated using the Linear Approximate Almost Ideal Demand
System (LA/AIDS) developed by Deaton and Muellbauer (1980), and the price-response
elasticities were estimated using the Bertrand price reactions functions.
Deaton and Muellbauer (1980) first developed the Almost Ideal Demand System
(AIDS). They listed the advantages of their system as follows: it gives an arbitrary first-
order approximation to any demand system; it satisfies the axioms of choice exactly; it
aggregates perfectly over consumers; it has a functional form which is consistent with
previous household budget data; it is simple to estimate in its linear approximate form;
and it can be used to test the restrictions of homogeneity and symmetry. Deaton and
Muellbauer (1980) noted that “although many of these desirable properties are possessed
by one or other of the Rotterdam or translog models, neither possesses all of them
simultaneously”. Blanciforti and Green (1983) noted an additional desirable property
25

that “the AIDS is indirectly nonadditive, allowing consumption of one good to affect the
marginal utility of another good; whereas the linear expenditure system (LES) is directly
additive, implying independent marginal utilities”. Therefore, the AIDS does not require
the strict substitution limitations implied by the additive demand models such as LES
(Blanciforti and Green, 1983). While the AIDS has several desirable properties, it may
be difficult to estimate. This is because the AIDS is non-linear. To simplify this
problem, Deaton and Muellbauer suggested using a linear approximation. Several studies
have shown that the AIDS and LA/AIDS models are equivalent or superior to other
common demand specifications, e.g., translog (Lewbel, 1989); Rotterdam (Gao, Wailes,
and Cramer, 1994); and LES (Green, Hassan, and Johnson, 1995). Because of their
advantages, the AIDS and LA/AIDS models have been employed in both macro- and
micro-demand analysis. A list of studies that have used either the AIDS or the LA/AIDS
or both to investigate consumer behavior in various food markets is presented in Table
2.1.
Deaton and Muellbauer start their approach by setting a specific class of
preferences, which represents exact aggregation over consumers (Muellbauer, 1975),
known as the price-independent, generalized-logarithmic (PIGLOG) consumer
preferences. The PIGLOG is represented through the consumer cost or expenditure
function, which is defined as the minimum expenditure necessary to attain a specific
utility level at given prices. The PIGLOG class is defined as:
log c(u, p) = (1 – u)log[a(p)] + u log[b(p)], (2.4)
where u denotes utility ranging from 0 to 1, p is a price vector, and a(p) and b(p) are
linearly homogeneous functions of prices to be specified. The expenditure function in
26
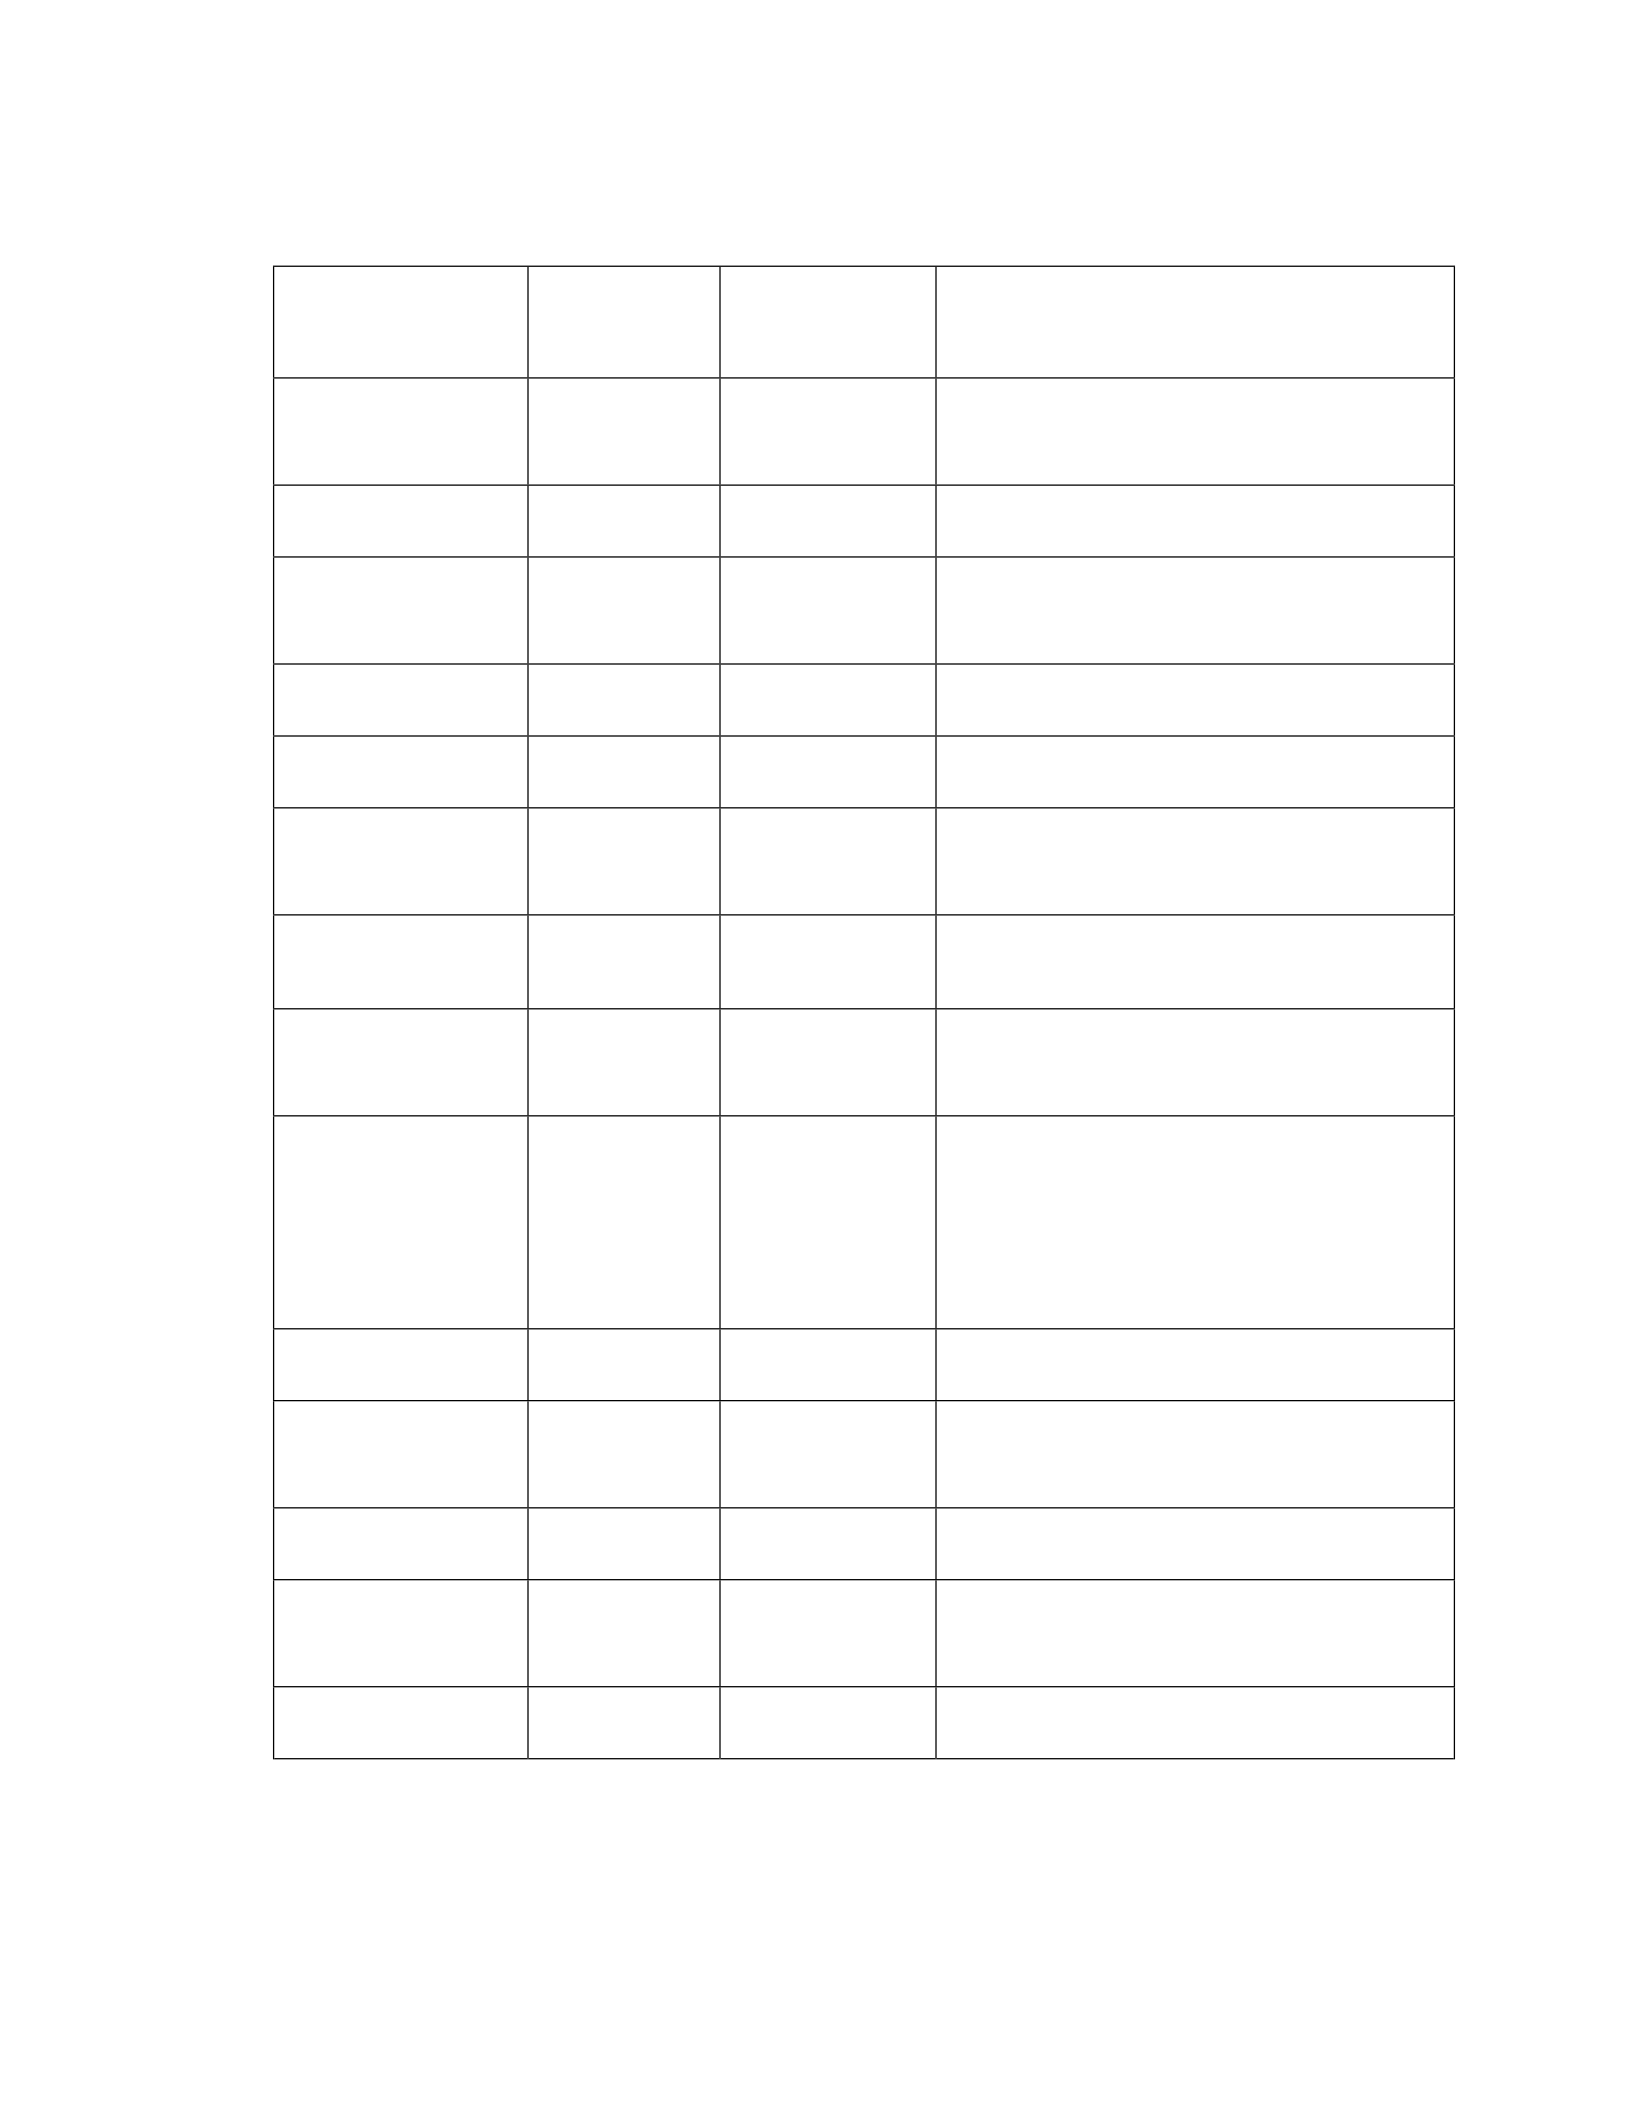
Table 2.1 Listing of Research on Food Product using the AIDS or LA/AIDS
Auther
(Published year)
Research
Time period
System Objective
Deaton and
Muellbauer
(1980)
1954 – 1974 AIDS and
LA/AIDS
Estimation of demand for eight
commodities in UK, and comparison
between AIDS and LA/AIDS
Blanciforti and
Green (1982)
1948 – 1978 AIDS and
LA/AIDS
Incorporation of habit effects in the
system to estimate demand system
Blanciforti and
Green (1983)
1948 – 1978 LES1 and
LA/AIDS
Estimation of demand for food groups
and comparison between LES and
LA/AIDS
Chalfant (1987) 1947 – 1978 LA/AIDS Investigation of the demand for meat
and fish products
Lewbel (1989) 1955 – 1984 Translog and
LA/AIDS
Testing and comparison between the
Translog and AIDS models
Green, Carman,
and McManus
(1991)
1957 – 1986 AIDS Estimation of advertising effects in
demand for dried fruits
Cotterill (1994) 1988 – 1990 LA/AIDS Estimation of market power in
carbonated soft drink industry
Gao, Wailes, and
Cramer (1994)
1987 – 1988 Rotterdam,
CBS2, and
LA/AIDS
Estimation of demand for rice and its
substitutes using several models
Song, Liu, and
Romilly (1997)
1960 – 1988 WLS3,
cointegration,
error
correction,
AIDS, and
TVP4
Analysis on demand for food in the
U.S. and the Netherlands, and
comparison of various econometric
methods
Richards, Kagan,
and Gao (1997)
1970 – 1991 LA/AIDS Investigation of the demand for
complex-carbohydrate products
Henneberry,
Piewthongngam,
and Qiang (1999)
1970 – 1992 LA/AIDS Estimation of demand functions for
fresh fruits and vegeTables
Vickner and
Davies (1999)
1994-1996 LA/AIDS Estimation of market power in
spaghetti sauce industry
Cotterill, Putsis,
and Dhar (2000)
1991 – 1992 LA/AIDS Analysis the competitive interaction
between private labels and national
brands on six individual categories
Teisl, Roe, and
Hicks (2000)
1988 – 1995 AIDS Investigation of the dolphin-safe-label
effect on the tuna demand
1LES-Linear Expenditure System, 2 CBS- the Central Bureau of Statistics model, 3 WLS-
Weighted Least Squares, and 4 TVP-Time-Varying Parameter Technique
27
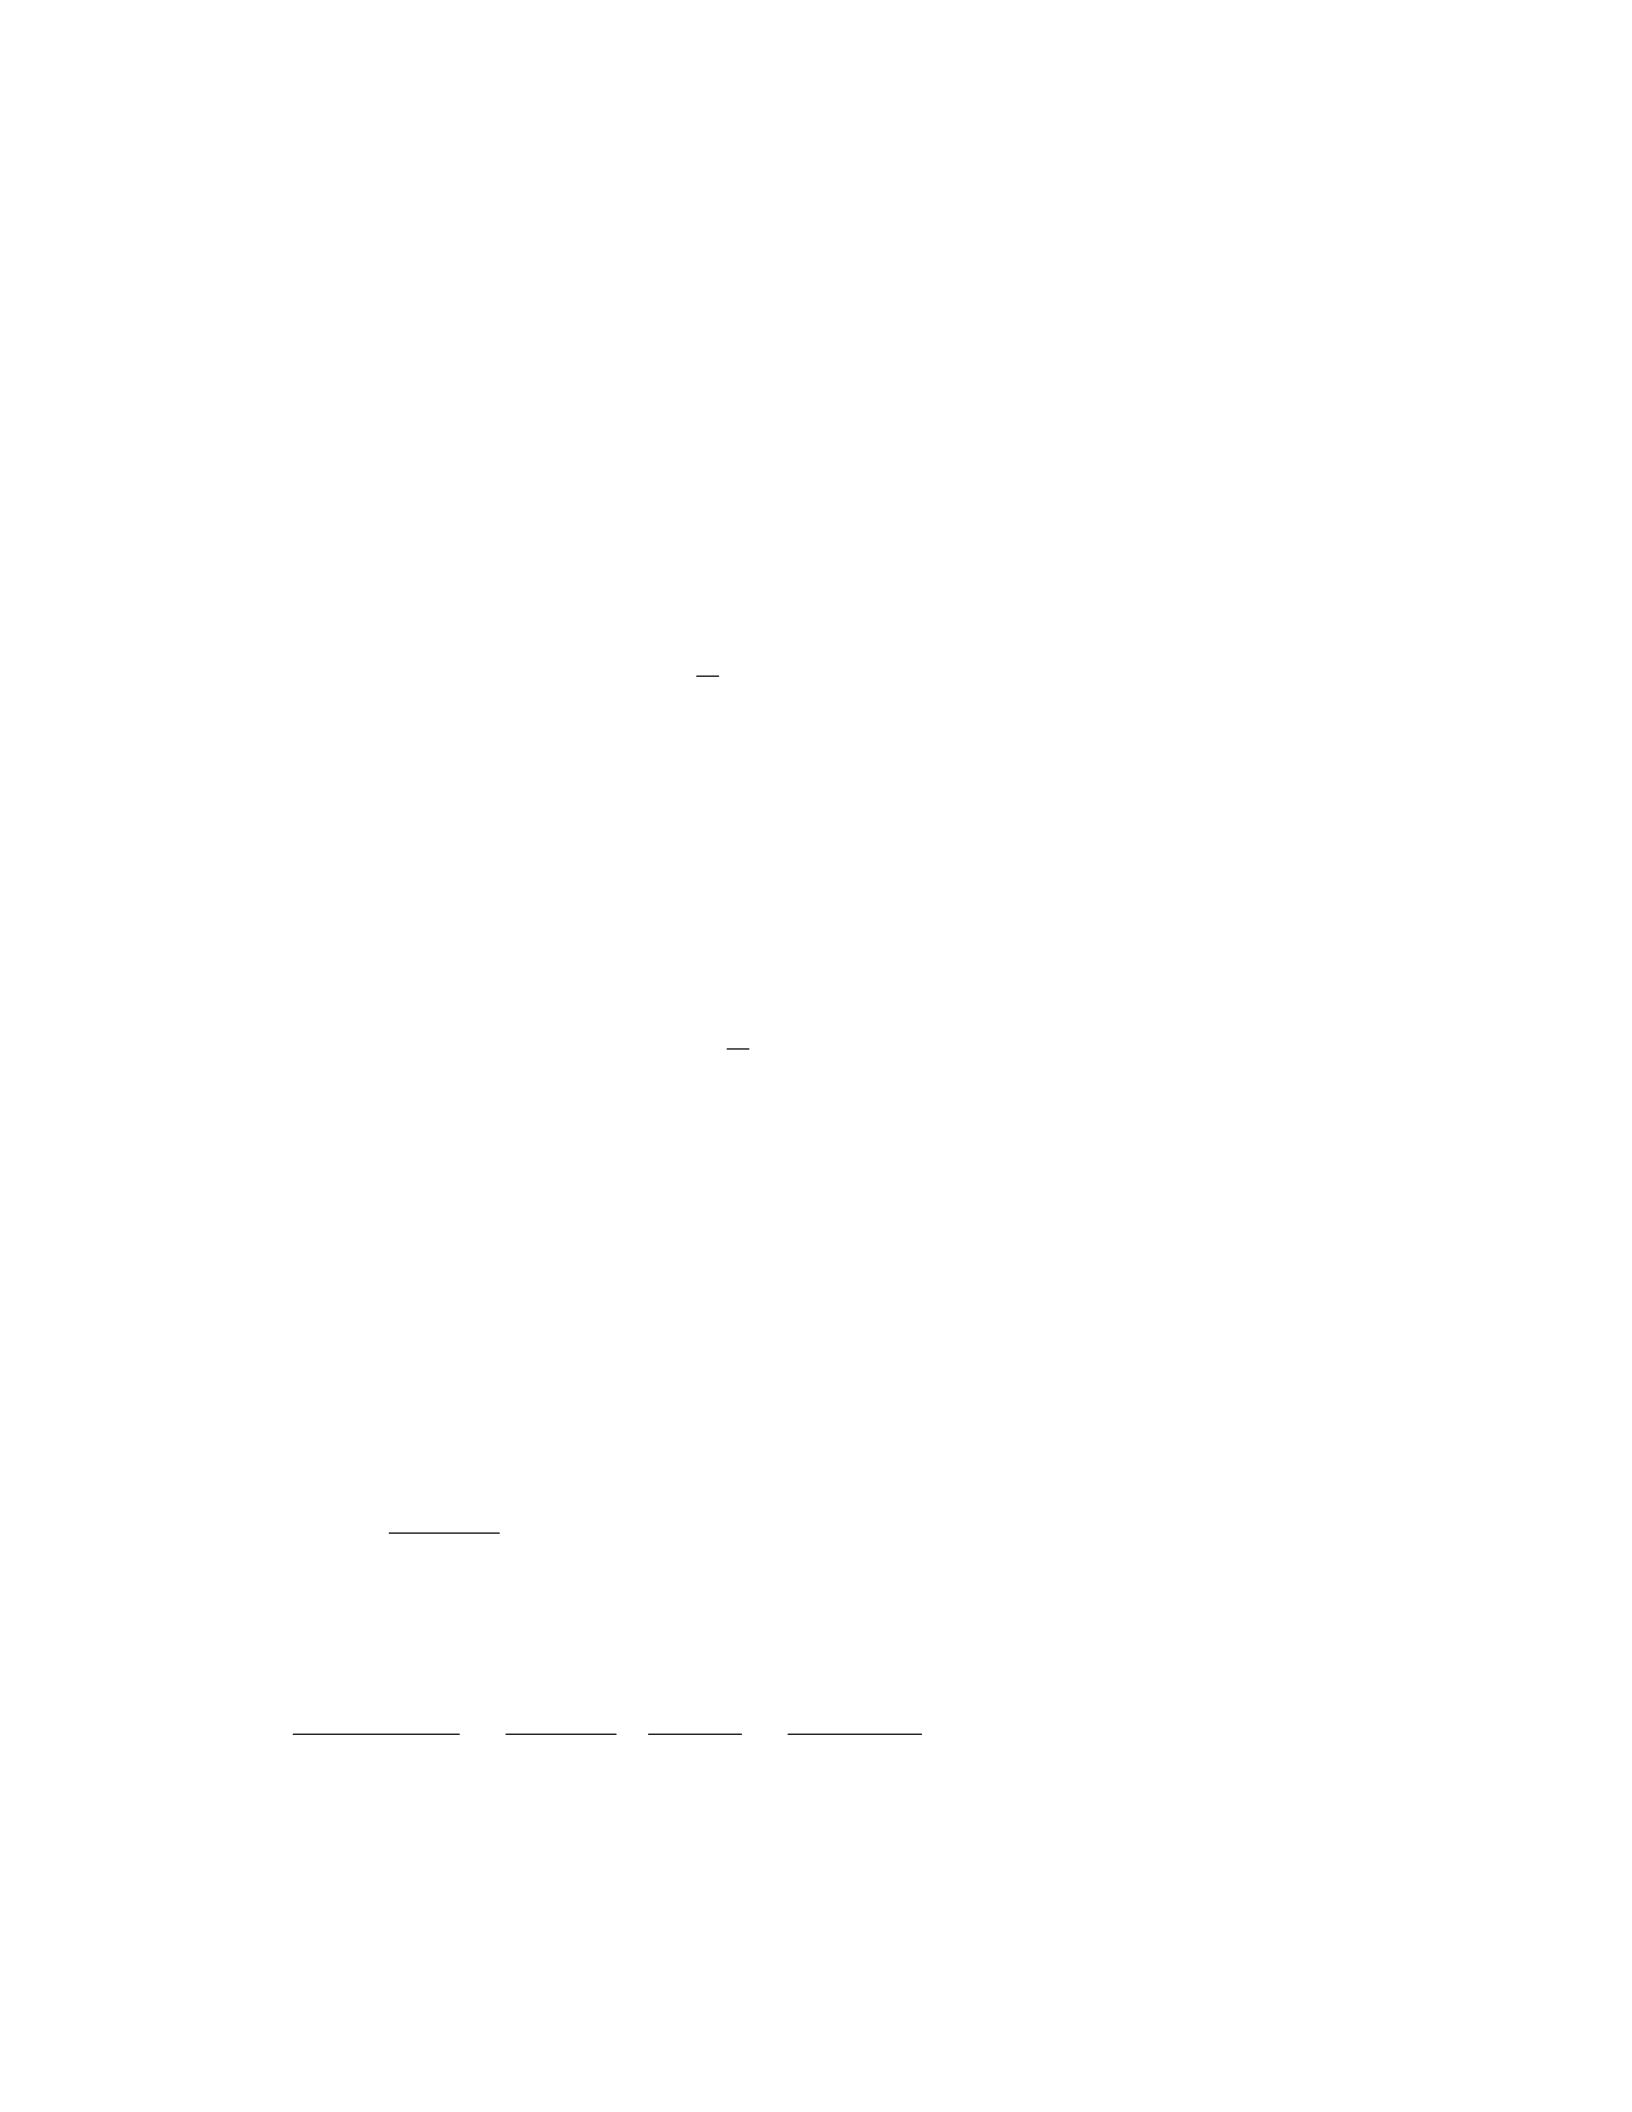
equation (2.4) includes two components. The expenditure log a(p) is interpreted as
necessary expenditure, whereas the expenditure log b(p) is interpreted as luxury
expenditure. It can be shown that the expenditure function is increasing in utility and
nondecreasing in prices.
Deaton and Muellbauer (1980) suggest the specific functional forms of log a(p) and log
b(p) as:
jiij
ji
ii pppaapa loglog
2
1
log)(log *
0
γ
∑∑+∑+= (2.5)
and
, (2.6)
k
k
k
pupapb
β
β
∏+= 0
)(log)(log
resulting in the cost function
0
),(log apuc =+ jiij
ji
ii
i
pppa loglog
2
1
log *
γ
∑∑+∑ + , (2.7)
k
k
k
pu
β
β
∏
0
where ai, βi, and are parameters. The cost function c(u, p) is linearly homogeneous in
p given that .
*
ij
γ
=
i0,1 ** =∑=∑=∑∑ jjijjijii a
βγγ
By differentiating equation (2.4) with respect to prices and using Shepard’s Lemma, they
obtain the compensated or Hicksian demand functions.
That is ii
i
qpuq
p
puc ==
∂
∂),(
),( . (2.8)
By multiplying both sides by pi/c(u, p) equation (2.8) becomes:
i
p
puc
log
),(log
∂
∂ = ),(
),(
puc
p
p
puc i
i
×
∂
∂ = ),(
),(
puc
puqp ii = w, (2.9) ),( pu
i
28
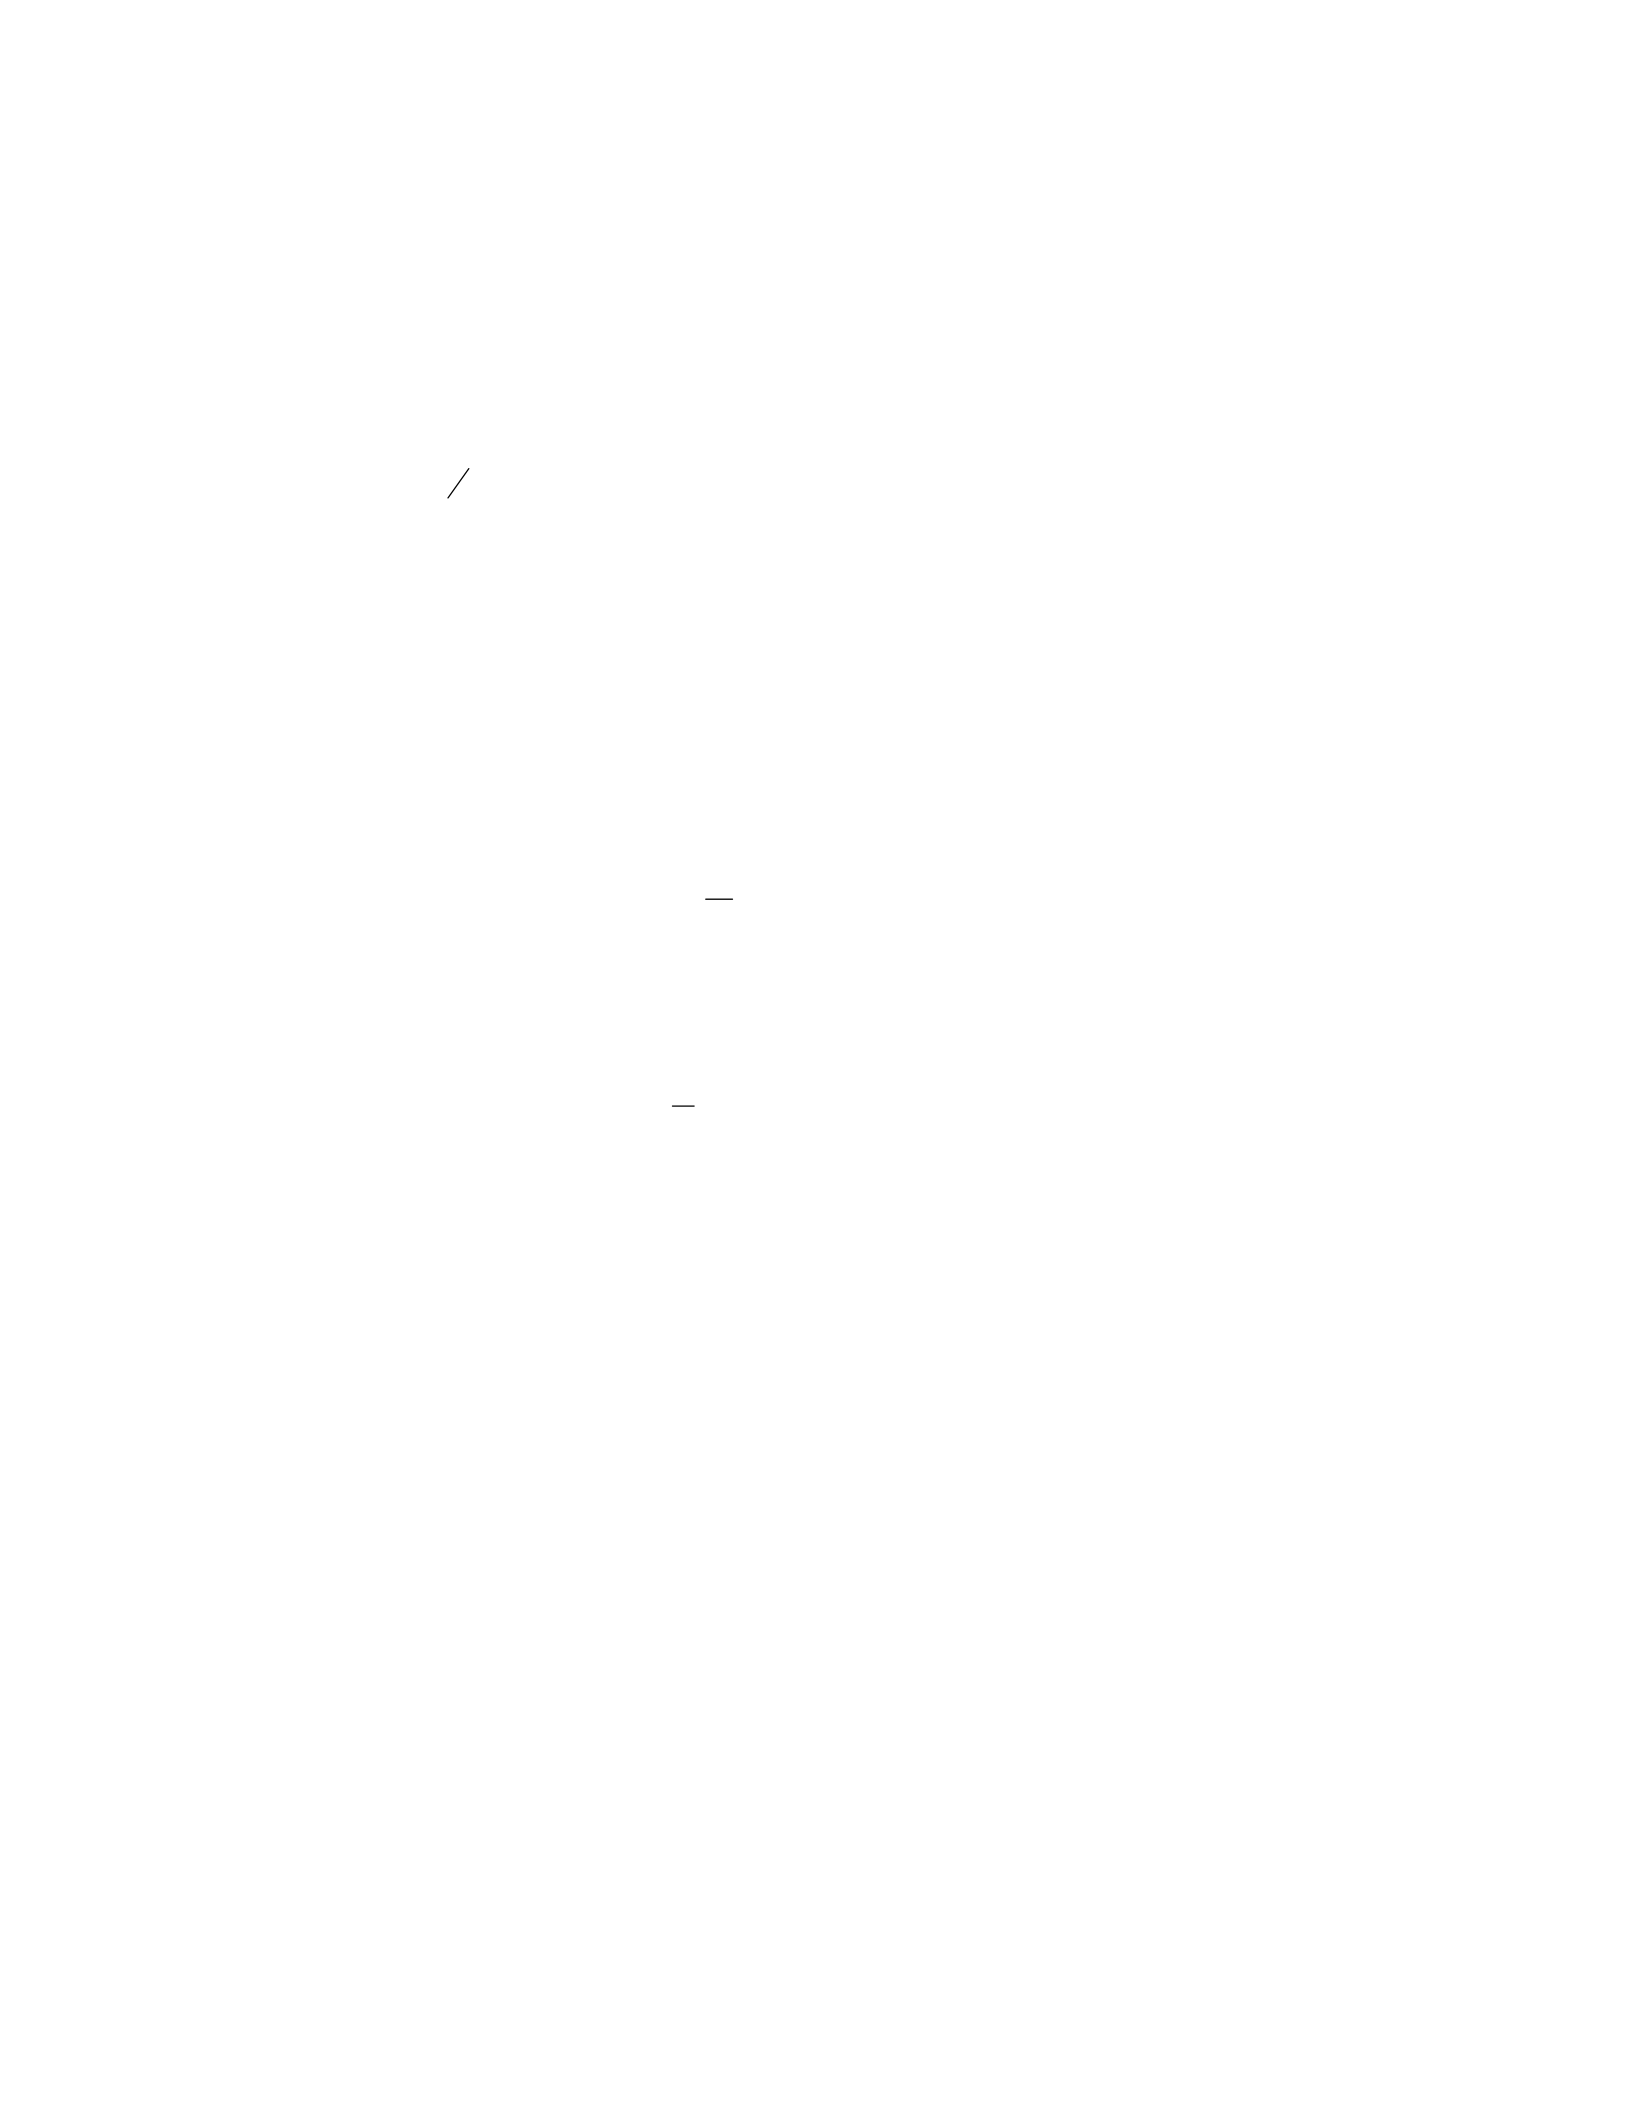
where w is the market share of good i.
),( pu
i
According to the cost function from equation (2.7), equation (2.9) becomes
i
w= , (2.10)
k
k
k
ijij
j
ipup
β
ββγφ
∏+∑+ 0
log
where )( **
2
1jiijij
γγγ
+= . (2.11)
Since total expenditure, Y, is equal to c in equilibrium for a utility-maximizing
consumer, by solving for u (indirect utility) in terms of and Yfrom equation (2.7),
and substituting the result into equation (2.10), we obtain the AIDS in budget share form
as:
),( pu
p
i
w=
+∑+ P
Y
pijij
j
iloglog
βγφ
, (2.12)
where P is a price index defined by
Plog = a +
0jiij
ji
ii
i
pppa loglog
2
1
log *
γ
∑∑+∑ (2.13)
The translog price index in equation (2.13) causes some empirical problems. First, its
specification makes the AIDS a non-linear econometric model, and therefore, it is
complicated to estimate the model (Deaton and Muellbauer, 1980). Second, the prices in
equation (2.13) are likely to be highly correlated, and the high correlation among prices
can cause collinearity problems. However, Buse (1996) used the AIDS model to
estimate meat consumption in the U.S. and concluded that the collinearity among prices
in the AIDS model was not a serious problem as was presumed in the literature.
Nevertheless, several studies have replaced the translog price index, log , by the Stone
index, , where , and is assumed to be approximately
P
*log Pii pwP log*log ∑= *P
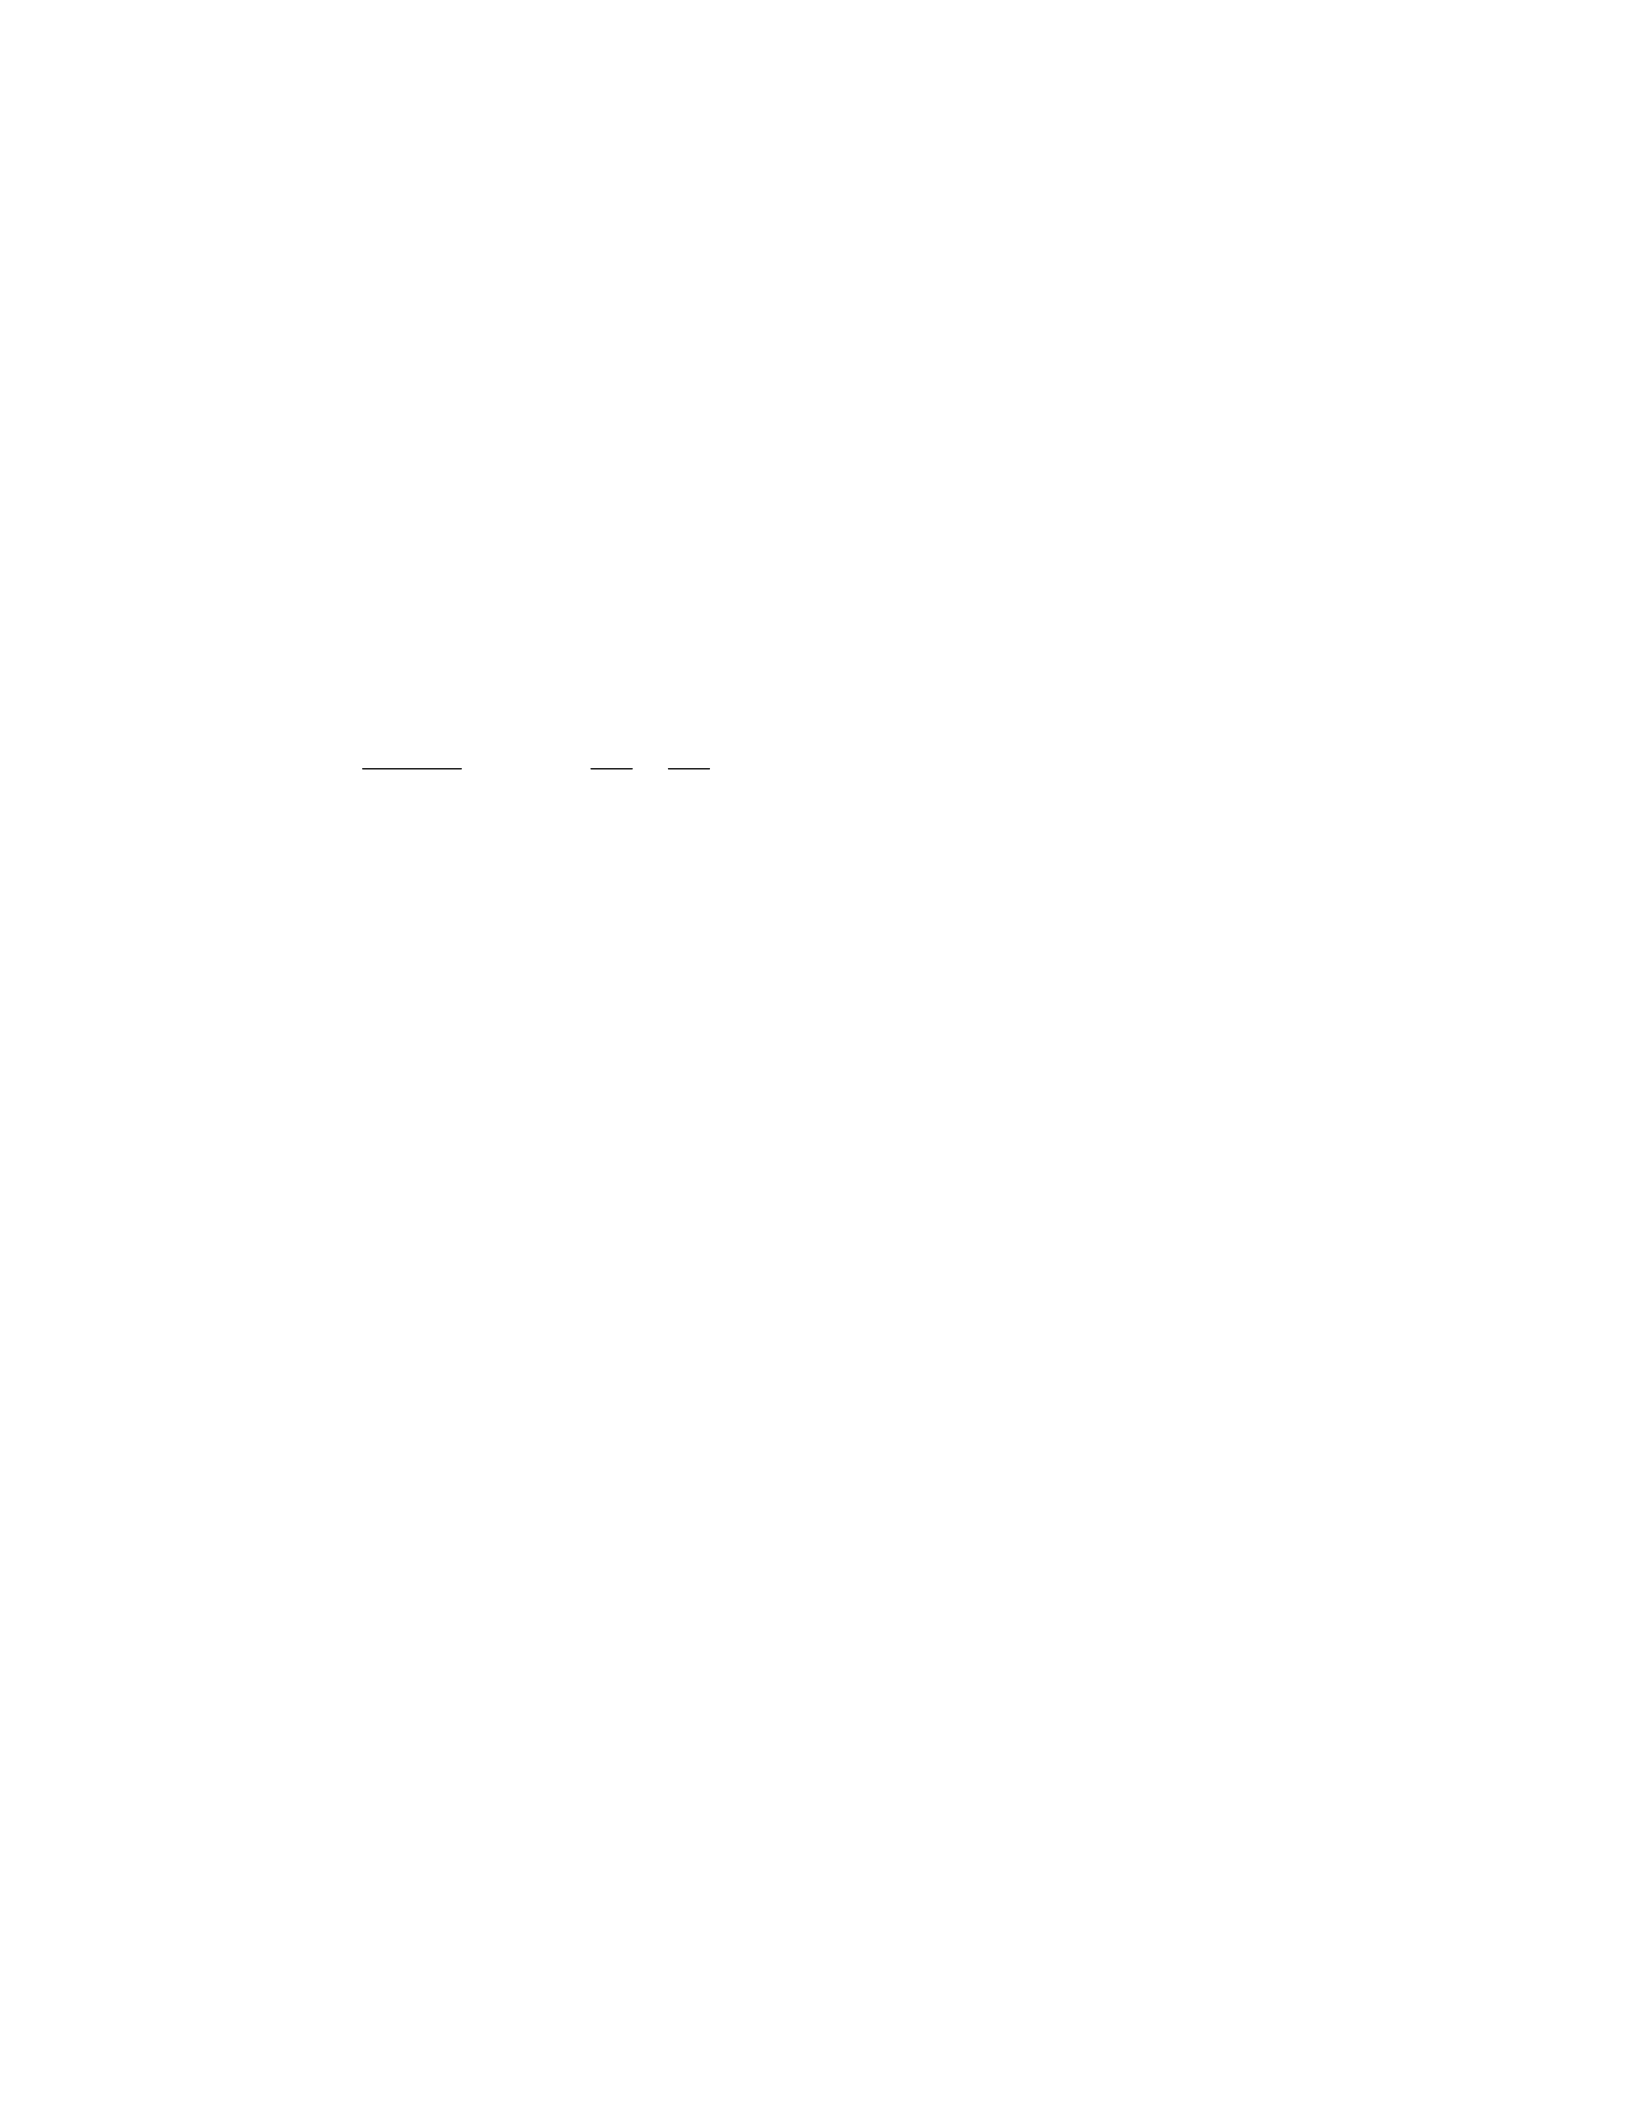
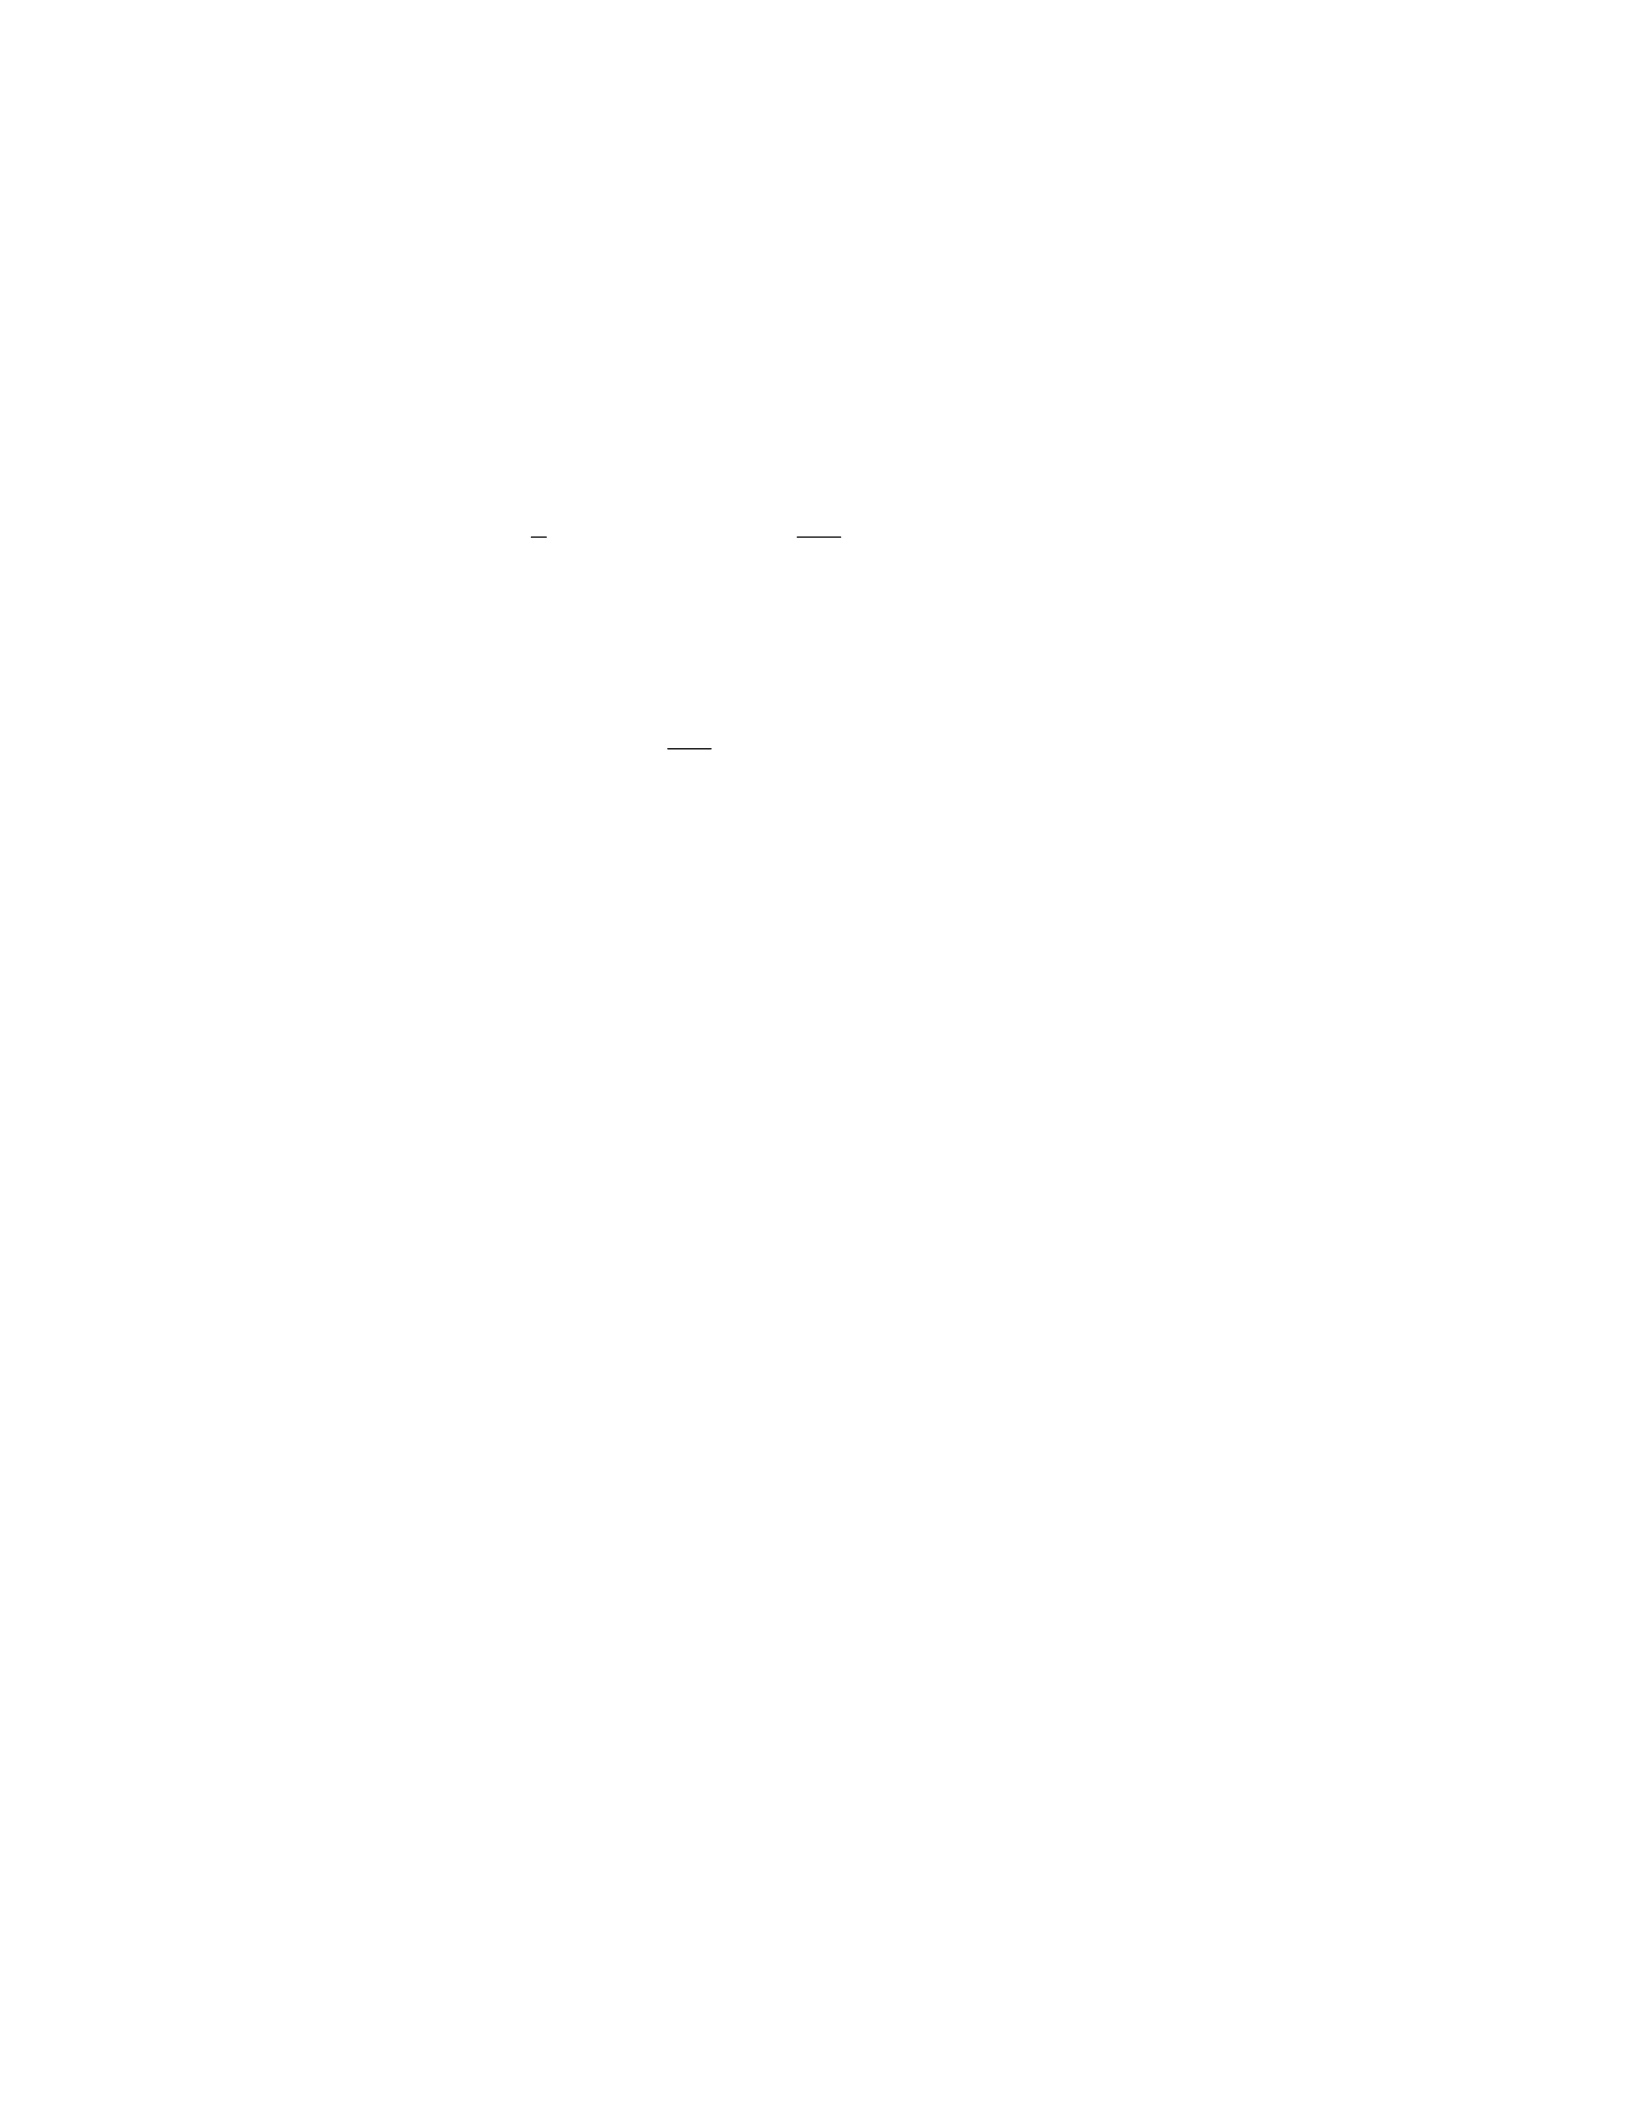
29
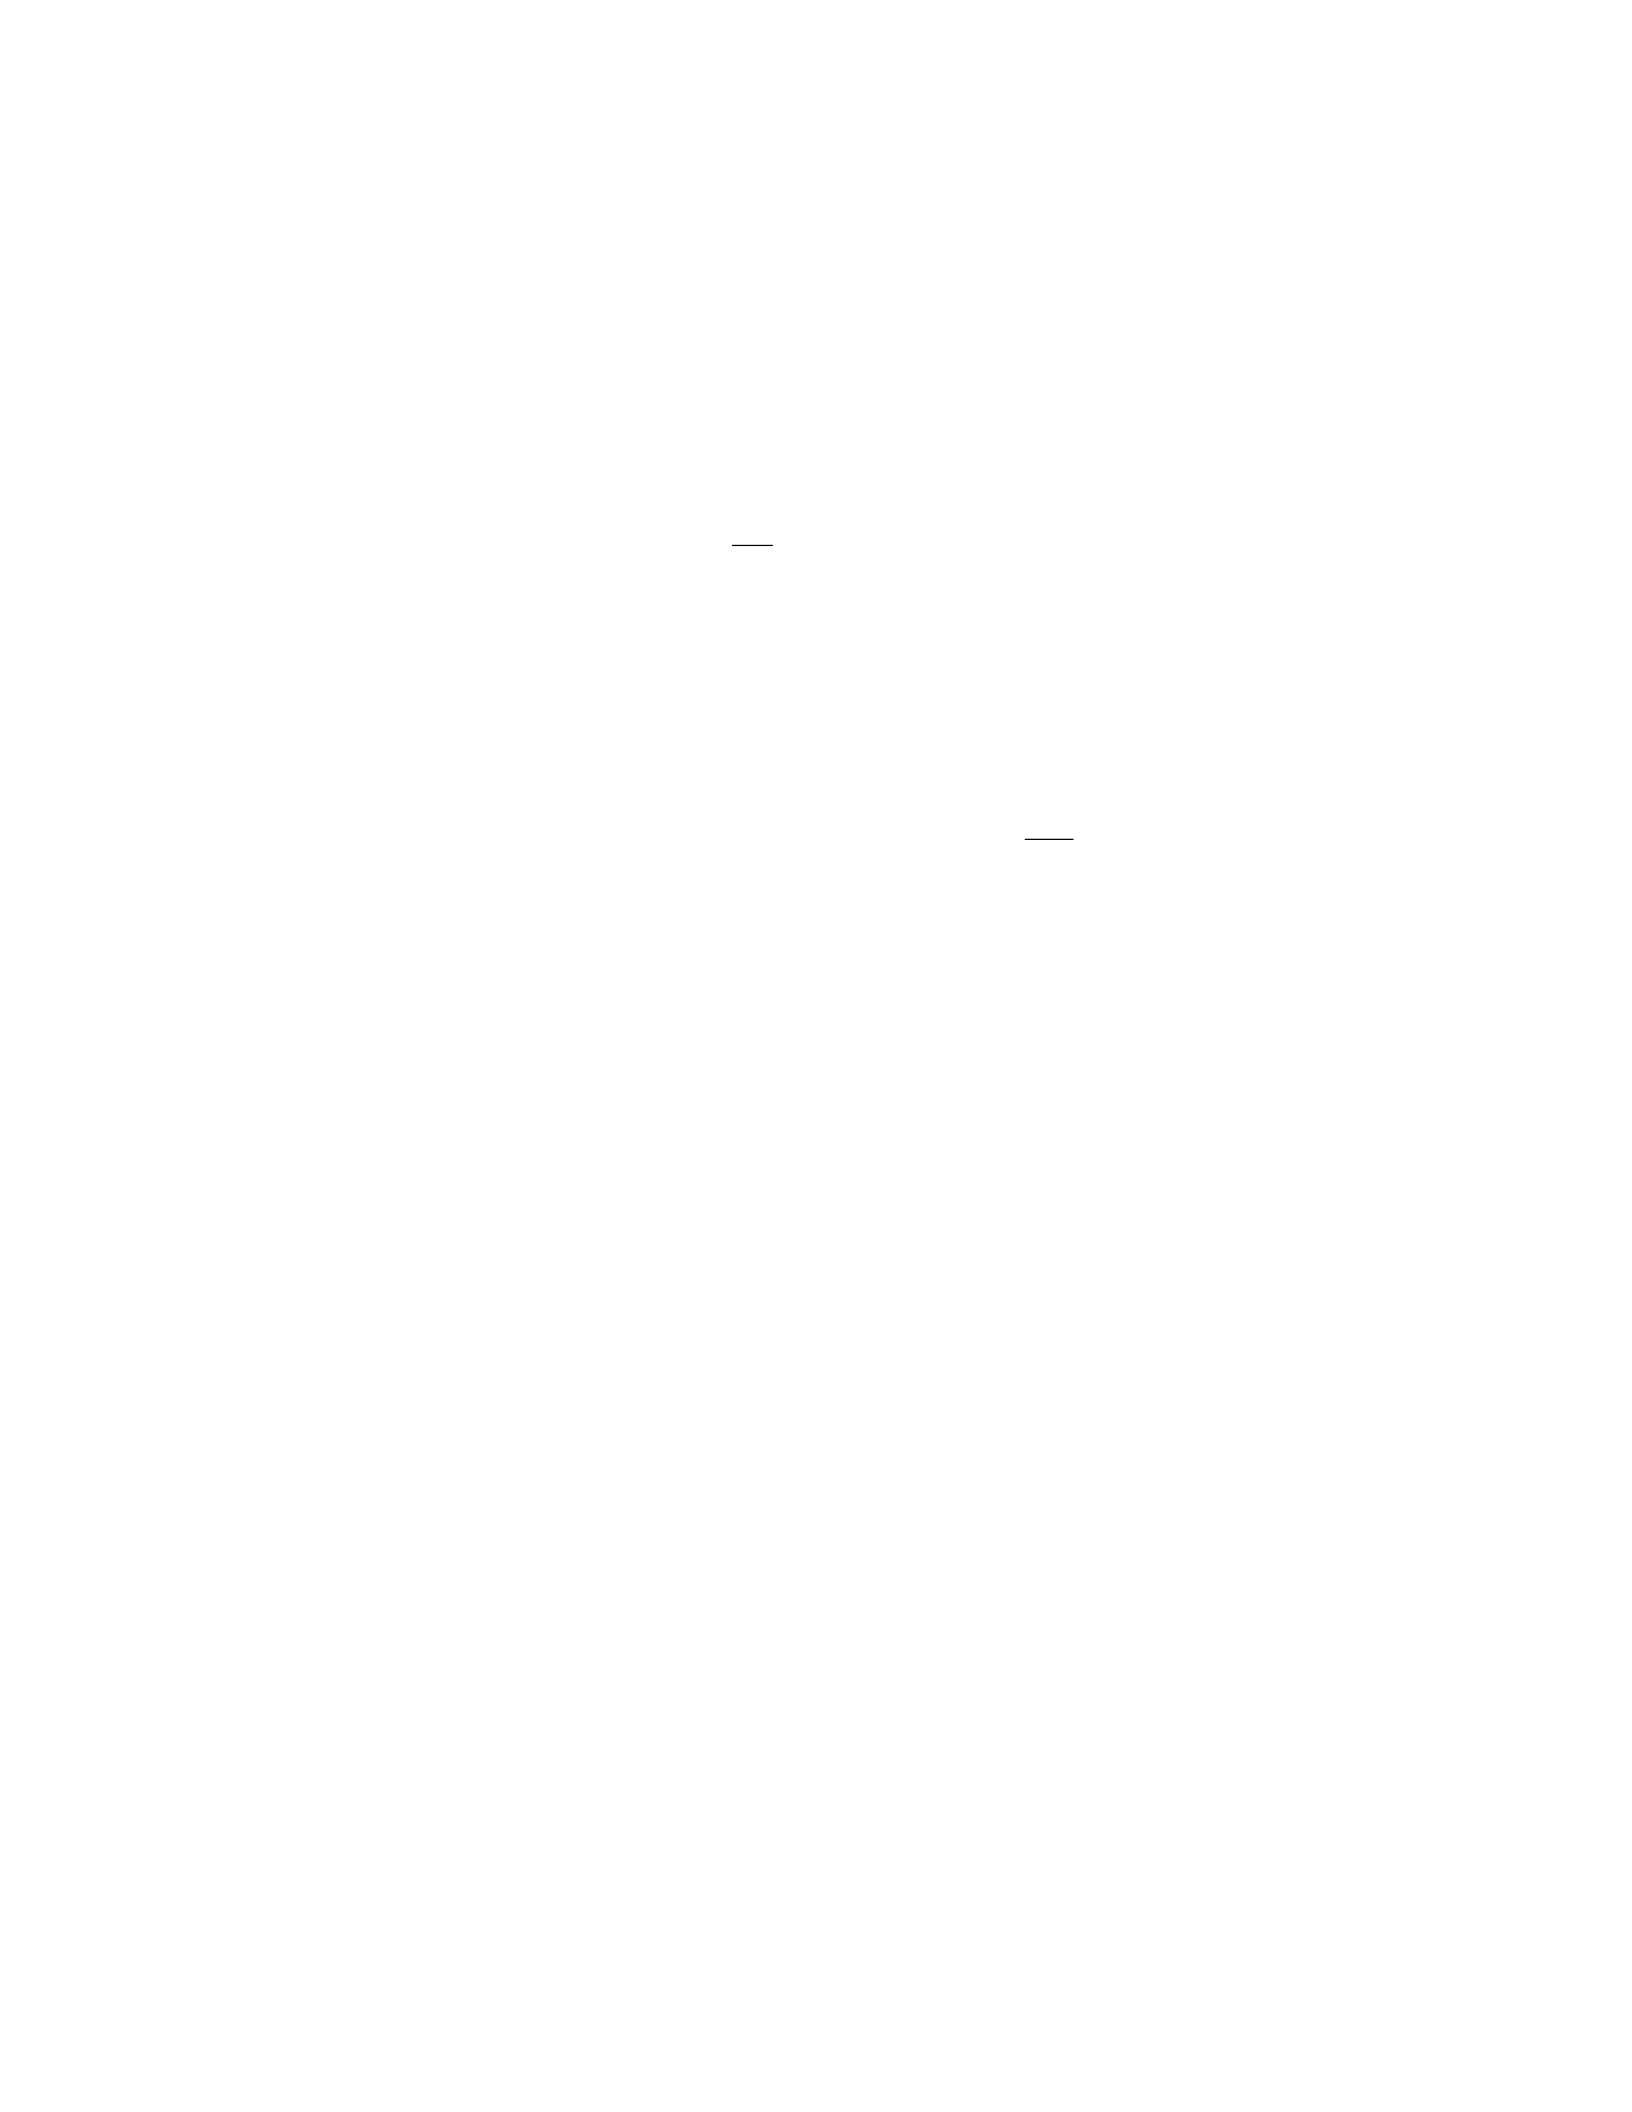
proportional to P, such that , and wis the ith firm’s market share
(Deaton and Muellbauer, 1980; Chalfant, 1987; Cotterill, 1994; and Vickner and Davies,
1999). Therefore, by using the Stone index the AIDS has been termed the “linear
approximate almost ideal demand system” (LA/AIDS). Thus equation (2.12) becomes
ePaP += 0
*i
i
P
Y
ω
+
*
log
i
β
log
ij
j
ijii pw
βγα
++= ∑log , (2.14)
where . Using the Stone index makes the LA/AIDS in equation (2.14) a
much simpler estimation problem. This can be done by calculating the Stone index
directly and then treating the total expenditure,
0
a
ii
φα
+=
*P
Y in equation (2.14), as a
predetermined variable before estimating equation (2.14) using OLS regressions (Deaton
and Muellbauer, 1980). Deaton and Muellbauer (1980) suggest that by using the Stone
index, the model becomes linear in the parameters, and the estimation can be done
equation by equation by OLS, which is equivalent to maximum likelihood estimation for
the system as a whole. Moreover, treating the Stone index as exogenous can reduce the
collinearity problem (Chen, 1998). Deaton and Muellbauer estimated an eight-
commodity demand system using aggregate annual UK data from 1954 to 1974 and
concluded that there was no significant difference between the parameters obtained from
the AIDS and the LA/AIDS. Alston, Foster, and Green (1994) conducted Monte Carlo
experiments to investigate whether the Stone index is a good approximation. They
concluded that “demand analysts can consequently have a certain degree of confidence
when estimating the LA/AIDS”. Therefore, the LA/AIDS model has been a popular tool
for researchers in the analysis of both macro- and micro-demand system (Deaton and
30
Muellbauer, 1980; Blanciforti and Green, 1983; Chalfant, 1987; Cotterill, 1994; Asche,
Bjorndal, and Salvanes, 1998; Henneberry, Piewthongngam, and Qiang, 1998; Vickner
and Davies, 1999).
Chalfant (1987) and Green and Alston (1990) suggested elasticity formulas that
can be used with the parameters obtained from the LA/AIDS and the Stone index. The
formula of the partial own- and cross price elasticities of demand ( ij
η
) suggested by
Chalfant (1987), and Green and Alston (1990) is:
j
i
i
i
ij
k
ij
j
i
ij w
wwPd
Qd
β
γ
δη
−+−== ln
ln , (2.15)
where is the Kronecker delta ( = 1 for i = j; = 0 for i ≠ j), and are
average market shares of brand i and j, and and are parameters estimated from the
LA/AIDS. Several studies used this elasticity formula in their work (Cotterill, 1994;
Richards, Kagan, and Gao, 1997; Asche, Bjorndal, and salvanes, 1998; Henneberry,
Piewthongngam, and Qiang, 1999, Vickner and Davies, 1999). Alston, Foster, and Green
(1994) conducted Monte Carlo experiments to investigate the appropriate formula to
compute elasticities. They found that equation (2.15) is quite accurate relative to
alternatives because it is a reasonably good approximation to the true AIDS.
k
ij
δ
k
ij
δ
k
ij
δ
i
wj
w
ij
γ
i
β
The studies of Cotterill (1994), Vickner and Davies (1999), and Cotterill, Putsis,
and Dhar (2000) are related to the first part of this dissertation. They estimated the
demand system using the LA/AIDS simultaneously with the supply system using price-
reaction functions. In addition, they estimated the LA/AIDS using the Stone index.
31

It has been found that the Stone index can cause econometric problems.
Pashardes (1993) examined the effect of using the Stone index by comparing analytical
expressions and empirical findings obtained from the AIDS model with and without the
Stone index approximation. Pashardes found that the Stone index causes the parameter
estimates to be biased. Buse (1994) investigated the LA/AIDS using the Stone index and
concluded that the seemingly unrelated estimator of the LA/AIDS was inconsistent.
Another problem of using the Stone index is the units-of-measurement problem.
According to the study of Cotterill, Putsis, and Dhar (2000), one assumption made in
their price-reaction functions was that, in order to observe a manufacturer’s wholesale
price (wi), the retailer’s price (Pi) is used as a proxy and assumed to be proportional to its
wholesale price. In other words, the wholesale price (wi) is scaled up by a constant
number (m) to represent a proportional mark up rule of the retailer’s price decision, that
is, Pi = mwi. Moschini (1995) suggested caution in using the Stone price index in the
LA/AIDS due to the units-of-measurement problem, such as when prices are scaled up.
Due to Moschini’s work, the LA/AIDS model with scaled prices could be shown to be
different from the original AIDS model, and thus the estimated parameters would
generally be biased. Moschini concluded that for the purpose of estimating the LA/AIDS
model, “the standard Stone index should be avoided” (Moschini, 1995). Moschini
suggested that a price index should meet a desirable property in which an appropriate
price index should be invariant to the units of measurement of prices. This desirable
property is called the commensurability property (Diewert, 1987; and Moschini, 1995).
However, Moschini suggested that the units-of-measurement problem may be solved by
using a price index that satisfies this property. Moschini recommended several price
32
indices that may be used to maintain the specification of the AIDS linear and that satisfy
the commensurability property. The indices recommended by Moschini were the
Tornqvist index, the corrected Stone index, and the Laspeyres price index.
The Tornqvist index is written as:
∑
=
+= n
ii
it
iit
T
tp
p
wwP
1
0
0
2
1log)()log( . (2.16)
The corrected Stone index is written as:
=∑
=0
1
loglog
i
it
it
n
i
tp
p
wP . (2.17)
The Laspeyres price index is written as:
)log()log(
1
0
it
n
i
i
L
tpwP ∑
=
=, (2.18)
where the zero superscript denotes base period values, such as mean values.
In a Monte Carlo experiment, Moschini found that the LA/AIDS could
approximate the AIDS well when the recommended price indices were used.
The Price-Reaction Functions
The LA/AIDS gives only own- and cross-price elasticities. In order to measure a
firm’s market power using the indices mentioned above, the conjectural price responses
or the price-response elasticities are needed. The price-response elasticities can be
obtained from the estimation of price-reaction functions. A firm’s price reaction function
is derived from the first order condition of the maximizing profit function of the firm,
assuming that the market is characterized as Bertrand competition with differentiated
33

products and that price is the strategic choice variable. Liang (1989) estimated demand
functions and price-reaction functions simultaneously to measure the degree of market
power in the ready-to-eat breakfast cereal industry. The demand and supply functions in
Liang’s work are linear. Cotterill (1994) studied the degree of market power in the
carbonated-soft drink industry. He extended Liang’s linear price-reaction functions to the
double-log specification, that is
iij
n
jji
ijii Cpp
νλφµ
+++= ∑=≠
loglog
1,
0, (2.19)
where
i
pand = the prices of brand i and j,
j
p
i
C= the vector of shift variables of brand i, and
ij
φ
= the price-elasticity parameters to be estimated, for i, j = 1, 2, …, n.
Previous Empirical Findings
The empirical findings of Cotterill (1994), and Vickner and Davies (1999) are
closely related to the first part of this study. Cotterill (1994) applied Baker and
Breshnahan’s (1985) demand approach and Liang’s price-reaction functions to his work.
He analyzed the degree of market power in the carbonated soft drink industry using
quarterly time-series scanner data from 1988 to 1990. To investigate the demand-side of
the market, he employed the LA/AIDS model in order to obtain the partial own and cross
price elasticities of demand for each brand. On the supply-side of the market, Cotterill
used the first-order conditions derived from an oligopolist's profit-maximizing function,
34

assuming that the market is characterized by Bertrand competition, to estimate the price-
response elasticities or the conjectural price response. He used error-components and
three-stage least squares estimation methods to estimate both the LA/AIDS and price-
reaction functions simultaneously. Cotterill used the RI, OI, and CQ to measure a
brand’s degree of market power using the estimated partial own-price, cross-price and
price-response elasticities. Cotterill found that indices of Coke, Pepsi, Seven-Up and
private labels behaved as expected. As the RI and OI are close to one, the estimated
brand is interpreted to have a high degree of market power. The CQ measures the
fraction of market power of the observed demand due to tacit collusion. Coke, for
example, was estimated to have the RI equal to .71 indicating a high level of unilateral
market power. Its OI was estimated to be equal to .84 showing a substantial amount of
unilateral and coordinated market power, whereas its CQ was estimated to be equal to
14.7 percent meaning that 14.7 percent of Coke’s market power is due to tacit collusion.
Following Cotterill’s approach, Vickner and Davies (1999) estimated market
power and pricing conduct in the domestic spaghetti sauce industry, a product-
differentiated oligopoly. Vickner and Davies employed the simultaneous equations of
the LA/AIDS model and the price-reaction functions to estimate the partial own- price
and cross-price elasticities, and the price-response elasticities. The estimates led to
inferences that the own-price elasticities were statistically significant and negative, and
that demand for each brand was elastic. Their explanation for the elastic demands was
that because the spaghetti sauce product was a durable good, consumers could stockpile
the products when they were on sale. On the supply side, the results supported Bertrand
competition in that the estimated price-response elasticities were generally upward
35

sloping. Following Cotterill’s study, Vickner and Davies measured the degree of market
power by using the RI, OI, and CQ. They found some evidence of market power in the
spaghetti sauce industry even though the extent was not as high as in the carbonated soft
drink industry estimated by Cotterill. They also found that brands within a specific
product category had high degree of tacit collusion. They pointed out in their study that
one firm in the industry was capable of maintaining its market power without tacit
collusion due to an advantage on its niche in the market.
The degree of market power is one of the crucial issues in industrial organization.
Cotterill’s and Vickner and Davies’ work is one of several ways in which industrial
organization economists have studied the degree of market power. Other studies of the
degree of market power, which used different approaches from this dissertation, include
those of Appelbaum (1982), Schroeter (1988), Liang (1989) and Nevo (2001).
One alternative is to estimate the mark-up, the difference between price and
marginal cost as a proportion of price, and is called the Lerner index. To analyze the
Lerner index, conjectural elasticity and price elasticity of demand have to be estimated
because the Lerner index is positively related to the conjectural elasticity and inversely
related to the elasticity of market demand. Appelbaum (1982) investigated four U.S.
manufacturing industries: textiles, rubber, electrical machinery, and tobacco. Schroeter
(1988) studied the beef packing industry. A disadvantage of the Lerner index is the
assumption of homogeneous products. Therefore, the degree of market power among
brands in an industry was not estimated. The estimated Lerner index for each industry
represented the degree of market power of that industry as a whole.
36

Liang (1989) estimated the degree of market power in a product-differentiated
oligopoly, the ready-to-eat breakfast cereal industry on the national level. Specifically,
he examined price competition between pairs of ready-to-eat breakfast cereal products.
The two brand demand functions and the two price-reaction functions were estimated
simultaneously for each of the observed supermarkets using a nonlinear three stage least
squares procedure. Price reaction elasticities were obtained from the estimated price-
reaction functions, and the price conjectural variations were obtained from the estimated
own- and cross-price elasticities of demand. Liang’s findings suggested that prices in the
ready-to-eat breakfast industry were highly non-competitive and the degree of pricing
interdependence varied across the brand pairs. The hypothesis of collusive pricing could
not be rejected if a brand had close substitutes. Conversely, a manufacturer was able to
set price independently if its brand was found to be sufficiently differentiated from close
substitutes. The major advantage of his approach was that it showed the difference
between market power ascribed to demand elasticities and market power ascribed to
collusive pricing conduct. A disadvantage of his study was that it estimated price
competition between pairs of products. In fact, strategic price interaction among all
brands in the industry should be taken into account in the analysis.
Nevo (2001) examined the nearly collusive-pricing behavior and intense non-
price competition in the ready-to-eat cereal industry by the estimation of price-cost
margins. Nevo used discrete choice models to estimate demand elasticities, which were
used to compute price-cost margins. Nevo concluded that observed high degrees of
price-cost margins were due to product differentiation. In addition, prices in the industry
were consistent with non-collusive pricing behavior.
37

Chapter Three
Data and Econometric Methodology
An objective of this dissertation is to estimate the degree of market power in the
canned tuna industry in a local market. The data used in this dissertation are scanner
data for the canned tuna industry collected from supermarkets in Knoxville, Tennessee.
The model specification in this dissertation is different from previous studies (Cotterill,
1994; and Vickner and Davies, 1999). It uses the corrected Stone index in the estimation
of LA/AIDS. Estimates using the traditional Stone index are also generated and
compared to those associated with the corrected Stone index. This chapter starts with a
discussion of the data and then outlines the empirical approach.
Data
The Use of Scanner Data
This study uses weekly scanner data from the canned tuna industry to estimate
firms’ market power. Scanning systems were introduced during the mid-1970s, and they
have become the industry standard. Scanner data are primary data that represent a readily
current and timely source of product-specific information including price, quantity,
expenditure, and marketing activities such as coupons, retail advertising and shelf-space
location for a large number of products available on a daily basis (Nayga, 1992).
Eastwood (1993) mentioned that the retailer’s motivation for the introduction of scanners
was primarily for time saving and more precision in the checkout process. Eastwood
38

(1993) argued that scanner data have desirable properties. First, the level of detail in
scanner data allows researchers to examine relationships among close substitutes and
complements. Second, the time period is more consistent than traditional data sets.
Third, the data can be obtained much more quickly than traditional data sets. Finally, they
can be used to test various merchandising hypotheses under market conditions. Thus,
the scanner data are a non-traditional data source, which can be used in empirical
research to investigate a product in terms of both demand and market structure.
There are some weaknesses associated with the use of scanner data. Capps and
Nayga (1991) indicated that limitations of scanner data include the sheer volume of
information, the lack of consumer socio-demographics, and the provision of information
only for food eaten at home. Eastwood (1993) addressed two problems in constructing
scanner data sets for marketing and demand research. The first problem involved
classifying scanner data for variable-weight items into consumer demand categories. The
second problem focused on the creation of an advertising data set that can be combined
with scanner data to evaluate market strategies. Scanner data have been actively used in
food marketing and economic research since the 1980s (Nayga, 1992). A list of research
in food demand using scanner data is presented in Table 3.1.
There are some market research companies that process scanner data into a usable
format for researchers, such as Information Resources, Incorporated (IRI), A.C. Nielsen,
and Efficient Market Services. The scanner data set used in this study is from IRI. The
company collects weekly scanner data from more than 32,000 supermarket, drug and
mass merchandiser outlets across the United States. Included in their data are sales,
share, prices, and marketing variables for thousands of consumer brands sold.
39
Table 3.1 Listing of Research on Food Demand using Scanner Data
Author
(Published year)
Research
Time Period
Objective
Jensen and Schroeter
(1992)
1985 – 1987 Investigation of the TV advertising’s effects on
beef demand
Capps (1989) 1986 – 1987 Estimation of retail demand relationships for
meat products
Capps and Nayga
(1990)
1986 – 1988 Evaluation of effect of length of time on
measured demand elasticities
Capps and
Lambregts (1991)
1987 – 1988 Estimation of demand functions for finfish and
shellfish products
Eastwood, Brooker,
and Gray (1994)
1988 – 1991 Evaluation of effects of supermarket
advertising on product sales
Cotterill (1994) 1988 – 1990 Estimation of market power in carbonated soft
drink industry
Haller (1994) 1988 – 1992 Estimation of price strategies in the catsup and
cottage cheese industries
Wessells and
Wallstrom (1999)
1988 – 1992
Testing the stability of canned salmon demand
Jones (1997) 1990 – 1991
Estimation of demand functions for breakfast
cereal and carbohydrate products, and
comparison on different income and location
Seo and Capps
(1997)
1991 – 1992
Estimation of regional variability of price and
expenditure elasticities on spaghetti sauce
products
Cotterill, Putsis, and
Dhar (2000)
1991 – 1992 Analysis the competitive interaction between
private labels and national brands on six
individual categories
Park and Senauer
(1996)
1994 Estimation of household brand-size choice
models for spaghetti products
Vickner and Davies
(1999)
1994 – 1996 Estimation of market power and pricing
conduct in spaghetti sauce industry
Vickner and Davies
(2000)
1994 – 1996 Estimation of strategic price-response on
canned fruit industry
Teisl, Roe, and
Hicks (2000)
1988 – 1995 Investigation of the dolphin-safe-label effect
on the tuna demand
40

Several studies have used scanner data relying on the IRI data (Haller, 1994;
Cotterill, 1994; Seo and Capps, 1997; Wessells and Wallstrom, 1999; and Vickner and
Davies, 1999). Cotterill (1994) suggested that scanner data were the most appropriate
source of data to analyze both demand and strategic interactions.
Previous studies (Cotterill, 1994; and Vickner and Davies, 1999) estimated the
degree of market power in oligopoly markets at the national level. These studies have not
captured market structure, pricing conduct, and demand at the local level. Nayga (1992)
suggested that scanner data from supermarkets in a particular location present a
controlled situation. The study of local market behavior would represent actual strategic
interaction among firms precisely based on the actual local demand. This dissertation has
chosen Knoxville, Tennessee as a representative local market.
The scanner data in this study were collected weekly by IRI for 157 weeks over
the period of January 4, 1998 to December 31, 2000 from 134 supermarkets in Knoxville,
Tennessee. Supermarkets from which IRI collected the data in this city have annual
sales of $2 million and above. There is no information from IRI about individual
supermarkets. Therefore, each variable in the data set represents time series data
aggregated from the 134 supermarkets, including Kroger, Food City and BI-LO. Neither
media advertising nor information about shoppers were available. This study assumes
that there was no change in the marketing of canned tuna by the store chains or the
processors or in the socioeconomic characteristics of shoppers over the three year period.
For each of the 157 weeks, the sales and price information for canned tuna are
standardized to account for differences in size. Package sizes and prices are converted
into standardized 16-oz. equivalent units. The data set from IRI indicates that there are
41
120 barcodes for canned tuna. Aggregating sales by brand indicator, there are three
leading brands that have total market shares that average over 80 percent of the market.
These three leading brands are Starkist, Chicken of the Sea, and Bumble Bee. Besides
the three leaders, there are other canned tuna brands, each of which possesses a small
fraction of market share. Therefore, all other canned tuna brands are aggregated into a
brand labeled Allother. All variables are listed in Table 3.2, and their descriptions
follow.
Endogenous Variables
There are two endogenous variables; the market share of brand i, , and the
average price per unit of brand i, . Brand i’s market share represents the percent of the
brand’s total dollar sales of all brands in the market. According to the LA/AIDS, this
it
w
i
p
Table 3.2 Variables Used in the Estimation
Variable Definition
i
w Dollar share of brand i
it
p Average price per 16-oz equivalent of brand i paid by the
consumers at time t
t
Y Total expenditure spent on all brands of canned tuna in the
market area at time t
FEATUREit Percent of incremental volume sales for brand i sold in the
presence of feature advertising only and no display at time t
DISPLAYit Percent of incremental volume sales for brand i sold in the
presence of display only and no feature advertising at time t
FEATURE&DISPLAYit Percent of incremental volume sales for brand i sold in the
presence of feature and display at time t
REDUCTIONit Percent of incremental volume sales for brand i sold in the
presence of price reduction only during at time t
i = Starkist, Bumble Bee, Chicken of the Sea, and Allother
42

variable is endogenous because it is determined by prices and total expenditure. Prices of
all package sizes and types of canned tuna (such as tuna in water and tuna in oil) of brand
i are aggregated and weighted into the average price per 16-oz. equivalent of brand i.
Explanatory variables
The total expenditure (Y) is the total dollar expenditure spent on all brands of
canned tuna in the market area during time t. According to the LA/AIDS, the total
expenditure in equilibrium is equal to a cost function (budget) of a utility-maximizing
consumer. The utility function associated with the LA/AIDS is weakly separable. Weak
separability allows for partitioning individual items into groups, which is consistent with
two-stage budgeting. That is, given weak separability, the consumers allocate income to
various groups and given the allocation to subgroups, choices are made among the
elements of the subgroups. With respect to canned tuna, the consumer is envisioned as
allocating expenditure to canned tuna and given the allocation, decides how much of the
various brands to buy. Therefore, the total expenditure on the canned tuna in the market
is predetermined and set as exogenous variable. The other exogenous variables are
promotion-activity variables including the percent of incremental volume sales with the
presence of feature only (FEATURE), the percent of incremental volume sales with the
presence of display only (DISPLAY), the percent of incremental volume sales with feature
and display (FEATURE&DISPLAY), and the percent of incremental volume sales with the
presence of price reduction (PREDUCTION).
t
43

IRI collected and calculated each brand’s total volume sales, which are comprised
of base sales and incremental sales. Base sales are calculated by IRI using a proprietary
model, which factors out promotional effects primarily by projecting volumes during
non-promotional periods versus promotional periods. Incremental sales are those sales
which actually represent the effects of promotional activities. Each brand’s promotional
activities are assumed exogenous for the relatively short time period considered here.
However, incremental sales from promotional activities of a brand are also included in
the brand market share, which is an endogenous variable. As a result, promotion-activity
variables may have an endogeneity problem. One remedy is to create dummy variables
that indicate whether promotional activities are conducted or not. However, this is not
possible here because some canned tuna brands such as Starkist and Allother have
promotional activities in at least one supermarket every week of the sample period.
Another alternative is to drop the variables that cause the problem. But this can cause
another problem of omitted variable bias and model identification for the simultaneous
equations and, therefore, should not be used here. Several studies have used promotion-
activity variables collected by IRI as exogenous variables in their estimations (Cotterill,
1994; Haller, 1994; Vickner and Davies, 1999, and Cotterill et al, 2000). Because of the
limitations of the available data and practically empirical difficulties, the promotion-
activity variables are treated as exogenous variables.
A Feature is a retailer print advertisement that is used to promote a specific
product or group of products. Field auditors (supermarkets) record features appearing in
newspapers, circulars and flyers. The percent of incremental volume sales for brand i
44

sold in the presence of feature advertising only and no display during time t is calculated
as:
FEATUREit, = (Incremental volume sales of brand i in stores with feature only / Total
volume sales of brand i) x 100.
A display is a temporary secondary location for a product in a store (i.e., in
addition to its normal stocking location). Displays are recorded by field auditors
(supermarkets) who identify each display by its location and the UPCs that are in the
display. Field auditors monitor and record display activity in sample stores on a weekly
basis. The general rule is that a secondary stocking unit must have at least 18 units of
product in order to be considered a display. The percent of incremental volume sales for
brand i sold in the presence of display only and no feature advertising during time t is
calculated as:
DISPLAYit = (Incremental volume sales of brand i in stores with display only / Total
volume sales of brand i) x 100.
The percent of incremental volume sales for brand i sold in the presence of feature
and display during time t is recorded by field auditors when features appearing in
newspapers, circulars, flyers, and display activity are both conducted in the same week.
This variable is calculated as:
FEATURE&DISPLAYit, = (Incremental volume sales of brand i in stores with feature and
display / Total volume sales of brand i) x 100.
45

Price reduction is a retailer promotional activity that is used to promote a specific
product or group of products. Prices of the products promoted are reduced below their
regular prices and that it is monitored and recorded by field auditors on a weekly basis.
The percent of incremental volume sales for brand i sold in the presence of price
reduction only during time t is calculated as:
REDUCTIONit = (Incremental volume sales of brand i in stores with price reduction only /
Total volume sales of brand i) x 100.
Econometric Methodology
This section starts with the estimation of the simultaneous equations that contain
the LA/AIDS and price reaction functions. Next, partial own- and cross-price elasticities
are calculated using the estimated parameters from the LA/AIDS. Then, followship
demand elasticities and observed price elasticities of demand for each brand are
calculated. Finally, the RI, OI, and CQ are estimated to measure the degree of market
power of the canned tuna industry in Knoxville.
Estimating Simultaneous Equations
To estimate the LA/AIDS model, the Stone index and the Corrected Stone index
time series must be generated. This study first uses the corrected Stone index in the
process of estimating the degree of market power. Then, the traditional Stone index is
used later with the same process for comparison. The corrected Stone index suggested by
Moschini (1995) is specified as:
46
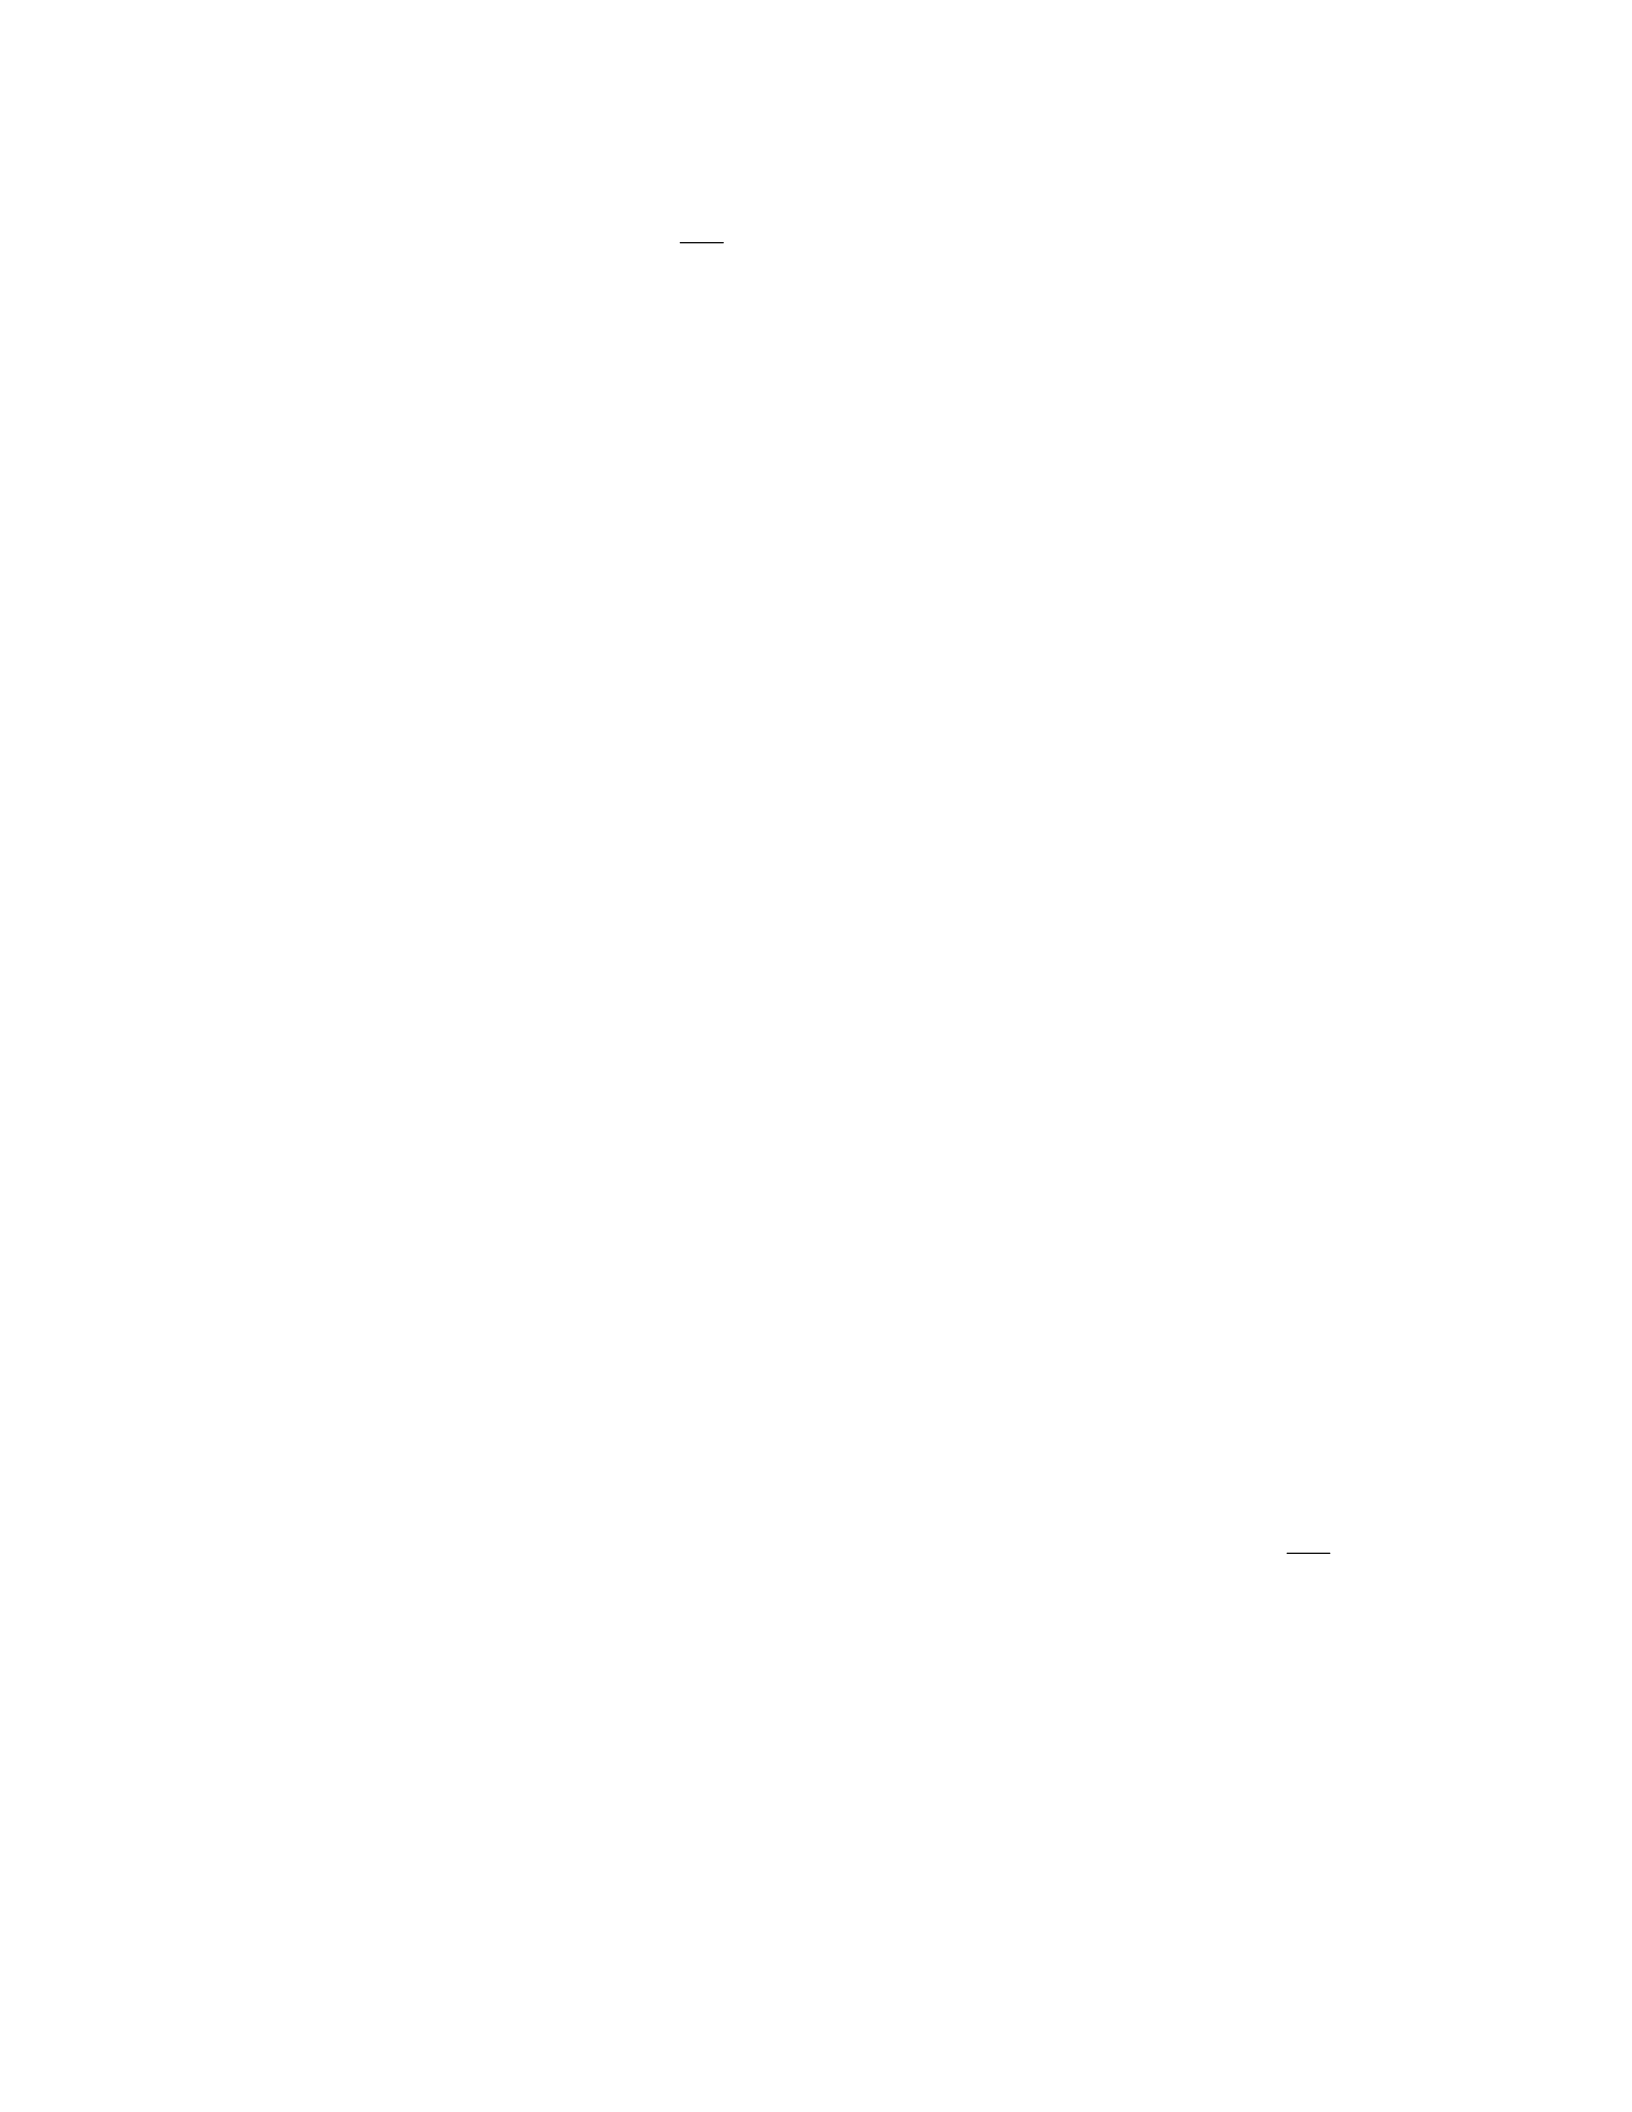
=∑
=0
1
*loglog
i
it
it
n
i
tp
p
wP , (3.1)
and the traditional Stone index is specified as:
∑
=
=n
i
itittpwP
1
loglog , (3.2)
where
it
p= the price of the ith brand at time t,
0
i
p= the average price of the ith brand over the time period,
it
w= the share of the ith brand at time t, and
subscript i = Starkist, Chicken of the Sea, Bumble Bee, and Allother.
Next, the expenditure (Y) on all brands at time t weighted by the corrected Stone index
at time t is calculated. In the estimation of the LA/AIDS, the weighted expenditure (Y)
is treated as a predetermined variable. Blanciforti and Green (1983) noted the use of the
price index considerably simplifies the estimation procedure but not without some cost.
If the Stone index is not treated as exogenous, the dependent variable,w, will appear on
both sides of the LA/AIDS and the resulting estimators will not necessarily possess
desirable sampling properties. However, if the Stone index was not treated exogenously,
the possible bias would be small because the term w was weighted by
t
*
t
it
it )
o
i
it
p
p
log( , which
is a fraction. Following Deaton and Muellbauer (1980), all previous studies that used the
Stone index in their LA/AIDS estimations ignored this econometric problem and treated
the Stone index exogenously in obtaining parameter estimates. In addition, each price
47
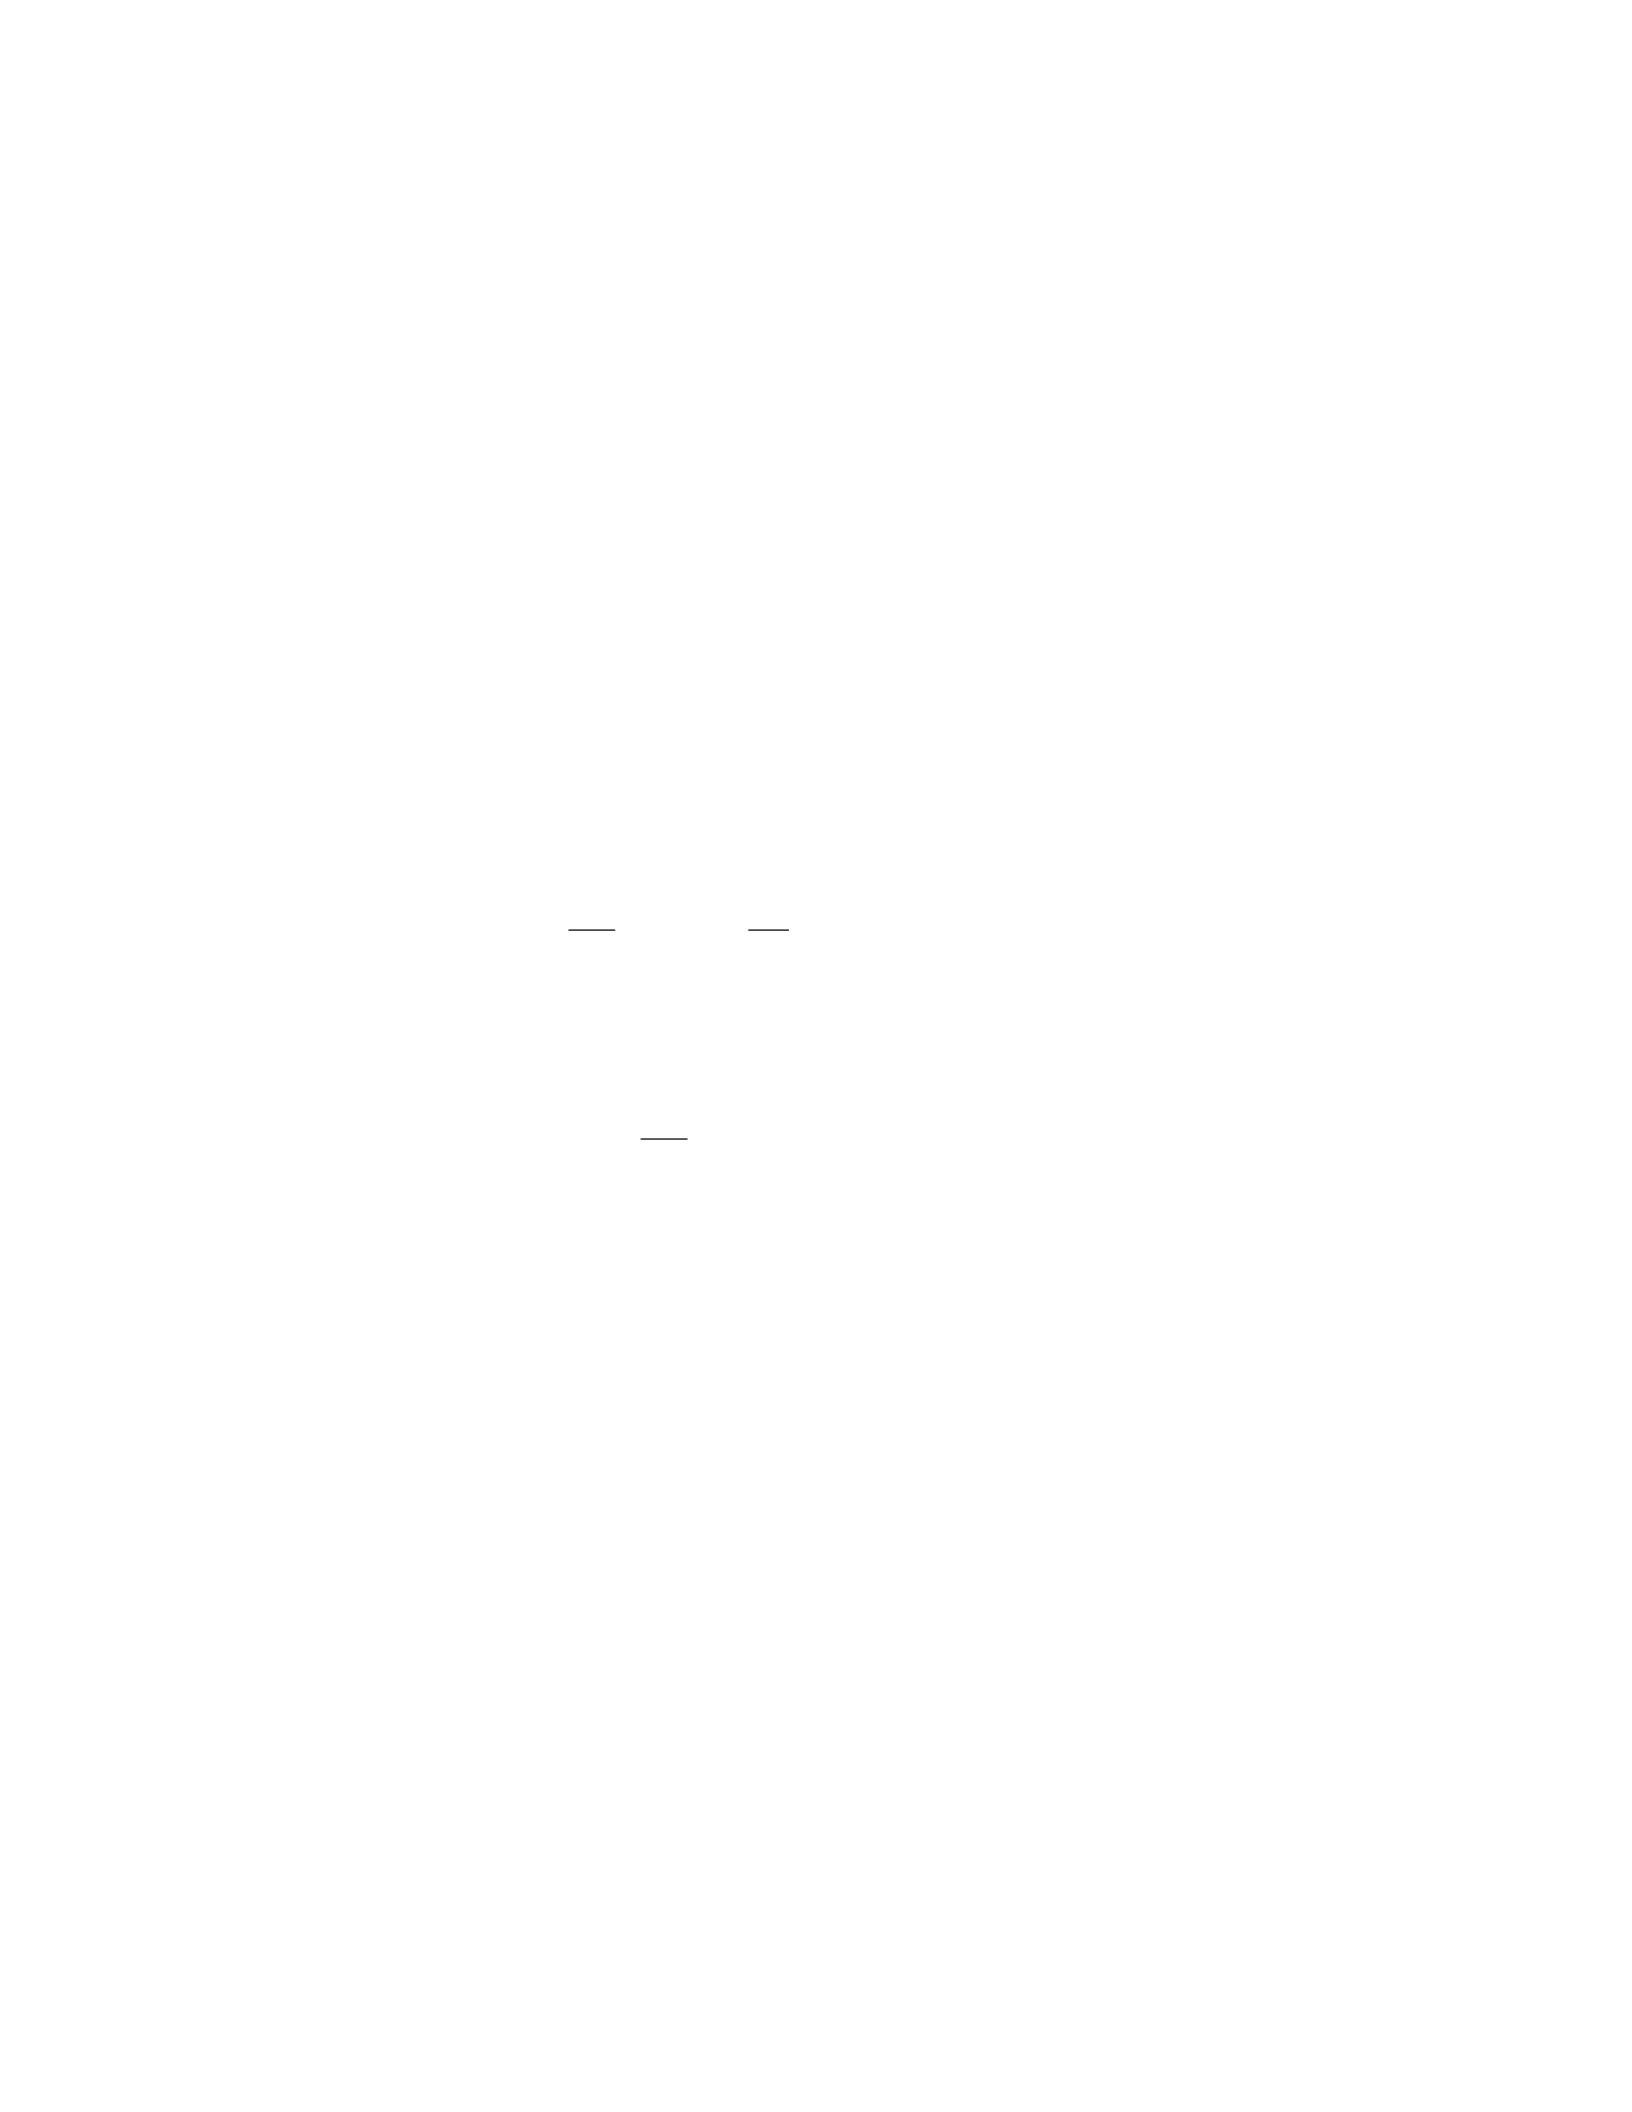
variable is normalized by its mean. Asche and Wessells (1997) noted that if prices are
normalized to one, the use of the elasticity formula suggested by Chalfant (1987), and
Green and Alston (1990) is valid in both the AIDS and LA/AIDS.
In equation (2.12), demand shift variables (Dit), such as promotional effects, can
be incorporated into the model (Heien and Pompelli, 1988; and Asche, Bjorndal, and
Salvanes, 1998) by allowing the intercept ( ) to be a function of them, that is
.
i
α
itkiii D
δαα
+=
*
By including demand shift variables and normalizing all prices, the LA/AIDS can be
written as:
it
t
t
i
j
jt
j
ijiit P
Y
p
p
w
ωβγα
+
++= ∑
=*0
4
1
*loglog , (3.3)
and the price reaction function is specified as:
ititmi
j
jt
jji
ijiit C
p
p
p
νλφµ
+++= ∑=≠ 0
4
1,
0loglog , (3.4)
where
,,, ijkii
γδα
,
,miij
λ
φ
, and = parameters to be estimated,
i
β
jt
p= the price of brand j at time t,
it
C= a vector of supply shift variables of brand i at time t,
0
j
p = the mean value of the jth price series,
t
Y= the total expenditure on canned tuna in the market weighted by the corrected stone
index at time t, and
i and j = Starkist, Chicken of the Sea, Bumble Bee, and Allother.
48

There are three sets of restrictions implied by economic theory imposed on the
parameters of the system (in the LA/AIDS):
Adding up: , , and (3.5)
1
*4
1=∑ =ii
α
0
4
1=∑ =iji
γ
0
4
1=∑ =ii
β
Homogeneity: j (3.6) 0=∑ ijj
γ
∀
Symmetry: ∀ i≠. (3.7)
jiij
γγ
=j
The adding up condition of the LA/AIDS model is satisfied by the data since
(Asche, Bjorndal, and Salvanes, 1997). Therefore, for four demand equations
only three demand equations of the leading firms (Starkist, Chicken of the Sea, and
Bumble Bee) are estimated, and then the parameter estimates for the fourth equation
(Allother) are generated from them. Thus, in this study the simultaneous equations
include three demand equations and four price reaction functions with seven endogenous
variables.
1=∑ i
w
The LA/AIDS and the price reaction functions are estimated simultaneously with
brand market shares (w) and prices ( ) as endogenous variables. The demand shift
vector D
i i
p
i captures brand i retail promotion activities. These activities include the percent
of incremental volume sales with the presence of display only (DISPLAY), the percent of
incremental volume with feature only (FEATURE), the percent of incremental volume sales
with the presence of both feature and display (FEATURE&DISPLAY), and the percent of
incremental volume with the presence of price reduction (REDUCTION). That is Di
{FEATURE≡i, DISPLAYi, FEATURE&DISPLAYi, REDUCTIONi}.
Several assumptions are made in order to estimate the price reaction functions.
No change in the cost structure of both manufacturers and retailers is assumed to have
49

occurred over the three year period. No change in production technology among canned
tuna processors is assumed to have taken place. In addition, changes in the prices of
inputs for the production of canned tuna affect firms similarly. Finally, no principal-
agent problem between the food producers and the retailers is assumed to exist, implying
that the manufacture-retail price margin was constant for each firm. Consequently, all
variations in price were attributed to brands’ pricing strategies. The shift variables (C)
in the price reaction functions include total expenditure (Y), brand i’s market share (w)
and its promotional activities (D
i
i
i).
The simultaneous system contains three demand equations and four price reaction
equations. The simultaneous system is identified by both order and rank conditions.
Since the demand and price equations are assumed to take place simultaneously based on
the Bertrand competition assumption, correlations of the disturbances across equations
could be present; therefore the three-stage least squares method (3SLS) is selected to
estimate the simultaneous equations.
With respect to 3SLS, the first stage starts with the regression of each endogenous
variable on the right hand side of each equation on all predetermined variables in the
model and obtains the estimated values of the endogenous variables. For the second
stage, the structural model is estimated using ordinary least squares method and the
endogenous variables on the right hand side of the model are replaced by the estimated
values obtained from the first stage. The third stage takes into account the correlation of
the disturbances across equations. A variance-covariance matrix is obtained by using the
two-stage least squares residuals from the second stage. Then, the Aitken generalized
50

least squares (GLS) estimation is applied to the structural equations using the variance-
covariance matrix.
The simultaneous equations are able to be estimated using 3SLS based on the
assumption that the structural error terms are homoskedastic and not autocorrelated.
However, when the observations are collected over time, the error terms are likely to be
autocorrelated. Blanciforti, Green and King (1986) found evidence of serial correlation
in the AIDS models of aggregate food groups. Yen and Chern (1992) estimated a
flexible demand system with correction for autocorrelation and compared results with
those obtained from the Translog and AIDS models. They concluded that correcting
serial correlation in demand system modeling was important. Heteroskedasticity is
normally encountered when dealing with micro economic data “but not when dealing
with aggregates observed over time unless the time period covered is very long”
(Kmenta, 1986). Because the scanner data used in this study were collected in the same
geographical area and for the same supermarkets over the three-year period,
heteroskedasticity might be encountered. Residuals that violate the assumption of no
autocorrelation and homoskedasticity are called nonspherical. Estimation of models with
nonsperical residuals yields estimated variances that are inconsistent. As a result, the
standard tests of significance and confidence intervals are not valid. Therefore, it is
important to test the autocorrelation and heteroskedasticity problems for each equation in
the system.
The Breusch-Pagan test is employed to test heteroskedasticity, and the sample
correlogram and Ljung-Box statistics (L-B statistics) are used to test for autocorrelation.
51

Specifically, the L-B statistics tests whether autocorrelation exists, and the sample
correlogram approximately indicates the order of autocorrelation.
If heteroskedasticity and/or autocorrelation are found, the simultaneous equations
are estimated using an improved estimation method called weighted three-stage least
squares (W3SLS). The W3SLS method can remedy the autocorrelation and
heteroskedasticity problems. The method is asymptotically efficient and gives consistent
estimates of both estimated parameters and their variance-covariance matrix (Kmenta,
1986). The procedures of the W3SLS are as follows.
Step 1: Each regression equation is estimated using the two-stage least squares method in
order to obtain the regression residuals. All explanatory variables are used as
instrumental variables.
Step 2: The regression residuals are tested for autocorrelation using sample correlogram
and Ljung-Box statistics (L-B statistics) and for heteroskedasticity using the Breusch-
Pagan test.
Step 3: If autocorrelation and/or heteroskedasticity are found, each equation is weighted
by a transformation matrix. Each equation’s transformation matrix is constructed based
on the Aitken generalized least squares (GLS) method. In other words, if a variance-
covariance matrix (Ω) of an equation is not equal to , that is E(e) , i and j =
1, 2,…, n, a transformation matrix (P) can be constructed such thatPor
.
I
2
σ
jieij
σ
=
′
P1−
Ω=
IPP =
′
Ω
Step 4: Each regression equation is pre-multiplied (i.e., weighted) by its transformation
matrix in order to get a transformed equation.
52
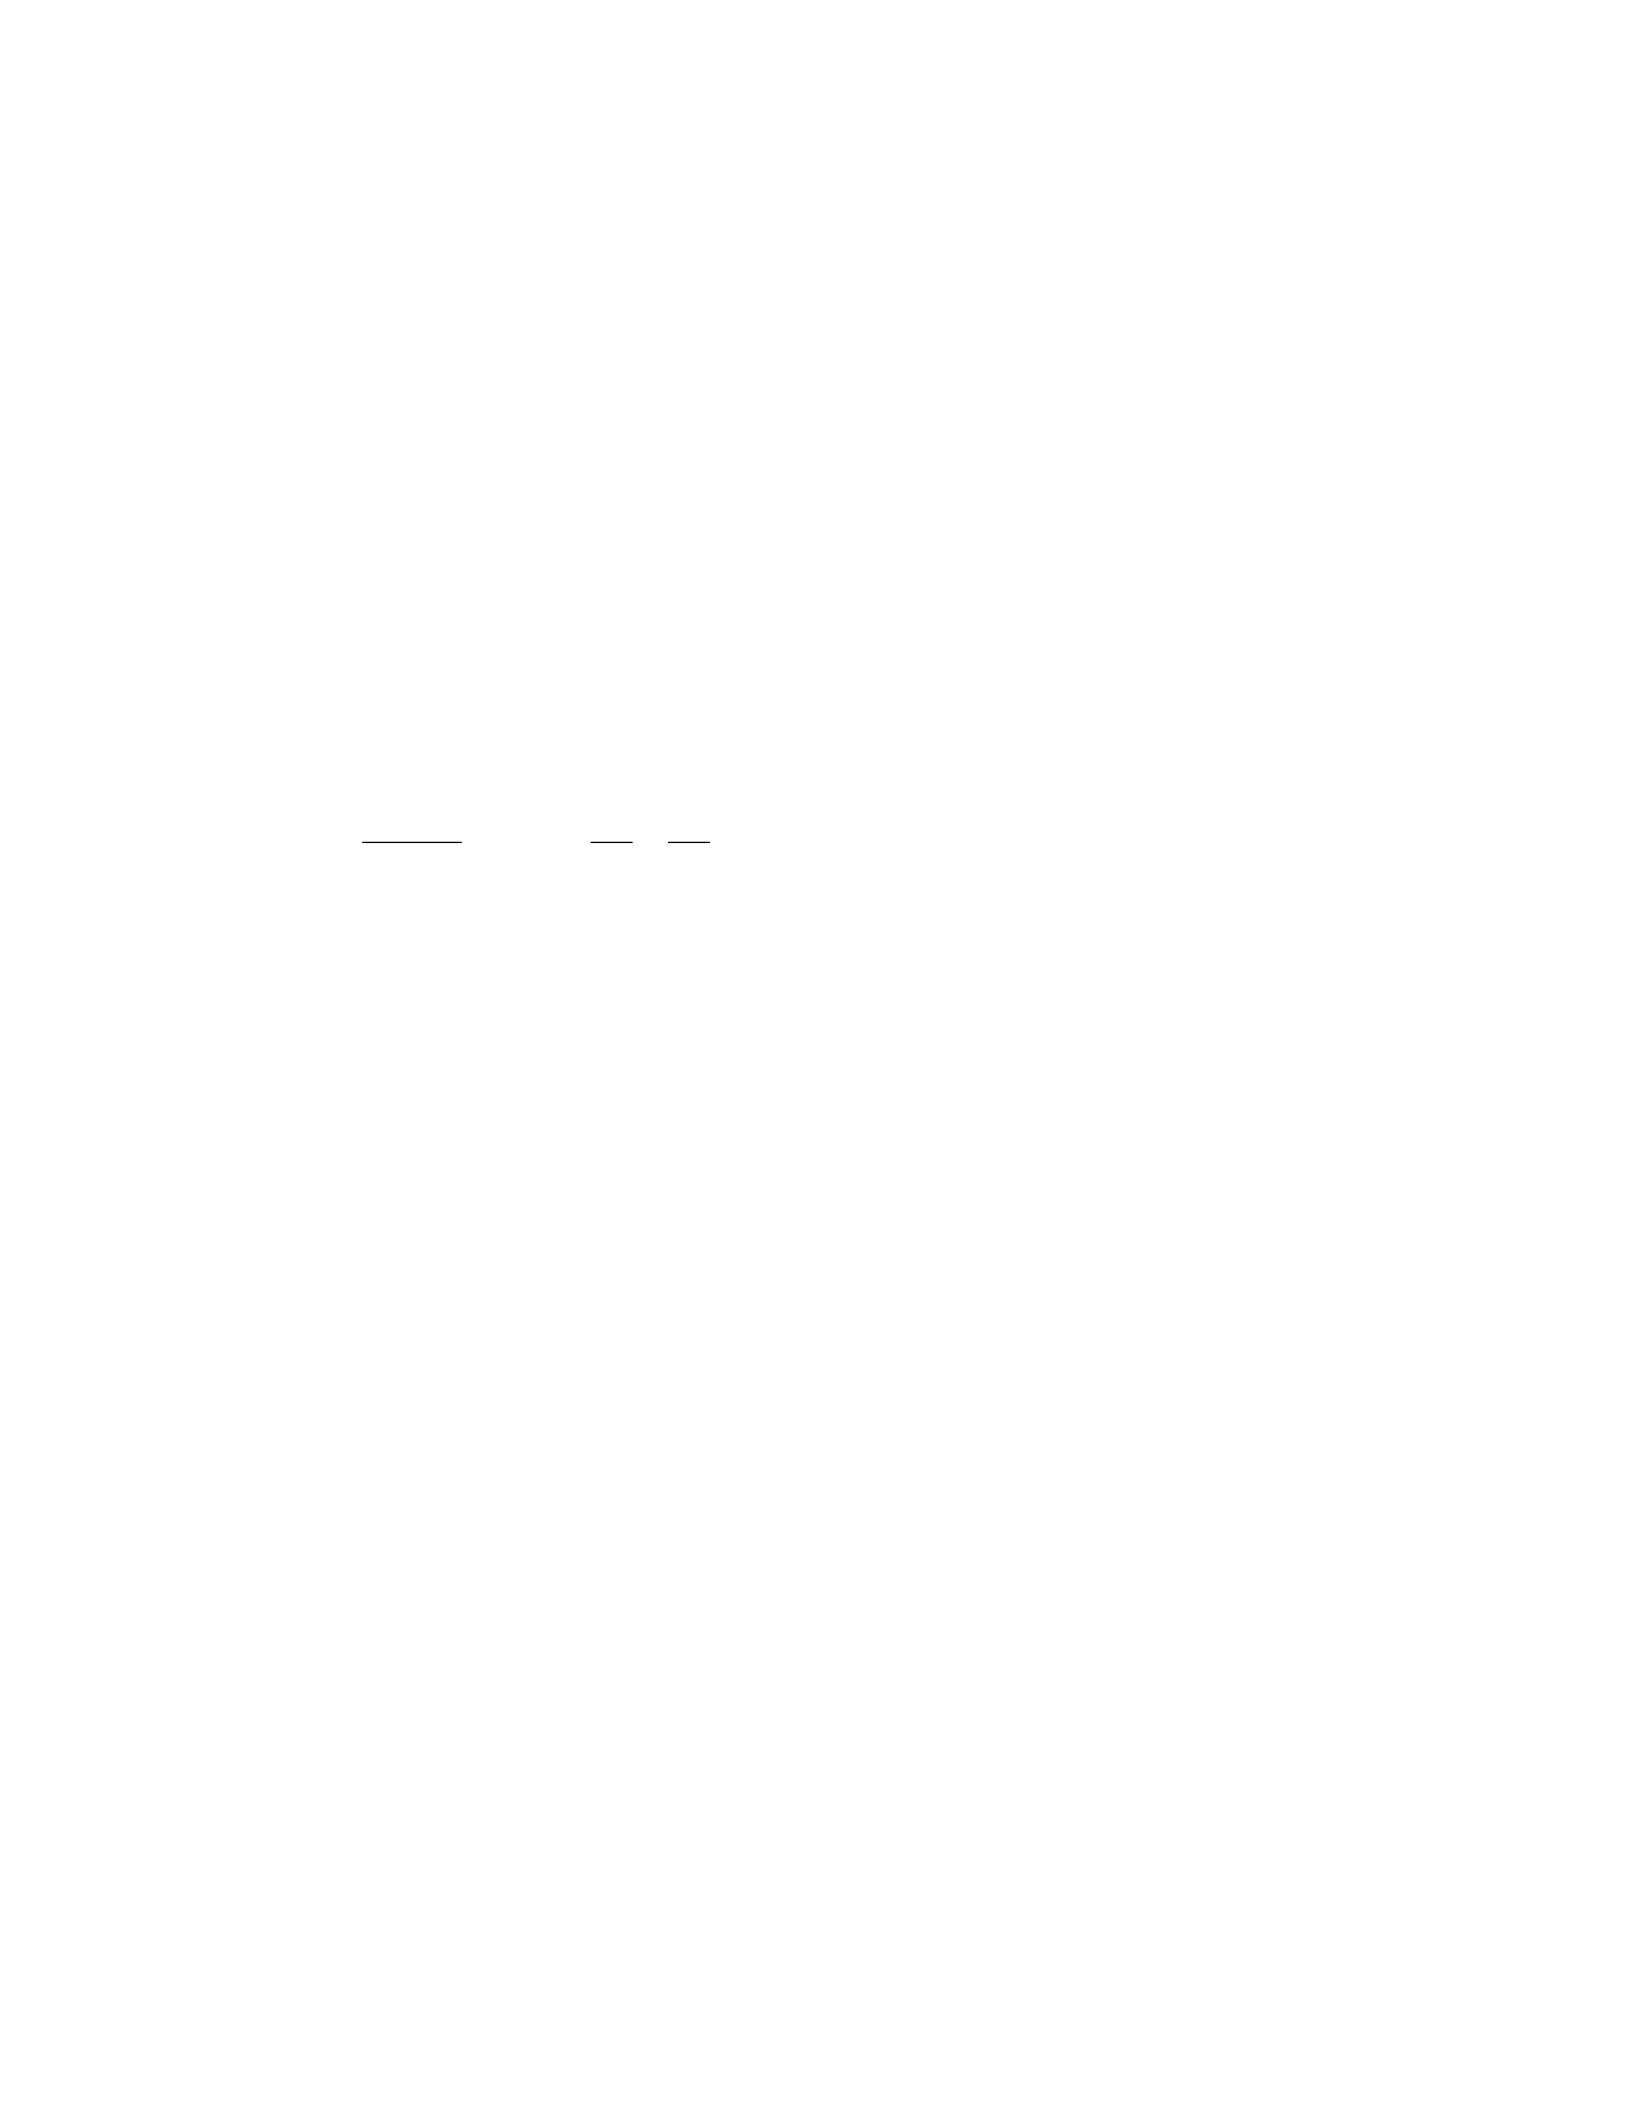
Step 5: All transformed equations are then estimated simultaneously using 3SLS.
Calculating Demand Elasticities
The parameter estimates obtained from the LA/AIDS are used to calculate partial
own- and cross-price elasticities, whereas price-response elasticities are obtained directly
from the parameter estimates from the price-reaction functions. The formula of the
partial own- and cross-price elasticities of demand ( ij
η
) suggested by Chalfant (1987),
and Green and Alston (1990) is:
j
i
i
i
ij
k
ij
j
i
ij w
wwPd
Qd
β
γ
δη
−+−== ln
ln , (3.11)
where is the Kronecker delta ( = 1 for i = j; = 0 for i ≠ j), wand ware average
market shares of brand i and j, and and are parameters estimated from the
LA/AIDS (i, j = Starkist, Chicken of the Sea, Bumble Bee, and Allother). Alston, Foster,
and Green (1994) conducted Monte Carlo experiments to investigate the appropriate
formula to compute elasticities from the LA/AIDS. They found that the formula in
equation (3.11) is quite accurate relative to alternatives since it is a reasonably good
approximation to the true AIDS.
k
ij
δ
k
ij
δ
k
ij
δ
i
β
i j
ij
γ
Following Chalfant (1987) and Cotterill (1994), standard errors of the partial
own- and cross-price elasticities, SE(ij
η
), are computed based on the standard errors of
the estimated parameters and the average budget shares that are treated as nonstochastic.
The standard errors are computed as:
53
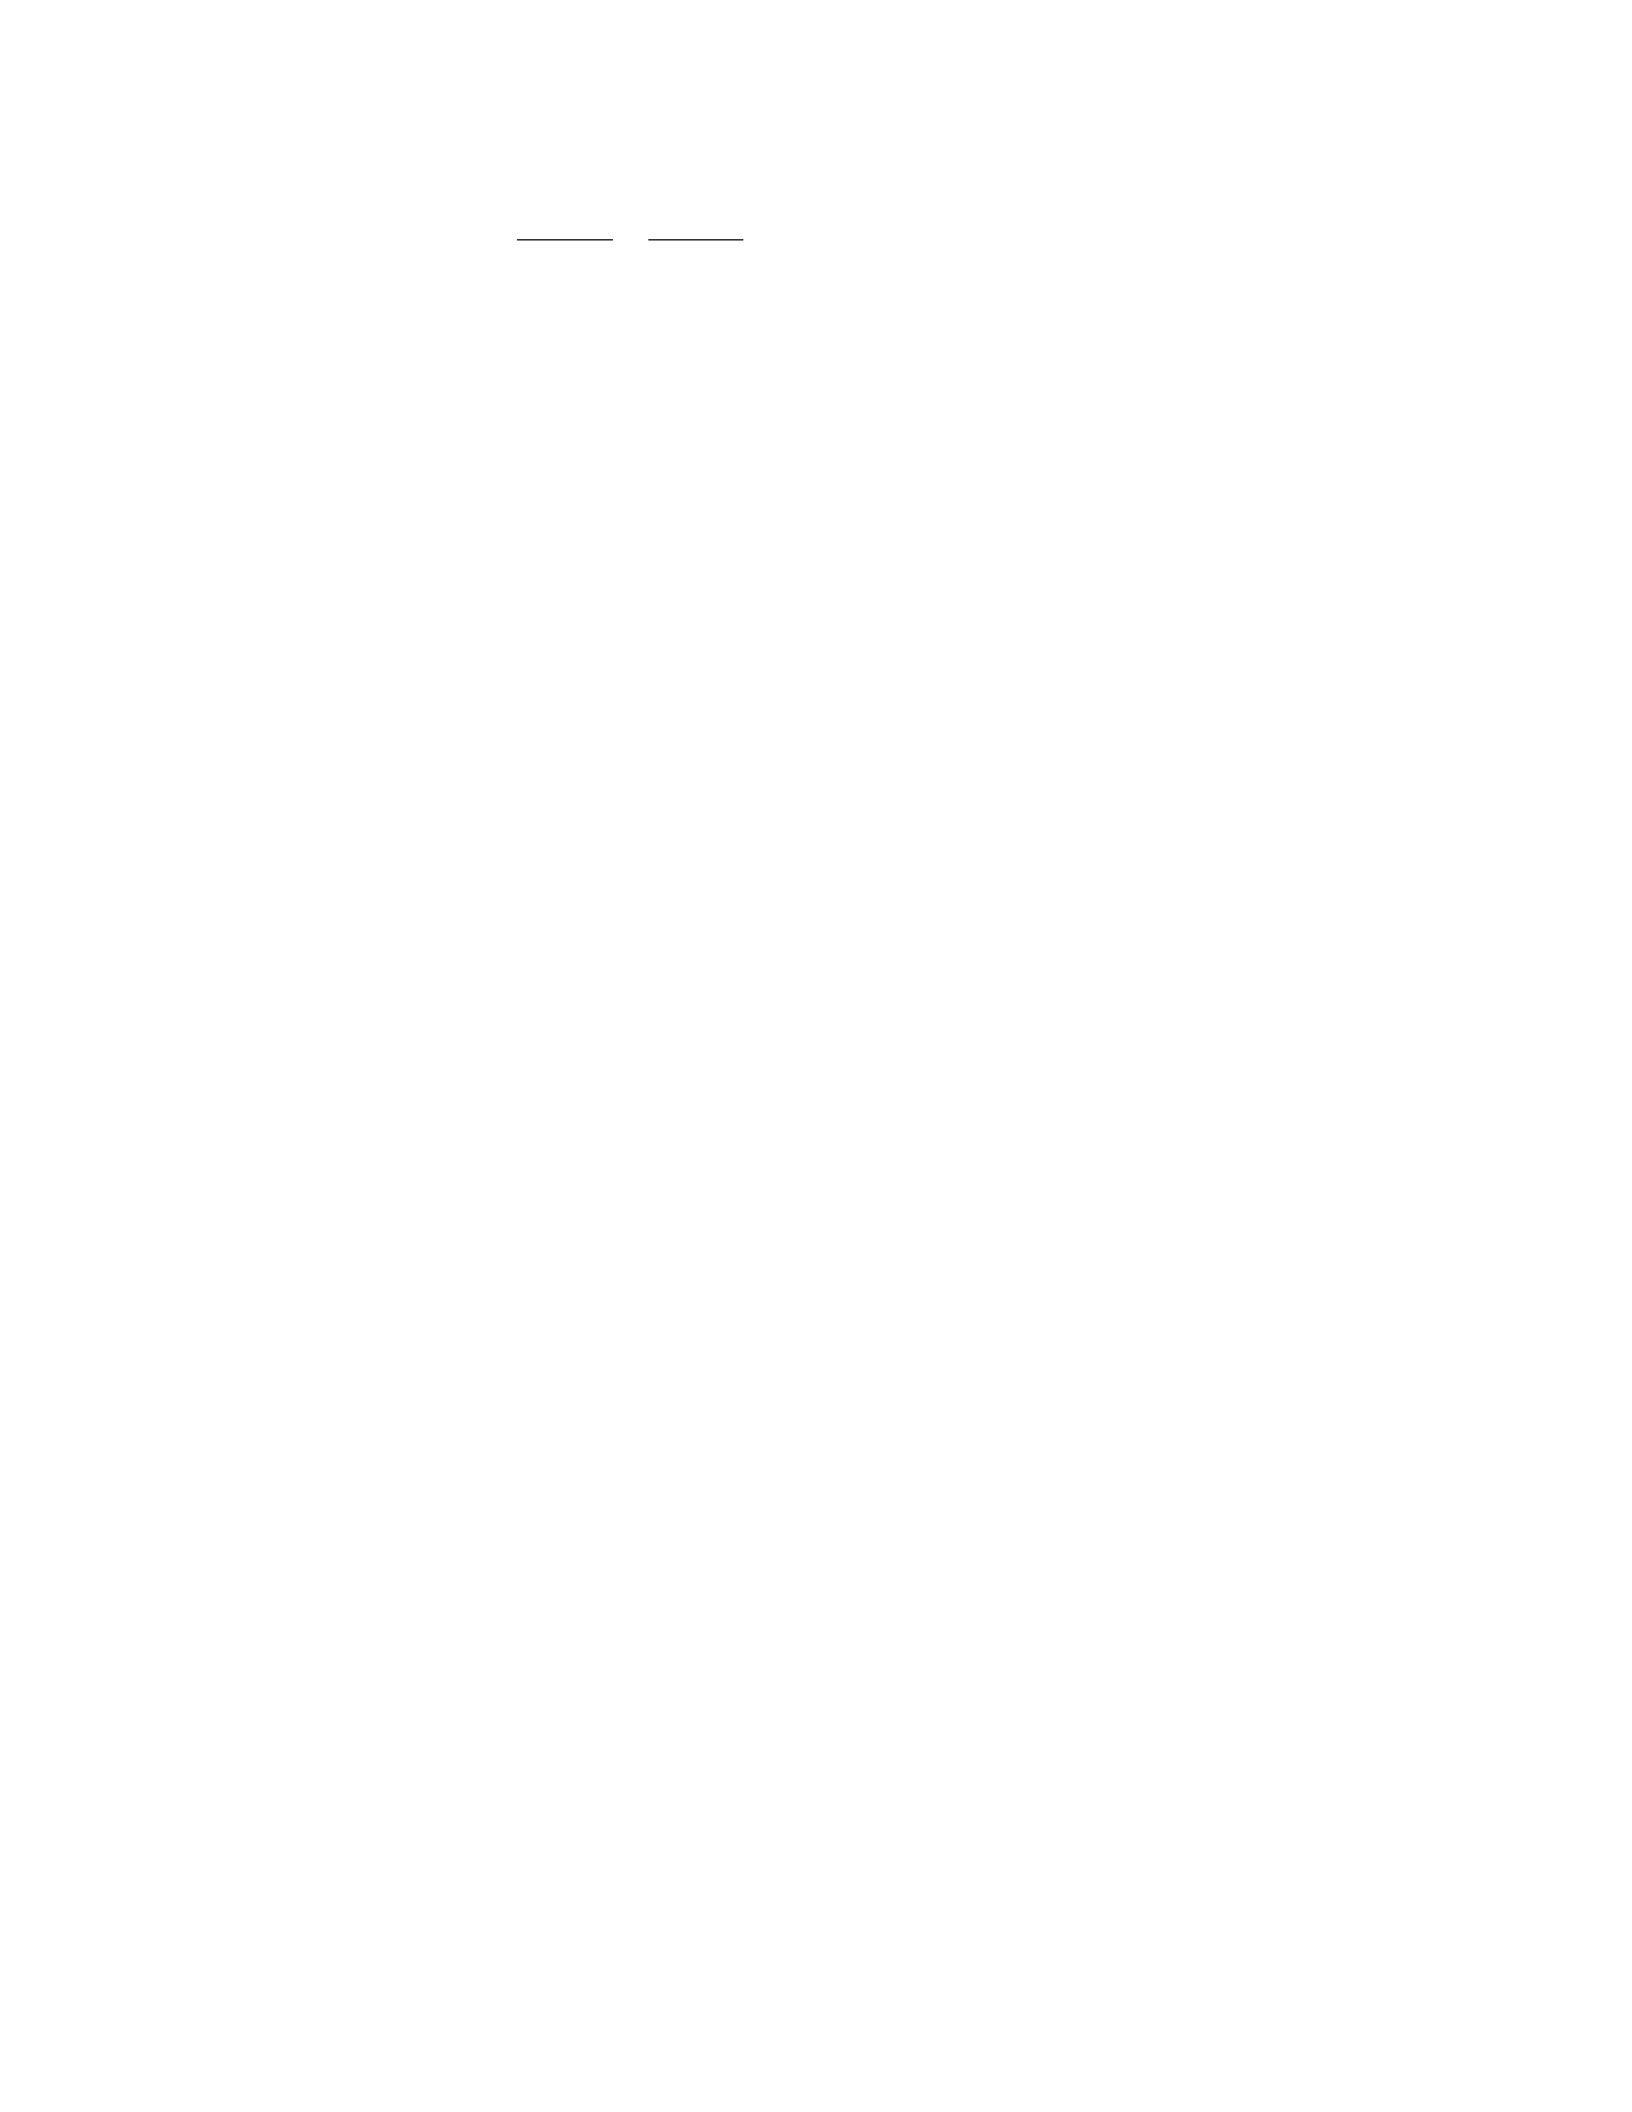
SE(ij
η
) = j
i
i
i
ij w
w
SE
w
SE )(
)(
β
γ
−, (3.12)
where and are standard errors of the estimated parameters from the
LA/AIDS, and wand ware average market shares of brand i and j.
)( ij
SE
γ
i
SE
β
(
j
)
i
Calculating Followship Demand Elasticities and Observed Demand Elasticities
After obtaining partial own- and cross-price elasticities, the fully collusive
elasticity and the observed demand elasticity of each brand are calculated. The fully
collusive elasticity of brand i, , can be obtained by adding up its partial own-price
elasticity (
F
i
η
ii
η
) and all cross-price elasticities ( ijji ≠,
η
) assuming that all price-response
elasticities are equal to one (full collusion), . The observed demand
elasticity of brand i, , is defined as , where represents rivals’
price-response elasticity or the conjectural price-response of firm j with respect to firm i’s
price (i≠j). The non-followship demand elasticity of brand i is its partial own-price
elasticity (
n
ji
ij
≠
∑
+
η
jiij
εηη
ii
F
i=
ηη
n
ji
ii ∑
≠
+
0
i
η
i
η
=
0
ji
ε
ii
η
).
Calculating Measures of the Degree of Market Power
The degree of market power of brands in the canned tuna industry is measured by
the Rothschild and O indices, and the Chamberlin Quotient. Fully collusive elasticities
and observable demand elasticities are used to calculate these measures.
54
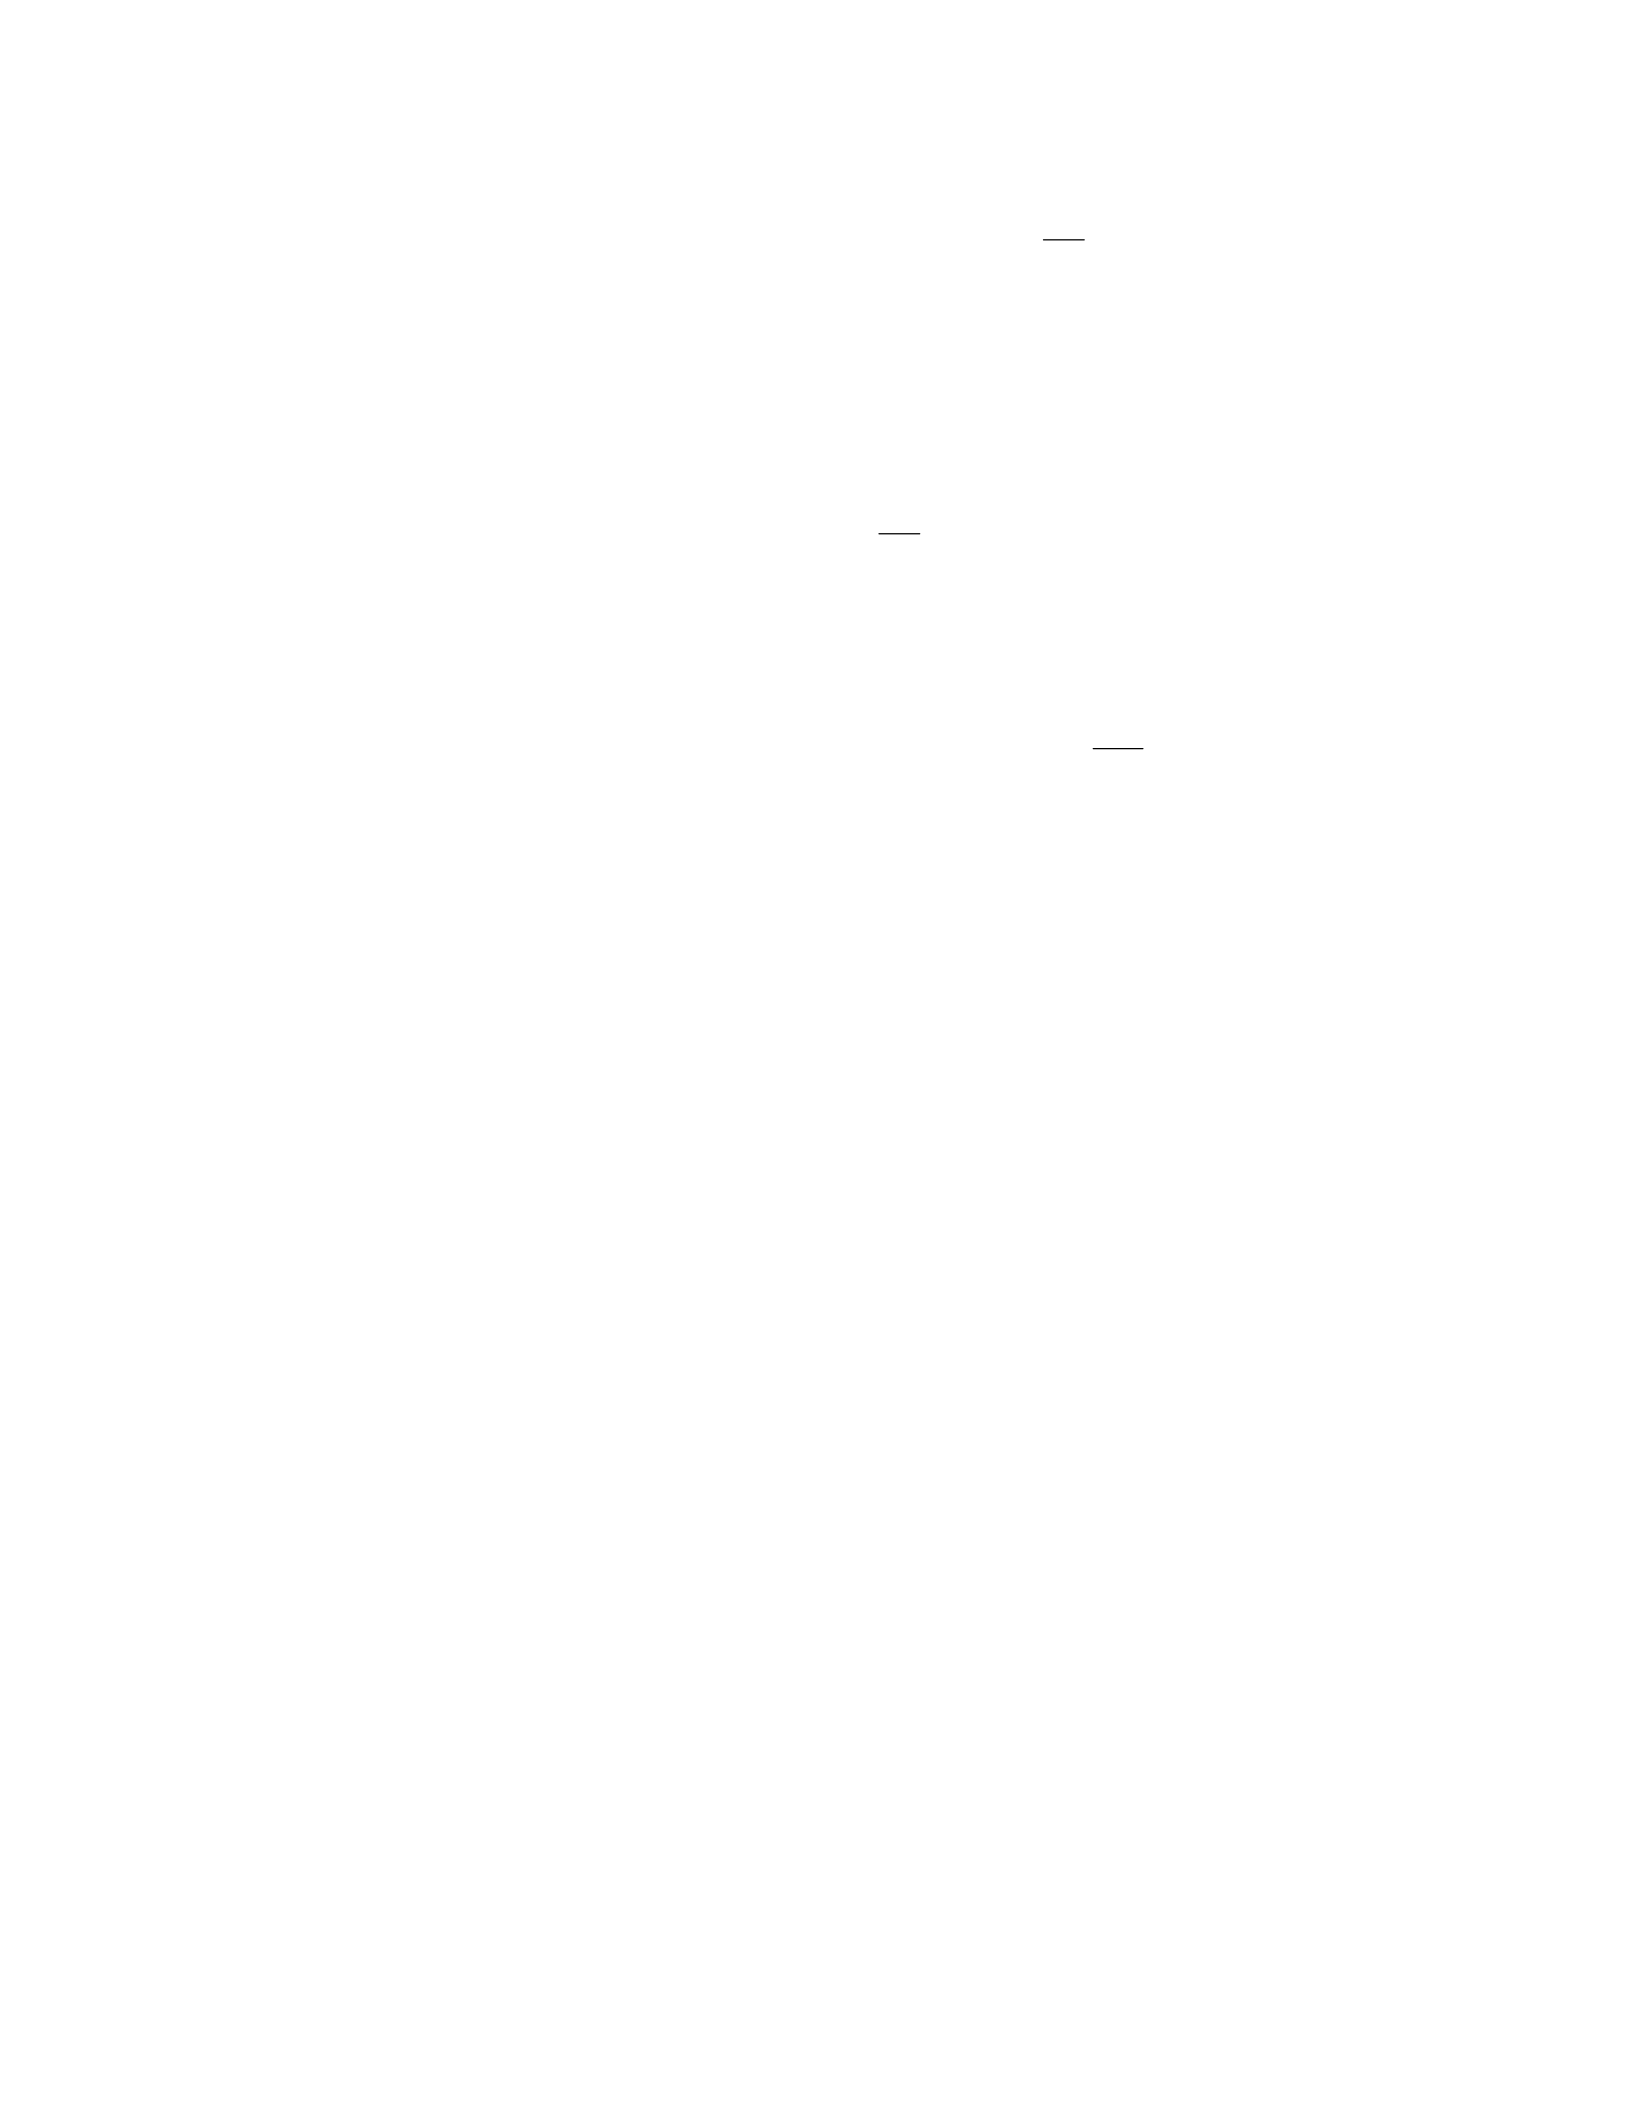
The Rothschild Index (RI) is specified as: RIi =
ii
F
i
η
η
(3.13)
where represents the fully collusive elasticity of brand i, and
F
i
η
ii
η
represents the non-
followship demand elasticity of brand i or its own-price elasticity.
The O Index is specified (OI) as: OIi = 0
i
F
i
η
η
, (3.14)
where represents the observable elasticity of demand for brand i.
0
i
η
The Chamberlin Quotient (CQ) is specified as: CQi = 1 –
i
i
OI
RI . (3.15)
Re-estimating Using the Stone Index
In order to see the empirical magnitude of the corrected version of the Stone
index, this study re-estimates the simultaneous equations using the Stone index in the
LA/AIDS, and then calculates the RI, OI, and CQ to compare the differences.
55

Chapter Four
Estimation and Results
This chapter starts with a statistical description of the scanner data for the canned
tuna industry used in the estimation. Building on the empirical model developed in the
previous chapters, it presents the estimation of the simultaneous equations with the
corrected Stone index in the LA/AIDS and remedies autocorrelation. Weighted three-
stage least squares are used for the final estimates of the model. The estimated
parameters obtained from the LA/AIDS are used to calculate partial own- and cross-price
elasticities. Next, the RI, OI, and CQ are calculated to measure the degree of market
power of each brand using the partial own-price and cross-price elasticities, and price-
response elasticities obtained from the estimation. The estimated price-reaction functions
are analyzed for strategic price responses among brands in the industry. Finally, the
process of estimating the degree of market power is repeated with the use of the
traditional Stone index in the LA/AIDS, and the results are compared.
Data Description
Weekly scanner data for canned tuna industry were collected by IRI for 157
weeks over the period of January 4, 1998 to December 31, 2000 from 134 supermarkets
in Knoxville, Tennessee. There are four brands, Starkist, Chicken of the Sea, Bumble
Bee, and Allother. Descriptive statistics for all variables and brands are presented in
Table 4.1.
56
Table 4.1 Descriptive Statistics for Canned Tuna: 1998 – 2000 (157 weekly observations)
Variable Mean Standard Deviation Min Max
Share (wi):
Starkist 0.666 0.059 0.415 0.823
Chicken of the Sea 0.146 0.036 0.071 0.316
Bumble Bee 0.048 0.015 0.023 0.144
Allother 0.139 0.048 0.061 0.343
Price (Pi):
Starkist 0.915 0.081 0.633 1.126
Chicken of the Sea 0.987 0.146 0.487 1.248
Bumble Bee 0.963 0.167 0.428 1.288
Allother 0.686 0.060 0.450 0.798
% Volume in Feature Ads only (Featurei):
Starkist 8.533 10.712 0.067 48.046
Chicken of the Sea 3.526 10.258 0.037 73.875
Bumble Bee 5.012 13.183 4.018 64.099
Allother 8.723 17.107 0.864 70.108
% Volume on Display only (Displayi):
Starkist 15.242 9.980 0.499 50.009
Chicken of the Sea 2.350 4.826 0.727 32.264
Bumble Bee 6.137 9.432 0.100 49.273
Allother 14.959 14.082 0.666 63.366
% Volume on Feature and Display (Feature and Displayi):
Starkist 10.291 12.127 1.347 62.497
Chicken of the Sea 3.614 10.222 2.089 54.276
Bumble Bee 3.922 14.191 7.107 80.696
Allother 7.413 15.193 0.880 65.874
% volume on Price Reduction (Reductioni):
Starkist 7.635 5.807 0.809 33.629
Chicken of the Sea 13.464 11.606 0.185 54.854
Bumble Bee 17.347 15.808 0.012 63.536
Allother 11.154 12.401 0.053 49.954
Total Expenditure (Y) 28845.11 4372.3 15973.69 50266.57
t
57
Starkist, Chicken of the Sea, and Bumble Bee are the three leading brands, which
had average combined market shares of about 86 percent of the canned tuna sales in
Knoxville area. Starkist’s average market share was 66.6%, the highest in the industry.
For Chicken of the sea, Bumble Bee and Allother, their market average shares were
14.6%, 4.8%, and 13.9% respectively. Chicken of the Sea had the highest average price
per unit ($0.99/unit), whereas the average price of Allother was the lowest ($0.69/unit).
Table 4.2 compares the canned tuna market shares between Knoxville market and
the U.S. market in 2000. The three leading brands’ market share (CR3) at the national
level was 82 percent lower than those in Knoxville market (85%). Starkist seemed to be
a popular brand in Knoxville market since its market share was 64 percent compared to
only 40% at the national level; however it was the leader in both market levels.
Interestingly, Bumble Bee had higher market share (22%) than Chicken of the Sea (20%)
at the national level, whereas its market share in Knoxville (5%) was lower than those of
Chicken of the Sea (16%). The market share of Allother in Knoxville (15%) was very
close to those for the whole country (16%).
Table 4.2 Comparing Market Shares between Knoxville and U.S. markets in 2000
Brand Knoxville Market U.S. Market*
Starkist 64 40
Chicken of the Sea 16 20
Bumble Bee 5 22
Allother 15 16
*Source: US Business Reporter, available at http://www.activemedia-guide.com/mrksh_profile.htm
58
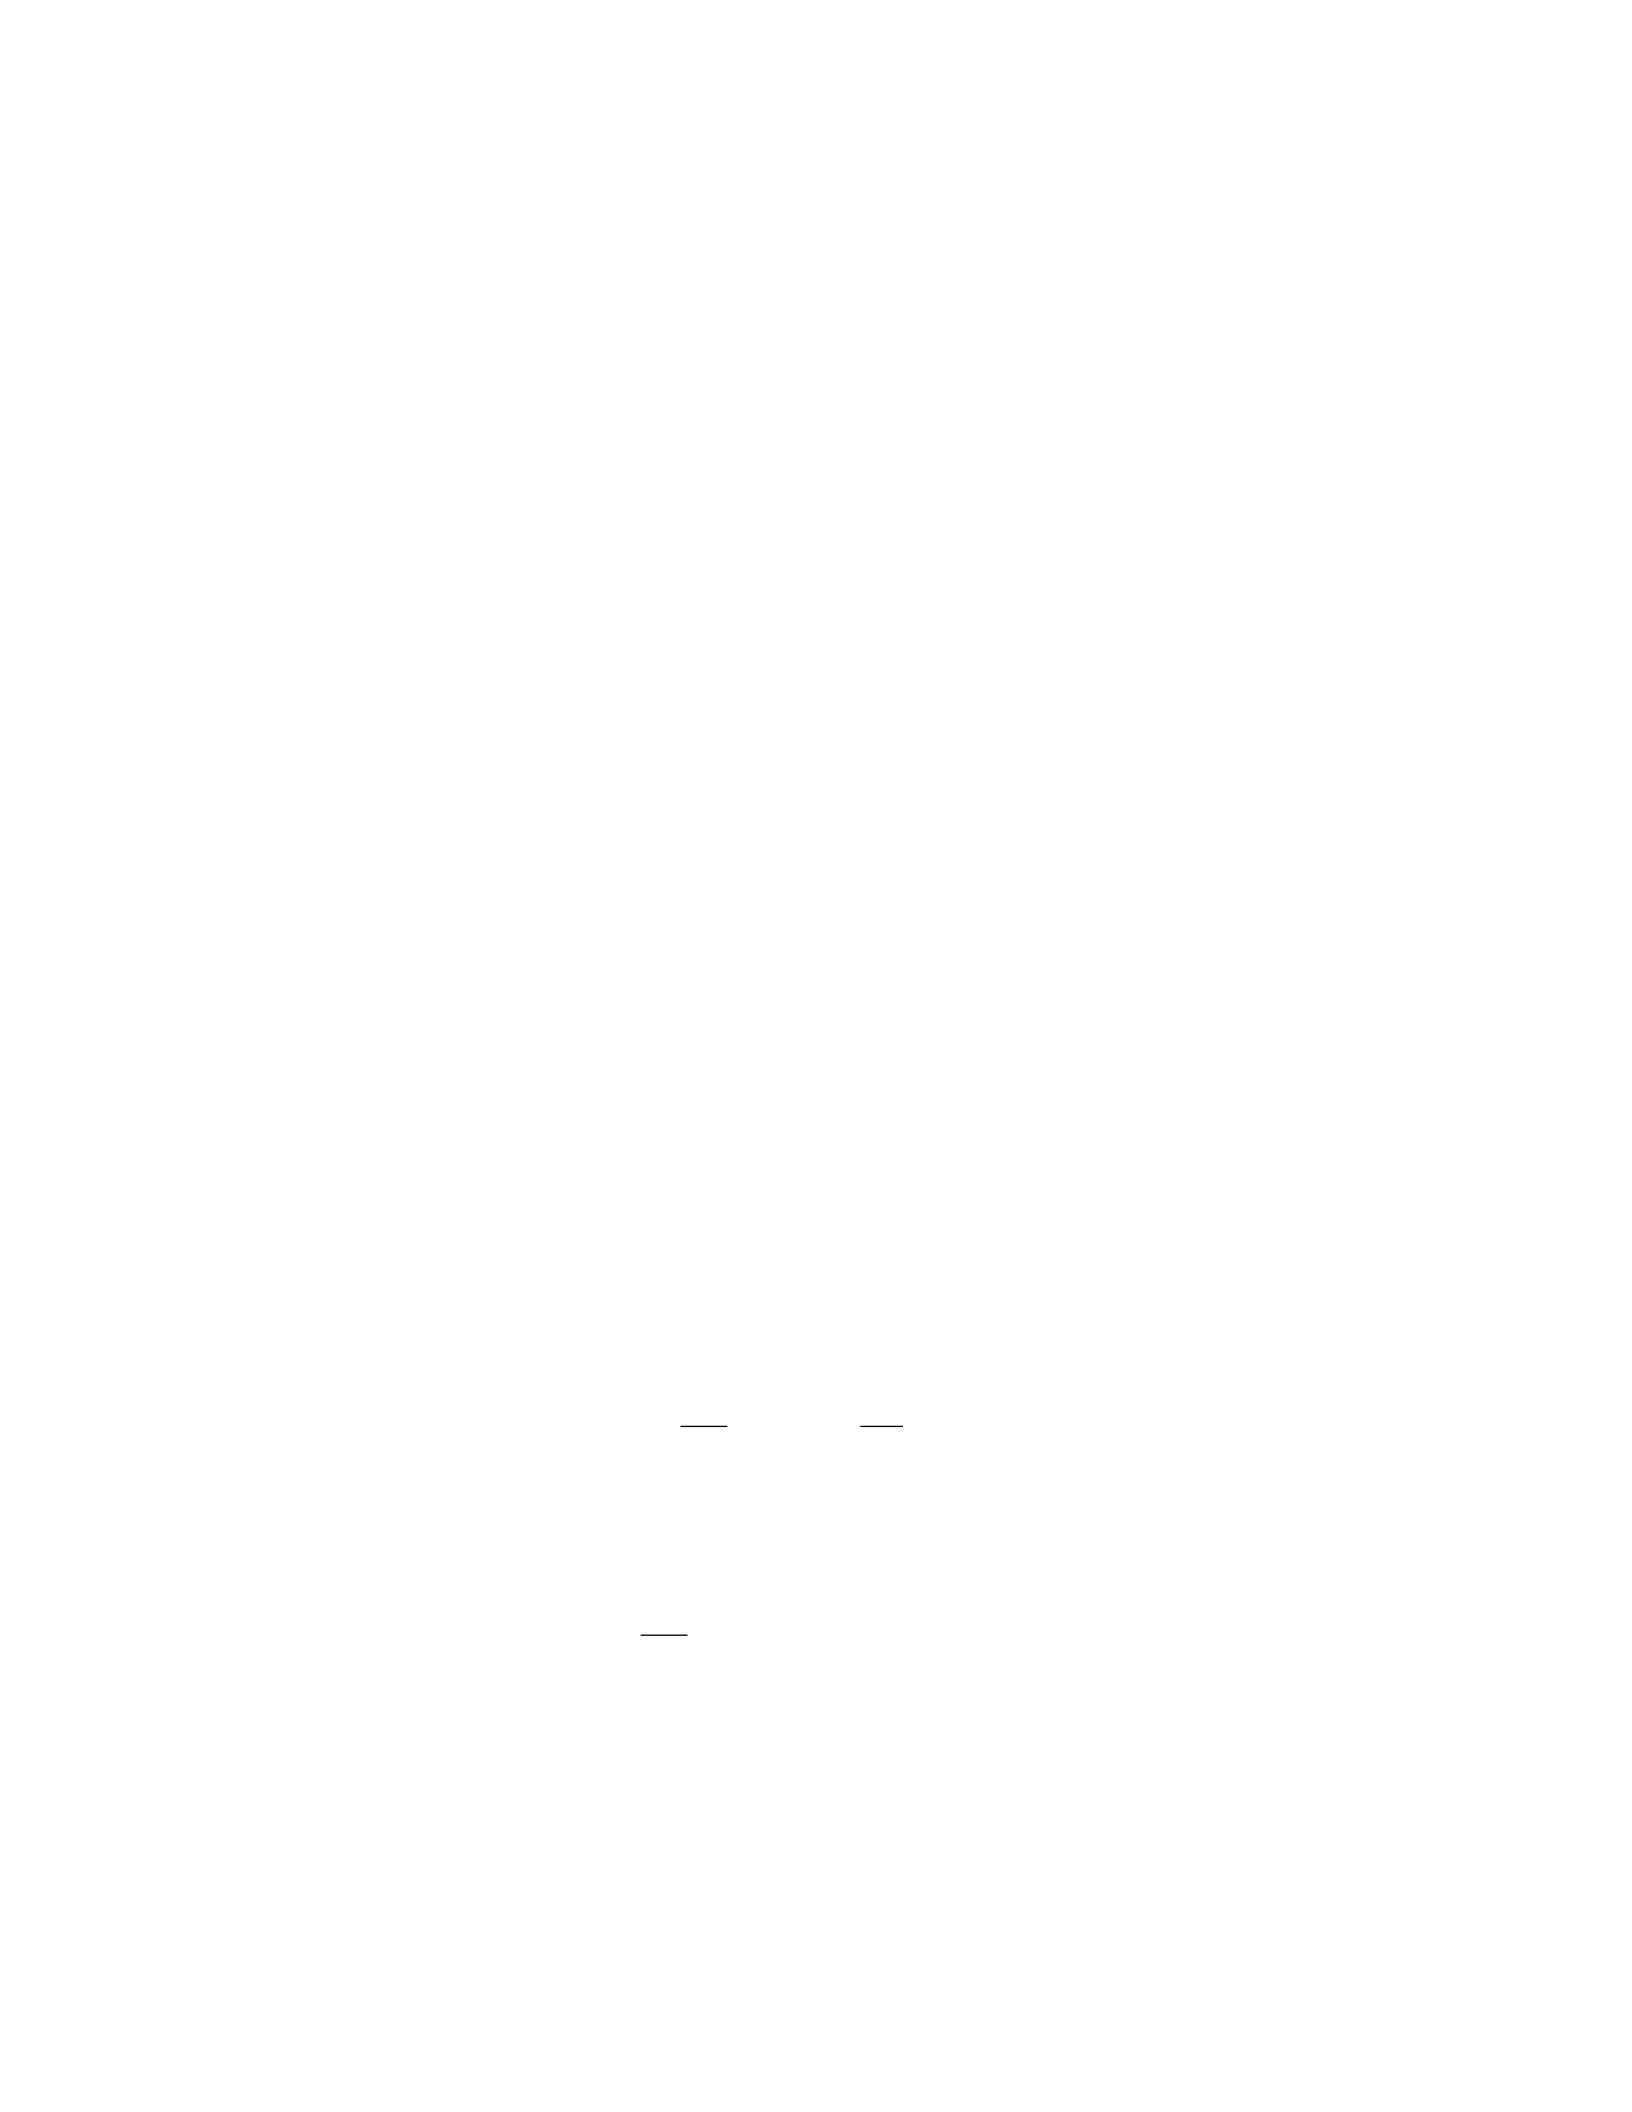
With respect to promotional activities, Starkist was the most successful brand in
the presence of feature advertising and display. It had the highest average percentage of
total volume sales in the presence of display (15.24%), and display and feature together
(10.29%). Starkist was the only brand that offered price reductions every week during
the observation period in at least one supermarket. However, its average percentage of
total sales in the price reduction category was only 7.64%. Bumble Bee had the highest
average percentage of total sales (17.35%) when it reduced its price. However, to
analyze how successful a brand was when it had a price reduction, the brand’s price
elasticity of demand should be taken into account. Finally, the average total expenditure
spent on all canned tuna brands within a week in Knoxville market was $28845.11.
Estimation Results
Simultaneous Equations
The simultaneous equations in this dissertation contain the LA/AIDS and price-
reaction functions. The LA/AIDS is specified as:
it
c
t
t
i
j
jt
j
ijitkiiit P
Y
p
p
Dw
ωβγδα
+
+++= ∑
=
loglog 0
4
1
, (4.1)
and the price reaction function is:
ititmi
j
jt
jji
ijiit C
p
p
p
νλφµ
+++= ∑=≠ 0
4
1,
0loglog , (4.2)
where
it
w = the market share of good i at time t,
59
it
pand = the price of brand i and j at time t,
jt
p
0
j
p = the mean value of the jth price series,
=∑
=0
1
loglog
i
it
it
n
i
c
tp
p
wP = the corrected Stone index,
t
Y = the total expenditure on the canned tuna in the market weighted by the corrected
stone index at time t,
it
D = a vector of demand shift variables of brand I at time t {FEATURE≡i, DISPLAYi,
FEATURE&DISPLAYi, REDUCTIONi},
it
C= a vector of supply shift variables of brand i at time t {w, Y, and D≡ii},
,,, ijkii
γδα
,
,kiij
λ
φ
, and = parameters to be estimated, and
i
β
i = Starkist, Chicken of the Sea, Bumble Bee, and Allother.
The LA/AIDS contains three equations (the demand equations of Starkist, Chicken of the
Sea, and Bumble Bee with the demand equation of Allother being dropped) and four price
reaction equations.
Testing for Heteroskedasticity
The Breusch-Pagan test is employed to detect heteroskedasticity for each
equation. The test is based on the assumption that the variance ( ) of each disturbance
term, , is a linear function of some explanatory variable. Therefore, it is not constant
over time depending on the variation of the related explanatory variable. The explanatory
variables in this dissertation include total expenditure, and promotional activities, which
2
σ
i
ε
60
are collected from 134 supermarkets. Although there are differences in size of
supermarkets, the data are aggregated and collected from the same supermarkets during
the time period. The data are treated like a representative supermarket. Thus, the
regression variances seem to be constant over the time period. Nonetheless, tests for
heteroskedasticity are conducted to be sure that there is no such problem involved in the
estimation. According to the Breusch-Pagan test, explanatory variables that are
suspected to cause heteroskedasticity are selected. In this study, the total expenditure
variable (Yt), which represents consumers’ total budgets spent on all canned tuna brands,
is selected. The test is done as follows.
1. Regress each equation using 2SLS in order to obtain its regression residuals (e).
t
2. Calculate a maximum likelihood estimator of , , where
2
σ
∧
2
σ
net
22 Σ=
∧
σ
.
3. Construct a variable such that .
t
f
∧
=22 /
σ
tt ef
4. Estimate equation
f to obtain the sum square of regression (SSR).
tt Ybb 21 +=
5. The null hypothesis of homoskedasticity is tested based on the Chi-square
statistic. That is QBP = SSR/2 ~ (degree of freedom = 1).
2
1
χ
The test results are shown in Table 4.3. The null hypotheses of homoskedasticity
for all equations in the system cannot be rejected at the 1% level of significance. The test
results imply that heteroskedasticity is not likely to occur in the estimation.
61
Table 4.3 Heteroskedasticity Test Results
Equation QBP [Prob ( 6.64) = 0.01] >
2
1
χ
Demand Starkist 1.68
Demand Chicken of the Sea 3.60
Demand Bumble Bee 0.01
Price reaction Starkist 6.25
Price reaction Chicken of the Sea 3.02
Price reaction Bumble Bee 2.89
Price reaction Allother 3.95
Testing for Autocorrelation
Since the observations comprise a time series, the residuals of each equation in
the model are potentially autocorrelated. The process of testing for autocorrelation is
started by regressing each equation using the 2SLS method in order to obtain regression
residuals. Each equation’s residuals are tested for autocorrelation by using a sample
correlogram and Ljung-Box statistic (L-B statistic). The L-B statistic tests whether
autocorrelation exists and the sample correlogram approximately indicates the order of
autocorrelation. The results from the L-B test indicate that all seven equations have
autocorrelation. According to sample correlograms, six out of seven equations are
suspected to be first-order autoregressive (AR1), whereas one equation (Chicken of the
Sea’s price reaction function) is likely to be second-order auto regressive (AR2).
The regression residuals of each equation are then regressed on their lagged
values. The residuals of Chicken of the Sea’s price reaction function are regressed on
their two period lags, whereas those of the other equations are regressed on their one
62
period lag. Mathematically, e, where e is the residual of equation i
at time t, t = 2,…, n , s = number of time lagged, s = 1 and 2, and uare interdependent
and identically distributed with zero mean and variance . The estimated coefficients
(ρ
itsit
s
isit ue += −
=
∑
2
1
ρ
it
2
u
σ
it
is) are presented in Table 4.4. All the estimated coefficients are statistically significant.
Therefore, it can be concluded that all equations are AR1 except for the price reaction
function of Chicken of the Sea that is AR2. The estimated autoregressive coefficients
shown in Table 4.4 are used to form a transformation matrix for use in W3SLS.
Estimation of W3SLS
According to Table 4.4, each equation in the simultaneous model is found to have
autocorrelation. This study uses W3SLS to correct the problem. The estimated
Table 4.4 Estimated Autoregressive Coefficients
Equation
ρ1 ρ2
Demand S 0.263*** -
Demand C 0.507*** -
Demand B 0.306*** -
Price reaction S 0.282*** -
Price reaction C 0.419*** 0.1936**
Price reaction B 0.282*** -
Price reaction A 0.308*** -
*** Significance at the 1% level, *** significance at the 5% level.
Subscript: S = Starkist, C = Chicken of the Sea, B = Bumble Bee, and A = Allother.
63

coefficients ( ) in Table 4.4 are used to form a transformation matrix for each
regression equation. After pre-multiplying each equation by its transformation matrix,
the transformed equations are estimated simultaneously using 3SLS. The estimated
parameters of the LA/AIDS are reported in Table 4.5. Significant estimated parameters
in Table 4.5 are used to calculate own- and cross-price elasticities of demand for each
brand.
is
ρ
According to the adding up condition, only three demand equations of Starkist,
Chicken of the Sea, and Bumble Bee are estimated, and then the parameter estimates for
the Allother demand equation ( and ) are generated from them. The effect of each
brand’s price on its share is negative and statistically significant. Prices of Chicken of the
Sea and Allother have positive effects on Starkist’s market share. Prices of Starkist and
Allother also have positive effects on Chicken of the Sea’s market share, but only the
price of Allother has positive effects on Bumble Bee’s market share. The positive effect
of a brand’s price on another brand’s market share is reasonable. When a brand increases
its price and the other brands do not follow, consumers may switch to buy a substitute,
resulting in an increase in the substitute brand’s market share. Bumble Bee’s price in
both Chicken of the Sea’s and Starkist’s equations is not statistically significant implying
that a change in Bumble Bee’s price has no effect on those two brands’ shares. Total
expenditure weighted by the corrected Stone index is statistically significant and has
negative effects on Starkist’ and Bumble Bee’s market shares. With respect to Starkist’s
promotional activities, DISPLAY, FEATURE, and DISPLAY&FEATURE are statistically
significant and have positive effects on Starkist’s share, even though the magnitudes are
AA
γ
A
β
64
Table 4.5 Estimation of the LA/AIDS model
ShareStarkist Share
Chicken of the Sea ShareBumble Bee
Intercept 1.526 0.015 0.284
(0.307)** (0.163) (0.064)**
PStarkist -0.503 0.196 0.010
(0.072) ** (0.025)** (0.013)
PChicken of the Sea 0.196 -0.261 -0.001
(0.025)** (0.024)** (0.007)
PBumble Bee 0.010 -0.001 -0.035
(0.013) (0.007) (0.014)**
PAllother 0.297 0.065 0.026
(0.064)** (0.030)* (0.014)*
Y/P* -0.088 0.015 -0.023
(0.030)** (0.016) (0.006)**
DISPLAY 0.002 -0.002 0.000
(0.000)** (0.000)** (0.000)
FEATURE 0.001 0.000 0.000
(0.000)** (0.000) (0.000)
DISPLAY&
FEATURE 0.001 -0.001 0.001
(0.000)* (0.000)** (0.000)**
PRICE
REDUCTION -0.001 -0.001 -0.000
(0.000) (0.000)** (0.000)
Adjusted R2 = 0.6684, Standard errors in parentheses,
* = Significance at 5% level, and * * = significance at 1% level
According to the adding up condition, = -0.388 and = 0.096.
AA
γ
A
β
65

not high. DISPLAY&FEATURE and PRICE REDUCTION have significant negative effects
on Chicken of the Sea’s market share.
The homogeneity and symmetry restrictions are imposed in the estimation:
Homogeneity: j, and (4.3) 0=∑ ijj
γ
∀
Symmetry: ∀ i≠. (4.4)
jiij
γγ
=j
The restrictions of homogeneity and symmetry are tested using an F test. This
test is based on the null hypothesis that the sample information is consistent with the
imposed restrictions. In other words, if the null hypothesis cannot be rejected, it implies
that the error structure of the respective unrestricted model do not differ from that of the
restricted model. If the null hypothesis is rejected, it implies that the imposed restrictions
are not supported by sample information. The computed F statistic of the imposed
restrictions are presented in Table 4.6
The computed F in Table 4.6 shows that the null hypotheses of the homogeneity
restrictions on Starkist and Chicken of the Sea demand equations cannot be rejected at
1%. The null hypothesis of symmetry restriction between Starkist and Bumble Bee
demand equations cannot be rejected at 1% level of significance. For the other two
symmetry restrictions, the null hypotheses are rejected. The results imply that the data
used in this dissertation seem to be consistent with the homogeneity restrictions; however
the data support only one symmetry restriction. Several studies of food demand have
also rejected the symmetry restriction. A list of studies in food demand that imposed
homogeneity and symmetry restrictions in the LA/AIDS is shown in Table 4.7. Deaton
and Muellbauer (1980) estimated the LA/AIDS on eight nondurable goods using annual
66
Table 4.6 Test Results for Imposed Restrictions
Property Restriction Computed F statistic
Homogeneity 0.02
∑
=
4
1
j
Sj
γ
Homogeneity 0.01
∑
=
4
1
j
Cj
γ
Homogeneity 22.39
∑
=
4
1
j
Bj
γ
**
Symmetry 27.11
CSSC
γγ
=**
Symmetry 4.90
BSSB
γγ
=
Symmetry 26.94
CBBC
γγ
=**
**Significance at the 1% level, subscript: S = Starkist, C = Chicken of the Sea, B = Bumble Bee,
and A = Allother. j = Starkist, Chicken of the Sea, Bumble Bee, and Allother.
Table 4.7 Listing of Research on Food Product That Imposed Restrictions on the
LA/AIDS
Auther (Published year) Homogeneity Symmetry
Deaton and Muellbauer (1980) Rejected Rejected
Blanciforti and Green (1982) Rejected -
Blanciforti and Green (1983) Rejected -
Chalfant (1987) Not reported Not reported
Green, Carman, and McManus (1991) Rejected Rejected
Cotterill (1994) Not reported Not reported
Richards, Kagan, and Gao (1997) Not rejected Not rejected
Vickner and Davies (1999) Rejecteda Rejecteda
Cotterill, Putsis, and Dhar (2000) Not reported Not reported
- means the restriction was not imposed. a partially rejected in the EC3SLS
67

British data and found that symmetry restriction was rejected. Green, Carman, and
McManus (1991) found that homogeneity and symmetry conditions were strongly
rejected in the estimation of demand on dried fruits. Satyanarayana et al (1999) found
rejection of symmetry in the estimation of demand for malt using the LA/AIDS. Vickner
and Davies (1999) estimated the degree of market power in the spaghetti sauce industry
and found that in their error-components 3SLS (EC3SLS) estimation six of the ten
symmetry restrictions on the LA/AIDS were rejected. However, they used the parameter
estimates from model with the imposed restrictions. Since the results from testing the
restrictions are consistent with those found in previous studies, the estimated results from
the LA/AIDS in this study are reported with the restrictions imposed.
Partial Own- and Cross- Price Elasticities
Before calculating the RI, OI, and CQ, partial own- and cross-price elasticities,
and price-response elasticities are needed. The parameter estimates obtained from the
LA/AIDS shown in Table 4.5 are used to calculate partial own- and cross-price
elasticities of demand for each brand, and price-response elasticities are obtained directly
from the parameter estimates from the price-reaction functions of the simultaneous
model.
The partial own- and cross-price elasticities of demand are shown in Table 4.8.
The partial own- and cross-price elasticities of demand for brand Allother in Table 4.8 are
calculated using parameter estimates derived from the adding up restrictions. Therefore,
the tests of significance for these elasticities are not shown in the Table. The own-price
elasticity of demand for each brand is found along the diagonal of the Table. All brands’
68
Table 4.8 Partial Own- and Cross-Price Elasticities
% ∆ Price
Starkist Chicken of the Sea Bumble Bee Allother
Starkist -1.67*** 0.31*** 0.02 0.46***
Chicken of the Sea 1.27*** -2.80*** -0.01 0.43**
Bumble Bee 0.51** 0.06 -1.71*** 0.61**
Allother 1.68 0.37 0.15 -3.89
Elasticities are read from left to right;
*** Significance at the 1% level, ** significance at the 5% level.
own-price elasticities are negative and elastic. The partial own-price elasticity of demand
for Starkist is -1.67, meaning that a 1% increase in the price of Starkist causes a 1.67%
decrease in its quantity sold. Allother’s partial own-price elasticity is the most elastic. A
brand’s elastic demand implies that if the brand raises its price and no other brands
follow, its revenue will decline. However, the brand is able to maintain or increase its
revenue and market share when it increases price, even though it faces an elastic demand,
if it has enough market power that can influence its rivals to follow.
The elastic demand of the canned tuna industry can be explained two ways.
First, although the products are differentiated by brand, they are substitutes. Consumers
can switch and buy an alternative brand if they consider an increase in price of a brand
too high. Second, canned tuna is a durable good. Consumers can stockpile their favorite
brands when prices are low. In this case each brand is an inter-temporal substitute for
itself (Tirole, 1988).
69

The cross-price elasticities are found off the diagonal of Table 4.8. Six out of
nine cross-price elasticities are statistically significant (not including those derived from
the adding up restriction). The significant cross-price elasticities of demand for all other
brands are positive, meaning that they are substitutes. The cross-price elasticity of
demand for Chicken of the Sea with respect to Starkist’s price is 1.27, which is elastic and
statistically significant, meaning that a 1% increase in the price of Starkist leads to a
1.27% increase in Chicken of the Sea’ s quantity sold. Chicken of the Sea and Allother
seem to be good substitutes for Starkist because their cross-price elasticities with respect
to Starkist’s price are high and elastic. On the other hand, the cross-price significant
elasticities of demand for Starkist with respect to the Chicken of the Sea and Allother’s
prices are inelastic. This suggests that consumers consider Starkist less substituTable
than those brands in the market. The cross-price elasticity of demand for Bumble Bee
with respect to Starkist’s price is 0.51 and statistically significant implying that Bumble
Bee can be a substitute for Starkist, even though it is not as good as Chicken of the Sea
and Allother.
Price-response Strategies
To calculate the RI, OI, and CQ, price-response elasticities of firms in the canned
tuna market are required. The parameter estimates from price reaction functions are
shown in Table 4.9. Due to the double-log specification, the estimated ij
φ
parameter in
equation (3.4) represents the price-response elasticities of firm i with respect to firm j’s
price. According to the existence of a Bertrand-Nash equilibrium, firms’ prices are
supposed to have a positive relationship. However, price-response elasticities in this
70
Table 4.9 Estimated Price Reaction Functions
PSK PCS PBB P
AO
Intercept 2.652 0.138 2.975 -0.680
(0.548)*** (0.881) (1.043)*** (0.763)
PSK - 0.667 -0.363 0.190
(0.174)*** (0.198)
* (0.205)
PCS 0.319 - -0.261 -0.066
(0.046)*** (0.078)*** (0.057)
PBB 0.010 -0.002 - 0.032
(0.025) (0.041) (0.038)
PAO 0.382 0.252 0.040 -
(0.102)*** (0.136)
* (0.160)
Y/P -0.163 0.048 -0.253 0.069
(0.051)*** (0.084) (0.097)*** (0.074)
SHARE -1.531 -3.622 -6.219 0.450
(0.167)*** (0.348)*** (-3.60)** (0.356)
DISPLAY 0.002 -0.007 -0.001 -0.002
(0.001)*** (0.001)*** (0.001) (0.000)***
FEATURE 0.002 -0.000 -0.004 -0.002
(0.001)** (0.001) (0.001)*** (0.000)***
DISPLAY& 0.001 -0.004 -0.004 -0.004
FEATURE (0.001) (0.001)*** (0.001)*** (0.001)***
REDUCTION -0.001 -0.006 -0.003 -0.002
(0.001) (0.001)*** (0.001)*** (0.000)***
Parameter estimates for each equation are read by column.
Adjusted R2 = 0.654, standard errors in parentheses,
* = Significance at 10% level, * * = significance at 5% level, *** = significance at 1% level
Subscript: SK = Starkist, CS = Chicken of the Sea, BB = Bumble Bee, and AO = Allother.
71

study are found to have both positive and negative relationships. An interpretation is that
positive price-response elasticities imply tacit collusion among brands, and negative
price-response elasticities imply price war. The price-response elasticity of Starkist with
respect to Chicken of the Sea’s price is 0.32 and statistically significant, meaning that if
Chicken of the Sea raises price by 1%, Starkist will raise its price by 0.32%. The price-
response elasticity of Chicken of the Sea with respect to Starkist’s price is 0.67 and
statistically significant. This asymmetry leads to an inference that a change in price of
Starkist has high influence on the price of Chicken of the Sea, but a change in price of
Chicken of the Sea has less influence on the price of Starkist. The price-response
elasticities of Bumble Bee with respect to prices of both Starkist and Chicken of the Sea
are negative and statistically significant. This implies that instead of tacitly colluding in
price with its rivals, Bumble Bee conducts a price war. For example, when Starkist
increases price by 1%, Bumble Bee decreases its price by 0.36%. According to the cross-
price elasticity of demand for Bumble Bee with respect to Starkist’s price (0.51) in Table
4.8, Bumble Bee seems to be a substitute for Starkist, but the degree of substitution is not
as close as for Chicken of the Sea and Allother (1.27 and 1.68, respectively). Therefore,
Bumble Bee’s strategy is to cut its price, in order to gain more sales in the market. The
price-response elasticities of Chicken of the Sea and Starkist with respect to Bumble
Bee’s price are not statistically significant. It implies that the two leading brands do not
respond to Bumble Bee’s price strategy. On the other hand, they positively respond to
the price set by Allother because their price-response elasticities with respect to
Allother’s price are statistically significant. Since the results lead to the inference that
none of the canned tuna brands in the market follow Bumble Bee’s price strategy, while
72

Bumble Bee can maintain its market share with a high price in the market, its market
power is not derived from coordinated market power or tacit collusion. These results can
be confirmed by considering the measures of market power in the next section. Twelve
of the 16 promotion-activity variables are statistically significant. Ten of the twelve
promotion activities of Chicken of the Sea, Bumble Bee and Allother have negative
effects on their respective prices and they are statistically significant. This implies that
when a promotional campaign is conducted, a brand tends to decrease its price. These
results are reasonable and easily explained. Since one of the objectives for conducting
promotional activities is to increase a brand’s revenue, and because those brand’s own-
price elasticities are elastic (Table 4.8), a decrease in price results in an increase in their
revenues. Interestingly, Starkist’s DISPLAY and FEATURE variables have positive
impacts on its price (Table 4.9) and share (Table 4.5) and they are statistically significant.
This leads to an inference that Starkist may have market power because it is able to
increase both price and market share when it uses such promotional activities. This
inference is supported by considering the measures of market power in the next section.
Measures of the Degree of Market Power
The degree of market power of brands in the canned tuna industry is measured by
the RI, OI, and CQ. Estimated non-followship, fully collusive, and observed demand
elasticities are used to calculate these measures. Brand i’s partial own-price elasticity
(ii
η
) represents the brand’s non-followship demand elasticity. The fully collusive
elasticities and the observed demand elasticities of brand i are calculated using the partial
73
own- and cross-price elasticities, and price-response elasticities shown in Table 4.8 and
4.9.
The fully collusive elasticity of brand i , , is defined as . The
observed demand elasticity of brand i, , is defined as , where
F
i
η
n
ji
ijii
F
i
≠
∑
+=
ηηη
ji
n
ji
ij
εη
∑
≠
+
0
i
η
iii
ηη
=
0
ij
η
is
the cross-price elasticity of demand for firm i with respect to a change in price of firm j,
and represents rivals’ price-response elasticity or the conjectural price-response of
firm j with respect to a change in price of firm i (i≠j).
ji
ε
2
The estimated elasticities and measures of market power are shown in Table 4.10.
The first row in Table 4.10 contains each brand’s non-followship demand elasticity (from
Table 4.8). The non-followship demand elasticity can be interpreted as a unilateral
measure of market power because it measures the responsiveness in quantity purchased a
brand experiences when it raises price but no rivals follow. Starkist, the largest brand in
the market, has the highest unilateral market power since its non-followship demand
elasticity is the lowest elasticity in absolute value. It means that when Starkist raises its
price, consumers change their quantities demanded less than they do when the other
brands change their prices. The aggregated small brands, Allother, seem to have the least
ability to maintain their unilateral market power because they have the highest elastic
demand in absolute value. This is reasonable since each brand in Allother possesses
small market share and has no power in the market. If it raised its price, its quantity
2 This dissertation uses all significant and insignificant parameter estimates to calculate the fully collusive
and observed demand elasticities. This is consistent with the way other research in this area has been done.
74
Table 4.10 Elasticities and Measures of Market Power
Starkist Chicken of the Sea Bumble Bee Allother
Non-followship
Elasticity ( ii
η
) -1.667 -2.802 -1.706 -3.887
Observed
Elasticity ( ) -1.377 -2.423 -1.682 -3.148
0
i
η
Fully Collusive
Elasticity ( ) -0.869 -1.106 -0.532 -1.690
F
i
η
RIi =
ii
F
i
η
η
0.522 0.395 0.312 0.435
OIi = 0
i
F
i
η
η
0.631 0.457 0.316 0.537
CQi = 1 –
i
i
OI
RI 0.174 0.137 0.014 0.190
demanded would considerably decrease.
The observed demand elasticities are shown in the second row of Table 4.10.
These elasticities take into account the effect of coordinated market power, which is the
sum of the product between cross price elasticities and price-response elasticities among
brands in the market. Each brand’s observed demand elasticity is less elastic than its
non-followship demand elasticity in absolute value because of the positive effect from
coordinated market power.
Each brand’s fully collusive elasticity shown in the third row of Table 4.10 is
calculated based on the assumption that the brand’s price-response elasticities equal one,
meaning that if the brand increases its price, all rivals will raise their prices at the same
75

rate. The fully collusive elasticities are useful in measuring the degree of market power
of each brand. The higher the market power a brand has, the farther is the brand’s
observed elasticity from its non-followship elasticity, and the closer to its fully collusive
elasticity.
The degree of market power of a brand in this study means that the brand is able
to set a high price without losing its market share. (According to Table 4.1, the average
price per unit (16 oz. equivalent) for the three leading canned tuna brands was 0.95 cents,
whereas the average price per unit for Allother was only 0.68 cents.) A brand’s market
power is derived from two sources. First, it arises from the brand characteristics such as
image and product differentiation including promotional activities such as display and
features. These factors construct the brand’s unilateral market power, and the RI
represents such power. Second, the brand’s market power is derived from tacit collusion.
Because firms in oligopoly are interdependent, they take into account their rivals’
strategies and try to respond in order to maximize their profits. A brand’s market power
due to tacit collusion means that the brand can influence its rivals to follow its strategy
(e.g., a price increase). The OI and CQ typically represent this kind of market power.
The RI shown in the fourth row of Table 4.10 measures a unilateral degree of
market power of each brand. It compares a brand’s fully collusive elasticity with non-
followship elasticity. The value of RI ranges from zero to one. The closer the RI is to
one, the greater the degree of market power. The results show that Starkist has the
highest unilateral degree of market power with the RI equal to 0.522. The RI of Chicken
of the Sea, Bumble Bee and Allother is 0.395, 0.312 and 0.435, respectively.
76
Since the observed elasticity takes into account both unilateral market power and
coordinated market power, it is crucial to investigate the results of the OI. The fifth row
in Table 4.10 presents the values of this index. Not surprisingly, Starkist, the biggest
brand in the market, has the highest degree of market power with its OI equal to 0.631.
According to the results, the degree of market power seems to be consistent with market
shares. A firm with high market share has a high degree of market power. The OI of
Allother, Chicken of the Sea, and Bumble Bee’s OI are 0.537, 0.457, and 0.316,
respectively. The RI and OI of Allother are slightly higher than those of Chicken of the
Sea and Bumble Bee. Note that the Allother’s market share (13.90 %) is aggregated
from many small competitive firms and the estimated coefficients from the aggregated
market-share equation are used to calculate the own-price and cross-price elasticities.
Therefore, it is possible that the high value of RI and OI of Allother is affected by the
aggregated market share. For this reason, it might not be appropriate to compare
Allother’s degree of market power with those of the three leading brands.
The last row in Table 4.10 shows the values of the CQ. The CQ measures the
fraction of market power of the observed demand due to tacit collusion. Basically, the
CQ of brand i is defined as CQi
i
i
OI
RI
−= 1 =
ii
i
η
η
0
−1. By simplifying the term on the
right hand side, CQi becomes
ii
ij
jiij
η
εη
∑
≠
−. It can be seen that the CQ of brand i measures
the portion of its coordinated market power ( ∑) with respect to its non-followship
elasticity. The higher coordinated market power due to tacit collusion a brand has, the
≠ji
jiij
εη
77
higher the brand’s CQ. The results from Table 4.10 show that Starkist derives
approximately 17.4% of its market power from tacit price collusion. Chicken of the Sea
obtains about 13.6% of its market power from tacit collusion.3 Interestingly, although
Bumble Bee can maintain its market power at third place (among the three leading
brands), its market power is derived less from the coordinated market power due to tacit
collusion because its CQ is only 1.4%. Bumble Bee’s CQ has confirmed the results of
price-response elasticities in Table 4.9 such that none of the canned tuna brands in the
market follows Bumble Bee’s price strategy. The CQ of Allother is 19.0% meaning that
Allother derives about 19% of its market power from tacit collusion. The coordinated
market power exists when a firm can influence its rivals to follow its strategy. Because
the average price per unit of Allother is the lowest in the market, when Allother increases
its price, the other brands are willing to cooperate by increasing their prices slightly in
order to gain more revenue from substitution.
Table 4.11 presents the findings from previous studies comparing with those
found in this study. Cotterill (1994) estimated the degree of market power in the
domestic carbonated soft drink industry. Vickner and Davies (1999) analyzed market
power in the domestic spaghetti sauce industry. Elasticities, RI, OI, and CQ are shown in
average values. The carbonated soft drink industry in the Cotterill study has the lowest
non-followship and observed elasticities on average compared to those obtained in this
study and in the Vickner and Davies study. Brands in the carbonated soft drink industry
in the Cotterill study seem to have high unilateral and coordinated market power since the
3 When only significant parameter estimates are used to calculate the measures of market power,
qualitatively, the results are unaltered with the exception of the CQ. Chicken of the Sea’s CQ (0.145) is
higher than Starkist’s CQ (0.125), meaning that Chicken of the Sea’s market power derived from tacit
collusion is higher than that of Starkist.
78
Table 4.11 Comparing Average Elasticities and Measures of Market Power
Canned Tuna Carbonated Soft Drink Spaghetti Sauce
Non-followship
Elasticity ( ii
η
) -2.52 -1.53 -4.97
Observed
Elasticity ( ) -2.16 -1.45 -4.03
0
i
η
Fully Collusive
Elasticity ( ) -1.05 -0.94 -1.43
F
i
η
RIi =
ii
F
i
η
η
0.42 0.67 0.28
OIi = 0
i
F
i
η
η
0.49 0.72 0.34
CQi = 1 –
i
i
OI
RI 0.11a 0.15b 0.32b
aAverage value for the three leading brands in the market
bAverage value for the two leading brands in the market
industry’s RI and OI on averages are very high (0.67 and 0.72 respectively). The average
RI and OI found in this study are less than those found in the Cotterill study but more
than those found in the Vickner and Davies study. The average fully collusive elasticity
obtained in this study (-1.05) is close to that found in the Cotterill study (-0.94). The
average CQs shown in Table 4.11 are comparable to those obtained from the two leading
brands in carbonated soft drink market (Cotterill, 1994) and in the spaghetti sauce market
(Vickner and Davies, 1999), and from the three leading brands in this study. The average
CQ found in the Vickner and Davies study is the highest (0.32). This leads to the
inference that market power of the two leading brands in the spaghetti sauce market was
derived more from tacit price collusion.
79

Summary of Results
This part estimates the degrees of market power and price-response strategies of
four canned tuna brands: Starkist, Chicken of the Sea, and Bumble Bee, and Allother. The
LA/AIDS and price reaction functions are estimated simultaneously using W3SLS. The
corrected Stone index is used in the LA/AIDS. The results can be summarized as
follows.
• According to the test of restrictions imposed in the LA/AIDS, one of the three
homogeneity restrictions and two of the three symmetry restrictions are
rejected. The estimated results are reported with restrictions imposed.
• There is a significant negative relationship between market share and price in
the canned tuna industry.
• The significant partial own-price elasticities of demand for all brands are
negative and elastic. Starkist has the lowest own-price elasticity in absolute
value, and Allother has the highest own-price elasticity in absolute value.
• Chicken of the Sea and Allother are better substitutes for Starkist than Bumble
Bee.
• Starkist, Chicken of the Sea, and Allother are cooperative in their price
strategies, whereas Bumble Bee conducts price war against Starkist and
Chicken of the Sea.
• Starkist, the highest market-share brand, has the highest market power both
unilateral and coordinated market power due to the lowest own-price elasticity
and highest RI, OI and CQ.
• Starkist and Chicken of the Sea can maintain their market power derived from
both unilateral and coordinated market power, whereas Bumble Bee can
maintain its market power without tacit collusion.
80

Estimating Results Using the Stone Index
This dissertation uses the corrected Stone index as was suggested by Moschini
(1995) to improve the estimation of the LA/AIDS in the simultaneous equations. In order
to estimate the effects of differences between the two indices, the LA/AIDS was also
estimated along with the price-reaction functions. The results are used to calculate the
RI, OI, and CQ. Two changes have been made in the simultaneous equations. First, the
total expenditure variable is weighted by the calculated traditional Stone index. Second,
all price series estimated in the simultaneous equations are not normalized by their
means. The latter is made in order to allow the use of the elasticity formula suggested by
Chalfant (1987), and Green and Alston (1990).
The simultaneous equations with the Stone index in the LA/AIDS are estimated
using the W3SLS method with correction for autocorrelation. The estimated parameters
from the LA/AIDS using the traditional Stone index and corrected Stone index are shown
in Table 4.12. The results show that parameter estimates from the two versions of indices
have the same sign and the differences are very small. Moreover, the standard errors of
each pair of estimated coefficients are very close. For example, the estimated coefficient
of Starkist’s price on its market share ( ) from the use of the corrected Stone Index is
equal to -0.503, whereas the estimated coefficient obtained from the use of Stone index is
SS
γ
-0.475 and both coefficients have very close standard errors (0.072 and 0.070,
respectively).
Table 4.13 displays the partial own- and cross-price elasticities of demand
calculated from estimated coefficients, which are obtained from the LA/AIDS using the
81
Table 4.12 Comparing Estimated Parameters from the LA/AIDS
Parameter Estimate using Estimate using
Corrected Stone Index Stone Index
γSS -0.503*** -0.475***
(0.072) (0.070)
γSC 0.196*** 0.191***
(0.025) (0.024)
γSB 0.010 0.010
(0.013) (0.012)
γSA 0.297*** 0.273***
(0.064) (0.062)
γCC -0.261*** -0.255***
(0.024) (0.023)
γCB -0.001 -0.001
(0.007) (0.007)
γCA 0.065** 0.064**
(0.030) (0.029)
γBB -0.035** -0.033**
(0.014) ((0.014)
γBA 0.026* 0.023
(0.014) (0.014)
γAA -0.388 -0.360
( - ) ( - )
βS -0.088*** -0.097***
(0.030) (0.029)
βC 0.015 0.008
(0.016) (0.015)
βB -0.023*** -0.024***
(0.006) (0.006)
βA 0.096 0.113
( - ) ( - )
*** Significance at the 1% level, ** significance at the 5% level, * significance at the 10% level.
Subscript: S = Starkist, C = Chicken of the Sea, B = Bumble Bee, and A = Allother.
(-) indicates that the parameters were derived using the adding up restrictions.
82
corrected Stone index and the traditional Stone index. Table 4.14 shows the price-
response elasticities for the two indices. Vuong (1989) proposed some new tests for
model selection and non-nested hypotheses based on likelihood-ratio statistics. However,
the tests were more suitable for cross-section than time series data. Since this study uses
time series data, the tests suggested by Voung are impropriate. However, the results from
both versions in Table 4.13 and 4.14 are calculated in ratios for relative comparisons and
are shown in Table 4.15 and 4.16. All ratios comparing between the two versions for the
partial own- and cross-price elasticities of demand shown in Table 4.15 are very close to
1 with the difference no more than 0.2. The ratios of the two versions for the price-
response elasticities are shown in Table 4.16. The ratios calculated from the significant
Table 4.13 Comparing Partial Own- and Cross-Price Elasticities
Index Starkist Chicken of
the Sea
Bumble
Bee
Allother
Corrected Stone Index
Starkist
Stone Index
-1.67***
-1.62***
0.31***
0.31***
0.02
0.02
0.46***
0.43***
Corrected Stone Index
Chicken
of the Sea Stone Index
1.27***
1.27***
-2.80***
-2.75***
-0.01
-0.01
0.43**
0.43**
Corrected Stone Index
Bumble
Bee Stone Index
0.51**
0.54**
0.06
0.06
-1.71***
-1.66***
0.61**
0.55**
Corrected Stone Index
Allother
Stone Index
1.68
1.42
0.37
0.34
0.15
0.13
-3.89
-3.70
Elasticities are read from left to right;
*** Significance at the 1% level, ** significance at the 5% level
83
Table 4.14 Comparing Price-response elasticities1
Index Starkist Chicken of
the Sea
Bumble
Bee
Allother
Corrected Stone Index
Starkist
Stone Index
-
-
0.32***
0.32***
0.01
0.02
0.38***
0.35***
Corrected Stone Index
Chicken
of the Sea Stone Index
0.67***
0.66***
-
-
-0.002
-0.004
0.25*
0.25*
Corrected Stone Index
Bumble
Bee Stone Index
-0.36*
-0.35*
-0.26***
-0.27***
-
-
0.04
0.01
Corrected Stone Index
Allother
Stone Index
0.19
0.18
-0.07
-0.07
0.03
0.03
-
-
1Elasticities are read from left to right;
*** Significance at the 1% level, * significance at the 10% level
Table 4.15 Ratios Comparing Partial Own- and Cross-Price Elasticities
Starkist Chicken of the
Sea
Bumble Bee Allother
Starkist 0.95* 1.00* 1.00 1.07*
Chicken of the Sea 1.00* 1.02* 1.00 1.00*
Bumble Bee 0.94* 1.00 1.06* 1.20*
Allother 1.18* 1.08 1.15 1.05
Each ratio = result from the use of the corrected Stone index / result from the use of the
traditional Stone index.
* Calculated from significant parameter estimates
84
Table 4.16 Ratios Comparing Price-Response Elasticities
Starkist Chicken of the
Sea
Bumble Bee Allother
Starkist - 1.00* 0.50 1.08*
Chicken of the Sea 1.01* - 0.50 1.00*
Bumble Bee 1.03* 0.96* - 4.00
Allother 1.05 1.00 1.00 -
Each ratio = result from the use of the corrected Stone index / result from the use of the
traditional Stone index.
* Calculated from significant parameter estimates
coefficients are close to one, indicating a small difference between the two versions.
The RI, OI, and CQ calculated from both versions are shown in Table 4.17. The
ratios of the measures are shown in Table 4.18. The scanner data used in this study seem
to be consistent with both price indices because their results are similar. For example,
the RI of Starkist estimated from the use of the corrected Stone index is 0.522, whereas
those estimated from the use of the Stone index is 0.530 with the ratio of 0.98.
Starkist’s OI estimated from the use of the corrected Stone index is 0.631, whereas those
estimated from the use of the corrected Stone index is 0.638 and the ratio is 0.99.
The empirical results in this dissertation lead to a conclusion that there only is a slight
difference from the use of the corrected Stone index and the traditional Stone index in the
LA/AIDS. However, these results are estimated from time- series scanner data in a single
local market covering a short time period. Moreover, the only product analyzed is
canned tuna. Therefore, it cannot be generalized that there is no difference between the
85
use of the two versions of the Stone index applied to other products or to other data.
Further studies will be needed to clarify this issue.
Table 4.17 Comparing Measures of Market Power
RI
Corrected Stone
Stone Index Index
OI
Corrected Stone
Stone Index Index
CQ
Corrected Stone
Stone Index Index
Starkist
0.522 0.530 0.631 0.638 0.174 0.169
Chicken of
the Sea
0.395 0.385 0.457 0.447 0.137 0.139
Bumble Bee
0.312 0.305 0.316 0.309 0.014 0.012
Allother
0.435 0.489 0.537 0.582 0.190 0.159
Average 0.416 0.426 0.485 0.494 0.128 0.120
Table 4.18 Ratios Comparing Measures of Market Power
RI OI CQ
Starkist
0.98 0.99 1.03
Chicken of the Sea
1.02 1.02 0.98
Bumble Bee
1.02 1.02 1.16
Allother
0.89 0.92 1.18
Average
0.98 0.98 1.06
86

Chapter Five
Conclusions
The first part of this dissertation estimated the degree of market power of brands
in the $2.1 billion canned tuna industry. The study investigated brands’ behaviors at the
local level and Knoxville, Tennessee was chosen as a representative local market.
Scanner data of prices, quantity sold, and promotional activities were collected weekly by
the IRI for 157 weeks over the period of January 4, 1998 to December 31, 2000 from 134
supermarkets in Knoxville. The canned tuna market was highly concentrated because the
highest three-firm market shares over the study period were more than 80 percent of the
total sales. There are four canned-tuna brands in this study; Starkist, Chicken of the Sea,
and Bumble Bee, and Allother.
A brand’s market power is derived from two sources. First, it comes from the
brand’s product differentiation such as advertising, packages, and image. These factors
construct the brand’s unilateral market power. Second, the brand’s market power is
derived from tacit collusion (coordinated market power) meaning that the brand can
influence its rivals to follow its price strategy. Three measures of market power are
employed in this study, the Rothschild and O Indices, and the Chamberlin Quotient.
In order to calculate a brand’s RI, OI, and CQ, the brand’s partial own- and cross-
price elasticities, and price-response elasticities are needed. Therefore, simultaneous
equations including both demand and supply equations are constructed. On the demand
side, the LA/AIDS is employed, whereas price-reaction functions are applied on the
87

supply side. The assumption of Bertrand competition with differentiated products is set
such that price is the strategic variable and that brands make their decisions at the same
time period.
Previous empirical studies (Cotterill, 1994 and Vickner and Davies, 1999)
estimated the degree of market power in carbonated soft drink and spaghetti sauce
markets using the Stone index in the LA/AIDS. However, some studies found that the
use of the Stone index in the LA/AIDS causes estimated parameters to be biased and
inconsistent (Pashardes, 1993 and Moschini, 1995). This dissertation uses the corrected
Stone index suggested by Moschini (1995) in the LA/AIDS estimation in order to
disentangle the problems.
The simultaneous equations with three demand equations and four price reaction
functions are estimated using W3SLS with a correction of autocorrelation. The
parameter estimates obtained from the LA/AIDS are used to calculate partial own- and
cross-price elasticities of demand for each brand, whereas price-response elasticities are
obtained directly from the parameter estimates from the price reaction functions. All
brands’ partial own-price elasticities are consistent with the law of demand, and found
elastic. The own-price elasticity of demand for Starkist is the least elastic. All canned
tuna brands in the market are substitutes since their cross-price elasticities are positive.
The estimated price-response elasticities represent strategic-price responses among
brands in the market. The results show that Starkist and Chicken of the Sea are
cooperative, whereas Bumble Bee conducts price war. When Starkist or Chicken of the
Sea raises their prices, Bumble Bee responds by cutting its price.
88

The degree of market power of a canned tuna brand is measured by the RI, OI,
and CQ. A brand with high degree of market power can not only set a high price and
maintain its level of market share, but also influence its rivals to follow its price strategy.
The RI measures the degree of unilateral market power of a brand. The OI measures both
the degree of unilateral and coordinated market power. The CQ measures percentage of
market power derived from tacit collusion. The results show that Starkist, the biggest
brand in the market, can maintain its market power at the highest level with the highest
RI, OI and CQ. Both Starkist’ and Chicken of the Sea’s market power is derived from
both unilateral and coordinated market power. Bumble Bee, the third leading firm in the
market, however, can maintain its unilateral market power without tacit collusion.
Finally, this study re-estimates the simultaneous equations with the use of the
traditional Stone index in the LA/AIDS. The parameter estimates from the estimation
using the Stone index are compared to those of the first version. The results from both
versions are found very close giving the interpretation of market power in the same
fashion.
89

PART 2: INVESTIGATING PRICE-RESPONSE STRATEGIES:
A DYNAMIC APPROACH
90

Chapter One
Introduction
In the first part of this study, strategic-price responses among firms were
investigated using the price-response elasticities obtained from the estimated price-
reaction functions. It was assumed that the canned tuna market was characterized by
Bertrand competition with differentiated products such that price was the strategic choice
variable, and firms made their decisions during the same time period. The findings
indicated that Bumble Bee conducted a price war against Starkist and Chicken of the Sea.
However, both Starkist and Chicken of the Sea did not respond to the Bumble Bee price
strategy during the same time period. The price-response results obtained from the first
part provide evidence only on static price behavior and do not describe any dynamic price
behavior. Vickner and Davies (2000) commented that current studies are not sufficient to
supply firms in the food industry “with practical, empirical procedures for estimating
strategic price response.”
A dynamic or supergame theory is able to explain strategic price response (Tirole,
1988). The supergame theory characterizes multiple outcomes. Cartwright et al. (1989)
examined the advantages and disadvantages of the static and dynamic price-correlation
tests and concluded that an application of a dynamic model such as a Granger-causality
test is a useful supplement to test price correlations. Multivariate-time series modeling
techniques, mainly as applied in macroeconomic analyses, support statistical concepts
that improve the study of dynamic price-response criteria.
91

This part extends the static model of part one to a dynamic approach. The
Bertrand-competition assumption is dropped in this part, and a firm is assumed to set its
price depending on its own past prices and those of rivals. A vector autoregressive
(VAR) model is employed and its applications are used to investigate the price
relationships. The Granger-causality test, the impulse response function (IRF) analysis,
and the forecast error variance decomposition (FEVD) analysis are applied to the VAR.
The Granger-causality test examines not only whether dynamic price-response
relationships exist, but also for types of strategic-price relationships such as price
leadership or price war. The IRF analysis graphically reveals the direction of the effect
of a one-time shock to one of the innovations on future values of the endogenous
variables, whereas the FEVD analysis measures proportions of a brand’s price variation
that can be explained by shocks to its own price and it rivals’ prices for each forecast
horizon.
The results obtained from this part disentangle a problem encountered from the
first part. Although Starkist and Chicken of the Sea do not respond Bumble Bee’s price
strategy during the same time period, the Granger-causality results show that both
Starkist and Chicken of the Sea respond negatively to Bumble Bee’s past price. This
means that both Starkist and Chicken of the Sea also conduct price war but in a dynamic
way. The results from the IRF and FEVD analyses also support the Granger-causality
test results for the three-leading canned-tuna brands’ relationships.
With respect to previous research in strategic-price relationships, Vickner and
Davies (2000) estimated strategic-price response between two leading brands in the
canned pineapple industry using the VAR and vector error correction model. The
92

Granger causality test and the IRF analysis were applied to investigate the price
relationships. However, confidence intervals were not included in the Vickner and
Davies IRF results. Confidence intervals are useful in determining the statistically
significant regions of the IRFs. Failing to include confidence intervals may affect the
interpretation of their estimated results. This dissertation improves on the analysis by
including the confidence intervals in the IRF analysis. Moreover, this dissertation
includes the FEVD analysis, which was not used in Vickner and Davies’ work, to
investigate firms’ price variations affected by their rivals’ price innovations.
The remainder of this part is structured as follows. Chapter Two presents the
econometric modeling approach and literature review. Chapter Three introduces the
econometric methodology used for the estimation. Chapter Four reports the findings, and
Chapter Five presents a conclusion. Further information on the data can be found in part
one.
93

Chapter Two
Econometric Modeling Approach and Literature Review
This chapter presents a framework for analysis of the strategic price responses
among brands in the canned tuna industry based on a dynamic system of equations. A
vector autoregressive (VAR) model is developed to investigate dynamic-strategic price
responses. The chapter begins with the empirical model and then provides a review of
the relevant literature. The empirical tools are presented first to facilitate an
understanding of the applied literature.
Econometric Modeling Approach
Bertrand competition assumes each firm simultaneously sets its profit-maximizing
price given the current prices other firms charge. The price-reaction functions in
equation (3.4) presented in the first part used only static information on price behaviors
among firms. They did not allow for the possibility of dynamic price behavior. In
practice, it is not necessary that firms’ decisions be based on prices during the same time
period. A firm’s price strategy can possibly depend on its past prices or its rivals’ past
prices. To investigate the potential for a dynamic strategic-price response, the Bertrand-
competition assumption used in the first part is dropped. A firm is assumed to set its
price depending on its own past prices and those of rivals. A dynamic, or supergame,
theory is able to explain strategic price response (Tirole, 1988). The supergame theory
characterizes multiple outcomes. Multivariate-time series modeling techniques provide
94

statistical concepts for the study of competitive price responses as a dynamic adjustment
process.
The modeling approach starts with the formulation of a general vector
autoregressive (VAR) model (Sims, 1980). The VAR model is specified as:
titi
k
i
tuPAP +∑= −
=1
, (2.1)
where is a column vector of n variables at time t, , is an (n x
n) matrix of parameters with no zero elements, i represents a time lag, for i = 1, 2,.., k,
and is a column vector of random errors which are assumed to be contemporaneously
correlated but not auto-correlated. Equation (2.1) is different from the structural-
equations approach, such as the price-reaction functions used in the first part, because no
zero restrictions are imposed on the model, meaning that there is no price variable
excluded from any equation of the model, and only endogenous variables are included
(Charemza and Deadman, 1997). Therefore, the model in equation (2.1) is called an
unrestricted VAR model. A firm in the canned tuna market is assumed to set its price
depending on its own past prices and those of rivals so the unrestricted VAR model in
equation (2.1) can be used to investigate firms’ pricing behaviors.
t
P
t
],...,,[ 21 ′
=n
tttt pppP i
A
u
Gujarati (1995) summarized advantages and disadvantages of using VAR models.
The advantages of VAR are as follows.
(1) The method is simple to use. Because all variables in VAR are endogenous,
one does not have to worry about determining which variables are endogenous
and which variables are exogenous.
95

(2) Estimation is simple. The OLS methods can be used to each equation
separately.
(3) In many cases, the forecasts obtained from VAR are better than those obtained
from the more complex simultaneous equation models.
Problems with VAR models are noted below.
(1) A VAR model is said to be a-theoretic, because it is not based on formal theory,
unlike the model of part one.
(2) VAR models are less suited for policy analysis, since policy parameters do not
explicitly appear.
(3) If the order of appropriate lag length is high, there will be many parameter
estimates. This may limit the degrees of freedom for hypothesis testing.
(4) All variables in the VAR model must be stationary. If the model contains a mix
of stationary and non-stationary variables, transforming the data will not be easy.
When dealing with dynamic time series data, the majority of recent empirical
studies found that the data are non-stationary because the means, variances, and
covariances of the variables are not constant over time (Charemza and Deadman, 1992).
Often, differencing a time series can lead to stationarity. For example, suppose that a
time series variable for brand 1, , is non-stationary and is generated by
1
t
p
, (2.2)
11
1
1
ttt epp += −
where erepresents an error term series of identically distributed stationary variables and
1
t
96

is iid ~ (0, ). By differencing by from both sides of the equation, the series
becomes stationary. That is
I
2
σ
1
t
p1
1−t
p
11
1
1
ttt epp =− −, (2.3)
In this case, is said to be integrated of order 1, I(1). A non-stationary series is said to
be integrated of order d, I(d), if it can be transformed to a stationary series by
differencing d times (Charemza and Deadman, 1992).
1
t
p
Dickey and Fuller (1979) have proposed a simple test for the order of integration
of in equation (2.2), called the DF test. The objective of the DF test is to test in
the autoregressive equation:
t
p1=
ρ
11
1
1
ttt epp += −
ρ
, (2.4)
The DF test, also known as the unit root test, is a test of the null hypothesis that in
equation (2.4) from the equivalent regression equation to (2.4), that is:
01 =−
ρ
11
1
1
ttt epp +=∆ −
δ
, (2.5)
where , and . 1−=
ρδ
1
1
11
−
−=∆ ttt ppp
If the null hypothesis is rejected, and the alternative can be accepted, the series
is stationary and ~ I(0). But if the null hypothesis cannot be rejected, it implies that
the series might be integrated of order 1 or higher or might not be integrated at all.
Therefore, the next step would be to test whether the order of integration is one. If ~
I(1), then ~ I(0). Hence we can repeat the test replacing with . In practice,
we can continue the process until we found an order of integration for (Charemza and
0<
δ
1
t
p
1
t
1
t
p
t
p
p∆
p
1
t
1
t
p1
t
p∆
1
t
p
97

Deadman, 1992). The DF test can also be used with drift and/or a linear deterministic
trend. The DF equation with drift and a linear deterministic trend is specified as:
11
1
1
tt
d
teptp +++=∆ −
δθµ
, (2.6)
where is a constant or intercept representing drift and t
µ
d is a linear deterministic trend.
The DF test can be used only if there is no autocorrelation. In the case that the
error term eis autocorrelated, the DF test can be modified to include enough lagged
difference terms so that the error terms are serially independent. The modified DF test is
called augmented Dickey-Fuller (ADF) test. The ADF equation with drift can be
specified as
1
t
∑
=
−− +∆++=∆ j
i
tititt ppp
1
111
1
1
νφδµ
, (2.7)
where
1
it
p−
∆ = ,
1
1
1
−−− −itit pp
i represents a time lag, for i = 1, 2,.., j, and
vt represents an error term series of identically distributed stationary variables and is iid ~
(0, ).
I
2
σ
The null hypothesis is still that = 0 or , that is, there exists a unit root in
series. Note that the ADF test can also be used with an inclusion of a linear deterministic
trend. The ADF test is extensively used in empirical research (e.g., Charemza and
Deadman, 1992; Benson et al.., 1995; Masih and Masih, 2000; Vickner and Davies,
2000). However, it is necessary to use the ADF test with care. Charemza and Deadman
(1992) commented that the choice of augmentation terms (the lagged difference terms) in
δ
1=
ρ
t
p
98

the ADF equation was important, but it was neglected in the literature. Too many
augmentations may cause a decrease in the power of the test, resulting in not rejecting the
null hypothesis too often. On the other hand, too few augmentations may affect the size
of the test, resulting in rejecting the null hypothesis of unit root too often.
An alternative test for a unit root is developed by Phillips and Perron (1988),
called The Phillips-Perron test or the PP test. The PP test generalizes the DF test to
situations that allow for fairly mild assumptions concerning the distribution of the errors.
That is, it is possible to test a unit root even though the error terms are not iid ~ (0, ).
The PP test starts with the following regression equations:
I
2
σ
11
1
1
ttt pp
ερα
++= −, (2.8)
where the error term has zero mean.
1
t
ε
There is no requirement that the error term is serially uncorrelated or homogeneous.
Unlike the DF assumptions of non-autocorrelation and homogeneity, the PP test allows
the disturbances to be weakly dependent and heterogeneously distributed (Enders, 1995).
Phillips and Perron (1988) characterized the distribution and derived test statistics that
can be used to test the coefficients under the null hypothesis that a unit root in the
series exists. Critical values for the PP statistics are the same as those given for the ADF
tests.
ρ
Choi (1992) conducted Monte Carlo experiments to study how the ADF and PP
tests for a unit root perform. They used data generated by aggregating-subinterval data
rather than the subinterval data themselves. The study concluded that for the aggregated
subinterval data the PP test was more powerful than the ADF test in finite sample.
99

Specifically, for the aggregate data the PP test has greater power to reject a false null
hypothesis of a unit root. However, Choi and Chung (1995) found in their Monte Carlo
experiments that for data with high sampling frequency, the PP test appears to be less
powerful than the Dickey-Fuller test in finite samples. Enders (1995) notes that, when
the true model has negative moving average terms, the ADF test is preferable; however,
when the true model has positive moving average terms, the PP test is more appropriate.
In practice, it is difficult to choose the most appropriate test because the true data-
generating process is never known. Therefore, both types of unit-root tests should be
used. If they support each other, one can have confidence in the results. If they do not
support each other, one of the two results has to be chosen. Additional analysis of the
type of data, the sample time period, or economic theory might be useful in considering
the most appropriate test (Enders, 1995).
If the variables in the vector P in equation (2.1) are found to be non-stationary,
the estimation of the VAR will give spurious results (Gujarati, 1995). There are two
ways to solve the problem. One way is to regress the unrestricted VAR on first
differences of all variables (if all variables are found to be I(1)). This process can
eliminate the non-stationarity from the variables; however it is not the best solution
(Patterson, 2000) and may involve a misspecification (Enders, 1995). The reason is that
valuable information about long-run relationships among variables would be lost from
taking the first differences.
t
Another way arises when the non-stationary variables are co-integrated. It is
possible that some linear combination of a set of non-stationary time series is stationary,
i.e., the set of series is co-integrated. If two or more variables have long-run equilibrium
100

relationship(s) or share common trend(s) or give a stationary linear combination, they are
said to be co-integrated (Masih and Masih, 2000). The presence of a co-integrating
relation forms the basis of a restricted VAR or a vector error correction (VEC) model.
The VAR model of k-th order in equation (2.1) can be re-parameterized in a VEC form
as:
titi
k
i
tt uPPP +∆Γ∑+Π=∆ −
−
=
−
1
1
1, (2.9)
where
i
Γ= – (Ai+1 + Ai+2 +…+ Ak), i = 1, …, k-1,
Π= –(I – A1 – A2 – …– Ak),
I is an identity matrix of order n,
and denotes first differences.
∆
A VEC model is a restricted VAR model designed for use with non-stationary
time series that are found to be co-integrated. The VEC model has co-integrating
relations constructed into the specification so that it restricts the long-run behavior of the
endogenous variables to converge to their co-integrating relationships, while allowing for
dynamic adjustment. According to the VEC model in equation (2.8), the co-integration
effects are represented by . The matrix (n×n) can be written as two (n×r)
matrices α and β, (1≤ r ≤ n – 1 = the number of co-integrated vectors), such that Π =
. The matrix
β
contains r co-integrating vectors representing long-run relationships
among P
1−
Πt
PΠ
βα
′
t-1. The matrix α consists of the parameters measuring the speed of adjustment
101

of each stationary co-integrating combination. The short-run dynamic responses are
explained by the elements in .
i
Γ
Applications of the VAR Analysis
Sims (1980) and Enders (1995) recommended that the goal of VAR analysis be to
investigate the interrelationships among the variables, not the parameter estimates. There
are (n + kn2) terms to be estimated in a VAR model, where n is the number of variables
and k is the number of lags. Because the models are over-parameterized, it is difficult
and not useful to interpret the relationships between variables from the coefficients in the
estimated VAR models. For this reason, researchers in this area have used the VAR
applications to study interrelationships among variables instead. Several applications of
the VAR analysis are used in this study. First, the VAR model allows the use of the
Granger causality test to clarify the relevant information. One may want to know
whether an increase of a brand’s price results in an increase in other brands’ prices when
they would not have changed otherwise, or whether the relationship works in the opposite
direction. Charemza and Deadman (1992) addressed the definition of Granger causality
in a simplified way that “x is a Granger cause of y, if present values of y can be predicted
with better accuracy by using past values of x rather than by not doing so, other
information being identical.” Assume that a firm in the canned tuna market sets its price
depending on its own past prices and those of rivals. Granger causality can be applied to
test such dynamic price reactions. Specifically, the Granger-causality test gives
information about strategic-price responses between a pair of firms. If firm i’s pricing
strategy depends on firm j’s past price, but it is not true in the opposite direction,
102

theoretically, firm j will be defined as a price leader, and firm i will be defined as a price
follower. If both firms’ price strategies depend on each other’s past prices, it can be
interpreted that they conduct warfare (Vickner and Davies, 2000).
The VAR model can be used to forecast the signs of the short-run responses of
variables by means of an impulse response function (IRF) when there is an exogenous
shock on one of the variables. Gujarati (1995) noted that the individual coefficients in
the estimated VAR models were often difficult to interpret so the researchers often used
IRF analysis instead. In the literature, a unitary change in a variable or an error term is
called a variable shock or innovation. An IRF allows a graphical representation of the
effect of a one-time shock to one of the innovations on future values of the endogenous
variables. If the innovations between equations are contemporaneously uncorrelated,
interpretation of the impulse response function is simple. A change in innovation of a
firm by one unit at time t is simply a shock to its own future price. With respect to
equation (2.1), a change in innovation of a firm by one unit at time t is equivalent to a
change in the firm’s price by one unit at time t (because all lag variables on the right hand
side of the VAR are predetermined), and because the error terms are contemporaneously
correlated, it not only can affect the firm’s price in the future, but can also be transmitted
to the other firms’ prices over time. IRFs can be derived by mathematically transforming
a VAR model into a vector-moving average (VMA) model. IRFs are matrices of
coefficients in a VMA model, in which its error terms are orthogonal, i.e., they are not
contemporaneously correlated (Charemza and Deadman, 1992, p. 161-164). In empirical
work, the process that transforms error terms to be orthogonal in order to identify impulse
responses is called a Choleski decomposition.
103

It is helpful to understand the properties of the forecast errors to reveal
interrelationships among variables in the system. Enders (1995) suggested that it is
convenient to describe the properties of the forecast errors from the VAR in terms of the
error sequence. It is possible to decompose the t-step (period) ahead forecast error
variance due to each one of the shocks. The forecast error variance decomposition
(FEVD) measures the proportion of the variation in a variable that is explained by its own
innovation as well as by the innovations in the other variables. Each step or time period
is called forecast horizon. If all variables of interest are endogenous, the forecast errors
variance of each error sequence will be explained by shocks at all forecast horizons
(Enders, 1995). In empirical research, it is normal for a variable to explain almost all of
its forecast error variance at short horizons, and smaller proportions at longer horizons.
Like IRF analysis, the Choleski decomposition is a necessary tool to identify FEVD.
Both IRFs and FEVDs are computed by most econometric packages which incorporate
VAR and VEC analysis. Therefore, the study of strategic-price response can be
characterized by the use of IRFs and FEVDs.
In sum, the VAR and VEC models can be applied to investigate the dynamic
interrelationships among price series in two ways. The first way is to use the Granger
causality test for firms’ price-response relationships such as leader-follower relationship
or warfare. The second way is to see when there is a unitary exogenous shock on a
brand’s price, how the other brands respond over time after the shock occurred. The IRF
analysis tells us about the direction in which a price series responds to shocks. The
FEVD analysis examines the proportions of the movements in a series due to its own
shocks and shocks from the other variables.
104

Literature Review
An econometric technique based on dynamic time-series methodology has been
emphasized in macroeconomic and monetary research since the early 1980s (Sims, 1980;
Litterman and Weiss, 1985; Friedman and Kuttner, 1993; and Thoma, 1994). Later,
dynamic time-series techniques, such as VAR and VEC models, were widely used in
applied microeconomic fields, e.g., energy economics, agricultural economics analysis
and industrial organization. A list of some of the studies that have used the time series
analysis in applied microeconomic fields is shown in Table 2.1.
Dynamic time series models, such as VAR and VEC, have been used to analyze
markets and pricing conduct. The VAR model proved to have high performance in
forecasting a price movement in agricultural-marketing products (Park, 1990, and
Gjolberg and Bengtsson, 1997).
The VAR applications such as the Granger-causality test, the IRF analysis, and
the FEVD analysis are used in this part. The Granger-causality test is employed to
investigate the price-response relationships among canned tuna brands in the market.
Several studies used the Granger-causality test to estimate relationships among variables
of interest. Cartwright et al. (1989) suggested that a dynamic time-series application,
such as the Granger-causality test, was a useful supplement to the price-correlation
analysis. Giot et al. (1999) investigated market leadership in European markets for
imported off-season fresh apples and grapes. With the use of the Granger-causality test,
they found that the major import market of Rotterdam significantly led the wholesale
markets in France and Germany for apples. Tiffin and Dawson (2000) examined the
105
Table 2.1 Listing of Research in Applied Microeconomics using Time Series Methods
Auther
(Published year)
Objective
Cartwright et al. (1989) Examining price correlation to determine the relevant
product and geographic market
Park (1990) Comparing the VAR performance to alternatives
Vogelvang (1992) Investigating long-run relationships of coffee prices
Vany and Walls (1993) Investigating long-run relationships of natural gas spot
prices in the U.S.
Benson et al. (1995) Examining long-run relationships for market delineation
Gjolberg and Bengtsson
(1997)
Comparing the VAR performance to alternatives
Urga (1999) Estimating inter-fuel substitution in U.S.
Ramanathan (1999) Estimating short- and long-run price and income
elasticities of gasoline demand in India
Giot et al. (1999) Testing market leadership in the European fresh fruit
market
Vany and Walls (1999) Investigating long-run relationships of electricity spot
prices in the U.S.
Tiffin and Dawson (2000) Investigating producer-retail price relationship in the UK
lamb market
Vickner and Davies
(2000)
Estimating strategic price-response in the canned
pineapple industry in the U.S.
Pagan et al. (2001) Investigating the impact of advertising expenditures on
citrus sales from the Texas Rio Grande Valley
Kaufmann and Cleveland
(2001)
Investigating oil production in the U.S.
relationships between the retail price and the producer price of lamb in England. They
found that lamb prices in the retail market significantly affected the producer prices but
not in the opposite direction. Pagan et al. (2001) analyzed the impact of advertising
expenditures on citrus sales from the Texas Rio Grande Valley. They found that
advertising expenditures Granger-caused increases in citrus sales, but it was not true in
the opposite direction.
106

The other useful applications of the VAR model are the IRF and FEVD analyses.
Benson et al. (1995) suggested that the multivariate time series techniques offer new
insights regarding antitrust market delineation. IRF and FEVD analyses were employed
in their research to analyze the speed and strength with which a price series responds to
shocks occurring in other series. Pagan et al. (2001) used the IRF and FEVD analyses
as additional tools to support the results obtained from the Granger-causality test. They
found that the IRF and FEVD findings were consistent with those obtained from the
Granger-causality test.
The previous research which is closely related to this part is that of Vickner and
Davies (2000). They estimated strategic price response in a product-differentiated
oligopoly, the canned pineapple industry, using national-level weekly scanner data from
June 1994 to October 1996. Two canned pineapple firms in the U.S., Del Monte and
Dole, were investigated. The study started with the ADF test to examine stationarity of
each firm’s price series and found that the price series of both Dole and Del Monte were
stationary with the deterministic time trend included without controlling for seasonality,
but only one of the two was stationary with the deterministic time trend included after
controlling for seasonality. However, without controlling for the time trend, a unit root
was found in the price series of both firms, and the study concluded that each price series,
without a time trend, was an integrated process of order 1 or I(1). The stationary price
series with the deterministic trend included was estimated using the VAR model. The
non-stationary price series without controlling the time trend was tested for co-integration
and estimated using the VEC model. They found that a linear combination between price
series of Dole and Del Monte existed that was stationary. The results from the
107

unrestricted VAR and VEC models were compared and found to be supported by each
other. The hypothesis of price leadership was tested using Granger causality. In
addition, the pricing relationships were analyzed by the IRF analysis. The results from
the Granger causality test showed that Dole was the leader in determining price in the
market, whereas Del Monte followed Dole’s pricing decisions. The results, in fact,
confirmed the price leadership hypothesis. The IRF analysis also supported the price
leadership hypothesis. Finally, the study suggested that an empirical time series analysis
may be used to support industrial organization theorists when studying dynamic games.
This part is different from the Vickner and Davies study in two ways. First, it
improves the price-response study by including confidence intervals in the IRF results,
which were not included in Vickner and Davies’ IRF analysis. Second, it includes the
FEVD analysis, which was not used in the Vickner and Davies study, to rigorously
investigate pricing relationships. The FEVD results can give additional information to
the IRF and Granger-causality results in estimating price-response effects.
In sum, the strategic-price responses among canned tuna brands can be
investigated using the VAR applications, including the Granger-causality test, the IRF
analysis, and the FEVD analysis. The Granger-causality test examines whether the
dynamic price-response relationships exist. The IRF analysis graphically reveals the
direction of the effect of a one-time shock to one of the innovations on future values of
the endogenous variables, whereas the FEVD analysis measures proportions of a brand’s
price variations that can be explained by shocks to its own price and it rivals’ prices for
each forecast horizon.
108

Chapter Three
Econometric Methodology
An objective in this part is to estimate strategic price responses among canned
tuna brands based on a dynamic approach. The Bertrand-competition assumption is
dropped and replaced by the assumption that a firm in the market sets its price depending
on its own past prices and those of rivals. This chapter starts with testing for unit roots
and the order of integration for each price series using the ADF and PP test. Several lag
length criteria are presented within the estimation of the VAR model. Presented next are
applications of the VAR model including pairwise Granger-causaltity tests and the
analysis of IRFs and FEVDs to investigate the dynamic price-response relationships.
Finally, the four price series are used. Further information on the data can be found in
part one.
Testing for Unit Root and Order of Integration
The four price series (Starkist, Chicken of the Sea, Bumble Bee, and Allother)
used in the first part are tested for unit roots and the order of integration. Empirical
research that uses a structural model based on a static approach typically ignores non-
stationarity and assumes that the time series are stationary (Gujarati, 1995). However,
the use of non-stationary variables in a dynamic time series regression gives spurious
results (Gujarati, 1995); therefore, testing for stationarity is a necessary process in
estimating dynamic time series models. The most efficient test, which is extensively
109

used in empirical research, is the ADF test. The ADF test can be used by including drift
and/or a linear deterministic trend. The ADF test for a price series used in this study
is specified as:
t
p
∑
=
−− +∆++=∆ j
i
tititt ppp
1
1
νφδµ
, (3.1)
where
t
p represents the observed price series,
t
p∆= ,
1−
−tt pp
it
p−
∆ = ,
1−−− −itit pp
i represents a time lag, for i = 1, 2,.., j,
µ
is a constant or intercept representing drift , and
vt represents an error term series of identically distributed stationary variables and is iid ~
(0, ).
I
2
σ
The ADF t-statistics is based on
, (3.2)
δ
σδ
ˆ
ˆ/)1
ˆ
(−=
t
ADF
where is the usual least squares estimated error of .
δ
σ
ˆ
ˆ
δ
ˆ
The null hypothesis is that = 0, that is, there exists a unit root in meaning that the
series is non-stationary. The ADF test includes enough lagged difference terms so that
the error term is serially independent, and that can be checked during the process.
δ
t
p
The PP test is also a powerful test for a unit root and, therefore, is employed. The
PP test is based on an initial least squares fit of the regression
110
. (3.3)
ttt pp
ερα
++= −1
Equation (3.3) is non-parametric because there is no assumption that the error term is
white noise. Let be generated by , where
t
ε
t
pttt Lp
εψε
)(==∆ )(L
ψ
is a power series in
the lag operator L and , the residual from equation (3.3), is zero-mean white noise with
variance .
t
ε
2
ε
σ
The PP t-statistic is specified as
2/12
1
2
10
2
ˆ
2/12
0})(/{}]
ˆ
/)ˆ
ˆ
{2/1}ˆ/)1
ˆ
{()
ˆ
/ˆ[( −
=
−−−−−= ∑ppTPP
T
t
tt
λγλσρλγ ρ
, (3.4)
where and are consistent estimators of the short- and long-run variances defined as
0
ˆ
γ
2
ˆ
λ
)( 2
0t
E
εγ
=;, and
222 )}1({
ψσλ ε
=)1/(
2
1−Σ= =
−Tpp t
T
t(Leybourne and Newbold, 1999).
The coefficient is tested under the null hypothesis that there exists a unit root in the
series.
ρ
Both the ADF and PP test are done using the EView software package. If all
price series are stationary, the dynamic-price reactions will be estimated using the VAR
model. If all price series are non-stationary, the dynamic-price reactions will be
estimated using the VECM and co-integration analysis.
Selecting for Lag Length
A proper lag length must be selected before the VAR model is utilized so that the
error terms of each equation in the model are not serially correlated. The VAR model
used in this study is specified as:
111
titi
k
i
tuPAP +∑+= −
=1
θ
, (3.5)
where
Pt is a column vector of price series of Starkist, Bumble Bee, Chicken of the Sea and
Allother,
θ
and are unknown parameters to be estimated, A
i represents a time lagged, for i = 1, 2,.., k, and
t
uis a column vector of random errors which are assumed to be contemporaneously
correlated but not auto-correlated at an appropriate lag length k.
The selection process uses a general-to-specific method. The maximum lag is
assumed and tested, and then the number of lags is decreased and tested until the
appropriate lag length is found. There are several criteria used to select the lag length.
These criteria are described as follows:
i) The Likelihood ratio test (LR)
Starting from the maximum lag, the LR tests the null hypothesis that the coefficients on
lag k are jointly zero using the statistic, and the number of lags is decreased one at a
time until the null hypothesis is rejected. The distribution has degrees of freedom
equal to k-1. The Likelihood ratio test is specified as:
2
χ
2
χ
}log){log( 1kk
cTLR Ω−Ω−= −, (3.6)
where T = number of observations, k = lag length,
c = the number of parameters per equation under the alternative, and
112
k
Ω= determinant of the estimated residual variance-covariance matrix obtained from the
VAR(k) model.
ii) The Akaike Information Criterion (AIC)
The AIC is calculated to select the model which has the minimal loss of information or
the smallest AIC. The AIC is specified as:
AIC (k) = N
k2log +ΩT, (3.7)
where N = total number of parameters estimated in all equations.
iii) The Schwarz Bayesian Criterion (SC)
SC (k) = )log(TN
k+Ω
log . (3.8)
The SC is derived for the case of normally and independently distributed residuals and is
the result of a Bayesian procedure of seeking the most appropriate model. The order k of
lag length is chosen so that AIC or SC criterion is minimized.
In this study, all three criteria are used to select the appropriate lag length for the
VECM estimation. To be sure that the selected lag length is appropriate and there is no
autocorrelation in the model, a test for autocorrelation based on the Lagrange multiplier
statistics (LM test) is performed. The LM test for k-th order autocorrelation requires two-
step estimation under the null hypothesis that there is no autocorrelation. The first step is
to estimate each equation in the VAR model in equation (3.5) and obtain the regression
residuals (u) for t = 1, … , T. In the second step, an auxiliary regression is estimated
with the tth residual, u, regressed on the original set of regressors and u.
The test is the joint significance of in the auxiliary regression. The LM test
t
t
ˆktt u−− ˆ
,...,
ˆ1
ktt uu −− ˆ
,...,
ˆ1
113

statistic is LM (k) = (, where Ris the R))( 2
a
RkT −2
a
2 obtained from the auxiliary
regression and k is the order of lag length. The LM test is asymptotically distributed as
(k) distribution.
2
χ
The VAR Estimation
With the appropriate lag length (k), the VAR model in equation (3.5) can be
estimated if all price series are stationary [I(0)]. Since the right hand side of equation
(3.5) contains only predetermined variables and the error terms are assumed to be serially
correlated with constant variance (asssuming the appropriate lag length is chosen), each
equation can be estimated using ordinary least squares (OLS). Moreover, OLS estimates
are consistent and asymptotically efficient. The estimation of the VAR model in
equation (3.5) is done using the EView software package. There are three applications of
the VAR analysis employed in this study in order to investigate the price-response
relationships among canned tuna brands. They are the Granger-causality test, impulse
response function (IRF) analysis, and forecast error variance decomposition (FEVD)
analysis.
Testing for Granger-Causality
The VAR model is employed in this study to test the assumption that a firm in the
market sets its price depending on its prices and rivals’ prices from the past periods.
Such an assumption can be tested using Granger-causality tests. According to the price-
response elasticities obtained from the price-reaction functions in the first part (Table
114

4.9), Bumble Bee’s price does not affect price strategies of Starkist and Chicken of the
Sea during the same time period. Since Bumble Bee is one of the three leading brands in
the market, it is interesting to test whether its past strategy affects the other two brands’
strategies. In other words, it can be tested that Bumble Bee’s price Granger-causes
Starkist’s and Chicken of the Sea’s price, and vice versa.
It is difficult and not useful to interpret the relationships between variables from
the coefficients in the estimated VAR models because the VAR models are over-
parameterized. Therefore, Granger-causality test results obtained from the estimated
VAR are the key solutions here. For each equation in the VAR, the joint significance of
each of the other lagged endogenous variables in that equation is tested based on the Chi-
square (Wald test) statistics. The Wald test calculates the test statistic by estimating the
unrestricted regression without imposing the coefficient restrictions specified by the null
hypothesis. The null hypothesis is that Pj does not Granger-cause Ph, where Pj is the lag
of an endogenous variable j on the right hand side of an equation and Ph is the
endogenous variable h on the left hand side of that equation (j and h are Starkist, Chicken
of the Sea, Bumble Bee, and Allother). The Wald statistic measures how close the
unrestricted estimates come to the restrictions under the null hypothesis. If the
restrictions are true, then the unrestricted estimates should not be different from those
without restrictions. A dynamic relationship between two brands can be classified into
three types. For example, a pair of price series between Starkist and Bumble Bee is
tested. If the null hypothesis that the lags of Starkist’s price do not Granger-cause
Bumble Bee’s price is rejected, whereas the null hypothesis that the lags of Bumble Bee’s
price do not Granger-cause Starkist’s price cannot be rejected, it can be interpreted that
115

Starkist is a price leader and Bumble Bee is a price follower. If both null hypotheses are
rejected, it can be interpreted that the two firms conduct warfare (Vickner and Davies,
2000). However, if both null hypotheses cannot be rejected, it can be concluded that they
are not interdependent in a dynamic way, i.e. they do not take into account each other’s
past price strategies.
Impulse Response Function and Forecast Error Variance Decomposition Analyses
To investigate pricing relationships rigorously, the IRF and FEVD analysis are
employed. If there is a unitary change in a brand’s price at time t, the IRFs will give
information about whether the brand’s price and its rivals’ prices respond to the shock in
a positive or negative direction at time t+1, t+2, etc. The IRF analysis reveals the
direction of the relationships graphically between variables from a shock of one variable,
whereas the FEVDs measure proportions of the forecast error variance of a brand’s price
that can be explained by shocks to its own price and its rivals’ prices. Theoretically, if
none of the forecast error variances in a brand’s price at all forecast horizons can be
explained by innovations on the other brands’ prices, the inference is the brand’s price
series is exogenous. If all price series are endogenous, the forecast error variance in a
brand’s price can be explained by shocks on its price and the other brands’ prices at all
forecast horizons. The effects from shocks are reported as percentages. For example, if
50 percent of the three-period-ahead error variance in Bumble Bee’s price can be
explained by innovations to Starkist’s price, then Starkist’s price has a large influence on
the progress of Bumble Bee’s price. The results from the IRF and FEVD analyses can
serve as a way to confirm the dynamic price-relationship results obtained from the
116

Granger-causality tests. Both IRFs and FEVDs are constructed from the VAR model
with orthogonal residuals using the Choleski decomposition.
117

