AGB 481 Strategic Pricing in Food Markets: In-Depth Study Notes
on Cost Structure Analysis
I. Learning Insights and Strategic Context for Food Pricing
As an
AGB481
student specializing in the strategic pricing of food products, my
central learning insight is that cost structure dictates strategy. For food
manufacturers—whether a large-scale meat packer, a dairy processor, or a boutique
artisanal baker—understanding the behavior of costs is not merely an accounting
exercise; it is the absolute foundation of setting a competitive and profitable price
floor. The nature of food production, which is often highly capital-intensive (heavy
investment in facilities, cold storage, processing equipment), makes the distinction
between Fixed Costs (FC) and Variable Costs (VC) particularly critical.

The food supply chain operates on tight margins, faces volatile commodity prices,
and often requires significant capacity to achieve economies of scale. A firm with
high fixed costs is said to have high operating leverage. This leverage is a double-
edged sword: high volumes translate to massive profits as the fixed costs are spread
thin, but low volumes can quickly drive the company into bankruptcy, as it struggles
to cover its essential commitments (like depreciation and rent). Therefore, cost
structure analysis is the bedrock for:
Price Floor Determination: Determining the minimum price at which a product can
be sold to avoid short-run or long-run losses.
Break-Even Analysis (BEA): Calculating the minimum volume required to justify the
initial investment and ongoing operational costs.
Make-or-Buy Decisions: Strategically choosing whether to produce an ingredient in-
house (involving fixed costs like equipment) or purchase it externally (a variable
cost).
Capacity Utilization: Assessing the ideal volume to maximize the utilization of fixed
assets, which is paramount in the perishable food sector.
A deep mastery of these concepts is indispensable for transitioning from a simple
cost accountant to a Strategic Pricing Analyst in the food industry.
II. Core Knowledge 1: Fundamental Cost Classification and 📝
Relevant Range
Costs are classified based on how they react to changes in the Activity Level (or
Volume
of Production). In food production, the activity level is usually measured in
units produced (e.g., pounds of pasta, gallons of milk, cartons of eggs).
A. Fixed Costs (
FC
)
Definition: Costs that remain constant in total regardless of changes in the level of
production volume within a specific boundary known as the
Relevant Range
.
Behavior (Per Unit): As volume increases, the fixed cost per unit decreases
(spreading the overhead). This is the essence of
economies of scale
.
Time Horizon: Fixed costs are generally associated with the costs required to
maintain the capacity to produce (i.e., long-run commitments).
Strategic Relevance: They determine the long-run viability and the degree of
Operating Leverage
.
B. Variable Costs (
VC
)
Definition: Costs that change in total in direct proportion to changes in the level of
production volume.
Behavior (Per Unit): The variable cost per unit remains constant.

Time Horizon: Variable costs are incurred only when production occurs and are
associated with the consumption of specific materials and labor directly tied to the
unit.
Strategic Relevance: They set the short-run price floor (the
Marginal Cost
of
production).
C. Mixed Costs (Semi-Variable Costs)
Definition: Costs that contain both a fixed component and a variable component.
They increase with volume, but not proportionally.
Behavior: The
Fixed Component
represents the minimum cost to maintain the
service (e.g., a base monthly utility charge), and the
Variable Component
reflects the
actual usage (e.g., electricity consumption tied to processing hours).
Accounting Necessity: For effective pricing and
CVP
analysis, mixed costs must be
accurately separated into their
FC
and
VC
components, often using methods like
the
High-Low
Method or
Regression Analysis
(Least-Squares Regression).
D. The
Relevant Range
Definition: The range of activity over which the fixed cost and variable cost per unit
assumptions hold true. It is the operating band where the companys current capital
structure (e.g., one factory, one set of machinery) is sufficient.
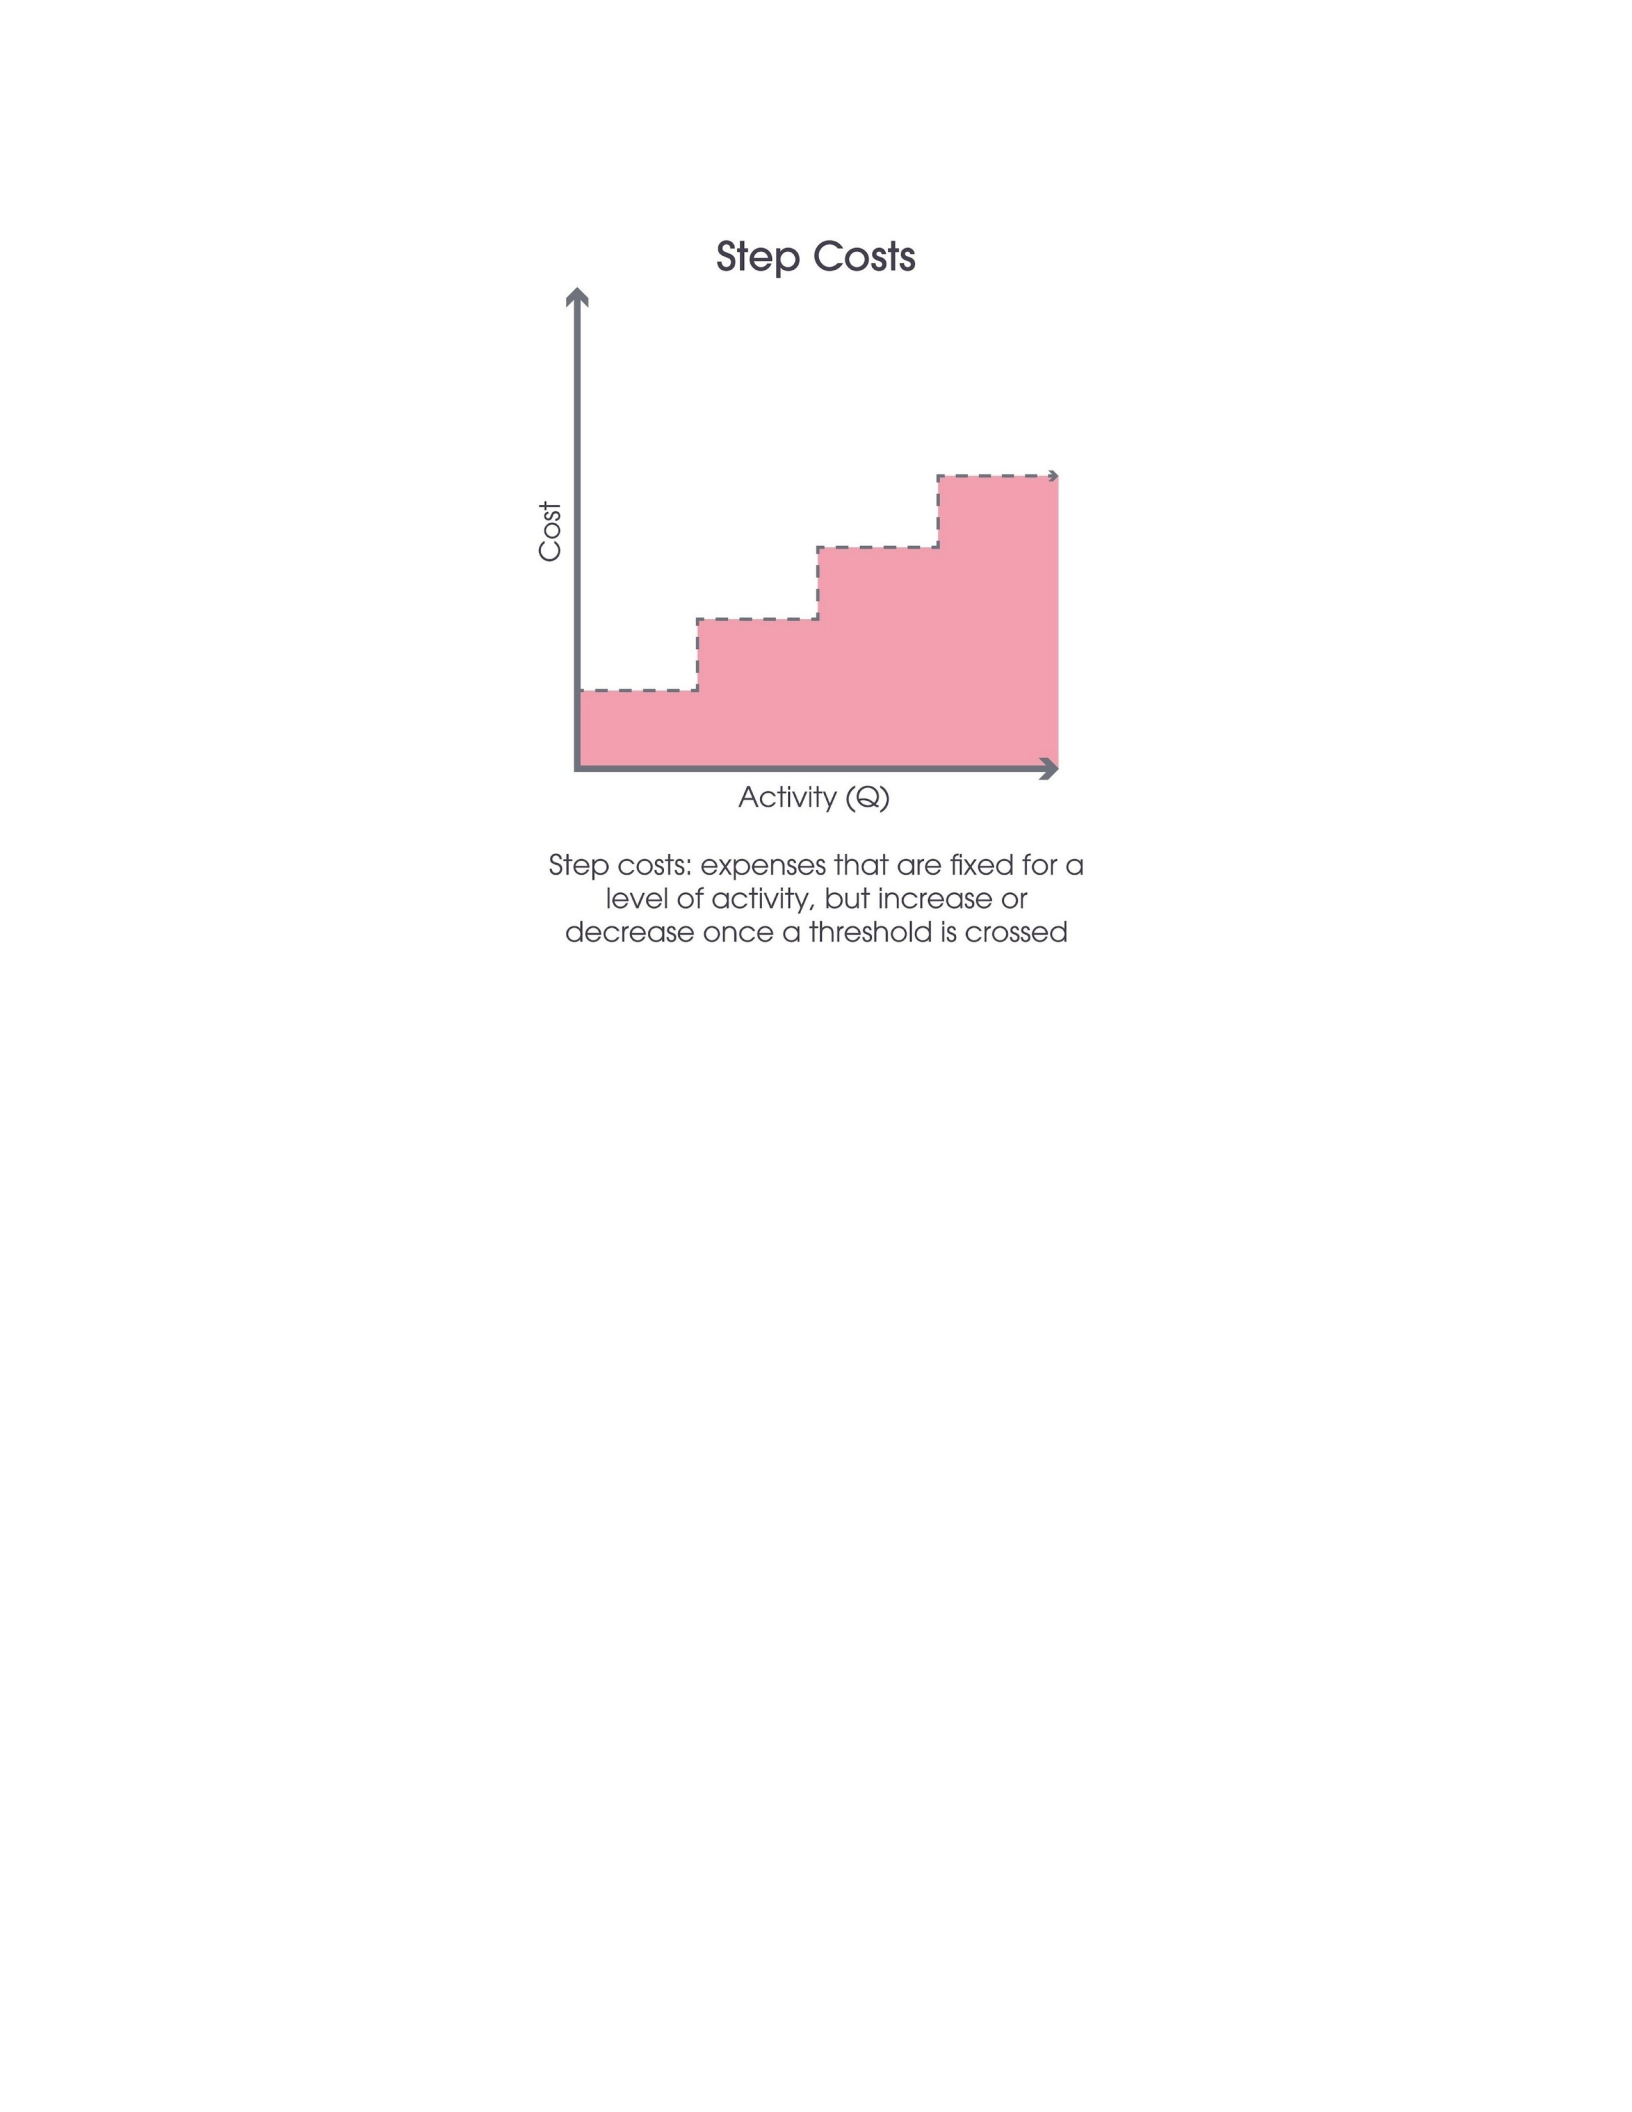
Strategic Importance: Outside the
Relevant Range
, fixed costs change dramatically
(they become Step-Fixed Costs).
Example: If a dairy plant reaches
100 %
capacity and must build a second plant to
increase production, the fixed cost for
Plant and Equipment Depreciation
and
Facility Lease
suddenly doubles.
AGB 481 Insight: Strategic pricing decisions must always consider whether an
increase in volume will push the firm outside its current
Relevant Range
,
necessitating a recalculation of the cost structure and the
Break-Even Point
.
III. Core Knowledge 2: Detailed Fixed Costs in Food Production🏗️
In the highly capital-intensive food and beverage sector, fixed costs represent the
substantial initial and ongoing investment required to maintain the operational
infrastructure necessary for processing food safely and efficiently. The scale and
nature of these costs create significant Barriers to Entry for new competitors.
1. \text{Property, Plant, and Equipment (PP&E) Depreciation}
Nature of the Cost: The systematic allocation of the cost of a tangible asset over its
useful life. It represents the cost of using the asset, not the cash expenditure.
Food Industry Context: This is the single largest fixed cost category for many food
processors. It includes:
Processing Machinery: Large-scale pasteurizers, homogenizers, deep freezers,
bottling lines, and automated sorting equipment. These assets are highly
specialized, have long useful lives, and depreciate based on time (e.g.,
Straight-Line Depreciation
) rather than output units, making the cost fixed.
Facilities: The physical plant structure, including cold storage warehouses, quality
control labs, and administrative offices.
Accounting Implication: The choice of depreciation method (e.g.,
Straight-Line
vs.
Accelerated Methods
like
Double-Declining Balance
) impacts the reported
Fixed Cost

in the
Income Statement
, thereby influencing the calculation of the
Break-Even Price
and corporate taxes.
2.
Facility Leases and Land Rent
Nature of the Cost: Contractual, periodic payments for the use of real estate.
Food Industry Context: Food grade facilities must meet rigorous sanitary standards
(
HACCP
compliance,
FDA
regulations) and are often strategically located near
agricultural inputs or distribution hubs. The annual lease payment remains fixed
regardless of whether the plant processes one ton or one thousand tons of product.
Strategic Implication: Long-term leases lock in a high fixed cost, requiring a long-
term commitment to production capacity.
3.
Salaries of Administrative and Non-Production Personnel
Nature of the Cost: Compensation paid on a time basis (monthly or annual salary)
regardless of the production output.
Food Industry Context: These include crucial roles that maintain the capacity and
compliance of the firm, such as:
Plant Manager
and
Supervisors
.
Quality Control and Assurance (QC/QA)
Staff: Essential for food safety; their salaries
are fixed, as testing must occur even at low volumes.
Sales and Marketing Executives
.
Administrative and Accounting Staff
.
Distinction from Direct Labor (VC): These salaried roles contrast sharply with direct
labor, who are often paid an hourly wage directly tied to the number of units
processed.
4.
Property Taxes and Insurance Premiums
Nature of the Cost: Taxes levied on the value of the fixed assets (
PP&E
) and
insurance premiums required to cover the facilities and equipment against damage,
contamination, or liability.
Food Industry Context: Insurance costs are particularly high in the food sector due
to the risk of product recalls, pathogen outbreaks, and cold chain failure. These
premiums are paid annually, irrespective of the volume produced in any given
month.
5.
Fixed Utility Charges and Maintenance Contracts
Nature of the Cost: The minimum charge required to keep essential services
functional, even if not producing.

Food Industry Context:
Base Utility Charges: The fixed connection fee for water, natural gas, and electricity.
Scheduled Maintenance: Preventive maintenance contracts for critical, expensive
equipment (e.g., refrigeration units) that must be serviced regularly to prevent
costly breakdowns, regardless of utilization rate. This is a crucial fixed cost for food
safety.
Strategic Implication: Operating Leverage
Definition: The measure of how sensitive a companys operating income is to a
change in sales volume. It is calculated as
Contribution Margin/Operating Income
.
High Operating Leverage (High FC): Food manufacturers with extensive, automated
plants (high
FC
) will see profits soar when sales increase, as each additional unit
sold contributes almost entirely to profit after covering the small variable cost.
Conversely, a small drop in sales can lead to a disproportionately large loss.
Pricing Strategy Consideration: A firm with high
FC
may aggressively price to
achieve high volume and minimize the
Fixed Cost Per Unit (FCPU)
, even if it means
accepting a lower
Contribution Margin
per unit.
IV. 🧺 Core Knowledge 3: Detailed Variable Costs in Food Production
Variable costs are incurred directly as a consequence of manufacturing a unit of
food product. Their proportional relationship to volume provides a clear indication
of the Marginal Cost of production, which is the absolute short-run floor for pricing
decisions.
1.
Direct Raw Materials (DRM)
Nature of the Cost: The core ingredients that physically become part of the finished
food product. The cost of these materials varies directly with the number of units
produced.
Food Industry Context (Volatile
VC
): The food market is unique because the cost of
DRM
(e.g., corn, milk, wheat, sugar, beef) is subject to extreme volatility due to
commodity markets, weather, and geopolitical factors.
Examples: Flour for baking, raw milk for dairy, cocoa beans for chocolate, bulk meat
for processed goods.
AGB 481 Implication (Cost Management): A significant part of strategic pricing in
this industry involves techniques to manage this
VC
volatility, such as Hedging
commodity purchases with futures contracts or employing
Standard Costing
systems
to benchmark and control
DRM
usage.
2.
Direct Packaging Materials

Nature of the Cost: Materials essential for containing, preserving, and labeling the
product. This cost is incurred per unit.
Food Industry Context: Packaging often involves highly specialized materials
necessary for shelf stability and consumer appeal.
Examples: Plastic containers, foil wrappers, cartons, printed labels, and inert gas for
modified atmosphere packaging (
MAP
).
Strategic Implication: Changes in packaging (e.g., switching to sustainable materials)
can significantly alter the
VC
per unit, requiring immediate adjustment to the
pricing strategy.
3.
Direct Labor (DL)
Nature of the Cost: The wages paid to workers who are physically involved in
transforming raw materials into finished goods. These workers are typically paid an
hourly rate.
Food Industry Context: Includes line workers, machine operators, butchers, bakers,
and assemblers. Their total wage bill increases directly with the number of hours
spent processing products.
Note: The compensation for temporary or seasonal workers hired specifically for
peak harvest or production cycles is a pure
VC
.
Accounting Implication:
Direct Labor
efficiency (e.g., units produced per labor hour)
directly impacts the
VC
per unit. Poor efficiency increases the
VC
, demanding a
higher price floor.
4.
Variable Manufacturing Overhead (VMOH)
Definition: Manufacturing costs, other than
DRM
and
DL
, that vary with the volume
of production.
Food Industry Examples:
Production Utilities: The cost of electricity and natural gas required to run the
processing lines, ovens, and chillers above the fixed base charge.
Consumable Supplies: Lubricants, cleaning chemicals (essential for sanitation
compliance), and minor replacement parts used in proportion to machine run-time.
Quality Testing: The cost of external laboratory testing per batch or per unit of
finished product.
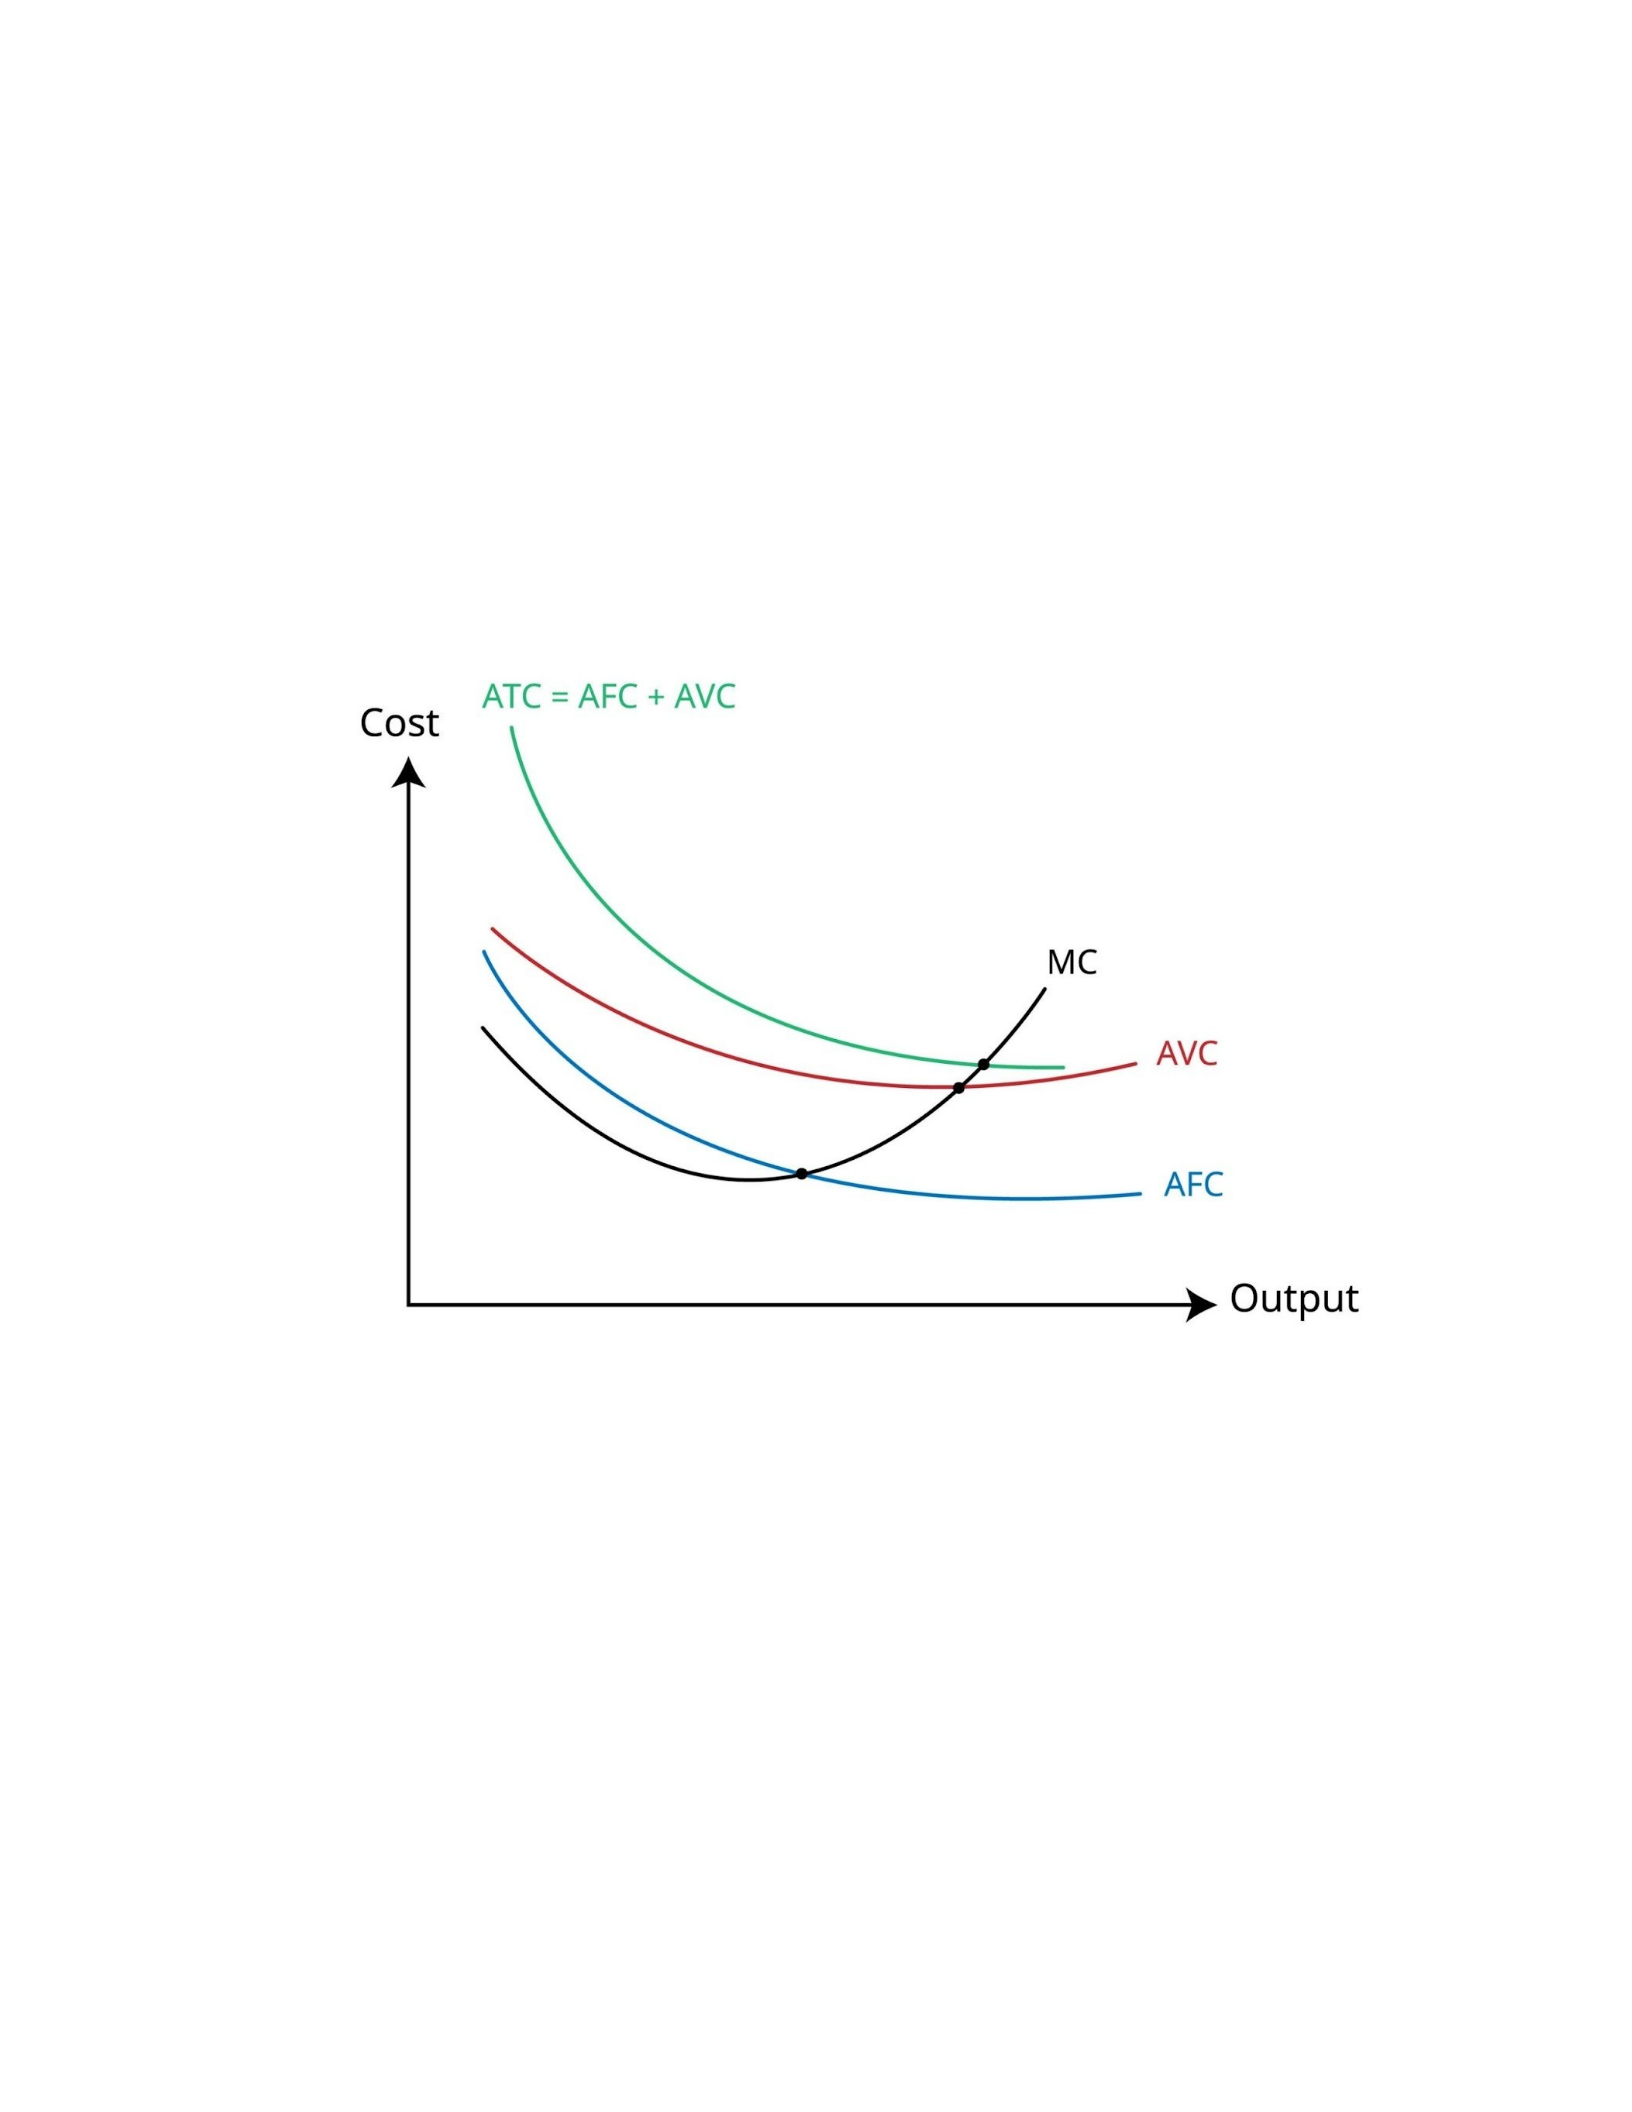
Strategic Implication: Marginal Cost and Short-Run Pricing
Marginal Cost (
MC
): For a single unit, the
MC
is effectively the
VC
per unit.
Short-Run Pricing Floor: In the short run, a food company can profitably accept any
price that covers its
Marginal Cost
plus a small amount to contribute to covering
FC
.
If a perishable product is about to spoil, accepting a price slightly above
VC
is better
than incurring a total loss.
Contribution Margin (CM): The excess of selling price over the
VC
per unit (
CM=Selling Price −VC
). This is the critical metric in
AGB481
, as the
CM
represents the amount available to cover
FC
and generate profit.
V. Core Knowledge 4: 📊
Cost-Volume-Profit (CVP)
Analysis and Strategic Pricing
The classification of costs into fixed and variable components is the prerequisite for
conducting a
CVP
Analysis (often called
Break-Even Analysis
), which is central to
strategic food pricing.
A.
Contribution Margin
Analysis
Total
Contribution Margin
(
TCM
): The total revenue remaining after deducting all
Total Variable Costs
(
TCM=Total Revenue −Total VC
).
Contribution Margin Ratio
(
CMR
): The percentage of each sales dollar that
contributes to covering
FC
and generating profit (
CMR=CM per Unit/Selling Price
,
or
TCM/Total Revenue
).
Strategic Use: The
CMR
allows pricing strategists to quickly estimate the impact of
sales increases or decreases on profit. A high
CMR
means the firm earns profit
rapidly once the
BEP
is met.
B.
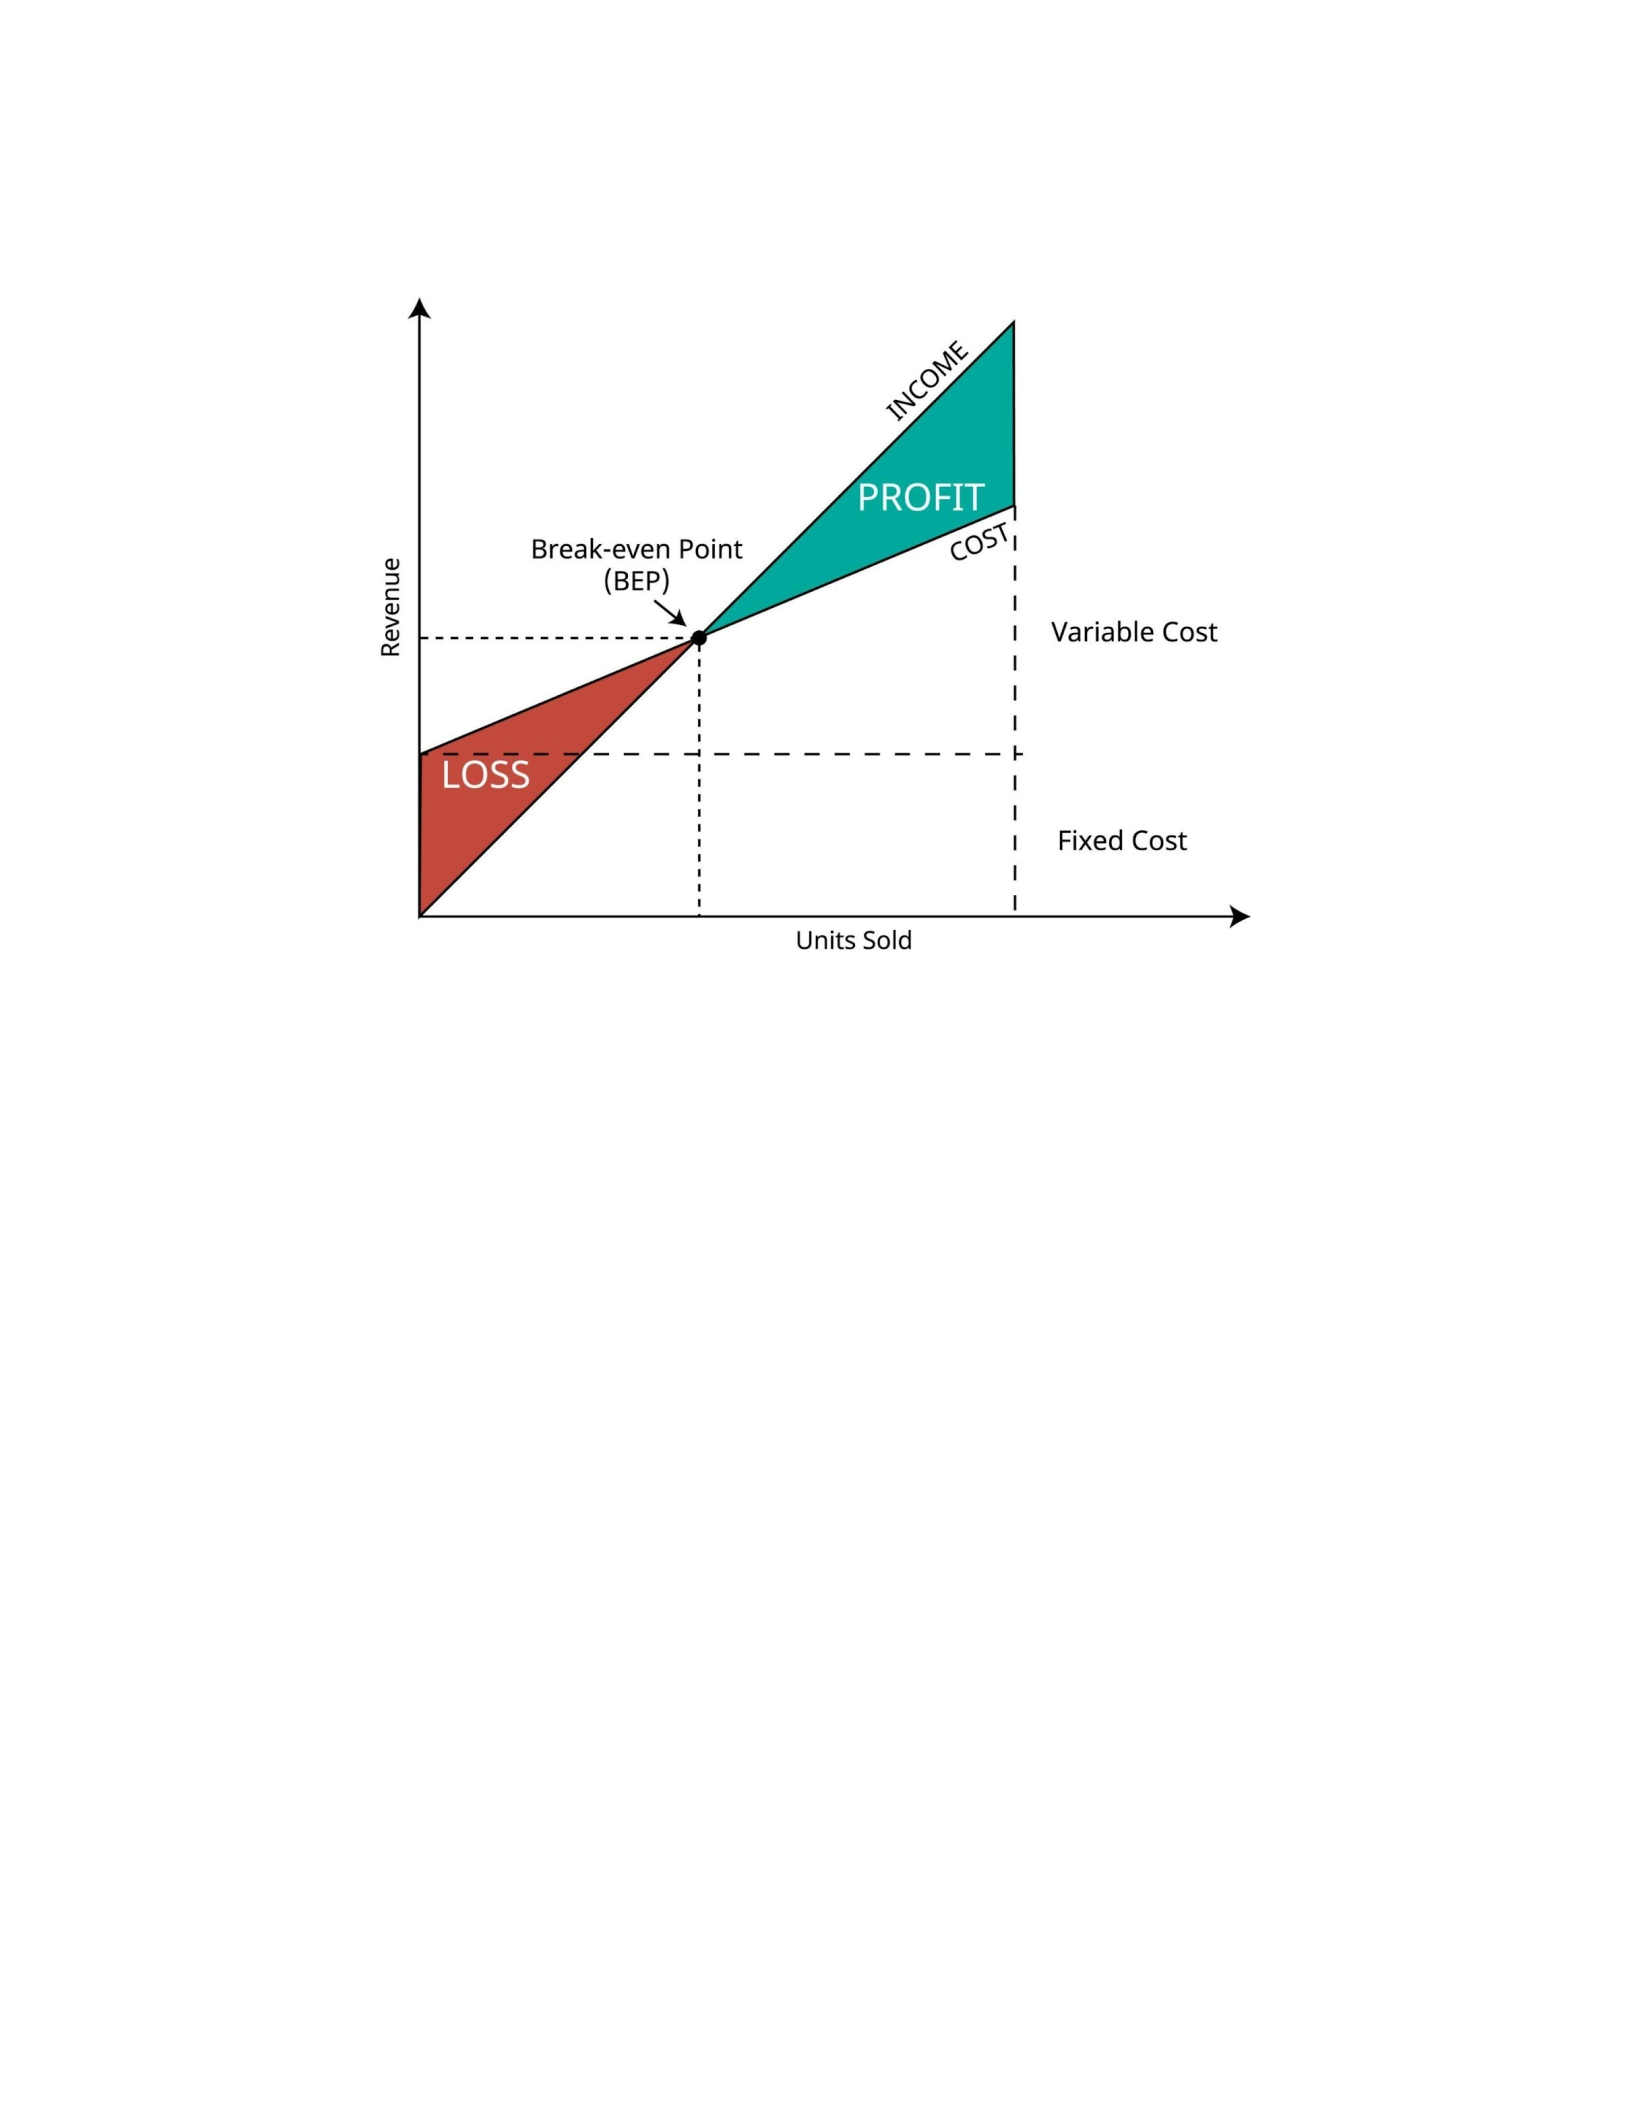
Break-Even Point (BEP)
Definition: The volume level (in units or sales dollars) at which
Total Revenue
equals
Total Costs
(
FC+VC
), resulting in zero profit.
Calculation (in Units):
BEP (Units)=Total Fixed Costs
Contribution Margin Per Unit
Calculation (in Sales Dollars):
BEP (Dollars)=Total Fixed Costs
Contribution Margin Ratio
AGB 481 Pricing Strategy: The
BEP
provides a direct assessment of Volume Risk. A
firm with a high
BEP
needs high sales velocity, which requires competitive and
attractive pricing. A food manufacturer targeting a niche market (low potential
volume) must ensure its
FC
are low enough (low
BEP
) to be viable.
C. Target Profit Analysis
A key extension of
CVP
is calculating the required volume to achieve a specific
target profit (
TP
).
Calculation (in Units):
Volume to Achieve TP=Total Fixed Costs+Target Profit
Contribution Margin Per Unit
Strategic Use: If a food firm needs to achieve a
15 %
Return on Investment (ROI)
(which translates to a
Target Profit
amount), this formula calculates the required
production and sales volume, thus setting the sales goal that the marketing and sales
teams must achieve. This directly influences the choice of distribution channels and
promotional pricing campaigns.
VI. Extended Examples and Scenario Analysis in Food Markets💼
To solidify these concepts for
AGB481
, let us analyze a commercial frozen dessert
manufacturer, "Arctic Creamery," specializing in premium organic ice cream pints.
Scenario 1: Initial Cost Structure (Relevant Range: 10,000 to 50,000 Pints/Month)
Arctic Creamery has analyzed its monthly cost data:
Fixed Costs (
FC
):
Warehouse Lease (Cold Storage):
$15,000
Depreciation (Freezing/Packaging Equipment):
$8,000
QA/Plant Manager Salaries:
$12,000
Total Monthly FC:
$35,000
Variable Costs (
VC
per Pint):
Raw Ingredients (Organic Cream, Sugar, Flavoring):
$2.50
Packaging (Pint Container, Seal):
$0.75
Direct Labor (Hourly Filling/Sealing):
$0.25
Variable Utilities (Freezing Energy):
$0.50
Total VC per Pint:
$4.00
Pricing Strategy Challenge: The wholesale selling price to a major grocery chain is
set at $6.50 per pint.
Calculation of
Contribution Margin
and
BEP
:
CM
per Pint:
$6.50 (Price)−$4.00 (VC)=$2.50
BEP
(Units):
$35,000 (FC)/$2.50 (CM per Unit)=14,000 Pints
Strategic Insight: Arctic Creamery must sell
14,000
pints per month just to cover its
fixed infrastructure costs. This
BEP
is a critical reference point for sales forecasting
and channel strategy.
Scenario 2: Pricing a Seasonal Order (Focus on Marginal Cost)

It is the low season (
January
), and Arctic Creamery is only producing
10,000
pints
per month (below
BEP
). A large discount retailer offers to buy
5,000
extra pints at a
special promotional price of
4.50 perpint , buttheywillnotbuyatthestandardwholesalepriceof
6.50.
Analysis using Cost Classification:
Short-Run Decision Rule: Accept the order if the special price is above the
Variable Cost
(
Marginal Cost
), as this price contributes positively to covering
Fixed Costs
.
Special Price
: $4.50
VC
per Pint: $4.00
Contribution Margin
of Special Order:
$4.50 −$4.00=$0.50
per pint.
Strategic Conclusion: Arctic Creamery should accept the order. While the price is
low, it contributes an extra
5,000 ×$0.50=$2,500
toward covering the
$35,000
in
FC
.
Since the company is currently losing money at
10,000
units, this incremental
revenue helps reduce the overall loss in the short run. This illustrates that
Variable Cost
sets the tactical price floor.
Scenario 3: Exceeding the
Relevant Range
(Step-Fixed Costs)
Sales explode, and Arctic Creamery needs to produce
60,000
pints per month, which
exceeds the current
Relevant Range
of
50,000
pints. To achieve this volume, they
must rent an additional smaller cold storage facility and hire an assistant plant
supervisor.
New
Step-Fixed Costs
:
New Cold Storage Lease:
+$4,000
Assistant Supervisor Salary:
+$3,000
Total Increase in FC:
+$7,000
New Total
FC
:
$35,000+$7,000=$42,000
Impact on
BEP
:
New
BEP
(Units):
$42,000 (New FC) /$2.50 (CM per Unit)=16,800 Pints
Strategic Insight: The
BEP
jumps from
14,000
to
16,800
pints. The strategic pricing
team must now ensure that the
60,000
-pint sales forecast is secure, as the firm is
locked into a higher cost structure. This phenomenon of Step-Fixed Costs highlights
why the
Relevant Range
is a crucial boundary for
AGB481
analysis.
VII. Consolidation of Core Terminology for 📝
AGB481
A robust vocabulary is essential for professional communication in strategic pricing:

Relevant Range
(
Relevant Range
): The volume range over which fixed and variable
cost per unit assumptions are valid. Exceeding this range often requires new
investment, altering
FC
.
Operating Leverage
(
Operating Leverage
): The extent to which a firm uses
Fixed Costs
in its operation. High leverage magnifies profit swings with volume changes.
Contribution Margin (CM)
(
Contribution Margin
): The revenue remaining after all
Variable Costs
have been covered; the amount available to contribute toward
Fixed Costs
and profit. (
Selling Price −VC
).
Break-Even Point (BEP)
(
Break-Even Point
): The point at which
Total Revenue
equals
Total Costs
, resulting in a zero operating profit.
Marginal Cost
(
Marginal Cost
): The cost incurred to produce one additional unit of
output. In cost accounting, this is effectively equal to the
Variable Cost
per unit.
Product Costing
(
Product Costing
): The process of accumulating and assigning
Fixed
and
Variable
manufacturing costs to a product. For
AGB481
, this determines the
Price Floor
.
Absorption Costing
(
Absorption Costing
): A traditional method where
Fixed Manufacturing Overhead
(
FMO
) is "absorbed" into the cost of each unit
produced (required for
GAAP
reporting).
Variable Costing
(
Variable Costing
): A management accounting method where
FMO
is treated as a period cost (expensed immediately). This method is far superior for
internal
CVP
and
Pricing Decisions
because it isolates the
CM
.
Sunk Cost
(
Sunk Cost
): A cost that has already been incurred and cannot be
recovered (e.g., historical depreciation). It is irrelevant for future pricing or
Make-or-Buy
decisions, which should focus only on future
FC
and
VC
.
Opportunity Cost
(
Opportunity Cost
): The potential benefit given up when choosing
one alternative over another (e.g., the profit forgone by using the factory space to
make Product A instead of Product B).
Cost Object
(
Cost Object
): Anything for which cost data are desired (e.g., a single pint
of ice cream, a specific department, or a sales territory).