


CERTIFIED PUBLIC ACCOUNTANTS’ PERCEPTIONS AND
EXPERIENCES OF ACCOUNTING ETHICS: A QUALITATIVE INQUIRY
CHAPTER 1. INTRODUCTION
Accounting ethics remain fundamental to the successful performance of accounting firms
(Agwor & Okafor, 2018; Gunz & Thorne, 2019; Ishaque, 2021). Sound ethical practices enhance
firms' reputations and prevent lawsuits against accounting firms (Fatemi et al., 2020; West,
2018). Firms that adhere to accounting ethics also attract more clients and increase public
confidence in their operations (Gunz & Thorne, 2019; Ishaque, 2021; West, 2018). Thus,
certified public accountants (CPAs) who demonstrate sound ethical behaviors project their firms'
image and foster societal confidence and interest in their practices. In contrast, CPAs who
perpetrate unethical professional behaviors may undermine their firms' reputation, losing public
confidence in their practices (Ahinful et al., 2017; Ishaque, 2021; Melé et al., 2017). For
example, a study by Cornerstone Research on federal securities class action filings revealed that
accounting breaches constituted more than 80% of total settlement dollars in 2020,
approximately 18% higher than the full settlement in 2019 (Cornerstone Research, 2021). Edi
and Enzelin (2022) also reported that an Indian company declared a profit of three hundred
sixtyone billion Indian rupees when it did not have the authorized reserves of 7 trillion Indian
rupees. These unethical financial reporting practices attracted adverse audit opinions and severe
penalties such as revocation of licenses, fines, and imprisonment (Carr et al., 2021; Gunz &
Thorne, 2019; West, 2017). Although some researchers blame these unethical practices on ethical
dilemmas that CPAs encounter in their day-to-day practices (Gunz & Thorne, 2019; Ishaque,

2021), others blame such unethical behaviors on CPAs' non-adherence to the professional
accounting code of conduct (Carr et al., 2021; Jelinek, 2018).
CPAs' professional accounting code of conduct violations constitute a severe breach,
given their role as guardians of the code (Al frijat & Albawwat, 2019; Carr et al., 2021). Instead
of following the tenets of the professional accounting code of conduct when faced with ethical
dilemmas, some CPAs choose to pursue their organization's objectives to the detriment of the
broader societal interest (Huterski et al., 2020; Jaijairam, 2017). Such non-adherence is subjected
to public scrutiny because the role of the CPAs is to comply with their professional code of
conduct and safeguard the public interest (Baud et al., 2021; Melé et al., 2017). To enforce CPAs'
compliance with the professional accounting code of conduct, accounting firms are instituting
measures to address ethical dilemmas within the work context. These measures include
internalizing professional ethics, enrollment in ethics compliance programs, and reward and
recognition programs (Baud et al., 2021; Ishaque, 2021; Sonnerfeldt & Loft, 2018). Melé et al.
(2017) asserted that although these measures could motivate CPAs to comply with their
professional code of ethics, they may not be a panacea to the growing unethical behaviors in
accounting institutions due to CPAs' philosophical orientations.
According to Dunn and Sainty (2020), CPAs' philosophical orientations influence their
evaluation of ethical dilemmas in the work context. These philosophical orientations comprise
utilitarianism, deontology, and virtue ethics, which inform their day-to-day ethical
decisionmaking processes in organizational settings (Dunn & Sainty, 2020; Morrison et al.,
2018). Utilitarianism refers to CPAs' assessment of the ethicality of their decisions based on the
consequences for society, while deontology entails a set of norms underpinning the "rightness"

and "wrongness" of behavior (Dunn & Sainty, 2020; Morrison et al., 2018). In contrast, virtue
ethics reflects CPAs' moral courage to make decisions regardless of the associated risks
(Kamińska-Stańczak & Silska-Gembka, 2021; Osafo et al., 2021). These dimensions of CPAs'
philosophical orientations provide a holistic picture of the internal and external forces underlying
their decision-making processes.
Aside from CPAs' philosophical orientations, CPAs' national culture also influences their
ethical decision-making processes. National culture defines a group of people's beliefs,
behaviors, and general orientation (Curtis et al., 2017; Gierusz et al., 2022). National culture also
varies from one group of people to another and from one geographical location to another,
leading to different perspectives, values, norms, beliefs, customs, aspirations, and practices (Al
frijat & Albawwat, 2019; Gierusz et al., 2022). Consequently, an ethical decision in one nation or
geographic location could differ from another, resulting in variations in decision-making
processes in accounting firms.
The statement of focus for this dissertation study revolves around delving into the
intricate realm of accounting ethics as perceived and experienced by Certified Public
Accountants (CPAs). The study aims to unravel the multifaceted dimensions of CPAs'
understanding and encounters with accounting ethics, shedding light on their personal ethical
beliefs compared to their profession's formalized ethical standards. It also seeks to uncover the
impact of training and professional reputation on their adherence to accounting ethics. By
exploring their experiences with ethical dilemmas in their careers, the study aspires to contribute
to a comprehensive understanding of the dynamics surrounding accounting ethics in the CPA
profession. Through qualitative interviews and thematic analysis, this research provides valuable

insights into the perceptions and experiences of CPAs, thus enriching the discourse on
accounting ethics within the accounting profession.
Background of the Study
Global crises due to financial scandals have heightened compliance with accounting
ethics in the business environment (Dharmasiri et al., 2022). According to Morrison et al. (2018),
ethics in accounting focuses on moral and ethical judgments. Accounting firms require CPAs to
evaluate the ethical consequences of their decisions and act in the business's best interest instead
of their own (Dunn & Sainty, 2020; Morrison et al., 2018). Accordingly, CPAs are under
increasing pressure to act professionally and ethically to build public confidence in accounting
firms (Dunn & Sainty, 2020; Zhatkin et al., 2017). Unethical CPAs create public mistrust and
elicit public scrutiny of their professional competence and practices (Ishaque, 2021; Melé et al.,
2017; Racko, 2019). Such mistrust and scrutiny undermine their firms' reputations and result in
increased compliance and regulatory monitoring. Thus, CPAs' strict compliance with ethical
accounting rules significantly elevates accounting firms' performance and reputation (Carr et al.,
2021; Gunz & Thorne, 2019).
Researchers have attributed growing corporate scandals in accounting firms to a lack of
business ethics and accounting professionalism (Dunn & Sainty, 2020; West, 2018). Accounting
firms' failure to embrace sound business ethics and professionalism continues to attract
regulatory and public scrutiny, exposing some firms’ involvement in corporate scandals (Akman
et al., 2020; Carr et al., 2021). For example, Dunn and Sainty (2020) cited the following firms
for perpetrating corporate scandals: Autonomy Corporation in the UK, Lehman Brothers in the
USA, Petrobras in Brazil, Sino-Forest Corporation in Canada, and Toshiba in Japan. Akman et
al. (2020) added that in 2001, WorldCom reported a profit of $1.4 billion instead of a loss of

$2.4 billion. Similarly, Tesco overstated its earnings in the first half of the year by £263 million,
while Sunbeam in 1997 included 62 million dollars in its profit obtained through fraudulent
transactions (Akman et al., 2020). These corporate scandals by renowned firms have heightened
public interest in accounting ethics and called for research into the causes and mechanisms
underlying the increase in organizational scandals (Akman et al., 2020; Carr et al., 2021).
A company's reward structure for the management team could also constitute a potential
source of ethical issues in organizations, according to Fiolleau and Kaplan (2017). This
development occurs when management influences professional accountants to manipulate
financial statements to pay management members lucrative financial rewards such as significant
bonuses and stock options (Edi & Enzelin, 2022; Fiolleau & Kaplan, 2017). An example of this
financial manipulation is earnings management. This concept relates to intentional and strategic
manipulations of financial statements to achieve a company's stated objectives (Al frijat &
Albawwat, 2019; Fiolleau & Kaplan, 2017). In this respect, organizational leaders and their
accountants "cook the books" to pay themselves significant bonuses they never earned (Ali &
Khan, 2022; Edi & Enzelin, 2022). These manipulations could have adverse implications for
firms' continued performance and sustainability. Consequently, without monitoring mechanisms
to mitigate these unethical behaviors, the temptation to manipulate financial statements could be
high and unmanageable (Armstrong, 2020; Fiolleau & Kaplan, 2017).
The accounting professional bodies and other government agencies have intensified their
supervision to curb CPAs' unethical behaviors in accounting firms and address corrupt practices
in organizational settings. In the United States, the American Institute of Certified Public
Accountants (AICPA) has mandated a code of conduct to regulate CPAs' professional conduct
(Morrison et al., 2018). This code guides CPAs' professional conduct and decision-making

processes, compelling them to be mindful of public interest in their activities (Dunn & Sainty,
2020; Huterski et al., 2020). According to Dunn and Sainty (2020), the code of conduct guides
appropriate and inappropriate ethical behaviors and activities. Although accounting firms have
entrenched professional codes of conduct in their organizational culture, unethical behaviors and
breaches involving CPAs continue to manifest in accounting firms, warranting further research
into CPAs' unethical behaviors and practices (Ali & Khan, 2022; Huterski et al., 2020).
This study focuses on CPAs' perceptions and experiences of accounting ethics. Reviewing
empirical studies and conceptual articles on accounting ethics provided the foundation for
studying this central phenomenon. The review uncovered the following research problem: CPAs'
failure to adhere to accounting ethics (Fatemi et al., 2020; Huterski et al., 2020;
Kamińska-Stańczak & Silska-Gembka, 2021). This problem warrants investigation because of
increased corporate scandals in organizations, especially accounting firms (Fatemi et al., 2020;
Ishaque, 2021). The accounting ethics literature also revealed the dominance of the quantitative
research paradigm in investigating the accounting ethics phenomenon in organizations (Huterski
et al., 2020; Jelinek, 2018; Kamińska-Stańczak & Silska-Gembka, 2021). The accounting ethics
phenomenon entails psychological, cultural, and social orientations (Dunn & Sainty, 2020;
Ishaque, 2021). Therefore, measuring this phenomenon using quantitative instruments could
impede an in-depth understanding of the accounting ethics phenomenon (Namazi & Rajabdorri,
2020; Poje & Zaman Groff, 2022).
This study also integrated the perspectives of agency and expectancy-valence (E-V)
theories to provide a broad conceptual structure for exploring CPAs' perceptions and experiences
of accounting ethics, which remain under-explored in the accounting literature
(KamińskaStańczak & Silska-Gembka, 2021; Nikula & Kivistö, 2018; West, 2018). Jensen and

Meckling (1976) conceptualized agency theory as a relationship between two or more people in
which one or more persons (the principal) engage another person (the agent) to perform some
service on the principal's behalf. In this regard, accounting firms acting as the principal in the
relationship delegate their decision-making authority to CPAs who serve as the agent in the
relationship. On the other hand, the expectancy-valence theory focuses on CPAs' motivation to
comply with the firm's strategic goals and objectives, including governance structures (Vroom,
1964). Integrating agency and E-V theories creates expectations and benefits that could motivate
CPAs to adhere to sound ethical practices in accounting firms (Fudge & Schlacter, 1999; Jensen
& Meckling, 1976;
Osafo et al., 2021; Vroom, 1964).
Need for the Study
The need for this study arises from accounting ethics' critical role in ensuring the
integrity, transparency, and trustworthiness of financial information, which is fundamental to
economic stability and decision-making (Melé et al., 2017; Racko, 2019). Accounting
professionals, especially Certified Public Accountants (CPAs), are entrusted with the
responsibility of upholding and practicing ethical standards in their work (Dunn & Sainty, 2020;
Ishaque, 2021; Morrison et al., 2018). However, there is a growing recognition that the
understanding and application of accounting ethics can be influenced by various factors,
including personal beliefs, professional reputation, training, and the ethical dilemmas
encountered in practice (Carr et al., 2021; Gunz & Thorne, 2019).
Understanding the perceptions and experiences of CPAs regarding accounting ethics is
crucial because it provides insights into how these professionals navigate the complex terrain of

ethical decision-making in their careers. This study explores the alignment or dissonance
between personal ethical beliefs and the formal ethical standards of the accounting profession.
Moreover, gaining insights into the ethical dilemmas CPAs face can inform the development of
better ethical guidelines and training programs (Morrison et al., 2018; Sonnerfeldt & Loft, 2018).
Additionally, recent accounting scandals and ethical lapses in the corporate world have
underscored the importance of maintaining high ethical standards within the accounting
profession (Antonelli et al., 2021; Edi & Enzelin, 2022; Fiolleau & Kaplan, 2017). The public
and stakeholders rely on CPAs to ensure the accuracy and reliability of financial information,
making it imperative to explore how CPAs perceive and engage with accounting ethics (Payne et
al., 2020; Tonglad & Khamwass, 2023; West, 2018).
The study is therefore needed to address the problem of CPAs' failure to comply with
accounting ethics in their organizations. Although significant research exists on accounting
ethics, little is known about CPAs' perceptions and experiences regarding accounting ethics
(Kamińska-Stańczak & Silska-Gembka, 2021; Namazi & Rajabdorri, 2020; Sonnerfeldt & Loft,
2018). For example, Kamińska-Stańczak and Silska-Gembka (2021) concluded that despite
existing literature on accounting ethics, limited studies have investigated CPAs' judgments and
decision-making processes in accounting firms. Kamińska-Stańczak and Silska-Gembka (2021)
also reinforced this knowledge gap in the accounting literature, suggesting that CPAs'
perceptions and experiences with ethical decision-making processes require further
examination to understand ethical practices and behaviors in accounting firms. Therefore, this
study fills a gap in the accounting literature by investigating the CPAs' perceptions and

experiences regarding accounting ethics in sampled accounting firms operating in Maryland,
USA.
Thus, this study's need is rooted in the significance of accounting ethics for the
accounting profession, the broader business community, and society at large. By examining
CPAs' perceptions and experiences, this study can enhance ethical practices within the
accounting profession, thus promoting trust, credibility, and ethical conduct in financial reporting
and decision-making.
Purpose of the Study
The primary purpose of this generic qualitative inquiry is to explore CPAs' perceptions
and experiences regarding accounting ethics in accounting firms operating in Maryland, USA.
This study aims to gain an in-depth understanding of how CPAs perceive and interpret the
concept of accounting ethics within the contemporary professional landscape. One way CPAs
can contribute to the financial health of their firms and foster public trust in financial reporting
practices is through the accounting ethics code of conduct (Namazi & Rajabdorri, 2020;
Sonnerfeldt & Loft, 2018). The study also explores the ethical dilemmas, challenges, and
decision-making processes that CPAs encounter in their day-to-day accounting practice.
Growing incidents of corporate scandals have subjected CPAs' ethical behaviors and actions to
public and academic scrutiny (Ali & Khan, 2022; Bellucci et al., 2021; Poje & Zaman Groff,
2022). Other objectives of the study are to investigate the role of ethical education, training,
and professional development in shaping the ethical behavior of CPAs and to identify potential
areas of improvement and best practices for promoting and sustaining high ethical standards

among CPAs and within the accounting profession. Thus, by addressing these research
objectives, this study aims to contribute valuable insights to the field of accounting ethics,
enhance the understanding of the ethical challenges faced by CPAs, and provide practical
recommendations for strengthening ethical decision-making and professionalism within the
accounting profession.
The generic qualitative design is suitable for exploring research participants' perceptions
and experiences of a phenomenon within a specific cultural context to reveal contextual and
individual factors underpinning the phenomenon (Caelli et al., 2003; Kostere & Kostere, 2021).
This design utilized the semi-structured interview method to collect data on CPAs' perceptions
and experiences regarding accounting ethics to help address the research problem, achieve the
study purpose, and answer the guiding research question. The study's findings were thematically
analyzed using Kostere and Kostere’s (2021) analytical framework and NVivo 14 qualitative
data analysis software.
Rationale
Accounting is built upon trust and integrity (Gunz & Thorne, 2019; Ishaque, 2021).
Certified Public Accountants (CPAs) play a pivotal role in maintaining this trust by adhering to a
code of ethics that guides their professional conduct. However, corporate scandals, including but
not limited to instances like Enron and WorldCom, and ethical lapses within the accounting
profession have raised concerns about the effectiveness of ethical guidelines, and the moral
climate within the industry has significantly eroded public trust in the accounting profession
(Dunn & Sainty, 2020; Huterski et al., 2020; West, 2018). Understanding the perceptions and
experiences of CPAs regarding accounting ethics is not only timely but essential for several

reasons. For instance, accounting professionals serve various stakeholders, including investors,
creditors, and the public (Ali & Khan, 2022; Bellucci et al., 2021; Poje & Zaman Groff, 2022).
The ethical decisions made by CPAs can have significant consequences on these stakeholders'
financial well-being and trust in the profession (Dunn & Sainty, 2020; Ishaque, 2021). Thus,
understanding CPAs' perceptions and experiences with ethical dilemmas is vital to protecting
stakeholders' interests. Exploring CPAs' perceptions and experiences of accounting ethics can
help identify gaps in ethics education and training. This knowledge can inform the development
of more effective ethical education programs for aspiring accountants and ongoing professional
development for practicing CPAs. CPAs work in various organizational settings, each with its
unique ethical culture. Exploring how corporate culture influences CPAs' ethical decisions can
provide insights into fostering a more ethical work environment.
Examining the perceptions and experiences of CPAs regarding accounting ethics is vital
in addressing ethical concerns within the profession, safeguarding stakeholders' interests, and
ensuring the continued trustworthiness of the accounting industry. This study will contribute to
academic literature and provide practical insights to guide policymakers, educators, and industry
practitioners in promoting ethical behavior among CPAs.
Research Question
The following research question guided the study: What are the perceptions and
experiences of certified public accountants regarding accounting ethics? This research question is
viewed through the lens of agency and E-V theories.

Definition of Terms
Accounting Ethics. Accounting ethics are guidelines and principles governing the
professional conduct of accountants (Namazi & Rajabdorri, 2020).
Agent. An agent is a person who performs services on behalf of a principal (Jensen &
Meckling, 1976). For this study, the CPA is the agent.
Certified Public Accountants (CPAs). CPAs are professional accountants with a certified
public accountant license (Merz & Groebner, 1982).
CPAs' Philosophical Orientation. CPAs' philosophical orientation refers to social and
moral lenses that guide CPAs' ethical decision-making processes (Dunn & Sainty, 2020).
Ethical Professional Behavior. Ethical professional behavior refers to behaviors that
conform to the professional accounting code of conduct (Arciniega et al., 2019).
Expectancy. Expectancy is the anticipation of receiving something of value in return for
action or effort (Vroom, 1964).
Instrumentality. Instrumentality is the effort invested in tasks that produce a positive
outcome (Osafo et al., 2021).
National Culture. National culture is the set of values, beliefs, customs, and norms that
define a group of people in a particular country (Gierusz et al., 2022).
Principal. A principal is a person who hires another person to perform a task or service
(Jensen & Meckling, 1976). In this study, the accounting firm is the principal.

Professional Accounting Code of Conduct. The professional accounting code of conduct
is a codified document that specifies accountants' ethical and unethical professional behaviors
and the penalties associated with ethical violations (Dunn & Sainty, 2020).
Unethical Professional Behavior. Unethical professional behavior refers to behavior that
conflicts with the professional accounting code of conduct (Arciniega et al., 2019).
Valence. Valence denotes the value people place on the desired outcomes they seek to
achieve through their efforts (Vroom, 1964).
Research Design
The generic qualitative design guided this inquiry. This qualitative approach helps
researchers understand human experiences, views, beliefs, and opinions regarding a phenomenon
under investigation (Cooper & Endacott, 2007; Kahlke, 2014; Kostere & Kostere, 2021). The
generic qualitative inquiry design is also the most appropriate as the study focuses on exploring
the perceptions and experiences of CPAs within a specific cultural context (Kostere & Kostere,
2021; Percy et al., 2015). These perceptions and experiences are external to the research
participants and cannot be explored through a phenomenological research design, which focuses
on the inner-lived experiences of research participants (Caelli et al., 2003; Percy et al., 2015).
Thus, the generic qualitative inquiry design presents the optimum design choice for investigating
the perceptions and experiences of CPAs regarding accounting ethics.
Further, the principles and core tenets of constructivism provided the philosophical foundation of
the study. Constructivism posits multiple realities, positioning research participants as active

crafters of what the world means to them (Caelli et al., 2003; Kahlke, 2014; Kołodziej, 2020).
This philosophical orientation also holds that the meaning of research phenomena is socially
constructed and varies from participant to participant (Kahlke, 2014; Kennedy, 2016). Consistent
with this philosophical orientation, this study explored how CPAs reconstructed their perceptions
and experiences regarding accounting ethics. A non-probability sampling approach was used to
recruit information-rich participants (Auta et al., 2017; Cooper & Endacott, 2007). More
specifically, a purposive sampling method was used to recruit CPAs with active licenses and
varied experiences in accounting ethics (Cannon et al., 2022; Kostere & Kostere, 2021). A third
party (userinterviews.com) was used to recruit research participants. The study data was
collected after receiving IRB approval.
Two PhD scholars with in-depth knowledge of accounting ethics reviewed the interview
questions to foster understanding and clarity. The suggestions of the two subject-matter experts
were incorporated into the final interview questions. This approach enhanced the credibility and
dependability of the interview questions (Cannon et al., 2022; Jorgensen & Duncan, 2015). Next,
mock interviews were conducted with two CPAs who met the inclusion criteria. The mock
interviews allowed the practice of interview techniques and field-testing interview questions to
ensure language accessibility and comprehension. Kostere and Kostere's (2021) 13-step
analytical framework and qualitative digital software, NVivo 14, were used to analyze the
interview transcripts. Kostere and Kostere's systematic analytical processes and qualitative
software enhanced the trustworthiness of the study's findings.
Assumptions, Limitations, and Delimitations

Assumptions
This study was grounded in the constructivist philosophical orientation, which holds that
an individual's interpretation of reality depends on their history, experiences, and views of the
world (Caelli et al., 2003; Kołodziej, 2020; Moon, 2019). Accordingly, participants' narratives
were acknowledged as conceptualizations and understandings of accounting ethics. These
realities were faithfully captured to enhance the study's trustworthiness (Auta et al., 2017;
Kahlke, 2014). Other assumptions underpinning the study comprise methodological, theoretical,
and topic-specific assumptions.
General Methodological Assumptions
A generic qualitative inquiry informed this study. This design collects firsthand data from
research participants (Auta et al., 2017; Percy et al., 2015). Therefore, the generic qualitative
inquiry was assumed to be the most appropriate design for investigating CPAs' perceptions and
experiences of accounting ethics (Kahlke, 2014; Percy et al., 2015). Besides, the researcher
assumed that the responses provided by the CPAs during the semi-structured Zoom interviews
reflected their honest and frank perceptions and experiences of the accounting ethics
phenomenon (Moon, 2019; Percy et al., 2015).
Theoretical Assumptions
The agency and E-V theories framed this study. The agency theory was assumed to
provide an understanding of the employment relationship between accounting firms and CPAs
(Jensen & Meckling, 1976; Nikula & Kivistö, 2018; Zogning, 2017), while the
expectancyvalence theory induced CPAs' motivation to comply with accounting ethics (Allini et
al., 2018; Osafo et al., 2021; Ozturk et al., 2017). It is also assumed that CPAs are more likely to

be motivated to act ethically when valence, instrumentality, and expectancy (VIE) are present, as
postulated by Vroom (1964). A further theoretical assumption of the study was that the
underpinning constructs of agency and E-V theories interact to explain mechanisms that motivate
and sustain CPAs' ethical compliance in accounting firms (Allini et al., 2018; Nikula & Kivistö,
2018; Osafo et al., 2021).
Topic-Specific Assumptions
Regarding the phenomenon-specific assumptions, accounting ethics is assumed to reflect
psychological and social orientation (Namazi & Rajabdorri, 2020; West, 2017). Therefore, this
phenomenon resides in CPAs' consciousness and manifests through CPAs' actions in
organizational settings. Accounting ethics is also considered a value-oriented phenomenon,
reflecting CPAs' personal, professional, and cultural values (Dunn & Sainty, 2020; Gierusz et al.,
2022). Accordingly, CPAs' personal, professional, and cultural assimilations could influence their
ethical decisions. It is further assumed that the accounting ethics phenomenon is complex and
cannot be subjected to measurement and statistical analyses (Al frijat & Albawwat, 2019; Carr et
al., 2021). Consequently, qualitative methodology offers the most appropriate approach for
illuminating the accounting ethics phenomenon.
Limitations
The generic qualitative approach was adopted to collect data on CPAs' perceptions and
experiences from a single, constrained geographic area rather than from different geographical
locations. However, there are places in the United States where CPAs work for businesses other
than accounting firms in Maryland. As a result, the perceptions and experiences of CPAs from

various organizations may inspire additional themes and understandings of the accounting
ethics phenomenon that this study should have addressed. Additionally, interviews were the
main instruments for data collection in this study. Therefore, there were constraints in knowing
whether the participants narrated their authentic and accurate perceptions and experiences of the
phenomenon investigated in this study using interviews as the sole medium for data collection.
Nonetheless, the interview questions were reviewed by subject-matter experts and field-tested
to promote clarity and understanding.
Design Limitations
Twelve CPAs recounted their perceptions and experiences regarding accounting ethics.
However, the fact that this quantity reflects a relatively small sample size was a fundamental
design limitation. Thus, a quantitative approach utilizing a large sample size could be used to
ascertain the perceptions and experiences of CPAs regarding accounting ethics and assess its
prevalence in accounting firms. Furthermore, researcher bias has been highlighted as one of the
key design issues in qualitative research (Hibbin et al., 2018; Reyes, 2020; Yang et al., 2020).
Consequently, qualitative researchers must be aware of potential sources of bias and take all
reasonable steps to mitigate researcher bias (Dawson et al., 2019; Kostere & Kostere, 2021). To
address potential researcher bias, the researcher used a reflective diary to record prior
knowledge, concepts, and theories about the accounting ethics phenomenon throughout the data
collection and analysis (Collins & Rocco, 2018; Ng, 2021; Subramani, 2019).

Delimitations
Two boundaries were imposed on this study. First, CPAs employed in accounting firms
in Maryland, USA, were recruited. Thus, other accounting professionals and students were
excluded from the study. The recruitment criteria required for this study were limited to CPAs
with at least a year of experience. This criterion also excluded other CPAs who still needed to
meet the work experience criteria. Second, the generic qualitative inquiry approach was adopted
for the study as the most optimal design choice to explore the research question (Cooper &
Endacott, 2007; Kahlke, 2014; Percy et al., 2015). The research question focuses on the
perceptions and experiences of CPAs regarding accounting ethics, which appears unfit to any of
the established qualitative designs such as phenomenology, grounded theory, and ethnography
(Caelli et al., 2003; Degeling & Rock, 2020; Kahlke, 2014).
Organization of the Remainder of the Study
Chapter 1 provided a broad orientation of the study. The chapter discussed the study's
foundational elements, including the need for the study, purpose, research questions, research
design, assumptions, limitations, and delimitations of the study. Chapter 2 analyzes and
synthesizes the theoretical and empirical literature to contextualize the research problem
warranting this study. The methodological approach, design, methods, and procedures of the
study are discussed in Chapter 3. Chapter 4 presents the study's findings, highlighting themes that
emerged from the data to answer the guiding research question. These themes orienting the
study's findings are discussed in Chapter 5.

CHAPTER 2. LITERATURE REVIEW
This chapter analyzes and synthesizes the relevant scholarly literature to contextualize the
research problem motivating the study. An efficient and well-executed literature review
contributes to new knowledge by identifying research gaps and suggesting avenues for future
studies. (Barczak, 2017; Palmatier et al., 2018; Snyder, 2019). As a contribution to the
accounting ethics literature, this study fills a significant research gap by following
recommendations for further research to explore CPAs' perceptions and experiences regarding
accounting ethics.
The chapter begins with methods for searching relevant literature on accounting ethics
and an overview of the agency and expectancy-valence theories that guided the study. Next, it
explores the following themes: accounting ethics, accounting ethics theories, professional
accountant ethical practices, ethical decision-making dilemmas, ethical decision-making models,
accounting ethics compliance enforcement, synthesis of the research findings, and critique of
previous research methods. The chapter concludes by summarizing the main conclusions from
the literature review and the research gap warranting the study.
Methods of Searching
In building robust theoretical and empirical foundations for this study, the researcher
explored the electronic library databases at Capella University for relevant accounting ethics
literature. Databases searched included ABI/INFORM Complete, Business Source Complete, and
EBSCOhost. The search had a subject-based approach, and the phrases "accounting ethics" and
"corporate scandals" were employed to guide the initial exploration of the databases. Other

keywords used separately and combined to retrieve relevant articles were accounting code of
conduct, accounting firms, accountants' ethical behaviors, accountants' unethical behaviors,
corporate scandals, certified public accountants, agency theory, expectancy-valence theory, and
generic qualitative inquiry. The following inclusion criteria were employed to locate sources
relevant to the topic: (a) peer-reviewed articles published from 2018 to 2023, (b) seminal articles,
and (c) seminal books. The exclusion criteria included the following: (a) non-peer-reviewed
articles, (b) peer-reviewed articles published before 2018 and not seminal, (c) editorials, and (d)
book chapters. These inclusion and exclusion criteria helped retrieve relevant sources to frame
the literature review, including the theoretical orientation informing the study.
Theoretical Orientation for the Study
The agency theory (Jensen & Meckling, 1976) and the E-V theory (Vroom, 1964)
informed this study. The agency theory provides an understanding of the contractual relationship
between accounting firms and CPAs (Jensen & Meckling, 1976; Nikula & Kivistö, 2018;
Zogning, 2017), while the E-V theory documents the inducements that motivate CPAs to comply
with the contractual agreement with the accounting firms and adhere to the professional
accounting code of conduct (Allini et al., 2018; Osafo et al., 2021; Ozturk et al., 2017). CPAs are
more likely to act ethically when their efforts to achieve their firms' objectives are rewarded.
Such an effort-reward balance may be a critical driver of positive future actions (Nikulina &
Wynstra, 2022; Vroom, 1964). Similarly, accounting firms and their CPAs could minimize
conflicts in employment relationships if both parties adhere to the tenets of the contract and act
ethically toward each other (Jensen & Meckling, 1976; Zogning, 2017). Thus, the underpinning
constructs of agency and E-V theories interact to explain mechanisms that motivate and sustain

CPAs' ethical compliance in accounting firms (Allini et al., 2018; Nikula & Kivistö, 2018; Osafo
et al., 2021).
Agency theory
The seminal work by Jensen and Meckling (1976) defines agency theory as a relationship
between two or more parties under which one or more parties (the principal) engage another
party (the agent) to perform a service on their behalf. This relationship involves the principal
delegating some decision-making authority to the agent. Although agency theory appears to be a
well-researched area, management scholars have yet to reach a consensus on the theory's origin
(Mitnick, 2021). Whereas Kivisto (2008) claimed that agency theory originated from
organizational theory, Mitnick (2021) asserted that the theory orients towards multiple theoretical
origins such as economics, finance, and law. Nonetheless, Mitnick (2021) identified Jensen and
Meckling's (1976) seminal study as the most influential work for exploring the complexities
existing between agents and their principals compared to the works of Berle and Means (1932)
and Smith (1776). Despite the confusion surrounding the seminal roots of agency theory, this
theory has been positioned as a robust explanatory mechanism for exploring the relationships
between employees and their firms (Ali et al., 2023; Pouryousefi & Freeman, 2019; Ross, 1973).
The fundamental tenet of agency theory involves monitoring the contractual relationship
between the principal and the agent. Pouryousefi and Freeman (2019) theorized the
principalagent relationship as a trust-based relationship, with the agent employed as a trusted
stakeholder to protect the principal's interests. In operationalizing this trust-based relationship,
principals delegate their responsibilities to their agents in return for remuneration for executing
those responsibilities (Allini et al., 2018; Mitnick, 2021). The agents' duties involve effective
decisionmaking to maximize the principals' investments (Ali et al., 2023; Kondzielnik, 2021).
Thus, agents are supposed to act in the principal's best interest. However, as Nikula and Kivistö
(2018) posited, agents' motivation frequently diverges from that of the principals. Agents pursue
their interests at the expense of their principals, resulting in a conflict of interest in the
employment relationship (Madhavan et al., 2023; Nikula & Kivistö, 2018). Thus, the principals'
inability to monitor agents' actions remains a fundamental gap in the agent-principal relationship
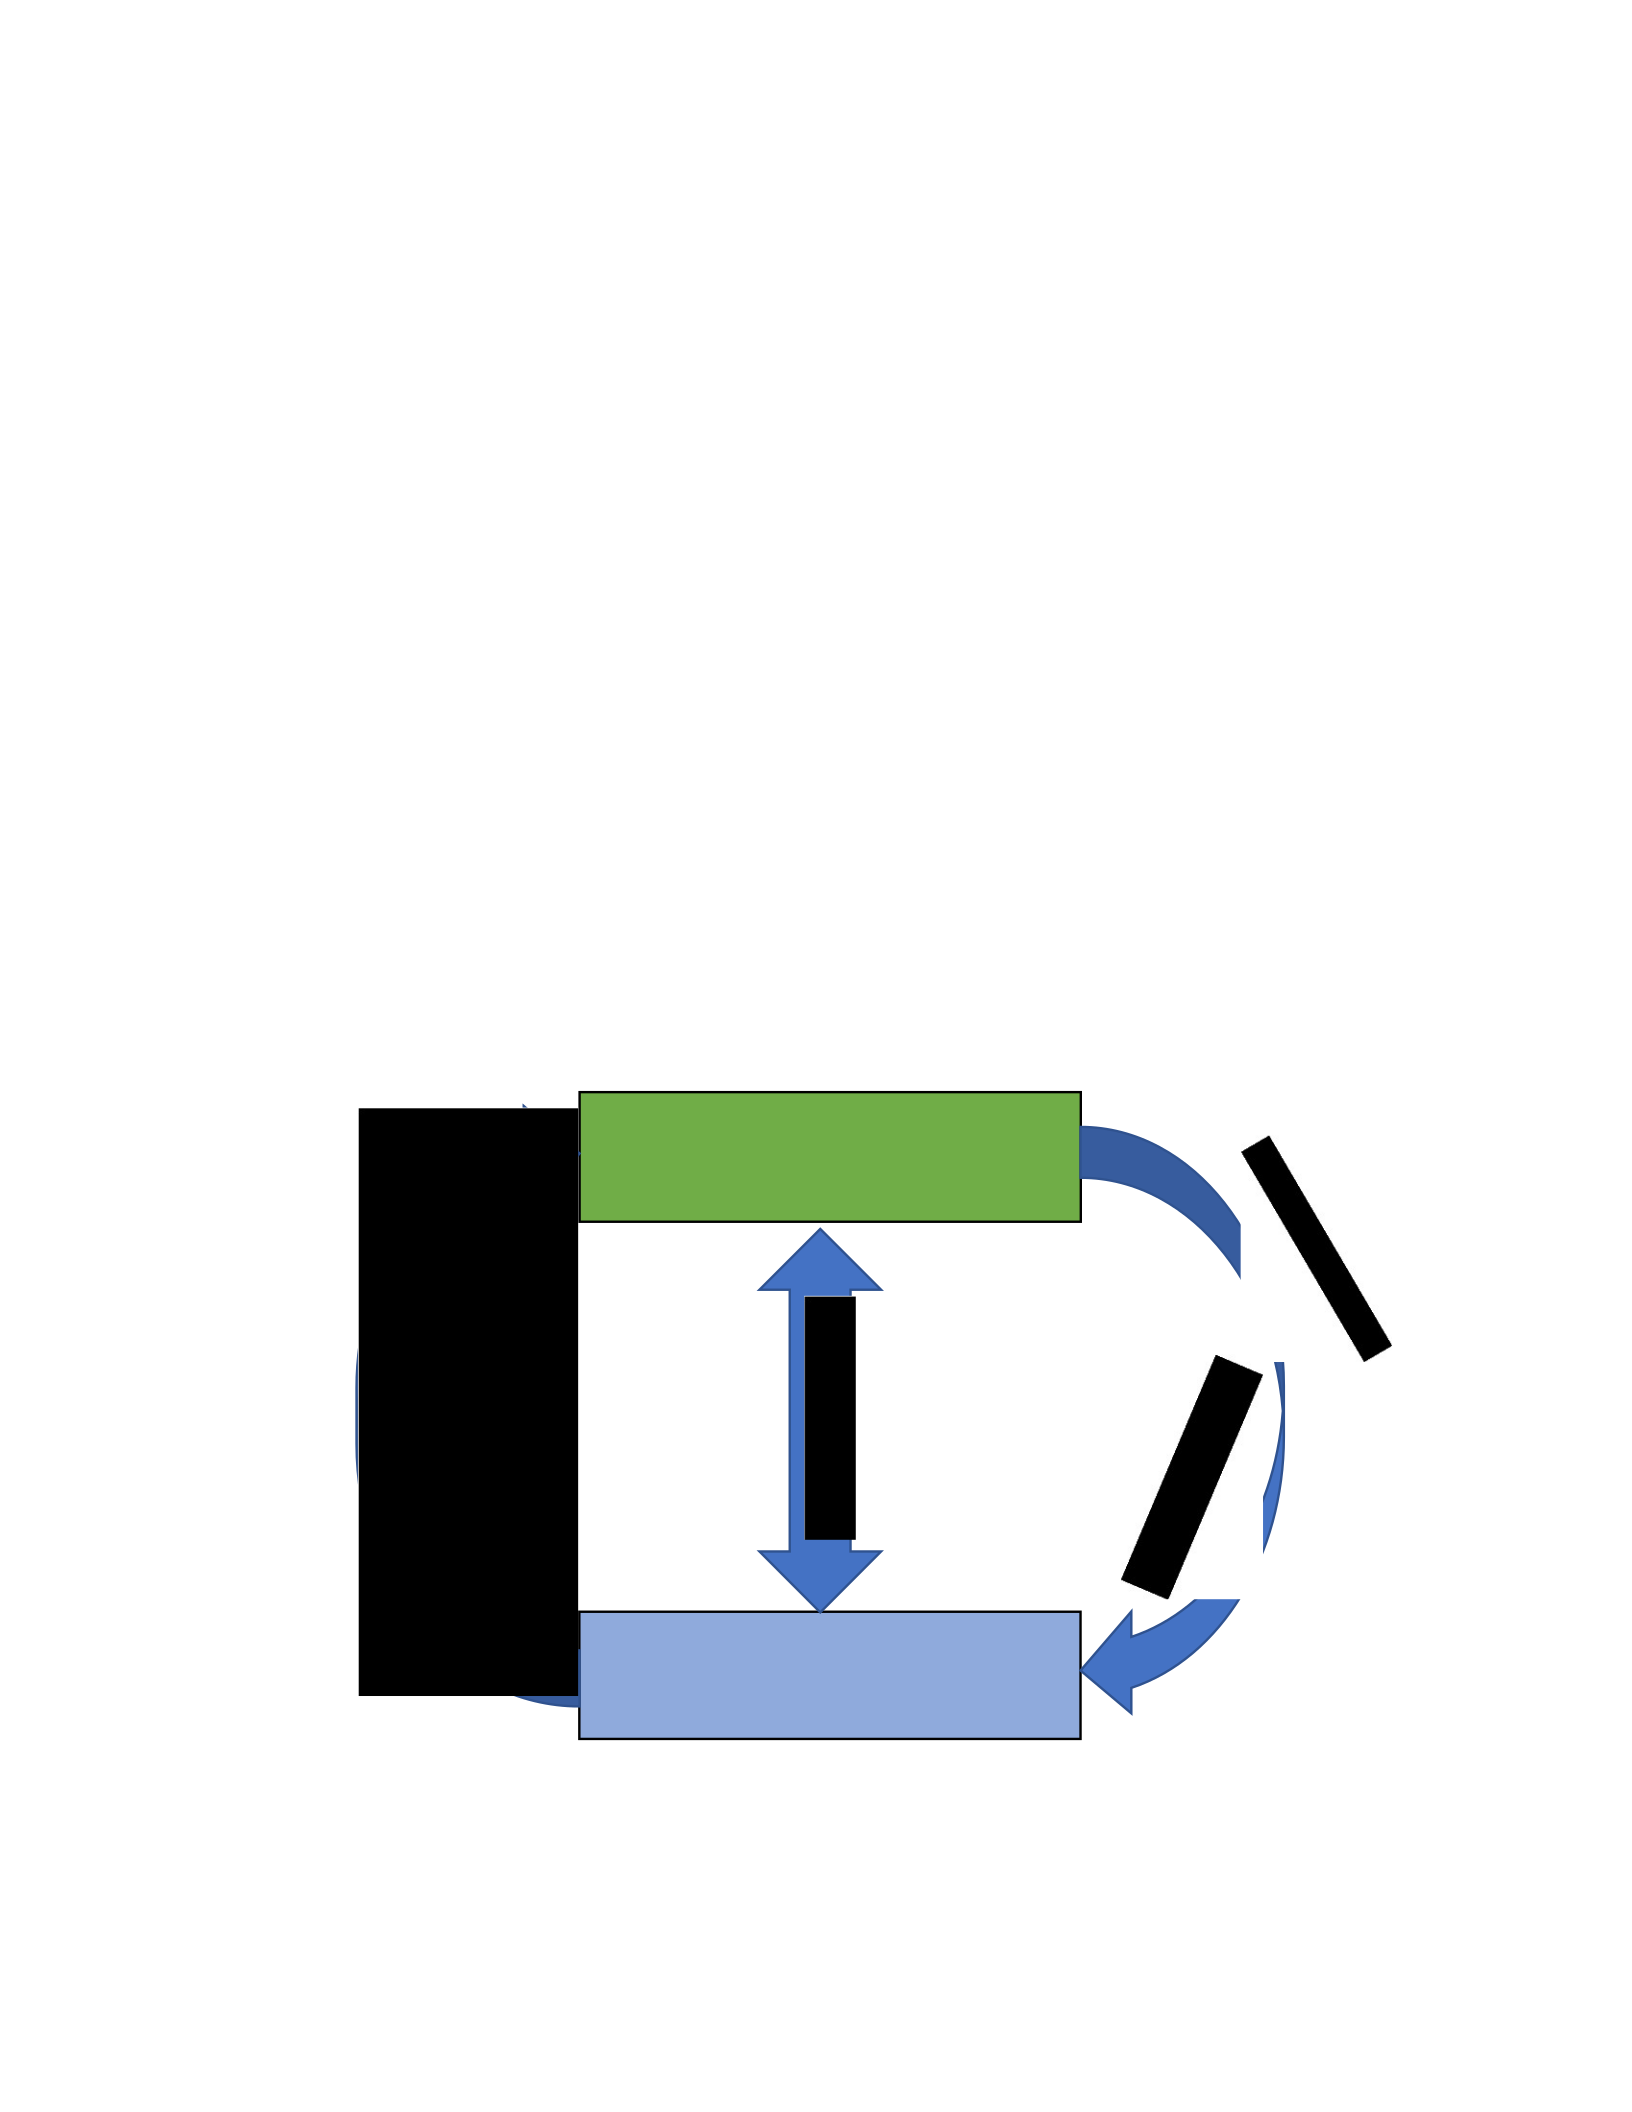
(Ali et al., 2023; Pouryousefi & Freeman, 2019). The agent-principal relationship is depicted in
Figure 1 below.
Figure 1
The Agent-Principal Relationship
Principal
(Accounting firm)
Agent
CPA( )
Acts and makes
decisions on behalf
of the principal
Conflict of Interest

As depicted in Figure 1, the principal (an accounting firm) delegates authority to and
rewards the agent (CPA) for meeting performance expectations assigned to the agent.
Correspondingly, the agent acts in the principal's best interest by acting ethically to create value
for the principal. Thus, a conflict of interest arises in the agent-principal relationship when CPAs
perpetrate mischief and pursue personal gains at the expense of their accounting firms (Jensen &
Meckling, 1976; Madhavan et al., 2023).
Expectancy-Valence (E-V) Theory
According to Tubbs et al. (1993), the E-V theory has been the most investigated theory of
work motivation. The premise of the E-V theory is that individuals choose their behavior among
alternatives based on what they believe will yield the most significant positive outcomes (Vroom,
1964). The theory further posits that specific behavior results from purposeful decisions among
alternatives that maximize pleasure and minimize burdens (Oppong & Safo Lartey, 2023; Osafo
et al., 2021; Vroom, 1964). Two assumptions underpin the E-V theory. First, individuals evaluate
the motivational force associated with each available behavioral option before engaging in that
behavior (Isaac et al., 2001; Nikulina & Wynstra, 2022). According to Vroom (1964), the
motivational force is the product of expectancy, while valence reflects the expected utility one
associates with an alternative. Second, individuals pursue a behavioral option with the most
significant motivational force (George & Humphrey, 2021; Vroom, 1964). Thus, the E-V theory
provides cognitive explanations of individuals' expectations regarding the extent to which they
believe they will derive maximum benefits from investing a certain degree of effort.
Based on Vroom's E-V theory, CPAs evaluate the benefits of complying with the
accounting ethics code of conduct. CPAs who expect to derive maximum benefits from
complying with the accounting ethics code of conduct are likely to adhere to the code (Dunn &
Sainty, 2020; Morales-Sánchez et al., 2020). In contrast, CPAs who perceive compliance with the
code will yield minimal personal incentives are likely to exhibit low compliance levels (Gunz &
Thorne, 2019; Melé et al., 2017). CPAs should, therefore, be encouraged to internalize the
accounting ethics code of conduct by giving them the necessary resources to boost their
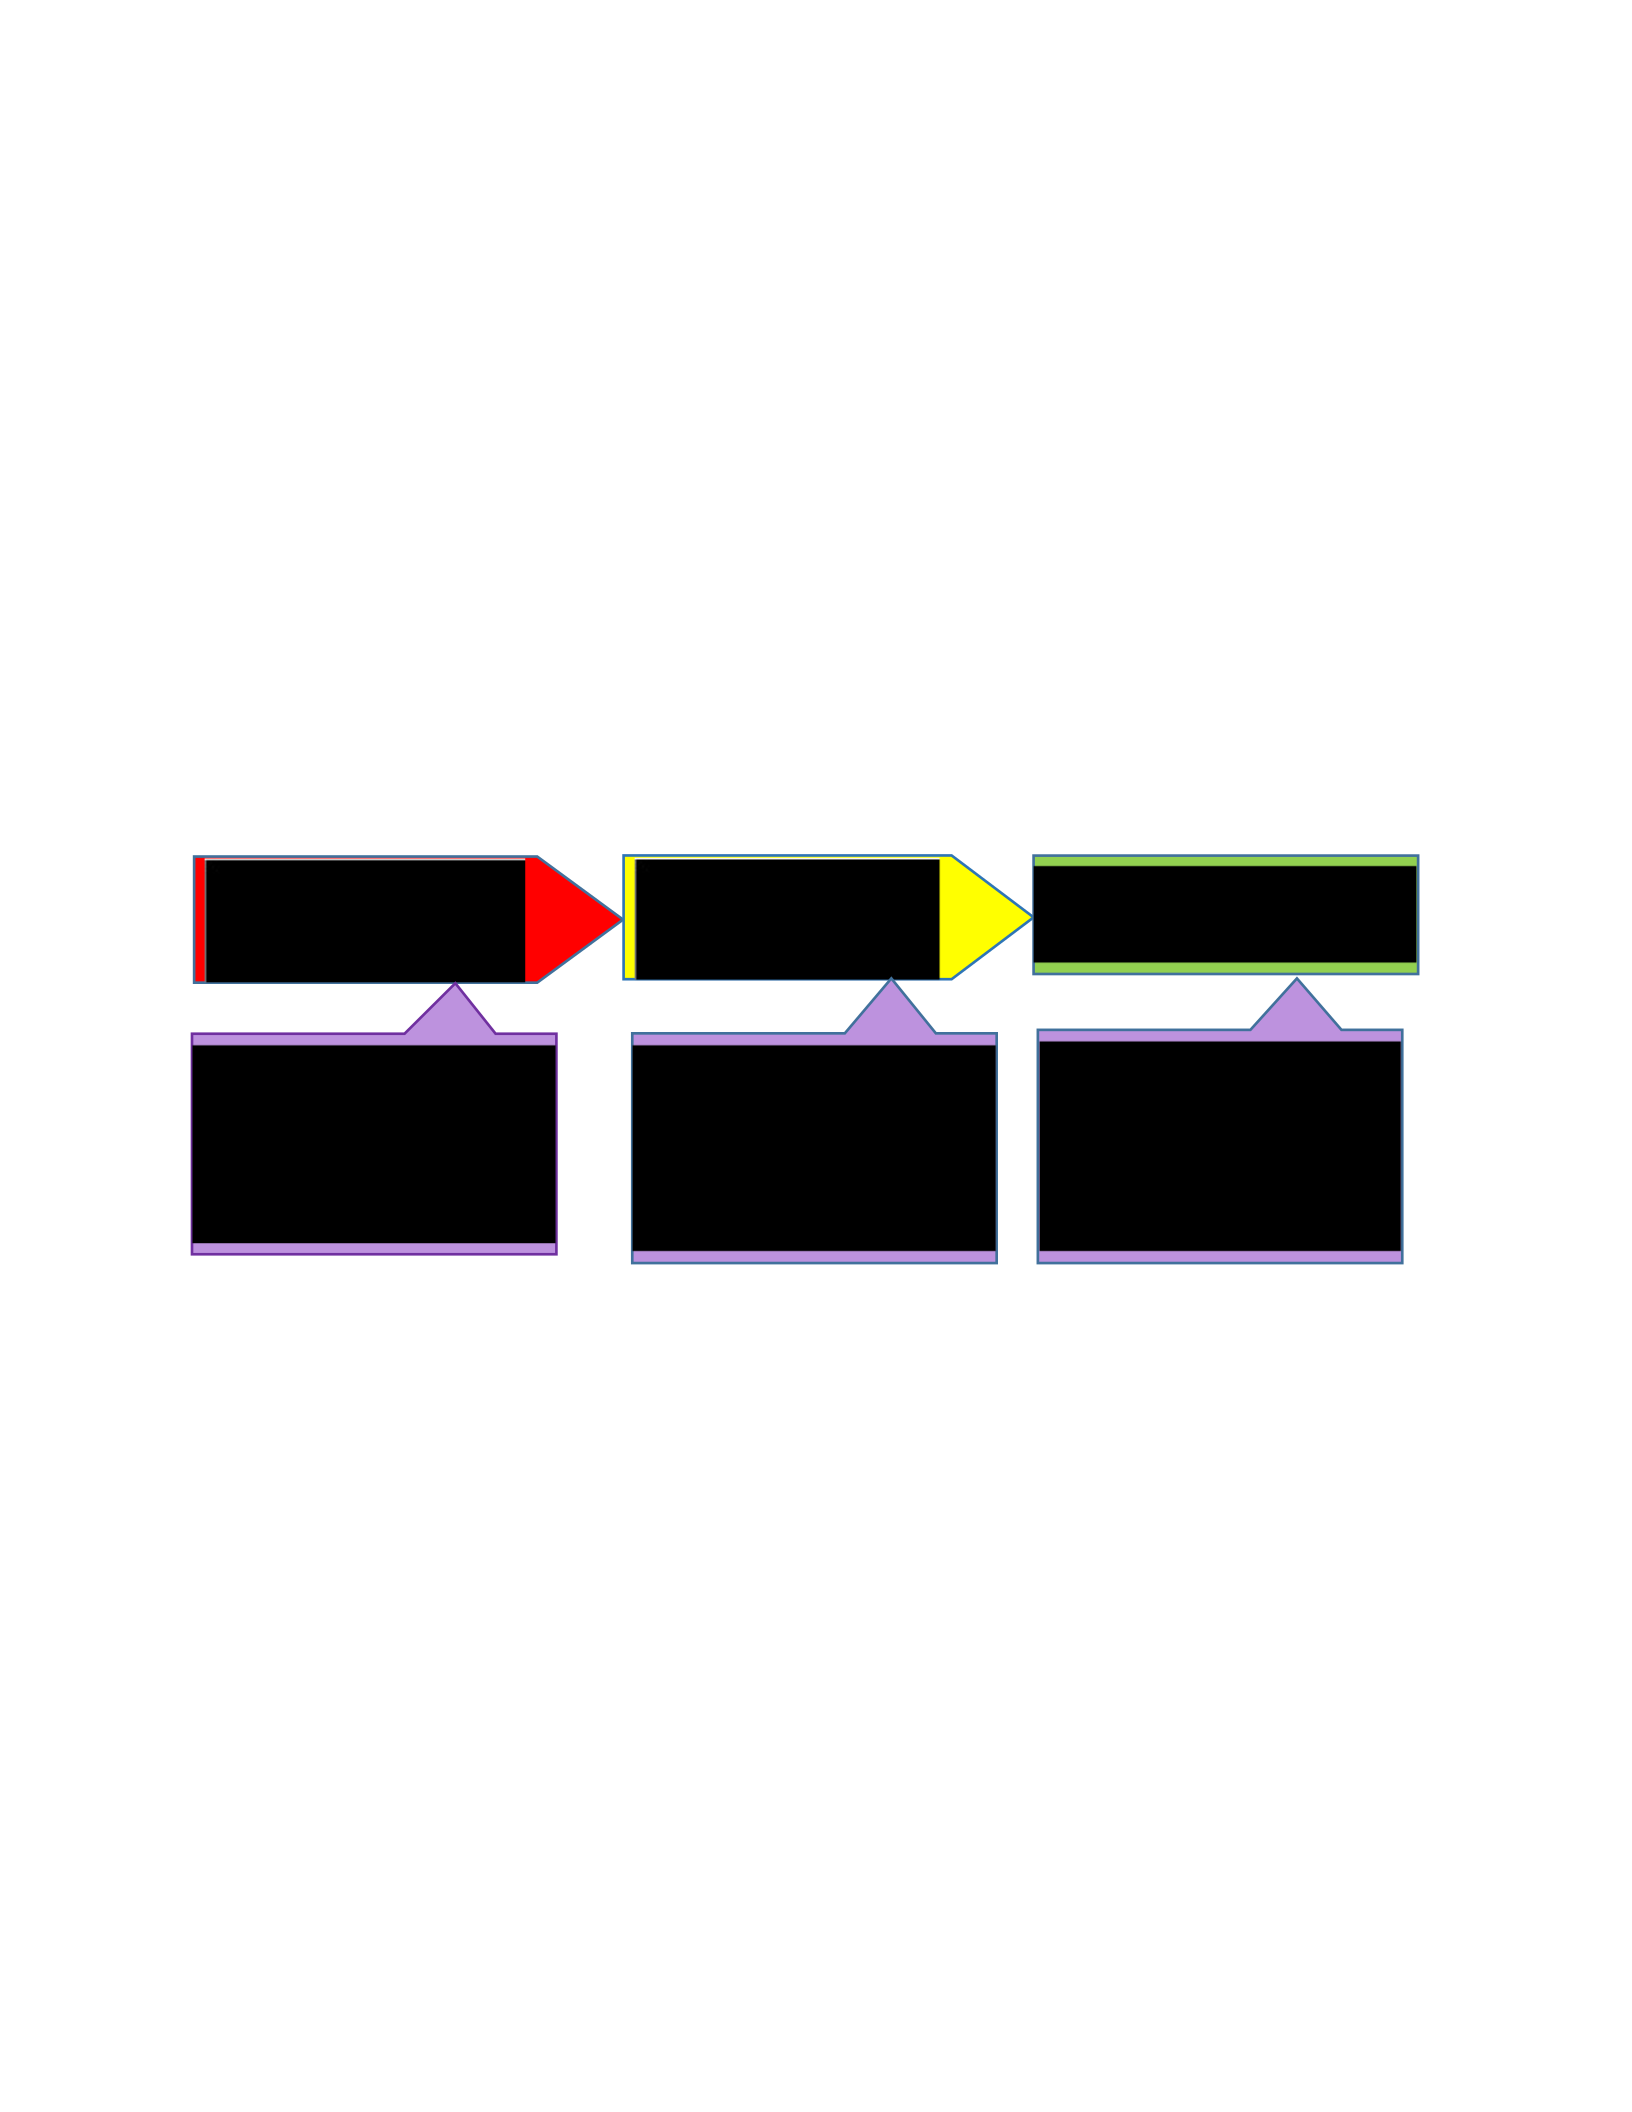
performance levels and increase their compliance with the code. Figure 2 displays the E-V theory
and CPAs' perceptions.
Figure 2
The E-V Theory and CPAs’ Perceptions
As depicted in Figure 2, the CPA expects that the effort put into the task will result in
good performance and that the excellent performance will yield a desired outcome with the
desired value of interest to the CPA. According to the E-V theory, the likelihood of success
diminishes as performance levels become challenging (George & Humphrey, 2021; Oppong &
Safo Lartey, 2023). On the contrary, valence activates high performance, and this performance
level reflects extraordinary achievement and drives positive intrinsic and extrinsic outcomes
Effort Performance
Expectancy
CPA s perceive the
probability that their
effort would result in
good performance.
Instrumentality
CPA s perceive that good
performance would yield
a desired
outcome(reward).
Valence
CPA s perceive that the
outcome has desirable
value.
Outcome

(Kominis & Emmanuel, 2007; Nikulina & Wynstra, 2022; Ong et al., 2022). Park and Sturman
(2022) noted that linking pay to performance outcomes can motivate CPAs to comply with the
accounting ethics code of conduct. Park and Sturman added that compensating CPAs for meeting
expected performance targets could be a plausible means of enforcing compliance with the code
of conduct.
Integrating Agency and Expectancy-Valence Theories
Integrating two theories to explore a phenomenon of interest provides a broad conceptual
lens to gain an in-depth understanding of the phenomenon (Ali et al., 2023; Osafo et al., 2021).
Such integration enables researchers to leverage the complementary strengths of separate theories
to reveal the complexities and nuances of the phenomenon. Theoretical integration also allows
the weaknesses in one theory to be attenuated by the strengths of the other theory (Oppong &
Safo Lartey, 2023). Agency theory provides explanatory mechanisms to structure the contractual
relationships between the principal and the agent (Jensen & Meckling, 1976; Madhavan et al.,
2023). However, the principal's inability to effectively monitor the agent's actions creates a
"black box," as the agent exploits this monitoring gap to pursue personal interests (West, 2018;
Zogning, 2017). Although a contractual relationship exists between the principal and the agent,
weak monitoring allows the agent discretionary powers to manipulate the firm's performance for
personal gains (Dunn & Sainty, 2020; Nikula & Kivistö, 2018). Thus, the agent feels
unmotivated to comply with the principal's directives for wealth maximization.
The E-V theory illuminates the "black box" in the agent-principal relationship by demonstrating
a link between effort, performance, and outcome (Oppong & Safo Lartey, 2023; Vroom, 1964).
When CPAs know that compliance with the accounting ethics code of conduct induces rewards

and non-compliance triggers punishment, they will feel motivated to act in the best interests of
their firms (Allini et al., 2018; Ozturk et al., 2017). As Vroom (1964) noted, the uniting concepts
of valence, instrumentality, and expectancy create an overarching model to elicit positive
behaviors. Thus, while agency theory structures the agent-principal relationship in contractual
terms, the E-V theory induces the agent to comply with the principal's directives. Review of
the Literature
Accounting Ethics
Accounting ethics is defined as the rules governing the professional conduct of
accounting professionals (Jaijairam, 2017; Kaptein, 2017; Namazi & Rajabdorri, 2020).
These rules are enshrined in the accounting association's bylaws. CPAs adhere to the
accounting profession's ethical practices to foster public confidence (Huterski et al., 2020;
Jelinek, 2018). Such compliance is critical to accounting firms' reputations and elevates CPAs'
professional integrity. Gunz and Thorne (2019) asserted that professional misconduct has
resulted in poor performance and reputational damage for most accounting firms. Therefore,
CPAs' failure to comply with the accounting ethics code of conduct attracts disciplinary
consequences as noncompliance creates negative perceptions and impairs public confidence
(Huterski et al., 2020; Ishaque, 2021; Kamińska-Stańczak & Silska-Gembka, 2021; West,
2018).
Unethical professional practices and associated financial scandals have heightened
compliance with accounting ethics in the business environment (Dunn & Sainty, 2020; West,
2018). According to Dunn and Sainty (2020), firms that have been found to have been involved
in financial scandals include Autonomy Corporation in the UK, Lehman Brothers in the USA,

Petrobras in Brazil, Sino-Forest Corporation in Canada, and Toshiba in Japan. These corporate
scandals have deepened public interest in accounting ethics. Additionally, other ethical issues
may exist other than the unethical behaviors of CPAs. For example, Huterski et al. (2020) and
Armstrong (2020) identified personal relationships among employees working with the same
business entity. When such relationships interfere with employee performance, they create
negative work output and diminish the firm's overall performance (Gunz & Thorne, 2019;
Huterski et al., 2020).
Fiolleau and Kaplan (2017) also argued that a company's reward structure for the
management team presents a potential source of an ethical issue. This development occurs when
management members influence professional accountants to misrepresent financial statements to
enable them to receive lucrative financial rewards (Edi & Enzelin, 2022; Fiolleau & Kaplan,
2017). To perpetrate such strategic manipulations of financial statements, management teams of
accounting firms also present false performance results that do not reflect the company's overall
performance (Edi & Enzelin, 2022; Fiolleau & Kaplan, 2017). Although the firm's performance
and financials exhibit positive shareholder returns, these portraits must reflect and accurately
represent the firm's performance. Consequently, accounting firms should implement a monitoring
mechanism to reduce the temptation to manipulate financial statements (Armstrong, 2020;
Fiolleau & Kaplan, 2017).
In response to ethical issues in accounting firms, professional bodies have increased their
supervision to curb CPAs' unethical behaviors (Kamalgharibi et al., 2023; Kartika & Pramuka,
2019). In the United States, AICPA mandated a code of conduct for CPAs (Jackson et al., 2023;

Morrison et al., 2018). The professional code of conduct influences CPAs' behavior and decision-
making and compels them to uphold the public interest (Dunn & Sainty, 2020; Hultman, 2019;
Huterski et al., 2020). According to Dunn and Sainty (2020), the code of ethics guides
appropriate and inappropriate ethical behaviors and activities. Additionally, accounting firms
train their CPAs in professional accounting requirements and the corresponding sanctions
associated with breaches (Morrison et al., 2018; West, 2017). These professional development
interventions elevate CPAs' ethical awareness and appreciation of relevant accounting ethics
theories.
Accounting Ethics Theories
Theories constitute the bedrock of scholarly research. They help researchers define the
boundaries of their studies, identify focal constructs, and interpret their findings (Black et al.,
2022; Chijioke et al., 2021; Sharif et al., 2020). Among the theories accounting scholars
frequently use to explore accounting phenomena, Vroom's E-V and agency theories dominate the
scholarly discourse due to their explanatory potency (Buckley, 2021; Mitnick, 2021; Osafo et al.,
2021). By using E-V and agency theories to guide their work, accounting scholars advance the
knowledge base of the accounting profession through theory extension, development, and
clarification (Chijioke et al., 2021; Oppong & Safo Lartey, 2023).
Agency Theory
Agency theory embraces a wide range of concepts, resulting in criticisms of the need for
conceptual clarity. For example, Saam (2007) argued that the conceptual underpinnings of
agency theory need to be more coherent. Despite these criticisms, a consensus exists on agency

theory's key concepts (Jensen & Meckling, 1976; Mitnick, 2021). These concepts comprise
principals, agents, relationships, and controls (Jensen & Meckling, 1976; Nikula & Kivistö,
2018; Zogning, 2017). Principals refer to owners or persons with delegating authority, whereas
agents are the "executors" of the principals' mandate (Kivisto, 2008; Saam, 2007). Relatedly,
relationships involve the contractual relationships between the principal and the agents
(Pouryousefi & Freeman, 2019), while controls entail monitoring mechanisms to align agents'
interests with those of the principal (Saam, 2007). The absence of control mechanisms could
motivate agents to pursue personal gains at the principals' expense (Nikula & Kivistö, 2018).
Such unethical behaviors could undermine an organization's growth and sustainability.
The agency theory's underlying assumption is delegating the principal authority to the
agent, invariably leading to a conflict of interest (Jensen & Meckling, 1976). This conflict
translates into the failure of accounting professionals to adhere to accounting ethics, resulting in
regulatory sanctions and the potential closure of their firms (Gunz & Thorne, 2019; Ishaque,
2021). Notwithstanding agency theory's inherent monitoring challenges, it explains the
contractual relationships between CPAs and their accounting firms (Jensen & Meckling, 1976;
Panda & Leepsa, 2017). These contractual relationships include decision-making, rewards, and
wealth maximization.
Researchers have employed the agency theory to explore accounting phenomena. Blom
and Niemann (2022) utilized the agency theory to investigate perpetrator-victim interactions,
where CPAs' unethical practices resulted in reputational damage and low performance levels of
their accounting firms. Nikula and Kivistö (2018) also applied agency theory to explore the
contractual relationship between two parties by investigating the relationships' underlying issues.

The findings of Nikula and Kivistö demonstrated that the agency theory can advance a general
understanding of the nature and dimensions of agency problems in agency relationships and the
potential for mitigating the impact of such issues. Organizations utilize agency theory to optimize
their capital structure (Grigore & Gurău, 2019; Lai et al., 2019). According to Panda and Leepsa
(2017), agency theory has been widely observed in academic fields like accounting, finance,
political science, sociology, and marketing. Pouryousefi and Freeman (2019), in agreement,
added that "the agency theory is a dominant approach in the economic study of organization and
management." Wells (2021) describes the agency theory as principal/agent interactions where
one party (the principal) designs a contract offer for the other party. The contract is an explicit or
implicit agreement binding the parties (Wells, 2021). Thus, the contract defines the terms of
interaction between the two parties.
Principals, Agents, and Agency Relationships
Pouryousefi and Freeman (2019), in agreement with Jensen and Meckling (1976) and
Zogning (2017), described the agency theory as a principal-agent relationship where two parties
interact, with one party representing the agent acting on behalf of the principal. Thus, the agent is
supposed to work in the principal's best interest. CPAs (agents) consider advancing the firm's
goal (principal) only in some cases (Lundberg, 2022; Nikula & Kivistö, 2018; Onjewu et al.,
2023). Nikula and Kivistö expanded the agency theory to include delegating tasks by the
principal to the agent in return for remuneration. Nikula and Kivistö further noted that principals
delegate tasks to their agents because they lack the requisite skills to perform their firms'
activities. Pouryousefi and Freeman (2019) also postulated that CPAs conduct business
transactions on behalf of their firms for compensation and other benefits. Thus, to achieve their

firms' mandate of wealth maximization, principals contract agents to execute their firms'
objectives on their behalf for rewards and recognition.
Furthermore, upon agreement between the two parties, the agent is expected to carry out
the contract on behalf of the principal in return for compensation (Pouryousefi & Freeman, 2019;
Wells, 2021). Thus, the principals in the agency agreement are assumed to have the bargaining
power to design an adequate compensation scheme that attracts agents of the right caliber. When
the compensation is sufficient, it motivates the agent to deliver high-quality services, as Onjewu
et al. purportedly (2023). Pouryousefi and Freeman (2019) identified goal incongruity,
information asymmetry, and contract design as the conditions to consider when determining
agent compensation. Pouryousefi and Freeman further explained that goal incongruity occurs
when the principal and the agent have different or conflicting interests. In this regard, the agent's
preference for the performance of the contract agreement does not match that of the principal.
They also described information asymmetry as a situation where the agents possess superior
information regarding their abilities, preferences, effort levels, and other services compared to
information possessed by the principal. Thus, the agents can access specific details the principal
does not include. This situation arises when CPAs handling clients' data have become privy to
particular clients' information that the accounting firm does not possess. Without adherence to
the ethics in accounting or the principal-agent contract conditions, CPAs can use this information
to enhance their gain (Hendrastuti & Harahap, 2023; Namazi & Rajabdorri, 2020; Sonnerfeldt &
Loft, 2018).
Pouryousefi and Freeman (2019) also highlighted the contract design as a core variable in
determining agents' compensation. They asserted that the principal oversees the contract design,

not the agent. However, when the agent has a divergent interest and has access to private
information, then the situation becomes more challenging for the principal to exercise control
over the contract (Lundberg, 2022; Nikula & Kivistö, 2018; Turrado García et al., 2023). In such
situations, the agent appears to oversee the contract design, assuming superiority over the
principal. Notwithstanding the agent's perceived control over the contract design, Pouryousefi
and Freeman (2019) stressed that the principal possesses the ultimate accountability for the
contract design. The principal decides the structure and terms of the interactions and extends the
take-it-or-leave-it offer to the agent. The agent, on the other hand, may accept or reject the bid.
Nonetheless, agents remain responsible for executing the contract terms once they get the
agreement (Davis et al., 2021; Hendrastuti & Harahap, 2023; Solomon et al., 2021). Thus, both
the agents and their principal have interests in the design and execution of the contract.
Similarly, Nikula and Kivistö (2018) identified two crucial conditions undermining
principal and agent relationships. These two conditions are like the first two conditions addressed
by Pouryousefi and Freeman (2019). Nikula and Kivistö (2018) present goal conflicts and
information asymmetries as constraints to optimal contractual options to monitor and incentivize
agents. Both conditions assumptions are valid in the accounting firm and certified public
accountant relationships (Nikula & Kivistö, 2018; Pouryousefi & Freeman, 2019). Accounting
firms and CPAs' interests may diverge while executing a client's job (Davis et al., 2021; Solomon
et al., 2021; Turrado García et al., 2023). Nevertheless, a congruence of preference between these
firms and their CPAs may exist regarding the allowable time to complete the task (Foreman et
al., 2021; Lundberg, 2022; Rooly, 2021). For instance, the more time CPAs spend on the job, the
higher their compensation, which could affect the profit margins of their firms (Lundberg, 2022;

Onjewu et al., 2023). Thus, the effort-reward relationship has been signaled as one of the critical
issues in the agent-principal relationship.
Agency Problem
An agent's opportunistic behavior harms the principal's interest in wealth maximization
(Davis et al., 2021; Onjewu et al., 2023; Solomon et al., 2021). Nikula and Kivistö (2018)
identified two types of agent opportunism underpinning agency theory: pre- and post-contractual
initiatives. The pre-contractual incentive, also known as adverse selection, evolves from the
principal's inability to determine the agent's identity. To address the pre-contractual incentive
problem, Nikula and Kivistö (2018) recommended instituting screening procedures during the
hiring process (pre-contractual problem-solution). Such screening processes could unearth
critical opportunistic behaviors that may undermine the principal's interest in the relationship.
The post-contractual incentive, also known as a moral hazard, describes the agent's
purposeful and intentional underperforming, shirking of responsibilities, or using unethical or
unapproved working methods that impair the principal's interest (Foreman et al., 2021;
Lundberg, 2022; Turrado García et al., 2023). Nikula and Kivistö (2018) noted that
postcontractual incentive problems arise when the principal cannot directly observe the agent's
actions, allowing the agent to provide distorted information. Agency theory suggests investing in
monitoring procedures and reward mechanisms to control the agent's efforts to address the
postcontractual incentive problem (Onjewu et al., 2023; Solomon et al., 2021). Thus, applying
the agent-principal model is pivotal to studying the unethical accounting behaviors of CPAs with
an information advantage over accounting firms (Carr et al., 2021; Gunz & Thorne, 2019).

Efforts to Address the Agency Problem
The agency theory's underlying assumption is delegating the principal authority to the
agent, which could lead to abuse and unethical accounting practices (Jensen & Meckling, 1976).
These unethical accounting practices include the failure of accounting professionals to adhere to
ethics in accounting, resulting in regulatory sanctions and the potential closure of their firms
(Gunz & Thorne, 2019; Ishaque, 2021). However, as much as the agency theory exposes the
lived experiences of CPAs' unethical accounting practices, it could also help implement various
governance mechanisms to control their actions (Jensen & Meckling, 1976; Panda & Leepsa,
2017). Pouryousefi and Freeman (2019) adopted the agency theory approach to address
perpetrator-victim interactions, as unethical accounting practices damage an organization's
reputation and adversely impact its performance (Blom & Niemann, 2022). Therefore, this study
draws on the agency theory to investigate the Certified Public Accountant's role in controlling
and manipulating the business transactions for the business entity (Pouryousefi & Freeman,
2019). Thus, the agency theory approach application will help to answer the research question,
"What are the perceived experiences of certified public accountants' ethical practices in
controlling and manipulating the business transactions for the business entity?"
Researchers have argued the need for a Certified public accountant to adhere to the
ethical standards of the accounting profession to sustain public confidence in the profession
(Namazi & Rajabdorri, 2020; Nau, 1924). For instance, Nau (1924) asserted that ethical
principles apply to the equitable relations between the certified public accountant and the
accounting firm. Nau's description of honest relations illustrates an agency perspective on the
relationship. Moxey (1922) posited that a certified public accountant could influence the

accounting firm's business activity by strictly complying with ethical rules and proper
professional conduct, and enforcement of honesty in the contract will also address the
agency's problem. The agency theory application to the principal and agent relationship is
more appropriate to address the research question, "What are the perceptions and experiences
of certified public accountants regarding accounting ethics?"
The study's findings may have practical implications for certified public accountants and
accounting firms. Through the lens of agency theory, this study aims to identify and report the
lived experiences of CPAs by emphasizing the relationship between the CPAs as "agents" and the
accounting firms as "principals." The accounting firm may seek their interest to the detriment of
the CPAs working in the accounting firm (Jensen & Meckling, 1976; Panda & Leepsa, 2017;
Zogning, 2017). As such, the agency theory, when applied, would minimize the issues exposed
by the agency theory by crafting the contract between the CPAs and the accounting firm to
protect the interest of both parties and maximize the wealth of the accounting firm (Jensen &
Meckling, 1976; Nikula & Kivistö, 2018; Zogning, 2017).
This study's findings may enlighten the practitioners and researchers in understanding
and analyzing the ethical accounting practice problem and mitigating the agency problem
(Jensen & Meckling, 1976; Nikula & Kivistö, 2018; Panda & Leepsa, 2017). Panda and Leepsa
(2017) posited that the principal and agent problems underpin the agency theory. Therefore, the
study may broaden the agency theory's conceptualization from the perspectives of CPAs and
accounting firms (Panda & Leepsa, 2017). Nevertheless, Panda and Leepsa (2017) argue that the
core ideas of agency theory still need to be explored. This approach implies that researchers can
expand the agency theory by applying it to a principal –third-party problem.

Expectancy-Valence Theory
The E-V theory posits that motivation is a multiplication of valence, instrumentality, and
expectancy (Vroom, 1964). According to Vroom (1964), humans' desires and attachment to
outcomes determine their actions and decisions. They believe certain actions produce these
outcomes, and specific primary outcomes are associated with secondary outcomes (Vroom,
1964). Researchers have used numerous theories to examine accounting ethics. For example,
Osafo et al. (2021) identified social learning theory, trickle-down model, meditated-moderated
model, and E-V theory as valuable lenses for investigating ethical behaviors in accounting firms.
However, the E-V theory provides a broader lens for exploring CPAs' ethical behaviors in
accounting compared to the trickle-down model and other frameworks espoused in the scholarly
literature (Allini et al., 2018; Osafo et al., 2021; Ozturk et al., 2017). The theory integrates the
concepts of valence, instrumentality, and expectancy to activate and sustain CPAs' motivation
and commitment to their firms (Kominis & Emmanuel, 2007; Sobaih & Moustafa, 2022; Tubbs
et al., 1993). Consistent with the E-V theory's underlying principles, when CPAs invest the effort
to achieve organizational outcomes, they expect compensation in return. Despite accounting
firms' increased focus on CPAs' motivation, CPAs' ethical behavior remains a critical challenge in
accounting firms due to corporate scandals (Kozáková et al., 2021; Miller & Shawver, 2018;
West, 2018). Nonetheless, researchers continue to leverage the E-V theory's underpinning
concepts of valence, instrumentality, and expectancy to examine CPAs' ethical behaviors in
accounting firms (Osafo et al., 2021; West, 2018).
However, the recurring accounting scandals such as Enron, Exxon, Johnson & Johnson,

Peanut Corporation of America, Tyco, WorldCom, Madoff's Wall Street Investments firms, and
Barclays LIBOR, among several others, shook the very foundations of the organizations involved
(Gunz & Thorne, 2019; Nowak, 2018; Osafo et al., 2021; Rogošić, 2020). In addition to the
negative impact of CPAs' unethical behavior, the frequency with which it occurs piques interest
in identifying models that examine CPAs' ethical behavior and find ways to motivate
CPAs to view accounting ethics as an implicit conviction rather than a set of rules to be followed
(Osafo et al., 2021). This study provides a 'richer' conceptual framework for understanding the
phenomenon of CPAs' motivation. The VIE model proposes the following three factors:
motivation is a consequence of the psychological value people place on the desired outcomes of
their actions (valence); people exert effort into tasks or behaviors they believe they can
accomplish (instrumentality); and that effort is intensified when people anticipate receiving a
reciprocal reward for their behaviors (expectancy) (Allini et al., 2018; Kominis & Emmanuel,
2007; Osafo et al., 2021; Ozturk et al., 2017; Tubbs et al., 1993; Vroom, 1964). Based on the VIE
model, the direct effect and interaction between the value of rewards, the attainability of targets,
the accuracy of measures used to gauge achievement, the transparency of the performance–
rewards relationship, and the motivation of CPAs can be evaluated using the VIE model to
ensure CPAs comply with accounting ethics (Kominis & Emmanuel, 2007; Mitchell, 1974;
Tubbs et al., 1993; Vroom, 1964).
Valence
Valence refers to the propensity of individuals to desire rewards (Vroom, 1964).
According to Vroom, employees' preferences vary and are influenced by the perceived value of
the benefits gained from engaging in a particular behavior. These benefits must be attractive

enough to motivate employees to behave in a specific manner to achieve positive organizational
outcomes. Some benefits influencing employees' efforts include increased salary, time off,
cordial relationships, promotion, ethical leadership, and job satisfaction (Allini et al., 2018;
Dunlop et al., 2022; Mitchell, 1974). Positive valence occurs when employees value the
perceived rewards; consequently, they exert more effort to achieve the associated outcomes
(Nowak, 2018; Vroom, 1964). Nonetheless, unmotivating rewards result in low performance and
employee disengagement (Dunlop et al., 2022; Nowak, 2018; Osafo et al., 2021). Therefore, to
motivate employees to adhere to ethical requirements, accounting firms must provide
performance rewards that inspire professional accountants to invest significant efforts in their
roles (Dunlop et al., 2022; Vroom, 1964). Osafo et al. (2021) postulated that CPAs who assign
high values to behavioral outcomes associated with honesty, integrity, trustworthiness, reliability,
and accountability are more likely to behave ethically when one or more of these values are the
expected outcomes of engaging in such behaviors.
Instrumentality
Instrumentality is the belief that good performance will result in a particular work
outcome (Osafo et al., 2021). Professional accountants exert more effort to achieve their goals
when they anticipate their efforts will yield positive work outcomes and corresponding rewards
(Kominis & Emmanuel, 2007; Nowak, 2018; Tubbs et al., 1993). For instance, Nowak (2018)
found that employees who expected their investments in a particular behavior would result in a
salary increase proportional to their efforts to achieve higher performance levels. Thus,
employees identify the best efforts among alternative actions to execute their contracts' terms
when expected rewards are assured (Dunlop et al., 2022; Nowak, 2018). CPAs are motivated

enough to know the exact effort needed to perform the contract and that the effort will determine
the reward. This approach allows accounting firms to set achievable objectives for the CPAs,
which invariably leads the accounting firm to achieve its own organizational goals.
Expectancy
Expectancy is the likelihood that effort will yield high-performance results (Vroom,
1964). Individuals exert significant efforts when the possibility of achieving a specific
performance objective is high (Sobaih & Moustafa, 2022; Tubbs et al., 1993). Employees
consider the efforts needed for the task and assess the probability of the efforts yielding an
expected outcome. These employees exhibit high self-efficacy to achieve optimal performance
levels (Kominis & Emmanuel, 2007; Osafo et al., 2021). In contrast, when the probability of
achieving performance goals is low, individuals are not motivated to expend effort to achieve
such goals (Ozturk et al., 2017; Vroom, 1964). Employees with low expectancy believe that the
probability of the efforts exerted will yield a different outcome. Accordingly, these individuals
need more self-confidence to exert significant efforts to achieve positive organizational results
and may invest little effort in completing the task (Dunlop et al., 2022; Nowak, 2018; Osafo et
al., 2021).
Researchers have argued that it is insufficient to encourage CPAs to behave ethically
when the conditions to facilitate such ethical behaviors are absent (Gunz & Thorne, 2019;
Nowak, 2018; Osafo et al., 2021; Zhatkin et al., 2017). As emphasized by Feng et al. (2018),
when value, instrumentality, and expectancy are present and actively linked with one another,
CPAs are more likely to behave ethically than when they are just encouraged to do so without the

presence of the underlying conditions. Concentrating on these three conditions can collectively
inspire ethical accounting behaviors, reducing the frequency of corporate scandals and frauds and
promoting ethical accounting practices (Allini et al., 2018; Nowak, 2018; Osafo et al., 2021;
Zhatkin et al., 2017).
Professional Accountant Ethical Practices
Empirical studies have shown that accounting practices could influence accounting firms
to commit financial misconduct (Edi & Enzelin, 2022; Fatemi et al., 2020). Edi and Enzelin
(2022) reported that an Indian company declared a profit of 361 billion Rp (Indian currency).
When it lacked the authorized reserves of 7.7 trillion Rp, these unethical financial reporting
practices attracted adverse audit opinions and other related penalties. Although some researchers
blame these unethical developments on ethical dilemmas that CPAs encounter in their day-to-day
practices (Ishaque, 2021; West, 2018), others blame such unethical behaviors on CPAs'
nonadherence to the accounting code of conduct (Carr et al., 2021; Jelinek, 2018). Unethical
professional conduct perpetrated by CPAs results in corporate accounting scandals and
undermines public confidence in CPAs (Ishaque, 2021; Melé et al., 2017). Thus, CPAs must
comply with the accounting code of conduct to enhance their firms' performance and reputation
(Carr et al., 2021; Gunz & Thorne, 2019).
The accounting code of conduct is a codified document that specifies accountants' ethical
and unethical professional behaviors and the penalties associated with ethical violations (Dunn &
Sainty, 2020; Feng et al., 2018). CPAs must upgrade their knowledge of sound accounting ethical
practices through continuous professional development (Marzuki et al., 2017; Namazi &

Rajabdorri, 2020). Additionally, educating CPAs provides avenues for ensuring that they comply
with the code of ethics of the accounting profession. However, despite these professional
development programs, most CPAs must follow the accounting code of conduct, leading to a loss
of public confidence in the accounting profession (Fatemi et al., 2020; Jaijairam, 2017). For
example, according to Cornerstone Research (2021), accounting cases made up 84% of total
settlement dollars in 2020 on federal securities class action filings. Additionally, Antonelli et al.
(2021) reported that some business entities closed due to the financial misconduct of accounting
professionals.
Empirical studies have shown that CPAs who violate the accounting ethics code of
conduct undergo a disciplinary process, which could revoke professional membership and
licenses (Jaijairam, 2017; Loeb, 1972). Such punitive measures seek to enforce professional
practices (Carr et al., 2021; West, 2017). Namazi and Rajabdorri (2020) explained that
reprimanding accounting professionals for non-compliance builds public confidence in
accounting and enforces professional discipline and integrity. Disciplinary sanctions deter CPAs
and oblige them to comply with the accounting ethics code of conduct. Despite the central role of
CPAs in implementing sound ethical practices, CPAs' perceptions and experiences of accounting
ethics still need to be explored in accounting literature (Carr et al., 2021; Namazi & Rajabdorri,
2020).
CPAs are responsible for enhancing their organization's reputation by producing clean and
accurate financial statements to support accounting information users such as investors, creditors,
and analysts (Jaijairam, 2017; West, 2018). Professional bodies also require CPAs to adhere to
the accounting code of ethics (Mardawi et al., 2021; Morrison et al., 2018). Several empirical

studies have also revealed the need for accounting professionals to adhere to the accounting code
of ethics to prevent adverse audit reports and intense public scrutiny (Dunn & Sainty, 2020; Feng
et al., 2018; Jaijairam, 2017; West, 2018). Nonetheless, most of these studies adopted the
positivist paradigm, which cannot discover the contextual nuances and complexities of growing
unethical behaviors in accounting firms (Bell et al., 2021; Edi & Enzelin, 2022; West, 2018).
Ethical Decision-Making Dilemma
An ethical decision-making dilemma arises when CPAs face decisions requiring them to
comply with either the accounting code of ethics or the accounting firm's objectives (Antonelli et
al., 2021; Kaptein, 2017). This situation occurs because CPAs employed by accounting firms are
subject to organizational and managerial authority and must adhere to the code of ethics (Arthur
et al., 2021; Barrainkua & Espinosa-Pike, 2020; Collins & Eddy, 2022). Previous studies have
investigated accounting professionals' organizational and professional commitment and the
potential conflict of interest that may arise between the two commitments (Arthur et al., 2021;
Barrainkua & Espinosa-Pike, 2020). CPAs face a conflict of interest when choosing between
their loyalty to their employer and adherence to the rules of the accounting profession (Antonelli
et al., 2021; Barrainkua & Espinosa-Pike, 2020). When faced with such an ethical conundrum,
CPAs may have to choose between their professional obligations and personal interests (Arthur
et al., 2021; Byza et al., 2019). For instance, a CPA could circumvent the tax law to favor family
and friends in preparing their tax returns, resulting in personal gains (Johnson & Ahn, 2021;
Jones & Iyer, 2020). CPAs may also face ethical dilemmas such as confidentiality agreements
that require them to maintain client information's confidentiality (Ishaque, 2021; Rogošić &
Bakotić, 2019). When CPAs must disclose client information to third parties, such as law

enforcement agencies or regulatory bodies, they face ethical dilemmas (Huterski et al., 2020;
Zager et al., 2019).
Another dilemma CPAs face is choosing between complying with the law, especially tax
laws, and providing accurate information. This dilemma results from the CPAs' compliance with
complex rules and regulations when preparing financial statements or tax returns, resulting in
unfavorable client outcomes (Arthur et al., 2021; Spalding & Lawrie, 2019). Additionally, CPAs
may face ethical dilemmas when dealing with contingent fees and commissions that could affect
their professional judgment (Huterski et al., 2020; Ishaque, 2021; Loscher et al., 2020). These
contingent fees and commissions create ethical dilemmas when CPAs deal with large amounts of
data that are challenging to analyze and interpret (Collins & Eddy, 2022; Huterski et al., 2020).
Although CPAs are mandated to follow the accounting code of ethics when faced with such
ethical dilemmas to serve the public's best interest, they frequently choose to follow their
organization's objectives to the detriment of the broader societal interest (Huterski et al., 2020;
Jaijairam, 2017). Such non-adherence attracts public scrutiny because CPAs must comply with
their professional code of ethics and safeguard the public interest (Baud et al., 2021; Melé et al.,
2017). Organizations have instituted measures to address ethical dilemmas within the work
context. These measures focus on an internalized sense of ethics for the firm's accounting
professionals, ethics compliance programs, and effective reward systems and recognition
programs to reward ethical conduct (Baud et al., 2021; Ishaque, 2021; Sonnerfeldt & Loft, 2018).
According to Melé et al. (2017), although these measures could entice CPAs to comply with the
accounting code of ethics, they are not a panacea to the growing unethical conduct in accounting

institutions. Melé et al. further explained that ethical dilemmas are rooted in CPAs' behavioral
outlook rather than structural or motivational challenges.
Models of Ethical Decision-Making
According to Dunn and Sainty (2020), ethical decision-making models focus on the
following factors: professional code of conduct, philosophical orientation, religious orientation,
cultural values, and moral maturity. Ethical decision-making models are complex and need to
address CPAs' adherence to the professional accounting code of conduct (Cardona et al., 2020;
Dunn & Sainty, 2020; West, 2017). Nonetheless, they are fundamental to compliance with the
accounting code of ethics and responsible accounting practices. Although other situational
factors such as firms' reward systems, bullying and intimidation from supervisors, and economic
pressure could influence ethical decision-making, CPAs are required to comply with the tenets of
their professional code of conduct (Byza et al., 2019; Dunn & Sainty, 2020; Zager et al., 2019).
Professional code of conduct
The professional accounting code of conduct is an enforceable document that specifies
accountants' ethical and unethical professional behaviors and the repercussions of ethical
violations (Dunn & Sainty, 2020; Spalding & Lawrie, 2019). The code of conduct requires
accounting professionals to be mindful of putting the interest of society ahead of the CPA's or the
client's interest. According to Payne et al. (2020), the American Institute of CPAs (AICPA) and
the Chartered Global Management Accountants (CGMAs) conducted a survey. They found that
35% of respondents experienced pressure from colleagues or managers to compromise their
organization's code of conduct. A global study conducted in 2015 also showed that pressure was

mounted on two-thirds of 648 respondents to act contrary to their professional ethics (Payne et
al., 2020).
The announcement of Federation of Accounting Professions No. 7/2019 regarding the
Code of Conduct for Professional Accountants, issued by the Board of the Federation of
Accounting Professions, stipulates that professional accountants must adhere to six fundamental
ethical principles (Tonglad & Khamwass, 2023). These ethical principles comprise (a) honesty in
all professional and business relationships, (b) objectivity and impartiality, (c) fairness, (d)
continuous improvement in professional knowledge, ability, vigilance, and adherence to
operational standards, (e) responsibility of complying with applicable laws and regulations and
avoiding any actions that could compromise the credibility of the profession, and (f)
accountability for presenting the operation's image by applicable laws, regulations, and
professional standards. CPAs' adherence to these ethical principles facilitates professional
integrity and sustained organizational performance (Cardona et al., 2020; Tonglad & Khamwass,
2023). However, such professional commitment and adherence depend on CPAs' philosophical
orientation (Dunn & Sainty, 2020; Ishaque, 2021).
Philosophical Orientation
Aside from the professional code of conduct, CPAs' philosophical orientation also
impacts their decision-making processes. Dunn and Sainty (2020) and Morrison et al. (2018)
identified utilitarianism, deontology, and virtue ethics as the three most common philosophical
orientations guiding organizational ethical decisions. Utilitarianism assesses the ethicality of the
decision based on the consequences on society, while deontology uses a set of norms to validate

the rightness and wrongness of behavior. In contrast, virtue ethics considers the motivation for
decision-making (Kamińska-Stańczak & Silska-Gembka, 2021; Morrison et al., 2018).
Researchers have observed that organizational leaders tend to adopt the utilitarian
approach when making ethical decision-making compared to other philosophical orientations
(Spalding & Lawrie, 2019; Tonglad & Khamwass, 2023). In contrast, accountants employ virtue
ethics when making professional and ethical decisions (Dunn & Sainty, 2020; KamińskaStańczak
& Silska-Gembka, 2021). Consistent with the organizational leaders' utilitarian approach, AICPA
expects professional accountants to follow the utilitarian approach, focusing on broad societal
interests (Baud et al., 2021; Miller & Shawver, 2018; Tonglad & Khamwass, 2023). As members
of the accounting profession, CPAs must uphold ethical standards and resist internal and external
pressures that could influence them to engage in unethical behaviors (Ishaque, 2021; Payne et al.,
2020; Santos & Lemes, 2022).
Religion orientation
CPAs' Religious orientation also guides their ethical decision-making processes. Religion
reflects a social force that shapes individuals' perceptions of appropriate or inappropriate ethical
behaviors (Dunn & Sainty, 2020; Santos & Lemes, 2022; Van Buren et al., 2020). For example,
Santos and Lemes (2022) found that deeply ingrained religious beliefs guide decision-making in
Muslim cultures. Previous studies have also shown that the strength of the CPAs' religious
beliefs, the degree of understanding and internalized religion, and the level of religious identity
influence ethical decision-making processes (Adelopo et al., 2023; Al-Ebel et al., 2020; Collins
& Eddy, 2022; Holy et al., 2022; Samad et al., 2022). Dunn and Sainty (2020) and Kaptein

(2017) also asserted that religious orientation is a multidimensional construct and includes
intrinsic, extrinsic, and quest dimensions. For instance, they described the intrinsic approach as
CPAs' faith that influences their way of life and the extrinsic dimension as CPAs' approach to
adjusting their religious beliefs to suit their personal and social lenses. In contrast, the quest
approach focuses on CPAs' inclinations to probe and question the decision-making processes to
reach the most viable solution (Samad et al., 2022; Zhatkin et al., 2017).
While professional accountants' religious orientation could guide ethical decisionmaking,
Al-Ebel et al. (2020) findings showed that the cultural norm of corruption could mediate this
relationship. These findings suggest that accountants could make unethical decisions when
corruption is the norm, irrespective of their religious persuasions. According to the study by
Sulaiman et al. (2022) and Santos and Lemes (2022), the influence of religious beliefs on the
interpretation of knowledge and experience has been a primary factor in many people's
decisionmaking over decades. Sulaiman et al. (2022) investigated 36 nations and found that
greater religiosity correlated with higher accounting quality. Bjornsen et al. (2019) and Oh and
Shin's (2020) studies involving various countries revealed similar results. These results suggest
that CPAs who embrace a high level of religiosity are likely to adhere to the accounting code of
ethics. The results further articulate religions' instrumental roles in instituting rules to govern
acceptable and unacceptable behaviors.
Cultural Orientation
Zhang and Wei (2022) define culture as all enduring forms of behavior, including
traditions, customs, moral values, and religious beliefs. Studies commonly define culture as
shared values and beliefs (Al-Ebel et al., 2020; Barrainkua & Espinosa-Pike, 2020). Culture

varies from one group of people to another, leading to different values, norms, and beliefs
(Al frijat & Albawwat, 2019; Van Rooij & Fine, 2018). Thus, an ethical decision in one
nation could be different from another. Therefore, the nature and cultural environment of
CPAs influences their ethical dispositions.
Organizations that ignore cultural differences in their workforce could hamper sustained
performance levels (Dunn & Sainty, 2020; Zhatkin et al., 2017). Zhatkin et al. (2017) posited that
culturally oriented CPAs would engage in positive ethical practices, as an individual's culture
influences their ethical decision-making processes. Dunn and Sainty (2020) also concluded that
culturally derived personal values would positively impact accountants' ethical decision-making
processes. For instance, Zhang and Wei (2022) studied 5,246 audit firms. They found that the
ethical culture of audit firms was significantly inversely related to the frequency of financial
restatements and the magnitude of earnings management in their client firms. This result reveals
that a culture of ethics could enhance accounting firms' image through quality performance and
sound ethical practices. In their study, Barrainkua and Espinosa-Pike (2020) also found that firms
with solid ethical cultures had sound norms supporting ethical conduct. Their organizational
leaders also encouraged and rewarded ethical behaviors and punished unethical conduct.
Therefore, accounting professionals' ethical behaviors positively influence their perceptions of a
robust ethical culture (Rogošić & Bakotić, 2019; Santos & Lemes, 2022; Seifert et al., 2023).

Moral Maturity
Dunn and Sainty (2020) define moral maturity as the capacity to differentiate between
right and wrong. Therefore, a CPA’s unethical behavior involves knowing what is right but doing
what is wrong. Such unethical aligns with DeTienne et al.'s (2021) postulation that it appears that
business scandals never end. This postulation supports increasing unethical behaviors in
accounting firms and other corporate entities. Nonetheless, morality develops over time as
individuals advance and learn to act ethically (Dunn & Sainty, 2020; Seifert et al., 2023). Thus,
as people mature, they are expected to behave ethically, as knowing and doing what is right
provides personal fulfillment.
The literature on pressures perceived by CPAs (Bjornsen et al., 2019; Cardona et al.,
2020; Collins & Eddy, 2022; Huterski et al., 2020) reveals that pressures are mostly mounted on
accounting professionals to act in a way that compromises their ethical values and professional
standards by both their superiors and their clients (Rogošić & Bakotić, 2019). These unethical
environments emanate from employers' or clients' expectations of CPAs to act in their clients' or
organizations' best interests. As Arthur et al. (2021) emphasized, it is customary to expect
accounting professionals to exercise personal morals informed by sound judgment in the best
interests of their organizations and clients. For instance, Rogošić and Bakotić (2019) argued that
CPAs are morally responsible for reporting wrongdoings while performing their jobs. However,
they often face ethical dilemmas about whether to report wrongdoing or not.
According to Latan et al. (2019), the Association of Certified Fraud Examiners (ACFE)
analyzed 2,690 cases from 125 countries in 2018 and found that whistleblowers uncovered 40%

of fraud cases. Other studies have shown that CPAs compromise reporting wrongdoing because
of reprimand, intimidation, and retaliation (Alleyne et al., 2018; Andon et al., 2018; Latan et al.,
2019; Riantika, 2021). For instance, Latan et al. (2019) reported that a manager threatened to fire
a CPA for disclosing organizational wrongdoing. Thus, the seriousness of corporate threats may
influence CPAs to refrain from reporting unethical practices in their organizations contrary to the
accounting code of ethics requirements.
Accounting Ethics Compliance Enforcement
Compliance enforcement entails measures accounting firms implement to address
unethical behaviors and practices (Namazi & Rajabdorri, 2020; Riantika, 2021). These measures
include jail time, fines, revocation of licenses, and closure of the accounting firm (Antonelli et
al., 2021; Jenkins et al., 2018; Namazi & Rajabdorri, 2020). Accounting firms also enroll their
CPAs in annual accounting ethics training and other professional development programs to
enhance their ethical competence and integrity (Morrison et al., 2018; Sonnerfeldt & Loft, 2018).
Despite the punitive measures instituted in organizations to ensure compliance, accounting firms
grapple with CPAs' unethical conduct. According to Jaijairam (2017), the professional attitudes
of CPAs remain critical contributors to unethical behavior in accounting firms. On the other
hand, other researchers attribute the professional misconduct of CPAs to their inability to
maintain self-control and moral conviction (Kaptein, 2017; West, 2017; Zhatkin et al., 2017).
These scholarly assertions lean more toward personal traits than organizational policies and
practices. Thus, exploring CPAs' perceptions of accounting ethics could reveal the underlying
factors responsible for breaches in the accounting code of ethics (Gunz & Thorne, 2019;
Jaijairam, 2017). Some of these sanctions include professional license revocation (Antonelli et

al., 2021; Morrison et al., 2018), fines (Sonnerfeldt & Loft, 2018), and jail time depending on the
financial crimes committed (Jenkins et al., 2018; Zhatkin et al., 2017).
CPAs' education and training in accounting ethics and professional development
interventions remain cardinal for instilling professional discipline in CPAs (Gunz & Thorne,
2019; Jenkins et al., 2018). Fatemi et al. (2020) and Kaptein (2017) argued that incorporating
accounting ethics into the curricula of accounting students would prepare them early in their
profession to embrace ethical behaviors during their formation period. Such earlier development
interventions would orient them toward the desired ethical practices advocated by financial
institutions and professional membership associations (Gunz & Thorne, 2019; Kaptein, 2017).
Training and development programs also prepare young accountants to build professional
resilience and moral courage to suppress unethical behaviors in accounting firms (Namazi &
Rajabdorri, 2020; Zhatkin et al., 2017).
Empirical research has shown the need for accounting professional bodies to become
more involved in CPAs' training in accounting ethics due to accelerating technological
developments and their associated risks (Marzuki et al., 2017; Namazi & Rajabdorri, 2020).
CPAs must possess integrity and moral ethics to instill confidence in accounting firms (Fatemi et
al., 2020; Johnson & Ahn, 2021). Additionally, educators should adopt new teaching methods to
educate students and accounting professionals in accounting ethics, corporate social
responsibility, and sustainability (Miller & Shawver, 2018; Montiel et al., 2020; Sholihin et al.,
2020). Accounting ethics training has also become an essential requirement of CPAs' certification
requirements, highlighting ethical competencies as foundational to accounting firms' reputation

(Fatemi et al., 2020; Gunz & Thorne, 2019). These ethical competencies comprise integrity,
honesty, fairness, and objectivity (Dunn & Sainty, 2020; Montiel et al., 2020).
Synthesis of the Research Findings
Growing unethical behaviors in accounting firms and other organizations continue to
attract significant attention from academics and practitioners (Dunn & Sainty, 2020; Holy et al.,
2022; Sarikhani & Ebrahimi, 2022). Findings from accounting literature show that accounting
professionals are morally and legally culpable for unethical behaviors. The widespread
involvement of accounting professionals in fraud has tarnished the profession's image, raising
concerns about public confidence in accounting professionals (Holy et al., 2022; Ishaque, 2021;
Payne et al., 2020). Several researchers have reported significant financial scandals involving
reputable organizations and accounting firms (Antonelli et al., 2021; Edi & Enzelin, 2022;
Fiolleau & Kaplan, 2017; Huterski et al., 2020; Ishaque, 2021; Sarikhani & Ebrahimi, 2022;
West, 2018). Professional accountants and their firms engaging in unethical financial practices
have been subjected to various sanctions such as imprisonment, fines, revocation of licenses, and
business closure (Carr et al., 2021; Jaijairam, 2017; Jelinek, 2018; Jenkins et al., 2018; Namazi
& Rajabdorri, 2020). Conversely, professional accountants who engage in ethical accounting
practices face personal conflicts and potential hostilities in the work environment and pressures
from their families (Namazi & Rajabdorri, 2020; Payne et al., 2020; Tonglad & Khamwass,
2023; West, 2018). As a result, professional accountants may seek other job opportunities to
protect their professional reputation (Payne et al., 2020; San-Jose & Retolaza, 2018; Satria,
2020).

According to Dunn and Sainty (2020), professional accountants are under significant
pressure to act professionally and ethically. Recent corporate scandals (Fatemi et al., 2020;
SanJose & Retolaza, 2018; Miller & Shawver, 2018; Zhatkin et al., 2017) have increased scrutiny
of business ethics and professional accounting. To bring accounting scandals to the barest
minimum, accounting firms ensure CPAs take annual accounting ethics code of conduct training,
and the AICPA requires CPE credit when CPAs renew their license (Morrison et al., 2018;
Sonnerfeldt & Loft, 2018). Research findings (Bjornsen et al., 2019; Cardona et al., 2020;
Collins & Eddy, 2022; Huterski et al., 2020) also have shown that CPAs are morally responsible
for reporting wrongdoings while performing their jobs. Other research findings indicate that
religious orientation can influence a CPA's ethical decision-making (Al-Ebel et al., 2020; Collins
& Eddy, 2022; Holy et al., 2022; Samad et al., 2022). For instance, Bjornsen et al. (2019) and Oh
and Shin (2020) indicate that religiosity increases ethical standards and that religious individuals
are less likely to engage in unethical behavior for fear of punishment by a higher power.
Research findings identified culturally derived orientation as a model of ethical decision-making
where accounting professionals' ethical behavior can be positively influenced by their
perceptions of a robust ethical culture (Barrainkua & Espinosa-Pike, 2020; Santos & Lemes,
2022; Rogošić & Bakotić, 2019; Seifert et al., 2023).
Integrating agency and E-V theories provides a broad conceptual lens for exploring
unethical and ethical behaviors in accounting firms. Agency theory provides an understanding of
the contractual arrangement between accounting firms and CPAs (Jensen & Meckling, 1976;
Nikula & Kivistö, 2018; Zogning, 2017), while E-V theory addresses CPAs' motivation to
comply with the tenets of the contractual agreement and the accounting ethics code of conduct

(Allini et al., 2018; Osafo et al., 2021; Ozturk et al., 2017). The lack of effective monitoring
mechanisms allowing agents to pursue personal gains to the detriment of the principal is
attenuated through the interactions among valence, instrumentality, and expectancy to activate
and sustain CPAs' motivation to meet the principal's expectations (Jensen & Meckling, 1976;
Nikula & Kivistö, 2018; Osafo et al., 2021; Vroom, 1964). Thus, CPAs feel motivated to adopt
sound ethical practices because they experience an effort-reward balance in the agent-principal
relationship.
Critique of Previous Research Methods
The extant accounting ethics literature has revealed the dominance of the positivist
research paradigm (Al frijat & Albawwat, 2019; Bell et al., 2021; Edi & Enzelin, 2022; Zhatkin
et al., 2017). For example, Al frijat and Albawwat (2019) conducted a quantitative survey
involving individuals from various industries and companies. They found that 75% of financial
accountants responded that their professional development in ethical compliance programs
would increase their ethical awareness. Zhatkin et al. (2017) also surveyed professional
accountants in Ukraine and found that 86% of the accountants knew the importance of the
accounting code of ethics to their professional development and growth. According to Bell et al.
(2021), the dominance of quantitative studies in the accounting ethics literature is attributed to
the numbers-driven nature of the accounting field. Accountants are responsible for preparing
financial statements and ensuring compliance with other quantitative metrics, such as production
figures (Edi & Enzelin, 2022). Subjecting complex accounting phenomena such as accounting
ethics to quantifications and measurements may not capture their nuanced meanings and
perceptions (Bell et al., 2021; Class et al., 2021). Qualitative studies could help uncover the

inherent meanings and nuances of complex phenomena within specific cultural contexts,
especially phenomena related to experiences and perceptions (Class et al., 2021; Kostere &
Kostere, 2021; Percy et al., 2015).
Research methodologists generally concur when research questions drive research
designs (Bolin et al., 2021; Doyle et al., 2020; Kahlke, 2014; Percy et al., 2015). The chosen
research design must provide robust and credible findings to answer the guiding research
questions. Consequently, the generic qualitative inquiry design emerges as the optimal design
choice to explore the following guiding research question derived from the accounting ethics
literature: How do certified public accountants perceive and experience accounting ethics?
Kahlke (2014) posited that the generic qualitative inquiry design is the most appropriate when a
research question(s) cannot be answered via well-established qualitative methods, such as
phenomenology, grounded theory, narrative inquiry, and ethnography.
Summary
Chapter 2 discussed, analyzed, and synthesized seminal and contemporary studies related
to accounting ethics. The review highlighted the significance of integrating agency and E-V
theories to provide a broad conceptual lens for exploring CPAs' experiences and perceptions of
accounting ethics. The study also revealed theoretical postulations and empirical findings about
accounting professionals' ethical and unethical behaviors. CPAs' ethical dilemmas and the
consequences of unethical behaviors, such as imprisonment, financial penalties, and revocation
of licenses, were also discussed. Additionally, the scholarly literature uncovered professional

educational and training interventions implemented in accounting firms to instill ethical
discipline in accounting professionals.
While the theoretical and empirical literature largely converged on the adverse impacts of
CPAs' unethical behaviors on accounting firms' reputations, most of these studies were informed
by the positivist paradigm. Oriented in measurement and quantification principles, the positivist
paradigm and its quantitative designs cannot capture CPAs' experiences and perceptions of
complex accounting phenomena such as accounting ethics. Additionally, while these quantitative
studies have confirmed the prevalence of CPAs' unethical behaviors in accounting firms, CPAs'
experiences and perceptions of accounting ethics remain under-explored. Thus, more research is
needed to understand CPAs' experiences and perceptions of accounting ethics. The next chapter,
Chapter 3, discusses the study design and methods for data collection and analysis.

CHAPTER 3. METHODOLOGY
Chapter 3 focuses on the research methodology and design employed in this study to
identify and report the perceptions and experiences of CPAs regarding accounting ethics. The
chapter contains the study's purpose and research question. In addition, it presents the research
design, the target population and participant selection, the procedures used to conduct the study,
the data collection instruments, and ethical considerations. The chapter concludes with a
summary of the key points covered in the main sections.
Purpose of the Study
This generic qualitative inquiry aimed to explore CPAs' perceptions and experiences
regarding accounting ethics in accounting firms operating in Maryland, USA. Although
significant research exists on accounting ethics, CPAs' perceptions and experiences regarding
accounting ethics remain underexplored in the accounting literature (Kamińska-Stańczak &
Silska-Gembka, 2021; Namazi & Rajabdorri, 2020; Sonnerfeldt & Loft, 2018). Thus, this study
addressed this research gap by utilizing a generic qualitative design to understand CPAs’
perceptions and experiences of the accounting ethics phenomenon within a specific cultural
context. Employing this qualitative design, I collected and analyzed interview data to gain deep
insights into the complexities and nuances of the accounting ethics phenomenon to guide
organizational leaders in implementing programs to improve ethical behaviors in accounting
firms (Ali & Khan, 2022; Dunn & Sainty, 2020; Namazi & Rajabdorri, 2020; West, 2018). The
study's findings would also enhance accounting ethics theory by illuminating contextual factors
influencing the accounting ethics phenomenon, as quantitative studies that have dominated
accounting ethics research appear incapable of articulating such context-specific underpinnings

(Al frijat & Albawwat, 2019; Bell et al., 2021; Edi & Enzelin, 2022).
Research Question
The following research question guided the study: What are the perceptions and
experiences of certified public accountants regarding accounting ethics? The research question
was viewed through the lens of agency and E-V theories.
Research Design
The generic qualitative design guided this study. According to seminal authors, the
generic qualitative approach offers the optimum research design choice when researchers seek to
understand phenomena that cannot be explored via established qualitative methodological
approaches such as phenomenology, grounded theory, case study, ethnography, and narrative
inquiry (Caelli et al., 2003; Kahlke, 2014). Additionally, the generic qualitative approach
emerges as the most appropriate design when researchers seek to explore perceived experiences
and the participants’ unique perspectives regarding those experiences in the real world (Kahlke,
2014; Kostere & Kostere, 2021). As the study focuses on examining the perceptions and
experiences of CPAs regarding accounting ethics in accounting firms operating in Maryland, the
generic qualitative approach provides the most suitable methodological pathway for acquiring
legitimate knowledge to answer the research question and achieve the study’s purpose (Ellis &
Hart, 2023; Kostere & Kostere, 2021; Percy et al., 2015). This approach adheres to the tenets of
constructivist epistemology, enabling research participants to share the personal meaning of their
experiences regarding a phenomenon under investigation (Bellamy et al., 2016; Caelli et al.,
2003; Kennedy, 2016).
Although other qualitative research designs were considered before selecting the generic
qualitative approach, these qualitative approaches were unfit to produce qualitative findings to

answer the guiding research question. For example, a phenomenological design focuses on the
internal lived experiences of researcher participants, while a case study approach investigates
participants' experiences within a bounded system (Bellamy et al., 2016; Percy et al., 2015).
Similarly, a grounded theory approach seeks to generate theory from participants' experiences,
which is different from the focus of the present study (Auta et al., 2017; Kahlke, 2014).
Relatedly, a narrative inquiry explores life stories and personal histories, whereas an
ethnographic design focuses on exploring the cultural beliefs and orientations of a group of
people (Bellamy et al., 2016; Caelli et al., 2003). Thus, compared to the generic qualitative
approach, these alternative qualitative designs appear unfit to explore research participants’
perceptions and experiences regarding the central phenomenon of this study. The generic
qualitative approach helped the researcher access CPAs’ outward experiences regarding the
accounting ethics phenomenon to answer the research question (Auta et al., 2017; Cooper &
Endacott, 2007; Ellis & Hart, 2023).
Target Population and Sample
The target population and the sample defined the study’s setting and limited boundaries
(AlDughaishi et al., 2023; Kostere & Kostere, 2021). The target population and its corresponding
sample also delineated the transferability of the study’s findings to other organizational contexts
(Cooper & Endacott, 2007; Ellis & Hart, 2023). As a subset of the target population, the sample
narrowed the scope of eligible participants and enhanced the feasibility of obtaining credible data
to answer the research question.
Population
The target population for this qualitative dissertation study comprises Certified Public
Accountants (CPAs) in Maryland, United States. According to the U.S. Bureau of Labor

Statistics, there are approximately 25,770 CPAs employed in Maryland (U.S. Bureau of Labor
Statistics, n.d.) CPAs represent a distinct professional group within the accounting field,
possessing specific qualifications, certifications, and expertise in financial reporting, auditing,
and compliance (Namazi & Rajabdorri, 2020; West, 2018) (U.S. Bureau of Labor Statistics, n.d.)
CPAs represent a distinct professional group within the accounting field, possessing specific
qualifications, certifications, and expertise in financial reporting, auditing, and compliance
(Namazi & Rajabdorri, 2020; West, 2018). Thus, these CPAs had taken the required professional
accounting examination courses and had been licensed by recognized accounting bodies to
practice as CPAs. This population encompasses entry-level and experienced CPAs working in
various sectors, including public accounting firms, corporate finance departments, government
agencies, and non-profit organizations. CPAs serve critical roles in ensuring the accuracy and
integrity of financial information, making them essential subjects for a study on accounting
ethics (Mardawi et al., 2021; Morrison et al., 2018).
Certified public accountants are also mandated under the accounting code of ethics to
regularly upgrade their knowledge and skills to stay current with accounting developments
(Fatemi et al., 2020; Johnson & Ahn, 2021; Namazi & Rajabdorri, 2020). These developments
include technological advancements, ethical issues, and compliance enforcement (Bell et al.,
2021; Dunn & Sainty, 2020; Edi & Enzelin, 2022). Thus, the study population’s characteristics
align with the broad insights needed to answer the research question.
Sample
The population of interest consisted of all CPAs licensed in Maryland, USA. Inherent in
their professional practices involves compliance with the accounting ethics code of conduct and
demonstrating sound ethical behaviors in their organizational contexts (Arciniega et al., 2019;

Dunn & Sainty, 2020). The sampling process commenced with establishing inclusion and
exclusion criteria, detailing attributes that qualify or disqualify participants for recruitment into
the study (AlDughaishi et al., 2023; Neergaard et al., 2009). The sample drawn from the target
population met the following inclusion criteria: (a) are certified public accountant, (b) have at
least a year of experience and work in Maryland, USA, (c) are between the ages of 21 and 65, (d)
willing to participate in the interview session and have the interview audio recorded, and (e)
must be fluent in the English language. The exclusion criteria are participants with no close
personal or professional relationships with the researcher. After the delineation of the inclusion
and exclusion criteria, the determination of the sample size followed. The study employed a
nonprobability strategy to recruit information-rich participants to share unique experiences and
perceptions about the accounting ethics phenomenon (Bellamy et al., 2016; Neergaard et al.,
2009). More specifically, the study utilized a purposive sampling method to select participants
who had experienced the accounting ethics phenomenon and could share their perceived
experiences (Cannon et al., 2022; Kostere & Kostere, 2021). The purposive sampling method
also helps researchers recruit participants based on the research question and the study’s purpose
(Bekele & Ago, 2022; Oshodi et al., 2019).
Twelve selected CPAs satisfied the inclusion criteria for the study. According to Bekele
and Ago (2022), the number of participants to interview remains a contentious issue among
qualitative researchers. Most scholars diverge on a universal rule for determining the required
number of participants to achieve data saturation; rather, it depends on the research question, the
nature of the research, the chosen strategy, and the purpose of the study, among many other
variables (Bekele & Ago, 2022; Sim et al., 2018; Vasileiou et al., 2018). While there is no rule
regarding the minimum number of participants required for a qualitative study, most qualitative
methodological experts agree that researchers should conduct interviews until they reach data
saturation (Caelli et al., 2003; Kahlke, 2014; Morse, 2015). Morse posited that data saturation
occurs in qualitative interviews, where additional interviews yield repeated information. This
study achieved data saturation after interviewing the 12th participant.
Procedures
The research was conducted using a generic qualitative approach and followed step-
bystep details in selecting participants, ensuring participant protection, and collecting and
analyzing data. The study used an interview guide derived from agency and E-V theories to
gather information from in-depth, semi-structured interviews with eligible CPAs.
Participant Selection
Purposive sampling was used in this qualitative study to identify CPAs qualified for the
study. The target sample size was twelve. The inclusion criteria for the study were that the
participant must have a CPA license, have at least a year of experience and work in Maryland,
U.S.A., must be between the ages 21 and 65, must be willing to participate in the interview
session, and have the audio recorded, and must be fluent in the English language. The exclusion
criteria were participants with no close personal or professional relationships with the researcher.
Capella's Institutional Review Board (IRB) approval was obtained before contacting the
thirdparty recruiter. Subsequently, the participants were contacted to ensure the study satisfies
Capella's ethical standards for research involving human subjects. After the IRB approval, a
third-party firm (www.userinterviews.com) was used to recruit participants for the study. The
inclusion criteria and exclusion criteria were included in the third-party website during sign-up.
The selection was not based on race, ethnicity, and socioeconomic class. The third-party firm
provided a list of qualified participants who were screened to ensure the individual met the study

criteria. Selected participants were sent the consent form to sign through an email and sent back
to me electronically before the scheduled interview date.
Protection of Participants
After screening the list of participants provided by the third party and confirming their
eligibility to participate, the consent form was provided to the participants. It is essential to
ensure the participant's safety, privacy, and well-being during the interview. The step-by-step
guide to protecting participants during the interviews included the interview consent form, which
was emailed to the selected participants for signature and return. This approach allowed
participants to ask questions and voice any concerns. Participants were also assured that their
anonymity and confidentiality would be protected and that data would be encrypted and kept
confidential by storing it on a password-protected computer at the researcher's home. The
consent form also stated that participation in this research was entirely voluntary, that no
monetary compensation would be provided, and that participants could opt out of the study if
they desired. This study underwent a rigorous ethical review process and received approval from
Capella’s Institutional Review Board (IRB). This approval ensured that the study adhered to
ethical standards and guidelines.
Expert Review
After obtaining IRB approval, three expert reviewers were solicited to field-test the
interview questions. The three experts were Ph.D. accounting scholars who reviewed the
interview questions to foster clarity and understanding. They reviewed the questions individually
to check for alignment with the guiding research question. The subject-matter experts suggested
improvements in the wording and sequencing of some interview questions (Jorgensen & Duncan,

2015; Kostere & Kostere, 2021). Their suggestions were incorporated into the reviewer's
interview questions before conducting mock interviews.
The mock interviews were conducted with two participants who satisfied the inclusion criteria.
The participants were interviewed in person, which lasted an average of 45 minutes. The mock
interviews enabled me to practice interview techniques and field test the interview questions to
promote participants’ understanding of the questions (Ellis & Hart, 2023; Sim et al., 2018). Like
the subject-matter experts’ review, suggestions from the mock interviews were incorporated into
the final interview questions.
Data Collection
I used the interview guide approved by the dissertation committee to collect data from
participants. The semi-structured interview guide consisted of seven open-ended and probing
questions that enabled me to gather detailed descriptions from CPAs regarding their perceptions
and experiences of the accounting ethics phenomenon. I began each semi-structured interview by
posing open-ended questions followed by prompts. The semi-structured interview entails a
conversational approach, requiring participants to share their perceptions and personal
experiences with researchers (Kostere & Kostere, 2021; Neergaard et al., 2009). An in-depth,
semi-structured interview was conducted via Zoom audio conferencing after activating the audio
recording and transcription features.
Kostere and Kostere’s (2021) step-by-step guide was followed to conduct the interviews.
1. I agreed on the interview date, time, and venue with the participants.
2. At the interview, I welcomed participants, thanked them for taking time out of their busy
schedules to participate, and reviewed the interview guide with them.

3. Review the consent form with each participant before asking questions based on the
semistructured interview guide.
4. I recorded each interview session.
5. After all interview questions were exhausted with each participant and data saturation was
reached, the participants were thanked for sharing their experiences regarding accounting ethics.
Each participant was interviewed for an average of 45 minutes. I transcribed the recorded
interviews verbatim before executing the data analysis. The transcribed data, the semi-structured
interview guide, and the consent form were password-protected on an external hard drive and
kept in a locked cabinet. All recruitment materials related to the study would only be shared
outside Capella University following proper legal and ethical procedures such as a garnishee
order or a court subpoena. The hard drive would be magnetically disassembled and degaussed,
and the circuit board would be shredded seven years after the study, as the law requires.
Data Analysis
Before performing the data analysis, I conducted member checking on the transcribed
data to confirm the accuracy of participants’ responses to the interview questions. The data
analysis followed Kostere and Kostere’s (2021) 13-step framework for analyzing qualitative
data:
Step 1: I reviewed and familiarized myself with the participants' descriptions. I also read
each transcript and highlighted meaningful sentences, phrases, or paragraphs.
Step 2: I reviewed the highlighted information and used the research question to decide
the relevance of each highlighted information. After the review, I realized some of the
highlighted pieces of information were interesting but unrelated to the research question.

Step 3: I eliminated irrelevant segments in the transcripts. These unrelated data were filed
in a separate folder.
Step 4: I coded each relevant piece of information, meaning units.
Step 5: I imported the transcripts with demarcated meaning units into NVivo 14
qualitative data analysis software for further analysis. I clustered the meaning units using this
qualitative data analysis software to understand emerging patterns.
Step 6: I completed Steps 1 to 5 for the first participant's data. I also coded and clustered
the first participant's data. I analyzed subsequent participants’ data, comparing them to the
clustered meaning units of the first participant. I also contrasted and combined participants’ data.
Step 7: I identified data corresponding to a specific pattern and selected appropriate
quotes to elucidate the pattern.
Step 8: I reviewed all patterns for overarching themes. This procedure entailed combining
and clustering similar patterns into themes.
Step 9: Patterns and themes were shifted or changed throughout the analysis process.
Step 10: After analyzing all the data, I arranged the themes to ensure they corresponded
with the supporting patterns. The patterns illuminated the themes.
Step 11: For each theme, I wrote a detailed analysis describing the scope and substance of
the theme.
Step 12: I described each pattern and supported it with quotes from the data.
Step 13: I synthesized the themes to form a composite synthesis to answer the research
question.
Qualitative researchers achieve the trustworthiness of their studies through credibility,
dependability, and transferability of their research activities (Kostere & Kostere, 2021; Morse,

2015). I implemented two strategies in this study to foster the credibility of its findings. These
strategies comprised prolonged engagement and member checking (Candela, 2019; Ellis & Hart,
2023; Morse, 2015). I spent more time with the participants during the interviews regarding
prolonged engagement to capture their perceived experiences with the accounting ethics
phenomenon. Additionally, preliminary meetings with participants to explain the purpose of the
study helped build trust with the participants (Kostere & Kostere, 2021; Moriah, 2018).
According to Willis et al. (2016), building trust and rapport with study participants motivates
them to share their authentic experiences regarding a phenomenon being investigated.
Dependability, on the other hand, entails measures researchers incorporate into their
studies to promote the repeatability of their findings (AIDughaishi et al., 2023; Doyle et al.,
2020). I achieved dependability in this study by justifying the rationale for choosing the generic
qualitative approach, as the study sought to explore CPAs’ experiences and perceptions regarding
accounting ethics (Auta et al., 2017; Ellis & Hart, 2023; Kahlke, 2014). I also maintained an
audit trail of the analysis using NVivo 14 data analysis software to document the processes
followed to derive the themes. Justifying the study design to ensure accurate data were collected
and maintaining an audit of the analytical processes enhanced the replicability of the study
findings.
Finally, transferability refers to the degree to which a qualitative study’s findings could
be from other settings and samples (Moriah, 2018; Tuval-Mashiach, 2021). I provided thick
descriptions of the study design, the participants, and the interview processes to guide people
interested in applying the study findings. Detailing these methodological parameters promoted
the study’s transferability across situations, locations, samples, and times (Doyle et al., 2020;
Kostere & Kostere, 2021).

Instruments
Qualitative instruments should aim to gather accurate data to enhance the trustworthiness
of the study’s findings (Kostere & Kostere, 2021; Neergaard et al., 2009). Although these
instruments range from interview guides to audio recordings, I was the primary instrument for
data collection and analysis (Collins & Rocco, 2018; Kostere & Kostere, 2021). Therefore, I
played an instrumental role in ensuring the study’s findings reflected participants’ descriptions of
their perceived experiences of the accounting ethics phenomenon investigated in the study.
The Role of the Researcher
Using the generic qualitative approach, I collected and analyzed CPAs’ experiences and
perceptions of accounting ethics to answer the research question guiding the study (Bellamy et
al., 2016; Ellis & Hart, 2023). I also developed a semi-structured interview guide based on
insights from agency and E-V theories and the literature surrounding accounting ethics (Jensen
& Meckling, 1976; Mitnick, 2021; Osafo et al., 2021; Vroom, 1964). Additionally, my
experience as a CPA spans over a decade, working for accounting firms and as a consultant.
Thus, I possess an insider’s knowledge and theoretical perspectives on the accounting ethics
phenomenon.
Although my guiding principle throughout my career as a CPA has been unwavering
adherence to the principles and regulations governing ethical accounting practices, accounting
professionals often face dilemmas such as conflicts of interest, pressure to manipulate financial
data, or biased accounting reporting (Edi & Enzelin, 2022; Gunz & Thorne, 2019; Huterski et al.,
2020). These ethical dilemmas occur in organizational settings; however, professionals
upholding sound ethical principles should guide their organizations and clients against such
unethical practices. Nonetheless, empirical studies uncover unethical behaviors among

accounting professionals (Dunn & Sainty, 2020; Hultman, 2019). These documented unethical
behaviors in accounting literature motivated me to pursue this topic in my doctoral dissertation.
Therefore, I have personal and professional interests in the accounting ethics phenomenon.
Given my professional background and knowledge, theories, and experiences with the
phenomenon under investigation, I could influence the study outcome if measures are not
implemented to prevent my preconceptions and experiences from interfering with the study’s
findings. However, my advanced qualitative courses during my Ph.D. program prepared me to
conduct ethical qualitative studies. I learned bracketing techniques and how to use a reflexive
journal to document emotions and thoughts throughout the research process (Amin et al., 2020;
Ellis & Hart, 2023). Thus, I used a reflexive journal to document my prior experiences and
knowledge throughout the research process and ensured they did not interfere with participants’
descriptions of their perceived experiences with the accounting ethics phenomenon investigated
in the study.
Guiding Interview Questions
1. Describe your understanding of accounting ethics. What does it mean to you?
2. Describe your personal ethical beliefs. In what ways are your personal ethical beliefs like
professional ethics for accountants, and in what ways are they different?
3. How and where did you obtain your accounting ethics training?
4. Describe circumstances that influence your compliance with accounting ethics requirements.
5. From your perspective, describe the accounting profession’s reputation regarding ethics and
why.
6. Describe the ethical accounting dilemmas you have encountered in your career.

7. What else would you like to discuss about accounting ethics that we still need to cover during
this interview?
Ethical Considerations
Dawson et al. (2019) stressed that research ethics is integral to the research process,
especially involving human subjects. Wallace and Sheldon (2015) also suggested that all studies
have inherent ethical issues, including research with minimal risks. This study adhered to the
ethical regulations documented in the Belmont Report (U.S. National Commission for the
Protection of Human Subjects of Biomedical and Behavioral Research, 1979). The principles of
the Belmont Report serve as a framework for research ethics in social sciences research (Cascella
& Aliotta, 2014; Wallace & Sheldon, 2015). The three principles are respect for others,
beneficence, and justice.
Respect for persons mandates that researchers obtain participants' consent without
pressure (Moriah, 2018; Wallace & Sheldon, 2015). This principle also obligates researchers to
capture participants' perspectives accurately without misrepresenting their voices and using the
data for research only (Hibbin et al., 2018; Mick, 2019). Thus, I provided participants with a
confidentiality guarantee of protection against unauthorized use of their data (Dawson et al.,
2019; Redman & Caplan, 2021). Beneficence, conversely, requires researchers to inform
participants about social and emotional risks associated with the study (Cascella & Aliotta, 2014;
Hardesty et al., 2019). I weighed the benefits and costs of the research and ensured that
participants' dignity and welfare were not compromised (Hibbin et al., 2018; Wallace & Sheldon,
2015).

Finally, the principle of justice ensures that only eligible participants are selected for a
study (Dawson et al., 2019; Wessels & Visagie, 2017). In compliance with this principle, I did
not base the recruitment decisions on race, ethnicity, and socioeconomic class (Cascella &
Aliotta, 2014; Mick, 2019). Nonetheless, the inclusion criteria ensured that only qualified
persons were recruited for the study (Redman & Caplan, 2021; Wallace & Sheldon, 2015).
Including ineligible participants would harm them psychologically and emotionally since they
lack the capacity, resulting in ethical violations in research involving human subjects (Moriah,
2018; Wessels & Visagie, 2017). Thus, the Belmont framework provided robust ethical
underpinnings to enhance the trustworthiness of the study’s findings.
Summary
This chapter justified the generic qualitative approach as the optimal design for exploring
CPAs’ perceptions and experiences regarding accounting ethics investigated in this study.
Informed by the constructivist epistemology, this qualitative design employed semi-structured
interviews to collect in-depth descriptions from the study participants. This epistemological
orientation also allowed CPAs to construct their real-world experiences of the phenomenon,
which were analyzed using Kostere and Kostere’s 13-step analytical framework and NVivo 14
qualitative data analysis software. Participants’ representations of their perceived experiences
were also assured through using a reflexive journal to document and prevent researcher biases
from interfering with participants’ worldviews. Prioritizing participants’ voices throughout the
interviews and the thematic data analysis, I uncovered salient themes regarding CPAs’
perceptions and experiences of the accounting ethics phenomenon. Chapter 4 presents the
findings of the data analysis.

CHAPTER 4. PRESENTATION OF THE DATA
This chapter delves into the study's outcomes, presents the data collected, details the
analysis techniques utilized, and reveals the study's findings. The findings provided a
comprehensive understanding of the perceptions and experiences of Certified Public Accountants
(CPAs) regarding accounting ethics. This study was guided by the primary research question:
“What are the perceptions and experiences of CPAs regarding accounting ethics?” In finding
answers to the research question, participants emphasized the critical role of ethics, integrity, and
adherence to professional standards in the accounting profession. Chapter four encompasses the
following sections: the study and the researcher, a description of the sample, research
methodology applied to the data analysis, presentation of data and results, and a summary of key
points produced from the data analysis.
Introduction: The Study and the Researcher
This generic qualitative inquiry study embarked on a profound exploration of the
intricate world of accounting ethics. In this terrain, the principles of integrity, objectivity, and
professional conduct are paramount (Dunn & Sainty, 2020). According to Kahlke (2014), a
generic qualitative inquiry approach is intrinsically inductive and interpretative and offers a
depth of understanding. Unlike quantitative research, which aims for statistical generalization,
qualitative study seeks to derive a conceptual understanding of a particular phenomenon (Kostere
& Kostere, 2021). It delves deep into experiences, attitudes, and perceptions, making it apt for
this study titled Certified Public Accountants’ Perceptions and Experiences of Accounting Ethics:
A Qualitative Inquiry. In this study, the primary aim is not to quantify but to grasp the intricate
nuances and perceptions of the participants. The qualitative approach, therefore, allows the study

to be grounded in CPAs' perceptions and lived experiences of accounting ethics. By capturing
their voice, the study can surface subtle insights, complex understandings, and dynamic
interactions within accounting ethics (Percy et al., 2015). This exploratory and flexible method
allows the study to be shaped by the participants' insights and emerging data.
As a researcher, my personal and academic journey has been intimately intertwined with
the accounting world. My years of academic pursuit, professional experience, and a fervent
commitment to ethical values have shaped this study's inception. Having spent considerable time
within the accounting profession, I have witnessed firsthand the ethical challenges and moral
dilemmas that CPAs encounter. This background fuels my dedication to understanding the
perceptions and experiences of CPAs regarding accounting ethics. In this journey, I serve as the
conduit through which the voices of twelve seasoned CPAs are channeled, striving to provide an
in-depth understanding of the ethical intricacies that underpin the profession (Jelinek, 2018). As
an observer and participant in the accounting world, I approached this study with a profound
curiosity and a commitment to contributing meaningful insights to the ongoing discourse on
accounting ethics. I applied bracketing techniques and used a reflexive journal to document my
emotions and thoughts throughout the process so that it did not interfere with participants'
descriptions of their perceived experiences with the accounting ethics phenomenon.
In their recent work (Ellis & Hart, 2023), it was emphasized that reflexivity, a
fundamental aspect of qualitative research, entails researchers engaging in introspection to
examine their personal biases, beliefs, and their role within the research process. Thus, it is vital
to recognize one's standpoint and how it might influence the research. For example, a researcher
with a background in accounting might have preconceived notions about ethics. Being reflexive
ensures that these biases do not skew interpretations (Amin et al., 2020). Building rapport with

the participants was essential in elucidating the perceptions and experiences of participants
during the interview. Patton (2015) noted that in qualitative interviews, establishing trust and
rapport is essential with participants to facilitate an open sharing of experiences and
perspectives.
It encourages honest sharing of experiences and perspectives.
Qualitative research is not linear. As data is collected, the researcher may adjust the line
of inquiry based on emerging themes or insights. This iterative process ensures the research stays
true to shared experiences and meanings (Smith & McGannon, 2018). Post-data collection, the
researcher immerses themselves in the data, identifying patterns, themes, and nuances, ensuring
the research accurately reflects participants' experiences (Kostere & Kostere, 2021). This process
is interpretative and requires the researcher to balance objectivity with empathy. The researcher
ensures that participants' identities are protected, their voices are accurately represented, and the
research process is transparent and ethically conducted (Merriam & Tisdell, 2016, p.260).
Description of the Sample
Population
The population of CPAs is geographically dispersed throughout the United States, encompassing
professionals from different regions, states, and metropolitan areas (Morrison et al., 2018;
Sonnerfeldt & Loft, 2018). This geographic diversity allows a comprehensive exploration of
accounting ethics perceptions and experiences across various local contexts. The population
includes individuals from diverse demographic backgrounds, including genders, ages, ethnicities,
and cultural backgrounds. This diversity within the CPA population ensures a holistic
examination of accounting ethics that considers the potential influence of demographic factors
on ethical perspectives and behaviors.

Research Sample
The sample for this qualitative dissertation study consists of 12 Certified Public
Accountants (CPAs) who have been actively practicing accounting for varying durations of time.
The participants were selected using a non-probability strategy to provide diverse experiences
and perspectives within the accounting profession (Bellamy et al., 2016; Neergaard et al., 2009).
They come from different geographic regions and work in various sectors, including public
accounting firms, corporate finance departments, and government agencies. The participants'
ages range from late 20s to early 60s, ensuring a broad spectrum of generational viewpoints.
Additionally, there is a mix of genders and ethnic backgrounds among the participants to capture
a comprehensive representation of the accounting profession's diversity. The participants were
chosen through purposeful sampling, considering their expertise, years of experience, and roles
within their respective organizations to ensure a well-rounded perspective on accounting ethics
(Cannon et al., 2022; Kostere & Kostere, 2021). All participants hold professional certifications
and licenses relevant to their practice as CPAs, and they have been actively involved in various
aspects of financial reporting, auditing, and compliance. This diverse and experienced sample
allows for a rich exploration of perceptions and experiences related to accounting ethics within
the profession (Bekele & Ago, 2022; Oshodi et al., 2019).
Protection of Participants
Protecting the participants in a research study is paramount to ensure their rights,
wellbeing, and confidentiality (Braun & Clarke, 2020; Percy et al., 2015). The procedures used to
protect the participants in this study adhere to ethical guidelines and best practices to ensure their
well-being, privacy, and confidentiality throughout the research process. As such, Capella

University’s Institutional Review Board (IRD) approval was obtained before recruiting
participants to ensure that the study satisfies Capella's ethical standards for research involving
human subjects. All selected CPAs received a clear and detailed informed consent form before
participating. This form outlined the purpose of the study, the voluntary nature of participation,
and the potential risks and benefits. Participants were given ample time to review the consent
form, ask questions, and provide informed consent. Each participant emailed the signed informed
consent form to me. To protect the identity and confidentiality of participants, all identifying
information, including names and contact details, was replaced with pseudonyms or participant
codes in the research data. Additionally, any information that could potentially identify a
participant's workplace or clients was generalized to ensure anonymity. Research data, including
interview transcripts and field notes, were securely stored and accessible only to the researcher
and authorized personnel. Digital data were encrypted, and hard copies were kept locked and
secure.
Research Methodology Applied to the Data Analysis
Thematic Analysis Steps
Thematic analysis was the primary method used for data analysis. This strategy involved
systematically identifying, analyzing, and reporting interview data patterns or themes (Braun &
Clarke, 2006). According to Braun and Clark, thematic analysis may be an essentialist or realist
methodology that reports the experiences, meanings, and reality of the participants, which
essentially is the essence of this study to identify and report the perceptions and experiences of
CPAs regarding accounting ethics. The data was analyzed through the lens of the research
question: “What are the perceptions and experiences of CPAs regarding accounting ethics?” and
used the data to answer the research question. The researcher used participant wording from the

transcript to capture the participant’s meaning in response to the research question, thereby
reducing researcher bias (Braun & Clarke, 2006; Kostere & Kostere, 2021). The researcher coded
data using inductive analysis, allowing themes to emerge while identifying common data streams
from participant interviews without a predetermined coding framework (Braun & Clarke, 2021).
Braun and Clarke noted that a theme captures an important aspect of the data concerning the
research question and represents some pattern or meaning within the data set. An inductive
strategy implies that the identified themes are closely related to the data (Braun & Clarke, 2020).
The researcher followed the step-by-step by Kostere and Kostere (2021).
Step 1. The interview record was transcribed by the first step, which involves reviewing
and familiarizing with the data collected from the first participant (interviews, journals, and field
notes). The researcher also listened to the recorded interview and cross-checked the generated
transcript for any mistakes. The researcher then read and reread the interview transcripts to
comprehend the participants' responses considering the investigated phenomenon. The researcher
intuitively highlighted any meaningful sentences, phrases, or paragraphs.
Step 2. The researcher examined the highlighted data and used the research question to
determine whether they were relevant to answering the research question. Some interesting
information in the transcript was irrelevant to the research question.
Step 3. All highlighted data that did not pertain to the research question were discarded.
Created and named a distinct file to store this information. This step was done so that the
researcher could revisit these data in the future and reevaluate them.
Step 4. After familiarizing himself with the interview transcript, the researcher proceeded
with the next step: creating codes. The researcher imported the interview transcripts into NVivo
14, a well-established Computer-Aided Qualitative Data Analysis Software (CAQDAS). Data
deemed relevant to the research question were called meaning units (Kostere & Kostere, 2021).
According to Kostere and Kostere, meaning units are comprised of direct quotes from the
transcripts of the interviews. The researcher used the NVivo 14 to generate codes for every
meaning in the transcript. According to Byrne (2022), codes are shorthand descriptive or
interpretive labels for information relevant to research questions. Table 1 below shows the initial
codes generated using Nvivo14.
Table 1
Initial Codes
Codes No. of
Participants
No.
References
Public Trust and Ethical Assurance 5 5
Accountability for Moral Judgment 3 3
Accounting Ethics as Guidance 3 3
Adherence to Accounting Procedures and Policies 1 1
Alignment of Personal and Professional Ethics 9 9
Adherence to Standards 1 1
Professional Ethics - Integrity, Objectivity, and Expertise 1 1
Uncompromising Ethical Principles 1 1
Impact of Accounting Scandals on Public Perception 5 5
Public Confidence in the Accounting Profession 4 5
High Regard for Ethics in the Accounting Profession 2 2
Maintaining Ethical Standards in Response to Reputation Concerns 1 1
Public Misconception of Accountants' Role 5 5
Emphasis on Moral Uprightness 3 3
Balancing Culture and Standards in Accounting 1 1
Ethical Gray Areas in Rule Interpretation 1 1
Ethical Dilemma in Financial Reporting 6 7
Balancing Transparency and Consequences 3 3
Professional Integrity and Client Ownership 2 2
Impact Awareness and Disclosure Decision 1 1
Professional Responsibility and Ethical Compliance 8 8
Ethical Dilemmas in Leadership 3 3
Independence Statement as a Crucial Ethical Safeguard 1 1
Robust Internal Controls 1 1
Licensing Requirement for Ethics Training 6 6
Ethics Education and Continuous Learning 5 5
Integral Role of Accounting Ethics Training 1 1
Ongoing Ethics Training and Compliance 1 1
Step 5. The process of developing patterns was initiated by merging coded meaning units
that were related or interconnected in some way. The original coding was modified as the names
for each identified pattern were determined.
Step 6. Patterns are "what is happening?" according to Kostere and Kostere (2021). The
meaning units were renamed as patterns were identified to align with related patterns. The
researcher verified that the quotes align with the pattern and that the names of the patterns make
sense by reading the quotations that align with each pattern.
Step 7. Quotes from the data were used to describe and clarify each pattern. The
researcher briefly described each pattern and its relationship to the research question.
Step 8. The researcher examined the initial transcript's patterns for the emergence of
overarching themes. This method entails combining and clustering related patterns to generate
themes. Braun and Clarke (2006) state that a theme captures something significant and represents
a level of meaning patterning within the data set.
Step 9. After analyzing all the data, align the themes with the supporting patterns. Under
the theme are listed the patterns. Each pattern is explained using direct transcript quotations. The
themes are elucidated using patterns.
Step 10. For each theme, a comprehensive analysis describing its scope and substance.
Step 11. Steps 1 through 10 were repeated for each participant's transcript.
Step 12. After analyzing the data from all participants, the recurring patterns and themes
were synthesized into a composite synthesis, which attempts to interpret the meanings of the
investigated question. Following this step resulted in five themes, and each theme has strands of
subthemes that expound on the theme noted beneath the theme, as shown in Table 2 below.
Table 2
Patterns with Excerpts and Resulting Themes
Research Question Patterns with Excerpts Merging Patterns into Themes
Perceptions of
CPAs on
Accounting Ethics
This part of the
question addresses
the CPAs' views
and understanding
of the ethical
framework that
guides their
professional
conduct. It focuses
on their awareness
of ethical
standards
1. Public Trust and Ethical
Assurance
Excerpt 1: Participant 3: “You're
acting ethically to where you
almost like you're acting where
someone is looking over your
shoulders.”
Excerpt 2: Participant 5:
“Accounting ethics fundamentally
signifies refraining from actions
that compromise the profession's
integrity and erode the trust placed
in us by the public.”
2. Public Misconception of
Accountants' Role
Theme 1:
Conceptualizing accounting
ethics
Explanation:
This theme addresses
participants’ interpretation of
accounting ethics and what it
signifies. It captures participant
responses that provide
definitions and explanations of
the concept of accounting
ethics from their perspective.
This theme identifies and
analyses participant definitions
and
principles and
their interpretation
of ethical behavior
within the
accounting
profession.
Excerpt 3: Participant 5: “There is a
misconception that accountants are
expected to identify and prevent
fraud before it occurs proactively.”
Excerpt 4: Participant 9: "The
public often has a limited view of
what accountants do. They don't see
our ethical dilemmas or our
responsibility to maintain trust."
3. Accounting Ethics as
Guidance Excerpt 5: Participant
1: “You can compare accounting
ethics to a GPS in a typical vehicle
that directs the driver.”
Excerpt 6: Participant 10: “Ethics
in accounting is the adherence to
specific rules and guidelines set by
accounting professional governing
bodies …”
4. Accountability for Moral
Judgment
descriptions of accounting
ethics.
Excerpt 7: Participant 2: "It's about
being accountable for your actions
and decisions. You need to make
judgments by the rules and ethical
guidelines set out by the profession."
Excerpt 8: Participant 6: "It's not
just about knowing what's right or
wrong; it's about being responsible
for your choices and actions as an
accountant."
5. Emphasis on Moral
Uprightness Excerpt 9: Participant
5: "Moral uprightness is at the core
of accounting ethics. It's about doing
what's right, not just what's legally
required."
Excerpt 10: Participant 7: "Moral
uprightness is a fundamental
principle in our profession. It
means always striving to do the
right thing, even when
challenging."
6. Adherence to Accounting
Procedures and Policies
Excerpt 11: Participant 2:
"Adherence to accounting
procedures and policies is
nonnegotiable. It ensures
consistency and reliability in
financial reporting."
Excerpt 12: Participant 9: "We are
required to follow accounting
procedures and policies to the
letter. Deviating from them is a
breach of ethics."
7. Ethical Gray Areas in Rule
Interpretation
Excerpt 13: Participant 5: "There
are situations where you find
yourself in these ethical gray areas.
It's not always black and white."
Excerpt 14: Participant 7: "Ethical
gray areas are tricky. You must
carefully navigate them, often
seeking advice and considering the
consequences."
8. Balancing Culture and
Standards in Accounting
Excerpt 15: Participant 9: "In some
cases, you have to balance the
cultural practices of a company
with the ethical standards in
accounting.
It can be challenging."
Excerpt 16: Participant 12:
"Culture plays a role in how we
approach accounting ethics.
Balancing local practices with
global standards is important."
9. Alignment of Personal and
Professional Ethics
Excerpt 17: Participant 3: "My
personal ethics beliefs align
closely with professional ethics for
accountants. I believe in doing the
right thing in my personal and
professional life."
Theme 2:
Personal Ethics versus
Professional Ethics
Explanation:
This theme represents instances
in the data where the
participant is asked to describe
their understanding of
accounting
Excerpt 18: Participant 7:
"Aligning personal and professional
ethics is essential. My values of
honesty and integrity match the
ethical standards in accounting."
10. Adherence to Standards
Excerpt 19: Participant 2:
"Adhering to standards is
nonnegotiable in accounting. It's
what separates professionals from
those who compromise on ethics."
Excerpt 20: Participant 8:
"Standards provide a clear path.
As accountants, we must follow
them rigorously to ensure
transparency and ethical conduct."
11. Uncompromising Ethical
Principles
Excerpt 21: Participant 5: "I
believe in uncompromising ethical
principles. There should be no room
for bending the rules or making
ethics and its meaning. It
encompasses their perspectives,
beliefs, and interpretations
regarding accounting ethics. This
theme identifies and analyzes
participant responses that
provide insights into their unique
understanding of ethics within
the accounting context.
exceptions regarding ethics in
accounting."
Excerpt 22: Participant 9: "Ethical
principles are like a moral
compass. They guide every
decision I make, and I don't
compromise on them."
12. Impact of Accounting Scandals
on Public Perception
Excerpt 23: Participant 1: "We had
issues with accounting challenges
where some companies even ended
up closing, including national
accounting firms. And we've also
had problems even in the banking
sector, where some banks have
folded up—or closed offices
because of accounting issues.”
Excerpt 24: Participant 4:
"Accounting scandals have eroded
public trust in the profession. People
are more skeptical of financial
reports and accountants now."
Theme 3:
Professional Reputation
Explanation:
This theme is used when the
participant explains the reasons
or factors that influence the
accounting profession's
reputation regarding ethics as
perceived from their
perspective. It captures
responses that provide insights
into the drivers or contributors
to the profession's ethical
reputation, including historical
events, industry practices, or
regulatory efforts.
13. High Regard for Ethics in
the Accounting Profession
Excerpt 25: Participant 1: "The
accounting profession holds ethics in
high regard and expects every
accountant to uphold accounting
ethics in the highest regard
possible."
Excerpt 26: Participant 2: "Integrity
is paramount in accounting. We are
trusted with financial information,
and any breach of that trust can
have severe consequences."
14. Public Confidence in the
Accounting Profession
Excerpt 27: Participant 4:
"Maintaining public confidence is
crucial for accounting. We need
people to trust our work,
especially regarding financial
reporting." Excerpt 28:
Participant 7: "Public confidence
is directly tied to our

reputation as accountants. It can
seriously affect the profession
if people don't trust us."
15. Maintaining Ethical Standards
Excerpt 29: Participant 5:
"Maintaining ethical standards is
non-negotiable in our profession.
I've seen colleagues who cut
corners, maybe to meet deadlines or
for personal gain, and it usually
backfires. I've always upheld the
highest ethical standards because I
believe it's not just about following
the rules but about doing what's
right."
Excerpt 30: Participant 8: "Ethical
standards are the bedrock of our
profession. Without them, we
wouldn't have the trust of our
clients or the public. I've been in
situations where there was pressure
to compromise on ethical standards,
but I've always chosen to stick to
them. It's about integrity and
reputation, and those are things
you can't afford to lose."
Experiences of
CPAs regarding
Accounting Ethics
This part of the
research question
captures the
reallife situations
and ethical
dilemmas CPAs
encounter in their
professional
careers. It
includes instances
where they had to
make decisions
that involved
ethical
16. Professional Responsibility
and Ethical Compliance
Excerpt 31: Participant 3:
"Professional responsibility and
ethical compliance go hand in hand
in our field. As accountants, we have
a duty not just to our clients but to
the public as well. I've always felt a
strong sense of responsibility in
upholding ethical standards. It's not
just about ticking boxes; it's about
ensuring that financial information
is accurate and trustworthy."
Excerpt 32: Participant 10: "Our
professional responsibility includes
ethical compliance. We are the
guardians of financial integrity,
Theme 4:
Accounting Ethical Dilemmas
in Professional Experience
Explanation:
This theme represents instances
in the data where the participant
describes specific ethical
dilemmas they have encountered
during their career in
accounting. It encompasses
responses that detail the nature
of ethical dilemmas, the
circumstances surrounding them,
and the challenges faced in
resolving them.
considerations, the
factors influencing
those decisions,
and the outcomes
of their choices.
This part of the
question also
covers the
circumstances
surrounding
acquiring
accounting ethics
training.
which comes with a great
responsibility. I remember a
situation where I had to make a
tough call regarding a client's
financial practices. It wasn't easy,
but I knew my professional
responsibility was to report it.
Ethics should always come first."
17. Ethical Dilemma in Financial
Reporting
Excerpt 33: Participant 5: "Ethical
dilemmas in financial reporting are
common. I recall a situation where
there was pressure to present our
financials in a way that would
please our investors, even though it
involved some creative accounting.
It was a tough call, but I firmly
believe that transparency and
accuracy should never be
compromised."
Excerpt 34: Participant 11: "An
ethical dilemma arises from a clash
between competing values, often
demanding a decision when faced
with equally attractive or
unattractive options. When
confronted with the decision to
manipulate financial numbers, I
encountered an ethical accounting
dilemma, particularly in recognizing
interest income on investments. The
situation's complexity stemmed
from the uncertainty surrounding the
actual realization of this income."
18. Balancing Transparency and
Consequences
Excerpt 35: Participant 3:
"Balancing transparency and
consequences is a delicate task.
I've been in situations where
revealing certain financial
information could
harm our stock price or investor
confidence. It's a tough decision
because you want to be honest,
but you must also consider the
impact on the organization and its
stakeholders."
Excerpt 36: Participant 10:
"Transparency is crucial in
accounting, but it's not always easy.
Sometimes, disclosing certain
financial issues could have legal
ramifications or damage our client
relationships. It's a constant
struggle to find the right balance
between being open and protecting
the organization's interests."
19. Licensing Requirement for
Ethics Training
Excerpt 37: Participant 2: “I am
taking accounting ethics training. I
take it annually. Before I started my
own company, every company I had
Theme 5:
Context of training
Explanation:
This theme is used when the
participant is inquired about
the context or circumstances
worked with always had some
annual ethics training. That you
needed to take, and then because I
am a CPA, I need to keep my CPE
licenses up. I needed CPE credits
to keep my CPA license.”
Excerpt 38: Participant 3: “I receive
ethics training through my job
annually. However, my original
ethics training was after completing
the CPA exam.”
20. Integral Role of Accounting
Ethics Training
Excerpt 39: Participant 7: “I am a
professional accountant with
training from my organization, a
prominent global accounting firm.
My expertise is grounded in a
comprehensive foundation,
encompassing academic
education, hands-on practical
experience, and continuous
development and
surrounding acquiring
accounting ethics training. It
focuses on understanding the
specific situations or
environments in which
individuals have received their
training in accounting ethics.
This theme identifies and
analyzes participant questions
about the context and
conditions under which ethics
training occurred.
training throughout my career. I
have undergone ethics training at
multiple levels, starting from my
college education, including my first
degree, master's degree, and Ph.D.”
Excerpt 40: Participant 8: “From
my time in college to my career and
daily work, as well as through
ongoing professional development
(including annual ethics training),
accounting ethics training has been a
consistent and integral part of my
journey.”
Presentation of Data and Results of the Analysis
This study addresses one research question in the data analysis: What are the perceptions
and experiences of CPAs regarding accounting ethics? This question encompasses two key
objectives. These are the perceptions of CPAs on accounting ethics and the experiences of CPAs
regarding accounting ethics. Analyzing the data revealed five main themes that addressed the
research question. The themes represent reoccurring observations gleaned from participant
interviews and presented through participant quotations. Direct quotes help the reader understand
the outward perceived experiences regarding accounting ethics phenomena in response to the
research question. The themes are grouped into two objectives to address the research question
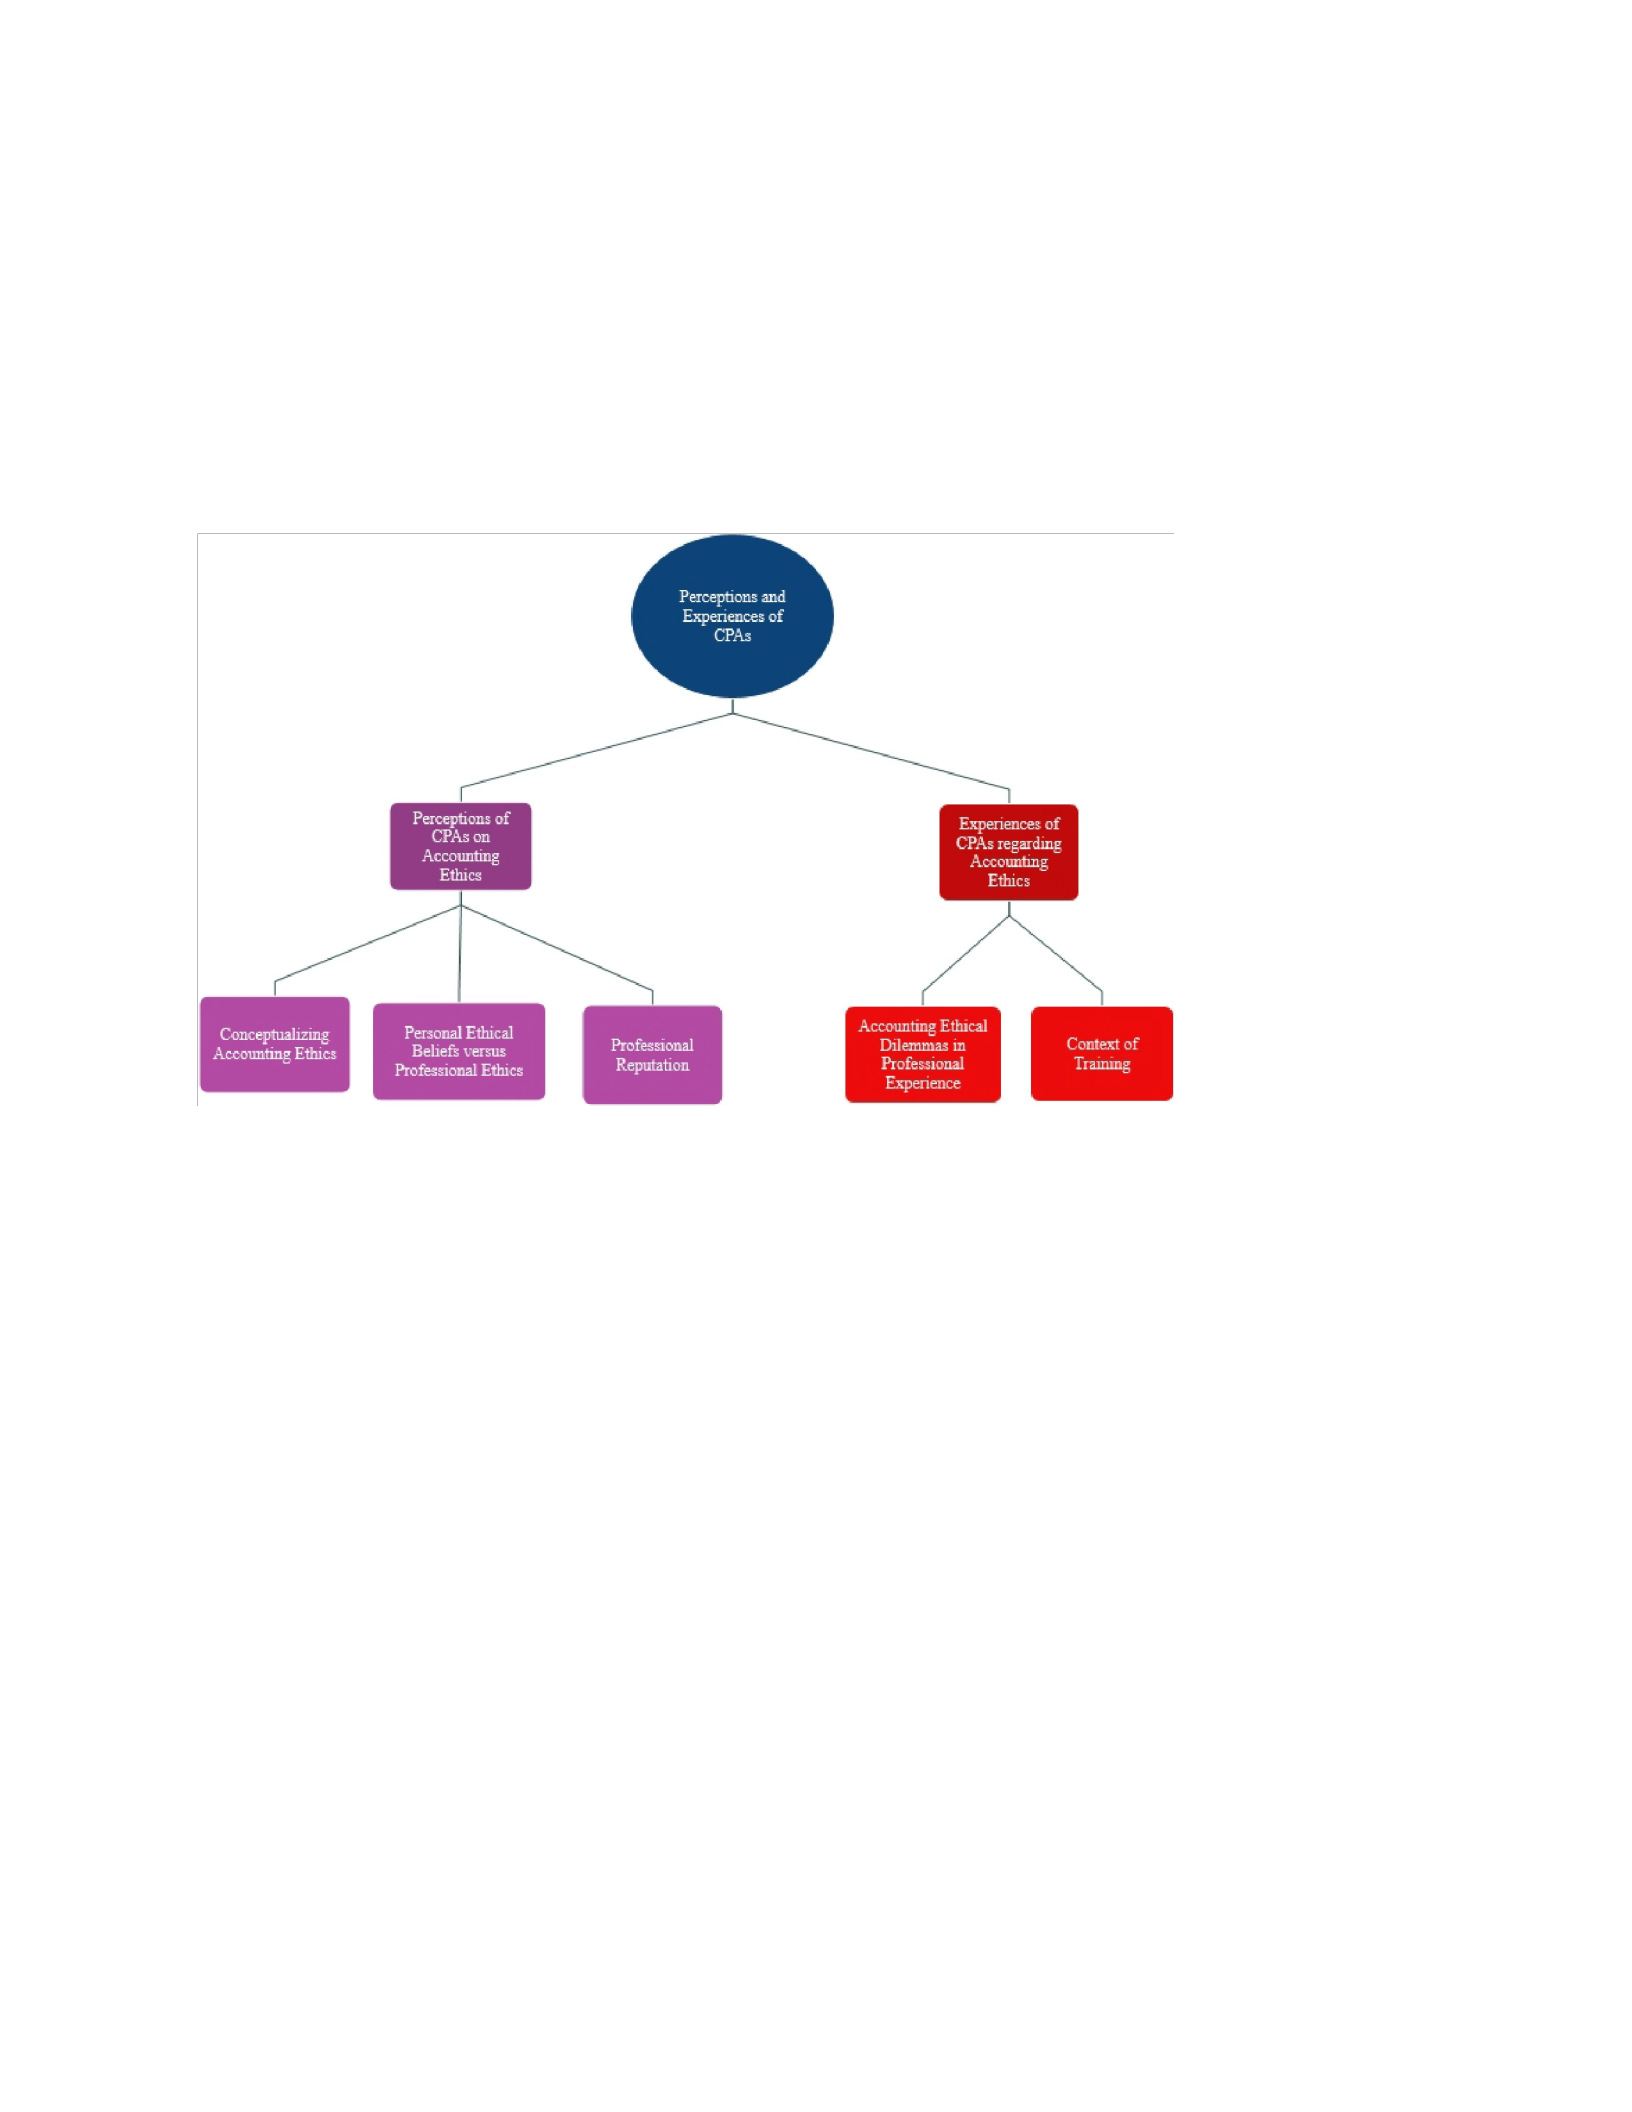
through the lens of agency theory and Vroom’s E-V theory. The first set is the perceptions of
CPAs regarding accounting ethics, and the second set is the experiences of CPAs regarding
accounting ethics. These sets are depicted in Figure 3 below.
Figure 3
Perceptions and Experiences of CPAs
From the themes generated through the data, the perceptions of CPAs on accounting ethics often
encompass their understanding and awareness of ethical principles (Conceptualizing accounting
ethics), personal ethical beliefs versus professional ethics, and the professional reputation that
governs their practice. CPAs recognize the importance of integrity, objectivity, and adherence to
ethical codes as fundamental components of their profession (Mardawi et al., 2021; Morrison et
al., 2018). On the other hand, their experiences in accounting ethics reflect the practical
application of these principles in their daily work. These experiences may involve ethical
challenges, such as dilemmas related to financial reporting, client pressures, or conflicts of
interest. CPAs' experiences provide insights into how they navigate and respond to ethical

dilemmas, whether by upholding ethical standards steadfastly or, in some cases, facing ethical
conflicts and making difficult decisions. By examining both perceptions and experiences, a
comprehensive understanding of how CPAs approach and grapple with accounting ethics
emerges, shedding light on the complexities of ethical decision-making in the accounting
profession. The dominant themes derived from the data mining are:
•Conceptualizing Accounting Ethics
•Personal Ethical Beliefs versus Professional Ethics
•Professional Reputation
•Context of Training
•Accounting Ethical Dilemmas in Professional Experience
Theme 1: Conceptualizing Accounting Ethics
This theme was derived when the participants were asked to share their understanding of
accounting ethics and what it signifies. It captured participant responses that provided definitions
and explanations of the concept of accounting ethics from their perspective. Participant 10
described accounting ethics as “the collective standards and guidelines that accounting
professionals must follow to prevent fraudulent practices and maintain public confidence in their
profession." Participant 12 noted that “ethics examines the rational justification for our moral
judgment. Accounting ethics concerns standards and guidelines that accounting professionals
must follow." Participant 11, in agreement with Participant 12, described accounting ethics as
“the clear understanding of what is morally right and having the conviction to act accordingly
because it aligns with principles of righteousness and integrity.” Participants unanimously
believed that accounting ethics were deeply intertwined with honesty, accuracy, morality, and
transparency. The data showed that most CPAs regarded ethics as the foundation of their

professional practice. These responses indicate the paramount importance of ethics in shaping
accountancy as a trusted profession. As shown in the literature, the code of conduct for
accounting is a formalized document that outlines the ethical and unethical practices of
accountants, along with the consequences for breaches of ethics (Dunn & Sainty, 2020; Feng et
al., 2018).
Eight subthemes emerged from the data regarding participants conceptualizing
accounting ethics. These are Public Trust and Ethical Assurance, Public Misconception of
Accountants' Role, Accounting Ethics as Guidance, Accountability for Moral Judgment,
Emphasis on Moral Uprightness, Adherence to Accounting Procedures and Policies, Ethical Gray
Areas in Rule Interpretation, and Balancing Culture and Standards in Accounting. Figure 4
depicts the recurring codes under conceptualizing accounting ethics.
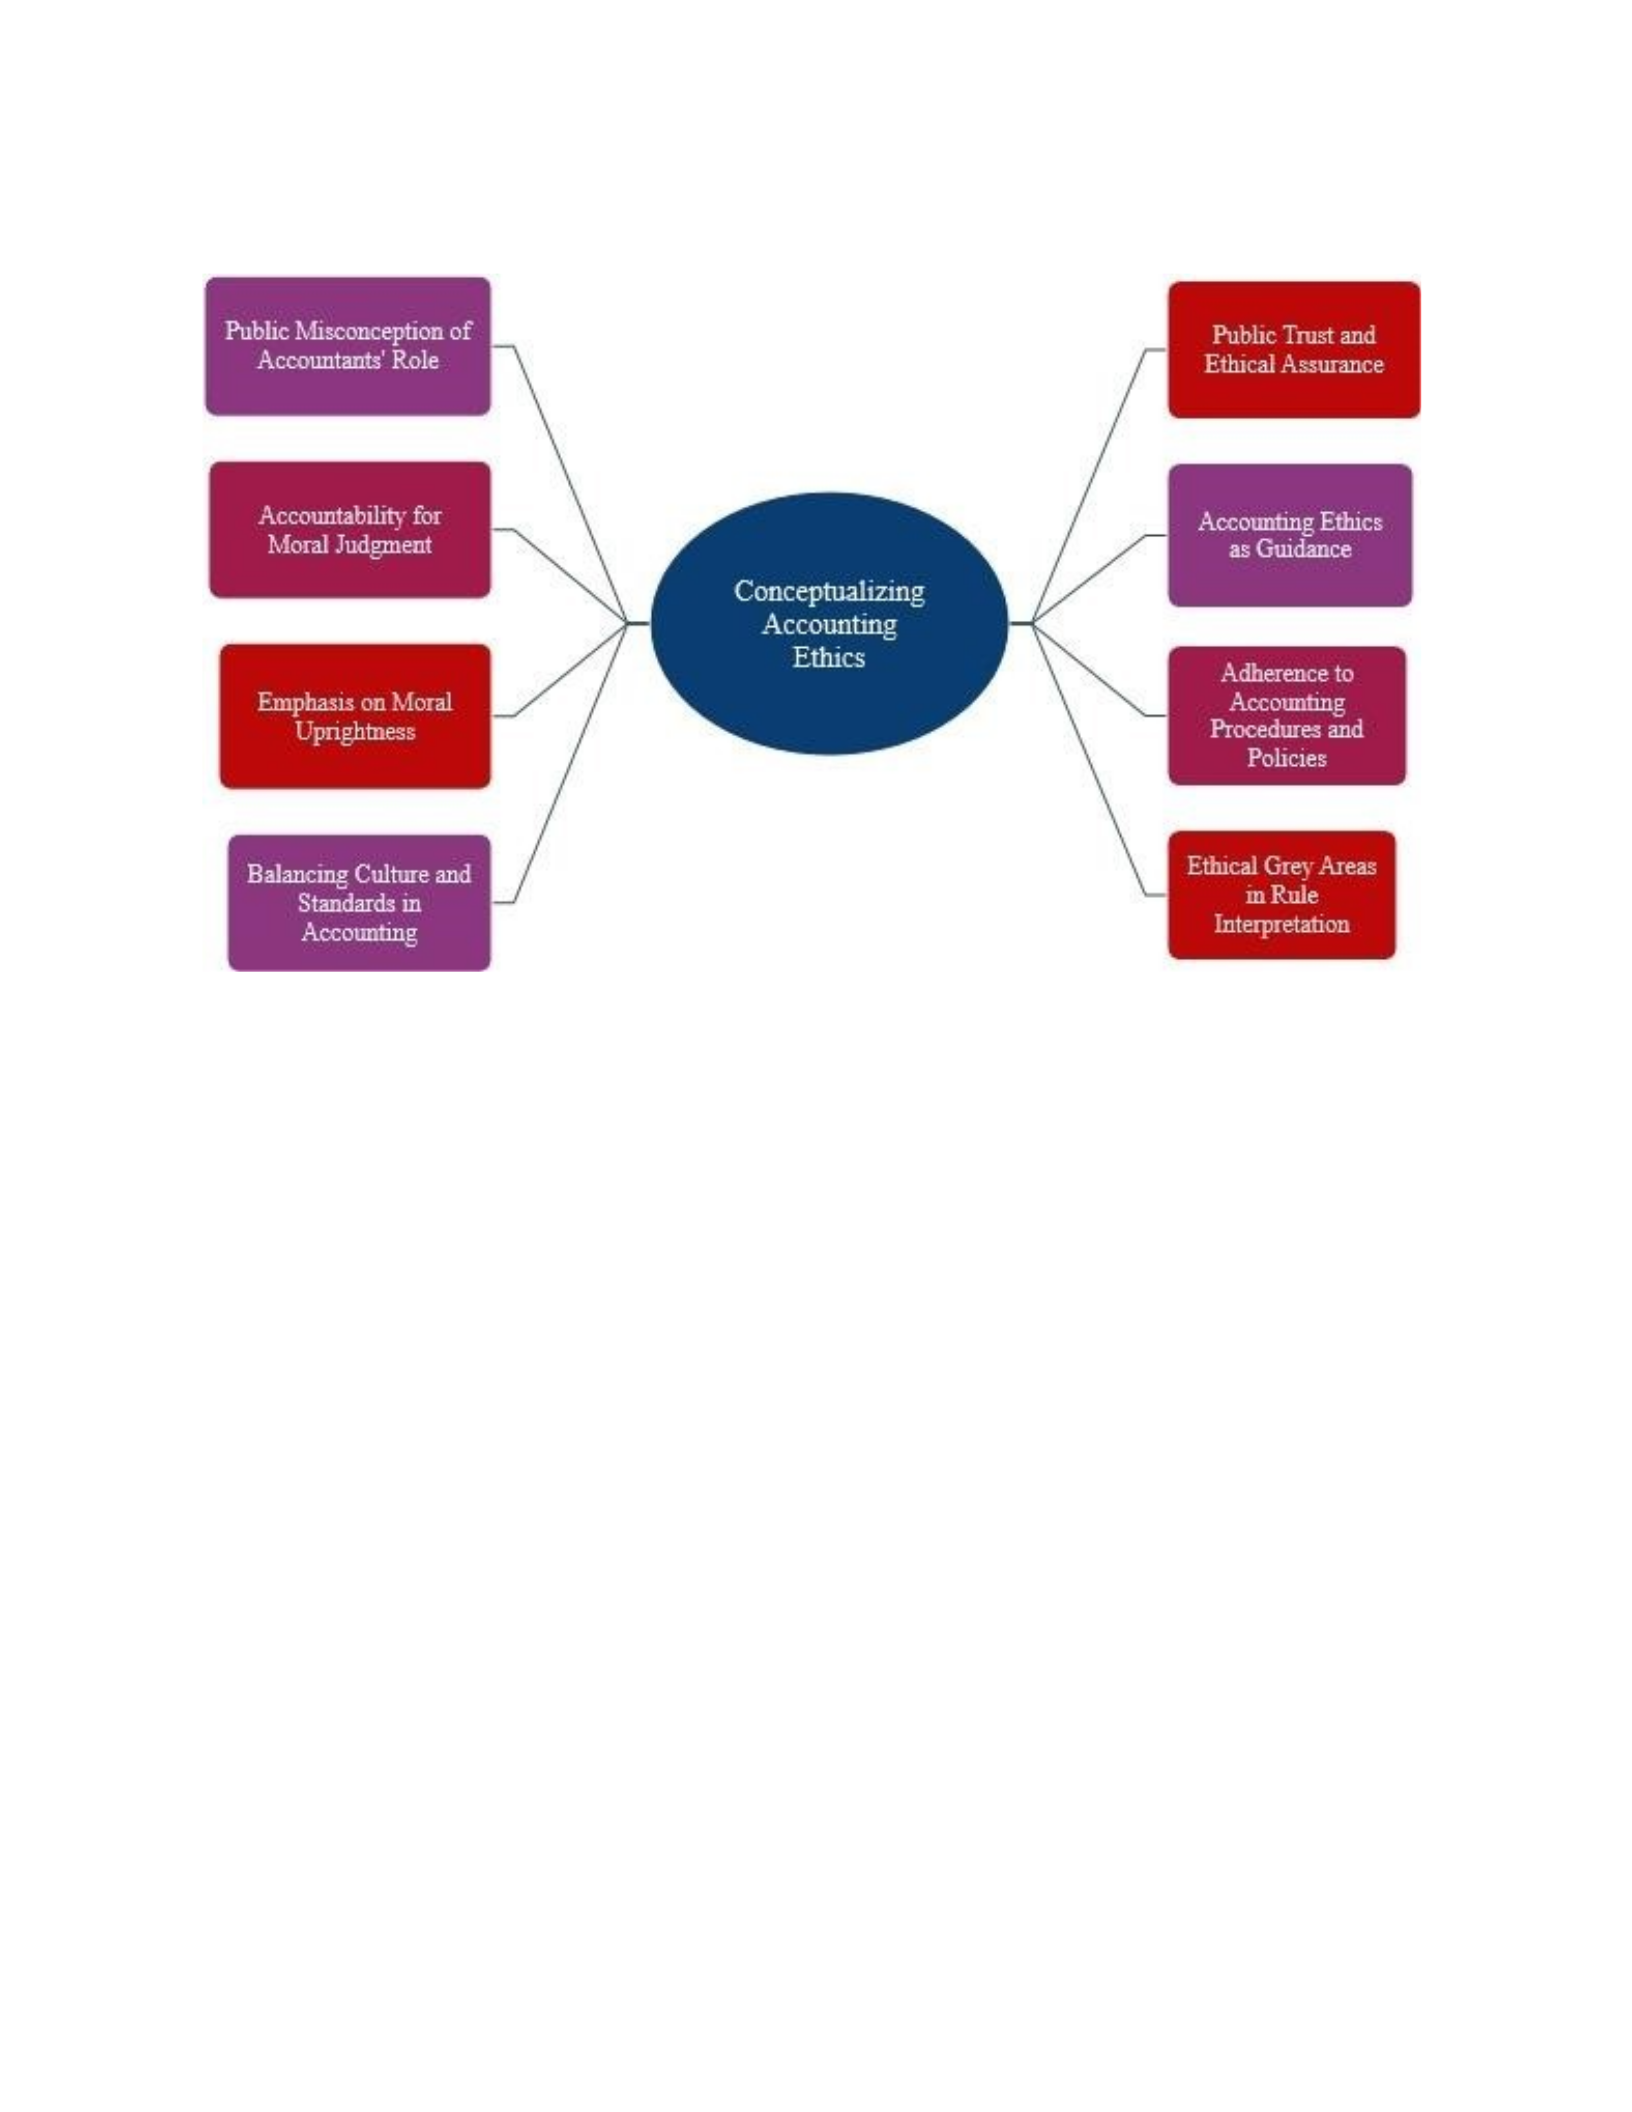
Figure 4
Subthemes under Conceptualizing Accounting Ethics
Public Trust and Ethical Assurance
Public Trust and Ethical Assurance emphasizes the perspective of participants who believe that
ethical practices in accounting are essential to uphold public confidence. It stresses the
responsibility of accountants and auditors to assure the public of their ethical and honest
performance. The subtheme suggests that ethical actions should be carried out as if one is
constantly being observed to ensure their behavior aligns with ethical standards. Participant 3
stated, “You're acting ethically to the point where you almost like you're acting where someone
is looking over your shoulders to make sure you're doing what you should be doing.” Participant
5, in concurrence, indicated:
Accounting ethics fundamentally signifies refraining from actions that compromise the
profession's integrity and erode the trust placed in us by the public. This necessitates

adhering to a specific code of conduct and ethical principles to ensure we consistently
uphold the public's trust and always deliver high-quality work with unwavering integrity.
The participant emphasized that maintaining the public's trust in accountants is pivotal.
Financial statements and other accounting outputs are foundational to economic decisions made
by individuals, investors, corporations, and policymakers. Any erosion of trust in this domain can
have widespread implications for financial stability and confidence (Ishaque, 2021; Melé et al.,
2017). Participant 5 response also underscores two essential attributes for accountants:
consistency and integrity. Consistency ensures that stakeholders can rely on the quality and
accuracy of the work overtime. Integrity ensures that the job is done with honesty, transparency,
and a commitment to the truth, even when faced with pressure or potential personal gain
(Huterski et al., 2020; Jelinek, 2018). By referencing the necessity of adhering to a specific code
of conduct, Participant 5 highlights that accounting ethics is not merely about personal judgment
but is guided by a standardized set of principles and guidelines. This subtheme is a roadmap for
accountants to ensure that their actions and decisions align with the profession's values (Marzuki
et al., 2017; Namazi & Rajabdorri, 2020). Participant 5 aptly captures the essence of accounting
ethics by emphasizing its foundational principles and the imperative of safeguarding public trust.
The emphasis on consistently delivering high-quality work grounded in integrity reinforces the
high standards expected of accounting professionals.
Public Misconception of Accountants’ Role
Public Misconception of Accountants’ Role emphasizes the need to enlighten the public
about the genuine responsibilities of accountants in presenting financial statements and not
necessarily to detect and prevent fraud. In this regard, participant 5 noted,

In the context of presenting financial statements, there is a misconception that accountants are
expected to proactively identify and prevent fraud before it occurs, which is inaccurate. It is
essential to educate the public that while accountants may encounter instances of fraud during
their procedures, their primary role is not always to detect fraud preemptively but to conduct
thorough assessments during their prescribed procedures. Participant 5 explanation touches upon
a common misconception regarding the role and responsibilities of accountants in the context of
fraud detection. Participant 9, in agreement with Participant 5, noted, "The public often has a
limited view of what accountants do. They don't see our ethical dilemmas or our responsibility to
maintain trust." The public must have a correct understanding of the roles and responsibilities of
accountants. A well-informed public can set realistic expectations and foster a more transparent
relationship with professionals in the accounting field (Kamińska-Stańczak & Silska-Gembka,
2021; West, 2018). The participants' responses illustrate how they perceive a public
misconception about the role of accountants, with many people having a narrow understanding
of their responsibilities and ethical decision-making.
Accountability for Moral Judgement
Accountability for moral judgment highlights the participant’s perspective that professional
accountants should be accountable for their moral judgment in upholding ethical standards
when presenting financial information to the public. Participant 6, to describe accounting
ethics, noted:
Ethics in accounting entails adhering to a moral compass that steers professional
accountants toward delivering information that the public can depend on to make
wellinformed decisions. Professional accountants must uphold their ethical
responsibility to present information to the public with impartiality. They should be
accountable for their moral judgment in this regard.

Participant 9 notably indicated that:
Ethics is the clear understanding of what is morally right and having the conviction to act
accordingly because it aligns with principles of righteousness and integrity. In the context
of the Accountancy profession, ethics involves applying these principles to abide by the
rules and standards that govern our practice.
Similarly, participant 7 noted:
It involves clearly understanding what actions are permissible and impermissible,
enhancing the quality of one's professional duties. When we delve into the domain of
accounting ethics, we acknowledge that accountants, like other professionals, are guided
by specific moral standards that they must adhere to in their work. These standards
encompass good faith, confidentiality, honesty, and unwavering integrity.
Participant 2, in agreement with the other participants, noted, "It's about being accountable for
your actions and decisions. You need to make judgments by the rules and ethical guidelines set
out by the profession." These responses highlight that accounting professionals are accountable
for their moral judgments and decisions, which should align with ethical guidelines and
principles.
Emphasis on Moral Uprightness
Emphasis on Moral Uprightness represents the overarching subtheme stressing the
significance of moral uprightness within the framework of ethical conduct. Participant 6
notes, "The main thing has to do with moral uprightness.” Participant 5: "Moral uprightness is
at the core of accounting ethics. It's about doing what's right, not just what's legally required."
Participant 7 noted, "Moral uprightness is a fundamental principle in our profession. It means
always striving to do the right thing, even when challenging." These responses emphasize the
significance of moral uprightness and doing what is morally right as a critical aspect of
accounting ethics.

Accounting Ethics as Guidance
Accounting Ethics as Guidance and Accountability for Moral Judgment and Emphasis on Moral
Uprightness had three participants echoing their importance. All three subthemes are interrelated
as the participants highlight moments in the data when participants express their perception of
accounting ethics as a definitive set of rules and guidelines that steer accountants in their
professional duties. Accounting ethics as guidance identifies moments in the data when
participants articulate their perception of accounting ethics as a distinct set of rules and
guidelines directing accountants in their professional responsibilities. Participant 1 noted that:
You can compare that to a GPS in a typical vehicle that provides direction to the driver. It
guides the driver from the point of destination to where the driver is going and shows the
driver where the exit is, where to turn, and so on. Similarly, for accountants, in executing
daily responsibilities, these accounting ethics guide the accountant in knowing which
direction to go in certain situations.
Participant 1 response makes an inference to the use of GPS. Just as a GPS provides precise
directions to a driver, accounting ethics offer clear guidelines for accountants. These guidelines
ensure that accountants act with integrity, transparency, and in the best interests of their
stakeholders (Dunn & Sainty, 2020; Montiel et al., 2020). Participant 9 noted that, Accounting
ethics is the various standards requirement of behavior within the profession that every
professional accountant in active practice must adhere to. To put it in simple terms, they are
codes of ethics, more like practice guidelines that will guide the behavior of every chartered
accountant globally. It is expected that your conduct adheres to a certain number of behavior
standards that have been said by every accountant wherever you are, so it guides your behavior.
Participant 10, in a more elaborate way, stipulated,
Accounting ethics is the collective standards and guidelines that accounting professionals
must follow to prevent fraudulent practices and maintain public confidence in their
profession. Ethics in accounting is the adherence to specific rules and procedures set by

accounting professional governing bodies that members should abide by to prevent
misuse of financial information in their management position. Examples of accounting
ethics are honesty, loyalty, integrity, and objectivity. In my daily routines, ethics help
shape how I conduct myself at the workplace in the discharge of my official duties. It
helps regulate my actions to ensure the name of the accounting profession is not brought
into disrepute.
Participant 10’s response paints a picture of accounting ethics as both a guiding framework and a
practical tool essential for ensuring credibility, trustworthiness, and professionalism in
accounting. Participants' responses emphasize that accounting ethics guide accountants in their
professional roles, helping them navigate ethical challenges and make the right decisions.
Accounting ethics encompass honesty, loyalty, integrity, and objectivity (Fatemi et al., 2020;
Johnson & Ahn, 2021). These values are fundamental to ensuring that accountants make
unbiased decisions, remain transparent in their work, and act in the best interest of their
stakeholders (Dunn & Sainty, 2020; Morrison et al., 2018).
Adherence to Accounting Procedures and Policies
Adherence to accounting procedures and policies identifies moments in the data when
participants articulate their perception of accounting ethics as a distinct set of rules and
guidelines directing accountants in their professional responsibilities. Participant 8 noted,
"Processing, recording, and reporting accounting entries according to the appropriate
GLs/posting logic, not overriding management controls, following established policies and
procedures, and not doing something that does not feel right." Participant 8 implies the
importance of adhering to established standards and protocols in accounting. Participant 9, in
concurrence, noted, "We are required to follow accounting procedures and policies to the letter.
Deviating from them is a breach of ethics." Participant 2 also noted, "Adherence to accounting
procedures and policies is non-negotiable. It ensures consistency and reliability in financial

reporting." These responses from the participants highlight the importance of adhering to
established accounting procedures and policies as a fundamental aspect of accounting ethics.
The comments also suggest the importance of adhering to internal controls within an
organization.
Management controls ensure that activities are carried out correctly and accurately (Fatemi et al.,
2020; West, 2018). Overriding these controls can result in mistakes, fraud, or other undesirable
outcomes (Carr et al., 2021; Gunz & Thorne, 2019).
Ethical Gray Areas in Rule Interpretation
Ethical grey areas in rule interpretation underscore the presence of ambiguous ethical zones
in accounting, especially during the interpretation of rules and standards. Participant 3
noted:
There are certain aspects where the rules and the regulations may not necessarily be
clearly articulated or very concise where they are black and white. Moreover, there is a
grey area where you can try to get your client in the best position based on your
unique understanding of the rules.
This response indicates that there might be instances where the lines between ethical and
unethical conduct require clearer demarcation, leading to interpretative challenges. Accountants
might grapple with these ambiguities while balancing their perceptions of the regulations.
Participant 5 noted, “There are situations where you find yourself in these ethical gray areas. It's
not always black and white." Participant 7 captures the situation as tricky. Participant 7 noted,
"Ethical gray areas are tricky. You must carefully navigate them, often seeking advice and
considering the consequences." These responses highlight the acknowledgment of ethical gray
areas in accounting and the need for careful consideration and decision-making in such
situations.

Balancing Culture and Standards in Accounting
The last subtheme under the theme of conceptual accounting ethics is balancing culture and
standards in accounting. This subtheme points to the intriguing interplay between local cultural
norms and global accounting standards, emphasizing the merit of studying how professionals
maneuver this balance in varied geographical settings. Delving into this dimension could
provide a deeper understanding and enrich the discourse surrounding the accounting profession.
Participant 9 noted:
Another area worth exploring is how the standards in different nations, or more precisely,
how the cultural context, influence the application of international standards. This is
because, in some countries, certain business practices may be considered acceptable,
whereas in other nations, they might not be embraced due to cultural differences.
Occasionally, a nation's culture can influence how these standards are adhered to. It might
be valuable if the interview also delves into the dynamics of balancing culture and
standards, depending on the specific geographical context. This additional perspective
could provide valuable insights.
The participant's statement offers a layered perspective on accounting ethics, particularly in the
global application of international standards and the potential influence of cultural norms. The
participant posits that a nation's culture can influence the degree of adherence to international
standards. This perspective suggests that even when international standards are in place, local
culture might affect how strictly these standards are followed, which directly ties into the
experiences of accounting ethics (Curtis et al., 2017; Gierusz et al., 2022). The participant
suggests that there is a dynamic balance between cultural norms and international standards. This
balance might vary depending on the geographical context, and understanding this balance can
provide valuable insights into the nuanced experiences of accounting professionals. The
participant also emphasizes that adding this cultural perspective would enrich the understanding

of accounting ethics. Participant 12 noted, “Culture plays a role in how we approach accounting
ethics. Balancing local practices with global standards is important."
These responses illustrate the challenge of balancing cultural practices within accounting
organizations while adhering to ethical standards. Hence, researchers can gain a more holistic
view of accounting ethics in different contexts by exploring how professionals balance cultural
norms and international standards, as noted by the participants. The participants’ responses offer
a significant contribution to the research question. To understand perceptions and experiences of
accounting ethics fully, one must consider the universal standards and the cultural contexts in
which these standards are applied. This perspective underscores the complexity of accounting
ethics in a globalized world.
Theme 2: Personal Ethical Beliefs versus Professional Ethics
This theme captures moments in the data where the participants elucidate their perception
of accounting ethics and its significance. It embodies their viewpoints, convictions, and
interpretations of accounting ethics. This theme identifies and analyzes participant responses that
provide insights into their unique understanding of ethics within the accounting context. Most
participants expressed their personal values' convergence with professional accounting standards.
However, a few struggled when personal ethics conflicted with organizational goals. Mining the
data revealed four subthemes that expound on the central theme. These subthemes are depicted in
Figure 5 below:
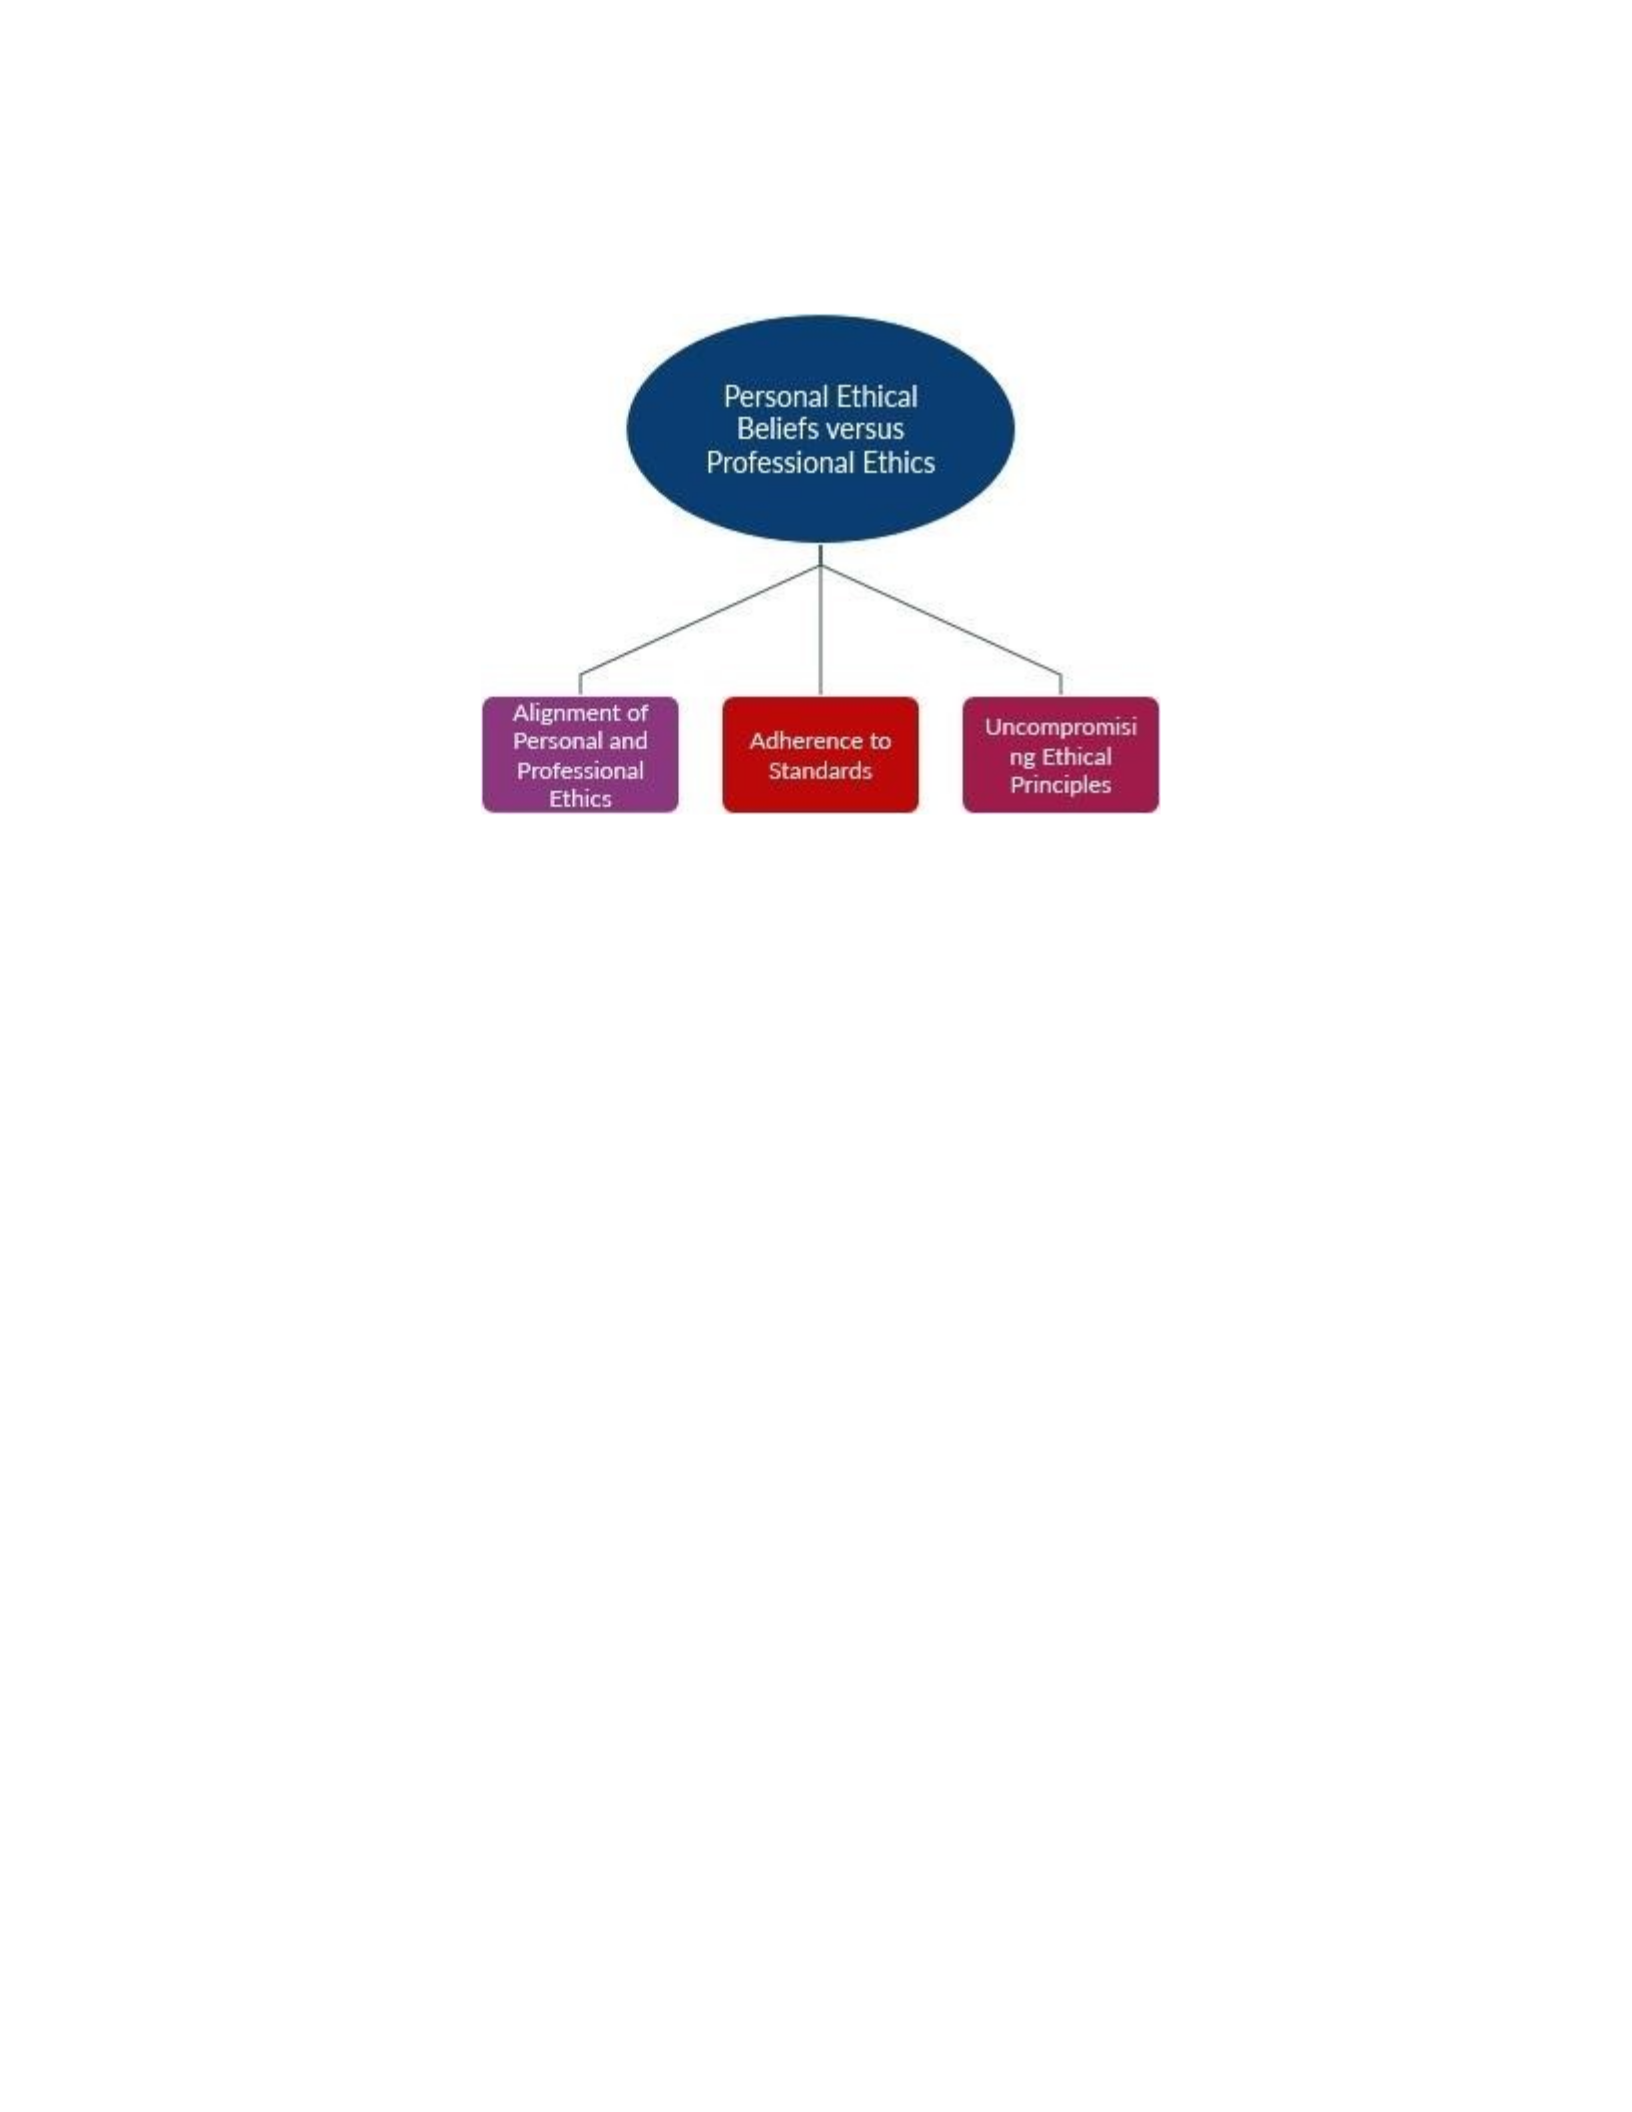
Figure 5
Subthemes under Personal Ethical Belief versus Professional Ethics
Alignment of Personal and Professional Ethics
The alignment of the Personal and Professional Ethics subtheme underscores the participant’s
statement's focus on the congruence between an individual's ethical values and the ethical
norms of the accounting profession, indicating a harmonious alignment. Participant 1 stated:
My ethical beliefs can be summarized in the responsibility to do the right thing. I have
the belief that I will do the right thing. My faith as a Christian is to do the right thing.
How is that similar to or different from accounting ethics? While my personal ethical
beliefs are informal, they are essentially ingrained in my personality as a person so that
when I get into certain situations, I can make judgments and discretions concerning
what to do, which will be the right thing to do in terms of professional ethics for
accompaniments, these are formalized rules or guidelines that are written and outline
specifically in various literature, including accounting textbooks, which specifies what
the rules are.
The participant's statement touches upon several themes and contrasts regarding personal and
professional ethics in accounting. The participant emphasizes a personal commitment to "do the
right thing." This sense of responsibility is a cornerstone of their ethical stance. The statement

further roots this personal ethical belief in their Christian faith, suggesting that religious values
significantly shape their moral compass.
Prior research indicates that the intensity of CPAs' religious convictions, the depth of their
religious comprehension and internalization, and the extent of their religious identity impact the
ethical decision-making processes (Al-Ebel et al., 2020; Collins & Eddy, 2022; Holy et al., 2022;
Samad et al., 2022). In contrast to personal ethics, the participant identifies accounting ethics as
"formalized rules or guidelines." Professional literature and textbooks explicitly outline, codify,
and reference these (Jaijairam, 2017; Kaptein, 2017; Namazi & Rajabdorri, 2020). They serve as
a structured framework to guide accountants' professional conduct, revealing how they
conceptualize accounting ethics. Participant 3 noted, "My personal ethical beliefs align closely
with professional ethics for accountants. I believe in doing the right thing in my personal and
professional life." While the participants do not explicitly state how their ethics align with
professional accounting ethics, the emphasis on "doing the right thing" in both realms suggests a
potential overlap.
However, the distinction between the intuitive, ingrained nature of personal ethics and the
formal, written nature of professional ethics indicates areas of divergence. This distinction is
better explained in Participant 2 response, stating that:
They are the same; they must be strong and build up over time, and you must be honest.
You need to be an ethical person. You need to have integrity; you need to be trustworthy.
It would be best if you were transparent. So those are the things. And if you do not have
those things, you cannot be a CPA because you cannot meet the professional
requirements.
While Participant 1 and 3 agree that personal and professional ethics overlap, Participant 2
agrees they are the same. Nonetheless, Participant 4 agrees with the other Participants to
distinguish between personal and professional ethics while stressing the importance of personal

integrity and its influence on professional conduct, emphasizing the need for trustworthiness and
reliability in the information provided to stakeholders.
Participant 4 stated that:
Ethics is distinct from the mandatory standards that accountants and auditors must adhere
to yearly. We undergo ethics training to ensure that we are well-informed and in
compliance with the laws and regulations governing our professions. The critical point is
that regardless of the nature of the work one is engaged in. There are always users or
stakeholders who rely on the information being provided. The validity and
trustworthiness of information hinge on its source, and individuals want assurance that
those providing the information possess a solid ethical compass. As an individual, your
ethics guide your actions in your personal and professional life. A solid ethical
foundation is essential in accounting, where credibility and integrity are paramount. Your
commitment to upholding ethical standards reflects your integrity and contributes to
people's confidence in the information you provide. It's clear that ethics plays a central
role in your professional practice, and this commitment is integral to maintaining the
trust and reliability of the information you generate and share.
Participant 4 believes there is a distinction between one's personal ethical beliefs and the
mandatory ethical standards for professions like accounting and auditing. While the latter
ensures compliance with laws and regulations through training and updates, the former is innate
and deeply personal. Regardless, participant 4 acknowledges the existence of individual ethical
beliefs that guide one's actions in both personal and professional arenas. While perhaps not
mandated, these personal ethics greatly influence professional conduct, especially accounting.
Conversely, Participant 6 completely aligns with Participants 2 and 3 in asserting that personal
ethical beliefs and professional ethics are indistinguishable. Participant 6 noted,
I strive to be morally upright and do the right things. My personal ethical beliefs stem from my
background and upbringing. My personal beliefs are in line with professional accounting ethics.
Moral virtues guide professional accountants. My personal ethical beliefs are in line with our
professional ethics. My personal ethical beliefs and professional accounting ethics are the same.

Unlike Participant 4, who distinguishes between personal ethical beliefs and mandatory ethical
standards, Participant 6 perceives no difference between the two realms. This comment suggests
that, for Participant 6, the ethical principles guiding their personal life seamlessly transition into
their professional role. Given this perspective, it is likely that Participant 6 believes that the core
of their professional identity and decision-making processes is deeply rooted in their convictions.
This blurring of boundaries implies an inherent integrity that remains consistent across various
situations and roles. Participant 7 states:
My ethical principles revolve around truthfulness, honesty, and principled conduct in all
my endeavors. Time management is another crucial aspect of my ethics, where I
prioritize punctuality. If I commit to a meeting at 10:00 a.m., whether it's for business,
church, or a personal friendship, I consider it imperative to honor that commitment. One's
word is a sacred promise, and maintaining truthfulness is essential in personal and
professional contexts. Consequently, I don't perceive professional ethical responsibilities
as distinct or imposed; they align naturally with my values and principles.
Participant 7's statement offers insight into their perception of Participant 6's beliefs regarding
integrating personal ethics and professional identity. Participant 7 surmises that Participant 6's
professional identity is not separate from their ethical beliefs. Instead, it is deeply embedded in
those convictions. This comment suggests that Participant 6 does not switch between different
sets of ethical standards in personal and professional settings; they have a unified approach.
Participant 10 identifies with the rest to say, “Among the personal ethics are faithfulness,
commitment to duty, integrity, honesty, etc. My personal ethical beliefs are aligned with that of
the accounting profession.” Participant 11 could not agree more by saying:
My ethics encompass my principles and values regarding my interactions with
individuals and the everyday situations that arise in life. Integrity and objectivity are two
fundamental principles that guide my decision-making in these interactions. In
professional ethics, accountants adhere to integrity, objectivity, competence, due care,
confidentiality, and professional behavior. The professional, ethical standards of integrity

and objectivity closely mirror my belief in the importance of integrity and objectivity in
all aspects of life.
In summary, while personal ethics are intensely individualistic and can be influenced by
upbringing and personal experiences, professional ethics provide a standardized set of guidelines
for the accounting profession. Despite these differences, some participants have significant
overlap and alignment, highlighting the importance of a holistic and integrated ethical approach
in both personal and professional domains. Alignment of personal and professional ethics
dominated the other codes.
Adherence to Standards
The other subthemes of strands from personal ethical beliefs versus professional ethics are
adherence to standards and uncompromising ethical principles. Adherence to the standards code
embodies the participant's commitment to upholding set standards and avoiding shortcuts. It
underscores their devotion to adhering to given protocols and directives in their position at their
current organization. Participant 3 noted:
My personal ethical beliefs stemmed from childhood. Everything is rooted in your
upbringing. I've always been a person who is very adamant about fairness, transparency,
and making sure that something is fully represented. So, how would that convey my
ethical beliefs? If you're supposed to do something a certain way, you must ensure you do
it the same way. Cutting corners is not something that I'm a proponent of.
This subtheme accentuates the significance of executing tasks correctly and refraining from
actions that might jeopardize ethical principles. Meanwhile, Participant 2 noted, "Adhering to
standards is non-negotiable in accounting. It's what separates professionals from those who
compromise on ethics." Participant 8 indicated, "Standards provide a clear path. As accountants,
we must follow them rigorously to ensure transparency and ethical conduct." These responses
emphasize the significance of adhering to accounting standards and ethical guidelines in the

accounting profession. Participants stress the importance of following these standards to
maintain professionalism and integrity.
Uncompromising Ethical Principles
The last subtheme of strands from personal ethical beliefs versus professional ethics theme
is uncompromising ethical principles. This subtheme reflects the importance of never
compromising on moral principles. It underscores the commitment to upholding high ethical
standards in the profession. Participant 12 noted:
I share the belief that ethics should never be compromised or treated lightly. However, I
also recognize that an over-dependence on clients for fees can create situations where ethical
considerations may be compromised, as has been observed in the past with some of the major
Audit firms, often referred to as the "big 4." This underscores the importance of balancing
professional integrity and financial considerations within the industry. The beginning of the
statement conveys Participant 12's firm belief in the unwavering importance of ethics. This
response reflects their commitment to upholding ethical standards and suggests that ethics is a
cornerstone of their professional conduct. The mention of the "big 4" clearly references past
instances where major audit firms faced criticism or controversy due to ethical lapses (Gunz &
Thorne, 2019; Ishaque, 2021; West, 2018). This illustrative example emphasizes the gravity and
tangible implications of such compromises in accounting. Participant 5 noted, "I believe in
uncompromising ethical principles. Regardless of the situation, I won't compromise my
integrity." Similarly, Participant 9 stated, "Ethical principles are like a moral compass for me.
They guide every decision I make, and I don't compromise on them." Overall, the participants
stressed the importance of ethics, acknowledged real-world challenges, and underscored the need
for a balanced approach to ensure ethical and financial sustainability (Dunn & Sainty, 2020;
Huterski et al., 2020). These responses highlight the participants' commitment to upholding

unwavering ethical principles in their professional conduct. Regardless of the circumstances,
they are firmly determined not to compromise their integrity.
Theme 3: Professional Reputation
The reputation of the accounting profession as perceived by the public and its importance
was another dominant theme. Participants acknowledged that the profession's reputation has been
built on trust and ethical conduct, and any breach could have significant implications. This theme
encapsulates the participant's explanation of the reasons or factors that influence the accounting
profession's reputation regarding ethics, as perceived from their perspective. It captures responses
that provide insights into the drivers or contributors to the profession's ethical reputation,
including historical events, industry practices, or regulatory efforts. Analyzing data revealed four
domineering strands of subthemes that expound on the central theme. These are shown in Figure
6 below.
Figure 6
Subthemes under Professional Reputation
Figure 8 above shows the strands of subthemes that expound on the Professional reputation
theme. These subthemes are the Impact of Accounting Scandals on Public Perception,
Public Confidence in the Accounting Profession, High Regard for Ethics in the Accounting
Profession, and Maintaining Ethical Standards.
Impact of Accounting Scandals on Public Perception
Impact of Accounting Scandals on Public Perception code highlights the undeniable influence
of accounting scandals, including the Erron and Anderson incident, on the public's perception of
the accounting and audit professions. It acknowledges that these events eroded trust and
confidence in these fields, leading to financial losses and a loss of faith in accountants' work
(Armstrong, 2020; Fiolleau & Kaplan, 2017; Kamalgharibi et al., 2023; Morrison et al., 2018).
Participant 4 noted:
The incident involving Erron and Anderson and other accounting scandals undeniably
impacted the public's perception of the accounting and audit professions. To a certain
extent, these events did erode trust in these fields. They resulted in financial losses for
many, particularly on the Stock Exchange, and contributed to a loss of confidence in the
work of accountants.

The statement suggests that such major scandals significantly impact the broader industry.
These events tarnish the reputations of the specific companies involved and negatively
impact the general public's perception of the entire accounting and audit profession.
Participant 6, in concurrence, noted that:
As is the case in any community, there may be instances where certain CPAs engage in
unethical behavior, potentially causing harm to the accounting profession's reputation.
One individual's misconduct can indeed have a detrimental effect on the entire
profession. That is why professional organizations like AICPA strive to address and
rectify such issues, including taking punitive measures against those whose actions
negatively impact the profession's standing.
Participant 6 and Participant 4 acknowledge the power of individual actions on collective
perception. It emphasizes that while it may be a single individual's misconduct, the ripple effect
can tarnish the image of the entire accounting profession. Participant 6 statement also highlights
that professional organizations need to set standards and actively work to enforce them. By
mentioning "address and rectify such issues" and "taking punitive measures," these bodies have
mechanisms to deal with violations, reaffirming their commitment to upholding the profession's
integrity. Participant 10 acknowledges the established ethical requirements in the accounting
field. This comment implies that accounting professionals must adhere to specific behaviors and
standards. However, some unscrupulous CPAs deviate from the expected behavior. The
consequences of these deviations are presented as more than just individual failures. Participant
10 highlights these deviations' negative ripple effect on the entire profession's reputation,
indicating a collective impact. Participant 9 noted:
The accounting profession's reputation is closely tied to its commitment to
professionalism and integrity. As professionals, we are responsible for upholding high
standards of integrity. When corporate stakeholders witness these virtues consistently
demonstrated within the profession, it aligns with the standards we aim to adhere to and
elevates our field's image. Conversely, failing to adhere to these professional standards
can have dire consequences. Violating international standards can erode credibility over
time, potentially limiting opportunities for collaboration and casting doubt on one's

professional standing. In essence, the image and reputation of the accounting profession
are heavily influenced by our adherence to ethical standards. This is at the core of our
profession's expertise and importance.
Participant 9, like the other participants, linked the accounting profession's reputation directly to
its unwavering commitment to professionalism and integrity. This comment creates a foundation
on which the accounting profession is built and underscores that professionalism is not optional
but a core value. Participant 9 echoed the sentiments of other participants, emphasizing that
disregarding professional standards extends beyond individual repercussions to broader
implications for the entire profession. Such deviations could lead to a decline in trust and
reduced opportunities for collaboration (Edi & Enzelin, 2022; Fiolleau & Kaplan, 2017). As
Participant 9 discussed, Participant 6 also noted,
Professional accountants are generally recognized for their commitment to upholding
stringent ethical standards, resulting in a solid overall reputation. However, as is the case
in any community, there may be instances where certain CPAs engage in unethical
behavior, potentially causing harm to the reputation of the accounting profession. One
individual's misconduct can indeed have a detrimental effect on the entire profession.
That is why professional organizations like AICPA strive to address and rectify such
issues, including taking punitive measures against those whose actions negatively impact
the profession's standing.
Participant 6 reinforces the ripple effect that one individual's unethical actions can have.
Participant 1 noted, "We had issues with accounting challenges where some companies even ended
up closing, including national accounting firms. And we've also had problems even in the banking
sector, where some banks have folded up—or closed offices because of accounting issues.” Thus, a
single accountant's misconduct can compromise the entire profession's perceived integrity,
emphasizing the professionals' collective responsibility. Notwithstanding the perceived integrity
of the accounting profession; Participant 9 highlights the proactive role played by professional
organizations like AICPA. These bodies recognize the potential risks of individual indiscretions

and actively take steps to address and correct them (Payne et al., 2020; Tonglad & Khamwass,
2023). The mention of "punitive measures" reinforces the idea that ethical violations are treated
with seriousness and that there are consequences for those who deviate from the accepted norms
(Morrison et al., 2018; West, 2017). These participants’ responses indicate that accounting
scandals have significantly impacted public perception, leading to decreased trust in the
accounting profession. Participants acknowledge the negative consequences of such scandals on
public trust and confidence in financial reporting.
High Regard for Ethics in the Accounting Profession
The high regard for ethics in the accounting profession subtheme represent instances in the
data where the participant emphasizes the accounting profession's high regard for ethics and its
commitment to ensuring the accuracy of financial statements and the prevention of accounting-
related challenges, including company closures and scandals. It reflects the expectation that
accountants uphold ethics to instill public confidence, especially for publicly traded companies.
This subtheme identifies and analyzes participant perspectives on the significance of ethics.
Participant 1 noted:
The accounting profession holds ethics in high regard and, if anything, ensures that
accurate financial statements are produced, and financial information is not misused in
written history. We had issues with accounting challenges where some companies even
ended up closing, including national accounting firms. Furthermore, we have had
problems even in the banking sector, where some banks have folded up—or closed
offices because of accounting issues. So, the accounting profession holds accounting
ethics in high regard and expects every accountant to uphold accounting ethics in the
highest regard possible.
Participant 1 acknowledged the central role ethics plays in the accounting profession. The
emphasis on "high regard" affirms that ethics is not merely a guideline but a core value within
the profession. Participant 1 provides a holistic view of the paramount importance of ethics

within the accounting profession, highlighting the potential consequences of ethical lapses and
the steadfast commitment to maintaining the highest ethical standards. The reflection on past
challenges serves as a cautionary tale, emphasizing the critical role each accountant plays in
upholding the reputation and integrity of the entire profession. Participant 12 noted:
The ethical and technical standards of the Accountancy professional are high. Ethical
violations in the Big 4 Accounting firms have led to fines and sanctions by the
appropriate authorities. Ethical violations should not be taken lightly since they affect the
recognition and respect the accounting profession demands.
In line with Participant 1’s assertion, Participant 12 addresses the significance of ethical
considerations within the accounting profession, emphasizing the juxtaposition of established
high standards with actual instances of ethical breaches. The conclusion emphasizes the broader
implications of individual or organizational ethical lapses. Participant 12 statement, in line with
the other participants on matters of unethical behaviors, indicated that ethical violations are not
just a matter of penalties for the culprits; they impact the collective reputation and the respect that
the entire accountancy profession commands. The participant signals that the stakes are high for
the involved parties and everyone within the field. Participant 12 statement underscores the
pivotal role of ethics within the accounting profession. While it acknowledges the commendable
standards set by the profession, it also highlights the real-world challenges and lapses,
underscoring the need for continuous vigilance and commitment to maintaining these standards.
The broader concern here is preserving the profession's reputation and the respect it garners,
which can be jeopardized by instances of ethical violations (Akman et al., 2020; Carr et al.,
2021). Participant 2 emphasizes the importance of high regard for accounting ethics. Participant 2
noted,
"Integrity is paramount in the accounting profession. We are trusted with financial information, and
any breach of that trust can have severe consequences." These statements highlight the perception

among participants that the accounting profession places a high level of importance on ethics and
integrity. They emphasize the significance of upholding ethical standards in the profession to maintain
public trust and credibility.
Public Confidence in the Accounting Profession
Public Confidence in the Accounting Profession is the next dominating subtheme under the
professional reputation theme. Public confidence in the accounting profession reflects the
importance of maintaining the public's trust and confidence. It indicates that the public views the
accounting profession favorably due to the rigorous ethical standards that help ensure the
accuracy and reliability of financial information presented to stakeholders. Participant 2 noted:
The reputation of the accounting profession is high. It has improved significantly since
the WorldCom era and all the issues in the early 2000s. So, since those incidents
happened, many people consult accountants with confidence, knowing that their
accountants can provide valuable services.
Participant 2 provides a snapshot of the accounting profession's journey, highlighting its
resilience and ability to bounce back and thrive after significant challenges. The use of
"since those incidences happened" suggests that in the wake of these scandals, there were
likely reforms, increased scrutiny, and changes within the accounting profession. As a result,
the
profession's reputation improved considerably after these events. Participant 3 noted:
You are responsible for asserting an opinion, meaning you have looked at and tested the
financial statements of a specific company and affirmed their completeness and accuracy.
You say you are telling the public that you have looked through a company's financial
statements and that they are complete, accurate, and representative of what happened in
that company for the year. So, the public held my definition of ethics in the accounting
profession to very high standards. The report that a CPA has signed gives the public
confidence that the CPA has done their due diligence on whatever presentation is made of
those financial statements. They assert that the information is complete and accurate

based on their understanding. Currently, the accounting profession has a good reputation.
I would say.
This statement provides insight into the accounting profession's role, responsibility, and
perceptions from Participant 3’s perspective. The phrase "telling the public” Underscores the
accountability and transparency accountants owe to external stakeholders. The accountant is not
merely performing a task for the company but is communicating financial health and integrity to
the broader public. Participant 3 statement can be linked to the conceptualizing accounting ethics
theme in that, by connecting the duty of asserting an opinion to the idea of ethics, Participant 3
suggests that performing this role with diligence, honesty, and integrity is central to the ethical
mandate of the profession. Participant 3 offers a holistic view of the accounting profession's
moral obligations, the public's trust, and the responsibility accountants bear in upholding and
reinforcing that trust. Similarly, Participant 11 noted:
The accounting profession has earned a reputation for ethical conduct, and this reputation
is of utmost importance. The general public's perception of accountants and their trust in
the decisions made by accountants directly influence their acceptance of the reports
presented by these professionals.
Participant 11 emphasizes the profound interrelationship between the reputation of the
accounting profession, its ethical standards, and the public's trust. The emphasis on "public
perception" indicates the significant role the broader society plays in the success and relevance
of the accounting profession. With positive public perception, the profession can maintain its
credibility and importance. Participant 11 underscores that the accounting profession's
reputation is not just a matter of pride or branding but a crucial factor affecting their work's
tangible outcomes. Participant 4 noted, "Maintaining public confidence is crucial for the
accounting profession. We need people to trust our work, especially regarding financial
reporting." The higher the trust in accountants, the smoother their interactions with clients,

stakeholders, and the public will be (Ishaque, 2021; Melé et al., 2017). Trust in accountants
indicates high regard for ethics in the accounting profession (Carr et al., 2021; Racko, 2019).
Participant 7 concludes, "Public confidence is directly tied to our reputation as accountants. It
can seriously affect the profession if people don't trust us." These statements reflect the
participants' recognition of the importance of public confidence in the accounting profession.
They acknowledge that public trust is essential, particularly in financial reporting and
accounting practices.
Maintaining Ethical Standards
The last subtheme of strands for the professional reputation theme is maintaining ethical
standards. Keeping the ethical standards code emphasizes the need for practitioners in the
accounting field to remain vigilant and resolute in upholding ethical standards as a response to
the adverse repercussions on the reputation of the accounting profession caused by self-serving
interests in the financial sector (Kamińska-Stańczak & Silska-Gembka, 2021; West, 2018).
Participant 5 noted:
Maintaining ethical standards is non-negotiable in our profession. I've seen colleagues
who cut corners, maybe to meet deadlines or for personal gain, and it usually backfires.
I've always upheld the highest ethical standards because it's not just about following the
rules but about doing what's right.
Similarly, Participant 8 noted,
Ethical standards are the bedrock of our profession. With them, we have the trust of our
clients and the public. I've been in situations where there was pressure to compromise on
ethical standards, but I've always chosen to stick to them. It's about integrity and
reputation, and those are things you can't afford to lose.
Participants 5 and 8 statements highlight the importance of maintaining ethical standards in the
accounting profession and how participants prioritize ethics and integrity in their work.
Theme 4: Accounting Ethical Dilemmas in Professional Experience
This theme represents instances in the data where the participant describes specific ethical
dilemmas they have encountered during their career in accounting. It encompasses responses that
detail the nature of ethical dilemmas, the circumstances surrounding them, and the challenges
faced in resolving them. Several participants recounted past experiences that tested their ethical
boundaries, emphasizing the challenges faced during these situations. Three strands of subthemes
make up the theme. These are depicted in Figure 7.
Figure 7
Subthemes under Accounting Ethical Dilemmas in Professional Experience
Figure 9 above shows the strands of subthemes that expound on accounting ethical
dilemmas in professional experience. These subthemes are professional responsibility and ethical
compliance, ethical dilemmas in financial reporting, balancing transparency, and consequences.

Professional Responsibility and Ethical Compliance
Professional responsibility and ethical compliance subthemes were prominent throughout
the data analyses. This subtheme applies when participants discuss their professional duty to
maintain accounting ethics and adhere to ethical guidelines. It captures their dedication to
promoting moral consciousness, following accounting ethical standards, covering financial
audits, and granting contract stipulations. This subtheme delves into and assesses participants'
views on the significance of professional obligation and ethical adherence in accounting.
Participant 1 noted:
I must ensure that my accounting and finance teams are ethically responsible, aware of
accounting ethics, and trained and positioned to do the right thing. However, outside that,
there are also the annual financial audits, where an independent outside audit firm comes
in to audit the financial statements of the company that also expects to make sure that the
rules are followed and that there is compliance, not just for financial statements, but also
programs requirement for grant contracts. We have upheld accounting ethics in the
highest regard and followed the rules to do the right thing.
Participant 1's statement touches upon the role of external audits, bringing attention to the
accounting industry's system of checks and balances. Participant 1 views these audits as
procedural necessities and vital to ensuring adherence to accounting ethics and standards. Thus,
Participant 1 emphasizes internal practices and external validation mechanisms to ensure ethical
conduct within their responsibility. They view moral responsibility as a combination of training,
vigilance, and adherence to established standards. Participant 5 noted:
The training courses are a regular refresher on accounting ethics standards, which we
engage in annually and consistently throughout the year. These courses reinforce our
commitment to ethical conduct, guiding us to make the right choices. The impact of this
ethics training on my adherence to accounting ethics has been profound since the
beginning of my career. It has helped me maintain a vigilant approach, ensuring I know
what is correct and what should be avoided, and it has provided clear guidance on who to
consult if assistance is needed.

Participant 5 credits their training courses for playing a significant role in molding their
professional ethical compass. These sessions have ensured a constant update on accounting
ethics standards while reinforcing a commitment to ethical conduct and practical steps in
handling ethical dilemmas. Participant 10 noted:
The fundamental principle guiding adherence to a specific ethical value is an individual's
commitment to uphold their integrity and avoid any perception of questionable character.
Given the professional obligation to adhere to ethical standards, maintaining moral
rectitude is an essential and constant requirement.
The mention of "avoid any perception of questionable character" highlights the importance of
actual ethical behavior and how others perceive one's actions. This comment recognizes that
public perception can have significant implications in professional settings, so one must act in a
way that is beyond reproach, not tarnishing the professional reputation, as noted in theme three
above. Participant 10 posits that integrity is at the heart of all ethical behaviors. While CPAs
acting ethically is a non-negotiable professional obligation, it is also crucial to be aware of how
one's actions are perceived to maintain moral uprightness consistently (Kamińska-Stańczak &
Silska-Gembka, 2021; Osafo et al., 2021). Just as Participant 10 reinforced the principle of
integrity to be professionally responsible and maintain ethical compliance, Participant 11
acknowledges the role of financial incentives in ensuring ethical behavior. They stress the
importance of intrinsic motivations like personal integrity and the collective reputation of the
accounting profession. This comment highlights a nuanced understanding of the multifaceted
motivations behind ethical adherence in a professional context. The participants’ statement
emphasizes the connection between professional responsibility and ethical compliance in
accounting, highlighting their commitment to upholding ethical standards as part of their
professional duties.

Ethical Dilemma in Financial Reporting
The next dominating subtheme was the ethical dilemma in financial reporting. This
subtheme highlights the ethical dilemma faced by accountants when pressured by superiors to
manipulate financial records, particularly in cases where corporate financial results do not meet
desired targets. It underscores the tension between meeting expectations and upholding ethical
principles. Participant 7 noted:
In some cases, corporate financial reporting may need to meet the expectations of
higherups. Costs of sales and overheads can be high, and pre-tax profits may not meet
desired targets. These situations often pose challenges when presenting results to the
board of directors, especially in organizations heavily reliant on revenue from services or
product sales, particularly during economic downturns.
Participant 7's statement highlights the pressures and challenges in corporate financial
reporting. There is an implicit suggestion that financial results may sometimes need to be
adjusted or presented in a certain way to meet the expectations of senior management or
stakeholders. This statement delves into the complex and often challenging world of corporate
financial reporting. It alludes to the ethical quandaries professionals may encounter when
balancing the accurate representation of financial health against the expectations of senior
stakeholders, especially in economically challenging times. Participant 8 noted similar situations
of pressure from above to alter the financial report to meet the expectations of senior managers.
Participant 8 noted:
Earlier in my career, when deadlines were tight and demanding, I was asked to sign off on
work papers that I either did not work on or, due to time constraints, had to sign off
hesitantly. In addition, due to constant budget restraints and projections of running over
the job, I have been asked to charge fewer hours to maintain the budget.
This statement begins by setting a backdrop of a high-pressure environment characterized
by tight deadlines, which many professionals in various industries can relate to. The individual is

under pressure to meet deadlines and quality requirements. Being asked to sign off on work
papers that the individual did not work on or was hesitant about signing off introduces an ethical
concern. It implies a potential breach of professional integrity and responsibility, as the
individual may endorse work without verifying its accuracy or completeness. Participant 8
statement provides a candid reflection on the real-world ethical challenges professionals face,
especially those in the early stages of their careers. It underscores the importance of robust
ethical training, mentorship, and organizational culture that prioritizes integrity over short-term
gains or appearances. Participant 11 noted:
An ethical dilemma arises from a clash between competing values, often demanding a
decision when faced with equally attractive or unattractive options. When confronted
with the decision to manipulate financial numbers, I encountered an ethical accounting
dilemma, particularly in recognizing interest income on investments. The situation's
complexity stemmed from the uncertainty surrounding the actual realization of this
income. On the one hand, I realized it would positively impact the year-end profit, which,
in turn, was tied to my bonus. However, on the other hand, I realized it would lead to a
more accurate representation of the financial situation but would adversely affect my
year-end assessment. This ethical dilemma posed a significant challenge, as I had to
navigate between economic incentives and the fundamental moral principle of accurately
representing financial information. Ultimately, I had to decide what aligned with my
ethical values, prioritizing transparency and accuracy over immediate financial gain. This
experience underscores the importance of upholding ethical standards, even when facing
financial incentives that may tempt one to compromise those principles.
Participant 11 describes a situation that became more complicated because of direct
personal implications: the connection between recognizing the income and the impact on their
year-end bonus. This action highlights the often explicit and unique nature of ethical dilemmas
where individual gains can be at odds with professional ethics. Participant 11 response provided a
reflective and personal account of the challenging ethical decisions accounting professionals may
face. It underscores the need for personal and organizational commitment to ethics and the long-
term importance of making decisions aligned with those ethical principles, even when there are

short-term incentives to act otherwise. Participant 10: "I once encountered a situation where my
boss pressured me to withhold certain information from a report." Participant 11: "An ethical
dilemma arises from a clash between competing values. I encountered an ethical accounting
dilemma when confronted with the decision to manipulate financial numbers." Participant 12:
"As an auditor, I faced a difficult decision: whether to report a case of cash suppression by a
branch manager who also happened to be the son of a board member." Ethical dilemma
influences range from internal motivators, like personal beliefs and values, to external factors,
including organizational culture, peer expectations, and training.
Balancing Transparency and Consequences
Balancing Transparency and Consequences reflects the participant's discussion of the
delicate balance that accountants, including finance executives like CPAs, must strike between
transparency and potential repercussions when facing ethical dilemmas in financial reporting. It
encapsulates that ethical decisions involve considering the trade-offs between presenting accurate
financial information and possible adverse consequences for the organization. This subtheme
identifies and analyzes participants’ perspectives on the challenge. Participant 9 noted:
As an Auditor, I found myself faced with a difficult decision: whether to report a case of
cash suppression by a branch manager who also happened to be the son of a Board
member, knowing that it might lead to his displeasure, or to prioritize my reputation as a
professional Accountant. I am pleased to say that I chose to report the matter to the
board, ultimately resulting in the branch manager's termination. This decision was made
to uphold integrity, objectivity, and professional ethics integral to the accounting
profession and maintain the trust and integrity of our organization's financial processes.
The statement reveals Participant 9’s commitment to professional ethics, even in the face
of potential backlash or personal consequences. The participant is an Auditor, inherently
demanding objectivity and adherence to ethical standards. The dilemma presented is a classic

case of conflict of interest: choosing between personal and professional relationships and
upholding professional standards. Given the branch manager's close ties to the board, the
situation becomes even more complex.
Similarly, Participant 6 faced a similar situation. Participant 6 noted,
A small business owner seeking a loan from a bank encountered challenges when their tax
returns showed a lower income, falling short of the loan requirements. They approached me,
requesting either an adjustment to the figures or creating a financial report displaying a higher
income.
This situation presents a classic ethical dilemma for accounting professionals and demonstrates
the challenges they often face when balancing client requests with ethical standards and
professional integrity. This scenario underscores the ethical challenges accountants face,
especially when working closely with clients who may be desperate or under financial stress.
The situation emphasizes the importance of professional ethics in accounting, where maintaining
accuracy and trustworthiness is paramount. The accountant must now decide how to address the
client's request while upholding professional integrity and guiding the client toward a legal and
ethical course of action. The participants' responses illustrate their experiences and challenges in
maintaining transparency in financial reporting while considering the potential consequences and
legal implications of their actions. Balancing these aspects can be complex and ethically
challenging for accountants.
Theme 5: Context of Training
This theme is used when the participant is inquired about the context or circumstances
surrounding acquiring accounting ethics training. It focuses on understanding the specific
situations or environments in which individuals have received their training in accounting ethics.
This theme identifies and analyzes participant questions about the context and conditions under
which ethics training occurred. Participants emphasized the role of formal and informal ethical
training in shaping their professional attitudes and behavior. The sources and frequency of this
training varied, but its influence on ethical compliance was evident. Two strands of subthemes
make up the context of the training theme. These are shown in Figure 8 below.
Figure 8
Subthemes Under Context of Training
Figure 10 depicts the subthemes of strands that comprise the context of the training
theme. These subthemes are licensing requirements for ethics training and the integral role of
accounting ethics training.
Licensing Requirement for Ethics Training
The subtheme licensing requirement for ethics training underscores that training in accounting
ethics is not just an optional part of an accountant's education but a crucial prerequisite for

licensing. This subtheme emphasizes the importance of the industry regarding ethical standards
and their proper understanding by professionals. Participant 2 noted,
I am taking accounting ethics training. I take it annually. Before I started my own
company, every company I had worked with always had some annual ethics training.
That you needed to take, and then because I am a CPA, I need to keep my CPE licenses
up. I needed CPE credits to keep my CPA license. I must take courses throughout the
year. Some of those courses include ethics. I am a part of the Association of Government
Accountants, and they provide annual training that includes ethics. Oh, and the last
piece is the AICPA. I am also a part of the AICPA; they also have ethics training.
Participant 2 is actively engaged in ongoing accounting ethics training, which they undertake
annually. This action shows a commitment to staying updated and continuously educated in their
field. Emphasis is placed on the necessity of continuing professional education (CPE) credits to
maintain their CPA license. Including ethics in these courses highlights the importance of ethical
considerations in the profession. Participant 2's response paints a picture of a professional deeply
committed to ethical practices, with a multi-pronged approach to ensure they are continuously
educated. This commitment is both a personal choice and a professional requirement, as
emphasized by licensing needs and membership in professional associations. Participant 3 noted:
I receive ethics training through my job annually. However, my original ethics training
was after completing the CPA exam. Once the CPA exam was conducted, an accepted
component was that you must take ethics training. You must take ethics training to ensure
that you understand the ramifications of your unethical operation and what that would
mean to your professional career.
Participant 3 responses showed that ethics training was mandatory after the completion of the
CPA exam, indicating the high priority given to ethical behavior within the accounting
profession. It is viewed as essential knowledge, not just supplementary. The response underscores
the significance of ethics in the accounting profession. The combination of foundational training
after the CPA exam and ongoing annual training suggests a robust system designed to inculcate
and reinforce ethical values throughout a professional's career (Morrison et al., 2018; Sonnerfeldt

& Loft, 2018). The focus on real-world consequences serves as both a deterrent against
misconduct and a reminder of the weight of responsibility that comes with the profession
(Kaptein, 2017; West, 2017). Participant 11 also noted, “I obtained my accounting ethics training
as part of the licensing requirements for accounting professionals, and I continue to receive
ongoing professional training in ethics annually.” Participant 11 underwent ethics training as a
fundamental prerequisite for licensing in the accounting field. This step indicates that ethical
considerations are not merely an optional add-on but a core requirement for professionals in this
domain. Participant 11 showcases the weightage given to ethical training in accounting right
from the licensing phase. Their dedication to ongoing training highlights a commitment to uphold
the highest ethical standards throughout their professional journey (Morrison et al., 2018; Zhatkin
et al., 2017). Participant 10 noted, "I furthered my understanding of ethical standards within the
accountancy profession by studying relevant manuals as mandated by licensure requirements."
The mention of "mandated by licensure requirements" signifies that the participant took personal
initiative and followed mandatory protocols. This action showcases their adherence to the formal
guidelines of the accounting profession. Participant 10 emphasizes the dual approach of
individual initiative and adherence to legal requirements to ensure a robust understanding of
ethical standards in the accountancy profession. Their response showcases a belief in continuous
learning and the value of formal resources in guiding ethical behavior.
Integral Role of Accounting Ethics Training
The last strand of the subtheme for the training context is the integral role of accounting
ethics training. This subtheme highlights the significance of accounting ethics training as a

consistent and essential component of the individual's educational and professional journey. It
emphasizes the enduring nature of ethics training throughout different phases of their career.
Participant 7 noted,
I am a professional accountant with training from my organization, a prominent global
accounting firm. My expertise is grounded in a comprehensive foundation, encompassing
academic education, hands-on practical experience, and continuous development and
training throughout my career. I have undergone ethics training at multiple levels, starting
from my college education, including my first degree, master's degree, and Ph.D.
The participants position themselves as highly qualified, continuously evolving professionals
with both academic depth and practical experience from a globally respected institution. The
emphasis on ethics suggests an understanding of the vital role of integrity in the accounting
profession. Similarly, Participant 8 noted, “From my time in college to my career and daily
work, as well as through ongoing professional development (including annual ethics training),
accounting ethics training has been a consistent and integral part of my journey.” The
participants portray themselves as deeply committed to the ethical dimensions of accounting
throughout their careers. Their dedication to ongoing learning and regular ethics training
implies a belief in the importance of staying current and always striving for best practices in the
field. These responses illustrate the various ways the participants have received their training in
accounting ethics, from formal education to ongoing professional development programs. They
underscore the emphasis placed on ethics training in accounting, highlighting its importance in
maintaining professional standards and competencies.
These themes provide a comprehensive overview of the perceptions and experiences of CPAs
regarding accounting ethics. They touch on conceptualizing accounting ethics, professional
reputation, personal ethical beliefs versus professional ethics, accounting ethical dilemmas in

professional experience, and the context of training. Across the 12 participants, there is a
consensus that accounting ethics are imperative standards and guidelines tailored to uphold
integrity and confidence in the profession. Personal ethics often mirror professional ones,
emphasizing the importance of integrity and objectivity. The professional reputation of
accountancy is generally seen as high, but ethical dilemmas are not uncommon. Training
contexts varied, with most participants citing a combination of formal education and self-
driven learning as their primary sources.
Summary
The findings of this qualitative study shed light on the perceptions and experiences of
Certified Public Accountants (CPAs) regarding accounting ethics. Several key themes and
insights have emerged through in-depth interviews with twelve seasoned CPAs. Overall, the
participants conveyed a solid commitment to ethical values within the accounting profession,
emphasizing integrity, honesty, and objectivity. They view ethics as a cornerstone of their
practice and understand it as the adherence to specific rules and guidelines governing their work.
One recurring theme is the alignment between personal and professional ethical beliefs.
Most participants expressed that their ethical values closely mirror the professional ethics
expected of accountants. This alignment underscores the integral role of individual integrity and
moral principles in accounting. Challenges in compliance with accounting ethics were also
highlighted. Participants mentioned instances where external pressures, such as financial
incentives or organizational culture, could lead to ethical dilemmas. However, the majority
emphasized the importance of upholding ethical standards despite such challenges, prioritizing
integrity and transparency over financial gain. The study's findings underscore the accounting
profession's reputation for ethics, emphasizing that ethical violations can have far-reaching

consequences, tarnishing the profession's image and eroding public trust. Participants
acknowledged the critical role of ethical standards in maintaining the profession's credibility.
Ethical dilemmas were a common experience among the participants, notably when financial
interests clashed with ethical principles. Participants faced difficult decisions in these cases,
often prioritizing ethics and integrity over short-term economic gains.
In conclusion, the findings of this study provide valuable insights into the perceptions and
experiences of CPAs regarding accounting ethics. The participant's commitment to ethical values
and willingness to navigate challenges while upholding them demonstrate the profession's
dedication to maintaining integrity and public trust. The study highlights the importance of
ongoing ethics training and the need for organizations to foster a culture of ethical conduct
within the accounting profession.

CHAPTER 5. DISCUSSION, IMPLICATIONS, RECOMMENDATIONS
To understand the intricate landscape of accounting ethics from the perspective of
Certified Public Accountants (CPAs), this qualitative research study delved deep into CPAs'
perceptions and experiences. Utilizing a generic qualitative inquiry, a detailed exploration was
conducted into the perceptions and experiences of 12 CPAs within a specific cultural setting. The
goal was to unveil the unique individual, and contextual factors influencing this understanding
and encounter accounting ethics. Chapter 3 discussed the purposive sampling method used to
select participants who had directly engaged in the accounting ethics phenomenon and could
share their perceptions and experiences. Chapter 4 presented the findings, where a thorough
thematic analysis was used to assess the responses from participants. Notably, responses to seven
(7) interview questions revealed the depth and nuances of each participant's experience with
accounting ethics.
This chapter analyzes data from 12 semi-structured interviews to describe their
perceptions and experiences regarding accounting ethics. NVivo 14 was used to identify the
predominant themes associated with CPAs' perceptions and experiences regarding accounting
ethics. Navigating through Chapter 5, expect an exhaustive analysis of the data obtained from 12
semi-structured interviews. This chapter synthesizes the results based on the data collected during
the investigation into each participant's perceptions and experiences. This synthesis considers the
responses to the research question and the relevant insights from prior research studies. This
chapter also includes a summary of the results, a discussion of the results, conclusions based on
the results, a comparison of findings with the theoretical framework and previous literature, an

interpretation of the findings, research limitations, implications for practice, recommendations
for further research, and concluding with an overall summary.
Summary of the Results
This sub-section summarizes the following sections of previous chapters: need for the
study, significance of the study, review of accounting ethics literature, theoretical frameworks,
methodology, and recapitulation of the study’s findings.
Need for the Study
The study addresses the problem of CPAs' failure to comply with accounting ethics in
their organizations. Although significant research exists on accounting ethics, CPAs' perceptions
and experiences regarding accounting ethics remain under-explored (Kamińska-Stańczak &
Silska-Gembka, 2021; Namazi & Rajabdorri, 2020). Other researchers documenting this
knowledge gap have also attributed this phenomenon to limited studies investigating CPAs'
judgments and decision-making processes in accounting firms (Dunn & Sainty, 2020; Ishaque,
2021; Morrison et al., 2018). Therefore, this study fills a gap in the accounting literature by
investigating the CPAs' perceptions and experiences regarding accounting ethics in sampled
accounting firms operating in Maryland, USA.
Significance of the Study
Various stakeholders, including investors, creditors, and the public, benefit from sound
accounting practices (Ali & Khan, 2022; Bellucci et al., 2021). CPAs' decisions impact these
stakeholders' financial well-being and trust in the profession (Dunn & Sainty, 2020; Ishaque,

2021). Consequently, understanding CPAs' perceptions and experiences with ethical dilemmas is
pivotal to protecting stakeholders' interests and boosting public confidence in the accounting
profession. Additionally, exploring CPAs' perceptions and experiences of accounting ethics can
help identify gaps in ethics education and training. Insights into these knowledge acquisition
processes could inform the development of more effective ethical education programs for
aspiring accountants and practicing CPAs. Such developmental interventions could also enhance
CPAs' ethical competence and facilitate compliance with ethical accounting practices (use
citations from accounting ethics training).
Review of Accounting Ethics Literature
The literature review highlighted significant themes that contextualized the problem
investigated in this study. Seminal and contemporary studies unearthed the following themes:
definition of accounting ethics (Kaptein, 2017; Namazi & Rajabdorri, 2020), accounting ethics
theories (Jensen & Meckling, 1976; Nikula & Kivistö, 2018), professional accountant ethics
practice (Edi & Enzelin, 2022; Fatemi et al., 2020), models of ethical decision-making (Cardona
et al., 2020; Dunn & Sainty, 2020), and accounting ethics compliance enforcement (Namazi &
Rajabdorri, 2020; Riantika, 2021).
Methodology
A qualitative, generic methodological approach was utilized for the study. When
inquiries are made into perceived experiences and the distinct viewpoints of participants
concerning those experiences in the physical world, the generic qualitative approach is deemed
the most suitable design (Caelli et al., 2003; Cooper & Endacott, 2007; Kahlke, 2014; Kostere &
Kostere, 2021). By following this methodology, which is grounded in constructivist

epistemology, participants in the study are willing to share the personal significance they
attribute to their encounters with the phenomenon being examined (Bellamy et al., 2016; Caelli
et al., 2003; Kennedy, 2016).
Theoretical Frameworks
This qualitative inquiry study was framed within the context of agency and
expectancyvalence (E-V) theories. Agency theory serves as a lens for understanding the
employment relationship between accounting firms and CPAs, drawing insights from works by
Jensen and Meckling (1976), Nikula and Kivistö (2018), and Zogning (2017). Simultaneously,
the expectancy-valence theory sheds light on CPAs' motivation to adhere to accounting ethics,
building upon research conducted by Allini et al. (2018), Osafo et al. (2021), and Ozturk et al.
(2017). Integrating these two theories to explore the accounting ethics phenomenon provided a
broad conceptual lens that gained an in-depth understanding of the phenomenon. Participants
universally stressed the importance of ethics, honesty, and unwavering adherence to professional
standards within the accounting discipline.
A review of the literature revealed that CPAs who assign high values to behavioral
outcomes associated with honesty, integrity, trustworthiness, reliability, and accountability are
more likely to behave ethically when one or more of these values are the expected outcomes of
engaging in such behaviors (Osafo et al., 2021). Participants underscored the fundamental
alignment between personal ethical values and those of the accounting profession, emphasizing
its role in averting conflicts of interest, preserving trust, and safeguarding the profession's
esteemed reputation. West (2018) posits that CPAs are responsible for enhancing the profession’s
reputation by producing clean and accurate financial statements to support accounting
information users such as investors, creditors, and analysts. Participants recognized that the

confluence of personal and professional ethics was pivotal in mitigating ethical dilemmas. They
acknowledged that a breach in ethical conduct could have far-reaching consequences, echoing the
sentiment that the accounting profession's integrity hinges on its practitioners' virtuous actions.
These statements are not farfetched as the literature reviewed showed CPAs' failure to comply
with the accounting ethics code of conduct attracts disciplinary consequences as non-compliance
creates negative perceptions and impairs public confidence
(Huterski et al., 2020; Ishaque, 2021; Kamińska-Stańczak & Silska-Gembka, 2021).
Recapitulation of the study’s findings
This generic qualitative inquiry research study was designed to answer the research
question: What are the perceptions and experiences of CPAs regarding accounting ethics? The
research findings provided a comprehensive understanding of the perceptions and experiences
of Certified Public Accountants (CPAs) regarding accounting ethics. The research data
analysis from 12 semi-structured interviews revealed the perceptions and experiences that
centered around five themes. The five themes are (a) conceptualizing accounting ethics, (b)
personal ethical beliefs versus professional ethics, (c) professional reputation, (d) accounting
ethical dilemmas in professional experience, and (e) context of training. The study is necessary
to address the issue of CPAs failing to adhere to accounting ethics within their organizations.
This study addresses a gap in the accounting literature by investigating the perceptions and
experiences of CPAs regarding accounting ethics.

Discussion of the Results
The research question explored in this generic qualitative inquiry was: What are the
perceptions and experiences of CPAs regarding accounting ethics? Twelve CPAs provided data
through semi-structured interviews to help answer the research questions. Following a
comprehensive analysis and categorization of the data, five prominent themes surfaced,
elucidating CPAs' perceptions and experiences concerning accounting ethics: (a) conceptualizing
accounting ethics, (b) personal ethical beliefs versus professional ethics, (c) professional
reputation, (d) accounting ethical dilemmas in professional experience, and (e) context of
training. In the responses from Participants 11 and 12, participants demonstrated a profound
understanding of accounting ethics as the foundation for their professional actions and
judgments. This understanding is intertwined with personal beliefs about right and wrong. For
instance, Participant 11 mentioned that their personal beliefs revolve around principles such as
integrity and objectivity, which are also pivotal in accounting. Participant 10, however, identified
faithfulness, commitment to duty, integrity, and honesty as qualities among personal ethics. In
this regard, Participant 10 noted that personal ethical beliefs align with the accounting
profession.
All participants agree that the accounting profession's reputation is founded on ethical
conduct. As Participant 11 put it, public perception directly affects the acceptance of accountant
reports. The accounting profession has earned a reputation for ethical conduct, and this
reputation is of utmost importance. The general public's perception of accountants and their trust
in the decisions made by accountants directly influence their acceptance of the reports presented
by these professionals. This perspective aligns with numerous studies emphasizing the

profession's dependency on public trust (Ishaque, 2021; Kamińska-Stańczak & Silska-Gembka,
2021; West, 2018).
Ethical dilemmas are inevitable in accounting (Carr et al., 2021; Jelinek, 2018).
Participant 12's recount of the dilemma regarding reporting cash suppression demonstrates that
professionals often grapple with complex ethical situations. Participant 12 explained the dilemma
auditors encounter in discharging their responsibilities. Participant 12 said a case of whether to
notify cash suppression by a branch manager who was also the son of a board member. These
dilemmas underscore the importance of robust ethical training and personal commitment to
integrity (Morrison et al., 2018; Sonnerfeldt & Loft, 2018). Participant 12's role as an internal
auditor underpins the value of internal oversight in maintaining ethical standards. Confidentiality
and accurate reporting were emphasized, pointing to the broader understanding in the literature
that internal auditing is a cornerstone for ethical conduct in organizations (Gunz & Thorne,
2019).
Formal training in accounting ethics is an integral part of professional development.
Almost all participants shared that their training combined formal education and continuous
professional development. Such ongoing training reinforces the significance of ethics in
maintaining the credibility of the accounting profession (Fatemi et al., 2020; Kaptein, 2017).
Participant 6 shared experiences similar to those of other participants who received training in
accounting ethics as part of their college education and as a requirement for obtaining
professional certification.
These findings are consistent with the underlying tenets of agency theory, positing that
ethical behavior serves as a mechanism to reduce agency conflicts. The motivations elucidated by
CPAs for their compliance with moral norms, as evidenced by factors like remuneration

packages, resonate strongly with Vroom's expectancy-valence theory. Additionally, these results
converge with extant accounting literature, affirming the enduring significance of ethical
standards and the severe ramifications of ethical transgressions within the profession (Allini et
al., 2018; Huterski et al., 2020; Ishaque, 2021; Ozturk et al., 2017). Even without explicit ethical
guidelines, participants' endorsements of working in the public's interest epitomize the
harmonization of personal values and professional ethos. The insights from the twelve
participants provided a rich tapestry of perspectives and experiences regarding accounting ethics.
Their shared experiences support the findings in the literature about the challenges and
imperatives of ethical conduct in the accounting profession. These discussions underscore the
profession's ongoing journey to reconcile individual beliefs, external influences, and professional
mandates in pursuing ethical excellence.
Conclusions Based on the Results
The study's findings answered the research question, "What are the perceptions and experiences
of CPAs regarding accounting ethics?" The study illuminated the central role of ethics in
accounting, with thematic analysis highlighting areas of congruence and conflict between
personal beliefs and professional standards among CPAs. The following five themes emerged
from the study: Conceptualizing accounting ethics, personal ethical beliefs versus professional
ethics, professional reputation, accounting ethical dilemmas, and professional experiences and
context of training) and 20 subthemes (public misconceptions of the accountant role,
accountability for moral judgment, emphasis on moral uprightness, balancing culture and
standards in accounting, public trust and ethical assurance, accounting ethics as guidance,
adherence to accounting procedures and policies, ethical grey areas in rule interpretation,
alignment of personal and professional ethics, adherence to standards, uncompromising of

ethical principles, the impact of accounting scandals on public perceptions, high regard for
ethics accounting profession, public confidence in the accounting profession, maintaining
ethical standards, professional responsibilities and ethical compliance, ethical dilemma in
financial reporting, balancing transparency and consequences, licensing requirement for ethics
training and integral role of accounting ethics training). These themes and subthemes reflect
CPAs' perceptions and experiences regarding accounting ethics. They also reveal that although
CPAs understand the requirements of the accounting profession, their operating environment
frequently poses ethical challenges that undermine their professional effectiveness.
Additionally, CPAs believe that public trust and assurance enhance their professional
reputation and boost their performance levels. Nonetheless, they face ethical dilemmas such as
conflicting personal beliefs and organizational requirements. Some of these administrative
requirements sometimes contradict the CPA's personal beliefs, resulting in scandals, fraud,
reputational damage, and other unethical behaviors. Finally, whereas conflicting demands
characterize CPAs, they are obliged under the accounting code of ethics to act ethically in
performing their accounting responsibilities.
Comparison of Findings with Theoretical Frameworks
and Previous Literature
Theoretical Frameworks
In investigating the central research question, "What are the perceptions and experiences
of CPAs regarding accounting ethics?" A thorough thematic analysis based on the responses of
12 participants was conducted. The analysis was informed by two established theoretical
frameworks: agency theory and Vroom's theory of motivation. Through this approach, five

prominent themes emerged in the research, shedding light on the intricate perceptions and
experiences of CPAs in accounting ethics.
As proposed by Jensen and Meckling (1976) and further elaborated upon by Madhavan et
al. (2023), agency theory is a valuable tool to elucidate the contractual relationship between
principals and agents. It becomes apparent that a challenge arises when principals cannot
effectively monitor their agents' actions, resulting in what is often referred to as a "black box." In
this context, agents may exploit this monitoring gap to pursue personal interests, as West (2018)
and Zogning (2017) noted.
On the other hand, Vroom's Expectancy-Valence (E-V) theory, as elucidated by Oppong
and Safo Lartey (2023) and initially proposed by Vroom (1964), provides insights into the
mechanisms at play within this agent-principal relationship. It illustrates the connection between
effort, performance, and outcomes, offering a lens through which we can understand the
motivations of CPAs in ethical decision-making. The study’s findings, particularly those
stemming from the responses of Participants 11 and 12, underscore the notion that professionals
often function as agents representing shareholders and other stakeholders. As posited by agency
theory, CPAs are mandated to act in the best interests of their principals (Nikula & Kivistö, 2018;
Panda & Leepsa, 2017). However, the study’s analysis reveals that personal beliefs, such as
integrity and objectivity, significantly influence their decision-making processes, suggesting the
relevance of Vroom's Theory of Motivation. CPAs perceive that ethical actions can lead to
desired outcomes, such as personal satisfaction or professional recognition (Osafo et al., 2021;
Vroom, 1964).
Furthermore, agency theory posits that mechanisms like reputation can align the interests
of agents and principals. Notably, all participants in the study emphasized the importance of

reputation, which can serve as a tool to mitigate agency problems and reduce information
asymmetry (Wells, 2021). The research conducted by Nikula and Kivistö further highlights the
potential of agency theory to enhance the understanding of agency problems within relationships
and the strategies available to address them. Businesses use agency theory to optimize their
capital structure (Grigore & Gurău, 2019; Lai et al., 2019).
The ethical dilemmas presented by Participant 12's account can also be analyzed through
agency theory, where accountants must decide whose interests to prioritize. Concurrently,
Vroom's theory suggests that perceived consequences may influence their actions, such as the
trade-off between job security and professional recognition, as demonstrated by Allini et al.
(2018) and Sobaih and Moustafa (2022). This potential conflict between integrity and financial
considerations, as highlighted by Participant 12, resonates with the challenges posed by goal
conflict in agency theory. Vroom's theory offers insights into how accountants might be
motivated to compromise their integrity if they anticipate significant benefits, such as financial
gains. Nevertheless, despite increased attention to CPAs' motivation, ethical behavior remains a
critical concern in accounting firms due to past corporate scandals (Kozáková et al., 2021; Miller
& Shawver, 2018; West, 2018). According to agency theory, conflicts can arise between agents
(accountants) and principals (stakeholders) due to differing goals and risk preferences (Jensen &
Meckling, 1976; Osafo et al., 2021). Participant 11's comments about balancing financial
incentives and ethical conduct exemplify this conflict, while Vroom's theory illuminates how
accountants may weigh motivational factors in their ethical decision-making (Sobaih &
Moustafa, 2022; Tubbs et al., 1993).
While formal training is a cornerstone of CPAs' professional development, Vroom's
theory suggests that professionals may be motivated to pursue continuous learning if they

perceive it as enhancing their job outcomes (Nowak, 2018; Vroom, 1964). As indicated by the
participant’s, ongoing training is likely pursued with the expectation of positive valence,
instrumental value, and expectancy (Osafo et al., 2021). CPAs believe comprehensive training,
encompassing formal and informal education, strengthens their ethical foundations. This
commitment to continuous learning reflects their intrinsic motivation to improve themselves and
their profession, driven by the desired outcomes of job success and professional growth. The role
of CPAs' education and training in accounting ethics and professional development interventions
remains pivotal in instilling professional discipline in CPAs (Gunz & Thorne, 2019; Jenkins et
al., 2018). Namazi and Rajabdorri (2020) assert that training and development programs prepare
CPAs to cultivate professional resilience and moral courage to combat unethical organizational
behaviors.
In summary, the perceptions and experiences of CPAs concerning accounting ethics are
multifaceted and influenced by personal beliefs, professional obligations, external pressures, and
inherent motivations. This study has provided an in-depth exploration of these challenges and
considerations, offering a comprehensive understanding of how CPAs navigate the ethical
landscape. Incorporating agency theory and Vroom's theory of motivation has provided valuable
lenses to interpret and analyze these narratives, yielding more profound insights into the
motivations and dynamics that shape accounting ethics.
Applied Conclusions
The findings of this research have direct implications for practicing CPAs and regulatory bodies
overseeing the profession. Understanding how CPAs perceive and experience accounting ethics
can inform the development of more effective ethics training programs and compliance
measures. The applied conclusions suggest the need for a comprehensive approach to ethics

training, spanning from initial licensure requirements to continuous education. This aligns with
the notion proposed by agency theory, as it emphasizes the importance of aligning agents (CPAs)
with the principals' (stakeholders) interests, which includes upholding ethical standards in
adherence to the existing literature on accounting ethics (Nikula & Kivistö, 2018; Panda &
Leepsa, 2017). By implementing such a holistic approach, CPAs can be better equipped to
maintain the highest ethical standards throughout their careers, contributing to the overall
trustworthiness of financial reporting and auditing.
Policy Recommendations
Based on the study, it is recommended that regulatory bodies and professional
organizations in the accounting field prioritize the creation of ethical cultures within firms. This
recommendation aligns with the agency theory's emphasis on mechanisms like reputation
aligning agent-principal interests, as fostering an ethical culture can mitigate agency problems
and reduce information asymmetry (Wells, 2021). Additionally, tailored ethics education that
addresses the specific challenges CPAs face in balancing ethical principles with organizational
pressures resonates with the practical application of Vroom's theory, emphasizing the importance
of real-world scenarios and ethical decision-making (Oppong & Safo Lartey, 2023; Vroom,
1964). These programs focus on understanding ethical principles and emphasize real-world
scenarios and ethical decision-making (Fatemi et al., 2020; Gunz & Thorne, 2019). Practical case
studies derived from the experiences shared by the participants can be incorporated to make the
training more relatable and impactful.
Furthermore, the need for regulatory bodies to refine and strengthen ethical guidelines
and codes of conduct, as indicated by the study's findings, corresponds with agency theory's
focus on addressing goal conflicts and reducing ambiguity (Jensen & Meckling, 1976; Osafo et

al., 2021). By providing more comprehensive guidance, regulatory bodies can assist CPAs in
navigating ethical gray areas and making principled decisions. Participant 7 noted that moral
gray areas are tricky. Therefore, CPAs must carefully navigate them, often seeking advice and
considering the consequences. Participant 5 emphasized situations where CPAs find themselves
in these ethical gray areas, which are not always black and white. Hence, there is a need for
regulatory bodies to refine and strengthen ethical guidelines and codes of conduct.
Policymakers are encouraged to explore mechanisms to protect whistleblowers, aligning with
agency theory's acknowledgment of potential retaliation against agents who report unethical
behavior (Jensen & Meckling, 1976; Osafo et al., 2021). This protection can promote a culture of
accountability within the profession. Participant 12 mentioned an ethical dilemma involving
reporting cash suppression by a branch manager, even when it risked personal repercussions. The
response reveals that CPAs sometimes face retaliation or fear retaliation for reporting unethical
behavior. Implementing robust whistleblower protections can encourage CPAs to report
wrongdoing without fear of adverse consequences.
Ethical Leadership Development
The importance of organizations investing in developing ethical leadership skills aligns with the
theoretical frameworks discussed in this study. Agency theory emphasizes the influence of
organizational culture and leadership on moral behavior (Nikula & Kivistö, 2018; Panda &
Leepsa, 2017). Encouraging ethical leadership can foster a culture of integrity and transparency
within firms, aligning with agency theory's objective of aligning agent and principal interests.
This approach will not only strengthen the professional's reputation but also contribute to the
long-term trust and sustainability of the accounting industry.

Industry Applications
Accounting firms and organizations can leverage the study's findings to improve their
ethical climates and practices, aligning with the themes of agency theory and Vroom's theory.
Open communication channels and support for CPAs facing ethical dilemmas correspond to the
agency theory's emphasis on mechanisms like reputation and monitoring to align interests (Wells,
2021). By incorporating insights into ethical culture enhancement, ethical decisionmaking
support, continuous professional development, and the restoration of public trust, the industry
can redefine its commitment to ethical standards and integrity. This research provides a roadmap
for organizations, regulators, and educational institutions to cultivate a generation of technically
proficient CPAs committed to ethical conduct. The industry can strengthen its reputation, regain
public trust, and ensure long-term sustainability in an ever-evolving financial landscape.
Ultimately, these applications underscore the vital role of ethics in shaping the future of the
accounting profession.
Social and Economic Impact
A more ethically conscious accounting profession can restore trust in financial reporting and
auditing, which can have significant societal and economic benefits (Carr et al., 2021; Gunz &
Thorne, 2019). Thus, Ethical behavior among CPAs is closely tied to the trust and reputation of
the accounting profession. Transparent and ethical accounting practices contribute to the stability
of financial markets and public business confidence (Ishaque, 2021; Kamińska-Stańczak &
Silska-Gembka, 2021). The practical implications of this study suggest that fostering a culture of
ethics can enhance public trust in financial reporting and auditing. A more trustworthy profession
contributes to the stability of financial markets and the economy's overall health. Ethical

practices in accounting are likely to contribute to the long-term sustainability of businesses and
organizations. Encouraging CPAs to prioritize ethical decision-making can help prevent financial
scandals and crises that can devastate businesses and the broader economy.
Future Research Directions
Future research in this field should focus on developing and evaluating practical tools and
interventions to enhance accounting ethics in practice. These may include the design of ethical
decision-making frameworks, the assessment of the effectiveness of ethics training, and the
implementation of ethical leadership initiatives within accounting organizations. Analyzing the
participant's responses to CPAs' perceptions and experiences of accounting ethics has generated
theoretical and applied insights. The theoretical findings contribute to the academic
understanding of accounting ethics. At the same time, the practical implications offer guidance
for CPAs, regulatory bodies, and organizations to promote ethical behavior within the accounting
profession. This research serves as a valuable contribution to the ongoing discourse on ethics in
accounting.
Interpretation of the Findings
Participants across the interviews consistently described accounting ethics as a set of
rules and guidelines that guide the behavior of accounting professionals. This definition is
consistent with existing literature. Jaijairam (2017), Kaptein (2017), and Namazi and Rajabdorri
(2020) define accounting ethics as the rules governing the professional conduct of CPAs.
Accounting firms have a fundamental expectation for CPAs to carefully assess the ethical
implications of their choices and prioritize the organization's best interests over personal
considerations (Dunn & Sainty, 2020; Morrison et al., 2018). This qualitative study explored the
perceptions and experiences of CPAs regarding accounting ethics, drawing insights from indepth

interviews with twelve participants. The interpretation of the findings reveals several key themes
that provide a comprehensive understanding of how CPAs perceive and navigate accounting
ethics within their professional roles. These themes shed light on the complex interplay between
personal ethical beliefs, professional ethical standards, and the broader implications for the
accounting profession. To fully comprehend the insights extracted from the discussions with the
12 CPAs, the findings were interpreted through the lens of the agency and Vroom's Expectancy-
Valence (E-V) theories and the broader literature on accounting ethics. The findings are explored
theme-by-theme below.
Theme 1: Conceptualizing Accounting Ethics
Participants in this study shared their perspectives on what accounting ethics means to
them, emphasizing its role as a guiding framework for accountants' professional conduct. This
theme underscores the fundamental role of ethical standards in shaping the CPAs' professional
identity and conduct (Gunz & Thorne, 2019). The conceptualization of accounting ethics was
likened to a moral compass that provides direction in navigating complex ethical dilemmas in
participants' roles. Participant 3 contributed to this theme, comparing accounting ethics to a
compass, noting, "Accounting ethics is like a compass that should guide accountants in making
decisions." This metaphor emphasizes the role of ethics as a navigational tool for accountants.
Morrison et al. (2018) highlight that accounting ethics involves moral and ethical judgments,
emphasizing the importance of ethical decision-making. These ethical principles serve as a moral
compass, steering accountants in the right direction when faced with challenging decisions. The
understanding and practice of ethics among CPAs can be seen through the lens of agency theory,
emphasizing the fiduciary responsibility of accountants (agents) to their clients or shareholders
(principals) (Mitnick, 2021). CPAs must act in the best interests of their principals, which

includes adhering to ethical standards (Nikula & Kivistö, 2018). This theme underscores that
most participants felt a strong sense of duty towards the entities they serve, understanding that
trust is critical to their professional relationships. Dunn and Sainty (2020) and Morrison et al.
(2018) emphasize that accounting firms expect CPAs to evaluate the ethical consequences of
their decisions and prioritize the business's best interests. This comment echoes the participants'
views that accounting ethics guide accountants to act in the organization's best interest.
Interpretations of Subthemes under Conceptualizing Accounting Ethics
The study's findings shed light on the multifaceted nature of conceptualizing accounting
ethics among Certified Public Accountants (CPAs). One prominent aspect emerged was the
"public misconception of accountants' role." Participants expressed frustration over the public's
limited understanding of the complexities and ethical challenges inherent in their profession, as
accountants are often perceived solely as number-crunchers rather than moral stewards of
financial integrity. Additionally, the study revealed that CPAs feel a heightened "accountability
for moral judgment" in their role, recognizing that their decisions carry significant ethical
implications for stakeholders. This sense of responsibility has fostered an "emphasis on moral
uprightness" among CPAs, who prioritize ethical conduct in their daily practice. However, CPAs
also grapple with the intricate task of "balancing culture and standards in accounting," as
organizational cultures may sometimes clash with established ethical standards, leading to ethical
dilemmas. Despite these challenges, CPAs emphasized the importance of "public trust and ethical
assurance." They viewed themselves as trust custodians in financial markets and stressed the
need for stringent ethical adherence to maintain this trust. This underscores the pivotal role of
"accounting ethics as guidance," where ethical principles act as guiding beacons in the
decisionmaking process. Nevertheless, CPAs acknowledged the presence of "ethical grey areas in

rule interpretation," highlighting the complexity of applying ethical guidelines to real-world
scenarios and emphasizing the need for ongoing ethical education and dialogue within the
profession.
In summary, the theme of "Conceptualizing Accounting Ethics" reveals that participants
perceive accounting ethics as a set of explicit rules and guidelines that serve as a moral compass
for accountants. These ethical principles provide direction and guidance in decision-making,
emphasizing the importance of adhering to these standards in the accounting profession.
Participants' perspectives align with existing literature that underscores the significance of ethical
judgment and prioritizes the organization's interests in accounting ethics (Dunn & Sainty, 2020;
Morrison et al., 2018). According to Osafo et al. (2021), the E-V theory emphasizes that
individuals are motivated to act in a certain way when they believe that their efforts will lead to a
desirable outcome (valence) and that their actions will result in that outcome (expectancy).
Hence, in accounting ethics, CPAs who conceptualize ethics positively (valence) and believe that
following ethical principles will lead to favorable outcomes (expectancy) are more likely to make
ethically sound decisions.
Theme 2: Personal Ethical Beliefs Versus Professional Ethics
The tension between personal ethical beliefs and professional ethics is a recurring theme.
Within this theme, participants reflected on the distinction between their moral beliefs and the
formalized professional ethics governing the accounting profession. They recognized that while
personal ethics revolve around doing the right thing based on individual values and principles,
professional ethics, as outlined by accounting associations, constitute formalized rules and
guidelines. In the agency theory, this tension can be seen as a conflict between the agent's values
and the principal's interests (Nikula & Kivistö, 2018). CPAs may need to align their personal

ethical beliefs with their professional obligations to act in the best interests of their clients or
organizations. Participants noted the importance of aligning personal ethics with professional
ethics, emphasizing that, despite the formality of professional standards, a commitment to ethical
behavior remains a fundamental aspect of their personal and professional lives.
This theme highlights the delicate balance between individual moral principles and the
structured ethical framework of the accounting profession. Participant 4 stated, "My personal
ethical beliefs can be summarized in the responsibility to do the right thing." This comment
exemplifies the participants' recognition of personal ethics as a commitment to moral
responsibility. Participant 7 shared, "It's about aligning what I believe is right with what is
expected professionally." This statement reflects that participants aim to harmonize personal and
professional ethics. The theme of "Personal Ethical Beliefs Versus Professional Ethics"
underscores participants' awareness of the distinction between their ethical values and the formal
ethical standards of the accounting profession. Kaptein (2017) discusses the interplay between
personal and professional ethics, highlighting the significance of aligning individual values with
professional standards. While personal ethics reflect individual commitments to doing what is
right, professional ethics comprise structured rules. Participants aim to reconcile these aspects,
emphasizing the importance of aligning their beliefs with the profession's expectations. This
theme reflects the delicate equilibrium between individual moral principles and the established
ethical framework of the accounting field. Jaijairam (2017) emphasizes that accounting ethics
involve adhering to formalized rules within the profession, which participants recognized in their
discussions. E-V theory suggests that CPAs' motivation to comply with accounting ethics is
influenced by the perceived outcomes of their actions (Allini et al., 2018). CPAs who believe that

adhering to professional ethics aligns with their values and leads to positive outcomes (valence)
are more likely to be motivated to act ethically.
Interpretations of Subthemes under Personal Ethical Beliefs Versus Professional Ethics
The research findings illuminate the intricate interplay between personal ethical beliefs
and professional ethics among CPAs. The "alignment of personal and professional ethics"
subtheme is critical to CPAs' experiences. Participants emphasized the importance of aligning
their moral compass with the ethical standards of their profession, highlighting the need for
congruence between personal values and professional conduct. Furthermore, the study
underscores the unwavering commitment of CPAs to "adherence to standards." CPAs are
resolute in upholding industry-specific ethical standards and guidelines, emphasizing their
role as guardians of financial integrity. Their dedication to maintaining these standards is
paramount, reflecting their steadfast commitment to ethical principles. The findings also
reveal that CPAs exhibit an "uncompromising ethical principles" stance, where they are
unwavering in their commitment to ethical conduct, even when faced with challenging ethical
dilemmas. This steadfast commitment underscores the profound influence of personal ethics
on their professional identity, highlighting the intricate dynamics between personal beliefs and
the ethical standards of the accounting profession.
Theme 3: Professional Reputation
The theme of "Professional Reputation" encompasses participants' recognition of the
paramount importance of ethics in shaping the accounting profession's reputation. Participants
highlighted that maintaining a positive reputation for ethical conduct is a fundamental concern in
accounting. Participant 2 mentioned, "Our reputation is everything. It's what clients, colleagues,
and the public see; ethics play a big part." This insight highlights the direct connection between

ethics and the professional's reputation. They emphasized that the accounting profession's
reputation is closely linked to its commitment to ethical standards. The agency theory
underscores the importance of trust and reputation in agency relationships (Onjewu et al., 2023).
Thus, CPAs' professional reputation is closely linked to the trust their clients or organizations
place in them. Adhering to accounting ethics can help build and maintain a positive reputation, as
it demonstrates their commitment to acting in the best interests of their principals (Solomon et
al., 2021). Participants acknowledged that even by a few individuals, ethical violations can have
far-reaching consequences, leading to negative perceptions of the profession. Participant 9 stated,
"One bad apple can spoil the whole bunch. Ethical violations can tarnish our profession's
reputation, affecting everyone." Within the E-V theory, maintaining a positive professional
reputation can be seen as a desirable outcome (valence) for CPAs. They may be motivated to act
ethically to protect and enhance their reputation, knowing that unethical behavior could lead to
negative consequences (Kozáková et al., 2021). This statement illustrates the participants'
awareness of the collective impact of ethical conduct on the profession's image. This theme
underscores the significance of ethical behavior in upholding the accounting profession's
integrity and public trust.
The professional reputation theme underscores participants' acknowledgment of ethics'
pivotal role in shaping the accounting profession's reputation. They emphasize that maintaining a
positive reputation built on ethical conduct is crucial for fostering trust among clients,
colleagues, and the public. Participants expressed concern that even isolated ethical violations
can tarnish the entire profession's image, highlighting the collective responsibility of accountants
to uphold ethical standards and preserve the profession's integrity and public trust. Huterski et al.
(2020) emphasize the profound impact of ethical violations on the accounting profession's

reputation, aligning with participants' concerns. This theme highlights the interconnectedness of
ethics and the profession's reputation. Jelinek (2018) discusses the importance of ethics in
shaping the public's perception of accountants, aligning with participants' views on reputation.
Interpretations of Subthemes under Professional Reputation
The major theme of professional reputation emerges as a central axis in the perceptions and
experiences of Certified Public Accountants (CPAs) regarding accounting ethics. One of the
critical facets of this theme is the "impact of accounting scandals on public perception."
Participants in the study consistently emphasized the lasting repercussions of past scandals,
which have cast a shadow on the accounting profession. One participant aptly stated, "The Enron
and WorldCom scandals left an indelible mark on our profession. It's not just about numbers
anymore; it's about restoring the trust eroded by those events." This heightened awareness of the
"impact of accounting scandals on public perception" fuels CPAs' "high regard for ethics in the
accounting profession." They recognize ethics as the linchpin of their professional identity and
are committed to upholding the highest standards. This commitment is driven by a profound duty
to "maintain public confidence in the accounting profession." The findings underscore that CPAs
view preserving their "Professional reputation" as intricately linked with the meticulous
maintenance of ethical standards, aligning their personal and professional values to rebuild and
sustain trust.
Theme 4: Accounting Ethical Dilemmas in Professional Experience
The theme of "Accounting Ethical Dilemmas in Professional Experience" delves into the
ethical challenges encountered by participants in their accounting careers. According to Ishaque
(2021), ethical dilemmas represent situations where the agent, which in this study is the CPA,
faces conflicting interests between personal gain and the interests of the principal (client or

organization). Ishaque noted that agency theory recognizes that such dilemmas can arise due to
information asymmetry and the agent's discretion. Hence, CPAs must navigate these dilemmas to
maintain trust and fulfill their fiduciary duty. Participants shared instances of confronting difficult
decisions that required balancing ethical principles with professional responsibilities. These
dilemmas often involved choices between personal gain and adherence to ethical guidelines.
Participants emphasized the importance of upholding ethical standards, even in the face of
financial incentives, to maintain professional integrity and transparency in financial reporting.
Participant 6 described an ethical dilemma: "I was pressured to withhold certain financial
information from a report, but I chose to adhere to ethical principles and report accurately." This
action illustrates the participant's commitment to ethical conduct.
The theme of Accounting Ethical Dilemmas in Professional Experience underscores
participants' real-world ethical challenges in their accounting careers. These dilemmas often
involve navigating between financial incentives and ethical principles. Participants consistently
prioritize ethical conduct, even when it means risking personal consequences or professional
repercussions. Participant 12 mentioned an ethical dilemma involving reporting cash suppression
by a branch manager, even when it threatened emotional consequences. This action highlights the
prioritization of ethical principles over immediate financial gain. Huterski et al. (2020) discuss
the importance of accountants facing ethical dilemmas and the need for them to prioritize ethical
conduct. This theme highlights the ethical complexities inherent in the accounting profession. It
underscores the commitment of accountants to uphold ethical standards and maintain
transparency in financial reporting, even in challenging situations. Ishaque (2021) emphasizes
the significance of accountants' ethical decision-making, aligning with participants' accounts of
dilemmas. In the E-V theory, facing ethical dilemmas can trigger motivation based on the

perceived outcomes of their choices (Nikula & Kivistö, 2018). Thus, CPAs who believe that
making ethically sound decisions will lead to positive consequences (valence) for themselves and
their principals are more likely to resolve these dilemmas ethically.
Interpretations of Subthemes under Accounting Ethical Dilemmas in Professional Experience
Within the central theme of "accounting ethical dilemmas in professional experience," the study
delves into the intricate dynamics surrounding CPAs' perceptions and experiences regarding
accounting ethics. Central to this theme is the concept of professional responsibility and ethical
compliance. The findings highlight the importance of CPAs adhering to ethical guidelines and
standards as guardians of financial integrity. They view their professional responsibility as a
solemn commitment to unwavering ethical compliance. However, the study also unveils the
inherent complexities of their profession, characterized by ethical dilemmas in financial
reporting. CPAs often find themselves at a crossroads, torn between the imperative to report
transparently and the potential consequences that may ensue. One participant stated, "Balancing
transparency and consequences is a constant struggle. We want to do what's right ethically, but
we also must consider the ramifications. It's a delicate tightrope walk." This intricate interplay
between professional responsibility, ethical dilemmas, and the delicate balance of transparency
and consequences underscores the multifaceted nature of CPAs' experiences within accounting
ethics.
Theme 5: Context of Training
The theme of "Context of Training" examines the influence of educational and
professional training on participants' understanding and commitment to accounting ethics.

Participants described their experiences with ethics-focused training during their academic and
professional journeys. Participant 2 mentioned the role of ethics training during academic
years: "Ethics was ingrained in us during our accounting program at the university." This
statement from Participant 2 reflects how early training can shape ethical foundations. They
emphasized the importance of ongoing education in ethics, particularly in the context of
licensure and certification requirements. Participant 11 highlighted the importance of
continuous professional training in ethics to ensure adherence to ethical standards. The training
laid a foundation for their ethical beliefs and guided their ethical decision-making in their
accounting careers.
The context of the training theme underscores the pivotal role of education and training in
shaping participants' understanding and commitment to accounting ethics. Fatemi et al. (2020)
discussed how ethics is integrated into accounting education, aligning with participants'
experiences during their academic training. Participants noted the impact of early ethics-focused
education during their academic years and the ongoing requirement for professional training in
ethics. This theme highlights the interconnectedness of education, training, and ethical conduct in
accounting. Sonnerfeldt and Loft (2018) emphasized the role of training in promoting ethical
behavior among accountants, confirming the participants' views on the importance of training.
They emphasized the role of formal training in instilling ethical values and guiding ethical
decision-making throughout participants' careers. Accounting ethics continuous training after
licensure must be balanced. Accounting ethics training has also become an essential requirement
of CPAs' certification requirements, highlighting ethical competencies as foundational to
accounting firms' reputation (Fatemi et al., 2020; Gunz & Thorne, 2019). Thus, ethical training
and education are essential components of preparing CPAs to act in the best interests of their

principals. The agency theory, therefore, emphasizes the role of training in reducing information
asymmetry. Training is also essential in the E-V theory, as it can influence CPAs' beliefs about
the outcomes of ethical behavior. Effective training can enhance the expectancy that acting
ethically will lead to positive results, motivating CPAs to make ethical choices.
Interpretations of Subthemes under Context of Training
Within the significant theme of the context of training, the research delves into the critical role
that training plays in shaping the perceptions and experiences of CPAs regarding accounting
ethics. A prominent aspect in this context is the "licensing requirement for ethics training." The
study findings highlight the significance of regulatory bodies and professional organizations
mandating ethics training as a prerequisite for CPA licensure. Participants emphasized the
importance of such requirements, stating that they instill a sense of responsibility and ethical
awareness from the outset of their careers. Moreover, the research underscores the integral role
of accounting ethics training in CPAs' professional development. The participants attested that
ethical education and training programs provide them with the necessary knowledge and tools to
navigate complex ethical dilemmas in their practice. As one participant stated, "Ethics training
isn't just a box to check: it's the foundation of our profession. It equips us to uphold the highest
standards of integrity throughout our careers." This recognition of the integral role of ethics
training highlights its pivotal place in shaping CPAs' ethical perspectives and equipping them to
meet the ethical challenges inherent in their profession.
The perceptions and experiences of CPAs offer a nuanced understanding of the
accounting ethics landscape. While the theoretical foundations are solid, real-world challenges
test the mettle of these professionals. Their narratives provide both hope and areas for

improvement. The profound respect for ethics and an understanding of the profession’s
vulnerability set the stage for continuous evolution and growth in accounting ethics.
Limitations
While this qualitative research study has shed light on the perceptions and experiences of
Certified Public Accountants (CPAs) regarding accounting ethics, it is essential to acknowledge
its limitations. Recognizing these limitations is crucial for a more comprehensive understanding
of the study's scope, implications, and potential areas for further research. This section discusses
the fundamental limitations when interpreting the findings and drawing conclusions. One of the
primary limitations of this study is the relatively small sample size. While the study included
twelve participants, it may only partially represent some CPAs' diverse perspectives and
experiences.
Additionally, the sample might have selection bias, as participants were recruited
voluntarily, which could lead to a skewed representation of individuals more inclined to discuss
ethical issues. Generalizing the results beyond the scope of this study should be done cautiously,
as variations in ethical perceptions and experiences may exist among CPAs in various settings.
The study relied on self-reported data obtained through interviews. Social desirability bias might
influence Participants' responses, where they provide answers, they perceive as socially
acceptable rather than reflecting their true beliefs and experiences (Thongkaew, 2020). This bias
could affect the accuracy of the data collected. Participants were asked to recall and discuss their
past experiences and ethical dilemmas in accounting. This act introduces the potential for recall
bias, as memory may not accurately represent past events. Participants may inadvertently omit or
exaggerate specific details, affecting the reliability of their narratives. Ethical standards in the
accounting profession can evolve due to changes in regulations, industry practices, and societal

expectations. The study's findings reflect the participants' experiences during a specific period
and may not capture the most up-to-date ethical considerations. The interpretation of the findings
is subject to potential bias based on the researchers' perspectives and preconceptions. Efforts
were made to minimize bias through rigorous analysis; however, some subjectivity may remain.
These limitations notwithstanding, this qualitative research study provides valuable
insights into the perceptions and experiences of CPAs concerning accounting ethics. While the
findings offer a foundation for understanding ethical decision-making in the profession, future
research should address these limitations and explore ethical dynamics in greater depth.
Implications for Practice
The implications for practice derived from the findings of this qualitative research study
on the perceptions and experiences of Certified Public Accountants (CPAs) regarding accounting
ethics are multifaceted and relevant to various stakeholders within the accounting profession,
including CPAs, accounting firms, regulatory bodies, and educational institutions. Here are the
critical implications for practice under two sections: implications for theory and knowledge base
in accounting and the practical implications for the broader community of stakeholders.
Implications for theory and knowledge base in accounting
Theory enrichment
This study contributes to the theoretical foundation of accounting ethics by providing rich
qualitative data that illuminates the perceptions and experiences of CPAs. It enhances
understanding of how accounting professionals interpret and navigate ethical challenges.
Researchers can use these findings to refine and expand ethical theories within accounting (Attia

& Edge, 2017). The experiences of CPAs can be used to test and validate existing theoretical
concepts in accounting ethics empirically. This empirical grounding can help refine these
concepts to reflect the accounting profession's realities better.
Theoretical Integration
The study's incorporation of agency theory and Vroom's E-V theory to analyze the data
demonstrates the value of theoretical integration in qualitative research. It highlights how
multiple theoretical perspectives can be synergistically employed to better understand complex
accounting phenomena in the accounting profession. Future studies may explore similar
integrative approaches to investigate other aspects of accounting ethics, combining theories from
various disciplines to gain a more holistic understanding of ethical issues. For instance,
integrating psychological theories with economic models could provide deeper insights into how
individual motivations and market forces interact to shape ethical or unethical behaviors in
accounting.
Ethical Decision-Making Models
The research findings can inform the development of ethical decision-making models tailored to
the accounting context. These models can incorporate the identified themes and factors
influencing CPAs' ethical perceptions and actions. Such models can be practical tools for
accountants and organizations to enhance ethical decision-making. The development of an
ethical decision-making model, informed by the findings of this study, can significantly improve
the practice of accounting. It provides a structured approach to navigating ethical challenges,
ultimately contributing to the integrity and trustworthiness of the accounting profession. The
model should outline a transparent decision-making process, guiding CPAs through identifying
options, evaluating consequences, and choosing the most ethical course of action.

Professional Ethics Education
The study underscores the importance of ethics education and training for CPAs. The
accounting profession can utilize these findings to enhance ethics curricula and training
programs. Emphasizing the themes identified in this research can better prepare future
accountants to navigate ethical dilemmas effectively. CPAs and aspiring accountants should
prioritize ongoing ethics training and education. This action includes formal coursework,
informal discussions, and mentorship to ensure professionals remain well-versed in ethical
principles and guidelines. Accounting firms should implement regular employee ethics training
programs to maintain ethical standards.
Practical Implications for the Wider Community of Stakeholders
Accounting Firms
Accounting firms can use the study's insights to strengthen their ethical culture and
practices. They can develop tailored training programs that address CPAs' specific ethical
challenges. Promoting a culture of ethical awareness and encouraging open communication
about ethical dilemmas can contribute to improved ethical decision-making within firms. Firms
should prioritize developing internal policies and codes of conduct aligned with ethical best
practices. This could involve regular ethical audits, establishing clear channels for reporting
unethical behavior, and fostering a work environment where ethical decision-making is valued
and rewarded. By doing so, accounting firms enhance their reputation and contribute to the
overall integrity of the financial reporting process, benefiting all stakeholders.

Regulatory Bodies
Regulatory authorities can consider the study's findings when reviewing and updating
ethical guidelines for the accounting profession. Insights into CPAs' perceptions and experiences
can inform the development of regulatory frameworks more aligned with real-world challenges.
There is an opportunity to revise existing regulations or introduce new ones that address the
specific ethical challenges identified in the study. Regulatory bodies can also play a pivotal role
in standardizing ethical practices, ensuring a uniform understanding and application of ethical
principles among all accounting practitioners.
Ethics Committees
Organizations and accounting associations responsible for overseeing ethics compliance can
benefit from the research using the identified themes to guide their assessments of ethical
behavior within the profession. These committees can leverage the findings to develop targeted
CPA interventions and guidance. These committees could also initiate industry-wide discussions
and workshops to disseminate key findings and encourage dialogue on ethical issues.
Additionally, they can serve as a resource for CPAs seeking guidance on complex ethical
dilemmas, thus playing an active role in shaping the ethical landscape of the profession.
CPA Training and Certification
The study highlights the importance of ongoing ethics training for CPAs. Professional
organizations and certification bodies can require CPAs to regularly engage in ethics education
and encourage participation in mentorship programs that emphasize ethical decision-making.
This involves theoretical training, practical case studies, and simulations that reflect real-world
ethical dilemmas. Training should also emphasize developing soft skills like critical thinking and

ethical reasoning, which are crucial for effective ethical decision-making. Certification programs
could include a more rigorous assessment of ethical competencies to ensure newly certified
CPAs are well-equipped to handle ethical challenges.
Clients and Investors
Clients and investors in public companies can gain confidence from knowing that the
accounting profession is committed to upholding ethical standards. When interacting with
accounting professionals, they can expect greater transparency, accountability, and integrity.
This assurance is crucial for building trust and confidence in financial reporting and advice.
Clients and investors should also be more proactive in demanding high ethical standards from
their accounting service providers. The study's findings emphasize the profession's dedication to
ethics and can enhance trust in financial reporting and auditing processes.
Educational Institutions
Accounting education institutions can integrate the study's findings into their curriculum
to prepare future CPAs for career ethical challenges. This integration should go beyond
traditional ethical theories and include case studies and examples from the study that illustrate the
real-world ethical challenges faced in the accounting profession. Institutions should also foster a
learning environment that encourages honest discussions and debates, preparing future
accounting professionals to navigate the ethical complexities of their profession. Emphasizing the
importance of ethical awareness and ethical decision-making can better equip accounting
graduates.

Public Perception
The study has implications for public perceptions of the accounting profession. The
research findings can help improve public perception of the accounting profession. By
highlighting the profession's commitment to ethics and transparency, the accounting profession
can counter negative stereotypes and foster greater trust in the work of accountants. Public
awareness campaigns and transparent reporting of ethical practices and dilemmas can help
educate the public about the efforts being made within the profession to uphold high ethical
standards, thereby enhancing the overall credibility and reliability of the profession in the eyes of
the public.
In conclusion, the study's implications for practice present a comprehensive blueprint for
enhancing ethical standards across various facets of the accounting profession. This study's
implications extend to theoretical advancements within the field of accounting and practical
applications that benefit the broader community of stakeholders. By addressing these
implications, the accounting profession can continue to evolve in its commitment to ethical
conduct, integrity, and public trust. Ultimately, the study advocates for a collaborative and
continuous effort towards upholding and developing ethical practices, ensuring that the
accounting profession adheres to the highest standards of integrity and actively contributes to the
trust and reliability essential in the global financial landscape.
Recommendations for Further Research
This study was designed to explore the perceptions and experiences of CPAs regarding
accounting ethics. The study did not extensively explore the influence of social and cultural
factors on CPAs' ethical perceptions and experiences. Cultural differences and societal norms
may significantly shape ethical frameworks; further research could investigate these aspects.

Comparative studies across different cultural contexts can provide valuable insights. Another
area worth noting is the impact of technology. Analyze the impact of technological
advancements, such as artificial intelligence and blockchain, on accounting ethics. Investigate
how technology influences ethical decision-making in areas like data privacy and
cybersecurity. Expand research to include the perspectives of various stakeholders, including
clients, investors, regulatory authorities, and ethics committees. Investigate how their
perceptions of CPAs' ethics align with or differ from their perceptions. These
recommendations aim to enhance further the understanding of accounting ethics and its
practical implications. They provide avenues for future research that can contribute to the
ongoing development of ethical standards and practices within the accounting profession.
Conclusion
This qualitative study delved into the perceptions and experiences of Certified Public
Accountants (CPAs) regarding accounting ethics. The findings shed light on the multifaceted
nature of accounting ethics and the factors that shape CPAs' ethical beliefs and behaviors. The
study identified five prominent themes: "Conceptualizing accounting ethics," "Personal ethical
beliefs versus professional ethics," "Professional Reputation," "Accounting ethical dilemmas in
professional experience," and "Context of training." Through thematic analysis, it became
evident that CPAs view accounting ethics as guidelines and principles that guide their
professional conduct. These ethics are integral to upholding their professional integrity and
maintaining public trust. Personal ethical beliefs, rooted in the broader framework of moral
values, closely align with professional ethics but may be influenced by external factors such as
financial incentives and organizational pressures (Helzer et al., 2023). The study also
emphasized the critical role of professional reputation in accounting. CPAs recognize that

maintaining an ethical reputation is essential for building trust with clients, colleagues, and the
public. Ethical dilemmas in professional practice were acknowledged, with participants
highlighting situations where the right course of action was only sometimes clear-cut. In such
cases, adherence to ethical principles and transparency prevailed. Contextual factors,
particularly training and education, shaped CPAs' ethical perspectives. Formal training
programs and continuing education requirements were identified as essential mechanisms for
instilling ethical values and updating knowledge of ethical standards.
Furthermore, the study explored these findings through the theoretical lenses of agency
theory and Vroom's Expectancy-Valence (E-V) theory. The agency theory highlighted the
challenges associated with agency relationships within accounting firms, particularly the
potential misalignment of interests between principals and agents. In contrast, the E-V theory
provided insights into the motivational aspects of ethical compliance, emphasizing the
importance of valence, instrumentality, and expectancy in driving CPAs' ethical behavior.
The practical implications of this research are significant. It underscores the importance
of ongoing ethics education and training for CPAs to navigate ethical dilemmas effectively.
Organizations and accounting associations should continue to prioritize ethics as a cornerstone of
the profession, recognizing its pivotal role in preserving public trust. Mentorship programs and
ethical leadership can further reinforce ethical values in accounting. In terms of limitations, this
study primarily focused on CPAs in one geographical region, and findings may only partially
capture the diversity of experiences in the accounting profession worldwide. Additionally, the
qualitative nature of the research limits the generalizability of findings to larger populations.
Future research could address these limitations by conducting cross-cultural studies and
quantitative analyses.

In conclusion, this study contributes to the ongoing discourse on accounting ethics,
offering valuable insights into the perceptions and experiences of CPAs. It highlights the intricate
interplay of personal ethics, professional standards, and contextual factors in shaping ethical
behavior within the accounting profession. Ultimately, the study underscores the enduring
significance of ethics as a guiding force in accounting.

