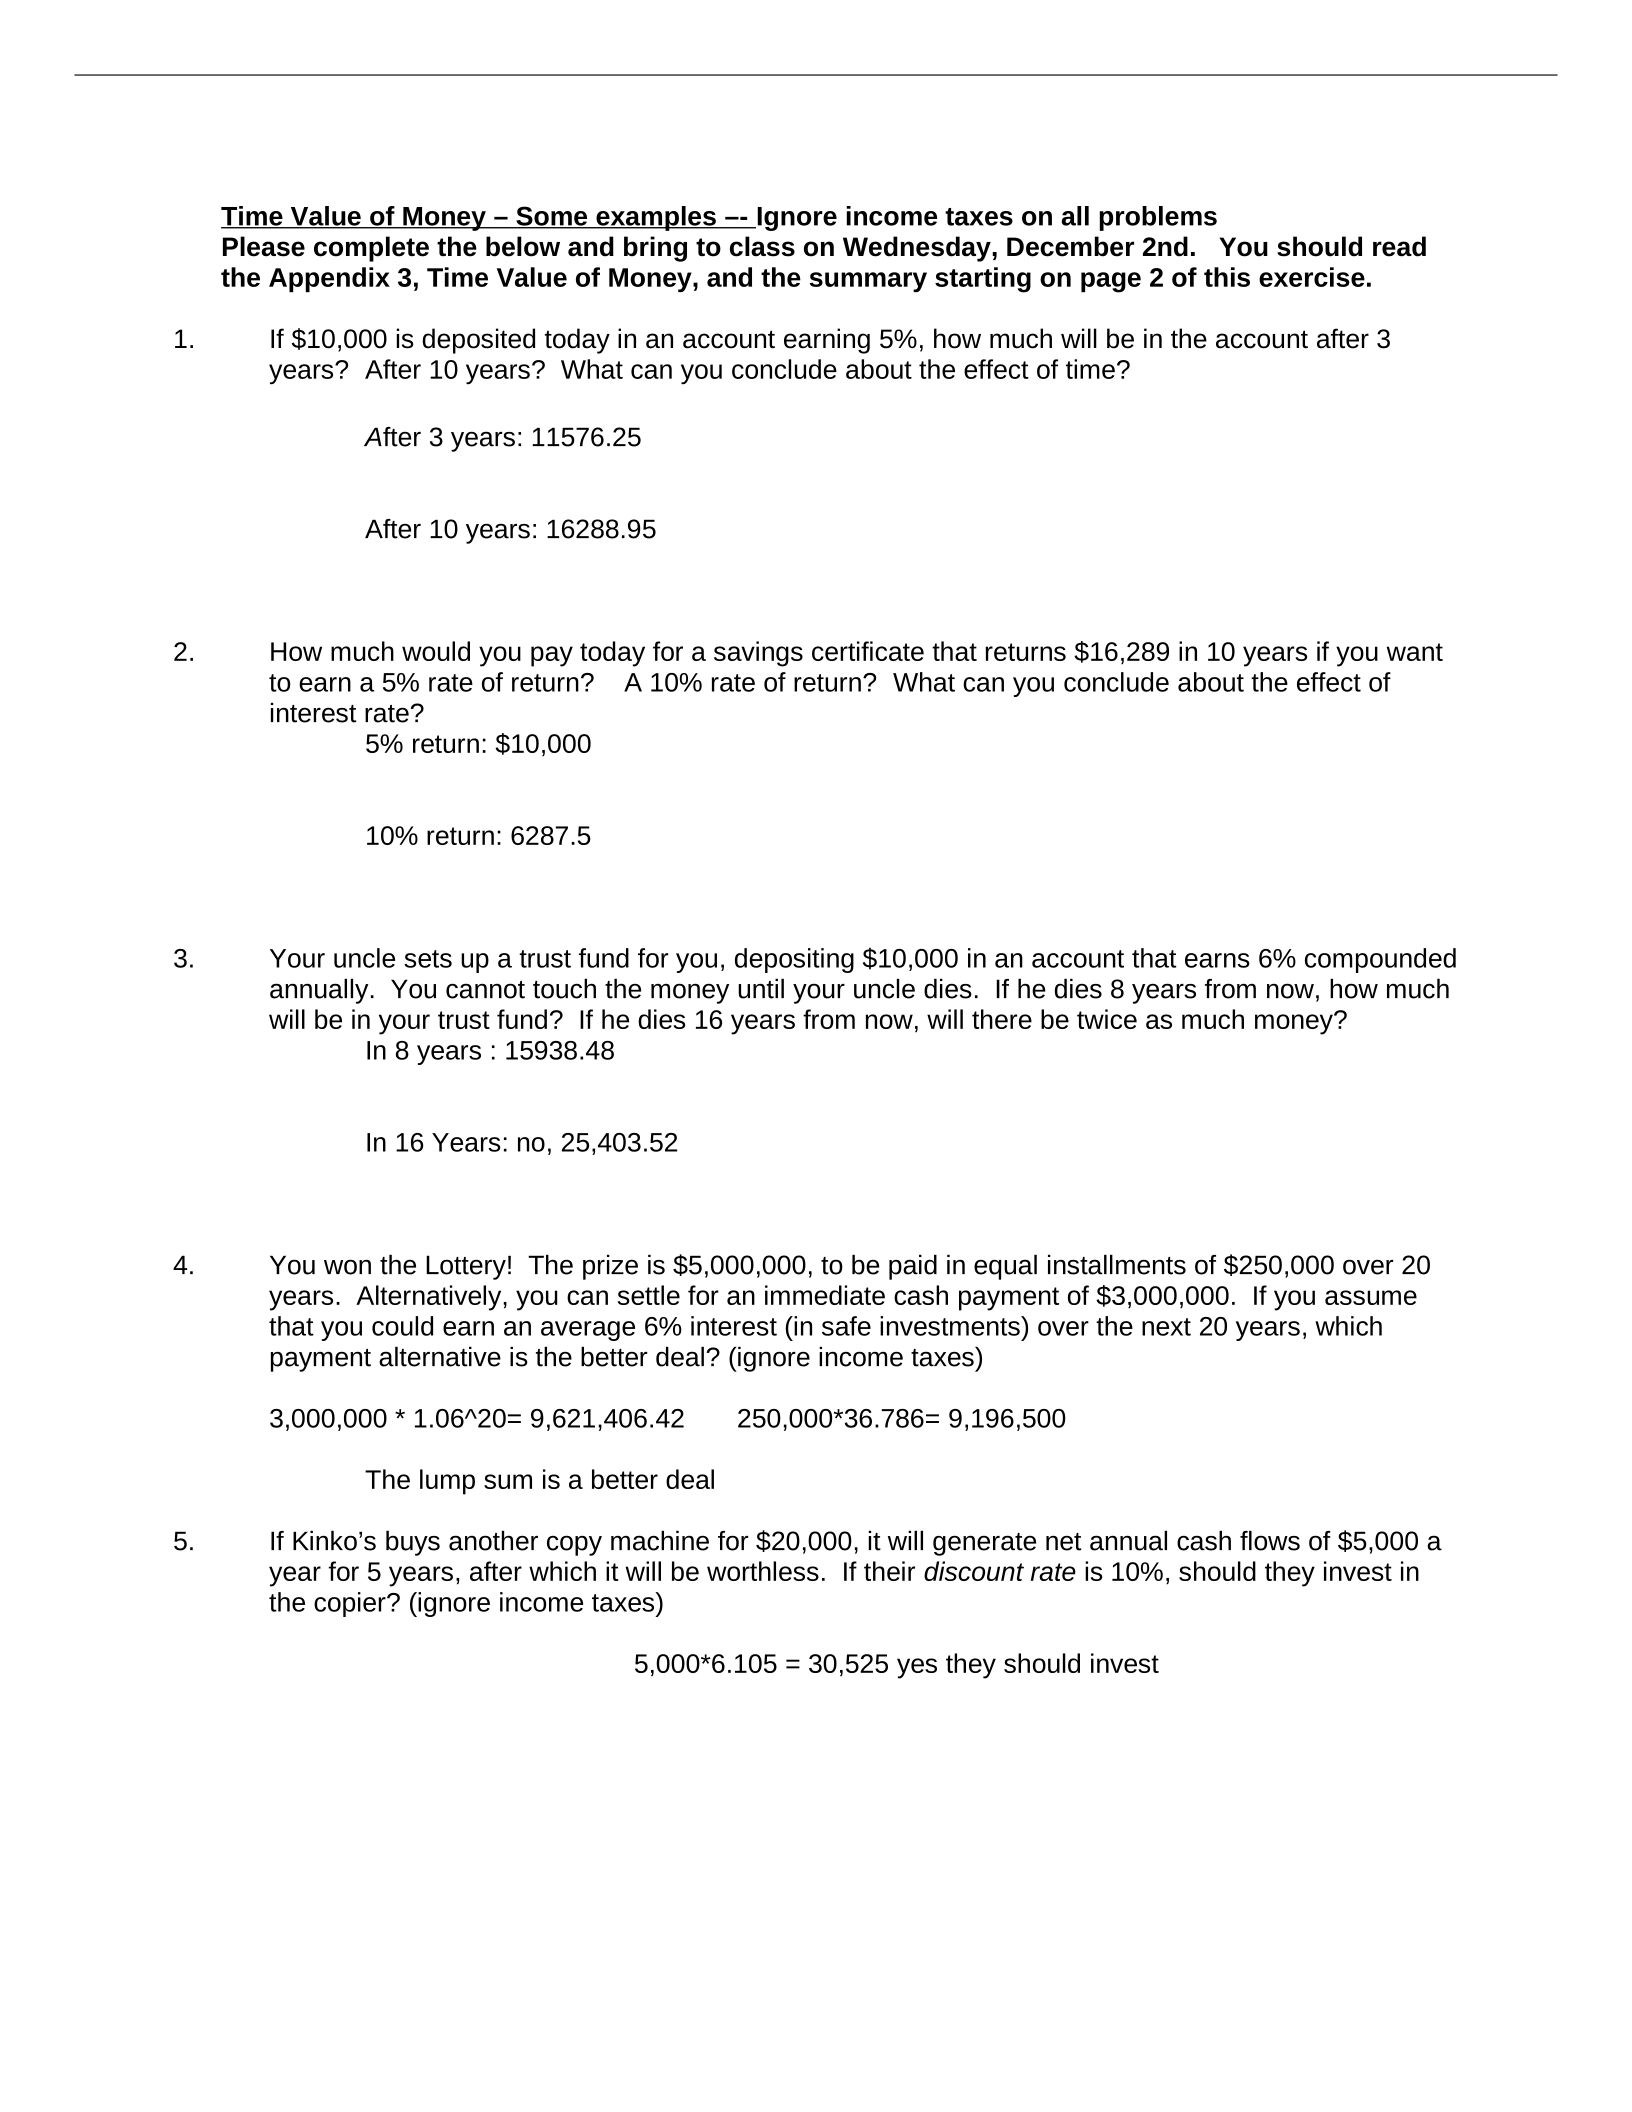
Time Value of Money – Some examples –- Ignore income taxes on all problems
Please complete the below and bring to class on Wednesday, December 2nd. You should read
the Appendix 3, Time Value of Money, and the summary starting on page 2 of this exercise.
1. If $10,000 is deposited today in an account earning 5%, how much will be in the account after 3
years? After 10 years? What can you conclude about the effect of time?
After 3 years: 11576.25
After 10 years: 16288.95
2. How much would you pay today for a savings certificate that returns $16,289 in 10 years if you want
to earn a 5% rate of return? A 10% rate of return? What can you conclude about the effect of
interest rate?
5% return: $10,000
10% return: 6287.5
3. Your uncle sets up a trust fund for you, depositing $10,000 in an account that earns 6% compounded
annually. You cannot touch the money until your uncle dies. If he dies 8 years from now, how much
will be in your trust fund? If he dies 16 years from now, will there be twice as much money?
In 8 years : 15938.48
In 16 Years: no, 25,403.52
4. You won the Lottery! The prize is $5,000,000, to be paid in equal installments of $250,000 over 20
years. Alternatively, you can settle for an immediate cash payment of $3,000,000. If you assume
that you could earn an average 6% interest (in safe investments) over the next 20 years, which
payment alternative is the better deal? (ignore income taxes)
3,000,000 * 1.06^20= 9,621,406.42 250,000*36.786= 9,196,500
The lump sum is a better deal
5. If Kinko’s buys another copy machine for $20,000, it will generate net annual cash flows of $5,000 a
year for 5 years, after which it will be worthless. If their discount rate is 10%, should they invest in
the copier? (ignore income taxes)
5,000*6.105 = 30,525 yes they should invest
ACC241: Time Value of Money
Name: Adam Newman Team:____________
ACC241: Time Value of Money
Name: Adam Newman Team:____________
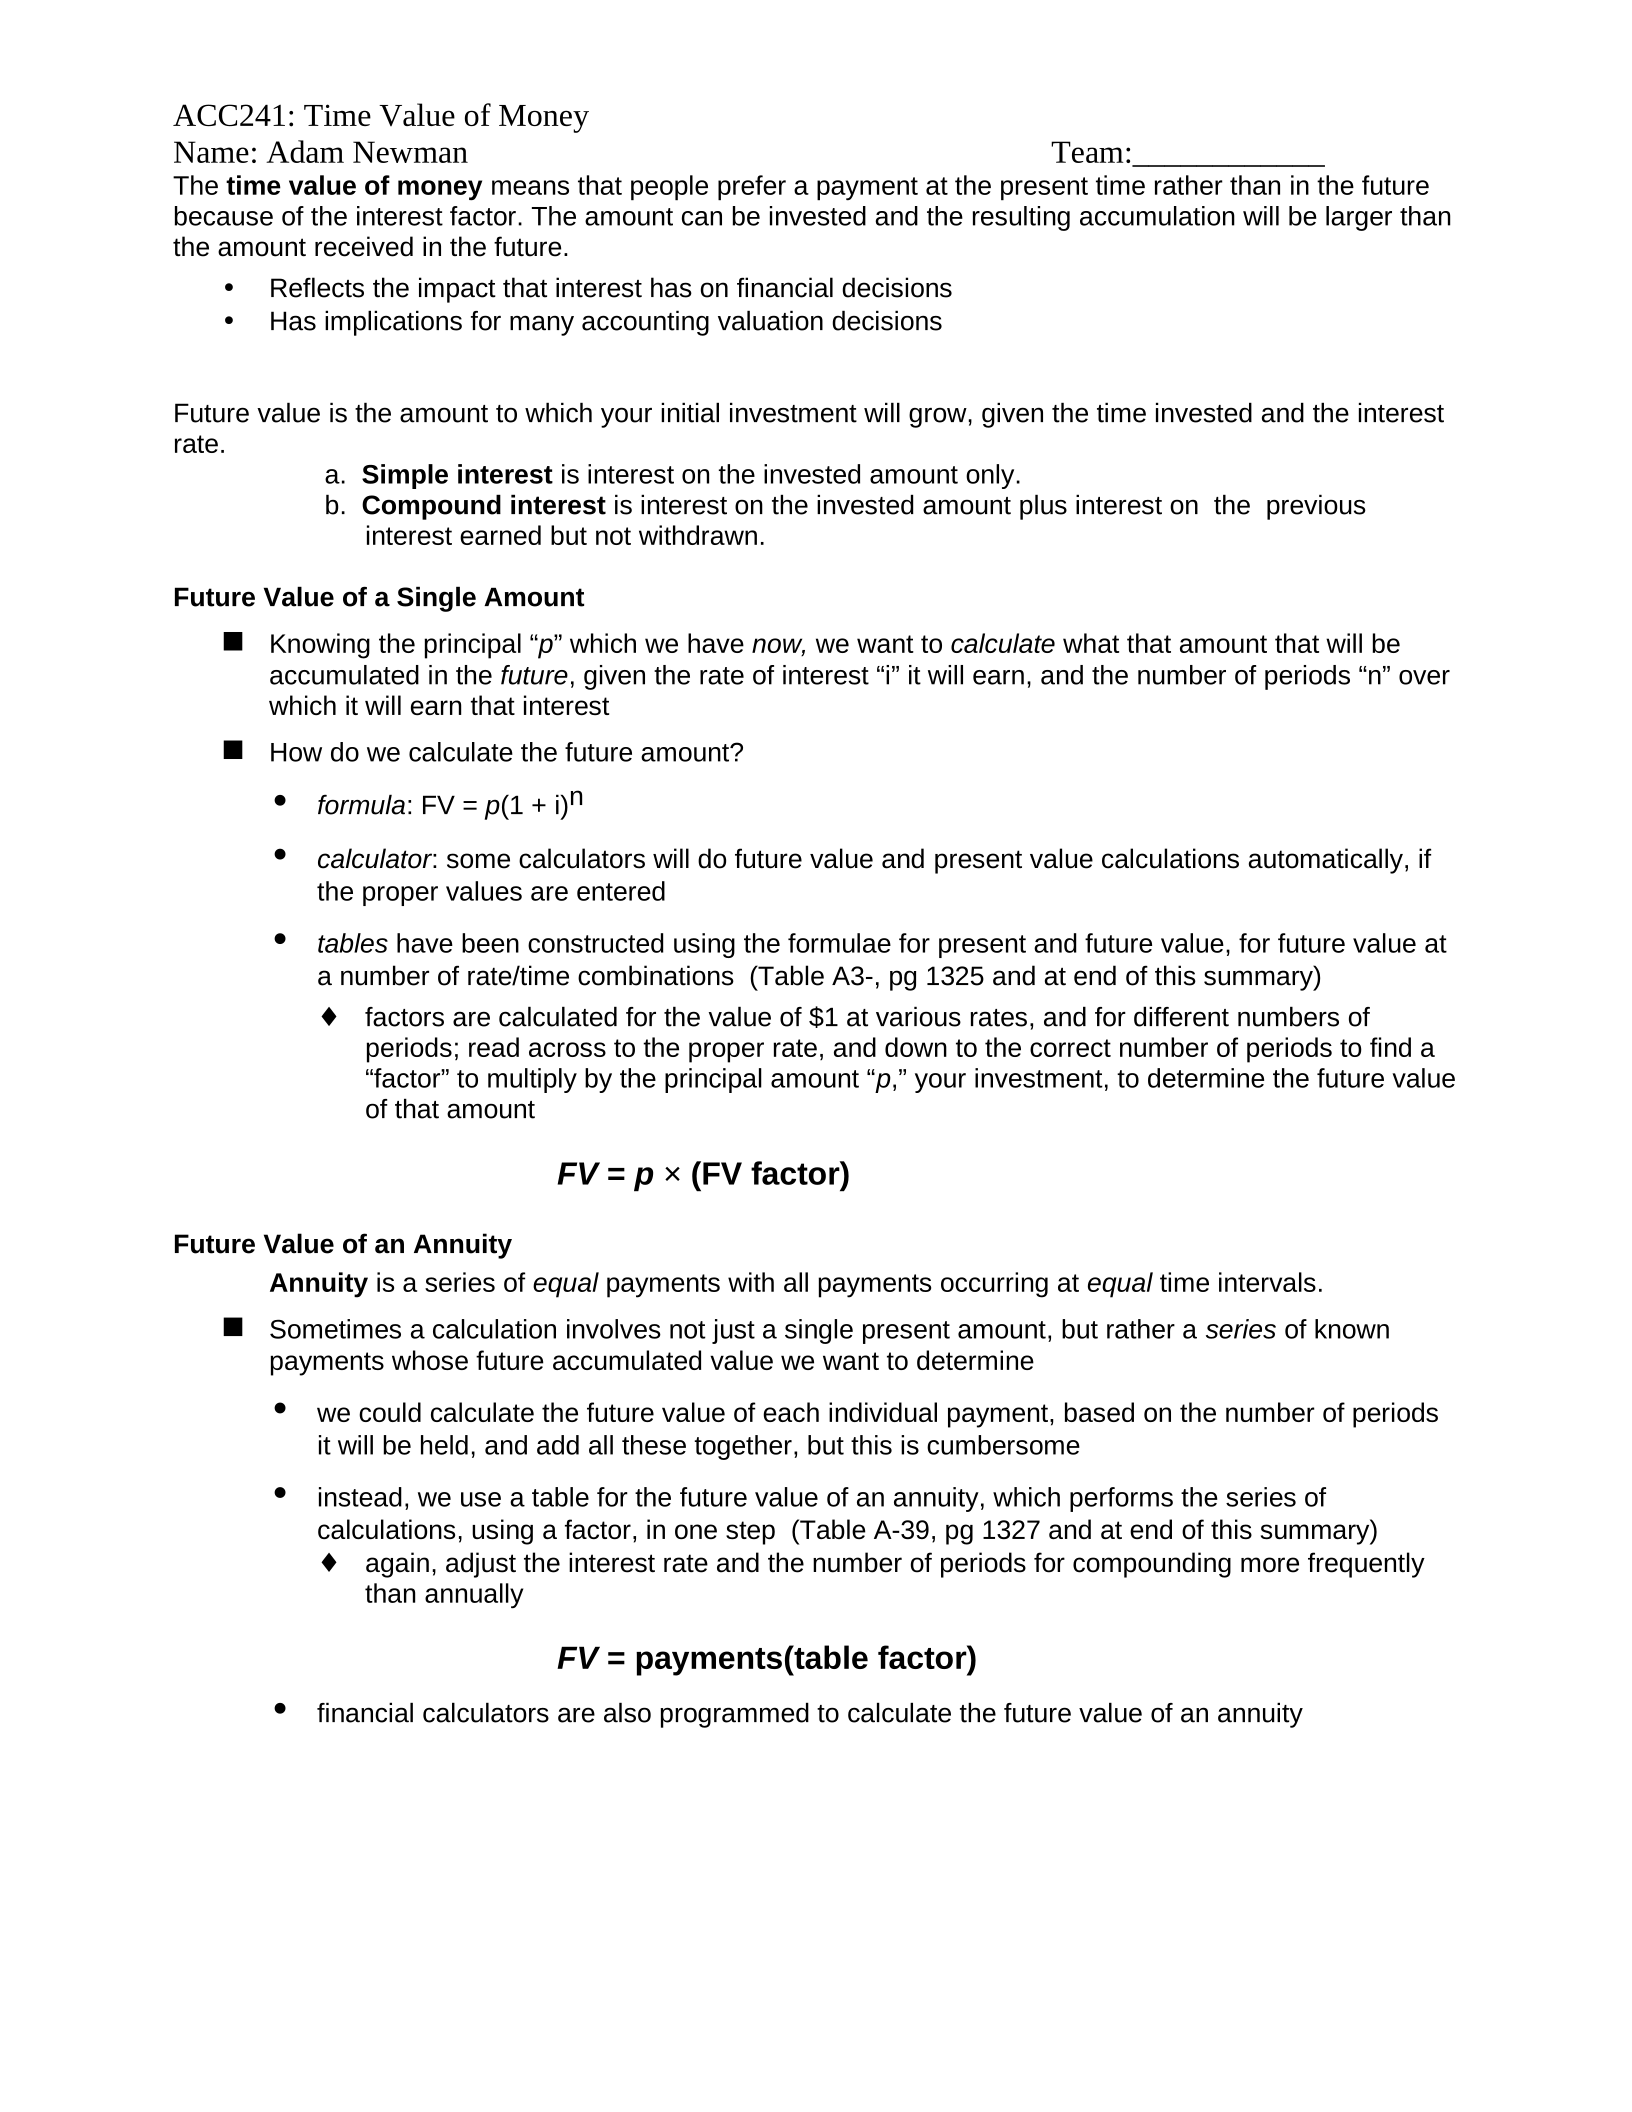
The time value of money means that people prefer a payment at the present time rather than in the future
because of the interest factor. The amount can be invested and the resulting accumulation will be larger than
the amount received in the future.
•Reflects the impact that interest has on financial decisions
•Has implications for many accounting valuation decisions
Future value is the amount to which your initial investment will grow, given the time invested and the interest
rate.
a. Simple interest is interest on the invested amount only.
b. Compound interest is interest on the invested amount plus interest on the previous
interest earned but not withdrawn.
Future Value of a Single Amount
Knowing the principal “p” which we have now, we want to calculate what that amount that will be
accumulated in the future, given the rate of interest “i” it will earn, and the number of periods “n” over
which it will earn that interest
How do we calculate the future amount?
•formula: FV = p(1 + i)n
•calculator: some calculators will do future value and present value calculations automatically, if
the proper values are entered
•tables have been constructed using the formulae for present and future value, for future value at
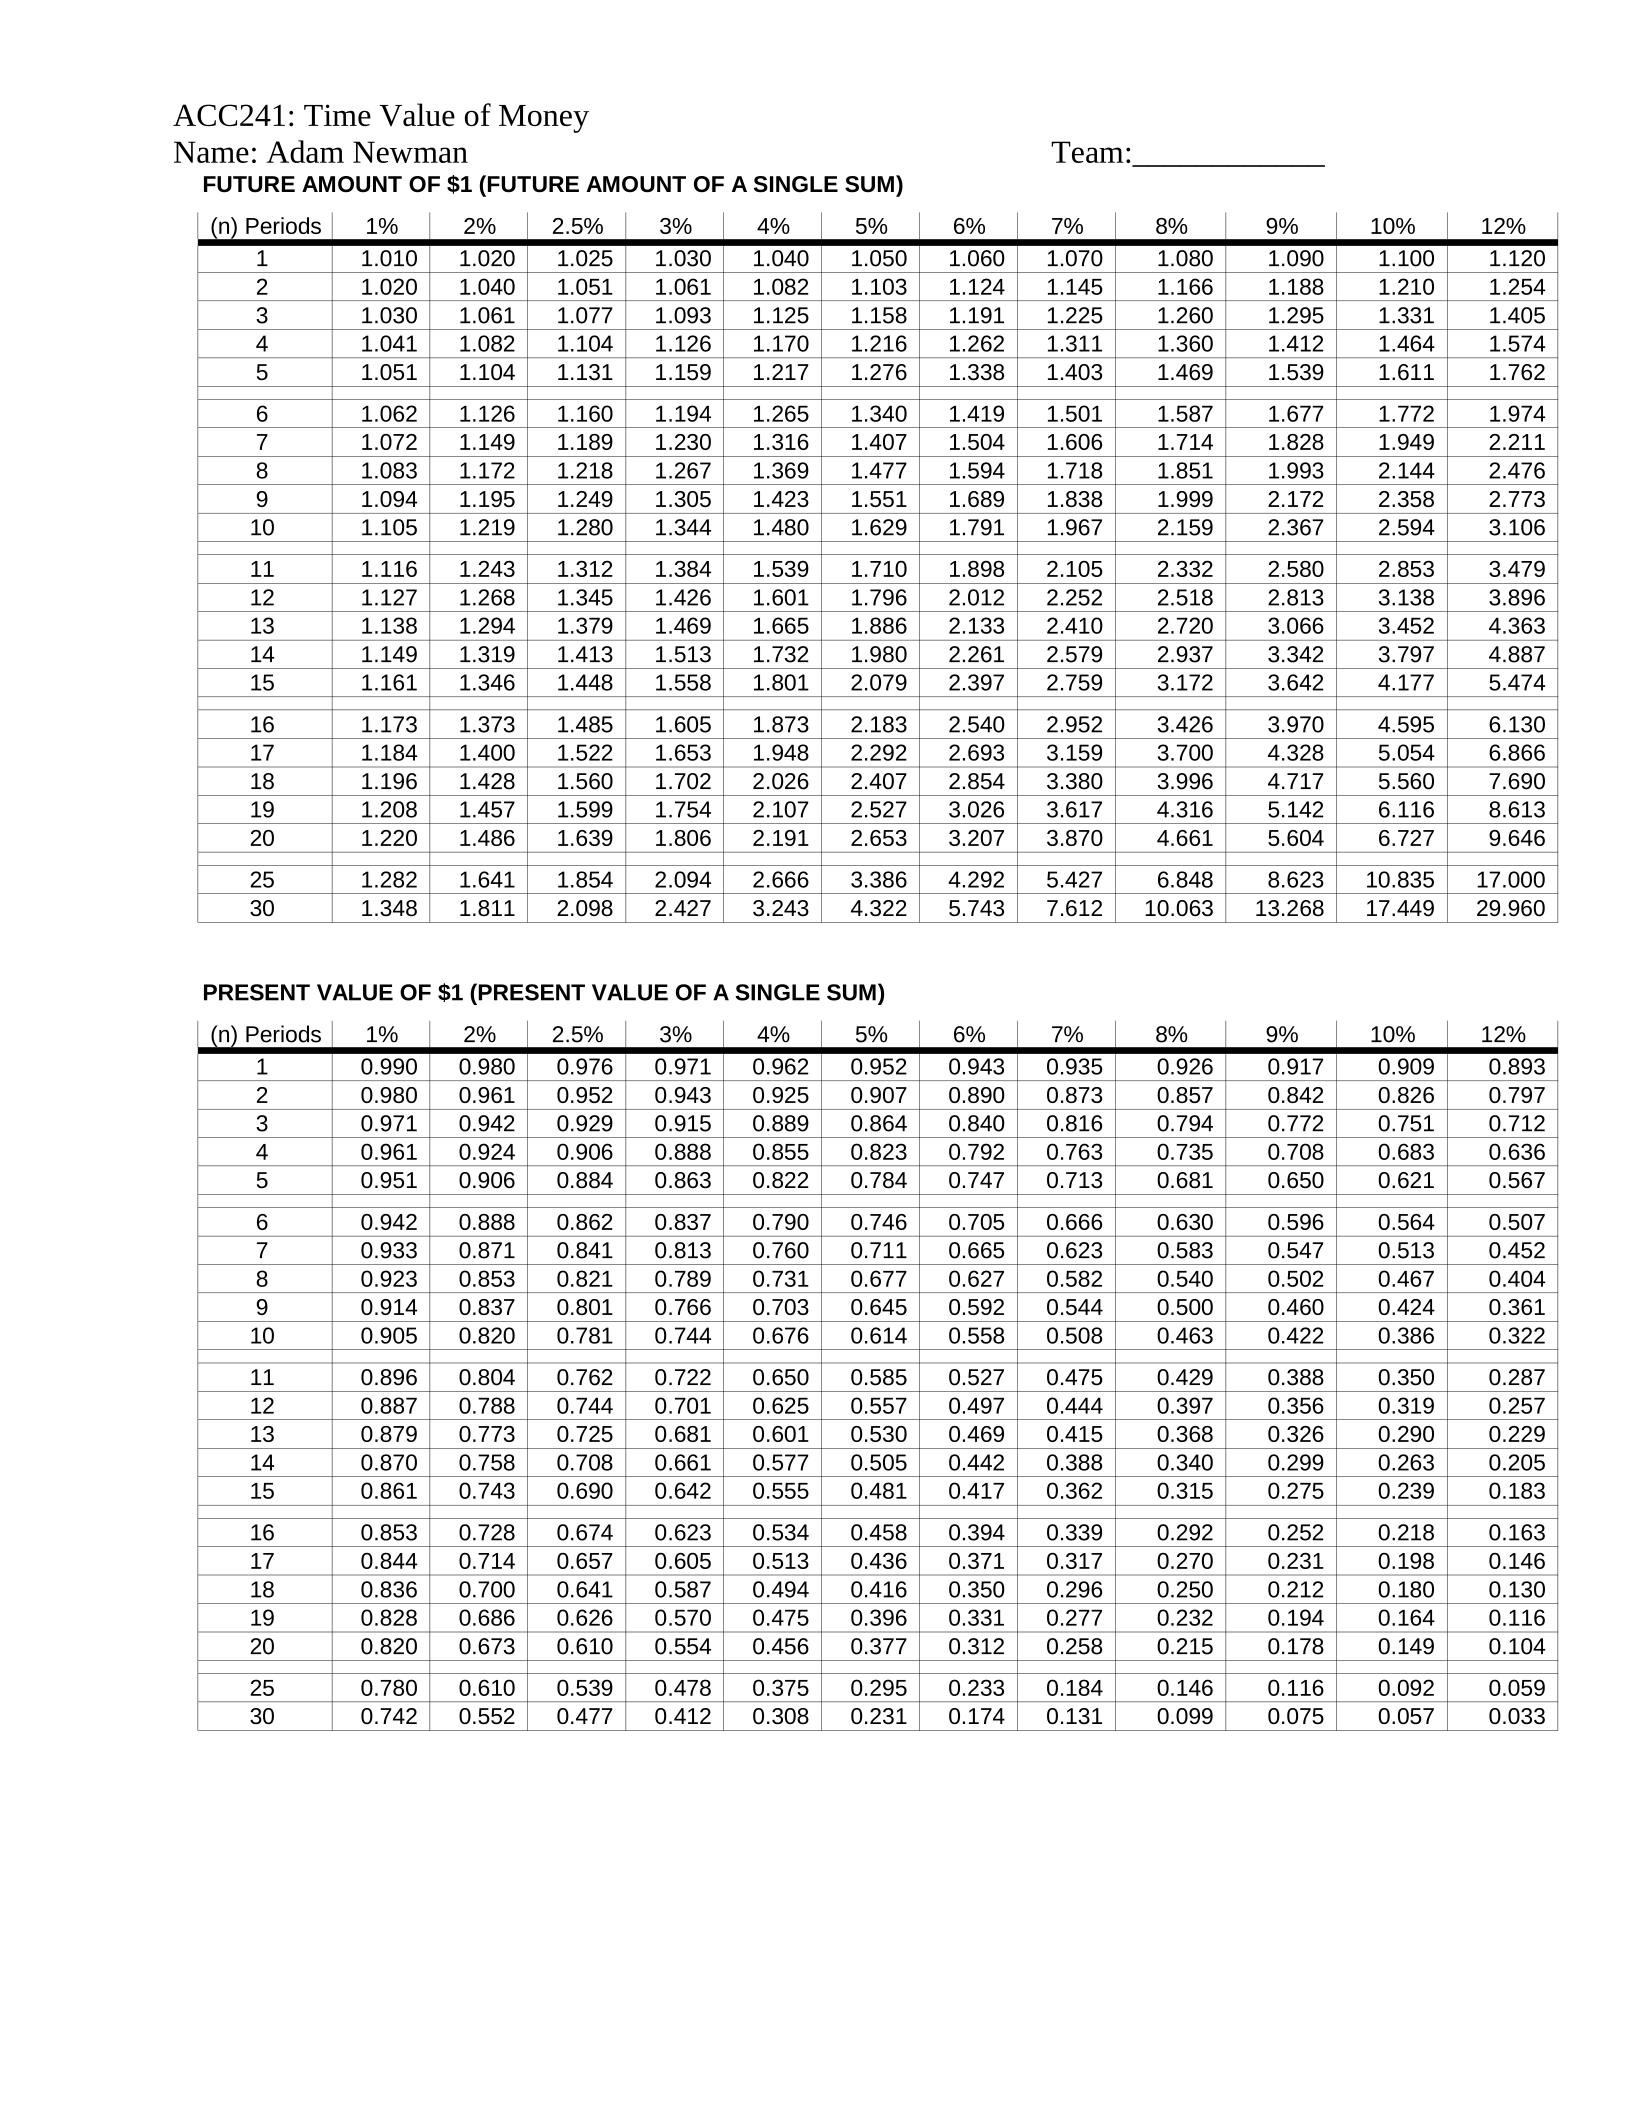
a number of rate/time combinations (Table A3-, pg 1325 and at end of this summary)
♦factors are calculated for the value of $1 at various rates, and for different numbers of
periods; read across to the proper rate, and down to the correct number of periods to find a
“factor” to multiply by the principal amount “p,” your investment, to determine the future value
of that amount
FV = p × (FV factor)
Future Value of an Annuity
Annuity is a series of equal payments with all payments occurring at equal time intervals.
Sometimes a calculation involves not just a single present amount, but rather a series of known
payments whose future accumulated value we want to determine
•we could calculate the future value of each individual payment, based on the number of periods
it will be held, and add all these together, but this is cumbersome
•instead, we use a table for the future value of an annuity, which performs the series of
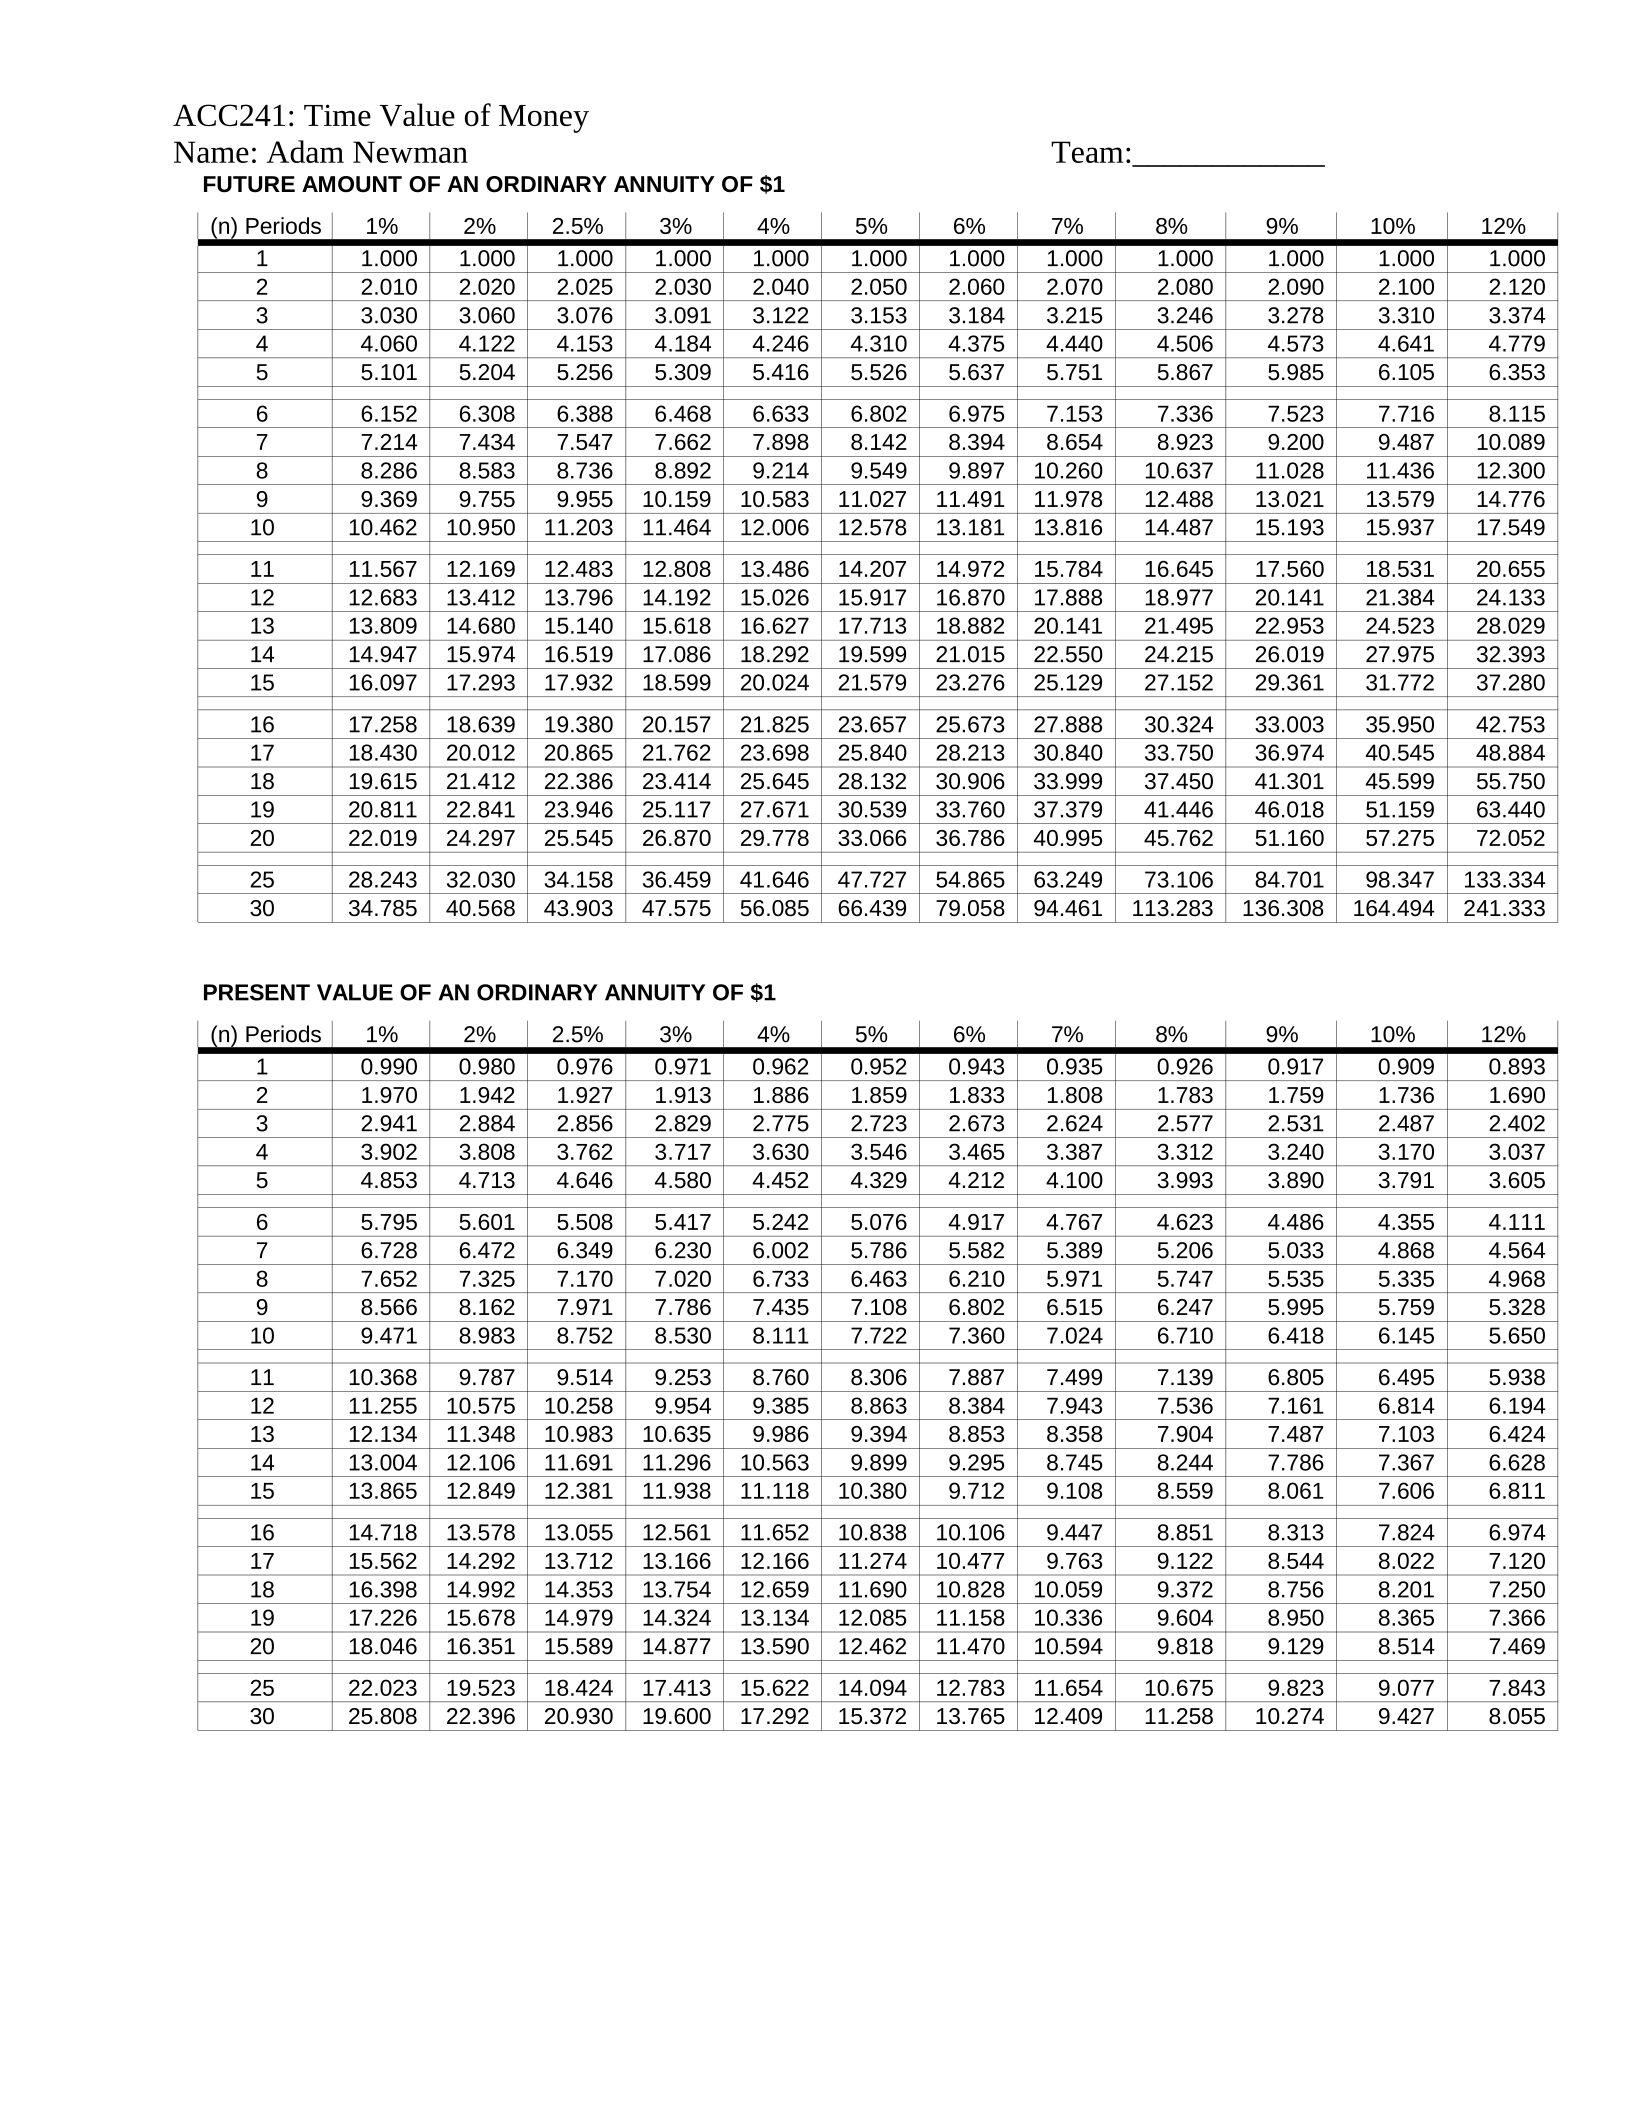
calculations, using a factor, in one step (Table A-39, pg 1327 and at end of this summary)
♦again, adjust the interest rate and the number of periods for compounding more frequently
than annually
FV = payments(table factor)
•financial calculators are also programmed to calculate the future value of an annuity
ACC241: Time Value of Money
Name: Adam Newman Team:____________
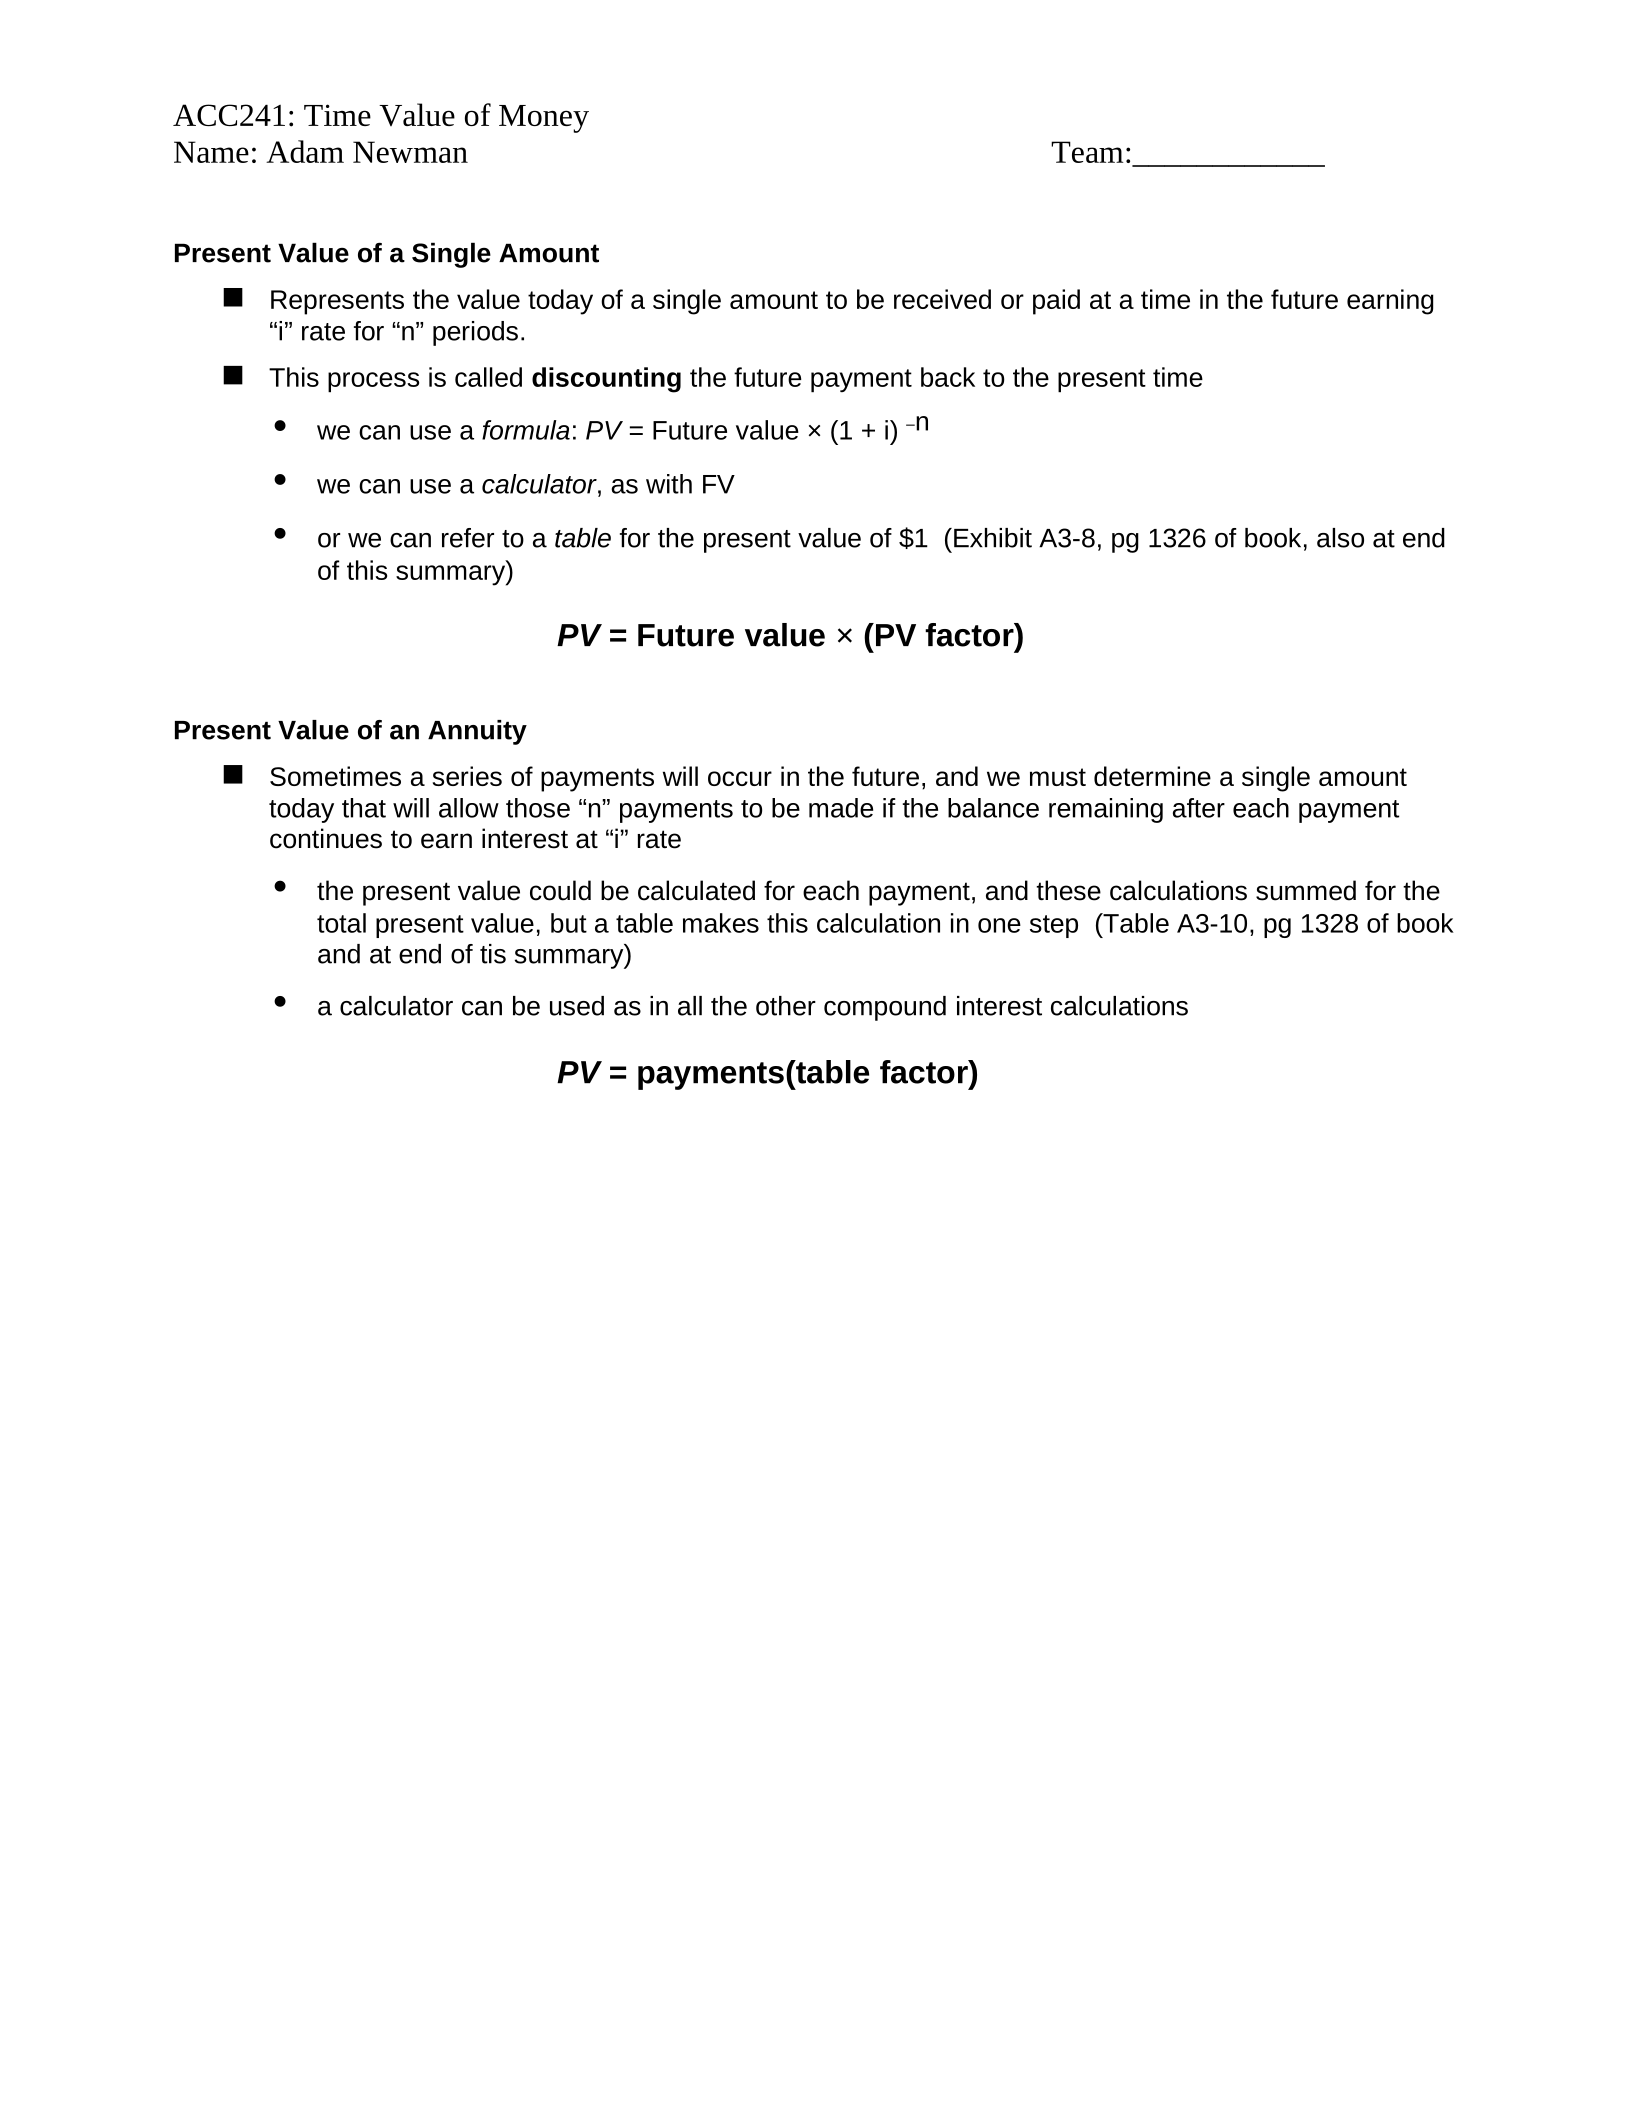
Present Value of a Single Amount
Represents the value today of a single amount to be received or paid at a time in the future earning
“i” rate for “n” periods.
This process is called discounting the future payment back to the present time
•we can use a formula: PV = Future value × (1 + i) –n
•we can use a calculator, as with FV
•or we can refer to a table for the present value of $1 (Exhibit A3-8, pg 1326 of book, also at end
of this summary)
PV = Future value × (PV factor)
Present Value of an Annuity
Sometimes a series of payments will occur in the future, and we must determine a single amount
today that will allow those “n” payments to be made if the balance remaining after each payment
continues to earn interest at “i” rate
•the present value could be calculated for each payment, and these calculations summed for the
total present value, but a table makes this calculation in one step (Table A3-10, pg 1328 of book
and at end of tis summary)
•a calculator can be used as in all the other compound interest calculations
PV = payments(table factor)
ACC241: Time Value of Money
Name: Adam Newman Team:____________
FUTURE AMOUNT OF $1 (FUTURE AMOUNT OF A SINGLE SUM)
(n) Periods 1% 2% 2.5% 3% 4% 5% 6% 7% 8% 9% 10% 12%
1 1.010 1.020 1.025 1.030 1.040 1.050 1.060 1.070 1.080 1.090 1.100 1.120
2 1.020 1.040 1.051 1.061 1.082 1.103 1.124 1.145 1.166 1.188 1.210 1.254
3 1.030 1.061 1.077 1.093 1.125 1.158 1.191 1.225 1.260 1.295 1.331 1.405
4 1.041 1.082 1.104 1.126 1.170 1.216 1.262 1.311 1.360 1.412 1.464 1.574
5 1.051 1.104 1.131 1.159 1.217 1.276 1.338 1.403 1.469 1.539 1.611 1.762
6 1.062 1.126 1.160 1.194 1.265 1.340 1.419 1.501 1.587 1.677 1.772 1.974
7 1.072 1.149 1.189 1.230 1.316 1.407 1.504 1.606 1.714 1.828 1.949 2.211
8 1.083 1.172 1.218 1.267 1.369 1.477 1.594 1.718 1.851 1.993 2.144 2.476
9 1.094 1.195 1.249 1.305 1.423 1.551 1.689 1.838 1.999 2.172 2.358 2.773
10 1.105 1.219 1.280 1.344 1.480 1.629 1.791 1.967 2.159 2.367 2.594 3.106
11 1.116 1.243 1.312 1.384 1.539 1.710 1.898 2.105 2.332 2.580 2.853 3.479
12 1.127 1.268 1.345 1.426 1.601 1.796 2.012 2.252 2.518 2.813 3.138 3.896
13 1.138 1.294 1.379 1.469 1.665 1.886 2.133 2.410 2.720 3.066 3.452 4.363
14 1.149 1.319 1.413 1.513 1.732 1.980 2.261 2.579 2.937 3.342 3.797 4.887
15 1.161 1.346 1.448 1.558 1.801 2.079 2.397 2.759 3.172 3.642 4.177 5.474
16 1.173 1.373 1.485 1.605 1.873 2.183 2.540 2.952 3.426 3.970 4.595 6.130
17 1.184 1.400 1.522 1.653 1.948 2.292 2.693 3.159 3.700 4.328 5.054 6.866
18 1.196 1.428 1.560 1.702 2.026 2.407 2.854 3.380 3.996 4.717 5.560 7.690
19 1.208 1.457 1.599 1.754 2.107 2.527 3.026 3.617 4.316 5.142 6.116 8.613
20 1.220 1.486 1.639 1.806 2.191 2.653 3.207 3.870 4.661 5.604 6.727 9.646
25 1.282 1.641 1.854 2.094 2.666 3.386 4.292 5.427 6.848 8.623 10.835 17.000
30 1.348 1.811 2.098 2.427 3.243 4.322 5.743 7.612 10.063 13.268 17.449 29.960
PRESENT VALUE OF $1 (PRESENT VALUE OF A SINGLE SUM)
(n) Periods 1% 2% 2.5% 3% 4% 5% 6% 7% 8% 9% 10% 12%
1 0.990 0.980 0.976 0.971 0.962 0.952 0.943 0.935 0.926 0.917 0.909 0.893
2 0.980 0.961 0.952 0.943 0.925 0.907 0.890 0.873 0.857 0.842 0.826 0.797
3 0.971 0.942 0.929 0.915 0.889 0.864 0.840 0.816 0.794 0.772 0.751 0.712
4 0.961 0.924 0.906 0.888 0.855 0.823 0.792 0.763 0.735 0.708 0.683 0.636
5 0.951 0.906 0.884 0.863 0.822 0.784 0.747 0.713 0.681 0.650 0.621 0.567
6 0.942 0.888 0.862 0.837 0.790 0.746 0.705 0.666 0.630 0.596 0.564 0.507
7 0.933 0.871 0.841 0.813 0.760 0.711 0.665 0.623 0.583 0.547 0.513 0.452
8 0.923 0.853 0.821 0.789 0.731 0.677 0.627 0.582 0.540 0.502 0.467 0.404
9 0.914 0.837 0.801 0.766 0.703 0.645 0.592 0.544 0.500 0.460 0.424 0.361
10 0.905 0.820 0.781 0.744 0.676 0.614 0.558 0.508 0.463 0.422 0.386 0.322
11 0.896 0.804 0.762 0.722 0.650 0.585 0.527 0.475 0.429 0.388 0.350 0.287
12 0.887 0.788 0.744 0.701 0.625 0.557 0.497 0.444 0.397 0.356 0.319 0.257
13 0.879 0.773 0.725 0.681 0.601 0.530 0.469 0.415 0.368 0.326 0.290 0.229
14 0.870 0.758 0.708 0.661 0.577 0.505 0.442 0.388 0.340 0.299 0.263 0.205
15 0.861 0.743 0.690 0.642 0.555 0.481 0.417 0.362 0.315 0.275 0.239 0.183
16 0.853 0.728 0.674 0.623 0.534 0.458 0.394 0.339 0.292 0.252 0.218 0.163
17 0.844 0.714 0.657 0.605 0.513 0.436 0.371 0.317 0.270 0.231 0.198 0.146
18 0.836 0.700 0.641 0.587 0.494 0.416 0.350 0.296 0.250 0.212 0.180 0.130
19 0.828 0.686 0.626 0.570 0.475 0.396 0.331 0.277 0.232 0.194 0.164 0.116
20 0.820 0.673 0.610 0.554 0.456 0.377 0.312 0.258 0.215 0.178 0.149 0.104
25 0.780 0.610 0.539 0.478 0.375 0.295 0.233 0.184 0.146 0.116 0.092 0.059
30 0.742 0.552 0.477 0.412 0.308 0.231 0.174 0.131 0.099 0.075 0.057 0.033
ACC241: Time Value of Money
Name: Adam Newman Team:____________
FUTURE AMOUNT OF AN ORDINARY ANNUITY OF $1
(n) Periods 1% 2% 2.5% 3% 4% 5% 6% 7% 8% 9% 10% 12%
1 1.000 1.000 1.000 1.000 1.000 1.000 1.000 1.000 1.000 1.000 1.000 1.000
2 2.010 2.020 2.025 2.030 2.040 2.050 2.060 2.070 2.080 2.090 2.100 2.120
3 3.030 3.060 3.076 3.091 3.122 3.153 3.184 3.215 3.246 3.278 3.310 3.374
4 4.060 4.122 4.153 4.184 4.246 4.310 4.375 4.440 4.506 4.573 4.641 4.779
5 5.101 5.204 5.256 5.309 5.416 5.526 5.637 5.751 5.867 5.985 6.105 6.353
6 6.152 6.308 6.388 6.468 6.633 6.802 6.975 7.153 7.336 7.523 7.716 8.115
7 7.214 7.434 7.547 7.662 7.898 8.142 8.394 8.654 8.923 9.200 9.487 10.089
8 8.286 8.583 8.736 8.892 9.214 9.549 9.897 10.260 10.637 11.028 11.436 12.300
9 9.369 9.755 9.955 10.159 10.583 11.027 11.491 11.978 12.488 13.021 13.579 14.776
10 10.462 10.950 11.203 11.464 12.006 12.578 13.181 13.816 14.487 15.193 15.937 17.549
11 11.567 12.169 12.483 12.808 13.486 14.207 14.972 15.784 16.645 17.560 18.531 20.655
12 12.683 13.412 13.796 14.192 15.026 15.917 16.870 17.888 18.977 20.141 21.384 24.133
13 13.809 14.680 15.140 15.618 16.627 17.713 18.882 20.141 21.495 22.953 24.523 28.029
14 14.947 15.974 16.519 17.086 18.292 19.599 21.015 22.550 24.215 26.019 27.975 32.393
15 16.097 17.293 17.932 18.599 20.024 21.579 23.276 25.129 27.152 29.361 31.772 37.280
16 17.258 18.639 19.380 20.157 21.825 23.657 25.673 27.888 30.324 33.003 35.950 42.753
17 18.430 20.012 20.865 21.762 23.698 25.840 28.213 30.840 33.750 36.974 40.545 48.884
18 19.615 21.412 22.386 23.414 25.645 28.132 30.906 33.999 37.450 41.301 45.599 55.750
19 20.811 22.841 23.946 25.117 27.671 30.539 33.760 37.379 41.446 46.018 51.159 63.440
20 22.019 24.297 25.545 26.870 29.778 33.066 36.786 40.995 45.762 51.160 57.275 72.052
25 28.243 32.030 34.158 36.459 41.646 47.727 54.865 63.249 73.106 84.701 98.347 133.334
30 34.785 40.568 43.903 47.575 56.085 66.439 79.058 94.461 113.283 136.308 164.494 241.333
PRESENT VALUE OF AN ORDINARY ANNUITY OF $1
(n) Periods 1% 2% 2.5% 3% 4% 5% 6% 7% 8% 9% 10% 12%
1 0.990 0.980 0.976 0.971 0.962 0.952 0.943 0.935 0.926 0.917 0.909 0.893
2 1.970 1.942 1.927 1.913 1.886 1.859 1.833 1.808 1.783 1.759 1.736 1.690
3 2.941 2.884 2.856 2.829 2.775 2.723 2.673 2.624 2.577 2.531 2.487 2.402
4 3.902 3.808 3.762 3.717 3.630 3.546 3.465 3.387 3.312 3.240 3.170 3.037
5 4.853 4.713 4.646 4.580 4.452 4.329 4.212 4.100 3.993 3.890 3.791 3.605
6 5.795 5.601 5.508 5.417 5.242 5.076 4.917 4.767 4.623 4.486 4.355 4.111
7 6.728 6.472 6.349 6.230 6.002 5.786 5.582 5.389 5.206 5.033 4.868 4.564
8 7.652 7.325 7.170 7.020 6.733 6.463 6.210 5.971 5.747 5.535 5.335 4.968
9 8.566 8.162 7.971 7.786 7.435 7.108 6.802 6.515 6.247 5.995 5.759 5.328
10 9.471 8.983 8.752 8.530 8.111 7.722 7.360 7.024 6.710 6.418 6.145 5.650
11 10.368 9.787 9.514 9.253 8.760 8.306 7.887 7.499 7.139 6.805 6.495 5.938
12 11.255 10.575 10.258 9.954 9.385 8.863 8.384 7.943 7.536 7.161 6.814 6.194
13 12.134 11.348 10.983 10.635 9.986 9.394 8.853 8.358 7.904 7.487 7.103 6.424
14 13.004 12.106 11.691 11.296 10.563 9.899 9.295 8.745 8.244 7.786 7.367 6.628
15 13.865 12.849 12.381 11.938 11.118 10.380 9.712 9.108 8.559 8.061 7.606 6.811
16 14.718 13.578 13.055 12.561 11.652 10.838 10.106 9.447 8.851 8.313 7.824 6.974
17 15.562 14.292 13.712 13.166 12.166 11.274 10.477 9.763 9.122 8.544 8.022 7.120
18 16.398 14.992 14.353 13.754 12.659 11.690 10.828 10.059 9.372 8.756 8.201 7.250
19 17.226 15.678 14.979 14.324 13.134 12.085 11.158 10.336 9.604 8.950 8.365 7.366
20 18.046 16.351 15.589 14.877 13.590 12.462 11.470 10.594 9.818 9.129 8.514 7.469
25 22.023 19.523 18.424 17.413 15.622 14.094 12.783 11.654 10.675 9.823 9.077 7.843
30 25.808 22.396 20.930 19.600 17.292 15.372 13.765 12.409 11.258 10.274 9.427 8.055