


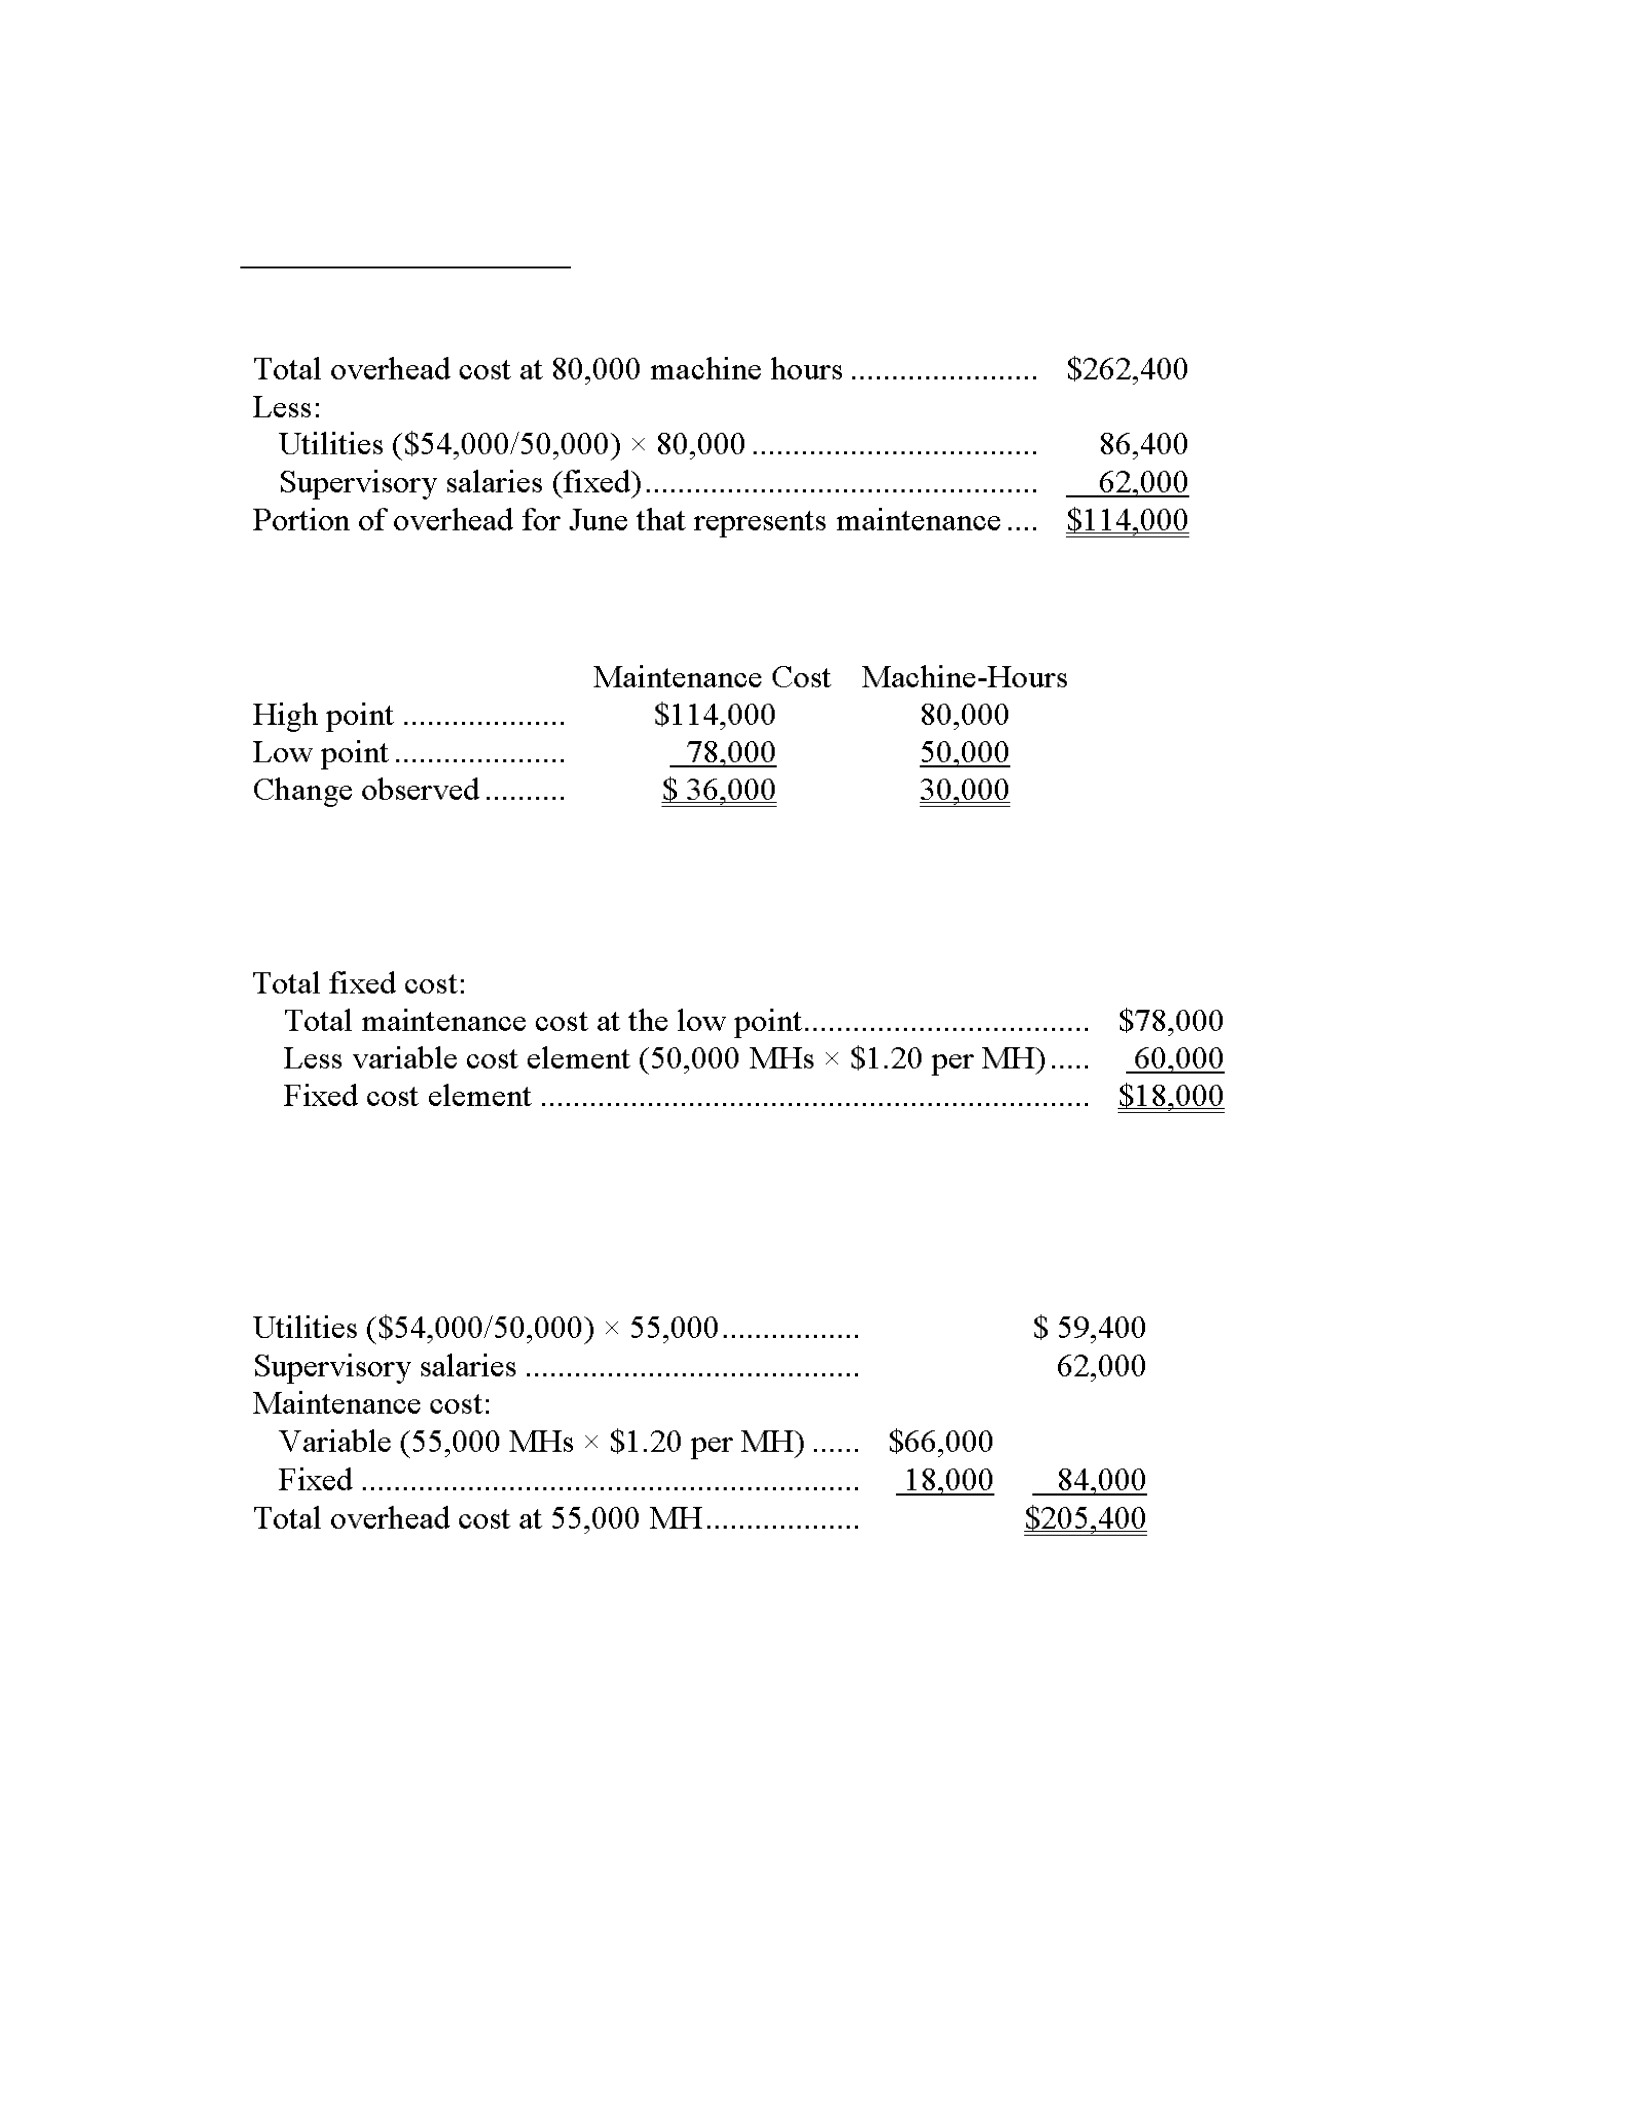
Item #1 – Cost Behavior
a.
b. High-low analysis of maintenance cost:
Variable cost:
Change in cost/Change in activity = $36,000/30,000 MHs = $1.20 per MHs
The cost formula is: Y = $18,000 + $1.20X
c. Total overhead at 55,000 machine hours:
ACC241 – Examination #2 Review Activity Solutions
ACC241 – Examination #2 Review Activity Solutions
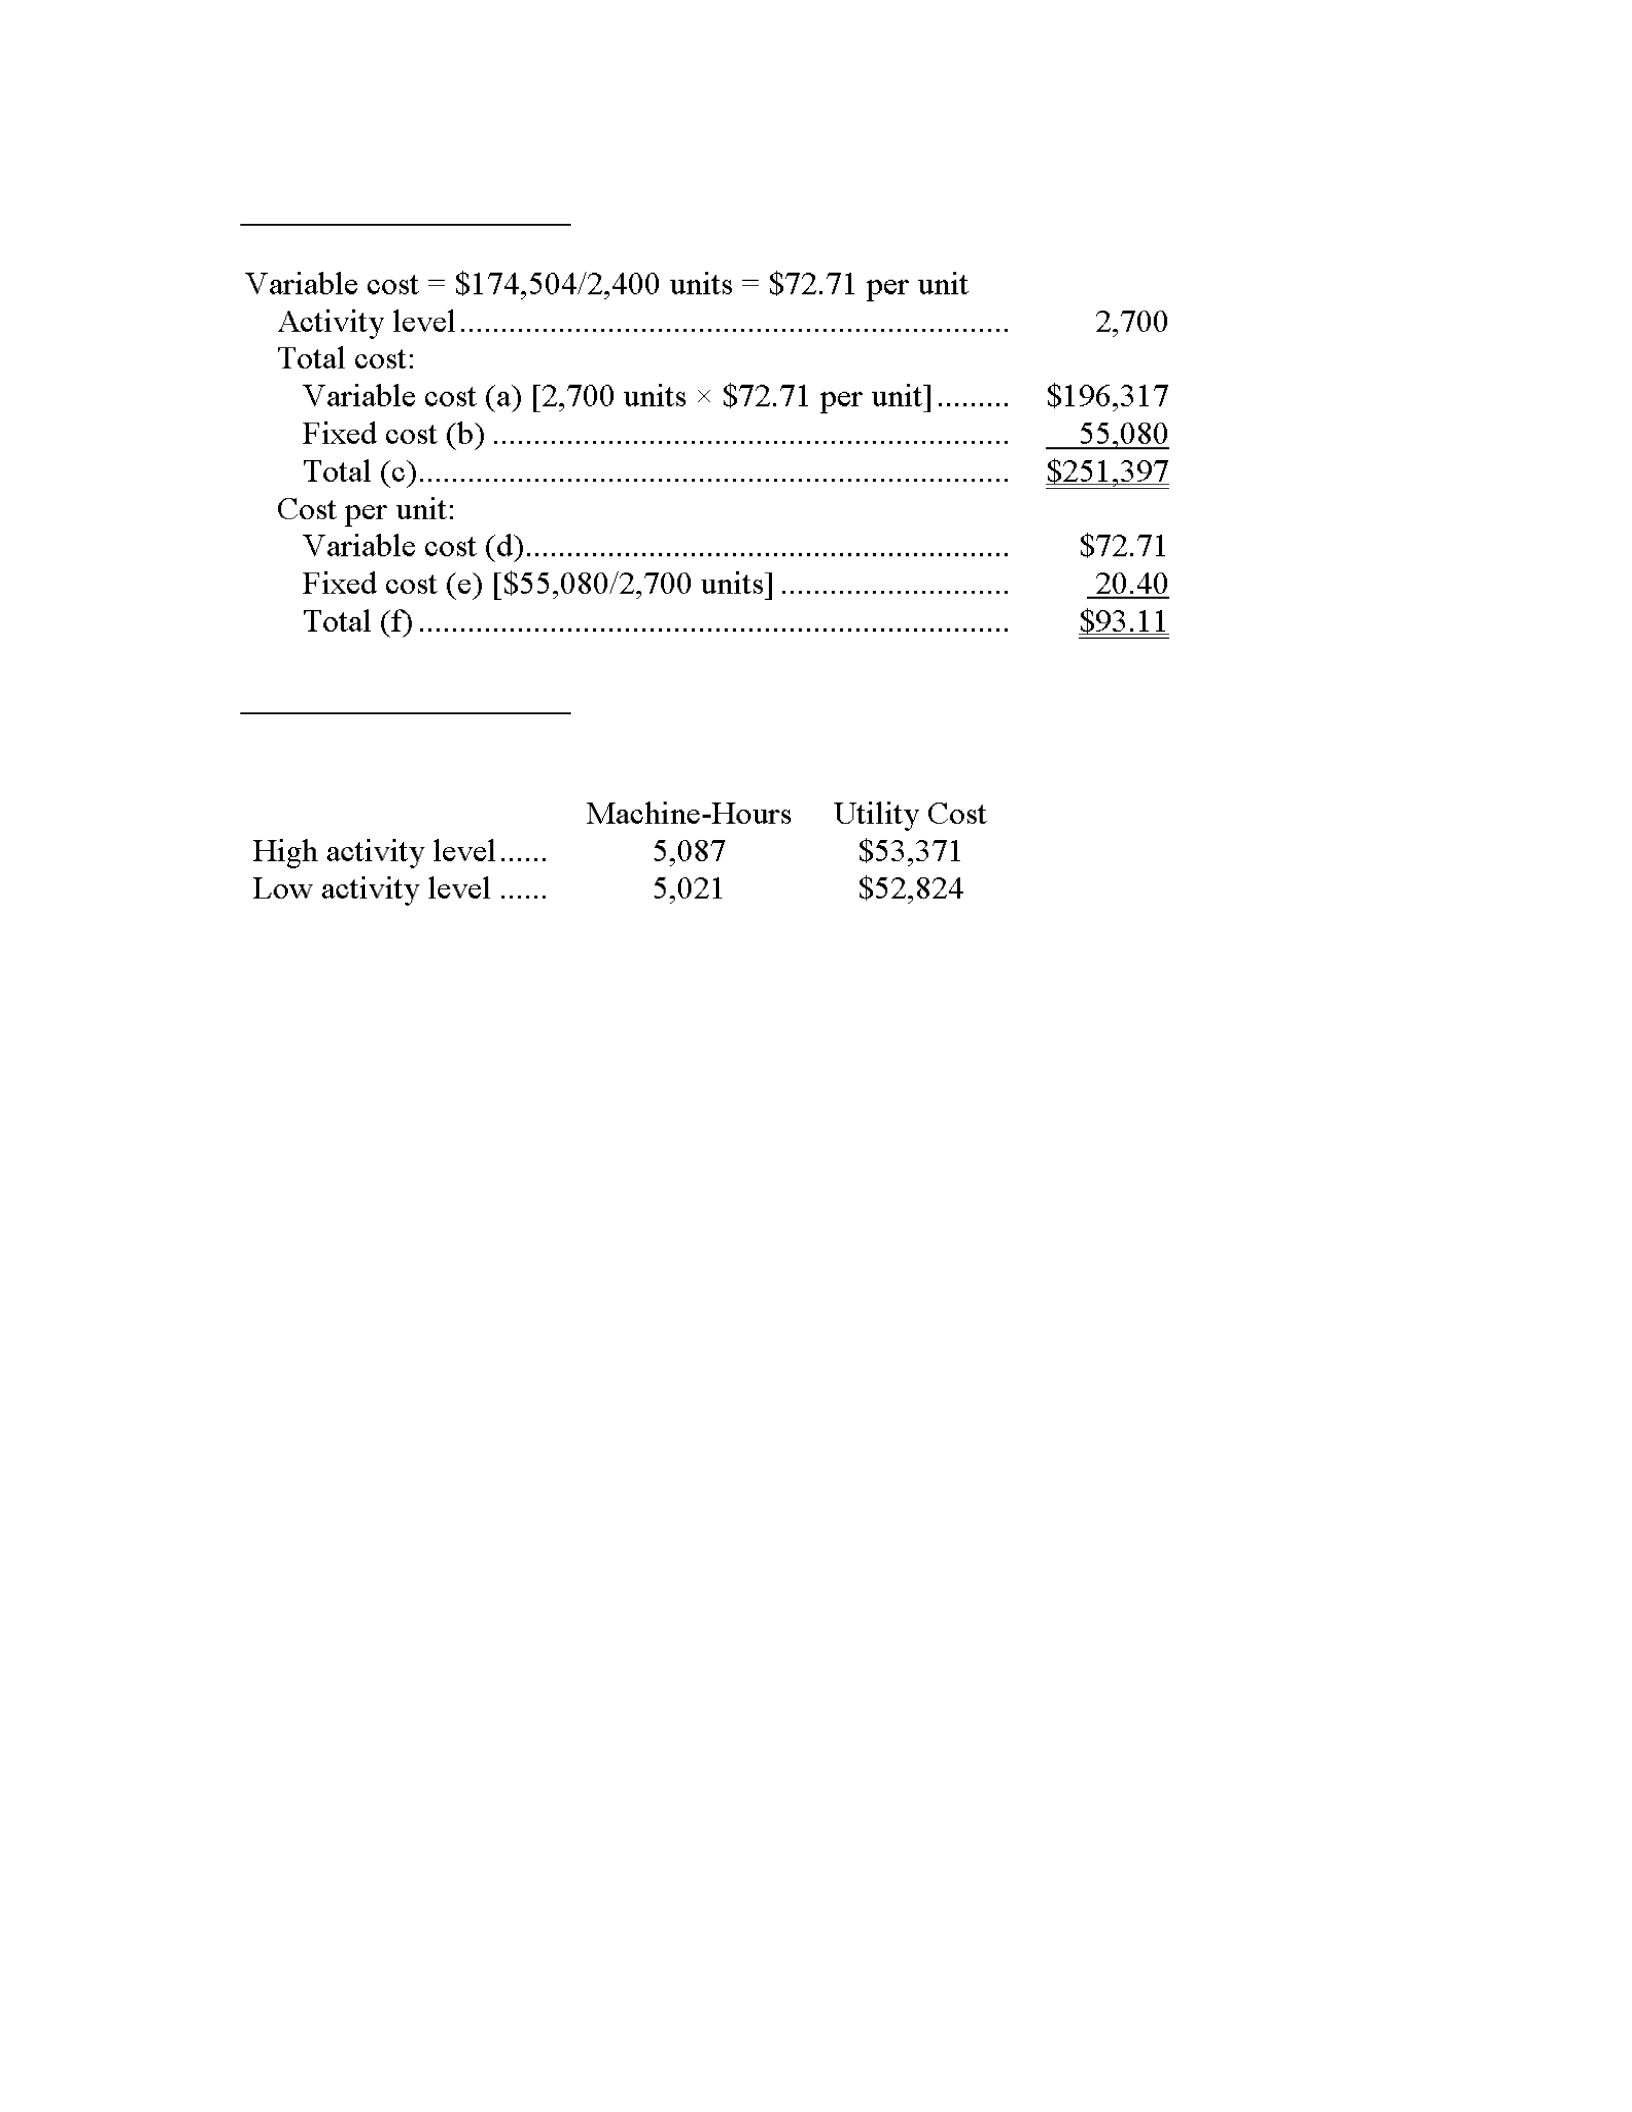
Item #2 – Cost Behavior
Item #3 – Cost Behavior
Variable cost = Change in cost Change in activity
= ($53,371 - $52,824) (5,087 - 5,021) = $8.29
Fixed cost element = Total cost - Variable cost element
= $52,824 - ($8.29 5,021) = $11,200
ACC241 – Examination #2 Review Activity Solutions
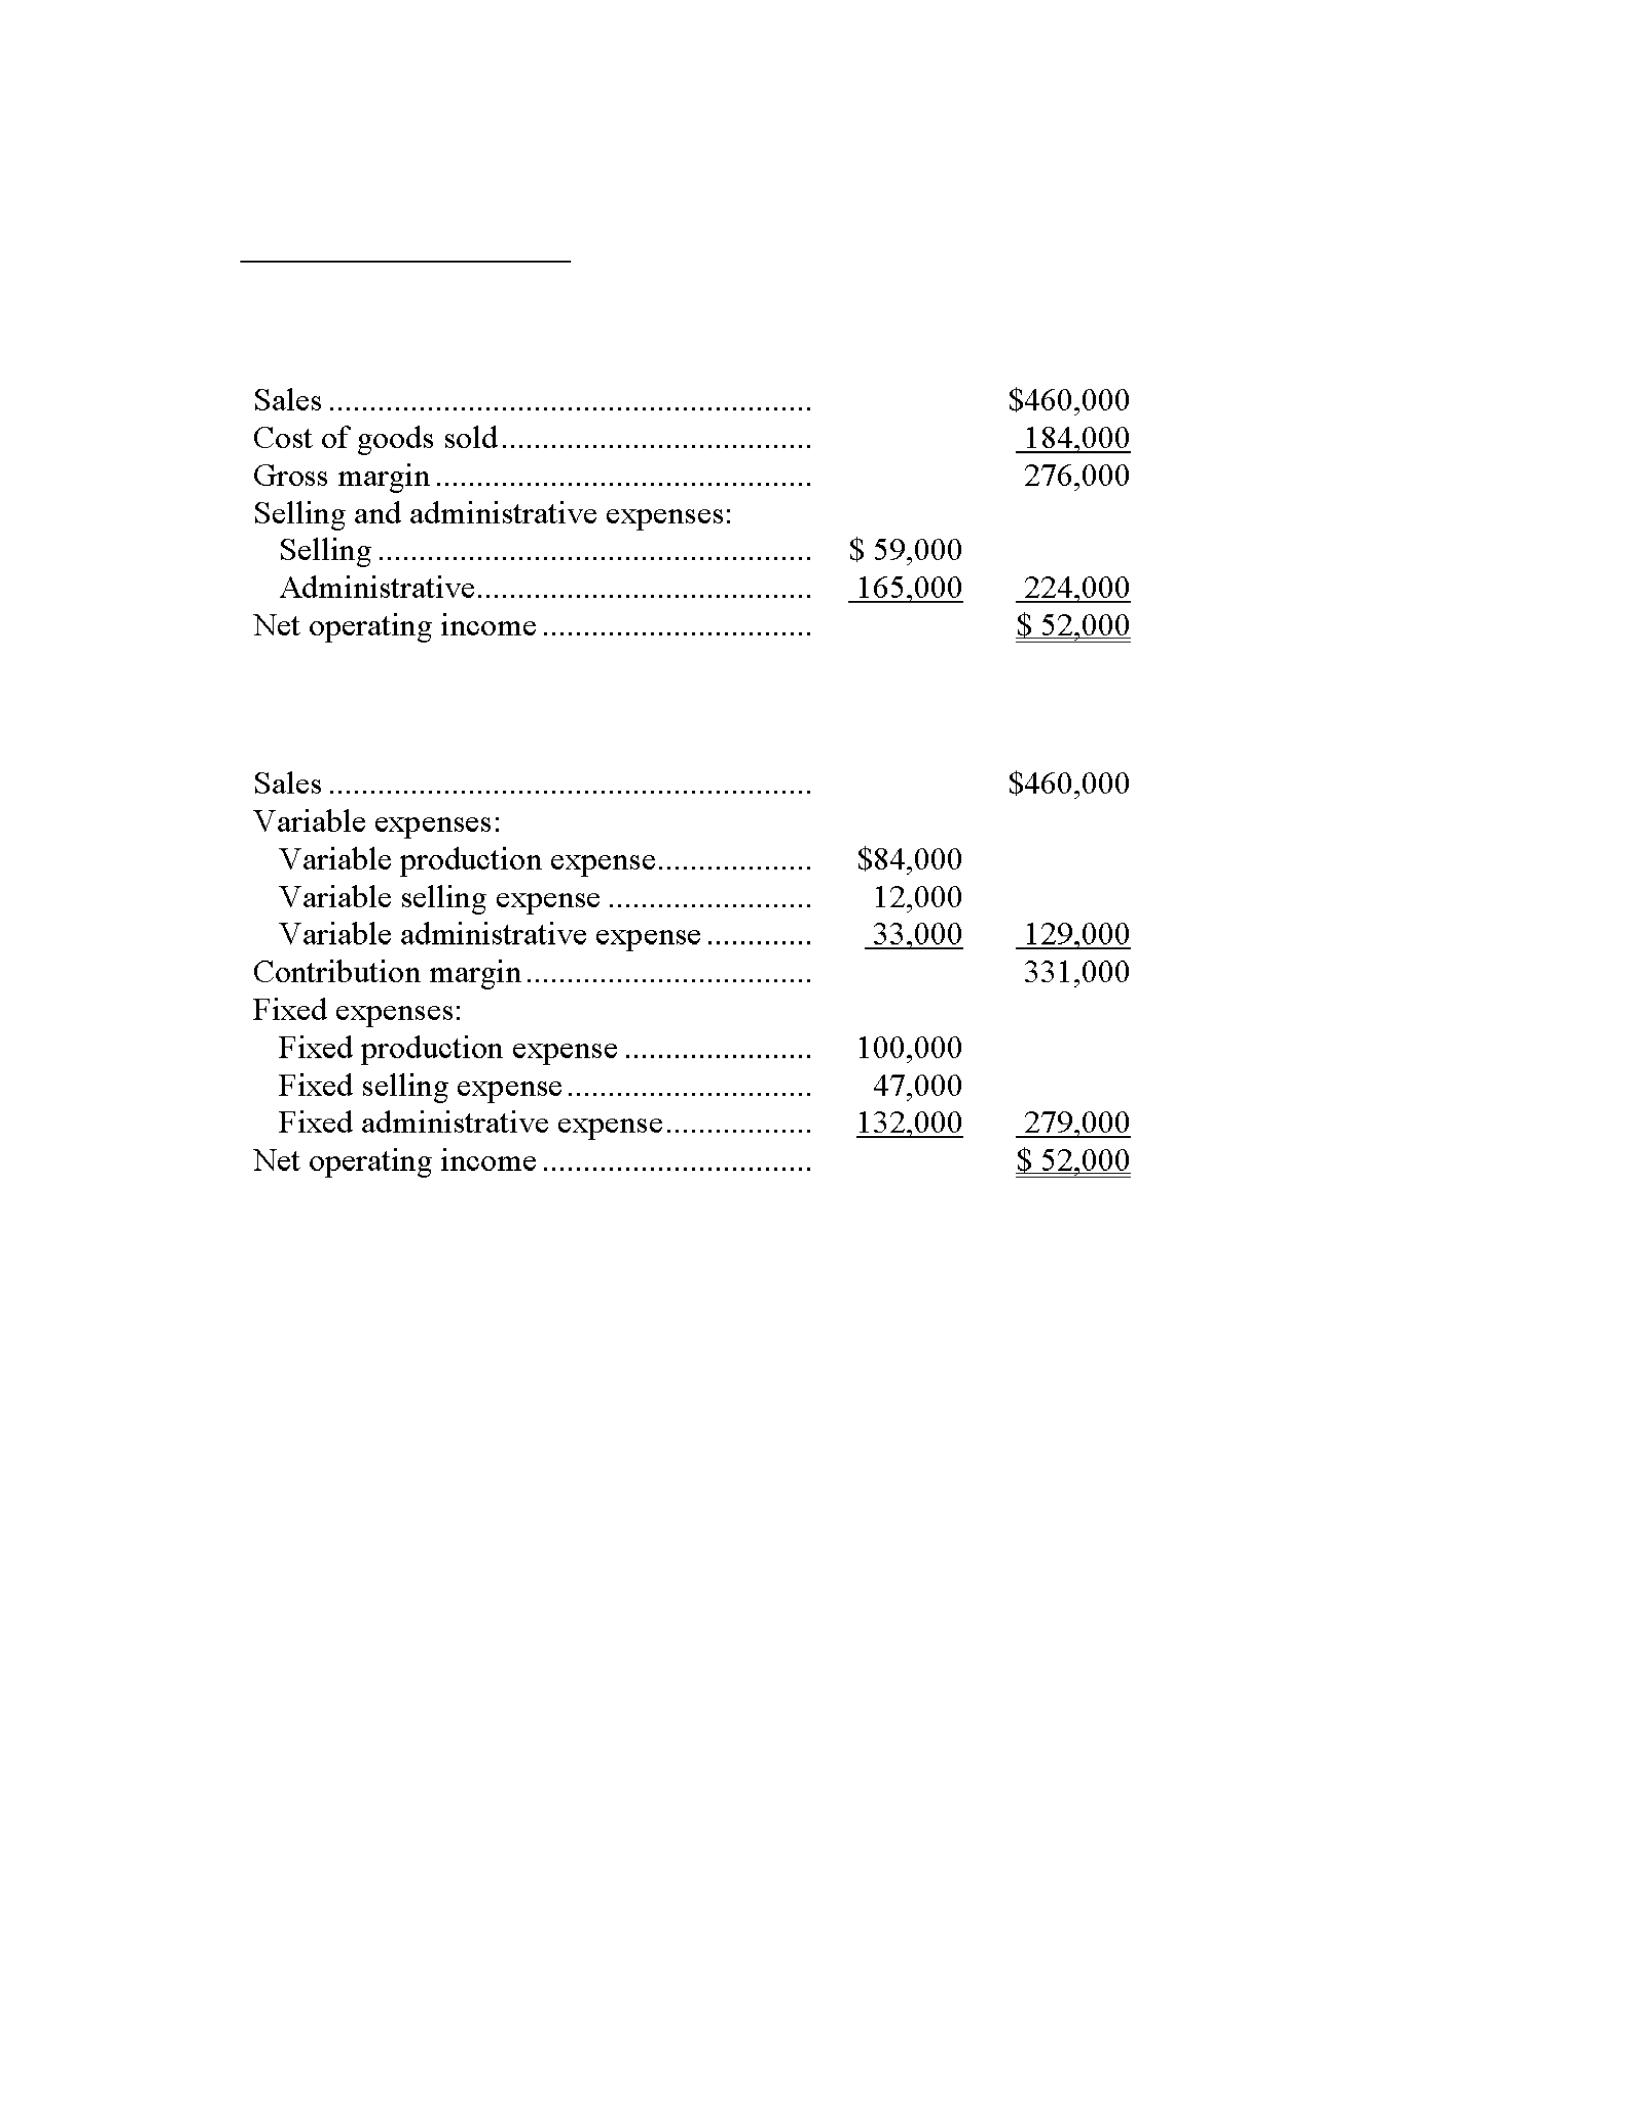
Item #4 – Cost Behavior
a. Traditional approach
b. Contribution approach
ACC241 – Examination #2 Review Activity Solutions
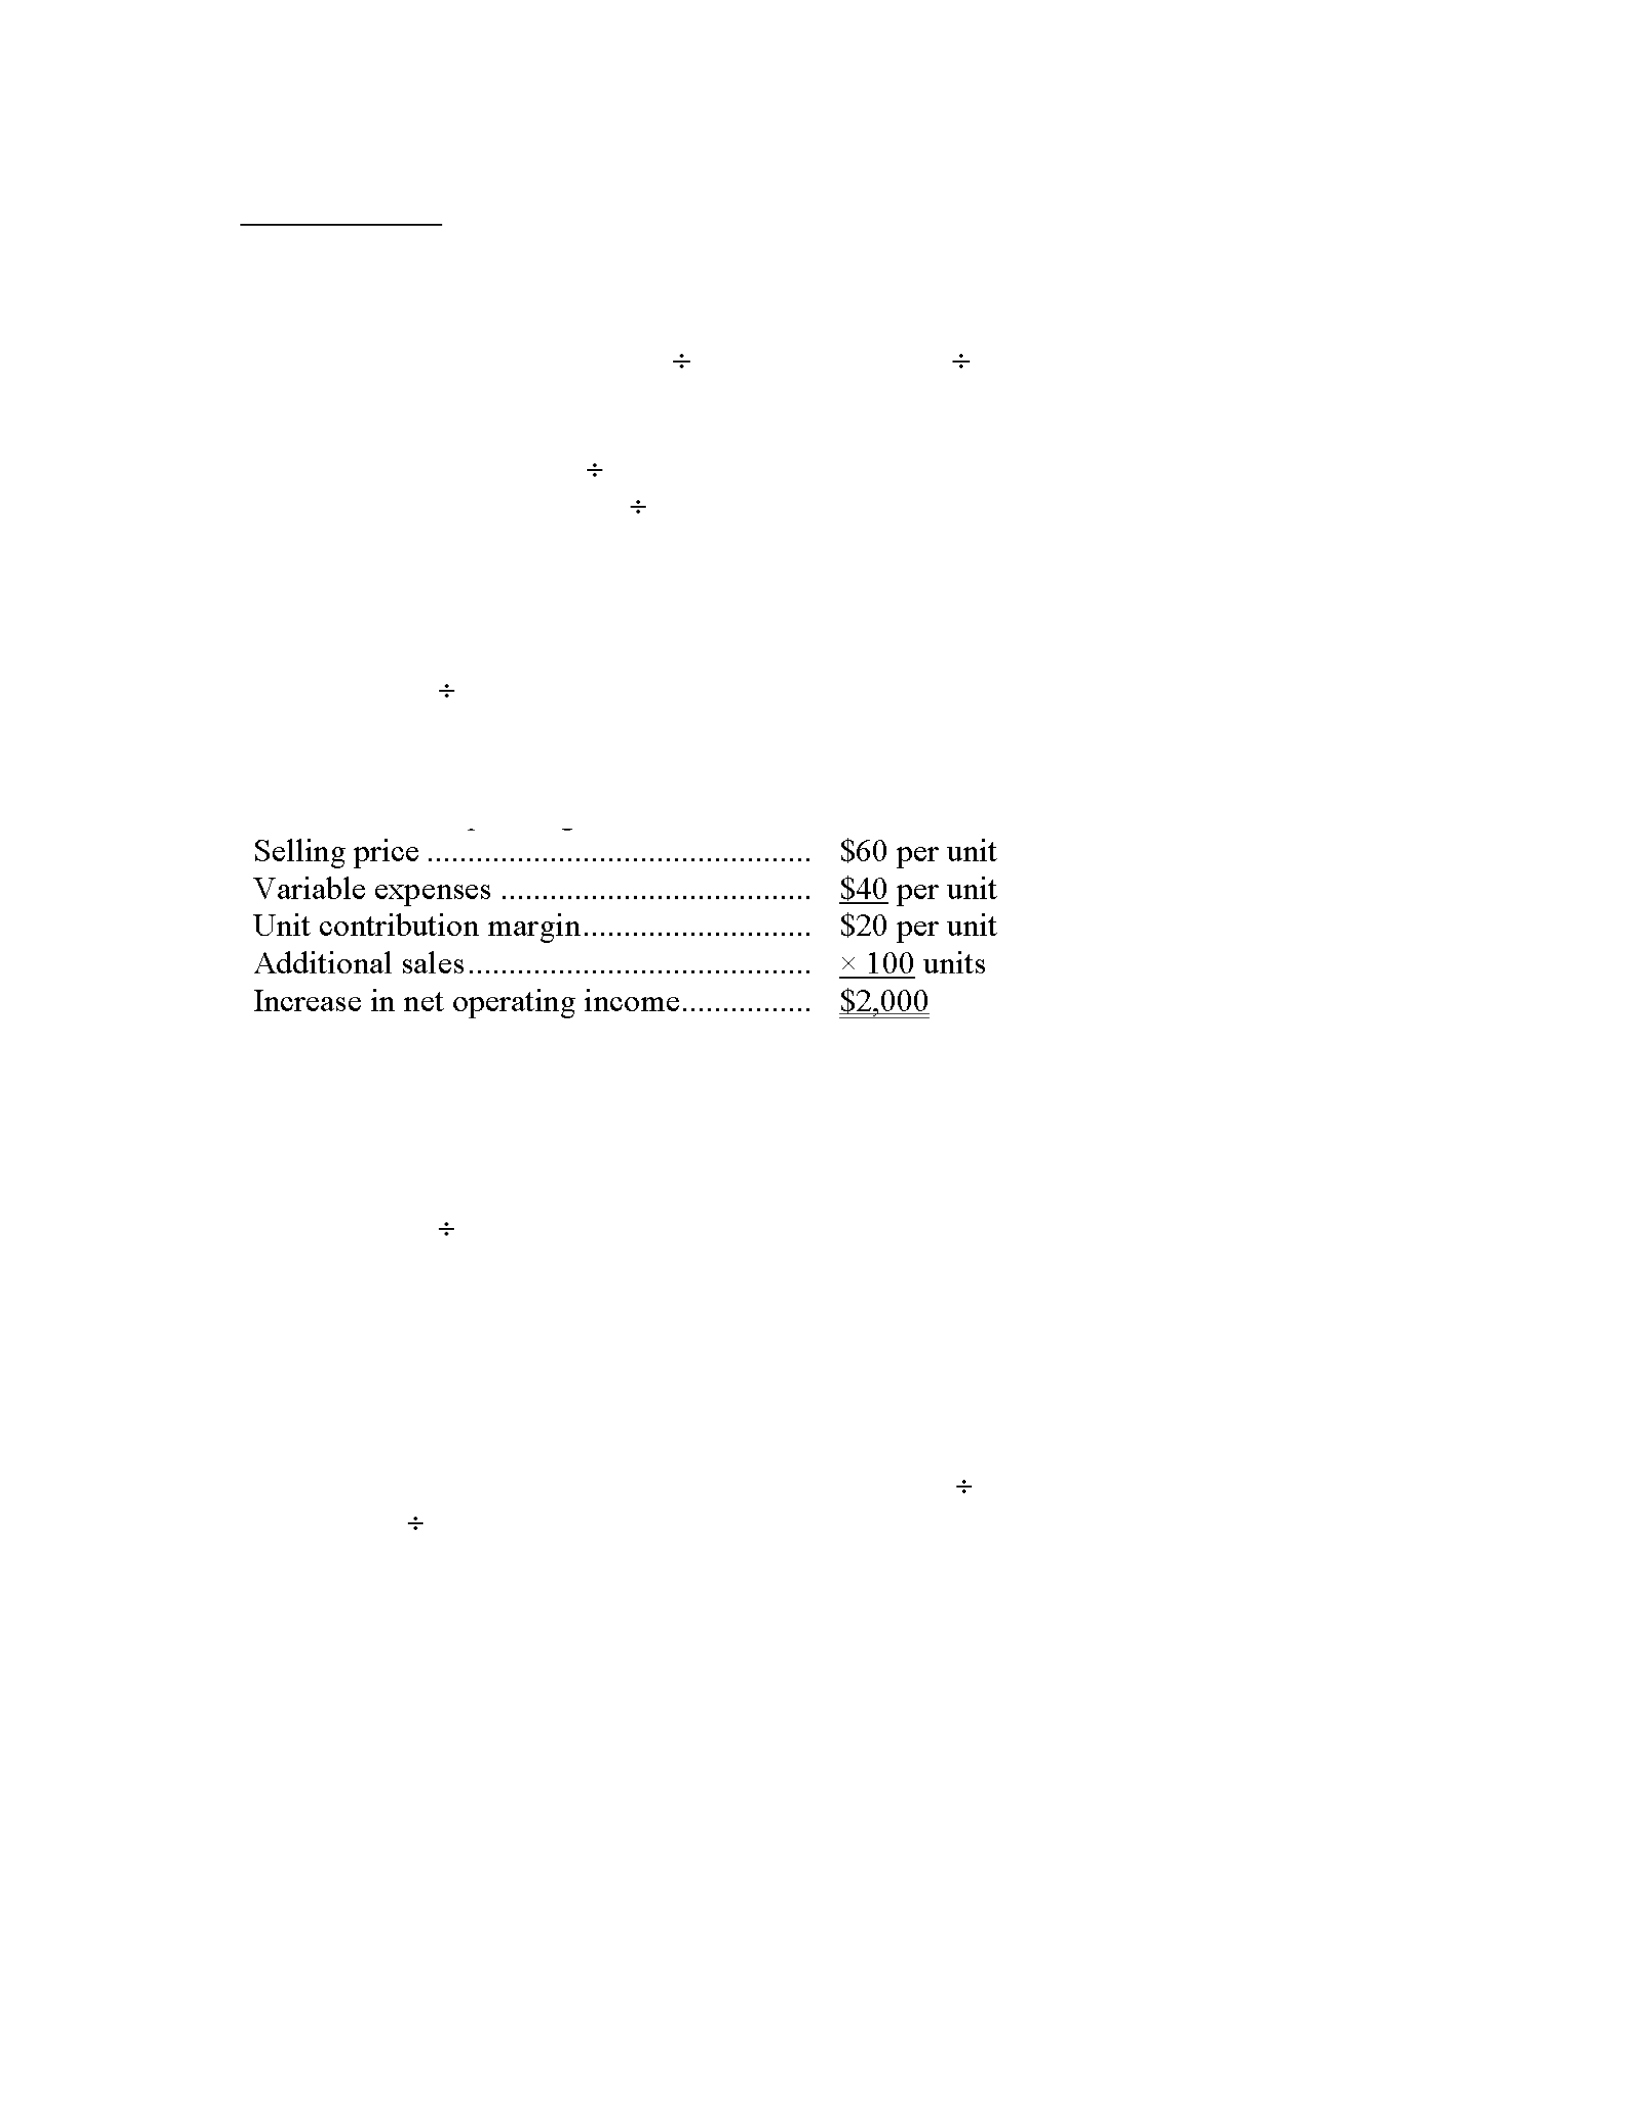
Item #5 – CVP
a. Contribution margin ratio:
CM ratio = Contribution margin Sales = $400,000 $1,200,000 = 0.333
b. Break-even units:
Selling price ($1,200,000 20,000 units) = $60 per unit
Variable expenses ($800,000 20,000 units) = $40 per unit
Sales = Variable expenses + Fixed expenses + Profit
$60Q = $40Q + $300,000 + $0
$20Q = $300,000
Q = $300,000 $20 per unit = 15,000 units
c. Increase in net operating income from additional sales of 100 units:
d. Sales to attain target profit:
Sales = Variable expenses + Fixed expenses + Profit
$60Q = $40Q + $300,000 + $125,000
$20Q = $425,000
Q = $425,000 $20 per unit = 21,250 units
e. Margin of safety in dollars:
Break-even sales = $60 per unit 15,000 units = $900,000
Margin of safety in dollars = Sales - Break-even sales
= $1,200,000 - $900,000 = $300,000
f. Degree of operating leverage = Contribution margin Net operating income
= $400,000 $100,000 = 4.0
ACC241 – Examination #2 Review Activity Solutions
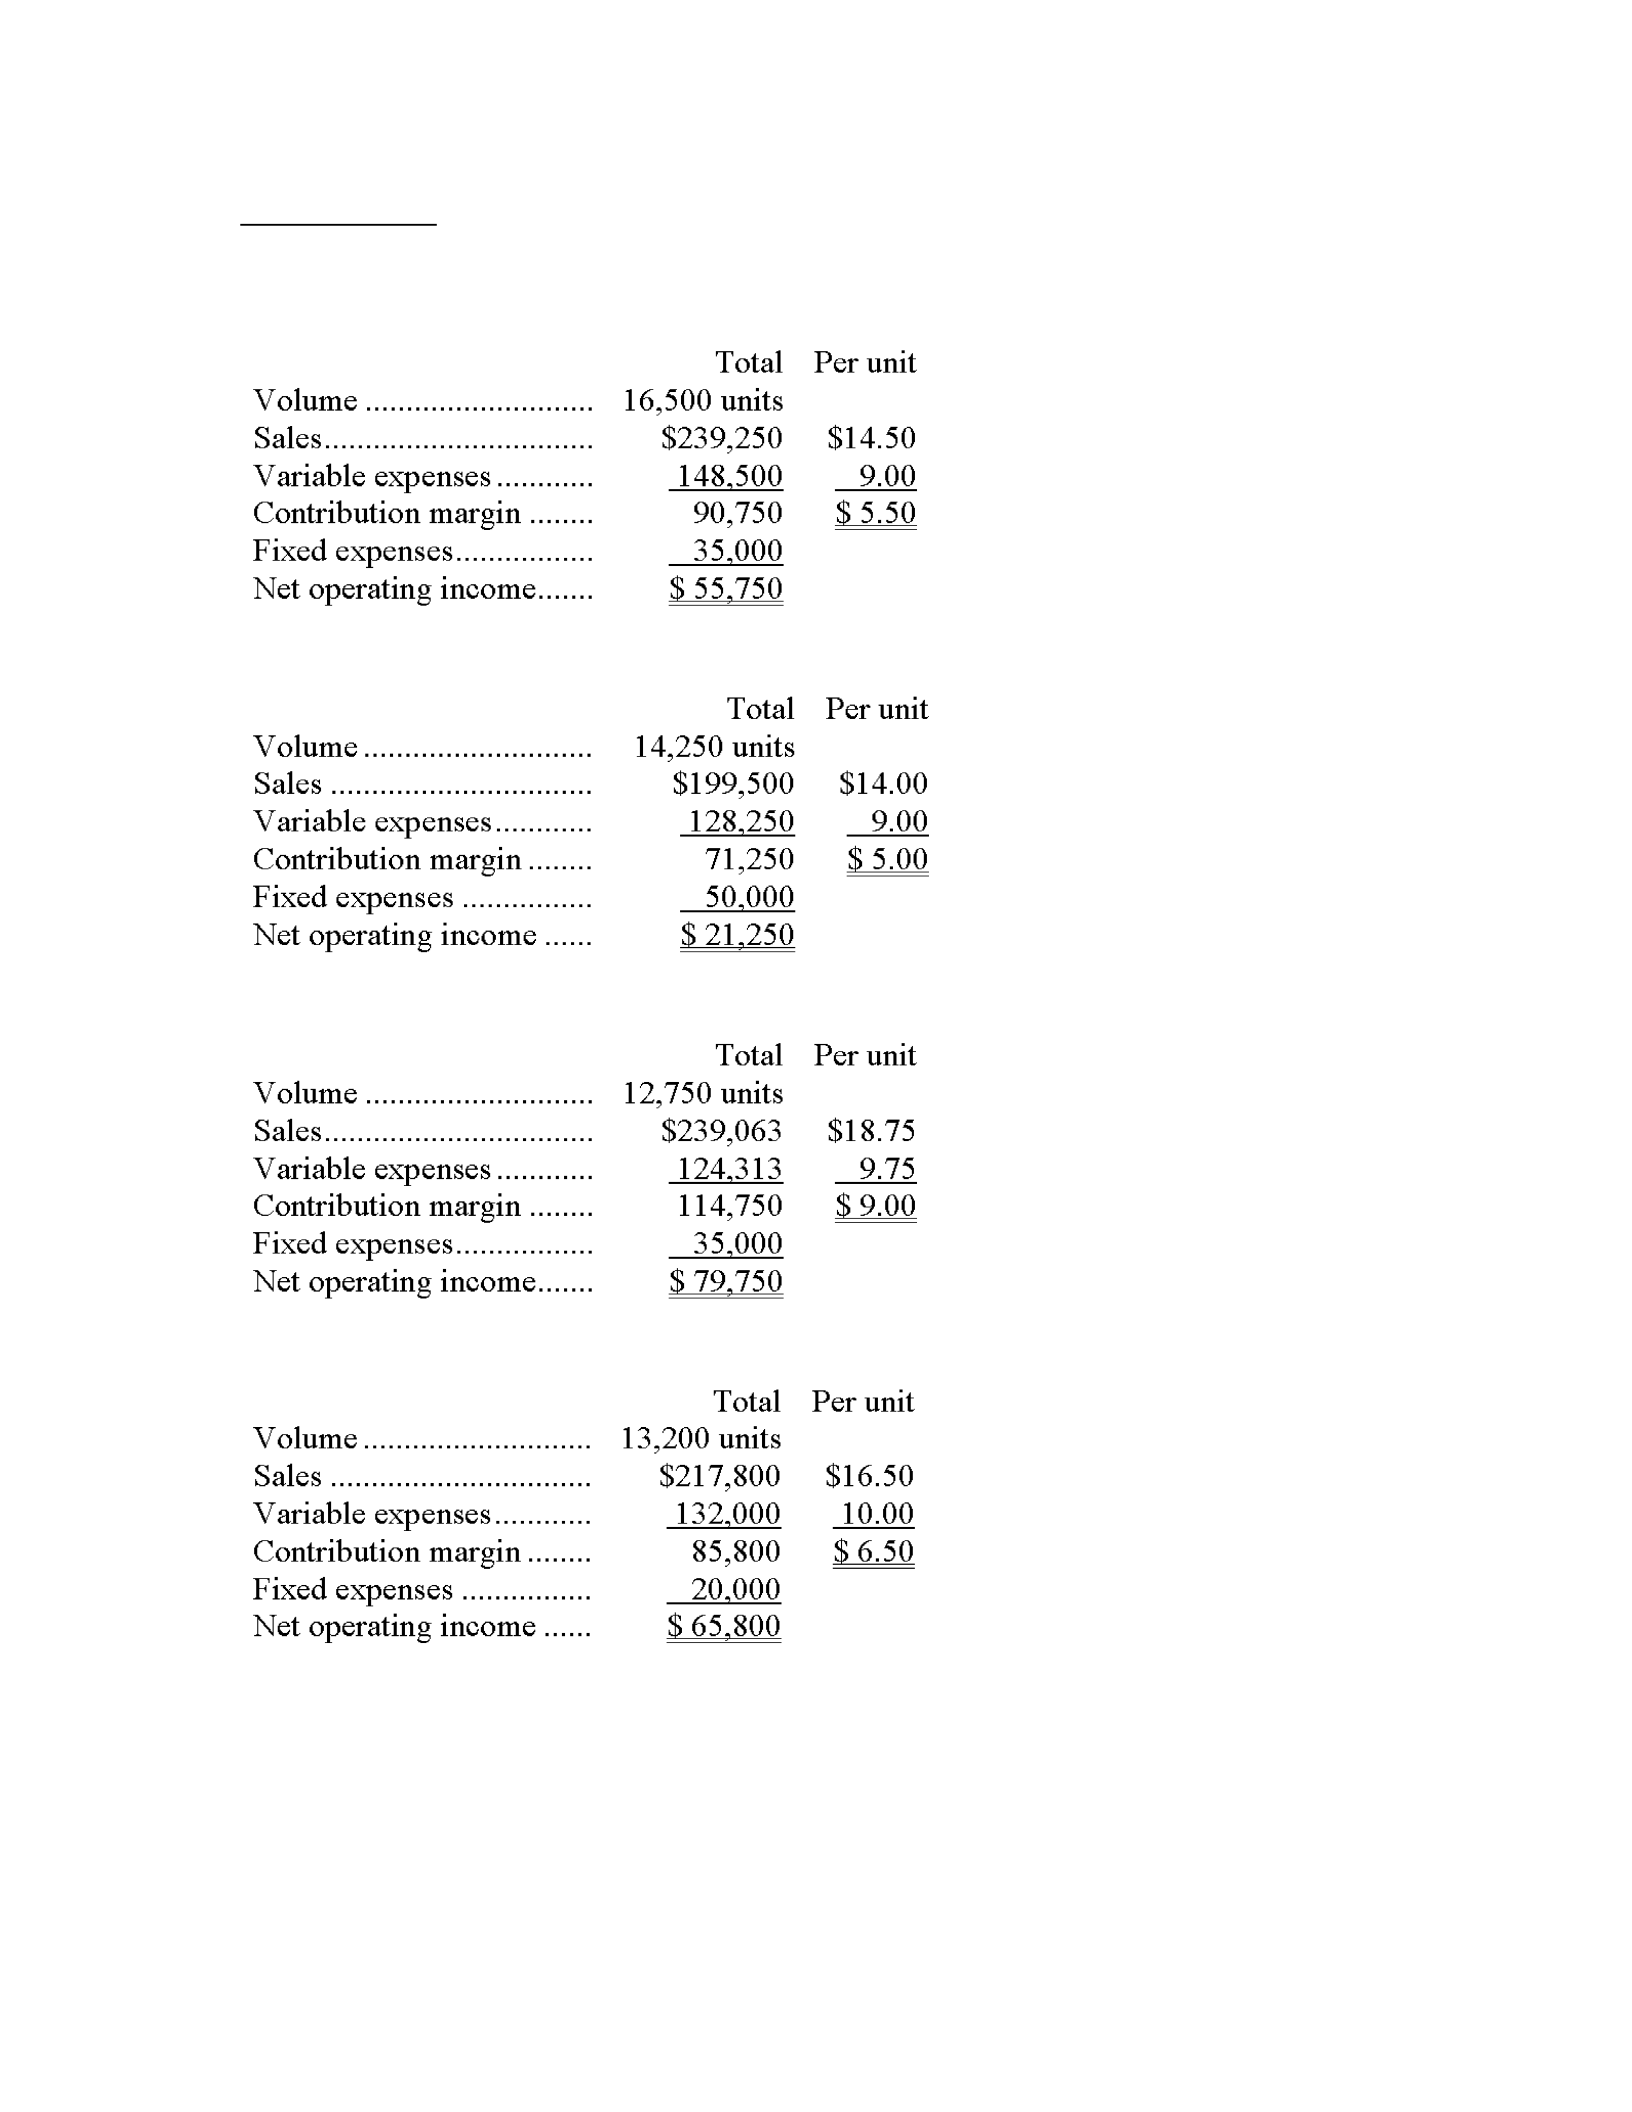
Item #6 - CVP
a.
b.
c.
d.
ACC241 – Examination #2 Review Activity Solutions
Item #7 – CVP
a. The contribution margin ratio is $15,000 $60,000 = 25%. Therefore, the break-even
in sales dollars is $18,000 25% = $72,000.
b. The variable cost ratio is $45,000 $60,000 = 75%. Therefore, the variable expenses
at the break-even point are $72,000 75% = $54,000.
c. 25% See part (a) above.
d.
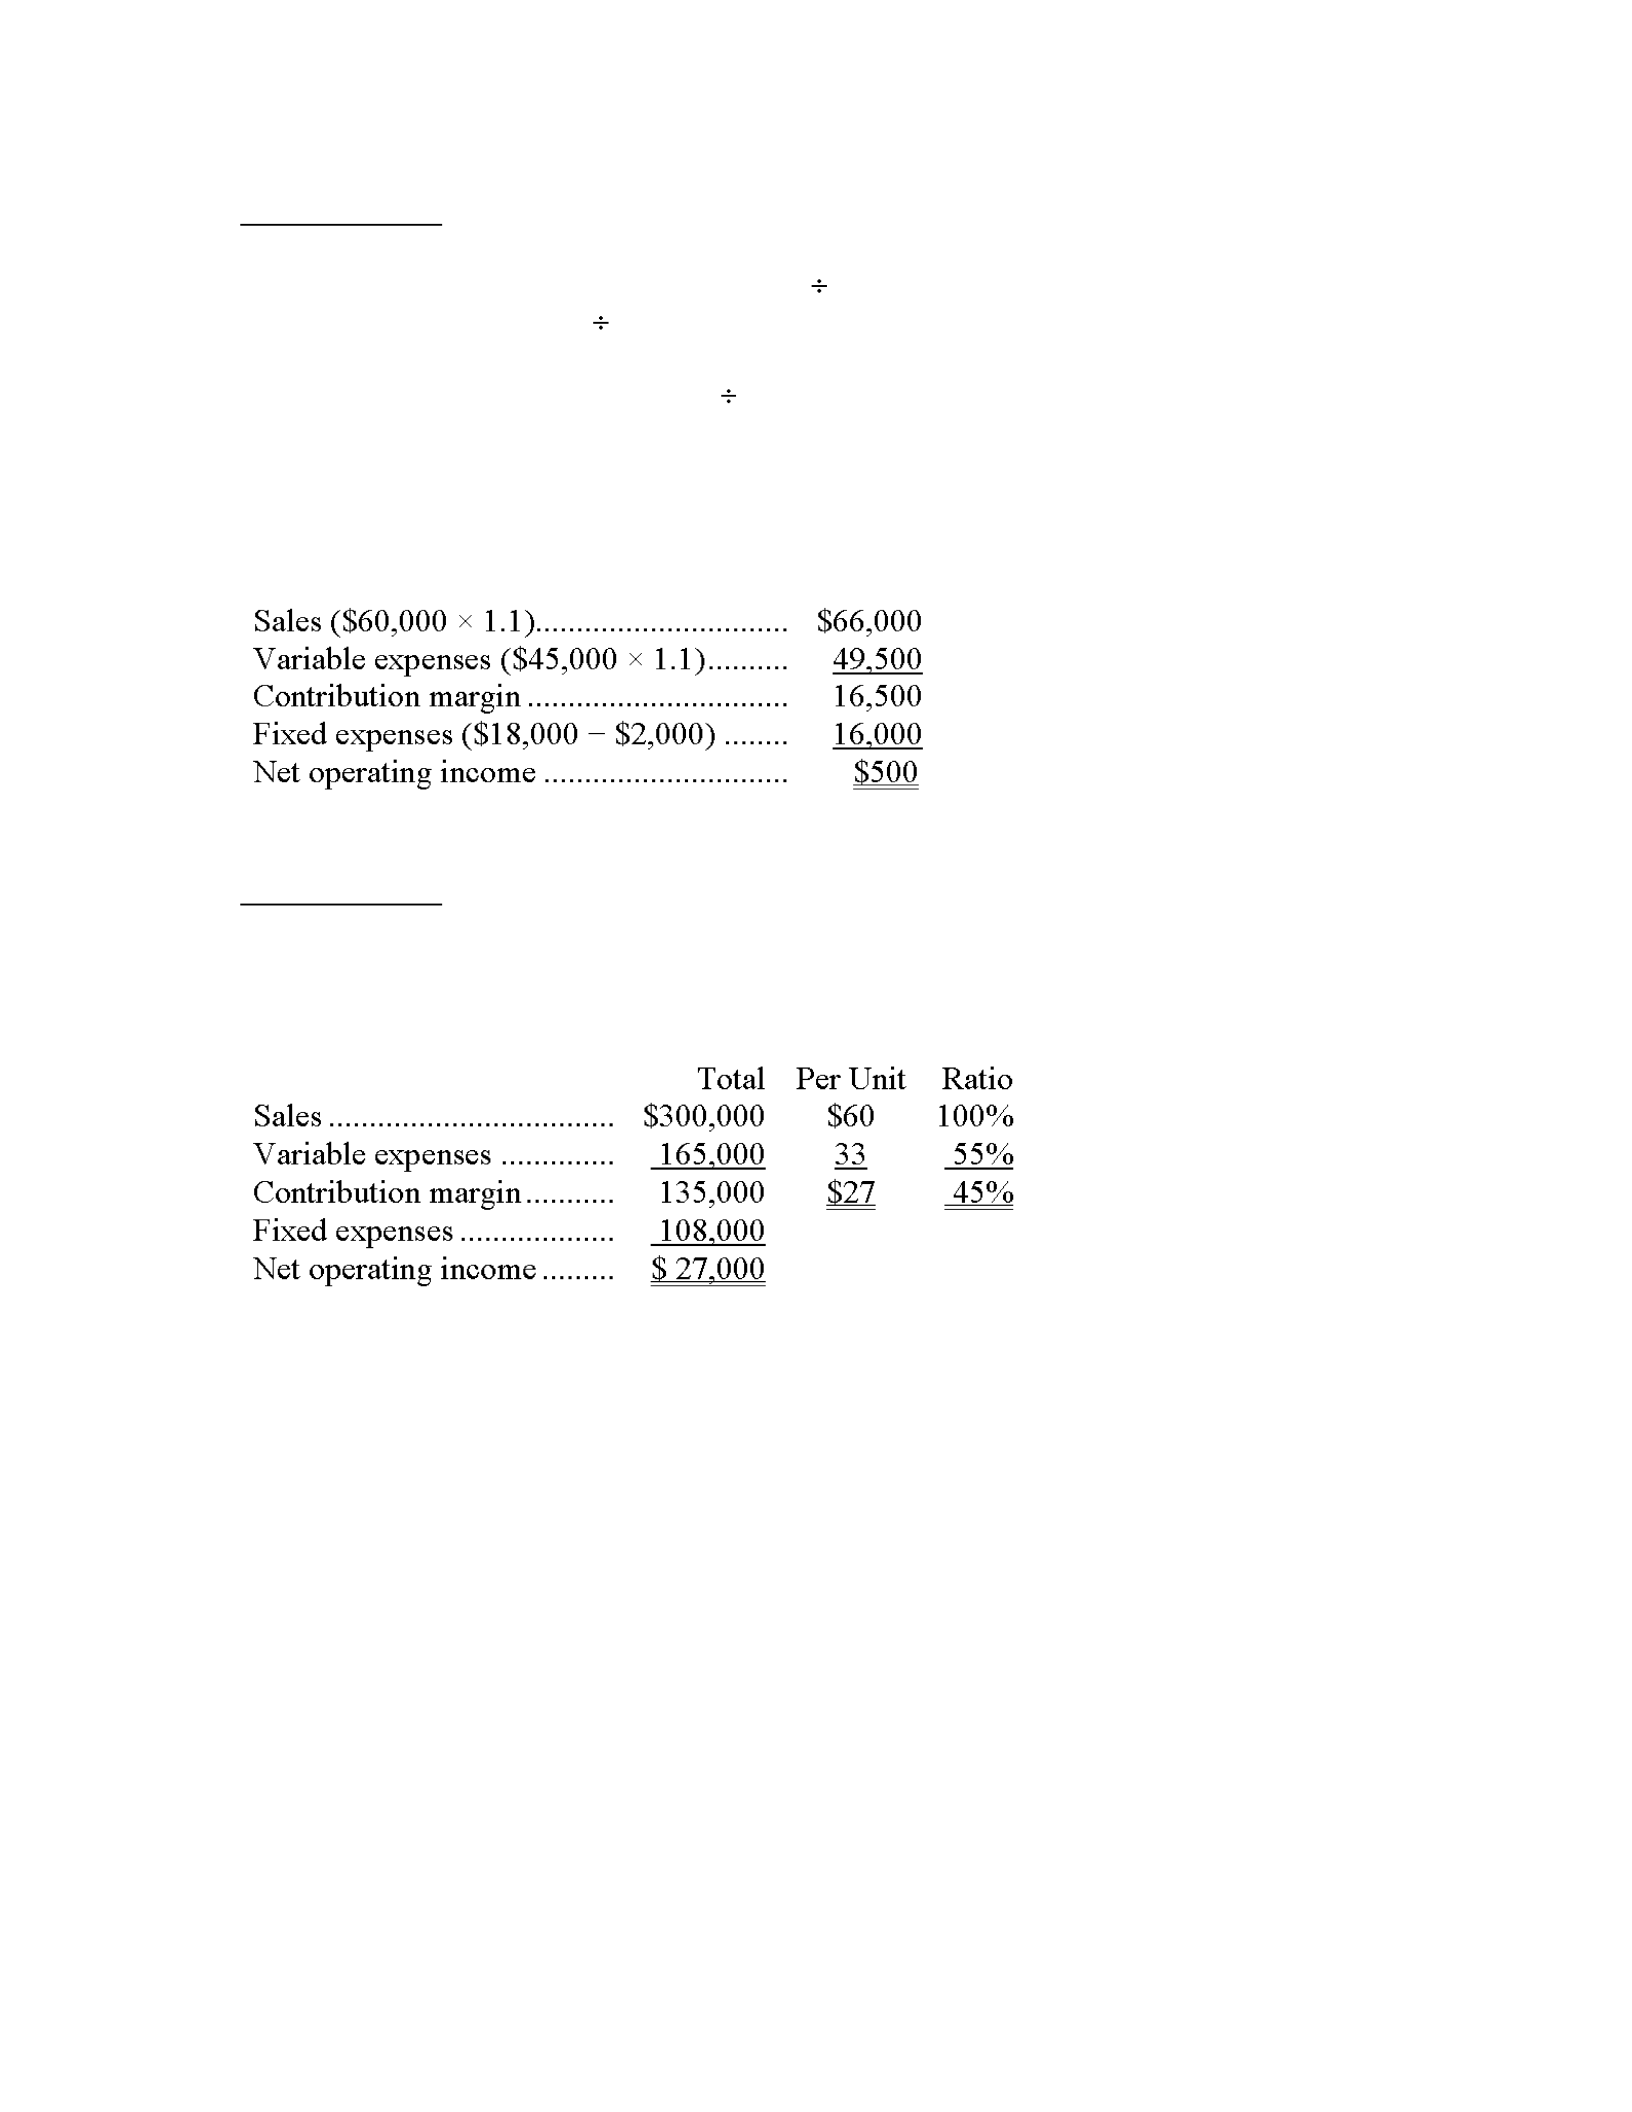
Item #8 – CVP
a. Variable expenses = 0.55 $300,000 = $165,000
Variable expenses per unit = 0.55 $60 = $33
b. Break-even in unit sales = $108,000/$27 per unit = 4,000 units
Break-even in dollar sales = $108,000/0.45 = $240,000
c. Dollar sales to attain target profit = ($108,000 + $54,000)/0.45 = $360,000
d. Margin of safety = $300,000 - $240,000 = $60,000
Margin of safety percentage = $60,000/$300,000 = 20%
ACC241 – Examination #2 Review Activity Solutions
Item #9 – CVP
a. Degree of operating leverage = Contribution margin/Net operating income
= $251,100/$41,300 = 6.08
b. Percent increase in net operating income
= Percent increase in sales Degree of operating leverage
= 19% 6.08 = 115.52%
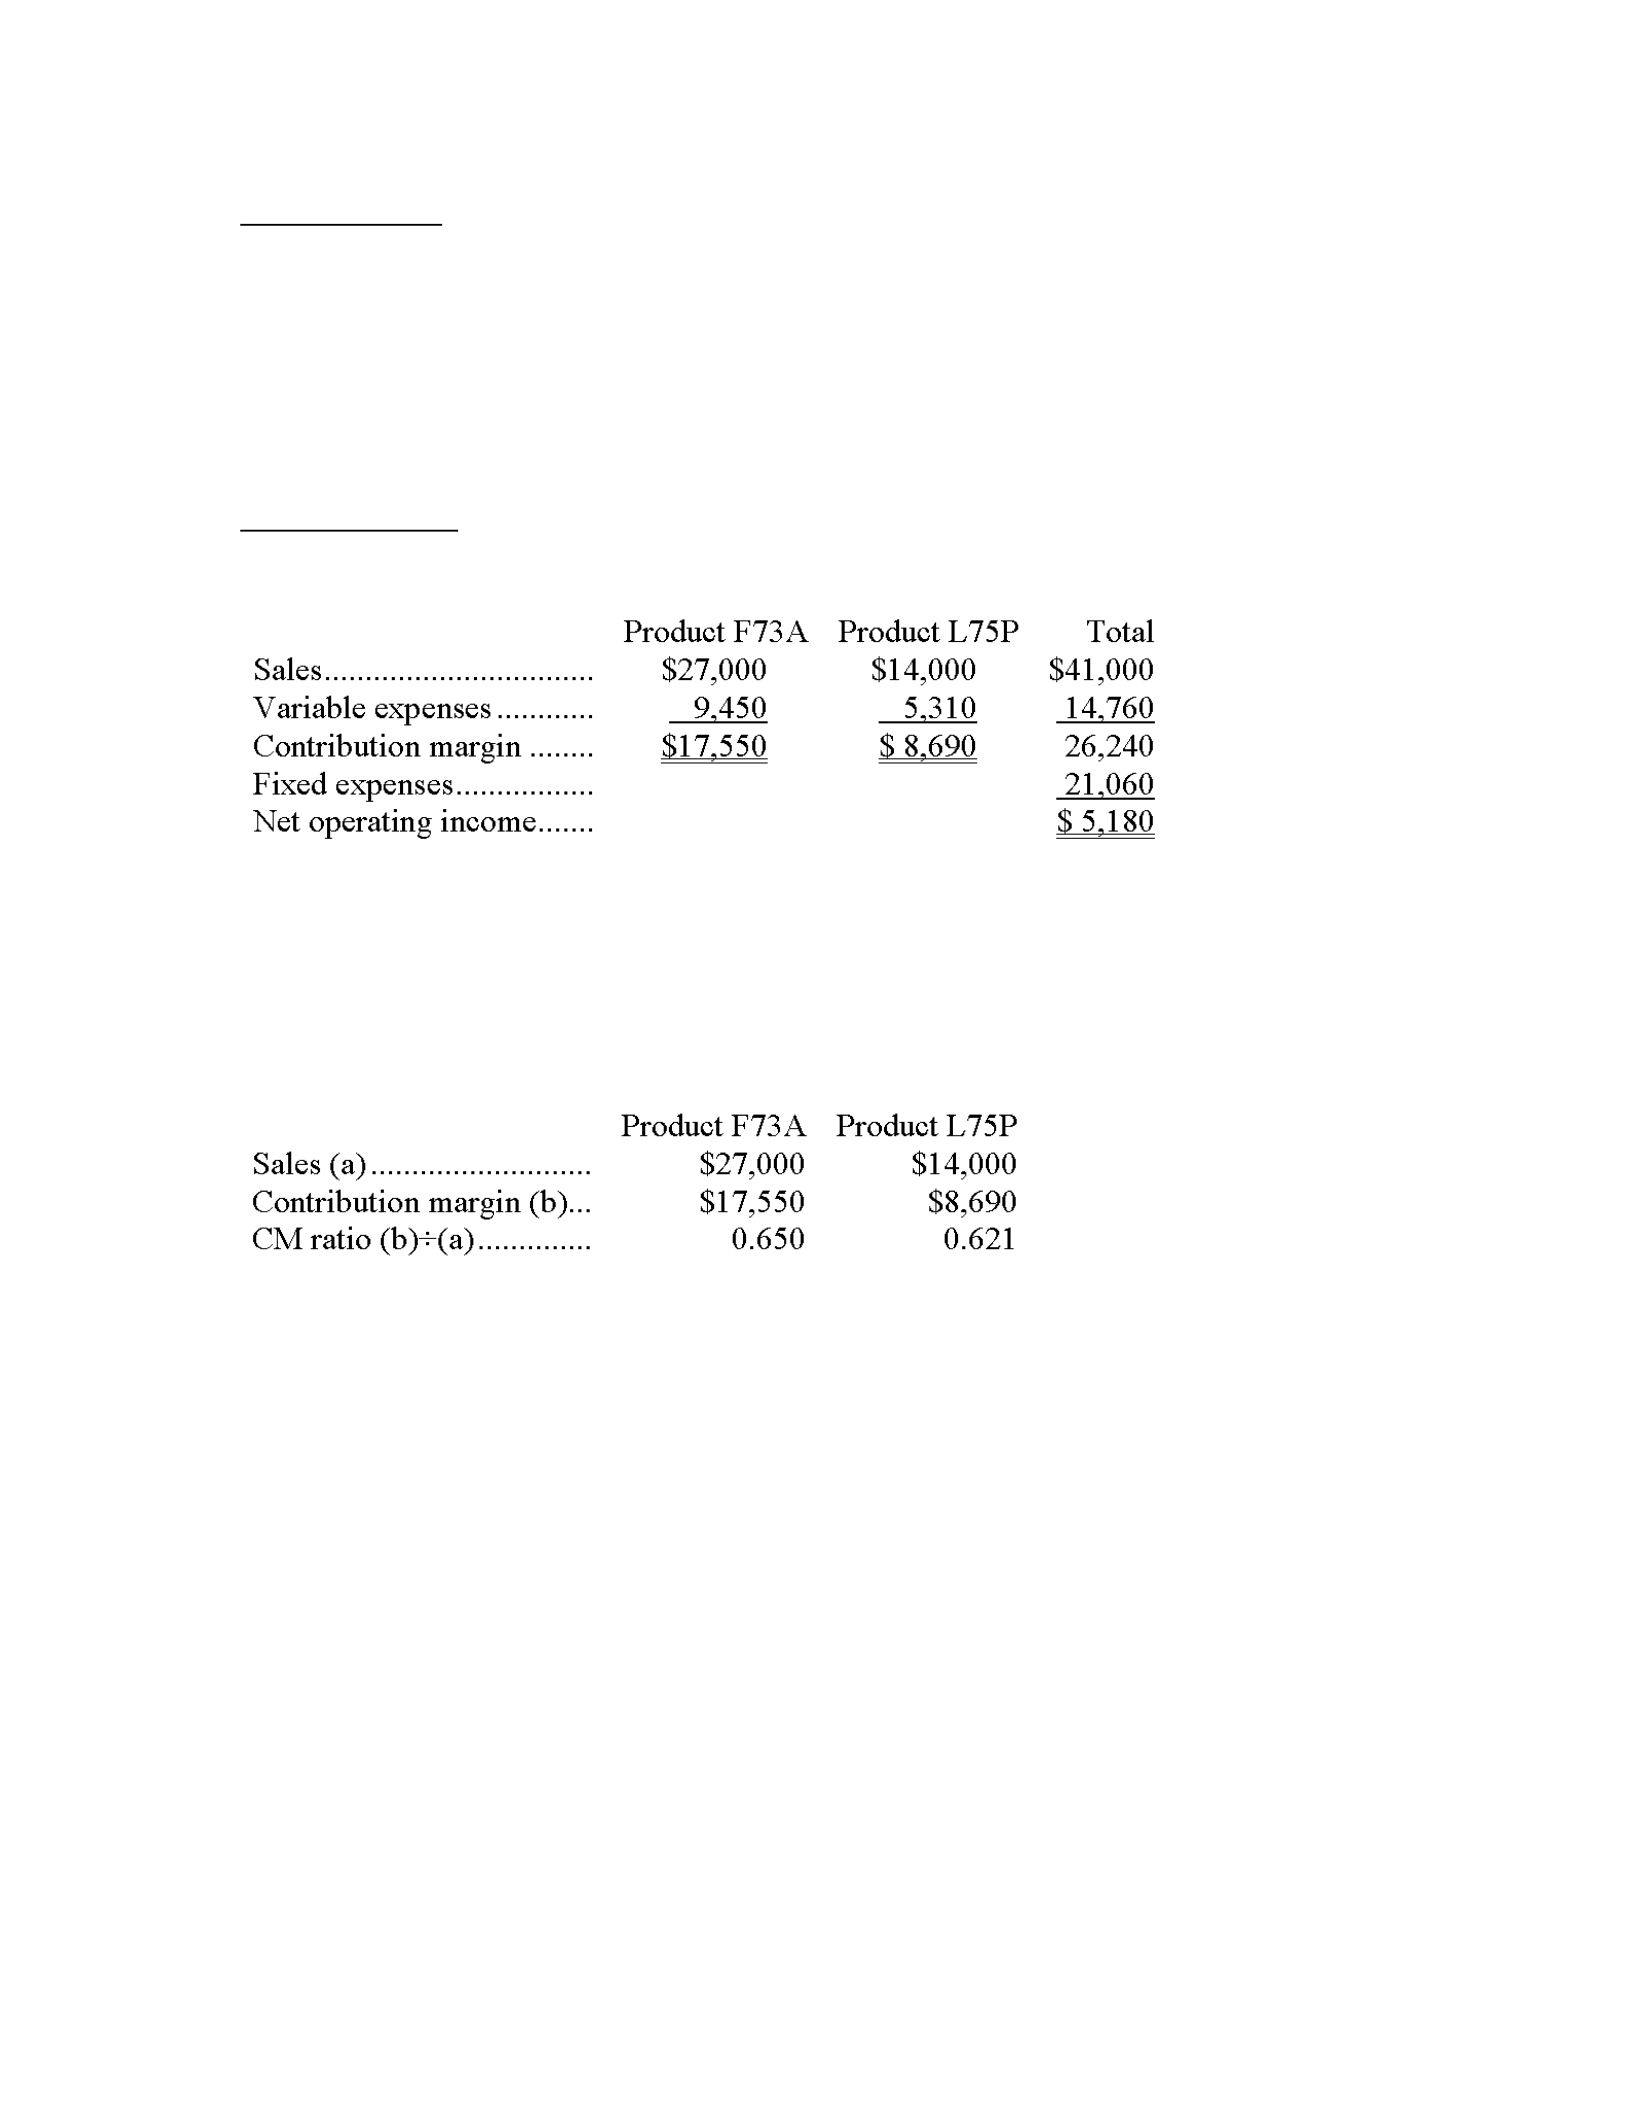
Item #10 – CVP
a.
Overall CM ratio = Total contribution margin/Total sales
= $26,240/$41,000 = 0.64
Break-even point in total sales dollars = Fixed expenses/Overall CM ratio
= $21,060/0.64 = $32,906
b.
Since Product F73A's CM ratio is greater than Product L75P's, a shift in the sales mix
toward Product F73A will result in a decrease in the company's overall break-even point.
ACC241 – Examination #2 Review Activity Solutions
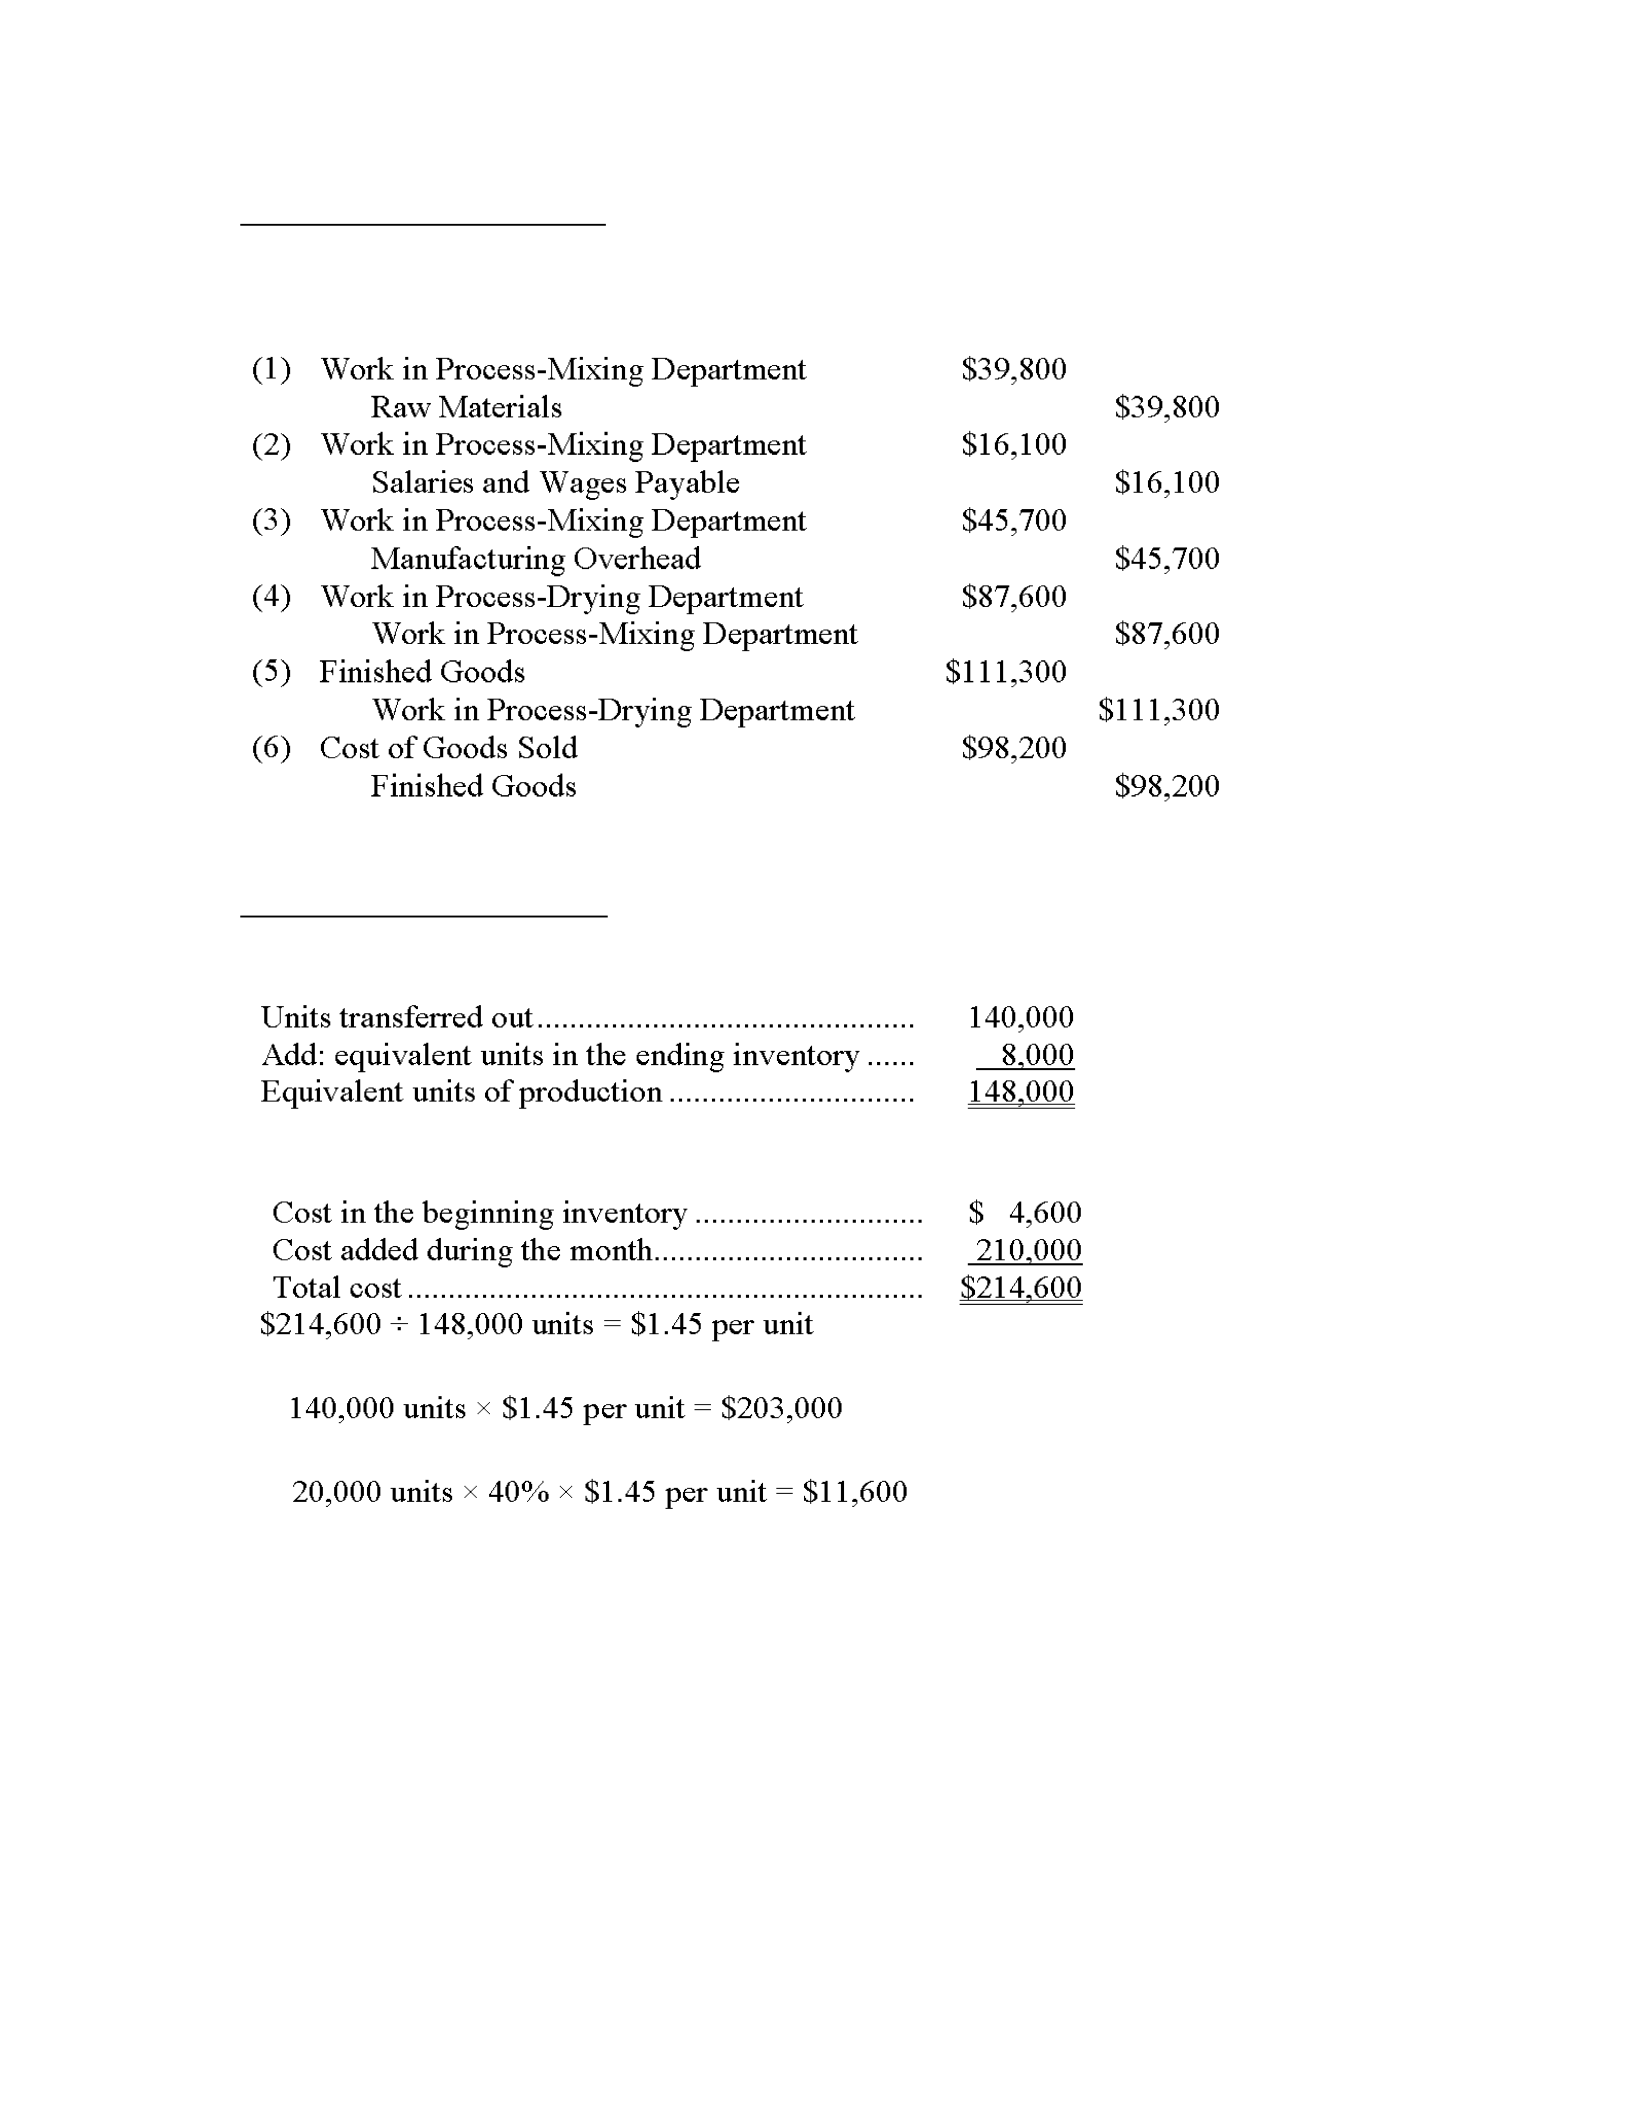
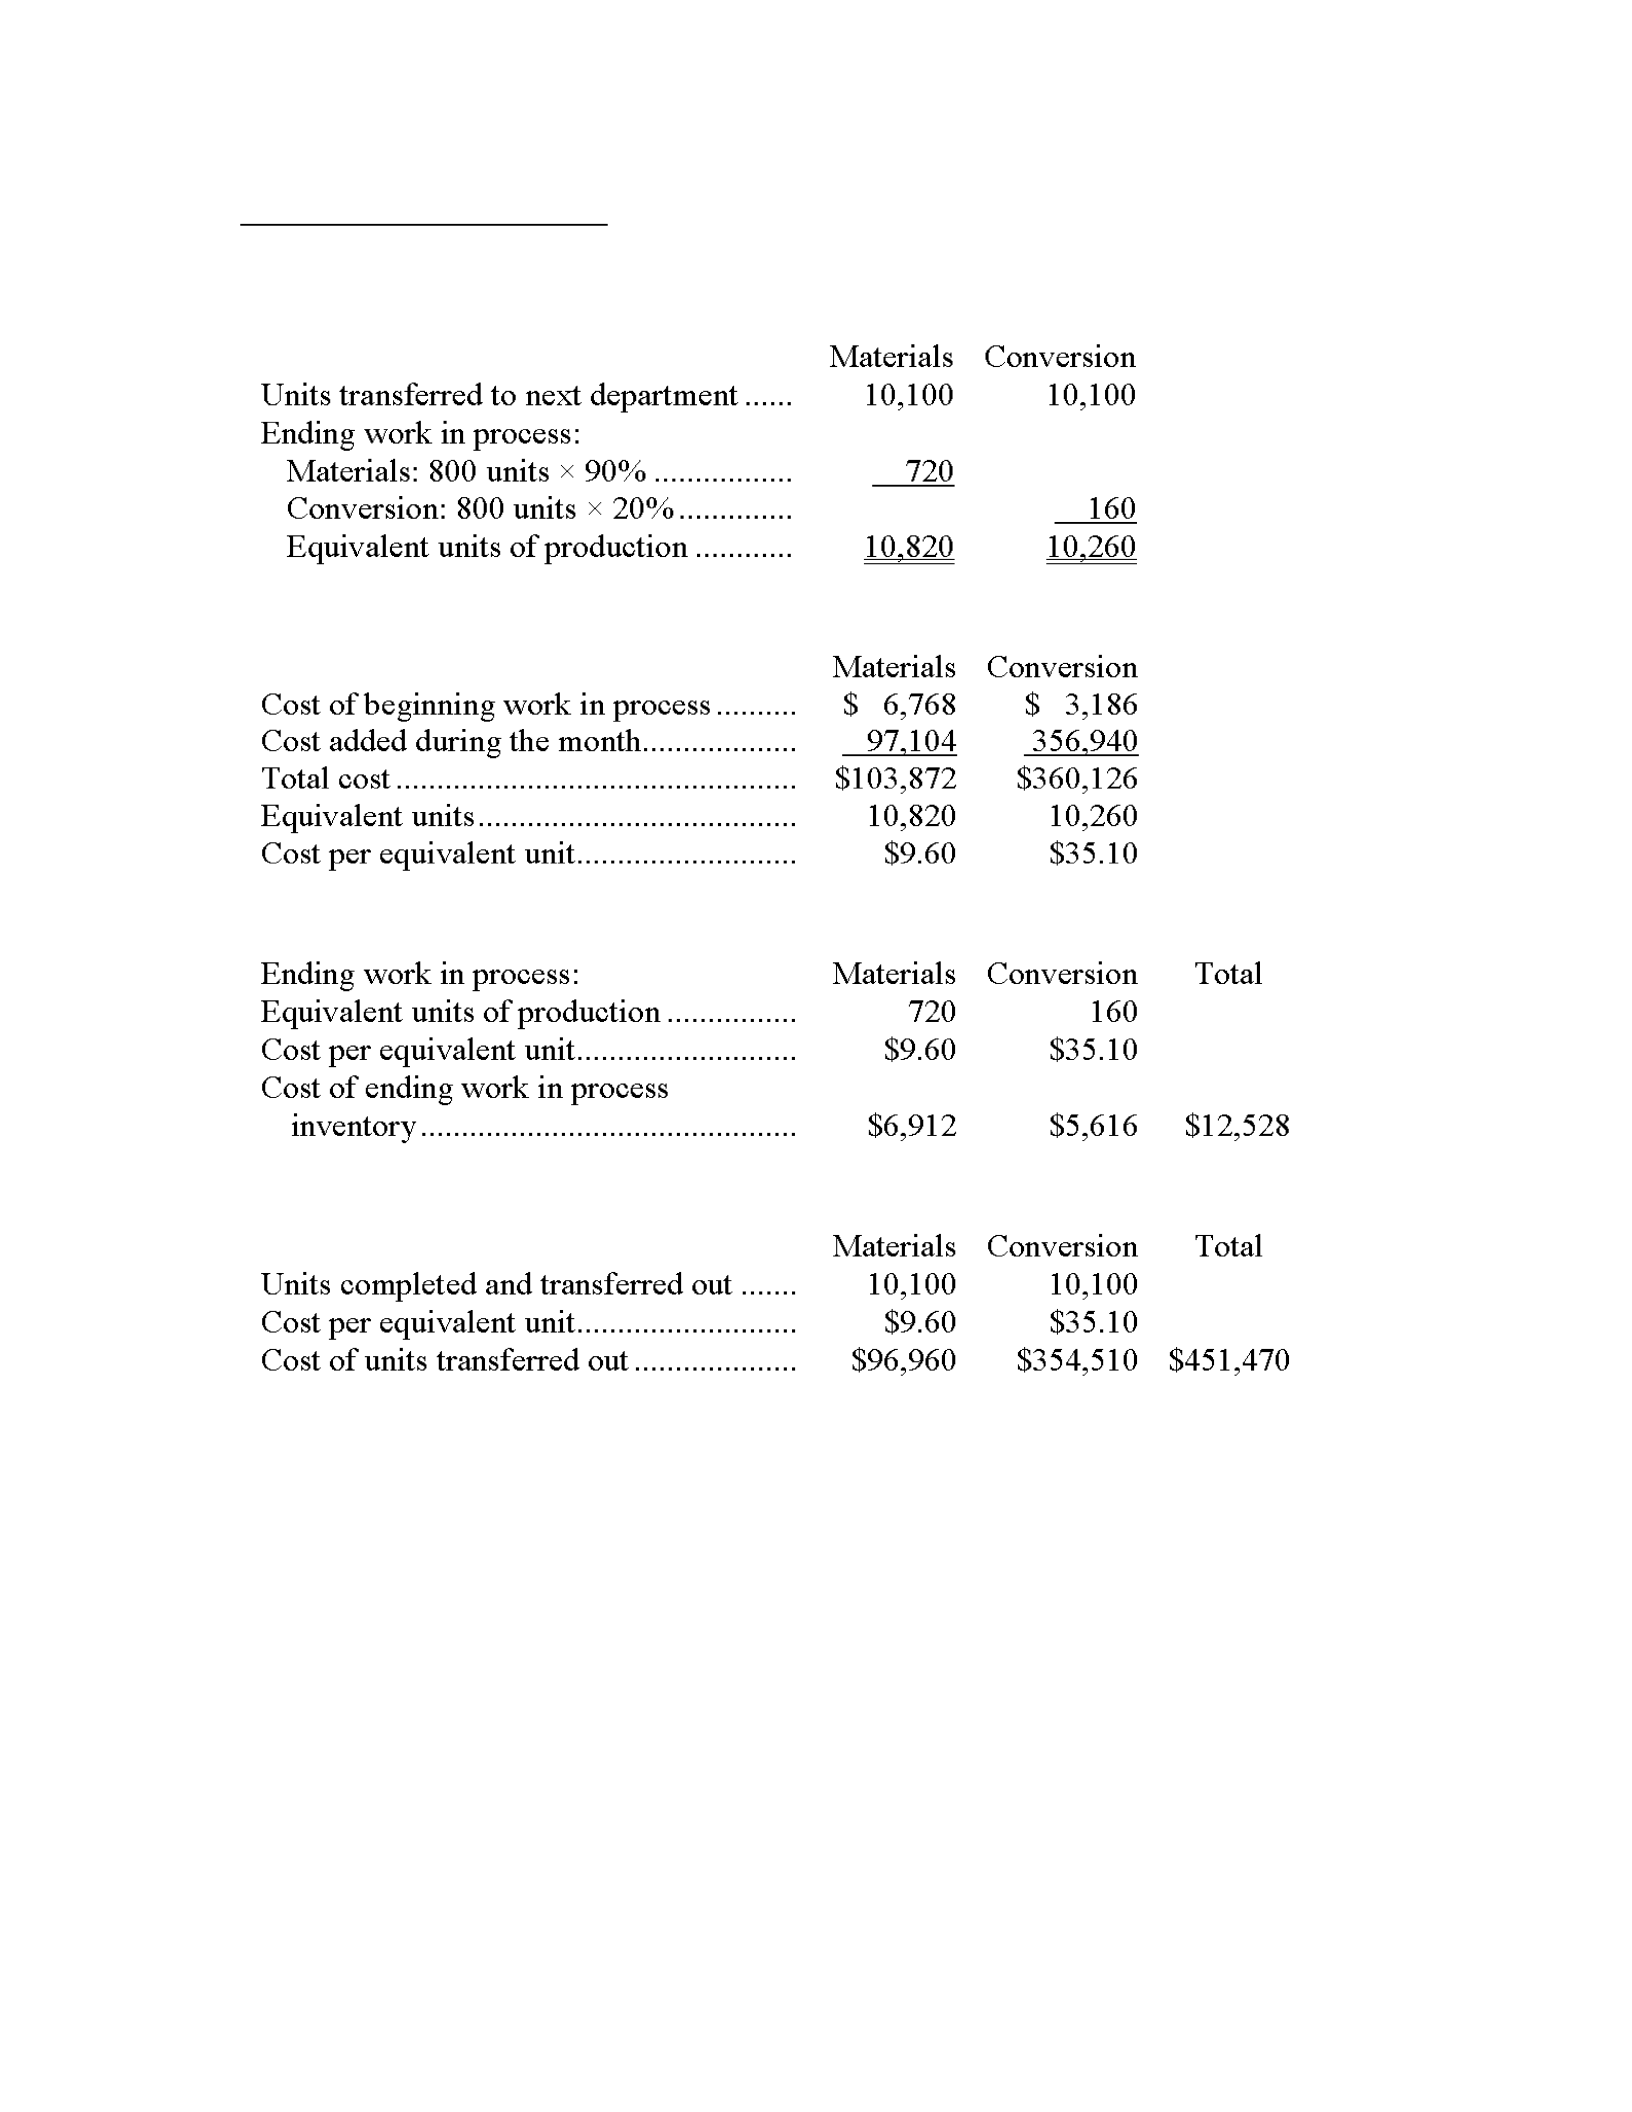
Item #11 – Process Costing
Prepare journal entries for each of the transactions listed above.
Item #12 – Process Costing
a.
b.
c.
d.
ACC241 – Examination #2 Review Activity Solutions
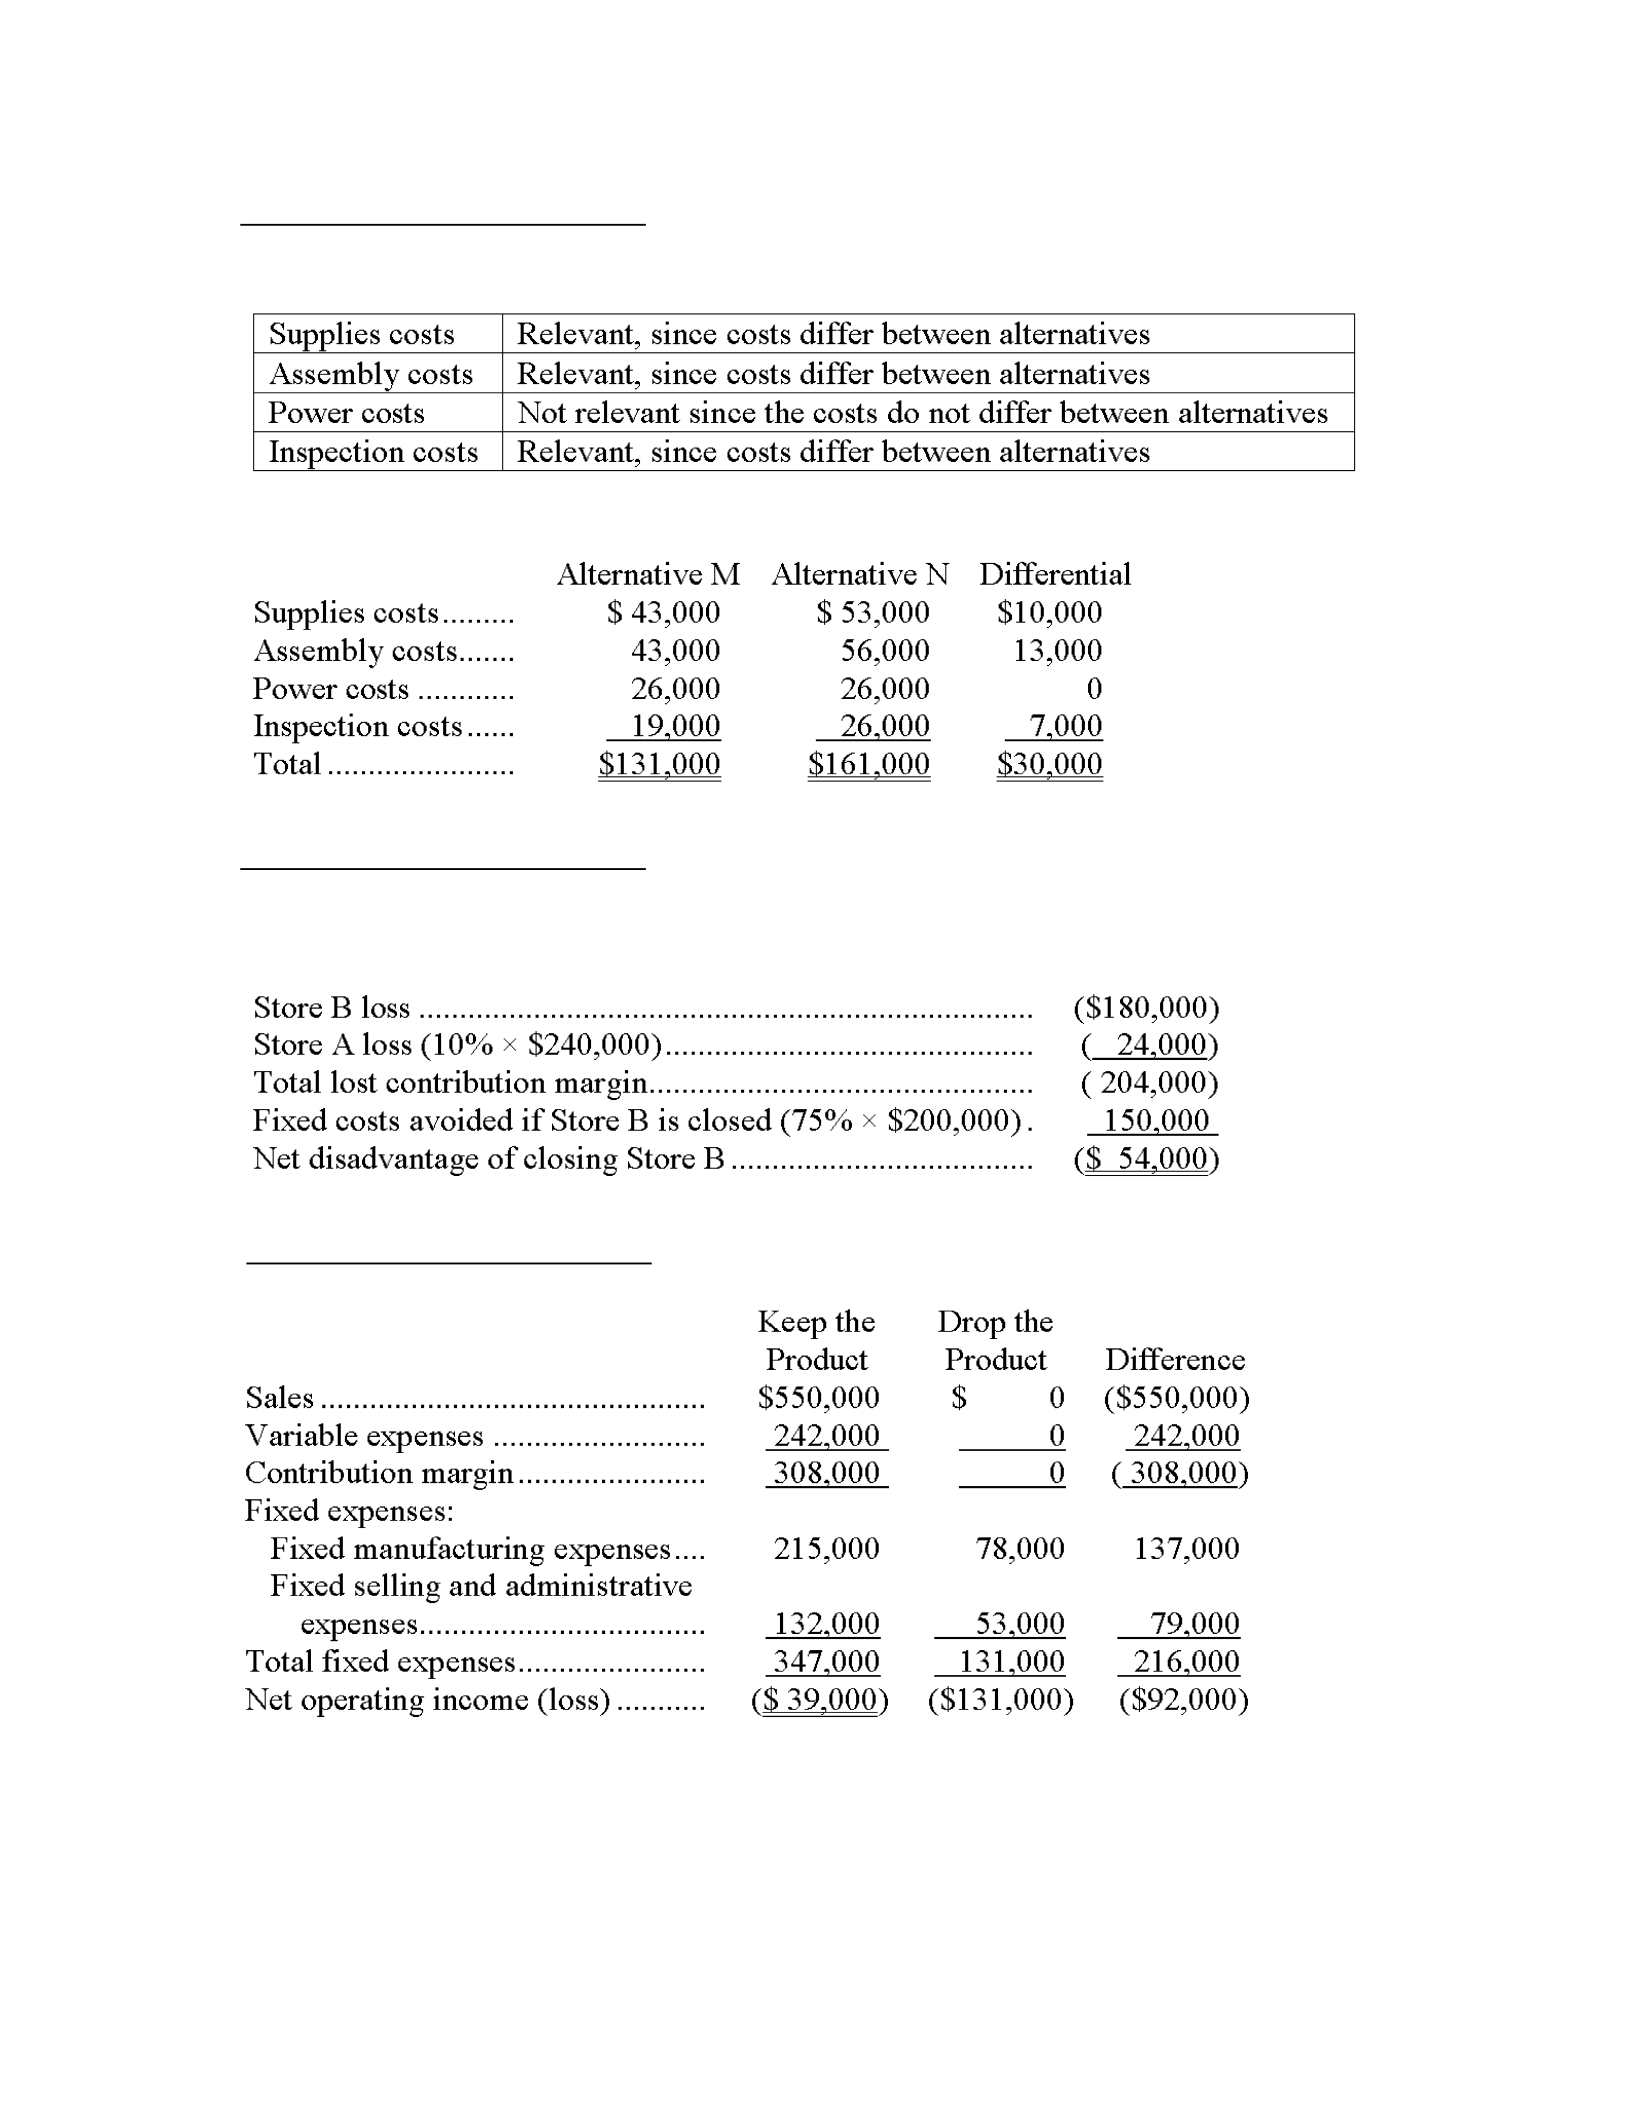
Item #13 – Process Costing
Weighted-average method:
a.
b.
c.
d.
ACC241 – Examination #2 Review Activity Solutions
Item #14 – Business Decisions
a.
b.
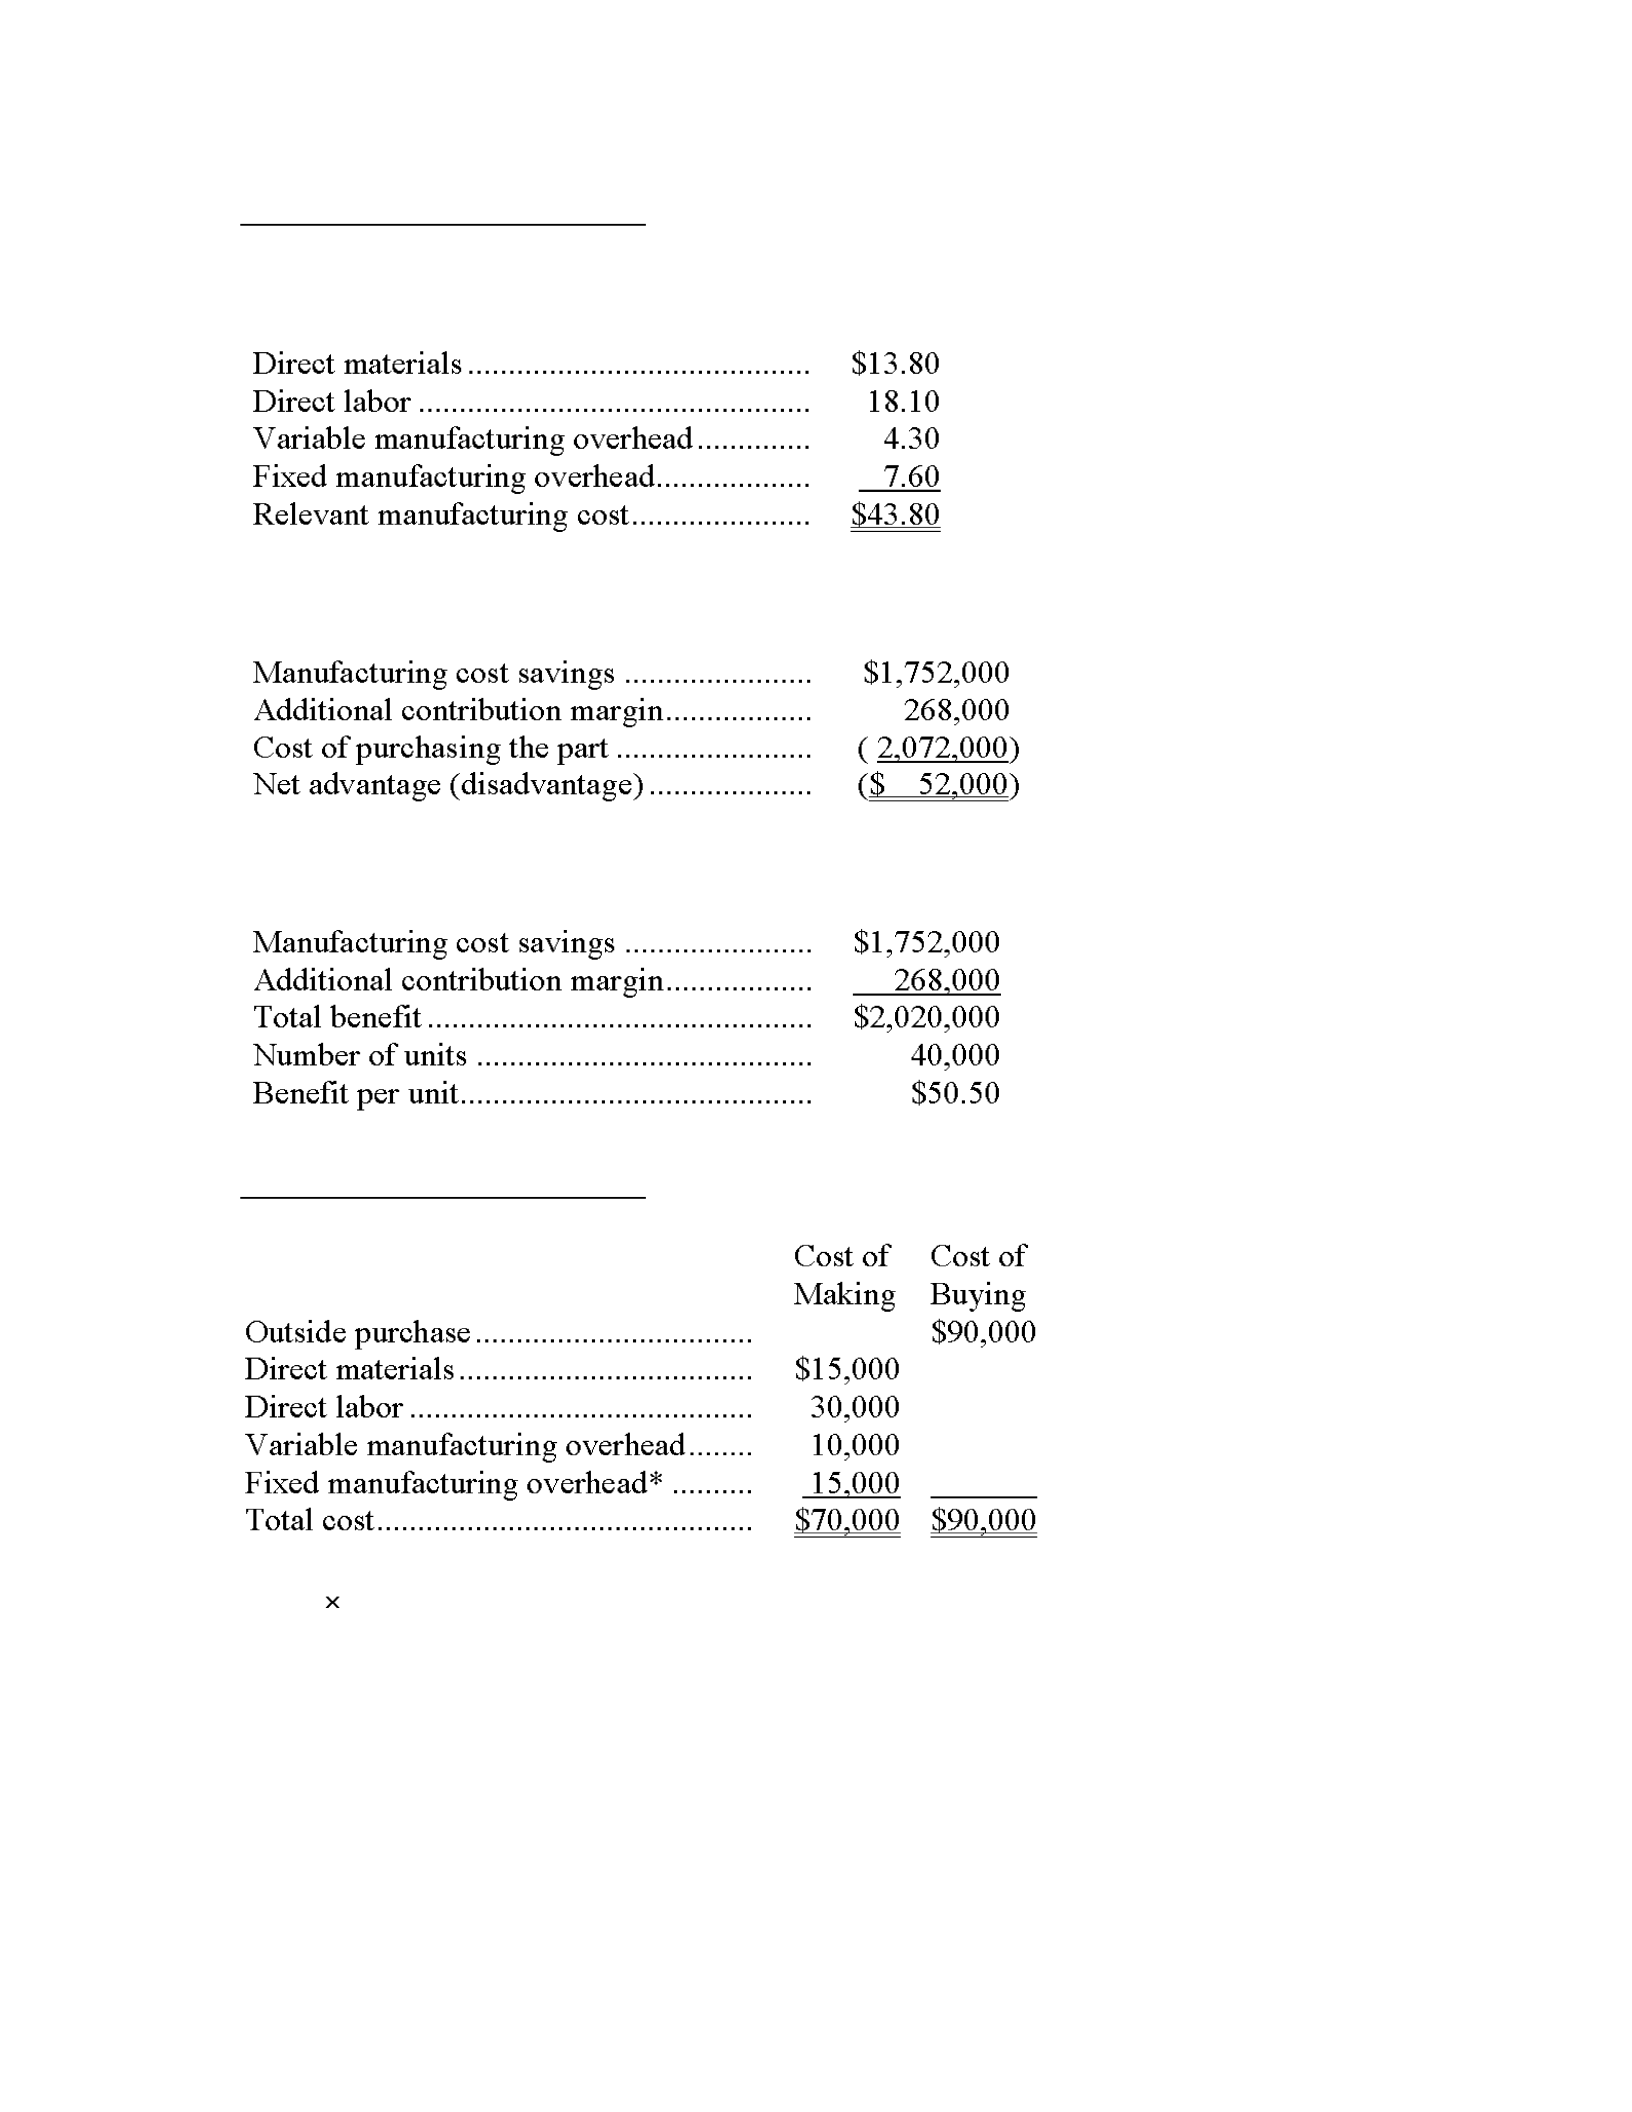
Item #15 – Business Decisions
Loss in contribution margin if Store B is closed:
Item #16 – Business Decisions
a. According to the company's accounting system, the product's net operating loss is
$39,000.
b. Net operating income would decline by $92,000 if product M12C were dropped.
Therefore, the product should not be dropped.
ACC241 – Examination #2 Review Activity Solutions
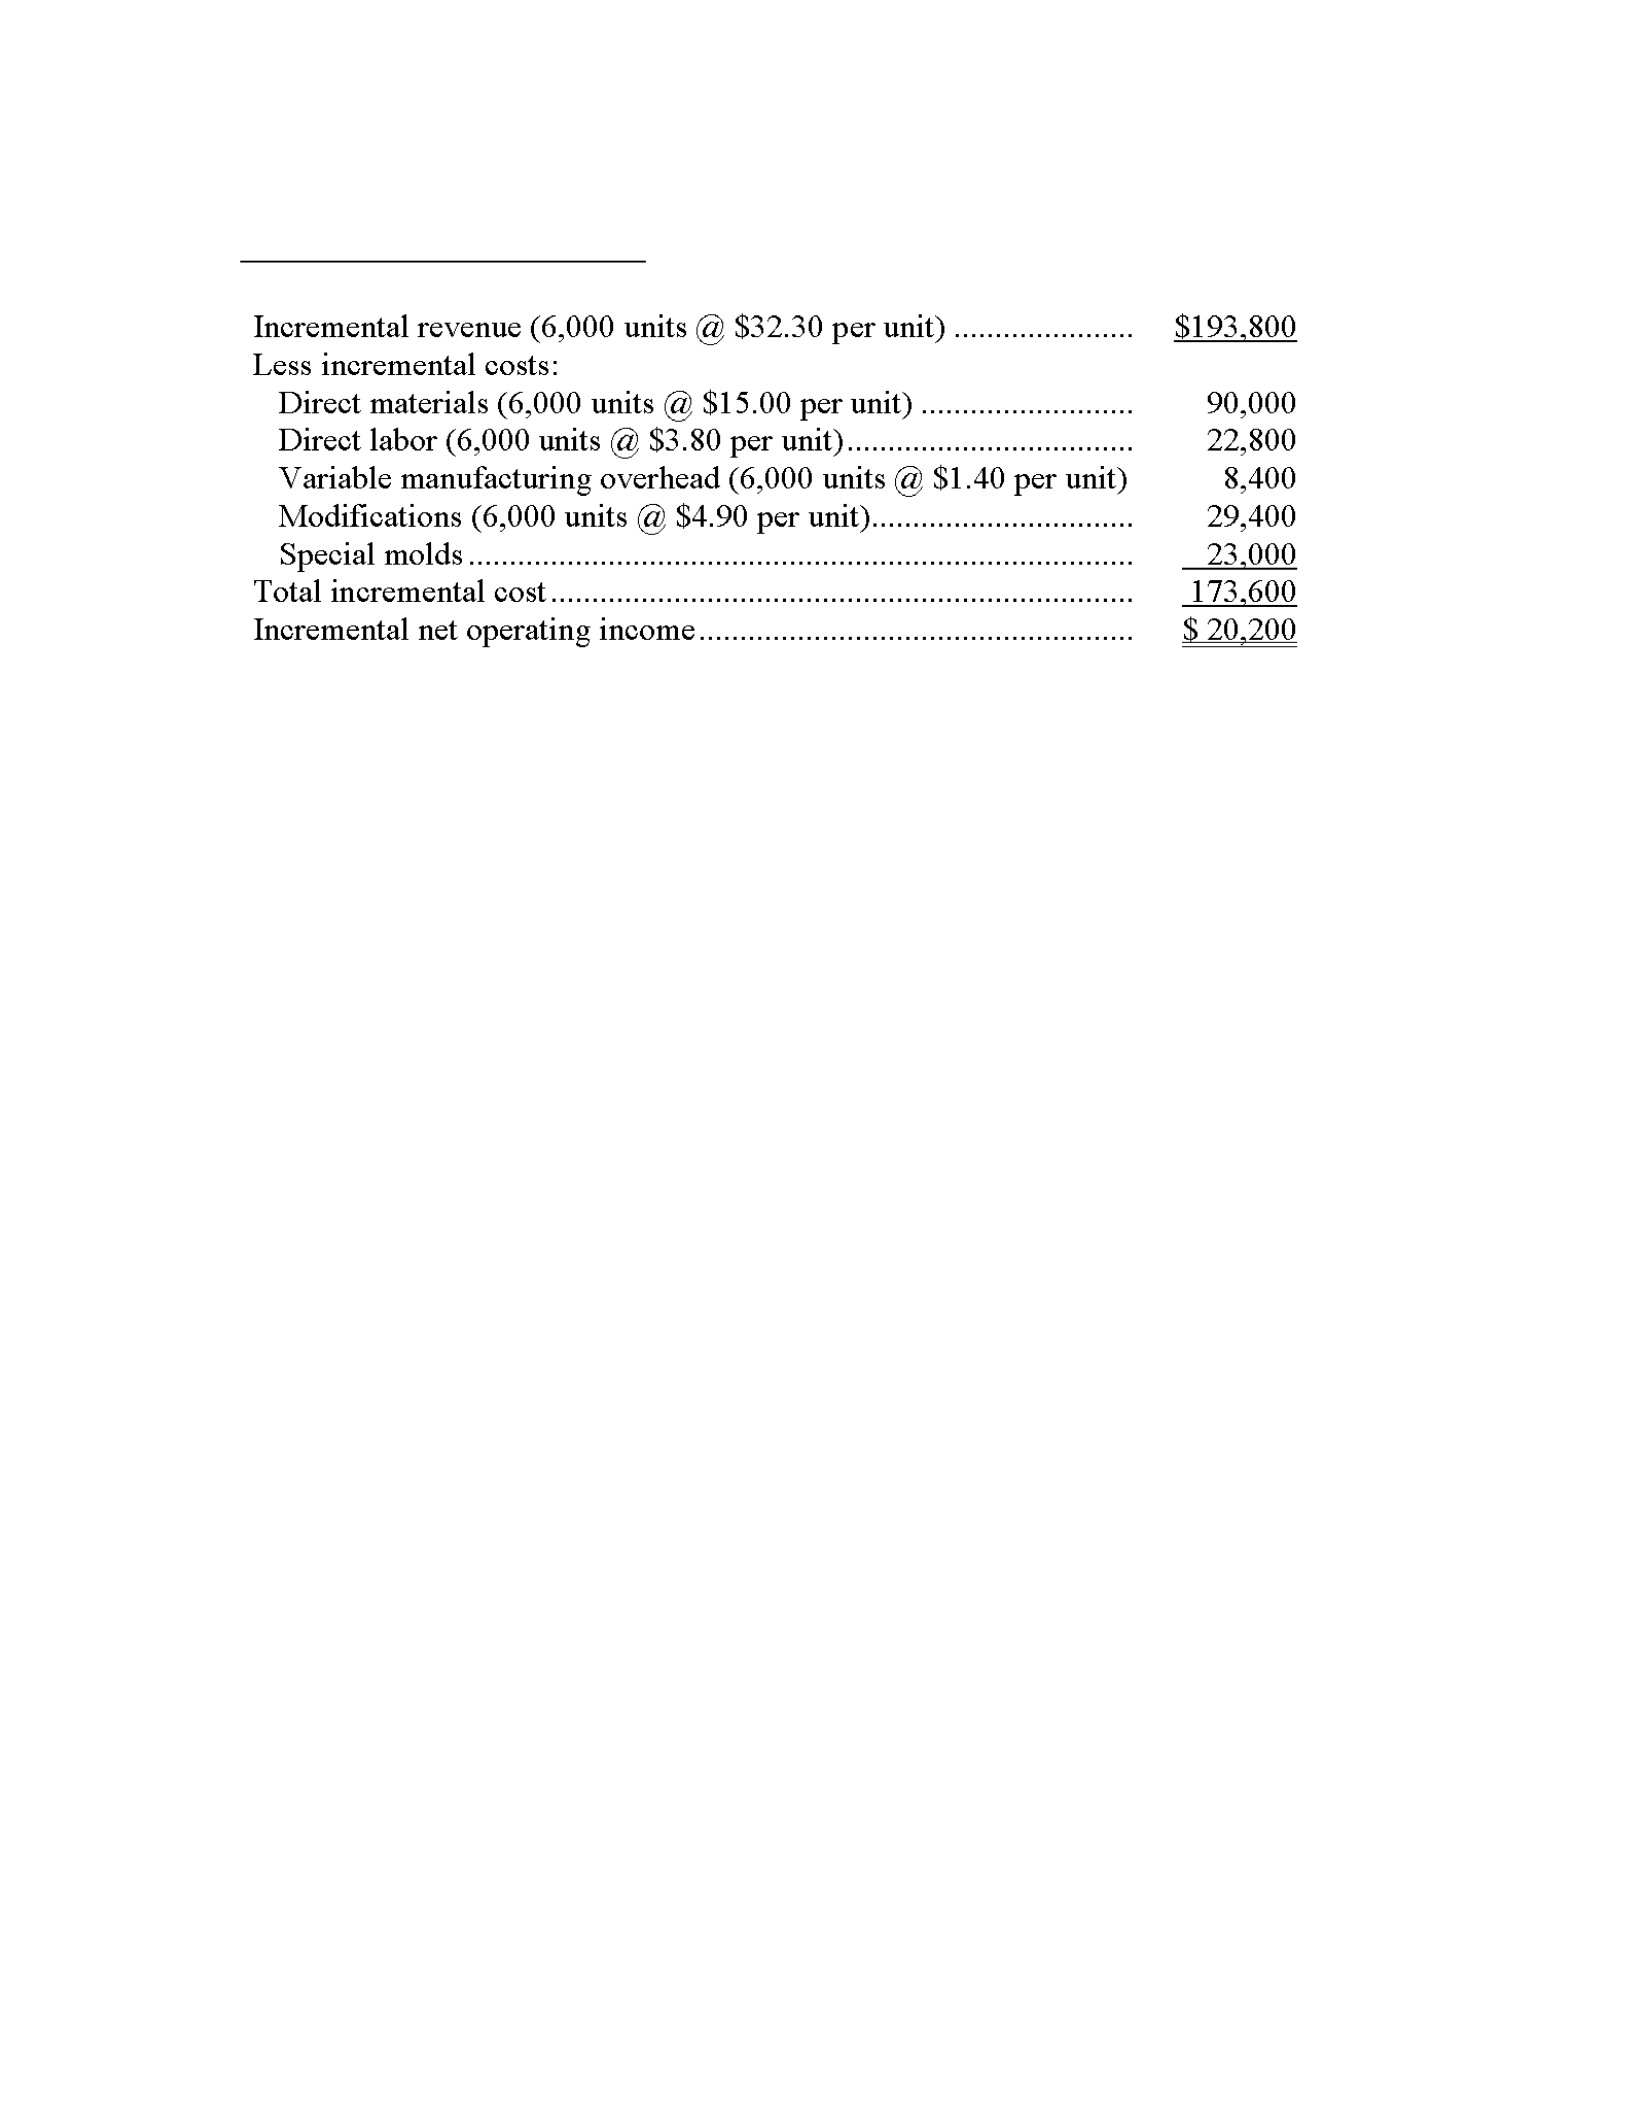
Item #17 – Business Decisions
a. Relevant cost per unit:
b. Net advantage (disadvantage):
c. Maximum acceptable purchase price:
Item #18 – Business Decisions
* 1/3 $45,000 = $15,000
Therefore, the annual advantage to make the parts is $20,000.
ACC241 – Examination #2 Review Activity Solutions
Item #19 – Business Decisions

