


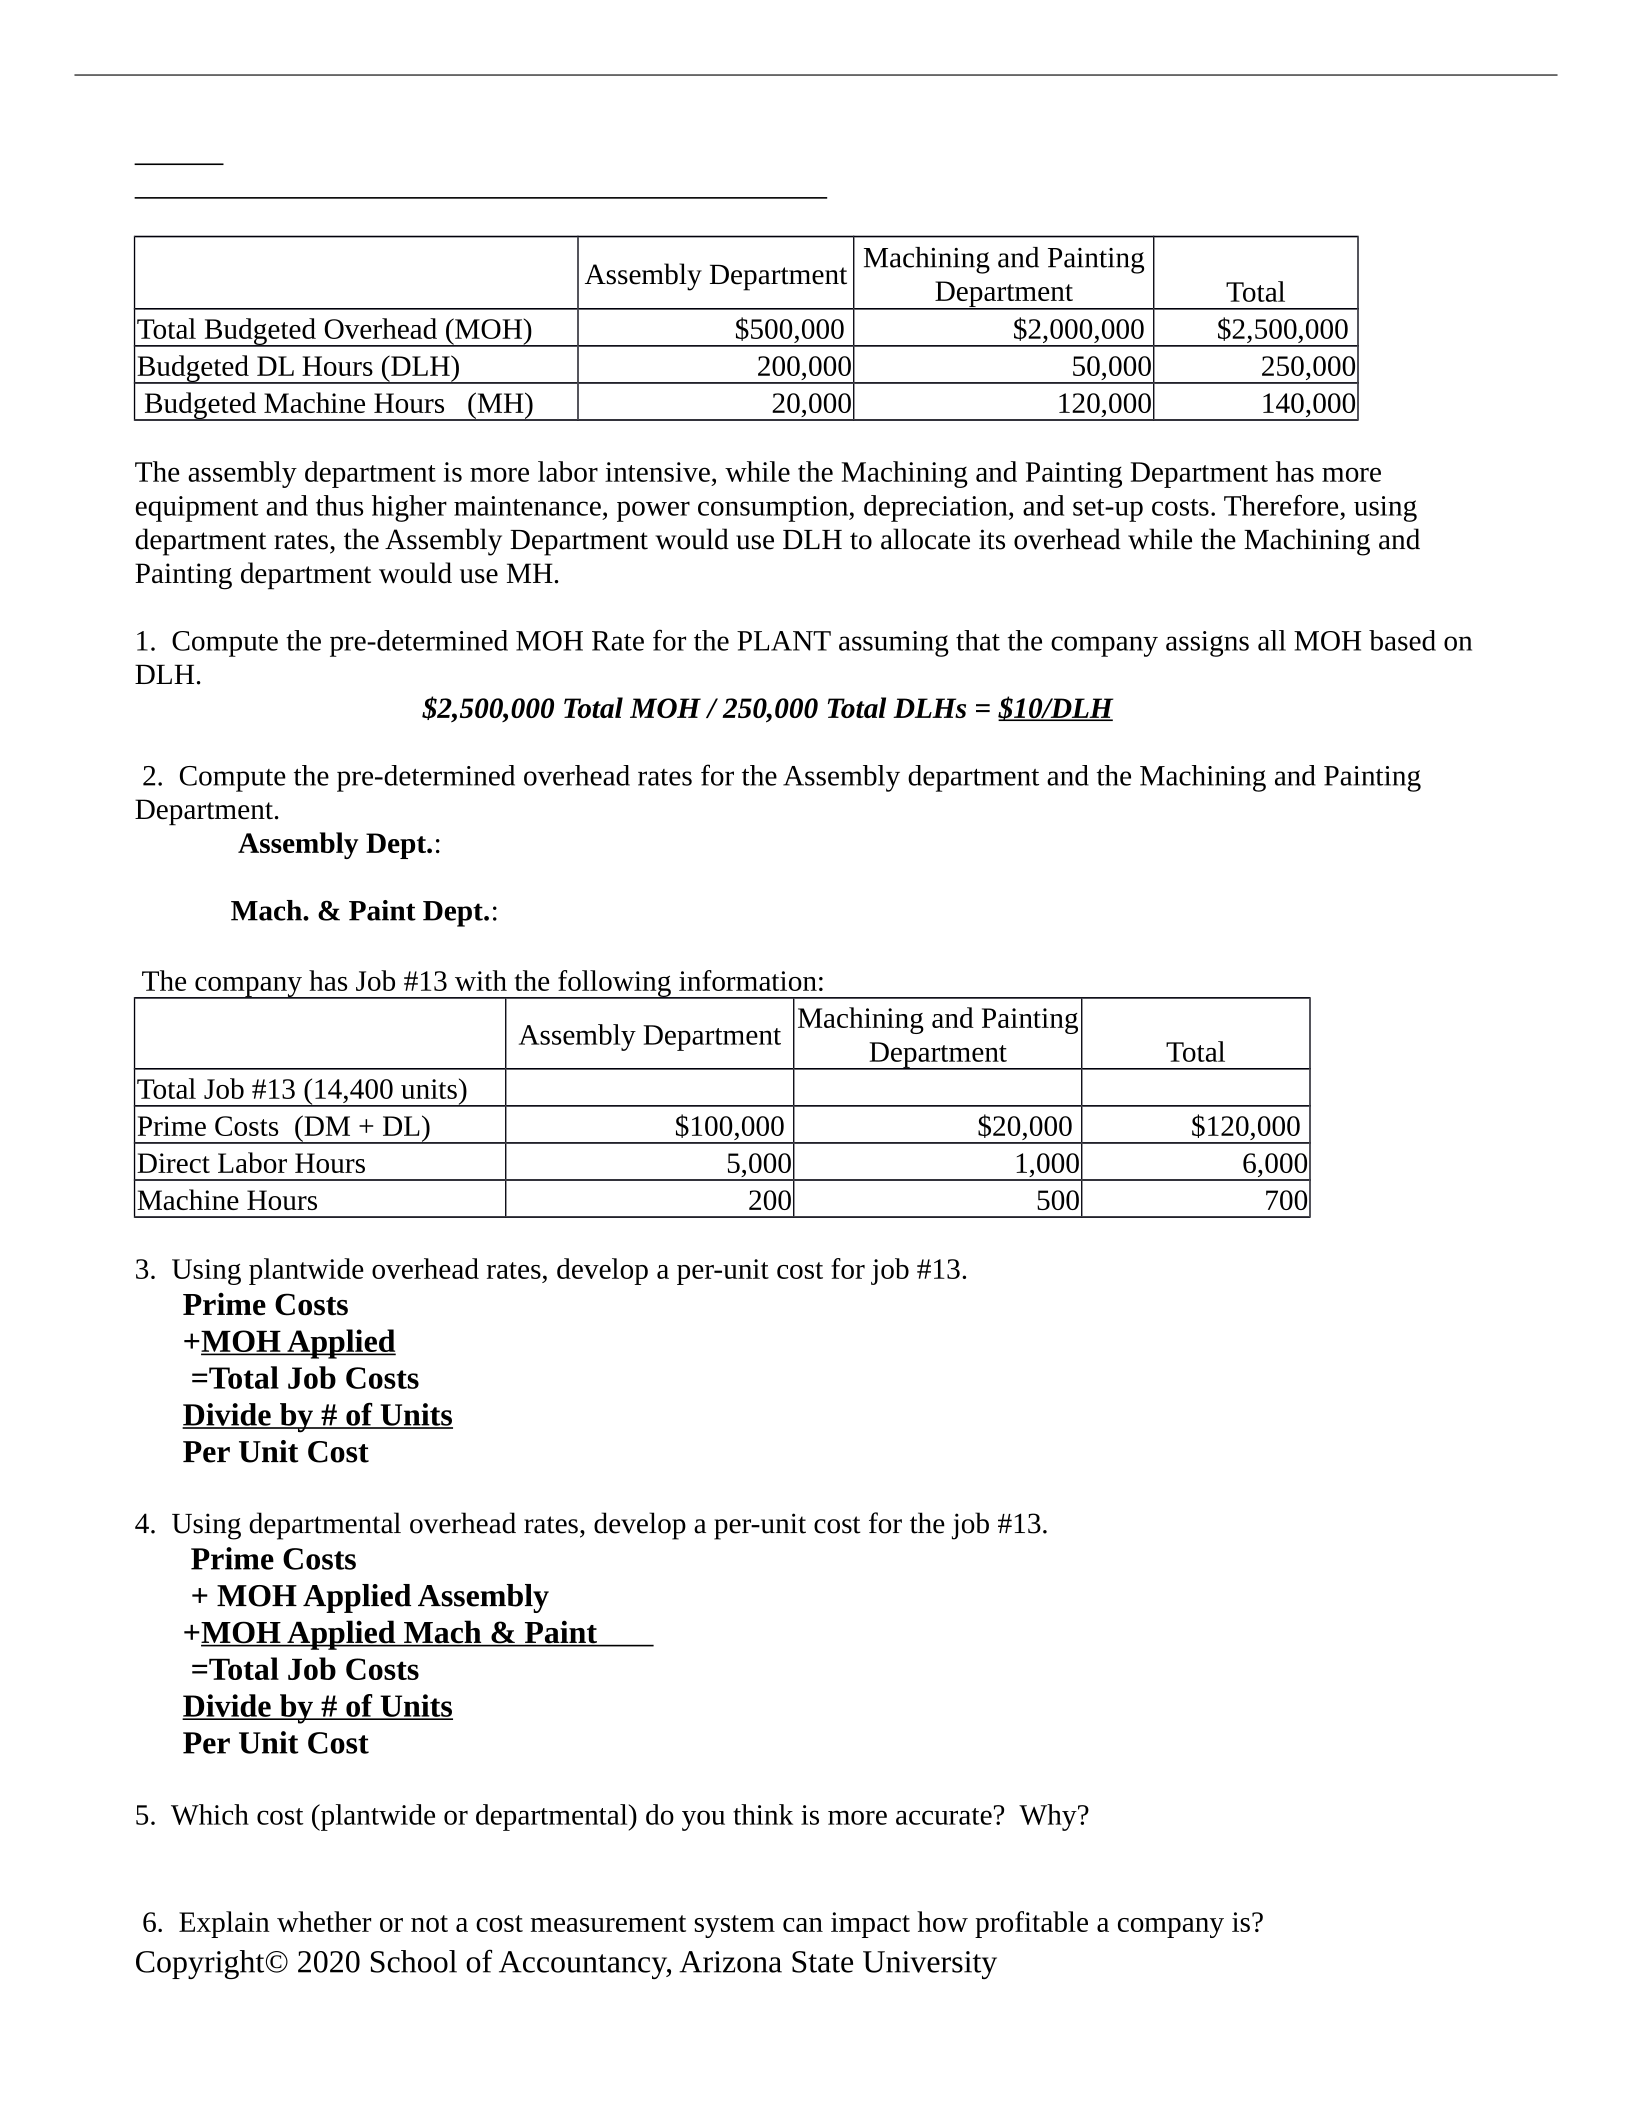
Assembly Department Machining and Painting
Department Total
Total Budgeted Overhead (MOH) $500,000 $2,000,000 $2,500,000
Budgeted DL Hours (DLH) 200,000 50,000 250,000
Budgeted Machine Hours (MH) 20,000 120,000 140,000
The assembly department is more labor intensive, while the Machining and Painting Department has more
equipment and thus higher maintenance, power consumption, depreciation, and set-up costs. Therefore, using
department rates, the Assembly Department would use DLH to allocate its overhead while the Machining and
Painting department would use MH.
1. Compute the pre-determined MOH Rate for the PLANT assuming that the company assigns all MOH based on
DLH.
$2,500,000 Total MOH / 250,000 Total DLHs = $10/DLH
2. Compute the pre-determined overhead rates for the Assembly department and the Machining and Painting
Department.
Assembly Dept.:
Mach. & Paint Dept.:
The company has Job #13 with the following information:
Assembly Department Machining and Painting
Department Total
Total Job #13 (14,400 units)
Prime Costs (DM + DL) $100,000 $20,000 $120,000
Direct Labor Hours 5,000 1,000 6,000
Machine Hours 200 500 700
3. Using plantwide overhead rates, develop a per-unit cost for job #13.
Prime Costs
+MOH Applied
=Total Job Costs
Divide by # of Units
Per Unit Cost
4. Using departmental overhead rates, develop a per-unit cost for the job #13.
Prime Costs
+ MOH Applied Assembly
+MOH Applied Mach & Paint
=Total Job Costs
Divide by # of Units
Per Unit Cost
5. Which cost (plantwide or departmental) do you think is more accurate? Why?
6. Explain whether or not a cost measurement system can impact how profitable a company is?
Copyright© 2020 School of Accountancy, Arizona State University
Ch. 4 –
Activity 1: Job cost with Departmental Overhead rates
Neta Corporation has the following 2 departments:
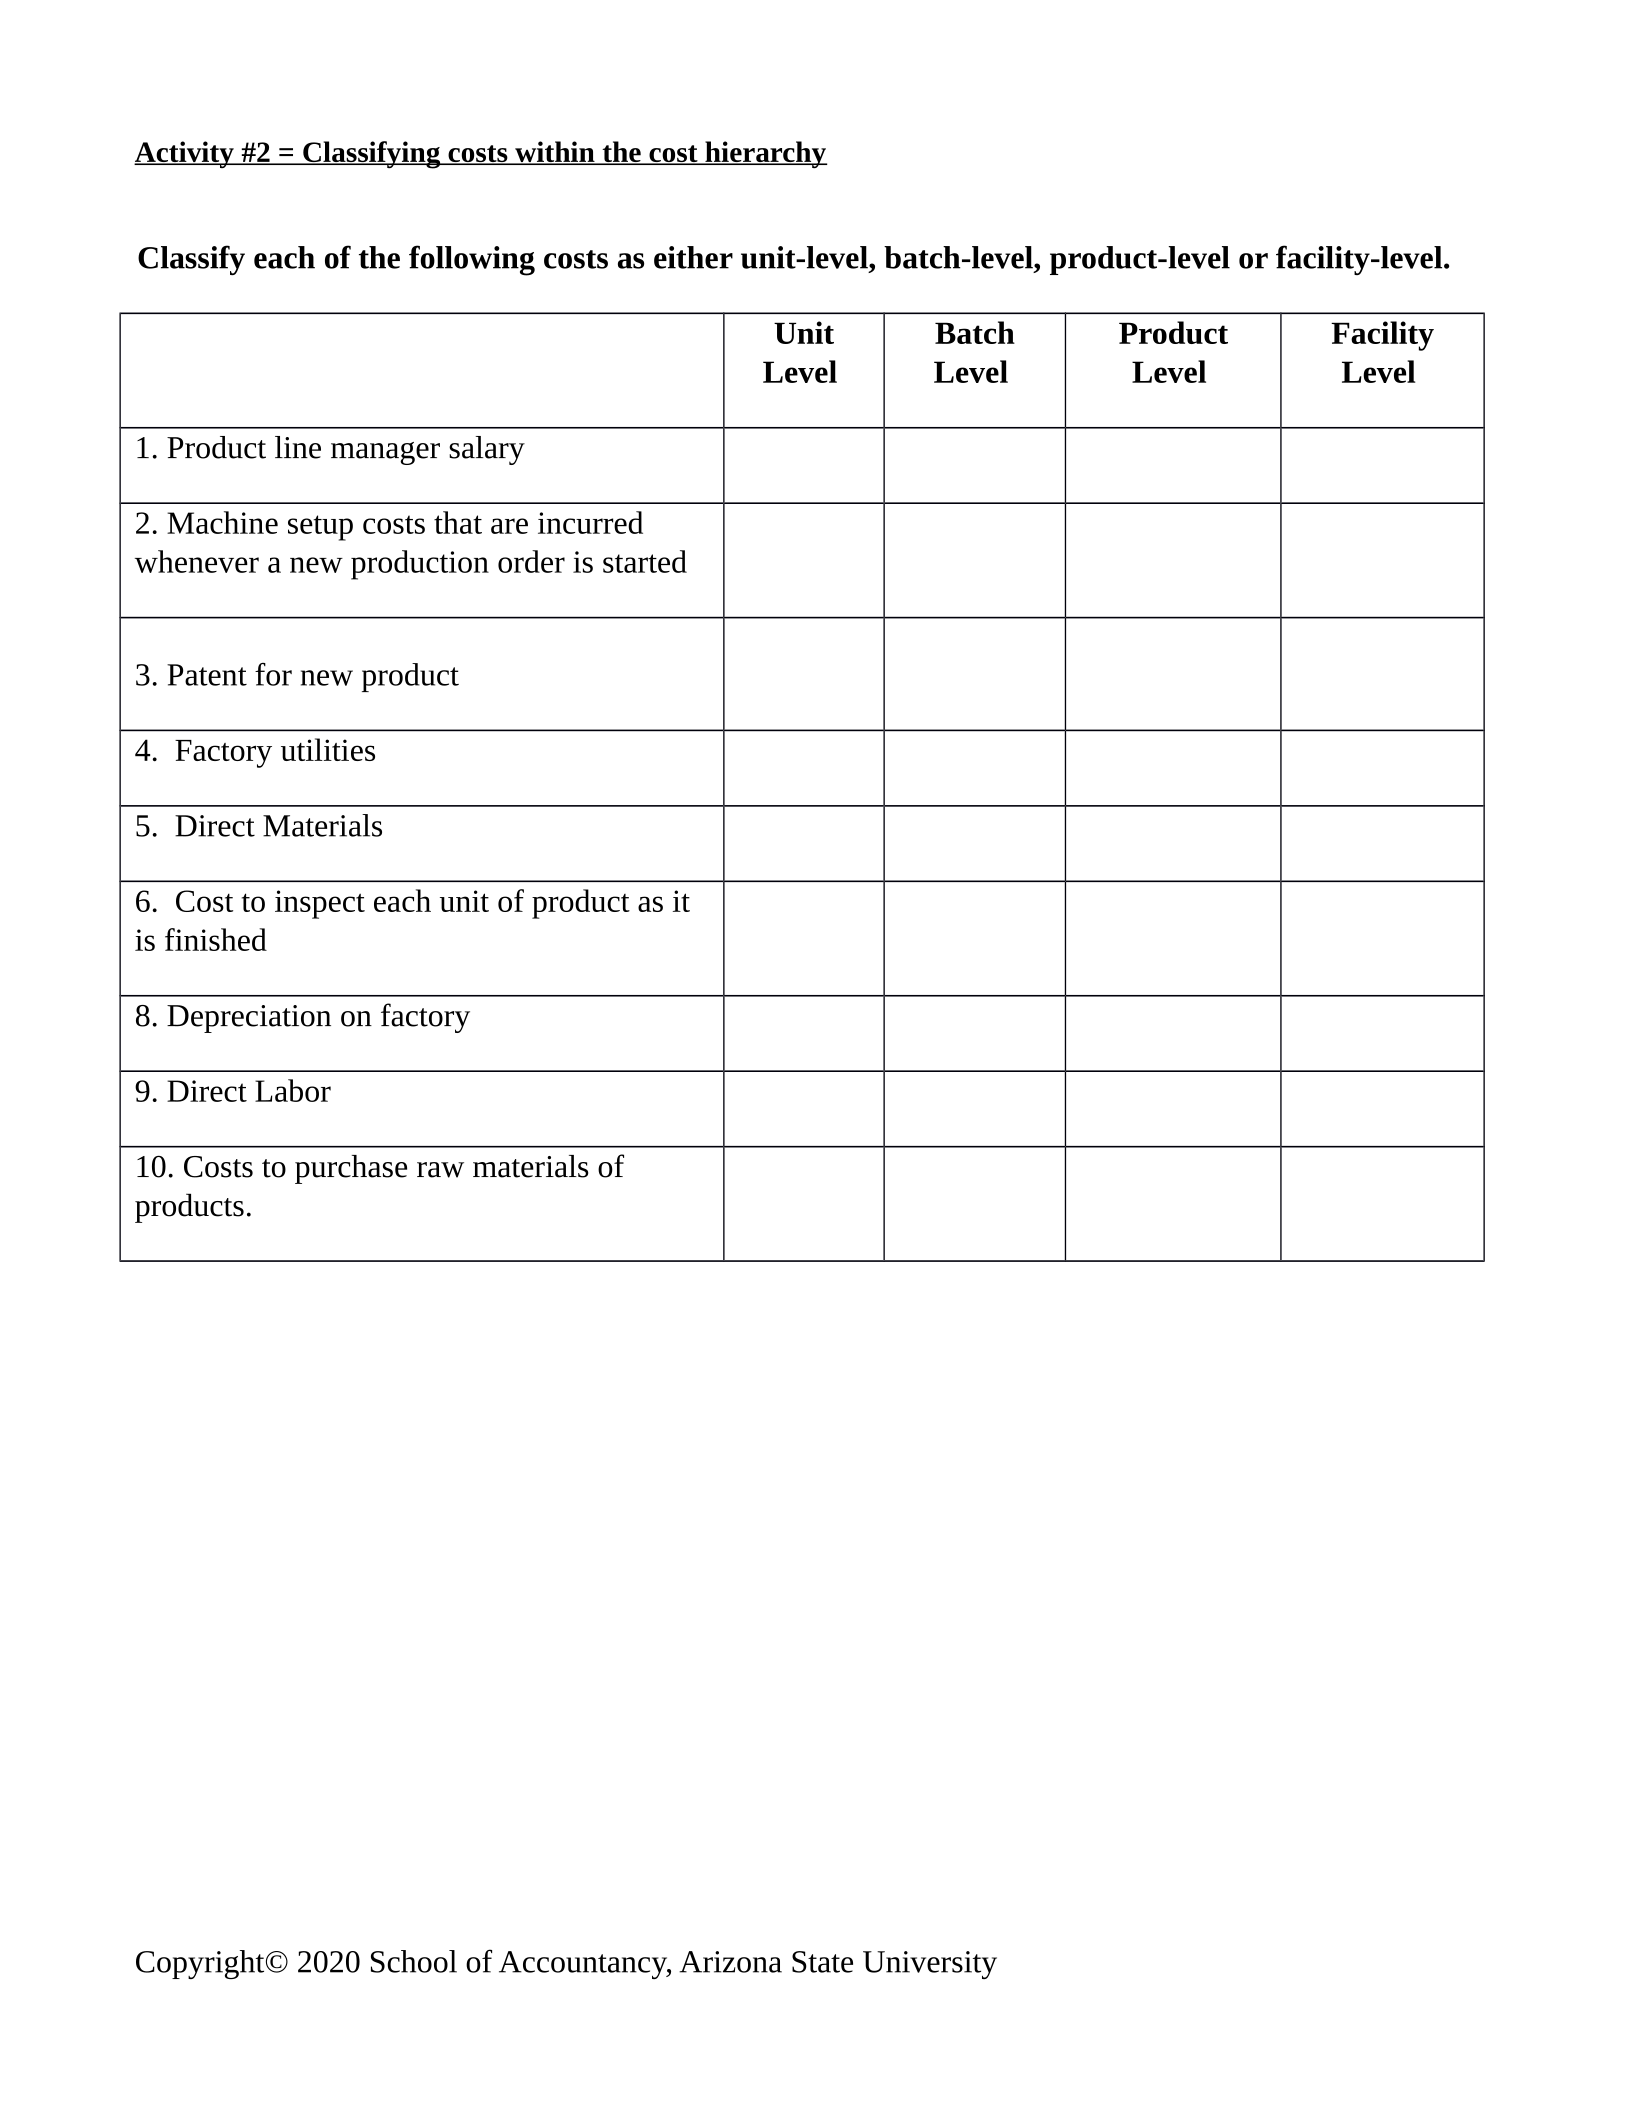
Activity #2 = Classifying costs within the cost hierarchy
Classify each of the following costs as either unit-level, batch-level, product-level or facility-level.
Unit
Level
Batch
Level
Product
Level
Facility
Level
1. Product line manager salary
2. Machine setup costs that are incurred
whenever a new production order is started
3. Patent for new product
4. Factory utilities
5. Direct Materials
6. Cost to inspect each unit of product as it
is finished
8. Depreciation on factory
9. Direct Labor
10. Costs to purchase raw materials of
products.
Copyright© 2020 School of Accountancy, Arizona State University
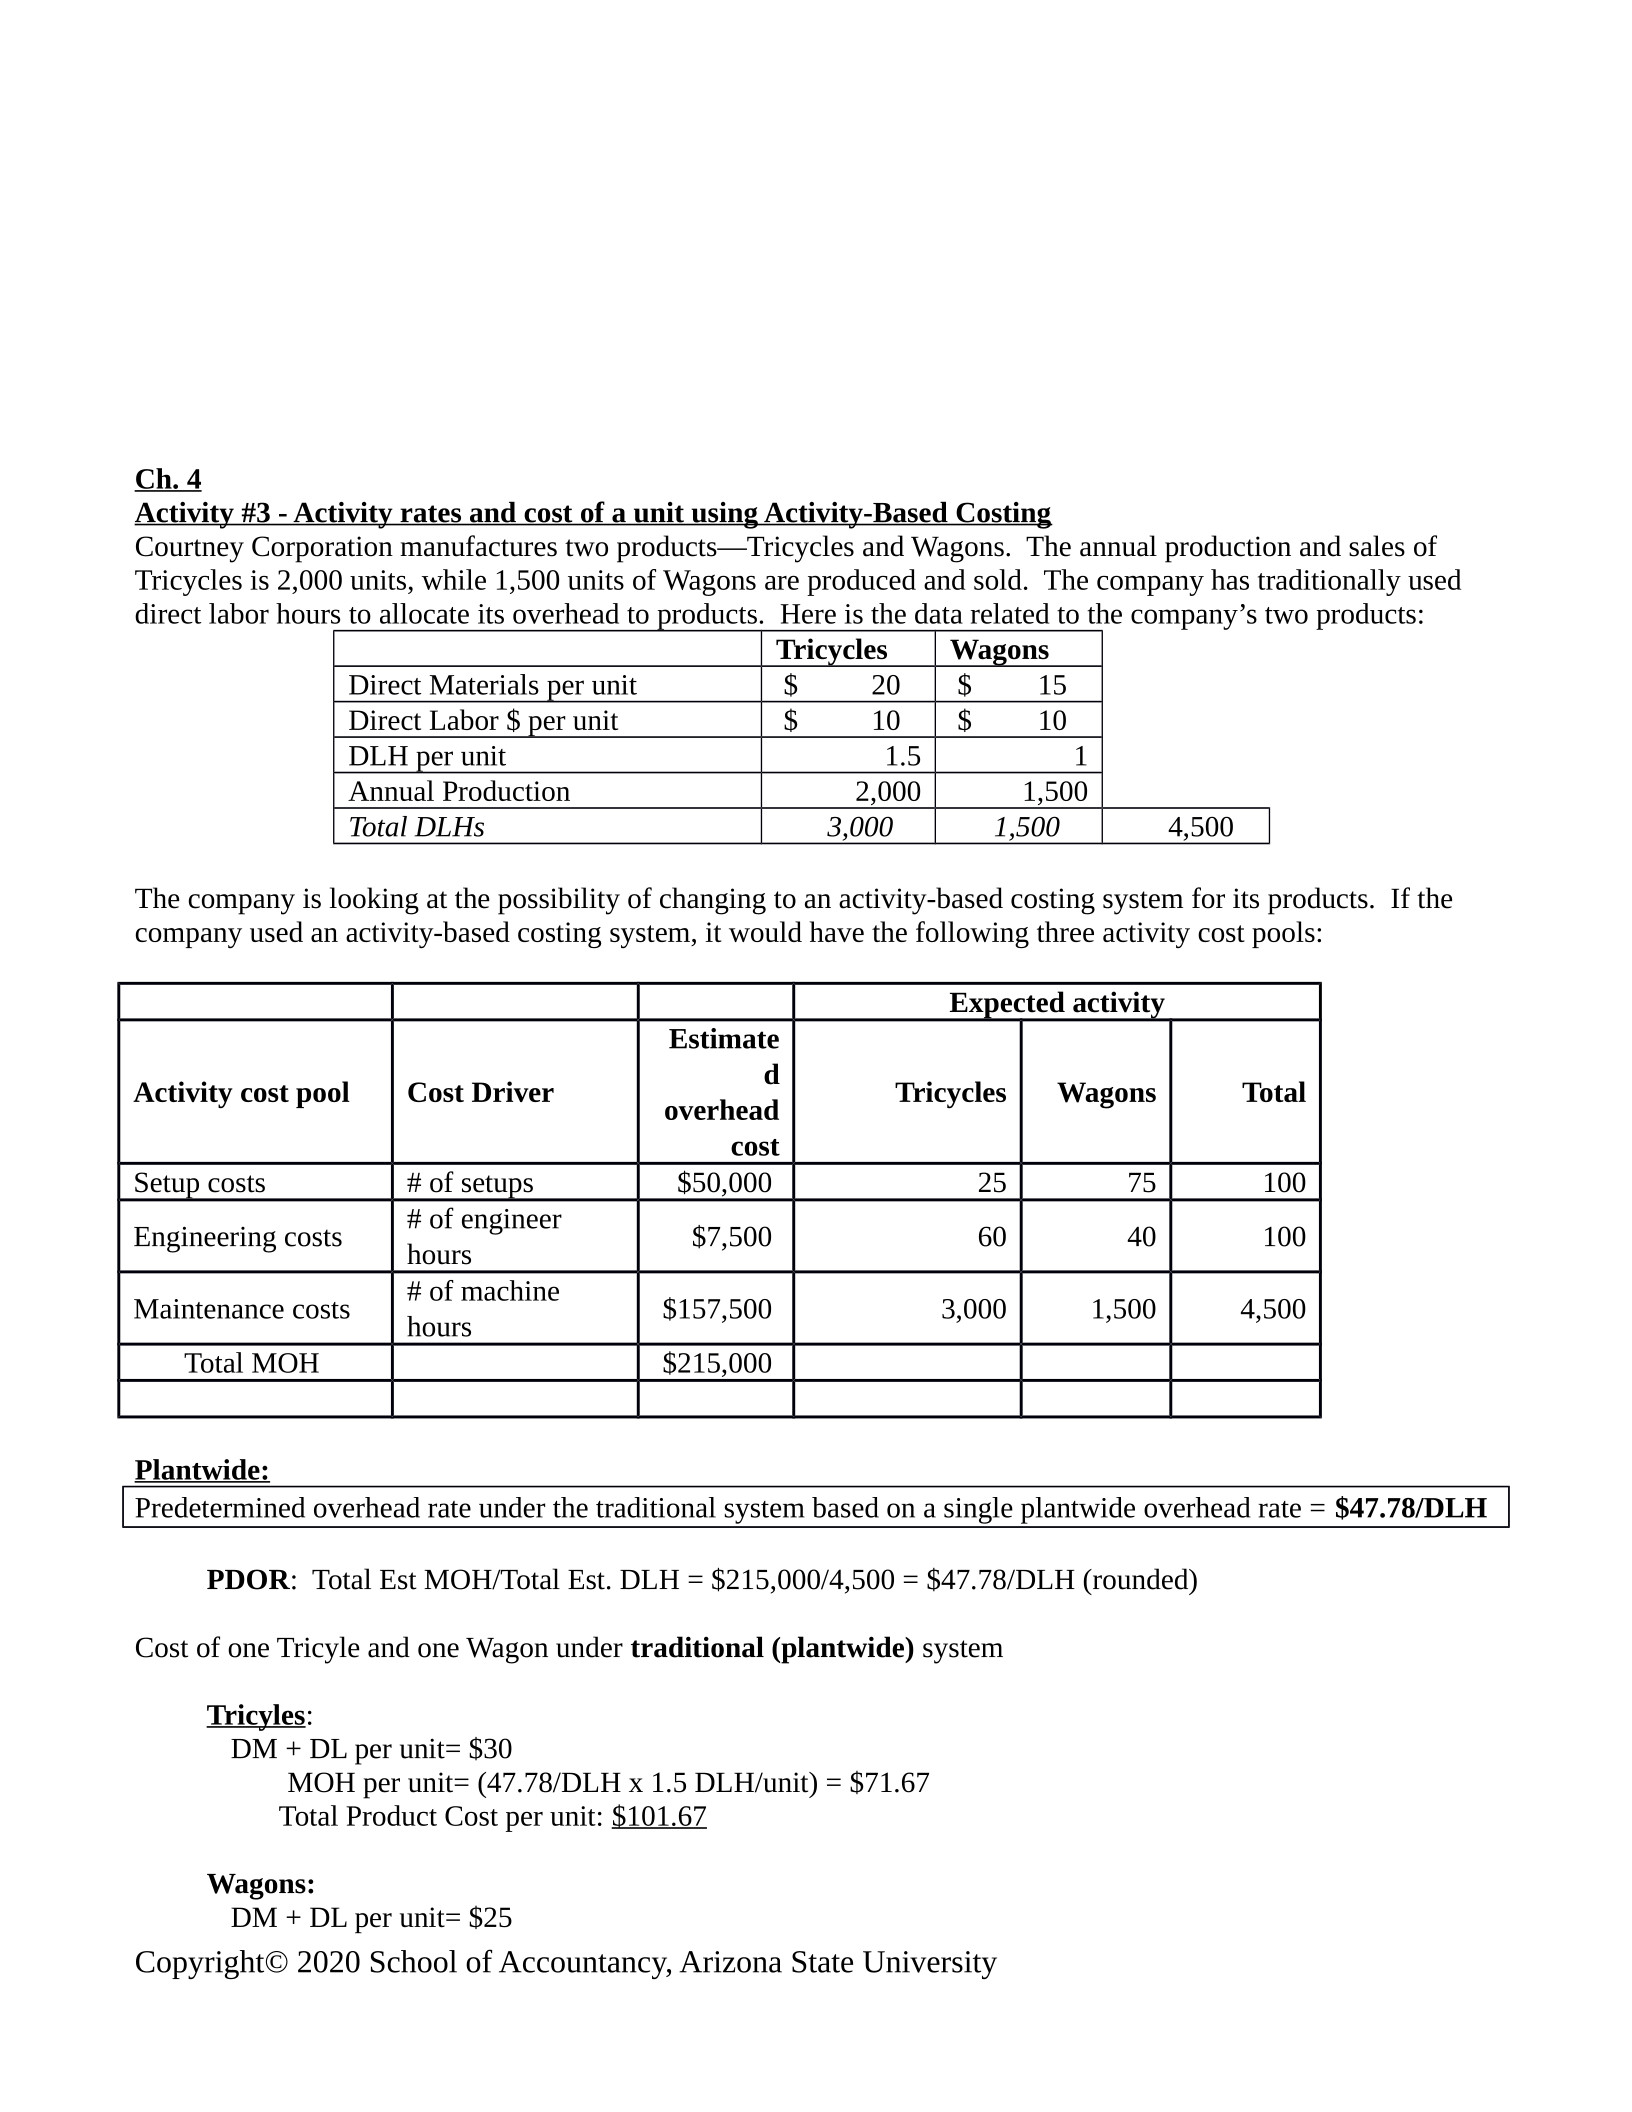
Ch. 4
Activity #3 - Activity rates and cost of a unit using Activity-Based Costing
Courtney Corporation manufactures two products—Tricycles and Wagons. The annual production and sales of
Tricycles is 2,000 units, while 1,500 units of Wagons are produced and sold. The company has traditionally used
direct labor hours to allocate its overhead to products. Here is the data related to the company’s two products:
Tricycles Wagons
Direct Materials per unit $ 20 $ 15
Direct Labor $ per unit $ 10 $ 10
DLH per unit 1.5 1
Annual Production 2,000 1,500
Total DLHs 3,000 1,500 4,500
The company is looking at the possibility of changing to an activity-based costing system for its products. If the
company used an activity-based costing system, it would have the following three activity cost pools:
Expected activity
Activity cost pool Cost Driver
Estimate
d
overhead
cost
Tricycles Wagons Total
Setup costs # of setups $50,000 25 75 100
Engineering costs # of engineer
hours $7,500 60 40 100
Maintenance costs # of machine
hours $157,500 3,000 1,500 4,500
Total MOH $215,000
Plantwide:
Predetermined overhead rate under the traditional system based on a single plantwide overhead rate = $47.78/DLH
PDOR: Total Est MOH/Total Est. DLH = $215,000/4,500 = $47.78/DLH (rounded)
Cost of one Tricyle and one Wagon under traditional (plantwide) system
Tricyles:
DM + DL per unit= $30
MOH per unit= (47.78/DLH x 1.5 DLH/unit) = $71.67
Total Product Cost per unit: $101.67
Wagons:
DM + DL per unit= $25
Copyright© 2020 School of Accountancy, Arizona State University
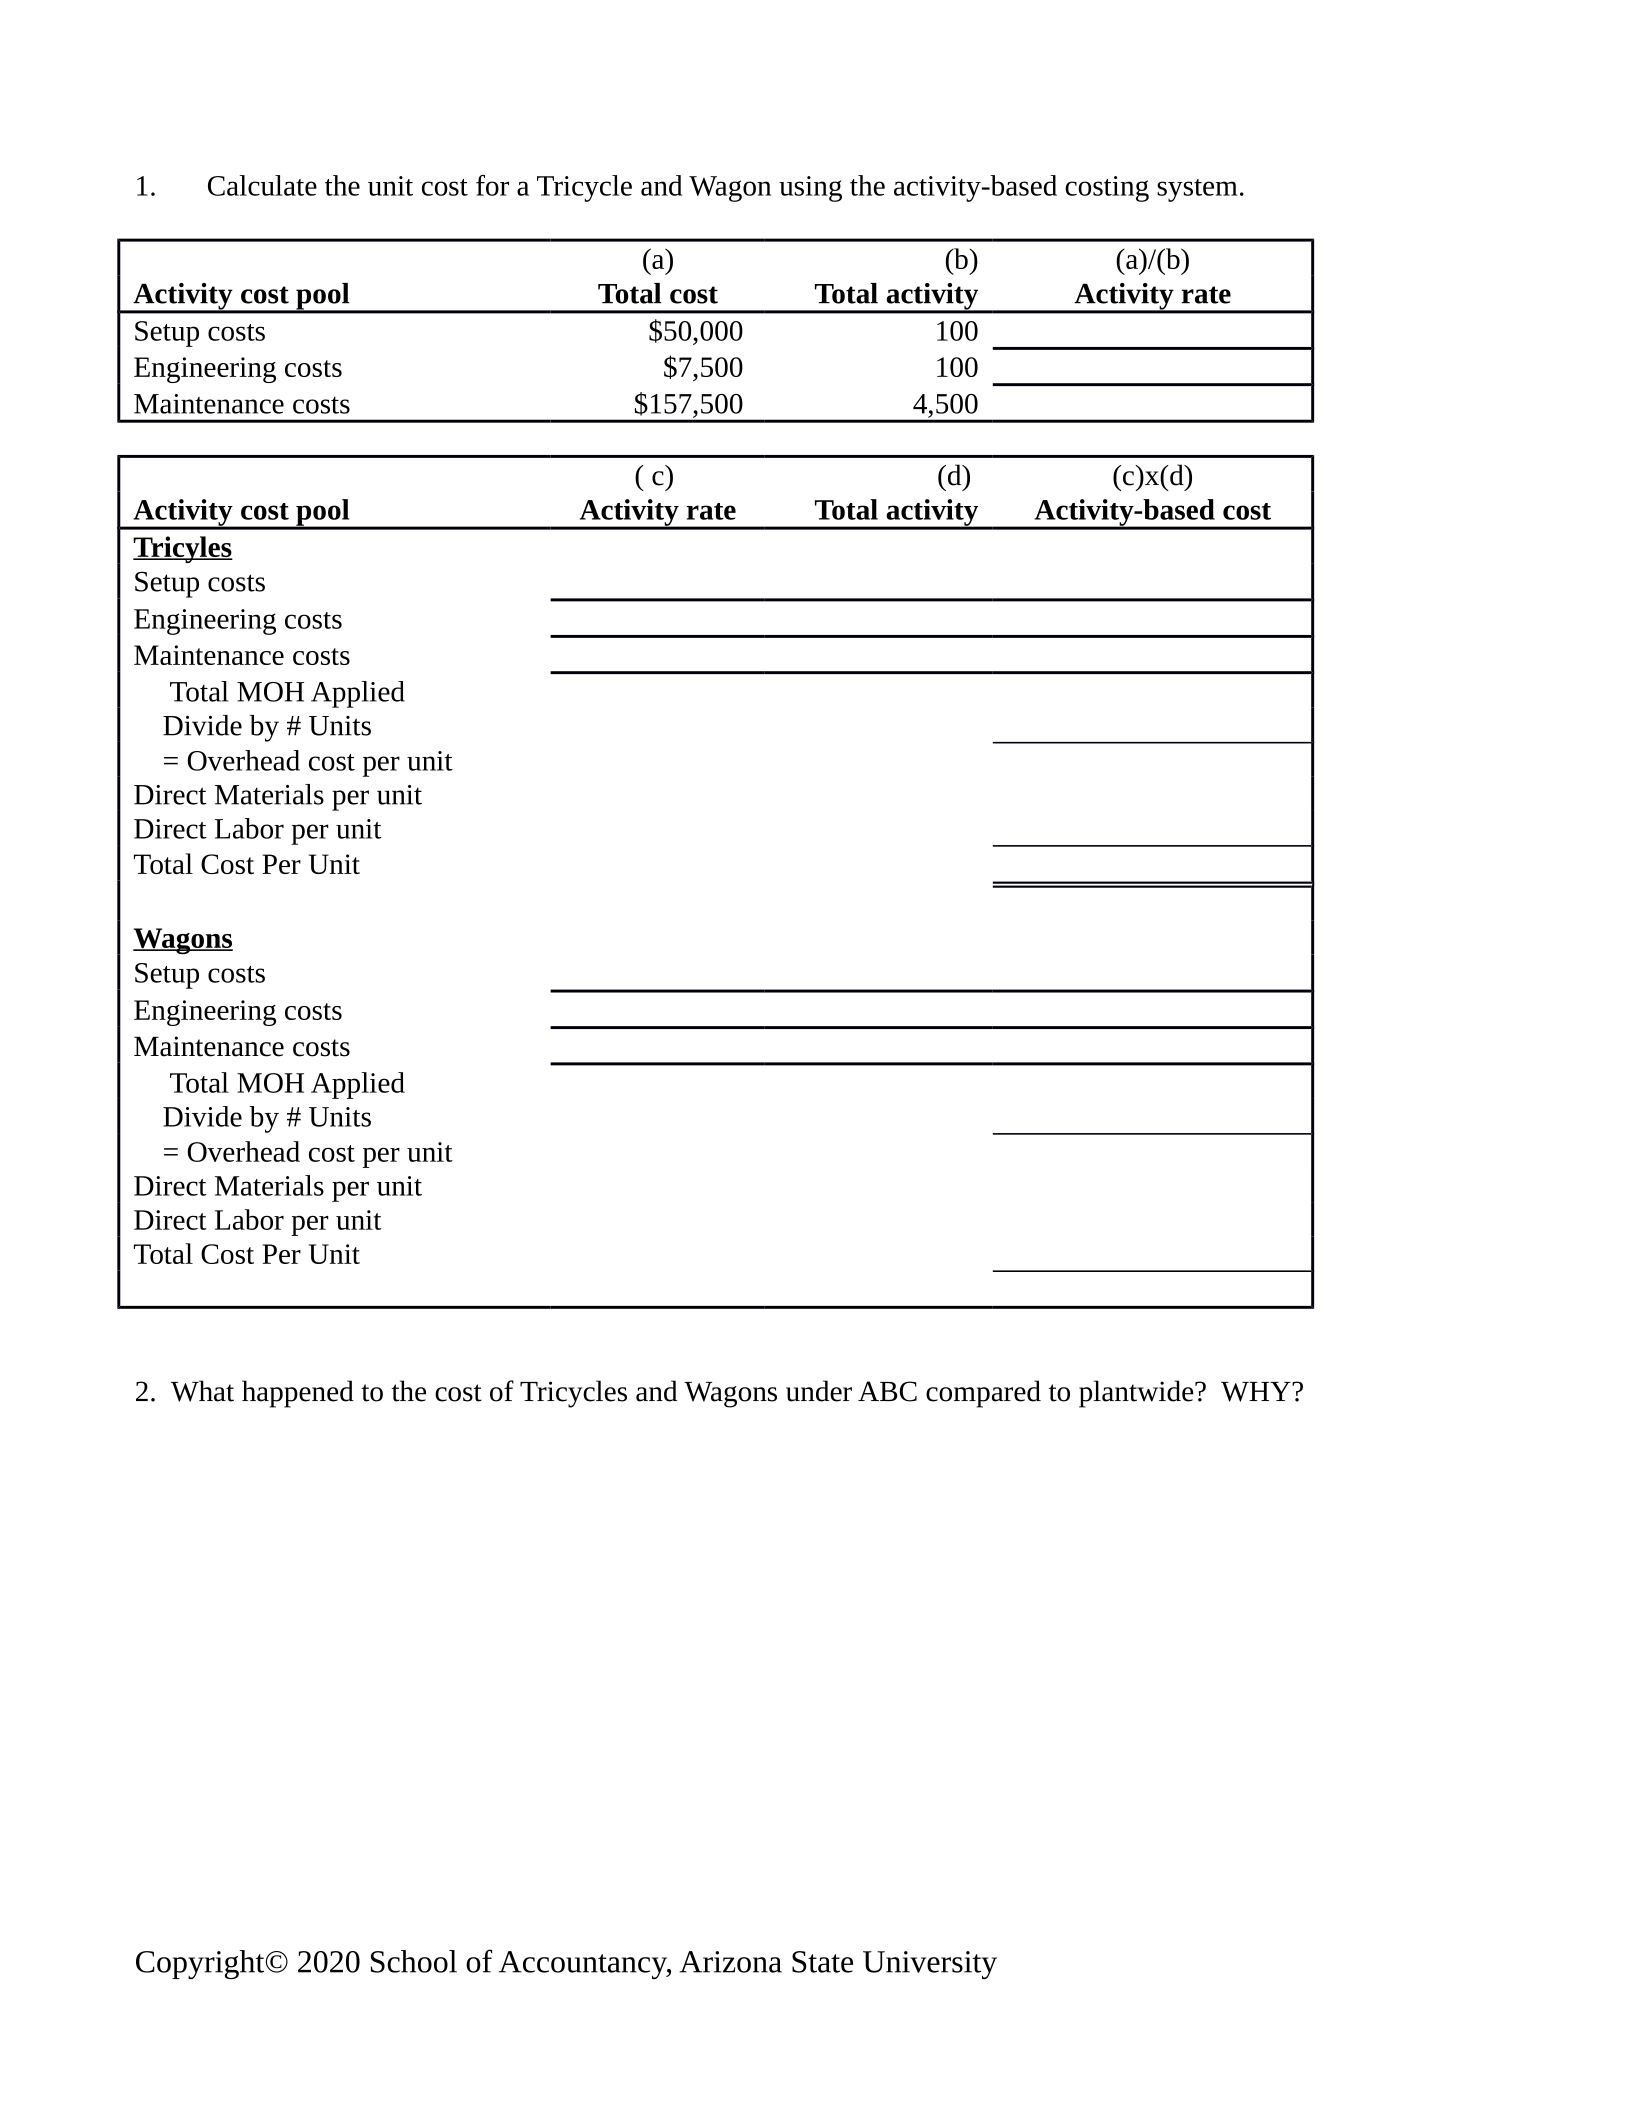
1. Calculate the unit cost for a Tricycle and Wagon using the activity-based costing system.
(a) (b) (a)/(b)
Activity cost pool Total cost Total activity Activity rate
Setup costs $50,000 100
Engineering costs $7,500 100
Maintenance costs $157,500 4,500
( c) (d) (c)x(d)
Activity cost pool Activity rate Total activity Activity-based cost
Tricyles
Setup costs
Engineering costs
Maintenance costs
Total MOH Applied
Divide by # Units
= Overhead cost per unit
Direct Materials per unit
Direct Labor per unit
Total Cost Per Unit
Wagons
Setup costs
Engineering costs
Maintenance costs
Total MOH Applied
Divide by # Units
= Overhead cost per unit
Direct Materials per unit
Direct Labor per unit
Total Cost Per Unit
2. What happened to the cost of Tricycles and Wagons under ABC compared to plantwide? WHY?
Copyright© 2020 School of Accountancy, Arizona State University
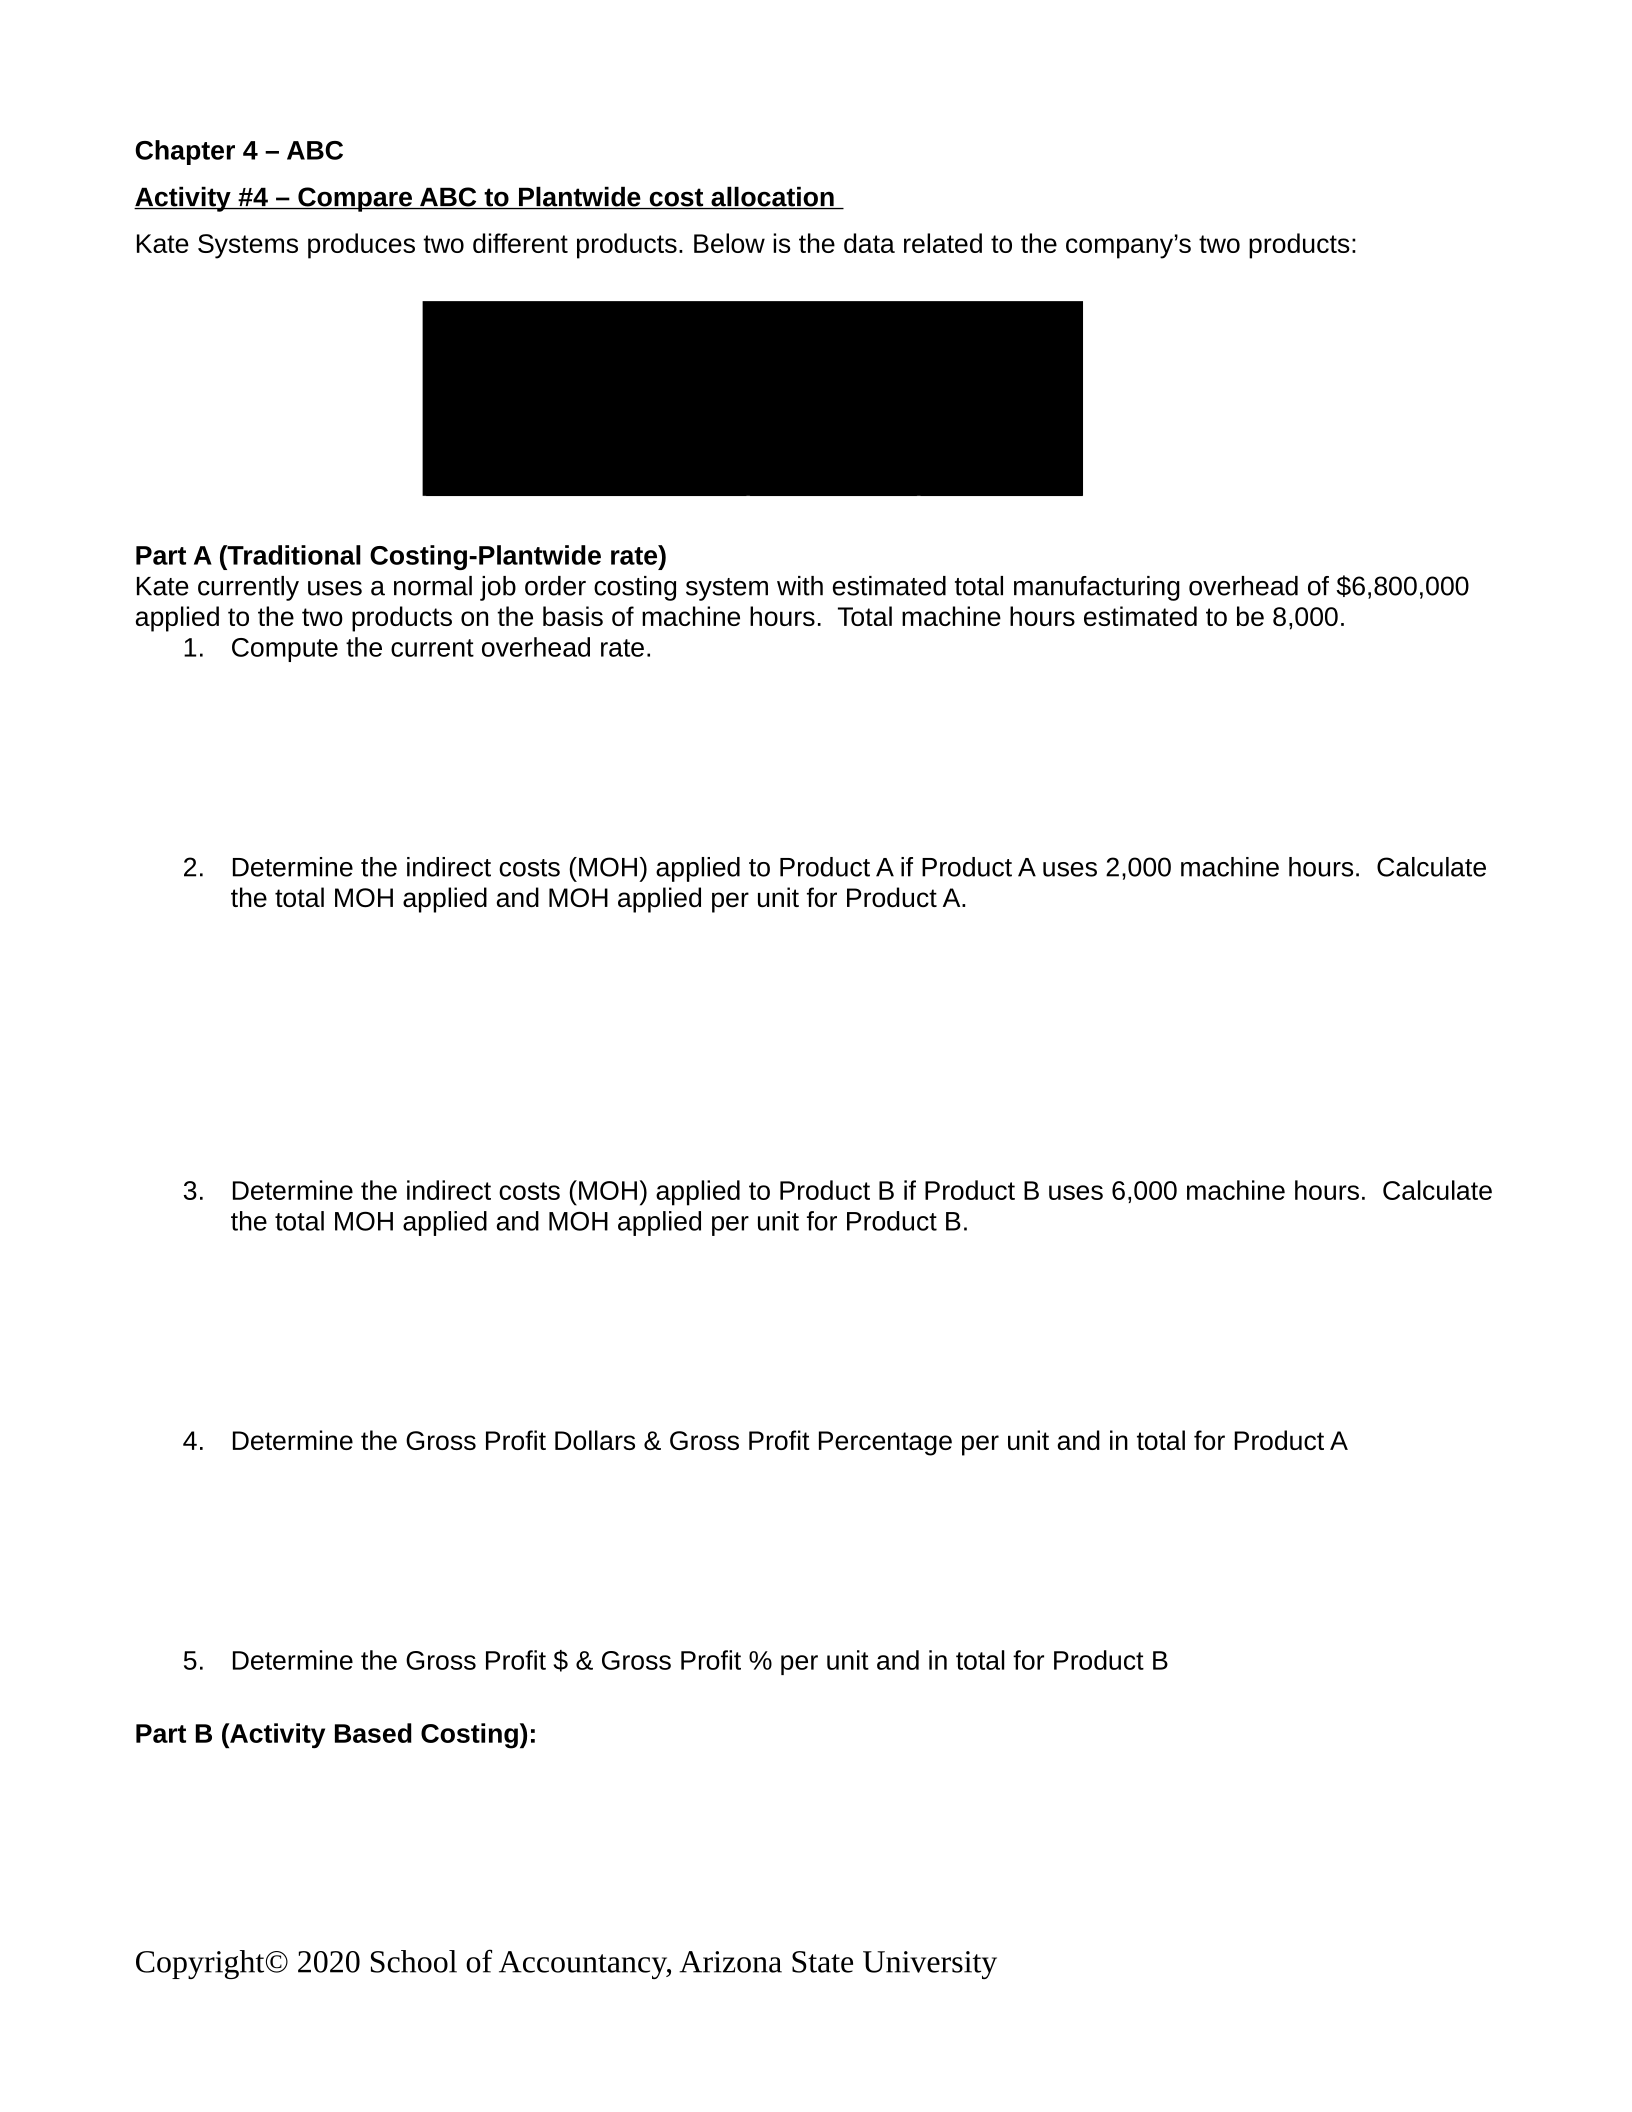
Chapter 4 – ABC
Activity #4 – Compare ABC to Plantwide cost allocation
Kate Systems produces two different products. Below is the data related to the company’s two products:
Part A (Traditional Costing-Plantwide rate)
Kate currently uses a normal job order costing system with estimated total manufacturing overhead of $6,800,000
applied to the two products on the basis of machine hours. Total machine hours estimated to be 8,000.
1. Compute the current overhead rate.
2. Determine the indirect costs (MOH) applied to Product A if Product A uses 2,000 machine hours. Calculate
the total MOH applied and MOH applied per unit for Product A.
3. Determine the indirect costs (MOH) applied to Product B if Product B uses 6,000 machine hours. Calculate
the total MOH applied and MOH applied per unit for Product B.
4. Determine the Gross Profit Dollars & Gross Profit Percentage per unit and in total for Product A
5. Determine the Gross Profit $ & Gross Profit % per unit and in total for Product B
Part B (Activity Based Costing):
Copyright© 2020 School of Accountancy, Arizona State University
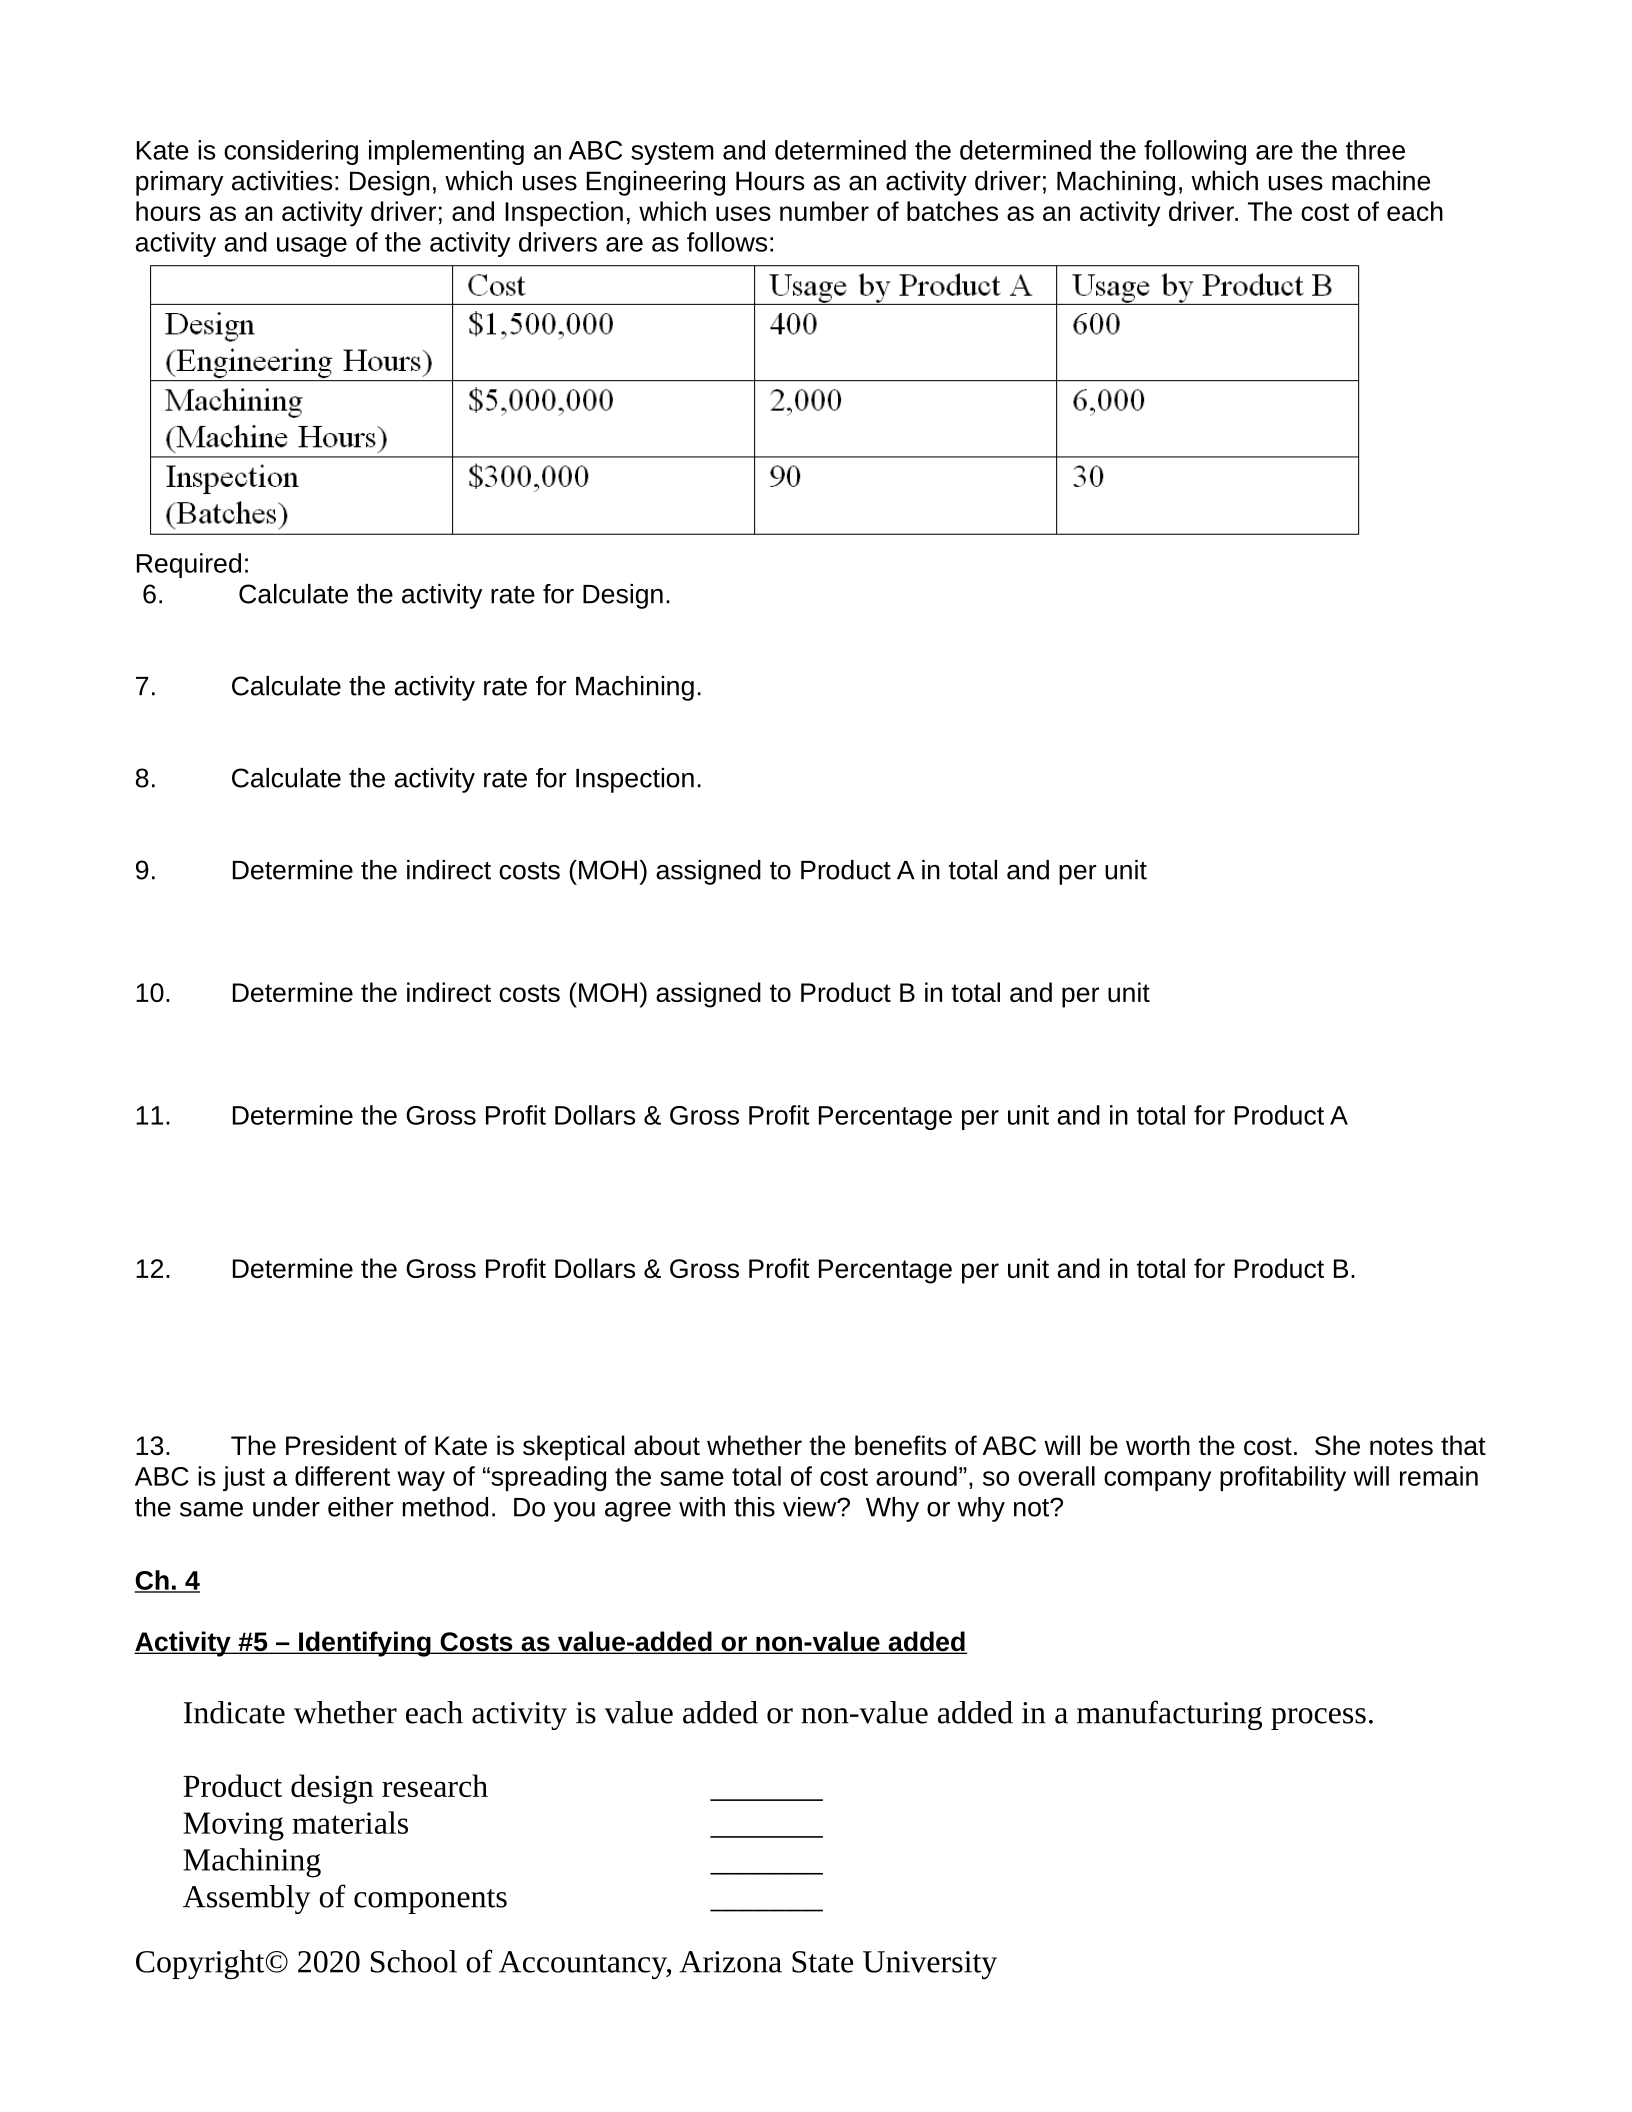
Kate is considering implementing an ABC system and determined the determined the following are the three
primary activities: Design, which uses Engineering Hours as an activity driver; Machining, which uses machine
hours as an activity driver; and Inspection, which uses number of batches as an activity driver. The cost of each
activity and usage of the activity drivers are as follows:
Required:
6. Calculate the activity rate for Design.
7. Calculate the activity rate for Machining.
8. Calculate the activity rate for Inspection.
9. Determine the indirect costs (MOH) assigned to Product A in total and per unit
10. Determine the indirect costs (MOH) assigned to Product B in total and per unit
11. Determine the Gross Profit Dollars & Gross Profit Percentage per unit and in total for Product A
12. Determine the Gross Profit Dollars & Gross Profit Percentage per unit and in total for Product B.
13. The President of Kate is skeptical about whether the benefits of ABC will be worth the cost. She notes that
ABC is just a different way of “spreading the same total of cost around”, so overall company profitability will remain
the same under either method. Do you agree with this view? Why or why not?
Ch. 4
Activity #5 – Identifying Costs as value-added or non-value added
Indicate whether each activity is value added or non-value added in a manufacturing process.
Product design research _______
Moving materials _______
Machining _______
Assembly of components _______
Copyright© 2020 School of Accountancy, Arizona State University
Finished goods inventory storage _______
Rework after a quality inspection _______
Painting product _______
Activity #6 – Classifying Costs of Quality
Indicate how each of the following costs would be classified as in regards to quality:
Prevention, Appraisal, Internal Failure, External Failure
Costs incurred to inspect products after manufacturing. _______
Costs incurred to handle customer complaints. _______
Costs incurred to train production employees. _______
Costs incurred for downtime of production equipment. _______
Copyright© 2020 School of Accountancy, Arizona State University
Powered by TCPDF (www.tcpdf.org)

