


Business and Corporate Laws: An Analysis of Canadian Credit
Card Contract
Background
This paper examines the legalities involved in Canadian credit card
contractual agreements and attempts to analyze and suggest measures
to rectify the shortcomings in the cardholder terms and conditions.
Many varieties of credit cards serving diverse consumer uses are
available in Canada and are issued by well-known banking and
financial companies.
These include Standard Credit Cards, Gold Credit Cards, Platinum
Credit Cards, and Student Credit Cards, all of these being available
across Canada at low and regular rates. Besides these, there are also
the US Dollar Credit Cards, the Secured Credit Cards, the Charge
Cards, and the Retail Credit Cards. The study tries to analyze an actual
credit card agreement as per the terms and conditions set out by a
leading card issuer bank in its credit card application.
When a card applicant signs the application, a card is issued to him or
her, and he uses the same, then he becomes a card-holder who is
bound by the terms and conditions of use of the card as stipulated by
the issuing company or bank. Since credit cards are both personal
credit instruments as also payment tools and the cardholder can
operate on his linked account at his convenient time, place, and ease,
it is no wonder that most Canadians are in possession of at least two
credit cards on average.

In all credit card transactions, the cardholder is directly under contract
with the issuing bank. But there are other parties like merchants, ISOs,
and Card Associations, (e.g., VISA and MasterCard). VISA and
MasterCard are the organizations that frame rules and offer card
services through their member banks and financial institutions. Thus
the actual business relationship is between the cardholder and the
issuing bank, the Card Association and the member issuing bank,
between the issuer bank and the merchants/POS, etc. The relationship
is for the mutual benefit of the contracting parties.
Thus, while a cardholder may opt for a card with a bank for the
advantages that he perceives it offers, the issuing bank hopes to
enhance its revenues, divert customers to alternate delivery channels
for optimizing the cost of operations, or some other reasons. The
merchants improve their sales riding on the credit availability and
technological benefits of credit cards. While such business and
contractual relationships are generally the same the world over,
Canadian law has some specific provisions that are unlike the laws of
other countries.
One reason is the way the Canadian provinces are organized and
administered. Thus, each province has its own separate consumer
protection and other such laws that are aligned with the national
objectives but still administered provincially and separately.
An understanding of the issues concerning the credit card means
gaining a deeper knowledge of the benefits, the associated risks, and
other such issues. In this respect, the Financial Consumer Agency of

Canada or FCAC, a body constituted under the Canadian Government
provides vital information on credit cards which may be enumerated
here for understanding the issues better (2009a, p. 4).
Credit cards aid in establishing a favorable credit history and earning a
positive credit rating for the cardholder. These plastic cards are easier
to carry in lieu of cash, provide credit readily for use of the cardholder
as per his needs, even offer incentives and rewards, and are generally
regarded as a safe and convenient payment mechanism that can be
made over the internet or telephone using the PIN.

Risks
There is the risk that the cardholder may become steeped in debt due
to the non-judicious use of the card. Another downside is that the
credit rating of the cardholder suffers if he makes delayed payments
on the card outstanding. Also, the cardholder agreement’s terms and
conditions are quite complex and difficult to understand. The form of
credit is also costlier than other forms of personal credit.
The FCAC also lists the things in a cardholder agreement that an
applicant needs to check before applying for the card and which are
provided as follows (2009a, p. 19):
1. The annual fees (or other fees applicable)
2. The minimum payments to be made monthly
3. The rates of interest on purchases, balance transfers, and cash
advances that the bank will charge
4. The method by which the interest will be calculated
5. The available grace period
6. What penalties or measures that late payments would entail for
the cardholder
7. Additional benefits on offer

8. The nature of support or service provided
The FCAC also lists the essential terms and conditions that should be
a part of any cardholder agreement which should accompany cards
sent by a bank to the card applicant (2009a, p. 6). These need to be
mentioned to address the key issues in the latter part of this paper.
1. What annual interest rate the card issuer will charge on the card
2. How the interest on card outstanding will be calculated and
recovered by the bank
3. What will be the grace period allowed by the bank
4. What will be the periodicity of the issue of statements to the
cardholder
5. Whether the cardholder is required to pay in full his outstanding
on account when he receives his statement and what will be the
penalty or additional charge if he does not so pay immediately
6. What minimum monthly payments will have to be made and
what will be the method of calculating the amount due payable
7. What would be the initial credit available on the card (credit
limit sanctioned)
8. What optional features are available on the card and at what
cost to the cardholder

9. Other fees or charges applicable from time to time
10.A phone number for contacting the card issuer on issues relating
to the card account during its business hours
Likewise, the cardholder’s statement must also provide the following
information (FCAC, 2009b, p. 7):
1. Details of all transactions during the period of the statement
2. The amount charged as fees and interest on the account
3. Dates of posting the transaction entries to the account
4. Amount payable by the cardholder and the date before which
this is to be done so as to give the benefit of the grace period to
the consumer
5. The break-up of amounts of purchase, cash advances, interests
and other fees charged, and the payments made into the account
during the statement period.
The issuer bank must also give an advance written notice at least 30
days prior to such alteration when it alters the original terms and
conditions of the cardholder agreement. But it need not give such
advance notice in case the bank changes the credit limit on the card,
extends the grace period, decreases a charge other than an interest
rate, alters its optional proposals, or effects a change in interest with
change in its base rate of interest. In such cases, however, the bank

must give written notice within 30 days of such alterations in the
contract (FCAC, 2009b, p. 8).
Methodology for Analysis
Leading credit card issuers in Canada are the BMO Bank of Montreal,
the Toronto Dominion Bank, the President’s Choice Bank, the Bank
of Nova Scotia, etc. Canada, as well as its provinces, has in place
some legal statutes for protecting consumers, financial bodies, and
business enterprises.
These include the Competition Act, the Consumer Protection Act, the
Collection Agencies Act, the Privacy Act, the Personal Information
Protection and Electronic Documents Act (PIPEDA), the Bank Act,
and the Civil Code, among other such legislation, aimed at ensuring
and protecting the rights of the consumer, facilitating fair competition,
guaranteeing personal information and privacy rights, etc.
Since these laws govern credit card agreements, the study and analysis
of the specific clauses incorporated in cardholder agreements as also
the related legal statutes could reveal how effective the Canadian laws
are in regulating credit card contracts, what are the perceived
shortcomings in the same, and what needs to be done to improve the
business and contract laws in the Canadian environment.
While most card issuers nowadays provide some ancillary benefits to
each type of card that they issue their customers, only those laws that
relate directly to the card issue and the contractual agreement were
studied in detail. There obviously are other laws like those concerning
Insurance, Mutual Funds, etc which form a set of ancillary laws. Many

card issuers provide benefits of insurance, mutual funds, etc on the
cards issued by them for meeting competition and also for providing
their client’s value-added services.
However, the related laws have not been studied as much as they do
not form essential elements of all cardholder agreements. Thus in the
study, the primary contract between the cardholder and the issuer bank
was examined on the basis of laws relating to contract, personal
privacy, consumer protection, right to privacy of information, etc
which had the most relevance to the issue of credit cards.
Description and Explanation of All Clauses of the Contract
An MBNA Credit Card cardholder agreement (Fig.1) was examined
for analyzing the underlying legal implications behind the key clauses
stipulated therein by the card-issuing bank. The stipulated terms and
conditions in the agreement were examined, the legal provisions
underlying the same pinpointed, and analysis was then done.
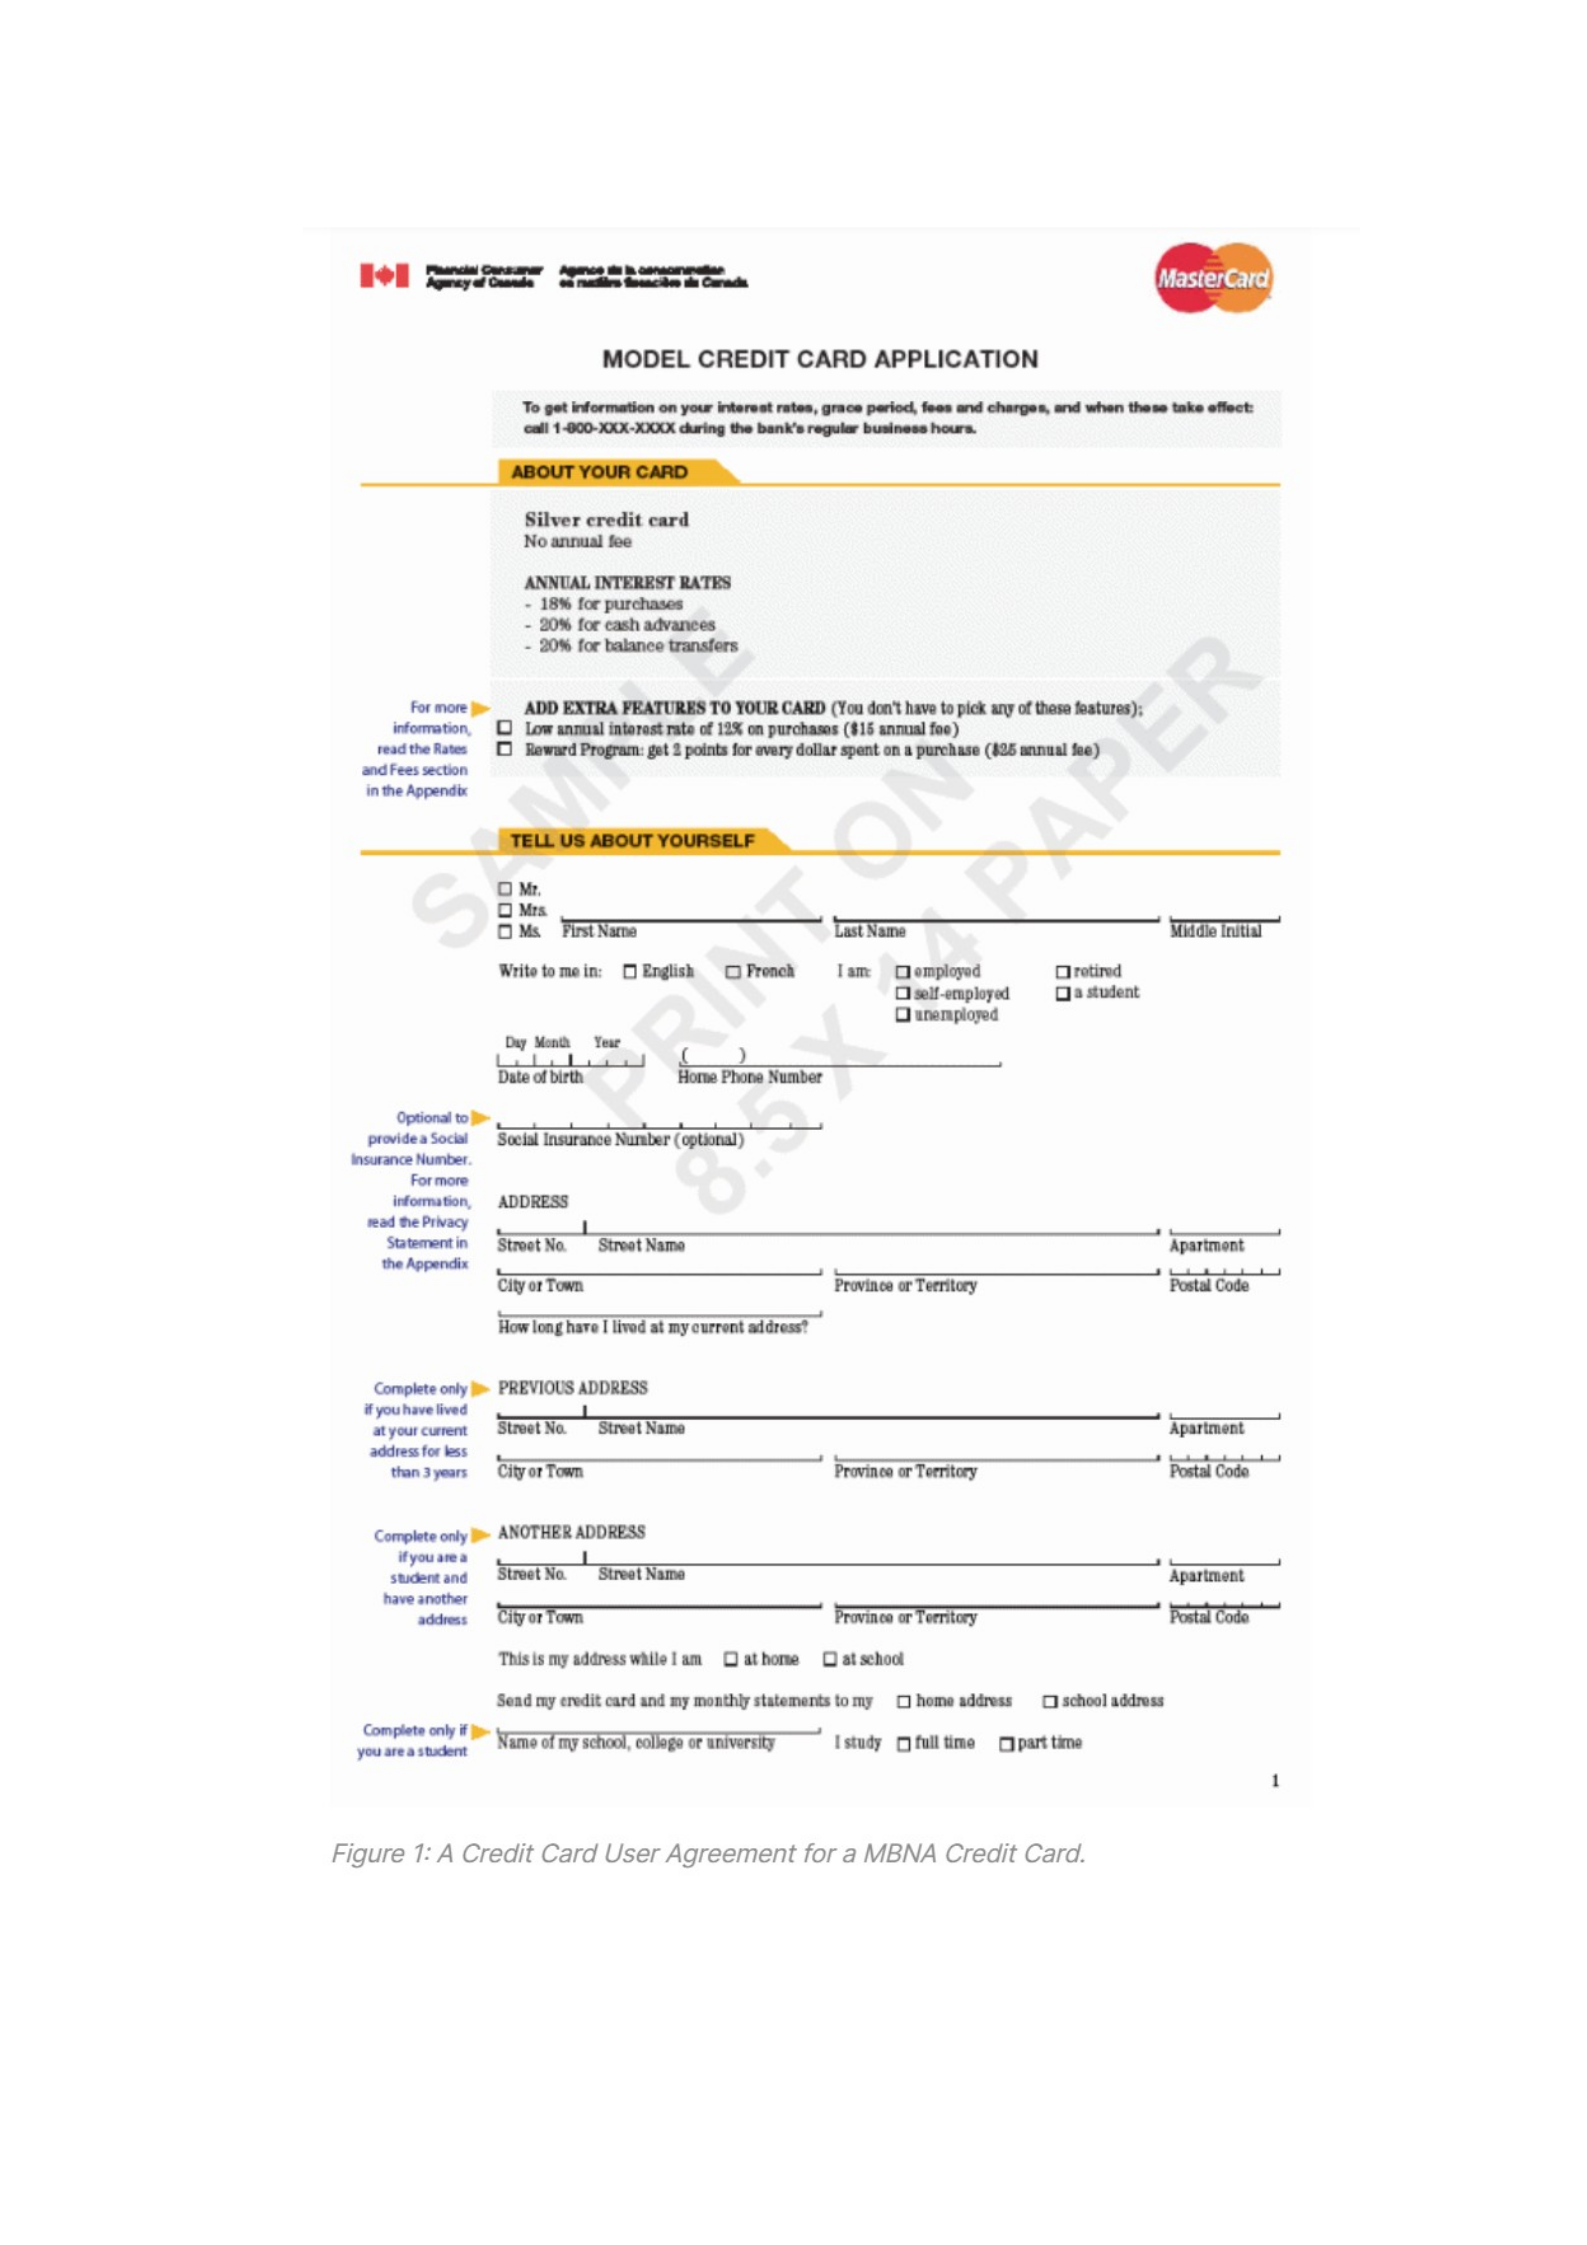

The first thing that was stated in the application was that only
Canadian citizens could apply for the card. This actually is a standard
requirement of all cardholder agreements for a card to be issued
within the country. Also, applicants were required to be 18 (often 19)
years or more. This also is in keeping with the majority age as
specified across the various provinces of Canada. While some
provinces stipulate an age of 18 years as the majority age, others
maintain this to be 19 years. But what followed immediately after the
age stipulation, was simply a marketing attempt on the part of the
issuing bank. The bank stated that if the application for the type of
card was not approved, which it could anyway do at its discretion, the
application could mean to stipulate that the bank could open a
Preferred Account for the applicant.
Another controversial clause appeared to be that of automatic
consideration for the upgrade of the account. The terms were such as
to preclude the free choice of the applicant. It simply meant that if the
bank did not, at its discretion, find the applicant suitable for issuing a
MasterCard Account, then it could without further information to the
applicant and quite arbitrarily, open a Preferred Account for the
applicant. This thus meant that the bank could protect its commercial
interests in so opening an account and realize any higher fees on the
same and that the applicant had no choice in the matter. This also
constituted unfair practice and could be termed as the unsolicited offer
of cards, goods, or services, which was prohibited by the provisions of
the Consumer Protection Act, 2002 as amended from time to time.

The second paragraph stated that the applicant (once he/she signed the
application) agreed to ‘everything’ written in the agreement. In
addition, the applicant also authorized a customer service
representative to contact him/her for selling other consumer loan
products. While the selling of further or other loan products could
enable the bank to further improve its loan portfolio and hence
revenues, how this related to the credit card application was difficult
to imagine. Also, the basic implication in any contract is that both
sides to a contract are able to exercise free choice in the matter, have
valid and lawful consideration for entering into the contract, specify
the terms and conditions as per the stated objectives of the contract
and as actually contemplated for performance, represent actual facts in
their agreement.
The parties are also understood to not mislead any of the other parties
to the contract, provide an opportunity to those other parties to exit the
contract within a reasonable time of making the contract, and also do
not arbitrarily impose certain things, including sudden and
inexplicable fees, on those other parties. Thus credit card terms and
conditions that impose certain irrelevant or unrelated obligations on
the parties to the contract can be termed both illegal and unfair
practice as also in contravention of both the Consumer Protection Act
and the Competition Act or even the common contract laws in force in
the country.
A still more contentious clause was that the applicant’s so applying
for the credit card of the bank would also allow the bank’s affiliates,
representatives, or service providers to monitor and or record the

telephone conversation for education and quality service. A simple
survey could very well serve the purpose of understanding the
requirements of a customer, which could then be analyzed by the bank
to improve service quality. How an infringement on the privacy of the
individual and eavesdropping on private conversations can be
supported by any laws of any democratic and civilized country is
beyond comprehension. Perhaps, in these times of heightened
terrorism and money laundering, a bank could only hope to pry on
personal phone conversations only and only if mandated by suitable
laws for enforcing the security of the country.
The next clause is related to the Privacy Rights of the applicant
cardholder. The applicant was taken by the bank to be bound by the
terms of the agreement so that MBNA Canada or its affiliates, agents,
or service providers could have access to private information on him
or her that could help identify those agencies on the credit status of the
person. The parties concerned were justified in protecting their own
interests and needed to adopt effective risk management practices.
However, whether the sharing of private information among others
could be acceptable in view of the legal protection available to
customers for safeguarding personal information and privacy is a
debatable point. While the statutory need to identify an applicant,
record his credit history and any relevant information as called for
under Canadian federal laws was understandable, the secondary
marketing avenue that the bank hoped to tap from the card issue,
appeared to be bad and unfair, or unsolicited business practice. The
agreement also authorized the bank to retain information on the

customer for future use even if the relationship between the two had
expired and for an indefinite period, which if not permitted by the
customer for any future marketing promotion, also appear
meaningless and unlawful.
Application of Legal Principles in the Credit Card Contract
Although electronic payments and electronic money like credit cards
are accepted mechanisms for use by Canadian businesses and
individuals, the dian laws are still to actually define electronic money.
Since the fees and charges of most credit cards are extremely high
even among developed countries, there is obviously little regulation
by the authorities in controlling the credit card fee structures, which
are often arbitrarily imposed on customers. Added to this are the high
interchange rates that ultimately add to the outgoes of the Canadian
consumer
And another important underlying requirement in the card agreement
under study as well as all credit proposals issued in Canada is that the
applicant should have a satisfactory credit history. This is a
fundamental principle used to identify the deserving credit seeker as
also a means of risk management that helps prevent loss to the creditor
bank.
However, the basic law is the contract law. Here the contracting
parties are the card issuing bank and the card applicant. Canadian
Contract Law is based on the English common law and is conceived
as a voluntary agreement between the parties concerned. While the
contract creates some legally enforceable obligations on the parties to

it, it itself needs to be clearly communicated, unconditional and
without changes. In Canada, contractual agreements are required to be
written ones. Some important concepts associated with a contract
include that of privities, offer and acceptance and consideration. The
contract law is also of a private nature. The capacity to contract is
restricted to individuals at least 18 or 19 years of age. Hence, the age
clause in credit card contractual agreements is as mandated by the law.
However, an undue influence should not be attempted by means of a
contractual clause and a genuine consent is essential for ensuring the
validity of a contract. In this respect the card under study appears to
unduly influence the prospective card applicant to follow the bank’s
terms of contract so that he or she may obtain the credit card applied
for. Also, the doctrine of privities in a contract act is absent in a
consumer protection act. Thus while the privities consideration
stresses on the principle of caveat emptor, the consumer is attempted
to be protected against undue commercial interests through the
provisions of the consumer protection law. This consideration is
wholely absent in the cardholder agreement studied. The agreement
nowhere mentions a replacement warranty or assures the applicant
that if he is satisfied with his or her card, the bank will accept back the
card. Thus the consumer protection act appears more on paper than
effective and neither ensures a warranty to be adopted by the bank nor
prevents it from adopting unfair market practices. The customer
applicant also has no choice in the matter of selection of the card
depending on his or her satisfaction with the quality of card or service
involved.

Another aspect of Canadian law is that of regulation in the manner in
which products are sold, advertised or marketed. The federal law in
this regard is the Competition Act. The Competition Act governs the
prescribed standards of advertising and marketing of a product or
service. However, provincially, protection is sought to be given to the
consumer of goods or services through the Consumer Protection Act.
In the case of the cardholder agreement under study, it cannot be said
that the applicant is being offered a choice of products and services at
fair prices. Rather some services or products are being imposed upon
the cardholder. The bank also appears to charge exorbitant fees. And,
the right of the consumer to be accorded protection against
unsatisfactory card services, and the right to adequate or suitable
compensation for the same is also notable for its absence from the
terms of agreement.
An important provision that is also absent is that of a clear disclosure
clause regarding the card issue and the charges associated with the use
of the same. Obviously, the card rates and charges mentioned prior to
the terms and conditions clauses are vague to say the least. Most
common applicants would not be able to comprehend all the complex
features represented. The clauses are also in very fine print and lack
clarity. But, the Bank Act provisions mandate full disclosure of terms
and conditions in credit card applications.
On a recent complaint from Ms Philippa Lawson of the Public Interest
Advocacy Centre based in Ontario against the MBNA Bank credit
card agreement provisions (www.piac.ca), the Privacy Commissioner
observed that the MBNA bank was not reasonably informing the

customer as to the purposes for which the customer’s personal
information would be used by it or its agencies and affiliates. He also
stated that the information in the cardholder agreement was not clear
or understandable to the customer, written in complex legal terms and
in very fine print, and also appeared to indicate that the personal
information could be unreasonably used in any arbitrary manner and
for disclosing the same to anyone that it unilaterally thought to be fit
without a clear and unforced consent from the cardholder.
He opined that the MBNA Privacy Policy Statement also was written
in such a way that it did not indicate that the customer had clear
choice and consent in the matter of card account selection. He again
found the bank guilty of unfair practices when it was divulging
customer information to third parties who provided services to the
bank’s customers although the bank did not clearly mention this in the
application format. He found that the bank’s card agreement actually
was in contravention of the provisions of the Privacy Act and the
customer was precluded from forming an informed consent while
accepting the cardholder agreement. The terms and conditions were in
clear contravention of the right to privacy of information of the
individual when the bank stated the use of personal information for its
secondary marketing efforts without the consent of the customer. And,
as mentioned before in this paper, the agreement did not provide the
applicant any easy, immediate or convenient means of withdrawing
himself or herself from the contract linked with optional practices of
the bank.

Major Contractual Provisions and Legal Corrective Measures
The Ministry of Small Business and Consumer Services of the
Government of Ontario, Canada has provided details of the basic
features and requirements in a contract on its website
(www.gov.on.ca). These provide a fair idea of the nature of
contractual agreements like the credit cardholder agreement. The
ministry identifies certain features of all contracts, which are provided
hereunder for a better understanding of the issues concerning credit
card contracts.
1. All contracts need to be clear and easily
understandable.$This means that contracts must be clear,
specific and unambiguous. The contracting parties must easily
understand all clauses. Legally, unambiguous contracts go in
favor of the consumer of goods or services who may be part of
a contract having unclear terms and conditions or language, in
cases of disputes.

2. There must be a period of cooling-off.CIt implies that both
parties to a contract need a cooling off period for exiting from
the contract. For contracts worth a consideration amount more
than $ 50, the legally prescribed period of cooling off is 10 days
within which any of the parties can back off from the agreement
even if the same has been agreed and signed upon. Cancellation
of a contract can best be done by fax or mail, in which case any
amount advanced has to be returned.
3. Goods or services that have been pre-paid.CWritten contracts
are mandatory for goods or services involving consideration
amounts more than $50 in cases where any part of the contract
will occur in the future. In addition to being written and clearly
stipulated, the contract must include full particulars of
transactions as also disclose completely all the terms of the
credit.
4. Disclosure of terms of credit in full.CAll credit sales of goods
or providing services on credit need to provide the consumer
full written particulars of charges and rates to be recovered by
the supplier of the credit goods or services. Additionally, the
financial details must clearly specify additional charges or fees
in case of failure or delay on the part of the debtor in repaying
back the loan or credit.
5. Referral selling.CNo offer or proposal to the consumer can be
false or misleading in intention or content. In other words, the
parties to a contract must only include terms that they intend to

comply with and also need to back up any contract with related
action.
6. Repossession.CThe law also protects the consumer who has
bought a good or service but paid at least two-thirds of the price
of the goods, so that in such cases the seller cannot take back
the goods so sold save and except by court order. However, in
the Canadian credit market, where the credit score or rating is of
vital significance for the borrower or account holder, the
situation could be damaging to the defaulting debtor if and
when the seller takes the defaulter debtor to court.
7. Unsolicited goods.CThe Canadian laws explicitly prohibit the
sale of unsolicited goods or credit cards to a consumer. The
buyer in such cases need not pay or accept such goods. But
once the consumer buys something with the card or uses the
card for a cash advance or purchase, then he is liable on the
same and cannot disclaim his ownership of the card or goods
and hence all payment liability there-against. The Consumer
Protection Act, 2002 envisages a monetary fine of $50,000 or
imprisonment up to two years less by one day in cases of
violations of some sections of the act. The similar fine in case
of corporate entities is as high as $250,000.
8. Consumer agreements must reveal all relevant details.CThe
law stipulates that, in cases where either of the parties to a
contract do not deliver on their part of the contract, or one party
does not disclose something that it was legally bound to

disclose prior to or during the operation of the contract, then the
aggrieved party shall have the right to cancel the contract
unilaterally within one year of signing of such contract.
9. Deliveries be made on time and redress for non-
compliance.COnce a delivery of a good is stipulated in a
contract and the good does not arrive within 30 days of the
deadline fixed, then the aggrieved party to the contract can
cancel the contract unilaterally. Sending a suitable letter to the
other party informing of such cancellation and the reason
thereof can well achieve this. However, once the aggrieved
party accepts the delivery of goods beyond the stipulated 30
days from the delivery date stipulated in the contract, he is
bound by the terms of the contract.
10.Remedies need to be timely.CIn case the buyer of goods as per
a contract takes the help of the cooling off period after which he
declines to accept the goods, the seller company has 15 days in
which to return the money taken from the buyer. The company
then has every right to take back the goods, although it may
need to bear the expenses of returning the goods to it.
11.Misrepresentation is illegal.CContractual terms should not be a
misrepresentation of actual facts. Thus, all financial charges or
fees mentioned in a contract should in actual fact be what are
actually charged to the consumer.
12.Unfair Practices.CThe law defines unfair practices and strictly
prohibits false or misleading sales representations. The act also

enables those subject to unfair practices to legally claim back
their money. The aggrieved person has the following options
available to him:
He can get the agreement rescinded by the seller within one
year of contract through fax or mail, by referring to the
provisions of the act.
He can sue the seller if the latter fails to comply with
cancellation request if more than 30 days have elapsed. The
same, if it involves an amount less than $ 10,000, can be done
easily in court by the aggrieved himself.
He can contact the Ministry of Government Services who might
suggest ways for action and the complainant can even file a
formal complaint which the Ministry can investigate and
prosecute the defaulting party.
In the light of the features of contracts previously discussed and the
application of the relevant laws stated to credit card agreements, it
appears that there are several shortcomings in credit cardholder
agreements that need to be addressed if the cardholder, who is a
consumer, is to be given a fair deal by the issuer bank.
One of the effective measures could be the establishment of a 24 hour
toll free 1-800 telephone service so that applicants could phone in
their complaints or intention to withdraw from a cardholder agreement
if they considered this to be necessary. This would ensure consumer
free choice. Also, the terms and conditions need to be clearer, couched

in simple terms understandable by laypersons, and also be written in
larger, intelligible print. The intending cardholder could then form an
informed opinion and exercise the right of free choice based on his
perception of utility and quality of the product or service. While
adhering to the basic form of written contractual agreements, the bank
would also need to consider the rights of the cardholder applicant,
which are sought to be protected by the Consumer Protection Act.
The agreement thus needs to provide an exit option from the terms and
conditions of the agreement in both paper and electronic forms. The
card and services offered also must be of the standards and quality
promised or represented to the prospective cardholder in the
agreement. While the bank needs to maintain prudent risk
management practices, comply with federal and provincial laws and
also meet its commercial needs, it must above all follow the
provisions of the Competition Act and the Consumer Protection Act in
being transparent, fair and above board in all its dealings with the
customers, including the provision of credit card services.
Recommendations and Takeaways
The PAIC had many years back stressed on the need to establish an
independent consumer protection bureau. It had also wanted in place
measures to improve disclosure and transparency practices among
credit card issuing banks and other financial service providers. But as
it stands even today, much needs to be done in the matter. Thus, the
cardholder agreement needs to include a clear fraud protection clause
as also mention what the limits to the cardholder liability actually will

be. Transactions in cash using PIN also need to be covered in the
fraud protection policy of the bank.
The Financial Consumer Agency of Canada (FCAC) has brought out a
model credit card application (Fig. 2). It is an innovative effort aimed
at properly regulating the credit card market. In the model application,
there is an Appendix that lists the details on the credit card fees and
rates charged by the bank. These cover the grace period, the interest
free period for purchases, the interest rates for purchases, cash
advances, and balance transfers, annual fees, the minimum payment
and other fees. A privacy statement is detailed where in the nature,
purpose of use, and intended user of customer personal information is
clearly spelt out.
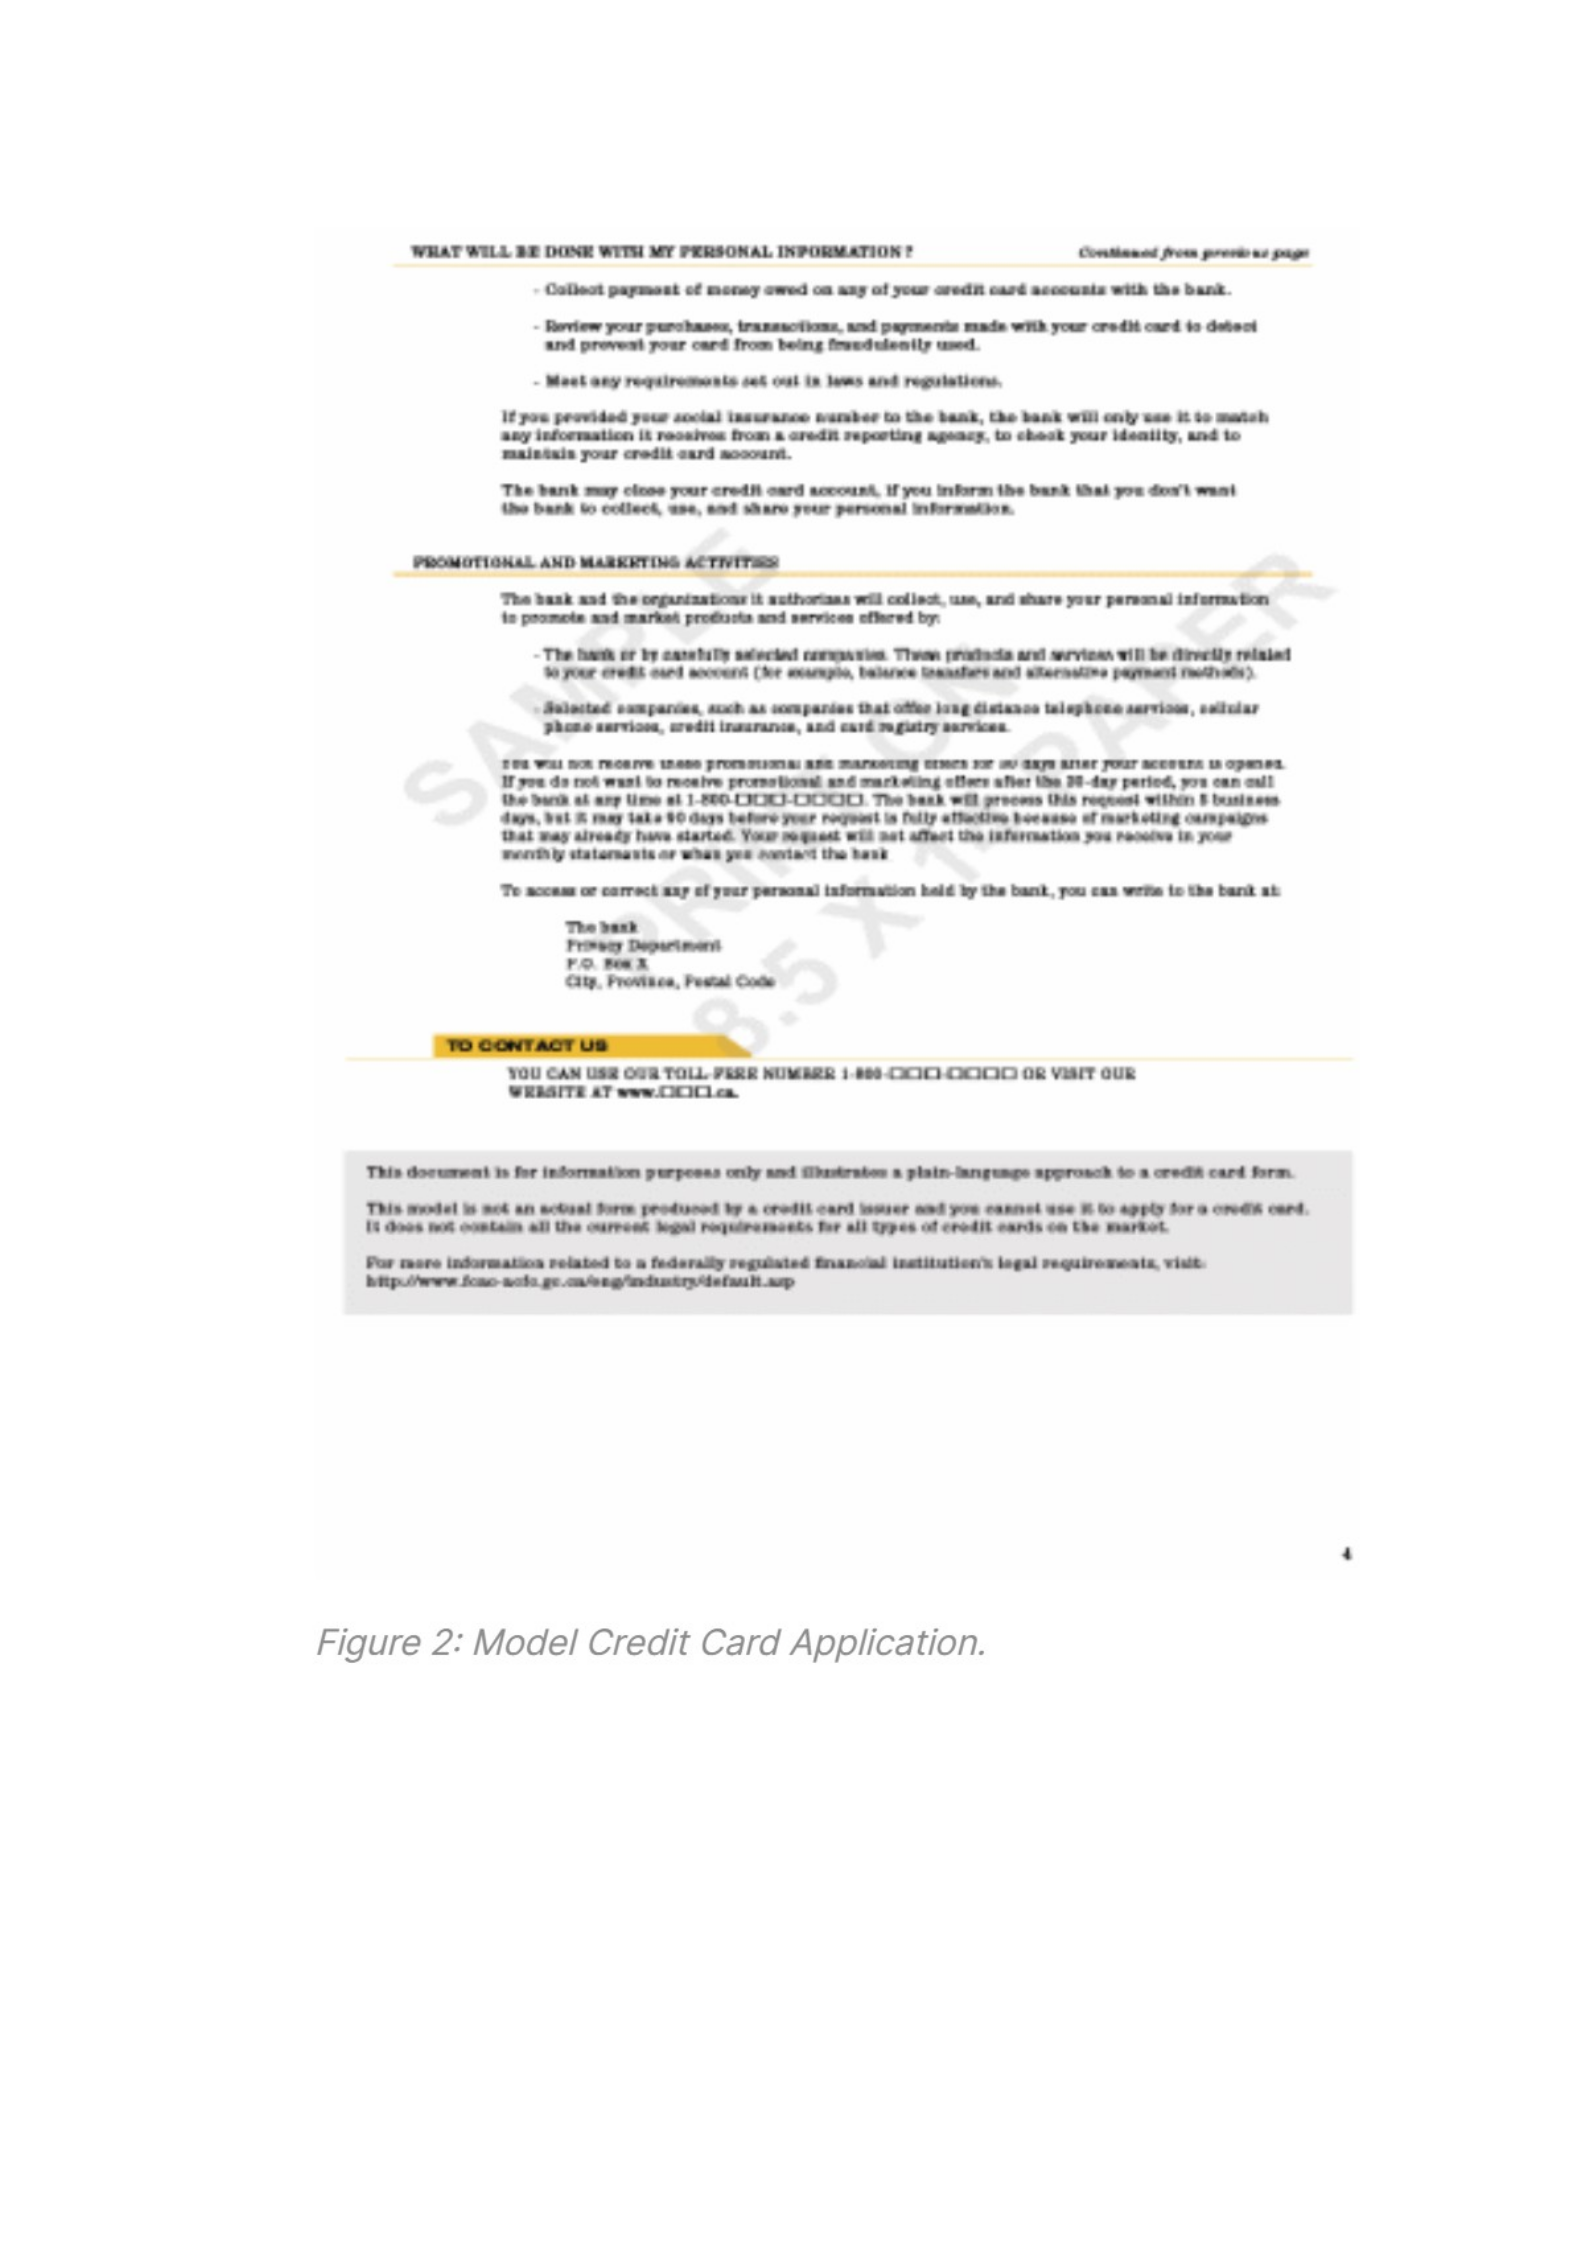
Also, a separate clause for marketing and promotional offers by the
bank is provided where a period of 30 days is stipulated as the
promotion-free period. The customer is also provided toll free 1-800
telephone numbers for calling the bank for suppressing the

promotional offer which would be implemented by the bank in case
the 30 day period lapsed without such phone call for suppressing the
offer from the customer is received by the bank. Adoption of the
model credit card application format or similar such formats would
regularize most anomalies found in the course of the study and
analysis and as reported in earlier paragraphs in this paper.
Obviously, the legal structures are in place in Canada that strive to
provide the credit card applicants and consumers ample protection in
terms of their contractual rights, equal competition policy, privacy
rights, and information privacy rights. However, a lot needs to be
initiated in actually ensuring the same is done. Banks and other
financial institutions are by nature doing commercial business
activities. They need to charge fees to maintain profitable operations.
However, in as much as their fees and interchange fees impact on the
ordinary citizen and taxpayer, the system needs a re-look. Also, the
rates of fees charged by all banks are highest even among developed
countries and is anywhere between 24 to 60 per cent, whereas the
prime bank rate is only 1 per cent.
Also, banks need to strictly adhere to disclosure and transparency
requirements, protect the individual right to personal information
privacy and also allow the consumer equal opportunity to reject or
accept the bank’s offer of product or services. Credit card agreements
need to include clauses informing the customer of his contractual
rights and also not adopt unfair practices for marketing variety of
products and services, which may be unwanted by the card applicants.
While the legal system in Canada is thus geared to strengthen the

individuals’ contractual rights and also establish fair business laws,
there are various shortcomings as pointed out and these need to be
addressed to fine-tune things in the legal and financial system of the
country.
In all countries, even in developed nations, regulation of credit cards
are not upto the standards that can be desired. The regulation is lax,
consumers are not amply protected, the consumers also themselves are
not aware of the related issues, their rights or obligations, and
governments of the day are bent more on catering to whims of
businessmen rather than on assuring and getting consumers a fair deal.
While a model credit card if imposed by a concerned government
would be one step in the right direction, increasingly arbitrary fees,
unfair deals and other such sorry features plague the credit card
industry in Canada in the present.
Perhaps, more than governmental efforts to redress consumer
grievances, the government would do better to educate the citizens of
their contractual rights, their obligations, what a credit card agreement
can or cannot contain and the need of the cardholder to be judicious in
signing the contract at the very outset. That consumer awareness can
prevent unfair deals from taking place is true not only in the credit
card business but also in most other businesses, conventional or
technology driven. That old saying then needs repetition in context:
“Prevention is better than Cure”.
References
Financial Consumer Agency of Canada (FCAC), “Model Credit Card
Application”, 2009: pp. retrieved from the World Wide Web 2009.

Financial Consumer Agency of Canada (FCAC), “Getting the Most
from Your Credit Card: Understanding the Terms and Conditions”,
2009a: pp. 1-25;
MBNA Canada Bank, 2008.
The Ministry of Small Business and Consumer Services, 2006,
Modified 2007,”Cosumer Protection: Your Rights”.
The Public Interest Advocacy Center (PIAC), 2009.

