


Macroeconomic Factors and Hong Kong Stock Returns
Abstract
Numerous studies have been carried out on the causal relationship
between macroeconomic factors and stock variables. However, these
studies have not reached common ground on the causal relationship
and direction of the said variables. This study aims at addressing the
causal relationship between the selected microeconomic variables
(inflation, exchange rates, monetary supply and real economy) in the
Hong Kong stock market. The data used covers the period between the
years 1991 to 2011. Granger causality model is used to establish these
relationships. The study findings reveal that inflation, interest rate and
foreign sale do Granger cause stock prices.
On the other hand, stock prices do Granger cause monetary supply,
interest rates, exchange rates, foreign sales and purchases. Also,
interest rates and foreign transaction negatively and positively
determine stock prices in Hong Kong stock exchange. Lastly, the
evidence tends to favour stock returns in the prediction of
macroeconomic variables.
Introduction
Overview
This chapter covers the background of the study, problem statement,
research objectives and hypotheses and the significance of the study.

Background to the study
Investment is generally described as the commitment of financial
resources on a particular venture. The biggest challenge facing most
investors or portfolio managers is the determination of the value of an
investment; whether it is worth its price (Abdalla & Murinde, 1997,
p.25). Investors need to consider the intrinsic value of any investment
using the prevailing market price before committing financial
resources. Since the estimation of financial asset value is not easy,
numerous methods of valuation have been developed over time
(Bodnar & Wong, 2000, p.4).
These valuation methods use various inputs, for instance, cash flows,
rates of inflation, interest rates, rate of returns, exchange rates, risk
premiums among others. These inputs greatly influence the aggregate
return on investment. Also, since companies are based in different
environments, they are exposed to different macroeconomic variables.
Thus, both internal and external conditions a firm is subjected to must
be taken into consideration during the process of investment valuation
(Bodnar & Wong, 2000, p.5).
Theoretically, macroeconomic factors are believed to be the main
cause of stock market volatility. Thus, they are considered to be the
key indicators of stock returns (Chatrath, Ramchander & Song, 1997,
p.2). According to Chatrath, Ramchander and Song (1997, p.3), the
volatility of market portfolio returns and the ratio of anticipated profits
to anticipated aggregate revenue to the economy are inversely
proportional. Nardari and Scruggs (2005, p. 1) argue that increased

uncertainty concerning future return is significantly related to the
economic downturn. Nonetheless, Nishat and Shaheen (2004, p. 620)
state that stock prices are the principal indicators and that the change
in stock prices always occurs before changes in business activities.
According to a study conducted by Chatrath, Ramchander & Song
(1997, p. 440), the evidence tends to favour stock returns in the
prediction of macroeconomic variables. Therefore, stock prices are
significant indicators for the impending economic conditions or
business cycle. This means that stock prices normally start to declines
prior to favourable economic conditions and vice versa. Furthermore,
interest rates have a significant effect on business operations. Any rise
in the interest rates, everything else held constant, will lead to an
increase in the capital cost. Thus, companies have to up their game in
a high-interest rate surrounding. Or else, the high-interest rate will
consume all the profits.
According to Maysami and Koh (2000) analysis, based on stock
portfolio instead of single stocks, found that interest rates negatively
impact on the entire portfolio returns. However, Tursoy, Gunsel and
Rjoub (2008. p.15) stress that there is no evidence to support the
relationship between the interest rate and stock returns. Flannery and
Protopapadakis (2001, p. 8) show that overnight interest rates have a
causal relationship with stock prices and that stock returns also have a
causal relationship with the overnight interest rates and the
government rates.

Zhao (1999, p. 508) indicate that the Chinese common stock returns
are inversely correlated to the expected inflation component, and
almost certainly to the unexpected component of the inflation rate. He
argues that the inverse relationship between inflation and real stock
returns is as a result of the substitute effects. Stock returns are
determined through estimation of the most significant real variable,
and the inverse relationship between stock return and inflation is
brought by the inverse correlation between inflation and real activities
in the economy.
Statement of the problem
In modern society, investing in equity seems to be a more and more
popular way of making more money for investors. Besides, issuing
stocks is also an efficient way of raising funds. Therefore, the waves
of stock price affect both individual investors and enterprises
(Daohua, 2005). According to some works of literature, stock prices
are normally affected by two main factors: internal and external
factors. Internal factor is the operational condition of a firm/company.
On the other hand, external factors/macroeconomic factors include
inflation, exchange rate, interest rate, GDP and so on (Dornbusch &
Fischer, 1980, p.960).
Macroeconomic factors considerably affect the stock index (Daohua,
2005). According to a number of works of literature, the correlation
between various macroeconomic variables and stock returns is well
defined, particularly in advanced economies. Although considerable
relationships between macroeconomic variables and stock prices have
been, researchers have not reached a common ground regarding the

relationship signals or the direction of causality (Hondroyiannis &
Papapetrou, 2001, p.24). This paper explores the causal relationship
between macroeconomic factors and stock returns. The study is
narrowed down to the Hong Kong stock market. To establish the
macroeconomic causes of the Hong Kong Stock Exchange (SEHK),
the study uses SEHK17 Index observed from 1991 to 2011. The
relationship between macroeconomic variables and stock returns are
tested in this study using annual data.
Objectives of the study
The general objective of this study is to explore the causal relationship
between macroeconomic factors and stock returns. In line with the
general objective, the study examined the following specific
objectives:
1. To establish the relationship between each macroeconomic
variables and stock returns.
2. To find out whether macroeconomic variables does Granger
cause stock prices.
3. To establish whether stock returns do Granger cause
macroeconomic variables.
Research Hypotheses
To meet the above objectives, the following hypotheses are tested:
H0:BThe macro-economic variables do not Granger cause the
SEHK-17 Index.
H1: The macro-economic variables do Granger cause the
SEHK-17 Index.

Justification of the Study
The researcher is a post-graduate student at the local university. The
findings of this study are of great value for policymakers and
regulatory authorities, especially the Capital Market Board. It provides
the policymakers with up to date information regarding Hong Kong
Stock market, which is significant for future decision making and
regulatory purpose. Also, the study will add to the researcher’s career
development over and above the intended academic purpose.
Scope of the Study
The scope of this study is in line with the general objective, which is
to explore the causal relationship between macroeconomic factors and
stock returns. Using primary data and applying statistical techniques,
the study explained the variables to meet the research objectives.
Literature Review
Introduction
In this chapter, the significant literature materials of the research are
reviewed, classifying financial models linked to the relationship
between macroeconomic factors and stock returns.
The relationship between Macro-Economic variables and Stock
Returns
During the valuation process, emphasis should be placed on both the
external and internal business environment. Reilly and Brown (2006,
p. 361) assert that the company’s internal and industrial environment
should be given a lot of attention during the valuation process.

Therefore, this approach emphasizes the significance of internal and
external environment in the valuation process.
The top-down approach stresses that internal and external
environments have a great impact on the overall stock, irrespective of
the nature and size of the company. On the other hand, the bottom-up
approach argues that it is probable to acquire stocks with high returns
irrespective of the prevailing economic conditions both internally and
externally. Therefore, both internal and external business surrounding
have a major impact on the stock values and return. Therefore, a
number of macroeconomic variables are considered to be more
significant to the risks that are familiar with most companies.
The relationship between macro-economic variables and stock prices
are demonstrated by numerous models, for instance, stock valuation
models. From the stock valuation model, it is very clear that stock
value and cash flow are more of the same. Therefore, any economic
factor that impacts cash flow and the overall rate of return also has an
impact on the share value (Nasseh & Strauss, 2000, p. 230). In
addition, many researchers postulate that the volatility of the stock
returns rises during the recession and declines during economic
prosperity (Schwert, 1989, p. 1115; Nardari & Scruggs, 2005, p.4).
Nardari and Scruggs (2005, p. 5) show that many incidents of high
uncertainty vis-à-vis prospective returns are linked to the economic
meltdown.
Stock returns and nominal interest rates (interest rates)

Numerous authors have reported a negative correlation between the
above two variables in their studies. One of the most significant
elements in the valuation process is the discount rate and always has
to be determined at the initial stages. This rate corresponds to the
volatility and time value of the stock. Time value of money
corresponds to the risk-free rate. A risk premium corresponds to risk
compensation, which is computed using a risk-free rate (Mui & Law,
1983, p.159). According to Stowe et al. (2007, p. 47), most investors
regard the discount rate as the suitable rate of return.
Principle interest rate is positively correlated to the risk-free interest.
When the interest rate goes up, the risk-free rate also rises.
Consequently, this leads to an increase in the overall market rate.
Ceteris paribus, the targeted prices of stocks would go down as a
result of the increased rate of return. The reverse is also possible.
When the interest rates decline, ceteris paribus, the stock prices will
go up because of the drop in the required rate of return. In addition,
the required rate of return would go up when the risk premium
escalates (Mui & Law, 1983, p.160).
Generally, Interest rates and stock returns ought to be inversely
correlated. Hondroyiannis and Papapetrou (2001, p. 440) indicate that
the anticipated returns on common stocks are scientifically correlated
to the general business risk and the interest rate risk. The results of the
study show that the interest rate risk among small businesses is
“downbeat”. In addition, the study reveals that the interest rate risk
premium significantly influences the expected returns among
businesses in the U.S and Mexico.

The impact of interest rate on stock prices and returns has also been
studied in the developing economies (Al-Sharkas, 2004; Jordan &
Tweneboah, 2008). As per Jordan and Tweneboah (2008), the
relationship between stock prices and interest rate in budding
economies, particularly in Africa is significantly negative. Maysami,
Howe and Hamzah (2004, p. 48) disclose that short-term and long-
term interest rates have a considerable positive and negative
relationship, respectively in Singapore stock market. According to the
study conducted by Abugri (2008) in a number of South and North
American economies, the relationship of stock returns and interest rate
is negative and significant. However, in Mexico, this relationship
tends to be insignificant in describing the movement of returns. As to
the Hong Kong case, the experiential results of Yu (1996, p. 52) show
that interest rate growth impacts stock returns negatively and is
significant in the short run. Wongbangpo and Sharma (2002, p. 29)
explain that the real interest rate on deposits and interest rate
differential variables have a very low negative correlation with stock
returns.
Stock price and Money Supply
Both non-liberal and liberal monetary policies can have a two-pronged
effect. In a liberal economy, the central government creates more
liquidity by encouraging laissez-fair market, resulting in an increase
and decrease in stock and bond prices, respectively. The reduced
interest rate would force the required rate of return also to go down
and therefore increase stock prices (Ozbay, 2009, p.6). In addition, an
increase in money supply denotes surplus liquidity accessible to

purchase stocks. In due course, this leads to a rise in stock prices
because of the increase in demand for common stock and other
consumer goods. In contrast, some experts argue that increased
liquidity may lead to higher inflation, thus increases the nominal
interest rate. The increased interest rate leads to an increased rate of
return; this eventually forces stock prices to go down (Ozbay, 2009,
p.7).
In a non-liberal monetary policy case, a decrease in money supply
leads to a decrease in capital and operational liquidity among
businesses and investors. Furthermore, this will increase the general
interest rate and thus, the cost of capital. On the other hand, when the
interest rate increases consumers becomes the most vulnerable,
especially through the high cost of housing and other general goods.
Nevertheless, inflation and money supply moves in the same direction
and therefore, when they decline, an interest rate will go down. When
this happens, stock prices will appreciate (Ozbay, 2009, p.8).
According to Reilly and Brown (2006, p. 362), a general increase in
money supply could act as a pointer to changes in stock prices.
However, a number of studies have questioned their finding. Beltratia
and Morana (2006, P. 152) insist that financial policies that affect the
volatilities of monetary supply and interest rates are the best in
handling stock market volatilities. In addition, although
macroeconomic volatility affects stock volatility, the evidence tends to
favour stock returns in the prediction of macroeconomic variables.

Freris (1991) studying the Hong Kong stock market mentions that
money supply is a strong risk factor contender. It has a considerable
impact on both returns and volatility of the stock. Errunza and Hogan
(1998, p. 362) state that stock returns are inversely correlated to the
money supply. They point out that money supply volatility does
Granger cause volatility in major European economies. Humpe and
Macmillan (2007, p.5) state that stock prices among Asian giants
(China and Japan) are inversely correlated to money supply; the
situation is reversed (though insignificant) in the U.S.
On the other hand, Maghayereh (2002, p. 4) found a negative
coefficient of money supply in Amman Stock Exchange, while Al-
Sharkas (2004, p. 105) reports a positive effect of money supply (M2)
on stock returns. Maysami, Howe and Hamzah (2004, p. 50)
established a positive relationship between money supply (M2) and
stock returns in the Singapore stock market. Abugiri (2008, p.340)
report a negative response between stock returns and the money
supply. He also indicates an insignificant relationship in some cases.
Nishat and Shaheen (2004, p.622) established a long-term relationship
between money supply and stock returns. In addition, his findings
show that money supply does Granger cause changes in stock prices.
Hong Kong studies also do not escape contradictions. Ho (1983, p.
222) show that money supply is positively correlated to stock returns
in the short-term dynamic model. He reveals that an increase in the
money supply has a significant effect on SEHK20 Index. Yu (1996, p.
55) stresses that the relationship between money supply and stock
returns does not exist. Furthermore, the findings of Muradoglu, Metin

and Argac (2001, p.642) show no cointegration relationship between
stock prices and monetary variables in a study they carried out for
almost a decade.
Daohua (2000, p.3) state that stock returns have no causal relationship
with the money supply. However, Ozturk (2008, p.65) contradicts this
finding. Ozturk shows a unidirectional relationship between the two
variables. Since different studies have a different opinion on this
subject, no consensus has been reached regarding the relationship
between the two variables. It depends on the economy and time.
Stock returns and Inflation level
The impact of inflation should be considered during the valuation
process. This is because inflation level varies from one economy to
the other. Theoretically, stock prices and stock valuation process is not
supposed to be influenced by inflation (Fisher, 1930). Patra and
Poshakwale (2006, p. 996) indicate that the sum of the anticipated
inflation rate and anticipated real return gives the nominal interest
rate.
Nominal interest rate (interest rate) is the prevailing interest rate,
whereas the real interest rate is the interest rate that is adjusted
following inflation. Experts posit that real interest rate can be stable in
the long-run. Thus, changes in the interest rates are as a result of
anticipated inflation and the dynamics of real interest rates (Ozbay,
2009, p.9). Fisher (1930) noted that nominal interest rate could be
broken down into anticipated real rate and anticipated inflation

element. He argued that the anticipated real returns is determined by
factors that are observable, and is not related to presumed inflation. In
other words, the real return on stocks and the anticipated inflation are
independent, and that nominal returns on stock differ at an individual
level with anticipated inflation.
Studies have not established a reliable link between inflation rates and
nominal stock returns. In addition, the results of his study indicate that
the regression coefficient between the two is largely negative. The
inverse correlation between inflation and stock prices has been
supported by many experts. This is because inflationary changes are
normally accompanied by lower growth earnings and increased
required real returns. In China, there is tangible experimental evidence
that inflation increase is linked to equity risk premium and a decrease
in stock prices (Zhao, 1999, p. 507). Increased inflation may force the
government to employ precautionary measures which may increase
nominal interest rates, thus increases the required rate of return.
In addition, inflation may falsify returns when historical data is used,
especially when adjustments are not made to reflect the level of
inflation in each period. Reported earnings that are pegged on
depreciation derived from chronological costs (used as replacement
costs) can give exaggerated returns. In the same way, a number of
inventory management systems can also misrepresent the said values.
Therefore, a firm operating in an environment with high inflation will
greatly suffer if it does not factor in inflation (Solnik & McLeavy,
2009, p. 243).

Yu (1996, p. 50) explains that nominal stock returns and inflation in
Tokyo, Hong Kong and Singapore are considerably linked to a
negative trend, meaning that stocks are exceedingly lacking
inflationary cover for the investors. Moreover, Yu (1996, p. 51) only
indicates a unidirectional causal relationship between stock returns
and interest. Flannery and Protopapadakis (2001, p. 12) point out that
the consumer price index and producer price index also have a
significant impact on stock values and returns. They report that stock
prices are inversely correlated to the consumer price index (CPI) in
American and a number of Asian stock markets. Similarly, in Canada
and Mexico, inflation is the principal negative determinant of stock
values/ prices (Humpe & Macmillan, 2007, p. 4). According to
Humpe and Macmillan (2007, p. 4), inflation does Granger cause
stock price movements in the American market. In addition,
Maghayereh (2002) reports a constant relationship between stock
returns and inflation.
However, Maysami, Howe and Hamzah (2004, p. 50) report a
significant positive correlation between the consumer price index and
stock returns. This is a complete contrast to the earlier studies that had
established a significant negative correlation between anticipated
inflation and stock returns. As for the case of Hong Kong, Tokyo and
Singapore, Yu (1996, p. 52) argue that negative correlation between
stock prices and inflation remains steady when other monetary
variables are incorporated in the model. Ozturk (2008, p.3) report a
negative causal relationship between stock returns and inflation.

Ho-Ki, Ho-Yin and Wu-Wing (2011, p.12) report a negative long-
term relationship between inflation and stock prices. Their study
concludes that the variables that represent real economic activity, for
instance, industrial production index (IPI), level of employment and
fixed investment significantly influence stock prices through inflation.
Yu (1996, p. 53) point out that unexpected inflation has a positive
impact on the returns of the developed portfolios. He adds that the
relationship between inflation and stock returns is unstable in the long
run and that there are disparities among nations in spite of the state of
their level of development.
Stock Returns and Exchange Rate Relations
Researchers have never agreed whether exchange rates and stock
returns have any form of relationship, particularly causal relationship.
However, in many studies, two models have been fronted to explain
the relationship between stock prices and exchange rate. These are
stock-oriented model and Flow-oriented model. Goods market
approach (Flow-oriented model) emphasizes on the relationship
between exchange rate and current account (Dornbusch & Fischer,
1980, p. 962). Dornbusch and Fischer (1980, p. 963) came up with a
model that determines exchanges rates by applying general price
index, security indices and economic prospects. The model focuses on
the causal relationship between foreign transactions and exchange rate
fluctuations.
They argue that there is a connection between the exchange rate
movement and the current account (Dornbusch & Fischer, 1980, p.
964). The flow-oriented model supposes that the exchange rate is

considerably influenced by external/foreign transaction. Both stock
oriented model and Flow-oriented model conceive that exchange rate
movements impact global competitiveness and balance of trade, hence
affect real economic variables like GDP and national income. In other
words, the flow-oriented model argues that exchange rate impacts the
level of business competition and the cost of borrowing fund. This
ultimately influences stock values (Dornbusch & Fischer, 1980, p.
965).
On an aggregate level, the impact of changes in the exchange rate on
stock returns would depend on the nature of the market and foreign
transactions. Therefore, the goods market model posits a positive
relationship between the two variables. The inference of positive
correlation between exchange rate and stock prices originates from the
assumption of employing quotation to direct exchange rate (Ho-Ki,
Ho-Yin & Wu-Wing, 2011, p.16).
In contrast, the stock-oriented model put more emphasis on the role of
capital account on business activities (Tahir & Ghani, 2004, p. 5). The
stock-oriented model postulates a negative correlation between
exchange rate and stock price. An increase in local stock price would
encourage capital flows, which in turn create more demand for local
currency and increase the exchange rate. A thriving stock market
enhances the local currency through direct and indirect means.
An increase in stock price encourages both local and foreign investors
to purchase local assets at the same time, disposing of overseas assets
to acquire local currency (Stavarek, 2004, p. 3). Such shifts in demand

and supply positively impact currency value. The indirect channel also
depends on supply and demand shifts. An increase in the prices of
stocks leads to increases in production (aggregate output). Increased
wealth raises the demand for local currency, and consequently, the
interest rate goes up to regulate borrowings. Increased interest rates
attract external capital and lead to high foreign demand for local
currency and, consequently, appreciation of the local currency
(Stavarek, 2004, p. 4).
In fact, the exchange rate fluctuations equally affect exports and
imports. When the local currency depreciates, imports become more
expensive. If the extra cost of imports is passed to the consumers, then
the earnings will not be affected by the currency fluctuation. However,
this is not always the case. Increase in the prices of foreign goods will
reduce their demand in the local market. In addition, demand for
domestic products will increase more than the imports, thereby
creating a substitution effect. Consequently, the number of companies
that depend on imports will go down, while those exporting their
products to foreign markets will increase (Solnik & McLeavey, 2009,
p. 245).
Stavarek (2004, p. 5) states that the intensity and direction of a causal
relationship between foreign exchange and stock market vary from
country to country, regardless of their economic status. Shuangcheng
and Guihua (2005, p. 23) postulate that there is a two-directional
causality between the exchange rate and Chinese stock markets both
in the short-term and long-term.

As for the Hong Kong case, the experimental findings of Yu (1996, p.
54) point out an expected increase in stock returns with the increase in
exchange rates. The results of Bodnar and Wong (2000) report that
companies that export their products abroad are highly susceptible to
exchange rate. The findings of Ma and Kao (1990, p. 445) show that a
stable long-term relationship between exchange rates and stock
indices is achievable. Additionally, they report inconclusive evidence
on the causality relationship between exchange rates and stock
indices. Lee (2012, p.120) emphasizes that the relationship between
stock returns and exchange rates is not certain, pointing out that the
Hong Kong stock exchange is neither the result nor cause variable of
exchange rate variables.
Real economy (industrial output) and Stock returns
The study uses proxies to represent the real economy. Studies have
shown that industrial production generally affects the overall state of
the economy and therefore, changes in industrial production would
indicate economic transformations. Indeed, the productive capacity of
any economy depends on the position and nature of its economy. The
state of the economy influences the productive capacity of local firms.
Thus, industrial production has considerable impact on aggregate
wealth, thus a positive correlation between stock prices and industrial
output (Fama, 1981, 547; Foresti, 2007).
Phillips and Xiao (1998, p.430) indicate that the large percentage of
variations in stock returns (SEHK) can be described by periodic
expected returns and prediction of real activity. They add that
fluctuation in the stock market (SEHK) volatility over time is

basically because of the fluctuations in the volatility regarding future
returns. Errunza and Hogan (1998, p. 361) indicate that industrial
production does Granger cause stock return in Europe.
Yu (1996) indicate that trade balance, employment level, and real
estate are the strong risk factor candidates, and they only affect the
stock return’s conditional volatility for SEHK (Hong Kong Stock
Market). Freris (1991, p. 96) indicate that SEHK stocks are positively
correlated with industrial production.
According to Nishat and Shaheen (2004, 628), there is a two-
directional Granger cause between industrial production and stock
returns. Therefore, industrial production significantly predicts stock
prices in many. Many other authors also indicate that industrial
production is positively and significantly correlated to stock returns
(Maghayereh, 2002, p. 14; Al-Sharkas, 2004, p.107; Nishat, &
Shaheen, 2004, p. 670). Abugri, 2008, p. 409 also indicates a positive
correlation between stock returns and industrial production among the
South American economies, except for Argentina and Mexico where
industrial production does not seem to have a strong impact on the
expected returns.
As for the case of Hong Kong, Ho-Ki, Ho-Yin and Wu-Wing (2011,
p.27) indicate a positive correlation between stock returns and
industrial production and a negative relationship between stock returns
and balance of trade. In addition, the results show that stocks in Hong
Kong stock exchange are neither the cause nor result of economic
variables. The findings of Phillips and Xiao (1998, p. 455) is proof

that there is a linear correlation between industrial production and
stock returns.
Hong Kong Stock Exchange
Hong Kong Stock Exchange (SEHK) was established in 1891 and is
based in Hong Kong, China. The market was operated by an
association of stockbrokers during that time. Later on, in 1914, it
changed its name to Hong Kong stock exchange which was a
conglomerate of numerous stock exchanges that had come together
either through merger or acquisition. The real merger took place after
the Second World War when Hong Kong Stock Brokers Association
joined the bandwagon. However, it retained the name Hong Kong
stock exchange (SEHK, 2011).
Later on, in the late 70s, Hong Kong Stockholders association was
founded, and it comprises of a number of entities such as Far East
Exchange Limited, Kam Ngan Stock Exchange Limited, and Kowloon
Stock Exchange Limited. In the late 80s, this association later merged
with other exchanges but retained its name. In the early 2000s, Hong
Kong Exchanges and Clearing, which is a holding company, was
formed to oversee the operations of the Hong Kong Stock Exchange.
Since the year 200, the Hong Kong stock exchange has been fairly
liberalized (SEHK, 2011).
It is the 3rd largest stock exchange in China, and the 6th largest in the
globe in terms of market capitalization (Ho-Ki, Ho-Yin & Wu-Wing,
2011, p.2). Hong Kong stock exchange is focused too much on stock
trading, and very little attention is given to bonds and other securities.

This is attributed to its historical background. In the early 60s, Hong
Kong city was dominated by miniature financial markets and only
accommodated small local companies. Therefore, the absence of large
foreign companies was an obstacle to the development of a high-level
security market. In addition, the Hong Kong government is self-
sufficient and always operate within its means. As a result, the
government does not rely on security floatation to finance the
budgetary deficit (SEHK, 2011).
Hong Kong stock market is the oldest stock market in Asia and dates
back to over 100 years. The stock market struggled a lot in the early
20th century, but since the late 60s, it has been developing at a faster
rate. The market was established by the British colonialists, and since
then, its operations have been carried out in a similar way to most
European stock market (SEHK, 2011). The market is dominated by
Chinese-owned companies and investors. However, with the
expansion of the market to an international level, foreign companies
and investors are also in large number.
Most of the practitioners and professional operating within this stock
market are graduates from the U.S. Hong Kong stock exchange also
incorporated global exchange rate system. This is an electronic system
that was launched in the early 2000s. The rules and decision-making
practices within the market are borrowed from the United States.
Since the year 2003, the Hong Kong stock exchange has been under
David Webb and numerous investor representatives (SEHK, 2011).

As per the end of November last year, the Hong Kong Stock Market
had listed about 1500 companies with an aggregate market
capitalization of HK$ 17 trillion. It operates under Hong Kong and
Clearing, which is a holding company (SEHK, 2011; Lee, 2012, 120).
Security exchange in Hong Kong city began in the late 19th century
through informal security exchange. After a succession of mergers and
acquisition, SEHK became the main trading joint for securities (Ho,
1983, p. 222). Currently, Hong Kong Stock Exchange ranks among
the top stock exchanges in the globe and was ranked the first in terms
of IPO funds in 2008, when it raised in excess of HK$248 billion from
the new companies (Martig, 2009, p. 1). The average value of stock
traded in Hong Kong stock exchange has always been on the rise,
except in 2007/2008, where it dipped by about 7 per cent. Similarly,
the average number of daily contracts also fell in that year. The total
value of traded equity also fell by 10 per cent. The SEHK indices were
being manipulated by the local economic conditions and the global
economic crisis experienced during that time (Ho-Ki, Ho-Yin & Wu-
Wing, 2011, p.3).
SEHK market indices are intended to compute stock prices and returns
traded generally and on a sector-by-sector basis. The SEHK-20 Index
is used as a yardstick in the Hong Kong stock exchange. Many studies
for Hong Kong market have used SEHK-20 as a substitute for stock
prices. However, in this study, we use SEHK-17 index. The SEHK-17
Index comprises of 17 stock chooses from the top companies, other
than investment trusts, traded in Hong Kong stock exchange in
accordance with the standard set by the SEHK (SEHK, 2011).

In 2011, the market value for SEHK-17 was approximately HK$10.5
trillion. This is approximately 60 per cent of the total market value of
the Hong Kong stock market. Since the structure of the SEHK-17 is
different from that of SEHK-20, the SEHK-17 price movement may
possibly be poles apart. Compared to SEHK-20, the SEHK-17 could
be less prone to speculations and manipulations since it comprises of
the top companies in SEHK. This is the reason why the study opts for
SEHK as a better alternative for stock returns. Furthermore, this helps
us to compare the present results with the earlier studies using SEHK-
20 (SEHK, 2011).
Research Methodology
Introduction
The methodology is the process of instructing ways of doing the
research. It is, therefore, convenient for conducting the research and
for analyzing the research questions. The process of methodology
insists that much care should be given to the type and nature of
procedures to be adhered to in accomplishing a given set of
procedures or objectives. This chapter is pertinent to the Hong Kong
Stock Exchange. To investigate the relationship between
macroeconomic variables and the SEHK-17 index, the study
emphasizes on causality among these factors applying Granger
causality test. The causality test was developed to assess the causal
relationship, among other statistical variables (Granger, 1969).
The following hypothesis has to be tried to meet the objectives of the
study; establishing the causal relationship between the
macroeconomic variables and stock return.

Null Hypothesis:BThe selected economic variables do not
Granger cause stock returns.
Alternative hypothesis: The selected economic variables do
Granger cause stock returns.
If we reject the null hypothesis, then we will conclude that the
selected macro-economic variables do Granger cause stock returns in
Hong Kong stock market.
Preliminary Analysis
Numerous economic series are used in the study to achieve the study
objectives. These are IPI (Industrial Production Index), CDGDP
(Currency Deficit to GDP), foreign Purchase (FP), foreign sale (FS),
price indices, nominal interest rate, currency basket, money supply
(MI, M2, M2Y, Central Bank Money), and Hong Kong Stock
exchange-17 index to represent the stock market. FP, FS and price
indices proxy goods market, while interest rate proxy money market.
Hong Kong and trade system have been fairly liberalized in the past
three decades. Since the onset of the millennium, the exchange rate in
China has always been determined through floatation. This means that
the exchange rate regime fluctuates from time to time. This is one of
the weaknesses of the study. The study uses a currency basket as an
alternative to the exchange rate. The currency basket in our study
comprises of a weighted average of the most common currencies in
Hong Kong; that is the U.S. dollar, Hong Kong Dollar and Euro. 1
U.S. dollar and 0.125HKD are used over the period between January
1991 to December 2001; 1 U.S. Dollar, 0.125 HKD and 0.77 Euro
over the period January 2002 to December 2011.

Weighted normal interest rate is used in place of the overnight interest
rate. Furthermore, yearly interest rates from the central bank database
are used instead of the treasury interest rate. Most of the relevant data
is acquired from the Central bank of China’s database. Foreign
purchase, foreign sale, and daily closing SEHK17 index are obtained
from the Hong Kong stock exchange database. Stock prices are
derived from the Hong Kong stock exchange monthly data.
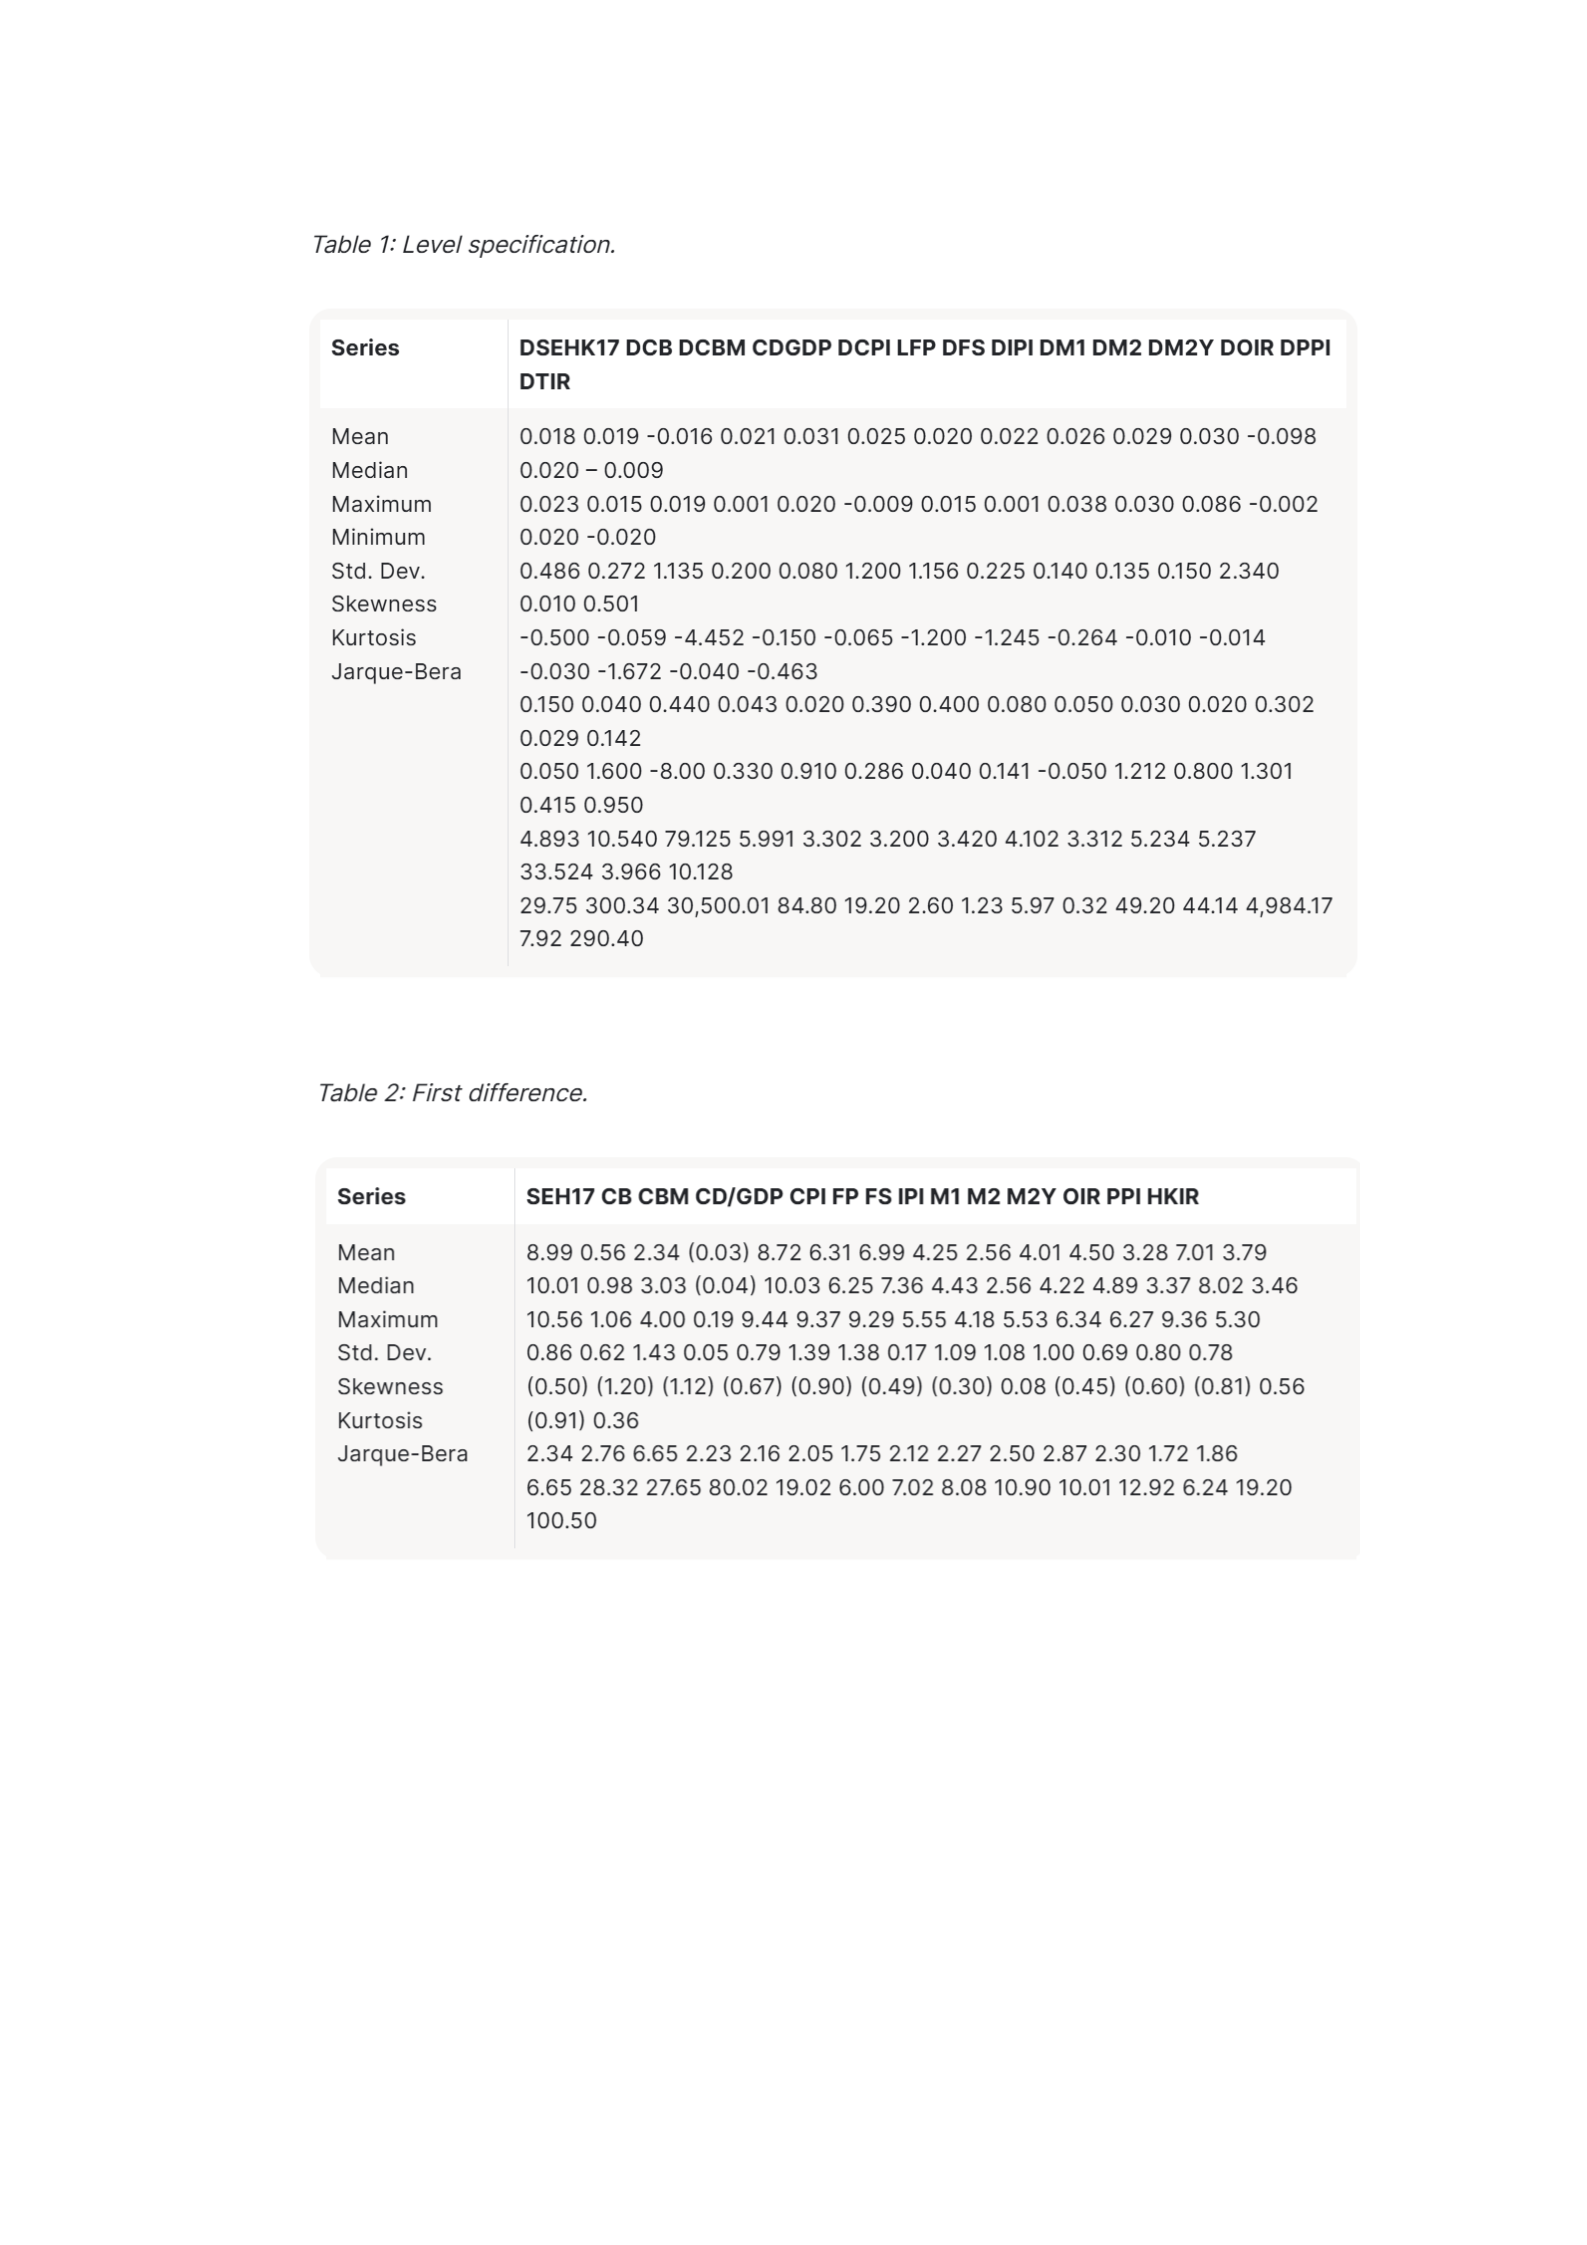
Monthly data is used to determine the level at which SEHK-17
reflects the real economy in Hong Kong. All the data, except
CD/GDP, have been transformed into the logarithm form. The study
covers the period between 1991 to 2011 financial years. The tables
below give summary statistics on levels and first- differences
respectively. The mean nominal return on the stock is 1.379. In
addition, China has normally experienced a relatively stable inflation
rate, just like most European countries. However, the inflation rate in
China was relatively higher than those of advanced economies.
Nonetheless, this rate has fallen to below 1.8 per cent lately.
Unit Root Test
According to statistical literature, time-series data is normally
understood to be non-stationery. Differenced series of prices/returns
are traditionally used in the studies of stock returns. The possibility of
data to be non-stationary can be because of overcrowded stationery
data and reversible first difference. Correspondingly, numerous

financial variables are well-known to exhibit these characteristics and
therefore, it is necessary to carry out a univariate assessment to check
whether the variables exhibit stationery or non-stationer
characteristics. This is done to avoid the spurious regression problem
prior to relationship analysis.
Key assumptions have to be made in time series analysis so as to
conduct a legitimate statistical inference. The model must be believed
to be covariance stationary. A stationary time series is a series with
non-fluctuating mean and variance. The following conditions must be
met: First, its expected value must remain invariable and fixed
persistently. Second, its variance is required to remain invariable and
fixed after a while. Lastly, its covariance must always remain
invariable and fixed persistently. None-stationery time series lacks
economic meaning since it yields spurious results.
Nonetheless, it is not advisable to change data into a stationary time
series if it is non-stationary. Statistically, before carrying out any
analysis, we must determine whether it is stationary or not. The
conventional method of determining whether data is stationary or non-
stationary is the Dickey-Fuller unit root test (DeFusco et al., 2007; p.
4005). Therefore, the study employs Augmented Dickey-Fuller test to
test the existence of unit root in the used variables (level and log
variables). This tests the following hypothesis:
Ho: The economic variables understudy has a unit root.
H1: The macro-economic variables understudy doesn’t have a unit
root.
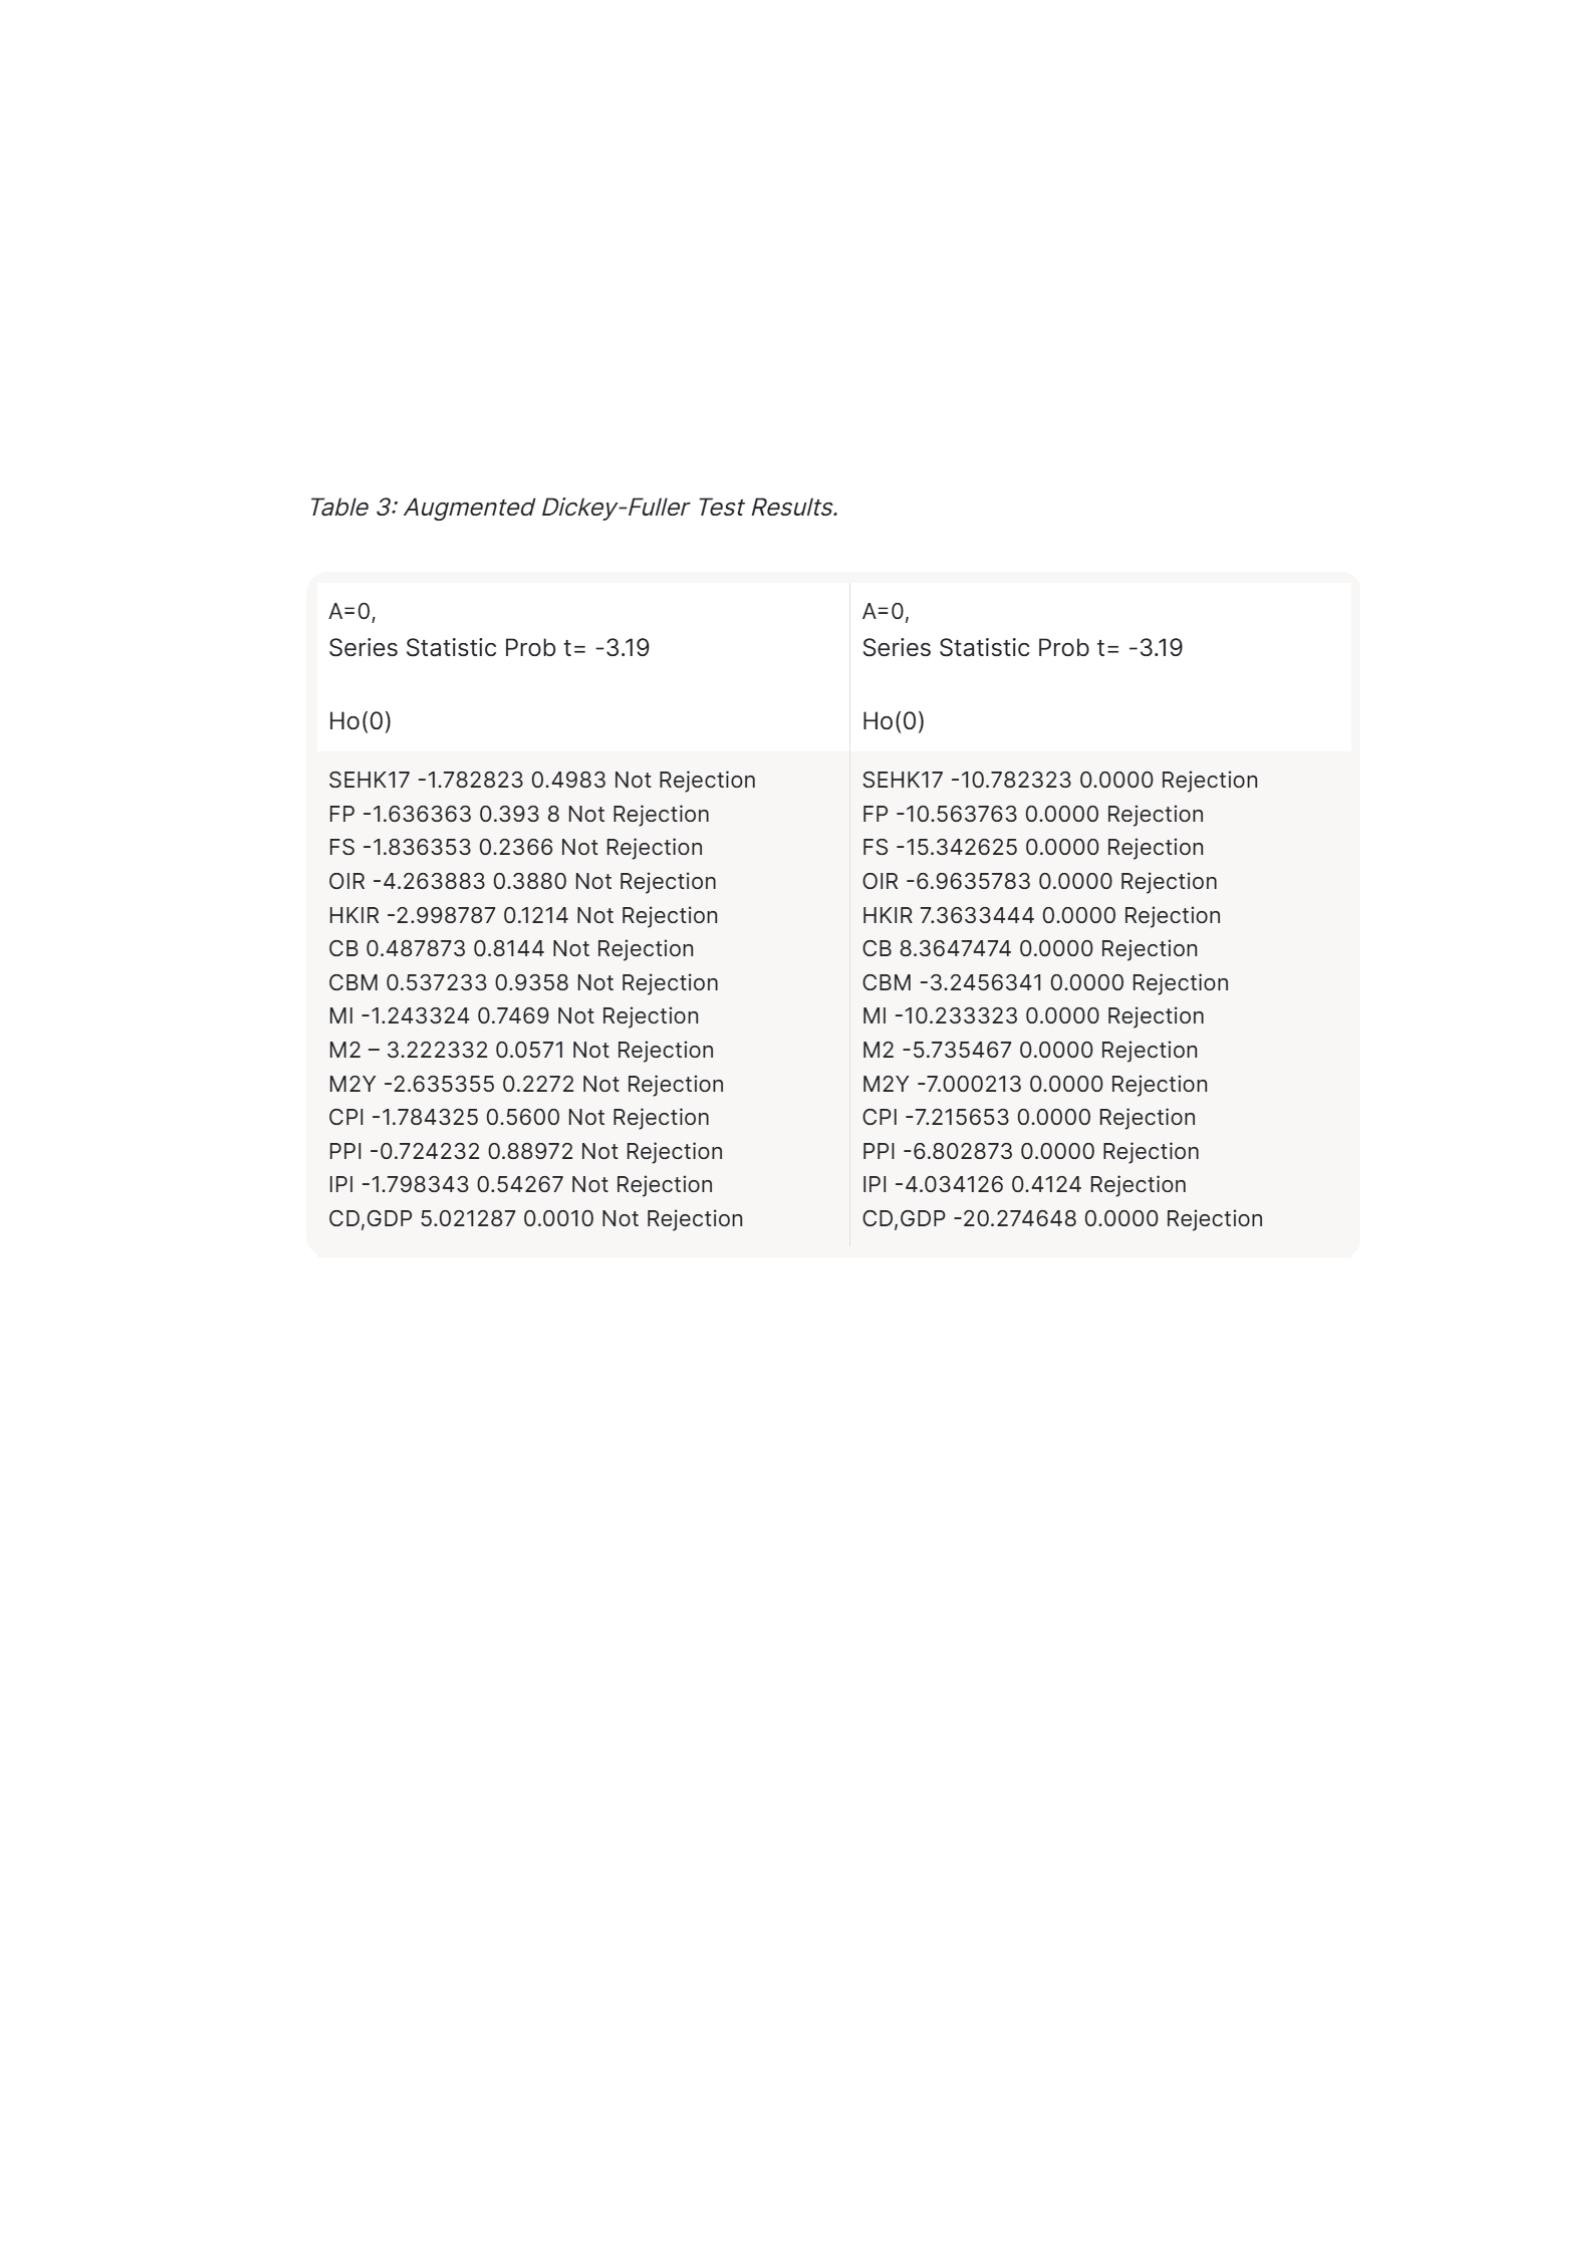
It tests the null hypothesis against the alternative. It is first conducted
on variables in levels. The results of the test are shown in the table
below.
The findings show unit root in log variables except for CD/GDP and
OIR. Hence, the null hypothesis can not be rejected except for the
overnight interest rate and currency deficit. We can model time series
data with a unit root. This can be achieved through first difference
autoregression (DeFusco et al., 2007; p. 4006).
Time series is differenced by generating a new series, for instance, Yt
in which each period is equivalent to the difference between Xt and
Xt-i. This kind of modelling is known as the first differencing since it
takes away the value of the time series in the initial period from the

present values. The results of the above test for the first difference are
presented in section two of the table above. The last column in section
two exhibit the same statistics when the test is carried out again on the
first differences of the macroeconomic variables that had a unit root in
the first level.
There is no known study that has opposed the unit root hypothesis,
and, on numerous occasions, the first difference does not indicate unit
root characteristics. In other words, there is no need to conduct a unit
root test in the first difference data. Since the Augmented Dickey-
Fuller test statistics for all the factors is lower than 5percent critical
value, we do not reject the null hypothesis. That is, the first difference
variables are stationary series.
Correlation Analysis
In finance study, it is always important to establish a relationship
between two or more variables. There are numerous methods for
examining the relationship between a given set of data. Scatter plots
and correlation analysis are well known for this work. Scatter plots are
two-dimensional graphs that are used to establish a relationship
between two variables. On the other hand, correlation analysis depicts
this relationship using a single digit. In summary, the correlation
analysis assesses the direction and relationship between variables. The
correlation coefficient is scaled between the positive one and the
negative one. A correlation coefficient that is greater than zero depicts
a positive linear relationship, and a coefficient that is less than zero
depicts a negative linear relationship between two variables. A
coefficient of zero depicts a non-linear relationship. The correlation
coefficient of the two variables is arrived at by the covariance of the
two variables by its standard deviation.
Despite its flaws, correlation analysis has been widely used to
compute the linear relationship between two or more variables
(DeFusco et al., 2007; p. 4005). This is an additional limitation to this
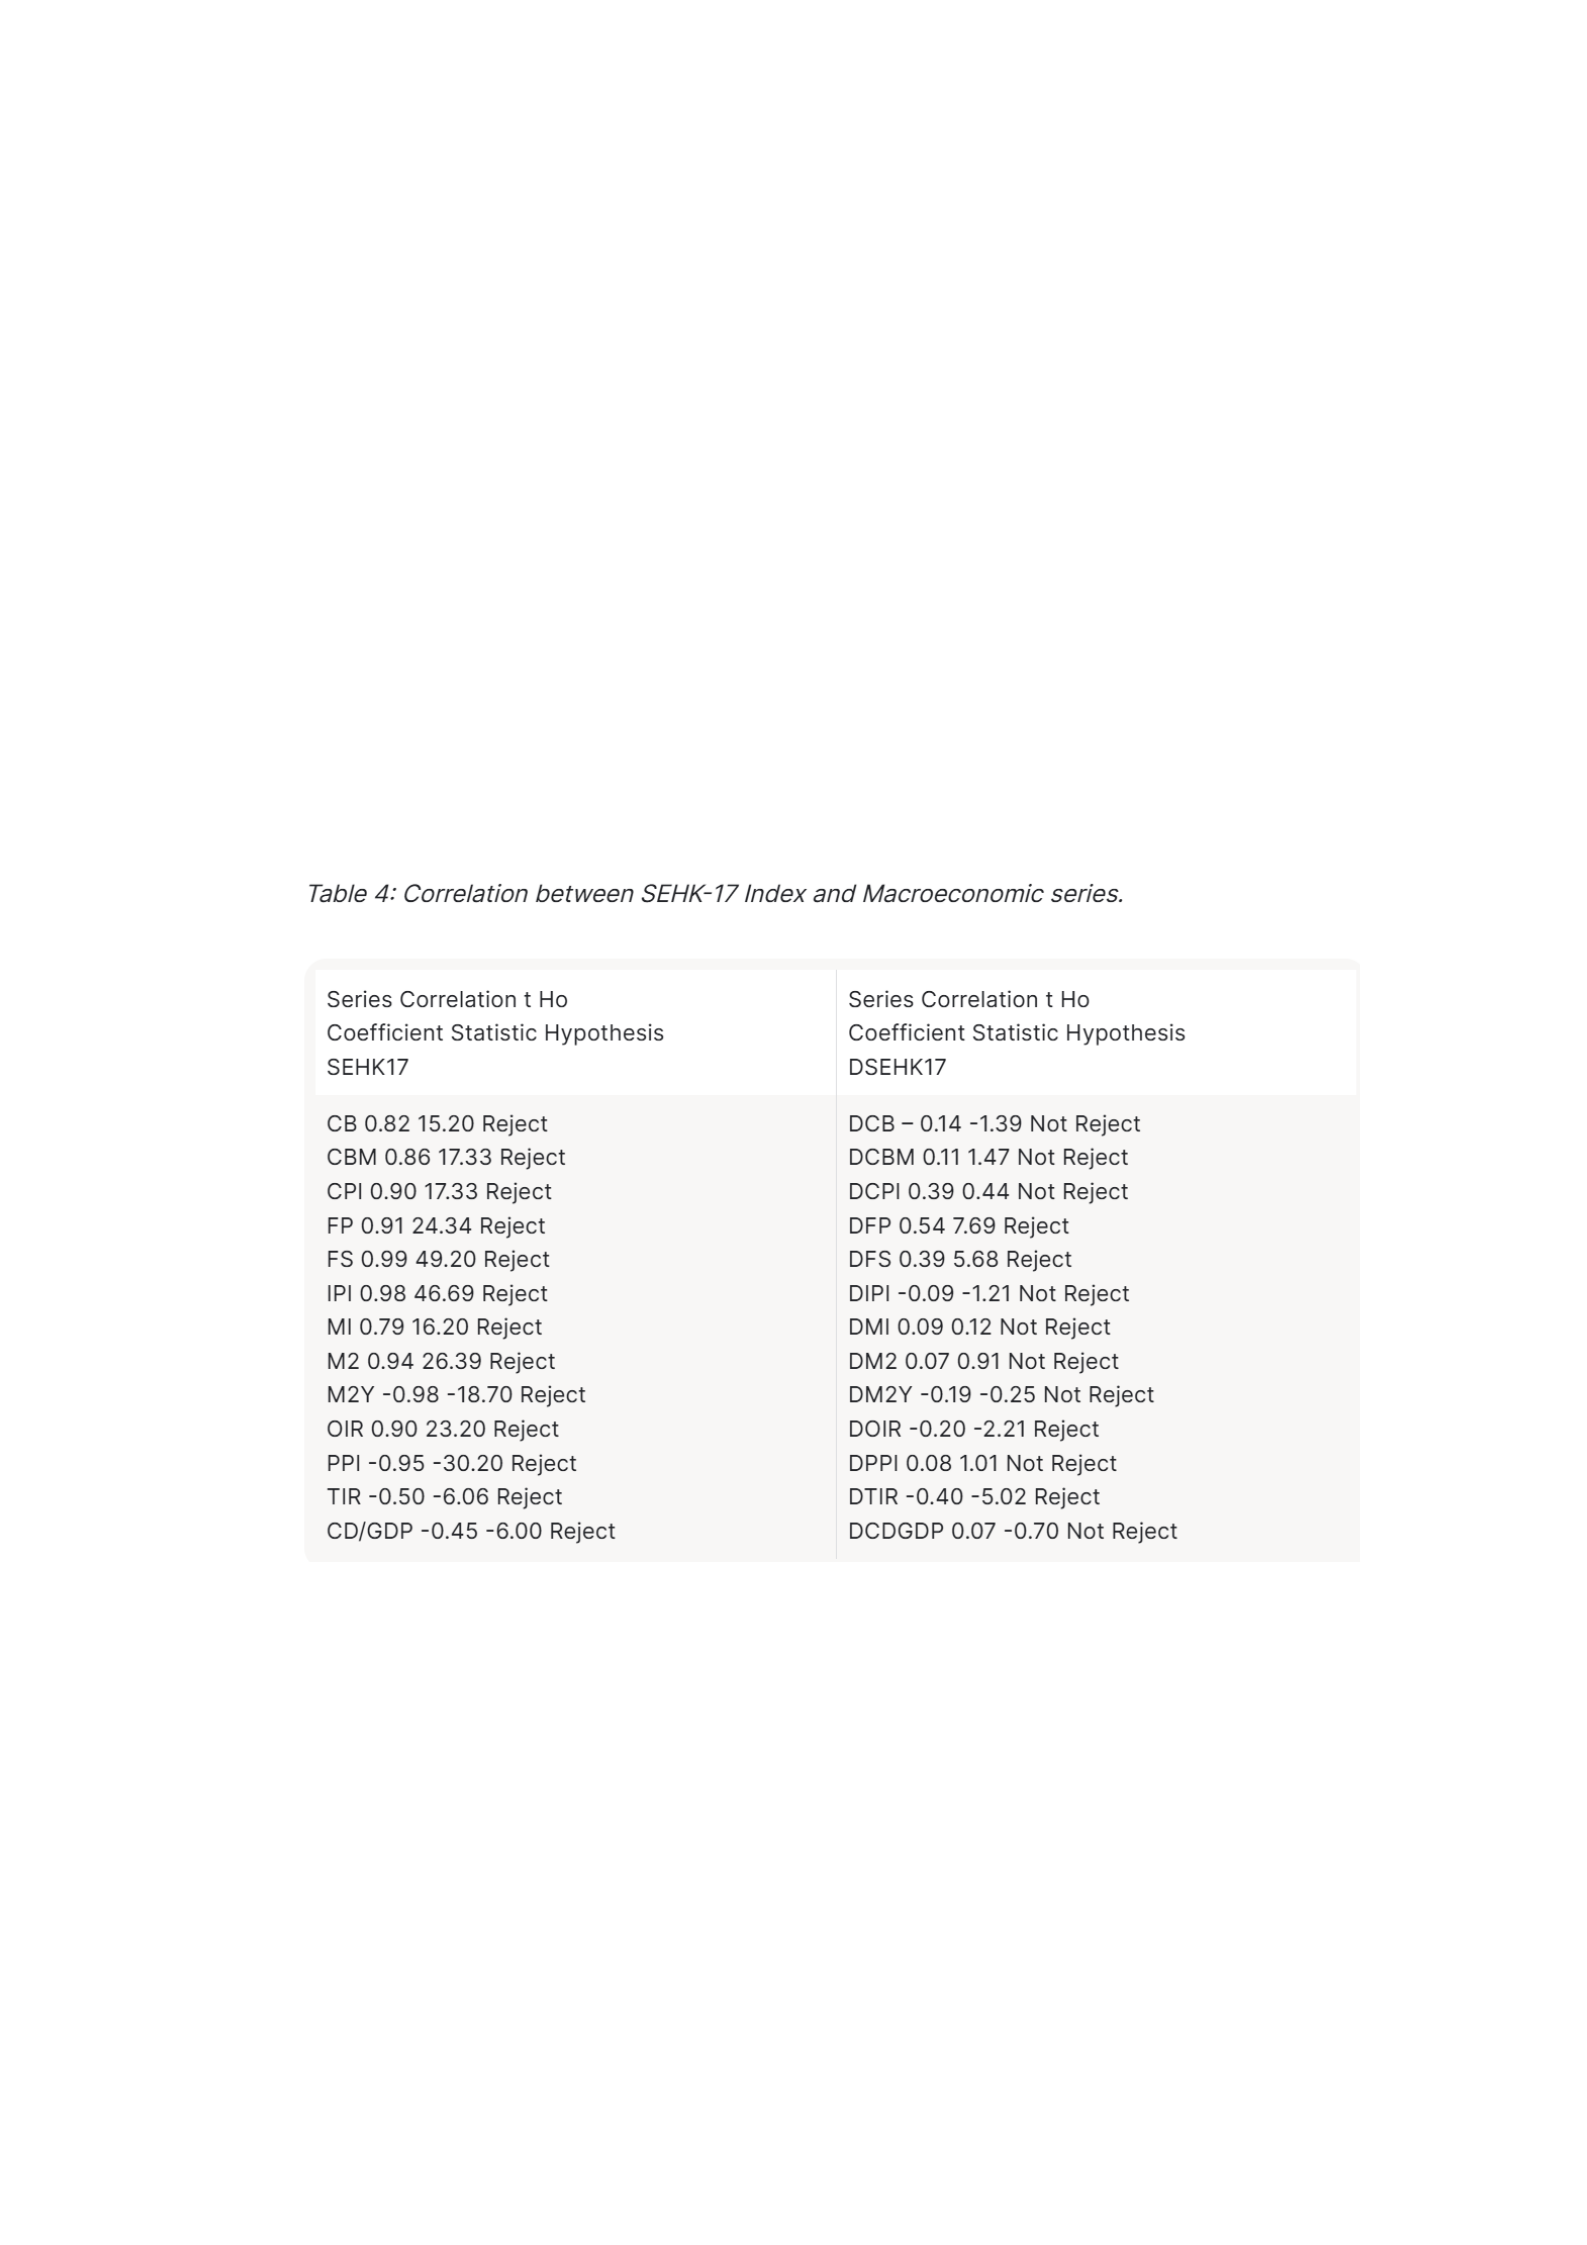
study. The table below shows a correlation matrix of the chosen
macroeconomic variables and the SEHK-17. In the right-hand side are
the correlation test levels in log form.
The study established a strong correlation between stock returns and
the chosen macroeconomic variables. However, the series computed
in this study generally increases or reduces in long-ran regardless of
the fact that they may seasonally change. If such a scenario arises,
there will be a risk of getting significant correlation results from data
that are not related. Correlation of this nature is referred to as spurious

correlation. Spurious correlation can be avoided by using the first
differenced log data.
Stock returns versus money supply
According to the study results, there is a low positive correlation
between DSEHK17 and respectively DCBM, DM1, DM2 and low
negative correlation between DSEHK17 and DMY2 used to represent
money supply. Nonetheless, the study reports an insignificant
correlation between the money supply and stock returns. In other
words, no relationship exists between stock prices and monetary
supply in Hong Kong stock market. This result is consistent with Yu
(1996, p. 55), Ozturk (2008, p.65), and Maysami, Howe and Hamzah
(2004, p. 50) who established a positive but insignificant relationship
between stock prices and money supply. In addition, Abugiri (2008,
p.340) established an insignificantly negative correlation between
stock returns and money supply in South America.
Theoretically, it is argued that excess liquidity can either reduce the
interest rate, which in turn reduces the cost of doing business or can
increase the rate of inflation in the economy. The liquidity fluctuation
ultimately affects the common stock. Nonetheless, the concrete
relationship between money supply and stock returns is an
experimental question, and the impact differs from time to time.
Inflation versus stock returns
In contrast with the findings from well-established economies, the
study shows a low, insignificant positive correlation between stock
returns and inflation rates, consistent with Fisher (1930). The

correlation coefficients between DSEHK17 and DCPI or DPPI used to
represent inflation are 0.398 and 0.087. These findings show that there
is no correlation between stock inflation and stock returns in Hong
Kong. This is consistent with Zhao (1999, p. 508).
In theory, the relationship between stock returns and inflation rate
impacts the ability of businesses to protect themselves against the
effects of; an economically sound market should have a high positive
relationship with inflation. Yu (1996, p. 50) show that stock indices in
Tokyo, Hong Kong and Singapore have a negative correlation, which
means that they are not good inflation hedges. Maghayereh (2002, p.
7), Humpe and Macmillan (2007, p. 4) and McLeavy (2009, p. 244)
representing both developing and developed economies report a
negative correlation between inflation and stock returns. However,
Maysami, Howe and Hamzah (2004, p. 50) report a positive
correlation between stock returns and inflation.
The actual link between inflation and stock returns is still also unclear
and depends on the economy to economy and time. Therefore, the
general notion that stock returns and inflation are negatively
correlated can not be said to the ultimate. Furthermore, even this is a
fact in many cases; some sectors in the economy have a number of
macroeconomic variables that responds very positively to inflation. In
such a case, the stock returns will also be affected positively by
inflation (Mui & Law, 1983, p.162).

Real economy versus Stock returns
IPI and stock returns have a correlation of 0.0879, whereas stock
returns and the CD/ GDP have a correlation of 0.0687. This means
that their relationship is positively and negatively low, respectively.
However, the study has established no relationship between stock
returns and real economy proxies. This finding is consistent with Yu
(1996). On the contrary, (Fama, 1981, 547), Phillips and Xiao (1998,
p.425), and Freris (1991, p. 96) among others report a positive
correlation between industrial production and stock returns. It is only
Abugri who reports an insignificant relationship between the two
variables in two South American markets.
Theoretically, increased industrial production means more cash flow
and returns on the stock. This is in line with the theories that posit that
stocks represent an investment for the future; for this reason,
economic growth should translate into increases stock returns. This is
because the increase in industrial production generally leads to higher
returns in most companies.
Exchange rate movement versus Stock returns
The study reveals that the relationship between rate proxies and stock
return does not exist in the Hong Kong stock exchange; it is
insignificant. This is consistent with studies of Abugri (2008, p. 403),
and Adam and Tweneboah (2008, p. 8). Shuangcheng and Guihua
(2005, p. 23), and Maysami, Howe and Hamzah (2004, p. 51) indicate
a positive relationship between stock prices and exchange rate in
Singapore and Hong Kong. Therefore, we can also make a conclusion
that there is no enough proof to claim a positive or negative

relationship between the two macroeconomic variables (stock returns
and exchange rate). In other words, there are numerous pieces of
evidence supporting both the stock-oriented model and the flow-
oriented model.
Interest rate versus Stock returns
The study shows a negative (but significant) relationship between
DSEHK17 and DOIR and DTIR. This means that there is a
significantly negative relationship between stock and interest rate in
Hong Kong. This is consistent with Tahir and Ghani (2004, p. 5) and
Adam and Tweneboah (2008, p. 8). The negative relationship is as a
result of the effect of the discount rate. In other words, interest rate
fluctuation affects the company’s value and shares through the
fluctuations in the required rate of return. It also affects the cost of
doing business.
Granger Causality Test
Throughout the study, we have argued that that the selected
macroeconomic variables considerably impact stock prices. Thus, it is
imperative for investors to consider them as risk factors before making
any investment decision. Therefore, the impact of macroeconomic
variables on stock prices has been studied all over the globe. Despite
numerous studies, researchers have not come to a common ground on
the direction of causality between the variables. Hence, it is significant
to experimentally test whether these macroeconomic factors have an
impact on the Hong Kong stock exchange.

The study adopts the causality test to investigate the relationship
between macroeconomic variables and returns and vice versa. This is
applied to the first differenced logarithm data. However, this test has a
number of limitations. The first limitation is the problem of
autocorrelation. This arises when two variables are found to be
correlated with another variable, but in reality, only one variable
causes the third. This may occur when the first two variables are
highly correlated. In addition, this Granger causality is very
susceptible to lag length.
The above weaknesses can be avoided by carrying out Vector
Autoregression estimates on the selected macro-economic variable.
Akaike information criterion is then used to choose the most suitable
lag length for each variable used in the case study. The lag length
selected can then be applied to the individual macroeconomic
variables. The study would test the following hypothesis in this part.
HO: The macroeconomic factors do not Granger cause the
SEHK17 index
H1: The macroeconomic factors do Granger cause the SEHK17
index
When F-table less than F computed then the null hypothesis is not
rejected. We can then proceed to test causality between
macroeconomic variables and stock returns (SEHK17).
Causality test between stock prices and money supply
This involves SEHK17 versus MI, M2, M2Y, and CB, as shown in the
table below.
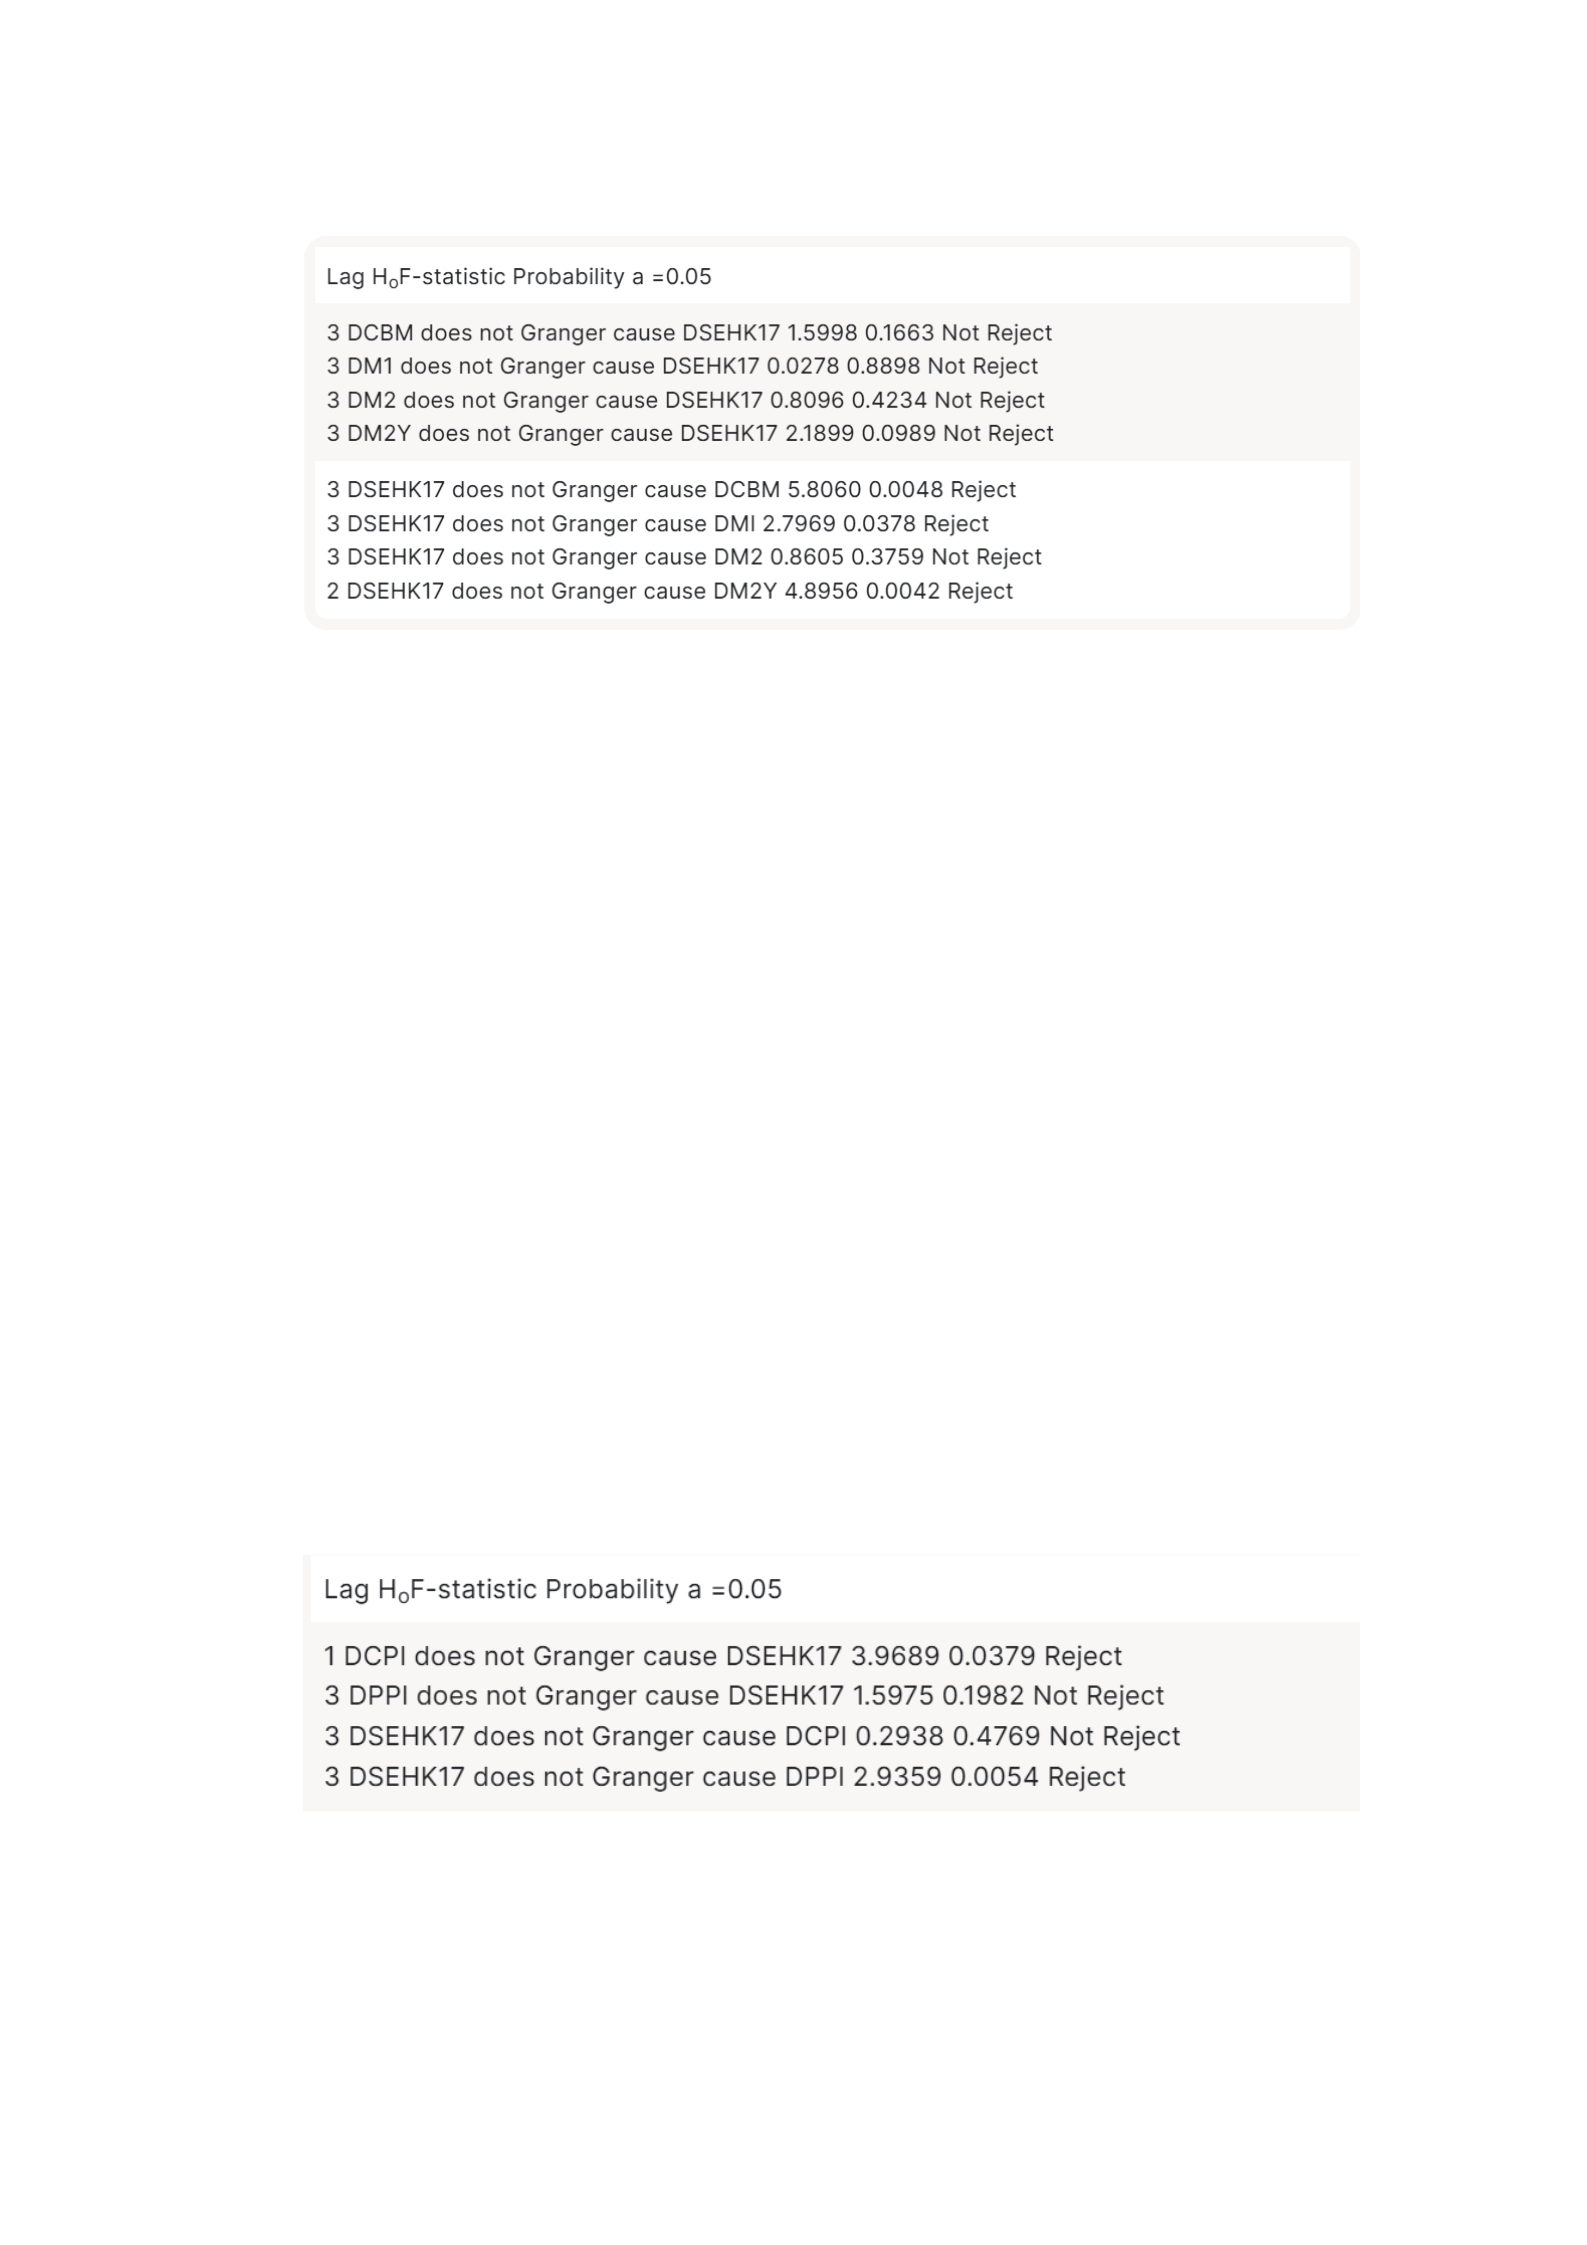
The results of the study indicate that monetary variables do not
Granger cause stock prices. This means that expansion of monetary
variables does not result in growth in stock investment. Therefore,
they do not predict share values and returns in SEHK. This is
consistent with Errunza and Hogan (1998, p. 362). Nonetheless, the
study can conclude in the case of Hong Kong that, with the exception
of M2, there is a causal relationship between stock returns and
monetary supply in that order. In other words, we can conclude that
SEHK17 is a significant indicator of the money supply.
Causality test between stock prices and inflation
The causal relationship between stock returns and inflation is
highlighted in the table below.
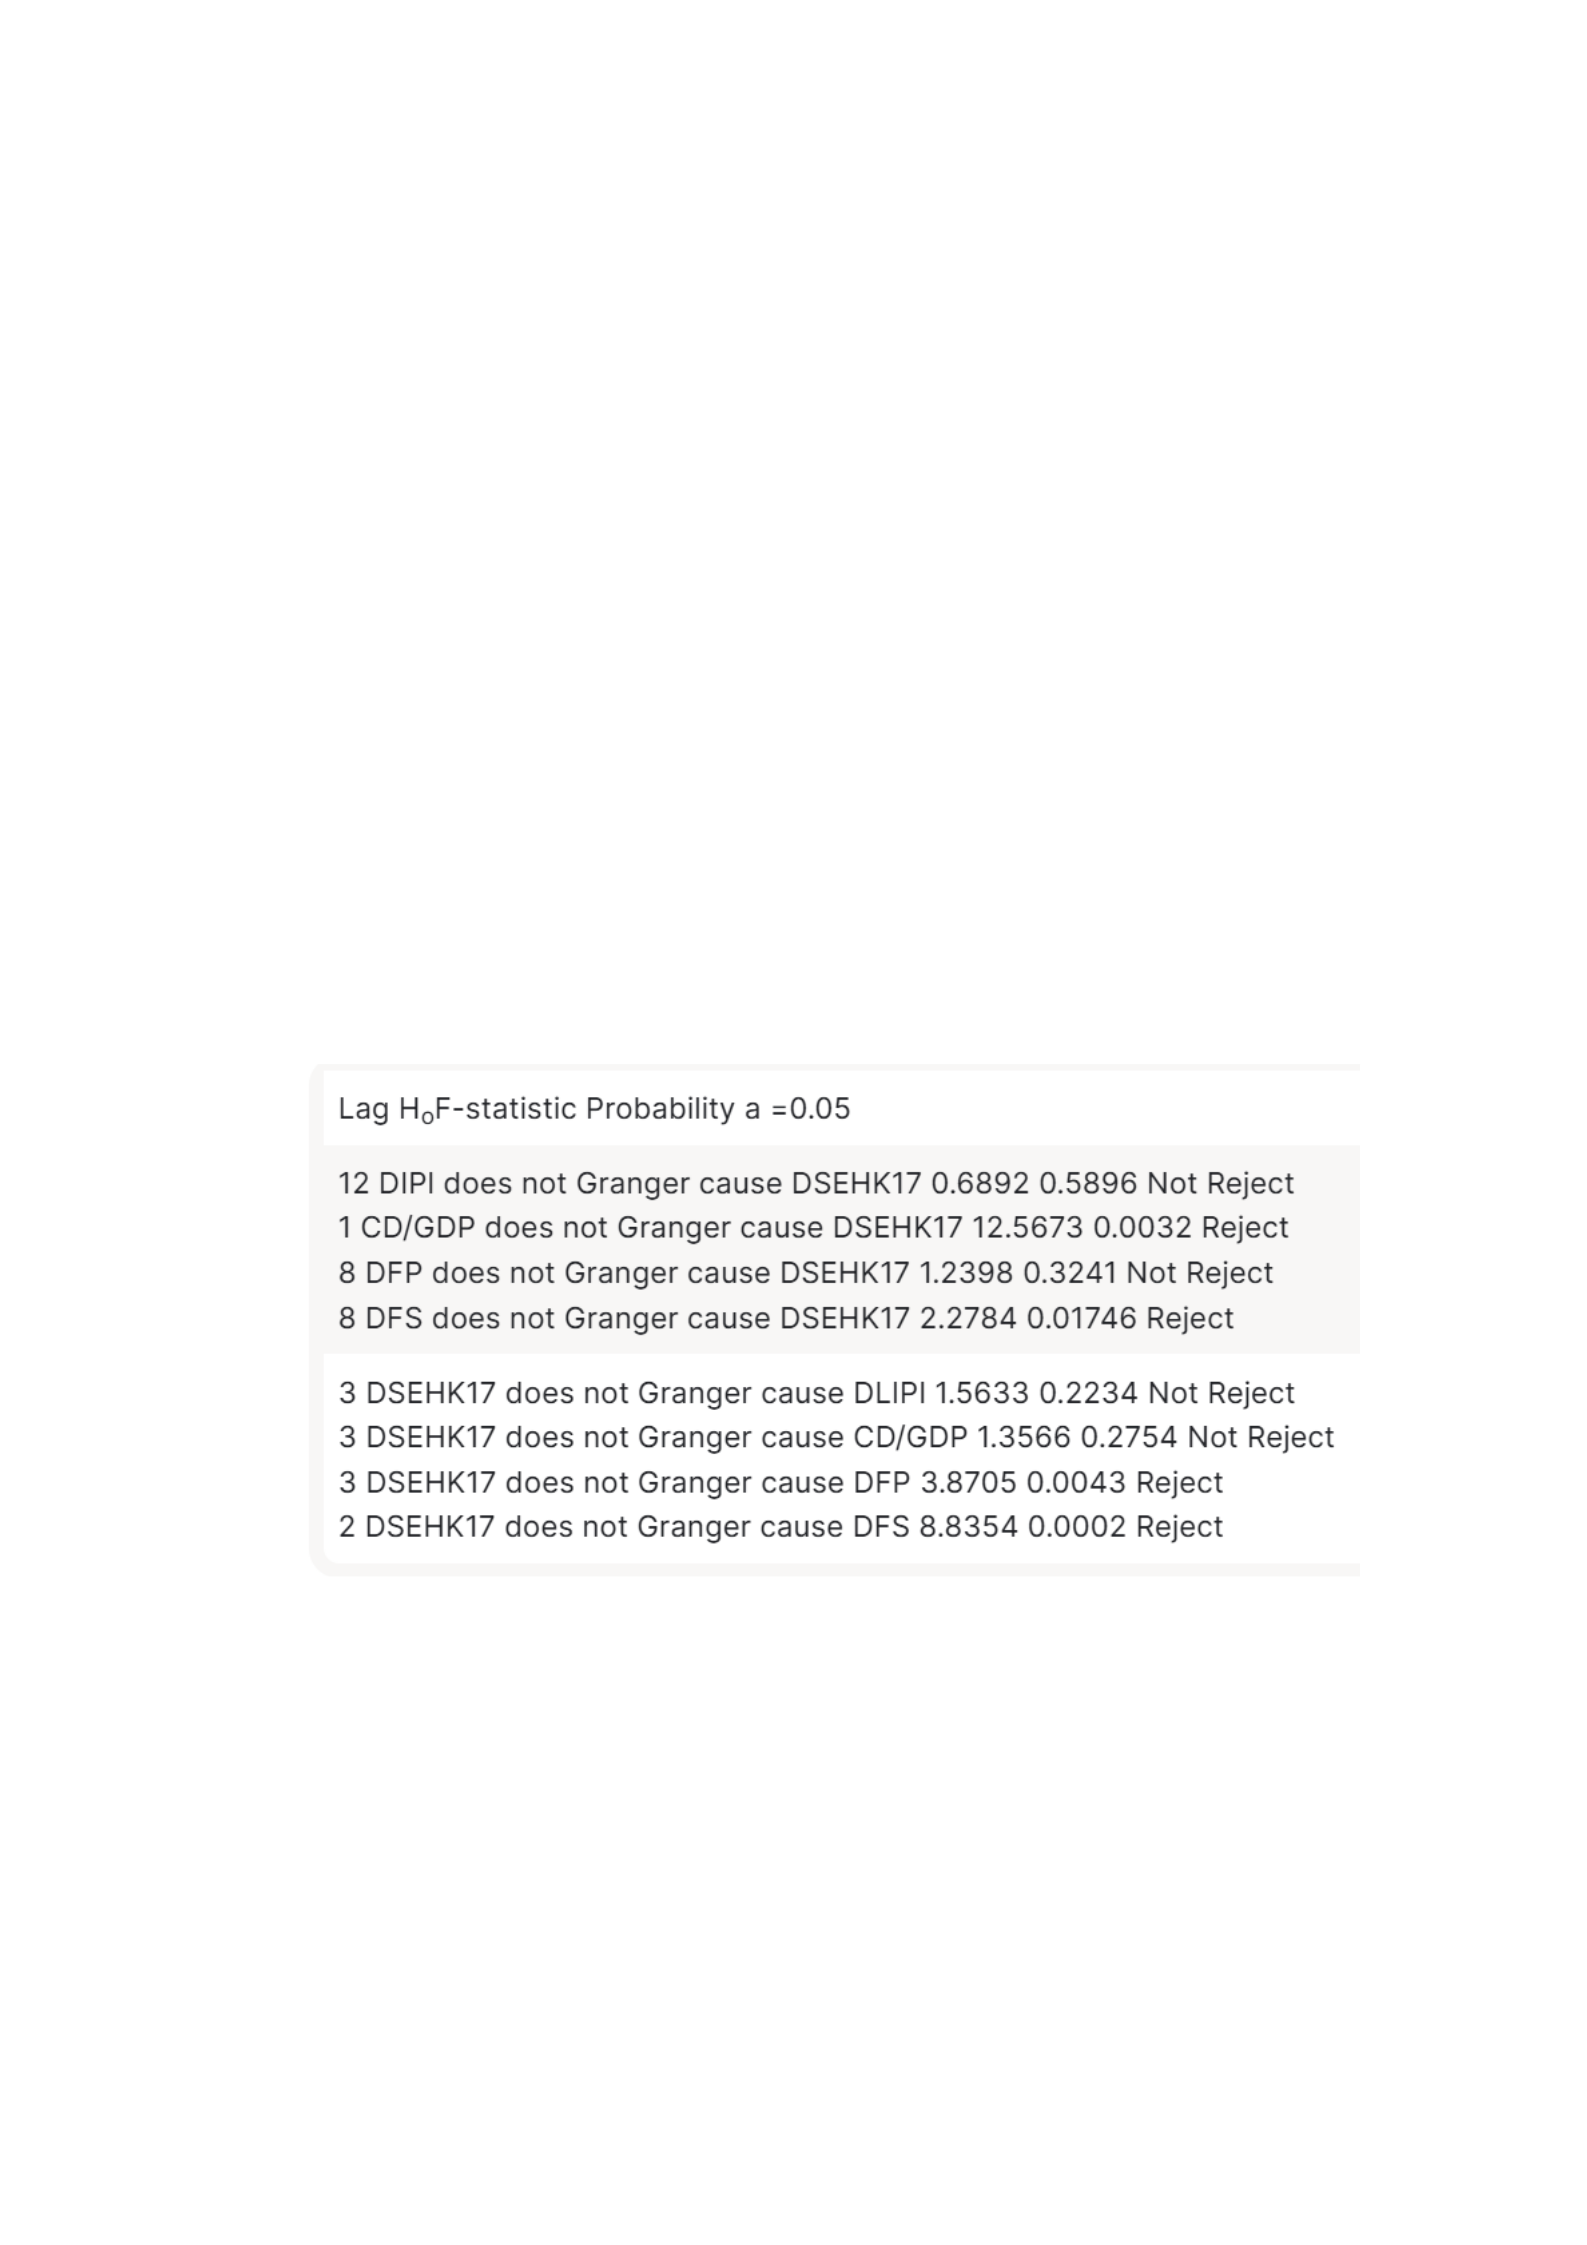
The results of the study tend to be paradoxical. It shows inflation
(represented by CPI) does Granger cause stock returns. This is in line
with Nishat and Shaheen (2004) who indicated a single directionality
between the two variables. Thus, the CPI index can be regarded as a
principle signal in predicting stock returns. On the contrary, the study
findings exhibit a one-directional causality between stock returns and
production price index in that. In this case, stock returns can be used
as a signal when predicting inflation. However, Ho-Ki, Ho-Yin and
Wu-Wing (2011, p.28) pointed out that there is no causal relationship
between inflation and stock returns. Therefore, our results may be
affected by the inflation proxies used.
Causality test between stock returns and the real economy
The findings of the study clearly show that there is no causal
relationship between industrial output and stock returns, and therefore
none of these variables can be used to predict each other. This is
consistent with Errunza and Hogan (1998, p. 362). In contrast, IPI is
effective on stock returns through inflation, meaning that it can be
significant in predicting stock prices. This is also consistent with
Nishat and Shaheen (2004). There is also a single-directional causality
moving from in the direction of CD/GDP to stock prices. This implies
an increase in current deficit leads to deterioration of the economy,
thus fall in stock prices. Lastly, the study indicates a causal
relationship between stock returns and foreign transactions. The
causality with FS and FP are unidirectional and bidirectional,
respectively. This implies that stock market growth encourages
foreign investment and vice versa.
Causality test between stock returns and exchange rate
The results indicate a one-directional causal relationship between the
two variables. Stock return do Granger cause exchange rate. This is
consistent with a number of works of literature such as Ho-Ki, Ho-Yin
and Wu-Wing (2011, p.32) and Tabak (2006), at the same times
contradicts other findings like Humpe and Macmillan (2007, p.5) and
Foresti (2006). Due to the above contradictions, the causal
relationship between the two variables is still not clear up to now.
Causality test between interest rate movements and stock returns
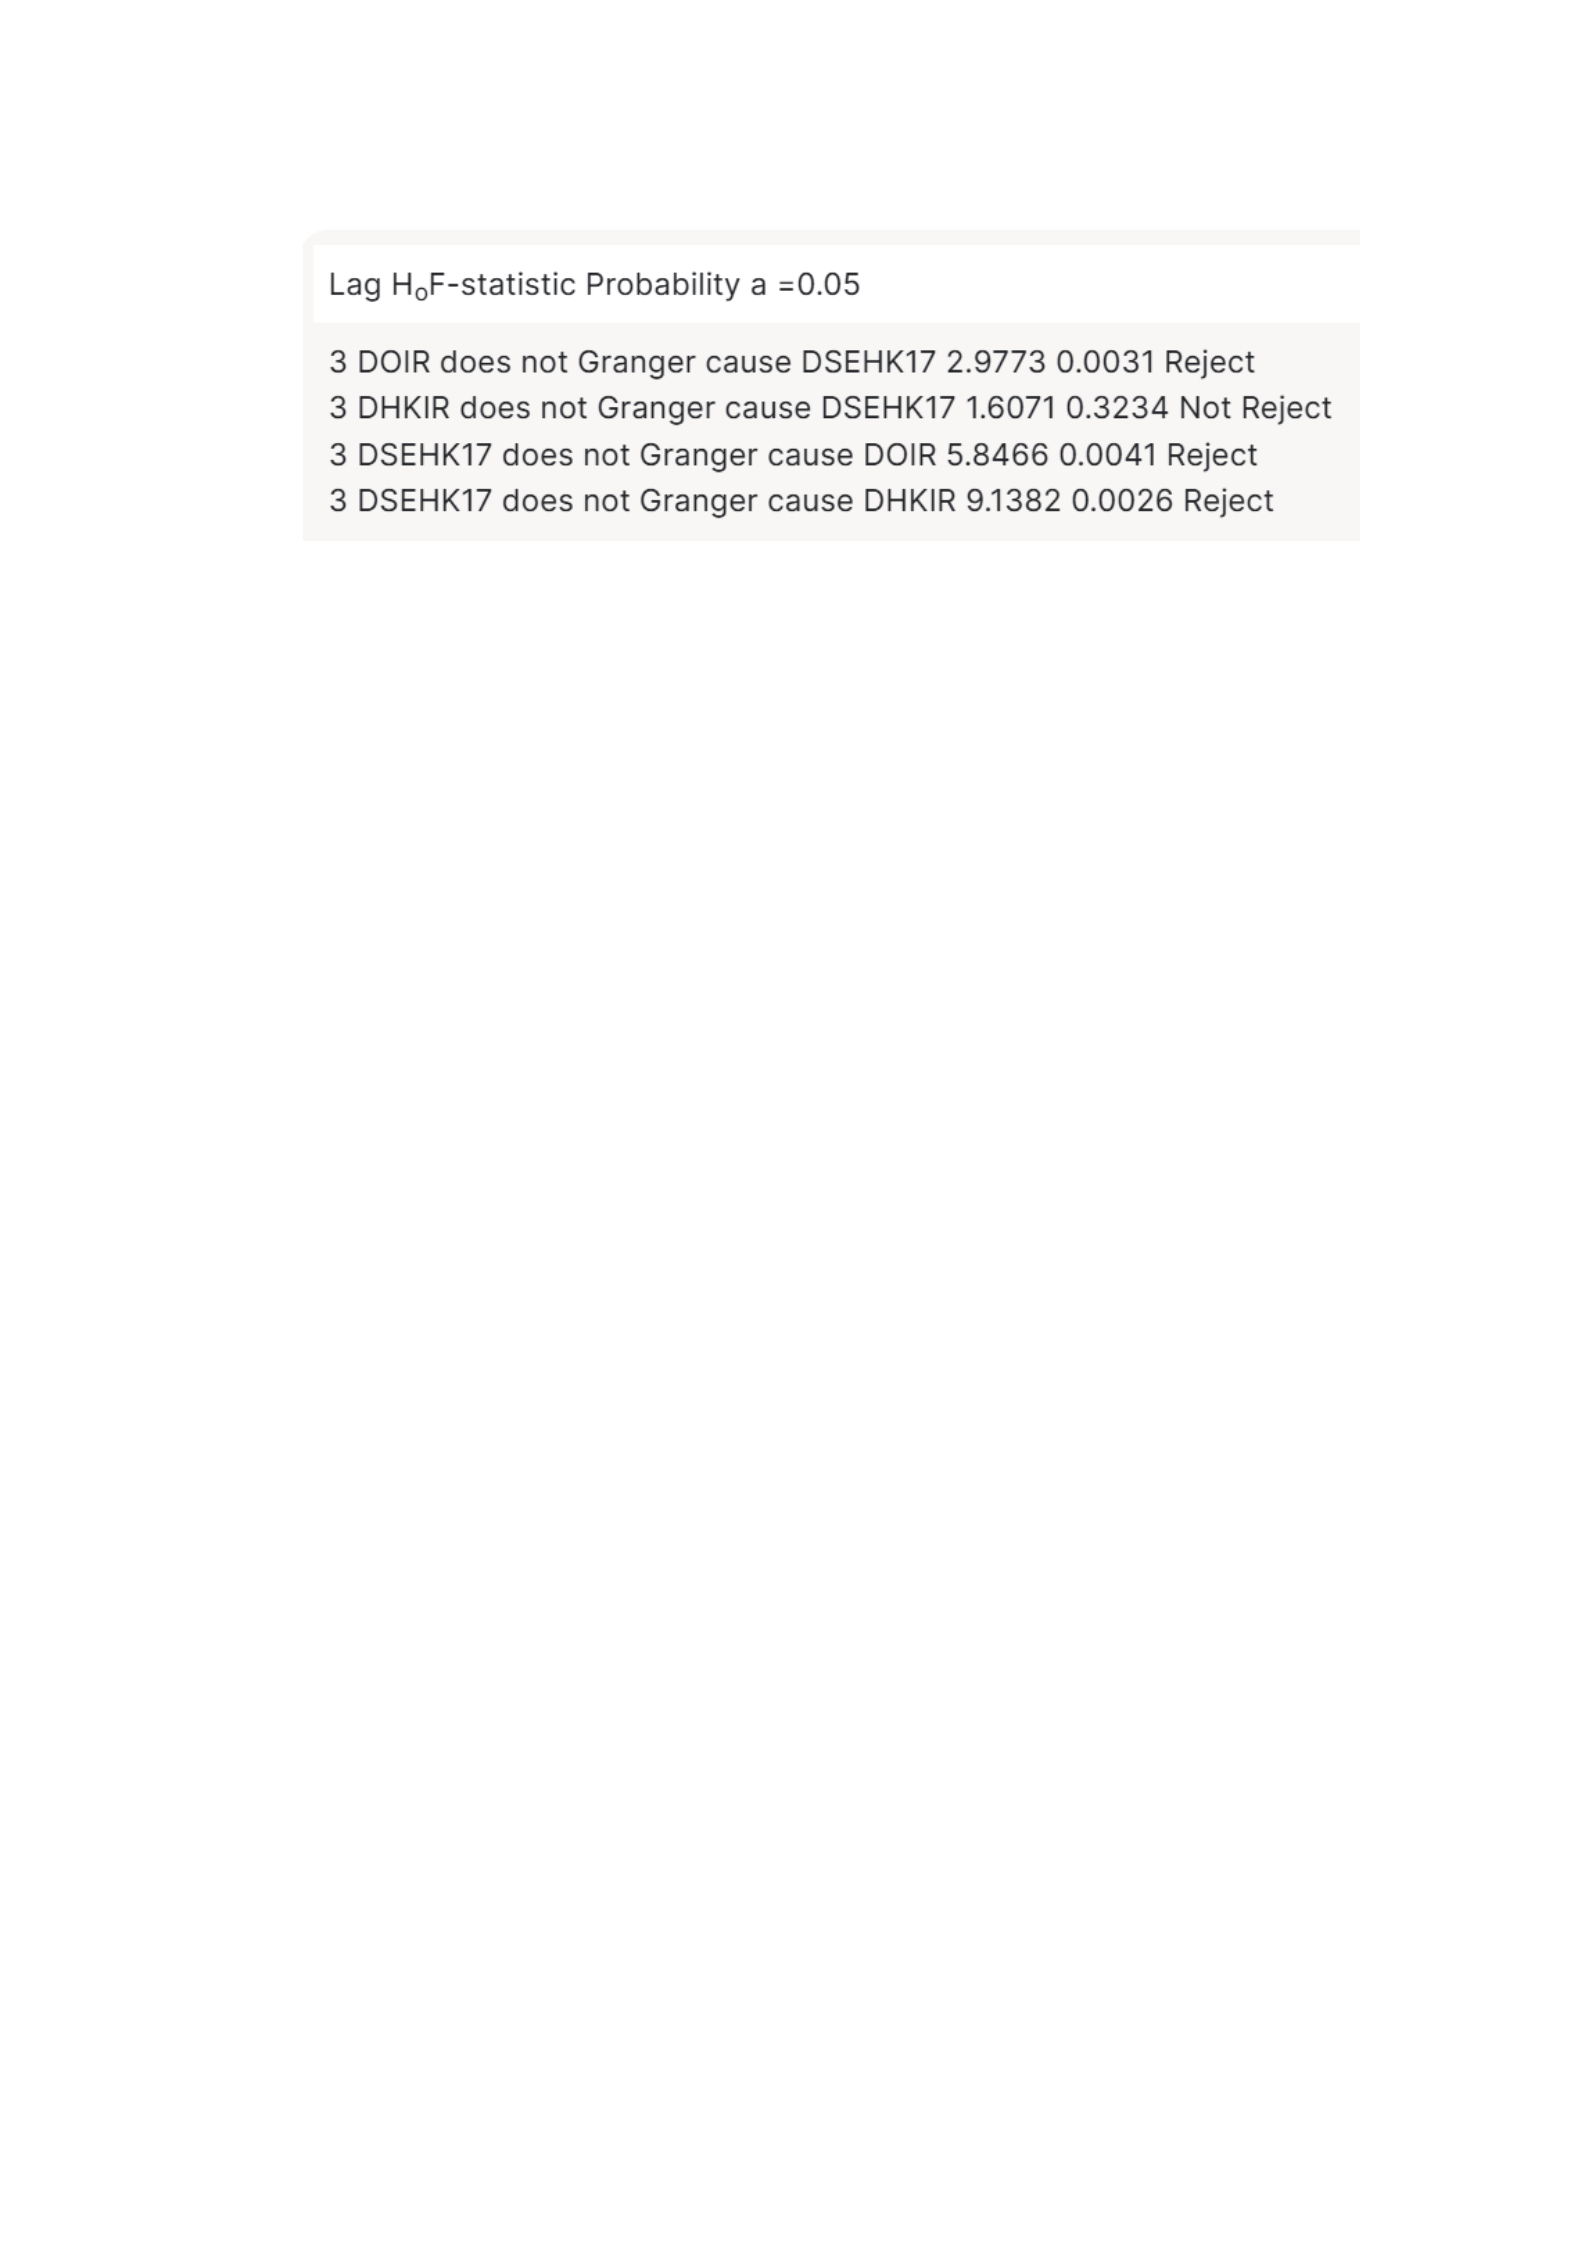
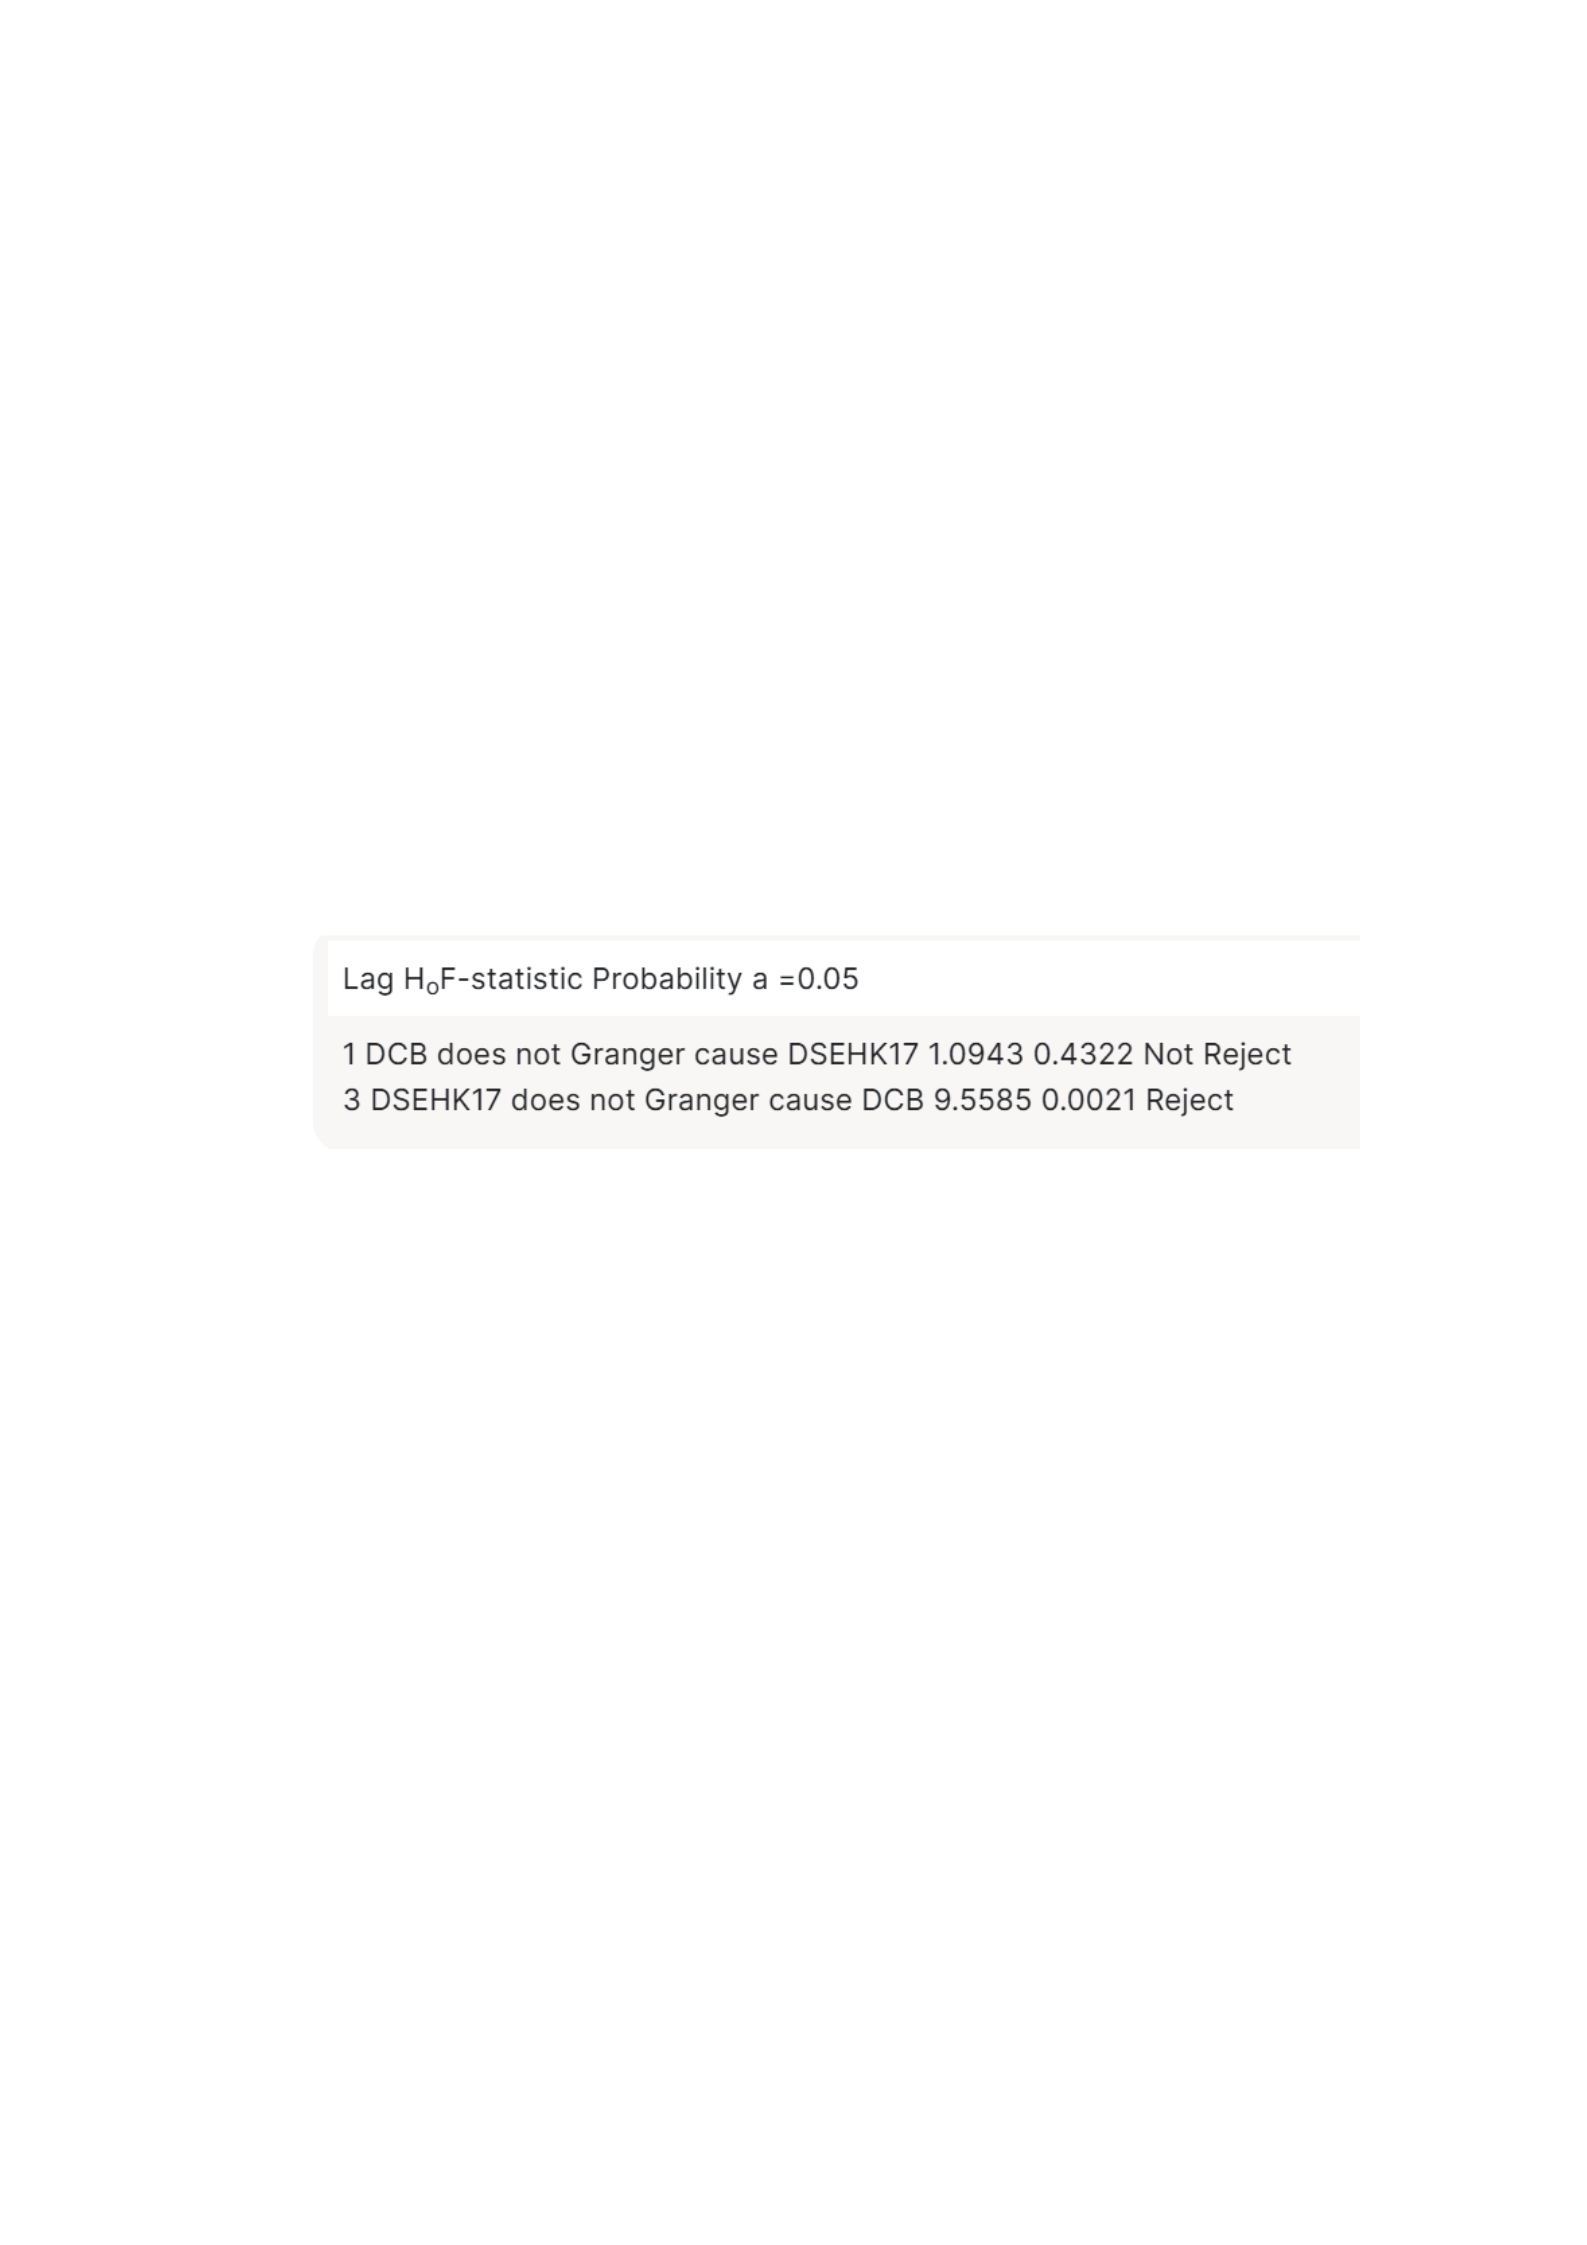
The study indicates two-directional causality between OIR and stock
returns. This is consistent with Ho-Ki, Ho-Yin and Wu-Wing (2011,
p.37). Similarly, Ozturk (2008) indicates that the interest rate has a
considerable effect in predicting stock market prices. In theory,
interest rate increase generally has a negative impact on asset values.
Similarly, the study shows a causative effect running from OIR to
stock prices.

Conclusion
Abundant researches have carried out to determine the causal
relationship between economic factors and stock returns globally. This
is crucial because a number of these factors are used to predict the
inherent value of securities. Theoretically, macroeconomic factors are
believed to be the main cause of stock market volatility. As a result,
they are regarded to be significant in predicting stock prices. In our
case study, the selected macroeconomic variables are examined over
the period between 1991-2011. According to a number of works of
literature, the causal relationship between various macroeconomic
variables and stock returns is well defined, particularly in advanced
economies. This is massively opposed by other researchers, and this is
confirmed by the study results. Some works of literature reveal that in
most cases, the overall level of stock prices tend to be high during
economic prosperity compared to the recession. The study points out
that characteristically, change in stock prices takes place just before
any changes in business activities occurs.
According to the findings of the study, the relationship between the
above macroeconomic variables and stock returns, with the exception
of foreign investor transaction, is statistically insignificant. Stock

returns have a non-constructive and a constructive causal relationship
with nominal interest rates and FS with respect to the.
With regard to casual relationships, the study indicates a two-way
causal relationship between stock returns and interest rate. This means
that with other factors held constant, the two variables can be used to
predict each. The findings of the study also indicate a one-sided affair
between stock returns and nominal interest rates in that order. The
study indicates that inflation and stock returns have a causal
relationship. This is against the economic principle of stock neutrality
with respect to inflation. On of the reason given is that inflation may
falsify returns when historical data is used, especially when
adjustments are not made to reflect the level of inflation in each
period. When inflation shoots up interest rates in general also
increases.
Tabak (2006, p.15) analysis of South American stock prices, show
that long-term relationship between the two variables does not exist.
However, there is a slight causality between them. In addition, his
study shows a non-linear causality from exchange rate to stock prices.
Horobet and Llie (2007) contradict Tabak’s findings. They record no
relationship between exchange rates and stock returns in Romania.
However, the use of the Johansen-Juselius method indicates a
relationship between the two variables in Romania and Brazil.
However, some researchers have pointed out that there is no causal
relationship between inflation and stock returns. Therefore, our results
may be affected by the inflation proxies used in the study.

With regard to the money supply, the study shows that monetary
variables have no effect on stock values and returns. However,
according to the findings, it can be construed that money supply
impacts stock return through consumer price index and overnight
interest rates. Thus, the money supply is a weak indicator of stock
returns in the Hong Kong stock market. The study results show
unidirectional causal relation from GDP to stock returns. The findings
of the study also indicate that monetary variables do not Granger
cause stock prices. This means that expansion of monetary variables
does not result in growth in stock investment. Therefore, they do not
predict share values and returns in the Hong Kong Stock Exchange.
Nonetheless, the study can conclude in the case of Hong Kong that,
with the exception of M2, there is a causal relationship between stock
returns and monetary supply in that order. In other words, we can
conclude that the Hong Kong Stock Exchange index is a significant
indicator of monetary supply.
Furthermore, the analysis shows that industrial production is neither
the result nor the cause variable of stock prices. Thus both can not be
used as indicators to predict each other. According to the findings to
some researchers, stock returns have a significantly positive response
on industrial production, especially in the Chinese economy.
Additionally, causality movement between stock returns and real
economy runs in that order. The findings of the study clearly show
that there is no causal relationship between industrial output and stock
returns, and therefore none of these variables can be used to predict
each other. In contrast, IPI is effective on stock returns through
inflation, meaning that it can be significant in predicting stock prices.

There is also a single-directional causality moving from in the
direction of CD/GDP to stock prices. This implies an increase in
current deficit leads to deterioration of the economy, thus fall in stock
prices. Lastly, the study indicates a causal relationship between stock
returns and foreign transactions. This means that stock market growth
encourages foreign investment and vice versa.
A number of studies have also indicated a positive and significant
long-run relationship between stock prices and independent
macroeconomic variables. They conclude that independent variables
are very effective on stock prices through inflation. In summary, these
studies show a positive correlation between stock returns and the real
economy in both developed and developing economies, as
conjectured. During awful economic times, business cash flows and
required rate of returns are heavily affected, and this normally has a
negative impact on share values. In addition, when the interest rates
increase to a level where most companies would find it very hard to
repay their debts, then their continued existence may be under threat.
In such a scenario, business owners will insist on a higher risk
premium. Consequently, the share value will deepen even further.
Industrial production index (IPI), level of employment and fixed
investment significantly influence stock prices through inflation.
Some studies point out that unexpected inflation has a positive impact
on the returns of business portfolios. He adds that the relationship
between inflation and stock returns is unstable in the long run and that
there are disparities among nations in spite of the state of their level of
development. In line with the study findings, it may be agreed that the

causal relationship running from returns on the stock is superiors than
the causal relationship running from macroeconomic variables to
returns on the stock. Therefore, the SEHK index can be considered as
a signal and a pointer to economic changes in Hong Kong.
References
Abdalla, I S & Murinde, V1997, “Exchange Rate and Stock Price
Interactions In Emerging Financial Markets: Evidence on India,
Korea, Pakistan, and Philippines”, Applied Financial Economics, 7,
pp. 25-35.
Abugri, B A 2008, “Empirical relationship between macroeconomic
volatility and stock returns: Evidence from Latin American markets‟,
International Review of Financial Analysis, vol.17, no. 2, pp. 396–
410.
Adam, AM & Tweneboah, G 2008, Macroeconomic Factors and
Stock Market Movement: Evidence from Ghana. Web.
Al-Sharkas, A 2004, “The Dynamic Relationship between
Macroeconomic Factors and the Jordanian stock market”,
International Journal of Applied Econometrics and Quantitative
Studies, vol.1 no.1, pp. 97-114.

Beltratia, A & Morana, C 2006, “Breaks and Persistency:
Macroeconomic Causes of Stock Market Volatility‟, Journal of
Econometrics, vol. 131, no.1-2, pp. 151–177.
Bodnar, G M, & Wong, M H 2000, “Estimating exchange rate
exposure some ‘weighty’ issues”, National Bureau of Economic
Research Working Paper 7497.
Chatrath, A., S, Ramchander, & Song, F, 1997, “Stock Prices,
Inflation and Output: Evidence from India”, Journal of Applied
Financial Economics, vol.7, pp. 439-445.
Daohua, D 2005, Analyze Hong Kong Stock Market’s Development
on Perspective of Statistics. Web.
DeFusco, R A, McLeavey, DW, Pinto, J E, & Runkle, DE, 2007,
Quantitative Investment Analysis, Second Edition, John Wiley &
Sons, Inc, New Jersey.
Dornbusch, R & Fischer, S 1980, “Exchange Rates and the Current
Account‟, The American Economic Review, vol. 70, no. 5, pp. 960-
971.
Errunza, V & Hogan, K 1998, “Macroeconomic determinants of
European stock market volatility‟, European Financial Management,
vol. 4, no. 3, pp. 361–377.

Fama, E F 1981, “Stock Returns, Real Activity, Inflation, and
Money‟, The American Economic Review, vol. 71, no. 4, pp. 545-
565.
Fisher, I 1930, The Theory of Interest. Web.
Flannery, M J & Protopapadakis, A 2001, Macroeconomic Factors Do
Influence Aggregate Stock Returns. Web.
Foresti, P 2006, Testing for Granger causality between stock prices
and economic growth. Web.
Freris, AF, 1991, The Financial Markets of Hong Kong, Routledge,
London.
Granger, C W J 1969, “Investigating Causal Relations by Econometric
Models and Cross-spectral Methods‟, Econometrica, vol. 37, no. 3,
pp. 424-438.
Ho-Ki, C, Ho-Yin, Y, & Wu-Wing, C, 2011, How Economic Factors
Affect the Movement of the Hong Kong Stock Market: A
Cointegration Analysis, Hang Seng Management College press, Hong
Kong.
Hondroyiannis, G & Papapetrou, E 2001, “Macroeconomic Influences
on the Stock Market”, Journal of Economics and Finance, vol.25, pp.
33-49.

Horobet, A & Ilie, L 2007, On the Dynamic Link between Stock
Prices and Exchange Rates: Evidence from Romania. Web.
Ho, YK 1983, Money Supply and Equity Prices in Hong Kong, in Ho,
YK and Law, CK (ed.), The Hong Kong Financial Markets: Empirical
Evidences, University Publisher and Printer, Hong Kong, pp. 211-233.
Humpe, A & Macmillan, P 2007), “Can macroeconomic variables
explain long term stock market movements? A comparison of the US
and Japan‟, Centre for Dynamic Macroeconomic Analysis Working
Paper Series, Web.
Lee, WC, 2012, “Cointegration and Granger Causality Tests of
Exchange Rate of Euro and Hong Kong Stock Market Index
Interactions”, International Research Journal of Finance and
Economics, no. 19, p. 119-124.
Ma, CK, & Kao, W 1990, “On Exchange rate changes and stock price
reactions”, Journal of Business Finance and Accounting, vol. 17 no.3,
pp. 441-449.
Martig, N 2009, Hong Kong Versus Shanghai. Web.
Maghayereh, A 2002, Causal Relations among Stock Prices and
Macroeconomic Variables in the Small, Open Economy of Jordan.
Web.

Maysami, R C, Howe, L C, & Hamzah, M A, 2004, “Relationship
between Macroeconomic Variables and Stock Market Indices:
Cointegration Evidence from Stock Exchange of Singapore’s All-S
Sector Indices‟, Journal Pengurusan, vol. 24, pp. 47-77.
Maysami, RC & Koh, TS 2000, “A vector error correction of the
Singapore stock market”, International Review of Economics and
Finance, vol.9, pp. 79-96.
Mui, Y M & Law, CK 1983, “The Expectation and Adjustment
Patterns of Stock Prices to New Interest Rates Information in Hong
Kong” in Ho, Y.K. and Law, C.K.(ed.), The Hong Kong Financial
Markets: Empirical Evidences, University Publisher & Printer, Hong
Kong, pp. 159-192.
Muradoglu, G, Metin, K, & Argac, R, 2001, “Is there a long run
relationship between stock returns and monetary variables: evidence
from an emerging market‟, Applied Financial Economics, vol. 11, pp.
641-649.
Nardari F & Scruggs, J T 2005, Why Does Stock Market Volatility
Change Over Time? A Time-Varying Variance Decomposition for
Stock Returns, EFA 2005 Moscow Meetings reviewed 29 September
2008. Web.
Nishat, M & Shaheen, R 2004, “Macroeconomic Factors and Pakistani
Equity Market‟, The Pakistan Development Review, vol. 43, no. 4,
pp. 619-637.

Nasseh, A & Strauss, J 2000, “Stock prices and domestic and
international macroeconomic activity: a cointegration approach”, The
Quarterly Review of Economics and finance, vol.40, pp.229-245.
Ozbay, E 2009, The relationship between stock returns and
macroeconomic factors: evidence from turkey, Thesis, University of
Exeter, Devon, England.
Ozturk, B 2008, The Effects of Macroeconomic Factors on Istanbul
Stock Exchange National 100 Index and Its Volatility, (1997-2006),
Thesis, Istanbul Technical University.
Patra, T & Poshakwale, S 2006, “Economic variables and stock
market returns: evidence from the Athens stock exchange”, Applied
Financial Economics, vol.16, pp.993–1005.
Phillips, PC & Xiao, Z 1998, “A Premier on Unit Root Testing”,
Journal of Economic Surveys, vol. 12, pp. 423-469.
Reilly, F K & Brown, K C 2006, Investment Analysis and Portfolio
Management, Eighty Edition, Thomson South-Western, Mason-Ohio.
SEHK, 2011, Hong Kong Stock Exchange-IPO Overview. Web.
Schwert, GW 1989, “Why Does Stock Market Volatility Change Over
Time‟, The Journal of Finance, vol. 44, no. 5, pp. 1115-1153.

Shuangcheng, L & Guihua, Y 2005, Empirical Analysis of Return and
Volatility Spill over in Chinese Stock Market, Journal of Hebei
University of Economics and Trade, vol. 5, pp. 21-24.
Solnik, B & McLeavey, D 2009, Global Investments, 6th Edition,
Pearson Prentice Hall, Boston.
Stavarek, D 2004, Stock Prices and Exchange Rates in the EU and the
USA: Evidence of their Mutual Interactions. Web.
Stowe, J D, Robinson, T R, Pinto, J E, & McLeavey, D W, 2007,
Equity Asset Valuation, John Wiley and Sons, Inc., New Jersey.
Tabak, B 2006, The Dynamic Relationship Between the Stock Prices
and Exchange Rates: evidence for Brazil, Banco Central Do Brazil.
Web.
Tahir, R & Ghani, A 2004, Relationship Between Exchange Rates and
Stock Prices: Empirical Evidence from Bahrain’s Financial Markets’,
EcoMod2004 International Conference on Policy Modelling. Web.
Tursoy, T, Gunsel, T, & Rjoub, H, 2008), “Macroeconomic Factors,
the APT and the Istanbul Stock Market‟, International Research
Journal of Finance and Economics, vol. 22 no. 4, pp. 15-30.
Wongbangpo, P & Sharma, SC 2002, “Stock Market and
Macroeconomic fundamental dynamic interactions: ASEAN-5
countries”, Journal of Asian Economics, vol. 13, pp. 27-51.

Yu, Q, 1996, “Stock Prices and Exchange Rates: Experience in
Leading East Asian Financial Centres – Tokyo, Hong Kong and
Singapore”, Singapore Economic Review, vol.41, pp. 47-60.
Zhao, X Q 1999, “Stock prices, inflation and output: evidence from
China”. Applied Economics Letters, vol.6 no.8, pp.509-511.

