


EFFECTIVE
ESTATE
AND
GIFT
TAX
STRATEGY
FOR
WEALTH
PRESERVATION
Estate
and
Gift
Tax
Exemptions
Family
Limited
Partnerships
(FLPs)
Currently
$12.92
million
in
2023,
anything
beyond
Allow
for
the
transfer
of
business
interests
to
family
the
exemptions
is
generally
taxed
at
the
40%
rate.
members,
often
at
a
reduced
tax
cost
due
to
valuation
discounts.
Our
Strategy
Intentionally
Defective
Grantor
Trusts
total
estate
and
gift
tax
liability
over
lifetime
and
at
Urea
death.
An
effective
tool
for
freezing
the
value
of
an
estate,
Leverage
exclusions
and
exemptions
to
minimize
allowing
future
growth
to
escape
taxation.
Estate
and
gift
taxes
can
be
a
complex
area,
but
with
the
right
strategy,
you
can
minimize
your
total
tax
liability
over
time.
By
leveraging
exclusions
and
exemptions,
as
well
as
utilizing
FLPs
and
IDGTs,
you
can
ensure
that
your
wealth
is
preserved.
THE
BENEFITS
OF
FAMILY
LIMITED
PARTNERSHIPS
(FLPS)
i
y,
Forming
an
FLP
provides
asset
Form
a
series
of
LLCs
for
real
estate
Transfer
ownership
interest
into
the
protection
and
tax
advantages
properties
FLP
An
FLP
is
a
legal
entity
that
allows
for
the
We
propose
forming
a
series
of
LLCs
for
Transfer
your
ownership
interest
in
these
LLCs
transfer
of
assets
within
the
family,
providing
your
different
real
estate
properties
and
into
the
FLP
to
take
advantage
of
the
benefits
benefits
like
asset
protection
and
potential
tax
transferring
your
ownership
interest
in
these
it
provides.
advantages.
LLCs
into
the
FLP.
Family
Limited
Partnerships
are
a
great
way
to
protect
assets
and
take
advantage
of
potential
tax
advantages.
By
forming
a
series of
LLCs
for
your
different
real
estate
properties
and
transferring
your
ownership
interest
in
these
LLCs
into
the
FLP,
you
can
reap
the
benefits
of
an
FLP.
UNDERSTANDING
INTENTIONALLY
DEFECTIVE
GRANTOR
TRUSTS
(IDGTS)
Intentionally
Defective
Grantor
Trusts
(IDGTs)
are
a
type
of
trust
that
can
be
used
to
reduce
the
size
of
an
estate
while
still
paying
income
taxes
on
the
trust's
income.
IDGTs
are
a
popular
estate
planning
tool
for
those
looking
to
minimize
their
tax
burden.
MINIMIZING
YOUR
INCOME
TAX
LIABILITY
THROUGH
FLPS
AND
IDGTS
all
©)
Utilize
FLPs
and
IDGTs
Sale
of
Partial
Interest
Taxable
Income
Use
Family
Limited
Partnerships
(FLPs)
and
Reduce
income
fax
liability
on
the
sale
of
Minimize
taxable
income
potentially
received
Intentionally
Defective
Grantor
Trusts
(IDGTs)
partial
interest
in
the
business
to
an
unrelated
by
the
business's
operations
over
the
next
24
to
minimize
income
tax
liability.
third
party.
months.
JUSTIFICATION
FOR
MINIMIZING
INCOME
TAX
LIABILITY
ON
SALE
OF
PARTIAL
INTEREST
Selling
a
partial
interest
in
a
business
can
be
a
complex
process,
but
leveraging
the
Unified
Lifetime
Exemption
credit
and
the
discounted
value
of
the
non-controlling
interest
can
help
minimize
the
tax
liability.
This
strategy
is
likely
to
result
in
lower
taxes
than
alternative
transaction
structures
without
the
use
of
FLP
and
IDGT.
OPTIMIZING
WEALTH
TRANSFER:
LIFE
INSURANCE,
ANNUITIES,
AND
CHARITABLE
GIVING
Life
Insurance:
Charitable
Giving:
65%
Can
provide
a
significant
amount
as
proceeds,
tay
Donations can
be
deducted
from
estate
worth,
passing
wealth
to
heirs,
preserving
assets,
and
reducing
the
tax
liability.
The
tax
rate
applied
to
the
providing
a
lump
sum
to
children
without
going
estate
will
be
higher
than
the
income
tax
rate
(40%
through
probate
court.
vs
37%).
Annuities:
;
Cash
Flow
and
Liquidity:
°
on
Provide
a
consistent
income
stream,
enhance
or
V
All
strategies
take
into
account
the
taxpayer's
preserve
the
principal
amount
while
minimizing
overall
cash
flow
and
liquidity
concerns,
risk,
and
allow
for
wealth
transfer
while
minimizing
considering
current
gift
tax
expenditures.
tax
burden.
Optimizing
wealth
transfer
through
life
insurance,
annuities,
and
charitable
giving
can
provide
significant
benefits
to
taxpayers
in
terms
of
preserving
assets,
minimizing
tax
burden,
and
providing
a
lump
sum
to
heirs
without
going
through
probate
court.
CASH
FLOW
AND
LIQUIDITY
CONSIDERATIONS:
STRATEGIES
FOR
CONTROL
AND
FLEXIBILITY
Cash
flow
and
liquidity
are
important
considerations
when
planning
an
estate
strategy.
Utilizing
family
limited
partnerships
(FLPs)
and
intentionally
defective
grantor
trusts
(IDGTs)
can
help
you
achieve
your
goals
while
still
maintaining
control
over
your
assets.
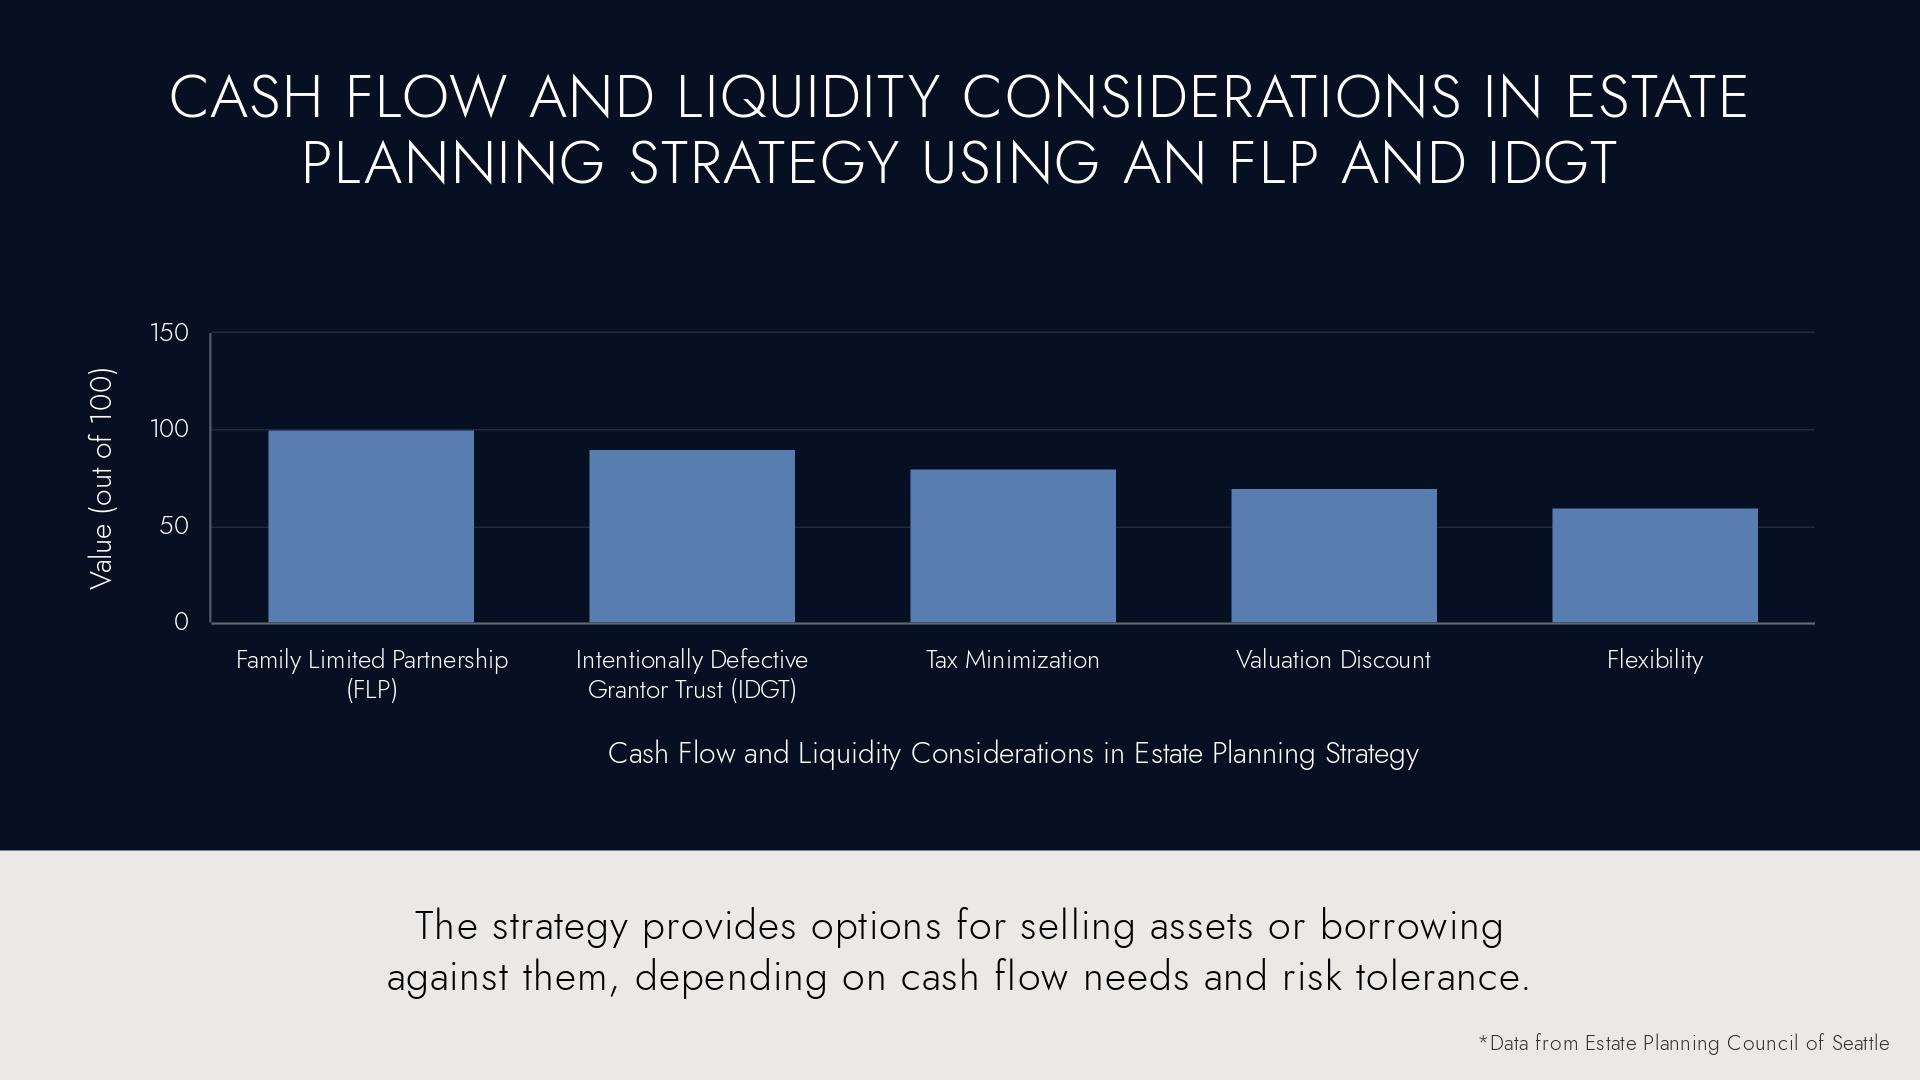
CASH
FLOW
AND
LIQUIDITY
CONSIDERATIONS
IN
ESTATE
PLANNING
STRATEGY
USING
AN
FLP
AND
IDGT
150
stele)
Value
(out
of
100)
(@))
vo)
Family
Limited
Partnership
Intentionally
Defective
Tax
Minimization
Valuation
Discount
Flexibility
(FLP)
Grantor
Trust
(IDGT)
Cash
Flow
and
Liquidity
Considerations
in
Estate
Planning
Strategy
The
strategy
provides
options
for
selling
assets
or
borrowing
against
them,
depending
on
cash
flow
needs
and
risk
tolerance.
*Data
from
Estate
Planning
Council
of
Seattle
SO-YEAR
PROJECTIONS
WITH
3%
ANNUAL
APPRECIATION
FOR
A
FAMILY
LIMITED
PARTNERSHIP
AND
INTENTIONALLY
DEFECTIVE
GRANTOR
TRUST
500
AQO
aD
come’)
cab)
1010)
©
=
100
@)
(cra
Year
5
Year
10
Year
15
Year
20
Year
25
Year
30
Years
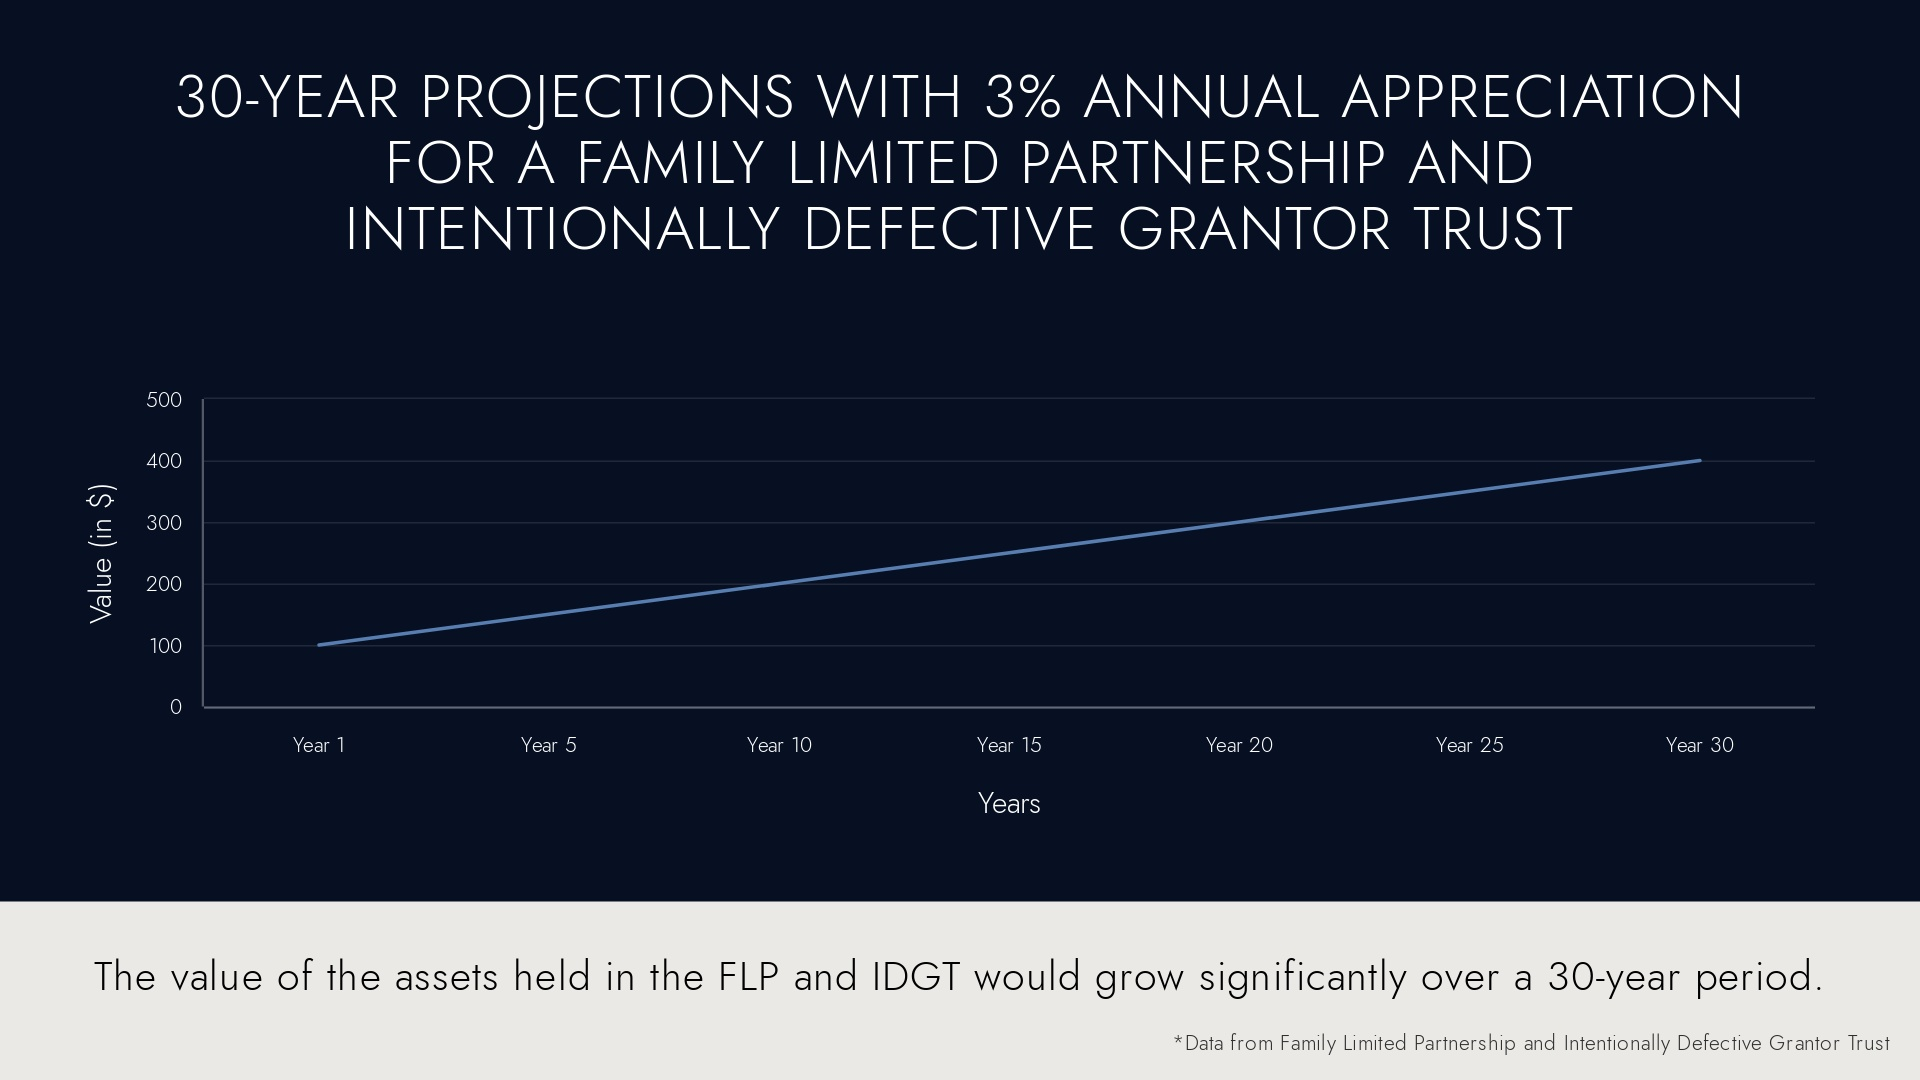
The
value
of
the
assets
held
in
the
FLP
and
IDGT
would
grow
significantly
over
a
30-year
period.
*Data
from
Family
Limited
Partnership
and
Intentionally
Defective
Grantor
Trust
POTENTIAL
LIFETIME
ESTATE
TAX
SAVINGS
AND
TAX
LIABILITIES
OVER
30
YEARS
COMPARISON
Total
Income
from
Real
Estate
Business
$200
million
$200
million
Total
Tax
|
§$80
million
|
S74
million
Net
Income
Over
Two
Years
|
$150
million
|
$116
million
Estate
Value
at
End
of
Two
Years
|
$2.037
billion
|
$2.174
billion
SO-YEAR
PROJECTIONS:
ESTATE
VALUE
GROWTH
AND
TAX
SAVINGS
Year
O
§2,037,000,000
§2,037,000,000
SO
Year
10
$2,719,000,000
|
§2,871,000,000
$48
million
Year
20
$3,541,000,000
|
$3,764,000,000
$72
million
Year
30
$4,521,000,000
|
$4,817,000,000
$96
million
*Data
from
'30-Year
Projections:
Estate
Value
Growth
and
Tax
Savings'
THE
FINANCIAL
BENEFITS
OF
LONG-TERM
TAX
PLANNING:
COMPARING
THE
IMPACT
OF
USING
STRATEGY
VS
NOT
USING
STRATEGY
Without
Strate
$80,000,000
$150,000,000
gy
With
Strategy
$74,000,000
$116,000,000
*Data
sourced
from
Internal
Revenue
Service
THE
CONSEQUENCES
OF
INSUFFICIENT
CASH
FOR
ESTATE
PLANNING
¢
Ze
Ay
Penalties
for
late
filing
and
payment
Interest
Ethical
Considerations
As
per
IRC
Section
6651,
penalties
can
be
Interest
that
may
be
incurred
if
there
is
not
There
are
ethical
considerations
of
not
having
substantial
enough
cash
on
hand
to
fund
gift
tax
or
enough
cash
on
hand
to
fund
gift
tax
or
income
fax.
income
fax.
It
is
important
to
understand
the
risks
of
insufficient
cash
when
it
comes
to
estate
planning,
and
to
be
aware
of
the
potential
penalties,
interest,
and
ethical
considerations
that
may
arise.
RISK
ANALYSIS:
INSUFFICIENT
CASH
FOR
TAX
PAYMENT
A
Options
for
Payment
Arrange
installment
agreement
with
Ethical
Compliance
Use
proceeds
from
life
insurance
to
buy
IRS
Open
and
honest
communication
about
estate
assets
in
the
amount
of
the
tax
liability
or
Allows
for
deferral
of
estate
tax
payments
for
tax
obligations
and
potential
consequences
of
arrange
an
installment
agreement
with
the IRS
closely
held
businesses
late
payment.
under
IRC
Section
6166.
There
are
several
options
available
to
fund
gift
tax
or
income
tax
incurred
trom
the
estate
planning,
each
with
its
own
advantages
and
disadvantages.
It
is
important
to
consider
all
options
carefully
before
making
a
decision.
THE
RISK
OF
AN
INACCURATE
APPRAISAL
Inaccurate
appraisals
can
have
serious
consequences,
including
financial
penalties,
interest,
and
ethical
considerations.
It
is
important
to
understand
the
risks
associated
with
inaccurate
appraisals.
RISK
OF
INNACURATE
APRRAISAL
cro
Potential
Consequences
Taka)
Penalties
If
an
inaccurate
appraisal
is
discovered
According
to
the
Internal
Revenue
Code
(IRC)
If
the
valuation
misstatement
is
"gross"
or
during
an
audit,
it
could
lead
to
additional
Section
6161,
the
IRS
may
grant
an
extension
"substantial,"
the
penalty
could
be
as
high
as
tax,
penalties,
and
interest.
The
IRS
could
also
of
time
for
payment
of
the
tax,
not
exceeding
40%
of
the
underpaid
tax.
impose
a
penalty
under
IRC
Section
6662
for
12
months.
Interest
will
accrue
as
per IRC
an
underpayment
of
tax
due
to
a
valuation
Section
6601
and
penalties
for
late
filing
and
misstatement.
payment
can
be
substantial.

