


Establishing the Value of the Marketing Projects Portfolio
Introduction
In previous chapters of this textbook, the emphasis has been on identifying the
marketing opportunities that exist in order for the organization to profit optimally. The
purpose of this chapter is to assist students in understanding the purpose and process
methods that a CMO could use in order to determine which projects should be supported
by the marketing unit of the organization for the coming fiscal year. In addition, the
proposed methods can be used as a pro forma planning tool for subsequent years. In this
chapter, the discussion will include: (a) an overview of the recommended process that a
CMO would use to evaluate the financials, (b) methods in valuating projects, (c)
determining the factors that might discount the initial valuation of projects, and (d)
applying financial concepts to establish a proposed portfolio of marketing projects to be
presented to and approved by the executive leadership team of the organization and
ultimately the shareholders.
Purpose and Overall Process of Determining Financial Bases
The need to conduct financial analyses for marketing projects is based on the
assumption that the organization has limited resources and thus is unable to fund all
market opportunities at the full levels requested by managers within the marketing unit.
Therefore, it is incumbent upon the CMO of the organization and possibly a marketing
strategic planning committee to determine which projects are to be funded and to what
extent they will receive funding. In the portfolio of marketing projects for the coming
budget fiscal year, there will be existing projects and proposed new projects. On at least
an annual basis, each existing and proposed project should be presented to the CMO from
the designated marketing team members responsible for the project complete with a
request for capital investment (funding, employees, use of facilities, distribution costs,
promotional costs, etc.). How should the CMO and the senior marketing team determine
the levels of investment for these projects?
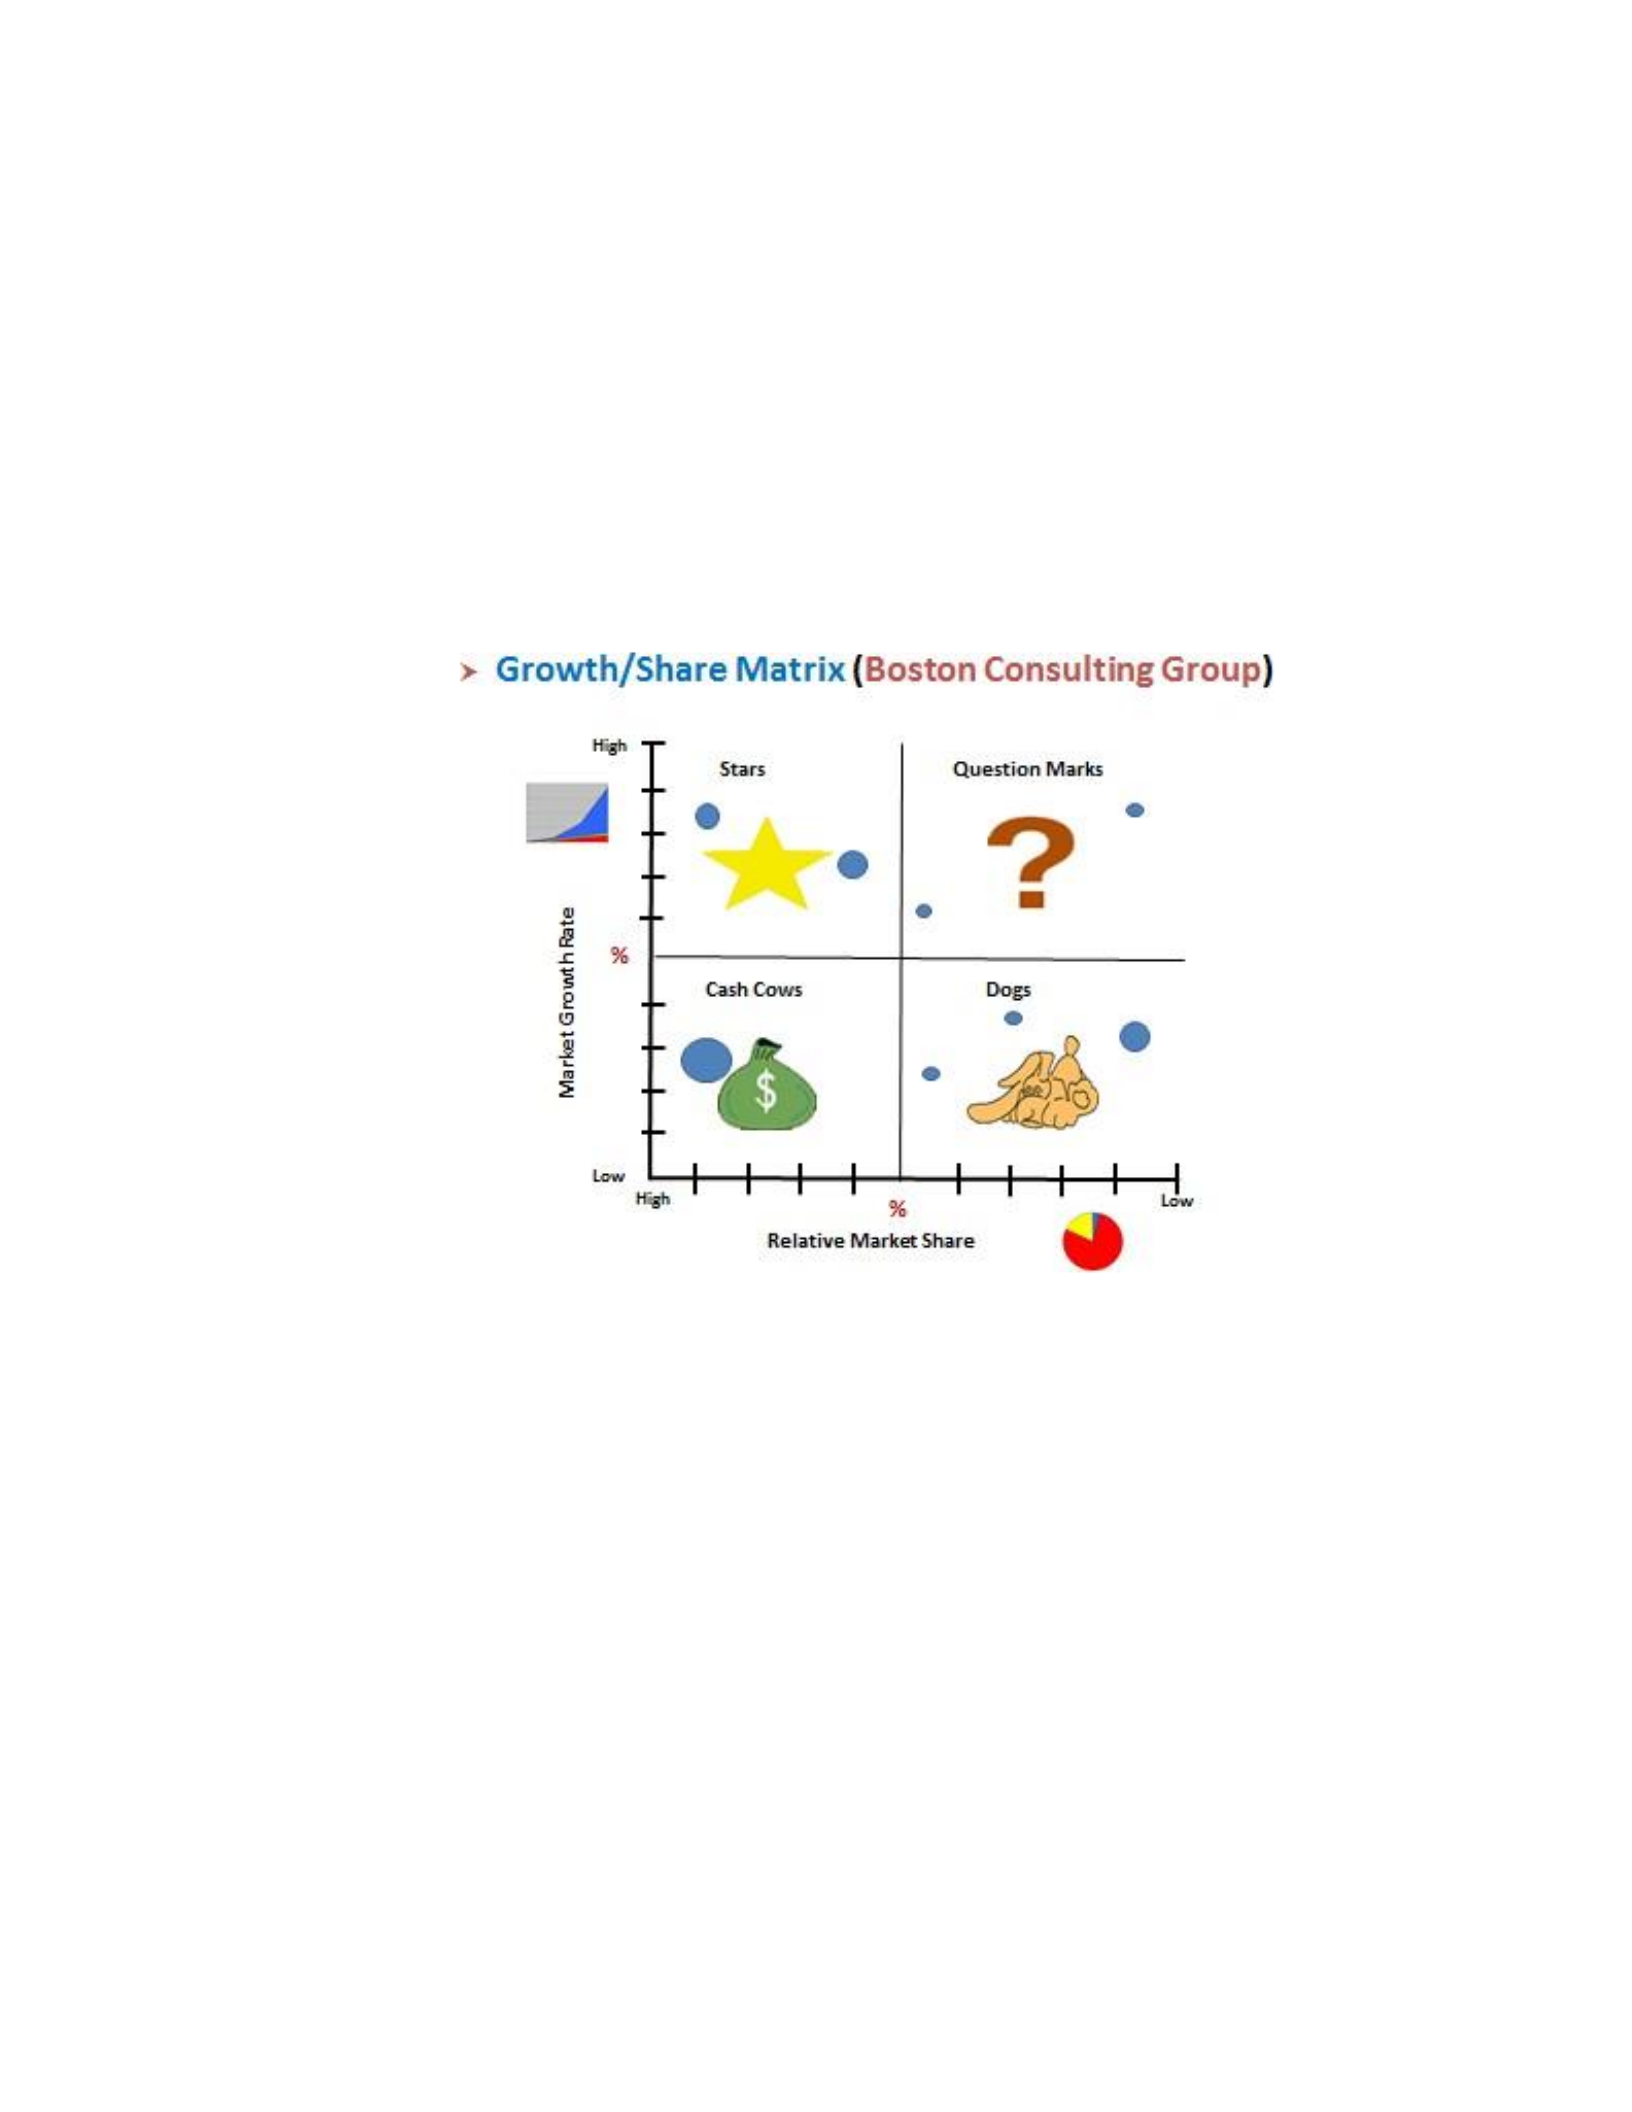
At the macro level of analysis, the Growth/Share Matrix model, discussed briefly
in Chapter 1 of this book and illustrated in Figure 10.1 of this chapter, should have a
major bearing on the decisions of how much funding goes to each project. From a general
perspective of using this model, the overall strategy would be to ensure that the Stars
receive their full funding, the Cash Cows would not become incapable of producing their
“milk” to benefit the other SBUs, the Question Marks would receive serious scrutiny, and
decisions would need to be made about how to convert the Dogs into a source of funds.
The rationale behind this general strategy is that Cash Cows have an established
loyal base and therefore require only a maintenance level of funding to ensure that the
brands within the Cash Cow SBUs do not lose market share. Due to the characteristic of
slow annual growth rate of the market for Cash Cows, additional investments to build the
Cash Cow brands would not reap the same reward as investing the same amount of
capital in the Stars brands that are experiencing high market growth and have achieved
high market share. Stars need as much funding as necessary to grow them to the extent
that the organization can afford to give them with the outlook that today’s Stars will
potentially become tomorrow’s Cash Cows of the organization. Not to be overlooked are
the Question Marks. They share the attribute of existing in a high growth market but have
not achieved significant market share yet. Therefore Question Marks require scrutiny by
the marketing management team to forecast the probabilities of their future as a Star or
one of never gaining sufficient market share and thus becoming Dogs in the future.
Figure 10.1
Growth/Share Matrix Model
Source: Adapted from The BCG Portfolio Matrix from the Product Portfolio Matrix ©1970, The Boston
Consulting Group.
The basis for why Question Marks have not achieved significant market share
needs to be examined. Is it because the brand is new to the market and is expected to
grow significantly in the next fiscal year? Was the brand too late in being launched into
the market and therefore missed the prime window of opportunity for future growth?
What is the forecasted market potential for the product category represented by the brand
and how close to that projected potential is the market now? In other words, which of the
Question Mark brands have the potential to become Stars and which could bypass Stars
and Cash Cows status and go straight to the status of Dogs? These considerations should
determine the amount of funding to be budgeted for each Question Mark brand. Now
what should be done about the Dogs?
Those brands that exist in low market growth and low market share (Dogs)
originate from two possible situations: products in the Decline stage of the Product Life

Cycle and Question Marks that never reached full market share potential for whatever
reasons. The challenge to the CMO is to determine how to turn the Dogs brands from
being a target of funding to being a source of funding. For example, is there another
organization, possibly a competitor, who would welcome the brand to that organization’s
portfolio of products? IBM used this strategy when it sold its Thinkpad brand to Lenovo,
a Chinese company. Sometimes, the raw assets being used to produce the Dogs brand can
be sold for cash to be used in funding Stars and Question Marks brands. Another source
of funds could be the sale of the brand itself as intellectual property with no tangible
assets exchanged. Kodak is a good example of this strategy by selling many of their
patents that they will not be using in the future. With a model of overall strategy for
determining the funding for proposed marketing projects, what is the process that a CMO
should follow to determine which marketing projects will be funded and to what extent
they will be funded?
The overall process for a CMO to evaluate the marketing projects and determine
the levels of support can be summarized by the following list. The remainder of this
chapter will be devoted to providing information on steps that can be taken to arrive at a
realistic forecasted value for each proposed marketing project in the coming budget fiscal
year.
1. Determine the overall marketing budget available for the budget fiscal
year.
2. Determine the projected value of each project in terms of units sold and
revenues earned.
3. Calculate the discounted value of revenues for each project (using tools
like Net Present Value, Probability Analysis, Situational Analysis, etc.).
4. Determine the projected variable costs necessary to achieve the projected
sales across the project time table.
5. Calculate the projected contributions to the organization’s bottom line
(gross margin).
6. Evaluate situational variables that might discount further or even add
value to each project.
7. Rank the proposed marketing projects by Growth/Share Matrix categories
into a Profitability Matrix model.
8. Allocate funding based on ranking of the projects and the Growth/Share
Matrix category to establish the overall portfolio strategy for the next
budget fiscal year.
9. Prepare the written marketing plan and verbal presentation to the
organization’s executive leadership team and potentially the directors of
the organization.
Step 1: Determine the overall marketing budget
The first step in the budgeting process for the CMO is to determine how much the
organization is willing to fund all marketing programs for the coming fiscal year. There
are various methods used by organizations to determine the budgeted amount. Among the

methods are (a) Affordability, (b) Percentage Increase, (c) Industry Standard, and (d)
Zero-Based Budgeting.
The Affordability method is based on the concept of what the organization
perceives it can afford to invest in projects for the coming fiscal year. Users of this
method focus on existing assets, past performance, and projected availability of future
cash reserves. This method does not allow for the possibilities that investments in
marketing projects can increase the asset portfolio of the organization. The unwillingness
to accept risks is the primary motivation for using the Affordability method of budgeting.
A CMO needs to be a part of an organization that perceives marketing programs as
investments to grow the organization and is willing to accept calculated risks with
reciprocal returns on investment.
The Percentage Increase method is another simple method of determining the
budgeted amount for future marketing programs and allows for some growth based on
criteria such as Cost-of-Living-Adjustments or market growth. However, its
shortcomings as a method are that the increases are based on historical performance and
do not consider the changes that may occur in the future. The same concerns exist for the
Industry Standard method which is determined by what other providers in the industry
are spending on marketing programs as a percentage of revenues, usually. In addition, the
Industry Standard method of budgeting supports the status quo of market share for the
organization and does not allow for an aggressive move to gain more market share. That
leaves the Zero-Based budgeting method as an alternative.
The Zero-Based budgeting method is based on the assumption that the past is the
past and all previous funding is ending. It is time to look to the future from a beginning
value of zero for all potential projects to be funded. This method is not about ignoring
past successes or failures, nor is it about ignoring ongoing projects that need continuing
funding. The philosophy of “Zero-Based budgeting” is about each existing project being
re-evaluated in the same manner as new, proposed projects based on the existing merits
in today’s market environment and on the projections of what will be happening in future
markets. Certainly, considerations need to be given to past performance but not to a
greater extent of consideration than current and future market conditions. However, as
additional considerations, the questions of affordability for the organization and how
much other organizations within the industry are investing in marketing projects can be
included in the final decision mix. Because the Zero-Based budget method is the
recommended method, the remainder of the discussion in this chapter will be from the
basis that the organization applies the Zero-Based method to its annual budgeting
process.
Step 2: Determine the projected value of revenues for each project
Once the CMO has an approved budget from the organization, evaluation of
marketing projects can begin to determine the portion of the overall budget that will be
allocated to each approved project. The discussion of budget in this chapter is based on
monetary measurements as representing the value of unit sales, labor costs, travel
expenses, use of facilities costs, administrative costs, etc. It should be noted that some
would suggest that values be calculated based on accounting financial reports. That
would include using depreciated assets and impacts on the various financial statements to
value income and expenses. However, it is recommended in this chapter that CMOs
primarily work through the financial evaluation process based on operational cash
considerations vs. using taxation considerations. Therefore, depreciated assets will not be
a consideration for the proposed valuation of marketing projects, but could become part
of the final analysis in terms of overall impact to the organization’s audited financial
reports.
The next step in determining the marketing projects to be funded for the coming
budget fiscal year involves identifying the potential revenues that can be achieved from
each project. Usually, project teams are assigned to develop the tactical marketing plans
for each brand within the organization. As part of the marketing plans, pro forma
forecasts should be made of the number of units that are expected to be sold and the
revenue dollars that should be raised from the sales. For existing brands, the forecasts are
based on historical sales trends for both the organization and the industry. In addition,
considerations should be given to future potential market sales based on the extent to
which the market has satisfied the needs of potential consumers of the product or service
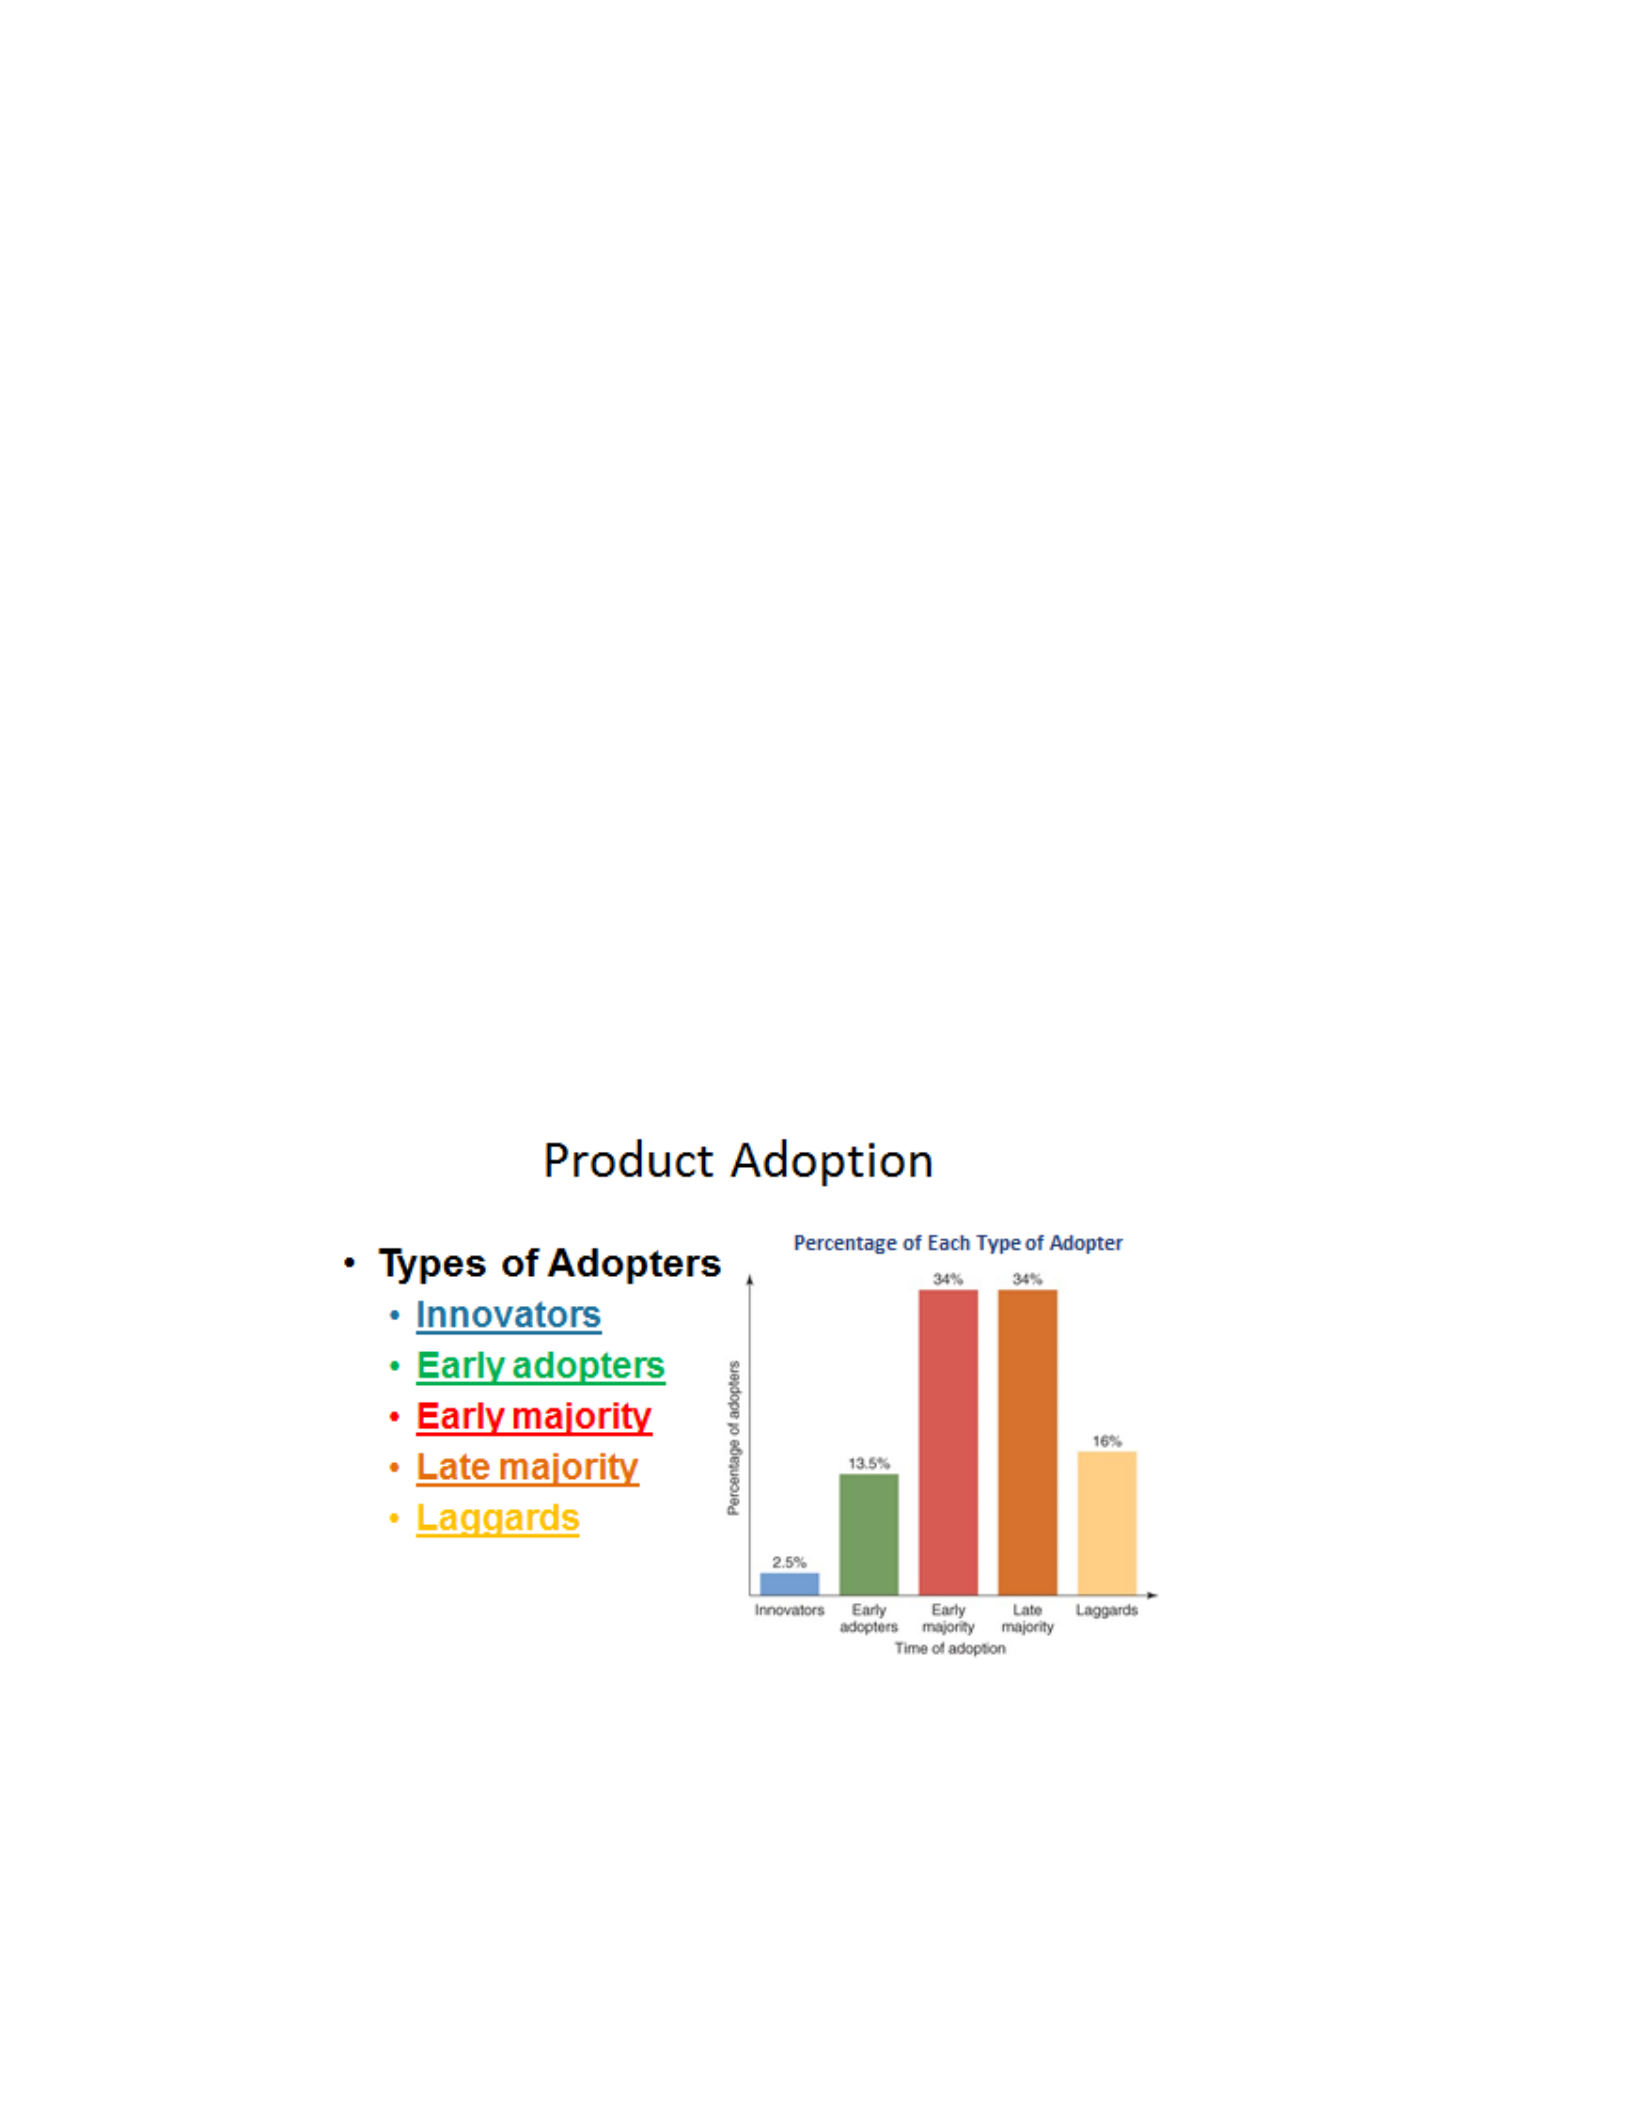
category sometimes referred to as market saturation. A formula that can be used to
determine the market potential is the Product Adoption model as illustrated in Figure 10.2
(Rogers, 1995).
Figure 10.2
Source: Rogers, E.M. (1995). Diffusions of innovations. New York: The Free Press.
Rogers found that there were five distinct groups of consumers who would
eventually purchase from a product category. These consumer groups were categorized as

(a) Innovators, (b) Early Adopters, (c) Early Majority, (d) Late Majority, and (e)
Laggards. The extent to which each group represents all adopters (purchasers) is
designated in percentages. Each group of adopters possesses similar purchase behaviors
within the group. For example, Innovators typically are from the wealthiest levels of
society and enjoy being the first in the community to own a new product. Early Adopters
are among the more influential members of a community and follow the lead of
Innovators in adopting the new product. Collectively, these two groups usually represent
16% of all consumers who will eventually purchase from the product category. From
there, one can estimate the remaining numbers of eventual purchasers.
For example, the Early Majority should represent approximately double the
number of purchasers to date among the Innovators and Early Adopters. If 100,000 units
of a product category were purchased by the Innovators and Early Adopters groups, one
could estimate that another 200,000 units would be purchased by the Early Majority
group. This could mean that the total market saturation would be reached at double the
300,000 units or a total of 600,000 units. The estimated units sold does not need to be
measured precisely but does give a reasonable estimate of the potential market demand
based on the historical purchase behavior of the five groups of consumers/adopters. The
key variable that can determine the eventual success of the product category is the timing
of how quickly the purchases are made by the first three groups. The faster the adoption
cycle, the more it benefits the pioneer organization that introduced the new product.
The goal of rolling out a new product is to achieve rapid adoption of it vs.
requiring an extended period of time for the new product to gain popularity. The best
strategic outcome would be to move through the various stages of product adoption
within months vs. years. In this way, competitors would have less chance to take
advantage of the new product category popularity and cause a significant erosion in
market share from the organization that introduced it. In addition, the longer that a new
product is provided by only one organization, the more connected to the product category
and potentially the larger the market share leadership role for that pioneer organization.
For example, consider the iPad in the tablet computer industry and GoPro in the personal
camera industry. Though the iPad has many competitors, Apple still enjoys market
leadership position at the time of this publication. GoPro still owns exclusive market
share to its unique product category. Erosion in market share is usually the result of the
market leader not continuing to innovate and provide relevant value to the consumer base
of the product category.
The Product Adoption model is helpful to the CMO for predicting the market
potential for existing products, but what about new products that have not entered the
market yet? If the new product is entering an existing product category, then the Product
Adoption model still applies from an industry or market level because the new product
serves only as an alternative choice to the same product category needs. If the new
product is like the GoPro camera, establishing a new product category, then the CMO’s
team will need to rely on market research to estimate the market potential at least through
the Introduction and early Growth stage of the Product Life Cycle. In ensuing budget
years, historical data can be used to project future sales. Upon completing the forecasted

revenues of existing and proposed marketing projects, the next step is to provide a
method for comparing the various marketing projects on an equal valuation basis.
Step 3: Calculate the discounted value of revenues
Because each marketing project has many variables in terms of potential sales, the
positions of the products within the various stages of the Product Life Cycle, the
forecasted length of the proposed marketing project, etc., a method for normalizing the
values needs to be applied so that a true “Apples-to-apples” comparison can be made.
The responsibility for producing the projections of each project should be on the
managers within the marketing unit of the organization and not on the CMO and/or the
marketing strategy committee. The duties of the latter strategic group are to evaluate what
has been produced by the tactical and operational team members of the marketing
department. The process that is described in this section should be designed into the
policies of the marketing unit for consistency in determining the values to be assessed by
the marketing strategy team. What should be considered when discounting the raw values
of forecasted revenues?
Time considerations.
The first consideration in normalizing revenue projections should be to ensure
that each project’s financials are presented in sub-annual time periods (months or
quarters) that roll up into annual figures. By producing smaller time periods, there is
allowance for measuring the impacts of cash flow throughout the entire fiscal year and
thus will provide a significant determinant for ranking the projects. For example, one
project may appear to be extremely attractive for investment but if the project timetable
creates a conflict with other valuable projects in terms of cash outflow at a time when the
organization will be short on cash that might generate an obstacle to being funded.
Net Present Value considerations.
The second consideration in normalizing revenue projections should be the net
present value (NPV) of each project. By using the NPV method, the CMO can evaluate
different projects with different payoffs over different time periods and arrive at a
comparative figure. The basic concept of NPV is that money earned today is more
valuable than money earned tomorrow. That is because money earned today is more
likely to be collected, is less exposed to risk factors, and will not be as affected by
inflation as money earned tomorrow. The formula for calculating NPV is illustrated in
Figure 10.3. However, NPV calculation tools are available online to “crunch the
numbers” easily. The variables required to use these tools are (1) initial investment
amount – expressed as a negative number; (2) desired discount rate; (3) length of time
that cash flows are anticipated; (4) the amount of cash inflow for each time period within
the “length of time” variable – usually based on a year’s after-tax cash flows (revenues
minus expenses)..
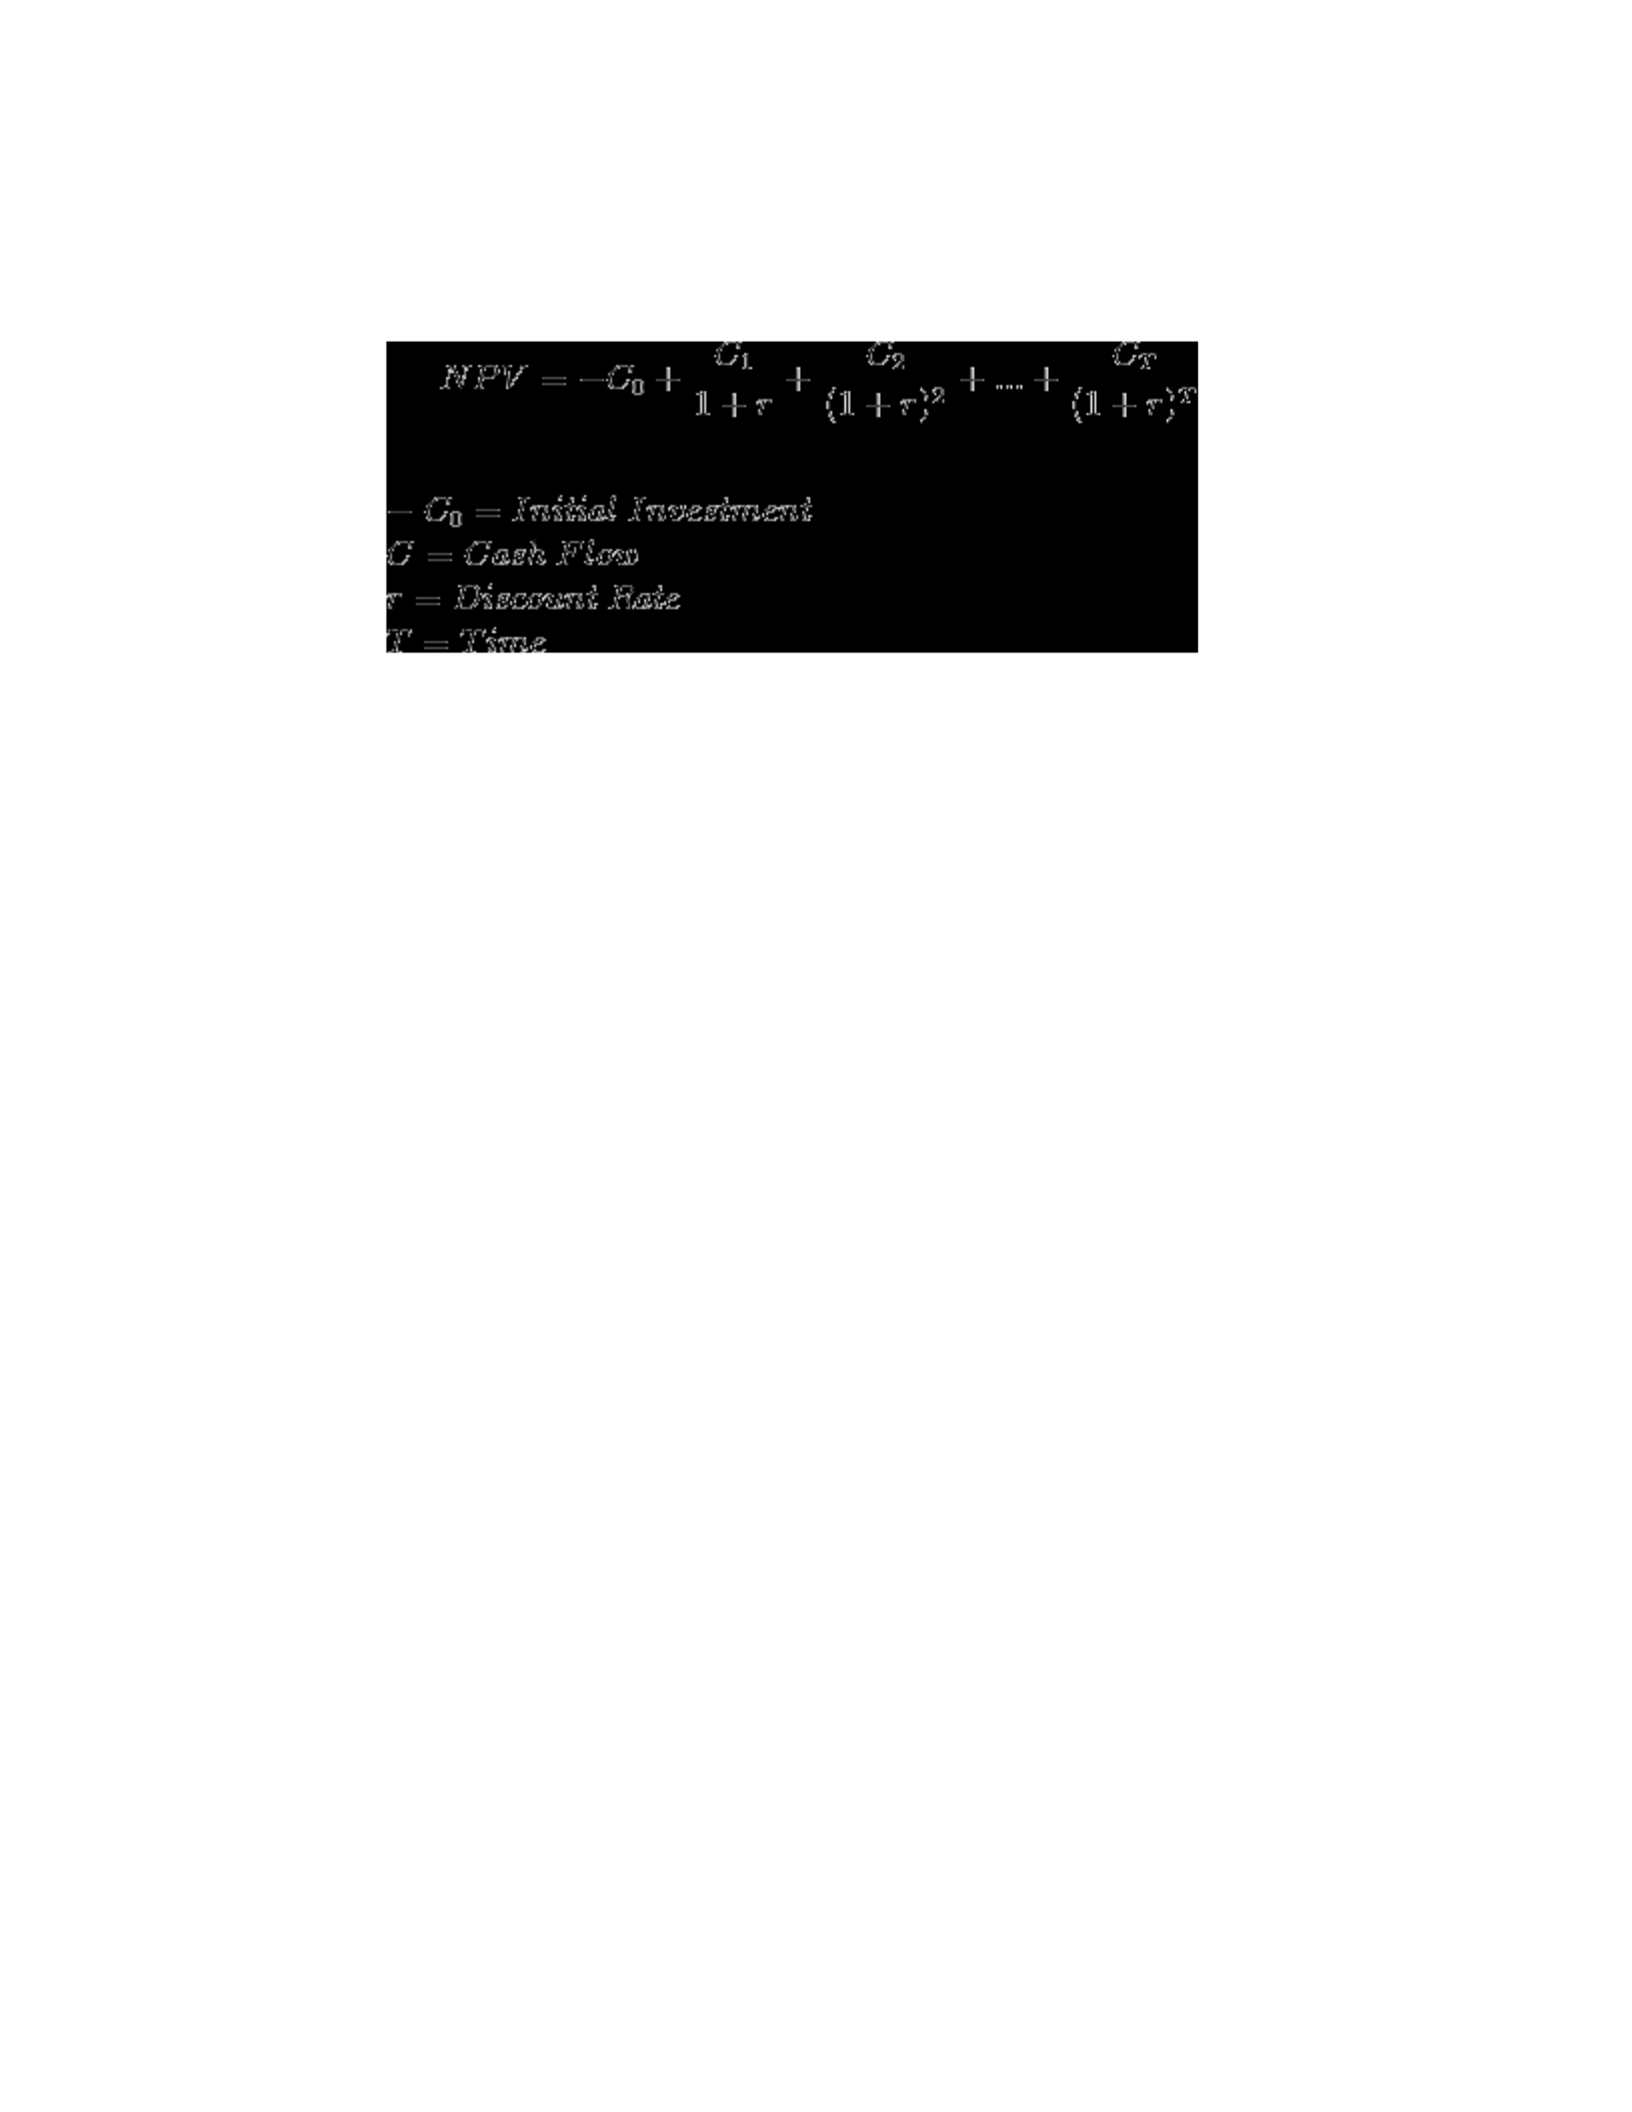
Figure 10.3
Net Present Value Formula
For example, assume there are two projects under consideration. One will cost
$100,000 initial investment and should result in a 3-year payoff of $500,000 ($75,000 in
Year 1; $150,000 in Year 2; $275,000 in Year 3). The discount rate within an
organization usually is set by the organization’s Chief Financial Officer and is based on
variables like risk factors or uncertainty of cash flows and availability of funds. The
higher the risk and uncertainty, the higher will be the discount rate (sometimes called the
cost of capital or hurdle rate). In this example, assume that the discount rate has been
established as 10% resulting in an NPV of $298,760.33.
By comparison, proposed project #2 requires $250,000 initial investment and
should result in a 5-year payoff of $1,300,000 ($100,000 in Year 1; $150,000 in Year 2;
$250,000 in Year 3; $300,000 in Year 4; $500,000 in Year 5). Using the same 10%
discount rate, the NPV would be $668,069.43. To compare the two projects, the raw
numbers would suggest that Project #2 has a greater return (520%, $1.3 million earned
over $250 thousand invested) than Project #1 (500%, $500 thousand earned over $100
thousand invested). However, the returns using NPV suggest that Project #1 provides the
greater return (299% vs. 267% for Project #2). The reason is that Project #1 provides a
return sooner than Project #2 and is less exposed to potential uncertainty in future cash
flows. The question to be considered at this point is, “How likely are these projects to
deliver the forecasted results?”
Probability Analysis considerations.
Probability Analysis is a process tool to discount the optimism of the project
leaders in their enthusiasm to gain funding. One basic method of evaluating scenarios is
to establish a value of Best Case, Worst Case, and Most Likely to occur. The Best Case
usually is the first scenario that is developed. If all goes as planned, with no obstacles
occurring, then the project can expect to achieve x revenues. The Worst Case scenario
should be calculated second and consider the scenario if all potential obstacles that could
occur do occur, then the project can expect to achieve y revenues. Usually, the Most
Likely scenario is a mathematical average of the two other scenarios. Use of the
Probability Analysis tool is a more sophisticated approach and provides the opportunity
to analyze the situation more thoroughly.
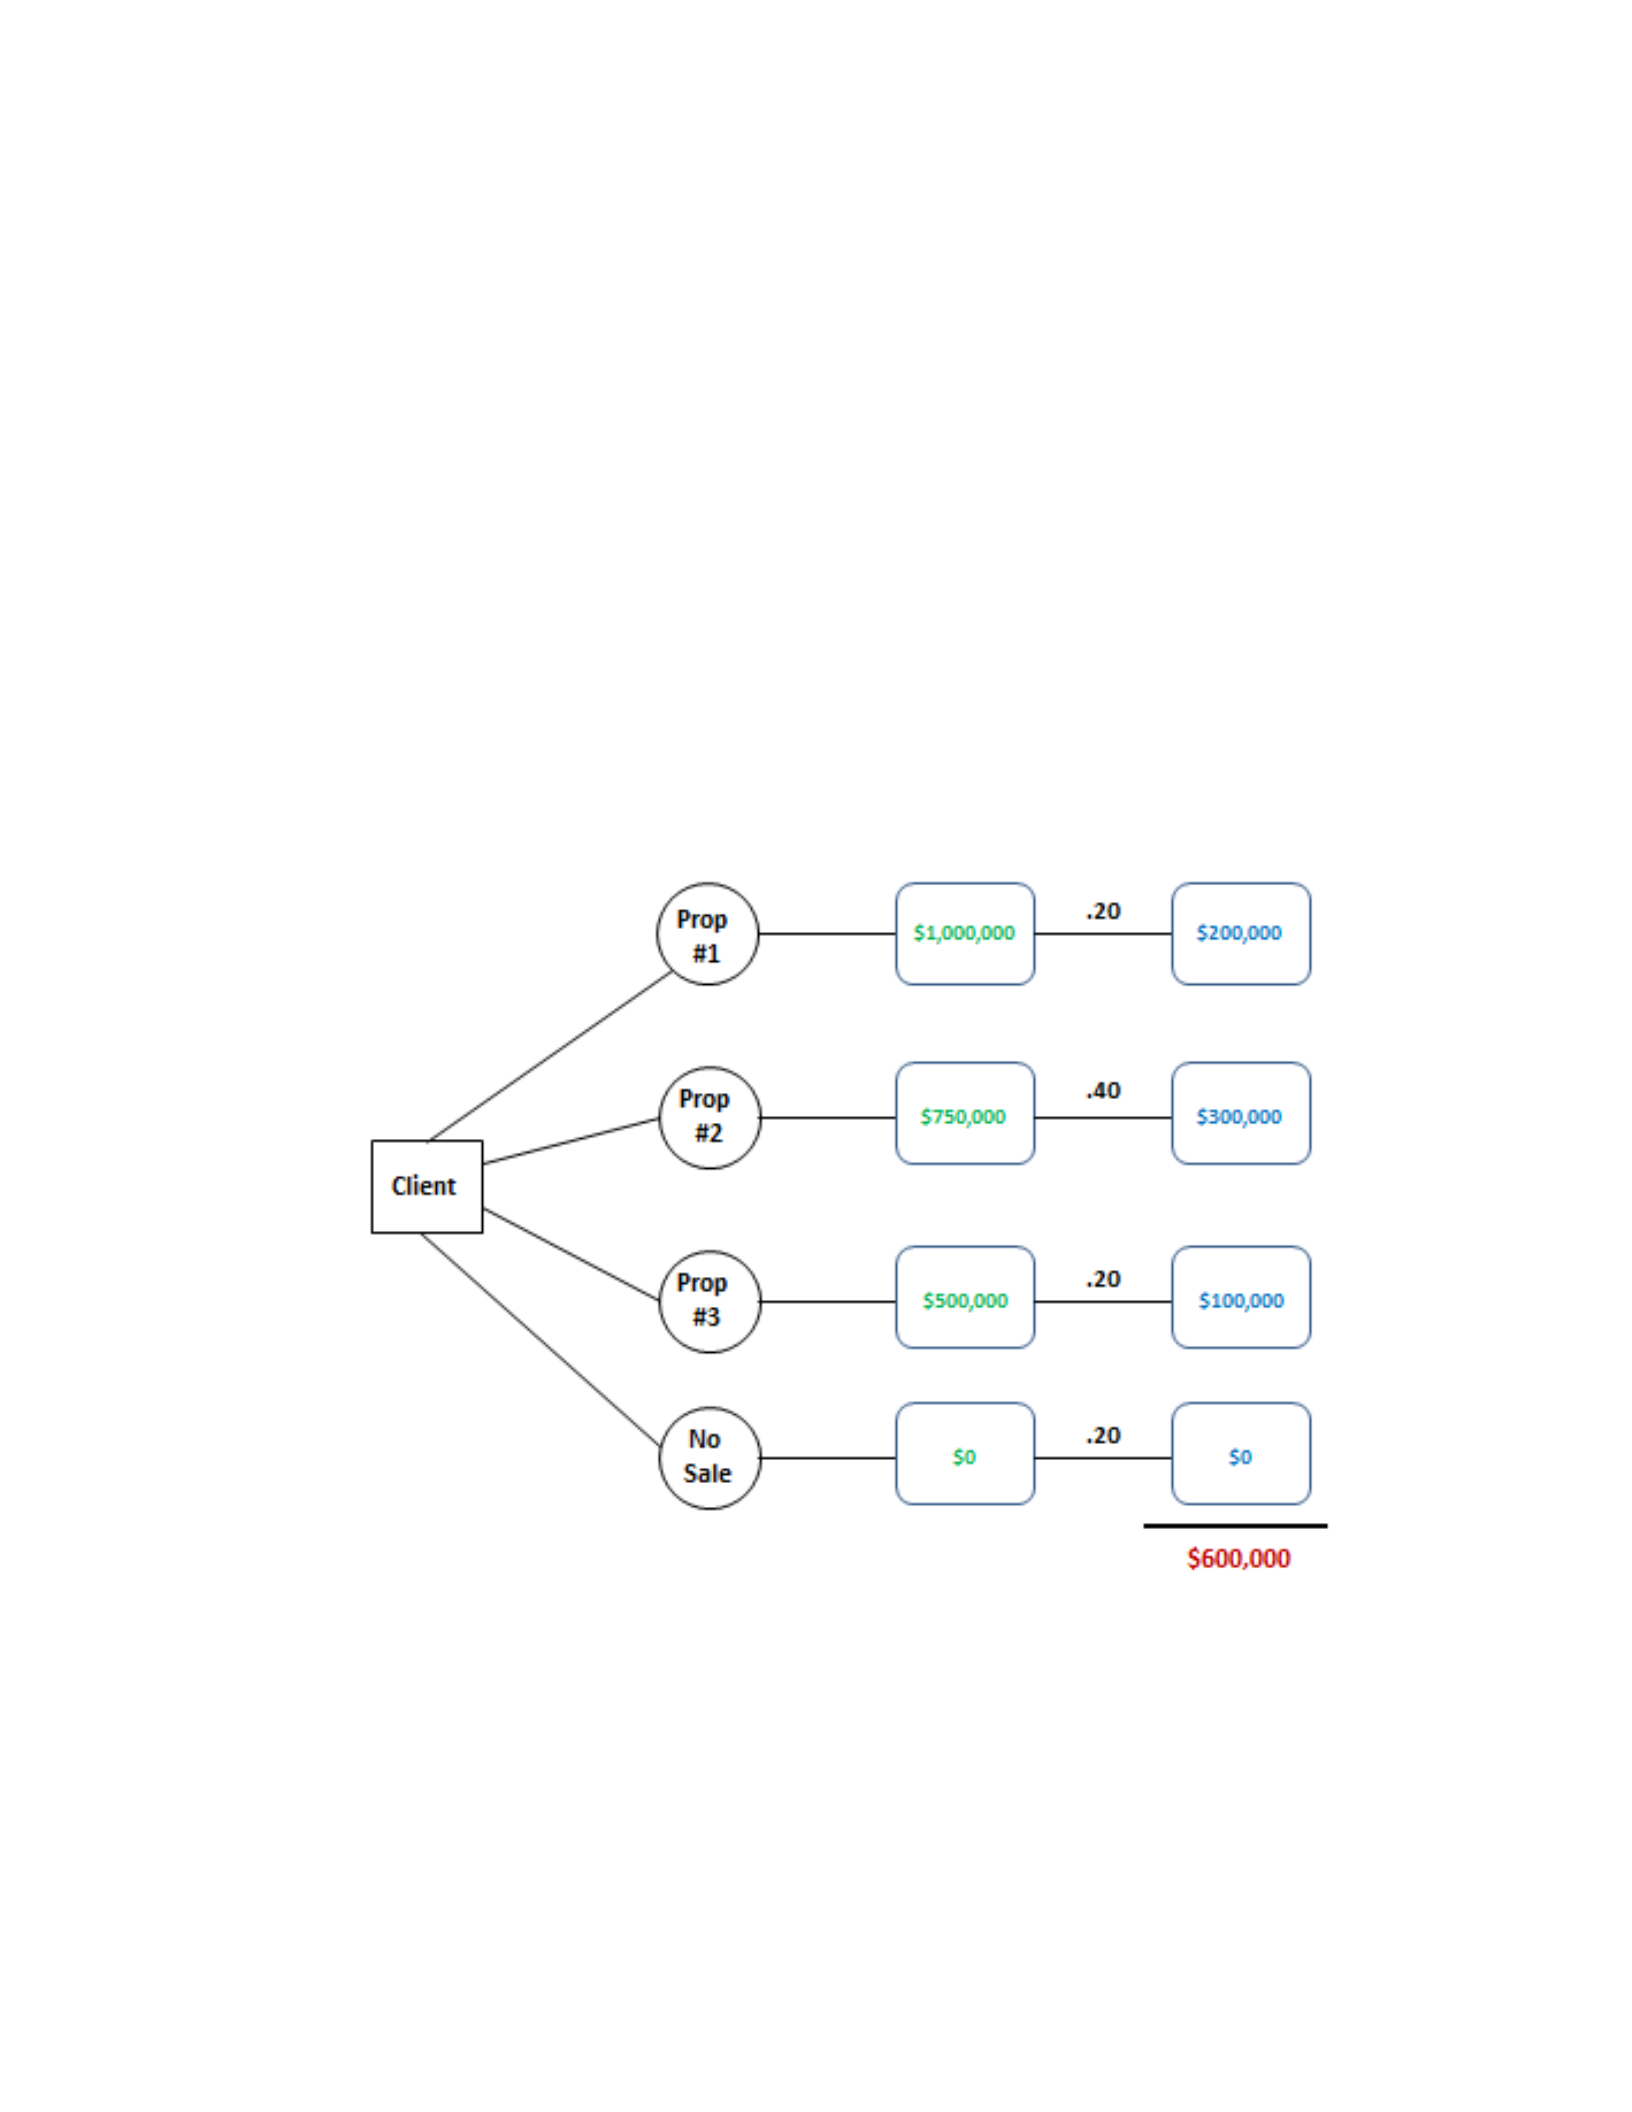
In the Probability Analysis process, the manager estimates the likelihood of each
potential outcome occurring and assigns a monetary value to each possible outcome. For
example, as illustrated in Figure 10.4, assume that three product proposals will be
presented to a potential client in the coming fiscal year. The account manager from the
organization for that client is called upon to make a prediction of the outcomes. The value
in terms of revenues to the organization of Proposal #1 is $1 million; the value of
Proposal #2 is $750 thousand; the value of Proposal #3 is $500 thousand. The account
manager predicts that the probability of the client purchasing Proposal #1 is 20%,
Proposal #2 at 40%, Proposal #3 at 20%, and 20% chance of a No Sale. In this example,
the net value of the Probability Analysis is $600,000.
Figure 10.4
Probability Analysis Example
Each forecasted sale should be subjected to the Probability Analysis method
before being added to the overall forecast for each product or service in order to provide a
more realistic valuation of the composite forecasted sales revenues. However, using
averages can produce wide fluctuations in actual revenue results. Therefore, an additional
method of measuring historical accuracy should be applied to the value of existing and
proposed marketing projects.
Historical accuracy of forecasts considerations.
The concept of measuring the historical accuracy of forecasts should be applied at
the macro level of the marketing unit and not at the individual sale or even project level
because the CMO wants to measure the accuracy of the forecaster and not the forecasts.
The CMO may choose to rate the accuracy of each forecaster individually or average the
accuracy ratings of all forecasters within a Strategic Business Unit (SBU). The
calculations need to be based on a personal forecaster level first before aggregating
results because a change in one forecaster on the team would result in a new historical
evaluation factor. Obtaining an historical accuracy of forecasts can be difficult to achieve
if there is a high turnover rate of forecasters within the organization. In that situation, the
CMO would continue to rate the historical accuracy of previous forecasters still on the
payroll and apply a mean accuracy rating for new forecasters.
Table 10.1
Historical Accuracy Example
Forecaster #1
Year 1
Year 2
Year 3
Average
Forecasted $
$10,000,000
$12,000,000
$15,000,000
Actual $
$12,000,000
$9,000,000
$20,000,000
$ Accuracy
$2,000,000
(3,000,000)
$5,000,000
% Accuracy
20%
(25%)
33%
Factor
1.2
0.75
1.33
1.09
Forecaster #2
Year 1
Year 2
Year 3
Average
Forecasted $
$5,000,000
$7,500,000
Actual $
$4,500,000
$6,000,000
Net $
($500,000)
($1,500,000)
% Accuracy
(10%)
(20%)
Factor
0.9
0.8
0.85
Forecaster #3
Year 1
Year 2
Year 3
Average
Forecasted $
$0
$0
$0
Actual $
Net $
% Accuracy
Factor
0.97
An example of the method to use in determining the value of historical accuracy
is illustrated in Table 10.1. Forecaster #1 has been providing forecasts for three years and
in two of those years, tends to under-forecast the actual results; Forecaster #1 is
conservative for whatever reasons. In Year 1, the revenue results for Forecaster #1 were
20% over the forecast provided by #1 and thus a 20% additional factor would normalize

Year 1 results. In Year 2, Forecaster #1 forecasted 25% more revenues than were
received for whatever reason. Maybe that employee was trying to compensate for the
previous year and trying to find his or her own accuracy level. However in Year 3, the
revenues again were over Forecaster #1’s estimate this time by 33%. Regardless of the
reasons, a discounted factor of 0.75 would be associated with the margin of error for Year
2 and a factor of 1.33 would be associated with the margin of error for Year 3. That
would give Forecaster #1 an average margin of error factor of 9% under estimated
revenues or, in decimal form, a factor of 1.09. In the coming forecast year, the CMO
would take Forecaster #1 estimate and multiple it by 1.09 to establish that forecaster’s
historical accuracy value.
Forecaster #2 has been forecasting for only two years. The same formulas would
apply as in the previous example for Forecaster #1The CMO could add weights to the
number of years each forecaster has provided estimates by providing a stronger weight
value to each additional year of forecasts. Another method of further analysis might be to
measure the standard deviation with each forecaster; Forecaster #2 appears to be more
accurate in his/her forecasts than Forecaster #1. However, staying with a simple average
scale may be sufficient for determining the historical accuracy factor. Finally, Forecaster
#3 is making his/her first forecast, and, because there is no history to measure, the CMO
would calculate the factor of 1.09 for Forecaster #1 and 0.85 for Forecaster #2 into a
standard factor of 0.97 for Forecaster #3 and any other new forecasters in the department.
Step 4: Determine the projected variable costs for each project
At this point, the CMO should have a reasonable grasp of the discounted revenue
values associated with each existing and proposed marketing projects for the coming
budget fiscal year. However, the ultimate goal in management is to maximize profits, not
revenues. Therefore, the classification of marketing projects cannot stop at determining
which projects will result in maximum revenues to the organization. The CMO needs to
identify the future variable costs associated with delivering the future revenues to the
organization so that a profit level can be determined. For the CMO, the profit level is
after deducting variable costs to determine gross margin or sometimes called
contribution margin. Fixed costs and net income are not the responsibility of the
marketing unit of the organization alone as are revenues. Fixed costs and net income are
the joint responsibility of the entire executive management team to include the CMO as
one participant on that team.
Variable costs include all expenditures required to produce the forecasted
revenues. These costs can include (a) labor and materials used in manufacturing of the
product or service, (b) the payments made to the various members of the supply and
distribution channels, (c) the funds invested in promoting the products and services, (d)
the sales commissions given to the salesforce, etc. Some organizations apply the salaries
of the marketing department to variable costs under the premise that marketing efforts of
the organization relate directly to the revenues produced. To quantify all variable costs
will require the CMO to collaborate with other leaders within the organization (e.g., the
Chief Operations Officer for research and production costs, the Chief Financial Officer

for debt costs, the Chief Information Officer for networking costs, etc.). Within the
marketing mix, the CMO should provide the costs for distribution and promotional
campaigns in addition to all internal expenses directly attributed to the production of
revenues.
Allocations of costs are made based on the extent to which the resources are to be
dedicated to a given project. For resources that are totally dedicated to a given project,
the formula is simple – 100% allocation. For resources that are shared with various
projects, the management team should have a policy that determines how to allocate the
expense of the resources to the projects. An example of such allocation could be to divide
the resources equally among the various projects to which the resources are dedicated.
The benefit of using this method is its simplicity but results in a vague analysis of the true
value of each project. Another method might be to allocate the costs based on the portion
(percentage) of each project’s revenues to the overall revenues produced. For example, if
Project A produced $10 million in revenue, Project B produced $7 million in revenue,
and Project C produced $5 million in revenue, the costs of the dedicated resources to all
three projects would be allocated as 45% to Project A, 32% to Project B, and the
remaining 23% of the costs to Project C.
Another method for the allocation of funds would be to account for the amount of
time that each resource was needed for each identified project. This could be expressed as
a percentage of total time available for the resource to be used within a fiscal year. To
calculate the amount of time would require maintaining time logs during the fiscal year of
which project was using the resources at any given time of productivity. Then the
percentage of time would be multiplied by the value of the resource to determine an
associated cost. In the case of labor resources, the value would be the loaded labor rate
(including base wages or salaries, bonuses or commissions, taxes, travel expenses, other
benefits, etc.) for the time used. In the case of equipment resources, it could be the
depreciated value of the equipment plus the variable costs of operating the equipment
(e.g., electricity, oil, replacement parts, maintenance labor, etc.) for the time used.
Internal cash flow considerations.
Another important consideration for the CMO is the impact that marketing project
actions might have on the cash flow of the organization. The decisions may not affect
whether or not to implement the marketing project but rather may affect the timing of
implementation. Typically, most cash flow components are constant (e.g., wages and
salaries of the labor force, allocated costs of equipment and facilities, etc.) but one
example of variable costs might be the rollout of a promotional campaign. If the
organization has other projects requiring unusually high outlay of cash during a particular
time period, adding another outlay of cash for a promotional campaign might be too
restrictive. This could result in the organization needing to borrow short-term capital to
fund all of the activities. If this were the case, the cost of debt might need to be added to
the variable costs of the marketing projects. The CMO should obtain the organization’s
pro forma cash flow statements from the Finance Department of the organization, and
coordinate a plan with the executive management team to avoid pressure points during

the fiscal year or at least initiate a conversation with the Chief Financial Officer on how
to coordinate the various projects of the organization. The goal of the CMO should be to
consider potential cash flow issues in the planning stage of the marketing plan rather than
being confronted blindly by potential conflicts in a meeting of the executive team.
To determine the cash flow issues, the middle managers within the marketing
department should be required to provide a forecasted monthly cash flow statement in
their marketing project proposals. Then a composite statement should be produced so that
months with high incremental costs could be identified and the projects associated with
those costs. The CMO will not want to take action at this point on the identified projects
in the event that the project may not be funded for other considerations. Rather, the
identified projects should be revisited after the preliminary funding decision has been
made and a revised composite cash flow statement should be developed to determine if
issues remain.
Step 5: Calculate the contribution margin for each project
When all variable costs for each project have been identified and quantified, they
are subtracted from the adjusted revenues associated with each project to establish the
gross margin for each marketing project. As stated previously, from an internal
viewpoint, gross margin is an Income Statement term of how much net revenue is
available to contribute to the overall fixed costs of operating the organization. For
internal purposes, a better term to use for gross margin is contribution margin. It is the
value that measures the efficiency of obtaining the revenues. After the contribution
margin has been calculated for each project, a percentage return on investment should be
calculated so that the various marketing projects can be compared with each other based
on a constant ratio value. This will establish the basis for a profitability ranking among
the projects. The CMO could set as policy a minimum contribution margin in order for
any project to be eligible for funding. If this policy existed, the marketing managers
would know in advance that they should not present a project for funding unless it met
the minimum return on marketing investment (ROMI) value.
After a preliminary list of marketing projects to be funded is assembled, an
additional calculation should be made to determine the total contribution margin dollars
represented by the proposed projects. From that calculation, it could be determined if the
overall pending marketing project portfolio would meet organizational gross margin
goals sufficient to grow the organization and satisfy stakeholders. If the total margins are
at an insufficient level, the CMO and the marketing team will need to determine what
combination of revenue-producing and cost-efficient projects will meet the contribution
margin goal even if additional marketing projects need to be developed or popular
existing projects reduced or even eliminated. Once the overall contribution margin target
is met, the CMO can proceed to the final analysis step before completing the proposed
marketing project portfolio for the coming budget fiscal year.

Step 6: Evaluate situational variables
As a final review step before allocating funding for the proposed marketing
projects, the CMO and marketing strategy team need to consider the current external
environmental forces. The most common environmental forces used in situational
analyses for marketing organizations are (1) Social, (2) Political, (3) Economic, (4)
Competitive, (5) Technological, (6) Legal, and (7) sustaining the Environment. The
acronym S.P.E.C.T.L.E. can be used to recall the components of this model. The overall
question to be asked by the CMO is whether or not there are significant environmental
pressures that might adversely affect or even serve as a catalyst for growth of any of the
proposed marketing projects.
For example, if a particular project involved a product that consumers were not
purchasing because of a down economy, the calculated value of that project might need
to be further discounted in value or the project postponed temporarily to determine if the
economy might recover and consumers return to purchasing the product. An example of
competitive and legal environmental forces providing a catalyst might be where a
competitor of the organization has been ordered by the courts to pay a fine to the
organization and discontinue a product that is directly competing with the organization’s
product. This could create an environment where the demand for the product is not being
met and the monetary reward could be used to increase supply of the organization’s
product. This would be factored as an added value to the previously calculated value.
One key factor to be considered among external environmental forces before
making the final funding allocation decisions is what will be the competitive responses to
each of the proposed marketing projects. Often, this impact is not considered by
marketing managers and yet competitive responses can have a major effect on the
projected value of a marketing plan. The CMO should include a requirement to provide a
competitive analysis in all marketing plans that are submitted for funding review.
Included in the competitive analysis should be a narrative description of past, present,
and projected future actions by key competitors, and statements made as to the extent
competitive situations were factored into the forecasted revenues in each marketing plan.
The CMO and the marketing strategy committee should review these statements and
determine the validity of the information provided based on the collective experience and
skilled observations of the senior marketing management team.
Step 7: Rank the proposed marketing projects into a Profitability Matrix
At this point in the funding process, it is time to allocate the available funds to the
various proposed marketing projects. Substantial review has been given to each project
and discounted values have been assessed to reach individual contribution margins. From
these numeric values, each project should be ranked in descending order. However, the
first step in this part of the process should be to segregate each project into its appropriate
Growth/Share Matrix category. At the beginning of this chapter, the case was made for
allocating funds among Question Marks, Stars, Cash Cows, and Dogs. The overarching
strategy should not be lost in this phase of the funding process. Primary sources of funds
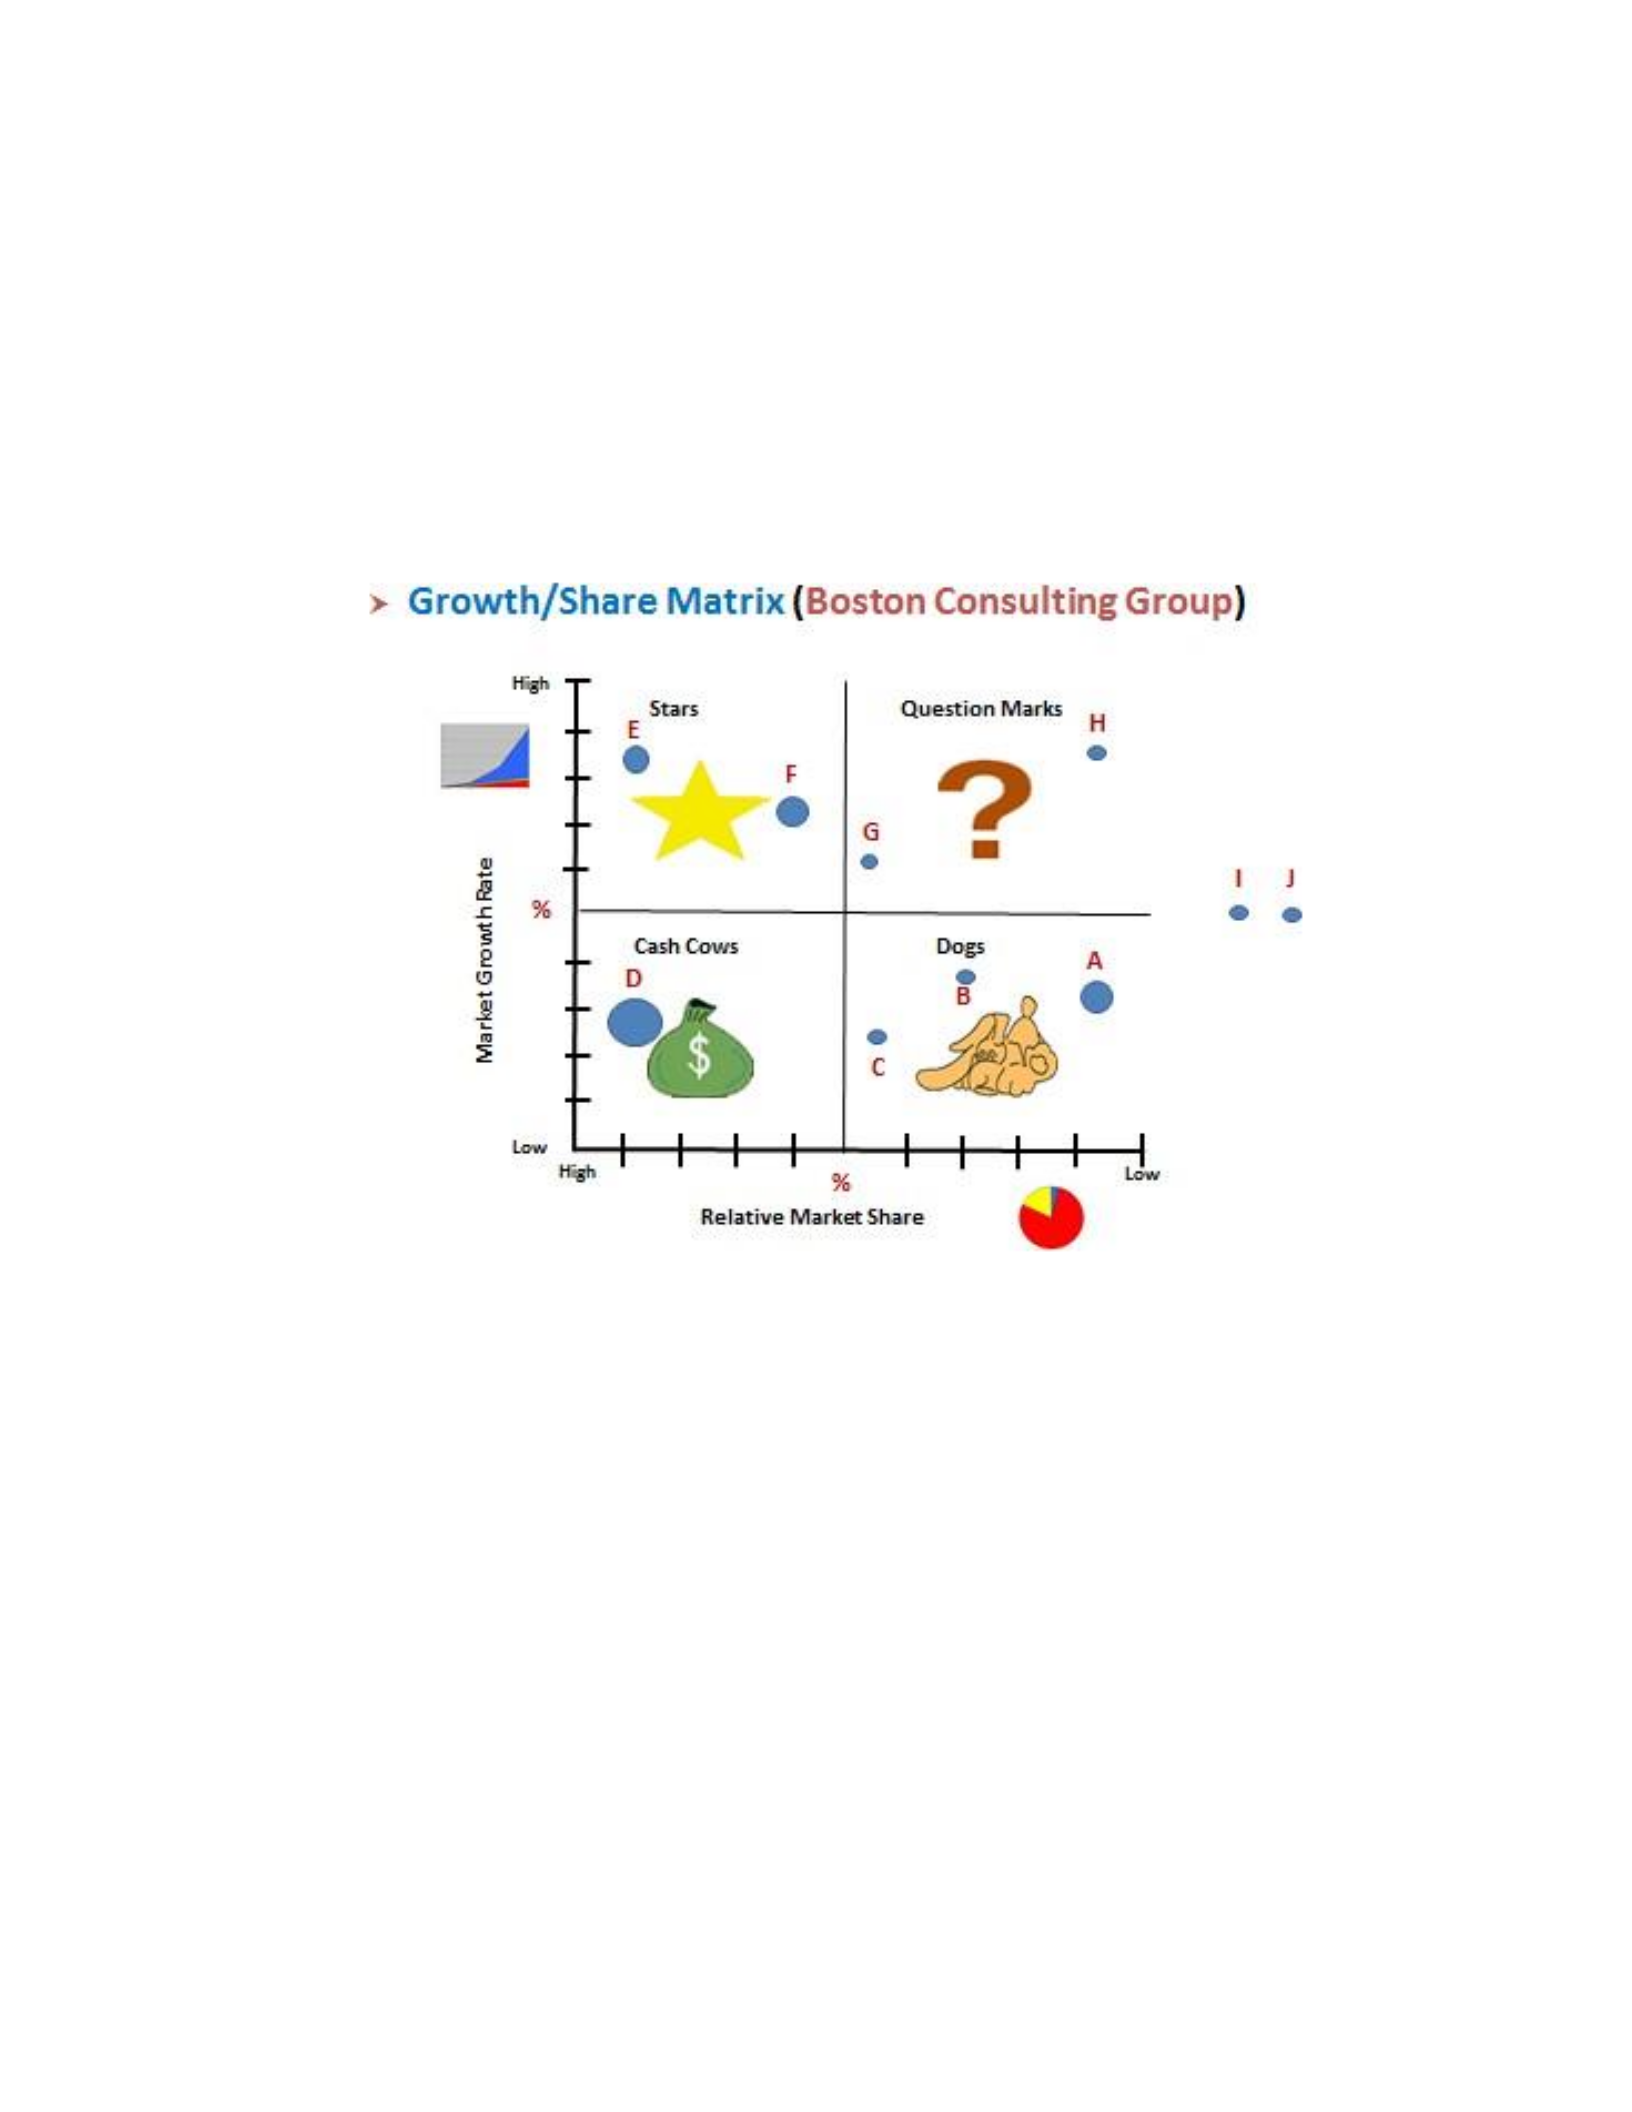
will come from healthy Cash Cows and unbundled Dogs. Primary targets of funds will be
Stars and selected Question Marks. The basic Growth/Share Matrix model illustrated
previously has been enhanced in Figure 10.5 to include a designation for each SBU and
the addition of two proposed marketing projects (I & J).
Figure 10.5
Growth/Share Matrix with Project Designations
Source: Adapted from The BCG Portfolio Matrix from the Product Portfolio Matrix ©1970, The Boston
Consulting Group.
Assume that the CMO of the organization has 10 proposed marketing projects in
the proposed portfolio for the coming fiscal year. These 10 projects are designated as A-J
in Figure 10.5. Projects I & J represent new projects that have not been introduced to the
market yet. How these projects might be ranked is illustrated in Table 10.2 with
Contribution Margins being ranked in descending order for all 10 projects. Because
projects I & J are new, they are not expected to have a net contribution margin yet. Their
ranking is based on the amount of funding to be given by the Marketing department in
descending order.
Step 8: Allocate funding to the overall proposed marketing project portfolio
Continuing with the Profitability Matrix example in Table 10.2, the amounts of
funding requested by the various project leaders and the amount of funding determined
by the CMO to be given are listed. The two Stars category projects (E & F) are fully
funded based on the requested funds from the project leaders. The rationale for giving
Project G more of its requested funds than Project H, which is forecasted to provide a
larger contribution margin than Project G, is based on the belief that the additional
investment in Project G may move it to a greater market share in the growing industry.
Table 10.2
Profitability Matrix Example
(millions)
Contribution
Margin $
Marketing
Funding Request
Marketing
Funding Given
% of Request
Stars
Project F
$60
$25
$25
100%
Project E
$45
$20
$20
100%
Stars Projects
$105
$45
$45
100%
Cash Cows
Project D
$125
$35
$21
60%
Cows Projects
$125
$35
$21
60%
Question Marks
Project H
$30
$22
$12
55%
Project G
$25
$17
$15
88%
Project I
$0
$11
$7
64%
Project J
$0
$9
$5
56%
(?) Projects
$55
$59
$39
66%
Dogs
Project C
$5
$3
$2
67%
Project A
$4
$5
($8)
Project B
$2
$3
($4)
Dogs Projects
$11
$11
($10)
Portfolio Totals
$296
$150
$95
63%
Reserves
$5
5%
TOTALS
$100
Note 1: The Contribution Margin is a result of revenues at discounted NPV less variable costs.
Note 2: The negative numbers among the Dogs represent savings in funding from sale of assets.
In the Dogs categories, Project C is forecasted to remain with the organization
through the coming budget fiscal year while the executive management team seeks a
feasible buyer of the assets associated with Project C. For projects A & B, buyers have
been identified and negotiations are ongoing with an anticipation of selling Project B in

the first half of the coming budget fiscal year and Project A being sold in the second half
of the year. The negative amounts of “funding given” by projects A & B reflect the
contribution from the sales of those two SBUs to the marketing department’s budget. The
policy in the organization may be that sales proceeds go into the general budget vs. the
marketing budget, in which case the values here would be zero. Notice that $5 million
has been kept in reserve to accommodate any unexpected needs for funding during the
year.
Step 9: Prepare the marketing plan and presentation
The final step in the funding process for the CMO is to produce the official
marketing plan that will be presented to the executive management team and ultimately
be included in the organization’s annual report to the stakeholders. In addition to the
description of the strategic plan and budgetary numbers to be reported, the CMO should
include the rationale that went into each of the significant decisions within the strategic
plan. As stated previously, some of the marketing plan is a result of collaboration with
other departments within the organization to arrive at the variable costs in order to
calculate the discounted contribution margin. It would be good practice for the CMO to
provide the leaders of those other departments with a copy of the marketing plan and ask
for concurrence by the leaders of the information contained within the plan before it is
finalized. In this way, there should be fewer surprises for the CMO in the planning
meeting.
Summary
In this chapter, a method of quantifying revenue and contribution margin values
was proposed in order for the CMO to determine which marketing projects would receive
funding for the coming budget fiscal year and to what extent. The Growth/Share Matrix
model was core to the strategies with the idea of ensuring that projects associated with
products and strategic business units in high growth markets and high market share
(Stars) would receive most, if not all, of the funding they needed to continue to benefit
the organization’s growth. Cash Cow projects would receive sufficient funding to
maintain market share in a low-growth market with excess profits of the Cash Cow SBUs
being invested as a source for Stars and some Question Marks projects. The Dogs
projects would receive attention in determining how to divest of their associated assets so
they could become a source of funds in addition to the Cash Cows.
A specific step-by-step process was recommended for a CMO to require of the
project leaders that they calculate for various discounts in their forecasted revenue
projections. Among these discounts were the concepts of Net Present Value, Probability
Analysis, and considerations of historical accuracy by the project leaders, the effect on
organizational cash flows, and external environmental forces that might affect the sales
forecasts. Using these analytical tools can assist the CMO in providing to the executive
leadership team of the organization a reasonable, and potentially, more accurate forecast
of revenues and contribution margins for the coming budget fiscal year.

